CONTACTS: | ||
Investors | ||
(305) 460-8728 | ||
Media | ||
(305) 441-8414 | ||
AMERANT BANCORP INC. REPORTS SECOND QUARTER RESULTS AND
BUSINESS UPDATES RELATED TO COVID-19 PANDEMIC
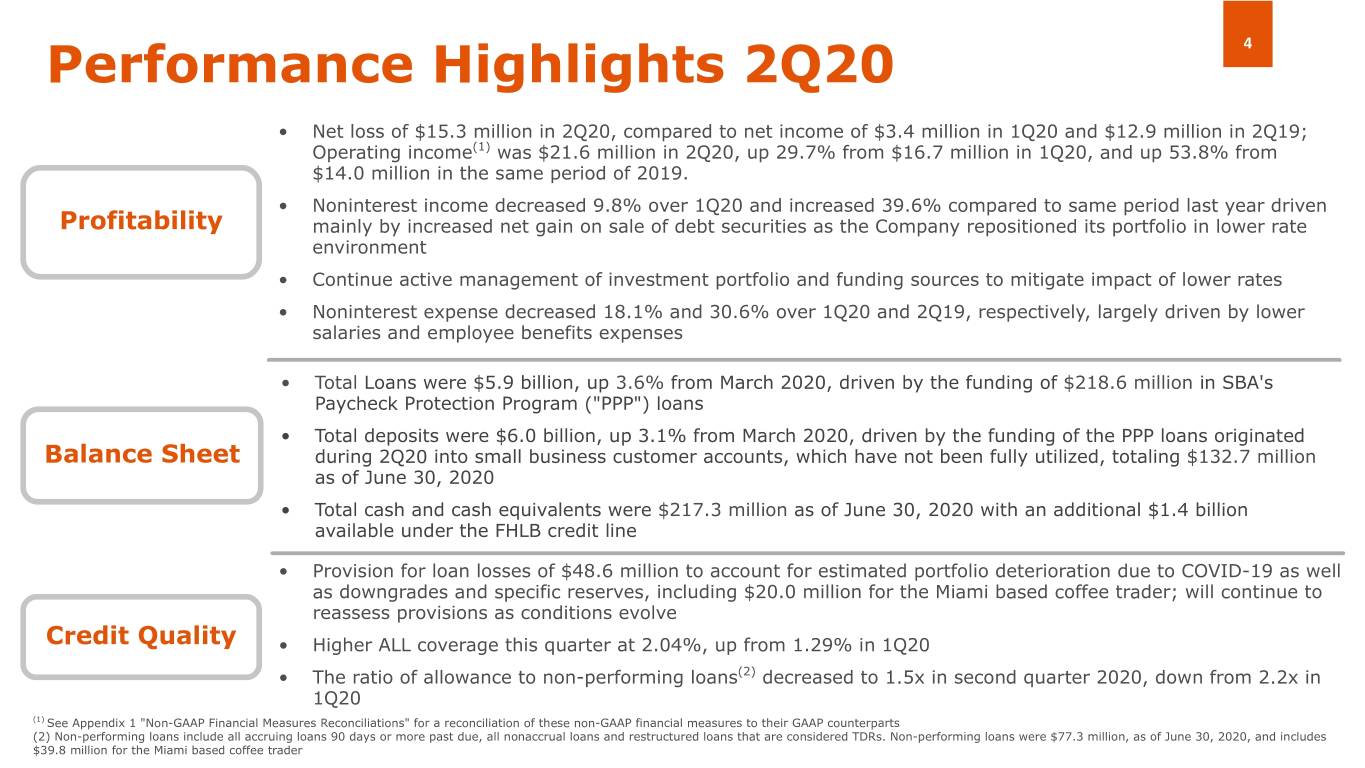
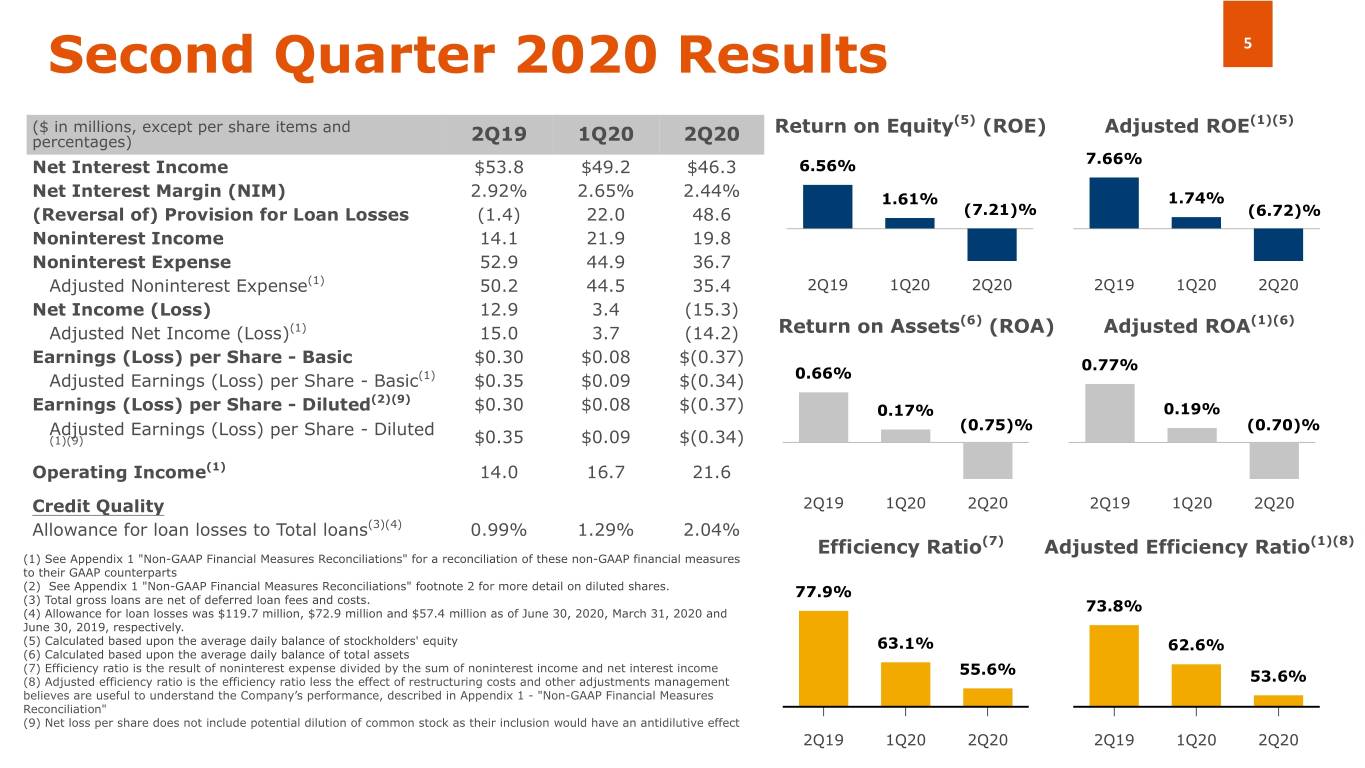
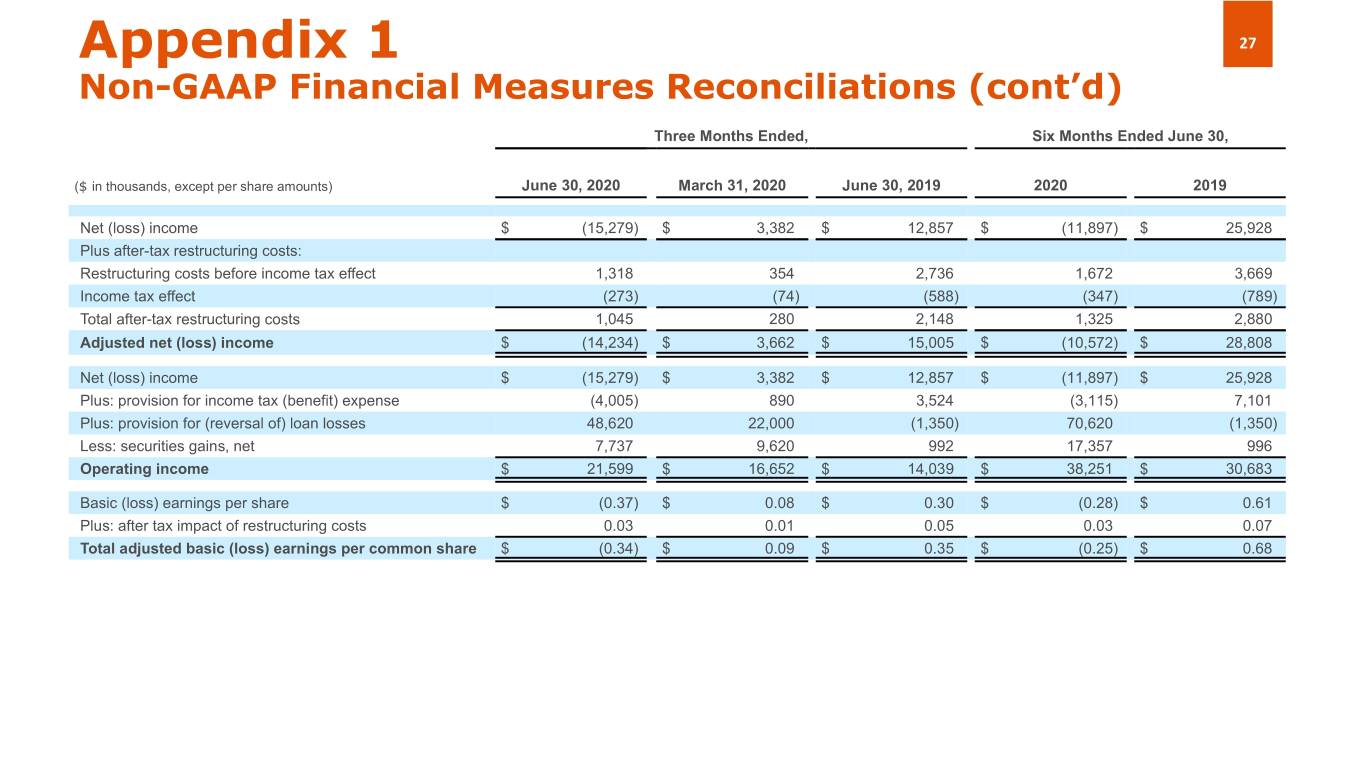
CORAL GABLES, FLORIDA, July 24, 2020. Amerant Bancorp Inc. (NASDAQ: AMTB and AMTBB) (the “Company” or “Amerant”) today reported second quarter of 2020 net loss of $15.3 million, compared to net income of $3.4 million reported in the first quarter and net income of $12.9 million reported in the three months ended June 30, 2019. Net loss for the six months ended June 30, 2020 was $11.9 million, compared to net income of $25.9 million reported in the six months ended June 30, 2019. Net loss per share was $0.37 in the second quarter of 2020, compared to $0.08 net income per diluted share in the first quarter of 2020, and $0.30 net income per diluted share in the second quarter of 2019. Net loss per share for the six months ended June 30, 2020 was $0.28, compared to $0.60 net income per diluted share for the six months ended June 30, 2019. Operating income was $21.6 million in the second quarter of 2020, up 29.7% from $16.7 million in the first quarter of 2020, and up 53.8% from $14.0 million in the same period of 2019. Operating income was $38.3 million for the six months ended June 30, 2020, up 24.7% from $30.7 million in the six months ended June 30, 2019.
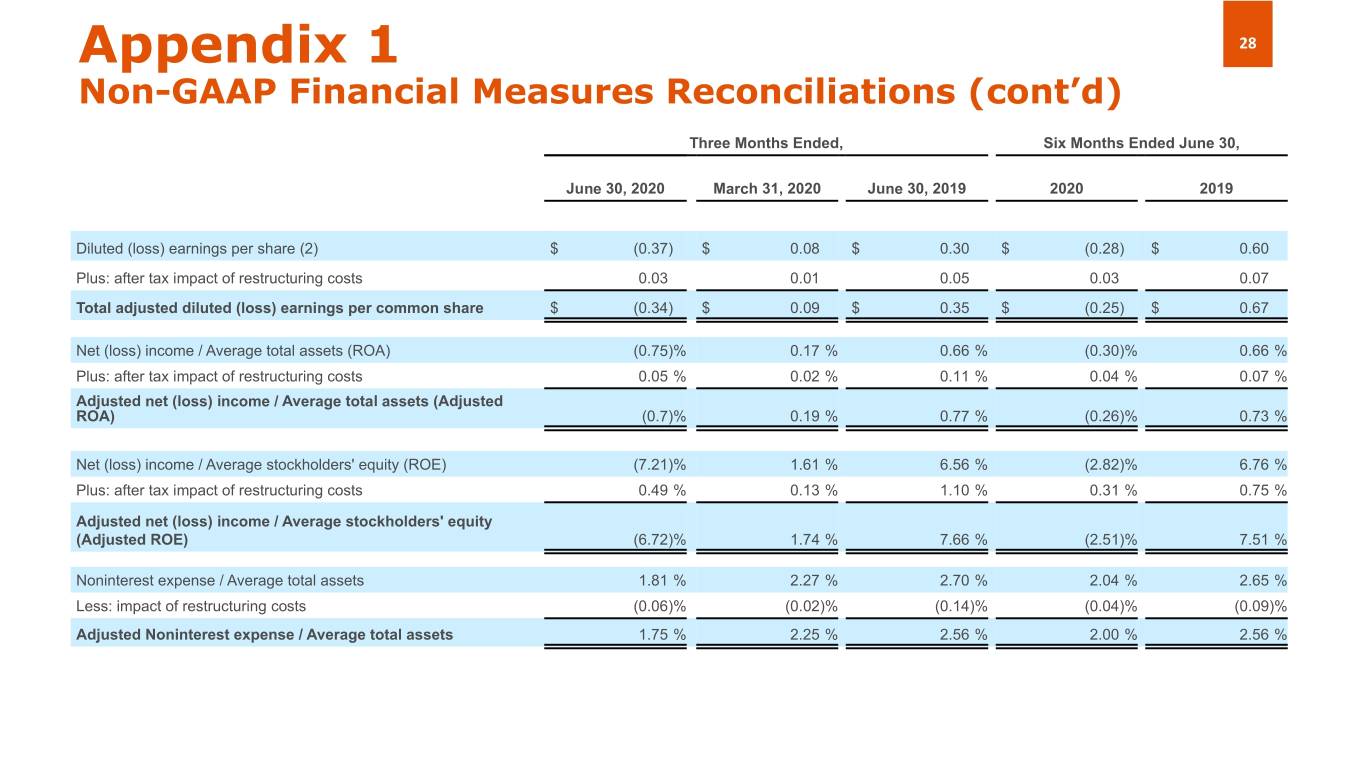
Annualized return on assets (“ROA”) and return on equity (“ROE”) were negative 0.75% and 7.21%, respectively, in the second quarter of 2020, compared to positive 0.17% and 1.61%, respectively, in the first quarter of 2020, and positive 0.66% and 6.56%, respectively, in the second quarter of 2019. ROA and ROE for the first six months of 2020 were negative 0.3% and 2.82%, respectively, compared to positive 0.66% and 6.76%, respectively, for the first six months of 2019.
Millar Wilson, Vice Chairman and Chief Executive Officer, said, “During the second quarter, we remained focused on driving excellence across our business, underscored by significant operating income, as we continue to navigate the unprecedented circumstances related to the COVID-19 pandemic. We continue to run our business while protecting the safety and well-being of our employees and customers. We bolstered our credit reserves to near-historic high coverage levels and continued to manage our balance sheet for long term success, selling select investment securities at attractive prices to help compensate for earnings declines associated with the current interest rate environment and incremental allowance for loan losses. Of note, in the second quarter we realized a gain of $7.5 million on the sale of 30-year Treasury securities, which we purchased in the first quarter of 2020 as a prepayment mitigation strategy.”
Mr. Wilson continued, “In the second quarter, we were excited to see our relationship-driven strategy and the hard work of our team pay-off. We had a surge in our domestic deposits and
1
were pleased to see that our foreign deposits even increased slightly compared to the first quarter of 2020. Moreover, during the second quarter we demonstrated the strength of our funding sources through the sale of our $60 million investment grade-rated senior notes. With this funding, we have $217.3 million in cash and cash equivalents as of the end of the second quarter which puts Amerant in a strong position to continue to navigate the current environment. Simultaneously, we continued implementing several COVID-19-related initiatives for the benefit of the Company’s customers and local communities, deepening our customer relationships, and decisively moving forward with our digital transformation and other efficiency initiatives, including launching our new Amerant Investments Mobile application.”
Mr. Wilson concluded, “Finally, in the second quarter, we were pleased to continue supporting our communities by providing over 2,000 PPP loans, totaling over $200 million. We are proud to have helped local small businesses retain employees and keep their doors open, and excited that we developed new customer relationships along the way. I am proud of the entire Amerant team for staying close to our customers and their unwavering commitment to driving our business forward, bonded by our reinvigorated mission, vision and values. Even during these unprecedented times, Amerant remains well-positioned to serve customers and create value for shareholders.”
Summary Results
The summary results of the second quarter ended June 30, 2020 include:
• | Net loss of $15.3 million, compared to net income of $3.4 million in the first quarter of 2020 and net income of $12.9 million in the same period of 2019. The net loss compared to net income in the first quarter of 2020 was primarily due to higher provision for loan losses and lower net interest income in the second quarter of 2020, offset by lower non-interest expenses. The net loss compared to net income in the same quarter last year was primarily due to higher provision for loan losses in the second quarter of 2020 and lower net interest income, offset by higher non-interest income and lower non-interest expenses. Operating income, which excludes provision for income tax, provision for loan losses or reversals and net gains on securities, increased to $21.6 million, up 29.7% from $16.7 million in the first quarter of 2020, and up 53.8% from $14.0 million in the same period of 2019. |
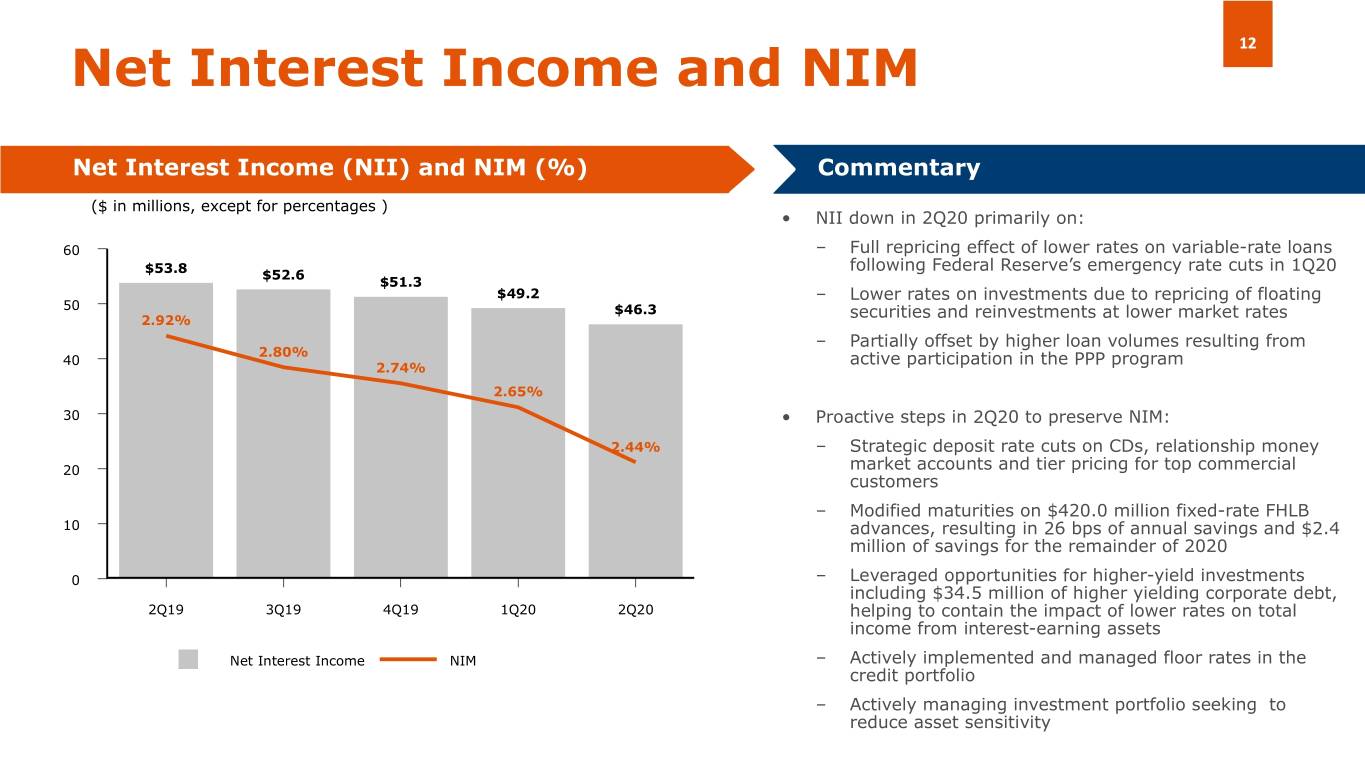
• | Net interest income (“NII”) was $46.3 million, down 5.9% from $49.2 million in the first quarter of 2020, and down 13.9% from $53.8 million in the same period of 2019. Lower NII versus the first quarter of 2020 is mainly due to a full quarter of lower market rates on variable-rate loans following the emergency rate cuts implemented by the Federal Reserve during March 2020, partially offset by higher average loan balances and lower deposit and professional funding costs. Compared to the second quarter 2019, lower NII in the second quarter of 2020 is attributed to a decline in average yields on interest-earning assets, partially offset by higher average interest-earning asset balances and lower deposit and professional funding costs. Net interest margin (“NIM”) was 2.44% in the second quarter of 2020, down from 2.65% and 2.92% in the first quarter of 2020 and the second quarter 2019, respectively. |
• | Credit quality remained sound and reserve coverage is strong despite recent developments associated with one large loan relationship. The Company continues to closely monitor the performance of its loan portfolio estimated to be impacted by the decline in business activity associated with the COVID-19 pandemic, and continues |
2
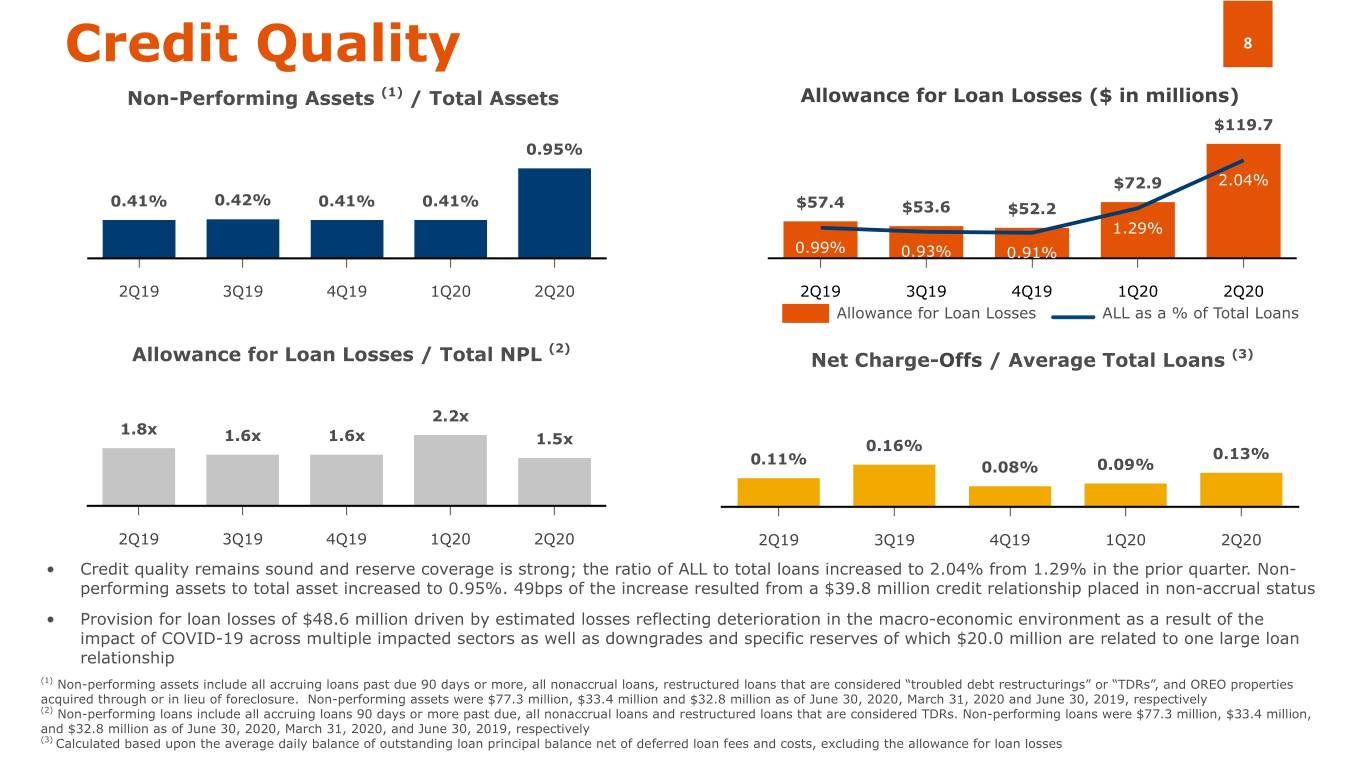
refining its estimated probable loss assumptions. The Company recorded a provision for loan losses of $48.6 million during the second quarter of 2020, compared to the provision of $22.0 million recorded in the first quarter of 2020. As a result, the Company increased its allowance for loan losses (“ALL”) to $119.7 million during the second quarter of 2020, compared to $72.9 million during the first quarter of 2020. In the second quarter of 2019, the Company released $1.4 million from the ALL. The ratio of the ALL to total loans was 2.04% as of June 30, 2020, up from 1.29% in the first quarter of 2020 and up from 0.99% in the same period last year. In the second quarter of 2020, the ratio of loan charge-offs to average total loans remained at a low level of 0.13%, up from 0.09% in the first quarter of 2020, and up from 0.11% in the second quarter of 2019.
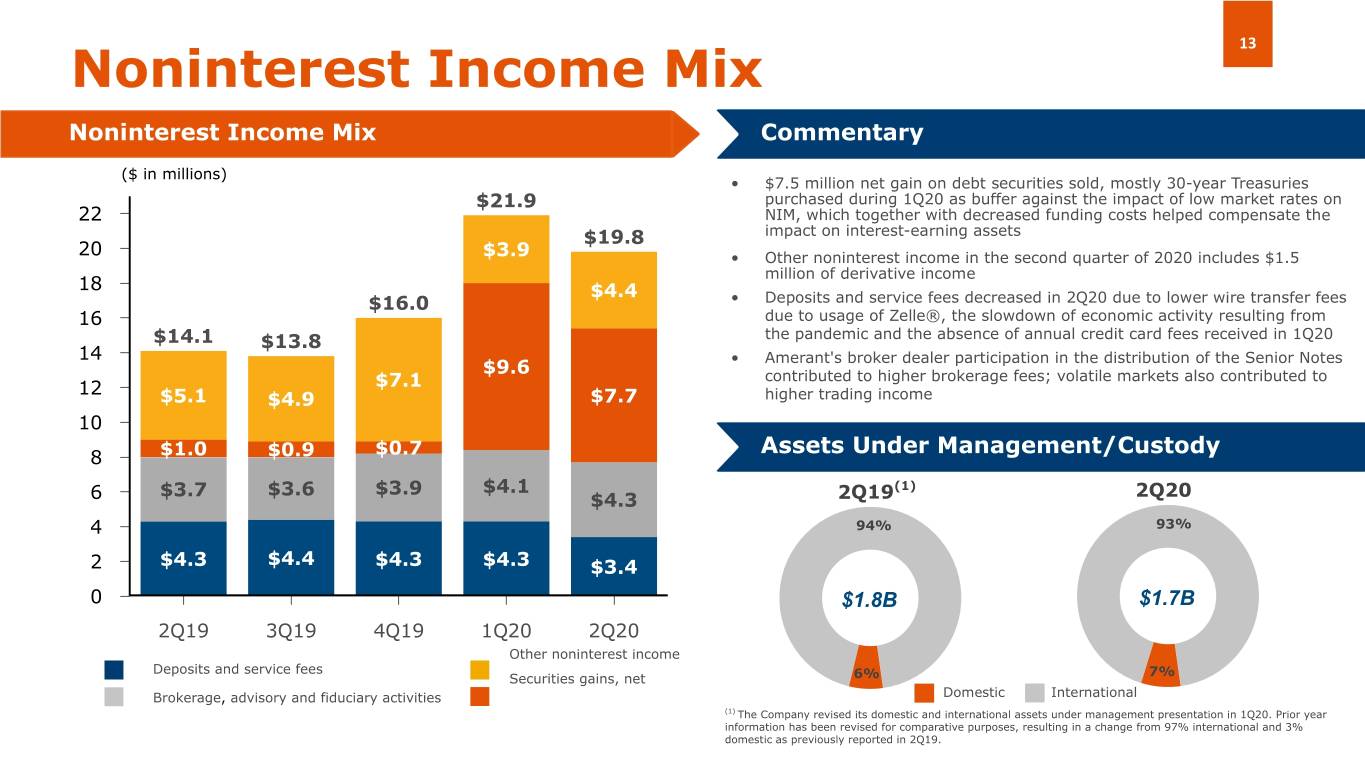
• | Noninterest income was $19.8 million, down 9.8% from $21.9 million in the first quarter of 2020, and up 39.6% from $14.1 million in the same period of 2019. The decrease from the first quarter of 2020 was due to $1.7 million less in net gains on the sale of debt securities, which was $7.5 million in the second quarter of 2020 compared to $9.2 million in the first quarter of 2020, partially offset by higher derivative income. The increase over the same quarter of 2019 was primarily due to the absence of net gains on the sale of securities in that period. |
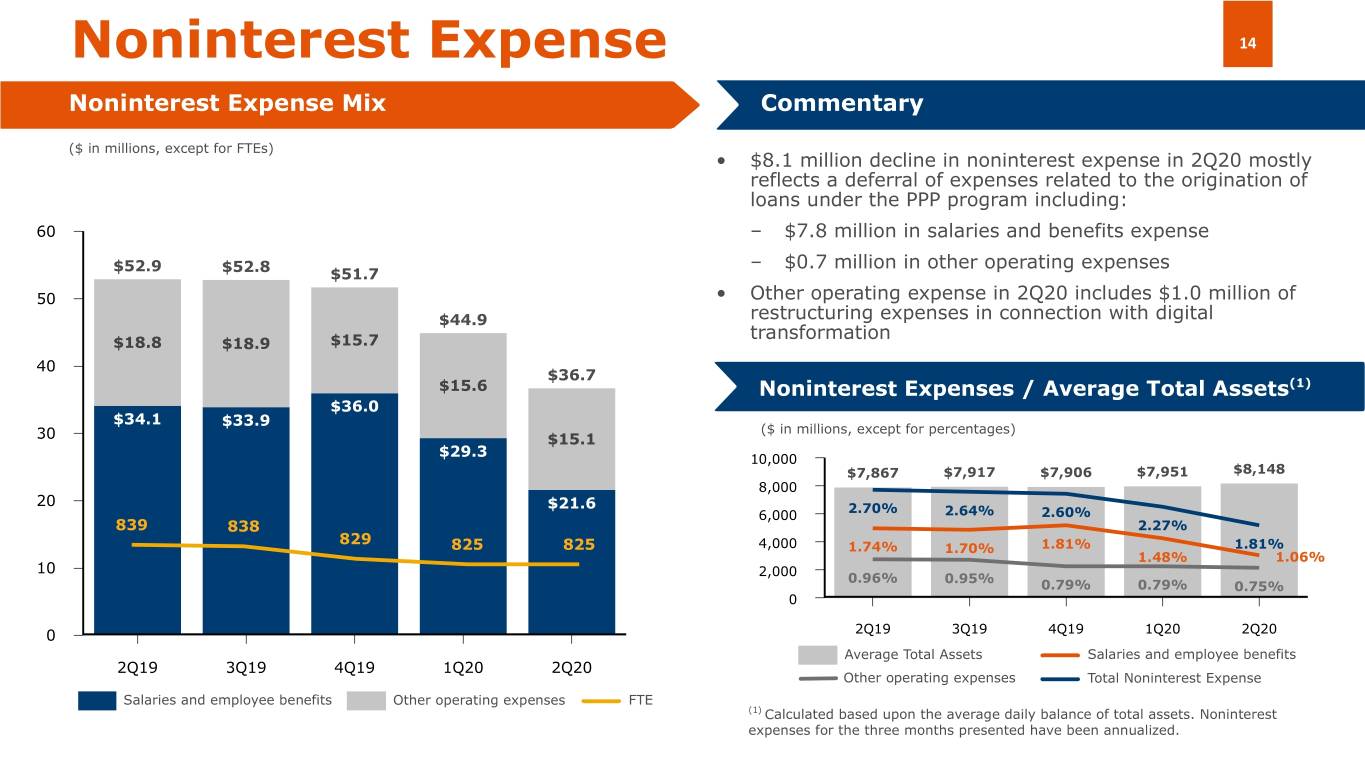
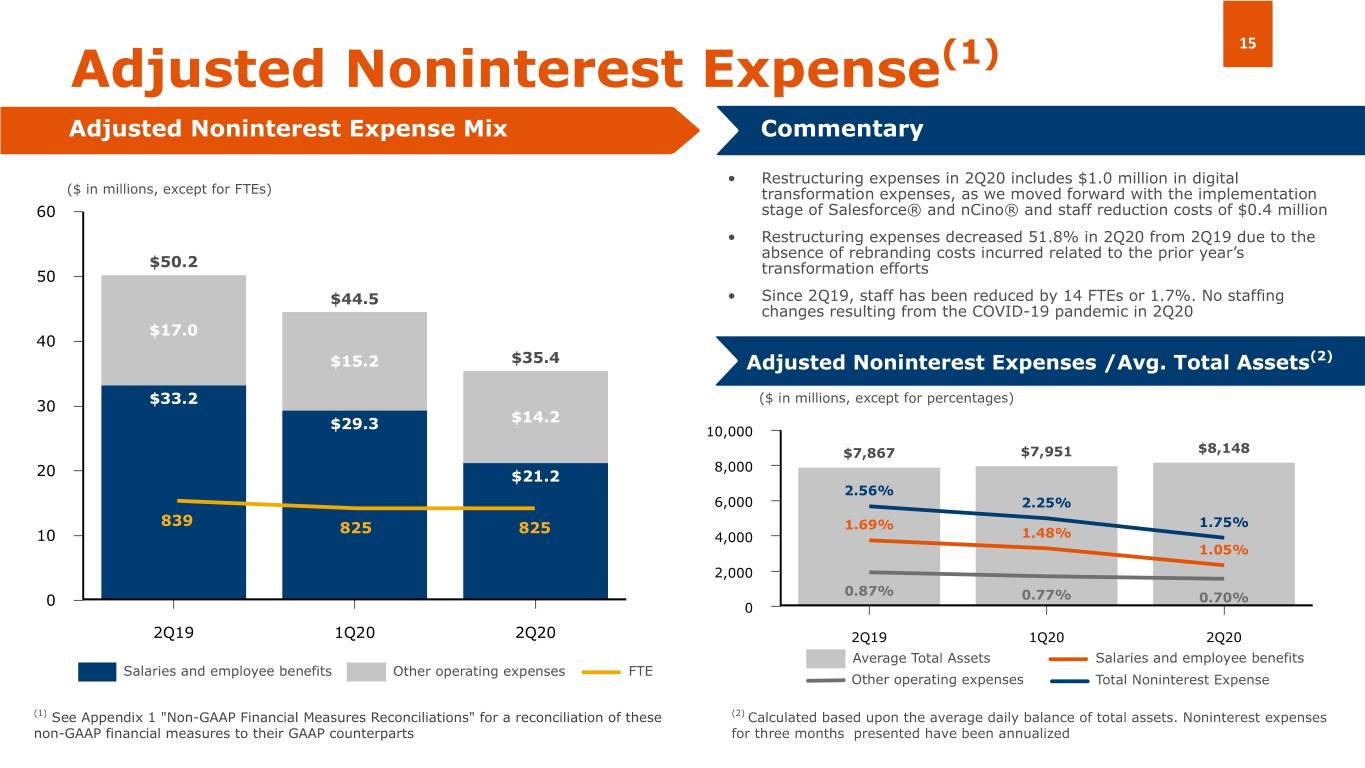
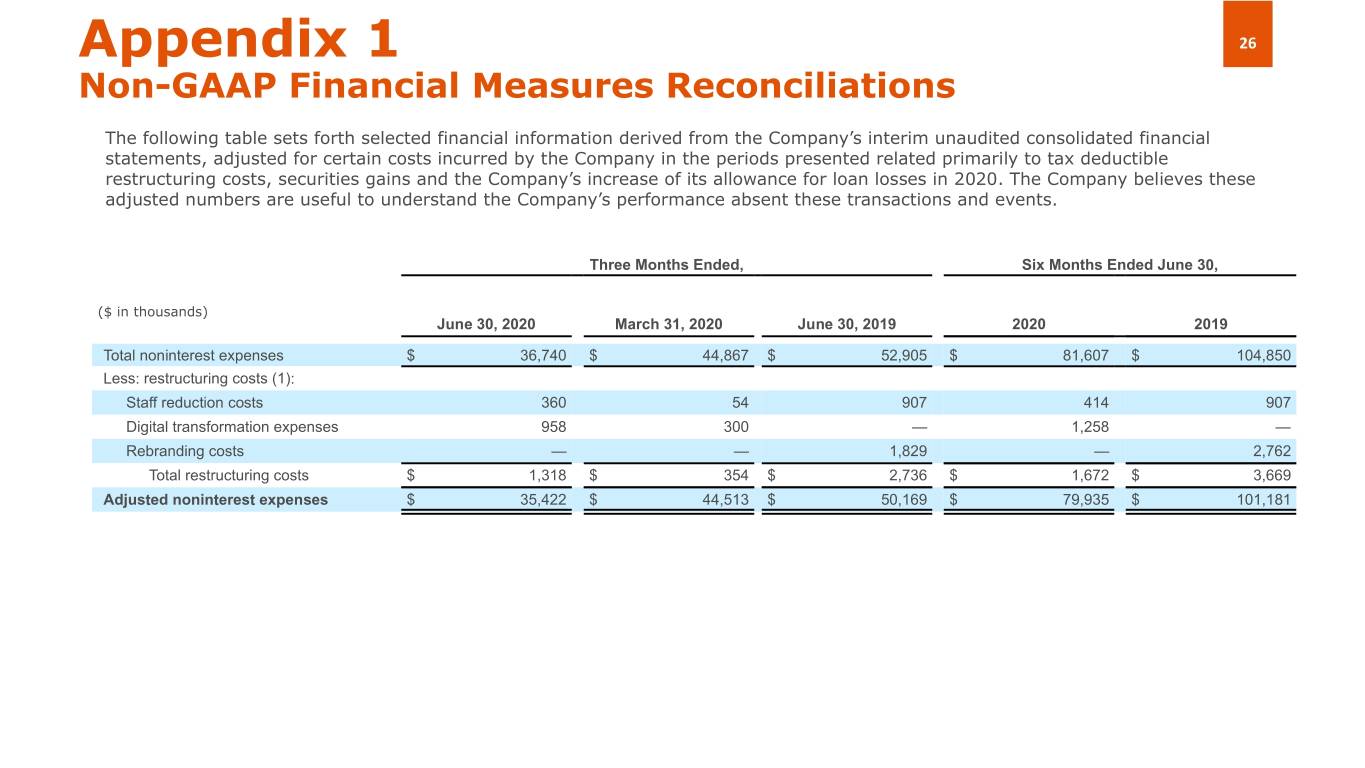
• | Noninterest expense was $36.7 million, down 18.1% from $44.9 million in the first quarter of 2020, and down 30.6% from $52.9 million in the second quarter of 2019. The quarter-over-quarter decline in noninterest expense was mainly driven by lower salaries and employee benefit expenses attributed to the deferral of direct origination costs associated with the Small Business Administration (“SBA”)’s Paycheck Protection Program ("PPP") loans funded this quarter. Non-refundable loan origination fees, net of direct costs of originating loans, are deferred and amortized over the term of the related loans as adjustments to interest income in accordance with generally accepted accounting principles (GAAP). Additionally, lower other operating expenses contributed to the decline in noninterest expense, partially offset by higher professional and other services fees. The year-over-year decline also resulted mainly from lower salaries and employee benefit expenses, and lower restructuring costs in the second quarter of 2020 related to Amerant’s transformation efforts. Adjusted noninterest expense was $35.4 million in the second quarter of 2020, down 20.4% from $44.5 million in the first quarter of 2020, and down 29.4% from $50.2 million in the second quarter of 2019. Adjusted noninterest expense in the second quarter of 2020 excludes $1.3 million in restructuring expenses, compared to $0.4 million in the first quarter of 2020 and $2.7 million in the same quarter last year. |
• | The efficiency ratio was 55.6% (53.6% adjusted for restructuring expenses), compared to 63.1% (62.6% adjusted for restructuring expenses) during the first quarter of 2020, and 77.9% (73.8% adjusted for restructuring expenses) for the corresponding period of 2019. These improvements in the second quarter of 2020 are mainly attributed to the lower noninterest expenses driven by the deferral of origination costs associated with PPP loans, as previously explained. |
• | Stockholders’ book value per common share decreased to $19.69, down 1.3% from $19.95 at March 31, 2020, and up 1.8%, from $19.35 at December 31, 2019. Tangible book value per common share declined to $19.18, down 1.3% from $19.43 at March 31, 2020, and up 1.8% from $18.84 at December 31, 2019. |
3
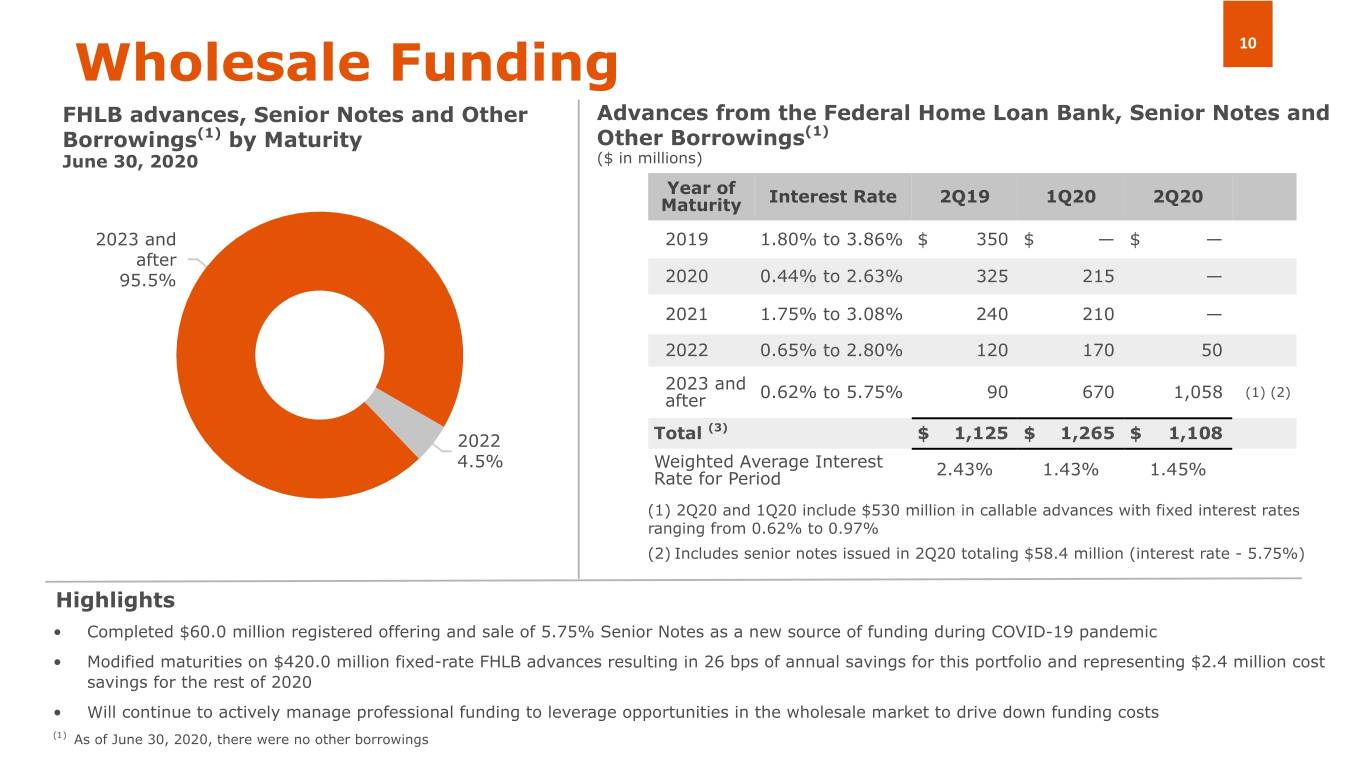
• | Completed the registered offering and sale of $60.0 million senior notes, which bear interest at an annual rate of 5.75% and are due in 2025 (the “Senior Notes”), significantly expanding the Company’s available funding sources. |
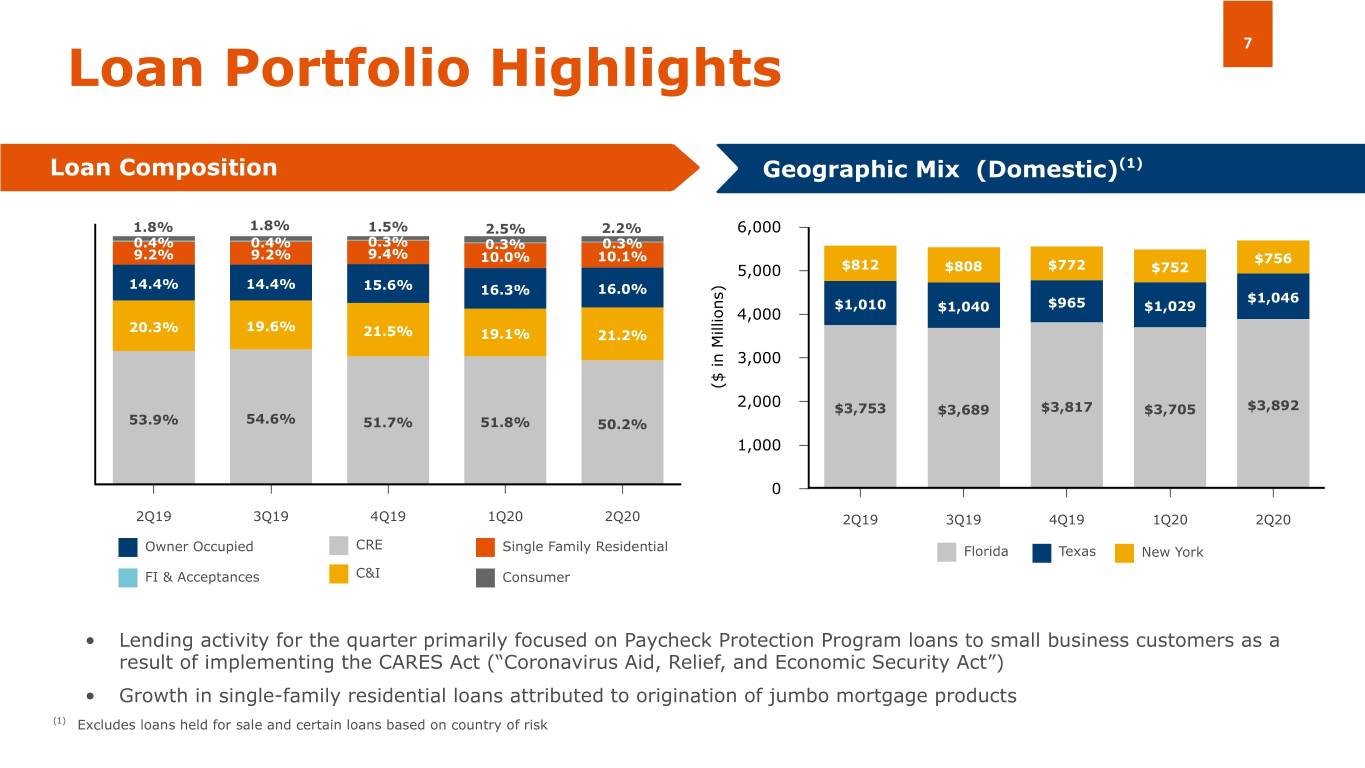
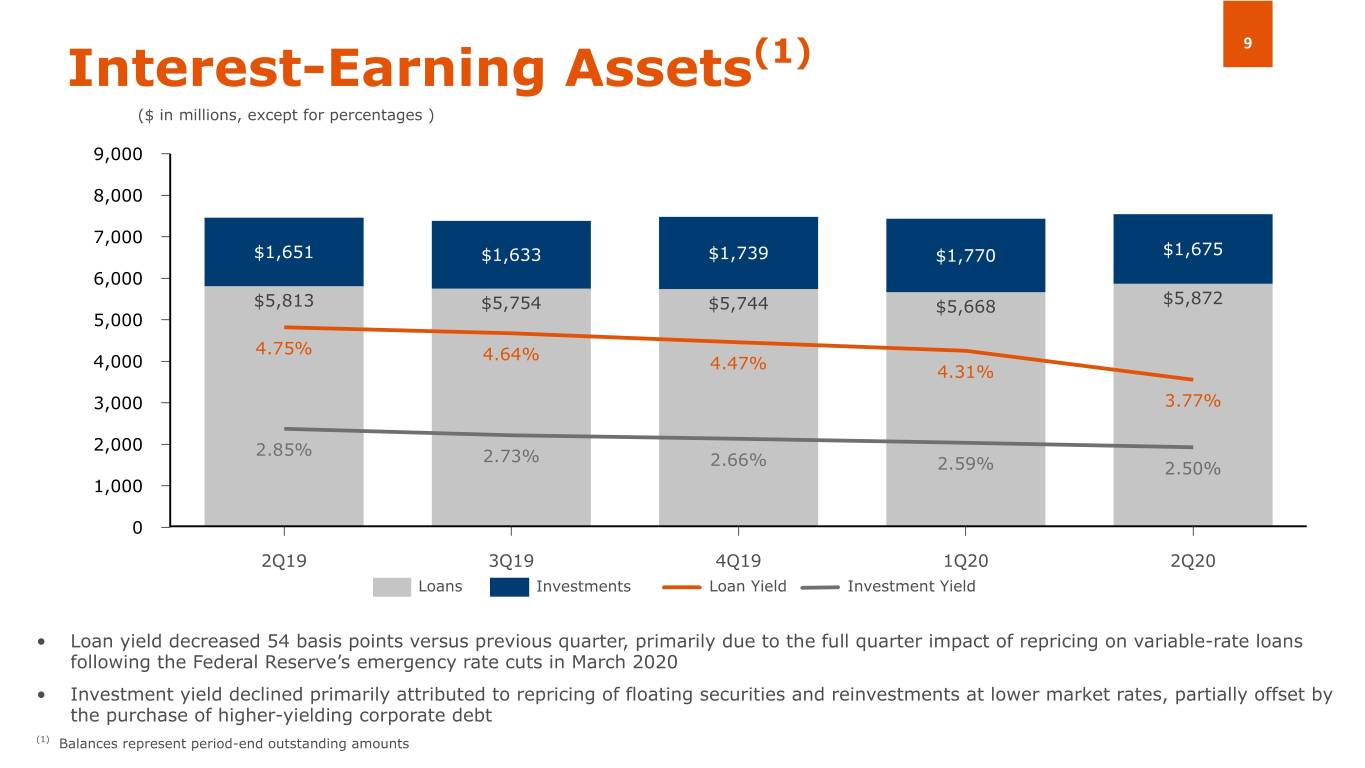
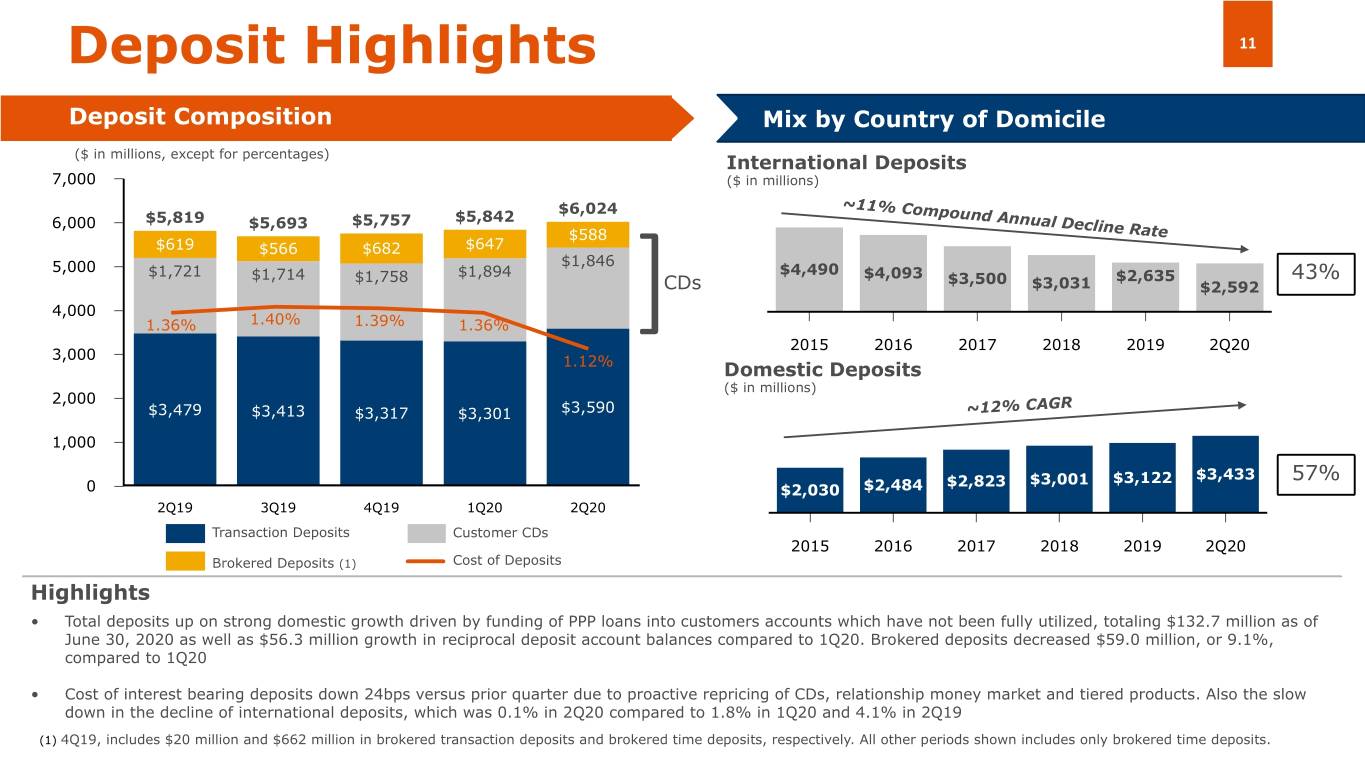
• | Total loans were $5.9 billion, up $203.9 million, or 3.6%, from $5.7 billion in the first quarter of 2020. Total deposits were $6.0 billion, up $182.5 million, or 3.1%, from $5.8 billion as of March 31, 2020. These increases are mainly driven by the Company’s participation in the PPP. |
4
Business Update Related to COVID-19
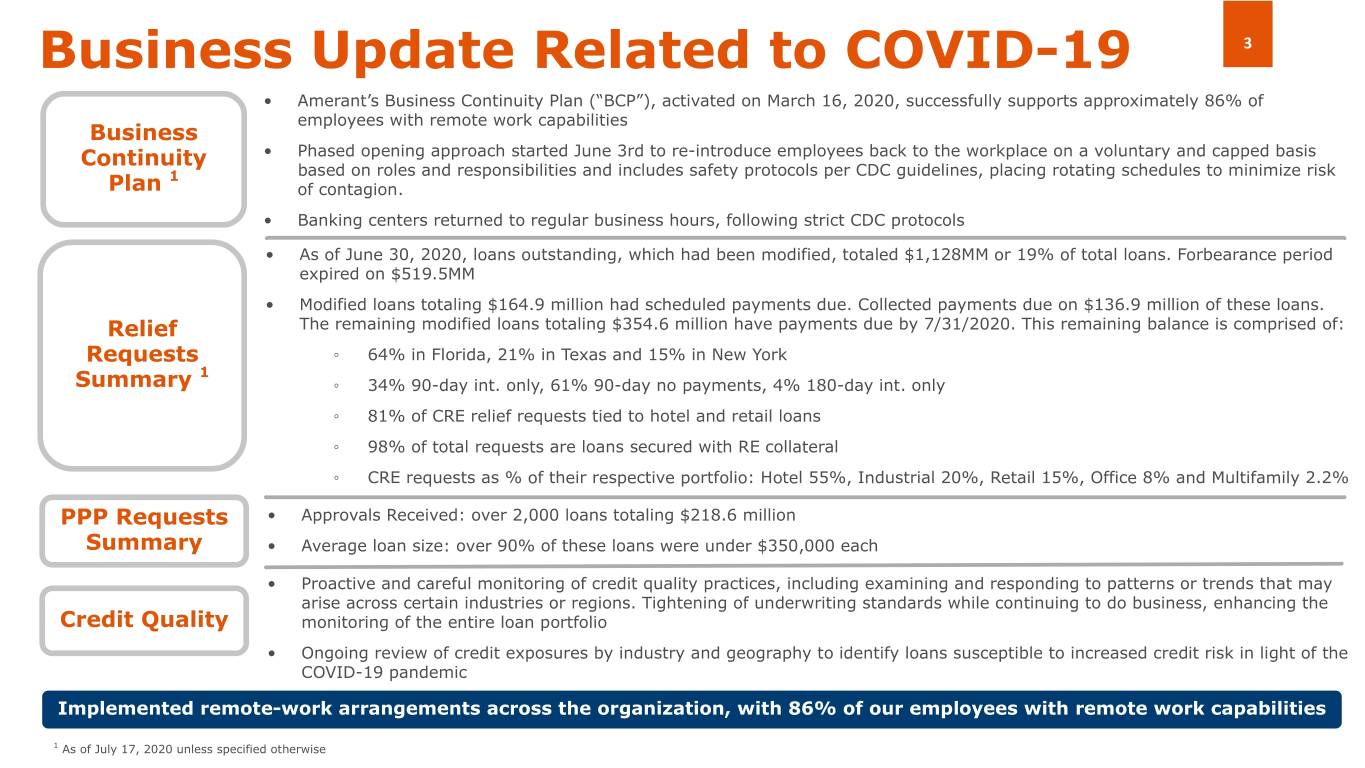
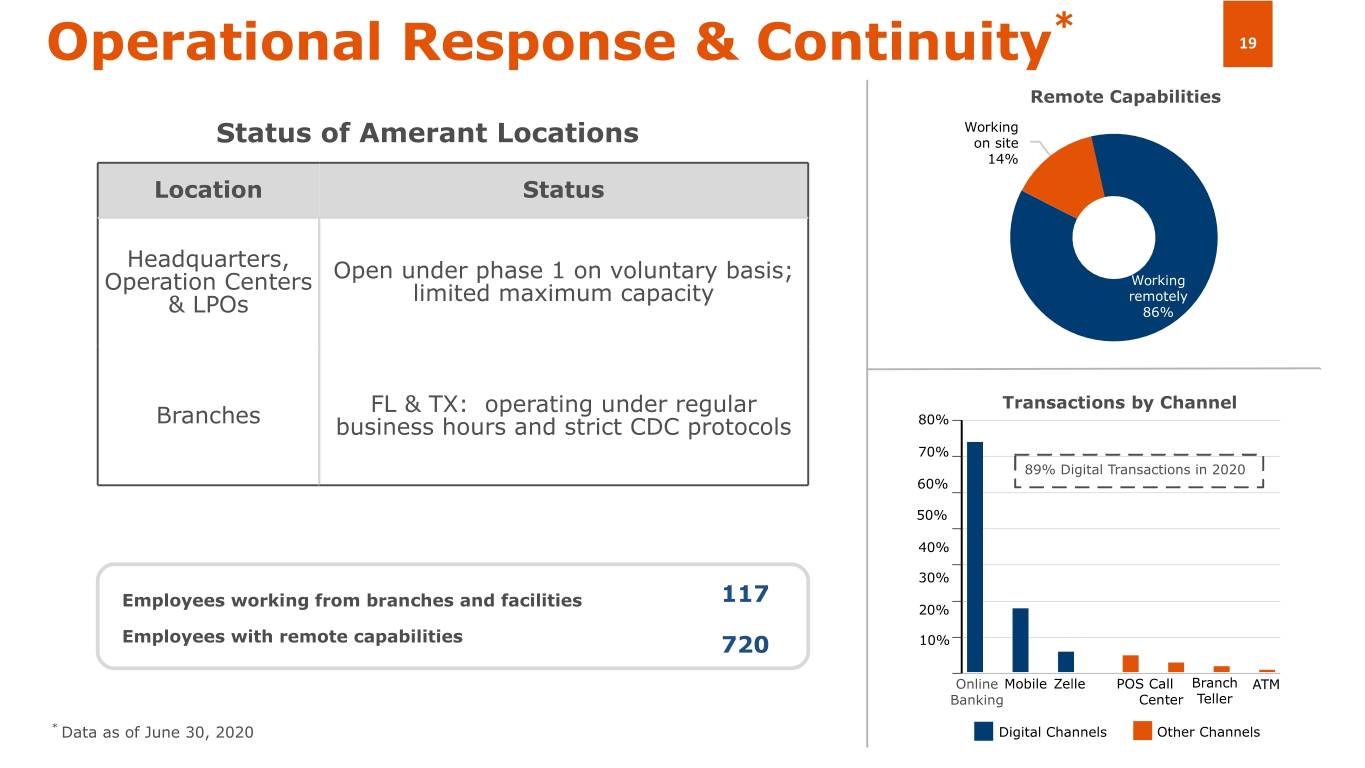
Amerant has continued several COVID-19-related initiatives in the second quarter of 2020 for the safety of the Company’s employees, customers, and local communities, and to continue to provide quality services in what is an increasingly complex situation. Notably, Amerant’s Business Continuity Plan (“BCP”), which was activated on March 16, 2020, successfully supports a remote work strategy by which approximately 86% of the employees have remote work capabilities. As counties across our markets started to re-open for business, on June 3rd, Amerant started Phase 1 of reintroducing employees working remotely back to the workplace. Given the increasing trend in COVID-19 cases in our markets, particularly in Florida and Texas, during the month of June and continuing in July, we are following a careful, phased-approach which includes a voluntary return of a limited number of employees, based on work location, roles and responsibilities, and various safety protocols. Banking centers have returned to regular business hours, following strict federal, state and local government guidelines supporting the safety of our employees and our customers. Amerant continues to focus on serving customers without interruption, while maintaining a safe environment.
Additionally, numerous initiatives and participation in the SBA’s PPP, which began early in the second quarter, continued throughout the quarter. Amerant waived ATM fees, late payment fees, and deposit account fees on a case-by-case basis, and offered individualized loan payment assistance such as interest payment deferral and forbearance options in an effort to support customers and communities. Measures related to waiving of fees, with the exception of late payment fees on loans, have been discontinued earlier in the third quarter.
Amerant did not implement any staffing changes related to the COVID-19 pandemic.
As the pandemic continues to evolve, the Executive Management Committee (“EMC”) has taken an even more active role in closely monitoring the Company’s credit and liquidity risks, and credit underwriting practices have been tightened. Forbearance status and general credit conditions are assessed on a daily basis, on different portions of the portfolio for both, new and existing loans, with an emphasis on loans in industries potentially more vulnerable to the financial impact of the COVID-19 pandemic, in order to best manage the Company’s credit quality under the current unusual and highly unpredictable circumstances.
Loan Mitigation Programs
In the second quarter of 2020, the Company continued offering loan payment relief options to customers impacted by the COVID-19 pandemic. As previously reported, these payment relief options include payment and interest-only payment deferral and/or forbearance options.
Loans which have been modified under these programs totaled $1.1 billion as of June 30, 2020, relatively flat compared to balances reported as of May 1, 2020. As of June 30, 2020, loans in these programs on which the interest-only and/or forbearance period expired at that date totaled $519.5 million, or 46% of total modified loans. Modified loans totaling $164.9 million had scheduled payments due through July 17, 2020. The Company collected payments due on 136.9 million of these loans through this date. Modified loans totaling $354.6 million
5
have payments due by July 31, 2020. In accordance with accounting and regulatory guidance, loans to borrowers benefiting from these measures are not considered Troubled Debt Restructurings (“TDRs”). The Company continues to closely monitor the performance of these loans under the terms of the temporary relief granted.
Paycheck Protection Program (PPP) Loans
On April 2, 2020, the Company began participating in the SBA’s PPP. These PPP loans provide businesses with emergency funds intended to cover payroll, rent, mortgage, healthcare, and utilities costs, among other essential expenses, during a limited period of time during the pandemic, and may be eligible for forgiveness under certain conditions. New legislation signed into law on July 4, 2020 extended the availability of loans under the SBA’s PPP from June 30, 2020 until August 8, 2020.
As of June 30, 2020, total PPP loans were $218.6 million, representing over 2,000 loans approved. Over 90% of these loans were under $350,000 each.
The Company received non-refundable fees of $7.8 million for the origination of PPP loans during the second quarter of 2020. The Company had salary and compensation benefits totaling $7.8 million, and other operational expenses totaling $0.7 million, directly related to the origination of these PPP loans. In accordance with GAAP, the Company deferred these non-refundable loan origination fees, net of the direct costs of loan originations, which are being amortized over the term of the related loans as adjustments to interest income.
Total deposits as of June 30, 2020, include $132.7 million of the unused portion of PPP loans funded in the quarter.
Credit Quality
The ratio of non-performing assets to total assets increased to 0.95% at the end of the second quarter of 2020, compared to 0.41% reported at the end of the first quarter of 2020 and second quarter of 2019. Non-performing loans increased $43.9 million, or 131.4% compared to the first quarter 2020, mainly due to one commercial loan relationship totaling $39.8 million and one CRE loan totaling $6.5 million placed in non-accrual status. This increase was offset primarily by the payoff of one owner occupied loan totaling $1.9 million and the charge-off of two commercial loans totaling $2.1 million.
Classified loans increased $51.0 million, or 140.3%, compared to the first quarter of 2020 mainly due to the downgrades mentioned above, coupled with the downgrade to substandard of one multi-loan relationship totaling $7.2 million, consisting of one commercial loan and one owner occupied loan, that remain in accrual status. Finally, special mention loans increased $3.2 million, mainly due to the downgrade to special mention of three commercial loans totaling $3.5 million, and two CRE loans totaling $2.2 million. This increase was mainly offset by the pay-downs of one construction loan totaling $2.6 million. All special mention loans remain current.
The Company recorded a provision for loan losses of $48.6 million during the second quarter of 2020, compared to $22.0 million in the first quarter of 2020. The Company had released $1.4 million in the second quarter of 2019. The increase during the second quarter of 2020 is mainly due to a provision of $28.2 million due to specific reserve requirements as a result of loan portfolio
6
deterioration and downgrades during the second quarter of 2020. In addition, the increase in the provision for loan losses during the second quarter of 2020 included $20.2 million driven by estimated probable losses reflecting deterioration in the macro-economic environment as a result of the COVID-19 pandemic across multiple impacted sectors.
The provision of $28.2 million in specific reserve requirements during the second quarter of 2020 includes $20.0 million related to certain loan arrangements with a Miami based U.S. coffee trader, which as of June 30, 2020, had loan arrangements with an outstanding balance of approximately $39.8 million. As disclosed by the Company on a current report on Form 8-K filed on July 16, 2020, the management of the Bank and the Company considered it necessary and prudent to provide, as of the close of the second quarter of 2020, for a loan loss reserve for this indebtedness which it initially estimated at approximately $17.0 million. On July 22, 2020, the Company received additional information from the assignee leading the liquidation procedure for the borrower and, based on an evaluation of this additional information, management of the Bank and the Company considered it necessary and prudent to increase the loan loss reserve for this indebtedness by an additional $3.1 million for a total of $20.0 million. As the liquidation procedure progresses and more information becomes available, management may decide to increase or decrease the loan loss reserve for this indebtedness. The Company intends to pursue any possible courses of actions available to it to mitigate the ultimate losses on this indebtedness and recover as much of the outstanding indebtedness as possible. Nevertheless, it is too early to determine if any of these possible courses of action are available to it and/or will be successful.
While it is difficult to estimate the extent of the impact of the COVID-19 pandemic on Amerant’s credit quality, Amerant continues to proactively and carefully monitor the Company’s credit quality practices, including examining and responding to patterns or trends that may arise across certain industries or regions. Importantly, while the Company continues to offer customized loan payment relief options, including interest-only payments and forbearance options, which are not considered TDRs, it will continue to assess its ability to offer such programs over time. The concentration of the loan portfolio remains stable compared to the first quarter of 2020.
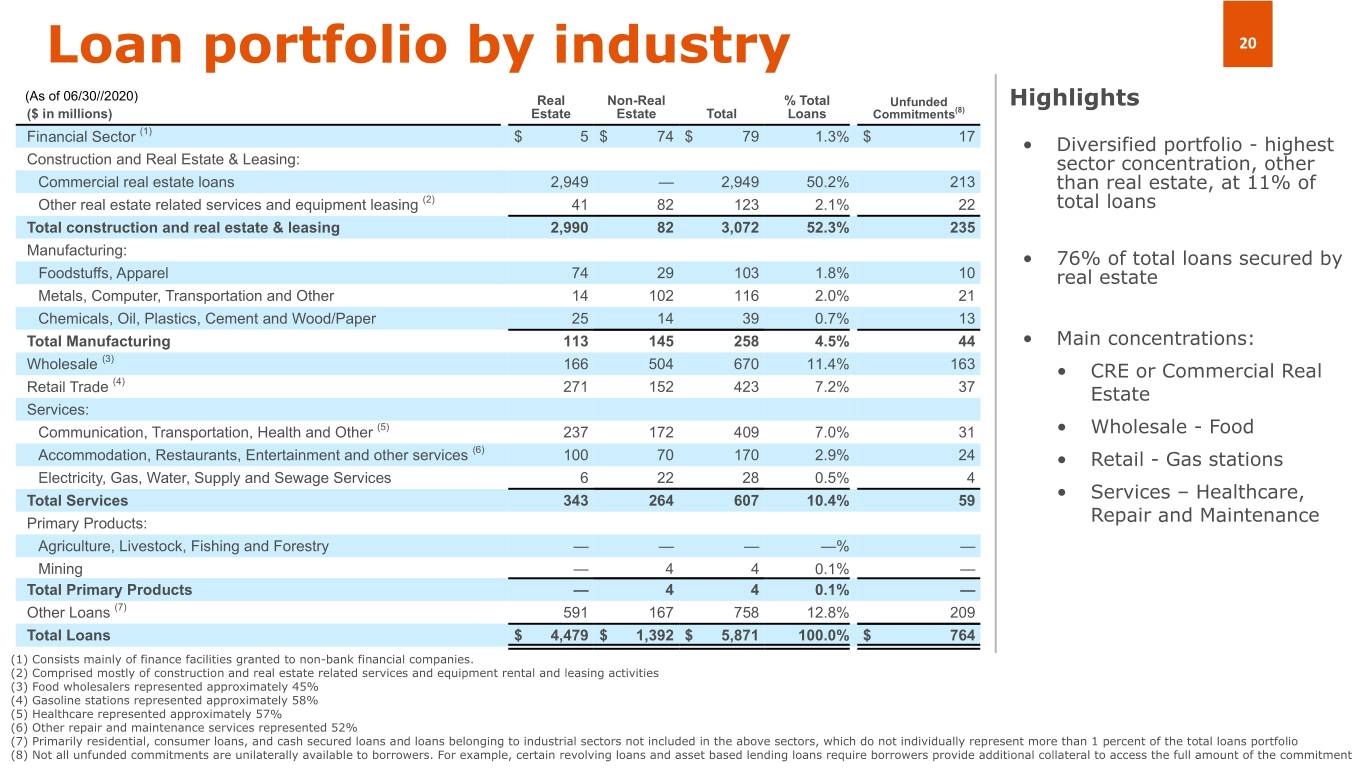
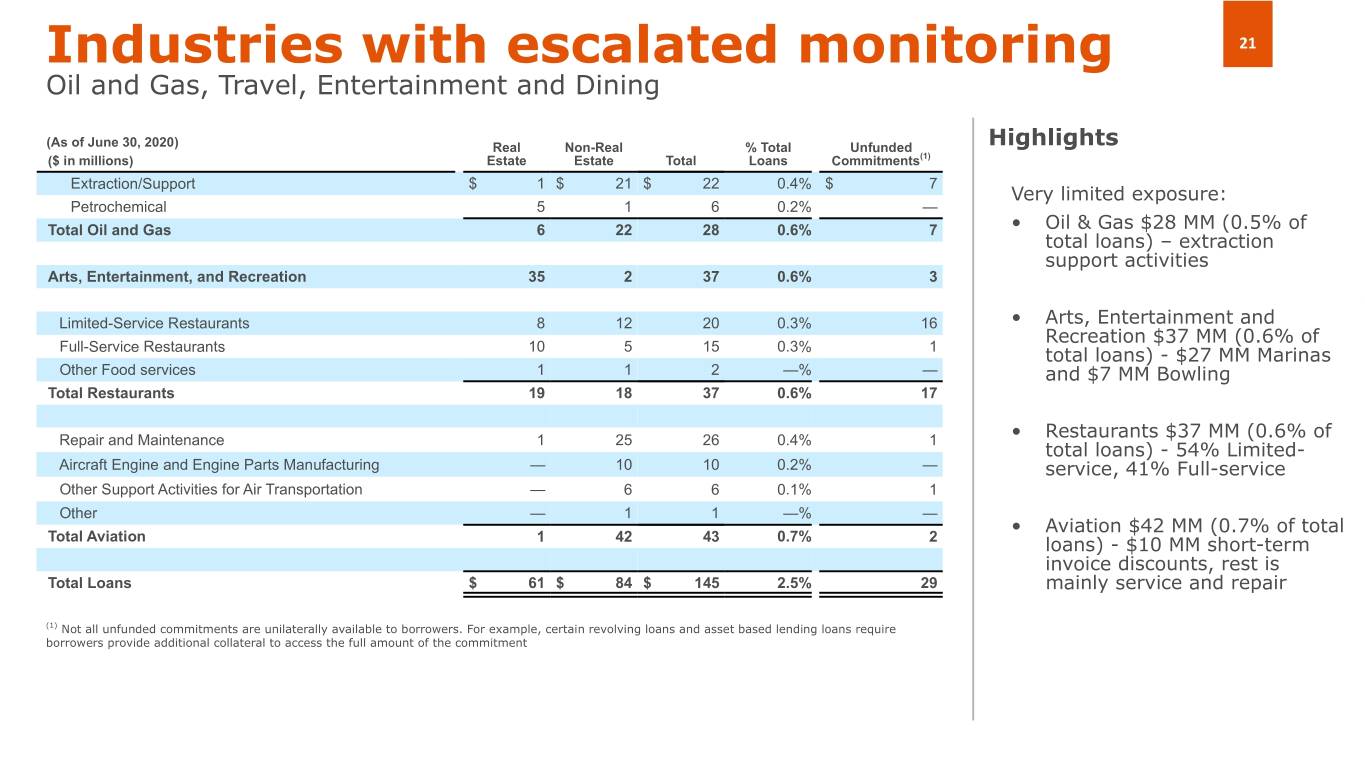
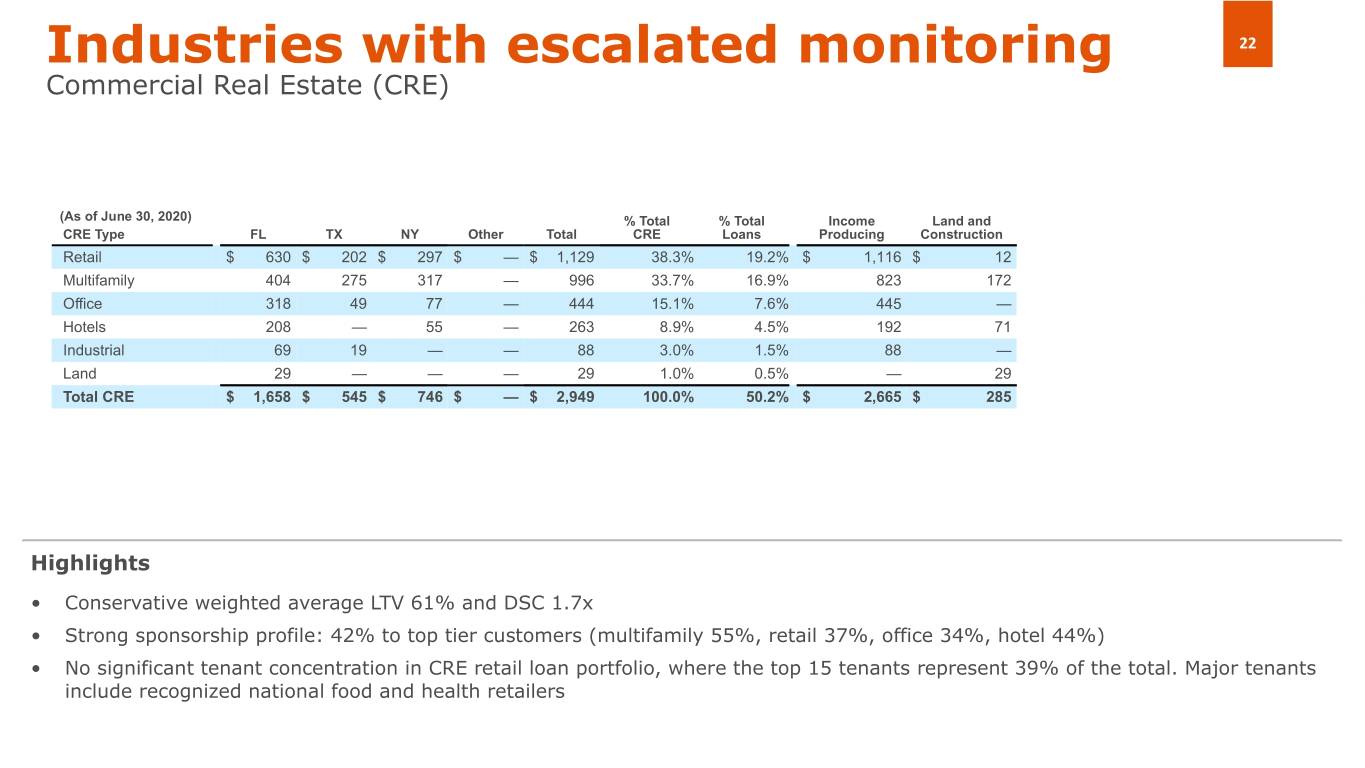
As of June 30, 2020, approximately 42% of the outstanding loan portfolio was tied to industries, or with collateral values, that are potentially more vulnerable to the financial impact of the COVID-19 pandemic. Approximately 67% of these loans are secured with real estate collateral. Except for loans to the real estate industry, the loan portfolio remains well diversified with the highest industry concentration representing 11% of total loans. At the close of June 30, 2020, the Company’s Commercial Real Estate (“CRE”) loan portfolio represented 50.2% of total loans, with an estimated weighted average Loan to Value (LTV) of 61% and an estimated weighted average Debt Service Coverage Ratio (DSCR) of 1.7x. Importantly, CRE loans to top tier customers, which are those considered to have the greatest strength and credit quality, represented approximately 42% of the CRE loan portfolio at that date.
Loans and Deposits
Total loans as of June 30, 2020 were $5.9 billion, up $203.9 million, or 3.6%, from $5.7 billion as of March 31, 2020. Total loans increased $127.9 million, or 2.2%, from December 31, 2019. These increases are mainly driven by the PPP loans originated during the second quarter of 2020 previously discussed, partially offset by the expected decline in other loan originations attributable
7
to lower economic activity, and more stringent credit guidelines, associated with the pandemic. Real estate loans were also higher quarter-over-quarter and year-to-date versus last year, more notably on the single-family residential loan portfolio, attributable to the growth in jumbo mortgages.
Total deposits as of June 30, 2020 were $6.0 billion, up $182.5 million, or 3.1%, from $5.8 billion as of March 31, 2020. This increase was mainly driven by the funds from the PPP loans originated during the second quarter of 2020, which small business customers have not fully utilized, totaling $132.7 million as of June 30, 2020. Additionally, higher deposits in the second quarter of 2020 include $56.3 million growth in reciprocal deposit account balances compared to the first quarter of 2020. As of June 30, 2020, reciprocal deposits totaled $67.8 million. During the second quarter of 2020, Amerant increasingly offered this deposit product to certain customers who want to make their deposits in excess of $250,000 fully eligible for FDIC insurance.
Online deposits increased $21.8 million, or 10.6%, compared to the first quarter of 2020. Total domestic deposits, excluding online deposit growth and the unused PPP-related deposit balances previously discussed, increased $24.5 million or 0.8%, compared to the first quarter of 2020. Brokered deposits declined $59.0 million, or 9.1%, compared to the first quarter of 2020. Foreign deposits, which includes deposits from other countries in addition to Venezuela, increased $3.5 million, or 0.1%, with respect to the first quarter of 2020, representing an annualized growth rate of 0.5%, compared to an annualized decline rate of 7.1% during the first quarter of 2020. Venezuelan customer deposits declined $22.0 million, or 1.0%, during the second quarter of 2020, an annualized decline rate of 4.0%. While customers in Venezuela continued to use their deposits to cover living expenses, the annualized decline rate of foreign deposits reversed in the second quarter. We attribute this increase to the combination of our team's sales efforts capturing more share of wallet, with the lower pace of the economic activity in Venezuela as a result of the COVID-19 pandemic.
Fostering deeper relationships with existing customers to capture additional share of wallet remains a priority, and the Company continues to enhance its customer engagement initiatives, including increased targeted call campaigns and providing relevant training to its sales teams in support of these efforts. The Company’s successful participation in the SBA’s PPP has introduced us to prospective commercial lending opportunities and new customer deposit relationships which will be strengthened by offering products and services that address the needs of these customers.
Net Interest Income and Net Interest Margin
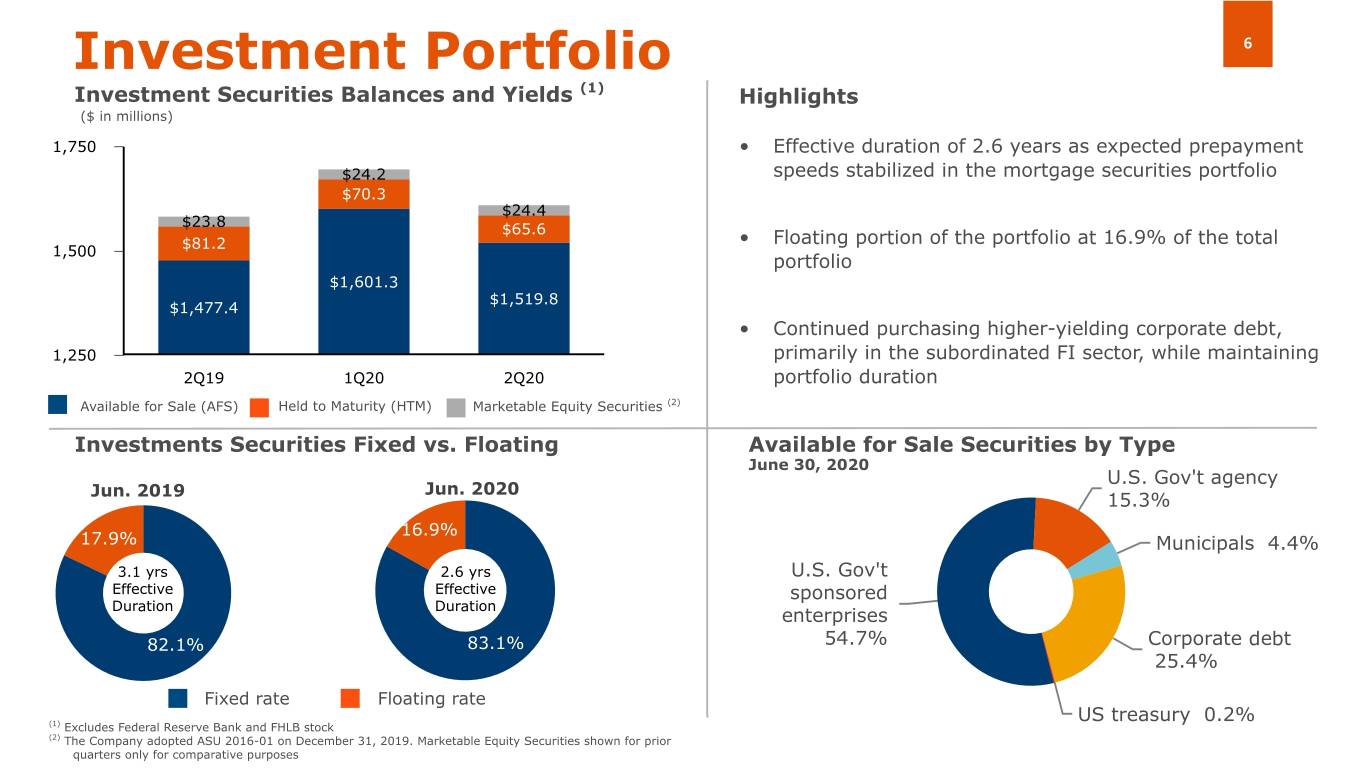
Second quarter of 2020 NII was $46.3 million, down 5.9% from $49.2 million in the first quarter of 2020 and down 13.9% from $53.8 million in the second quarter of 2019. Lower NII versus the first quarter of 2020 is mainly due to the full effect of lower market rates on variable-rate loans following the emergency rate cuts implemented by the Federal Reserve during March of 2020. Interest income from investment securities and interest earning deposits were also negatively impacted by lower rates. Partially offsetting this decline were higher loan balances resulting from the funding of PPP loans and lower costs of deposits as Amerant continued to proactively reprice customer deposits and chose not to replace higher-cost maturing brokered deposits. In addition, the second quarter of 2020 saw lower cost of wholesale funding, primarily driven by the previously-reported restructuring of FHLB advances completed early in April. Additionally, the impact of lower rates in the investment portfolio was partially offset by the purchase of $34.5 million in higher-yielding corporate debt, primarily in the subordinated financial institution sector, during the second quarter of 2020.
8
The decline in NII compared to the second quarter of 2019 was primarily due to the decline in yields of interest-earning assets resulting from the Federal Reserve emergency rate cuts in March 2020 previously discussed. This decline was partially offset by lower costs of deposits and FHLB borrowings as well as lower interest expense due to the redemption of trust preferred securities in prior quarters. NIM for the second quarter of 2020 was 2.44%, a decrease of 21 basis points from 2.65% in the prior quarter and 48 basis points from 2.92% in the second quarter of 2019.
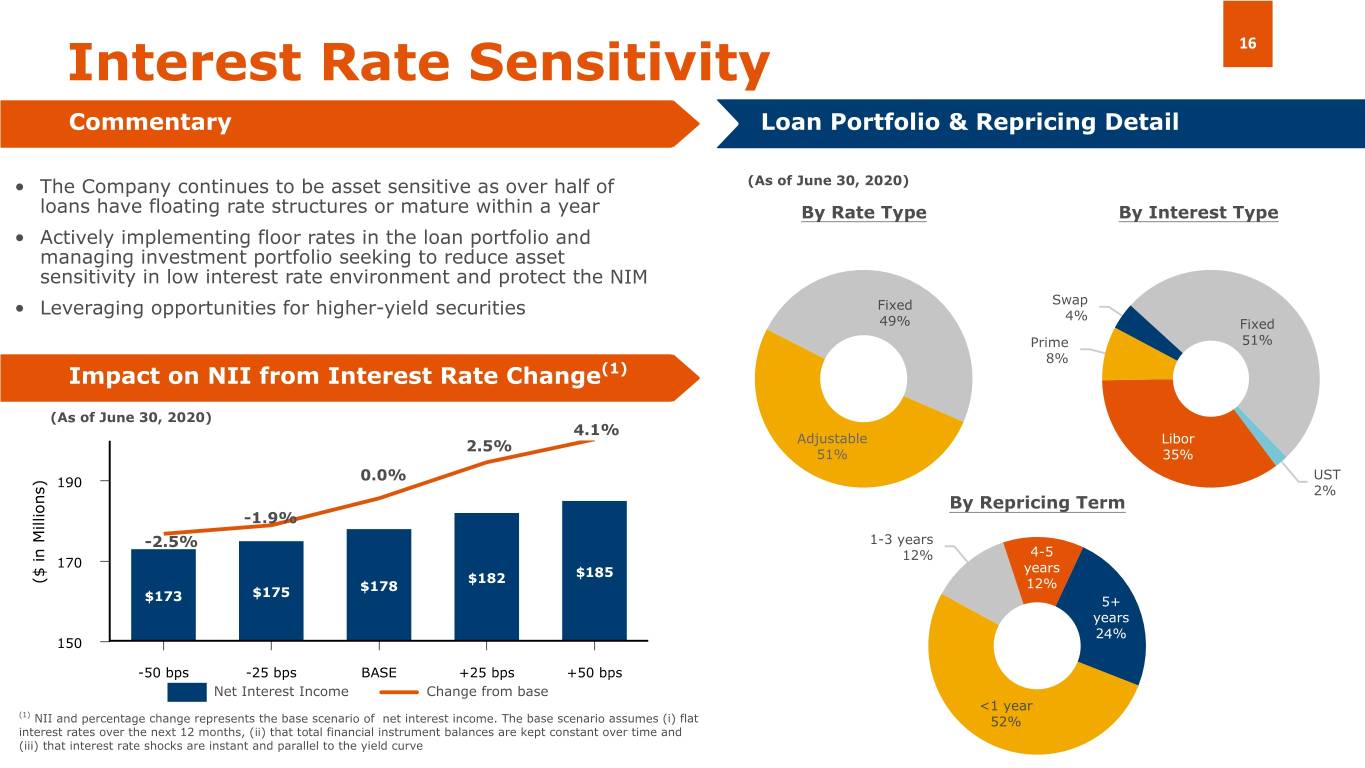
While the current COVID-19 interest rate environment and the potential runoff of Amerant’s low-cost foreign deposits will continue to pressure NII and NIM, the Company is taking decisive action to manage these headwinds. Specifically, in the second quarter, Amerant continued to actively implement and manage floor rates in the loan portfolio, aggressively reprice deposits, leverage low-cost wholesale funding opportunities, maximize high-yield investments, and seek to reduce asset sensitivity. Importantly, in April 2020, the Company modified maturities on $420.0 million fixed-rate FHLB advances, resulting in 26 bps of annual savings for this portfolio and $2.4 million of cost savings for the remainder of 2020. Amerant will continue to take steps to mitigate the current interest rate environment and continued runoff of foreign deposits.
Noninterest income
In the second quarter of 2020, noninterest income was $19.8 million, down from $21.9 million in the first quarter of 2020. The decline was mainly driven by lower net gains on sale of investments of $1.7 million and lower deposit and other services fees of $0.9 million compared to the first quarter of 2020. Partially offsetting these declines was an increase in derivative income driven by higher customer activity.
In the second quarter of 2020, Amerant realized a net gain of $7.5 million on sale of debt securities, particularly 30-year Treasury securities, which had been purchased during the first quarter of this year. The Company continues to actively manage its strong balance sheet and the duration of its investment portfolio, including further opportunistic sales of securities, as a buffer against the impact of low market interest rates on the Company’s NIM. Deposit and other services fees declined in the second quarter of 2020 compared to the first quarter of 2020 driven by lower service charges and wire transfer fees attributable to the implementation of Zelle®, the slowdown of economic activity due to the pandemic and the absence of annual credit card fees received in the first quarter of 2020.
The year-over-year increase in noninterest income of $5.6 million, or 39.6%, in the second quarter of 2020 was driven primarily by the gains on sale of debt securities in the current period which significantly outweighed the gains recognized in the year-ago period. Additionally, derivative income increased by $0.9 million year-over-year driven by higher customer activity while brokerage and advisory fees increased $0.6 million, or 15.8%, compared to the year-ago period due to the increase of advisory services within the overall level of assets under management (“AUM”) and higher volume of customer trading activity as a result of increased market volatility. These increases were partially offset by a decline on deposit and other service fees of $0.9 million, or 20.8% driven by lower wire transfer fees attributed to the slowdown of economic activity due to the pandemic as well as the implementation of Zelle®, lower credit card fee income due to the previously-announced changes to Amerant's international credit card program, and the absence of fees associated with services previously provided to the Company’s former parent and its affiliates.
9
The Company’s assets under management and custody totaled $1.72 billion as of June 30, 2020, increasing $143.5 million, or 9.1% from $1.57 billion as of March 31, 2020, and decreasing $71.5 million, or 4.0% from $1.79 billion as of June 30, 2019. The increase from the first quarter of 2020 is mainly attributable to higher valuations resulting from the market rebound from first-quarter-lows. Amerant Investments Inc, the Company’s broker dealer and investment advisory services subsidiary, successfully participated in the distribution of the Senior Notes, which contributed to higher brokerage fees. The decrease from the second quarter of 2019 is largely due to COVID-19 headwinds, partially offset by account growth as Amerant’s sales team continued to execute against the Company’s previously-announced relationship-centric strategy. The Company launched Amerant Investments Mobile, an application that facilitates customers’ engagement with their Amerant investment accounts and further supports our customer focus and sales efforts. New customer relationship balances brought in by the Company’s acquisition of Elant Bank and Trust Ltd. in the fourth quarter of 2019 also partially offset the year-over-year AUM decline.
Noninterest expense
Second quarter of 2020 noninterest expense was $36.7 million, down $8.1 million or 18.1%, from $44.9 million in the first quarter of 2020, mainly driven by lower salaries and employee benefit expenses due to the deferral of $7.8 million of expenses directly related to the origination of loans under the SBA’s PPP program previously discussed, as well as lower other operating expenses. Partially offsetting the decline was an increase of $1.0 million, or 33.9%, in professional and other services fees due to expenses in connection with our ongoing digital transformation efforts.
Noninterest expense for the quarter ended June 30, 2020, decreased $16.2 million, or 30.6% compared to $52.9 million in the same period of 2019, mostly due to lower salaries and employee benefits expenses associated with the 2018 and 2019 staff reductions and the decline in stock-based compensation expense this quarter, the aforementioned deferral of expenses directly related to PPP loan originations in the second quarter of 2020, and the absence of rebranding costs incurred last year related to Amerant’s transformation efforts.
Restructuring expenses in the quarter ended June 30, 2020 consisted of $1.3 million, an increase of $1.0 million or 272.3%, compared to the prior quarter, due to digital transformation and staff reduction expenses. Restructuring expenses in the second quarter of 2020 decreased $1.4 million, or 51.8%, from the same quarter last year due to the absence of rebranding costs related to the prior year’s transformation efforts.
At Amerant we continue working in line with our strategy to drive efficiencies across the organization while improving our customers’ journey. Amerant continued its Company-wide digital transformation by making steady progress on its planned adoption of the Salesforce® Customer Relationship Management (“CRM”) and nCino® loan origination platforms. In addition, the Company is in the process of implementing additional enhancements to its operating processes, including more notably a new approach for servicing calls from its customers, and moving forward with the closure of one banking center in Florida, and another in Texas. These closures are the result of extensive analyses of the profitability of the Company’s retail banking network and their current and expected individual contributions to achieving the Company’s strategic goals.
Capital Resources and Liquidity
10
Stockholders’ equity was $830.2 million on June 30, 2020, down $10.9 million, or 1.3%, from $841.1 million on March 31, 2020, and down $4.5 million, or 0.5%, from $834.7 million on December 31, 2019. The decrease in stockholder’s equity during the second quarter 2020 is mainly the result of the Company’s net loss in the second quarter of 2020, partially offset by higher valuations of the Company’s debt securities available for sale attributable to the decline in market interest rates in the same period. The decrease compared to the fourth quarter 2019 was mainly due to the net loss in the six months ended June 30, 2020 and the repurchase of $15.2 million of Class B Common Stock completed in the first quarter of 2020, partially offset by higher valuations of the Company’s debt securities available for sale compared to December 31, 2019. Book value per common share was $19.69 at June 30, 2020 compared to $19.95 on March 31, 2020 and $19.35 at December 31, 2019. Tangible book value per common share was $19.18 at June 30, 2020 compared to $19.43 on March 31, 2020 and $18.84 at December 31, 2019.
The Company’s capital continues to be strong and well in excess of the minimum regulatory requirements to be considered “well-capitalized” at June 30, 2020.
The liquidity position is strong supported by cash and cash equivalents of $217.3 million for the second quarter of 2020 compared to $271.1 million on March 31, 2020 and $121.3 million on December 31, 2019.
On June 23, 2020 the Company closed the registered offering of the Senior Notes. The Senior Notes bear interest at an annual rate of 5.75% and are unsecured and unsubordinated and rank equally with all of the Company’s existing and future unsecured and unsubordinated indebtedness. The Senior Notes are fully and unconditionally guaranteed by the Company’s wholly-owned subsidiary, Amerant Florida Bancorp Inc. The Company intends to use the net proceeds from this offering for general corporate purposes.
Second Quarter 2020 Earnings Conference Call
As previously announced, the Company will hold an earnings conference call on Friday, July 24th, 2020 at 9:30 a.m. (Eastern Time) to discuss its second quarter 2020 results. The conference call and presentation materials can be accessed via webcast by logging on from the Investor Relations section of the company’s website at https://investor.amerantbank.com. The online replay will remain available for approximately one month following the call through the above link.
About Amerant Bancorp Inc.
The Company is a bank holding company headquartered in Coral Gables, Florida. The Company operates through its subsidiaries, Amerant Bank, N.A. (the “Bank”), Amerant Investments, Inc., Amerant Trust, N.A. and Elant Bank and Trust Ltd. The Company provides individuals and businesses in the U.S., as well as select international clients, with deposit, credit and wealth management services. The Bank, which has operated for over 40 years, is the largest community bank headquartered in Florida. The Bank operates 27 banking centers—19 in South Florida and 8 in the Houston, Texas area—and loan production offices in Dallas, Texas and New York, New York.
Zelle®, Salesforce® and nCino® are registered trademarks of Early Warning Services LLC, Salesforce.com, inc., and nCino, Inc, respectively, used in accordance with contractual terms.
11
Visit our investor relations page at https://investor.amerantbank.com for additional information.
Cautionary Notice Regarding Forward-Looking Statements
This press release contains “forward-looking statements” within the meaning of the Securities Act of 1933 and the Securities Exchange Act of 1934, including, without limitation, future financial and operating results; costs and revenues; economic conditions generally and in our markets and among our customer base; the challenges and uncertainties caused by the COVID-19 pandemic; the measures we have taken in response to the COVID-19 pandemic; our participation in the PPP Loan program; loan demand; changes in the mix of our earning assets and our deposit and wholesale liabilities; net interest margin; yields on earning assets; interest rates and yield curves (generally and those applicable to our assets and liabilities); credit quality, including loan performance, non-performing assets, provisions for loan losses, charge-offs, other-than-temporary impairments and collateral values; market trends; rebranding and staff realignment costs and expected savings; customer preferences; and anticipated closures of banking centers in Florida and Texas, as well as statements with respect to our objectives, expectations and intentions and other statements that are not historical facts. All statements other than statements of historical fact are statements that could be forward-looking statements. You can identify these forward-looking statements through our use of words such as “may,” “will,” “anticipate,” “assume,” “should,” “indicate,” “would,” “believe,” “contemplate,” “expect,” “estimate,” “continue,” “plan,” “point to,” “project,” “could,” “intend,” “target,” “goals,” “outlooks,” “modeled,” and other similar words and expressions of the future.
Forward-looking statements, including those as to our beliefs, plans, objectives, goals, expectations, anticipations, estimates and intentions, involve known and unknown risks, uncertainties and other factors, which may be beyond our control, and which may cause the Company’s actual results, performance, achievements, or financial condition to be materially different from future results, performance, achievements, or financial condition expressed or implied by such forward-looking statements. You should not rely on any forward-looking statements as predictions of future events. You should not expect us to update any forward-looking statements. All written or oral forward-looking statements attributable to us are expressly qualified in their entirety by this cautionary notice, together with those risks and uncertainties described in “Risk factors” in our annual report on Form 10-K for the fiscal year ended December 31, 2019, in our quarterly report on Form 10-Q for the fiscal quarter ended March 31, 2020 and in our other filings with the U.S. Securities and Exchange Commission (the “SEC”), which are available at the SEC’s website www.sec.gov.
Interim Financial Information
Unaudited financial information as of and for interim periods, including as of and for the three and six month periods ended June 30, 2020 and 2019, may not reflect our results of operations for our fiscal year ending, or financial condition as of December 31, 2020, or any other period of time or date.
Non-GAAP Financial Measures
The Company supplements its financial results that are determined in accordance with accounting principles generally accepted in the United States of America (“GAAP”) with non-GAAP financial measures, such as “adjusted noninterest income”, “adjusted noninterest expense”, “adjusted net income (loss)”, “operating income”, “adjusted net income (loss) per share (basic and diluted)”,
12
“adjusted return on assets (ROA)”, “adjusted return on equity (ROE)”, and other ratios. This supplemental information is not required by, or are not presented in accordance with, U.S. generally accepted accounting principles (“GAAP”). The Company refers to these financial measures and ratios as “non-GAAP financial measures” and they should not be considered in isolation or as a substitute for the GAAP measures presented herein.
We use certain non-GAAP financial measures, including those mentioned above, both to explain our results to shareholders and the investment community and in the internal evaluation and management of our businesses. Our management believes that these non-GAAP financial measures and the information they provide are useful to investors since these measures permit investors to view our performance using the same tools that our management uses to evaluate our past performance and prospects for future performance, especially in light of the additional costs we have incurred in connection with the Company’s restructuring activities that began in 2018 and continued into 2020, the one-time gain on sale of the vacant Beacon land in the fourth quarter of 2019, the Company’s increases of its allowance for loan losses and net gains on sales of securities in the first and second quarters of 2020. While we believe that these non-GAAP financial measures are useful in evaluating our performance, this information should be considered as supplemental and not as a substitute for or superior to the related financial information prepared in accordance with GAAP. Additionally, these non-GAAP financial measures may differ from similar measures presented by other companies.
Exhibit 2 reconciles these non-GAAP financial measures to reported results.
13
Exhibit 1- Selected Financial Information
The following table sets forth selected financial information derived from our unaudited and audited consolidated financial statements.
(in thousands) | June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | June 30, 2019 | ||||||||||||||
Consolidated Balance Sheets | |||||||||||||||||||
Total assets | $ | 8,130,723 | $ | 8,098,810 | $ | 7,985,399 | $ | 7,864,260 | $ | 7,926,826 | |||||||||
Total investments | 1,674,811 | 1,769,987 | 1,739,410 | 1,632,985 | 1,650,632 | ||||||||||||||
Total gross loans (1) | 5,872,271 | 5,668,327 | 5,744,339 | 5,753,709 | 5,812,755 | ||||||||||||||
Allowance for loan losses | 119,652 | 72,948 | 52,223 | 53,640 | 57,404 | ||||||||||||||
Total deposits | 6,024,702 | 5,842,212 | 5,757,143 | 5,692,848 | 5,819,381 | ||||||||||||||
Advances from the FHLB and other borrowings | 1,050,000 | 1,265,000 | 1,235,000 | 1,170,000 | 1,125,000 | ||||||||||||||
Senior notes (2) | 58,419 | — | — | — | — | ||||||||||||||
Junior subordinated debentures (3) | 64,178 | 64,178 | 92,246 | 92,246 | 118,110 | ||||||||||||||
Stockholders' equity | 830,198 | 841,117 | 834,701 | 825,751 | 806,368 | ||||||||||||||
Assets under management and custody (4) | 1,715,804 | 1,572,322 | 1,815,848 | 1,713,012 | 1,787,257 | ||||||||||||||
Three Months Ended | Six Months Ended June 30, | ||||||||||||||||||||||||||
(in thousands, except percentages and per share amounts) | June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | June 30, 2019 | 2020 | 2019 | ||||||||||||||||||||
Consolidated Results of Operations | |||||||||||||||||||||||||||
Net interest income | $ | 46,323 | $ | 49,229 | $ | 51,262 | $ | 52,600 | $ | 53,789 | $ | 95,552 | $ | 109,226 | |||||||||||||
Provision for (reversal of) loan losses | 48,620 | 22,000 | (300 | ) | (1,500 | ) | (1,350 | ) | 70,620 | (1,350 | ) | ||||||||||||||||
Noninterest income | 19,753 | 21,910 | 15,971 | 13,836 | 14,147 | 41,663 | 27,303 | ||||||||||||||||||||
Noninterest expense | 36,740 | 44,867 | 51,730 | 52,737 | 52,905 | 81,607 | 104,850 | ||||||||||||||||||||
Net (loss) income | (15,279 | ) | 3,382 | 13,475 | 11,931 | 12,857 | (11,897 | ) | 25,928 | ||||||||||||||||||
Effective income tax rate | 20.77 | % | 20.83 | % | 14.73 | % | 21.50 | % | 21.51 | % | 20.75 | % | 21.50 | % | |||||||||||||
Common Share Data | |||||||||||||||||||||||||||
Stockholders' book value per common share | $ | 19.69 | $ | 19.95 | $ | 19.35 | $ | 19.11 | $ | 18.66 | $ | 19.69 | $ | 18.66 | |||||||||||||
Tangible stockholders' equity (book value) per common share (5) | $ | 19.18 | $ | 19.43 | $ | 18.84 | $ | 18.63 | $ | 18.18 | $ | 19.18 | $ | 18.18 | |||||||||||||
Basic (loss) earnings per common share | $ | (0.37 | ) | $ | 0.08 | $ | 0.32 | $ | 0.28 | $ | 0.30 | $ | (0.28 | ) | $ | 0.61 | |||||||||||
Diluted (loss) earnings per common share (6) | $ | (0.37 | ) | $ | 0.08 | $ | 0.31 | $ | 0.28 | $ | 0.30 | $ | (0.28 | ) | $ | 0.60 | |||||||||||
Basic weighted average shares outstanding | 41,720 | 42,185 | 42,489 | 42,466 | 42,466 | 41,953 | 42,610 | ||||||||||||||||||||
Diluted weighted average shares outstanding (6) | 41,720 | 42,533 | 43,050 | 42,915 | 42,819 | 41,953 | 42,865 | ||||||||||||||||||||
14
Three Months Ended | Six Months Ended June 30, | |||||||||||||||||||
June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | June 30, 2019 | 2020 | 2019 | ||||||||||||||
Other Financial and Operating Data (7) | ||||||||||||||||||||
Profitability Indicators (%) | ||||||||||||||||||||
Net interest income / Average total interest earning assets (NIM) (8) | 2.44 | % | 2.65 | % | 2.74 | % | 2.80 | % | 2.92 | % | 2.55 | % | 2.94 | % | ||||||
Net (loss) income / Average total assets (ROA) (9) | (0.75 | )% | 0.17 | % | 0.68 | % | 0.60 | % | 0.66 | % | (0.30 | )% | 0.66 | % | ||||||
Net (loss) income / Average stockholders' equity (ROE) (10) | (7.21 | )% | 1.61 | % | 6.44 | % | 5.81 | % | 6.56 | % | (2.82 | )% | 6.76 | % | ||||||
Capital Indicators (%) | ||||||||||||||||||||
Total capital ratio (11) | 14.34 | % | 14.54 | % | 14.78 | % | 14.77 | % | 14.70 | % | 14.34 | % | 14.70 | % | ||||||
Tier 1 capital ratio (12) | 13.08 | % | 13.38 | % | 13.94 | % | 13.93 | % | 13.85 | % | 13.08 | % | 13.85 | % | ||||||
Tier 1 leverage ratio (13) | 10.39 | % | 10.82 | % | 11.32 | % | 11.15 | % | 11.32 | % | 10.39 | % | 11.32 | % | ||||||
Common equity tier 1 capital ratio (CET1) (14) | 12.13 | % | 12.42 | % | 12.60 | % | 12.57 | % | 12.14 | % | 12.13 | % | 12.14 | % | ||||||
Tangible common equity ratio (15) | 9.97 | % | 10.14 | % | 10.21 | % | 10.26 | % | 9.93 | % | 9.97 | % | 9.93 | % | ||||||
Asset Quality Indicators (%) | ||||||||||||||||||||
Non-performing assets / Total assets (16) | 0.95 | % | 0.41 | % | 0.41 | % | 0.42 | % | 0.41 | % | 0.95 | % | 0.41 | % | ||||||
Non-performing loans / Total loans (1) (17) | 1.32 | % | 0.59 | % | 0.57 | % | 0.57 | % | 0.56 | % | 1.32 | % | 0.56 | % | ||||||
Allowance for loan losses / Total non-performing loans (18) | 154.87 | % | 218.49 | % | 158.60 | % | 163.42 | % | 175.28 | % | 154.87 | % | 175.28 | % | ||||||
Allowance for loan losses / Total loans (1) (18) | 2.04 | % | 1.29 | % | 0.91 | % | 0.93 | % | 0.99 | % | 2.04 | % | 0.99 | % | ||||||
Net charge-offs / Average total loans (19) | 0.13 | % | 0.09 | % | 0.08 | % | 0.16 | % | 0.11 | % | 0.11 | % | 0.11 | % | ||||||
Efficiency Indicators (% except FTE) | ||||||||||||||||||||
Noninterest expense / Average total assets | 1.81 | % | 2.27 | % | 2.60 | % | 2.64 | % | 2.70 | % | 2.04 | % | 2.65 | % | ||||||
Salaries and employee benefits / Average total assets | 1.06 | % | 1.48 | % | 1.81 | % | 1.70 | % | 1.74 | % | 1.27 | % | 1.71 | % | ||||||
Other operating expenses/ Average total assets (20) | 0.75 | % | 0.79 | % | 0.79 | % | 0.95 | % | 0.96 | % | 0.77 | % | 0.95 | % | ||||||
Efficiency ratio (21) | 55.60 | % | 63.07 | % | 76.94 | % | 79.38 | % | 77.87 | % | 59.47 | % | 76.80 | % | ||||||
Full-Time-Equivalent Employees (FTEs) | 825 | 825 | 829 | 838 | 839 | 825 | 839 | |||||||||||||
15
Three Months Ended | Six Months Ended June 30, | ||||||||||||||||||||||||||
(in thousands, except per share amounts and percentages) | June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | June 30, 2019 | 2020 | 2019 | ||||||||||||||||||||
Adjusted Selected Consolidated Results of Operations and Other Data (5) | |||||||||||||||||||||||||||
Adjusted noninterest income | $ | 19,753 | $ | 21,910 | $ | 13,176 | $ | 13,836 | $ | 14,147 | $ | 41,663 | $ | 27,303 | |||||||||||||
Adjusted noninterest expense | 35,422 | 44,513 | 51,616 | 51,474 | 50,169 | 79,935 | 101,181 | ||||||||||||||||||||
Adjusted net (loss) income | (14,234 | ) | 3,662 | 11,407 | 12,923 | 15,005 | (10,572 | ) | 28,808 | ||||||||||||||||||
Operating income | 21,599 | 16,652 | 14,800 | 12,793 | 14,039 | 38,251 | 30,683 | ||||||||||||||||||||
Adjusted basic (loss) earnings per common share | (0.34 | ) | 0.09 | 0.27 | 0.30 | 0.35 | (0.25 | ) | 0.68 | ||||||||||||||||||
Adjusted (loss) earnings per diluted common share (6) | (0.34 | ) | 0.09 | 0.26 | 0.30 | 0.35 | (0.25 | ) | 0.67 | ||||||||||||||||||
Adjusted net (loss) income / Average total assets (Adjusted ROA) (9) | (0.70 | )% | 0.19 | % | 0.57 | % | 0.65 | % | 0.77 | % | (0.26 | )% | 0.73 | % | |||||||||||||
Adjusted net (loss) income / Average stockholders' equity (Adjusted ROE) (10) | (6.72 | )% | 1.74 | % | 5.45 | % | 6.30 | % | 7.66 | % | (2.51 | )% | 7.51 | % | |||||||||||||
Adjusted noninterest expense / Average total assets | 1.75 | % | 2.25 | % | 2.59 | % | 2.58 | % | 2.56 | % | 2.00 | % | 2.56 | % | |||||||||||||
Adjusted salaries and employee benefits / Average total assets | 1.05 | % | 1.48 | % | 1.80 | % | 1.67 | % | 1.69 | % | 1.26 | % | 1.69 | % | |||||||||||||
Adjusted other operating expenses/ Average total assets (20) | 0.70 | % | 0.77 | % | 0.79 | % | 0.91 | % | 0.87 | % | 0.74 | % | 0.88 | % | |||||||||||||
Adjusted efficiency ratio (22) | 53.61 | % | 62.57 | % | 80.10 | % | 77.48 | % | 73.84 | % | 58.26 | % | 74.11 | % | |||||||||||||
__________________
(1) | Total gross loans are net of deferred loan fees and costs. At September 30, 2019, total loans include $1.9 million in loans held for sale. There were no loans held for sale at any of the other dates presented. |
(2) | During the second quarter of 2020, the Company completed a $60 million offering of Senior Notes with a coupon rate of 5.75%. Senior Notes are presented net of direct issuance cost which is deferred and amortized over 5 years. |
(3) | During the three months ended March 31, 2020 and September 30, 2019, the Company redeemed $26.8 million of its 8.90% trust preferred securities and $25.0 million of its 10.60% and 10.18% trust preferred securities, respectively. The Company simultaneously redeemed the junior subordinated debentures associated with these trust preferred securities. |
(4) Assets held for clients in an agency or fiduciary capacity which are not assets of the Company and therefore are not included in the consolidated financial statements.
(5) This presentation contains adjusted financial information determined by methods other than GAAP. This adjusted financial information is reconciled to GAAP in Exhibit 2 - Non-GAAP Financial Measures Reconciliation.
(6) As of June 30, 2020, March 31, 2020, December 31, 2019, September 30, 2019, and June 30, 2019, potential dilutive instruments consisted of unvested shares of restricted stock and restricted stock units mainly related to the Company’s IPO in 2018 totaling 491,360, 482,316, 530,620, 789,652 and 789,652, respectively. As of June 30, 2020, potential dilutive instruments were not included in the diluted earnings per share computation because the Company reported a net loss and their inclusion would have an antidilutive effect. For all other periods presented, potential dilutive instruments were included in the
16
diluted earnings per share computation because, when the unamortized deferred compensation cost related to these shares was divided by the average market price per share at those dates, fewer shares would have been purchased than restricted shares assumed issued. Therefore, at those dates, such awards resulted in higher diluted weighted average shares outstanding than basic weighted average shares outstanding, and had a dilutive effect in per share earnings.
(7) | Operating data for the periods presented have been annualized. |
(8) | NIM is defined as NII divided by average interest-earning assets, which are loans, securities, deposits with banks and other financial assets which yield interest or similar income. |
(9) | Calculated based upon the average daily balance of total assets. |
(10) | Calculated based upon the average daily balance of stockholders’ equity. |
(11) | Total stockholders’ equity divided by total risk-weighted assets, calculated according to the standardized regulatory capital ratio calculations. |
(12) | Tier 1 capital divided by total risk-weighted assets. |
(13) | Tier 1 capital divided by quarter to date average assets. Tier 1 capital is composed of Common Equity Tier 1 (CET 1) capital plus outstanding qualifying trust preferred securities of $62.3 million at June 30, 2020 and March 31, 2020, $89.1 million as of December 31, 2019 and September 30, 2019, and $114.1 million at June 30, 2019. See footnote 2 for more information about trust preferred securities redemption transactions in the first quarter of 2020 and third quarter of 2019. |
(14)Common Equity Tier 1 (CET 1) capital divided by total risk-weighted assets.
(15) | Tangible common equity is calculated as the ratio of common equity less goodwill and other intangibles divided by total assets less goodwill and other intangible assets. Other intangibles assets are included in other assets in the Company’s consolidated balance sheets. |
(16)Non-performing assets include all accruing loans past due by 90 days or more, all nonaccrual loans, restructured loans that are considered “troubled debt restructurings” or “TDRs”, and OREO properties acquired through or in lieu of foreclosure. Non-performing assets were $77.3 million, $33.4 million, $33.0 million, $32.8 million and $32.8 million as of June 30, 2020, March 31, 2020, December 31, 2019, September 30, 2019 and June 30, 2019, respectively.
(17)Non-performing loans include all accruing loans past due by 90 days or more, all nonaccrual loans and restructured loans that are considered TDRs. Non-performing loans were $77.3 million, $33.4 million, $32.9 million, $32.8 million and $32.8 million as of June 30, 2020, March 31, 2020, December 31, 2019, September 30, 2019 and June 30, 2019, respectively.
(18)Allowance for loan losses was $119.7 million, $72.9 million, $52.2 million, $53.6 million and $57.4 million as of June 30, 2020, March 31, 2020, December 31, 2019, September 30, 2019 and June 30, 2019, respectively.
(19)Calculated based upon the average daily balance of outstanding loan principal balance net of deferred loan fees and costs, excluding the allowance for loan losses.
(20)Other operating expenses is the result of total noninterest expense less salary and employee benefits.
(21)Efficiency ratio is the result of noninterest expense divided by the sum of noninterest income and NII.
(22)Adjusted efficiency ratio is the efficiency ratio less the effect of restructuring costs, described in Exhibit 2 - Non-GAAP Financial Measures Reconciliation.
17
Exhibit 2- Non-GAAP Financial Measures Reconciliation
The following table sets forth selected financial information derived from the Company’s interim unaudited and annual audited consolidated financial statements, adjusted for certain costs incurred by the Company in the periods presented related to tax deductible restructuring costs, an after-tax gain of $2.2 million on the sale of vacant Beacon land in the fourth quarter of 2019, the Company’s increases of its allowance for loan losses and net gains on sales of securities in the first and second quarters of 2020. The Company believes these adjusted numbers are useful to understand the Company’s performance absent these transactions and events.
Three Months Ended, | Six Months Ended June 30, | |||||||||||||||||||||
(in thousands) | June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | June 30, 2019 | 2020 | 2019 | |||||||||||||||
Total noninterest income | $ | 19,753 | $ | 21,910 | $ | 15,971 | $ | 13,836 | $ | 14,147 | $ | 41,663 | $ | 27,303 | ||||||||
Less: gain on sale of vacant Beacon land | — | — | (2,795 | ) | — | — | — | — | ||||||||||||||
Adjusted noninterest income | $ | 19,753 | $ | 21,910 | $ | 13,176 | $ | 13,836 | $ | 14,147 | $ | 41,663 | $ | 27,303 | ||||||||
Total noninterest expenses | $ | 36,740 | $ | 44,867 | $ | 51,730 | $ | 52,737 | $ | 52,905 | $ | 81,607 | $ | 104,850 | ||||||||
Less: restructuring costs (1): | ||||||||||||||||||||||
Staff reduction costs | 360 | 54 | 114 | 450 | 907 | 414 | 907 | |||||||||||||||
Digital transformation expenses | 958 | 300 | — | — | — | 1,258 | — | |||||||||||||||
Rebranding costs | — | — | — | 813 | 1,829 | — | 2,762 | |||||||||||||||
Other costs | — | — | — | — | — | — | — | |||||||||||||||
Total restructuring costs | $ | 1,318 | $ | 354 | $ | 114 | $ | 1,263 | $ | 2,736 | $ | 1,672 | $ | 3,669 | ||||||||
Adjusted noninterest expenses | $ | 35,422 | $ | 44,513 | $ | 51,616 | $ | 51,474 | $ | 50,169 | $ | 79,935 | $ | 101,181 | ||||||||
Net (loss) income | $ | (15,279 | ) | $ | 3,382 | $ | 13,475 | $ | 11,931 | $ | 12,857 | $ | (11,897 | ) | $ | 25,928 | ||||||
Plus after-tax restructuring costs: | ||||||||||||||||||||||
Restructuring costs before income tax effect | 1,318 | 354 | 114 | 1,263 | 2,736 | 1,672 | 3,669 | |||||||||||||||
Income tax effect | (273 | ) | (74 | ) | 59 | (271 | ) | (588 | ) | (347 | ) | (789 | ) | |||||||||
Total after-tax restructuring costs | 1,045 | 280 | 173 | 992 | 2,148 | 1,325 | 2,880 | |||||||||||||||
Less after-tax gain on sale of vacant Beacon land: | ||||||||||||||||||||||
Gain on sale of vacant Beacon land before income tax effect | — | — | (2,795 | ) | — | — | — | — | ||||||||||||||
Income tax effect | — | — | 554 | — | — | — | — | |||||||||||||||
Total after-tax gain on sale of vacant Beacon land | — | — | (2,241 | ) | — | — | — | — | ||||||||||||||
Adjusted net (loss) income | $ | (14,234 | ) | $ | 3,662 | $ | 11,407 | $ | 12,923 | $ | 15,005 | $ | (10,572 | ) | $ | 28,808 | ||||||
18
Three Months Ended, | Six Months Ended June 30, | |||||||||||||||||||||
(in thousands, except percentages and per share amounts) | June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | June 30, 2019 | 2020 | 2019 | |||||||||||||||
Net (loss) income | $ | (15,279 | ) | $ | 3,382 | $ | 13,475 | $ | 11,931 | $ | 12,857 | $ | (11,897 | ) | $ | 25,928 | ||||||
Plus: provision for income tax (benefit) expense | (4,005 | ) | 890 | 2,328 | 3,268 | 3,524 | (3,115 | ) | 7,101 | |||||||||||||
Plus: provision for (reversal of) loan losses | 48,620 | 22,000 | (300 | ) | (1,500 | ) | (1,350 | ) | 70,620 | (1,350 | ) | |||||||||||
Less: securities gains, net | 7,737 | 9,620 | 703 | 906 | 992 | 17,357 | 996 | |||||||||||||||
Operating income | $ | 21,599 | $ | 16,652 | $ | 14,800 | $ | 12,793 | $ | 14,039 | $ | 38,251 | $ | 30,683 | ||||||||
Basic (loss) earnings per share | $ | (0.37 | ) | $ | 0.08 | $ | 0.32 | $ | 0.28 | $ | 0.30 | $ | (0.28 | ) | $ | 0.61 | ||||||
Plus: after tax impact of restructuring costs | 0.03 | 0.01 | — | 0.02 | 0.05 | 0.03 | 0.07 | |||||||||||||||
Less: after tax gain on sale of vacant Beacon land | — | — | (0.05 | ) | — | — | — | — | ||||||||||||||
Total adjusted basic (loss) earnings per common share | $ | (0.34 | ) | $ | 0.09 | $ | 0.27 | $ | 0.30 | $ | 0.35 | $ | (0.25 | ) | $ | 0.68 | ||||||
Diluted (loss) earnings per share (2) | $ | (0.37 | ) | $ | 0.08 | $ | 0.31 | $ | 0.28 | $ | 0.30 | $ | (0.28 | ) | $ | 0.60 | ||||||
Plus: after tax impact of restructuring costs | 0.03 | 0.01 | — | 0.02 | 0.05 | 0.03 | 0.07 | |||||||||||||||
Less: after tax gain on sale of vacant Beacon land | — | — | (0.05 | ) | — | — | — | — | ||||||||||||||
Total adjusted diluted (loss) earnings per common share | $ | (0.34 | ) | $ | 0.09 | $ | 0.26 | $ | 0.30 | $ | 0.35 | $ | (0.25 | ) | $ | 0.67 | ||||||
Net (loss) income / Average total assets (ROA) | (0.75 | )% | 0.17 | % | 0.68 | % | 0.60 | % | 0.66 | % | (0.30 | )% | 0.66 | % | ||||||||
Plus: after tax impact of restructuring costs | 0.05 | % | 0.02 | % | 0.01 | % | 0.05 | % | 0.11 | % | 0.04 | % | 0.07 | % | ||||||||
Less: after tax gain on sale of vacant Beacon land | — | % | — | % | (0.12 | )% | — | % | — | % | — | % | — | % | ||||||||
Adjusted net (loss) income / Average total assets (Adjusted ROA) | (0.7 | )% | 0.19 | % | 0.57 | % | 0.65 | % | 0.77 | % | (0.26 | )% | 0.73 | % | ||||||||
Net (loss) income / Average stockholders' equity (ROE) | (7.21 | )% | 1.61 | % | 6.44 | % | 5.81 | % | 6.56 | % | (2.82 | )% | 6.76 | % | ||||||||
Plus: after tax impact of restructuring costs | 0.49 | % | 0.13 | % | 0.08 | % | 0.49 | % | 1.10 | % | 0.31 | % | 0.75 | % | ||||||||
Less: after tax gain on sale of vacant Beacon land | — | % | — | % | (1.07 | )% | — | % | — | % | — | % | — | % | ||||||||
Adjusted net (loss) income / Average stockholders' equity (Adjusted ROE) | (6.72 | )% | 1.74 | % | 5.45 | % | 6.30 | % | 7.66 | % | (2.51 | )% | 7.51 | % | ||||||||
Noninterest expense / Average total assets | 1.81 | % | 2.27 | % | 2.60 | % | 2.64 | % | 2.70 | % | 2.04 | % | 2.65 | % | ||||||||
Less: impact of restructuring costs | (0.06 | )% | (0.02 | )% | (0.01 | )% | (0.06 | )% | (0.14 | )% | (0.04 | )% | (0.09 | )% | ||||||||
Adjusted Noninterest expense / Average total assets | 1.75 | % | 2.25 | % | 2.59 | % | 2.58 | % | 2.56 | % | 2.00 | % | 2.56 | % | ||||||||
19
Three Months Ended, | Six Months Ended June 30, | |||||||||||||||||||||
(in thousands, except per share amounts and percentages) | June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | June 30, 2019 | 2020 | 2019 | |||||||||||||||
Salaries and employee benefits / Average total assets | 1.06 | % | 1.48 | % | 1.81 | % | 1.70 | % | 1.74 | % | 1.27 | % | 1.71 | % | ||||||||
Less: impact of restructuring costs | (0.01 | )% | — | % | (0.01 | )% | (0.03 | )% | (0.05 | )% | (0.01 | )% | (0.02 | )% | ||||||||
Adjusted salaries and employee benefits / Average total assets | 1.05 | % | 1.48 | % | 1.80 | % | 1.67 | % | 1.69 | % | 1.26 | % | 1.69 | % | ||||||||
Other operating expenses / Average total assets | 0.75 | % | 0.79 | % | 0.79 | % | 0.95 | % | 0.96 | % | 0.77 | % | 0.95 | % | ||||||||
Less: impact of restructuring costs | (0.05 | )% | (0.02 | )% | — | % | (0.04 | )% | (0.09 | )% | (0.03 | )% | (0.07 | )% | ||||||||
Adjusted other operating expenses / Average total assets | 0.70 | % | 0.77 | % | 0.79 | % | 0.91 | % | 0.87 | % | 0.74 | % | 0.88 | % | ||||||||
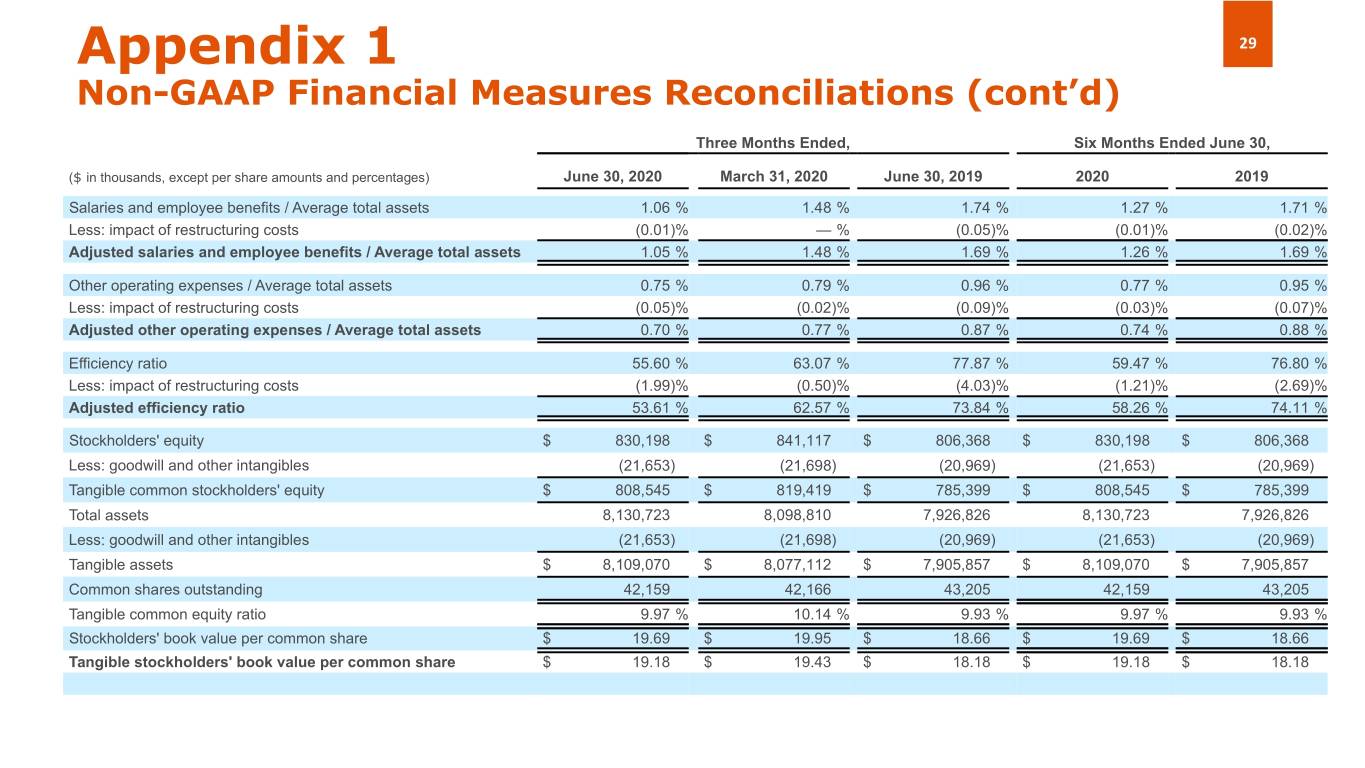
Efficiency ratio | 55.60 | % | 63.07 | % | 76.94 | % | 79.38 | % | 77.87 | % | 59.47 | % | 76.80 | % | ||||||||
Less: impact of restructuring costs | (1.99 | )% | (0.50 | )% | (0.17 | )% | (1.90 | )% | (4.03 | )% | (1.21 | )% | (2.69 | )% | ||||||||
Adjusted efficiency ratio | 53.61 | % | 62.57 | % | 80.10 | % | 77.48 | % | 73.84 | % | 58.26 | % | 74.11 | % | ||||||||
Stockholders' equity | $ | 830,198 | $ | 841,117 | $ | 834,701 | $ | 825,751 | $ | 806,368 | 830,198 | 806,368 | ||||||||||
Less: goodwill and other intangibles | (21,653 | ) | (21,698 | ) | (21,744 | ) | (20,933 | ) | (20,969 | ) | (21,653 | ) | (20,969 | ) | ||||||||
Tangible common stockholders' equity | $ | 808,545 | $ | 819,419 | $ | 812,957 | $ | 804,818 | $ | 785,399 | $ | 808,545 | $ | 785,399 | ||||||||
Total assets | 8,130,723 | 8,098,810 | 7,985,399 | 7,864,260 | 7,926,826 | 8,130,723 | $ | 7,926,826 | ||||||||||||||
Less: goodwill and other intangibles | (21,653 | ) | (21,698 | ) | (21,744 | ) | (20,933 | ) | (20,969 | ) | (21,653 | ) | (20,969 | ) | ||||||||
Tangible assets | $ | 8,109,070 | $ | 8,077,112 | $ | 7,963,655 | $ | 7,843,327 | $ | 7,905,857 | $ | 8,109,070 | $ | 7,905,857 | ||||||||
Common shares outstanding | 42,159 | 42,166 | 43,146 | 43,205 | 43,205 | 42,159 | 43,205 | |||||||||||||||
Tangible common equity ratio | 9.97 | % | 10.14 | % | 10.21 | % | 10.26 | % | 9.93 | % | 9.97 | % | 9.93 | % | ||||||||
Stockholders' book value per common share | $ | 19.69 | $ | 19.95 | $ | 19.35 | $ | 19.11 | $ | 18.66 | $ | 19.69 | $ | 18.66 | ||||||||
Tangible stockholders' book value per common share | $ | 19.18 | $ | 19.43 | $ | 18.84 | $ | 18.63 | $ | 18.18 | $ | 19.18 | $ | 18.18 | ||||||||
____________
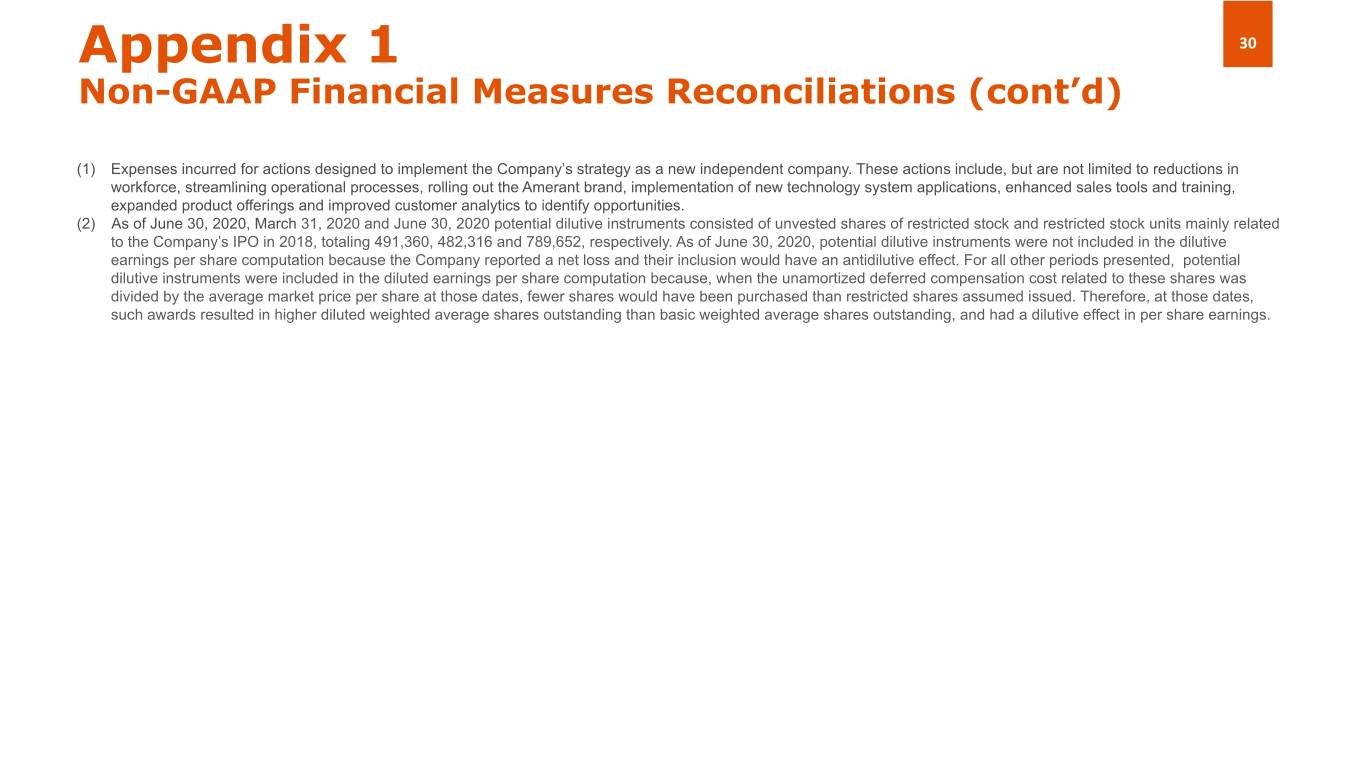
(1) | Expenses incurred for actions designed to implement the Company’s strategy as a new independent company. These actions include, but are not limited to reductions in workforce, streamlining operational processes, rolling out the Amerant brand, implementation of new technology system applications, enhanced sales tools and training, expanded product offerings and improved customer analytics to identify opportunities. |
(2) As of June 30, 2020, March 31,2020, December 31, 2019, September 30, 2019, and June 30, 2019 potential dilutive instruments consisted of unvested shares of restricted stock and restricted stock units mainly related to the Company’s IPO in 2018 totaling 491,360, 482,316, 530,620, 789,652 and 789,652, respectively. As of June 30, 2020, potential dilutive instruments were not included in the diluted earnings per share computation because the Company reported a net loss and their inclusion would have an antidilutive effect. For all other periods presented, potential dilutive instruments were included in the diluted earnings per share computation because, when the unamortized deferred compensation cost related to these shares was divided by the average market price per share at those dates, fewer shares would have been purchased than restricted shares assumed issued. Therefore, at those dates, such awards resulted in higher diluted weighted average shares outstanding than basic weighted average shares outstanding, and had a dilutive effect in per share earnings.
20
Exhibit 3 - Average Balance Sheet, Interest and Yield/Rate Analysis
The following tables present average balance sheet information, interest income, interest expense and the corresponding average yields earned and rates paid for the periods presented. The average balances for loans include both performing and nonperforming balances. Interest income on loans includes the effects of discount accretion and the amortization of non-refundable loan origination fees, net of direct loan origination costs, accounted for as yield adjustments. Average balances represent the daily average balances for the periods presented.
Three Months Ended | ||||||||||||||||||||||||||
June 30, 2020 | March 31, 2020 | June 30, 2019 | ||||||||||||||||||||||||
(in thousands, except percentages) | Average Balances | Income/ Expense | Yield/ Rates | Average Balances | Income/ Expense | Yield/ Rates | Average Balances | Income/ Expense | Yield/ Rates | |||||||||||||||||
Interest-earning assets: | ||||||||||||||||||||||||||
Loan portfolio, net (1) | $ | 5,712,548 | $ | 53,483 | 3.77 | % | $ | 5,573,627 | $ | 59,788 | 4.31 | % | $ | 5,641,686 | $ | 66,801 | 4.75 | % | ||||||||
Debt securities available for sale (2) | 1,545,335 | 9,283 | 2.42 | % | 1,549,502 | 9,497 | 2.47 | % | 1,498,544 | 10,173 | 2.72 | % | ||||||||||||||
Debt securities held to maturity (3) | 68,237 | 308 | 1.82 | % | 72,472 | 400 | 2.22 | % | 82,728 | 506 | 2.45 | % | ||||||||||||||
Equity securities with readily determinable fair value not held for trading | 24,303 | 121 | 2.00 | % | 24,052 | 131 | 2.19 | % | 23,736 | 141 | 2.38 | % | ||||||||||||||
Federal Reserve Bank and FHLB stock | 69,801 | 916 | 5.28 | % | 71,192 | 1,037 | 5.86 | % | 65,861 | 1,066 | 6.49 | % | ||||||||||||||
Deposits with banks | 215,406 | 56 | 0.10 | % | 171,848 | 462 | 1.08 | % | 88,247 | 539 | 2.45 | % | ||||||||||||||
Total interest-earning assets | 7,635,630 | 64,167 | 3.38 | % | 7,462,693 | 71,315 | 3.84 | % | 7,400,802 | 79,226 | 4.29 | % | ||||||||||||||
Total non-interest-earning assets less allowance for loan losses | 512,569 | 488,651 | 466,318 | |||||||||||||||||||||||
Total assets | $ | 8,148,199 | $ | 7,951,344 | $ | 7,867,120 | ||||||||||||||||||||
Interest-bearing liabilities: | ||||||||||||||||||||||||||
Checking and saving accounts - | ||||||||||||||||||||||||||
Interest bearing DDA | $ | 1,122,405 | $ | 104 | 0.04 | % | $ | 1,071,558 | $ | 135 | 0.05 | % | $ | 1,207,811 | $ | 301 | 0.10 | % | ||||||||
Money market | 1,112,363 | 1,521 | 0.55 | % | 1,136,501 | 3,249 | 1.15 | % | 1,143,072 | 3,997 | 1.40 | % | ||||||||||||||
Savings | 320,644 | 48 | 0.06 | % | 322,682 | 17 | 0.02 | % | 369,538 | 17 | 0.02 | % | ||||||||||||||
Total checking and saving accounts | 2,555,412 | 1,673 | 0.26 | % | 2,530,741 | 3,401 | 0.54 | % | 2,720,421 | 4,315 | 0.64 | % | ||||||||||||||
Time deposits | 2,484,219 | 12,406 | 2.01 | % | 2,461,073 | 13,484 | 2.20 | % | 2,314,614 | 12,740 | 2.21 | % | ||||||||||||||
Total deposits | 5,039,631 | 14,079 | 1.12 | % | 4,991,814 | 16,885 | 1.36 | % | 5,035,035 | 17,055 | 1.36 | % | ||||||||||||||
Securities sold under agreements to repurchase | 474 | — | — | % | — | — | — | % | — | — | — | % | ||||||||||||||
Advances from the FHLB and other borrowings (4) | 1,163,022 | 3,110 | 1.08 | % | 1,195,714 | 4,412 | 1.48 | % | 1,071,978 | 6,292 | 2.35 | % | ||||||||||||||
Senior notes | 5,136 | 84 | 6.58 | % | — | — | — | % | — | — | — | % | ||||||||||||||
Junior subordinated debentures | 64,178 | 571 | 3.58 | % | 73,123 | 789 | 4.34 | % | 118,110 | 2,090 | 7.10 | % | ||||||||||||||
Total interest-bearing liabilities | 6,272,441 | 17,844 | 1.14 | % | 6,260,651 | 22,086 | 1.42 | % | 6,225,123 | 25,437 | 1.64 | % | ||||||||||||||
Non-interest-bearing liabilities: | ||||||||||||||||||||||||||
Non-interest bearing demand deposits | 916,980 | 757,599 | 793,197 | |||||||||||||||||||||||
Accounts payable, accrued liabilities and other liabilities | 106,738 | 88,894 | 62,677 | |||||||||||||||||||||||
Total non-interest-bearing liabilities | 1,023,718 | 846,493 | 855,874 | |||||||||||||||||||||||
Total liabilities | 7,296,159 | 7,107,144 | 7,080,997 | |||||||||||||||||||||||
Stockholders’ equity | 852,040 | 844,200 | 786,123 | |||||||||||||||||||||||
Total liabilities and stockholders' equity | $ | 8,148,199 | $ | 7,951,344 | $ | 7,867,120 | ||||||||||||||||||||
Excess of average interest-earning assets over average interest-bearing liabilities | $ | 1,363,189 | $ | 1,202,042 | $ | 1,175,679 | ||||||||||||||||||||
Net interest income | $ | 46,323 | $ | 49,229 | $ | 53,789 | ||||||||||||||||||||
Net interest rate spread | 2.24 | % | 2.42 | % | 2.65 | % | ||||||||||||||||||||
Net interest margin (5) | 2.44 | % | 2.65 | % | 2.92 | % | ||||||||||||||||||||
Ratio of average interest-earning assets to average interest-bearing liabilities | 121.73 | % | 119.20 | % | 118.89 | % | ||||||||||||||||||||
21
Six Months Ended June 30, | |||||||||||||||||
2020 | 2019 | ||||||||||||||||
(in thousands, except percentages) | Average Balances | Income/ Expense | Yield/ Rates | Average Balances | Income/ Expense | Yield/ Rates | |||||||||||
Interest-earning assets: | |||||||||||||||||
Loan portfolio, net (1) | $ | 5,643,088 | $ | 113,271 | 4.04 | % | $ | 5,674,606 | $ | 133,523 | 4.74 | % | |||||
Securities available for sale (2) | 1,547,418 | 18,781 | 2.44 | % | 1,515,627 | 20,923 | 2.78 | % | |||||||||
Securities held to maturity (3) | 70,355 | 708 | 2.02 | % | 83,665 | 1,092 | 2.63 | % | |||||||||
Equity securities with readily determinable fair value not held for trading | 24,178 | 252 | 2.10 | % | 23,334 | 281 | 2.43 | % | |||||||||
Federal Reserve Bank and FHLB stock | 70,497 | 1,952 | 5.57 | % | 66,657 | 2,171 | 6.57 | % | |||||||||
Deposits with banks | 193,627 | 518 | 0.54 | % | 127,551 | 1,543 | 2.44 | % | |||||||||
Total interest-earning assets | 7,549,163 | 135,482 | 3.61 | % | 7,491,440 | 159,533 | 4.29 | % | |||||||||
Total non-interest-earning assets less allowance for loan losses | 500,363 | 473,237 | |||||||||||||||
Total assets | $ | 8,049,526 | $ | 7,964,677 | |||||||||||||
Interest-bearing liabilities: | |||||||||||||||||
Checking and saving accounts - | |||||||||||||||||
Interest bearing DDA | $ | 1,097,489 | $ | 239 | 0.04 | % | $ | 1,235,056 | $ | 575 | 0.09 | % | |||||
Money market | 1,124,432 | 4,770 | 0.85 | % | 1,150,805 | 7,714 | 1.35 | % | |||||||||
Savings | 321,663 | 65 | 0.04 | % | 376,443 | 33 | 0.02 | % | |||||||||
Total checking and saving accounts | 2,543,584 | 5,074 | 0.40 | % | 2,762,304 | 8,322 | 0.61 | % | |||||||||
Time deposits | 2,472,646 | 25,890 | 2.11 | % | 2,368,185 | 25,293 | 2.15 | % | |||||||||
Total deposits | 5,016,230 | 30,964 | 1.24 | % | 5,130,489 | 33,615 | 1.32 | % | |||||||||
Securities sold under agreements to repurchase | 237 | — | — | % | — | — | — | % | |||||||||
Advances from the FHLB and other borrowings (4) | 1,179,368 | 7,522 | 1.28 | % | 1,086,586 | 12,497 | 2.32 | % | |||||||||
Senior notes | 2,568 | 84 | 6.58 | % | — | — | — | % | |||||||||
Junior subordinated debentures | 68,650 | 1,360 | 3.98 | % | 118,110 | 4,195 | 7.16 | % | |||||||||
Total interest-bearing liabilities | 6,267,053 | 39,930 | 1.28 | % | 6,335,185 | 50,307 | 1.60 | % | |||||||||
Non-interest-bearing liabilities: | |||||||||||||||||
Non-interest bearing demand deposits | 836,782 | 786,674 | |||||||||||||||
Accounts payable, accrued liabilities and other liabilities | 97,816 | 69,367 | |||||||||||||||
Total non-interest-bearing liabilities | 934,598 | 856,041 | |||||||||||||||
Total liabilities | 7,201,651 | 7,191,226 | |||||||||||||||
Stockholders’ equity | 847,875 | 773,451 | |||||||||||||||
Total liabilities and stockholders' equity | $ | 8,049,526 | $ | 7,964,677 | |||||||||||||
Excess of average interest-earning assets over average interest-bearing liabilities | $ | 1,282,110 | $ | 1,156,255 | |||||||||||||
Net interest income | $ | 95,552 | $ | 109,226 | |||||||||||||
Net interest rate spread | 2.33 | % | 2.69 | % | |||||||||||||
Net interest margin (5) | 2.55 | % | 2.94 | % | |||||||||||||
Ratio of average interest-earning assets to average interest-bearing liabilities | 120.46 | % | 118.25 | % | |||||||||||||
___________
(1) Average non-performing loans of $50.4 million, $32.8 million and $24.5 million for the three months ended June 30, 2020, March 31, 2020 and June 30, 2019, respectively, and $41.6 million and $22.1 million for the six month periods ended June 30, 2020, and 2019, respectively, are included in the average loan portfolio, net.
(2) | Includes nontaxable securities with average balances of $62.2 million, $49.4 million and $122.9 million for the three months ended June 30, 2020, March 31, 2020 and June 30, 2019, respectively, and $55.8 million and $140.4 million for the six month periods ended June 30, 2020, and 2019, respectively. The tax equivalent yield for these nontaxable securities was 3.77%, 3.88% and 4.05% for the three months ended June 30, 2020, March 31, 2020 and June 30, 2019, respectively, and 3.82% and 4.03% for the six month periods ended June 30, 2020, and 2019, respectively. In 2020 and 2019, the tax equivalent yields were calculated by assuming a 21% tax rate and dividing the actual yield by 0.79. |
(3) | Includes nontaxable securities with average balances of $68.2 million, $72.5 million and $82.7 million for the three months ended June 30, 2020, March 31, 2020 and June 30, 2019, respectively, and $70.4 million and $83.7 million for the six month periods ended June 30, 2020, and 2019, respectively. The tax equivalent yield for these nontaxable securities was 2.30%, 2.81% and 3.10% for the three months ended June 30, 2020, March 31, 2020 and June 30, 2019, respectively, and 2.56% and |
22
3.33% for the six month periods ended June 30, 2020, and 2019, respectively. In 2020 and 2019, the tax equivalent yields were calculated assuming a 21% tax rate and dividing the actual yield by 0.79.
(4) | The terms of the FHLB advance agreements require the Bank to maintain certain investment securities or loans as collateral for these advances. |
(5) | NIM is defined as NII divided by average interest-earning assets, which are loans, securities available for sale and held to maturity, deposits with banks and other financial assets which yield interest or similar income. |
Exhibit 4 - Noninterest Income
This table shows the amounts of each of the categories of noninterest income for the periods presented.
Three Months Ended | Six Months Ended June 30, | |||||||||||||||||||||||||||
June 30, 2020 | March 31, 2020 | June 30, 2019 | 2020 | 2019 | ||||||||||||||||||||||||
(in thousands, except percentages) | Amount | % | Amount | % | Amount | % | Amount | % | Amount | % | ||||||||||||||||||
Deposits and service fees | $ | 3,438 | 17.4 | % | $ | 4,290 | 19.6 | % | $ | 4,341 | 30.7 | % | $ | 7,728 | 18.6 | % | $ | 8,427 | 30.9 | % | ||||||||
Brokerage, advisory and fiduciary activities | 4,325 | 21.9 | % | 4,133 | 18.9 | % | 3,736 | 26.4 | % | 8,458 | 20.3 | % | 7,424 | 27.2 | % | |||||||||||||
Change in cash surrender value of bank owned life insurance (“BOLI”)(1) | 1,427 | 7.2 | % | 1,414 | 6.5 | % | 1,419 | 10.0 | % | 2,841 | 6.8 | % | 2,823 | 10.3 | % | |||||||||||||
Cards and trade finance servicing fees | 273 | 1.4 | % | 395 | 1.8 | % | 1,419 | 10.0 | % | 668 | 1.6 | % | 2,334 | 8.6 | % | |||||||||||||
(Loss) gain on early extinguishment of FHLB advances, net | (66 | ) | (0.3 | )% | (7 | ) | — | % | — | — | % | (73 | ) | (0.2 | )% | 557 | 2.0 | % | ||||||||||
Data processing and fees for other services | — | — | % | — | — | % | 365 | 2.6 | % | — | — | % | 885 | 3.2 | % | |||||||||||||
Securities gains, net (2) | 7,737 | 39.2 | % | 9,620 | 43.9 | % | 992 | 7.0 | % | 17,357 | 41.7 | % | 996 | 3.7 | % | |||||||||||||
Other noninterest income (3) | 2,619 | 13.2 | % | 2,065 | 9.3 | % | 1,875 | 13.3 | % | 4,684 | 11.2 | % | 3,857 | 14.1 | % | |||||||||||||
Total noninterest income | $ | 19,753 | 100.0 | % | $ | 21,910 | 100.0 | % | $ | 14,147 | 100.0 | % | $ | 41,663 | 100.0 | % | $ | 27,303 | 100.0 | % | ||||||||
__________________
(1) | Changes in cash surrender value of BOLI are not taxable. |
(2) Includes net gain on sale of debt securities of $7.5 million and $9.2 million during the three months ended June 30, 2020 and March 31, 2020, respectively, and unrealized gain on change in market value of mutual fund of $0.2 million and $0.4 million during the three months ended June 30, 2020 and March 31, 2020, respectively.
(3) | Includes rental income, income from derivative and foreign currency exchange transactions with customers, and valuation income on the investment balances held in the non-qualified deferred compensation plan. |
23
Exhibit 5 - Noninterest Expense
This table shows the amounts of each of the categories of noninterest expense for the periods presented.
Three Months Ended | Six Months Ended June 30, | ||||||||||||||||||||||||||||
June 30, 2020 | March 31, 2020 | June 30, 2019 | 2020 | 2019 | |||||||||||||||||||||||||
(in thousands, except percentages) | Amount | % | Amount | % | Amount | % | Amount | % | Amount | % | |||||||||||||||||||
Salaries and employee benefits | $ | 21,570 | 58.7 | % | $ | 29,326 | 65.4 | % | $ | 34,057 | 64.4 | % | $ | 50,896 | 62.4 | % | $ | 67,494 | 64.4 | % | |||||||||
Occupancy and equipment | 4,220 | 11.5 | % | 3,803 | 8.5 | % | 4,232 | 8.0 | % | 8,023 | 9.8 | % | 8,274 | 7.9 | % | ||||||||||||||
Professional and other services fees | 3,965 | 10.8 | % | 2,954 | 6.6 | % | 3,954 | 7.5 | % | 6,919 | 8.5 | % | 7,398 | 7.1 | % | ||||||||||||||
Telecommunications and data processing | 3,157 | 8.6 | % | 3,464 | 7.7 | % | 3,233 | 6.1 | % | 6,621 | 8.1 | % | 6,259 | 6.0 | % | ||||||||||||||
Depreciation and amortization | 1,960 | 5.3 | % | 1,959 | 4.4 | % | 2,010 | 3.8 | % | 3,919 | 4.8 | % | 3,952 | 3.8 | % | ||||||||||||||
FDIC assessments and insurance | 1,240 | 3.4 | % | 1,118 | 2.5 | % | 1,177 | 2.2 | % | 2,358 | 2.9 | % | 2,570 | 2.5 | % | ||||||||||||||
Other operating expenses (1) | 628 | 1.7 | % | 2,243 | 4.9 | % | 4,242 | 8.0 | % | 2,871 | 3.5 | % | 8,903 | 8.3 | % | ||||||||||||||
Total noninterest expense | $ | 36,740 | 100.0 | % | $ | 44,867 | 100.0 | % | $ | 52,905 | 100.0 | % | $ | 81,607 | 100.0 | % | $ | 104,850 | 100.0 | % | |||||||||
___________
(1) Includes advertising, marketing, charitable contributions, community engagement, postage and courier expenses, provisions for possible losses on contingent loans, and debits which mirror the valuation income on the investment balances held in the non-qualified deferred compensation plan in order to adjust the liability to participants of the deferred compensation plan.
24
Exhibit 6 - Consolidated Balance Sheets
(in thousands, except share data) | June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | June 30, 2019 | ||||||||||||||
Assets | |||||||||||||||||||
Cash and due from banks | $ | 35,651 | $ | 22,303 | $ | 28,035 | $ | 32,363 | $ | 25,813 | |||||||||
Interest earning deposits with banks | 181,698 | 248,750 | 93,289 | 68,964 | 64,504 | ||||||||||||||
Cash and cash equivalents | 217,349 | 271,053 | 121,324 | 101,327 | 90,317 | ||||||||||||||
Securities | |||||||||||||||||||
Debt securities available for sale | 1,519,784 | 1,601,303 | 1,568,752 | 1,485,202 | 1,501,222 | ||||||||||||||
Debt securities held to maturity | 65,616 | 70,336 | 73,876 | 77,611 | 81,240 | ||||||||||||||
Equity securities with readily determinable fair value not held for trading (1) | 24,425 | 24,225 | 23,848 | — | — | ||||||||||||||
Federal Reserve Bank and Federal Home Loan Bank stock | 64,986 | 74,123 | 72,934 | 70,172 | 68,170 | ||||||||||||||
Securities | 1,674,811 | 1,769,987 | 1,739,410 | 1,632,985 | 1,650,632 | ||||||||||||||
Loans held for sale | — | — | — | 1,918 | — | ||||||||||||||
Loans held for investment, gross | 5,872,271 | 5,668,327 | 5,744,339 | 5,751,791 | 5,812,755 | ||||||||||||||
Less: Allowance for loan losses | 119,652 | 72,948 | 52,223 | 53,640 | 57,404 | ||||||||||||||
Loans held for investment, net | 5,752,619 | 5,595,379 | 5,692,116 | 5,698,151 | 5,755,351 | ||||||||||||||
Bank owned life insurance | 214,693 | 213,266 | 211,852 | 210,414 | 208,965 | ||||||||||||||
Premises and equipment, net | 128,327 | 128,232 | 128,824 | 126,497 | 124,456 | ||||||||||||||
Deferred tax assets, net | 15,647 | 4,933 | 5,480 | 5,392 | 7,014 | ||||||||||||||
Goodwill | 19,506 | 19,506 | 19,506 | 19,193 | 19,193 | ||||||||||||||
Accrued interest receivable and other assets | 107,771 | 96,454 | 66,887 | 68,383 | 70,898 | ||||||||||||||
Total assets | $ | 8,130,723 | $ | 8,098,810 | $ | 7,985,399 | $ | 7,864,260 | $ | 7,926,826 | |||||||||
Liabilities and Stockholders' Equity | |||||||||||||||||||
Deposits | |||||||||||||||||||
Demand | |||||||||||||||||||
Noninterest bearing | $ | 956,351 | $ | 779,842 | $ | 763,224 | $ | 805,032 | $ | 785,727 | |||||||||
Interest bearing | 1,186,613 | 1,088,033 | 1,098,323 | 1,123,767 | 1,183,051 | ||||||||||||||
Savings and money market | 1,447,661 | 1,432,891 | 1,475,257 | 1,484,336 | 1,510,832 | ||||||||||||||
Time | 2,434,077 | 2,541,446 | 2,420,339 | 2,279,713 | 2,339,771 | ||||||||||||||
Total deposits | 6,024,702 | 5,842,212 | 5,757,143 | 5,692,848 | 5,819,381 | ||||||||||||||
Advances from the Federal Home Loan Bank and other borrowings | 1,050,000 | 1,265,000 | 1,235,000 | 1,170,000 | 1,125,000 | ||||||||||||||
Senior notes | 58,419 | — | — | — | — | ||||||||||||||
Junior subordinated debentures held by trust subsidiaries | 64,178 | 64,178 | 92,246 | 92,246 | 118,110 | ||||||||||||||
Accounts payable, accrued liabilities and other liabilities | 103,226 | 86,303 | 66,309 | 83,415 | 57,967 | ||||||||||||||
Total liabilities | 7,300,525 | 7,257,693 | 7,150,698 | 7,038,509 | 7,120,458 | ||||||||||||||
Stockholders’ equity | |||||||||||||||||||
Class A common stock | 2,887 | 2,888 | 2,893 | 2,899 | 2,899 | ||||||||||||||
Class B common stock | 1,329 | 1,329 | 1,775 | 1,775 | 1,775 | ||||||||||||||
Additional paid in capital | 359,028 | 358,277 | 419,048 | 418,821 | 417,338 | ||||||||||||||
Treasury stock | — | — | (46,373 | ) | (46,373 | ) | (46,373 | ) | |||||||||||
Retained earnings | 432,227 | 447,506 | 444,124 | 431,521 | 419,590 | ||||||||||||||
Accumulated other comprehensive income | 34,727 | 31,117 | 13,234 | 17,108 | 11,139 | ||||||||||||||
Total stockholders' equity | 830,198 | 841,117 | 834,701 | 825,751 | 806,368 | ||||||||||||||
Total liabilities and stockholders' equity | $ | 8,130,723 | $ | 8,098,810 | $ | 7,985,399 | $ | 7,864,260 | $ | 7,926,826 | |||||||||
__________________
(1) The Company adopted ASU 2016-01 on December 31, 2019. Equity securities with readily available fair value not held for trading consist of mutual funds which were included as part of available for sale securities prior to December 31, 2019. The fair value of these mutual funds as of September 30, 2019 and June 30, 2019 totaled $24.0 million and $23.8 million, respectively.
25
Exhibit 7 - Loans
Loans by Type
The loan portfolio consists of the following loan classes:
(in thousands) | June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | June 30, 2019 | ||||||||||||||
Real estate loans | |||||||||||||||||||
Commercial real estate | |||||||||||||||||||
Non-owner occupied | $ | 1,841,075 | $ | 1,875,293 | $ | 1,891,802 | $ | 1,933,662 | $ | 1,872,493 | |||||||||
Multi-family residential | 823,450 | 834,016 | 801,626 | 942,851 | 968,080 | ||||||||||||||
Land development and construction loans | 284,766 | 225,179 | 278,688 | 268,312 | 291,304 | ||||||||||||||
2,949,291 | 2,934,488 | 2,972,116 | 3,144,825 | 3,131,877 | |||||||||||||||
Single-family residential | 589,713 | 569,340 | 539,102 | 527,468 | 535,563 | ||||||||||||||
Owner occupied | 938,511 | 923,260 | 894,060 | 825,601 | 836,334 | ||||||||||||||
4,477,515 | 4,427,088 | 4,405,278 | 4,497,894 | 4,503,774 | |||||||||||||||
Commercial loans | 1,247,455 | 1,084,751 | 1,234,043 | 1,127,484 | 1,180,736 | ||||||||||||||
Loans to financial institutions and acceptances | 16,597 | 16,576 | 16,552 | 24,815 | 25,006 | ||||||||||||||
Consumer loans and overdrafts | 130,704 | 139,912 | 88,466 | 101,598 | 103,239 | ||||||||||||||
Total loans | $ | 5,872,271 | $ | 5,668,327 | $ | 5,744,339 | $ | 5,751,791 | $ | 5,812,755 | |||||||||
26
Non-Performing Assets
This table shows a summary of our non-performing assets by loan class, which includes non-performing loans and other real estate owned, or OREO, at the dates presented. Non-performing loans consist of (i) nonaccrual loans; (ii) accruing loans 90 days or more contractually past due as to interest or principal; and (iii) restructured loans that are considered TDRs.
(in thousands) | June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | June 30, 2019 | ||||||||||||||
Non-Accrual Loans(1) | |||||||||||||||||||
Real Estate Loans | |||||||||||||||||||
Commercial real estate (CRE) | |||||||||||||||||||
Non-owner occupied | $ | 8,426 | $ | 1,936 | $ | 1,936 | $ | 1,936 | $ | 1,964 | |||||||||
Multi-family residential | — | — | — | — | 657 | ||||||||||||||
8,426 | 1,936 | 1,936 | 1,936 | 2,621 | |||||||||||||||
Single-family residential | 7,975 | 7,077 | 7,291 | 9,033 | 9,432 | ||||||||||||||
Owner occupied | 11,828 | 13,897 | 14,130 | 11,921 | 10,528 | ||||||||||||||
28,229 | 22,910 | 23,357 | 22,890 | 22,581 | |||||||||||||||
Commercial loans (2) | 48,961 | 9,993 | 9,149 | 9,605 | 10,032 | ||||||||||||||
Consumer loans and overdrafts | 70 | 467 | 416 | 116 | 114 | ||||||||||||||
Total Non-Accrual Loans | $ | 77,260 | $ | 33,370 | $ | 32,922 | $ | 32,611 | $ | 32,727 | |||||||||
Past Due Accruing Loans(3) | |||||||||||||||||||
Real Estate Loans | |||||||||||||||||||
Single-family residential | $ | — | $ | 5 | $ | — | $ | — | $ | — | |||||||||
Commercial | — | — | — | — | — | ||||||||||||||
Consumer loans and overdrafts | — | 12 | 5 | 213 | 23 | ||||||||||||||
Total Past Due Accruing Loans | — | 17 | 5 | 213 | 23 | ||||||||||||||
Total Non-Performing Loans | 77,260 | 33,387 | 32,927 | 32,824 | 32,750 | ||||||||||||||
Other Real Estate Owned | 42 | 42 | 42 | — | — | ||||||||||||||
Total Non-Performing Assets | $ | 77,302 | $ | 33,429 | $ | 32,969 | $ | 32,824 | $ | 32,750 | |||||||||
__________________
(1) | Includes loan modifications that met the definition of TDRs which may be performing in accordance with their modified loan terms. As of June 30, 2020, March 31, 2020 and December 31, 2019, non-performing TDRs include $9.3 million, $9.7 million and $9.8 million, respectively, in a multiple loan relationship to a South Florida borrower. |
(2) | As of June 30, 2020, includes a $39.8 million commercial relationship placed in nonaccrual status during the second quarter of 2020. |
(3) | Loans past due 90 days or more but still accruing. |
27
Loans by Credit Quality Indicators
This tables shows the Company’s loans by credit quality indicators. We have no purchased credit-impaired loans.
June 30, 2020 | March 31, 2020 | June 30, 2019 | ||||||||||||||||||||||||||||||||||||
(in thousands) | Special Mention | Substandard | Doubtful | Total (1) | Special Mention | Substandard | Doubtful | Total (1) | Special Mention | Substandard | Doubtful | Total (1) | ||||||||||||||||||||||||||
Real Estate Loans | ||||||||||||||||||||||||||||||||||||||
Commercial Real Estate (CRE) | ||||||||||||||||||||||||||||||||||||||
Non-owner occupied | $ | 2,127 | $ | 7,242 | $ | 1,936 | $ | 11,305 | $ | — | $ | 757 | $ | 1,936 | $ | 2,693 | $ | 6,251 | $ | 1,964 | $ | — | $ | 8,215 | ||||||||||||||
Multi-family residential | — | — | — | — | — | — | — | — | — | 657 | — | 657 | ||||||||||||||||||||||||||
Land development and construction loans | 7,196 | — | — | 7,196 | 9,852 | — | — | 9,852 | — | — | — | — | ||||||||||||||||||||||||||
9,323 | 7,242 | 1,936 | 18,501 | 9,852 | 757 | 1,936 | 12,545 | 6,251 | 2,621 | — | 8,872 | |||||||||||||||||||||||||||
Single-family residential | — | 8,127 | — | 8,127 | — | 7,082 | — | 7,082 | — | 9,432 | — | 9,432 | ||||||||||||||||||||||||||
Owner occupied | 7,884 | 14,142 | — | 22,026 | 7,190 | 14,005 | — | 21,195 | 9,476 | 13,940 | — | 23,416 | ||||||||||||||||||||||||||
17,207 | 29,511 | 1,936 | 48,654 | 17,042 | 21,844 | 1,936 | 40,822 | 15,727 | 25,993 | — | 41,720 | |||||||||||||||||||||||||||
Commercial loans (2) | 5,664 | 35,211 | 20,822 | 61,697 | 2,587 | 9,459 | 2,643 | 14,689 | 5,332 | 11,490 | 539 | 17,361 | ||||||||||||||||||||||||||
Consumer loans and overdrafts | — | 81 | — | 81 | — | 41 | 434 | 475 | — | 4,421 | — | 4,421 | ||||||||||||||||||||||||||
$ | 22,871 | $ | 64,803 | $ | 22,758 | $ | 110,432 | $ | 19,629 | $ | 31,344 | $ | 5,013 | $ | 55,986 | $ | 21,059 | $ | 41,904 | $ | 539 | $ | 63,502 | |||||||||||||||
__________
(1) There were no loans categorized as “Loss” as of the dates presented.
(2) As of June 30, 2020, includes a $39.8 million in a commercial relationship placed in nonaccrual status and downgraded during the second quarter of 2020 ($20.5 million downgraded to substandard and $19.3 million downgraded to doubtful).
Exhibit 8 - Deposits by Country of Domicile
This tables shows the Company’s deposits by country of domicile of the depositor as of the dates presented.
(in thousands) | June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | June 30, 2019 | ||||||||||||||
Domestic | $ | 3,432,971 | $ | 3,253,972 | $ | 3,121,827 | $ | 2,999,687 | $ | 3,014,269 | |||||||||
Foreign: | |||||||||||||||||||
Venezuela | 2,202,340 | 2,224,353 | 2,270,970 | 2,345,938 | 2,465,718 | ||||||||||||||
Others | 389,391 | 363,887 | 364,346 | 347,223 | 339,394 | ||||||||||||||
Total foreign | 2,591,731 | 2,588,240 | 2,635,316 | 2,693,161 | 2,805,112 | ||||||||||||||
Total deposits | $ | 6,024,702 | $ | 5,842,212 | $ | 5,757,143 | $ | 5,692,848 | $ | 5,819,381 | |||||||||
28