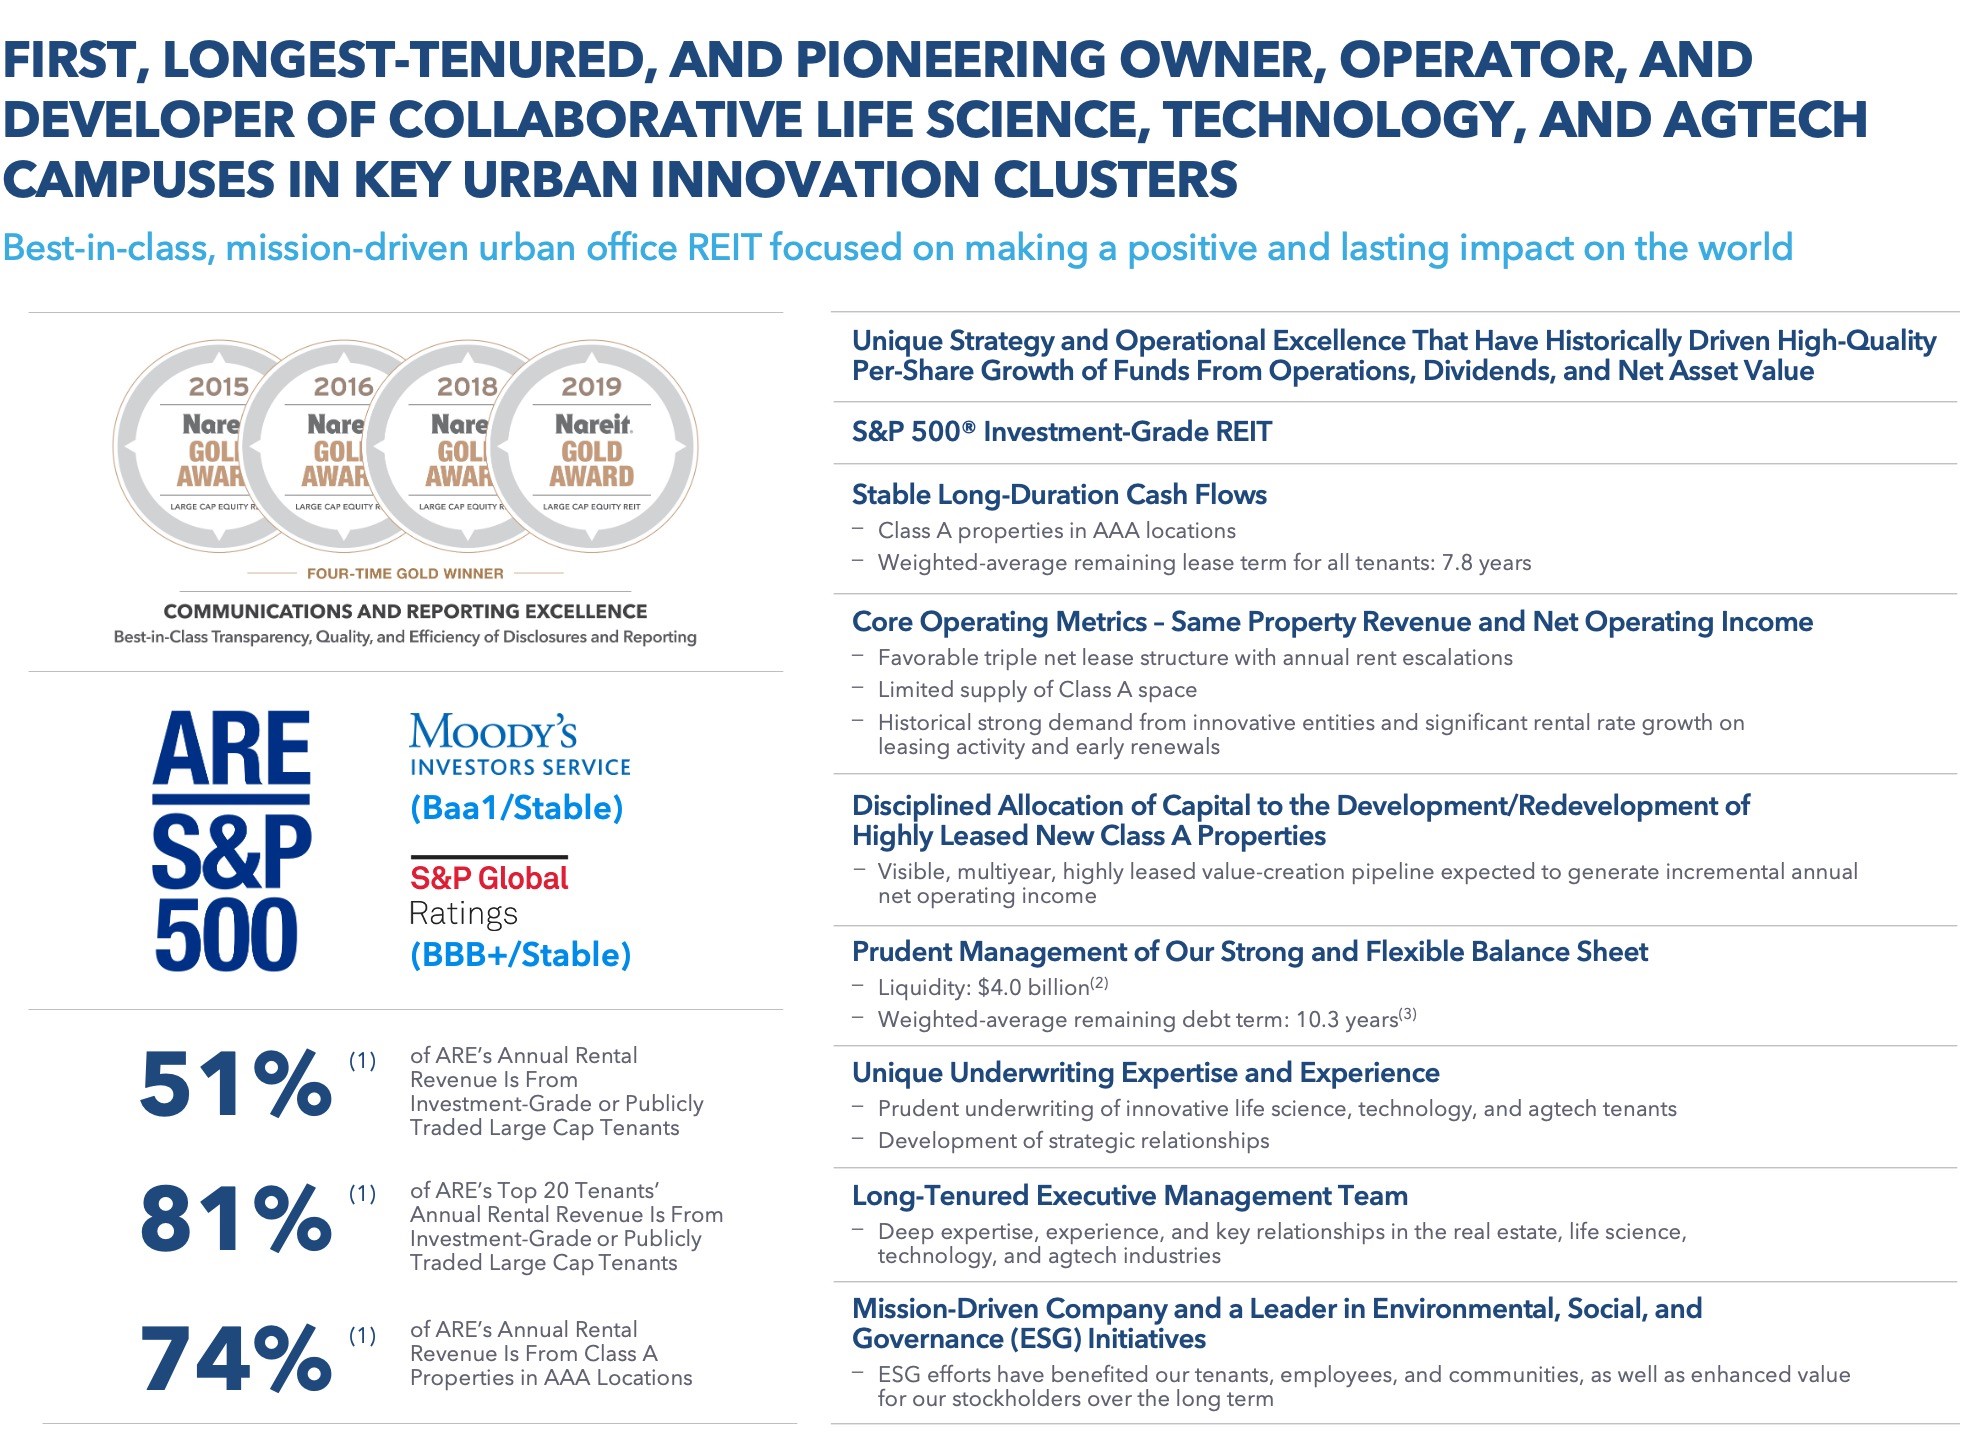
(1) | Refer to “Annual Rental Revenue,” “Class A Properties and AAA Locations,” and “Investment-Grade or Publicly Traded Large Cap Tenants” in the “Definitions and Reconciliations” of our Supplemental Information for additional details. |
(2) | Liquidity as of March 31, 2020, proforma for our additional $750.0 million unsecured senior line of credit completed in April 2020. |
(3) | Refer to “Summary of Debt” in the “Key Credit Metrics” of our Supplemental Information for additional details. |
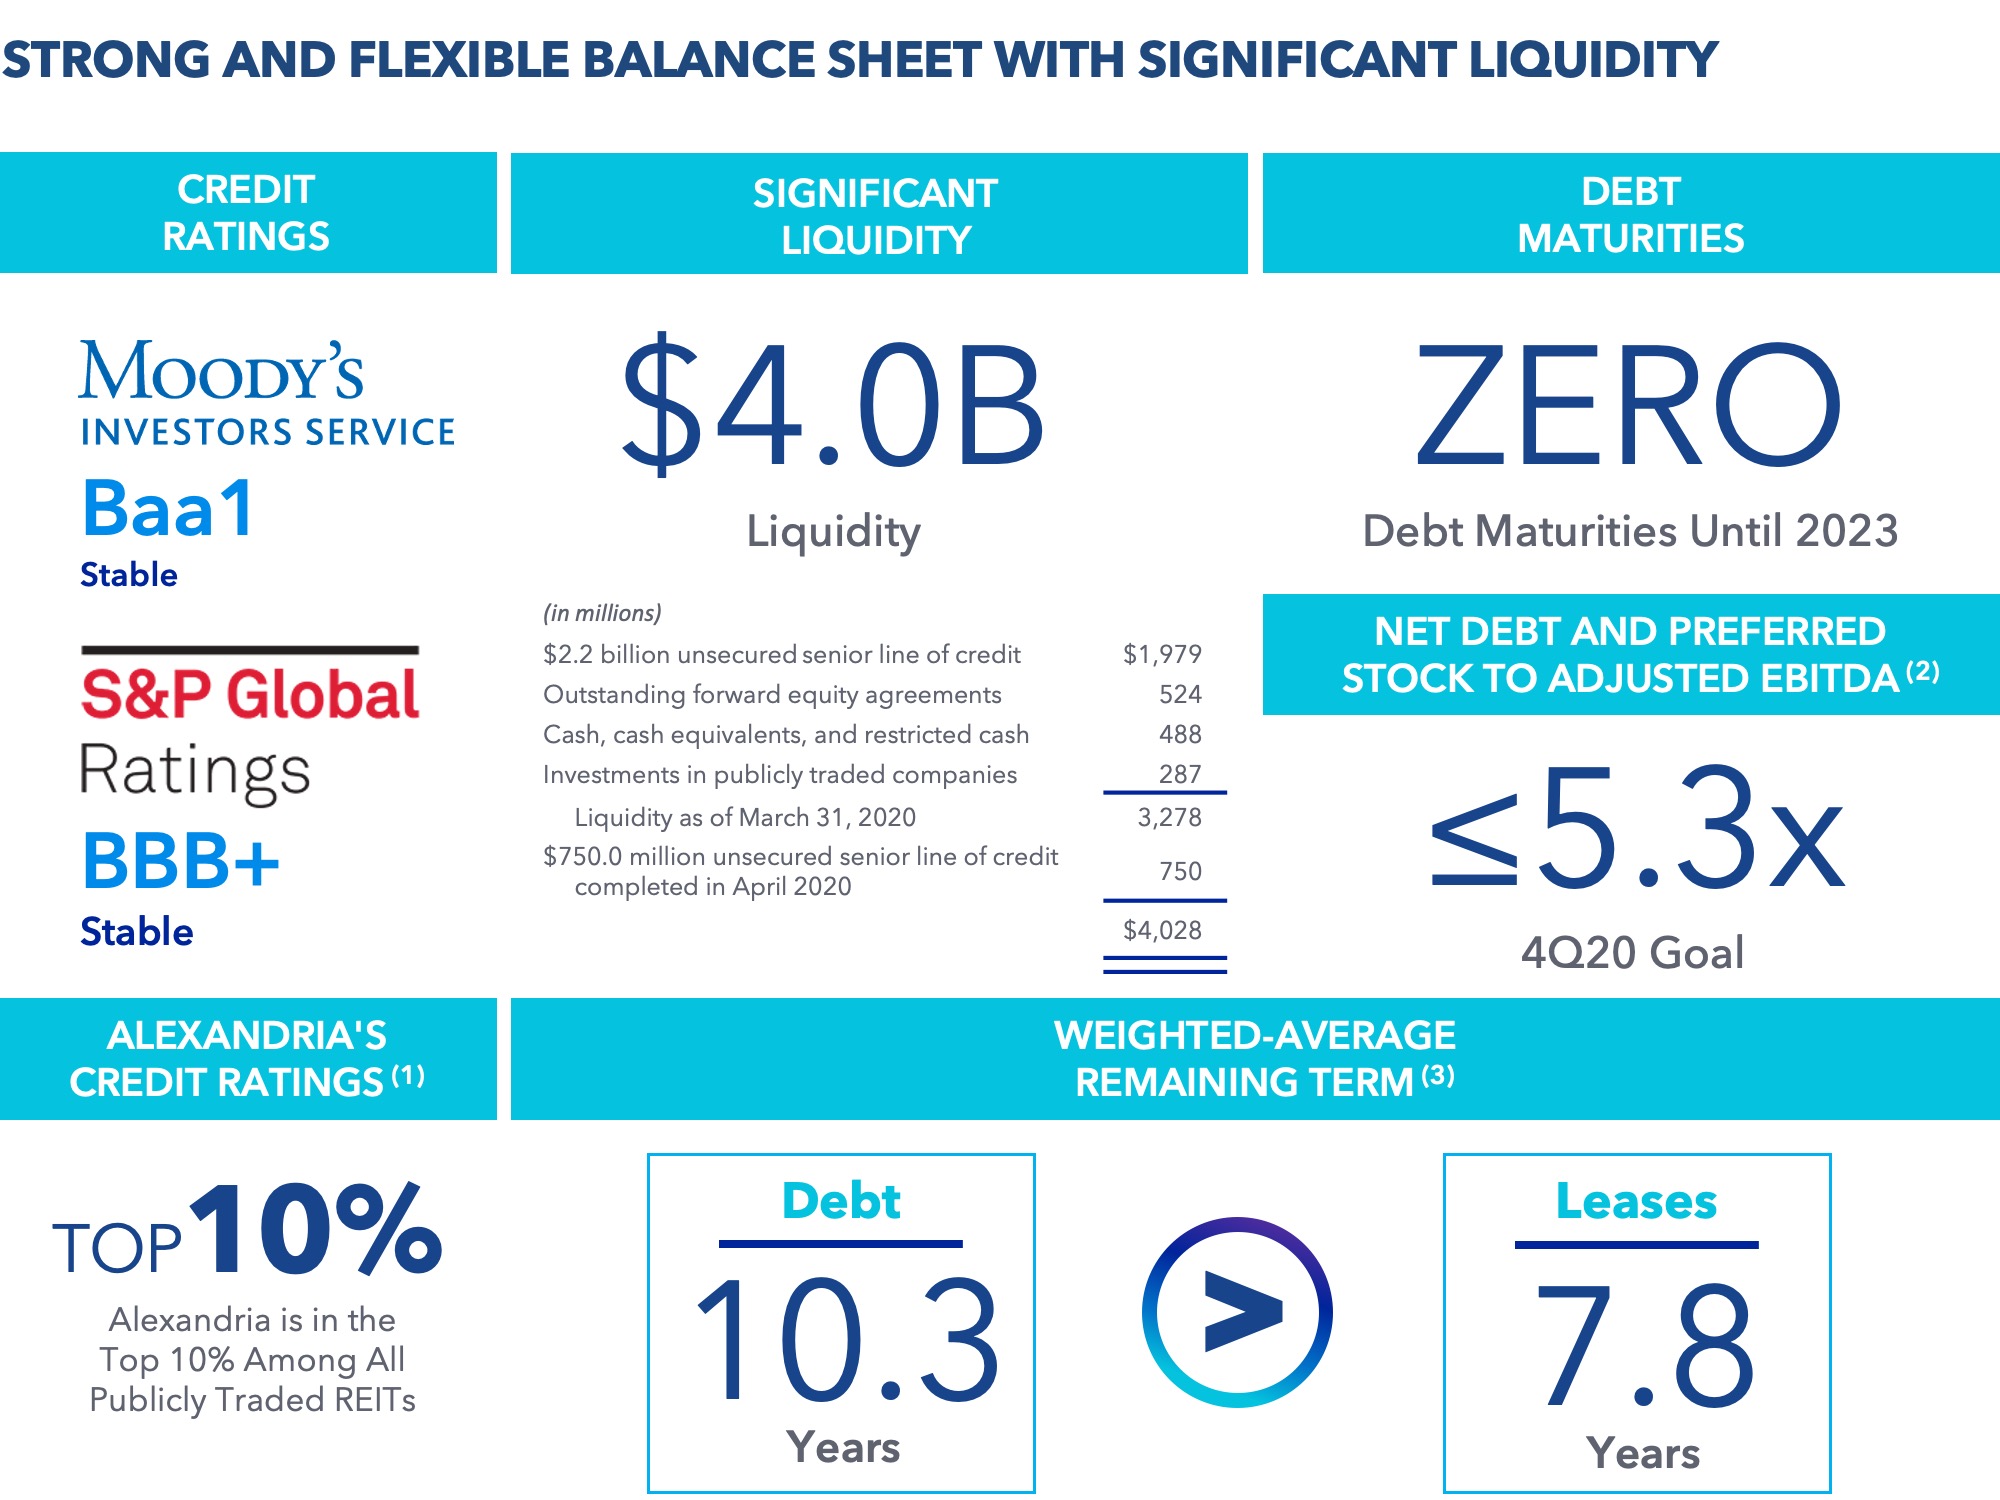
(1) | Represents credit rating levels from Moody’s Investors Service and S&P Global Ratings in comparison to those of all publicly traded REITs (excluding mortgage REITs) as of December 31, 2019. |
(2) | Quarter annualized. |
(3) | As of March 31, 2020. |
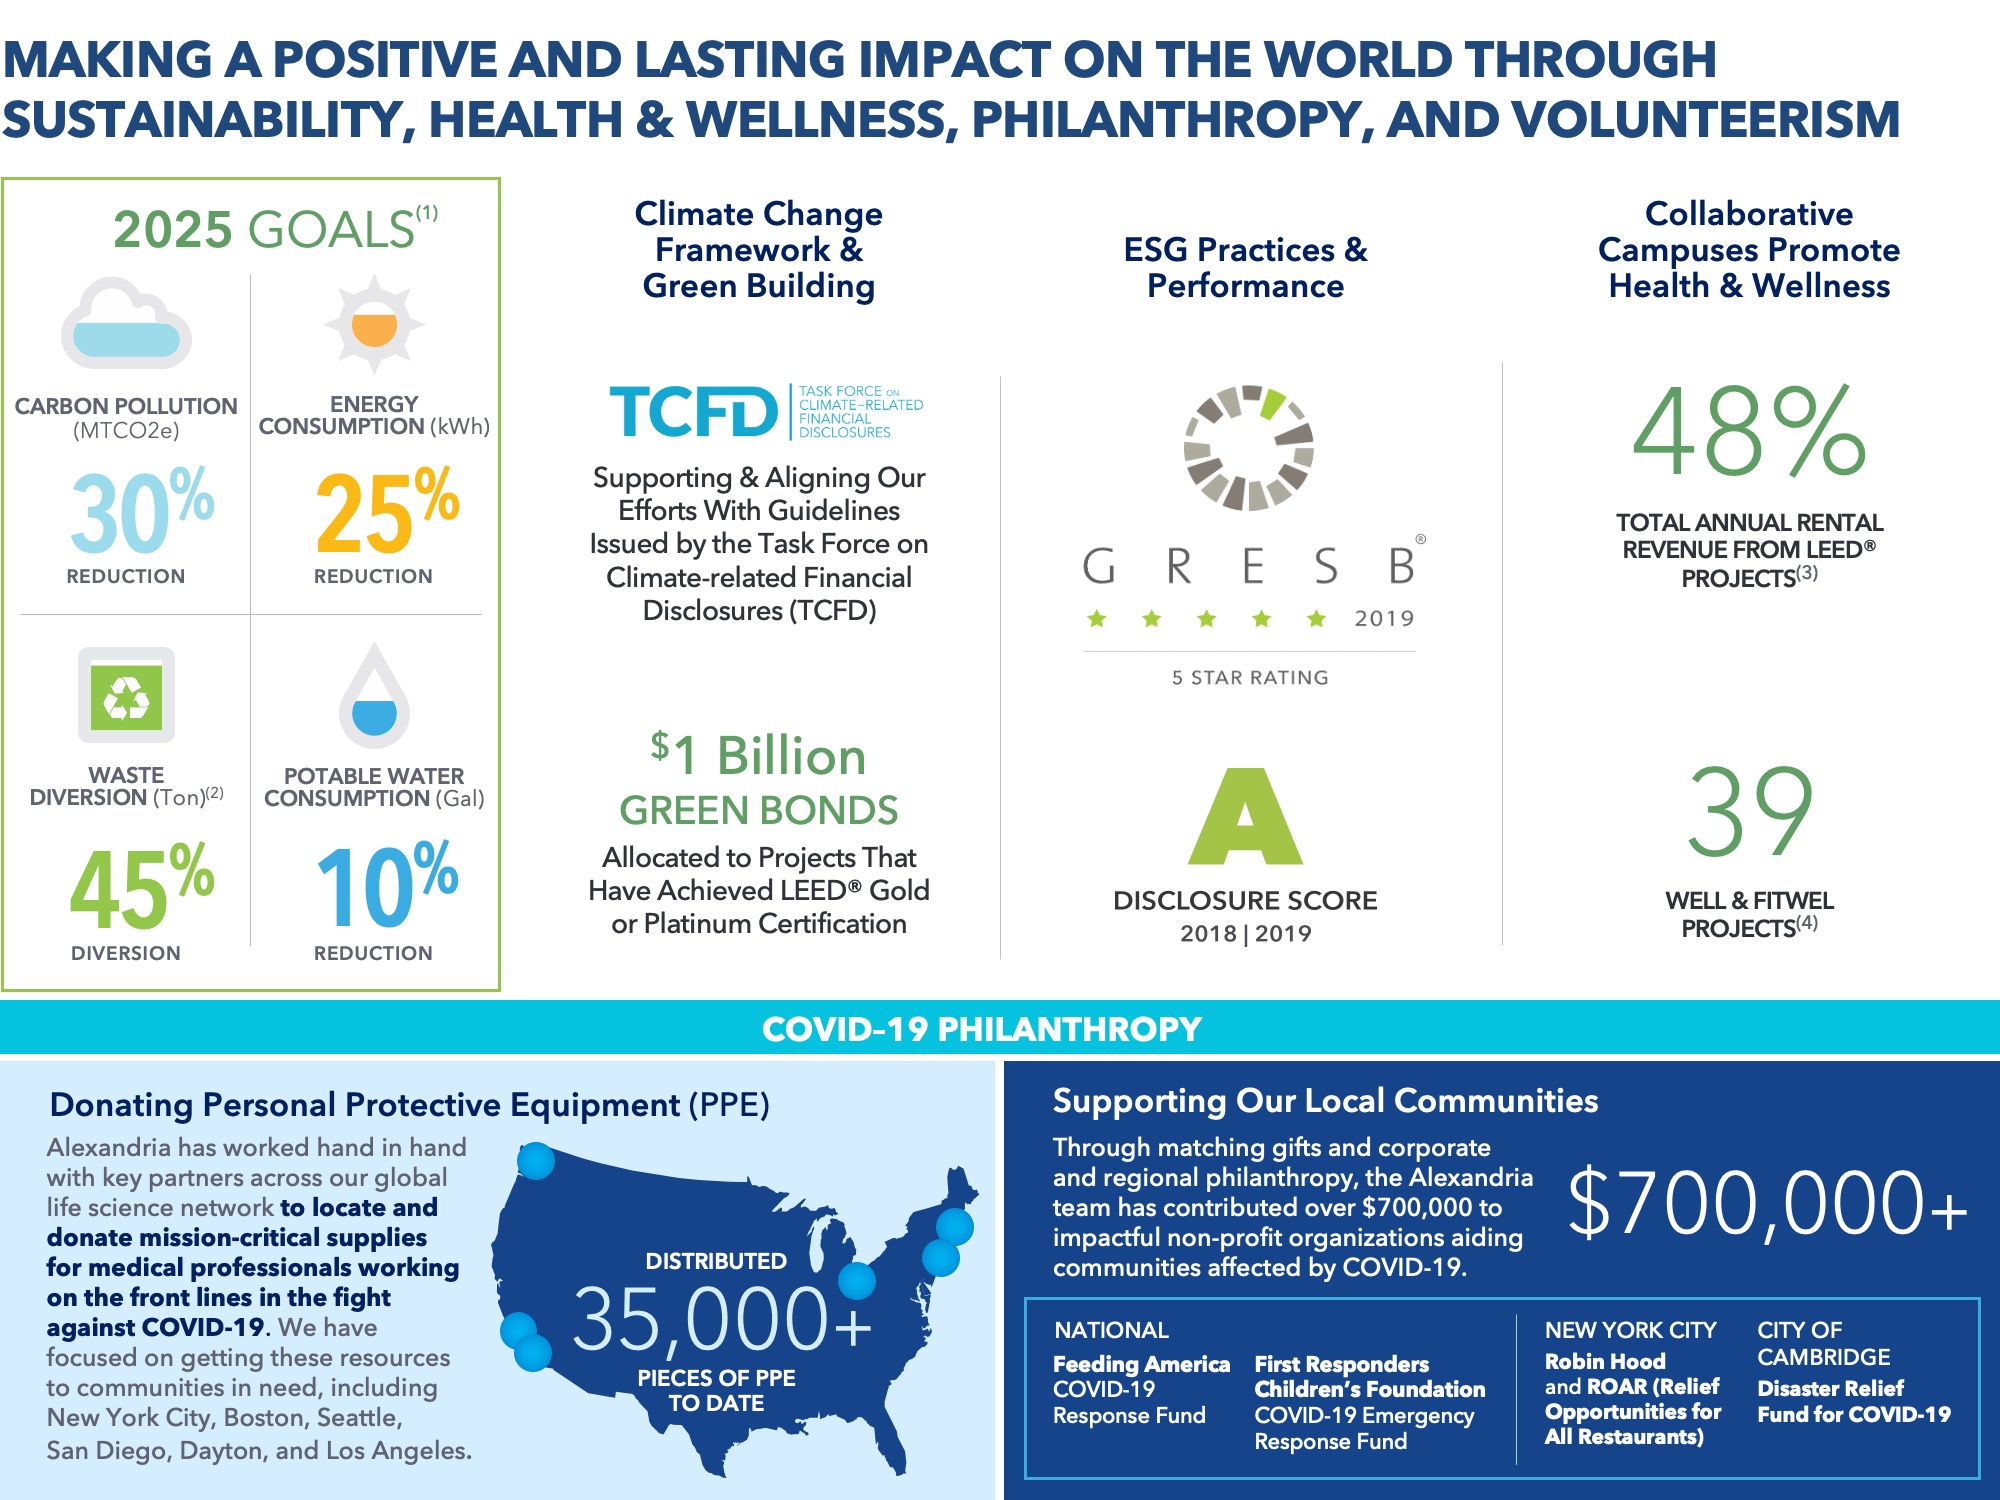
(1) | Relative to a 2015 baseline for buildings in operation that Alexandria directly manages. |
(2) | Relative to a 2015 baseline for buildings in operation that Alexandria indirectly and directly manages. |
(3) | Upon completion of 16 projects in process targeting LEED certification. |
(4) | Upon completion of 27 projects in process targeting either WELL or Fitwel certification. |
 | |
Table of Contents | |
March 31, 2020 | |
EARNINGS PRESS RELEASE | Page | Page | ||
SUPPLEMENTAL INFORMATION | Page | Page | ||
External Growth / Investments in Real Estate | ||||
New Class A Development and Redevelopment Properties: | ||||
Internal Growth | ||||
Balance Sheet Management | ||||
Definitions and Reconciliations | ||||
This document includes “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Please refer to page 11 of this Earnings Press Release and our Supplemental Information for further information. |
This document is not an offer to sell or a solicitation to buy securities of Alexandria Real Estate Equities, Inc. Any offers to sell or solicitations to buy our securities shall be made only by means of a prospectus approved for that purpose. Unless otherwise indicated, the “Company,” “Alexandria,” “ARE,” “we,” “us,” and “our” refer to Alexandria Real Estate Equities, Inc. and our consolidated subsidiaries. |
Alexandria Real Estate Equities, Inc. All Rights Reserved. © 2020 | vi | |
Alexandria Real Estate Equities, Inc.
Reports:
1Q20 Revenues of $439.9 million, Up 22.6% Over 1Q19;
1Q20 Net Income per Share – Diluted of $0.14;
1Q20 FFO per Share – Diluted, As Adjusted, of $1.82; and Operational Excellence
and Strong and Flexible Balance Sheet With Significant Liquidity
PASADENA, Calif. – April 27, 2020 – Alexandria Real Estate Equities, Inc. (NYSE:ARE)
announced financial and operating results for the first quarter ended March 31, 2020.
Key highlights | |||||||||||||||
Operating results (in millions, except per share amounts) | Amount | Per Share | |||||||||||||
1Q20 | 1Q19 | 1Q20 | 1Q19 | ||||||||||||
Total revenues up 22.6% | $ | 439.9 | $ | 358.8 | |||||||||||
Net income attributable to Alexandria’s common stockholders – diluted | $ | 16.8 | $ | 123.6 | $ | 0.14 | $ | 1.11 | |||||||
Funds from operations attributable to Alexandria’s common stockholders – diluted, as adjusted | $ | 221.4 | $ | 189.8 | $ | 1.82 | $ | 1.71 | |||||||
Alexandria and its tenants at the forefront of fighting COVID-19
Effective diagnostics, therapies, and vaccines are desperately needed to test for, treat, and ultimately prevent COVID-19. Over 60 of our life science tenants are at the forefront of increasing testing capacity, advancing new and repurposed therapies, and developing preventative vaccines for COVID-19. Our ground-up development projects include mission-critical research space focused on COVID-19. Refer to “Alexandria and Its Tenants Are at the Forefront of Fighting COVID-19” of this Earnings Press Release for further information.
Strong and flexible balance sheet with significant liquidity
• | $4.0 billion of liquidity as of March 31, 2020, proforma for our additional $750.0 million unsecured senior line of credit completed in April 2020. |
• | Zero debt maturing until 2023. |
• | 10.3 years weighted-average remaining term of debt as of March 31, 2020. |
• | $1.0 billion issuance of forward equity sales agreements, executed in January 2020, at a public offering price of $155.00 per share, before underwriting discounts, with $500.0 million settled in March 2020. |
• | Investment-grade credit rating ranking in the top 10% among all publicly traded REITs, Baa1/Stable from Moody’s Investors Service and BBB+/Stable from S&P Global Ratings, both as of March 31, 2020. |
Continued dividend strategy to share cash flows with stockholders
Common stock dividend declared for 1Q20 of $1.03 per common share, aggregating $4.06 per common share for the twelve months ended March 31, 2020, up 26 cents, or 7%, over the twelve months ended March 31, 2019. Our FFO payout ratio of 58% for the three months ended March 31, 2020, allows us to share cash flows from operating activities with our stockholders while also retaining a significant portion for reinvestment.
A REIT industry-leading, high-quality tenant roster
• | 51% of annual rental revenue from investment-grade or publicly traded large cap tenants. |
• | Weighted-average remaining lease term of 7.8 years. |
Record-low accounts receivable balance
• | As of April 24, 2020: |
• | Our tenant receivables balance was $7.3 million, representing our lowest balance since 2012. |
• | We have collected 98.4% of April 2020 rents and tenant recoveries. |
High-quality revenues and cash flows, strong Adjusted EBITDA margin, and operational excellence
Percentage of annual rental revenue in effect from: | |||||
Investment-grade or publicly traded large cap tenants | 51 | % | |||
Class A properties in AAA locations | 74 | % | |||
Occupancy of operating properties in North America | 95.1 | % | (1) | ||
Operating margin | 71 | % | |||
Adjusted EBITDA margin | 68 | % | |||
Weighted-average remaining lease term: | |||||
All tenants | 7.8 | years | |||
Top 20 tenants | 11.4 | years | |||
(1) | Includes 686,988 RSF, or 2.4%, of vacancy in our North America markets, representing lease-up opportunities at properties recently acquired, primarily at our SD Tech by Alexandria campus (joint venture), 601, 611, and 651 Gateway Boulevard (joint venture), and 5505 Morehouse Drive. Excluding these vacancies, occupancy of operating properties in North America was 97.5% as of March 31, 2020. Refer to “Occupancy” in this Supplemental Information for addition details regarding vacancy from recently acquired properties. |
Net operating income and internal growth
• | Net operating income (cash basis) of $1.1 billion for 1Q20 annualized, up $204.1 million, or 22.9%, compared to 1Q19 annualized. |
• | 95% of our leases contain contractual annual rent escalations approximating 3%. |
• | 2.4% and 6.1% (cash basis) same property net operating income growth for 1Q20 over 1Q19. |
• | Minimal 2020 contractual lease expirations aggregating 4.0% of annual rental revenue. |
• | Strong rental rate increases of 46.3% for 1Q20, representing our highest quarterly rental rate increase over the past 10 years. |
1Q20 | |||
Total leasing activity – RSF | 703,355 | ||
Lease renewals and re-leasing of space: | |||
RSF (included in total leasing activity above) | 557,367 | ||
Rental rate increases | 46.3% | ||
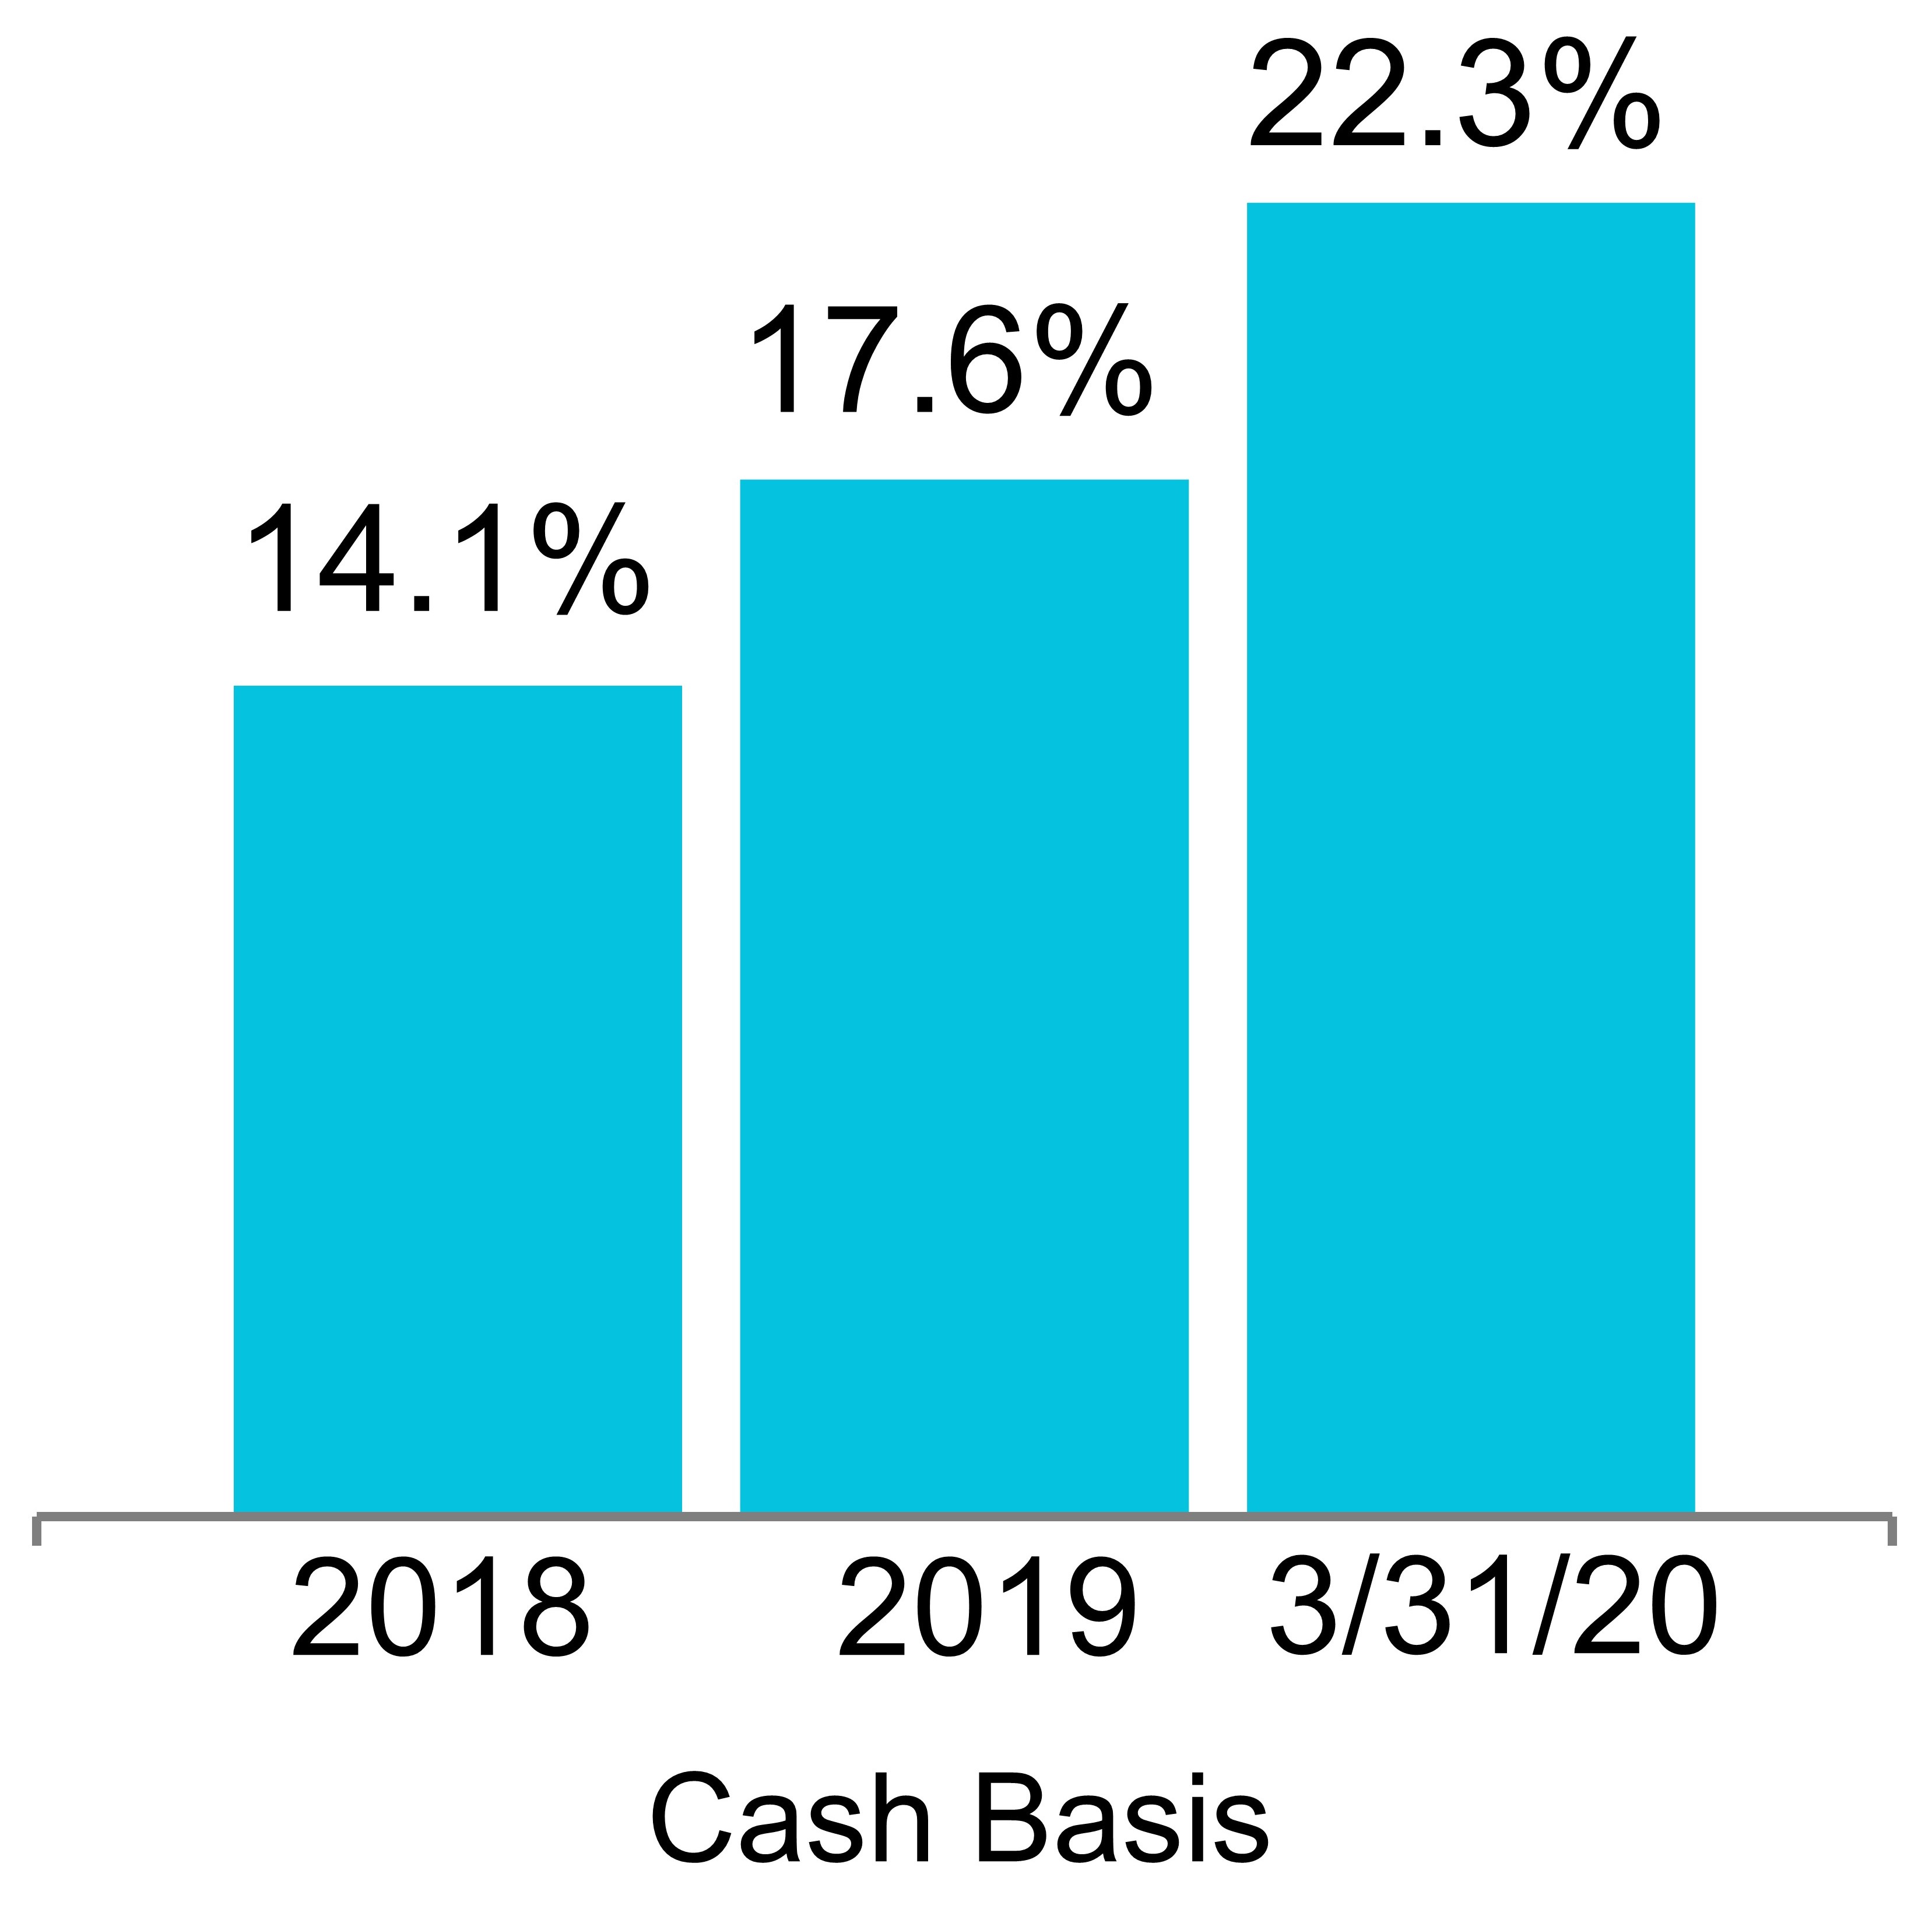
Rental rate increases (cash basis) | 22.3% | ||
2020 guidance update and significant reductions in construction spend, acquisitions, and equity-type capital
Refer to next page for specific details.
| |
First Quarter Ended March 31, 2020, Financial and Operating Results (continued) | |
March 31, 2020 | |
Key items included in operating results
Key items included in net income attributable to Alexandria’s common stockholders: | |||||||||||||||
(In millions, except per share amounts) | Amount | Per Share – Diluted | |||||||||||||
1Q20 | 1Q19 | 1Q20 | 1Q19 | ||||||||||||
Unrealized (losses) gains on non-real estate investments(1) | $ | (17.1 | ) | $ | 72.2 | $ | (0.14 | ) | $ | 0.65 | |||||
Impairment of real estate(2) | (9.6 | ) | — | (0.08 | ) | — | |||||||||
Impairment of non-real estate investments(1) | (19.8 | ) | — | (0.16 | ) | — | |||||||||
Loss on early extinguishment of debt | — | (7.4 | ) | — | (0.07 | ) | |||||||||
Preferred stock redemption charge | — | (2.6 | ) | — | (0.02 | ) | |||||||||
Total | $ | (46.5 | ) | $ | 62.2 | $ | (0.38 | ) | $ | 0.56 | |||||
(1) Refer to “Investments” on page 45 of our Supplemental Information for additional details. (2) Includes a $7.6 million impairment on our investment in a recently developed retail property held by our unconsolidated real estate joint venture. | |||||||||||||||
Certain items impacting 2020 guidance
Per Share Impact | |||
Reduction in retail and transient/short-term parking revenue 2Q20-4Q20 | 8 | cents | |
Issuance of unsecured senior notes payable and updated timing of development and redevelopment deliveries, offset by improvement in EBITDA from our core operations | — | ||
Total | 8 | cents | |
Significant reductions in 2020 construction spend, acquisitions, and equity-type capital
A significant portion of our historical annual construction spend forecast included amounts related to future development projects with no aboveground vertical construction and was not committed to a specific tenant. Due to the current dislocation of capital and other markets caused by COVID-19, we have reduced our construction spend forecast to focus primarily on projects that are partially or fully leased. We also expect to continue certain future pipeline expenditures to minimize the impact of a temporary pause. As a result, we have reduced our construction spend forecast for 2020 from $1.6 billion to $960 million (at the midpoint of guidance). We also reduced our forecasted acquisitions for 2020 from $950 million to $650 million. The aggregate $940 million reduction in uses of capital in 2020 reduced our remaining forecast of sources of capital from real estate dispositions, partial interest sales, and common equity from $925 million to zero dollars.
Importantly, upon improvement of market conditions, we have the option, on a project-by-project basis, to address demand for our development and redevelopment projects.
Highly leased value-creation pipeline, including COVID-19-focused R&D space
• | Current projects aggregating 2.9 million RSF, including COVID-19-focused R&D spaces, are highly leased at 61% and will generate significant revenue and cash flows. |
• | Annual net operating income (cash basis), including our share of unconsolidated real estate joint ventures, is expected to increase $37 million upon the burn-off of initial free rent on recently delivered projects. |
• | In March 2020, we successfully upzoned the square footage available for the ground-up development of office/laboratory space at 325 Binney Street in our Cambridge submarket to 402,000 SF from 164,000 SF. |
Completion of acquisitions with significant value-creation opportunities in key submarkets
• | During 1Q20, we completed the acquisition of eight properties for an aggregate purchase price of $484.6 million. The acquisitions comprise 1.1 million RSF, including 106,021 RSF of current and future value-creation opportunities. |
• | In addition to the completed acquisitions above, we also formed a real estate joint venture with subsidiaries of Boston Properties, Inc., in which we are targeting a 51% ownership interest over time. We are the managing member and have consolidated this joint venture. As of March 31, 2020, our ownership interest in the real estate joint venture was 44.8%. |
• | Our partner contributed real estate assets with a total fair market value of $350.0 million, which comprise three office buildings, aggregating 776,003 RSF, at 601, 611, and 651 Gateway Boulevard, and land supporting 260,000 SF of future development. |
• | We contributed real estate assets with a total fair market value of $281.9 million, which comprise three operating properties, aggregating 313,262 RSF, and land supporting 377,000 SF of future development. |
Balance sheet management
Key metrics as of March 31, 2020
• | $24.3 billion of total market capitalization. |
• | $17.0 billion of total equity capitalization. |
• | $4.0 billion of liquidity as of March 31, 2020, proforma for our additional $750.0 million unsecured senior line of credit completed in April 2020. |
1Q20 | Goal | |||||||
Quarter | Trailing | 4Q20 | ||||||
Annualized | 12 Months | Annualized | ||||||
Net debt and preferred stock to Adjusted EBITDA | 5.5x | 6.0x | Less than or equal to 5.3x | |||||
Fixed-charge coverage ratio | 4.5x | 4.2x | Greater than or equal to 4.4x | |||||
Value-creation pipeline of new Class A development and redevelopment projects as a percentage of gross investments in real estate | 1Q20 | ||
Current projects 68% leased/negotiating | 6% | ||
Income-producing/potential cash flows/covered land play(1) | 5% | ||
Land | 2% | ||
(1) | Includes projects that have existing buildings that are generating or can generate operating cash flows. Also includes development rights associated with existing operating campuses. |
| |
First Quarter Ended March 31, 2020, Financial and Operating Results (continued) | |
March 31, 2020 | |
Key capital events
• | In January 2020, we completed $1.0 billion of forward equity sales agreements to sell an aggregate of 6.9 million shares of our common stock (including the exercise of an underwriters’ option) at a public offering price of $155.00 per share, before underwriting discounts. In March 2020, we settled 3.4 million shares from our forward equity sales agreements and received proceeds of $500.0 million. As of April 27, 2020, 3.5 million shares of our common stock remain outstanding under forward equity sales agreements, for which we expect to receive proceeds of $524.3 million to be further adjusted as provided in the sales agreements. We expect to settle the remaining outstanding forward equity sales agreements in 2020. |
• | Over the trailing five quarters, we have completed the issuances of $3.4 billion in unsecured senior notes, with a weighted-average interest rate of 3.95% and a weighted-average maturity as of March 31, 2020, of 15.4 years, including our March 2020 offering of $700.0 million of unsecured senior notes payable at an interest rate of 4.90%, due in 2030, for net proceeds of $691.6 million. |
• | In February 2020, we entered into a new “at-the-market” common stock offering program (“ATM program”), which allows us to sell up to an aggregate of $850.0 million of our common stock. As of March 31, 2020, we have available $843.7 million remaining under our ATM program. |
• | In March 2020, our unconsolidated joint venture at 1655 and 1725 Third Street, in which we own a 10% interest, located in Mission Bay/SoMa, refinanced an existing variable-rate secured construction loan with a fixed-rate loan with terms as follows: |
100% at Joint Venture Level | Amended Agreement | Change | ||
Aggregate commitments | $600.0 million | Increase of $225.0 million | ||
Maturity date | March 2025 | Extended by 45 months | ||
Interest rate | Fixed at 4.50% | Previously LIBOR + 3.70% | ||
• | In April 2020, we closed an additional unsecured senior line of credit with $750.0 million of available commitments. The new unsecured senior line of credit matures on April 14, 2022, and bears interest at LIBOR + 1.05%. Pursuant to the terms of the agreement, we are required to repay the facility, if applicable, and reduce commitments available upon receiving the net proceeds from certain qualifying events, including new corporate debt and 50% of proceeds from the issuance of common stock, as provided in the credit agreement. Including our existing $2.2 billion unsecured senior line of credit, commitments available under our unsecured credit facilities aggregate $2.95 billion. |
Investments
• | Our investments in publicly traded companies and privately held entities aggregate a carrying amount of $1.1 billion, including an adjusted cost basis of $739.0 million and unrealized gains of $384.5 million, as of March 31, 2020. |
• | We recognized an investment loss during 1Q20 of $21.8 million, comprising $15.1 million in realized gains, $19.8 million in impairments related to privately held non-real estate investments, and $17.1 million in unrealized losses. |
Industry leadership, strategic initiatives, and corporate responsibility
• | In March 2020, the Navy SEAL Foundation honored Joel S. Marcus, our executive chairman and founder, and the company with the 2020 Navy SEAL Foundation Patriot Award, which highlights our contributions and unwavering support for the Naval Special Warfare community. We have proudly supported the Navy SEAL Foundation in its mission to provide immediate and ongoing support and assistance to the Naval Special Warfare community and their families since 2010. |
• | In January 2020, Alexandria Venture Investments, our strategic venture capital arm, was recognized for a third consecutive year as the most active biopharma investor by new deal volume by Silicon Valley Bank in its “2020 Healthcare Investments and Exits Report.” Alexandria’s venture activity provides us with, among other things, mission-critical data and knowledge on innovations and trends. |
• | In January 2020, we announced our first national $100,000 AgTech Innovation Prize competition to recognize startup and early-stage agtech and foodtech companies that demonstrate innovative approaches to addressing challenges related to agriculture, food, and nutrition. |
• | In February 2020, Alexandria LaunchLabs® at the Alexandria Center® at One Kendall Square earned the Fitwel Impact Award for the highest Fitwel certification of all time, as well as the highest score in 2019 for a commercial interior space, in the Fitwel 2020 Best in Building Health awards program. This marks the second consecutive year Alexandria LaunchLabs – Cambridge has held the record for Fitwel's top certification score. The award recognizes our commitment to supporting high levels of health, wellness, and productivity through the design, construction, and operation of our best-in-class buildings and spaces. |
Subsequent events
• | In April 2020, we completed the sale of a partial interest in properties at 9808 and 9868 Scranton Road in our Sorrento Mesa submarket, aggregating 219,628 RSF, to the existing SD Tech by Alexandria consolidated real estate joint venture, of which we own 50.0%. We received proceeds of $51.1 million for the 50% interest in the properties that our joint venture partner acquired through the joint venture. We continue to control and consolidate this joint venture; therefore, we accounted for this sale as an equity transaction with no gain or loss recognized in earnings. |
• | We had a pending acquisition of an operating tech office property for which our revised economic projections declined from our initial underwriting. In April 2020, we recognized an impairment charge of $10 million to reduce the carrying amount of this pre-acquisition deposit to zero dollars, concurrently with submission of our notice to terminate the transaction. |
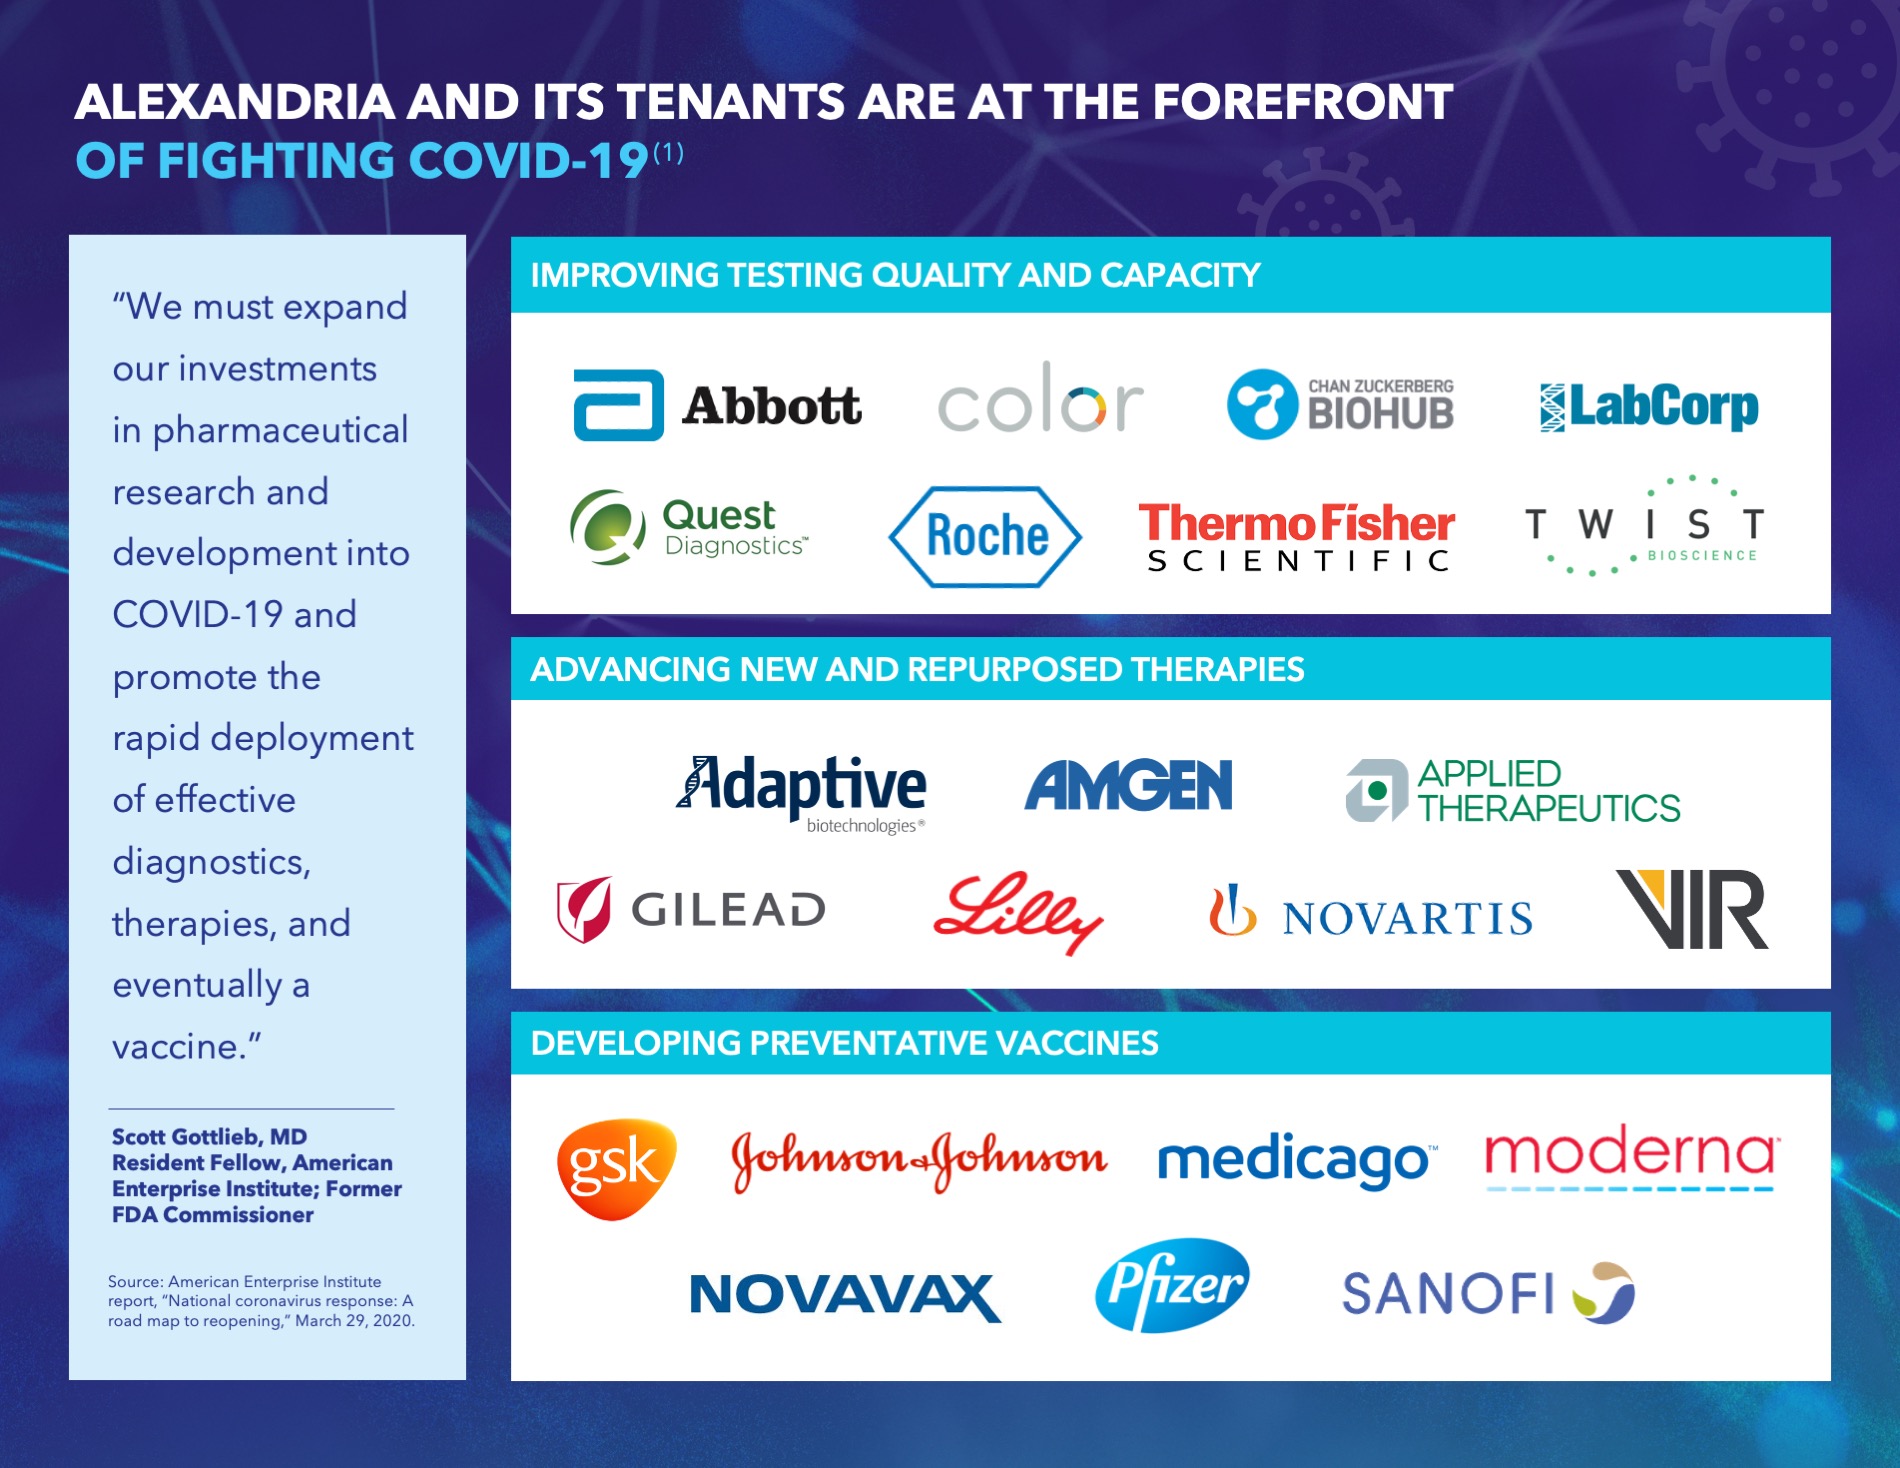
(1) Represents an illustrative subset of our over 60 tenants focused on COVID-19-related efforts, with some of these companies working on multiple efforts that span testing, treatment, and/or vaccine development.
Alexandria Fighting COVID-19 on Multiple Fronts | | |
March 31, 2020 | ||
Alexandria and its tenants are at the forefront of fighting COVID-19
Effective diagnostics, therapies, and vaccines are desperately needed to combat the global COVID-19 pandemic. By maintaining essential business operations across our campuses, Alexandria has enabled several of our life science tenants to continue mission-critical COVID-related research and development. The heroic work being done by so many of our tenants and campus community members to help test for, treat, and prevent COVID-19, as well as provide medical supplies and protective equipment to neighboring hospitals, is profound and inspiring. We are currently tracking over 60 tenants across our cluster markets focused on COVID programs.
Improving testing quality and capacity
Abbott Laboratories, Color Genomics, Laboratory Corporation of America Holdings, Quest Diagnostics, Roche, Thermo Fisher Scientific Inc., and others are working tirelessly to expand the capacity to determine who actively has COVID-19, who has been exposed to, and who has developed immunity against the virus. The availability of widespread screening and serological testing of this nature is critical for a safe and healthy return to society.
Advancing new and repurposed therapies
Over 140 experimental drug treatments and vaccines are being studied in over 250 clinical trials around the world, a substantial number of which are sponsored by our tenants and investment portfolio companies.
Headlining efforts across our tenant base include:
• | Gilead Sciences, Inc.’s remdesivir is in late-stage studies for the treatment of moderate and severe COVID-19 patients. Though variable outcomes have been reported, additional Phase III study results are expected in mid- to late May, which, if positive, will likely form the basis for FDA approval. |
• | Adaptive Biotechnologies Corporation is partnered with Amgen to identify and develop therapeutic antibodies from the blood of patients who are actively fighting or have recently recovered from COVID-19. |
• | Vir Biotechnology, Inc., in collaboration with GlaxoSmithKline, is utilizing its neutralizing antibody platform to identify antibodies that could be used as therapeutic or preventative options to combat COVID-19. |
• | Applied Therapeutics, Inc.’s lead clinical-stage asset is now being studied in COVID-19 patients with acute lung inflammation and cardiomyopathy, two of the predominant causes of COVID-19-associated mortality. |
Many other Alexandria tenants and investments, including AbbVie Inc., Amgen Inc., Eli Lilly and Company, Novartis AG, Pfizer Inc., are similarly endeavoring to develop novel therapies and repurpose existing and investigational drugs to provide near-term treatments for moderate and severe COVID-19 patients and those at highest risk.
Developing preventative vaccines
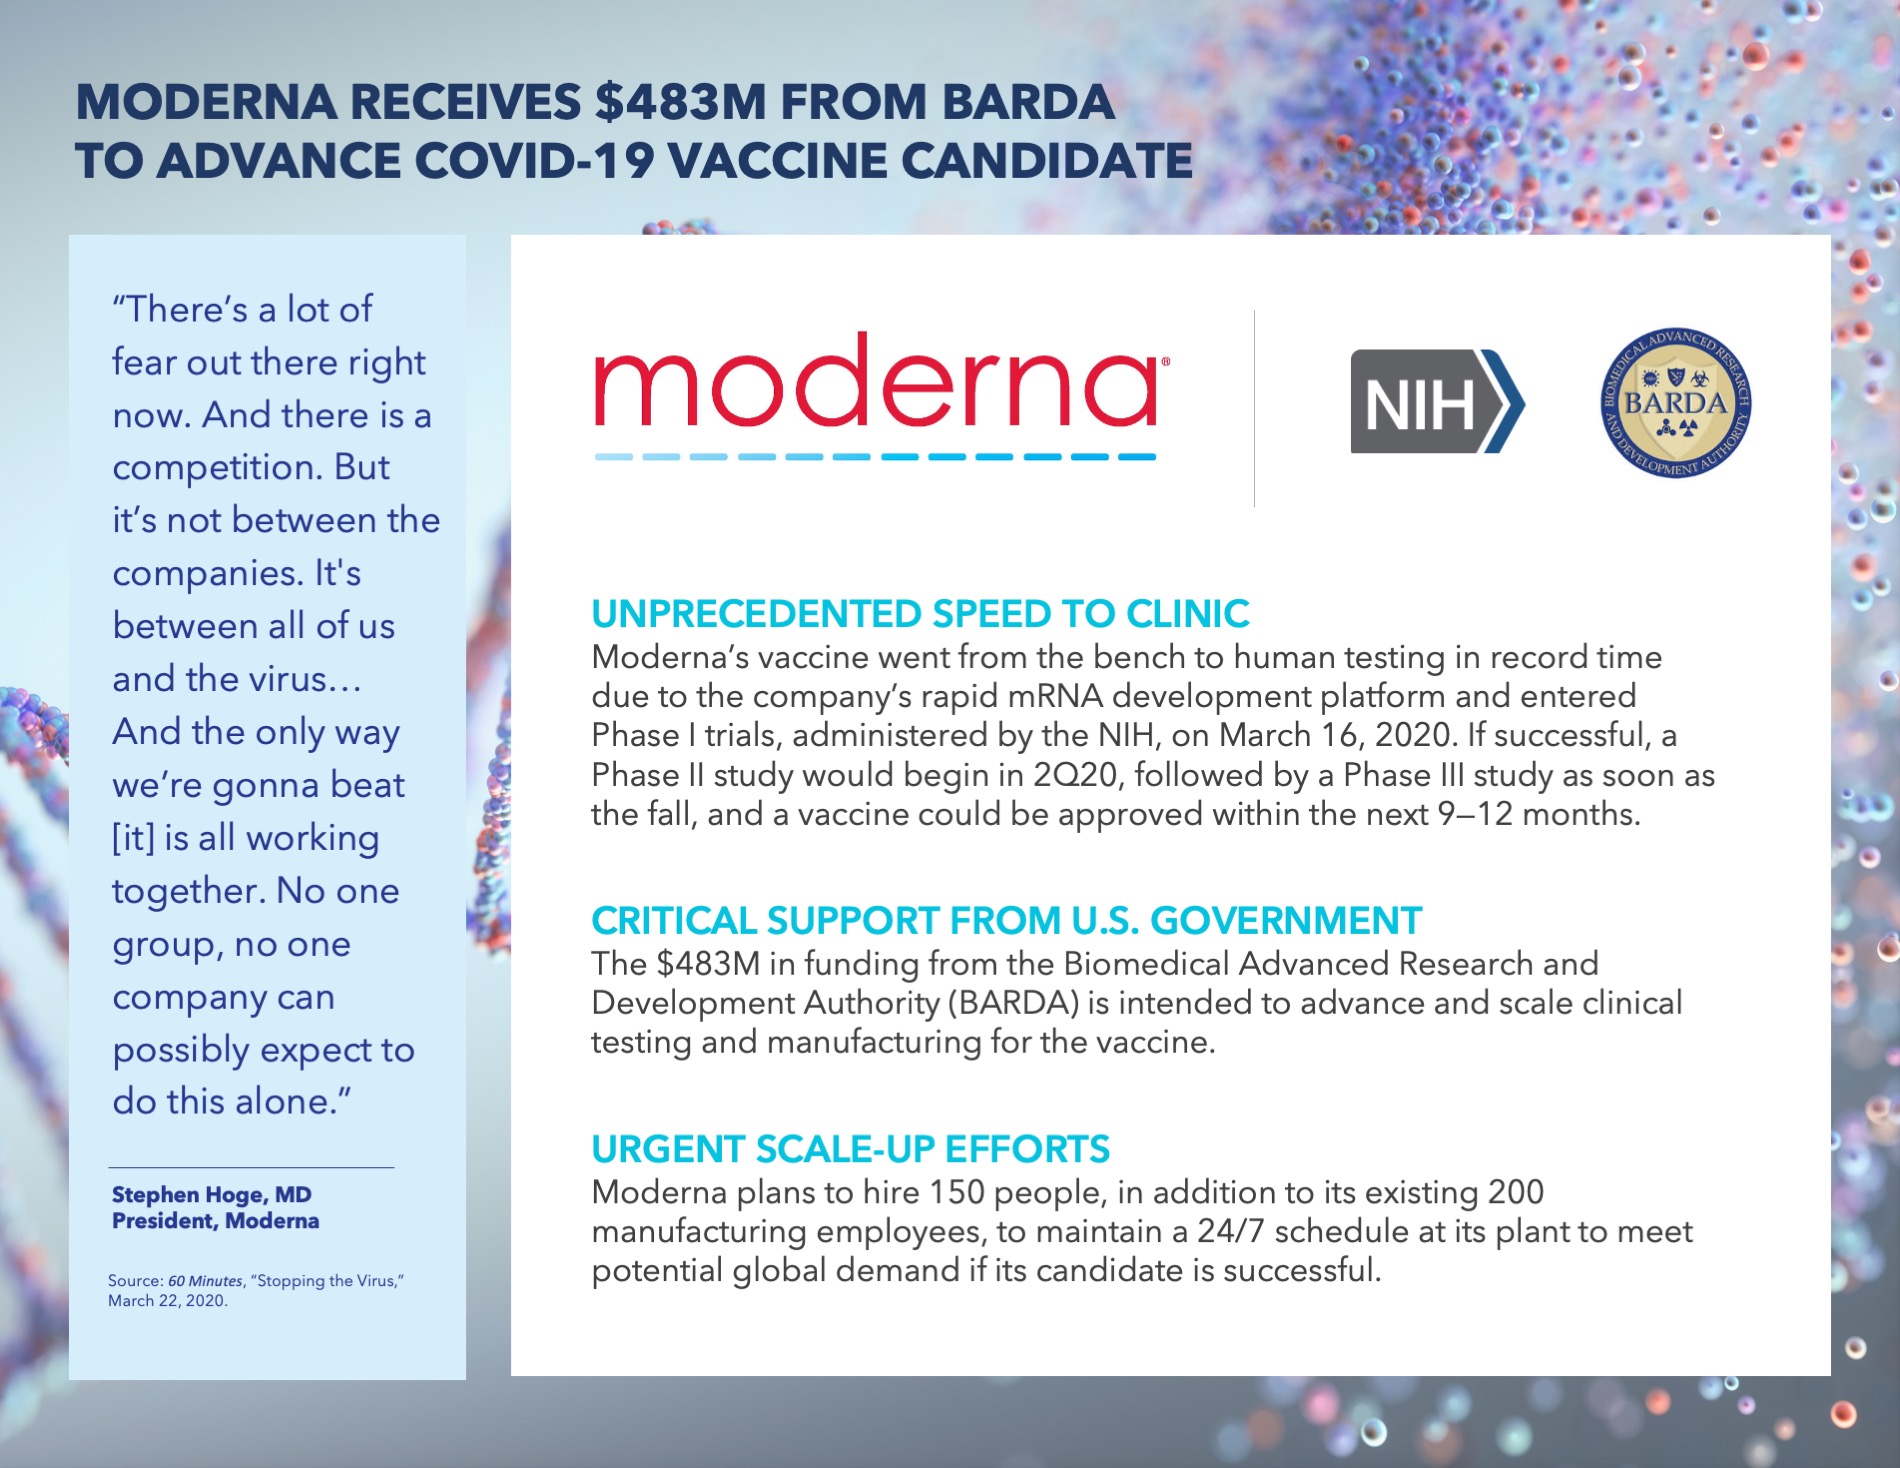
A prophylactic vaccine represents the effective end of this global COVID-19 pandemic. Our tenant Moderna, Inc., in collaboration with the National Institute of Allergy and Infectious Diseases, has fast-tracked its mRNA-based vaccine into the clinic. The U.S. Biomedical Advanced Research and Development Authority (BARDA) has committed up to $483 million to support the clinical development and manufacturing scale-up of Moderna’s mRNA vaccine candidate, mRNA-1273, to help expedite FDA approval over the next nine to twelve months and facilitate the supply of tens of millions of doses per month thereafter.
Other tenants, including Arcturus Therapeutics, GlaxoSmithKline, Johnson & Johnson, Medicago Inc., Novavax, Inc., Pfizer Inc., and Sanofi, are leveraging their vaccine development expertise and technology platforms to similarly bring vaccine candidates into clinical trials, with the goal of expediting the delivery of a safe and effective vaccine to the public in 2021.
Alexandria Fighting COVID-19 on Multiple Fronts | | |
March 31, 2020 | ||
Alexandria’s strategic initiatives and philanthropic efforts to fight COVID-19
Through industry thought leadership, impactful strategic initiatives, and philanthropic efforts, Alexandria’s best-in-class team has made significant and meaningful contributions to help mitigate the impact of, and ultimately end, the global COVID-19 pandemic.
Alexandria Summit
In March 2020, the Alexandria Summit®, in collaboration with Mark McClellan, MD, PhD, and the Duke-Margolis Center for Health Policy, hosted a virtual Policy Forum webinar aimed at driving strategies and policies for achieving the widespread availability of rapid, efficient COVID-19 diagnostic testing capabilities necessary to reduce social distancing and physical isolation measures and mitigate the associated impact on the overall well-being of Americans and on the economic health of the nation.
Mission-critical personal protective equipment
Working hand in hand with key partners across our global life science network, the Alexandria team sourced and donated over 35,000 pieces of personal protective equipment to 12 hospitals and others in communities in need, including New York City, Boston, Seattle, San Diego, Dayton, and Los Angeles, for medical professionals working on the front lines in the fight against COVID-19.
Philanthropic giving
Through strategic philanthropic giving and the Company’s matching gift programs, Alexandria donated, in aggregate, over $700,000 to several highly impactful national organizations performing important work to support a myriad of efforts in communities affected by this global public health emergency, including the following:
• | Feeding America – COVID-19 Response Fund: the fund from the nation’s largest hunger-relief organization with a network of 200 member food banks, is supporting the food banks that help people facing hunger during the school closures, job disruptions, and health risks, during the COVID-19 pandemic. |
• | First Responders Children’s Foundation COVID-19 Emergency Response Fund: providing support to first responders on the front lines of the COVID-19 pandemic, and their families who are enduring financial hardship due to the outbreak. |
Additionally, Alexandria provided mission-critical support to several non-profit organizations in some of the nation’s COVID-19 hot spots, including the following:
• | Robin Hood’s COVID-19 Relief Fund from New York City’s largest poverty-fighting organization, is providing immediate, short-term grants to support non-profits that are on the front lines in the fight against COVID-19 so they can move swiftly to serve affected communities. |
• | Relief Opportunities for All Restaurants (ROAR) is providing financial relief directly to employees of restaurants who have lost their jobs as a result of the COVID-19 pandemic. |
• | City of Cambridge Disaster Fund for COVID-19 is providing emergency assistance in partnership with non-profit organizations to individuals and families in Cambridge who are experiencing extreme financial hardship caused by the COVID-19 crisis. |
Acquisitions | |
March 31, 2020 | |
(Dollars in thousands) | |
Property | Submarket/Market | Date of Purchase | Number of Properties | Operating Occupancy | Square Footage | Unlevered Yields | Purchase Price | ||||||||||||||||||||||||
Future Development | Operating With Future Development/ Redevelopment | Operating | Initial Stabilized | Initial Stabilized (Cash) | |||||||||||||||||||||||||||
Completed 1Q20: | |||||||||||||||||||||||||||||||
275 Grove Street | Route 128/ Greater Boston | 1/10/20 | 1 | 99 | % | — | — | 509,702 | 8.0% | 6.7% | $ | 226,512 | |||||||||||||||||||
601, 611, and 651 Gateway Boulevard (51% interest in consolidated JV)(1) | South San Francisco/ San Francisco | 1/28/20 | 3 | 73 | % | (2) | 260,000 | 300,010 | 475,993 | (1) | (1) | (1) | |||||||||||||||||||
3330 and 3412 Hillview Avenue | Greater Stanford/ San Francisco | 2/5/20 | 2 | 100 | % | — | — | 106,316 | 7.6% | 4.2% | 105,000 | ||||||||||||||||||||
9808 and 9868 Scranton Road(3) | Sorrento Mesa/ San Diego | 1/10/20 | 2 | 88 | % | — | — | 219,628 | 7.3% | 6.8% | 102,250 | (3) | |||||||||||||||||||
Other | Various | 3 | 38 | % | 35,000 | 71,021 | 180,960 | N/A | N/A | 50,817 | |||||||||||||||||||||
11 | 79 | % | 295,000 | 371,031 | 1,492,599 | 484,579 | |||||||||||||||||||||||||
Subsequent to 1Q20: | |||||||||||||||||||||||||||||||
975-1075 Commercial Street and 915-1063 Old County Road | Greater Stanford/ San Francisco | 4/14/20 | — | N/A | 700,000 | 26,738 | — | (4) | (4) | 113,250 | |||||||||||||||||||||
Pending acquisitions | Various | 1 | 510,188 | 42,300 | — | N/A | N/A | 52,171 | |||||||||||||||||||||||
2020 acquisitions | 12 | 1,505,188 | 440,069 | 1,492,599 | $ | 650,000 | |||||||||||||||||||||||||
2020 guidance range | $600,000 - $700,000 | ||||||||||||||||||||||||||||||
Mercer Mega Block | Lake Union/Seattle | TBD(5) | — | N/A | 800,000 | — | — | (4) | (4) | $ | 143,500 | ||||||||||||||||||||
(1) | Refer to “Completion of Acquisitions with Significant Value-Creation Opportunities in Key Submarkets” in this Earnings Press Release for additional details on this transaction. |
(2) | Includes 203,492 RSF of vacancy as of March 31, 2020. Refer to “Occupancy” in our Supplemental Information for additional details. |
(3) | In April 2020, we completed the sale of a partial interest in properties at 9808 and 9868 Scranton Road to the existing SD Tech by Alexandria consolidated real estate joint venture, of which we own 50.0%. We received proceeds of $51.1 million for the 50% interest in the properties that our joint venture partner acquired through the joint venture. We continue to control and consolidate this joint venture; therefore, we accounted for this sale as an equity transaction with no gain or loss recognized in earnings. |
(4) | We expect to provide total estimated costs and related yields for development and redevelopment projects in the future, subsequent to the commencement of construction. |
(5) | We are diligently working through various long-lead time due diligence items, with certain deadlines extending into early 2021. We are working toward completion of all due diligence items as soon as possible. |
Guidance | |
March 31, 2020 | |
(Dollars in millions, except per share amounts) | |
Guidance for 2020 has been updated to reflect our current view of existing market conditions and assumptions for the year ending December 31, 2020, including the estimated impact stemming from the COVID-19 pandemic on our financial and operating results. Key updates to our 2020 guidance include the following:
• | A projected reduction in funds from operations, per share – diluted, as adjusted, primarily consisting of: |
◦ | a reduction of eight cents, or one percent, in projected revenues from our retail tenancy and transient/short-term parking over the remaining three quarters of 2020, for which we expect the impact to be weighted toward 2Q20 (as of March 31, 2020, only 0.8% of our annual rental revenue was related to retail tenants); and |
◦ | approximately net neutral impact related to (i) higher interest costs related to the issuance of our $700.0 million unsecured senior notes payable in March 2020 and (ii) updated timing of deliveries of our current development and redevelopment projects as a result COVID-19-related construction disruptions, including various executive orders restricting construction activities, offset by (iii) an improvement in EBITDA from our core operations, including early lease renewals and re-leasing of space; and |
• | A reduction in our forecasted remaining required sources of capital from real estate dispositions, partial interest sales, and common equity from $925 million to zero dollars as a result of a reduction in construction and acquisitions by an aggregate $940 million at the midpoints of each respective guidance range. Importantly, upon improvement of market conditions, we have the option, on a project-by-project basis, to address demand for our development and redevelopment projects. |
Refer to the following tables for complete details on our updated 2020 guidance assumptions compared to our prior 2020 guidance assumptions disclosed on February 3, 2020. There can be no assurance that actual amounts will not be materially higher or lower than these expectations. Also, refer to our discussion of “forward-looking statements” on page 11 of this Earnings Press Release for additional details.
Projected 2020 Earnings per Share and Funds From Operations per Share Attributable to Alexandria’s Common Stockholders – Diluted | |||||||||
As of 4/27/20 | As of 2/3/20 | ||||||||
Earnings per share(1) | $1.69 to $1.79 | $2.17 to $2.37 | |||||||
Depreciation and amortization of real estate assets | 5.15 | 5.15 | |||||||
Impairment of real estate – rental properties(2) | 0.06 | — | |||||||
Allocation to unvested restricted stock awards | (0.04) | (0.04) | |||||||
Funds from operations per share | $6.86 to $6.96 | $7.28 to $7.48 | |||||||
Unrealized losses on non-real estate investments | 0.14 | — | |||||||
Impairment of non-real estate investments | 0.16 | — | |||||||
Impairment of real estate(3) | 0.10 | — | |||||||
Allocation to unvested restricted stock awards | (0.01) | — | |||||||
Funds from operations per share, as adjusted(1) | $7.25 to $7.35 | $7.28 to $7.48 | |||||||
Midpoint | $7.30 | $7.38 | |||||||
As of 4/27/20 | As of 2/3/20 | ||||||||||||||||
Key Assumptions | Low | High | Low | High | |||||||||||||
Occupancy percentage in North America as of December 31, 2020(4) | 94.8% | 95.4% | 95.4% | 96.0% | |||||||||||||
Lease renewals and re-leasing of space: | |||||||||||||||||
Rental rate increases | 28.0% | 31.0% | 28.0% | 31.0% | |||||||||||||
Rental rate increases (cash basis) | 14.0% | 17.0% | 14.0% | 17.0% | |||||||||||||
Same property performance: | |||||||||||||||||
Net operating income increase | 1.0% | 3.0% | 1.5% | 3.5% | |||||||||||||
Net operating income increase (cash basis) | 4.5% | 6.5% | 5.0% | 7.0% | |||||||||||||
Straight-line rent revenue(5) | $ | 98 | $ | 108 | $ | 113 | $ | 123 | |||||||||
General and administrative expenses | $ | 121 | $ | 126 | $ | 121 | $ | 126 | |||||||||
Capitalization of interest | $ | 102 | $ | 112 | $ | 108 | $ | 118 | |||||||||
Interest expense | $ | 185 | $ | 195 | $ | 169 | $ | 179 | |||||||||
(1) | Excludes unrealized gains or losses after March 31, 2020, that are required to be recognized in earnings and are excluded from funds from operations per share, as adjusted. |
(2) | Includes a $7.6 million impairment on our investment in a recently developed retail property held by our unconsolidated real estate joint venture. |
(3) | Includes eight cents related to an impairment charge of $10 million recognized in April 2020, related to a pending acquisition of an operating tech office property for which our revised economic projections declined from our initial underwriting, and we reduced the carrying amount of this pre-acquisition deposit to zero dollars, concurrently with submission of our notice to terminate the transaction. |
(4) | Occupancy guidance has been reduced by 60 bps at the midpoint of the range and includes approximately 50% of our RSF related to our leased retail space as of March 31, 2020. |
(5) | The projected reduction in straight-line rent revenue comprises: (i) about half related to the updated timing of deliveries of our current development and redevelopment projects, as a result of COVID-19-related construction disruptions, including various executive orders restricting construction activities; (ii) roughly one-third from reductions to rental income (related to deferred rents) for specific tenants, including retail tenants, and a general allowance for a pool of deferred rent balances which we do not expect to collect in full; and (iii) the remaining change is related to a reduction in projected acquisitions, including the termination of an operating tech office property acquisition in April 2020. |
Guidance (continued) | |
March 31, 2020 | |
(Dollars in millions) | |
Key Credit Metrics | ||||
2020 Guidance | ||||
As of 4/27/20 | As of 2/3/20 | |||
Net debt and preferred stock to Adjusted EBITDA – 4Q20 annualized | Less than or equal to 5.3x | Less than or equal to 5.2x | ||
Fixed-charge coverage ratio – 4Q20 annualized | Greater than or equal to 4.4x | Greater than 4.5x | ||
As of 4/27/20 | As of 2/3/20 | ||||||||||||||||||||||||||||
Key Sources and Uses of Capital | Range | Midpoint | Certain Completed Items | Range | Midpoint | ||||||||||||||||||||||||
Sources of capital: | |||||||||||||||||||||||||||||
Net cash provided by operating activities after dividends | $ | 185 | $ | 225 | $ | 205 | $ | 200 | $ | 240 | $ | 220 | |||||||||||||||||
Incremental debt | 355 | 315 | 335 | see below | 400 | 360 | 380 | ||||||||||||||||||||||
970 | 1,170 | 1,070 | $ | 1,076 | (1) | 1,850 | 2,050 | 1,950 | |||||||||||||||||||||
Total sources of capital | $ | 1,510 | $ | 1,710 | $ | 1,610 | $ | 2,450 | $ | 2,650 | $ | 2,550 | |||||||||||||||||
Uses of capital: | |||||||||||||||||||||||||||||
Construction (see page 43 for additional information) | $ | 910 | $ | 1,010 | $ | 960 | $ | 1,550 | $ | 1,650 | $ | 1,600 | |||||||||||||||||
Acquisitions (see page 8 for additional information)(2) | 600 | 700 | 650 | $ | 598 | 900 | 1,000 | 950 | |||||||||||||||||||||
Total uses of capital | $ | 1,510 | $ | 1,710 | $ | 1,610 | $ | 2,450 | $ | 2,650 | $ | 2,550 | |||||||||||||||||
Incremental debt (included above): | |||||||||||||||||||||||||||||
Issuance of unsecured senior notes payable | $ | 700 | $ | 700 | $ | 700 | $ | 700 | $ | 550 | $ | 650 | $ | 600 | |||||||||||||||
$3.0 billion unsecured senior lines of credit and other | (345 | ) | (385 | ) | (365 | ) | (150 | ) | (290 | ) | (220 | ) | |||||||||||||||||
Incremental debt | $ | 355 | $ | 315 | $ | 335 | $ | 400 | $ | 360 | $ | 380 | |||||||||||||||||
(1) | In January 2020, we completed $1.0 billion of forward equity sales agreements to sell an aggregate of 6.9 million shares of our common stock (including the exercise of an underwriters’ option) at a public offering price of $155.00 per share, before underwriting discounts. In March 2020, we settled 3.4 million shares from our forward equity sales agreements and received proceeds of $500.0 million. As of April 27, 2020, 3.5 million shares of our common stock remain outstanding under forward equity sales agreements, for which we expect to receive proceeds of $524.3 million to be further adjusted as provided in the sales agreements. We expect to settle the remaining outstanding forward equity sales agreements in 2020. In April 2020, we completed the sale of a partial interest in properties at 9808 and 9868 Scranton Road in our Sorrento Mesa submarket to the existing SD Tech by Alexandria consolidated real estate joint venture, of which we own 50.0%. We received proceeds of $51.1 million for the 50% interest in the properties that our joint venture partner acquired through the joint venture. |
(2) | Excludes the formation of a consolidated joint venture with Boston Properties, Inc. through non-cash contributions of real estate. Refer to “2020 Acquisitions” in this Earnings Press Release for additional details. |
| |
Earnings Call Information and About the Company | |
March 31, 2020 | |
We will host a conference call on Tuesday, April 28, 2020, at 3:00 p.m. Eastern Time (“ET”)/noon Pacific Time (“PT”), which is open to the general public, to discuss our financial and operating results for the first quarter ended March 31, 2020. To participate in this conference call, dial (833) 366-1125 or (412) 902-6738 shortly before 3:00 p.m. ET/noon PT and ask the operator to join the call for Alexandria Real Estate Equities, Inc. The audio webcast can be accessed at www.are.com in the “For Investors” section. A replay of the call will be available for a limited time from 5:00 p.m. ET/2:00 p.m. PT on Tuesday, April 28, 2020. The replay number is (877) 344-7529 or (412) 317-0088, and the access code is 10139230.
Additionally, a copy of this Earnings Press Release and Supplemental Information for the first quarter ended March 31, 2020, is available in the “For Investors” section of our website at www.are.com or by following this link: http://www.are.com/fs/2020q1.pdf.
For any questions, please contact Joel S. Marcus, executive chairman and founder; Stephen A. Richardson, co-chief executive officer; Peter M. Moglia, co-chief executive officer and co-chief investment officer; Dean A. Shigenaga, co-president and chief financial officer; or Sara M. Kabakoff, vice president – corporate communications, at (626) 578-0777; or Paula Schwartz, managing director of Rx Communications Group, at (917) 322-2216.
About the Company
Alexandria Real Estate Equities, Inc. (NYSE:ARE), an S&P 500® urban office real estate investment trust (“REIT”), is the first, longest-tenured, and pioneering owner, operator, and developer uniquely focused on collaborative life science, technology, and agtech campuses in AAA innovation cluster locations, with a total market capitalization of $24.3 billion as of March 31, 2020, and an asset base in North America of 41.5 million square feet (“SF”). The asset base in North America includes 28.8 million RSF of operating properties and 2.1 million RSF of Class A properties undergoing construction, 6.5 million RSF of near-term and intermediate-term development and redevelopment projects, and 4.1 million SF of future development projects. Founded in 1994, Alexandria pioneered this niche and has since established a significant market presence in key locations, including Greater Boston, San Francisco, New York City, San Diego, Seattle, Maryland, and Research Triangle. Alexandria has a longstanding and proven track record of developing Class A properties clustered in urban life science, technology, and agtech campuses that provide our innovative tenants with highly dynamic and collaborative environments that enhance their ability to successfully recruit and retain world-class talent and inspire productivity, efficiency, creativity, and success. Alexandria also provides strategic capital to transformative life science, technology, and agtech companies through our venture capital arm. We believe our unique business model and diligent underwriting ensure a high-quality and diverse tenant base that results in higher occupancy levels, longer lease terms, higher rental income, higher returns, and greater long-term asset value. For additional information on Alexandria, please visit www.are.com.
***********
This document includes “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Such forward-looking statements include, without limitation, statements regarding our 2020 earnings per share attributable to Alexandria’s common stockholders – diluted, 2020 funds from operations per share attributable to Alexandria’s common stockholders – diluted, net operating income, and our projected sources and uses of capital. You can identify the forward-looking statements by their use of forward-looking words, such as “forecast,” “guidance,” “goals,” “projects,” “estimates,” “anticipates,” “believes,” “expects,” “intends,” “may,” “plans,” “seeks,” “should,” or “will,” or the negative of those words or similar words. These forward-looking statements are based on our current expectations, beliefs, projections, future plans and strategies, anticipated events or trends, and similar expressions concerning matters that are not historical facts, as well as a number of assumptions concerning future events. There can be no assurance that actual results will not be materially higher or lower than these expectations. These statements are subject to risks, uncertainties, assumptions, and other important factors that could cause actual results to differ materially from the results discussed in the forward-looking statements. Factors that might cause such a difference include, without limitation, our failure to obtain capital (debt, construction financing, and/or equity) or refinance debt maturities, increased interest rates and operating costs, adverse economic or real estate developments in our markets (including the impact of the ongoing COVID-19 pandemic), our failure to successfully place into service and lease any properties undergoing development or redevelopment and our existing space held for future development or redevelopment (including new properties acquired for that purpose), our failure to successfully operate or lease acquired properties, decreased rental rates, increased vacancy rates or failure to renew or replace expiring leases, defaults on or non-renewal of leases by tenants, adverse general and local economic conditions, an unfavorable capital market environment, decreased leasing activity or lease renewals, and other risks and uncertainties detailed in our filings with the Securities and Exchange Commission (“SEC”). Accordingly, you are cautioned not to place undue reliance on such forward-looking statements. All forward-looking statements are made as of the date of this Earnings Press Release, and unless otherwise stated, we assume no obligation to update this information and expressly disclaim any obligation to update or revise any forward-looking statements, whether as a result of new information, future events, or otherwise. For more discussion relating to risks and uncertainties that could cause actual results to differ materially from those anticipated in our forward-looking statements, and risks to our business in general, please refer to our SEC filings, including our most recent annual report on Form 10-K and any subsequent quarterly reports on Form 10-Q.
For additional discussion of the risks and other potential impacts posed by the outbreak of the COVID-19 pandemic and uncertainties we, our tenants, and the global and national economies face as a result, see the sections entitled “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in our quarterly report on Form 10-Q filed with the SEC on April 27, 2020.
Alexandria®, Lighthouse Design® logo, Building the Future of Life-Changing Innovation™, Alexandria Center®, Alexandria Technology Square®, Alexandria Summit®, Alexandria Technology Center®, Alexandria Innovation Center®, LaunchLabs®, and GradLabs™ are trademarks of Alexandria Real Estate Equities, Inc. All other company names, trademarks, and logos referenced herein are the property of their respective owners.
Consolidated Statements of Operations | |
March 31, 2020 | |
(Dollars in thousands, except per share amounts) | |
Three Months Ended | ||||||||||||||||||||
3/31/20 | 12/31/19 | 9/30/19 | 6/30/19 | 3/31/19 | ||||||||||||||||
Revenues: | ||||||||||||||||||||
Income from rentals | $ | 437,605 | $ | 404,721 | $ | 385,776 | $ | 371,618 | $ | 354,749 | ||||||||||
Other income | 2,314 | 3,393 | 4,708 | 2,238 | 4,093 | |||||||||||||||
Total revenues | 439,919 | 408,114 | 390,484 | 373,856 | 358,842 | |||||||||||||||
Expenses: | ||||||||||||||||||||
Rental operations | 129,103 | 121,852 | 116,450 | 105,689 | 101,501 | |||||||||||||||
General and administrative | 31,963 | 29,782 | 27,930 | 26,434 | 24,677 | |||||||||||||||
Interest | 45,739 | 45,493 | 46,203 | 42,879 | 39,100 | |||||||||||||||
Depreciation and amortization | 175,496 | 140,518 | 135,570 | 134,437 | 134,087 | |||||||||||||||
Impairment of real estate | 2,003 | 12,334 | — | — | — | |||||||||||||||
Loss on early extinguishment of debt | — | — | 40,209 | — | 7,361 | |||||||||||||||
Total expenses | 384,304 | 349,979 | 366,362 | 309,439 | 306,726 | |||||||||||||||
Equity in (losses) earnings of unconsolidated real estate joint ventures | (3,116 | ) | (1) | 4,777 | 2,951 | 1,262 | 1,146 | |||||||||||||
Investment (loss) income | (21,821 | ) | (2) | 152,667 | (63,076 | ) | 21,500 | 83,556 | ||||||||||||
Gain on sales of real estate | — | 474 | — | — | — | |||||||||||||||
Net income (loss) | 30,678 | 216,053 | (36,003 | ) | 87,179 | 136,818 | ||||||||||||||
Net income attributable to noncontrolling interests | (11,913 | ) | (13,612 | ) | (11,199 | ) | (8,412 | ) | (7,659 | ) | ||||||||||
Net income (loss) attributable to Alexandria Real Estate Equities, Inc.’s stockholders | 18,765 | 202,441 | (47,202 | ) | 78,767 | 129,159 | ||||||||||||||
Dividends on preferred stock | — | — | (1,173 | ) | (1,005 | ) | (1,026 | ) | ||||||||||||
Preferred stock redemption charge | — | — | — | — | (2,580 | ) | ||||||||||||||
Net income attributable to unvested restricted stock awards | (1,925 | ) | (2,823 | ) | (1,398 | ) | (1,432 | ) | (1,955 | ) | ||||||||||
Net income (loss) attributable to Alexandria Real Estate Equities, Inc.’s common stockholders | $ | 16,840 | $ | 199,618 | $ | (49,773 | ) | $ | 76,330 | $ | 123,598 | |||||||||
Net income (loss) per share attributable to Alexandria Real Estate Equities, Inc.’s common stockholders: | ||||||||||||||||||||
Basic | $ | 0.14 | $ | 1.75 | $ | (0.44 | ) | $ | 0.68 | $ | 1.11 | |||||||||
Diluted | $ | 0.14 | $ | 1.74 | $ | (0.44 | ) | $ | 0.68 | $ | 1.11 | |||||||||
Weighted-average shares of common stock outstanding: | ||||||||||||||||||||
Basic | 121,433 | 114,175 | 112,120 | 111,433 | 111,054 | |||||||||||||||
Diluted | 121,785 | 114,974 | 112,120 | 111,501 | 111,054 | |||||||||||||||
Dividends declared per share of common stock | $ | 1.03 | $ | 1.03 | $ | 1.00 | $ | 1.00 | $ | 0.97 | ||||||||||
(1) | Includes a $7.6 million impairment on our investment in a recently developed retail property held by our unconsolidated real estate joint venture. |
(2) | Refer to “Investments” of our Supplemental Information for additional details. |
Consolidated Balance Sheets | |
March 31, 2020 | |
(In thousands) | |
3/31/20 | 12/31/19 | 9/30/19 | 6/30/19 | 3/31/19 | ||||||||||||||||
Assets | ||||||||||||||||||||
Investments in real estate | $ | 15,832,182 | $ | 14,844,038 | $ | 13,618,280 | $ | 12,872,824 | $ | 12,410,350 | ||||||||||
Investments in unconsolidated real estate joint ventures | 325,665 | 346,890 | 340,190 | 334,162 | 290,405 | |||||||||||||||
Cash and cash equivalents | 445,255 | 189,681 | 410,675 | 198,909 | 261,372 | |||||||||||||||
Restricted cash | 43,116 | 53,008 | 42,295 | 39,316 | 54,433 | |||||||||||||||
Tenant receivables | 14,976 | (1) | 10,691 | 10,668 | 9,228 | 9,645 | ||||||||||||||
Deferred rent | 663,926 | 641,844 | 615,817 | 585,082 | 558,103 | |||||||||||||||
Deferred leasing costs | 269,458 | 270,043 | 252,772 | 247,468 | 241,268 | |||||||||||||||
Investments | 1,123,482 | 1,140,594 | 990,454 | 1,057,854 | 1,000,904 | |||||||||||||||
Other assets | 983,875 | 893,714 | 777,003 | 694,627 | 653,726 | |||||||||||||||
Total assets | $ | 19,701,935 | $ | 18,390,503 | $ | 17,058,154 | $ | 16,039,470 | $ | 15,480,206 | ||||||||||
Liabilities, Noncontrolling Interests, and Equity | ||||||||||||||||||||
Secured notes payable | $ | 347,136 | $ | 349,352 | $ | 351,852 | $ | 354,186 | $ | 356,461 | ||||||||||
Unsecured senior notes payable | 6,736,999 | 6,044,127 | 6,042,831 | 5,140,914 | 5,139,500 | |||||||||||||||
Unsecured senior line of credit | 221,000 | 384,000 | 343,000 | 514,000 | — | |||||||||||||||
Unsecured senior bank term loan | — | — | — | 347,105 | 347,542 | |||||||||||||||
Accounts payable, accrued expenses, and other liabilities | 1,352,554 | 1,320,268 | 1,241,276 | 1,157,417 | 1,171,377 | |||||||||||||||
Dividends payable | 129,981 | 126,278 | 115,575 | 114,379 | 110,412 | |||||||||||||||
Total liabilities | 8,787,670 | 8,224,025 | 8,094,534 | 7,628,001 | 7,125,292 | |||||||||||||||
Commitments and contingencies | ||||||||||||||||||||
Redeemable noncontrolling interests | 12,013 | 12,300 | 12,099 | 10,994 | 10,889 | |||||||||||||||
Alexandria Real Estate Equities, Inc.’s stockholders’ equity: | ||||||||||||||||||||
7.00% Series D cumulative convertible preferred stock | — | — | 57,461 | 57,461 | 57,461 | |||||||||||||||
Common stock | 1,243 | 1,208 | 1,132 | 1,120 | 1,112 | |||||||||||||||
Additional paid-in capital | 9,336,949 | 8,874,367 | 7,743,188 | 7,581,573 | 7,518,716 | |||||||||||||||
Accumulated other comprehensive loss | (15,606 | ) | (9,749 | ) | (11,549 | ) | (11,134 | ) | (10,712 | ) | ||||||||||
Alexandria Real Estate Equities, Inc.’s stockholders’ equity | 9,322,586 | 8,865,826 | 7,790,232 | 7,629,020 | 7,566,577 | |||||||||||||||
Noncontrolling interests | 1,579,666 | 1,288,352 | 1,161,289 | 771,455 | 777,448 | |||||||||||||||
Total equity | 10,902,252 | 10,154,178 | 8,951,521 | 8,400,475 | 8,344,025 | |||||||||||||||
Total liabilities, noncontrolling interests, and equity | $ | 19,701,935 | $ | 18,390,503 | $ | 17,058,154 | $ | 16,039,470 | $ | 15,480,206 | ||||||||||
(1) | As of April 24, 2020, our tenant receivables balance was $7.3 million, representing our lowest balance since 2012. |
Funds From Operations and Funds From Operations per Share | |
March 31, 2020 | |
(In thousands) | |
The following table presents a reconciliation of net income (loss) attributable to Alexandria’s common stockholders, the most directly comparable financial measure presented in accordance with generally accepted accounting principles (“GAAP”), including our share of amounts from consolidated and unconsolidated real estate joint ventures, to funds from operations attributable to Alexandria’s common stockholders – diluted, and funds from operations attributable to Alexandria’s common stockholders – diluted, as adjusted, for the periods below:
Three Months Ended | ||||||||||||||||||||
3/31/20 | 12/31/19 | 9/30/19 | 6/30/19 | 3/31/19 | ||||||||||||||||
Net income (loss) attributable to Alexandria’s common stockholders | $ | 16,840 | $ | 199,618 | $ | (49,773 | ) | $ | 76,330 | $ | 123,598 | |||||||||
Depreciation and amortization of real estate assets(1) | 172,628 | 137,761 | 135,570 | 134,437 | 134,087 | |||||||||||||||
Noncontrolling share of depreciation and amortization from consolidated real estate JVs | (15,870 | ) | (10,176 | ) | (8,621 | ) | (6,744 | ) | (5,419 | ) | ||||||||||
Our share of depreciation and amortization from unconsolidated real estate JVs | 2,643 | 2,702 | 1,845 | 973 | 846 | |||||||||||||||
Gain on sales of real estate | — | (474 | ) | — | — | — | ||||||||||||||
Impairment of real estate – rental properties | 7,644 | (2) | 12,334 | — | — | — | ||||||||||||||
Assumed conversion of 7.00% Series D cumulative convertible preferred stock | — | — | — | 1,005 | 1,026 | |||||||||||||||
Allocation to unvested restricted stock awards | (847 | ) | (1,809 | ) | — | (1,445 | ) | (2,054 | ) | |||||||||||
Funds from operations attributable to Alexandria’s common stockholders – diluted(1) | 183,038 | 339,956 | 79,021 | 204,556 | 252,084 | |||||||||||||||
Unrealized losses (gains) on non-real estate investments | 17,144 | (148,268 | ) | 70,043 | (11,058 | ) | (72,206 | ) | ||||||||||||
Impairment of non-real estate investments | 19,780 | (3) | 9,991 | 7,133 | — | — | ||||||||||||||
Impairment of real estate | 2,003 | — | — | — | — | |||||||||||||||
Loss on early extinguishment of debt | — | — | 40,209 | — | 7,361 | |||||||||||||||
Loss on early termination of interest rate hedge agreements | — | — | 1,702 | — | — | |||||||||||||||
Preferred stock redemption charge | — | — | — | — | 2,580 | |||||||||||||||
Removal of assumed conversion of 7.00% Series D cumulative convertible preferred stock | — | — | — | (1,005 | ) | (1,026 | ) | |||||||||||||
Allocation to unvested restricted stock awards | (591 | ) | 1,760 | (1,002 | ) | 179 | 990 | |||||||||||||
Funds from operations attributable to Alexandria’s common stockholders – diluted, as adjusted | $ | 221,374 | $ | 203,439 | $ | 197,106 | $ | 192,672 | $ | 189,783 | ||||||||||
(1) | Calculated in accordance with standards established by the Nareit Board of Governors. Refer to “Funds From Operations and Funds From Operations, As Adjusted, Attributable to Alexandria’s Common Stockholders” in the “Definitions and Reconciliations” of our Supplemental Information for additional details. |
(2) | Relates to our investment in a recently developed retail property held by our unconsolidated real estate joint venture. |
(3) | Primarily relates to two privately held non-real estate investments. |
Funds From Operations and Funds From Operations per Share (continued) | |
March 31, 2020 | |
(In thousands, except per share amounts) | |
The following table presents a reconciliation of net income (loss) per share attributable to Alexandria’s common stockholders, the most directly comparable financial measure presented in accordance with GAAP, including our share of amounts from consolidated and unconsolidated real estate joint ventures, to funds from operations per share attributable to Alexandria’s common stockholders – diluted, and funds from operations per share attributable to Alexandria’s common stockholders – diluted, as adjusted, for the periods below. Per share amounts may not add due to rounding.
Three Months Ended | ||||||||||||||||||||
3/31/20 | 12/31/19 | 9/30/19 | 6/30/19 | 3/31/19 | ||||||||||||||||
Net income (loss) per share attributable to Alexandria’s common stockholders – diluted | $ | 0.14 | $ | 1.74 | $ | (0.44 | ) | $ | 0.68 | $ | 1.11 | |||||||||
Depreciation and amortization of real estate assets | 1.31 | 1.13 | 1.14 | 1.15 | 1.17 | |||||||||||||||
Impairment of real estate – rental properties | 0.06 | (1) | 0.11 | — | — | — | ||||||||||||||
Allocation to unvested restricted stock awards | (0.01 | ) | (0.02 | ) | — | — | (0.02 | ) | ||||||||||||
Funds from operations per share attributable to Alexandria’s common stockholders – diluted(1) | 1.50 | 2.96 | 0.70 | 1.83 | 2.26 | |||||||||||||||
Unrealized losses (gains) on non-real estate investments | 0.14 | (1.29 | ) | 0.62 | (0.10 | ) | (0.65 | ) | ||||||||||||
Impairment of non-real estate investments | 0.16 | (1) | 0.09 | 0.06 | — | — | ||||||||||||||
Impairment of real estate | 0.02 | — | — | — | — | |||||||||||||||
Loss on early extinguishment of debt | — | — | 0.36 | — | 0.07 | |||||||||||||||
Loss on early termination of interest rate hedge agreements | — | — | 0.02 | — | — | |||||||||||||||
Preferred stock redemption charge | — | — | — | — | 0.02 | |||||||||||||||
Allocation to unvested restricted stock awards | — | 0.01 | (0.01 | ) | — | 0.01 | ||||||||||||||
Funds from operations per share attributable to Alexandria’s common stockholders – diluted, as adjusted | $ | 1.82 | $ | 1.77 | $ | 1.75 | $ | 1.73 | $ | 1.71 | ||||||||||
Weighted-average shares of common stock outstanding(2) for calculations of: | ||||||||||||||||||||
Earnings per share – diluted | 121,785 | 114,974 | 112,120 | 111,501 | 111,054 | |||||||||||||||
Funds from operations – diluted, per share | 121,785 | 114,974 | 112,562 | 112,077 | 111,635 | |||||||||||||||
Funds from operations – diluted, as adjusted, per share | 121,785 | 114,974 | 112,562 | 111,501 | 111,054 | |||||||||||||||
(1) | Refer to footnotes on the previous page for additional details. |
(2) | Refer to “Weighted-Average Shares of Common Stock Outstanding – Diluted” in the “Definitions and Reconciliations” of our Supplemental Information for additional details. |
SUPPLEMENTAL
INFORMATION
| |
Company Profile | |
March 31, 2020 | |
Alexandria Real Estate Equities, Inc. (NYSE:ARE), an S&P 500® urban office REIT, is the first, longest-tenured, and pioneering owner, operator, and developer uniquely focused on collaborative life science, technology, and agtech campuses in AAA innovation cluster locations, with a total market capitalization of $24.3 billion as of March 31, 2020, and an asset base in North America of 41.5 million SF. The asset base in North America includes 28.8 million RSF of operating properties and 2.1 million RSF of Class A properties undergoing construction, 6.5 million RSF of near-term and intermediate-term development and redevelopment projects, and 4.1 million SF of future development projects. Founded in 1994, Alexandria pioneered this niche and has since established a significant market presence in key locations, including Greater Boston, San Francisco, New York City, San Diego, Seattle, Maryland, and Research Triangle. Alexandria has a longstanding and proven track record of developing Class A properties clustered in urban life science, technology, and agtech campuses that provide our innovative tenants with highly dynamic and collaborative environments that enhance their ability to successfully recruit and retain world-class talent and inspire productivity, efficiency, creativity, and success. Alexandria also provides strategic capital to transformative life science, technology, and agtech companies through our venture capital arm. We believe our unique business model and diligent underwriting ensure a high-quality and diverse tenant base that results in higher occupancy levels, longer lease terms, higher rental income, higher returns, and greater long-term asset value. For additional information on Alexandria, please visit www.are.com.
Tenant base
Alexandria is known for our high-quality and diverse tenant base, with 51% of our annual rental revenue generated from tenants that are investment-grade rated or publicly traded large cap companies. The quality, diversity, breadth, and depth of our significant relationships with our tenants provide Alexandria with high-quality and stable cash flows. Alexandria’s underwriting team and long-term industry relationships positively distinguish us from all other publicly traded REITs and real estate companies.
Executive and senior management team
Alexandria’s executive and senior management team has unique experience and expertise in creating, owning, and operating highly dynamic and collaborative campuses in key urban life science, technology, and agtech cluster locations that inspire innovation. From the development of high-quality, sustainable real estate, to the ongoing cultivation of collaborative environments with unique amenities and events, the Alexandria team has a first-in-class reputation of excellence in our niche. Alexandria’s highly experienced management team also includes regional market directors with leading reputations and longstanding relationships within the life science, technology, and agtech communities in their respective urban innovation clusters. We believe that our expertise, experience, reputation, and key relationships in the real estate, life science, technology, and agtech industries provide Alexandria significant competitive advantages in attracting new business opportunities.
Alexandria’s executive and senior management team consists of 44 individuals, averaging 25 years of real estate experience, including 14 years with Alexandria. Our executive management team alone averages 18 years of experience with Alexandria.
EXECUTIVE MANAGEMENT TEAM | ||
Joel S. Marcus | Stephen A. Richardson | |
Executive Chairman & Founder | Co-Chief Executive Officer | |
Peter M. Moglia | Dean A. Shigenaga | |
Co-Chief Executive Officer & Co-Chief Investment Officer | Co-President & Chief Financial Officer | |
Thomas J. Andrews | Daniel J. Ryan | |
Co-President & Regional Market Director – Greater Boston | Co-Chief Investment Officer & Regional Market Director – San Diego | |
Jennifer J. Banks | Lawrence J. Diamond | |
Co-Chief Operating Officer, General Counsel & Corporate Secretary | Co-Chief Operating Officer & Regional Market Director – Maryland | |
Vincent R. Ciruzzi | John H. Cunningham | |
Chief Development Officer | Executive Vice President – Regional Market Director – New York City | |
Terezia C. Nemeth | Marc E. Binda | |
Executive Vice President – Regional Market Director – San Francisco | Executive Vice President – Finance & Treasurer | |
Andres R. Gavinet | Joseph Hakman | |
Chief Accounting Officer | Chief Strategic Transactions Officer | |
| |
Investor Information | |
March 31, 2020 | |
Corporate Headquarters | New York Stock Exchange Trading Symbol | Information Requests | |||
26 North Euclid Avenue | Common stock: ARE | Phone: | (626) 578-0777 | ||
Pasadena, California 91101 | Email: | ||||
Web: | www.are.com | ||||
Equity Research Coverage |
Alexandria is currently covered by the following research analysts. This list may be incomplete and is subject to change as firms initiate or discontinue coverage of our company. Please note that any opinions, estimates, or forecasts regarding our historical or predicted performance made by these analysts are theirs alone and do not represent opinions, estimates, or forecasts of Alexandria or our management. Alexandria does not by our reference or distribution of the information below imply our endorsement of or concurrence with any opinions, estimates, or forecasts of these analysts. Interested persons may obtain copies of analysts’ reports on their own as we do not distribute these reports. Several of these firms may, from time to time, own our stock and/or hold other long or short positions in our stock and may provide compensated services to us. |
Bank of America Merrill Lynch | Citigroup Global Markets Inc. | J.P. Morgan Securities LLC | Robert W. Baird & Co. Incorporated | |||
Jamie Feldman / Elvis Rodriguez | Michael Bilerman / Emmanuel Korchman | Anthony Paolone | David Rodgers / Nicholas Thillman | |||
(646) 855-5808 / (646) 855-1589 | (212) 816-1383 / (212) 816-1382 | (212) 622-6682 | (216) 737-7341 / (414) 298-5053 | |||
BTIG, LLC | Evercore ISI | Mizuho Securities USA Inc. | SMBC Nikko Securities America, Inc. | |||
Tom Catherwood / James Sullivan | Sheila McGrath / Wendy Ma | Omotayo Okusanya / Venkat Kommineni | Richard Anderson / Jay Kornreich | |||
(212) 738-6140 / (212) 738-6139 | (212) 497-0882 / (212) 497-0870 | (646) 949-9672 / (646) 949-9754 | (646) 521-2351 / (646) 424-3202 | |||
CFRA | Green Street Advisors, Inc. | RBC Capital Markets | ||||
Kenneth Leon | Daniel Ismail / Chris Darling | Michael Carroll / Jason Idoine | ||||
(646) 517-2552 | (949) 640-8780 / (949) 640-8780 | (440) 715-2649 / (440) 715-2651 | ||||
Fixed Income Coverage | Rating Agencies | |||||
Barclays Capital Inc. | Wells Fargo & Company | Moody’s Investors Service | S&P Global Ratings | |||
Srinjoy Banerjee / Devon Zhou | Thierry Perrein / Kevin McClure | (212) 553-0376 | Fernanda Hernandez / Michael Souers | |||
(212) 526-3521 / (212) 526-6961 | (704) 410-3262 / (704) 410-3252 | (212) 438-1347 / (212) 438-2508 | ||||
J.P. Morgan Securities LLC | ||||||
Mark Streeter / Ian Snyder | ||||||
(212) 834-5086 / (212) 834-3798 | ||||||
Financial and Asset Base Highlights | |
March 31, 2020 | |
(Dollars in thousands, except per share amounts) | |
Three Months Ended (unless stated otherwise) | ||||||||||||||||||||
3/31/20 | 12/31/19 | 9/30/19 | 6/30/19 | 3/31/19 | ||||||||||||||||
Selected financial data from consolidated financial statements and related information | ||||||||||||||||||||
Rental revenues | $ | 337,942 | $ | 308,418 | $ | 293,182 | $ | 289,625 | $ | 274,563 | ||||||||||
Tenant recoveries | $ | 99,663 | $ | 96,303 | $ | 92,594 | $ | 81,993 | $ | 80,186 | ||||||||||
General and administrative expenses | $ | 31,963 | $ | 29,782 | $ | 27,930 | $ | 26,434 | $ | 24,677 | ||||||||||
General and administrative expenses as a percentage of net operating income – trailing 12 months | 10.2% | 10.0% | 9.7% | 9.5% | 9.5% | |||||||||||||||
Operating margin | 71% | 70% | 70% | 72% | 72% | |||||||||||||||
Adjusted EBITDA margin | 68% | 68% | 68% | 69% | 70% | |||||||||||||||
Adjusted EBITDA – quarter annualized | $ | 1,239,016 | $ | 1,148,620 | $ | 1,099,908 | $ | 1,063,056 | $ | 1,029,944 | ||||||||||
Adjusted EBITDA – trailing 12 months | $ | 1,137,650 | $ | 1,085,382 | $ | 1,040,449 | $ | 1,004,724 | $ | 966,781 | ||||||||||
Net debt at end of period | $ | 6,870,571 | $ | 6,582,089 | $ | 6,333,459 | $ | 6,154,885 | $ | 5,565,623 | ||||||||||
Net debt to Adjusted EBITDA – quarter annualized | 5.5x | 5.7x | 5.8x | 5.8x | 5.4x | |||||||||||||||
Net debt to Adjusted EBITDA – trailing 12 months | 6.0x | 6.1x | 6.1x | 6.1x | 5.8x | |||||||||||||||
Net debt and preferred stock to Adjusted EBITDA – quarter annualized | 5.5x | 5.7x | 5.8x | 5.8x | 5.5x | |||||||||||||||
Net debt and preferred stock to Adjusted EBITDA – trailing 12 months | 6.0x | 6.1x | 6.1x | 6.2x | 5.8x | |||||||||||||||
Fixed-charge coverage ratio – quarter annualized | 4.5x | 4.2x | 3.9x | 4.2x | 4.5x | |||||||||||||||
Fixed-charge coverage ratio – trailing 12 months | 4.2x | 4.2x | 4.1x | 4.2x | 4.2x | |||||||||||||||
Unencumbered net operating income as a percentage of total net operating income | 95% | 95% | 95% | 94% | 95% | |||||||||||||||
Closing stock price at end of period | $ | 137.06 | $ | 161.58 | $ | 154.04 | $ | 141.09 | $ | 142.56 | ||||||||||
Common shares outstanding (in thousands) at end of period | 124,326 | 120,800 | 113,173 | 111,986 | 111,181 | |||||||||||||||
Total equity capitalization at end of period | $ | 17,040,078 | $ | 19,518,915 | $ | 17,522,382 | $ | 15,887,660 | $ | 15,936,979 | ||||||||||
Total market capitalization at end of period | $ | 24,345,213 | $ | 26,296,394 | $ | 24,260,065 | $ | 22,243,865 | $ | 21,780,482 | ||||||||||
Dividend per share – quarter/annualized | $1.03/$4.12 | $1.03/$4.12 | $1.00/$4.00 | $1.00/$4.00 | $0.97/$3.88 | |||||||||||||||
Dividend payout ratio for the quarter | 58% | 61% | 57% | 58% | 57% | |||||||||||||||
Dividend yield – annualized | 3.0% | 2.5% | 2.6% | 2.8% | 2.7% | |||||||||||||||
Amounts related to operating leases: | ||||||||||||||||||||
Operating lease liabilities | $ | 293,173 | $ | 271,809 | $ | 270,614 | $ | 243,585 | $ | 244,601 | ||||||||||
Rent expense | $ | 4,781 | $ | 4,609 | $ | 4,705 | $ | 4,482 | $ | 4,492 | ||||||||||
Capitalized interest | $ | 24,680 | $ | 23,822 | $ | 24,558 | $ | 21,674 | $ | 18,509 | ||||||||||
Weighted-average interest rate for capitalization of interest during the period | 3.80% | 3.88% | 4.00% | 4.14% | 3.96% | |||||||||||||||
Financial and Asset Base Highlights (continued) | |
March 31, 2020 | |
(Dollars in thousands, except annual rental revenue per occupied RSF amounts) | |
Three Months Ended (unless stated otherwise) | ||||||||||||||||||||
3/31/20 | 12/31/19 | 9/30/19 | 6/30/19 | 3/31/19 | ||||||||||||||||
Amounts included in funds from operations and non-revenue-enhancing capital expenditures | ||||||||||||||||||||
Straight-line rent revenue | $ | 20,597 | $ | 24,400 | $ | 27,394 | $ | 25,476 | $ | 26,965 | ||||||||||
Amortization of acquired below-market leases | $ | 15,964 | $ | 8,837 | $ | 5,774 | $ | 8,054 | $ | 7,148 | ||||||||||
Straight-line rent expense on ground leases | $ | 171 | $ | 219 | $ | 320 | $ | 226 | $ | 246 | ||||||||||
Stock compensation expense | $ | 9,929 | $ | 10,239 | $ | 10,935 | $ | 11,437 | $ | 11,029 | ||||||||||
Amortization of loan fees | $ | 2,247 | $ | 2,241 | $ | 2,251 | $ | 2,380 | $ | 2,233 | ||||||||||
Amortization of debt premiums | $ | 888 | $ | 907 | $ | 1,287 | $ | 782 | $ | 801 | ||||||||||
Non-revenue-enhancing capital expenditures: | ||||||||||||||||||||
Building improvements | $ | 3,198 | $ | 3,295 | $ | 2,901 | $ | 2,876 | $ | 2,381 | ||||||||||
Tenant improvements and leasing commissions | $ | 12,923 | $ | 14,648 | $ | 11,964 | $ | 13,901 | $ | 8,709 | ||||||||||
Operating statistics and related information (at end of period) | ||||||||||||||||||||
Number of properties – North America | 302 | 291 | 269 | 257 | 250 | |||||||||||||||
RSF – North America (including development and redevelopment projects under construction) | 30,924,356 | 29,098,433 | 27,288,263 | 26,321,122 | 25,323,299 | |||||||||||||||
Total square feet – North America | 41,514,374 | 39,170,786 | 38,496,276 | 37,120,560 | 33,688,294 | |||||||||||||||
Annual rental revenue per occupied RSF – North America | $ | 51.18 | $ | 51.04 | $ | 51.00 | $ | 50.27 | $ | 49.56 | ||||||||||
Occupancy of operating properties – North America | 95.1% | (1) | 96.8% | 96.6% | 97.4% | 97.2% | ||||||||||||||
Occupancy of operating and redevelopment properties – North America | 92.9% | 94.4% | 94.5% | 96.4% | 95.5% | |||||||||||||||
Weighted-average remaining lease term (in years) | 7.8 | 8.1 | 8.3 | 8.4 | 8.4 | |||||||||||||||
Total leasing activity – RSF | 703,355 | 1,752,124 | 1,241,677 | 819,949 | 1,248,972 | |||||||||||||||
Lease renewals and re-leasing of space – change in average new rental rates over expiring rates: | ||||||||||||||||||||
Rental rate increases | 46.3% | 37.0% | 27.9% | 32.5% | 32.9% | |||||||||||||||
Rental rate increases (cash basis) | 22.3% | 21.7% | 11.2% | 17.8% | 24.3% | |||||||||||||||
RSF (included in total leasing activity above) | 557,367 | 571,650 | 758,113 | 587,930 | 509,415 | |||||||||||||||
Same property – percentage change over comparable quarter from prior year: | ||||||||||||||||||||
Net operating income increase | 2.4% | 2.0% | 2.5% | 4.3% | 2.3% | |||||||||||||||
Net operating income increase (cash basis) | 6.1% | 4.0% | 5.7% | 9.5% | 10.2% | |||||||||||||||
(1) | Refer to “Occupancy” in this Supplemental Information for additional details. |
| |
High-Quality, Diverse, and Innovative Tenants | |
March 31, 2020 | |
Long-Duration Cash Flows From High-Quality, Diverse, and
Innovative Tenants
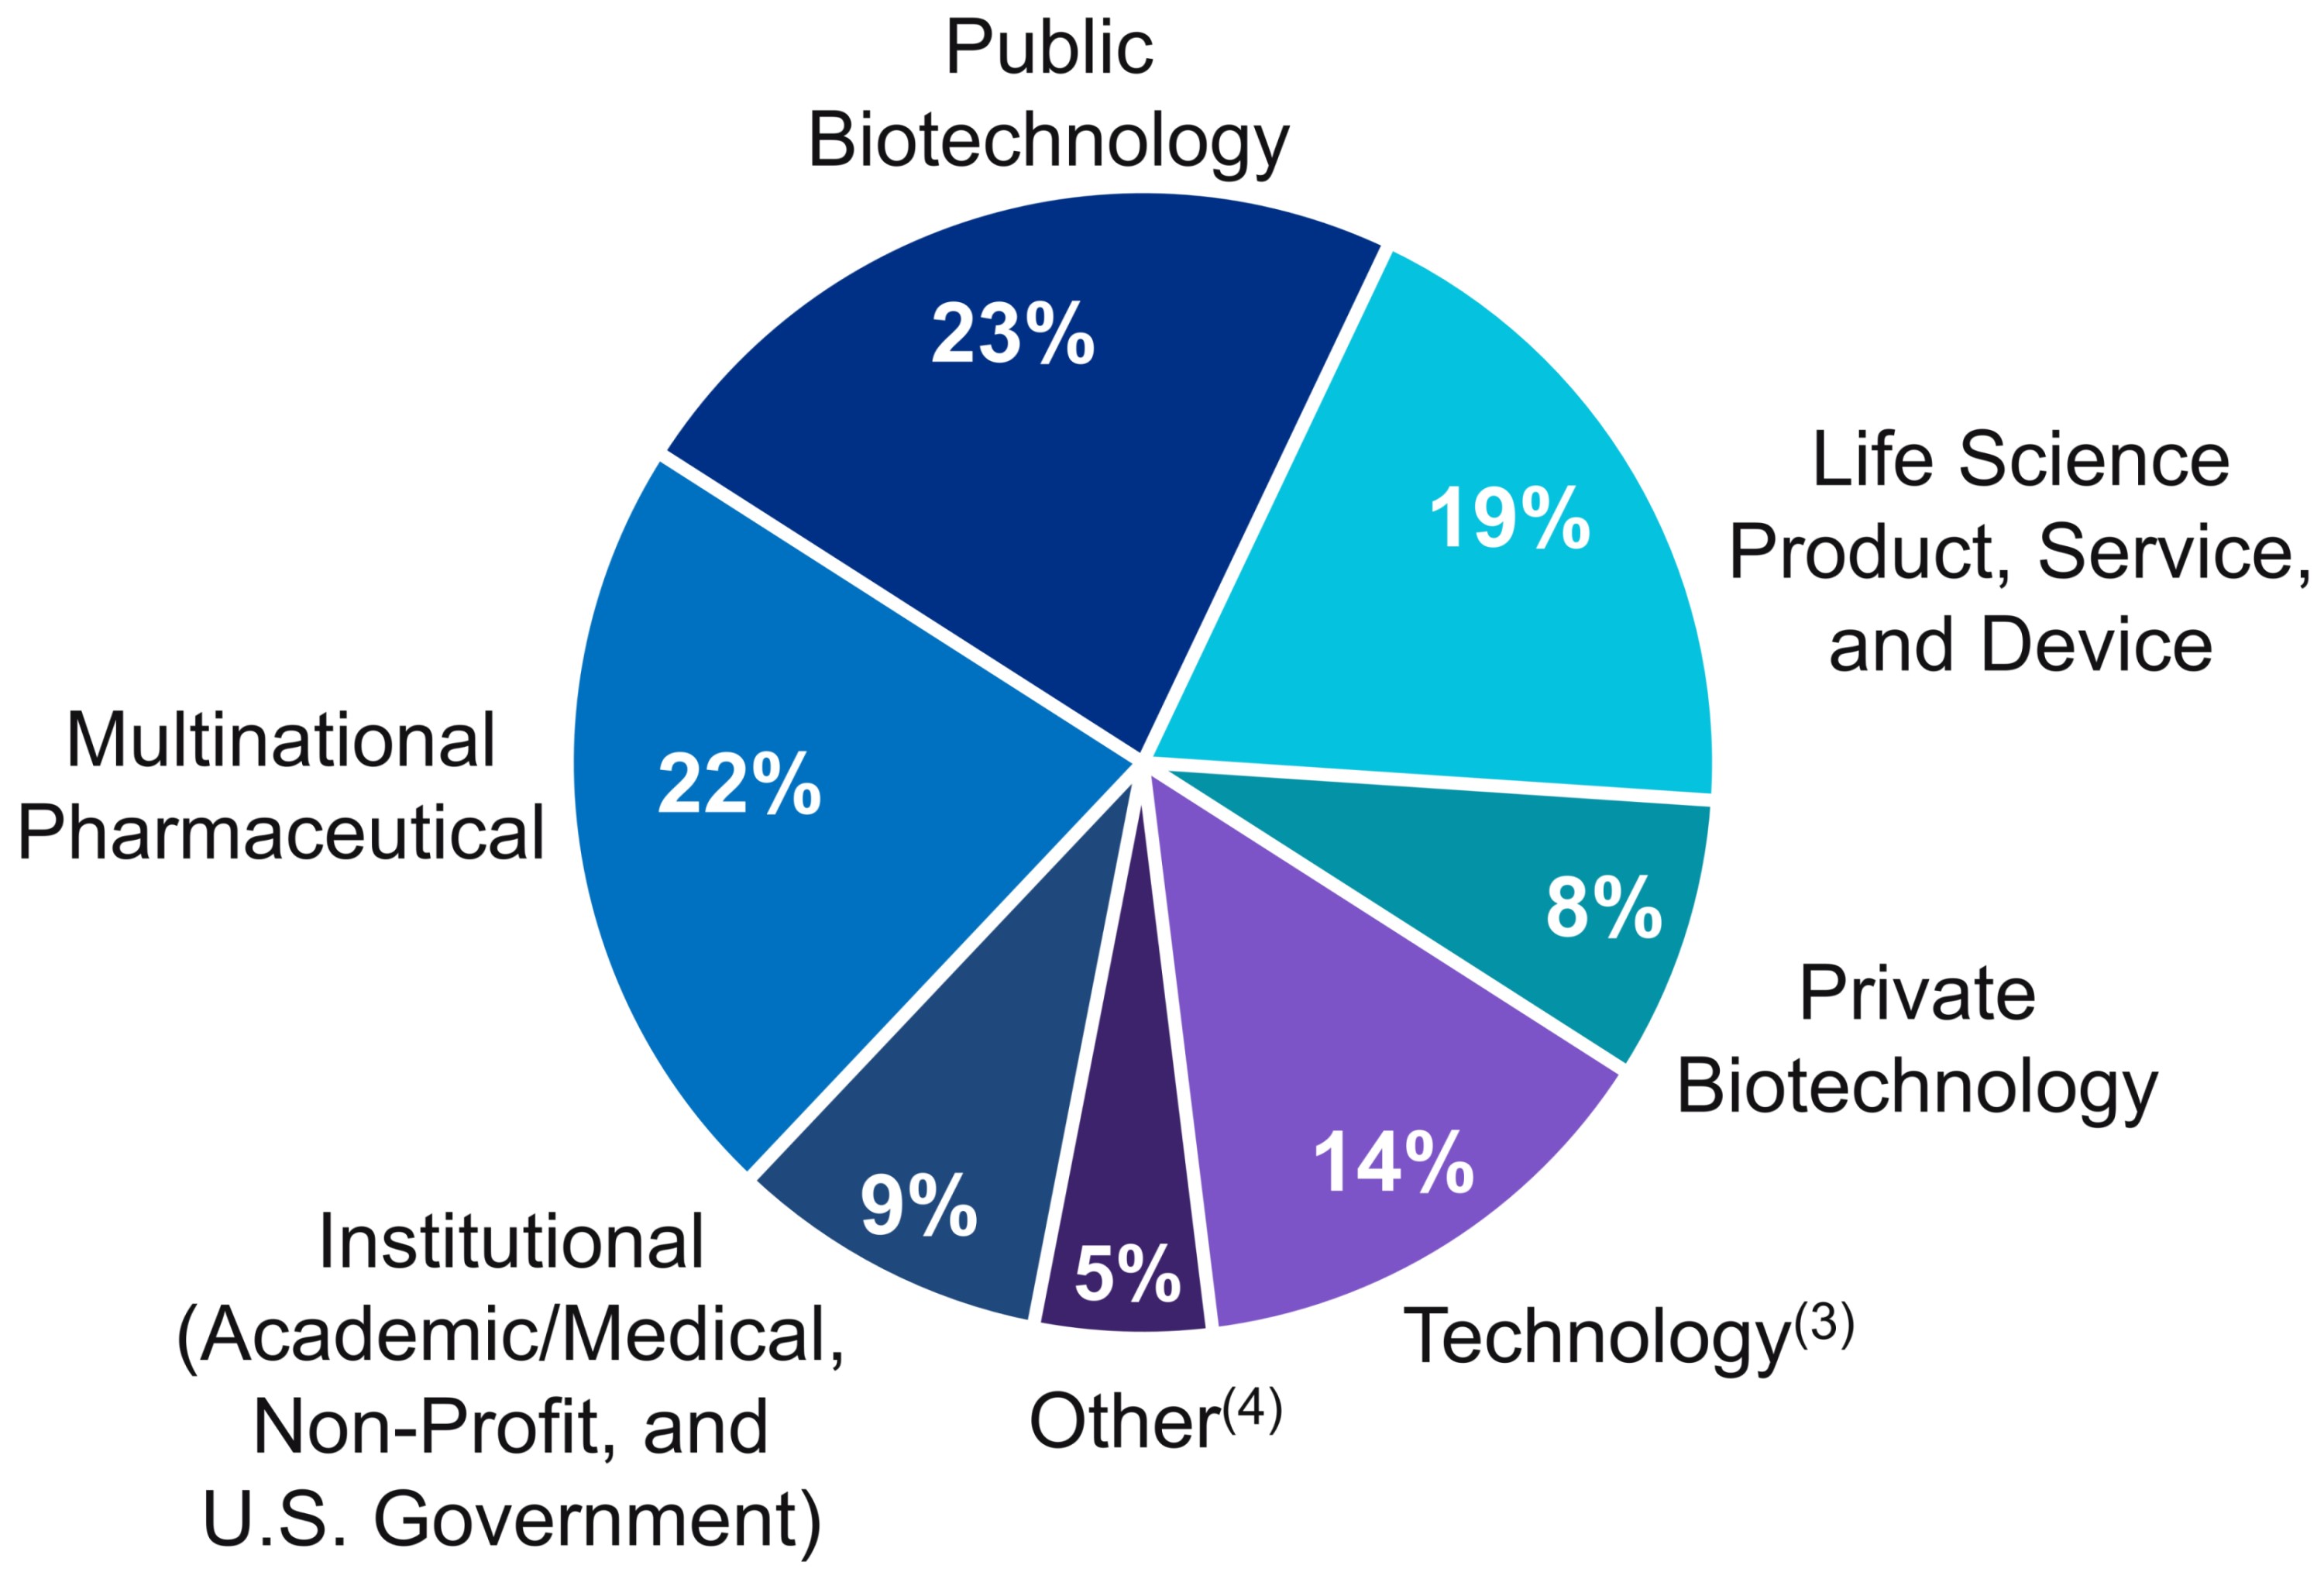
Investment-Grade or Publicly Traded Large Cap Tenants | Tenant Mix | ||||
 | |||||
51% | |||||
of ARE’s Annual Rental Revenue(1) | |||||
Long-Duration Lease Terms | |||||
7.8 Years | |||||
Weighted-Average Remaining Term(2) | |||||
Percentage of ARE’s Annual Rental Revenue(1) | |||||
(1) | Represents annual rental revenue in effect as of March 31, 2020. |
(2) | Based on aggregate annual rental revenue in effect as of March 31, 2020. Refer to “Annual Rental Revenue” in the “Definitions and Reconciliations” of this Supplemental Information for additional details on our methodology on annual rental revenue from unconsolidated real estate joint ventures. |
(3) | 66% of our annual rental revenue for technology tenants is from investment-grade or publicly traded large cap tenants. |
(4) | Our other tenants, aggregating 5.0% of our annual rental revenue, comprise 4.2% of annual rental revenue from Professional Services, Finance, Telecommunications, and Construction/Real Estate companies and only 0.8% from retail‑related tenants. |
| |
Class A Properties in AAA Locations | |
March 31, 2020 | |
High-Quality Cash Flows From Class A Properties in AAA Locations
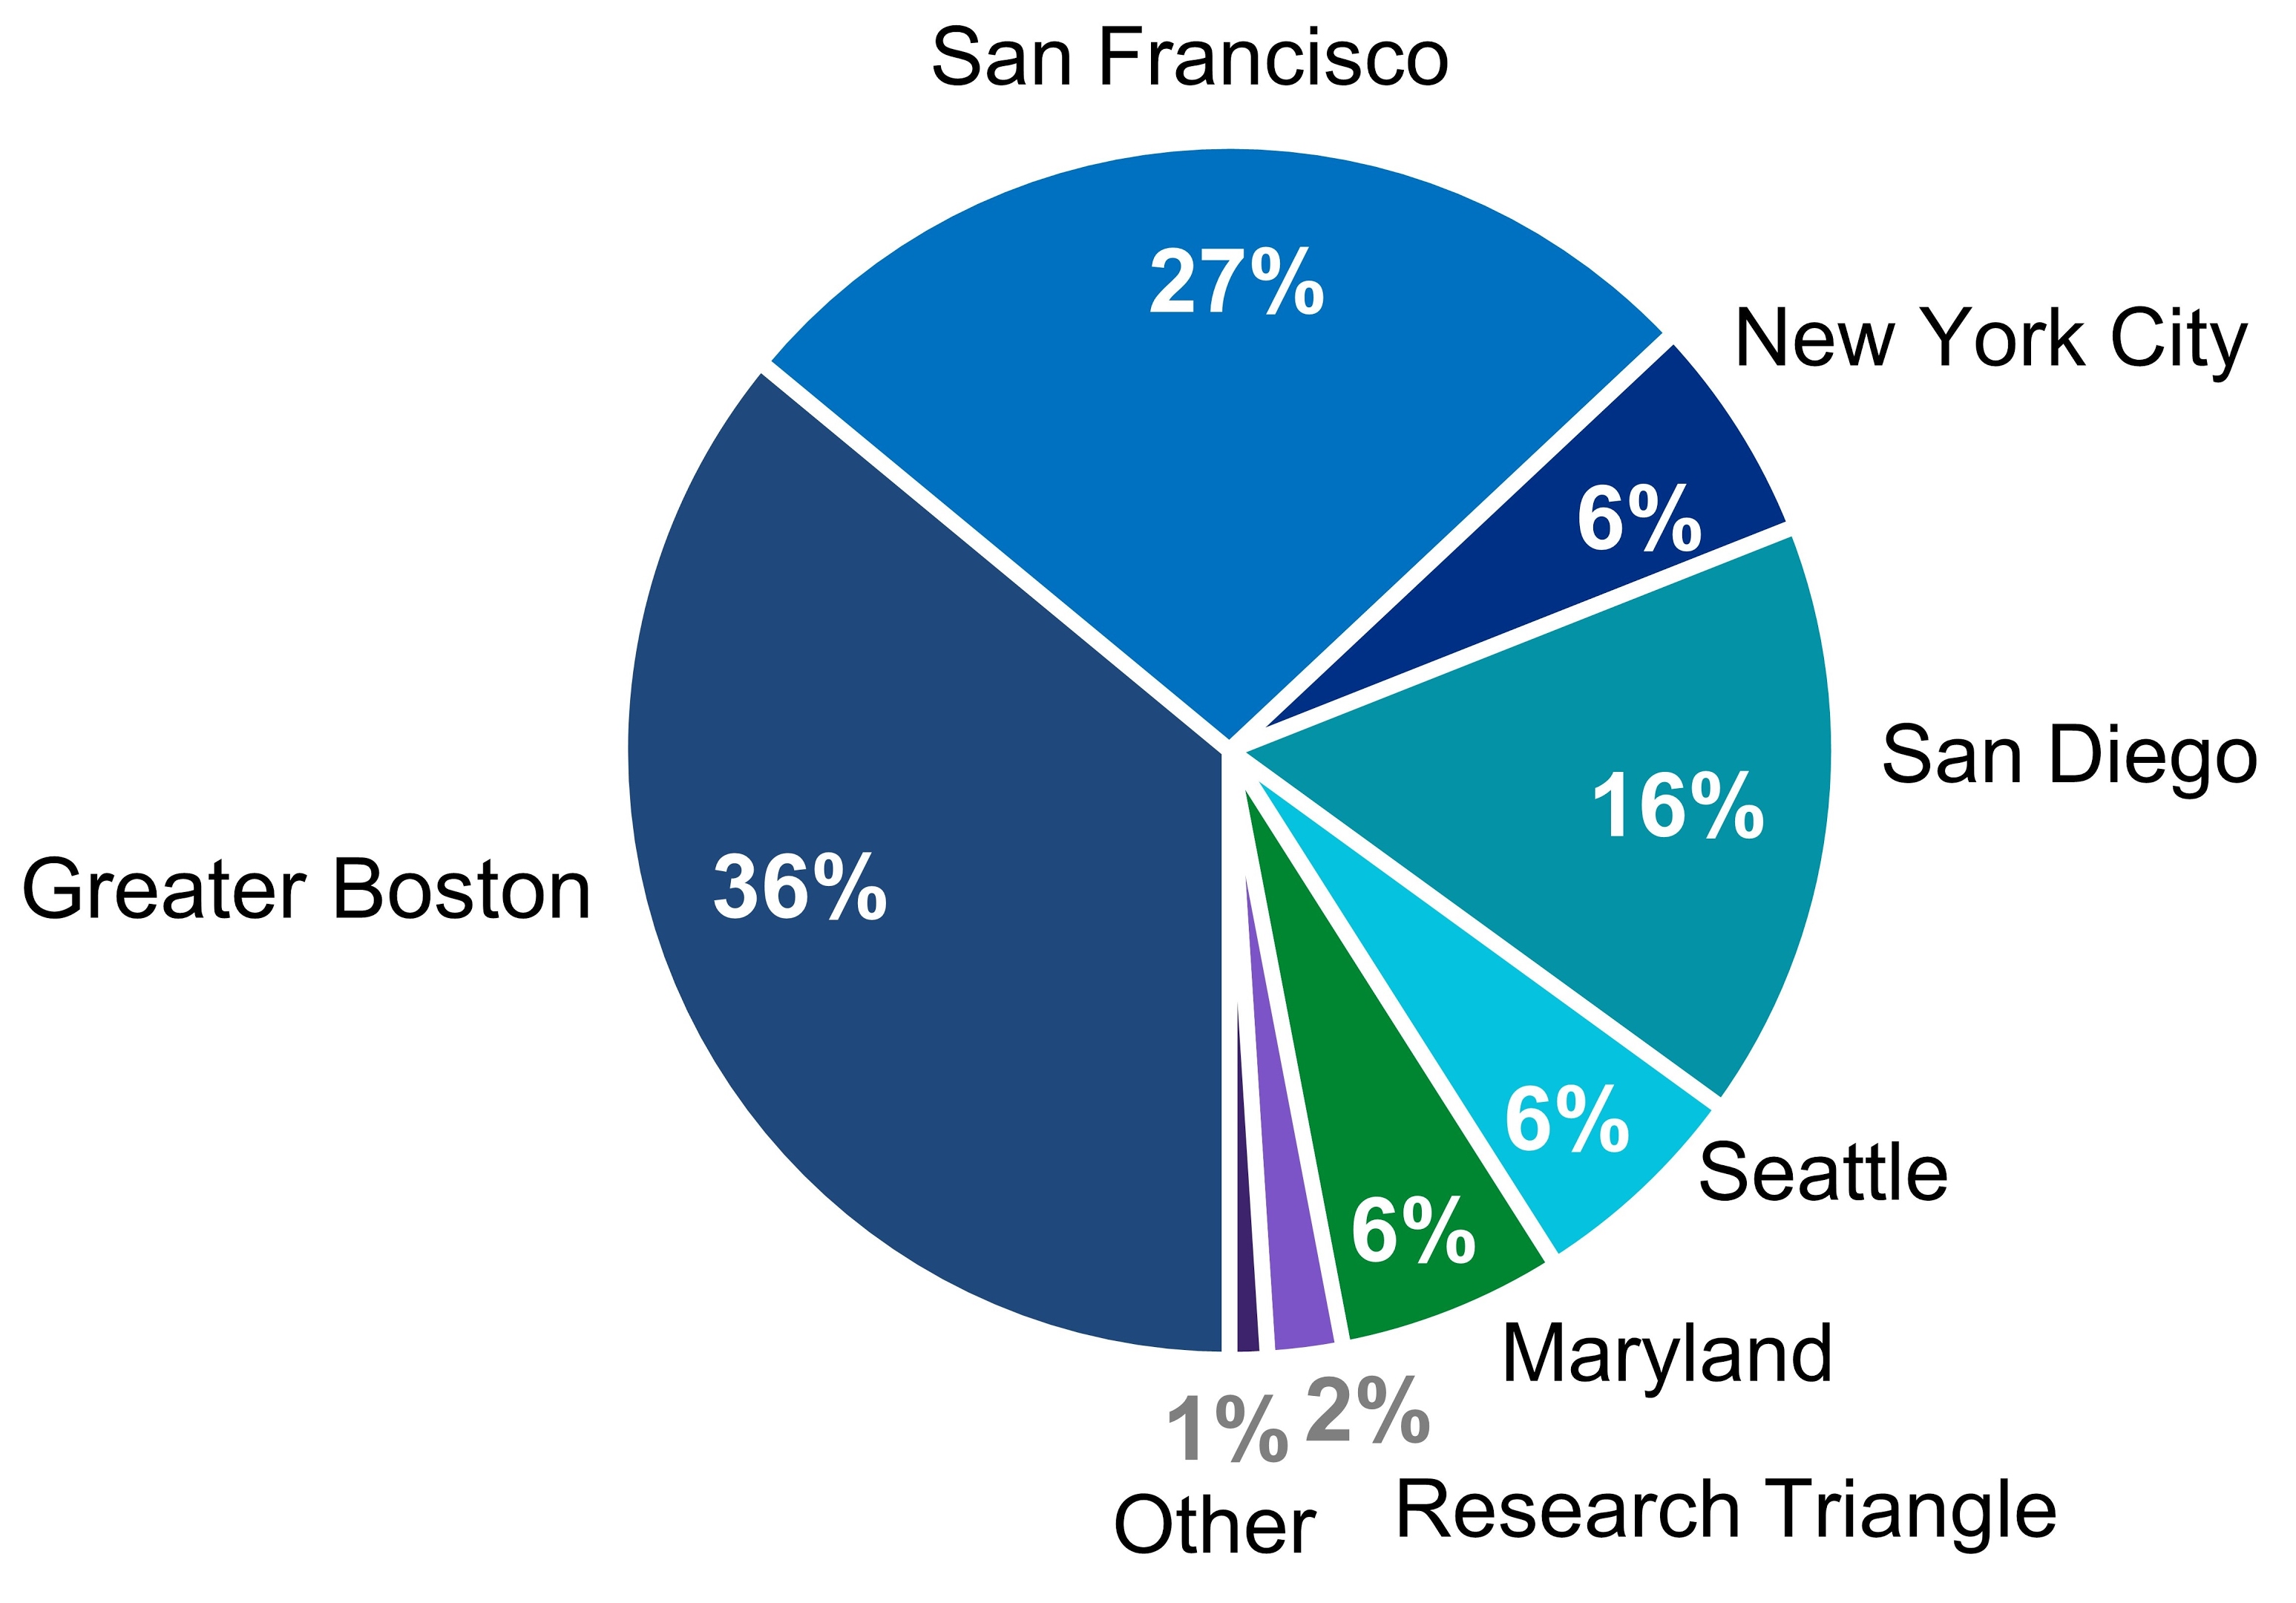
Class A Properties in AAA Locations | AAA Locations | |||
 | ||||
74% | ||||
of ARE’s | ||||
Annual Rental Revenue(1) | ||||
Percentage of ARE’s Annual Rental Revenue(1) | ||||
(1) | Represents annual rental revenue in effect as of March 31, 2020. |
| |
Occupancy | |
March 31, 2020 | |
Solid Historical Occupancy(1) | Occupancy Across Key Locations(2) | |||
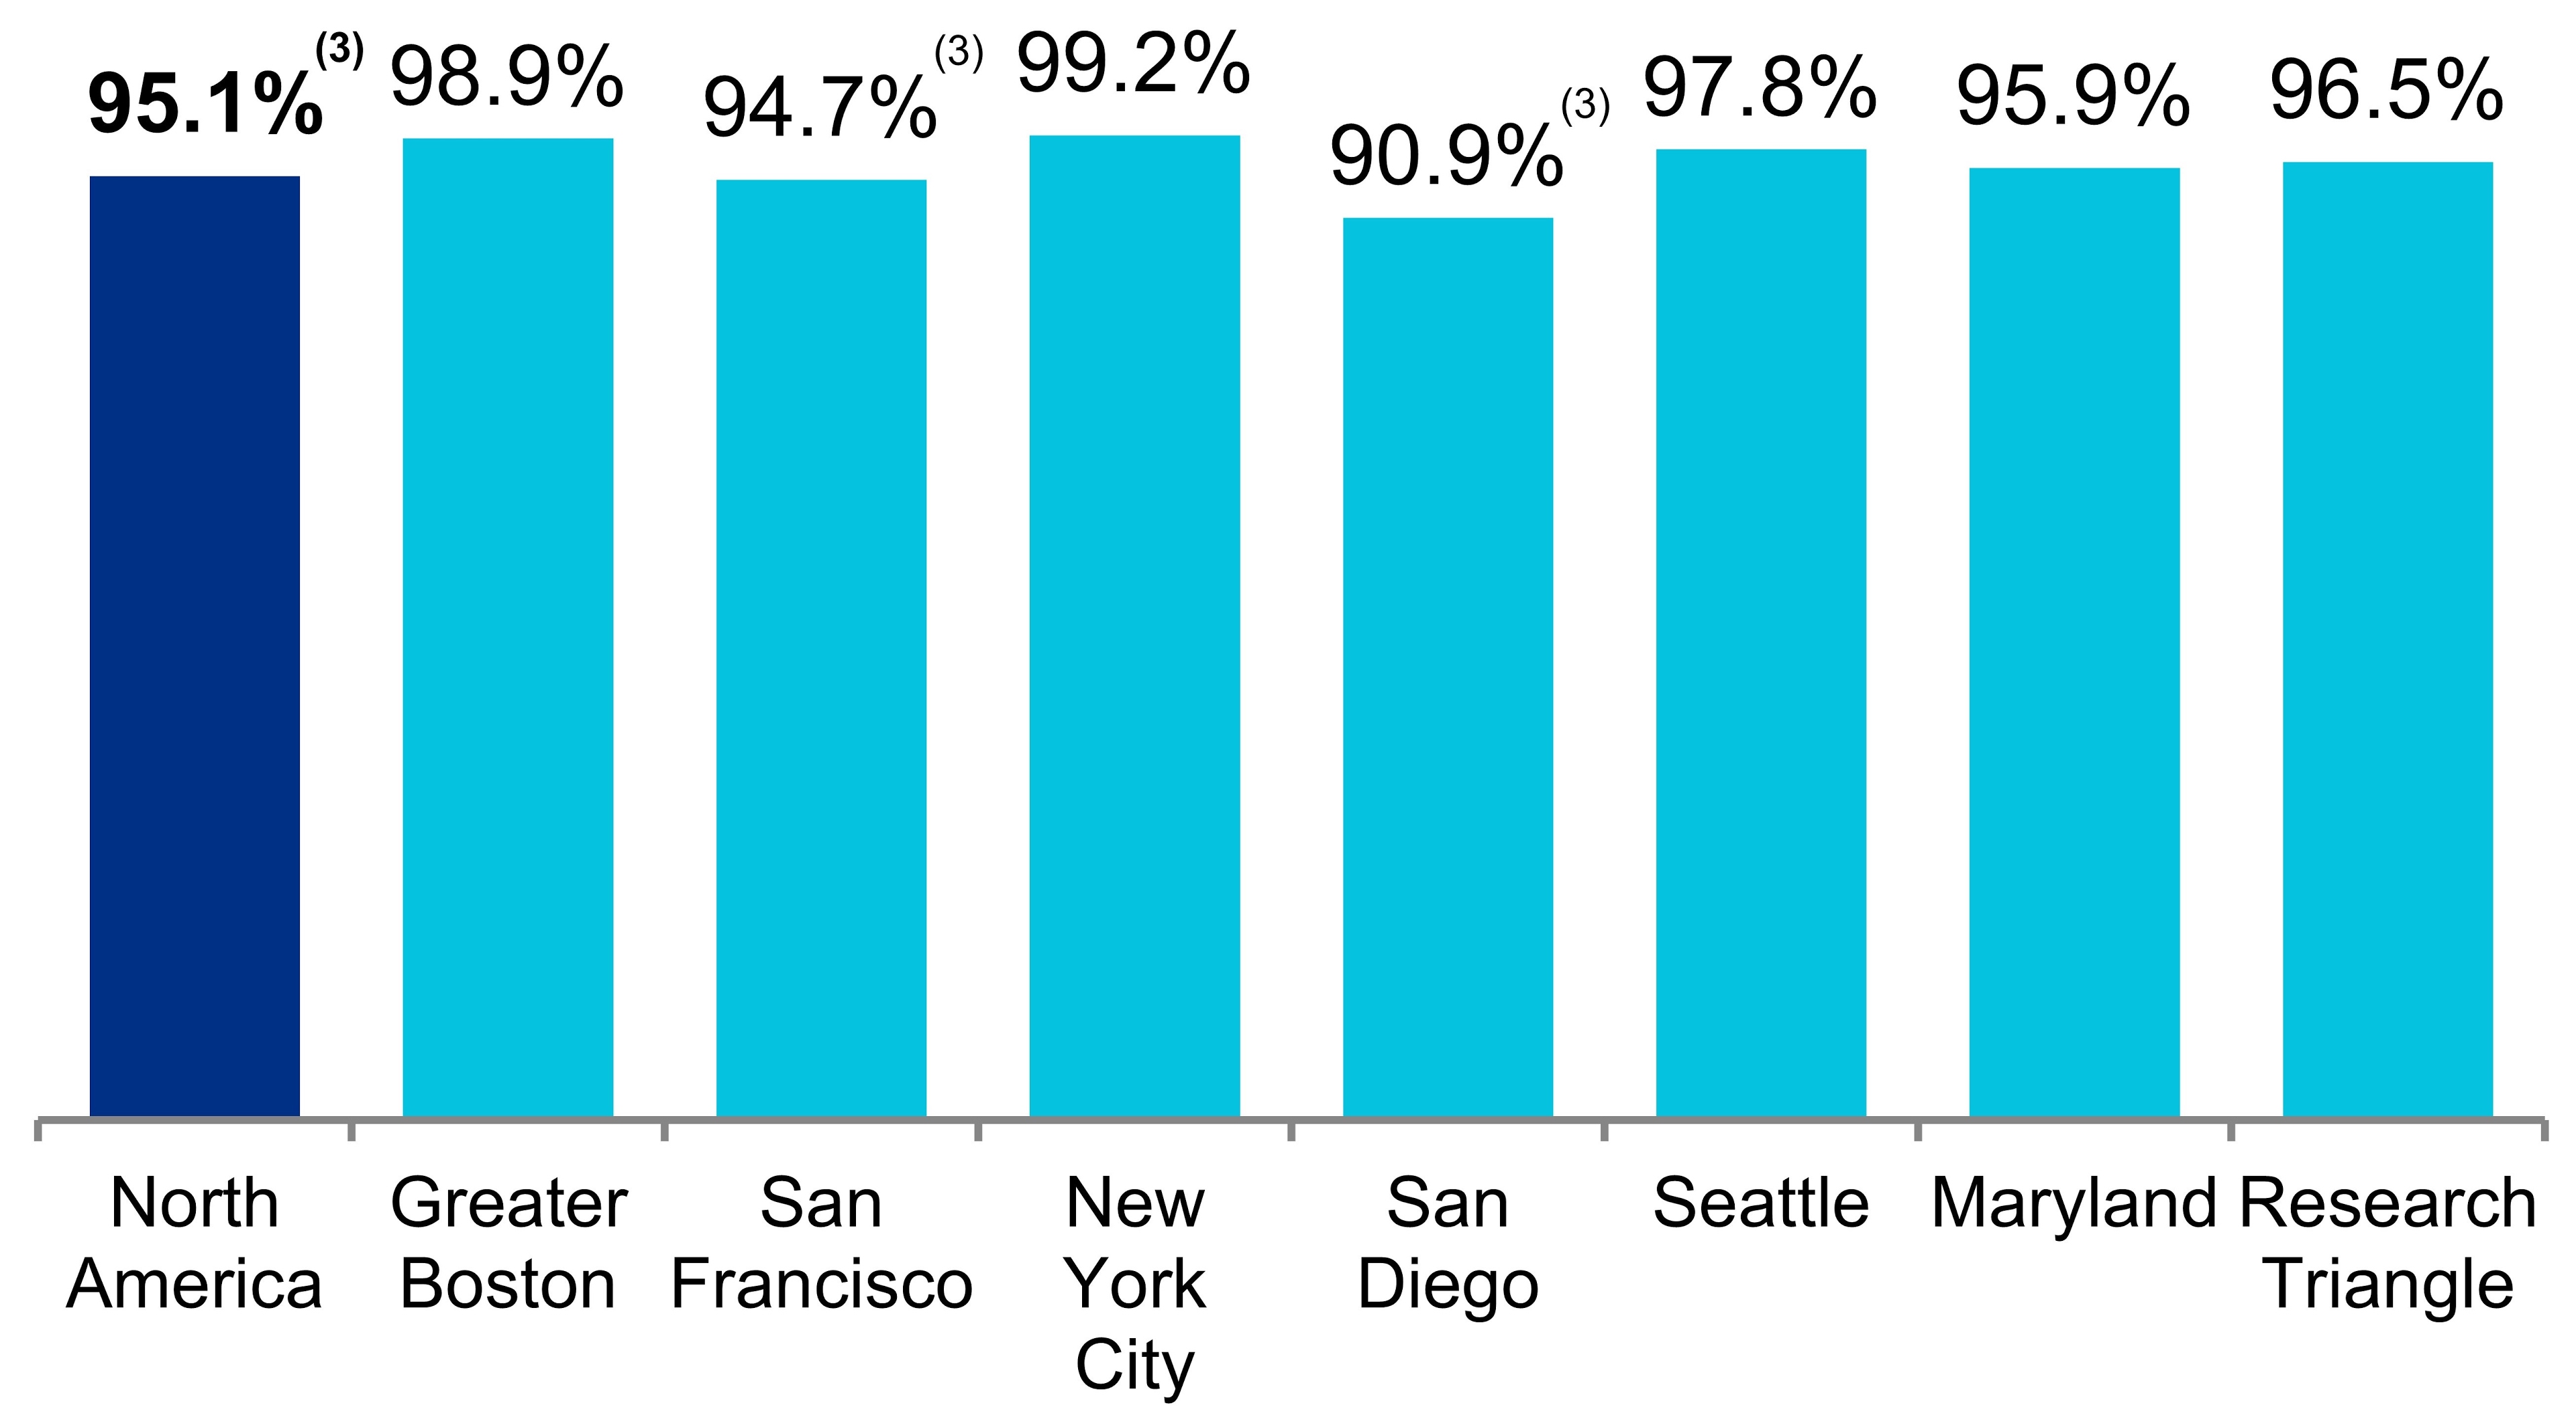 | ||||
96% | ||||
Over 10 Years | ||||
(1) | Represents average occupancy of operating properties in North America as of each December 31 for the last 10 years and as of March 31, 2020. |
(2) | As of March 31, 2020. |
(3) | Includes 686,988 RSF, or 2.4%, of vacancy in our North America markets (noted below), representing lease-up opportunities at properties recently acquired. Excluding these vacancies, occupancy of operating properties in North America was 97.5% as of March 31, 2020. Projected occupancy for 2Q20 includes 704,351 RSF, or 2.4%, of vacancy from these recently acquired properties. Refer to “Acquisitions” in our Earnings Press Release for additional details. |
1Q20 | 2Q20 (projected) | |||||||||||||||||||
Vacant | Occupancy Impact | Vacant | Occupancy Impact | |||||||||||||||||
Property | Submarket/Market | RSF | Region | Consolidated | RSF | Region | Consolidated | |||||||||||||
601, 611, and 651 Gateway Boulevard | South San Francisco/San Francisco | 203,492 | 2.6 | % | 0.7 | % | 198,528 | 2.5 | % | 0.7 | % | |||||||||
SD Tech by Alexandria | Sorrento Mesa/San Diego | 221,845 | 3.7 | % | 0.8 | 215,986 | 3.6 | % | 0.7 | |||||||||||
5505 Morehouse Drive | Sorrento Mesa/San Diego | 71,016 | 1.2 | % | 0.2 | 71,016 | 1.2 | % | 0.2 | |||||||||||
Other acquisitions | Various | 190,635 | N/A | 0.7 | 218,821 | N/A | 0.8 | |||||||||||||
686,988 | 2.4 | % | 704,351 | 2.4 | % | |||||||||||||||
| |
Key Operating Metrics | |
March 31, 2020 | |
Historical Same Property Net Operating Income | Favorable Lease Structure(1) | ||||||||||
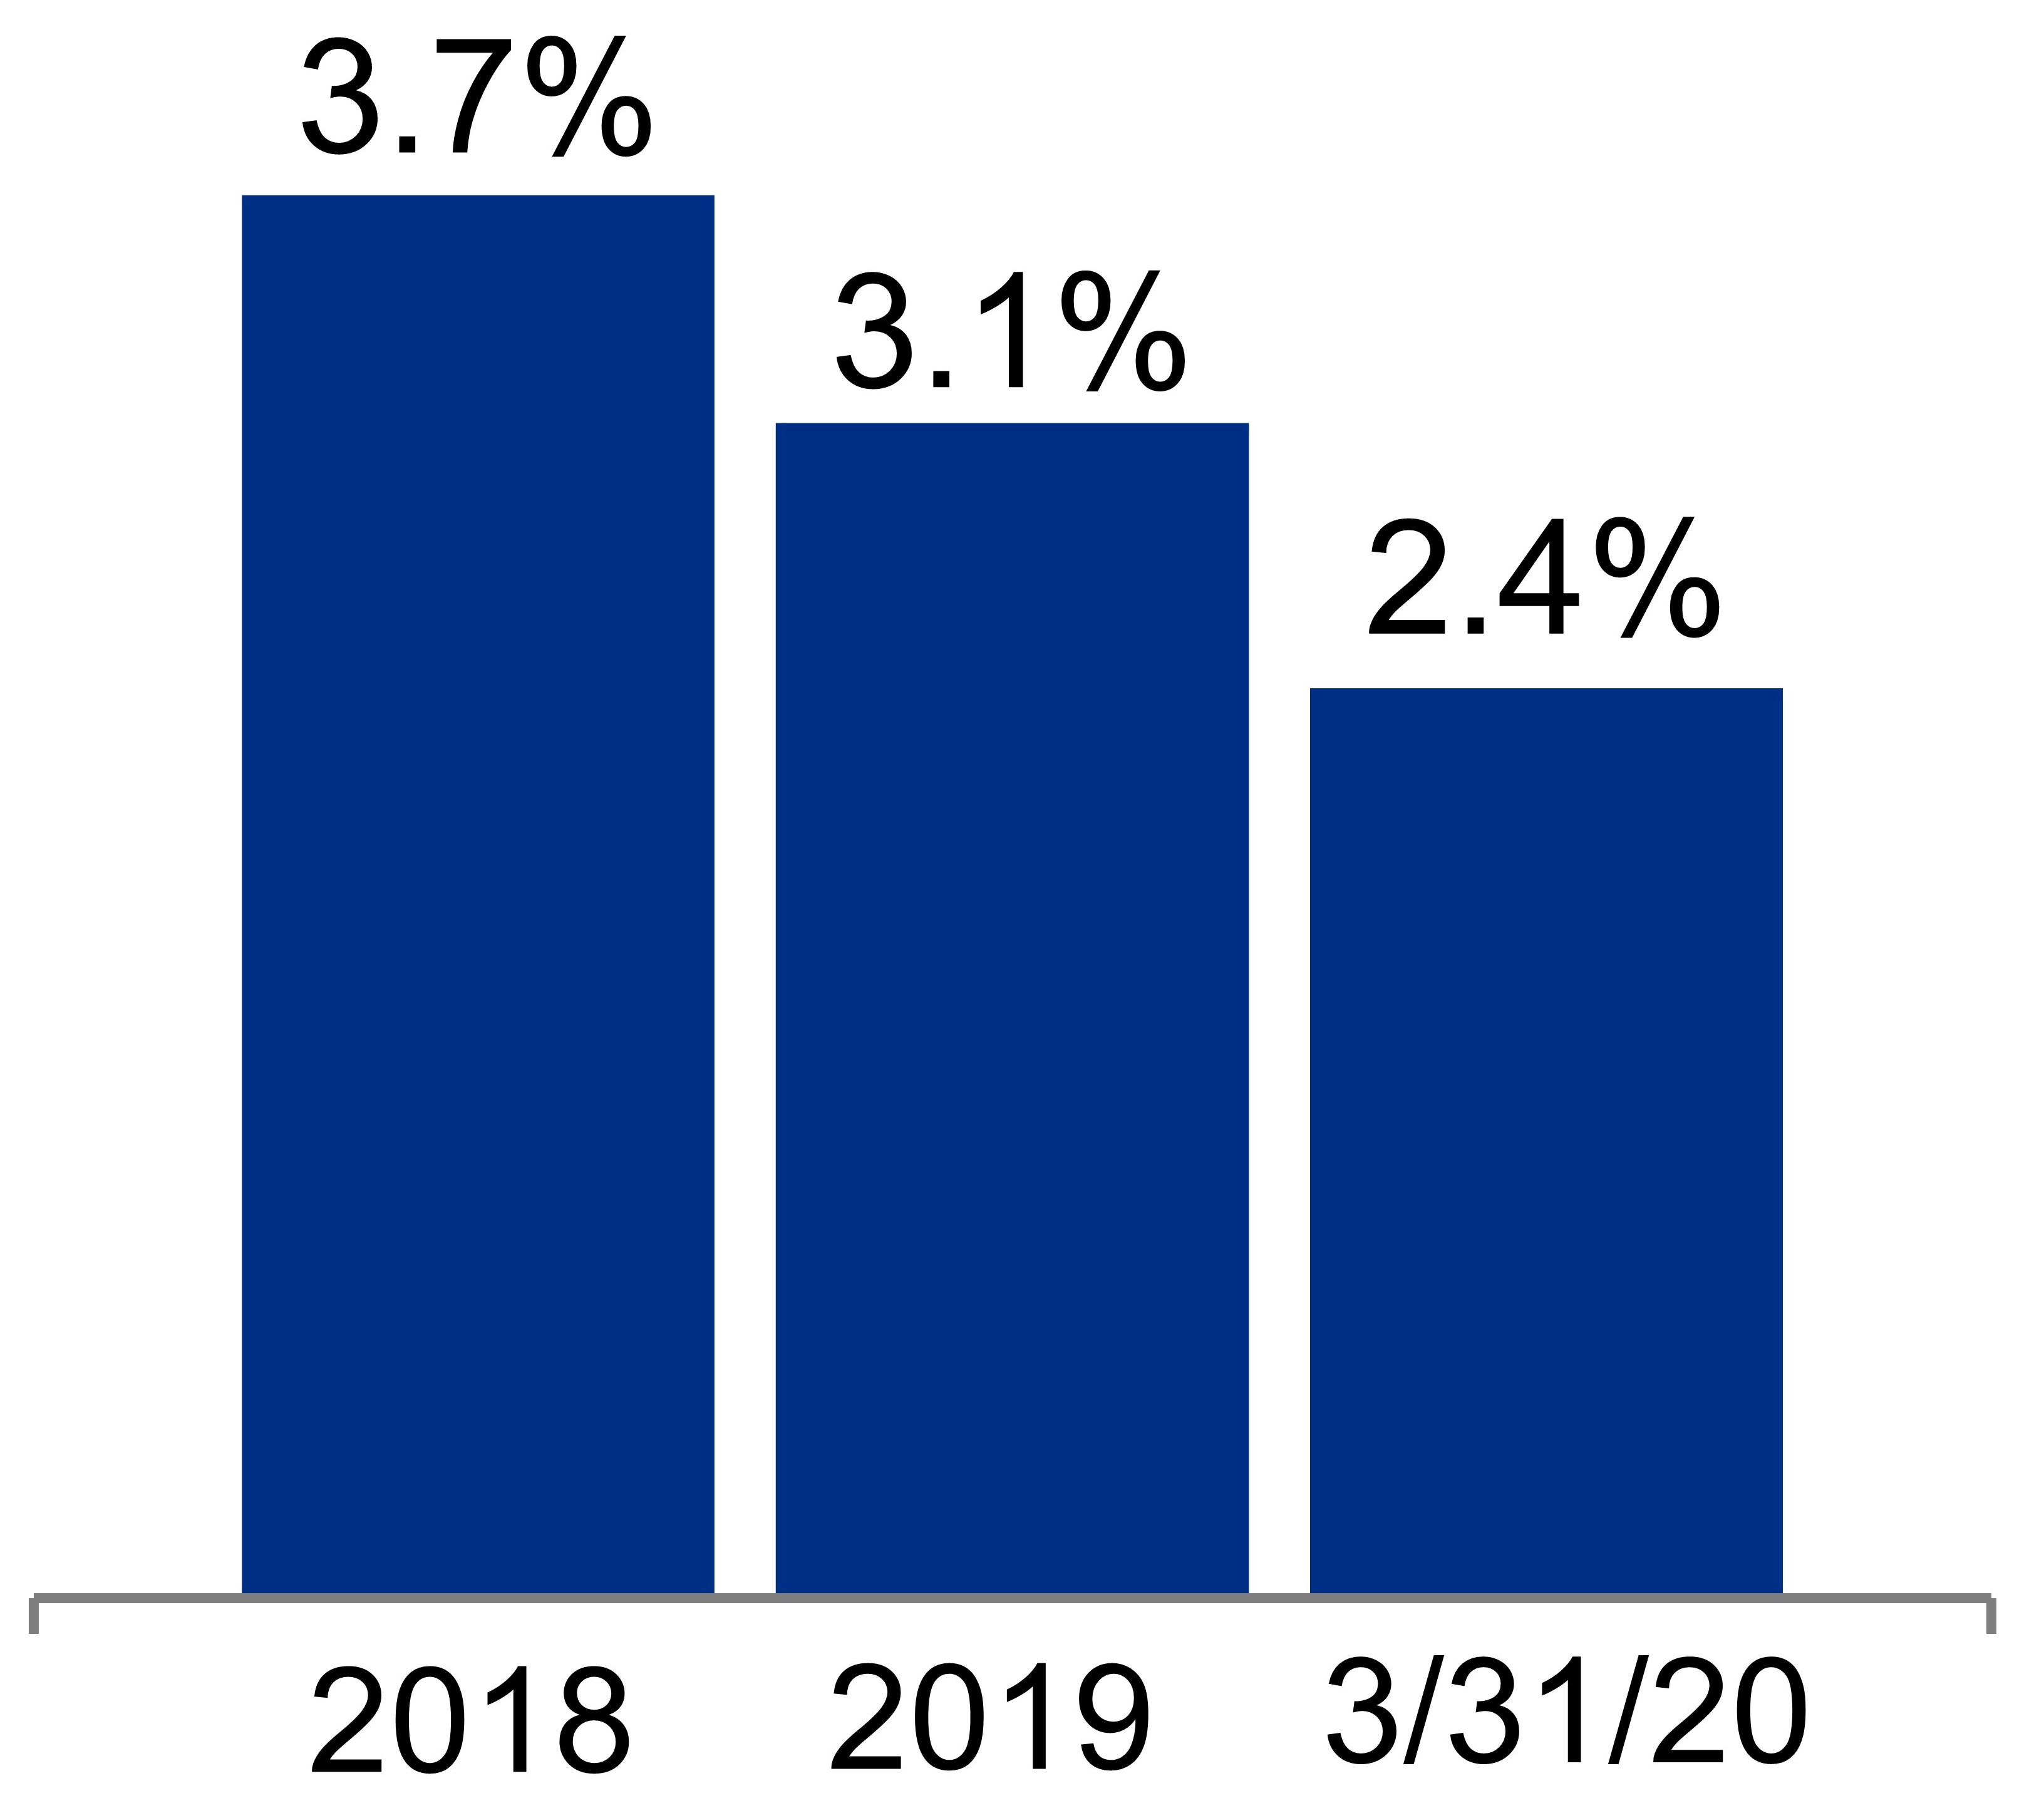 | 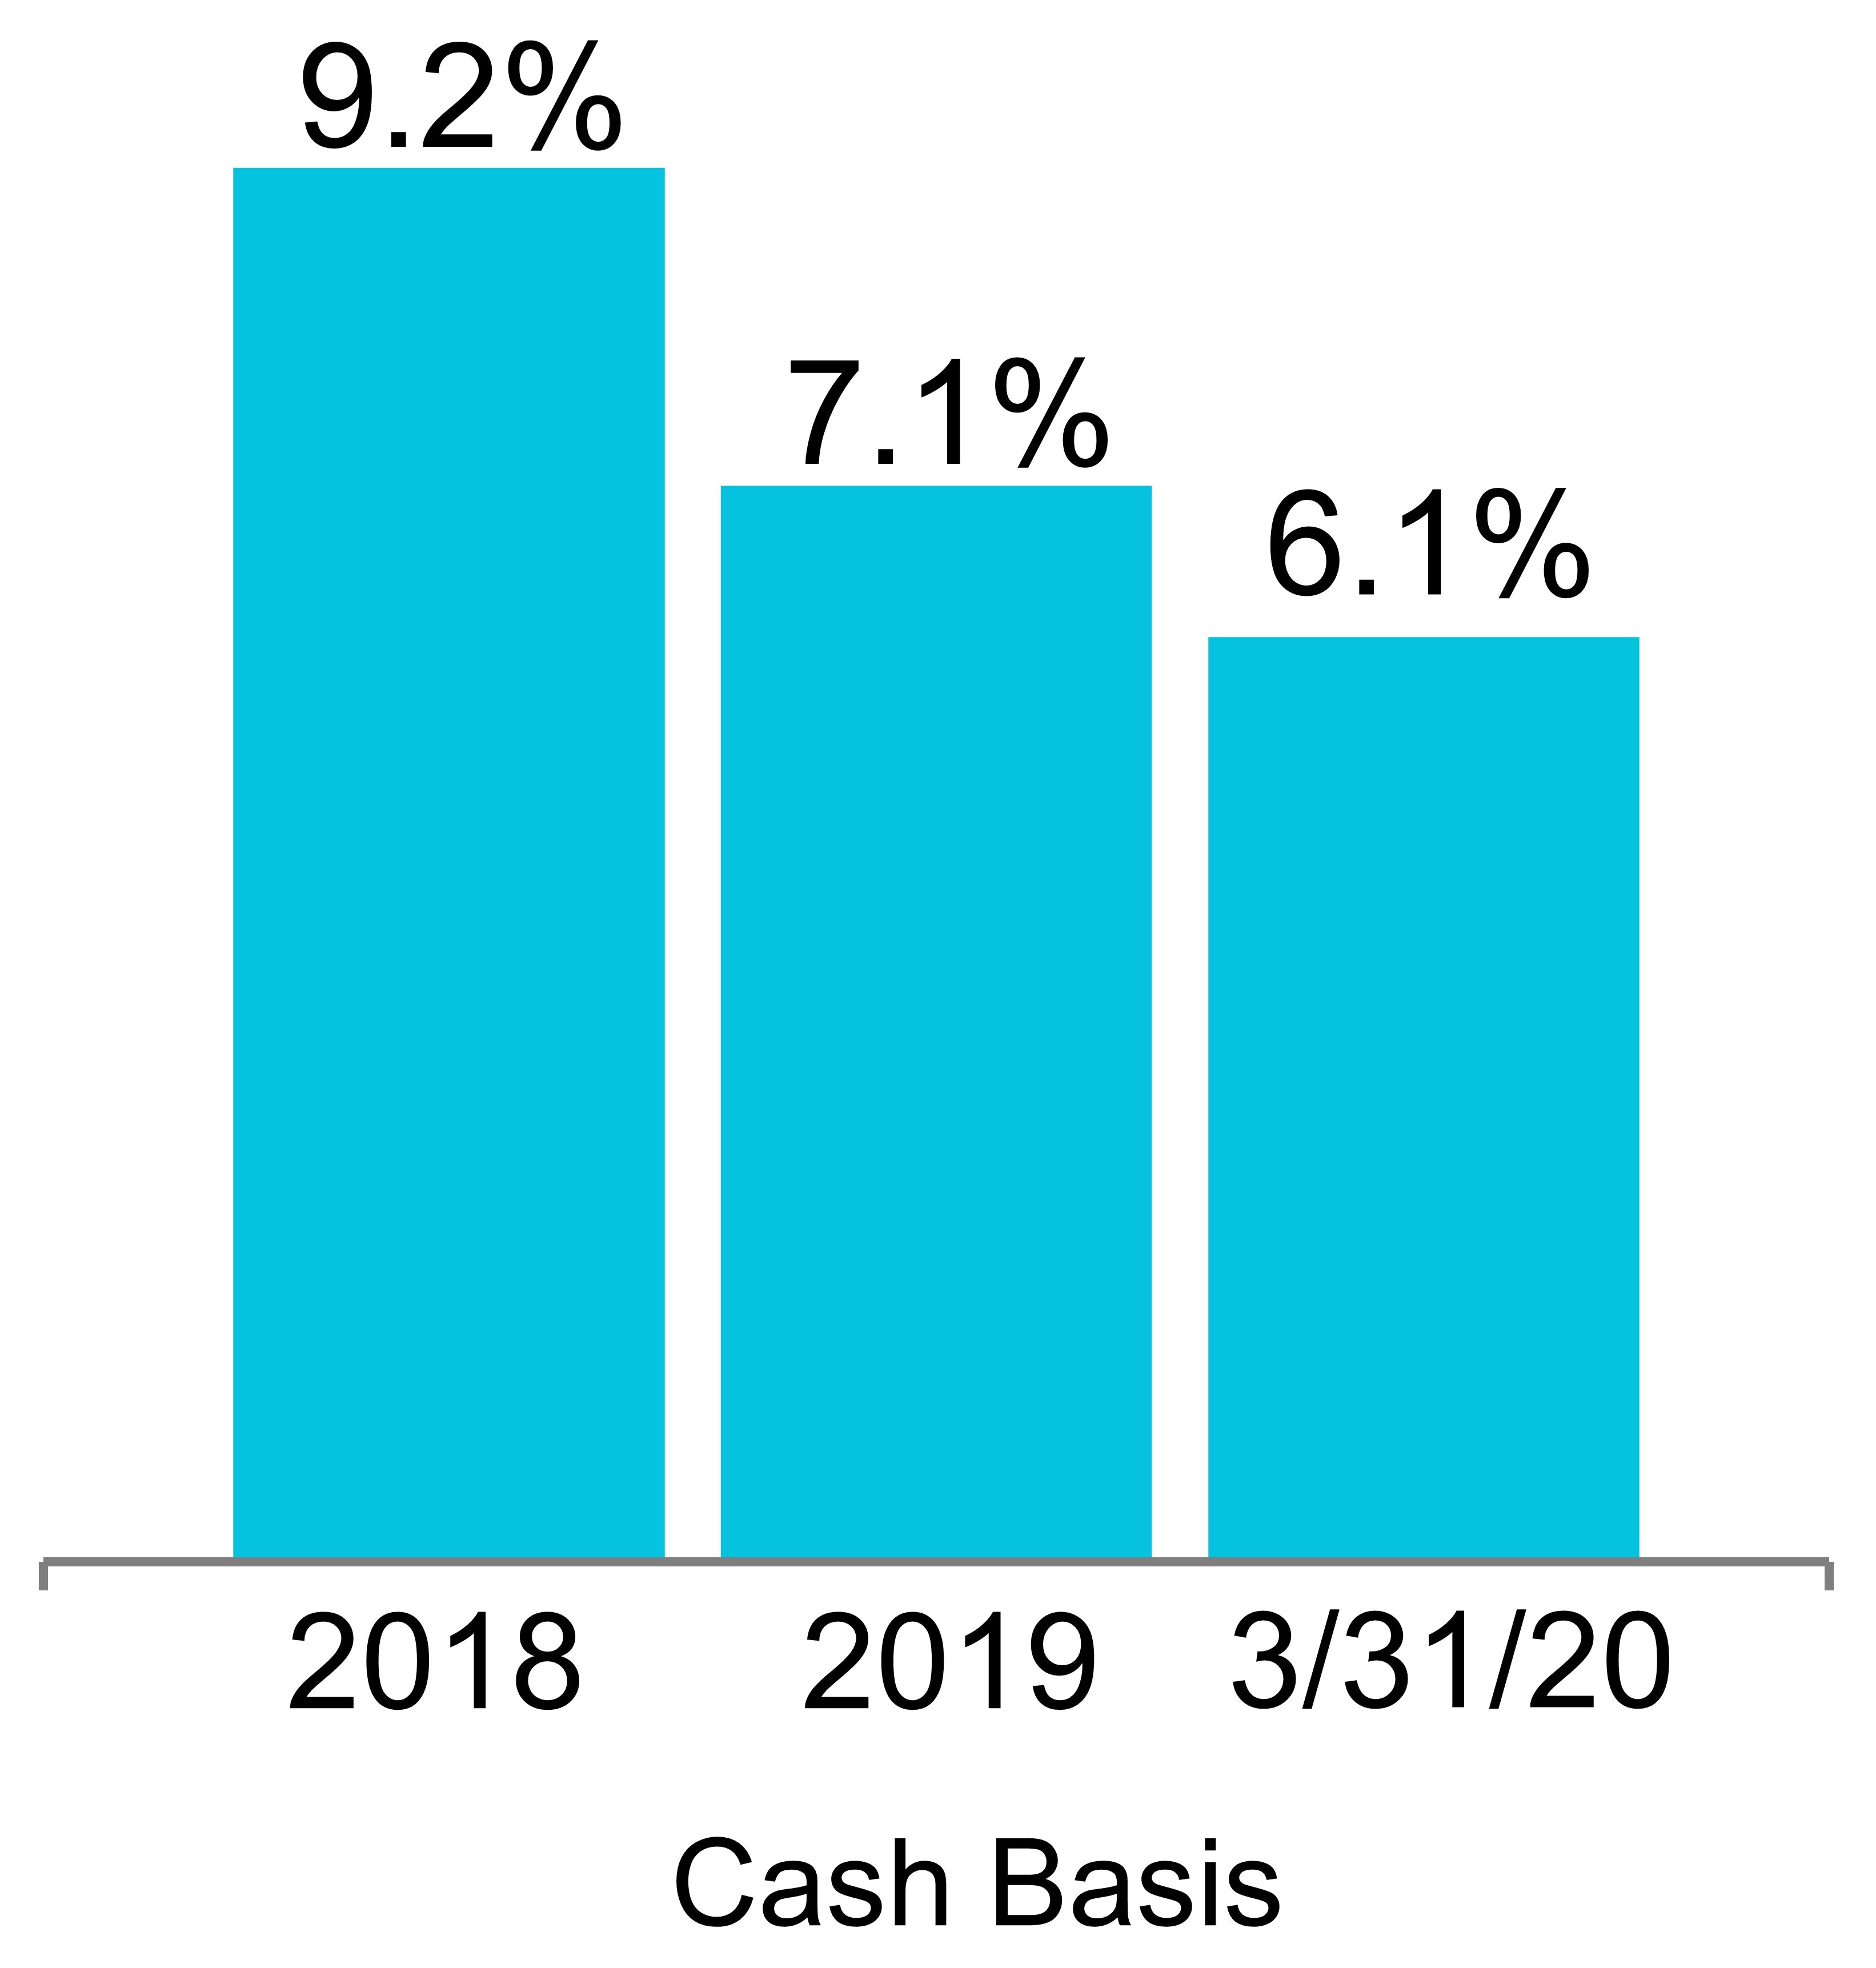 | Strategic Lease Structure by Owner and Operator of Collaborative Life Science, Technology, and AgTech Campuses | |||||||||
Increasing cash flows | |||||||||||
Percentage of leases containing annual rent escalations | 95 | % | |||||||||
Stable cash flows | |||||||||||
Percentage of triple net leases | 93 | % | (2) | ||||||||
Lower capex burden | |||||||||||
Percentage of leases providing for the recapture of capital expenditures | 92 | % | (2) | ||||||||
Historical Rental Rates: Renewed/Re-Leased Space | Margins(3) | ||||||||||
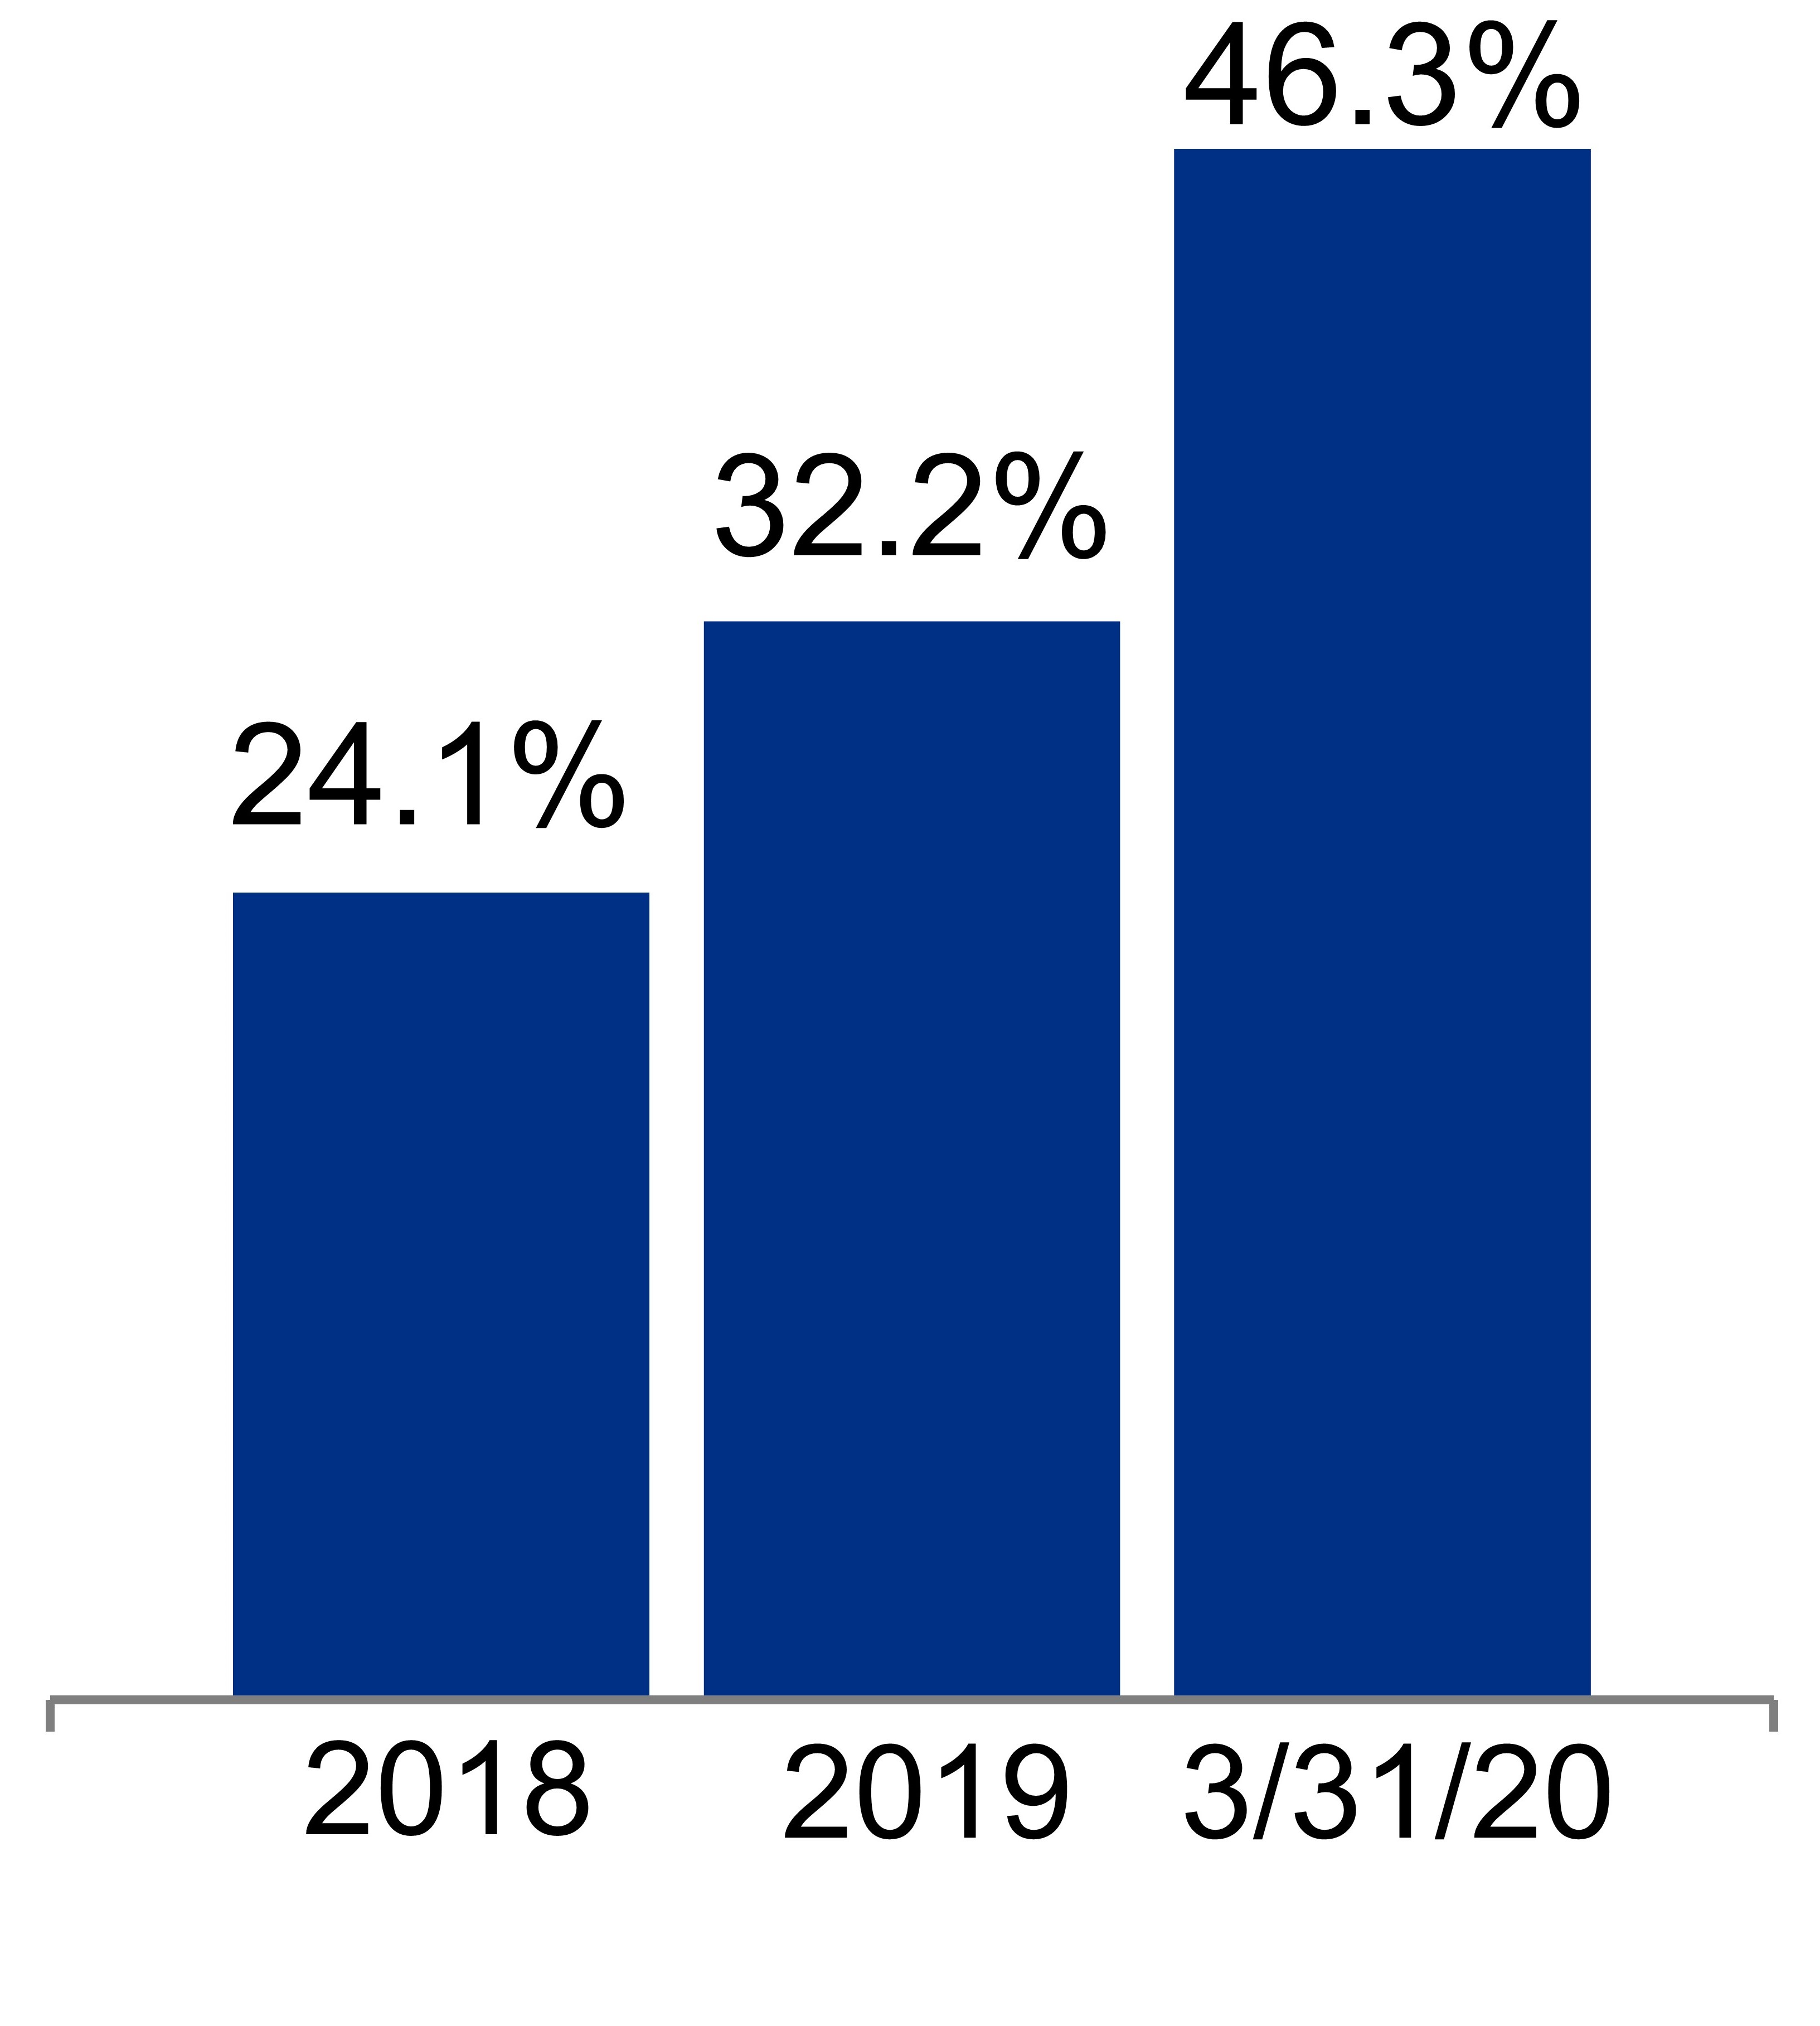 |  | ||||||||||
Operating | Adjusted EBITDA | ||||||||||
71% | 68% | ||||||||||
(1) | Percentages calculated based on RSF as of March 31, 2020. |
(2) | Includes 1.1 million RSF of full service gross leases related to properties that were acquired in 1Q20. Excluding these leases, the percentage of triple net leases and percentage of leases providing for the recapture of capital expenditures were 97% and 96%, respectively. |
(3) | Represents percentages for the three months ended March 31, 2020. |
Same Property Performance | |
March 31, 2020 | |
(Dollars in thousands) | |
Three Months Ended | Three Months Ended | |||||
Same Property Financial Data | March 31, 2020 | Same Property Statistical Data | March 31, 2020 | |||
Percentage change over comparable period from prior year: | Number of same properties | 214 | ||||
Net operating income increase | 2.4% | Rentable square feet | 21,224,263 | |||
Net operating income increase (cash basis) | 6.1% | Occupancy – current-period average | 96.8% | |||
Operating margin | 72% | Occupancy – same-period prior-year average | 96.9% | |||
Three Months Ended March 31, | ||||||||||||||||
2020 | 2019 | $ Change | % Change | |||||||||||||
Income from rentals: | ||||||||||||||||
Same properties | $ | 266,152 | $ | 259,138 | $ | 7,014 | 2.7 | % | ||||||||
Non-same properties | 71,790 | 15,425 | 56,365 | 365.4 | ||||||||||||
Rental revenues | 337,942 | 274,563 | 63,379 | 23.1 | ||||||||||||
Same properties | 83,595 | 76,844 | 6,751 | 8.8 | ||||||||||||
Non-same properties | 16,068 | 3,342 | 12,726 | 380.8 | ||||||||||||
Tenant recoveries | 99,663 | 80,186 | 19,477 | 24.3 | ||||||||||||
Income from rentals | 437,605 | 354,749 | 82,856 | 23.4 | ||||||||||||
Same properties | 84 | 163 | (79 | ) | (48.5 | ) | ||||||||||
Non-same properties | 2,230 | 3,930 | (1,700 | ) | (43.3 | ) | ||||||||||
Other income | 2,314 | 4,093 | (1,779 | ) | (43.5 | ) | ||||||||||
Same properties | 349,831 | 336,145 | 13,686 | 4.1 | ||||||||||||
Non-same properties | 90,088 | 22,697 | 67,391 | 296.9 | ||||||||||||
Total revenues | 439,919 | 358,842 | 81,077 | 22.6 | ||||||||||||
Same properties | 98,550 | 90,702 | 7,848 | 8.7 | ||||||||||||
Non-same properties | 30,553 | 10,799 | 19,754 | 182.9 | ||||||||||||
Rental operations | 129,103 | 101,501 | 27,602 | 27.2 | ||||||||||||
Same properties | 251,281 | 245,443 | 5,838 | 2.4 | ||||||||||||
Non-same properties | 59,535 | 11,898 | 47,637 | 400.4 | ||||||||||||
Net operating income | $ | 310,816 | $ | 257,341 | $ | 53,475 | 20.8 | % | ||||||||
Net operating income – same properties | $ | 251,281 | $ | 245,443 | $ | 5,838 | 2.4 | % | ||||||||
Straight-line rent revenue | (15,146 | ) | (23,497 | ) | 8,351 | (35.5 | ) | |||||||||
Amortization of acquired below-market leases | (4,638 | ) | (3,830 | ) | (808 | ) | 21.1 | |||||||||
Net operating income – same properties (cash basis) | $ | 231,497 | $ | 218,116 | $ | 13,381 | 6.1 | % | ||||||||
Refer to “Same Property Comparisons” in the “Definitions and Reconciliations” of this Supplemental Information for a reconciliation of same properties to total properties. “Definitions and Reconciliations” also contains definitions of “Tenant Recoveries” and “Net Operating Income” and their respective reconciliations from the most directly comparable financial measures presented in accordance with GAAP.
Leasing Activity | |
March 31, 2020 | |
(Dollars per RSF) | |
Three Months Ended | Year Ended | |||||||||||||||||||||||
March 31, 2020 | December 31, 2019 | |||||||||||||||||||||||
Including Straight-Line Rent | Cash Basis | Including Straight-Line Rent | Cash Basis | |||||||||||||||||||||
Leasing activity: | ||||||||||||||||||||||||
Renewed/re-leased space(1) | ||||||||||||||||||||||||
Rental rate changes | 46.3% | 22.3% | 32.2% | 17.6% | ||||||||||||||||||||
New rates | $47.45 | $44.11 | $58.65 | $56.19 | ||||||||||||||||||||
Expiring rates | $32.44 | $36.08 | $44.35 | $47.79 | ||||||||||||||||||||
RSF | 557,367 | 2,427,108 | ||||||||||||||||||||||
Tenant improvements/leasing commissions | $23.19 | $20.28 | ||||||||||||||||||||||
Weighted-average lease term | 5.4 years | 5.7 years | ||||||||||||||||||||||
Developed/redeveloped/previously vacant space leased | ||||||||||||||||||||||||
New rates | $50.42 | $50.50 | $55.95 | $52.19 | ||||||||||||||||||||
RSF | 145,988 | (2) | 2,635,614 | |||||||||||||||||||||
Tenant improvements/leasing commissions | $12.80 | $13.74 | ||||||||||||||||||||||
Weighted-average lease term | 5.8 years | 9.8 years | ||||||||||||||||||||||
Leasing activity summary (totals): | ||||||||||||||||||||||||
New rates | $48.07 | $45.43 | $57.25 | $54.11 | ||||||||||||||||||||
RSF | 703,355 | (3) | 5,062,722 | |||||||||||||||||||||
Tenant improvements/leasing commissions | $21.03 | $16.88 | ||||||||||||||||||||||
Weighted-average lease term | 5.5 years | 7.8 years | ||||||||||||||||||||||
Lease expirations(1) | ||||||||||||||||||||||||
Expiring rates | $32.44 | $36.10 | $43.43 | $46.59 | ||||||||||||||||||||
RSF | 797,851 | 2,822,434 | ||||||||||||||||||||||
Leasing activity includes 100% of results for each property in which we have an investment in North America.
(1) | Excludes month-to-month leases aggregating 41,107 RSF and 41,809 RSF as of March 31, 2020, and December 31, 2019, respectively. |
(2) | As of April 27, 2020, our value-creation pipeline was 68% leased or negotiating. |
(3) | During the three months ended March 31, 2020, we granted tenant concessions/free rent averaging one month with respect to the 703,355 RSF leased. Approximately 74% of the leases executed during the three months ended March 31, 2020, did not include concessions for free rent. |
| |
Contractual Lease Expirations | |
March 31, 2020 | |
Year | RSF | Percentage of Occupied RSF | Annual Rental Revenue (Per RSF)(1) | Percentage of Total Annual Rental Revenue | ||||||||||||||||||||
2020 | (2) | 1,434,876 | 5.3 | % | $ | 38.69 | 4.0 | % | ||||||||||||||||
2021 | 1,442,812 | 5.3 | % | $ | 42.79 | 4.5 | % | |||||||||||||||||
2022 | 2,537,835 | 9.3 | % | $ | 41.71 | 7.7 | % | |||||||||||||||||
2023 | 2,856,125 | 10.5 | % | $ | 45.33 | 9.4 | % | |||||||||||||||||
2024 | 2,339,722 | 8.6 | % | $ | 46.28 | 7.9 | % | |||||||||||||||||
2025 | 2,101,406 | 7.7 | % | $ | 47.86 | 7.3 | % | |||||||||||||||||
2026 | 1,649,262 | 6.0 | % | $ | 48.90 | 5.9 | % | |||||||||||||||||
2027 | 2,369,275 | 8.7 | % | $ | 50.88 | 8.8 | % | |||||||||||||||||
2028 | 1,687,790 | 6.2 | % | $ | 60.73 | 7.4 | % | |||||||||||||||||
2029 | 1,402,104 | 5.1 | % | $ | 56.92 | 5.8 | % | |||||||||||||||||
Thereafter | 7,501,816 | 27.3 | % | $ | 57.68 | 31.3 | % | |||||||||||||||||
Market | 2020 Contractual Lease Expirations (in RSF) | Annual Rental Revenue (Per RSF)(1) | 2021 Contractual Lease Expirations (in RSF) | Annual Rental Revenue (Per RSF)(1) | ||||||||||||||||||||||||||||||||||||||
Leased | Negotiating/ Anticipating | Targeted for Redevelopment | Remaining Expiring Leases(3) | Total(2) | Leased | Negotiating/ Anticipating | Targeted for Redevelopment | Remaining Expiring Leases | Total | |||||||||||||||||||||||||||||||||
Greater Boston | 162,968 | 18,248 | 75,754 | (4) | 267,427 | 524,397 | $ | 45.93 | — | 12,434 | 79,101 | (4) | 228,443 | 319,978 | $ | 42.29 | ||||||||||||||||||||||||||
San Francisco | 63,065 | — | — | 167,148 | 230,213 | 44.24 | 29,538 | 12,471 | — | 411,548 | 453,557 | 51.32 | ||||||||||||||||||||||||||||||
New York City | 19,647 | 3,407 | — | 19,000 | 42,054 | 91.41 | — | — | — | 15,416 | 15,416 | 116.82 | ||||||||||||||||||||||||||||||
San Diego | 37,201 | 44,806 | — | 251,502 | (5) | 333,509 | 31.22 | 634 | 74,557 | — | 217,603 | 292,794 | 41.76 | |||||||||||||||||||||||||||||
Seattle | 12,727 | — | — | 11,790 | 24,517 | 37.56 | — | 15,704 | — | 36,616 | 52,320 | 45.46 | ||||||||||||||||||||||||||||||
Maryland | 17,295 | 8,155 | — | 76,889 | 102,339 | 19.65 | — | — | — | 120,663 | 120,663 | 24.85 | ||||||||||||||||||||||||||||||
Research Triangle | 31,776 | 3,612 | — | 50,180 | 85,568 | 17.05 | 6,493 | 34,553 | — | 107,912 | 148,958 | 27.47 | ||||||||||||||||||||||||||||||
Canada | 2,241 | — | — | 20,953 | 23,194 | 12.03 | — | — | — | 18,394 | 18,394 | 23.77 | ||||||||||||||||||||||||||||||
Non-cluster markets | — | 6,285 | — | 62,800 | 69,085 | 32.57 | — | — | — | 20,732 | 20,732 | 47.14 | ||||||||||||||||||||||||||||||
Total | 346,920 | 84,513 | 75,754 | 927,689 | 1,434,876 | $ | 38.69 | 36,665 | 149,719 | 79,101 | 1,177,327 | 1,442,812 | $ | 42.79 | ||||||||||||||||||||||||||||
Percentage of expiring leases | 24 | % | 6 | % | 5 | % | 65 | % | 100 | % | 3 | % | 10 | % | 5 | % | 82 | % | 100 | % | ||||||||||||||||||||||
(1) | Represents amounts in effect as of March 31, 2020. |
(2) | Excludes month-to-month leases aggregating 41,107 RSF as of March 31, 2020. |
(3) | The largest remaining contractual lease expiration in 2020 is 93,521 RSF related to a recently acquired property in our South San Francisco submarket. |
(4) | Represents office space aggregating 154,855 RSF at The Arsenal on the Charles, a campus acquired on December 17, 2019, in our Cambridge/Inner Suburbs submarket, that is targeted for redevelopment into office/laboratory space upon expiration of the respective existing leases. We are currently redeveloping 153,157 RSF into laboratory space. |
(5) | Includes 112,012 RSF at 9363, 9373, and 9393 Towne Centre Drive in our University Town Center submarket, a future development site. |
Top 20 Tenants | |
March 31, 2020 | |
(Dollars in thousands, except average market cap amounts) | |
81% of Top 20 Annual Rental Revenue From Investment-Grade
or Publicly Traded Large Cap Tenants(1)
Tenant | Remaining Lease Term(1) (in years) | Aggregate RSF | Annual Rental Revenue(1) | Percentage of Aggregate Annual Rental Revenue(1) | Investment-Grade Credit Ratings | Average Market Cap(1) (in billions) | ||||||||||||||||||||||||
Moody’s | S&P | |||||||||||||||||||||||||||||
1 | Bristol-Myers Squibb Company | 8.5 | 900,050 | $ | 52,243 | 3.9 | % | A2 | A+ | $ | 101.8 | |||||||||||||||||||
2 | Takeda Pharmaceutical Company Ltd. | 9.4 | 606,249 | 39,251 | 2.9 | Baa2 | BBB+ | $ | 57.3 | |||||||||||||||||||||
3 | Facebook, Inc. | 11.8 | 903,786 | 38,946 | 2.9 | — | — | $ | 544.4 | |||||||||||||||||||||
4 | Illumina, Inc. | 10.4 | 891,495 | 35,907 | 2.7 | — | BBB | $ | 45.2 | |||||||||||||||||||||
5 | Sanofi | 8.2 | 494,693 | 33,845 | 2.5 | A1 | AA | $ | 113.0 | |||||||||||||||||||||
6 | Eli Lilly and Company | 9.3 | 526,139 | 32,905 | 2.4 | A2 | A+ | $ | 117.0 | |||||||||||||||||||||
7 | Novartis AG | 8.1 | 441,894 | 31,302 | 2.3 | A1 | AA- | $ | 224.4 | |||||||||||||||||||||
8 | Roche | 2.5 | (2) | 664,800 | 29,422 | 2.2 | Aa3 | AA | $ | 253.4 | ||||||||||||||||||||
9 | Uber Technologies, Inc. | 62.7 | (3) | 1,009,188 | 27,379 | 2.0 | — | — | $ | 59.3 | ||||||||||||||||||||
10 | bluebird bio, Inc. | 7.2 | 312,805 | 23,149 | 1.7 | — | — | $ | 5.7 | |||||||||||||||||||||
11 | Moderna, Inc. | 10.2 | 382,388 | 22,421 | 1.7 | — | — | $ | 6.4 | |||||||||||||||||||||
12 | Maxar Technologies(4) | 5.2 | 478,000 | 21,577 | 1.6 | — | — | $ | 0.6 | |||||||||||||||||||||
13 | Massachusetts Institute of Technology | 8.7 | 257,626 | 21,144 | 1.6 | Aaa | AAA | $ | — | |||||||||||||||||||||
14 | Merck & Co., Inc. | 13.4 | 321,063 | 20,082 | 1.5 | A1 | AA- | $ | 213.1 | |||||||||||||||||||||
15 | New York University | 11.5 | 201,284 | 19,011 | 1.4 | Aa2 | AA- | $ | — | |||||||||||||||||||||
16 | Pfizer Inc. | 4.9 | 416,979 | 17,759 | 1.3 | A1 | AA- | $ | 213.2 | |||||||||||||||||||||
17 | Stripe, Inc. | 7.5 | 295,333 | 17,736 | 1.3 | — | — | $ | — | |||||||||||||||||||||
18 | athenahealth, Inc.(4) | 12.3 | 409,710 | 17,686 | 1.3 | — | — | $ | — | |||||||||||||||||||||
19 | Amgen Inc. | 4.0 | 407,369 | 16,838 | 1.2 | Baa1 | A- | $ | 121.7 | |||||||||||||||||||||
20 | United States Government | 7.7 | 287,638 | 16,512 | 1.2 | Aaa | AA+ | $ | — | |||||||||||||||||||||
Total/weighted-average | 11.4 | (4) | 10,208,489 | $ | 535,115 | 39.6 | % | |||||||||||||||||||||||
(1) | Based on aggregate annual rental revenue in effect as of March 31, 2020. Refer to “Annual Rental Revenue” and “Investment-Grade or Publicly Traded Large Cap Tenants” in the “Definitions and Reconciliations” of this Supplemental Information for additional details on our methodology on annual rental revenue from unconsolidated real estate joint ventures and average daily market capitalization. |
(2) | Includes 197,787 RSF expiring in 2022 at our recently acquired property at 651 Gateway Boulevard in our South San Francisco submarket. Upon expiration of the lease, 651 Gateway Boulevard will be redeveloped into a Class A office/laboratory building. |
(3) | Includes: i) a ground lease for land at 1455 and 1515 Third Street (two buildings aggregating 422,980 RSF), and ii) a lease at 1655 and 1725 Third Street (two buildings aggregating 586,208 RSF) owned by our unconsolidated joint venture in which we have an ownership interest of 10%. Annual rental revenue is presented using 100% of the annual rental revenue of our consolidated properties and our share of annual rental revenue for our unconsolidated real estate joint ventures. Refer to footnote 1 for additional details. Excluding the ground lease, the weighted-average remaining lease term for our top 20 tenants was 8.7 years as of March 31, 2020. |
(4) | Located at properties acquired during 4Q19. |
Summary of Properties and Occupancy | |
March 31, 2020 | |
(Dollars in thousands, except per RSF amounts) | |
Summary of properties
Market | RSF | Number of Properties | Annual Rental Revenue | |||||||||||||||||||||||||||
Operating | Development | Redevelopment | Total | % of Total | Total | % of Total | Per RSF | |||||||||||||||||||||||
Greater Boston | 7,704,626 | — | 153,157 | 7,857,783 | 25 | % | 67 | $ | 482,648 | 36 | % | $ | 63.33 | |||||||||||||||||
San Francisco | 7,703,973 | 841,178 | 347,912 | 8,893,063 | 29 | 60 | 366,846 | 27 | 57.58 | |||||||||||||||||||||
New York City | 1,127,580 | — | 140,098 | 1,267,678 | 4 | 5 | 79,277 | 6 | 71.70 | |||||||||||||||||||||
San Diego | 6,022,510 | 202,383 | — | 6,224,893 | 20 | 78 | 215,714 | 16 | 39.42 | |||||||||||||||||||||
Seattle | 1,458,305 | 100,086 | — | 1,558,391 | 5 | 15 | 75,818 | 6 | 53.14 | |||||||||||||||||||||
Maryland | 2,782,842 | 261,096 | 37,838 | 3,081,776 | 10 | 43 | 77,131 | 6 | 29.09 | |||||||||||||||||||||
Research Triangle | 1,224,904 | — | — | 1,224,904 | 4 | 16 | 32,669 | 2 | 27.63 | |||||||||||||||||||||
Canada | 188,967 | — | — | 188,967 | 1 | 2 | 4,762 | — | 26.91 | |||||||||||||||||||||
Non-cluster markets | 435,039 | — | — | 435,039 | 1 | 13 | 10,774 | 1 | 37.98 | |||||||||||||||||||||
Properties held for sale | 191,862 | — | — | 191,862 | 1 | 3 | 2,943 | — | N/A | |||||||||||||||||||||
North America | 28,840,608 | 1,404,743 | 679,005 | 30,924,356 | 100 | % | 302 | $ | 1,348,582 | 100 | % | $ | 51.18 | |||||||||||||||||
2,083,748 | ||||||||||||||||||||||||||||||
Summary of occupancy
Operating Properties | Operating and Redevelopment Properties | |||||||||||||||||
Market | 3/31/20 | 12/31/19 | 3/31/19 | 3/31/20 | 12/31/19 | 3/31/19 | ||||||||||||
Greater Boston | 98.9 | % | 99.1 | % | 98.2 | % | 97.0 | % | 97.1 | % | 97.7 | % | ||||||
San Francisco | 94.7 | (1) | 98.3 | 99.8 | 90.6 | 93.6 | 98.4 | |||||||||||
New York City | 99.2 | 99.2 | 98.7 | 88.1 | 88.1 | 87.7 | ||||||||||||
San Diego | 90.9 | (1) | 92.3 | 94.2 | 90.9 | 92.3 | 94.2 | |||||||||||
Seattle | 97.8 | 98.7 | 97.7 | 97.8 | 98.7 | 97.7 | ||||||||||||
Maryland | 95.9 | 96.7 | 97.0 | 94.6 | 95.2 | 95.3 | ||||||||||||
Research Triangle | 96.5 | 96.5 | 97.3 | 96.5 | 96.5 | 87.8 | ||||||||||||
Subtotal | 95.6 | 97.0 | 97.6 | 93.3 | 94.6 | 95.8 | ||||||||||||
Canada | 93.6 | 93.7 | 93.5 | 93.6 | 93.7 | 93.5 | ||||||||||||
Non-cluster markets | 65.2 | 80.1 | 81.1 | 65.2 | 80.1 | 81.1 | ||||||||||||
North America | 95.1 | % | (1) | 96.8 | % | 97.2 | % | 92.9 | % | 94.4 | % | 95.5 | % | |||||
(1) | Refer to “Occupancy” in this Supplemental Information for additional details. |
Refer to “Definitions and Reconciliations” in this Supplemental Information for additional details.
Property Listing | |
March 31, 2020 | |
(Dollars in thousands) | |
Market / Submarket / Address | RSF | Number of Properties | Annual Rental Revenue | Occupancy Percentage | ||||||||||||||||||||||||||
Operating | Operating and Redevelopment | |||||||||||||||||||||||||||||
Operating | Development | Redevelopment | Total | |||||||||||||||||||||||||||
Greater Boston | ||||||||||||||||||||||||||||||
Cambridge/Inner Suburbs | ||||||||||||||||||||||||||||||
Alexandria Center® at Kendall Square | 2,365,487 | — | — | 2,365,487 | 10 | $ | 168,979 | 98.9 | % | 98.9 | % | |||||||||||||||||||
50, 60, 75/125(1), 100, and 225(1) Binney Street, 161 and 215 First Street, 150 Second Street, 300 Third Street, and 11 Hurley Street | ||||||||||||||||||||||||||||||
Alexandria Technology Square® | 1,181,635 | — | — | 1,181,635 | 7 | 100,696 | 98.4 | 98.4 | ||||||||||||||||||||||
100, 200, 300, 400, 500, 600, and 700 Technology Square | ||||||||||||||||||||||||||||||
The Arsenal on the Charles | 683,131 | — | 153,157 | 836,288 | 11 | 26,425 | 100.0 | 81.7 | ||||||||||||||||||||||
311, 321, and 343 Arsenal Street, 300 and 400 North Beacon Street, 1, 2, and 3 Kingsbury Avenue, and 100, 200, and 400 Talcott Avenue | ||||||||||||||||||||||||||||||
Alexandria Center® at One Kendall Square | 815,156 | — | — | 815,156 | 10 | 70,494 | 99.3 | ` | 99.3 | |||||||||||||||||||||
One Kendall Square – Buildings 100, 200, 300, 400, 500, 600/700, 1400, 1800, 2000, and 399 Binney Street | ||||||||||||||||||||||||||||||
480 and 500 Arsenal Street | 234,260 | — | — | 234,260 | 2 | 11,088 | 100.0 | 100.0 | ||||||||||||||||||||||
640 Memorial Drive | 225,504 | — | — | 225,504 | 1 | 13,815 | 100.0 | 100.0 | ||||||||||||||||||||||
780 and 790 Memorial Drive | 99,658 | — | — | 99,658 | 2 | 8,009 | 100.0 | 100.0 | ||||||||||||||||||||||
167 Sidney Street and 99 Erie Street | 54,549 | — | — | 54,549 | 2 | 4,023 | 100.0 | 100.0 | ||||||||||||||||||||||
79/96 13th Street (Charlestown Navy Yard) | 25,309 | — | — | 25,309 | 1 | 620 | 100.0 | 100.0 | ||||||||||||||||||||||
Cambridge/Inner Suburbs | 5,684,689 | — | 153,157 | 5,837,846 | 46 | 404,149 | 99.1 | 96.5 | ||||||||||||||||||||||
Seaport Innovation District | ||||||||||||||||||||||||||||||
5 Necco Street | 87,163 | — | — | 87,163 | 1 | 4,646 | 86.6 | 86.6 | ||||||||||||||||||||||
Route 128 | ||||||||||||||||||||||||||||||
275 Grove Street | 509,702 | — | — | 509,702 | 1 | 24,696 | 99.2 | 99.2 | ||||||||||||||||||||||
Alexandria Park at 128 | 343,882 | — | — | 343,882 | 8 | 12,228 | 100.0 | 100.0 | ||||||||||||||||||||||
3 and 6/8 Preston Court, 29, 35, and 44 Hartwell Avenue, 35 and 45/47 Wiggins Avenue, and 60 Westview Street | ||||||||||||||||||||||||||||||
225, 266, and 275 Second Avenue | 317,617 | — | — | 317,617 | 3 | 13,932 | 100.0 | 100.0 | ||||||||||||||||||||||
100 Tech Drive | 200,431 | — | — | 200,431 | 1 | 8,455 | 100.0 | 100.0 | ||||||||||||||||||||||
19 Presidential Way | 144,892 | — | — | 144,892 | 1 | 5,051 | 99.4 | 99.4 | ||||||||||||||||||||||
100 Beaver Street | 82,330 | — | — | 82,330 | 1 | 3,165 | 80.0 | 80.0 | ||||||||||||||||||||||
285 Bear Hill Road | 26,270 | — | — | 26,270 | 1 | 1,167 | 100.0 | 100.0 | ||||||||||||||||||||||
Route 128 | 1,625,124 | — | — | 1,625,124 | 16 | 68,694 | 98.7 | 98.7 | ||||||||||||||||||||||
Route 495 | ||||||||||||||||||||||||||||||
111 and 130 Forbes Boulevard | 155,846 | — | — | 155,846 | 2 | 1,745 | 100.0 | 100.0 | ||||||||||||||||||||||
20 Walkup Drive | 91,045 | — | — | 91,045 | 1 | 649 | 100.0 | 100.0 | ||||||||||||||||||||||
30 Bearfoot Road | 60,759 | — | — | 60,759 | 1 | 2,765 | 100.0 | 100.0 | ||||||||||||||||||||||
Route 495 | 307,650 | — | — | 307,650 | 4 | 5,159 | 100.0 | 100.0 | ||||||||||||||||||||||
Greater Boston | 7,704,626 | — | 153,157 | 7,857,783 | 67 | $ | 482,648 | 98.9 | % | 97.0 | % | |||||||||||||||||||
(1) We own a partial interest in this property through a real estate joint venture. Refer to “Joint Venture Financial Information” of this Supplemental Information for additional details. | ||||||||||||||||||||||||||||||
Property Listing (continued) | |
March 31, 2020 | |
(Dollars in thousands) | |
Market / Submarket / Address | RSF | Number of Properties | Annual Rental Revenue | Occupancy Percentage | ||||||||||||||||||||||||||
Operating | Operating and Redevelopment | |||||||||||||||||||||||||||||
Operating | Development | Redevelopment | Total | |||||||||||||||||||||||||||
San Francisco | ||||||||||||||||||||||||||||||
Mission Bay/SoMa | ||||||||||||||||||||||||||||||
Alexandria Center® for Science and Technology – Mission Bay | 1,990,262 | — | — | 1,990,262 | 9 | $ | 88,190 | 100.0 | % | 100.0 | % | |||||||||||||||||||
1455, 1515, 1655(1), and 1725(1) Third Street, 409 and 499 Illinois Street(1), 1500(1) and 1700 Owens Street, and 455 Mission Bay Boulevard South | ||||||||||||||||||||||||||||||
510 Townsend Street | 295,333 | — | — | 295,333 | 1 | 17,736 | 100.0 | 100.0 | ||||||||||||||||||||||
945 Market Street | — | — | 255,765 | 255,765 | 1 | — | N/A | — | ||||||||||||||||||||||
505 Brannan Street | 148,146 | — | — | 148,146 | 1 | 12,132 | 100.0 | 100.0 | ||||||||||||||||||||||
260 Townsend Street | 66,682 | — | — | 66,682 | 1 | 5,741 | 100.0 | 100.0 | ||||||||||||||||||||||
Mission Bay/SoMa | 2,500,423 | — | 255,765 | 2,756,188 | 13 | 123,799 | 100.0 | 90.7 | ||||||||||||||||||||||
South San Francisco | ||||||||||||||||||||||||||||||
Alexandria Technology Center® – Gateway | 1,410,469 | — | — | 1,410,469 | 11 | 50,864 | 73.8 | 73.8 | ||||||||||||||||||||||
600, 601(1), 611(1), 630, 650, 651(1), 681(1), 685(1), 701(1), 901, and 951 Gateway Boulevard | ||||||||||||||||||||||||||||||
213, 249, 259, 269, and 279 East Grand Avenue | 919,704 | — | — | 919,704 | 5 | 48,326 | 99.3 | 99.3 | ||||||||||||||||||||||
201 Haskins Way | — | 315,000 | — | 315,000 | 1 | — | N/A | N/A | ||||||||||||||||||||||
400 and 450 East Jamie Court | 163,035 | — | — | 163,035 | 2 | 9,436 | 100.0 | 100.0 | ||||||||||||||||||||||
500 Forbes Boulevard(1) | 155,685 | — | — | 155,685 | 1 | 6,619 | 100.0 | 100.0 | ||||||||||||||||||||||
7000 Shoreline Court | 136,395 | — | — | 136,395 | 1 | 6,977 | 100.0 | 100.0 | ||||||||||||||||||||||
341 and 343 Oyster Point Boulevard | 107,960 | — | — | 107,960 | 2 | 5,767 | 100.0 | 100.0 | ||||||||||||||||||||||
849/863 Mitten Road/866 Malcolm Road | 103,857 | — | — | 103,857 | 1 | 4,203 | 90.8 | 90.8 | ||||||||||||||||||||||
South San Francisco | 2,997,105 | 315,000 | — | 3,312,105 | 24 | 132,192 | 87.1 | 87.1 | ||||||||||||||||||||||
Greater Stanford | ||||||||||||||||||||||||||||||
Menlo Gateway(1) | 772,983 | — | — | 772,983 | 3 | 29,837 | 100.0 | 100.0 | ||||||||||||||||||||||
100 Independence Drive and 125 and 135 Constitution Drive | ||||||||||||||||||||||||||||||
Alexandria District for Science and Technology | — | 526,178 | — | 526,178 | 2 | — | N/A | N/A | ||||||||||||||||||||||
825 and 835 Industrial Road | ||||||||||||||||||||||||||||||
3825 and 3875 Fabian Way | 478,000 | — | — | 478,000 | 2 | 21,577 | 100.0 | 100.0 | ||||||||||||||||||||||
Alexandria Stanford Life Science District | 190,270 | — | 92,147 | 282,417 | 3 | 13,902 | 100.0 | 67.4 | ||||||||||||||||||||||
3160, 3165, and 3170 Porter Drive | ||||||||||||||||||||||||||||||
Alexandria PARC | 197,498 | — | — | 197,498 | 4 | 11,350 | 98.7 | 98.7 | ||||||||||||||||||||||
2100, 2200, 2300, and 2400 Geng Road | ||||||||||||||||||||||||||||||
960 Industrial Road | 110,000 | — | — | 110,000 | 1 | 3,077 | 100.0 | 100.0 | ||||||||||||||||||||||
3330 and 3412 Hillview Avenue | 106,316 | — | — | 106,316 | 2 | 9,387 | 100.0 | 100.0 | ||||||||||||||||||||||
2425 Garcia Avenue/2400/2450 Bayshore Parkway | 99,208 | — | — | 99,208 | 1 | 4,257 | 100.0 | 100.0 | ||||||||||||||||||||||
Shoreway Science Center | 82,462 | — | — | 82,462 | 2 | 5,472 | 100.0 | 100.0 | ||||||||||||||||||||||
75 and 125 Shoreway Road | ||||||||||||||||||||||||||||||
1450 Page Mill Road | 77,634 | — | — | 77,634 | 1 | 8,009 | 100.0 | 100.0 | ||||||||||||||||||||||
3350 West Bayshore Road | 60,000 | — | — | 60,000 | 1 | 2,191 | 62.3 | 62.3 | ||||||||||||||||||||||
2625/2627/2631 Hanover Street | 32,074 | — | — | 32,074 | 1 | 1,796 | 100.0 | 100.0 | ||||||||||||||||||||||
Greater Stanford | 2,206,445 | 526,178 | 92,147 | 2,824,770 | 23 | 110,855 | 98.9 | 94.9 | ||||||||||||||||||||||
San Francisco | 7,703,973 | 841,178 | 347,912 | 8,893,063 | 60 | $ | 366,846 | 94.7 | % | 90.6 | % | |||||||||||||||||||
(1) We own a partial interest in this property through a real estate joint venture. Refer to “Joint Venture Financial Information” of this Supplemental Information for additional details. | ||||||||||||||||||||||||||||||
Property Listing (continued) | |
March 31, 2020 | |
(Dollars in thousands) | |
Market / Submarket / Address | RSF | Number of Properties | Annual Rental Revenue | Occupancy Percentage | ||||||||||||||||||||||||||
Operating | Operating and Redevelopment | |||||||||||||||||||||||||||||
Operating | Development | Redevelopment | Total | |||||||||||||||||||||||||||
New York City | ||||||||||||||||||||||||||||||
New York City | ||||||||||||||||||||||||||||||
Alexandria Center® for Life Science – New York City | 740,972 | — | — | 740,972 | 3 | $ | 64,254 | 98.8 | % | 98.8 | % | |||||||||||||||||||
430 and 450 East 29th Street | ||||||||||||||||||||||||||||||
219 East 42nd Street | 349,947 | — | — | 349,947 | 1 | 14,006 | 100.0 | 100.0 | ||||||||||||||||||||||
Alexandria Center® – Long Island City | 36,661 | — | 140,098 | 176,759 | 1 | 1,017 | 100.0 | 20.7 | ||||||||||||||||||||||
30-02 48th Avenue | ||||||||||||||||||||||||||||||
New York City | 1,127,580 | — | 140,098 | 1,267,678 | 5 | 79,277 | 99.2 | 88.1 | ||||||||||||||||||||||
San Diego | ||||||||||||||||||||||||||||||
Torrey Pines | ||||||||||||||||||||||||||||||
ARE Spectrum | 336,461 | — | — | 336,461 | 3 | 17,793 | 100.0 | 100.0 | ||||||||||||||||||||||
3215 Merryfield Row and 3013 and 3033 Science Park Road | ||||||||||||||||||||||||||||||
ARE Torrey Ridge | 294,326 | — | — | 294,326 | 3 | 12,402 | 87.8 | 87.8 | ||||||||||||||||||||||
10578, 10618, and 10628 Science Center Drive | ||||||||||||||||||||||||||||||
ARE Sunrise | 236,635 | — | — | 236,635 | 3 | 8,425 | 99.7 | 99.7 | ||||||||||||||||||||||
10931/10933 and 10975 North Torrey Pines Road, 3010 Science Park Road, and 10996 Torreyana Road | ||||||||||||||||||||||||||||||
ARE Nautilus | 220,651 | — | — | 220,651 | 4 | 10,613 | 100.0 | 100.0 | ||||||||||||||||||||||
3530 and 3550 John Hopkins Court and 3535 and 3565 General Atomics Court | ||||||||||||||||||||||||||||||
3545 Cray Court | 116,556 | — | — | 116,556 | 1 | — | — | — | ||||||||||||||||||||||
11119 North Torrey Pines Road | 72,506 | — | — | 72,506 | 1 | 3,676 | 100.0 | 100.0 | ||||||||||||||||||||||
Torrey Pines | 1,277,135 | — | — | 1,277,135 | 15 | 52,909 | 88.0 | 88.0 | ||||||||||||||||||||||
University Town Center | ||||||||||||||||||||||||||||||
Campus Pointe by Alexandria | 1,419,058 | 202,383 | — | 1,621,441 | 10 | 58,292 | 99.9 | 99.9 | ||||||||||||||||||||||
9880, 10210(1),10260(1), 10290(1), and 10300(1) Campus Point Drive and 4110(1), 4150(1), 4161(1), 4224(1), and 4242(1) Campus Point Court | ||||||||||||||||||||||||||||||
5200 Illumina Way(1) | 792,687 | — | — | 792,687 | 6 | 29,977 | 100.0 | 100.0 | ||||||||||||||||||||||
University District | 518,744 | — | — | 518,744 | 8 | 20,336 | 100.0 | 100.0 | ||||||||||||||||||||||
9363, 9373, 9393, and 9625(1) Towne Centre Drive, 4755, 4757, and 4767 Nexus Center Drive and 4796 Executive Drive | ||||||||||||||||||||||||||||||
University Town Center | 2,730,489 | 202,383 | — | 2,932,872 | 24 | $ | 108,605 | 99.9 | % | 99.9 | % | |||||||||||||||||||
(1) We own a partial interest in this property through a real estate joint venture. Refer to “Joint Venture Financial Information” of this Supplemental Information for additional details. | ||||||||||||||||||||||||||||||
Property Listing (continued) | |
March 31, 2020 | |
(Dollars in thousands) | |
Market / Submarket / Address | RSF | Number of Properties | Annual Rental Revenue | Occupancy Percentage | ||||||||||||||||||||||||||
Operating | Operating and Redevelopment | |||||||||||||||||||||||||||||
Operating | Development | Redevelopment | Total | |||||||||||||||||||||||||||
San Diego (continued) | ||||||||||||||||||||||||||||||
Sorrento Mesa | ||||||||||||||||||||||||||||||
SD Tech by Alexandria(1) | 888,960 | — | — | 888,960 | 13 | $ | 21,139 | 64.0 | % | 64.0 | % | |||||||||||||||||||
9605, 9645, 9675, 9685, 9725, 9735, 9805, 9808(2), 9855, and 9868(2) Scranton Road, 10055 and 10075 Barnes Canyon, and 5505 Morehouse Drive(2) | ||||||||||||||||||||||||||||||
Summers Ridge Science Park | 316,531 | — | — | 316,531 | 4 | 11,077 | 100.0 | 100.0 | ||||||||||||||||||||||
9965, 9975, 9985, and 9995 Summers Ridge Road | ||||||||||||||||||||||||||||||
10121 and 10151 Barnes Canyon Road | 102,392 | — | — | 102,392 | 2 | 2,689 | 100.0 | 100.0 | ||||||||||||||||||||||
ARE Portola | 101,857 | — | — | 101,857 | 3 | 3,603 | 100.0 | 100.0 | ||||||||||||||||||||||
6175, 6225, and 6275 Nancy Ridge Drive | ||||||||||||||||||||||||||||||
5810/5820 Nancy Ridge Drive | 82,272 | — | — | 82,272 | 1 | 2,364 | 100.0 | 100.0 | ||||||||||||||||||||||
7330 Carroll Road | 66,244 | — | — | 66,244 | 1 | 2,431 | 100.0 | 100.0 | ||||||||||||||||||||||
5871 Oberlin Drive | 33,817 | — | — | 33,817 | 1 | — | — | — | ||||||||||||||||||||||
Sorrento Mesa | 1,592,073 | — | — | 1,592,073 | 25 | 43,303 | 77.8 | 77.8 | ||||||||||||||||||||||
Sorrento Valley | ||||||||||||||||||||||||||||||
3911, 3931, 3985, 4025, 4031, 4045, and 4075 Sorrento Valley Boulevard | 191,378 | — | — | 191,378 | 7 | 5,215 | 88.1 | 88.1 | ||||||||||||||||||||||
11025, 11035, 11045, 11055, 11065, and 11075 Roselle Street | 121,655 | — | — | 121,655 | 6 | 2,710 | 84.6 | 84.6 | ||||||||||||||||||||||
Sorrento Valley | 313,033 | — | — | 313,033 | 13 | 7,925 | 86.7 | 86.7 | ||||||||||||||||||||||
I-15 Corridor | ||||||||||||||||||||||||||||||
13112 Evening Creek Drive | 109,780 | — | — | 109,780 | 1 | 2,972 | 100.0 | 100.0 | ||||||||||||||||||||||
San Diego | 6,022,510 | 202,383 | — | 6,224,893 | 78 | 215,714 | 90.9 | 90.9 | ||||||||||||||||||||||
Seattle | ||||||||||||||||||||||||||||||
Lake Union | ||||||||||||||||||||||||||||||
The Eastlake Life Science Campus by Alexandria – North Campus | 631,070 | — | — | 631,070 | 5 | 34,593 | 99.2 | 99.2 | ||||||||||||||||||||||
1616 and 1551 Eastlake Avenue East, 188 and 199 East Blaine Street, and 1600 Fairview Avenue East | ||||||||||||||||||||||||||||||
The Eastlake Life Science Campus by Alexandria – South Campus | 206,134 | 100,086 | — | 306,220 | 3 | 11,658 | 100.0 | 100.0 | ||||||||||||||||||||||
1165, 1201, and 1208 Eastlake Avenue East | ||||||||||||||||||||||||||||||
400 Dexter Avenue North | 290,111 | — | — | 290,111 | 1 | 15,051 | 100.0 | 100.0 | ||||||||||||||||||||||
2301 5th Avenue | 197,135 | — | — | 197,135 | 1 | 9,968 | 99.1 | 99.1 | ||||||||||||||||||||||
219 Terry Avenue North | 30,705 | — | — | 30,705 | 1 | 1,835 | 100.0 | 100.0 | ||||||||||||||||||||||
601 Dexter Avenue North | 18,680 | — | — | 18,680 | 1 | 425 | 100.0 | 100.0 | ||||||||||||||||||||||
Lake Union | 1,373,835 | 100,086 | — | 1,473,921 | 12 | 73,530 | 99.5 | 99.5 | ||||||||||||||||||||||
Elliott Bay | ||||||||||||||||||||||||||||||
3000/3018 Western Avenue | 47,746 | — | — | 47,746 | 1 | 1,839 | 100.0 | 100.0 | ||||||||||||||||||||||
410 West Harrison Street and 410 Elliott Avenue West | 36,724 | — | — | 36,724 | 2 | 449 | 32.1 | 32.1 | ||||||||||||||||||||||
Elliott Bay | 84,470 | — | — | 84,470 | 3 | 2,288 | 70.5 | 70.5 | ||||||||||||||||||||||
Seattle | 1,458,305 | 100,086 | — | 1,558,391 | 15 | $ | 75,818 | 97.8 | % | 97.8 | % | |||||||||||||||||||
(1) We own a partial interest in this property through a real estate joint venture. Refer to “Joint Venture Financial Information” of this Supplemental Information for additional details. (2) We own 100% of this property. | ||||||||||||||||||||||||||||||
Property Listing (continued) | |
March 31, 2020 | |
(Dollars in thousands) | |
Market / Submarket / Address | RSF | Number of Properties | Annual Rental Revenue | Occupancy Percentage | ||||||||||||||||||||||||||
Operating | Operating and Redevelopment | |||||||||||||||||||||||||||||
Operating | Development | Redevelopment | Total | |||||||||||||||||||||||||||
Maryland | ||||||||||||||||||||||||||||||
Rockville | ||||||||||||||||||||||||||||||
9800, 9900, 9920, and 9950 Medical Center Drive | 383,956 | 261,096 | — | 645,052 | 8 | $ | 13,874 | 89.5 | % | 89.5 | % | |||||||||||||||||||
9704, 9708, 9712, and 9714 Medical Center Drive | 214,725 | — | — | 214,725 | 4 | 7,862 | 100.0 | 100.0 | ||||||||||||||||||||||
1330 Piccard Drive | 131,511 | — | — | 131,511 | 1 | 3,569 | 100.0 | 100.0 | ||||||||||||||||||||||
9605 Medical Center Drive | 115,691 | — | — | 115,691 | 1 | 3,163 | 83.7 | 83.7 | ||||||||||||||||||||||
1500 and 1550 East Gude Drive | 90,489 | — | — | 90,489 | 2 | 1,804 | 100.0 | 100.0 | ||||||||||||||||||||||
14920 and 15010 Broschart Road | 86,703 | — | — | 86,703 | 2 | 2,283 | 100.0 | 100.0 | ||||||||||||||||||||||
1405 Research Boulevard | 72,170 | — | — | 72,170 | 1 | 2,424 | 100.0 | 100.0 | ||||||||||||||||||||||
5 Research Place | 63,852 | — | — | 63,852 | 1 | 2,734 | 100.0 | 100.0 | ||||||||||||||||||||||
5 Research Court | 51,520 | — | — | 51,520 | 1 | 1,787 | 100.0 | 100.0 | ||||||||||||||||||||||
9920 Belward Campus Drive | 51,181 | — | — | 51,181 | 1 | 1,687 | 100.0 | 100.0 | ||||||||||||||||||||||
12301 Parklawn Drive | 49,185 | — | — | 49,185 | 1 | 1,329 | 100.0 | 100.0 | ||||||||||||||||||||||
Rockville | 1,310,983 | 261,096 | — | 1,572,079 | 23 | 42,516 | 95.5 | 95.5 | ||||||||||||||||||||||
Gaithersburg | ||||||||||||||||||||||||||||||
Alexandria Technology Center® – Gaithersburg I | 613,438 | — | — | 613,438 | 9 | 15,798 | 93.8 | 93.8 | ||||||||||||||||||||||
9, 25, 35, 45, 50, and 55 West Watkins Mill Road and 910, 930, and 940 Clopper Road | ||||||||||||||||||||||||||||||
Alexandria Technology Center® – Gaithersburg II | 277,247 | — | 37,838 | 315,085 | 6 | 7,319 | 98.7 | 86.9 | ||||||||||||||||||||||
704 Quince Orchard Road(1), 708 Quince Orchard Road, and 19, 20, 21, and 22 Firstfield Road | ||||||||||||||||||||||||||||||
401 Professional Drive | 63,154 | — | — | 63,154 | 1 | 1,590 | 89.9 | 89.9 | ||||||||||||||||||||||
950 Wind River Lane | 50,000 | — | — | 50,000 | 1 | 1,004 | 100.0 | 100.0 | ||||||||||||||||||||||
620 Professional Drive | 27,950 | — | — | 27,950 | 1 | 1,191 | 100.0 | 100.0 | ||||||||||||||||||||||
Gaithersburg | 1,031,789 | — | 37,838 | 1,069,627 | 18 | 26,902 | 95.4 | 92.0 | ||||||||||||||||||||||
Beltsville | ||||||||||||||||||||||||||||||
8000/9000/10000 Virginia Manor Road | 191,884 | — | — | 191,884 | 1 | 2,575 | 96.6 | 96.6 | ||||||||||||||||||||||
Northern Virginia | ||||||||||||||||||||||||||||||
14225 Newbrook Drive | 248,186 | — | — | 248,186 | 1 | 5,138 | 100.0 | 100.0 | ||||||||||||||||||||||
Maryland | 2,782,842 | 261,096 | 37,838 | 3,081,776 | 43 | $ | 77,131 | 95.9 | % | 94.6 | % | |||||||||||||||||||
(1) We own a partial interest in this property through a real estate joint venture. Refer to “Joint Venture Financial Information” of this Supplemental Information for additional details. | ||||||||||||||||||||||||||||||
Property Listing (continued) | |
March 31, 2020 | |
(Dollars in thousands) | |
Market / Submarket / Address | RSF | Number of Properties | Annual Rental Revenue | Occupancy Percentage | ||||||||||||||||||||||||||
Operating | Operating and Redevelopment | |||||||||||||||||||||||||||||
Operating | Development | Redevelopment | Total | |||||||||||||||||||||||||||
Research Triangle | ||||||||||||||||||||||||||||||
Research Triangle | ||||||||||||||||||||||||||||||
Alexandria Center® for AgTech, Phase I – Research Triangle | 180,400 | — | — | 180,400 | 1 | $ | 5,396 | 95.1 | % | 95.1 | % | |||||||||||||||||||
5 Laboratory Drive | ||||||||||||||||||||||||||||||
Alexandria Technology Center® – Alston | 186,870 | — | — | 186,870 | 3 | 3,848 | 93.7 | 93.7 | ||||||||||||||||||||||
100, 800, and 801 Capitola Drive | ||||||||||||||||||||||||||||||
108/110/112/114 TW Alexander Drive | 158,417 | — | — | 158,417 | 1 | 4,681 | 100.0 | 100.0 | ||||||||||||||||||||||
Alexandria Innovation Center® – Research Triangle | 136,455 | — | — | 136,455 | 3 | 3,729 | 98.9 | 98.9 | ||||||||||||||||||||||
7010, 7020, and 7030 Kit Creek Road | ||||||||||||||||||||||||||||||
6 Davis Drive | 100,000 | — | — | 100,000 | 1 | 1,987 | 94.4 | 94.4 | ||||||||||||||||||||||
7 Triangle Drive | 96,626 | — | — | 96,626 | 1 | 3,156 | 100.0 | 100.0 | ||||||||||||||||||||||
2525 East NC Highway 54 | 82,996 | — | — | 82,996 | 1 | 3,651 | 100.0 | 100.0 | ||||||||||||||||||||||
407 Davis Drive | 81,956 | — | — | 81,956 | 1 | 1,644 | 100.0 | 100.0 | ||||||||||||||||||||||
601 Keystone Park Drive | 77,395 | — | — | 77,395 | 1 | 1,410 | 100.0 | 100.0 | ||||||||||||||||||||||
6040 George Watts Hill Drive | 61,547 | — | — | 61,547 | 1 | 2,148 | 100.0 | 100.0 | ||||||||||||||||||||||
5 Triangle Drive | 32,120 | — | — | 32,120 | 1 | 479 | 54.2 | 54.2 | ||||||||||||||||||||||
6101 Quadrangle Drive | 30,122 | — | — | 30,122 | 1 | 540 | 100.0 | 100.0 | ||||||||||||||||||||||
Research Triangle | 1,224,904 | — | — | 1,224,904 | 16 | 32,669 | 96.5 | 96.5 | ||||||||||||||||||||||
Canada | 188,967 | — | — | 188,967 | 2 | 4,762 | 93.6 | 93.6 | ||||||||||||||||||||||
Non-cluster markets | 435,039 | — | — | 435,039 | 13 | 10,774 | 65.2 | 65.2 | ||||||||||||||||||||||
North America, excluding properties held for sale | 28,648,746 | 1,404,743 | 679,005 | 30,732,494 | 299 | 1,345,639 | 95.1 | % | 92.9 | % | ||||||||||||||||||||
Properties held for sale | 191,862 | — | — | 191,862 | 3 | 2,943 | 69.0 | % | 69.0 | % | ||||||||||||||||||||
Total – North America | 28,840,608 | 1,404,743 | 679,005 | 30,924,356 | 302 | $ | 1,348,582 | |||||||||||||||||||||||
Investments in Real Estate | |
March 31, 2020 | |
(Dollars in thousands) | |
As of April 27, 2020, some of our ground‑up development projects have had to pause construction and some have continued. Local and state governments, however, may designate certain of our construction projects to be essential healthcare operations and allow construction to continue during quarantines. The City of Boston implemented a moratorium on construction effective March 17, 2020. We have no ground‑up development projects located in Boston undergoing aboveground vertical construction; however, we have certain tenant improvements and other renovations that may be subject to this moratorium unless the City of Boston grants an exclusion for these projects as essential healthcare operations and/or essential construction projects for essential healthcare operations. Construction workers are observing “social distancing” and following rules that restrict gatherings of large groups of people in close proximity, as well as other appropriate following other measures that may slow the pace of construction.
Effective March 28, 2020, the governor of the state of New York modified his existing Executive Order 202.6 to restrict non-essential construction projects in the state of New York. Essential construction projects, as determined by the Empire State Development Corporation, are exempted from this prohibition. On March 31, 2020, an updated shelter-in-place order directed that construction projects in six San Francisco Bay Area counties in California be halted, with certain exemptions granted to essential businesses, which include certain healthcare operations directly related to COVID-19.
On March 23, 2020, the governor of the state of Washington amended his proclamation 20-05 to prohibit all non-essential business in Washington State from conducting business, with exceptions for essential critical infrastructure workers. The description of essential workers included construction workers who support the construction, operation, and maintenance of construction sites and construction projects for all essential facilities, services, and projects related to essentials industries, such as the healthcare industry, including workers who perform critical clinical research and development needed for COVID-19 response.
A significant portion of our historical annual construction spend forecast included amounts related to future development projects with no aboveground vertical construction and not committed to a specific tenant. Due to the dislocation of capital and other markets caused by COVID-19 on, we have reduced our construction spend forecast to focus primarily on projects that are partially or fully leased; we also expect to continue certain future pipeline expenditures to minimize the impact of a temporary pause. As a result, we have reduced our construction spend forecast for 2020 from $1.6 billion to $960 million (at the midpoint of guidance).
Importantly, upon improvement of market conditions, we have the option, on a project-by-project basis, to address demand for our development and redevelopment projects.
Development and Redevelopment | ||||||||||||||||||||||||||||
Operating | Under Construction | Near Term | Intermediate Term | Future | Subtotal | Total | ||||||||||||||||||||||
Investments in real estate | ||||||||||||||||||||||||||||
Book value as of March 31, 2020(1) | $ | 16,203,062 | $ | 1,096,177 | $ | 504,469 | $ | 644,834 | $ | 191,034 | $ | 2,436,514 | $ | 18,639,576 | ||||||||||||||
Square footage | ||||||||||||||||||||||||||||
Operating | 28,840,608 | — | — | — | — | — | 28,840,608 | |||||||||||||||||||||
New Class A development and redevelopment properties | — | 2,083,748 | 2,127,925 | 5,377,112 | 4,880,477 | 14,469,262 | 14,469,262 | |||||||||||||||||||||
Value-creation square feet currently included in rental properties(2) | — | — | — | (973,636 | ) | (821,860 | ) | (1,795,496 | ) | (1,795,496 | ) | |||||||||||||||||
Total square footage | 28,840,608 | 2,083,748 | 2,127,925 | 4,403,476 | 4,058,617 | 12,673,766 | 41,514,374 | |||||||||||||||||||||
(1) | Balances exclude our share of the cost basis associated with our unconsolidated properties, which is classified as investments in unconsolidated real estate joint ventures in our consolidated balance sheets. |
(2) | Refer to the definition of “Investments in Real Estate” in “Definitions and Reconciliations” of this Supplemental Information for additional detail on value-creation square feet currently included in rental properties. |
New Class A Development and Redevelopment Properties: Current Projects | | |
March 31, 2020 | ||
The Arsenal on the Charles | 945 Market Street | 201 Haskins Way | Alexandria District for Science and Technology | 3160 Porter Drive | ||||
Greater Boston/ Cambridge/Inner Suburbs | San Francisco/Mission Bay/SoMa | San Francisco/South San Francisco | San Francisco/Greater Stanford | San Francisco/Greater Stanford | ||||
153,157 RSF | 255,765 RSF | 315,000 RSF | 526,178 RSF | 92,147 RSF | ||||
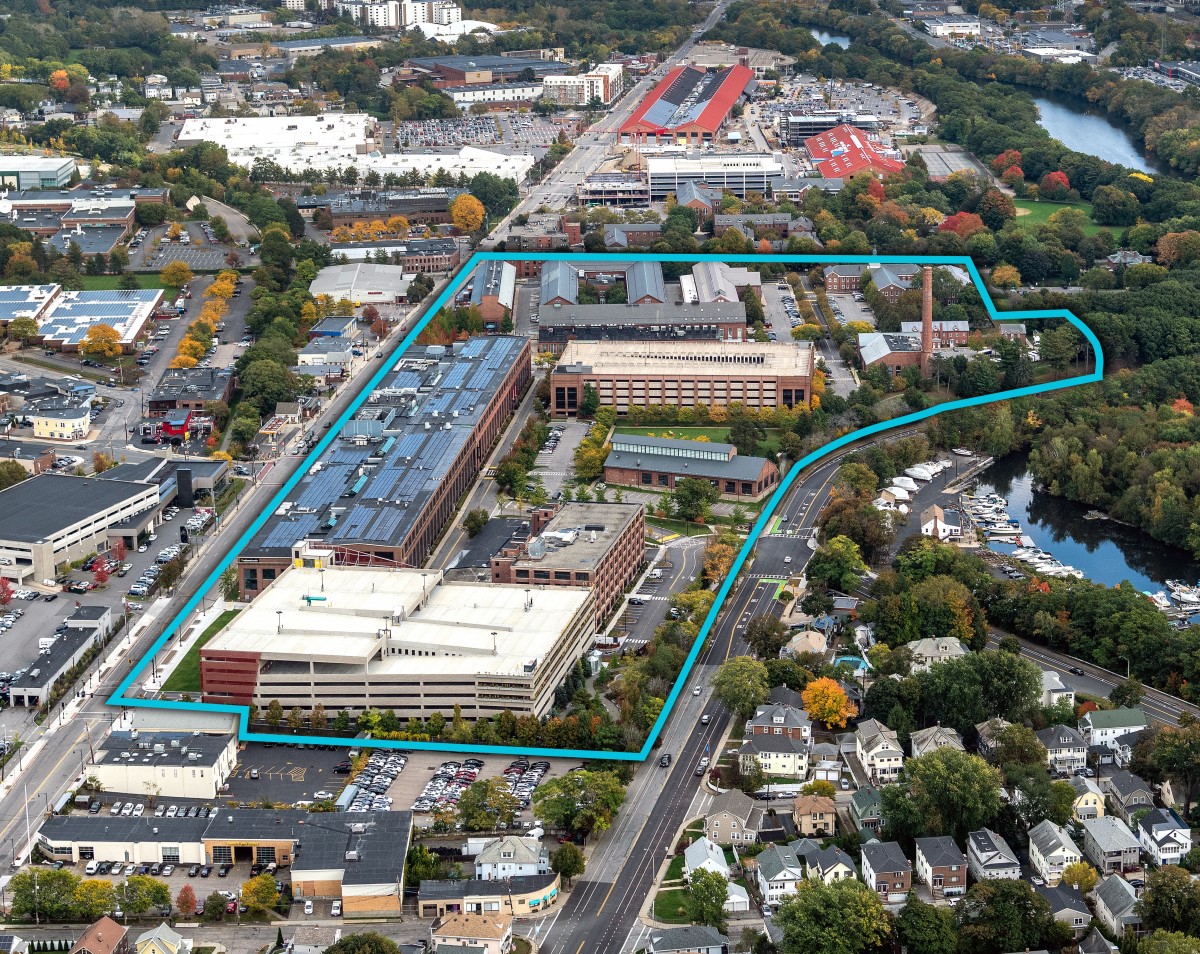 | 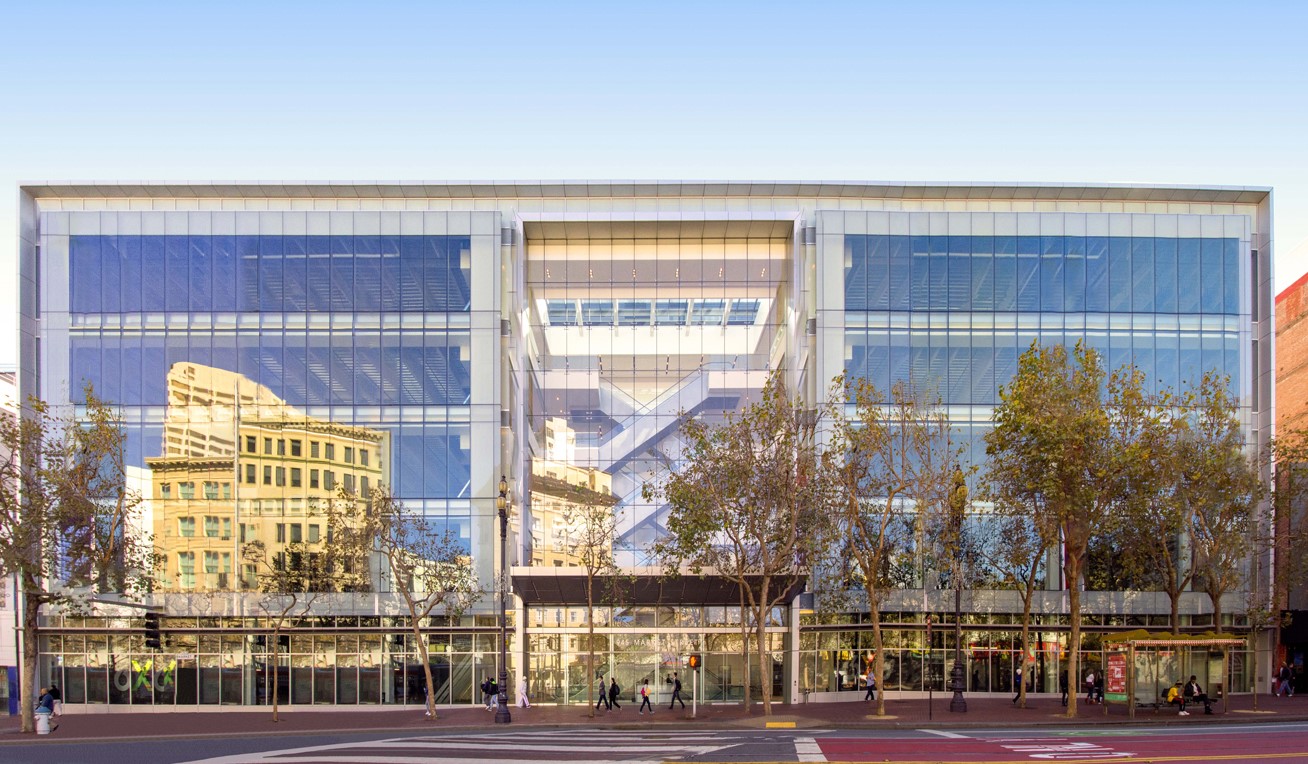 | 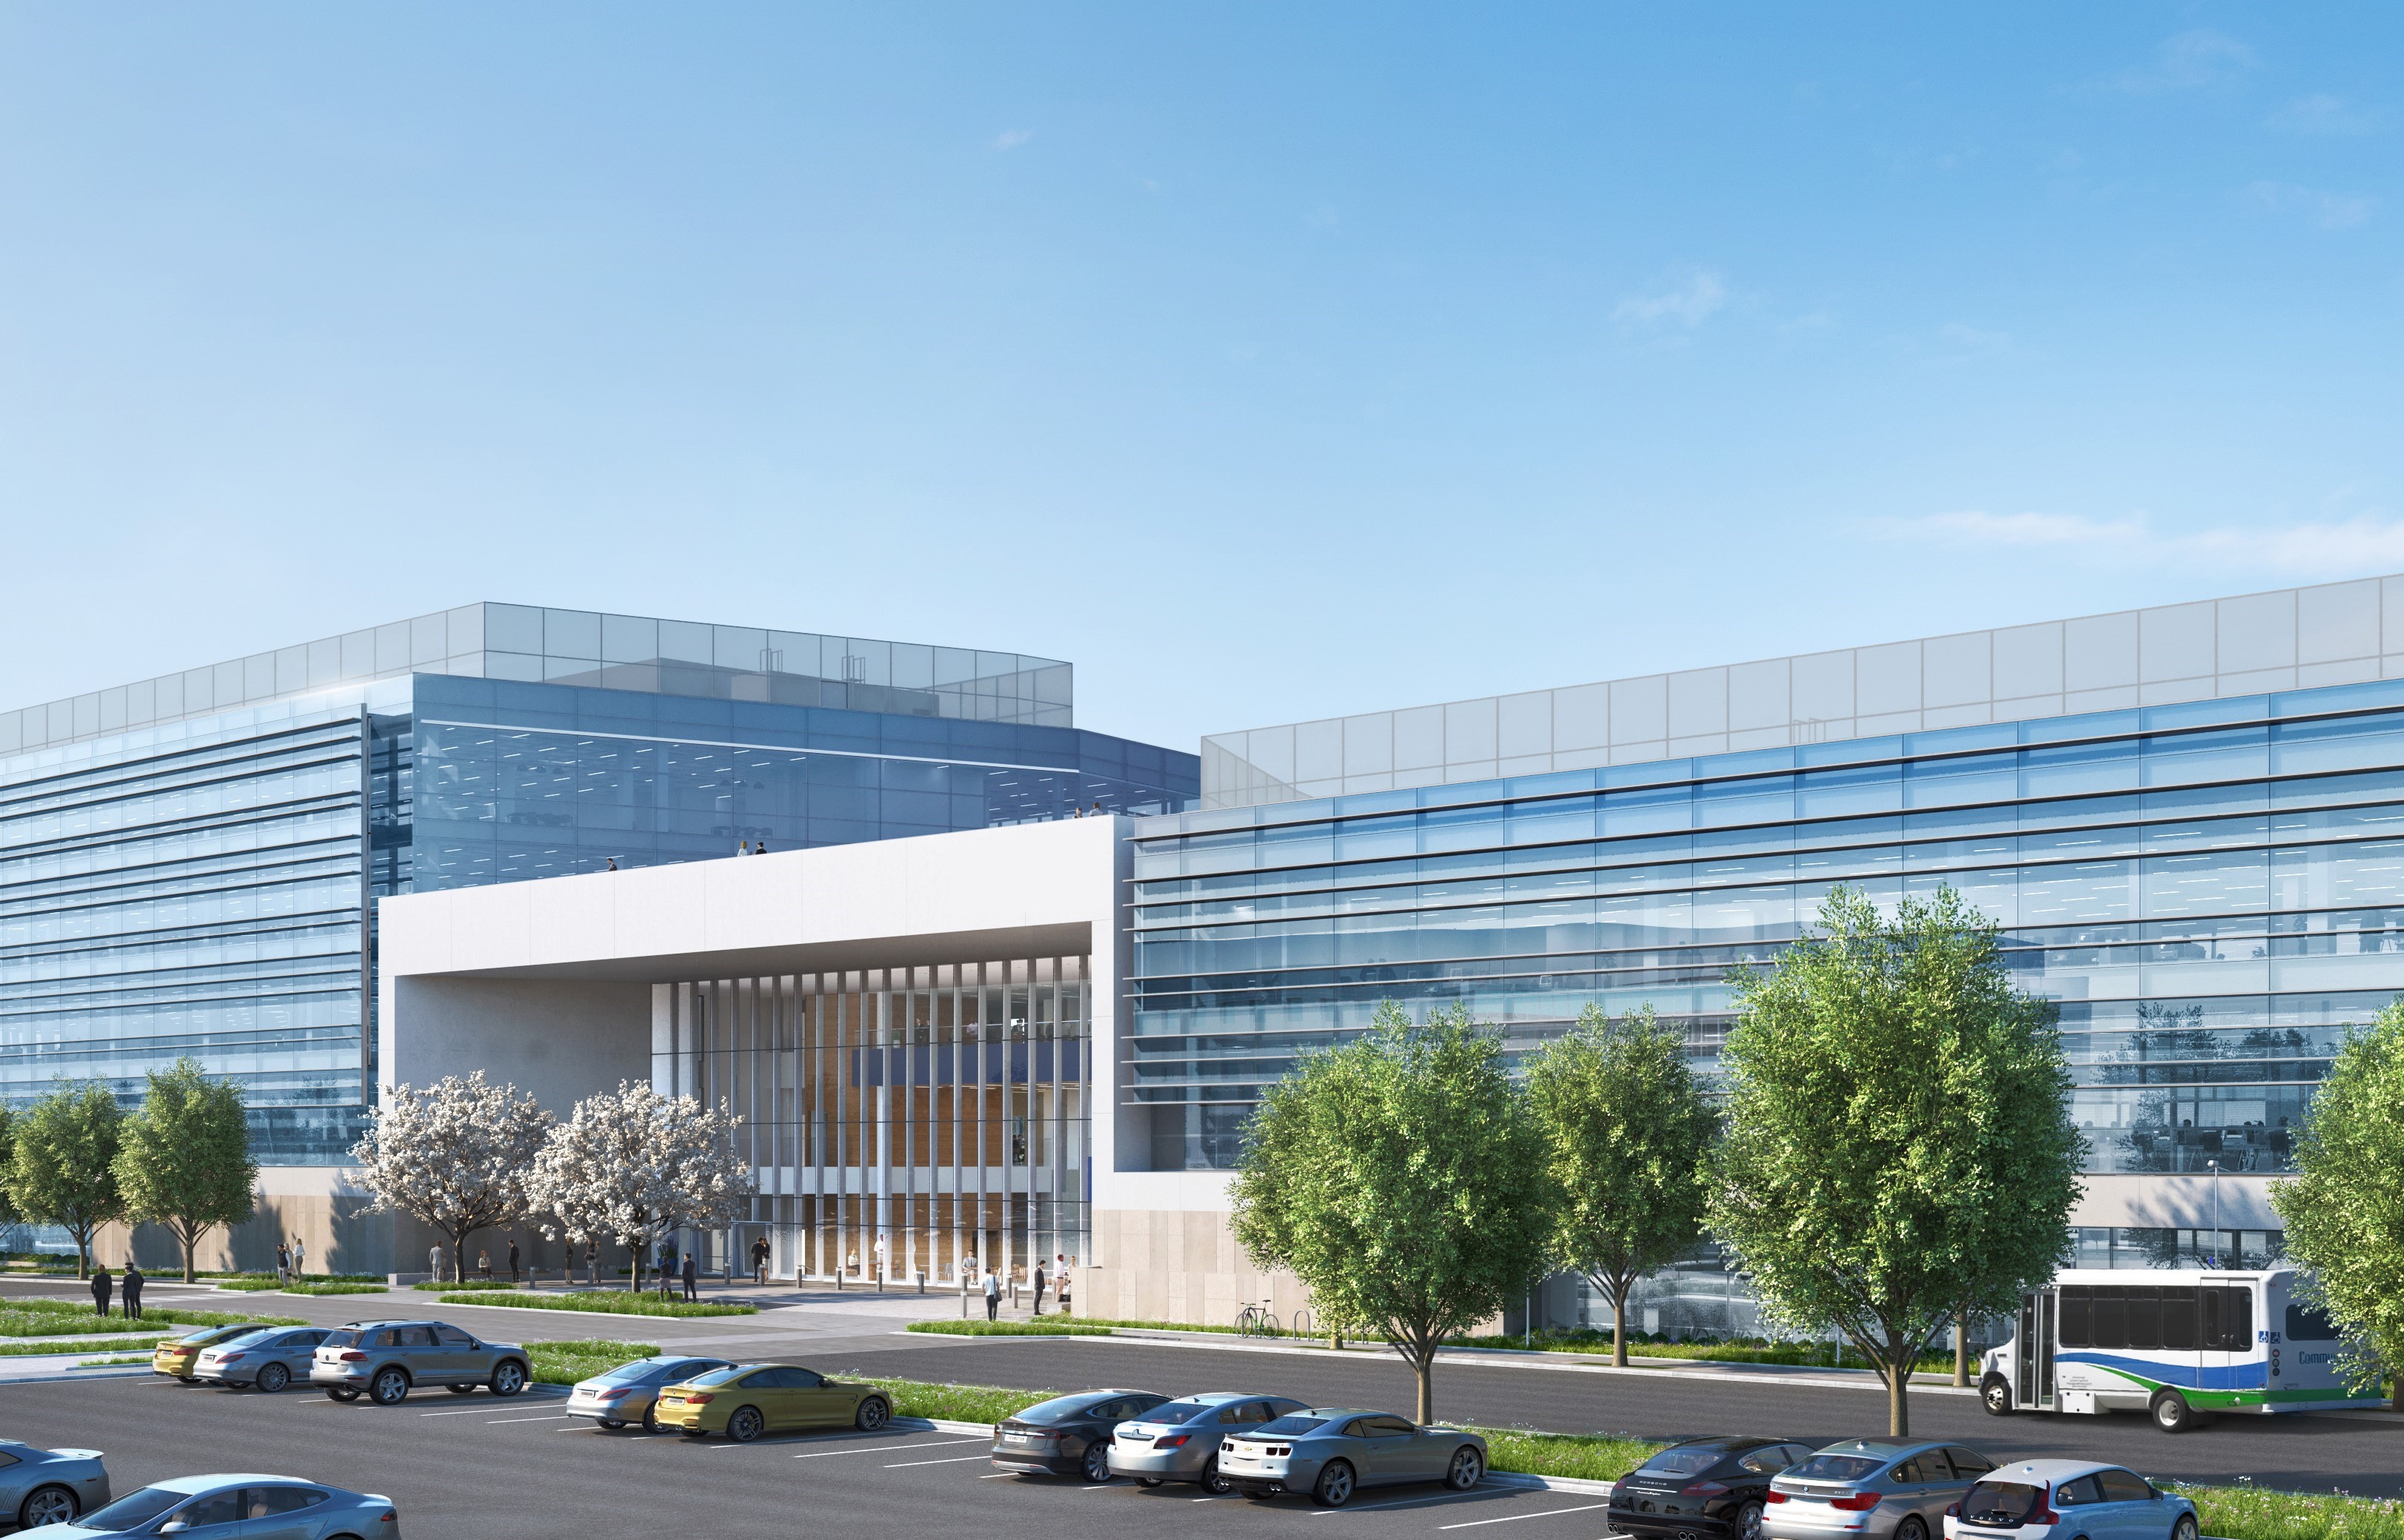 |  |  | ||||
Alexandria Center® – Long Island City | 9880 Campus Point Drive and 4150 Campus Point Court | 1165 Eastlake Avenue East | 9800 Medical Center Drive | 9950 Medical Center Drive | ||||
New York City/New York City | San Diego/University Town Center | Seattle/Lake Union | Maryland/Rockville | Maryland/Rockville | ||||
140,098 RSF | 202,383 RSF | 100,086 RSF | 176,832 RSF | 84,264 RSF | ||||
 |  |  |  |  | ||||
New Class A Development and Redevelopment Properties: Current Projects (continued) | | |
March 31, 2020 | ||
Property/Market/Submarket | Square Footage | Percentage | Temporary Pause in Construction | |||||||||||||||||||||
Dev/Redev | In Service | CIP | Total | Leased | Leased/Negotiating | Initial Occupancy(1) | ||||||||||||||||||
Developments and redevelopments under construction | ||||||||||||||||||||||||
The Arsenal on the Charles/Greater Boston/Cambridge/Inner Suburbs | Redev | 683,131 | (2) | 153,157 | 836,288 | 82 | % | 95 | % | ü | 2021 | |||||||||||||
945 Market Street/San Francisco/Mission Bay/SoMa | Redev | — | 255,765 | 255,765 | — | — | ü | 2020 | ||||||||||||||||
201 Haskins Way/San Francisco/South San Francisco | Dev | — | 315,000 | 315,000 | 33 | 33 | ü | 4Q20-1Q21 | ||||||||||||||||
Alexandria District for Science and Technology/San Francisco/Greater Stanford | Dev | — | 526,178 | 526,178 | 56 | 65 | (3) | 4Q20-1Q21 | ||||||||||||||||
3160 Porter Drive/San Francisco/Greater Stanford | Redev | — | 92,147 | 92,147 | — | — | ü | 1H21 | ||||||||||||||||
Alexandria Center® – Long Island City/New York City/New York City | Redev | 36,661 | 140,098 | 176,759 | 21 | 28 | (3) | 4Q20-1Q21 | ||||||||||||||||
9880 Campus Point Drive and 4150 Campus Point Court/San Diego/ University Town Center(4) | Dev | 66,719 | 202,383 | 269,102 | 89 | 95 | 4Q19 | |||||||||||||||||
1165 Eastlake Avenue East/Seattle/Lake Union | Dev | — | 100,086 | 100,086 | 100 | 100 | (3) | 4Q20-1Q21 | ||||||||||||||||
9800 Medical Center Drive/Maryland/Rockville | Dev | — | 176,832 | 176,832 | 100 | 100 | 2H20 | |||||||||||||||||
9950 Medical Center Drive/Maryland/Rockville | Dev | — | 84,264 | 84,264 | 100 | 100 | 2H20 | |||||||||||||||||
704 Quince Orchard Road/Maryland/Gaithersburg(5) | Redev | 42,194 | 37,838 | 80,032 | 70 | 83 | 4Q18 | |||||||||||||||||
Total | 828,705 | 2,083,748 | 2,912,453 | 61 | % | 68 | % | |||||||||||||||||
ü | As of April 27, 2020, construction at these projects were subject to a directive to temporarily pause all non-essential construction in the city, county, and/or state. |
(1) | Initial occupancy dates are subject to leasing and/or market conditions. Construction disruptions resulting from COVID-19 and various executive orders restricting construction activities may further impact construction and occupancy forecast are reflected and will continue to be monitored closely. Multi-tenant projects may have occupancy by tenants over a period of time. Stabilized occupancy may vary depending on single tenancy versus multi-tenancy. |
(2) | We expect to redevelop 154,855 RSF of occupied space into office/laboratory space upon expiration of the existing leases in 3Q20 and 1Q21. |
(3) | Temporary pause in construction was effected in March 2020, with certain COVID-19 related construction activities resuming as of April 27, 2020. |
(4) | Refer to footnote 2 on the next page. |
(5) | 704 Quince Orchard is an unconsolidated real estate joint venture. RSF represents 100%. |
New Class A Development and Redevelopment Properties: Current Projects (continued) | |
| |
March 31, 2020 | |
(Dollars in thousands) | |
Our Ownership Interest | Unlevered Yields | ||||||||||||||||||||||||||||
Property/Market/Submarket | In Service | CIP | Cost to Complete | Total at Completion | Initial Stabilized | Initial Stabilized (Cash Basis) | |||||||||||||||||||||||
Developments and redevelopments under construction | |||||||||||||||||||||||||||||
The Arsenal on the Charles/Greater Boston/Cambridge/Inner Suburbs | 100 | % | $ | 461,427 | $ | 67,084 | TBD | ||||||||||||||||||||||
945 Market Street/San Francisco/Mission Bay/SoMa | 99.5 | % | — | 194,045 | |||||||||||||||||||||||||
201 Haskins Way/San Francisco/South San Francisco | 100 | % | — | 190,485 | 123,515 | 314,000 | 6.6 | % | 6.5 | % | |||||||||||||||||||
Alexandria District for Science and Technology/San Francisco/Greater Stanford | 100 | % | — | 326,674 | 262,326 | 589,000 | 6.4 | % | 6.1 | % | |||||||||||||||||||
3160 Porter Drive/San Francisco/Greater Stanford | 100 | % | — | 34,383 | TBD | ||||||||||||||||||||||||
Alexandria Center® – Long Island City/New York City/New York City | 100 | % | 16,195 | 83,930 | 84,175 | 184,300 | 5.5 | % | 5.6 | % | |||||||||||||||||||
9880 Campus Point Drive and 4150 Campus Point Court/San Diego/ University Town Center(1) | (1 | ) | 73,621 | 60,462 | 120,917 | 255,000 | 6.3 | % | (2) | 6.4 | % | (2) | |||||||||||||||||
1165 Eastlake Avenue East/Seattle/Lake Union | 100 | % | — | 62,181 | 75,819 | 138,000 | 6.5 | % | (3) | 6.3 | % | (3) | |||||||||||||||||
9800 Medical Center Drive/Maryland/Rockville | 100 | % | — | 46,390 | 49,010 | 95,400 | 7.7 | % | 7.2 | % | |||||||||||||||||||
9950 Medical Center Drive/Maryland/Rockville | 100 | % | — | 30,542 | 23,758 | 54,300 | 7.3 | % | 6.8 | % | |||||||||||||||||||
Consolidated projects | 551,243 | 1,096,176 | |||||||||||||||||||||||||||
704 Quince Orchard Road/Maryland/Gaithersburg(4) | 56.8 | % | 5,740 | 5,153 | 2,407 | 13,300 | 8.9 | % | 8.8 | % | |||||||||||||||||||
Total | $ | 556,983 | $ | 1,101,329 | |||||||||||||||||||||||||
(1) | Refer to “Joint Venture Financial Information” and “Definitions and Reconciliations” of this Supplemental Information for additional details. |
(2) | Represents a two-phase development project as follows: |
• | Initial phase represents 9880 Campus Point Drive, a 98,000 RSF project to develop Alexandria GradLabs™, a highly flexible, first-of-its-kind life science platform designed to provide post-seed-stage life science companies with turnkey, fully furnished office/laboratory suites and an accelerated, scalable path for growth. As of March 31, 2020, 202,383 RSF and 66,719 RSF is classified in construction in process and in-service, respectively. The R&D building located at 9880 Campus Point Drive was demolished and as of March 31, 2020, continues to be included in our same property performance results. Refer to “Same Property Comparison” in the “Definitions and Reconciliations” of this Supplemental Information for additional details. |
• | Subsequent phase represents 4150 Campus Point Court, a 171,102 RSF, 100% leased project undergoing pre-construction that we expect to commence vertical construction in 1Q21, with occupancy expected in 2022. |
• | Project costs represent development costs for 9880 Campus Point Drive and 4150 Campus Point Court. Unlevered yields represent expected aggregate returns for Campus Pointe by Alexandria, including 9880, 10290, and 10300 Campus Point Drive and 4150 Campus Point Court. |
(3) | Unlevered yields represent anticipated aggregate returns for 1165 Eastlake Avenue, an amenity-rich research headquarter for Adaptive Biotechnologies Corporation, and 1208 Eastlake Avenue, an adjacent multi-tenant office/laboratory building. |
(4) | 704 Quince Orchard is an unconsolidated real estate joint venture. Cost and yield amounts represent our share. |
New Class A Development and Redevelopment Properties: Summary of Pipeline | |
March 31, 2020 | |
(Dollars in thousands) | |
Property/Submarket | Our Ownership Interest | Book Value | Square Footage | |||||||||||||||||||||
Development and Redevelopment | ||||||||||||||||||||||||
Under Construction | Near Term | Intermediate Term | Future | Total | ||||||||||||||||||||
Greater Boston | ||||||||||||||||||||||||
The Arsenal on the Charles/Cambridge/Inner Suburbs | 100 | % | $ | 83,276 | 153,157 | — | — | 200,000 | 353,157 | |||||||||||||||
15 Necco Street/Seaport Innovation District | 98.8 | % | 175,832 | — | 293,000 | — | — | 293,000 | ||||||||||||||||
215 Presidential Way/Route 128 | 100 | % | 6,392 | — | 112,000 | — | — | 112,000 | ||||||||||||||||
325 Binney Street/Cambridge | 100 | % | 110,840 | — | — | 402,000 | — | 402,000 | ||||||||||||||||
99 A Street/Seaport Innovation District | 96.2 | % | 41,524 | — | — | 235,000 | — | 235,000 | ||||||||||||||||
10 Necco Street/Seaport Innovation District | 100 | % | 86,231 | — | — | 175,000 | — | 175,000 | ||||||||||||||||
Alexandria Technology Square®/Cambridge | 100 | % | 7,787 | — | — | — | 100,000 | 100,000 | ||||||||||||||||
100 Tech Drive/Route 128 | 100 | % | — | — | — | — | 300,000 | 300,000 | ||||||||||||||||
231 Second Avenue/Route 128 | 100 | % | 1,107 | — | — | — | 32,000 | 32,000 | ||||||||||||||||
Other value-creation projects | 100 | % | 9,467 | — | — | — | 41,955 | 41,955 | ||||||||||||||||
522,456 | 153,157 | 405,000 | 812,000 | 673,955 | 2,044,112 | |||||||||||||||||||
San Francisco | ||||||||||||||||||||||||
201 Haskins Way/South San Francisco | 100 | % | 190,485 | 315,000 | — | — | — | 315,000 | ||||||||||||||||
Alexandria District for Science and Technology/Greater Stanford | 100 | % | 326,674 | 526,178 | — | — | — | 526,178 | ||||||||||||||||
945 Market Street/Mission Bay/SoMa | 99.5 | % | 194,045 | 255,765 | — | — | — | 255,765 | ||||||||||||||||
3160 Porter Drive/Greater Stanford | 100 | % | 34,383 | 92,147 | — | — | — | 92,147 | ||||||||||||||||
88 Bluxome Street/Mission Bay/SoMa | 100 | % | 234,511 | — | 1,070,925 | (1) | — | — | 1,070,925 | |||||||||||||||
Alexandria Technology Center® – Gateway/South San Francisco | 44.8 | % | 40,577 | — | 217,000 | 300,010 | (2) | 291,000 | 808,010 | |||||||||||||||
505 Brannan Street, Phase II/Mission Bay/SoMa | 99.7 | % | 18,345 | — | — | 165,000 | — | 165,000 | ||||||||||||||||
960 Industrial Road/Greater Stanford | 100 | % | 107,245 | — | — | 587,000 | (2) | — | 587,000 | |||||||||||||||
3825 and 3875 Fabian Way/Greater Stanford | 100 | % | — | — | 250,000 | (2) | 228,000 | (2) | 478,000 | |||||||||||||||
East Grand Avenue/South San Francisco | 100 | % | 5,995 | — | — | — | 90,000 | 90,000 | ||||||||||||||||
Other value-creation projects | 100 | % | 43,774 | — | — | 191,000 | 25,000 | 216,000 | ||||||||||||||||
$ | 1,196,034 | 1,189,090 | 1,287,925 | 1,493,010 | 634,000 | 4,604,025 | ||||||||||||||||||
(1) Includes a 488,899 RSF lease with Pinterest, Inc., for which we expect demolition of the existing building to commence in January 2021. In April 2020, the City of San Francisco began discussion on the potential temporary use of the existing building. Their goal is to increase social distancing for residents in existing homeless shelters by relocating some residents on a temporary basis to 88 Bluxome Street. Our existing tenant is carefully considering the request of the city and may enter into a very short-term arrangement for the temporary use of the facility. We expect any arrangement to end before the planned demolition of the building in order to commence construction. (2) Represents total square footage upon completion of development or redevelopment of a new Class A property. RSF presented includes rentable square footage of buildings currently in operation at properties for their inherent future development opportunities, with the intent to demolish the existing property upon expiration of the existing in-place leases and commencement of future construction. Refer to “Definitions and Reconciliations” of this Supplemental Information for additional detail on value-creation square feet currently included in rental properties. | ||||||||||||||||||||||||
New Class A Development and Redevelopment Properties: Summary of Pipeline (continued) | |
March 31, 2020 | |
(Dollars in thousands) | |
Property/Submarket | Our Ownership Interest | Book Value | Square Footage | |||||||||||||||||||||
Development and Redevelopment | ||||||||||||||||||||||||
Under Construction | Near Term | Intermediate Term | Future | Total | ||||||||||||||||||||
New York City | ||||||||||||||||||||||||
Alexandria Center® – Long Island City/New York City | 100 | % | $ | 83,930 | 140,098 | — | — | — | 140,098 | |||||||||||||||
Alexandria Center® for Life Science – New York City/New York City | 100 | % | 37,197 | — | — | 550,000 | (1) | — | 550,000 | |||||||||||||||
47-50 30th Street/New York City | 100 | % | 27,551 | — | — | 135,938 | — | 135,938 | ||||||||||||||||
219 East 42nd Street/New York City | 100 | % | — | — | — | — | 579,947 | (2) | 579,947 | |||||||||||||||
148,678 | 140,098 | — | 685,938 | 579,947 | 1,405,983 | |||||||||||||||||||
San Diego | ||||||||||||||||||||||||
Campus Pointe by Alexandria/University Town Center | (3 | ) | 113,220 | 202,383 | — | 390,164 | (4) | 359,281 | (4) | 951,828 | ||||||||||||||
3115 Merryfield Row/Torrey Pines | 100 | % | 43,839 | — | 125,000 | — | — | 125,000 | ||||||||||||||||
10931 and 10933 Torrey Pines Road/Torrey Pines | 100 | % | — | — | — | 242,000 | (4) | — | 242,000 | |||||||||||||||
University District/University Town Center | 100 | % | — | — | — | 400,000 | (4)(5) | — | 400,000 | |||||||||||||||
SD Tech by Alexandria/Sorrento Mesa | 50 | % | 31,682 | — | — | 332,000 | 388,000 | 720,000 | ||||||||||||||||
Townsgate by Alexandria/Del Mar Heights | 100 | % | 20,664 | — | — | 185,000 | — | 185,000 | ||||||||||||||||
5200 Illumina Way/University Town Center | 51 | % | 11,772 | — | — | — | 451,832 | 451,832 | ||||||||||||||||
Vista Wateridge/Sorrento Mesa | 100 | % | 4,022 | — | — | — | 163,000 | 163,000 | ||||||||||||||||
4045 and 4075 Sorrento Valley Boulevard/Sorrento Valley | 100 | % | 7,545 | — | — | — | 149,000 | (4) | 149,000 | |||||||||||||||
Other value-creation projects | 100 | % | — | — | — | — | 50,000 | 50,000 | ||||||||||||||||
232,744 | 202,383 | 125,000 | 1,549,164 | 1,561,113 | 3,437,660 | |||||||||||||||||||
Seattle | ||||||||||||||||||||||||
1165 Eastlake Avenue East/Lake Union | 100 | % | 62,181 | 100,086 | — | — | — | 100,086 | ||||||||||||||||
1150 Eastlake Avenue East/Lake Union | 100 | % | 38,847 | — | — | 260,000 | — | 260,000 | ||||||||||||||||
701 Dexter Avenue North/Lake Union | 100 | % | 44,472 | — | — | 217,000 | — | 217,000 | ||||||||||||||||
601 Dexter Avenue North/Lake Union | 100 | % | 31,984 | — | — | — | 188,400 | (4) | 188,400 | |||||||||||||||
Other value-creation projects | 100 | % | 5,507 | — | — | — | 35,000 | 35,000 | ||||||||||||||||
$ | 182,991 | 100,086 | — | 477,000 | 223,400 | 800,486 | ||||||||||||||||||
(1) In recent quarters, we have been negotiating a long-term ground lease for the future site of a new building approximating 550,000 RSF. In March 2020, due to the anticipated projected impacts of COVID-19 on New York City, the city commenced preparation of the site as a temporary morgue to store the remains of individuals who died as a result of COVID-19. The use of this site by the City has resulted in delays to deadlines for both ground lease negotiations and ultimately the timing to commence and complete key milestone construction dates. (2) Includes 349,947 RSF in operation with an opportunity to either convert the existing office space into office/laboratory space through future redevelopment or to expand the building by an additional 230,000 RSF through ground-up development. The building is currently occupied by Pfizer Inc. with a remaining lease term of approximately five years. (3) Refer to “Joint Venture Financial Information” of this Supplemental Information for additional details on our ownership interest. (4) Represents total square footage upon completion of development of a new Class A property. Square footage presented includes rentable square footage of buildings currently in operation at properties for their inherent future development opportunities, with the intent to demolish the existing property upon expiration of the existing in-place leases and commencement of future construction. Refer to “Definitions and Reconciliations” of this Supplemental Information for additional detail on value-creation square feet currently included in rental properties. (5) Includes 112,012 RSF at the University District project in our University Town Center submarket, which is currently under evaluation for development, subject to future market conditions. | ||||||||||||||||||||||||
New Class A Development and Redevelopment Properties: Summary of Pipeline (continued) | |
March 31, 2020 | |
(Dollars in thousands) | |
Property/Submarket | Our Ownership Interest | Book Value | Square Footage | |||||||||||||||||||||
Development and Redevelopment | ||||||||||||||||||||||||
Under Construction | Near Term | Intermediate Term | Future | Total | ||||||||||||||||||||
Maryland | ||||||||||||||||||||||||
704 Quince Orchard Road/Gaithersburg | 56.8 | % | $ | — | (1) | 37,838 | — | — | — | 37,838 | ||||||||||||||
9800 Medical Center Drive/Rockville | 100 | % | 47,641 | 176,832 | — | — | 64,000 | 240,832 | ||||||||||||||||
9950 Medical Center Drive/Rockville | 100 | % | 30,542 | 84,264 | — | — | — | 84,264 | ||||||||||||||||
14200 Shady Grove Road/Rockville | 100 | % | 26,502 | — | — | 290,000 | 145,000 | 435,000 | ||||||||||||||||
104,685 | 298,934 | — | 290,000 | 209,000 | 797,934 | |||||||||||||||||||
Research Triangle | ||||||||||||||||||||||||
Alexandria Center® for AgTech, Phase II/Research Triangle | 100 | % | 17,182 | — | 160,000 | — | — | 160,000 | ||||||||||||||||
8 Davis Drive/Research Triangle | 100 | % | 8,748 | — | 150,000 | 70,000 | — | 220,000 | ||||||||||||||||
6 Davis Drive/Research Triangle | 100 | % | 15,003 | — | — | — | 800,000 | 800,000 | ||||||||||||||||
Other value-creation projects | 100 | % | 4,150 | — | — | — | 76,262 | 76,262 | ||||||||||||||||
45,083 | — | 310,000 | 70,000 | 876,262 | 1,256,262 | |||||||||||||||||||
Other value-creation projects | 100 | % | 3,842 | — | — | — | 122,800 | 122,800 | ||||||||||||||||
Total | 2,436,513 | 2,083,748 | 2,127,925 | 5,377,112 | 4,880,477 | 14,469,262 | (2) | |||||||||||||||||
975-1075 Commercial Street and 915-1063 Old County Road/Greater Stanford | (3 | ) | (3) | — | — | — | 700,000 | 700,000 | ||||||||||||||||
Mercer Mega Block/Lake Union | (3 | ) | (3) | — | — | — | 800,000 | 800,000 | ||||||||||||||||
Key pending acquisitions | — | — | — | — | 1,500,000 | 1,500,000 | ||||||||||||||||||
$ | 2,436,513 | 2,083,748 | 2,127,925 | 5,377,112 | 6,380,477 | 15,969,262 | ||||||||||||||||||
(1) | This property is held by an unconsolidated real estate joint venture. Refer to “Joint Venture Financial Information” of this Supplemental Information for additional details on our ownership interest. |
(2) | Total square footage includes 1,795,496 RSF of buildings currently in operation that will be redeveloped or replaced with new development RSF upon commencement of future construction. Refer to “Definitions and Reconciliations” of this Supplemental Information for additional detail on value-creation square feet currently included in rental properties. |
(3) | Refer to “Acquisitions” in our Earnings Press Release for additional details. |
Construction Spending | |
March 31, 2020 | |
(Dollars in thousands) | |
Three Months Ended | |||||||
Construction Spending | March 31, 2020 | ||||||
Additions to real estate – consolidated projects | $ | 373,499 | |||||
Investments in unconsolidated real estate joint ventures | 2,592 | ||||||
Contributions from noncontrolling interests | (2,756 | ) | |||||
Construction spending (cash basis)(1) | 373,335 | ||||||
Change in accrued construction | (39,061 | ) | |||||
Construction spending for the three months ended March 31, 2020 | 334,274 | ||||||
Projected construction spending for the nine months ending December 31, 2020 | 625,726 | ||||||
Guidance midpoint | $ | 960,000 | |||||
Year Ending | |||||||
Projected Construction Spending | December 31, 2020 | ||||||
Development, redevelopment, and pre-construction projects | $ | 800,000 | |||||
Contributions from noncontrolling interests (consolidated real estate joint ventures) | (20,000 | ) | |||||
Generic laboratory infrastructure | 144,000 | ||||||
Non-revenue-enhancing capital expenditures | 36,000 | ||||||
Guidance midpoint | $ | 960,000 | |||||
Non-Revenue-Enhancing Capital Expenditures(2) | Three Months Ended | Recent Average Per RSF(3) | ||||||||||||
March 31, 2020 | ||||||||||||||
Amount | Per RSF | |||||||||||||
Building improvements | $ | 3,198 | $ | 0.12 | $ | 0.49 | ||||||||
Tenant improvements and leasing costs: | ||||||||||||||
Re-tenanted space | $ | 3,936 | $ | 31.21 | $ | 25.21 | ||||||||
Renewal space | 8,987 | 20.84 | 16.37 | |||||||||||
Total tenant improvements and leasing costs/weighted-average | $ | 12,923 | $ | 23.19 | $ | 19.71 | ||||||||
(1) | Includes revenue-enhancing projects and non-revenue-enhancing capital expenditures. |
(2) | Excludes amounts that are recoverable from tenants, related to revenue-enhancing capital expenditures, or related to properties that have undergone redevelopment. |
(3) | Represents the average for a five-year period from 2016 through 2019 and three months ended March 31, 2020, annualized. |
Joint Venture Financial Information | |
March 31, 2020 | |
(Dollars in thousands) | |
Consolidated Real Estate Joint Ventures | Unconsolidated Real Estate Joint Ventures | |||||||||||
Property/Market/Submarket | Noncontrolling Interest Share(1) | Property/Market/Submarket | Our Ownership Share(2) | |||||||||
225 Binney Street/Greater Boston/Cambridge | 70.0 | % | 1655 and 1725 Third Street/San Francisco/Mission Bay/SoMa | 10.0 | % | |||||||
75/125 Binney Street/Greater Boston/Cambridge | 60.0 | % | Menlo Gateway/San Francisco/Greater Stanford | 49.0 | % | |||||||
409 and 499 Illinois Street/San Francisco/Mission Bay/SoMa | 40.0 | % | 704 Quince Orchard Road/Maryland/Gaithersburg | 56.8 | % | (3) | ||||||
1500 Owens Street/San Francisco/Mission Bay/SoMa | 49.9 | % | ||||||||||
Alexandria Technology Center® – Gateway/San Francisco/South San Francisco(4) | 55.2 | % | ||||||||||
500 Forbes Boulevard/San Francisco/South San Francisco | 90.0 | % | ||||||||||
Campus Pointe by Alexandria/San Diego/University Town Center(5) | 45.0 | % | ||||||||||
5200 Illumina Way/San Diego/University Town Center | 49.0 | % | ||||||||||
9625 Towne Centre Drive/San Diego/University Town Center | 49.9 | % | ||||||||||
SD Tech by Alexandria/San Diego/Sorrento Mesa | 50.0 | % | ||||||||||
(1) | In addition to the consolidated real estate joint ventures listed, various partners hold insignificant noncontrolling interests in six other joint ventures in North America. |
(2) | In addition to the unconsolidated real estate joint ventures listed, we hold an interest in two other insignificant unconsolidated real estate joint venture in North America. |
(3) | Represents our ownership interest; our voting interest is limited to 50%. |
(4) | Includes 601, 611, 651, 681, 685, 701, and 751 Gateway Boulevard and excess land in our South San Francisco submarket. Noncontrolling interest share is anticipated to be 49% as we make further contributions over time. |
(5) | Excludes 9880 Campus Point Drive in our University Town Center submarket. |
As of March 31, 2020 | |||||||||
Noncontrolling Interest Share of Consolidated Real Estate JVs | Our Share of Unconsolidated Real Estate JVs | ||||||||
Investments in real estate | $ | 1,449,462 | $ | 460,425 | |||||
Cash, cash equivalents, and restricted cash | 42,788 | 18,711 | |||||||
Other assets | 169,291 | 46,579 | |||||||
Secured notes payable (refer to page 48) | — | (181,129 | ) | ||||||
Other liabilities | (69,862 | ) | (18,921 | ) | |||||
Redeemable noncontrolling interests | (12,013 | ) | — | ||||||
$ | 1,579,666 | $ | 325,665 | ||||||
Three Months Ended March 31, 2020 | |||||||||
Noncontrolling Interest Share of Consolidated Real Estate JVs | Our Share of Unconsolidated Real Estate JVs | ||||||||
Total revenues | $ | 37,777 | $ | 10,644 | |||||
Rental operations | (10,095 | ) | (1,418 | ) | |||||
27,682 | 9,226 | ||||||||
General and administrative | (117 | ) | (84 | ) | |||||
Interest | — | (1,971 | ) | ||||||
Depreciation and amortization | (15,870 | ) | (2,643 | ) | |||||
Impairment of real estate | — | (7,644 | ) | ||||||
Fixed returns allocated to redeemable noncontrolling interests(1) | 218 | — | |||||||
$ | 11,913 | $ | (3,116 | ) | |||||
Straight-line rent and below-market lease revenue | $ | 1,962 | $ | 5,853 | |||||
Funds from operations(2) | $ | 27,783 | $ | 7,171 | |||||
(1) | Represents an allocation of joint venture earnings to redeemable noncontrolling interests primarily in one property in our South San Francisco submarket. These redeemable noncontrolling interests earn a fixed return on their investment rather than participate in the operating results of the property. |
(2) | Refer to “Funds from Operations and Funds from Operations Per Share” in our Earnings Press Release and “Funds From Operations and Funds From Operations, As Adjusted, Attributable to Alexandria’s Common Stockholders” in the “Definitions and Reconciliations” in this Supplemental Information for the definition and reconciliation from the most directly comparable GAAP measure. |
Investments | |
March 31, 2020 | |
(Dollars in thousands) | |
We present our equity investments at fair value whenever fair value or net asset value (“NAV”) is readily available. Adjustments for our limited partnership investments represent changes in reported NAV as a practical expedient to estimate fair value. For investments without readily available fair values, we adjust the carrying amount whenever such investments have an observable price change, and further adjustments are not made until another price change, if any, is observed. Refer to “Investments” in the “Definitions and Reconciliations” of this Supplemental Information for additional details.
Three Months Ended March 31, 2020 | Year Ended December 31, 2019 | |||||||||
Realized (losses) gains | $ | (4,677 | ) | (1) | $ | 33,158 | (2) | |||
Unrealized (losses) gains | (17,144 | ) | 161,489 | |||||||
Investment (loss) income | $ | (21,821 | ) | $ | 194,647 | |||||
Investments | Cost | Unrealized Gains (Losses) | Carrying Amount | ||||||||||||
Fair value: | |||||||||||||||
Publicly traded companies | $ | 140,762 | $ | 146,464 | (3) | $ | 287,226 | ||||||||
Entities that report NAV | 285,557 | 165,617 | 451,174 | ||||||||||||
Entities that do not report NAV: | |||||||||||||||
Entities with observable price changes | 51,254 | 72,418 | 123,672 | ||||||||||||
Entities without observable price changes | 261,410 | — | 261,410 | ||||||||||||
March 31, 2020 | $ | 738,983 | $ | 384,499 | $ | 1,123,482 | |||||||||
December 31, 2019 | $ | 738,951 | $ | 401,643 | $ | 1,140,594 | |||||||||
(1) | Includes realized gains of $15.1 million and impairments primarily related to two privately held non-real estate investments of $19.8 million for the three months ended March 31, 2020. |
(2) | Includes realized gains of $50.3 million and impairments related to privately held non-real estate investments of $17.1 million for the year ended December 31, 2019. |
(3) | Includes gross unrealized gains and losses of $175.6 million and $29.1 million, respectively. |
Public/Private Mix (Cost) | ||
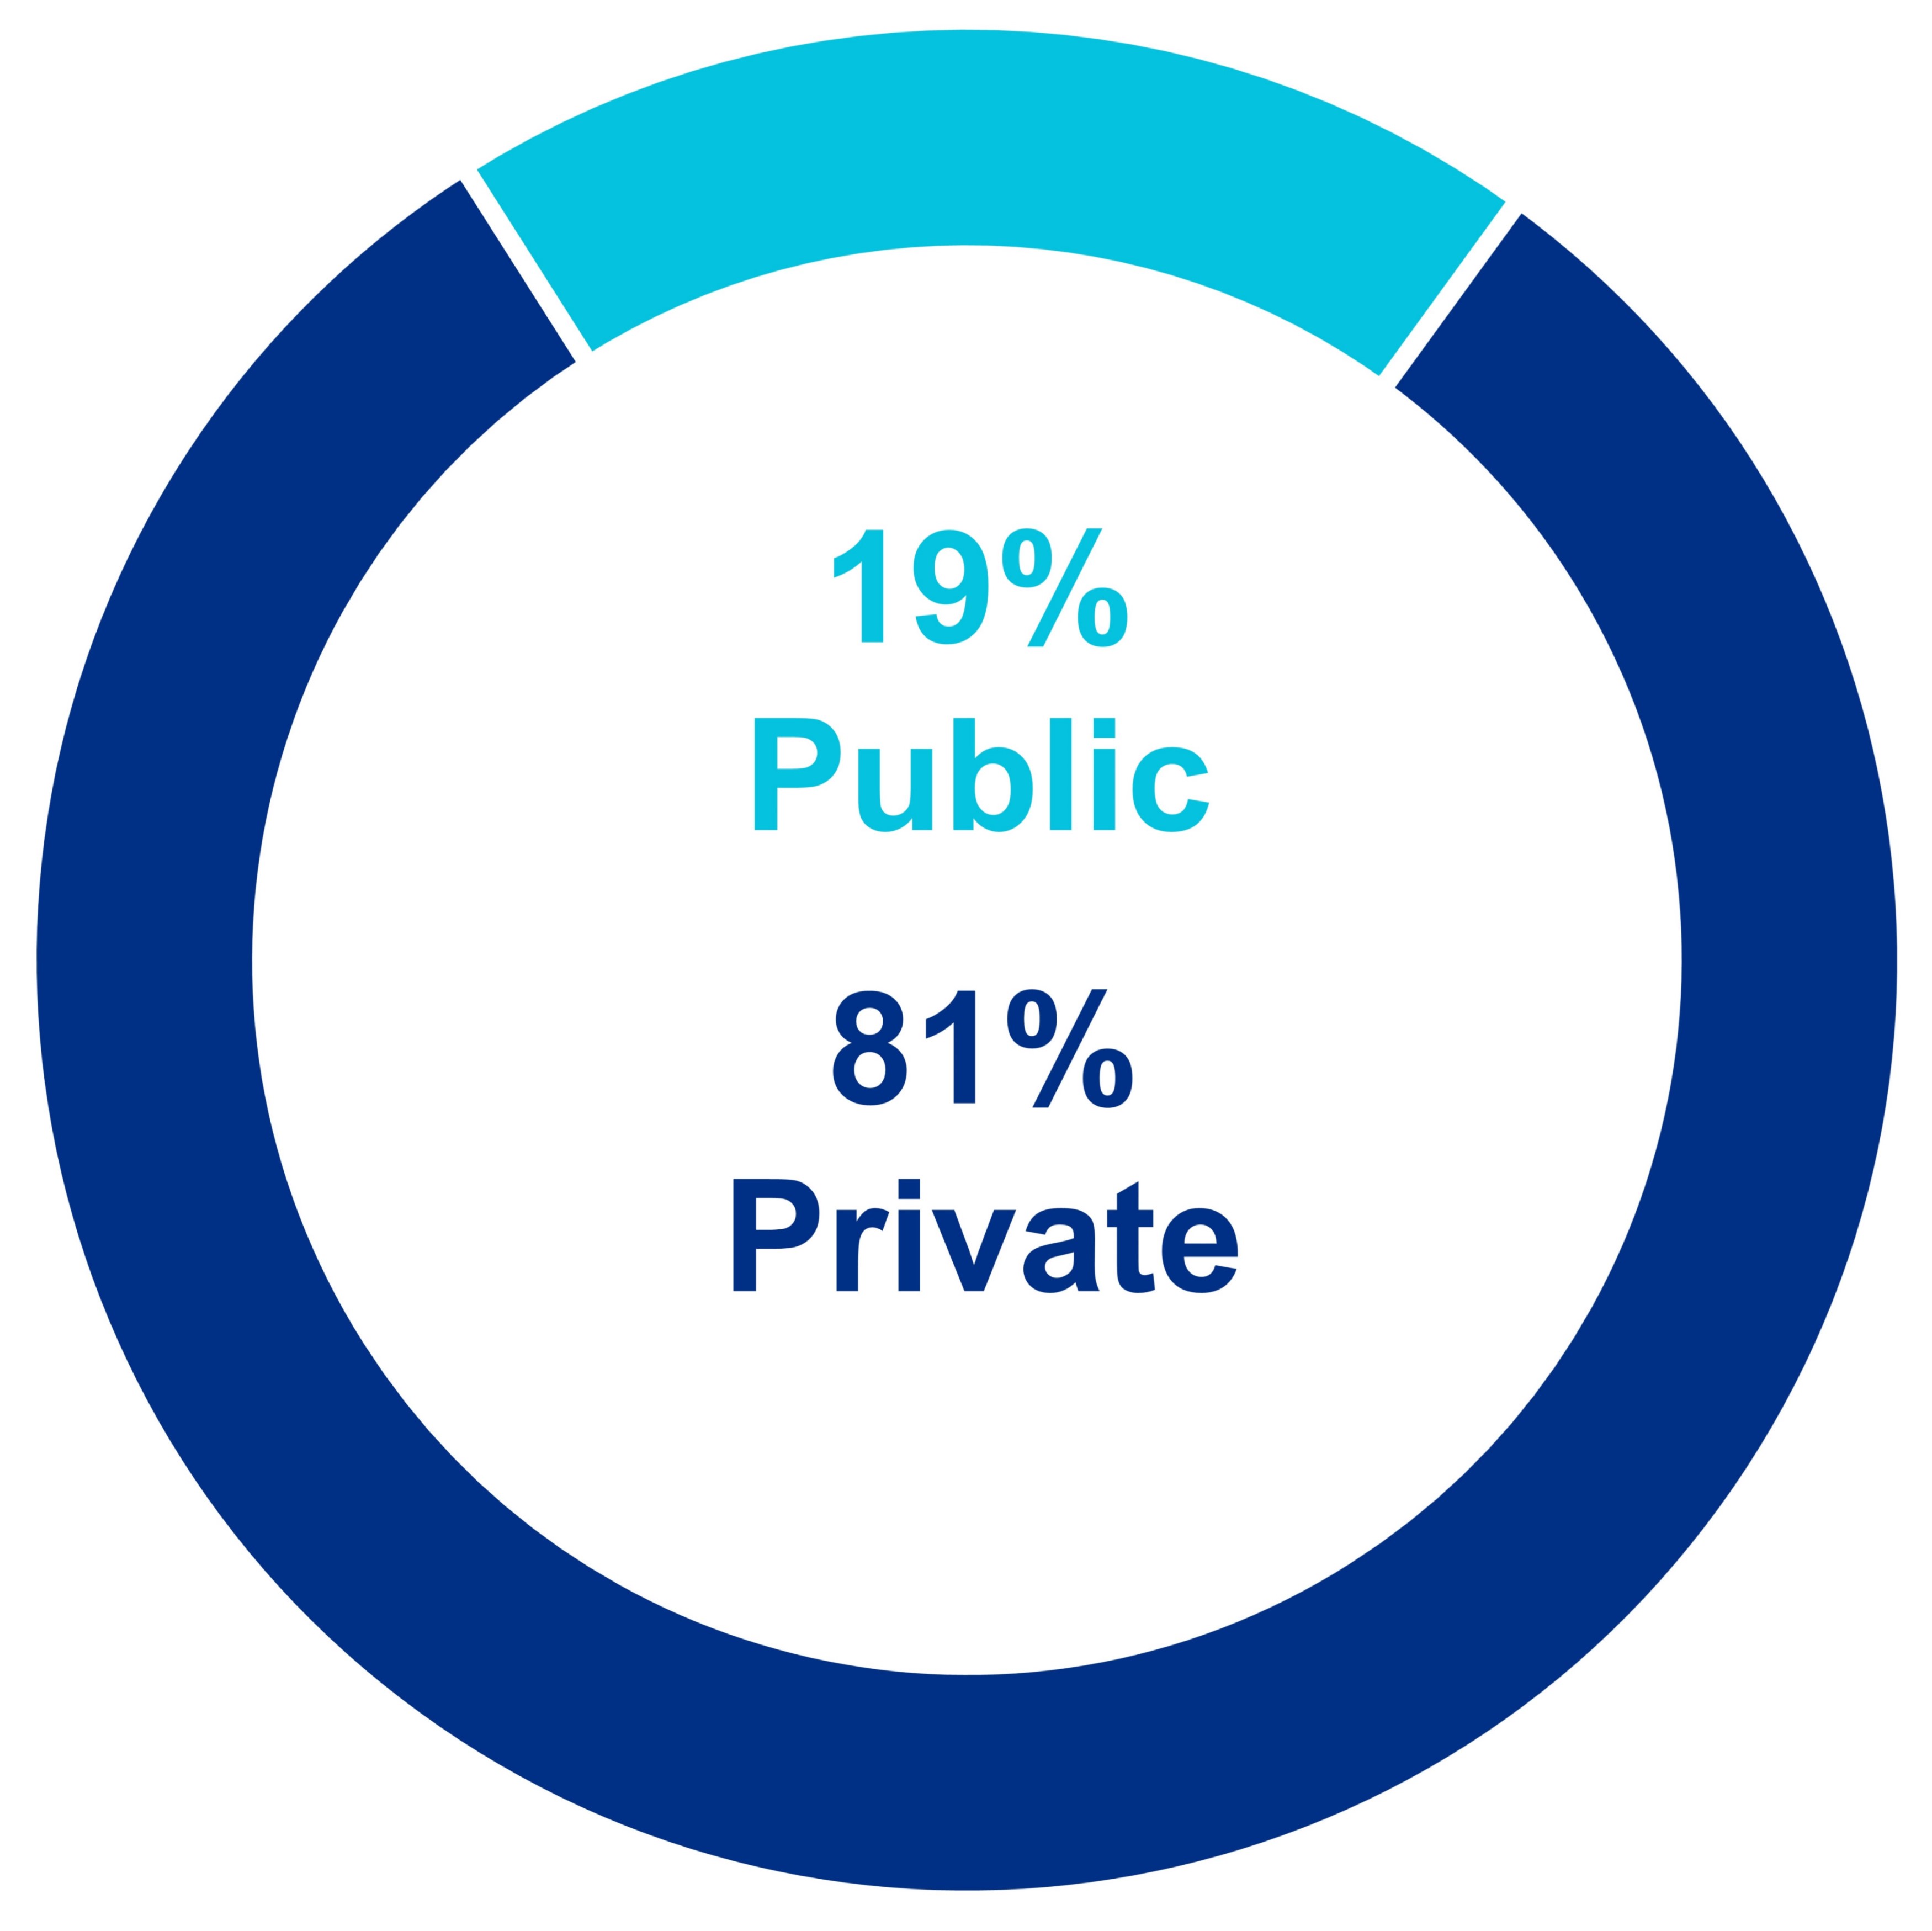 | ||
Tenant/Non-Tenant Mix (Cost) | ||
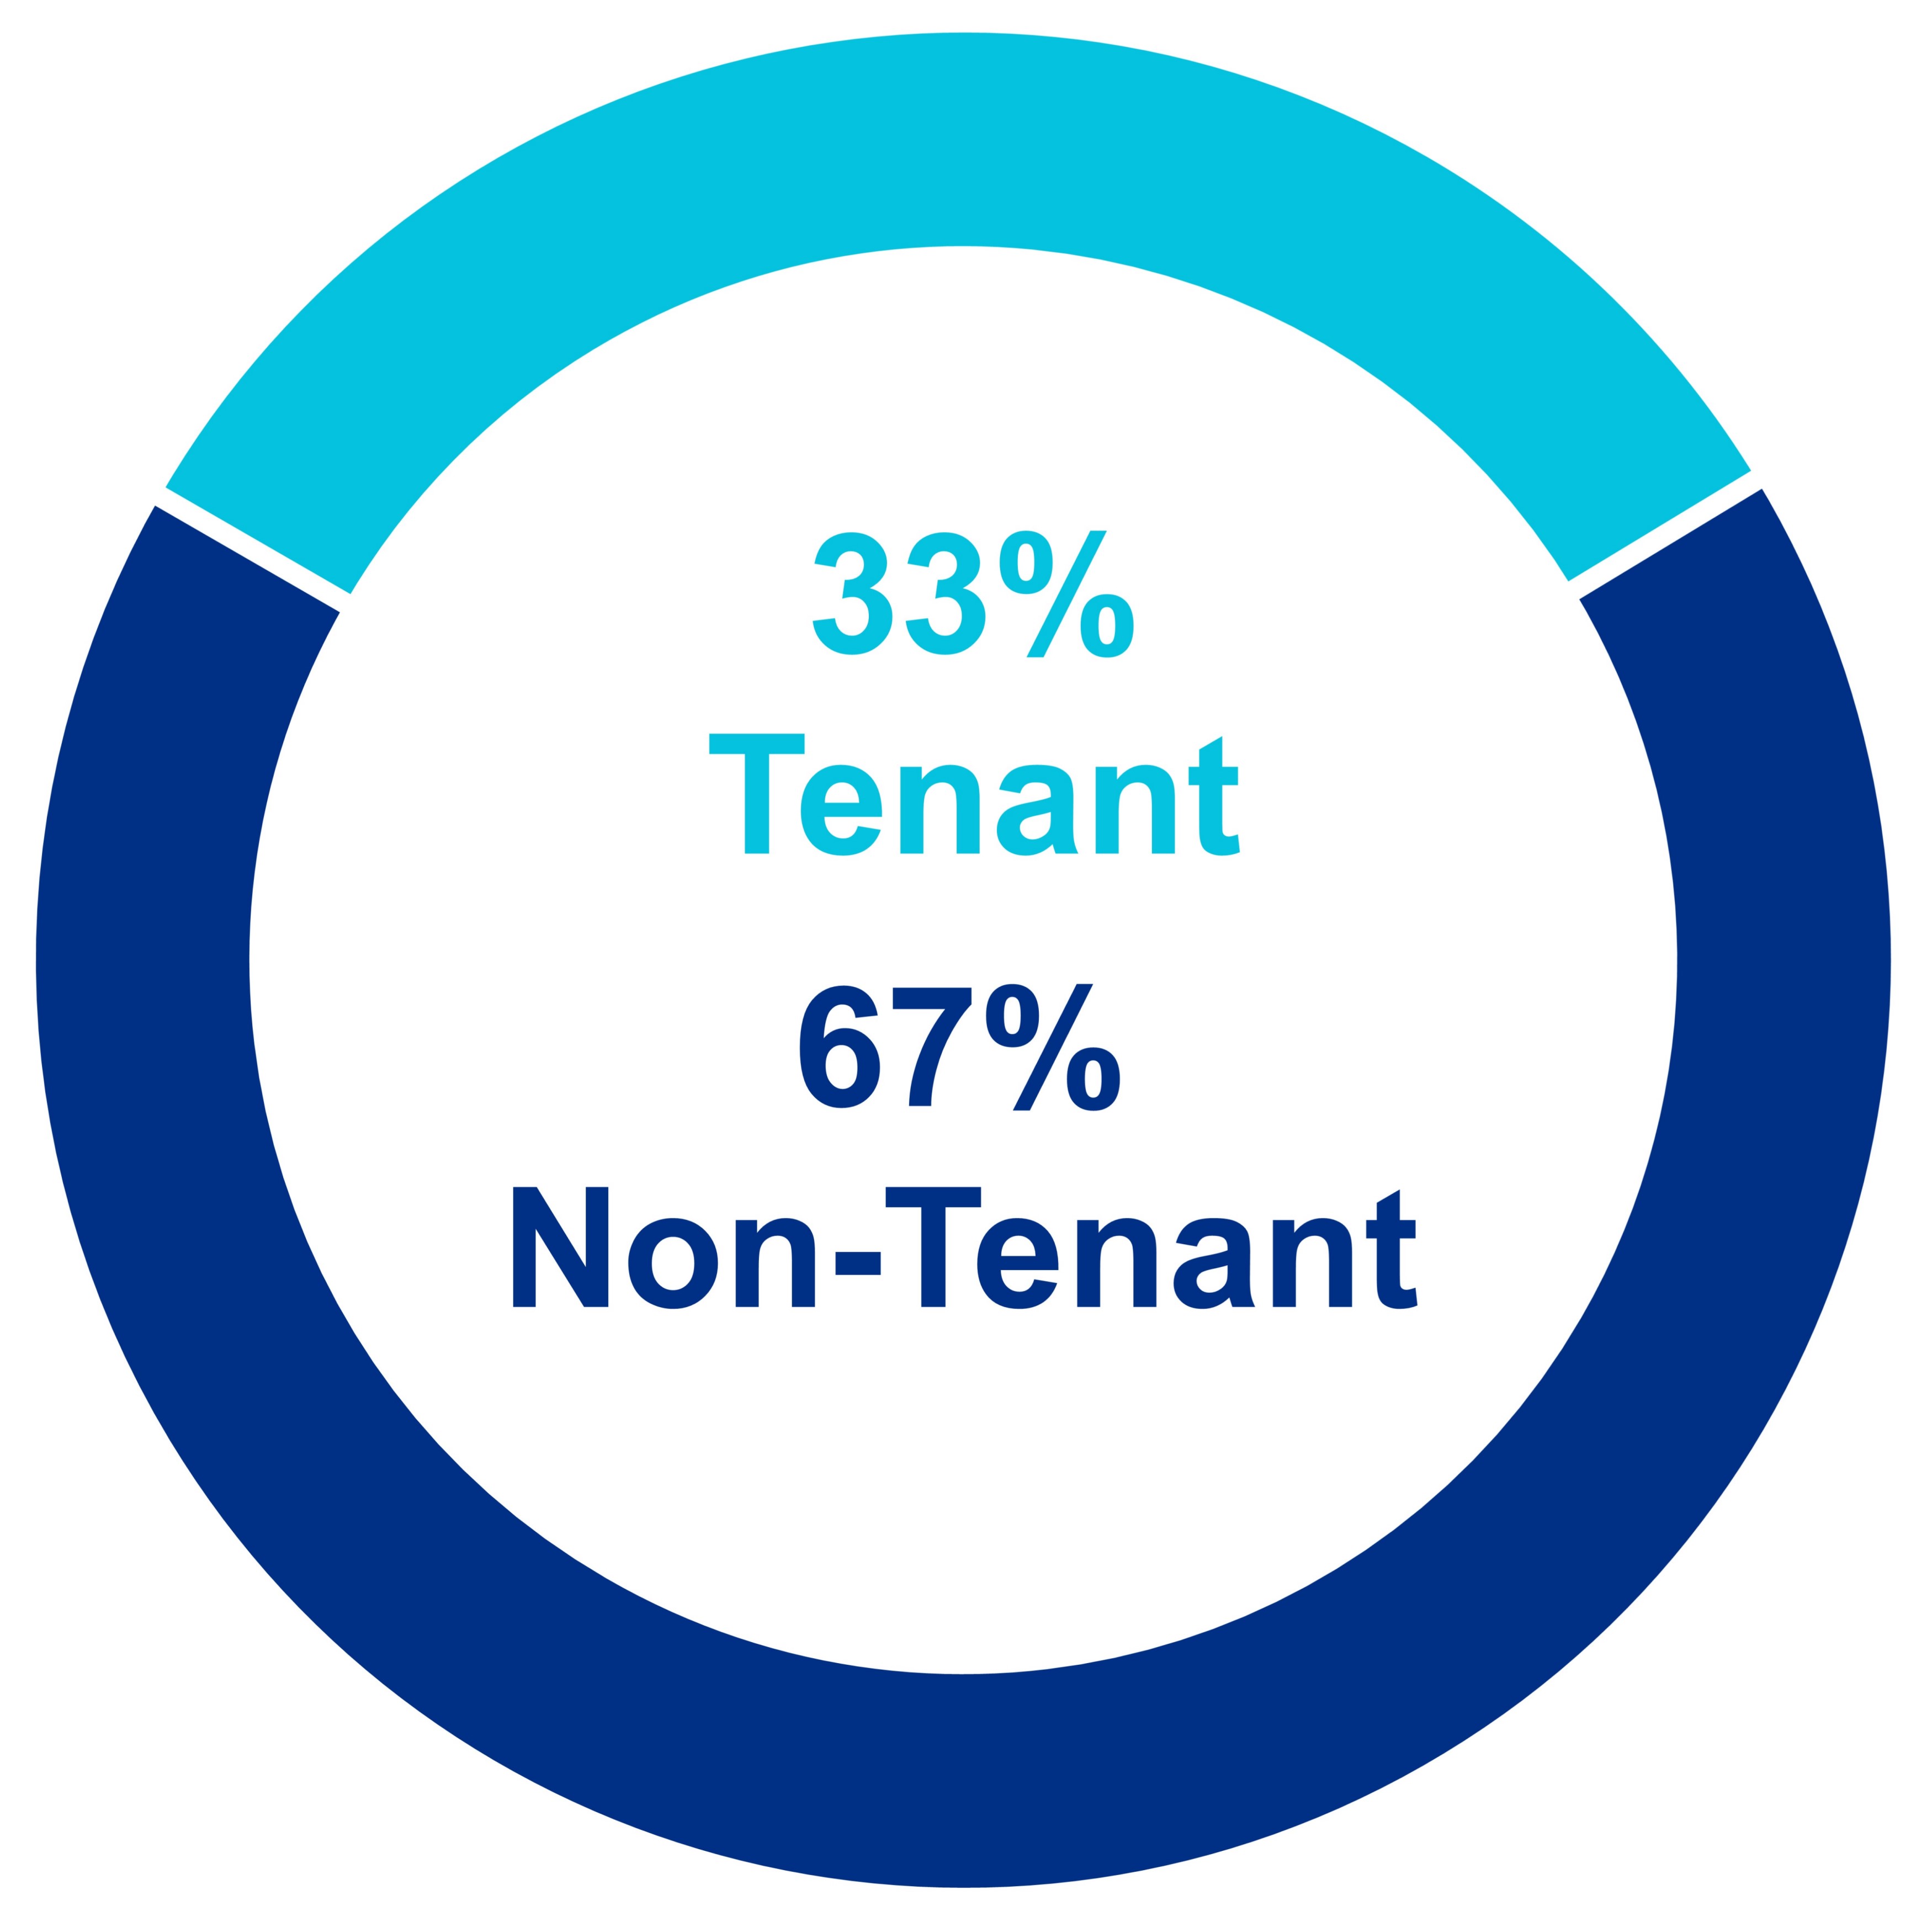 | ||
| |
Key Credit Metrics | |
March 31, 2020 | |
Liquidity | Debt Issuances Over the Trailing Five Quarters | |||||||||
$4.0B | ||||||||||
Issuances of Unsecured Senior Notes Payable | $3.4 Billion | |||||||||
Weighted-Average Interest Rate | 3.95% | |||||||||
(in millions) | ||||||||||
$2.2 billion unsecured senior line of credit | $ | 1,979 | ||||||||
Outstanding forward equity sales agreements | 524 | Weighted-Average Remaining Term as of March 31, 2020 | 15.4 years | |||||||
Cash, cash equivalents, and restricted cash | 488 | |||||||||
Investments in publicly traded companies | 287 | |||||||||
Liquidity as of March 31, 2020 | 3,278 | |||||||||
$750.0 million unsecured senior line of credit completed in April 2020 | 750 | |||||||||
Total | $ | 4,028 | ||||||||
Net Debt and Preferred Stock to Adjusted EBITDA(1) | Fixed-Charge Coverage Ratio(1) | |||||||||
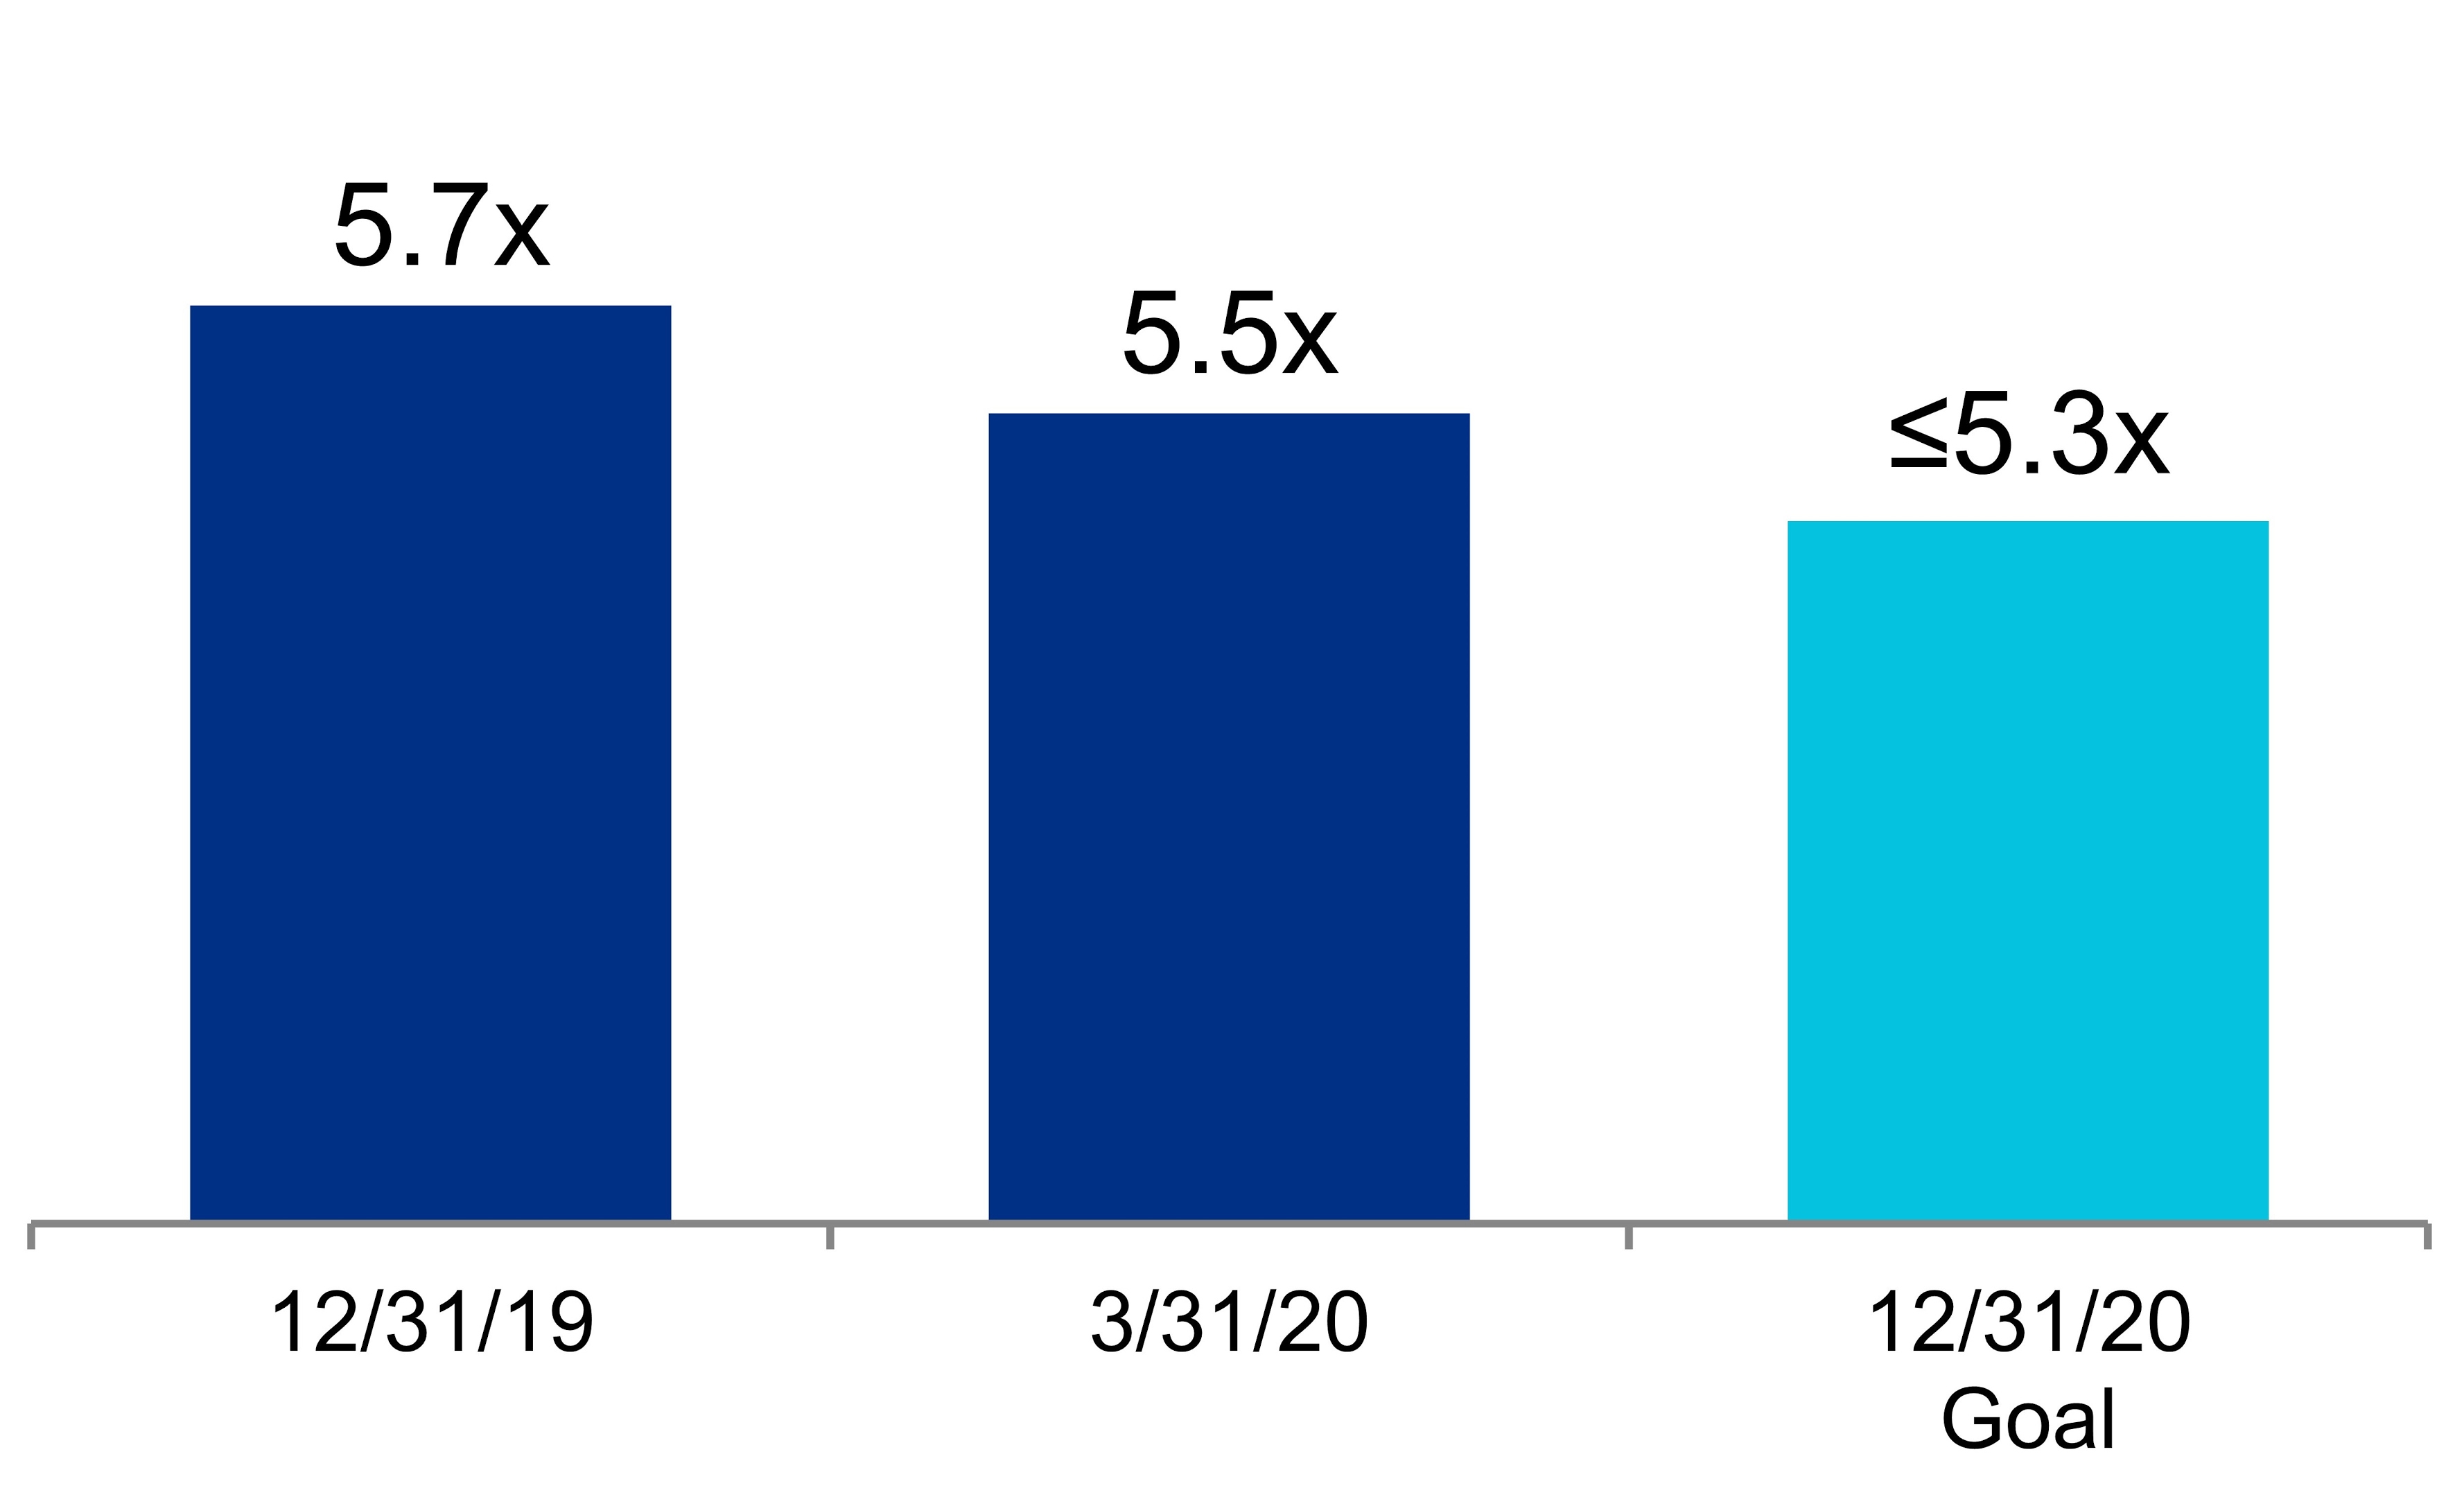 | 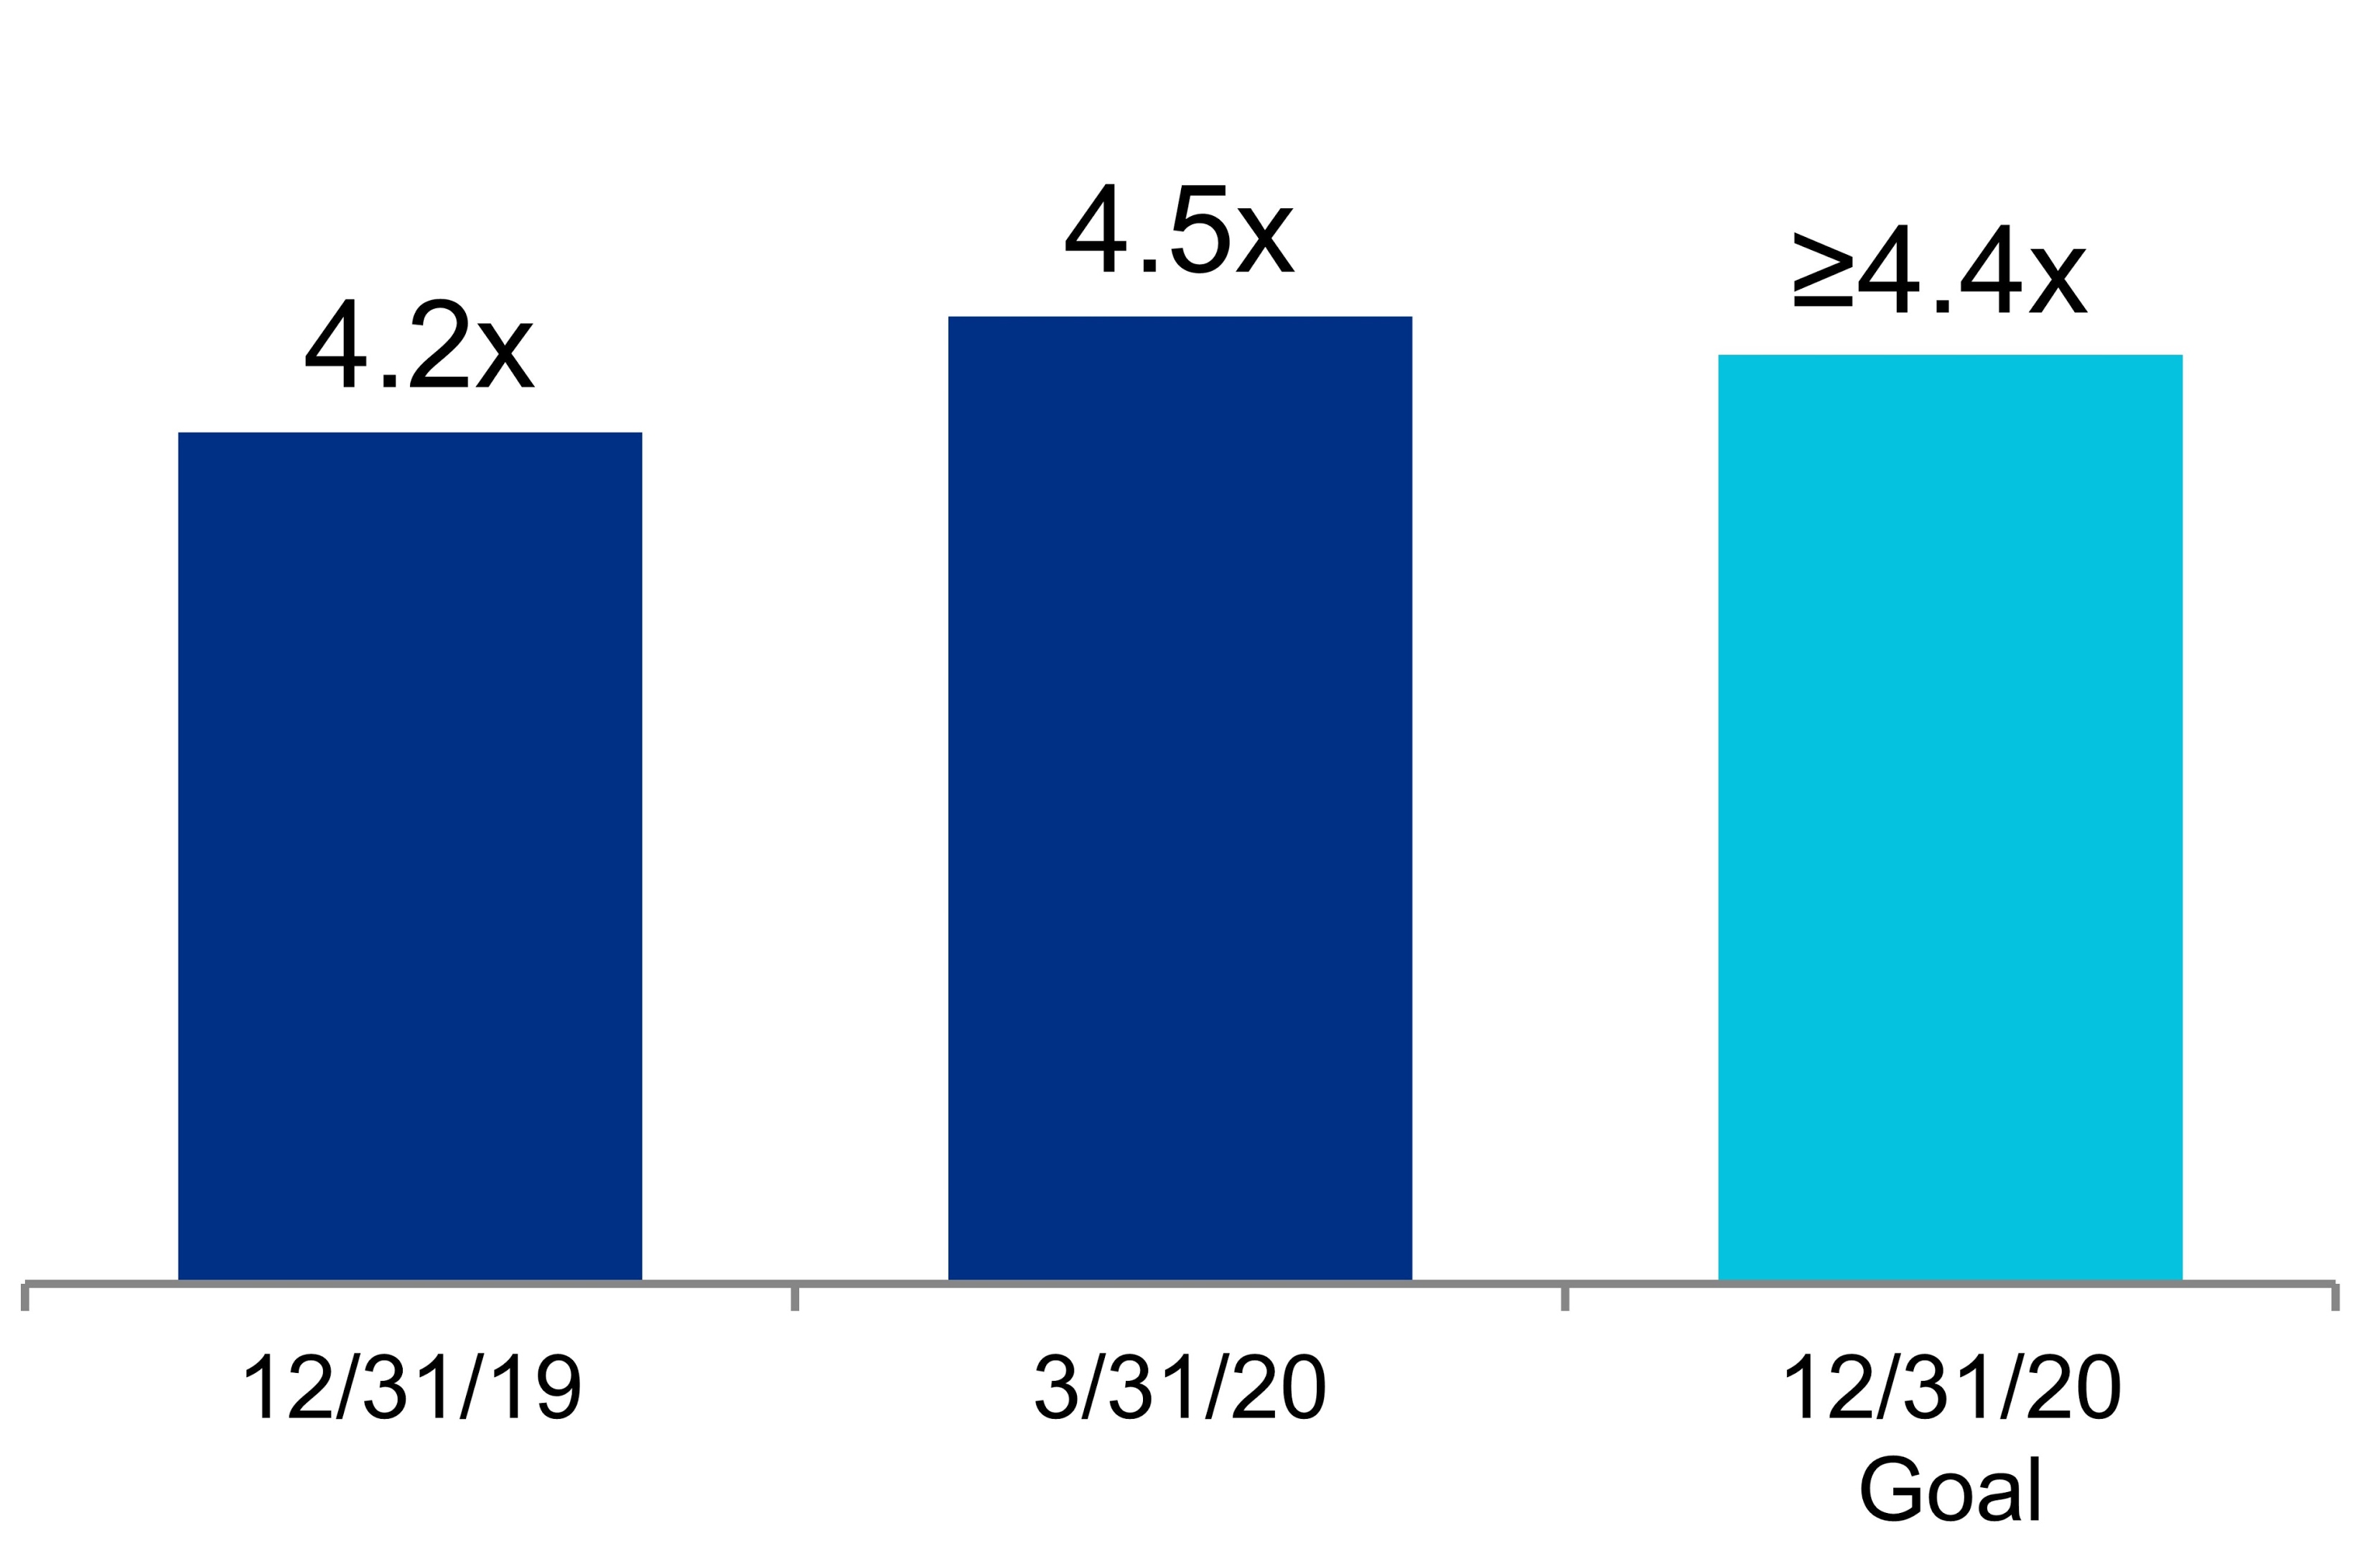 | |||||||||
(1) | Quarter annualized. |
| |
Summary of Debt | |
March 31, 2020 | |
Debt maturities chart
(In millions)
Weighted-Average Remaining Term of 10.3 Years
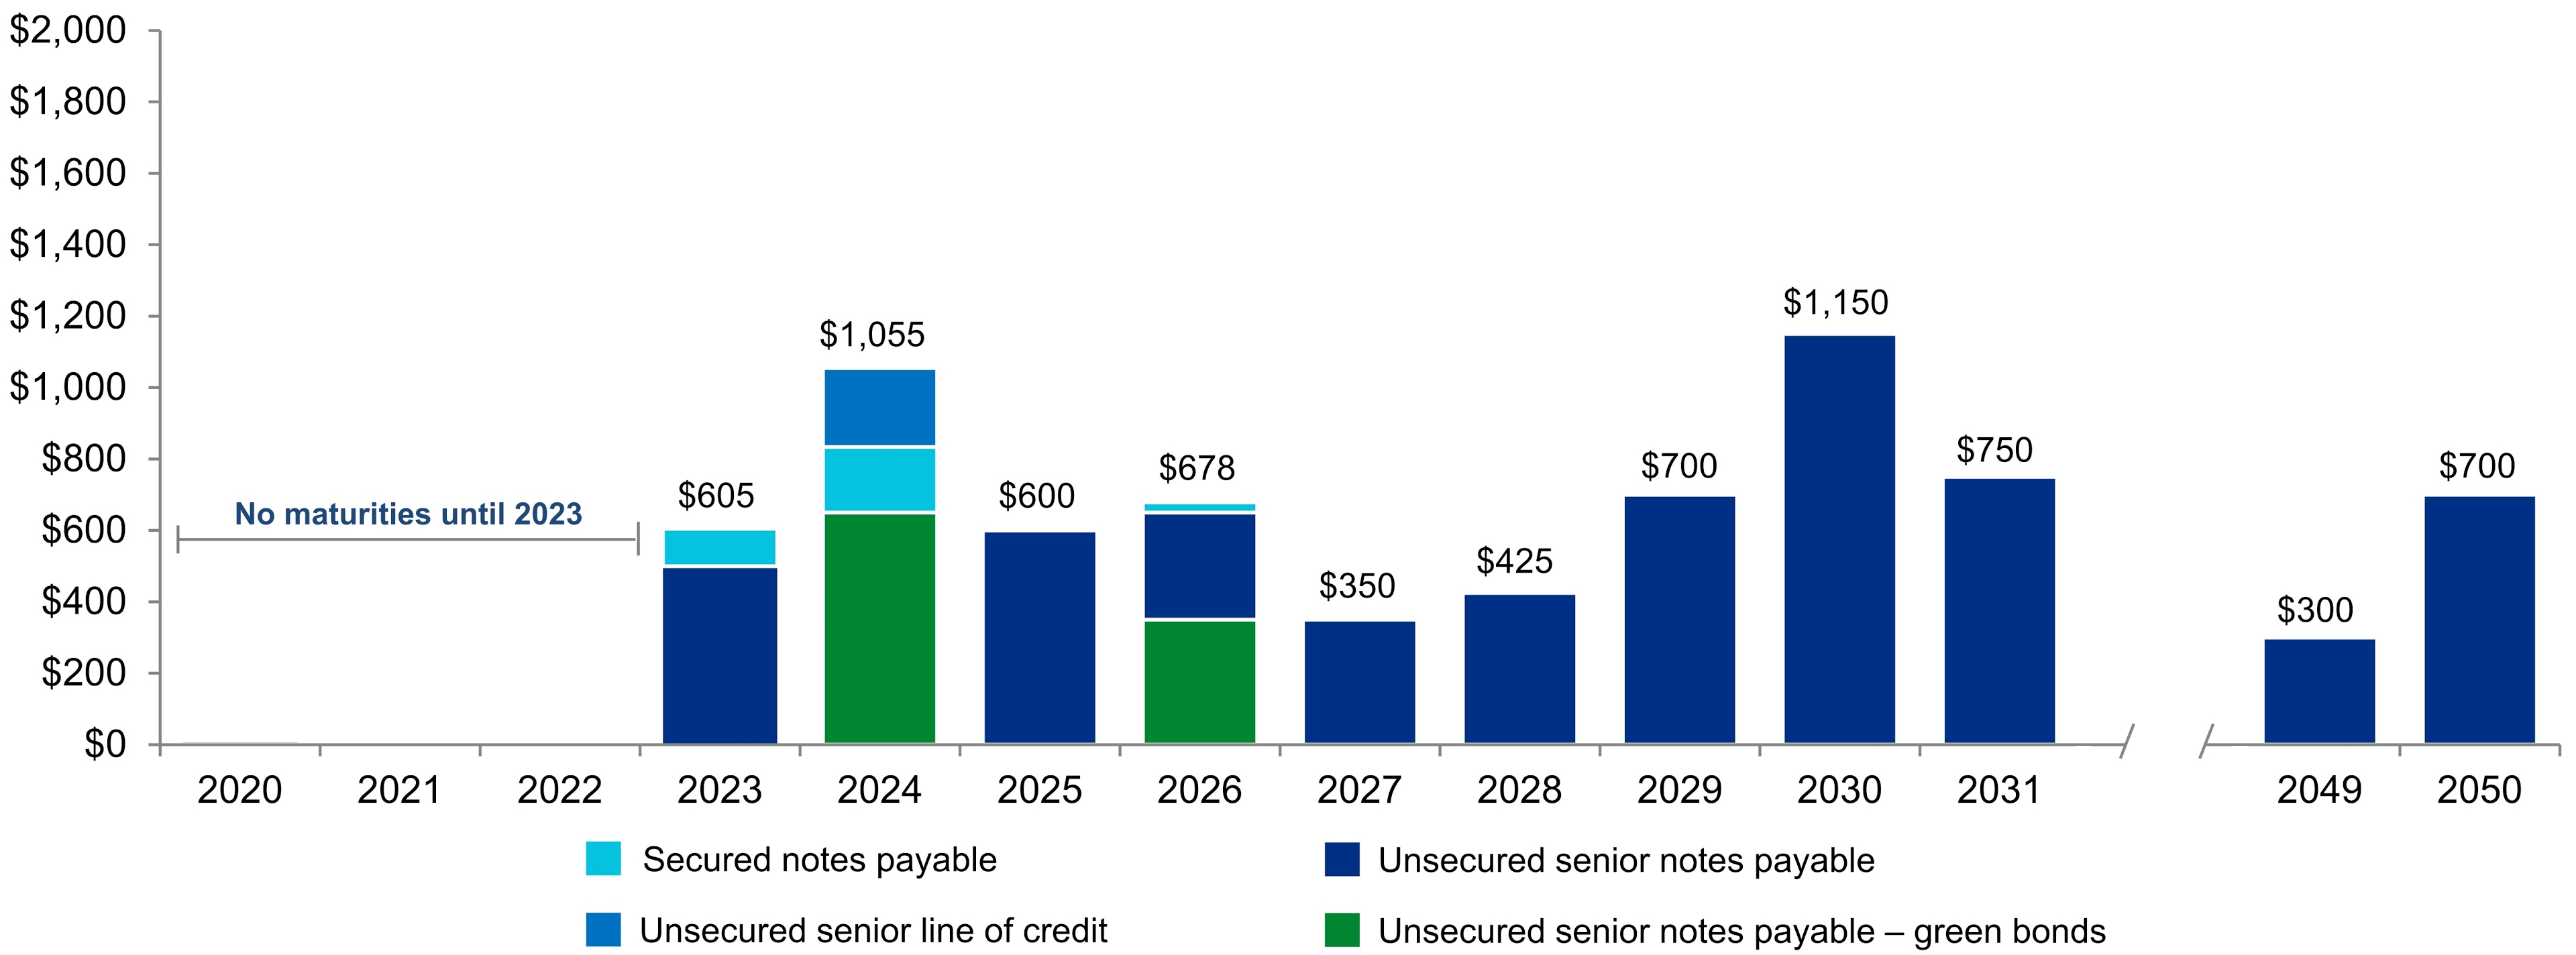 | ||
Summary of Debt (continued) | |
March 31, 2020 | |
(Dollars in thousands) | |
Fixed-rate and variable-rate debt | Fixed-Rate Debt | Variable-Rate Debt | Total | Percentage | Weighted-Average | |||||||||||||||
Interest Rate(1) | Remaining Term (in years) | |||||||||||||||||||
Secured notes payable | $ | 347,136 | $ | — | $ | 347,136 | 4.8 | % | 3.57 | % | 3.8 | |||||||||
Unsecured senior notes payable | 6,736,999 | — | 6,736,999 | 92.2 | 4.10 | 10.9 | ||||||||||||||
$2.2 billion unsecured senior line of credit(2) | — | 221,000 | 221,000 | 3.0 | 2.12 | 3.8 | ||||||||||||||
Total/weighted average | $ | 7,084,135 | $ | 221,000 | $ | 7,305,135 | 100.0 | % | 4.01 | % | 10.3 | |||||||||
Percentage of total debt | 97 | % | 3 | % | 100 | % | ||||||||||||||
(1) | Represents the weighted-average interest rate as of the end of the applicable period, including expense/income related to the amortization of loan fees, amortization of debt premiums (discounts), and other bank fees. |
(2) | Includes our commercial paper program, which had no outstanding balance as of March 31, 2020. In April 2020, we closed an additional unsecured senior line of credit with $750.0 million of aggregate commitments available for borrowing. |
Debt covenants | Unsecured Senior Notes Payable | $2.2 Billion Unsecured Senior Line of Credit | |||||||
Debt Covenant Ratios(1) | Requirement | March 31, 2020 | Requirement | March 31, 2020 | |||||
Total Debt to Total Assets | ≤ 60% | 34% | ≤ 60.0% | 30.1% | |||||
Secured Debt to Total Assets | ≤ 40% | 2% | ≤ 45.0% | 1.4% | |||||
Consolidated EBITDA to Interest Expense | ≥ 1.5x | 6.4x | ≥ 1.50x | 3.81x | |||||
Unencumbered Total Asset Value to Unsecured Debt | ≥ 150% | 277% | N/A | N/A | |||||
Unsecured Interest Coverage Ratio | N/A | N/A | ≥ 1.75x | 5.89x | |||||
(1) | All covenant ratio titles utilize terms as defined in the respective debt and credit agreements. EBITDA is not calculated pursuant to the definition set forth by the SEC in Exchange Act Release No. 47226. |
Unconsolidated real estate joint ventures’ debt | |||||||||||||||||||
Unconsolidated Joint Venture | Our Share | Maturity Date | Stated Rate | Interest Rate(1) | 100% at JV Level Debt Balance(2) | ||||||||||||||
704 Quince Orchard Road | 56.8 | % | 3/16/23 | L+1.95% | 2.90 | % | $ | 9,954 | |||||||||||
1655 and 1725 Third Street(3) | 10.0 | % | 3/10/25 | 4.50% | 4.81 | % | 590,844 | ||||||||||||
Menlo Gateway, Phase II | 49.0 | % | 5/1/35 | 4.53% | 4.59 | % | 98,807 | ||||||||||||
Menlo Gateway, Phase I | 49.0 | % | 8/10/35 | 4.15% | 4.18 | % | 141,475 | ||||||||||||
$ | 841,080 | ||||||||||||||||||
(1) | Includes interest expense and amortization of loan fees. |
(2) | Represents outstanding principal, net of unamortized deferred financing costs, as of March 31, 2020. |
(3) | In March 2020, we completed the refinancing of a secured construction loan with an outstanding balance of $313.2 million and interest rate of L+3.70% to a fixed-rate loan that bears an interest rate of 4.50%. |
Summary of Debt (continued) | |
March 31, 2020 | |
(Dollars in thousands) | |
Debt | Stated Rate | Interest Rate(1) | Maturity Date(2) | Principal Payments Remaining for the Periods Ending December 31, | Principal | Unamortized (Deferred Financing Cost), (Discount)/Premium | Total | |||||||||||||||||||||||||||||||||||||||
2020 | 2021 | 2022 | 2023 | 2024 | Thereafter | |||||||||||||||||||||||||||||||||||||||||
Secured notes payable | ||||||||||||||||||||||||||||||||||||||||||||||
San Diego | 4.66 | % | 4.90 | % | 1/1/23 | $ | 1,328 | $ | 1,852 | $ | 1,942 | $ | 26,259 | $ | — | $ | — | $ | 31,381 | $ | (181 | ) | $ | 31,200 | ||||||||||||||||||||||
Greater Boston | 3.93 | % | 3.19 | 3/10/23 | 1,179 | 1,629 | 1,693 | 74,517 | — | — | 79,018 | 1,637 | 80,655 | |||||||||||||||||||||||||||||||||
Greater Boston | 4.82 | % | 3.40 | 2/6/24 | 2,407 | 3,394 | 3,564 | 3,742 | 183,527 | — | 196,634 | 10,336 | 206,970 | |||||||||||||||||||||||||||||||||
San Francisco | 4.14 | % | 4.42 | 7/1/26 | — | — | — | — | — | 28,200 | 28,200 | (617 | ) | 27,583 | ||||||||||||||||||||||||||||||||
San Francisco | 6.50 | % | 6.50 | 7/1/36 | 25 | 26 | 28 | 30 | 32 | 587 | 728 | — | 728 | |||||||||||||||||||||||||||||||||
Secured debt weighted-average interest rate/subtotal | 4.55 | % | 3.57 | 4,939 | 6,901 | 7,227 | 104,548 | 183,559 | 28,787 | 335,961 | 11,175 | 347,136 | ||||||||||||||||||||||||||||||||||
Commercial paper program(3) | N/A | N/A | (3) | N/A | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||
$2.2 billion unsecured senior line of credit | L+0.825 | % | 2.12 | 1/28/24 | — | — | — | — | 221,000 | — | 221,000 | — | 221,000 | |||||||||||||||||||||||||||||||||
Unsecured senior notes payable | 3.90 | % | 4.04 | 6/15/23 | — | — | — | 500,000 | — | — | 500,000 | (1,915 | ) | 498,085 | ||||||||||||||||||||||||||||||||
Unsecured senior notes payable – green bond | 4.00 | % | 4.03 | 1/15/24 | — | — | — | — | 650,000 | — | 650,000 | (497 | ) | 649,503 | ||||||||||||||||||||||||||||||||
Unsecured senior notes payable | 3.45 | % | 3.62 | 4/30/25 | — | — | — | — | — | 600,000 | 600,000 | (4,452 | ) | 595,548 | ||||||||||||||||||||||||||||||||
Unsecured senior notes payable | 4.30 | % | 4.50 | 1/15/26 | — | — | — | — | — | 300,000 | 300,000 | (2,823 | ) | 297,177 | ||||||||||||||||||||||||||||||||
Unsecured senior notes payable – green bond | 3.80 | % | 3.96 | 4/15/26 | — | — | — | — | — | 350,000 | 350,000 | (2,961 | ) | 347,039 | ||||||||||||||||||||||||||||||||
Unsecured senior notes payable | 3.95 | % | 4.13 | 1/15/27 | — | — | — | — | — | 350,000 | 350,000 | (3,430 | ) | 346,570 | ||||||||||||||||||||||||||||||||
Unsecured senior notes payable | 3.95 | % | 4.07 | 1/15/28 | — | — | — | — | — | 425,000 | 425,000 | (3,299 | ) | 421,701 | ||||||||||||||||||||||||||||||||
Unsecured senior notes payable | 4.50 | % | 4.60 | 7/30/29 | — | — | — | — | — | 300,000 | 300,000 | (2,072 | ) | 297,928 | ||||||||||||||||||||||||||||||||
Unsecured senior notes payable | 2.75 | % | 2.87 | 12/15/29 | — | — | — | — | — | 400,000 | 400,000 | (3,989 | ) | 396,011 | ||||||||||||||||||||||||||||||||
Unsecured senior notes payable | 4.70 | % | 4.81 | 7/1/30 | — | — | — | — | — | 450,000 | 450,000 | (3,811 | ) | 446,189 | ||||||||||||||||||||||||||||||||
Unsecured senior notes payable | 4.90 | % | 5.05 | (4) | 12/15/30 | — | — | — | — | — | 700,000 | 700,000 | (8,423 | ) | 691,577 | |||||||||||||||||||||||||||||||
Unsecured senior notes payable | 3.375 | % | 3.48 | 8/15/31 | — | — | — | — | — | 750,000 | 750,000 | (7,370 | ) | 742,630 | ||||||||||||||||||||||||||||||||
Unsecured senior notes payable | 4.85 | % | 4.93 | 4/15/49 | — | — | — | — | — | 300,000 | 300,000 | (3,418 | ) | 296,582 | ||||||||||||||||||||||||||||||||
Unsecured senior notes payable | 4.00 | % | 3.91 | 2/1/50 | — | — | — | — | — | 700,000 | 700,000 | 10,459 | 710,459 | |||||||||||||||||||||||||||||||||
Unsecured debt weighted-average/subtotal | 4.04 | — | — | — | 500,000 | 871,000 | 5,625,000 | 6,996,000 | (38,001 | ) | 6,957,999 | |||||||||||||||||||||||||||||||||||
Weighted-average interest rate/total | 4.01 | % | $ | 4,939 | $ | 6,901 | $ | 7,227 | $ | 604,548 | $ | 1,054,559 | $ | 5,653,787 | $ | 7,331,961 | $ | (26,826 | ) | $ | 7,305,135 | |||||||||||||||||||||||||
Balloon payments | $ | — | $ | — | $ | — | $ | 600,487 | $ | 1,054,221 | $ | 5,653,200 | $ | 7,307,908 | $ | — | $ | 7,307,908 | ||||||||||||||||||||||||||||
Principal amortization | 4,939 | 6,901 | 7,227 | 4,061 | 338 | 587 | 24,053 | (26,826 | ) | (2,773 | ) | |||||||||||||||||||||||||||||||||||
Total debt | $ | 4,939 | $ | 6,901 | $ | 7,227 | $ | 604,548 | $ | 1,054,559 | $ | 5,653,787 | $ | 7,331,961 | $ | (26,826 | ) | $ | 7,305,135 | |||||||||||||||||||||||||||
Fixed-rate/hedged variable-rate debt | $ | 4,939 | $ | 6,901 | $ | 7,227 | $ | 604,548 | $ | 833,559 | $ | 5,653,787 | $ | 7,110,961 | $ | (26,826 | ) | $ | 7,084,135 | |||||||||||||||||||||||||||
Unhedged variable-rate debt | — | — | — | — | 221,000 | — | 221,000 | — | 221,000 | |||||||||||||||||||||||||||||||||||||
Total debt | $ | 4,939 | $ | 6,901 | $ | 7,227 | $ | 604,548 | $ | 1,054,559 | $ | 5,653,787 | $ | 7,331,961 | $ | (26,826 | ) | $ | 7,305,135 | |||||||||||||||||||||||||||
Weighted-average stated rate on maturing debt | N/A | N/A | N/A | 3.94% | 3.70% | 4.01% | ||||||||||||||||||||||||||||||||||||||||
(1) | Represents the weighted-average interest rate as of the end of the applicable period, including amortization of loan fees, amortization of debt premiums (discounts), and other bank fees. |
(2) | Reflects any extension options that we control. |
(3) | In March 2020, we increased the aggregate amount we may issue from time to time under our commercial paper program from $750.0 million to $1.0 billion. This program provides us with the ability to issue commercial paper notes bearing interest at short-term fixed rates, generally with a maturity of 30 days or less and with a maximum maturity of 397 days from the date of issuance. Borrowings under the program will be used to fund short-term capital needs and are backed by our $2.2 billion unsecured senior line of credit. In the event we are unable to issue commercial paper notes or refinance outstanding commercial paper notes under terms equal to or more favorable than those under the $2.2 billion unsecured senior line of credit, we expect to borrow under the $2.2 billion unsecured senior line of credit at L+0.825%. The commercial paper notes sold during the three months ended March 31, 2020, were issued at a weighted-average yield to maturity of 1.84%. |
(4) | Issued on March 26, 2020. |
| |
Definitions and Reconciliations | |
March 31, 2020 | |
This section contains additional details for sections throughout this Supplemental Information package and the accompanying Earnings Press Release, as well as explanations and reconciliations of certain non-GAAP financial measures and the reasons why we use these supplemental measures of performance and believe they provide useful information to investors. Additional detail can be found in our most recent annual report on Form 10-K and subsequent quarterly reports on Form 10-Q, as well as other documents filed with or furnished to the SEC from time to time.
Adjusted EBITDA and Adjusted EBITDA margin
The following table reconciles net income (loss) and revenues, the most directly comparable financial measures calculated and presented in accordance with GAAP, to Adjusted EBITDA and revenues, as adjusted, respectively:
Three Months Ended | |||||||||||||||||||
(Dollars in thousands) | 3/31/20 | 12/31/19 | 9/30/19 | 6/30/19 | 3/31/19 | ||||||||||||||
Net income (loss) | $ | 30,678 | $ | 216,053 | $ | (36,003 | ) | $ | 87,179 | $ | 136,818 | ||||||||
Interest expense | 45,739 | 45,493 | 46,203 | 42,879 | 39,100 | ||||||||||||||
Income taxes | 1,341 | 1,269 | 887 | 890 | 1,297 | ||||||||||||||
Depreciation and amortization | 175,496 | 140,518 | 135,570 | 134,437 | 134,087 | ||||||||||||||
Stock compensation expense | 9,929 | 10,239 | 10,935 | 11,437 | 11,029 | ||||||||||||||
Loss on early extinguishment of debt | — | — | 40,209 | — | 7,361 | ||||||||||||||
Gain on sales of real estate | — | (474 | ) | — | — | — | |||||||||||||
Unrealized losses (gains) on non-real estate investments | 17,144 | (148,268 | ) | 70,043 | (11,058 | ) | (72,206 | ) | |||||||||||
Impairment of real estate | 9,647 | 12,334 | — | — | — | ||||||||||||||
Impairment of non-real estate investments | 19,780 | 9,991 | 7,133 | — | — | ||||||||||||||
Adjusted EBITDA | $ | 309,754 | $ | 287,155 | $ | 274,977 | $ | 265,764 | $ | 257,486 | |||||||||
Revenues | $ | 439,919 | $ | 408,114 | $ | 390,484 | $ | 373,856 | $ | 358,842 | |||||||||
Non-real estate investments – total realized (losses) gains | (4,677 | ) | 4,399 | 6,967 | 10,442 | 11,350 | |||||||||||||
Impairment of non-real estate investments | 19,780 | 9,991 | 7,133 | — | — | ||||||||||||||
Revenues, as adjusted | $ | 455,022 | $ | 422,504 | $ | 404,584 | $ | 384,298 | $ | 370,192 | |||||||||
Adjusted EBITDA margin | 68% | 68% | 68% | 69% | 70% | ||||||||||||||
We use Adjusted EBITDA as a supplemental performance measure of our operations, for financial and operational decision-making, and as a supplemental means of evaluating period-to-period comparisons on a consistent basis. Adjusted EBITDA is calculated as earnings before interest, taxes, depreciation, and amortization (“EBITDA”), excluding stock compensation expense, gains or losses on early extinguishment of debt, gains or losses on sales of real estate, and impairments of real estate. Adjusted EBITDA also excludes unrealized gains or losses and significant realized gains and impairments that result from our non-real estate investments. These non-real estate investment amounts are classified in our consolidated statements of operations outside of revenues.
We believe Adjusted EBITDA provides investors with relevant and useful information as it allows investors to evaluate the operating performance of our business activities without having to account for differences recognized because of real estate and non-real estate investment and disposition decisions, financing decisions, capital structure, capital market transactions, and variances resulting from the volatility of market conditions outside of our control. For example, we exclude gains or losses on the early
extinguishment of debt to allow investors to measure our performance independent of our indebtedness and capital structure. We believe that adjusting for the effects of impairments and gains or losses on sales of real estate, and significant impairments and significant gains on the sale of non-real estate investments allows investors to evaluate performance from period to period on a consistent basis without having to account for differences recognized because of real estate and non-real estate investment and disposition decisions. We believe that excluding charges related to stock compensation and unrealized gains or losses facilitates for investors a comparison of our business activities across periods without the volatility resulting from market forces outside of our control. Adjusted EBITDA has limitations as a measure of our performance. Adjusted EBITDA does not reflect our historical expenditures or future requirements for capital expenditures or contractual commitments. While Adjusted EBITDA is a relevant measure of performance, it does not represent net income (loss) or cash flows from operations calculated and presented in accordance with GAAP, and it should not be considered as an alternative to those indicators in evaluating performance or liquidity.
Our calculation of Adjusted EBITDA margin divides Adjusted EBITDA by our revenues, as adjusted. We believe that revenues, as adjusted, provides a denominator for Adjusted EBITDA margin that is calculated on a basis more consistent with that of the Adjusted EBITDA numerator. Specifically, revenues, as adjusted, includes the same realized gains on, and impairments of, non-real estate investments that are included in the reconciliation of Adjusted EBITDA. We believe that the consistent application of results from our non-real estate investments to both the numerator and denominator of Adjusted EBITDA margin provides a more useful calculation for the comparison across periods.
Annual rental revenue
Annual rental revenue represents the annualized fixed base rental amount, in effect as of the end of the period, related to our operating RSF. Annual rental revenue is presented using 100% of the annual rental revenue of our consolidated properties and our share of annual rental revenue for our unconsolidated real estate joint ventures. Annual rental revenue per RSF is computed by dividing annual rental revenue by the sum of 100% of the RSF of our consolidated properties and our share of the RSF of properties held in unconsolidated real estate joint ventures. As of March 31, 2020, approximately 93% of our leases (on an RSF basis) were triple net leases, which require tenants to pay substantially all real estate taxes, insurance, utilities, repairs and maintenance, common area expenses, and other operating expenses (including increases thereto) in addition to base rent. Annual rental revenue excludes these operating expenses recovered from our tenants. Amounts recovered from our tenants related to these operating expenses, along with base rent, are classified in income from rentals in our consolidated statements of operations.
Cash interest
Cash interest is equal to interest expense calculated in accordance with GAAP plus capitalized interest, less amortization of loan fees and debt premiums (discounts). Refer to the definition of fixed-charge coverage ratio for a reconciliation of interest expense, the most directly comparable financial measure calculated and presented in accordance with GAAP, to cash interest.
| |
Definitions and Reconciliations (continued) | |
March 31, 2020 | |
Class A properties and AAA locations
Class A properties are properties clustered in AAA locations that provide innovative tenants with highly dynamic and collaborative environments that enhance their ability to successfully recruit and retain world-class talent and inspire productivity, efficiency, creativity, and success. Class A properties generally command higher annual rental rates than other classes of similar properties.
AAA locations are in close proximity to concentrations of specialized skills, knowledge, institutions, and related businesses. Such locations are generally characterized by high barriers to entry for new landlords, high barriers to exit for tenants, and a limited supply of available space.
Development, redevelopment, and pre-construction
A key component of our business model is our disciplined allocation of capital to the development and redevelopment of new Class A properties, and property enhancements identified during the underwriting of certain acquired properties, located in collaborative life science, technology, and agtech campuses in AAA urban innovation clusters. These projects are generally focused on providing high-quality, generic, and reusable spaces that meet the real estate requirements of, and are reusable by, a wide range of tenants. Upon completion, each value-creation project is expected to generate a significant increase in rental income, net operating income, and cash flows. Our development and redevelopment projects are generally in locations that are highly desirable to high-quality entities, which we believe results in higher occupancy levels, longer lease terms, higher rental income, higher returns, and greater long-term asset value.
Development projects generally consist of the ground-up development of generic and reusable facilities. Redevelopment projects consist of the permanent change in use of office, warehouse, and shell space into office/laboratory, tech office, or agtech space. We generally will not commence new development projects for aboveground construction of new Class A office/laboratory, tech office, and agtech space without first securing significant pre-leasing for such space, except when there is solid market demand for high-quality Class A properties.
Pre-construction activities include entitlements, permitting, design, site work, and other activities preceding commencement of construction of aboveground building improvements. The advancement of pre-construction efforts is focused on reducing the time required to deliver projects to prospective tenants. These critical activities add significant value for future ground-up development and are required for the vertical construction of buildings. Ultimately, these projects will provide high-quality facilities and are expected to generate significant revenue and cash flows.
Dividend payout ratio (common stock)
Dividend payout ratio (common stock) is the ratio of the absolute dollar amount of dividends on our common stock (shares of common stock outstanding on the respective record dates multiplied by the related dividend per share) to funds from operations attributable to Alexandria’s common stockholders – diluted, as adjusted.
Dividend yield
Dividend yield for the quarter represents the annualized quarter dividend divided by the closing common stock price at the end of the quarter.
Fixed-charge coverage ratio
Fixed-charge coverage ratio is a non-GAAP financial measure representing the ratio of Adjusted EBITDA to fixed charges. We believe this ratio is useful to investors as a supplemental measure of our ability to satisfy fixed financing obligations and preferred stock dividends. Cash interest is equal to interest expense calculated in accordance with GAAP plus capitalized interest, less amortization of loan fees and debt premiums (discounts).
The following table reconciles interest expense, the most directly comparable financial measure calculated and presented in accordance with GAAP, to cash interest and fixed charges:
Three Months Ended | |||||||||||||||||||
(Dollars in thousands) | 3/31/20 | 12/31/19 | 9/30/19 | 6/30/19 | 3/31/19 | ||||||||||||||
Adjusted EBITDA | $ | 309,754 | $ | 287,155 | $ | 274,977 | $ | 265,764 | $ | 257,486 | |||||||||
Interest expense | $ | 45,739 | $ | 45,493 | $ | 46,203 | $ | 42,879 | $ | 39,100 | |||||||||
Capitalized interest | 24,680 | 23,822 | 24,558 | 21,674 | 18,509 | ||||||||||||||
Amortization of loan fees | (2,247 | ) | (2,241 | ) | (2,251 | ) | (2,380 | ) | (2,233 | ) | |||||||||
Amortization of debt premiums | 888 | 907 | 1,287 | 782 | 801 | ||||||||||||||
Cash interest | 69,060 | 67,981 | 69,797 | 62,955 | 56,177 | ||||||||||||||
Dividends on preferred stock | — | — | 1,173 | 1,005 | 1,026 | ||||||||||||||
Fixed charges | $ | 69,060 | $ | 67,981 | $ | 70,970 | $ | 63,960 | $ | 57,203 | |||||||||
Fixed-charge coverage ratio: | |||||||||||||||||||
– quarter annualized | 4.5x | 4.2x | 3.9x | 4.2x | 4.5x | ||||||||||||||
– trailing 12 months | 4.2x | 4.2x | 4.1x | 4.2x | 4.2x | ||||||||||||||
| |
Definitions and Reconciliations (continued) | |
March 31, 2020 | |
Funds from operations and funds from operations, as adjusted, attributable to Alexandria’s common stockholders
GAAP-basis accounting for real estate assets utilizes historical cost accounting and assumes that real estate values diminish over time. In an effort to overcome the difference between real estate values and historical cost accounting for real estate assets, the Nareit Board of Governors established funds from operations as an improved measurement tool. Since its introduction, funds from operations has become a widely used non-GAAP financial measure among equity REITs. We believe that funds from operations is helpful to investors as an additional measure of the performance of an equity REIT. Moreover, we believe that funds from operations, as adjusted, allows investors to compare our performance to the performance of other real estate companies on a consistent basis, without having to account for differences recognized because of real estate investment and disposition decisions, financing decisions, capital structure, capital market transactions, and variances resulting from the volatility of market conditions outside of our control. On January 1, 2019, we adopted standards established by the Nareit Board of Governors in its November 2018 White Paper (the “Nareit White Paper”) on a prospective basis. The Nareit White Paper defines funds from operations as net income (computed in accordance with GAAP), excluding gains or losses on sales of real estate, and impairments of real estate, plus depreciation and amortization of operating real estate assets, and after adjustments for our share of consolidated and unconsolidated partnerships and real estate joint ventures. Impairments represent the write-down of assets when fair value over the recoverability period is less than the carrying value due to changes in general market conditions and do not necessarily reflect the operating performance of the properties during the corresponding period.
We compute funds from operations, as adjusted, as funds from operations calculated in accordance with the Nareit White Paper, excluding significant gains, losses, and impairments realized on non-real estate investments, unrealized gains or losses on non-real estate investments, gains or losses on early extinguishment of debt, gains or losses on early termination of interest rate hedge agreements, preferred stock redemption charges, deal costs, the income tax effect related to such items, and the amount of such items that is allocable to our unvested restricted stock awards. Neither funds from operations nor funds from operations, as adjusted, should be considered as alternatives to net income (determined in accordance with GAAP) as indications of financial performance, or to cash flows from operating activities (determined in accordance with GAAP) as measures of liquidity, nor are they indicative of the availability of funds for our cash needs, including our ability to make distributions.
The following table reconciles net income to funds from operations for the share of consolidated real estate joint ventures attributable to noncontrolling interests and our share of unconsolidated real estate joint ventures:
Three Months Ended March 31, 2020 | |||||||
(In thousands) | Noncontrolling Interest Share of Consolidated Real Estate JVs | Our Share of Unconsolidated Real Estate JVs | |||||
Net income (loss) | $ | 11,913 | $ | (3,116 | ) | ||
Depreciation and amortization | 15,870 | 2,643 | |||||
Impairment of real estate | — | 7,644 | |||||
Funds from operations | $ | 27,783 | $ | 7,171 | |||
Initial stabilized yield (unlevered)
Initial stabilized yield is calculated as the estimated amounts of net operating income at stabilization divided by our investment in the property. Our initial stabilized yield excludes the benefit of leverage. Our cash rents related to our value-creation projects are generally expected to increase over time due to contractual annual rent escalations. Our estimates for initial stabilized yields, initial stabilized yields (cash basis), and total costs at completion represent our initial estimates at the commencement of the project. We expect to update this information upon completion of the project, or sooner if there are significant changes to the expected project yields or costs.
• | Initial stabilized yield reflects rental income, including contractual rent escalations and any rent concessions over the term(s) of the lease(s), calculated on a straight-line basis. |
• | Initial stabilized yield (cash basis) reflects cash rents at the stabilization date after initial rental concessions, if any, have elapsed and our total cash investment in the property. |
Investment-grade or publicly traded large cap tenants
Investment-grade or publicly traded large cap tenants represent tenants that are investment-grade rated or publicly traded companies with an average daily market capitalization greater than $10 billion for the twelve months ended March 31, 2020, as reported by Bloomberg Professional Services. In addition, we monitor the credit quality and related material changes of our tenants. Material changes that cause a tenant’s market capitalization to decline below $10 billion, which are not immediately reflected in the twelve-month average, may result in their exclusion from this measure.
Investments
We hold investments in publicly traded companies and privately held entities primarily involved in the life science, technology, and agtech industries. We recognize, measure, present, and disclose these investments as follows:
Statements of Operations | ||||||
Balance Sheet | Gains and Losses | |||||
Carrying Amount | Unrealized | Realized | ||||
Difference between proceeds received upon disposition and historical cost | ||||||
Publicly traded companies | Fair value | Changes in fair value | ||||
Privately held entities without readily determinable fair values that: | ||||||
Report NAV | Fair value, using NAV as a practical expedient | Changes in NAV, as a practical expedient to fair value | ||||
Do not report NAV | Cost, adjusted for observable price changes and impairments | Observable price changes | Impairments to reduce costs to fair value, which result in an adjusted cost basis and the differences between proceeds received upon disposition and adjusted or historical cost | |||
| |
Definitions and Reconciliations (continued) | |
March 31, 2020 | |
For investments in privately held entities that do not report NAV per share, an observable price is a price observed in an orderly transaction for an identical or similar investment of the same issuer. Observable price changes result from, among other things, equity transactions for the same issuer executed during the reporting period, including subsequent equity offerings or other reported equity transactions related to the same issuer. For these transactions to be considered observable price changes of the same issuer, we evaluate whether these transactions have similar rights and obligations, including voting rights, distribution preferences, conversion rights, and other factors, to the investments we hold.
Investments in real estate
The following table reconciles our investments in real estate as of March 31, 2020:
(In thousands) | Investments in Real Estate | ||||
Gross investments in real estate | $ | 18,639,576 | |||
Less: accumulated depreciation | (2,836,981 | ) | |||
Net investments in real estate – North America | 15,802,595 | ||||
Net investments in real estate – Asia | 29,587 | ||||
Investments in real estate | $ | 15,832,182 | |||
The following table represents RSF of buildings in operation as of March 31, 2020, that will be redeveloped or replaced with new development RSF upon commencement of future construction:
Property/Submarket | RSF | |||
Intermediate-term projects: | ||||
651 Gateway Boulevard/South San Francisco | 300,010 | |||
3825 Fabian Way/Greater Stanford | 250,000 | |||
960 Industrial Road/Greater Stanford | 110,000 | |||
9363, 9373, and 9393 Towne Centre Drive/University Town Center | 112,012 | |||
10260 Campus Point Drive/University Town Center | 109,164 | |||
10931 and 10933 North Torrey Pines Road/Torrey Pines | 92,450 | |||
973,636 | ||||
Future projects: | ||||
3875 Fabian Way/Greater Stanford | 228,000 | |||
219 East 42nd Street/New York City | 349,947 | |||
4161 Campus Point Court/University Town Center | 159,884 | |||
4110 Campus Point Court/University Town Center | 14,423 | |||
4045 Sorrento Valley Boulevard/Sorrento Valley | 10,926 | |||
4075 Sorrento Valley Boulevard/Sorrento Valley | 40,000 | |||
601 Dexter Avenue North/Lake Union | 18,680 | |||
821,860 | ||||
Total value-creation RSF currently included in rental properties | 1,795,496 | |||
Joint venture financial information
We present components of balance sheet and operating results information related to our joint ventures, which are not presented, or intended to be presented, in accordance with GAAP. We present the proportionate share of certain financial line items as follows: (i) for each real estate joint venture that we consolidate in our financial statements, which are controlled by us through contractual rights or majority voting rights, but of which we own less than 100%, we apply the noncontrolling interest economic ownership percentage to each financial item to arrive at the amount of such cumulative noncontrolling interest share of each component presented; and (ii) for each real estate joint venture that we do not control and do not consolidate, and are instead controlled jointly or by our joint venture partners through contractual rights or majority voting rights, we apply our economic ownership percentage to each financial item to arrive at our proportionate share of each component presented.
The components of balance sheet and operating results information related to joint ventures do not represent our legal claim to those items. For each entity that we do not wholly own, the joint venture agreement generally determines what equity holders can receive upon capital events, such as sales or refinancing, or in the event of a liquidation. Equity holders are normally entitled to their respective legal ownership of any residual cash from a joint venture only after all liabilities, priority distributions, and claims have been repaid or satisfied.
We believe this information can help investors estimate the balance sheet and operating results information related to our partially owned entities. Presenting this information provides a perspective not immediately available from consolidated financial statements and one that can supplement an understanding of the joint venture assets, liabilities, revenues, and expenses included in our consolidated results.
The components of balance sheet and operating results information related to joint ventures are limited as an analytical tool as the overall economic ownership interest does not represent our legal claim to each of our joint ventures’ assets, liabilities, or results of operations. In addition, joint venture financial information may include financial information related to the unconsolidated real estate joint ventures that we do not control. We believe that in order to facilitate for investors a clear understanding of our operating results and our total assets and liabilities, joint venture financial information should be examined in conjunction with our consolidated statements of operations and balance sheets. Joint venture financial information should not be considered an alternative to our consolidated financial statements, which are prepared in accordance with GAAP.
Key items included in net income attributable to Alexandria’s common stockholders
We present a tabular comparison of items, whether gain or loss, that may facilitate a high-level understanding of our results and provide context for the disclosures included in this Supplemental Information, our most recent annual report on Form 10-K, and our subsequent quarterly reports on Form 10-Q. We believe such tabular presentation promotes a better understanding for investors of the corporate-level decisions made and activities performed that significantly affect comparison of our operating results from period to period. We also believe this tabular presentation will supplement for investors an understanding of our disclosures and real estate operating results. Gains or losses on sales of real estate and impairments of held for sale assets are related to corporate-level decisions to dispose of real estate. Gains or losses on early extinguishment of debt, gains or losses on early termination of interest rate hedge agreements, and preferred stock redemption charges are related to corporate-level financing decisions focused on our capital structure strategy. Significant realized and unrealized gains or losses on non-real estate investments and impairments of real estate and non-real estate investments are not related to the operating performance of our real estate assets as they result from strategic, corporate-level non-real estate investment decisions and external market conditions. Impairments of non-real estate investments are not related to the operating performance of our real estate as they represent the write-down of non-
| |
Definitions and Reconciliations (continued) | |
March 31, 2020 | |
real estate investments when their fair values decline below their respective carrying values due to changes in general market or other conditions outside of our control. Significant items, whether a gain or loss, included in the tabular disclosure for current periods are described in further detail in this Supplemental Information.
Lease accounting
On January 1, 2019, we adopted new lease accounting standards that set out the principles for the recognition, measurement, presentation, and disclosure of leases for both parties to a lease agreement (i.e., lessees and lessors). The new lease accounting standards did not result in material changes in neither the amount nor the timing of lease-related revenues that we recognized from our tenants. However, the new standards affected our financial statement presentation primarily in three specific areas.
Key differences between the prior accounting standard and the new lease accounting standards:
Prior to January 1, 2019, we classified rental revenues and tenant recoveries as separate line items on our consolidated statements of operations. Effective January 1, 2019, based on our election of a practical expedient, we are required to disclose the combined components of rental revenues and tenant recoveries as a single lease component, which is classified on our consolidated statements of operations as income from rentals. As a result, we do not disclose tenant recoveries as a separate GAAP revenue measure. Refer to the definition of tenant recoveries below for additional details on tenant recoveries revenue and its usefulness to investors.
The new lease accounting standard requires that lessors and lessees capitalize, as initial direct costs, only incremental costs of a lease that would not have been incurred if the lease had not been obtained. Effective January 1, 2019, costs that we incur to negotiate or arrange a lease, regardless of its outcome, such as for fixed employee compensation, tax, or legal advice to negotiate lease terms, and other costs, are expensed as incurred.
Under the package of practical expedients and optional transition method that we elected on January 1, 2019, we are not required to reassess whether initial direct leasing costs capitalized prior to the adoption of the new lease accounting standard in connection with the leases that commenced prior to January 1, 2019, qualify for capitalization under the new lease accounting standard. Therefore, we continue to amortize these initial direct leasing costs over the respective lease term.
In addition, the new lease accounting standards require companies to recognize a lease liability and a corresponding right-of-use asset on the consolidated balance sheets, and to represent the net present value of future rental payments related to operating leases in which we are the lessee. As a result, on January 1, 2019, we recognized a lease liability classified in accounts payable, accrued expenses, and other liabilities on our consolidated balance sheets, and a corresponding right‑of‑use asset included in other assets on our consolidated balance sheets, related to our ground leases existing as of January 1, 2019, for which we are the lessee. The net present value of the remaining future rental payments of our ground leases was calculated for each operating lease using the respective remaining lease term and a corresponding estimated incremental borrowing rate, which is the estimated interest rate that we would have to pay to borrow on a collateralized basis over a similar term for an amount equal to the lease payments.
Net cash provided by operating activities after dividends
Net cash provided by operating activities after dividends includes the deduction for distributions to noncontrolling interests. For purposes of this calculation, changes in operating assets and liabilities are excluded as they represent timing differences.
Net debt to Adjusted EBITDA and net debt and preferred stock to Adjusted EBITDA
Net debt to Adjusted EBITDA and net debt and preferred stock to Adjusted EBITDA are non-GAAP financial measures that we believe are useful to investors as supplemental measures in evaluating our balance sheet leverage. Net debt is equal to the sum of total consolidated debt less cash, cash equivalents, and restricted cash. Net debt and preferred stock is equal to the sum of net debt, as discussed above, plus preferred stock outstanding as of the end of the period. Refer to the definition of Adjusted EBITDA and Adjusted EBITDA margin for further information on the calculation of Adjusted EBITDA.
The following table reconciles debt to net debt, and to net debt and preferred stock, and computes the ratio of each to Adjusted EBITDA:
(Dollars in thousands) | 3/31/20 | 12/31/19 | 9/30/19 | 6/30/19 | 3/31/19 | |||||||||||||||
Secured notes payable | $ | 347,136 | $ | 349,352 | $ | 351,852 | $ | 354,186 | $ | 356,461 | ||||||||||
Unsecured senior notes payable | 6,736,999 | 6,044,127 | 6,042,831 | 5,140,914 | 5,139,500 | |||||||||||||||
Unsecured senior line of credit | 221,000 | 384,000 | 343,000 | 514,000 | — | |||||||||||||||
Unsecured senior bank term loan | — | — | — | 347,105 | 347,542 | |||||||||||||||
Unamortized deferred financing costs | 53,807 | 47,299 | 48,746 | 36,905 | 37,925 | |||||||||||||||
Cash and cash equivalents | (445,255 | ) | (189,681 | ) | (410,675 | ) | (198,909 | ) | (261,372 | ) | ||||||||||
Restricted cash | (43,116 | ) | (53,008 | ) | (42,295 | ) | (39,316 | ) | (54,433 | ) | ||||||||||
Net debt | $ | 6,870,571 | $ | 6,582,089 | $ | 6,333,459 | $ | 6,154,885 | $ | 5,565,623 | ||||||||||
Net debt | $ | 6,870,571 | $ | 6,582,089 | $ | 6,333,459 | $ | 6,154,885 | $ | 5,565,623 | ||||||||||
7.00% Series D Convertible Preferred Stock | — | — | 57,461 | 57,461 | 57,461 | |||||||||||||||
Net debt and preferred stock | $ | 6,870,571 | $ | 6,582,089 | $ | 6,390,920 | $ | 6,212,346 | $ | 5,623,084 | ||||||||||
Adjusted EBITDA: | ||||||||||||||||||||
– quarter annualized | $ | 1,239,016 | $ | 1,148,620 | $ | 1,099,908 | $ | 1,063,056 | $ | 1,029,944 | ||||||||||
– trailing 12 months | $ | 1,137,650 | $ | 1,085,382 | $ | 1,040,449 | $ | 1,004,724 | $ | 966,781 | ||||||||||
Net debt to Adjusted EBITDA: | ||||||||||||||||||||
– quarter annualized | 5.5 | x | 5.7 | x | 5.8 | x | 5.8 | x | 5.4 | x | ||||||||||
– trailing 12 months | 6.0 | x | 6.1 | x | 6.1 | x | 6.1 | x | 5.8 | x | ||||||||||
Net debt and preferred stock to Adjusted EBITDA: | ||||||||||||||||||||
– quarter annualized | 5.5 | x | 5.7 | x | 5.8 | x | 5.8 | x | 5.5 | x | ||||||||||
– trailing 12 months | 6.0 | x | 6.1 | x | 6.1 | x | 6.2 | x | 5.8 | x | ||||||||||
| |
Definitions and Reconciliations (continued) | |
March 31, 2020 | |
Net operating income, net operating income (cash basis), and operating margin
The following table reconciles net income to net operating income, and to net operating income (cash basis):
Three Months Ended | ||||||||
(Dollars in thousands) | 3/31/20 | 3/31/19 | ||||||
Net income | $ | 30,678 | $ | 136,818 | ||||
Equity in losses (earnings) of unconsolidated real estate joint ventures | 3,116 | (1,146 | ) | |||||
General and administrative expenses | 31,963 | 24,677 | ||||||
Interest expense | 45,739 | 39,100 | ||||||
Depreciation and amortization | 175,496 | 134,087 | ||||||
Impairment of real estate | 2,003 | — | ||||||
Loss on early extinguishment of debt | — | 7,361 | ||||||
Investment loss (income) | 21,821 | (83,556 | ) | |||||
Net operating income | 310,816 | 257,341 | ||||||
Straight-line rent revenue | (20,597 | ) | (26,965 | ) | ||||
Amortization of acquired below-market leases | (15,964 | ) | (7,148 | ) | ||||
Net operating income (cash basis) | $ | 274,255 | $ | 223,228 | ||||
Net operating income (cash basis) – annualized | $ | 1,097,020 | $ | 892,912 | ||||
Net operating income (from above) | $ | 310,816 | $ | 257,341 | ||||
Total revenues | $ | 439,919 | $ | 358,842 | ||||
Operating margin | 71% | 72% | ||||||
Net operating income is a non-GAAP financial measure calculated as net income, the most directly comparable financial measure calculated and presented in accordance with GAAP, excluding equity in the earnings of our unconsolidated real estate joint ventures, general and administrative expenses, interest expense, depreciation and amortization, impairments of real estate, gains or losses on early extinguishment of debt, gains or losses on sales of real estate, and investment income or loss. We believe net operating income provides useful information to investors regarding our financial condition and results of operations because it primarily reflects those income and expense items that are incurred at the property level. Therefore, we believe net operating income is a useful measure for investors to evaluate the operating performance of our consolidated real estate assets. Net operating income on a cash basis is net operating income adjusted to exclude the effect of straight-line rent and amortization of acquired above- and below-market lease revenue adjustments required by GAAP. We believe that net operating income on a cash basis is helpful to investors as an additional measure of operating performance because it eliminates straight-line rent revenue and the amortization of acquired above- and below-market leases.
Furthermore, we believe net operating income is useful to investors as a performance measure for our consolidated properties because, when compared across periods, net operating income reflects trends in occupancy rates, rental rates, and operating costs, which provide a perspective not immediately apparent from net income or loss. Net operating income can be used to measure the initial stabilized yields of our properties by calculating net operating income generated by a property divided by our investment in the property. Net operating income excludes certain components from net income in order to provide results that are more closely related to the results of operations of our properties. For example, interest expense is not necessarily linked to the operating performance of a real estate asset and is often incurred
at the corporate level rather than at the property level. In addition, depreciation and amortization, because of historical cost accounting and useful life estimates, may distort comparability of operating performance at the property level. Impairments of real estate have been excluded in deriving net operating income because we do not consider impairments of real estate to be property-level operating expenses. Impairments of real estate relate to changes in the values of our assets and do not reflect the current operating performance with respect to related revenues or expenses. Our impairments of real estate represent the write-down in the value of the assets to the estimated fair value less cost to sell. These impairments result from investing decisions or a deterioration in market conditions. We also exclude realized and unrealized investment income or loss, which results from investment decisions that occur at the corporate level related to non-real estate investments in publicly traded companies and certain privately held entities. Therefore, we do not consider these activities to be an indication of operating performance of our real estate assets at the property level. Our calculation of net operating income also excludes charges incurred from changes in certain financing decisions, such as losses on early extinguishment of debt, as these charges often relate to corporate strategy. Property operating expenses included in determining net operating income primarily consist of costs that are related to our operating properties, such as utilities, repairs, and maintenance; rental expense related to ground leases; contracted services, such as janitorial, engineering, and landscaping; property taxes and insurance; and property-level salaries. General and administrative expenses consist primarily of accounting and corporate compensation, corporate insurance, professional fees, office rent, and office supplies that are incurred as part of corporate office management. We calculate operating margin as net operating income divided by total revenues.
We believe that in order to facilitate for investors a clear understanding of our operating results, net operating income should be examined in conjunction with net income or loss as presented in our consolidated statements of operations. Net operating income should not be considered as an alternative to net income or loss as an indication of our performance, nor as an alternative to cash flows as a measure of our liquidity or our ability to make distributions.
Operating statistics
We present certain operating statistics related to our properties, including number of properties, RSF, occupancy percentage, leasing activity, and contractual lease expirations as of the end of the period. We believe these measures are useful to investors because they facilitate an understanding of certain trends for our properties. We compute the number of properties, RSF, occupancy percentage, leasing activity, and contractual lease expirations at 100% for all properties in which we have an investment, including properties owned by our consolidated and unconsolidated real estate joint ventures. For operating metrics based on annual rental revenue, refer to our discussion of annual rental revenue herein.
Same property comparisons
As a result of changes within our total property portfolio during the comparative periods presented, including changes from assets acquired or sold, properties placed into development or redevelopment, and development or redevelopment properties recently placed into service, the consolidated total income from rentals, as well as rental operating expenses in our operating results, can show significant changes from period to period. In order to supplement an evaluation of our results of operations over a given quarterly or annual period, we analyze the operating performance for all consolidated properties that were fully operating for the entirety of the comparative periods presented, referred to as same properties. We separately present quarterly and year-to-date same property results to align with the interim financial information required by the SEC in our management’s discussion and analysis of our financial condition and results of operations. These same properties are analyzed separately from properties acquired subsequent to the first day in the earliest comparable quarterly or year-to-date period presented, properties that underwent development or redevelopment at any time during the comparative periods, unconsolidated real estate joint ventures, properties classified as held for sale, and corporate entities (legal entities
| |
Definitions and Reconciliations (continued) | |
March 31, 2020 | |
performing general and administrative functions), which are excluded from same property results. Additionally, lease termination fees, if any, are excluded from the results of same properties.
The following table reconciles the number of same properties to total properties for the three months ended March 31, 2020:
Development – under construction | Properties | |||
9800 Medical Center Drive | 1 | |||
9950 Medical Center Drive | 1 | |||
Alexandria District for Science and Technology | 2 | |||
201 Haskins Way | 1 | |||
1165 Eastlake Avenue East | 1 | |||
4150 Campus Point Court | 1 | |||
7 | ||||
Development – placed into service after January 1, 2019 | Properties | |||
399 Binney Street | 1 | |||
279 East Grand Avenue | 1 | |||
188 East Blaine Street | 1 | |||
3 | ||||
Redevelopment – under construction | Properties | |||
Alexandria Center® – Long Island City | 1 | |||
945 Market Street | 1 | |||
3160 Porter Drive | 1 | |||
The Arsenal on the Charles | 4 | |||
7 | ||||
Redevelopment – placed into service after January 1, 2019 | Properties | |||
Alexandria PARC | 4 | |||
681 and 685 Gateway Boulevard | 2 | |||
266 and 275 Second Avenue | 2 | |||
Alexandria Center® for AgTech, Phase I | 1 | |||
9 | ||||
Acquisitions after January 1, 2019 | Properties | |||
25, 35, and 45 West Watkins Mill Road | 3 | |||
3170 Porter Drive | 1 | |||
Shoreway Science Center | 2 | |||
3911, 3931, and 4075 Sorrento Valley Boulevard | 3 | |||
260 Townsend Street | 1 | |||
5 Necco Street | 1 | |||
601 Dexter Avenue North | 1 | |||
4224/4242 Campus Point Court and 10210 Campus Point Drive | 3 | |||
3825 and 3875 Fabian Way | 2 | |||
SD Tech by Alexandria | 10 | |||
The Arsenal on the Charles | 7 | |||
275 Grove Street | 1 | |||
601, 611, and 651 Gateway Boulevard | 3 | |||
3330 and 3412 Hillview Avenue | 2 | |||
9808 and 9868 Scranton Road | 2 | |||
9605 Medical Center Drive | 1 | |||
5505 Morehouse Drive | 1 | |||
Other | 9 | |||
53 | ||||
Unconsolidated real estate JVs | 6 | |||
Properties held for sale | 3 | |||
Total properties excluded from same properties | 88 | |||
Same properties | 214 | (1) | ||
Total properties in North America as of March 31, 2020 | 302 | |||
(1) | Includes 9880 Campus Point Drive and 3545 Cray Court. The 9880 Campus Point Drive building was occupied through January 2018 and is currently in active development, and 3545 Cray Court is currently undergoing renovations. |
Stabilized occupancy date
The stabilized occupancy date represents the estimated date on which the project is expected to reach occupancy of 95% or greater.
Tenant recoveries
Tenant recoveries represent revenues comprising reimbursement of real estate taxes, insurance, utilities, repairs and maintenance, common area expenses, and other operating expenses and earned in the period during which the applicable expenses are incurred and the tenant’s obligation to reimburse us arises.
We classify rental revenues and tenant recoveries generated through the leasing of real estate assets within revenue in income from rentals in our consolidated statements of operations. We provide investors with a separate presentation of rental revenues and tenant recoveries in “Same Property Performance” of this Supplemental Information because we believe it promotes investors’ understanding of our operating results. We believe that the presentation of tenant recoveries is useful to investors as a supplemental measure of our ability to recover operating expenses under our triple net leases, including recoveries of utilities, repairs and maintenance, insurance, property taxes, common area expenses, and other operating expenses, and of our ability to mitigate the effect to net income for any significant variability to components of our operating expenses.
The following table reconciles income from rentals to tenant recoveries:
Three Months Ended | |||||||||||||||||||
(In thousands) | 3/31/20 | 12/31/19 | 9/30/19 | 6/30/19 | 3/31/19 | ||||||||||||||
Income from rentals | $ | 437,605 | $ | 404,721 | $ | 385,776 | $ | 371,618 | $ | 354,749 | |||||||||
Rental revenues | (337,942 | ) | (308,418 | ) | (293,182 | ) | (289,625 | ) | (274,563 | ) | |||||||||
Tenant recoveries | $ | 99,663 | $ | 96,303 | $ | 92,594 | $ | 81,993 | $ | 80,186 | |||||||||
Total equity capitalization
Total equity capitalization is equal to the sum of outstanding shares of 7.00% Series D cumulative convertible preferred stock (“Series D Convertible Preferred Stock”) and common stock multiplied by the related closing price of each class of security at the end of each period presented.
Total market capitalization
Total market capitalization is equal to the sum of total equity capitalization and total debt.
| |
Definitions and Reconciliations (continued) | |
March 31, 2020 | |
Unencumbered net operating income as a percentage of total net operating income
Unencumbered net operating income as a percentage of total net operating income is a non-GAAP financial measure that we believe is useful to investors as a performance measure of the results of operations of our unencumbered real estate assets as it reflects those income and expense items that are incurred at the unencumbered property level. Unencumbered net operating income is derived from assets classified in continuing operations, which are not subject to any mortgage, deed of trust, lien, or other security interest, as of the period for which income is presented.
The following table summarizes unencumbered net operating income as a percentage of total net operating income:
Three Months Ended | |||||||||||||||||||
(Dollars in thousands) | 3/31/20 | 12/31/19 | 9/30/19 | 6/30/19 | 3/31/19 | ||||||||||||||
Unencumbered net operating income | $ | 295,001 | $ | 270,903 | $ | 259,128 | $ | 251,397 | $ | 243,191 | |||||||||
Encumbered net operating income | 15,815 | 15,359 | 14,906 | 16,770 | 14,150 | ||||||||||||||
Total net operating income | $ | 310,816 | $ | 286,262 | $ | 274,034 | $ | 268,167 | $ | 257,341 | |||||||||
Unencumbered net operating income as a percentage of total net operating income | 95% | 95% | 95% | 94% | 95% | ||||||||||||||
Weighted-average interest rate for capitalization of interest
The weighted-average interest rate required for calculating capitalization of interest pursuant to GAAP represents a weighted-average rate based on the rates applicable to borrowings outstanding during the period, including expense/income related to interest rate hedge agreements, amortization of loan fees, amortization of debt premiums (discounts), and other bank fees. A separate calculation is performed to determine our weighted-average interest rate for capitalization for each month. The rate will vary each month due to changes in variable interest rates, outstanding debt balances, the proportion of variable-rate debt to fixed-rate debt, the amount and terms of interest rate hedge agreements, and the amount of loan fee and premium (discount) amortization.
The following table presents the weighted-average interest rate for capitalization of interest:
Three Months Ended | |||||||||
3/31/20 | 12/31/19 | 9/30/19 | 6/30/19 | 3/31/19 | |||||
Weighted-average interest rate for capitalization of interest | 3.80% | 3.88% | 4.00% | 4.14% | 3.96% | ||||
Weighted-average shares of common stock outstanding – diluted
From time to time, we enter into capital market transactions, including forward equity sales agreements (“Forward Agreements”), to fund acquisitions, to fund construction of our highly leased development and redevelopment projects, and for general working capital purposes. We are required to consider the potential dilutive effect of our forward equity sales agreements under the treasury stock method while the forward equity sales agreements are outstanding. As of March 31, 2020, we had Forward Agreements outstanding to sell an aggregate of 3.5 million shares of common stock.
Prior to the conversion of our remaining outstanding shares in October 2019, we considered the effect of assumed conversion of our outstanding 7.00% Series D Convertible Preferred Stock when determining potentially dilutive incremental shares to our common stock. When calculating the assumed conversion, we add back to net income or loss the dividends paid on our Series D Convertible Preferred Stock to the numerator and then include additional common shares assumed to have been issued (as displayed in the table below) to the denominator of the per share calculation. The effect of the assumed conversion is considered separately for our per share calculations of net income or loss; funds from operations, computed in accordance with the definition in the Nareit White Paper; and funds from operations, as adjusted. Prior to the conversion of our remaining outstanding shares in October 2019, our Series D Convertible Preferred Stock was dilutive and assumed to be converted when quarterly and annual basic EPS, funds from operations, or funds from operations, as adjusted, exceeded approximately $1.75 and $7.00 per share, respectively, subject to conversion ratio adjustments and the impact of repurchases of our Series D Convertible Preferred Stock. The effect of the assumed conversion was included when it was dilutive on a per share basis. The dilutive effect to both numerator and denominator may result in a per share effect of less than a half cent, which would appear as zero in our per share calculation, even when the dilutive effect to the numerator alone appears in our reconciliation.
The weighted-average shares of common stock outstanding used in calculating EPS – diluted, FFO per share – diluted, and FFO per share – diluted, as adjusted, during each period are calculated as follows:
Three Months Ended | ||||||||||||||
(In thousands) | 3/31/20 | 12/31/19 | 9/30/19 | 6/30/19 | 3/31/19 | |||||||||
Basic shares for EPS | 121,433 | 114,175 | 112,120 | 111,433 | 111,054 | |||||||||
Forward Agreements | 352 | 761 | — | 68 | — | |||||||||
Series D Convertible Preferred Stock | — | 38 | — | — | — | |||||||||
Diluted shares for EPS | 121,785 | 114,974 | 112,120 | 111,501 | 111,054 | |||||||||
Basic shares for EPS | 121,433 | 114,175 | 112,120 | 111,433 | 111,054 | |||||||||
Forward Agreements | 352 | 761 | 442 | 68 | — | |||||||||
Series D Convertible Preferred Stock | — | 38 | — | 576 | 581 | |||||||||
Diluted shares for FFO | 121,785 | 114,974 | 112,562 | 112,077 | 111,635 | |||||||||
Basic shares for EPS | 121,433 | 114,175 | 112,120 | 111,433 | 111,054 | |||||||||
Forward Agreements | 352 | 761 | 442 | 68 | — | |||||||||
Series D Convertible Preferred Stock | — | 38 | — | — | — | |||||||||
Diluted shares for FFO, as adjusted | 121,785 | 114,974 | 112,562 | 111,501 | 111,054 | |||||||||