Exhibit 99.1
 | NEWS RELEASE Investor Contact: Brian Mathena, Senior Vice President, Director of Investor Relations 920-491-7059 Media Contact: Jennifer Kaminski, Vice President, Public Relations Senior Manager 920-491-7576 |
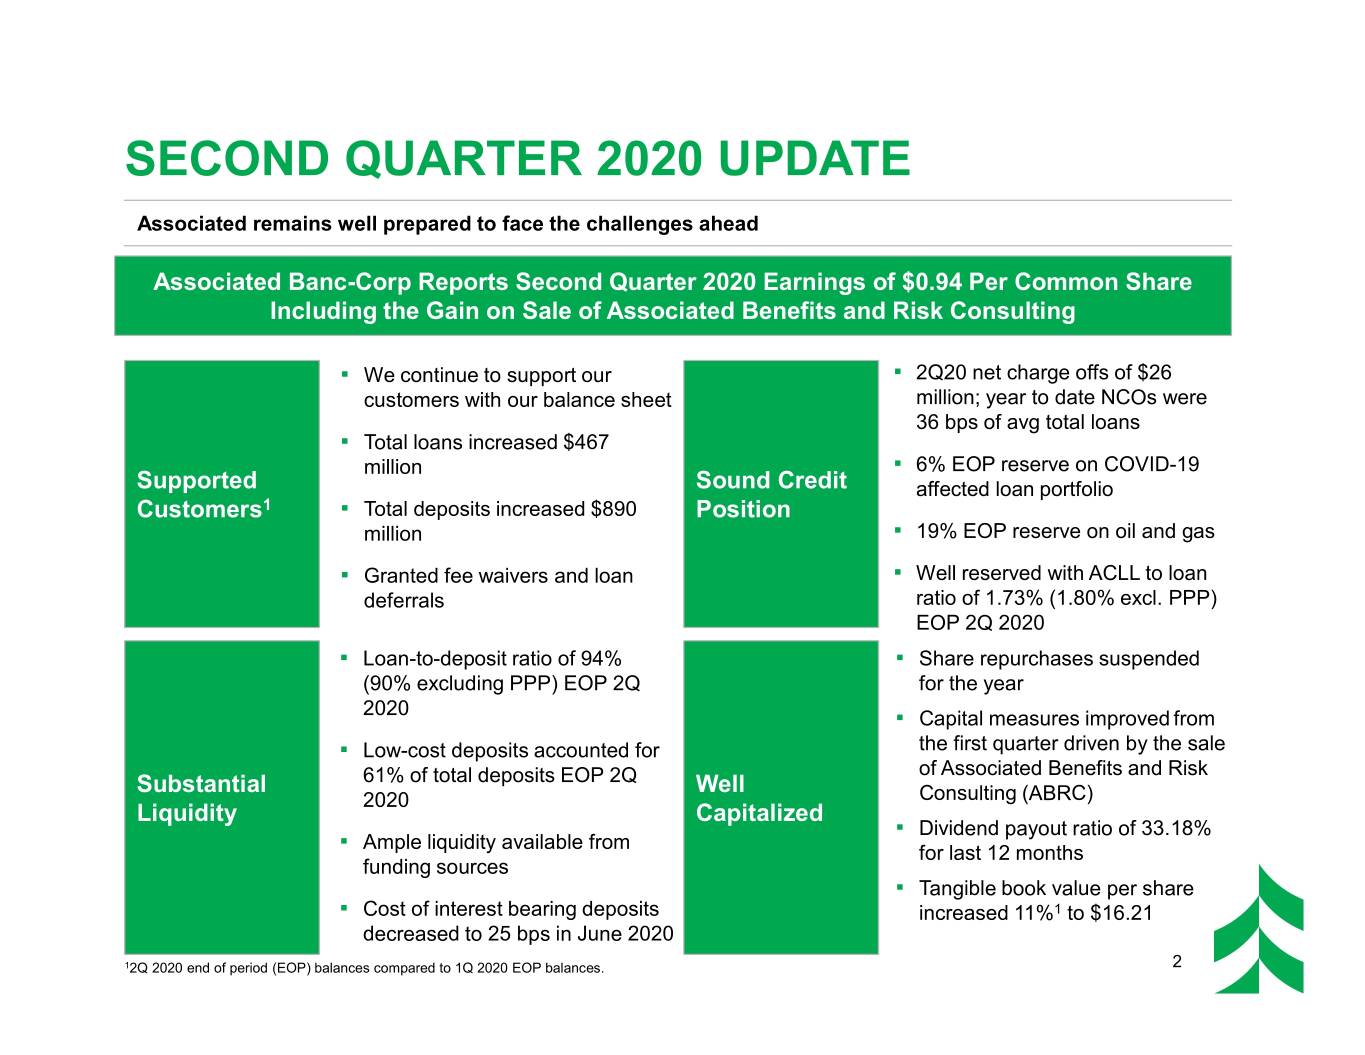
Associated Banc-Corp Reports Second Quarter 2020 Earnings of $0.94 Per Common Share
Including the Gain on Sale of Associated Benefits and Risk Consulting
GREEN BAY, Wis. -- July 23, 2020 -- Associated Banc-Corp (NYSE: ASB) ("Associated" or "Company") today reported net income available to common equity ("earnings") of $145 million, or $0.94 per common share, for the quarter ended June 30, 2020. Second quarter earnings, excluding the net gain on the sale of Associated Benefits and Risk Consulting ("ABRC"), were $0.26 per common share1. These amounts compare to net income available to common equity of $42 million, or $0.27 per common share for the quarter ended March 31, 2020. Year to date earnings were $1.20 per common share, or $0.53 per common share1 excluding the net gain on sale of ABRC, compared to $0.99 per common share in the same period last year.
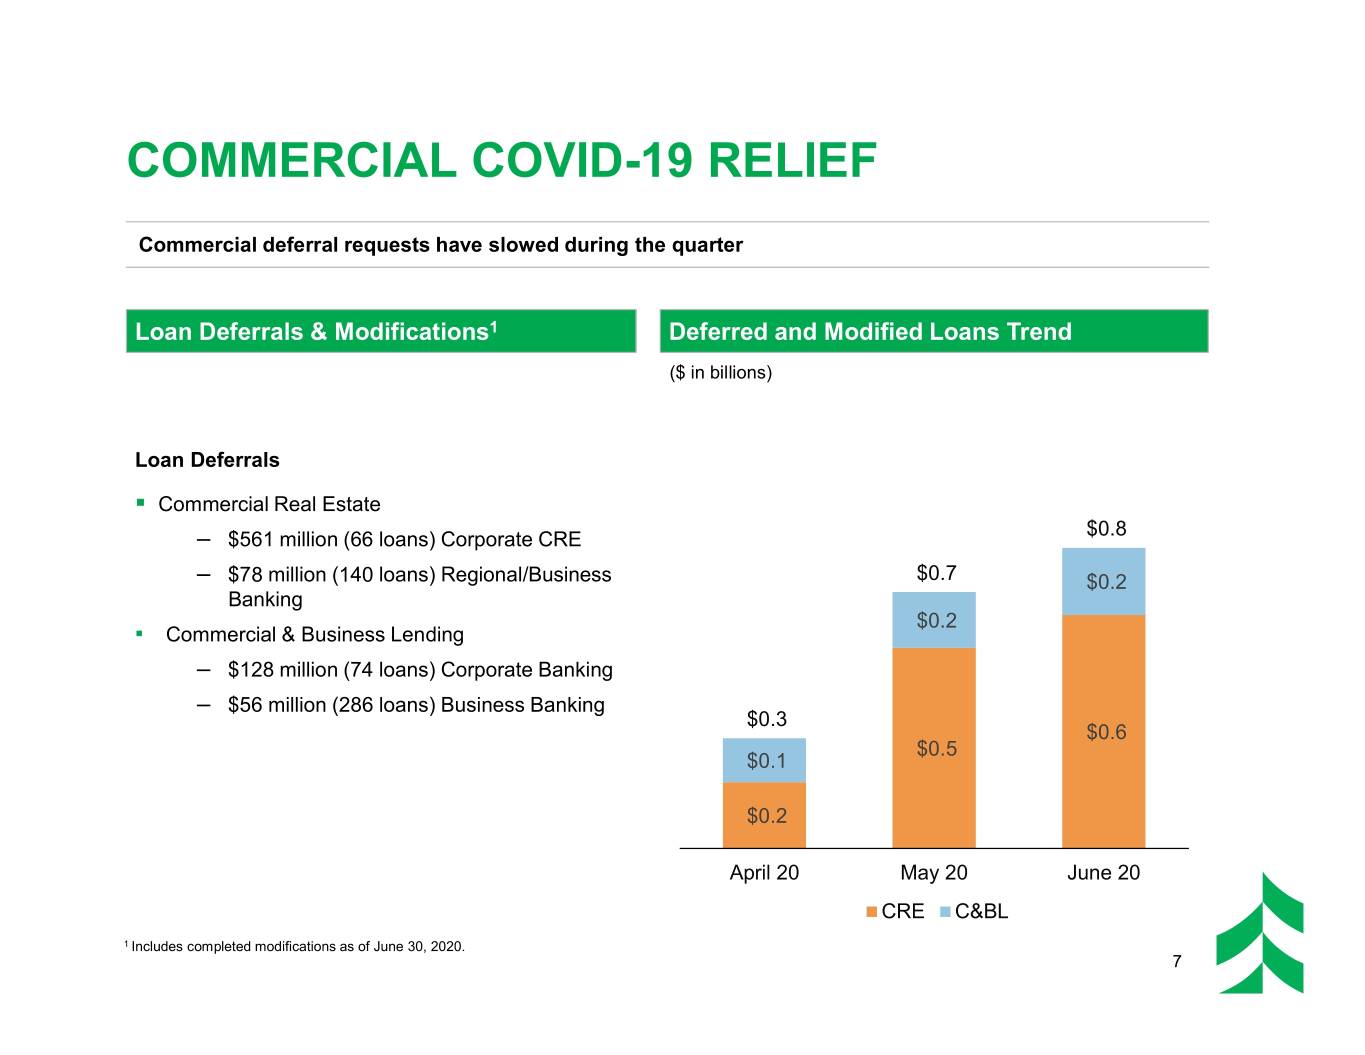
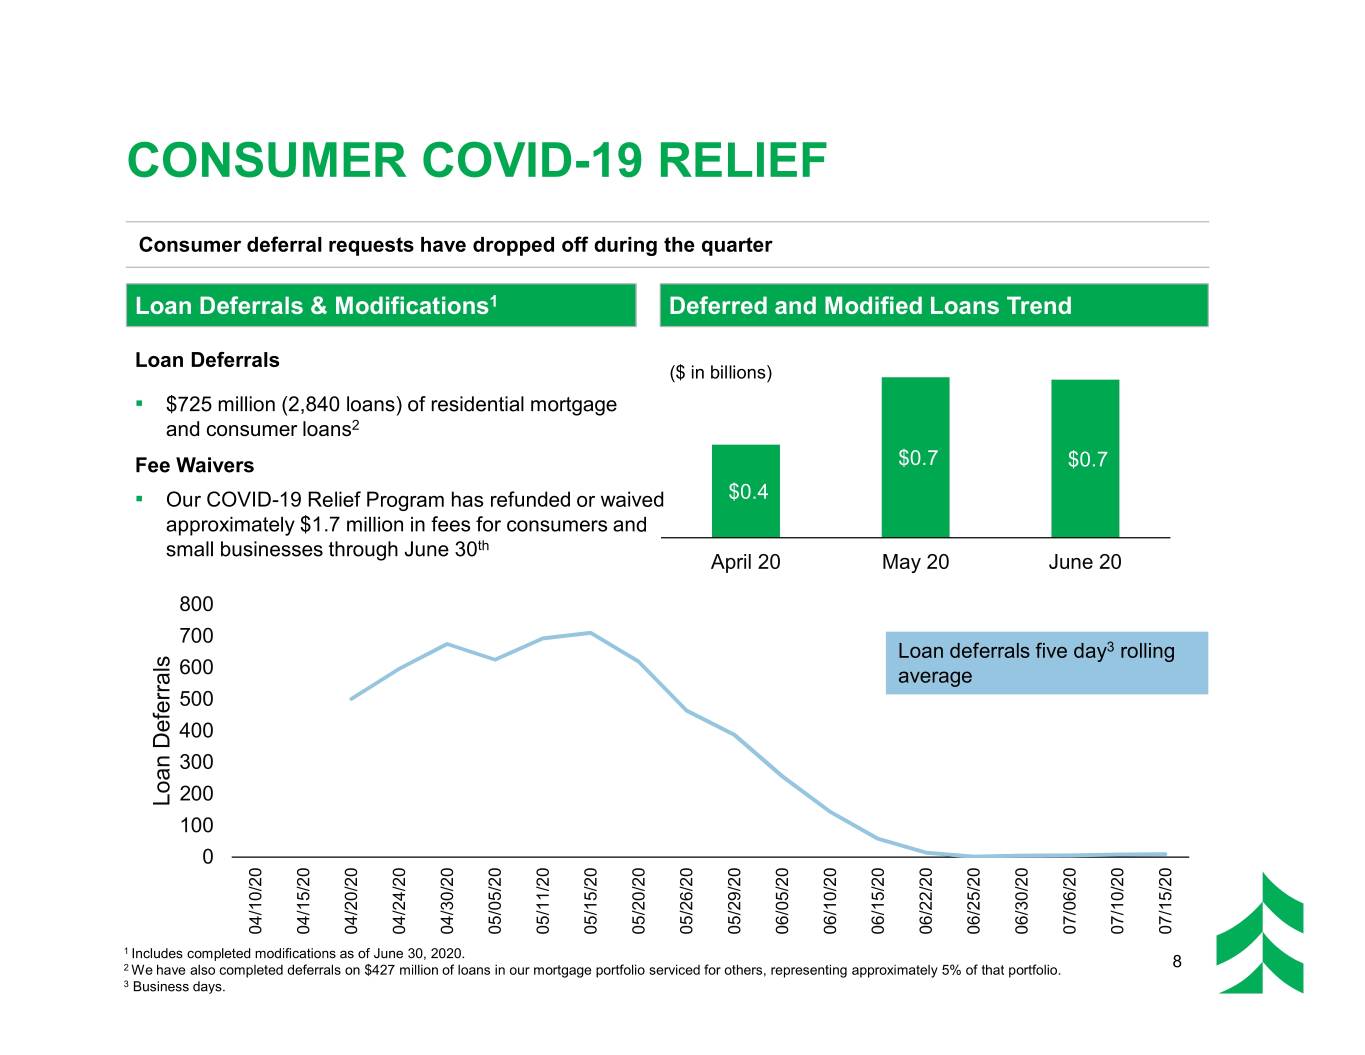
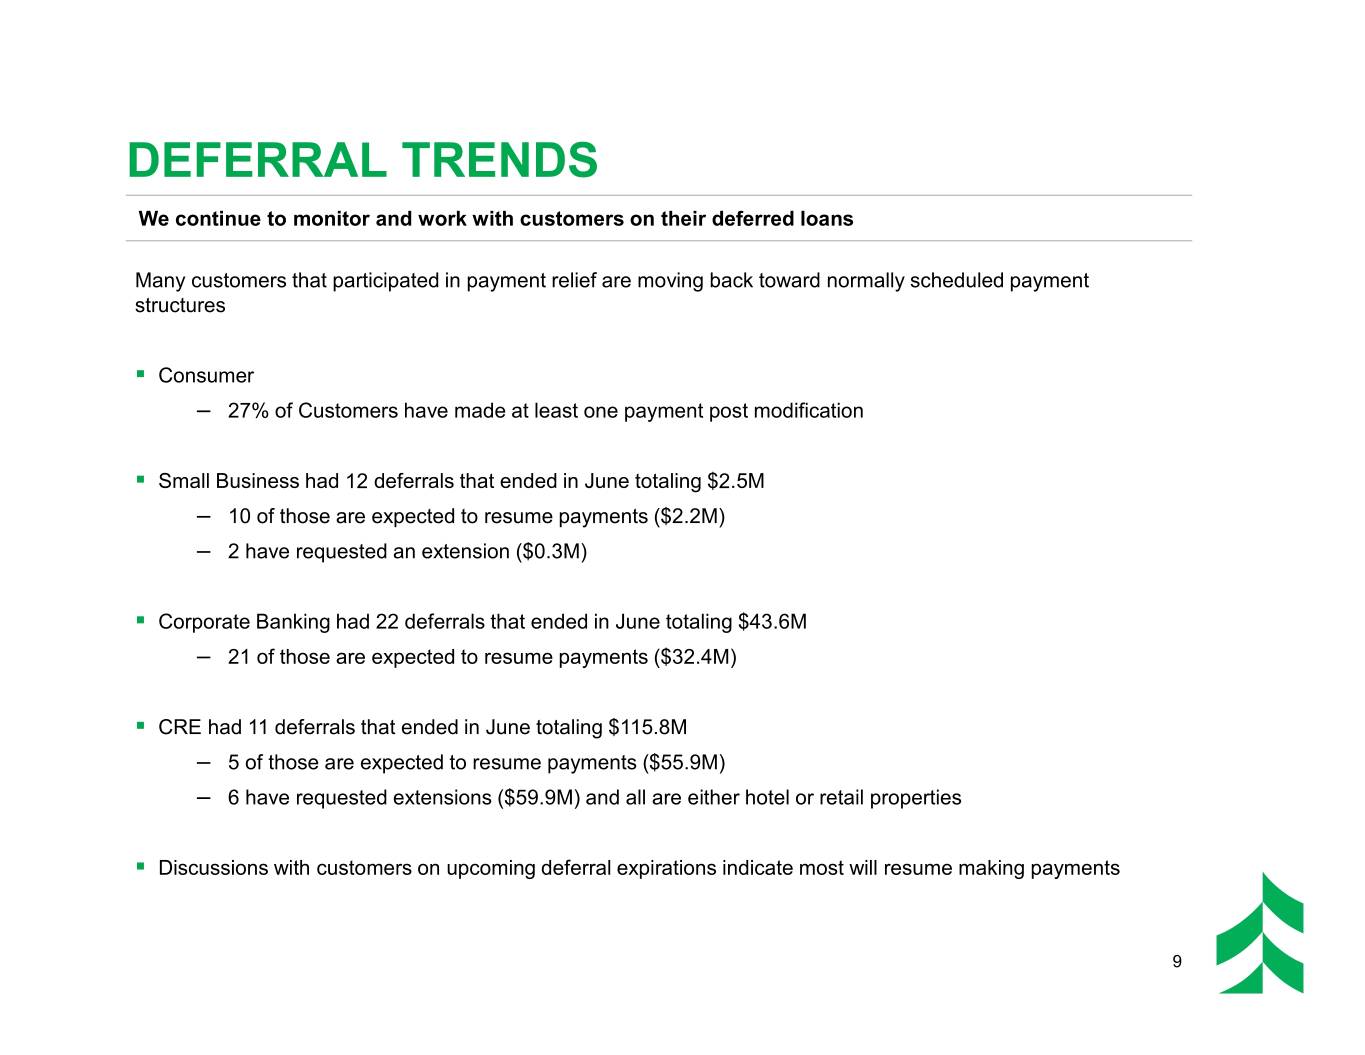
"We have successfully supported our customers during this turbulent quarter" said President and CEO Philip B. Flynn. "We have provided over $1 billion of PPP funding, deferred and modified loans, waived fees to provide relief, and helped to distribute nearly half a billion of other stimulus support to our customer base. We have been a pillar of strength to our customers and communities through this period of time."
"During this quarter, we closed the strategic sale of ABRC which bolstered our CET1 and tangible capital levels. Further, we issued $100 million of preferred stock which also enhanced our risk weighted and total capital levels. We have also grown checking and savings balances to record levels in the Company's history. Taking these actions together, we have positioned ourselves with ample capital and liquidity to continue to support our customers."
SECOND QUARTER 2020 SUMMARY (all comparisons to the first quarter of 2020)
• | Average loans of $25.2 billion were up 8%, or $1.9 billion |
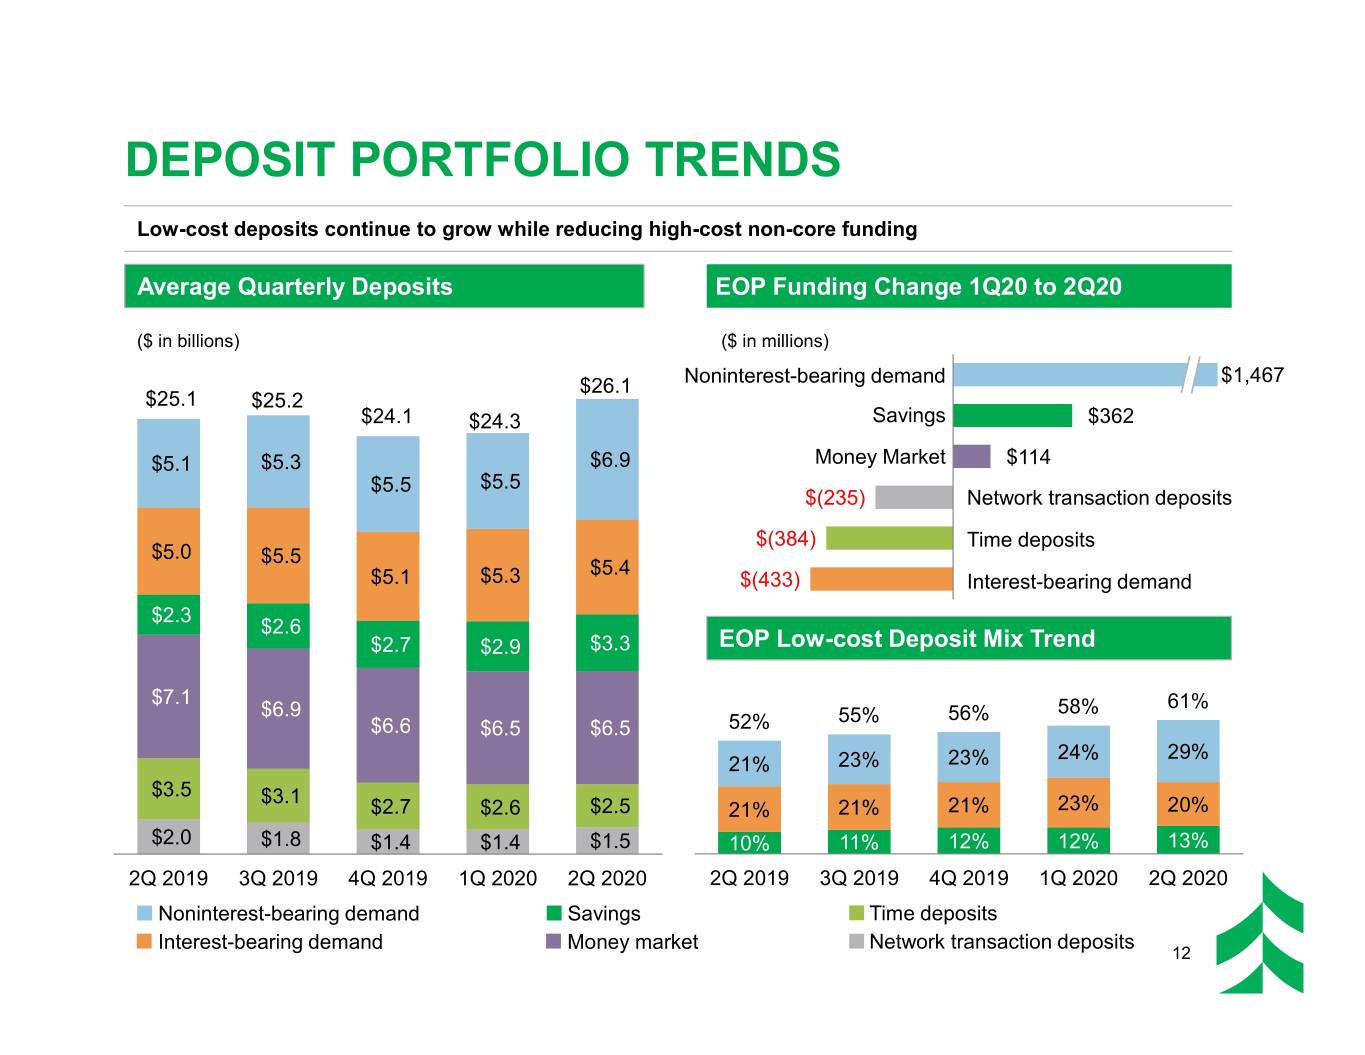
• | Average deposits of $26.1 billion were up 8%, or $1.9 billion |
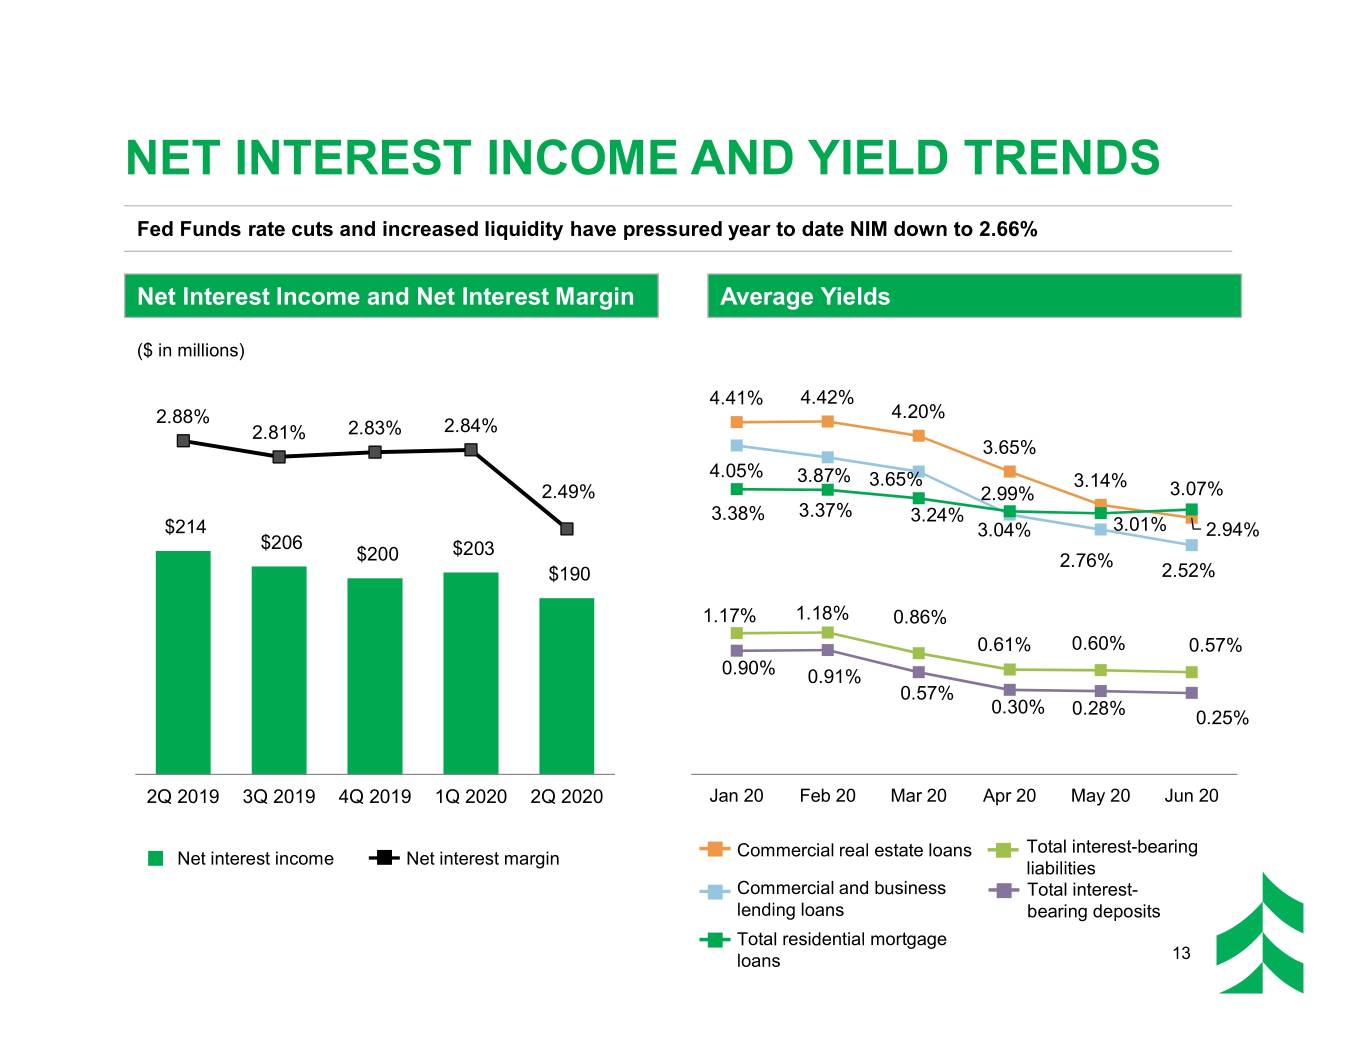
• | Net interest income of $190 million decreased $13 million, or 6% |
• | Net interest margin of 2.49% declined 35 basis points from 2.84% |
• | Provision for credit losses was $61 million up $8 million, or 15% |
• | Noninterest income of $254 million driven by $157 million of net asset gains |
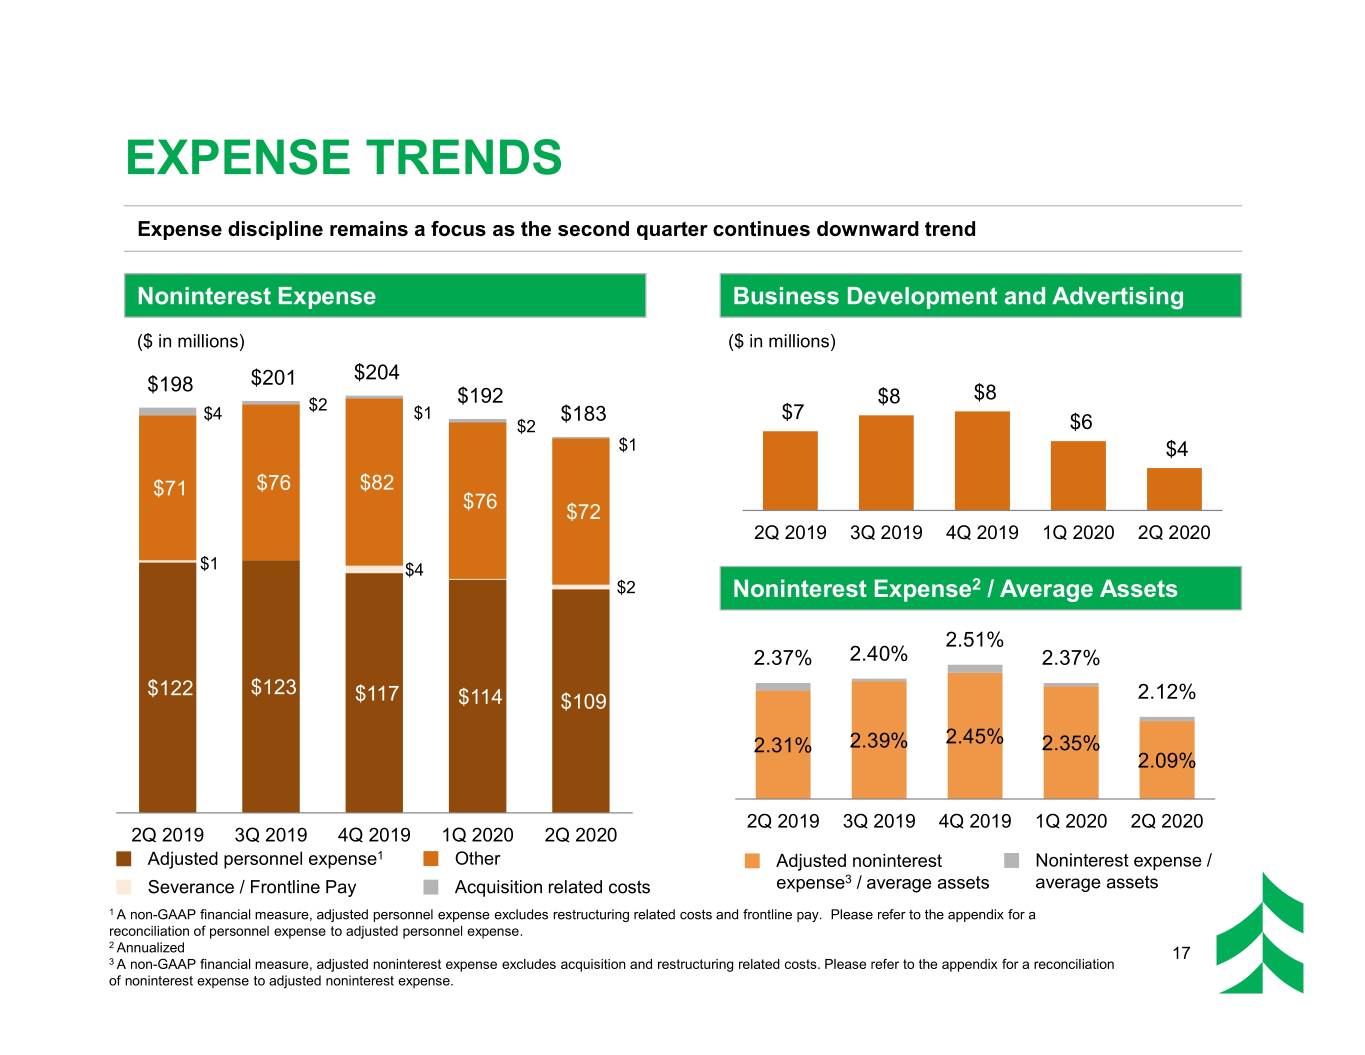
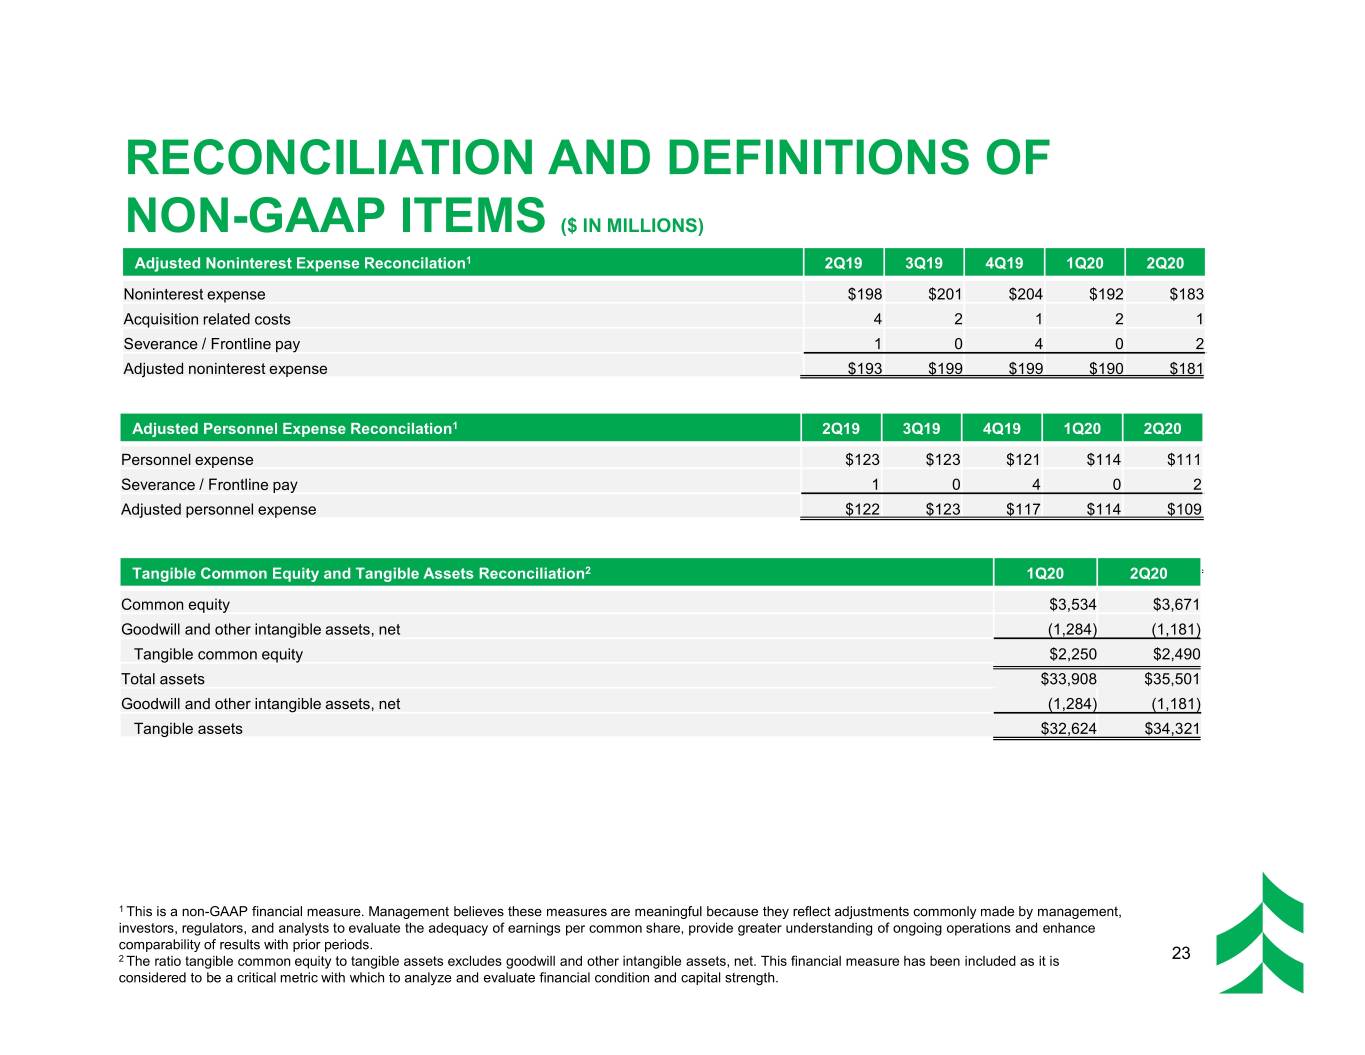
• | Noninterest expense of $183 million decreased $9 million, or 5% |
• | Income before taxes of $200 million increased $144 million |
• | Pre-tax pre-provision income1 of $261 million up $152 million |
• | Tangible book value per share was $16.21, up 11% |
1This is a non-GAAP financial measure. Management believes these measures are meaningful because they reflect adjustments commonly made by management, investors, regulators, and analysts to evaluate the adequacy of earnings per common share, provide greater understanding of ongoing operations and enhance comparability of results with prior periods. See page 10 of the attached tables for a reconciliation of GAAP financial measures to non-GAAP financial measures.
Loans
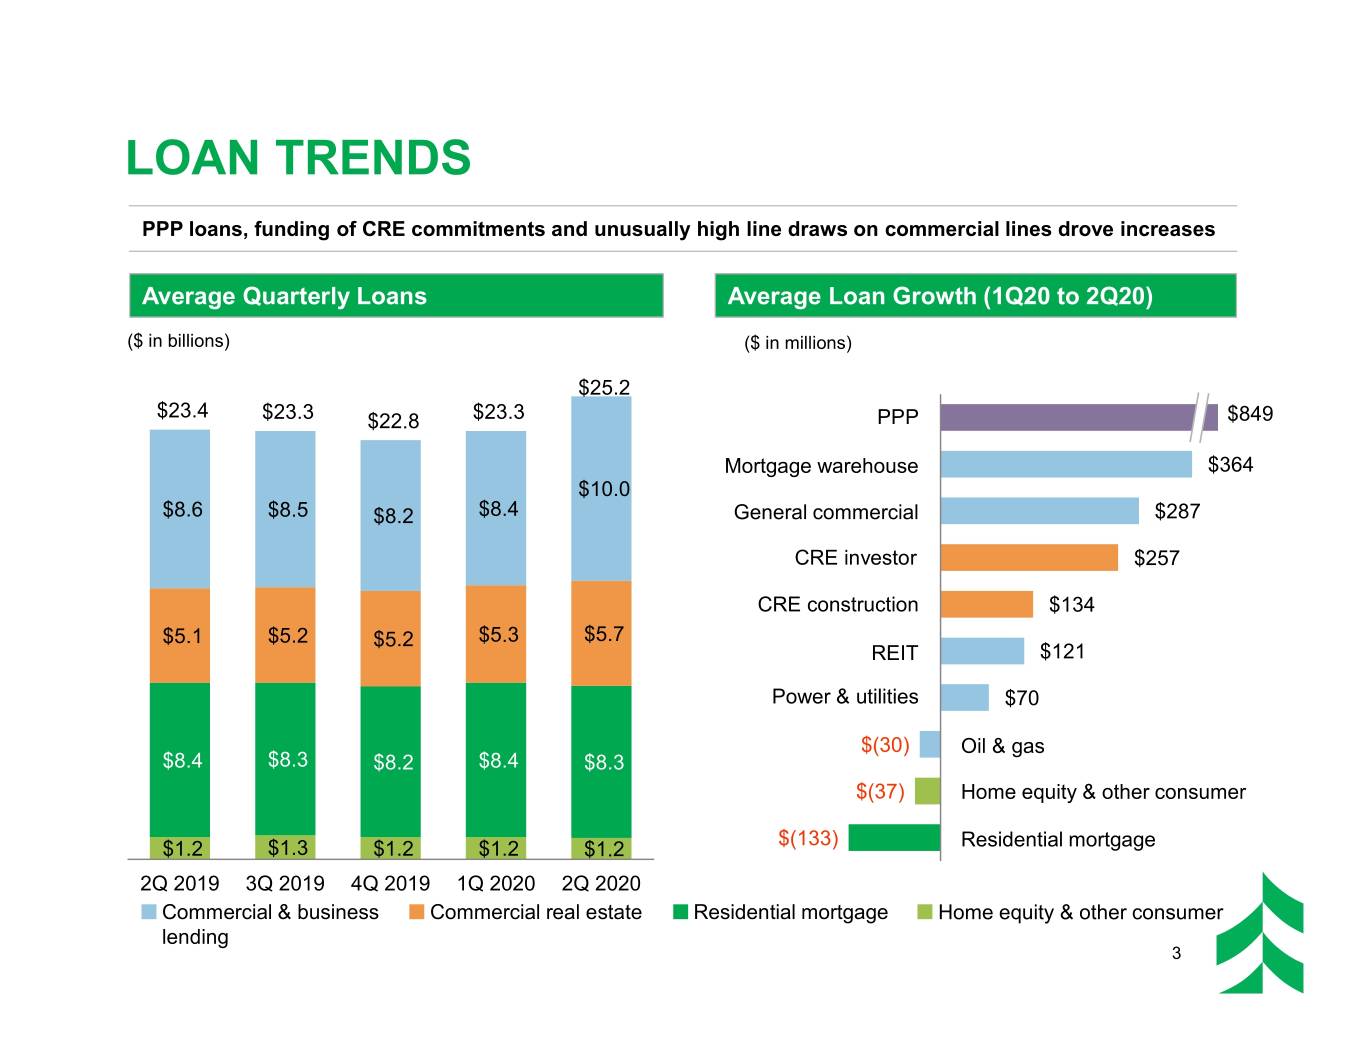
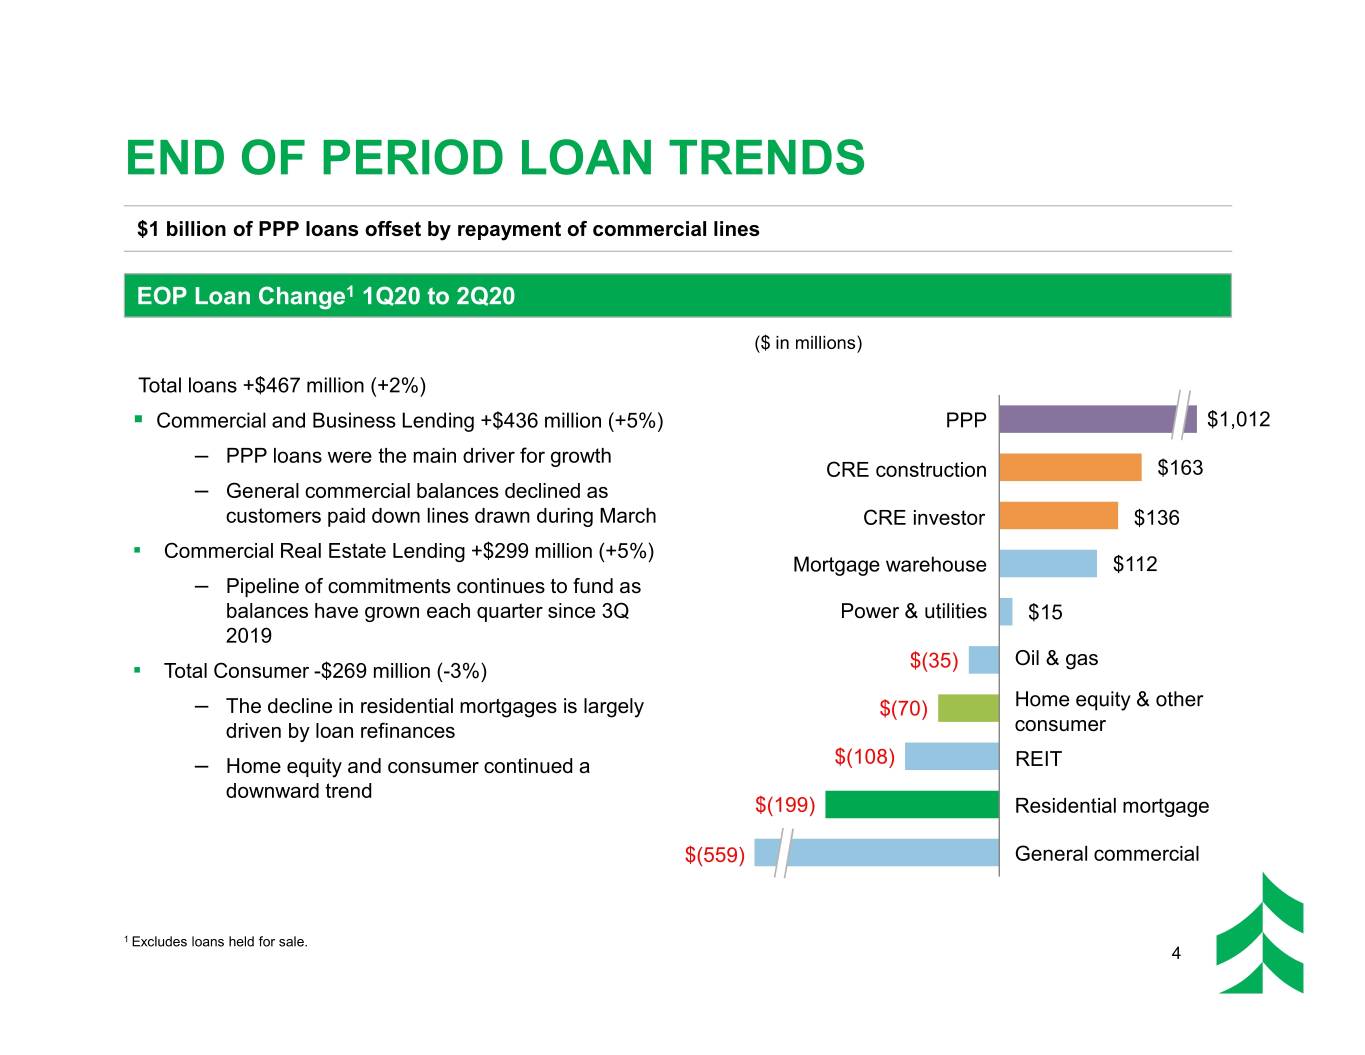
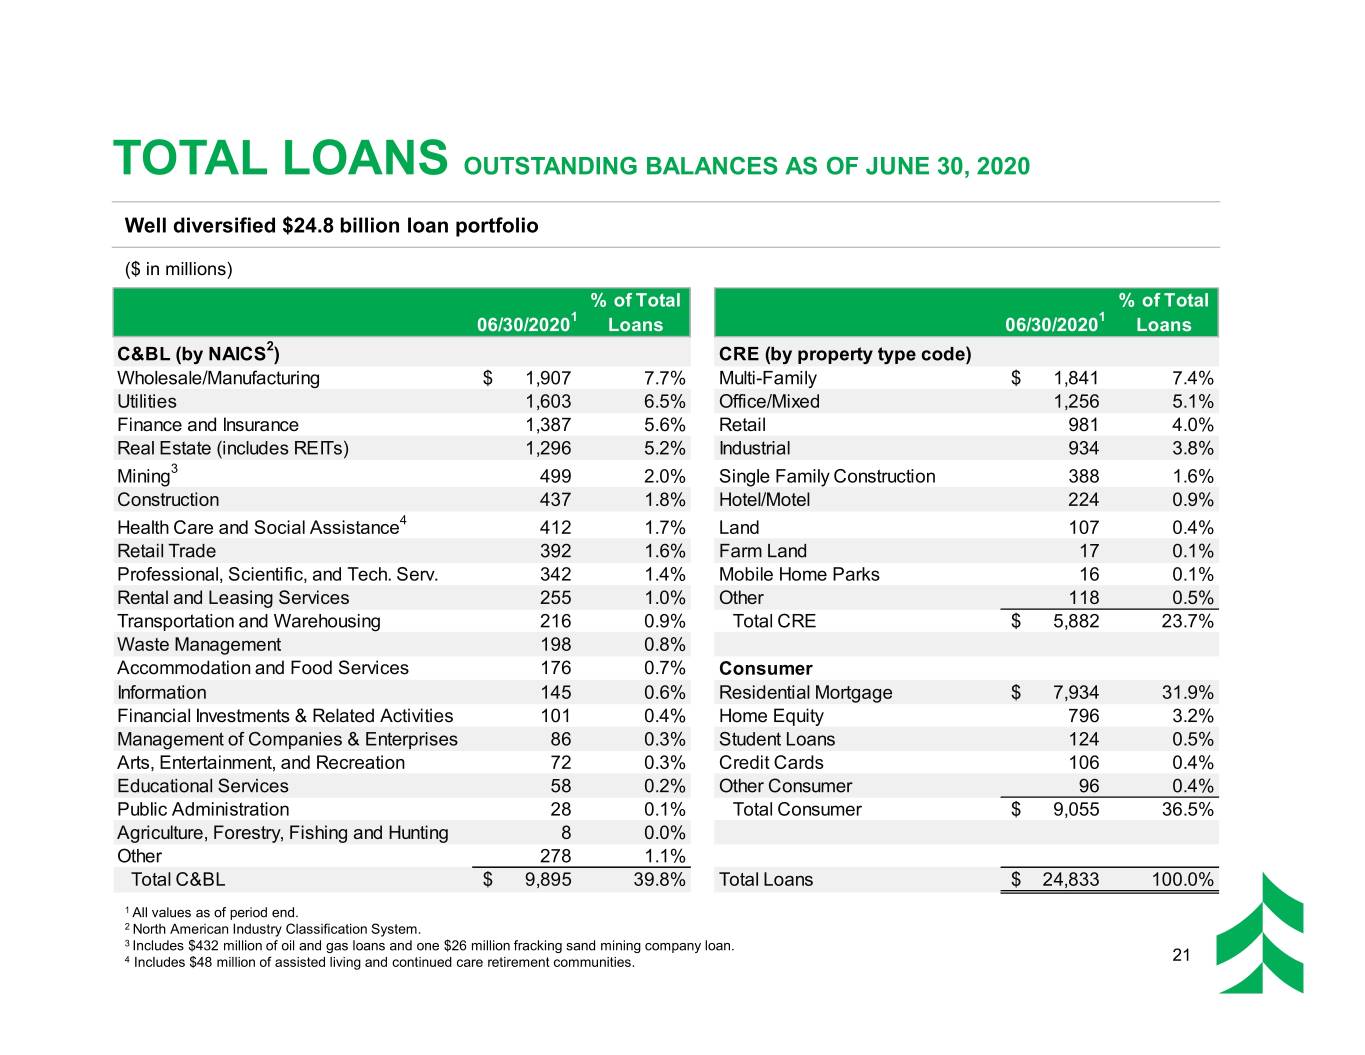
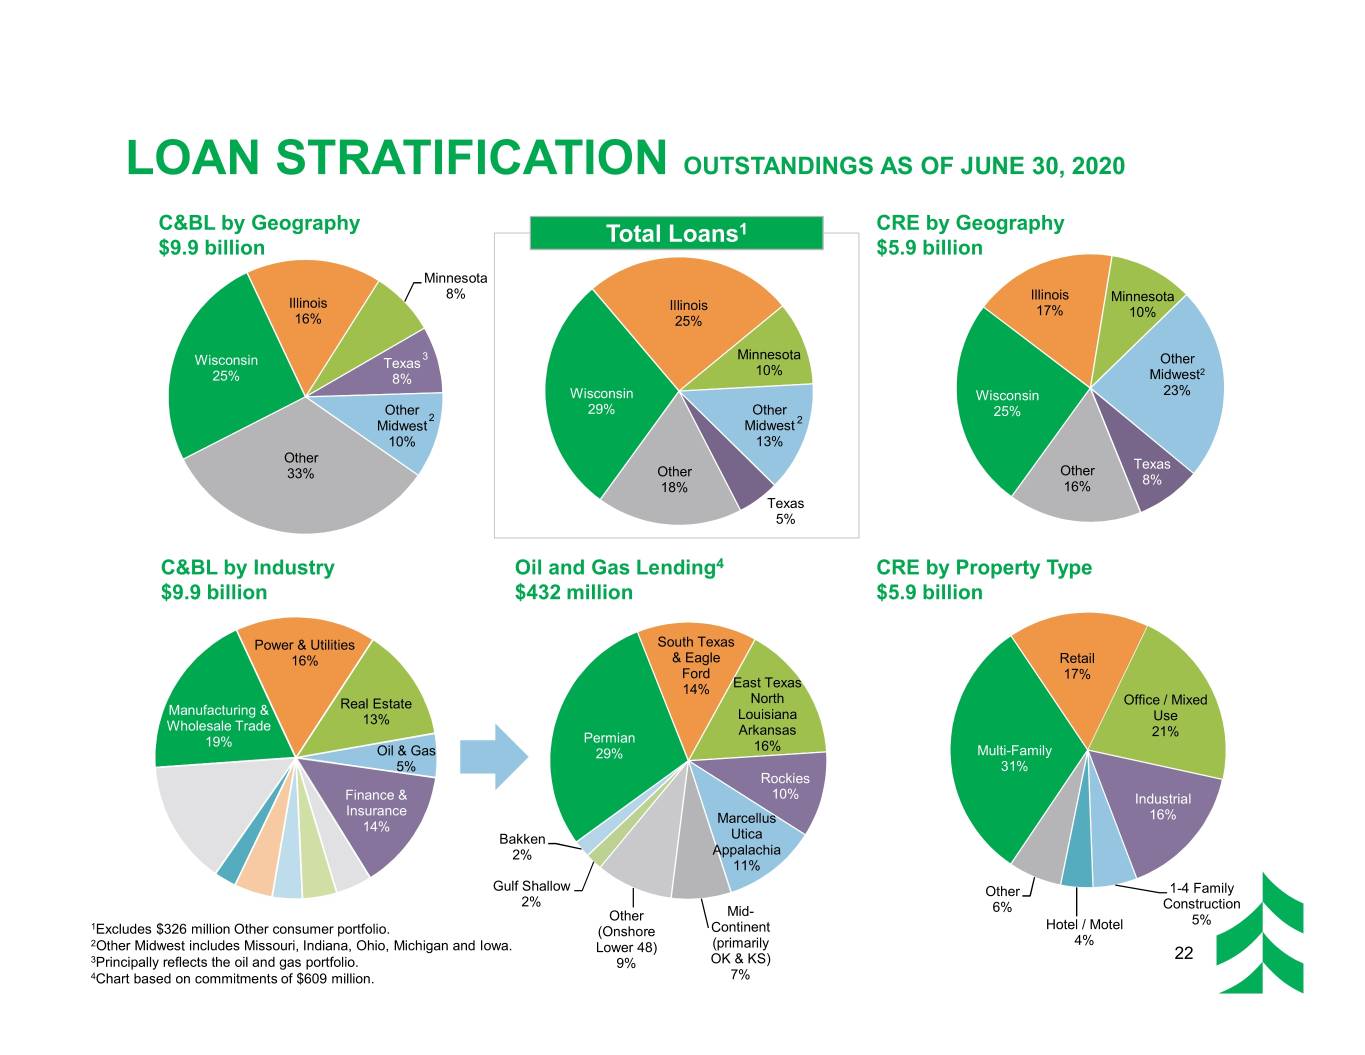
Second quarter 2020 average loans of $25.2 billion were up 8%, or $1.9 billion from the first quarter 2020 and were up 8%, or $1.8 billion from the same period last year. The increases were largely driven by PPP loans, commercial line draws, and CRE loans. With respect to second quarter average balances by loan category:
• | Commercial and business lending increased $1.7 billion from the first quarter 2020 and increased $1.4 billion compared to the same period last year to $10.0 billion. The increase was driven by approximately $850 million of PPP loans plus line draws on other commercial loans. |
• | Commercial real estate lending increased $391 million from the first quarter 2020 and $589 million from the same period last year to $5.7 billion. The change was largely due to the funding of existing commitments and slowing payoffs. |
• | Consumer lending was $9.4 billion, down $170 million from the first quarter 2020 and down $173 million from the same period last year. This was predominantly driven by the sale of a $188 million mortgage portfolio during the second quarter 2020. |
Deposits
Second quarter 2020 average deposits of $26.1 billion were up $1.9 billion, or 8%, compared to the first quarter 2020 and were up $1.1 billion from the same period last year. The increases in balances are due to customers holding proceeds from PPP loans and other government stimulus programs in their deposit accounts, along with higher savings rates in general.
With respect to second quarter 2020 average balances by deposit category:
• | Noninterest-bearing demand deposits increased $1.4 billion from the first quarter and $1.8 billion from the same period last year to $6.9 billion. |
• | Savings increased $391 million from the first quarter and $940 million from the same period last year to $3.3 billion. |
• | Interest-bearing demand deposits increased $138 million from the first quarter and $461 million from the same period last year to $5.4 billion. |
• | Network transaction deposits increased $111 million from the first quarter but decreased $480 million from the same period last year to $1.5 billion. |
• | Money market deposits decreased $42 million from the first quarter and decreased $622 million from the same period last year to $6.5 billion. |
• | Time deposits decreased $166 million from the first quarter and decreased $1.1 billion from the same period last year to $2.5 billion. |
Net Interest Income and Net Interest Margin
Second quarter 2020 net interest income of $190 million was down 6%, or $13 million, and the net interest margin decreased 35 basis points from the first quarter of 2020. Second quarter 2020 net interest income decreased 11%, or $24 million, and the net interest margin decreased 39 basis points from the same period last year to 2.49%. The decreases in net interest income and net interest margin from the first quarter are due to reductions in the Fed Funds rate and increased liquidity during the second quarter.
• | The average yield on total earning assets for the second quarter of 2020 decreased 73 basis points from the prior quarter and decreased 116 basis points from the same period last year to 2.94%. |
• | The average cost of total interest-bearing liabilities for the second quarter of 2020 decreased 46 basis points from the prior quarter and decreased 94 basis points from the same period last year to 0.60%. |
• | The net free funds benefit for the second quarter of 2020 decreased eight basis points from the prior quarter and decreased 17 basis points compared to the same period last year. |
Noninterest Income
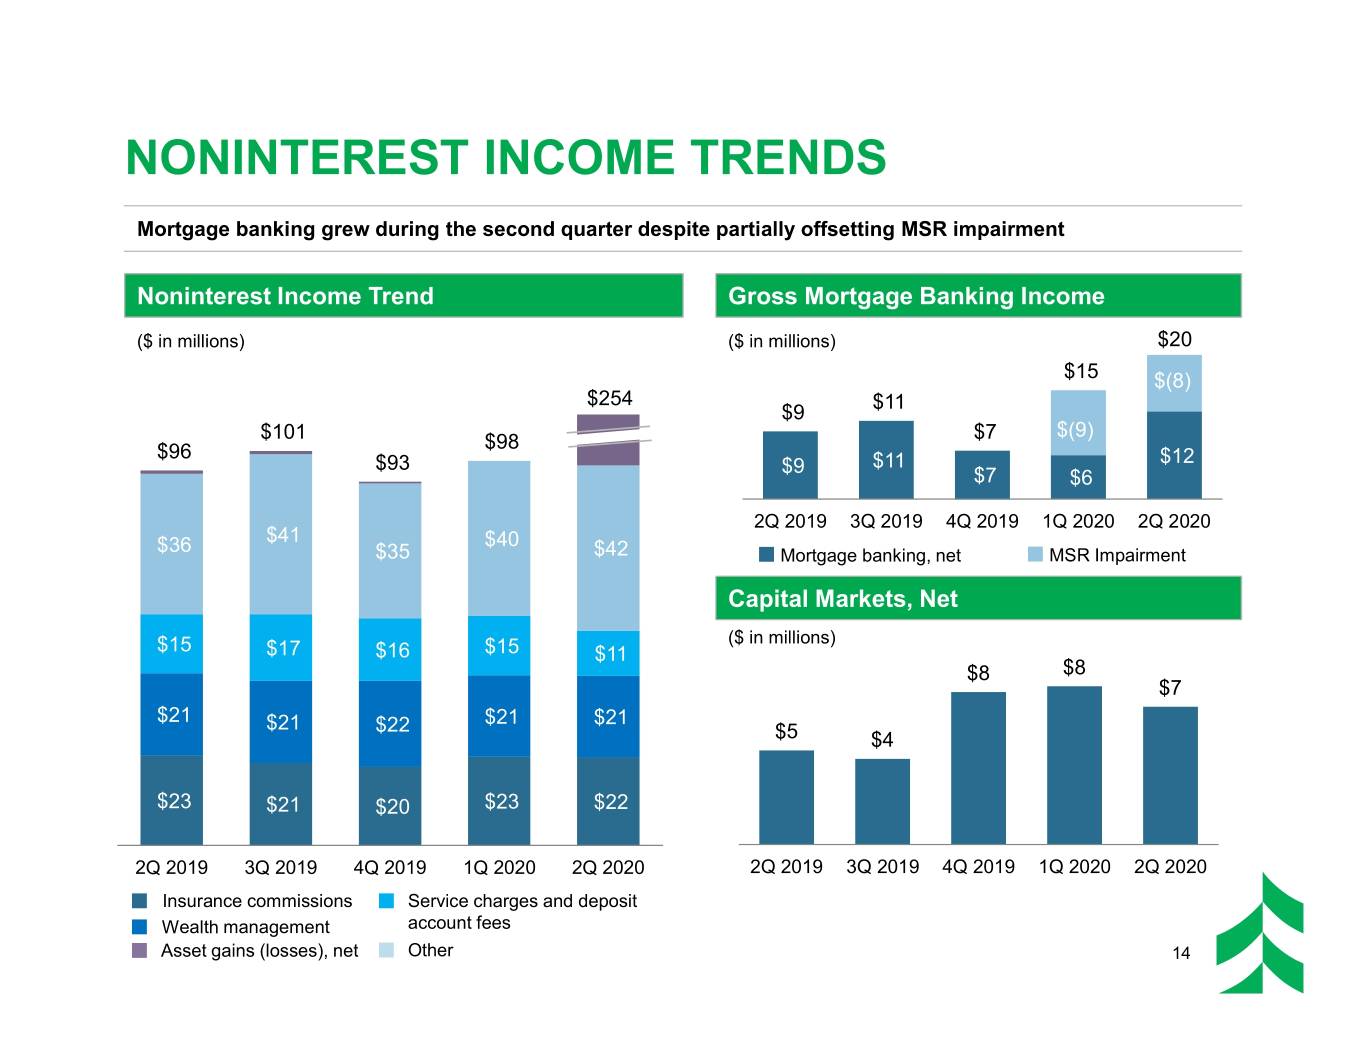
Second quarter of 2020 total noninterest income of $254 million increased $156 million from the prior quarter and increased $159 million from the same period last year.
With respect to second quarter 2020 noninterest income line items:
• | Net mortgage banking income was $12 million for the second quarter, up $6 million from the previous quarter and up $3 million from the same period last year. Gross mortgage banking income was $20 million, partially offset by $8 million of mortgage servicing rights impairment. |
• | Capital markets income was down $1 million from the previous quarter and up $2 million from the same period last year. |
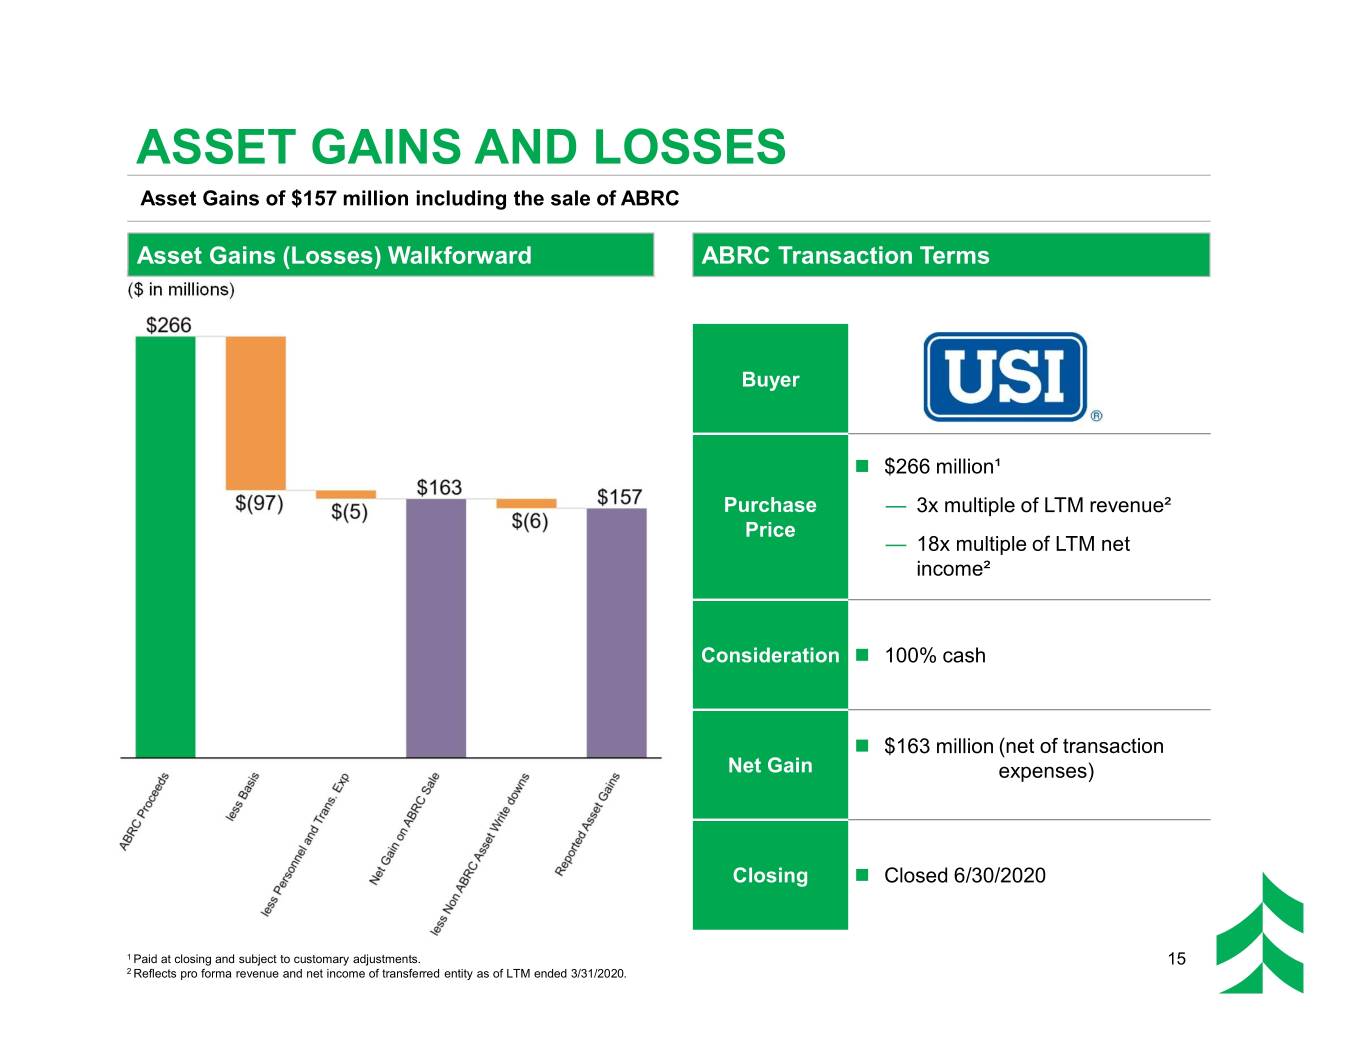
• | Asset gains (losses), net were $157 million for the second quarter. This included the $163 million net gain on sale of ABRC offset by other asset write-downs of $6 million. |
Noninterest Expense
Second quarter 2020 total noninterest expense of $183 million decreased $9 million from the prior quarter and decreased $14 million compared to the same period last year.
With respect to second quarter 2020 noninterest expense line items:
• | Personnel expense decreased $3 million from the prior quarter and $12 million from the same period last year. |
• | Technology expense was flat from the prior quarter but increased $1 million from the same period last year. |
• | Occupancy expense decreased $2 million from the prior quarter but was up $1 million from the same period last year. |
• | Business development and advertising expense was down $2 million from the prior quarter and was down $3 million from the same period last year. |
Taxes
The second quarter 2020 effective tax rate was 26% compared to 18% in both the prior quarter and the same period last year. The higher effective tax rate for the second quarter was driven by the one-time gain on the sale of ABRC.
Credit
The second quarter 2020 provision for credit losses was $61 million, up from $53 million in the prior quarter and up from $8 million in the same period last year, driven by increased charge offs and further reserve builds.
With respect to second quarter 2020 credit quality:
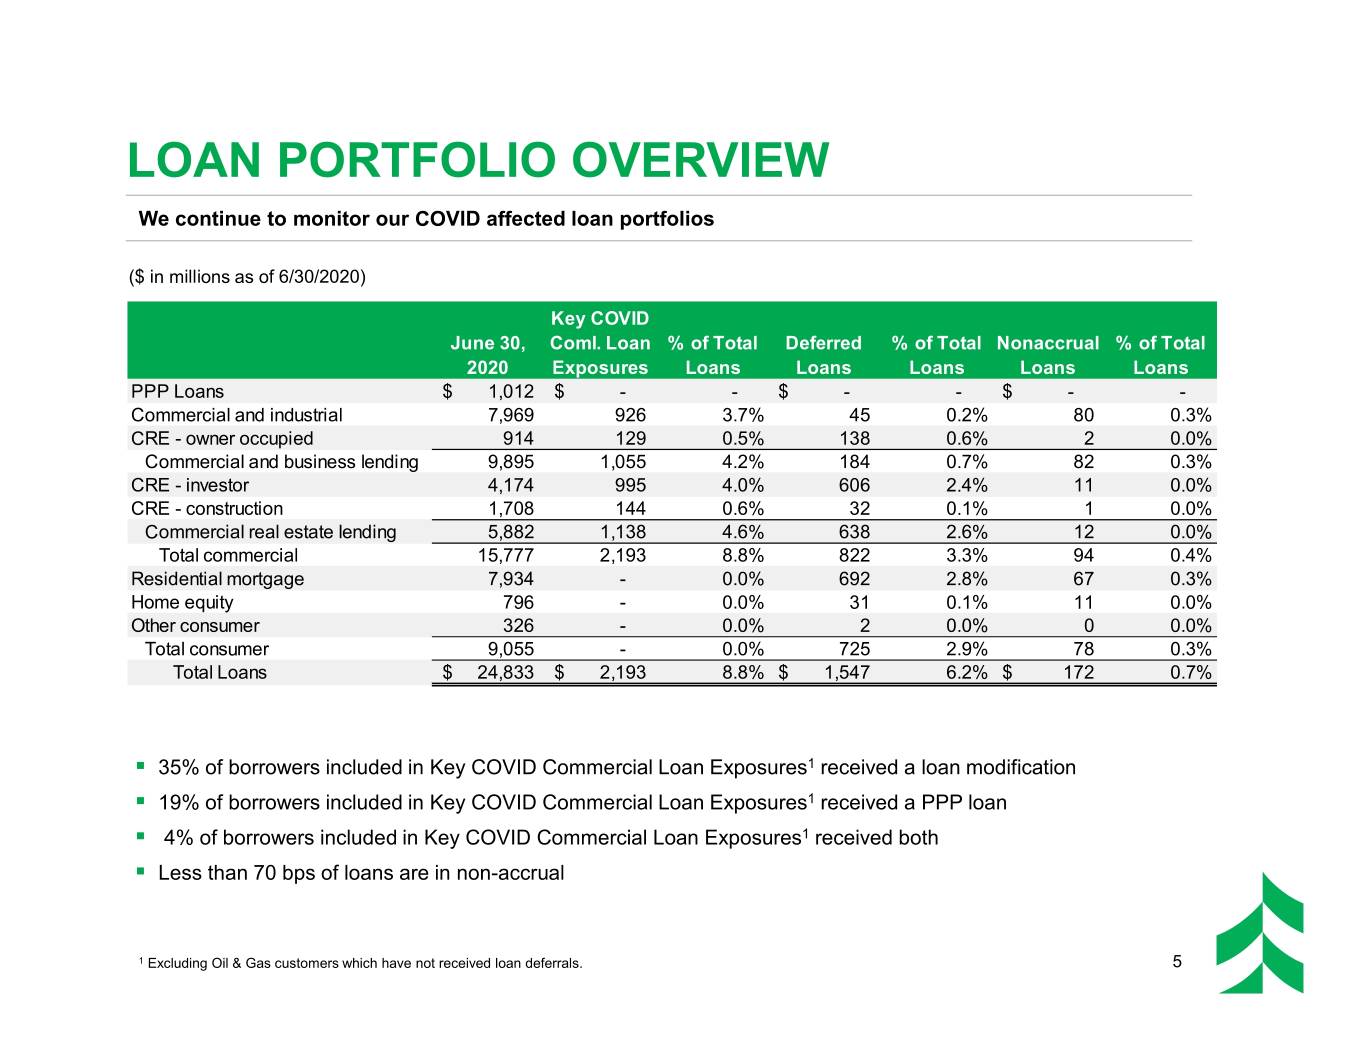
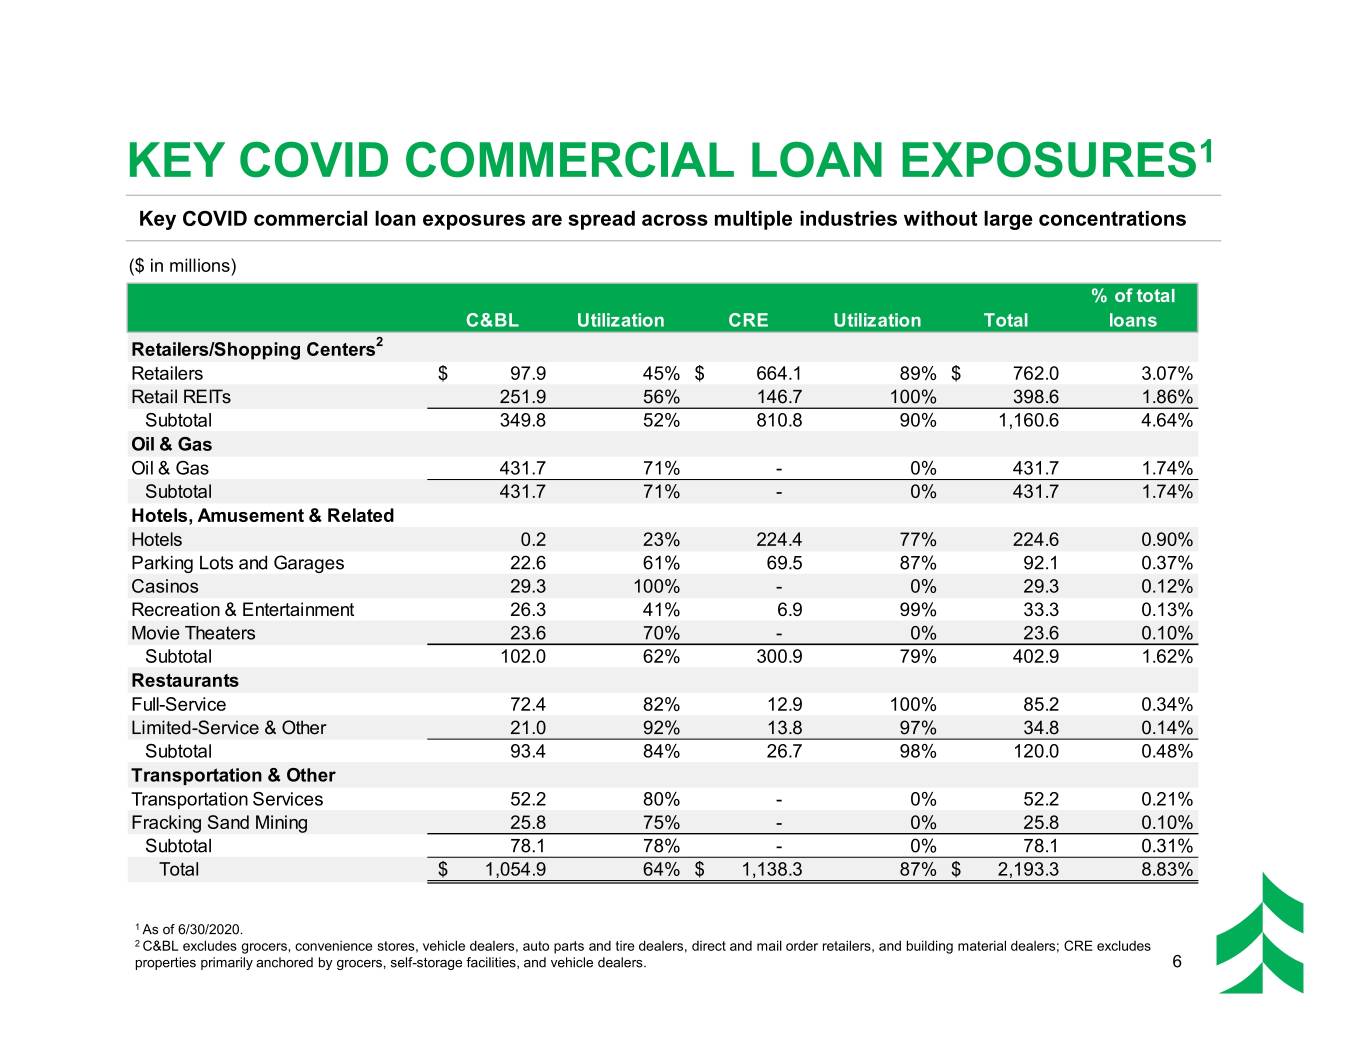
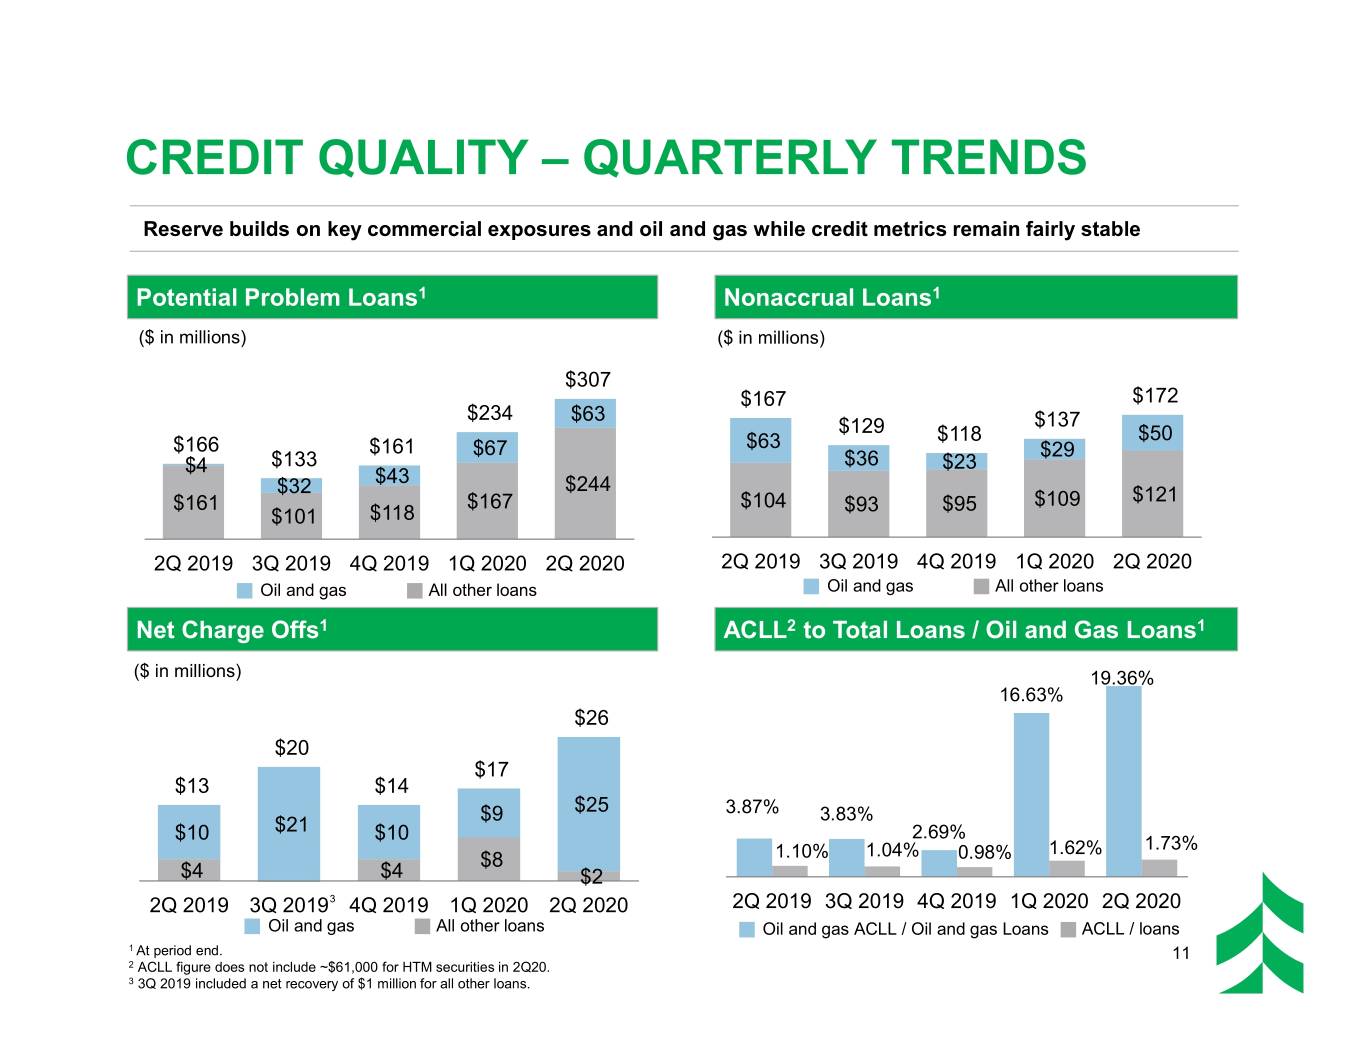
• | Potential problem loans of $307 million were up $73 million, or 31%, from the prior quarter and up $141 million, or 85%, from the same period last year. The increase was driven by general C&I loans and CRE loans in COVID-19 affected industries. |
• | Nonaccrual loans of $172 million were up $35 million from the prior quarter and up $5 million from the same period last year. The nonaccrual loans to total loans ratio was 0.69% in the second quarter, up from 0.56% in the prior quarter and down from 0.72% in the same period last year. |
• | Net charge offs of $26 million were up $9 million from the prior quarter and up $13 million from the same period last year. |
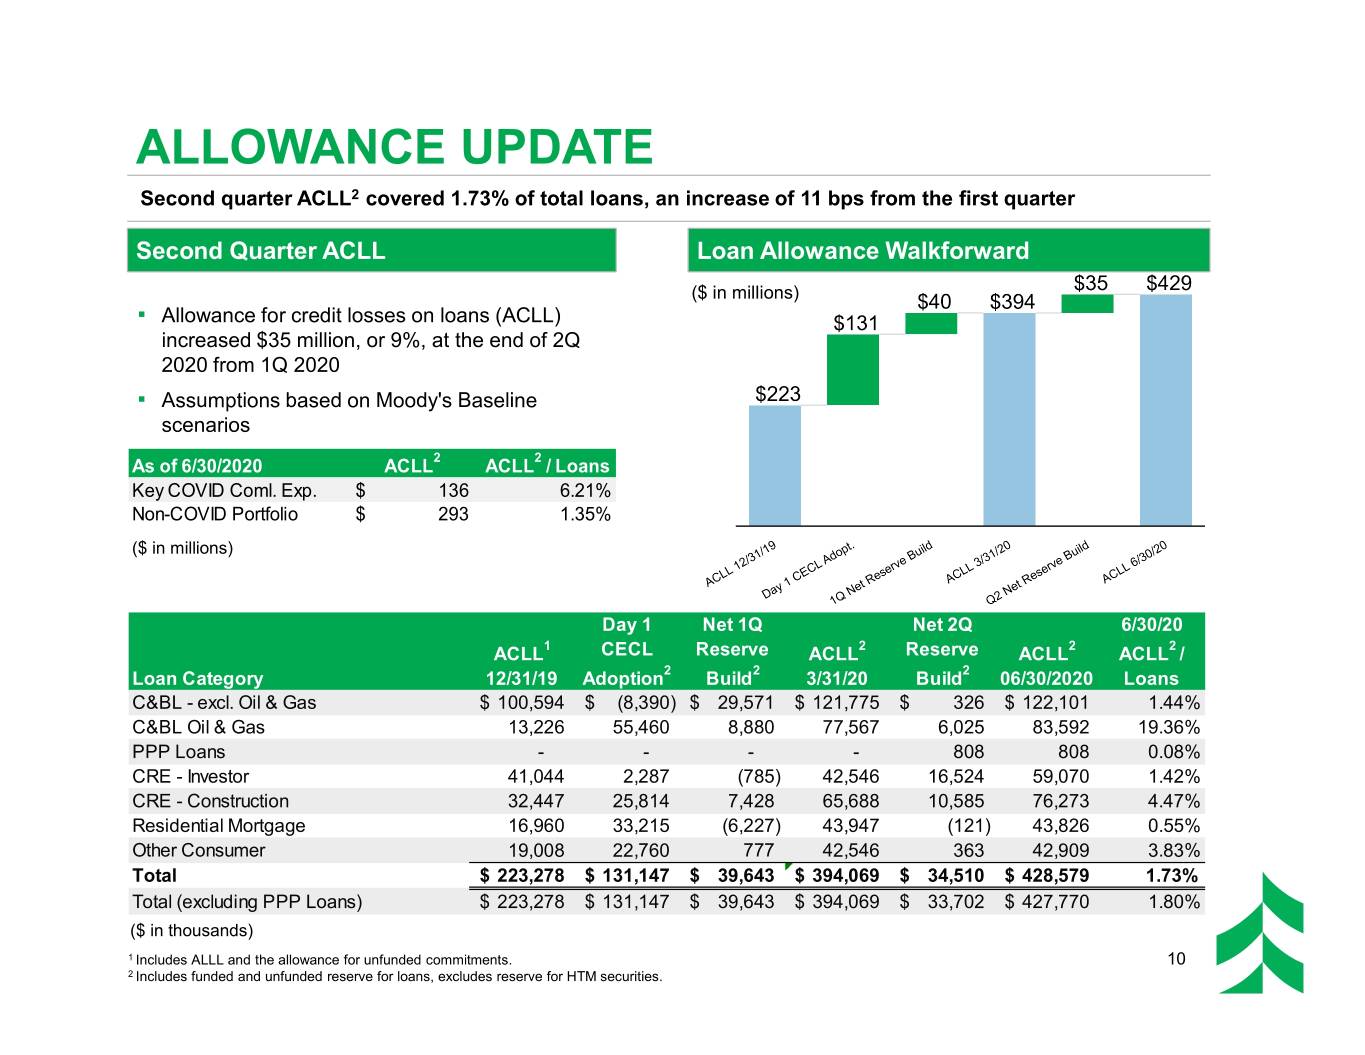
• | The allowance for credit losses on loans (ACLL) of $429 million was up $35 million from the prior quarter and up $173 million compared to the same period last year. The ACLL to total loans ratio was 1.73% in the second quarter, up from 1.62% in the prior quarter and 1.10% in the same period last year. |
Capital
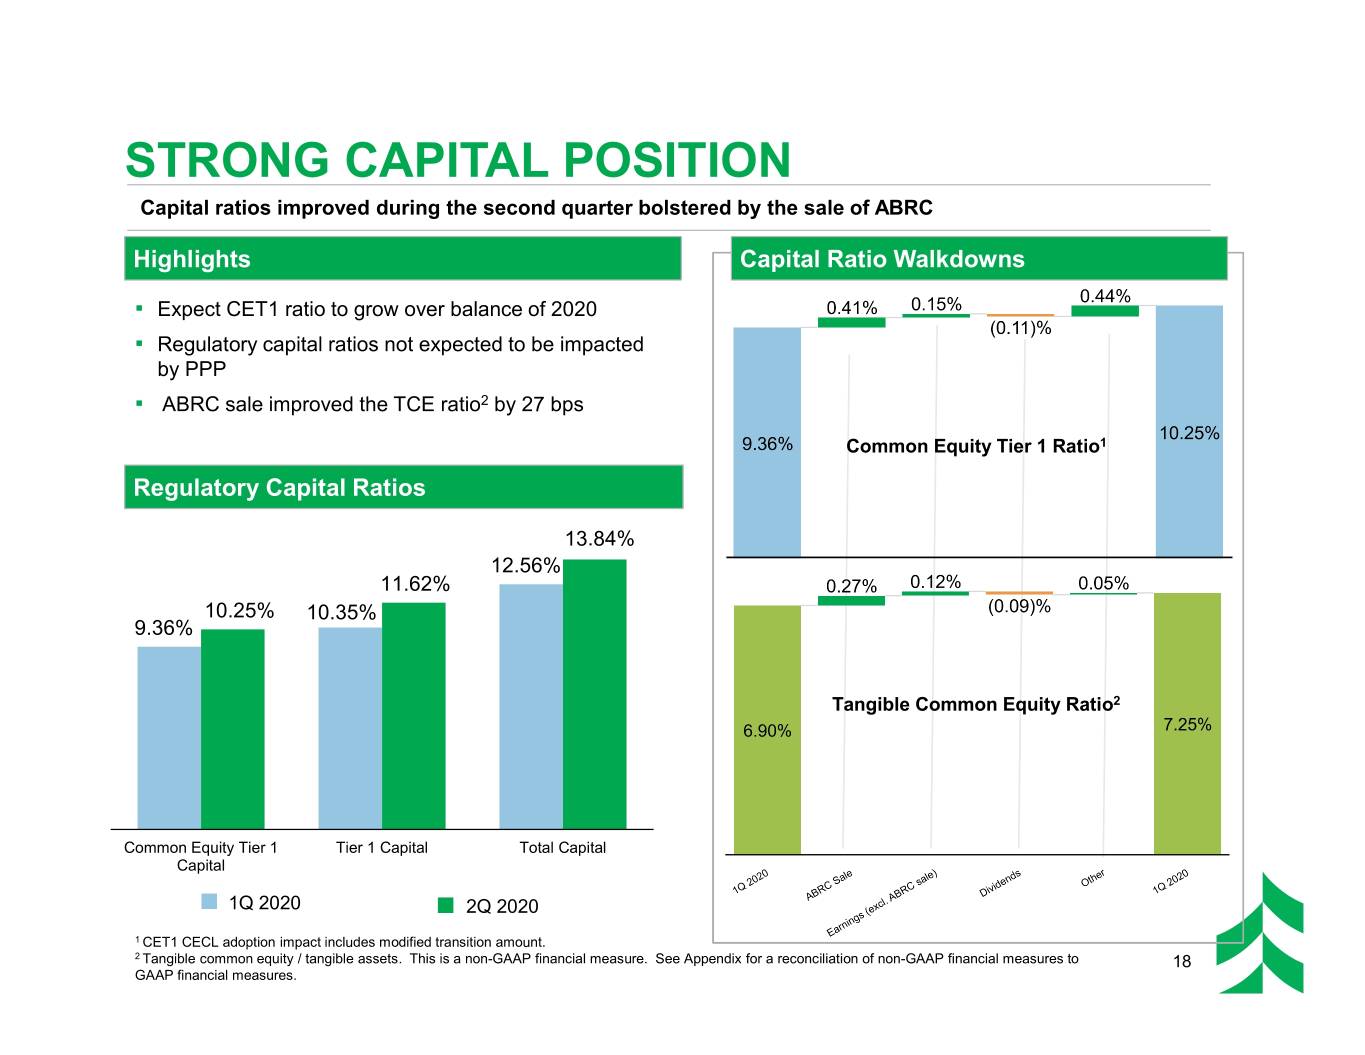
The Company’s capital position remains strong, with a CET1 capital ratio of 10.3% at June 30, 2020. The Company’s capital ratios continue to be in excess of the Basel III “well-capitalized” regulatory benchmarks on a fully phased in basis.
SECOND QUARTER 2020 EARNINGS RELEASE CONFERENCE CALL
The Company will host a conference call for investors and analysts at 4:00 p.m. Central Time (CT) today, July 23, 2020. Interested parties can access the live webcast of the call through the Investor Relations section of the Company's website, http://investor.associatedbank.com. Parties may also dial into the call at 877-407-8037 (domestic) or 201-689-8037 (international) and request the Associated Banc-Corp second quarter 2020 earnings call. The second quarter 2020 financial tables with an accompanying slide presentation will be available on the Company's website just prior to the call. An audio archive of the webcast will be available on the Company's website approximately fifteen minutes after the call is over.
ABOUT ASSOCIATED BANC-CORP
Associated Banc-Corp (NYSE: ASB) has total assets of $36 billion and is one of the top 50 publicly traded U.S. bank holding companies. Headquartered in Green Bay, Wisconsin, Associated is a leading Midwest banking franchise, offering a full range of financial products and services from more than 240 banking locations serving more than 120 communities throughout Wisconsin, Illinois and Minnesota, and commercial financial services in Indiana, Michigan, Missouri, Ohio and Texas. Associated Bank, N.A. is an Equal Housing Lender, Equal Opportunity Lender and Member FDIC. More information about Associated Banc-Corp is available at www.associatedbank.com.
FORWARD-LOOKING STATEMENTS
Statements made in this document which are not purely historical are forward-looking statements, as defined in the Private Securities Litigation Reform Act of 1995. This includes any statements regarding management’s plans, objectives, or goals for future operations, products or services, and forecasts of its revenues, earnings, or other measures of performance. Such forward-looking statements may be identified by the use of words such as “believe,” “expect,” “anticipate,” “plan,” “estimate,” “should,” “will,” “intend,” "target," “outlook,” or similar expressions. Forward-looking statements are based on current management expectations and, by their nature, are subject to risks and uncertainties. Actual results may differ materially from those contained in the forward-looking statements. Factors which may cause actual results to differ materially from those contained in such forward-looking statements include those identified in the Company’s most recent Form 10-K and subsequent SEC filings. Such factors are incorporated herein by reference.
NON-GAAP FINANCIAL MEASURES
This press release and related materials may contain references to measures which are not defined in generally accepted accounting principles (“GAAP”). Information concerning these non-GAAP financial measures can be found in the financial tables. Management believes these measures are meaningful because they reflect adjustments commonly made by management, investors, regulators, and analysts to evaluate the adequacy of earnings per common share, provide a greater understanding of ongoing operations and enhance comparability of results with prior periods.
# # #
Associated Banc-Corp Consolidated Balance Sheets (Unaudited) | |||||||||||||||||||||
($ in thousands) | Jun 30, 2020 | Mar 31, 2020 | Seql Qtr $ Change | Dec 31, 2019 | Sep 30, 2019 | Jun 30, 2019 | Comp Qtr $ Change | ||||||||||||||
Assets | |||||||||||||||||||||
Cash and due from banks | $ | 443,500 | $ | 480,337 | $ | (36,837 | ) | $ | 373,380 | $ | 523,435 | $ | 382,985 | $ | 60,515 | ||||||
Interest-bearing deposits in other financial institutions | 1,569,006 | 176,440 | 1,392,566 | 207,624 | 236,010 | 172,708 | 1,396,298 | ||||||||||||||
Federal funds sold and securities purchased under agreements to resell | 185 | 22,455 | (22,270 | ) | 7,740 | 100 | 1,385 | (1,200 | ) | ||||||||||||
Investment securities held to maturity, net, at amortized cost(a) | 2,077,225 | 2,149,373 | (72,148 | ) | 2,205,083 | 2,200,419 | 2,806,064 | (728,839 | ) | ||||||||||||
Investment securities available for sale, at fair value | 3,149,773 | 2,928,787 | 220,986 | 3,262,586 | 3,436,289 | 3,283,456 | (133,683 | ) | |||||||||||||
Equity securities | 15,091 | 15,063 | 28 | 15,090 | 15,096 | 15,066 | 25 | ||||||||||||||
Federal Home Loan Bank and Federal Reserve Bank stocks, at cost | 206,281 | 222,922 | (16,641 | ) | 227,347 | 207,443 | 202,758 | 3,523 | |||||||||||||
Residential loans held for sale | 196,673 | 366,330 | (169,657 | ) | 136,280 | 137,655 | 129,303 | 67,370 | |||||||||||||
Commercial loans held for sale | 3,565 | — | 3,565 | 15,000 | 11,597 | 11,000 | (7,435 | ) | |||||||||||||
Loans | 24,832,671 | 24,365,633 | 467,038 | 22,821,440 | 22,754,710 | 23,249,967 | 1,582,704 | ||||||||||||||
Allowance for loan losses(b) | (363,803 | ) | (337,793 | ) | (26,010 | ) | (201,371 | ) | (214,425 | ) | (233,659 | ) | (130,144 | ) | |||||||
Loans, net | 24,468,868 | 24,027,841 | 441,027 | 22,620,068 | 22,540,285 | 23,016,308 | 1,452,560 | ||||||||||||||
Bank and corporate owned life insurance | 676,196 | 674,026 | 2,170 | 671,948 | 670,739 | 668,638 | 7,558 | ||||||||||||||
Tax credit and other investments | 303,132 | 315,909 | (12,777 | ) | 279,969 | 256,220 | 222,812 | 80,320 | |||||||||||||
Premises and equipment, net | 434,042 | 438,469 | (4,427 | ) | 435,284 | 436,268 | 432,058 | 1,984 | |||||||||||||
Goodwill | 1,107,902 | 1,191,388 | (83,486 | ) | 1,176,230 | 1,176,230 | 1,176,019 | (68,117 | ) | ||||||||||||
Mortgage servicing rights, net | 49,403 | 58,289 | (8,886 | ) | 67,306 | 68,168 | 66,175 | (16,772 | ) | ||||||||||||
Other intangible assets, net | 72,759 | 92,723 | (19,964 | ) | 88,301 | 91,089 | 93,915 | (21,156 | ) | ||||||||||||
Interest receivable | 87,097 | 92,377 | (5,280 | ) | 91,196 | 96,315 | 110,528 | (23,431 | ) | ||||||||||||
Other assets | 640,765 | 655,328 | (14,563 | ) | 506,046 | 493,105 | 455,688 | 185,077 | |||||||||||||
Total assets | $ | 35,501,464 | $ | 33,908,056 | $ | 1,593,408 | $ | 32,386,478 | $ | 32,596,460 | $ | 33,246,869 | $ | 2,254,595 | |||||||
Liabilities and stockholders’ equity | |||||||||||||||||||||
Noninterest-bearing demand deposits | $ | 7,573,942 | $ | 6,107,386 | $ | 1,466,556 | $ | 5,450,709 | $ | 5,503,223 | $ | 5,354,987 | $ | 2,218,955 | |||||||
Interest-bearing deposits | 18,977,502 | 19,554,194 | (576,692 | ) | 18,328,355 | 18,919,339 | 19,919,235 | (941,733 | ) | ||||||||||||
Total deposits | 26,551,444 | 25,661,580 | 889,864 | 23,779,064 | 24,422,562 | 25,274,222 | 1,277,222 | ||||||||||||||
Federal funds purchased and securities sold under agreements to repurchase | 142,293 | 133,007 | 9,286 | 433,097 | 78,028 | 83,195 | 59,098 | ||||||||||||||
Commercial paper | 39,535 | 33,647 | 5,888 | 32,016 | 30,416 | 28,787 | 10,748 | ||||||||||||||
PPPLF | 1,009,760 | — | 1,009,760 | — | — | — | 1,009,760 | ||||||||||||||
FHLB advances | 2,657,016 | 3,214,194 | (557,178 | ) | 3,180,967 | 2,877,727 | 2,742,941 | (85,925 | ) | ||||||||||||
Other long-term funding | 548,937 | 549,644 | (707 | ) | 549,343 | 796,799 | 796,403 | (247,466 | ) | ||||||||||||
Allowance for unfunded commitments(b) | 64,776 | 56,276 | 8,500 | 21,907 | 22,907 | 21,907 | 42,869 | ||||||||||||||
Accrued expenses and other liabilities(b) | 463,245 | 469,236 | (5,991 | ) | 467,961 | 447,166 | 399,619 | 63,626 | |||||||||||||
Total liabilities | 31,477,007 | 30,117,584 | 1,359,423 | 28,464,355 | 28,675,605 | 29,347,075 | 2,129,932 | ||||||||||||||
Stockholders’ equity | |||||||||||||||||||||
Preferred equity | 353,846 | 256,716 | 97,130 | 256,716 | 256,716 | 256,716 | 97,130 | ||||||||||||||
Common equity(b) | 3,670,612 | 3,533,755 | 136,857 | 3,665,407 | 3,664,139 | 3,643,077 | 27,535 | ||||||||||||||
Total stockholders’ equity | 4,024,457 | 3,790,471 | 233,986 | 3,922,124 | 3,920,855 | 3,899,794 | 124,663 | ||||||||||||||
Total liabilities and stockholders’ equity | $ | 35,501,464 | $ | 33,908,056 | $ | 1,593,408 | $ | 32,386,478 | $ | 32,596,460 | $ | 33,246,869 | $ | 2,254,595 | |||||||
Numbers may not sum due to rounding.
(a) Beginning in 2020, the investment securities held to maturity are reported net of the related allowance for credit losses. Prior periods were unadjusted due to the modified retrospective application of ASU 2016-13.
(b) At January 1, 2020, the adoption of ASU 2016-13 resulted in an increase to the allowance for loan losses of $112 million and an increase to the allowance for unfunded commitments of $19 million for a total increase to the allowance for credit losses on loans of $131 million. A corresponding after tax decrease to common equity of $98 million was recorded along with a deferred tax asset of $33 million resulting in a decrease to accrued expenses and other liabilities. Prior periods were unadjusted due to the modified retrospective application of ASU 2016-13.
Page 1
Associated Banc-Corp Consolidated Statements of Income (Unaudited) | |||||||||||||||||||||||||||||
($ in thousands, except per share data) | Comp Qtr | YTD | YTD | Comp YTD | |||||||||||||||||||||||||
2Q20 | 2Q19 | $ Change | % Change | Jun 2020 | Jun 2019 | $ Change | % Change | ||||||||||||||||||||||
Interest income | |||||||||||||||||||||||||||||
Interest and fees on loans | $ | 191,895 | $ | 260,784 | $ | (68,889 | ) | (26 | )% | $ | 416,681 | $ | 519,637 | $ | (102,956 | ) | (20 | )% | |||||||||||
Interest and dividends on investment securities | |||||||||||||||||||||||||||||
Taxable | 16,103 | 26,710 | (10,607 | ) | (40 | )% | 36,375 | 55,764 | (19,389 | ) | (35 | )% | |||||||||||||||||
Tax-exempt | 14,616 | 14,643 | (27 | ) | — | % | 29,498 | 28,459 | 1,039 | 4 | % | ||||||||||||||||||
Other interest | 2,231 | 3,995 | (1,764 | ) | (44 | )% | 5,535 | 8,221 | (2,686 | ) | (33 | )% | |||||||||||||||||
Total interest income | 224,845 | 306,133 | (81,288 | ) | (27 | )% | 488,090 | 612,081 | (123,991 | ) | (20 | )% | |||||||||||||||||
Interest expense | |||||||||||||||||||||||||||||
Interest on deposits | 13,178 | 67,050 | (53,872 | ) | (80 | )% | 49,844 | 129,823 | (79,979 | ) | (62 | )% | |||||||||||||||||
Interest on federal funds purchased and securities sold under agreements to repurchase | 51 | 286 | (235 | ) | (82 | )% | 420 | 913 | (493 | ) | (54 | )% | |||||||||||||||||
Interest on other short-term funding | 683 | 37 | 646 | N/M | 721 | 88 | 633 | N/M | |||||||||||||||||||||
Interest on FHLB advances | 15,470 | 17,744 | (2,274 | ) | (13 | )% | 33,096 | 37,298 | (4,202 | ) | (11 | )% | |||||||||||||||||
Interest on long-term funding | 5,591 | 7,396 | (1,805 | ) | (24 | )% | 11,195 | 14,792 | (3,597 | ) | (24 | )% | |||||||||||||||||
Total interest expense | 34,973 | 92,513 | (57,540 | ) | (62 | )% | 95,276 | 182,914 | (87,638 | ) | (48 | )% | |||||||||||||||||
Net interest income | 189,872 | 213,619 | (23,747 | ) | (11 | )% | 392,814 | 429,167 | (36,353 | ) | (8 | )% | |||||||||||||||||
Provision for credit losses | 61,000 | 8,000 | 53,000 | N/M | 114,001 | 14,000 | 100,001 | N/M | |||||||||||||||||||||
Net interest income after provision for credit losses | 128,872 | 205,619 | (76,747 | ) | (37 | )% | 278,813 | 415,167 | (136,354 | ) | (33 | )% | |||||||||||||||||
Noninterest income | |||||||||||||||||||||||||||||
Insurance commissions and fees | 22,430 | 22,985 | (555 | ) | (2 | )% | 45,038 | 48,449 | (3,411 | ) | (7 | )% | |||||||||||||||||
Wealth management fees(a) | 20,916 | 20,691 | 225 | 1 | % | 41,732 | 40,870 | 862 | 2 | % | |||||||||||||||||||
Service charges and deposit account fees | 11,484 | 15,426 | (3,942 | ) | (26 | )% | 26,706 | 30,542 | (3,836 | ) | (13 | )% | |||||||||||||||||
Card-based fees | 8,893 | 10,131 | (1,238 | ) | (12 | )% | 18,490 | 19,392 | (902 | ) | (5 | )% | |||||||||||||||||
Other fee-based revenue | 4,774 | 5,178 | (404 | ) | (8 | )% | 9,272 | 9,161 | 111 | 1 | % | ||||||||||||||||||
Capital markets, net | 6,910 | 4,726 | 2,184 | 46 | % | 14,845 | 7,916 | 6,929 | 88 | % | |||||||||||||||||||
Mortgage banking, net | 12,263 | 9,466 | 2,797 | 30 | % | 18,407 | 14,178 | 4,229 | 30 | % | |||||||||||||||||||
Bank and corporate owned life insurance | 3,625 | 3,352 | 273 | 8 | % | 6,719 | 7,144 | (425 | ) | (6 | )% | ||||||||||||||||||
Asset gains (losses), net(b) | 157,361 | 871 | 156,490 | N/M | 157,284 | 1,438 | 155,846 | N/M | |||||||||||||||||||||
Investment securities gains (losses), net | 3,096 | 463 | 2,633 | N/M | 9,214 | 2,143 | 7,071 | N/M | |||||||||||||||||||||
Other | 2,737 | 2,547 | 190 | 7 | % | 5,090 | 5,807 | (717 | ) | (12 | )% | ||||||||||||||||||
Total noninterest income | 254,490 | 95,837 | 158,653 | 166 | % | 352,796 | 187,040 | 165,756 | 89 | % | |||||||||||||||||||
Noninterest expense | |||||||||||||||||||||||||||||
Personnel | 111,350 | 123,228 | (11,878 | ) | (10 | )% | 225,551 | 243,279 | (17,728 | ) | (7 | )% | |||||||||||||||||
Technology | 21,174 | 20,114 | 1,060 | 5 | % | 41,973 | 39,126 | 2,847 | 7 | % | |||||||||||||||||||
Occupancy | 14,464 | 13,830 | 634 | 5 | % | 30,532 | 30,302 | 230 | 1 | % | |||||||||||||||||||
Business development and advertising | 3,556 | 6,658 | (3,102 | ) | (47 | )% | 9,382 | 13,293 | (3,911 | ) | (29 | )% | |||||||||||||||||
Equipment | 5,312 | 5,577 | (265 | ) | (5 | )% | 10,751 | 11,245 | (494 | ) | (4 | )% | |||||||||||||||||
Legal and professional | 5,058 | 4,668 | 390 | 8 | % | 10,217 | 8,619 | 1,598 | 19 | % | |||||||||||||||||||
Loan and foreclosure costs | 3,605 | 1,814 | 1,791 | 99 | % | 6,725 | 3,961 | 2,764 | 70 | % | |||||||||||||||||||
FDIC assessment | 5,250 | 4,500 | 750 | 17 | % | 10,750 | 8,250 | 2,500 | 30 | % | |||||||||||||||||||
Other intangible amortization | 2,872 | 2,324 | 548 | 24 | % | 5,686 | 4,551 | 1,135 | 25 | % | |||||||||||||||||||
Acquisition related costs(c) | 518 | 3,734 | (3,216 | ) | (86 | )% | 2,238 | 4,366 | (2,128 | ) | (49 | )% | |||||||||||||||||
Other | 10,249 | 11,331 | (1,082 | ) | (10 | )% | 21,791 | 22,459 | (668 | ) | (3 | )% | |||||||||||||||||
Total noninterest expense | 183,407 | 197,779 | (14,372 | ) | (7 | )% | 375,598 | 389,450 | (13,852 | ) | (4 | )% | |||||||||||||||||
Income before income taxes | 199,955 | 103,678 | 96,277 | 93 | % | 256,012 | 212,756 | 43,256 | 20 | % | |||||||||||||||||||
Income tax expense | 51,238 | 19,017 | 32,221 | 169 | % | 61,457 | 41,409 | 20,048 | 48 | % | |||||||||||||||||||
Net income | 148,718 | 84,661 | 64,057 | 76 | % | 194,555 | 171,347 | 23,208 | 14 | % | |||||||||||||||||||
Preferred stock dividends | 4,144 | 3,801 | 343 | 9 | % | 7,945 | 7,601 | 344 | 5 | % | |||||||||||||||||||
Net income available to common equity | $ | 144,573 | $ | 80,860 | $ | 63,713 | 79 | % | $ | 186,611 | $ | 163,746 | $ | 22,865 | 14 | % | |||||||||||||
Earnings per common share | |||||||||||||||||||||||||||||
Basic | $ | 0.94 | $ | 0.49 | $ | 0.45 | 92 | % | $ | 1.21 | $ | 1.00 | $ | 0.21 | 21 | % | |||||||||||||
Diluted | $ | 0.94 | $ | 0.49 | $ | 0.45 | 92 | % | $ | 1.20 | $ | 0.99 | $ | 0.21 | 21 | % | |||||||||||||
Average common shares outstanding | |||||||||||||||||||||||||||||
Basic | 152,393 | 162,180 | (9,787 | ) | (6 | )% | 153,547 | 163,049 | (9,502 | ) | (6 | )% | |||||||||||||||||
Diluted | 153,150 | 163,672 | (10,522 | ) | (6 | )% | 154,360 | 164,518 | (10,158 | ) | (6 | )% | |||||||||||||||||
N/M = Not meaningful
Numbers may not sum due to rounding.
(a) Includes trust, asset management, brokerage, and annuity fees.
(b) 2Q20 and YTD 2020 include a gain of $163 million from the sale of Associated Benefits & Risk Consulting. 2Q19 and YTD 2019 include less than $1 million of Huntington related asset losses.
(c) | Includes Huntington branch and First Staunton acquisition related costs only. |
Page 2
Associated Banc-Corp Consolidated Statements of Income (Unaudited) - Quarterly Trend | |||||||||||||||||||||||||||||||||
($ in thousands, except per share data) | Seql Qtr | Comp Qtr | |||||||||||||||||||||||||||||||
2Q20 | 1Q20 | $ Change | % Change | 4Q19 | 3Q19 | 2Q19 | $ Change | % Change | |||||||||||||||||||||||||
Interest income | |||||||||||||||||||||||||||||||||
Interest and fees on loans | $ | 191,895 | $ | 224,786 | $ | (32,891 | ) | (15 | )% | $ | 229,883 | $ | 248,579 | $ | 260,784 | $ | (68,889 | ) | (26 | )% | |||||||||||||
Interest and dividends on investment securities | |||||||||||||||||||||||||||||||||
Taxable | 16,103 | 20,272 | (4,169 | ) | (21 | )% | 21,056 | 23,485 | 26,710 | (10,607 | ) | (40 | )% | ||||||||||||||||||||
Tax-exempt | 14,616 | 14,882 | (266 | ) | (2 | )% | 14,615 | 14,491 | 14,643 | (27 | ) | — | % | ||||||||||||||||||||
Other interest | 2,231 | 3,304 | (1,073 | ) | (32 | )% | 3,556 | 4,865 | 3,995 | (1,764 | ) | (44 | )% | ||||||||||||||||||||
Total interest income | 224,845 | 263,244 | (38,399 | ) | (15 | )% | 269,110 | 291,420 | 306,133 | (81,288 | ) | (27 | )% | ||||||||||||||||||||
Interest expense | |||||||||||||||||||||||||||||||||
Interest on deposits | 13,178 | 36,666 | (23,488 | ) | (64 | )% | 45,877 | 61,585 | 67,050 | (53,872 | ) | (80 | )% | ||||||||||||||||||||
Interest on federal funds purchased and securities sold under agreements to repurchase | 51 | 368 | (317 | ) | (86 | )% | 521 | 145 | 286 | (235 | ) | (82 | )% | ||||||||||||||||||||
Interest on other short-term funding | 683 | 39 | 644 | N/M | 28 | 33 | 37 | 646 | N/M | ||||||||||||||||||||||||
Interest on FHLB advances | 15,470 | 17,626 | (2,156 | ) | (12 | )% | 16,623 | 15,896 | 17,744 | (2,274 | ) | (13 | )% | ||||||||||||||||||||
Interest on long-term funding | 5,591 | 5,604 | (13 | ) | — | % | 5,918 | 7,396 | 7,396 | (1,805 | ) | (24 | )% | ||||||||||||||||||||
Total interest expense | 34,973 | 60,303 | (25,330 | ) | (42 | )% | 68,967 | 85,054 | 92,513 | (57,540 | ) | (62 | )% | ||||||||||||||||||||
Net interest income | 189,872 | 202,942 | (13,070 | ) | (6 | )% | 200,142 | 206,365 | 213,619 | (23,747 | ) | (11 | )% | ||||||||||||||||||||
Provision for credit losses | 61,000 | 53,001 | 7,999 | 15 | % | — | 2,000 | 8,000 | 53,000 | N/M | |||||||||||||||||||||||
Net interest income after provision for credit losses | 128,872 | 149,941 | (21,069 | ) | (14 | )% | 200,142 | 204,365 | 205,619 | (76,747 | ) | (37 | )% | ||||||||||||||||||||
Noninterest income | |||||||||||||||||||||||||||||||||
Insurance commissions and fees | 22,430 | 22,608 | (178 | ) | (1 | )% | 19,701 | 20,954 | 22,985 | (555 | ) | (2 | )% | ||||||||||||||||||||
Wealth management fees(a) | 20,916 | 20,816 | 100 | — | % | 21,582 | 21,015 | 20,691 | 225 | 1 | % | ||||||||||||||||||||||
Service charges and deposit account fees | 11,484 | 15,222 | (3,738 | ) | (25 | )% | 16,032 | 16,561 | 15,426 | (3,942 | ) | (26 | )% | ||||||||||||||||||||
Card-based fees | 8,893 | 9,597 | (704 | ) | (7 | )% | 9,906 | 10,456 | 10,131 | (1,238 | ) | (12 | )% | ||||||||||||||||||||
Other fee-based revenue | 4,774 | 4,497 | 277 | 6 | % | 4,696 | 5,085 | 5,178 | (404 | ) | (8 | )% | |||||||||||||||||||||
Capital markets, net | 6,910 | 7,935 | (1,025 | ) | (13 | )% | 7,647 | 4,300 | 4,726 | 2,184 | 46 | % | |||||||||||||||||||||
Mortgage banking, net | 12,263 | 6,143 | 6,120 | 100 | % | 6,760 | 10,940 | 9,466 | 2,797 | 30 | % | ||||||||||||||||||||||
Bank and corporate owned life insurance | 3,625 | 3,094 | 531 | 17 | % | 3,364 | 4,337 | 3,352 | 273 | 8 | % | ||||||||||||||||||||||
Asset gains (losses), net(b) | 157,361 | (77 | ) | 157,438 | N/M | 398 | 877 | 871 | 156,490 | N/M | |||||||||||||||||||||||
Investment securities gains (losses), net | 3,096 | 6,118 | (3,022 | ) | (49 | )% | 26 | 3,788 | 463 | 2,633 | N/M | ||||||||||||||||||||||
Other | 2,737 | 2,352 | 385 | 16 | % | 2,822 | 2,537 | 2,547 | 190 | 7 | % | ||||||||||||||||||||||
Total noninterest income | 254,490 | 98,306 | 156,184 | 159 | % | 92,934 | 100,850 | 95,837 | 158,653 | 166 | % | ||||||||||||||||||||||
Noninterest expense | |||||||||||||||||||||||||||||||||
Personnel | 111,350 | 114,200 | (2,850 | ) | (2 | )% | 120,614 | 123,170 | 123,228 | (11,878 | ) | (10 | )% | ||||||||||||||||||||
Technology | 21,174 | 20,799 | 375 | 2 | % | 22,731 | 20,572 | 20,114 | 1,060 | 5 | % | ||||||||||||||||||||||
Occupancy | 14,464 | 16,069 | (1,605 | ) | (10 | )% | 16,933 | 15,164 | 13,830 | 634 | 5 | % | |||||||||||||||||||||
Business development and advertising | 3,556 | 5,826 | (2,270 | ) | (39 | )% | 8,316 | 7,991 | 6,658 | (3,102 | ) | (47 | )% | ||||||||||||||||||||
Equipment | 5,312 | 5,439 | (127 | ) | (2 | )% | 5,970 | 6,335 | 5,577 | (265 | ) | (5 | )% | ||||||||||||||||||||
Legal and professional | 5,058 | 5,160 | (102 | ) | (2 | )% | 5,559 | 5,724 | 4,668 | 390 | 8 | % | |||||||||||||||||||||
Loan and foreclosure costs | 3,605 | 3,120 | 485 | 16 | % | 3,262 | 1,638 | 1,814 | 1,791 | 99 | % | ||||||||||||||||||||||
FDIC assessment | 5,250 | 5,500 | (250 | ) | (5 | )% | 4,000 | 4,000 | 4,500 | 750 | 17 | % | |||||||||||||||||||||
Other intangible amortization | 2,872 | 2,814 | 58 | 2 | % | 2,712 | 2,686 | 2,324 | 548 | 24 | % | ||||||||||||||||||||||
Acquisition related costs(c) | 518 | 1,721 | (1,203 | ) | (70 | )% | 1,325 | 1,629 | 3,734 | (3,216 | ) | (86 | )% | ||||||||||||||||||||
Other | 10,249 | 11,543 | (1,294 | ) | (11 | )% | 12,187 | 12,021 | 11,331 | (1,082 | ) | (10 | )% | ||||||||||||||||||||
Total noninterest expense | 183,407 | 192,191 | (8,784 | ) | (5 | )% | 203,609 | 200,930 | 197,779 | (14,372 | ) | (7 | )% | ||||||||||||||||||||
Income before income taxes | 199,955 | 56,056 | 143,899 | N/M | 89,467 | 104,286 | 103,678 | 96,277 | 93 | % | |||||||||||||||||||||||
Income tax expense | 51,238 | 10,219 | 41,019 | N/M | 17,364 | 20,947 | 19,017 | 32,221 | 169 | % | |||||||||||||||||||||||
Net income | 148,718 | 45,838 | 102,880 | N/M | 72,103 | 83,339 | 84,661 | 64,057 | 76 | % | |||||||||||||||||||||||
Preferred stock dividends | 4,144 | 3,801 | 343 | 9 | % | 3,801 | 3,801 | 3,801 | 343 | 9 | % | ||||||||||||||||||||||
Net income available to common equity | $ | 144,573 | $ | 42,037 | $ | 102,536 | N/M | $ | 68,303 | $ | 79,539 | $ | 80,860 | $ | 63,713 | 79 | % | ||||||||||||||||
Earnings per common share | |||||||||||||||||||||||||||||||||
Basic | $ | 0.94 | $ | 0.27 | $ | 0.67 | N/M | $ | 0.43 | $ | 0.50 | $ | 0.49 | $ | 0.45 | 92 | % | ||||||||||||||||
Diluted | $ | 0.94 | $ | 0.27 | $ | 0.67 | N/M | $ | 0.43 | $ | 0.49 | $ | 0.49 | $ | 0.45 | 92 | % | ||||||||||||||||
Average common shares outstanding | |||||||||||||||||||||||||||||||||
Basic | 152,393 | 154,701 | (2,308 | ) | (1 | )% | 156,994 | 159,126 | 162,180 | (9,787 | ) | (6 | )% | ||||||||||||||||||||
Diluted | 153,150 | 155,619 | (2,469 | ) | (2 | )% | 158,472 | 160,382 | 163,672 | (10,522 | ) | (6 | )% | ||||||||||||||||||||
N/M = Not meaningful
Numbers may not sum due to rounding.
(a) Includes trust, asset management, brokerage, and annuity fees.
(b) | 2Q20 includes a gain of $163 million from the sale of Associated Benefits & Risk Consulting. 2Q19 includes less than $1 million of Huntington related asset losses. |
(c) Includes Huntington branch and First Staunton acquisition related costs only.
Page 3
Associated Banc-Corp Selected Quarterly Information | |||||||||||||||||||||
($ in millions except per share data and COVID-19 loan modifications; shares repurchased and outstanding in thousands) | YTD Jun 2020 | YTD Jun 2019 | 2Q20 | 1Q20 | 4Q19 | 3Q19 | 2Q19 | ||||||||||||||
Per common share data | |||||||||||||||||||||
Dividends | $ | 0.36 | $ | 0.34 | $ | 0.18 | $ | 0.18 | $ | 0.18 | $ | 0.17 | $ | 0.17 | |||||||
Market value: | |||||||||||||||||||||
High | 21.94 | 23.67 | 17.03 | 21.94 | 22.51 | 21.67 | 23.15 | ||||||||||||||
Low | 10.85 | 19.77 | 11.48 | 10.85 | 18.96 | 18.64 | 19.81 | ||||||||||||||
Close | 13.68 | 21.14 | 13.68 | 12.79 | 22.04 | 20.25 | 21.14 | ||||||||||||||
Book value | 23.89 | 22.40 | 23.89 | 22.99 | 23.32 | 23.00 | 22.40 | ||||||||||||||
Tangible book value / share | 16.21 | 14.59 | 16.21 | 14.64 | 15.28 | 15.05 | 14.59 | ||||||||||||||
Performance ratios (annualized) | |||||||||||||||||||||
Return on average assets | 1.16 | % | 1.03 | % | 1.72 | % | 0.57 | % | 0.89 | % | 1.00 | % | 1.02 | % | |||||||
Noninterest expense / average assets | 2.24 | % | 2.35 | % | 2.12 | % | 2.37 | % | 2.51 | % | 2.40 | % | 2.37 | % | |||||||
Effective tax rate | 24.01 | % | 19.46 | % | 25.62 | % | 18.23 | % | 19.41 | % | 20.09 | % | 18.34 | % | |||||||
Dividend payout ratio(a) | 29.75 | % | 34.00 | % | 19.15 | % | 66.67 | % | 41.86 | % | 34.00 | % | 34.69 | % | |||||||
Net interest margin | 2.66 | % | 2.89 | % | 2.49 | % | 2.84 | % | 2.83 | % | 2.81 | % | 2.88 | % | |||||||
Selected trend information | |||||||||||||||||||||
Average full time equivalent employees(b) | 4,666 | 4,663 | 4,701 | 4,631 | 4,696 | 4,782 | 4,666 | ||||||||||||||
Branch count | 249 | 249 | 248 | 248 | 247 | ||||||||||||||||
Assets under management, at market value(c) | $ | 11,755 | $ | 10,454 | $ | 12,104 | $ | 11,604 | $ | 11,475 | |||||||||||
Mortgage loans originated for sale during period | $ | 861 | $ | 459 | $ | 550 | $ | 310 | $ | 267 | $ | 365 | $ | 297 | |||||||
Mortgage loan settlements during period(d) | $ | 1,022 | $ | 432 | $ | 725 | $ | 297 | $ | 268 | $ | 617 | $ | 272 | |||||||
Mortgage portfolio loans transferred to held for sale during period | $ | 200 | $ | — | $ | — | $ | 200 | $ | — | $ | 243 | $ | — | |||||||
Mortgage portfolio serviced for others | $ | 8,454 | $ | 8,549 | $ | 8,489 | $ | 8,692 | $ | 8,509 | |||||||||||
Mortgage servicing rights, net / mortgage portfolio serviced for others | 0.58 | % | 0.68 | % | 0.79 | % | 0.78 | % | 0.78 | % | |||||||||||
Shares repurchased during period(e) | 4,264 | 3,063 | — | 4,264 | 2,256 | 2,892 | 1,754 | ||||||||||||||
Shares outstanding, end of period | 153,616 | 162,662 | 153,616 | 153,690 | 157,171 | 159,291 | 162,662 | ||||||||||||||
Payment Protection Program fees, net | |||||||||||||||||||||
Total fees established | $ | 27 | N/A | $ | 27 | N/A | N/A | N/A | N/A | ||||||||||||
Fees recognized | (3 | ) | N/A | (3 | ) | N/A | N/A | N/A | N/A | ||||||||||||
Remaining Payment Protection Program fee balance | $ | 24 | N/A | $ | 24 | N/A | N/A | N/A | N/A | ||||||||||||
Completed loan deferrals and modifications under COVID-19 relief program ($ in thousands) | |||||||||||||||||||||
Commercial and industrial | $ | 45,415 | $ | 345 | N/A | N/A | N/A | ||||||||||||||
Commercial real estate—owner occupied | 138,267 | — | N/A | N/A | N/A | ||||||||||||||||
Commercial and business lending | 183,682 | 345 | N/A | N/A | N/A | ||||||||||||||||
Commercial real estate—investor | 606,058 | 595 | N/A | N/A | N/A | ||||||||||||||||
Real estate construction | 32,214 | — | N/A | N/A | N/A | ||||||||||||||||
Commercial real estate lending | 638,272 | 595 | N/A | N/A | N/A | ||||||||||||||||
Total commercial | 821,955 | 940 | N/A | N/A | N/A | ||||||||||||||||
Residential mortgage | 692,307 | 428 | N/A | N/A | N/A | ||||||||||||||||
Home equity | 30,554 | — | N/A | N/A | N/A | ||||||||||||||||
Other consumer | 2,060 | — | N/A | N/A | N/A | ||||||||||||||||
Total consumer | 724,921 | 428 | N/A | N/A | N/A | ||||||||||||||||
Total COVID-19 loan modifications | $ | 1,546,876 | $ | 1,368 | N/A | N/A | N/A | ||||||||||||||
Selected quarterly ratios | |||||||||||||||||||||
Loans / deposits | 93.53 | % | 94.95 | % | 95.97 | % | 93.17 | % | 91.99 | % | |||||||||||
Stockholders’ equity / assets | 11.34 | % | 11.18 | % | 12.11 | % | 12.03 | % | 11.73 | % | |||||||||||
Risk-based capital(f)(g) | |||||||||||||||||||||
Total risk-weighted assets | $ | 25,865 | $ | 25,866 | $ | 24,296 | $ | 24,313 | $ | 24,466 | |||||||||||
Common equity Tier 1 | $ | 2,651 | $ | 2,421 | $ | 2,481 | $ | 2,482 | $ | 2,481 | |||||||||||
Common equity Tier 1 capital ratio | 10.25 | % | 9.36 | % | 10.21 | % | 10.21 | % | 10.14 | % | |||||||||||
Tier 1 capital ratio | 11.62 | % | 10.35 | % | 11.26 | % | 11.26 | % | 11.19 | % | |||||||||||
Total capital ratio | 13.83 | % | 12.56 | % | 13.21 | % | 13.26 | % | 13.25 | % | |||||||||||
Tier 1 leverage ratio | 9.08 | % | 8.50 | % | 8.83 | % | 8.57 | % | 8.49 | % | |||||||||||
Mortgage banking, net | |||||||||||||||||||||
Mortgage servicing fees, net(h) | $ | 1 | $ | 6 | $ | (1 | ) | $ | 2 | $ | 2 | $ | 2 | $ | 3 | ||||||
Gains (losses) and fair value adjustments on loans held for sale | 31 | 9 | 21 | 10 | 5 | 4 | 7 | ||||||||||||||
Fair value adjustment on portfolio loans transferred to held for sale | 3 | — | — | 3 | — | 4 | — | ||||||||||||||
Mortgage servicing rights (impairment) recovery | (17 | ) | — | (8 | ) | (9 | ) | — | — | — | |||||||||||
Mortgage banking, net | $ | 18 | $ | 14 | $ | 12 | $ | 6 | $ | 7 | $ | 11 | $ | 9 | |||||||
Numbers may not sum due to rounding.
(a) | Ratio is based upon basic earnings per common share. |
(b) | Average full time equivalent employees without overtime. |
(c) | Excludes assets held in brokerage accounts. |
(d) | During the third quarter of 2019, the Corporation sold approximately $240 million of portfolio mortgages that were transferred during the period, resulting in increased settlements. |
(e) | Does not include repurchases related to tax withholding on equity compensation. |
(f) | The Federal Reserve establishes regulatory capital requirements, including well-capitalized standards for the Corporation. The regulatory capital requirements effective for the Corporation follow Basel III, subject to certain transition provisions. |
(g) | June 30, 2020 data is estimated. |
(h) | Includes mortgage origination and servicing fees, net of mortgage servicing rights amortization. |
Page 4
Associated Banc-Corp Selected Asset Quality Information | |||||||||||||||||||||
($ in thousands) | Jun 30, 2020 | Mar 31, 2020 | Seql Qtr % Change | Dec 31, 2019 | Sep 30, 2019 | Jun 30, 2019 | Comp Qtr % Change | ||||||||||||||
Allowance for loan losses | |||||||||||||||||||||
Balance at beginning of period | $ | 337,793 | $ | 201,371 | 68 | % | $ | 214,425 | $ | 233,659 | $ | 235,081 | 44 | % | |||||||
Cumulative effect of ASU 2016-13 adoption (CECL) | N/A | 112,457 | N/A | N/A | N/A | ||||||||||||||||
January 1, 2020 | N/A | 313,828 | N/A | N/A | N/A | ||||||||||||||||
Provision for loan losses | 52,500 | 37,500 | 40 | % | 1,000 | 1,000 | 12,000 | N/M | |||||||||||||
Allowance for PCD loans for bank acquisition | N/A | 3,504 | N/A | N/A | N/A | ||||||||||||||||
Charge offs | (28,351 | ) | (19,308 | ) | 47 | % | (16,752 | ) | (26,313 | ) | (15,761 | ) | 80 | % | |||||||
Recoveries | 1,861 | 2,268 | (18 | )% | 2,699 | 6,079 | 2,339 | (20 | )% | ||||||||||||
Net charge offs | (26,490 | ) | (17,040 | ) | 55 | % | (14,054 | ) | (20,234 | ) | (13,421 | ) | 97 | % | |||||||
Balance at end of period | $ | 363,803 | $ | 337,793 | 8 | % | $ | 201,371 | $ | 214,425 | $ | 233,659 | 56 | % | |||||||
Allowance for unfunded commitments | |||||||||||||||||||||
Balance at beginning of period | $ | 56,276 | $ | 21,907 | 157 | % | $ | 22,907 | $ | 21,907 | $ | 25,836 | 118 | % | |||||||
Cumulative effect of ASU 2016-13 adoption (CECL) | N/A | 18,690 | N/A | N/A | N/A | ||||||||||||||||
January 1, 2020 | N/A | 40,597 | N/A | N/A | N/A | ||||||||||||||||
Provision for unfunded commitments | 8,500 | 15,500 | (45 | )% | (1,000 | ) | 1,000 | (4,000 | ) | N/M | |||||||||||
Amount recorded at acquisition | — | 179 | (100 | )% | — | — | 70 | (100 | )% | ||||||||||||
Balance at end of period | $ | 64,776 | $ | 56,276 | 15 | % | $ | 21,907 | $ | 22,907 | $ | 21,907 | 196 | % | |||||||
Allowance for credit losses on loans (ACLL)(a) | $ | 428,579 | $ | 394,069 | 9 | % | $ | 223,278 | $ | 237,331 | $ | 255,566 | 68 | % | |||||||
Provision for credit losses on loans(b) | $ | 61,000 | $ | 53,000 | 15 | % | $ | — | $ | 2,000 | $ | 8,000 | N/M | ||||||||
($ in thousands) | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | Sep 30, 2019 | Jun 30, 2019 | ||||||||||||||||
Net (charge offs) recoveries | |||||||||||||||||||||
PPP Loans | $ | — | $ | — | N/M | $ | — | $ | — | $ | — | N/M | |||||||||
Commercial and industrial | (24,919 | ) | (15,049 | ) | 66 | % | (11,917 | ) | (19,918 | ) | (12,177 | ) | 105 | % | |||||||
Commercial real estate—owner occupied | 1 | — | N/M | — | 1,483 | (104 | ) | (101 | )% | ||||||||||||
Commercial and business lending | (24,919 | ) | (15,048 | ) | 66 | % | (11,917 | ) | (18,435 | ) | (12,281 | ) | 103 | % | |||||||
Commercial real estate—investor | 28 | — | N/M | — | (3 | ) | 3 | N/M | |||||||||||||
Real estate construction | (3 | ) | 11 | (127 | )% | 72 | 20 | 151 | (102 | )% | |||||||||||
Commercial real estate lending | 25 | 11 | 127 | % | 72 | 17 | 153 | (84 | )% | ||||||||||||
Total commercial | (24,893 | ) | (15,037 | ) | 66 | % | (11,845 | ) | (18,418 | ) | (12,127 | ) | 105 | % | |||||||
Residential mortgage | (215 | ) | (912 | ) | (76 | )% | (1,415 | ) | (393 | ) | (365 | ) | (41 | )% | |||||||
Home equity | (303 | ) | 71 | N/M | 480 | (275 | ) | 239 | N/M | ||||||||||||
Other consumer | (1,078 | ) | (1,162 | ) | (7 | )% | (1,274 | ) | (1,148 | ) | (1,169 | ) | (8 | )% | |||||||
Total consumer | (1,596 | ) | (2,003 | ) | (20 | )% | (2,208 | ) | (1,816 | ) | (1,294 | ) | 23 | % | |||||||
Total net (charge offs) recoveries | $ | (26,490 | ) | $ | (17,040 | ) | 55 | % | $ | (14,054 | ) | $ | (20,234 | ) | $ | (13,421 | ) | 97 | % | ||
(In basis points) | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | Sep 30, 2019 | Jun 30, 2019 | ||||||||||||||||
Net charge offs to average loans (annualized) | |||||||||||||||||||||
PPP Loans | — | — | — | — | — | ||||||||||||||||
Commercial and industrial | (121 | ) | (81 | ) | (65 | ) | (104 | ) | (64 | ) | |||||||||||
Commercial real estate—owner occupied | — | — | — | 63 | (4 | ) | |||||||||||||||
Commercial and business lending | (100 | ) | (72 | ) | (58 | ) | (86 | ) | (57 | ) | |||||||||||
Commercial real estate—investor | — | — | — | — | — | ||||||||||||||||
Real estate construction | — | — | 2 | 1 | 5 | ||||||||||||||||
Commercial real estate lending | — | — | 1 | — | 1 | ||||||||||||||||
Total commercial | (64 | ) | (44 | ) | (35 | ) | (53 | ) | (35 | ) | |||||||||||
Residential mortgage | (1 | ) | (4 | ) | (7 | ) | (2 | ) | (2 | ) | |||||||||||
Home equity | (15 | ) | 3 | 22 | (12 | ) | 11 | ||||||||||||||
Other consumer | (128 | ) | (134 | ) | (145 | ) | (129 | ) | (132 | ) | |||||||||||
Total consumer | (7 | ) | (8 | ) | (9 | ) | (8 | ) | (5 | ) | |||||||||||
Total net charge offs | (42 | ) | (29 | ) | (24 | ) | (35 | ) | (23 | ) | |||||||||||
($ in thousands) | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | Sep 30, 2019 | Jun 30, 2019 | ||||||||||||||||
Credit Quality | |||||||||||||||||||||
Nonaccrual loans | $ | 171,607 | $ | 136,717 | 26 | % | $ | 118,380 | $ | 128,939 | $ | 166,707 | 3 | % | |||||||
Other real estate owned (OREO) | 20,264 | 22,530 | (10 | )% | 21,101 | 19,625 | 18,355 | 10 | % | ||||||||||||
Other nonperforming assets | 909 | 6,004 | (85 | )% | 6,004 | 6,004 | — | N/M | |||||||||||||
Total nonperforming assets | $ | 192,780 | $ | 165,251 | 17 | % | $ | 145,485 | $ | 154,568 | $ | 185,062 | 4 | % | |||||||
Loans 90 or more days past due and still accruing | $ | 1,466 | $ | 2,255 | (35 | )% | $ | 2,259 | $ | 1,986 | $ | 2,088 | (30 | )% | |||||||
Allowance for loan losses to loans | N/A | N/A | 0.88 | % | 0.94 | % | 1.00 | % | |||||||||||||
Allowance for credit losses to loans | 1.73 | % | 1.62 | % | 0.98 | % | 1.04 | % | 1.10 | % | |||||||||||
Allowance for loan losses to nonaccrual loans | N/A | N/A | 170.10 | % | 166.30 | % | 140.16 | % | |||||||||||||
Allowance for credit losses to nonaccrual loans | 249.74 | % | 288.24 | % | 188.61 | % | 184.07 | % | 153.30 | % | |||||||||||
Nonaccrual loans to total loans | 0.69 | % | 0.56 | % | 0.52 | % | 0.57 | % | 0.72 | % | |||||||||||
Nonperforming assets to total loans plus OREO | 0.78 | % | 0.68 | % | 0.64 | % | 0.68 | % | 0.80 | % | |||||||||||
Nonperforming assets to total assets | 0.54 | % | 0.49 | % | 0.45 | % | 0.47 | % | 0.56 | % | |||||||||||
Year-to-date net charge offs to year-to-date average loans (annualized) | 0.36 | % | 0.29 | % | 0.24 | % | 0.24 | % | 0.18 | % | |||||||||||
(a) | Excludes approximately $61,000 of allowance for held to maturity investment securities |
(b) | March 31, 2020 excludes less than $1,000 of provision for held to maturity investment securities |
Page 5
Associated Banc-Corp Selected Asset Quality Information (continued) | |||||||||||||||||||||
(In thousands) | Jun 30, 2020 | Mar 31, 2020 | Seql Qtr % Change | Dec 31, 2019 | Sep 30, 2019 | Jun 30, 2019 | Comp Qtr % Change | ||||||||||||||
Nonaccrual loans | |||||||||||||||||||||
Commercial and industrial | $ | 80,239 | $ | 58,854 | 36 | % | $ | 46,312 | $ | 56,536 | $ | 84,151 | (5 | )% | |||||||
Commercial real estate—owner occupied | 1,932 | 1,838 | 5 | % | 67 | 68 | 571 | N/M | |||||||||||||
Commercial and business lending | 82,171 | 60,692 | 35 | % | 46,380 | 56,604 | 84,722 | (3 | )% | ||||||||||||
Commercial real estate—investor | 11,172 | 1,091 | N/M | 4,409 | 4,800 | 1,485 | N/M | ||||||||||||||
Real estate construction | 503 | 486 | 3 | % | 493 | 542 | 427 | 18 | % | ||||||||||||
Commercial real estate lending | 11,675 | 1,577 | N/M | 4,902 | 5,342 | 1,912 | N/M | ||||||||||||||
Total commercial | 93,846 | 62,269 | 51 | % | 51,282 | 61,946 | 86,634 | 8 | % | ||||||||||||
Residential mortgage | 66,656 | 64,855 | 3 | % | 57,844 | 57,056 | 68,166 | (2 | )% | ||||||||||||
Home equity | 10,829 | 9,378 | 15 | % | 9,104 | 9,828 | 11,835 | (9 | )% | ||||||||||||
Other consumer | 276 | 215 | 28 | % | 152 | 109 | 72 | N/M | |||||||||||||
Total consumer | 77,761 | 74,448 | 4 | % | 67,099 | 66,993 | 80,073 | (3 | )% | ||||||||||||
Total nonaccrual loans | $ | 171,607 | $ | 136,717 | 26 | % | $ | 118,380 | $ | 128,939 | $ | 166,707 | 3 | % | |||||||
Jun 30, 2020 | Mar 31, 2020 | Seql Qtr % Change | Dec 31, 2019 | Sep 30, 2019 | Jun 30, 2019 | Comp Qtr % Change | |||||||||||||||
Restructured loans (accruing)(a) | |||||||||||||||||||||
Commercial and industrial | $ | 16,321 | $ | 16,056 | 2 | % | $ | 16,678 | $ | 15,398 | $ | 16,850 | (3 | )% | |||||||
Commercial real estate—owner occupied | 1,441 | 2,091 | (31 | )% | 1,676 | 1,912 | 1,970 | (27 | )% | ||||||||||||
Commercial and business lending | 17,762 | 18,146 | (2 | )% | 18,353 | 17,311 | 18,820 | (6 | )% | ||||||||||||
Commercial real estate—investor | 114 | 281 | (59 | )% | 293 | 304 | 315 | (64 | )% | ||||||||||||
Real estate construction | 313 | 339 | (8 | )% | 298 | 227 | 232 | 35 | % | ||||||||||||
Commercial real estate lending | 427 | 620 | (31 | )% | 591 | 531 | 547 | (22 | )% | ||||||||||||
Total commercial | 18,189 | 18,767 | (3 | )% | 18,944 | 17,842 | 19,367 | (6 | )% | ||||||||||||
Residential mortgage | 4,178 | 4,654 | (10 | )% | 3,955 | 3,228 | 17,645 | (76 | )% | ||||||||||||
Home equity | 1,717 | 1,719 | — | % | 1,896 | 2,017 | 7,247 | (76 | )% | ||||||||||||
Other consumer | 1,219 | 1,245 | (2 | )% | 1,246 | 1,243 | 1,222 | — | % | ||||||||||||
Total consumer | 7,114 | 7,618 | (7 | )% | 7,097 | 6,487 | 26,114 | (73 | )% | ||||||||||||
Total restructured loans (accruing) | $ | 25,303 | $ | 26,384 | (4 | )% | $ | 26,041 | $ | 24,329 | $ | 45,481 | (44 | )% | |||||||
Nonaccrual restructured loans (included in nonaccrual loans) | $ | 25,362 | $ | 24,204 | 5 | % | $ | 22,494 | $ | 16,293 | $ | 24,332 | 4 | % | |||||||
Jun 30, 2020 | Mar 31, 2020 | Seql Qtr % Change | Dec 31, 2019 | Sep 30, 2019 | Jun 30, 2019 | Comp Qtr % Change | |||||||||||||||
Accruing Loans 30-89 Days Past Due | |||||||||||||||||||||
Commercial and industrial | $ | 716 | $ | 976 | (27 | )% | $ | 821 | $ | 426 | $ | 4,909 | (85 | )% | |||||||
Commercial real estate—owner occupied | 199 | 51 | N/M | 1,369 | 2,646 | 2,018 | (90 | )% | |||||||||||||
Commercial and business lending | 916 | 1,027 | (11 | )% | 2,190 | 3,073 | 6,926 | (87 | )% | ||||||||||||
Commercial real estate—investor | 13,874 | 14,462 | (4 | )% | 1,812 | 636 | 1,382 | N/M | |||||||||||||
Real estate construction | 385 | 179 | 115 | % | 97 | 595 | 151 | 155 | % | ||||||||||||
Commercial real estate lending | 14,260 | 14,641 | (3 | )% | 1,909 | 1,232 | 1,532 | N/M | |||||||||||||
Total commercial | 15,175 | 15,668 | (3 | )% | 4,099 | 4,304 | 8,459 | 79 | % | ||||||||||||
Residential mortgage | 3,023 | 10,102 | (70 | )% | 9,274 | 8,063 | 9,756 | (69 | )% | ||||||||||||
Home equity | 3,108 | 7,001 | (56 | )% | 5,647 | 4,798 | 5,827 | (47 | )% | ||||||||||||
Other consumer | 1,482 | 1,777 | (17 | )% | 2,083 | 2,203 | 1,838 | (19 | )% | ||||||||||||
Total consumer | 7,613 | 18,879 | (60 | )% | 17,005 | 15,063 | 17,422 | (56 | )% | ||||||||||||
Total accruing loans 30-89 days past due | $ | 22,788 | $ | 34,547 | (34 | )% | $ | 21,104 | $ | 19,367 | $ | 25,881 | (12 | )% | |||||||
Jun 30, 2020 | Mar 31, 2020 | Seql Qtr % Change | Dec 31, 2019 | Sep 30, 2019 | Jun 30, 2019 | Comp Qtr % Change | |||||||||||||||
Potential Problem Loans | |||||||||||||||||||||
Commercial and industrial | $ | 195,432 | $ | 149,747 | 31 | % | $ | 110,308 | $ | 59,427 | $ | 58,658 | N/M | ||||||||
Commercial real estate—owner occupied | 15,919 | 15,802 | 1 | % | 19,889 | 22,624 | 24,237 | (34 | )% | ||||||||||||
Commercial and business lending | 211,350 | 165,550 | 28 | % | 130,197 | 82,051 | 82,895 | 155 | % | ||||||||||||
Commercial real estate—investor | 88,237 | 61,030 | 45 | % | 29,449 | 49,353 | 77,766 | 13 | % | ||||||||||||
Real estate construction | 2,170 | 1,753 | 24 | % | — | 544 | 3,166 | (31 | )% | ||||||||||||
Commercial real estate lending | 90,407 | 62,783 | 44 | % | 29,449 | 49,897 | 80,932 | 12 | % | ||||||||||||
Total commercial | 301,758 | 228,333 | 32 | % | 159,646 | 131,948 | 163,828 | 84 | % | ||||||||||||
Residential mortgage | 3,157 | 3,322 | (5 | )% | 1,451 | 1,242 | 1,983 | 59 | % | ||||||||||||
Home equity | 1,921 | 2,238 | (14 | )% | — | — | 32 | N/M | |||||||||||||
Total consumer | 5,078 | 5,559 | (9 | )% | 1,451 | 1,242 | 2,014 | 152 | % | ||||||||||||
Total potential problem loans | $ | 306,836 | $ | 233,892 | 31 | % | $ | 161,097 | $ | 133,189 | $ | 165,842 | 85 | % | |||||||
N/M = Not meaningful
N/A = Not applicable
Numbers may not sum due to rounding.
(a) Does not include any restructured loans related to COVID-19 in accordance with regulatory guidance
Page 6
Associated Banc-Corp Net Interest Income Analysis - Fully Tax-Equivalent Basis - Sequential and Comparable Quarter | ||||||||||||||||||||||||||
Three Months Ended | ||||||||||||||||||||||||||
June 30, 2020 | March 31, 2020 | June 30, 2019 | ||||||||||||||||||||||||
($ in thousands) | Average Balance | Interest Income /Expense | Average Yield /Rate | Average Balance | Interest Income /Expense | Average Yield /Rate | Average Balance | Interest Income /Expense | Average Yield /Rate | |||||||||||||||||
Assets | ||||||||||||||||||||||||||
Earning assets | ||||||||||||||||||||||||||
Loans (a) (b) (c) | ||||||||||||||||||||||||||
Commercial PPP lending | $ | 848,761 | $ | 4,841 | 2.29 | % | $ | — | $ | — | — | % | $ | — | $ | — | — | % | ||||||||
Commercial and business lending | 9,192,910 | 64,097 | 2.80 | % | 8,380,113 | 80,217 | 3.85 | % | 8,621,609 | 103,029 | 4.79 | % | ||||||||||||||
Commercial real estate lending | 5,720,262 | 46,057 | 3.24 | % | 5,329,568 | 57,499 | 4.34 | % | 5,130,954 | 66,522 | 5.19 | % | ||||||||||||||
Total commercial | 15,761,933 | 114,995 | 2.93 | % | 13,709,681 | 137,716 | 4.04 | % | 13,752,563 | 169,551 | 4.94 | % | ||||||||||||||
Residential mortgage | 8,271,757 | 62,860 | 3.04 | % | 8,404,351 | 69,961 | 3.33 | % | 8,378,082 | 72,692 | 3.47 | % | ||||||||||||||
Retail | 1,157,116 | 14,368 | 4.98 | % | 1,194,586 | 17,473 | 5.86 | % | 1,223,726 | 19,095 | 6.25 | % | ||||||||||||||
Total loans | 25,190,806 | 192,223 | 3.06 | % | 23,308,618 | 225,149 | 3.88 | % | 23,354,371 | 261,338 | 4.48 | % | ||||||||||||||
Investment securities | ||||||||||||||||||||||||||
Taxable | 3,129,113 | 16,103 | 2.06 | % | 3,460,224 | 20,272 | 2.34 | % | 4,523,260 | 26,710 | 2.36 | % | ||||||||||||||
Tax-exempt(a) | 1,922,392 | 18,270 | 3.80 | % | 1,974,247 | 18,603 | 3.77 | % | 1,943,485 | 18,304 | 3.77 | % | ||||||||||||||
Other short-term investments | 1,016,976 | 2,231 | 0.88 | % | 473,604 | 3,304 | 2.81 | % | 479,590 | 3,995 | 3.34 | % | ||||||||||||||
Investments and other | 6,068,481 | 36,604 | 2.41 | % | 5,908,075 | 42,179 | 2.86 | % | 6,946,335 | 49,009 | 2.82 | % | ||||||||||||||
Total earning assets | 31,259,287 | $ | 228,826 | 2.94 | % | 29,216,693 | $ | 267,329 | 3.67 | % | 30,300,707 | $ | 310,347 | 4.10 | % | |||||||||||
Other assets, net | 3,586,656 | 3,360,311 | 3,138,111 | |||||||||||||||||||||||
Total assets | $ | 34,845,943 | $ | 32,577,005 | $ | 33,438,818 | ||||||||||||||||||||
Liabilities and stockholders' equity | ||||||||||||||||||||||||||
Interest-bearing liabilities | ||||||||||||||||||||||||||
Interest-bearing deposits | ||||||||||||||||||||||||||
Savings | $ | 3,260,040 | $ | 429 | 0.05 | % | $ | 2,868,840 | $ | 1,800 | 0.25 | % | $ | 2,319,556 | $ | 1,686 | 0.29 | % | ||||||||
Interest-bearing demand | 5,445,267 | 1,442 | 0.11 | % | 5,307,230 | 8,755 | 0.66 | % | 4,984,511 | 15,309 | 1.23 | % | ||||||||||||||
Money market | 6,496,841 | 1,902 | 0.12 | % | 6,538,658 | 10,806 | 0.66 | % | 7,118,594 | 20,883 | 1.18 | % | ||||||||||||||
Network transaction deposits | 1,544,737 | 539 | 0.14 | % | 1,434,128 | 4,601 | 1.29 | % | 2,024,604 | 12,456 | 2.47 | % | ||||||||||||||
Time deposits | 2,469,899 | 8,866 | 1.44 | % | 2,636,231 | 10,703 | 1.63 | % | 3,544,317 | 16,717 | 1.89 | % | ||||||||||||||
Total interest-bearing deposits | 19,216,785 | 13,178 | 0.28 | % | 18,785,088 | 36,666 | 0.79 | % | 19,991,581 | 67,050 | 1.35 | % | ||||||||||||||
Federal funds purchased and securities sold under agreements to repurchase | 204,548 | 51 | 0.10 | % | 194,406 | 368 | 0.76 | % | 115,694 | 286 | 0.99 | % | ||||||||||||||
Commercial Paper | 37,526 | 7 | 0.08 | % | 34,282 | 28 | 0.33 | % | 30,612 | 37 | 0.49 | % | ||||||||||||||
PPPLF | 774,500 | 676 | 0.35 | % | — | — | — | % | — | — | — | % | ||||||||||||||
Other short-term funding | — | — | — | % | 16,997 | 11 | 0.25 | % | — | — | — | % | ||||||||||||||
FHLB advances | 2,810,867 | 15,470 | 2.21 | % | 3,231,999 | 17,626 | 2.19 | % | 3,171,353 | 17,744 | 2.24 | % | ||||||||||||||
Long-term funding | 548,757 | 5,591 | 4.08 | % | 549,465 | 5,604 | 4.08 | % | 796,169 | 7,396 | 3.72 | % | ||||||||||||||
Total short and long-term funding | 4,376,199 | 21,795 | 2.00 | % | 4,027,149 | 23,637 | 2.36 | % | 4,113,829 | 25,463 | 2.48 | % | ||||||||||||||
Total interest-bearing liabilities | 23,592,983 | $ | 34,973 | 0.60 | % | 22,812,237 | $ | 60,303 | 1.06 | % | 24,105,410 | $ | 92,513 | 1.54 | % | |||||||||||
Noninterest-bearing demand deposits | 6,926,401 | 5,506,861 | 5,089,928 | |||||||||||||||||||||||
Other liabilities | 480,041 | 416,107 | 390,585 | |||||||||||||||||||||||
Stockholders’ equity | 3,846,517 | 3,841,800 | 3,852,894 | |||||||||||||||||||||||
Total liabilities and stockholders’ equity | $ | 34,845,943 | $ | 32,577,005 | $ | 33,438,818 | ||||||||||||||||||||
Interest rate spread | 2.34 | % | 2.61 | % | 2.56 | % | ||||||||||||||||||||
Net free funds | 0.15 | % | 0.23 | % | 0.32 | % | ||||||||||||||||||||
Fully tax-equivalent net interest income and net interest margin ("NIM") | $ | 193,853 | 2.49 | % | $ | 207,026 | 2.84 | % | $ | 217,834 | 2.88 | % | ||||||||||||||
Fully tax-equivalent adjustment | 3,981 | 4,084 | 4,215 | |||||||||||||||||||||||
Net interest income | $ | 189,872 | $ | 202,942 | $ | 213,619 | ||||||||||||||||||||
Numbers may not sum due to rounding.
(a) | The yield on tax-exempt loans and securities is computed on a fully tax-equivalent basis using a tax rate of 21% and is net of the effects of certain disallowed interest deductions. |
(b) | Nonaccrual loans and loans held for sale have been included in the average balances. |
(c) | Interest income includes amortization of net deferred loan origination costs and net accreted purchase loan discount. |
Page 7
Associated Banc-Corp Net Interest Income Analysis - Fully Tax-Equivalent Basis - Year Over Year | ||||||||||||||||||||||
Six Months Ended June 30, | ||||||||||||||||||||||
2020 | 2019 | |||||||||||||||||||||
($ in thousands) | Average Balance | Interest Income /Expense | Average Yield / Rate | Average Balance | Interest Income /Expense | Average Yield / Rate | ||||||||||||||||
Assets | ||||||||||||||||||||||
Earning assets | ||||||||||||||||||||||
Loans (a) (b) (c) | ||||||||||||||||||||||
Commercial PPP lending | $ | 424,380 | $ | 4,841 | 2.29 | % | $ | — | $ | — | — | % | ||||||||||
Commercial and business lending | 8,786,511 | 144,314 | 3.30 | % | 8,499,564 | 203,327 | 4.82 | % | ||||||||||||||
Commercial real estate lending | 5,524,915 | 103,556 | 3.77 | % | 5,124,476 | 132,034 | 5.19 | % | ||||||||||||||
Total commercial | 14,735,807 | 252,711 | 3.45 | % | 13,624,040 | 335,361 | 4.96 | % | ||||||||||||||
Residential mortgage | 8,338,054 | 132,821 | 3.19 | % | 8,372,299 | 146,673 | 3.50 | % | ||||||||||||||
Retail | 1,175,851 | 31,841 | 5.43 | % | 1,233,297 | 38,450 | 6.25 | % | ||||||||||||||
Total loans | 24,249,712 | 417,372 | 3.45 | % | 23,229,636 | 520,485 | 4.51 | % | ||||||||||||||
Investment securities | ||||||||||||||||||||||
Taxable | 3,294,669 | 36,375 | 2.21 | % | 4,749,307 | 55,764 | 2.35 | % | ||||||||||||||
Tax-exempt (a) | 1,948,320 | 36,873 | 3.79 | % | 1,894,689 | 35,573 | 3.76 | % | ||||||||||||||
Other short-term investments | 745,290 | 5,535 | 1.49 | % | 474,050 | 8,221 | 3.49 | % | ||||||||||||||
Investments and other | 5,988,278 | 78,783 | 2.63 | % | 7,118,047 | 99,558 | 2.80 | % | ||||||||||||||
Total earning assets | 30,237,990 | $ | 496,155 | 3.29 | % | 30,347,682 | $ | 620,043 | 4.11 | % | ||||||||||||
Other assets, net(d) | 3,473,484 | 3,083,709 | ||||||||||||||||||||
Total assets | $ | 33,711,474 | $ | 33,431,391 | ||||||||||||||||||
Liabilities and stockholders' equity | ||||||||||||||||||||||
Interest-bearing liabilities | ||||||||||||||||||||||
Interest-bearing deposits | ||||||||||||||||||||||
Savings | $ | 3,064,440 | $ | 2,228 | 0.15 | % | $ | 2,209,804 | $ | 2,836 | 0.26 | % | ||||||||||
Interest-bearing demand | 5,376,249 | 10,197 | 0.38 | % | 4,862,763 | 29,229 | 1.21 | % | ||||||||||||||
Money market | 6,517,749 | 12,708 | 0.39 | % | 7,252,639 | 41,669 | 1.16 | % | ||||||||||||||
Network transaction deposits | 1,489,433 | 5,141 | 0.69 | % | 2,124,262 | 26,082 | 2.48 | % | ||||||||||||||
Time deposits | 2,553,065 | 19,569 | 1.54 | % | 3,334,305 | 30,007 | 1.82 | % | ||||||||||||||
Total interest-bearing deposits | 19,000,936 | 49,844 | 0.53 | % | 19,783,773 | 129,823 | 1.32 | % | ||||||||||||||
Federal funds purchased and securities sold under agreements to repurchase | 199,477 | 420 | 0.42 | % | 146,357 | 913 | 1.26 | % | ||||||||||||||
Commercial Paper | 35,904 | 35 | 0.20 | % | 36,096 | 88 | 0.49 | % | ||||||||||||||
PPPLF | 387,250 | 676 | 0.35 | % | — | — | — | % | ||||||||||||||
Other short-term funding | 8,498 | 11 | 0.25 | % | — | — | — | % | ||||||||||||||
FHLB advances | 3,021,433 | 33,096 | 2.20 | % | 3,404,213 | 37,298 | 2.21 | % | ||||||||||||||
Long-term funding | 549,111 | 11,195 | 4.08 | % | 795,964 | 14,792 | 3.72 | % | ||||||||||||||
Total short and long-term funding | 4,201,674 | 45,432 | 2.17 | % | 4,382,630 | 53,091 | 2.44 | % | ||||||||||||||
Total interest-bearing liabilities | 23,202,610 | $ | 95,276 | 0.83 | % | 24,166,403 | $ | 182,914 | 1.53 | % | ||||||||||||
Noninterest-bearing demand deposits | 6,216,631 | 5,036,537 | ||||||||||||||||||||
Other liabilities(d) | 448,074 | 394,334 | ||||||||||||||||||||
Stockholders’ equity | 3,844,158 | 3,834,116 | ||||||||||||||||||||
Total liabilities and stockholders’ equity | $ | 33,711,474 | $ | 33,431,391 | ||||||||||||||||||
Interest rate spread | 2.46 | % | 2.58 | % | ||||||||||||||||||
Net free funds | 0.20 | % | 0.31 | % | ||||||||||||||||||
Fully tax-equivalent net interest income and net interest margin ("NIM") | $ | 400,879 | 2.66 | % | $ | 437,128 | 2.89 | % | ||||||||||||||
Fully tax-equivalent adjustment | 8,066 | 7,962 | ||||||||||||||||||||
Net interest income | $ | 392,814 | $ | 429,167 | ||||||||||||||||||
Numbers may not sum due to rounding.
(a) | The yield on tax-exempt loans and securities is computed on a fully tax-equivalent basis using a tax rate of 21% and is net of the effects of certain disallowed interest deductions. |
(b) | Nonaccrual loans and loans held for sale have been included in the average balances. |
(c) | Interest income includes amortization of net deferred loan origination costs and net accreted purchase loan discount. |
(d) During the third quarter of 2019, the Corporation made a change in accounting policy to offset derivative assets and liabilities and cash collateral with the same counterparty where it has a legally enforceable master netting agreement in place. Adoption of this change was voluntary and has been adopted retrospectively with all prior periods presented herein restated.
Page 8
Associated Banc-Corp Loan and Deposit Composition | ||||||||||||||||||||||||||
($ in thousands) | ||||||||||||||||||||||||||
Period end loan composition | Jun 30, 2020 | Mar 31, 2020 | Seql Qtr % Change | Dec 31, 2019 | Sep 30, 2019 | Jun 30, 2019 | Comp Qtr % Change | |||||||||||||||||||
PPP Loans | $ | 1,012,033 | $ | — | N/M | $ | — | $ | — | $ | — | N/M | ||||||||||||||
Commercial and industrial | 7,968,709 | 8,517,974 | (6 | )% | 7,354,594 | 7,495,623 | 7,579,384 | 5 | % | |||||||||||||||||
Commercial real estate—owner occupied | 914,385 | 940,687 | (3 | )% | 911,265 | 915,524 | 942,811 | (3 | )% | |||||||||||||||||
Commercial and business lending | 9,895,127 | 9,458,661 | 5 | % | 8,265,858 | 8,411,147 | 8,522,194 | 16 | % | |||||||||||||||||
Commercial real estate—investor | 4,174,125 | 4,038,036 | 3 | % | 3,794,517 | 3,803,277 | 3,779,201 | 10 | % | |||||||||||||||||
Real estate construction | 1,708,189 | 1,544,858 | 11 | % | 1,420,900 | 1,356,508 | 1,394,815 | 22 | % | |||||||||||||||||
Commercial real estate lending | 5,882,314 | 5,582,894 | 5 | % | 5,215,417 | 5,159,784 | 5,174,016 | 14 | % | |||||||||||||||||
Total commercial | 15,777,441 | 15,041,555 | 5 | % | 13,481,275 | 13,570,932 | 13,696,210 | 15 | % | |||||||||||||||||
Residential mortgage | 7,933,518 | 8,132,417 | (2 | )% | 8,136,980 | 7,954,801 | 8,277,479 | (4 | )% | |||||||||||||||||
Home equity | 795,671 | 844,901 | (6 | )% | 852,025 | 879,642 | 916,213 | (13 | )% | |||||||||||||||||
Other consumer | 326,040 | 346,761 | (6 | )% | 351,159 | 349,335 | 360,065 | (9 | )% | |||||||||||||||||
Total consumer | 9,055,230 | 9,324,079 | (3 | )% | 9,340,164 | 9,183,778 | 9,553,757 | (5 | )% | |||||||||||||||||
Total loans | $ | 24,832,671 | $ | 24,365,633 | 2 | % | $ | 22,821,440 | $ | 22,754,710 | $ | 23,249,967 | 7 | % | ||||||||||||
Period end deposit and customer funding composition | Jun 30, 2020 | Mar 31, 2020 | Seql Qtr % Change | Dec 31, 2019 | Sep 30, 2019 | Jun 30, 2019 | Comp Qtr % Change | |||||||||||||||||||
Noninterest-bearing demand | $ | 7,573,942 | $ | 6,107,386 | 24 | % | $ | 5,450,709 | $ | 5,503,223 | $ | 5,354,987 | 41 | % | ||||||||||||
Savings | 3,394,930 | 3,033,039 | 12 | % | 2,735,036 | 2,643,950 | 2,591,173 | 31 | % | |||||||||||||||||
Interest-bearing demand | 5,847,349 | 6,170,071 | (5 | )% | 5,329,717 | 5,434,955 | 6,269,035 | (7 | )% | |||||||||||||||||
Money market | 7,486,319 | 7,717,739 | (3 | )% | 7,640,798 | 7,930,676 | 7,691,775 | (3 | )% | |||||||||||||||||
Brokered CDs | 4,225 | 65,000 | (94 | )% | 5,964 | 16,266 | 77,543 | (95 | )% | |||||||||||||||||
Other time | 2,244,680 | 2,568,345 | (13 | )% | 2,616,839 | 2,893,493 | 3,289,709 | (32 | )% | |||||||||||||||||
Total deposits | 26,551,444 | 25,661,580 | 3 | % | 23,779,064 | 24,422,562 | 25,274,222 | 5 | % | |||||||||||||||||
Customer funding(a) | 178,398 | 142,174 | 25 | % | 103,113 | 108,369 | 104,973 | 70 | % | |||||||||||||||||
Total deposits and customer funding | $ | 26,729,842 | $ | 25,803,754 | 4 | % | $ | 23,882,177 | $ | 24,530,932 | $ | 25,379,195 | 5 | % | ||||||||||||
Network transaction deposits(b) | $ | 1,496,958 | $ | 1,731,996 | (14 | )% | $ | 1,336,286 | $ | 1,527,910 | $ | 1,805,141 | (17 | )% | ||||||||||||
Net deposits and customer funding (Total deposits and customer funding, excluding Brokered CDs and network transaction deposits) | $ | 25,228,660 | $ | 24,006,758 | 5 | % | $ | 22,539,927 | $ | 22,986,756 | $ | 23,496,510 | 7 | % | ||||||||||||
Quarter average loan composition | Jun 30, 2020 | Mar 31, 2020 | Seql Qtr % Change | Dec 31, 2019 | Sep 30, 2019 | Jun 30, 2019 | Comp Qtr % Change | |||||||||||||||||||
PPP Loans | $ | 848,761 | $ | — | N/M | $ | — | $ | — | $ | — | N/M | ||||||||||||||
Commercial and industrial | $ | 8,263,270 | $ | 7,455,528 | 11 | % | $ | 7,291,592 | $ | 7,574,448 | $ | 7,688,462 | 7 | % | ||||||||||||
Commercial real estate—owner occupied | 929,640 | 924,585 | 1 | % | 916,484 | 927,820 | 933,146 | — | % | |||||||||||||||||
Commercial and business lending | 10,041,671 | 8,380,113 | 20 | % | 8,208,076 | 8,502,268 | 8,621,609 | 16 | % | |||||||||||||||||
Commercial real estate—investor | 4,113,895 | 3,857,277 | 7 | % | 3,806,168 | 3,768,377 | 3,806,828 | 8 | % | |||||||||||||||||
Real estate construction | 1,606,367 | 1,472,292 | 9 | % | 1,388,857 | 1,388,653 | 1,324,126 | 21 | % | |||||||||||||||||
Commercial real estate lending | 5,720,262 | 5,329,568 | 7 | % | 5,195,025 | 5,157,031 | 5,130,954 | 11 | % | |||||||||||||||||
Total commercial | 15,761,933 | 13,709,681 | 15 | % | 13,403,101 | 13,659,299 | 13,752,563 | 15 | % | |||||||||||||||||
Residential mortgage | 8,271,757 | 8,404,351 | (2 | )% | 8,167,795 | 8,337,230 | 8,378,082 | (1 | )% | |||||||||||||||||
Home equity | 819,680 | 845,422 | (3 | )% | 864,144 | 901,291 | 869,248 | (6 | )% | |||||||||||||||||
Other consumer | 337,436 | 349,164 | (3 | )% | 348,295 | 354,249 | 354,478 | (5 | )% | |||||||||||||||||
Total consumer | 9,428,873 | 9,598,937 | (2 | )% | 9,380,233 | 9,592,770 | 9,601,809 | (2 | )% | |||||||||||||||||
Total loans(c) | $ | 25,190,806 | $ | 23,308,618 | 8 | % | $ | 22,783,334 | $ | 23,252,068 | $ | 23,354,371 | 8 | % | ||||||||||||
Quarter average deposit composition | Jun 30, 2020 | Mar 31, 2020 | Seql Qtr % Change | Dec 31, 2019 | Sep 30, 2019 | Jun 30, 2019 | Comp Qtr % Change | |||||||||||||||||||
Noninterest-bearing demand | $ | 6,926,401 | $ | 5,506,861 | 26 | % | $ | 5,470,496 | $ | 5,324,481 | $ | 5,089,928 | 36 | % | ||||||||||||
Savings | 3,260,040 | 2,868,840 | 14 | % | 2,714,191 | 2,618,188 | 2,319,556 | 41 | % | |||||||||||||||||
Interest-bearing demand | 5,445,267 | 5,307,230 | 3 | % | 5,138,116 | 5,452,674 | 4,984,511 | 9 | % | |||||||||||||||||
Money market | 6,496,841 | 6,538,658 | (1 | )% | 6,594,681 | 6,933,230 | 7,118,594 | (9 | )% | |||||||||||||||||
Network transaction deposits | 1,544,737 | 1,434,128 | 8 | % | 1,438,908 | 1,764,961 | 2,024,604 | (24 | )% | |||||||||||||||||
Time deposits | 2,469,899 | 2,636,231 | (6 | )% | 2,746,978 | 3,107,670 | 3,544,317 | (30 | )% | |||||||||||||||||
Total deposits | $ | 26,143,186 | $ | 24,291,949 | 8 | % | $ | 24,103,371 | $ | 25,201,203 | $ | 25,081,509 | 4 | % | ||||||||||||
N/M = Not meaningful
Numbers may not sum due to rounding.
(a) | Includes repurchase agreements and commercial paper. |
(b) | Included above in interest-bearing demand and money market. |
(c) | Nonaccrual loans and loans held for sale have been included in the average balances. |
Page 9
Associated Banc-Corp Non-GAAP Financial Measures Reconciliation | ||||||||||||||||||||||||
($ in millions, except per share data) | YTD Jun 2020 | YTD Jun 2019 | 2Q20 | 1Q20 | 4Q19 | 3Q19 | 2Q19 | |||||||||||||||||
Tangible common equity reconciliation(a) | ||||||||||||||||||||||||
Common equity | $ | 3,671 | $ | 3,534 | $ | 3,665 | $ | 3,664 | $ | 3,643 | ||||||||||||||
Goodwill and other intangible assets, net | (1,181 | ) | (1,284 | ) | (1,265 | ) | (1,267 | ) | (1,270 | ) | ||||||||||||||
Tangible common equity | $ | 2,490 | $ | 2,250 | $ | 2,401 | $ | 2,397 | $ | 2,373 | ||||||||||||||
Tangible assets reconciliation(a) | ||||||||||||||||||||||||
Total assets | $ | 35,501 | $ | 33,908 | $ | 32,386 | $ | 32,596 | $ | 33,247 | ||||||||||||||
Goodwill and other intangible assets, net | (1,181 | ) | (1,284 | ) | (1,265 | ) | (1,267 | ) | (1,270 | ) | ||||||||||||||
Tangible assets | $ | 34,321 | $ | 32,624 | $ | 31,122 | $ | 31,329 | $ | 31,977 | ||||||||||||||
Average tangible common equity and average common equity tier 1 reconciliation(a) | ||||||||||||||||||||||||
Common equity | $ | 3,576 | $ | 3,577 | $ | 3,566 | $ | 3,585 | $ | 3,658 | $ | 3,647 | $ | 3,596 | ||||||||||
Goodwill and other intangible assets, net | (1,277 | ) | (1,246 | ) | (1,281 | ) | (1,272 | ) | (1,266 | ) | (1,269 | ) | (1,247 | ) | ||||||||||
Tangible common equity | 2,299 | 2,332 | 2,285 | 2,313 | 2,392 | 2,378 | 2,349 | |||||||||||||||||
Modified CECL transitional amount | 109 | N/A | 115 | 101 | N/A | N/A | N/A | |||||||||||||||||
Accumulated other comprehensive loss (income) | 9 | 99 | 8 | 10 | 37 | 42 | 82 | |||||||||||||||||
Deferred tax assets (liabilities), net | 46 | 46 | 45 | 47 | 48 | 49 | 46 | |||||||||||||||||
Average common equity Tier 1 | $ | 2,462 | $ | 2,476 | $ | 2,453 | $ | 2,471 | $ | 2,476 | $ | 2,469 | $ | 2,477 | ||||||||||
Average tangible assets reconciliation(a) | ||||||||||||||||||||||||
Total assets | $ | 33,711 | $ | 33,427 | $ | 34,846 | $ | 32,577 | $ | 32,182 | $ | 33,154 | $ | 33,439 | ||||||||||
Goodwill and other intangible assets, net | (1,277 | ) | (1,246 | ) | (1,281 | ) | (1,272 | ) | (1,266 | ) | (1,269 | ) | (1,247 | ) | ||||||||||
Tangible assets | $ | 32,435 | $ | 32,182 | $ | 33,565 | $ | 31,305 | $ | 30,916 | $ | 31,885 | $ | 32,192 | ||||||||||
Selected trend information(b) | ||||||||||||||||||||||||
Insurance commissions and fees | $ | 45 | $ | 48 | $ | 22 | $ | 23 | $ | 20 | $ | 21 | $ | 23 | ||||||||||
Wealth management fees(c) | 42 | 41 | 21 | 21 | 22 | 21 | 21 | |||||||||||||||||
Service charges and deposit account fees | 27 | 31 | 11 | 15 | 16 | 17 | 15 | |||||||||||||||||
Card-based fees | 18 | 19 | 9 | 10 | 10 | 10 | 10 | |||||||||||||||||
Other fee-based revenue | 9 | 9 | 5 | 4 | 5 | 5 | 5 | |||||||||||||||||
Fee-based revenue | 141 | 148 | 68 | 73 | 72 | 74 | 74 | |||||||||||||||||
Other | 212 | 39 | 186 | 26 | 21 | 27 | 21 | |||||||||||||||||
Total noninterest income | $ | 353 | $ | 187 | $ | 254 | $ | 98 | $ | 93 | $ | 101 | $ | 96 | ||||||||||
Pre-tax pre-provision income(d) | ||||||||||||||||||||||||
Income before income taxes | $ | 256 | $ | 213 | $ | 200 | $ | 56 | $ | 89 | $ | 104 | $ | 104 | ||||||||||
Provision for credit losses | 114 | 14 | 61 | 53 | — | 2 | 8 | |||||||||||||||||
Pre-tax pre-provision income | $ | 370 | $ | 227 | $ | 261 | $ | 109 | $ | 89 | $ | 106 | $ | 112 | ||||||||||
Selected equity and performance ratios(a)(e) | ||||||||||||||||||||||||
Tangible common equity / tangible assets | 7.25 | % | 6.90 | % | 7.71 | % | 7.65 | % | 7.42 | % | ||||||||||||||
Return on average equity | 10.18 | % | 9.01 | % | 15.55 | % | 4.80 | % | 7.31 | % | 8.47 | % | 8.81 | % | ||||||||||
Return on average tangible common equity | 16.32 | % | 14.16 | % | 25.45 | % | 7.31 | % | 11.33 | % | 13.27 | % | 13.81 | % | ||||||||||
Return on average common equity Tier 1 | 15.24 | % | 13.33 | % | 23.71 | % | 6.84 | % | 10.94 | % | 12.78 | % | 13.09 | % | ||||||||||
Return on average tangible assets | 1.21 | % | 1.07 | % | 1.78 | % | 0.59 | % | 0.93 | % | 1.04 | % | 1.05 | % | ||||||||||
Efficiency ratio reconciliation(f) | ||||||||||||||||||||||||
Federal Reserve efficiency ratio | 54.26 | % | 63.01 | % | 43.49 | % | 70.37 | % | 69.14 | % | 66.55 | % | 62.71 | % | ||||||||||
Fully tax-equivalent adjustment | (0.59 | )% | (0.81 | )% | (0.39 | )% | (0.96 | )% | (0.91 | )% | (0.90 | )% | (0.84 | )% | ||||||||||
Other intangible amortization | (0.77 | )% | (0.74 | )% | (0.65 | )% | (0.95 | )% | (0.93 | )% | (0.89 | )% | (0.75 | )% | ||||||||||
Fully tax-equivalent efficiency ratio | 52.91 | % | 61.48 | % | 42.46 | % | 68.47 | % | 67.32 | % | 64.78 | % | 61.13 | % | ||||||||||
Acquisition related costs adjustment | (0.30 | )% | (0.71 | )% | (0.12 | )% | (0.58 | )% | (0.45 | )% | (0.53 | )% | (1.21 | )% | ||||||||||
Provision for unfunded commitments adjustment | (3.22 | )% | 0.40 | % | (1.91 | )% | (5.18 | )% | 0.34 | % | (0.33 | )% | 1.28 | % | ||||||||||
Asset gains (losses), net adjustment | 13.23 | % | 0.14 | % | 22.10 | % | (0.02 | )% | 0.09 | % | 0.18 | % | 0.17 | % | ||||||||||
Adjusted efficiency ratio | 62.62 | % | 61.31 | % | 62.53 | % | 62.70 | % | 67.30 | % | 64.11 | % | 61.36 | % | ||||||||||
Acquisition Related Costs & Gain on Sale of ABRC | YTD 2020 | YTD 2020 per share data(g) | 2Q 2020 | 2Q 2020 per share data(g) | 1Q 2020 | 1Q 2020 per share data(g) | ||||||||||||||||||
GAAP earnings | $ | 187 | $ | 1.20 | $ | 145 | $ | 0.94 | $ | 42 | $ | 0.27 | ||||||||||||
Acquisition related costs, net of tax | 2 | 0.01 | — | — | 1 | 0.01 | ||||||||||||||||||
Earnings, excluding acquisition related costs(d) | $ | 188 | $ | 1.21 | $ | 145 | $ | 0.94 | $ | 43 | $ | 0.28 | ||||||||||||
GAAP earnings | $ | 187 | $ | 1.20 | $ | 145 | $ | 0.94 | $ | 42 | $ | 0.27 | ||||||||||||
Gain on sale of ABRC, net of tax | 104 | 0.67 | 104 | 0.68 | — | — | ||||||||||||||||||
Earnings, excluding gain on sale of ABRC(d) | $ | 82 | $ | 0.53 | $ | 40 | $ | 0.26 | $ | 42 | $ | 0.27 | ||||||||||||
Numbers may not sum due to rounding.
(a) | The ratio tangible common equity to tangible assets excludes goodwill and other intangible assets, net. This financial measure has been included as it is considered to be a critical metric with which to analyze and evaluate financial condition and capital strength. |
(b) | These financial measures have been included as they provide meaningful supplemental information to assess trends in the Corporation’s results of operations. |
(c) | Includes trust, asset management, brokerage, and annuity fees. |
(d) | Management believes these measures are meaningful because they reflect adjustments commonly made by management, investors, regulators, and analysts to evaluate the adequacy of earnings per common share and provide greater understanding of ongoing operations and enhanced comparability of results with prior periods. |
(e) | These capital measurements are used by management, regulators, investors, and analysts to assess, monitor and compare the quality and composition of our capital with the capital of other financial services companies. |
(f) | The efficiency ratio as defined by the Federal Reserve guidance is noninterest expense (which includes the provision for unfunded commitments) divided by the sum of net interest income plus noninterest income, excluding investment securities gains / losses, net. The fully tax-equivalent efficiency ratio is noninterest expense (which includes the provision for unfunded commitments), excluding other intangible amortization, divided by the sum of fully tax-equivalent net interest income plus noninterest income, excluding investment securities gains / losses, net. The adjusted efficiency ratio is noninterest expense, which excludes the provision for unfunded commitments, other intangible amortization, and acquisition related costs, divided by the sum of fully tax-equivalent net interest income plus noninterest income, excluding investment securities gains (losses), net, acquisition related costs, and asset gains (losses), net. Management believes the adjusted efficiency ratio is a meaningful measure as it enhances the comparability of net interest income arising from taxable and tax-exempt sources and provides a better measure as to how the Corporation is managing its expenses by adjusting for acquisition related costs, provision for unfunded commitments, and asset gains (losses), net. |
(g) | Diluted earnings and per share data presented after-tax. |
Page 10