Exhibit 99.1
Contact: Robert M. Gorman - (804) 523‑7828
Executive Vice President / Chief Financial Officer
ATLANTIC UNION BANKSHARES REPORTS FIRST QUARTER RESULTS
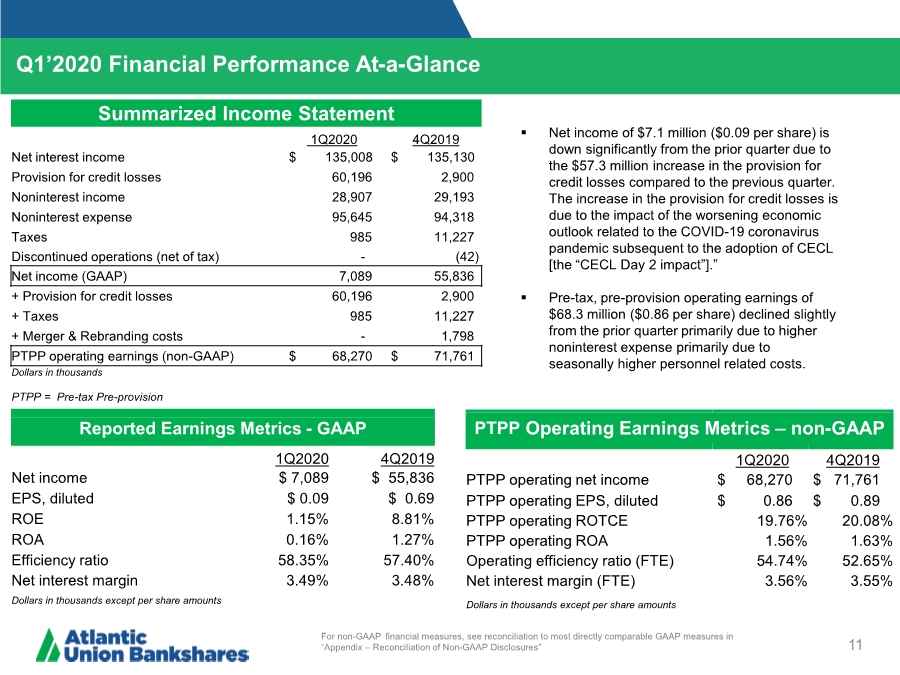
Richmond, Va., April 28, 2020 – Atlantic Union Bankshares Corporation (the “Company” or “Atlantic Union”) (Nasdaq: AUB) today reported net income of $7.1 million and diluted earnings per share of $0.09 for its first quarter ended March 31, 2020. Pre-tax pre-provision earnings(1) were $68.3 million, or $0.86 per share(1), in the first quarter ended March 31, 2020.
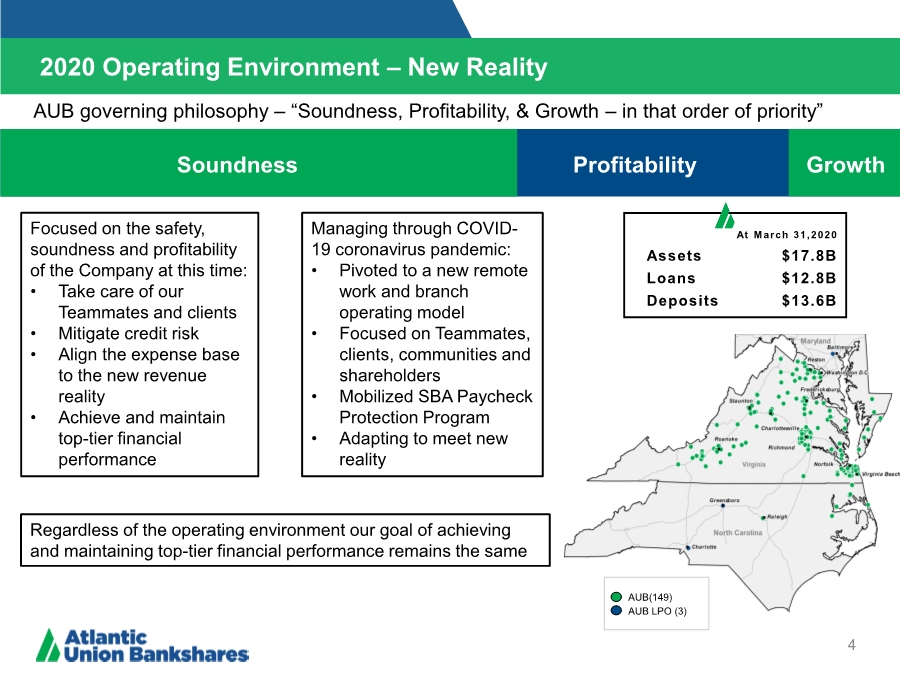
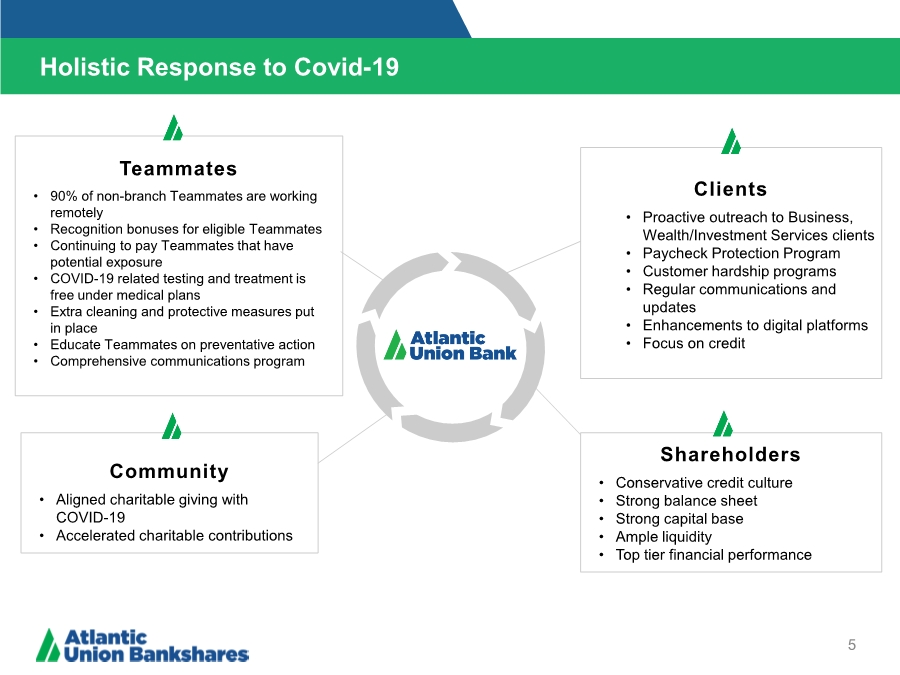
“Atlantic Union began 2020 with momentum and an ambitious set of work ahead of us, but as the situation surrounding the COVID-19 coronavirus pandemic unfolded, we quickly adjusted our thinking,” said John C. Asbury, President and CEO of Atlantic Union. “We believe that we pivoted smoothly to a new operating model with over 90% of non-branch personnel working remotely, demonstrating we’ve built a resilient organization that can react and innovate rapidly to changing economic conditions. We are laser focused on taking care of our teammates, our clients, and our communities during this uncertain time.
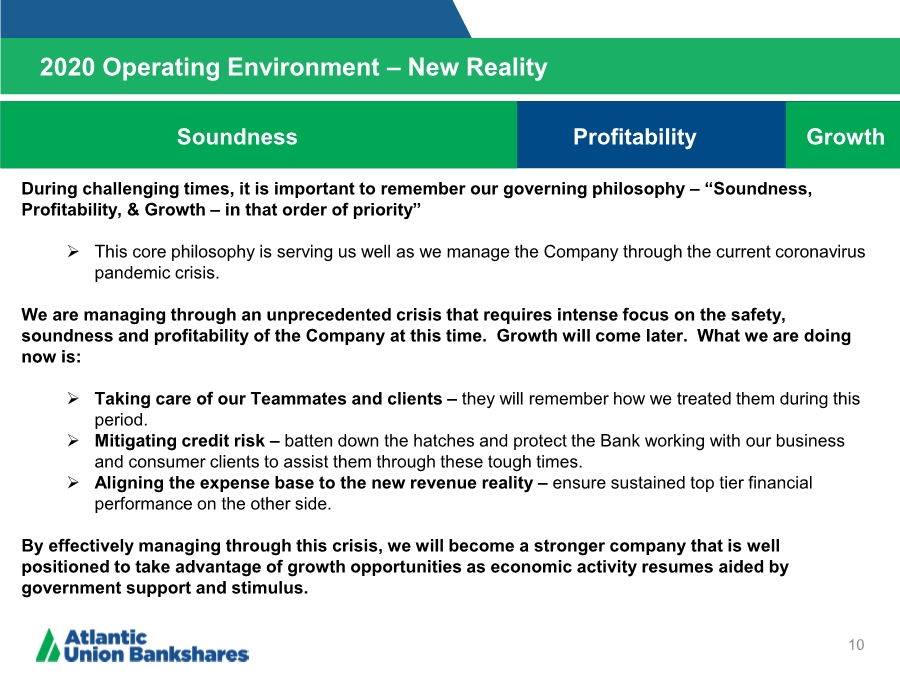
Our first quarter financial results were impacted by the implementation of CECL and the deteriorating economic environment related to COVID-19, which resulted in a material increase in the Company’s provision for credit losses. We also recognize the possibility of a much lower for longer rate environment post COVID-19, and we will align the Company’s expense structure accordingly in order to maintain top tier financial performance. We continue to operate under the mantra of soundness, profitability, and growth – in that order of priority. A sound bank is the highest priority for Atlantic Union. Our conservative credit culture served our shareholders well during the “Great Recession,” and we anticipate that this culture will carry us through the current crisis and what comes afterwards.”
Adoption of Current Expected Credit Loss (“CECL”)
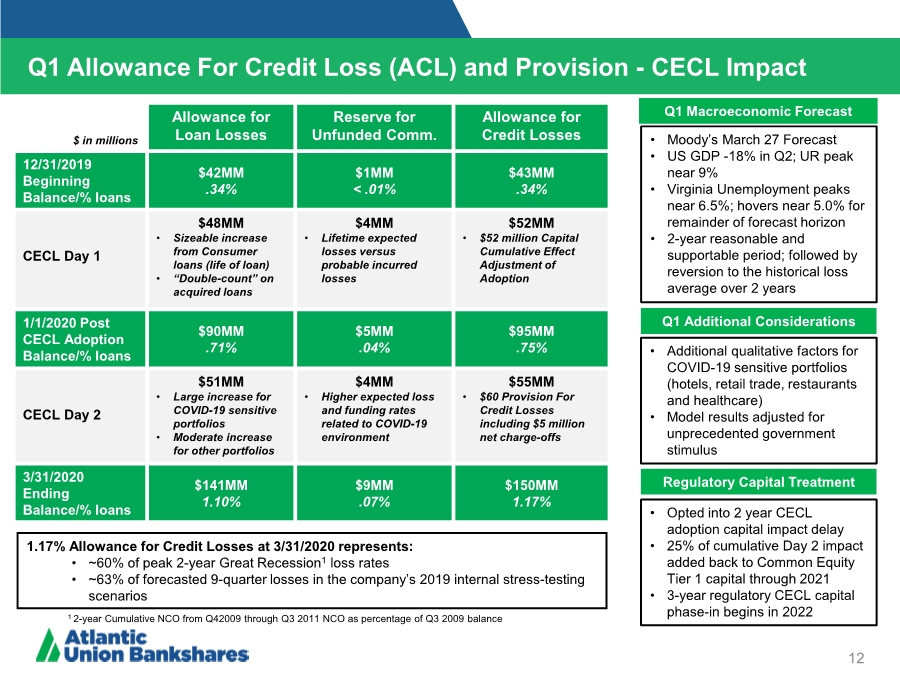
On January 1, 2020, the Company adopted the CECL methodology for estimating credit losses, which resulted in an increase of $51.7 million in the allowance for credit losses (“ACL”) on January 1, 2020. The impact of the worsening economic forecast related to COVID-19 global pandemic (“COVID-19”) subsequent to the adoption of CECL further increased the ACL by $55.1 million to $150.0 million at March 31, 2020.
Small Business Administration (“SBA”) Paycheck Protection Program (“PPP”)
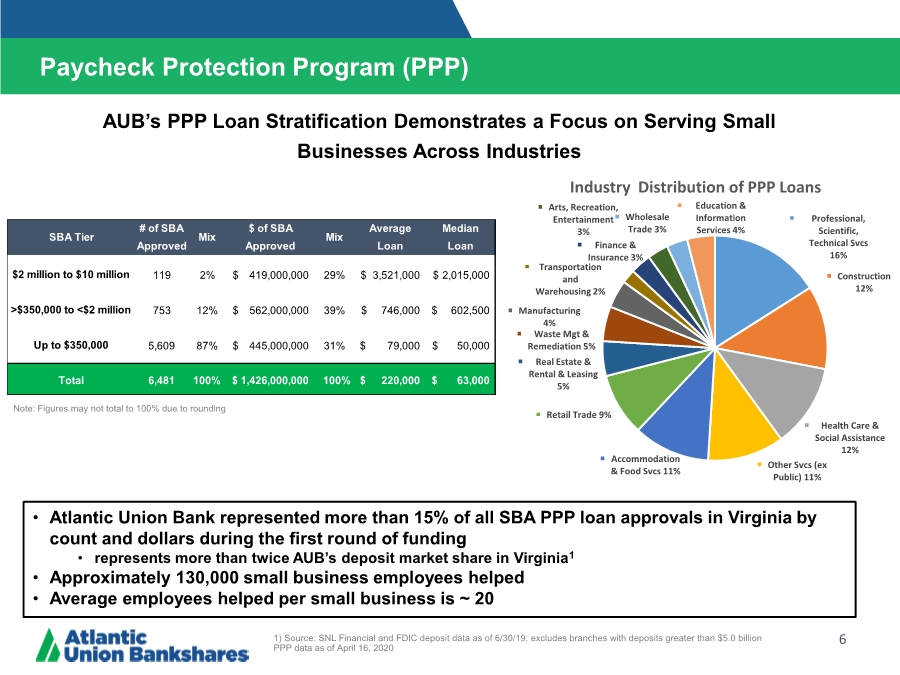
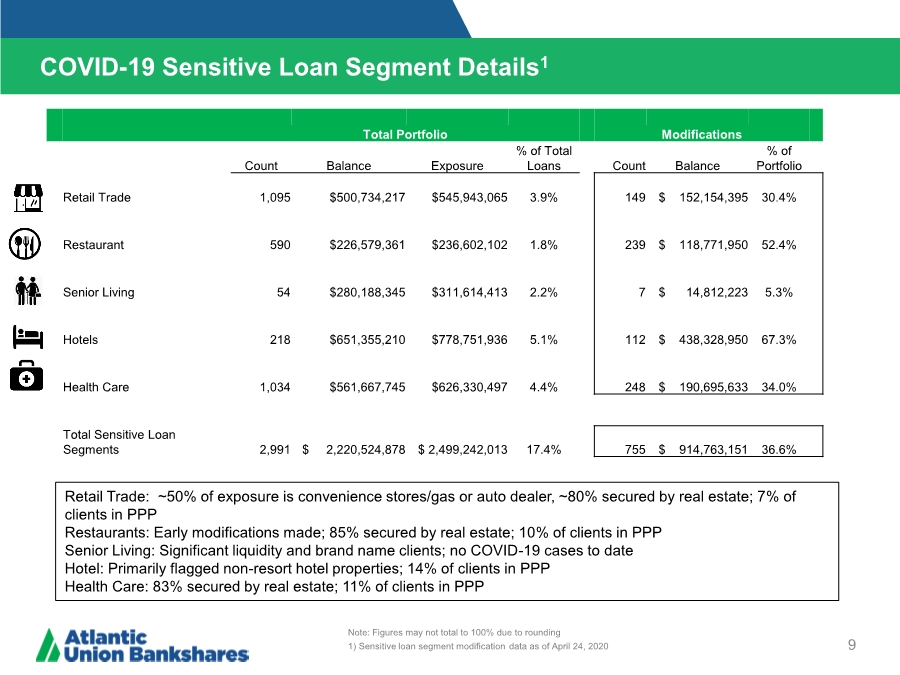
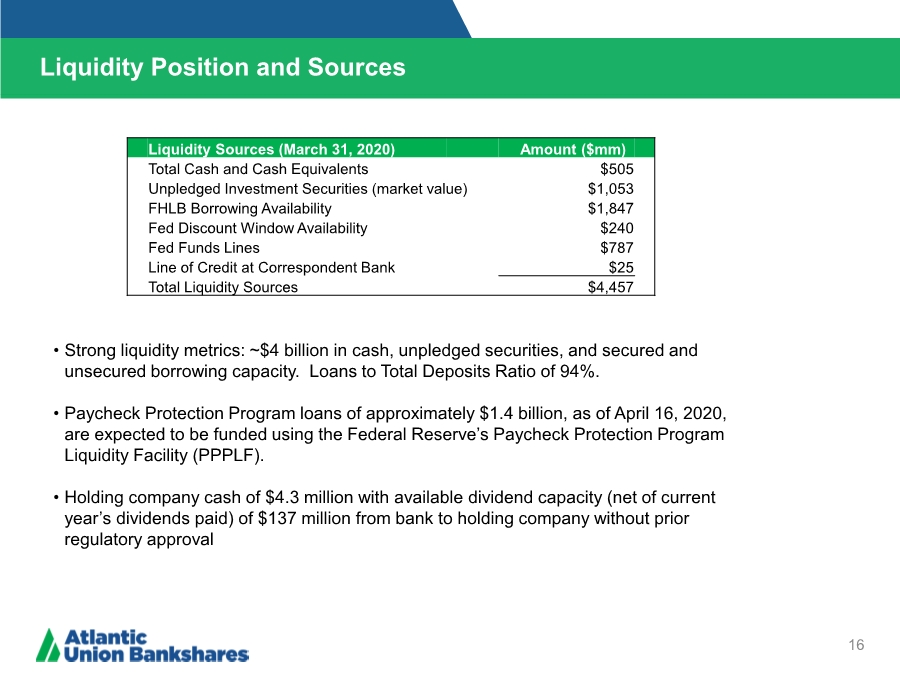
The Company participated in the SBA PPP under the Coronavirus Aid, Relief, and Economic Security (“CARES”) Act, which was intended to provide economic relief to small businesses that have been adversely impacted by COVID-19. As of April 16, 2020, the Company had secured funding for nearly 6,500 loans with a total value of approximately $1.4 billion. The Company continues to fund eligible small business requests now that Congress has appropriated additional funds for the PPP.
(1) These are financial measures not calculated in accordance with generally accepted accounting principles (“GAAP”). For a reconciliation of these non-GAAP financial measures, see Alternative Performance Measures (non-GAAP) section of the Key Financial Results.
NET INTEREST INCOME
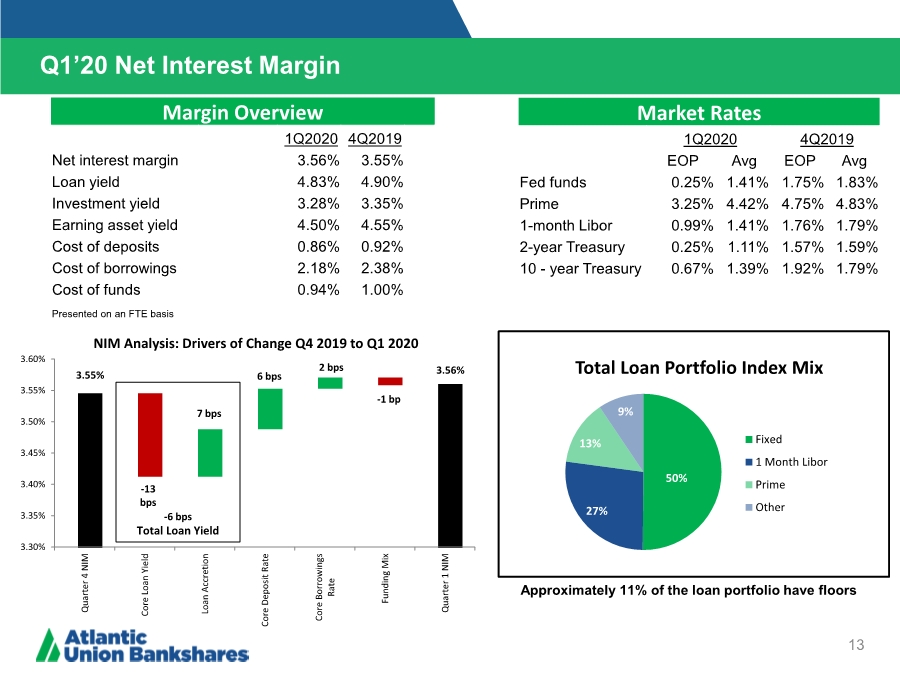
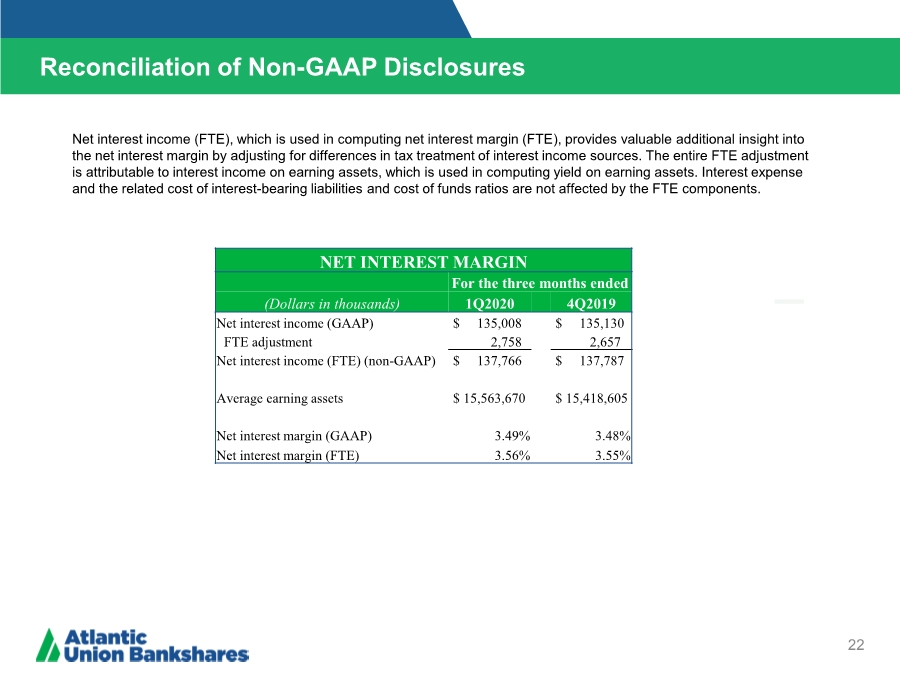
For the first quarter of 2020, net interest income was $135.0 million, a slight decrease from $135.1 million reported in the fourth quarter of 2019. Net interest income (FTE)(1) was $137.8 million in the first quarter of 2020, consistent with the fourth quarter of 2019. The first quarter net interest margin increased 1 basis point to 3.49% from 3.48% in the previous quarter, while the net interest margin (FTE)(1) increased 1 basis point to 3.56% from 3.55% during the same period. The increases in the net interest margin and net interest margin (FTE) were principally due to a 6 basis point decrease in cost of funds, partially offset by a 5 basis point decrease in the yield on earning assets (FTE)(1).
The Company’s net interest margin (FTE) includes the impact of acquisition accounting fair value adjustments. During the first quarter of 2020, net accretion related to acquisition accounting increased $2.8 million from the prior quarter to $9.4 million for the quarter ended March 31, 2020. The fourth quarter of 2019, first quarter of 2020, and the remaining estimated net accretion impact are reflected in the following table (dollars in thousands):
|
|
|
|
|
|
Deposit |
|
|
|
|
|
|
|
|
|
|
Loan |
|
Accretion |
|
Borrowings |
|
|
|
|||
|
|
|
Accretion |
|
(Amortization) |
|
Amortization |
|
Total |
||||
|
For the quarter ended December 31, 2019 |
|
$ |
6,612 |
|
$ |
148 |
|
$ |
(123) |
|
$ |
6,637 |
|
For the quarter ended March 31, 2020 |
|
|
9,528 |
|
|
50 |
|
|
(138) |
|
|
9,440 |
|
For the remaining nine months of 2020 |
|
|
9,285 |
|
|
83 |
|
|
(495) |
|
|
8,873 |
|
For the years ending (estimated): |
|
|
|
|
|
|
|
|
|
|
|
|
|
2021 |
|
|
9,938 |
|
|
14 |
|
|
(807) |
|
|
9,145 |
|
2022 |
|
|
7,974 |
|
|
(43) |
|
|
(829) |
|
|
7,102 |
|
2023 |
|
|
5,700 |
|
|
(32) |
|
|
(852) |
|
|
4,816 |
|
2024 |
|
|
4,576 |
|
|
(4) |
|
|
(877) |
|
|
3,695 |
|
2025 |
|
|
3,481 |
|
|
(1) |
|
|
(900) |
|
|
2,580 |
|
Thereafter |
|
|
15,935 |
|
|
— |
|
|
(9,873) |
|
|
6,062 |
(1) These are financial measures not calculated in accordance with GAAP. For a reconciliation of these non-GAAP financial measures, see Alternative Performance Measures (non-GAAP) section of the Key Financial Results.
ASSET QUALITY
Overview
During the first quarter of 2020, the Company experienced increases in nonperforming assets (“NPAs”) primarily due to the inclusion of assets not previously reported as nonperforming that are now considered such under CECL. Past due loan levels as a percentage of total loans held for investment at March 31, 2020 were down from past due loan levels at December 31, 2019 and up from past due loan levels at March 31, 2019. Net charge-off levels increased slightly from the fourth quarter of 2019 and were primarily related to the third-party consumer loan portfolio. The allowance for credit losses increased from December 31, 2019, as a result of the adoption of CECL as well as a worsening economic forecast due to the impact of COVID-19, which also led to an increase in the provision for credit losses.
Nonperforming Assets
At March 31, 2020, NPAs totaled $48.5 million, an increase of $15.5 million from December 31, 2019. NPAs as a percentage of total outstanding loans at March 31, 2020 were 0.38%, an increase of 12 basis points from 0.26% at December 31, 2019. The increase in NPAs is due to the addition of $14.4 million of loans previously accounted for as purchased credit impaired (“PCI”). The Company’s adoption of CECL resulted in a change in the accounting and reporting related to PCI loans which are now defined as purchased credit deteriorated (“PCD”) and evaluated at the loan level instead of being evaluated in pools under PCI accounting. All prior period nonaccrual and past due loan metrics discussed herein have not been restated for CECL accounting and exclude PCI-related loan balances.
The following table shows a summary of nonperforming asset balances at the quarter ended (dollars in thousands):
|
|
|
March 31, |
|
December 31, |
|
September 30, |
|
June 30, |
|
March 31, |
|||||
|
|
|
2020 |
|
2019 |
|
2019 |
|
2019 |
|
2019 |
|||||
|
Nonaccrual loans |
|
$ |
44,022 |
|
$ |
28,232 |
|
$ |
30,032 |
|
$ |
27,462 |
|
$ |
24,841 |
|
Foreclosed properties |
|
|
4,444 |
|
|
4,708 |
|
|
6,385 |
|
|
6,506 |
|
|
7,353 |
|
Total nonperforming assets |
|
$ |
48,466 |
|
$ |
32,940 |
|
$ |
36,417 |
|
$ |
33,968 |
|
$ |
32,194 |
The following table shows the activity in nonaccrual loans for the quarter ended (dollars in thousands):
|
|
|
March 31, |
|
December 31, |
|
September 30, |
|
June 30, |
|
March 31, |
|||||
|
|
|
2020 |
|
2019 |
|
2019 |
|
2019 |
|
2019 |
|||||
|
Beginning Balance |
|
$ |
28,232 |
|
$ |
30,032 |
|
$ |
27,462 |
|
$ |
24,841 |
|
$ |
26,953 |
|
Net customer payments |
|
|
(3,451) |
|
|
(5,741) |
|
|
(3,612) |
|
|
(3,108) |
|
|
(2,314) |
|
Additions |
|
|
6,059 |
|
|
5,631 |
|
|
8,327 |
|
|
6,321 |
|
|
3,297 |
|
Impact of CECL adoption |
|
|
14,381 |
|
|
— |
|
|
— |
|
|
— |
|
|
— |
|
Charge-offs |
|
|
(1,199) |
|
|
(1,690) |
|
|
(884) |
|
|
(592) |
|
|
(1,626) |
|
Loans returning to accruing status |
|
|
— |
|
|
— |
|
|
(1,103) |
|
|
— |
|
|
(952) |
|
Transfers to foreclosed property |
|
|
— |
|
|
— |
|
|
(158) |
|
|
— |
|
|
(517) |
|
Ending Balance |
|
$ |
44,022 |
|
$ |
28,232 |
|
$ |
30,032 |
|
$ |
27,462 |
|
$ |
24,841 |
The following table shows the activity in foreclosed properties for the quarter ended (dollars in thousands):
|
|
|
March 31, |
|
December 31, |
|
September 30, |
|
June 30, |
|
March 31, |
|||||
|
|
|
2020 |
|
2019 |
|
2019 |
|
2019 |
|
2019 |
|||||
|
Beginning Balance |
|
$ |
4,708 |
|
$ |
6,385 |
|
$ |
6,506 |
|
$ |
7,353 |
|
$ |
6,722 |
|
Additions of foreclosed property |
|
|
615 |
|
|
62 |
|
|
645 |
|
|
271 |
|
|
900 |
|
Valuation adjustments |
|
|
(44) |
|
|
(375) |
|
|
(62) |
|
|
(433) |
|
|
(51) |
|
Proceeds from sales |
|
|
(854) |
|
|
(1,442) |
|
|
(737) |
|
|
(638) |
|
|
(171) |
|
Gains (losses) from sales |
|
|
19 |
|
|
78 |
|
|
33 |
|
|
(47) |
|
|
(47) |
|
Ending Balance |
|
$ |
4,444 |
|
$ |
4,708 |
|
$ |
6,385 |
|
$ |
6,506 |
|
$ |
7,353 |
Past Due Loans
Past due loans still accruing interest totaled $75.1 million or 0.59% of total loans held for investment at March 31, 2020, compared to $76.6 million or 0.61% of total loans held for investment at December 31, 2019, and $51.4 million or 0.43% of total loans held for investment at March 31, 2019. Of the total past due loans still accruing interest $12.9 million or 0.10% of total loans held for investment were loans past due 90 days or more at March 31, 2020, compared to $13.4 million or 0.11% of total loans held for investment at December 31, 2019, and $11.0 million or 0.09% of total loans held for investment at March 31, 2019.
Net Charge-offs
For the first quarter of 2020, net charge-offs were $5.0 million, or 0.16% of total average loans on an annualized basis, compared to $4.6 million, or 0.15%, for the prior quarter, and $4.2 million, or 0.15%, for the first quarter last year. The majority of net charge-offs in the first quarter of 2020 were related to the third-party consumer loan portfolio.
Provision for Credit Losses
The provision for credit losses for the first quarter of 2020 was $60.2 million, an increase of $57.3 million compared to the previous quarter. The provision for credit losses for the first quarter of 2020 included $56.3 million in provision for loan losses and $3.9 million in provision for unfunded commitments. The increase in the provision for credit losses was due to the impact of the worsening economic forecast due to the impact of COVID-19 under CECL accounting for credit losses.
Allowance for Credit Losses
At March 31, 2020, the ACL was $150.0 million and included an allowance for loan and lease losses (“ALLL”) of $141.0 million and a reserve for unfunded commitments (“RUC”) of $9.0 million. The ACL increased $106.8 million from December 31, 2019, primarily due to the adoption of CECL (the “CECL Day 1 impact”) as well as the impact of the worsening economic forecast related to COVID-19 subsequent to the adoption of CECL (the “CECL Day 2 impact”).
The ALLL increased $98.7 million from December 31, 2019, due to the CECL Day 1 impact of $47.5 million and the CECL Day 2 impact of $51.2 million. The ALLL as a percentage of the total loan portfolio was 1.10% at March 31, 2020 and 0.34% at December 31, 2019. The ratio of the ALLL to nonaccrual loans was 320.4% at March 31, 2020, compared to 149.8% at December 31, 2019.
The RUC increased $8.1 million from December 31, 2019, due to the CECL Day 1 impact of $4.2 million and the CECL Day 2 impact of $3.9 million.
NONINTEREST INCOME
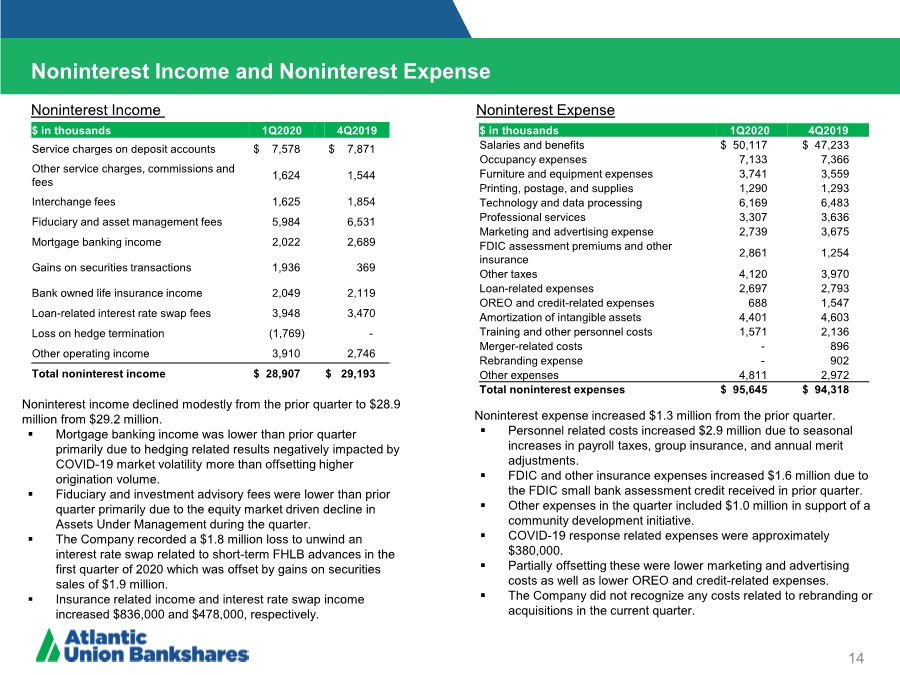
Noninterest income decreased $286,000 to $28.9 million for the quarter ended March 31, 2020 from $29.2 million in the prior quarter. Mortgage banking income was lower by $667,000 primarily due to hedging-related results negatively impacted by COVID-19-driven mortgage market volatility more than offsetting the impact of higher loan origination volumes. Fiduciary and asset management fees declined $547,000 from the prior quarter primarily due to lower investment advisory fees resulting from the equity market driven drop in Assets Under Management during the quarter. Service charges on deposit accounts declined $293,000 primarily due to lower overdraft fees, and interchange fees declined $229,000 from the prior quarter. In addition, the Company recorded a $1.8 million loss to unwind an interest rate swap related to short-term FHLB advances in the first quarter of 2020. These declines were partially offset by increases in insurance-related revenue of $836,000, loan-related interest rate swap income of $478,000, and gains on sales of securities of $1.6 million from the prior quarter.
NONINTEREST EXPENSE
Noninterest expense increased $1.3 million for the quarter ended March 31, 2020 from $94.3 million in the prior quarter. Salaries and benefits increased $2.9 million primarily related to seasonal increases in payroll taxes, group insurance, and annual merit adjustments. FDIC and other insurance expenses increased $1.6 million due to an FDIC small bank assessment credit received in the fourth quarter of 2019. Other expenses in the first quarter of 2020 included $1.0 million in support of a community development initiative and approximately $380,000 of expenses incurred related to the Company’s response to COVID-19. These increases were partially offset by declines in marketing and advertising expense of approximately $936,000 as well as OREO and credit-related expense of approximately $859,000 due to lower OREO valuation adjustments. Additionally, there were no merger-related or rebranding costs recognized in the first quarter of 2020 compared to $896,000 and $902,000, respectively, in the fourth quarter of 2019.
INCOME TAXES
The effective tax rate for the three months ended March 31, 2020 was 12.2% compared to 16.7% for the three months ended December 31, 2019. The decline in effective tax rate is primarily related to excess tax benefits related to share-based compensation recorded.
BALANCE SHEET
At March 31, 2020, total assets were $17.8 billion, an increase of $284.4 million, or approximately 6.5% (annualized), from December 31, 2019, and an increase of $949.7 million, or approximately 5.6% from March 31, 2019. The increase in assets from the previous quarter was primarily due to loan growth during the first quarter of 2020. The increase from the prior year was primarily a result of loan growth.
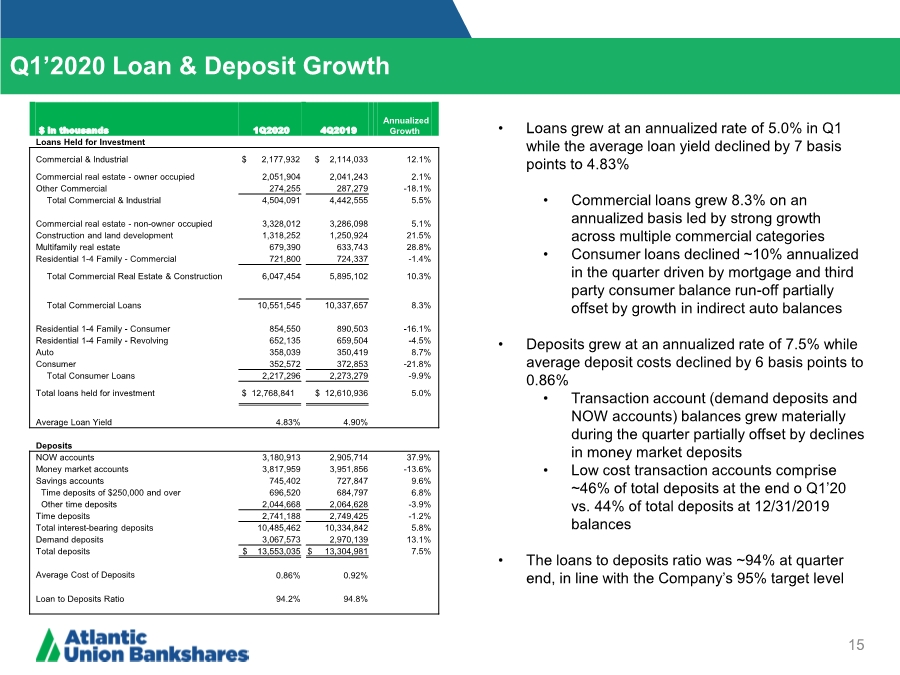
At March 31, 2020, loans held for investment (net of deferred fees and costs) were $12.8 billion, an increase of $157.9 million, or 5.0% (annualized), from December 31, 2019, while average loans increased $266.2 million, or 8.7% (annualized), from the prior quarter. Loans held for investment increased $816.5 million, or 6.8% from March 31, 2019, while quarterly average loans increased $1.5 billion, or 13.2% from the prior year. The quarterly average increase from the first quarter of 2019 is due to the full-quarter impact of loans acquired in February of 2019.
At March 31, 2020, total deposits were $13.6 billion, an increase of $248.1 million, or approximately 7.5% (annualized), from December 31, 2019, while average deposits increased $43.9 million, or 1.3% (annualized), from prior quarter. Deposits increased $1.1 billion, or 8.5% from March 31, 2019, while quarterly average deposits increased $1.9 billion, or 16.4% from the prior year. The quarterly average increase from the first quarter of 2019 is due to the full-quarter impact of deposits acquired in February of 2019.
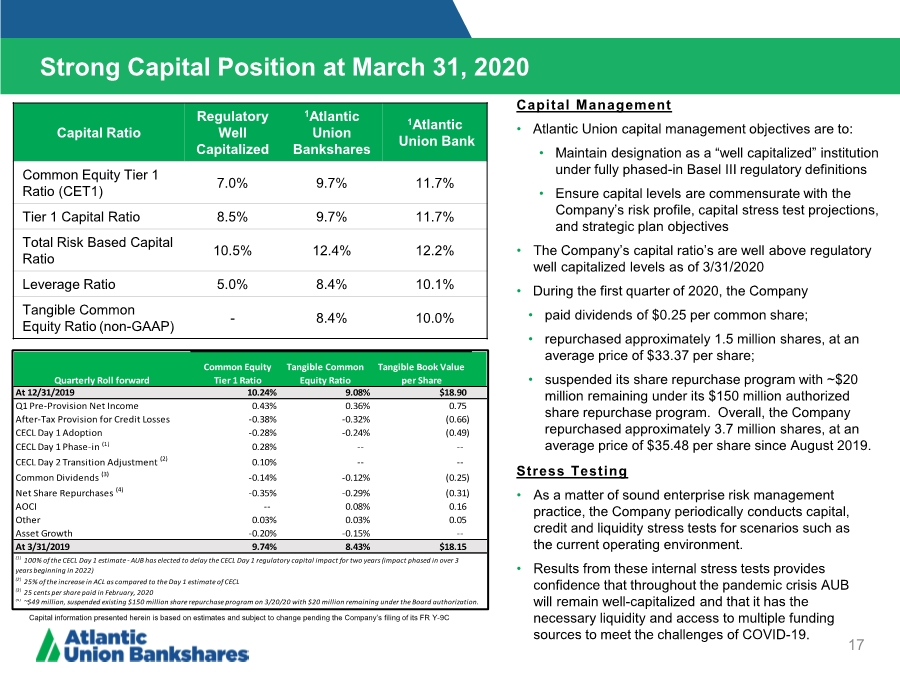
The following table shows the Company’s capital ratios at the quarters ended:
|
|
|
March 31, |
|
December 31, |
|
March 31, |
|
|
|
|
2020 |
|
2019 |
|
2019 |
|
|
Common equity Tier 1 capital ratio (1) |
|
9.74 |
% |
10.24 |
% |
10.26 |
% |
|
Tier 1 capital ratio (1) |
|
9.74 |
% |
10.24 |
% |
10.26 |
% |
|
Total capital ratio (1) |
|
12.36 |
% |
12.63 |
% |
12.73 |
% |
|
Leverage ratio (Tier 1 capital to average assets) (1) |
|
8.44 |
% |
8.79 |
% |
9.51 |
% |
|
Common equity to total assets |
|
13.59 |
% |
14.31 |
% |
14.56 |
% |
|
Tangible common equity to tangible assets (2) |
|
8.43 |
% |
9.08 |
% |
9.09 |
% |
|
(1) |
All ratios at March 31, 2020 are estimates and subject to change pending the Company’s filing of its FR Y9-C. All other periods are presented as filed. |
|
(2) |
For a reconciliation of this non-GAAP financial measure, see Alternative Performance Measures (non-GAAP) section of the Key Financial Results. |
During the first quarter of 2020, the Company declared and paid cash dividends of $0.25 per common share, consistent with the fourth quarter of 2019 and an increase of $0.02, or 8.7% compared to the first quarter of 2019. On July 10, 2019, the Company announced that its Board of Directors had authorized a share repurchase program to purchase up to $150 million of the Company’s common stock through June 30, 2021 in open market transactions or privately negotiated transactions. On March 20, 2020, the Company suspended its share repurchase program, which had $20 million remaining in authorization at the time. The Company repurchased an aggregate of approximately 3.7 million shares, at an average price of $35.48 per share, to date under the authorization, prior to suspension.
ABOUT ATLANTIC UNION BANKSHARES CORPORATION
Headquartered in Richmond, Virginia, Atlantic Union Bankshares Corporation (Nasdaq: AUB) is the holding company for Atlantic Union Bank. Atlantic Union Bank has 149 branches and approximately 170 ATMs located throughout Virginia, and in portions of Maryland and North Carolina. Middleburg Financial is a brand name used by Atlantic Union Bank and certain affiliates when providing trust, wealth management, private banking, and investment advisory products and services. Certain non-bank affiliates of Atlantic Union Bank include: Old Dominion Capital Management, Inc., and its subsidiary, Outfitter Advisors, Ltd., Dixon, Hubard, Feinour, & Brown, Inc., and Middleburg Investment Services, LLC, which provide investment advisory and/or brokerage services; and Union Insurance Group, LLC, which offers various lines of insurance products.
FIRST QUARTER 2020 EARNINGS RELEASE CONFERENCE CALL
Atlantic Union Bank will hold a conference call on Tuesday, April 28, 2020 at 9:00 a.m. Eastern Daylight Time during which management will review the first quarter 2020 financial results and provide an update on recent activities. Interested parties may participate in the call toll-free by dialing (866) 220‑4170; international callers wishing to participate may do so by dialing (864) 663‑5235. The conference ID number is 1273006. Management will conduct a listen-only webcast with accompanying slides, which can be found at: https://edge.media-server.com/mmc/p/2tfrj3my.
A replay of the webcast, and the accompanying slides, will be available by the end of day on April 28 on the Company’s website at: https://investors.atlanticunionbank.com/.
NON-GAAP FINANCIAL MEASURES
In reporting the results of the quarter ended March 31, 2020, the Company has provided supplemental performance measures on a tax-equivalent, tangible, operating, or pre-tax pre-provision basis. These non-GAAP financial measures are a supplement to GAAP, which is used to prepare the Company’s financial statements, and should not be considered in isolation or as a substitute for comparable measures calculated in accordance with GAAP. In addition, the Company’s non-GAAP financial measures may not be comparable to non-GAAP financial measures of other companies. The Company uses the non-GAAP financial measures discussed herein in its analysis of the Company’s performance. The Company’s management believes that these non-GAAP financial measures provide additional understanding of ongoing operations, enhance comparability of results of operations with prior periods and show the effects of significant gains and charges in the periods presented without the impact of items or events that may obscure trends in the Company’s
underlying performance. For a reconciliation of these measures to their most directly comparable GAAP measures and additional information about these non-GAAP financial measures, see Alternative Performance Measures (non-GAAP) section of the Key Financial Results.
FORWARD-LOOKING STATEMENTS
Certain statements in this press release may constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Forward-looking statements are statements that include, without limitation, projections, predictions, expectations, or beliefs about future events or results that are not statements of historical fact. Such forward-looking statements are based on various assumptions as of the time they are made, and are inherently subject to known and unknown risks, uncertainties, and other factors, some of which cannot be predicted or quantified, that may cause actual results, performance, or achievements to be materially different from those expressed or implied by such forward-looking statements. Forward-looking statements are often accompanied by words that convey projected future events or outcomes such as “expect,” “believe,” “estimate,” “plan,” “project,” “anticipate,” “intend,” “will,” “may,” “view,” “opportunity,” “potential,” or words of similar meaning or other statements concerning opinions or judgment of the Company and its management about future events. Although the Company believes that its expectations with respect to forward-looking statements are based upon reasonable assumptions within the bounds of its existing knowledge of its business and operations, there can be no assurance that actual results, performance, or achievements of, or trends affecting, the Company will not differ materially from any projected future results, performance, or achievements expressed or implied by such forward-looking statements. Actual future results, performance, achievements or trends may differ materially from historical results or those anticipated depending on a variety of factors, including, but not limited to:
|
· |
changes in interest rates; |
|
· |
general economic and financial market conditions, in the United States generally and particularly in the markets in which the Company operates and which its loans are concentrated, including the effects of declines in real estate values, an increase in unemployment levels and slowdowns in economic growth, including as a result of COVID-19; |
|
· |
the quality or composition of the loan or investment portfolios and changes therein; |
|
· |
demand for loan products and financial services in the Company’s market area; |
|
· |
the Company’s ability to manage its growth or implement its growth strategy; |
|
· |
the introduction of new lines of business or new products and services; |
|
· |
the Company’s ability to recruit and retain key employees; |
|
· |
the incremental cost and/or decreased revenues associated with exceeding $10 billion in assets; |
|
· |
real estate values in the Bank’s lending area; |
|
· |
an insufficient ACL; |
|
· |
changes in accounting principles relating to loan loss recognition (CECL); |
|
· |
the Company’s liquidity and capital positions; |
|
· |
concentrations of loans secured by real estate, particularly commercial real estate; |
|
· |
the effectiveness of the Company’s credit processes and management of the Company’s credit risk; |
|
· |
the Company’s ability to compete in the market for financial services; |
|
· |
technological risks and developments, and cyber threats, attacks, or events; |
|
· |
the potential adverse effects of unusual and infrequently occurring events, such as weather-related disasters, terrorist acts or public health events (such as COVID-19), and of governmental and societal responses thereto; these potential adverse effects may include, without limitation, adverse effects on the ability of the Company's borrowers to satisfy their obligations to the Company, on the value of collateral securing loans, on the demand for the Company's loans or its other products and services, on incidents of cyberattack and fraud, on the Company’s liquidity or capital positions, on risks posed by reliance on third-party service providers, on other aspects of the Company's business operations and on financial markets and economic growth; |
|
· |
performance by the Company’s counterparties or vendors; |
|
· |
deposit flows; |
|
· |
the availability of financing and the terms thereof; |
|
· |
the level of prepayments on loans and mortgage-backed securities; |
|
· |
legislative or regulatory changes and requirements, including the impact of the CARES Act and other legislative and regulatory reactions to COVID-19; |
|
· |
potential claims, damages, and fines related to litigation or government actions, including litigation or actions arising from the Company’s participation in and administration of programs related to COVID-19, including, among other things, the CARES Act; |
|
· |
the effects of changes in federal, state or local tax laws and regulations; |
|
· |
monetary and fiscal policies of the U.S. government including policies of the U.S. Department of the Treasury and the Federal Reserve; |
|
· |
changes to applicable accounting principles and guidelines; and |
|
· |
other factors, many of which are beyond the control of the Company. |
Please refer to the “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” sections of the Company’s Annual Report on Form 10‑K for the year ended December 31, 2019 and comparable “Risk Factors” sections of the Company’s Quarterly Reports on Form 10‑Q and related disclosures in other filings, which have been filed with the SEC and are available on the SEC’s website at www.sec.gov. All of the forward-looking statements made in this press release are expressly qualified by the cautionary statements contained or referred to herein. The actual results or developments anticipated may not be realized or, even if substantially realized, they may not have the expected consequences to or effects on the Company or its businesses or operations. Readers are cautioned not to rely too heavily on the forward-looking statements contained in this press release. Forward-looking statements speak only as of the date they are made and the Company does not undertake any obligation to update, revise or clarify these forward-looking statements, whether as a result of new information, future events or otherwise.
ATLANTIC UNION BANKSHARES CORPORATION AND SUBSIDIARIES
KEY FINANCIAL RESULTS
(Dollars in thousands, except share data)
|
|
|
As of & For Three Months Ended |
|
|||||||
|
|
|
03/31/20 |
|
12/31/19 |
|
03/31/19 |
|
|||
|
Results of Operations |
|
(unaudited) |
|
(unaudited) |
|
(unaudited) |
|
|||
|
Interest and dividend income |
|
$ |
171,325 |
|
$ |
174,211 |
|
$ |
165,652 |
|
|
Interest expense |
|
|
36,317 |
|
|
39,081 |
|
|
38,105 |
|
|
Net interest income |
|
|
135,008 |
|
|
135,130 |
|
|
127,547 |
|
|
Provision for credit losses |
|
|
60,196 |
|
|
2,900 |
|
|
3,792 |
|
|
Net interest income after provision for credit losses |
|
|
74,812 |
|
|
132,230 |
|
|
123,755 |
|
|
Noninterest income |
|
|
28,907 |
|
|
29,193 |
|
|
24,938 |
|
|
Noninterest expenses |
|
|
95,645 |
|
|
94,318 |
|
|
106,728 |
|
|
Income before income taxes |
|
|
8,074 |
|
|
67,105 |
|
|
41,965 |
|
|
Income tax expense |
|
|
985 |
|
|
11,227 |
|
|
6,249 |
|
|
Income from continuing operations |
|
|
7,089 |
|
|
55,878 |
|
|
35,716 |
|
|
Discontinued operations, net of tax |
|
|
— |
|
|
(42) |
|
|
(85) |
|
|
Net income |
|
$ |
7,089 |
|
$ |
55,836 |
|
$ |
35,631 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Interest earned on earning assets (FTE) (1) |
|
$ |
174,083 |
|
$ |
176,868 |
|
$ |
168,400 |
|
|
Net interest income (FTE) (1) |
|
|
137,766 |
|
|
137,787 |
|
|
130,295 |
|
|
Total revenue (FTE) (1) |
|
|
166,673 |
|
|
166,980 |
|
|
155,233 |
|
|
Pre-tax pre-provision earnings (8) |
|
|
68,270 |
|
|
71,761 |
|
|
64,201 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Key Ratios |
|
|
|
|
|
|
|
|
|
|
|
Earnings per common share, diluted |
|
$ |
0.09 |
|
$ |
0.69 |
|
$ |
0.47 |
|
|
Return on average assets (ROA) |
|
|
0.16 |
% |
|
1.27 |
% |
|
0.92 |
% |
|
Return on average equity (ROE) |
|
|
1.15 |
% |
|
8.81 |
% |
|
6.37 |
% |
|
Efficiency ratio |
|
|
58.35 |
% |
|
57.40 |
% |
|
69.99 |
% |
|
Net interest margin |
|
|
3.49 |
% |
|
3.48 |
% |
|
3.72 |
% |
|
Net interest margin (FTE) (1) |
|
|
3.56 |
% |
|
3.55 |
% |
|
3.80 |
% |
|
Yields on earning assets (FTE) (1) |
|
|
4.50 |
% |
|
4.55 |
% |
|
4.92 |
% |
|
Cost of interest-bearing liabilities |
|
|
1.23 |
% |
|
1.33 |
% |
|
1.44 |
% |
|
Cost of deposits |
|
|
0.86 |
% |
|
0.92 |
% |
|
0.86 |
% |
|
Cost of funds |
|
|
0.94 |
% |
|
1.00 |
% |
|
1.12 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
Operating Measures (4) |
|
|
|
|
|
|
|
|
|
|
|
Net operating earnings |
|
$ |
7,089 |
|
$ |
57,258 |
|
$ |
50,519 |
|
|
Operating earnings per share, diluted |
|
$ |
0.09 |
|
$ |
0.71 |
|
$ |
0.66 |
|
|
Operating ROA |
|
|
0.16 |
% |
|
1.30 |
% |
|
1.31 |
% |
|
Operating ROE |
|
|
1.15 |
% |
|
9.03 |
% |
|
9.03 |
% |
|
Operating ROTCE (2) (3) |
|
|
2.87 |
% |
|
16.01 |
% |
|
16.37 |
% |
|
Operating efficiency ratio (FTE) (1)(7) |
|
|
54.74 |
% |
|
52.65 |
% |
|
54.10 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
Per Share Data |
|
|
|
|
|
|
|
|
|
|
|
Earnings per common share, basic |
|
$ |
0.09 |
|
$ |
0.69 |
|
$ |
0.47 |
|
|
Earnings per common share, diluted |
|
|
0.09 |
|
|
0.69 |
|
|
0.47 |
|
|
Cash dividends paid per common share |
|
|
0.25 |
|
|
0.25 |
|
|
0.23 |
|
|
Market value per share |
|
|
21.90 |
|
|
37.55 |
|
|
32.33 |
|
|
Book value per common share |
|
|
30.99 |
|
|
31.58 |
|
|
30.16 |
|
|
Tangible book value per common share (2) |
|
|
18.15 |
|
|
18.90 |
|
|
17.69 |
|
|
Price to earnings ratio, diluted |
|
|
60.50 |
|
|
13.72 |
|
|
16.96 |
|
|
Price to book value per common share ratio |
|
|
0.71 |
|
|
1.19 |
|
|
1.07 |
|
|
Price to tangible book value per common share ratio (2) |
|
|
1.21 |
|
|
1.99 |
|
|
1.83 |
|
|
Weighted average common shares outstanding, basic |
|
|
79,290,352 |
|
|
80,439,007 |
|
|
76,472,189 |
|
|
Weighted average common shares outstanding, diluted |
|
|
79,317,382 |
|
|
80,502,269 |
|
|
76,533,066 |
|
|
Common shares outstanding at end of period |
|
|
78,710,448 |
|
|
80,001,185 |
|
|
82,037,354 |
|
|
|
|
As of & For Three Months Ended |
|
|||||||
|
|
|
03/31/20 |
|
12/31/19 |
|
03/31/19 |
|
|||
|
Capital Ratios |
|
(unaudited) |
|
(unaudited) |
|
(unaudited) |
|
|||
|
Common equity Tier 1 capital ratio (5) |
|
|
9.74 |
% |
|
10.24 |
% |
|
10.26 |
% |
|
Tier 1 capital ratio (5) |
|
|
9.74 |
% |
|
10.24 |
% |
|
10.26 |
% |
|
Total capital ratio (5) |
|
|
12.36 |
% |
|
12.63 |
% |
|
12.73 |
% |
|
Leverage ratio (Tier 1 capital to average assets) (5) |
|
|
8.44 |
% |
|
8.79 |
% |
|
9.51 |
% |
|
Common equity to total assets |
|
|
13.59 |
% |
|
14.31 |
% |
|
14.56 |
% |
|
Tangible common equity to tangible assets (2) |
|
|
8.43 |
% |
|
9.08 |
% |
|
9.09 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
Financial Condition |
|
|
|
|
|
|
|
|
|
|
|
Assets |
|
$ |
17,847,376 |
|
$ |
17,562,990 |
|
$ |
16,897,655 |
|
|
Loans held for investment |
|
|
12,768,841 |
|
|
12,610,936 |
|
|
11,952,310 |
|
|
Securities |
|
|
2,655,306 |
|
|
2,631,437 |
|
|
2,804,353 |
|
|
Earning Assets |
|
|
15,813,780 |
|
|
15,576,208 |
|
|
14,909,318 |
|
|
Goodwill |
|
|
935,560 |
|
|
935,560 |
|
|
927,760 |
|
|
Amortizable intangibles, net |
|
|
69,298 |
|
|
73,669 |
|
|
88,553 |
|
|
Deposits |
|
|
13,553,035 |
|
|
13,304,981 |
|
|
12,489,330 |
|
|
Borrowings |
|
|
1,514,464 |
|
|
1,513,748 |
|
|
1,753,103 |
|
|
Stockholders' equity |
|
|
2,425,450 |
|
|
2,513,102 |
|
|
2,459,465 |
|
|
Tangible common equity (2) |
|
|
1,420,592 |
|
|
1,503,873 |
|
|
1,443,152 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Loans held for investment, net of deferred fees and costs |
|
|
|
|
|
|
|
|
|
|
|
Construction and land development |
|
$ |
1,318,252 |
|
$ |
1,250,924 |
|
$ |
1,326,679 |
|
|
Commercial real estate - owner occupied |
|
|
2,051,904 |
|
|
2,041,243 |
|
|
1,921,464 |
|
|
Commercial real estate - non-owner occupied |
|
|
3,328,012 |
|
|
3,286,098 |
|
|
2,970,453 |
|
|
Multifamily real estate |
|
|
679,390 |
|
|
633,743 |
|
|
591,431 |
|
|
Commercial & Industrial |
|
|
2,177,932 |
|
|
2,114,033 |
|
|
1,866,625 |
|
|
Residential 1-4 Family - Commercial |
|
|
721,800 |
|
|
724,337 |
|
|
743,101 |
|
|
Residential 1-4 Family - Consumer |
|
|
854,550 |
|
|
890,503 |
|
|
937,710 |
|
|
Residential 1-4 Family - Revolving |
|
|
652,135 |
|
|
659,504 |
|
|
672,087 |
|
|
Auto |
|
|
358,039 |
|
|
350,419 |
|
|
300,631 |
|
|
Consumer |
|
|
352,572 |
|
|
372,853 |
|
|
397,491 |
|
|
Other Commercial |
|
|
274,255 |
|
|
287,279 |
|
|
224,638 |
|
|
Total loans held for investment |
|
$ |
12,768,841 |
|
$ |
12,610,936 |
|
$ |
11,952,310 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Deposits |
|
|
|
|
|
|
|
|
|
|
|
NOW accounts |
|
$ |
3,180,913 |
|
$ |
2,905,714 |
|
$ |
2,643,228 |
|
|
Money market accounts |
|
|
3,817,959 |
|
|
3,951,856 |
|
|
3,579,249 |
|
|
Savings accounts |
|
|
745,402 |
|
|
727,847 |
|
|
798,670 |
|
|
Time deposits of $250,000 and over |
|
|
696,520 |
|
|
684,797 |
|
|
463,198 |
|
|
Other time deposits |
|
|
2,044,668 |
|
|
2,064,628 |
|
|
2,040,872 |
|
|
Time deposits |
|
|
2,741,188 |
|
|
2,749,425 |
|
|
2,504,070 |
|
|
Total interest-bearing deposits |
|
$ |
10,485,462 |
|
$ |
10,334,842 |
|
$ |
9,525,217 |
|
|
Demand deposits |
|
|
3,067,573 |
|
|
2,970,139 |
|
|
2,964,113 |
|
|
Total deposits |
|
$ |
13,553,035 |
|
$ |
13,304,981 |
|
$ |
12,489,330 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Averages |
|
|
|
|
|
|
|
|
|
|
|
Assets |
|
$ |
17,559,921 |
|
$ |
17,437,552 |
|
$ |
15,699,743 |
|
|
Loans held for investment |
|
|
12,593,923 |
|
|
12,327,692 |
|
|
11,127,390 |
|
|
Loans held for sale |
|
|
50,721 |
|
|
75,038 |
|
|
14,999 |
|
|
Securities |
|
|
2,621,437 |
|
|
2,608,942 |
|
|
2,645,429 |
|
|
Earning assets |
|
|
15,563,670 |
|
|
15,418,605 |
|
|
13,891,248 |
|
|
Deposits |
|
|
13,346,857 |
|
|
13,302,955 |
|
|
11,469,935 |
|
|
Time deposits |
|
|
2,755,500 |
|
|
2,847,366 |
|
|
2,325,218 |
|
|
Interest-bearing deposits |
|
|
10,421,419 |
|
|
10,265,986 |
|
|
8,934,995 |
|
|
Borrowings |
|
|
1,442,525 |
|
|
1,369,035 |
|
|
1,790,656 |
|
|
Interest-bearing liabilities |
|
|
11,863,944 |
|
|
11,635,021 |
|
|
10,725,651 |
|
|
Stockholders' equity |
|
|
2,485,646 |
|
|
2,515,303 |
|
|
2,268,395 |
|
|
Tangible common equity (2) |
|
|
1,478,803 |
|
|
1,509,001 |
|
|
1,334,051 |
|
|
|
|
As of & For Three Months Ended |
|
|||||||
|
|
|
03/31/20 |
|
12/31/19 |
|
03/31/19 |
|
|||
|
Asset Quality |
|
(unaudited) |
|
(unaudited) |
|
(unaudited) |
|
|||
|
Allowance for Credit Losses (ACL) |
|
|
|
|
|
|
|
|
|
|
|
Beginning balance, Allowance for loan and lease losses (ALLL) |
|
$ |
42,294 |
|
$ |
43,820 |
|
$ |
41,045 |
|
|
Add: Day 1 impact from adoption of CECL |
|
|
47,484 |
|
|
— |
|
|
— |
|
|
Add: Recoveries |
|
|
2,160 |
|
|
2,292 |
|
|
1,696 |
|
|
Less: Charge-offs |
|
|
7,151 |
|
|
6,918 |
|
|
5,939 |
|
|
Add: Provision for loan losses |
|
|
56,256 |
|
|
3,100 |
|
|
4,025 |
|
|
Ending balance, ALLL |
|
$ |
141,043 |
|
$ |
42,294 |
|
$ |
40,827 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Beginning balance, Reserve for unfunded commitment (RUC) |
|
$ |
900 |
|
$ |
1,100 |
|
$ |
900 |
|
|
Add: Day 1 impact from adoption of CECL |
|
|
4,160 |
|
|
— |
|
|
— |
|
|
Add: Impact of acquisition accounting |
|
|
— |
|
|
— |
|
|
1,033 |
|
|
Add: Provision for unfunded commitments |
|
|
3,940 |
|
|
(200) |
|
|
(233) |
|
|
Ending Balance, RUC |
|
$ |
9,000 |
|
$ |
900 |
|
$ |
1,700 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Total ACL |
|
$ |
150,043 |
|
$ |
43,194 |
|
$ |
42,527 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
ALLL / total outstanding loans |
|
|
1.10 |
% |
|
0.34 |
% |
|
0.34 |
% |
|
Net charge-offs / total average loans |
|
|
0.16 |
% |
|
0.15 |
% |
|
0.15 |
% |
|
Provision for loan losses/ total average loans |
|
|
1.80 |
% |
|
0.10 |
% |
|
0.15 |
% |
|
|
` |
|
|
|
|
|
|
|
|
|
|
Nonperforming Assets(6) |
|
|
|
|
|
|
|
|
|
|
|
Construction and land development |
|
$ |
3,234 |
|
$ |
3,703 |
|
$ |
5,513 |
|
|
Commercial real estate - owner occupied |
|
|
11,250 |
|
|
6,003 |
|
|
3,307 |
|
|
Commercial real estate - non-owner occupied |
|
|
1,642 |
|
|
381 |
|
|
1,787 |
|
|
Multifamily real estate |
|
|
53 |
|
|
— |
|
|
— |
|
|
Commercial & Industrial |
|
|
3,431 |
|
|
1,735 |
|
|
721 |
|
|
Residential 1-4 Family - Commercial |
|
|
7,040 |
|
|
4,301 |
|
|
4,244 |
|
|
Residential 1-4 Family - Consumer |
|
|
13,088 |
|
|
9,292 |
|
|
7,119 |
|
|
Residential 1-4 Family - Revolving |
|
|
3,547 |
|
|
2,080 |
|
|
1,395 |
|
|
Auto |
|
|
550 |
|
|
563 |
|
|
523 |
|
|
Consumer and all other |
|
|
187 |
|
|
174 |
|
|
232 |
|
|
Nonaccrual loans |
|
$ |
44,022 |
|
$ |
28,232 |
|
$ |
24,841 |
|
|
Foreclosed property |
|
|
4,444 |
|
|
4,708 |
|
|
7,353 |
|
|
Total nonperforming assets (NPAs) |
|
$ |
48,466 |
|
$ |
32,940 |
|
$ |
32,194 |
|
|
Construction and land development |
|
$ |
317 |
|
$ |
189 |
|
$ |
1,997 |
|
|
Commercial real estate - owner occupied |
|
|
1,690 |
|
|
1,062 |
|
|
2,908 |
|
|
Commercial real estate - non-owner occupied |
|
|
2,037 |
|
|
1,451 |
|
|
— |
|
|
Multifamily real estate |
|
|
377 |
|
|
474 |
|
|
— |
|
|
Commercial & Industrial |
|
|
517 |
|
|
449 |
|
|
313 |
|
|
Residential 1-4 Family - Commercial |
|
|
777 |
|
|
674 |
|
|
1,490 |
|
|
Residential 1-4 Family - Consumer |
|
|
4,407 |
|
|
4,515 |
|
|
2,476 |
|
|
Residential 1-4 Family - Revolving |
|
|
2,005 |
|
|
3,357 |
|
|
518 |
|
|
Auto |
|
|
127 |
|
|
272 |
|
|
153 |
|
|
Consumer and all other |
|
|
622 |
|
|
953 |
|
|
1,098 |
|
|
Loans ≥ 90 days and still accruing |
|
$ |
12,876 |
|
$ |
13,396 |
|
$ |
10,953 |
|
|
Total NPAs and loans ≥ 90 days |
|
$ |
61,342 |
|
$ |
46,336 |
|
$ |
43,147 |
|
|
NPAs / total outstanding loans |
|
|
0.38 |
% |
|
0.26 |
% |
|
0.27 |
% |
|
NPAs / total assets |
|
|
0.27 |
% |
|
0.19 |
% |
|
0.19 |
% |
|
ALLL / nonaccrual loans |
|
|
320.39 |
% |
|
149.81 |
% |
|
164.35 |
% |
|
ALLL/ nonperforming assets |
|
|
291.01 |
% |
|
128.40 |
% |
|
126.82 |
% |
|
Past Due Detail(6) |
|
|
|
|
|
|
|
|
|
|
|
Construction and land development |
|
$ |
2,786 |
|
$ |
4,563 |
|
$ |
1,019 |
|
|
Commercial real estate - owner occupied |
|
|
10,779 |
|
|
3,482 |
|
|
4,052 |
|
|
Commercial real estate - non-owner occupied |
|
|
2,087 |
|
|
457 |
|
|
760 |
|
|
Multifamily real estate |
|
|
623 |
|
|
223 |
|
|
596 |
|
|
Commercial & Industrial |
|
|
4,893 |
|
|
8,698 |
|
|
2,565 |
|
|
Residential 1-4 Family - Commercial |
|
|
4,145 |
|
|
1,479 |
|
|
4,059 |
|
|
Residential 1-4 Family - Consumer |
|
|
15,667 |
|
|
16,244 |
|
|
5,889 |
|
|
Residential 1-4 Family - Revolving |
|
|
4,308 |
|
|
10,190 |
|
|
5,020 |
|
|
Auto |
|
|
1,967 |
|
|
2,525 |
|
|
2,152 |
|
|
Consumer and all other |
|
|
1,613 |
|
|
2,592 |
|
|
1,963 |
|
|
Loans 30-59 days past due |
|
$ |
48,868 |
|
$ |
50,453 |
|
$ |
28,075 |
|
|
|
|
As of & For Three Months Ended |
|
|||||||
|
|
|
03/31/20 |
|
12/31/19 |
|
03/31/19 |
|
|||
|
Past Due Detail cont'd(6) |
|
(unaudited) |
|
(unaudited) |
|
(unaudited) |
|
|||
|
Construction and land development |
|
$ |
316 |
|
$ |
482 |
|
$ |
526 |
|
|
Commercial real estate - owner occupied |
|
|
1,444 |
|
|
2,184 |
|
|
480 |
|
|
Commercial real estate - non-owner occupied |
|
|
2,765 |
|
|
— |
|
|
4,129 |
|
|
Multifamily real estate |
|
|
1,994 |
|
|
— |
|
|
— |
|
|
Commercial & Industrial |
|
|
1,218 |
|
|
1,598 |
|
|
438 |
|
|
Residential 1-4 Family - Commercial |
|
|
1,066 |
|
|
2,207 |
|
|
1,365 |
|
|
Residential 1-4 Family - Consumer |
|
|
570 |
|
|
3,072 |
|
|
2,196 |
|
|
Residential 1-4 Family - Revolving |
|
|
1,286 |
|
|
1,784 |
|
|
1,753 |
|
|
Auto |
|
|
311 |
|
|
236 |
|
|
297 |
|
|
Consumer and all other |
|
|
2,362 |
|
|
1,233 |
|
|
1,197 |
|
|
Loans 60-89 days past due |
|
$ |
13,332 |
|
$ |
12,796 |
|
$ |
12,381 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Troubled Debt Restructurings |
|
|
|
|
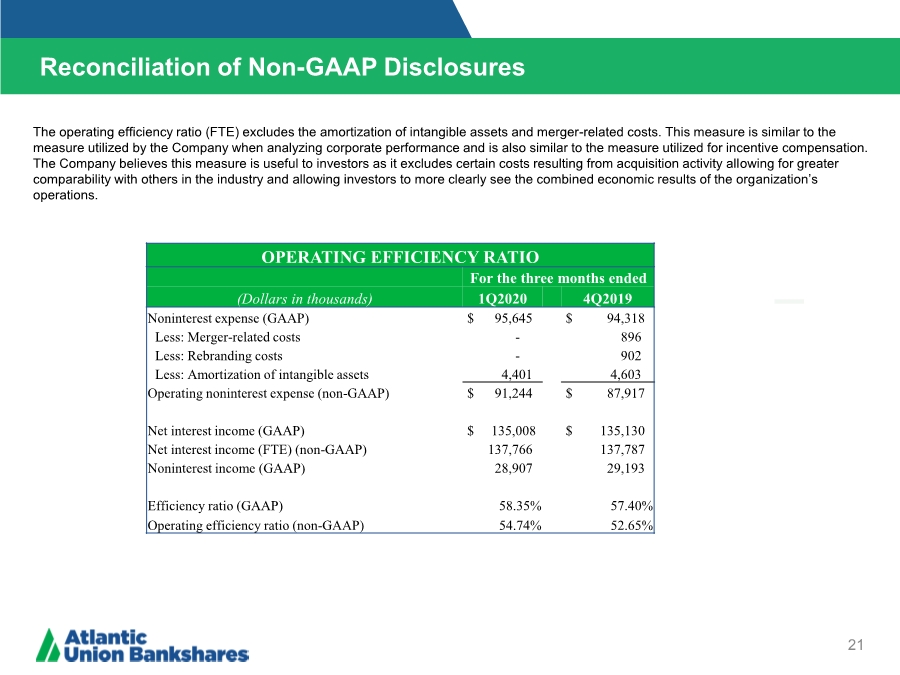
|
|
|
|
|
|
|
Performing |
|
$ |
14,865 |
|
$ |
15,686 |
|
$ |
20,809 |
|
|
Nonperforming |
|
|
5,491 |
|
|
3,810 |
|
|
4,682 |
|
|
Total troubled debt restructurings |
|
$ |
20,356 |
|
$ |
19,496 |
|
$ |
25,491 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Alternative Performance Measures (non-GAAP) |
|
|
|
|
|
|
|
|
|
|
|
Net interest income (FTE) |
|
|
|
|
|
|
|
|
|
|
|
Net interest income (GAAP) |
|
$ |
135,008 |
|
$ |
135,130 |
|
$ |
127,547 |
|
|
FTE adjustment |
|
|
2,758 |
|
|
2,657 |
|
|
2,748 |
|
|
Net interest income (FTE) (non-GAAP) (1) |
|
$ |
137,766 |
|
$ |
137,787 |
|
$ |
130,295 |
|
|
Noninterest income (GAAP) |
|
|
28,907 |
|
|
29,193 |
|
|
24,938 |
|
|
Total revenue (FTE) (non-GAAP) (1) |
|
$ |
166,673 |
|
$ |
166,980 |
|
$ |
155,233 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Average earning assets |
|
$ |
15,563,670 |
|
$ |
15,418,605 |
|
$ |
13,891,248 |
|
|
Net interest margin |
|
|
3.49 |
% |
|
3.48 |
% |
|
3.72 |
% |
|
Net interest margin (FTE) (1) |
|
|
3.56 |
% |
|
3.55 |
% |
|
3.80 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
Tangible Assets |
|
|
|
|
|
|
|
|
|
|
|
Ending assets (GAAP) |
|
$ |
17,847,376 |
|
$ |
17,562,990 |
|
$ |
16,897,655 |
|
|
Less: Ending goodwill |
|
|
935,560 |
|
|
935,560 |
|
|
927,760 |
|
|
Less: Ending amortizable intangibles |
|
|
69,298 |
|
|
73,669 |
|
|
88,553 |
|
|
Ending tangible assets (non-GAAP) |
|
$ |
16,842,518 |
|
$ |
16,553,761 |
|
$ |
15,881,342 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Tangible Common Equity (2) |
|
|
|
|
|
|
|
|
|
|
|
Ending equity (GAAP) |
|
$ |
2,425,450 |
|
$ |
2,513,102 |
|
$ |
2,459,465 |
|
|
Less: Ending goodwill |
|
|
935,560 |
|
|
935,560 |
|
|
927,760 |
|
|
Less: Ending amortizable intangibles |
|
|
69,298 |
|
|
73,669 |
|
|
88,553 |
|
|
Ending tangible common equity (non-GAAP) |
|
$ |
1,420,592 |
|
$ |
1,503,873 |
|
$ |
1,443,152 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Average equity (GAAP) |
|
$ |
2,485,646 |
|
$ |
2,515,303 |
|
$ |
2,268,395 |
|
|
Less: Average goodwill |
|
|
935,560 |
|
|
930,457 |
|
|
858,658 |
|
|
Less: Average amortizable intangibles |
|
|
71,283 |
|
|
75,845 |
|
|
75,686 |
|
|
Average tangible common equity (non-GAAP) |
|
$ |
1,478,803 |
|
$ |
1,509,001 |
|
$ |
1,334,051 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Operating Measures (4) |
|
|
|
|
|
|
|
|
|
|
|
Net income (GAAP) |
|
$ |
7,089 |
|
$ |
55,836 |
|
$ |
35,631 |
|
|
Plus: Merger and rebranding-related costs, net of tax |
|
|
— |
|
|
1,422 |
|
|
14,888 |
|
|
Net operating earnings (non-GAAP) |
|
$ |
7,089 |
|
$ |
57,258 |
|
$ |
50,519 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Noninterest expense (GAAP) |
|
$ |
95,645 |
|
$ |
94,318 |
|
$ |
106,728 |
|
|
Less: Merger Related Costs |
|
|
— |
|
|
896 |
|
|
18,122 |
|
|
Less: Rebranding Costs |
|
|
— |
|
|
902 |
|
|
407 |
|
|
Less: Amortization of intangible assets |
|
|
4,401 |
|
|
4,603 |
|
|
4,218 |
|
|
Operating noninterest expense (non-GAAP) |
|
$ |
91,244 |
|
$ |
87,917 |
|
$ |
83,981 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Net interest income (FTE) (non-GAAP) (1) |
|
$ |
137,766 |
|
$ |
137,787 |
|
$ |
130,295 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Noninterest income (GAAP) |
|
|
28,907 |
|
|
29,193 |
|
|
24,938 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Efficiency ratio |
|
|
58.35 |
% |
|
57.40 |
% |
|
69.99 |
% |
|
Operating efficiency ratio (FTE)(7) |
|
|
54.74 |
% |
|
52.65 |
% |
|
54.10 |
% |
|
|
|
As of & For Three Months Ended |
|
|||||||
|
|
|
03/31/20 |
|
12/31/19 |
|
03/31/19 |
|
|||
|
|
|
(unaudited) |
|
(unaudited) |
|
(unaudited) |
|
|||
|
Operating ROTCE (2)(3) |
|
|
|
|
|
|
|
|
|
|
|
Operating Net Income (non-GAAP) |
|
$ |
7,089 |
|
$ |
57,258 |
|
$ |
50,519 |
|
|
Plus: Amortization of intangibles, tax effected |
|
|
3,477 |
|
|
3,636 |
|
|
3,332 |
|
|
Net Income before amortization of intangibles (non-GAAP) |
|
$ |
10,566 |
|
$ |
60,894 |
|
$ |
53,851 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Average tangible common equity (non-GAAP) |
|
$ |
1,478,803 |
|
$ |
1,509,001 |
|
$ |
1,334,051 |
|
|
Operating return on average tangible common equity (non-GAAP) |
|
|
2.87 |
% |
|
16.01 |
% |
|
16.37 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
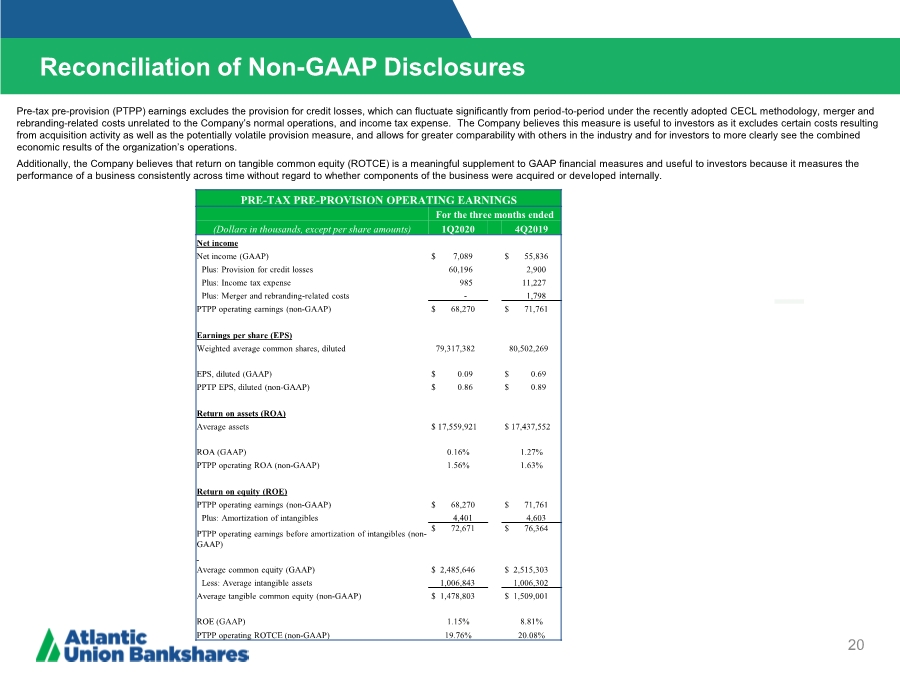
Pre-tax pre-provision earnings (8) |
|
|
|
|
|
|
|
|
|
|
|
Net income (GAAP) |
|
$ |
7,089 |
|
$ |
55,836 |
|
$ |
35,631 |
|
|
Plus: Provision for credit losses |
|
|
60,196 |
|
|
2,900 |
|
|
3,792 |
|
|
Plus: Income tax expense |
|
|
985 |
|
|
11,227 |
|
|
6,249 |
|
|
Plus: Merger and rebranding-related costs |
|
|
— |
|
|
1,798 |
|
|
18,529 |
|
|
Pre-tax pre-provision earnings (non-GAAP) |
|
$ |
68,270 |
|
$ |
71,761 |
|
$ |
64,201 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Mortgage Origination Volume |
|
|
|
|
|
|
|
|
|
|
|
Refinance Volume |
|
$ |
68,382 |
|
$ |
50,555 |
|
$ |
11,969 |
|
|
Construction Volume |
|
|
7,837 |
|
|
14,571 |
|
|
— |
|
|
Purchase Volume |
|
|
64,492 |
|
|
63,836 |
|
|
32,107 |
|
|
Total Mortgage loan originations |
|
$ |
140,711 |
|
$ |
128,962 |
|
$ |
44,076 |
|
|
% of originations that are refinances |
|
|
48.6 |
% |
|
39.2 |
% |
|
27.2 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
Wealth |
|
|
|
|
|
|
|
|
|
|
|
Assets under management ("AUM") |
|
$ |
4,783,228 |
|
$ |
5,650,757 |
|
$ |
5,425,804 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Other Data |
|
|
|
|
|
|
|
|
|
|
|
End of period full-time employees |
|
|
2,011 |
|
|
1,989 |
|
|
1,947 |
|
|
Number of full-service branches |
|
|
149 |
|
|
149 |
|
|
155 |
|
|
Number of full automatic transaction machines ("ATMs") |
|
|
169 |
|
|
169 |
|
|
197 |
|
|
(1) |
These are non-GAAP financial measures. Net interest income (FTE) and total revenue (FTE), which are used in computing net interest margin (FTE) and operating efficiency ratio (FTE), respectively, provide valuable additional insight into the net interest margin and the efficiency ratio by adjusting for differences in tax treatment of interest income sources. The entire FTE adjustment is attributable to interest income on earning assets, which is used in computing yield on earning assets. Interest expense and the related cost of interest-bearing liabilities and cost of funds ratios are not affected by the FTE components. |
|
(2) |
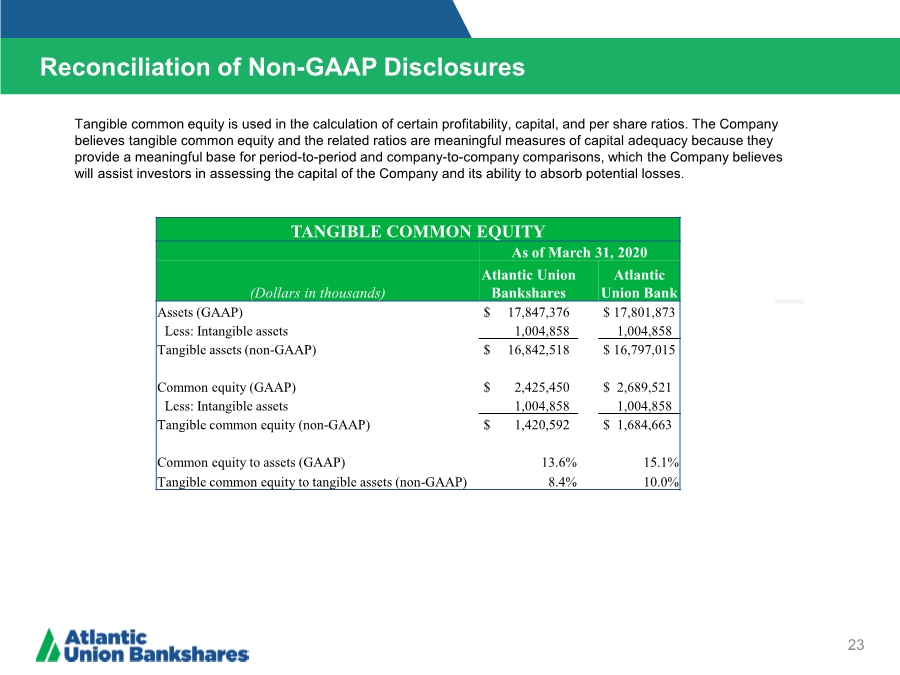
These are non-GAAP financial measures. Tangible common equity is used in the calculation of certain profitability, capital, and per share ratios. The Company believes tangible common equity and the related ratios are meaningful measures of capital adequacy because they provide a meaningful base for period-to-period and company-to-company comparisons, which the Company believes will assist investors in assessing the capital of the Company and its ability to absorb potential losses. |
|
(3) |
These are non-GAAP financial measures. The Company believes that ROTCE is a meaningful supplement to GAAP financial measures and useful to investors because it measures the performance of a business consistently across time without regard to whether components of the business were acquired or developed internally. |
|
(4) |
These are non-GAAP financial measures. Operating measures exclude merger and rebranding-related costs unrelated to the Company’s normal operations. The Company believes these measures are useful to investors as they exclude certain costs resulting from acquisition activity and allow investors to more clearly see the combined economic results of the organization’s operations. |
|
(5) |
All ratios at March 31, 2020 are estimates and subject to change pending the Company’s filing of its FR Y9‑C. All other periods are presented as filed. |
|
(6) |
Amounts are not directly comparable due to the Company’s adoption of CECL on January 1, 2020. Prior to January 1, 2020, nonaccrual and past due loan information excluded PCI-related loan balances. |
|
(7) |
The operating efficiency ratio (FTE) excludes the amortization of intangible assets and merger-related costs. This measure is similar to the measure utilized by the Company when analyzing corporate performance and is also similar to the measure utilized for incentive compensation. The Company believes this measure is useful to investors as it excludes certain costs resulting from acquisition activity allowing for greater comparability with others in the industry and allowing investors to more clearly see the combined economic results of the organization’s operations. |
|
(8) |
This is a non-GAAP financial measure. Pre-tax pre-provision earnings excludes the provision for credit losses, which can fluctuate significantly from period-to-period under the recently adopted CECL methodology, merger and rebranding-related costs unrelated to the Company’s normal operations, and income tax expense. The Company believes this measure is useful to investors as it excludes certain costs resulting from acquisition activity as well as the potentially volatile provision measure, and allows for greater comparability with others in the industry and for investors to more clearly see the combined economic results of the organization’s operations. |
ATLANTIC UNION BANKSHARES CORPORATION AND SUBSIDIARIES
CONSOLIDATED BALANCE SHEETS
(Dollars in thousands, except share data)
|
|
March 31, |
|
December 31, |
|
March 31, |
|||
|
|
2020 |
|
2019 |
|
2019 |
|||
|
ASSETS |
|
(unaudited) |
|
|
(audited) |
|
|
(unaudited) |
|
Cash and cash equivalents: |
|
|
|
|
|
|
|
|
|
Cash and due from banks |
$ |
197,521 |
|
$ |
163,050 |
|
$ |
165,041 |
|
Interest-bearing deposits in other banks |
|
292,154 |
|
|
234,810 |
|
|
116,900 |
|
Federal funds sold |
|
15,284 |
|
|
38,172 |
|
|
1,652 |
|
Total cash and cash equivalents |
|
504,959 |
|
|
436,032 |
|
|
283,593 |
|
Securities available for sale, at fair value |
|
1,972,903 |
|
|
1,945,445 |
|
|
2,109,062 |
|
Securities held to maturity, at carrying value |
|
552,176 |
|
|
555,144 |
|
|
559,380 |
|
Restricted stock, at cost |
|
130,227 |
|
|
130,848 |
|
|
135,911 |
|
Loans held for sale, at fair value |
|
76,690 |
|
|
55,405 |
|
|
28,712 |
|
Loans held for investment, net of deferred fees and costs |
|
12,768,841 |
|
|
12,610,936 |
|
|
11,952,310 |
|
Less allowance for loan and lease losses |
|
141,043 |
|
|
42,294 |
|
|
40,827 |
|
Total loans held for investment, net |
|
12,627,798 |
|
|
12,568,642 |
|
|
11,911,483 |
|
Premises and equipment, net |
|
161,139 |
|
|
161,073 |
|
|
172,522 |
|
Goodwill |
|
935,560 |
|
|
935,560 |
|
|
927,760 |
|
Amortizable intangibles, net |
|
69,298 |
|
|
73,669 |
|
|
88,553 |
|
Bank owned life insurance |
|
324,980 |
|
|
322,917 |
|
|
317,990 |
|
Other assets |
|
491,646 |
|
|
377,587 |
|
|
361,580 |
|
Assets of discontinued operations |
|
— |
|
|
668 |
|
|
1,109 |
|
Total assets |
$ |
17,847,376 |
|
$ |
17,562,990 |
|
$ |
16,897,655 |
|
LIABILITIES |
|
|
|
|
|
|
|
|
|
Noninterest-bearing demand deposits |
$ |
3,067,573 |
|
$ |
2,970,139 |
|
$ |
2,964,113 |
|
Interest-bearing deposits |
|
10,485,462 |
|
|
10,334,842 |
|
|
9,525,217 |
|
Total deposits |
|
13,553,035 |
|
|
13,304,981 |
|
|
12,489,330 |
|
Securities sold under agreements to repurchase |
|
56,781 |
|
|
66,053 |
|
|
73,774 |
|
Other short-term borrowings |
|
380,000 |
|
|
370,200 |
|
|
939,700 |
|
Long-term borrowings |
|
1,077,683 |
|
|
1,077,495 |
|
|
739,629 |
|
Other liabilities |
|
354,427 |
|
|
230,519 |
|
|
194,565 |
|
Liabilities of discontinued operations |
|
— |
|
|
640 |
|
|
1,192 |
|
Total liabilities |
|
15,421,926 |
|
|
15,049,888 |
|
|
14,438,190 |
|
Commitments and contingencies |
|
|
|
|
|
|
|
|
|
STOCKHOLDERS' EQUITY |
|
|
|
|
|
|
|
|
|
Common stock, $1.33 par value, shares authorized of 200,000,000 at both March 31, 2020 and December 31, 2019, and 100,000,000 at March 31, 2019, respectively; shares issued and outstanding of 78,710,448 at March 31, 2020, 80,001,185 at December 31, 2019, and 82,037,354 at March 31, 2019. |
|
104,086 |
|
|
105,827 |
|
|
108,475 |
|
Additional paid-in capital |
|
1,743,429 |
|
|
1,790,305 |
|
|
1,859,588 |
|
Retained earnings |
|
529,606 |
|
|
581,395 |
|
|
483,005 |
|
Accumulated other comprehensive income (loss) |
|
48,329 |
|
|
35,575 |
|
|
8,397 |
|
Total stockholders' equity |
|
2,425,450 |
|
|
2,513,102 |
|
|
2,459,465 |
|
Total liabilities and stockholders' equity |
$ |
17,847,376 |
|
$ |
17,562,990 |
|
$ |
16,897,655 |
ATLANTIC UNION BANKSHARES CORPORATION AND SUBSIDIARIES
CONSOLIDATED STATEMENTS OF INCOME
(Dollars in thousands, except share data)
|
|
Three Months Ended |
|||||||
|
|
March 31, |
|
December 31, |
|
March 31, |
|||
|
|
2020 |
|
2019 |
|
2019 |
|||
|
|
(Unaudited) |
|
(Unaudited) |
|
(Unaudited) |
|||
|
Interest and dividend income: |
|
|
|
|
|
|
|
|
|
Interest and fees on loans |
$ |
151,127 |
|
$ |
152,513 |
|
$ |
144,115 |
|
Interest on deposits in other banks |
|
862 |
|
|
1,686 |
|
|
473 |
|
Interest and dividends on securities: |
|
|
|
|
|
|
|
|
|
Taxable |
|
11,627 |
|
|
12,378 |
|
|
13,081 |
|
Nontaxable |
|
7,709 |
|
|
7,634 |
|
|
7,983 |
|
Total interest and dividend income |
|
171,325 |
|
|
174,211 |
|
|
165,652 |
|
Interest expense: |
|
|
|
|
|
|
|
|
|
Interest on deposits |
|
28,513 |
|
|
30,884 |
|
|
24,430 |
|
Interest on short-term borrowings |
|
1,340 |
|
|
1,166 |
|
|
6,551 |
|
Interest on long-term borrowings |
|
6,464 |
|
|
7,031 |
|
|
7,124 |
|
Total interest expense |
|
36,317 |
|
|
39,081 |
|
|
38,105 |
|
Net interest income |
|
135,008 |
|
|
135,130 |
|
|
127,547 |
|
Provision for credit losses |
|
60,196 |
|
|
2,900 |
|
|
3,792 |
|
Net interest income after provision for credit losses |
|
74,812 |
|
|
132,230 |
|
|
123,755 |
|
Noninterest income: |
|
|
|
|
|
|
|
|
|
Service charges on deposit accounts |
|
7,578 |
|
|
7,871 |
|
|
7,158 |
|
Other service charges, commissions and fees |
|
1,624 |
|
|
1,544 |
|
|
1,664 |
|
Interchange fees |
|
1,625 |
|
|
1,854 |
|
|
5,045 |
|
Fiduciary and asset management fees |
|
5,984 |
|
|
6,531 |
|
|
5,054 |
|
Mortgage banking income |
|
2,022 |
|
|
2,689 |
|
|
1,454 |
|
Gains on securities transactions |
|
1,936 |
|
|
369 |
|
|
151 |
|
Bank owned life insurance income |
|
2,049 |
|
|
2,119 |
|
|
2,055 |
|
Loan-related interest rate swap fees |
|
3,948 |
|
|
3,470 |
|
|
1,460 |
|
Other operating income |
|
2,141 |
|
|
2,746 |
|
|
897 |
|
Total noninterest income |
|
28,907 |
|
|
29,193 |
|
|
24,938 |
|
Noninterest expenses: |
|
|
|
|
|
|
|
|
|
Salaries and benefits |
|
50,117 |
|
|
47,233 |
|
|
48,007 |
|
Occupancy expenses |
|
7,133 |
|
|
7,366 |
|
|
7,399 |
|
Furniture and equipment expenses |
|
3,741 |
|
|
3,559 |
|
|
3,396 |
|
Printing, postage, and supplies |
|
1,290 |
|
|
1,293 |
|
|
1,242 |
|
Technology and data processing |
|
6,169 |
|
|
6,483 |
|
|
5,676 |
|
Professional services |
|
3,307 |
|
|
3,636 |
|
|
2,958 |
|
Marketing and advertising expense |
|
2,739 |
|
|
3,675 |
|
|
2,383 |
|
FDIC assessment premiums and other insurance |
|
2,861 |
|
|
1,254 |
|
|
2,639 |
|
Other taxes |
|
4,120 |
|
|
3,970 |
|
|
3,764 |
|
Loan-related expenses |
|
2,697 |
|
|
2,793 |
|
|
2,289 |
|
OREO and credit-related expenses |
|
688 |
|
|
1,547 |
|
|
684 |
|
Amortization of intangible assets |
|
4,401 |
|
|
4,603 |
|
|
4,218 |
|
Training and other personnel costs |
|
1,571 |
|
|
2,136 |
|
|
1,144 |
|
Merger-related costs |
|
— |
|
|
896 |
|
|
18,122 |
|
Rebranding expense |
|
— |
|
|
902 |
|
|
407 |
|
Other expenses |
|
4,811 |
|
|
2,972 |
|
|
2,400 |
|
Total noninterest expenses |
|
95,645 |
|
|
94,318 |
|
|
106,728 |
|
Income from continuing operations before income taxes |
|
8,074 |
|
|
67,105 |
|
|
41,965 |
|
Income tax expense |
|
985 |
|
|
11,227 |
|
|
6,249 |
|
Income from continuing operations |
$ |
7,089 |
|
$ |
55,878 |
|
$ |
35,716 |
|
Discontinued operations: |
|
|
|
|
|
|
|
|
|
Income (loss) from operations of discontinued mortgage segment |
$ |
— |
|
$ |
(56) |
|
$ |
(115) |
|
Income tax expense (benefit) |
|
— |
|
|
(14) |
|
|
(30) |
|
Income (loss) on discontinued operations |
|
— |
|
|
(42) |
|
|
(85) |
|
Net income |
|
7,089 |
|
|
55,836 |
|
|
35,631 |
|
Basic earnings per common share |
$ |
0.09 |
|
$ |
0.69 |
|
$ |
0.47 |
|
Diluted earnings per common share |
$ |
0.09 |
|
$ |
0.69 |
|
$ |
0.47 |
AVERAGE BALANCES, INCOME AND EXPENSES, YIELDS AND RATES (TAXABLE EQUIVALENT BASIS)
|
|
For the Quarter Ended |
||||||||||||||
|
|
March 31, 2020 |
|
December 31, 2019 |
||||||||||||
|
|
Average |
|
Interest |
|
Yield / |
|
Average |
|
Interest |
|
Yield / |
||||
|
|
(unaudited) |
|
|
(unaudited) |
|||||||||||
|
Assets: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Securities: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Taxable |
$ |
1,664,449 |
|
$ |
11,627 |
|
2.81% |
|
$ |
1,666,082 |
|
$ |
12,378 |
|
2.95% |
|
Tax-exempt |
|
956,988 |
|
|
9,759 |
|
4.10% |
|
|
942,860 |
|
|
9,663 |
|
4.07% |
|
Total securities |
|
2,621,437 |
|
|
21,386 |
|
3.28% |
|
|
2,608,942 |
|
|
22,041 |
|
3.35% |
|
Loans, net (3) (4) |
|
12,593,923 |
|
|
151,313 |
|
4.83% |
|
|
12,327,692 |
|
|
152,345 |
|
4.90% |
|
Other earning assets |
|
348,310 |
|
|
1,384 |
|
1.60% |
|
|
481,971 |
|
|
2,482 |
|
2.04% |
|
Total earning assets |
|
15,563,670 |
|
$ |
174,083 |
|
4.50% |
|
|
15,418,605 |
|
$ |
176,868 |
|
4.55% |
|
Allowance for credit losses |
|
(90,141) |
|
|
|
|
|
|
|
(44,739) |
|
|
|
|
|
|
Total non-earning assets |
|
2,086,392 |
|
|
|
|
|
|
|
2,063,686 |
|
|
|
|
|
|
Total assets |
$ |
17,559,921 |
|
|
|
|
|
|
$ |
17,437,552 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Liabilities and Stockholders' Equity: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Interest-bearing deposits: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Transaction and money market accounts |
$ |
6,933,345 |
|
$ |
14,521 |
|
0.84% |
|
$ |
6,683,093 |
|
$ |
16,042 |
|
0.95% |
|
Regular savings |
|
732,574 |
|
|
157 |
|
0.09% |
|
|
735,527 |
|
|
190 |
|
0.10% |
|
Time deposits (5) |
|
2,755,500 |
|
|
13,835 |
|
2.02% |
|
|
2,847,366 |
|
|
14,652 |
|
2.04% |
|
Total interest-bearing deposits |
|
10,421,419 |
|
|
28,513 |
|
1.10% |
|
|
10,265,986 |
|
|
30,884 |
|
1.19% |
|
Other borrowings (6) |
|
1,442,525 |
|
|
7,804 |
|
2.18% |
|
|
1,369,035 |
|
|
8,197 |
|
2.38% |
|
Total interest-bearing liabilities |
|
11,863,944 |
|
|
36,317 |
|
1.23% |
|
|
11,635,021 |
|
$ |
39,081 |
|
1.33% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Noninterest-bearing liabilities: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Demand deposits |
|
2,925,438 |
|
|
|
|
|
|
|
3,036,969 |
|
|
|
|
|
|
Other liabilities |
|
284,893 |
|
|
|
|
|
|
|
250,259 |
|
|
|
|
|
|
Total liabilities |
|
15,074,275 |
|
|
|
|
|
|
|
14,922,249 |
|
|
|
|
|
|
Stockholders' equity |
|
2,485,646 |
|
|
|
|
|
|
|
2,515,303 |
|
|
|
|
|
|
Total liabilities and stockholders' equity |
$ |
17,559,921 |
|
|
|
|
|
|
$ |
17,437,552 |
|
|
|
|
|
|
Net interest income |
|
|
|
$ |
137,766 |
|
|
|
|
|
|
$ |
137,787 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Interest rate spread |
|
|
|
|
|
|
3.27% |
|
|
|
|
|
|
|
3.22% |
|
Cost of funds |
|
|
|
|
|
|
0.94% |
|
|
|
|
|
|
|
1.00% |
|
Net interest margin |
|
|
|
|
|
|
3.56% |
|
|
|
|
|
|
|
3.55% |
|
(1) |
Income and yields are reported on a taxable equivalent basis using the statutory federal corporate tax rate of 21%. |
|
(2) |
Rates and yields are annualized and calculated from actual, not rounded amounts in thousands, which appear above. |
|
(3) |
Nonaccrual loans are included in average loans outstanding. |
|
(4) |
Interest income on loans includes $9.5 million and $6.6 million for the three months ended March 31, 2020 and December 31, 2019, respectively, in accretion of the fair market value adjustments related to acquisitions. |
|
(5) |
Interest expense on time deposits includes $50,000 and $148,000 for the three months ended March 31, 2020 and December 31, 2019, respectively, in accretion of the fair market value adjustments related to acquisitions. |
|
(6) |
Interest expense on borrowings includes $138,000 and $123,000 for the three months ended March 31, 2020 and December 31, 2019, in amortization of the fair market value adjustments related to acquisitions. |