FOR IMMEDIATE RELEASE
PRESS RELEASE
Avidbank Holdings, Inc. Announces Financial Results for the Third Quarter of 2025
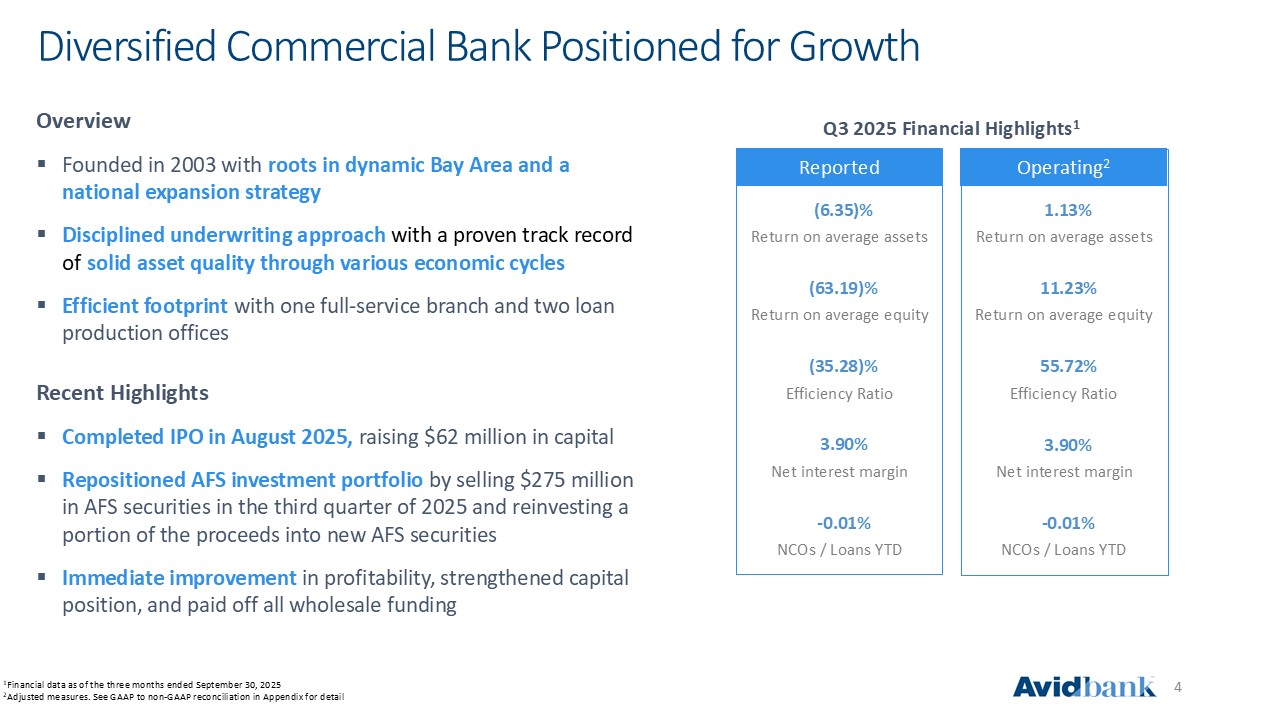
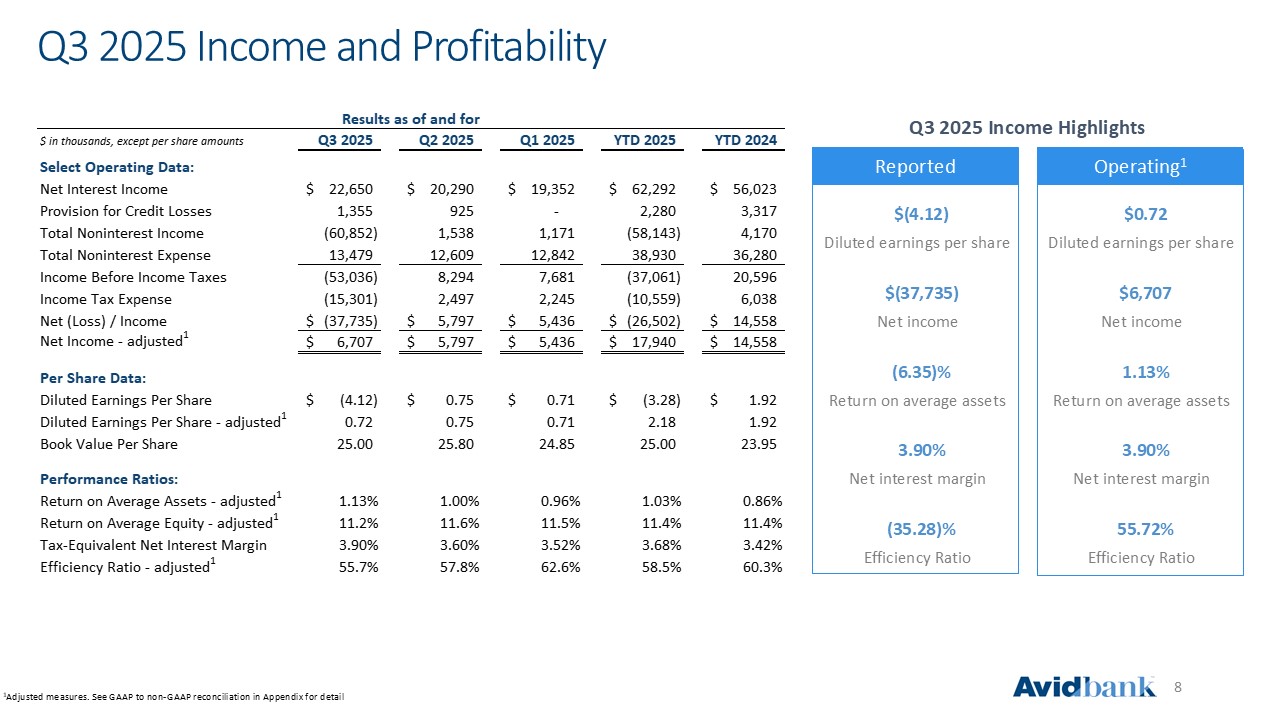
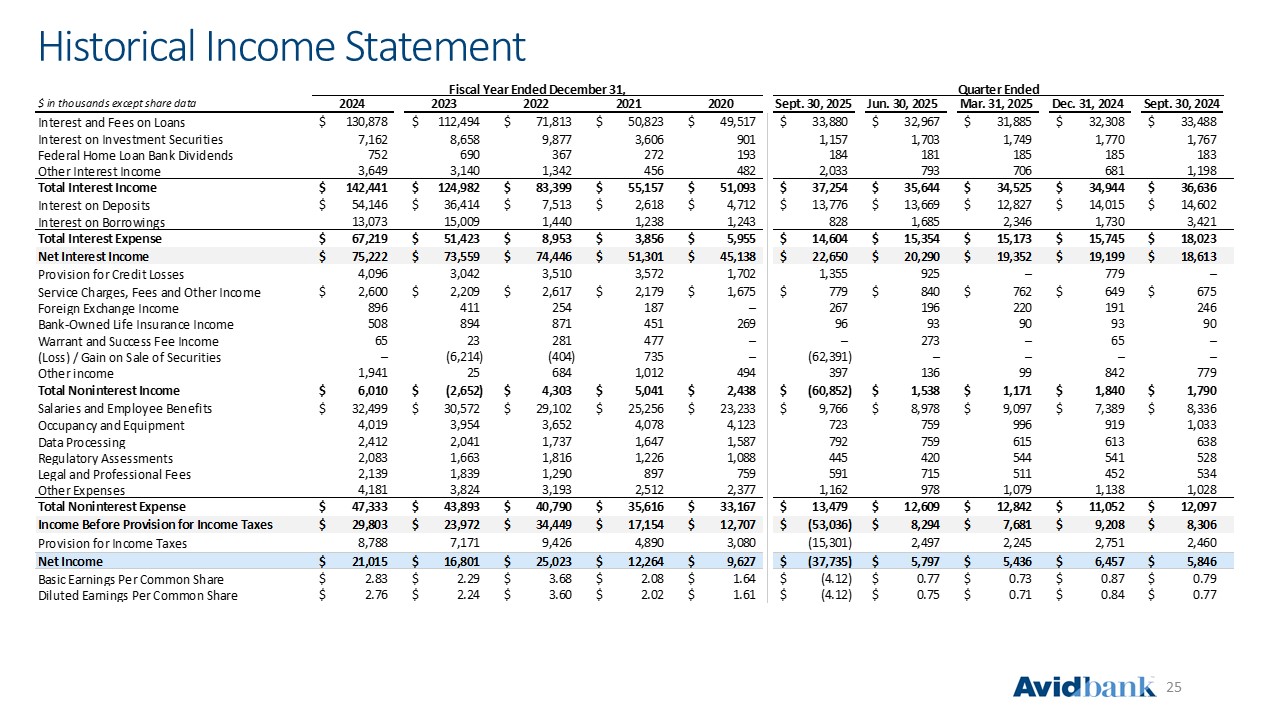
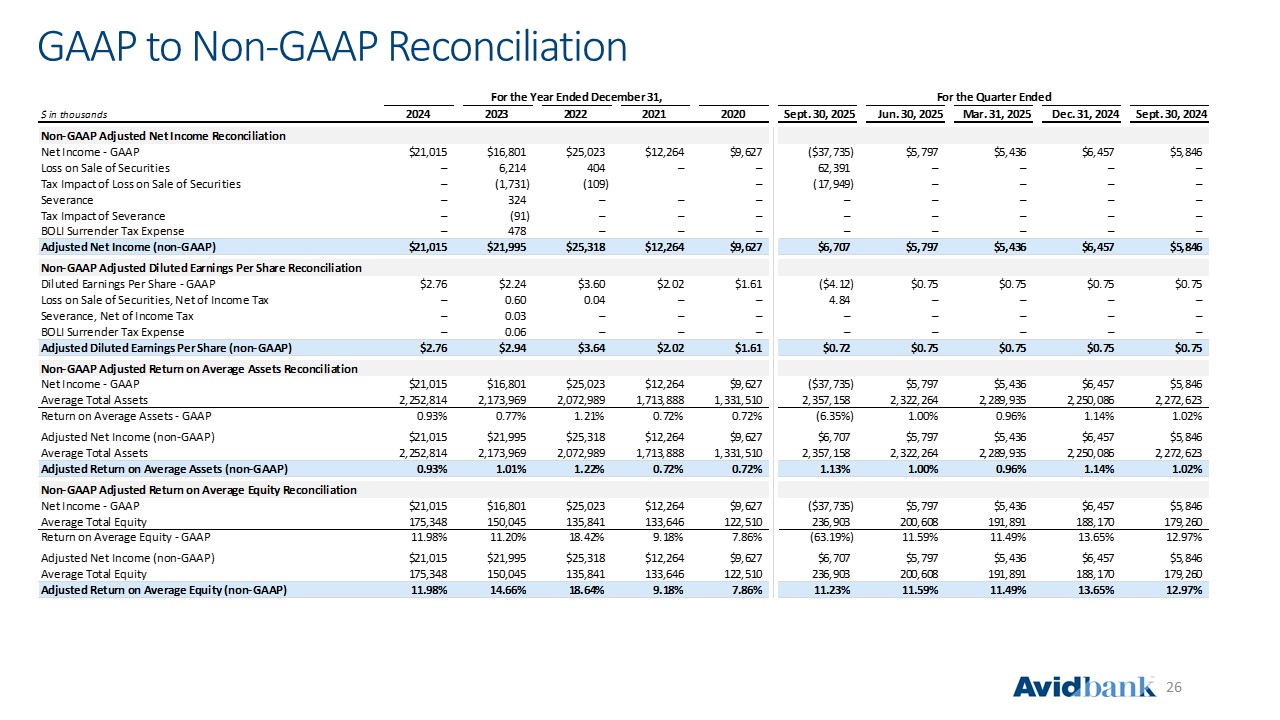
SAN JOSE, CA (ACCESS Newswire) – October 23, 2025 – Avidbank Holdings, Inc. (NASDAQ: AVBH) (the “Company” or “Avidbank Holdings”), the holding company for Avidbank, a California state-chartered bank (the “Bank”), announced a net loss for the third quarter of 2025 of $37.7 million, or ($4.12) per diluted share, compared to net income of $5.8 million, or $0.75 per diluted share, for the second quarter of 2025 and $5.8 million, or $0.77 per diluted share, for the third quarter of 2024. Results for the third quarter included a $62.4 million loss on the sale of available-for-sale securities. Excluding that item, adjusted net income(1) totaled $6.7 million, or $0.72 per adjusted diluted share(1) for the third quarter of 2025.
Significant events for the third quarter of 2025 included the following:
|
· |
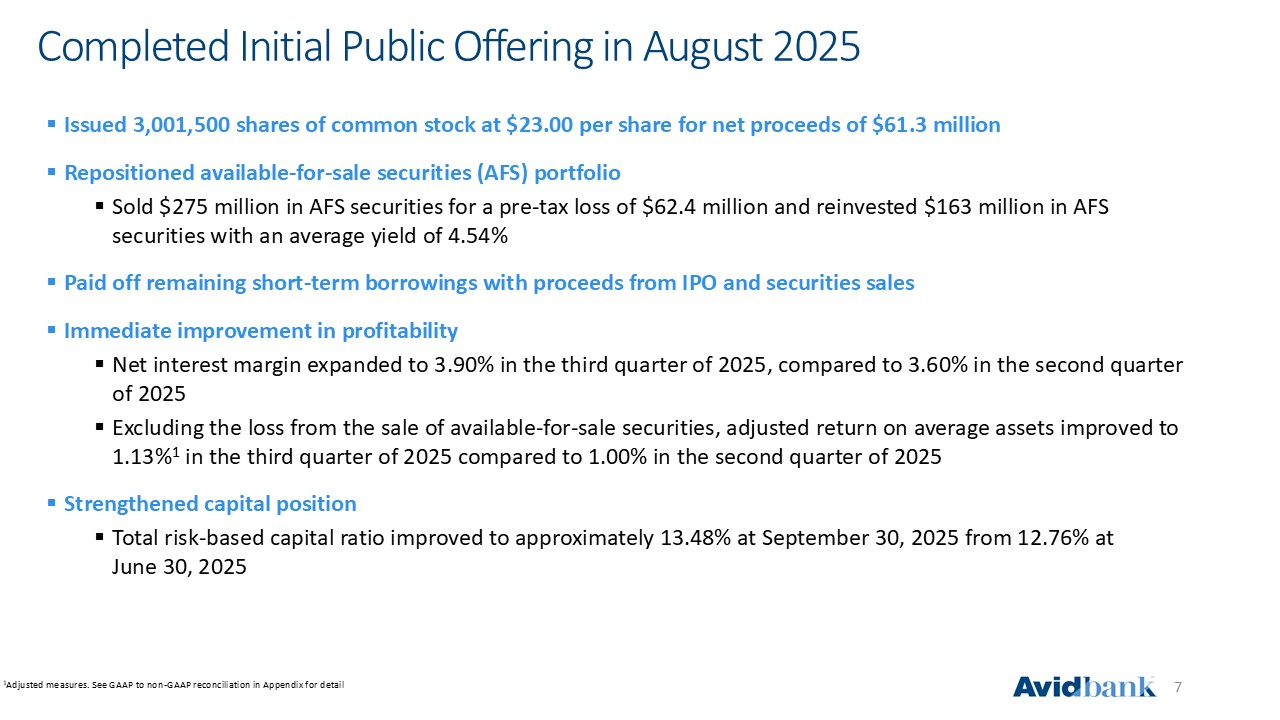
In August 2025, the Company completed an initial public offering (“IPO”) of its common stock, issuing an aggregate total of 3,001,500 shares of common stock at the public offering price of $23.00 per share. After deductions for underwriting fees and commissions and estimated offering expenses, the Company’s net proceeds from the initial public offering totaled $61.3 million. |
|
· |
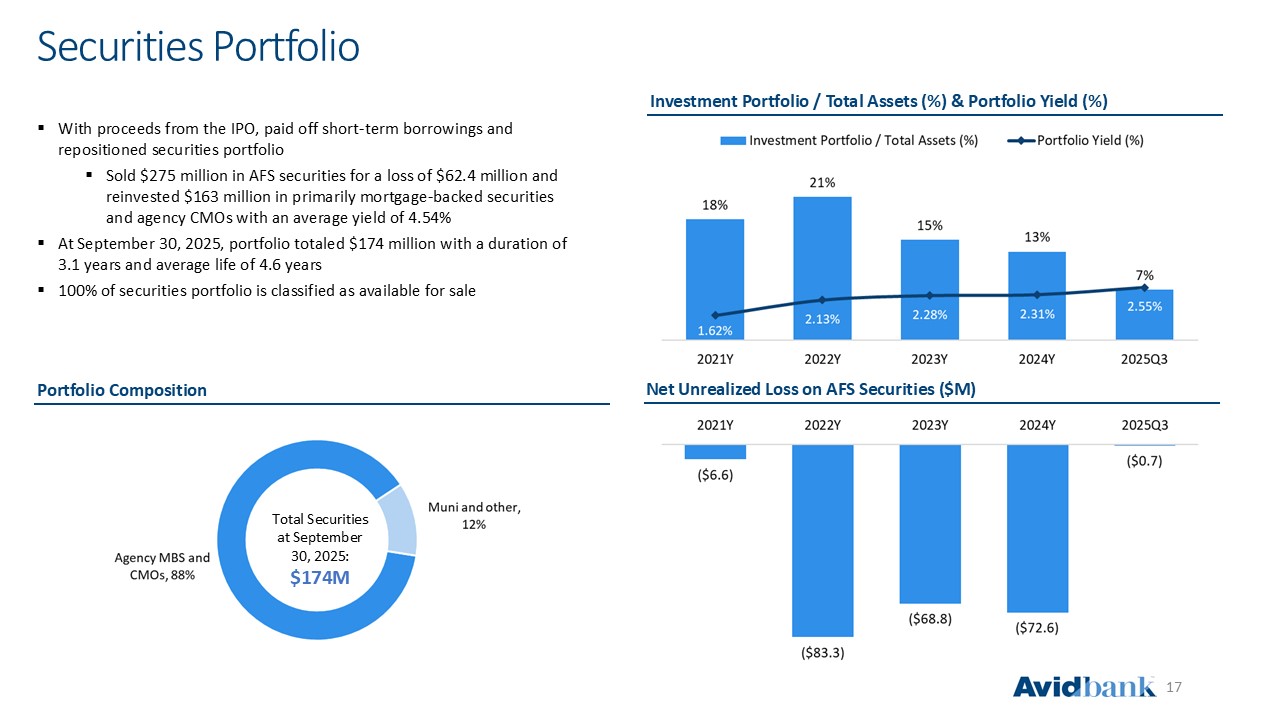
Sold $274.7 million in available-for-sale securities for a loss of $62.4 million; purchased $163.2 million in available-for-sale securities with an average purchase yield of 4.54% and a duration of 2.8 years; and paid off short-term borrowings using proceeds from the IPO and securities sales. |
Third Quarter 2025 Highlights
|
· |
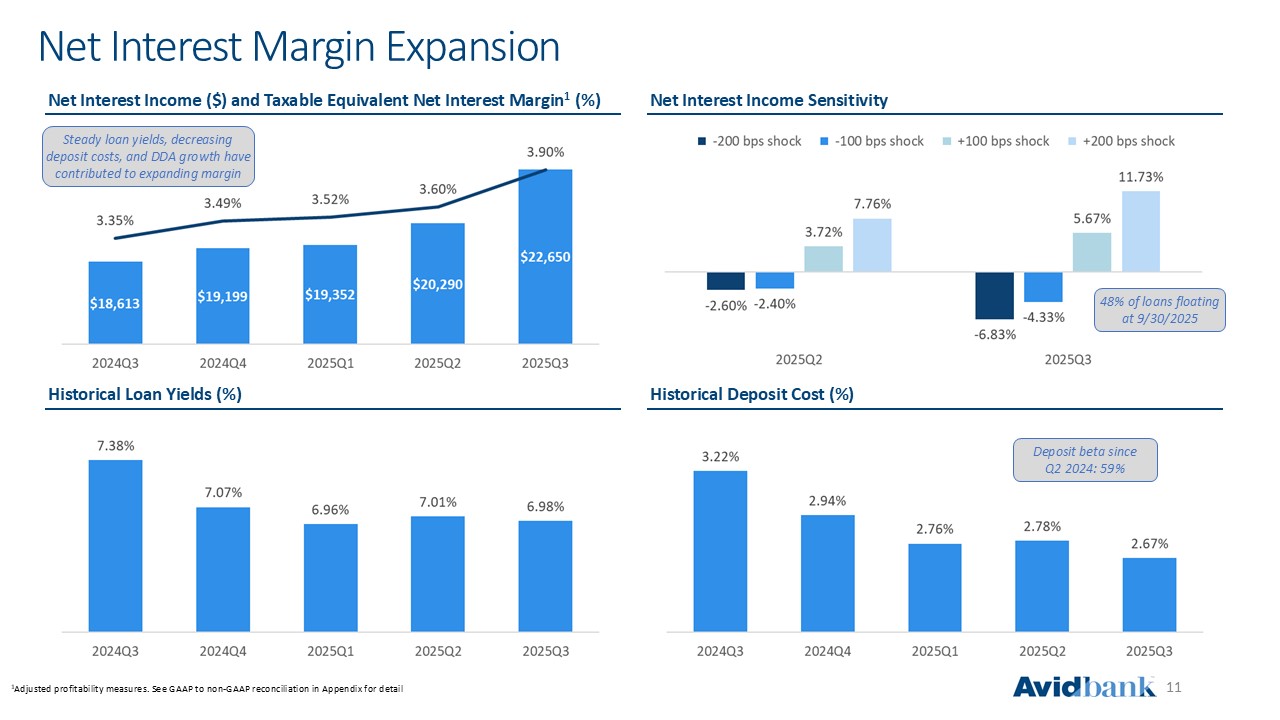
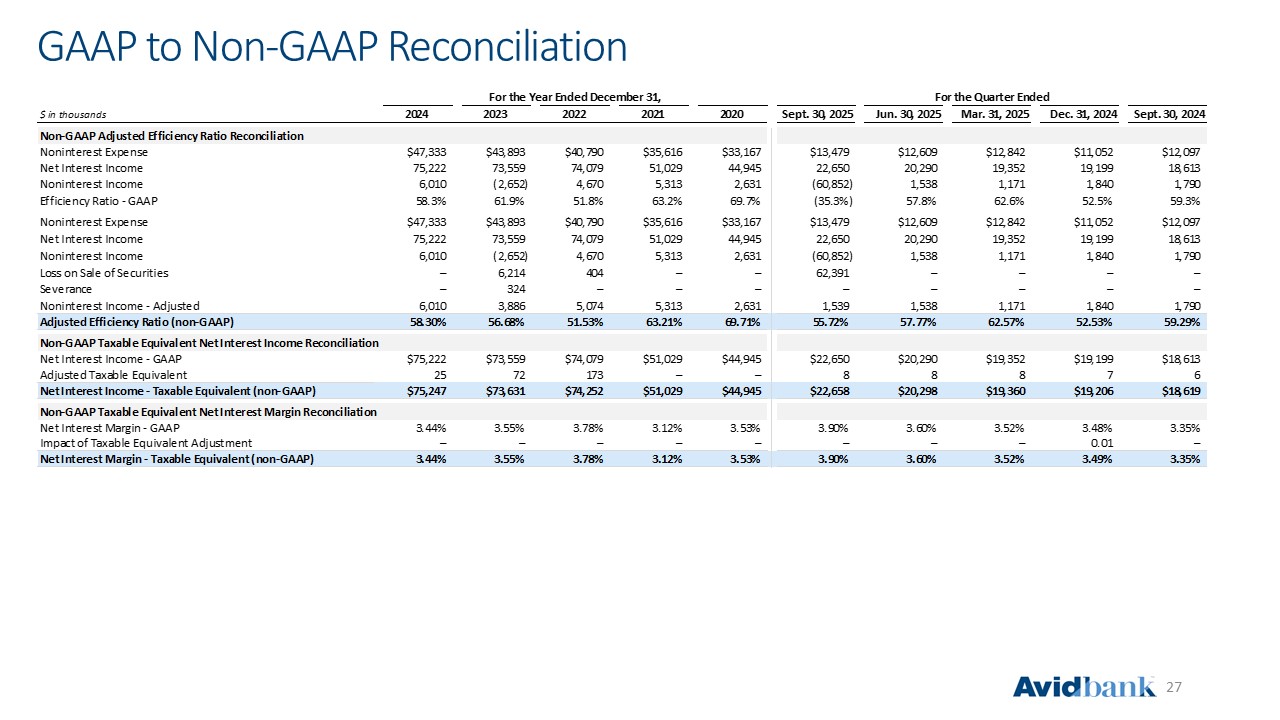
Net interest margin expanded to 3.90% in the third quarter of 2025, compared to 3.60% in the second quarter of 2025. |
|
· |
Return on average assets was (6.35%) compared to 1.00% in the second quarter of 2025 and 1.02% in the third quarter of 2024. Excluding the loss from the sale of available-for-sale securities, adjusted return on average assets(1) improved to 1.13% in the third quarter of 2025 compared to 1.00% in the prior quarter. |
|
· |
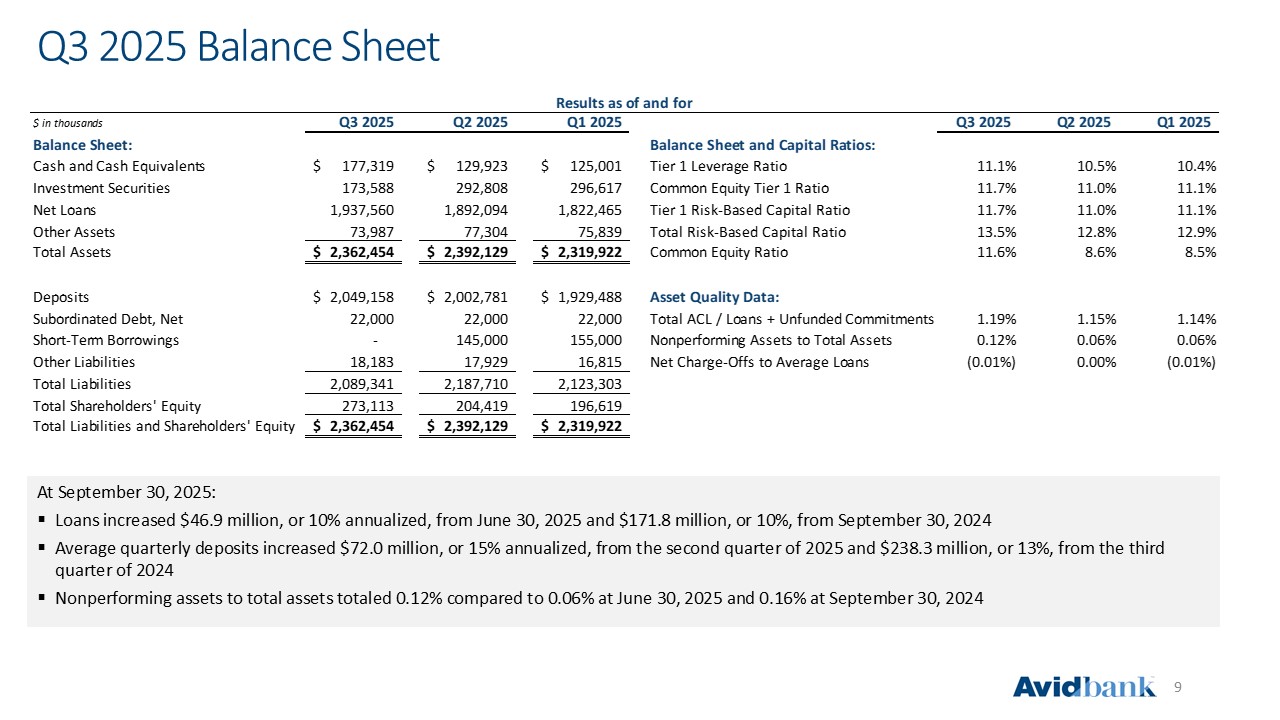
Period-end loans, net of deferred loan fees increased $46.9 million, or 10% annualized, from June 30, 2025 and $171.8 million, or 10%, from September 30, 2024. |
|
· |
Average deposits increased $72.0 million, or 15% annualized, from the second quarter of 2025 and $238.3 million, or 13%, from the third quarter of 2024. |
|
· |
The efficiency ratio was (35.28%) compared to 57.77% in the second quarter of 2025 and 59.29% in the third quarter of 2024. Excluding the loss from the sale of available-for-sale securities, the adjusted efficiency ratio(1) improved to 55.72% in the third quarter. |
|
· |
Book value per share was $25.00 at September 30, 2025, a decrease of $0.80 from June 30, 2025, and an increase of $1.05 from September 30, 2024. |
|
· |
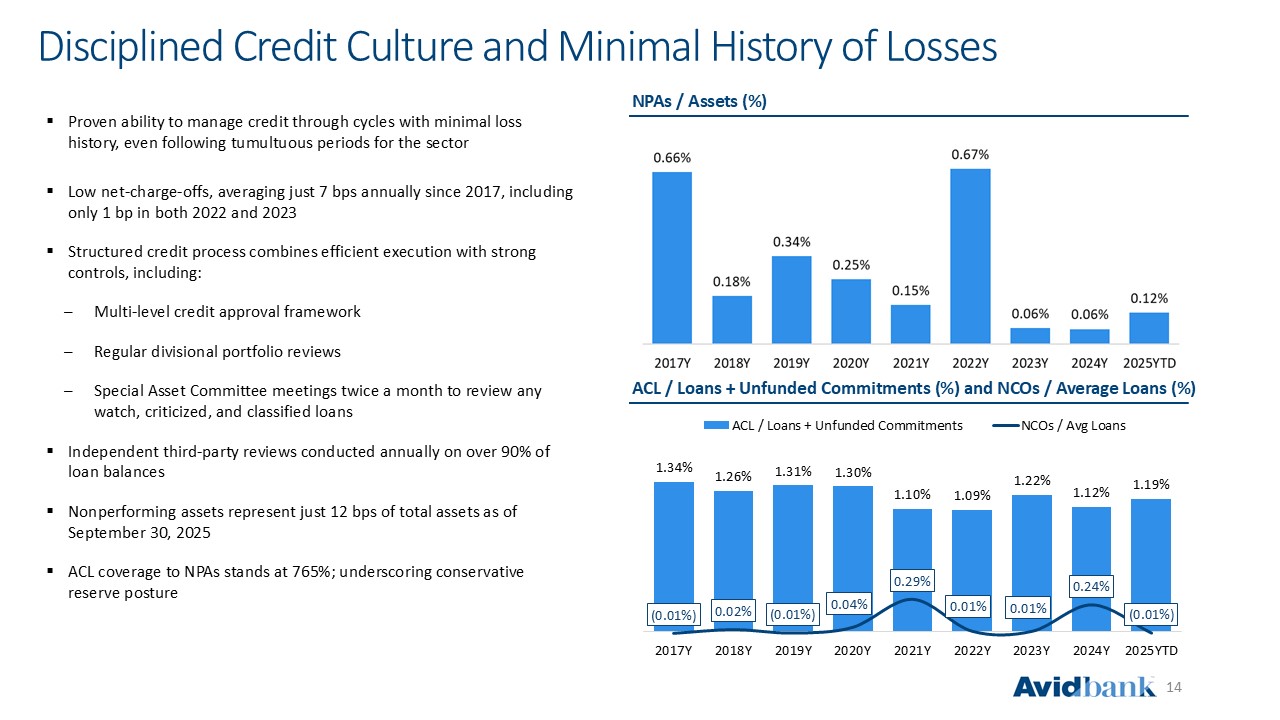
Nonperforming assets to total assets totaled 0.12% as of September 30, 2025 compared to 0.06% at June 30, 2025 and 0.16% at September 30, 2024. |
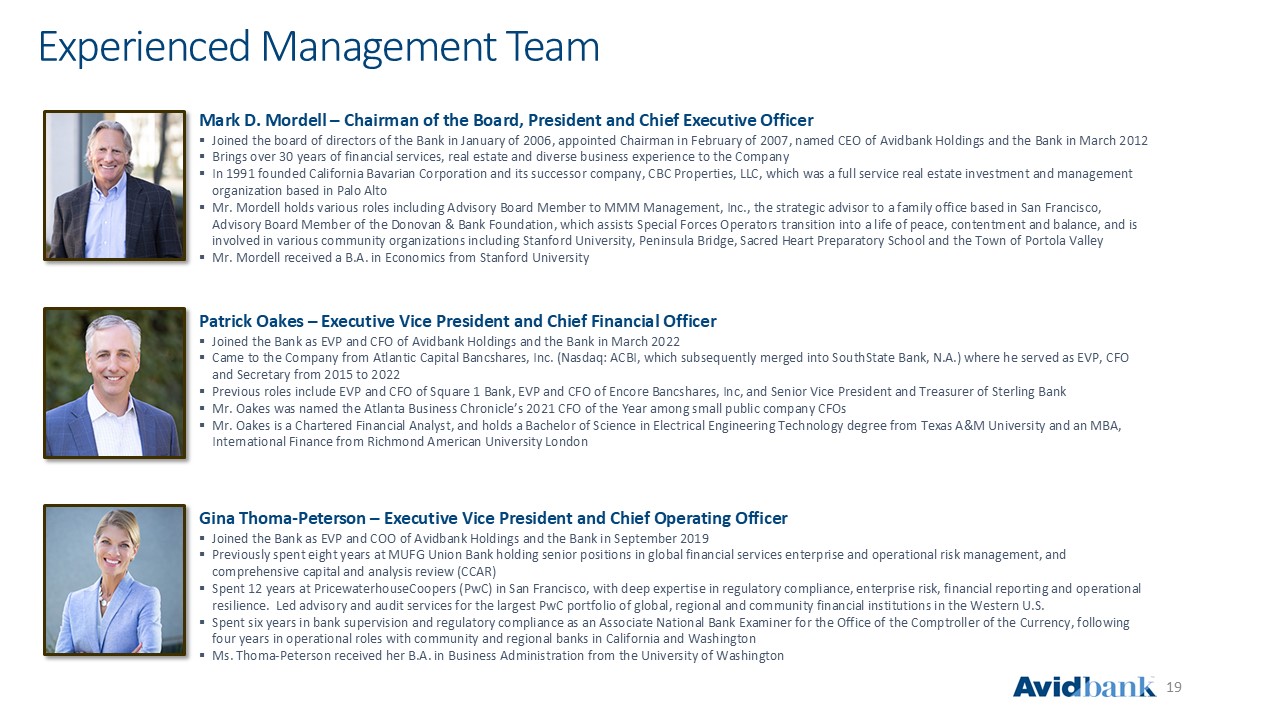
“The third quarter of 2025 was pivotal for Avidbank as we completed our successful IPO which enabled us to reposition our securities portfolio and position Avidbank for future long-term success,” said Mark D. Mordell, Chairman and Chief Executive Officer. “In addition to the IPO, we believe our strong loan and deposit growth and improved profitability reflect the strength of our franchise and the trust we’ve built with our clients. While the repositioning of our securities portfolio impacted third quarter results, it should significantly enhance our future profitability. We are optimistic about the opportunities ahead and remain focused on delivering sustainable growth and value for our shareholders."
|
(1) |
A non-GAAP performance measure. We provide detailed reconciliations in the “Non-GAAP Performance and Financial Measures Reconciliation” table. |
Avidbank Holdings, Inc. Third Quarter 2025 Financial Results Press Release
Results of Operations
Net interest income totaled $22.7 million for the third quarter of 2025, an increase of $2.4 million, or 46% annualized, from the second quarter of 2025, and an increase of $4.0 million, or 22%, from the third quarter of 2024. Net interest margin was 3.90% in the third quarter of 2025, an increase of 30 basis points compared to the second quarter of 2025, and a 55-basis-point increase compared to the third quarter of 2024. The increase in net interest margin compared to the prior quarter was primarily driven by lower average short-term borrowings, an increase in average noninterest-bearing demand deposits, and lower cost of deposits as well as improvement in interest income due to the sale of low-yielding securities as part of the repositioning of our available-for-sale securities portfolio.
The yield on securities increased in the third quarter of 2025 to 2.55% compared to 2.34% in the second quarter of 2025 and 2.26% in the third quarter of 2024 due to the sale of lower-yielding available-for-sale securities during the third quarter of 2025. The yield on loans in the third quarter of 2025 was 6.98%, a decrease of 3 basis points from the second quarter of 2025 and a decrease of 40 basis points from the third quarter of 2024. The decrease in loan yields was driven by reductions in the prime rate. The yield on interest-earning assets increased 10 basis points during the third quarter of 2025 compared to the second quarter of 2025 while overall funding costs declined by 9 basis points.
The cost of interest-bearing deposits in the third quarter of 2025 was 3.50%, a decrease of 4 basis points compared to the second quarter of 2025 and a decrease of 66 basis points compared to the third quarter of 2024. The cost of deposits in the third quarter of 2025 was 2.67%, a decrease of 11 basis points from the second quarter of 2025 and a decrease of 55 basis points from the third quarter of 2024.
The provision for credit losses was $1.4 million in the third quarter of 2025, compared to $925,000 in the second quarter of 2025 and $0 in the third quarter of 2024. The provision was higher in the third quarter of 2025 compared to the second quarter primarily due to higher loan balances and the addition of one nonaccrual loan.
Noninterest income was ($60.9) million in the third quarter of 2025 compared to $1.5 million in the second quarter of 2025 and $1.8 million in the third quarter of 2024. The third quarter of 2025 included a $62.4 million loss on the sale of securities resulting from the repositioning of the available-for-sale securities portfolio, partially offset by an increase in other investments income due to fair value adjustments and distributions.
Noninterest expense totaled $13.5 million for the third quarter of 2025, compared to $12.6 million in the second quarter of 2025 and $12.1 million in the third quarter of 2024. The increase from the second quarter was primarily due to higher salaries and benefits expense driven by an increase in incentives expense, IPO-related expenses and lower capitalized loan origination costs during the third quarter of 2025. Partially offsetting the increase in noninterest expense was a decrease in legal and professional fees of $124,000 due to elevated expense related to proxy matters along with general corporate and securities matters in the second quarter of 2025. There were 151 full-time equivalent employees on September 30, 2025, compared to 149 on June 30, 2025.
Financial Condition
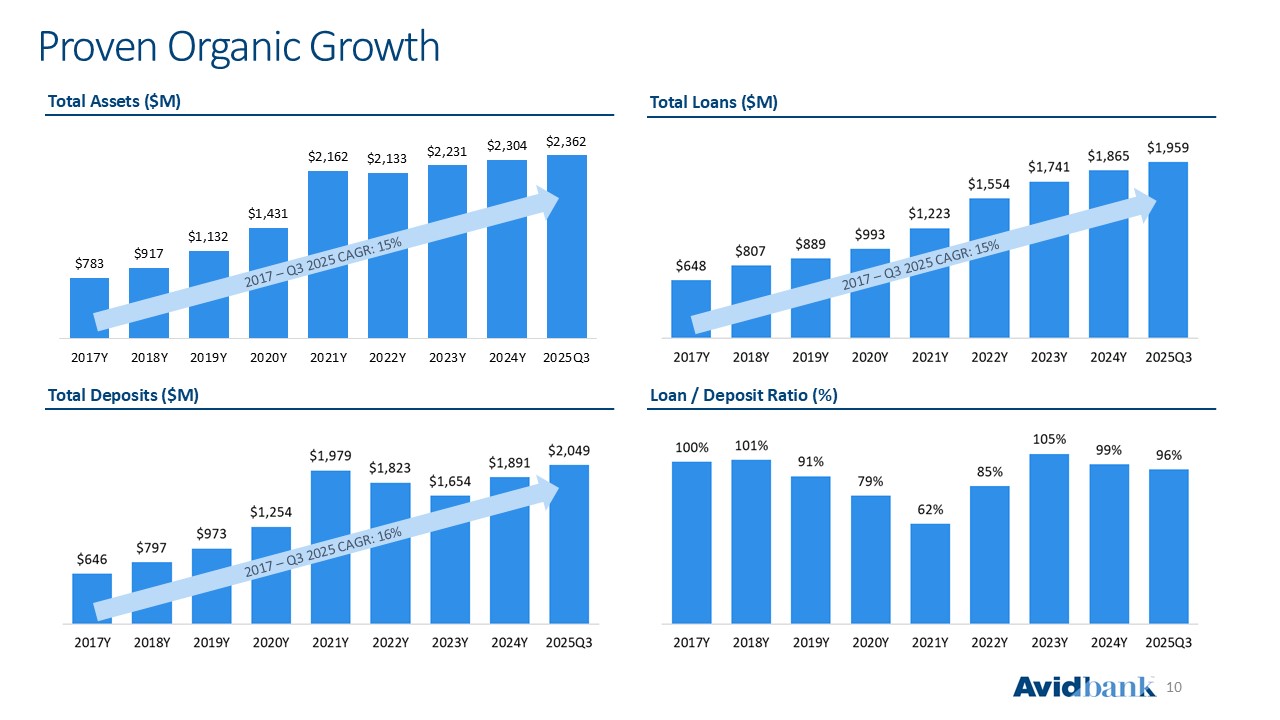
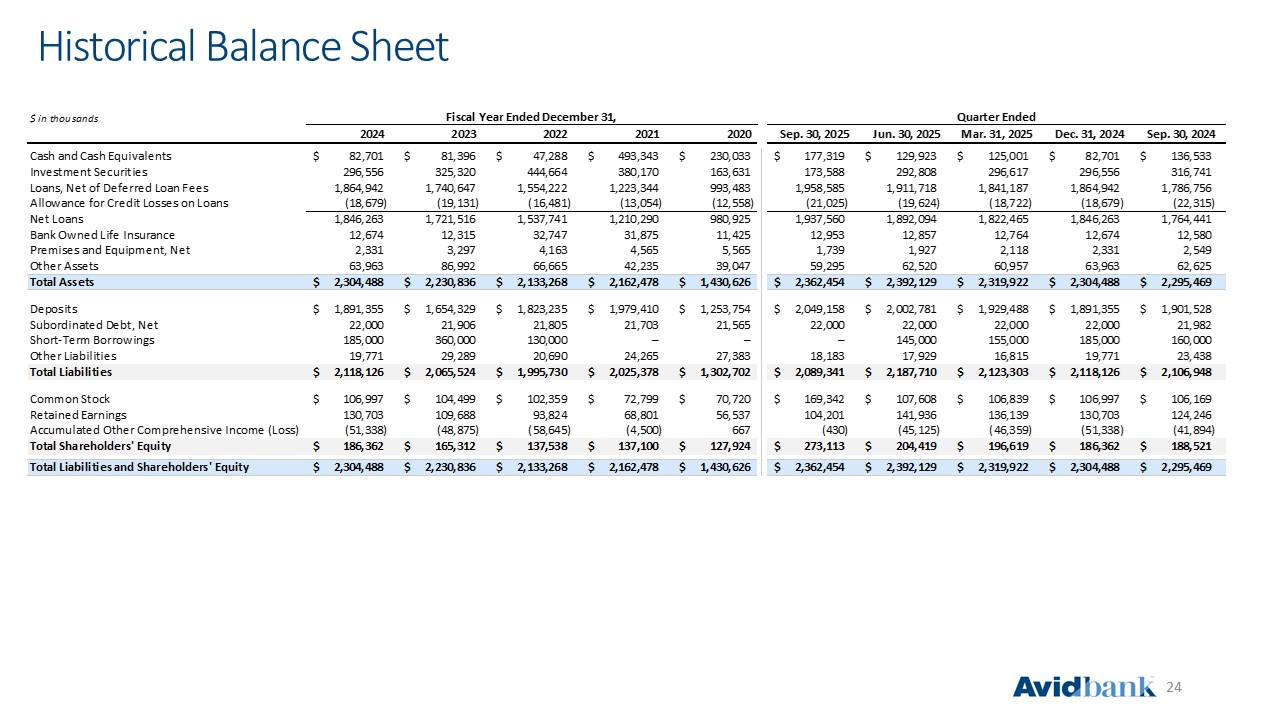
Total assets were $2.36 billion as of September 30, 2025, compared to $2.39 billion as of June 30, 2025, and $2.30 billion at September 30, 2024. Cash and cash equivalents were $177.3 million on September 30, 2025, compared to $129.9 million on June 30, 2025, and $136.5 million on September 30, 2024.
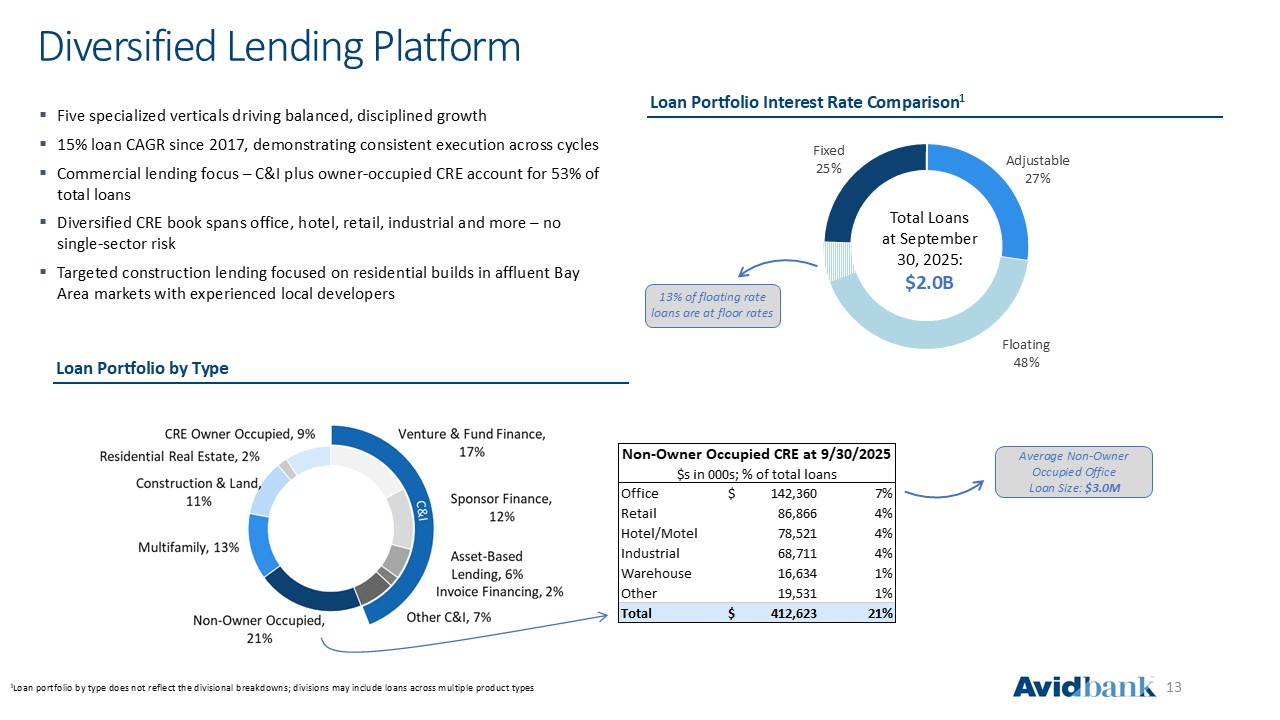
Loans, net of deferred loan fees, on September 30, 2025, totaled $1.96 billion, an increase of $46.9 million, or 10% annualized, from June 30, 2025, and an increase of $171.8 million, or 10%, from September 30, 2024. The increase in loans during the third quarter of 2025 included an increase of $16.5 million in commercial and industrial loans, $8.4 million in multi-family loans and $7.8 million in owner occupied loans.
The allowance for credit losses on loans was $21.0 million on September 30, 2025, representing an increase of $1.4 million from June 30, 2025 and a decrease of $1.3 million compared to September 30, 2024. The allowance for credit losses – loans and unfunded commitments to total loans was 1.19% on September 30, 2025, compared to 1.15% on June 30, 2025 and 1.37% as of September 30, 2024. Nonperforming loans to total loans was 0.14% at September 30, 3025, up 7 basis points compared to June 30, 2025 and down 6 basis points from September 30, 2024.
The available-for-sale securities portfolio totaled $173.6 million as of September 30, 2025, compared to $292.8 million at June 30, 2025, and $316.7 million as of September 30, 2024. The net unrealized loss for the available-for-sale portfolio totaled $689,000 as of September 30, 2025, compared to $63.4 million at June 30, 2025 and $59.0 million as of September 30, 2024. The decrease during the third quarter of 2025 was due to the sale of securities resulting from repositioning our available-for-sale securities portfolio.
2
Avidbank Holdings, Inc. Third Quarter 2025 Financial Results Press Release
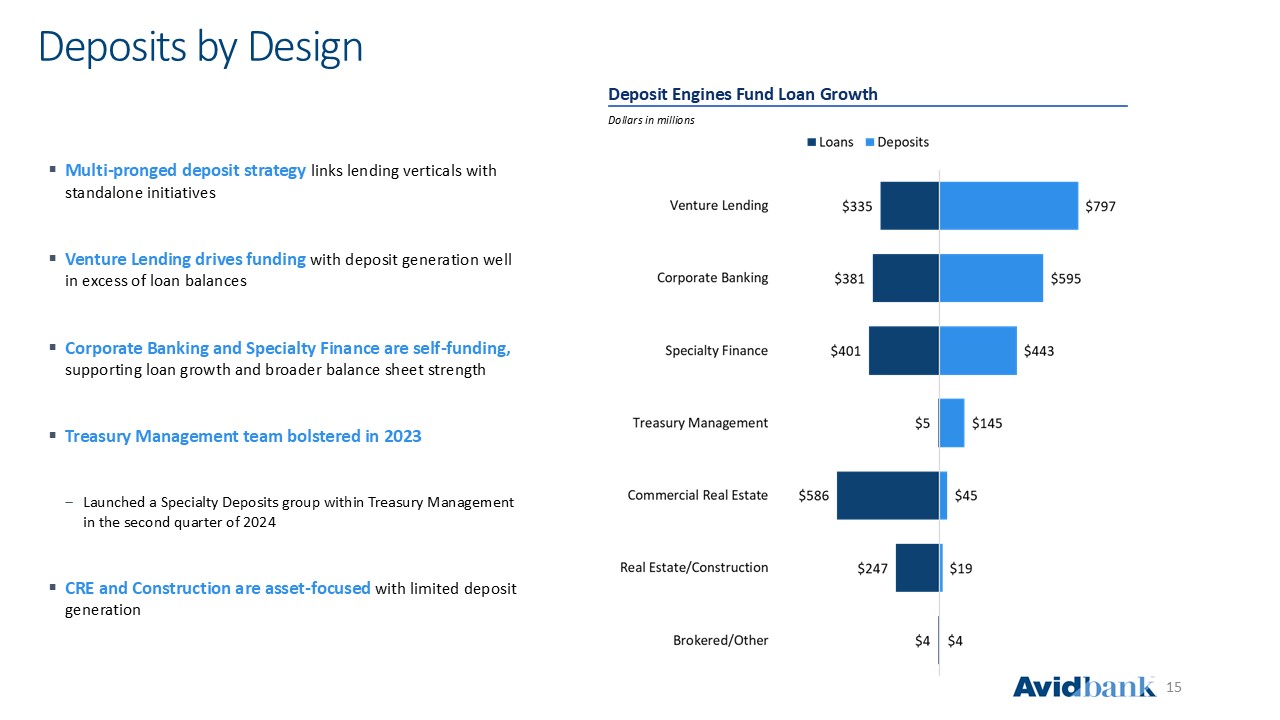
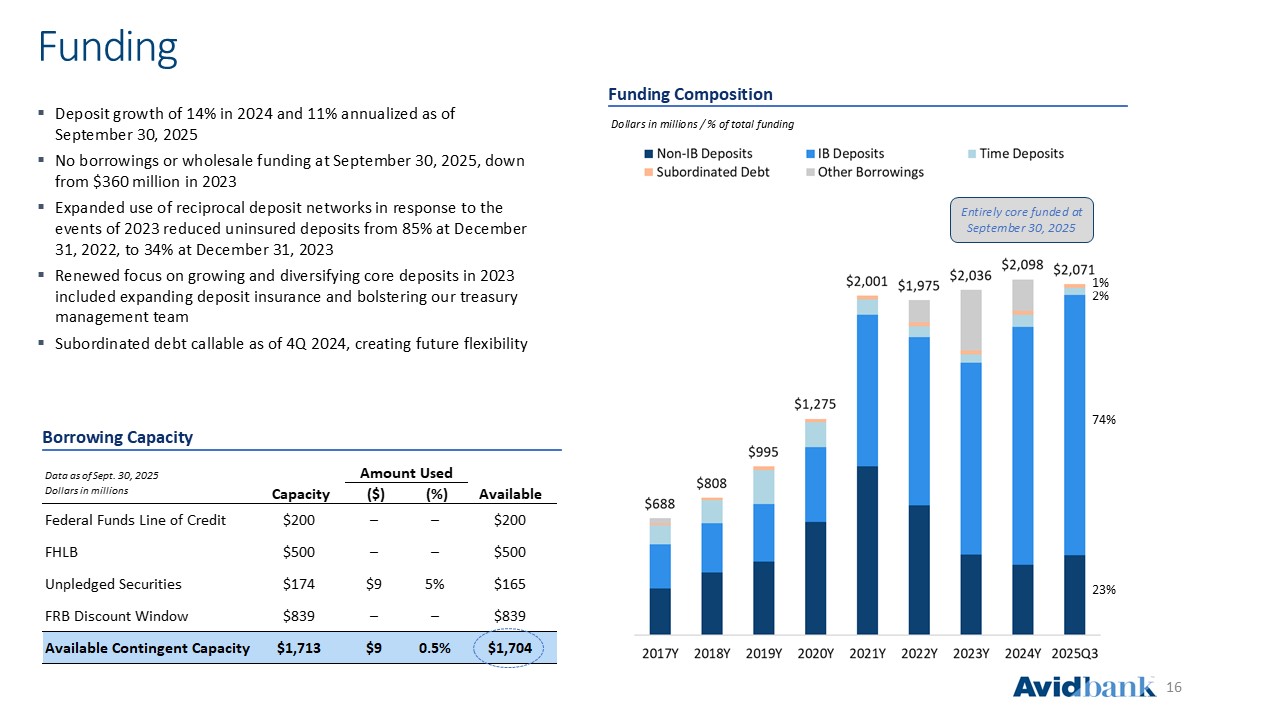
Deposits were $2.05 billion on September 30, 2025, an increase of $46.4 million, or 9% annualized, from June 30, 2025, and an increase of $147.6 million, or 8% from September 30, 2024. The change in deposits during the third quarter of 2025 included a $65.3 million increase in money market and savings and an increase of $28.2 million in noninterest-bearing demand deposits, partially offset by an $18.3 million decrease in interest-bearing checking and a $25.0 million decrease in non-reciprocal brokered deposits. Quarterly average deposits for the third quarter of 2025 were $2.04 billion, an increase of $72.0 million from the second quarter of 2025, and an increase of $238.3 million from the third quarter of 2024. Average noninterest-bearing demand deposits increased $57.7 million compared to the second quarter of 2025.
There were no short-term borrowings outstanding at September 30, 2025, compared to $145.0 million at June 30, 2025, and $160.0 million at September 30, 2024. Part of the proceeds from the IPO and the sale of securities during the third quarter of 2025 were used to pay off outstanding short-term borrowings. Average short-term borrowings decreased $74.9 million in the third quarter of 2025 compared to the second quarter of 2025.
Book value per share was $25.00 on September 30, 2025, a decrease of $0.80 compared to June 30, 2025, and an increase of $1.05 compared to September 30, 2024. The decrease was due to new shares issued as part of the IPO during the third quarter of 2025. Total shareholders’ equity was $273.1 million on September 30, 2025, an increase of $68.7 million compared to June 30, 2025, and an increase of $84.6 million from September 30, 2024. The change from June 30, 2025 to September 30, 2025 included net proceeds from the IPO totaling $61.3 million, a decrease in retained earnings of $37.7 million offset by an improvement in accumulated other comprehensive loss of $44.7 million, due to the recognized loss on the sale of available-for-sale securities.
Other Information
The Company will host a conference call on October 24, 2025, at 11:00 a.m. (Eastern Time) / 8:00 a.m. (Pacific Time) to discuss the third quarter of 2025 earnings results. Investors may call in by dialing (800) 715-9871 within the US and +1(646) 307-1963 for all other locations (Conference ID: 6048183). Participants may also pre-register for the conference by navigating to https://events.q4inc.com/attendee/814049300. Access detail will be provided via email upon completion of registration.
Alternatively, individuals may listen to a live webcast of the presentation by visiting the link on the Company's website at www.avidbank.com under About Us, Investor Relations. An audio replay of the live webcast is expected to be available by the evening of October 24, 2025, through the Investor Relations section of the Company's website. The recording will be available for one year from the day of posting. Information which may be discussed on the conference call is provided in an earnings supplement presentation available on the Company’s website and furnished with the SEC and available at www.sec.gov.
About Avidbank Holdings
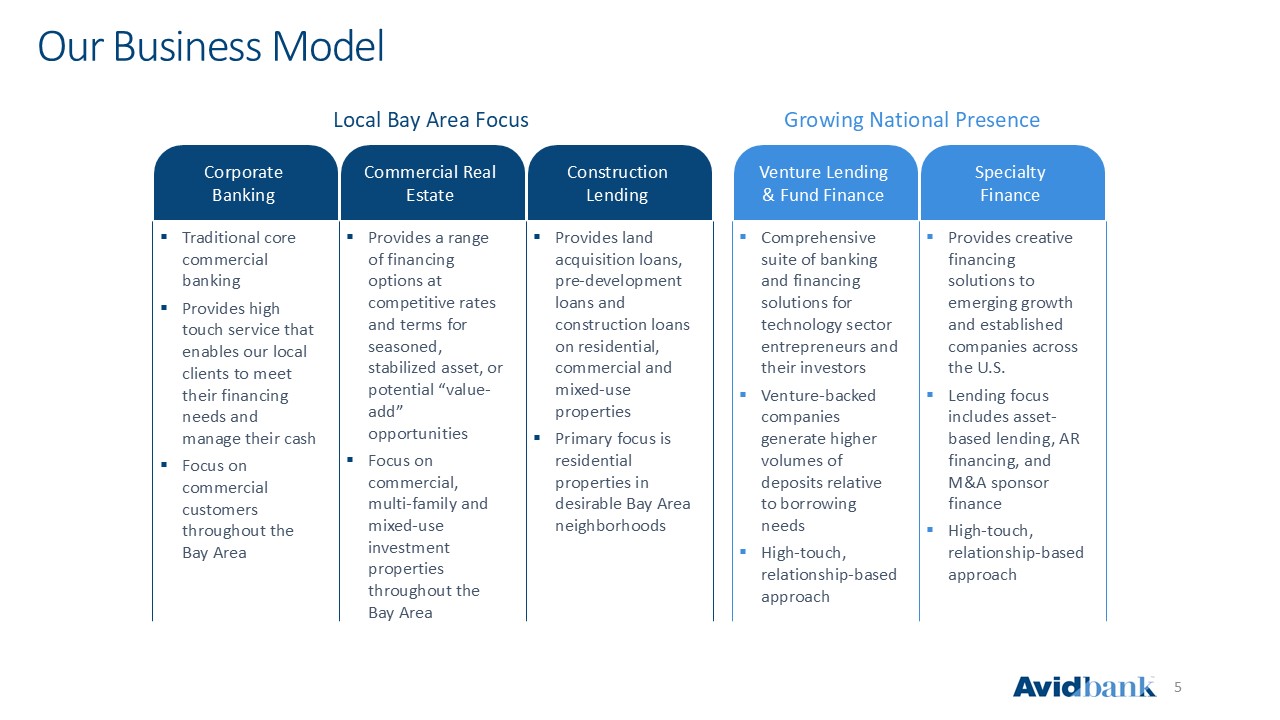
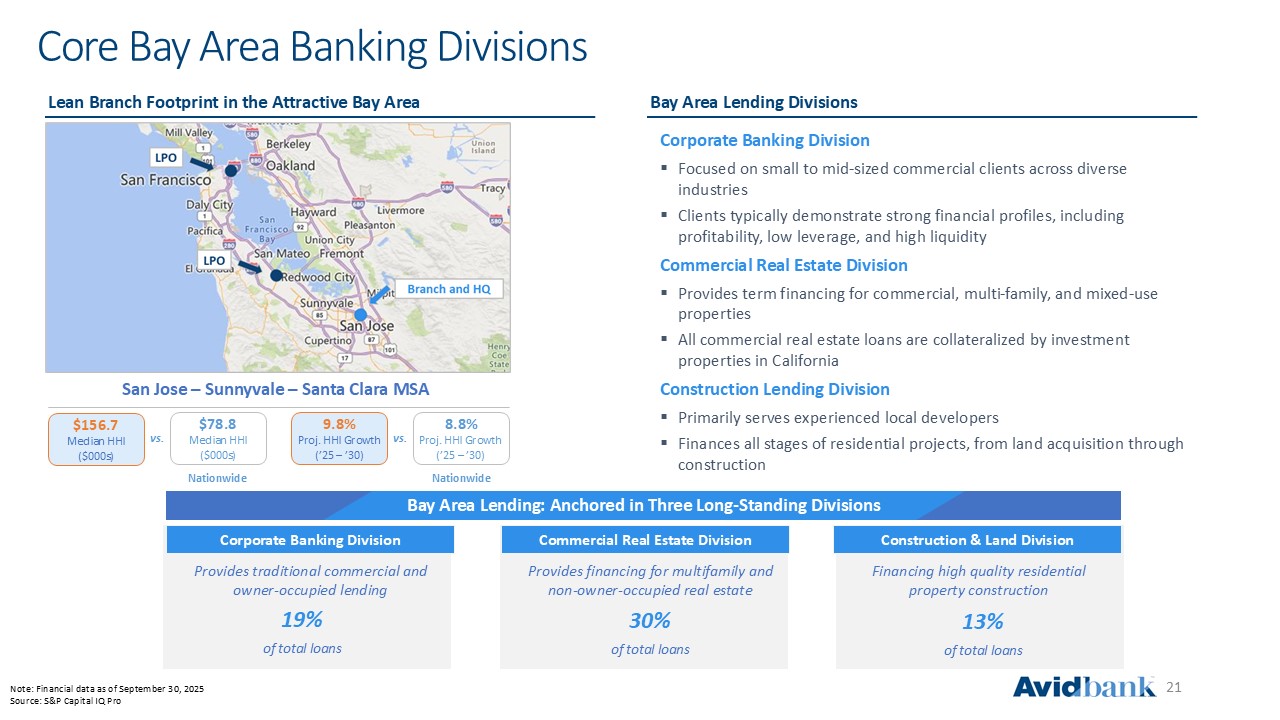
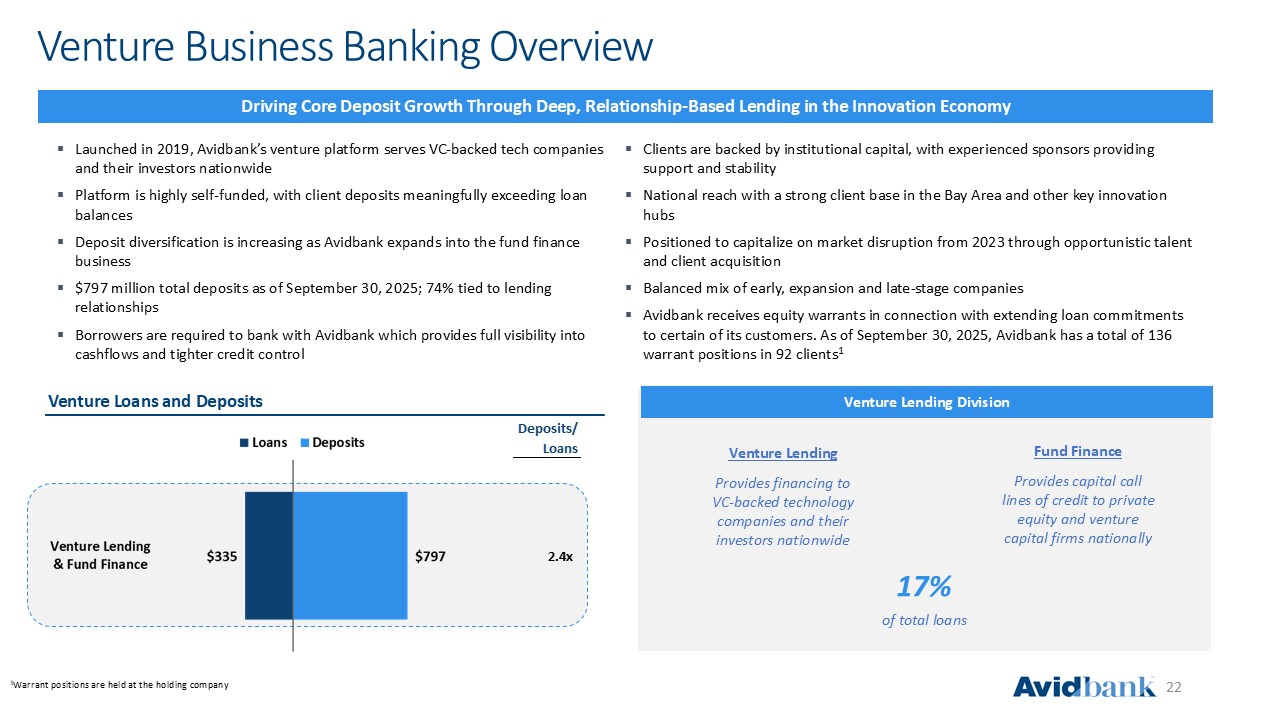
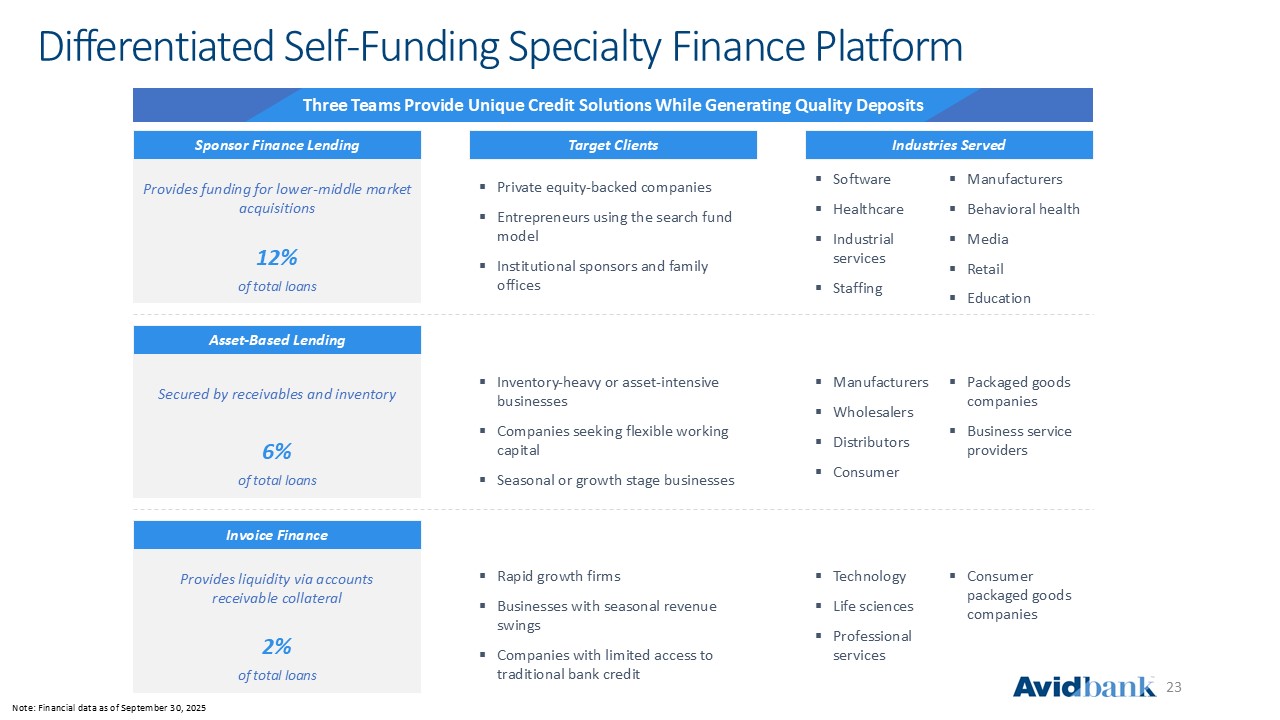
Avidbank Holdings, Inc. (NASDAQ: AVBH), headquartered in San Jose, California, offers innovative financial solutions and services. We specialize in commercial & industrial lending, venture lending, structured finance, asset-based lending, sponsor finance, fund finance, and real estate construction and commercial real estate lending. Avidbank provides a different approach to banking. We do what we say.
Non-GAAP Financial Measures
This press release includes financial information prepared in accordance with accounting principles generally accepted in the United States (“GAAP”). This press release also includes non-GAAP financial information, which should be considered supplemental to, not a substitute for, or superior to, the financial measure calculated in accordance with GAAP. Management has presented these non-GAAP financial measures because we believe that these measures provide useful information to management and investors that is supplementary to our financial condition, results of operations and cash flows computed in accordance with GAAP. Management believes that adjusted net income, adjusted diluted earnings per share, adjusted return on average assets, adjusted return on average equity, adjusted efficiency ratio, taxable equivalent net interest income and taxable equivalent net interest margin are reasonable measures to understand the Company’s core operating performance and are important to many investors who are interested in understanding our profitability prospects from our core operations.
However, we acknowledge that our non-GAAP financial measures have a number of limitations. As such, you should not view these disclosures as a substitute for results determined in accordance with GAAP, and they are not necessarily comparable to non-GAAP financial measures that other banking companies use. Other banking
3
Avidbank Holdings, Inc. Third Quarter 2025 Financial Results Press Release
companies may use names similar to those we use for the non-GAAP financial measures we disclose but may calculate them differently. You should understand how we and other companies each calculate their non-GAAP financial measures when making comparisons. For a description of the non-GAAP financial information included herein and reconciliations to the most directly comparable GAAP measure, see the "Non-GAAP Performance and Financial Measures Reconciliation" table.
Forward-Looking Statements
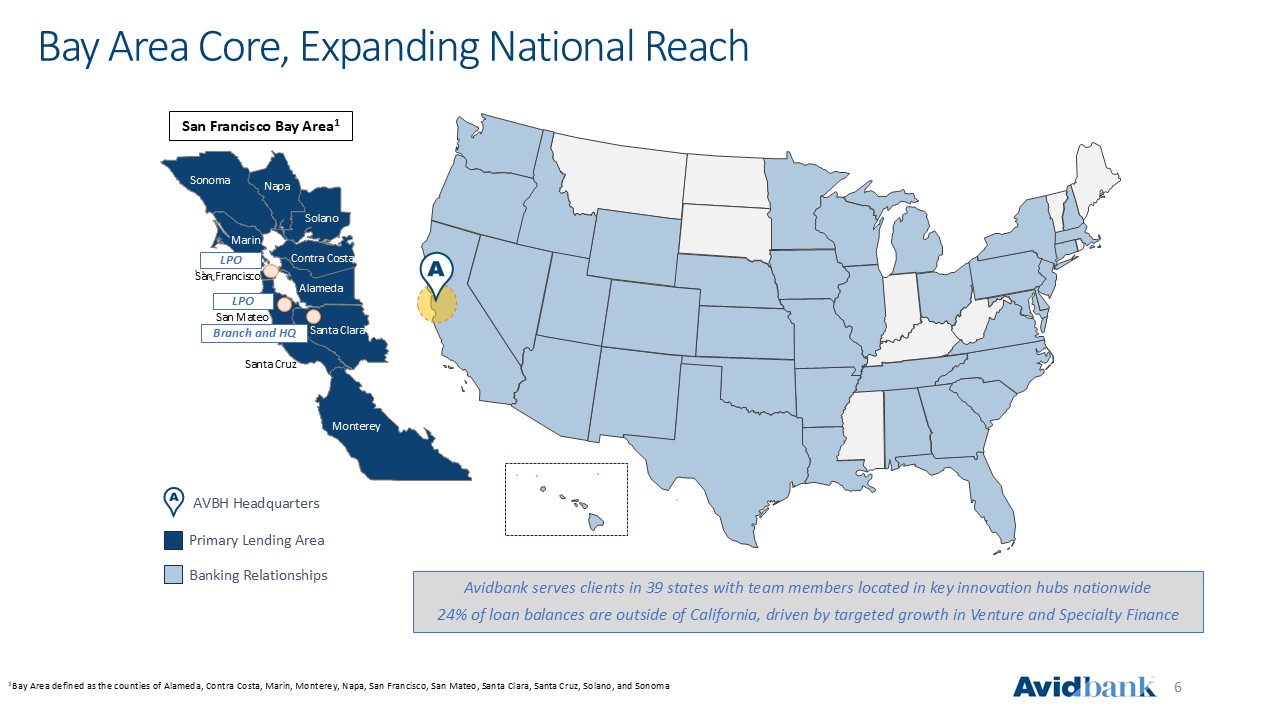
This press release contains forward-looking statements within the meaning of U.S. federal securities laws, which involve risks and uncertainties. You should not place undue reliance on forward-looking statements because they are subject to numerous uncertainties and factors relating to our operations and business, all of which are difficult to predict and many of which are beyond our control. Forward-looking statements include information concerning our possible or assumed future results of operations, including descriptions of our business strategy and expectations. These forward-looking statements are generally identified by the use of forward-looking terminology, including the terms “anticipate,” “believe,” “could,” “estimate,” “expect,” “intend,” “may,” “plan,” “potential,” “predict,” “project,” “should,” “target,” “will,” “would” and, in each case, their negative or other variations or comparable terminology and expressions. The results, events and circumstances reflected in the forward-looking statements may not be achieved or occur, and actual results, events, or circumstances could differ materially from those described in the forward-looking statements. We caution that the forward-looking information and statements are based largely on our expectations and are subject to a number of known and unknown risks and uncertainties that are subject to change based on factors which are, in many instances, beyond our control. Such forward-looking statements are based on various assumptions (some of which may be beyond our control) and are subject to risks and uncertainties, which change over time, and other factors which could cause actual results to differ materially from those currently anticipated. Such risks and uncertainties include, but are not limited to: uncertain market conditions and economic trends nationally, regionally and particularly in the Bay Area (which we define as the counties of Alameda, Contra Costa, Marin, Monterey, Napa, San Francisco, San Mateo, Santa Clara, Santa Cruz, Solano, and Sonoma) and California; economic conditions affecting the venture capital and private equity industries, including any decline in overall portfolio company investment, merger and acquisition activity and other liquidity events affecting venture and private equity fund and their portfolio companies; risks related to the concentration of our business in California, and specifically within the Bay Area, including risks associated with any downturn in the real estate sector; our inability to successfully reposition our available-for-sale securities portfolio utilizing the proceeds from our public offering; incurrence of any losses in connection with any repositioning of our available-for-sale securities portfolio utilizing the proceeds from our recently completed public offering; the effects of a prolonged government shutdown; the occurrence of significant natural disasters, including fires and earthquakes, and acts of war or terrorism; our ability to conduct our business could be disrupted by natural or man-made disasters, including the effects of pandemic viruses; changes in market interest rates that affect the pricing of our loans and deposits and our net interest income; risks related to our strategic focus on lending to small to medium-sized businesses; the sufficiency of the assumptions and estimates we make in establishing reserves for potential loan losses and the value of loan collateral and securities; our ability to attract and retain executive officers and key employees and their customer and community relationships; adverse changes in the financial performance and/or condition of our borrowers and, as a result, increased loan delinquency rates, deterioration in asset quality and losses in our loan portfolio; the costs of and effects of legal and regulatory developments, including legal proceedings and lawsuits we are or may become subject to; the results of regulatory examinations or reviews and the effect of and our ability to comply with, any regulations or regulatory orders or actions we are or may become subject to; our level of nonperforming assets and the costs associated with resolving problem loans; our ability to maintain adequate liquidity and to raise necessary capital to fund our growth strategy and operations or to meet increased minimum regulatory capital levels; the effects of increased competition from a wide variety of local, regional, national and other providers of financial services; technological changes and developments; negative trends in our market capitalization and adverse changes in the price of our common stock; risks associated with unauthorized access, cyber-crime and other threats to data security; the effects of any acquisitions or dispositions we may make or evaluate, and the costs associated with any potential or actual acquisition or disposition; our ability to comply with various governmental and regulatory requirements applicable to financial institutions, including supervisory actions by federal and state banking agencies; the impact of recent and future legislative and regulatory changes, including changes in banking, accounting, securities and tax laws and regulations and their application by our regulators, and economic stimulus programs; governmental monetary and fiscal policies, including the policies of the Federal Reserve and policies related to tariffs; our ability to implement, maintain and improve effective internal controls; our use of the net proceeds from our recent public offering; and our success at managing any of the risks involved any of the foregoing items. Additional factors that could cause actual results to differ materially from those expressed in the forward-looking statements are discussed in the Company's filings with the SEC, including the Company’s most recent quarterly report on Form 10-Q, under the heading “Risk Factors” and available at the SEC’s Internet site www.sec.gov. The foregoing factors should not be considered exhaustive. New risks and uncertainties may emerge from time to time, and it is not possible for us to predict their occurrence or how they will affect us. If one or more of the factors affecting our forward-looking information and
4
Avidbank Holdings, Inc. Third Quarter 2025 Financial Results Press Release
statements proves incorrect, then our actual results, performance or achievements could differ materially from those expressed in, or implied by, forward-looking information. Therefore, we caution you not to place undue reliance on our forward-looking information and statements. We disclaim any duty to revise or update the forward-looking statements, whether written or oral, to reflect actual results or changes in the factors affecting the forward-looking statements, except as specifically required by law.
Contact:
Patrick Oakes
Executive Vice President and Chief Financial Officer
408-200-7390
5
Avidbank Holdings, Inc. Third Quarter 2025 Financial Results Press Release
|
|
||||||||||||||||||||
|
AVIDBANK HOLDINGS, INC. |
||||||||||||||||||||
|
Selected Financial Data (Unaudited) |
||||||||||||||||||||
|
(In thousands, except share and per share amounts) |
For the Nine |
|||||||||||||||||||
|
|
For the Three Months Ended |
Months Ended |
||||||||||||||||||
|
|
Sept. 30, |
June 30, |
March 31, |
Dec. 31, |
Sept. 30, |
Sept. 30, |
Sept. 30, |
|||||||||||||
|
|
2025 |
2025 |
2025 |
2024 |
2024 |
2025 |
2024 |
|||||||||||||
|
INCOME HIGHLIGHTS |
||||||||||||||||||||
|
Net (loss) / income |
$ |
(37,735) |
$ |
5,797 |
$ |
5,436 |
$ |
6,457 |
$ |
5,846 |
$ |
(26,502) |
$ |
14,558 | ||||||
|
Net income-adjusted (2) |
$ |
6,707 |
$ |
5,797 |
$ |
5,436 |
$ |
6,457 |
$ |
5,846 |
$ |
17,940 |
$ |
14,558 | ||||||
|
PER SHARE DATA |
||||||||||||||||||||
|
Basic (loss) / earnings per share |
$ |
(4.12) |
$ |
0.77 |
$ |
0.73 |
$ |
0.87 |
$ |
0.79 |
$ |
(3.28) |
$ |
1.96 | ||||||
|
Diluted (loss) / earnings per share |
(4.12) | 0.75 | 0.71 | 0.84 | 0.77 | (3.28) | 1.92 | |||||||||||||
|
Diluted earnings per share-adjusted (2) |
0.72 | 0.75 | 0.71 | 0.84 | 0.77 | 2.18 | 1.92 | |||||||||||||
|
Book value per share |
25.00 | 25.80 | 24.85 | 23.57 | 23.95 | 25.00 | 23.95 | |||||||||||||
|
PERFORMANCE MEASURES |
||||||||||||||||||||
|
Return on average assets (1) |
(6.35)% |
1.00% | 0.96% | 1.14% | 1.02% |
(1.53)% |
0.86% | |||||||||||||
|
Return on average assets-adjusted (1) (2) |
1.13% | 1.00% | 0.96% | 1.14% | 1.02% | 1.03% | 0.86% | |||||||||||||
|
Return on average equity (1) |
(63.19)% |
11.59% | 11.49% | 13.65% | 12.97% |
(16.88)% |
11.37% | |||||||||||||
|
Return on average equity-adjusted (1) (2) |
11.23% | 11.59% | 11.49% | 13.65% | 12.97% | 11.42% | 11.37% | |||||||||||||
|
Net interest margin (1) |
3.90% | 3.60% | 3.52% | 3.48% | 3.35% | 3.68% | 3.42% | |||||||||||||
|
Net interest margin - taxable equivalent (1) (2) |
3.90% | 3.60% | 3.52% | 3.49% | 3.35% | 3.68% | 3.42% | |||||||||||||
|
Efficiency ratio |
(35.28)% |
57.77% | 62.57% | 52.53% | 59.29% | 938.30% | 60.27% | |||||||||||||
|
Efficiency ratio-adjusted (2) |
55.72% | 57.77% | 62.57% | 52.53% | 59.29% | 58.51% | 60.27% | |||||||||||||
|
Average loans to average deposits |
94.14% | 95.69% | 98.55% | 95.86% | 99.90% | 96.05% | 101.62% | |||||||||||||
|
CAPITAL |
||||||||||||||||||||
|
Tier 1 leverage ratio (3) |
11.10% | 10.53% | 10.39% | 10.35% | 9.93% | 11.10% | 9.93% | |||||||||||||
|
Common equity tier 1 capital ratio (3) |
11.68% | 11.02% | 11.10% | 10.59% | 10.75% | 11.68% | 10.75% | |||||||||||||
|
Tier 1 risk-based capital ratio (3) |
11.68% | 11.02% | 11.10% | 10.59% | 10.75% | 11.68% | 10.75% | |||||||||||||
|
Total risk-based capital ratio (3) |
13.48% | 12.76% | 12.86% | 12.30% | 12.92% | 13.48% | 12.92% | |||||||||||||
|
Common equity ratio |
11.56% | 8.55% | 8.48% | 8.09% | 8.21% | 11.56% | 8.21% | |||||||||||||
|
SHARES OUTSTANDING |
||||||||||||||||||||
|
Number of common shares outstanding |
10,925,102 | 7,923,946 | 7,912,184 | 7,906,761 | 7,871,818 | 10,925,102 | 7,871,818 | |||||||||||||
|
Average common shares outstanding - basic |
9,168,707 | 7,534,264 | 7,488,051 | 7,455,650 | 7,434,726 | 8,069,830 | 7,416,173 | |||||||||||||
|
Average common shares outstanding - diluted |
9,168,707 | 7,686,385 | 7,682,884 | 7,661,711 | 7,622,428 | 8,069,830 | 7,584,349 | |||||||||||||
|
ASSET QUALITY |
||||||||||||||||||||
|
Total allowance for credit losses-loans and unfunded commitments |
1.19% | 1.15% | 1.14% | 1.12% | 1.37% | 1.19% | 1.37% | |||||||||||||
|
Nonperforming assets to total assets |
0.12% | 0.06% | 0.06% | 0.06% | 0.16% | 0.12% | 0.16% | |||||||||||||
|
Nonperforming loans to total loans |
0.14% | 0.07% | 0.07% | 0.07% | 0.20% | 0.14% | 0.20% | |||||||||||||
|
Net charge-offs to average loans (1) |
(0.01)% |
0.00% |
(0.01)% |
0.93% | 0.02% |
(0.01)% |
0.01% | |||||||||||||
|
AVERAGE BALANCES |
||||||||||||||||||||
|
Loans, net of deferred loan fees |
$ |
1,924,537 |
$ |
1,887,263 |
$ |
1,858,716 |
$ |
1,815,933 |
$ |
1,804,107 |
$ |
1,890,413 |
$ |
1,791,479 | ||||||
|
Investment securities |
181,154 | 293,640 | 296,422 | 308,502 | 311,450 | 256,650 | 312,723 | |||||||||||||
|
Total assets |
2,357,158 | 2,322,264 | 2,289,935 | 2,250,086 | 2,272,623 | 2,323,365 | 2,253,729 | |||||||||||||
|
Deposits |
2,044,228 | 1,972,215 | 1,885,993 | 1,894,321 | 1,805,935 | 1,968,059 | 1,762,857 | |||||||||||||
|
Shareholders' equity |
236,903 | 200,608 | 191,891 | 188,170 | 179,260 | 209,965 | 171,043 | |||||||||||||
|
(1) Annualized for the periods presented. |
||||||||||||||||||||
|
(2) A non-GAAP performance measure. We provide detailed reconciliations in the "Non-GAAP Performance and Financial Measures Reconciliation" table. |
||||||||||||||||||||
|
(3) Ratios presented are for Avidbank Holdings, Inc. and are estimated for the three and nine months ended September 30, 2025. |
||||||||||||||||||||
6
Avidbank Holdings, Inc. Third Quarter 2025 Financial Results Press Release
|
AVIDBANK HOLDINGS, INC. |
||||||||||||||
|
Consolidated Statements of Financial Condition (Unaudited) |
||||||||||||||
|
(In thousands) |
||||||||||||||
|
|
September 30, |
June 30, |
March 31, |
December 31, |
September 30, |
|||||||||
|
|
2025 |
2025 |
2025 |
2024 |
2024 |
|||||||||
|
Assets |
||||||||||||||
|
Cash and due from banks |
$ |
12,006 |
$ |
2,800 |
$ |
18,866 |
$ |
8,662 |
$ |
15,172 | ||||
|
Due from Federal Reserve Bank and interest-bearing deposits in banks |
165,313 | 127,123 | 106,135 | 74,039 | 121,361 | |||||||||
|
Total cash and cash equivalents |
177,319 | 129,923 | 125,001 | 82,701 | 136,533 | |||||||||
|
Investment securities available-for-sale |
173,588 | 292,808 | 296,617 | 296,556 | 316,741 | |||||||||
|
Loans, net of deferred loan fees |
1,958,585 | 1,911,718 | 1,841,187 | 1,864,942 | 1,786,756 | |||||||||
|
Allowance for credit losses on loans |
(21,025) | (19,624) | (18,722) | (18,679) | (22,315) | |||||||||
|
Loans, net of allowance for credit losses on loans |
1,937,560 | 1,892,094 | 1,822,465 | 1,846,263 | 1,764,441 | |||||||||
|
Bank owned life insurance |
12,953 | 12,857 | 12,764 | 12,674 | 12,580 | |||||||||
|
Premises and equipment, net |
1,739 | 1,927 | 2,118 | 2,331 | 2,549 | |||||||||
|
Accrued interest receivable and other assets |
59,295 | 62,520 | 60,957 | 63,963 | 62,625 | |||||||||
|
Total assets |
$ |
2,362,454 |
$ |
2,392,129 |
$ |
2,319,922 |
$ |
2,304,488 |
$ |
2,295,469 | ||||
|
|
||||||||||||||
|
Liabilities and Shareholders' Equity |
||||||||||||||
|
Deposits: |
||||||||||||||
|
Noninterest-bearing demand |
$ |
471,770 |
$ |
443,540 |
$ |
419,823 |
$ |
414,327 |
$ |
405,528 | ||||
|
Interest-bearing checking |
1,069,344 | 1,087,621 | 965,467 | 993,219 | 1,026,898 | |||||||||
|
Money market and savings |
465,198 | 399,849 | 399,010 | 338,578 | 336,166 | |||||||||
|
Time |
42,846 | 46,770 | 58,273 | 74,468 | 75,033 | |||||||||
|
Non-reciprocal brokered (1) |
– |
25,001 | 86,915 | 70,763 | 57,903 | |||||||||
|
Total deposits |
2,049,158 | 2,002,781 | 1,929,488 | 1,891,355 | 1,901,528 | |||||||||
|
Subordinated debt, net |
22,000 | 22,000 | 22,000 | 22,000 | 21,982 | |||||||||
|
Short-term borrowings |
– |
145,000 | 155,000 | 185,000 | 160,000 | |||||||||
|
Accrued interest payable and other liabilities |
18,183 | 17,929 | 16,815 | 19,771 | 23,438 | |||||||||
|
Total liabilities |
2,089,341 | 2,187,710 | 2,123,303 | 2,118,126 | 2,106,948 | |||||||||
|
|
||||||||||||||
|
Shareholders' Equity |
||||||||||||||
|
Common stock |
169,342 | 107,608 | 106,839 | 106,997 | 106,169 | |||||||||
|
Retained earnings |
104,201 | 141,936 | 136,139 | 130,703 | 124,246 | |||||||||
|
Accumulated other comprehensive loss |
(430) | (45,125) | (46,359) | (51,338) | (41,894) | |||||||||
|
Total shareholders' equity |
273,113 | 204,419 | 196,619 | 186,362 | 188,521 | |||||||||
|
Total liabilities and shareholders' equity |
$ |
2,362,454 |
$ |
2,392,129 |
$ |
2,319,922 |
$ |
2,304,488 |
$ |
2,295,469 | ||||
|
|
||||||||||||||
|
(1) FDIC regulations impose a general cap on reciprocal deposits that may be exempt from brokered deposits classification equal to 20% of the Bank’s total liabilities. As of September 30, 2025, June 30, 2025, March 31, 2025, December 31, 2024 and September 30, 2024, an additional $522.5 million, $495.4 million, $447.8 million, $470.0 million and $509.3 million of our deposits were considered brokered deposits by the FDIC due to being in excess of the general cap, respectively. |
||||||||||||||
7
Avidbank Holdings, Inc. Third Quarter 2025 Financial Results Press Release
|
|
||||||||||||||||||||
|
AVIDBANK HOLDINGS, INC. |
||||||||||||||||||||
|
Consolidated Statements of Operations (Unaudited) |
||||||||||||||||||||
|
(in thousands, except share and per share amounts) |
||||||||||||||||||||
|
|
For the Nine |
|||||||||||||||||||
|
|
For the Three Months Ended |
Months Ended |
||||||||||||||||||
|
|
Sept. 30, |
June 30, |
March 31, |
Dec. 31, |
Sept. 30, |
Sept. 30, |
Sept. 30, |
|||||||||||||
|
|
2025 |
2025 |
2025 |
2024 |
2024 |
2025 |
2024 |
|||||||||||||
|
Interest and fees on loans |
$ |
33,880 |
$ |
32,967 |
$ |
31,885 |
$ |
32,308 |
$ |
33,488 |
$ |
98,732 |
$ |
98,570 | ||||||
|
Interest on investment securities |
1,157 | 1,703 | 1,749 | 1,770 | 1,767 | 4,609 | 5,392 | |||||||||||||
|
Federal Home Loan Bank dividends |
184 | 181 | 185 | 185 | 183 | 550 | 567 | |||||||||||||
|
Other interest income |
2,033 | 793 | 706 | 681 | 1,198 | 3,532 | 2,968 | |||||||||||||
|
Total interest income |
37,254 | 35,644 | 34,525 | 34,944 | 36,636 | 107,423 | 107,497 | |||||||||||||
|
Deposit interest expense |
13,776 | 13,669 | 12,827 | 14,015 | 14,602 | 40,272 | 40,130 | |||||||||||||
|
Interest on short-term borrowings |
385 | 1,242 | 1,911 | 1,437 | 3,121 | 3,538 | 10,443 | |||||||||||||
|
Interest on subordinated debt |
443 | 443 | 435 | 293 | 300 | 1,321 | 901 | |||||||||||||
|
Total interest expense |
14,604 | 15,354 | 15,173 | 15,745 | 18,023 | 45,131 | 51,474 | |||||||||||||
|
Net interest income |
22,650 | 20,290 | 19,352 | 19,199 | 18,613 | 62,292 | 56,023 | |||||||||||||
|
Provision for credit losses |
1,355 | 925 |
– |
779 |
– |
2,280 | 3,317 | |||||||||||||
|
Net interest income after provision for credit losses |
21,295 | 19,365 | 19,352 | 18,420 | 18,613 | 60,012 | 52,706 | |||||||||||||
|
Service charges and bank fees |
779 | 840 | 762 | 649 | 675 | 2,381 | 1,951 | |||||||||||||
|
Foreign exchange income |
267 | 196 | 220 | 191 | 246 | 683 | 706 | |||||||||||||
|
Income from bank owned life insurance |
96 | 93 | 90 | 93 | 90 | 279 | 415 | |||||||||||||
|
Warrant and success fee income |
– |
273 |
– |
65 |
– |
273 |
– |
|||||||||||||
|
Loss on sale of securities |
(62,391) |
– |
– |
– |
– |
(62,391) |
– |
|||||||||||||
|
Other investment income |
315 | (23) | 47 | 637 | 240 | 339 | 454 | |||||||||||||
|
Other income |
82 | 159 | 52 | 205 | 539 | 293 | 644 | |||||||||||||
|
Total noninterest income |
(60,852) | 1,538 | 1,171 | 1,840 | 1,790 | (58,143) | 4,170 | |||||||||||||
|
Salaries and benefit expenses |
9,766 | 8,978 | 9,097 | 7,389 | 8,336 | 27,841 | 25,111 | |||||||||||||
|
Occupancy and equipment expenses |
723 | 759 | 996 | 919 | 1,033 | 2,478 | 3,099 | |||||||||||||
|
Data processing |
792 | 759 | 615 | 613 | 638 | 2,166 | 1,799 | |||||||||||||
|
Regulatory assessments |
445 | 420 | 544 | 541 | 528 | 1,409 | 1,542 | |||||||||||||
|
Legal and professional fees |
591 | 715 | 511 | 452 | 534 | 1,817 | 1,686 | |||||||||||||
|
Other operating expenses |
1,162 | 978 | 1,079 | 1,138 | 1,028 | 3,219 | 3,043 | |||||||||||||
|
Total noninterest expense |
13,479 | 12,609 | 12,842 | 11,052 | 12,097 | 38,930 | 36,280 | |||||||||||||
|
Income before income taxes |
(53,036) | 8,294 | 7,681 | 9,208 | 8,306 | (37,061) | 20,596 | |||||||||||||
|
(Benefit) / provision for income taxes |
(15,301) | 2,497 | 2,245 | 2,751 | 2,460 | (10,559) | 6,038 | |||||||||||||
|
Net (loss) / income |
$ |
(37,735) |
$ |
5,797 |
$ |
5,436 |
$ |
6,457 |
$ |
5,846 |
$ |
(26,502) |
$ |
14,558 | ||||||
|
|
||||||||||||||||||||
|
Basic (loss) / earnings per common share |
$ |
(4.12) |
$ |
0.77 |
$ |
0.73 |
$ |
0.87 |
$ |
0.79 |
$ |
(3.28) |
$ |
1.96 | ||||||
|
Diluted (loss) / earnings per common share |
(4.12) | 0.75 | 0.71 | 0.84 | 0.77 | (3.28) | 1.92 | |||||||||||||
|
|
||||||||||||||||||||
|
Weighted average shares - basic |
9,168,707 | 7,534,264 | 7,488,051 | 7,455,650 | 7,434,726 | 8,069,830 | 7,416,173 | |||||||||||||
|
Weighted average shares - diluted |
9,168,707 | 7,686,385 | 7,682,884 | 7,661,711 | 7,622,428 | 8,069,830 | 7,584,349 | |||||||||||||
8
Avidbank Holdings, Inc. Third Quarter 2025 Financial Results Press Release
|
AVIDBANK HOLDINGS, INC. |
||||||||||||||||
|
Average Balance Sheets and Net Interest Margin Analysis (Unaudited) |
||||||||||||||||
|
(In thousands) |
||||||||||||||||
|
|
||||||||||||||||
|
|
For the Three Months Ended |
|||||||||||||||
|
|
September 30, 2025 |
June 30, 2025 |
||||||||||||||
|
|
Interest |
Yields |
Interest |
Yields |
||||||||||||
|
|
Average |
Income/ |
or |
Average |
Income/ |
or |
||||||||||
|
|
Balance |
Expense |
Rates (5) |
Balance |
Expense |
Rates (5) |
||||||||||
|
Assets |
||||||||||||||||
|
Interest-earning assets: |
||||||||||||||||
|
Loans, net of deferred fees (1) |
$ |
1,924,537 |
$ |
33,880 | 6.98% |
$ |
1,887,263 |
$ |
32,967 | 7.01% | ||||||
|
Fed funds sold / interest-bearing deposits |
189,921 | 2,033 | 4.25% | 73,552 | 793 | 4.32% | ||||||||||
|
Investment securities |
||||||||||||||||
|
Taxable investment securities |
178,637 | 1,126 | 2.50% | 291,074 | 1,672 | 2.30% | ||||||||||
|
Non-taxable investment securities (2) |
2,517 | 39 | 6.15% | 2,566 | 39 | 6.10% | ||||||||||
|
Total investment securities |
181,154 | 1,165 | 2.55% | 293,640 | 1,711 | 2.34% | ||||||||||
|
FHLB stock |
8,409 | 184 | 8.68% | 8,409 | 181 | 8.63% | ||||||||||
|
Total interest-earning assets |
2,304,021 | 37,262 | 6.42% | 2,262,864 | 35,652 | 6.32% | ||||||||||
|
Noninterest-earning assets: |
||||||||||||||||
|
Cash and due from banks |
7,019 | 10,120 | ||||||||||||||
|
All other assets (3) |
46,118 | 49,280 | ||||||||||||||
|
Total assets |
$ |
2,357,158 |
$ |
2,322,264 | ||||||||||||
|
Liabilities and Shareholders' Equity |
||||||||||||||||
|
Interest-bearing liabilities: |
||||||||||||||||
|
Interest-bearing demand deposits |
$ |
1,074,064 |
$ |
9,961 | 3.68% |
$ |
1,038,372 |
$ |
9,483 | 3.66% | ||||||
|
Money market and savings |
433,135 | 3,336 | 3.06% | 398,438 | 3,094 | 3.11% | ||||||||||
|
Time deposits |
43,897 | 365 | 3.30% | 47,398 | 400 | 3.38% | ||||||||||
|
Non-reciprocal brokered deposits |
10,283 | 114 | 4.40% | 62,853 | 692 | 4.42% | ||||||||||
|
Total interest-bearing deposits |
1,561,379 | 13,776 | 3.50% | 1,547,061 | 13,669 | 3.54% | ||||||||||
|
Short-term borrowings |
33,500 | 385 | 4.56% | 108,374 | 1,242 | 4.60% | ||||||||||
|
Subordinated debt |
22,000 | 443 | 7.99% | 22,000 | 443 | 8.08% | ||||||||||
|
Total interest-bearing liabilities |
1,616,879 | 14,604 | 3.58% | 1,677,435 | 15,354 | 3.67% | ||||||||||
|
Noninterest-bearing liabilities: |
||||||||||||||||
|
Demand deposits |
482,849 | 425,154 | ||||||||||||||
|
Accrued expenses and other liabilities |
20,527 | 19,067 | ||||||||||||||
|
Shareholders' equity |
236,903 | 200,608 | ||||||||||||||
|
Total liabilities and shareholders' equity |
$ |
2,357,158 |
$ |
2,322,264 | ||||||||||||
|
|
||||||||||||||||
|
Net interest spread |
2.83% | 2.65% | ||||||||||||||
|
Net interest income and margin (4) |
$ |
22,658 | 3.90% |
$ |
20,298 | 3.60% | ||||||||||
|
Non-taxable equivalent net interest margin |
3.90% | 3.60% | ||||||||||||||
|
Cost of deposits |
$ |
2,044,228 |
$ |
13,776 | 2.67% |
$ |
1,972,215 |
$ |
13,669 | 2.78% | ||||||
|
(1) Nonperforming loans are included in average loan balances. No adjustment has been made for these loans in the calculation of yields. Interest income on loans includes net amortization of deferred loan fees / (costs) of $444 thousand and $314 thousand, for the three months ended September 30, 2025 and June 30, 2025, respectively. |
||||||||||||||||
|
(2) Interest income on tax-exempt securities has been increased to reflect comparable interest on taxable securities. The rate used was 21%, reflecting the statutory federal income tax rate. |
||||||||||||||||
|
(3) Including negative balance on average allowance for credit losses on loans of $20.1 million and $19.1 million, respectively. |
||||||||||||||||
|
(4) Net interest margin is net interest income divided by total interest-earning assets. |
||||||||||||||||
|
(5) Annualized for the periods presented. |
||||||||||||||||
|
|
9
Avidbank Holdings, Inc. Third Quarter 2025 Financial Results Press Release
|
AVIDBANK HOLDINGS, INC. |
|||||||||||||||||
|
Average Balance Sheets and Net Interest Margin Analysis (Unaudited) |
|||||||||||||||||
|
(In thousands) |
|||||||||||||||||
|
|
|||||||||||||||||
|
|
For the Three Months Ended |
||||||||||||||||
|
|
September 30, 2025 |
September 30, 2024 |
|||||||||||||||
|
|
Interest |
Yields |
Interest |
Yields |
|||||||||||||
|
|
Average |
Income/ |
or |
Average |
Income/ |
or |
|||||||||||
|
|
Balance |
Expense |
Rates (5) |
Balance |
Expense |
Rates (5) |
|||||||||||
|
Assets |
|||||||||||||||||
|
Interest-earning assets: |
|||||||||||||||||
|
Loans, net of deferred fees (1) |
$ |
1,924,537 |
$ |
33,880 | 6.98% |
$ |
1,804,107 |
$ |
33,488 | 7.38% | |||||||
|
Fed funds sold / interest-bearing deposits |
189,921 | 2,033 | 4.25% | 87,228 | 1,198 | 5.46% | |||||||||||
|
Investment securities |
|||||||||||||||||
|
Taxable investment securities |
178,637 | 1,126 | 2.50% | 309,624 | 1,745 | 2.24% | |||||||||||
|
Non-taxable investment securities (2) |
2,517 | 39 | 6.15% | 1,826 | 28 | 6.10% | |||||||||||
|
Total investment securities |
181,154 | 1,165 | 2.55% | 311,450 | 1,773 | 2.26% | |||||||||||
|
FHLB stock |
8,409 | 184 | 8.68% | 8,409 | 183 | 8.66% | |||||||||||
|
Total interest-earning assets |
2,304,021 | 37,262 | 6.42% | 2,211,194 | 36,642 | 6.59% | |||||||||||
|
Noninterest-earning assets: |
|||||||||||||||||
|
Cash and due from banks |
7,019 | 12,943 | |||||||||||||||
|
All other assets (3) |
46,118 | 48,486 | |||||||||||||||
|
Total assets |
$ |
2,357,158 |
$ |
2,272,623 | |||||||||||||
|
Liabilities and Shareholders' Equity |
|||||||||||||||||
|
Interest-bearing liabilities: |
|||||||||||||||||
|
Interest-bearing demand deposits |
$ |
1,074,064 |
$ |
9,961 | 3.68% |
$ |
903,542 |
$ |
9,801 | 4.32% | |||||||
|
Money market and savings |
433,135 | 3,336 | 3.06% | 348,125 | 3,067 | 3.50% | |||||||||||
|
Time deposits |
43,897 | 365 | 3.30% | 75,972 | 810 | 4.24% | |||||||||||
|
Non-reciprocal brokered deposits |
10,283 | 114 | 4.40% | 69,670 | 924 | 5.28% | |||||||||||
|
Total interest-bearing deposits |
1,561,379 | 13,776 | 3.50% | 1,397,309 | 14,602 | 4.16% | |||||||||||
|
Short-term borrowings |
33,500 | 385 | 4.56% | 237,370 | 3,121 | 5.23% | |||||||||||
|
Subordinated debt |
22,000 | 443 | 7.99% | 21,970 | 300 | 5.44% | |||||||||||
|
Total interest-bearing liabilities |
1,616,879 | 14,604 | 3.58% | 1,656,649 | 18,023 | 4.33% | |||||||||||
|
Noninterest-bearing liabilities: |
|||||||||||||||||
|
Demand deposits |
482,849 | 408,626 | |||||||||||||||
|
Accrued expenses and other liabilities |
20,527 | 28,088 | |||||||||||||||
|
Shareholders' equity |
236,903 | 179,260 | |||||||||||||||
|
Total liabilities and shareholders' equity |
$ |
2,357,158 |
$ |
2,272,623 | |||||||||||||
|
|
|||||||||||||||||
|
Net interest spread |
2.83% | 2.26% | |||||||||||||||
|
Net interest income and margin (4) |
$ |
22,658 | 3.90% |
$ |
18,619 | 3.35% | |||||||||||
|
Non-taxable equivalent net interest margin |
3.90% | 3.35% | |||||||||||||||
|
Cost of deposits |
$ |
2,044,228 |
$ |
13,776 | 2.67% |
$ |
1,805,935 |
$ |
14,602 | 3.22% | |||||||
|
(1) Nonperforming loans are included in average loan balances. No adjustment has been made for these loans in the calculation of yields. Interest income on loans includes net amortization of deferred loan fees / (costs) of $444 thousand and $383 thousand, for the three months ended September 30, 2025 and September 30, 2024, respectively. |
|||||||||||||||||
|
(2) Interest income on tax-exempt securities has been increased to reflect comparable interest on taxable securities. The rate used was 21%, reflecting the statutory federal income tax rate. |
|||||||||||||||||
|
(3) Including negative balance on average allowance for credit losses on loans of $20.1 million and $22.4 million, respectively. |
|||||||||||||||||
|
(4) Net interest margin is net interest income divided by total interest-earning assets. (5) Annualized for the periods presented. |
|||||||||||||||||
10
Avidbank Holdings, Inc. Third Quarter 2025 Financial Results Press Release
|
AVIDBANK HOLDINGS, INC. |
||||||||||||||||
|
Average Balance Sheets and Net Interest Margin Analysis (Unaudited) |
||||||||||||||||
|
(In thousands) |
||||||||||||||||
|
|
||||||||||||||||
|
|
For the Nine Months Ended |
|||||||||||||||
|
|
September 30, 2025 |
September 30, 2024 |
||||||||||||||
|
|
Interest |
Yields |
Interest |
Yields |
||||||||||||
|
|
Average |
Income/ |
or |
Average |
Income/ |
or |
||||||||||
|
|
Balance |
Expense |
Rates (5) |
Balance |
Expense |
Rates (5) |
||||||||||
|
Assets |
||||||||||||||||
|
Interest earning assets: |
||||||||||||||||
|
Loans, net of deferred fees (1) |
$ |
1,890,413 |
$ |
98,732 | 6.98% |
$ |
1,791,479 |
$ |
98,570 | 7.35% | ||||||
|
Fed funds sold/interest bearing deposits |
109,743 | 3,532 | 4.30% | 72,424 | 2,968 | 5.47% | ||||||||||
|
Investment securities |
||||||||||||||||
|
Taxable investment securities |
254,061 | 4,517 | 2.38% | 310,891 | 5,325 | 2.29% | ||||||||||
|
Non-taxable investment securities (2) |
2,589 | 116 | 5.99% | 1,832 | 84 | 6.12% | ||||||||||
|
Total investment securities |
256,650 | 4,633 | 2.41% | 312,723 | 5,409 | 2.31% | ||||||||||
|
FHLB stock |
8,409 | 550 | 8.74% | 8,409 | 567 | 9.01% | ||||||||||
|
Total interest-earning assets |
2,265,215 | 107,447 | 6.34% | 2,185,035 | 107,514 | 6.57% | ||||||||||
|
Noninterest-earning assets: |
||||||||||||||||
|
Cash and due from banks |
9,975 | 12,723 | ||||||||||||||
|
All other assets (3) |
48,175 | 55,971 | ||||||||||||||
|
Total assets |
$ |
2,323,365 |
$ |
2,253,729 | ||||||||||||
|
Liabilities and Shareholders' Equity |
||||||||||||||||
|
Interest-bearing liabilities: |
||||||||||||||||
|
Interest-bearing demand deposits |
$ |
1,023,572 |
$ |
27,974 | 3.65% |
$ |
811,505 |
$ |
25,272 | 4.16% | ||||||
|
Money market and savings |
405,844 | 9,301 | 3.06% | 318,811 | 7,935 | 3.32% | ||||||||||
|
Time deposits |
50,466 | 1,323 | 3.51% | 76,725 | 2,400 | 4.18% | ||||||||||
|
Non-reciprocal brokered deposits |
49,978 | 1,674 | 4.48% | 113,199 | 4,523 | 5.34% | ||||||||||
|
Total interest-bearing deposits |
1,529,860 | 40,272 | 3.52% | 1,320,240 | 40,130 | 4.06% | ||||||||||
|
Short-term borrowings |
103,495 | 3,538 | 4.57% | 271,427 | 10,443 | 5.14% | ||||||||||
|
Subordinated debt |
22,000 | 1,321 | 8.03% | 21,944 | 901 | 5.48% | ||||||||||
|
Total interest-bearing liabilities |
1,655,355 | 45,131 | 3.65% | 1,613,611 | 51,474 | 4.26% | ||||||||||
|
Noninterest-bearing liabilities: |
||||||||||||||||
|
Demand deposits |
438,199 | 442,617 | ||||||||||||||
|
Accrued expenses and other liabilities |
19,846 | 26,458 | ||||||||||||||
|
Shareholders' equity |
209,965 | 171,043 | ||||||||||||||
|
Total liabilities and shareholders' equity |
$ |
2,323,365 |
$ |
2,253,729 | ||||||||||||
|
|
||||||||||||||||
|
Net interest spread |
2.70% | 2.31% | ||||||||||||||
|
Net interest income and margin (4) |
$ |
62,316 | 3.68% |
$ |
56,040 | 3.42% | ||||||||||
|
Non-taxable equivalent net interest margin |
3.68% | 3.42% | ||||||||||||||
|
Cost of deposits |
$ |
1,968,059 |
$ |
40,272 | 2.74% |
$ |
1,762,857 |
$ |
40,130 | 3.04% | ||||||
|
(1) Nonperforming loans are included in average loan balances. No adjustment has been made for these loans in the calculation of yields. Interest income on loans includes amortization of deferred loan fees / (costs) of $1.4 million and $1.2 million, for the nine months ended September 30, 2025 and September 30, 2024, respectively. |
||||||||||||||||
|
(2) Interest income on tax-exempt securities has been increased to reflect comparable interest on taxable securities. The rate used was 21%, reflecting the statutory federal income tax rate. |
||||||||||||||||
|
(3) Including negative balance on average allowance for credit losses on loans of $19.3 million and $20.5 million, respectively. |
||||||||||||||||
|
(4) Net interest margin is net interest income divided by total interest-earning assets. |
||||||||||||||||
|
(5) Annualized for the periods presented. |
||||||||||||||||
11
Avidbank Holdings, Inc. Third Quarter 2025 Financial Results Press Release
|
|
||||||||||||||||||||
|
AVIDBANK HOLDINGS, INC. |
||||||||||||||||||||
|
Asset Quality Data (Unaudited) |
||||||||||||||||||||
|
(In thousands) |
||||||||||||||||||||
|
|
||||||||||||||||||||
|
|
Sept. 30, |
June 30, |
March 31, |
Dec. 31, |
Sept. 30, |
As of/For the Year-to-Date Period Ended September 30, |
||||||||||||||
|
|
2025 |
2025 |
2025 |
2024 |
2024 |
2025 |
2024 |
|||||||||||||
|
Allowance for Credit Losses on Loans |
||||||||||||||||||||
|
Balance, beginning of period |
$ |
19,624 |
$ |
18,722 |
$ |
18,679 |
$ |
22,315 |
$ |
22,410 |
$ |
18,679 |
$ |
19,131 | ||||||
|
Provision for credit losses on loans |
1,364 | 891 |
– |
630 |
– |
2,255 | 3,279 | |||||||||||||
|
Charge-offs |
– |
– |
– |
(4,266) | (95) |
– |
(95) | |||||||||||||
|
Recoveries |
37 | 11 | 43 |
– |
– |
91 |
– |
|||||||||||||
|
Balance, end of period |
$ |
21,025 |
$ |
19,624 |
$ |
18,722 |
$ |
18,679 |
$ |
22,315 |
$ |
21,025 |
$ |
22,315 | ||||||
|
Allowance for Credit Losses on Unfunded Commitments |
||||||||||||||||||||
|
Balance, beginning of period |
$ |
2,281 |
$ |
2,247 |
$ |
2,247 |
$ |
2,098 |
$ |
2,098 |
$ |
2,247 |
$ |
2,060 | ||||||
|
Provision for unfunded commitments |
(9) | 34 |
– |
149 |
– |
25 | 38 | |||||||||||||
|
Balance, end of period |
$ |
2,272 |
$ |
2,281 |
$ |
2,247 |
$ |
2,247 |
$ |
2,098 |
$ |
2,272 |
$ |
2,098 | ||||||
|
Total allowance for credit losses - loans and unfunded commitments |
$ |
23,297 |
$ |
21,905 |
$ |
20,969 |
$ |
20,926 |
$ |
24,413 |
$ |
23,297 |
$ |
24,413 | ||||||
|
Provision for credit losses |
||||||||||||||||||||
|
Provision for credit losses on loans |
$ |
1,364 |
$ |
891 |
$ |
– |
$ |
630 |
$ |
– |
$ |
2,255 |
$ |
3,279 | ||||||
|
Provision for unfunded commitments |
(9) | 34 |
– |
149 |
– |
25 | 38 | |||||||||||||
|
Total provision for credit losses |
$ |
1,355 |
$ |
925 |
$ |
– |
$ |
779 |
$ |
– |
$ |
2,280 |
$ |
3,317 | ||||||
|
Nonperforming Assets |
||||||||||||||||||||
|
Loans accounted for on a non-accrual basis |
$ |
2,748 |
$ |
1,332 |
$ |
1,340 |
$ |
1,347 |
$ |
3,621 |
$ |
2,748 |
$ |
3,621 | ||||||
|
Loans past due 90 days or more and still accruing |
– |
– |
– |
– |
– |
– |
– |
|||||||||||||
|
Nonperforming loans |
2,748 | 1,332 | 1,340 | 1,347 | 3,621 | 2,748 | 3,621 | |||||||||||||
|
Other real estate owned |
– |
– |
– |
– |
– |
– |
– |
|||||||||||||
|
Nonperforming assets |
$ |
2,748 |
$ |
1,332 |
$ |
1,340 |
$ |
1,347 |
$ |
3,621 |
$ |
2,748 |
$ |
3,621 | ||||||
|
Nonperforming Loans by Type: |
||||||||||||||||||||
|
Commercial |
$ |
2,748 |
$ |
1,332 |
$ |
1,340 |
$ |
1,347 |
$ |
3,621 |
$ |
2,748 |
$ |
3,621 | ||||||
|
Total Nonperforming loans |
$ |
2,748 |
$ |
1,332 |
$ |
1,340 |
$ |
1,347 |
$ |
3,621 |
$ |
2,748 |
$ |
3,621 | ||||||
|
|
||||||||||||||||||||
|
Asset Quality Ratios |
||||||||||||||||||||
|
Allowance for credit losses on loans to total loans |
1.07% | 1.03% | 1.02% | 1.00% | 1.25% | 1.07% | 1.25% | |||||||||||||
|
Total allowance for credit losses-loans and unfunded commitments |
1.19% | 1.15% | 1.14% | 1.12% | 1.37% | 1.19% | 1.37% | |||||||||||||
|
Allowance for credit losses on loans to nonperforming loans |
765.10% | 1473.27% | 1397.16% | 1386.71% | 616.27% | 765.10% | 616.27% | |||||||||||||
|
Nonperforming assets to total assets |
0.12% | 0.06% | 0.06% | 0.06% | 0.16% | 0.12% | 0.16% | |||||||||||||
|
Nonperforming loans to total loans |
0.14% | 0.07% | 0.07% | 0.07% | 0.20% | 0.14% | 0.20% | |||||||||||||
|
Net charge-offs to average loans (1) |
-0.01% |
0.00% |
-0.01% |
0.93% | 0.02% |
-0.01% |
0.01% | |||||||||||||
|
Criticized loans to total loans |
1.48% | 1.87% | 1.43% | 2.27% | 1.62% | 1.48% | 1.62% | |||||||||||||
|
Classified loans to total loans |
0.44% | 0.38% | 0.20% | 0.22% | 0.51% | 0.44% | 0.51% | |||||||||||||
|
(1) Annualized for the periods presented. |
||||||||||||||||||||
|
|
12
Avidbank Holdings, Inc. Third Quarter 2025 Financial Results Press Release
|
AVIDBANK HOLDINGS, INC. |
|||||||||||||||||||||
|
Loans and Deposits (Unaudited) |
|||||||||||||||||||||
|
(In thousands) |
|||||||||||||||||||||
|
|
Current |
Year |
|||||||||||||||||||
|
|
Sept. 30, |
June 30, |
March 31, |
Dec. 31, |
Sept. 30, |
Quarter |
Over Year |
||||||||||||||
|
|
2025 |
2025 |
2025 |
2024 |
2024 |
Change |
Change |
||||||||||||||
|
Loans |
|||||||||||||||||||||
|
Commercial and industrial loans |
$ |
871,524 |
$ |
855,049 |
$ |
803,920 |
$ |
816,963 |
$ |
759,492 |
$ |
16,475 |
$ |
112,032 | |||||||
|
Commercial real estate |
|||||||||||||||||||||
|
Multi-family |
249,802 | 241,399 | 227,003 | 216,018 | 199,929 | 8,403 | 49,873 | ||||||||||||||
|
Owner Occupied |
176,171 | 168,393 | 142,764 | 142,650 | 141,139 | 7,778 | 35,032 | ||||||||||||||
|
Non-Owner Occupied |
412,623 | 407,955 | 405,788 | 414,551 | 406,007 | 4,668 | 6,616 | ||||||||||||||
|
Construction and land |
209,750 | 204,973 | 226,641 | 246,301 | 253,325 | 4,777 | (43,575) | ||||||||||||||
|
Residential |
36,399 | 31,560 | 32,985 | 27,494 | 25,799 | 4,839 | 10,600 | ||||||||||||||
|
Total real estate loans |
1,084,745 | 1,054,280 | 1,035,181 | 1,047,014 | 1,026,199 | 30,465 | 58,546 | ||||||||||||||
|
Other loans |
2,316 | 2,389 | 2,086 | 965 | 1,065 | (73) | 1,251 | ||||||||||||||
|
Total loans, net of deferred fees |
$ |
1,958,585 |
$ |
1,911,718 |
$ |
1,841,187 |
$ |
1,864,942 |
$ |
1,786,756 |
$ |
46,867 |
$ |
171,829 | |||||||
|
|
|||||||||||||||||||||
|
Deposits |
|||||||||||||||||||||
|
Noninterest-bearing demand |
$ |
471,770 |
$ |
443,540 |
$ |
419,823 |
$ |
414,327 |
$ |
405,528 |
$ |
28,230 |
$ |
66,242 | |||||||
|
Interest-bearing checking |
1,069,344 | 1,087,621 | 965,467 | 993,219 | 1,026,898 | (18,277) | 42,446 | ||||||||||||||
|
Money market and savings |
465,198 | 399,849 | 399,010 | 338,578 | 336,166 | 65,349 | 129,032 | ||||||||||||||
|
Time |
42,846 | 46,770 | 58,273 | 74,468 | 75,033 | (3,924) | (32,187) | ||||||||||||||
|
Non-reciprocal brokered (1) |
– |
25,001 | 86,915 | 70,763 | 57,903 | (25,001) | (57,903) | ||||||||||||||
|
Total deposits |
$ |
2,049,158 |
$ |
2,002,781 |
$ |
1,929,488 |
$ |
1,891,355 |
$ |
1,901,528 |
$ |
46,377 |
$ |
147,630 | |||||||
|
|
|||||||||||||||||||||
|
Average Deposits |
|||||||||||||||||||||
|
Noninterest-bearing demand |
$ |
482,849 |
$ |
425,154 |
$ |
405,746 |
$ |
422,807 |
$ |
408,626 |
$ |
57,695 |
$ |
74,223 | |||||||
|
Interest-bearing checking |
1,074,064 | 1,038,372 | 956,994 | 994,121 | 903,542 | 35,692 | 170,522 | ||||||||||||||
|
Money market and savings |
433,135 | 398,438 | 385,434 | 351,126 | 348,125 | 34,697 | 85,010 | ||||||||||||||
|
Time |
43,897 | 47,398 | 60,282 | 77,203 | 75,972 | (3,501) | (32,075) | ||||||||||||||
|
Non-reciprocal brokered |
10,283 | 62,853 | 77,537 | 49,064 | 69,670 | (52,570) | (59,387) | ||||||||||||||
|
Total deposits |
$ |
2,044,228 |
$ |
1,972,215 |
$ |
1,885,993 |
$ |
1,894,321 |
$ |
1,805,935 |
$ |
72,013 |
$ |
238,293 | |||||||
|
|
|||||||||||||||||||||
|
(1) FDIC regulations impose a general cap on reciprocal deposits that may be exempt from brokered deposits classification equal to 20% of the Bank’s total liabilities. As of September 30, 2025, June 30, 2025, March 31, 2025, December 31, 2024 and September 30, 2024, an additional $522.5 million, $495.4 million, $447.8 million, $470.0 million and $509.3 million of our deposits were considered brokered deposits by the FDIC due to being in excess of the general cap, respectively. |
|||||||||||||||||||||
13
Avidbank Holdings, Inc. Third Quarter 2025 Financial Results Press Release
|
AVIDBANK HOLDINGS, INC. |
|||||||||||||||||||||||
|
Non-GAAP Performance and Financial Measures Reconciliation (Unaudited) |
|||||||||||||||||||||||
|
(In thousands) |
|||||||||||||||||||||||
|
|
|||||||||||||||||||||||
|
Management believes that adjusted net income, adjusted diluted earnings per share, adjusted return on average assets, adjusted return on average equity, adjusted efficiency ratio, taxable equivalent net interest income and taxable equivalent net interest margin are reasonable measures to understand the Company’s core operating performance and are important to many investors who are interested in understanding our profitability prospects from our core operations. In addition, management reviews yields on certain asset categories and the net interest margin of the Company on a fully taxable equivalent basis. The non-GAAP taxable equivalent net interest income and net interest margin adjustments facilitate performance comparisons between taxable and tax-free assets by increasing the tax-free income by an amount equivalent to the Federal income taxes that would have been paid if this income were taxable at the Company's 21% Federal statutory rate. |
|||||||||||||||||||||||
|
|
|||||||||||||||||||||||
|
|
For the Three Months Ended |
For the Nine Months Ended |
|||||||||||||||||||||
|
|
Sept. 30, |
June 30, |
March 31, |
Dec. 31, |
Sept. 30, |
Sept. 30, |
Sept. 30, |
||||||||||||||||
|
|
2025 |
2025 |
2025 |
2024 |
2024 |
2025 |
2024 |
||||||||||||||||
|
Non-GAAP adjusted net income reconciliation |
|||||||||||||||||||||||
|
Net income - GAAP |
$ |
(37,735) |
$ |
5,797 |
$ |
5,436 |
$ |
6,457 |
$ |
5,846 |
$ |
(26,502) |
$ |
14,558 | |||||||||
|
Loss on sale of securities |
62,391 |
– |
– |
– |
– |
62,391 |
– |
||||||||||||||||
|
Tax impact of loss on sale of securities |
(17,949) |
– |
– |
– |
– |
(17,949) |
– |
||||||||||||||||
|
Net income - adjusted (non-GAAP) |
$ |
6,707 |
$ |
5,797 |
$ |
5,436 |
$ |
6,457 |
$ |
5,846 |
$ |
17,940 |
$ |
14,558 | |||||||||
|
|
|||||||||||||||||||||||
|
Non-GAAP adjusted diluted earnings per share reconciliation |
|||||||||||||||||||||||
|
Diluted earnings per share - GAAP |
$ |
(4.12) |
$ |
0.75 |
$ |
0.71 |
$ |
0.84 |
$ |
0.77 |
$ |
(3.28) |
$ |
1.92 | |||||||||
|
Loss on sale of securities, net of income tax |
4.84 |
– |
– |
– |
– |
5.46 |
– |
||||||||||||||||
|
Diluted earnings per share - adjusted (non-GAAP) |
$ |
0.72 |
$ |
0.75 |
$ |
0.71 |
$ |
0.84 |
$ |
0.77 |
$ |
2.18 |
$ |
1.92 | |||||||||
|
|
|||||||||||||||||||||||
|
Non-GAAP adjusted return on average assets reconciliation |
|||||||||||||||||||||||
|
Net income - GAAP |
$ |
(37,735) |
$ |
5,797 |
$ |
5,436 |
$ |
6,457 |
$ |
5,846 |
$ |
(26,502) |
$ |
14,558 | |||||||||
|
Average total assets |
2,357,158 | 2,322,264 | 2,289,935 | 2,250,086 | 2,272,623 | 2,323,365 | 2,253,729 | ||||||||||||||||
|
Return on average assets - GAAP (1) |
(6.35) |
% |
1.00 |
% |
0.96 |
% |
1.14 |
% |
1.02 |
% |
(1.53) |
% |
0.86 |
% |
|||||||||
|
|
|||||||||||||||||||||||
|
Net income - adjusted (non-GAAP) |
$ |
6,707 |
$ |
5,797 |
$ |
5,436 |
$ |
6,457 |
$ |
5,846 |
$ |
17,940 |
$ |
14,558 | |||||||||
|
Average total assets |
2,357,158 | 2,322,264 | 2,289,935 | 2,250,086 | 2,272,623 | 2,323,365 | 2,253,729 | ||||||||||||||||
|
Return on average assets - adjusted (non-GAAP) (1) |
1.13 |
% |
1.00 |
% |
0.96 |
% |
1.14 |
% |
1.02 |
% |
1.03 |
% |
0.86 |
% |
|||||||||
|
|
|||||||||||||||||||||||
|
Non-GAAP adjusted return on average equity reconciliation |
|||||||||||||||||||||||
|
Net income - GAAP |
$ |
(37,735) |
$ |
5,797 |
$ |
5,436 |
$ |
6,457 |
$ |
5,846 |
$ |
(26,502) |
$ |
14,558 | |||||||||
|
Average total equity |
236,903 | 200,608 | 191,891 | 188,170 | 179,260 | 209,965 | 171,043 | ||||||||||||||||
|
Return on average equity - GAAP (1) |
(63.19) |
% |
11.59 |
% |
11.49 |
% |
13.65 |
% |
12.97 |
% |
(16.88) |
% |
11.37 |
% |
|||||||||
|
|
|||||||||||||||||||||||
|
Net income - adjusted (non-GAAP) |
$ |
6,707 | 5,797 | 5,436 | 6,457 | 5,846 | 17,940 | 14,558 | |||||||||||||||
|
Average total equity |
236,903 | 200,608 | 191,891 | 188,170 | 179,260 | 209,965 | 171,043 | ||||||||||||||||
|
Return on average equity - adjusted (non-GAAP) (1) |
11.23 |
% |
11.59 |
% |
11.49 |
% |
13.65 |
% |
12.97 |
% |
11.42 |
% |
11.37 |
% |
|||||||||
14
Avidbank Holdings, Inc. Third Quarter 2025 Financial Results Press Release
|
Non-GAAP adjusted efficiency ratio reconciliation |
|||||||||||||||||||||||
|
Noninterest expense |
$ |
13,479 |
$ |
12,609 |
$ |
12,842 |
$ |
11,052 |
$ |
12,097 |
$ |
38,930 |
$ |
36,280 | |||||||||
|
Net interest income |
22,650 | 20,290 | 19,352 | 19,199 | 18,613 | 62,292 | 56,023 | ||||||||||||||||
|
Noninterest income |
(60,852) | 1,538 | 1,171 | 1,840 | 1,790 | (58,143) | 4,170 | ||||||||||||||||
|
Efficiency ratio - GAAP |
(35.28) |
% |
57.77 |
% |
62.57 |
% |
52.53 |
% |
59.29 |
% |
938.30 |
% |
60.27 |
% |
|||||||||
|
|
|||||||||||||||||||||||
|
Noninterest expense |
$ |
13,479 |
$ |
12,609 |
$ |
12,842 |
$ |
11,052 |
$ |
12,097 |
$ |
38,930 |
$ |
36,280 |
– |
||||||||
|
Net interest income |
22,650 | 20,290 | 19,352 | 19,199 | 18,613 | 62,292 | 56,023 | ||||||||||||||||
|
Noninterest income |
(60,852) | 1,538 | 1,171 | 1,840 | 1,790 | (58,143) | 4,170 | ||||||||||||||||
|
Loss on sale of securities |
62,391 |
– |
– |
– |
– |
62,391 |
– |
||||||||||||||||
|
Noninterest income – adjusted (non-GAAP) |
1,539 | 1,538 | 1,171 | 1,840 | 1,790 | 4,248 | 4,170 | ||||||||||||||||
|
Efficiency ratio - adjusted (non-GAAP) |
55.72 |
% |
57.77 |
% |
62.57 |
% |
52.53 |
% |
59.29 |
% |
58.51 |
% |
60.27 |
% |
|||||||||
|
|
|||||||||||||||||||||||
|
Non-GAAP taxable equivalent net interest income reconciliation |
|||||||||||||||||||||||
|
Net interest income - GAAP |
$ |
22,650 |
$ |
20,290 |
$ |
19,352 |
$ |
19,199 |
$ |
18,613 |
$ |
62,292 |
$ |
56,023 | |||||||||
|
Taxable equivalent adjustment |
8 | 8 | 8 | 7 | 6 | 24 | 17 | ||||||||||||||||
|
Net interest income - taxable equivalent (non-GAAP) |
$ |
22,658 |
$ |
20,298 |
$ |
19,360 |
$ |
19,206 |
$ |
18,619 |
$ |
62,316 |
$ |
56,040 | |||||||||
|
|
|||||||||||||||||||||||
|
Non-GAAP taxable equivalent net interest margin reconciliation |
|||||||||||||||||||||||
|
Net interest margin - GAAP (1) |
3.90 |
% |
3.60 |
% |
3.52 |
% |
3.48 |
% |
3.35 |
% |
3.68 |
% |
3.42 |
% |
|||||||||
|
Impact of taxable equivalent adjustment |
– |
– |
– |
0.01 |
– |
– |
– |
||||||||||||||||
|
Net interest margin - taxable equivalent (non-GAAP) (1) |
3.90 |
% |
3.60 |
% |
3.52 |
% |
3.49 |
% |
3.35 |
% |
3.68 |
% |
3.42 |
% |
|||||||||
|
|
|
(1) |
Annualized for the periods presented. |
15