U
0000831001false00008310012020-04-152020-04-150000831001us-gaap:CommonStockMember2020-04-152020-04-150000831001c:VelocitySharesShortLIBORETNsDueAugust162032OfCGMHIMember2020-04-152020-04-150000831001c:VelocitySharesLongLIBORETNsDueAugust162032OfCGMHIMember2020-04-152020-04-150000831001c:VelocityShares3xLongCrudeOilETNsLinkedToTheSPGSCICrudeOilIndexERDueDecember152031OfCGMHIMember2020-04-152020-04-150000831001c:VelocityShares3xInverseCrudeOilETNsLinkedToTheSPGSCICrudeOilIndexERDueDecember152031OfCGMHIMember2020-04-152020-04-150000831001c:SixPointEightTwoNinePercentFixedRateFloatingRateEnhancedTrustPreferredSecuritiesOfCitigroupCapitalXVIIIMember2020-04-152020-04-150000831001c:SevenPointSixTwoFivePercentTrustPreferredSecuritiesOfCitigroupCapitalIIIMember2020-04-152020-04-150000831001c:SevenPointEightSevenFivePercentFixedRateFloatingRateTrustPreferredSecuritiesOfCitigroupCapitalXIIIMember2020-04-152020-04-150000831001c:ExchangeTradedNotesBasedOnThePerformanceOfTheVelocitySharesDaily4XLongUSDVs.JPYIndexDueDecember152032OfCGMHIMember2020-04-152020-04-150000831001c:ExchangeTradedNotesBasedOnThePerformanceOfTheVelocitySharesDaily4XLongUSDVs.GBPIndexDueDecember152032OfCGMHIMember2020-04-152020-04-150000831001c:ExchangeTradedNotesBasedOnThePerformanceOfTheVelocitySharesDaily4XLongUSDVs.EURIndexDueDecember152032OfCGMHIMember2020-04-152020-04-150000831001c:ExchangeTradedNotesBasedOnThePerformanceOfTheVelocitySharesDaily4XLongUSDVs.CHFIndexDueDecember152032OfCGMHIMember2020-04-152020-04-150000831001c:ExchangeTradedNotesBasedOnThePerformanceOfTheVelocitySharesDaily4XLongUSDVs.AUDIndexDueDecember152032OfCGMHIMember2020-04-152020-04-150000831001c:ExchangeTradedNotesBasedOnThePerformanceOfTheVelocitySharesDaily4XLongJPYVs.USDIndexDueDecember152032OfCGMHIMember2020-04-152020-04-150000831001c:ExchangeTradedNotesBasedOnThePerformanceOfTheVelocitySharesDaily4XLongGBPVs.USDIndexDueDecember152032OfCGMHIMember2020-04-152020-04-150000831001c:ExchangeTradedNotesBasedOnThePerformanceOfTheVelocitySharesDaily4XLongEURVs.USDIndexDueDecember152032OfCGMHIMember2020-04-152020-04-150000831001c:ExchangeTradedNotesBasedOnThePerformanceOfTheVelocitySharesDaily4XLongCHFVs.USDIndexDueDecember152032OfCGMHIMember2020-04-152020-04-150000831001c:ExchangeTradedNotesBasedOnThePerformanceOfTheVelocitySharesDaily4XLongAUDVs.USDIndexDueDecember152032OfCGMHIMember2020-04-152020-04-150000831001c:DepositorySharesRepresenting11000thInterestInShareOf7.125NoncumulativePreferredStockSeriesJMember2020-04-152020-04-150000831001c:DepositorySharesRepresenting11000thInterestInAShareOf6.875NoncumulativePreferredStockSeriesKMember2020-04-152020-04-150000831001c:DepositorySharesRepresenting11000thInterestInAShareOf6.300NoncumulativePreferredStockSeriesSMember2020-04-152020-04-150000831001c:CTracksExchangeTradedNotesOnTheMillerHowardMLPFundamentalIndexSeriesBDueJuly132026Member2020-04-152020-04-150000831001c:CTracksExchangeTradedNotesMillerHowardStrategicDividendReinvestorDueSeptember162024Member2020-04-152020-04-150000831001c:CTracksExchangeTradedNotesBasedOnThePerformanceOfTheMillerHowardMLPFundamentalIndexDueSeptember282023Member2020-04-152020-04-15

​

UNITED STATES

SECURITIES AND EXCHANGE COMMISSION

WASHINGTON, D.C. 20549

FORM 8-K

​

CURRENT REPORT

​
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934

​

Date of Report (Date of earliest event reported) April 15, 2020

Citigroup Inc.

(Exact name of registrant as specified in its charter)

​

​

​

​

Delaware

1-9924

52-1568099

(State or other jurisdiction
of incorporation)

(Commission
File Number)

(IRS Employer
Identification No.)

​

​

​

388 Greenwich Street, New York,
NY

(Address of principal executive offices)

​

10013
(Zip Code)

​

(212) 559-1000

(Registrant's telephone number,
including area code)

​

Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:

​

☐ Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425)

​

☐ Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12)

​

☐ Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))

​

☐ Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))

​

Securities registered pursuant to Section 12(b) of the Securities Exchange Act of 1934 formatted in Inline XBRL: See Exhibit 99.3

​

Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter). Emerging growth company ☐

​

If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ◻

​

​

CITIGROUP INC.

Current Report on Form 8-K

​

Item 2.02 Results of Operations and Financial Condition.

​

On April 15, 2020, Citigroup Inc. announced its results for the quarter ended March 31, 2020. A copy of the related press release, filed as Exhibit 99.1 to this Form 8-K, is incorporated herein by reference in its entirety and shall be deemed to be “filed” for purposes of the Securities Exchange Act of 1934, as amended (the Act).

​

In addition, a copy of the Citigroup Inc. Quarterly Financial Data Supplement for the quarter ended March 31, 2020 is being furnished as Exhibit 99.2 to this Form 8-K and shall not be deemed to be “filed” for purposes of Section 18 of the Act or otherwise subject to the liabilities of that section.

​

Item 9.01 Financial Statements and Exhibits.

​
(d) Exhibits.

​

​

​

​

Exhibit Number

​

​

​

​

​

99.1

​

Citigroup Inc. press release dated April 15, 2020.

99.2

​

Citigroup Inc. Quarterly Financial Data Supplement for the quarter ended March 31, 2020.

99.3

​

Citigroup Inc. securities registered pursuant to Section 12(b) of the Securities Exchange Act of 1934 as of the filing date.

104.1

​

See the cover page of this Current Report on Form 8-K, formatted in Inline XBRL.

​

​

SIGNATURE

​

Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.

​

​

​

​

​

​

CITIGROUP INC.

Dated: April 15, 2020

​

​

​

By:

/s/ Jeffrey R. Walsh

​

​

Jeffrey R. Walsh

​

​

Interim Controller and Chief Accounting Officer

​

​

(Principal Accounting Officer)

​

​

​

Exhibit 99.1

For Immediate Release

Citigroup Inc. (NYSE: C)

April 15, 2020


Picture 13

FIRST QUARTER 2020 RESULTS AND KEY METRICS

Picture 1


CEO COMMENTARY

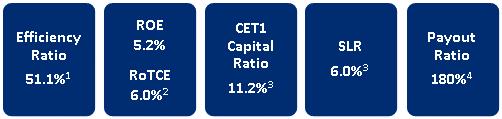
NET INCOME OF $2.5 BILLION ($1.05 PER SHARE)

REVENUES OF $20.7 BILLION

RETURNED $4.0 BILLION OF CAPITAL TO COMMON SHAREHOLDERS

REPURCHASED 41 MILLION COMMON SHARES5

BOOK VALUE PER SHARE OF $83.75

TANGIBLE BOOK VALUE PER SHARE OF $71.526


New York, April 15, 2020 – Citigroup Inc. today reported net income for the first quarter 2020 of $2.5 billion, or $1.05 per diluted share, on revenues of $20.7 billion. This compared to net income of $4.7 billion, or $1.87 per diluted share, on revenues of $18.6 billion for the first quarter 2019.


Revenues increased 12% from the prior-year period, primarily reflecting higher revenues in Fixed Income Markets and Equity Markets, and the benefit of mark-to-market gains on loan hedges in the corporate lending portfolio, all in the Institutional Clients Group (ICG). Net income declined 46% from the prior-year period, driven by higher loan loss reserves, reflecting the impact of changes in Citi’s economic outlook on estimated lifetime losses under the new Current Expected Credit Loss standard (CECL). Earnings per share of $1.05 decreased 44% from the prior-year period, as the decline in net income was partially offset by a 10% reduction in average diluted shares outstanding.


Percentage comparisons throughout this press release are calculated for the first quarter 2020 versus the first quarter 2019, unless otherwise specified.


Michael Corbat, Citi CEO, said, “Our earnings for the first quarter were significantly impacted by the  COVID-19 pandemic. We managed our expenses with discipline and had good revenue performance as the economic shocks caused by the pandemic weren’t felt until late in the quarter. However, the deteriorating economic outlook and the transition to the new Current Expected Credit Loss standard (CECL) caused us to build significant loan loss reserves.

“COVID-19 is a public health crisis with severe economic ramifi-cations.  All of the work we have done in recent years has put us in a very strong position from a capital, liquidity and balance sheet pers-pective. While no one knows the severity or longevity of the virus’ impact on the global economy,  we have the resources we need to serve our clients without jeopard-izing our safety and soundness.  

“I want to thank our 200,000 people around the world who have had to work differently but have brought their same dedication and pride to their jobs each and every day. They have supported our clients, our communities and each other and I could not be prouder of them,” Mr. Corbat concluded.


1


Citigroup
($ in millions, except as otherwise noted)


1Q'20


4Q'19


1Q'19


QoQ%


YoY%

Global Consumer Banking


8,174


8,459


8,090


(3)%


1%

Institutional Clients Group


12,484


9,377


10,018


33%


25%

Corporate / Other


73


542


468


(87)%


(84)%

Total Revenues


$

20,731


$

18,378


$

18,576


13%


12%


Expenses


$

10,594


$

10,454


$

10,584


1%


-


Net Credit Losses


2,108


1,944


1,948


8%


8%

Credit Reserve Build / (Release)(a)


4,893


253


20


NM


NM

Other Provisions(b)


26


25


12


4%


NM

Total Cost of Credit


$

7,027


$

2,222


$

1,980


NM


NM


Income from Continuing Operations Before Taxes


$

3,110


$

5,702


$

6,012


(45)%


(48)%

Provision for Income Taxes


576


703


1,275


(18)%


(55)%

Income from Continuing Operations


$

2,534


$

4,999


$

4,737


(49)%


(47)%

Net Income (Loss) from Discontinued Operations


(18)


(4)


(2)


NM


NM

Non-Controlling Interest


(6)


16


25


NM


NM

Citigroup Net Income


$

2,522


$

4,979


$

4,710


(49)%


(46)%


Revenues


North America


10,171


8,567


8,269


19%


23%

EMEA


3,470


2,738


3,170


27%


9%

Latin America


2,617


2,674


2,540


(2)%


3%

Asia


4,400


3,857


4,129


14%


7%

Corporate / Other


73


542


468


(87)%


(84)%


EOP Assets ($B)


2,220


1,951


1,958


14%


13%

EOP Loans ($B)


721


699


682


3%


6%

EOP Deposits ($B)


1,185


1,071


1,030


11%


15%


Common Equity Tier 1 Capital Ratio(3)


11.2%


11.8%


11.9%


Supplementary Leverage Ratio(3)


6.0%


6.2%


6.4%


Return on Average Common Equity


5.2%


10.6%


10.2%


Book Value per Share


$

83.75


$

82.90


$

77.09


1%


9%

Tangible Book Value per Share


$

71.52


$

70.39


$

65.55


2%


9%


Note:  Please refer to the Appendices and Footnotes at the end of this press release for additional information.

(a) Includes provision for unfunded lending commitments.

(b) Includes provisions for benefits and claims, HTM debt securities and other assets.


Citigroup

Citigroup revenues of $20.7 billion in the first quarter 2020 increased 12%, primarily reflecting the higher revenues in Fixed Income and Equity Markets, as well as the benefit of mark-to-market gains on loan hedges in Corporate Lending.


Citigroup operating expenses of $10.6 billion in the first quarter 2020 were largely unchanged,  as continued investments in the franchise,  higher compensation and volume-related expenses were offset by productivity savings and the wind-down of legacy assets.


Citigroup cost of credit of $7.0 billion in the first quarter 2020 compared to $2.0 billion in the prior-year period,  reflecting the loan loss reserve builds related to the impact of changes in Citi’s economic outlook on estimated lifetime losses under the CECL standard.


Citigroup net income of $2.5 billion in the first quarter 2020 declined 46%, driven by the higher cost of credit, partially offset by the higher revenues and a lower effective tax rate. Citigroup’s effective tax rate was 19% in the current quarter compared to 21% in the first quarter 2019, reflecting a small benefit associated with stock-based incentive compensation.


2

Citigroup’s allowance for loan losses was $20.8 billion at quarter end, or 2.91% of total loans, compared to $12.3 billion, or 1.82% of total loans, at the end of the prior-year period. Total non-accrual assets grew 12% from the prior-year period to $4.2  billion. Consumer non-accrual loans declined 13% to $1.7 billion and corporate non-accrual loans grew 43% to $2.5  billion.


Citigroup’s end-of-period loans were $721 billion as of quarter end, up 6% from the prior-year period. Excluding the impact of foreign exchange translation7, end-of-period loans grew 8%, driven by 9% aggregate growth in ICG and Global Consumer Banking (GCB), partially offset by the continued wind-down of legacy assets in Corporate / Other.


Citigroup’s end-of-period deposits were $1.2 trillion as of quarter end, an increase of 15% from the prior-year period. In constant dollars, Citigroup’s end-of-period deposits increased 17%, driven by 8% growth in GCB and 21% growth in ICG.


Citigroup’s book value per share of $83.75 and tangible book value per share of $71.52 each increased 9% versus the prior-year period, driven by the net income and the reduced share count. At quarter end, Citigroup’s CET1 Capital ratio was 11.2%, down from the prior quarter, primarily driven by growth in risk-weighted assets. Citigroup’s SLR for the first quarter 2020 was 6.0%, a decrease from the prior quarter. During the quarter, Citigroup repurchased 41 million common shares and returned a total of $4.0 billion to common shareholders in the form of common share repurchases and dividends.


Global Consumer Banking
($ in millions, except as otherwise noted)


1Q'20


4Q'19


1Q'19


QoQ%


YoY%

North America


5,224


5,253


5,000


(1)%


4%

Latin America


1,199


1,377


1,272


(13)%


(6)%

Asia(a)


1,751


1,829


1,818


(4)%


(4)%

Total Revenues


$

8,174


$

8,459


$

8,090


(3)%


1%


Expenses


$

4,368


$

4,373


$

4,416


-


(1)%


Net Credit Losses


1,983


1,842


1,868


8%


6%

Credit Reserve Build / (Release)(b)


2,828


122


93


NM


NM

Other Provisions(c)


20


25


12


(20)%


67%

Total Cost of Credit


$

4,831


$

1,989


$

1,973


NM


NM


Net Income (Loss)


$

(754)


$

1,575


$

1,320


NM


NM


Retail Banking


3,046


3,124


3,106


(2)%


(2)%

Cards


5,128


5,335


4,984


(4)%


3%

Total Revenues


$

8,174


$

8,459


$

8,090


(3)%


1%


Key Indicators ($B)


Retail Banking Average Loans


123


123


118


-


4%

Retail Banking Average Deposits


290


283


272


3%


7%

Investment AUMs


145


175


160


(17)%


(10)%

Cards Average Loans


167


168


163


-


3%

Cards Purchase Sales


128


152


128


(16)%


-


Note:  Please refer to the Appendices and Footnotes at the end of this press release for additional information.

(a) Asia GCB includes the results of operations of GCB activities in certain EMEA countries for all periods presented.

(b) Includes provision for unfunded lending commitments.

(c) Includes provisions for benefits and claims, HTM debt securities and other assets.

3


Global Consumer Banking

GCB revenues of $8.2 billion increased 1% on a reported basis and 2% in constant dollars, as growth in North America GCB was partially offset by lower revenues in Asia GCB, reflecting the early impact of the COVID-19 pandemic on customer behavior.


North America GCB revenues of $5.2 billion increased 4%. Citi-Branded Cards revenues of $2.3 billion increased 7%, reflecting volume growth as well as spread expansion.  Retail Banking revenues of $1.1 billion were largely unchanged, as deposit growth and higher mortgage revenues were offset by lower deposit spreads. Citi Retail Services revenues of $1.7 billion increased 4%, reflecting a reduction in partner payments and higher average loans.


Latin America GCB revenues of $1.2 billion declined 6% on a reported basis and were largely unchanged in constant dollars.  Excluding the impact of a residual gain in the prior-year period on the sale of an asset management business,  revenues increased 3% in constant dollars,  driven by deposit growth and improved spreads in cards.


Asia GCB revenues of $1.8 billion declined 4% on a reported basis and 1%  in constant dollars as growth in investment and FX revenues was more than offset by lower revenues in cards, reflecting lower sales volumes due to COVID-19.


GCB operating expenses of $4.4 billion decreased 1% versus the prior year. In constant dollars, expenses were largely unchanged, as efficiency savings were offset by continued investments in the franchise and volume-driven growth.


GCB cost of credit of $4.8 billion increased significantly on a reported basis and in constant dollars. The increase reflects larger loan loss reserve builds related to the impact of changes in Citi’s economic outlook on estimated lifetime losses under the CECL standard.


GCB net loss of $(0.8) billion compared to income of $1.3 billion in the prior-year period, in reported and constant dollars,  driven by the higher cost of credit, partially offset by the higher revenues and the lower expenses.


4


Institutional Clients Group
($ in millions)


1Q'20


4Q'19


1Q'19


QoQ%


YoY%

Treasury & Trade Solutions


2,423


2,608


2,539


(7)%


(5)%

Investment Banking


1,350


1,351


1,354


-


-

Private Bank(a)


949


847


880


12%


8%

Corporate Lending(a)


448


732


749


(39)%


(40)%

Total Banking


5,170


5,538


5,522


(7)%


(6)%

Fixed Income Markets


4,790


2,898


3,452


65%


39%

Equity Markets


1,169


516


842


NM


39%

Securities Services


645


647


638


-


1%

Other


(106)


(129)


(205)


18%


48%

Total Markets & Securities Services


6,498


3,932


4,727


65%


37%

Product Revenues(a)


$

11,668


$

9,470


$

10,249


23%


14%

Gain / (Loss) on Loan Hedges


816


(93)


(231)


NM


NM

Total Revenues


$

12,484


$

9,377


$

10,018


33%


25%


Expenses


$

5,810


$

5,446


$

5,619


7%


3%


Net Credit Losses


127


115


78


10%


63%

Credit Reserve Build / (Release)(b)


1,869


131


(46)


NM


NM

Other Provisions(c)


 8


-


-


NM


NM

Total Cost of Credit


$

2,004


$

246


$

32


NM


NM


Net Income


$

3,627


$

2,867


$

3,401


27%


7%


Revenues


North America


4,947


3,314


3,269


49%


51%

EMEA


3,470


2,738


3,170


27%


9%

Latin America


1,418


1,297


1,268


9%


12%

Asia


2,649


2,028


2,311


31%


15%


Note:  Please refer to the Appendices and Footnotes at the end of this press release for additional information.

(a) Excludes gain / (loss) on credit derivatives as well as the mark-to-market on loans at fair value. For additional information, please refer to Footnote 8.

(b) Includes provision for unfunded lending commitments.

(c) Includes provisions for benefits and claims, HTM debt securities and other assets.


Institutional Clients Group

ICG revenues of $12.5 billion increased 25%, as strong performance in Fixed Income and Equity Markets, and mark-to-market gains on loan hedges,  were partially offset by lower revenues in Corporate Lending and Treasury and Trade Solutions.


Banking revenues of $6.0 billion increased 13% versus the prior year (including gain / (loss) on loan hedges)8.  Treasury and Trade Solutions revenues of $2.4 billion declined 5% on a reported basis and 2% in constant dollars, as strong client engagement and growth in deposits were more than offset by the impact of lower rates.  Investment Banking revenues of $1.4 billion were largely unchanged,  as growth in advisory and equity underwriting were offset by a decline in debt underwriting. Advisory revenues increased 2% to $386 million, equity underwriting revenues increased 5% to $180 million and debt underwriting revenues declined 2% to $784 million. Private Bank revenues of $949 million increased 8% (excluding gain / (loss) on loan hedges), driven by higher lending and deposit volumes, as well as increased capital markets activity partially offset by lower deposit spreads.  Corporate Lending revenues of $448 million declined 40% (excluding gain / (loss) on loan hedges), primarily reflecting an adjustment to the residual value of a  lease financing, as well as other marks on the portfolio.


Markets and Securities Services revenues of $6.5 billion increased 37%. Fixed Income Markets revenues of $4.8 billion increased 39%, reflecting strength in rates and currencies and commodities.  Equity Markets revenues of $1.2 billion increased 39%, with strong performance in derivatives, including an increase in client activity, due to higher volatility.  Securities Services revenues of $645 million increased 1% on a reported basis and 5% in constant dollars, reflecting higher client activity and deposit volumes partially offset by lower spreads.

5


ICG net income of $3.6  billion increased 7%, as the revenue growth was partially offset by higher cost of credit and expenses. ICG operating expenses increased 3% to $5.8 billion, as efficiency savings were more than offset by higher compensation costs, continued investments, and volume-driven growth.  ICG cost of credit included net credit losses of $127 million, compared to $78 million in the prior-year period, and a net loan loss reserve build of $1.9  billion compared to a release of $46 million in the prior-year period, reflecting loan loss reserve builds related to the impact of changes in Citi’s economic outlook on estimated lifetime losses under the CECL standard.


Corporate / Other
($ in millions)


1Q'20


4Q'19


1Q'19


QoQ%


YoY%

Revenues


$

73


$

542


$

468


(87)%


(84)%


Expenses


$

416


$

635


$

549


(34)%


(24)%


Net Credit Losses


(2)


(13)


 2


85%


NM

Credit Reserve Build / (Release)(a)


196


 -


(27)


NM


NM

Other Provisions(b)


(2)


 -


 -


NM


NM

Total Cost of Credit


$

192


$

(13)


$

(25)


NM


NM


Income (Loss) from Continuing Operations before Taxes


$

(535)


$

(80)


$

(56)


NM


NM


Income Taxes (Benefits)


(198)


(623)


(61)


68%


NM


Net Income


$

(351)


$

537


$

(11)


NM


NM


 (a) Includes provision for unfunded lending commitments.

(b) Includes provisions for benefits and claims, HTM debt securities and other assets.


Corporate / Other

Corporate / Other revenues of $73 million declined 84%, reflecting the wind-down of legacy assets, the impact of lower rates and marks on legacy securities.

Corporate / Other expenses of $416 million declined 24%, driven by the wind-down of legacy assets, partially offset by higher infrastructure costs as well as incremental costs associated with COVID-19, including special compensation awarded to 75,000 employees most directly impacted by the pandemic.

Corporate / Other loss from continuing operations before taxes of $(535) million compared to $(56) million in the prior-year period driven by higher cost of credit, reflecting loan loss reserves on Citi’s residual legacy portfolio under the CECL standard, and the lower revenues,  partially offset by the decrease in expenses.


6

Citigroup will host a conference call today at 10:00 AM (ET). A live webcast of the presentation, as well as financial results and presentation materials, will be available at https://www.citigroup.com/citi/investor. Dial-in numbers for the conference call are as follows: (866) 516-9582 in the U.S. and Canada; (973) 409-9210 outside of the U.S. and Canada. The conference code for both numbers is 3653669.


Additional financial, statistical and business-related information, as well as business and segment trends, is included in a Quarterly Financial Data Supplement. Both this earnings release and Citigroup’s First Quarter 2020 Quarterly Financial Data Supplement are available on Citigroup’s website at www.citigroup.com.


Citigroup, the leading global bank, has approximately 200 million customer accounts and does business in more than 160 countries and jurisdictions. Citigroup provides consumers, corporations, governments and institutions with a broad range of financial products and services, including consumer banking and credit, corporate and investment banking, securities brokerage, transaction services, and wealth management.


Additional information may be found at www.citigroup.com | Twitter: @Citi | YouTube: www.youtube.com/citi | Blog: http://blog.citigroup.com | Facebook: www.facebook.com/citi | LinkedIn: www.linkedin.com/company/citi


Certain statements in this release are “forward-looking statements” within the meaning of the rules and regulations of the U.S. Securities and Exchange Commission (SEC). These statements are based on management’s current expectations and are subject to uncertainty and changes in circumstances. These statements are not guarantees of future results or occurrences. Actual results and capital and other financial condition may differ materially from those included in these statements due to a variety of factors. These factors include, among others, macroeconomic and other challenges and uncertainties resulting from the COVID-19 pandemic, such as the extent and duration of the impact on public health, the U.S. and global economies, financial markets and consumer and corporate customers and clients, including economic activity, employment levels and market liquidity, as well as the various actions taken in response to the challenges and uncertainties by governments, central banks and others, including Citi, and the precautionary statements included in this release. These factors also consist of those contained in Citigroup’s filings with the SEC, including without limitation the “Risk Factors” section of Citigroup’s 2019 Form 10- K. Any forward-looking statements made by or on behalf of Citigroup speak only as to the date they are made, and Citi does not undertake to update forward-looking statements to reflect the impact of circumstances or events that arise after the date the forward-looking statements were made.


Contacts:


Press: Jennifer Lowney

(212) 793-3141

Investors:

Elizabeth Lynn

(212) 559-2718


Fixed Income Investors:

Thomas Rogers

(212) 559-5091


7

Appendix A


Citigroup
($ in millions)


1Q'20

Net Income


$

2,522

Less: Preferred Dividends


291

Net Income to Common Shareholders


$

2,231


Common Share Repurchases


2,925

Common Dividends


1,081

Total Capital Returned to Common Shareholders


$

4,006


Payout Ratio


180%


Average TCE


$

148,852


RoTCE


6.0%


8

Appendix B


Citigroup
($ in billions)


1Q'20


1Q'19

Reported EOP Loans


$

721


$

682

Impact of FX Translation


 -


(15)

EOP Loans in Constant Dollars


$

721


$

668


Reported EOP Deposits


$

1,185


$

1,030

Impact of FX Translation


 -


(21)

EOP Deposits in Constant Dollars


$

1,185


$

1,009

Note:  Totals may not sum due to rounding.


Global Consumer Banking
($ in millions)


1Q'20


1Q'19

Reported Revenues


$

8,174


$

8,090

Impact of FX Translation


 -


(115)

Revenues in Constant Dollars


$

8,174


$

7,975


Reported Expenses


$

4,368


$

4,416

Impact of FX Translation


 -


(66)

Expenses in Constant Dollars


$

4,368


$

4,350


Reported Cost of Credit


$

4,831


$

1,973

Impact of FX Translation


 -


(26)

Cost of Credit in Constant Dollars


$

4,831


$

1,947


Reported Net Income


$

(754)


$

1,320

Impact of FX Translation


 -


(15)

Net Income in Constant Dollars


$

(754)


$

1,305

Note:  Totals may not sum due to rounding.


Latin America Consumer Banking
($ in millions)


1Q'20


1Q'19

Reported Revenues


$

1,199


$

1,272

Impact of FX Translation


 -


(74)

Revenues in Constant Dollars


$

1,199


$

1,198

Note:  Totals may not sum due to rounding.


Asia Consumer Banking(1) 
($ in millions)


1Q'20


1Q'19

Reported Revenues


$

1,751


$

1,818

Impact of FX Translation


 -


(41)

Revenues in Constant Dollars


$

1,751


$

1,777

Note:  Totals may not sum due to rounding.


(1)  Asia GCB includes the results of operations in EMEA GCB for all periods presented.


Treasury and Trade Solutions
($ in millions)


1Q'20


1Q'19

Reported Revenues


$

2,423


$

2,539

Impact of FX Translation


 -


(67)

Revenues in Constant Dollars


$

2,423


$

2,472

Note:  Totals may not sum due to rounding.


Securities Services
($ in millions)


1Q'20


1Q'19

Reported Revenues


$

645


$

638

Impact of FX Translation


 -


(22)

Revenues in Constant Dollars


$

645


$

616


Note:  Totals may not sum due to rounding.


9

Appendix C


($ in millions)


1Q'20(1)


4Q'19


1Q'19


Citigroup Common Stockholders' Equity(2)


$

174,503


$

175,414


$

178,427

Add: Qualifying noncontrolling interests


138


154


144

Regulatory Capital Adjustments and Deductions:


Add: CECL transition and 25% provision deferral(3)


4,316


 -


 -

Less:


Accumulated net unrealized gains (losses) on cash flow hedges, net of tax(4)


2,020


123


(442)

Cumulative unrealized net gain (loss) related to changes in fair value of financial
liabilities attributable to own creditworthiness, net of tax
(5)


2,838


(679)


(67)

Intangible Assets:


Goodwill, net of related deferred tax liabilities (DTLs)(6)


20,123


21,066


21,768

Identifiable intangible assets other than mortgage servicing rights (MSRs),
net of related DTLs


3,953


4,087


4,390

Defined benefit pension plan net assets


1,052


803


811

Deferred tax assets (DTAs) arising from net operating loss, foreign tax credit
and general business credit carry-forwards


12,259


12,370


11,756


Common Equity Tier 1 Capital (CET1)(3)


$

136,712


$

137,798


$

140,355


Risk-Weighted Assets (RWA)(3)(7)


$

1,224,218


$

1,166,523


$

1,178,628


Common Equity Tier 1 Capital Ratio (CET1 / RWA)


11.2%


11.8%


11.9%


Note:     Citi’s reportable CET1 Capital ratios were derived under the U.S. Basel III Advanced Approaches framework as of March 31, 2020, and the U.S. Basel III Standardized Approach framework for all prior periods presented. This reflects the lower of the CET1 Capital ratios under both the Standardized Approach and the Advanced Approaches under the Collins Amendment.

(1)

Preliminary.

(2)

Excludes issuance costs related to outstanding preferred stock in accordance with Federal Reserve Board regulatory reporting requirements.

(3)

Please refer to Footnote 3 at the end of this press release for additional information.

(4)

Common Equity Tier 1 Capital is adjusted for accumulated net unrealized gains (losses) on cash flow hedges included in accumulated other comprehensive income that relate to the hedging of items not recognized at fair value on the balance sheet.

(5)

The cumulative impact of changes in Citigroup’s own creditworthiness in valuing liabilities for which the fair value option has been elected, and own-credit valuation adjustments on derivatives, are excluded from Common Equity Tier 1 Capital, in accordance with the U.S. Basel III rules.

(6)

Includes goodwill “embedded” in the valuation of significant common stock investments in unconsolidated financial institutions.

(7)

RWA excludes assets acquired pursuant to a non-recourse loan provided under the Money Market Mutual Fund Liquidity Facility, as permitted by the US banking agencies’ March 2020 interim final rule.


Appendix D


($ in millions)


1Q'20(1)


4Q'19


1Q'19


Common Equity Tier 1 Capital (CET1)(2)


$

136,712


$

137,798


$

140,355


Additional Tier 1 Capital (AT1)(3)


17,600


18,007


18,002


Total Tier 1 Capital (T1C) (CET1 + AT1)


$

154,312


$

155,805


$

158,357


Total Leverage Exposure (TLE)(2)(4)


$

2,586,513


$

2,507,891


$

2,463,603


Supplementary Leverage Ratio (T1C / TLE)


6.0%


6.2%


6.4%


(1)        Preliminary.

(2)        Please refer to Footnote 3 at the end of this press release for additional information.

(3)        Additional Tier 1 Capital primarily includes qualifying noncumulative perpetual preferred stock and qualifying trust preferred securities.

(4)        TLE excludes assets acquired pursuant to a non-recourse loan provided under the Money Market Mutual Fund Liquidity Facility, as permitted by the US banking agencies’ March 2020 interim final rule.


Appendix E


($ and shares in millions, except per share amounts)


1Q'20(1)


4Q'19


1Q'19


Common Stockholders' Equity


$

174,351


$

175,262


$

178,272

Less:


Goodwill


21,264


22,126


22,037

Intangible Assets (other than MSRs)


4,193


4,327


4,645

Tangible Common Equity (TCE)


$

148,894


$

148,809


$

151,590


Common Shares Outstanding (CSO)


2,082


2,114


2,313


Tangible Book Value Per Share (TCE / CSO)


$

 71.52


$

70.39


$

 65.55


 (1)        Preliminary.

10


1 Citigroup’s total expenses divided by total revenues.


2 Preliminary. Citigroup’s return on average tangible common equity (RoTCE) is a non-GAAP financial measure. RoTCE represents annualized net income available to common shareholders as a percentage of average tangible common equity (TCE). For the components of the calculation, see Appendix A.


3 Ratios as of March 31, 2020 are preliminary. Commencing January 1, 2020, Citigroup’s Common Equity Tier 1 (CET1) Capital ratio and Supplementary Leverage Ratio (SLR) reflect certain deferrals based on the modified regulatory capital transition provision related to the Current Expected Credit Loss (CECL) methodology. Excluding the deferrals based on the modified CECL transition provision, Citigroup’s CET1 Capital ratio and SLR as of March 31, 2020 would be 10.8% and 5.8%, respectively, on a fully reflected basis.


Citigroup has elected to apply the modified transition provision related to the impact of the CECL accounting standard on regulatory capital, as provided by the US banking agencies’ March 2020 interim final rule. Under the modified CECL transition provision, the allowance for credit losses (after-tax) upon the January 1, 2020 CECL adoption date has been deferred and will phase in to regulatory capital at 25% per year commencing January 1, 2022. For the ongoing impact of CECL, Citigroup is allowed to adjust the allowance for credit losses in an amount equal to 25% of the change in the allowance for credit losses (pre-tax) recognized through earnings for each period between January 1, 2020 and December 31, 2021. The cumulative adjustments to the allowance for credit losses between January 1, 2020 and December 31, 2021 will also phase in to regulatory capital at 25% per year commencing January 1, 2022, along with the deferred impacts related to the January 1, 2020 CECL adoption date.  The corresponding adjustments on average on-balance sheet assets are also reflected in Total Leverage Exposure. Additionally, the increase in deferred tax assets (DTA) arising from temporary differences upon the January 1, 2020 adoption date has been deducted from risk-weighted assets (RWA) and will phase in to RWA at 25% per year commencing January 1, 2022.


For the composition of Citigroup’s CET1 Capital and ratio, see Appendix C. For the composition of Citigroup’s SLR, see Appendix D.


4 Citigroup’s payout ratio is the sum of common dividends and common share repurchases divided by net income available to common shareholders. For the components of the calculation, see Appendix A.


5  On March 15, 2020, Citigroup announced it had joined other major U.S. banks in suspending stock repurchases to support clients in light of the COVID-19 pandemic, in an announcement made by the Financial Services Forum. Through March 13, 2020, Citigroup had returned approximately $57.4 billion in capital over the past three Comprehensive Capital Analysis and Review (CCAR) cycles, and had been approved to return roughly $62.3 billion in capital over the three-year period. Citigroup stated there was no change to its dividend policy.


6  Citigroup’s tangible book value per share is a non-GAAP financial measure. For a reconciliation of this measure to reported results, see Appendix E.


7  Results of operations excluding the impact of foreign exchange translation (constant dollar basis) are non-GAAP financial measures. For a reconciliation of these measures to reported results, see Appendix B.


8  Credit derivatives are used to economically hedge a portion of the private bank and corporate loan portfolio that includes both accrual loans and loans at fair value. Gains / (losses) on loan hedges includes the mark-to-market on the credit derivatives and the mark-to-market on the loans in the portfolio that are at fair value. In the first quarter 2020, gains / (losses) on loan hedges included $754 million related to Corporate Lending and $62 million related to the Private Bank, compared to losses of $231 million related to Corporate Lending in the prior-year period. The fixed premium costs of these hedges are netted against the Private Bank and Corporate Lending revenues to reflect the cost of credit protection. Citigroup’s results of operations excluding the impact of gains / (losses) on loan hedges are non-GAAP financial measures.


11
Exhibit 99.2


Picture 4


CITIGROUP -- QUARTERLY FINANCIAL DATA SUPPLEMENT


1Q20


Page


Citigroup Consolidated


Financial Summary


1


Consolidated Statement of Income


2


Consolidated Balance Sheet


3


Segment Detail


Net Revenues


4


Income and Regional Average Assets and ROA


5


Global Consumer Banking (GCB)


6


Retail Banking and Cards Key Indicators


7


North America


8 - 10


Latin America(1)


11 - 12


Asia(2)


13 - 14


Institutional Clients Group (ICG)


15


Revenues by Business


16


Corporate / Other


17


Citigroup Supplemental Detail


Average Balances and Interest Rates


18


Deposits


19


Loans (EOP)


20


Consumer Loan Delinquencies and Ratios


90+ Days


21


30-89 Days


22


Allowance for Credit Losses on Loans and Unfunded Lending Commitments


23 - 24


Components of Provision for Loan Losses


25


Non-Accrual Assets


26


CET1 Capital and Supplementary Leverage Ratios, Tangible Common Equity,


27


Book Value Per Share and Tangible Book Value Per Share


(1)

Latin America GCB consists of Citi's consumer banking operations in Mexico.

(2)

Asia GCB includes the results of operations of GCB activities in certain EMEA countries for all periods presented.


CITIGROUP -- FINANCIAL SUMMARY

(In millions of dollars, except per share amounts, and as otherwise noted)


1Q


2Q


3Q


4Q


1Q


1Q20 Increase/
(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19

Total Revenues, Net of Interest Expense


$

18,576


$

18,758


$

18,574


$

18,378


$

20,731


13%


12%

Total Operating Expenses


10,584


10,500


10,464


10,454


10,594


1%


-

Net Credit Losses (NCLs)


1,948


1,963


1,913


1,944


2,108


8%


8%

Credit Reserve Build / (Release) for Loans


(4)


126


149


179


4,336


NM


NM

Provision / (Release) for Unfunded Lending Commitments


24


(15)


9


74


557


NM


NM

Provisions for Benefits and Claims, HTM Debt Securities and Other Assets


12


19


17


25


26


4%


NM

Provisions for Credit Losses and for Benefits and Claims


$

1,980


$

2,093


$

2,088


$

2,222


$

7,027


NM


NM

Income from Continuing Operations before Income Taxes


$

6,012


$

6,165


$

6,022


$

5,702


$

3,110


(45%)


(48%)

Income Taxes(1)(2)


1,275


1,373


1,079


703


576


(18%)


(55%)

Income from Continuing Operations


$

4,737


$

4,792


$

4,943


$

4,999


$

2,534


(49%)


(47%)

Income (Loss) from Discontinued Operations, net of Taxes


(2)


17


(15)


(4)


(18)


NM


NM

Net Income before Noncontrolling Interests


$

4,735


$

4,809


$

4,928


$

4,995


$

2,516


(50%)


(47%)

Net Income (Loss) Attributable to Noncontrolling Interests


25


10


15


16


(6)


NM


NM

Citigroup's Net Income


$

4,710


$

4,799


$

4,913


$

4,979


$

2,522


(49%)


(46%)


Diluted Earnings Per Share:


Income from Continuing Operations


$

1.87


$

1.94


$

2.08


$

2.15


$

1.06


(51%)


(43%)

Citigroup's Net Income


$

1.87


$

1.95


$

2.07


$

2.15


$

1.05


(51%)


(44%)


Shares (in millions):


Average Basic


2,340.4


2,286.1


2,220.8


2,149.4


2,097.9


(2%)


(10%)

Average Diluted


2,342.4


2,289.0


2,237.1


2,166.8


2,113.7


(2%)


(10%)

Common Shares Outstanding, at period end


2,312.5


2,259.1


2,183.2


2,114.1


2,081.8


(2%)


(10%)


Preferred Dividends


$

262


$

296


$

254


$

296


$

291


(2%)


11%


Income Allocated to Unrestricted Common Shareholders - Basic


Income from Continuing Operations


$

4,391


$

4,436


$

4,647


$

4,653


$

2,228


(52%)


(49%)

Citigroup's Net Income


$

4,389


$

4,453


$

4,632


$

4,649


$

2,210


(52%)


(50%)


Income Allocated to Unrestricted Common Shareholders - Diluted


Income from Continuing Operations


$

4,391


$

4,436


$

4,656


$

4,661


$

2,235


(52%)


(49%)

Citigroup's Net Income


$

4,389


$

4,453


$

4,641


$

4,657


$

2,217


(52%)


(49%)


Regulatory Capital Ratios and Performance Metrics:


Common Equity Tier 1 (CET1) Capital Ratio(3)(4)(5)


11.91

%  


11.89

%  


11.58

%  


11.81

%  


11.2

%  


Tier 1 Capital Ratio(3)(4)(5)


13.44

%  


13.40

%  


13.20

%  


13.36

%  


12.6

%  


Total Capital Ratio(3)(4)(5)


16.41

%  


16.33

%  


16.07

%  


15.97

%  


15.1

%  


Supplementary Leverage Ratio (SLR)(4)(5)(6)


6.43

%  


6.36

%  


6.27

%  


6.21

%  


6.0

%  


Return on Average Assets


0.98

%  


0.97

%  


0.97

%  


0.99

%  


0.49

%  


Return on Average Common Equity


10.2

%  


10.1

%  


10.4

%  


10.6

%  


5.2

%  


Efficiency Ratio (Total Operating Expenses/Total Revenues, net)


57.0

%  


56.0

%  


56.3

%  


56.9

%  


51.1

%  


Balance Sheet Data (in billions of dollars, except per share amounts)(4):


Total Assets


$

1,958.4


$

1,988.2


$

2,014.8


$

1,951.2


$

2,219.8


14%


13%

Total Average Assets


1,939.4


1,979.1


2,000.1


1,996.6


2,079.7


4%


7%

Total Deposits


1,030.4


1,045.6


1,087.8


1,070.6


1,184.9


11%


15%

Citigroup's Stockholders' Equity


196.3


197.4


196.4


193.2


192.3


-


(2%)

Book Value Per Share


77.09


79.40


81.02


82.90


83.75


1%


9%

Tangible Book Value Per Share(7)


65.55


67.64


69.03


70.39


71.52


2%


9%


Direct Staff (in thousands)


203


200


199


200


201


1%


(1%)


(1)

4Q19 includes discrete tax items of roughly $540 million, including an approximate $430 million benefit of a reduction in Citi’s valuation allowance related to its Deferred Tax Assets (DTAs).

(2)

3Q19 includes discrete tax items of roughly $230 million, including an approximate $180 million benefit of a reduction in Citi’s valuation allowance related to its DTAs. 

(3)

Citi's reportable CET1 Capital and Tier 1 Capital ratios were derived under the U.S. Basel III Advanced Approaches framework as of March 31, 2020, and the U.S. Basel III Standardized Approach framework for all prior periods presented, whereas Citi's reportable Total Capital ratios were derived under the U.S. Basel III Advanced Approaches framework for all periods presented. The reportable ratios represent the lower of each of the three risk-based capital ratios (CET1 Capital, Tier 1 Capital and Total Capital) under both the Standardized Approach and the Advanced Approaches under the Collins Amendment. For the composition of Citi's CET1 Capital and ratio, see page 27. 

(4)

March 31, 2020 is preliminary.

(5)

See footnote 4 on page 27

(6)

For the composition of Citi's SLR, see page 27.

(7)

Tangible book value per share is a non-GAAP financial measure. For a reconciliation of this measure to reported results, see page 27.


Note:  Ratios and variance percentages are calculated based on the displayed amounts. Due to averaging and roundings, quarterly earnings per share may not sum to the YTD totals.

NM  Not meaningful.

Reclassified to conform to the current period's presentation.

Page 1

CITIGROUP CONSOLIDATED STATEMENT OF INCOME

(In millions of dollars)


1Q


2Q


3Q


4Q


1Q


1Q20 Increase/
(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19


Revenues


Interest revenue


$

19,076


$

19,712


$

19,177


$

18,545


$

17,139


(8%)


(10%)

Interest expense


7,317


7,762


7,536


6,548


5,647


(14%)


(23%)

Net interest revenue


11,759


11,950


11,641


11,997


11,492


(4%)


(2%)


Commissions and fees


2,926


2,881


2,906


3,033


3,021


-


3%

Principal transactions


2,804


1,874


2,802


1,412


5,261


NM


88%

Administrative and other fiduciary fees


839


869


880


823


854


4%


2%

Realized gains (losses) on investments


130


468


361


515


432


(16%)


NM

Other-than-temporary impairment losses on investments and other assets


(8)


(5)


(14)


(5)


(55)


NM


NM

Other revenue


126


721


(2)


603


(274)


NM


NM

Total non-interest revenues


6,817


6,808


6,933


6,381


9,239


45%


36%

Total revenues, net of interest expense


18,576


18,758


18,574


18,378


20,731


13%


12%


Provisions for Credit Losses and for Benefits and Claims


Net credit losses


1,948


1,963


1,913


1,944


2,108


8%


8%

Credit reserve build / (release) for loans


(4)


126


149


179


4,336


NM


NM

Provision for loan losses


1,944


2,089


2,062


2,123


6,444


NM


NM

Provision for Held-to-maturity (HTM) debt securities


-


-


-


-


6


NM


NM

Provision for Other assets


-


-


-


-


(4)


NM


NM

Provision for policyholder benefits and claims


12


19


17


25


24


(4%)


100%

Provision for unfunded lending commitments


24


(15)


9


74


557


NM


NM

Total provisions for credit losses and for benefits and claims


1,980


2,093


2,088


2,222


7,027


NM


NM


Operating Expenses


Compensation and benefits


5,658


5,381


5,329


5,065


5,654


12%


-

Premises and equipment


564


569


580


615


565


(8%)


-

Technology / communication expense


1,720


1,724


1,783


1,850


1,723


(7%)


-

Advertising and marketing expense


359


434


378


345


328


(5%)


(9%)

Other operating


2,283


2,392


2,394


2,579


2,324


(10%)


2%

Total operating expenses


10,584


10,500


10,464


10,454


10,594


1%


-


Income from Continuing Operations before


Income Taxes


6,012


6,165


6,022


5,702


3,110


(45%)


(48%)

Provision for income taxes (1)(2)


1,275


1,373


1,079


703


576


(18%)


(55%)


Income (Loss) from Continuing Operations


4,737


4,792


4,943


4,999


2,534


(49%)


(47%)

Discontinued Operations


Income (Loss) from Discontinued Operations


(2)


(10)


(15)


(4)


(18)


NM


NM

Provision (benefits) for income taxes


-


(27)


-


-


-


-


-

Income (Loss) from Discontinued Operations, net of taxes


(2)


17


(15)


(4)


(18)


NM


NM


Net Income before Noncontrolling Interests


4,735


4,809


4,928


4,995


2,516


(50%)


(47%)


Net Income (Loss) attributable to noncontrolling interests


25


10


15


16


(6)


NM


NM

Citigroup's Net Income


$

4,710


$

4,799


$

4,913


$

4,979


$

2,522


(49%)


(46%)


(1)

4Q19 includes discrete tax items of roughly $540 million, including an approximate $430 million benefit of a reduction in Citi’s valuation allowance related to its Deferred Tax Assets (DTAs).

(2)

3Q19 includes discrete tax items of roughly $230 million, including an approximate $180 million benefit of a reduction in Citi’s valuation allowance related to its DTAs.


NM  Not meaningful.

Reclassified to conform to the current period's presentation.

Page 2

CITIGROUP CONSOLIDATED BALANCE SHEET

(In millions of dollars)


1Q20 Increase/


March 31,


June 30,


September 30,


December 31,

March 31,


(Decrease) from


2019


2019


2019


2019


2020 (1)


4Q19


1Q19

Assets


Cash and due from banks (including segregated cash and other deposits)


$

24,448


$

24,997


$

24,086


$

23,967


$

23,755


(1%)


(3%)

Deposits with banks


181,445


178,246


196,357


169,952


262,165


54%


44%

Securities borrowed and purchased under agreements to resell


264,495


259,769


261,125


251,322


262,536


4%


(1%)

Brokerage receivables


44,500


50,027


54,215


39,857


68,555


72%


54%

Trading account assets


286,511


306,831


306,824


276,140


365,000


32%


27%

Investments


Available-for-sale and non-marketable equity securities


275,132


273,435


275,425


280,265


308,219


10%


12%

Held-to-maturity debt securities


66,842


68,693


75,841


80,775


82,315


2%


23%

Equity securities


7,307


7,574


7,117


7,523


8,349


11%


14%

Total investments


349,281


349,702


358,383


368,563


398,883


8%


14%

Loans, net of unearned income


Consumer


290,968


296,505


297,400


309,548


288,430


(7%)


(1%)

Corporate


391,378


392,165


394,343


389,935


432,590


11%


11%

Loans, net of unearned income


682,346


688,670


691,743


699,483


721,020


3%


6%

Allowance for loan losses


(12,329)


(12,466)


(12,530)


(12,783)


(20,841)


(63%)


(69%)

Total loans, net


670,017


676,204


679,213


686,700


700,179


2%


5%

Goodwill


22,037


22,065


21,822


22,126


21,264


(4%)


(4%)

Intangible assets (including MSRs)


5,196


5,026


4,844


4,822


4,560


(5%)


(12%)

Other assets


110,483


115,359


107,933


107,709


112,873


5%


2%

Total assets


$

1,958,413


$

1,988,226


$

2,014,802


$

1,951,158


$

2,219,770


14%


13%


Liabilities


Non-interest-bearing deposits in U.S. offices


$

101,354


$

95,659


$

99,731


$

98,811


$

113,371


15%


12%

Interest-bearing deposits in U.S. offices


373,339


382,738


407,872


401,418


462,327


15%


24%

Total U.S. deposits


474,693


478,397


507,603


500,229


575,698


15%


21%

Non-interest-bearing deposits in offices outside the U.S.


80,594


82,750


82,723


85,692


85,439


-


6%

Interest-bearing deposits in offices outside the U.S.


475,068


484,460


497,443


484,669


523,774


8%


10%

Total international deposits


555,662


567,210


580,166


570,361


609,213


7%


10%


Total deposits


1,030,355


1,045,607


1,087,769


1,070,590


1,184,911


11%


15%

Securities loaned and sold under agreements to resell


190,372


181,133


195,047


166,339


222,324


34%


17%

Brokerage payables


62,656


69,839


63,342


48,601


74,368


53%


19%

Trading account liabilities


136,392


136,294


135,596


119,894


163,995


37%


20%

Short-term borrowings


39,322


42,442


35,230


45,049


54,951


22%


40%

Long-term debt


243,566


252,189


242,238


248,760


266,098


7%


9%

Other liabilities(2)


58,735


62,612


58,510


57,979


60,141


4%


2%

Total liabilities


$

1,761,398


$

1,790,116


$

1,817,732


$

1,757,212


$

2,026,788


15%


15%


Equity


Stockholders' equity


Preferred stock


$

17,980


$

17,980


$

19,480


$

17,980


$

17,980


-


-

Common stock


31


31


31


31


31


-


-

Additional paid-in capital


107,551


107,657


107,741


107,840


107,550


-


-

Retained earnings


154,859


158,321


161,797


165,369


163,438


(1%)


6%

Treasury stock


(47,861)


(51,427)


(56,541)


(61,660)


(64,147)


(4%)


(34%)

Accumulated other comprehensive income (loss)


(36,308)


(35,203)


(36,135)


(36,318)


(32,521)


10%


10%

Total common equity


$

178,272


$

179,379


$

176,893


$

175,262


$

174,351


(1%)


(2%)


Total Citigroup stockholders' equity


$

196,252


$

197,359


$

196,373


$

193,242


$

192,331


-


(2%)

Noncontrolling interests


763


751


697


704


651


(8%)


(15%)

Total equity


197,015


198,110


197,070


193,946


192,982


-


(2%)

Total liabilities and equity


$

1,958,413


$

1,988,226


$

2,014,802


$

1,951,158


$

2,219,770


14%


13%


(1)

Preliminary.

(2)

Includes allowance for credit losses for unfunded lending commitments. See page 23 for amounts by period.


NM Not meaningful.

Reclassified to conform to the current period's presentation.


Page 3


SEGMENT DETAIL

NET REVENUES

(In millions of dollars)


1Q20 Increase/


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019 


2019 


2019 


2019


2020


4Q19


1Q19


Global Consumer Banking


North America


$

5,000


$

4,966


$

5,179


$

5,253


$

5,224


(1%)


4%


Latin America


1,272


1,320


1,269


1,377


1,199


(13%)


(6%)


Asia(1)


1,818


1,847


1,841


1,829


1,751


(4%)


(4%)


Total


8,090


8,133


8,289


8,459


8,174


(3%)


1%


Institutional Clients Group


North America


3,269


3,632


3,244


3,314


4,947


49%


51%


EMEA


3,170


2,960


3,138


2,738


3,470


27%


9%


Latin America


1,268


1,307


1,294


1,297


1,418


9%


12%


Asia


2,311


2,156


2,175


2,028


2,649


31%


15%


Total


10,018


10,055


9,851


9,377


12,484


33%


25%


Corporate / Other


468


570


434


542


73


(87%)


(84%)


Total Citigroup - Net Revenues


$

18,576


$

18,758


$

18,574


$

18,378


$

20,731


13%


12%


(1)

Asia GCB includes the results of operations of GCB activities in certain EMEA countries for all periods presented.


NM Not meaningful.

Reclassified to conform to the current period's presentation.

Page 4

SEGMENT DETAIL

INCOME

(In millions of dollars)


1Q20 Increase/


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19


Income (Loss) from Continuing Operations


Global Consumer Banking


North America


$

707


$

663


$

884


$

970


$

(910)


NM


NM


Latin America


216


234


217


234


(36)


NM


NM


Asia (1)


397


404


402


374


191


(49%)


(52%)


Total


1,320


1,301


1,503


1,578


(755)


NM


NM


Institutional Clients Group


North America


748


1,050


818


895


896


-


20%


EMEA


1,125


1,005


1,060


677


1,035


53%


(8%)


Latin America


540


519


487


565


526


(7%)


(3%)


Asia


999


851


864


741


1,169


58%


17%


Total


3,412


3,425


3,229


2,878


3,626


26%


6%


Corporate / Other


5


66


211


543


(337)


NM


NM


Income From Continuing Operations


$

4,737


$

4,792


$

4,943


$

4,999


$

2,534


(49%)


(47%)


Discontinued Operations


(2)


17


(15)


(4)


(18)


NM


NM


Net Income Attributable to Noncontrolling Interests


25


10


15


16


(6)


NM


NM


Total Citigroup - Net Income


$

4,710


$

4,799


$

4,913


$

4,979


$

2,522


(49%)


(46%)


Average Assets (in billions)


North America


$

999


$

1,028


$

1,054


$

1,053


$

1,113


6%


11%


EMEA(1)


363


370


363


357


378


6%


4%


Latin America


126


128


130


133


129


(3%)


2%


Asia(1)


352


355


356


359


366


2%


4%


Corporate / Other


99


98


97


95


94


(1%)


(5%)


Total


$

1,939


$

1,979


$

2,000


$

1,997


$

2,080


4%


7%


Return on Average Assets (ROA) on Net Income (Loss)


North America


0.59%


0.67%


0.64%


0.70%


0.00%


EMEA(1)


1.24%


1.08%


1.14%


0.74%


1.09%


Latin America


2.43%


2.36%


2.15%


2.38%


1.53%


Asia(1)


1.61%


1.42%


1.41%


1.22%


1.50%


Corporate / Other


(0.05%)


0.34%


0.78%


2.24%


(1.50%)


Total


0.98%


0.97%


0.97%


0.99%


0.49%


(1)

Asia GCB includes the results of operations of GCB activities in certain EMEA countries for all periods presented.


NM  Not meaningful.

Reclassified to conform to the current period's presentation.

Page 5

GLOBAL CONSUMER BANKING

Page 1

(In millions of dollars, except as otherwise noted)


1Q20 Increase/ 


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19

Net Interest Revenue


$

6,940


$

6,957


$

7,127


$

7,181


$

7,072


(2%)


2%

Non-Interest Revenue


1,150


1,176


1,162


1,278


1,102


(14%)


(4%)

Total Revenues, Net of Interest Expense


8,090


8,133


8,289


8,459


8,174


(3%)


1%

Total Operating Expenses


4,416


4,471


4,368


4,373


4,368


-


(1%)

Net Credit Losses


1,868


1,870


1,802


1,842


1,983


8%


6%

Credit Reserve Build / (Release) for Loans


96


94


129


120


2,829


NM


NM

Provision for Unfunded Lending Commitments


(3)


-


2


2


(1)


NM


67%

Provisions   for Benefits and Claims,  HTM Debt Securities and Other Assets


12


19


17


25


20


(20%)


67%

Provisions for Credit Losses and for Benefits and Claims (LLR & PBC)


1,973


1,983


1,950


1,989


4,831


NM


NM

Income (Loss) from Continuing Operations before Taxes


1,701


1,679


1,971


2,097


(1,025)


NM


NM

Income Taxes (Benefits)


381


378


468


519


(270)


NM


NM

Income (Loss) from Continuing Operations


1,320


1,301


1,503


1,578


(755)


NM


NM

Noncontrolling Interests


-


1


2


3


(1)


NM


(100%)

Net Income (Loss)


$

1,320


$

1,300


$

1,501


$

1,575


$

(754)


NM


NM

EOP Assets (in billions)


$

379


$

390


$

394


$

407


$

403


(1%)


6%

Average Assets (in billions)


$

380


$

384


$

392


$

399


$

406


2%


7%

Return on Average Assets (ROA)


1.41%


1.36%


1.52%


1.57%


(0.75%)


Efficiency Ratio


55%


55%


53%


52%


53%


Net Credit Losses as a % of Average Loans


2.70%


2.68%


2.52%


2.51%


2.75%


Revenue by Business


Retail Banking


$

3,106


$

3,202


$

3,117


$

3,124


$

3,046


(2%)


(2%)

Cards (1)


4,984


4,931


5,172


5,335


5,128


(4%)


3%

Total


$

8,090


$

8,133


$

8,289


$

8,459


$

8,174


(3%)


1%


Net Credit Losses by Business


Retail Banking


$

233


$

225


$

225


$

227


$

235


4%


1%

Cards (1)


1,635


1,645


1,577


1,615


1,748


8%


7%

Total


$

1,868


$

1,870


$

1,802


$

1,842


$

1,983


8%


6%


Income from Continuing Operations by Business


Retail Banking


$

409


$

517


$

492


$

424


$

120


(72%)


(71%)

Cards (1)


911


784


1,011


1,154


(875)


NM


NM

Total


$

1,320


$

1,301


$

1,503


$

1,578


$

(755)


NM


NM


Foreign Currency (FX) Translation Impact


Total Revenue - as Reported


$

8,090


$

8,133


$

8,289


$

8,459


$

8,174


(3%)


1%

Impact of FX Translation (2)


(115)


(104)


(72)


(120)


-


Total Revenues - Ex-FX (2)


$

7,975


$

8,029


$

8,217


$

8,339


$

8,174


(2%)


2%


Total Operating Expenses – as Reported


$

4,416


$

4,471


$

4,368


$

4,373


$

4,368


-


(1%)

Impact of FX Translation (2)


(66)


(56)


(38)


(67)


-


Total Operating Expenses - Ex-FX (2)


$

4,350


$

4,415


$

4,330


$

4,306


$

4,368


1%


-


Total Provisions for LLR & PBC - as Reported


$

1,973


$

1,983


$

1,950


$

1,989


$

4,831


NM


NM

Impact of FX Translation (2)


(26)


(25)


(16)


(22)


-


Total Provisions for LLR & PBC - Ex-FX (2)


$

1,947


$

1,958


$

1,934


$

1,967


$

4,831


NM


NM


Net Income (Loss) – as Reported


$

1,320


$

1,300


$

1,501


$

1,575


$

(754)


NM


NM

Impact of FX Translation (2)


(15)


(16)


(12)


(21)


-


Total Net Income (Loss) - Ex-FX (2)


$

1,305


$

1,284


$

1,489


$

1,554


$

(754)


NM


NM


(1)

Includes both Citi-Branded Cards and Citi Retail Services.

(2)

Reflects the impact of foreign currency (FX) translation into U.S. dollars at the 1Q20 average exchange rates for all periods presented.

Citigroup's results of operations excluding the impact of FX translation are non-GAAP financial measures.


NM  Not meaningful.

Reclassified to conform to the current period's presentation.

Page 6

GLOBAL CONSUMER BANKING

Page 2


1Q20 Increase/ 


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19

Retail Banking Key Indicators (in billions of dollars, except as otherwise noted)


Branches (actual)


2,404


2,399


2,394


2,348


2,333


(1%)


(3%)

Accounts (in millions)


54.9


55.5


55.8


55.9


55.9


-


2%

Average Deposits


$

271.7


$

275.2


$

276.8


$

282.6


$

290.1


3%


7%

Investment Sales


$

21.1


$

22.8


$

23.9


$

22.7


$

29.6


30%


40%

Investment Assets under Management (AUMs)


$

160.1


$

164.3


$

165.6


$

174.8


$

144.6


(17%)


(10%)

Average Loans


$

117.9


$

118.1


$

119.5


$

123.0


$

123.1


-


4%

EOP Loans:


Mortgages


$

80.8


$

81.9


$

83.0


$

85.1


$

83.3


(2%)


3%

Personal, Small Business and Other


37.3


37.8


37.6


39.7


36.9


(7%)


(1%)

EOP Loans


$

118.1


$

119.7


$

120.6


$

124.8


$

120.2


(4%)


2%


Total Net Interest Revenue (in millions)(1)


$

2,097


$

2,119


$

2,069


$

2,048


$

1,981


(3%)


(6%)

As a % of Average Loans


7.21%


7.20%


6.87%


6.61%


6.47%


Net Credit Losses (in millions)


$

233


$

225


$

225


$

227


$

235


4%


1%

As a % of Average Loans


0.80%


0.76%


0.75%


0.73%


0.77%


Loans 90+ Days Past Due (in millions)(2)


$

394


$

416


$

392


$

438


$

429


(2%)


9%

As a % of EOP Loans


0.34%


0.35%


0.33%


0.35%


0.36%


Loans 30-89 Days Past Due (in millions)(2)


$

744


$

831


$

803


$

816


$

794


(3%)


7%

As a % of EOP Loans


0.63%


0.70%


0.67%


0.66%


0.66%


Cards Key Indicators (in millions of dollars, except as otherwise noted)


EOP Open Accounts (in millions)


140.1


139.5


138.2


138.3


137.3


(1%)


(2%)

Purchase Sales (in billions)


$

128.0


$

142.0


$

141.8


$

152.0


$

127.6


(16%)


-


Average Loans (in billions)(3)


$

162.7


$

162.0


$

164.6


$

168.0


$

167.2


-


3%

EOP Loans (in billions)(3)


$

160.3


$

165.1


$

165.8


$

175.1


$

159.1


(9%)


(1%)

Average Yield(4)


13.95%


13.87%


13.87%


13.62%


13.59%


Total  Net Interest Revenue(5)


$

4,843


$

4,838


$

5,058


$

5,133


$

5,091


(1%)


5%

As a % of Average Loans(5)


12.07%


11.98%


12.19%


12.12%


12.25%


Net Credit Losses


$

1,635


$

1,645


$

1,577


$

1,615


$

1,748


8%


7%

As a % of Average Loans


4.08%


4.07%


3.80%


3.81%


4.20%


Net Credit Margin(6)


$

3,350


$

3,286


$

3,598


$

3,722


$

3,378


(9%)


1%

As a % of Average Loans(6)


8.35%


8.14%


8.67%


8.79%


8.13%


Loans 90+ Days Past Due


$

2,111


$

2,010


$

2,078


$

2,299


$

2,174


(5%)


3%

As a % of EOP Loans


1.32%


1.22%


1.25%


1.31%


1.37%


Loans 30-89 Days Past Due


$

2,007


$

1,952


$

2,153


$

2,185


$

2,076


(5%)


3%

As a % of EOP Loans


1.25%


1.18%


1.30%


1.25%


1.30%


(1)

Also includes net interest revenue related to the average deposit balances in excess of the average loan portfolio.

(2)

The Loans 90+ Days Past Due and 30-89 Days Past Due and related ratios exclude U.S. mortgage loans that are guaranteed by U.S. government-sponsored agencies. See footnote 2 on page 9.

(3)

Average loans, EOP loans and the related consumer delinquency amounts and ratios include interest and fees receivables balances.

(4)

Average yield is gross interest revenue earned on loans divided by average loans.

(5)

Net interest revenue includes certain fees that are recorded as interest revenue.

(6)

Net credit margin is total revenues, net of interest expense, less net credit losses and policy benefits and claims.


Reclassified to conform to the current period's presentation.


Page 7

GLOBAL CONSUMER BANKING

NORTH AMERICA

Page 1

(In millions of dollars, except as otherwise noted)


1Q20 Increase/ 


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19


Net Interest Revenue


$

4,897


$

4,869


$

5,041


$

5,062


$

5,036


(1%)


3%

Non-Interest Revenue


103


97


138


191


188


(2%)


83%

Total Revenues, Net of Interest Expense (1)


5,000


4,966


5,179


5,253


5,224


(1%)


4%

Total Operating Expenses


2,572


2,621


2,511


2,450


2,536


4%


(1%)

Net Credit Losses


1,408


1,417


1,350


1,408


1,526


8%


8%

Credit Reserve Build / (Release)


118


81


161


109


2,362


NM


NM

Provision for Unfunded Lending Commitments


(3)


-


2


2


(1)


NM


67%

Provisions for Benefits and Claims, HTM Debt Securities and Other Assets


6


6


4


3


5


67%


(17%)

Provisions for Loan Losses and for Benefits and Claims


1,529


1,504


1,517


1,522


3,892


NM


NM

Income (Loss) from Continuing Operations before Taxes


899


841


1,151


1,281


(1,204)


NM


NM

Income Taxes (Benefits)


192


178


267


311


(294)


NM


NM

Income (Loss) from Continuing Operations


707


663


884


970


(910)


NM


NM

Noncontrolling Interests


-


-


-


-


-


-


-

Net Income (Loss)


$

707


$

663


$

884


$

970


$

(910)


NM


NM

Average Assets (in billions)


$

226


$

229


$

235


$

237


$

246


4%


9%

Return on Average Assets


1.27%


1.16%


1.49%


1.62%


(1.49%)


Efficiency Ratio


51%


53%


48%


47%


49%


Net Credit Losses as a % of Average Loans


3.08%


3.07%


2.84%


2.90%


3.18%


Revenue by Business


Retail Banking


$

1,131


$

1,159


$

1,131


$

1,108


$

1,130


2%


-

Citi-Branded Cards


2,195


2,197


2,334


2,439


2,347


(4%)


7%

Citi Retail Services


1,674


1,610


1,714


1,706


1,747


2%


4%

Total


$

5,000


$

4,966


$

5,179


$

5,253


$

5,224


(1%)


4%


Net Credit Losses by Business


Retail Banking


$

39


$

40


$

40


$

42


$

37


(12%)


(5%)

Citi-Branded Cards


706


723


712


723


795


10%


13%

Citi Retail Services


663


654


598


643


694


8%


5%

Total


$

1,408


$

1,417


$

1,350


$

1,408


$

1,526


8%


8%


Income from Continuing Operations by Business


Retail Banking


$

21


$

56


$

67


$

52


$

(73)


NM


NM

Citi-Branded Cards


382


364


441


555


(529)


NM


NM

Citi Retail Services


304


243


376


363


(308)


NM


NM

Total


$

707


$

663


$

884


$

970


$

(910)


NM


NM


(1)

1Q18 includes an approximate $150 million gain on the sale of the Hilton Card portfolio.

NM  Not meaningful.

Reclassified to conform to the current period's presentation.

Page 8

GLOBAL CONSUMER BANKING

NORTH AMERICA

Page 2


1Q20 Increase/


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19


Retail Banking Key Indicators (in billions of dollars, except as otherwise noted)


Branches (actual)


689


688


687


687


686


-


-

Accounts (in millions)


9.0


9.1


9.1


9.1


9.1


-


1%

Average Deposits


$

149.6


$

151.6


$

153.6


$

156.2


$

161.3


3%


8%

Investment Sales


$

8.8


$

9.6


$

9.6


$

9.8


$

12.4


27%


41%

Investment AUMs


$

65.9


$

68.2


$

68.5


$

72.2


$

62.0


(14%)


(6%)


Average Loans


$

47.6


$

47.8


$

48.6


$

49.8


$

50.5


1%


6%


EOP Loans:


Mortgages


$

44.7


$

45.3


$

46.3


$

47.5


$

47.9


1%


7%

Personal, Small Business and Other


3.0


2.9


2.8


2.8


2.9


4%


(3%)

Total EOP Loans


$

47.7


$

48.2


$

49.1


$

50.3


$

50.8


1%


6%


Mortgage Originations (1)


$

2.0


$

3.9


$

5.0


$

6.0


$

4.1


(32%)


NM


Third Party Mortgage Servicing Portfolio (EOP)


$

44.9


$

44.5


$

44.2


$

43.8


$

43.9


-


(2%)


Net Servicing and Gain/(Loss) on Sale (in millions)


$

31.8


$

31.3


$

32.9


$

38.2


$

86.3


NM


NM


Saleable Mortgage Rate Locks


$

1.1


$

1.5


$

1.9


$

2.0


$

2.9


45%


NM


Net Interest Revenue on Loans (in millions)


$

180


$

175


$

171


$

178


$

184


3%


2%

As a % of Avg. Loans


1.53%


1.47%


1.40%


1.42%


1.47%


Net Credit Losses (in millions)


$

39


$

40


$

40


$

42


$

37


(12%)


(5%)

As a % of Avg. Loans


0.33%


0.34%


0.33%


0.33%


0.29%


Loans 90+ Days Past Due (in millions) (2)


$

132


$

133


$

125


$

146


$

161


10%


22%

As a % of EOP Loans


0.28%


0.28%


0.26%


0.29%


0.32%


Loans 30-89 Days Past Due (in millions) (2)


$

263


$

341


$

313


$

334


$

298


(11%)


13%

As a % of EOP Loans


0.56%


0.72%


0.65%


0.67%


0.59%


(1)

Originations of residential first mortgages.

(2)

The Loans 90+ Days Past Due and 30-89 Days Past Due and related ratios exclude U.S. mortgage loans that are guaranteed by U.S. government-sponsored agencies since the potential loss predominantly resides with the U.S. agencies.

The amounts excluded for Loans 90+ Days Past Due and (EOP Loans) were $173 million and ($0.6 billion), $162 million and ($0.6 billion), and $150 million and ($0.6 billion), $135 million and ($0.5 billion), and $124 million and ($0.5 billion) as of March 31, 2019, June 30, 2019, September 30, 2019, December 31, 2019 and March 31, 2020, respectively.

The amounts excluded for Loans 30-89 Days Past Due and (EOP Loans) were $78 million and ($0.6 billion), $89 million and ($0.6 billion), $78 million and ($0.6 billion), $72 million and ($0.5 billion), and $64 million and ($0.5 billion) as of March 31, 2019, June 30, 2019, September 30, 2019, December 31, 2019 and March 31, 2020, respectively.

NM  Not meaningful.

Reclassified to conform to the current period's presentation.

Page 9

GLOBAL CONSUMER BANKING

NORTH AMERICA

Page 3


1Q20 Increase/


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19


Citi-Branded Cards Key Indicators (in millions of dollars, except as otherwise noted) (1)


EOP Open Accounts (in millions)


34.8


34.8


34.7


34.9


35.0


-


1%

Purchase Sales (in billions)


$

83.6


$

93.2


$

93.5


$

98.1


$

85.8


(13%)


3%

Average Loans (in billions) (1)


$

87.7


$

88.4


$

90.5


$

92.4


$

92.3


-


5%

EOP Loans (in billions) (1)


$

87.0


$

90.6


$

91.5


$

96.3


$

88.4


(8%)


2%

Average Yield (2)


11.24%


11.13%


11.19%


10.96%


10.86%


(1%)


(3%)


Total Net Interest Revenue (3)


$

1,972


$

1,974


$

2,084


$

2,144


$

2,142


-


9%

As a % of Avg. Loans (3)


9.12%


8.96%


9.14%


9.21%


9.33%


Net Credit Losses


$

706


$

723


$

712


$

723


$

795


10%


13%

As a % of Average Loans


3.26%


3.28%


3.12%


3.10%


3.46%


Net Credit Margin (4)


$

1,487


$

1,470


$

1,621


$

1,715


$

1,550


(10%)


4%

As a % of Avg. Loans (4)


6.88%


6.67%


7.11%


7.36%


6.75%


Loans 90+ Days Past Due


$

828


$

799


$

807


$

915


$

891


(3%)


8%

As a % of EOP Loans


0.95%


0.88%


0.88%


0.95%


1.01%


Loans 30-89 Days Past Due


$

731


$

705


$

800


$

814


$

770


(5%)


5%

As a % of EOP Loans


0.84%


0.78%


0.87%


0.85%


0.87%


Citi Retail Services Key Indicators (in millions of dollars, except as otherwise noted) (1)


EOP Open Accounts


84.6


84.1


83.0


82.9


81.9


(1%)


(3%)

Purchase Sales (in billions)


$

18.6


$

22.5


$

21.7


$

25.1


$

18.0


(28%)


(3%)

Average Loans (in billions) (1)


$

50.2


$

49.1


$

49.7


$

50.5


$

50.5


-


1%

EOP Loans (in billions) (1)


$

48.9


$

49.6


$

50.0


$

52.9


$

48.9


(8%)


-

Average Yield (2)


18.17%


18.10%


18.08%


17.66%


17.78%


1%


(2%)


Total Net Interest Revenue (3)


$

2,078


$

2,036


$

2,136


$

2,121


$

2,119


-


2%

As a % of Avg. Loans (3)


16.79%


16.63%


17.05%


16.66%


16.88%


Net Credit Losses


$

663


$

654


$

598


$

643


$

694


8%


5%

As a % of Average Loans


5.36%


5.34%


4.77%


5.05%


5.53%


Net Credit Margin (4)


$

1,007


$

953


$

1,113


$

1,061


$

1,048


(1%)


4%

As a % of Avg. Loans (4)


8.14%


7.79%


8.88%


8.34%


8.35%


Loans 90+ Days Past Due


$

918


$

840


$

923


$

1,012


$

958


(5%)


4%

As a % of EOP Loans


1.88%


1.69%


1.85%


1.91%


1.96%


Loans 30-89 Days Past Due


$

859


$

831


$

943


$

945


$

903


(4%)


5%

As a % of EOP Loans


1.76%


1.68%


1.89%


1.79%


1.85%


(1)

Average loans, EOP loans and the related consumer delinquency amounts and ratios include interest and fees receivables balances.

(2)

Average yield is calculated as gross interest revenue earned on loans divided by average loans.

(3)

Net interest revenue includes certain fees that are recorded as interest revenue.

(4)

Net credit margin represents total revenues, net of interest expense, less net credit losses and policy benefits and claims.


Reclassified to conform to the current period's presentation.

Page 10

GLOBAL CONSUMER BANKING

LATIN AMERICA (1) 

Page  1

(In millions of dollars, except as otherwise noted)


1Q20 Increase/ 


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19


Net Interest Revenue


$

877


$

918


$

913


$

931


$

887


(5%)


1%


Non-Interest Revenue (2)


395


402


356


446


312


(30%)


(21%)


Total Revenues, Net of Interest Expense


1,272


1,320


1,269


1,377


1,199


(13%)


(6%)


Total Operating Expenses


673


704


724


782


699


(11%)


4%


Net Credit Losses


296


279


275


259


277


7%


(6%)


Credit Reserve Build / (Release)


(2)


3


(34)


(5)


265


NM


NM


Provision for Unfunded Lending Commitments


-


-


-


-


-


-


-


Provisions for Benefits and Claims, HTM Debt Securities and Other Assets


6


13


13


22


15


(32%)


NM


Provisions for Credit Losses and for Benefits and Claims (LLR & PBC)


300


295


254


276


557


NM


86%


Income (Loss) from Continuing Operations before Taxes


299


321


291


319


(57)


NM


NM


Income Taxes (Benefits)


83


87


74


85


(21)


NM


NM


Income (Loss) from Continuing Operations


216


234


217


234


(36)


NM


NM


Noncontrolling Interests


-


-


-


-


-


-


-


Net Income (Loss)


$

216


$

234


$

217


$

234


$

(36)


NM


NM


Average Assets (in billions)


$

33


$

34


$

35


$

37


$

35


(5%)


6%


Return on Average Assets


2.65%


2.76%


2.46%


2.51%


(0.41%)


Efficiency Ratio


53%


53%


57%


57%


58%


Net Credit Losses as a % of Average Loans


6.98%


6.54%


6.42%


5.91%


6.67%


Revenue by Business


Retail Banking


$

899


$

903


$

851


$

932


$

783


(16%)


(13%)


Citi-Branded Cards


373


417


418


445


416


(7%)


12%


Total


$

1,272


$

1,320


$

1,269


$

1,377


$

1,199


(13%)


(6%)


Net Credit Losses by Business


Retail Banking


$

136


$

123


$

119


$

116


$

130


12%


(4%)


Citi-Branded Cards


160


156


156


143


147


3%


(8%)


Total


$

296


$

279


$

275


$

259


$

277


7%


(6%)


Income from Continuing Operations by Business


Retail Banking


$

161


$

164


$

134


$

141


$

(23)


NM


NM


Citi-Branded Cards


55


70


83


93


(13)


NM


NM


Total


$

216


$

234


$

217


$

234


$

(36)


NM


NM


FX Translation Impact


Total Revenue - as Reported


$

1,272


$

1,320


$

1,269


$

1,377


$

1,199


(13%)


(6%)


Impact of FX Translation (3)


(74)


(73)


(54)


(84)


-


Total Revenues - Ex-FX (3)


$

1,198


$

1,247


$

1,215


$

1,293


$

1,199


(7%)


-


Total Operating Expenses - as Reported


$

673


$

704


$

724


$

782


$

699


(11%)


4%


Impact of FX Translation (3)


(36)


(37)


(30)


(45)


-


Total Operating Expenses - Ex-FX (3)


$

637


$

667


$

694


$

737


$

699


(5%)


10%


Total Provisions for LLR & PBC - as Reported


$

300


$

295


$

254


$

276


$

557


NM


86%


Impact of FX Translation (3)


(19)


(20)


(12)


(18)


-


Total Provisions for LLR & PBC - Ex-FX (3)


$

281


$

275


$

242


$

258


$

557


NM


98%


Net Income (Loss) - as Reported


$

216


$

234


$

217


$

234


$

(36)


NM


NM


Impact of FX Translation (3)


(12)


(12)


(8)


(14)


-


Total Net Income (Loss) - Ex-FX (3)


$

204


$

222


$

209


$

220


$

(36)


NM


NM


(1)Latin America GCB consists of Citi's consumer banking operations in Mexico.

(2)3Q18 includes an approximate $250 million gain on the sale of an asset management business.

(3)Reflects the impact of foreign currency (FX) translation into U.S. dollars at the 1Q20 average exchange rates for all periods presented. 

Citigroup's results of operations excluding the impact of FX translation are non-GAAP financial measures.

NM Not meaningful.

Reclassified to conform to the current period's presentation.

Page 11

GLOBAL CONSUMER BANKING

LATIN AMERICA

Page  2


1Q20 Increase/ 


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19


Retail Banking Key Indicators (in billions of dollars, except as otherwise noted)


Branches (actual)


1,464


1,459


1,458


1,419


1,411


(1%)


(4%)

Accounts (in millions)


30.0


30.3


30.3


30.1


29.9


(1%)


-

Average Deposits


$

22.7


$

22.8


$

22.5


$

23.0


$

22.9


-


1%

Investment Sales


$

3.4


$

3.4


$

3.4


$

3.7


$

3.7


-


9%

Investment AUMs


$

30.2


$

30.7


$

31.7


$

33.7


$

26.6


(21%)


(12%)

Average Loans


$

11.5


$

11.5


$

11.4


$

11.6


$

11.1


(4%)


(3%)

EOP Loans:


Mortgages


$

4.1


$

4.2


$

4.2


$

4.4


$

3.5


(20%)


(15%)

Personal, Small Business and Other


7.2


7.2


7.0


7.3


5.7


(22%)


(21%)

Total EOP Loans


$

11.3


$

11.4


$

11.2


$

11.7


$

9.2


(21%)


(19%)


Total Net Interest Revenue (in millions)(1)


$

574


$

578


$

572


$

578


$

548


(5%)


(5%)

As a % of Average Loans (1)


20.24%


20.16%


19.91%


19.77%


19.86%


Net Credit Losses (in millions)


$

136


$

123


$

119


$

116


$

130


12%


(4%)

As a % of Average Loans


4.80%


4.29%


4.14%


3.97%


4.71%


Loans 90+ Days Past Due (in millions)


$

95


$

108


$

97


$

106


$

90


(15%)


(5%)

As a % of EOP Loans


0.84%


0.95%


0.87%


0.91%


0.98%


Loans 30-89 Days Past Due (in millions)


$

185


$

191


$

191


$

180


$

140


(22%)


(24%)

As a % of EOP Loans


1.64%


1.68%


1.71%


1.54%


1.52%


Citi-Branded Cards Key Indicators (in billions of dollars, except as otherwise noted)


EOP Open Accounts (in millions)


5.5


5.4


5.3


5.3


5.2


(2%)


(5%)

Purchase Sales


$

4.4


$

4.7


$

4.7


$

5.4


$

4.0


(26%)


(9%)

Average Loans (2) 


$

5.7


$

5.6


$

5.6


$

5.8


$

5.6


(3%)


(2%)

EOP Loans (2)


$

5.6


$

5.7


$

5.5


$

6.0


$

4.5


(25%)


(20%)

Average Yield (3)


23.68%


25.21%


24.97%


24.91%


25.03%


-


6%


Total Net Interest Revenue (in millions) (4)


$

303


$

340


$

341


$

353


$

339


(4%)


12%

As a % of Average Loans (4)


21.56%


24.35%


24.16%


24.15%


24.35%


Net Credit Losses (in millions)


$

160


$

156


$

156


$

143


$

147


3%


(8%)

As a % of Average Loans


11.38%


11.17%


11.05%


9.78%


10.56%


Net Credit Margin (in millions) (5)


$

220


$

268


$

269


$

307


$

274


(11%)


25%

As a % of Average Loans (5)


15.65%


19.20%


19.06%


21.00%


19.68%


Loans 90+ Days Past Due (in millions)


$

165


$

169


$

152


$

165


$

121


(27%)


(27%)

As a % of EOP Loans


2.95%


2.96%


2.76%


2.75%


2.69%


Loans 30-89 Days Past Due (in millions)


$

161


$

159


$

161


$

159


$

132


(17%)


(18%)

As a % of EOP Loans


2.88%


2.79%


2.93%


2.65%


2.93%


(1)

Also includes net interest revenue related to the region's average deposit balances in excess of the average loan portfolio.

(2)

Average loans, EOP loans and the related consumer delinquency amounts and ratios include interest and fees receivables balances.

(3)

Average yield is gross interest revenue earned on loans divided by average loans.

(4)

Net interest revenue includes certain fees that are recorded as interest revenue.

(5)

Net credit margin is total revenues, net of interest expense, less net credit losses and policy benefits and claims.

NM Not meaningful.

Reclassified to conform to the current period's presentation.

Page 12

GLOBAL CONSUMER BANKING

ASIA (1)

PAGE 1

(In millions of dollars, except as otherwise noted)


1Q20 Increase/


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19


Net Interest Revenue


$

1,166


$

1,170


$

1,173


$

1,188


$

1,149


(3%)


(1%)

Non-Interest Revenue


652


677


668


641


602


(6%)


(8%)

Total Revenues, Net of Interest Expense


1,818


1,847


1,841


1,829


1,751


(4%)


(4%)

Total Operating Expenses


1,171


1,146


1,133


1,141


1,133


(1%)


(3%)

Net Credit Losses


164


174


177


175


180


3%


10%

Credit Reserve Build / (Release)


(20)


10


2


16


202


NM


NM

Provision for Unfunded Lending Commitments


-


-


-


-


-


-


-

Provisions for Benefits and Claims, HTM Debt Securities and Other Assets


-


-


-


-


-


-


-

Provisions for Credit Losses and for Benefits and Claims (LLR & PBC)


144


184


179


191


382


100%


NM

Income from Continuing Operations before Taxes


503


517


529


497


236


(53%)


(53%)

Income Taxes


106


113


127


123


45


(63%)


(58%)

Income from Continuing Operations


397


404


402


374


191


(49%)


(52%)

Noncontrolling Interests


-


1


2


3


(1)


NM


(100%)

Net Income


$

397


$

403


$

400


$

371


$

192


(48%)


(52%)

Average Assets (in billions)


$

121


$

121


$

122


$

125


$

125


-


3%

Return on Average Assets


1.33%


1.34%


1.30%


1.18%


0.62%


Efficiency Ratio


64%


62%


62%


62%


65%


Net Credit Losses as a % of Average Loans


0.85%


0.90%


0.90%


0.86%


0.90%


Revenue by Business


Retail Banking


$

1,076


$

1,140


$

1,135


$

1,084


$

1,133


5%


5%

Citi-Branded Cards


742


707


706


745


618


(17%)


(17%)

Total


$

1,818


$

1,847


$

1,841


$

1,829


$

1,751


(4%)


(4%)


Net Credit Losses by Business


Retail Banking


$

58


$

62


$

66


$

69


$

68


(1%)


17%

Citi-Branded Cards


106


112


111


106


112


6%


6%

Total


$

164


$

174


$

177


$

175


$

180


3%


10%


Income from Continuing Operations by Business


Retail Banking


$

227


$

297


$

291


$

231


$

216


(6%)


(5%)

Citi-Branded Cards


170


107


111


143


(25)


NM


NM

Total


$

397


$

404


$

402


$

374


$

191


(49%)


(52%)


FX Translation Impact


Total Revenue - as Reported


$

1,818


$

1,847


$

1,841


$

1,829


$

1,751


(4%)


(4%)

Impact of FX Translation (2)


(41)


(31)


(18)


(36)


-


Total Revenues - Ex-FX (2)


$

1,777


$

1,816


$

1,823


$

1,793


$

1,751


(2%)


(1%)


Total Operating Expenses - as Reported


$

1,171


$

1,146


$

1,133


$

1,141


$

1,133


(1%)


(3%)

Impact of FX Translation (2)


(30)


(19)


(8)


(22)


-


Total Operating Expenses - Ex-FX (2)


$

1,141


$

1,127


$

1,125


$

1,119


$

1,133


1%


(1%)


Provisions for LLR & PBC - as Reported


$

144


$

184


$

179


$

191


$

382


100%


NM

Impact of FX Translation (2)


(7)


(5)


(4)


(4)


-


Total Provisions for LLR & PBC - Ex-FX (2)


$

137


$

179


$

175


$

187


$

382


NM


NM


Net Income - as Reported


$

397


$

403


$

400


$

371


$

192


(48%)


(52%)

Impact of FX Translation (2)


(3)


(4)


(4)


(7)


-


Total Net Income - Ex-FX (2)


$

394


$

399


$

396


$

364


$

192


(47%)


(51%)


(1)Asia GCB includes the results of operations of GCB activities in certain EMEA countries for all periods presented.

(2)Reflects the impact of foreign currency (FX) translation into U.S. dollars at the 1Q20 average exchange rates for all periods presented.

Citigroup's results of operations excluding the impact of FX translation are non-GAAP financial measures.


NM Not meaningful.

Reclassified to conform to the current period's presentation.

Page 13

GLOBAL CONSUMER BANKING

ASIA (1)

PAGE 2


1Q20 Increase/ 


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19


Retail Banking Key Indicators (in billions of dollars, except as otherwise noted)


Branches (actual)


251


252


249


242


236


(2%)


(6%)

Accounts (in millions)


15.9


16.1


16.4


16.7


16.9


1%


6%

Average Deposits


$

99.4


$

100.8


$

100.7


$

103.4


$

105.9


2%


7%

Investment Sales


$

8.9


$

9.8


$

10.9


$

9.2


$

13.5


47%


52%

Investment AUMs


$

64.0


$

65.4


$

65.4


$

68.9


$

56.0


(19%)


(13%)

Average Loans


$

58.8


$

58.8


$

59.5


$

61.6


$

61.5


-


5%

EOP Loans:


Mortgages


$

32.0


$

32.4


$

32.5


$

33.2


$

31.9


(4%)


-

Personal, Small Business and Other


27.1


27.7


27.8


29.6


28.3


(4%)


4%

Total EOP Loans


$

59.1


$

60.1


$

60.3


$

62.8


$

60.2


(4%)


2%


Total Net Interest Revenue (in millions)(2)


$

676


$

682


$

676


$

673


$

658


(2%)


(3%)

As a % of Average Loans (2)


4.66%


4.65%


4.51%


4.33%


4.30%


Net Credit Losses (in millions)


$

58


$

62


$

66


$

69


$

68


(1%)


17%

As a % of Average Loans


0.40%


0.42%


0.44%


0.44%


0.44%


Loans 90+ Days Past Due (in millions)


$

167


$

175


$

170


$

186


$

178


(4%)


7%

As a % of EOP Loans


0.28%


0.29%


0.28%


0.30%


0.30%


Loans 30-89 Days Past Due (in millions)


$

296


$

299


$

299


$

302


$

356


18%


20%

As a % of EOP Loans


0.50%


0.50%


0.50%


0.48%


0.59%


Citi-Branded Cards Key Indicators (in billions of dollars, except as otherwise noted)


EOP Open Accounts (in millions)


15.2


15.2


15.2


15.2


15.2


-


-

Purchase Sales


$

21.4


$

21.6


$

21.9


$

23.4


$

19.8


(15%)


(7%)

Average Loans (3)


$

19.1


$

18.9


$

18.8


$

19.3


$

18.8


(3%)


(2%)

EOP Loans (3)


$

18.8


$

19.2


$

18.8


$

19.9


$

17.3


(13%)


(8%)

Average Yield (4)


12.42%


12.33%


12.39%


12.42%


12.37%


-


-


Total Net Interest Revenue (in millions)(5)


$

490


$

488


$

497


$

515


$

491


(5%)


-

As a % of Average Loans(6)


10.40%


10.36%


10.49%


10.59%


10.50%


Net Credit Losses (in millions)


$

106


$

112


$

111


$

106


$

112


6%


6%

As a % of Average Loans


2.25%


2.38%


2.34%


2.18%


2.40%


Net Credit Margin (in millions)(6)


$

636


$

595


$

595


$

639


$

506


(21%)


(20%)

As a % of Average Loans(6)


13.50%


12.63%


12.56%


13.14%


10.83%


Loans 90+ Days Past Due


$

200


$

202


$

196


$

207


$

204


(1%)


2%

As a % of EOP Loans


1.06%


1.05%


1.04%


1.04%


1.18%


Loans 30-89 Days Past Due


$

256


$

257


$

249


$

267


$

271


1%


6%

As a % of EOP Loans


1.36%


1.34%


1.32%


1.34%


1.57%


(1)Asia GCB includes the results of operations of GCB activities in certain EMEA countries for all periods presented.

(2)Also includes net interest revenue related to the region's average deposit balances in excess of the average loan portfolio.

(3)Average loans, EOP loans and the related consumer delinquency amounts and ratios include interest and fees receivables balances.

(4)Average yield is gross interest revenue earned on loans divided by average loans.

(5)Net interest revenue includes certain fees that are recorded as interest revenue.

(6)Net credit margin is total revenues, net of interest expense, less net credit losses and policy benefits and claims.


Reclassified to conform to the current period's presentation.


Page 14

INSTITUTIONAL CLIENTS GROUP

(In millions of dollars, except as otherwise noted)


1Q20 Increase/


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019 


2019 


2019 


2019 


2020 


4Q19


1Q19


Commissions and Fees


$

1,154


$

1,079


$

1,126


$

1,103


$

1,222


11%


6%

Administration and Other Fiduciary Fees


683


709


707


657


691


5%


1%

Investment Banking


1,113


1,101


1,045


1,181


1,231


4%


11%

Principal Transactions


2,638


1,936


2,583


1,405


5,359


NM


NM

Other (1)


280


721


319


509


(114)


NM


NM

Total Non-Interest Revenue


5,868


5,546


5,780


4,855


8,389


73%


43%

Net Interest Revenue (including Dividends)


4,150


4,509


4,071


4,522


4,095


(9%)


(1%)

Total Revenues, Net of Interest Expense


10,018


10,055


9,851


9,377


12,484


33%


25%

Total Operating Expenses


5,619


5,548


5,611


5,446


5,810


7%


3%

Net Credit Losses


78


91


110


115


127


10%


63%

Credit Reserve Build / (Release)


(74)


52


36


57


1,316


NM


NM

Provision for Unfunded Lending Commitments


28


(11)


7


74


553


NM


NM

Provisions for Benefits and Claims, HTM Debt Securities and Other Assets


-


-


-


-


8


NM


NM

Provisions for Credit Losses and for Benefits and Claims


32


132


153


246


2,004


NM


NM

Income from Continuing Operations before Taxes


4,367


4,375


4,087


3,685


4,670


27%


7%

Income Taxes


955


950


858


807


1,044


29%


9%

Income from Continuing Operations


3,412


3,425


3,229


2,878


3,626


26%


6%

Noncontrolling Interests


11


10


8


11


(1)


NM


NM

Net Income


$

3,401


$

3,415


$

3,221


$

2,867


$

3,627


27%


7%

EOP Assets (in billions)


$

1,472


$

1,501


$

1,525


$

1,447


$

1,723


19%


17%

Average Assets (in billions)


1,460


1,497


1,511


1,503


1,580


5%


8%

Return on Average Assets (ROA)


0.94%


0.91%


0.85%


0.76%


0.92%


Efficiency Ratio


56%


55%


57%


58%


47%


Revenue by Region


North America


$

3,269


$

3,632


$

3,244


$

3,314


$

4,947


49%


51%

EMEA


3,170


2,960


3,138


2,738


3,470


27%


9%

Latin America


1,268


1,307


1,294


1,297


1,418


9%


12%

Asia


2,311


2,156


2,175


2,028


2,649


31%


15%

Total Revenues, net of Interest Expense


$

10,018


$

10,055


$

9,851


$

9,377


$

12,484


33%


25%


Income (loss) from Continuing Operations by Region


North America


$

748


$

1,050


$

818


$

895


$

896


-


20%

EMEA


1,125


1,005


1,060


677


1,035


53%


(8%)

Latin America


540


519


487


565


526


(7%)


(3%)

Asia


999


851


864


741


1,169


58%


17%

Income from Continuing Operations


$

3,412


$

3,425


$

3,229


$

2,878


$

3,626


26%


6%


Average Loans by Region (in billions)


North America


$

185


$

188


$

189


$

191


$

196


3%


6%

EMEA


84


85


88


89


88


(1%)


5%

Latin America


42


41


39


38


38


-


(10%)

Asia


74


73


73


73


73


-


(1%)

Total


$

385


$

387


$

389


$

391


$

395


1%


3%


EOP Deposits by Region (in billions)


North America


$

349


$

356


$

393


$

375


$

444


19%


28%

EMEA


197


196


195


190


210


11%


7%

Latin America


34


34


34


36


36


-


6%

Asia


159


166


173


167


188


12%


18%

Total


$

739


$

752


$

795


$

768


$

878


14%


19%


EOP Deposits by Business (in billions)


Treasury and Trade Solutions


$

512


$

525


$

548


$

536


$

621


16%


21%

All Other ICG Businesses


227


227


247


232


257


11%


13%

Total


$

739


$

752


$

795


$

768


$

878


14%


19%


(1)

2Q19 includes a $355 million gain on Citi's investment in Tradeweb.


NM Not meaningful.

Reclassified to conform to the current period's presentation.

Page 15

INSTITUTIONAL CLIENTS GROUP

REVENUES BY BUSINESS

(In millions of dollars, except as otherwise noted)


1Q20 Increase/


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019 


2019 


2019 


2019 


2020 


4Q19


1Q19

Revenue Details


Investment Banking


Advisory


$

378


$

232


$

276


$

373


$

386


3%


2%

Equity Underwriting


172


314


247


240


180


(25%)


5%

Debt Underwriting


804


737


705


738


784


6%


(2%)

Total Investment Banking


1,354


1,283


1,228


1,351


1,350


-


-

Treasury and Trade Solutions


2,539


2,587


2,559


2,608


2,423


(7%)


(5%)

Corporate Lending - Excluding Gain/(Loss) on Loan Hedges


749


725


715


732


448


(39%)


(40%)

Private Bank


880


866


865


847


949


12%


8%

Total Banking Revenues (Ex-Gain/(Loss) on Loan Hedges)(1)


$

5,522


$

5,461


$

5,367


$

5,538


$

5,170


(7%)


(6%)


Corporate Lending - Gain/(Loss) on Loan Hedges(1)


(231)


(75)


(33)


(93)


816


NM


NM

Total Banking Revenues including G/(L) on Loan Hedges(1)


$

5,291


$

5,386


$

5,334


$

5,445


$

5,986


10%


13%


Fixed Income Markets


$

3,452


$

3,323


$

3,211


$

2,898


$

4,790


65%


39%

Equity Markets


842


790


760


516


1,169


NM


39%

Securities Services


638


682


664


647


645


-


1%

Other


(205)


(126)


(118)


(129)


(106)


18%


48%

Total Markets and Securities Services


$

4,727


$

4,669


$

4,517


$

3,932


$

6,498


65%


37%


Total Revenues, net of Interest Expense


$

10,018


$

10,055


$

9,851


$

9,377


$

12,484


33%


25%


Taxable-equivalent adjustments (2)


$

104


$

105


$

122


$

117


$

86


(26%)


(17%)


Total ICG Revenues including taxable-equivalent adjustments(2)


$

10,122


$

10,160


$

9,973


$

9,494


$

12,570


32%


24%


Commissions and Fees


$

174


$

198


$

194


$

216


$

189


(13%)


9%

Principal Transactions (3)


2,377


1,870


2,080


1,334


3,549


NM


49%

Other (4)


150


533


183


251


(59)


NM


NM

Total Non-Interest Revenue


$

2,701


$

2,601


$

2,457


$

1,801


$

3,679


NM


36%

Net Interest Revenue


751


722


754


1,097


1,111


1%


48%

Total Fixed Income Markets


$

3,452


$

3,323


$

3,211


$

2,898


$

4,790


65%


39%


Rates and Currencies


$

2,402


$

2,118


$

2,491


$

2,214


$

4,038


82%


68%

Spread Products / Other Fixed Income


1,050


1,205


720


684


752


10%


(28%)

Total Fixed Income Markets


$

3,452


$

3,323


$

3,211


$

2,898


$

4,790


65%


39%


Commissions and Fees


$

293


$

274


$

287


$

267


$

362


36%


24%

Principal Transactions (3)


396


7


388


(16)


774


NM


95%

Other


7


10


2


153


8


(95%)


14%

Total Non-Interest Revenue


$

696


$

291


$

677


$

404


$

1,144


NM


64%

Net Interest Revenue


146


499


83


112


25


(78%)


(83%)

Total Equity Markets


$

842


$

790


$

760


$

516


$

1,169


NM


39%


(1)Credit derivatives are used to economically hedge a portion of the corporate loan portfolio that includes both accrual loans and loans at fair value. Gain/(loss) on loan hedges includes the mark-to-market on the credit derivatives partially offset by the mark-to-market on the loans in the portfolio that are at fair value. Hedges on accrual loans reflect the mark-to-market on credit derivatives used to economically hedge the corporate loan accrual portfolio. The fixed premium costs of these hedges are netted against the private bank and corporate lending revenues to reflect the cost of credit protection. Citigroup’s results of operations excluding the impact of gain/(loss) on loan hedges are non-GAAP financial measures.

(2)Primarily relates to income tax credits related to affordable housing and alternative energy investments as well as tax exempt income from municipal bond investments.

(3)Excludes principal transactions revenues of ICG businesses other than Markets, primarily treasury and trade solutions and the private bank.

(4)2Q19 includes a $355 million gain on Citi's investment in Tradeweb.


NM Not meaningful.

Reclassified to conform to the current period's presentation.

Page 16

CORPORATE / OTHER (1)

(In millions of dollars, except as otherwise noted)


1Q20 Increase/


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19

Net Interest Revenue


$

669


$

484


$

443


$

294


$

325


11%


(51%)

Non-interest revenue


(201)


86


(9)


248


(252)


NM


(25%)

Total Revenues, Net of Interest Expense


468


570


434


542


73


(87%)


(84%)

Total Operating Expenses


549


481


485


635


416


(34%)


(24%)

Net Credit Losses


2


2


1


(13)


(2)


85%


NM

Credit Reserve Build / (Release)


(26)


(20)


(16)


2


191


NM


NM

Provisions for Benefits and Claims, HTM Debt Securities and Other Assets


-


-


-


-


(2)


NM


NM

Provision for Unfunded Lending Commitments


(1)


(4)


-


(2)


5


NM


NM

Total provisions for credit losses and for benefits and claims


(25)


(22)


(15)


(13)


192


NM


NM

Income from Continuing Operations before Taxes


(56)


111


(36)


(80)


(535)


NM


NM

Income Taxes (Benefits) (2)(3)(4)


(61)


45


(247)


(623)


(198)


68%


NM

Income (Loss) from Continuing Operations


5


66


211


543


(337)


NM


NM

Income (Loss) from Discontinued Operations, net of taxes


(2)


17


(15)


(4)


(18)


NM


NM

Noncontrolling Interests


14


(1)


5


2


(4)


NM


NM

Net Income (Loss)


$

(11)


$

84


$

191


$

537


$

(351)


NM


NM

EOP Assets (in billions)


$

107


$

97


$

96


$

97


$

94


(3%)


(12%)

Average Assets (in billions)


99


98


97


95


94


(1%)


(5%)

Return on Average Assets


(0.05%)


0.34%


0.78%


2.24%


(1.50%)


Efficiency Ratio


117%


84%


112%


117%


570%


Consumer - North America - Key Indicators


Average Loans (in billions of dollars)


$

13.6


$

12.3


$

11.2


$

10.4


$

9.4


(10%)


(31%)

EOP Loans (in billions of dollars)


12.6


12.0


11.0


10.0


9.1


(9%)


(28%)

Net Interest Revenue


104


81


75


77


74


(4%)


(29%)

As a % of Average Loans


3.10%


2.64%


2.66%


2.94%


3.17%


Net Credit Losses (Recoveries)


$

1


$

4


$

1


$

(12)


$

-


100%


(100%)

As a % of Average Loans


0.03%


0.13%


0.04%


(0.46%)


0.00%


Loans 90+ Days Past Due (4)


$

354


$

327


$

293


$

278


$

281


1%


(21%)

As a % of EOP Loans


2.97%


2.97%


2.82%


3.02%


3.23%


Loans 30-89 Days Past Due (4)


$

348


$

334


$

288


$

295


$

252


(15%)


(28%)

As a % of EOP Loans


2.92%


3.04%


2.77%


3.21%


2.90%


(1)

Includes certain unallocated costs of global staff functions (including finance, risk, human resources, legal and compliance), other corporate expenses and unallocated global operations and technology expenses and income taxes, as well as Corporate Treasury, certain North America legacy consumer loan portfolios, other legacy assets and discontinued operations.

(2)

4Q19 includes discrete tax items of roughly $540 million, including an approximate $430 million benefit of a reduction in Citi’s valuation allowance related to its Deferred Tax Assets (DTAs).

(3)

3Q19 includes discrete tax items of roughly $230 million, including an approximate $180 million benefit of a reduction in Citi’s valuation allowance related to its DTAs.

(4)

The Loans 90+ Days Past Due and 30-89 Days Past Due and related ratios exclude U.S. mortgage loans that are guaranteed by U.S. government-sponsored agencies since the potential loss predominantly resides with the U.S. agencies.

The amounts excluded for Loans 90+ Days Past Due and (EOP Loans) for each period were $309 million and ($0.7 billion), $273 million and ($0.7 billion), $249 million and ($0.6 billion), $172 million and ($0.4 billion), and $167 million and ($0.4 billion) as of March 31, 2019, June 30, 2019, September 30, 2019, December 31, 2019, and March 31, 2020, respectively.


The amounts excluded for Loans 30-89 Days Past Due and (EOP Loans) for each period were $118 million and ($0.7 billion), $124 million and ($0.7 billion), and $110 million and ($0.6 billion), $55 million and ($0.4 billion), and $58 million and ($0.4 billion) as of March 31, 2019, June 30, 2019, September 30, 2019, December 31, 2019, and March 31, 2020, respectively.


NM Not meaningful.

Reclassified to conform to the current period's presentation.

Page 17

AVERAGE BALANCES AND INTEREST RATES (1)(2)(3)(4)(5)

Taxable Equivalent Basis


Average Volumes


Interest


% Average Rate (4)


First


Fourth


First


First


Fourth


First


First


Fourth


First


Quarter


Quarter


Quarter


Quarter


Quarter


Quarter


Quarter


Quarter


Quarter


In millions of dollars, except as otherwise noted


2019


2019


2020(5)


2019


2019


2020(5)


2019


2019


2020(5)


Assets


Deposits with Banks


$

171,369


$

195,268


$

207,130


$

607


$

603


$

527


1.44

%  

1.23

%  

1.02

%


Securities Borrowed and Purchased under Resale Agreements(6)


275,639


256,022


268,900


1,790


1,451


1,208


2.63

%  

2.25

%  

1.81

%


Trading Account Assets(7)


220,577


243,597


252,458


1,692


1,957


1,594


3.11

%  

3.19

%  

2.54

%


Investments


351,008


367,733


381,335


2,578


2,421


2,305


2.98

%  

2.61

%  

2.43

%


Total Loans (net of Unearned Income)(8)


679,209


692,631


694,675


11,990


11,828


11,268


7.16

%  

6.78

%  

6.52

%


Other Interest-Earning Assets


66,925


58,609


68,737


483


333


283


2.93

%  

2.25

%  

1.66

%


Total Average Interest-Earning Assets


$

1,764,727


$

1,813,860


$

1,873,235


$

19,140


$

18,593


$

17,185


4.40

%  

4.07

%  

3.69

%


Liabilities


Deposits (Excluding Deposit Insurance and FDIC Assessment)


$

839,389


$

911,039


$

934,451


$

2,834


$

2,753


$

2,389


1.37

%  

1.20

%  

1.03

%


Deposit Insurance and FDIC Assessment


-


-


-


193


200


225


Total Deposits


839,389


911,039


934,451


3,027


2,953


2,614


1.46

%  

1.29

%  

1.13

%


Securities Loaned and Sold under Repurchase Agreements(6)


183,937


188,153


198,510


1,589


1,320


1,085


3.50

%  

2.78

%  

2.20

%


Trading Account Liabilities(7)


95,290


78,920


84,500


327


316


239


1.39

%  

1.59

%  

1.14

%


Short-Term Borrowings


99,180


97,079


106,560


652


489


384


2.67

%  

2.00

%  

1.45

%


Long-Term Debt(9)


196,963


197,972


202,192


1,722


1,470


1,325


3.55

%  

2.95

%  

2.64

%


Total Average Interest-Bearing Liabilities


$

1,414,759


$

1,473,163


$

1,526,213


$

7,317


$

6,548


$

5,647


2.10

%  

1.76

%  

1.49

%


Total Average Interest-Bearing Liabilities (Excluding Deposit Insurance and FDIC Assessment)


$

1,414,759


$

1,473,163


$

1,526,213


$

7,124


$

6,348


$

5,422


2.04

%  

1.71

%  

1.43

%


Net Interest Revenue as a % of Average Interest-Earning Assets (NIM)


$

11,823


$

12,045


$

11,538


2.72

%  

2.63

%  

2.48

%


NIR as a % of Average Interest-Earning Assets (NIM) (excluding deposit insurance and FDIC Assessment)


$

12,016


$

12,245


$

11,763


2.76

%  

2.68

%  

2.53

%


1Q20 Increase (Decrease) from:


(24)

bps

(15)

bps


1Q20 Increase (Decrease) (Excluding Deposit Insurance and FDIC Assessment) from:


(23)

bps

(15)

bps


(1)Interest Revenue includes the taxable equivalent adjustments (based on the U.S. federal statutory tax rate of 21%) of $64 million for 1Q19, $48 million for 4Q19 and $46 million for 1Q20.

(2)Citigroup average balances and interest rates include both domestic and international operations.

(3)Monthly averages have been used by certain subsidiaries where daily averages are unavailable.

(4)Average rate percentage is calculated as annualized interest over average volumes.

(5)First quarter of 2020 is preliminary.

(6)Average volumes of securities borrowed or purchased under agreements to resell and securities loaned or sold under agreements to repurchase are reported net pursuant to FIN 41; the related interest excludes the impact of ASU 2013-01 (Topic 210).

(7)Interest expense on trading account liabilities of ICG is reported as a reduction of interest revenue. Interest revenue and interest expense on cash collateral positions are reported in trading account assets and trading account liabilities, respectively.

(8)Nonperforming loans are included in the average loan balances.

(9)Excludes hybrid financial instruments with changes in fair value recorded in Principal transactions.


Reclassified to conform to the current period's presentation.

Page 18

DEPOSITS

(In billions of dollars)


1Q20 Increase/


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019 


2019 


2019 


2019 


2020 


4Q19


1Q19

Global Consumer Banking


North America


$

154.1


$

153.0


$

155.8


$

160.5


$

166.4


4%


8%

Latin America


22.5


22.9


21.8


23.8


19.8


(17%)


(12%)

Asia (1)


101.8


102.7


102.3


106.7


107.8


1%


6%

Total


278.4


278.6


279.9


291.0


294.0


1%


6%


ICG


North America


348.5


355.9


393.2


374.2


444.6


19%


28%

EMEA


196.7


195.9


194.7


189.9


210.0


11%


7%

Latin America


34.1


34.0


34.3


36.2


36.1


-


6%

Asia


159.3


166.2


172.7


167.4


187.6


12%


18%

Total


738.6


752.0


794.9


767.7


878.3


14%


19%


Corporate/Other


13.4


15.0


13.0


11.9


12.6


6%


(6%)


Total Deposits - EOP


$

1,030.4


$

1,045.6


$

1,087.8


$

1,070.6


$

1,184.9


11%


15%


Total Deposits - Average


$

1,017.1


$

1,039.9


$

1,066.3


$

1,089.5


$

1,114.5


2%


10%


Foreign Currency (FX) Translation Impact


Total EOP Deposits - as Reported


$

1,030.4


$

1,045.6


$

1,087.8


$

1,070.6


$

1,184.9


11%


15%

Impact of FX Translation (2)


(21.3)


(22.3)


(12.7)


(22.8)


-


Total EOP Deposits - Ex-FX (2)


$

1,009.1


$

1,023.3


$

1,075.1


$

1,047.8


$

1,184.9


13%


17%


(1)

Asia GCB includes deposits of certain EMEA countries for all periods presented.

(2)

Reflects the impact of FX translation into U.S. dollars at the first quarter of 2020 exchange rates for all periods presented.

Citigroup's results of operations excluding the impact of FX translation are non-GAAP financial measures.


Reclassified to conform to the current period's presentation.

Page 19

EOP LOANS

(In billions of dollars)


1Q20 Increase/


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19

Global Consumer Banking


North America


Credit Cards


$

135.9


$

140.2


$

141.5


$

149.2


$

137.3


(8%)


1%

Retail Banking


47.7


48.2


49.1


50.3


50.8


1%


6%

Total


183.6


188.4


190.6


199.5


188.1


(6%)


2%


Latin America


Credit Cards


5.6


5.7


5.5


6.0


4.5


(25%)


(20%)

Retail Banking


11.3


11.4


11.2


11.7


9.2


(21%)


(19%)

Total


16.9


17.1


16.7


17.7


13.7


(23%)


(19%)


Asia (1)


Credit Cards


18.8


19.2


18.8


19.9


17.3


(13%)


(8%)

Retail Banking


59.1


60.1


60.3


62.8


60.2


(4%)


2%

Total


77.9


79.3


79.1


82.7


77.5


(6%)


(1%)


Total GCB Consumer Loans


Credit Cards


160.3


165.1


165.8


175.1


159.1


(9%)


(1%)

Retail Banking


118.1


119.7


120.6


124.8


120.2


(4%)


2%

Total GCB


278.4


284.8


286.4


299.9


279.3


(7%)


-


Total Corporate/Other - Consumer


12.6


11.7


11.0


9.6


9.1


(5%)


(28%)

Total Consumer Loans


$

291.0


$

296.5


$

297.4


$

309.5


$

288.4


(7%)


(1%)


Corporate Loans - by Region


North America


$

190.5


$

191.4


$

190.9


$

190.9


$

223.5


17%


17%

EMEA


86.0


87.8


91.9


87.4


93.8


7%


9%

Latin America


41.2


40.2


38.1


39.1


41.3


6%


-

Asia


73.7


72.8


73.4


72.5


74.0


2%


-

Total Corporate Loans


391.4


392.2


394.3


389.9


432.6


11%


11%


Corporate Loans - by Product


Corporate Lending


162.0


159.6


156.9


152.6


192.2


26%


19%

Private Bank


99.6


102.6


105.3


109.0


112.0


3%


12%

Treasury and Trade Solutions


77.5


77.2


76.7


74.7


75.5


1%


(3%)

Markets and Securities Services


52.3


52.8


55.4


53.6


52.9


(1%)


1%

Total Corporate Loans


391.4


392.2


394.3


389.9


432.6


11%


11%


Total Loans


$

682.3


$

688.7


$

691.7


$

699.5


$

721.0


3%


6%


Foreign Currency (FX) Translation Impact


Total EOP Loans - as Reported


$

682.3


$

688.7


$

691.7


$

699.5


$

721.0


3%


6%

Impact of FX Translation (2)


(14.6)


(14.8)


(8.8)


(15.5)


-


Total EOP Loans - Ex-FX (2)


$

667.7


$

673.9


$

682.9


$

684.0


$

721.0


5%


8%


(1)

Asia GCB includes loans of certain EMEA countries for all periods presented.

(2)

Reflects the impact of FX translation into U.S. dollars at the first quarter of 2020 exchange rates for all periods presented.

Citigroup's results of operations excluding the impact of FX translation are non-GAAP financial measures.


Reclassified to conform to the current period's presentation.

Page 20

SUPPLEMENTAL DETAIL

CONSUMER LOANS 90+ DAYS DELINQUENCIES AND RATIOS

BUSINESS VIEW

(In millions of dollars, except EOP loan amounts in billions of dollars)


Loans 90+ Days Past Due (1)


EOP Loans


1Q


2Q


3Q


4Q


1Q


1Q


2019


2019


2019


2019


2020


2020

Global Consumer Banking(2)


Total


$

2,505


$

2,426


$

2,470


$

2,737


$

2,603


$

279.3

Ratio


0.90%


0.85%


0.86%


0.91%


0.93%


Retail Banking(2)


Total


$

394


$

416


$

392


$

438


$

429


$

120.2

Ratio


0.34%


0.35%


0.33%


0.35%


0.36%


North America(2)


$

132


$

133


$

125


$

146


$

161


$

50.8

Ratio


0.28%


0.28%


0.26%


0.29%


0.32%


Latin America


$

95


$

108


$

97


$

106


$

90


$

9.2

Ratio


0.84%


0.95%


0.87%


0.91%


0.98%


Asia(3)


$

167


$

175


$

170


$

186


$

178


$

60.2

Ratio


0.28%


0.29%


0.28%


0.30%


0.30%


Cards


Total


$

2,111


$

2,010


$

2,078


$

2,299


$

2,174


$

159.1

Ratio


1.32%


1.22%


1.25%


1.31%


1.37%


North America - Citi-Branded


$

828


$

799


$

807


$

915


$

891


$

88.4

Ratio


0.95%


0.88%


0.88%


0.95%


1.01%


North America - Retail Services


$

918


$

840


$

923


$

1,012


$

958


$

48.9

Ratio


1.88%


1.69%


1.85%


1.91%


1.96%


Latin America


$

165


$

169


$

152


$

165


$

121


$

4.5

Ratio


2.95%


2.96%


2.76%


2.75%


2.69%


Asia(3)


$

200


$

202


$

196


$

207


$

204


$

17.3

Ratio


1.06%


1.05%


1.04%


1.04%


1.18%


Corporate/Other - Consumer(2)


$

354


$

327


$

293


$

278


$

281


$

9.1

Ratio


2.97%


2.97%


2.82%


3.02%


3.23%


Total Citigroup(2)


$

2,859


$

2,753


$

2,763


$

3,015


$

2,884


$

288.4

Ratio


0.99%


0.93%


0.93%


0.98%


1.00%


(1)

The ratio of 90+ Days Past Due is calculated based on end-of-period loans, net of unearned income.

(2)

The 90+ Days Past Due and related ratios for North America Retail Banking and Corporate/Other North America exclude U.S. mortgage loans that are guaranteed by U.S. government-sponsored agencies since the potential loss predominantly resides with the U.S. agencies. See footnote 2 on page 9 and footnote 1 on page 17.

(3)

Asia includes delinquency amounts, ratios and loans of certain EMEA countries for all periods presented.


Reclassified to conform to the current period's presentation.


Page 21

SUPPLEMENTAL DETAIL

CONSUMER LOANS 30-89 DAYS DELINQUENCIES AND RATIOS

BUSINESS VIEW

(In millions of dollars, except EOP loan amounts in billions of dollars)


Loans 30-89 Days Past Due (1)


EOP Loans


1Q


2Q


3Q


4Q


1Q


1Q


2019


2019


2019


2019


2020


2020


Global Consumer Banking(2)


Total


$

2,751


$

2,783


$

2,956


$

3,001


$

2,870


$

279.3


Ratio


0.99%


0.98%


1.03%


1.00%


1.03%


Retail Banking(2)


Total


$

744


$

831


$

803


$

816


$

794


$

120.2


Ratio


0.63%


0.70%


0.67%


0.66%


0.66%


North America(2)


$

263


$

341


$

313


$

334


$

298


$

50.8


Ratio


0.56%


0.72%


0.65%


0.67%


0.59%


Latin America


$

185


$

191


$

191


$

180


$

140


$

9.2


Ratio


1.64%


1.68%


1.71%


1.54%


1.52%


Asia (3)


$

296


$

299


$

299


$

302


$

356


$

60.2


Ratio


0.50%


0.50%


0.50%


0.48%


0.59%


Cards


Total


$

2,007


$

1,952


$

2,153


$

2,185


$

2,076


$

159.1


Ratio


1.25%


1.18%


1.30%


1.25%


1.30%


North America - Citi-Branded


$

731


$

705


$

800


$

814


$

770


$

88.4


Ratio


0.84%


0.78%


0.87%


0.85%


0.87%


North America - Retail Services


$

859


$

831


$

943


$

945


$

903


$

48.9


Ratio


1.76%


1.68%


1.89%


1.79%


1.85%


Latin America


$

161


$

159


$

161


$

159


$

132


$

4.5


Ratio


2.88%


2.79%


2.93%


2.65%


2.93%


Asia (3)


$

256


$

257


$

249


$

267


$

271


$

17.3


Ratio


1.36%


1.34%


1.32%


1.34%


1.57%


Corporate/Other - Consumer(2)


$

348


$

334


$

288


$

295


$

252


$

9.1


Ratio


2.92%


3.04%


2.77%


3.21%


2.90%


Total Citigroup(2)


$

3,099


$

3,117


$

3,244


$

3,296


$

3,122


$

288.4


Ratio


1.07%


1.05%


1.10%


1.07%


1.09%


(1)

The ratio of 30-89 Days Past Due is calculated based on end-of-period loans, net of unearned income.

(2)

The 30-89 Days Past Due and related ratios for North America Retail Banking and Corporate/Other North America exclude U.S. mortgage loans that are guaranteed by U.S. government-sponsored agencies since the potential loss predominantly resides with the U.S. agencies. See footnote 2 on page 9 and footnote 1 on page 17.

(3)

Asia includes delinquency amounts, ratios and loans of certain EMEA countries for all periods presented.


Reclassified to conform to the current period's presentation.

Page 22

ALLOWANCE FOR CREDIT LOSSES ON LOANS AND UNFUNDED LENDING COMMITMENTS Page 1

(In millions of dollars)


1Q20 Increase/


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19


Total Citigroup


Allowance for Loan Losses at Beginning of Period(1)


$

12,315


$

12,329


$

12,466


$

12,530


$

12,783


Adjustment to Opening Balance for CECL Adoption(1)


-


-


-


-


4,201


NM


NM


Adjusted Balance, Beginning of Period


12,315


12,329


12,466


12,530


16,984


36%


38%


Gross Credit (Losses)


(2,345)


(2,354)


(2,281)


(2,361)


(2,479)


(5%)


(6%)


Gross Recoveries


397


391


368


417


371


(11%)


(7%)


Net Credit (Losses) / Recoveries (NCLs)


(1,948)


(1,963)


(1,913)


(1,944)


(2,108)


8%


8%


NCLs


1,948


1,963


1,913


1,944


2,108


8%


8%


Net Reserve Builds / (Releases)


67


53


132


112


4,112


NM


NM


Net Specific Reserve Builds / (Releases)


(71)


73


17


67


224


NM


NM


Provision for Loan Losses


1,944


2,089


2,062


2,123


6,444


NM


NM


Other(2)(3)(4)(5)(6)(7)


18


11


(85)


74


(479)


NM


NM


Allowance for Loan Losses at End of Period(1) (a)


$

12,329


$

12,466


$

12,530


$

12,783


$

20,841


Allowance for Unfunded Lending Commitments(8) (a)


$

1,391


$

1,376


$

1,385


$

1,456


$

1,813


Provision (Release) for Unfunded Lending Commitments


$

24


$

(15)


$

9


$

74


$

557


Total Allowance for Loans, Leases and Unfunded Lending Commitments [Sum of (a)]


$

13,720


$

13,842


$

13,915


$

14,239


$

22,654


Total Allowance for Loan Losses as a Percentage of Total Loans(9)


1.82

%  


1.82

%  


1.82

%  


1.84

%  


2.91

%  


Consumer


Allowance for Loan Losses at Beginning of Period(1)


$

9,504


$

9,598


$

9,679


$

9,727


$

9,897


Adjustment to Opening Balance for CECL Adoption(1)


-


-


-


-


4,922


NM


NM


Adjusted Balance, Beginning of Period


9,504


9,598


9,679


9,727


14,819


52%


56%


Net Credit Losses (NCLs)


(1,869)


(1,874)


(1,803)


(1,830)


(1,981)


8%


6%


NCLs


1,869


1,874


1,803


1,830


1,981


8%


6%


Net Reserve Builds / (Releases)


63


3


95


107


2,844


NM


NM


Net Specific Reserve Builds / (Releases)


8


70


18


11


176


NM


NM


Provision for Loan Losses


1,940


1,947


1,916


1,948


5,001


NM


NM


Other(2)(3)(4)(5)(6)(7)


23


8


(65)


52


(449)


NM


NM


Allowance for Loan Losses at End of Period(1) (b)


$

9,598


$

9,679


$

9,727


$

9,897


$

17,390


Consumer Allowance for Unfunded Lending Commitments(8) (b)


$

-


$

-


$

2


$

4


$

-


Provision (Release) for Unfunded Lending Commitments


$

(3)


$

-


$

2


$

2


$

(1)


Total Allowance for Loans, Leases and Unfunded Lending Commitments [Sum of (b)]


$

9,598


$

9,679


$

9,729


$

9,901


$

17,390


Consumer Allowance for Loan Losses as a Percentage of Total Consumer Loans


3.30

%  


3.26

%  


3.27

%  


3.20

%  


6.03

%  


Corporate


Allowance for Loan Losses at Beginning of Period(1)


$

2,811


$

2,731


$

2,787


$

2,803


$

2,886


Adjustment to Opening Balance for CECL Adoption(1)


-


-


-


-


(721)


NM


NM


Adjusted Balance, Beginning of Period


2,811


2,731


2,787


2,803


2,165


(23%)


(23%)


Net Credit (Losses) / Recoveries (NCLs)


(79)


(89)


(110)


(114)


(127)


11%


61%


NCLs


79


89


110


114


127


11%


61%


Net Reserve Builds / (Releases)


4


50


37


5


1,268


NM


NM


Net Specific Reserve Builds / (Releases)


(79)


3


(1)


56


48


(14%)


NM


Provision for Loan Losses


4


142


146


175


1,443


NM


NM


Other(2)


(5)


3


(20)


22


(30)


Allowance for Loan Losses at End of Period(1) (c)


$

2,731


$

2,787


$

2,803


$

2,886


$

3,451


Corporate Allowance for Unfunded Lending Commitments(8) (c)


$

1,391


$

1,376


$

1,383


$

1,452


$

1,813


Provision (Release) for Unfunded Lending Commitments


$

27


$

(15)


$

7


$

72


$

558


Total Allowance for Loans, Leases and Unfunded Lending Commitments [Sum of (c)]


$

4,122


$

4,163


$

4,186


$

4,338


$

5,264


Corporate Allowance for Loan Losses as a Percentage of Total Corporate Loans(9)


0.70

%  


0.72

%  


0.72

%  


0.75

%  


0.81

%  


Footnotes to these tables are on the following page (page 24).


Page 23

ALLOWANCE FOR CREDIT LOSSES ON LOANS AND UNFUNDED LENDING COMMITMENTS 

Page 2


The following footnotes relate to the tables on the prior page (page 23).


(1)

On January 1, 2020, Citi adopted Accounting Standards Update (ASC) 326, Financial Instruments – Credit Losses (CECL). The ASU introduces a new credit loss methodology requiring earlier recognition of credit losses while also providing additional transparency about credit risk. On January 1, 2020, Citi recorded a $4.2 billion, or an approximate 29%, pretax increase in the Allowance for credit losses, along with a $3.1 billion after-tax decrease in Retained earnings and a deferred tax asset increase of $1.1 billion. This transition impact reflects (i) a $4.9 billion build to the Allowance for credit losses for Citi’s consumer exposures, primarily driven by the impact on credit card receivables of longer estimated tenors under the CECL lifetime expected credit loss methodology compared to shorter estimated tenors under the probable loss methodology under prior U.S. GAAP, net of recoveries; and (ii) a release of $0.8 billion of reserves related to Citi’s corporate net loan loss exposures, largely due to more precise contractual maturities that result in shorter remaining tenors, incorporation of recoveries and use of more specific historical loss data based on an increase in portfolio segmentation across industries and geographies.Attribution of the allowance is made for analytical purposes only, and the entire allowance is available to absorb losses in the portfolios. The balances on page 23 do not include approximately $0.1 billion of allowance for HTM debt securities and other assets at March 31, 2020.


(2)

Includes all adjustments to the allowance for credit losses, such as changes in the allowance from acquisitions, dispositions, securitizations, foreign currency translation (FX translation), purchase accounting adjustments, etc.


(3)

1Q19 Consumer includes an increase of approximately $26 million related to FX translation.


(4)

2Q19 Consumer includes an increase of approximately $13 million related to FX translation.


(5)

3Q19 Consumer includes a decrease of approximately $65 million related to FX translation.


(6)

4Q19 Consumer includes a reduction of approximately $33 million related to the sale or transfers to HFS of various loan portfolios. In addition, the fourth quarter includes an increase of approximately $86 million related to FX translation.


(7)

1Q20 Consumer includes a decrease of approximately $456 million related to FX translation. The Corporate Allowance is predominantly sourced in U.S. dollars.


(8)

Represents additional credit reserves recorded as other liabilities on the Consolidated Balance Sheet.


(9)

March 31, 2019, June 30, 2019, September 30, 2019, December 31, 2019 and March 31, 2020 exclude $3.9 billion, $3.8 billion, $3.8 billion, $4.1 billion and $4.0 billion, respectively, of loans which are carried at fair value.


NM  Not meaningful.

Reclassified to conform to the current period's presentation.

Page 24

COMPONENTS OF PROVISION FOR LOAN LOSSES

(In millions of dollars)


1Q20 Increase/


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19


Global Consumer Banking


Net Credit Losses


$

1,868


$

1,870


$

1,802


$

1,842


$

1,983


8%


6%

Credit Reserve Build / (Release)


96


94


129


120


2,829


NM


NM

North America


Net Credit Losses


1,408


1,417


1,350


1,408


1,526


8%


8%

Credit Reserve Build / (Release)


118


81


161


109


2,362


NM


NM

Retail Banking


Net Credit Losses


39


40


40


42


37


(12%)


(5%)

Credit Reserve Build / (Release)


(3)


(4)


(1)


(2)


178


NM


NM

Citi-Branded Cards


Net Credit Losses


706


723


712


723


795


10%


13%

Credit Reserve Build / (Release)


76


64


141


115


1,294


NM


NM

Citi Retail Services


Net Credit Losses


663


654


598


643


694


8%


5%

Credit Reserve Build / (Release)


45


21


21


(4)


890


NM


NM

Latin America


Net Credit Losses


296


279


275


259


277


7%


(6%)

Credit Reserve Build / (Release)


(2)


3


(34)


(5)


265


NM


NM

Retail Banking


Net Credit Losses


136


123


119


116


130


12%


(4%)

Credit Reserve Build / (Release)


1


(14)


(28)


(22)


122


NM


NM

Citi-Branded Cards


Net Credit Losses


160


156


156


143


147


3%


(8%)

Credit Reserve Build / (Release)


(3)


17


(6)


17


143


NM


NM

Asia (1)


Net Credit Losses


164


174


177


175


180


3%


10%

Credit Reserve Build / (Release)


(20)


10


2


16


202


NM


NM

Retail Banking


Net Credit Losses


58


62


66


69


68


(1%)


17%

Credit Reserve Build / (Release)


4


3


5


7


107


NM


NM

Citi-Branded Cards


Net Credit Losses


106


112


111


106


112


6%


6%

Credit Reserve Build / (Release)


(24)


7


(3)


9


95


NM


NM


Institutional Clients Group (ICG)


Net Credit Losses


78


91


110


115


127


10%


63%

Credit Reserve Build / (Release)


(74)


52


36


57


1,316


NM


NM


Corporate / Other


Net Credit Losses


2


2


1


(13)


(2)


85%


NM

Credit Reserve Build / (Release)


(26)


(20)


(16)


2


191


NM


NM


Total Provision for Loan Losses


$

1,944


$

2,089


$

2,062


$

2,123


$

6,444


NM


NM


(1)

Asia GCB includes NCLs and credit reserve builds (releases) for certain EMEA countries for all periods presented.


NM Not meaningful.

Reclassified to conform to the current period's presentation.

Page 25

NON-ACCRUAL ASSETS

(In millions of dollars)


1Q20 Increase/


1Q


2Q


3Q


4Q


1Q


(Decrease) from


2019


2019


2019


2019


2020


4Q19


1Q19

Non-Accrual Loans(1)


Corporate Non-Accrual Loans by Region


North America


$

1,061


$

913


$

1,056


$

1,214


$

1,138


(6%)


7%

EMEA


317


321


307


430


720


67%


NM

Latin America


305


353


399


473


447


(5%)


47%

Asia


49


80


84


71


179


NM


NM

Total


$

1,732


$

1,667


$

1,846


$

2,188


$

2,484


14%


43%


Consumer Non-Accrual Loans by Region(2)


North America


$

1,090


$

1,082


$

1,013


$

905


$

926


2%


(15%)

Latin America


614


629


595


632


489


(23%)


(20%)

Asia(3)


251


260


258


279


284


2%


13%

Total


$

1,955


$

1,971


$

1,866


$

1,816


$

1,699


(6%)


(13%)


Other Real Estate Owned (OREO)(4)


Institutional Clients Group


$

31


$

34


$

20


$

18


$

19


6%


(39%)

Global Consumer Banking


18


11


10


6


4


(33%)


(78%)

Corporate/Other


49


37


42


37


27


(27%)


(45%)

Total


$

98


$

82


$

72


$

61


$

50


(18%)


(49%)


OREO by Region


North America


$

63


$

47


$

51


$

39


$

35


(10%)


(44%)

EMEA


1


1


1


1


1


-


-

Latin America


13


14


14


14


6


(57%)


(54%)

Asia


21


20


6


7


8


14%


(62%)

Total


$

98


$

82


$

72


$

61


$

50


(18%)


(49%)


Non-Accrual Assets (NAA)(5)


Corporate Non-Accrual Loans


$

1,732


$

1,667


$

1,846


$

2,188


$

2,484


14%


43%

Consumer Non-Accrual Loans


1,955


1,971


1,866


1,816


1,699


(6%)


(13%)

Non-Accrual Loans (NAL)


3,687


3,638


3,712


4,004


4,183


4%


13%

OREO


98


82


72


61


50


(18%)


(49%)

Non-Accrual Assets (NAA)


$

3,785


$

3,720


$

3,784


$

4,065


$

4,233


4%


12%


NAL as a % of Total Loans


0.54%


0.53%


0.54%


0.57%


0.58%


NAA as a % of Total Assets


0.19%


0.19%


0.19%


0.21%


0.19%


Allowance for Loan Losses as a % of NAL


334%


343%


338%


319%


498%


(1)

Corporate loans are placed on non-accrual status based upon a review by Citigroup's risk officers. Corporate non-accrual loans may still be current on interest payments. With limited exceptions, the following practices are applied for Consumer loans: consumer loans, excluding credit cards and mortgages, are placed on non-accrual status at 90 days past due, and are charged off at 120 days past due; residential mortgage loans are placed on non-accrual status at 90 days past due and written down to net realizable value at 180 days past due. Consistent with industry conventions, Citigroup generally accrues interest on credit card loans until such loans are charged off, which typically occurs at 180 days contractual delinquency. As such, the non-accrual loan disclosures do not include credit card loans.

(2)

For 4Q19 and prior, excludes Statement of Position (SOP) 03-3 purchased distressed loans. For 1Q20, non-accrual loans include purchased credit default loans.

(3)

Asia GCB includes balances for certain EMEA countries for all periods presented.

(4)

Represents the carrying value of all property acquired by foreclosure or other legal proceedings when Citigroup has taken possession of the collateral. Also includes former premises and property for use that is no longer contemplated.

(5)

There is no industry-wide definition of non-accrual assets. As such, analysis against the industry is not always comparable.


NM  Not meaningful.

Reclassified to conform to the current period's presentation.

Page 26

CITIGROUP

CET1 CAPITAL AND SUPPLEMENTARY LEVERAGE RATIOS, TANGIBLE COMMON EQUITY, BOOK VALUE PER

SHARE AND TANGIBLE BOOK VALUE PER SHARE

(In millions of dollars or shares, except per share amounts and ratios)


March 31,


June 30,


September 30,


December 31,


March 31,

Common Equity Tier 1 Capital Ratio and Components(1)


2019


2019


2019


2019


2020(2)

Citigroup Common Stockholders' Equity(3)


$

178,427 


$

179,534


$

177,052


$

175,414


$

174,503

Add: Qualifying noncontrolling interests


144 


154


145


154


138

Regulatory Capital Adjustments and Deductions:


Add:


CECL transition and 25% provision deferral(4)


-


-


-


-


4,316

Less:


Accumulated net unrealized gains (losses) on cash flow hedges, net of tax(5)


(442)


75


328


123


2,020

Cumulative unrealized net gain (loss) related to changes in fair value of financial


liabilities attributable to own creditworthiness, net of tax(6)


(67) 


(85)


181


(679)


2,838

Intangible Assets:


Goodwill, net of related deferred tax liabilities (DTLs)(7)


21,768 


21,793


21,498


21,066


20,123

Identifiable intangible assets other than mortgage servicing rights


(MSRs), net of related DTLs


4,390 


4,264


4,132


4,087


3,953

Defined benefit pension plan net assets


811 


969


990


803


1,052

Deferred tax assets (DTAs) arising from net operating loss, foreign tax credit


and general business credit carry-forwards


11,756 


11,547


11,487


12,370


12,259

Common Equity Tier 1 Capital (CET1)


$

140,355 


$

141,125


$

138,581


$

137,798


$

136,712

Risk-Weighted Assets (RWA)(4)(9)


$

1,178,628 


$

1,187,328


$

1,197,050


$

1,166,523


$

1,224,218

Common Equity Tier 1 Capital Ratio (CET1/RWA)


11.91%


11.89%


11.58%


11.81%


11.2%


Supplementary Leverage Ratio and Components


Common Equity Tier 1 Capital (CET1)(4)


$

140,355 


$

141,125


$

138,581


$

137,798


$

136,712

Additional Tier 1 Capital (AT1)(8)


18,002 


17,981


19,452


18,007


17,600

Total Tier 1 Capital (T1C) (CET1 + AT1)


$

158,357 


$

159,106


$

158,033


$

155,805


$

154,312

Total Leverage Exposure (TLE)(4)(9)


$

2,463,603 


$

2,499,787


$

2,520,352


$

2,507,891


$

2,586,513

Supplementary Leverage Ratio (T1C/TLE)


6.43%


6.36%


6.27%


6.21%


6.0%


Tangible Common Equity, Book Value Per Share and Tangible Book Value Per Share


Common Stockholders' Equity


$

178,272 


$

179,379


$

176,893


$

175,262


$

174,351

Less:


Goodwill


22,037 


22,065


21,822


22,126


21,264

Intangible assets (other than MSRs)


4,645 


4,518


4,372


4,327


4,193

Tangible Common Equity (TCE)


$

151,590 


$

152,796


$

150,699


$

148,809


$

148,894

Common Shares Outstanding (CSO)


2,312.5 


2,259.1


2,183.2


2,114.1


2,081.8

Book Value Per Share (Common Equity/CSO)


$

77.09 


$

79.40


$

81.02


$

82.90


$

83.75

Tangible Book Value Per Share (TCE/CSO)


$

65.55 


$

67.64


$

69.03


$

70.39


$

71.52


(1)

See footnote 3 on page 1.

(2)

Preliminary.

(3)

Excludes issuance costs related to outstanding preferred stock in accordance with Federal Reserve Board regulatory reporting requirements.

(4)

Citi has elected to apply the modified transition provision related to the impact of the CECL accounting standard on regulatory capital, as provided by the U.S. banking agencies’ March 2020 interim final rule. Under the modified CECL transition provision, the allowance for credit losses (after-tax) upon the January 1, 2020 CECL adoption date have been deferred and will phase-in to regulatory capital at 25% per year commencing January 1, 2022. For the ongoing impact of CECL, Citi is allowed to adjust the allowance for credit losses in an amount equal to 25% of the change in the allowance for credit losses (pre-tax) recognized through earnings for each period between January 1, 2020 and December 31, 2021. The cumulative adjustments to the allowance for credit losses between January 1, 2020 and December 31, 2021 will also phase-in to regulatory capital at 25% per year commencing January 1, 2022, along with the deferred impacts related to the January 1, 2020 CECL adoption date. The corresponding adjustments on average on-balance sheet assets are also reflected in Total Leverage Exposure. Additionally, the increase in DTAs arising from temporary differences upon the January 1, 2020 CECL adoption date has been deducted from RWA and will phase-in to RWA at 25% per year commencing January 1, 2022.

(5)

Common Equity Tier 1 Capital is adjusted for accumulated net unrealized gains (losses) on cash flow hedges included in accumulated other comprehensive income that relate to the hedging of items not recognized at fair value on the balance sheet.

(6)

The cumulative impact of changes in Citigroup’s own creditworthiness in valuing liabilities for which the fair value option has been elected, and own-credit valuation adjustments on derivatives, are excluded from Common Equity Tier 1 Capital, in accordance with the U.S. Basel III rules.

(7)

Includes goodwill “embedded” in the valuation of significant common stock investments in unconsolidated financial institutions.

(8)

Additional Tier 1 Capital primarily includes qualifying noncumulative perpetual preferred stock and qualifying trust preferred securities.

(9)

RWA and TLE exclude assets acquired pursuant to a non-recourse loan provided under the Money Market Mutual Fund Liquidity Facility, as permitted by the U.S. banking agencies’ March 2020 interim final rule.


Reclassified to conform to the current period's presentation.

Page 27

Exhibit 99.3

​

Citigroup Inc. securities registered pursuant to Section 12(b) of the Securities Exchange Act of 1934:

​

​

Title of each class

Ticker Symbol(s)

Title for iXBRL

Name of each exchange on
which registered


​


Common Stock, par value $.01 per share 

C

Common Stock, par value $.01 per share

New York Stock Exchange


​

​


Depositary Shares, each representing 1/1,000th interest in a share of 7.125% Fixed/Floating Rate Noncumulative Preferred Stock, Series J

C Pr J

Dep Shs, represent 1/1,000th interest in a share of 7.125% Fix/Float Rate Noncum Pref Stk, Ser J

New York Stock Exchange


​

​


Depositary Shares, each representing 1/1,000th interest in a share of 6.875% Fixed/Floating Rate Noncumulative Preferred Stock, Series K 

C Pr K

Dep Shs, represent 1/1,000th interest in a share of 6.875% Fix/Float Rate Noncum Pref Stk, Ser K

New York Stock Exchange


​

​


Depositary Shares, each representing 1/1,000th interest in a share of 6.300% Noncumulative Preferred Stock, Series S 

C Pr S

Depositary Shares, represent 1/1,000th interest in a share of 6.300% Noncum Pref Stock, Ser S

New York Stock Exchange


​

​


7.625% Trust Preferred Securities of Citigroup Capital III (and registrant’s guaranty with respect thereto) 

C/36Y

7.625% TRUPs of Cap III (and registrant’s guaranty)

New York Stock Exchange


​

​


7.875% Fixed Rate / Floating Rate Trust Preferred Securities (TruPS®) of Citigroup Capital XIII (and registrant’s guaranty with respect thereto) 

C N

7.875% FXD / FRN TruPS of Cap XIII (and registrant’s guaranty)

New York Stock Exchange


​

​


6.829% Fixed Rate / Floating Rate Enhanced Trust Preferred Securities (Enhanced TruPS®) of Citigroup Capital XVIII (and registrant’s guaranty with respect thereto)

C/67BP

6.829% FXD / FRN Enhanced TruPS of Cap XVIII (and registrant’s guaranty)

New York Stock Exchange


​

​


C-Tracks Exchange-Traded Notes Based on the Performance of the Miller/Howard MLP Fundamental Index Due September 28, 2023 

MLPC

C-Tracks ETN Miller/Howard MLP Fundamental Index Due Sept 2023

NYSE Arca


​

​


C-Tracks Exchange-Traded Notes Miller/Howard Strategic Dividend Reinvestor Due September 16, 2024 

DIVC

C-Tracks ETN Miller/Howard Strategic Dividend Reinvestor Due Sept 2024

NYSE Arca


​

​


C-Tracks Exchange-Traded Notes on the Miller/Howard MLP Fundamental Index, Series B, Due July 13, 2026 of Citigroup Global Markets Holdings Inc. (“CGMHI”) (and registrant’s guaranty with respect thereto) 

MLPE

C-Tracks ETN Miller/Howard Fund, Ser B, Due July 2026 of CGMHI (and registrant’s guaranty)

NYSE Arca


​

​


Exchange-Traded Notes Based on the Performance of the VelocityShares® Daily 4X Long USD vs. JPY Index due December 15, 2032 of CGMHI (and registrant’s guaranty with respect thereto)  

DJPY

ETN VelocityShares Daily 4X Long USD vs JPY Ind due Dec 2032 of CGMHI (and registrant’s guaranty)

NYSE Arca

​

​

​

​

Exchange-Traded Notes Based on the Performance of the VelocityShares® Daily 4X Long USD vs. GBP Index due December

DGBP

ETN VelocityShares Daily 4X Long USD vs GBP Ind due Dec 2032 of CGMHI (and registrant’s guaranty)

NYSE Arca

15, 2032 of CGMHI (and registrant’s guaranty with respect thereto)  


​

​


Exchange-Traded Notes Based on the Performance of the VelocityShares® Daily 4X Long USD vs. EUR Index due December 15, 2032 of CGMHI (and registrant’s guaranty with respect thereto) 

DEUR

ETN VelocityShares Daily 4X Long USD vs EUR Ind due Dec 2032 of CGMHI (and registrant’s guaranty)

NYSE Arca


​

​


Exchange-Traded Notes Based on the Performance of the VelocityShares® Daily 4X Long USD vs. CHF Index due December 15, 2032 of CGMHI (and registrant’s guaranty with respect thereto) 

DCHF

ETN VelocityShares Daily 4X Long USD vs CHF Ind due Dec 2032 of CGMHI (and registrant’s guaranty)

NYSE Arca


​

​


Exchange-Traded Notes Based on the Performance of the VelocityShares® Daily 4X Long USD vs. AUD Index due December 15, 2032 of CGMHI (and registrant’s guaranty with respect thereto)

DAUD

ETN VelocityShares Daily 4X Long USD vs AUD Ind due Dec 2032 of CGMHI (and registrant’s guaranty)

NYSE Arca


​

​


Exchange-Traded Notes Based on the Performance of the VelocityShares® Daily 4X Long JPY vs. USD Index due December 15, 2032 of CGMHI (and registrant’s guaranty with respect thereto) 

UJPY

ETN VelocityShares Daily 4X Long JPY vs USD Ind due Dec 2032 of CGMHI (and registrant’s guaranty )

NYSE Arca


​

​


Exchange-Traded Notes Based on the Performance of the VelocityShares® Daily 4X Long EUR vs. USD Index due December 15, 2032 of CGMHI (and registrant’s guaranty with respect thereto)


UEUR

ETN VelocityShares Daily 4X Long EUR vs USD Ind due Dec 2032 of CGMHI (and registrant’s guaranty )

NYSE Arca

Exchange-Traded Notes Based on the Performance of the VelocityShares® Daily 4X Long GBP vs. USD Index due December 15, 2032 of CGMHI (and registrant’s guaranty with respect thereto)


UGBP

ETN VelocityShares Daily 4X Long GBP vs USD Ind due Dec 2032 of CGMHI (and registrant’s guaranty )

NYSE Arca

Exchange-Traded Notes Based on the Performance of the VelocityShares® Daily 4X Long CHF vs. USD Index due December 15, 2032 of CGMHI (and registrant’s guaranty with respect thereto) 

UCHF

ETN VelocityShares Daily 4X Long CHF vs USD Ind due Dec 2032 of CGMHI (and registrant’s guaranty)

NYSE Arca


​

​


Exchange-Traded Notes Based on the Performance of the VelocityShares® Daily 4X Long AUD vs. USD Index due December 15, 2032 of CGMHI (and registrant’s guaranty with respect thereto) 

UAUD

ETN VelocityShares Daily 4X Long AUD vs USD Ind due Dec 2032 of CGMHI (and registrant’s guaranty)

NYSE Arca


​

​


VelocityShares® Long LIBOR ETNs due August 16, 2032 of CGMHI (and registrant’s guaranty with respect thereto) 

ULBR

VelocityShares Long LIBOR ETNs due Aug 2032 of CGMHI (and registrant’s guaranty)

NYSE Arca


​

​


VelocityShares® Short LIBOR ETNs due August 16, 2032 of CGMHI (and registrant’s guaranty with respect thereto)  

DLBR

VelocityShares Short LIBOR ETNs due Aug 2032 of CGMHI (and registrant’s guaranty)

NYSE Arca

​

​

​

​

Medium-Term Senior Notes, Series N, Callable Step-Up Coupon Notes Due March

C/36A

MTN, Series N, Callable Step-Up Coupon Notes Due Mar 2036 of CGMHI (and registrant’s guaranty)

New York Stock Exchange

31, 2036 of CGMHI (and registrant’s guaranty with respect thereto)  


​

​


Medium-Term Senior Notes, Series G, Callable Fixed Rate Notes Due January 13, 2027

C27C

MTN, Series G, Callable Fixed Rate Notes Due Jan 2027

New York Stock Exchange

​