U
0000831001false00008310012022-04-142022-04-140000831001us-gaap:CommonStockMember2022-04-142022-04-140000831001c:SeriesNMediumTermSeniorNotesDueSept2028Member2022-04-142022-04-140000831001c:SeriesNMediumTermSeniorNotesDueSept2026Member2022-04-142022-04-140000831001c:SeriesNMediumTermSeniorNotesDueOct2028Member2022-04-142022-04-140000831001c:SeriesNMediumTermSeniorNotesDueMar2036Member2022-04-142022-04-140000831001c:SeriesNMediumTermSeniorNotesDueMar2029Member2022-04-142022-04-140000831001c:SeriesNMediumTermSeniorNotesDueFeb2036Member2022-04-142022-04-140000831001c:SeriesNMediumTermSeniorNotesDueDec2035Member2022-04-142022-04-140000831001c:Seriesnmediumtermseniornotesdueapr2028Member2022-04-142022-04-140000831001c:SeriesKPreferredStockMember2022-04-142022-04-140000831001c:SeriesJPreferredStockMember2022-04-142022-04-140000831001c:CitigroupCapitalXiiiMember2022-04-142022-04-140000831001c:CitigroupCapitalIiiMember2022-04-142022-04-14

​

UNITED STATES

SECURITIES AND EXCHANGE COMMISSION

WASHINGTON, D.C. 20549

FORM 8-K

​

CURRENT REPORT

​

Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934

​

Date of Report (Date of earliest event reported) April 14, 2022

Citigroup Inc.

(Exact name of registrant as specified in its charter)

​

​

​

​

​

​

​

Delaware

1-9924

52-1568099

(State or other jurisdiction
of incorporation)

(Commission
File Number)

(IRS Employer
Identification No.)

​

​

​

388 Greenwich Street, New York,
NY

(Address of principal executive offices)

​

10013
(Zip Code)

​

(212) 559-1000

(Registrant's telephone number,
including area code)

​

Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:

​

☐ Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425)

​

☐ Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12)

​

☐ Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))

​

☐ Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))

​

Securities registered pursuant to Section 12(b) of the Securities Exchange Act of 1934 formatted in Inline XBRL:  See Exhibit 99.3

​

Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).

​

Emerging growth company ☐

​

If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ◻

​

​

CITIGROUP INC.

Current Report on Form 8-K

​

Item 2.02 Results of Operations and Financial Condition.

​

On April 14, 2022, Citigroup Inc. announced its results for the quarter ended March 31, 2022. A copy of the related press release, filed as Exhibit 99.1 to this Form 8-K, is incorporated herein by reference in its entirety and shall be deemed to be “filed” for purposes of the Securities Exchange Act of 1934, as amended (the Act).

​

In addition, a copy of the Citigroup Inc. Quarterly Financial Data Supplement for the quarter ended March 31, 2022 is being furnished as Exhibit 99.2 to this Form 8-K and shall not be deemed to be “filed” for purposes of Section 18 of the Act or otherwise subject to the liabilities of that section.

​

Item 9.01 Financial Statements and Exhibits.

​
(d) Exhibits.

​

Exhibit Number


​

​

​

​

99.1

​

Citigroup Inc. press release dated April 14, 2022.

​

​

​

99.2

​

Citigroup Inc. Quarterly Financial Data Supplement for the quarter ended March 31, 2022.

​

​

​

99.3

​

Citigroup Inc. securities registered pursuant to Section 12(b) of the Securities Exchange Act of 1934 as of the filing date.

​

​

​

104.1

​

See the cover page of this Current Report on Form 8-K, formatted in Inline XBRL.

​

​

​

​

SIGNATURE

​

Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.

​

​

​

CITIGROUP INC.

​

​

​

Dated: April 14, 2022

​

​

​

By:

/s/ Johnbull E. Okpara

​

​

Johnbull E. Okpara

​

​

Controller and Chief Accounting Officer

​

​

(Principal Accounting Officer)

​

​

​

​

Exhibit 99.1

​

​

​

For Immediate Release

Citigroup Inc. (NYSE: C)

April 14, 2022


Graphic

FIRST QUARTER 2022 RESULTS AND KEY METRICS

Graphic

​

​

CEO COMMENTARY

RETURNED $4.0 BILLION OF CAPITAL TO COMMON SHAREHOLDERS

PAYOUT RATIO OF 100%3

BOOK VALUE PER SHARE OF $92.03

TANGIBLE BOOK VALUE PER SHARE OF $79.034

​

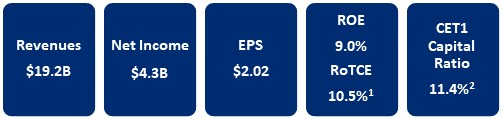
New York, April 14, 2022 – Citigroup Inc. today reported net income for the first quarter 2022 of $4.3 billion, or $2.02 per diluted share, on revenues of $19.2 billion. This compared to net income of $7.9 billion, or $3.62 per diluted share, on revenues of $19.7 billion for the first quarter 2021.

Revenues decreased 2% from the prior-year period, as higher net interest income driven by Services in Institutional Clients Group (ICG) and Personal Banking and Wealth Management (PBWM) was more than offset by lower non-interest revenue across businesses.

Net income of $4.3 billion decreased 46% from the prior-year period, driven by higher cost of credit, higher expenses, and the lower revenues. Results for the quarter included Asia Consumer divestiture-related impacts of approximately $677 million ($588 million after-tax)5, recorded in Legacy Franchises.

Earnings per share of $2.02 decreased 44% from the prior-year period, reflecting the lower net income, partly offset by a 6% decline in shares outstanding.

Percentage comparisons throughout this press release are calculated for the first quarter 2022 versus the first quarter 2021, unless otherwise specified.

​

​

Citi CEO Jane Fraser said, “While the geopolitical and macro environment has become more volatile, we are executing the strategy we announced at our recent Investor Day. Given our emphasis on Services, I am particularly pleased with our performance in Treasury and Trade Solutions. Fee growth, trade loans and cross-border transactions — buoyed by higher rates — led to year over year revenue growth of 18%. Securities Services also performed well, with revenue up 6%. In Markets, our traders navigated the environment quite well, aided by our mix, with strong gains in FX and commodities.  However, the current macro backdrop impacted Investment Banking as we saw a contraction in capital market activity. This remains a key area of investment for us.”

“We continue to see the health and resilience of the U.S. consumer through our cost of credit and their payment rates. We had good engagement in key drivers such as cards loan growth and vigorous purchase sales growth, so we like where this business is headed. While geopolitics dampened performance in Wealth Management, we are hiring bankers, enhancing our client offerings and continuing to add clients in both the Private Bank and in Citigold.”

“We returned $4 billion to our shareholders during the first quarter and we now have about 6% fewer common shares outstanding than we did a year ago. While we are making necessary investments in our infrastructure, risk and controls and our businesses, we remain committed to improving our returns over the medium term,” Ms. Fraser concluded.

​

​

1


First Quarter Financial Results

​

​

​

​

​

​

​

​

​

Citigroup
($ in millions, except per share amounts and as otherwise noted)


1Q'22


4Q'21


1Q'21


QoQ%


YoY%

Institutional Clients Group

​

$

11,160

​

$

8,908

​

$

11,388

​

25%

​

(2)%

Personal Banking and Wealth Management

​

​

5,905

​

​

5,785

​

​

5,992

​

2%

​

(1)%

Legacy Franchises

​

​

1,931

​

​

2,193

​

​

2,243

​

(12)%

​

(14)%

Corporate / Other

​

​

190

​

​

131

​

​

44

​

45%

​

NM

Total revenues, net of interest expense

​

​

19,186

​

​

17,017

​

​

19,667

​

13%

​

(2)%

​

​

​

​

​

​

​

​

Total operating expenses

​

​

13,165

​

​

13,532

​

​

11,413

​

(3)%

​

15%

​

​

​

​

​

​

​

​

Net credit losses

​

​

872

​

​

866

​

​

1,748

​

1%

​

(50)%

Net ACL build / (release)(a)

​

​

(138)

​

​

(1,369)

​

​

(3,853)

​

90%

​

96%

Other provisions(b)

​

​

21

​

​

38

​

​

50

​

(45)%

​

(58)%

Total cost of credit

​

​

755

​

​

(465)

​

​

(2,055)

​

NM

​

NM

​

​

​

​

​

​

​

​

Income from continuing operations before income taxes

​

​

5,266

​

​

3,950

​

​

10,309

​

33%

​

(49)%

Provision for income taxes

​

​

941

​

​

771

​

​

2,332

​

22%

​

(60)%

Income from continuing operations

​

​

4,325

​

​

3,179

​

​

7,977

​

36%

​

(46)%

Income (loss) from discontinued operations, net of taxes

​

​

(2)

​

​

-

​

​

(2)

​

NM

​

-

Net income attributable to non-controlling interest

​

​

17

​

​

6

​

​

33

​

NM

​

(48)%

Citigroup's net income

​

$

4,306

​

$

3,173

​

$

7,942

​

36%

​

(46)%

​

​

​

​

​

​

​

​

Income (loss) from continuing operations, net of taxes

​

​

​

​

​

​

​

​

Institutional Clients Group

​

​

2,658

​

​

2,330

​

​

5,430

​

14%

​

(51)%

Personal Banking and Wealth Management

​

​

1,860

​

​

1,613

​

​

2,420

​

15%

​

(23)%

Legacy Franchises

​

​

(385)

​

​

(620)

​

​

320

​

38%

​

NM

Corporate / Other

​

​

192

​

​

(144)

​

​

(193)

​

NM

​

NM

​

​

​

​

​

​

​

​

EOP loans ($B)

​

​

660

​

​

668

​

​

666

​

(1)%

​

(1)%

EOP assets ($B)

​

​

2,394

​

​

2,291

​

​

2,314

​

4%

​

3%

EOP deposits ($B)

​

​

1,334

​

​

1,317

​

​

1,301

​

1%

​

3%

​

​

​

​

​

​

​

​

Book value per share

​

$

92.03

​

$

92.21

​

$

88.18

​

-

​

4%

Tangible book value per share(4)

​

$

79.03

​

$

79.16

​

$

75.50

​

-

​

5%

Common Equity Tier 1 (CET1) Capital ratio(2)

​

​

11.4%

​

​

12.2%

​

​

11.6%

​

​

Supplementary Leverage ratio (SLR)(2)

​

​

5.6%

​

​

5.7%

​

​

6.9%

​

​

Return on average common equity

​

​

9.0%

​

​

6.4%

​

​

17.2%

​

​

Return on average tangible common equity (RoTCE)(1)

​

​

10.5%

​

​

7.4%

​

​

20.1%

​

​

Note: Please refer to the Appendices and Footnotes at the end of this press release for additional information.

(a) Includes credit reserve build / (release) for loans and provision for credit losses on unfunded lending commitments.

(b) Includes provisions for policyholder benefits and claims, HTM debt securities and other assets.

​

Citigroup

Citigroup revenues of $19.2 billion in the first quarter 2022 decreased 2%, as higher net interest income in Services and PBWM was more than offset by lower non-interest revenue across Banking and Global Wealth Management, as well as lower revenues in Legacy Franchises.

Citigroup operating expenses of $13.2 billion in the first quarter 2022 increased 15%. Excluding the Asia Consumer divestiture-related costs, operating expenses increased 10%, driven by continued investments in Citi’s transformation, business-led investments and volume-related expenses, partially offset by productivity savings.

Citigroup cost of credit of $755 million in the first quarter 2022 compared to $(2.1) billion in the prior-year period, as lower net credit losses were more than offset by a lower net release in the allowance for credit losses (ACL). The net release included a $1.9 billion ACL build related to Citi’s exposures in Russia and the broader impact of the conflict in Ukraine on the macroeconomic environment.

Citigroup net income of $4.3 billion in the first quarter 2022 decreased 46% from the prior-year period, driven by the higher cost of credit, the higher expenses, and the lower revenues. Citigroup’s effective tax rate was 18% in the current quarter versus 23% in the first quarter 2021. The lower tax rate this quarter reflects the resolution of certain tax audit items.

​

2


Citigroup’s total allowance for credit losses on loans was $15.4 billion at quarter end, with a reserve-to-funded loans ratio of 2.35%, compared to $21.6 billion, or 3.29% of funded loans, at the end of the prior-year period. Total non-accrual assets decreased 34% from the prior-year period to $3.4 billion. Consumer non-accrual loans decreased 36% to $1.5 billion, while corporate non-accrual loans of $1.9 billion decreased 31% from the prior-year period.

Citigroup’s end-of-period loans were $660 billion as of quarter end, down 1% versus the prior-year period.

Citigroup’s end-of-period deposits were $1.3 trillion as of quarter end, an increase of 3% versus the prior-year period, driven by an 11% increase in PBWM and a 3% increase in ICG.

Citigroup’s book value per share of $92.03 and tangible book value per share of $79.03 increased 4% and 5%, respectively, largely driven by accumulated net income and lower shares outstanding. At quarter end, Citigroup’s CET1 Capital ratio was 11.4% versus 12.2% in the prior quarter. Citigroup’s SLR for the first quarter 2022 was 5.6% versus 5.7% in the prior quarter. During the quarter, Citigroup repurchased approximately 50 million common shares and returned a total of $4.0 billion to common shareholders in the form of repurchases and dividends.

​

​

​

​

​

​

​

​

​

Institutional Clients Group
($ in millions, except as otherwise noted)


1Q'22


4Q'21


1Q'21


QoQ%


YoY%

Securities Services

​

$

858

​

$

854

​

$

812

​

-

​

6%

Treasury and Trade Solutions

​

​

2,590

​

​

2,404

​

​

2,188

​

8%

​

18%

Total Services revenues

​

​

3,448

​

​

3,258

​

​

3,000

​

6%

​

15%

Fixed Income Markets

​

​

4,299

​

​

2,425

​

​

4,346

​

77%

​

(1)%

Equity Markets

​

​

1,527

​

​

918

​

​

1,587

​

66%

​

(4)%

Total Markets revenues

​

​

5,826

​

​

3,343

​

​

5,933

​

74%

​

(2)%

Investment Banking

​

​

1,028

​

​

1,553

​

​

1,798

​

(34)%

​

(43)%

Corporate Lending(a)

​

​

689

​

​

733

​

​

735

​

(6)%

​

(6)%

Total Banking revenues(a)

​

​

1,717

​

​

2,286

​

​

2,533

​

(25)%

​

(32)%

Product revenues, net of interest expense(a)

​

​

10,991

​

​

8,887

​

​

11,466

​

24%

​

(4)%

Gain / (loss) on loan hedges

​

​

169

​

​

21

​

​

(78)

​

NM

​

NM

Total revenues, net of interest expense

​

​

11,160

​

​

8,908

​

​

11,388

​

25%

​

(2)%

​

​

​

​

​

​

​

​

Total operating expenses

​

​

6,723

​

​

6,225

​

​

5,932

​

8%

​

13%

​

​

​

​

​

​

​

​

Net credit losses

​

​

30

​

​

82

​

​

175

​

(63)%

​

(83)%

Net ACL build / (release)(b)

​

​

948

​

​

(373)

​

​

(1,709)

​

NM

​

NM

Other provisions(c)

​

​

(7)

​

​

10

​

​

(5)

​

NM

​

(40)%

Total cost of credit

​

​

971

​

​

(281)

​

​

(1,539)

​

NM

​

NM

​

​

​

​

​

​

​

​

Net income

​

$

2,640

​

$

2,320

​

$

5,393

​

14%

​

(51)%

​

​

​

​

​

​

​

​

Services Key Drivers

​

​

​

​

​

​

​

​

Cross border transaction value ($B)

​

​

76

​

​

78

​

​

65

​

(3)%

​

17%

Commercial card spend volume ($B)

​

​

11

​

​

11

​

​

7

​

-

​

54%

US dollar clearing volume (#MM)

​

​

36

​

​

38

​

​

35

​

(4)%

​

2%

Assets under custody and/or administration (AUC/AUA) ($T)

​

​

23

​

​

24

​

​

21

​

(3)%

​

8%

Note: Please refer to the Appendices and Footnotes at the end of this press release for additional information.

(a) Excludes gain / (loss) on credit derivatives as well as the mark-to-market on loans at fair value. For additional information, please refer to Footnote 6.

(b) Includes credit reserve build / (release) for loans and provision for credit losses on unfunded lending commitments.

(c) Includes provisions for HTM debt securities and other assets.

​

​

Institutional Clients Group

ICG revenues of $11.2 billion decreased 2%, largely driven by Investment Banking, partially offset by an increase in Services revenue.

Services revenues of $3.4 billion increased 15% versus the prior year. Treasury and Trade Solutions revenues of $2.6 billion increased 18%, driven by net interest income on higher deposits balances and spreads as well as strong fee growth. Securities Services revenues of $858 million increased 6%, as net interest income grew 17%, driven by higher interest rates across currencies, and fee revenues grew 2% due to higher assets under custody.

​

3


Markets revenues of $5.8 billion were down 2% versus a strong quarter in the prior year. In the quarter, activity levels benefited from client repositioning and strong risk management, driven by the Federal Reserve’s interest rate increases and overall  geopolitical and macroeconomic uncertainty. Fixed Income Markets revenues of $4.3 billion decreased 1%, as strong client engagement in FX, commodities, and rates was offset by less activity in spread products. Equity Markets revenues of $1.5 billion were down 4% compared to a very strong quarter in the prior year period, reflecting strong equity derivatives performance and growth in prime finance balances.

Banking revenues of $1.7 billion decreased 32% versus the prior year (excluding gain / (loss) on loan hedges)6, as heightened geopolitical uncertainty and the overall macroeconomic backdrop reduced activity in debt and equity capital markets. Investment Banking revenues decreased 43% due to less capital markets activity, partially offset by growth in advisory. Corporate Lending revenues of $689 million decreased 6% (excluding gain / (loss) on loan hedges), primarily driven by lower average loans.

ICG operating expenses of $6.7 billion increased 13%, driven by transformation investments, business-led investments, and volume-related expenses, partially offset by productivity savings.

ICG cost of credit of $971 million compared with $(1.5) billion in the prior-year period, largely driven by a $1.5 billion ACL build related to Citi’s exposures in Russia and the broader impact of the conflict in Ukraine on the macroeconomic environment.

ICG net income of $2.6 billion decreased 51% from the prior year, largely driven by the higher expenses and the higher cost of credit.

​

Personal Banking and Wealth Management
($ in millions, except as otherwise noted)


1Q'22


4Q'21


1Q'21


QoQ%


YoY%

Branded Cards

​

$

2,090

​

$

2,073

​

$

2,104

​

1%

​

(1)%

Retail Services

​

​

1,299

​

​

1,290

​

​

1,305

​

1%

​

-

Retail Banking

​

​

595

​

​

624

​

​

635

​

(5)%

​

(6)%

Total US Personal Banking revenues

​

​

3,984

​

​

3,987

​

​

4,044

​

-

​

(1)%

Private Bank

​

​

780

​

​

688

​

​

786

​

13%

​

(1)%

Wealth at Work

​

​

183

​

​

177

​

​

171

​

3%

​

7%

Citigold

​

​

958

​

​

933

​

​

991

​

3%

​

(3)%

Total Global Wealth Management revenues

​

​

1,921

​

​

1,798

​

​

1,948

​

7%

​

(1)%

Total revenues, net of interest expense

​

​

5,905

​

​

5,785

​

​

5,992

​

2%

​

(1)%

​

​

​

​

​

​

​

​

Total operating expenses

​

​

3,889

​

​

4,017

​

​

3,422

​

(3)%

​

14%

​

​

​

​

​

​

​

​

Net credit losses

​

​

691

​

​

568

​

​

990

​

22%

​

(30)%

Net ACL build / (release)(a)

​

​

(1,064)

​

​

(869)

​

​

(1,553)

​

(22)%

​

31%

Other provisions(b)

​

​

(3)

​

​

5

​

​

6

​

NM

​

NM

Total cost of credit

​

​

(376)

​

​

(296)

​

​

(557)

​

(27)%

​

32%

​

​

​

​

​

​

​

​

Net income (loss)

​

$

1,860

​

$

1,613

​

$

2,420

​

15%

​

(23)%

​

​

​

​

​

​

​

​

Key Indicators ($B)

​

​

​

​

​

​

​

​

US Personal Banking average loans

​

​

161

​

​

162

​

​

159

​

(1)%

​

1%

US Personal Banking average deposits

​

​

118

​

​

114

​

​

108

​

4%

​

9%

US cards average loans

​

​

128

​

​

128

​

​

123

​

-

​

5%

US credit card spend volume(c)

​

​

128

​

​

142

​

​

105

​

(10)%

​

23%

Global Wealth Management client assets

​

​

788

​

​

814

​

​

756

​

(3)%

​

4%

Global Wealth Management average loans

​

​

151

​

​

150

​

​

144

​

1%

​

5%

Global Wealth Management average deposits

​

​

329

​

​

323

​

​

289

​

2%

​

14%

Note: Please refer to the Appendices and Footnotes at the end of this press release for additional information.

(a) Includes credit reserve build / (release) for loans and provision for credit losses on unfunded lending commitments.

(b) Includes provisions for policyholder benefits and claims, HTM debt securities and other assets.

(c) Credit card spend volume was previously referred to as card purchase sales

​

Personal Banking and Wealth Management

PBWM  revenues of $5.9 billion decreased 1% versus the prior year, as higher net interest income was more than offset by lower non-interest revenue.

​

​

4


US Personal Banking revenues of $4.0 billion decreased 1%. Branded Cards revenues of $2.1 billion decreased 1% on higher payment rates and higher acquisition and rewards costs, reflecting increases in new accounts and customer engagement. Retail Services revenues of $1.3 billion were largely unchanged, as higher net interest income was offset by higher partner payments, driven by improved credit performance. Retail Banking revenues of $595 million decreased 6%, largely driven by lower mortgage originations.

Global Wealth Management revenues of $1.9 billion decreased 1%, primarily due to lower client activity in investments, particularly in Asia.

PBWM operating expenses of $3.9 billion increased 14%, driven by transformation and business-led investments, and higher volume-driven expenses, partially offset by productivity savings.

PBWM cost of credit of $(376) million compared to $(557) million in the prior-year period, as lower net credit losses were more than offset by a lower net ACL release.

PBWM net income of $1.9 billion decreased 23%, largely driven by the lower revenues, the higher expenses, and a lower net ACL release.

​

​

​

​

​

​

​

​

​

Legacy Franchises
($ in millions, except as otherwise noted)


1Q'22


4Q'21


1Q'21


QoQ%


YoY%

Asia Consumer

​

$

787

​

$

948

​

$

1,075

​

(17)%

​

(27)%

Mexico Consumer/SBMM(a)

​

​

1,139

​

​

1,168

​

​

1,137

​

(2)%

​

-

Legacy Holdings Assets

​

​

5

​

​

77

​

​

31

​

(94)%

​

(84)%

Total Legacy revenues, net of interest expense

​

​

1,931

​

​

2,193

​

​

2,243

​

(12)%

​

(14)%

​

​

​

​

​

​

​

​

Total operating expenses

​

​

2,293

​

​

2,971

​

​

1,752

​

(23)%

​

31%

​

​

​

​

​

​

​

​

Net credit losses

​

​

151

​

​

216

​

​

583

​

(30)%

​

(74)%

Net ACL build / (release)(b)

​

​

(22)

​

​

(127)

​

​

(591)

​

83%

​

96%

Other provisions(c)

​

​

31

​

​

23

​

​

52

​

35%

​

(40)%

Total cost of credit

​

​

160

​

​

112

​

​

44

​

43%

​

NM

​

​

​

​

​

​

​

​

Net income (loss)

​

$

(383)

​

$

(616)

​

$

323

​

38%

​

NM

​

​

​

​

​

​

​

​

Key Indicators ($B)

​

​

​

​

​

​

​

​

Asia Consumer EOP loans

​

​

20

​

​

41

​

​

54

​

(53)%

​

(64)%

Asia Consumer EOP deposits

​

​

18

​

​

43

​

​

55

​

(60)%

​

(68)%

Mexico Consumer/SBMM EOP loans(a)

​

​

21

​

​

20

​

​

20

​

4%

​

3%

Mexico Consumer/SBMM EOP deposits(a)

​

​

34

​

​

33

​

​

33

​

4%

​

4%

Legacy Holdings EOP loans

​

​

4

​

​

4

​

​

6

​

(5)%

​

(39)%

Note: Please refer to the Appendices and Footnotes at the end of this press release for additional information.

(a) SBMM refers to Small Business & Middle Market Banking.

(b) Includes credit reserve build / (release) for loans and provision for credit losses on unfunded lending commitments.

(c) Includes provisions for policyholder benefits and claims, HTM debt securities and other assets.

​

Legacy Franchises

Legacy Franchises revenues of $1.9 billion decreased 14% versus the prior year, largely resulting from the Korea wind down, as well as the muted investment activity in Asia.

Legacy Franchises expenses of $2.3 billion increased 31%, reflecting the Asia Consumer divestiture-related costs.

Legacy Franchises cost of credit of $160 million compared to $44 million in the prior-year period, as lower net credit losses were more than offset by a lower net ACL release.

Legacy Franchises net income of $(383) million compared to $323 million in the prior-year period, reflecting the lower revenues, the higher expenses, and the higher cost of credit.

​

5


​

Corporate / Other
($ in millions)


1Q'22


4Q'21


1Q'21


QoQ%


YoY%

Revenues, net of interest expense

​

$

190

​

$

131

​

$

44

​

45%

​

NM

​

​

​

​

​

​

​

​

Total operating expenses

​

​

260

​

​

319

​

​

307

​

(18)%

​

(15)%

​

​

​

​

​

​

​

​

Total cost of credit(a)

​

​

-

​

​

-

​

​

(3)

​

-

​

100%

​

​

​

​

​

​

​

​

Income (loss) from continuing operations

​

​

192

​

​

(144)

​

​

(193)

​

NM

​

NM

​

​

​

​

​

​

​

​

Net income (loss)

​

$

189

​

$

(144)

​

$

(194)

​

NM

​

NM

(a) Includes provisions for HTM debt securities and other assets.

​

Corporate / Other

Corporate / Other revenues of $190 million increased significantly, largely driven by higher revenue from the investment portfolio.

Corporate / Other expenses of $260 million decreased 15% versus the prior-year period, largely due to lower compensation costs.

Corporate / Other income from continuing operations of $192 million compared to a loss of $(193) million in the prior-year period, largely driven by the higher revenues and the lower expenses.

​

6


​

Citigroup will host a conference call today at 11:00 AM (ET). A live webcast of the presentation, as well as financial results and presentation materials, will be available at https://www.citigroup.com/citi/investor/pres.htm. Dial-in numbers for the conference call are as follows: (866) 516-9582 in the U.S. and Canada; (973) 409-9210 outside of the U.S. and Canada. The conference code for both numbers is 8238026.

Additional financial, statistical and business-related information, as well as business and segment trends, is included in a Quarterly Financial Data Supplement. Both this earnings release and Citigroup’s First Quarter 2022 Quarterly Financial Data Supplement are available on Citigroup’s website at www.citigroup.com.

Citi, the leading global bank, has approximately 200 million customer accounts and does business in more than 160 countries and jurisdictions. Citi provides consumers, corporations, governments and institutions with a broad range of financial products and services, including consumer banking and credit, corporate and investment banking, securities brokerage, transaction services, and wealth management.

Additional information may be found at www.citigroup.com | Twitter: @Citi | YouTube: www.youtube.com/citi | Blog: http://blog.citigroup.com | Facebook: www.facebook.com/citi | LinkedIn: www.linkedin.com/company/citi

Certain statements in this release are “forward-looking statements” within the meaning of the rules and regulations of the Private Securities Litigation and Reform Act of 1995. These statements are based on management’s current expectations and are subject to uncertainty and changes in circumstances. These statements are not guarantees of future results or occurrences. Actual results and capital and other financial condition may differ materially from those included in these statements due to a variety of factors. These factors include, among others: the impacts related to or resulting from Russia’s military action in Ukraine, including the imposition of additional sanctions and export controls, as well as the broader impacts to financial markets and the global macroeconomic and geopolitical environments; higher inflation and its impacts; higher interest rates and the impacts on macroeconomic conditions, customer and client behavior, as well as Citi’s funding costs; macroeconomic and other challenges and uncertainties related to the COVID-19 pandemic, such as the impacts to the U.S. and global economies; consummation of Citi’s exits and wind-down, and the impact of any additional CTA or other losses; and the precautionary statements included in this release. These factors also consist of those contained in Citigroup’s filings with the U.S. Securities Exchange and Commission, including without limitation the “Risk Factors” section of Citigroup’s 2021 Form 10-K. Any forward-looking statements made by or on behalf of Citigroup speak only as to the date they are made, and Citi does not undertake to update forward-looking statements to reflect the impact of circumstances or events that arise after the date the forward-looking statements were made.

​

Contacts:

​

​

​

Investors: Jennifer Landis (212) 559-2718

​

​

Press:

Danielle Romero-Apsilos

(212) 816-2264

​

Fixed Income Investors:

Thomas Rogers

(212) 559-5091

​

7


8


Appendix A

​

​

​

​

​

Citigroup
($in millions)


​

1Q'22

Net Income

​

$

4,306

Less: Preferred Dividends

​

​

279

Net Income to Common Shareholders

​

$

4,027

​

​

​

​

Common Share Repurchases

​

​

3,000

Common Dividends

​

​

1,014

Total Capital Returned to Common Shareholders

​

$

4,014

​

​

​

​

Payout Ratio

​

​

100%

​

​

​

​

Average TCE

​

$

155,270

​

​

​

​

RoTCE

​

​

10.5%

​

Appendix B

​

​

​

​

​

​

​

​

​

​

Citigroup
($in millions, unless otherwise noted)


1Q'22


1Q'21


YoY%

Reported revenues

​

$

19,186

​

$

19,667

​

(2)%

Less:

​

​

​

​

​

​

​

​

Impact of gain / (loss) on sale related to Asia divestitures(1)

​

​

(118)

​

​

-

​

-

Adjusted revenues

​

$

19,304

​

$

19,667

​

(2)%

​

​

​

​

​

​

​

​

​

Reported expenses

​

$

13,165

​

$

11,413

​

15%

Less:

​

​

​

​

​

​

​

​

Impact of costs related to Asia divestitures(2)

​

​

559

​

​

-

​

-

Adjusted expenses

​

$

12,606

​

$

11,413

​

10%

Note:

Totals may not sum due to rounding. Results of operations excluding these Asia divestiture-related costs are non-GAAP financial measures.

(1)

Reflects the impact of a pre-tax loss of approximately $(118) million (approximately $(81) million after-tax) in 1Q22 related to the sale of the Australia consumer business, which consisted of an ACL release of $(104) million and a net revenue impact of $(14) million due to contractual adjustments of the divestiture recorded in Other Revenue.

(2)

Reflects the impact of costs largely related to a goodwill write-down of approximately $535 million (approximately $489 million after-tax) that were incurred in the Asia Consumer reporting unit of Legacy Franchises due to the re-segmentation and sequencing of divestitures and costs related to the Korea Voluntary Early Retirement Program (VERP) of approximately $24 million (approximately $18 million after-tax) in 1Q22.

​

9


10


Appendix C

​

​

​

​

​

​

​

​

​

​

​

($in millions)


​

1Q'22(1)


​

4Q'21


​

1Q'21

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Citigroup Common Stockholders' Equity(2)

​

$

178,845

​

$

183,108

​

$

182,402

Add: Qualifying noncontrolling interests

​

​

126

​

​

143

​

​

132

Regulatory Capital Adjustments and Deductions:

​

​

​

​

​

​

​

​

​

Add: CECL transition provision(3)

​

​

2,271

​

​

3,028

​

​

4,359

Less:

​

​

​

​

​

​

​

​

​

Accumulated net unrealized gains (losses) on cash flow hedges, net of tax

​

​

(1,440)

​

​

101

​

​

1,037

Cumulative unrealized net gain (loss) related to changes in fair value of financial liabilities attributable to own creditworthiness, net of tax

​

​

27

​

​

(896)

​

​

(1,172)

Intangible Assets:

​

​

​

​

​

​

​

​

​

Goodwill, net of related deferred tax liabilities (DTLs)(4)

​

​

20,120

​

​

20,619

​

​

20,854

Identifiable intangible assets other than mortgage servicing rights (MSRs), net of related DTLs

​

​

3,698

​

​

3,800

​

​

4,054

Defined benefit pension plan net assets; other

​

​

2,230

​

​

2,080

​

​

1,485

Deferred tax assets (DTAs) arising from net operating loss, foreign tax credit and general business credit carry-forwards

​

​

11,701

​

​

11,270

​

​

11,691

Excess over 10% / 15% limitations for other DTAs, certain common stock investments, and MSRs(5)

​

​

1,157

​

​

-

​

​

-

​

​

​

​

​

​

​

​

​

​

Common Equity Tier 1 Capital (CET1)(6)

​

$

143,749

​

$

149,305

​

$

148,944

​

​

​

​

​

​

​

​

​

​

Risk-Weighted Assets (RWA)(3)(6)

​

$

1,264,581

​

$

1,219,175

​

$

1,287,619

​

​

​

​

​

​

​

​

​

​

Common Equity Tier 1 Capital Ratio (CET1 / RWA)(6)

​

​

11.4%

​

​

12.2%

​

​

11.6%

Note:

Citi’s reportable CET1 Capital ratios were derived under the Basel III Standardized Approach framework as of March 31, 2022 and December 31, 2021, and the Basel III Advanced Approaches framework as of March 31, 2021. This reflects the more binding CET1 Capital ratios under both the Standardized Approach and the Advanced Approaches under the Collins Amendment.

(1)

Preliminary.

(2)

Excludes issuance costs related to outstanding preferred stock in accordance with Federal Reserve Board regulatory reporting requirements.

(3)

Please refer to Footnote 2 at the end of this press release for additional information.

(4)

Includes goodwill “embedded” in the valuation of significant common stock investments in unconsolidated financial institutions.

(5)

Assets subject to 10%/15% limitations include MSRs, DTAs arising from temporary differences and significant common stock investments in unconsolidated financial institutions. As of March 31, 2022, the deduction related only to DTAs arising from temporary differences that exceeded the 10% limitation.

(6)

Certain prior period amounts and ratios have been revised to conform with enhancements made in the current period.

​

Appendix D

($in millions)


​

1Q'22(1)


​

4Q'21


​

1Q'21

​

​

​

​

​

​

​

​

​

​

Common Equity Tier 1 Capital (CET1)(2)

​

$

143,749

​

$

149,305

​

$

148,944

​

​

​

​

​

​

​

​

​

​

Additional Tier 1 Capital (AT1)(3)

​

​

20,264

​

​

20,263

​

​

21,540

​

​

​

​

​

​

​

​

​

​

Total Tier 1 Capital (T1C) (CET1 + AT1)(5)

​

$

164,013

​

$

169,568

​

$

170,484

​

​

​

​

​

​

​

​

​

​

Total Leverage Exposure (TLE)(2)(4)(5)

​

$

2,936,715

​

$

2,957,764

​

$

2,454,564

​

​

​

​

​

​

​

​

​

​

Supplementary Leverage Ratio (T1C / TLE)(5)

​

​

5.6%

​

​

5.7%

​

​

6.9%

(1)Preliminary.

(2)Please refer to Footnote 2 at the end of this press release for additional information.

(3)Additional Tier 1 Capital primarily includes qualifying noncumulative perpetual preferred stock and qualifying trust preferred securities.

(4)Commencing with the second quarter of 2020 and continuing through the first quarter of 2021, Citigroup's TLE temporarily excluded U.S. Treasuries and deposits at Federal Reserve banks. For additional information, please refer to the "Capital Resources" section of Citi's 2021 Annual Report on Form 10-K.

(5)Certain prior period amounts and ratios have been revised to conform with enhancements made in the current period.

Appendix E

($ and shares in millions, except per share amounts)


​

1Q'22(1)


​

4Q'21


​

1Q'21

​

​

​

​

​

​

​

​

​

​

Common Stockholders' Equity

​

$

178,714

​

$

182,977

​

$

182,269

Less:

​

​

​

​

​

​

​

​

​

Goodwill

​

​

19,865

​

​

21,299

​

​

21,905

Intangible Assets (other than MSRs)

​

​

4,002

​

​

4,091

​

​

4,308

Goodwill and Identifiable Intangible Assets (other than MSRs) Related to Assets Held-for-Sale

​

​

1,384

​

​

510

​

​

-

Tangible Common Equity (TCE)

​

$

153,463

​

$

157,077

​

$

156,056

​

​

​

​

​

​

​

​

​

​

Common Shares Outstanding (CSO)

​

​

1,942

​

​

1,984

​

​

2,067

​

​

​

​

​

​

​

​

​

​

Tangible Book Value

​

$

79.03

​

$

79.16

​

$

75.50

​

(1)Preliminary.

​

11


1 Preliminary. Citigroup’s return on average tangible common equity (RoTCE) is a non-GAAP financial measure. RoTCE represents annualized net income available to common shareholders as a percentage of average tangible common equity (TCE). For the components of the calculation, see Appendix A.

2 Ratios as of March 31, 2022 are preliminary. Citigroup’s Common Equity Tier 1 (CET1) Capital ratio and Supplementary Leverage ratio (SLR) reflect certain deferrals based on the modified regulatory capital transition provision related to the Current Expected Credit Losses (CECL) standard. Excluding these deferrals, Citigroup’s CET1 Capital ratio and SLR as of March 31, 2022 would be 11.2% and 5.5%, respectively, on a fully reflected basis. For additional information, please refer to the “Capital Resources” section of Citi’s 2021 Annual Report on Form 10-K. Certain prior-period amounts have been revised to conform with enhancements made in the current period.

For the composition of Citigroup’s CET1 Capital and ratio, see Appendix C. For the composition of Citigroup’s SLR, see Appendix D.

3 Citigroup’s payout ratio is the sum of common dividends and common share repurchases divided by net income available to common shareholders. For the components of the calculation, see Appendix A.

4 Citigroup’s tangible book value per share is a non-GAAP financial measure. For a reconciliation of this measure to reported results, see Appendix E.

5 First quarter 2022 revenues include the impact of a pre-tax loss of approximately $(118) million (approximately $(81) million after-tax) related to the sale of the Australia consumer business, which consisted of an ACL release of $(104) million and a net revenue impact of $(14) million due to contractual adjustments of the divestiture recorded in Other Revenue. First quarter 2022 operating expenses include Asia divestiture-related costs largely related to a goodwill write-down of approximately $535 million (approximately $489 million after-tax) that were incurred in the Asia Consumer reporting unit of Legacy Franchises due to the re-segmentation and sequencing of divestitures, as well as costs related to the Korea Voluntary Early Retirement Program (VERP) of approximately $24 million (approximately $18 million after-tax). Results of operations excluding these Asia divestiture-related costs are non-GAAP financial measures. For a reconciliation to reported results, please refer to Appendix B.

6 Credit derivatives are used to economically hedge a portion of the Corporate Loan portfolio that includes both accrual loans and loans at fair value. Gains / (losses) on loan hedges includes the mark-to-market on the credit derivatives and the mark-to-market on the loans in the portfolio that are at fair value. In the first quarter 2022, gains / (losses) on loan hedges included $169 million related to Corporate Lending, compared to $(78) million in the prior-year period. The fixed premium costs of these hedges are netted against the Corporate Lending revenues to reflect the cost of credit protection. Citigroup’s results of operations excluding the impact of gains / (losses) on loan hedges are non-GAAP financial measures.

12

Exhibit 99.2

​

Graphic

​

​

​

CITIGROUP -- QUARTERLY FINANCIAL DATA SUPPLEMENT

1Q22

​

​

​

​

​

​

​

Page

​

​

Citigroup

​

​

​

Financial Summary

1

​

​

Consolidated Statement of Income

2

​

​

Consolidated Balance Sheet

3

​

​

Operating Segment and Reporting Unit - Net Revenues and Income

4

​

​

​

​

​

​

Institutional Clients Group (ICG)

5

​

​

Reporting Unit Revenues

6

​

​

Personal Banking and Wealth Management (PBWM)

7

​

​

Metrics

8

​

​

Legacy Franchises

9

​

​

Corporate / Other

10

​

​

​

​

​

​

Citigroup Supplemental Detail

​

​

​

Average Balances and Interest Rates

11

​

​

EOP Loans

12

​

​

Deposits

13

​

​

Allowance for Credit Losses (ACL) Rollforward

14

​

​

Allowance for Credit Losses on Loans and Unfunded Lending Commitments

15 - 16

​

​

Non-Accrual Assets

17

​

​

CET1 Capital and Supplementary Leverage Ratios, Tangible Common Equity,

18

​

​

Book Value Per Share and Tangible Book Value Per Share

​

​

​

​

​

​

​

​

​

​


​

CITIGROUP FINANCIAL SUMMARY

(In millions of dollars, except per share amounts and as otherwise noted)

​

​

​

​

​

​

​

​

​

​

​

​


​


​


​


​


​


1Q22 Increase/

​

​

​

1Q

​

2Q

​

3Q

​

4Q

​

1Q

​

(Decrease) from

​

​

​

2021

​

2021

​

2021

​

2021

​

2022

​

4Q21


1Q21

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total revenues, net of interest expense(1)(2)

​

$

19,667

​

$

17,753

​

$

17,447

​

$

17,017

​

$

19,186

​

13%

​

(2%)

​

Total operating expenses(1)(3)

​

​

11,413

​

​

11,471

​

​

11,777

​

​

13,532

​

​

13,165

​

(3%)

​

15%

​

Net credit losses (NCLs)

​

​

1,748

​

​

1,320

​

​

961

​

​

866

​

​

872

​

1%

​

(50%)

​

Credit reserve build / (release) for loans

​

​

(3,227)

​

​

(2,446)

​

​

(1,149)

​

​

(1,176)

​

​

(612)

​

48%

​

81%

​

Provision / (release) for unfunded lending commitments

​

​

(626)

​

​

44

​

​

(13)

​

​

(193)

​

​

474

​

NM

​

NM

​

Provisions for benefits and claims, HTM debt securities and other assets

​

​

50

​

​

16

​

​

9

​

​

38

​

​

21

​

(45%)

​

(58%)

​

Provisions for credit losses and for benefits and claims

​

​

(2,055)

​

​

(1,066)

​

​

(192)

​

​

(465)

​

​

755

​

NM

​

NM

​

Income from continuing operations before income taxes

​

​

10,309

​

​

7,348

​

​

5,862

​

​

3,950

​

​

5,266

​

33%

​

(49%)

​

Income taxes(4)

​

​

2,332

​

​

1,155

​

​

1,193

​

​

771

​

​

941

​

22%

​

(60%)

​

Income from continuing operations

​

​

7,977

​

​

6,193

​

​

4,669

​

​

3,179

​

​

4,325

​

36%

​

(46%)

​

Income (loss) from discontinued operations, net of taxes

​

​

(2)

​

​

10

​

​

(1)

​

​

-

​

​

(2)

​

NM

​

-

​

Net income before noncontrolling interests

​

​

7,975

​

​

6,203

​

​

4,668

​

​

3,179

​

​

4,323

​

36%

​

(46%)

​

Net income (loss) attributable to noncontrolling interests

​

​

33

​

​

10

​

​

24

​

​

6

​

​

17

​

NM

​

(48%)

​

Citigroup's net income

​

$

7,942

​

$

6,193

​

$

4,644

​

$

3,173

​

$

4,306

​

36%

​

(46%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Diluted earnings per share:

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Income from continuing operations

​

$

3.62

​

$

2.84

​

$

2.15

​

$

1.46

​

$

2.02

​

38%

​

(44%)

​

Citigroup's net income

​

$

3.62

​

$

2.85

​

$

2.15

​

$

1.46

​

$

2.02

​

38%

​

(44%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Preferred dividends

​

$

292

​

$

253

​

$

266

​

$

229

​

$

279

​

22%

​

(4%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Income allocated to unrestricted common shareholders - basic

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Income from continuing operations

​

$

7,586

​

$

5,889

​

$

4,353

​

$

2,924

​

$

4,004

​

37%

​

(47%)

​

Citigroup's net income

​

$

7,584

​

$

5,899

​

$

4,352

​

$

2,924

​

$

4,002

​

37%

​

(47%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Income allocated to unrestricted common shareholders - diluted

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Income from continuing operations

​

$

7,593

​

$

5,897

​

$

4,361

​

$

2,932

​

$

4,012

​

37%

​

(47%)

​

Citigroup's net income

​

$

7,591

​

$

5,907

​

$

4,360

​

$

2,932

​

$

4,010

​

37%

​

(47%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Shares (in millions):

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Average basic

​

​

2,082.0

​

​

2,056.5

​

​

2,009.3

​

​

1,984.3

​

​

1,971.7

​

(1%)

​

(5%)

​

Average diluted

​

​

2,096.6

​

​

2,073.0

​

​

2,026.2

​

​

2,001.6

​

​

1,988.2

​

(1%)

​

(5%)

​

Common shares outstanding, at period end

​

​

2,067.0

​

​

2,026.8

​

​

1,984.3

​

​

1,984.4

​

​

1,941.9

​

(2%)

​

(6%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Regulatory capital ratios and performance metrics:

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Common Equity Tier 1 (CET1) Capital ratio(5)(6)(7)

​

​

11.57%

​

​

11.77%

​

​

11.65%

​

​

12.25%

​

​

11.4%

​

​

​

​

​

Tier 1 Capital ratio(5)(6)(7)

​

​

13.24%

​

​

13.28%

​

​

13.15%

​

​

13.91%

​

​

13.0%

​

​

​

​

​

Total Capital ratio(5)(6)(7)

​

​

15.36%

​

​

15.58%

​

​

15.37%

​

​

16.04%

​

​

14.8%

​

​

​

​

​

Supplementary Leverage ratio (SLR)(5)(7)(8)

​

​

6.95%

​

​

5.84%

​

​

5.80%

​

​

5.73%

​

​

5.6%

​

​

​

​

​

Return on average assets

​

​

1.39%

​

​

1.06%

​

​

0.79%

​

​

0.53%

​

​

0.74%

​

​

​

​

​

Return on average common equity

​

​

17.2%

​

​

13.0%

​

​

9.5%

​

​

6.4%

​

​

9.0%

​

​

​

​

​

Average tangible common equity (TCE) (in billions of dollars)

​

$

154.7

​

$

156.9

​

$

157.4

​

$

157.0

​

$

155.3

​

(1%)

​

-

​

Return on average tangible common equity (RoTCE)

​

​

20.1%

​

​

15.2%

​

​

11.0%

​

​

7.4%

​

​

10.5%

​

​

​

​

​

Efficiency ratio (total operating expenses/total revenues, net)

​

​

58.0%

​

​

64.6%

​

​

67.5%

​

​

79.5%

​

​

68.6%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Balance sheet data (in billions of dollars, except per share amounts):

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total assets

​

$

2,314.3

​

$

2,327.9

​

$

2,361.9

​

$

2,291.4

​

$

2,394.1

​

4%

​

3%

​

Total average assets

​

​

2,316.8

​

​

2,341.8

​

​

2,346.0

​

​

2,386.2

​

​

2,374.0

​

(1%)

​

2%

​

Total loans

​

​

666.0

​

​

676.8

​

​

664.8

​

​

667.8

​

​

659.7

​

(1%)

​

(1%)

​

Total deposits

​

​

1,301.0

​

​

1,310.3

​

​

1,347.5

​

​

1,317.2

​

​

1,333.7

​

1%

​

3%

​

Citigroup's stockholders' equity

​

​

202.5

​

​

202.2

​

​

200.9

​

​

202.0

​

​

197.7

​

(2%)

​

(2%)

​

Book value per share

​

​

88.18

​

​

90.86

​

​

92.16

​

​

92.21

​

​

92.03

​

-

​

4%

​

Tangible book value per share

​

​

75.50

​

​

77.87

​

​

79.07

​

​

79.16

​

​

79.03

​

-

​

5%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Direct staff (in thousands)

​

​

211

​

​

214

​

​

220

​

​

223

​

​

228

​

2%

​

8%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

(1)
During the fourth quarter of 2021, Citi reclassified deposit insurance expenses from Interest expense to Other operating expenses for all periods presented. For additional information, see Note 1 to the Consolidated Financial Statements in Citi's 2021 Annual Report on Form 10-K.
(2)
The third quarter of 2021 includes an approximate $680 million loss on sale (an approximate $580 million after-tax), related to Citi's agreement to sell its Australia consumer banking business.
(3)
The fourth quarter of 2021 includes approximately $1.052 billion in expenses (approximately $792 million after-tax), primarily related to charges incurred from the voluntary early retirement plan (VERP) in connection with the wind-down of Citi's consumer banking business in Korea.
(4)
2021 includes an approximate $600 million benefit from a reduction in Citi’s valuation allowance related to its Deferred Tax Assets (DTAs).
(5)
1Q22 is preliminary.
(6)
Citi's reportable CET1 Capital and Tier 1 Capital ratios were derived under the Basel III Advanced Approaches framework as of March 31, 2021, and the Basel III Standardized Approach framework for the subsequent periods presented. Citi's reportable Total Capital ratios were derived under the Basel III Advanced Approaches framework for all periods presented. These reportable ratios reflect the more binding ratios under both the Standardized Approach and the Advanced Approaches under the Collins Amendment. For the composition of Citi's CET1 Capital and ratio, see page 18.
(7)
Citi's regulatory capital ratios reflect certain deferrals based on the modified regulatory capital transition provision related to the Current Expected Credit Losses (CECL) standard. For additional information, see "Capital Resources" in Citi's 2021 Annual Report on Form 10-K.
(8)
For the composition of Citi's SLR, see page 18.

​

Note: Ratios and variance percentages are calculated based on the displayed amounts.

NM Not meaningful.

Reclassified to conform to the current period's presentation.

​

​

​

​

​

Page 1


CITIGROUP CONSOLIDATED STATEMENT OF INCOME

(In millions of dollars)

​


​


1Q22 Increase/

​

​

1Q

​

2Q

​

3Q

​

4Q

​

1Q

​

(Decrease) from

​

​

2021

​

2021

​

2021

​

2021

​

2022

​

4Q21

​

1Q21

Revenues

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Interest revenue

​

$

12,534

​

$

12,463

​

$

12,650

​

$

12,828

​

$

13,151

​

3%

​

5%

Interest expense(1)

​

​

2,028

​

​

1,985

​

​

1,959

​

​

2,009

​

​

2,280

​

13%

​

12%

Net interest income (NII)

​

​

10,506

​

​

10,478

​

​

10,691

​

​

10,819

​

​

10,871

​

-

​

3%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Commissions and fees

​

​

3,670

​

​

3,374

​

​

3,399

​

​

3,229

​

​

2,568

​

(20%)

​

(30%)

Principal transactions

​

​

3,913

​

​

2,304

​

​

2,233

​

​

1,704

​

​

4,590

​

NM

​

17%

Administrative and other fiduciary fees

​

​

961

​

​

1,022

​

​

1,007

​

​

953

​

​

966

​

1%

​

1%

Realized gains (losses) on investments

​

​

401

​

​

137

​

​

117

​

​

10

​

​

80

​

NM

​

(80%)

Impairment losses on investments and other assets

​

​

(69)

​

​

(13)

​

​

(30)

​

​

(94)

​

​

(90)

​

4%

​

(30%)

Provision for credit losses on AFS debt securities(2)

​

​

-

​

​

-

​

​

(1)

​

​

(2)

​

​

-

​

100%

​

-

Other revenue (loss)

​

​

285

​

​

451

​

​

31

​

​

398

​

​

201

​

(49%)

​

(29%)

Total non-interest revenues (NIR)

​

​

9,161

​

​

7,275

​

​

6,756

​

​

6,198

​

​

8,315

​

34%

​

(9%)

Total revenues, net of interest expense

​

​

19,667

​

​

17,753

​

​

17,447

​

​

17,017

​

​

19,186

​

13%

​

(2%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Provisions for credit losses and for benefits and claims

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Net credit losses

​

​

1,748

​

​

1,320

​

​

961

​

​

866

​

​

872

​

1%

​

(50%)

Credit reserve build / (release) for loans

​

​

(3,227)

​

​

(2,446)

​

​

(1,149)

​

​

(1,176)

​

​

(612)

​

48%

​

81%

Provision for credit losses on loans

​

​

(1,479)

​

​

(1,126)

​

​

(188)

​

​

(310)

​

​

260

​

NM

​

NM

Provision for credit losses on held-to-maturity (HTM) debt securities

​

​

(11)

​

​

4

​

​

(10)

​

​

14

​

​

(2)

​

NM

​

82%

Provision for credit losses on other assets

​

​

9

​

​

(3)

​

​

(3)

​

​

(3)

​

​

(4)

​

(33%)

​

NM

Policyholder benefits and claims

​

​

52

​

​

15

​

​

22

​

​

27

​

​

27

​

-

​

(48%)

Provision for credit losses on unfunded lending commitments

​

​

(626)

​

​

44

​

​

(13)

​

​

(193)

​

​

474

​

NM

​

NM

Total provisions for credit losses and for benefits and claims(3)

​

​

(2,055)

​

​

(1,066)

​

​

(192)

​

​

(465)

​

​

755

​

NM

​

NM

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Operating expenses

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Compensation and benefits

​

​

6,001

​

​

5,982

​

​

6,058

​

​

7,093

​

​

6,820

​

(4%)

​

14%

Premises and equipment

​

​

576

​

​

558

​

​

560

​

​

620

​

​

543

​

(12%)

​

(6%)

Technology / communication

​

​

1,852

​

​

1,895

​

​

1,997

​

​

2,084

​

​

2,016

​

(3%)

​

9%

Advertising and marketing

​

​

270

​

​

340

​

​

402

​

​

478

​

​

311

​

(35%)

​

15%

Other operating(1)

​

​

2,714

​

​

2,696

​

​

2,760

​

​

3,257

​

​

3,475

​

7%

​

28%

Total operating expenses

​

​

11,413

​

​

11,471

​

​

11,777

​

​

13,532

​

​

13,165

​

(3%)

​

15%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Income from continuing operations before income taxes

​

​

10,309

​

​

7,348

​

​

5,862

​

​

3,950

​

​

5,266

​

33%

​

(49%)

Provision for income taxes(4)

​

​

2,332

​

​

1,155

​

​

1,193

​

​

771

​

​

941

​

22%

​

(60%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Income (loss) from continuing operations

​

​

7,977

​

​

6,193

​

​

4,669

​

​

3,179

​

​

4,325

​

36%

​

(46%)

Discontinued operations

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Income (loss) from discontinued operations

​

​

(2)

​

​

10

​

​

(1)

​

​

-

​

​

(2)

​

NM

​

-

Provision (benefit) for income taxes

​

​

-

​

​

-

​

​

-

​

​

-

​

​

-

​

-

​

-

Income (loss) from discontinued operations, net of taxes

​

​

(2)

​

​

10

​

​

(1)

​

​

-

​

​

(2)

​

NM

​

-

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Net income before noncontrolling interests

​

​

7,975

​

​

6,203

​

​

4,668

​

​

3,179

​

​

4,323

​

36%

​

(46%)

Net income (loss) attributable to noncontrolling interests

​

​

33

​

​

10

​

​

24

​

​

6

​

​

17

​

NM

​

(48%)

Citigroup's net income

​

$

7,942

​

$

6,193

​

$

4,644

​

$

3,173

​

$

4,306

​

36%

​

(46%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

(1)See footnote 1 on page 1.
(2)This presentation is in accordance with ASC 326, which requires the provision for credit losses on AFS securities to be included in revenue.
(3)This total excludes the provision for credit losses on AFS securities, which is disclosed separately above.
(4)See footnote 4 on page 1.

​

NM Not meaningful.

Reclassified to conform to the current period's presentation.

​

Page 2


CITIGROUP CONSOLIDATED BALANCE SHEET

(In millions of dollars)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​


​


1Q22 Increase/

​

​

March 31,

​

June 30,

​

September 30,

​

December 31,

​

March 31,

​

(Decrease) from

​

​

2021

​

2021

​

2021

​

2021

​

2022(1)

​

4Q21

​

1Q21

Assets

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Cash and due from banks (including segregated cash and other deposits)

​

$

26,204

​

$

27,117

​

$

28,906

​

$

27,515

​

$

27,768

​

1%

​

6%

Deposits with banks, net of allowance

​

​

298,478

​

​

272,121

​

​

294,902

​

​

234,518

​

​

244,319

​

4%

​

(18%)

Securities borrowed and purchased under agreements to resell, net of allowance

​

​

315,072

​

​

309,047

​

​

337,696

​

​

327,288

​

​

345,410

​

6%

​

10%

Brokerage receivables, net of allowance

​

​

60,465

​

​

61,138

​

​

59,487

​

​

54,340

​

​

89,218

​

64%

​

48%

Trading account assets

​

​

360,659

​

​

370,950

​

​

342,914

​

​

331,945

​

​

357,997

​

8%

​

(1%)

Investments

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Available-for-sale debt securities, net of allowance

​

​

304,036

​

​

302,977

​

​

295,573

​

​

288,522

​

​

264,774

​

(8%)

​

(13%)

Held-to-maturity debt securities, net of allowance

​

​

161,742

​

​

176,742

​

​

198,056

​

​

216,963

​

​

242,547

​

12%

​

50%

Equity securities

​

​

7,181

​

​

7,344

​

​

7,220

​

​

7,337

​

​

7,281

​

(1%)

​

1%

Total investments

​

​

472,959

​

​

487,063

​

​

500,849

​

​

512,822

​

​

514,602

​

-

​

9%

Loans, net of unearned income

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Consumer(2)

​

​

375,532

​

​

380,804

​

​

369,292

​

​

376,534

​

​

350,328

​

(7%)

​

(7%)

Corporate(3)

​

​

290,456

​

​

296,030

​

​

295,472

​

​

291,233

​

​

309,341

​

6%

​

7%

Loans, net of unearned income

​

​

665,988

​

​

676,834

​

​

664,764

​

​

667,767

​

​

659,669

​

(1%)

​

(1%)

Allowance for credit losses on loans (ACLL)

​

​

(21,638)

​

​

(19,238)

​

​

(17,715)

​

​

(16,455)

​

​

(15,393)

​

6%

​

29%

Total loans, net

​

​

644,350

​

​

657,596

​

​

647,049

​

​

651,312

​

​

644,276

​

(1%)

​

-

Goodwill

​

​

21,905

​

​

22,060

​

​

21,573

​

​

21,299

​

​

19,865

​

(7%)

​

(9%)

Intangible assets (including MSRs)

​

​

4,741

​

​

4,687

​

​

4,553

​

​

4,495

​

​

4,522

​

1%

​

(5%)

Other assets, net of allowance

​

​

109,433

​

​

116,089

​

​

123,947

​

​

125,879

​

​

146,128

​

16%

​

34%

Total assets

​

$

2,314,266

​

$

2,327,868

​

$

2,361,876

​

$

2,291,413

​

$

2,394,105

​

4%

​

3%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Liabilities

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Non-interest-bearing deposits in U.S. offices

​

$

138,192

​

$

149,373

​

$

145,103

​

$

158,552

​

$

153,666

​

(3%)

​

11%

Interest-bearing deposits in U.S. offices

​

​

497,335

​

​

485,589

​

​

567,902

​

​

543,283

​

​

557,327

​

3%

​

12%

Total U.S. deposits

​

​

635,527

​

​

634,962

​

​

713,005

​

​

701,835

​

​

710,993

​

1%

​

12%

Non-interest-bearing deposits in offices outside the U.S.

​

​

101,662

​

​

101,723

​

​

94,016

​

​

97,270

​

​

98,579

​

1%

​

(3%)

Interest-bearing deposits in offices outside the U.S.

​

​

563,786

​

​

573,596

​

​

540,507

​

​

518,125

​

​

524,139

​

1%

​

(7%)

Total international deposits

​

​

665,448

​

​

675,319

​

​

634,523

​

​

615,395

​

​

622,718

​

1%

​

(6%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total deposits

​

​

1,300,975

​

​

1,310,281

​

​

1,347,528

​

​

1,317,230

​

​

1,333,711

​

1%

​

3%

Securities loaned and sold under agreements to resell

​

​

219,168

​

​

221,817

​

​

209,184

​

​

191,285

​

​

204,494

​

7%

​

(7%)

Brokerage payables

​

​

60,907

​

​

59,416

​

​

60,501

​

​

61,430

​

​

91,324

​

49%

​

50%

Trading account liabilities

​

​

179,117

​

​

174,706

​

​

179,286

​

​

161,529

​

​

188,059

​

16%

​

5%

Short-term borrowings

​

​

32,087

​

​

31,462

​

​

29,683

​

​

27,973

​

​

30,144

​

8%

​

(6%)

Long-term debt

​

​

256,335

​

​

264,575

​

​

258,274

​

​

254,374

​

​

253,954

​

-

​

(1%)

Other liabilities(4)

​

​

62,404

​

​

62,701

​

​

75,810

​

​

74,920

​

​

94,066

​

26%

​

51%

Total liabilities

​

$

2,110,993

​

$

2,124,958

​

$

2,160,266

​

$

2,088,741

​

$

2,195,752

​

5%

​

4%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Equity

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Stockholders' equity

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Preferred stock

​

$

20,280

​

$

17,995

​

$

17,995

​

$

18,995

​

$

18,995

​

-

​

(6%)

Common stock

​

​

31

​

​

31

​

​

31

​

​

31

​

​

31

​

-

​

-

Additional paid-in capital

​

​

107,694

​

​

107,820

​

​

107,922

​

​

108,003

​

​

108,050

​

-

​

-

Retained earnings

​

​

174,816

​

​

179,686

​

​

183,024

​

​

184,948

​

​

187,962

​

2%

​

8%

Treasury stock, at cost

​

​

(65,261)

​

​

(68,253)

​

​

(71,246)

​

​

(71,240)

​

​

(73,744)

​

(4%)

​

(13%)

Accumulated other comprehensive income (loss) (AOCI)(5)

​

​

(35,011)

​

​

(35,120)

​

​

(36,851)

​

​

(38,765)

​

​

(43,585)

​

(12%)

​

(24%)

Total common equity

​

$

182,269

​

$

184,164

​

$

182,880

​

$

182,977

​

$

178,714

​

(2%)

​

(2%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total Citigroup stockholders' equity

​

$

202,549

​

$

202,159

​

$

200,875

​

$

201,972

​

$

197,709

​

(2%)

​

(2%)

Noncontrolling interests

​

​

724

​

​

751

​

​

735

​

​

700

​

​

644

​

(8%)

​

(11%)

Total equity

​

​

203,273

​

​

202,910

​

​

201,610

​

​

202,672

​

​

198,353

​

(2%)

​

(2%)

Total liabilities and equity

​

$

2,314,266

​

$

2,327,868

​

$

2,361,876

​

$

2,291,413

​

$

2,394,105

​

4%

​

3%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

(1)Preliminary.
(2)Consumer loans include loans managed by PBWM and Legacy Franchises (other than Mexico Small Business & Middle-Market Banking (Mexico SBMM) loans).
(3)Corporate loans include loans managed by ICG and Legacy Franchises-Mexico SBMM.
(4)Includes allowance for credit losses for unfunded lending commitments. See page 15.
(5)As discussed in note 2 on page 1, Citi's third quarter of 2021 results include an approximate $680 million loss on sale (an approximate $580 million after-tax), related to Citi’s agreement to sell its Australia consumer banking business. The loss primarily reflects the impact of an approximate $625 million ($475 million (after-tax)) currency translation adjustment (CTA) loss (net of hedges) at September 30, 2021, December 31, 2021 and March 31, 2022, already reflected in the Accumulated Other Comprehensive Income (AOCI) component of equity. Upon closing, the CTA balance will be removed from the AOCI component of equity, resulting in a neutral impact from CTA to Citi’s Common Equity Tier 1 Capital.

​

NM Not meaningful.

Reclassified to conform to the current period's presentation.

​

Page 3


OPERATING SEGMENT AND REPORTING UNIT DETAILS

(In millions of dollars)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

1Q22 Increase/

​


1Q


2Q


3Q


4Q


1Q


(Decrease) from

​

​

2021

​

2021

​

2021

​

2021

​

2022

​

4Q21

​

1Q21

Net revenues

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Institutional Clients Group

​

$

11,388

​

$

9,549

​

$

9,991

​

$

8,908

​

$

11,160

​

25%

​

(2%)

Personal Banking and Wealth Management

​

​

5,992

​

​

5,698

​

​

5,852

​

​

5,785

​

​

5,905

​

2%

​

(1%)

Legacy Franchises

​

​

2,243

​

​

2,279

​

​

1,536

​

​

2,193

​

​

1,931

​

(12%)

​

(14%)

Corporate/Other

​

​

44

​

​

227

​

​

68

​

​

131

​

​

190

​

45%

​

NM

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total net revenues

​

$

19,667

​

$

17,753

​

$

17,447

​

$

17,017

​

$

19,186

​

13%

​

(2%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Income from continuing operations

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Institutional Clients Group

​

$

5,430

​

$

3,433

​

$

3,115

​

$

2,330

​

$

2,658

​

14%

​

(51%)

Personal Banking and Wealth Management

​

​

2,420

​

​

1,805

​

​

1,896

​

​

1,613

​

​

1,860

​

15%

​

(23%)

Legacy Franchises

​

​

320

​

​

492

​

​

(201)

​

​

(620)

​

​

(385)

​

38%

​

NM

Corporate/Other

​

​

(193)

​

​

463

​

​

(141)

​

​

(144)

​

​

192

​

NM

​

NM

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Income from continuing operations

​

$

7,977

​

$

6,193

​

$

4,669

​

$

3,179

​

$

4,325

​

36%

​

(46%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Discontinued operations

​

​

(2)

​

​

10

​

​

(1)

​

​

-

​

​

(2)

​

NM

​

-

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Net income attributable to noncontrolling interests

​

​

33

​

​

10

​

​

24

​

​

6

​

​

17

​

NM

​

(48%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Net income

​

$

7,942

​

$

6,193

​

$

4,644

​

$

3,173

​

$

4,306

​

36%

​

(46%)

​

NM Not meaningful.

Reclassified to conform to the current period's presentation.

​

​

Page 4


INSTITUTIONAL CLIENTS GROUP

(In millions of dollars, except as otherwise noted)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​


​


​


​


​


1Q22 Increase/

​


1Q


2Q


3Q


4Q


1Q


(Decrease) from

​

​

2021

​

2021

​

2021

​

2021

​

2022

​

4Q21

​

1Q21

Commissions and fees

​

$

1,110

​

$

1,071

​

$

1,055

​

$

1,064

​

$

1,130


6%

​

2%

Administration and other fiduciary fees

​


657

​


698

​


676

​


662

​


672


2%

​

2%

Investment banking

​


1,787

​


1,568

​


1,685

​


1,669

​


1,039


(38%)

​

(42%)

Principal transactions

​


3,745

​


2,135

​


2,229

​


1,654

​


4,442


NM

​

19%

Other

​


356

​


317

​


608

​


91

​


93


2%

​

(74%)

Total non-interest revenue

​


7,655

​


5,789

​


6,253

​


5,140

​


7,376


44%

​

(4%)

Net interest income (including dividends)

​


3,733

​


3,760

​


3,738

​


3,768

​


3,784


-

​

1%

Total revenues, net of interest expense

​


11,388

​


9,549

​


9,991

​


8,908

​


11,160


25%

​

(2%)

Total operating expenses

​


5,932

​


5,829

​


5,963

​


6,225

​


6,723


8%

​

13%

Net credit losses on loans

​


175

​


68

​


31

​


82

​


30


(63%)

​

(83%)

Credit reserve build / (release) for loans

​


(1,103)

​


(812)

​


14

​


(192)

​


596


NM

​

NM

Provision for credit losses on unfunded lending commitments

​


(606)

​


47

​


(13)

​


(181)

​


352


NM

​

NM

Provisions for credit losses for HTM debt securities and other assets

​


(5)

​


3

​


(8)

​


10

​


(7)


NM

​

(40%)

Provision for credit losses

​


(1,539)

​


(694)

​


24

​


(281)

​


971


NM

​

NM

Income from continuing operations before taxes

​


6,995

​


4,414

​


4,004

​


2,964

​


3,466


17%

​

(50%)

Income taxes

​


1,565

​


981

​


889

​


634

​


808


27%

​

(48%)

Income from continuing operations

​


5,430

​


3,433

​


3,115

​


2,330

​


2,658


14%

​

(51%)

Noncontrolling interests

​


37

​


12

​


24

​


10

​


18


80%

​

(51%)

Net income

​

$

5,393

​

$

3,421

​

$

3,091

​

$

2,320

​

$

2,640


14%

​

(51%)

EOP assets (in billions)

​

$

1,636

​

$

1,654

​

$

1,670

​

$

1,613

​

$

1,704


6%

​

4%

Average assets (in billions)

​


1,649

​


1,667

​


1,660

​


1,698

​


1,685


(1%)

​

2%

Efficiency ratio

​


52%

​


61%


60%

​


70%

​


60%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Revenue by reporting unit

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Services

​

$

3,000

​

$

3,140

​

$

3,141

​

$

3,258

​

$

3,448


6%

​

15%

Markets

​


5,933

​


4,255

​


4,387

​


3,343

​


5,826


74%

​

(2%)

Banking

​


2,455

​


2,154

​


2,463

​


2,307

​


1,886


(18%)

​

(23%)

Total revenues, net of interest expense

​

$

11,388

​

$

9,549

​

$

9,991

​

$

8,908

​

$

11,160


25%

​

(2%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Revenue by region

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

North America

​

$

4,475

​

$

3,279

​

$

3,727

​

$

3,278

​

$

3,722


14%

​

(17%)

EMEA

​


3,602

​


3,127

​


2,981

​


2,705

​


4,030


49%

​

12%

Latin America

​


1,000

​


1,035

​


1,129

​


1,113

​


1,141


3%

​

14%

Asia

​


2,311

​


2,108

​


2,154

​


1,812

​


2,267


25%

​

(2%)

Total revenues, net of interest expense

​

$

11,388

​

$

9,549

​

$

9,991

​

$

8,908

​

$

11,160


25%

​

(2%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Income (loss) from continuing operations by region

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

North America

​

$

2,529

​

$

1,074

​

$

718

​

$

768

​

$

589


(23%)

​

(77%)

EMEA

​


1,440

​


1,101

​


990

​


672

​


928


38%

​

(36%)

Latin America

​


500

​


507

​


580

​


473

​


359


(24%)

​

(28%)

Asia

​


961

​


751

​


827

​


417

​


782


88%

​

(19%)

Income from continuing operations

​

$

5,430

​

$

3,433

​

$

3,115

​

$

2,330

​

$

2,658


14%

​

(51%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Average loans by reporting unit (in billions)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Services

​

$

70

​

$

74

​

$

76

​

$

77

​

$

81


5%

​

16%

Banking

​


197

​


197

​


196

​


195

​


194


(1%)

​

(2%)

Markets

​


14

​


16

​


17

​


17

​


14


(18%)

​

-

Total

​

$

281

​

$

287

​

$

289

​

$

289

​

$

289


-

​

3%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Average deposits by reporting unit (in billions)

​


​


​


​


​


​

​

​

Treasury and trade solutions (TTS)

​

$

653

​

$

652

​

$

668

​

$

684

​

$

664


(3%)

​

2%

Securities services

​


128

​


137

​


135

​


140

​


135


(4%)

​

5%

Services

​


781

​


789

​


803

​


824

​


799


(3%)

​

2%

Markets

​


28

​


29

​


28

​


28

​


27


(4%)

​

(4%)

Total

​

$

809

​

$

818

​

$

831

​

$

852

​

$

826


(3%)

​

2%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Services Key Drivers (in billions of dollars, except as otherwise noted)

​


​


​


​


​


​

​

​

AUC/AUA (in trillions of dollars)

​

$

21.2

​

$

22.7

​

$

22.6

​

$

23.7

​

$

23.0


(3%)

​

8%

Cross border transaction value

​

$

64.5

​

$

67.8

​

$

69.0

​

$

78.2

​

$

75.6


(3%)

​

17%

U.S.-dollar clearing volume (in millions)

​


35.4

​


36.0

​


37.0

​


37.8

​


36.1


(4%)

​

2%

Commercial card spend volume

​

$

7.4

​

$

9.3

​

$

10.5

​

$

11.4

​

$

11.4


-

​

54%


NM Not meaningful.

Reclassified to conform to the current period's presentation.

Page 5


INSTITUTIONAL CLIENTS GROUP

REPORTING UNIT REVENUES

(In millions of dollars, except as otherwise noted)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​


​


​


​


​


1Q22 Increase/

​


1Q


2Q


3Q


4Q


1Q


(Decrease) from

​

​

2021

​

2021

​

2021

​

2021

​

2022

​

4Q21

​

1Q21

Services


​


​

​


​

​


​

​


​

​


​


Net interest income

​

$

1,617

​

$

1,640

​

$

1,613

​

$

1,682

​

$

1,907

​

13%

​

18%

Non-interest revenue

​


1,383

​


1,500

​


1,528

​


1,576

​


1,541

​

(2%)

​

11%

Total Services revenues

​

$

3,000

​

$

3,140

​

$

3,141

​

$

3,258

​

$

3,448

​

6%

​

15%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Net interest income

​

$

1,405

​

$

1,427

​

$

1,389

​

$

1,444

​

$

1,659

​

15%

​

18%

Non-interest revenue

​


783

​


858

​


908

​


960

​


931

​

(3%)

​

19%

Treasury and trade solutions

​

$

2,188

​

$

2,285

​

$

2,297

​

$

2,404

​

$

2,590

​

8%

​

18%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Net interest income

​

$

212

​

$

213

​

$

224

​

$

238

​

$

248

​

4%

​

17%

Non-interest revenue

​


600

​


642

​


620

​


616

​


610

​

(1%)

​

2%

Securities services

​

$

812

​

$

855

​

$

844

​

$

854

​

$

858

​

-

​

6%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Markets

​


​


​


​


​


​

​

​

​

Net interest income

​

$

1,309

​

$

1,379

​

$

1,265

​

$

1,250

​

$

1,109

​

(11%)

​

(15%)

Non-interest revenue

​


4,624

​


2,876

​


3,122

​


2,093

​


4,717

​

NM

​

2%

Total Markets revenues

​

$

5,933

​

$

4,255

​

$

4,387

​

$

3,343

​

$

5,826

​

74%

​

(2%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Fixed income markets

​

$

4,346

​

$

3,111

​

$

3,040

​

$

2,425

​

$

4,299

​

77%

​

(1%)

Equity markets

​


1,587

​


1,144

​


1,347

​


918

​


1,527

​

66%

​

(4%)

Total

​

$

5,933

​

$

4,255

​

$

4,387

​

$

3,343

​

$

5,826

​

74%

​

(2%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Rates and currencies

​

$

3,024

​

$

1,978

​

$

2,112

​

$

1,721

​

$

3,231

​

88%

​

7%

Spread products / other fixed income

​


1,322

​


1,133

​


928

​


704

​


1,068

​

52%

​

(19%)

Total fixed income markets revenues

​

$

4,346

​

$

3,111

​

$

3,040

​

$

2,425

​

$

4,299

​

77%

​

(1%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Banking

​


​


​


​


​


​

​

​

​

Net interest income

​

$

807

​

$

741

​

$

860

​

$

836

​

$

768

​

(8%)

​

(5%)

Non-interest revenue

​


1,648

​


1,413

​


1,603

​


1,471

​


1,118

​

(24%)

​

(32%)

Total Banking revenues, including gain/(loss) on loan hedges

​

$

2,455

​

$

2,154

​

$

2,463

​

$

2,307

​

$

1,886

​

(18%)

​

(23%)

Investment banking

​


​


​


​


​


​

​

​

​

Advisory

​

$

281

​

$

405

​

$

539

​

$

571

​

$

347

​

(39%)

​

23%

Equity underwriting

​


835

​


484

​


468

​


462

​


185

​

(60%)

​

(78%)

Debt underwriting

​


682

​


614

​


770

​


520

​


496

​

(5%)

​

(27%)

Total investment banking

​


1,798

​


1,503

​


1,777

​


1,553

​


1,028

​

(34%)

​

(43%)

Corporate lending - excluding gain/(loss) on loan hedges(1)

​


735

​


688

​


732

​


733

​


689

​

(6%)

​

(6%)

Total Banking revenues (ex-gain/(loss) on loan hedges)(1)

​

$

2,533

​

$

2,191

​

$

2,509

​

$

2,286

​

$

1,717

​

(25%)

​

(32%)

Gain/(loss) on loan hedges(1)

​


(78)

​


(37)

​


(46)

​


21

​


169

​

NM

​

NM

Total Banking revenues including gain/(loss) on loan hedges(1)

​

$

2,455

​

$

2,154

​

$

2,463

​

$

2,307

​

$

1,886

​

(18%)

​

(23%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total ICG revenues, net of interest expense

​

$

11,388

​

$

9,549

​

$

9,991

​

$

8,908

​

$

11,160

​

25%

​

(2%)

Taxable-equivalent adjustments(2)

​


114

​


181

​


105

​


159

​


100

​

(37%)

​

(12%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total ICG revenues - including taxable-equivalent adjustments(2)

​

$

11,502

​

$

9,730

​

$

10,096

​

$

9,067

​

$

11,260

​

24%

​

(2%)

​


(1)Credit derivatives are used to economically hedge a portion of the corporate loan portfolio that includes both accrual loans and loans at fair value. Gain/(loss) on loan hedges includes the mark-to-market on the credit derivatives partially offset by the mark-to-market on the loans in the portfolio that are at fair value. Hedges on accrual loans reflect the mark-to-market on credit derivatives used to economically hedge the corporate loan accrual portfolio. The fixed premium costs of these hedges are netted against the corporate lending revenues to reflect the cost of credit protection. Citigroup’s results of operations excluding the impact of gain/(loss) on loan hedges are non-GAAP financial measures.
(2)Primarily relates to income tax credits related to affordable housing and alternative energy investments as well as tax exempt income from municipal bond investments.

​

NM Not meaningful.

Reclassified to conform to the current period's presentation.

​

​

​

Page 6


PERSONAL BANKING AND WEALTH MANAGEMENT

(In millions of dollars, except as otherwise noted)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​


​


​


​


​


1Q22 Increase/

​


1Q


2Q


3Q


4Q


1Q


(Decrease) from

​

​

2021

​

2021

​

2021

​

2021

​

2022

​

4Q21

​

1Q21

Net interest income

​

$

5,165

​

$

4,985

​

$

5,174

​

$

5,322

​

$

5,385


1%

​

4%

Non-interest revenue

​


827

​


713

​


678

​


463

​


520


12%

​

(37%)

Total revenues, net of interest expense

​


5,992

​


5,698

​


5,852

​


5,785

​


5,905


2%

​

(1%)

Total operating expenses

​


3,422

​


3,547

​


3,624

​


4,017

​


3,889


(3%)

​

14%

Net credit losses on loans

​


990

​


862

​


641

​


568

​


691


22%

​

(30%)

Credit reserve build / (release) for loans

​


(1,542)

​


(1,040)

​


(836)

​


(866)

​


(1,062)


(23%)

​

31%

Provision for credit losses on unfunded lending commitments

​


(11)

​


5

​


(7)

​


(3)

​


(2)


33%

​

82%

Provisions for benefits and claims, and other assets

​


6

​


3

​


1

​


5

​


(3)


NM

​

NM

Provisions for credit losses and for benefits and claims (PBC)

​


(557)

​


(170)

​


(201)

​


(296)

​


(376)


(27%)

​

32%

Income (loss) from continuing operations before taxes

​


3,127

​


2,321

​


2,429

​


2,064

​


2,392


16%

​

(24%)

Income taxes (benefits)

​


707

​


516

​


533

​


451

​


532


18%

​

(25%)

Income (loss) from continuing operations

​


2,420

​


1,805

​


1,896

​


1,613

​


1,860


15%

​

(23%)

Noncontrolling interests

​


-

​


-

​


-

​


-

​


-


-

​

-

Net income (loss)

​

$

2,420

​

$

1,805

​

$

1,896

​

$

1,613

​

$

1,860


15%

​

(23%)

EOP assets (in billions)

​

$

461

​

$

452

​

$

477

​

$

464

​

$

476


3%

​

3%

Average assets (in billions)

​


458

​


458

​


474

​


476

​


474


-

​

3%

Efficiency ratio

​


57%


62%


62%

​


69%


66%


​

​

​

Revenue by reporting unit and component

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Branded cards

​

$

2,104

​

$

1,968

​

$

2,045

​

$

2,073

​

$

2,090


1%

​

(1%)

Retail services

​


1,305

​


1,210

​


1,277

​


1,290

​


1,299


1%

​

-

Retail banking

​


635

​


618

​


629

​


624

​


595


(5%)

​

(6%)

U.S. Personal Banking

​


4,044

​


3,796

​


3,951

​


3,987

​


3,984


-

​

(1%)

Private bank

​


786

​


747

​


722

​


688

​


779


13%

​

(1%)

Wealth at Work

​


171

​


171

​


172

​


177

​


183


3%

​

7%

Citigold

​


991

​


984

​


1,007

​


933

​


959


3%

​

(3%)

Global Wealth Management

​


1,948

​


1,902

​


1,901

​


1,798

​


1,921


7%

​

(1%)

Total

​

$

5,992

​

$

5,698

​

$

5,852

​

$

5,785

​

$

5,905


2%

​

(1%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Average loans by reporting unit (in billions)

​


​


​


​


​


​

​

​

U.S. Personal Banking

​

$

159

​

$

157

​

$

158

​

$

162

​

$

161


(1%)

​

1%

Global Wealth Management

​


144

​


147

​


151

​


150

​


151


1%

​

5%

Total

​

$

303

​

$

304

​

$

309

​

$

312

​

$

312


-

​

3%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Average deposits by reporting unit (in billions)

​


​


​


​


​


​

​

​

U.S. Personal Banking

​

$

108

​

$

113

​

$

114

​

$

114

​

$

118


4%

​

9%

Global Wealth Management

​


289

​


297

​


310

​


323

​


329


2%

​

14%

Total

​

$

397

​

$

410

​

$

424

​

$

437

​

$

447


2%

​

13%


NM Not meaningful.

Reclassified to conform to the current period's presentation.

​

Page 7


PERSONAL BANKING AND WEALTH MANAGEMENT

Metrics

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​


​


​


​


​


1Q22 Increase/

​


1Q


2Q


3Q


4Q


1Q


(Decrease) from

​

​

2021

​

2021

​

2021

​

2021

​

2022

​

4Q21

​

1Q21

U.S. Personal Banking Key Indicators (in billions of dollars, except as otherwise noted)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

New account acquisitions (in thousands)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Branded cards


​

797


​

907


​

995


​

1,069


​

991


(7%)

​

24%

Retail services


​

2,204


​

2,792


​

2,526


​

3,126


​

2,178


(30%)

​

(1%)

Credit card spend volume

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Branded cards

​

$

85.8

​

$

103.5

​

$

106.0

​

$

115.2

​

$

106.8


(7%)

​

24%

Retail services

​


18.7

​


23.6

​


22.7

​


27.1

​


21.4


(21%)

​

14%

Average loans(1)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Branded cards

​

$

78.7

​

$

79.4

​

$

81.9

​

$

84.5

​

$

84.0


(1%)

​

7%

Retail services

​


43.8

​


42.3

​


42.4

​


43.8

​


44.2


1%

​

1%

EOP loans(1)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Branded cards

​

$

78.5

​

$

82.1

​

$

82.8

​

$

87.9

​

$

85.9


(2%)

​

9%

Retail services

​


42.5

​


42.7

​


42.7

​


46.0

​


44.1


(4%)

​

4%

NII as a % of average loans(2)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Branded cards

​


9.49%

​


8.90%

​


9.00%

​


8.93%

​


9.16%

​

​

​

​

Retail services

​


16.23%

​


15.70%

​


16.54%

​


16.55%

​


16.93%

​

​

​

​

NCLs as a % of average loans

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Branded cards

​


2.84%

​


2.36%

​


1.73%

​


1.33%

​


1.46%

​

​

​

​

Retail services

​


3.45%

​


3.09%

​


2.23%

​


2.10%

​


2.31%

​

​

​

​

Loans 90+ days past due as a % of EOP loans

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Branded cards

​


0.75%

​


0.56%

​


0.44%

​


0.44%

​


0.47%

​

​

​

​

Retail services

​


1.39%

​


1.08%

​


0.99%

​


1.05%

​


1.15%

​

​

​

​

Loans 30-89 days past due as a % of EOP loans

​


​


​


​


​


​

​

​

​

Branded cards

​


0.62%

​


0.43%

​


0.45%

​


0.46%

​


0.49%

​

​

​

​

Retail services

​


1.21%

​


0.97%

​


1.10%

​


1.17%

​


1.27%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Average deposits

​

$

108

​

$

113

​

$

114

​

$

114

​

$

118


4%

​

9%

Branches (actual)

​


687

​


659

​


658

​


658

​


658


-

​

(4%)

Mortgage originations

​

$

4.4

​

$

4.1

​

$

3.4

​

$

3.4

​

$

3.1


(9%)

​

(30%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Global Wealth Management Key Indicators (in billions of dollars)

​


​


​


​


​


​

​

​

Client assets

​

$

756

​

$

790

​

$

789

​

$

814

​

$

788


(3%)

​

4%

Average loans

​


144

​


147

​


151

​


150

​


151


1%

​

5%

Average deposits

​


289

​


297

​


310

​


323

​


329


2%

​

14%

U.S. Mortgage originations

​


4.0

​


5.0

​


3.8

​


3.5

​


3.7


6%

​

(8%)

​


(1)Average loans, EOP loans and the related consumer delinquency amounts and ratios include interest and fees receivables balances.
(2)Net interest income includes certain fees that are recorded as interest revenue.

​

Reclassified to conform to the current period's presentation.

​

Page 8


LEGACY FRANCHISES(1)

(In millions of dollars, except as otherwise noted)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

1Q22 Increase/

​

​

1Q

​

2Q

​

3Q

​

4Q

​

1Q

​

(Decrease) from

​


2021


2021


2021


2021


2022


4Q21


1Q21

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Net interest income

​

$

1,563

​

$

1,621

​

$

1,532

​

$

1,534

​

$

1,508


(2%)

​

(4%)

Non-interest revenue(2)

​


680

​


658

​


4

​


659

​


423


(36%)

​

(38%)

Total revenues, net of interest expense

​


2,243

​


2,279

​


1,536

​


2,193

​


1,931


(12%)

​

(14%)

Total operating expenses(3)

​


1,752

​


1,788

​


1,748

​


2,971

​


2,293


(23%)

​

31%

Net credit losses on loans

​


583

​


390

​


289

​


216

​


151


(30%)

​

(74%)

Credit reserve build / (release) for loans

​


(582)

​


(594)

​


(327)

​


(118)

​


(146)


(24%)

​

75%

Provision for credit losses on unfunded lending commitments

​


(9)

​


(8)

​


7

​


(9)

​


124


NM

​

NM

Provisions for benefits and claims, HTM debt securities and other assets

​


52

​


8

​


17

​


23

​


31


35%

​

(40%)

Provisions for credit losses and for benefits and claims (PBC)

​


44

​


(204)

​


(14)

​


112

​


160


43%

​

NM

Income from continuing operations before taxes

​


447

​


695

​


(198)

​


(890)

​


(522)


41%

​

NM

Income taxes (benefits)

​


127

​


203

​


3

​


(270)

​


(137)


49%

​

NM

Income (loss) from continuing operations

​


320

​


492

​


(201)

​


(620)

​


(385)


38%

​

NM

Noncontrolling interests

​


(3)

​


(2)

​


(1)

​


(4)

​


(2)


50%

​

33%

Net income (loss)

​

$

323

​

$

494

​

$

(200)

​

$

(616)

​

$

(383)


38%

​

NM

EOP assets (in billions)

​

$

129

​

$

131

​

$

124

​

$

125

​

$

122


(2%)

​

(5%)

Average assets (in billions)

​


129

​


128

​


126

​


123

​


124


1%

​

(4%)

Efficiency ratio

​


78%

​


78%

​


114%

​


135%

​


119%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Revenue by reporting unit and component

​


​


​


​


​


​

​

​

Asia Consumer

​

$

1,075

​

$

1,052

​

$

330

​

$

948

​

$

787


(17%)

​

(27%)

Mexico Consumer/SBMM

​


1,137

​


1,184

​


1,162

​


1,168

​


1,139


(2%)

​

-

Legacy Holdings Assets

​


31

​


43

​


44

​


77

​


5


(94%)

​

(84%)

Total

​

$

2,243

​

$

2,279

​

$

1,536

​

$

2,193

​

$

1,931


(12%)

​

(14%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Asia Consumer - Key Indicators (in billions of dollars)

​


​


​


​


​


​

​

​

EOP loans

​

$

54.0

​

$

53.5

​

$

42.9

​

$

41.1

​

$

19.5


(53%)

​

(64%)

EOP deposits

​


54.6

​


54.0

​


46.6

​


43.3

​


17.5


(60%)

​

(68%)

Average loans

​


54.9

​


54.2

​


46.4

​


42.3

​


23.1


(45%)

​

(58%)

Net credit losses on loans as a % of average loans

​


1.67%

​


1.13%

​

​

1.10%

​


0.96%

​


0.79%

​

​

​

​

Loans 90+ days past due as a % of EOP loans

​


0.68%

​


0.65%

​

​

0.60%

​


0.51%

​


0.28%

​

​

​

​

Loans 30-89 days past due as a % of EOP loans

​


0.85%

​


0.87%

​

​

0.80%

​


0.69%

​


0.32%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Mexico Consumer/SBMM - Key Indicators (in billions of dollars)

​


​


​


​


​


​

​

​

EOP loans

​

$

20.1

​

$

20.0

​

$

19.4

​

$

20.0

​

$

20.7


4%

​

3%

EOP deposits

​


32.6

​


33.0

​


31.4

​


32.7

​


33.9


4%

​

4%

Average loans

​


20.6

​


20.2

​


19.6

​


19.4

​


19.6


1%

​

(5%)

Net credit losses on loans as a % of average loans

​


7.38%

​


5.14%

​


3.70%

​


2.72%

​


2.55%

​

​

​

​

Loans 90+ days past due as a % of EOP loans (Mexico Consumer only)

​


2.35%

​


1.84%

​


1.52%

​


1.38%

​


1.32%

​

​

​

​

Loans 30-89 days past due as a % of EOP loans (Mexico Consumer only)

​


2.08%

​


1.60%

​


1.46%

​


1.30%

​


1.30%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Legacy Holdings Assets - Key Indicators (in billions of dollars)

​


​


​


​


​


​

​

​

EOP loans

​

$

6.1

​

$

5.0

​

$

4.2

​

$

3.9

​

$

3.7


(5%)

​

(39%)

​


(1)

Legacy Franchises consists of the consumer franchises in 13 markets across Asia and EMEA that Citi intends to exit (Asia Consumer), the consumer, small business & middle-market banking (Mexico SBMM) operations in Mexico (collectively Mexico Consumer/SBMM); and Legacy Holdings Assets (primarily North America consumer mortgage loans and other legacy assets).

(2)

See footnote 2 on page 1.

(3)

See footnote 3 on page 1.

​

NM Not meaningful.

Reclassified to conform to the current period's presentation.

​

Page 9


CORPORATE / OTHER(1)

(In millions of dollars, except as otherwise noted)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

1Q22 Increase/

​

​

1Q

​

2Q

​

3Q

​

4Q

​

1Q

​

(Decrease) from

​


2021


2021


2021


2021


2022


4Q21


1Q21

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Net interest income

​

$

45

​

$

112

​

$

247

​

$

195

​

$

194


(1%)

​

NM

Non-interest revenue

​


(1)

​


115

​


(179)

​


(64)

​


(4)


94%

​

NM

Total revenues, net of interest expense

​


44

​


227

​


68

​


131

​


190


45%

​

NM

Total operating expenses

​


307

​


307

​


442

​


319

​


260


(18%)

​

(15%)

Provisions for HTM debt securities and other assets

​


(3)

​


2

​


(1)

​


-

​


-


-

​

100%

Income (loss) from continuing operations before taxes

​


(260)

​


(82)

​


(373)

​


(188)

​


(70)


63%

​

73%

Income taxes (benefits)

​


(67)

​


(545)

​


(232)

​


(44)

​


(262)


NM

​

NM

Income (loss) from continuing operations

​


(193)

​


463

​


(141)

​


(144)

​


192


NM

​

NM

Income (loss) from discontinued operations, net of taxes

​


(2)

​


10

​


(1)

​


-

​


(2)


NM

​

-

Noncontrolling interests

​


(1)

​


-

​


1

​


-

​


1


100%

​

NM

Net income (loss)

​

$

(194)

​

$

473

​

$

(143)

​

$

(144)

​

$

189


NM

​

NM

EOP assets (in billions)

​

$

88

​

$

91

​

$

91

​

$

89

​

$

92


3%

​

5%

​


(1)

Includes certain unallocated costs of global staff functions (including finance, risk, human resources, legal and compliance), other corporate expenses and unallocated global operations and technology expenses and income taxes, as well as Corporate Treasury and discontinued operations.

NM Not meaningful.

Reclassified to conform to the current period's presentation.

​

Page 10


AVERAGE BALANCES AND INTEREST RATES(1)(2)(3)(4)(5)

Taxable Equivalent Basis

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Average Volumes

​

Interest

​

% Average Rate (4)


​

​

​

First

​

Fourth

​

First

​

First

​

Fourth

​

First

​

First

​

Fourth

​

First


​

​

​

Quarter

​

Quarter

​

Quarter

​

Quarter

​

Quarter

​

Quarter

​

Quarter

​

Quarter

​

Quarter


​

In millions of dollars, except as otherwise noted


2021


2021


2022(5)


2021


2021


2022(5)


2021


2021


2022(5)


​

Assets


​


​


​


​


​


​


​

​

Deposits with banks

​

$

307,340

​

$

295,330

​

$

260,536

​

$

145

​

$

159

​

$

296


0.19%

​

0.21%

​

0.46%

​

​

Securities borrowed and purchased under resale agreements(6)

​


306,381

​


341,256

​


343,636

​


294

​


289

​


394


0.39%

​

0.34%

​

0.46%

​

​

Trading account assets(7)

​


307,817

​


269,149

​


270,460

​


1,338

​


1,276

​


1,148


1.76%

​

1.88%

​

1.72%

​

​

Investments

​


457,949

​


512,181

​


518,820

​


1,780

​


1,951

​


2,067


1.58%

​

1.51%

​

1.62%

​

​

Consumer loans

​


378,085

​


371,481

​


352,230

​


6,702

​


6,618

​


6,262


7.19%

​

7.07%

​

7.21%

​

​

Corporate loans

​


287,885

​


295,927

​


296,346

​


2,231

​


2,328

​


2,477


3.14%

​

3.12%

​

3.39%

​

​

Total loans (net of unearned income)(8)

​


665,970

​


667,408

​


648,576

​


8,933

​


8,946

​


8,739


5.44%

​

5.32%

​

5.46%

​

​

Other interest-earning assets

​


76,091

​


86,527

​


119,816

​


97

​


249

​


549


0.52%

​

1.14%

​

1.86%

​

​

Total average interest-earning assets

​

$

2,121,548

​

$

2,171,851

​

$

2,161,844

​

$

12,587

​

$

12,870

​

$

13,193


2.41%

​

2.35%

​

2.47%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Liabilities

​


​


​


​


​


​


​


​


​

​

Deposits(9)

​


1,073,827

​


1,111,944

​


1,080,105

​


712

​


778

​


871


0.27%

​

0.28%

​

0.33%

​

​

Securities loaned and sold under repurchase agreements(6)

​


235,263

​


221,948

​


210,101

​


253

​


212

​


282


0.44%

​

0.38%

​

0.54%

​

​

Trading account liabilities(7)

​


117,364

​


114,233

​


114,313

​


114

​


112

​


147


0.39%

​

0.39%

​

0.52%

​

​

Short-term borrowings and other interest-bearing liabilities

​


93,344

​


103,523

​


138,861

​


31

​


51

​


55


0.13%

​

0.20%

​

0.16%

​

​

Long-term debt(10)

​


206,264

​


175,804

​


170,927

​


918

​


856

​


925


1.80%

​

1.93%

​

2.19%

​

​

Total average interest-bearing liabilities

​

$

1,726,062

​

$

1,727,452

​

$

1,714,307

​

$

2,028

​

$

2,009

​

$

2,280


0.48%

​

0.46%

​

0.54%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Net interest income as a % of average interest-earning assets (NIM)(9)

​


​


​


​

$

10,559

​

$

10,861

​

$

10,913


2.02%

​

1.98%

​

2.05%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

1Q22 increase (decrease) from:

​


​


​


​


​


​


​


3

bps

7

bps

​

​

​

​

(1)Interest revenue and Net interest income include the taxable equivalent adjustments (based on the U.S. federal statutory tax rate of 21%) of $53 million for 1Q21, $42 million for 4Q21 and $42 million for 1Q22
(2)Citigroup average balances and interest rates include both domestic and international operations
(3)Monthly averages have been used by certain subsidiaries where daily averages are unavailable
(4)Average rate percentage is calculated as annualized interest over average volumes.
(5)First quarter of 2022 is preliminary.
(6)Average volumes of securities borrowed or purchased under agreements to resell and securities loaned or sold under agreements to repurchase are reported net pursuant to FIN 41; the related interest excludes the impact of ASU 2013-01 (Topic 210).
(7)Interest expense on trading account liabilities of ICG is reported as a reduction of interest revenue. Interest revenue and interest expense on cash collateral positions are reported in trading account assets and trading account liabilities, respectively.
(8)Nonperforming loans are included in the average loan balances
(9)See footnote 1 on page 1.
(10)Excludes hybrid financial instruments with changes in fair value recorded in Principal transactions revenue

​

Reclassified to conform to the current period's presentation.

​

Page 11


EOP LOANS(1)(2)

(In billions of dollars)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

1Q22 Increase/ 

​

​

1Q

​

2Q

​

3Q

​

4Q

​

1Q

​

(Decrease) from

​

​

2021

​

2021

​

2021

​

2021

​

2022

​

4Q21

​

1Q21

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Corporate loans - by region


​


​


​


​


​


​


North America

​

$

126.6

​

$

127.6

​

$

127.7

​

$

126.7

​

$

129.2


2%

​

2%

EMEA

​


76.6

​


77.6

​


77.4

​


75.7

​


81.2


7%

​

6%

Latin America

​


31.7

​


32.6

​


31.6

​


32.2

​


35.9


11%

​

13%

Asia

​


55.6

​


58.2

​


58.8

​


56.6

​


63.0


11%

​

13%

Total corporate loans

​

$

290.5

​

$

296.0

​

$

295.5

​

$

291.2

​

$

309.3


6%

​

6%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Corporate loans - by reporting unit

​


​


​


​


​


​


Services

​

$

72.7

​

$

77.5

​

$

79.8

​

$

75.2

​

$

86.7


15%

​

19%

Markets

​


16.0

​


17.3

​


17.5

​


15.1

​


14.6


(3%)

​

(9%)

Banking

​


195.1

​


194.7

​


191.8

​


194.2

​


200.9


3%

​

3%

Legacy Franchises - Mexico SBMM

​


6.7

​


6.5

​


6.4

​


6.7

​


7.1


6%

​

6%

Total corporate loans

​

$

290.5

​

$

296.0

​

$

295.5

​

$

291.2

​

$

309.3


6%

​

6%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Personal Banking and Wealth Management

​


​


​


​


​


​


Branded cards

​

$

78.5

​

$

82.1

​

$

82.8

​

$

87.9

​

$

85.9


(2%)

​

9%

Retail services

​


42.5

​


42.7

​


42.7

​


46.0

​


44.1


(4%)

​

4%

Retail banking

​


35.6

​


34.3

​


33.5

​


33.1

​


33.3


1%

​

(6%)

U.S. Personal Banking

​

$

156.6

​

$

159.1

​

$

159.0

​

$

167.0

​

$

163.3


(2%)

​

4%

Global Wealth Management

​


145.4

​


149.7

​


150.2

​


151.2

​


150.2


(1%)

​

3%

Total

​

$

302.0

​

$

308.8

​

$

309.2

​

$

318.2

​

$

313.5


(1%)

​

4%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Legacy Franchises - Consumer

​


​


​


​


​


​


Asia Consumer(3)

​

$

54.0

​

$

53.5

​

$

42.9

​

$

41.1

​

$

19.5


(53%)

​

(64%)

Mexico Consumer

​


13.4

​


13.5

​


13.0

​


13.3

​


13.6


2%

​

1%

Legacy Holdings Assets

​


6.1

​


5.0

​


4.2

​


3.9

​


3.7


(5%)

​

(39%)

Total

​

$

73.5

​

$

72.0

​

$

60.1

​

$

58.3

​

$

36.8


(37%)

​

(50%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total consumer loans

​

$

375.5

​

$

380.8

​

$

369.3

​

$

376.5

​

$

350.3


(7%)

​

(7%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total loans

​

$

666.0

​

$

676.8

​

$

664.8

​

$

667.8

​

$

659.7


(1%)

​

(1%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

(1)Corporate loans include loans managed by ICG and Legacy Franchises-Mexico SBMM.
(2)Consumer loans include loans managed by PBWM and Legacy Franchises (other than Mexico Small Business & Middle-Market Banking (Mexico SBMM) loans).
(3)Asia Consumer includes loans of certain EMEA countries for all periods presented.

​

Reclassified to conform to the current period's presentation.

​

Page 12


DEPOSITS

(In billions of dollars)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

1Q22 Increase/ 

​

​

1Q

​

2Q

​

3Q

​

4Q

​

1Q

​

(Decrease) from

​

​

2021

​

2021

​

2021

​

2021

​

2022

​

4Q21

​

1Q21

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

ICG by region


​


​


​


​


​


​


North America

​

$

385.1

​

$

379.1

​

$

408.0

​

$

382.8

​

$

390.5


2%

​

1%

EMEA

​


205.3

​


204.3

​


200.3

​


193.1

​


208.6


8%

​

2%

Latin America

​


36.5

​


36.7

​


38.8

​


37.7

​


38.9


3%

​

7%

Asia

​


171.3

​


178.4

​


185.5

​


175.8

​


187.5


7%

​

9%

Total

​

$

798.2

​

$

798.5

​

$

832.6

​

$

789.4

​

$

825.5


5%

​

3%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

ICG by reporting unit

​


​


​


​


​


​


Treasury and trade solutions

​

$

639.8

​

$

634.9

​

$

667.8

​

$

627.9

​

$

657.5


5%

​

3%

Securities services

​


129.9

​


135.2

​


136.7

​


133.8

​


138.7


4%

​

7%

Services

​

$

769.7

​

$

770.1

​

$

804.5

​

$

761.7

​

$

796.2


5%

​

3%

Markets

​


27.0

​


26.5

​


26.7

​


26.4

​


27.8


5%

​

3%

Banking

​


1.5

​


1.9

​


1.4

​


1.3

​


1.5


15%

​

-

Total

​

$

798.2

​

$

798.5

​

$

832.6

​

$

789.4

​

$

825.5


5%

​

3%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Personal Banking and Wealth Management

​


​


​


​


​


​


U.S. Personal Banking

​

$

112.9

​

$

113.1

​

$

113.5

​

$

116.8

​

$

119.5


2%

​

6%

Global Wealth Management

​


293.4

​


303.9

​


316.5

​


329.2

​


332.1


1%

​

13%

Total

​

$

406.3

​

$

417.0

​

$

430.0

​

$

446.0

​

$

451.6


1%

​

11%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Legacy Franchises

​


​


​


​


​


​


Asia Consumer(1)

​

$

54.6

​

$

54.0

​

$

46.6

​

$

43.3

​

$

17.5


(60%)

​

(68%)

Mexico Consumer/SBMM

​


32.6

​


33.0

​


31.4

​


32.7

​


33.9


4%

​

4%

Legacy Holdings Assets

​


-

​


-

​


-

​


-

​


-


-

​

-

Total

​

$

87.2

​

$

87.0

​

$

78.0

​

$

76.0

​

$

51.4


(32%)

​

(41%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Corporate/Other

​


9.3

​


7.8

​


6.9

​


5.8

​


5.2


(10%)

​

(44%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total deposits - EOP

​

$

1,301.0

​

$

1,310.3

​

$

1,347.5

​

$

1,317.2

​

$

1,333.7


1%

​

3%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total deposits - average

​

$

1,304.0

​

$

1,321.3

​

$

1,343.0

​

$

1,370.3

​

$

1,334.3


(3%)

​

2%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

(1)Asia Consumer includes deposits of certain EMEA countries for all periods presented.

​

Reclassified to conform to the current period's presentation.

​

Page 13


ALLOWANCE FOR CREDIT LOSSES (ACL) ROLLFORWARD

(In millions of dollars, except for ratios)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Build

​

​

​

​

​

​

​

​

ACLL/EOP

​

​

Balance

​

​

Builds / (releases)

​

FY 2021

​

​

Balance

​

(Release)

​

1Q22

​

​

Balance

​

Loans

​

​

12/31/20

​

​

1Q21

​

2Q21

​

3Q21

​

4Q21

​

​

FY 2021

​

FX/Other

​

​

12/31/21

​

1Q22

​

FX/Other

​

​

3/31/22

​

3/31/22

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Allowance for credit losses on loans (ACLL)


​


​


​


​


​


​


​


​


​


​


​


​


ICG

​

$

4,356

​

​

$

(1,103)

​

$

(812)

​

$

14

​

$

(192)

​

​

$

(2,093)

​

$

(22)

​

​

$

2,241

​

$

596

​

$

5

​

​

$

2,842


Legacy Franchises corporate (Mexico SBMM)

​


420

​

​


(124)

​


(51)

​


(61)

​


(1)

​

​


(237)

​


(9)

​

​


174

​


5

​


4

​

​


183


Total corporate ACLL

​

$

4,776

​

​

$

(1,227)

​

$

(863)

​

$

(47)

​

$

(193)

​

​

$

(2,330)

​

$

(31)

​

​

$

2,415

​

$

601

​

$

9

​

​

$

3,025


1.00%

U.S. Cards

​

$

14,665

​

​

$

(1,301)

​

$

(840)

​

$

(763)

​

$

(921)

​

​

$

(3,825)

​

$

-

​

​

$

10,840

​

$

(1,009)

​

$

-

​

​

$

9,831


7.56%

Retail banking and Global Wealth Management

​


1,643

​

​


(241)

​


(200)

​


(73)

​


55

​

​


(459)

​


(3)

​

​


1,181

​


(53)

​


(5)

​

​


1,123


Total PBWM

​

$

16,308

​

​

$

(1,542)

​

$

(1,040)

​

$

(836)

​

$

(866)

​

​

$

(4,284)

​

$

(3)

​

​

$

12,021

​

$

(1,062)

​

$

(5)

​

​

$

10,954


Legacy Franchises consumer

​


3,872

​

​


(458)

​


(543)

​


(266)

​


(117)

​

​


(1,384)

​


(469)

​

​


2,019

​


(151)

​


(454)

​

​


1,414


Total consumer ACLL

​

$

20,180

​

​

$

(2,000)

​

$

(1,583)

​

$

(1,102)

​

$

(983)

​

​

$

(5,668)

​

$

(472)

​

​

$

14,040

​

$

(1,213)

​

$

(459)

​

​

$

12,368


3.53%

Total ACLL

​

$

24,956

​

​

$

(3,227)

​

$

(2,446)

​

$

(1,149)

​

$

(1,176)

​

​

$

(7,998)

​

$

(503)

​

​

$

16,455

​

$

(612)

​

$

(450)

​

​

$

15,393


2.35%

Allowance for unfunded lending commitments (ACLUC)

​


2,655

​

​


(626)

​


44

​


(13)

​


(193)

​

​


(788)

​


4

​

​


1,871

​


474

​


(2)

​

​


2,343


Total ACLL and ACLUC

​


27,611

​

​


​


​


​


​

​


​


​

​


18,326

​


​


​

​


17,736


Other(1)

​


146

​

​


1

​


1

​


(13)

​


11

​

​


-

​


2

​

​


148

​


(6)

​


(6)

​

​


136


Total allowance for credit losses (ACL)

​

$

27,757

​

​

$

(3,852)

​

$

(2,401)

​

$

(1,175)

​

$

(1,358)

​

​

$

(8,786)

​

$

(497)

​

​

$

18,474

​

$

(144)

​

$

(458)

​

​

$

17,872


​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

(1)    Includes ACL on HTM securities and Other assets.

​

Reclassified to conform to the current period's presentation.

​

Page 14


ALLOWANCE FOR CREDIT LOSSES ON LOANS AND UNFUNDED LENDING COMMITMENTS

Page 1

(In millions of dollars)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

1Q22 Increase/

​

​

1Q

​

2Q

​

3Q

​

4Q

​

1Q

​

(Decrease) from

​


2021


2021


2021


2021


2022


4Q21


1Q21

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total Citigroup

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Allowance for credit losses on loans (ACLL) at beginning of period


$

24,956


$

21,638


$

19,238


$

17,715


$

16,455


(7%)

​

(34%)

Gross credit (losses) on loans

​

​

(2,208)

​

​

(1,844)

​

​

(1,389)

​

​

(1,279)

​

​

(1,240)


3%


44%

Gross recoveries on loans

​

​

460

​

​

524

​

​

428

​

​

413

​

​

368


(11%)


(20%)

Net credit (losses) / recoveries on loans (NCLs)

​

​

(1,748)

​

​

(1,320)

​

​

(961)

​

​

(866)

​

​

(872)


1%


(50%)

Replenishment of NCLs

​

​

1,748

​

​

1,320

​

​

961

​

​

866

​

​

872


1%


(50%)

Net reserve builds / (releases) for loans

​

​

(3,227)

​

​

(2,446)

​

​

(1,149)

​

​

(1,176)

​

​

(612)


48%


81%

Provision for credit losses on loans (PCLL)

​

​

(1,479)

​

​

(1,126)

​

​

(188)

​

​

(310)

​

​

260


NM


NM

Other, net(1)(2)(3)(4)(5)(6)

​

​

(91)

​

​

46

​

​

(374)

​

​

(84)

​

​

(450)


NM


NM

ACLL at end of period (a)


$

21,638


$

19,238


$

17,715


$

16,455


$

15,393


(6%)


(29%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Allowance for credit losses on unfunded lending commitments (ACLUC)(7) (a)


$

2,012


$

2,073


$

2,063


$

1,871


$

2,343


25%


16%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Provision (release) for credit losses on unfunded lending commitments


$

(626)


$

44


$

(13)


$

(193)


$

474


NM

​

NM

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total allowance for credit losses on loans, leases and unfunded lending commitments [sum of (a)]


$

23,650


$

21,311


$

19,778


$

18,326


$

17,736


(3%)

​

(25%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​


​

Total ACLL as a percentage of total loans(8)

​

​

3.29%

​

​

2.88%

​

​

2.69%

​

​

2.49%

​

​

2.35%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Consumer

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

ACLL at beginning of period


$

20,180


$

18,096


$

16,566


$

15,105


$

14,040


(7%)

​

(30%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

NCLs

​

​

(1,563)

​

​

(1,243)

​

​

(922)

​

​

(781)

​

​

(841)


8%


(46%)

Replenishment of NCLs

​

​

1,563

​

​

1,243

​

​

922

​

​

781

​

​

841


8%


(46%)

Net reserve builds / (releases) for loans

​

​

(2,000)

​

​

(1,583)

​

​

(1,102)

​

​

(983)

​

​

(1,213)


(23%)


39%

Provision for credit losses on loans (PCLL)

​

​

(437)

​

​

(340)

​

​

(180)

​

​

(202)

​

​

(372)


(84%)


15%

Other, net(1)(2)(3)(4)(5)(6)

​

​

(84)

​

​

53

​

​

(359)

​

​

(82)

​

​

(459)


NM


NM

ACLL at end of period (b)


$

18,096


$

16,566


$

15,105


$

14,040


$

12,368


(12%)


(32%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Consumer ACLUC(7) (b)


$

42


$

44


$

35


$

29


$

139


NM

​

NM

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Provision (release) for credit losses on unfunded lending commitments


$

(15)


$

1


$

(9)


$

(5)


$

109


NM


NM

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total allowance for credit losses on loans, leases and unfunded lending commitments [sum of (b)]


$

18,138


$

16,610


$

15,140


$

14,069


$

12,507


(11%)


(31%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Consumer ACLL as a percentage of total consumer loans

​

​

4.82%

​

​

4.35%

​

​

4.09%

​

​

3.73%

​

​

3.53%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Corporate

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

ACLL at beginning of period


$

4,776


$

3,542


$

2,672


$

2,610


$

2,415


(7%)

​

(49%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

NCLs

​

​

(185)

​

​

(77)

​

​

(39)

​

​

(85)

​

​

(31)


(64%)

​

(83%)

Replenishment of NCLs

​

​

185

​

​

77

​

​

39

​

​

85

​

​

31


(64%)

​

(83%)

Net reserve builds / (releases) for loans

​

​

(1,227)

​

​

(863)

​

​

(47)

​

​

(193)

​

​

601


NM


NM

Provision for credit losses on loans (PCLL)

​

​

(1,042)

​

​

(786)

​

​

(8)

​

​

(108)

​

​

632


NM


NM

Other, net(1)

​

​

(7)

​

​

(7)

​

​

(15)

​

​

(2)

​

​

9


NM


NM

ACLL at end of period (c)


$

3,542


$

2,672


$

2,610


$

2,415


$

3,025


25%


(15%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Corporate ACLUC(7) (c)


$

1,970


$

2,029


$

2,028


$

1,842


$

2,204


20%


12%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Provision (release) for credit losses on unfunded lending commitments


$

(611)


$

43


$

(4)


$

(188)


$

365


NM


NM

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total allowance for credit losses on loans, leases and unfunded lending commitments [sum of (c)]


$

5,512


$

4,701


$

4,638


$

4,257


$

5,229


23%


(5%)

Corporate ACLL as a percentage of total corporate loans(7)

​

​

1.25%

​

​

0.93%

​

​

0.91%

​

​

0.85%

​

​

1.00%

​

​

​

​


Footnotes to this table are on the following page (page 16).

​

Page 15


ALLOWANCE FOR CREDIT LOSSES ON LOANS AND UNFUNDED LENDING COMMITMENTS

Page 2

​

​

​

​

​

The following footnotes relate to the table on the preceding page (page 15):

​

(1)Includes all adjustments to the allowance for credit losses, such as changes in the allowance from acquisitions, dispositions, securitizations, foreign currency translation (FX translation), purchase accounting adjustments, etc.
(2)1Q21 consumer includes a decrease of approximately $84 million related to FX translation.
(3)2Q21 consumer includes an increase of approximately $53 million related to FX translation.
(4)3Q21 includes an approximate $280 million reclass related to the announced sale of Citi's consumer banking operations in Australia. The ACLL was reclassified to Other assets during 3Q21. 3Q21 consumer also includes a decrease of approximately $80 million related to FX translation.
(5)4Q21 includes an approximate $90 million reclass related to the announced sale of Citi's consumer banking operations in the Philippines. The ACLL was reclassified to Other assets during 4Q21. 4Q21 consumer also includes a decrease of approximately $6 million related to FX translation.
(6)1Q22 includes an approximate $350 million reclass related to the announced sales of Citi's consumer banking businesses in Thailand, India, Malaysia, Taiwan, Indonesia, Bahrain, and Vietnam. The ACLL was reclassified to Other assets during 1Q22. 1Q22 consumer also includes a decrease of approximately $100 million related to FX translation.
(7)Represents additional credit reserves recorded as other liabilities on the Consolidated Balance Sheet.
(8)March 31, 2021, June 30, 2021, September 30, 2021, December 31, 2021 and March 31, 2022 exclude $7.5 billion, $7.7 billion, $7.2 billion, $6.1 billion, and $5.7 billion respectively, of loans that are carried at fair value.

​

NM Not meaningful.

Reclassified to conform to the current period's presentation.

​

Page 16


NON-ACCRUAL ASSETS

(In millions of dollars)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

1Q22 Increase/

​

​

​

1Q

​

​

2Q

​

​

3Q

​

​

4Q

​

​

1Q

​

(Decrease) from

​


​

2021


​

2021


​

2021


​

2021


​

2022


4Q21


1Q21

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Corporate non-accrual loans by region(1)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

North America


$

1,211


$

895


$

923


$

510


$

462


(9%)


(62%)

EMEA

​

​

562

​

​

447

​

​

407

​

​

367

​

​

688


87%


22%

Latin America

​

​

739

​

​

767

​

​

679

​

​

568

​

​

631


11%


(15%)

Asia

​

​

204

​

​

141

​

​

110

​

​

108

​

​

85


(21%)


(58%)

Total


$

2,716


$

2,250


$

2,119


$

1,553


$

1,866


20%


(31%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Corporate non-accrual loans(1)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Banking


$

2,362


$

1,852


$

1,739


$

1,239


$

1,323


7%


(44%)

Services

​

​

84

​

​

81

​

​

74

​

​

70

​

​

297


NM


NM

Markets

​

​

20

​

​

12

​

​

13

​

​

12

​

​

13


8%


(35%)

Mexico SBMM

​

​

250

​

​

305

​

​

293

​

​

232

​

​

233


-


(7%)

Total


$

2,716


$

2,250


$

2,119


$

1,553


$

1,866


20%


(31%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Consumer non-accrual loans(1)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Personal Banking and Global Wealth Management


$

817


$

711


$

637


$

680


$

586


(14%)


(28%)

Asia Consumer(2)

​

​

292

​

​

303

​

​

259

​

​

209

​

​

38


(82%)


(87%)

Mexico Consumer

​

​

720

​

​

612

​

​

549

​

​

524

​

​

512


(2%)


(29%)

Legacy Holdings Assets - Consumer

​

​

545

​

​

506

​

​

425

​

​

413

​

​

381


(8%)


(30%)

Total


$

2,374


$

2,132


$

1,870


$

1,826


$

1,517


(17%)


(36%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Total non-accrual loans (NAL)


$

5,090


$

4,382


$

3,989


$

3,379


$

3,383


-


(34%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Other real estate owned (OREO)(3)


$

43


$

33


$

21


$

27


$

26


(4%)


(40%)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

NAL as a percentage of total loans

​

​

0.76%

​

​

0.65%

​

​

0.60%

​

​

0.51%

​

​

0.51%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

ACLL as a percentage of NAL

​

​

425%

​

​

439%

​

​

444%

​

​

487%

​

​

455%

​

​

​

​

​


(1)Corporate loans are placed on non-accrual status based upon a review by Citigroup's risk officers. Corporate non-accrual loans may still be current on interest payments. With limited exceptions, the following practices are applied for consumer loans: consumer loans, excluding credit cards and mortgages, are placed on non-accrual status at 90 days past due, and are charged off at 120 days past due; residential mortgage loans are placed on non-accrual status at 90 days past due and written down to net realizable value at 180 days past due. Consistent with industry conventions, Citigroup generally accrues interest on credit card loans until such loans are charged off, which typically occurs at 180 days contractual delinquency. As such, the non-accrual loan disclosures do not include credit card loans. The balances above represent non-accrual loans within Consumer Loans and Corporate Loans on the Consolidated Balance Sheet.
(2)Asia Consumer includes balances for certain EMEA countries for all periods presented.
(3)Represents the carrying value of all property acquired by foreclosure or other legal proceedings when Citigroup has taken possession of the collateral. Also includes former premises and property for use that is no longer contemplated.

​

NM Not meaningful.

Reclassified to conform to the current period's presentation.

​

Page 17


CITIGROUP

CET1 CAPITAL AND SUPPLEMENTARY LEVERAGE RATIOS, TANGIBLE COMMON EQUITY, BOOK VALUE

PER SHARE AND TANGIBLE BOOK VALUE PER SHARE

(In millions of dollars or shares, except per share amounts and ratios)

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​


March 31,


June 30,


September 30,


December 31,


March 31,

Common Equity Tier 1 Capital Ratio and Components(1)

​

2021

​

2021

​

2021(2)

​

2021(2)

​

2022(2)(3)

Citigroup common stockholders' equity(4)


$

182,402


$

184,289


$

183,005


$

183,108


$

178,845

Add: qualifying noncontrolling interests

​

​

132

​

​

138

​

​

136

​

​

143

​

​

126

Regulatory capital adjustments and deductions:

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Add:

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

CECL transition and provisionl(5)

​

​

4,359

​

​

3,774

​

​

3,389

​

​

3,028

​

​

2,271

Less:

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Accumulated net unrealized gains (losses) on cash flow hedges, net of tax

​

​

1,037

​

​

864

​

​

663

​

​

101

​

​

(1,440)

Cumulative unrealized net gain (loss) related to changes in fair value of financial liabilities attributable to own creditworthiness, net of tax

​

​

(1,172)

​

​

(1,258)

​

​

(1,317)

​

​

(896)

​

​

27

Intangible assets:

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Goodwill, net of related deferred tax liabilities (DTLs)(6)

​

​

20,854

​

​

20,999

​

​

20,689

​

​

20,619

​

​

20,120

Identifiable intangible assets other than mortgage servicing rights (MSRs), net of related DTLs

​

​

4,054

​

​

3,986

​

​

3,899

​

​

3,800

​

​

3,698

Defined benefit pension plan net assets; other

​

​

1,485

​

​

2,040

​

​

2,068

​

​

2,080

​

​

2,230

Deferred tax assets (DTAs) arising from net operating loss, foreign tax credit and general business credit carry-forwards

​

​

11,691

​

​

11,192

​

​

10,897

​

​

11,270

​

​

11,701

Excess over 10% / 15% limitations for other DTAs, certain common stock investments and MSRs(9)

​

​

-

​

​

-

​

​

-

​

​

-

​

​

1,157

Common Equity Tier 1 Capital (CET1)


$

148,944


$

150,378


$

149,631


$

149,305


$

143,749

Risk-Weighted Assets (RWA)(5)

​

$

1,287,619


$

1,277,234


$

1,284,316


$

1,219,175


$

1,264,581

Common Equity Tier 1 Capital ratio (CET1/RWA)

​

​

11.57%

​

​

11.77%

​

​

11.65%

​

​

12.25%

​

​

11.4%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Supplementary Leverage Ratio and Components

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Common Equity Tier 1 Capital (CET1)(5)


$

148,944

​

$

150,378

​

$

149,631

​

$

149,305

​

$

143,749

Additional Tier 1 Capital (AT1)(7)

​

​

21,540

​

​

19,258

​

​

19,271

​

​

20,263

​

​

20,264

Total Tier 1 Capital (T1C) (CET1 + AT1)


$

170,484

​

$

169,636

​

$

168,902

​

$

169,568

​

$

164,013

Total Leverage Exposure (TLE)(5)(8)

​

$

2,454,564

​

$

2,903,760

​

$

2,911,050

​

$

2,957,764

​

$

2,936,715

Supplementary Leverage ratio (T1C/TLE)

​

​

6.95%

​

​

5.84%

​

​

5.80%

​

​

5.73%

​

​

5.6%

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Tangible Common Equity, Book Value and Tangible Book Value Per Share

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Common stockholders' equity


$

182,269


$

184,164


$

182,880


$

182,977

​

$

178,714

Less:

​

​

​

​

​

​

​

​

​

​

​

​

​

​

​

Goodwill

​

​

21,905

​

​

22,060

​

​

21,573

​

​

21,299

​

​

19,865

Intangible assets (other than MSRs)

​

​

4,308

​

​

4,268

​

​

4,144

​

​

4,091

​

​

4,002

Goodwill and identifiable intangible assets (other than MSRs) related to assets HFS

​

​

-

​

​

-

​

​

257

​

​

510

​

​

1,384

Tangible common equity (TCE)


$

156,056


$

157,836


$

156,906


$

157,077


$

153,463

Common shares outstanding (CSO)

​

​

2,067.0

​

​

2,026.8

​

​

1,984.3

​

​

1,984.4

​

​

1,941.9

Book value per share (common equity/CSO)


$

88.18


$

90.86


$

92.16


$

92.21


$

92.03

Tangible book value per share (TCE/CSO)


$

75.50


$

77.87


$

79.07


$

79.16


$

79.03

​


(1)See footnote 6 on page 1.
(2)See footnote 5 on page 3.
(3)Preliminary.
(4)Excludes issuance costs related to outstanding preferred stock in accordance with Federal Reserve Board regulatory reporting requirements.
(5)See footnote 7 on page 1.
(6)Includes goodwill “embedded” in the valuation of significant common stock investments in unconsolidated financial institutions.
(7)Additional Tier 1 Capital primarily includes qualifying noncumulative perpetual preferred stock and qualifying trust preferred securities.
(8)Commencing with the second quarter of 2020 and continuing through the first quarter of 2021, Citigroup's TLE temporarily excluded U.S. Treasuries and deposits at Federal Reserve banks. For additional information, See "Capital Resources" in Citi's 2021 Annual Report on Form 10-K.
(9)Assets subject to 10%/15% limitations include MSRs, DTAs arising from temporary differences and significant common stock investments in unconsolidated financial institutions. As of March 31, 2022, the deduction related only to DTAs arising from temporary differences that exceeded the 10% limitation.

​

Reclassified to conform to the current period's presentation.

Page 18


​

​

​

​

​

​

​

​

Exhibit 99.3

​

​

​

​

Citigroup Inc. securities registered pursuant to Section 12(b) of the Securities Exchange Act of 1934:

​

​

​

​

Title of each class

Ticker
Symbol(s)

Title for iXBRL

Name of each
exchange on
which registered

​

​

Common Stock, par value $.01 per share

C

Common Stock, par value $.01 per share 

New York Stock Exchange

Depositary Shares, each representing 1/1,000th interest in a share of 7.125% Fixed/Floating Rate Noncumulative Preferred Stock, Series J

C Pr J

Dep Shs, represent 1/1,000th interest in a share of 7.125% Fix/Float Rate Noncum Pref Stk, Ser J

New York Stock Exchange

Depositary Shares, each representing 1/1,000th interest in a share of 6.875% Fixed/Floating Rate Noncumulative Preferred Stock, Series K

C Pr K

Dep Shs, represent 1/1,000th interest in a share of 6.875% Fix/Float Rate Noncum Pref Stk, Ser K 

New York Stock Exchange

7.625% Trust Preferred Securities of Citigroup Capital III (and registrant’s guaranty with respect thereto)

C/36Y

7.625% TRUPs of Cap III (and registrant’s guaranty) 

New York Stock Exchange

7.875% Fixed Rate / Floating Rate Trust Preferred Securities (TruPS®) of Citigroup Capital XIII (and registrant’s guaranty with respect thereto)

C N

7.875% FXD / FRN TruPS of Cap XIII (and registrant’s guaranty) 

New York Stock Exchange

Medium-Term Senior Notes, Series N, Callable Step-Up Coupon Notes Due March 31, 2036 of CGMHI (and registrant’s guaranty with respect thereto)

C/36A

MTN, Series N, Callable Step-Up Coupon Notes Due Mar 2036 of CGMHI (and registrant’s guaranty) 

New York Stock Exchange

Medium-Term Senior Notes, Series N, Callable Step-Up Coupon Notes Due February 26, 2036 of CGMHI (and registrant's guaranty with respect thereto)

C/36

MTN, Series N, Callable Step-Up Coupon Notes Due Feb 2036 of CGMHI (and registrant's guaranty)

New York Stock Exchange

Medium-Term Senior Notes, Series N, Callable Fixed Rate Notes Due December 18, 2035 of CGMHI (and registrant's guaranty with respect thereto)

C/35

MTN, Series N, Callable Fixed Rate Notes Due Dec 2035 of CGMHI (and registrant's guaranty)

New York Stock Exchange

Medium-Term Senior Notes, Series N, Callable Fixed Rate Notes Due April 26, 2028 of CGMHI (and registrant’s guaranty with respect thereto)

C/28

MTN, Series N, Callable Fixed Rate Notes Due Apr 2028 of CGMHI (and registrant’s guaranty)

New York Stock Exchange

Medium-Term Senior Notes, Series N, Floating Rate Notes Due September 17, 2026 of CGMHI (and registrant’s guaranty with respect thereto)

C/26

MTN, Series N, Floating Rate Notes Due Sept 2026 of CGMHI (and registrat’s guaranty)

New York Stock Exchange

​

​

Medium-Term Senior Notes, Series N, Floating Rate Notes Due September 15, 2028 of CGMHI (and registrant’s guaranty with respect thereto)

C/28A

MTN, Series N, Floating Rate Notes Due Sept 2028 of CGMHI (and registrat’s guaranty)

New York Stock Exchange

Medium-Term Senior Notes, Series N, Floating Rate Notes Due October 6, 2028 of CGMHI (and registrant’s guaranty with respect thereto)

C/28B

MTN, Series N, Floating Rate Notes Due Oct 2028 of CGMHI (and registrat’s guaranty)

New York Stock Exchange

Medium-Term Senior Notes, Series N, Floating Rate Notes Due March 21, 2029 of CGMHI (and registrant’s guaranty with respect thereto)

C/29A

MTN, Series N, Floating Rate Notes Due Mar 2029 of CGMHI (and registrant’s guaranty)

New York Stock Exchange

​