Form 8-K
CITIZENS FINANCIAL GROUP INC/RI false 0000759944 0000759944 2020-04-17 2020-04-17 0000759944 us-gaap:CommonStockMember 2020-04-17 2020-04-17 0000759944 us-gaap:SeriesDPreferredStockMember 2020-04-17 2020-04-17 0000759944 us-gaap:SeriesEPreferredStockMember 2020-04-17 2020-04-17
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d)
OF THE SECURITIES EXCHANGE ACT OF 1934
Date of Report (Date of earliest event reported): April 17, 2020
CITIZENS FINANCIAL GROUP, INC.
(Exact name of registrant as specified in its charter)
|
|
|
|
|
| Delaware |
|
001-36636 |
|
05-0412693 |
| (State or other jurisdiction of incorporation ) |
|
(Commission File No.) |
|
(IRS Employer Identification No.) |
| |
|
|
| One Citizens Plaza Providence, RI |
|
02903 |
| (Address of principal executive offices) |
|
(Zip code) |
Registrant’s telephone number, including area code: (401) 456-7000
Not Applicable
(Former name or former address, if changed since last report.)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| ☐ |
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) |
| ☐ |
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) |
| ☐ |
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) |
| ☐ |
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) |
Securities registered pursuant to Section 12(b) of the Act:
|
|
|
|
|
| Title of each class |
|
Trading symbol(s) |
|
Name of each exchange on which registered |
| Common stock, $0.01 par value per share |
|
CFG |
|
New York Stock Exchange |
| Depositary Shares, each representing a 1/40th interest in a share of 6.350% Fixed-to-Floating Rate Non- Cumulative Perpetual Preferred Stock, Series D |
|
CFG PrD |
|
New York Stock Exchange |
| Depositary Shares, each representing a 1/40th interest in a share of 5.000% Fixed-Rate Non-Cumulative Perpetual Preferred Stock, Series E |
|
CFG PrE |
|
New York Stock Exchange |
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 under the Securities Act (17 CFR 230.405) or Rule 12b-2 under the Exchange Act (17 CFR 240.12b-2).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition.
On April 17, 2020, Citizens Financial Group, Inc. (the “Company”) issued a press release announcing its first quarter 2020 earnings and posted on its website the press release and a financial supplement. Copies of the press release and financial supplement are being furnished as Exhibits 99.1 and 99.3, respectively.
Item 7.01 Regulation FD Disclosure.
For the benefit of investors, the Company has posted on its website an investor presentation in connection with its earnings conference call. A copy of the investor presentation is being furnished as Exhibit 99.2.
The information in this Form 8-K and Exhibits attached hereto are being furnished pursuant to Items 2.02 and 7.01, respectively, and shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, nor shall this information be deemed incorporated by reference into any filings under the Securities Act of 1933, as amended.
Item 9.01 Financial Statements and Exhibits.
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
|
|
|
| CITIZENS FINANCIAL GROUP, Inc. |
| |
|
|
| |
|
|
| By: |
|
/s/ John F. Woods |
| |
|
John F. Woods |
| |
|
Vice Chairman and Chief Financial Officer |
Date: April 17, 2020
Exhibit 99.1
Citizens Financial Group, Inc. Reports First Quarter Net Income of $34 million
and EPS of $0.03 with Underlying Net Income of $59 million and EPS of $0.09*
CECL-related reserve build of $463 million, or $0.85 per share, tied to
COVID-19 impacts
CET1 ratio remains strong at 9.4%
Record noninterest income up 16% year over year, paced by record results in Mortgage and Wealth
Tangible book value per share of $32 up 8% year over year
PROVIDENCE, RI (April 17, 2020) Citizens Financial Group, Inc. (NYSE: CFG or “Citizens”) today reported first quarter net income
of $34 million, compared with $439 million in first quarter 2019, with earnings per share of $0.03, compared with $0.92 per share in first quarter 2019. First quarter 2020 results reflect a net $25 million, or $(0.06) per share, after-tax reduction from notable items compared with a net $4 million, or $(0.01) per share, in first quarter 2019 and a net $4 million, or $(0.01) per share, in fourth quarter 2019. First quarter 2020
Return on Average Tangible Common Equity* (“ROTCE”) of 0.4% compares with 13.0% in first quarter 2019.
On an Underlying basis,
which excludes notable items, first quarter 2020 net income available to common stockholders of $37 million compares with $428 million in first quarter 2019 and $431 million in fourth quarter 2019. Underlying EPS of $0.09 per share
compares with $0.93 in first quarter 2019 and $0.99 in fourth quarter 2019. Underlying first quarter 2020 ROTCE of 1.1% compares with 13.1% in first quarter 2019 and 12.5% in fourth quarter 2019. Tangible book value per common share of $31.97
increased 8% from first quarter 2019 and remained relatively stable with fourth quarter 2019.
In first quarter 2020, Citizens adopted the
Current Expected Credit Loss (“CECL”) accounting standard and recorded first quarter 2020 provision for credit losses of $600 million pre-tax, or $1.10 per share
after-tax, including a reserve build under CECL of $463 million pre-tax, or $0.85 per share after-tax, tied to COVID-19 impacts. On an Underlying basis and before the $463 million COVID-19 CECL-related reserve build, first quarter 2020 net income available to common stockholders
reflecting net charge-offs totaled $402 million, EPS was $0.94 per share, and ROTCE was 12.0%.
Citizens saw spot loan growth of
$8.4 billion, or 7% in first quarter 2020 compared with fourth quarter 2019, including $7.2 billion of commercial client line draws under revolving credit facilities. We remain strongly capitalized and maintain ample liquidity to assist
companies in navigating these challenging times. At March 31, 2020, CET1 capital was 9.4%, spot LDR was 95.5%, and LCR was fully compliant. Citizens has worked with borrowers on forbearance, and as of April 15, 2020 had seventy thousand
consumers in forbearance and was working proactively with commercial customers seeking flexibility on loan terms and conditions. In addition, Citizens has been active in securing financing through the U.S. Small Business Administration Payment
Protection Program (“PPP”) for its small business customers.
*References in this release to “Underlying”
results exclude notable items and are Non-GAAP Financial Measures. Where there is a reference to “Underlying” results in a paragraph, all measures that follow these references are on the same basis. Additional information regarding the
impact of notable items and Acquisitions on our results is described in this release. Please see the end of this release for important information on our use of Key Performance Metrics and Non-GAAP Financial Measures, as applicable, and their
reconciliation to GAAP financial measures. References in this release to balance sheet items are on an average basis and loans exclude loans held for sale (“LHFS”) unless otherwise noted. References to net interest margin are on a fully
taxable equivalent (“FTE”) basis and all references to earnings per share represent fully diluted per common share. References to consolidated and/or commercial loans, loan growth, nonaccrual loans and allowance for loan losses
include leases. The “Company” refers to Citizens. Current reporting-period regulatory capital ratios are preliminary. Select totals may not sum due to rounding.
Citizens Financial Group, Inc.
“We are dealing with unprecedented times, but I am pleased to say that Citizens remains
financially strong, and focused on serving the needs of our customers, colleagues and communities,” said Chairman and Chief Executive Officer Bruce Van Saun. “Our first quarter results were quite strong before the impact of the CECL
provision build, which was impacted by COVID-19’s effect on the economy. I would like to personally thank our colleagues for their outstanding efforts through this challenging period, and I offer my
heartfelt empathy for the struggles that many in our community are facing.”
Citizens also announced today that its board of directors
declared a second quarter 2020 common stock dividend of $0.39 per share. The dividend is payable on May 13, 2020 to shareholders of record at the close of business on April 29, 2020. The quarterly dividend is 22% higher than the year-ago quarter. In order to ensure capital remains strong to meet further loan demand, the Company will cease stock repurchases through December 31, 2020.
CECL accounting change and regulatory capital impact
As previously announced, the Company’s Day-1 impact of CECL adoption added $451 million to the
Allowance for Credit Losses (“ACL”) resulting in an ACL to Loan and Lease Coverage Ratio (“ACLR”) of 1.47%. Subsequently, in first quarter 2020, the Company added $463 million to the ACL. These additions resulted in a
March 31, 2020 total ACL of $2.2 billion and an ACLR of 1.73%. For regulatory capital purposes, in connection with the Federal Reserve Board’s final interim rule as of April 3, 2020, 100% of the $451 million Day-1 impact will be deferred over a two-year period ending January 1, 2022, at which time it will be phased in on a pro-rata
basis over a three-year period ending January 1, 2025. Additionally, 25% of the $463 million first quarter 2020 reserve build, or $116 million, will be phased in over the same time frame.
First quarter 2020 vs. first quarter 2019
Key highlights
| |
• |
|
First quarter highlights include revenue growth of $69 million, or 4%, reflecting stable net interest income
and a 16% increase in noninterest income driven by record results in mortgage banking, partially offset by COVID-19 impacts that resulted in lower service charges and fees, card fees, capital markets fees and
foreign exchange and interest rate products revenue. |
| |
• |
|
First quarter 2020 results reflect a net $25 million after-tax
reduction, or $(0.06) per share, from notable items compared with a net $4 million after-tax reduction, or $(0.01) per share, in first quarter 2019. |
| |
• |
|
Results reflect an efficiency ratio of 61.1% and ROTCE of 0.4%; Underlying efficiency ratio of 59.1% and ROTCE of
1.1% reflect the challenging environment presented by COVID-19, in particular the CECL provision impact. |
| |
• |
|
Provision for credit losses of $600 million includes a $463 million reserve build tied to CECL adoption
and the impact of COVID-19 on macroeconomic scenario modeling. |
2
Citizens Financial Group, Inc.
| |
• |
|
Period-end
loan-to-deposit ratio of 95.5% compares with 94.9%. |
| |
• |
|
Tangible book value per share of $31.97 increased 8%. Fully diluted average common shares outstanding decreased
33.1 million shares, or 7%. |
Results
| |
• |
|
Total revenue increased $69 million, or 4%, reflecting strength in noninterest income and stable net interest
income. |
| |
• |
|
Net interest income was flat, reflecting 4% growth in interest-earning assets, offset by the impact of the lower
rate and challenging yield-curve environment. |
| |
• |
|
Net interest margin of 3.10% decreased 15 basis points, reflecting the impact of lower interest rates, which was
partially offset by improved deposit mix as well as the continued mix shift towards better-returning assets. Interest-bearing deposit costs decreased 33 basis points, reflecting strong pricing discipline. |
| |
• |
|
Record noninterest income of $497 million increased $69 million, or 16%, driven by record results in
mortgage banking given increased origination volumes and higher mortgage servicing rights hedging gains, as well as record trust and investment services fees. Capital markets fees and foreign exchange and interest rate products reflect good
underlying business performance, partially offset by COVID-19 impacts. Other income declined from first quarter 2019 levels that included gains related to asset dispositions and efficiency initiatives.
|
| |
• |
|
Noninterest expense increased 8%. Underlying noninterest expense of $979 million increased 5%, reflecting
higher salaries and employee benefits and revenue-driven compensation, as well as an increase in outside services and equipment and software expense, partially offset by lower occupancy. |
| |
• |
|
Provision for credit losses of $600 million includes $463 million associated with COVID-19 and compares with $85 million in first quarter 2019. Higher charge-offs reflect several uncorrelated losses in commercial and the impact of seasoning in retail growth portfolios. |
Balance Sheet
| |
• |
|
Period-end loan growth of $9.9 billion, or 8%, reflects 14% growth in
commercial, which includes the $7.2 billion impact of higher line of credit utilization tied to COVID-19 disruption, and 3% growth in retail. |
| |
• |
|
Period-end deposit growth of $9.6 billion, or 8%, kept pace with loan
growth as most commercial customers left their funds from line draws on deposit with us. |
| |
• |
|
Average interest-earning assets increased $5.4 billion, or 4%, driven by 3% loan growth, which includes the
$1.0 billion average impact of higher commercial line of credit utilization tied to COVID-19 disruption. |
| |
• |
|
Average deposits increased $6.2 billion, or 5%, reflecting growth in money market accounts, savings, checking
with interest and demand deposits, partially offset by a decrease in term deposits. |
| |
• |
|
The average loan-to-deposits ratio
improved to 95.6% from 97.7%; period-end loan-to-deposit ratio of 95.5% compares with 94.9% in first quarter 2019.
|
| |
• |
|
Nonaccrual loans to loans ratio of 0.61% compares with 0.63% as of March 31, 2019. |
3
Citizens Financial Group, Inc.
| |
• |
|
Allowance coverage of nonaccrual loans of 283% compares with 179% as of March 31, 2019, reflecting the first
quarter 2020 implementation of CECL and the significant provision associated with COVID-19. |
| |
• |
|
Capital remains strong, with a common equity tier 1 (“CET1”) risk-based capital ratio of 9.4% which
incorporates an approximately 25 basis point impact tied to higher commercial line of credit utilization. |
| |
• |
|
Repurchased 7.5 million shares of common stock at a weighted average price of $35.77 in the quarter.
Including common dividends, returned $438 million to shareholders. |
Year-over-year update on plan execution
Consumer Banking
| |
• |
|
Continued balance sheet momentum, with 3% loan growth, or 5% before the impact of
on-balance sheet loan sale activity, including continued growth in more attractive risk-adjusted return categories. Funding kept pace, with 3% deposit growth, including 8% growth in demand deposits.
|
| |
• |
|
Record fee income results in mortgage banking and wealth. |
| |
• |
|
Citizens Access®, our nationwide digital platform, ended
the quarter with deposits of $6.1 billion. |
Commercial Banking
| |
• |
|
Strong balance sheet performance with 4% loan growth, driven by geographic, product and client-focused expansion
strategies, along with 12% deposit growth. |
| |
• |
|
Continue to benefit from investments in broadening and enhancing our capabilities and the diversification of our fee-based businesses, as we continue to gain market share in key product areas. |
Efficiency and strategic initiatives
| |
• |
|
The transformational TOP 6 program is on track, with a target of approximately
$300-$325 million in pre-tax run-rate benefit by year-end 2021. Some Q2 saves will
be deferred until later in the year, to be offset by other expense actions. |
| |
• |
|
Citizens is continuing to fund its major strategic initiatives, and is considering new opportunities arising from
the current environment in an effort to drive higher customer and revenue growth coming out of the crisis. |
First
quarter 2020 vs. fourth quarter 2019
Key highlights
| |
• |
|
First quarter highlights include revenue of $1.7 billion, up 1%, reflecting 1% growth in both net interest
income and noninterest income. |
| |
• |
|
First quarter 2020 results reflect a net $25 million after-tax
reduction, or $(0.06) per share, from notable items compared with a net $4 million after-tax reduction, or ($0.01) per share, in fourth quarter 2019. |
| |
• |
|
Results reflect an efficiency ratio of 61.1%; Underlying efficiency ratio of 59.1% compares with 58.0% in fourth
quarter 2019, reflecting broadly stable revenue and a seasonal increase in expenses. |
4
Citizens Financial Group, Inc.
| |
• |
|
Provision for credit losses of $600 million includes a $463 million reserve build tied to the impact of
the COVID-19 macroeconomic scenario given CECL adoption. |
| |
• |
|
ROTCE of 0.4% reflects higher provisions under CECL associated with
COVID-19 impacts. Underlying ROTCE of 1.1% compares with 12.5% in fourth quarter 2019. |
| |
• |
|
Tangible book value per common share of $31.97 remained relatively stable. Fully diluted average common shares
outstanding decreased 7.1 million, or 2%. |
Results
| |
• |
|
Total revenue of $1.7 billion increased 1%, reflecting growth in net interest income and record noninterest
income. |
| |
• |
|
Net interest income of $1.2 billion increased 1%, as the benefit of interest-earning asset growth and
improved mix was partially offset by the impact of lower interest rates and day count. |
| |
• |
|
Net interest margin of 3.10% increased 4 basis points, as improved loan spreads and mix, given elevated LIBOR
rates, as well as disciplined deposit pricing and mix more than offset the negative impact of lower interest rates. Interest-bearing deposit costs decreased 15 basis points. |
| |
• |
|
Record noninterest income of $497 million increased 1% reflecting record mortgage banking fees and trust and
investment services fees. Capital markets fees and foreign exchange and interest rate products reflect solid underlying performance, partially offset by a $21 million mark to market loss on loan/bond trading assets and a $15 million
decrease in CVA adjustment. |
| |
• |
|
Noninterest expense of $1.0 billion increased $26 million, or 3%, including the impact of notable items.
On an Underlying basis, noninterest expense of $979 million increased $30 million, or 3%, largely reflecting the impact of seasonally higher payroll taxes associated with incentive compensation, along with higher revenue-based compensation
tied to mortgage originations. Results also reflect increased equipment and software expense, partially offset by lower other operating expense and outside services. |
| |
• |
|
Provision for credit losses of $600 million reflects a $463 million reserve build associated with COVID-19. |
Balance sheet
| |
• |
|
Average interest-earning assets increased $2.0 billion, or 1%, driven by 1.8% loan growth, and included the
$1.0 billion impact of higher commercial line of credit utilization. Average loan growth also reflects a $922 million average impact tied to the sale of $1.6 billion of on-balance sheet
residential mortgage loans in connection with balance sheet optimization strategies. Average loans increased 2.6% before the impact of this sales activity. |
| |
• |
|
Period-end loan growth of $8.4 billion, or 7%, was driven by a 15%
increase in commercial, which included a $7.2 billion impact from higher line of credit utilization. |
| |
• |
|
Average deposits were relatively stable, as growth in checking with interest, money market accounts and savings
was largely offset by a decrease in term and demand deposits. |
| |
• |
|
Period-end deposit growth of $8.2 billion, or 7%, kept pace with loan
growth. |
| |
• |
|
Average loan-to-deposit ratio of
95.6% compares with 94.6% in fourth quarter 2019; period-end loan-to-deposit ratio of 95.5% compares to 95.0% in fourth quarter
2019. |
| |
• |
|
Nonaccrual loans to loan ratio of 0.61% compares to 0.59% as of December 31, 2019. |
| |
• |
|
Allowance coverage of nonaccrual loans of 283% reflects the first quarter 2020 implementation of CECL and the
first quarter provision impact associated with COVID-19, and compares with 184% as of December 31, 2019. |
5
Citizens Financial Group, Inc.
Earnings highlights:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
Quarterly Trends |
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 change from |
|
| ($s in millions, except per share data) |
|
|
|
1Q20 |
|
|
4Q19 |
|
|
1Q19 |
|
|
|
|
4Q19 |
|
|
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
| Earnings |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$/bps |
|
|
% |
|
|
|
|
$/bps |
|
|
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net interest income |
|
|
|
$ |
1,160 |
|
|
$ |
1,143 |
|
|
$ |
1,160 |
|
|
|
|
$ |
17 |
|
|
|
1 |
% |
|
|
|
$ |
— |
|
|
|
— |
% |
| Noninterest income |
|
|
|
|
497 |
|
|
|
494 |
|
|
|
428 |
|
|
|
|
|
3 |
|
|
|
1 |
|
|
|
|
|
69 |
|
|
|
16 |
|
| Total revenue |
|
|
|
|
1,657 |
|
|
|
1,637 |
|
|
|
1,588 |
|
|
|
|
|
20 |
|
|
|
1 |
|
|
|
|
|
69 |
|
|
|
4 |
|
| Noninterest expense |
|
|
|
|
1,012 |
|
|
|
986 |
|
|
|
937 |
|
|
|
|
|
26 |
|
|
|
3 |
|
|
|
|
|
75 |
|
|
|
8 |
|
| Pre-provision profit |
|
|
|
|
645 |
|
|
|
651 |
|
|
|
651 |
|
|
|
|
|
(6 |
) |
|
|
(1 |
) |
|
|
|
|
(6 |
) |
|
|
(1 |
) |
| Provision for credit losses |
|
|
|
|
600 |
|
|
|
110 |
|
|
|
85 |
|
|
|
|
|
490 |
|
|
|
|
NM |
|
|
|
|
515 |
|
|
|
|
NM |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income |
|
|
|
|
34 |
|
|
|
450 |
|
|
|
439 |
|
|
|
|
|
(416 |
) |
|
|
(92 |
) |
|
|
|
|
(405 |
) |
|
|
(92 |
) |
| Preferred dividends |
|
|
|
|
22 |
|
|
|
23 |
|
|
|
15 |
|
|
|
|
|
(1 |
) |
|
|
(4 |
) |
|
|
|
|
7 |
|
|
|
47 |
|
| Net income available to common stockholders |
|
|
|
$ |
12 |
|
|
$ |
427 |
|
|
$ |
424 |
|
|
|
|
$ |
(415 |
) |
|
|
(97 |
) % |
|
|
|
$ |
(412 |
) |
|
|
(97 |
) % |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| After-tax notable Items |
|
|
|
|
25 |
|
|
|
4 |
|
|
|
4 |
|
|
|
|
|
21 |
|
|
|
|
NM |
|
|
|
|
21 |
|
|
|
|
NM |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Underlying net income |
|
|
|
$ |
59 |
|
|
$ |
454 |
|
|
$ |
443 |
|
|
|
|
$ |
(395 |
) |
|
|
(87 |
) % |
|
|
|
$ |
(384 |
) |
|
|
(87 |
) % |
| Underlying net income available to common stockholders |
|
|
|
$ |
37 |
|
|
$ |
431 |
|
|
$ |
428 |
|
|
|
|
$ |
(394 |
) |
|
|
(91 |
) % |
|
|
|
$ |
(391 |
) |
|
|
(91 |
) % |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average common shares outstanding |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Basic (in millions) |
|
|
|
|
427.7 |
|
|
|
434.7 |
|
|
|
460.7 |
|
|
|
|
|
(7.0 |
) |
|
|
(2 |
) |
|
|
|
|
(33.0 |
) |
|
|
(7 |
) |
| Diluted (in millions) |
|
|
|
|
429.4 |
|
|
|
436.5 |
|
|
|
462.5 |
|
|
|
|
|
(7.1 |
) |
|
|
(2 |
) |
|
|
|
|
(33.1 |
) |
|
|
(7 |
) |
| Diluted earnings per share |
|
|
|
$ |
0.03 |
|
|
$ |
0.98 |
|
|
$ |
0.92 |
|
|
|
|
$ |
(0.95 |
) |
|
|
(97 |
) % |
|
|
|
$ |
(0.89 |
) |
|
|
(97 |
) % |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Underlying diluted earnings per share |
|
|
|
$ |
0.09 |
|
|
$ |
0.99 |
|
|
$ |
0.93 |
|
|
|
|
$ |
(0.90 |
) |
|
|
(91 |
) % |
|
|
|
$ |
(0.84 |
) |
|
|
(90 |
) % |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Key performance metrics* |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net interest margin |
|
|
|
|
3.09 |
% |
|
|
3.04 |
% |
|
|
3.23 |
% |
|
|
|
|
5 |
bps |
|
|
|
|
|
|
|
|
(14 |
) bps |
|
|
|
|
| Net interest margin, FTE |
|
|
|
|
3.10 |
|
|
|
3.06 |
|
|
|
3.25 |
|
|
|
|
|
4 |
|
|
|
|
|
|
|
|
|
(15 |
) |
|
|
|
|
| Effective income tax rate |
|
|
|
|
24.1 |
|
|
|
16.8 |
|
|
|
22.4 |
|
|
|
|
|
737 |
|
|
|
|
|
|
|
|
|
171 |
|
|
|
|
|
| Efficiency ratio |
|
|
|
|
61 |
|
|
|
60 |
|
|
|
59 |
|
|
|
|
|
82 |
|
|
|
|
|
|
|
|
|
210 |
|
|
|
|
|
| Underlying efficiency ratio |
|
|
|
|
59 |
|
|
|
58 |
|
|
|
59 |
|
|
|
|
|
106 |
|
|
|
|
|
|
|
|
|
41 |
|
|
|
|
|
| Return on average common equity |
|
|
|
|
0.2 |
|
|
|
8.3 |
|
|
|
8.6 |
|
|
|
|
|
(806 |
) |
|
|
|
|
|
|
|
|
(838 |
) |
|
|
|
|
| Return on average tangible common equity |
|
|
|
|
0.4 |
|
|
|
12.4 |
|
|
|
13.0 |
|
|
|
|
|
(1,203 |
) |
|
|
|
|
|
|
|
|
(1,264 |
) |
|
|
|
|
| Underlying return on average tangible common equity |
|
|
|
|
1.1 |
|
|
|
12.5 |
|
|
|
13.1 |
|
|
|
|
|
(1,139 |
) |
|
|
|
|
|
|
|
|
(1,202 |
) |
|
|
|
|
| Return on average total assets |
|
|
|
|
0.08 |
|
|
|
1.08 |
|
|
|
1.11 |
|
|
|
|
|
(100 |
) |
|
|
|
|
|
|
|
|
(103 |
) |
|
|
|
|
| Underlying return on average total tangible assets |
|
|
|
|
0.15 |
% |
|
|
1.14 |
% |
|
|
1.17 |
% |
|
|
|
|
(99 |
) bps |
|
|
|
|
|
|
|
|
(102 |
) bps |
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Capital adequacy(1,2) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Common equity tier 1 capital ratio |
|
|
|
|
9.4 |
% |
|
|
10.0 |
% |
|
|
10.5 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total capital ratio |
|
|
|
|
12.5 |
|
|
|
13.0 |
|
|
|
13.4 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Tier 1 leverage ratio |
|
|
|
|
9.6 |
|
|
|
10.0 |
|
|
|
10.0 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Allowance for credit losses to loans and leases |
|
|
|
|
1.73 |
|
|
|
1.09 |
|
|
|
1.13 |
|
|
|
|
|
64 |
bps |
|
|
|
|
|
|
|
|
60 |
bps |
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Asset quality(2) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Nonaccrual loans and leases to loans and leases |
|
|
|
|
0.61 |
% |
|
|
0.59 |
% |
|
|
0.63 |
% |
|
|
|
|
2 |
bps |
|
|
|
|
|
|
|
|
(2 |
) bps |
|
|
|
|
| Allowance for credit losses to nonaccrual loans and leases |
|
|
|
|
283 |
|
|
|
184 |
|
|
|
179 |
|
|
|
|
|
NM |
|
|
|
|
|
|
|
|
|
NM |
|
|
|
|
|
| Net charge-offs as a % of average loans and leases |
|
|
|
|
0.46 |
% |
|
|
0.41 |
% |
|
|
0.31 |
% |
|
|
|
|
5 |
bps |
|
|
|
|
|
|
|
|
15 |
bps |
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
1) Current reporting-period regulatory capital ratios are preliminary.
2) Capital adequacy and asset-quality ratios calculated on a
period-end basis, except net charge-offs.
6
Citizens Financial Group, Inc.
Notable items:
First quarter 2020 and fourth quarter 2019 results reflect notable items primarily related to TOP 6 transformational and revenue and efficiency
initiatives. First quarter 2020 and 2019 results also reflect notable items related to integration costs primarily tied to the August 1, 2018 Franklin American Mortgage Company (“FAMC”) acquisition. Fourth quarter 2019 results also
include a tax benefit largely tied to legacy tax matters. These notable items have been excluded from reported results to better reflect Underlying operating results.
Total estimated after-tax FAMC integration costs are expected to be in the
$40-$45 million range, with the integration substantially complete by second quarter 2020. Cumulative after-tax integration costs related to FAMC totaled
$32 million through the end of first quarter 2020.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Notable items-integration costs |
|
|
|
1Q20 |
|
|
|
|
4Q19 |
|
|
|
|
1Q19 |
|
|
|
|
Cumulative
after-tax
integration costs |
|
| ($s in millions, except per share data) |
|
|
|
Pre-tax |
|
|
After-tax |
|
|
EPS |
|
|
|
|
Pre-tax |
|
|
After-tax |
|
|
EPS |
|
|
|
|
Pre-tax |
|
|
After-tax |
|
|
EPS |
|
|
|
|
FAMC |
|
|
Other |
|
|
Total |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest income |
|
|
|
$ |
— |
|
|
$ |
— |
|
|
$ |
— |
|
|
|
|
$ |
— |
|
|
$ |
— |
|
|
$ |
— |
|
|
|
|
$ |
— |
|
|
$ |
— |
|
|
$ |
— |
|
|
|
|
$ |
(3 |
) |
|
$ |
— |
|
|
$ |
(3 |
) |
| Salaries &
benefits |
|
|
|
$ |
— |
|
|
$ |
— |
|
|
$ |
— |
|
|
|
|
$ |
— |
|
|
$ |
— |
|
|
$ |
— |
|
|
|
|
$ |
(1 |
) |
|
$ |
(1 |
) |
|
$ |
— |
|
|
|
|
$ |
(10 |
) |
|
$ |
— |
|
|
$ |
(10 |
) |
| Equipment &
software |
|
|
|
|
(1 |
) |
|
|
(1 |
) |
|
|
— |
|
|
|
|
|
(1 |
) |
|
|
(1 |
) |
|
|
— |
|
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
(2 |
) |
|
|
— |
|
|
|
(2 |
) |
| Outside services |
|
|
|
|
(3 |
) |
|
|
(2 |
) |
|
|
(0.01 |
) |
|
|
|
|
(1 |
) |
|
|
(1 |
) |
|
|
— |
|
|
|
|
|
(4 |
) |
|
|
(3 |
) |
|
|
(0.01 |
) |
|
|
|
|
(13 |
) |
|
|
(4 |
) |
|
|
(17 |
) |
| Occupancy |
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
(1 |
) |
|
|
— |
|
|
|
(1 |
) |
| Other expense |
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
(3 |
) |
|
|
— |
|
|
|
(3 |
) |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest expense |
|
|
|
$ |
(4 |
) |
|
$ |
(3 |
) |
|
$ |
(0.01 |
) |
|
|
|
$ |
(2 |
) |
|
$ |
(2 |
) |
|
$ |
— |
|
|
|
|
$ |
(5 |
) |
|
$ |
(4 |
) |
|
$ |
(0.01 |
) |
|
|
|
$ |
(29 |
) |
|
|
(4 |
) |
|
$ |
(33 |
) |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total Integration costs |
|
|
|
$ |
(4 |
) |
|
$ |
(3 |
) |
|
$ |
(0.01 |
) |
|
|
|
$ |
(2 |
) |
|
$ |
(2 |
) |
|
$ |
— |
|
|
|
|
$ |
(5 |
) |
|
$ |
(4 |
) |
|
$ |
(0.01 |
) |
|
|
|
$ |
(32 |
) |
|
$ |
(4 |
) |
|
$ |
(36 |
) |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Other notable items-primarily tax and TOP |
|
|
|
1Q20 |
|
|
|
|
4Q19 |
|
|
|
|
1Q19 |
|
|
|
|
|
|
| ($s in millions, except per share data) |
|
|
|
Pre-tax |
|
|
After-tax |
|
|
EPS |
|
|
|
|
Pre-tax |
|
|
After-tax |
|
|
EPS |
|
|
|
|
Pre-tax |
|
|
After-tax |
|
|
EPS |
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Tax notable items |
|
|
|
$ |
— |
|
|
$ |
— |
|
|
$ |
— |
|
|
|
|
$ |
— |
|
|
$ |
24 |
|
|
$ |
0.06 |
|
|
|
|
$ |
— |
|
|
$ |
— |
|
|
$ |
— |
|
|
|
| Other notable
items—TOP & other actions |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Salaries &
benefits |
|
|
|
|
(10 |
) |
|
|
(7 |
) |
|
|
(0.02 |
) |
|
|
|
|
(6 |
) |
|
|
(5 |
) |
|
|
(0.01 |
) |
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
| Equipment &
software |
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
(2 |
) |
|
|
(1 |
) |
|
|
— |
|
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
| Outside services |
|
|
|
|
(15 |
) |
|
|
(12 |
) |
|
|
(0.02 |
) |
|
|
|
|
(19 |
) |
|
|
(14 |
) |
|
|
(0.03 |
) |
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
| Occupancy |
|
|
|
|
(4 |
) |
|
|
(3 |
) |
|
|
(0.01 |
) |
|
|
|
|
(8 |
) |
|
|
(6 |
) |
|
|
(0.01 |
) |
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest expense |
|
|
|
$ |
(29 |
) |
|
$ |
(22 |
) |
|
$ |
(0.05 |
) |
|
|
|
$ |
(35 |
) |
|
$ |
(26 |
) |
|
$ |
(0.05 |
) |
|
|
|
$ |
— |
|
|
$ |
— |
|
|
$ |
— |
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total other notable items |
|
|
|
$ |
(29 |
) |
|
$ |
(22 |
) |
|
$ |
(0.05 |
) |
|
|
|
$ |
(35 |
) |
|
$ |
(2 |
) |
|
$ |
— |
|
|
|
|
$ |
— |
|
|
$ |
— |
|
|
$ |
— |
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total notable items |
|
|
|
$ |
(33 |
) |
|
$ |
(25 |
) |
|
$ |
(0.06 |
) |
|
|
|
$ |
(37 |
) |
|
$ |
(4 |
) |
|
$ |
(0.01 |
) |
|
|
|
$ |
(5 |
) |
|
$ |
(4 |
) |
|
$ |
(0.01 |
) |
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
7
Citizens Financial Group, Inc.
The following table provides information on Underlying results before the impact of notable
items.
Underlying results:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
Quarterly Trends
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 change from
|
|
| ($s in millions, except per share data) |
|
1Q20 |
|
|
4Q19 |
|
|
1Q19 |
|
|
|
|
|
4Q19 |
|
|
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
| Net interest income |
|
$ |
1,160 |
|
|
$ |
1,143 |
|
|
$ |
1,160 |
|
|
|
|
|
|
|
1 |
% |
|
|
|
|
— |
% |
| Noninterest income |
|
|
497 |
|
|
|
494 |
|
|
|
428 |
|
|
|
|
|
|
|
1 |
|
|
|
|
|
16 |
|
| |
|
|
|
|
|
|
|
|
|
| Total revenue |
|
$ |
1,657 |
|
|
$ |
1,637 |
|
|
$ |
1,588 |
|
|
|
|
|
|
|
1 |
% |
|
|
|
|
4 |
% |
| Noninterest expense |
|
|
1,012 |
|
|
|
986 |
|
|
|
937 |
|
|
|
|
|
|
|
3 |
|
|
|
|
|
8 |
|
| Notable items |
|
|
33 |
|
|
|
37 |
|
|
|
5 |
|
|
|
|
|
|
|
(11 |
) |
|
|
|
|
NM |
|
| |
|
|
|
|
|
|
|
|
|
| Underlying noninterest expense |
|
$ |
979 |
|
|
$ |
949 |
|
|
$ |
932 |
|
|
|
|
|
|
|
3 |
% |
|
|
|
|
5 |
% |
| Underlying pre-provision profit |
|
|
678 |
|
|
|
688 |
|
|
|
656 |
|
|
|
|
|
|
|
(1 |
) |
|
|
|
|
3 |
|
| Provision for credit losses |
|
|
600 |
|
|
|
110 |
|
|
|
85 |
|
|
|
|
|
|
|
NM |
|
|
|
|
|
NM |
|
| |
|
|
|
|
|
|
|
|
|
| Net income available to common stockholders |
|
|
12 |
|
|
|
427 |
|
|
|
424 |
|
|
|
|
|
|
|
(97 |
) |
|
|
|
|
(97 |
) |
| Underlying net income available to common stockholders |
|
|
37 |
|
|
|
431 |
|
|
|
428 |
|
|
|
|
|
|
|
(91 |
) |
|
|
|
|
(91 |
) |
| |
|
|
|
|
|
|
|
|
|
| Key performance metrics* |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
| Diluted EPS |
|
$ |
0.03 |
|
|
$ |
0.98 |
|
|
$ |
0.92 |
|
|
|
|
|
|
|
(97 |
) % |
|
|
|
|
(97 |
) % |
| Underlying EPS |
|
$ |
0.09 |
|
|
$ |
0.99 |
|
|
$ |
0.93 |
|
|
|
|
|
|
|
(91 |
) % |
|
|
|
|
(90 |
) % |
| Efficiency ratio |
|
|
61 |
% |
|
|
60 |
% |
|
|
59 |
% |
|
|
|
|
|
|
82 |
bps |
|
|
|
|
210 |
bps |
| Underlying efficiency ratio |
|
|
59 |
|
|
|
58 |
|
|
|
59 |
|
|
|
|
|
|
|
106 |
|
|
|
|
|
41 |
|
| |
|
|
|
|
|
|
|
|
|
| Operating leverage |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
(1.4 |
) |
|
|
|
|
(3.7 |
) |
| Underlying operating leverage |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
(1.9 |
) % |
|
|
|
|
(0.7 |
) % |
| |
|
|
|
|
|
|
|
8
Citizens Financial Group, Inc.
Discussion of results:
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net interest income |
|
|
|
|
|
|
|
|
|
|
1Q20 change from
|
|
| ($s in millions) |
|
1Q20 |
|
|
4Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
$/bps |
|
|
|
|
% |
|
|
|
|
$/bps |
|
|
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Interest income: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Interest and fees on loans and leases and loans held for sale |
|
$ |
1,326 |
|
|
$ |
1,335 |
|
|
$ |
1,396 |
|
|
$ |
(9 |
) |
|
|
|
|
(1 |
) % |
|
|
|
$ |
(70 |
) |
|
|
(5 |
) % |
| Investment securities |
|
|
147 |
|
|
|
159 |
|
|
|
166 |
|
|
|
(12 |
) |
|
|
|
|
(8 |
) |
|
|
|
|
(19 |
) |
|
|
(11 |
) |
| Interest-bearing deposits in banks |
|
|
5 |
|
|
|
7 |
|
|
|
8 |
|
|
|
(2 |
) |
|
|
|
|
(29 |
) |
|
|
|
|
(3 |
) |
|
|
(38 |
) |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total interest income |
|
$ |
1,478 |
|
|
$ |
1,501 |
|
|
$ |
1,570 |
|
|
$ |
(23 |
) |
|
|
|
|
(2 |
) % |
|
|
|
$ |
(92 |
) |
|
|
(6 |
) % |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Interest expense: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Deposits |
|
$ |
227 |
|
|
$ |
263 |
|
|
$ |
287 |
|
|
$ |
(36 |
) |
|
|
|
|
(14 |
) % |
|
|
|
$ |
(60 |
) |
|
|
(21 |
) % |
| Short-term borrowed funds |
|
|
1 |
|
|
|
2 |
|
|
|
2 |
|
|
|
(1 |
) |
|
|
|
|
(100 |
) |
|
|
|
|
(1 |
) |
|
|
(50 |
) |
| Long-term borrowed funds |
|
|
90 |
|
|
|
93 |
|
|
|
121 |
|
|
|
(3 |
) |
|
|
|
|
(3 |
) |
|
|
|
|
(31 |
) |
|
|
(26 |
) |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total interest expense |
|
$ |
318 |
|
|
$ |
358 |
|
|
$ |
410 |
|
|
$ |
(40 |
) |
|
|
|
|
(11 |
) % |
|
|
|
$ |
(92 |
) |
|
|
(22 |
) % |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net interest income |
|
$ |
1,160 |
|
|
$ |
1,143 |
|
|
$ |
1,160 |
|
|
$ |
17 |
|
|
|
|
|
1 |
% |
|
|
|
$ |
— |
|
|
|
— |
% |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net interest margin, FTE |
|
|
3.10 |
% |
|
|
3.06 |
% |
|
|
3.25 |
% |
|
|
4 |
bps |
|
|
|
|
|
|
|
|
|
|
(15 |
) bps |
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
Net interest income of $1.2 billion was stable with first quarter 2019 levels, despite the lower rate and
challenging yield-curve environment, given 4% growth in interest-earning assets. Net interest margin of 3.10% decreased 15 basis points as the impact of lower interest rates was partially offset by improved deposit mix as well as continued mix shift
towards better-returning assets.
Compared with fourth quarter 2019, net interest income of $1.2 billion was 1% higher as the benefit
interest-earning asset growth and improved loan mix was partially offset by the negative impact of rates and day count. The net interest margin of 3.10% increased 4 basis points, reflecting the benefit of elevated LIBOR on loan spreads, as well as
disciplined deposit pricing and mix, which more than offset the negative impact of lower interest rates. Interest-bearing deposit costs decreased 15 basis points.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest Income |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 change from
|
|
| ($s in millions) |
|
|
|
1Q20 |
|
|
4Q19 |
|
|
1Q19 |
|
|
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
|
$ |
|
|
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Service charges and fees |
|
|
|
$ |
118 |
|
|
$ |
128 |
|
|
$ |
123 |
|
|
|
|
$ |
(10 |
) |
|
|
(8 |
) % |
|
$ |
(5 |
) |
|
|
(4 |
) % |
| Mortgage banking fees |
|
|
|
|
159 |
|
|
|
80 |
|
|
|
43 |
|
|
|
|
|
79 |
|
|
|
99 |
|
|
|
116 |
|
|
|
NM |
|
| Card fees |
|
|
|
|
56 |
|
|
|
64 |
|
|
|
59 |
|
|
|
|
|
(8 |
) |
|
|
(13 |
) |
|
|
(3 |
) |
|
|
(5 |
) |
| Capital markets fees |
|
|
|
|
43 |
|
|
|
66 |
|
|
|
54 |
|
|
|
|
|
(23 |
) |
|
|
(35 |
) |
|
|
(11 |
) |
|
|
(20 |
) |
| Trust and investment services fees |
|
|
|
|
53 |
|
|
|
52 |
|
|
|
47 |
|
|
|
|
|
1 |
|
|
|
2 |
|
|
|
6 |
|
|
|
13 |
|
| Foreign exchange and interest rate products |
|
|
|
|
24 |
|
|
|
49 |
|
|
|
36 |
|
|
|
|
|
(25 |
) |
|
|
(51 |
) |
|
|
(12 |
) |
|
|
(33 |
) |
| Letter of credit and loan fees |
|
|
|
|
34 |
|
|
|
35 |
|
|
|
33 |
|
|
|
|
|
(1 |
) |
|
|
(3 |
) |
|
|
1 |
|
|
|
3 |
|
| Securities gains, net |
|
|
|
|
— |
|
|
|
4 |
|
|
|
8 |
|
|
|
|
|
(4 |
) |
|
|
(100 |
) |
|
|
(8 |
) |
|
|
(100 |
) |
| Other income(1) |
|
|
|
|
10 |
|
|
|
16 |
|
|
|
25 |
|
|
|
|
|
(6 |
) |
|
|
(38 |
) |
|
|
(15 |
) |
|
|
(60 |
) |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest income |
|
|
|
$ |
497 |
|
|
$ |
494 |
|
|
$ |
428 |
|
|
|
|
$ |
3 |
|
|
|
1 |
% |
|
$ |
69 |
|
|
|
16 |
% |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| 1) Other income includes bank-owned life insurance and
other income. |
|
Record noninterest income of $497 million increased $69 million, or 16%, from first quarter 2019. Results reflect record
results in mortgage banking and trust and investment services fees. These results were partially offset by COVID-19 impacts in service charges and fees, card fees, capital markets and foreign exchange and
interest rate products. Mortgage banking fees of $159 million reflect increased origination volumes and improved gain on sale margins, as well as higher mortgage servicing rights hedging gains. Capital markets fees of $43 million decreased
$11 million, as market disruption in March resulted in a $21 million mark to market loss on loan/bond trading assets. Foreign exchange and interest rate products revenue of $24 million declined by $12 million, primarily due to a
$10 million decrease in net credit valuation adjustment given the fall in rates. Other income declined from first quarter 2019 levels that included higher gains related to asset dispositions and efficiency initiatives.
9
Citizens Financial Group, Inc.
Compared with fourth quarter 2019, noninterest income was relatively stable, as record results in
mortgage banking and trust and investment services fees were partially offset by the impacts of COVID-19 disruption on other categories. Capital markets fees decreased $23 million from record fourth
quarter 2019 levels given the mark to market loss. Foreign exchange and interest rate products income decreased $25 million from record fourth quarter 2019 levels, which includes a $15 million decrease in net credit valuation adjustment.
Services charges and fees and card fees declined, reflecting impacts from seasonality as well as the COVID-19 disruption. Other income decreased reflecting costs associated with
tax-advantaged investments and lower leasing income.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest Expense |
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 change from
|
|
| ($s in millions) |
|
1Q20 |
|
|
4Q19 |
|
|
1Q19 |
|
|
|
|
4Q19 |
|
|
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
|
|
|
$ |
|
|
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Salaries and employee benefits |
|
$ |
549 |
|
|
$ |
502 |
|
|
$ |
509 |
|
|
|
|
$ |
47 |
|
|
|
9 |
% |
|
|
|
$ |
40 |
|
|
|
8 |
% |
| Equipment and software expense |
|
|
133 |
|
|
|
133 |
|
|
|
125 |
|
|
|
|
|
— |
|
|
|
— |
|
|
|
|
|
8 |
|
|
|
6 |
|
| Outside services |
|
|
135 |
|
|
|
142 |
|
|
|
110 |
|
|
|
|
|
(7 |
) |
|
|
(5 |
) |
|
|
|
|
25 |
|
|
|
23 |
|
| Occupancy |
|
|
84 |
|
|
|
88 |
|
|
|
83 |
|
|
|
|
|
(4 |
) |
|
|
(5 |
) |
|
|
|
|
1 |
|
|
|
1 |
|
| Other operating expense |
|
|
111 |
|
|
|
121 |
|
|
|
110 |
|
|
|
|
|
(10 |
) |
|
|
(8 |
) |
|
|
|
|
1 |
|
|
|
1 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest expense |
|
$ |
1,012 |
|
|
$ |
986 |
|
|
$ |
937 |
|
|
|
|
$ |
26 |
|
|
|
3 |
% |
|
|
|
$ |
75 |
|
|
|
8 |
% |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Notable items |
|
$ |
33 |
|
|
$ |
37 |
|
|
$ |
5 |
|
|
|
|
$ |
(4 |
) |
|
|
(11 |
)% |
|
|
|
$ |
28 |
|
|
|
NM |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Underlying, as
applicable |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Salaries and employee benefits |
|
$ |
539 |
|
|
$ |
496 |
|
|
$ |
508 |
|
|
|
|
$ |
43 |
|
|
|
9 |
% |
|
|
|
$ |
31 |
|
|
|
6 |
% |
| Equipment and software expense |
|
|
132 |
|
|
|
130 |
|
|
|
125 |
|
|
|
|
|
2 |
|
|
|
2 |
|
|
|
|
|
7 |
|
|
|
6 |
|
| Outside services |
|
|
117 |
|
|
|
122 |
|
|
|
106 |
|
|
|
|
|
(5 |
) |
|
|
(4 |
) |
|
|
|
|
11 |
|
|
|
10 |
|
| Occupancy |
|
|
80 |
|
|
|
80 |
|
|
|
83 |
|
|
|
|
|
— |
|
|
|
— |
|
|
|
|
|
(3 |
) |
|
|
(4 |
) |
| Other operating expense |
|
|
111 |
|
|
|
121 |
|
|
|
110 |
|
|
|
|
|
(10 |
) |
|
|
(8 |
) |
|
|
|
|
1 |
|
|
|
1 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Underlying noninterest expense |
|
$ |
979 |
|
|
$ |
949 |
|
|
$ |
932 |
|
|
|
|
$ |
30 |
|
|
|
3 |
% |
|
|
|
$ |
47 |
|
|
|
5 |
% |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
First quarter 2020 noninterest expense of $1.0 billion increased $75 million, or 8%, from first quarter
2019. Underlying noninterest expense of $979 million increased $47 million, or 5%, largely reflecting higher salaries and employee benefits given the impact of annual merit increases and revenue-based compensation tied to mortgage
originations. Results also reflect higher equipment and software expense given continued investments in technology as well as higher outside services largely tied to growth initiatives. These results were partially offset by a reduction in
occupancy.
Compared with fourth quarter 2019, noninterest expense increased $26 million, or 3%. Underlying noninterest expense of
$979 million increased $30 million, or 3%, driven by higher salaries and employee benefits tied to seasonally higher payroll taxes, 401k matching and stock-based compensation costs, as well as higher revenue-based compensation tied to
mortgage originations. Results also reflect an increase in equipment and software expense driven by increased technology spend, partially offset by lower other operating expense and outside services.
10
Citizens Financial Group, Inc.
The first quarter 2020 effective tax rate was 24.1%. On an Underlying basis, the effective tax
rate of 24.5% compares with 22.4% for first quarter 2019 and 21.5% for fourth quarter 2019. The increase from fourth quarter 2019 was primarily driven by the impact of stock-based compensation, due to lower
pre-tax income.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Consolidated balance sheet review(1)
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 change from
|
|
| ($s in millions) |
|
1Q20 |
|
|
4Q19 |
|
|
1Q19 |
|
|
|
|
4Q19 |
|
|
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
$/bps
|
|
|
%
|
|
|
|
|
$/bps
|
|
|
%
|
|
| Total assets |
|
$ |
176,719 |
|
|
$ |
165,733 |
|
|
$ |
161,342 |
|
|
|
|
$ |
10,986 |
|
|
|
7 |
% |
|
|
|
$ |
15,377 |
|
|
|
10 |
% |
| Total loans and leases |
|
|
127,528 |
|
|
|
119,088 |
|
|
|
117,615 |
|
|
|
|
|
8,440 |
|
|
|
7 |
|
|
|
|
|
9,913 |
|
|
|
8 |
|
| Total loans held for sale |
|
|
3,261 |
|
|
|
3,330 |
|
|
|
1,252 |
|
|
|
|
|
(69 |
) |
|
|
(2 |
) |
|
|
|
|
2,009 |
|
|
|
160 |
|
| Deposits |
|
|
133,475 |
|
|
|
125,313 |
|
|
|
123,916 |
|
|
|
|
|
8,162 |
|
|
|
7 |
|
|
|
|
|
9,559 |
|
|
|
8 |
|
| Stockholders’ equity |
|
|
21,950 |
|
|
|
22,201 |
|
|
|
21,531 |
|
|
|
|
|
(251 |
) |
|
|
(1 |
) |
|
|
|
|
419 |
|
|
|
2 |
|
| Stockholders’ common equity |
|
|
20,380 |
|
|
|
20,631 |
|
|
|
20,399 |
|
|
|
|
|
(251 |
) |
|
|
(1 |
) |
|
|
|
|
(19 |
) |
|
|
— |
|
| Tangible common equity |
|
$ |
13,639 |
|
|
$ |
13,893 |
|
|
$ |
13,649 |
|
|
|
|
$ |
(254 |
) |
|
|
(2 |
) % |
|
|
|
$ |
(10 |
) |
|
|
— |
% |
| Loan-to-deposit ratio (period-end)(2) |
|
|
95.5 |
% |
|
|
95.0 |
% |
|
|
94.9 |
% |
|
|
|
|
51 |
bps |
|
|
|
|
|
|
|
|
62 |
bps |
|
|
|
|
| Loans to deposit ratio (average)(2) |
|
|
95.6 |
|
|
|
94.6 |
|
|
|
97.7 |
|
|
|
|
|
97 |
|
|
|
|
|
|
|
|
|
(210 |
) |
|
|
|
|
| Common equity tier 1 capital ratio(3) |
|
|
9.4 |
|
|
|
10.0 |
|
|
|
10.5 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total capital ratio(3) |
|
|
12.5 |
% |
|
|
13.0 |
% |
|
|
13.4 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
1)
Represents period end unless otherwise noted.
2) Excludes loans held for sale.
3) Current reporting period regulatory capital ratios are preliminary.
Total assets of $176.7 billion at March 31, 2020, increased $15.4 billion, or 10%, from March 31, 2019, reflecting an
$11.9 billion increase in loans and loans held for sale, which was largely driven by an increase in commercial line of credit utilization given the impact of COVID-19 disruption. Results also reflect a
$2.2 billion increase in the investment portfolio and a $1.5 billion increase in customer-related derivative assets. Compared with December 31, 2019, total assets increased $11.0 billion, driven by an $8.4 billion increase
in loans and loans held for sale given the higher COVID-19-related line of credit utilization as well as a $2.4 billion increase in the investment portfolio and a
$1.2 billion increase in customer-related derivative assets.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Interest-earning assets |
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 change from
|
|
| ($s in millions) |
|
1Q20 |
|
|
4Q19 |
|
|
1Q19 |
|
|
|
|
4Q19 |
|
|
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
| Period-end interest-earning assets |
|
|
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
|
|
|
$ |
|
|
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Investments and interest-bearing deposits |
|
$ |
29,535 |
|
|
$ |
27,177 |
|
|
$ |
27,331 |
|
|
|
|
$ |
2,358 |
|
|
|
9 |
% |
|
|
|
$ |
2,204 |
|
|
|
8 |
% |
| Commercial loans and leases |
|
|
66,032 |
|
|
|
57,538 |
|
|
|
57,689 |
|
|
|
|
|
8,494 |
|
|
|
15 |
|
|
|
|
|
8,343 |
|
|
|
14 |
|
| Retail loans |
|
|
61,496 |
|
|
|
61,550 |
|
|
|
59,926 |
|
|
|
|
|
(54 |
) |
|
|
— |
|
|
|
|
|
1,570 |
|
|
|
3 |
|
| Total loans and leases |
|
|
127,528 |
|
|
|
119,088 |
|
|
|
117,615 |
|
|
|
|
|
8,440 |
|
|
|
7 |
|
|
|
|
|
9,913 |
|
|
|
8 |
|
| Loans held for sale, at fair value |
|
|
2,911 |
|
|
|
1,946 |
|
|
|
1,186 |
|
|
|
|
|
965 |
|
|
|
50 |
|
|
|
|
|
1,725 |
|
|
|
145 |
|
| Other loans held for sale |
|
|
350 |
|
|
|
1,384 |
|
|
|
66 |
|
|
|
|
|
(1,034 |
) |
|
|
(75 |
) |
|
|
|
|
284 |
|
|
|
NM |
|
| Total loans and leases and loans held for sale |
|
|
130,789 |
|
|
|
122,418 |
|
|
|
118,867 |
|
|
|
|
|
8,371 |
|
|
|
7 |
|
|
|
|
|
11,922 |
|
|
|
10 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total period-end interest-earning assets |
|
$ |
160,324 |
|
|
$ |
149,595 |
|
|
$ |
146,198 |
|
|
|
|
$ |
10,729 |
|
|
|
7 |
% |
|
|
|
$ |
14,126 |
|
|
|
10 |
% |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average interest-earning assets |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Investments and interest-bearing deposits |
|
$ |
27,202 |
|
|
$ |
27,280 |
|
|
$ |
26,638 |
|
|
|
|
$ |
(78 |
) |
|
|
— |
% |
|
|
|
$ |
564 |
|
|
|
2 |
% |
| Commercial loans and leases |
|
|
59,510 |
|
|
|
57,661 |
|
|
|
57,707 |
|
|
|
|
|
1,849 |
|
|
|
3 |
|
|
|
|
|
1,803 |
|
|
|
3 |
|
| Retail loans |
|
|
61,545 |
|
|
|
61,244 |
|
|
|
59,942 |
|
|
|
|
|
301 |
|
|
|
— |
|
|
|
|
|
1,603 |
|
|
|
3 |
|
| Total loans and leases |
|
|
121,055 |
|
|
|
118,905 |
|
|
|
117,649 |
|
|
|
|
|
2,150 |
|
|
|
2 |
|
|
|
|
|
3,406 |
|
|
|
3 |
|
| Loans held for sale, at fair value |
|
|
1,890 |
|
|
|
2,209 |
|
|
|
1,035 |
|
|
|
|
|
(319 |
) |
|
|
(14 |
) |
|
|
|
|
855 |
|
|
|
83 |
|
| Other loans held for sale |
|
|
799 |
|
|
|
517 |
|
|
|
191 |
|
|
|
|
|
282 |
|
|
|
55 |
|
|
|
|
|
608 |
|
|
|
NM |
|
| Total loans and leases and loans held for sale |
|
|
123,744 |
|
|
|
121,631 |
|
|
|
118,875 |
|
|
|
|
|
2,113 |
|
|
|
2 |
|
|
|
|
|
4,869 |
|
|
|
4 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total average interest-earning assets |
|
$ |
150,946 |
|
|
$ |
148,911 |
|
|
$ |
145,513 |
|
|
|
|
$ |
2,035 |
|
|
|
1 |
% |
|
|
|
$ |
5,433 |
|
|
|
4 |
% |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Period-end interest-earning assets of $160.3 billion increased $14.1 billion, or
10%, from March 31, 2019, driven by an $11.9 billion, or 10%, increase in loans and loans held for sale, reflecting an $8.3 billion increase in commercial and a $1.6 billion increase in retail. Results reflect the impact of the
sale of $1.6 billion of on-balance sheet residential mortgage loans in connection with balance sheet optimization strategies. Compared with December 31, 2019,
period-end interest-earning assets increased $10.7 billion, or 7%, largely due to an $8.5 billion increase in commercial loans, which included the $7.2 billion impact of higher line of credit
utilization tied to COVID-19 disruption, as well as a $2.4 billion increase in the investment portfolio. The average effective duration of the securities portfolio decreased to 2.1 years as of
March 31, 2020 from 3.8 years at March 31, 2019, and 3.7 years at December 31, 2019, given lower long-term rates that drove an increase in securities prepayment speeds.
11
Citizens Financial Group, Inc.
Average interest-earning assets of $150.9 billion in first quarter 2020 increased
$5.4 billion, or 4%, from first quarter 2019, reflecting a $4.9 billion, or 4%, increase in loans and loans held for sale which included a $1.6 billion increase in retail and a $1.8 billion increase in commercial which included
the impact of higher line of credit utilization tied to COVID-19 disruption. Retail loan growth was driven by education and other retail, partially offset by lower home equity. Commercial loan growth was
driven by strength in commercial and industrial loans and commercial real estate, and reflected the $1.0 billion impact from COVID-19-related line of credit
utilization as well as the benefit of geographic, product and client-focused expansion strategies, partially offset by planned reductions in commercial leases.
Compared with fourth quarter 2019, average interest-earning assets increased $2.0 billion, or 1%, reflecting a $1.8 billion increase in
commercial loans and a $301 million increase in retail loans. Growth in commercial reflects higher line utilization, as well as strength in commercial real estate. Retail loan results reflect a $922 million reduction tied to the sale of on-balance sheet residential mortgage loans in connection with balance sheet optimization strategies. Loan growth was 2.6% before the impact of this sales activity.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Deposits |
|
|
|
|
|
|
|
|
|
|
1Q20 change from |
|
| ($s in millions) |
|
1Q20 |
|
|
4Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
| Period-end deposits |
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
$ |
|
% |
|
| Demand deposits |
|
$ |
32,398 |
|
|
$ |
29,233 |
|
|
$ |
28,383 |
|
|
$ |
3,165 |
|
|
|
11 |
% |
|
$ |
4,015 |
|
|
|
14 |
% |
| Checking with interest |
|
|
25,358 |
|
|
|
24,840 |
|
|
|
23,482 |
|
|
|
518 |
|
|
|
2 |
|
|
|
1,876 |
|
|
|
8 |
|
| Savings |
|
|
14,702 |
|
|
|
13,779 |
|
|
|
13,239 |
|
|
|
923 |
|
|
|
7 |
|
|
|
1,463 |
|
|
|
11 |
|
| Money market accounts |
|
|
42,972 |
|
|
|
38,725 |
|
|
|
35,972 |
|
|
|
4,247 |
|
|
|
11 |
|
|
|
7,000 |
|
|
|
19 |
|
| Term deposits |
|
|
18,045 |
|
|
|
18,736 |
|
|
|
22,840 |
|
|
|
(691 |
) |
|
|
(4 |
) |
|
|
(4,795 |
) |
|
|
(21 |
) |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total period-end deposits |
|
$ |
133,475 |
|
|
$ |
125,313 |
|
|
$ |
123,916 |
|
|
$ |
8,162 |
|
|
|
7 |
% |
|
$ |
9,559 |
|
|
|
8 |
% |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average deposits |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Demand deposits |
|
$ |
29,362 |
|
|
$ |
29,928 |
|
|
$ |
28,465 |
|
|
$ |
(566 |
) |
|
|
(2 |
) % |
|
$ |
897 |
|
|
|
3 |
% |
| Checking with interest |
|
|
24,612 |
|
|
|
23,545 |
|
|
|
22,987 |
|
|
|
1,067 |
|
|
|
5 |
|
|
|
1,625 |
|
|
|
7 |
|
| Savings |
|
|
14,201 |
|
|
|
13,582 |
|
|
|
12,626 |
|
|
|
619 |
|
|
|
5 |
|
|
|
1,575 |
|
|
|
12 |
|
| Money market accounts |
|
|
39,839 |
|
|
|
38,809 |
|
|
|
35,209 |
|
|
|
1,030 |
|
|
|
3 |
|
|
|
4,630 |
|
|
|
13 |
|
| Term deposits |
|
|
18,616 |
|
|
|
19,788 |
|
|
|
21,127 |
|
|
|
(1,172 |
) |
|
|
(6 |
) |
|
|
(2,511 |
) |
|
|
(12 |
) |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total average deposits |
|
$ |
126,630 |
|
|
$ |
125,652 |
|
|
$ |
120,414 |
|
|
$ |
978 |
|
|
|
1 |
% |
|
$ |
6,216 |
|
|
|
5 |
% |
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Total period-end deposits of $133.5 billion at March 31, 2020
increased $9.6 billion, or 8%, from March 31, 2019, reflecting growth in money market accounts, demand deposits, checking with interest and savings, partially offset by a decrease in term deposits.
Compared with December 31, 2019, total period-end deposits increased $8.2 billion, driven by
growth in money market accounts and demand deposits, savings and checking with interest, partially offset by a decrease in term deposits. Citizens Access® deposits totaled $6.1 billion at
March 31, 2020, up from $5.8 billion at December 31, 2019.
First quarter 2020 average deposits of $126.6 billion
increased $6.2 billion, or 5%, from first quarter 2019, reflecting growth in money market accounts, checking with interest, savings and demand deposits, partially offset by a decrease in term deposits.
12
Citizens Financial Group, Inc.
Compared with fourth quarter 2019, average deposits were relatively stable, as growth in checking
with interest, money market accounts and savings was largely offset by a decrease in term deposits and demand deposits.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Borrowed Funds |
|
|
|
|
|
|
|
|
|
1Q20 change from |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ($s in millions) |
|
1Q20 |
|
|
4Q19 |
|
|
1Q19 |
|
4Q19 |
|
1Q19 |
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
| Period-end borrowed funds |
|
|
|
|
|
|
|
|
|
$ |
|
% |
|
$ |
|
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Short-term borrowed funds(1) |
|
$ |
1,059 |
|
|
$ |
274 |
|
|
$ |
679 |
|
|
$ |
785 |
|
|
|
NM |
|
|
$ |
380 |
|
|
|
56 |
% |
| Long-term borrowed funds(1) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| FHLB advances |
|
|
8,007 |
|
|
|
5,008 |
|
|
|
2,508 |
|
|
|
2,999 |
|
|
|
60 |
|
|
|
5,499 |
|
|
|
219 |
|
| Senior debt |
|
|
6,775 |
|
|
|
7,382 |
|
|
|
7,558 |
|
|
|
(607 |
) |
|
|
(8 |
) |
|
|
(783 |
) |
|
|
(10 |
) |
| Subordinated debt and other debt |
|
|
1,655 |
|
|
|
1,657 |
|
|
|
1,659 |
|
|
|
(2 |
) |
|
|
— |
|
|
|
(4 |
) |
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total borrowed funds |
|
$ |
17,496 |
|
|
$ |
14,321 |
|
|
$ |
12,404 |
|
|
$ |
3,175 |
|
|
|
22 |
% |
|
$ |
5,092 |
|
|
|
41 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average borrowed funds |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Short-term borrowed funds(1) |
|
$ |
644 |
|
|
$ |
504 |
|
|
$ |
698 |
|
|
$ |
140 |
|
|
|
28 |
% |
|
$ |
(54 |
) |
|
|
(8 |
) % |
| Long-term borrowed funds(1) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| FHLB advances |
|
|
5,138 |
|
|
|
3,259 |
|
|
|
5,694 |
|
|
|
1,879 |
|
|
|
58 |
|
|
|
(556 |
) |
|
|
(10 |
) |
| Senior debt |
|
|
7,263 |
|
|
|
7,914 |
|
|
|
7,391 |
|
|
|
(651 |
) |
|
|
(8 |
) |
|
|
(128 |
) |
|
|
(2 |
) |
| Subordinated debt and other debt |
|
|
1,656 |
|
|
|
1,657 |
|
|
|
1,651 |
|
|
|
(1 |
) |
|
|
— |
|
|
|
5 |
|
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total average borrowed funds |
|
$ |
14,701 |
|
|
$ |
13,334 |
|
|
$ |
15,434 |
|
|
$ |
1,367 |
|
|
|
10 |
% |
|
$ |
(733 |
) |
|
|
(5 |
) % |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1) Beginning in 1Q19, borrowed funds balances are based on original maturity and
prior periods have been revised consistent with the current presentation.
Total borrowed funds of $17.5 billion at March 31, 2020
increased $5.1 billion, or 41%, from March 31, 2019, reflecting a $5.5 billion increase in long-term FHLB borrowings and a $380 million increase in short-term borrowings, partially offset by a $783 million decrease in senior
debt. Compared with December 31, 2019, total borrowed funds increased $3.2 billion reflecting a $3.0 billion increase in long-term FHLB borrowings, and a $785 million increase in short-term borrowings, partially offset by a
$607 million decrease in senior debt.
Average borrowed funds of $14.7 billion decreased $733 million, or 5%, from first
quarter 2019, reflecting a $556 million decrease in long-term FHLB borrowings, a $128 million decrease in senior debt and a $54 million decrease in short-term borrowings. Compared with December 31, 2019 average borrowed funds
increased $1.4 billion, or 10%, reflecting a $1.9 billion increase in long-term FHLB borrowings and a $140 million increase in short-term borrowings, partially offset by a $651 million decrease in senior debt.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Capital |
|
|
|
|
|
|
|
|
|
1Q20 change from |
| ($s and shares in millions except per share data) |
|
1Q20 |
|
|
4Q19 |
|
|
1Q19 |
|
4Q19 |
|
1Q19 |
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
| Period-end capital |
|
|
|
|
|
|
|
|
|
$ |
|
% |
|
|
$ |
|
|
% |
| Stockholders’ equity |
|
$ |
21,950 |
|
|
$ |
22,201 |
|
|
$ |
21,531 |
|
|
$ |
(251 |
) |
|
|
(1 |
) % |
|
$ |
419 |
|
|
|
2 |
% |
| Stockholders’ common equity |
|
|
20,380 |
|
|
|
20,631 |
|
|
|
20,399 |
|
|
|
(251 |
) |
|
|
(1 |
) |
|
|
(19 |
) |
|
|
— |
|
| Tangible common equity |
|
|
13,639 |
|
|
|
13,893 |
|
|
|
13,649 |
|
|
|
(254 |
) |
|
|
(2 |
) |
|
|
(10 |
) |
|
|
— |
|
| Tangible book value per common share |
|
$ |
31.97 |
|
|
$ |
32.08 |
|
|
$ |
29.6 |
|
|
$ |
(0.11 |
) |
|
|
— |
|
|
$ |
2.37 |
|
|
|
8 |
|
| Common shares - at end of period |
|
|
426.6 |
|
|
|
433.1 |
|
|
|
461.1 |
|
|
|
(6.5 |
) |
|
|
(2 |
) |
|
|
(34.5 |
) |
|
|
(7 |
) |
| Common shares - average (diluted) |
|
|
429.4 |
|
|
|
436.5 |
|
|
|
462.5 |
|
|
|
(7.1 |
) |
|
|
(2 |
) % |
|
|
(33.1 |
) |
|
|
(7 |
) |
| Common equity tier 1 capital
ratio(1) |
|
|
9.4 |
% |
|
|
10.0 |
% |
|
|
10.5 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total capital ratio(1) |
|
|
12.5 |
|
|
|
13.0 |
|
|
|
13.4 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Tier 1 leverage ratio(1) |
|
|
9.6 |
% |
|
|
10.0 |
% |
|
|
10.0 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| 1) |
Current reporting-period regulatory capital ratios are preliminary. |
At March 31, 2020, our Basel III capital ratios remained well in excess of applicable regulatory requirements with a CET1 capital ratio of
9.4% compared with 10.0% at December 31, 2019 and 10.5% at March 31, 2019, and a total capital ratio of 12.5% compared with total capital ratios of 13.0% as of December 31, 2019 and 13.4% as of March 31, 2019.
13
Citizens Financial Group, Inc.
Tangible book value per common share of $31.97 was relatively stable compared with fourth quarter
2019 and increased 8% from first quarter 2019.
During first quarter 2020, the company repurchased 7.5 million shares of common stock at
a weighted-average price of $35.77, and including common dividends, returned $438 million to shareholders. These results compare with $558 million returned to common shareholders in fourth quarter 2019 and $349 million in first
quarter 2019.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Credit quality review |
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 change from |
| ($s in millions) |
|
1Q20 |
|
|
4Q19 |
|
|
1Q19 |
|
|
|
|
4Q19 |
|
|
1Q19 |
| |
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
$/bps |
|
|
% |
|
|
$/bps |
|
|
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Nonaccrual loans and leases |
|
$ |
780 |
|
|
$ |
703 |
|
|
$ |
744 |
|
|
|
|
$ |
77 |
|
|
|
11 % |
|
|
$ |
36 |
|
|
5 % |
| 90+ days past due and accruing |
|
|
27 |
|
|
|
25 |
|
|
|
32 |
|
|
|
|
|
2 |
|
|
|
8 |
|
|
|
(5) |
|
|
(16) |
| Net charge-offs |
|
|
137 |
|
|
|
122 |
|
|
|
89 |
|
|
|
|
|
15 |
|
|
|
12 |
|
|
|
48 |
|
|
54 |
| Provision for credit losses |
|
|
600 |
|
|
|
110 |
|
|
|
85 |
|
|
|
|
|
490 |
|
|
|
NM |
|
|
|
515 |
|
|
NM |
| Allowance for credit losses |
|
$ |
2,210 |
|
|
$ |
1,296 |
|
|
$ |
1 ,329 |
|
|
|
|
$ |
914 |
|
|
|
71 % |
|
|
$ |
881 |
|
|
66 % |
| Nonaccrual loans and leases to loans and leases |
|
|
0.61 % |
|
|
|
0.59 % |
|
|
|
0.63 |
|
|
% |
|
|
2 bps |
|
|
|
|
|
|
|
(2) bps |
|
|
|
| Net charge-offs as a % of total loans and leases |
|
|
0.46 |
|
|
|
0.41 |
|
|
|
0.31 |
|
|
|
|
|
5 |
|
|
|
|
|
|
|
15 |
|
|
|
| Allowance for credit losses to loans and leases |
|
|
1.73 |
|
|
|
1.09 |
|
|
|
1.13 |
|
|
|
|
|
64 |
|
|
|
|
|
|
|
60 |
|
|
|
| Allowance for credit losses to nonaccrual loans and leases |
|
|
283.5 % |
|
|
|
184.3 % |
|
|
|
178.7 |
|
|
% |
|
|
NM |
|
|
|
|
|
|
|
NM |
|
|
|
| |
|
|
|
|
|
|
Nonacccrual loans increased $36 million, or 5%, compared with March 31, 2019, as a $102 million
increase in commercial was partially offset by a $66 million decrease in retail reflecting improvement in home equity and education. Compared to December 31, 2019, nonaccrual loans of $780 million increased $77 million, or 11%,
reflecting a $69 million increase in commercial and an $8 million increase in retail. The nonaccrual loans to loans ratio of 0.61% at March 31, 2020 increased 2 basis points from 0.59% at December 31, 2019 and improved 2 basis
points from 0.63% at March 31, 2019.
Net charge-offs of $137 million increased $48 million from first quarter 2019, reflecting
a $20 million increase in commercial, reflecting several uncorrelated commercial losses, and a $28 million increase in retail driven by seasoning in growth portfolios. Compared with fourth quarter 2019, net charge-offs increased
$15 million driven by a $17 million increase in commercial, partially offset by a $2 million reduction in retail.
First
quarter 2020 net charge-offs were 46 basis points of average loans compared with 31 basis points in first quarter 2019 and 41 basis points in fourth quarter 2019.
Provision for credit losses of $600 million includes a $463 million reserve build associated with
COVID-19 and compares with $85 million in first quarter 2019 and $110 million in fourth quarter 2019.
The allowance for credit losses of $2.2 billion includes impacts from the adoption of CECL on January 1, 2020. This compares with
$1.3 billion at March 31, 2019 and $1.3 billion at December 31, 2019.
The allowance for credit losses to loans ratio was
1.73% as of March 31, 2020, compared with 1.13% as of March 31, 2019, and 1.09% as of December 31, 2019. The allowance for credit losses to nonaccrual loans ratio of 283% as of March 31, 2020 compares to 179% as of March 31,
2019, and 184% as of December 31, 2019.
14
Citizens Financial Group, Inc.
Corresponding Financial Tables and Information
Investors are encouraged to review the foregoing summary and discussion of Citizens’ earnings and financial condition in conjunction with the
detailed financial tables and other information available on the Investor Relations portion of the company’s website at
www.citizensbank.com/about-us.
Media: Peter Lucht—781.655.2289
Investors: Ellen A. Taylor—203.900.6854
Conference
Call
CFG management will host a live conference call today with details as follows:
|
|
|
| Time: |
|
9:00 am ET |
|
|
| Dial-in: |
|
(844) 767-5679, conference ID 2469575 |
Webcast/Presentation: The live webcast will be available at http://investor.citizensbank.com under Events & Presentations.
Replay Information: A replay of the conference call will be available beginning at 12:00 pm ET on April 17 through May 17, 2020. Please
dial (866) 207-1041 and enter access code 3857257. The webcast replay will be available at http://investor.citizensbank.com under Events & Presentations.
About Citizens Financial Group, Inc.
Citizens Financial Group, Inc. is one of the nation’s oldest and largest financial institutions, with $176.7 billion in assets as of
March 31, 2020. Headquartered in Providence, Rhode Island, Citizens offers a broad range of retail and commercial banking products and services to individuals, small businesses, middle-market companies, large corporations and institutions.
Citizens helps its customers reach their potential by listening to them and by understanding their needs in order to offer tailored advice, ideas and solutions. In Consumer Banking, Citizens provides an integrated experience that includes mobile and
online banking, a 24/7 customer contact center and the convenience of approximately 2,800 ATMs and approximately 1,000 branches in 11 states in the New England, Mid-Atlantic and Midwest regions. Consumer
Banking products and services include a full range of banking, lending, savings, wealth management and small business offerings. In Commercial Banking, Citizens offers a broad complement of financial products and solutions, including lending and
leasing, deposit and treasury management services, foreign exchange, interest rate and commodity risk management solutions, as well as loan syndication, corporate finance, merger and acquisition, and debt and equity capital markets capabilities.
More information is available at www.citizensbank.com or visit us on Twitter, LinkedIn or Facebook.
15
Citizens Financial Group, Inc.
Key Performance Metrics and Non-GAAP Financial Measures and
Reconciliations
(in millions, except share, per-share and ratio data)
Key Performance Metrics:
Our Management uses certain key
performance metrics (KPMs) to gauge our progress against strategic and operational goals, as well as to compare our performance against peers. The KPMs are referred to in our Registration Statements on Form
S-1 and our external financial reports filed with the Securities and Exchange Commission. The KPMs include:
| |
• |
|
Return on average tangible common equity (ROTCE); |
| |
• |
|
Operating leverage; and |
| |
• |
|
Common equity tier 1 capital ratio. |
Established targets for the KPMs are based on Management-reporting results which are currently referred to by the Company as
“Underlying” results. In historical periods, these results may have been referred to as “Adjusted” or “Adjusted/Underlying” results. We believe that Underlying results, which exclude notable items, provide the best
representation of our underlying financial progress toward the KPMs as the results exclude items that our Management does not consider indicative of our on-going financial performance. We have consistently
shown investors our KPMs on a Management-reporting basis since our initial public offering in September of 2014. KPMs that reflect Underlying results are considered non-GAAP financial measures.
Non-GAAP Financial Measures:
This document contains non-GAAP financial measures denoted as Underlying results. In historical periods,
these results may have been referred to as Adjusted or Adjusted/Underlying results. Underlying results for any given reporting period exclude certain items that may occur in that period which Management does not consider indicative of the
Company’s on-going financial performance. We believe these non-GAAP financial measures provide useful information to investors because they are used by our
Management to evaluate our operating performance and make day-to-day operating decisions. In addition, we believe our Underlying results in any given reporting period
reflect our on-going financial performance in that period and, accordingly, are useful to consider in addition to our GAAP financial results. We further believe the presentation of Underlying results increases
comparability of period-to-period results. The following tables present reconciliations of our non-GAAP measures to the most
directly comparable GAAP financial measures.
Other companies may use similarly titled non-GAAP
financial measures that are calculated differently from the way we calculate such measures. Accordingly, our non-GAAP financial measures may not be comparable to similar measures used by such companies. We
caution investors not to place undue reliance on such non-GAAP financial measures, but to consider them with the most directly comparable GAAP measures. Non-GAAP
financial measures have limitations as analytical tools and should not be considered in isolation or as a substitute for our results reported under GAAP.
16
Citizens Financial Group, Inc.
Key performance metrics, non-GAAP financial measures and
reconciliations
(in millions, except share, per-share and ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
QUARTERLY TRENDS |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
|
|
|
1Q20 |
|
|
4Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
|
$ |
|
|
% |
|
| Noninterest income, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest income (GAAP) |
|
|
A |
|
|
|
$497 |
|
|
|
$494 |
|
|
|
$428 |
|
|
|
$3 |
|
|
|
1 % |
|
|
|
$69 |
|
|
|
16 % |
|
| Less: Notable items |
|
|
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest income, Underlying (non-GAAP) |
|
|
B |
|
|
|
$497 |
|
|
|
$494 |
|
|
|
$428 |
|
|
|
$3 |
|
|
|
1 % |
|
|
|
$69 |
|
|
|
16 % |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue (GAAP) |
|
|
C |
|
|
|
$1,657 |
|
|
|
$1,637 |
|
|
|
$1,588 |
|
|
|
$20 |
|
|
|
1 % |
|
|
|
$69 |
|
|
|
4 % |
|
| Less: Notable items |
|
|
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue, Underlying (non-GAAP) |
|
|
D |
|
|
|
$1,657 |
|
|
|
$1,637 |
|
|
|
$1,588 |
|
|
|
$20 |
|
|
|
1 % |
|
|
|
$69 |
|
|
|
4 % |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest expense, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest expense (GAAP) |
|
|
E |
|
|
|
$1,012 |
|
|
|
$986 |
|
|
|
$937 |
|
|
|
$26 |
|
|
|
3 % |
|
|
|
$75 |
|
|
|
8 % |
|
| Less: Notable items |
|
|
|
|
|
|
33 |
|
|
|
37 |
|
|
|
5 |
|
|
|
(4) |
|
|
|
(11) |
|
|
|
28 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest expense, Underlying (non-GAAP) |
|
|
F |
|
|
|
$979 |
|
|
|
$949 |
|
|
|
$932 |
|
|
|
$30 |
|
|
|
3 % |
|
|
|
$47 |
|
|
|
5 % |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Pre-provision profit: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue (GAAP) |
|
|
C |
|
|
|
$1,657 |
|
|
|
$1,637 |
|
|
|
$1,588 |
|
|
|
$20 |
|
|
|
1 % |
|
|
|
$69 |
|
|
|
4 % |
|
| Less: Noninterest expense (GAAP) |
|
|
E |
|
|
|
1,012 |
|
|
|
986 |
|
|
|
937 |
|
|
|
26 |
|
|
|
3 |
|
|
|
75 |
|
|
|
8 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Pre-provision profit (GAAP) |
|
|
|
|
|
|
$645 |
|
|
|
$651 |
|
|
|
$651 |
|
|
|
($6) |
|
|
|
(1%) |
|
|
|
($6) |
|
|
|
(1%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Pre-provision profit, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue, Underlying (non-GAAP) |
|
|
D |
|
|
|
$1,657 |
|
|
|
$1,637 |
|
|
|
$1,588 |
|
|
|
$20 |
|
|
|
1 % |
|
|
|
$69 |
|
|
|
4 % |
|
| Less: Noninterest expense, Underlying (non-GAAP) |
|
|
F |
|
|
|
979 |
|
|
|
949 |
|
|
|
932 |
|
|
|
30 |
|
|
|
3 |
|
|
|
47 |
|
|
|
5 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Pre-provision profit, Underlying (non-GAAP) |
|
|
|
|
|
|
$678 |
|
|
|
$688 |
|
|
|
$656 |
|
|
|
($10) |
|
|
|
(1%) |
|
|
|
$22 |
|
|
|
3 % |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income before income tax expense, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income before income tax expense (GAAP) |
|
|
G |
|
|
|
$45 |
|
|
|
$541 |
|
|
|
$566 |
|
|
|
($496) |
|
|
|
(92%) |
|
|
|
($521) |
|
|
|
(92%) |
|
| Less: Expense before income tax benefit related to notable items |
|
|
|
|
|
|
(33) |
|
|
|
(37) |
|
|
|
(5) |
|
|
|
4 |
|
|
|
11 |
|
|
|
(28) |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income before income tax expense, Underlying (non-GAAP) |
|
|
H |
|
|
|
$78 |
|
|
|
$578 |
|
|
|
$571 |
|
|
|
($500) |
|
|
|
(87%) |
|
|
|
($493) |
|
|
|
(86%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income tax expense, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income tax expense (GAAP) |
|
|
I |
|
|
|
$11 |
|
|
|
$91 |
|
|
|
$127 |
|
|
|
($80) |
|
|
|
(88%) |
|
|
|
($116) |
|
|
|
(91%) |
|
| Less: Income tax benefit related to notable items |
|
|
|
|
|
|
(8) |
|
|
|
(33) |
|
|
|
(1) |
|
|
|
25
|
|
|
|
76 |
|
|
|
(7) |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income tax expense, Underlying (non-GAAP) |
|
|
J |
|
|
|
$19 |
|
|
|
$124 |
|
|
|
$128 |
|
|
|
($105) |
|
|
|
(85%) |
|
|
|
($109) |
|
|
|
(85%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income (GAAP) |
|
|
K |
|
|
|
$34 |
|
|
|
$450 |
|
|
|
$439 |
|
|
|
($416) |
|
|
|
(92%) |
|
|
|
($405) |
|
|
|
(92%) |
|
| Add: Notable items, net of income tax benefit |
|
|
|
|
|
|
25 |
|
|
|
4 |
|
|
|
4 |
|
|
|
21 |
|
|
|
NM |
|
|
|
21 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income, Underlying (non-GAAP) |
|
|
L |
|
|
|
$59 |
|
|
|
$454 |
|
|
|
$443 |
|
|
|
($395) |
|
|
|
(87%) |
|
|
|
($384) |
|
|
|
(87%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income available to common stockholders, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income available to common stockholders (GAAP) |
|
|
M |
|
|
|
$12 |
|
|
|
$427 |
|
|
|
$424 |
|
|
|
($415) |
|
|
|
(97%) |
|
|
|
($412) |
|
|
|
(97%) |
|
| Add: Notable items, net of income tax benefit |
|
|
|
|
|
|
25 |
|
|
|
4 |
|
|
|
4 |
|
|
|
21 |
|
|
|
NM |
|
|
|
21 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income available to common stockholders, Underlying (non-GAAP) |
|
|
N |
|
|
|
$37 |
|
|
|
$431 |
|
|
|
$428 |
|
|
|
($394) |
|
|
|
(91%) |
|
|
|
($391) |
|
|
|
(91%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
17
Citizens Financial Group, Inc.
Key performance metrics, non-GAAP financial measures and reconciliations (continued)
(in millions, except share, per-share and ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
QUARTERLY TRENDS |
| |
|
|
|
|
|
|
|
|
|
1Q20 Change |
| |
|
|
|
1Q20 |
|
4Q19 |
|
1Q19 |
|
4Q19 |
|
1Q19 |
| |
|
|
|
|
|
|
|
|
|
$/bps |
|
% |
|
$/bps |
|
% |
| Operating leverage: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue (GAAP) |
|
C |
|
$ |
1,657 |
|
|
$ |
1,637 |
|
|
$ |
1,588 |
|
|
$ |
20 |
|
|
|
1.30 |
% |
|
$ |
69 |
|
|
|
4.35 |
% |
| Less: Noninterest expense (GAAP) |
|
E |
|
|
1,012 |
|
|
|
986 |
|
|
|
937 |
|
|
|
26 |
|
|
|
2.68 |
|
|
|
75 |
|
|
|
8.06 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Operating leverage |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
(1.38 |
%) |
|
|
|
|
|
|
(3.71 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Operating leverage, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue, Underlying (non-GAAP) |
|
D |
|
$ |
1,657 |
|
|
$ |
1,637 |
|
|
$ |
1,588 |
|
|
$ |
20 |
|
|
|
1.30 |
% |
|
$ |
69 |
|
|
|
4.35 |
% |
| Less: Noninterest expense, Underlying (non-GAAP) |
|
F |
|
|
979 |
|
|
|
949 |
|
|
|
932 |
|
|
|
30 |
|
|
|
3.16 |
|
|
|
47 |
|
|
|
5.09 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Operating leverage, Underlying (non-GAAP) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
(1.86 |
%) |
|
|
|
|
|
|
(0.74 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Efficiency ratio and efficiency ratio, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Efficiency ratio |
|
E/C |
|
|
61.10 |
% |
|
|
60.28 |
% |
|
|
59.00 |
% |
|
|
82 |
bps |
|
|
|
|
|
|
210 |
bps |
|
|
|
|
| Efficiency ratio, Underlying (non-GAAP) |
|
F/D |
|
|
59.08 |
|
|
|
58.02 |
|
|
|
58.67 |
|
|
|
106 |
bps |
|
|
|
|
|
|
41 |
bps |
|
|
|
|
| Effective income tax rate and effective income tax rate, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Effective income tax rate |
|
I/G |
|
|
24.13 |
% |
|
|
16.76 |
% |
|
|
22.42 |
% |
|
|
737 |
bps |
|
|
|
|
|
|
171 |
bps |
|
|
|
|
| Effective income tax rate, Underlying (non-GAAP) |
|
J/H |
|
|
24.52 |
|
|
|
21.52 |
|
|
|
22.44 |
|
|
|
300 |
bps |
|
|
|
|
|
|
208 |
bps |
|
|
|
|
| Return on average common equity and return on average common equity, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average common equity (GAAP) |
|
0 |
|
$ |
20,223 |
|
|
$ |
20,400 |
|
|
$ |
19,942 |
|
|
($ |
177 |
) |
|
|
(1 |
%) |
|
$ |
281 |
|
|
|
1 |
% |
| Return on average common equity |
|
M/O |
|
|
0.24 |
% |
|
|
8.30 |
% |
|
|
8.62 |
% |
|
|
(806 |
) bps |
|
|
|
|
|
|
(838 |
) bps |
|
|
|
|
| Return on average common equity, Underlying (non-GAAP) |
|
N/O |
|
|
0.74 |
|
|
|
8.36 |
|
|
|
8.71 |
|
|
|
(762 |
) bps |
|
|
|
|
|
|
(797 |
) bps |
|
|
|
|
| Return on average tangible common equity and return on average tangible common equity, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average common equity (GAAP) |
|
O |
|
$ |
20,223 |
|
|
$ |
20,400 |
|
|
$ |
19,942 |
|
|
($ |
177 |
) |
|
|
(1 |
%) |
|
$ |
281 |
|
|
|
1 |
% |
| Less: Average goodwill (GAAP) |
|
|
|
|
7,046 |
|
|
|
7,044 |
|
|
|
7,018 |
|
|
|
2 |
|
|
|
— |
|
|
|
28 |
|
|
|
— |
|
| Less: Average other intangibles (GAAP) |
|
|
|
|
67 |
|
|
|
69 |
|
|
|
59 |
|
|
|
(2 |
) |
|
|
(3 |
) |
|
|
8 |
|
|
|
14 |
|
| Add: Average deferred tax liabilities related to goodwill (GAAP) |
|
|
|
|
374 |
|
|
|
373 |
|
|
|
368 |
|
|
|
1 |
|
|
|
— |
|
|
|
6 |
|
|
|
2 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average tangible common equity |
|
P |
|
$ |
13,484 |
|
|
$ |
13,660 |
|
|
$ |
13,233 |
|
|
($ |
176 |
) |
|
|
(1 |
%) |
|
$ |
251 |
|
|
|
2 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Return on average tangible common equity |
|
M/P |
|
|
0.36 |
% |
|
|
12.39 |
% |
|
|
13.00 |
% |
|
|
(1,203 |
) bps |
|
|
|
|
|
|
(1,264 |
) bps |
|
|
|
|
| Return on average tangible common equity, Underlying (non-GAAP) |
|
N/P |
|
|
1.10 |
|
|
|
12.49 |
|
|
|
13.12 |
|
|
|
(1,139 |
) bps |
|
|
|
|
|
|
(1,202 |
) bps |
|
|
|
|
| Return on average total assets and return on average total assets, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average total assets (GAAP) |
|
Q |
|
$ |
167,177 |
|
|
$ |
164,646 |
|
|
$ |
160,415 |
|
|
$ |
2,531 |
|
|
|
2 |
% |
|
$ |
6,762 |
|
|
|
4 |
% |
| Return on average total assets |
|
K/Q |
|
|
0.08 |
% |
|
|
1.08 |
% |
|
|
1.11 |
% |
|
|
(100 |
) bps |
|
|
|
|
|
|
(103 |
) bps |
|
|
|
|
| Return on average total assets, Underlying (non-GAAP) |
|
L/Q |
|
|
0.14 |
|
|
|
1.09 |
|
|
|
1.12 |
|
|
|
(95 |
) bps |
|
|
|
|
|
|
(98 |
) bps |
|
|
|
|
| Return on average total tangible assets and return on average total tangible assets, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average total assets (GAAP) |
|
Q |
|
$ |
167,177 |
|
|
$ |
164,646 |
|
|
$ |
160,415 |
|
|
$ |
2,531 |
|
|
|
2 |
% |
|
$ |
6,762 |
|
|
|
4 |
% |
| Less: Average goodwill (GAAP) |
|
|
|
|
7,046 |
|
|
|
7,044 |
|
|
|
7,018 |
|
|
|
2 |
|
|
|
— |
|
|
|
28 |
|
|
|
— |
|
| Less: Average other intangibles (GAAP) |
|
|
|
|
67 |
|
|
|
69 |
|
|
|
59 |
|
|
|
(2 |
) |
|
|
(3 |
) |
|
|
8 |
|
|
|
14 |
|
| Add: Average deferred tax liabilities related to goodwill (GAAP) |
|
|
|
|
374 |
|
|
|
373 |
|
|
|
368 |
|
|
|
1 |
|
|
|
— |
|
|
|
6 |
|
|
|
2 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average tangible assets |
|
R |
|
$ |
160,438 |
|
|
$ |
157,906 |
|
|
$ |
153,706 |
|
|
$ |
2,532 |
|
|
|
2 |
% |
|
$ |
6,732 |
|
|
|
4 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Return on average total tangible assets |
|
K/R |
|
|
0.09 |
% |
|
|
1.13 |
% |
|
|
1.16 |
% |
|
|
(104 |
) bps |
|
|
|
|
|
|
(107 |
) bps |
|
|
|
|
| Return on average total tangible assets, Underlying (non-GAAP) |
|
L/R |
|
|
0.15 |
|
|
|
1.14 |
|
|
|
1.17 |
|
|
|
(99 |
) bps |
|
|
|
|
|
|
(102 |
) bps |
|
|
|
|
18
Citizens Financial Group, Inc.
Key performance metrics, non-GAAP financial measures and reconciliations (continued)
(in millions, except share, per-share and ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
QUARTERLY TRENDS |
| |
|
|
|
|
|
|
|
|
|
1Q20 Change |
| |
|
|
|
1Q20 |
|
4Q19 |
|
1Q19 |
|
4Q19 |
|
1Q19 |
| |
|
|
|
|
|
|
|
|
|
$/bps |
|
% |
|
$/bps |
|
% |
| Tangible book value per common share: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Common shares—at period-end (GAAP) |
|
S |
|
|
426,586,533 |
|
|
|
433,121,083 |
|
|
|
461,116,723 |
|
|
|
(6,534,550 |
) |
|
|
(2 |
%) |
|
|
(34,530,190 |
) |
|
|
(7 |
%) |
| Common stockholders’ equity (GAAP) |
|
|
|
|
$20,380 |
|
|
|
$20,631 |
|
|
|
$20,399 |
|
|
|
($251 |
) |
|
|
(1 |
) |
|
|
($19 |
) |
|
|
— |
|
| Less: Goodwill (GAAP) |
|
|
|
|
7,050 |
|
|
|
7,044 |
|
|
|
7,040 |
|
|
|
6 |
|
|
|
— |
|
|
|
10 |
|
|
|
— |
|
| Less: Other intangible assets (GAAP) |
|
|
|
|
66 |
|
|
|
68 |
|
|
|
80 |
|
|
|
(2 |
) |
|
|
(3 |
) |
|
|
(14 |
) |
|
|
(18 |
) |
| Add: Deferred tax liabilities related to goodwill (GAAP) |
|
|
|
|
375 |
|
|
|
374 |
|
|
|
370 |
|
|
|
1 |
|
|
|
— |
|
|
|
5 |
|
|
|
1 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Tangible common equity |
|
T |
|
|
$13,639 |
|
|
|
$13,893 |
|
|
|
$13,649 |
|
|
|
($254 |
) |
|
|
(2 |
%) |
|
|
($10 |
) |
|
|
— |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Tangible book value per common share |
|
T/S |
|
|
$31.97 |
|
|
|
$32.08 |
|
|
|
$29.60 |
|
|
|
($0.11 |
) |
|
|
— |
% |
|
|
$2.37 |
|
|
|
8 |
% |
| Net income per average common share - basic and diluted and net income per average common share - basic and diluted, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average common shares outstanding - basic (GAAP) |
|
U |
|
|
427,718,421 |
|
|
|
434,684,606 |
|
|
|
460,713,172 |
|
|
|
(6,966,185 |
) |
|
|
(2 |
%) |
|
|
(32,994,751 |
) |
|
|
(7 |
%) |
| Average common shares outstanding - diluted (GAAP) |
|
V |
|
|
429,388,855 |
|
|
|
436,500,829 |
|
|
|
462,520,680 |
|
|
|
(7,111,974 |
) |
|
|
(2 |
) |
|
|
(33,131,825 |
) |
|
|
(7 |
) |
| Net income per average common share - basic (GAAP) |
|
M/U |
|
|
$0.03 |
|
|
|
$0.98 |
|
|
|
$0.92 |
|
|
|
($0.95 |
) |
|
|
(97 |
) |
|
|
($0.89 |
) |
|
|
(97 |
) |
| Net income per average common share - diluted (GAAP) |
|
M/V |
|
|
0.03 |
|
|
|
0.98 |
|
|
|
0.92 |
|
|
|
(0.95 |
) |
|
|
(97 |
) |
|
|
(0.89 |
) |
|
|
(97 |
) |
| Net income per average common share - basic, Underlying (non-GAAP) |
|
N/U |
|
|
0.09 |
|
|
|
0.99 |
|
|
|
0.93 |
|
|
|
(0.90 |
) |
|
|
(91 |
) |
|
|
(0.84 |
) |
|
|
(90 |
) |
| Net income per average common share - diluted, Underlying (non-GAAP) |
|
N/V |
|
|
0.09 |
|
|
|
0.99 |
|
|
|
0.93 |
|
|
|
(0.90 |
) |
|
|
(91 |
) |
|
|
(0.84 |
) |
|
|
(90 |
) |
19
Citizens Financial Group, Inc.
Key performance metrics, non-GAAP financial measures and reconciliations (continued)
(in millions, except share, per-share and ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
QUARTERLY TRENDS |
| |
|
|
|
|
|
|
|
1Q20 Change |
| |
|
1Q20 |
|
4Q19 |
|
1Q19 |
|
4Q19 |
|
1Q19 |
| |
|
|
|
|
|
|
|
$/bps |
|
% |
|
$/bps |
|
% |
| Salaries and employee benefits, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Salaries and employee benefits (GAAP) |
|
|
$549 |
|
|
|
$502 |
|
|
|
$509 |
|
|
|
$47 |
|
|
|
9 |
% |
|
|
$40 |
|
|
|
8 |
% |
| Less: Notable items |
|
|
10 |
|
|
|
6 |
|
|
|
1 |
|
|
|
4 |
|
|
|
67 |
|
|
|
9 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Salaries and employee benefits, Underlying (non-GAAP) |
|
|
$539 |
|
|
|
$496 |
|
|
|
$508 |
|
|
|
$43 |
|
|
|
9 |
% |
|
|
$31 |
|
|
|
6 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Equipment and software expense, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Equipment and software expense (GAAP) |
|
|
$133 |
|
|
|
$133 |
|
|
|
$125 |
|
|
|
$— |
|
|
|
— |
% |
|
|
$8 |
|
|
|
6 |
% |
| Less: Notable items |
|
|
1 |
|
|
|
3 |
|
|
|
— |
|
|
|
(2 |
) |
|
|
(67 |
) |
|
|
1 |
|
|
|
100 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Equipment and software expense, Underlying (non-GAAP) |
|
|
$132 |
|
|
|
$130 |
|
|
|
$125 |
|
|
|
$2 |
|
|
|
2 |
% |
|
|
$7 |
|
|
|
6 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Outside services, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Outside services (GAAP) |
|
|
$135 |
|
|
|
$142 |
|
|
|
$110 |
|
|
|
($7 |
) |
|
|
(5 |
%) |
|
|
$25 |
|
|
|
23 |
% |
| Less: Notable items |
|
|
18 |
|
|
|
20 |
|
|
|
4 |
|
|
|
(2 |
) |
|
|
(10 |
) |
|
|
14 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Outside services, Underlying (non-GAAP) |
|
|
$117 |
|
|
|
$122 |
|
|
|
$106 |
|
|
|
($5 |
) |
|
|
(4 |
%) |
|
|
$11 |
|
|
|
10 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Occupancy, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Occupancy (GAAP) |
|
|
$84 |
|
|
|
$88 |
|
|
|
$83 |
|
|
|
($4 |
) |
|
|
(5 |
%) |
|
|
$1 |
|
|
|
1 |
% |
| Less: Notable items |
|
|
4 |
|
|
|
8 |
|
|
|
— |
|
|
|
(4 |
) |
|
|
(50 |
) |
|
|
4 |
|
|
|
100 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Occupancy, Underlying (non-GAAP) |
|
|
$80 |
|
|
|
$80 |
|
|
|
$83 |
|
|
|
$— |
|
|
|
— |
% |
|
|
($3 |
) |
|
|
(4 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
20
Citizens Financial Group, Inc.
Key performance metrics, non-GAAP financial measures and
reconciliations - Underlying excluding the impact of COVID-19 on provision for credit losses
(in millions, except
share, per-share and ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
QUARTERLY TRENDS |
| |
|
|
|
|
|
|
|
|
|
1Q20 Change |
| |
|
|
|
1Q20 |
|
4Q19 |
|
1Q19 |
|
4Q19 |
|
1Q19 |
| |
|
|
|
|
|
|
|
|
|
$/bps |
|
% |
|
$/bps |
|
% |
| Net income available to common shareholders, Underlying excluding the impact of COVID-19: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income available to common shareholders (GAAP) |
|
A |
|
|
$12 |
|
|
|
$427 |
|
|
|
$424 |
|
|
|
($415 |
) |
|
|
(97 |
%) |
|
|
($412 |
) |
|
|
(97 |
%) |
| Add: Notable items |
|
|
|
|
25 |
|
|
|
4 |
|
|
|
4 |
|
|
|
21 |
|
|
|
NM |
|
|
|
21 |
|
|
|
NM |
|
| Add: Impact of COVID-19 |
|
|
|
|
365 |
|
|
|
— |
|
|
|
— |
|
|
|
365 |
|
|
|
100 |
|
|
|
365 |
|
|
|
100 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income available to common shareholders, Underlying excluding the impact of COVID-19 (non-GAAP) |
|
B |
|
|
$402 |
|
|
|
$431 |
|
|
|
$428 |
|
|
|
($29 |
) |
|
|
(7 |
%) |
|
|
($26 |
) |
|
|
(6 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Return on average tangible common equity, Underlying excluding the impact of COVID-19: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average common equity (GAAP) |
|
|
|
|
$20,223 |
|
|
|
$20,400 |
|
|
|
$19,942 |
|
|
|
($177 |
) |
|
|
(1 |
%) |
|
|
$281 |
|
|
|
1 |
% |
| Less: Average goodwill (GAAP) |
|
|
|
|
7,046 |
|
|
|
7,044 |
|
|
|
7,018 |
|
|
|
2 |
|
|
|
— |
|
|
|
28 |
|
|
|
— |
|
| Less: Average other intangibles (GAAP) |
|
|
|
|
67 |
|
|
|
69 |
|
|
|
59 |
|
|
|
(2 |
) |
|
|
(3 |
) |
|
|
8 |
|
|
|
14 |
|
| Add: Average deferred tax liabilities related to goodwill (GAAP) |
|
|
|
|
374 |
|
|
|
373 |
|
|
|
368 |
|
|
|
1 |
|
|
|
— |
|
|
|
6 |
|
|
|
2 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average tangible common equity |
|
C |
|
|
$13,484 |
|
|
|
$13,660 |
|
|
|
$13,233 |
|
|
|
($176 |
) |
|
|
(1 |
%) |
|
|
$251 |
|
|
|
2 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Return on average tangible common equity |
|
A/C |
|
|
0.36 |
% |
|
|
12.39 |
% |
|
|
13.00 |
% |
|
|
(1,203 |
) bps |
|
|
|
|
|
|
(1,264 |
) bps |
|
|
|
|
| Return on average tangible common equity, Underlying excluding the impact of COVID-19 (non-GAAP) |
|
B/C |
|
|
12.00 |
|
|
|
12.49 |
|
|
|
13.12 |
|
|
|
(49 |
) bps |
|
|
|
|
|
|
(112 |
) bps |
|
|
|
|
| Net income per average common share - basic and diluted, Underlying excluding the impact of COVID-19: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average common shares outstanding - basic (GAAP) |
|
D |
|
|
427,718,421 |
|
|
|
434,684,606 |
|
|
|
460,713,172 |
|
|
|
(6,966,185 |
) |
|
|
(2 |
%) |
|
|
(32,994,751 |
) |
|
|
(7 |
%) |
| Average common shares outstanding - diluted (GAAP) |
|
E |
|
|
429,388,855 |
|
|
|
436,500,829 |
|
|
|
462,520,680 |
|
|
|
(7,111,974 |
) |
|
|
(2 |
) |
|
|
(33,131,825 |
) |
|
|
(7 |
) |
| Net income per average common share - basic (GAAP) |
|
A/D |
|
|
$0.03 |
|
|
|
$0.98 |
|
|
|
$0.92 |
|
|
|
($0.95 |
) |
|
|
(97 |
) |
|
|
($0.89 |
) |
|
|
(97 |
) |
| Net income per average common share - diluted (GAAP) |
|
A/E |
|
|
0.03 |
|
|
|
0.98 |
|
|
|
0.92 |
|
|
|
(0.95 |
) |
|
|
(97 |
) |
|
|
(0.89 |
) |
|
|
(97 |
) |
| Net income per average common share - basic, Underlying excluding the impact of COVID-19 (non-GAAP) |
|
B/D |
|
|
0.94 |
|
|
|
0.99 |
|
|
|
0.93 |
|
|
|
(0.05 |
) |
|
|
(5 |
) |
|
|
0.01 |
|
|
|
1 |
|
| Net income per average common share - diluted, Underlying excluding the impact of COVID-19
(non-GAAP) |
|
B/E |
|
|
0.94 |
|
|
|
0.99 |
|
|
|
0.93 |
|
|
|
(0.05 |
) |
|
|
(5 |
) |
|
|
0.01 |
|
|
|
1 |
|
21
Citizens Financial Group, Inc.
Forward-Looking Statements
This document contains forward-looking statements within the meaning of Private Securities Litigation Reform Act of 1995. Statements regarding
potential future share repurchases and future dividends, as well as the potential effects of the COVID-19 pandemic on our business, operations, financial performance and prospects, are forward-looking
statements. Also, any statement that does not describe historical or current facts is a forward-looking statement. These statements often include the words “believes,” “expects,” “anticipates,” “estimates,”
“intends,” “plans,” “goals,” “targets,” “initiatives,” “potentially,” “probably,” “projects,” “outlook” or similar expressions or future conditional verbs such
as “may,” “will,” “should,” “would,” and “could.”
Forward-looking statements are based upon the current
beliefs and expectations of management, and on information currently available to management. Our statements speak as of the date hereof, and we do not assume any obligation to update these statements or to update the reasons why actual results
could differ from those contained in such statements in light of new information or future events. We caution you, therefore, against relying on any of these forward-looking statements. They are neither statements of historical fact nor guarantees
or assurances of future performance. While there is no assurance that any list of risks and uncertainties or risk factors is complete, important factors that could cause actual results to differ materially from those in the forward-looking
statements include the following, without limitation:
| |
• |
|
Negative economic and political conditions that adversely affect the general economy, housing prices, the job market,
consumer confidence and spending habits which may affect, among other things, the level of nonperforming assets, charge-offs and provision expense; |
| |
• |
|
The rate of growth in the economy and employment levels, as well as general business and economic conditions, and
changes in the competitive environment; |
| |
• |
|
Our ability to implement our business strategy, including the cost savings and efficiency components, and achieve our
financial performance goals; |
| |
• |
|
The COVID-19 pandemic and its effects on the economic and business
environments in which we operate; |
| |
• |
|
Our ability to meet heightened supervisory requirements and expectations; |
| |
• |
|
Liabilities and business restrictions resulting from litigation and regulatory investigations; |
| |
• |
|
Our capital and liquidity requirements (including under regulatory capital standards, such as the U.S. Basel III
capital rules) and our ability to generate capital internally or raise capital on favorable terms; |
| |
• |
|
The effect of changes in interest rates on our net interest income, net interest margin and our mortgage
originations, mortgage servicing rights and mortgages held for sale; |
| |
• |
|
Changes in interest rates and market liquidity, as well as the magnitude of such changes, which may reduce interest
margins, impact funding sources and affect the ability to originate and distribute financial products in the primary and secondary markets; |
| |
• |
|
The effect of changes in the level of checking or savings account deposits on our funding costs and net interest
margin; |
| |
• |
|
Financial services reform and other current, pending or future legislation or regulation that could have a negative
effect on our revenue and businesses; |
| |
• |
|
A failure in or breach of our operational or security systems or infrastructure, or those of our third party vendors
or other service providers, including as a result of cyber-attacks; and |
| |
• |
|
Management’s ability to identify and manage these and other risks. |
In addition to the above factors, we also caution that the actual amounts and timing of any future common stock dividends or share repurchases will be subject to
various factors, including our capital position, financial performance, capital impacts of strategic initiatives, market conditions, and regulatory and accounting considerations, as well as any other factors that our Board of Directors deems
relevant in making such a determination. Therefore, there can be no assurance that we will repurchase shares or pay any dividends to holders of our common stock, or as to the amount of any such repurchases or dividends. Further, statements about the
effects of the COVID-19 pandemic on our business, operations, financial performance and prospects may constitute forward-looking statements and are subject to the risk that the actual impacts may differ,
possibly materially, from what is reflected in those forward-looking statements due to factors and future developments that are uncertain, unpredictable and in many cases beyond our control, including the scope and duration of the pandemic, actions
taken by governmental authorities in response to the pandemic, and the direct and indirect impact of the pandemic on our customers, third parties and us.
More information about factors that could cause actual results to differ materially from those described in the forward-looking
statements can be found under “Risk Factors” in our Annual Report on Form 10-K for the year ended
December 31, 2019.
Note: Per share amounts and ratios presented in this document are calculated using whole dollars.
CFG-IR
22
1Q20 Financial Results April 17, 2020
Exhibit 99.2
Forward-looking statements and use of
key performance metrics and non-GAAP financial measures Forward-Looking Statements. This document contains forward-looking statements within the meaning of Private Securities Litigation Reform Act of 1995. Statements regarding potential future share
repurchases and future dividends, as well as the potential effects of the COVID-19 pandemic on our business, operations, financial performance and prospects, are forward-looking statements. Also, any statement that does not describe historical or
current facts is a forward-looking statement. These statements often include the words “believes,” “expects,” “anticipates,” “estimates,” “intends,” “plans,”
“goals,” “targets,” “initiatives,” “potentially,” “probably,” “projects,” “outlook” or similar expressions or future conditional verbs such as “may,”
“will,” “should,” “would,” and “could.” Forward-looking statements are based upon the current beliefs and expectations of management, and on information currently available to management. Our
statements speak as of the date hereof, and we do not assume any obligation to update these statements or to update the reasons why actual results could differ from those contained in such statements in light of new information or future events. We
caution you, therefore, against relying on any of these forward-looking statements. They are neither statements of historical fact nor guarantees or assurances of future performance. While there is no assurance that any list of risks and
uncertainties or risk factors is complete, important factors that could cause actual results to differ materially from those in the forward-looking statements include the following, without limitation: Negative economic and political conditions that
adversely affect the general economy, housing prices, the job market, consumer confidence and spending habits which may affect, among other things, the level of nonperforming assets, charge-offs and provision expense; The rate of growth in the
economy and employment levels, as well as general business and economic conditions, and changes in the competitive environment; Our ability to implement our business strategy, including the cost savings and efficiency components, and achieve our
financial performance goals; The COVID-19 pandemic and its effects on the economic and business environments in which we operate; Our ability to meet heightened supervisory requirements and expectations; Liabilities and business restrictions
resulting from litigation and regulatory investigations; Our capital and liquidity requirements (including under regulatory capital standards, such as the U.S. Basel III capital rules) and our ability to generate capital internally or raise capital
on favorable terms; The effect of changes in interest rates on our net interest income, net interest margin and our mortgage originations, mortgage servicing rights and mortgages held for sale; Changes in interest rates and market liquidity, as well
as the magnitude of such changes, which may reduce interest margins, impact funding sources and affect the ability to originate and distribute financial products in the primary and secondary markets; The effect of changes in the level of checking or
savings account deposits on our funding costs and net interest margin; Financial services reform and other current, pending or future legislation or regulation that could have a negative effect on our revenue and businesses; A failure in or breach
of our operational or security systems or infrastructure, or those of our third party vendors or other service providers, including as a result of cyber-attacks; and Management’s ability to identify and manage these and other risks. In
addition to the above factors, we also caution that the actual amounts and timing of any future common stock dividends or share repurchases will be subject to various factors, including our capital position, financial performance, capital impacts of
strategic initiatives, market conditions, and regulatory and accounting considerations, as well as any other factors that our Board of Directors deems relevant in making such a determination. Therefore, there can be no assurance that we will
repurchase shares or pay any dividends to holders of our common stock, or as to the amount of any such repurchases or dividends. Further, statements about the effects of the COVID-19 pandemic on our business, operations, financial performance and
prospects may constitute forward-looking statements and are subject to the risk that the actual impacts may differ, possibly materially, from what is reflected in those forward-looking statements due to factors and future developments that are
uncertain, unpredictable and in many cases beyond our control, including the scope and duration of the pandemic, actions taken by governmental authorities in response to the pandemic, and the direct and indirect impact of the pandemic on our
customers, third parties and us. Further, statements about the estimated impact of CECL are forward-looking statements and are subject to the risk that the actual impact of CECL may differ, possibly materially, from what is reflected in those
statements due to, among other things, changes in macroeconomic conditions and any of the other variables discussed on page 6, as well as changes based on continuing review of models and assumptions. More information about factors that could cause
actual results to differ materially from those described in the forward-looking statements can be found under “Risk Factors” in our Annual Report on Form 10-K for the year ended December 31, 2019. Key Performance Metrics and Non-GAAP
Financial Measures and Reconciliations Key Performance Metrics: Our Management uses certain key performance metrics (KPMs) to gauge our progress against strategic and operational goals, as well as to compare our performance against peers. The KPMs
are referred to in our Registration Statements on Form S-1 and our external financial reports filed with the Securities and Exchange Commission. The KPMs include: Return on average tangible common equity (ROTCE); Efficiency ratio; Operating
leverage; and Common equity tier 1 capital ratio. Established targets for the KPMs are based on Management-reporting results which are currently referred to by the Company as “Underlying” results. In historical periods, these results may
have been referred to as “Adjusted” or “Adjusted/Underlying” results. We believe that Underlying results, which exclude notable items, provide the best representation of our underlying financial progress toward the KPMs as
the results exclude items that our Management does not consider indicative of our on-going financial performance. We have consistently shown investors our KPMs on a Management-reporting basis since our initial public offering in September of 2014.
KPMs that reflect Underlying results are considered non-GAAP financial measures. Non-GAAP Financial Measures: This document contains non-GAAP financial measures denoted as Underlying results and Underlying excluding the impact of COVID-19 on the
provision for credit losses. In historical periods, these results may have been referred to as Adjusted or Adjusted/Underlying results. Underlying results for any given reporting period exclude certain items that may occur in that period which
Management does not consider indicative of the Company’s on-going financial performance. We believe these non-GAAP financial measures provide useful information to investors because they are used by our Management to evaluate our operating
performance and make day-to-day operating decisions. In addition, we believe our Underlying results in any given reporting period reflect our on-going financial performance in that period and, accordingly, are useful to consider in addition to our
GAAP financial results. We further believe the presentation of Underlying results increases comparability of period-to-period results. The Appendix presents reconciliations of our non-GAAP measures to the most directly comparable GAAP financial
measures. Underlying excluding the impact of COVID-19 on the provision for credit losses reflects information valuable to investors given the outsized impact of the pandemic which is not expected to have a similar ongoing impact to our results given
the timing of the impact of adoption of CECL and the unprecedented nature of the COVID-19 pandemic Other companies may use similarly titled non-GAAP financial measures that are calculated differently from the way we calculate such measures.
Accordingly, our non-GAAP financial measures may not be comparable to similar measures used by such companies. We caution investors not to place undue reliance on such non-GAAP financial measures, but to consider them with the most directly
comparable GAAP measures. Non-GAAP financial measures have limitations as analytical tools and should not be considered in isolation or as a substitute for our results reported under GAAP.
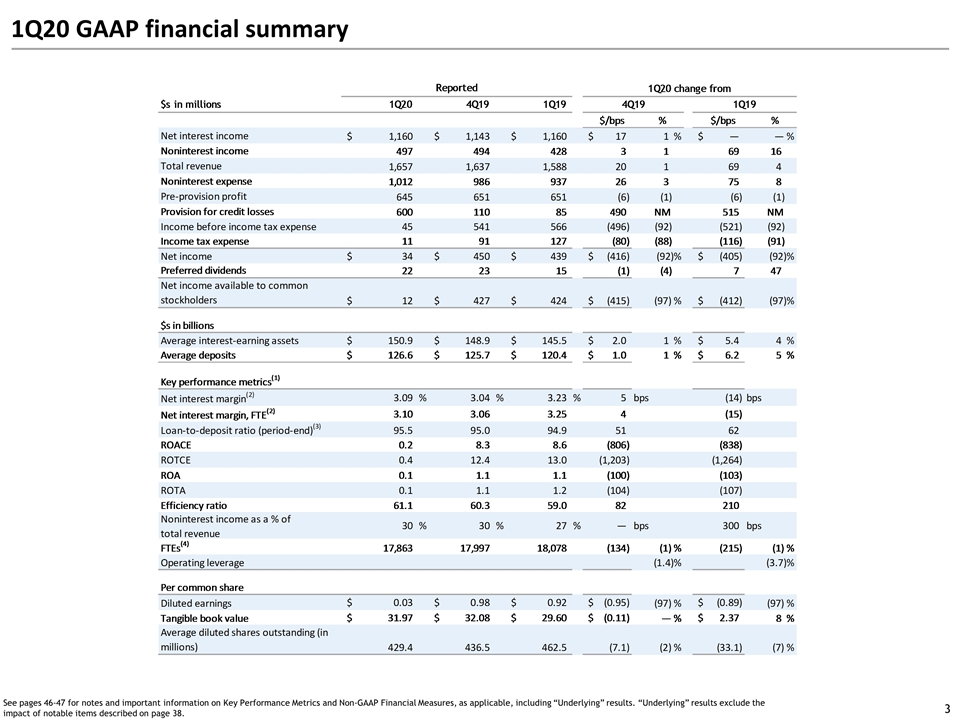
1Q20 GAAP financial summary See pages
46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page
38.
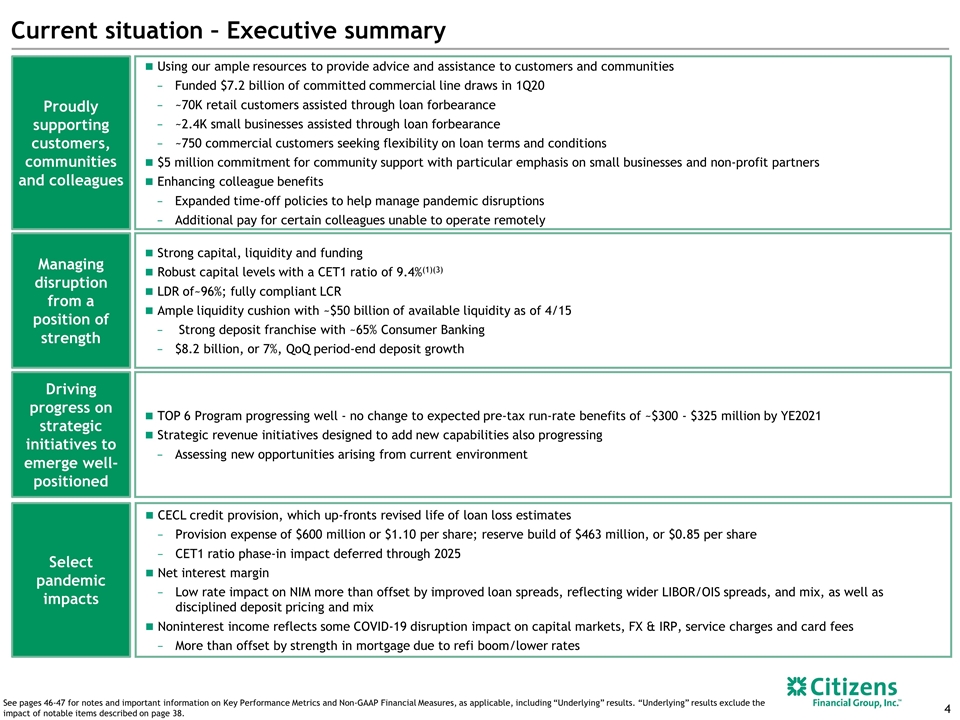
Driving progress on strategic
initiatives to emerge well-positioned TOP 6 Program progressing well - no change to expected pre-tax run-rate benefits of ~$300 - $325 million by YE2021 Strategic revenue initiatives designed to add new capabilities also progressing Assessing new
opportunities arising from current environment Managing disruption from a position of strength Strong capital, liquidity and funding Robust capital levels with a CET1 ratio of 9.4%(1)(3) LDR of~96%; fully compliant LCR Ample liquidity cushion with
~$50 billion of available liquidity as of 4/15 Strong deposit franchise with ~65% Consumer Banking $8.2 billion, or 7%, QoQ period-end deposit growth Current situation – Executive summary Proudly supporting customers, communities and
colleagues Using our ample resources to provide advice and assistance to customers and communities Funded $7.2 billion of committed commercial line draws in 1Q20 ~70K retail customers assisted through loan forbearance ~2.4K small businesses assisted
through loan forbearance ~750 commercial customers seeking flexibility on loan terms and conditions $5 million commitment for community support with particular emphasis on small businesses and non-profit partners Enhancing colleague benefits
Expanded time-off policies to help manage pandemic disruptions Additional pay for certain colleagues unable to operate remotely See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as
applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. Select pandemic impacts CECL credit provision, which up-fronts revised life of loan loss estimates
Provision expense of $600 million or $1.10 per share; reserve build of $463 million, or $0.85 per share CET1 ratio phase-in impact deferred through 2025 Net interest margin Low rate impact on NIM more than offset by improved loan spreads, reflecting
wider LIBOR/OIS spreads, and mix, as well as disciplined deposit pricing and mix Noninterest income reflects some COVID-19 disruption impact on capital markets, FX & IRP, service charges and card fees More than offset by strength in mortgage due
to refi boom/lower rates
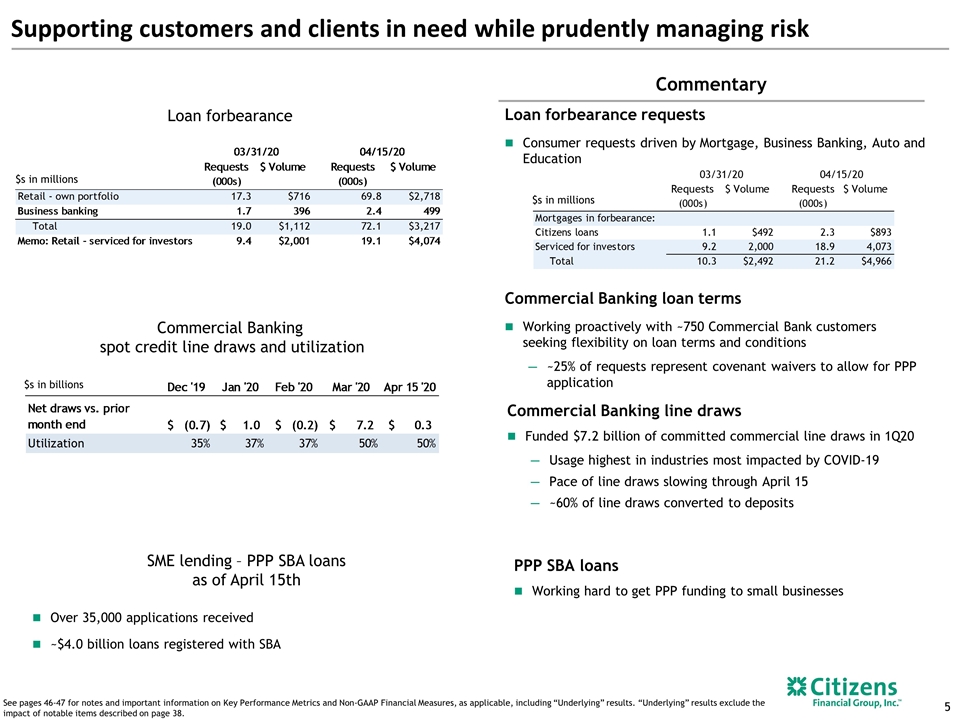
Supporting customers and clients in
need while prudently managing risk Commentary Loan forbearance requests Consumer requests driven by Mortgage, Business Banking, Auto and Education $s in billions See pages 46-47 for notes and important information on Key Performance Metrics and
Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. Commercial Banking spot credit line draws and utilization Loan
forbearance SME lending – PPP SBA loans as of April 15th Highlights Consumer Banking: Offering hardship relief with payment terms, late fees, service charge rebates and no-penalty access to CDs XX,XXX loan modifications serviced through April
15] Modifications up to 6 months for current impacted borrowers not treated as TDR [Repossessions and foreclosures paused] [Hold for color on portfolios most impacted] Commercial Banking: Funded [$7.2] billion of committed commercial line draws in
1Q20 [~xx% of line draws converted to deposits] [Pace of line draws slowing through April 15] [Hold for color on industries color utilization note: need to discuss] Placeholder increase in deposits PPP SBA loans Working hard to get PPP funding to
small businesses Commercial Banking line draws Funded $7.2 billion of committed commercial line draws in 1Q20 Usage highest in industries most impacted by COVID-19 Pace of line draws slowing through April 15 ~60% of line draws converted to deposits
Over 35,000 applications received ~$4.0 billion loans registered with SBA Commercial Banking loan terms Working proactively with ~750 Commercial Bank customers seeking flexibility on loan terms and conditions ~25% of requests represent covenant
waivers to allow for PPP application $s in millions $s in millions
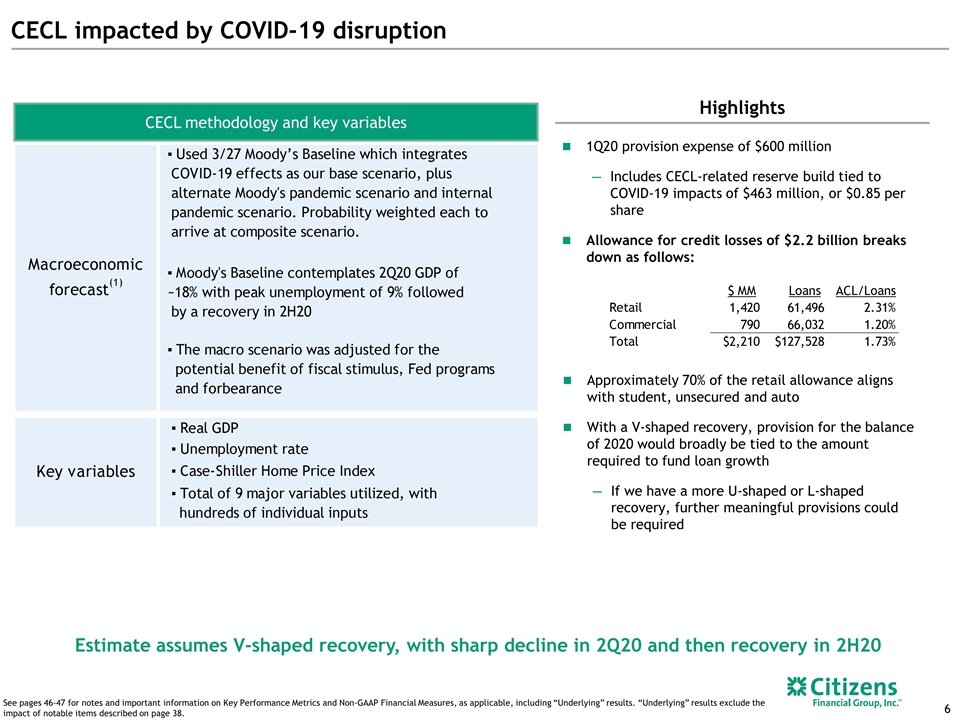
CECL impacted by COVID-19 disruption
Highlights 1Q20 provision expense of $600 million Includes CECL-related reserve build tied to COVID-19 impacts of $463 million, or $0.85 per share Allowance for credit losses of $2.2 billion breaks down as follows: Estimate assumes V-shaped
recovery, with sharp decline in 2Q20 and then recovery in 2H20 CECL methodology and key variables Approximately 70% of the retail allowance aligns with student, unsecured and auto With a V-shaped recovery, provision for the balance of 2020 would
broadly be tied to the amount required to fund loan growth If we have a more U-shaped or L-shaped recovery, further meaningful provisions could be required See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP
Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38.
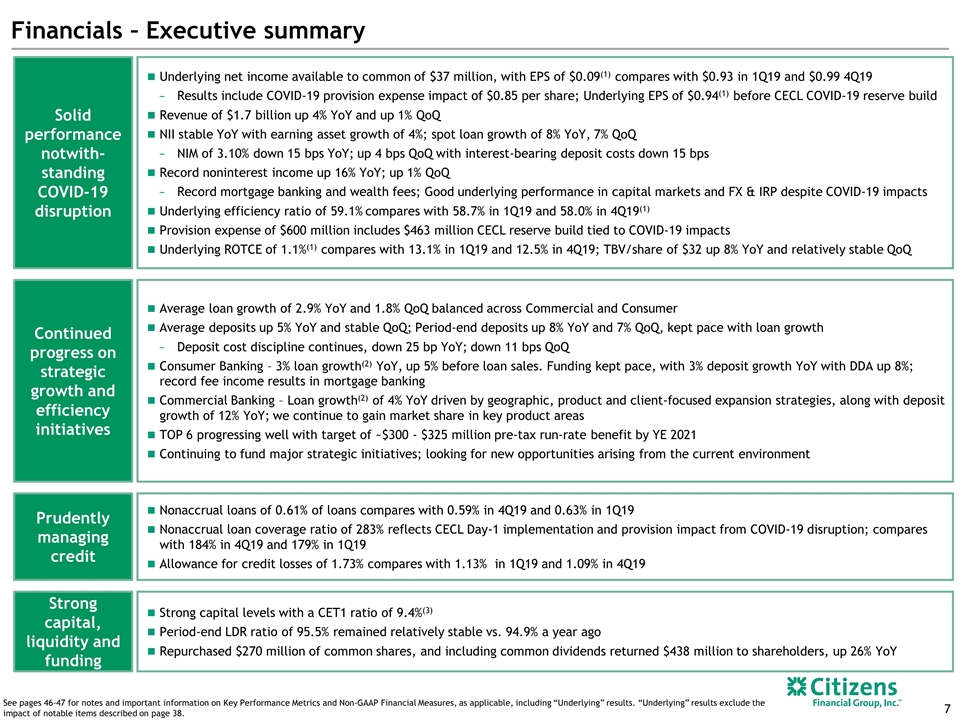
Financials – Executive summary
Prudently managing credit Nonaccrual loans of 0.61% of loans compares with 0.59% in 4Q19 and 0.63% in 1Q19 Nonaccrual loan coverage ratio of 283% reflects CECL Day-1 implementation and provision impact from COVID-19 disruption; compares with 184% in
4Q19 and 179% in 1Q19 Allowance for credit losses of 1.73% compares with 1.13% in 1Q19 and 1.09% in 4Q19 Continued progress on strategic growth and efficiency initiatives Average loan growth of 2.9% YoY and 1.8% QoQ balanced across Commercial and
Consumer Average deposits up 5% YoY and stable QoQ; Period-end deposits up 8% YoY and 7% QoQ, kept pace with loan growth Deposit cost discipline continues, down 25 bp YoY; down 11 bps QoQ Consumer Banking – 3% loan growth(2) YoY, up 5% before
loan sales. Funding kept pace, with 3% deposit growth YoY with DDA up 8%; record fee income results in mortgage banking Commercial Banking – Loan growth(2) of 4% YoY driven by geographic, product and client-focused expansion strategies, along
with deposit growth of 12% YoY; we continue to gain market share in key product areas TOP 6 progressing well with target of ~$300 - $325 million pre-tax run-rate benefit by YE 2021 Continuing to fund major strategic initiatives; looking for new
opportunities arising from the current environment Strong capital, liquidity and funding Strong capital levels with a CET1 ratio of 9.4%(3) Period-end LDR ratio of 95.5% remained relatively stable vs. 94.9% a year ago Repurchased $270 million of
common shares, and including common dividends returned $438 million to shareholders, up 26% YoY Solid performance notwith-standing COVID-19 disruption Underlying net income available to common of $37 million, with EPS of $0.09(1) compares with $0.93
in 1Q19 and $0.99 4Q19 Results include COVID-19 provision expense impact of $0.85 per share; Underlying EPS of $0.94(1) before CECL COVID-19 reserve build Revenue of $1.7 billion up 4% YoY and up 1% QoQ NII stable YoY with earning asset growth of
4%; spot loan growth of 8% YoY, 7% QoQ NIM of 3.10% down 15 bps YoY; up 4 bps QoQ with interest-bearing deposit costs down 15 bps Record noninterest income up 16% YoY; up 1% QoQ Record mortgage banking and wealth fees; Good underlying performance in
capital markets and FX & IRP despite COVID-19 impacts Underlying efficiency ratio of 59.1% compares with 58.7% in 1Q19 and 58.0% in 4Q19(1) Provision expense of $600 million includes $463 million CECL reserve build tied to COVID-19 impacts
Underlying ROTCE of 1.1%(1) compares with 13.1% in 1Q19 and 12.5% in 4Q19; TBV/share of $32 up 8% YoY and relatively stable QoQ See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as
applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38.
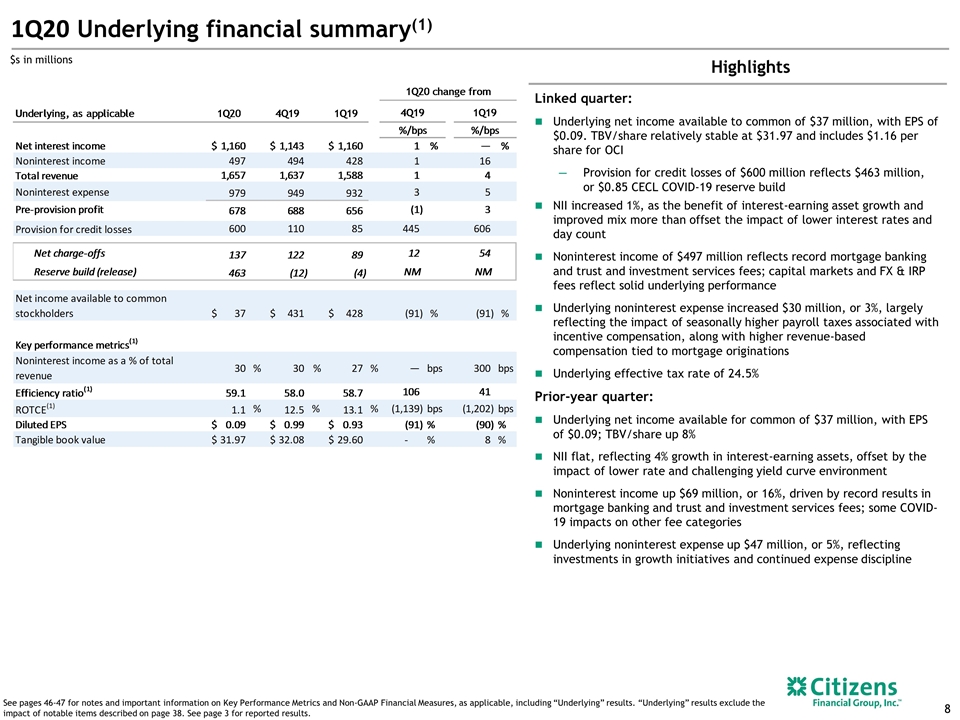
Highlights 1Q20 Underlying financial
summary(1) Linked quarter: Underlying net income available to common of $37 million, with EPS of $0.09. TBV/share relatively stable at $31.97 and includes $1.16 per share for OCI Provision for credit losses of $600 million reflects $463 million, or
$0.85 CECL COVID-19 reserve build NII increased 1%, as the benefit of interest-earning asset growth and improved mix more than offset the impact of lower interest rates and day count Noninterest income of $497 million reflects record mortgage
banking and trust and investment services fees; capital markets and FX & IRP fees reflect solid underlying performance Underlying noninterest expense increased $30 million, or 3%, largely reflecting the impact of seasonally higher payroll taxes
associated with incentive compensation, along with higher revenue-based compensation tied to mortgage originations Underlying effective tax rate of 24.5% Prior-year quarter: Underlying net income available for common of $37 million, with EPS of
$0.09; TBV/share up 8% NII flat, reflecting 4% growth in interest-earning assets, offset by the impact of lower rate and challenging yield curve environment Noninterest income up $69 million, or 16%, driven by record results in mortgage banking and
trust and investment services fees; some COVID-19 impacts on other fee categories Underlying noninterest expense up $47 million, or 5%, reflecting investments in growth initiatives and continued expense discipline See pages 46-47 for notes and
important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. See page 3 for
reported results. $s in millions
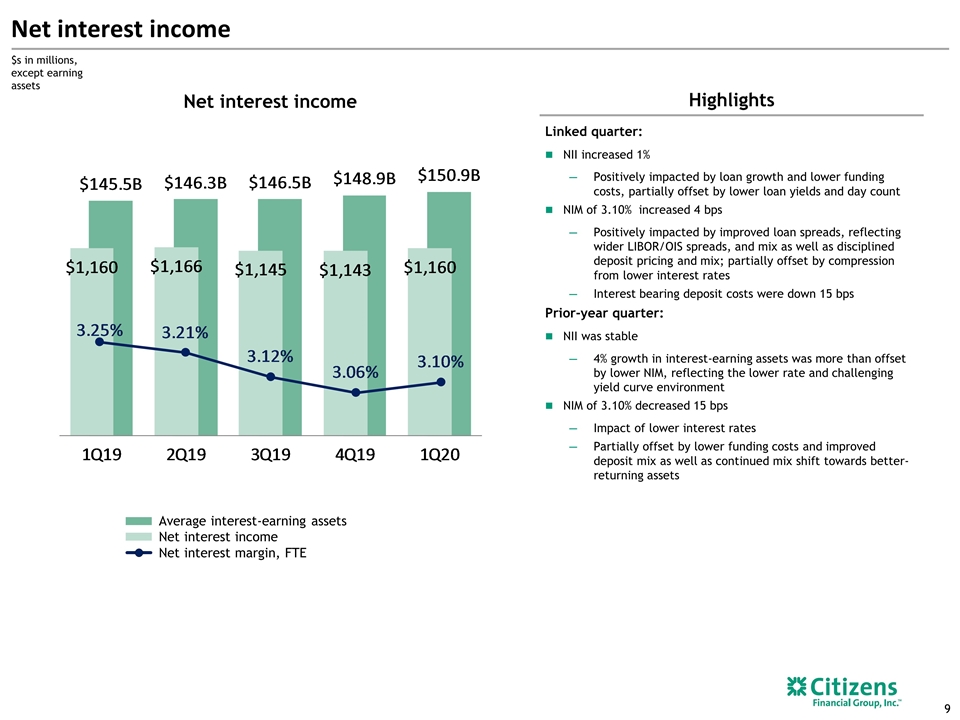
Highlights Net interest income Linked
quarter: NII increased 1% Positively impacted by loan growth and lower funding costs, partially offset by lower loan yields and day count NIM of 3.10% increased 4 bps Positively impacted by improved loan spreads, reflecting wider LIBOR/OIS spreads,
and mix as well as disciplined deposit pricing and mix; partially offset by compression from lower interest rates Interest bearing deposit costs were down 15 bps Prior-year quarter: NII was stable 4% growth in interest-earning assets was more than
offset by lower NIM, reflecting the lower rate and challenging yield curve environment NIM of 3.10% decreased 15 bps Impact of lower interest rates Partially offset by lower funding costs and improved deposit mix as well as continued mix shift
towards better-returning assets Net interest income $s in millions, except earning assets Average interest-earning assets Net interest income Net interest margin, FTE
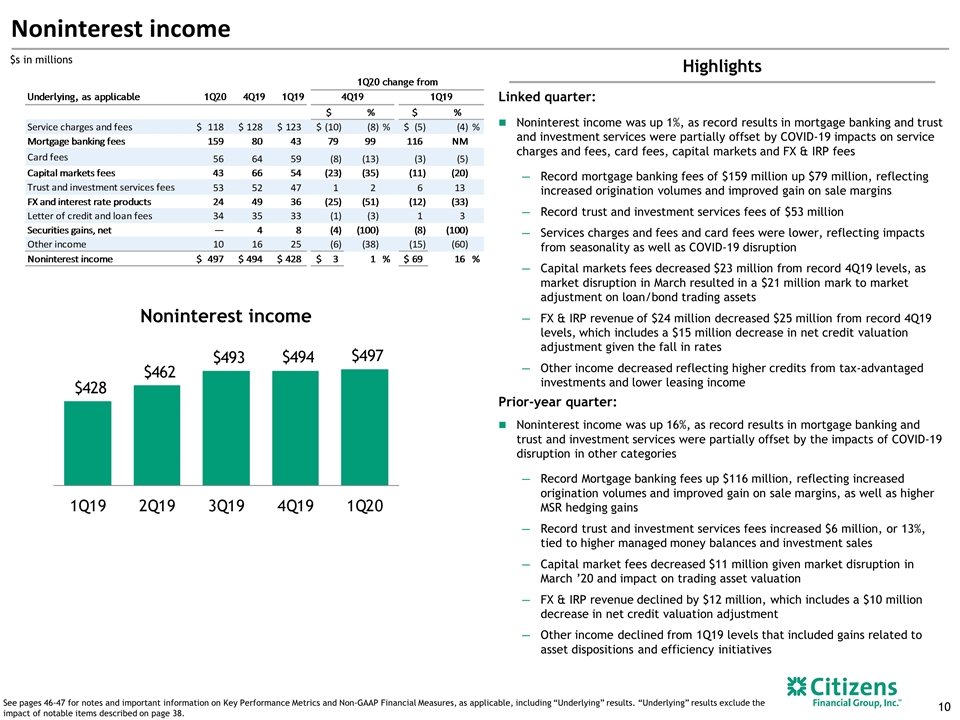
Noninterest income Highlights Linked
quarter: Noninterest income was up 1%, as record results in mortgage banking and trust and investment services were partially offset by COVID-19 impacts on service charges and fees, card fees, capital markets and FX & IRP fees Record mortgage
banking fees of $159 million up $79 million, reflecting increased origination volumes and improved gain on sale margins Record trust and investment services fees of $53 million Services charges and fees and card fees were lower, reflecting impacts
from seasonality as well as COVID-19 disruption Capital markets fees decreased $23 million from record 4Q19 levels, as market disruption in March resulted in a $21 million mark to market adjustment on loan/bond trading assets FX & IRP revenue of
$24 million decreased $25 million from record 4Q19 levels, which includes a $15 million decrease in net credit valuation adjustment given the fall in rates Other income decreased reflecting higher credits from tax-advantaged investments and lower
leasing income Prior-year quarter: Noninterest income was up 16%, as record results in mortgage banking and trust and investment services were partially offset by the impacts of COVID-19 disruption in other categories Record Mortgage banking fees up
$116 million, reflecting increased origination volumes and improved gain on sale margins, as well as higher MSR hedging gains Record trust and investment services fees increased $6 million, or 13%, tied to higher managed money balances and
investment sales Capital market fees decreased $11 million given market disruption in March ’20 and impact on trading asset valuation FX & IRP revenue declined by $12 million, which includes a $10 million decrease in net credit valuation
adjustment Other income declined from 1Q19 levels that included gains related to asset dispositions and efficiency initiatives $s in millions See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial
Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. Noninterest income
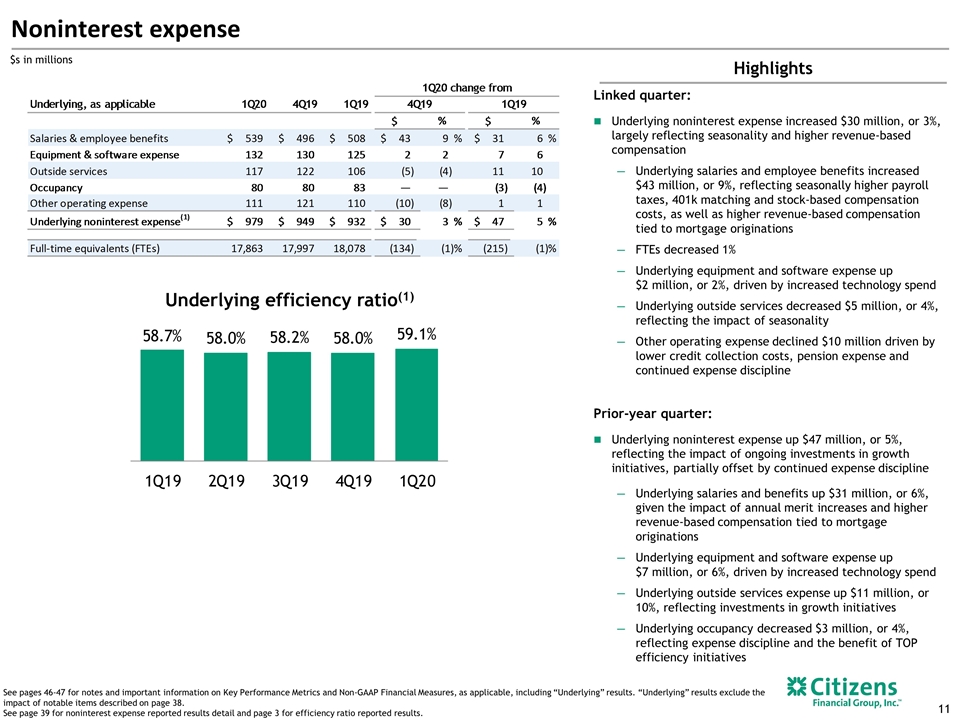
$s in millions Noninterest expense
Highlights Linked quarter: Underlying noninterest expense increased $30 million, or 3%, largely reflecting seasonality and higher revenue-based compensation Underlying salaries and employee benefits increased $43 million, or 9%, reflecting
seasonally higher payroll taxes, 401k matching and stock-based compensation costs, as well as higher revenue-based compensation tied to mortgage originations FTEs decreased 1% Underlying equipment and software expense up $2 million, or 2%, driven by
increased technology spend Underlying outside services decreased $5 million, or 4%, reflecting the impact of seasonality Other operating expense declined $10 million driven by lower credit collection costs, pension expense and continued expense
discipline Prior-year quarter: Underlying noninterest expense up $47 million, or 5%, reflecting the impact of ongoing investments in growth initiatives, partially offset by continued expense discipline Underlying salaries and benefits up $31
million, or 6%, given the impact of annual merit increases and higher revenue-based compensation tied to mortgage originations Underlying equipment and software expense up $7 million, or 6%, driven by increased technology spend Underlying outside
services expense up $11 million, or 10%, reflecting investments in growth initiatives Underlying occupancy decreased $3 million, or 4%, reflecting expense discipline and the benefit of TOP efficiency initiatives See pages 46-47 for notes and
important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. See page 39 for
noninterest expense reported results detail and page 3 for efficiency ratio reported results. Underlying efficiency ratio(1)
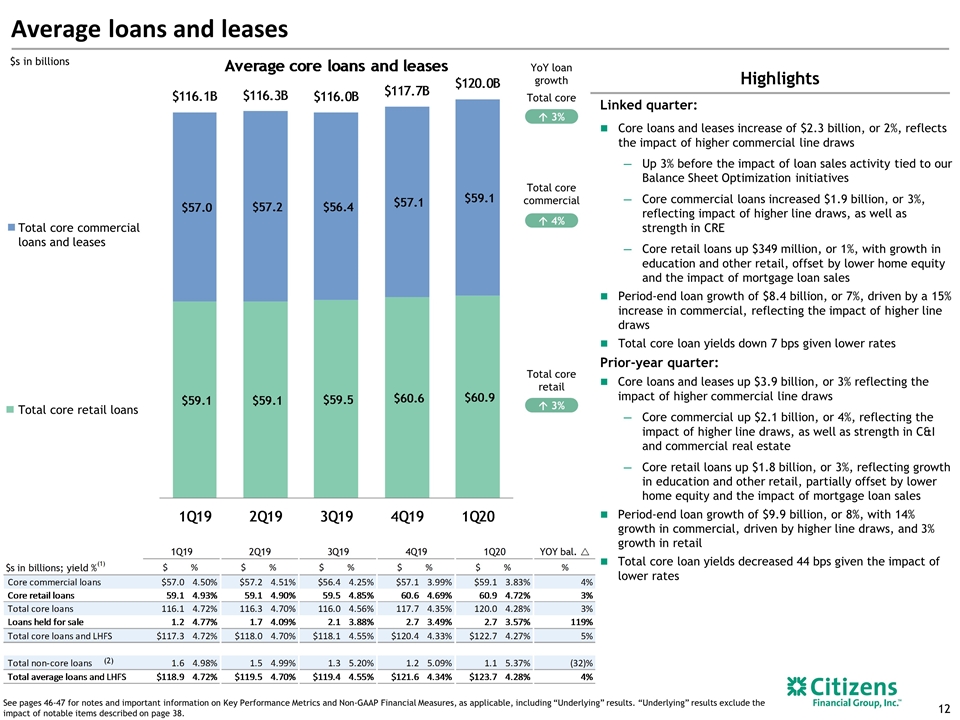
Average loans and leases Highlights
YoY loan growth á 3% á 3% á 4% Total core Total core retail Total core commercial Total core commercial loans and leases Total core retail loans (2) Linked quarter: Core loans and leases increase of $2.3 billion, or 2%, reflects the
impact of higher commercial line draws Up 3% before the impact of loan sales activity tied to our Balance Sheet Optimization initiatives Core commercial loans increased $1.9 billion, or 3%, reflecting impact of higher line draws, as well as strength
in CRE Core retail loans up $349 million, or 1%, with growth in education and other retail, offset by lower home equity and the impact of mortgage loan sales Period-end loan growth of $8.4 billion, or 7%, driven by a 15% increase in commercial,
reflecting the impact of higher line draws Total core loan yields down 7 bps given lower rates Prior-year quarter: Core loans and leases up $3.9 billion, or 3% reflecting the impact of higher commercial line draws Core commercial up $2.1 billion, or
4%, reflecting the impact of higher line draws, as well as strength in C&I and commercial real estate Core retail loans up $1.8 billion, or 3%, reflecting growth in education and other retail, partially offset by lower home equity and the impact
of mortgage loan sales Period-end loan growth of $9.9 billion, or 8%, with 14% growth in commercial, driven by higher line draws, and 3% growth in retail Total core loan yields decreased 44 bps given the impact of lower rates See pages 46-47 for
notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. $s in
billions
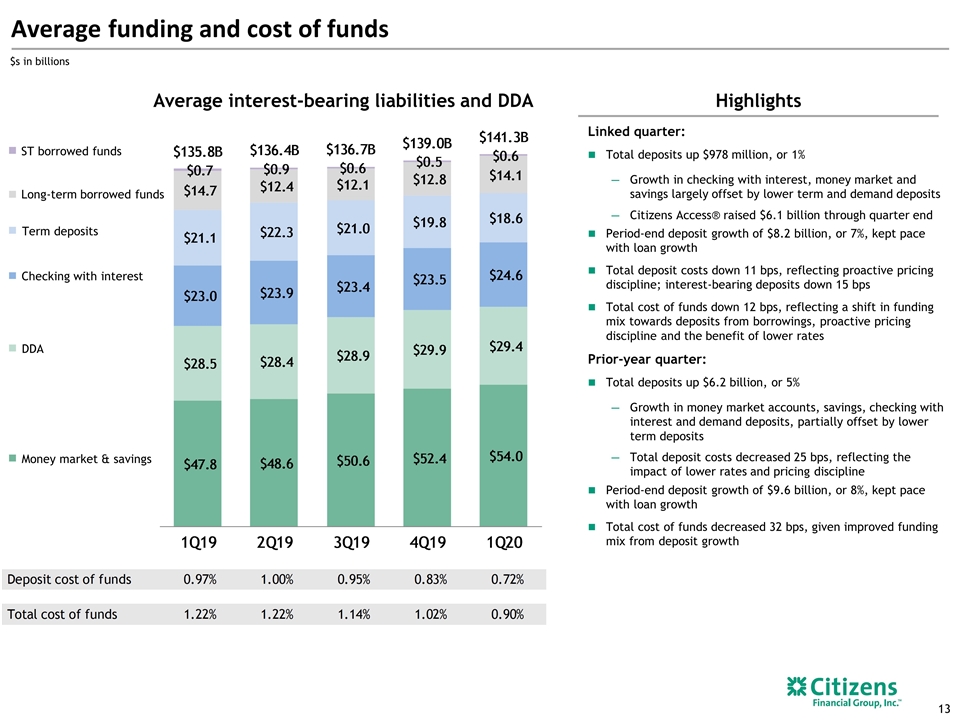
Linked quarter: Total deposits up
$978 million, or 1% Growth in checking with interest, money market and savings largely offset by lower term and demand deposits Citizens Access® raised $6.1 billion through quarter end Period-end deposit growth of $8.2 billion, or 7%, kept pace
with loan growth Total deposit costs down 11 bps, reflecting proactive pricing discipline; interest-bearing deposits down 15 bps Total cost of funds down 12 bps, reflecting a shift in funding mix towards deposits from borrowings, proactive pricing
discipline and the benefit of lower rates Prior-year quarter: Total deposits up $6.2 billion, or 5% Growth in money market accounts, savings, checking with interest and demand deposits, partially offset by lower term deposits Total deposit costs
decreased 25 bps, reflecting the impact of lower rates and pricing discipline Period-end deposit growth of $9.6 billion, or 8%, kept pace with loan growth Total cost of funds decreased 32 bps, given improved funding mix from deposit growth Average
funding and cost of funds Highlights $s in billions Average interest-bearing liabilities and DDA Long-term borrowed funds ST borrowed funds Term deposits Checking with interest DDA Money market & savings
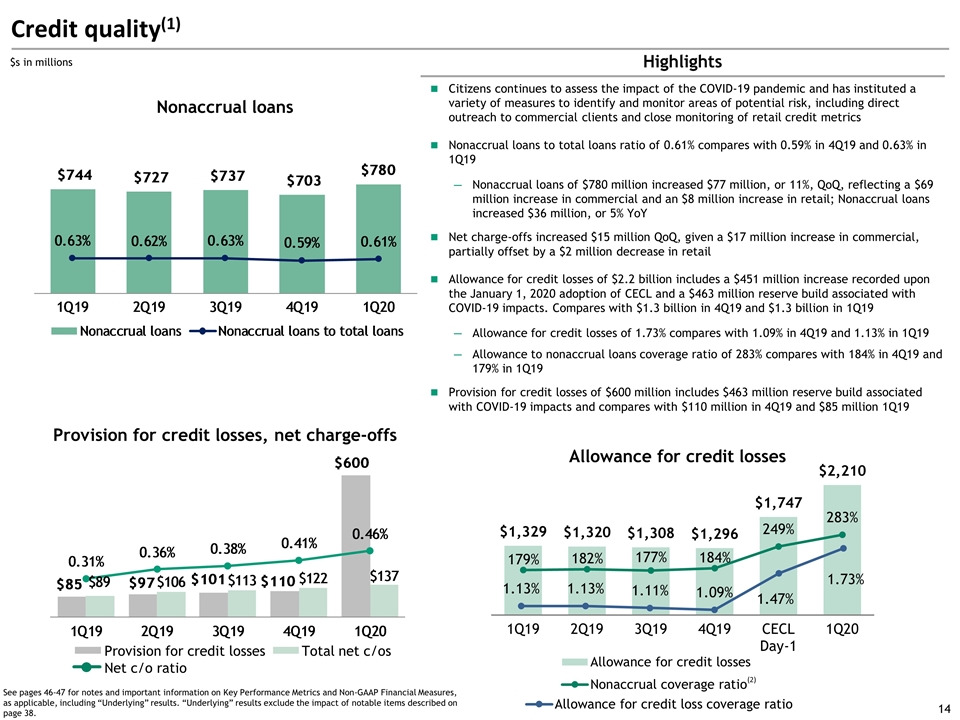
Citizens continues to assess the
impact of the COVID-19 pandemic and has instituted a variety of measures to identify and monitor areas of potential risk, including direct outreach to commercial clients and close monitoring of retail credit metrics Nonaccrual loans to total loans
ratio of 0.61% compares with 0.59% in 4Q19 and 0.63% in 1Q19 Nonaccrual loans of $780 million increased $77 million, or 11%, QoQ, reflecting a $69 million increase in commercial and an $8 million increase in retail; Nonaccrual loans increased $36
million, or 5% YoY Net charge-offs increased $15 million QoQ, given a $17 million increase in commercial, partially offset by a $2 million decrease in retail Allowance for credit losses of $2.2 billion includes a $451 million increase recorded upon
the January 1, 2020 adoption of CECL and a $463 million reserve build associated with COVID-19 impacts. Compares with $1.3 billion in 4Q19 and $1.3 billion in 1Q19 Allowance for credit losses of 1.73% compares with 1.09% in 4Q19 and 1.13% in 1Q19
Allowance to nonaccrual loans coverage ratio of 283% compares with 184% in 4Q19 and 179% in 1Q19 Provision for credit losses of $600 million includes $463 million reserve build associated with COVID-19 impacts and compares with $110 million in 4Q19
and $85 million 1Q19 Credit quality(1) $s in millions (2) Nonaccrual loans Allowance for credit losses Highlights Provision for credit losses, net charge-offs Provision for credit losses Total net c/os Net c/o ratio See pages 46-47 for notes and
important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38.
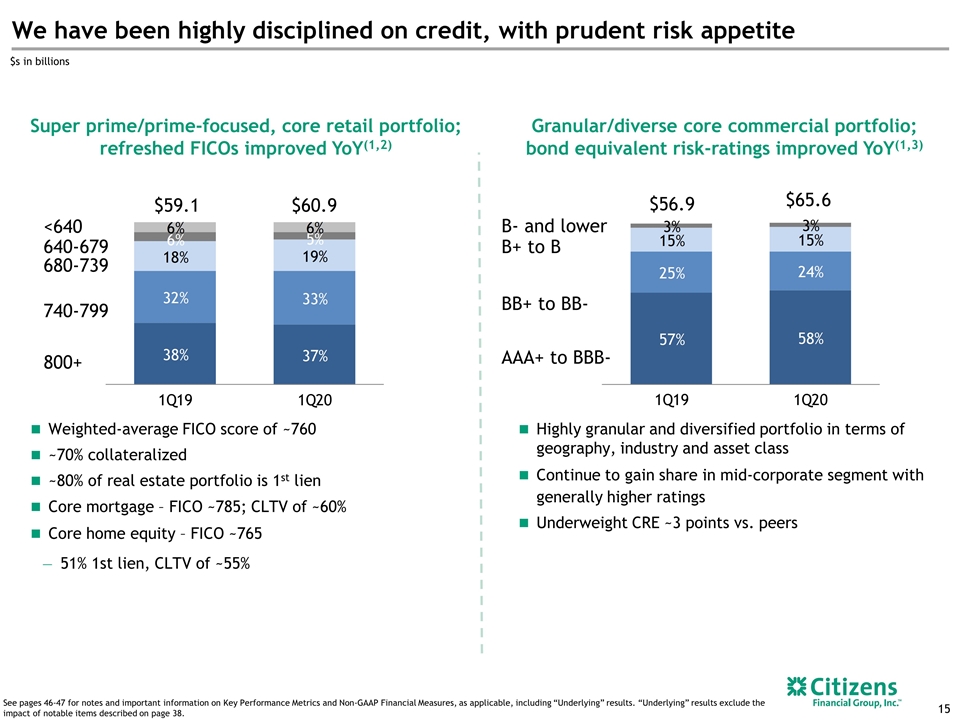
We have been highly disciplined on
credit, with prudent risk appetite Weighted-average FICO score of ~760 ~70% collateralized ~80% of real estate portfolio is 1st lien Core mortgage – FICO ~785; CLTV of ~60% Core home equity – FICO ~765 51% 1st lien, CLTV of ~55% Highly
granular and diversified portfolio in terms of geography, industry and asset class Continue to gain share in mid-corporate segment with generally higher ratings Underweight CRE ~3 points vs. peers 800+ 740-799 680-739 640-679 <640 $60.9 $59.1
$56.9 $65.6 B- and lower B+ to B BB+ to BB- AAA+ to BBB- Granular/diverse core commercial portfolio; bond equivalent risk-ratings improved YoY(1,3) Super prime/prime-focused, core retail portfolio; refreshed FICOs improved YoY(1,2) $s in billions
See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described
on page 38.
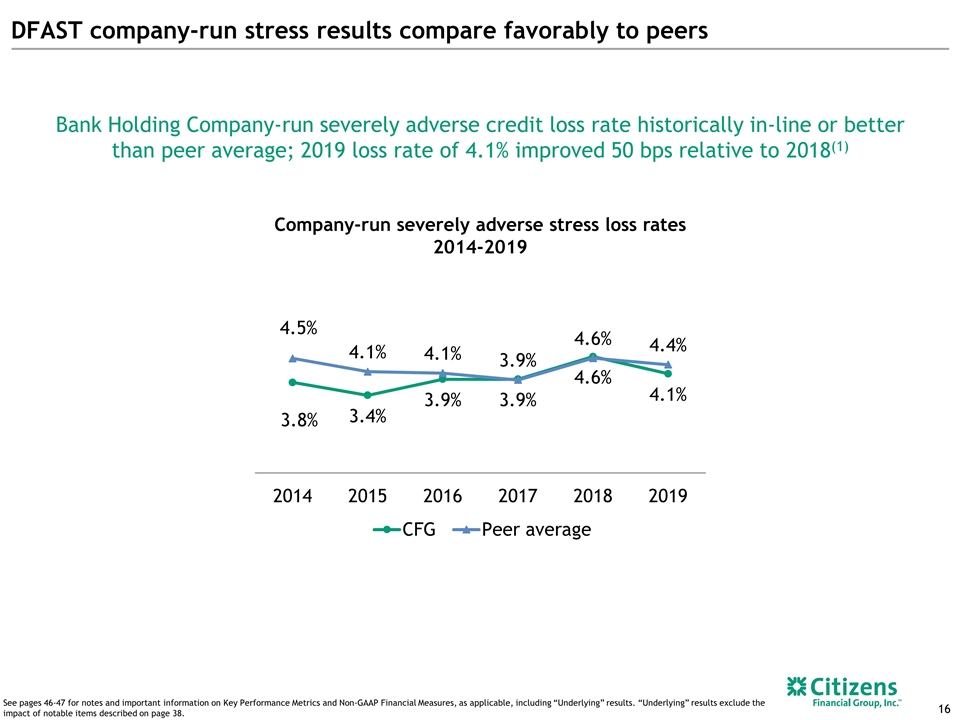
DFAST company-run stress results
compare favorably to peers Bank Holding Company-run severely adverse credit loss rate historically in-line or better than peer average; 2019 loss rate of 4.1% improved 50 bps relative to 2018(1) Company-run severely adverse stress loss rates
2014-2019 See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items
described on page 38.
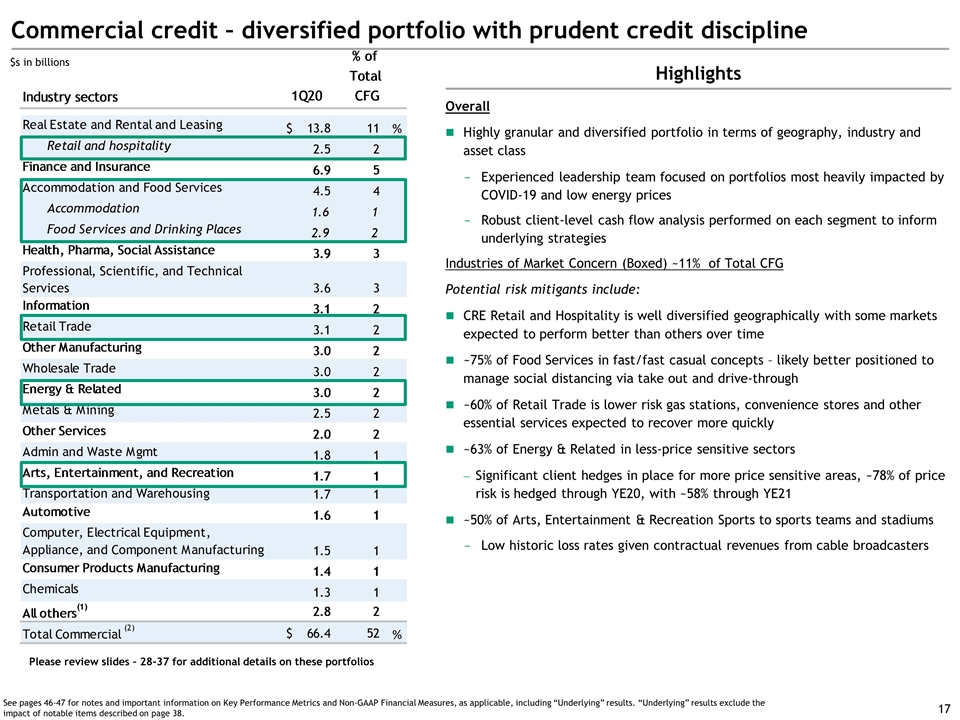
Commercial credit –
diversified portfolio with prudent credit discipline Overall Highly granular and diversified portfolio in terms of geography, industry and asset class Experienced leadership team focused on portfolios most heavily impacted by COVID-19 and low energy
prices Robust client-level cash flow analysis performed on each segment to inform underlying strategies Industries of Market Concern (Boxed) ~11% of Total CFG Potential risk mitigants include: CRE Retail and Hospitality is well diversified
geographically with some markets expected to perform better than others over time ~75% of Food Services in fast/fast casual concepts – likely better positioned to manage social distancing via take out and drive-through ~60% of Retail Trade is
lower risk gas stations, convenience stores and other essential services expected to recover more quickly ~63% of Energy & Related in less-price sensitive sectors Significant client hedges in place for more price sensitive areas, ~78% of price
risk is hedged through YE20, with ~58% through YE21 ~50% of Arts, Entertainment & Recreation Sports to sports teams and stadiums Low historic loss rates given contractual revenues from cable broadcasters Discussed w/S&C they suggest this is
the version $s in billions Placeholder for bullets – adding additional color on risk mitigation Highlights All other states(1) MA NY PA CA TX IL FL OH CT NJ MD GA MI VA See pages 46-47 for notes and important information on Key Performance
Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. Please review slides – 28-37 for additional details
on these portfolios
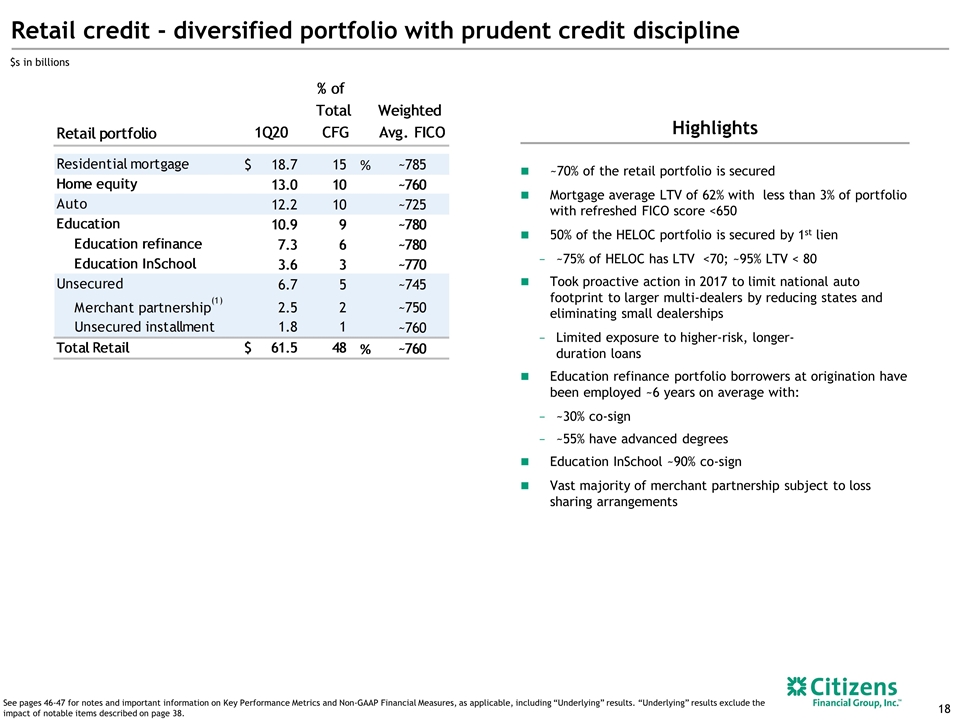
Retail credit - diversified
portfolio with prudent credit discipline Home Equity Indirect Auto Residential Mortgage Education Refi Credit Cards Other Non-Core Education InSchool $X.X billion 1Q20 retail portfolio(1) Highlights ~70% of the retail portfolio is secured Mortgage
average LTV of 62% with less than 3% of portfolio with refreshed FICO score <650 50% of the HELOC portfolio is secured by 1st lien ~75% of HELOC has LTV <70; ~95% LTV < 80 Took proactive action in 2017 to limit national auto footprint to
larger multi-dealers by reducing states and eliminating small dealerships Limited exposure to higher-risk, longer- duration loans Education refinance portfolio borrowers at origination have been employed ~6 years on average with: ~30% co-sign ~55%
have advanced degrees Education InSchool ~90% co-sign Vast majority of merchant partnership subject to loss sharing arrangements See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as
applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. $s in billions IR Note: Need to add footnote to merchant partnership FICO exclusion. Need to do math
on HELOC & Mortgage.
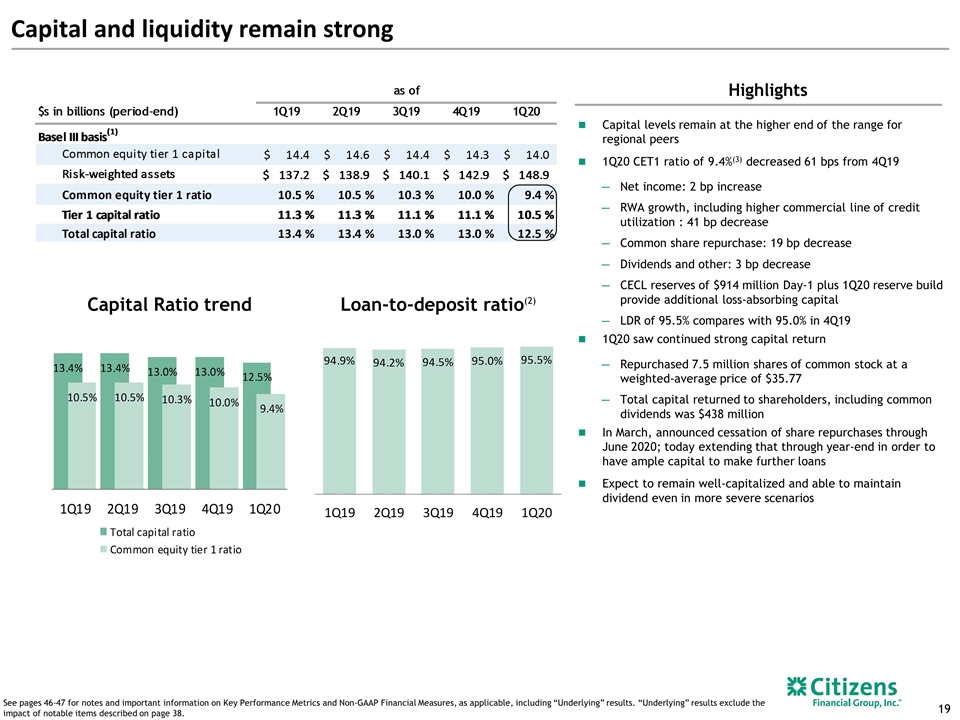
Capital levels remain at the higher
end of the range for regional peers 1Q20 CET1 ratio of 9.4%(3) decreased 61 bps from 4Q19 Net income: 2 bp increase RWA growth, including higher commercial line of credit utilization : 41 bp decrease Common share repurchase: 19 bp decrease Dividends
and other: 3 bp decrease CECL reserves of $914 million Day-1 plus 1Q20 reserve build provide additional loss-absorbing capital LDR of 95.5% compares with 95.0% in 4Q19 1Q20 saw continued strong capital return Repurchased 7.5 million shares of common
stock at a weighted-average price of $35.77 Total capital returned to shareholders, including common dividends was $438 million In March, announced cessation of share repurchases through June 2020; today extending that through year-end in order to
have ample capital to make further loans Expect to remain well-capitalized and able to maintain dividend even in more severe scenarios Capital and liquidity remain strong Highlights Capital Ratio trend Loan-to-deposit ratio(2) See pages 46-47 for
notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page
38.
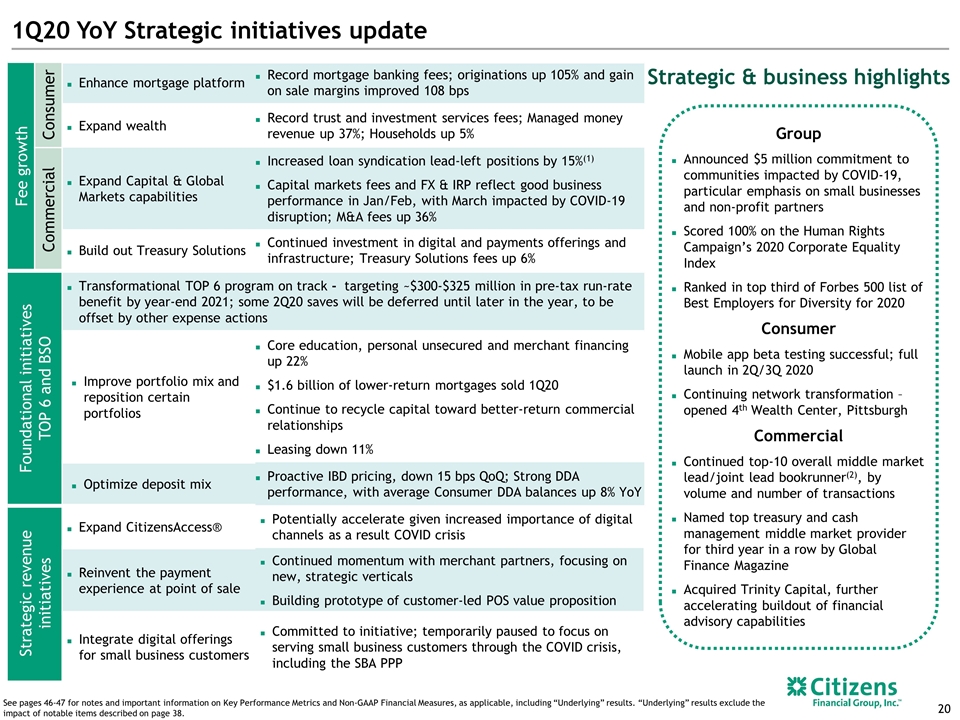
1Q20 YoY Strategic initiatives
update Fee growth Consumer Enhance mortgage platform Record mortgage banking fees; originations up 105% and gain on sale margins improved 108 bps Expand wealth Record trust and investment services fees; Managed money revenue up 37%; Households up 5%
Commercial Expand Capital & Global Markets capabilities Increased loan syndication lead-left positions by 15%(1) Capital markets fees and FX & IRP reflect good business performance in Jan/Feb, with March impacted by COVID-19 disruption;
M&A fees up 36% Build out Treasury Solutions Continued investment in digital and payments offerings and infrastructure; Treasury Solutions fees up 6% Foundational initiatives TOP 6 and BSO Transformational TOP 6 program on track - targeting
~$300-$325 million in pre-tax run-rate benefit by year-end 2021; some 2Q20 saves will be deferred until later in the year, to be offset by other expense actions Improve portfolio mix and reposition certain portfolios Core education, personal
unsecured and merchant financing up 22% $1.6 billion of lower-return mortgages sold 1Q20 Continue to recycle capital toward better-return commercial relationships Leasing down 11% Optimize deposit mix Proactive IBD pricing, down 15 bps QoQ; Strong
DDA performance, with average Consumer DDA balances up 8% YoY Strategic revenue initiatives Expand CitizensAccess® Potentially accelerate given increased importance of digital channels as a result COVID crisis Reinvent the payment experience at
point of sale Continued momentum with merchant partners, focusing on new, strategic verticals Building prototype of customer-led POS value proposition Integrate digital offerings for small business customers Committed to initiative; temporarily
paused to focus on serving small business customers through the COVID crisis, including the SBA PPP Strategic & business highlights Group Announced $5 million commitment to communities impacted by COVID-19, particular emphasis on small
businesses and non-profit partners Scored 100% on the Human Rights Campaign’s 2020 Corporate Equality Index Ranked in top third of Forbes 500 list of Best Employers for Diversity for 2020 Consumer Mobile app beta testing successful; full
launch in 2Q/3Q 2020 Continuing network transformation – opened 4th Wealth Center, Pittsburgh Commercial Continued top-10 overall middle market lead/joint lead bookrunner(2), by volume and number of transactions Named top treasury and cash
management middle market provider for third year in a row by Global Finance Magazine Acquired Trinity Capital, further accelerating buildout of financial advisory capabilities See pages 46-47 for notes and important information on Key Performance
Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38.
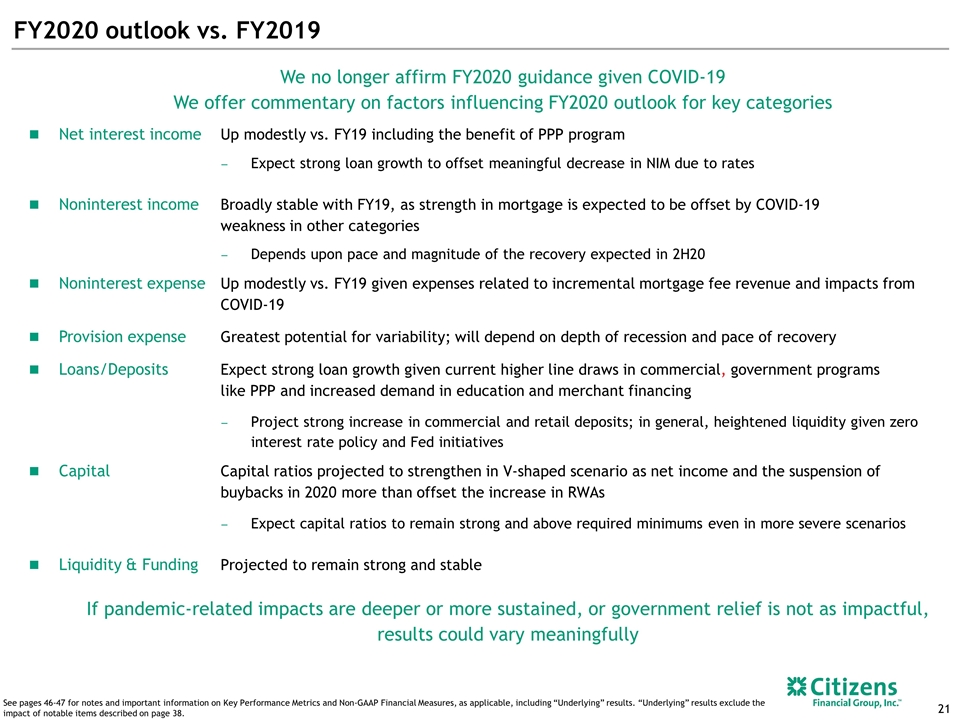
FY2020 outlook vs. FY2019 See pages
46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page
38. Net interest income Up modestly vs. FY19 including the benefit of PPP program Expect strong loan growth to offset meaningful decrease in NIM due to rates Noninterest income Broadly stable with FY19, as strength in mortgage is expected to be
offset by COVID-19 weakness in other categories Depends upon pace and magnitude of the recovery expected in 2H20 Noninterest expense Up modestly vs. FY19 given expenses related to incremental mortgage fee revenue and impacts from COVID-19 Provision
expense Greatest potential for variability; will depend on depth of recession and pace of recovery Loans/Deposits Expect strong loan growth given current higher line draws in commercial, government programs like PPP and increased demand in education
and merchant financing Project strong increase in commercial and retail deposits; in general, heightened liquidity given zero interest rate policy and Fed initiatives Capital Capital ratios projected to strengthen in V-shaped scenario as net income
and the suspension of buybacks in 2020 more than offset the increase in RWAs Expect capital ratios to remain strong and above required minimums even in more severe scenarios Liquidity & Funding Projected to remain strong and stable We no longer
affirm FY2020 guidance given COVID-19 We offer commentary on factors influencing FY2020 outlook for key categories If pandemic-related impacts are deeper or more sustained, or government relief is not as impactful, results could vary
meaningfully
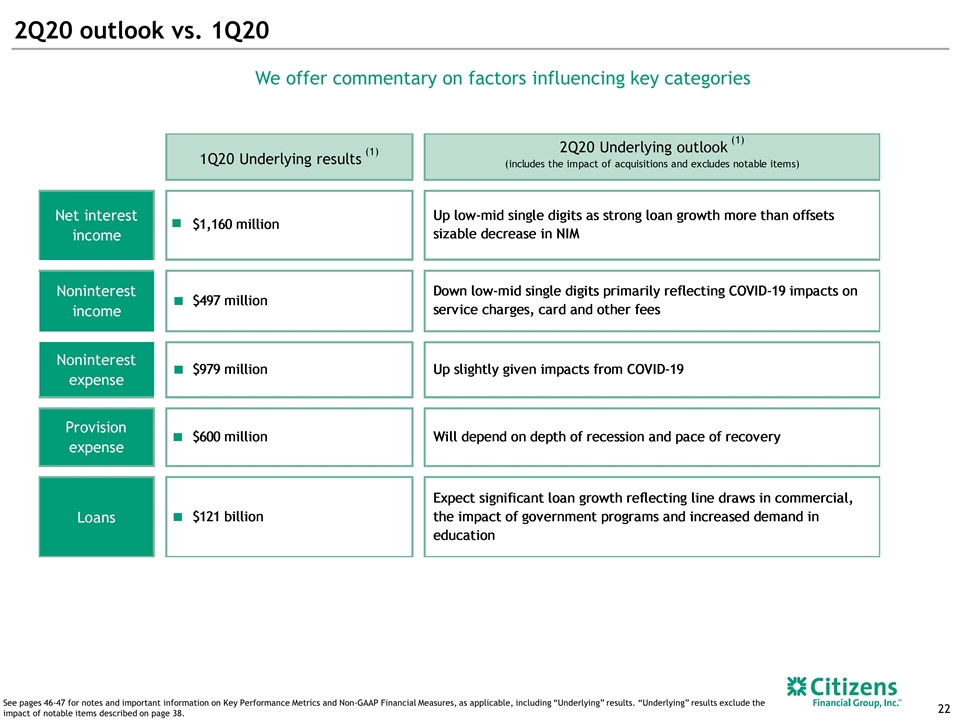
2Q20 outlook vs. 1Q20 See pages
46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page
38. We offer commentary on factors influencing key categories
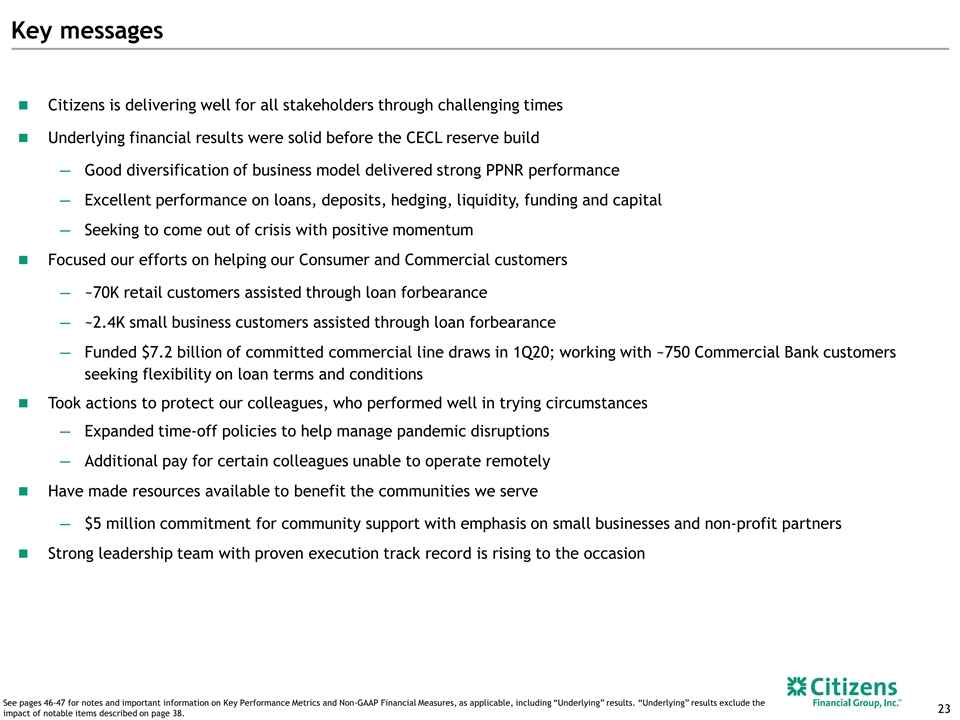
Key messages Citizens is delivering
well for all stakeholders through challenging times Underlying financial results were solid before the CECL reserve build Good diversification of business model delivered strong PPNR performance Excellent performance on loans, deposits, hedging,
liquidity, funding and capital Seeking to come out of crisis with positive momentum Focused our efforts on helping our Consumer and Commercial customers ~70K retail customers assisted through loan forbearance ~2.4K small business customers assisted
through loan forbearance Funded $7.2 billion of committed commercial line draws in 1Q20; working with ~750 Commercial Bank customers seeking flexibility on loan terms and conditions Took actions to protect our colleagues, who performed well in
trying circumstances Expanded time-off policies to help manage pandemic disruptions Additional pay for certain colleagues unable to operate remotely Have made resources available to benefit the communities we serve $5 million commitment for
community support with emphasis on small businesses and non-profit partners Strong leadership team with proven execution track record is rising to the occasion See pages 46-47 for notes and important information on Key Performance Metrics and
Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38.
Appendix
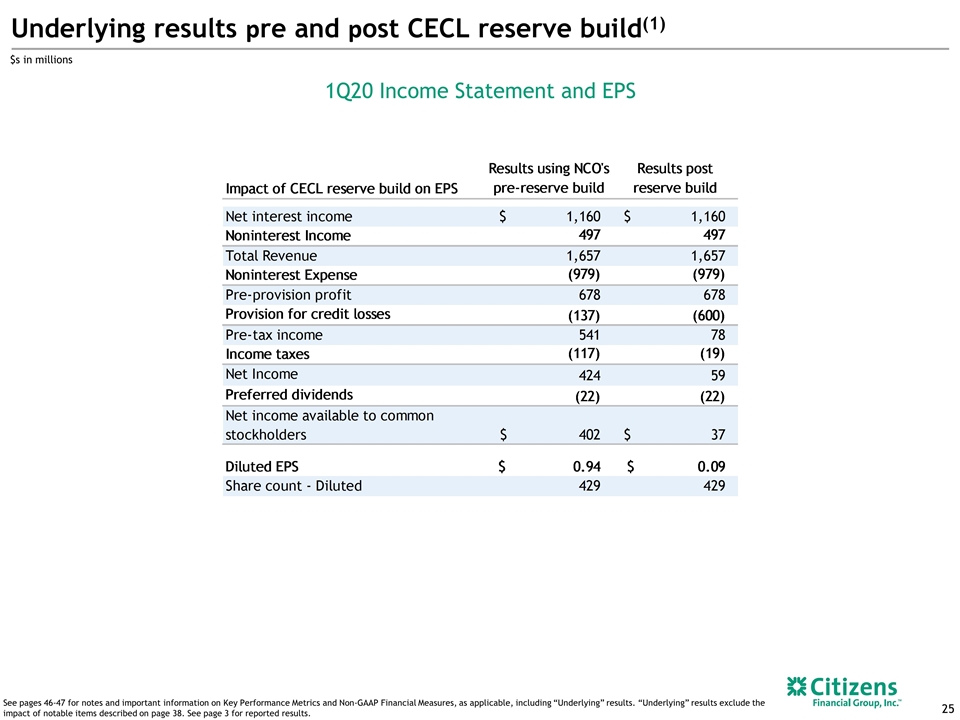
Underlying results pre and post CECL
reserve build(1) See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of
notable items described on page 38. See page 3 for reported results. $s in millions 1Q20 Income Statement and EPS
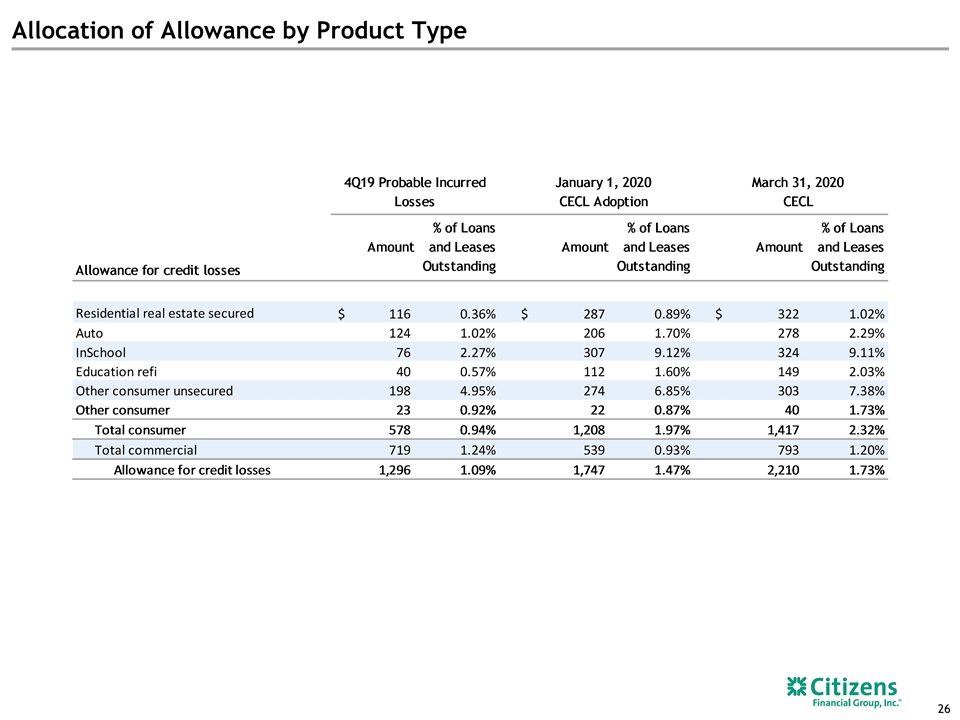
Allocation of Allowance by Product
Type
Analysis of selected loan portfolios
page CRE: Retail & Hospitality 28 Accommodation & Food Services 29 Retail Trade 30 Energy & Related 31 Arts, Entertainment & Recreation 32 Core mortgage portfolio overview 33 Core home equity portfolio 34 Auto 35 Education 36
Unsecured 37
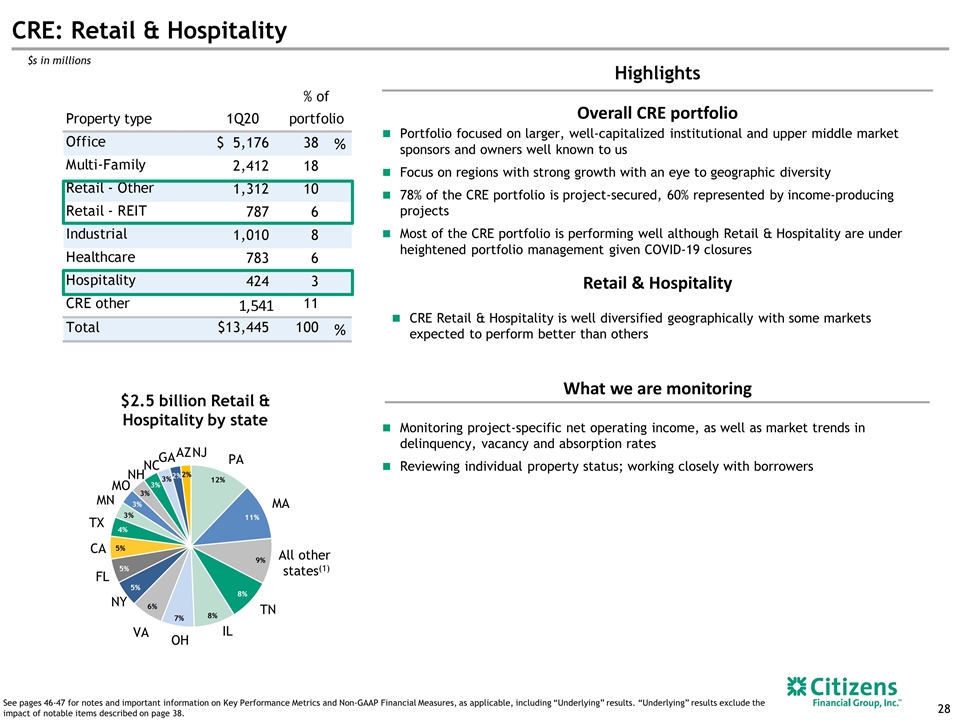
CRE: Retail & Hospitality
Portfolio focused on larger, well-capitalized institutional and upper middle market sponsors and owners well known to us Focus on regions with strong growth with an eye to geographic diversity 78% of the CRE portfolio is project-secured, 60%
represented by income-producing projects Most of the CRE portfolio is performing well although Retail & Hospitality are under heightened portfolio management given COVID-19 closures by Property Type Office Multi-family Industrial Land Retail
Non-CRE Collateral Highlights Hospitality Other CRE collateral Healthcare Unsecured Indirect retail outstandings are real estate loans where the underlying tenants under the borrower are retailers 48% with an equivalent risk rating of BB or higher
~90% of investor CRE retail loans are income-producing 94% of investor CRE retail portfolio is secured by multi-tenant centers (diverse income streams, variety of tenants and lower impact of a single store closure) 61% are mix of neighborhood retail
centers & power centers (“big box” & smaller retailer mix) Highlights Remain underweight CRE vs. peers by [~3] points; [12%] of total loans vs. [16.5%] for peers [80%] of the CRE portfolio is project-secured [~60%] represented by
income-producing projects [~15%] REITs, with a particular focus on mid-caps Need to get average hold size; and rework geographic splits this Need to get average hold size; and rework geographic splits this Update for 1Q 1Q20 $X.X billion Commercial
Real Estate Line of Business(1) See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the
impact of notable items described on page 38. IR Note: Need to turn pies into tables and move to left; highlights on right. What we are monitoring Monitoring project-specific net operating income, as well as market trends in delinquency, vacancy and
absorption rates Reviewing individual property status; working closely with borrowers $s in millions Discussed w/MG – think we should keep info on entire portfolio because investors are used to seeing the entire CRE slide in our deck and may
suspect or wonder why we didn’t include. Overall CRE portfolio Retail & Hospitality CRE Retail & Hospitality is well diversified geographically with some markets expected to perform better than others $2.5 billion Retail &
Hospitality by state All other states(1) CA TX NY FL PA NC TN NH MA MN IL OH VA MO GA AZ NJ Property type 1Q20 % of portfolio Office $5,175.7750875241691 38.495662613406338 % Multi-Family 2,412.1793086168755 17.940972947488298 Retail - Other 1,312
9.7582117643656723 Retail - REIT 787 5.853439526338251 Industrial 1,010.4934333265873 7.5157080098336602 Healthcare 782.97341145848338 5.8234911241461109 Hospitality 423.53802712401546 3.1501324382147833 CRE other 1,541.1271031133458
11.462381576206889 Total $13,445.86371163476 100.00000000000001 % 13445.140784489997 Check point -5.4413326521171257E-2 Geography 1Q20 % of portfolio Out of Footprint $7,846.99097640952 58.363261936639219 % Mid-Atlantic 2,980.9655546619601
22.171412457828644 New England 1,315.50240408895 9.7842614600854549 Midwest 1,301.68184932957 9.6814688533453328 Total $13,445.14078449 100.00040470789865 % Check point 0 Facility type 1Q20 % of portfolio Income Producing $8,016.5779837399996
59.624592675980573 % REIT 2,347.1176581700001 17.457066420964104 Construction 2,338.8840976500001 17.395827985652456 Other 324.12572670999998 2.4107374081669928 Unsecured 292.15289636 2.1729343218396777 Land 126.28242186 0.93924589529484814 Total
$13,445.140784489999 96.888224490764131 % Check point $0
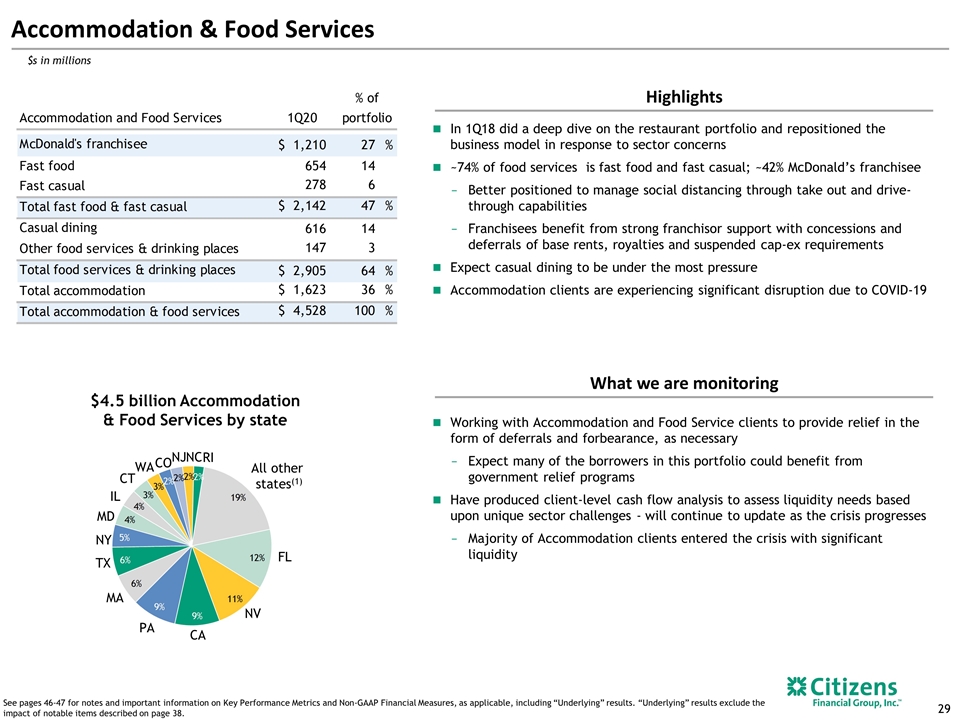
In 1Q18 did a deep dive on the
restaurant portfolio and repositioned the business model in response to sector concerns ~74% of food services is fast food and fast casual; ~42% McDonald’s franchisee Better positioned to manage social distancing through take out and
drive-through capabilities Franchisees benefit from strong franchisor support with concessions and deferrals of base rents, royalties and suspended cap-ex requirements Expect casual dining to be under the most pressure Accommodation clients are
experiencing significant disruption due to COVID-19 Accommodation & Food Services Highlights $s in millions IR Note: need to change state pie to NAISC code. Need to add loans outstanding. Need to make pies same size. Need to add footnotes. See
pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on
page 38. Total loans outstanding(2) Accommodations & Food Services All other loans What we are monitoring Working with Accommodation and Food Service clients to provide relief in the form of deferrals and forbearance, as necessary Expect many of
the borrowers in this portfolio could benefit from government relief programs Have produced client-level cash flow analysis to assess liquidity needs based upon unique sector challenges - will continue to update as the crisis progresses Majority of
Accommodation clients entered the crisis with significant liquidity All other states(1) CA TX NY FL PA CO CT NC IL NJ MD RI MA WA $4.5 billion Accommodation & Food Services by state NV
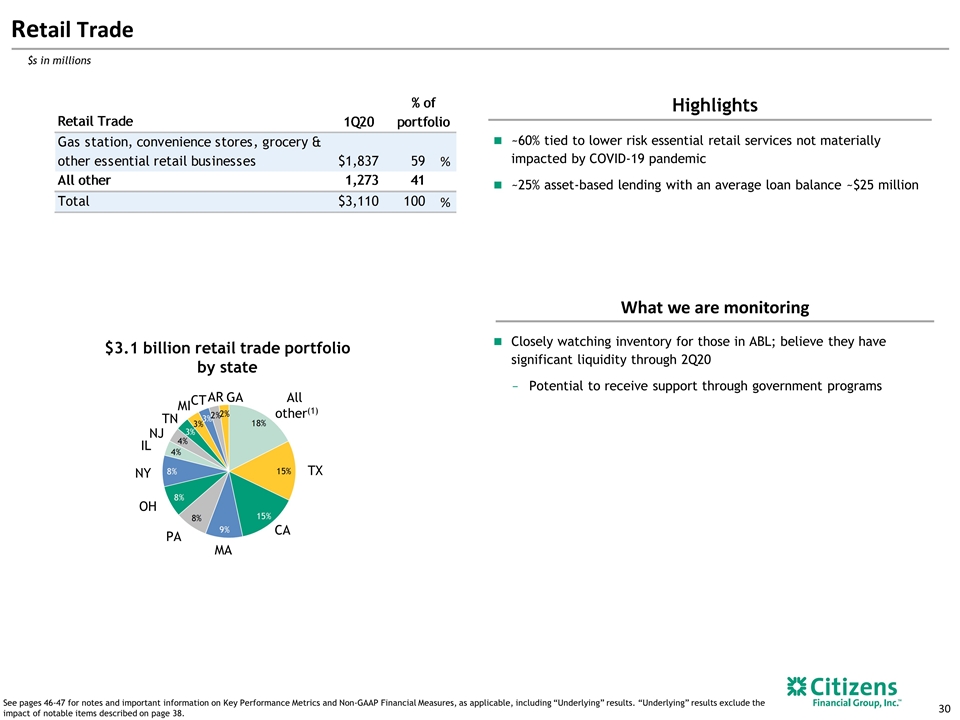
Retail Trade Highlights *All Other
includes: Furniture and Home Furnishing, Electronics and Appliance and Miscellaneous ~60% tied to lower risk essential retail services not materially impacted by COVID-19 pandemic ~25% asset-based lending with an average loan balance ~$25 million
(2) Need to get average hold size; and rework geographic splits this Update for 1Q Need to simplify graphic to the right too complicated to understand quickly also, not sure about the differentiation in how grocery anchored will perform vs. mall
department store vs. all other multi-tenant retail Working with CRE team to refine. 1Q20 $X.X billion direct retail portfolio(1) See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as
applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. IR Note: Need to turn pie into table and move to left; highlights on right What we are monitoring
Total portfolio of 43 accounts and $2.2B of TCL (may not all be in the Retail NAICS used by IR) Breakdown by sector as follows: Grocery Stores (20%), Specialty (bookstores, musical instruments) (28%), Drug Stores (2%), Apparel (25%), General
Merchandise & Dept Stores (25%) Risk today is that the traditional liquidation model will not work during this period, but expectation is that stores will re-open gradually Going into the crisis, ABL retail clients had a fair amount of
liquidity. Companies have furloughed employees and not paid rents to preserve liquidity since. Expectation that this will get them through May Grocery Store comps up 30-50% since the lockdown. Other essentials (e.g., hardware stores, drugstores)
also doing okay E-commerce is up 50-100% over the same period last year so for retailers that have it, it is helping to soften the blow Closely watching inventory for those in ABL; believe they have significant liquidity through 2Q20 Potential to
receive support through government programs $s in millions $3.1 billion retail trade portfolio by state MA PA All other(1) NY TN CA GA MI NJ TX OH IL AR CT
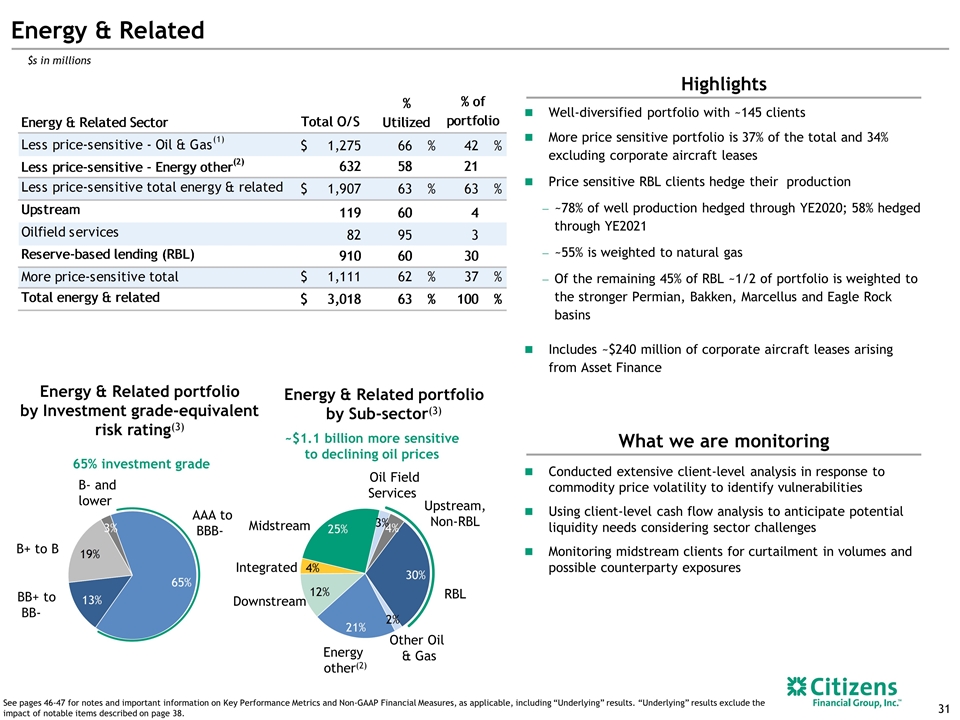
Energy & Related ~$1.1 billion
more sensitive to declining oil prices Midstream Integrated Downstream RBL Upstream, Non-RBL Oil Field Services Energy & Related portfolio by Sub-sector(3) (1) $s in millions B- and lower AAA to BBB- BB+ to BB- B+ to B 65% investment grade
Energy & Related portfolio by Investment grade-equivalent risk rating(3) Energy other(2) Highlights Well-diversified portfolio with ~145 clients More price sensitive portfolio is 37% of the total and 34% excluding corporate aircraft leases Price
sensitive RBL clients hedge their production ~78% of well production hedged through YE2020; 58% hedged through YE2021 ~55% is weighted to natural gas Of the remaining 45% of RBL ~1/2 of portfolio is weighted to the stronger Permian, Bakken,
Marcellus and Eagle Rock basins Includes ~$240 million of corporate aircraft leases arising from Asset Finance What we are monitoring Conducted extensive client-level analysis in response to commodity price volatility to identify vulnerabilities
Using client-level cash flow analysis to anticipate potential liquidity needs considering sector challenges Monitoring midstream clients for curtailment in volumes and possible counterparty exposures Other Oil & Gas Opt. 1 See pages 46-47 for
notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page
38.
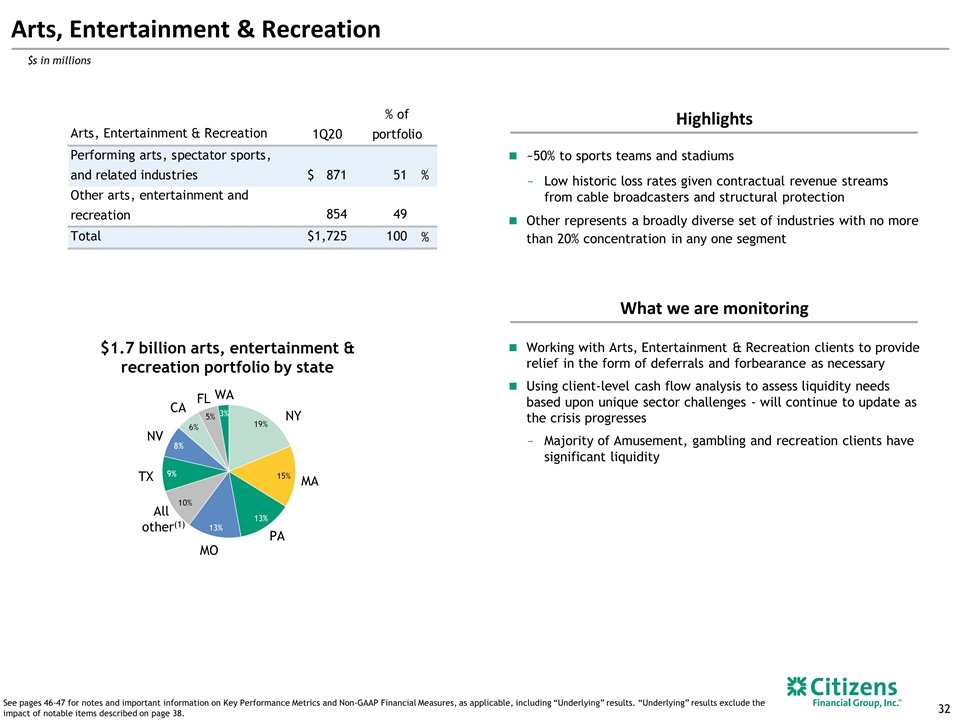
What we are monitoring Arts,
Entertainment & Recreation ~50% to sports teams and stadiums Low historic loss rates given contractual revenue streams from cable broadcasters and structural protection Other represents a broadly diverse set of industries with no more than 20%
concentration in any one segment Highlights $s in millions $1.7 billion arts, entertainment & recreation portfolio by state See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as
applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. MA PA All other(1) NY MO CA WA FL NV IR Note: Need to add footnotes Working with Arts, Entertainment
& Recreation clients to provide relief in the form of deferrals and forbearance as necessary Using client-level cash flow analysis to assess liquidity needs based upon unique sector challenges - will continue to update as the crisis progresses
Majority of Amusement, gambling and recreation clients have significant liquidity TX Arts, Entertainment & Recreation 1Q20 % of portfolio Performing arts, spectator sports, and related industries $871.21910240000022 50.508031788507047 % Other
arts, entertainment and recreation 853.69289981000009 49.49196821149296 Total $1,724.9120022100003 100 %
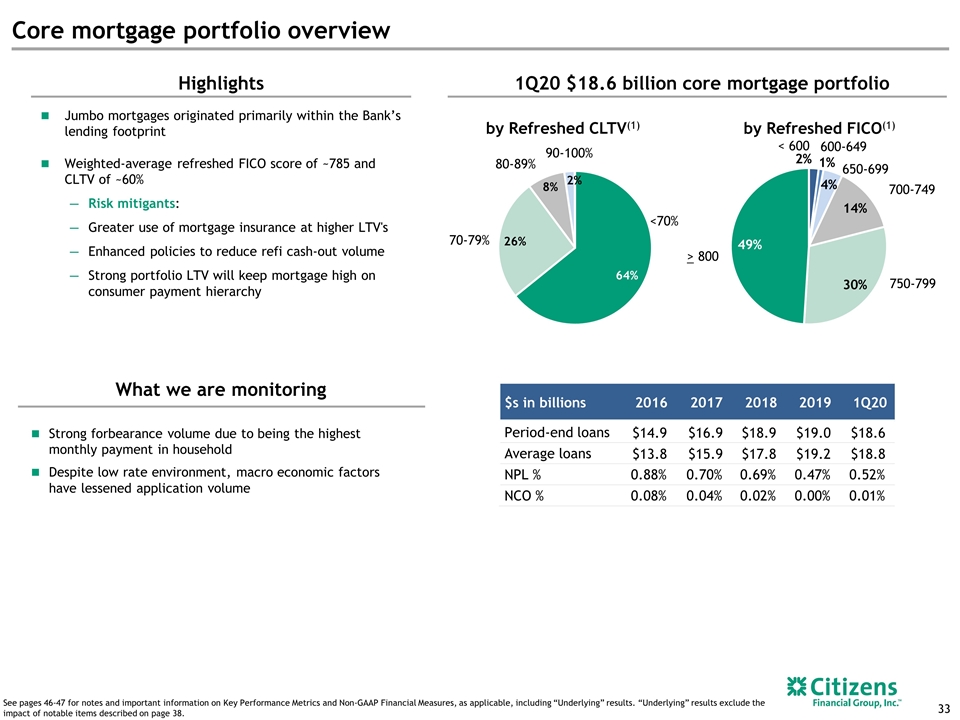
Core mortgage portfolio overview
Highlights Jumbo mortgages originated primarily within the Bank’s lending footprint Weighted-average refreshed FICO score of ~785 and CLTV of ~60% Risk mitigants: Greater use of mortgage insurance at higher LTV's Enhanced policies to reduce
refi cash-out volume Strong portfolio LTV will keep mortgage high on consumer payment hierarchy 1Q20 $18.6 billion core mortgage portfolio Origination detail(2) $s in billions $s in billions 2016 2017 2018 2019 1Q20 Period-end loans $14.9 $16.9
$18.9 $19.0 $18.6 Average loans $13.8 $15.9 $17.8 $19.2 $18.8 NPL % 0.88% 0.70% 0.69% 0.47% 0.52% NCO % 0.08% 0.04% 0.02% 0.00% 0.01% See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as
applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. Strong forbearance volume due to being the highest monthly payment in household Despite low rate
environment, macro economic factors have lessened application volume by Refreshed CLTV(1) by Refreshed FICO(1) 90-100% 80-89% <70% < 600 600-649 700-749 > 800 650-699 750-799 2% 1% What we are monitoring 70-79%
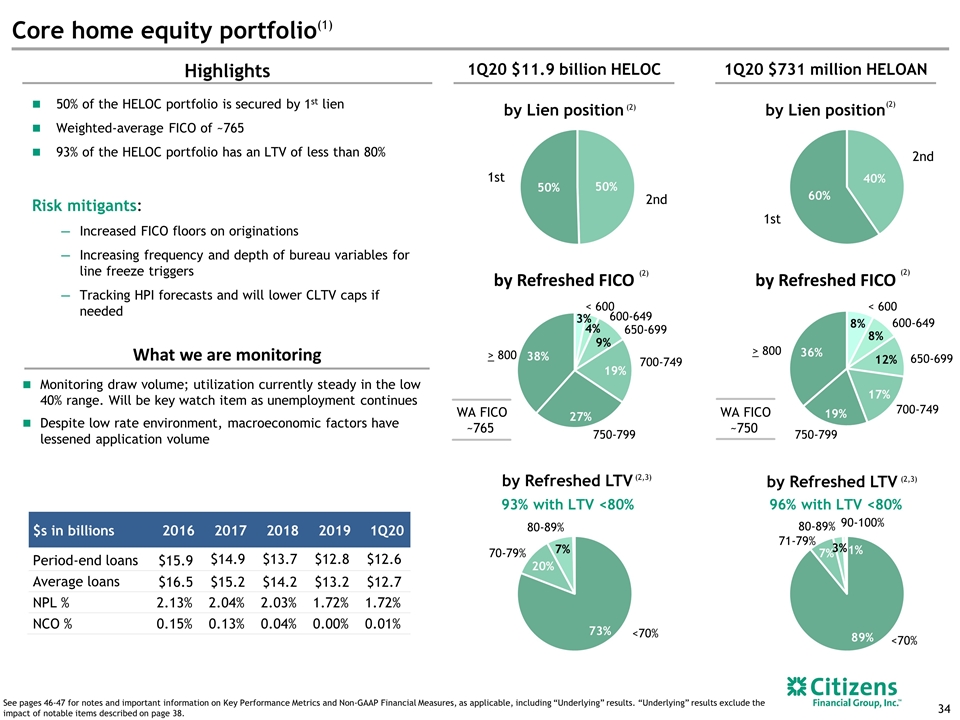
Highlights Core home equity
portfolio(1) 50% of the HELOC portfolio is secured by 1st lien Weighted-average FICO of ~765 93% of the HELOC portfolio has an LTV of less than 80% $s in billions 2016 2017 2018 2019 1Q20 Period-end loans $15.9 $14.9 $13.7 $12.8 $12.6 Average loans
$16.5 $15.2 $14.2 $13.2 $12.7 NPL % 2.13% 2.04% 2.03% 1.72% 1.72% NCO % 0.15% 0.13% 0.04% 0.00% 0.01% See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including
“Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. What we are monitoring Monitoring draw volume; utilization currently steady in the low 40% range. Will be key watch item as
unemployment continues Despite low rate environment, macroeconomic factors have lessened application volume 93% with LTV <80% by Lien position by Lien position 2nd 1st 2nd 1st (2) (2) 1Q20 $11.9 billion HELOC 1Q20 $731 million HELOAN by Refreshed
LTV by Refreshed FICO by Refreshed FICO <70% 71-79% <70% 70-79% 80-89% WA FICO ~765 WA FICO ~750 96% with LTV <80% (2) (2,3) (2) (2,3) by Refreshed LTV 80-89% < 600 600-649 700-749 > 800 650-699 750-799 < 600 600-649 700-749 >
800 650-699 750-799 Risk mitigants: Increased FICO floors on originations Increasing frequency and depth of bureau variables for line freeze triggers Tracking HPI forecasts and will lower CLTV caps if needed 90-100%
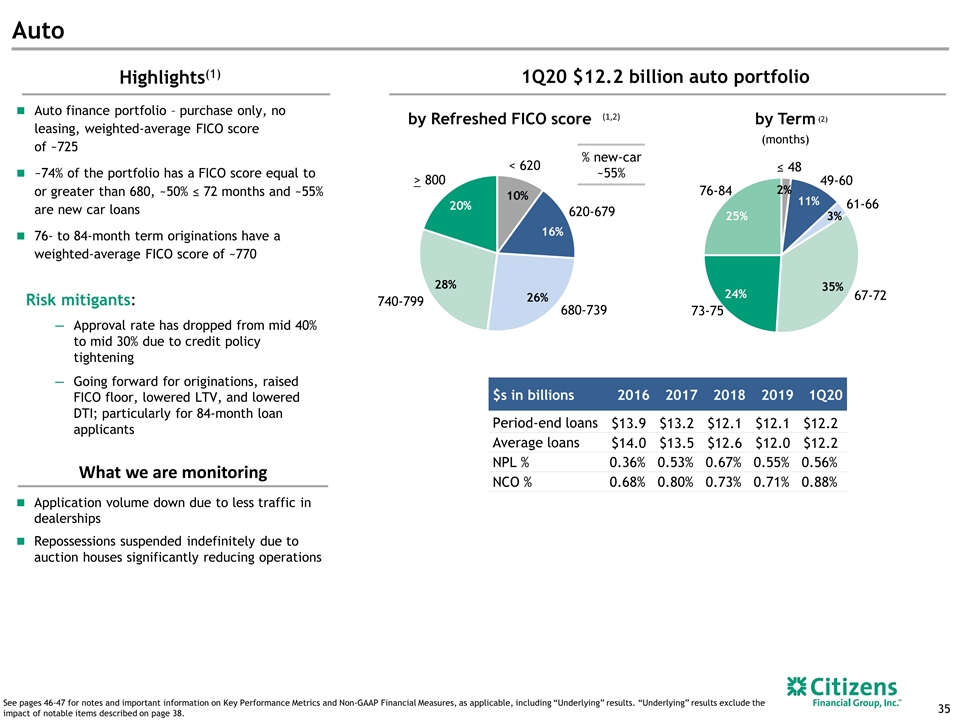
Auto Highlights(1) by Refreshed FICO
score ≤ 48 49-60 76-84 61-66 67-72 73-75 (1,2) 1Q20 $12.2 billion auto portfolio % new-car ~55% by Term (months) Auto finance portfolio – purchase only, no leasing, weighted-average FICO score of ~725 ~74% of the portfolio has a FICO
score equal to or greater than 680, ~50% ≤ 72 months and ~55% are new car loans 76- to 84-month term originations have a weighted-average FICO score of ~770 620-679 680-739 > 800 < 620 740-799 $s in billions 2016 2017 2018 2019 1Q20
Period-end loans $13.9 $13.2 $12.1 $12.1 $12.2 Average loans $14.0 $13.5 $12.6 $12.0 $12.2 NPL % 0.36% 0.53% 0.67% 0.55% 0.56% NCO % 0.68% 0.80% 0.73% 0.71% 0.88% (2) See pages 46-47 for notes and important information on Key Performance Metrics and
Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. What we are monitoring Application volume down due to less traffic in
dealerships Repossessions suspended indefinitely due to auction houses significantly reducing operations Risk mitigants: Approval rate has dropped from mid 40% to mid 30% due to credit policy tightening Going forward for originations, raised FICO
floor, lowered LTV, and lowered DTI; particularly for 84-month loan applicants
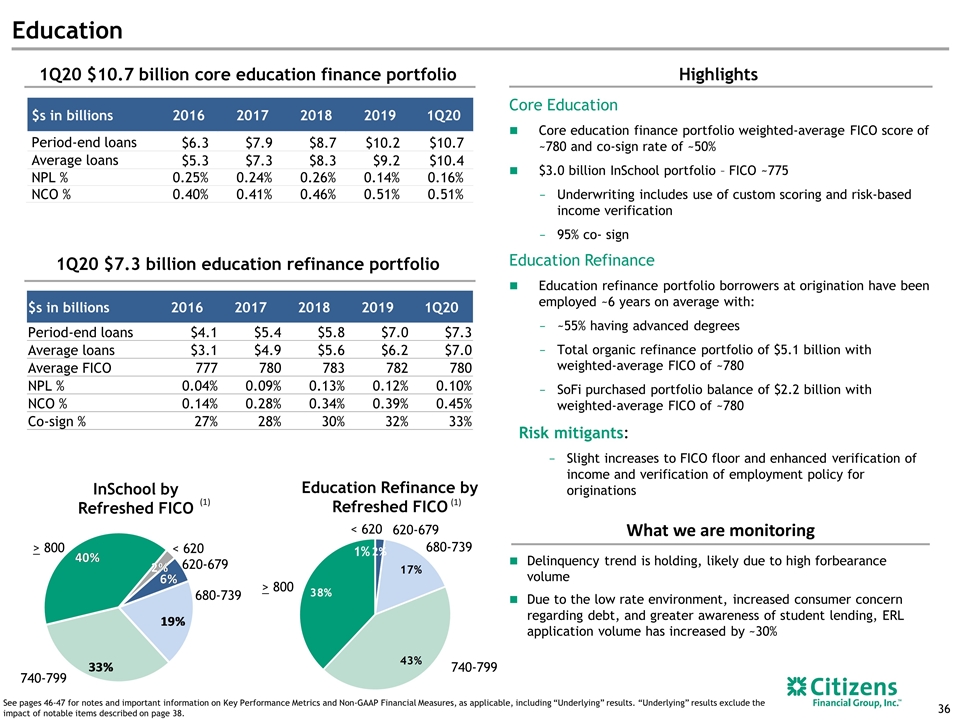
Core Education Core education
finance portfolio weighted-average FICO score of ~780 and co-sign rate of ~50% $3.0 billion InSchool portfolio – FICO ~775 Underwriting includes use of custom scoring and risk-based income verification 95% co- sign Education Refinance
Education refinance portfolio borrowers at origination have been employed ~6 years on average with: ~55% having advanced degrees Total organic refinance portfolio of $5.1 billion with weighted-average FICO of ~780 SoFi purchased portfolio balance of
$2.2 billion with weighted-average FICO of ~780 Education Highlights 1Q20 $10.7 billion core education finance portfolio 1Q20 $7.3 billion education refinance portfolio $s in billions 2016 2017 2018 2019 1Q20 Period-end loans $6.3 $7.9 $8.7 $10.2
$10.7 Average loans $5.3 $7.3 $8.3 $9.2 $10.4 NPL % 0.25% 0.24% 0.26% 0.14% 0.16% NCO % 0.40% 0.41% 0.46% 0.51% 0.51% $s in billions 2016 2017 2018 2019 1Q20 Period-end loans $4.1 $5.4 $5.8 $7.0 $7.3 Average loans $3.1 $4.9 $5.6 $6.2 $7.0
Average FICO 777 780 783 782 780 NPL % 0.04% 0.09% 0.13% 0.12% 0.10% NCO % 0.14% 0.28% 0.34% 0.39% 0.45% Co-sign % 27% 28% 30% 32% 33% See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as
applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. 620-679 680-739 > 800 740-799 Education Refinance by Refreshed FICO InSchool by Refreshed FICO (1)
620-679 680-739 > 800 < 620 740-799 What we are monitoring Delinquency trend is holding, likely due to high forbearance volume Due to the low rate environment, increased consumer concern regarding debt, and greater awareness of student
lending, ERL application volume has increased by ~30% < 620 1% Risk mitigants: Slight increases to FICO floor and enhanced verification of income and verification of employment policy for originations (1)
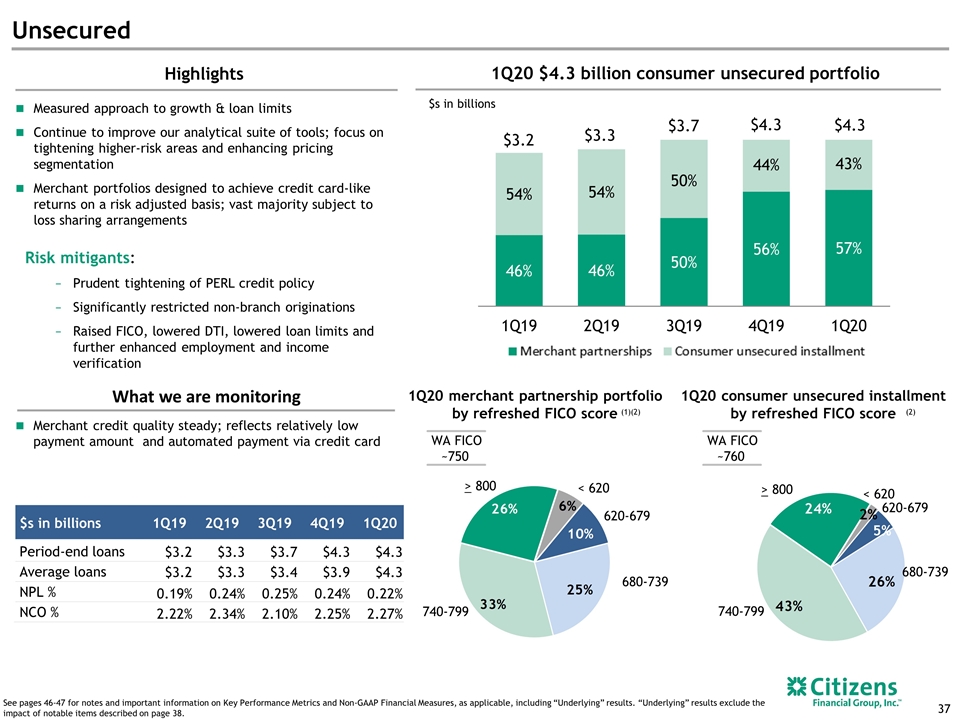
Risk mitigants: Prudent tightening
of PERL credit policy Significantly restricted non-branch originations Raised FICO, lowered DTI, lowered loan limits and further enhanced employment and income verification Measured approach to growth & loan limits Continue to improve our
analytical suite of tools; focus on tightening higher-risk areas and enhancing pricing segmentation Merchant portfolios designed to achieve credit card-like returns on a risk adjusted basis; vast majority subject to loss sharing arrangements
Unsecured Highlights 1Q20 $4.3 billion consumer unsecured portfolio $s in billions 1Q20 merchant partnership portfolio by refreshed FICO score 1Q20 consumer unsecured installment by refreshed FICO score WA FICO ~760 (1)(2) WA FICO ~750 620-679
680-739 > 800 < 620 740-799 620-679 680-739 > 800 < 620 740-799 $s in billions 1Q19 2Q19 3Q19 4Q19 1Q20 Period-end loans $3.2 $3.3 $3.7 $4.3 $4.3 Average loans $3.2 $3.3 $3.4 $3.9 $4.3 NPL % 0.19% 0.24% 0.25% 0.24% 0.22% NCO % 2.22%
2.34% 2.10% 2.25% 2.27% Launched merchant-partnership financing in 3Q15 Developing strategic partnerships designed around high-quality merchant partnership offerings Partnerships structured to achieve card-like risk-adjusted returns Announced
Microsoft/Amazon partnership Launched unsecured-installment product focused on super-prime and high-prime borrowers in 2016 Average term ~5 years with weighted-average FICO of ~760 NCO trends reflect expected seasoning See pages 46-47 for notes and
important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results. “Underlying” results exclude the impact of notable items described on page 38. What we are
monitoring Merchant credit quality steady; reflects relatively low payment amount and automated payment via credit card (2)
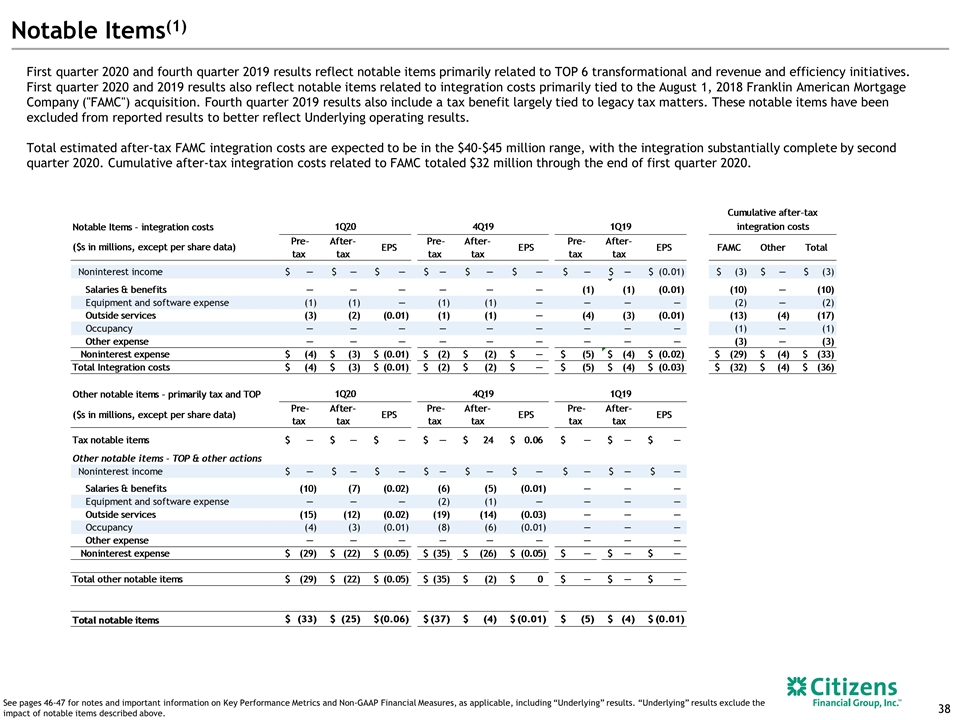
Notable Items(1) First quarter 2020
and fourth quarter 2019 results reflect notable items primarily related to TOP 6 transformational and revenue and efficiency initiatives. First quarter 2020 and 2019 results also reflect notable items related to integration costs primarily tied to
the August 1, 2018 Franklin American Mortgage Company ("FAMC") acquisition. Fourth quarter 2019 results also include a tax benefit largely tied to legacy tax matters. These notable items have been excluded from reported results to better reflect
Underlying operating results. Total estimated after-tax FAMC integration costs are expected to be in the $40-$45 million range, with the integration substantially complete by second quarter 2020. Cumulative after-tax integration costs related to
FAMC totaled $32 million through the end of first quarter 2020. See pages 46-47 for notes and important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, including “Underlying” results.
“Underlying” results exclude the impact of notable items described above.
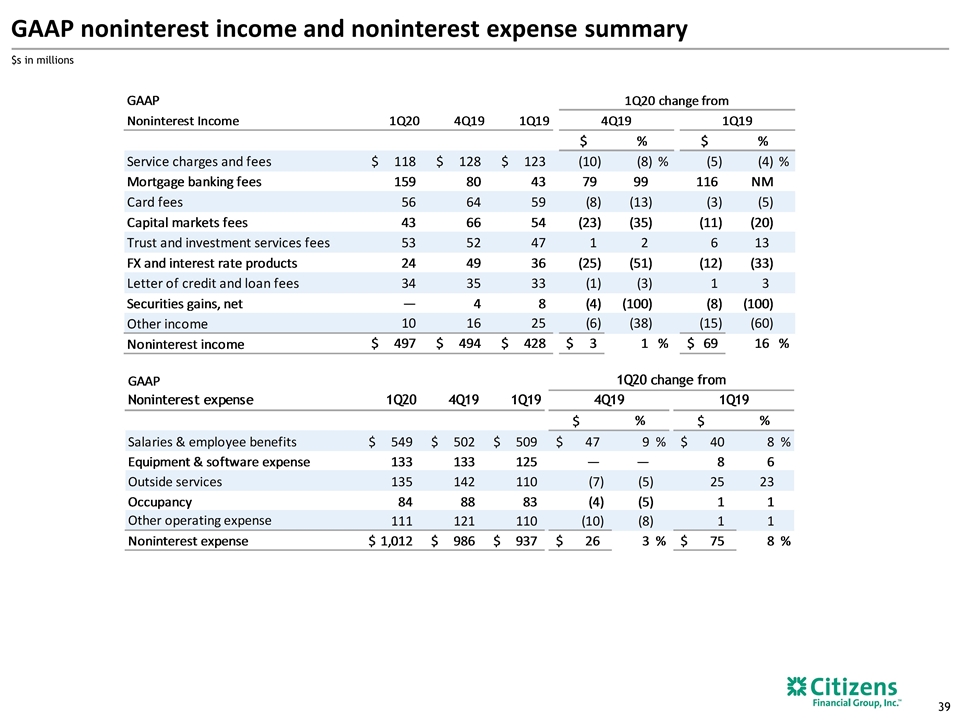
GAAP noninterest income and
noninterest expense summary $s in millions
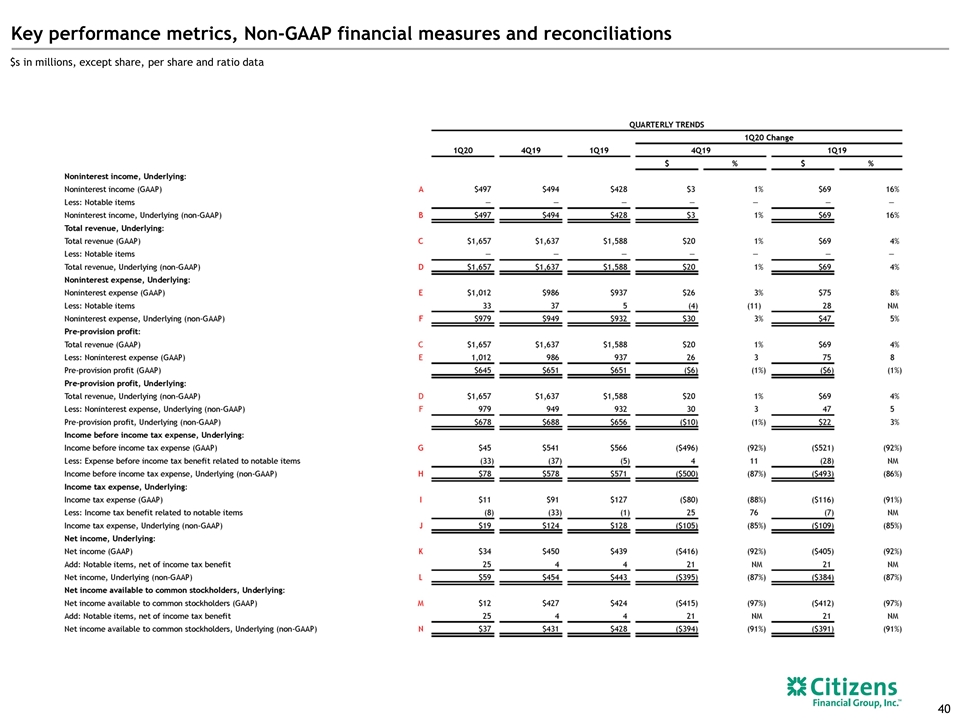
Key performance metrics, Non-GAAP
financial measures and reconciliations $s in millions, except share, per share and ratio data
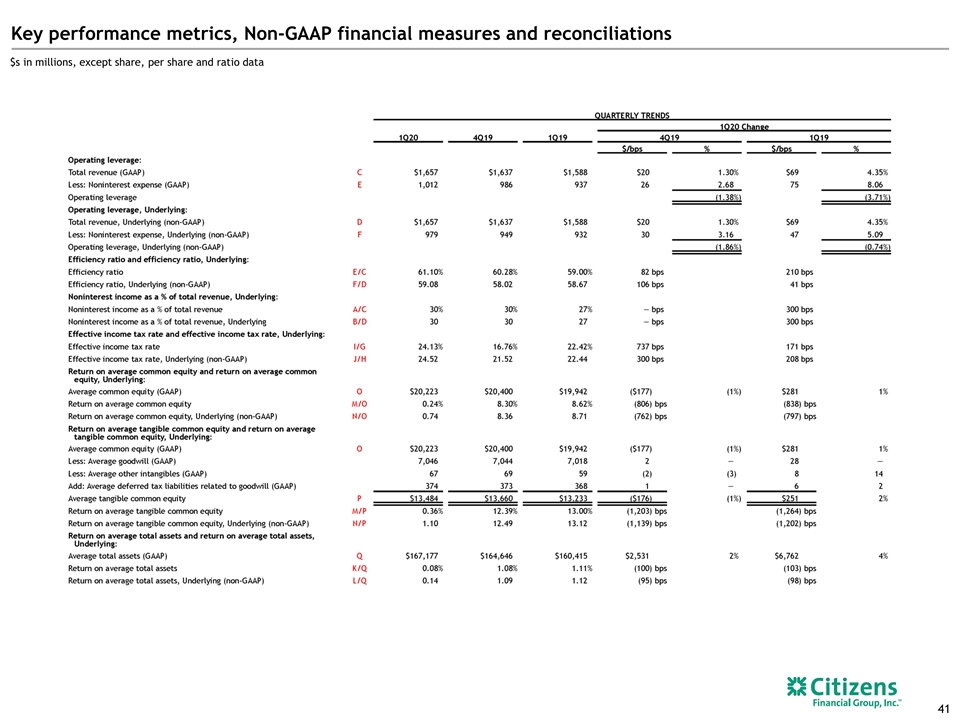
Key performance metrics, Non-GAAP
financial measures and reconciliations $s in millions, except share, per share and ratio data
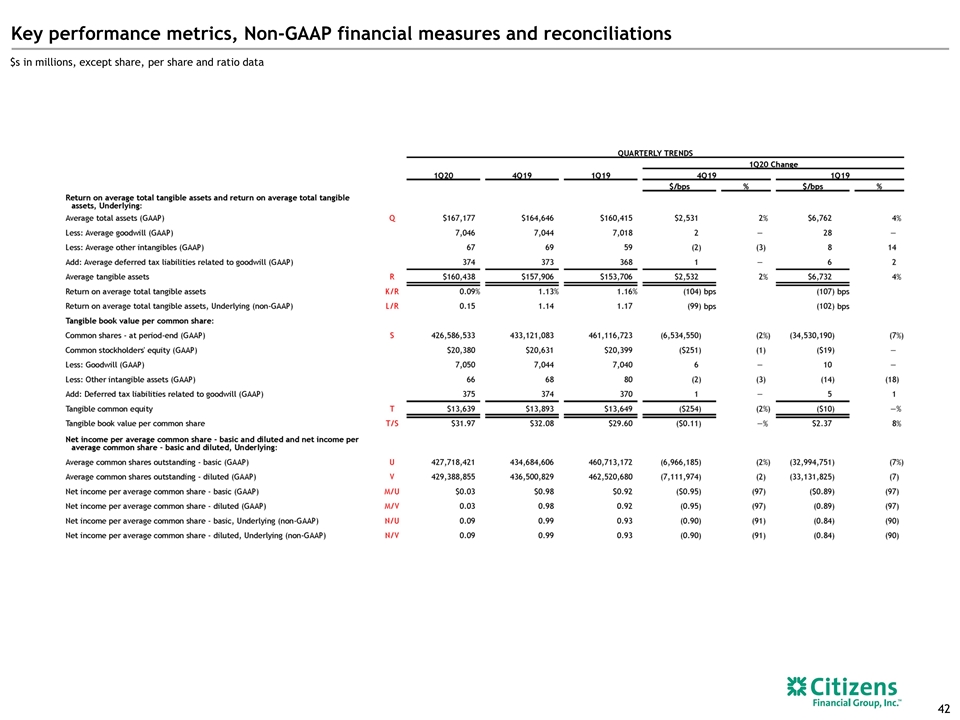
Key performance metrics, Non-GAAP
financial measures and reconciliations $s in millions, except share, per share and ratio data
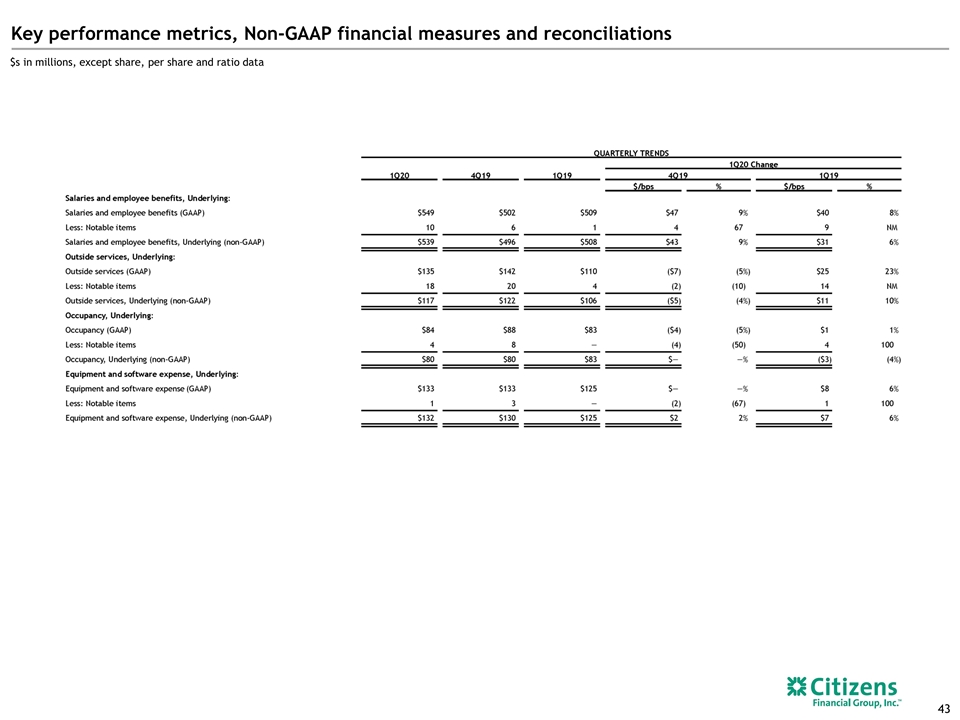
Key performance metrics, Non-GAAP
financial measures and reconciliations $s in millions, except share, per share and ratio data
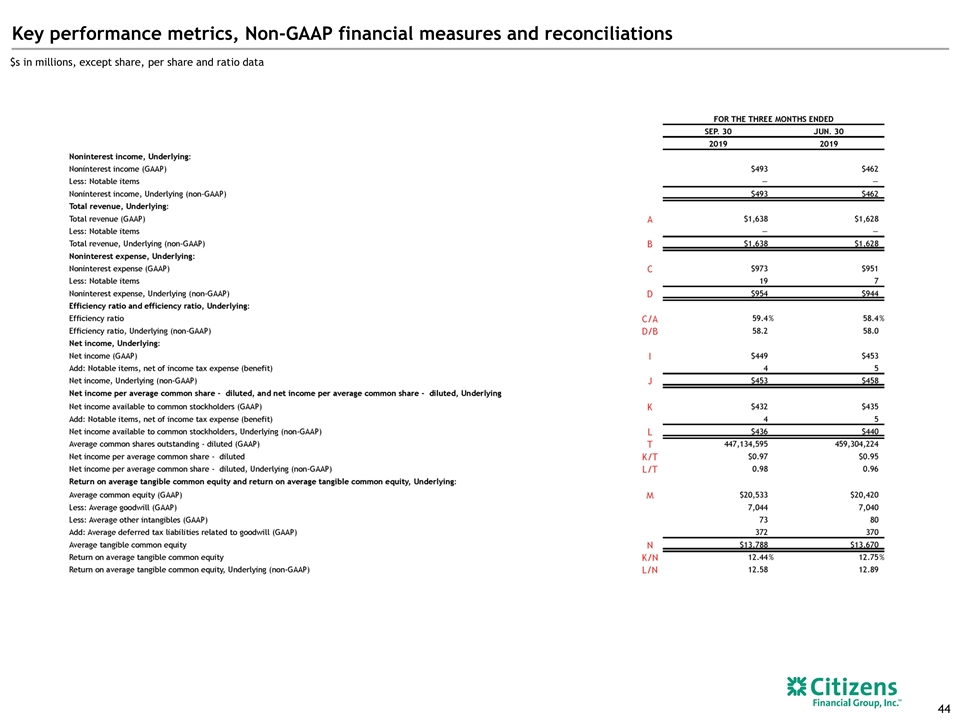
$s in millions, except share, per
share and ratio data Key performance metrics, Non-GAAP financial measures and reconciliations
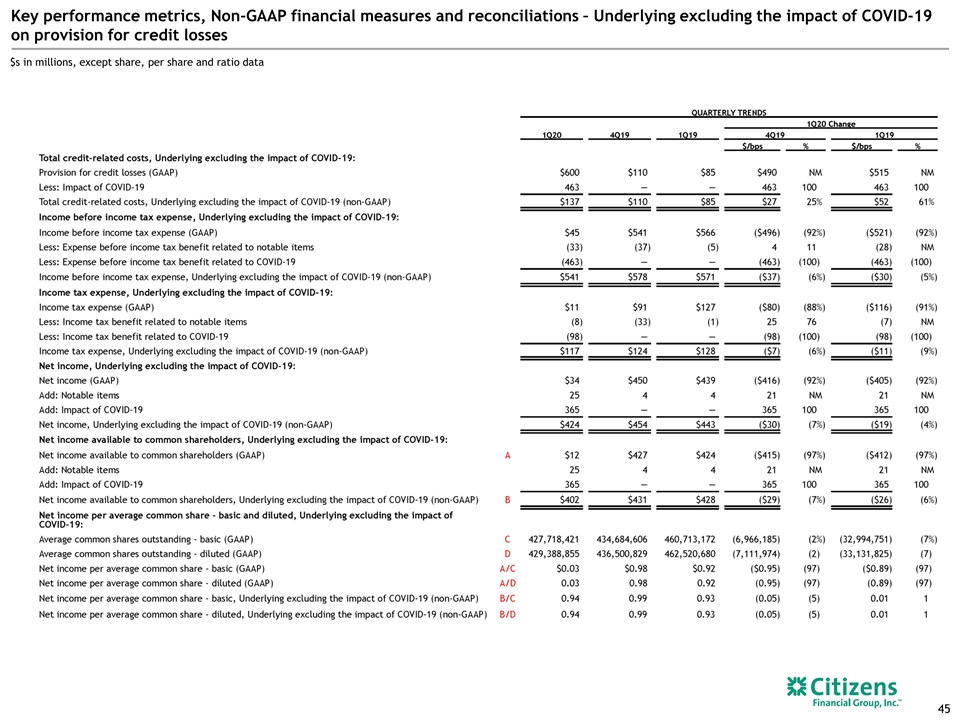
Key performance metrics, Non-GAAP
financial measures and reconciliations – Underlying excluding the impact of COVID-19 on provision for credit losses $s in millions, except share, per share and ratio data
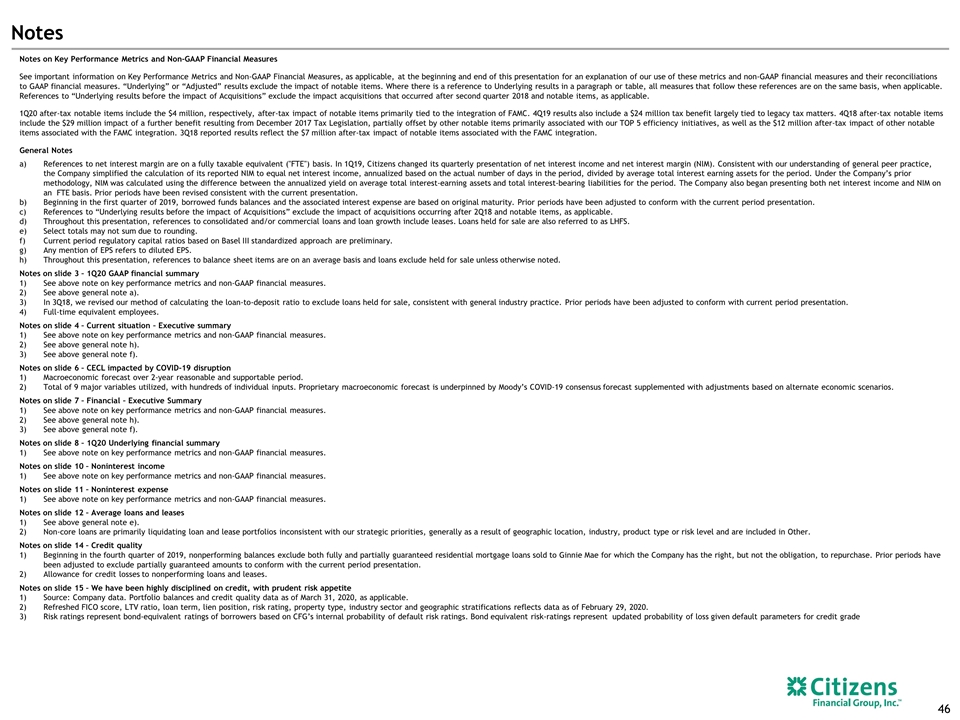
Notes on Key Performance Metrics and
Non-GAAP Financial Measures See important information on Key Performance Metrics and Non-GAAP Financial Measures, as applicable, at the beginning and end of this presentation for an explanation of our use of these metrics and non-GAAP financial
measures and their reconciliations to GAAP financial measures. “Underlying” or “Adjusted” results exclude the impact of notable items. Where there is a reference to Underlying results in a paragraph or table, all measures
that follow these references are on the same basis, when applicable. References to “Underlying results before the impact of Acquisitions” exclude the impact acquisitions that occurred after second quarter 2018 and notable items, as
applicable. 1Q20 after-tax notable items include the $4 million, respectively, after-tax impact of notable items primarily tied to the integration of FAMC. 4Q19 results also include a $24 million tax benefit largely tied to legacy tax matters. 4Q18
after-tax notable items include the $29 million impact of a further benefit resulting from December 2017 Tax Legislation, partially offset by other notable items primarily associated with our TOP 5 efficiency initiatives, as well as the $12 million
after-tax impact of other notable items associated with the FAMC integration. 3Q18 reported results reflect the $7 million after-tax impact of notable items associated with the FAMC integration. General Notes References to net interest margin are on
a fully taxable equivalent ("FTE") basis. In 1Q19, Citizens changed its quarterly presentation of net interest income and net interest margin (NIM). Consistent with our understanding of general peer practice, the Company simplified the calculation
of its reported NIM to equal net interest income, annualized based on the actual number of days in the period, divided by average total interest earning assets for the period. Under the Company’s prior methodology, NIM was calculated using the
difference between the annualized yield on average total interest-earning assets and total interest-bearing liabilities for the period. The Company also began presenting both net interest income and NIM on an FTE basis. Prior periods have been
revised consistent with the current presentation. Beginning in the first quarter of 2019, borrowed funds balances and the associated interest expense are based on original maturity. Prior periods have been adjusted to conform with the current period
presentation. References to “Underlying results before the impact of Acquisitions” exclude the impact of acquisitions occurring after 2Q18 and notable items, as applicable. Throughout this presentation, references to consolidated and/or
commercial loans and loan growth include leases. Loans held for sale are also referred to as LHFS. Select totals may not sum due to rounding. Current period regulatory capital ratios based on Basel III standardized approach are preliminary. Any
mention of EPS refers to diluted EPS. Throughout this presentation, references to balance sheet items are on an average basis and loans exclude held for sale unless otherwise noted. Notes on slide 3 – 1Q20 GAAP financial summary See above note
on key performance metrics and non-GAAP financial measures. See above general note a). In 3Q18, we revised our method of calculating the loan-to-deposit ratio to exclude loans held for sale, consistent with general industry practice. Prior periods
have been adjusted to conform with current period presentation. Full-time equivalent employees. Notes on slide 4 – Current situation – Executive summary See above note on key performance metrics and non-GAAP financial measures. See above
general note h). See above general note f). Notes on slide 6 – CECL impacted by COVID-19 disruption Macroeconomic forecast over 2-year reasonable and supportable period. Total of 9 major variables utilized, with hundreds of individual inputs.
Proprietary macroeconomic forecast is underpinned by Moody’s COVID-19 consensus forecast supplemented with adjustments based on alternate economic scenarios. Notes on slide 7 – Financial – Executive Summary See above note on key
performance metrics and non-GAAP financial measures. See above general note h). See above general note f). Notes on slide 8 – 1Q20 Underlying financial summary See above note on key performance metrics and non-GAAP financial measures. Notes on
slide 10 – Noninterest income See above note on key performance metrics and non-GAAP financial measures. Notes on slide 11 – Noninterest expense See above note on key performance metrics and non-GAAP financial measures. Notes on slide 12
– Average loans and leases See above general note e). Non-core loans are primarily liquidating loan and lease portfolios inconsistent with our strategic priorities, generally as a result of geographic location, industry, product type or risk
level and are included in Other. Notes on slide 14 – Credit quality Beginning in the fourth quarter of 2019, nonperforming balances exclude both fully and partially guaranteed residential mortgage loans sold to Ginnie Mae for which the Company
has the right, but not the obligation, to repurchase. Prior periods have been adjusted to exclude partially guaranteed amounts to conform with the current period presentation. Allowance for credit losses to nonperforming loans and leases. Notes on
slide 15 – We have been highly disciplined on credit, with prudent risk appetite Source: Company data. Portfolio balances and credit quality data as of March 31, 2020, as applicable. Refreshed FICO score, LTV ratio, loan term, lien position,
risk rating, property type, industry sector and geographic stratifications reflects data as of February 29, 2020. Risk ratings represent bond-equivalent ratings of borrowers based on CFG’s internal probability of default risk ratings. Bond
equivalent risk-ratings represent updated probability of loss given default parameters for credit grade Notes
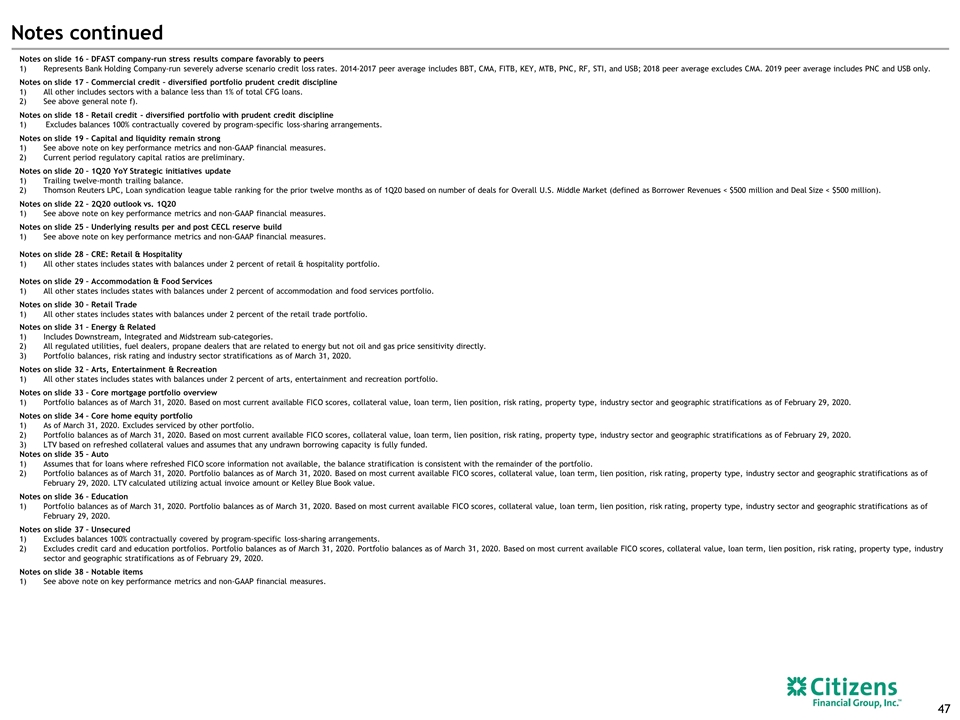
Notes on slide 16 – DFAST
company-run stress results compare favorably to peers Represents Bank Holding Company-run severely adverse scenario credit loss rates. 2014-2017 peer average includes BBT, CMA, FITB, KEY, MTB, PNC, RF, STI, and USB; 2018 peer average excludes CMA.
2019 peer average includes PNC and USB only. Notes on slide 17 – Commercial credit – diversified portfolio prudent credit discipline All other includes sectors with a balance less than 1% of total CFG loans. See above general note f).
Notes on slide 18 – Retail credit - diversified portfolio with prudent credit discipline Excludes balances 100% contractually covered by program-specific loss-sharing arrangements. Notes on slide 19 – Capital and liquidity remain strong
See above note on key performance metrics and non-GAAP financial measures. Current period regulatory capital ratios are preliminary. Notes on slide 20 – 1Q20 YoY Strategic initiatives update Trailing twelve-month trailing balance. Thomson
Reuters LPC, Loan syndication league table ranking for the prior twelve months as of 1Q20 based on number of deals for Overall U.S. Middle Market (defined as Borrower Revenues < $500 million and Deal Size < $500 million). Notes on slide 22
– 2Q20 outlook vs. 1Q20 See above note on key performance metrics and non-GAAP financial measures. Notes on slide 25 – Underlying results per and post CECL reserve build See above note on key performance metrics and non-GAAP financial
measures. Notes on slide 28 – CRE: Retail & Hospitality All other states includes states with balances under 2 percent of retail & hospitality portfolio. Notes on slide 29 – Accommodation & Food Services All other states
includes states with balances under 2 percent of accommodation and food services portfolio. Notes on slide 30 – Retail Trade All other states includes states with balances under 2 percent of the retail trade portfolio. Notes on slide 31
– Energy & Related Includes Downstream, Integrated and Midstream sub-categories. All regulated utilities, fuel dealers, propane dealers that are related to energy but not oil and gas price sensitivity directly. Portfolio balances, risk
rating and industry sector stratifications as of March 31, 2020. Notes on slide 32 – Arts, Entertainment & Recreation All other states includes states with balances under 2 percent of arts, entertainment and recreation portfolio. Notes on
slide 33 – Core mortgage portfolio overview Portfolio balances as of March 31, 2020. Based on most current available FICO scores, collateral value, loan term, lien position, risk rating, property type, industry sector and geographic
stratifications as of February 29, 2020. Notes on slide 34 – Core home equity portfolio As of March 31, 2020. Excludes serviced by other portfolio. Portfolio balances as of March 31, 2020. Based on most current available FICO scores,
collateral value, loan term, lien position, risk rating, property type, industry sector and geographic stratifications as of February 29, 2020. LTV based on refreshed collateral values and assumes that any undrawn borrowing capacity is fully funded.
Notes on slide 35 – Auto Assumes that for loans where refreshed FICO score information not available, the balance stratification is consistent with the remainder of the portfolio. Portfolio balances as of March 31, 2020. Portfolio balances as
of March 31, 2020. Based on most current available FICO scores, collateral value, loan term, lien position, risk rating, property type, industry sector and geographic stratifications as of February 29, 2020. LTV calculated utilizing actual invoice
amount or Kelley Blue Book value. Notes on slide 36 – Education Portfolio balances as of March 31, 2020. Portfolio balances as of March 31, 2020. Based on most current available FICO scores, collateral value, loan term, lien position, risk
rating, property type, industry sector and geographic stratifications as of February 29, 2020. Notes on slide 37 – Unsecured Excludes balances 100% contractually covered by program-specific loss-sharing arrangements. Excludes credit card and
education portfolios. Portfolio balances as of March 31, 2020. Portfolio balances as of March 31, 2020. Based on most current available FICO scores, collateral value, loan term, lien position, risk rating, property type, industry sector and
geographic stratifications as of February 29, 2020. Notes on slide 38 – Notable items See above note on key performance metrics and non-GAAP financial measures. Notes continued
Exhibit 99.3
First Quarter 2020
1
The information in this Financial Supplement is preliminary and based on company data available at the time of the earnings
presentation. It speaks only as of the particular date or dates included in the accompanying pages. The Company does not undertake an obligation to, and disclaims any duty to, update any of the information provided. Any forward-looking statements in
this Financial Supplement are subject to the forward-looking statements language contained in the Company’s reports filed with the SEC pursuant to the Securities Exchange Act of 1934, which can be found on the SEC’s website
(www.sec.gov) or on the Company’s website (www.citizensbank.com). The Company’s future financial performance is subject to the risks and uncertainties described in its SEC filings.
Footnotes that are denoted by a letter apply to multiple pages and can be found in the appendix. Footnotes that are denoted by a number apply to a particular
page and can be found at the bottom of the page.
2
CONSOLIDATED FINANCIAL HIGHLIGHTS
(in millions, except share, per-share and ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
QUARTERLY TRENDS |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$/bps |
|
|
% |
|
|
$/bps |
|
|
% |
|
| SELECTED OPERATING DATA |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue |
|
$ |
1,657 |
|
|
$ |
1,637 |
|
|
$ |
1,638 |
|
|
$ |
1,628 |
|
|
$ |
1,588 |
|
|
$ |
20 |
|
|
|
1 |
% |
|
$ |
69 |
|
|
|
4 |
% |
| Noninterest expense |
|
|
1,012 |
|
|
|
986 |
|
|
|
973 |
|
|
|
951 |
|
|
|
937 |
|
|
|
26 |
|
|
|
3 |
|
|
|
75 |
|
|
|
8 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Profit before provision for credit losses |
|
|
645 |
|
|
|
651 |
|
|
|
665 |
|
|
|
677 |
|
|
|
651 |
|
|
|
(6 |
) |
|
|
(1 |
) |
|
|
(6 |
) |
|
|
(1 |
) |
| Provision for credit losses |
|
|
600 |
|
|
|
110 |
|
|
|
101 |
|
|
|
97 |
|
|
|
85 |
|
|
|
490 |
|
|
|
NM |
|
|
|
515 |
|
|
|
NM |
|
| NET INCOME |
|
|
34 |
|
|
|
450 |
|
|
|
449 |
|
|
|
453 |
|
|
|
439 |
|
|
|
(416 |
) |
|
|
(92 |
) |
|
|
(405 |
) |
|
|
(92 |
) |
| Net income, UnderlyingA |
|
|
59 |
|
|
|
454 |
|
|
|
453 |
|
|
|
458 |
|
|
|
443 |
|
|
|
(395 |
) |
|
|
(87 |
) |
|
|
(384 |
) |
|
|
(87 |
) |
| Net income available to common stockholders |
|
|
12 |
|
|
|
427 |
|
|
|
432 |
|
|
|
435 |
|
|
|
424 |
|
|
|
(415 |
) |
|
|
(97 |
) |
|
|
(412 |
) |
|
|
(97 |
) |
| Net income available to common stockholders,
UnderlyingA |
|
|
37 |
|
|
|
431 |
|
|
|
436 |
|
|
|
440 |
|
|
|
428 |
|
|
|
(394 |
) |
|
|
(91 |
) |
|
|
(391 |
) |
|
|
(91 |
) |
| PER COMMON SHARE DATA |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Basic earnings |
|
$ |
0.03 |
|
|
$ |
0.98 |
|
|
$ |
0.97 |
|
|
$ |
0.95 |
|
|
$ |
0.92 |
|
|
($ |
0.95 |
) |
|
|
(97 |
%) |
|
($ |
0.89 |
) |
|
|
(97 |
%) |
| Diluted earnings |
|
|
0.03 |
|
|
|
0.98 |
|
|
|
0.97 |
|
|
|
0.95 |
|
|
|
0.92 |
|
|
|
(0.95 |
) |
|
|
(97 |
) |
|
|
(0.89 |
) |
|
|
(97 |
) |
| Basic earnings, UnderlyingA |
|
|
0.09 |
|
|
|
0.99 |
|
|
|
0.98 |
|
|
|
0.96 |
|
|
|
0.93 |
|
|
|
(0.90 |
) |
|
|
(91 |
) |
|
|
(0.84 |
) |
|
|
(90 |
) |
| Diluted earnings, UnderlyingA |
|
|
0.09 |
|
|
|
0.99 |
|
|
|
0.98 |
|
|
|
0.96 |
|
|
|
0.93 |
|
|
|
(0.90 |
) |
|
|
(91 |
) |
|
|
(0.84 |
) |
|
|
(90 |
) |
| Cash dividends declared and paid per common share |
|
|
0.39 |
|
|
|
0.36 |
|
|
|
0.36 |
|
|
|
0.32 |
|
|
|
0.32 |
|
|
|
0.03 |
|
|
|
8 |
|
|
|
0.07 |
|
|
|
22 |
|
| Book value per common share |
|
|
47.78 |
|
|
|
47.63 |
|
|
|
46.67 |
|
|
|
45.61 |
|
|
|
44.24 |
|
|
|
0.15 |
|
|
|
— |
|
|
|
3.54 |
|
|
|
8 |
|
| Tangible book value per common share |
|
|
31.97 |
|
|
|
32.08 |
|
|
|
31.48 |
|
|
|
30.88 |
|
|
|
29.60 |
|
|
|
(0.11 |
) |
|
|
— |
|
|
|
2.37 |
|
|
|
8 |
|
| Dividend payout ratio |
|
|
1,398 |
% |
|
|
37 |
% |
|
|
37 |
% |
|
|
34 |
% |
|
|
35 |
% |
|
|
NM |
|
|
|
|
|
|
|
NM |
|
|
|
|
|
| Dividend payout ratio, UnderlyingA |
|
|
451 |
|
|
|
36 |
|
|
|
37 |
|
|
|
33 |
|
|
|
34 |
|
|
|
NM |
|
|
|
|
|
|
|
NM |
|
|
|
|
|
| COMMON SHARES OUTSTANDING |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average: Basic |
|
|
427,718,421 |
|
|
|
434,684,606 |
|
|
|
445,703,987 |
|
|
|
458,154,335 |
|
|
|
460,713,172 |
|
|
|
(6,966,185 |
) |
|
|
(2 |
%) |
|
|
(32,994,751 |
) |
|
|
(7 |
%) |
| Diluted |
|
|
429,388,855 |
|
|
|
436,500,829 |
|
|
|
447,134,595 |
|
|
|
459,304,224 |
|
|
|
462,520,680 |
|
|
|
(7,111,974 |
) |
|
|
(2 |
) |
|
|
(33,131,825 |
) |
|
|
(7 |
) |
| Common shares at period-end |
|
|
426,586,533 |
|
|
|
433,121,083 |
|
|
|
443,913,525 |
|
|
|
457,903,826 |
|
|
|
461,116,723 |
|
|
|
(6,534,550 |
) |
|
|
(2 |
) |
|
|
(34,530,190 |
) |
|
|
(7 |
) |
3
CONSOLIDATED FINANCIAL HIGHLIGHTS, CONTINUED
(in millions, except ratio and headcount data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
QUARTERLY TRENDS |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$/bps |
|
|
% |
|
|
$/bps |
|
|
% |
|
| FINANCIAL RATIOS |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net interest margin |
|
|
3.09 |
% |
|
|
3.04 |
% |
|
|
3.10 |
% |
|
|
3.20 |
% |
|
|
3.23 |
% |
|
|
5 |
bps |
|
|
|
|
|
|
(14 |
) bps |
|
|
|
|
| Net interest margin, FTE1 |
|
|
3.10 |
|
|
|
3.06 |
|
|
|
3.12 |
|
|
|
3.21 |
|
|
|
3.25 |
|
|
|
4 |
bps |
|
|
|
|
|
|
(15 |
) bps |
|
|
|
|
| Return on average common equity |
|
|
0.24 |
|
|
|
8.30 |
|
|
|
8.35 |
|
|
|
8.54 |
|
|
|
8.62 |
|
|
|
(806 |
) bps |
|
|
|
|
|
|
(838 |
) bps |
|
|
|
|
| Return on average common equity, UnderlyingA
|
|
|
0.74 |
|
|
|
8.36 |
|
|
|
8.45 |
|
|
|
8.63 |
|
|
|
8.71 |
|
|
|
(762 |
) bps |
|
|
|
|
|
|
(797 |
) bps |
|
|
|
|
| Return on average tangible common equity |
|
|
0.36 |
|
|
|
12.39 |
|
|
|
12.44 |
|
|
|
12.75 |
|
|
|
13.00 |
|
|
|
(1,203 |
) bps |
|
|
|
|
|
|
(1,264 |
) bps |
|
|
|
|
| Return on average tangible common equity, UnderlyingA
|
|
|
1.10 |
|
|
|
12.49 |
|
|
|
12.58 |
|
|
|
12.89 |
|
|
|
13.12 |
|
|
|
(1,139 |
) bps |
|
|
|
|
|
|
(1,202 |
) bps |
|
|
|
|
| Return on average total assets |
|
|
0.08 |
|
|
|
1.08 |
|
|
|
1.10 |
|
|
|
1.13 |
|
|
|
1.11 |
|
|
|
(100 |
) bps |
|
|
|
|
|
|
(103 |
) bps |
|
|
|
|
| Return on average total assets, UnderlyingA
|
|
|
0.14 |
|
|
|
1.09 |
|
|
|
1.11 |
|
|
|
1.14 |
|
|
|
1.12 |
|
|
|
(95 |
) bps |
|
|
|
|
|
|
(98 |
) bps |
|
|
|
|
| Return on average total tangible assets |
|
|
0.09 |
|
|
|
1.13 |
|
|
|
1.15 |
|
|
|
1.17 |
|
|
|
1.16 |
|
|
|
(104 |
) bps |
|
|
|
|
|
|
(107 |
) bps |
|
|
|
|
| Return on average total tangible assets, UnderlyingA
|
|
|
0.15 |
|
|
|
1.14 |
|
|
|
1.16 |
|
|
|
1.19 |
|
|
|
1.17 |
|
|
|
(99 |
) bps |
|
|
|
|
|
|
(102 |
) bps |
|
|
|
|
| Effective income tax rate |
|
|
24.13 |
|
|
|
16.76 |
|
|
|
20.46 |
|
|
|
21.86 |
|
|
|
22.42 |
|
|
|
737 |
bps |
|
|
|
|
|
|
171 |
bps |
|
|
|
|
| Effective income tax rate, UnderlyingA |
|
|
24.52 |
|
|
|
21.52 |
|
|
|
22.29 |
|
|
|
21.89 |
|
|
|
22.44 |
|
|
|
300 |
bps |
|
|
|
|
|
|
208 |
bps |
|
|
|
|
| Efficiency ratio |
|
|
61.10 |
|
|
|
60.28 |
|
|
|
59.40 |
|
|
|
58.41 |
|
|
|
59.00 |
|
|
|
82 |
bps |
|
|
|
|
|
|
210 |
bps |
|
|
|
|
| Efficiency ratio, UnderlyingA |
|
|
59.08 |
|
|
|
58.02 |
|
|
|
58.22 |
|
|
|
58.02 |
|
|
|
58.67 |
|
|
|
106 |
bps |
|
|
|
|
|
|
41 |
bps |
|
|
|
|
| Noninterest income as a % of total revenue |
|
|
30 |
% |
|
|
30 |
% |
|
|
30 |
% |
|
|
28 |
% |
|
|
27 |
% |
|
|
— |
bps |
|
|
|
|
|
|
300 |
bps |
|
|
|
|
| Noninterest income as a % of total revenue, UnderlyingA
|
|
|
30 |
% |
|
|
30 |
% |
|
|
30 |
% |
|
|
28 |
% |
|
|
27 |
% |
|
|
— |
bps |
|
|
|
|
|
|
300 |
bps |
|
|
|
|
| CAPITAL RATIOS - PERIOD-END
(PRELIMINARY) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| CET1 capital ratio |
|
|
9.4 |
% |
|
|
10.0 |
% |
|
|
10.3 |
% |
|
|
10.5 |
% |
|
|
10.5 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Tier 1 capital ratio |
|
|
10.5 |
|
|
|
11.1 |
|
|
|
11.1 |
|
|
|
11.3 |
|
|
|
11.3 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total capital ratio |
|
|
12.5 |
|
|
|
13.0 |
|
|
|
13.0 |
|
|
|
13.4 |
|
|
|
13.4 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Tier 1 leverage ratio |
|
|
9.6 |
|
|
|
10.0 |
|
|
|
9.9 |
|
|
|
10.1 |
|
|
|
10.0 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Tangible common equity ratio |
|
|
8.0 |
|
|
|
8.7 |
|
|
|
8.9 |
|
|
|
9.1 |
|
|
|
8.8 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| SELECTED BALANCE SHEET DATA |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Loans-to-deposits
ratio (period-end balances)B |
|
|
95.54 |
% |
|
|
95.03 |
% |
|
|
94.52 |
% |
|
|
94.22 |
% |
|
|
94.92 |
% |
|
|
51 |
bps |
|
|
|
|
|
|
62 |
bps |
|
|
|
|
| Loans-to-deposits
ratio (average balances)B |
|
|
95.60 |
|
|
|
94.63 |
|
|
|
94.62 |
|
|
|
95.64 |
|
|
|
97.70 |
|
|
|
97 |
bps |
|
|
|
|
|
|
(210 |
) bps |
|
|
|
|
| Full-time equivalent colleagues |
|
|
17,863 |
|
|
|
17,997 |
|
|
|
18,116 |
|
|
|
18,207 |
|
|
|
18,078 |
|
|
|
(134 |
) |
|
|
(1 |
) |
|
|
(215 |
) |
|
|
(1 |
) |
| 1 |
Net interest income and net interest margin is presented on a fully taxable-equivalent (“FTE”) basis
using the federal statutory tax rate of 21%. The FTE impact is predominantly attributable to commercial loans for the periods presented. |
4
CONSOLIDATED STATEMENTS OF OPERATIONS (unaudited)
(in millions)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
QUARTERLY TRENDS |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
|
$ |
|
|
% |
|
| INTEREST INCOME |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Interest and fees on loans and leases |
|
$ |
1,302 |
|
|
$ |
1,312 |
|
|
$ |
1,356 |
|
|
$ |
1,392 |
|
|
$ |
1,381 |
|
|
($ |
10 |
) |
|
|
(1 |
%) |
|
($ |
79 |
) |
|
|
(6 |
%) |
| Interest and fees on loans held for sale |
|
|
15 |
|
|
|
18 |
|
|
|
19 |
|
|
|
15 |
|
|
|
11 |
|
|
|
(3 |
) |
|
|
(17 |
) |
|
|
4 |
|
|
|
36 |
|
| Interest and fees on other loans held for sale |
|
|
9 |
|
|
|
5 |
|
|
|
2 |
|
|
|
2 |
|
|
|
4 |
|
|
|
4 |
|
|
|
80 |
|
|
|
5 |
|
|
|
125 |
|
| Investment securities |
|
|
147 |
|
|
|
159 |
|
|
|
153 |
|
|
|
164 |
|
|
|
166 |
|
|
|
(12 |
) |
|
|
(8 |
) |
|
|
(19 |
) |
|
|
(11 |
) |
| Interest-bearing deposits in banks |
|
|
5 |
|
|
|
7 |
|
|
|
8 |
|
|
|
7 |
|
|
|
8 |
|
|
|
(2 |
) |
|
|
(29 |
) |
|
|
(3 |
) |
|
|
(38 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total interest income |
|
|
1,478 |
|
|
|
1,501 |
|
|
|
1,538 |
|
|
|
1,580 |
|
|
|
1,570 |
|
|
|
(23 |
) |
|
|
(2 |
) |
|
|
(92 |
) |
|
|
(6 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| INTEREST EXPENSE |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Deposits |
|
|
227 |
|
|
|
263 |
|
|
|
297 |
|
|
|
308 |
|
|
|
287 |
|
|
|
(36 |
) |
|
|
(14 |
) |
|
|
(60 |
) |
|
|
(21 |
) |
| Short-term borrowed fundsC |
|
|
1 |
|
|
|
2 |
|
|
|
2 |
|
|
|
4 |
|
|
|
2 |
|
|
|
(1 |
) |
|
|
(50 |
) |
|
|
(1 |
) |
|
|
(50 |
) |
| Long-term borrowed funds |
|
|
90 |
|
|
|
93 |
|
|
|
94 |
|
|
|
102 |
|
|
|
121 |
|
|
|
(3 |
) |
|
|
(3 |
) |
|
|
(31 |
) |
|
|
(26 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total interest expense |
|
|
318 |
|
|
|
358 |
|
|
|
393 |
|
|
|
414 |
|
|
|
410 |
|
|
|
(40 |
) |
|
|
(11 |
) |
|
|
(92 |
) |
|
|
(22 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net interest income |
|
|
1,160 |
|
|
|
1,143 |
|
|
|
1,145 |
|
|
|
1,166 |
|
|
|
1,160 |
|
|
|
17 |
|
|
|
1 |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| NONINTEREST INCOME |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Service charges and fees |
|
|
118 |
|
|
|
128 |
|
|
|
128 |
|
|
|
126 |
|
|
|
123 |
|
|
|
(10 |
) |
|
|
(8 |
) |
|
|
(5 |
) |
|
|
(4 |
) |
| Mortgage banking fees |
|
|
159 |
|
|
|
80 |
|
|
|
117 |
|
|
|
62 |
|
|
|
43 |
|
|
|
79 |
|
|
|
99 |
|
|
|
116 |
|
|
|
NM |
|
| Card fees |
|
|
56 |
|
|
|
64 |
|
|
|
67 |
|
|
|
64 |
|
|
|
59 |
|
|
|
(8 |
) |
|
|
(13 |
) |
|
|
(3 |
) |
|
|
(5 |
) |
| Capital markets fees |
|
|
43 |
|
|
|
66 |
|
|
|
39 |
|
|
|
57 |
|
|
|
54 |
|
|
|
(23 |
) |
|
|
(35 |
) |
|
|
(11 |
) |
|
|
(20 |
) |
| Trust and investment services fees |
|
|
53 |
|
|
|
52 |
|
|
|
50 |
|
|
|
53 |
|
|
|
47 |
|
|
|
1 |
|
|
|
2 |
|
|
|
6 |
|
|
|
13 |
|
| Foreign exchange and interest rate products |
|
|
24 |
|
|
|
49 |
|
|
|
35 |
|
|
|
35 |
|
|
|
36 |
|
|
|
(25 |
) |
|
|
(51 |
) |
|
|
(12 |
) |
|
|
(33 |
) |
| Letter of credit and loan fees |
|
|
34 |
|
|
|
35 |
|
|
|
34 |
|
|
|
33 |
|
|
|
33 |
|
|
|
(1 |
) |
|
|
(3 |
) |
|
|
1 |
|
|
|
3 |
|
| Securities gains, net |
|
|
— |
|
|
|
4 |
|
|
|
3 |
|
|
|
4 |
|
|
|
8 |
|
|
|
(4 |
) |
|
|
(100 |
) |
|
|
(8 |
) |
|
|
(100 |
) |
| Other income |
|
|
10 |
|
|
|
16 |
|
|
|
20 |
|
|
|
28 |
|
|
|
25 |
|
|
|
(6 |
) |
|
|
(38 |
) |
|
|
(15 |
) |
|
|
(60 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total noninterest income |
|
|
497 |
|
|
|
494 |
|
|
|
493 |
|
|
|
462 |
|
|
|
428 |
|
|
|
3 |
|
|
|
1 |
|
|
|
69 |
|
|
|
16 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| TOTAL REVENUE |
|
|
1,657 |
|
|
|
1,637 |
|
|
|
1,638 |
|
|
|
1,628 |
|
|
|
1,588 |
|
|
|
20 |
|
|
|
1 |
|
|
|
69 |
|
|
|
4 |
|
| Provision for credit losses |
|
|
600 |
|
|
|
110 |
|
|
|
101 |
|
|
|
97 |
|
|
|
85 |
|
|
|
490 |
|
|
|
NM |
|
|
|
515 |
|
|
|
NM |
|
| NONINTEREST EXPENSE |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Salaries and employee benefits |
|
|
549 |
|
|
|
502 |
|
|
|
508 |
|
|
|
507 |
|
|
|
509 |
|
|
|
47 |
|
|
|
9 |
|
|
|
40 |
|
|
|
8 |
|
| Equipment and software expense |
|
|
133 |
|
|
|
133 |
|
|
|
130 |
|
|
|
126 |
|
|
|
125 |
|
|
|
— |
|
|
|
— |
|
|
|
8 |
|
|
|
6 |
|
| Outside services |
|
|
135 |
|
|
|
142 |
|
|
|
128 |
|
|
|
118 |
|
|
|
110 |
|
|
|
(7 |
) |
|
|
(5 |
) |
|
|
25 |
|
|
|
23 |
|
| Occupancy |
|
|
84 |
|
|
|
88 |
|
|
|
80 |
|
|
|
82 |
|
|
|
83 |
|
|
|
(4 |
) |
|
|
(5 |
) |
|
|
1 |
|
|
|
1 |
|
| Other operating expense |
|
|
111 |
|
|
|
121 |
|
|
|
127 |
|
|
|
118 |
|
|
|
110 |
|
|
|
(10 |
) |
|
|
(8 |
) |
|
|
1 |
|
|
|
1 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total noninterest expense |
|
|
1,012 |
|
|
|
986 |
|
|
|
973 |
|
|
|
951 |
|
|
|
937 |
|
|
|
26 |
|
|
|
3 |
|
|
|
75 |
|
|
|
8 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income before income tax expense |
|
|
45 |
|
|
|
541 |
|
|
|
564 |
|
|
|
580 |
|
|
|
566 |
|
|
|
(496 |
) |
|
|
(92 |
) |
|
|
(521 |
) |
|
|
(92 |
) |
| Income tax expense |
|
|
11 |
|
|
|
91 |
|
|
|
115 |
|
|
|
127 |
|
|
|
127 |
|
|
|
(80 |
) |
|
|
(88 |
) |
|
|
(116 |
) |
|
|
(91 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income |
|
$ |
34 |
|
|
$ |
450 |
|
|
$ |
449 |
|
|
$ |
453 |
|
|
$ |
439 |
|
|
($ |
416 |
) |
|
|
(92 |
%) |
|
($ |
405 |
) |
|
|
(92 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income, UnderlyingA |
|
$ |
59 |
|
|
$ |
454 |
|
|
$ |
453 |
|
|
$ |
458 |
|
|
$ |
443 |
|
|
($ |
395 |
) |
|
|
(87 |
%) |
|
($ |
384 |
) |
|
|
(87 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income available to common stockholders |
|
$ |
12 |
|
|
$ |
427 |
|
|
$ |
432 |
|
|
$ |
435 |
|
|
$ |
424 |
|
|
($ |
415 |
) |
|
|
(97 |
%) |
|
($ |
412 |
) |
|
|
(97 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income available to common stockholders, UnderlyingA |
|
$ |
37 |
|
|
$ |
431 |
|
|
$ |
436 |
|
|
$ |
440 |
|
|
$ |
428 |
|
|
($ |
394 |
) |
|
|
(91 |
%) |
|
($ |
391 |
) |
|
|
(91 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
5
CONSOLIDATED BALANCE SHEETS (unaudited)
(in millions)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| PERIOD-END BALANCES |
|
AS OF |
|
|
MARCH 31, 2020 CHANGE |
|
| |
|
Mar 31, 2020 |
|
|
Dec 31, 2019 |
|
|
Sept 30, 2019 |
|
|
June 30, 2019 |
|
|
Mar 31, 2019 |
|
|
December 31, 2019 |
|
|
March 31, 2019 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
|
$ |
|
|
% |
|
| ASSETS |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Cash and due from banks |
|
$ |
1,155 |
|
|
$ |
1,175 |
|
|
$ |
1,638 |
|
|
$ |
996 |
|
|
$ |
923 |
|
|
($ |
20 |
) |
|
|
(2 |
%) |
|
$ |
232 |
|
|
|
25 |
% |
| Interest-bearing cash and due from banks |
|
|
2,903 |
|
|
|
2,211 |
|
|
|
2,204 |
|
|
|
2,039 |
|
|
|
1,513 |
|
|
|
692 |
|
|
|
31 |
|
|
|
1,390 |
|
|
|
92 |
|
| Interest-bearing deposits in banks |
|
|
280 |
|
|
|
297 |
|
|
|
158 |
|
|
|
186 |
|
|
|
167 |
|
|
|
(17 |
) |
|
|
(6 |
) |
|
|
113 |
|
|
|
68 |
|
| Debt securities available for sale, at fair value |
|
|
22,307 |
|
|
|
20,613 |
|
|
|
21,502 |
|
|
|
21,698 |
|
|
|
21,504 |
|
|
|
1,694 |
|
|
|
8 |
|
|
|
803 |
|
|
|
4 |
|
| Debt securities held to maturity |
|
|
3,071 |
|
|
|
3,202 |
|
|
|
3,319 |
|
|
|
3,447 |
|
|
|
3,345 |
|
|
|
(131 |
) |
|
|
(4 |
) |
|
|
(274 |
) |
|
|
(8 |
) |
| Equity securities, at fair value |
|
|
47 |
|
|
|
47 |
|
|
|
47 |
|
|
|
47 |
|
|
|
198 |
|
|
|
— |
|
|
|
— |
|
|
|
(151 |
) |
|
|
(76 |
) |
| Equity securities, at cost |
|
|
927 |
|
|
|
807 |
|
|
|
734 |
|
|
|
706 |
|
|
|
604 |
|
|
|
120 |
|
|
|
15 |
|
|
|
323 |
|
|
|
53 |
|
| Loans held for sale, at fair value |
|
|
2,911 |
|
|
|
1,946 |
|
|
|
1,993 |
|
|
|
1,750 |
|
|
|
1,186 |
|
|
|
965 |
|
|
|
50 |
|
|
|
1,725 |
|
|
|
145 |
|
| Other loans held for sale |
|
|
350 |
|
|
|
1,384 |
|
|
|
22 |
|
|
|
455 |
|
|
|
66 |
|
|
|
(1,034 |
) |
|
|
(75 |
) |
|
|
284 |
|
|
|
NM |
|
| Loans and leasesB |
|
|
127,528 |
|
|
|
119,088 |
|
|
|
117,880 |
|
|
|
116,838 |
|
|
|
117,615 |
|
|
|
8,440 |
|
|
|
7 |
|
|
|
9,913 |
|
|
|
8 |
|
| Less: Allowance for loan and lease losses |
|
|
(2,171 |
) |
|
|
(1,252 |
) |
|
|
(1,263 |
) |
|
|
(1,227 |
) |
|
|
(1,245 |
) |
|
|
(919 |
) |
|
|
(73 |
) |
|
|
(926 |
) |
|
|
(74 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net loans and leasesB |
|
|
125,357 |
|
|
|
117,836 |
|
|
|
116,617 |
|
|
|
115,611 |
|
|
|
116,370 |
|
|
|
7,521 |
|
|
|
6 |
|
|
|
8,987 |
|
|
|
8 |
|
| Derivative assets |
|
|
1,968 |
|
|
|
807 |
|
|
|
1,027 |
|
|
|
833 |
|
|
|
465 |
|
|
|
1,161 |
|
|
|
144 |
|
|
|
1,503 |
|
|
|
NM |
|
| Premises and equipment |
|
|
746 |
|
|
|
761 |
|
|
|
747 |
|
|
|
740 |
|
|
|
746 |
|
|
|
(15 |
) |
|
|
(2 |
) |
|
|
— |
|
|
|
— |
|
| Bank-owned life insurance |
|
|
1,736 |
|
|
|
1,725 |
|
|
|
1,720 |
|
|
|
1,711 |
|
|
|
1,705 |
|
|
|
11 |
|
|
|
1 |
|
|
|
31 |
|
|
|
2 |
|
| Goodwill |
|
|
7,050 |
|
|
|
7,044 |
|
|
|
7,044 |
|
|
|
7,040 |
|
|
|
7,040 |
|
|
|
6 |
|
|
|
— |
|
|
|
10 |
|
|
|
— |
|
| Due from broker |
|
|
— |
|
|
|
— |
|
|
|
257 |
|
|
|
249 |
|
|
|
92 |
|
|
|
— |
|
|
|
— |
|
|
|
(92 |
) |
|
|
(100 |
) |
| Other assetsB |
|
|
5,911 |
|
|
|
5,878 |
|
|
|
5,333 |
|
|
|
5,241 |
|
|
|
5,418 |
|
|
|
33 |
|
|
|
1 |
|
|
|
493 |
|
|
|
9 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| TOTAL ASSETS |
|
$ |
176,719 |
|
|
$ |
165,733 |
|
|
$ |
164,362 |
|
|
$ |
162,749 |
|
|
$ |
161,342 |
|
|
$ |
10,986 |
|
|
|
7% |
|
|
$ |
15,377 |
|
|
|
10 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| LIABILITIES AND STOCKHOLDERS’ EQUITY |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| LIABILITIES |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Deposits: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest-bearing |
|
$ |
32,398 |
|
|
$ |
29,233 |
|
|
$ |
29,939 |
|
|
$ |
28,192 |
|
|
$ |
28,383 |
|
|
$ |
3,165 |
|
|
|
11 |
% |
|
$ |
4,015 |
|
|
|
14 |
% |
| Interest-bearing |
|
|
101,077 |
|
|
|
96,080 |
|
|
|
94,775 |
|
|
|
95,812 |
|
|
|
95,533 |
|
|
|
4,997 |
|
|
|
5 |
|
|
|
5,544 |
|
|
|
6 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total deposits |
|
|
133,475 |
|
|
|
125,313 |
|
|
|
124,714 |
|
|
|
124,004 |
|
|
|
123,916 |
|
|
|
8,162 |
|
|
|
7 |
|
|
|
9,559 |
|
|
|
8 |
|
| Short-term borrowed fundsC |
|
|
1,059 |
|
|
|
274 |
|
|
|
1,077 |
|
|
|
1,441 |
|
|
|
679 |
|
|
|
785 |
|
|
|
NM |
|
|
|
380 |
|
|
|
56 |
|
| Derivative liabilities |
|
|
234 |
|
|
|
120 |
|
|
|
161 |
|
|
|
106 |
|
|
|
173 |
|
|
|
114 |
|
|
|
95 |
|
|
|
61 |
|
|
|
35 |
|
| Deferred taxes, net |
|
|
782 |
|
|
|
866 |
|
|
|
752 |
|
|
|
767 |
|
|
|
676 |
|
|
|
(84 |
) |
|
|
(10 |
) |
|
|
106 |
|
|
|
16 |
|
| Long-term borrowed funds: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| FHLB advances |
|
|
8,007 |
|
|
|
5,008 |
|
|
|
3,007 |
|
|
|
2,258 |
|
|
|
2,508 |
|
|
|
2,999 |
|
|
|
60 |
|
|
|
5,499 |
|
|
|
219 |
|
| Senior debt |
|
|
6,775 |
|
|
|
7,382 |
|
|
|
8,143 |
|
|
|
7,624 |
|
|
|
7,558 |
|
|
|
(607 |
) |
|
|
(8 |
) |
|
|
(783 |
) |
|
|
(10 |
) |
| Subordinated debt and other debt |
|
|
1,655 |
|
|
|
1,657 |
|
|
|
1,656 |
|
|
|
1,656 |
|
|
|
1,659 |
|
|
|
(2 |
) |
|
|
— |
|
|
|
(4 |
) |
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total long-term borrowed funds |
|
|
16,437 |
|
|
|
14,047 |
|
|
|
12,806 |
|
|
|
11,538 |
|
|
|
11,725 |
|
|
|
2,390 |
|
|
|
17 |
|
|
|
4,712 |
|
|
|
40 |
|
| Due to broker |
|
|
— |
|
|
|
— |
|
|
|
206 |
|
|
|
257 |
|
|
|
93 |
|
|
|
— |
|
|
|
— |
|
|
|
(93 |
) |
|
|
(100 |
) |
| Other liabilities |
|
|
2,782 |
|
|
|
2,912 |
|
|
|
2,795 |
|
|
|
2,619 |
|
|
|
2,549 |
|
|
|
(130 |
) |
|
|
(4 |
) |
|
|
233 |
|
|
|
9 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| TOTAL LIABILITIES |
|
|
154,769 |
|
|
|
143,532 |
|
|
|
142,511 |
|
|
|
140,732 |
|
|
|
139,811 |
|
|
|
11,237 |
|
|
|
8 |
|
|
|
14,958 |
|
|
|
11 |
|
| STOCKHOLDERS’ EQUITY |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Preferred stock: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| $25.00 par value, 100,000,000 shares authorized for each of the periods presented |
|
|
1,570 |
|
|
|
1,570 |
|
|
|
1,133 |
|
|
|
1,133 |
|
|
|
1,132 |
|
|
|
— |
|
|
|
— |
|
|
|
438 |
|
|
|
39 |
|
| Common stock: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| $0.01 par value, 1,000,000,000 shares authorized for each of the periods presented |
|
|
6 |
|
|
|
6 |
|
|
|
6 |
|
|
|
6 |
|
|
|
6 |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
| Additional paid-in capital |
|
|
18,901 |
|
|
|
18,891 |
|
|
|
18,876 |
|
|
|
18,860 |
|
|
|
18,847 |
|
|
|
10 |
|
|
|
— |
|
|
|
54 |
|
|
|
— |
|
| Retained earnings |
|
|
6,011 |
|
|
|
6,498 |
|
|
|
6,229 |
|
|
|
5,959 |
|
|
|
5,672 |
|
|
|
(487 |
) |
|
|
(7 |
) |
|
|
339 |
|
|
|
6 |
|
| Treasury stock, at cost |
|
|
(4,623 |
) |
|
|
(4,353 |
) |
|
|
(3,953 |
) |
|
|
(3,453 |
) |
|
|
(3,333 |
) |
|
|
(270 |
) |
|
|
(6 |
) |
|
|
(1,290 |
) |
|
|
(39 |
) |
| Accumulated other comprehensive income (loss) |
|
|
85 |
|
|
|
(411 |
) |
|
|
(440 |
) |
|
|
(488 |
) |
|
|
(793 |
) |
|
|
496 |
|
|
|
NM |
|
|
|
878 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| TOTAL STOCKHOLDERS’ EQUITY |
|
|
21,950 |
|
|
|
22,201 |
|
|
|
21,851 |
|
|
|
22,017 |
|
|
|
21,531 |
|
|
|
(251 |
) |
|
|
(1) |
|
|
|
419 |
|
|
|
2 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| TOTAL LIABILITIES AND STOCKHOLDERS’ EQUITY |
|
$ |
176,719 |
|
|
$ |
165,733 |
|
|
$ |
164,362 |
|
|
$ |
162,749 |
|
|
$ |
161,342 |
|
|
$ |
10,986 |
|
|
|
7% |
|
|
$ |
15,377 |
|
|
|
10 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Memo: Total tangible common equity |
|
$ |
13,639 |
|
|
$ |
13,893 |
|
|
$ |
13,976 |
|
|
$ |
14,141 |
|
|
$ |
13,649 |
|
|
($ |
254 |
) |
|
|
(2 |
%) |
|
($ |
10 |
) |
|
|
— |
% |
6
LOANS AND DEPOSITS
(in millions)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| PERIOD-END BALANCES |
|
AS OF |
|
|
MARCH 31, 2020 CHANGE |
|
| |
|
Mar 31, 2020 |
|
|
Dec 31, 2019 |
|
|
Sept 30, 2019 |
|
|
June 30, 2019 |
|
|
Mar 31, 2019 |
|
|
Dec 31, 2019 |
|
|
March 31, 2019 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
|
$ |
|
|
% |
|
| LOANS AND LEASES |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
$ |
49,092 |
|
|
$ |
41,479 |
|
|
$ |
41,356 |
|
|
$ |
41,156 |
|
|
$ |
41,497 |
|
|
$ |
7,613 |
|
|
|
18 |
% |
|
$ |
7,595 |
|
|
|
18 |
% |
| Commercial real estate |
|
|
14,502 |
|
|
|
13,522 |
|
|
|
12,820 |
|
|
|
13,123 |
|
|
|
13,372 |
|
|
|
980 |
|
|
|
7 |
|
|
|
1,130 |
|
|
|
8 |
|
| Leases |
|
|
2,438 |
|
|
|
2,537 |
|
|
|
2,557 |
|
|
|
2,684 |
|
|
|
2,820 |
|
|
|
(99 |
) |
|
|
(4 |
) |
|
|
(382 |
) |
|
|
(14 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total commercial loans and leases |
|
|
66,032 |
|
|
|
57,538 |
|
|
|
56,733 |
|
|
|
56,963 |
|
|
|
57,689 |
|
|
|
8,494 |
|
|
|
15 |
|
|
|
8,343 |
|
|
|
14 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Residential mortgagesB |
|
|
18,721 |
|
|
|
19,083 |
|
|
|
19,699 |
|
|
|
19,192 |
|
|
|
19,174 |
|
|
|
(362 |
) |
|
|
(2 |
) |
|
|
(453 |
) |
|
|
(2 |
) |
| Home equityD |
|
|
12,992 |
|
|
|
13,154 |
|
|
|
13,423 |
|
|
|
13,640 |
|
|
|
13,870 |
|
|
|
(162 |
) |
|
|
(1 |
) |
|
|
(878 |
) |
|
|
(6 |
) |
| Automobile |
|
|
12,157 |
|
|
|
12,120 |
|
|
|
12,070 |
|
|
|
12,000 |
|
|
|
11,992 |
|
|
|
37 |
|
|
|
— |
|
|
|
165 |
|
|
|
1 |
|
| Education |
|
|
10,887 |
|
|
|
10,347 |
|
|
|
9,729 |
|
|
|
9,305 |
|
|
|
9,274 |
|
|
|
540 |
|
|
|
5 |
|
|
|
1,613 |
|
|
|
17 |
|
| Other retailE |
|
|
6,739 |
|
|
|
6,846 |
|
|
|
6,226 |
|
|
|
5,738 |
|
|
|
5,616 |
|
|
|
(107 |
) |
|
|
(2 |
) |
|
|
1,123 |
|
|
|
20 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total retail loansB |
|
|
61,496 |
|
|
|
61,550 |
|
|
|
61,147 |
|
|
|
59,875 |
|
|
|
59,926 |
|
|
|
(54 |
) |
|
|
— |
|
|
|
1,570 |
|
|
|
3 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total loans and leasesB |
|
$ |
127,528 |
|
|
$ |
119,088 |
|
|
$ |
117,880 |
|
|
$ |
116,838 |
|
|
$ |
117,615 |
|
|
$ |
8,440 |
|
|
|
7 |
% |
|
$ |
9,913 |
|
|
|
8 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Loans held for sale, at fair value |
|
|
2,911 |
|
|
|
1,946 |
|
|
|
1,993 |
|
|
|
1,750 |
|
|
|
1,186 |
|
|
|
965 |
|
|
|
50 |
|
|
|
1,725 |
|
|
|
145 |
|
| Other loans held for sale |
|
|
350 |
|
|
|
1,384 |
|
|
|
22 |
|
|
|
455 |
|
|
|
66 |
|
|
|
(1,034 |
) |
|
|
(75 |
) |
|
|
284 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Loans and leases and loans held for saleB
|
|
$ |
130,789 |
|
|
$ |
122,418 |
|
|
$ |
119,895 |
|
|
$ |
119,043 |
|
|
$ |
118,867 |
|
|
$ |
8,371 |
|
|
|
7 |
% |
|
$ |
11,922 |
|
|
|
10 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| DEPOSITS |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Demand |
|
$ |
32,398 |
|
|
$ |
29,233 |
|
|
$ |
29,939 |
|
|
$ |
28,192 |
|
|
$ |
28,383 |
|
|
$ |
3,165 |
|
|
|
11 |
% |
|
$ |
4,015 |
|
|
|
14 |
% |
| Checking with interest |
|
|
25,358 |
|
|
|
24,840 |
|
|
|
24,403 |
|
|
|
25,021 |
|
|
|
23,482 |
|
|
|
518 |
|
|
|
2 |
|
|
|
1,876 |
|
|
|
8 |
|
| Regular savings |
|
|
14,702 |
|
|
|
13,779 |
|
|
|
13,479 |
|
|
|
13,495 |
|
|
|
13,239 |
|
|
|
923 |
|
|
|
7 |
|
|
|
1,463 |
|
|
|
11 |
|
| Money market accounts |
|
|
42,972 |
|
|
|
38,725 |
|
|
|
36,826 |
|
|
|
35,329 |
|
|
|
35,972 |
|
|
|
4,247 |
|
|
|
11 |
|
|
|
7,000 |
|
|
|
19 |
|
| Term deposits |
|
|
18,045 |
|
|
|
18,736 |
|
|
|
20,067 |
|
|
|
21,967 |
|
|
|
22,840 |
|
|
|
(691 |
) |
|
|
(4 |
) |
|
|
(4,795 |
) |
|
|
(21 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total deposits |
|
$ |
133,475 |
|
|
$ |
125,313 |
|
|
$ |
124,714 |
|
|
$ |
124,004 |
|
|
$ |
123,916 |
|
|
$ |
8,162 |
|
|
|
7 |
% |
|
$ |
9,559 |
|
|
|
8 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
7
AVERAGE BALANCE SHEETS
(in millions)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
QUARTERLY TRENDS |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
|
$ |
|
|
% |
|
| ASSETS |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Interest-bearing cash and due from banks and deposits in banks |
|
$ |
1,859 |
|
|
$ |
1,970 |
|
|
$ |
1,474 |
|
|
$ |
1,229 |
|
|
$ |
1,497 |
|
|
($ |
111 |
) |
|
|
(6 |
%) |
|
$ |
362 |
|
|
|
24 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Taxable investment securities |
|
|
25,339 |
|
|
|
25,305 |
|
|
|
25,635 |
|
|
|
25,620 |
|
|
|
25,136 |
|
|
|
34 |
|
|
|
— |
|
|
|
203 |
|
|
|
1 |
|
| Non-taxable investment securities |
|
|
4 |
|
|
|
5 |
|
|
|
5 |
|
|
|
5 |
|
|
|
5 |
|
|
|
(1 |
) |
|
|
(20 |
) |
|
|
(1 |
) |
|
|
(20 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total investment securities |
|
|
25,343 |
|
|
|
25,310 |
|
|
|
25,640 |
|
|
|
25,625 |
|
|
|
25,141 |
|
|
|
33 |
|
|
|
— |
|
|
|
202 |
|
|
|
1 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Investment securities and interest-bearing deposits |
|
|
27,202 |
|
|
|
27,280 |
|
|
|
27,114 |
|
|
|
26,854 |
|
|
|
26,638 |
|
|
|
(78 |
) |
|
|
— |
|
|
|
564 |
|
|
|
2 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
|
43,152 |
|
|
|
42,012 |
|
|
|
41,476 |
|
|
|
41,755 |
|
|
|
41,562 |
|
|
|
1,140 |
|
|
|
3 |
|
|
|
1,590 |
|
|
|
4 |
|
| Commercial real estate |
|
|
13,876 |
|
|
|
13,103 |
|
|
|
12,892 |
|
|
|
13,379 |
|
|
|
13,272 |
|
|
|
773 |
|
|
|
6 |
|
|
|
604 |
|
|
|
5 |
|
| Leases |
|
|
2,482 |
|
|
|
2,546 |
|
|
|
2,615 |
|
|
|
2,745 |
|
|
|
2,873 |
|
|
|
(64 |
) |
|
|
(3 |
) |
|
|
(391 |
) |
|
|
(14 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total commercial loans and leases |
|
|
59,510 |
|
|
|
57,661 |
|
|
|
56,983 |
|
|
|
57,879 |
|
|
|
57,707 |
|
|
|
1,849 |
|
|
|
3 |
|
|
|
1,803 |
|
|
|
3 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Residential mortgagesB |
|
|
18,866 |
|
|
|
19,495 |
|
|
|
19,405 |
|
|
|
19,232 |
|
|
|
19,094 |
|
|
|
(629 |
) |
|
|
(3 |
) |
|
|
(228 |
) |
|
|
(1 |
) |
| Home equityD |
|
|
13,042 |
|
|
|
13,265 |
|
|
|
13,501 |
|
|
|
13,754 |
|
|
|
14,075 |
|
|
|
(223 |
) |
|
|
(2 |
) |
|
|
(1,033 |
) |
|
|
(7 |
) |
| Automobile |
|
|
12,173 |
|
|
|
12,099 |
|
|
|
12,036 |
|
|
|
11,984 |
|
|
|
12,070 |
|
|
|
74 |
|
|
|
1 |
|
|
|
103 |
|
|
|
1 |
|
| Education |
|
|
10,610 |
|
|
|
9,888 |
|
|
|
9,459 |
|
|
|
9,235 |
|
|
|
9,069 |
|
|
|
722 |
|
|
|
7 |
|
|
|
1,541 |
|
|
|
17 |
|
| Other retailE |
|
|
6,854 |
|
|
|
6,497 |
|
|
|
5,873 |
|
|
|
5,699 |
|
|
|
5,634 |
|
|
|
357 |
|
|
|
5 |
|
|
|
1,220 |
|
|
|
22 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total retail loansB |
|
|
61,545 |
|
|
|
61,244 |
|
|
|
60,274 |
|
|
|
59,904 |
|
|
|
59,942 |
|
|
|
301 |
|
|
|
— |
|
|
|
1,603 |
|
|
|
3 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total loans and leasesB |
|
|
121,055 |
|
|
|
118,905 |
|
|
|
117,257 |
|
|
|
117,783 |
|
|
|
117,649 |
|
|
|
2,150 |
|
|
|
2 |
|
|
|
3,406 |
|
|
|
3 |
|
| Loans held for sale, at fair value |
|
|
1,890 |
|
|
|
2,209 |
|
|
|
1,970 |
|
|
|
1,528 |
|
|
|
1,035 |
|
|
|
(319 |
) |
|
|
(14 |
) |
|
|
855 |
|
|
|
83 |
|
| Other loans held for sale |
|
|
799 |
|
|
|
517 |
|
|
|
134 |
|
|
|
158 |
|
|
|
191 |
|
|
|
282 |
|
|
|
55 |
|
|
|
608 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total interest-earning assetsB |
|
|
150,946 |
|
|
|
148,911 |
|
|
|
146,475 |
|
|
|
146,323 |
|
|
|
145,513 |
|
|
|
2,035 |
|
|
|
1 |
|
|
|
5,433 |
|
|
|
4 |
|
| Allowance for loan and lease losses |
|
|
(1,708 |
) |
|
|
(1,260 |
) |
|
|
(1,226 |
) |
|
|
(1,247 |
) |
|
|
(1,243 |
) |
|
|
(448 |
) |
|
|
(36 |
) |
|
|
(465 |
) |
|
|
(37 |
) |
| Goodwill |
|
|
7,046 |
|
|
|
7,044 |
|
|
|
7,044 |
|
|
|
7,040 |
|
|
|
7,018 |
|
|
|
2 |
|
|
|
— |
|
|
|
28 |
|
|
|
— |
|
| Other noninterest-earning assetsB |
|
|
10,893 |
|
|
|
9,951 |
|
|
|
9,817 |
|
|
|
9,373 |
|
|
|
9,127 |
|
|
|
942 |
|
|
|
9 |
|
|
|
1,766 |
|
|
|
19 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| TOTAL ASSETS |
|
$ |
167,177 |
|
|
$ |
164,646 |
|
|
$ |
162,110 |
|
|
$ |
161,489 |
|
|
$ |
160,415 |
|
|
$ |
2,531 |
|
|
|
2 |
% |
|
$ |
6,762 |
|
|
|
4 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| LIABILITIES AND STOCKHOLDERS’ EQUITY |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| LIABILITIES |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Checking with interest |
|
$ |
24,612 |
|
|
$ |
23,545 |
|
|
$ |
23,422 |
|
|
$ |
23,919 |
|
|
$ |
22,987 |
|
|
$ |
1,067 |
|
|
|
5 |
% |
|
$ |
1,625 |
|
|
|
7 |
% |
| Money market accounts |
|
|
39,839 |
|
|
|
38,809 |
|
|
|
37,161 |
|
|
|
35,228 |
|
|
|
35,209 |
|
|
|
1,030 |
|
|
|
3 |
|
|
|
4,630 |
|
|
|
13 |
|
| Regular savings |
|
|
14,201 |
|
|
|
13,582 |
|
|
|
13,442 |
|
|
|
13,324 |
|
|
|
12,626 |
|
|
|
619 |
|
|
|
5 |
|
|
|
1,575 |
|
|
|
12 |
|
| Term deposits |
|
|
18,616 |
|
|
|
19,788 |
|
|
|
20,951 |
|
|
|
22,292 |
|
|
|
21,127 |
|
|
|
(1,172 |
) |
|
|
(6 |
) |
|
|
(2,511 |
) |
|
|
(12 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total interest-bearing deposits |
|
|
97,268 |
|
|
|
95,724 |
|
|
|
94,976 |
|
|
|
94,763 |
|
|
|
91,949 |
|
|
|
1,544 |
|
|
|
2 |
|
|
|
5,319 |
|
|
|
6 |
|
| Short-term borrowed fundsC |
|
|
644 |
|
|
|
504 |
|
|
|
600 |
|
|
|
863 |
|
|
|
698 |
|
|
|
140 |
|
|
|
28 |
|
|
|
(54 |
) |
|
|
(8 |
) |
| FHLB advances |
|
|
5,138 |
|
|
|
3,259 |
|
|
|
2,478 |
|
|
|
3,155 |
|
|
|
5,694 |
|
|
|
1,879 |
|
|
|
58 |
|
|
|
(556 |
) |
|
|
(10 |
) |
| Senior debt |
|
|
7,263 |
|
|
|
7,914 |
|
|
|
8,000 |
|
|
|
7,573 |
|
|
|
7,391 |
|
|
|
(651 |
) |
|
|
(8 |
) |
|
|
(128 |
) |
|
|
(2 |
) |
| Subordinated debt and other debt |
|
|
1,656 |
|
|
|
1,657 |
|
|
|
1,656 |
|
|
|
1,658 |
|
|
|
1,651 |
|
|
|
(1 |
) |
|
|
— |
|
|
|
5 |
|
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total long-term borrowed funds |
|
|
14,057 |
|
|
|
12,830 |
|
|
|
12,134 |
|
|
|
12,386 |
|
|
|
14,736 |
|
|
|
1,227 |
|
|
|
10 |
|
|
|
(679 |
) |
|
|
(5 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total borrowed funds |
|
|
14,701 |
|
|
|
13,334 |
|
|
|
12,734 |
|
|
|
13,249 |
|
|
|
15,434 |
|
|
|
1,367 |
|
|
|
10 |
|
|
|
(733 |
) |
|
|
(5 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total interest-bearing liabilities |
|
|
111,969 |
|
|
|
109,058 |
|
|
|
107,710 |
|
|
|
108,012 |
|
|
|
107,383 |
|
|
|
2,911 |
|
|
|
3 |
|
|
|
4,586 |
|
|
|
4 |
|
| Total demand deposits |
|
|
29,362 |
|
|
|
29,928 |
|
|
|
28,945 |
|
|
|
28,389 |
|
|
|
28,465 |
|
|
|
(566 |
) |
|
|
(2 |
) |
|
|
897 |
|
|
|
3 |
|
| Other liabilities |
|
|
4,053 |
|
|
|
3,819 |
|
|
|
3,789 |
|
|
|
3,536 |
|
|
|
3,584 |
|
|
|
234 |
|
|
|
6 |
|
|
|
469 |
|
|
|
13 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| TOTAL LIABILITIES |
|
|
145,384 |
|
|
|
142,805 |
|
|
|
140,444 |
|
|
|
139,937 |
|
|
|
139,432 |
|
|
|
2,579 |
|
|
|
2 |
|
|
|
5,952 |
|
|
|
4 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| STOCKHOLDERS’ EQUITY |
|
|
21,793 |
|
|
|
21,841 |
|
|
|
21,666 |
|
|
|
21,552 |
|
|
|
20,983 |
|
|
|
(48 |
) |
|
|
— |
|
|
|
810 |
|
|
|
4 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| TOTAL LIABILITIES AND STOCKHOLDERS’ EQUITY |
|
$ |
167,177 |
|
|
$ |
164,646 |
|
|
$ |
162,110 |
|
|
$ |
161,489 |
|
|
$ |
160,415 |
|
|
$ |
2,531 |
|
|
|
2 |
% |
|
$ |
6,762 |
|
|
|
4 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Memo: Total loans and leases, including loans held for sale |
|
$ |
123,744 |
|
|
$ |
121,631 |
|
|
$ |
119,361 |
|
|
$ |
119,469 |
|
|
$ |
118,875 |
|
|
$ |
2,113 |
|
|
|
2 |
% |
|
$ |
4,869 |
|
|
|
4 |
% |
| Total deposits (interest-bearing and demand) |
|
$ |
126,630 |
|
|
$ |
125,652 |
|
|
$ |
123,921 |
|
|
$ |
123,152 |
|
|
$ |
120,414 |
|
|
$ |
978 |
|
|
|
1 |
% |
|
$ |
6,216 |
|
|
|
5 |
% |
| Total average tangible common equity |
|
$ |
13,484 |
|
|
$ |
13,660 |
|
|
$ |
13,788 |
|
|
$ |
13,670 |
|
|
$ |
13,233 |
|
|
($ |
176 |
) |
|
|
(1 |
%) |
|
$ |
251 |
|
|
|
2 |
% |
8
AVERAGE ANNUALIZED YIELDS AND RATES
(in millions, except rates)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
QUARTERLY TRENDS |
|
| |
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
| |
|
Rate |
|
|
Income/Expense |
|
|
Rate |
|
|
Income/Expense |
|
|
Rate |
|
|
Income/Expense |
|
|
Rate |
|
|
Income/Expense |
|
|
Rate |
|
|
Income/Expense |
|
| INTEREST-EARNING ASSETS |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Interest-bearing cash and due from banks and deposits in banks |
|
|
1.12 |
% |
|
$ |
5 |
|
|
|
1.49 |
% |
|
$ |
7 |
|
|
|
2.09 |
% |
|
$ |
8 |
|
|
|
2.16 |
% |
|
$ |
7 |
|
|
|
2.19 |
% |
|
$ |
8 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Taxable investment securities |
|
|
2.32 |
|
|
|
147 |
|
|
|
2.47 |
|
|
|
159 |
|
|
|
2.38 |
|
|
|
153 |
|
|
|
2.56 |
|
|
|
164 |
|
|
|
2.64 |
|
|
|
166 |
|
| Non-taxable investment securities |
|
|
2.60 |
|
|
|
— |
|
|
|
2.60 |
|
|
|
— |
|
|
|
2.60 |
|
|
|
— |
|
|
|
2.60 |
|
|
|
— |
|
|
|
2.60 |
|
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total investment securities |
|
|
2.32 |
|
|
|
147 |
|
|
|
2.47 |
|
|
|
159 |
|
|
|
2.38 |
|
|
|
153 |
|
|
|
2.56 |
|
|
|
164 |
|
|
|
2.64 |
|
|
|
166 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Investment securities and interest-bearing deposits |
|
|
|
|
|
|
152 |
|
|
|
|
|
|
|
166 |
|
|
|
|
|
|
|
161 |
|
|
|
|
|
|
|
171 |
|
|
|
|
|
|
|
174 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
|
3.82 |
|
|
|
417 |
|
|
|
3.95 |
|
|
|
424 |
|
|
|
4.17 |
|
|
|
442 |
|
|
|
4.45 |
|
|
|
471 |
|
|
|
4.43 |
|
|
|
460 |
|
| Commercial real estate |
|
|
3.96 |
|
|
|
139 |
|
|
|
4.26 |
|
|
|
142 |
|
|
|
4.70 |
|
|
|
155 |
|
|
|
4.91 |
|
|
|
166 |
|
|
|
4.98 |
|
|
|
165 |
|
| Leases |
|
|
2.83 |
|
|
|
18 |
|
|
|
2.77 |
|
|
|
18 |
|
|
|
2.85 |
|
|
|
19 |
|
|
|
2.89 |
|
|
|
19 |
|
|
|
2.85 |
|
|
|
21 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total commercial loans and leases |
|
|
3.81 |
|
|
|
574 |
|
|
|
3.97 |
|
|
|
584 |
|
|
|
4.23 |
|
|
|
616 |
|
|
|
4.48 |
|
|
|
656 |
|
|
|
4.48 |
|
|
|
646 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Residential mortgagesB |
|
|
3.47 |
|
|
|
164 |
|
|
|
3.40 |
|
|
|
165 |
|
|
|
3.53 |
|
|
|
171 |
|
|
|
3.65 |
|
|
|
176 |
|
|
|
3.67 |
|
|
|
175 |
|
| Home equityD |
|
|
4.69 |
|
|
|
152 |
|
|
|
4.73 |
|
|
|
159 |
|
|
|
5.24 |
|
|
|
178 |
|
|
|
5.28 |
|
|
|
180 |
|
|
|
5.27 |
|
|
|
183 |
|
| Automobile |
|
|
4.34 |
|
|
|
131 |
|
|
|
4.32 |
|
|
|
132 |
|
|
|
4.25 |
|
|
|
129 |
|
|
|
4.19 |
|
|
|
125 |
|
|
|
4.04 |
|
|
|
120 |
|
| Education |
|
|
5.64 |
|
|
|
149 |
|
|
|
5.76 |
|
|
|
143 |
|
|
|
5.89 |
|
|
|
141 |
|
|
|
5.97 |
|
|
|
137 |
|
|
|
5.99 |
|
|
|
134 |
|
| Other retailE |
|
|
7.77 |
|
|
|
132 |
|
|
|
7.83 |
|
|
|
129 |
|
|
|
8.21 |
|
|
|
121 |
|
|
|
8.24 |
|
|
|
118 |
|
|
|
8.87 |
|
|
|
123 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total retail loansB |
|
|
4.75 |
|
|
|
728 |
|
|
|
4.72 |
|
|
|
728 |
|
|
|
4.88 |
|
|
|
740 |
|
|
|
4.92 |
|
|
|
736 |
|
|
|
4.96 |
|
|
|
735 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total loans and leasesB |
|
|
4.29 |
|
|
|
1,302 |
|
|
|
4.36 |
|
|
|
1,312 |
|
|
|
4.56 |
|
|
|
1,356 |
|
|
|
4.71 |
|
|
|
1,392 |
|
|
|
4.72 |
|
|
|
1,381 |
|
| Loans held for sale, at fair value |
|
|
3.28 |
|
|
|
15 |
|
|
|
3.38 |
|
|
|
18 |
|
|
|
3.71 |
|
|
|
19 |
|
|
|
3.93 |
|
|
|
15 |
|
|
|
4.35 |
|
|
|
11 |
|
| Other loans held for sale |
|
|
4.31 |
|
|
|
9 |
|
|
|
3.89 |
|
|
|
5 |
|
|
|
6.42 |
|
|
|
2 |
|
|
|
5.67 |
|
|
|
2 |
|
|
|
7.03 |
|
|
|
4 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total interest-earning assetsB |
|
|
3.91 |
|
|
|
1,478 |
|
|
|
3.98 |
|
|
|
1,501 |
|
|
|
4.15 |
|
|
|
1,538 |
|
|
|
4.30 |
|
|
|
1,580 |
|
|
|
4.34 |
|
|
|
1,570 |
|
| INTEREST-BEARING LIABILITIES |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Checking with interest |
|
|
0.60 |
|
|
|
37 |
|
|
|
0.71 |
|
|
|
42 |
|
|
|
0.88 |
|
|
|
52 |
|
|
|
0.96 |
|
|
|
57 |
|
|
|
0.91 |
|
|
|
52 |
|
| Money market accounts |
|
|
0.94 |
|
|
|
93 |
|
|
|
1.12 |
|
|
|
110 |
|
|
|
1.24 |
|
|
|
116 |
|
|
|
1.30 |
|
|
|
114 |
|
|
|
1.26 |
|
|
|
110 |
|
| Regular savings |
|
|
0.51 |
|
|
|
18 |
|
|
|
0.52 |
|
|
|
17 |
|
|
|
0.59 |
|
|
|
20 |
|
|
|
0.62 |
|
|
|
21 |
|
|
|
0.56 |
|
|
|
17 |
|
| Term deposits |
|
|
1.70 |
|
|
|
79 |
|
|
|
1.88 |
|
|
|
94 |
|
|
|
2.05 |
|
|
|
109 |
|
|
|
2.09 |
|
|
|
116 |
|
|
|
2.08 |
|
|
|
108 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total interest-bearing deposits |
|
|
0.94 |
|
|
|
227 |
|
|
|
1.09 |
|
|
|
263 |
|
|
|
1.24 |
|
|
|
297 |
|
|
|
1.30 |
|
|
|
308 |
|
|
|
1.27 |
|
|
|
287 |
|
| Short-term borrowed fundsC |
|
|
0.76 |
|
|
|
1 |
|
|
|
1.07 |
|
|
|
2 |
|
|
|
1.43 |
|
|
|
2 |
|
|
|
1.81 |
|
|
|
4 |
|
|
|
1.37 |
|
|
|
2 |
|
| FHLB advances |
|
|
1.87 |
|
|
|
24 |
|
|
|
1.98 |
|
|
|
16 |
|
|
|
1.92 |
|
|
|
12 |
|
|
|
2.63 |
|
|
|
21 |
|
|
|
2.70 |
|
|
|
39 |
|
| Senior debt |
|
|
2.69 |
|
|
|
49 |
|
|
|
3.02 |
|
|
|
60 |
|
|
|
3.21 |
|
|
|
65 |
|
|
|
3.41 |
|
|
|
64 |
|
|
|
3.53 |
|
|
|
65 |
|
| Subordinated debt and other debt |
|
|
4.13 |
|
|
|
17 |
|
|
|
4.20 |
|
|
|
17 |
|
|
|
4.13 |
|
|
|
17 |
|
|
|
4.08 |
|
|
|
17 |
|
|
|
4.06 |
|
|
|
17 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total long-term borrowed funds |
|
|
2.56 |
|
|
|
90 |
|
|
|
2.91 |
|
|
|
93 |
|
|
|
3.07 |
|
|
|
94 |
|
|
|
3.30 |
|
|
|
102 |
|
|
|
3.27 |
|
|
|
121 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total borrowed funds |
|
|
2.48 |
|
|
|
91 |
|
|
|
2.84 |
|
|
|
95 |
|
|
|
3.00 |
|
|
|
96 |
|
|
|
3.20 |
|
|
|
106 |
|
|
|
3.18 |
|
|
|
123 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total interest-bearing liabilities |
|
|
1.14 |
|
|
|
318 |
|
|
|
1.30 |
|
|
|
358 |
|
|
|
1.45 |
|
|
|
393 |
|
|
|
1.54 |
|
|
|
414 |
|
|
|
1.54 |
|
|
|
410 |
|
| INTEREST RATE SPREAD |
|
|
2.77 |
|
|
|
|
|
|
|
2.68 |
|
|
|
|
|
|
|
2.70 |
|
|
|
|
|
|
|
2.77 |
|
|
|
|
|
|
|
2.80 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| NET INTEREST MARGIN AND NET INTEREST INCOME |
|
|
3.09 |
% |
|
$ |
1,160 |
|
|
|
3.04 |
% |
|
$ |
1,143 |
|
|
|
3.10 |
% |
|
$ |
1,145 |
|
|
|
3.20 |
% |
|
$ |
1,166 |
|
|
|
3.23 |
% |
|
$ |
1,160 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| NET INTEREST MARGIN AND NET INTEREST INCOME, FTE1
|
|
|
3.10 |
% |
|
$ |
1,164 |
|
|
|
3.06 |
% |
|
$ |
1,147 |
|
|
|
3.12 |
% |
|
$ |
1,150 |
|
|
|
3.21 |
% |
|
$ |
1,172 |
|
|
|
3.25 |
% |
|
$ |
1,166 |
|
| Memo: Total deposit costs |
|
|
0.72 |
% |
|
$ |
227 |
|
|
|
0.83 |
% |
|
$ |
263 |
|
|
|
0.95 |
% |
|
$ |
297 |
|
|
|
1.00 |
% |
|
$ |
308 |
|
|
|
0.97 |
% |
|
$ |
287 |
|
| 1 |
Net interest income and net interest margin is presented on a fully taxable-equivalent (“FTE”) basis
using the federal statutory tax rate of 21%. The FTE impact is predominantly attributable to commercial loans for the periods presented. |
9
SEGMENT FINANCIAL HIGHLIGHTS - CONSUMER BANKING
(in millions, except ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
QUARTERLY TRENDS |
|
| CONSUMER BANKING |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$/bps |
|
|
% |
|
|
$/bps |
|
|
% |
|
| Net interest income |
|
$ |
793 |
|
|
$ |
796 |
|
|
$ |
799 |
|
|
$ |
799 |
|
|
$ |
788 |
|
|
($ |
3 |
) |
|
|
— |
% |
|
$ |
5 |
|
|
|
1 |
% |
| Noninterest income |
|
|
357 |
|
|
|
296 |
|
|
|
336 |
|
|
|
277 |
|
|
|
247 |
|
|
|
61 |
|
|
|
21 |
|
|
|
110 |
|
|
|
45 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue |
|
|
1,150 |
|
|
|
1,092 |
|
|
|
1,135 |
|
|
|
1,076 |
|
|
|
1,035 |
|
|
|
58 |
|
|
|
5 |
|
|
|
115 |
|
|
|
11 |
|
| Noninterest expense |
|
|
738 |
|
|
|
718 |
|
|
|
718 |
|
|
|
715 |
|
|
|
700 |
|
|
|
20 |
|
|
|
3 |
|
|
|
38 |
|
|
|
5 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Profit before provision for credit losses |
|
|
412 |
|
|
|
374 |
|
|
|
417 |
|
|
|
361 |
|
|
|
335 |
|
|
|
38 |
|
|
|
10 |
|
|
|
77 |
|
|
|
23 |
|
| Provision for credit losses |
|
|
97 |
|
|
|
97 |
|
|
|
83 |
|
|
|
78 |
|
|
|
67 |
|
|
|
— |
|
|
|
— |
|
|
|
30 |
|
|
|
45 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income before income tax expense |
|
|
315 |
|
|
|
277 |
|
|
|
334 |
|
|
|
283 |
|
|
|
268 |
|
|
|
38 |
|
|
|
14 |
|
|
|
47 |
|
|
|
18 |
|
| Income tax expense |
|
|
79 |
|
|
|
68 |
|
|
|
83 |
|
|
|
70 |
|
|
|
66 |
|
|
|
11 |
|
|
|
16 |
|
|
|
13 |
|
|
|
20 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income |
|
$ |
236 |
|
|
$ |
209 |
|
|
$ |
251 |
|
|
$ |
213 |
|
|
$ |
202 |
|
|
$ |
27 |
|
|
|
13 |
% |
|
$ |
34 |
|
|
|
17 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| AVERAGE BALANCES |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total assets |
|
$ |
68,415 |
|
|
$ |
68,069 |
|
|
$ |
66,365 |
|
|
$ |
65,485 |
|
|
$ |
65,007 |
|
|
$ |
346 |
|
|
|
1 |
% |
|
$ |
3,408 |
|
|
|
5 |
% |
| Total loans and leases1,B |
|
|
65,343 |
|
|
|
65,157 |
|
|
|
63,553 |
|
|
|
62,678 |
|
|
|
62,163 |
|
|
|
186 |
|
|
|
— |
|
|
|
3,180 |
|
|
|
5 |
|
| Deposits |
|
|
85,228 |
|
|
|
85,477 |
|
|
|
85,595 |
|
|
|
85,660 |
|
|
|
82,569 |
|
|
|
(249 |
) |
|
|
— |
|
|
|
2,659 |
|
|
|
3 |
|
| Interest-earning assetsB |
|
|
65,393 |
|
|
|
65,208 |
|
|
|
63,605 |
|
|
|
62,731 |
|
|
|
62,216 |
|
|
|
185 |
|
|
|
— |
|
|
|
3,177 |
|
|
|
5 |
|
| KEY METRICS |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net interest margin |
|
|
4.88 |
% |
|
|
4.85 |
% |
|
|
4.99 |
% |
|
|
5.11 |
% |
|
|
5.14 |
% |
|
|
3 |
bps |
|
|
|
|
|
|
(26 |
) bps |
|
|
|
|
| Efficiency ratio |
|
|
64.16 |
|
|
|
65.74 |
|
|
|
63.28 |
|
|
|
66.43 |
|
|
|
67.62 |
|
|
|
(158 |
) bps |
|
|
|
|
|
|
(346 |
) bps |
|
|
|
|
| Loans-to-deposits
ratio (period-end balances)B |
|
|
72.94 |
|
|
|
74.15 |
|
|
|
73.61 |
|
|
|
71.13 |
|
|
|
71.17 |
|
|
|
(121 |
) bps |
|
|
|
|
|
|
177 |
bps |
|
|
|
|
| Loans-to-deposits
ratio (average balances)B |
|
|
74.07 |
|
|
|
73.37 |
|
|
|
72.11 |
|
|
|
71.57 |
|
|
|
74.27 |
|
|
|
70 |
bps |
|
|
|
|
|
|
(20 |
) bps |
|
|
|
|
| Return on average total tangible assets |
|
|
1.39 |
|
|
|
1.22 |
|
|
|
1.50 |
|
|
|
1.31 |
|
|
|
1.26 |
|
|
|
17 |
bps |
|
|
|
|
|
|
13 |
bps |
|
|
|
|
| 1 |
Includes loans held for sale. |
10
SEGMENT FINANCIAL HIGHLIGHTS - CONSUMER BANKING, CONTINUED
(in millions, except ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
QUARTERLY TRENDS |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$/bps |
|
|
% |
|
|
$/bps |
|
|
% |
|
| MORTGAGE BANKING FEES |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Production revenue |
|
$ |
136 |
|
|
$ |
61 |
|
|
$ |
80 |
|
|
$ |
49 |
|
|
$ |
31 |
|
|
$ |
75 |
|
|
|
123 |
% |
|
$ |
105 |
|
|
|
NM |
|
| Mortgage servicing revenue |
|
|
17 |
|
|
|
16 |
|
|
|
12 |
|
|
|
9 |
|
|
|
14 |
|
|
|
1 |
|
|
|
6 |
|
|
|
3 |
|
|
|
21 |
|
| MSR valuation changes, net of hedge impact |
|
|
6 |
|
|
|
4 |
|
|
|
25 |
|
|
|
4 |
|
|
|
(2 |
) |
|
|
2 |
|
|
|
50 |
|
|
|
8 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total mortgage banking fees |
|
$ |
159 |
|
|
$ |
81 |
|
|
$ |
117 |
|
|
$ |
62 |
|
|
$ |
43 |
|
|
$ |
78 |
|
|
|
96 |
% |
|
$ |
116 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Gain on sale of secondary originations |
|
|
2.36 |
% |
|
|
0.98 |
% |
|
|
1.40 |
% |
|
|
1.13 |
% |
|
|
1.28 |
% |
|
|
138 |
bps |
|
|
|
|
|
|
108 |
bps |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| RESIDENTIAL REAL ESTATE ORIGINATIONS |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Retail |
|
$ |
2,523 |
|
|
$ |
3,196 |
|
|
$ |
2,771 |
|
|
$ |
2,115 |
|
|
$ |
1,313 |
|
|
($ |
673 |
) |
|
|
(21 |
%) |
|
$ |
1,210 |
|
|
|
92 |
% |
| Third Party |
|
|
4,813 |
|
|
|
5,750 |
|
|
|
5,080 |
|
|
|
3,921 |
|
|
|
2,260 |
|
|
|
(937 |
) |
|
|
(16 |
) |
|
|
2,553 |
|
|
|
113 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total |
|
$ |
7,336 |
|
|
$ |
8,946 |
|
|
$ |
7,851 |
|
|
$ |
6,036 |
|
|
$ |
3,573 |
|
|
($ |
1,610 |
) |
|
|
(18 |
%) |
|
$ |
3,763 |
|
|
|
105 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Originated for sale |
|
|
83 |
% |
|
|
80 |
% |
|
|
80 |
% |
|
|
81 |
% |
|
|
81 |
% |
|
|
300 |
bps |
|
|
|
|
|
|
200 |
bps |
|
|
|
|
| Originated for investment |
|
|
17 |
|
|
|
20 |
|
|
|
20 |
|
|
|
19 |
|
|
|
19 |
|
|
|
(300 |
) bps |
|
|
|
|
|
|
(200 |
) bps |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total |
|
|
100 |
% |
|
|
100 |
% |
|
|
100 |
% |
|
|
100 |
% |
|
|
100 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| MORTGAGE SERVICING INFORMATION (UPB) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Loans serviced for others |
|
$ |
79,157 |
|
|
$ |
77,526 |
|
|
$ |
74,610 |
|
|
$ |
72,518 |
|
|
$ |
70,847 |
|
|
$ |
1,631 |
|
|
|
2 |
% |
|
$ |
8,310 |
|
|
|
12 |
% |
| Owned loans serviced |
|
|
21,057 |
|
|
|
20,831 |
|
|
|
19,969 |
|
|
|
19,258 |
|
|
|
18,437 |
|
|
|
226 |
|
|
|
1 |
|
|
|
2,620 |
|
|
|
14 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total |
|
$ |
100,214 |
|
|
$ |
98,357 |
|
|
$ |
94,579 |
|
|
$ |
91,776 |
|
|
$ |
89,284 |
|
|
$ |
1,857 |
|
|
|
2 |
% |
|
$ |
10,930 |
|
|
|
12 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| MSR CARRYING VALUE1 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| MSR at fair value |
|
$ |
577 |
|
|
$ |
642 |
|
|
$ |
510 |
|
|
$ |
531 |
|
|
$ |
563 |
|
|
($ |
65 |
) |
|
|
(10 |
%) |
|
$ |
14 |
|
|
|
2 |
% |
| MSR at lower of cost or market |
|
|
— |
|
|
|
182 |
|
|
|
177 |
|
|
|
189 |
|
|
|
212 |
|
|
|
(182 |
) |
|
|
(100 |
) |
|
|
(212 |
) |
|
|
(100 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total |
|
$ |
577 |
|
|
$ |
824 |
|
|
$ |
687 |
|
|
$ |
720 |
|
|
$ |
775 |
|
|
($ |
247 |
) |
|
|
(30 |
%) |
|
($ |
198 |
) |
|
|
(26 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| 1 |
Beginning in the first quarter of 2020, mortgage servicing rights previously accounted for at lower of cost or
market are now accounted for at fair value. |
11
SEGMENT FINANCIAL HIGHLIGHTS - COMMERCIAL BANKING
(in millions, except ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
QUARTERLY TRENDS |
|
| COMMERCIAL BANKING |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$/bps |
|
|
% |
|
|
$/bps |
|
|
% |
|
| Net interest income |
|
$ |
365 |
|
|
$ |
363 |
|
|
$ |
360 |
|
|
$ |
371 |
|
|
$ |
372 |
|
|
$ |
2 |
|
|
|
1 |
% |
|
($ |
7 |
) |
|
|
(2 |
%) |
| Noninterest income |
|
|
125 |
|
|
|
175 |
|
|
|
133 |
|
|
|
149 |
|
|
|
150 |
|
|
|
(50 |
) |
|
|
(29 |
) |
|
|
(25 |
) |
|
|
(17 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue |
|
|
490 |
|
|
|
538 |
|
|
|
493 |
|
|
|
520 |
|
|
|
522 |
|
|
|
(48 |
) |
|
|
(9 |
) |
|
|
(32 |
) |
|
|
(6 |
) |
| Noninterest expense |
|
|
221 |
|
|
|
219 |
|
|
|
213 |
|
|
|
217 |
|
|
|
209 |
|
|
|
2 |
|
|
|
1 |
|
|
|
12 |
|
|
|
6 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Profit before provision for credit losses |
|
|
269 |
|
|
|
319 |
|
|
|
280 |
|
|
|
303 |
|
|
|
313 |
|
|
|
(50 |
) |
|
|
(16 |
) |
|
|
(44 |
) |
|
|
(14 |
) |
| Provision for credit losses |
|
|
43 |
|
|
|
24 |
|
|
|
27 |
|
|
|
25 |
|
|
|
21 |
|
|
|
19 |
|
|
|
79 |
|
|
|
22 |
|
|
|
105 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income before income tax expense |
|
|
226 |
|
|
|
295 |
|
|
|
253 |
|
|
|
278 |
|
|
|
292 |
|
|
|
(69 |
) |
|
|
(23 |
) |
|
|
(66 |
) |
|
|
(23 |
) |
| Income tax expense |
|
|
47 |
|
|
|
64 |
|
|
|
57 |
|
|
|
62 |
|
|
|
65 |
|
|
|
(17 |
) |
|
|
(27 |
) |
|
|
(18 |
) |
|
|
(28 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income |
|
$ |
179 |
|
|
$ |
231 |
|
|
$ |
196 |
|
|
$ |
216 |
|
|
$ |
227 |
|
|
($ |
52 |
) |
|
|
(23 |
%) |
|
($ |
48 |
) |
|
|
(21 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| AVERAGE BALANCES |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total assets |
|
$ |
59,005 |
|
|
$ |
56,407 |
|
|
$ |
55,614 |
|
|
$ |
56,135 |
|
|
$ |
55,630 |
|
|
$ |
2,598 |
|
|
|
5 |
% |
|
$ |
3,375 |
|
|
|
6 |
% |
| Total loans and leases1 |
|
|
56,555 |
|
|
|
54,523 |
|
|
|
53,814 |
|
|
|
54,653 |
|
|
|
54,436 |
|
|
|
2,032 |
|
|
|
4 |
|
|
|
2,119 |
|
|
|
4 |
|
| Deposits |
|
|
33,545 |
|
|
|
32,715 |
|
|
|
31,491 |
|
|
|
30,273 |
|
|
|
29,823 |
|
|
|
830 |
|
|
|
3 |
|
|
|
3,722 |
|
|
|
12 |
|
| Interest-earning assets |
|
|
57,016 |
|
|
|
54,905 |
|
|
|
54,087 |
|
|
|
54,950 |
|
|
|
54,724 |
|
|
|
2,111 |
|
|
|
4 |
|
|
|
2,292 |
|
|
|
4 |
|
| KEY METRICS |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net interest margin |
|
|
2.57 |
% |
|
|
2.62 |
% |
|
|
2.64 |
% |
|
|
2.71 |
% |
|
|
2.76 |
% |
|
|
(5 |
) bps |
|
|
|
|
|
|
(19) |
bps |
|
|
|
|
| Efficiency ratio |
|
|
45.06 |
|
|
|
40.60 |
|
|
|
43.35 |
|
|
|
41.58 |
|
|
|
40.11 |
|
|
|
446 |
bps |
|
|
|
|
|
|
495 |
bps |
|
|
|
|
| Loans-to-deposits
ratio (period-end balances) |
|
|
164.10 |
|
|
|
165.24 |
|
|
|
163.62 |
|
|
|
173.48 |
|
|
|
180.53 |
|
|
|
(114 |
) bps |
|
|
|
|
|
|
(1,643 |
) bps |
|
|
|
|
| Loans-to-deposits
ratio (average balances) |
|
|
167.18 |
|
|
|
165.80 |
|
|
|
170.01 |
|
|
|
179.49 |
|
|
|
181.23 |
|
|
|
138 |
bps |
|
|
|
|
|
|
(1,405 |
) bps |
|
|
|
|
| Return on average total tangible assets |
|
|
1.22 |
|
|
|
1.63 |
|
|
|
1.40 |
|
|
|
1.54 |
|
|
|
1.66 |
|
|
|
(41 |
) bps |
|
|
|
|
|
|
(44 |
) bps |
|
|
|
|
| 1 |
Includes loans held for sale. |
12
SEGMENT FINANCIAL HIGHLIGHTS – OTHER
(in millions)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
QUARTERLY TRENDS |
|
| OTHER1 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
|
$ |
|
|
% |
|
| Net interest income |
|
$ |
2 |
|
|
($ |
16 |
) |
|
($ |
14 |
) |
|
($ |
4 |
) |
|
$ |
— |
|
|
$ |
18 |
|
|
|
NM |
|
|
$ |
2 |
|
|
|
100 |
% |
| Noninterest income |
|
|
15 |
|
|
|
23 |
|
|
|
24 |
|
|
|
36 |
|
|
|
31 |
|
|
|
(8 |
) |
|
|
(35 |
) |
|
|
(16 |
) |
|
|
(52 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue |
|
|
17 |
|
|
|
7 |
|
|
|
10 |
|
|
|
32 |
|
|
|
31 |
|
|
|
10 |
|
|
|
143 |
|
|
|
(14 |
) |
|
|
(45 |
) |
| Noninterest expense |
|
|
53 |
|
|
|
49 |
|
|
|
42 |
|
|
|
19 |
|
|
|
28 |
|
|
|
4 |
|
|
|
8 |
|
|
|
25 |
|
|
|
89 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| (Loss) profit before provision for credit losses |
|
|
(36 |
) |
|
|
(42 |
) |
|
|
(32 |
) |
|
|
13 |
|
|
|
3 |
|
|
|
6 |
|
|
|
14 |
|
|
|
(39 |
) |
|
|
NM |
|
| Provision for credit losses |
|
|
460 |
|
|
|
(11 |
) |
|
|
(9 |
) |
|
|
(6 |
) |
|
|
(3 |
) |
|
|
471 |
|
|
|
NM |
|
|
|
463 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| (Loss) income before income tax benefit |
|
|
(496 |
) |
|
|
(31 |
) |
|
|
(23 |
) |
|
|
19 |
|
|
|
6 |
|
|
|
(465 |
) |
|
|
NM |
|
|
|
(502 |
) |
|
|
NM |
|
| Income tax benefit |
|
|
(115 |
) |
|
|
(41 |
) |
|
|
(25 |
) |
|
|
(5 |
) |
|
|
(4 |
) |
|
|
(74 |
) |
|
|
(180 |
) |
|
|
(111 |
) |
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net (loss) income |
|
($ |
381 |
) |
|
$ |
10 |
|
|
$ |
2 |
|
|
$ |
24 |
|
|
$ |
10 |
|
|
($ |
391 |
) |
|
|
NM |
|
|
($ |
391 |
) |
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| AVERAGE BALANCES |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total assets |
|
$ |
39,757 |
|
|
$ |
40,170 |
|
|
$ |
40,131 |
|
|
$ |
39,869 |
|
|
$ |
39,778 |
|
|
($ |
413 |
) |
|
|
(1 |
%) |
|
($ |
21 |
) |
|
|
— |
% |
| Total loans and leases2 |
|
|
1,846 |
|
|
|
1,951 |
|
|
|
1,994 |
|
|
|
2,138 |
|
|
|
2,276 |
|
|
|
(105 |
) |
|
|
(5 |
) |
|
|
(430 |
) |
|
|
(19 |
) |
| Deposits |
|
|
7,857 |
|
|
|
7,460 |
|
|
|
6,835 |
|
|
|
7,219 |
|
|
|
8,022 |
|
|
|
397 |
|
|
|
5 |
|
|
|
(165 |
) |
|
|
(2 |
) |
| Interest-earning assets |
|
|
28,537 |
|
|
|
28,798 |
|
|
|
28,783 |
|
|
|
28,642 |
|
|
|
28,573 |
|
|
|
(261 |
) |
|
|
(1 |
) |
|
|
(36 |
) |
|
|
— |
|
| 1 |
Includes the financial impact of non-core, liquidating loan portfolios and
other non-core assets, our treasury activities, wholesale funding activities, securities portfolio, community development assets and other unallocated assets, liabilities, capital, revenues, provision for
credit losses, expenses and income tax expense, not attributed to our Consumer Banking or Commercial Banking segments. |
| 2 |
Includes loans held for sale. |
13
CREDIT-RELATED INFORMATION
(in millions, except ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
AS OF |
|
|
MARCH 31, 2020 CHANGE |
|
| |
|
Mar 31, 2020 |
|
|
Dec 31, 2019 |
|
|
Sept 30, 2019 |
|
|
June 30, 2019 |
|
|
Mar 31, 2019 |
|
|
Dec 31, 2019 |
|
|
Mar 31, 2019 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$/bps |
|
|
% |
|
|
$/bps |
|
|
% |
|
| NONACCRUAL LOANS AND LEASES1
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
$ |
305 |
|
|
$ |
240 |
|
|
$ |
228 |
|
|
$ |
198 |
|
|
$ |
208 |
|
|
$ |
65 |
|
|
|
27 |
% |
|
$ |
97 |
|
|
|
47 |
% |
| Commercial real estate |
|
|
8 |
|
|
|
2 |
|
|
|
49 |
|
|
|
4 |
|
|
|
4 |
|
|
|
6 |
|
|
|
NM |
|
|
|
4 |
|
|
|
100 |
|
| Leases |
|
|
1 |
|
|
|
3 |
|
|
|
4 |
|
|
|
17 |
|
|
|
— |
|
|
|
(2 |
) |
|
|
(67 |
) |
|
|
1 |
|
|
|
100 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total commercial loans and leases |
|
|
314 |
|
|
|
245 |
|
|
|
281 |
|
|
|
219 |
|
|
|
212 |
|
|
|
69 |
|
|
|
28 |
|
|
|
102 |
|
|
|
48 |
|
| Residential mortgages2 |
|
|
101 |
|
|
|
93 |
|
|
|
91 |
|
|
|
98 |
|
|
|
102 |
|
|
|
8 |
|
|
|
9 |
|
|
|
(1 |
) |
|
|
(1 |
) |
| Home equityD |
|
|
242 |
|
|
|
246 |
|
|
|
247 |
|
|
|
278 |
|
|
|
288 |
|
|
|
(4 |
) |
|
|
(2 |
) |
|
|
(46 |
) |
|
|
(16 |
) |
| Automobile |
|
|
69 |
|
|
|
67 |
|
|
|
69 |
|
|
|
62 |
|
|
|
70 |
|
|
|
2 |
|
|
|
3 |
|
|
|
(1 |
) |
|
|
(1 |
) |
| Education |
|
|
21 |
|
|
|
18 |
|
|
|
17 |
|
|
|
40 |
|
|
|
43 |
|
|
|
3 |
|
|
|
17 |
|
|
|
(22 |
) |
|
|
(51 |
) |
| Other retailE |
|
|
33 |
|
|
|
34 |
|
|
|
32 |
|
|
|
30 |
|
|
|
29 |
|
|
|
(1 |
) |
|
|
(3 |
) |
|
|
4 |
|
|
|
14 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total retail loans |
|
|
466 |
|
|
|
458 |
|
|
|
456 |
|
|
|
508 |
|
|
|
532 |
|
|
|
8 |
|
|
|
2 |
|
|
|
(66 |
) |
|
|
(12 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Nonaccrual loans and leases |
|
|
780 |
|
|
|
703 |
|
|
|
737 |
|
|
|
727 |
|
|
|
744 |
|
|
|
77 |
|
|
|
11 |
|
|
|
36 |
|
|
|
5 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Repossessed assets |
|
|
44 |
|
|
|
45 |
|
|
|
40 |
|
|
|
32 |
|
|
|
34 |
|
|
|
(1 |
) |
|
|
(2 |
) |
|
|
10 |
|
|
|
29 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Nonaccrual loans and leases and repossessed assets |
|
$ |
824 |
|
|
$ |
748 |
|
|
$ |
777 |
|
|
$ |
759 |
|
|
$ |
778 |
|
|
$ |
76 |
|
|
|
10 |
% |
|
$ |
46 |
|
|
|
6 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| NONACCRUAL LOANS AND LEASES BY PRODUCT3
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
$ |
314 |
|
|
$ |
245 |
|
|
$ |
281 |
|
|
$ |
219 |
|
|
$ |
212 |
|
|
$ |
69 |
|
|
|
28 |
% |
|
$ |
102 |
|
|
|
48 |
% |
| Retail |
|
|
510 |
|
|
|
503 |
|
|
|
496 |
|
|
|
540 |
|
|
|
566 |
|
|
|
7 |
|
|
|
1 |
|
|
|
(56 |
) |
|
|
(10 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total nonaccrual loans and leases |
|
$ |
824 |
|
|
$ |
748 |
|
|
$ |
777 |
|
|
$ |
759 |
|
|
$ |
778 |
|
|
$ |
76 |
|
|
|
10 |
% |
|
$ |
46 |
|
|
|
6 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ASSET QUALITY RATIOS |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Allowance for credit losses to loans and leasesB
|
|
|
1.73 |
% |
|
|
1.09 |
% |
|
|
1.11 |
% |
|
|
1.13 |
% |
|
|
1.13 |
% |
|
|
64 bps |
|
|
|
|
|
|
|
60 bps |
|
|
|
|
|
| Allowance for credit losses to nonaccrual loans and leases |
|
|
283.48 |
|
|
|
184.31 |
|
|
|
177.42 |
|
|
|
181.54 |
|
|
|
178.68 |
|
|
|
NM |
|
|
|
|
|
|
|
NM |
|
|
|
|
|
| Nonaccrual loans and leases to loans and leasesB
|
|
|
0.61 |
|
|
|
0.59 |
|
|
|
0.63 |
|
|
|
0.62 |
|
|
|
0.63 |
|
|
|
2 |
|
|
|
|
|
|
|
(2 |
) |
|
|
|
|
| 1 |
Beginning in the first quarter of 2020 and upon the adoption of ASU
2016-13, Financial Instruments—Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments, nonperforming loans and leases are now referred to as nonaccrual loans and leases
and other nonperforming assets are referred to as repossessed assets. |
| 2 |
Beginning in the fourth quarter of 2019, nonaccrual balances exclude both fully and partially guaranteed
residential mortgage loans sold to Ginnie Mae for which the Company has the right, but not the obligation, to repurchase. Prior periods have been adjusted to exclude partially guaranteed amounts to conform with the current period presentation.
|
| 3 |
Nonaccrual loans and leases by product includes repossessed assets. |
14
CREDIT-RELATED INFORMATION, CONTINUED
(in millions, except ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
AS OF |
|
|
MARCH 31, 2020 CHANGE |
|
| |
|
Mar 31, 2020 |
|
|
Dec 31, 2019 |
|
|
Sept 30, 2019 |
|
|
June 30, 2019 |
|
|
Mar 31, 2019 |
|
|
Dec 31, 2019 |
|
|
Mar 31, 2019 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$/bps |
|
|
% |
|
|
$/bps |
|
|
% |
|
| LOANS AND LEASES 90 DAYS OR MORE PAST DUE AND
ACCRUING |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
$ |
— |
|
|
$ |
2 |
|
|
$ |
1 |
|
|
$ |
4 |
|
|
$ |
1 |
|
|
($ |
2 |
) |
|
|
(100 |
%) |
|
($ |
1 |
) |
|
|
(100 |
%) |
| Leases |
|
|
— |
|
|
|
— |
|
|
|
1 |
|
|
|
1 |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total commercial loans and leases |
|
|
— |
|
|
|
2 |
|
|
|
2 |
|
|
|
5 |
|
|
|
1 |
|
|
|
(2 |
) |
|
|
(100 |
) |
|
|
(1 |
) |
|
|
(100 |
) |
| Residential mortgages |
|
|
14 |
|
|
|
13 |
|
|
|
15 |
|
|
|
14 |
|
|
|
20 |
|
|
|
1 |
|
|
|
8 |
|
|
|
(6 |
) |
|
|
(30 |
) |
| Education |
|
|
2 |
|
|
|
2 |
|
|
|
3 |
|
|
|
3 |
|
|
|
2 |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
| Other retailE |
|
|
11 |
|
|
|
8 |
|
|
|
10 |
|
|
|
9 |
|
|
|
9 |
|
|
|
3 |
|
|
|
38 |
|
|
|
2 |
|
|
|
22 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total retail loans |
|
|
27 |
|
|
|
23 |
|
|
|
28 |
|
|
|
26 |
|
|
|
31 |
|
|
|
4 |
|
|
|
17 |
|
|
|
(4 |
) |
|
|
(13 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total loans and leases |
|
|
27 |
|
|
|
25 |
|
|
|
30 |
|
|
|
31 |
|
|
|
32 |
|
|
|
2 |
|
|
|
8 |
|
|
|
(5 |
) |
|
|
(16 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
15
CREDIT-RELATED INFORMATION, CONTINUED
(in millions)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
QUARTERLY TRENDS |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
|
$ |
|
|
% |
|
| CHARGE-OFFS, RECOVERIES AND RELATED RATIOS |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| GROSS CHARGE-OFFS |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
$ |
47 |
|
|
$ |
24 |
|
|
$ |
20 |
|
|
$ |
40 |
|
|
$ |
3 |
|
|
$ |
23 |
|
|
|
96 |
% |
|
$ |
44 |
|
|
|
NM |
|
| Commercial real estate |
|
|
— |
|
|
|
9 |
|
|
|
10 |
|
|
|
— |
|
|
|
20 |
|
|
|
(9 |
) |
|
|
(100 |
) |
|
|
(20 |
) |
|
|
(100 |
) |
| Leases |
|
|
— |
|
|
|
1 |
|
|
|
5 |
|
|
|
5 |
|
|
|
3 |
|
|
|
(1 |
) |
|
|
(100 |
) |
|
|
(3 |
) |
|
|
(100 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total commercial loans and leases |
|
|
47 |
|
|
|
34 |
|
|
|
35 |
|
|
|
45 |
|
|
|
26 |
|
|
|
13 |
|
|
|
38 |
|
|
|
21 |
|
|
|
81 |
|
| Residential mortgages |
|
|
1 |
|
|
|
2 |
|
|
|
2 |
|
|
|
2 |
|
|
|
2 |
|
|
|
(1 |
) |
|
|
(50 |
) |
|
|
(1 |
) |
|
|
(50 |
) |
| Home equityD |
|
|
8 |
|
|
|
10 |
|
|
|
11 |
|
|
|
11 |
|
|
|
7 |
|
|
|
(2 |
) |
|
|
(20 |
) |
|
|
1 |
|
|
|
14 |
|
| Automobile |
|
|
39 |
|
|
|
38 |
|
|
|
37 |
|
|
|
30 |
|
|
|
38 |
|
|
|
1 |
|
|
|
3 |
|
|
|
1 |
|
|
|
3 |
|
| Education |
|
|
18 |
|
|
|
20 |
|
|
|
18 |
|
|
|
18 |
|
|
|
16 |
|
|
|
(2 |
) |
|
|
(10 |
) |
|
|
2 |
|
|
|
13 |
|
| Other retailE |
|
|
61 |
|
|
|
58 |
|
|
|
56 |
|
|
|
50 |
|
|
|
49 |
|
|
|
3 |
|
|
|
5 |
|
|
|
12 |
|
|
|
24 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total retail loans |
|
|
127 |
|
|
|
128 |
|
|
|
124 |
|
|
|
111 |
|
|
|
112 |
|
|
|
(1 |
) |
|
|
(1 |
) |
|
|
15 |
|
|
|
13 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total gross charge-offs |
|
$ |
174 |
|
|
$ |
162 |
|
|
$ |
159 |
|
|
$ |
156 |
|
|
$ |
138 |
|
|
$ |
12 |
|
|
|
7 |
% |
|
$ |
36 |
|
|
|
26 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| GROSS RECOVERIES |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
$ |
3 |
|
|
$ |
7 |
|
|
$ |
3 |
|
|
$ |
12 |
|
|
$ |
2 |
|
|
($ |
4 |
) |
|
|
(57 |
%) |
|
$ |
1 |
|
|
|
50 |
% |
| Commercial real estate |
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
| Leases |
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total commercial loans and leases |
|
|
3 |
|
|
|
7 |
|
|
|
3 |
|
|
|
12 |
|
|
|
2 |
|
|
|
(4 |
) |
|
|
(57 |
) |
|
|
1 |
|
|
|
50 |
|
| Residential mortgages |
|
|
1 |
|
|
|
1 |
|
|
|
1 |
|
|
|
2 |
|
|
|
5 |
|
|
|
— |
|
|
|
— |
|
|
|
(4 |
) |
|
|
(80 |
) |
| Home equityD |
|
|
11 |
|
|
|
10 |
|
|
|
12 |
|
|
|
10 |
|
|
|
17 |
|
|
|
1 |
|
|
|
10 |
|
|
|
(6 |
) |
|
|
(35 |
) |
| Automobile |
|
|
12 |
|
|
|
11 |
|
|
|
15 |
|
|
|
16 |
|
|
|
15 |
|
|
|
1 |
|
|
|
9 |
|
|
|
(3 |
) |
|
|
(20 |
) |
| Education |
|
|
4 |
|
|
|
4 |
|
|
|
4 |
|
|
|
4 |
|
|
|
4 |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
| Other retailE |
|
|
6 |
|
|
|
7 |
|
|
|
11 |
|
|
|
6 |
|
|
|
6 |
|
|
|
(1 |
) |
|
|
(14 |
) |
|
|
— |
|
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total retail loans |
|
|
34 |
|
|
|
33 |
|
|
|
43 |
|
|
|
38 |
|
|
|
47 |
|
|
|
1 |
|
|
|
3 |
|
|
|
(13 |
) |
|
|
(28 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total gross recoveries |
|
$ |
37 |
|
|
$ |
40 |
|
|
$ |
46 |
|
|
$ |
50 |
|
|
$ |
49 |
|
|
($ |
3 |
) |
|
|
(8 |
%) |
|
($ |
12 |
) |
|
|
(24 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| NET CHARGE-OFFS (RECOVERIES) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
$ |
44 |
|
|
$ |
17 |
|
|
$ |
17 |
|
|
$ |
28 |
|
|
$ |
1 |
|
|
$ |
27 |
|
|
|
159 |
% |
|
$ |
43 |
|
|
|
NM |
|
| Commercial real estate |
|
|
— |
|
|
|
9 |
|
|
|
10 |
|
|
|
— |
|
|
|
20 |
|
|
|
(9 |
) |
|
|
(100 |
) |
|
|
(20 |
) |
|
|
(100 |
) |
| Leases |
|
|
— |
|
|
|
1 |
|
|
|
5 |
|
|
|
5 |
|
|
|
3 |
|
|
|
(1 |
) |
|
|
(100 |
) |
|
|
(3 |
) |
|
|
(100 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total commercial loans and leases |
|
|
44 |
|
|
|
27 |
|
|
|
32 |
|
|
|
33 |
|
|
|
24 |
|
|
|
17 |
|
|
|
63 |
|
|
|
20 |
|
|
|
83 |
|
| Residential mortgages |
|
|
— |
|
|
|
1 |
|
|
|
1 |
|
|
|
— |
|
|
|
(3 |
) |
|
|
(1 |
) |
|
|
(100 |
) |
|
|
3 |
|
|
|
100 |
|
| Home equityD |
|
|
(3 |
) |
|
|
— |
|
|
|
(1 |
) |
|
|
1 |
|
|
|
(10 |
) |
|
|
(3 |
) |
|
|
(100 |
) |
|
|
7 |
|
|
|
70 |
|
| Automobile |
|
|
27 |
|
|
|
27 |
|
|
|
22 |
|
|
|
14 |
|
|
|
23 |
|
|
|
— |
|
|
|
— |
|
|
|
4 |
|
|
|
17 |
|
| Education |
|
|
14 |
|
|
|
16 |
|
|
|
14 |
|
|
|
14 |
|
|
|
12 |
|
|
|
(2 |
) |
|
|
(13 |
) |
|
|
2 |
|
|
|
17 |
|
| Other retailE |
|
|
55 |
|
|
|
51 |
|
|
|
45 |
|
|
|
44 |
|
|
|
43 |
|
|
|
4 |
|
|
|
8 |
|
|
|
12 |
|
|
|
28 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total retail loans |
|
|
93 |
|
|
|
95 |
|
|
|
81 |
|
|
|
73 |
|
|
|
65 |
|
|
|
(2 |
) |
|
|
(2 |
) |
|
|
28 |
|
|
|
43 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total net charge-offs |
|
$ |
137 |
|
|
$ |
122 |
|
|
$ |
113 |
|
|
$ |
106 |
|
|
$ |
89 |
|
|
$ |
15 |
|
|
|
12 |
% |
|
$ |
48 |
|
|
|
54 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
16
CREDIT-RELATED INFORMATION, CONTINUED
(in millions, except rates)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
QUARTERLY TRENDS |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$/bps |
|
|
% |
|
|
$/bps |
|
|
% |
|
| ANNUALIZED NET CHARGE-OFF (RECOVERY)
RATES |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
|
0.41 |
% |
|
|
0.16 |
% |
|
|
0.16 |
% |
|
|
0.27 |
% |
|
|
0.01 |
% |
|
|
25 bps |
|
|
|
|
|
|
|
40 bps |
|
|
|
|
|
| Commercial real estate |
|
|
— |
|
|
|
0.26 |
|
|
|
0.31 |
|
|
|
— |
|
|
|
0.62 |
|
|
|
(26) bps |
|
|
|
|
|
|
|
(62) bps |
|
|
|
|
|
| Leases |
|
|
0.07 |
|
|
|
0.19 |
|
|
|
0.80 |
|
|
|
0.72 |
|
|
|
0.42 |
|
|
|
(12) bps |
|
|
|
|
|
|
|
(35) bps |
|
|
|
|
|
| Total commercial loans and leases |
|
|
0.30 |
|
|
|
0.19 |
|
|
|
0.22 |
|
|
|
0.23 |
|
|
|
0.17 |
|
|
|
11 bps |
|
|
|
|
|
|
|
13 bps |
|
|
|
|
|
| Residential mortgages |
|
|
0.01 |
|
|
|
0.02 |
|
|
|
0.01 |
|
|
|
0.01 |
|
|
|
(0.07 |
) |
|
|
(1) bps |
|
|
|
|
|
|
|
8 bps |
|
|
|
|
|
| Home equityD |
|
|
(0.10 |
) |
|
|
0.02 |
|
|
|
(0.04 |
) |
|
|
0.01 |
|
|
|
(0.26 |
) |
|
|
(12) bps |
|
|
|
|
|
|
|
16 bps |
|
|
|
|
|
| Automobile |
|
|
0.88 |
|
|
|
0.85 |
|
|
|
0.74 |
|
|
|
0.49 |
|
|
|
0.77 |
|
|
|
3 bps |
|
|
|
|
|
|
|
11 bps |
|
|
|
|
|
| Education |
|
|
0.55 |
|
|
|
0.65 |
|
|
|
0.58 |
|
|
|
0.62 |
|
|
|
0.51 |
|
|
|
(10) bps |
|
|
|
|
|
|
|
4 bps |
|
|
|
|
|
| Other retailE |
|
|
3.21 |
|
|
|
3.09 |
|
|
|
3.08 |
|
|
|
3.11 |
|
|
|
3.06 |
|
|
|
12 bps |
|
|
|
|
|
|
|
15 bps |
|
|
|
|
|
| Total retail loans |
|
|
0.61 |
|
|
|
0.61 |
|
|
|
0.53 |
|
|
|
0.49 |
|
|
|
0.44 |
|
|
|
— bps |
|
|
|
|
|
|
|
17 bps |
|
|
|
|
|
| Total loans and leases |
|
|
0.46 |
% |
|
|
0.41 |
% |
|
|
0.38 |
% |
|
|
0.36 |
% |
|
|
0.31 |
% |
|
|
5 bps |
|
|
|
|
|
|
|
15 bps |
|
|
|
|
|
| Memo: Average loans |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
$ |
43,152 |
|
|
$ |
42,012 |
|
|
$ |
41,476 |
|
|
$ |
41,755 |
|
|
$ |
41,562 |
|
|
$ |
1,140 |
|
|
|
3 |
% |
|
$ |
1,590 |
|
|
|
4 |
% |
| Commercial real estate |
|
|
13,876 |
|
|
|
13,103 |
|
|
|
12,892 |
|
|
|
13,379 |
|
|
|
13,272 |
|
|
|
773 |
|
|
|
6 |
|
|
|
604 |
|
|
|
5 |
|
| Leases |
|
|
2,482 |
|
|
|
2,546 |
|
|
|
2,615 |
|
|
|
2,745 |
|
|
|
2,873 |
|
|
|
(64 |
) |
|
|
(3 |
) |
|
|
(391 |
) |
|
|
(14 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total commercial loans and leases |
|
|
59,510 |
|
|
|
57,661 |
|
|
|
56,983 |
|
|
|
57,879 |
|
|
|
57,707 |
|
|
|
1,849 |
|
|
|
3 |
|
|
|
1,803 |
|
|
|
3 |
|
| Residential mortgages |
|
|
18,866 |
|
|
|
19,495 |
|
|
|
19,405 |
|
|
|
19,232 |
|
|
|
19,094 |
|
|
|
(629 |
) |
|
|
(3 |
) |
|
|
(228 |
) |
|
|
(1 |
) |
| Home equityD |
|
|
13,042 |
|
|
|
13,265 |
|
|
|
13,501 |
|
|
|
13,754 |
|
|
|
14,075 |
|
|
|
(223 |
) |
|
|
(2 |
) |
|
|
(1,033 |
) |
|
|
(7 |
) |
| Automobile |
|
|
12,173 |
|
|
|
12,099 |
|
|
|
12,036 |
|
|
|
11,984 |
|
|
|
12,070 |
|
|
|
74 |
|
|
|
1 |
|
|
|
103 |
|
|
|
1 |
|
| Education |
|
|
10,610 |
|
|
|
9,888 |
|
|
|
9,459 |
|
|
|
9,235 |
|
|
|
9,069 |
|
|
|
722 |
|
|
|
7 |
|
|
|
1,541 |
|
|
|
17 |
|
| Other retailE |
|
|
6,854 |
|
|
|
6,497 |
|
|
|
5,873 |
|
|
|
5,699 |
|
|
|
5,634 |
|
|
|
357 |
|
|
|
5 |
|
|
|
1,220 |
|
|
|
22 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total retail loans |
|
|
61,545 |
|
|
|
61,244 |
|
|
|
60,274 |
|
|
|
59,904 |
|
|
|
59,942 |
|
|
|
301 |
|
|
|
— |
|
|
|
1,603 |
|
|
|
3 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total loans and leases |
|
$ |
121,055 |
|
|
$ |
118,905 |
|
|
$ |
117,257 |
|
|
$ |
117,783 |
|
|
$ |
117,649 |
|
|
$ |
2,150 |
|
|
|
2 |
% |
|
$ |
3,406 |
|
|
|
3 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
17
CREDIT-RELATED INFORMATION, CONTINUED
(in millions)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
QUARTERLY TRENDS |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
|
$ |
|
|
% |
|
| SUMMARY OF CHANGES IN THE COMPONENTS
OF THE ALLOWANCE FOR CREDIT LOSSES |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Allowance for loan and lease losses - beginning |
|
$ |
1,252 |
|
|
$ |
1,263 |
|
|
$ |
1,227 |
|
|
$ |
1,245 |
|
|
$ |
1,242 |
|
|
($ |
11 |
) |
|
|
(1 |
%) |
|
$ |
10 |
|
|
|
1 |
% |
| Cumulative effect of change in accounting principle: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
|
(176 |
) |
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
(176 |
) |
|
|
(100 |
) |
|
|
(176 |
) |
|
|
(100 |
) |
| Retail |
|
|
629 |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
629 |
|
|
|
100 |
|
|
|
629 |
|
|
|
100 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total cumulative effect of change in accounting principle |
|
|
453 |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
453 |
|
|
|
100 |
|
|
|
453 |
|
|
|
100 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Allowance for loan and lease losses - beginning, adjusted |
|
|
1,705 |
|
|
|
1,263 |
|
|
|
1,227 |
|
|
|
1,245 |
|
|
|
1,242 |
|
|
|
442 |
|
|
|
35 |
|
|
|
463 |
|
|
|
37 |
|
| Charge-offs: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
|
47 |
|
|
|
34 |
|
|
|
35 |
|
|
|
45 |
|
|
|
26 |
|
|
|
13 |
|
|
|
38 |
|
|
|
21 |
|
|
|
81 |
|
| Retail |
|
|
127 |
|
|
|
128 |
|
|
|
124 |
|
|
|
111 |
|
|
|
112 |
|
|
|
(1 |
) |
|
|
(1 |
) |
|
|
15 |
|
|
|
13 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total charge-offs |
|
|
174 |
|
|
|
162 |
|
|
|
159 |
|
|
|
156 |
|
|
|
138 |
|
|
|
12 |
|
|
|
7 |
|
|
|
36 |
|
|
|
26 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Recoveries: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
|
3 |
|
|
|
7 |
|
|
|
3 |
|
|
|
12 |
|
|
|
2 |
|
|
|
(4 |
) |
|
|
(57 |
) |
|
|
1 |
|
|
|
50 |
|
| Retail |
|
|
34 |
|
|
|
33 |
|
|
|
43 |
|
|
|
38 |
|
|
|
47 |
|
|
|
1 |
|
|
|
3 |
|
|
|
(13 |
) |
|
|
(28 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total recoveries |
|
|
37 |
|
|
|
40 |
|
|
|
46 |
|
|
|
50 |
|
|
|
49 |
|
|
|
(3 |
) |
|
|
(8 |
) |
|
|
(12 |
) |
|
|
(24 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net charge-offs |
|
|
137 |
|
|
|
122 |
|
|
|
113 |
|
|
|
106 |
|
|
|
89 |
|
|
|
15 |
|
|
|
12 |
|
|
|
48 |
|
|
|
54 |
|
| Provision for loan and lease losses: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
|
298 |
|
|
|
(11 |
) |
|
|
64 |
|
|
|
22 |
|
|
|
25 |
|
|
|
309 |
|
|
|
NM |
|
|
|
273 |
|
|
|
NM |
|
| Retail |
|
|
305 |
|
|
|
122 |
|
|
|
85 |
|
|
|
66 |
|
|
|
67 |
|
|
|
183 |
|
|
|
150 |
|
|
|
238 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total provision for loan and lease losses |
|
|
603 |
|
|
|
111 |
|
|
|
149 |
|
|
|
88 |
|
|
|
92 |
|
|
|
492 |
|
|
|
NM |
|
|
|
511 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Allowance for loan and lease losses - ending |
|
$ |
2,171 |
|
|
$ |
1,252 |
|
|
$ |
1,263 |
|
|
$ |
1,227 |
|
|
$ |
1,245 |
|
|
$ |
919 |
|
|
|
73 |
% |
|
$ |
926 |
|
|
|
74 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Reserve for unfunded lending commitments - beginning |
|
$ |
44 |
|
|
$ |
45 |
|
|
$ |
93 |
|
|
$ |
84 |
|
|
$ |
91 |
|
|
($ |
1 |
) |
|
|
(2 |
%) |
|
($ |
47 |
) |
|
|
(52 |
%) |
| Cumulative effect of change in accounting principle |
|
|
(2 |
) |
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
(2 |
) |
|
|
(100 |
) |
|
|
(2 |
) |
|
|
(100 |
) |
| Provision for unfunded lending commitments |
|
|
(3 |
) |
|
|
(1 |
) |
|
|
(48 |
) |
|
|
9 |
|
|
|
(7 |
) |
|
|
(2 |
) |
|
|
(200 |
) |
|
|
4 |
|
|
|
57 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Reserve for unfunded lending commitments - ending |
|
$ |
39 |
|
|
$ |
44 |
|
|
$ |
45 |
|
|
$ |
93 |
|
|
$ |
84 |
|
|
($ |
5 |
) |
|
|
(11 |
%) |
|
($ |
45 |
) |
|
|
(54 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total allowance for credit losses - ending |
|
$ |
2,210 |
|
|
$ |
1,296 |
|
|
$ |
1,308 |
|
|
$ |
1,320 |
|
|
$ |
1,329 |
|
|
$ |
914 |
|
|
|
71 |
% |
|
$ |
881 |
|
|
|
66 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Memo: Total allowance for credit losses by product |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Commercial |
|
$ |
790 |
|
|
$ |
718 |
|
|
$ |
757 |
|
|
$ |
773 |
|
|
$ |
775 |
|
|
$ |
72 |
|
|
|
10 |
% |
|
$ |
15 |
|
|
|
2 |
% |
| Retail |
|
|
1,420 |
|
|
|
578 |
|
|
|
551 |
|
|
|
547 |
|
|
|
554 |
|
|
|
842 |
|
|
|
146 |
|
|
|
866 |
|
|
|
156 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total allowance for credit losses |
|
$ |
2,210 |
|
|
$ |
1,296 |
|
|
$ |
1,308 |
|
|
$ |
1,320 |
|
|
$ |
1,329 |
|
|
$ |
914 |
|
|
|
71 |
% |
|
$ |
881 |
|
|
|
66 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
18
CAPITAL AND RATIOS
(in millions, except ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
AS OF |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
MARCH 31, 2020 CHANGE |
|
| |
|
Mar 31, 2020 |
|
|
Dec 31, 2019 |
|
|
Sept 30, 2019 |
|
|
June 30, 2019 |
|
|
Mar 31, 2019 |
|
|
Dec 31, 2019 |
|
|
Mar 31, 2019 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
|
$ |
|
|
% |
|
| CAPITAL RATIOS AND COMPONENTS (PRELIMINARY) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| CET1 capital |
|
$ |
14,007 |
|
|
$ |
14,304 |
|
|
$ |
14,416 |
|
|
$ |
14,629 |
|
|
$ |
14,442 |
|
|
($ |
297 |
) |
|
|
(2 |
%) |
|
($ |
435 |
) |
|
|
(3 |
%) |
| Tier 1 capital |
|
|
15,577 |
|
|
|
15,874 |
|
|
|
15,549 |
|
|
|
15,762 |
|
|
|
15,574 |
|
|
|
(297 |
) |
|
|
(2 |
) |
|
|
3 |
|
|
|
— |
|
| Total capital |
|
|
18,592 |
|
|
|
18,542 |
|
|
|
18,237 |
|
|
|
18,582 |
|
|
|
18,403 |
|
|
|
50 |
|
|
|
— |
|
|
|
189 |
|
|
|
1 |
|
| Risk-weighted assets |
|
|
148,946 |
|
|
|
142,915 |
|
|
|
140,136 |
|
|
|
138,879 |
|
|
|
137,246 |
|
|
|
6,031 |
|
|
|
4 |
|
|
|
11,700 |
|
|
|
9 |
|
| Adjusted average assets1 |
|
|
161,715 |
|
|
|
158,782 |
|
|
|
156,355 |
|
|
|
155,956 |
|
|
|
155,171 |
|
|
|
2,933 |
|
|
|
2 |
|
|
|
6,544 |
|
|
|
4 |
|
| CET1 capital ratio |
|
|
9.4 |
% |
|
|
10.0 |
% |
|
|
10.3 |
% |
|
|
10.5 |
% |
|
|
10.5 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Tier 1 capital ratio |
|
|
10.5 |
|
|
|
11.1 |
|
|
|
11.1 |
|
|
|
11.3 |
|
|
|
11.3 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total capital ratio |
|
|
12.5 |
|
|
|
13.0 |
|
|
|
13.0 |
|
|
|
13.4 |
|
|
|
13.4 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Tier 1 leverage ratio |
|
|
9.6 |
|
|
|
10.0 |
|
|
|
9.9 |
|
|
|
10.1 |
|
|
|
10.0 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| TANGIBLE COMMON EQUITY (PERIOD-END) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Common stockholders’ equity |
|
$ |
20,380 |
|
|
$ |
20,631 |
|
|
$ |
20,718 |
|
|
$ |
20,884 |
|
|
$ |
20,399 |
|
|
($ |
251 |
) |
|
|
(1 |
%) |
|
($ |
19 |
) |
|
|
— |
% |
| Less: Goodwill |
|
|
7,050 |
|
|
|
7,044 |
|
|
|
7,044 |
|
|
|
7,040 |
|
|
|
7,040 |
|
|
|
6 |
|
|
|
— |
|
|
|
10 |
|
|
|
— |
|
| Less: Other intangible assets |
|
|
66 |
|
|
|
68 |
|
|
|
71 |
|
|
|
74 |
|
|
|
80 |
|
|
|
(2 |
) |
|
|
(3 |
) |
|
|
(14 |
) |
|
|
(18 |
) |
| Add: Deferred tax liabilities2 |
|
|
375 |
|
|
|
374 |
|
|
|
373 |
|
|
|
371 |
|
|
|
370 |
|
|
|
1 |
|
|
|
— |
|
|
|
5 |
|
|
|
1 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total tangible common equity |
|
$ |
13,639 |
|
|
$ |
13,893 |
|
|
$ |
13,976 |
|
|
$ |
14,141 |
|
|
$ |
13,649 |
|
|
($ |
254 |
) |
|
|
(2 |
%) |
|
($ |
10 |
) |
|
|
— |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| TANGIBLE COMMON EQUITY (AVERAGE) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Common stockholders’ equity |
|
$ |
20,223 |
|
|
$ |
20,400 |
|
|
$ |
20,533 |
|
|
$ |
20,420 |
|
|
$ |
19,942 |
|
|
($ |
177 |
) |
|
|
(1 |
%) |
|
$ |
281 |
|
|
|
1 |
% |
| Less: Goodwill |
|
|
7,046 |
|
|
|
7,044 |
|
|
|
7,044 |
|
|
|
7,040 |
|
|
|
7,018 |
|
|
|
2 |
|
|
|
— |
|
|
|
28 |
|
|
|
— |
|
| Less: Other intangible assets |
|
|
67 |
|
|
|
69 |
|
|
|
73 |
|
|
|
80 |
|
|
|
59 |
|
|
|
(2 |
) |
|
|
(3 |
) |
|
|
8 |
|
|
|
14 |
|
| Add: Deferred tax liabilities2 |
|
|
374 |
|
|
|
373 |
|
|
|
372 |
|
|
|
370 |
|
|
|
368 |
|
|
|
1 |
|
|
|
— |
|
|
|
6 |
|
|
|
2 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total tangible common equity |
|
$ |
13,484 |
|
|
$ |
13,660 |
|
|
$ |
13,788 |
|
|
$ |
13,670 |
|
|
$ |
13,233 |
|
|
($ |
176 |
) |
|
|
(1 |
%) |
|
$ |
251 |
|
|
|
2 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| INTANGIBLE ASSETS (PERIOD-END) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Goodwill |
|
$ |
7,050 |
|
|
$ |
7,044 |
|
|
$ |
7,044 |
|
|
$ |
7,040 |
|
|
$ |
7,040 |
|
|
$ |
6 |
|
|
|
— |
% |
|
$ |
10 |
|
|
|
— |
% |
| Other intangible assets |
|
|
66 |
|
|
|
68 |
|
|
|
71 |
|
|
|
74 |
|
|
|
80 |
|
|
|
(2 |
) |
|
|
(3 |
) |
|
|
(14 |
) |
|
|
(18 |
) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total intangible assets |
|
$ |
7,116 |
|
|
$ |
7,112 |
|
|
$ |
7,115 |
|
|
$ |
7,114 |
|
|
$ |
7,120 |
|
|
$ |
4 |
|
|
|
— |
% |
|
($ |
4 |
) |
|
|
— |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| 1 |
Adjusted average assets include quarterly average assets, less deductions for disallowed goodwill and other
intangible assets, net of deferred tax liabilities related to tax deductible goodwill, and the accumulated other comprehensive income impact related to the adoption of post-retirement benefit plan guidance under GAAP. |
| 2 |
Deferred tax liabilities relate to tax-deductible goodwill, which is netted
against goodwill when calculating tangible common equity. |
19
KEY PERFORMANCE METRICS, NON-GAAP FINANCIAL
MEASURES AND RECONCILIATIONS
(in millions, except share, per-share and ratio data)
Our Management uses certain key performance metrics (KPMs) to gauge our progress against strategic and operational goals, as well
as to compare our performance against peers. The KPMs are referred to in our quarterly earnings materials and other financial reports filed with the Securities and Exchange Commission. The KPMs include:
| • |
|
Return on average tangible common equity (ROTCE); |
| • |
|
Operating leverage; and |
| • |
|
Common equity tier 1 capital ratio. |
Established targets for the KPMs are based on Management-reporting results which are currently referred to by the Company as “Underlying” results. We
believe that Underlying results, which exclude notable items, provide the best representation of our underlying financial progress toward the KPMs as the results exclude items that our Management does not consider indicative of our on-going financial performance. KPMs that reflect Underlying results are considered non-GAAP financial measures.
Non-GAAP Financial Measures
This document contains non-GAAP financial measures denoted as Underlying results. Underlying results for any given
reporting period exclude certain items that may occur in that period which Management does not consider indicative of the Company’s on-going financial performance. We believe these non-GAAP financial measures provide useful information to investors because they are used by our Management to evaluate our operating performance and make day-to-day operating decisions. In addition, we believe our Underlying results in any given reporting period reflect our on-going financial performance in that period
and, accordingly, are useful to consider in addition to our GAAP financial results. We further believe the presentation of Underlying results increases comparability of
period-to-period results. The following tables present reconciliations of our non-GAAP measures to the most directly comparable
GAAP financial measures.
Other companies may use similarly titled non-GAAP financial measures that are calculated
differently from the way we calculate such measures. Accordingly, our non-GAAP financial measures may not be comparable to similar measures used by such companies. We caution investors not to place undue
reliance on such non-GAAP financial measures, but to consider them with the most directly comparable GAAP measures. Non-GAAP financial measures have limitations as
analytical tools and should not be considered in isolation or as a substitute for our results reported under GAAP.
20
KEY PERFORMANCE METRICS, NON-GAAP FINANCIAL MEASURES AND
RECONCILIATIONS, CONTINUED
(in millions, except share, per-share and ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
|
QUARTERLY TRENDS |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
|
|
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
|
$ |
|
|
% |
|
| Noninterest income, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest income (GAAP) |
|
|
A |
|
|
$ |
497 |
|
|
$ |
494 |
|
|
$ |
493 |
|
|
$ |
462 |
|
|
$ |
428 |
|
|
$ |
3 |
|
|
|
1 |
% |
|
$ |
69 |
|
|
|
16 |
% |
| Less: Notable items |
|
|
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest income, Underlying (non-GAAP) |
|
|
B |
|
|
$ |
497 |
|
|
$ |
494 |
|
|
$ |
493 |
|
|
$ |
462 |
|
|
$ |
428 |
|
|
$ |
3 |
|
|
|
1 |
% |
|
$ |
69 |
|
|
|
16 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue (GAAP) |
|
|
C |
|
|
$ |
1,657 |
|
|
$ |
1,637 |
|
|
$ |
1,638 |
|
|
$ |
1,628 |
|
|
$ |
1,588 |
|
|
$ |
20 |
|
|
|
1 |
% |
|
$ |
69 |
|
|
|
4 |
% |
| Less: Notable items |
|
|
|
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue, Underlying (non-GAAP) |
|
|
D |
|
|
$ |
1,657 |
|
|
$ |
1,637 |
|
|
$ |
1,638 |
|
|
$ |
1,628 |
|
|
$ |
1,588 |
|
|
$ |
20 |
|
|
|
1 |
% |
|
$ |
69 |
|
|
|
4 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest expense, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest expense (GAAP) |
|
|
E |
|
|
$ |
1,012 |
|
|
$ |
986 |
|
|
$ |
973 |
|
|
$ |
951 |
|
|
$ |
937 |
|
|
$ |
26 |
|
|
|
3 |
% |
|
$ |
75 |
|
|
|
8 |
% |
| Less: Notable items |
|
|
|
|
|
|
33 |
|
|
|
37 |
|
|
|
19 |
|
|
|
7 |
|
|
|
5 |
|
|
|
(4 |
) |
|
|
(11 |
) |
|
|
28 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest expense, Underlying (non-GAAP) |
|
|
F |
|
|
$ |
979 |
|
|
$ |
949 |
|
|
$ |
954 |
|
|
$ |
944 |
|
|
$ |
932 |
|
|
$ |
30 |
|
|
|
3 |
% |
|
$ |
47 |
|
|
|
5 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Pre-provision profit: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue (GAAP) |
|
|
C |
|
|
$ |
1,657 |
|
|
$ |
1,637 |
|
|
$ |
1,638 |
|
|
$ |
1,628 |
|
|
$ |
1,588 |
|
|
$ |
20 |
|
|
|
1 |
% |
|
$ |
69 |
|
|
|
4 |
% |
| Less: Noninterest expense (GAAP) |
|
|
E |
|
|
|
1,012 |
|
|
|
986 |
|
|
|
973 |
|
|
|
951 |
|
|
|
937 |
|
|
|
26 |
|
|
|
3 |
|
|
|
75 |
|
|
|
8 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Pre-provision profit (GAAP) |
|
|
|
|
|
$ |
645 |
|
|
$ |
651 |
|
|
$ |
665 |
|
|
$ |
677 |
|
|
$ |
651 |
|
|
($ |
6 |
) |
|
|
(1 |
%) |
|
($ |
6 |
) |
|
|
(1 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Pre-provision profit, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue, Underlying (non-GAAP) |
|
|
D |
|
|
$ |
1,657 |
|
|
$ |
1,637 |
|
|
$ |
1,638 |
|
|
$ |
1,628 |
|
|
$ |
1,588 |
|
|
$ |
20 |
|
|
|
1 |
% |
|
$ |
69 |
|
|
|
4 |
% |
| Less: Noninterest expense, Underlying (non-GAAP) |
|
|
F |
|
|
|
979 |
|
|
|
949 |
|
|
|
954 |
|
|
|
944 |
|
|
|
932 |
|
|
|
30 |
|
|
|
3 |
|
|
|
47 |
|
|
|
5 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Pre-provision profit, Underlying (non-GAAP) |
|
|
|
|
|
$ |
678 |
|
|
$ |
688 |
|
|
$ |
684 |
|
|
$ |
684 |
|
|
$ |
656 |
|
|
($ |
10 |
) |
|
|
(1 |
%) |
|
$ |
22 |
|
|
|
3 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income before income tax expense, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income before income tax expense (GAAP) |
|
|
G |
|
|
$ |
45 |
|
|
$ |
541 |
|
|
$ |
564 |
|
|
$ |
580 |
|
|
$ |
566 |
|
|
($ |
496 |
) |
|
|
(92 |
%) |
|
($ |
521 |
) |
|
|
(92 |
%) |
| Less: Expense before income tax benefit related to notable items |
|
|
|
|
|
|
(33 |
) |
|
|
(37 |
) |
|
|
(19 |
) |
|
|
(7 |
) |
|
|
(5 |
) |
|
|
4 |
|
|
|
11 |
|
|
|
(28 |
) |
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income before income tax expense, Underlying
(non-GAAP) |
|
|
H |
|
|
$ |
78 |
|
|
$ |
578 |
|
|
$ |
583 |
|
|
$ |
587 |
|
|
$ |
571 |
|
|
($ |
500 |
) |
|
|
(87 |
%) |
|
($ |
493 |
) |
|
|
(86 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income tax expense, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income tax expense (GAAP) |
|
|
I |
|
|
$ |
11 |
|
|
$ |
91 |
|
|
$ |
115 |
|
|
$ |
127 |
|
|
$ |
127 |
|
|
($ |
80 |
) |
|
|
(88 |
%) |
|
($ |
116 |
) |
|
|
(91 |
%) |
| Less: Income tax benefit related to notable items |
|
|
|
|
|
|
(8 |
) |
|
|
(33 |
) |
|
|
(15 |
) |
|
|
(2 |
) |
|
|
(1 |
) |
|
|
25 |
|
|
|
76 |
|
|
|
(7 |
) |
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Income tax expense, Underlying (non-GAAP) |
|
|
J |
|
|
$ |
19 |
|
|
$ |
124 |
|
|
$ |
130 |
|
|
$ |
129 |
|
|
$ |
128 |
|
|
($ |
105 |
) |
|
|
(85 |
%) |
|
($ |
109 |
) |
|
|
(85 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income (GAAP) |
|
|
K |
|
|
$ |
34 |
|
|
$ |
450 |
|
|
$ |
449 |
|
|
$ |
453 |
|
|
$ |
439 |
|
|
($ |
416 |
) |
|
|
(92 |
%) |
|
($ |
405 |
) |
|
|
(92 |
%) |
| Add: Notable items, net of income tax benefit |
|
|
|
|
|
|
25 |
|
|
|
4 |
|
|
|
4 |
|
|
|
5 |
|
|
|
4 |
|
|
|
21 |
|
|
|
NM |
|
|
|
21 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income, Underlying (non-GAAP) |
|
|
L |
|
|
$ |
59 |
|
|
$ |
454 |
|
|
$ |
453 |
|
|
$ |
458 |
|
|
$ |
443 |
|
|
($ |
395 |
) |
|
|
(87 |
%) |
|
($ |
384 |
) |
|
|
(87 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income available to common stockholders, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income available to common stockholders (GAAP) |
|
|
M |
|
|
$ |
12 |
|
|
$ |
427 |
|
|
$ |
432 |
|
|
$ |
435 |
|
|
$ |
424 |
|
|
($ |
415 |
) |
|
|
(97 |
%) |
|
($ |
412 |
) |
|
|
(97 |
%) |
| Add: Notable items, net of income tax benefit |
|
|
|
|
|
|
25 |
|
|
|
4 |
|
|
|
4 |
|
|
|
5 |
|
|
|
4 |
|
|
|
21 |
|
|
|
NM |
|
|
|
21 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income available to common stockholders, Underlying
(non-GAAP) |
|
|
N |
|
|
$ |
37 |
|
|
$ |
431 |
|
|
$ |
436 |
|
|
$ |
440 |
|
|
$ |
428 |
|
|
($ |
394 |
) |
|
|
(91 |
%) |
|
($ |
391 |
) |
|
|
(91 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
21
KEY PERFORMANCE METRICS, NON-GAAP FINANCIAL MEASURES AND
RECONCILIATIONS, CONTINUED
(in millions, except share, per-share and ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
QUARTERLY TRENDS |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
|
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$/bps |
|
|
% |
|
|
$/bps |
|
|
% |
|
| Operating leverage: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue (GAAP) |
|
C |
|
$ |
1,657 |
|
|
$ |
1,637 |
|
|
$ |
1,638 |
|
|
$ |
1,628 |
|
|
$ |
1,588 |
|
|
$ |
20 |
|
|
|
1.30 |
% |
|
$ |
69 |
|
|
|
4.35 |
% |
| Less: Noninterest expense (GAAP) |
|
E |
|
|
1,012 |
|
|
|
986 |
|
|
|
973 |
|
|
|
951 |
|
|
|
937 |
|
|
|
26 |
|
|
|
2.68 |
|
|
|
75 |
|
|
|
8.06 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Operating leverage |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
(1.38 |
%) |
|
|
|
|
|
|
(3.71 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Operating leverage, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue, Underlying (non-GAAP) |
|
D |
|
$ |
1,657 |
|
|
$ |
1,637 |
|
|
$ |
1,638 |
|
|
$ |
1,628 |
|
|
$ |
1,588 |
|
|
$ |
20 |
|
|
|
1.30 |
% |
|
$ |
69 |
|
|
|
4.35 |
% |
| Less: Noninterest expense, Underlying (non-GAAP) |
|
F |
|
|
979 |
|
|
|
949 |
|
|
|
954 |
|
|
|
944 |
|
|
|
932 |
|
|
|
30 |
|
|
|
3.16 |
|
|
|
47 |
|
|
|
5.09 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Operating leverage, Underlying (non-GAAP) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
(1.86 |
%) |
|
|
|
|
|
|
(0.74 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Efficiency ratio and efficiency ratio, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Efficiency ratio |
|
E/C |
|
|
61.10 |
% |
|
|
60.28 |
% |
|
|
59.40 |
% |
|
|
58.41 |
% |
|
|
59.00 |
% |
|
|
82 bps |
|
|
|
|
|
|
|
210 bps |
|
|
|
|
|
| Efficiency ratio, Underlying (non-GAAP) |
|
F/D |
|
|
59.08 |
|
|
|
58.02 |
|
|
|
58.22 |
|
|
|
58.02 |
|
|
|
58.67 |
|
|
|
106 bps |
|
|
|
|
|
|
|
41 bps |
|
|
|
|
|
| Noninterest income as a % of total revenue, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest income as a % of total revenue |
|
A/C |
|
|
30 |
% |
|
|
30 |
% |
|
|
30 |
% |
|
|
28 |
% |
|
|
27 |
% |
|
|
— bps |
|
|
|
|
|
|
|
300 bps |
|
|
|
|
|
| Noninterest income as a % of total revenue, Underlying |
|
B/D |
|
|
30 |
|
|
|
30 |
|
|
|
30 |
|
|
|
28 |
|
|
|
27 |
|
|
|
— bps |
|
|
|
|
|
|
|
300 bps |
|
|
|
|
|
| Effective income tax rate and effective income tax rate, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Effective income tax rate |
|
I/G |
|
|
24.13 |
% |
|
|
16.76 |
% |
|
|
20.46 |
% |
|
|
21.86 |
% |
|
|
22.42 |
% |
|
|
737 bps |
|
|
|
|
|
|
|
171 bps |
|
|
|
|
|
| Effective income tax rate, Underlying (non-GAAP) |
|
J/H |
|
|
24.52 |
|
|
|
21.52 |
|
|
|
22.29 |
|
|
|
21.89 |
|
|
|
22.44 |
|
|
|
300 bps |
|
|
|
|
|
|
|
208 bps |
|
|
|
|
|
| Return on average common equity and return on average common equity, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average common equity (GAAP) |
|
O |
|
$ |
20,223 |
|
|
$ |
20,400 |
|
|
$ |
20,533 |
|
|
$ |
20,420 |
|
|
$ |
19,942 |
|
|
($ |
177 |
) |
|
|
(1 |
%) |
|
$ |
281 |
|
|
|
1 |
% |
| Return on average common equity |
|
M/O |
|
|
0.24 |
% |
|
|
8.30 |
% |
|
|
8.35 |
% |
|
|
8.54 |
% |
|
|
8.62 |
% |
|
|
(806) bps |
|
|
|
|
|
|
|
(838) bps |
|
|
|
|
|
| Return on average common equity, Underlying
(non-GAAP) |
|
N/O |
|
|
0.74 |
|
|
|
8.36 |
|
|
|
8.45 |
|
|
|
8.63 |
|
|
|
8.71 |
|
|
|
(762) bps |
|
|
|
|
|
|
|
(797) bps |
|
|
|
|
|
| Return on average tangible common equity and return on average tangible common equity,
Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average common equity (GAAP) |
|
O |
|
$ |
20,223 |
|
|
$ |
20,400 |
|
|
$ |
20,533 |
|
|
$ |
20,420 |
|
|
$ |
19,942 |
|
|
($ |
177 |
) |
|
|
(1 |
%) |
|
$ |
281 |
|
|
|
1 |
% |
| Less: Average goodwill (GAAP) |
|
|
|
|
7,046 |
|
|
|
7,044 |
|
|
|
7,044 |
|
|
|
7,040 |
|
|
|
7,018 |
|
|
|
2 |
|
|
|
— |
|
|
|
28 |
|
|
|
— |
|
| Less: Average other intangibles (GAAP) |
|
|
|
|
67 |
|
|
|
69 |
|
|
|
73 |
|
|
|
80 |
|
|
|
59 |
|
|
|
(2 |
) |
|
|
(3 |
) |
|
|
8 |
|
|
|
14 |
|
| Add: Average deferred tax liabilities related to goodwill (GAAP) |
|
|
|
|
374 |
|
|
|
373 |
|
|
|
372 |
|
|
|
370 |
|
|
|
368 |
|
|
|
1 |
|
|
|
— |
|
|
|
6 |
|
|
|
2 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average tangible common equity |
|
P |
|
$ |
13,484 |
|
|
$ |
13,660 |
|
|
$ |
13,788 |
|
|
$ |
13,670 |
|
|
$ |
13,233 |
|
|
($ |
176 |
) |
|
|
(1 |
%) |
|
$ |
251 |
|
|
|
2 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Return on average tangible common equity |
|
M/P |
|
|
0.36 |
% |
|
|
12.39 |
% |
|
|
12.44 |
% |
|
|
12.75 |
% |
|
|
13.00 |
% |
|
|
(1,203) bps |
|
|
|
|
|
|
|
(1,264) bps |
|
|
|
|
|
| Return on average tangible common equity, Underlying
(non-GAAP) |
|
N/P |
|
|
1.10 |
|
|
|
12.49 |
|
|
|
12.58 |
|
|
|
12.89 |
|
|
|
13.12 |
|
|
|
(1,139) bps |
|
|
|
|
|
|
|
(1,202) bps |
|
|
|
|
|
| Return on average total assets and return on average total assets, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average total assets (GAAP) |
|
Q |
|
$ |
167,177 |
|
|
$ |
164,646 |
|
|
$ |
162,110 |
|
|
$ |
161,489 |
|
|
$ |
160,415 |
|
|
$ |
2,531 |
|
|
|
2 |
% |
|
$ |
6,762 |
|
|
|
4 |
% |
| Return on average total assets |
|
K/Q |
|
|
0.08 |
% |
|
|
1.08 |
% |
|
|
1.10 |
% |
|
|
1.13 |
% |
|
|
1.11 |
% |
|
|
(100) bps |
|
|
|
|
|
|
|
(103) bps |
|
|
|
|
|
| Return on average total assets, Underlying (non-GAAP) |
|
L/Q |
|
|
0.14 |
|
|
|
1.09 |
|
|
|
1.11 |
|
|
|
1.14 |
|
|
|
1.12 |
|
|
|
(95) bps |
|
|
|
|
|
|
|
(98) bps |
|
|
|
|
|
22
KEY PERFORMANCE METRICS, NON-GAAP FINANCIAL MEASURES AND
RECONCILIATIONS, CONTINUED
(in millions, except share, per-share and ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
QUARTERLY TRENDS |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
|
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$/bps |
|
|
% |
|
|
$/bps |
|
|
% |
|
| Return on average total tangible assets and return on average total tangible assets,
Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average total assets (GAAP) |
|
Q |
|
$ |
167,177 |
|
|
$ |
164,646 |
|
|
$ |
162,110 |
|
|
$ |
161,489 |
|
|
$ |
160,415 |
|
|
$ |
2,531 |
|
|
|
2 |
% |
|
$ |
6,762 |
|
|
|
4 |
% |
| Less: Average goodwill (GAAP) |
|
|
|
|
7,046 |
|
|
|
7,044 |
|
|
|
7,044 |
|
|
|
7,040 |
|
|
|
7,018 |
|
|
|
2 |
|
|
|
— |
|
|
|
28 |
|
|
|
— |
|
| Less: Average other intangibles (GAAP) |
|
|
|
|
67 |
|
|
|
69 |
|
|
|
73 |
|
|
|
80 |
|
|
|
59 |
|
|
|
(2 |
) |
|
|
(3 |
) |
|
|
8 |
|
|
|
14 |
|
| Add: Average deferred tax liabilities related to goodwill (GAAP) |
|
|
|
|
374 |
|
|
|
373 |
|
|
|
372 |
|
|
|
370 |
|
|
|
368 |
|
|
|
1 |
|
|
|
— |
|
|
|
6 |
|
|
|
2 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average tangible assets |
|
R |
|
$ |
160,438 |
|
|
$ |
157,906 |
|
|
$ |
155,365 |
|
|
$ |
154,739 |
|
|
$ |
153,706 |
|
|
$ |
2,532 |
|
|
|
2 |
% |
|
$ |
6,732 |
|
|
|
4 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Return on average total tangible assets |
|
K/R |
|
|
0.09 |
% |
|
|
1.13 |
% |
|
|
1.15 |
% |
|
|
1.17 |
% |
|
|
1.16 |
% |
|
|
(104) bps |
|
|
|
|
|
|
|
(107) bps |
|
|
|
|
|
| Return on average total tangible assets, Underlying
(non-GAAP) |
|
L/R |
|
|
0.15 |
|
|
|
1.14 |
|
|
|
1.16 |
|
|
|
1.19 |
|
|
|
1.17 |
|
|
|
(99) bps |
|
|
|
|
|
|
|
(102) bps |
|
|
|
|
|
| Tangible book value per common share: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Common shares - at period-end (GAAP) |
|
S |
|
|
426,586,533 |
|
|
|
433,121,083 |
|
|
|
443,913,525 |
|
|
|
457,903,826 |
|
|
|
461,116,723 |
|
|
|
(6,534,550 |
) |
|
|
(2 |
%) |
|
|
(34,530,190 |
) |
|
|
(7 |
%) |
| Common stockholders’ equity (GAAP) |
|
|
|
$ |
20,380 |
|
|
$ |
20,631 |
|
|
$ |
20,718 |
|
|
$ |
20,884 |
|
|
$ |
20,399 |
|
|
($ |
251 |
) |
|
|
(1 |
) |
|
($ |
19 |
) |
|
|
— |
|
| Less: Goodwill (GAAP) |
|
|
|
|
7,050 |
|
|
|
7,044 |
|
|
|
7,044 |
|
|
|
7,040 |
|
|
|
7,040 |
|
|
|
6 |
|
|
|
— |
|
|
|
10 |
|
|
|
— |
|
| Less: Other intangible assets (GAAP) |
|
|
|
|
66 |
|
|
|
68 |
|
|
|
71 |
|
|
|
74 |
|
|
|
80 |
|
|
|
(2 |
) |
|
|
(3 |
) |
|
|
(14 |
) |
|
|
(18 |
) |
| Add: Deferred tax liabilities related to goodwill (GAAP) |
|
|
|
|
375 |
|
|
|
374 |
|
|
|
373 |
|
|
|
371 |
|
|
|
370 |
|
|
|
1 |
|
|
|
— |
|
|
|
5 |
|
|
|
1 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Tangible common equity |
|
T |
|
$ |
13,639 |
|
|
$ |
13,893 |
|
|
$ |
13,976 |
|
|
$ |
14,141 |
|
|
$ |
13,649 |
|
|
($ |
254 |
) |
|
|
(2 |
%) |
|
($ |
10 |
) |
|
|
— |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Tangible book value per common share |
|
T/S |
|
$ |
31.97 |
|
|
$ |
32.08 |
|
|
$ |
31.48 |
|
|
$ |
30.88 |
|
|
$ |
29.60 |
|
|
($ |
0.11 |
) |
|
|
— |
% |
|
$ |
2.37 |
|
|
|
8 |
% |
| Net income per average common share - basic and diluted and net income per average common share -
basic and diluted, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average common shares outstanding - basic (GAAP) |
|
U |
|
|
427,718,421 |
|
|
|
434,684,606 |
|
|
|
445,703,987 |
|
|
|
458,154,335 |
|
|
|
460,713,172 |
|
|
|
(6,966,185 |
) |
|
|
(2 |
%) |
|
|
(32,994,751 |
) |
|
|
(7 |
%) |
| Average common shares outstanding - diluted (GAAP) |
|
V |
|
|
429,388,855 |
|
|
|
436,500,829 |
|
|
|
447,134,595 |
|
|
|
459,304,224 |
|
|
|
462,520,680 |
|
|
|
(7,111,974 |
) |
|
|
(2 |
) |
|
|
(33,131,825 |
) |
|
|
(7 |
) |
| Net income per average common share - basic (GAAP) |
|
M/U |
|
$ |
0.03 |
|
|
$ |
0.98 |
|
|
$ |
0.97 |
|
|
$ |
0.95 |
|
|
$ |
0.92 |
|
|
($ |
0.95 |
) |
|
|
(97 |
) |
|
($ |
0.89 |
) |
|
|
(97 |
) |
| Net income per average common share - diluted (GAAP) |
|
M/V |
|
|
0.03 |
|
|
|
0.98 |
|
|
|
0.97 |
|
|
|
0.95 |
|
|
|
0.92 |
|
|
|
(0.95 |
) |
|
|
(97 |
) |
|
|
(0.89 |
) |
|
|
(97 |
) |
| Net income per average common share - basic, Underlying
(non-GAAP) |
|
N/U |
|
|
0.09 |
|
|
|
0.99 |
|
|
|
0.98 |
|
|
|
0.96 |
|
|
|
0.93 |
|
|
|
(0.90 |
) |
|
|
(91 |
) |
|
|
(0.84 |
) |
|
|
(90 |
) |
| Net income per average common share - diluted, Underlying
(non-GAAP) |
|
N/V |
|
|
0.09 |
|
|
|
0.99 |
|
|
|
0.98 |
|
|
|
0.96 |
|
|
|
0.93 |
|
|
|
(0.90 |
) |
|
|
(91 |
) |
|
|
(0.84 |
) |
|
|
(90 |
) |
| Dividend payout ratio and dividend payout ratio, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Cash dividends declared and paid per common share |
|
W |
|
$ |
0.39 |
|
|
$ |
0.36 |
|
|
$ |
0.36 |
|
|
$ |
0.32 |
|
|
$ |
0.32 |
|
|
$ |
0.03 |
|
|
|
8 |
% |
|
$ |
0.07 |
|
|
|
22 |
% |
| Dividend payout ratio |
|
W/(M/U) |
|
|
1,398 |
% |
|
|
37 |
% |
|
|
37 |
% |
|
|
34 |
% |
|
|
35 |
% |
|
|
NM |
|
|
|
|
|
|
|
NM |
|
|
|
|
|
| Dividend payout ratio, Underlying (non-GAAP) |
|
W/(N/U) |
|
|
451 |
|
|
|
36 |
|
|
|
37 |
|
|
|
33 |
|
|
|
34 |
|
|
|
NM |
|
|
|
|
|
|
|
NM |
|
|
|
|
|
23
KEY PERFORMANCE METRICS, NON-GAAP FINANCIAL MEASURES AND
RECONCILIATIONS, CONTINUED
(in millions, except share, per-share and ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
QUARTERLY TRENDS |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
1Q20 Change |
|
| |
|
1Q20 |
|
|
4Q19 |
|
|
3Q19 |
|
|
2Q19 |
|
|
1Q19 |
|
|
4Q19 |
|
|
1Q19 |
|
| |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
$ |
|
|
% |
|
|
$ |
|
|
% |
|
| Salaries and employee benefits, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Salaries and employee benefits (GAAP) |
|
$ |
549 |
|
|
$ |
502 |
|
|
$ |
508 |
|
|
$ |
507 |
|
|
$ |
509 |
|
|
$ |
47 |
|
|
|
9 |
% |
|
$ |
40 |
|
|
|
8 |
% |
| Less: Notable items |
|
|
10 |
|
|
|
6 |
|
|
|
5 |
|
|
|
2 |
|
|
|
1 |
|
|
|
4 |
|
|
|
67 |
|
|
|
9 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Salaries and employee benefits, Underlying (non-GAAP) |
|
$ |
539 |
|
|
$ |
496 |
|
|
$ |
503 |
|
|
$ |
505 |
|
|
$ |
508 |
|
|
$ |
43 |
|
|
|
9 |
% |
|
$ |
31 |
|
|
|
6 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Equipment and software expense, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Equipment and software expense (GAAP) |
|
$ |
133 |
|
|
$ |
133 |
|
|
$ |
130 |
|
|
$ |
126 |
|
|
$ |
125 |
|
|
$ |
— |
|
|
|
— |
% |
|
$ |
8 |
|
|
|
6 |
% |
| Less: Notable items |
|
|
1 |
|
|
|
3 |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
(2 |
) |
|
|
(67 |
) |
|
|
1 |
|
|
|
100 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Equipment and software expense, Underlying (non-GAAP) |
|
$ |
132 |
|
|
$ |
130 |
|
|
$ |
130 |
|
|
$ |
126 |
|
|
$ |
125 |
|
|
$ |
2 |
|
|
|
2 |
% |
|
$ |
7 |
|
|
|
6 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Outside services, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Outside services (GAAP) |
|
$ |
135 |
|
|
$ |
142 |
|
|
$ |
128 |
|
|
$ |
118 |
|
|
$ |
110 |
|
|
($ |
7 |
) |
|
|
(5 |
%) |
|
$ |
25 |
|
|
|
23 |
% |
| Less: Notable items |
|
|
18 |
|
|
|
20 |
|
|
|
14 |
|
|
|
5 |
|
|
|
4 |
|
|
|
(2 |
) |
|
|
(10 |
) |
|
|
14 |
|
|
|
NM |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Outside services, Underlying (non-GAAP) |
|
$ |
117 |
|
|
$ |
122 |
|
|
$ |
114 |
|
|
$ |
113 |
|
|
$ |
106 |
|
|
($ |
5 |
) |
|
|
(4 |
%) |
|
$ |
11 |
|
|
|
10 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Occupancy, Underlying: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Occupancy (GAAP) |
|
$ |
84 |
|
|
$ |
88 |
|
|
$ |
80 |
|
|
$ |
82 |
|
|
$ |
83 |
|
|
($ |
4 |
) |
|
|
(5 |
%) |
|
$ |
1 |
|
|
|
1 |
% |
| Less: Notable items |
|
|
4 |
|
|
|
8 |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
(4 |
) |
|
|
(50 |
) |
|
|
4 |
|
|
|
100 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Occupancy, Underlying (non-GAAP) |
|
$ |
80 |
|
|
$ |
80 |
|
|
$ |
80 |
|
|
$ |
82 |
|
|
$ |
83 |
|
|
$ |
— |
|
|
|
— |
% |
|
($ |
3 |
) |
|
|
(4 |
%) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
24
KEY PERFORMANCE METRICS, NON-GAAP FINANCIAL MEASURES AND
RECONCILIATIONS - SEGMENTS
(in millions, except ratio data)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
FIRST QUARTER 2020 |
|
|
FOURTH QUARTER 2019 |
|
|
THIRD QUARTER 2019 |
|
| |
|
|
|
Consumer
Banking |
|
|
Commercial
Banking |
|
|
Other |
|
|
Consolidated |
|
|
Consumer
Banking |
|
|
Commercial
Banking |
|
|
Other |
|
|
Consolidated |
|
|
Consumer
Banking |
|
|
Commercial
Banking |
|
|
Other |
|
|
Consolidated |
|
| Net income (loss) available to common stockholders: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income (loss) |
|
A |
|
$ |
236 |
|
|
$ |
179 |
|
|
($ |
381 |
) |
|
$ |
34 |
|
|
$ |
209 |
|
|
$ |
231 |
|
|
$ |
10 |
|
|
$ |
450 |
|
|
$ |
251 |
|
|
$ |
196 |
|
|
$ |
2 |
|
|
$ |
449 |
|
| Less: Preferred stock dividends |
|
|
|
|
— |
|
|
|
— |
|
|
|
22 |
|
|
|
22 |
|
|
|
— |
|
|
|
— |
|
|
|
23 |
|
|
|
23 |
|
|
|
— |
|
|
|
— |
|
|
|
17 |
|
|
|
17 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income (loss) available to common stockholders |
|
B |
|
$ |
236 |
|
|
$ |
179 |
|
|
($ |
403 |
) |
|
$ |
12 |
|
|
$ |
209 |
|
|
$ |
231 |
|
|
($ |
13 |
) |
|
$ |
427 |
|
|
$ |
251 |
|
|
$ |
196 |
|
|
($ |
15 |
) |
|
$ |
432 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Return on average total tangible assets: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average total assets (GAAP) |
|
|
|
$ |
68,415 |
|
|
$ |
59,005 |
|
|
$ |
39,757 |
|
|
$ |
167,177 |
|
|
$ |
68,069 |
|
|
$ |
56,407 |
|
|
$ |
40,170 |
|
|
$ |
164,646 |
|
|
$ |
66,365 |
|
|
$ |
55,614 |
|
|
$ |
40,131 |
|
|
$ |
162,110 |
|
| Less: Average goodwill (GAAP) |
|
|
|
|
122 |
|
|
|
48 |
|
|
|
6,876 |
|
|
|
7,046 |
|
|
|
122 |
|
|
|
46 |
|
|
|
6,876 |
|
|
|
7,044 |
|
|
|
122 |
|
|
|
46 |
|
|
|
6,876 |
|
|
|
7,044 |
|
| Average other intangibles (GAAP) |
|
|
|
|
43 |
|
|
|
6 |
|
|
|
18 |
|
|
|
67 |
|
|
|
63 |
|
|
|
6 |
|
|
|
— |
|
|
|
69 |
|
|
|
66 |
|
|
|
7 |
|
|
|
— |
|
|
|
73 |
|
| Add: Average deferred tax liabilities related to goodwill (GAAP) |
|
|
|
|
1 |
|
|
|
1 |
|
|
|
372 |
|
|
|
374 |
|
|
|
1 |
|
|
|
1 |
|
|
|
371 |
|
|
|
373 |
|
|
|
1 |
|
|
|
1 |
|
|
|
370 |
|
|
|
372 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average tangible assets |
|
C |
|
$ |
68,251 |
|
|
$ |
58,952 |
|
|
$ |
33,235 |
|
|
$ |
160,438 |
|
|
$ |
67,885 |
|
|
$ |
56,356 |
|
|
$ |
33,665 |
|
|
$ |
157,906 |
|
|
$ |
66,178 |
|
|
$ |
55,562 |
|
|
$ |
33,625 |
|
|
$ |
155,365 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Return on average total tangible assets |
|
A/C |
|
|
1.39 |
% |
|
|
1.22 |
% |
|
|
NM |
|
|
|
0.09 |
% |
|
|
1.22 |
% |
|
|
1.63 |
% |
|
|
NM |
|
|
|
1.13 |
% |
|
|
1.50 |
% |
|
|
1.40 |
% |
|
|
NM |
|
|
|
1.15 |
% |
| Efficiency ratio: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest expense (GAAP) |
|
D |
|
$ |
738 |
|
|
$ |
221 |
|
|
$ |
53 |
|
|
$ |
1,012 |
|
|
$ |
718 |
|
|
$ |
219 |
|
|
$ |
49 |
|
|
$ |
986 |
|
|
$ |
718 |
|
|
$ |
213 |
|
|
$ |
42 |
|
|
$ |
973 |
|
| Net interest income (GAAP) |
|
|
|
|
793 |
|
|
|
365 |
|
|
|
2 |
|
|
|
1,160 |
|
|
|
796 |
|
|
|
363 |
|
|
|
(16 |
) |
|
|
1,143 |
|
|
|
799 |
|
|
|
360 |
|
|
|
(14 |
) |
|
|
1,145 |
|
| Noninterest income (GAAP) |
|
|
|
|
357 |
|
|
|
125 |
|
|
|
15 |
|
|
|
497 |
|
|
|
296 |
|
|
|
175 |
|
|
|
23 |
|
|
|
494 |
|
|
|
336 |
|
|
|
133 |
|
|
|
24 |
|
|
|
493 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue (GAAP) |
|
E |
|
$ |
1,150 |
|
|
$ |
490 |
|
|
$ |
17 |
|
|
$ |
1,657 |
|
|
$ |
1,092 |
|
|
$ |
538 |
|
|
$ |
7 |
|
|
$ |
1,637 |
|
|
$ |
1,135 |
|
|
$ |
493 |
|
|
$ |
10 |
|
|
$ |
1,638 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Efficiency ratio |
|
D/E |
|
|
64.16 |
% |
|
|
45.06 |
% |
|
|
NM |
|
|
|
61.10 |
% |
|
|
65.74 |
% |
|
|
40.60 |
% |
|
|
NM |
|
|
|
60.28 |
% |
|
|
63.28 |
% |
|
|
43.35 |
% |
|
|
NM |
|
|
|
59.40 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
|
|
|
SECOND QUARTER 2019 |
|
|
FIRST QUARTER 2019 |
|
| |
|
|
|
Consumer
Banking |
|
|
Commercial
Banking |
|
|
Other |
|
|
Consolidated |
|
|
Consumer
Banking |
|
|
Commercial
Banking |
|
|
Other |
|
|
Consolidated |
|
| Net income (loss) available to common stockholders: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income |
|
A |
|
$ |
213 |
|
|
$ |
216 |
|
|
$ |
24 |
|
|
$ |
453 |
|
|
$ |
202 |
|
|
$ |
227 |
|
|
$ |
10 |
|
|
$ |
439 |
|
| Less: Preferred stock dividends |
|
|
|
|
— |
|
|
|
— |
|
|
|
18 |
|
|
|
18 |
|
|
|
— |
|
|
|
— |
|
|
|
15 |
|
|
|
15 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Net income (loss) available to common stockholders |
|
B |
|
$ |
213 |
|
|
$ |
216 |
|
|
$ |
6 |
|
|
$ |
435 |
|
|
$ |
202 |
|
|
$ |
227 |
|
|
($ |
5 |
) |
|
$ |
424 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Return on average total tangible assets: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average total assets (GAAP) |
|
|
|
$ |
65,485 |
|
|
$ |
56,135 |
|
|
$ |
39,869 |
|
|
$ |
161,489 |
|
|
$ |
65,007 |
|
|
$ |
55,630 |
|
|
$ |
39,778 |
|
|
$ |
160,415 |
|
| Less: Average goodwill (GAAP) |
|
|
|
|
119 |
|
|
|
45 |
|
|
|
6,876 |
|
|
|
7,040 |
|
|
|
119 |
|
|
|
23 |
|
|
|
6,876 |
|
|
|
7,018 |
|
| Average other intangibles (GAAP) |
|
|
|
|
73 |
|
|
|
7 |
|
|
|
— |
|
|
|
80 |
|
|
|
55 |
|
|
|
4 |
|
|
|
— |
|
|
|
59 |
|
| Add: Average deferred tax liabilities related to goodwill (GAAP) |
|
|
|
|
— |
|
|
|
— |
|
|
|
370 |
|
|
|
370 |
|
|
|
— |
|
|
|
— |
|
|
|
368 |
|
|
|
368 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Average tangible assets |
|
C |
|
$ |
65,293 |
|
|
$ |
56,083 |
|
|
$ |
33,363 |
|
|
$ |
154,739 |
|
|
$ |
64,833 |
|
|
$ |
55,603 |
|
|
$ |
33,270 |
|
|
$ |
153,706 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Return on average total tangible assets |
|
A/C |
|
|
1.31 |
% |
|
|
1.54 |
% |
|
|
NM |
|
|
|
1.17 |
% |
|
|
1.26 |
% |
|
|
1.66 |
% |
|
|
NM |
|
|
|
1.16 |
% |
| Efficiency ratio: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Noninterest expense (GAAP) |
|
D |
|
$ |
715 |
|
|
$ |
217 |
|
|
$ |
19 |
|
|
$ |
951 |
|
|
$ |
700 |
|
|
$ |
209 |
|
|
$ |
28 |
|
|
$ |
937 |
|
| Net interest income (GAAP) |
|
|
|
|
799 |
|
|
|
371 |
|
|
|
(4 |
) |
|
|
1,166 |
|
|
|
788 |
|
|
|
372 |
|
|
|
— |
|
|
|
1,160 |
|
| Noninterest income (GAAP) |
|
|
|
|
277 |
|
|
|
149 |
|
|
|
36 |
|
|
|
462 |
|
|
|
247 |
|
|
|
150 |
|
|
|
31 |
|
|
|
428 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Total revenue (GAAP) |
|
E |
|
$ |
1,076 |
|
|
$ |
520 |
|
|
$ |
32 |
|
|
$ |
1,628 |
|
|
$ |
1,035 |
|
|
$ |
522 |
|
|
$ |
31 |
|
|
$ |
1,588 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Efficiency ratio |
|
D/E |
|
|
66.43 |
% |
|
|
41.58 |
% |
|
|
NM |
|
|
|
58.41 |
% |
|
|
67.62 |
% |
|
|
40.11 |
% |
|
|
NM |
|
|
|
59.00 |
% |
25
Appendix
| A |
These are non-GAAP financial measures. For further information on these
measures, refer to “Key Performance Metrics, Non-GAAP Financial Measures and Reconciliations.” |
| B |
Beginning in the first quarter of 2020, both fully and partially guaranteed residential mortgage loans sold to
Ginnie Mae for which the Company has the right, but not the obligation, to repurchase have been reclassified from loans and leases to other assets. |
| C |
In the first quarter of 2020, we reclassified federal funds purchased and securities sold under agreement to
repurchase and other short-term borrowed funds to short-term borrowed funds. Prior periods have been adjusted to conform with the current period presentation. |
| D |
In the first quarter of 2020, home equity loans, home equity lines of credit, home equity loans serviced by others
and home equity lines of credit serviced by others are included in home equity. Prior periods have been adjusted to conform with current period presentation. |
| E |
In the first quarter of 2020, credit card and other retail are included in other retail. Prior periods have been
adjusted to conform with current period presentation. |
26