As filed with the U.S. Securities and Exchange Commission on April 27, 2026


UNITED STATES

SECURITIES AND EXCHANGE COMMISSION

Washington, D.C. 20549


FORM 20-F


☐ REGISTRATION STATEMENT PURSUANT TO SECTION 12(b) OR (g) OF THE SECURITIES EXCHANGE ACT OF 1934


OR


☒ ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934


For the fiscal year ended December 31, 2025


OR


☐ TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934


OR


☐ SHELL COMPANY REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934


Commission file number 001-35401


CEMENTOS PACASMAYO S.A.A.

(Exact name of Registrant as specified in its charter)


PACASMAYO CEMENT CORPORATION

(Translation of Registrant’s name into English)


Republic of Peru

(Jurisdiction of incorporation or organization)


Calle La Colonia 150, Urbanización El Vivero
Surco, Lima
Peru

(Address of principal executive offices)


Gabriela Dañino, Esq., General Counsel
Tel. +51-1-317-6000
Calle La Colonia 150
Urb. El Vivero - Lima, Peru

(Name, telephone, email and/or facsimile number and address of company contact person)


Securities registered pursuant to Section 12(b) of the Act.


Title of each class   Trading Symbol(s)   Name of each exchange on which registered
American Depositary Shares evidenced by American Depositary Receipts, each American Depositary Share representing five common shares of the Registrant, par value S/1.00 per share (“ADSs”)   CPAC   New York Stock Exchange
Common Shares, par value S/1.00 per share       New York Stock Exchange*


*Not for trading purposes, but only in connection with the listing of American Depositary Shares pursuant to the requirements of the Securities and Exchange Commission. Our Common Shares are listed on the Lima Stock Exchange.


Securities registered pursuant to Section 12(g) of the Act: None


Securities for which there is a reporting obligation pursuant to Section 15(d) of the Act: None


Indicate the number of outstanding shares of each of the issuer’s classes of capital or common stock as of the close of the period covered by the annual report:


As of December 31, 2025 423,868,449 common shares
4,238,397 non-voting investment shares*


*Excluding 36,040,497 non-voting investment shares held in treasury.


Indicate by check mark if the Registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☐ No ☒


If this report is an annual or transition report, indicate by check mark if the Registrant is not required to file reports pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934. Yes ☐ No ☒


Note - Checking the box above will not relieve any registrant required to file reports pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934 from their obligations under those Sections.


Indicate by check mark whether the Registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the Registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐


Indicate by check mark whether the Registrant has submitted electronically every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§ 203.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files).

Yes ☒ No ☐


Indicate by check mark whether the Registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer or an emerging growth company. See definition of “large accelerated filer,” “accelerated filer,” and “emerging growth company” in Rule 12b-2 of the Exchange Act. (Check one):


Large accelerated filer ☐ Accelerated filer ☒ Non-accelerated filer ☐
    Emerging growth company ☐


If an emerging growth company that prepares its financial statements in accordance with U.S. GAAP, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards† provided pursuant to Section 13(a) of the Exchange Act. ☐


†The term “new or revised financial accounting standard” refers to any update issued by the Financial Accounting Standards Board to its Accounting Standards Codification after April 5, 2012.


Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☒


If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the Registrant included in the filing reflect the correction of an error to previously issued financial statements. ☐


Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the Registrant’s executive officers during the relevant recovery period pursuant to §240.10D-1(b). ☐


Indicate by check mark which basis of accounting the Registrant has used to prepare the financial statements included in this filing:


U.S. GAAP ☐ International Financial Reporting Standards as issued by the International Accounting Standards Board ☒ Other ☐


If “Other” has been checked in response to the previous question, indicate by check mark which financial statement item the Registrant has elected to follow. Item 17 ☐ Item 18 ☐


If this is an annual report, indicate by check mark whether the Registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ☐ No ☒


TABLE OF CONTENTS


PRESENTATION OF FINANCIAL AND OTHER INFORMATION iii
FORWARD-LOOKING STATEMENTS iv
Part I    
  Item 1. IDENTITY OF DIRECTORS, SENIOR MANAGEMENT AND ADVISERS 1
    A. Directors and senior management 1
    B. Advisers 1
    C. Auditors 1
  Item 2     OFFER STATISTICS AND EXPECTED TIMETABLE 1
    A. Offer statistics 1
    B. Method and expected timetable 1
  Item 3. KEY INFORMATION 1
    A. [Reserved] 1
    B. Capitalization and Indebtedness 1
    C. Reasons for the Offer and Use of Proceeds 1
    D. Risk Factors 1
  Item 4. INFORMATION ON THE COMPANY 22
    A. History and Development of the Company 22
    B. Business Overview 25
    C. Organizational Structure 49
    D. Property, Plants and Equipment 51
  Item 4A. UNRESOLVED STAFF COMMENTS 89
  Item 5. OPERATING AND FINANCIAL REVIEW AND PROSPECTS 89
    A. Operating Results 89
    B.

Liquidity and Capital Resources

100
    C. Research and Development, Patents and Licenses, Etc. 102
    D. Trend Information 103
    E. Critical Accounting Estimates 105
  Item 6. DIRECTORS, SENIOR MANAGEMENT AND EMPLOYEES 105
    A. Directors and Senior Management 105
    B. Compensation 110
    C. Board Practices 112
    D. Employees 113
    E. Share Ownership 114
    F. Disclosure of a Registrant’s Action to Recover Erroneously Awarded Compensation 114
  Item 7. MAJOR SHAREHOLDERS AND RELATED PARTY TRANSACTIONS 115
    A. Major Shareholders 115
    B. Related Party Transactions 117
    C. Interests of Experts and Counsel 118
  Item 8. FINANCIAL INFORMATION 118
    A. Consolidated Statements and Other Financial Information. 118
    B. Significant Changes 119


i


  Item 9. THE OFFER AND LISTING 119
    A. Offer and Listing Details 119
    B. Plan of Distribution 120
    C. Markets 120
    D. Selling Shareholders 121
    E. Dilution 121
    F. Expenses of the Issue 122
  Item 10. ADDITIONAL INFORMATION 122
  A. Share Capital 122
  B. Memorandum and Articles of Association 122
  C. Material Contracts 126
    D. Exchange Controls 126
    E. Taxation 127
    F. Dividends and Paying Agents 132
    G. Statement by Experts 132
    H. Documents on Display 132
    I. Subsidiary Information 132
    J. Annual Report to Security Holders 132
  Item 11. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK 133
  Item 12. DESCRIPTION OF SECURITIES OTHER THAN EQUITY SECURITIES 133
    A. Debt Securities 133
    B. Warrants and Rights 133
    C. Other Securities 133
    D. American Depositary Shares 133
Part II
  Item 13. DEFAULTS, DIVIDEND ARREARAGES AND DELINQUENCIES 135
  Item 14. MATERIAL MODIFICATIONS TO THE RIGHTS OF SECURITY HOLDERS AND USE OF PROCEEDS 135
  Item 15. CONTROLS AND PROCEDURES 135
    A. Disclosure Controls and Procedures 135
    B. Management’s Annual Report on Internal Control Over Financial Reporting 135
    C. Attestation Report of the Independent Registered Public Accounting Firm 135
    D. Changes in Internal Control Over Financial Reporting 136
  Item 16. [RESERVED] 136
  Item 16A. AUDIT COMMITTEE FINANCIAL EXPERT 136
  Item 16B. CODE OF ETHICS 136
  Item 16C. PRINCIPAL ACCOUNTANT FEES AND SERVICES 136
  Item 16D. EXEMPTIONS FROM THE LISTING STANDARDS FOR AUDIT COMMITTEES 137
  Item 16E. PURCHASES OF EQUITY SECURITIES BY THE ISSUER AND AFFILIATED PURCHASERS 137
  Item 16F. CHANGE IN REGISTRANT’S CERTIFYING ACCOUNTANT 137
  Item 16G. CORPORATE GOVERNANCE 137
  Item 16H. MINE SAFETY DISCLOSURE 137
  Item 16I. DISCLOSURE REGARDING FOREIGN JURISDICTIONS THAT PREVENT INSPECTIONS 138
  Item 16J. INSIDER TRADING POLICIES 138
  Item 16K. CYBERSECURITY 138
Part III  
  Item 17. FINANCIAL STATEMENTS 140
  Item 18. FINANCIAL STATEMENTS 140
  Item 19. EXHIBITS 140
INDEX TO CONSOLIDATED FINANCIAL STATEMENTS F-1


ii


PRESENTATION OF FINANCIAL AND OTHER INFORMATION


Certain Definitions


All references to “we,” “us,” “our,” “our company,” “Pacasmayo,” and “Cementos Pacasmayo” in this annual report on Form 20-F are to Cementos Pacasmayo S.A.A., a publicly held corporation (sociedad anónima abierta) organized under the laws of Peru, and, unless the context requires otherwise, its consolidated subsidiaries. References to “our controlling shareholder” are to Inversiones ASPI S.A. The term “U.S. Dollar” or “U.S. Dollars” and the symbol “US$” refer to the legal currency of the United States; and the term “Sol” or “Soles” and the symbol “S/” refer to the legal currency of Peru.


Financial Information


Our consolidated financial statements included in this annual report on Form 20-F have been prepared in Soles and in accordance with International Financial Reporting Standards (“IFRS”) as issued by the International Accounting Standards Board (“IASB”) and audited in accordance with the standards of the Public Company Accounting Oversight Board (United States).


We have translated some of the Soles amounts appearing in this annual report on Form 20-F into U.S. Dollars for convenience purposes only. Unless the context otherwise requires, the rate used to translate Soles amounts to U.S. Dollars was S/3.363 to US$1.00 as of December 31, 2025, which was the average accounting exchange rate (tipo de cambio contable) reported on December 31, 2025, by the Peruvian Superintendence of Banks, Insurance and Private Pension Fund Administrators (Superintendencia de Banca, Seguros y AFPs, or “SBS”). The Federal Reserve Bank of New York does not report a noon buying rate for Soles. The U.S. Dollar equivalent information presented in this annual report on Form 20-F is provided solely for convenience of the reader and should not be construed as implying that the Soles amounts represent, or could have been or could be converted into, U.S. Dollars at such rates or at any other rate.


Certain figures included in this annual report on Form 20-F have been subject to rounding adjustments. Accordingly, figures shown as totals in certain tables may not be arithmetic aggregations of the figures that precede them.


In this annual report on Form 20-F, we present EBITDA, EBITDA margin, Adjusted EBITDA and Adjusted EBITDA margin, which are financial measures that are not recognized under IFRS. We refer to such financial measures as “non-IFRS” financial measures. A non-IFRS financial measure is generally defined as one that purports to measure financial performance, financial position or cash flows of the subject reporting company but excludes or includes amounts that would not be so adjusted in the most comparable IFRS measure. We present EBITDA, EBITDA margin, Adjusted EBITDA and Adjusted EBITDA margin, because we believe they provide the reader with supplemental measures of the financial performance of our core operations that facilitate period-to-period comparisons of EBITDA and adjusted EBITDA on a consistent basis. EBITDA, EBITDA margin, Adjusted EBITDA and Adjusted EBITDA margin, should not be used as an alternative to profit or operating profit, operating margin as an indicator of operating performance, as an alternative to cash flow provided by operating activities or as a measure of liquidity (in each case, as determined in accordance with IFRS). We define EBITDA as net profit minus finance income and plus finance costs, income tax expense, and depreciation and amortization, and plus or minus gain from exchange difference, net. We define adjusted EBITDA as EBITDA minus the impairment of our vertical kilns. EBITDA, EBITDA margin, Adjusted EBITDA and Adjusted EBITDA margin, as calculated by us, may not be comparable to similarly titled measures reported by other companies, including those in the cement industry. For a calculation of EBITDA and Adjusted EBITDA and a reconciliation to the most directly comparable IFRS financial measure, see “Item 4. Information on the Company—B. Business Overview—Overview—Non-IFRS Financial Measures and Reconciliation.”


Market Information


We make estimates in this annual report on Form 20-F regarding our competitive position and market share, as well as the market size and expected growth of the construction sector and cement industry in Peru. We have made these estimates on the basis of our management’s knowledge and statistics and other information available from the following sources:


●the Central Bank of Peru (Banco Central de Reserva del Perú, or the “BCRP”);


●the National Statistical Institute of Peru (Instituto Nacional de Estadística e Informática, or “INEI”);


●the Association of Cement Producers of Peru (Asociación de Productores de Cemento, or “ASOCEM”);


●the Ministry of Housing, Construction and Sanitation (Ministerio de Vivienda, Construcción y Saneamiento);


●ADUANET, a website administered by the Peruvian Tax Superintendence (Superintendencia Nacional de Administración Tributaria, or “SUNAT”);


●the Peruvian Chamber of Construction (Cámara Peruana de la Construcción); and


●the Global Competitiveness Index prepared by the World Economic Forum.


We believe these estimates to be accurate as of the date of this annual report on Form 20-F.


iii


FORWARD-LOOKING STATEMENTS


This annual report on Form 20-F contains forward-looking statements within the meaning of the U.S. Private Securities Litigation Reform Act of 1995. Forward-looking statements convey our current expectations or forecasts of future events. These statements involve known and unknown risks, uncertainties and other factors, including those listed under “Item 3. Key Information—D. Risk Factors,” which may cause our actual results, performance or achievements to differ materially from the forward-looking statements that we make.


Forward-looking statements typically are identified by words or phrases such as “may,” “will,” “expect,” “anticipate,” “aim,” “estimate,” “intend,” “project,” “plan,” “believe,” “potential,” “continue,” “is/are likely to,” or other similar expressions. Any or all of our forward- looking statements in this annual report on Form 20-F may turn out to be inaccurate. Our actual results could differ materially from those contained in forward-looking statements due to a number of factors, including:


●political, economic and social risk inherent to conducting business in Peru;


●exchange rates, inflation rates and interest rates;


●the entry of new competitors into the market we serve;


●construction activity levels, particularly in the northern region of Peru;


●private investment and public spending in construction projects;


●natural disasters, such as floods and earthquakes affecting the northern region of Peru, and global events, such as public health crises and epidemics/pandemics and the worldwide effects thereof and responses thereto;


●availability and prices of energy, admixtures and raw materials;


●changes in the regulatory framework, including tax, environmental and other laws;


●the effects of climate change


●the successful expansion of our production capacity;


●our ability to compete with potential substitutes of cement products that may be introduced in the Peruvian construction industry;


●our ability to maintain and expand our distribution network;


●international conflicts, such as the current one between Russia and Ukraine, the one in Gaza and in Iran, among others, and the worldwide effects and responses thereto;


●changes in international trade tariffs, such as those between the United States and China, and the rest of the world, and the worldwide effects and responses thereto;


●increased cybersecurity threats;


●our ability to retain and attract skilled employees; and


●other factors discussed under “Item 3. Key Information—D. Risk Factors.”


The forward-looking statements in this annual report on Form 20-F represent our expectations and forecasts as of the date of this annual report on Form 20-F. Except as required by law, we undertake no obligation to update or revise publicly any forward-looking statements, whether as a result of new information, future events or otherwise, after the date of this annual report on Form 20-F.


iv


Part I


Item 1. IDENTITY OF DIRECTORS, SENIOR MANAGEMENT AND ADVISERS


A.Directors and senior management


Not applicable.


B.Advisers


Not applicable.


C.Auditors


Not applicable.


Item 2. OFFER STATISTICS AND EXPECTED TIMETABLE


A.Offer statistics


Not applicable.


B.Method and expected timetable


Not applicable.


Item 3. KEY INFORMATION


A.[Reserved]


B.Capitalization and Indebtedness


Not applicable.


C.Reasons for the Offer and Use of Proceeds


Not applicable.


D.Risk Factors


Summary of Risk Factors


An investment in our common shares and ADSs is subject to a number of risks, including risks relating to global macroeconomic conditions, to Peru, to our Business and Industry and risks relating to our common shares and ADSs. The following list summarizes some, but not all, of these risks. Please read the information in the section entitled “Detailed Risk Factors” for a more thorough description of these and other risks.


Risk Relating to Global Macroeconomic Conditions


●Global macroeconomic conditions may have an adverse effect on economic conditions in Peru and, therefore, on our business, financial condition and results of operations.


●International conflicts, such as the current war between Russia and Ukraine, and the war between Israel and Hamas, or the United States, Israel and Iran, as well as other geopolitical tensions or conflicts have put upward pressure on international prices, increasing inflation, and therefore could adversely affect our business, financial condition, and results of operations.


●Increases in global freight costs could adversely affect international prices, which, in turn, may increase inflation and therefore adversely affect our business, financial condition and results of operations.


1


Risks Relating to Peru


●Political, social and economic developments in Peru including political instability, rates of inflation and unemployment could have a material adverse effect on our business, financial condition and results of operations.


●A depreciation or devaluation of the Sol could have a material adverse effect on our business, financial condition and results of operations.


●The implementation of restrictive exchange rate policies and other similar laws by the Peruvian government could adversely affect our business, financial condition and results of operations.


●Increased rates of inflation in Peru could have an adverse effect on the Peruvian long-term credit market, as well as the Peruvian economy generally and, therefore, on our business, financial condition and results of operations.


Risks Relating to our Business and Industry


●We are subject to the possible entry of domestic or international competitors into our market, which could decrease our market share and profitability.


●Demand for our cement products is highly related to housing construction in northern Peru, which, in turn, is affected by economic conditions in the region.


●A reduction in private or public construction projects in the northern region of Peru would have a material adverse effect on our business, financial condition and results of operations.


●Our business, financial condition and results of operations may be adversely affected by increases in energy prices or shortages in the supply of energy, as well as third-party raw materials.


●A change of control of our company occurred in March of 2026, which could lead to shifts in our strategy, management, and corporate governance.


●Regulatory information requests regarding certain transaction-related expenses recorded in 2025 may result in litigation or administrative proceedings.


Risk Relating to our Common Shares and ADSs


●The market price of ADSs may fluctuate significantly, and you could lose all or part of your investment.


●Our controlling shareholder has significant influence over us and his interests could conflict with the interests of other shareholders.


●Holders of ADSs may be unable to exercise voting rights with respect to our common shares underlying the ADSs at our shareholders’ meetings.


●The ability of holders of ADSs to receive payments of cash dividends may be limited


2


Detailed Risk Factors


Risk Relating to Global Macroeconomics Conditions


Global macroeconomic conditions may have an adverse effect on economic conditions in Peru and, therefore, on our business, financial condition and results of operations.


Our operations and customers are located in Peru. As a result, our business, financial condition and results of operations, like those of most companies in Peru, may be adversely affected by the level of economic activity in the country. However, the Peruvian economy is significantly influenced by global macroeconomic trends, geopolitical stability, and international financial markets. Although we do not engage in direct export or import activities, we are not insulated from external shocks. For example, the United States, China and Europe are important recipients of Peru’s exports, and therefore a slowdown in one or more of these economies will affect Peru’s economic activity. Global volatility—such as fluctuations in the prices of commodities like copper and gold—directly impacts Peru’s fiscal revenue and trade balance, which can lead to reduced public infrastructure spending and a contraction in private investment. Furthermore, while we utilize domestic energy sources, our cost structure remains sensitive to global energy benchmarks; spikes in international oil or coal prices can drive up domestic logistics and manufacturing costs, such as a result of the ongoing conflicts in Iran. Additionally, restrictive global monetary policies or increased risk aversion in international markets can lead to higher domestic interest rates and currency depreciation of the Sol against the U.S. Dollar. Such conditions could increase our financing costs, limit the availability of credit for construction projects, and reduce the purchasing power of our “self-construction” customers, ultimately resulting in decreased demand for cement and related building materials.


In particular, the cement sector is closely related to the following main macroeconomic variables: (i) the expansion or contraction of the economy as measured by gross domestic product (“GDP”), (ii) domestic demand, (iii) private investment and (iv) public spending. In this regard, prolonged conditions, at the global level, that adversely affect one or more of these variables would negatively affect the cement sector, which may have an adverse effect on our business, financial condition and results of operations.


In 2025, the Peruvian economy demonstrated unexpected resilience despite continued global geopolitical friction, including the conflicts in Ukraine and the Middle East. Peru’s GDP grew by approximately 3.3% in 2025, exceeding initial projections due to record-high terms of trade—driven by historic copper and gold prices—and the commencement of major logistics projects such as the Port of Chancay. These global tailwinds allowed the Central Reserve Bank of Peru (BCRP) to maintain monetary stability, ending the year with inflation at approximately 1.5% and the reference interest rate at 4.25%.


However, the global outlook for 2026 remains clouded by rising trade protectionism and potential tariff escalations among our major trading partners, including the United States and China. Any global slowdown that depresses metal prices would likely result in a reduction in Peru’s tax revenues and a subsequent slowdown in the public works projects that drive our cement demand. Finally, while the acute phase of the COVID-19 pandemic has passed, the occurrence of future regional or global health crises, as well as extreme climate events such as El Niño, remains a latent risk that could cause sudden disruptions to our supply chains, labor availability, and the general pace of construction activity in Northern Peru.


International conflicts, such as the current war between Russia and Ukraine, and the war between Israel and Hamas, or the United States, Israel and Iran, as well as other geopolitical tensions or conflicts have put upward pressure on international prices, increasing inflation, and therefore could adversely affect our business, financial condition, and results of operations.


Military conflict between Russia and Ukraine and the ongoing war between Israel and Hamas or the United States, Israel and Iran, have created sustained economic uncertainty and volatility in global markets since they began in 2022. Throughout 2025 and into early 2026, these conflicts, alongside renewed regional instability in the Middle East involving Iran and the Persian Gulf, have continued to disrupt global supply chains and trade flows. Although the long-term impact of these events remains unpredictable, they have led to (i) credit and capital market disruptions, (ii) lower global growth projections, and (iii) persistent upward pressure on the international prices of energy and commodities.


3


While the dynamics of these conflicts have evolved, they continue to impact our cost structure. Russia remains a significant global producer of energy, and recent instability in Iran and in Iraq— critical contributors to global oil supply—has introduced new volatility into the energy markets. Iraq, one of the world’s largest oil exporters, was forced to declare force majeure on its southern oilfields in March 2026, resulting in a nearly 70% reduction in its national production. These events caused global oil benchmarks to surge to over $115 per barrel. Furthermore, the military conflict between Israel and Iran, including U.S. participation, has further heightened geopolitical tensions globally, and the resulting disruption to the Strait of Hormuz has contributed to significant volatility in global energy markets. Peru is a net importer of oil, and as such it has been affected by increased and volatile prices. Moreover, we use coal in our operations that, although mostly sourced locally, has a price that is correlated to the global price of energy. Under our current electricity contracts, prices for electricity are determined by formulas tied to market variables including the U.S. Producer Price Index (PPI), global oil prices, and the import price of bituminous coal. Consequently, geopolitical tensions that drive global energy prices upward directly increase our operational costs, potentially reducing our margins.


In 2025 and more recently, global economic stability has been threatened by escalating trade tensions, particularly between major economies. The imposition of new tariffs by the United States on countries like Canada, Mexico and China and on Europe and Asia sparked fears of a global trade war, leading to significant market volatility. The application of tariffs on Peruvian exports, such as agricultural products and fishmeal, could adversely affect the demand for these products and hence reduce the disposable income of Peruvian entities and persons engaged in producing these exports. Since our customers, mainly from the self-construction segment, are employed by companies in these sectors, a decrease in their income could adversely affect the demand for our products.


Additionally, energy security has continued to be a pressing issue, with conflicts and geopolitical maneuvers affecting global energy supplies and prices, including instability in international maritime shipping routes which may impact the cost of imported equipment and supplies.


The foregoing conflicts and any other geopolitical tensions may lead, among others, to increased protectionism or barriers to immigration, a general reduction of international trade in goods and services, or a reduction in the integration of financial markets. These tensions have affected both diplomatic and economic ties, and heightened tensions could reduce levels of trade, investments, technological exchanges, and other economic activities among major economies. Additionally, sanctions may create supply constraints and drive inflation. For our company, the inflationary pressures generated by these conflicts and/or protectionism could adversely affect our business, financial condition and results of operations.


Increases in global freight costs could adversely affect international prices, which, in turn, may increase inflation and therefore adversely affect our business, financial condition and results of operations.


Although global freight prices have decreased from the peak levels experienced in 2022, 2025 was marked by renewed volatility and significant spikes in shipping rates. Throughout the year, container and bulk freight costs remained well above pre-pandemic benchmarks, driven by a convergence of geopolitical and climate-related disruptions. Security threats in the Red Sea and Suez Canal continued to force the rerouting of vessels around the Cape of Good Hope, increasing transit times and fuel consumption. Furthermore, escalating tensions in the Middle East involving Iran and the Persian Gulf—specifically threats to the Strait of Hormuz—have led to increased insurance premiums and higher “bunker fuel” surcharges, which are passed on to shippers.


In 2025, freight markets also experienced a “front-loading” phenomenon, as global importers rushed to secure vessel space and equipment ahead of anticipated new tariffs and trade restrictions between major economies. This rush was in anticipation of new tariffs and trade restrictions expected to be implemented between key economies. This surge in demand created localized shortages of shipping capacity, particularly on routes originating from Asia, leading to temporary but sharp increases in freight rates. While we do not export our products, we rely on international markets for capital equipment, specialized spare parts, and certain industrial supplies. Global freight disruptions directly increase the landed cost of these essential inputs.


Additionally, climate-related risks—such as the continued volatility of water levels in the Panama Canal—remain a latent threat to the efficiency of maritime corridors serving the Pacific coast of South America. Any sustained increase in global logistics costs contributes to “imported inflation” in Peru, raising the cost of energy and raw materials domestically. These inflationary pressures can erode the purchasing power of our customers and increase our operational expenses, which may have a material adverse effect on our business, financial condition, and results of operations.


4


Risks Relating to Peru


Political, social and economic developments in Peru including political instability, rates of inflation and unemployment could have a material adverse effect on our business, financial condition and results of operations.


All of our operations and customers and the majority of our suppliers are located in Peru. Accordingly, our business, financial condition and results of operations depend on the level of economic activity in Peru. These could be affected by changes in economic and other policies of the Peruvian government, and by other economic and political developments in Peru, including devaluation or depreciation, currency exchange controls, inflation, economic downturns, political instability, corruption scandals, social disturbances and terrorism.


While historical terrorist activity remains largely confined to the Valle de los Ríos Apurímac, Ene y Mantaro (“VRAEM”) region, Peru has seen a significant and concerning escalation in organized crime and urban insecurity throughout 2025. In Northern Peru—our primary region of operation—there has been a marked increase in extortion and “cobro de cupos” (protection money rackets) specifically targeting the construction sector, including small-scale developers and individual home-builders. This climate of insecurity has, in some instances, led to the temporary suspension of construction projects and increased costs related to private security and insurance. Furthermore, illegal mining continues to expand in the Amazon and Andean regions, fueled by high gold prices. The infiltration of organized crime into these unregulated sectors has exacerbated regional violence and environmental degradation, deterring both domestic and foreign investment and potentially depressing regional economic growth.


Peru has experienced a period of significant political volatility marked by frequent changes in executive leadership and a highly fragmented Congress. Following the impeachment and arrest of former President Pedro Castillo in December 2022 after his failed attempt to dissolve Congress, Dina Boluarte assumed the presidency. While her administration oversaw a period of relative macroeconomic stability in 2025, it faced persistent low approval ratings and ongoing friction with a divided legislature. On October 10, 2025, Peru’s Congress voted to impeach and remove President Dina Boluarte for permanent moral incapacity following months of investigations and political confrontation. Pursuant to the constitutional line of succession, an interim successor, José Jerí, was sworn in pending the definition of an electoral timetable. However, on February 17, 2026, José Jerí was removed from office by Congress following preliminary investigations over allegations of illegal sponsorship of private interests and influence-peddling to the detriment of the state. In response, Congress elected José María Balcázar, as Peru’s new interim president.


As of the date of this annual report on Form 20-F, Peru is entering the 2026 General Election cycle. Historically, election periods in Peru are characterized by heightened uncertainty and a “wait-and-see” approach from private investors. The current political landscape remains highly fragmented, with dozens of registered parties and no clear consensus candidate. There is a risk that the upcoming elections could lead to the rise of a populist administration seeking to implement radical shifts in fiscal policy, increase taxation on the private sector, or attempt to modify the 1993 Constitution to expand the State’s role in the economy. Any such shifts toward less business-friendly policies could lead to capital flight, currency depreciation of the Sol against the U.S. Dollar, and a contraction in the private investment that drives demand for our products.


Despite a recovery in GDP growth to approximately 3.3% in 2025, Peru’s economy remains vulnerable to fluctuations in domestic demand and public spending. Inflation, while successfully anchored by the Central Reserve Bank (BCRP) at 1.5% by the end of 2025, could be pressured by future social unrest or global supply shocks. Because our “self-construction” customer base is highly sensitive to disposable income levels and access to credit, any spike in unemployment or interest rates could lead to a material decrease in cement volumes. We cannot provide assurance that future government policies to preempt or respond to social disturbances or economic downturns will not adversely affect the Peruvian economy and, consequently, our business and financial results.


5


A depreciation or devaluation of the Sol could have a material adverse effect on our business, financial condition and results of operations.


We are subject to foreign exchange risk because of a mismatch between the currency of our revenue and the currency of our costs. While substantially all of our revenues are denominated in Soles, as of December 31, 2025, approximately 18.3% of our costs were denominated in, or indexed to, the U.S. Dollar. This includes critical operational inputs such as imported spare parts, specialized machinery, and energy contracts that are adjusted based on U.S. Dollar-indexed formulas. Consequently, any significant depreciation or devaluation of the Sol against the U.S. Dollar would increase our operating expenses in Sol terms, potentially compressing our profit margins.


Historically, the sol/U.S. Dollar exchange rate has been sensitive to Peruvian political stability and global metal prices. As we enter the 2026 general election cycle, increased political uncertainty has historically led to capital flight and downward pressure on the Sol. If the Sol experiences a sharp devaluation due to electoral outcomes, a downgrade in Peru’s sovereign credit rating, or a shift in the Central Reserve Bank’s (BCRP) intervention policies, our financial condition and results of operations could be materially and adversely affected.


The implementation of restrictive exchange rate policies and other similar laws by the Peruvian government could adversely affect our business, financial condition and results of operations.


Since 1991, the Peruvian economy has operated under a market-oriented regime, with a focus on the dismantling of protectionist and interventionist policies. Currently, foreign exchange rates are determined by market supply and demand, with the Central Reserve Bank of Peru (BCRP) conducting regular open-market operations to mitigate excessive volatility in the Sol’s value against the U.S. Dollar. However, the stability of this framework is subject to political continuity.


As of the date of this annual report on Form 20-F, Peru is approaching General Elections, featuring a highly fragmented field of candidates with widely diverging economic platforms. Certain populist or nationalist factions have historically proposed moving away from the current free-market model toward more interventionist states, which could include the implementation of capital controls or restrictive exchange rate policies. We cannot assure you that the next administration or the Peruvian Congress will not institute such measures in the future.


Any such restrictive policy could have a material adverse effect on our business. While we do not currently have any outstanding indebtedness denominated in U.S. Dollars, we remain exposed to currency risk through our operational cost structure. As of December 31, 2025, approximately 18.3% of our production costs were denominated in, or indexed to, the U.S. Dollar, including some imported raw materials and certain energy-related contracts. Restrictive exchange policies could increase the difficulty of fulfilling these U.S. Dollar-denominated costs and limit our ability to secure essential supplies from international vendors.


Furthermore, such policies could require us to seek government authorization to make payments in U.S. Dollars. This would materially and adversely affect our ability to pay dividends in U.S. Dollars to holders of our American Depositary Shares (“ADSs”). It could also restrict our flexibility to access international capital markets for future financing needs should domestic liquidity be insufficient. A shift toward an interventionist regime could lead to a significant loss of investor confidence and a contraction in private investment, which partially drives the Peruvian construction sector, ultimately impacting our results of operations.


6


Increased rates of inflation in Peru could have an adverse effect on the Peruvian long-term credit market, as well as the Peruvian economy generally and, therefore, on our business, financial condition and results of operations.


In the past, Peru has suffered through periods of high and hyper-inflation, which has materially undermined the Peruvian economy and the government’s ability to create conditions that support economic growth. In response to increased inflation, the BCRP, which sets the Peruvian basic interest rate, may increase or decrease the basic interest rate in an attempt to control inflation or foster economic growth. Increases in the base interest rate could adversely affect our results of operations, increasing the cost of certain funding. Additionally, a return to a high-inflation environment would also undermine Peru’s foreign competitiveness, with negative effects on the level of economic activity and employment, while increasing our operating costs and adversely impacting our operating margins if we are unable to pass the increased costs on to our customers. Although inflation was 1.5% for 2025, below the previous five-year average of 4.3%, inflation rates in Peru may rise in the future as a result of supply shocks, including rises in prices of energy, increased freight costs, and/or an increase in domestic demand. See “—Increases in global freight costs could adversely affect international prices, which, in turn, may increase inflation and therefore adversely affect our business, financial condition and results of operations.”


Changes in tax laws or their interpretation may increase our tax burden and, as a result, negatively affect our business.


The Peruvian Congress and government regularly implement changes to tax laws that may increase our tax burden, or the tax burden of our subsidiaries. These changes may include modifications in our taxable base, tax rates and, on occasion, the enactment of temporary taxes that in some cases have become permanent taxes or changes to VAT (value added tax) exemptions applicable to certain of our operations in the Amazonian region. We are unable to estimate the outcomes that these changes may have on business. In that sense, the Peruvian government recently introduced several changes related to transfer pricing rules and formal obligations in order to comply with BEPS (base erosion and profit shifting) Guidelines on transactions performed between related parties or with the intervention of low or no-tax jurisdictions, such as the obligation to file new local-files, master-files and country-by-country reports with the Peruvian tax authority, and to adjust taxable bases accordingly for income tax purposes. Additionally, the government has implemented changes concerning thin capitalization requirements, which may limit the ability of companies to claim interest deductions for tax purposes where specified debt-to-equity thresholds are exceeded. The government has also adopted a general anti-avoidance rule, or GAAR, which grants the national tax and customs authority the power to recharacterize certain transactions on the basis of their economic substance rather than their legal form.


The effects of any tax reforms that could be proposed in the future and any other changes that result from the enactment of additional reforms have not been, and cannot be, quantified. However, any changes to our tax regime or interpretations thereof (including in connection with the tax rates, tax base (base imponible), deductions rules, payments in advance regime (regimen de pagos a cuenta), time of payment or the establishment of new taxes thereof) may result in increases in our overall costs and/or our overall compliance costs, which could negatively affect our results of operations.


Our operations could be adversely affected by an earthquake, flood or other natural disasters.


Severe weather conditions and other natural disasters in areas in which we operate may materially adversely affect our operations. Peru is affected by El Niño, an oceanic and atmospheric phenomenon that causes a warming of temperatures in the Pacific Ocean, resulting in heavy rains off the coast of Peru and various other effects in other parts of the world. The effects of El Niño, which typically occurs every two to seven years, which affected both 2023 and 2024, include flooding and the destruction of fish populations and agriculture, and, accordingly, have a negative impact on Peru’s economy. For example, in March 2023, Cyclone Yaku generated intense rainfall, which resulted in flooding and landslides, which severely damaged some areas in the north of Peru. Although our facilities were not significantly affected, our ability to ship cement was compromised by the destruction of infrastructure and flooding of roads. According to the April 2026 report from the National Oceanic and Atmospheric Administration (NOAA), there is a 61% probability of an El Niño transition emerging during the May–July 2026 period and persisting through the end of the year. Given the cyclical nature of these phenomena, we anticipate that El Niño and La Niña events will continue to affect the Peruvian climate periodically, and we cannot provide assurance that the potential onset of such conditions—particularly in the vulnerable northern region of Peru—will not have a material adverse effect on our operations, logistical infrastructure, or financial results.


7


Peru also is located in an area that experiences seismic activity and occasionally is affected by earthquakes. For example, in 2007, an earthquake with a magnitude of 7.9 on the Richter scale struck the central coast of Peru, severely damaging the region south of Lima. Although the North is not typically affected by earthquakes, we cannot assure you that such an event will not occur and if it does, it could adversely affect our business and results of operations.


Our operations could be adversely affected by government-mandated plant closures.


Public health crises, such as epidemics or pandemics, as well as other events deemed to be public emergencies, may result in the government requiring us to cease our operations. For example, in March 2020, the Peruvian government ordered a state of emergency due to the COVID-19 outbreak, and required us to close our operations for approximately two months in 2020. This closure had a materially adverse effect on our business, financial condition, and results of operations, in particular during the state of emergency. Although our business recovered well following the required period of closure, we cannot assure you that the government will not take similar measures in the future as a result of public health crises or other public emergencies that may have an impact on the Peruvian economy as a whole, the construction sector, our customers’ ability to purchase cement and cement-based products, and/or our customers’ ability to pay for products we have previously sold to them.


Our operations are subject to physical challenges related to climate change.


Climate change may have an adverse impact on the regions where our operations are located. Some of the risks of climate change include heavy precipitation or extremely high temperatures. Extreme precipitation, leading to flooding, may damage the roads and potentially reduce our productivity and increase our costs. Roads blocked as a consequence of floods could also affect our ability to both ship our finished products and receive raw materials, negatively affecting our business and results of operations.


In addition to these physical risks, the regulatory landscape surrounding climate and environmental, social and governance (“ESG”) matters continues to evolve. In recent years, various guidelines and regulations have been issued recommending or requiring companies to adopt policies and procedures aimed at enhancing the approach to ESG-related matters, including climate-related disclosures. Although certain regulatory initiatives, such as the SEC’s climate disclosure rules proposed in 2024, have not ultimately been adopted, we cannot rule out future attempts to enact rules requiring climate-related disclosures or other ESG-related obligations. The adoption of new guidelines and regulations on ESG matters could limit our business or the businesses of our subsidiaries, restrict our ability or the ability of our subsidiaries to recruit new customers, increase compliance requirements or result in higher operating or funding costs, among other effects that we cannot predict at this time given the still-developing nature of the regulatory environment related to ESG matters.


The Peruvian economy could be adversely affected by economic developments in regional or global markets.


Although economic conditions vary from country to country, investors’ perceptions of the events occurring in one country may adversely affect cash flows and securities from issuers in other countries, including Peru. Peru’s economy is highly susceptible to fluctuations in regional and global markets due to its significant dependence on commodity exports, particularly minerals. A decline in global demand or disruptions in international trade could lead to reduced export revenues and, in turn, government income. Additionally, tighter financial conditions or geopolitical instability can trigger capital outflows, currency depreciation, and inflationary pressures, affecting private and public investment and exacerbating social inequality in the country. Adverse developments in regional or global markets or a perceived increase in risks associated with investing in emerging markets could adversely affect the Peruvian economy and, consequently, our business, financial condition and results of operations.


8


An additional source of risk relates to the economic and trade policies that may be adopted by the current U.S. administration. The implementation of import tariffs or other trade restrictions, retaliatory measures by the Peruvian government, or unsuccessful trade negotiations between the two countries could result in heightened trade barriers, sanctions, and increased costs. While the impact of such measures has been limited to date, we cannot provide assurance that these policies will not adversely affect the Peruvian economy or certain of our customers, which could in turn have a negative impact on our business, financial condition and results of operations.


A decline in the prices of certain commodities in the international markets could have a material adverse effect on our financial condition and results of operations.


In 2025, traditional exports, in particular mineral products, fishing products, agricultural products and petroleum and its derivatives, represented 74.3% of Peru’s total exports, according to the figures published by the BCRP. Changes in commodity prices in the international markets may have an adverse impact on Peruvian government finances, which could affect both investor confidence and the sustainability of government expenditure and social programs. Thus, a decline in commodity prices could, ultimately, affect the political environment in Peru, especially as regional and local governments are particularly reliant on tax revenue from mining operations. Lower commodity prices could also affect the retail sector, leading to, for example, a decline in purchasing power and consumer spending.


Corruption and ongoing high-profile corruption investigations may hinder the growth of the Peruvian economy and have a negative impact on our business and operations.


Starting in 2017, Peru has gone through a series of government institutional crises due to, among other things, several corruption scandals involving prominent political figures, mainly past Presidents, and some large construction companies. Some of these corruption scandals resulted in impeachment or resignations, such as that of former President Pedro Pablo Kuczynski in 2018 and former President Martín Vizcarra in 2020, and more recently former President Pedro Castillo in 2022.


In addition, several corruption scandals regarding authorities at municipal, regional and national government levels are also ongoing, and former and current government officials have been detained. President Boluarte is currently under investigation for alleged illegal campaign contributions in 2021 and for appointing political allies to public positions, including her brother Nicanor who was recently arrested. We cannot predict how these or future corruption scandals or investigations may affect the Peruvian economy, hinder the growth of the Peruvian economy and indirectly have a material adverse effect on our business, financial condition and results of operations.


Although recent history indicates that the macroeconomic stability of the country may remain unaffected by political turmoil, we cannot provide any assurance that political turmoil will not in the future have a material effect on the political or economic stability of the country, and therefore, could have a material adverse effect on our business, financial condition and results of operations.


The surge in extortion-related crime may undermine public security and stability in Peru, posing operational risks and potential disruptions to our business and results of operations.


In 2025, extortion continued to pose a major public security challenge in Peru, with 26,585 reported cases nationwide, up from 22,361 in 2024, according to SIDPOL data published by Peru’s Ministry of Interior. Organized crime groups targeted a wide array of sectors, including transport, retail, and education, often employing violent tactics to enforce their demands. Despite government measures like declaring states of emergency and deploying military forces, the persistence of these crimes underscores the challenges the country faces in restoring public security and trust. Our customers, which are small business owners, are currently suffering from these extortions, therefore affecting their ability to purchase cement, due to decreased disposable income.


9


Risks Relating to our Business and Industry


We are subject to the possible entry of domestic or international competitors into our market, which could decrease our market share and profitability.


The cement market in Peru is competitive and is currently served mainly by three main groups, which together supply most of the cement consumed in the country, although there are smaller producers and some imports. In August 2024, Holcim Ltd, a Swiss-based company, entered the Peruvian construction market with the acquisition of two Peruvian companies (Compañía Minera Agregados Calcareos S.A. (Comacsa), an aggregates and white cement producer, and Mixercon S.A., one of the former cement grinding facilities with concrete located in the Lima area). At the beginning of 2025, it also purchased Compañía Minera Luren, specialized in the marketing of quicklime and silico-lime bricks. Also, on March 30, 2026, as reported to us by our shareholder Inversiones ASPI S.A., Holcim has acquired 99.99% of the shares representing the capital stock of Inversiones ASPI S.A., which in turn is the holder of 50.01% of the capital stock of Cementos Pacasmayo S.A.A. For further information, see “―A change of control of our company occurred in March 2026, which could lead to shifts in our strategy, management, and corporate governance” and “Item 4. Information on the Company—A. History and Development of the Company—Recent Developments.” In the cement industry, the location of a production plant tends to limit the market a plant can serve because transportation costs are high, reducing profit margins. Historically, we have supplied the northern region of Peru while two other groups have supplied the central (which includes the Lima metropolitan area) and southern regions of Peru, driven principally by the location of production facilities and distribution focus. However, competition could intensify if other manufacturers decide to enter our market.


We may face increased competition if the other Peruvian cement manufacturers, despite incremental freight costs, expand their distribution of cement to the northern region of Peru, or if they develop a cement plant in the north, particularly if the cement markets in Lima or other areas of Peru become saturated. For example, Caliza Inca is looking to install a grinding facility in the North of Peru. In the past, some foreign cement manufacturers have announced plans to build cement plants in the central region of the country. If competition intensifies in the central region of Peru as a result of the construction of any such plants or otherwise, it may have price repercussions in our market.


We also face the possibility of competition from the entry into our market of imported clinker for grinding facilities, cement or other materials or products. We could also face competition from foreign manufacturers, which may have significantly greater financial resources than us, particularly as production capacity continues to exceed depressed demand in other parts of the world and transportation costs decrease.


We may not be able to maintain our market share if we cannot match our competitors’ prices or keep pace with the development of new products. If any of these events were to occur, our business, financial condition and results of operations could be adversely affected.


Demand for our cement products is highly related to housing construction in northern Peru, which, in turn, is affected by economic conditions in the region.


Cement consumption is highly related to construction levels. Demand for our cement products depends, in large part, on residential construction in the north of Peru, which consists mostly of low-income families gradually building or improving their own homes without technical assistance, which we refer to as self-construction (auto-construcción). We estimate that in 2025, self-construction (auto-construcción) accounted for approximately 73.9% of our cement sales. Residential construction, in turn, is highly correlated to prevailing economic conditions in Peru. A decline in economic conditions would reduce household disposable income and cause a significant reduction in residential construction, leading to a decrease in demand for cement. As a result, a deterioration of economic conditions in the northern region of Peru would have a material adverse effect on our financial performance and results of operations. We cannot assure you that growth in Peru’s GDP, or the contribution to GDP growth attributable to the northern region of the country, will continue at the recent pace or at all, as the economy continues to be affected by external factors such as inflationary pressure, and political uncertainty continues.


A reduction in private or public construction projects in the northern region of Peru would have a material adverse effect on our business, financial condition and results of operations.


We estimate that in 2025, approximately 14.0% of our cement sales were derived from private construction (other than self-construction (auto-construcción)) and 12.1% from public construction in the north of Peru. Significant interruptions or delays in, or the termination of, private or public construction projects may adversely affect our business, financial condition and results of operations. Private and public construction levels in our market depend on investments in the region which, in turn, are affected by economic conditions.


10


While the “Reconstruction with Changes” (ARCC) program and its associated UK Government-to-Government (G2G) agreement expired in late 2023, the Peruvian government has transitioned these responsibilities to the National Infrastructure Authority (Autoridad Nacional de Infraestructura or “ANIN”). ANIN was created to centralize and expedite major projects, and in early 2026, it unveiled a pipeline of strategic investments in health, education, and water management for the northern region. However, the transition to this new governance structure involves inherent risks of administrative delays and shifting budget priorities.


Public spending in 2026 may be affected by the general election cycle in Peru. Historical trends suggest that infrastructure spending and private investment can fluctuate significantly during election years due to political uncertainty and potential shifts in cabinet-level leadership. A sustained reduction in public or private infrastructure spending in the northern region of Peru would have a material adverse effect on our business, financial condition, and results of operations.


Our business, financial condition and results of operations may be adversely affected by increases in energy prices or shortages in the supply of energy, as well as third-party raw materials.


Electricity and coal account for a significant percentage of our production costs. In 2025, the cost of electricity represented approximately 13.8% of our cement production costs, while coal represented approximately 17.1%. Our cost structure is highly sensitive to geopolitical tensions and international conflicts, which can significantly increase our operational expenses and disrupt our supply chain.


The ongoing war between Russia and Ukraine and the conflict in the Middle East have created sustained volatility in global energy markets. More recently, in early 2026, a major military escalation led to the effective closure of the Strait of Hormuz, triggering a severe global oil supply disruption. Although we source our anthracite coal from domestic suppliers, the price of coal is largely driven by global energy benchmarks and is highly correlated with the price of oil. Consequently, any spike in international oil prices directly increases our coal procurement costs and adversely affects our results of operations. We do not have long-term coal supply agreements, nor do we engage in hedging transactions for coal prices, leaving us fully exposed to these market fluctuations. See “—Increases in global freight costs could adversely affect international prices, which, in turn, may increase inflation and therefore adversely affect our business, financial condition and results of operations” and “—International conflicts, such as the current war between Russia and Ukraine, and the war between Israel and Hamas or the United States, Israel and Iran, as well as other geopolitical tensions or conflicts have put upward pressure on international prices, increasing inflation, and therefore could adversely affect our business, financial condition, and results of operations.”


Furthermore, we are subject to electricity price volatility. We have a long-term electricity supply agreement with Electroperú S.A. to serve our Pacasmayo and Piura facilities through May 2026, after which Orygen Perú S.A.A. will supply electricity to those facilities from June 2026 through May 2031, and an agreement with Electro Oriente S.A. (ELOR) for our Rioja facility through December 2029. Our electricity costs are subject to adjustment formulas that take into consideration market variables such as the U.S. Producer Price Index (PPI) and global energy prices. As approximately 18.3% of our total costs are denominated in or indexed to the U.S. Dollar, the combination of high global energy prices and a potential depreciation of the Sol could result in a “double impact” on our margins.


Our operations also depend on the stability of the Peruvian Electricity Interconnection System (SEIN). Any interruptions or failures in the SEIN, or localized disruptions such as the seven-week outage at our Rioja facility in 2023, can halt production and force us to incur significantly higher logistics costs to supply our customers from alternative plants. We have no back-up power systems at our facilities, and we cannot assure you that we would be able to access alternative energy sources at comparable prices during a shortage or rationing event. If we are unable to pass these increased energy and logistics costs on to our customers through higher cement prices, our business, financial condition, and results of operations will be materially and adversely affected.


Changes in the cost or availability of admixtures and raw materials supplied by third parties may adversely affect our business, financial condition and results of operations.


We use certain admixtures and raw materials in the production of cement, such as gypsum, blast furnace slag and iron that we obtain from third parties. In 2025, our cost of admixtures and raw materials supplied by third parties as a percentage of our cement production costs was approximately 2.7%. Moreover, although we expanded our clinker capacity in 2023, we continue to use a small amount of imported clinker from existing inventories, representing 2.6% of our cement production costs in 2025. We do not have long-term contracts for the supply of admixtures or raw materials that we use and if existing suppliers cease operations or reduce or eliminate production of these products, our costs to procure these materials may increase significantly or we may be obligated to procure alternatives to replace these products.


11


We may undertake future acquisitions that may not achieve expected benefits.


Our strategic initiatives include pursuing acquisitions that tend to diversify our existing portfolio of products and services and expand our geographic footprint. In the future, we may decide to expand by acquiring other companies in Peru or abroad. Any future acquisitions will depend on our ability to identify suitable candidates, negotiate acceptable terms, and obtain financing for the acquisitions. If future acquisitions are significant, they could change the scale of our business and expose us to new geographic, political, operating and financial risks. In addition, each acquisition involves a number of risks, such as the diversion of our management’s attention from our existing business to integrating the operations and personnel of the acquired business, possible adverse effects on our results of operations during the integration process, our inability to achieve the intended objectives of the combination and potential unknown liabilities associated with the acquired assets.


We may not be able to obtain the funding required to implement future strategies.


Our strategies to continue to expand our cement production capacity and distribution network require significant capital expenditures. We cannot assure you that we will generate sufficient cash flow from operations, or that we will have access to external financing sources, to adequately fund such capital expenditures. Our access to external sources of financing will depend on many factors, including factors beyond our control, such as conditions in the global capital markets and investors’ risk perception of investing in Peru and in emerging markets generally. Any equity or debt financing, if available, may not be on terms that are favorable to us. If our access to external financing is limited, we may not be able to execute our strategy, which could adversely affect our business, financial condition and results of operations.


In addition, the “club deal” loan we entered into in 2021, contain covenants that limit our ability and that of our restricted subsidiaries to incur additional indebtedness if we do not meet certain financial ratios. If we are unable to incur additional debt to fund our future strategies, our business could be adversely affected.


We are subject to risks related to litigation and administrative proceedings that could adversely affect our business and financial performance in the event of an unfavorable ruling.


The nature of our business exposes us to litigation relating to product liability claims, labor, health and safety matters, environmental matters, regulatory, tax and administrative proceedings, governmental investigations, tort claims and contract disputes, among other matters. In the past, we have been subject to antitrust and tax proceedings or investigations. While we contest these matters vigorously and make insurance claims when appropriate, litigation is inherently costly and unpredictable, making it difficult to accurately estimate the outcome of actual or potential litigation. Although we establish provisions as we deem necessary, the amounts that we reserve could vary significantly from any amounts we actually pay due to the inherent uncertainties in the estimation process. We cannot assure you that these or other legal proceedings will not materially affect our ability to conduct our business, financial condition and results of operations in the event of an unfavorable ruling.


Our business is subject to a number of operational risks, which may adversely affect our business, financial condition and results of operations.


Our business is subject to several industry-specific operational risks, including accidents, natural disasters, labor disputes and equipment failures. Such occurrences could result in damage to our production facilities and equipment, and/or the injury or death of our employees and others involved in our production process. Moreover, such accidents or failures could lead to environmental damage, loss of resources or intermediate goods, delays or the interruption of production activities and monetary losses, as well as damage to our reputation. Our insurance may not be sufficient to cover losses from these events, which could adversely affect our business, financial condition and results of operations.


12


In addition, key equipment at our facilities, such as our mills and kilns, may deteriorate sooner than we currently estimate. Such deterioration of our assets may result in additional maintenance or capital expenditures and could cause delays or the interruption of our production activities. If these assets do not generate the cash flows we expect, and we are not able to procure replacement assets in an economically feasible manner, our business, financial condition and results of operations may be materially and adversely affected.


Our business depends on the continued operation of our Pacasmayo and Piura facilities.


Our production facilities in Pacasmayo and Piura are essential to our business. In 2025, approximately 88.9% of our total cement and all of our quicklime was produced at our Pacasmayo and Piura facilities. These plants are subject to normal hazards of operating any cement production facility, including accidents, natural disasters and unexpected malfunctioning of the equipment. Any interruption in the operation of our Pacasmayo or Piura facilities or a decrease in the effective capacity of these facilities would adversely affect our results of operations.


The introduction of cement substitutes into the market and the development of new construction techniques could have a material adverse effect on our business, financial condition and results of operations.


Materials such as plastic, aluminum, ceramics, glass, wood and steel can be used in construction as a substitute for cement. In addition, other construction techniques, such as the use of drywall, could decrease the demand for cement and concrete. In Peru, drywall has only been introduced into the housing construction market in recent years and it is not widely used. However, the use of drywall for housing construction could increase significantly in the future as it becomes more popular. In addition, research aimed at developing new construction techniques and modern materials may introduce new products in the future. The use of substitutes for cement could cause a significant reduction in the demand and prices for our cement products.


Our success depends on key members of our management and board of directors


Our success depends largely on the efforts and strategic vision of our executive management team and our board of directors. The loss of the services of some or all of our executive management team or members of our board of directors could have a material adverse effect on our business, financial condition and results of operations.


The execution of our business plan also depends on our ongoing ability to attract and retain additional qualified employees capable of operating our plants. Due to the limited pool of skilled workers in the north of Peru or workers from other regions willing to relocate to the north of Peru, we may not be successful in attracting and retaining the personnel we require. If we are unable to hire, train and retain qualified employees at a reasonable cost, we may be unable to successfully operate our business or reach full planned production levels in a timely manner and, as a result, our business, financial condition and results of operations could be adversely affected.


Our operations and sales are highly concentrated in the northern region of Peru.


All of our operations are located in the northern region of Peru, including our production facilities and the quarries from where we obtain limestone to produce cement. In addition, substantially all our cement products are sold to consumers in this market. As a result, any adverse economic, political, or social conditions affecting the northern region of Peru, as well as natural disasters and weather conditions, such as the El Niño climate pattern, among other factors that may affect this region, could have a material adverse effect on our business, financial condition and results of operations. For example, in March 2023, Cyclone Yaku generated intense rainfall, which resulted in flooding and mudslides, which severely damaged some areas in the north of Peru, particularly the city of Pacasmayo, where we operate. Although there was no severe physical damage to our properties, we were affected by temporary road interruptions, inadequate workforce turnout, temporary disruptions in the supply of products, and delays in the delivery of our products.


We are subject to increasingly stringent environmental, health, and safety regulations and may be exposed to significant liability, compliance costs, and reputational risks.


Our operations are subject to extensive Peruvian environmental, health, and safety (“EHS”) laws and regulations. These govern, among other things, the generation, storage, and handling of hazardous materials; air emissions (including greenhouse gases); wastewater discharges; and the protection of biodiversity and the health of our employees.


13


As a cement producer, our manufacturing process is inherently carbon-intensive. We are subject to regulations regarding maximum permissible limits (LMPs) for air emissions and environmental quality standards (ECAs). In recent years, there has been a global and domestic trend toward stricter regulation of greenhouse gas (“GHG”) emissions to combat climate change. While Peru has not yet implemented a formal carbon tax, any future domestic or international regulations—such as carbon pricing or stricter emission caps—could require us to make significant capital expenditures to upgrade our kilns or transition to alternative fuels. We cannot assure you that our current efforts to reduce our carbon footprint will be sufficient to meet future regulatory requirements, which could lead to substantial fines or the suspension of our operating permits.


Also our facilities in Pacasmayo, Piura, and Rioja rely on consistent access to water. Northern Peru is a region characterized by water scarcity and is highly susceptible to the “El Niño” phenomenon, which can cause both severe droughts and catastrophic flooding. Stricter water-use regulations or increased competition for water resources from the agricultural and mining sectors could limit our production capacity or increase our costs. Furthermore, any accidental discharge of wastewater or hazardous substances into natural water sources could result in severe legal penalties and the loss of our “social license” to operate in these communities.


We are also subject to certain mining closure risks, as our operations include the extraction of raw materials (limestone, clays, etc.), which subjects us to the oversight of the Ministry of Energy and Mines (MINEM). We are required to maintain and periodically update mining closure plans and provide financial guarantees to ensure the remediation of our quarry sites. If the estimated costs of these closure obligations increase due to stricter environmental standards, our financial condition could be adversely affected.


Lastly, pursuant to Peruvian law, we can be held strictly liable for environmental damages caused by our operations, regardless of fault. This includes potential liabilities arising from the actions of our predecessors or at third-party disposal sites. We are also required to maintain a health and safety committee and develop rigorous internal codes to protect our workforce. Any failure to comply with these EHS standards could result in criminal sanctions, substantial civil liability, and significant damage to our reputation, which may deter investment and adversely affect our business, financial condition, and results of operations.


Social disturbances, protests, and conflicts with local communities or criminal organizations may have a material adverse effect on our business and results of operations.


Our business, financial condition and results of operations depend on the level of social stability in Peru. Mining and hydrocarbons remain fundamental pillars of the Peruvian economy, accounting for approximately 11.2% of the country’s GDP in 2025, according to the Central Reserve Bank of Peru (BCRP). However, industrial and extractive operations frequently face opposition from local communities and interest groups who may perceive these activities as harmful to the environment or traditional agricultural livelihoods.


Historically, Peru has experienced prolonged social conflicts that have paralyzed major projects. For example, the Las Bambas copper mine has faced repeated road blockades and operational halts due to community demands, a situation that remained volatile throughout 2025. While we have historically maintained constructive relationships with the communities surrounding our quarries and facilities, we cannot assure you that this stability will continue. As Peru enters the 2026 General Election cycle, we anticipate an increase in social demands and the potential for politically motivated strikes or demonstrations that could disrupt our logistics and distribution channels.


More recently, the nature of social conflict in Peru has evolved to include significant interference from organized crime and illegal mining networks. In 2024 and 2025, Compañía Minera Poderosa, a major gold producer in Northern Peru suffered a series of violent attacks. The prevalence of such criminal activity in Northern Peru, including widespread extortion and “cobro de cupos” in the construction sector, creates an environment of high insecurity. These conflicts can lead to (i) the forced suspension of our quarrying activities, (ii) blockades of the Northern Pan-American Highway and other critical transit routes, (iii) increased expenditures for private security and infrastructure protection, and (iv) a general deterrent to the private construction investment that drives demand for our products. Any escalation of violence or social unrest, particularly if the government is unable to restore order in regional hotspots, could have a material adverse effect on our business, financial condition, and results of operations.


14


Compliance with international climate change agreements and the transition to a low-carbon economy may result in significant capital expenditures and increased operational costs.


We are subject to increasing global and domestic pressure to align our operations with international climate goals. Peru is a signatory to the Paris Agreement and, in November 2025, submitted its Third Nationally Determined Contribution (NDC), which commits the country to achieving carbon neutrality by 2050. These international commitments are increasingly being translated into domestic regulations, including the “National Strategy on Climate Change to 2050” and the expansion of the “Peru Carbon Footprint” platform. The implementation of these agreements may lead to the introduction of mandatory carbon pricing, carbon taxes, or emission cap-and-trade systems in Peru. While such mechanisms are not yet fully operational for our sector, any future requirement to purchase carbon credits or licenses for our atmospheric emissions would directly increase our production costs.


Furthermore, to maintain our “social license” and remain competitive in international financial markets, we may be required to accelerate capital expenditures for “green” technology, such as the transition to alternative fuels (co-processing) or the installation of carbon capture systems. We are also exposed to “transition risks” driven by shifts in investor preferences and potential “Carbon Border Adjustment Mechanisms” (CBAM) in major economies. If Peru’s climate regulations do not keep pace with international standards, our access to global capital markets could be restricted, or our costs of financing could increase. We cannot assure you that our current decarbonization initiatives will be sufficient to comply with future, more stringent international climate protocols. Any failure to adapt to these evolving standards could have a material adverse effect on our business, financial condition, and results of operations.


Changes in regulations or in the interpretation of existing regulations by Peruvian authorities may adversely affect our business, financial condition and results of operations.


Our operations are governed by an extensive and complex regulatory framework in Peru, encompassing tax, environmental, labor, antitrust, antibribery, health and safety, and mining matters. While we believe our facilities and concessions are currently operating in material compliance with all applicable laws, the Peruvian regulatory environment is characterized by frequent changes and, at times, inconsistent interpretations by administrative agencies.


In particular, we are subject to the oversight of various regulatory bodies, including the National Superintendency of Tax Administration (Superintendencia Nacional de Administración Tributaria – SUNAT), the Agency for Environmental Assessment and Enforcement (Organismo de Evaluación y Fiscalización Ambiental – OEFA), and the National Institute for the Defense of Free Competition and the Protection of Intellectual Property (Instituto Nacional de Defensa de la Competencia y de la Protección de la Propiedad Intelectual, – INDECOPI). These authorities have broad discretionary powers to audit our operations and interpret regulations. For example, any shift in SUNAT’s interpretation of tax stability treaties or deductible expenses could result in significant tax contingencies, fines, and interest. Similarly, as the dominant cement producer in Northern Peru, we are subject to close scrutiny by INDECOPI regarding competition laws; any change in the interpretation of “market dominance” or the implementation of stricter anti-monopoly regulations could limit our pricing flexibility or growth strategies.


Furthermore, our mining activities are subject to royalties and specialized canons. As Peru enters the 2026 General Election cycle, there is an increased risk that the Peruvian Congress may introduce populist legislative proposals to increase mining royalties, modify labor benefits (via the National Superintendency of Labor Inspection (Superintendencia Nacional de Fiscalización Laboral) – SUNAFIL), or alter the terms of our existing concessions. We cannot assure you that future regulatory changes, or a more aggressive enforcement stance by the government, will not require us to make unplanned capital expenditures, alter our production processes, or incur significantly higher compliance costs, any of which could have a material adverse effect on our business, financial condition and results of operations.


Any dispute with the labor unions that represent our employees could have an adverse effect on our business, financial condition and results of operations.


As of December 31, 2025, approximately 17.9% of our employees were members of employee unions. Although we consider our relations with our employees are currently positive, we cannot assure you that we will not experience work slowdowns, work stoppages, strikes or other labor disputes in the future, which could adversely affect our business, financial condition and results of operations.


15


New projects may require the prior approval of local indigenous communities.


On September 7, 2011, Peru enacted Law No. 29785, regarding the Prior Consultation Right of Local Indigenous Communities, in accordance with the International Labor Organization (ILO) Convention No. 169. This law establishes a mandatory prior consultation procedure (procedimiento de consulta previa) that the Peruvian government must carry out with local indigenous communities whose collective rights may be directly affected by legislative or administrative measures, including the granting of new mining or industrial concessions. While Law No. 29785 does not grant a formal “veto right” to these communities—leaving the final decision to the discretion of the Peruvian government—recent judicial and regulatory shifts have increased the burden of compliance. In January 2024, a landmark ruling by the Constitutional Bench of the High Court in Lima reinforced that the right to prior consultation applies not only to administrative acts but also to all legislative measures affecting indigenous rights.


Furthermore, in November 2025, the Peruvian government completed the prior consultation stage for the new “National Policy on Indigenous Peoples to 2040” (PNPI 2040), reaching over 120 agreements with national indigenous organizations. Once fully implemented, this policy is expected to introduce stricter oversight mechanisms for monitoring the fulfillment of consultation agreements and expand the technical requirements for promoting entities. Additionally, the 2025 National Census has faced significant protests from indigenous organizations, who allege that the methodology used by the National Institute of Statistics and Informatics (INEI) may lead to an undercounting of indigenous populations. Any such undercounting or exclusion could result in legal challenges to the identification of “affected peoples” in our future project areas.


Furthermore, the expiration of the National Action Plan on Business and Human Rights (2021-2025) in December 2025 has created a period of regulatory uncertainty regarding the future standards for corporate “due diligence” in indigenous territories. To the extent that our new projects or expansions in Northern Peru require legislative or administrative measures that impact local indigenous communities, we may face significant delays or be unable to undertake such projects unless the government first conducts a successful consultation procedure. We cannot assure you that evolving interpretations of this law, or the enactment of the PNPI 2040, will not increase our operational costs or lead to social conflicts that adversely affect our business, financial condition, and results of operations.


The instruments pursuant to which our principal indebtedness was issued contain financial and other covenants, and any default under any of these instruments may have a material adverse effect on our financial condition and cash flows.


In January 2019, we issued an aggregate of S/570 million in debt securities in two issuances under our local bond program: one in the aggregate principal amount of S/260 million bearing interest a rate of 6.68750% with a term of 10 years, and another in the aggregate principal amount of S/310 million bearing interest at a rate of 6.84375% with a term of 15 years. Failure to comply with the covenants under the agreements governing our local bonds could result in an event of default under the indenture. Furthermore, in 2021, we entered into a “club deal” loan in the amount of S/860 million, which contains restrictive covenants, as well as financial covenants requiring us to meet certain financial ratios tests. Failure to meet or satisfy any of these covenants could result in an event of default under our “club deal” loan.


Failures in our information technology systems and information security (cybersecurity) systems can adversely impact our operations and reputation.


Our business is increasingly dependent on sophisticated information technology and automated industrial control systems (Operational Technology or “OT”) to manage our administrative processes, manufacturing plants, supply chain, and commercial operations. The proper functioning of these systems is critical to our ability to produce cement, manage logistics across Northern Peru, and process payments.


As cybersecurity threats have become more frequent and sophisticated, including the rise of AI-driven phishing, ransomware-as-a-service, and advanced persistent threats (APTs)—our vulnerability to system disruptions may have increased. Unlike traditional IT risks, a breach of our OT systems could result in the physical shutdown of our kilns in Pacasmayo, Piura, or Rioja, potentially leading to equipment damage, safety hazards for our personnel, and prolonged production stoppages. In 2025, the global industrial sector saw a marked increase in supply-chain attacks targeting third-party software providers, which could indirectly compromise our internal networks.


16


To address these inherent risks, we have implemented cybersecurity tools, backup solutions, and recovery procedures based on the NIST Cybersecurity Framework 2.0 and ISO/IEC 27001:2022 standards. In addition, we maintain disaster recovery plans and conduct regular vulnerability assessments. However, the rapid evolution of cyber threats means these measures may not be sufficient to prevent all unauthorized access or system failures. Furthermore, any significant theft of personal data—particularly regarding our “self-construction” customers or employees—could violate the Peruvian Personal Data Protection Law (Law No. 29733), leading to severe regulatory fines, legal liabilities, and a loss of trust among our stakeholders. Therefore, we make every effort to continuously enhance the cybersecurity controls that safeguard our information assets.


As of December 31, 2025, we do not maintain specialized insurance coverage for cybersecurity risks, but we do have a dedicated digital forensics and incident response (DFIR Retainer) service. Consequently, any financial losses arising from a cyberattack—including ransom payments, system restoration costs, legal fees, or lost revenue during a shutdown—would be borne entirely by the Company. We cannot assure you that a major cyber incident will not have a material adverse effect on our business, financial condition, and results of operations, but we undertake initiatives to mitigate the risk of such an incident.


We are incorporating artificial intelligence technologies into our processes. These technologies may present business, compliance, and reputational risks.


Recent technological advances in artificial intelligence and machine-learning technology both present opportunities and pose risks to us. If we fail to keep pace with rapidly evolving technological developments in artificial intelligence, our competitive position and business results may suffer. At the same time, the use of artificial intelligence has recently become the source of significant media attention and political debate. The introduction of these technologies, particularly generative AI, into our operations may result in new or expanded risks and liabilities, including due to enhanced governmental or regulatory scrutiny, litigation, compliance issues, ethical concerns, confidentiality or security risks, as well as other factors that could adversely affect our business, reputation, and financial results. In addition, our personnel could, unbeknownst to us, improperly utilize artificial intelligence and machine learning-technology while carrying out their responsibilities. The use of artificial intelligence can lead to unintended consequences, including generating content that appears correct but is factually inaccurate, misleading or otherwise flawed, or that results in unintended biases and discriminatory outcomes, which could harm our reputation and business and expose us to risks related to inaccuracies or errors in the output of such technologies and the risk that using such technologies could result in leakage of our confidential information.


A change of control of our company occurred in March of 2026, which could lead to shifts in our strategy, management, and corporate governance.


On December 15, 2025, the controlling shareholders of Inversiones ASPI S.A. (“ASPI”), entered into a share purchase agreement with Holcim Ltd (“Holcim”), a limited liability company incorporated under the laws of Switzerland, pursuant to which Holcim agreed to acquire 99.99% of the shares of ASPI, which holds a 50.01% majority stake in our company, subject to the completion of certain conditions precedent (the “Transaction”). On March 30, 2026, as reported to us by our shareholder ASPI, the Transaction was consummated. As a result, Holcim has acquired 99.99% of the shares representing the capital stock of ASPI, which in turn is the holder of 50.01% of the capital stock of Pacasmayo. For further information, see “Item 4. Information on the Company—A. History and Development of the Company—Recent Developments.”


This change of control could result in changes to our business, including:


  ● Strategic Realignment: Holcim may implement its “NextGen Growth 2030” strategy, which could prioritize different capital allocation models, sustainability targets, or operational integration with Holcim’s other Peruvian assets.


●Mandatory Tender Offer (OPA): Under Peruvian law, the acquisition of a controlling stake requires Holcim to launch a mandatory tender offer for at least 50% of the remaining outstanding shares. The timing, price, and outcome of such an offer could significantly affect the liquidity and trading price of our common shares and American Depositary Shares (ADSs) on the New York Stock Exchange.


●Alignment and Governance: Following the closing, our interests will be considered alongside Holcim’s. As a majority shareholder, Holcim will have the ability to elect a majority of our directors and influence the outcome of most matters requiring shareholder approval, including dividend policies and significant corporate transactions


17


●Interest on de-listing: On April 6, 2026, Holcim filed with the United States Securities and Exchange Commission (SEC) the Schedule 13D form.


Holcim reported therein that, once the Mandatory Tender Offer (OPA) that it is obliged to launch regarding shares of Pacasmayo is completed, Holcim intends to delist the Common Shares (traded in the form of American Depositary Shares) from the New York Stock Exchange and deregister the Common Shares under the Exchange Act.


Please note that this public communication has been made exclusively by Holcim and it constitutes only an intention manifested by such controlling shareholder, without representing a decision adopted by Pacasmayo nor a definitive fact.


Regulatory information requests regarding certain transaction-related expenses recorded in 2025 may result in litigation or administrative proceedings.


Since February 27, 2026, and in connection with certain expenses incurred and recorded as “Expenses associated with the Holcim acquisition” in our audited financial statements for the fiscal year ended December 31, 2025, the Peruvian Securities Commission (Superintendencia del Mercado de Valores, or “SMV”) has delivered to Pacasmayo a series of information requests regarding the nature, adequate disclosure and connection of the company’s activities of these expenses.


While we consider these expenses to be valid and pre-existing obligations of Pacasmayo, associated with Holcim Ltd's acquisition of a controlling interest there is a risk of formal sanctioning proceedings being initiated by the SMV or of shareholder disputes arising. Should the SMV determine that these expenses were not adequately assumed, recorded, or disclosed, an adverse outcome under the relevant sanctioning proceedings could result in administrative sanctions such as corrective measures and/or fines, which could impact our reputation and financial condition.


Risks Relating to our Common Shares and ADSs


The market price of ADSs may fluctuate significantly, and you could lose all or part of your investment.


Volatility in the market price of the ADSs may prevent you from being able to sell your ADSs at or above the price you paid for them. The market price and liquidity of the market for the ADSs may be significantly affected by numerous factors, some of which are beyond our control and may not be directly related to our operating performance. These factors include, among others:


●actual or anticipated changes in our results of operations, or failure to meet expectations of financial market analysts and investors;


●investor perceptions of our prospects or our industry;


●operating performance of companies comparable to us and increased competition in our industry;


●new laws or regulations or new interpretations of laws and regulations applicable to our business;


18


●general economic trends in Peru;


●catastrophic events, such as earthquakes and other natural disasters; and


●developments and perceptions of risks in Peru and in other countries.


Our controlling shareholder has significant influence over us and his interests could conflict with the interests of other shareholders.


As of March 31, 2026, our controlling shareholder beneficially owned 50.01% of our outstanding common shares. As a result, our controlling shareholder has the ability to determine the outcome of substantially all matters submitted for a vote to our shareholders and thus exercise control over our business policies and affairs, including, among others, the following:


●the composition of our board of directors and, consequently, any determinations of our board with respect to our business direction and policy, including the appointment and removal of our executive officers;


●determinations with respect to mergers, other business combinations and other transactions, including those that may result in a change of control;


●whether dividends are paid or other distributions are made and the amount of any such dividends or distributions;


●whether we offer preemptive and accretion rights to holders of our common shares in the event of a capital increase;


●sales and dispositions of our assets; and


●the amount of debt financing we incur.


Our controlling shareholder may direct us to take actions that could be contrary to the interests of our other shareholders and may be able to prevent other shareholders from blocking these actions or from causing different actions to be taken. Also, our controlling shareholder may prevent change of control transactions that might otherwise provide the shareholders with an opportunity to dispose of or realize a premium on their investment in our common shares and ADSs. We also have a new controlling shareholder as of March 2026, Holcim, which filed a Schedule 13D with the SEC on April 6, 2026 and stated its intention to (i) delist our common shares (traded in the form of American Depositary Shares) from the New York Stock Exchange (NYSE) and (ii) deregister our common shares under the Exchange Act.


We cannot assure you that our controlling shareholder will act in a manner consistent with our other shareholders’ best interests. See “—A change of control of our company occurred in March 2026, which could lead to shifts in our strategy, management, and corporate governance” and “Item 4. Information on the Company—A. History and Development of the Company—Recent Developments.”


Holders of ADSs may be unable to exercise voting rights with respect to our common shares underlying the ADSs at our shareholders’ meetings.


Holders of ADSs may exercise voting rights with respect to the common shares represented by the ADSs only in accordance with the deposit agreement relating to the ADSs. Holders of our common shares will receive notice of shareholders’ meetings through publication of a notice 25 days in advance, pursuant to Peruvian law, in the official gazette in Peru, a Peruvian newspaper of general circulation, the bulletin of the Lima Stock Exchange and the website of the SMV, and will be able to exercise their voting rights by either attending the meeting in person or voting by proxy. ADS holders will not receive notice directly from us. Instead, pursuant to the deposit agreement, we will notify the depositary, which will mail to holders of ADSs the notice of the meeting and a statement as to the manner in which voting instructions may be given. To exercise their voting rights, ADS holders must instruct the depositary how to exercise the voting rights for the common shares which underlie their ADSs. Due to these additional procedural steps involving the depositary, the process for exercising voting rights may take longer for ADS holders than for holders of our common shares.


Holders of ADSs also may not receive voting materials in time to instruct the depositary to vote the common shares underlying their ADSs. In addition, the depositary and its agents are not responsible for failing to carry out voting instructions of the holders of ADS or for the manner of carrying out such instructions, unless such failure can be attributable to gross negligence, bad faith or willful misconduct on the part of the depositary or its agents. Accordingly, holders of ADSs may not be able to exercise voting rights, and they will have little, if any, recourse if the underlying common shares are not voted as requested.


19


The ability of holders of ADSs to receive payments of cash dividends may be limited.


Our shareholders’ ability to receive cash dividends may be limited by the ability of the depositary to convert cash dividends paid in Soles into U.S. Dollars. Under the terms of our deposit agreement with the depositary for the ADSs, the depositary will convert any cash dividend or other cash distribution we pay on the common shares underlying the ADSs into U.S. Dollars, if it can do so on a reasonable basis and can transfer the U.S. Dollars to the United States. If this conversion is not possible or if any government approval is needed and cannot be obtained, the deposit agreement allows the depositary to distribute the foreign currency only to those ADS holders to whom it is possible to do so. If the exchange rate fluctuates significantly during a time when the depositary cannot convert the foreign currency, holders of ADSs may lose some or all of the value of the dividend distribution.


Holders of ADSs may be unable to exercise pre-emptive or accretion rights with respect to the common shares underlying their ADSs.


Under Peruvian corporate law, if we issue new common shares as part of a capital increase, unless otherwise agreed to by holders of 40% of our outstanding common shares, our shareholders will generally have the right to subscribe to a proportional number of common shares of the class held by them to maintain their existing ownership percentage, which is known as preemptive rights. In addition, shareholders are entitled to the right to subscribe for the unsubscribed common shares of either the class held by them or other classes which remain unsubscribed at the end of a preemptive rights offering, on a pro rata basis, which is known as accretion rights. Holders of ADSs may not be able to exercise the preemptive or accretion rights relating to common shares underlying the ADSs unless a registration statement under the U.S. Securities Act of 1933, as amended (the “Securities Act”), is effective with respect to those rights or an exemption from the registration requirements of the Securities Act is available. We are not obligated to file a registration statement with respect to the common shares relating to these preemptive and accretion rights and we cannot assure you that we will file any such registration statement. Unless we file a registration statement or an exemption from registration is available, holders of ADSs may receive only the net proceeds from the sale of their preemptive and accretion rights by the depositary or, if the preemptive and accretion rights cannot be sold, they will be allowed to lapse. As a result, U.S. holders of ADSs may suffer dilution of their interest in our company upon future capital increases.


We are entitled to amend the deposit agreement under which the ADSs were issued, and to change the rights of ADS holders under the terms of such agreement, without the prior consent of the ADS holders.


We are entitled to amend the deposit agreement and to change the rights of the ADS holders under the terms of such agreement, without the prior consent of the ADS holders. Any change related to an increase in deposits or charges for book-entry securities services or any modification that might hinder the rights of the ADS holders will be effective within 30 days after the ADS holders have received notice of such change or modification and such holders will have no right to any compensation whatsoever.


Our status as a foreign private issuer allows us to follow alternate standards to the corporate governance standards of the New York Stock Exchange, which may limit the protections afforded to investors.


We are a “foreign private issuer” within the meaning of the New York Stock Exchange corporate governance standards. Under New York Stock Exchange rules, a foreign private issuer may elect to comply with the practices of its home country and not to comply with certain corporate governance requirements applicable to U.S. companies with securities listed on the exchange. We currently follow certain Peruvian practices concerning corporate governance and intend to continue to do so. Accordingly, holders of ADSs will not have the same protections afforded to shareholders of companies that are subject to all New York Stock Exchange corporate governance requirements.


For example, the New York Stock Exchange listing standards provide that the board of directors of a U.S. listed company must have a majority of independent directors at the time the company ceases to be a “controlled company.” Under Peruvian corporate governance practices, a Peruvian company is not required to have a majority of independent members on its board of directors.


20


The listing standards for the New York Stock Exchange also require that U.S. listed companies; at the time they cease to be “controlled companies,” have a nominating/corporate governance committee and a compensation committee (in addition to an audit committee). Each of these committees must consist solely of independent directors and must have a written charter that addresses certain matters specified in the listing standards. Under Peruvian law, a Peruvian company may, but is not required to, form special governance committees, which may be composed partially or entirely of non-independent directors.


In addition, New York Stock Exchange rules require the independent non-executive directors of U.S. listed companies to meet on a regular basis without management being present. There is no similar requirement under Peruvian law.


The New York Stock Exchange’s listing standards also require U.S. listed companies to adopt and disclose corporate governance guidelines. In November 2013, the Peruvian Securities Commission and a committee of regulatory agencies and associations prepared and published a list of suggested non-mandatory corporate governance guidelines called the “Good Corporate Governance Code for Peruvian Companies.” Although we have implemented a number of these measures, we are not required to comply with the corporate governance guidelines by law or regulation, only to disclose whether or not we are in compliance.


Our exemption as a “foreign private issuer” from certain rules under the U.S. securities laws results in less information about us being available to investors than for U.S. companies.


As a “foreign private issuer” in the United States, we are exempt from certain rules under the Exchange Act, including certain disclosure obligations and procedural requirements for proxy solicitations under Section 14, the “short-swing” profit recovery provisions of Section 16, the requirement to file periodic reports and financial statements as frequently or as promptly as U.S. domestic issuers, and compliance with Regulation FD. In June 2025, the SEC issued a concept release soliciting public comment on potential changes to the definition of “foreign private issuer” under U.S. securities laws. If we were to lose our foreign private issuer status, we would be required to comply with all disclosure and procedural requirements applicable to U.S. domestic issuers, which would significantly increase our legal, accounting, and other expenses.


In addition, the recently enacted “Holding Foreign Insiders Accountable Act” extends Section 16 reporting requirements to directors and officers of foreign private issuers. As a result, our directors and officers are currently subject to such Section 16 reporting requirements. If we or our directors and officers fail to comply with any applicable disclosure requirements, we may be subject to penalties and our reputation may be harmed, which in turn may have a negative impact on our business, reputation, and the market price of our securities.


Minority shareholders in Peru are not afforded equivalent protections as minority shareholders in other jurisdictions and investors may face difficulties in commencing judicial and arbitration proceedings against our company or our controlling shareholder.


Our company is organized and existing under the laws of Peru, and our controlling shareholder is resident in Peru. Accordingly, investors may face difficulties in serving process on our company, our officers and directors or our controlling shareholder in other jurisdictions, and in enforcing decisions granted by courts located in other jurisdictions against our company, our officers and directors or our controlling shareholder that are based on securities laws of jurisdictions other than Peru.


In Peru, there are no proceedings to file class action suits or shareholder derivative actions with respect to issues arising between minority shareholders and an issuer, its controlling shareholders or directors and officers. Furthermore, the procedural requirements to file actions by shareholders differ from those of other jurisdictions, such as in the United States. As a result, it may be more difficult for our minority shareholders to enforce their rights against us, our directors, officers or controlling shareholder as compared to the shareholders of a U.S. company. The deposit agreement provides that the depositary has no obligation to commence or become involved in any judicial proceedings and any other legal actions relating to the ADSs or the deposit agreement, either on behalf of the ADS holders or on behalf of any other person.


The ability of investors to enforce civil liabilities under U.S. securities laws may be limited.


Most of our directors or executive officers are not residents of the United States. All or a substantial portion of our assets and those of our directors and executive officers are located outside of the United States. As a result, it may not be possible for investors in our securities to affect service of process within the United States upon such persons or to enforce in U.S. courts or outside of the United States judgments obtained against such persons outside of the United States.


21


We are a company organized and existing under the laws of Peru, and there is no existing treaty between the United States and Peru for the reciprocal enforcement of foreign judgments. It is not clear whether a Peruvian court would accept jurisdiction and impose civil liability if proceedings were commenced in a foreign jurisdiction predicated solely upon U.S. federal securities laws.


Item 4. INFORMATION ON THE COMPANY


A.History and Development of the Company


Our History


Cementos Pacasmayo S.A.A. was incorporated in Lima, Peru in 1949, by a group of private investors that founded the company to serve the cement market in the northern region of Peru. Cementos Pacasmayo began its operations in 1957 and is a publicly held corporation (sociedad anónima abierta) organized under the laws of Peru. Our executive offices are located at Calle La Colonia 150, Urbanización El Vivero, Surco, Lima, Peru. Our telephone number at this location is + (511) 317-6000. Our website address is www.cementospacasmayo.com.pe. Information on or accessible through our website is not a part of, nor incorporated by reference in, this annual report on Form 20-F.


Cementos Pacasmayo S.A.A. and Hochschild Mining plc together constituted the two businesses of the Hochschild Group, which has operated in Latin America for more than 100 years. Hochschild Mining plc is incorporated in the United Kingdom and its shares have been listed on the London Stock Exchange since 2006. Cementos Pacasmayo has been listed on the Lima Stock Exchange since 1995. As of March 31, 2026, Eduardo Hochschild, directly and indirectly, owned and controlled 38.27% of the shares of Hochschild Mining plc. On March 30, 2026, Holcim Ltd (“Holcim”) completed the acquisition of 99.99% of the capital stock of Inversiones Aspi S.A. (“ASPI”). Prior to this transaction, Eduardo Hochschild, owned this 99.99% of ASPI. As a result of this transaction, through ASPI, Holcim now directly and indirectly, owns and controls 50.01% of Cementos Pacasmayo S.A.A. (the “Company”), resulting in a change of control. The Hochschild Group traces its origins to 1911, when Mauricio Hochschild, a German mining engineer, founded a group of companies in South America that came to be known as the Hochschild Group. Following World War I, the Hochschild Group expanded into Bolivia where it developed significant interests in tin. The Hochschild Group commenced operations in Peru in 1925 and in 1945 Luis Hochschild, the nephew of Mauricio Hochschild (and the father of Eduardo Hochschild), joined the Hochschild Group’s Peruvian operations.


During the first decades of its operations, the Hochschild Group focused on the commercialization of minerals, although it later began operating its own mines and other industrial companies. During World War II, the Hochschild Group was a key supplier of tin and other metals to the allied forces.


The Hochschild Group acquired its initial ownership interest in us in 1956. Set forth below are key developments in our company’s history.


●In 1957, we began our operations with the installation of our first clinker line with an installed production capacity of approximately 110,000 metric tons per year. In 1966 and 1977, we added a second and third clinker line, respectively, increasing our installed clinker production capacity to approximately 830,000 metric tons per year.


●In November 1984, the South American mining and industrial operations of the Hochschild Group were sold to the Anglo American Corporation of South Africa which, in the same month, sold the Peruvian operations of the Hochschild Group, including its interest in Cementos Pacasmayo and predecessors of Hochschild Mining plc, to a group of companies controlled by Luis Hochschild.


●In 1995, we launched our distribution network to commercialize and distribute our products throughout the northern region of Peru. In that same year, we also listed our common shares for trading on the Lima Stock Exchange, currently under the ticker symbol “CPACASC1.”


22


●In 1998, we acquired from the Peruvian government our Rioja facility, located in the northeast of Peru. At the time, the Rioja facility had one clinker line with an installed cement production capacity of approximately 35,000 metric tons per year.


●In 2010, we reached an aggregate total installed cement production capacity of 3.1 million in our Pacasmayo and Rioja facilities and completed the conversion of our Waelz kiln, retrofitting it to produce quicklime or calcine zinc interchangeably.


●In March 2012, we completed our initial equity offering of 22,296,800 ADSs in the United States and listed the ADSs on the New York Stock Exchange.


●In February 2013, we issued US$300 million in our inaugural international bond offering. A portion of the proceeds from this offering were used to prepay amounts outstanding on our secured loan agreement with BBVA Banco Continental, and the remaining proceeds were used to fund a portion of the capital expenditures related to the construction and operation of our new Piura plant and our cement business.


●In September 2015, we began producing cement at our new plant in Piura, adding 1.6 million metric tons of annual cement production capacity. In January 2016, we began producing clinker at our new plant in Piura, finishing the start-up of the plant, adding one million metric tons of annual clinker production capacity.


●During 2018, we implemented the ISO 37001 anti-bribery management systems, obtaining certification in January 2019. This certification confirms that our management systems are designed to help prevent, detect and respond to bribery and comply with anti-bribery laws and voluntary commitments applicable to our activities.


●In November 2018, we launched an offer to purchase for cash a portion of the US$300 million principal amount of our outstanding 4.50% Senior Notes due 2023. The offer expired on December 7, 2018 and we purchased a total of US$168,388,000, or approximately 56.13% of the total outstanding amount of our 4.500% Senior Notes due 2023.


●On January 8, 2019, the General Shareholders’ Meeting approved the creation of a local bond program in an aggregate principal amount up to S/1,000 million. On January 31, 2019, we issued an aggregate principal amount of S/570 million in debt securities under our local bond program: one in the aggregate principal amount of S/260 million accruing interest at a rate of 6.68750% per annum with term to maturity of 10 years, and the other in the aggregate principal amount of S/310 million accruing interest at a rate of 6.84375% per annum with a term to maturity of 15 years. The proceeds were used to purchase a portion of our 4.50% Senior Notes due 2023. The rates and terms obtained reduce our financial cost structure, with lower cost of capital, an extended maturity and less exposure to exchange rate fluctuations.


●In 2021, given the exponential growth in the demand for cement, we decided to invest in the capacity optimization of our Pacasmayo plant in order to produce an additional estimated 660,000 metric tons of clinker, and thus reduce the consumption of imported clinker.


●During 2022, we implemented the ISO 37301 compliance management system, obtaining the certification in January 2023.


●In 2023, we finished investing approximately US$83.5 million in a more efficient kiln for our Pacasmayo plant. This investment was fully aligned with our medium- and long-term strategy as it demonstrates on the one hand, our firm belief in the future growth of our country and, on the other hand, our commitment to carbon neutrality, as this new kiln lowers our emissions.


●In 2025, we were included in the annual Dow Jones Sustainability Index (DJSI MILA), for the seventh consecutive year. Additionally, for the sixth consecutive year, at the beginning of 2026 we were included in The Sustainability Yearbook 2026, achieving a top 10%.


23


●On December 15, 2025, the controlling shareholders of Inversiones ASPI S.A. (“ASPI”), entered into a share purchase agreement with Holcim Ltd (“Holcim”), pursuant to which Holcim agreed to acquire 99.99% of the shares of ASPI, which holds a 50.01% majority stake in our company.


●In March 2026, Holcim successfully completed the acquisition, as a result, Holcim now exercises effective control over our company.


Recent Developments


On December 15, 2025, Holcim entered into a Share Purchase Agreement (the “Purchase Agreement”) with (i) the marital community property (sociedad conyugal) formed by Eduardo Hochschild Beeck, a Peruvian citizen and resident, and Mariana Violeta Correa Sabogal de Hochschild, a Peruvian citizen and resident, (ii) Farragut Holdings, Inc., a Cayman limited company ((i) and (ii) collectively, the “Sellers”) and (iii) Eduardo Hochschild Beeck, as representative of the Sellers, pursuant to which Holcim agreed to acquire from the Sellers 99.99% of the issued and outstanding shares of common stock of Inversiones ASPI S.A., a Peruvian sociedad anonima (“ASPI” and the “ASPI Shares”) in exchange for an aggregate cash purchase price of S/1,850,370,000 (the “ASPI Acquisition”). The ASPI Acquisition was consummated on March 30, 2026. The purchase price for the ASPI Acquisition was funded from Holcim’s working capital. ASPI owns 50.01% of the issued and outstanding common shares of Cementos Pacasmayo, which common shares are indirectly owned by Holcim following the ASPI Acquisition.


Under the terms of the Purchase Agreement and based on Peruvian law, Holcim shall launch and complete a public tender offer for at least an additional 24.99% of the common shares of Cementos Pacasmayo within the timeframe permitted under Peruvian law (the “Public Tender Offer”). Within ten (10) Peruvian business days following the closing of the ASPI Acquisition, Holcim must request that the Peruvian Securities Market Superintendency (the “SMV”) appoint a valuation entity to determine the minimum price Holcim may offer for the common shares of Cementos Pacasmayo in the Public Tender Offer. Under Peruvian law, the Public


Tender Offer must be carried out within a period of six (6) months following the closing of the ASPI Acquisition, or within five (5) Peruvian business days following the submission of the valuation report by the valuation firm to the SMV. Holcim intends to conduct the Public Tender Offer in accordance with U.S. and Peruvian law and in accordance with the terms of the Purchase Agreement.


As of the date of this annual report on Form 20-F, Holcim has not launched the Public Tender Offer.


Also, on April 6, 2026, Holcim filed a Schedule 13D with the SEC, in which it stated its intention to, once the Mandatory Tender Offer (OPA) is completed, (i) delist our common shares (traded in the form of American Depositary Shares) from the New York Stock Exchange (NYSE) and (ii) deregister our common shares under the Exchange Act. As of the date of this annual report on Form 20-F, such communication has been made exclusively by Holcim as our new controlling shareholder and constitutes only an intention manifested by said shareholder, without representing a decision adopted by the Company nor a definitive fact.


The foregoing description of the Purchase Agreement does not purport to be complete and is qualified in its entirety by reference to the full text of the Purchase Agreement, a copy of which is filed as Exhibit 99.1 to the Schedule 13D filed by ASPI and Holcim and is incorporated herein by reference. ASPI and Holcim have filed the Purchase Agreement to provide investors and securityholders with information regarding its terms. It is not intended to provide any other factual information about the Company, ASPI or Holcim. The Purchase Agreement contains representations, warranties and covenants that the parties to the Purchase Agreement made to one another as of specific dates. The assertions embodied in those representations, warranties and covenants were made solely for purposes of the Purchase Agreement and the allocation of risk between the parties thereto and may be subject to important qualifications and limitations agreed to by the parties in connection with negotiating their terms, including being qualified by confidential disclosures exchanged between the parties in connection with the execution of the Purchase Agreement. Further, the representations and warranties may be subject to a contractual standard of materiality that may be different from what may be viewed as material to investors or securityholders. Moreover, information concerning the subject matter of the representations and warranties may change after the date of the Purchase Agreement. Accordingly, investors should not necessarily rely on the representations and warranties contained in the Purchase Agreement as representations regarding the current status of the businesses related to the Purchase Agreement.


24


B.Business Overview


Overview


We are a Peruvian cement company, and the only cement manufacturer serving in the northern region of Peru. With almost 70 years of operating history, we produce, distribute and sell cement and cement-related materials, such as precast products and ready-mix concrete. Our products are primarily used in construction, which has been one of the fastest growing segments of the Peruvian economy in recent years. We also produce and sell quicklime for use in mining operations, although it represents a very small percentage of our overall revenues.


In 2025, our cement, concrete and precast shipments were approximately 3.0 million metric tons, representing an estimated 22.4% share of total cement shipments in Peru according to INEI. Our sales volumes in 2025 increased by 7.2% compared to 2024. We believe the construction sector has significant potential to grow with the continued deficit in infrastructure and the persistent housing deficit in the country.


We own three cement production facilities, our flagship Pacasmayo facility located in the northwest region of Peru, our Piura facility located around 300 kilometers north of Pacasmayo, and our smaller Rioja facility located in the northeast. Our facilities have a total installed annual cement production capacity of approximately 4.9 million metric tons. We also have an installed annual production capacity of 240,000 metric tons of quicklime. We own concession rights to several quarries with reserves of limestone and other raw materials located near our facilities.


We provide consumers with high-quality and value-added cement products and, as a result, we believe we have developed strong brand recognition and customer loyalty in our market. We have developed one of the largest independent retail distribution networks for construction materials in Peru. Through our network of 287 independent retailers and 334 hardware stores as of December 31, 2025, we distribute our cement products as well as other construction materials manufactured by third parties, such as steel rebar, cables and pipes, in the northern region of Peru. We also sell our cement products directly to other retailers that are not part of our distribution network and to private construction companies and government entities.


On December 15, 2025, the controlling shareholders of ASPI which holds a 50.01% majority stake in Pacasmayo, entered into a share purchase agreement with Holcim, a limited company incorporated under the laws of Switzerland, pursuant to which Holcim agreed to acquire 99.99% of the shares of ASPI subject to the completion of certain conditions precedent (the “Transaction”). On March 30, 2026, as reported to us by our shareholder ASPI, all the Transaction was consummated. As a result, Holcim has acquired 99.99% of the shares representing the capital stock of ASPI. In connection with the Transaction, Pacasmayo has incurred in certain expenses recorded as “Expenses associated with the Holcim acquisition” in our audited financial statements for the fiscal year ended December 31, 2025. These expenses include a one-time remunerative performance bonus in favor of our CEO, based on the growth of Pacasmayo and its profitability during his tenure and triggered by the Transaction. For further information on the Transaction, see “Item 4. Information on the Company—A. History and Development of the Company—Recent Developments.”


25


The following table sets forth certain macroeconomic data for Peru and operating and financial data for our company for the periods indicated.


   As of and for the year ended December 31, 
   2025   2024   2023 
   (in percentage, except as otherwise indicated) 
Economic data(1):               
Change in GDP   3.3%   3.5%   (0.7)%
Change in construction sector in Peru   5.7%   3.6%   (8.0)%
Operating data:               
Capacity (thousands of metric tons per year):               
Installed cement capacity   4,940    4,940    4,940 
Installed clinker capacity   3,035    3,035    3,035 
Production (thousands of metric tons):               
Cement production   3,052    2,832    2,946 
Clinker production   2,053    2,124    2,097 
Utilization rate at Pacasmayo plant(2):               
Cement   62.9%   57.5%   57.1%
Clinker   67.7%   72.5%   62.5%
Utilization rate at Rioja plant(2):               
Cement   77.3%   72.8%   58.8%
Clinker   85.8%   83.7%   69.0%
Utilization rate at Piura plant(2):               
Cement   55.4%   52.7%   64.5%
Clinker   62.2%   61.5%   80.7%
                
Gross profit (S/ million)   806.9    728.5    689.4 
Gross profit margin(3)   38.1%   36.8%   35.4%
EBITDA (S/ million)   506.6    549.3    481.8 
EBITDA margin(4)   23.9%   27.8%   24.7%
Adjusted EBITDA(5) (S/ million)   506.6    549.3    518.4 
Adjusted EBITDA margin(6)   23.9%   27.8%   24.7%
Profit (S/ million)   154.2    198.9    168.9 
Profit margin   7.3%   10.1%   8.7%


(1)Source: BCRP.
(2)We define utilization rate as production for the specified period divided by installed capacity of that period.
(3)We define gross profit margin as gross profit divided by net sales.
(4)We define EBITDA as net profit minus finance income and plus finance costs, income tax expense, and depreciation and amortization, and plus or minus gain from exchange difference, net. We define EBITDA Margin as EBITDA divided by sales of goods. For further information, see “—Non-IFRS Financial Measures and Reconciliation.”
(5)We define Adjusted EBITDA as EBITDA minus the impairment of our vertical kilns. For further information, see “—Non-IFRS Financial Measures and Reconciliation.”
(6)We define Adjusted EBITDA Margin as Adjusted EBITDA divided by sales of goods. For further information, see “—Non-IFRS Financial Measures and Reconciliation.”


26


Non-IFRS Financial Measures and Reconciliation


We define EBITDA as net profit minus finance income and plus finance costs, income tax expense, and depreciation and amortization, and plus or minus gain from exchange difference, net. We define EBITDA Margin as EBITDA divided by sales of goods. We define Adjusted EBITDA as EBITDA minus the impairment of our vertical kilns. We define Adjusted EBITDA Margin as Adjusted EBITDA divided by sales of goods.


EBITDA and Adjusted EBITDA should not be construed as alternatives to profit or operating profit, as indicators of operating performance, as alternatives to cash flow provided by operating activities or as measures of liquidity (in each case, as determined in accordance with IFRS). EBITDA and Adjusted EBITDA, as calculated by us, may not be comparable to similarly titled measures reported by other companies, including those in the cement industry.


The following table sets forth the reconciliation of our net profit to EBITDA and Adjusted EBITDA and our EBITDA Margin and Adjusted EBITDA Margin:


   For the year ended December 31, 
   2025   2025   2024   2023 
  

(in millions of US$)(1)

   (in millions of S/) 
                 
Net profit   45.9    154.2    198.9    168.9 
Income tax expense   33.8    113.8    97.3    76.8 
Finance income   (3.4)   (11.3)   (6.3)   (7.2)
Finance costs   27.7    93.0    100.3    104.0 
(Gain) Loss from exchange difference, net   (0.8)   (2.6)   0.9    (4.9)
Depreciation and amortization   47.4    159.5    158.2    144.2 
EBITDA   150.6    506.6    549.3    481.8 
Sales of Goods   629.5    2,116.9    1,978.1    1,950.1 
EBITDA Margin   23.9%   23.9%   27.8%   24.7%
Impairment of vertical kilns   —    —    —    36.6 
Adjusted EBITDA   150.6    506.6    549.3    518.3 
Adjusted EBITDA Margin   23.9%   23.9%   27.8%   26.6%


(1)Calculated for convenience only using the average accounting exchange rate of S/3.363 to US$1.00 as of December 31, 2025.


Peruvian Cement Market


Peru had GDP growth of 3.3% in 2025, mainly due to the recovery of primary sectors, particularly metallic mining, fishing and related manufacturing, as well as an increase in construction supported by higher public investment. Additionally, lower demand for non-traditional exports, mainly due to less demand from the North American market, affected external sector performance. Furthermore, climatic anomalies and supply chain disruptions posed challenges to production in key industries, contributing to volatility in private sector income and business confidence. From 2021 to 2025 GDP grew at a compound annual growth rate (“CAGR”) of 2.4%. Growth during this period was accompanied by low inflation, which averaged 4.3% per year. In addition, as of December 17, 2025, the government’s net international reserves amounted to approximately US$93.5 billion, and, as of December 31, 2025, the sovereign’s long-term debt rating was investment grade from each of the three major international credit rating agencies. This economic growth resulted, among other key trends, in significant poverty reduction, with a decrease in the percentage of the country’s population living below the poverty line from approximately 48.6% in 2004 to approximately 27.6% in 2024.


27


We sell substantially all our cement in the northern region of Peru, which in 2025 accounted for approximately 32.8% of the country’s population and 20.1% of national GDP. Two other groups sold most of the cement consumed in each of the central and southern regions of Peru, with 4.2% of all the cement consumed in the country coming from imports, and approximately 5.8% coming from other producers. From 2021 to 2025, total cement consumption in Peru decreased 1.4% according to the INEI. Peru continues to have a significant housing deficit, estimated by the INEI at 1.7 million homes nationwide. In Peru, cement is mainly sold to a highly fragmented consumer base, consisting primarily of households that buy cement in bags to gradually build or improve their own homes without professional technical assistance, a segment known in our industry as self-construction (auto-construcción). We estimate that in 2025 sales to the self-construction (auto-construcción) segment accounted for approximately 73.9% of our total sales of cement, private construction projects accounted for 14.0%, and public construction projects accounted for the remaining 12.1%. Approximately 81.4% of our total cement sales in 2025 were in the form of bagged cement, substantially all of which was sold through retailers.


Even though our ready-mix sales are still a small proportion of our sales, we expect this trend to change as infrastructure becomes a bigger driver of demand in the upcoming years.


Impairment of Vertical Kilns


At the end of 2023, our board of directors, advised by management, recognized a specific impairment for the net value of the assets of the vertical clinker kilns located at the Pacasmayo cement plant for a net cost of S/36,551,000. This deterioration estimate was carried out as a consequence of replacing the old technology of these kilns due to the entry into operation of a new horizontal kiln in the Pacasmayo plant, which is more efficient and produces fewer emissions. This amount was recorded in the impairment of property, plants and equipment item in the consolidated statement of profit or loss.


Competitive Strengths


Our principal competitive strengths include the following:


Strong corporate governance standards and international recognition


Our common shares are listed on the Lima Stock Exchange and the ADSs are listed on the New York Stock Exchange. We are subject to the disclosure requirements of the U.S. Securities and Exchange Commission (the “SEC”) and the Peruvian Securities Commission and we must comply with and adopt internal compliance standards to increase transparency and improve corporate governance standards including an audit committee and appointment of independent directors. Furthermore, we were included for the sixth consecutive year as part of the 2024 DJSI MILA Pacific Alliance Index. This index is made up of those companies that demonstrate superior performance among their peers under social, environmental and economic criteria. This achievement comes as a result of Pacasmayo’s effort to improve in all of these criteria and to work towards ambitious goals in terms of long-term sustainability. We are committed not only to remain in the Index but to improve our performance, as we are convinced that the focus on sustainability is key to our business and our stakeholders. In February 2026, we were selected to be part of The Sustainability Yearbook 2026, for the sixth consecutive year. In this edition, we obtained, for the first time, a score within the top 10% of S&P Global’s Corporate Sustainability Assessment (CSA) in the building materials industry. To appear in the Yearbook, companies must score at least 30 points, rank within the top 15% of their industry by number, and be within 30% of the industry leader’s CSA score. With around 9,200 companies evaluated around the world, we see an inclusion in the yearbook is a true statement of excellence in corporate sustainability.


Track record of cash flow generation and strong results through multiple business cycles


We have historically generated strong cash flow and high profit margins mainly due to the following key factors:


●our leadership position in the northern region of Peru; and


●our extensive distribution network, operational flexibility and efficiency, and focus on innovation.


These factors helped us generate net profit of S/154.2 million and EBITDA of S/506.6 million in 2025. This solid financial position and our ability to consistently generate operating cash flow also allows us to obtain relatively low interest rates.


28


Best-in-class operating efficiencies with vertical integration and strong brand recognition


Our quarries are located in close proximity to our plants, enabling us to minimize transportation costs. We strive to enhance our operational efficiency by focusing on lowering costs and improving profitability. We also benefit from our vertically integrated operations, participating in the entire chain of production from the quarries, which we own directly, to the related products such as quicklime, ready–mix, precast and our large distribution network. We have developed one of the largest independent retail distribution networks for construction materials in Peru, known as “DINO,” consisting of 287 independent retailers and 334 hardware stores as of December 31, 2025, primarily small, local stores in the northern region, through which we distribute our cement products, as well as construction materials manufactured by third parties. We use our distribution network, together with our strategically located commercial offices, to promote our products and stay abreast of market developments. We have developed this network through years of fostering relationships with retailers in the region, which we believe would be difficult for a competitor to replicate. Our distribution network has enabled us to build strong recognition for our Pacasmayo brand among retailers and end-consumers in our market, which we believe is important to our business, particularly because our cement is principally sold in bags to retail consumers.


Disciplined capital expenditure plan with attractive risk / return profile


We seek to minimize risk while securing an adequate return on our development projects. In 2015, we completed construction of our new plant in Piura, the third largest city in northern Peru, which has an annual production capacity of 1.6 million metric tons of cement. The Piura plant improved our competitive position in the northern region of Peru. With production from three plants, we are able to serve our market more efficiently. This state-of-the-art plant is one of the most modern in Latin America. It also reduces transportation costs by enabling the dispatching of cement from plants within close proximity to the point of sale.


In 2021, we decided to invest approximately US$83.5 million to optimize our current capacity at our Pacasmayo plant, in order to produce an additional estimated 660,000 metric tons of clinker per year. This optimization was completed during the second half of 2023, allowing us to minimize the use of imported clinker from existing inventories, and therefore achieving higher margins.


Emphasis on innovation and research and development


We place significant emphasis on research, development and innovation to align our products with customer requirements, improve operational efficiency and support the development of more eco-efficient solutions. These efforts are supported by our R&D Committee, a multidisciplinary team of engineering specialists focused on applied construction solutions. Through this committee, we have advanced the development of new products and maintained an active role in applied research, including securing direct funding for research on new cementitious materials in collaboration with Universidad de Ingeniería y Tecnología (UTEC), as well as obtaining tax benefits under the framework of Peruvian Law No. 30309. Our product portfolio includes specialized solutions such as cement designed for applications in coastal areas, where structures may be more exposed to sulfate-related deterioration and where durability is a key objective. We also continue to promote our High Early-Strength (HE) cement, which complies with the ASTM C1157 standard. This product has an approximately 8% lower clinker content than our traditional Type I cement, which may contribute to a lower carbon footprint. We initially target this product to the artisanal precast segment, while assessing opportunities to expand its use across other business units. We support adoption of our differentiated products through technical outreach and product education efforts directed at retailers and end consumers.


In terms of innovation, we have positioned digital transformation as a core strategic pillar to bridge technological gaps in the construction sector, strengthen competitiveness, and deliver high-impact, customer-centric solutions. Through initiatives such as Mundo Pacasmayo, the company drives the professionalization of construction workers via Construye Experto—an integrated ecosystem that goes beyond training. It combines technical education, practical tools (such as material calculators and product guidance), and data-driven insights to better understand on-site needs and behaviors. With a community of over 48,000 users and more than 100 courses available, Construye Experto not only builds capabilities but also generates actionable information from real construction projects, enabling more relevant solutions, closer relationships with users, and continuous improvement of the value proposition. In the industrial segment, our Pacas Pro platform stands out by offering comprehensive and innovative tech-driven solutions, achieving 84% customer satisfaction in concrete services.


Additionally, we have launched user-focused initiatives such as Metros Habitables and Ayu, aimed at improving the self-construction (auto-construcción) processes and facilitating access to building materials without the incurrence of debt. Internally, Pacasmayo fosters organizational innovation and has strengthened its data and AI strategy, reaching an advanced level of digital maturity. This comprehensive transformation reflects our commitment to building a more efficient, sustainable, and people-centered future in construction.


29


Strong relationship with local communities


Since we began operations almost 70 years ago, we have been committed to improving the quality of life of the communities surrounding our plants, whose members we regularly employ. We have developed close and cooperative relationships with the local communities, which are supported by several social responsibility initiatives we have undertaken. For example, the family of our controlling shareholder founded Asociación Tecsup, a leading non-profit institute in Peru that provides technical education to students as well as UTEC, a leading technical university. We provide scholarships and financial aid to local qualified students interested in studying at Tecsup.


We are committed to building the future by strengthening opportunities in the communities where we operate. In 2024, the Community Relations team established four strategic objectives with short-, medium-, and long-term goals (2024–2030). A key part of this strategy is fostering trust-based relationships, guided by principles such as the Community Engagement and Good Conduct Decalogues. Faced with the regional challenge of transforming vulnerable homes into healthy spaces, we and the Inter-American Cement Federation and Habitat for Humanity signed a collaboration agreement on July 1, 2025, reaffirming the commitment to development in the northern part of the country by integrating the “Sueños en Concreto” (dreams in concrete) program into the Latin American initiative “100,000 Floors to Play On.” This strategic alliance with FICEM and Habitat for Humanity strengthens our goal of replacing dirt floors with concrete. No community conflicts were reported in 2025, which we believe reflects the effectiveness of these measures.


Highly experienced and professional management and board of directors


Our management team, with an average of 13.17 years of experience in the cement industry in Peru, has extensive technical and local market expertise and has led our company through our recent growth. We have developed a strong professional business culture and a team of highly qualified executives. We also have a well-regarded and experienced board of directors that includes business leaders from Peru and abroad.


Our Strategies


Our objective is to maximize shareholder value, while honoring our commitment to the environment and abiding by our social responsibility goals. We aim to be a leading company that provides building solutions anticipating the needs of our clients and that contributes to the continued development of our country. We intend to achieve our objective through the following principal strategies:


Continue to focus on our core business of supplying the demand for cement


We plan to continue to meet the demand for cement in our market, while controlling production costs. We intend to continue to serve the current cement market, as well as increasing cement demand through the production of new cement-based products. Our principal goal is to maintain our market share in the northern region of Peru without reducing the profitability of our business, as to continue developing building solutions to satisfy our clients’ needs.


Deepen our commercial relationship with retailers and end-consumers


We plan to enhance our commercial relationships with retailers and end-consumers in our market, both to maintain brand loyalty and to foster demand for our cement products. We will continue to support retailers in our DINO distribution network by providing product education, training sessions, rewards programs, and assistance in financing purchases of our products. In addition, we continue with our door-to-door commercial strategy for cement sales. We believe that these initiatives have been successful in strengthening our relationship with retailers and end-consumers.


30


Continue to focus on being the preferred provider of building solutions


We strive to be the supplier of choice for cement consumers in the northern region of Peru, whether its individuals building their homes or private construction companies or governmental entities undertaking projects of any size. We continue to focus on providing consumers with efficient and customized building solutions for their construction needs. Over the past several years, we have evolved from being a single type cement manufacturer to offering six different types of cement products, under two brands, and other building solutions, such as assembly gravity walls, sheet piles, precast beams, among others. We focus on innovation and are constantly searching for ways to improve building practices, inspired by our culture based on sustainability. For example, we offer cement that contains special properties that protect against sulfate erosion, as well as other products designed to meet the needs of consumers in the northern region of Peru. For the industrial segment and under our PacasPro brand, we continue with the digitalization of the purchasing process and of the use of our products and services. For our mass channel and self-builders we have Mundo Pacasmayo, an ecosystem that integrates physical and digital solutions, improves the purchasing experience and contributes to the professionalization and formalization of the construction market. Our mission is to provide a comprehensive solution for all project types and thus respond to the unique needs of each client, generating savings and efficiencies in the construction processes. During 2023, the company began the reconstruction of the two runways and the perimeter fence of Piura Airport, not only as a cement and concrete provider, but with direct involvement in the construction, as well as part of a consortium. The modernization of the airport aims to stimulate the tourism industry in the region and exceed the 1.08 million passengers transported during 2025.


Selectively pursue acquisitions


We will continue to evaluate and may selectively pursue strategic acquisitions of cement and complementary businesses that expand our geographic footprint and diversify our portfolio of products. Our management team has significant operating experience and industry knowledge in the production and commercialization of cement and cement-related materials, and we believe this experience will enable us to identify and pursue attractive acquisitions that will maximize shareholder value.


Continue to strengthen our enterprise risk management


We continue to strengthen our enterprise risk management methods and processes that allow us to identify, assess and monitor the legal, commercial, operational, financial and reputational risks, as well as fraud, corruption between private parties, bribery, tax evasion, customs offenses, accounting offenses, collusion, influence peddling, money laundering and financing of terrorism risks, determining the existing controls and establishing a plan along with other areas in order to mitigate existing risks. Along these lines, since 2018, we have implemented the ISO 37001 Anti-bribery management systems obtaining the certification every year since 2019. This certification confirms that our management system is designed to help prevent, detect and respond to bribery and comply with anti-bribery laws and voluntary commitments applicable to its activities. We believe this certification reiterates our commitment to global anti-bribery best practices and high standards of transparency and good corporate governance. Also, to continue to strengthen our management systems, in 2022 we implemented the ISO 37301 compliance management system obtaining the certification every year since 2023.


Maintain high environmental, social and governance standards


We are committed to maintaining high environmental, social and corporate governance standards. We are focused on developing and strengthening a favorable social environment for the continuity and growth of our operations, prioritizing our social investment in innovative education, health and local development programs in coordination with other stakeholders to contribute to sustainable development. Furthermore, we were included for the sixth consecutive year as part of the 2024 DJSI MILA Pacific Alliance Index. This index is made up of those companies that demonstrate superior performance among their peers under social, environmental and economic criteria. This achievement comes as a result of Pacasmayo’s effort to improve in all of these criteria and to work towards ambitious goals in terms of long-term sustainability. We are committed not only to remain in the Index but to improve our performance, as we are convinced that the focus on sustainability is key to our business and our stakeholders.


31


In 2023, we launched the EcoSaco, a cement bag that completely disintegrates within the concrete mix, generating zero waste. For us, this is much more than a cement bag, it’s a solution that has the potential to revolutionize the market, particularly the self-construction (auto-construcción) segment. As with any transformational change, it requires much effort in order to gradually change culturally established paradigms and consumer habits. This is precisely why we are so glad that the EcoSaco won the Semana Economica ESG Sustainability Price, both in the Sustainable Product Innovation Category and the Grand Prize, awarded to the project with the greatest environmental, social and economic impact. The EcoSaco also obtained the “Gran Effie”, as well as a Gold Effie that was awarded in the “Innovation in product marketing” category and a Silver Effie in the “Positive change in the environment” category. The Effie awards are a symbol of outstanding achievement, recognized worldwide, that honor all types of effective marketing.


In February 2026, we were selected to be part of The Sustainability Yearbook 2026, for the sixth consecutive year. In this edition, we obtained, for the first time, a score within the top 10% of S&P Global’s Corporate Sustainability Assessment (CSA) in the building materials industry. To appear in the Yearbook, companies must score at least 30 points, rank within the top 15% of their industry by number, and be within 30% of the industry leader’s CSA score. With around 9,200 companies evaluated around the world, we see an inclusion in the yearbook is a true statement of excellence in corporate sustainability.


Our Products


Our core products are cement and other cement-related materials. We also produce quicklime. In 2025, cement, concrete, mortar, pavement and precast accounted for 97.5% of our net sales and quicklime accounted for 0.4%. We also sell and distribute construction materials, such as steel rebar, cables and pipes, manufactured by large third-party manufacturing companies, and others which in 2025 represented 2.0% of our net sales.


The following table sets forth a breakdown of our shipments by type of product for the periods indicated:


   For the year ended December 31, 
   2025   2024   2023 
   (in thousands of metric tons) 
Cement, concrete, mortar, pavement and precast   3,049    2,846    2,953 
Quicklime   16    18    30 


The following table sets forth a breakdown of our total net sales by product for the periods indicated:


   For the year ended December 31, 
   2025   2024   2023 
   (in millions of S/) 
Cement, concrete, mortar, pavement and precast   2,064.7    1,906.8    1,850.2 
Construction Supplies(1)   41.7    56.9    74.1 
Quicklime   9.5    14.2    25.7 
Others   1.0    0.2    0.1 
Total   2,116.9    1,978.1    1,950.1 


(1)Refers to construction materials manufactured by third parties that we distribute. Construction supplies include the following products: steel rebar, wires, nails, corrugated iron, electric conductors, plastic tubes and accessories, among others.


Cement


Cement is a powdered mixture of ground minerals that, when mixed with water, adheres to other materials and hardens to form a rock-like substance. Cement is generally mixed with other materials, such as gravel and sand, forming concrete with a high degree of compressive strength that is able to withstand substantial pressure.


32


Cement types are generally classified as either Portland cement or blended hydraulic cement. Portland cement is a hydraulic cement produced by pulverizing clinker, consisting essentially of crystalline hydraulic calcium silicates and calcium sulfate. Blended hydraulic cement consists of a mixture of Portland cement clinker and mineral admixtures, such as blast furnace slag, pozzolanic materials and limestone.


We produce predominantly blended cement, which represented 85.8% of our cement sales in 2025. Cementos Pacasmayo has been promoting the use of blended cement in the Peruvian market for over 25 years. This type of cement requires less clinker and reduces carbon dioxide emissions of our operations and production. Our global clinker/cement ratio is estimated at 71.1%, below the average value for similar producers globally of approximately 75.0%, according to ‘Getting the Numbers Right (GNR)’ by the Global Cement and Concrete Association (the “GCCA”) in 2023.


We produce a range of cement products suitable for various uses, such as residential and commercial construction and civil engineering. We currently offer seven types of cement products, each designed for specific applications and various technical requirements:


●Type ICo. Extraforte Cement: Portland composite cement used in general construction, flooring, and structural applications. Due to its mineral additions, it requires less clinker in its production and is associated with a lower carbon footprint than more clinker-intensive cement types. It is widely used in northern Peru because of its versatility, ease of application and compressive strength development.


●Type HS. Cement used in concrete that is exposed to severe sulfate action, principally where soil or ground water has high sulfate content. It is recommended for port construction, industrial plants and construction of sewage sites.


●Type HE. High-early-strength cement, optimized for structural elements like columns and foundations. Ideal for precast elements and quick formwork removal. It is a cement with strengths similar to Type I but has a lower carbon footprint.


●Type GU. Mochica GU: Cement is a general-purpose hydraulic cement, ideal for non-specialized applications. Ensures good workability and consistent performance in construction projects.


●Type MS. Mochica MS Cement: Sulfate-resistant cement designed for humid and saline soils. Contains mineral additives that enhance durability and protect structures from moisture and salt damage.


●Type I. This type of cement is for general purposes and suitable if special properties are not needed. It is generally used for constructing pavements, floors, reinforced concrete buildings, bridges, reservoirs, pipes, masonry units and precast concrete products. Commonly used in general construction, but has a higher carbon footprint compared to blended cements.


●Type V. Type V cement is used in concrete exposed to severe sulfate action, principally in places where soil or ground water has high sulfate content. It is generally used in hydraulic construction, such as irrigation canals, tunnels, water conduits and drains. While highly durable, it has a higher carbon footprint than blended cements.


We believe that our Type MS, Type HS and Type V cement products are particularly suitable for construction in the northern coastal region of Peru, where sulfate and chloride concentrations from soil, ground water and sea water affect the durability of construction structures. By educating retailers about the different cement characteristics and conducting marketing campaigns, we believe we have been successful in building demand for our cement products. Our research and development department is also equipped to produce custom-tailored cement products on demand. In addition, through our dedicated research and development team, we have significantly reduced the amount of clinker required for cement production, minimizing capital expenditures and substantially lowering carbon dioxide (CO2) emissions. As a company, our goal is to continue increasing the use of blended cements due to their technical, economic and most importantly, environmental benefits.


33


We market and distribute our cement primarily in 42.5 kilogram bags. Most of our bagged cement is sold to the retail sector consisting primarily of households that buy bags of cement to build or expand their own homes over time with little or no formal technical assistance (commonly referred to as self-construction (auto-construcción)). The bags are made of Kraft paper to preserve the quality of the cement. Our bags include information relating to the composition of our cement, handling instructions, production dates and storage instructions. Our cement bags have different colors to easily identify the different types of cement. Once bagged at our Pacasmayo, Rioja and Piura facilities, our cement is loaded onto trucks operated by third parties. Cement in bulk is sold to large industrial consumers.


In 2023, we initiated the certification of all our products under Peru’s mandatory quality certification framework for cement. We selected the most stringent evaluation pathway—Scheme 5—and underwent the certification process with ICONTEC, an internationally recognized certification body for products, services, and management systems. As a result, we successfully certified our entire cement portfolio, achieving the highest level of compliance established by the Supreme Decree regulating the commercialization of cement in Peru. This milestone reinforces our commitment to quality, transparency, and regulatory excellence across all our operations. The certification is grounded in the requirements of the Cement Technical Regulations, which define the physical, chemical, and performance characteristics that cement must meet at both production and commercialization stages. In accordance with these regulations, all cement producers and importers in Peru must comply with these standards to ensure market access and safeguard product reliability. Our certification process involved a comprehensive and rigorous audit of our quality management system, encompassing raw material sourcing, production processes, final product control, storage, distribution, and commercialization. This evaluation was conducted across our three production plants and extended to our authorized points of sale, ensuring full traceability, consistency, and compliance throughout the entire value chain. Maintaining product certification is a mandatory requirement. Under Scheme 5, ongoing compliance is sought through periodic evaluations conducted by ICONTEC at each plant, including production control, product design verification through random sampling, and the assessment of the quality management system. In 2024 and 2025, we successfully maintained our certification with no non-conformities identified, which we believe reflects the robustness and consistency of our quality processes.


Furthermore, in 2024, we implemented Environmental Product Declarations (EPDs) for our Extraforte, Fortimax, and Type I cements, making us the first cement company in Peru to achieve this milestone. These declarations align with the latest requirements of Peru’s Sustainable Building Code, reinforcing our commitment to environmental responsibility and sustainable construction practices.


Concrete Products


We also produce and sell concrete products principally in the form of ready-mix concrete used in large construction sites, as well as precast, bricks, pavers and other precast materials.


●Ready-mix concrete. Ready-mix is a blend of cement, aggregates (sand and stone), admixtures and water. It is manufactured and delivered to construction sites in a form that is ready to use. This mixture hardens to form a building material, ranging from sidewalks to skyscrapers. We have 23 fixed and mobile ready-mix plants.


●Precast. We produce and sell concrete precast products, such as paving units, or paver stones for pedestrian walkways, as well as other bricks for partition walls and concrete precast for structural and non-structural uses. Some examples of concrete precast are:


●New Jersey Walls: safety barriers used to separate traffic flows.


●Corner block: a product that complements the structures built with our precast, giving better functionality to any corner.


34


●Beam block: a product that is used to confine the upper part of walls built with our precast.


●Concrete pipes: precast reinforced concrete pipes that are installed without the need to open pit ditches or dredging of maritime floors. The main use of concrete pipe is to collect seawater (inlet pipe) and to bring brackish water back out to sea (outfall pipe). For example, we have built a 1.5 kilometer long underwater outfall project for the Talara Refinery, where it is necessary to build a water collection system for its fire and cooling system using concrete pipes.


●Sheet piles presented and assembled: concrete piles that can be pre-stressed or reinforced (they are two different types of manufacturing) that sink one alongside the other, forming a containment structure, used as riparian defenses. We manufacture pre-stressed and reinforced sheet piles that can form a coastal defense for rivers, ensuring the containment of water during rainy events, reducing the vulnerability of cities to floods.


●New cement-based products. We have developed, and are in the process of developing more cement-based products that are innovative and easy building solutions. Some of these products are:


●Mortar for brick laying: Pre-dosed and bagged dry masonry mortar for block and brick laying.


●Mortar for plaster: Pre-dosed mortar to plaster interiors and exteriors, walls and ceilings. Allows smooth finishes and thin applications.


●Caravista Concrete: Concrete designed to be exposed without any additional coating or paint.


●Tremie Concrete: Concrete designed to be placed under water at depths greater than 1.5 meters.


●Mortar for brick laying: Pre-dosed and bagged dry masonry mortar for block and brick laying.


●Viaforte Type MH: Cement of moderate heat of special hydration for stabilization of soils and road bases. The cement provides greater workability and less risk of cracking on site, also ensuring greater durability to the structure.


●Bagged Dry Concrete: Pre-dosed mixture of cement, aggregates (Stone and Sand) and additives, that only requires the addition of water indicated on the package and mixing (manual or mechanical) to be used immediately.


Quicklime


We produce and distribute quicklime, which has several industrial uses. Quicklime serves as a neutralizer, lubricant, drying and absorbing material, disinfectant, and as a raw material. Quicklime has various applications, including in the steel, food, fishing and chemical industries. It is also used in mining operations to treat water and industrial residues, in agriculture as a fertilizer enhancer and, to a lesser extent, in other industries. In Peru, quicklime is mainly used in the mining industry, as an additive to treat water residues. We produce quicklime in finely and coarsely ground varieties and sell it either in bags of one metric ton or in bulk, according to clients’ requirement. Quicklime currently represents a small percentage of our revenues.


35


Production Process


Cement Production Process


The diagram below depicts the standard cement production process, which consists of the following main stages:


●extraction and transportation of limestone or coquina (seashells) from the quarry;


●grinding and homogenization to make the raw material of consistent quality;


●clinkerization;


●cement grinding;


●storage in silos; and


●packaging, loading and distribution.


Extraction of raw materials. To produce cement, limestone/coquina are extracted from our quarries. We use explosives to loosen the limestone and deploy bulldozers to remove dirt and the overburden covering the limestone. We crush the limestone in our primary and secondary cone crusher and the resulting limestone is loaded into trucks and hauled to our Pacasmayo facility from the adjacent quarry where it is stored. In the case of Piura, our surface miner drills out our coquina quarry and then it is also loaded into trucks and hauled to the Piura plant.


36


Grinding and homogenization. Limestone/coquina, clay and sand are mixed with iron that is acquired from third parties. The quality of the resulting raw meal is monitored by examining samples of each batch and processing them through our quality control x-ray software that automatically measures the mix of materials to confirm the blend is in compliance with our quality standards. Subsequently, the raw meal is sent to a blending silo and then to a storage silo from where it is fed into the pre-heater.


Clinkerization. The raw meal is heated at a temperature of approximately 1,450 degrees Celsius in our kilns. The intense heat causes the limestone and other materials in the mixture to react inside the kiln, turning the mixture into clinker. Clinker is then cooled to a temperature of approximately 200 degrees Celsius and stored in a silo or in an outdoor yard.


Cement grinding. After being cooled, clinker, together with gypsum and some admixtures, is fed into a ball mill or into a vertical roller mill where it is ground into a fine powder to produce cement. In this form, cement reacts as a binding agent that, when mixed with water, sand, stone and other aggregates, is transformed into concrete or mortar.


Storage in silos. After passing through the ball mills, the cement is transferred on conveyor belts and stored in concrete silos in order to preserve its quality until distribution.


Packaging, loading and transport. Cement is transferred through another conveyor belt from the silo to be packaged in 42.5 kilogram bags and then loaded into trucks operated by third parties to be transported for distribution. Bulk cement may be transported (unpackaged) on especially designed trucks that deliver large amounts of cement directly to the work site.


Quicklime Production Process


Quicklime is produced by crushing limestone with a calcium carbonate content of at least 95% by calcinating it in a rotary kiln. The limestone for quicklime comes from our quarries. The crushing of the limestone is done at the quarry and the calcination process takes place only at our Pacasmayo facility. We produce quicklime in finely and coarsely ground varieties and sell both varieties in big bags as well as in bulk.


Raw Materials and Energy Sources


Limestone and Other Calcareous Resources


We obtain limestone required to produce clinker and quicklime principally from land where we have concession rights. For our Pacasmayo plant, we extract limestone from our Acumulación Tembladera quarry located approximately 60 kilometers from the plant, and for our Rioja plant, we extract limestone from our Calizas Tioyacu quarry which is adjacent to our Rioja plant. For our Piura plant, we extract coquina from Virrilá quarry, located approximately 120 kilometers from the plant.


Acumulación Tembladera. We have a concession with an indefinite term to extract limestone and other minerals from our Acumulación Tembladera quarry, a 3,390 hectares open-pit mine located in the district of Yonan, in the department of Cajamarca. We acquired this concession in November 2002.


Calizas Tioyacu. For our Rioja production, we have a concession with an indefinite term to extract limestone and other minerals from a 400 hectares open-pit mine near our Rioja facility in the district of Elias Soplin Vargas, in the department of San Martín. We acquired this concession in February 1998.


37


Virrilá. For our Piura production, we also have a group of concessions with an indefinite term to extract coquina and other minerals from our Virrilá quarry, a 931 hectares open-pit mine located in the district of Sechura, in the department of Piura. We acquired these concessions between 2000 and 2008.


Bayóvar 4. For our Piura production, we also have rights with an indefinite term related to extract coquina and other minerals from our Bayóvar 4 quarry, a 22,326-hectare open-pit mine located in the district of Sechura, in the department of Piura. We entered into this agreement in October 2007.


In addition to our Acumulación Tembladera, Calizas Tioyacu, Bayovar 4 and Virrilá quarries, we also own concession rights to various other calcareous material quarries consisting, in total, of approximately 40,767 hectares located in the northern region of Peru. None of these quarries are in operation as of the date of this annual report on Form 20-F.


Clay, Sand and Other Raw Materials and Admixtures


The other raw materials that we use to produce clinker are clay, sand and iron, as well as other admixtures.


Clay


For cement production in our Rioja facility, we extract clay from our Pajonal quarry, a 400 hectares open-pit concession located in the district and province of Rioja, department of San Martin. This concession was granted to us by the MEM in 1998. The term of the concession is indefinite, provided we pay an annual concession fee and meet minimum annual production requirements.


We have not calculated our clay reserves, as we believe there is an abundant supply of clay in our concessions and more broadly in the northern region where we operate.


Sand


For cement production in our Pacasmayo facility, we use sand which we buy from third parties. Our Rioja facility does not utilize sand as a raw material given the type of cement it produces.


We have not calculated our sand reserves, as we believe there is an abundant supply of sand in our concessions and more broadly in the northern region where we operate.


Iron


We use small quantities of iron in our cement production, which we purchase from third parties at market prices.


Coal


We purchase mostly anthracite coal from local suppliers and small amounts of semi-bituminous coal from local suppliers, in each case at spot market prices. Anthracite coal tends to be less expensive than bituminous coal. We store coal at our premises and in our warehouse facilities, adjacent to the Salaverry port and in Trujillo, where we currently have sufficient stock of coal to maintain our production levels for the next year.


In December 2009 and February 2010, we entered into option agreements to acquire coal mining concessions as a means to secure a steady and reliable source for our coal requirements and to reduce the volatility in costs related to coal. In 2011, we exercised certain options under these agreements to acquire coal mining concessions for 908.5 hectares near our Pacasmayo facility for a total purchase price of US$4.5 million. In 2013, we exercised our remaining options to purchase an additional coal mining concession for 501.2 hectares for US$1.0 million, thereby completing the acquisition of the related coal mining concessions.


38


Pozzolanic Materials and Other Admixtures


Our cement production also requires small amounts of other admixtures, such as pozzolanic materials, gypsum and blast furnace slag.


For cement production in our Pacasmayo facility, we use pozzolanic materials obtained from our Cunyac quarry, a 200 hectares open-pit concession located in the district of Sexi, province of Santa Cruz, department of Cajamarca. The concession was granted to us by the MEM in 2008. The term of the concession is indefinite, provided we pay an annual concession fee and meet minimum annual production requirements.


We also own several other concessions containing pozzolanic material which have not currently been explored. In addition, our use of pozzolanic materials may be substituted with clinker or other admixtures. Other admixtures, such as gypsum and blast furnace slag, are purchased at market prices from third-party suppliers. If we are unable to acquire raw materials or admixtures from current suppliers, we believe that other sources of raw materials and admixtures would be available without significant interruption to our business.


Energy Sources


Electricity


As of December 31, 2025, all of the electricity requirements for our Pacasmayo and Piura facilities were supplied by Electroperú, and all of the electricity requirements for our Rioja facility were supplied by ELOR.


We have a long-term electricity supply agreement with Electroperú S.A. to serve our Pacasmayo and Piura facilities through May 2026, after which Orygen Perú S.A.A. will supply electricity to those facilities from June 2026 through May 2031 and an agreement with Electro Oriente S.A. (ELOR) for our Rioja facility through December 2029. Our electricity costs are subject to adjustment formulas that take into consideration market variables such as the U.S. Producer Price Index (PPI) and global energy prices. As approximately 18.3% of our total costs are denominated in or indexed to the U.S. Dollar, the combination of high global energy prices and a potential depreciation of the Sol could result in a “double impact” on our margins. 


In addition, we have an electricity supply contract with ELOR to supply our Rioja facility through December 2029. ELOR supplies the Rioja facility with 6.7 megawatts of electricity during peak hours and 8.0 megawatts during off-peak hours. Payments for electricity are based on a formula that takes into consideration our energy consumption and certain market variables, such as the U.S. Dollar exchange rate, inflation, the local price of natural gas, the global price of oil and the import price of bituminous coal.


Other Production Materials


We use other materials in the cement production process, including paper bags to package cement, which we purchase principally from local suppliers; plastic bags used to package quicklime, which we purchase from local suppliers; and water to cool the kiln exhaust gases and for our crushing operations at our Acumulación Tembladera quarry, which we obtain principally from a well located at our Pacasmayo facility and from the Jequetepeque river. Water used in our production process is maintained in a closed system at our plants and re-processed for utilization in our production process.


Consumer Base


The retail cement sector in Peru is characterized by households that purchase single bags of cement to gradually build or improve their homes with little or no professional assistance. This sector is known as self-construction (auto-construcción). Families in this sector tend to invest a large portion of their savings in building or improving their own homes. Self-construction (auto-construcción) is often conducted with the help of a foreman (maestro de obra) who generally has experience in construction. Our retail marketing plans typically target the maestro de obra who is usually the decision maker when buying cement and other related construction materials.


We also sell directly to small, medium and large private construction companies working on a variety of construction projects, from housing complexes to commercial developments. In the public sector, we provide cement for national, regional and local governments carrying out construction projects including housing complexes and public construction, ranging from local schools and hospitals to large infrastructure.


39


Sales and Distribution


Distribution


Our market extends from the Ecuadorian border in the north of Peru to the city of Barranca in the south (approximately 180 kilometers north of Lima), to the rainforest in the east and the Pacific Ocean in the west. Our market covers the provinces of Amazonas, Cajamarca, La Libertad, Lambayeque, Piura and Tumbes in the north; and San Martín and Loreto in the northeast.


Our Pacasmayo, Piura and Rioja facilities supply the entire northern region of Peru, interchangeably subject to where it is most efficient to ship from at the moment, depending on the distance and type of cement being produced, among other factors.


In 2025, approximately 81.4% of our total cement shipments were in the form of bagged cement, substantially all of which was sold through retailers both within and outside of our distribution network. The remaining 18.6% of our cement was sold in bulk or in shipments of precast products or ready-mix concrete directly to large construction companies.


We have developed one of the largest independent retail distribution networks for construction materials in Peru, consisting of 334 hardware stores, with which we have a distribution agreement. In addition, we also distribute to other independent retailers located throughout the northern region of Peru with whom we do not have contractual relationships. We have built our distribution network by investing in strengthening our relationship with retailers.


Even though our ready-mix sales are still a small proportion of our sales, we expect this trend to change as infrastructure becomes a bigger driver of demand in the upcoming years. Additionally, we sell and distribute other construction materials manufactured by third parties that are used alongside cement, such as steel rebar, plastic pipes and electrical wires, among others.


Marketing and Brand Awareness


We use our distribution network, together with our strategically located local commercial offices, to promote our products and brands, as well as to keep us informed of market developments. We believe our distribution network has enabled us to build strong recognition for our Pacasmayo brand among maestros de obra, retailers and end consumers which we believe is important to our business, particularly because our cement is principally sold in bags to retail consumers.


Our marketing expenses in 2025 were approximately S/15.6 million, or 0.74% of our sales. Historically, our marketing strategy has been to develop brand loyalty by providing high-quality products, tailored to the needs of our customers, and customer service accompanied by complimentary training for the maestros de obra, who are typically the decision makers in the self-construction (auto-construcción) segment.


We seek to develop strong ties with our distributors by promoting income generating opportunities for them. For instance, we give them priority when hiring transportation to distribute our cement throughout our territory. Also, our large salesforce has the ability to cover most of the construction sites in northern Peru generating business opportunities that are then channeled through our distributors. Finally, our distributors enjoy various commercial and marketing benefits such as rebates, special promotions, special credit conditions, and loyalty programs.


We have been working consistently in recent years to focus time and attention on our client’s needs, in an effort to go beyond just selling cement and its byproducts, to providing solutions and innovating. The self-construction segment has been the primary driver behind the growth in sales volume in the past couple years. We have focused on several fronts to enhance the customer experience and to facilitate access to our solutions. We have developed Mundo Pacasmayo (Pacasmayo World), which is a virtual ecosystem made up of digital solutions that serves to join supply and demand and offers a superior purchasing experience leveraged on intensive use of technology to generate more value for our users. The digital solutions are targeted and customized for the different users, such as foremen, hardware stores, and the self-builder.


Quality Control


In Peru, cement production is subject to standardization (normalización) regulations approved by the National Institute for the Protection of Competition and Intellectual Property (Instituto Nacional de Defensa de la Competencia y de la Protección de la Propiedad Intelectual, or “INDECOPI”). Although the standardization regulations are not mandatory, they are useful in achieving an optimum level of management. As of the date of this annual report on Form 20-F, we comply with all standardization regulations applicable to our products.


40


We have established a quality assurance program in accordance with ISO Standard 9001-2008, certified by SGS del Perú S.A.C., a company that provides inspection, verification, testing and certification services. We monitor quality at every stage of the cement production process. In our facilities, we periodically test the quality of our raw materials. These tests include chemical, physical and x-ray tests. We perform similar examinations of the clinker we produce. Additionally, we also perform regular quality tests on our finished products.


We have a quality control area with computerized systems to access real-time information on the quality of our products. As part of our quality control process, we monitor the performance of our different cement products, monitor the performance of additives in our cement and review monthly statistical analysis on the resistance of cement, among other things.


In 2023, we initiated the certification of all our products under Peru’s mandatory quality certification framework for cement. We selected the most stringent evaluation pathway—Scheme 5—and underwent the certification process with ICONTEC, an internationally recognized certification body for products, services, and management systems. As a result, we successfully certified our entire cement portfolio, achieving the highest level of compliance established by the Supreme Decree regulating the commercialization of cement in Peru. This milestone reinforces our commitment to quality, transparency, and regulatory excellence across all our operations. The certification is grounded in the requirements of the Cement Technical Regulations, which define the physical, chemical, and performance characteristics that cement must meet at both production and commercialization stages. In accordance with these regulations, all cement producers and importers in Peru must comply with these standards to ensure market access and safeguard product reliability. Our certification process involved a comprehensive and rigorous audit of our quality management system, encompassing raw material sourcing, production processes, final product control, storage, distribution, and commercialization. This evaluation was conducted across our three production plants and extended to our authorized points of sale, ensuring full traceability, consistency, and compliance throughout the entire value chain. Maintaining product certification is a mandatory requirement. Under Scheme 5, ongoing compliance is sought through periodic evaluations conducted by ICONTEC at each plant, including production control, product design verification through random sampling, and the assessment of the quality management system. In 2024 and 2025, we successfully maintained our certification with no non-conformities identified, which we believe reflects the robustness and consistency of our quality processes.


Competitive Position


Peru’s cement production is segmented into three main geographic regions: the northern region, the central region, including Lima’s metropolitan area, and the southern region. We are the only cement manufacturer in the northern region of Peru. The central region is principally served by UNACEM (formerly known as Cementos Lima and Cemento Andino), some imports, Caliza Cemento Inca and Holcim. The south is principally served by Cementos Yura. In 2025, our cement shipments were approximately 3.0 million metric tons, representing an estimated 22.4% share of total cement shipments in Peru according to INEI.


Regulatory Matters


Overview


Although our core business is the production of cement, we hold a number of mining concessions granted by the Peruvian government for the supply of limestone and other raw materials required for cement production. As a result, we are subject both to the mining and the general industrial legal framework in Peru. The regulatory framework applicable to our cement production may be divided into rules and regulations relating to: (i) the mining and crushing of limestone and clay; and (ii) the production process.


Mining Regulations


The General Mining Law (Texto Único Ordenado de la Ley General de la Minería) approved by Supreme Decree No. 014-92-EM, published in the Peruvian Official Gazette, El Peruano, on June 3, 1992, is the primary law governing both metallic and non-metallic mining activities in Peru and is supplemented by implementing guidelines and policies regarding mining and the processing of minerals enacted by the MEM. Under the General Mining Law, mining activities (except storage, reconnaissance, prospecting and trade) are carried out exclusively through various forms of concessions. Mining concessions are granted by the Geological, Mining and Metallurgical Institute (Instituto Geológico Minero y Metalúrgico, or “INGEMMET”), and all other concessions, including our mineral processing concessions, are granted by the Directorate General for Mining of the MEM. Any act, transfer, termination or agreement related to these concessions must be registered with the Mining Rights Registry, which is part of the National Public Registry System, to be effective against the Peruvian government and third parties.


41


Holders of concessions or mining claims must comply with several obligations, including the payment of an annual concession fee (derecho de vigencia) of US$3.00 per applicable hectare. The annual concession fee is due and payable on or prior to June 30 of each year. Failure to pay the annual concession fee for two consecutive years will result in the termination of the mining concession.


Mining activities require holders to obtain title to the surface land from individual landowners, peasant communities or the Peruvian government. Mining concessions are granted for an unlimited period, subject to the achievement of minimum annual production levels. Two different regimes apply depending on the date the concession was granted:


Under Legislative Decree No. 1320 and Supreme Decree No. 011-2017-EM, since January 1, 2019, if the annual minimum production or investment has not been met, the annual penalty and the causes to terminate a mining concession will be determined by the General Mining Law for all concessions, as described below.


For concessions granted until 2008, the following rules apply:


●the minimum annual production target is equivalent to one tax unit (approximately S/5,500 or US$1,635.4) per year per hectare, in case of metallic mining concessions, and 10% of one tax unit (approximately US$163.5) per year per hectare, in the case of non-metallic mining concessions;


●the minimum production level is to be achieved no later than the end of the tenth year from the date of grant;


●if the minimum production level is not achieved within that period, an annual penalty equivalent to 2% of the minimum annual production level is due until such level is achieved;


●if the minimum production level is not achieved by the end of the fifteenth year, an annual penalty equivalent to 5% of the minimum annual production level is due until such level is achieved;


●if the minimum production level is not achieved by the end of the twentieth year, an annual penalty equivalent to 10% of the minimum annual production level is due until such level is achieved; and


●if the minimum production level is not achieved by the end of the thirtieth year, the mining concession expires.


Any penalty must be paid prior to June 30 of each year. Failure to pay the penalty for two consecutive years results in the termination of the mining concession.


Since January 1, 2020, these penalties are applied to concessions granted in 2009 and thereafter.


The foregoing penalties and fines are not applicable to mining concessions granted by the government through private investment promotion initiatives, which will be subject to the minimum production and investment levels set forth in such contracts.


42


In addition to the payment of the annual concession fee and the penalty, holders of mining concessions must, pursuant to the Mining Royalty Law, pay a royalty for the exploitation of metallic and non-metallic resources. Prior to the amendment of the Mining Royalty Law described below, the amount of the royalty was determined on a monthly basis. For those minerals with an international market price (gold, silver, copper, zinc, lead and tin), the amounts were computed by applying the rates to the value of the concentrate or its equivalent, according to the applicable international market price. The historic rate scales were established in the Mining Royalty Law’s regulations as shown in the following table:


Annual sales (in millions of US$)   Rate  
Up to 60     1 %
Between 60 and up to 120     2 %
More than 120     3 %


In case of minerals without an international reference market price (minerals other than gold, silver, copper, zinc, lead and tin), the mining royalty amounted to 1% of the value of the final product obtained from the mineral separation process, net of any costs incurred in the mineral separation process (componente minero).


However, the Mining Royalty Law was amended on September 29, 2011 to increase the tax payable on metallic and non-metallic mineral resources. Effective October 1, 2011, the royalty for the exploitation of metallic and non-metallic resources is payable on a quarterly basis in an amount equal to the greater of (i) an amount determined in accordance with the following statutory scale of tax rates based on a company’s operating profit margin and applied to the company’s operating profit, as adjusted by certain non-deductible expenses, and (ii) 1% of a company’s net sales, in each case, during the applicable quarter. The royalty rate applied to the company’s operating profit is based on its operating profit margin according to the following statutory scale of rates:


Operating Margin   Applicable
Rate (%)
 
0% - 10%     1.00  
10% - 15%     1.75  
15% - 20%     2.50  
20% - 25%     3.25  
25% - 30%     4.00  
30% - 35%     4.75  
35% - 40%     5.50  
40% - 45%     6.25  
45% - 50%     7.00  
50% - 55%     7.75  
55% - 60%     8.50  
60% - 65%     9.25  
65% - 70%     10.00  
70% - 75%     10.75  
75% - 80%     11.50  
More than 80%     12.00  


Mining royalty payments will be deductible for income tax purposes in the fiscal year in which such payments are made.


43


We believed that certain portions of the regulations of the Mining Royalty Law were unconstitutional, because they impose a mining royalty tax on non-mining activities. For instance, for cement companies, the amended Mining Royalty Law and its regulations established that the mining royalty tax was calculated based on the total operating profit or net sales, as opposed to operating profit or net sales attributable exclusively to mining products, such as limestone, used to produce cement. Accordingly, in December 2011, we filed a claim to declare that the mining royalty tax applicable for the exploitation of non-metallic mining resources be calculated based on the value of the final product obtained from the mineral separation process, net of any costs incurred in the mineral separation process (“componente minero”).


In November 2013, the Peruvian Constitutional Court affirmed the constitutional challenge we filed against the new regulation of the Mining Royalty Law, in a final and unappealable ruling, on the grounds that the new regulation violates the constitutional right of property, as well as the principles of legal reserve and proportionality. Therefore, the new regulation is rendered inapplicable to our operation. As a result, we continued to use as a basis for the calculation of the mining royalty the value of the concentrate or mining component, and not the value of the product obtained from the industrial or manufacturing process.


On March 22, 2021, the Company received Tax Court Resolution No. 00905-4-21 that declared the Mining Royalty should be calculated based on the total operating profit or net sales, as opposed to operating profit or net sales attributable exclusively to mining products, such as limestone, used to produce cement, for the years 2008 and 2009. This contradicted what was established by the Constitutional Court mentioned above. Considering this contradiction, the Company initiated two legal proceedings: (i) a constitutional process to denounce the repression of homogeneous harmful acts, filed on March 31, 2021; and, (ii) a contentious-administrative claim filed before the ordinary court, the object of which was the annulment and return of collateral, filed on June 22, 2021.


As of the date of this annual report on Form 20-F, both proceedings were ruled in favor of the Company. As a result, the SUNAT should, either directly or through enforcement, return the amounts paid by the Company in respect of the Tax Court Resolution described above, amounting to S/29,559,000. As of August 20, 2025, SUNAT made a partial refund of S/18,441,000, leaving an outstanding balance of S/11,118,000 to be collected as of December 31, 2025. In the opinion of management and its external legal advisors, there is a very high probability of obtaining this amount in full.


Finally, holders of mining concessions are required at the beginning of their operations to submit a mining closure plan that must contain a description of the steps to restore the areas and facilities of each mining operation area to pre-mining condition. Holders of mining concessions are required to secure completion of the restorative measures by means of the following guarantees: (i) banking guarantee or credit insurance; (ii) cash guarantees; (iii) trusts; or (iv) those indicated in the Peruvian Civil Code.


In August 2021, Law No. 31347, that modifies the Mine Closure Law (Law No. 28090), specifying aspects such as mandatory, administrative and oversight powers, opportunity for presentation and approval, applicable guarantees, periodic reports to be presented to various authorities, among others was approved.


As of December 31, 2025, we primarily owned non-metallic mining concessions and limited metallic mining concessions with respect to iron. Substantially all of our concessions were granted prior to 2008. Our mining rights and concessions are in full force and effect under applicable Peruvian laws. We believe that we were in compliance in all material respects with the terms and requirements applicable to our mining rights and concessions.


Production Process


The cement production process along with other manufacturing activities are governed by General Industry Law (Ley General de Industrias), Law No. 23407, published in El Peruano on May 29, 1982, which establishes basic rules that promote and regulate activities in the manufacturing industry. The Ministry of Production is vested with authority to promote private investments in connection with industrial, processing and manufacturing activities, the surveillance of sustainable exploitation of natural resources (except for those extractive activities involving primary transformation of natural products), the protection of the environment, and the supervision of the quality of manufactured products. All industrial companies are subject to the General Industry Law and its regulations to the extent that the company’s gross income is primarily derived from industrial activities. Pursuant to Supreme Decree No. 009-2011-MINAM, the supervisory and monitoring functions of the Ministry of Production were transferred to the OEFA in 2013.


44


Technical Regulation on Hydraulic Cement


On January 21, 2022, the Government published D.S. 1-2022-PRODUCE, which approves the Technical Regulation on hydraulic cement used in buildings and constructions in general, to clarify minimum cement safety compliance requirements. Such regulation entered into force on July 22, 2023, pursuant to D.S. 10-2022-PRODUCE.


Environmental Regulations


Industrial companies, and in particular those in the cement sector, are required to comply with various environmental regulations, such as the Law on the national environmental impact assessment system approved by Legislative Decree No. 27446 and its regulations approved by Supreme Decree No. 019-2009-MINAM, which establish the environmental impact assessment process. Public and private investment projects that involve activities, constructions or works that may cause negative environmental impacts must comply with this law. Projects are categorized according to environmental risk under this law.


The environmental management regulations for the manufacturing industry and internal trade, approved by Supreme Decree No. 017-2015-PRODUCE, as amended, promote and regulate environmental management, as well as the conservation and sustainable use of natural resources in the development of manufacturing and domestic trade activities. It also regulates the application of management instruments, procedures, environmental protection measures and promotes cleaner production agreements, giving priority to the principle of prevention.


In terms of air emissions, the Ministry of the Environment has adopted legally binding environmental quality standards (maximum permissible limits) for cement industries (approved by Supreme Decree No. 001-2020-MINAM). These standards are legally enforceable and must be met by all operations in the cement industry.


Resolution No. 004-2018-OEFA/CD and 006-2018-OEFA/CD define administrative infractions and establish a scale of penalties related to environmental management instruments and obligations related to monitoring, environmental management, the development of industrial activities and the handling of hazardous materials and inputs. applicable to those administered in the manufacturing industry and domestic trade sector that are under the scope of competence of the Environmental Assessment and Control Agency. Infractions are classified according to their severity as minor, serious and very serious offenses and the monetary penalty imposed will depend on this.


By means of Board of Directors Resolution No. 023-2013-OEFA/CD and No. 0312015-OEFA/CD, of the Environmental Assessment and Control Agency (Organismo de Evaluación y Fiscalización Ambiental – “OEFA”), OEFA is in charge of the monitoring, supervision, control and sanction in environmental matters in the cement and concrete sector of the manufacturing industry, of the industrial subsector of the Ministry of Production - PRODUCE.


The Law on Integrated Solid Waste Management approved by Decree Law No. 1278 and its regulations approved by Supreme Decree No. 014-2017-MINAM and its amendments, seek to ensure the constant maximization of efficiency in the use of materials, and to regulate the management and handling of solid waste, which includes the minimization of the generation of solid waste at the source. the material and energy recovery of solid waste, as well as the proper final disposal of the same.


Law No. 30754, published on April 18, 2018, approved the Framework Law on Climate Change. This law establishes the principles, approaches, and general provisions for coordinating, articulating, designing, executing, informing, monitoring, evaluating, and disseminating public policies for the comprehensive, participatory, and transparent management of climate change adaptation and mitigation. It also established that the Ministry of the Environment shall set guidelines to incorporate climate risk and vulnerability analysis, as well as climate change mitigation and adaptation measures, in the evaluation of investment projects subject to the National Environmental Plan Impact Assessment System.


This law aims to reduce the country’s vulnerability to climate change, take advantage of low-carbon growth opportunities, and comply with the international commitments assumed by the government of Peru before the United Nations Framework Convention on Climate Change, with an intergenerational approach.


45


The Regulations of the Framework Law on Climate Change were approved on December 31, 2019, by Supreme Decree No. 013-2019-MINAM. The objectives set out in these Regulations will be achieved through the implementation of climate change adaptation and mitigation measures, the creation of systems that contribute to the accounting of carbon dioxide emissions, the reduction of carbon dioxide emissions and the promotion of private sector participation in implementation. of sustainable and low-carbon projects. As of the date of this annual report on Form 20-F, however, no concrete measures or targets have been set, nor have any deadlines been set for their implementation.


There is currently no type of emissions trading scheme in Peruvian law.


On January 25, 2022, Supreme Decree No. 003-2022-MINAM was published, declaring a climate emergency of national interest and establishing guidelines and priority actions for climate change mitigation and adaptation.


In September 2023, the International Sustainability Standards Committee issued the first international sustainability and climate standards: IFRS S1 General Requirements for the Information to be Disclosed on Sustainability related to Financial Information and IFRS S2 Weather-related Disclosures. The purpose of these standards is for entities to disclose information about their risks and opportunities related to sustainability and climate that is useful to the primary users of financial information for decision-making. The Company is currently assessing these standards and the methodology for their implementation.


In March 2026, the application of these standards became a legal requirement, formalized by Resolution No. 001-2026-EF/30. Its objective is to establish a common framework that allows companies and institutions to disclose information about their risks and opportunities related to sustainability and climate that is useful to the primary users of financial information for decision-making. This resolution is expected to come into force in January 2029.


Since 2025, Cementos Pacasmayo has been participating in the DivulAcción IFRS S2 program, promoted by LACADI (Latin American Climate Asset Disclosure Initiative) and funded by Germany’s Federal Ministry for Economic Affairs and Climate Action (BMWK) through the International Climate Initiative (IKI). This program aims to accelerate the disclosure of climate-related financial information. It was carried out in five phases: assessment; analysis of physical and transition risks; evaluation of resilience and identification of strategic areas; preparation of the proposed disclosure; and integration of climate change into corporate governance. As a result, a draft IFRS S2 report has been prepared in collaboration with the risk, accounting and finance, climate change, and sustainability teams, and is expected to be published by the end of June 2026.


Prior Consultation with Local Indigenous Communities


On September 7, 2011, Peru enacted Law No. 29785, Prior Consultation Right of Local Indigenous Communities. The law was enacted in order to implement Convention No. 169 of the International Labor Organization on Local Indigenous Communities in Independent Countries, previously ratified by Peru through Legislative Decree No. 26253. This law, which became effective on December 6, 2011, establishes a prior consultation procedure to be undertaken by the Peruvian government in favor of local indigenous communities, whose collective rights may be directly affected by new legislative or administrative measures, including the granting of new mining concessions. Regulation implementing this law was approved on April 3, 2012, by Supreme Decree No. 001-2012-MC, which defines the local indigenous communities that are entitled to the prior consultation rights and establishes the different stages that comprise the prior consultation procedure.


Consultation procedures for mining and processing concessions are carried out by the MEM prior to the granting of a new processing concession.


According to the recent practice of the Geologic Institute of Mining and Metallurgy (Instituto Geológico Minero Metalúrgico), the granting of mining concessions does not qualify as an “administrative measure” that potentially affects the rights of indigenous people because it does not grant per se a right to explore and exploit mineral deposits. Accordingly, the granting of mining concessions has not been included among measures that require consultation procedures with indigenous people. According to Ministerial Resolution No. 003-2013-MEM-DM, the MEM has established that consultation procedures are applicable prior to the commencement of: (i) exploration activities (Autorización de inicio de actividades de exploración); (ii) exploitation activities (Autorización de inicio o reinicio de las actividades de desarrollo, preparación y explotación - incluye plan de minado y botaderos); and (iii) processing concessions (otorgamiento de concesión de beneficio).


46


Local indigenous communities do not have a veto right; upon completion of this prior consultation procedure, the Peruvian government can discretionarily approve or reject the applicable legislative or administrative measure. In addition, any sale, lease or other act of disposal of surface land owned by local indigenous communities is subject to the approval of an assembly composed of the members of such communities according to the following rules:


●for local indigenous communities located on the coast, approval of not less than 50% of members attending the assembly is required; and


●for local indigenous communities located in the highlands and the Amazon region, approval of at least 2/3 of all members attending the assembly is required.


Permits and Licenses


Mining Concessions


According to the General Mining Law, a mining concession is required in order to extract mineral resources needed to produce cement. The mining concession grants the right to explore and exploit the mineral resources located in a solid of indefinite depth, limited by the vertical plane corresponding to the sides of square, rectangle or polygon referred to by the Universal Transversal Mercator coordinates. The Geological Mining and Metallurgical Institute (Instituto Geológico Minero y Metalúrgico) is in charge of managing the procedure of granting mining concessions, which includes the receipt of the request, the granting and the termination of mining concessions.


Explosives.


Mining concessionaires are required to obtain the following permits to operate and store explosives:


●Certificate of Mining Operation (Certificado de Operación Minera), granted by the MEM;


●Semiannual Authorization for Use of Explosives, granted by the General Bureau of Explosives of the Ministry of Interior (Superintendencia Nacional de Control de Servicios de Seguridad, Armas, Municiones y Explosivos de Uso Civil, or “SUCAMEC”);


●Manipulation of Explosives License for each individual that intends to handle explosives, granted by the SUCAMEC; and


●Explosive’s Warehouse Operation License, granted by SUCAMEC.


Water and Wastewaters


To use water resources in cement industry activities, it is necessary to obtain a water right granted by the Water Management Authority (Autoridad Nacional del Agua, or “ANA”) prior to the use of underground or fresh water sources. If the proposed activities will generate domestic or industrial wastewaters, which will be discharged into natural water sources or soil, authorization from ANA is required, with a favorable opinion of the General Bureau of Environmental Health (Dirección General de Salud Ambiental, or “DIGESA”).


Hazardous Waste


Hazardous waste generated as a consequence of cement production activities must be disposed of in specialized landfills. The transportation of solid waste outside the limits of the industrial complex must be conducted exclusively through specialized companies registered with DIGESA and MINAM. Industries are free to contract with an EO-RS (a company that provides solid waste services such as transportation, treatment or disposal) or with an EC-RS (a company that carries out commercialization activities aiming at the reuse of solid waste). Yet in order to limit their liability in case of environmental harm, industries must make sure the EO-RS and EC-RS they retain count with all necessary permits to collect, transport and dispose of hazardous wastes.


47


Chemical Feedstock


The commercialization, transportation and use of controlled chemical feedstock (Insumos Químicos y Productos Fiscalizados, or “IQPF”) is restricted, because of their potential use in the production of illegal drugs or controlled substances. Companies that require an IQPF must obtain an IQPF User Certificate (Certificado de Usuario de IQPF) from the General Bureau of Chemical Feedstock of the Ministry of Interior (Unidad Antidrogas de la Policía Nacional del Perú, or “DIRANDRO”). Companies such as ours are also required to register with the Ministry of Production any IQPF activities they plan to carry out (Registro Único para el Control de IQPF).


Fuel Storage


Any company that purchases fuels for its own activities and has facilities to receive and store fuel with a minimum capacity of one meter cubed (264.170 gallons) is required to (i) receive from the Mining and Energy Investment Supervision Body (Organismo Supervisor de la Inversión en Energía y Minería, or “OSINERGMIN”) prior permission to build and operate said installations, and (ii) be registered with the Registry of Direct Fuel Consumers, in order to obtain the SCOP Code (Código del Sistema de Control de Órdenes de Pedido) necessary to purchase fuel.


Cultural Heritage Protection


If the design and development of cement industry activities involves the removal of topsoil, a Certificate of Non-Existence of Archaeological Ruins (Certificado de Inexistencia de Restos Arqueológicos, or “CIRA”) from the Ministry of Culture (Ministerio de Cultura) with respect to the area under construction must be obtained. The CIRA shall either certify that on the surface of the evaluated area no archaeological sites or features were discovered or shall identify their exact location and extent in order to implement precautionary measures to protect the archaeological artifact. The CIRA is valid for an unlimited period but will become void should any archaeological artifacts be accidentally discovered during the construction works or due to any natural cause. In such an instance, the company must stop the construction work immediately and notify the Ministry of Culture. Failure to stop the construction work may generate civil and criminal liabilities. Under certain exceptional circumstances, Peruvian legislation allows the removal of archeological artifacts when the area is required for development of projects that are of national interest.


Labor Regulations


Peruvian legislation allows hiring employees through: (i) a fixed-term contract, (ii) a contract for an indefinite duration; or (iii) a contract for part-time employment.


Effective January 1, 2025, the minimum monthly wage established in Peru is S/1,130 per month. Peruvian labor legislation establishes a maximum 8-hour work day or 48 hours per week for employees older than 18 years. For overtime, employers must pay at least an additional 25% and an additional 35% over the regular hourly wage for the first two hours and for any additional hours, respectively. Employees are entitled to a minimum rest of 24 consecutive hours per week.


Regardless of the type of employment contract, pursuant to Peruvian law full-time employees are entitled to receive:


(i) an additional 10% of the minimum wage, provided that they are responsible for (a) one or more children under the age of 18 or (b) persons who are up to 24 years of age if they are pursuing higher education,


(ii) two additional months’ salary per year, one in July and one in December (pursuant to Law No. 29351, said payments were not subject to any social contribution, except for income tax; consequently, employers paid directly to their employees as an extraordinary bonus, the amount of the contribution to the Social Health Insurance (ESSALUD) for such payments, equivalent to 9% of the bonus paid),


(iii) thirty calendar days of annual paid vacation per year,


(iv) life insurance, since the first day at work,


48


(v) a compensation for years of service (CTS) equal to 1.16% of a monthly salary and is deposited each year in May and November, provided they work an average of at least four hours per day for the same employer,


(vi) benefits from the Peruvian Social Health Insurance (ESSALUD) to which employers must contribute a rate equivalent to 9% of their employees’ income, and


(vii) a percentage of the company’s annual income net of taxes (10% in the case of income derived from industrial cement operations, and 8% in the case of income derived from our mining or commercial activities), provided the company has twenty or more employees.


On June 25, 2021, Law No. 31246 was published, which modified the current Law on Safety and Health at Work to guarantee the right of workers to safety and health at work in the face of epidemiological and health risk.


Free and Fair Competition Protection


In Peru, businesses are generally not required to receive the prior authorization of the antitrust authority, which in Peru is INDECOPI. However, in order to promote economic efficiency and protect consumers, anti-competitive behavior is subject to sanctions under applicable law. Behavior that is prohibited according to national law includes: (i) the abuse of a dominant market position, (ii) concerted horizontal practices and (iii) concerted vertical practices. Moreover, under the Unfair Competition Law it is illegal to act in a way that may hinder the competitive process. An unfair behavior is one that is objectively contrary to the entrepreneurial good faith, ethical behavior and efficiency in a market economy.


On January 7, 2021, Law No. 31112, Law that establishes the Prior Control of Business Concentration Operations, was published in the Official Gazette “El Peruano”, which entered into force in January 2021, together with its Regulations, approved by Supreme Decree No. 039-2021-PCM. This law establishes a system of prior control of business concentration operations in order to promote effective competition and economic efficiency in the markets for the welfare of consumers.


C.Organizational Structure


On March 30, 2026, Holcim Ltd (“Holcim”) completed the acquisition of 99.99% of the capital stock of Inversiones Aspi S.A. (“ASPI”). Prior to this transaction, Eduardo Hochschild, owned this 99.99% of ASPI. As a result of this transaction, through ASPI, Holcim now directly and indirectly, owns and controls 50.01% of Cementos Pacasmayo S.A.A. (the “Company”), which resulted in a change of control. Pursuant to Peruvian securities regulations, Holcim has announced its intention to conduct a mandatory public tender offer (the “Tender Offer”) to acquire additional outstanding shares. For further information, see “Item 4. Information on the Company—A. History and Development of the Company—Recent Developments.”


All of our operating subsidiaries are incorporated in Peru. The following chart sets forth our simplified corporate structure, operating subsidiaries only, as of the date of this annual report on Form 20-F.


49
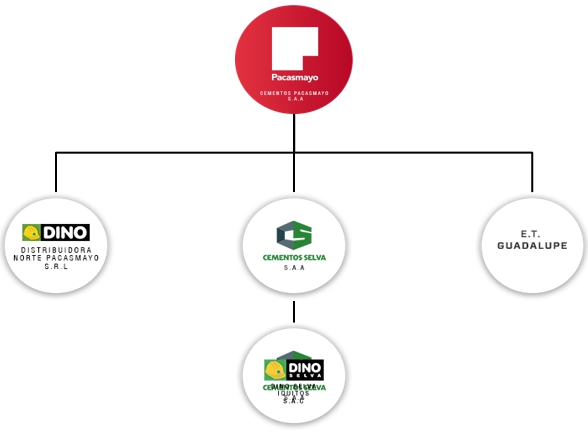


The following is a brief description of the principal activities of our consolidated subsidiaries.


●Cementos Selva S.A.C. is engaged in the production and marketing of cement and other construction materials in the northeast region of Peru. It also owns all of the equity shares of Dinoselva Iquitos S.A.C. (a cement and construction materials distributor in the north of Peru, which also produces and sells precast, cement bricks and ready-mix concrete) and in Acuícola Los Paiches S.A.C. (a fish farm entity).


●Distribuidora Norte Pacasmayo S.R.L. is mainly engaged in selling cement produced by the Company. Additionally, it produces and sells precast, cement bricks and ready-mix concrete.


●Empresa de Transmisión Guadalupe S.A.C. is mainly engaged in providing electric energy transmission services to the Company.


Other immaterial, non-operating subsidiaries


●Salmueras Sudamericanas S.A.C. (“Salmueras”) was engaged in the exploration of a brine project located in the northern region of Peru. In December 2017, the Company decided not to continue with the activities related to this project.


●Soluciones Takay S.A.C. is a platform that connects families that want to build with certified professionals.


●150Krea Inc., a company incorporated in June 2021 in the United States, is engaged in providing leasing services for intangible assets. It is not currently in operation.


●Corporación Materiales Piura S.A.C. is a non-operating company that owns some mining properties located in Piura.


50


Other immaterial, operating subsidiaries


●Créalo 150 Solutions: Business and information systems consulting. It should be noted that another of our subsidiaries is 150Krea Inc. which is a company incorporated in June 2021 in the United States, dedicated to providing leasing services of intangible assets. It is not currently in operation.


Participation in Consortia


●Consorcio Constructor del Norte del Perú began operating during 2023 and is mainly dedicated to the rehabilitation and improvement of the runway, as well as the installation of the perimeter fence at Piura airport.


D.Property, Plants and Equipment


Properties


We own our headquarters office in Lima, Peru, at Calle La Colonia 150, Urbanización El Vivero, Surco. We also own our plants, warehouses, transportation facilities and the office space at our production facilities, including our workers’ facilities. In addition, we own a warehouse occupying approximately 25,000 square meters at the Salaverry port facility.


Area of Operation


We own and operate three cement production facilities. Our largest facility is located in the city of Pacasmayo, department of La Libertad, approximately 667 kilometers north of Lima. The second facility is located in the city of Piura, department of Piura, approximately 330 kilometers north of Pacasmayo. This facility started cement production in September 2015. We also own and operate a smaller cement facility, located in the city of Rioja, department of San Martín, approximately 468 kilometers east of the Panamericana Norte highway. From our Pacasmayo and Piura facilities we supply cement principally to the coastal and highland regions of northern Peru, including the cities of Piura, Chiclayo, Cajamarca, Trujillo and Chimbote. From our Rioja facility, we supply cement to the northeastern region of Peru, including the cities of Moyobamba, Tarapoto, Loreto, among others.


51


Pacasmayo Facility


As of December 31, 2025, our Pacasmayo facility had four horizontal kilns, which produce clinker (one of which also currently produces quicklime), and an additional Waelz rotary kiln that produces quicklime. One of these horizontal kilns with a total installed annual clinker production capacity of 660,000 metric tons was added in 2023. In addition, we formerly had six vertical shaft kilns with a total installed annual clinker production capacity of 465,120 metric tons. We made a provision for the impairment of these vertical shaft kilns at the end of 2023. As a result of these changes, the current clinker capacity at our Pacasmayo plant is 1,755,600 metric tons. Additionally, our facility has a primary and secondary cone crusher located near our Acumulación Tembladera limestone quarry. The main crusher has installed crushing capacity of 800 metric tons per hour and the secondary crusher has installed crushing capacity of 170 metric tons per hour. Our Pacasmayo facility also features three cement finishing mills with installed annual cement production capacity of 2.9 million metric tons. Our Pacasmayo facility is also equipped with silos containing storage capacity for 26,700 metric tons of cement.


As of December 31, 2025, our Pacasmayo facility had installed production capacity of approximately 240,000 metric tons of quicklime per year, including the annual installed capacity of one of our clinker kilns and our Waelz rotary kiln, which are equipped to also produce quicklime.


Piura Facility


Annual installed production capacity of our Piura plant is 1.6 million metric tons of cement and 990,000 metric tons of clinker. Our Piura plant operates with one horizontal kiln with installed clinker production capacity of 990,000 metric tons per year, as well as a cement mill with installed cement production capacity of 1.6 million metric tons per year. Our Piura plant also has three storage silos with storage capacity of 25,300 metric tons of cement.


Rioja Facility


Annual installed production capacity of our Rioja plant is 440,000 metric tons of cement and 289,080 metric tons of clinker.


Our Rioja facility currently operates with a small cone crusher and four vertical shaft kilns with total annual installed clinker production capacity of 289,080 metric tons and three cement finishing mills with total annual installed cement production capacity of 440,000 metric tons. Our Rioja plant is also equipped with silos with a storage capacity of 1,750 metric tons of cement.


Other Facilities


We also currently have 23 fixed and mobile ready-mix concrete and precast facilities located in the northern cities of Chimbote, Trujillo, Chiclayo, Piura, Cajamarca, Pacasmayo, Tarapoto and Tumbes, among others. These facilities allow us to supply ready-mix concrete and precast materials to small, medium and large construction projects throughout the entire northern region of Peru. As of December 31, 2025, our ready-mix operations had 216 mixer trucks, 33 concrete pumps and two pavers available to deliver ready-mix concrete.


Capacity and Volumes


The table below sets forth our clinker, cement and quicklime production capacity and volumes in our Pacasmayo and Rioja facilities for the periods indicated.


   As of and for the year ended December 31, 
   2025   2024   2023 
   Capacity   Production   Utilization rate(1)   Capacity   Production   Utilization rate(1)   Capacity   Production   Utilization rate(1) 
Cement:  (in thousands of metric tons, except percentages) 
Pacasmayo facility   2,900    1,825    62.9%   2,900    1,668    57.5%   2,900    1,656    57.1%
Piura facility   1,600    887    55.4%   1,600    843    52.7%   1,600    1,032    64.5%
Rioja facility   440    340    77.3%   440    320    72.7%   440    259    58.9%
Total   4,940    3,052    61.8%   4,940    2,831    57.3%   4,940    2,947    59.7%
Clinker(2):                                             
Pacasmayo facility   1,756    1,189    67.7%   1,756    1,273    72.5%   1,756    1,098    62.5%
Piura facility   990    616    62.2%   990    609    61.5%   990    799    80.7%
Rioja facility   289    248    85.8%   289    242    83.4%   289    200    69.2%
Total   3,035    2,053    67.6%   3,035    2,124    70.0%   3,035    2,097    69.1%
Quicklime(3):                                             
Pacasmayo facility   240    16    6.7%   240    18    7.5%   240    30    12.5%


(1)We define utilization rate as production for the specified period divided by installed capacity of that period.
(2)We currently estimate clinker capacity using 330 production days.
(3)Our Rioja facility does not produce quicklime. In addition, one of our clinker kilns and our Waelz rotary kiln are equipped to produce quicklime.


52


Summary Disclosure (229.1303)


Map of Mining Concessions of Cementos Pacasmayo S.A.A. and subsidiaries.


Figure 1 shows the map of Peru and the location of the Peruvian mining properties of Cementos Pacasmayo and subsidiaries, in the northern part of the country. The mining properties are located in Piura, Lambayeque, Cajamarca, Amazonas, Ica, Cusco, San Martin, La Libertad and Ancash Regions.


Figure 1 General map of the mining properties and industrial facilities of Cementos Pacasmayo S.A.A. and subsidiaries
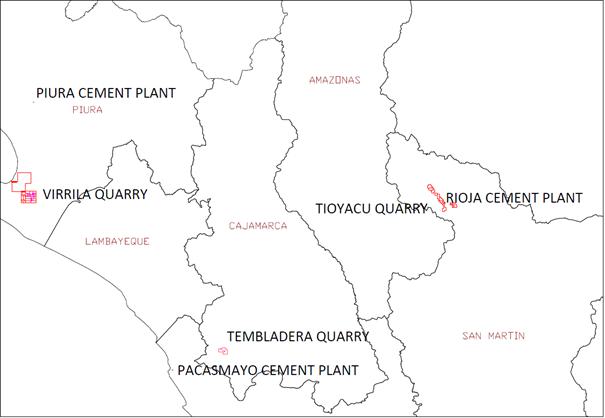


General description of mining properties and operations


Cementos Pacasmayo S.A.A.’s access to its mining properties in Peru are obtained through mining rights granted by the INGEMMET.


Mineral properties in Peru are classified according to the type of material, i.e. metallic and non-metallic.


Cementos Pacasmayo has mining properties in exploration, development and production stages. Cementos Pacasmayo has three material properties (Tembladera, Virrila, and Tioyacu), all of which are in the production stage.


Distribuidora Norte Pacasmayo SRL obtained ownership of new mining properties, which are shown in Annex 1.


53


Table 1 provides an overview of Cementos Pacasmayo’s material properties, including relevant information for each quarry.


Table 1 Main mining properties of Cementos Pacasmayo S.A.A. and subsidiaries


Mining Property   Mining concessions   Location of the mining concession   Percentage of ownership interests     Operator   Surface area (ha)     Stage
of the
mining concession
  Permits     Key condition of permit   Type of mine / material   Beneficiation plant and other installations   Production 2025
(Ton)
    Production 2024
(Ton)
    Production 2023
(Ton)
 
Tembladera   Acumulación Tembladera   Cajamarca     100 %   San Martin Contratistas Generales SA     3,391     Production     Yes     EIA(2) and others   Open Pit / Limestone   Industrial facilities(3)     1,618,832 (4)     1,722,804       1,842,375  
Virrila   UEA(1) Virrila   Piura     100 %   Inversiones y Servicio Felicitas SRL     38,226     Production     Yes     EIA(2) and others   Open Pit / Coquina   Industrial facilities(3)     904,620       901,977       932,933  
Tioyacu   UEA(1)  Rioja   San Martin     100 %   Cementos Selva S.A.C     9,600     Production     Yes     EIA(2) and others   Open Pit / Limestone   Industrial facilities(3)     398,766 (5)     267,009       351,644  


(1)The administrative economic unit (unidad económica administrativa – “UEA”) represents a grouping of two or more mining concessions incorporated to the National Mining Cadastre with definitive character, of the same kind of substance and of the same mining owner.
(2)Environmental Impact Assessment (EIA).
(3)Cement plants are governed by the laws of the industrial sector.
(4)The 2025 production of the Tembladera quarry was lower compared to 2024 due to the corrective maintenance works on the primary crusher between October and December 2025.
(5)The 2025 production of the Tioyacu quarry was higher compared to 2024 due to the limestone requirement of the Rioja plant.


Summary of Mineral Resources and Mineral Reserves


Tables 2 and 3 summarize the mineral resources and reserves, respectively, of the mining properties of Cementos Pacasmayo and its subsidiaries.


Table 2 Summary of Mineral Resources (exclusive of Reserves) of Cementos Pacasmayo S.A.A. and subsidiaries as of December 31, 2025.


   Measured Mineral   Indicated Mineral   Measured + Indicated   Inferred Mineral 
   Resources   Resources   Mineral Resourc   Resources 
    Amount
(Million
Tonnes)
    Grades/
Qualities
(% CaO)
    Amount
(Million
Tonnes)
    Grades/
Qualities
(% CaO)
    Amount
(Million
Tonnes)
    Grades/
Qualities
(% CaO)
    Amount
(Million
Tonnes)
    Grades/
Qualities
(% CaO)
 
Limestone:                                        
Acumulación Tembladera   135.1    49.85    39.2    50.58    174.3    50.01    41.5    50.61 
UEA Rioja   25.8    49.52    4.8    48.29    30.6    49.33    7.2    49.11 
Coquina:                                        
UEA Virrila   21.8    49.80    26.8    48.98    48.6    49.35    4.4    46.70 


Table 2 is based on the following cement prices: Tembladera/Pacasmayo (S/642.9 per ton), Virrila/Piura (S/708.6 per ton) and Tioyacu/Rioja (S/754 per ton). The mineral resource estimates are at the point of delivery to the cement plant (point of reference). Also the assumptions (e.g., prices, costs and other economic assumptions) used to establish economic viability during the mineral reserves estimation can be found in the Cementos Pacasmayo S.A.A. and Cementos Selva S.A.C Technical Report Summaries (TRS) 20-F 229.601 (Item 601) Exhibits 96.1, 96.2 and 96.3 of our annual report on Form 20-F.


54


Table 3 Summary of Mineral Reserves of Cementos Pacasmayo S.A.A. and subsidiaries’ properties as of December 31, 2025.


   Proven Mineral
Reserves
   Probable Mineral
Reserves
   Total Mineral
Reserves
 
   Amount
(Million
Tonnes)
   Grades/
Qualities
(%CaO)
   Amount
(Million
Tonnes)
   Grades/
Qualities
(%CaO)
   Amount
(Million
Tonnes)
   Grades/
Qualities
(%CaO)
 
Limestone:                              
Acumulación Tembladera   67.8    49.83    5.1    50.56    72.9    49.88 
UEA Rioja   10.3    51.20    1.3    49.30    11.6    51.0 
Coquina:                              
UEA Virrila   39.9    51.86    0.9    49.83    40.8    51.82 


Table 3 is based on the following cement prices: Tembladera/Pacasmayo (S/642.9 per ton), Virrila/Piura (S/708.6 per ton) and Tioyacu/Rioja (S/754 per ton). The mineral resource estimates are at the point of delivery to the cement plant (point of reference). Also the assumptions (e.g., prices, costs and other economic assumptions) used to establish economic viability during the mineral reserves estimation can be found in the Cementos Pacasmayo S.A.A. and Cementos Selva S.A.C Technical Report Summaries (TRS) 20-F 229.601 (Item 601) Exhibits 96.1, 96.2 and 96.3 of our annual report on Form 20-F.


Tembladera Quarry and Pacasmayo Cement Plant Individual Disclosure (229.1304)


Name of mineral concession   Location of the properties   Type and amount of
ownership interests
  Operator   Surface (Has)   Stage of Property   Permits   Type of mine / material   Beneficiation plant and other
installations
  Production of 2025   Production of 2024   Production of 2023
Carraspiña   Lambayeque   100%   NA   100   Exploration   No   Non Metallic   No   0   0   0
Pacherrez   Lambayeque   100%   NA   200   Exploration   No   Non Metallic   No   0   0   0
Reque 1   Lambayeque   100%   NA   1,000   Exploration   No   Non Metallic   No   0   0   0
Reque 2   Lambayeque   100%   NA   1,000   Exploration   No   Non Metallic   No   0   0   0
Reque 7   Lambayeque   100%   NA   1,000   Exploration   No   Non Metallic   No   0   0   0
Reque 8   Lambayeque   100%   NA   1,000   Exploration   No   Non Metallic   No   0   0   0
Reque 9   Lambayeque   100%   NA   1,000   Exploration   No   Non Metallic   No   0   0   0


Property description


Location


The Acumulación Tembladera property is located in Yonan district, Contumaza province, Cajamarca region, Peru at longitude -79.123393° and latitude -7.245671°. It is located 60 km from the cement plant.


The area of the mining concession is 3,390.97 hectares. The mining rights are granted by INGEMMET of the Energy and Mines Sector through a Presidential Resolution.


Cementos Pacasmayo S.A.A. owns the mining concession and it is registered with the name Acumulación Tembladera as a non-metallic mining concession.


Pacasmayo cement plant and Acumulación Tembladera mining concession are shown in Figure 2 while the locations of the Acumulación Tembladera and the cement plant are shown separately in Figures 3 and 4, respectively.


Figure 2 Pacasmayo cement plant and Acumulación Tembladera
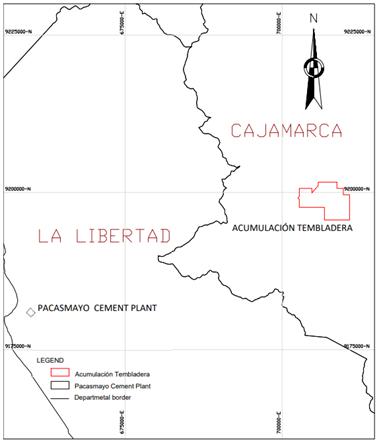


55


Figure 3 Acumulación Tembladera


Figure 4 Pacasmayo cement plant


56


Infrastructure


The Tembladera quarry has the necessary infrastructure for normal operations. Facilities for electric power, water supply, fuel, access and roads have been installed.


Energy is supplied by Hidrandina S.A. Company, which obtains energy from the national grid. Energy distribution is overhead and at medium voltage of 2.3 kV. The quarry also has an electrical sub-station. The sub-station area is 1,062 m2.


Water is obtained from the village canal, which flows near the quarry. The water is used for minor activities within the quarry, such as access and road watering, limestone watering in mining areas, post-blasting watering, watering of green areas, and consumption by restrooms.


A contractor manages the fuel system. The fuel storage and dispatch system has the necessary equipment to supply fuel to the mobile and fixed units within the quarry. Trained personnel and safety measures are in place to handle fuel safely.


The Tembladera quarry can be accessed by air from Lima to Trujillo (1 hour) and by land from Trujillo to Tembladera Quarry. The route is from Trujillo to Pacasmayo (112.6 kilometers), from Pacasmayo to Ciudad de Dios (14.3 kilometers) and from Ciudad de Dios to Tembladera (50 kilometers) and Tembladera - Security point (0.8 kilometers), for a total of 747.1 kilometers. The entire route is paved. Alternatively, the quarry can be accessed by air from Lima to Chiclayo, time average 1.15 hours of flight, and from Chiclayo to Ciudad de Dios (86.8 kilometers) and from Ciudad de Dios to Tembladera (50 kilometers) and Tembladera – Security point (0.8 kilometers.). The entire route is paved.


The Tembladera quarry’s personnel come from the town of Tembladera, adjacent to the quarry. Others come from Cajamarca and La Libertad region.


Personnel from the town of Tembladera are transported to the quarry in buses and pickup trucks.


Mining concession ownership and area


The Acumulación Tembladera was granted by Resolution No. 01989-2002-INACC/J of the National Institute of Concessions and Cadastre (Instituto Nacional de Concesiones y Catastro).


The procedure to obtain a mining concession is established in the General Mining Law (DS-014-92-EM) and its Regulation D.L 020-2020-EM.


The mining concession is in the owner’s name of Cementos Pacasmayo S.A.A. and is also registered with the name Acumulación Tembladera as a NON METALLIC quarry.


Cementos Pacasmayo S.A.A has the surface rights to the area of operation in the Tembladera quarry.


Cementos Pacasmayo S.A.A. pays the right of use for the concession Acumulación Tembladera with unique code 010001801L. These payments must be made from the first working day of January to June 30th of each year, providing the financial entities the unique code of its mining right. The Acumulación Tembladera concession payment is equivalent to US$3.00 per hectare.


57


Royalties


Law No. 28258 approved the Peruvian Mining Royalty Law on June 24, 2004, which was amended by Law No. 29788 of September 28, 2011. Cementos Pacasmayo S.A.A. currently pays the Mining Royalty (see note 25 to the consolidated financial statements).


The payment to the Peruvian government is made through SUNAT, which is the entity designated to control this consideration for the use of natural resources. Such payment is made through an application that the tax authority has made available to those required to pay.


If the mining royalty is not declared or paid, penalties for infractions and default interest for non-compliance are incurred. However, failure to pay these fines is not a cause for the loss of the mining concession.


Mining activities on the property and production at the cement plant


Tembladera quarry


The Tembladera quarry, located in the Acumulación Tembladera mining concession, is currently in the production stage. The Tembladera quarry is an open-pit mine that uses explosives to fragment the limestone rock. After crushing, the material is loaded onto trucks to be transported from the quarry to the cement plant located in Pacasmayo.


Figure 5 shows the flowsheet of mining processes at the Tembladera quarry. Further details of the process are provided in Exhibit 96.1 of this annual report on Form 20-F.


Figure 5 Diagram of mining process of the Tembladera quarry


The Tembladera quarry has been operating for 68 years. The amount of limestone to be mined is planned annually through the mining plan.


58


The equipment at the Tembladera quarry is in optimum condition to maintain continuity of operations. Maintenance and optimization of the equipment is carried out periodically and is supervised by the operator of the quarry. The equipment is in good condition and operational. Further details of the equipment are provided in Exhibit 96.1 of this annual report on Form 20-F.


Pacasmayo industrial cement plant


The cement plant is under the laws of the industrial sector, according to current Peruvian regulations.


The Pacasmayo plant is located at Pacasmayo District, Pacasmayo Province, La Libertad Region. This plant is 67.3 km from Tembladera quarry. This facility receives material from the Tembladera quarry. The Pacasmayo plant produces various products for the construction industry, the main product being cement. Different types of cement are produced depending on their applications, using limestone, sand, iron and clays as raw materials. The specific mix of raw materials produces the clinker necessary to produce cement.


The standard cement production process consists of the following main stages:


●Extraction and transportation of limestone;


●Raw material storage;


●Grinding and homogenization to make the raw material of consistent quality;


●Clinkerization;


●Cement grinding;


●Storage in silos; and


●Packaging, loading and distribution.


Figure 6 shows the flowsheet for raw material processing, clinker and cement production. Further details of the process are provided in Exhibit 96.1 of this annual report on Form 20-F.


Figure 6 Pacasmayo industrial cement plant process block diagram


59


The Pacasmayo plant has been in operation for 68 years. The equipment at the Pacasmayo plant is in optimal condition to avoid any interruption in cement production. Maintenance and optimization of the equipment is carried out periodically and is supervised by Cementos Pacasmayo personnel. The Pacasmayo plant is currently being optimized with a modern, state-of-the-art clinker production line in order to increase production. The equipment is in good condition and operational. Further details of the equipment are provided in Exhibit 96.1 of this annual report on Form 20-F.


Facilities


The total cost of the mining concession, mine development costs, land, buildings and other facilities, machinery and equipment, furniture and fixtures, transportation units, computer equipment and tools, quarry rehabilitation costs, capitalized interest and work in progress amounted to S/708,402,047 as of December 31, 2025.


Tembladera quarry


The Tembladera quarry has facilities such as offices, explosives magazine for blasting, electrical substation, maintenance shop, lubricant warehouse, gas station, oil tank, guardhouse, limestone field, dining room, laboratory, truck scale, ore belt, loading tunnel, meteorological station, safety trench and septic tank.


Pacasmayo plant


The Pacasmayo plant has facilities such as maintenance workshops, warehouses, laboratories, administrative offices, and cement production lines that support cement production.


History


By means of Resolution No. 01989-2002-INACC/J dated November 4, 2002, the National Institute of Mining Cadastre and Concessions granted Cementos Pacasmayo S.A.A., the non-metallic concession title called “Acumulación Tembladera” with code No. 01-00018-01-L.


The property dates back to its oldest integral concession: “Norte No. 1” granted by the Regional Mining Office of Cajamarca by ministerial resolution No. 267 of June 30, 1950, for the benefit of Cementos Portland del Norte S.A., starting operations as Cementos Pacasmayo S.A.A., from 1957 until 2013 when Calizas del Norte S.A.C. (CALNOR) was incorporated. CALNOR started activities from January 2014 until May 2016. San Martin Contratistas Generales S.A. started activities in October 2016 and continues in operation.


In December 2022, Cementos Pacasmayo started a diamond drilling campaign of 8 drill holes to confirm mineral resources and reserves. Drilling activities continue in the first month of 2023.


Between October and December 2025, the Tembladera quarry did not dispatch material to the Pacasmayo plant due to corrective maintenance works on internal components of the primary crusher, during that period, limestone was consumed from strategic stocks. However, waste removal activities continued during October and November, and the construction of a safety wall in the pit was completed in December.


60


Property encumbrances


Cementos Pacasmayo S.A.A. does not make any payments with respect to encumbrances for the Acumulación Tembladera property. The Acumulación Tembladera mining concession currently has no outstanding payments with respect to infractions and penalties.


Concessions


The Acumulación Tembladera mining concession is a production stage property with estimated Mineral Reserves.


Geology


The ore deposit contains limestone with a grade suitable for cement production. The limestone is contained within the Cajamarca Formation, belonging to the Upper Cretaceous (Turonian floor, around 90 MA). This Formation overlies the Quilquiñan Group, and intrajacent to the Celendín Formation.


Table 4 shows the stratigraphic column of the area of the Tembladera quarry and briefly describes the Cajamarca Formation and the Upper Cretaceous Celendín Formation that outcrop in the project area. Figure 6 shows the local geology of the quarry.


Table 4 Stratigraphic Column of the Tembladera quarry


System Series Stratigraphic Unit Intrusive rocks Lithologic Description
Quaternary Recent Fluvial Deposit Qr-fl     Fluvial origin
Alluvial Deposit Qr-al     Alluvial origin
Tertiary Lower     Andesite T-an Intrusion of andesitic dykes longitudinally into the deposit rock mass.
Cretaceous Upper Celendin Formation Ks-ce     Thin layers of clayey nodular limestone, interbedded with marls and lutites.
Cajamarca Formation Ks-c     Limestone of marine origin of whitish to light gray color.
Quilquiñan Group Ks-q     Lutites and marls with some calcareous intercalations.


Figure 7 Geological section of Tembladera quarry


61


Resources and Reserves


Table 5 shows the Mineral Resources at the Tembladera quarry at the end of the 2025 fiscal year.


Table 5 Mineral Resources (exclusive of Reserves) at the end of the 2025 fiscal year based on cement price of S/642.9 per ton. The mineral resource estimates are at the point of delivery to the cement plant (point of reference)


    Amount
(Million
Tonnes)
    Grades/
qualities
(% CaO)
    Grades/
qualities
(% MgO)
    Grades/
qualities (%Al2O3)
    Cut-off grades
(% CaO)
 
Measured resources     135.1       49.85       1.79       1.63       48.5  
Indicated resources     39.2       50.58       1.56       1.39       48.5  
Measured + Indicated resources     174.3       50.01       1.74       1.58       48.5  
Inferred resources     41.5       50.61       1.56       1.38       48.5  


The Mineral Resources estimation considered the expected price of cement, the complete forecast horizon contemplates 30 year projection. Clinker is used for cement production through the addition of other non-metallic minerals.


Table 6 shows the mineral reserves at the Tembladera quarry.


Table 6 Mineral Reserves at the end of the 2025 fiscal year based on cement price of S/642.9 per ton. Mineral reserve estimates are at the point of delivery to the cement plant (point of reference)


    Amount
(Million
Tonnes)
    Grades/
qualities
(% CaO)
    Grades/
qualities
(% MgO)
    Grades/
qualities
(%Al2O3)
    Cut-off
grades
(% CaO)
 
Proven reserves     67.8       49.83       1.49       1.51       48.5  
Probable reserves     5.1       50.56       1.28       1.39       48.5  
Total reserves     72.9       49.88       1.48       1.50       48.5  


The mineral reserves estimation considered the expected price of cement. The complete forecast horizon contemplates a total of 30 years. Clinker is used for cement production through the addition of other non-metallic minerals.


62


Reconciliation of Mineral Resources and Reserves at the end of the fiscal year


Table 7 shows the difference between the mineral resource estimates at the end of this fiscal year and the previous fiscal year.


Table 7 Resources for the last two fiscal years expressed in millions of tons.


   Resources as
at Dec. 31,
2025
   Resources as
at Dec. 31,
2024
   Discrepancy
Measured resources   135.1    131.1   The difference is due to the annual consumption of limestone used in the cement plant.
Indicated resources   39.2    39.2   There is no difference in tons.
Measured + Indicated resources   174.3    170.3   The difference is due to the annual consumption of limestone used in the cement plant.
Inferred resources   41.5    41.3   The variation is due to an adjustment in the geological model and the topography.


*The prices assumed for the Mineral Resources estimation in the economic model can be found in the Cementos Pacasmayo S.A.A. Technical Report Summary (TRS) of the Tembladera Quarry and Pacasmayo Cement Plant 20-F 229.601 (Item 601) Exhibit 96.1 filing. All mineral resources are estimated at cement plant. The updated average price is S/642.9 per ton of cement at nominal values, perpetuity is included at the end of the 30-year projection.


Table 8 shows the difference between the mineral reserve estimates at the end of this fiscal year and the previous fiscal year.


Table 8 Reserves for the last two fiscal years expressed in millions of tons.


   Reserves  as
at Dec. 31,
2025
   Reserves  as
at Dec. 31,
2024
   Discrepancy
Proven reserves   67.8    75.3   The difference is due to the annual consumption of limestone used in the cement plant.
Probable reserves   5.1    4.9   The variation is due to a readjustment of the mining plan.


*The prices assumed for the Mineral Reserves estimation in the economic model can be found in the Cementos Pacasmayo S.A.A. Technical Report Summary (TRS) Tembladera Quarry and Pacasmayo plant 20-F 229.601 (Item 601) Exhibit 96.1 filing. All mineral Reserves are estimated at cement plant. The updated average price is S/642.9 per ton of cement, average of the 30-year projection, at nominal values.


63


Cementos Pacasmayo has previously disclosed mineral resources and reserves at the Tembladera quarry in its 20-F filed on April 29, 2025. Cementos Pacasmayo previously filed a TRS to support its disclosure of mineral resources and reserves at the Tembladera quarry as Exhibit 96.1 of its 20-F filed on April 29, 2025. Cementos Pacasmayo is updating that TRS with the new TRS filed as Exhibit 96.1 of this annual report on Form 20-F to ensure the material assumptions are current. The main reasons for this update are prices, costs, cement demand and other economic assumptions. Further details are provided in Exhibit 96.1 of that annual report on Form 20-F.


Exploration


Cementos Pacasmayo did not conduct any exploration activity at the Tembladera quarry during the 2025 fiscal year.


Virrilá Individual Disclosure (229.1304)


Property description


Location


The Virrila property is located in the Sechura District, Sechura Province, Piura Region, Peru at longitude -80.758952° and latitude -5.933999°. The concessions are registered in INGEMET (Instituto Geológico Minero y Metalúrgico) as Virrila 3, Virrila 4, Virrila 6, Virrila 7, Virrila 8, Virrila 9, Virrila 10, Virrila 11, Virrila 12, Virrila 13, Virrila 14, Virrila 15, Virrila 16, Virrila 17, Virrila 18, Virrila 19, Virrila 20, Virrila 21, Virrila 22, Virrila 23 and Bayovar N° 4 with mining activity.


The area of the mining property is 38,226.00 hectares. The mining rights are granted by INGEMMET of the Energy and Mines Sector through a Presidential Resolution.


Cementos Pacasmayo S.A.A. owns the mining property and it is registered with the name “Unidad Económica Administrativa” (UEA) Virrila as a non-metallic quarry.


Cementos Pacasmayo currently has an agreement with the Fundación Comunal San Martin de Sechura for the use of the surface land associated with the production area of the Virrila quarry.


Piura Cement Plant and UEA Virrila are shown in Figure 8 while the locations of the UEA Virrila property and Piura cement plant are shown in Figures 9 and 10, respectively.


64


Figure 8 Piura cement plant and UEA Virrila


65


Figure 9 UEA Virrila property
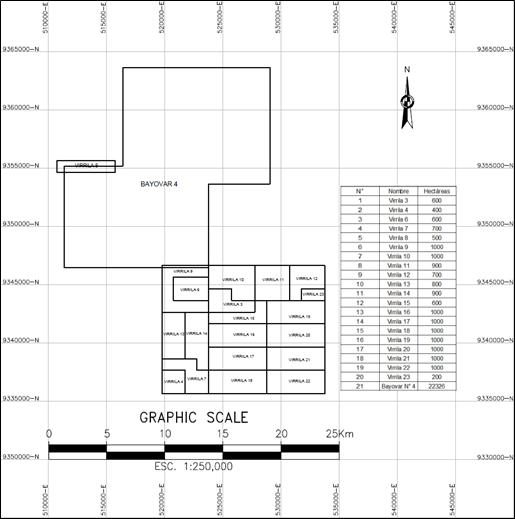


Figure 10 Piura cement plant
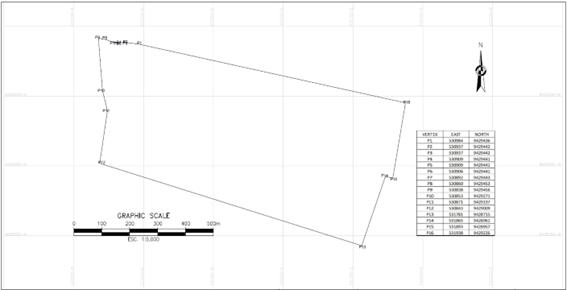


66


Infrastructure


The Virrila quarry has the necessary infrastructure for normal operations. Facilities for electric power, water supply, fuels, accesses and roads have been installed.


Virrila quarry is supplied with fuel by diesel oil tanker trucks. Fuel distribution is the responsibility of an authorized contractor company.


The Virrila quarry is supplied with energy by electric generators.


The Virrila quarry can be accessed by air from Lima to Piura (1.5 hour) and by land from Piura to Virrila quarry, along the north Panamerican highway, to the Bayovar intersection and then to the Virrila quarry. Estimated travel time is 2 hours.


Personnel for the Virrila quarry come from the town of Sechura, near the quarry. Others are from Piura.


Personnel from the Sechura Township are transported to the quarry in buses and pickup trucks. The contractor is responsible for the logistics of personnel operating in the quarry.


Mining concession ownership and area


INGEMMET granted mining rights to Cementos Pacasmayo on March 31, 2016 by Presidential Resolution N° 0147-2016-INGEMMET/PCD/PM including nine (9) non-metallic mining rights in the ¨Unidad Económica Administrativa¨ (UEA) Virrila, with code N° 01-00011-00-U of Cementos Pacasmayo S.A.A.


Presidential Resolution N° 2869-2015-INGEMMET/PCD/PM dated September 30, 2015 added twelve (12) non-metallic mining rights to ¨Unidad Económica Administrativa¨ (UEA) Virrila, with code N° 01-00011-00-U of Cementos Pacasmayo S.A.A. bringing the total to 21 mining rights.


Royalties


Law No. 28258 is the Peruvian Mining Royalty Law, which was approved on June 24, 2004 and amended by Law No. 29788 of September 28, 2011. Cementos Pacasmayo S.A.A. currently pays the Mining Royalty (see note 24 to the consolidated financial statements).


The payment to the Peruvian government is made through SUNAT, which is the entity designated to control this consideration for the use of natural resources. Such payment is made through an application that the tax authority has made available to those required to pay.


In case the mining royalty is not declared or paid, penalties for infractions and default interest for non-compliance are incurred. However, failure to pay these fines is not a cause for the loss of the mining concession.

Mining activities on the property.


The Virrila quarry located in the Virrila EAU is currently in the production stage. This is an open-pit mine where surface miners are used to fragment the coquina, which is loaded onto trucks by front-end loaders and transported to the cement plant located in Piura which is 120 kilometers from UEA Virrila.


67


Figure 11 shows the flowsheet of mining processes at the Virrila quarry. Further details of the process are provided in Exhibit 96.2 of this annual report on Form 20-F.


Figure 11 Diagram of mining process of the Virrila quarry


The Virrila quarry has been operating for 10 years. The amount of coquina to be mined is planned annually through the mining plan.


The equipment in operation at the Virrila quarry is in optimum condition to maintain continuity of operations. Maintenance and optimization of the equipment is carried out periodically and is supervised by the operator of the quarry. The equipment is in good condition and operational. Further details of the equipment are provided in Exhibit 96.2 of this annual report on Form 20-F.


Piura cement plant


The cement plant is under the laws of the industrial sector, according to current Peruvian regulations.


The cement plant is located at Veintiséis de Octubre District, Piura Province and Piura Region. This facility receives material from the Virrila quarry. The cement plant produces various products for the construction industry, the main product being cement. Different types of cement are produced depending on their applications, and using coquina, sand, iron and clays as raw materials. The specific mix of raw materials produces the clinker necessary to produce cement.


The standard cement production process consists of the following main stages:


●Extraction and transportation of coquina;


●Raw material storage;


●Grinding and homogenization to make the raw material of consistent quality;


●Clinkerization;


●Cement grinding;


●Storage in silos; and


●Packaging, loading and distribution.


68


Figure 12 shows the flowsheet for raw material processing, clinker and cement production. Further details of the process are provided in Exhibit 96.2 of this annual report on Form 20-F.


Figure 12 Piura plant process block diagram


The equipment in operation at the Piura plant is in optimal condition to avoid any interruption in cement production. Maintenance and optimization of the equipment is carried out periodically and is supervised by Cementos Pacasmayo S.A.A. personnel. The equipment is in good condition and operational. Further details of the equipment are provided in Exhibit 96.2 of this annual report on Form 20-F.


Facilities


The total cost of the mining concession, mine development costs, land, buildings and other facilities, machinery and equipment, furniture and fixtures, transportation units, computer equipment and tools, quarry rehabilitation costs, capitalized interest and work in progress amounts to S/803,579,828 as of December 31, 2025.


Virrila quarry


The Virrila quarry has facilities such as offices, dining room, infirmary, vehicle parking lots, lubricant warehouse, chemical baths, maintenance shop, sample preparation laboratory, industrial water tank, truck scale, hopper for weighing, wastewater treatment pond, and satellite and radio antenna.


Piura plant


The Piura plant has facilities such as maintenance workshops, warehouses, laboratories, administrative offices, and cement production lines that support cement production.


History


The quarry is a non-metallic deposit of coquina material, source of different types of cements for construction; Cementos Pacasmayo S.A.A. owns the deposit.


The Virrila quarry started operations in 2015. The mining contractor San Martin Contratistas Generales S.A. was in charge of the production from the beginning of operations until March 14, 2020. The mining contractor Posada Perú S.A.C. started operations at the Virrila quarry on September 14, 2020 until December 30, 2021.


On January 3, 2022, the mining contractor San Martin Contratistas Generales S.A. was hired to transport the coquina from the Virrila quarry to the Piura plant.


From May to June 2023 Cementos Pacasmayo carried out a drilling campaign in order to confirm mineral reserves in Zone 2 and 4 (see Exhibit 96.2 of 20-F filed on April 29, 2024).


From May to September 2023, Virrila quarry stopped operations due to the closure of the road caused by the overflow of the La Niña lagoon provoked by cyclone Yaku. Likewise, the Piura plant stopped its clinker production operations (raw meal milling, coal milling and reception of raw materials) from July to September to avoid exceeding the strategic inventories (clinker). The cement grinding, receiving (cement additions), packaging and dispatching processes remained active to cover the cement demand. Virrila quarry restarted operations in October.


From January to March 2024, Virrila quarry shipped coquina from its stockpiles to the Piura Plant. The company in charge of loading the material was Peruvian Master S.A. From May to October 2024, Sechura Ingenieria y Contrucción E.I.R.L. was in charge of operations of the quarry. After October 2024 the quarry stopped operations according to the 2024 mining plan. Likewise, the Piura plant stopped its clinker production operations (raw meal milling, coal milling and reception of raw materials) from March to May 2024 and from November to December 2024 was to avoid exceeding the strategic inventories (clinker). The cement grinding, receiving (cement additions), packaging and dispatching processes remained active to cover the cement demand.


69


During the month of January, operations remained suspended in accordance with the 2025 Mining Plan. From February to December 2025, the Virrila Quarry dispatched coquina material to the Piura Plant, both from the operational area and from existing stockpiles. The company responsible for the material loading activities was Inversiones y Servicios Felicitas S.R.L. Likewise, the Piura plant stopped its clinker production operations (raw meal milling, coal milling and reception of raw materials) January and September to December to avoid exceeding the strategic inventories (clinker). The cement grinding, receiving (cement additions), packaging and dispatching processes remained active to cover the cement demand.


Property encumbrances


Cementos Pacasmayo S.A.A. does not make any payments with respect to encumbrances for the UEA Virrila concessions. The UEA Virrila concessions currently have no outstanding payments with respect to infractions and penalties.


Concessions


The UEA Virrila is a production stage property with estimated mineral reserves.


Geology


The lithostratigraphy of the area consists of Cenozoic sedimentary units, locally formed by Tertiary units and covered by Quaternary deposits; the Tablazo Lobitos and Quaternary deposits of ancient alluvial, lacustrine and Aeolian origin form these units. Table 9 shows the stratigraphic column of the area of the Virrila quarry while Figure 13 shows a geologic section of the geology of the quarry.


Table 9 Stratigraphic Column of the Virrila quarry


Era System Symbol Serie Stratigraphic Unit
Cenozoic Quaternary Qh-e Holocene Eolic deposits
Qp-tt Pleistocene Tablazo Talara
Tertiary Tm-zi Miocene Lower Zapallal Formation


Figure 13 Geological section of the Virrila quarry


70


Resources and Reserves


Table 10 shows the mineral resources at the Virrila quarry at the end of the 2025 fiscal year.


Table 10 Mineral Resources (exclusive of Reserves) at the end of the 2025 fiscal year based on cement price of S/708.6 per ton. The mineral resource estimates are at the point of delivery to the cement plant (point of reference).


   Amount
(Million
Tonnes)
   Grades/
qualities
(% CaO)
   Grades/
qualities
(% SO3)
   Grades/
qualities
(% MgO)
   Cut-off
grades
(% CaO)
 
Measured resources   21.8    49.80    0.54    0.62    48.5 
Indicated resources   26.8    48.98    1.06    1.18    48.5 
Measured + indicated resources   48.6    49.35    0.83    0.93    48.5 
Inferred resources   4.4    46.70    2.11    1.54    48.5 


The mineral resource estimation considered the expected price of cement. The complete forecast horizon contemplates a total of 30 years of projection. Clinker is used for cement production through the addition of other non-metallic minerals.


Table 11 Mineral Reserves at the end of the 2025 fiscal year based on cement price of S/708.6 per ton. Mineral reserve estimates are at the point of delivery to the cement plant (point of reference).


    Amount
(Million Tonnes)
    Grades/
qualities
(% CaO)
    Grades/
qualities
(% SO3)
    Grades/
qualities
(% MgO)
    Cut-off
grades
(% CaO)
 
Proven reserves     39.9       51.86       0.36       0.71       48.5  
Probable reserves     0.9       49.83       0.64       0.84       48.5  
Total reserves     40.8       51.82       0.36       0.71       48.5  


The mineral reserves estimation considered the expected price of cement. The complete forecast horizon contemplates a total of 30 years of projection. Clinker is used for cement production through the addition of other non-metallic minerals.


Reconciliation of Resources and Reserves at fiscal year-end


Table 12 shows the difference between the mineral resource estimates at the end of 2025 fiscal year and the 2024 fiscal year.


Table 12 Resources for the last two fiscal years expressed in millions of tons.


   Resources as
at Dec. 31,
2025
   Resources as
at Dec. 31,
2024
   Discrepancy
Measured Resources   21.8    20.5   The difference is due to the annual consumption of coquina used in the cement plant.
Indicated Resources   26.8    30.2   The difference is due to the annual consumption of coquina used in the cement plant.
Measured + Indicated Resources   48.6    50.7   The difference is due to the annual consumption of coquina used in the cement plant.
Inferred Resources   4.4    4.4   There is no difference in tons.


*The prices assumed for the Mineral Resources estimation in the economic model can be found in the Cementos Pacasmayo S.A.A. Technical Report Summary (TRS) of the Virrila Quarry and Piura plant 20-F 229.601 (Item 601) Exhibit 96.2 filing. All Resources are estimated at cement plant. The updated average price is S/708.6 per ton of cement, average of the 30-year projection, at nominal values.


71


Table 13 shows the difference between the mineral reserve estimates at the end of the 2025 fiscal year and the 2024 fiscal year.


Table 13 Reserves for the last two fiscal years expressed in millions of tons.


   Reserves as
at Dec. 31,
2025
   Reserves as
at Dec. 31,
2024
   Discrepancy
Proven Reserves   39.9    38.7   The difference is due to the annual consumption of coquina used in the cement plant.
Probable Reserves   0.9    0.6   The difference is due to the annual consumption of coquina used in the cement plant.


*The prices assumed for the Mineral Reserves estimation in the economic model can be found in the Cementos Pacasmayo S.A.A. Technical Report Summary (TRS) Virrila Quarry and Piura Cement Plant 20-F 229.601 (Item 601) Exhibit 96.2 1 filing. All Reserves are estimated at cement plant. The updated average price is S/708.6 per ton of cement, average of the 30-year projection, at nominal values.


Cementos Pacasmayo has previously disclosed mineral resources and reserves at the Virrila quarry in its 20-F filed on April 29, 2025. Cementos Pacasmayo previously filed a TRS to support its disclosure of mineral resources and reserves at the Virrila quarry as Exhibit 96.2 of its 20-F filed on April 29, 2025. Cementos Pacasmayo is updating that TRS with the new TRS filed as Exhibit 96.2 of this annual report on Form 20-F to ensure the material assumptions are current. The main reasons for this update are prices, costs and cement demand. Further details are provided in Exhibit 96.2 of that annual report on Form 20-F.


Exploration


Cementos Pacasmayo did not conduct any exploration activity at the Virrila quarry during the 2025 fiscal year.


Tioyacu Individual Disclosure (229.1304)


Property description


Location


The Tioyacu property is located in Elias Soplin Vargas district, Rioja province, San Martin region, Peru at longitude -77.284376° and latitude -5.999057°. It is located 5 km from the cement plant.


The mining rights registered with INGEMMET are as follows Moyobamba 98, Pajonal 2, Rioja 1, Rioja 2, Rioja 3, Rioja 5, Rioja 6, Rioja 7, Rioja 8, Rioja 9, Calizas Tioyacu, Arcillas el Pajonal, Pajonal 3 and Pajonal 4. The area of the mining property is 9,600 hectares.


The mining rights (the mining concession title) are granted by INGEMMET of the Energy and Mines Sector through a Presidential Resolution.


Cementos Selva S.A.C. owns the mining property and it is registered with the name “Unidad Económica Administrativa” (UEA) Rioja as a NON METALLIC mining property.


Rioja cement plant and UEA Rioja are shown in Figure 14 while the locations of the UEA Rioja property and Rioja cement plant are shown in Figures 15 and 16, respectively.


72


Figure 14 Rioja cement plant and UEA Rioja
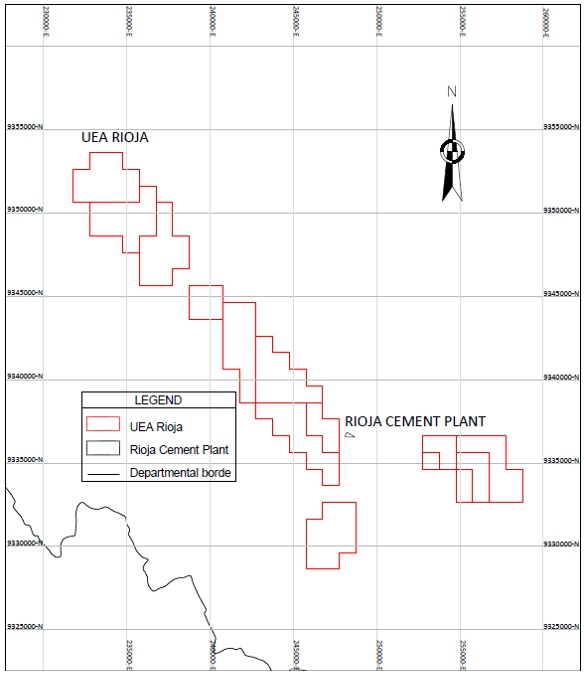


73


Figure 15 UEA Rioja property
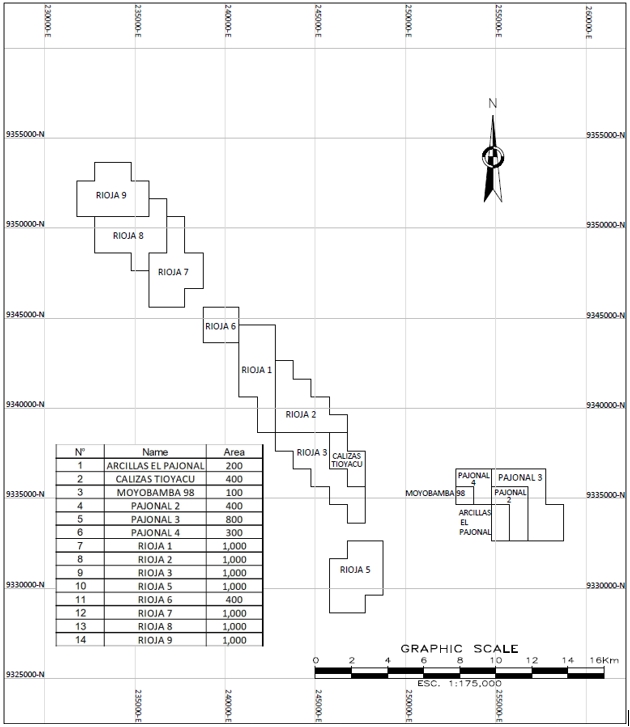


Figure 16 Rioja cement plant
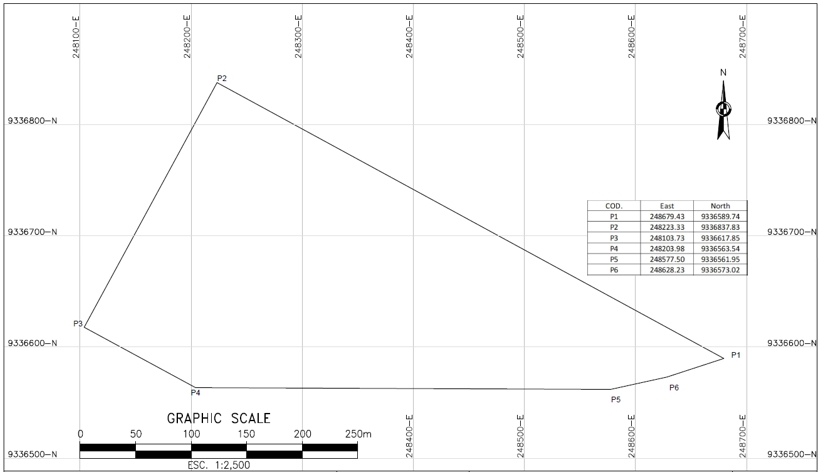


74


Infrastructure


As of December 31, 2025, we understand that the Tioyacu quarry has the necessary infrastructure for normal operations. Facilities for electric power, water supply, fuel, access and roads have been installed.


The Rioja plant owned by Cementos Selva S.A.C., a wholly-owned subsidiary of Cementos Pacasmayo, currently has adequate infrastructure (such as workshops, service stations, restrooms, and others).


The Tioyacu quarry can be accessed from the coast by air from Lima to Tarapoto, time average 1.10 hours of flight, and from Tarapoto to Rioja (139 kilometers) and from Rioja to the Cementos Selva S.A.C. plant (15 kilometers). Alternatively, one can access the site by road from Lima to Rioja, a distance of 1107 kilometers on paved road.


The personnel at Tioyacu quarry come from the Elias Soplin Vargas district. Others are from Rioja and Nueva Cajamarca.


Mining concessions ownership and area


Calizas Tioyacu concession was approved by Resolution 0960-96-RPM granted by the Public Mining Registry.


The procedure to obtain a mining concession is stipulated in the General Mining Law (DS-014-92-EM) and its Regulation D.L 020-2020-EM.


Cementos Selva S.A.C. is the owner of the mining concession and, is registered under the name Calizas Tioyacu as a NON METALLIC quarry.


Tioyacu quarry has a Usufruct and Easement Agreement for the use and easement of the surface where mining activities are carried out. The agreement was signed with Corporación de Desarrollo de San Martin (COREDESAM).


Cementos Selva S.A.C. pays the concession fee for the Calizas Tioyacu concession with unique code 010912495. These payments must be made from the first working day of January to June 30th of each year, providing the Financial Entities the UNIQUE CODE of its mining right. In the case of the Calizas Tioyacu concession, the payment is equivalent to US$3 per hectare.


Royalties


The Peruvian Mining Royalty Law was approved on June 24, 2004 by Law No. 28258, which was amended by Law No. 29788 of September 28, 2011. Cementos Selva S.A.C. currently pays the Mining Royalty (see note 24 to the consolidated financial statements).


The payment to the Peruvian government is made through SUNAT, which is the entity designated to control this consideration for the use of natural resources. Such payment is made through an application that the tax authority has made available to those required to pay.


If the mining royalty is not declared or paid, fines for infractions and late payment interest for non-compliance are incurred. However, failure to pay these fines is not a cause for the loss of the mining concession.


Mining activities on the property


Tioyacu quarry


The Tioyacu quarry located in the Calizas Tioyacu mining concession is currently in the production stage. The Tioyacu quarry is an open-pit mine that uses explosives to fragment the limestone rock, which is then loaded onto trucks by front-end loaders and transported to the Rioja plant.


75


Figure 17 shows a flowsheet of mining processes at the Tioyacu quarry. Further details of the process are provided in Exhibit 96.3 of this annual report on Form 20-F.


Figure 17 Diagram of mining process of the Tioyacu quarry


The Tioyacu quarry has been operating for 25 years for Cementos Selva S.A.C. The material extracted from the quarry is used to supply the Rioja Cement Plant, which has also been in operation for 25 years. The amount of limestone to be mined is planned annually through the mining plan.


The equipment in operation at the Tioyacu quarry is in optimum condition to maintain continuity of operations. Maintenance and optimization of the equipment is carried out periodically and is supervised by the operator of the quarry. The equipment is in good condition and operational. Further details of the equipment are provided in Exhibit 96.3 of this annual report on Form 20-F.


Rioja cement plant


The cement plant is under the laws of the industrial sector, per current Peruvian regulations.


The Rioja cement plant is located in the district of Elías Soplin Vargas, La Rioja province, San Martin region, 5 kilometers from the quarry. This facility receives material from the Tioyacu quarry. The cement plant produces various products for the construction industry, the main product being cement. Different types of cement are produced depending on their applications, using limestone, sand, iron and clays as raw materials. The specific mix of raw materials produces the clinker necessary to produce cement.


The standard cement production process consists of the following main stages:


●Extraction and transportation of limestone;


●Raw material storage;


●Crushing and Drying of Raw Materials;


●Grinding and homogenization to make the raw material of consistent quality;


●Clinkerization;


●Cement grinding;


●Storage in silos; and


●Packaging, loading and distribution.


76


Figure 18 shows the flowsheet for raw material processing, as well as clinker and cement production. Further details of the process are provided in Exhibit 96.3 of this annual report on Form 20-F


Figure 18 Rioja plant process block diagram
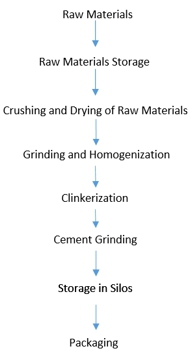


The equipment in operation at the Rioja plant is in optimal condition to avoid any interruption in cement production. Maintenance and optimization of the equipment is carried out periodically and is supervised by Cementos Selva S.A.C personnel. The equipment is in good condition and operational. Further details of the equipment are provided in Exhibit 96.3 of this annual report on Form 20-F.


Facilities


The total cost of the mining concession, mine development costs, land, buildings and other constructions, machinery and equipment, furniture and fixtures, transportation units, computer equipment and tools, quarry rehabilitation costs, capitalized interest and work in progress amounted to S/122,500,031 as of December 31, 2025.


Tioyacu quarry


The Tioyacu quarry does not have maintenance and administrative facilities because the Cementos Selva S.A.C plant is near the quarry and provides the necessary facilities for quarry operations.


Rioja plant


The Rioja plant has facilities such as maintenance workshops, warehouses, laboratories, administrative offices, and cement production lines that support cement production and Tioyacu quarry.


History


The Tioyacu quarry began operations as Cementos Rioja S.A. in 2000. Prior to this, Cementos Rioja S.A. had successfully won the bid for the “Cement Plant with Vertical Kiln of Rioja”, promoted by CEPRI Cemento Rioja at the Public Auction of February 6, 1998. Ownership was then transferred by the Regional Government of San Martin by public deed on March 28, 1988, to Cementos Rioja S.A.


The development of the project, and the non-metallic mining concession – Calizas Tioyacu, among others, were a part of the transfer in favor of Cementos Rioja S.A. by Empresa Minera del Perú, by public deed dated April 8, 1998.


According to the provisions of the General Mining Law (D.S. No. 014-92-EM) in its article 9°, the industrial cement plant is not an integral or accessory part of the mining concession, nor does it carry out mining activities, it is a different property dedicated to the industrial manufacturing of cement.


77


On March 1, 2022, Cementos Selva S.A. changed its corporate name to Cementos Selva S.A.C. (CSSAC). During December 2023, Cementos Selva started a diamond drilling campaign of 6 drill holes to confirm mineral reserves.


On 2024, no blasting activities were carried out from May to September in the Tioyacu quarry due to delays from the authority for permits. During the month of November diamond drilling was carried out at the Tioyacu quarry in order to update the quarry’s resources and mineral reserves.


Property encumbrances


Cementos Selva S.A.C. does not make any payments with respect to encumbrances for the Tioyacu quarry. Tioyacu quarry currently has no outstanding payments with respect to infractions and penalties.


Concessions


The Calizas Tioyacu is a production stage property with estimated mineral reserves.


Geology


The ore deposit contains limestone with a grade suitable for cement production. The limestone is contained within the Condorsinga Formation. This Formation is part of the Pucará Group. Figure 19 shows the stratigraphic column of the area of the Tioyacu quarry while Figure 20 shows the local geology of the quarry.


Figure 19 Rioja plant process block diagram
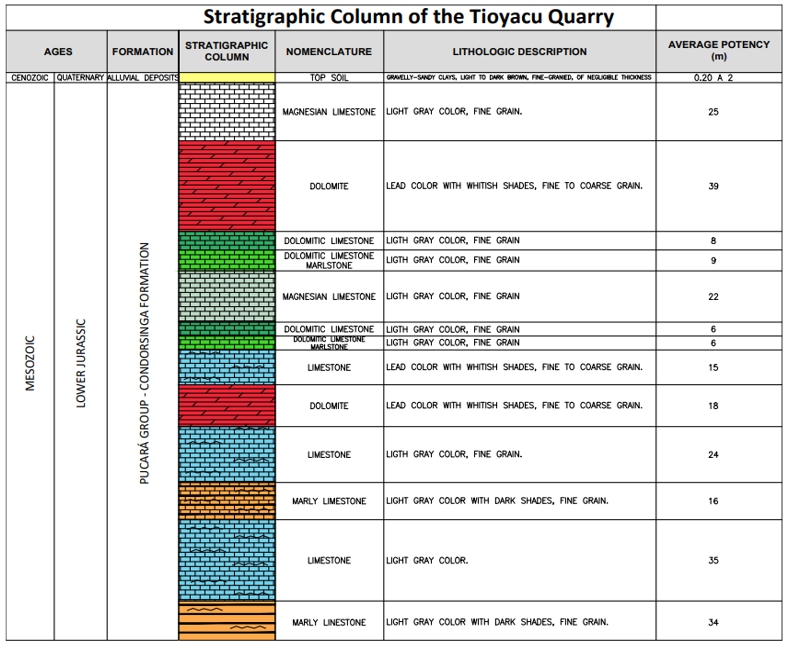


78


Figure 20 Geological section of the Tioyacu quarry


Resources and Reserves


Table 14 shows the mineral resources at the Tioyacu quarry at the end of the 2025 fiscal year.


Table 14 Limestone Resources (exclusive of Reserves) at the end of the 2025 fiscal year based on cement price of S/754 per ton. The mineral resource estimates are at the point of delivery to the cement plant (point of reference).


   Amount
(Million Ton)
   Grades/
qualities
(% CaO)
   Grades/
qualities
(% SiO2)
   Grades/
qualities
(% K2O)
   Cut-off
grades
(%CaO)
 
Measured resources   25.8    49.52    6.88    0.25    51.00(1)
Indicated resources   4.8    48.29    7.92    0.26    51.00(1)
Measured + Indicated resources   30.6    49.33    7.04    0.25    51.00(1)
Inferred resources   7.2    49.11    1.70    0.11    51.00(1)


79


Table 15 Limestone Reserves at the end of the 2025 fiscal year based on cement price of S/754 per ton. The mineral reserve estimates are at the point of delivery to the cement plant (point of reference).


    Amount
(Million
Ton)
    Grades/
qualities
(% CaO)
    Grades/
qualities
(% SiO2)
    Grades/
qualities
(% K2O)
    Cut-off
grades
(%CaO)
 
Proven reserves     10.3       51.2       3.21       0.18       51.00  
Probable reserves     1.3       49.3       5.40       0.17       51.00  
Total reserves     11.6       51.0       3.46       0.18       51.00  


The estimation of mineral reserves considered the expected price of cement. The complete forecast horizon contemplates a total of 26 years of projection. Clinker is used for cement production through the addition of other non-metallic minerals.


Reconciliation of Resources and Reserves at the end of the fiscal year


Table 16 shows the difference between the mineral resource estimates at the end of the 2025 fiscal year and the 2024 fiscal year.


Table 16 Resources for the two fiscal years expressed in millions of tons.


   Resources as
at Dec. 31,
2025
   Resources as
at Dec. 31,
2024
   Discrepancy
Measured resources   25.8    22.5   Recategorization of inferred resources and restructuring of the model by diamond drilling
Indicated resources   4.8    4.9   Recategorization of inferred resources and restructuring of the model by diamond drilling
Measured + Indicated resources   30.6    27.4   Recategorization of inferred resources and restructuring of the model by diamond drilling
Inferred resources   7.2    9.0   Recategorization of inferred resources and restructuring of the model by diamond drilling


*The prices assumed for the Mineral Resource estimation in the economic model can be found in the Cementos Selva S.A.C. Technical Report Summary (TRS) of the Tioyacu Quarry and Rioja Cement Plant 20-F 229.601 (Item 601) Exhibit 96.3. All mineral resources are estimated as quantities at cement plant. The updated average price is S/754 per ton of cement, average of the 26-year projection, at nominal values.


80


Table 17 Reserves for the last two fiscal years expressed in millions of tons.


   Reserves as
at Dec. 31,
2025
   Reserves as
at Dec. 31,
2024
   Discrepancy
Proven reserves   10.3    6.3   Recategorization of probable to proven reserves
Probable reserves   1.3    4.9   Recategorization of probable to proven reserves


*The prices assumed for the Mineral Reserves estimation in the economic model can be found in the Cementos Selva S.A.C. Technical Report Summary (TRS) of the Tioyacu Quarry and Rioja Cement Plant 20-F 229.601 (Item 601) Exhibit 96.3. All mineral reserves are estimated as quantities at cement plant. The updated average price is S/754 per ton of cement, average of the 26-year projection, at nominal values.


Cementos Pacasmayo has previously disclosed mineral resources and reserves at the Tioyacu quarry in its 20-F filed on April 29, 2025. Cementos Pacasmayo previously filed a TRS to support its disclosure of mineral resources and reserves at the Tioyacu quarry as Exhibit 96.3 of its 20-F filed on April 29, 2025. Cementos Pacasmayo is updating that TRS with the new TRS filed as Exhibit 96.3 of this annual report on Form 20-F to ensure the material assumptions are current. The main reasons for this update are price, cost and cement demand. Further details are provided in Exhibit 96.3 of that annual report on Form 20-F.


Other Activities


Cementos Selva S.A.C did not conduct any exploration activity at the Tioyacu quarry during the 2025 fiscal year.


Internal Control Disclosure (229.1305)


Internal Controls


Cementos Pacasmayo S.A.A, has implemented the necessary controls and procedures for quality assurance (QA) and quality control (QC) of the company’s production activities and associated information for the estimation of mineral resources and reserves. Cementos Pacasmayo has also implemented quality management systems for its production activities and the quality management system has been ISO 9001 certified since 2015.


The QA and QC measures are applied to exploration, quarry production (mining), and cement plant processing activities. For laboratory analysis of exploration samples used in mineral resource and reserve estimates, Cementos Pacasmayo uses a program of duplicate samples, standards and blanks to evaluate the reliability of the laboratory results that its qualified persons rely on for mineral resource and reserve estimates. Its qualified persons also verify the data prior to using the data in their work.


As part of the quality control activities, Cementos Pacasmayo periodically hires an external laboratory to verify Cementos Pacasmayo´s laboratory results obtained during the exploration activities, which are part of the geological database and subsequently used in the estimation of resources and reserves.


81


In each of its operations, Cementos Pacasmayo, following the Quality Management System, applies the quality control procedures specific to each stage of the process such as exploration activities, limestone/coquina production, reception of raw materials in the cement plant, crushing of raw materials, coal grinding, cement grinding and raw materials or products in the Cement Plants (e.g., clinker, other materials and cement).


Quality control procedures include sample security such as chain of custody for reliable information.


Cementos Pacasmayo has a chemical analysis laboratory at each of its cement plants where procedures based on international standards are used for the chemical and physical analysis of raw materials, clinker, and other materials; mainly used in limestone and cement production. Methodologies including the insertion of blanks, duplicates, and standards are applied as part of the Quality Plan.


Cementos Pacasmayo has a data management department whose goal is to verify the quality of the information and its incorporation into the geological database, so that it can be used in studies and interpretations, geological modeling, and estimation of mineral resources and reserves.


Data verification activities apply to exploration, limestone/coquina production and cement processing data.


At the cement plant, the quality plan uses the PDCA (Plan, Do, Check, Act) cycle, which allows Cementos Pacasmayo to verify the quality of information during cement production activities.


Cementos Pacasmayo has implemented internal controls to ensure its mineral Resource and Reserves estimates are compliant with Regulation S-K 1300 requirements, including ensuring that mineral resource and reserve estimates are prepared by qualified persons who are members of the Peruvian Engineers Association, an organization that regulates the legal professional practice of engineers in Peru.


Mineral resource and reserve estimates at the end of each fiscal year are and will continue to be reviewed by our Mining Operations Department to ensure compliance with S-K 1300. Cementos Pacasmayo engineers and geologists reconcile actual production with estimates of mineral resources and reserves annually to verify accuracy of the estimates. The comprehensive risk inherent in Cementos Pacasmayo’s estimates of mineral resources and reserves are consistent with industry best practices.


Insurance


We maintain a comprehensive insurance program to mitigate property and casualty risks. We maintain a comprehensive insurance program Our plants and equipment are covered against customary industry risks, including machinery breakdown, property damage, earthquakes, tremors, underground fires, storm surge, tidal waves, and tsunamis, among others. Coverage also extends to business interruption affecting our cement manufacturing operations. In addition, we carry commercial insurance for workers’ compensation and general liability exposures. We believe that our coverage, limits and deductibles are appropriate for our operations and consistent with those maintained by comparable manufactures in Peru.


Sustainability Performance


We report our sustainability performance information to the Getting the Numbers Right (“GNR”) database, inspired by the guiding principles of the Cement Sustainability Initiative (the “CSI”), a sector-project of the World Business Council for Sustainable Development (the “WBCSD”) among other cement companies in Latin America through the Inter-American Cement Federation (the “FICEM”).


82


In August 2018, we joined the GCCA and the GCCA announced the formation of a strategic partnership with the WBCSD to facilitate sustainable development of the cement and concrete sectors and their value chains. As part of a new agreement, the work carried out by the CSI and the GNR database was transferred from the WBCSD to the GCCA on January 1, 2019. In 2023, our CEO, Humberto Reynaldo Nadal was elected board member of the GCCA for the 2024-2026 and was re-elected for the 2026-2028 period.


In 2019, we became members of Innovandi Global Cement and Concrete Research Network which is GCCA’s Innovation arm, which runs key programs to develop innovations to help the industry decarbonize and produce carbon neutral concrete by 2050.


In 2020, member companies of the Global Cement and Concrete Association came together as leaders in the sector to commit to producing carbon neutral concrete by 2050, in line with global climate targets – accelerating the CO2 reductions.


Since 2019, we have been included as part of the DJS MILA Pacific Alliance Index. This index is made up of those companies that demonstrate superior performance among their peers under social, environmental and economic criteria. This achievement comes as a result of Pacasmayo’s effort to improve in all of these criteria and to work towards ambitious goals in terms of long-term sustainability. We are committed not only to remain in the Index but to improve our performance, as we are convinced that the focus on sustainability is key to our business and our stakeholders. We participated in the Carbon Disclosure Project (CDP) for the first time, and we are committed to participate every year in this project going forward. CDP is a not-for-profit charity that runs the global disclosure system for investors, companies, cities, states and regions to manage their environmental impacts.


In 2023, we inaugurated a new kiln at our Pacasmayo plant, which, in addition to adding 660,000 metric tons of clinker capacity per year, will help us on our path to carbon neutrality and allow us to achieve energy efficiency.


In February 2026, we were selected to be part of The Sustainability Yearbook for the sixth consecutive year. In this edition, we obtained, for the first time, a score within the top 10% of S&P Global’s Corporate Sustainability Assessment (CSA) in the building materials industry. To appear in the Yearbook, companies must score within the top 15% of their industry globally and have a gap of less than 30% from the leader’s Global ESG score.


Social Performance


We are committed to the development and quality of life of communities that surround the area where we operate. We have developed a good relationship with the local communities surrounding our plant facilities since we started operations in Pacasmayo. We have a number of social responsibility programs aimed at improving health and education in the area. Below is a brief description of a few of our social initiatives.


Tecsup.  Tecsup is a leading not-for-profit institute in Peru that provides technical education. It was founded by the family of our controlling shareholder, and we support it by providing financial assistance to promising students living near our plants to study at the Trujillo campus of Tecsup. Through its three campuses in Peru, Tecsup has graduated over 214  students in various technical fields, some of whom currently work for us and our affiliated companies.


83


Center for Technological Training. We have three training centers at our facilities where we teach students and adults business and technical skills. Our centers are staffed with instructors from Tecsup. The goal of the center is to help develop the professional skills of the local population, especially of students and teachers at the educational institutions in the towns of Tembladera, Pacasmayo and Sechura. In 2025, this program benefited over 1,838  stakeholders.


Abilities Strengthening. This program seeks to provide training to local stakeholders such as grassroots organizations, local entrepreneurs. The objective of the program is to strengthen their skills and knowledge by providing courses and seminars especially designed for that purpose. The program is funded by us and in 2025 benefited 212  stakeholders.


Universidad de Ingeniería y Tecnología – UTEC (University of Engineering and Technology) is an educational nonprofit proposal that since 2012 is aimed at the development of people in the engineering field, looking to satisfy the need for these types of professionals in the labor market by implementing a curriculum in line with the trends and demands that globalization poses to modern engineering, with an integrated approach to innovative teaching models. We support it by providing financial aid for its operations. To enhance students’ knowledge, UTEC also has various national and international alliances with top organizations.


Acuícola Los Paiches. Through our social venture, Acuícola Los Paiches S.A.C., we studied the reproductive forms of the “paiche” (arapaima giga), a native fish species that was on the edge of extinction. After years of studies and scientific testing, we have successfully bred this species in captivity, and we have obtained thousands of fingerlings.


Floor Improvement Project. To promote the urban development of our areas of influence, we set out to improve the infrastructure conditions of homes, through the substitution of dirt floors for concrete floors to contribute to the improvement of the quality of life and habitability conditions of the towns surrounding our operations. In 2025, more than 10,000 people joined this initiative and with our support they have managed to build concrete floors in their homes. Likewise, we have contributed 21,250 bags of cement to build a total of 71,000 square meters of concrete floors. This project has motivated the participants to invest financial resources and contribute labor to improve their homes.


Risk Management


Risk Management Description


At Cementos Pacasmayo, we manage risks in a structured manner to address operational, compliance, and information security risks, as well as the traceability of ESG and climate change risks that may influence our long-term objectives. This approach aims to support senior management in decision-making by reducing negative impacts, seizing opportunities, and managing prevention and mitigation plans. In addition, it allows us to promote the continuous improvement of our processes.


84


Risk Management Process


Our methodology is based on the Australian/New Zealand Standard for Risk Management (AS/NZS 4360) and is aligned with the ISO 31000 Risk Management standard.


1.Scope, Context, Criteria:


●Scope: Collaborators who play an active role in decision-making at Cementos Pacasmayo and its subsidiaries participate in the risk management process, including corporate projects.


●Context: A comprehensive understanding of the external and internal environments in which the organization operates is established, considering them as key elements in the analysis process. To evaluate the external environment, the PESTEL tool is used, covering political, economic, social, technological, ecological, and legal aspects. Likewise, for internal analysis, a detailed evaluation of each process is conducted by the risk manager responsible.


●Criteria: Risk Appetite: In situations where the assessment determines that the risk level is classified as “Very Low” or “Low,” the organization will assume the risk without taking additional mitigation measures, as it falls within the acceptable risk limits set by the organization.


●Risk Tolerance: In situations where the assessment determines that the risk level is classified as “Medium,” the organization considers the risk acceptable but may require control or monitoring measures to maintain or reduce the level.


●Mandatory Treatment: When the risk level is classified as “High” or “Very High,” the process owner must implement stronger controls to mitigate the risk and establish more rigorous monitoring. The objective of these controls is to reduce the risk to at least a “Medium” level, in line with the limits of the company’s risk tolerance.


2.Risk Assessment:


We conduct risk assessments through our management platform, based on the best practices of the ISO 31000:2018 standard. In addition, we use the BowTie Diagram methodology to identify the risk together and its respective causes, consequences, and controls, which facilitates its analysis and subsequent evaluation.


●Identification: The objective of risk identification is to recognize events that may occur within the organization and the consequences that could affect the achievement of corporate objectives. In 2025, we manage more than 160 risks, including operational, compliance, and information security risks, through discussions with risk owners and their teams. This process facilitates the exchange of perspectives on potential threats, enabling the identification of their impacts and the definition of the measures required to prevent or mitigate them.


Classification according to:


Type: Operational, Compliance, or Information Security


Group: Paralyzing, Emerging, and others


Sustainability: Environmental, Social, and Governance


85


●Analysis: Three key variables are evaluated: impact, probability, and the effectiveness of associated controls. Impact is analyzed from legal, reputational, and economic perspectives, while probability measures the likelihood of a risk occurring and the tendency toward its materialization, both assessed using five levels of evaluation. Control effectiveness is assessed based on their design and implementation. Assigning controls to risks is essential, as it allows the evaluation of the level of reduction in impact and the associated frequency for each risk. We include both qualitative and quantitative analyses to estimate financial impact.


●Evaluation: The results of the assessment of the three variables associated with each risk allow the determination of the levels of Inherent Risk (IR) and Residual Risk (RR), which are classified into five ranges, from “Very Low” to “Very High.”


3.Risk Treatment


For each risk, we define treatment plans based on four strategies: accept, share, reduce, or avoid. Controls and mitigation actions are aligned with the defined risk appetite and aim to prevent negative impacts or reduce their likelihood.


In addition, we are advancing in the final testing phase of our Business Continuity Plan, which forms part of our preparation for crises and disruptive events.


4.Monitoring and Supervision


The dynamic environment in which Pacasmayo, its subsidiaries, and its projects operate, both nationally and globally, requires periodic review and updating of risks and their components. The overall calibration is carried out once a year, while the 28 strategic risks are assessed quarterly. These reviews are conducted through discussions with the owners of each risk and the management team, where risks are identified, analyzed, and the necessary actions for their treatment are determined.


The 2025 results show that 10 strategic risks are aligned with our risk appetite, 13 fall within tolerance levels, and 5 continue to be managed at a High level.


5.Communication and Consultation


The Risk Management team is responsible for promoting understanding of the process among the responsible areas through the dissemination of information, clarification of questions, and strengthening of knowledge. To this end, it carries out various activities such as in-person and virtual training sessions, discussion forums, and activations across different sites.


6.Recording and Reporting


At the end of each year, the Risk team presents a detailed report on the activities carried out in relation to risk management within the organization. This document includes Key Risk Indicators (KRIs), risk matrices, the results of the risk management maturity assessment, and the corresponding action plans.


86


Risk Management Organization


Manager and
team
responsible for
risk management
  Risks
Management
Director and
Risk
Management Team
  Risks committee   Audit Committee   Internal Audit
They are responsible for evaluating and treating risks through preventive and mitigation controls. Risk management coordinates with them to develop and monitor these metrics.   The Risk Management team, led by the Risk Management Director, implements the corporate risk management strategy and assumes responsibility for establishing guidelines for comprehensive risk management by developing policies and procedures and defining the methodology to be followed in accordance with the ISO 31000:2018 guidelines. In addition, it guides risk owners and their teams in managing their risks, promoting an organizational culture focused on prevention.   The Risk Committee, composed of our Chief Executive Officer and the Risk Director, is responsible for overseeing the implementation of our corporate risk management strategy. We meet quarterly to monitor and analyze the 29 strategic risks, classified according to the main management areas: People, Legal, Commercial, Supply Chain, Operations, Construction Solutions, Innovation and Digital Transformation, and Finance, as well as those associated with new products and projects. Through this committee, we submit the risk management plan for review and approval by the Chief Executive Officer, and subsequently present it to the Audit Committee for evaluation. In addition, the committee acts as a coordinating body that ensures the strategic alignment of risk management actions, strengthening the effectiveness of controls and contributing to the achievement of corporate objectives.    The control body, composed of three independent board members, reports directly to the Board. Participants include external and internal auditors, the Compliance Officer, the CFO, and the Risk Manager. This body monitors risk management action plans and improvement initiatives. Additionally, it may suggest actions if it identifies opportunities or threats that could impact the organization.   The Internal Audit area is responsible for overseeing our management processes and, within the framework of Risk Management, conducts annual audits of the process. As part of its responsibilities, it issues a report detailing gaps and opportunities for improvement, validates the effectiveness of existing controls, and monitors the progress of action plans associated with identified risks.


Climate Related Risks


ESG risk management includes risks related to climate change. Therefore, they are analyzed through the same risk management stages and are part of Pacasmayo’s 2030 Sustainability Plan. This risk assessment includes risks that could occur in the short, medium or long term, and of different types, such as physical risks and transition risks, among others.


We have clear objectives to manage climate risks and opportunities, aiming to reduce our emissions by 20% and achieve more than 20% co-processing by 2030. All of this goes hand in hand with the implementation of operational contingency plans and the conditioning of plant infrastructure to ensure continuity, as well as the testing of emergency and crisis response plans.


For this purpose, we are aligned with the recommendations of the Task Force on Climate-related Financial Disclosures (TCFD) for risks related to climate change. For example, one risk would be that our employees’ health would be affected by heat waves or lack of water, as well as a stop in our operations due to water stress, landslides or forest fires. We are also exposed to the possibility of not being able to dispatch finished products, as well as supplying raw materials to production plants due to disabled access roads.


In 2025, we enhanced our climate risk management by integrating forward-looking climate scenarios and conducting a more detailed and technically robust assessment of physical risks across our operations and value chain. Through our CLIMATRIX initiative, we transitioned from qualitative assessments to data-driven evidence. We use the S&P Global Climanomics platform to quantify these risks using CMIP6 climate models. This methodology allows us to calculate the modeled average annual loss (MAAL), which translates climate hazards into measurable financial impacts by integrating event probability with the specific vulnerability of our assets. The use of specialized analytical tools strengthened the identification and assessment of these risks, supporting more informed decision-making. All identified climate-related risks are regularly reported to executive and management committees to improve the understanding of the exposure and vulnerability of our assets.


We intend to continue integrating transition risks through scenario analyses aligned with market trends and future regulatory developments, ensuring that climate-related risks remain embedded in our governance and strategic processes.


87


Emerging Risks


Emerging risks are those that have an impact in the long-term. The risks considered here include all recently identified risks that could have a long-term impact on the company’s business or industry, although in some cases they may have already begun to impact the company’s business.


Risk Description   Potential Impact   Mitigation Actions   Evidence of Mitigation Actions
Economic Risk: Economic impact resulting from the introduction of cement substitute products in the construction industry.   Medium to high: This risk may result in a potential decrease in the demand for traditional cement, affecting revenues and market share. Additionally, it could increase pressure to invest in research and development of competitive alternatives, which would imply higher costs. There is also the possibility of facing stricter regulatory requirements related to sustainability, requiring the adaptation of processes or products to more demanding standards and increasing operational expenses. In a market where sustainability perception is key, the company’s reputation could also be affected if it fails to position itself as an innovative and environmentally responsible player.   Among the controls implemented, we highlight a portfolio of sustainable options, and continuous investment in research through our R&D area. In addition, we carry out constant monitoring of market trends and proactively adapt to environmental regulations. We complement these actions with awareness campaigns and customer education programs to strengthen the preference for cement. At the same time, we optimize costs and design contingency plans that ensure our competitiveness and resilience in response to changes in demand.  

●     Continuous investment in research and development (R&D) to generate competitive alternatives.


● Development of a portfolio of sustainable solutions.

             
Environmental Risk: Water resource scarcity affecting operational continuity due to climate change and ecosystem degradation.   Medium to high: Climate change, combined with ecosystem degradation, may reduce water availability in the areas where cement plants operate, generating conflicts over access to this resource among the industry, local communities, and other sectors. This may lead to operational disruptions, higher costs due to the need to secure alternative water sources or implement water-saving technologies, and even regulatory sanctions if environmental regulations are not met. In addition, the reputational impact may be significant, as the perception that a company contributes to water stress in a region can affect its relationship with communities and business partners, putting the long-term sustainability of the business at risk.   Pacasmayo continuously collects rainfall data to assess potential reductions in water resources, complemented by water stress studies conducted by specialized consultants. In addition, the Business Continuity Plan includes maintaining stock of raw materials, finished products, and maintenance materials, as well as operating under a multi-plant scheme to ensure operational continuity. It also provides internal and external accommodation for personnel designated by the organization, establishes agreements with clinics, ensures the availability of satellite phones to maintain reliable communication, and includes tools that enable remote work when necessary.   Business Continuity Plan


88


ITEM 4A. UNRESOLVED STAFF COMMENTS


Not applicable.


Item 5. OPERATING AND FINANCIAL REVIEW AND PROSPECTS


A.Operating Results


Overview


We are a Peruvian cement company, and the only cement manufacturer serving in the northern region of Peru. With almost 70 years of operating history, we produce, distribute and sell cement and cement-related materials, such as precast products and ready-mix concrete. Our products are primarily used in construction. We also produce and sell quicklime for use in mining operations.


In 2025, our cement sales volume was approximately 3.0 million metric tons, representing an estimated 22.4% share of Peru’s total cement sales that year according to INEI. That same year, we also sold approximately 16 thousand metric tons of quicklime.


We own three cement production facilities, our Pacasmayo and Piura facilities located in the northwest region of Peru, and our smaller Rioja facility located in the northeast. Our facilities have a total installed annual cement production capacity of approximately 4.9 million metric tons and 3.1 million metric tons of clinker capacity. We also have installed annual production capacity of 240,000 metric tons of quicklime. We own concession rights to several quarries with reserves of limestone/coquina and other raw materials located near our facilities.


Factors Affecting our Results of Operations


Revenue Drivers


In 2025, approximately 81.4% of our total cement sales were in the form of bagged cement, substantially all of which was sold through retailers both within and outside of our distribution network. The remaining 18.6% of our cement was sold in bulk or in shipments of precast products or ready-mix concrete directly to large construction companies. Our retail sales are directed to both the self-construction (auto-construcción) segment and construction companies that buy cement for a variety of small construction works, including minor residential, commercial and infrastructure projects. Cement destined for large private and public projects, such as housing complexes, highways, irrigation channels, hospitals, schools, mining and industrial facilities, is typically sold in bulk or in shipments of precast products or ready-mix concrete.


We estimate that sales to the self-construction (auto-construcción) segment accounted for approximately 73.9% of our total cement sales in 2025, 75.4% in 2024 and 76.3% in 2023; private construction projects, both large and small, accounted for approximately 14.0% of our total cement sales in 2025, 15.1% in 2024, and 13.9% in 2023; and public construction projects accounted for the remaining 12.1% in of our total cement sales in 2025, 9.5% in 2024, and 9.8% in 2023. The self-construction segment has proven its resilience in times of crisis. As the Peruvian economy becomes less informal, and there is more stability and confidence from the private sector, private construction projects and infrastructure are expected to become increasingly more important to our business.


89


Our cement sales are largely driven by residential construction (both self-construction (auto-construcción) and small and large housing developments undertaken by construction companies), which is generally affected by economic conditions in the northern region of Peru. Self-construction (auto-construcción) is particularly affected by levels of disposable household income, as low-income families tend to invest most of their savings in developing their homes. Larger residential construction is more susceptible to the economic outlook, the availability of financing and prevailing investment levels in the region. GDP in the northern region of Peru is estimated to have increased by 2.0% in 2025, 3.8% in 2024, and 0.9% in 2023. Our cement volumes, which represented most of the cement sales in the northern region of Peru, grew by 6.4% in 2025, by 3.9% in 2024 and contracted by 7.9% in 2023, in terms of metric tons.


Our cement sales are also driven, to a lesser extent, by commercial developments and infrastructure projects. Commercial and other private construction projects are also affected by the level of public and private investment in the region, while public infrastructure projects depend on the priorities and financial resources of the national, regional and local governments. Since 2020, there has been a significant reduction in activity relating to these projects, due initially to the economic impact of the COVID-19 pandemic, as well as subsequent political uncertainty. Although there was some recovery during 2025, there is still a substantial lag in private investment, which decreased by 1.1% in 2025.


Cost Drivers


We obtain limestone and coquina required to produce clinker and quicklime, as well as sand, clay and pozzolanic materials required to produce cement principally from land where we have concession rights. In addition, we purchase from third parties’ admixtures and certain raw materials that we use in our production process, including gypsum, blast furnace slag, iron and other materials. Admixtures and raw materials used in our cement production process do not include construction supplies that we acquire from third parties for resale through our distribution network along with our cement products. Raw materials accounted for an estimated 26.9% of our cost of production in 2025, 27.8% in 2024 and 29.2% in 2023.


Coal is one of the main raw materials used in our production process, in particular in our kilns. We purchase anthracite coal from nearby coal mines. We do not have long-term coal supply agreements, and we do not engage in hedging transactions in connection with the price of coal. Coal accounted for an estimated 17.1% of our costs of production in 2025, 17.8% in 2024 and 22.5% in 2023.


Electricity is used in our facilities mainly to power our cement mills. We power our Pacasmayo and Piura facilities with electricity purchased from Electroperú, with which we have a supply agreement expiring in May 2026. Beginning in June 2026, those facilities will be supplied with electricity by Orygen Perú S.A.A. pursuant to a supply agreement through May 2031. Our Rioja facility is powered primarily with electricity from ELOR, with which we have an agreement expiring in December 2029. Under these agreements, the price of electricity is based on a formula that takes into consideration our consumption of electricity and certain market variables, including the international price of oil. Electricity accounted for approximately 13.8% of our cost of production in 2025, 15.0% in 2024 and 15.3% in 2023. Electricity costs tend to be lower during the rainy season, from January to March of each year, as our region is served primarily by hydro-electric power plants.


The cost of imported clinker as a percentage of our cement production costs was approximately 2.6% in 2025, compared to 5.0% in 2024 and 3.7% in 2023.


Personnel expenses represented 8.6% of our total cost of production in 2025, 6.9% in 2024 and 6.2% in 2023. The increase in 2025 is mainly due to the collective bargaining negotiations with our labor unions, which is negotiated every three years and has a closing bonus during the first year.


90


Third-party Construction Supplies


In addition to selling our own products, we also sell and distribute construction supplies manufactured by third parties, such as steel rebar, wires and pipes that are typically used in construction along with our cement. Our profit margins from the sale of third party construction supplies are significantly lower than the margins on our cement products and they are affected by fluctuations in product prices and the exchange rate between the Sol and the U.S. Dollar between the time we purchase these products and the time we resell them. We sell these products primarily as a service to retailers in our distribution network in an effort to support the sale of our cement products.


Mining Royalty Tax


The mining royalty tax for the exploitation of metallic and non-metallic minerals is payable on a quarterly basis in an amount equal to the greater of (i) an amount determined in accordance with a statutory scale of tax rates based on a company’s operating profit margin that is applied to its operating profit, as adjusted by certain non-deductible expenses and (ii) 1% of a company’s net sales, in each case during the applicable quarter. These amounts are determined based on our unconsolidated financial statements and those of our subsidiaries with operations that are under the scope of the Mining Royalty Law. Mining royalty payments are deductible for income tax purposes in the fiscal year in which such payments are made. For additional information, see note 25 to our consolidated financial statements included in this annual report on Form 20-F.


Operating Segments


We have three operating segments: (i) cement, concrete, mortar, pavement and precast, (ii) quicklime and (iii) sales of construction supplies. For additional information on our operating segments, see note 28 to our consolidated financial statements included in this annual report on Form 20-F.


New Accounting Pronouncements


For a description of new interpretations and improvements to IFRS in effect since 2025, see notes 2.3.17 and 4 to our consolidated financial statements included in this annual report on Form 20-F.


Critical Accounting Policies


The following is a discussion of our application of critical accounting policies that require our management to make certain assumptions about matters that are uncertain at the time the accounting estimate is made, where our management could reasonably use different estimates, or where accounting changes may reasonably occur from period to period, and in each case would have a material effect on our financial statements. For additional information, see note 3 to our annual audited consolidated financial statements included in this annual report on Form 20-F.


91


Determination of Useful Live of Assets for Depreciation and Amortization Purposes


Depreciation of mining concessions and mine development costs are charged to cost of production on a units-of-production basis using proved reserves. Other assets are depreciated on a straight-line-basis over their estimated useful lives, as follows:


Buildings and other construction:

  Years 
Minor facilities related to buildings   Between 10 and 35 
Administrative facilities   Between 20 and 51 
Main production structures   Between 20 and 56 
Minor production structures   Between 20 and 35 
Machinery and equipment:     
Mills   Between 24 and 45 
Horizontal and vertical furnaces, crushers and grinders   Between 23 and 36 
Electricity facilities and other minors   Between 10 and 35 
Furniture and fixtures   10 
Transportation units:     
Heavy units   Between 5 and 15 
Light units   Between 5 and 10 
Computer equipment   Between 3 and 10 
Tools   Between 5 and 10 


The asset’s residual value, useful lives and methods of depreciation are reviewed at each reporting period and adjusted prospectively if appropriate.


An item of property, plant and equipment and any significant part initially recognized is derecognized upon disposal or when no future economic benefits are expected from its use or disposal. Any gain or loss arising on derecognition of the asset (calculated as the difference between the net disposal proceeds and the carrying amount of the asset) is included in the consolidated statement of profit or loss when the asset is derecognized.


Revenue Recognition


Revenue is measured at the fair value of the consideration received or receivable, considering contractually defined terms of payment and excluding taxes or duties.


The following specific recognition criteria must also be met before revenue is recognized:


Sales of goods


Revenue from sale of goods is recognized at the point in time when control of the asset is transferred to the customer, generally on delivery of the goods.


We consider whether there are other promises in the contract that are separate performance obligations to which a portion of the transaction price needs to be allocated. In determining the transaction price for the sale of goods, we consider the effects of variable consideration, the existence of significant financing components, noncash consideration, and consideration payable to the customer (if any).


92


Rendering of services


In the business segments of cement, concrete, mortar, precast, quicklime and construction supplies, we provide transportation services. These services are sold together with the sale of the goods to the customer.


Transportation services are satisfied when the transport service is concluded, which coincides with the moment of delivery of the goods to the customers.


Paving services


In the paving business, to satisfy performance obligations over time, we recognize revenue by measuring progress as progress is made (transferring control of the services) in accordance with the relevant contract.


To measure the progress of the paving service, we use the resource method, which states that revenue should be recognized on the basis of the efforts or resources incurred to satisfy the performance obligation (for example, resources consumed, labor hours expended, costs incurred, elapsed time or machinery hours used) in relation to the total resources expected to satisfy the performance obligation.


Interest income


For all financial instruments measured at amortized cost and interest-bearing financial assets, interest income is recorded using the effective interest rate (EIR). EIR is the rate that exactly discounts the estimated future cash payments or receipts over the expected life of the financial instrument or a shorter period, where appropriate, to the net carrying amount of the financial asset or liability. Interest income is included in finance income in the consolidated statement of profit or loss.


Impairment of Non-Financial Assets


We assess at each reporting date whether there is an indication that an asset may be impaired. If any indication exists, or when annual impairment testing for an asset is required, (goodwill and intangible assets with indefinite useful lives), we estimate the asset’s recoverable amount. An asset’s recoverable value is the higher of an asset’s or cash-generating unit’s fair value less costs of disposal and its value in use, and is determined for an individual asset, unless the asset does not generate net cash inflows that are largely independent of those from other assets or groups of assets. Where the carrying amount of an asset’s cash-generating unit exceeds its recoverable amount, the asset is considered impaired and is written down to its recoverable amount. In assessing value in use, the estimated future cash flows are discounted to their present value using a pre-tax discount rate that reflects current market assessments of the time value of money and the risks specific to the asset. In determining fair value less costs of disposal, recent market transactions are taken into account. If no such transactions can be identified, an appropriate valuation model is used. These calculations are corroborated by valuation multiples, quoted share prices for publicly traded companies or other available fair value indicators.


As of December 31, 2025, 2024 and 2023, goodwill related to the acquisition of assets made by our subsidiary Distribuidora Norte Pacasmayo S.R.L. amounted to S/4,459,000. We have assessed the recoverable amount of our goodwill and have determined that there are no indicators of an impairment loss of this asset as of December 31, 2025 and 2024. In 2023, management recognized a specific impairment to retirement for the net value of the assets of the vertical clinker kilns located at the Pacasmayo cement plant for a net cost of S/36,551,000. This deterioration estimate was carried out as a consequence of replacing the old technology of these kilns due to the entry into operation of the Clinker Lines Optimization Project – Kiln 4 in the Pacasmayo plant, which is more efficient and produces fewer emissions. This amount was recorded in the impairment of property, plant and equipment item in the consolidated statement of profit or loss. As of December 31, 2025, management had not identified impairment for long-lived assets.


93


We base our impairment calculation on detailed budgets and forecast calculations, which are prepared separately from our cash generation units to which the individual assets are allocated. Impairment losses of continuing operations, including impairment on inventories, are recognized in the consolidated statement of profit or loss in expense categories consistent with the function of the impaired asset.


An assessment is made at each reporting date as to whether there is any indication that previously recognized impairment losses may no longer exist or have decreased. If such indication exists, we estimate the asset’s or cash-generating unit’s recoverable amount. A previously recognized impairment loss is reversed only if there has been a change in the assumptions used to determine the asset’s recoverable amount since the last impairment loss was recognized. The reversal is limited so that the carrying amount of the asset does not exceed its recoverable amount, nor exceed the carrying amount that would have been determined, net of depreciation, had no impairment loss been recognized for the asset in prior years. Such reversal is recognized in the consolidated statement of profit or loss. Exploration and evaluation assets are tested for impairment annually as of December 31, either individually or at the cash-generating unit level, as appropriate and when circumstances indicate that the carrying value may be impaired.


Deferred Tax


Deferred tax is determined on temporary differences between the tax bases of assets and liabilities and their carrying amounts for financial reporting purposes at the reporting date.


Deferred tax liabilities are recognized for all taxable temporary differences, except in respect of taxable temporary differences associated with investments in subsidiaries, associates and interests in joint arrangements, when the timing of the reversal of the temporary differences can be controlled and it is probable that the temporary differences will not reverse in the foreseeable future.


Deferred tax assets are recognized for all deductible temporary differences, and for the future offset of unused tax credits and carryforward tax losses, provided they are considered recoverable.


The carrying amount of deferred tax assets is reviewed at each reporting date and reduced to the extent that it is no longer probable that sufficient taxable profit will be available to allow all or part of the deferred tax asset to be utilized. Unrecognized deferred tax assets are re-assessed at each reporting date and are recognized to the extent that it has become probable that future taxable profits will allow the deferred tax asset to be recovered.


Deferred tax assets and liabilities are measured at the tax rates that are expected to apply in the year when the asset is realized or the liability is settled, based on tax rates (and tax laws) that have been enacted or substantively enacted at the reporting date.


Deferred tax related to items recognized outside profit or loss are recognized outside the consolidated statement of profit or loss. Deferred tax items are recognized in correlation to the underlying transaction either in OCI or directly in equity.


94


Results of Operations


Comparison of Year Ended December 31, 2025 to Year Ended December 31, 2024


   For the year ended
December 31,
     
   2025   2024   Variation 
   (in millions of S/)   (%) 
Sales of goods   2,116.9    1,978.1    7.0%
Cost of sales   (1,310.0)   (1,249.6)   4.8%
Gross profit   806.9    728.5    10.8%
Operating income (expenses):               
Administrative expenses   (291.5)   (253.4)   15.0%
Selling and distribution expenses   (92.8)   (81.4)   14.0%
Other operating (expense) income, net   (75.5)   (2.7)   n.m. 
Total operating expenses, net   (459.8)   (337.5)   36.2%
Operating profit    347.0    391.0    (11.2)%
Other income (expenses):               
Finance income   11.3    6.3    79.4%
Finance costs   (93.0)   (100.3)   (7.3)%
Loss from exchange difference, net   2.6    (0.8)   n.m. 
Total other expenses, net   (79.1)   (94.8)   (16.6)%
Profit before income tax   268.0    296.2    (9.5)%
Income tax expense   (113.8)   (97.3)   17.0%
Profit for the year   154.2    198.9    (22.5)%


n.m. = not meaningful.


Sales of Goods


The following table sets forth a breakdown of our sales of goods by segment for 2025 and 2024:


   For the year ended December 31, 
   2025   2024 
   (in millions of S/)   (in %)   (in millions of S/)   (in %) 
Cement, concrete, mortar, pavement and precast   2,064.7    97.5    1,906.8    96.4 
Construction supplies   41.7    2.0    56.9    2.9 
Other   10.5    0.5    14.4    0.7 
Total sales of goods  2,116.9   100.0   1,978.1   100.0 


Our total sales of goods increased by 7.0%, or S/138.8 million, to S/2,116.9 million in 2025 from S/1,978.1 million in 2024. This increase was primarily due to the following factors:


●a 8.3%, or S/157.9 million, increase in sales of cement, concrete, mortar, pavement and precast mainly due to increased sales of bagged cement and for infrastructure projects;


95


●a 26.7%, or S/15.2 million, decrease in the sale of construction supplies, mainly due to decreased sales of steel rebars; and


●a 27.1% or S/3.9 million, decrease in the sale of other material.


The following table sets forth the composition of our sales of cement, concrete, mortar, pavement and precast for 2025 and 2024:


   For the year ended
December 31,
     
   2025   2024   Variation 
   (in millions of S/)   (%) 
Cement   1,745.2    1,605.5    8.7 
Concrete and mortar   254.1    183.6    38.4 
Pavement   34.3    87.6    (60.8)
Precast   31.1    30.1    3.3 
Total   2,064.7    1,906.8    8.3 


Our total sales of cement, concrete, mortar, pavement and precast increased by 8.3%, or S/157.9 million, to S/2,064.7 million in 2025 from S/1,906.8 million in 2024. This increase was primarily due to the following factors:


●a 8.7%, or S/139.7 million, increase in cement sales revenues in 2025 mainly due to a 7.7% increase in demand, and a 1.0% increase in average pricing;


●a 38.4%, or S/70.5 million, increase in concrete and mortar sales revenue, mainly due to a 9.1% increase in sales volume of concrete and mortar, as public and private investment demand increased during 2025, as well as a 29.3% increase in the average prices of concrete;


●a 60.8%, or S/53.3 million, decrease in pavement sales revenue, mainly due to a high comparative basis, as the Piura airport project experienced peak sales during 2024, and significantly decreased during 2025 as it approached its completion.; and


●a 3.3%, or S/0.9 million, increase in precast revenue, mainly due to a 6.5% increase in volumes as demand from the public sector for reconstruction-related projects increased, partially offset by a 3.2% decrease in the average price of precast products.


Cost of Sales


The following table sets forth a breakdown of our cost of sales by segment for 2025 and 2024:


   For the year ended December 31, 
   2025   2024 
   (in millions
of S/)
   (in %)   (in millions
of S/)
   (in %) 
Cement, concrete, mortar, pavement and precast   (1,247.5)   95.2    (1,178.0)   94.3 
                     
Construction supplies   (41.0)   3.1    (54.9)   4.4 
Other   (21.5)   1.7    (16.7)   1.3 
Total cost of sales   (1,310.0)   100.0    (1,249.6)   100.0 


Our total cost of sales increased by 4.8%, or S/60.4 million, to S/1,310.0 million in 2025, from S/1,249.6 million in 2024, primarily due to the following factors:


●a 5.9%, or S/69.5 million, increase in the cost of sales of cement, concrete, mortar, pavement and precast, mainly due to the higher sales volumes.


96


●a 25.3%, or S/13.9 million, decrease in the cost of sales of construction supplies, mainly due to lower sales volumes; and


●a 28.7%, or S/4.8 million, increase in the cost of sales of other materials.


The following table sets forth the composition of our cost of sales of cement, concrete, mortar, pavement and precast for 2025 and 2024:


   For the year ended
December 31,
     
   2025   2024   Variation 
   (in millions of S/)   (%) 
Cement   (921.0)   (878.1)   4.9 
Concrete and mortar   (227.2)   (169.2)   34.3 
Pavement   (71.3)   (103.0)   (30.8)
Precast   (28.0)   (27.7)   1.1 
Total   (1,247.5)   (1,178.0)   5.9 


Our cost of sales represented 61.9% of our sales revenue in 2025, compared to 63.2% in 2024. Our total cost of sales of cement, concrete, mortar, pavement and precast increased by 5.9%, or S/69.4 million, in 2025, primarily due to the following factors:


●a 4.9%, or S/42.9 million, increase in the cost of sales of cement, mainly due to an increase in volume sold (7.7%), offset by a decrease in production costs ((2.9)%) due to cost optimization, as well as lower costs of raw materials;


●a 34.3%, or S/58 million, increase in the cost of sales of concrete and mortar mainly due to an increase in volume sold (9.1%), and higher production costs (25.2%);


●a 30.8%, or S/31.7 million, decrease in the cost of sales of pavement, mainly due to the decrease in sales mentioned above, as a result of the Piura airport project reaching completion during 2025.; and


●a 1.1% or S/0.3 million, increase in the cost of sales of precast, mainly due to increased sales volume (6.5)% partially offset by a decrease in production cost ((5.4)%).


Gross Profit


The following table sets forth a breakdown of our gross profit and gross profit margin (gross profit as a percentage of net sales) by segment for 2025 and 2024:


   For the year ended December 31, 
   2025   2024 
   Gross profit   Gross profit margin   Gross profit   Gross profit margin 
   (in millions
of S/)
   %   (in millions
of S/)
   % 
Cement, concrete, mortar, pavement and precast   817.2    39.6    728.8    36.8 
                     
Construction supplies   0.7    n.m.    2.0    0.1 
Other   (11.0)   (0.5)   (2.3)   (0.1)
Total gross profit   806.9    38.1    728.5    36.8 


n.m. = not meaningful.


Total gross profit increased by 10.8%, or S/78.4 million, to S/806.9 million in 2025, from S/728.5 million in 2024, mainly due to operational efficiencies and lower cost of raw materials. Our gross profit margin for 2025 was 38.1%, 1.3 percentage points higher than in 2024.


97


The following table sets forth a breakdown of our gross profit and gross profit margin for the cement, concrete, pavement and mortar and precast segment for 2025 and 2024:


   Year ended December 31,     
   2025   2024     
                   Gross 
       Gross       Gross   profit 
   Gross   profit   Gross    profit   margin 
   profit   margin   profit   margin   variation 
   (in millions
of S/)
   (%)   (in millions
of S/)
   (%)   (in percentage
points)
 
Cement   824.2    39.9    727.4    38.1.    1.8 
Concrete and mortar   26.9    1.3    14.4    0.8    0.5 
Pavement   (37.0)   (1.8)   (15.4)   (0.8)   (1.0)
Precast   3.1    0.2    2.4    0.1    0.1 
Total gross profit   817.2    39.6    728.8    38.2    1.4 


Gross profit margin for cement, concrete, pavement, mortar, and precast segment increased by 1.4 percentage points in 2025 compared to 2024. This increase was due mainly to an increase in cement margin (1.8 percentage points) mainly due to cost efficiencies because of lower use of imported clinker, lower costs of raw materials, as well as higher average prices. This increase was partially offset by lower margins in concrete and pavement.


Operating Income (Expenses)


Our operating expenses primarily reflect administrative and selling and distribution expenses. In 2025, our operating expenses increased by S/122.3 million to S/459.8 million from S/337.5 million in 2024, mainly due to the collective bargaining negotiations with our labor unions, which is negotiated every three years and has a closing bonus during the first year.


Administrative Expenses


The following table sets forth the composition of our administrative expenses for 2025 and 2024:


   Year ended December 31, 
   2025   2024 
   (in millions of S/) 
Personnel expenses   165.0    136.8 
Third-party services   81.8    74.1 
Board of directors compensation   5.4    6.0 
Depreciation and amortization   17.5    17.1 
Other   21.8    19.4 
Total   291.5    253.4 


Our administrative expenses increased by 15.0%, or S/38.1 million, to S/291.5 million in 2025 from S/253.4 million in 2024. Personnel expenses increased by S/28.2 million because of higher personnel expenses driven by the collective bargaining negotiations with our labor unions, which is negotiated every three years and has a closing bonus during the first year.


Administrative expenses related to the cement, concrete, mortar, pavement and precast segment accounted for approximately 97.9% of total administrative expenses for 2025 remaining in line with 2024. Administrative expenses related to the construction supplies and other segments accounted for approximately 1.1% and 1.0%, respectively, of total administrative expenses for 2025 remaining in line with 2024.


98


Selling and Distribution Expenses


The following table sets forth the components of our selling and distribution expenses for 2025 and 2024:


   Year ended December 31, 
   2025   2024 
   (in millions of S/) 
Personnel expenses   49.0    43.7 
Advertising and promotion expenses   15.6    9.1 
Third party services   16.3    15.0 
Information technology related services   2.4    4.7 
Depreciation and amortization   5.7    6.0 
Other   3.8    2.9 
Total   92.8    81.4 


Our total selling and distribution expenses increased by 14.0%, or S/11.4 million, to S/92.8 million in 2025 from S/81.4 million in 2024, primarily due to increased advertising and promotion expenses during the first nine months of the year, as well as the previously mentioned union bonus.


Selling and distribution expenses related to the cement, concrete, mortar, pavement and precast segment represented approximately 97.9% of total selling and distribution expenses for 2025 remaining in line with 2024. Selling and distribution expenses related to construction supplies and other segments represented approximately 1.1% and 1.0% respectively, of total selling and distribution expenses for 2025 remaining in line with 2024.


Other Operating Expenses


Our other operating expenses increased S/72.8 million, to S/75.5 million in 2025 from S/2.7 million in 2024, mainly due to higher one-off expenses associated with the indirect acquisition of the company by Holcim.


Total Expenses, Net


Our total expenses decreased by S/15.7 million, from S/94.8 million to S/79.1 million, mainly due to decreased financial costs resulting from lower financial obligations, as we amortized the principal of our debt in 2025.


Income Tax Expense


Our income tax expense increased by 17.0%, or S/16.5 million, to S/113.8 million for 2025 from S/97.3 million for 2024, mainly due to an increase in profit before income tax. Our effective tax rate for 2025 was 42.5% and was 33.0% in 2024.


Profit for the Year


As a result of the foregoing, our profit for 2025 decreased by 22.5%, or S/44.7 million, from S/154.2 million for 2025 to S/198.9 million for 2024, mainly due to higher expenses associated with the indirect acquisition of the company by Holcim.


Comparison of Year Ended December 31, 2024 to Year Ended December 31, 2023


For a discussion of our results of operations for the years ended December 31, 2024, and 2023, see “Item 5. Operating and Financial Review and Prospects—A. Operating Results—Results of Operations—Comparison of Year Ended December 31, 2024 to Year Ended December 31, 2023” of our annual report on Form 20-F for the fiscal year ended December 31, 2024, filed with the SEC on April 29, 2025.


99


B.Liquidity and Capital Resources


Capital Expenditures


Our main cash requirements are our operating expenses, capital expenditures relating to the maintenance and expansion of our facilities, the servicing of our debt, the payment of dividends and payment of taxes. Our primary sources of cash have been cash flow from operating activities, and our issuance of debt securities and, to a lesser extent, loans and other financings. We believe that these sources of cash will be sufficient to cover our working capital needs in the ordinary course of our business.


Cash Flows


The table below sets forth certain components of our cash flows for the years ended December 31, 2025, 2024 and 2023.


   Year ended December 31, 
   2025   2024   2023 
   (in millions of S/) 
Net cash flows from operating activities   360.6    321.1    412.3 
Net cash flows used in investing activities   (115.4)   (76.6)   (289.4)
Net cash flows used in financing activities   (264.4)   (261.3)   (115.4)
Increase (decrease) in cash   (19.2)   (16.8)   7.5 


Cash Flows from Operating Activities


Net cash flows from operating activities increased by 12.3% or S/39.5 million, to S/360.6 million in 2025 from S/321.1 million in 2024, mainly due to the decrease in inventories, net of higher payments related to income tax.


Net cash flows from operating activities decreased by 22.1% or S/91.2 million, to S/321.1 million in 2024 from S/412.3 million in 2023, mainly due to less use of stock of inventories during 2024 compared to 2023 and increase of accounts receivable due to consortium in 2024.


Cash Flows used in Investing Activities


Net cash flows used in investing activities were S/115.4 million for 2025, as compared to S/76.6 million for 2024, and were primarily related to the investment activities that were high in fiscal year 2025, due to increased purchases of property, plant, and equipment.


Net cash flows used in investing activities were S/76.6 million for 2024, as compared to S/289.4 million for 2023, and were primarily related to the investment activities that were high in fiscal year 2023, due to the construction of the Clinker Line Optimization Project - Kiln 4 in the city of Pacasmayo.


Cash Flows used in Financing Activities


Net cash flows used in financing activities were S/264.4 million for 2025, as compared to S/261.3 million for 2024 and were primarily due to higher loan payments.


Net cash flows used in financing activities were S/261.3 million for 2024, as compared to S/115.4 million for 2023 and were primarily due to the increase in financing activities, corresponding mainly to higher loan repayments. Net of cash flow from settlement of derivative financial instruments.


Off-balance Sheet Arrangements


As of December 31, 2025, we did not have any off-balance sheet arrangements.


Indebtedness


On February 8, 2023, we repaid in full at scheduled maturity the outstanding US$131,612,000 aggregate principal amount of our 4.50% Senior Notes due 2023 using proceeds from our “club deal” credit line described below, and we also settled the US$132,000,000 in related derivative financial instruments.


100


As of December 31, 2025, the Company’s total outstanding debt, as shown in the financial statements, reached S/1,412.2 million (US$ 419.3 million). This debt is mainly composed of two local bonds issued in January 2019 and the club deal obtained in 2021.


As of December 31, 2025   Amount   Interest Rate   Maturity Date
    (in millions of S/)   (in %)    
Mid-term promissory notes:            
Banco GNB Perú   19.0   5.00%   January 8, 2026
Interbank   57.0   5.07%   January 8, 2026
Interbank   38.0   4.92%   February 15, 2026
Scotiabank   37.2   4.70%   March 5, 2026
Banco de Crédito del Perú   36.0   4.82%   May 22, 2026
Banco de Crédito del Perú   38.0   4.72%   November 12, 2026
BBVA Perú   38.0   4.64%   November 24, 2026
Banco de Crédito del Perú   38.0   4.58%   November 26, 2026
Banco de Crédito del Perú   76.0   4.53%   November 30, 2026
Club deal:            
Banco de Crédito del Perú   232.8   5.82%   December 1, 2028
Scotiabank   232.8   5.82%   December 1, 2028
Senior Notes due:            
2029   259.8   6.69%   February 1, 2029
2034   309.6   6.84%   February 1, 2034


Local Bonds. On January 8, 2019, the General Shareholders’ Meeting approved the issuance of a local bond program for up to S/1,000 million. On January 31, 2019, we issued two series of local bonds in the aggregate principal amount of S/570 million. One in the aggregate principal amount of S/260 million bearing interest at a rate of 6.68750% for a term of 10 years, and the other in the aggregate principal amount of S/310 million bearing interest at a rate of 6.84375% for a term of 15 years. The rates and terms obtained benefit our financial costs structure, with lower cost of capital, an extended maturity and less exposure to currency fluctuations.


The Senior Notes in Soles issued in 2019 are guaranteed by the following Company’s subsidiaries: Cementos Selva S.A.C., Distribuidora Norte Pacasmayo S.R.L., Empresa de Transmisión Guadalupe S.A.C. and Dinoselva Iquitos S.A.C.


Medium-term “Club Deal” Corporate Loan. On August 6, 2021, we entered into a medium-term corporate loan in a “Club Deal” format with Banco de Crédito del Perú S.A. and Scotiabank Perú S.A.A. The loan amounts to S/860,000,000 we used the proceeds for the payment of all of the Company’s financial obligations that the Company maintains with a maturity of February 2023 or earlier. The loan includes a grace / availability period of 18 months from August 6, 2021 and a payment term of seven years from the last disbursement in February 2023. The loan will be paid in 22 equal quarterly installments and has an annual interest of 5.82%.


Under this loan, the Company must comply with the following financial covenants:


a.maintain a debt ratio (Financial Debt / EBITDA)  <= 3.50;


b.maintain a debt service coverage ratio (FCSD / SD) >=1.15; and


c.maintain a debt service coverage ratio (EBITDA / SD) >= 1.50.


In addition, the Company is required to comply with certain customary restrictive and affirmative covenants. As of December 31, 2025 and 2024, the Company was in compliance with the ratios and other obligations contained in the Club Deal.


Short-term loans. As of December 31, 2025, we had obtained nine loans, each in the amount of S/377,200,000, four with Banco de Crédito del Perú S.A., two with Interbank, one with Banco GNB Perú, one with Scotiabank and one with BBVA Perú and for working capital. Each of these loans has a medium-term maturity and accrues interest at an effective annual rate of between 4.53 and 5.07 percent.


101


During 2025, the net gain generated by the exchange difference was approximately S/2,619,000 and, during 2024, the net loss from exchange difference amounted to S/836,000. These results are presented in the caption “Gain(loss) from exchange difference, net” of the consolidated statement of profit and loss.


Capital Expenditures


We expect to spend approximately S/100 million per year over the next three years on recurring capital expenditures necessary to operate our plants and equipment. The table below sets forth our total capital expenditures incurred in 2025, 2024 and 2023.


   For the year ended December 31, 
   2025   2024   2023 
   (in millions of S/) 
Pacasmayo plant projects   45.1    30.1    251.1 
Concrete and aggregates equipment   62.9    37.0    18.2 
Rioja plant projects   4.7    6.6    9.4 
Piura plant projects   29.1    15.8    17.6 
Other investing activities   2.5    7.4    3.0 
Total   144.3    96.9    299.3 


C.Research and Development, Patents and Licenses, Etc.


Since 2016, Pacasmayo has undertaken a structured innovation and digital transformation process aimed at improving how the Company operates, adapts to uncertainty, and develops new capabilities. Over time, this has enabled the Company to expand innovation initiatives across different areas while progressively decentralizing their execution.


As part of this evolution, Pacasmayo has expanded its focus from cement production to construction solutions, and increasingly toward a broader understanding of the end user: the inhabitant. This shift reflects the need to address not only material performance but also the conditions under which housing is built, improved and used.


In addition to strengthening its product research capabilities, the Company has incorporated a complementary focus on understanding the behaviors and needs of key participants in the construction ecosystem including self-builders, construction workers, transporters and households. This approach supports the identification of new opportunities aligned with how construction takes place in its markets.


In 2024, Pacasmayo opened a research and development laboratory focused on optimizing cement performance across different applications. This facility strengthens the Company’s technical capabilities and reinforces its commitment to quality and continuous improvement.


Also in 2024, the Company consolidated its innovation model by placing the inhabitant at the center of its approach, structuring its efforts around iterative cycles of exploration, testing, execution, and learning. As a result, Pacasmayo defined initial strategic diversification pathways focused on the inhabitant and the broader self-construction ecosystem, including financing solutions, real estate and productive housing, home improvement, and new construction materials. These areas expand the Company’s scope beyond traditional products while addressing key gaps in housing development.


In 2025, Pacasmayo formalized its strategic foresight capabilities, including scenario analysis, executive engagement, and the development of trend-based insights. These capabilities support long-term decision-making and strengthen the Company’s ability to anticipate and shape future opportunities.


Furthermore, the Company continues to attract and develop talent aligned with its innovation efforts. This talent brings complementary capabilities and profiles that differ from traditional roles within the organization, including disciplines such as industrial design, architecture, engineering, business, journalism and anthropology. This multidisciplinary approach enables the Company to understand problems from multiple perspectives and develop solutions that connect user needs, technological possibilities and business logic. The combination of these capabilities with the Company’s existing expertise allows Pacasmayo to expand its innovation capacity and achieve outcomes beyond the sum of both.


102


D.Trend Information


Cement Market


The Peruvian Cement Market


Peru’s cement production is segmented into three principal geographic regions: the northern region, the central region, including Lima’s metropolitan area, and the southern region. The table below sets forth selected data with respect to each region in Peru and the corresponding cement manufacturers. Market share data is based on metric tons of cement delivered during 2025.


Geographic Breakdown


Northern Region (thousands of metric tons)
Plant  % share   2025   2024   2023   2022   2021 
Pacasmayo Group   22.4    3,049    2,835    2,951    3,437    3,626 
Imports   -    -    -    -    2    40 
Total   22.4    3,049    2,835    2,951    3,439    3,666 


Central Region (thousands of metric tons)
Plant   % share    2025    2024    2023    2022    2021 
UNACEM   41.2    5,597    5,462    5,617    6,297    5,838 
Caliza Inca   7.0    947    751    585    515    492 
Imports   2.6    352    206    145    202    691 
Total   50.8    6,896    6,419    6,347    7,014    7,021 


Southern Region (thousands of metric tons)
Plant   % share    2025    2024    2023    2022    2021 
Grupo Yura   19.4    2,636    2,535    2,581    3,047    2,904 
Imports   1.6    223    68    65    67    150 
Total   21.0    2,859    2,603    2,646    3,114    3,054 
Other   5.8    790    562    423    427    877 
Total All Regions   100.00    13,594    12,419    12,367    13,994    14,618 


Sources: ASOCEM, INEI, ADUANET (SUNAT).


Although a large part of housing construction is mainly concentrated in the Lima metropolitan area, located in the central region of Peru, the housing market in the provinces of Peru, including the northern region, has grown significantly in recent years. Despite this trend, Peru continues to face a significant housing deficit, with 10.1% of households nationwide affected in 2024, according to the INEI. Economic growth, particularly in the mining and agribusiness sectors, rising employment levels and the implementation of real estate projects, resulted in the creation of higher paying jobs, which ultimately resulted in the expansion of the housing market. However, the COVID-19 pandemic took a toll on it and, in 2020, poverty levels increased 9.9 percentage points. According to the latest available data, the poverty rate in 2024 decreased by 1.4 percentage points to 27.6%, compared to 29.0% in 2023.


Peru continues to have a significant deficit in infrastructure. In recent years, significant efforts have been made to channel investments into the infrastructure sector through a series of initiatives that range from the creation of financial instruments (such as the infrastructure investment and trust funds) to regulatory changes, to promotion of more public private partnerships (for example “taxes for infrastructure” which allows private companies to use part of their tax payments to directly finance infrastructure works) to allowing for other executors, such as the government to government agreements that have recently been signed by Peru and other governments to ensure promptly execution without corruption.


103


Distribution and Logistics


The Peruvian cement market is geographically segmented into three distinct regions, defined primarily by the location of established production facilities and the logistical challenges of cement transportation. We are the leading producer in the Northern Region, while UNACEM and Yura dominate the Central and Southern regions, respectively. Due to high transportation costs and the specialized equipment required for cement storage, a plant’s proximity to its distribution network is a critical factor in maintaining operational efficiency and market share.


On March 30, 2026, as reported to us by our shareholder Inversiones ASPI S.A., Holcim has acquired 99.99% of the shares representing the capital stock of Inversiones ASPI S.A., which in turn is the holder of 50.01% of the capital stock of Cementos Pacasmayo S.A.A. For further information, see “Item 3. Key Information―D. Risk Factors―Risks Relating to our Business and Industry―A change of control of our company occurred in the second quarter of 2026, which could lead to significant shifts in our strategy, management, and corporate governance.


Strategic Acquisition by Holcim Ltd and Change of Control


The competitive landscape in Peru has recently undergone a significant transformation driven by the entry and expansion of Holcim Ltd, a global leader in innovative and sustainable building solutions. Holcim’s entry into the Peruvian market began in August 2024 with the acquisitions of Comacsa (an aggregates and white cement producer) and Mixercon S.A. (a concrete and grinding company based in Lima). This expansion continued in March 2025 with the acquisition of Compañía Minera Luren and its subsidiaries.


This consolidation culminated in a fundamental change in our corporate ownership. Following an agreement signed in December 2025, our majority shareholder, Inversiones ASPI S.A., informed us that on March 30, 2026, Holcim acquired 99.99% of the capital stock of Inversiones ASPI S.A. As a result of this transaction, Holcim now indirectly holds 50.01% of the capital stock of Cementos Pacasmayo S.A.A. For further information, see “Item 4. Information on the Company—A. History and Development of the Company—Recent Developments.”


Operations and Logistics


In the Peruvian market, cement is primarily sold in 42.5 kilogram bags (standardized to approximately 94 pounds), catering to the significant “self-construction” segment of the market, though we also provide bulk sales to meet the needs of large-scale infrastructure and industrial projects.


Strategic location remains our primary competitive advantage. Our facilities in northern Peru allow us to minimize the time and resources required to reach our network of independent distributors and third-party merchants. By optimizing our logistics and distribution chain, we believe we maintain high barriers to entry and ensure consistent service levels across our regional footprint.


Cement can be stored in silos for up to 12 months if the silo is completely humidity proof. The typical vehicles used for the transport of cement are adapted to maintain the necessary environment during shipment. The proximity of production plants and storage centers to distribution centers, third-party vendors and retail outlets, creates a more efficient supply chain and minimizes the time and resources required to transport products from the production line to the construction site. The streamlined nature of this process ensures that cement products in the northern region of Peru, for example, reach customers within approximately one week of production. A cement company’s success is inherently linked to the sophistication of its distribution network and its emphasis on quality assurance throughout the supply chain.


Competitive Dynamics


●The Peruvian cement market is primarily split into three geographic regions. This regional segmentation is largely a result of the logistical complexities and high transportation costs associated with cement distribution. Following the change of control of our Company in March 2026, the competitive landscape is now characterized by the following participants:


●The Holcim Group (Northern and Central Peru): Following its acquisition of a controlling interest in Cementos Pacasmayo in early 2026, Holcim has established its presence in the Northern Region (through Cementos Pacasmayo and Cementos Selva). Holcim also maintains a presence in the Central Region through its other business units: Mixercon (concrete and grinding), Comacsa (white cement and aggregates), and Minera Luren Lacasa (lime and precast products)


104


●UNACEM, which principally serves the Central Region;


●Cementos Yura which primarily serve the Southern Region;


●Caliza Cemento Inca, located in Cajamarquilla, Lima which principally serves the Central Region; and


●In addition to domestic production, the market faces competition from cement importers that primarily supply the Lima area and, increasingly, coastal provinces. Notably, the start of operations at the Chancay Port has introduced new logistical dynamics, potentially facilitating the entry of cement imports.


According to recent industry data from ASOCEM, imports grew in early 2026, intensifying competition in coastal markets where transportation costs for domestic players are less of a barrier.


Sector Characteristics


The competitiveness of cement companies in Peru continues to be driven by:


●Cost Structure Optimization: Success is highly dependent on managing the costs of energy, fuel (particularly coal and petcoke), raw materials, and regional logistics.


●Regional Dominance: Competition remains largely confined to geographic distribution zones due to the “high-volume, low-value” nature of the product.


●Market Drivers: There remains a high correlation between cement demand and “auto-construcción” (self-construction), which represents a significant portion of the market, as well as public infrastructure and private mining investments.


●Fragmented Consumer Base: The market is characterized by a vast network of small-scale retail consumers, requiring extensive and efficient distribution through hardware stores (ferreterías) and franchise networks like our DINO network.


E.Critical Accounting Estimates


Our consolidated financial statements are prepared in conformity with IFRS, as issued by the IASB. For more information on our critical accounting estimates, see note 3 to our consolidated financial statements included in this annual report on Form 20-F.


Item 6.DIRECTORS, SENIOR MANAGEMENT AND EMPLOYEES


A.Directors and Senior Management


General


Our business and affairs are managed by the board of directors in accordance with our by-laws and Peruvian Corporate Law No. 26887 (“Peruvian Corporate Law”). Our by-laws provide for a board of directors of between seven and eleven members. Between three and five alternate directors may be elected by the shareholders to act on behalf of any director who is absent from meetings or who is unable to exercise his or her duties, when and for whatever period fixed by the chairman of the board. Alternate directors have the same responsibilities, duties and powers of directors to the extent they are called to replace them.


Our Board of Directors consists of seven members elected for three-year renewable terms. While the current Board was elected at the Annual Mandatory Shareholders’ Meeting on March 24, 2026, its composition changed shortly thereafter following the completion of the change of control. Specifically, on March 30, 2026, Mr. Eduardo Hochschild and Ms. Ana Sofia Hochschild resigned from their positions and were replaced by Mr. Simon Kronenberg and Mr. Santiago Ojea. Pursuant to our bylaws, the Board must elect a Chairman and Vice Chairman from among its members during the first session held after an election of directors. This session was held on March 30, 2026 and Mr. Humberto Nadal was appointed Chairman and Mr. Raimundo Morales as Vice Chairman. For further information on our change of control, see “Item 4. Information on the Company—A. History and Development of the Company—Recent Developments.”


105


The board of directors typically meets in regularly scheduled quarterly meetings and when called by the chairman of the board or a person representing the chairman. Resolutions must be adopted by a majority of the directors present at the meeting and the chairman is entitled to cast the deciding vote in the event of a tie.


Duties and Liabilities of Directors


Pursuant to Article 177 of Peruvian Corporate Law, directors are jointly and severally liable to a corporation, shareholders and third parties for any damages caused by abuse of power, fraud, willful misconduct or gross negligence. In addition, pursuant to Article 3 of Law No. 29720, as of June 26, 2011, directors of companies listed on the Lima Stock Exchange are also strictly liable for any damages caused as a result of any transactions in which they were involved and which resulted in damages or other losses to the corporation. A director cannot be found liable if the director expressed disagreement at the time the vote was cast or upon learning of such a transaction and if there is a record expressing such opposition.


Our by-laws prohibit a director from voting on matters in which such director has an interest. In addition, Article 180 of the Peruvian Corporate Law requires a director with a conflicting interest on a specific matter to disclose such interest and abstain from the deliberation and decision-making process with respect to such matter. A director who violates this requirement is liable for any damages caused to us and may be removed by a majority of the board of directors upon request of any member of the board or by a majority vote of the shareholders.


Our by-laws stipulate that Directors’ compensation is determined by the Mandatory Annual General Shareholders’ Meeting at the time it reviews our annual audited financial statements. The fixed portion of the Chairman’s compensation shall be twice the amount allocated to any other director. If directors are part of one or more committees, their compensation may include an additional amount for the work performed as members of such committees. The additional compensation of the directors may not exceed the aggregate fixed portion of the compensation that the directors are entitled to receive. Our by-laws do not restrict Directors from voting upon matters relating to their own compensation.


Our by-laws do not prohibit our directors from borrowing from us. However, Article 179 of the Peruvian Corporate Law provides that directors of a company may enter into an agreement with such company only if the related loan agreement relates to operations the company performs in the regular course of business and in an arms’-length transaction. Further, a company may provide a loan to a director or grant securities in such director’s favor only in connection with operations that the company usually performs with third parties. Agreements, credits, loans or guarantees that do not meet the requirements set forth above require prior approval from at least two thirds of the members of the Company’s Board of Directors. Directors are jointly liable to the company and the Company’s creditors for contracts, credit, loans or securities executed or granted without complying with Article 179 of the Peruvian Corporate Law.


Neither our by-laws nor Peruvian Corporate Law contain age limit requirements for the retirement or non-retirement of directors.


Board of Directors


The following sets forth our directors and their respective positions as of December 31, 2025.


Name   Position   Year of Birth
Eduardo Hochschild Beeck*   Chairman of the Board   1963
José Raimundo Morales Dasso*   Vice Chairman of the Board   1946
Ana María Botella Serrano   Independent Director   1953
Esteban Chong León   Independent Director   1958
Ana Sofía Hochschild Correa*   Director   1998
Venkat Krishnamurthy   Independent Director   1971
Humberto Reynaldo Nadal Del Carpio*   Director, Chief Executive Officer   1964


*Subsequent to December 31, 2025, and effective March 30, 2026, Mr. Eduardo Hochschild Beeck and Ms. Ana Sofia Hochschild Correa resigned as Directors. Effective the same date, Mr. Simon Rolf Kronenberg(Position: Director) and Mr. Santiago Maria Ojea Quintana (Position: Director) were appointed as Directors to replace them. On the same date, Mr. Humberto Reynaldo Nadal del Carpio was appointed Chairman of the Board, and Mr. Jose Raimundo Morales Dasso was appointed Vice Chairman of the Board


106


The following sets forth selected biographical information for each of the members of our board of directors. The average tenure of board members is 11.71 years. The business address of each of our current directors is Calle La Colonia 150, Urb. El Vivero, Surco, Lima, Peru.


Eduardo Hochschild Beeck. Mr. Hochschild has been a Director since April 1991 and is currently Chairman of the Board of Directors. He is a Mechanical Engineer from Tufts University, Boston, United States. Mr. Hochschild is also Chairman of Hochschild Mining plc, Aclara Resources Inc., Inversiones ASPI and the Board of Directors of UTEC, Asociación Amanatari and TECSUP.


José Raimundo Morales Dasso. Mr. Morales has been a Director since March 2008 and currently serves as Vice Chairman of the Board of Cementos Pacasmayo. He is Vice Chairman of the Board of Directors of Credicorp LTD., Banco de Crédito del Perú S.A. and Pacífico Cía. Seguros y Reaseguros. He is also a member of the Board of Directors of Atlantic Security Holding Corporation, Grupo Crédito S.A., Solución Empresa Administradora Hipotecaria S.A., Fosfatos del Pacífico S.A. and Grupo Romero. He served as General Manager of BCP from 1990 to 2008 and previously held various positions at Bank of America and Wells Fargo Bank between 1970 and 1980. Mr. Morales holds a degree in Economics and Business Administration from Universidad del Pacífico in Lima, Peru, and a Master’s in Business Administration from the Wharton Graduate School of Finance at the University of Pennsylvania, United States.


Ana María Botella Serrano. Mrs. Botella has been a Director since July 9, 2020. Previously, she was Alternate Director from September 1, 2019 to July 9, 2020. She holds a degree in Law from the Complutense University of Madrid and belongs by competitive examination to the Senior Corps of Civil Administrators of the Spanish State. As a civil servant she has worked in the Ministry of the Interior, the Civil Government of La Rioja, the Ministry of Public Works, the Treasury Delegation of Valladolid and the Ministry of Finance. In 2003 she was elected Councilwoman of the Madrid City Council and has been Second Deputy Mayor. In the Madrid City Council she has held the Government Delegation of Employment and Social Services, from where she directed development cooperation projects. Several of these projects were developed in Peru and it is worth mentioning the water purification in the Peruvian Amazon for 300,000 people. She was decorated by the Quito City Council, by the city of Lima, by the Congress of the Republic of Peru and by the Peruvian Diplomatic Service. She also occupied the Delegation of Environment and Mobility. In December 2011 she was sworn in as Mayor of Madrid City Council, a position she held until June 2015. She is currently Executive President of the Integra Foundation and Program Director of the Atlantic Institute of Government.


Esteban Chong León. Mr. Chong has been a Director since March 24, 2023. Mr. Chong holds a Bachelor’s degree in Accounting from Universidad del Pacífico and a Master’s in Business Administration from the University of Pittsburgh (United States). He holds a diploma in International Financial Reporting Standards from The Association of Chartered Certified Accountants (United Kingdom) and in Corporate Governance of Board of Directors from Northwestern University – Kellogg School of Management (United States). He is Head Professor, at the Universidad del Pacífico. He is a retired partner at PricewaterhouseCoopers Peru with more than 36 years of professional experience, 20 of them as a partner. He held various positions at PricewaterhouseCoopers including Territory Senior Partner for Peru and Bolivia, Head of Assurance for Peru, partner in charge of Risk Management, Member of the Regional Executive Committee and Representative to the Regional Board (Theater Oversight Board), where he was Chairman of the Admissions Committee. He is currently a Director of Inmobiliaria Los Alerces, KR Comercial and KR Proyectos and is a member of the Board of Trustees of the International Potato Center (CIP).


Ana Sofia Hochschild Correa. Ms. Hochschild has been a Director since March 24, 2023. She holds a bachelor’s degree in Psychology from IE University in Madrid, with a special focus on organizational psychology and knowledge in digital transformation. She is a graduate of the Master’s Degree in Educational Leadership, Organizations, and Entrepreneurship at Harvard University, and has experience at companies such as Sony, Ernst & Young, and XR Ventures. She currently serves as Director of Voxel School and leads various initiatives focused on the education sector. Ms. Hochschild is Eduardo Hochschild’s daughter.


Venkat Krishnamurthy. Mr. Krishnamurthy has been a Director since July 9, 2020. He holds a Bachelor of Science from the Indian Institute of Technology in Kanpur, where he received the Presidential Gold Medal and a PhD in Computer Science from Stanford University. Mr. Krishnamurthy is a serial entrepreneur, who has created disruptive business and technology breakthroughs in Computer Graphics, Enterprise Software, Social Networks, Internet Marketing, IOT, CAD, Laser Scanning, Manufacturing, Metrology, Orthodontics, EAS/Security and Supply Chain. He is currently co-founder at Alignable, North America’s largest network for small and medium businesses and Gita Krishnamurthy Vidyalaya, a free school for under-privileged children in South India, as well as board member at privately held internet travel business Grand Circle Corporation. He is an Academy Award winner for Technical Achievement (2001) for pioneering inventions in the area of animation-ready higher order (polynomial) surface reconstruction from 3-D scanners. Previously, he co-founded Invisalign, Paraform/Metris, now Nikon Metrology, CTO at OATSystems, now Checkpoint’s RFID/IOT division and Instructor at MIT Professional Education on Radical Innovation. For his achievements, Mr. Krishnamurthy was awarded the Distinguished Alumnus Award from IIT Kanpur in 2024.


107


Humberto Reynaldo Nadal Del Carpio. Mr. Nadal joined the Company as Corporate Development Manager in June 2007, has been a Director since March 2008 and CEO since April 2011. He is currently Vice Chairman of Ferreycorp S.A.A. and Ferreyros S.A. since August 2020, and independent member of the Board of Directors of Ferreycorp S.A.A. and Ferreyros S.A. since March 2017 and a Director of HCIG S.A. since 2024. He is also CEO and Vice Chairman of Inversiones ASPI, the controlling shareholder of Cementos Pacasmayo. In addition, he is CEO and a director of Fosfatos del Pacífico and FOSSAL, a director of the Asociación de Productores de Cemento (ASOCEM), and former chairman and current member of the Board of Trustees of Universidad del Pacífico. He is a director of the GCCA, a global association that brings together most of the world’s cement producing companies. He is director of FICEM, an association of cement producers in Latin America that comprises 80% of the companies in the region. He is a member of the Advisory Board of the Faculty of Humanities, Arts and Social Sciences of the Universidad de Ingeniería y Tecnología (UTEC). Previously, he was Chairman of the Board of Directors of Fondo Mi Vivienda. Member of the G-50 group. He is an economist graduated from Universidad del Pacífico and has an MBA from Georgetown University.


Simon Rolf Kronenberg. Mr. Kronenberg was appointed as Board member effective March 30, 2026. Mr. Kronenberg was born in Switzerland in 1980. He holds a Master’s degree in Business Administration from the University of St. Gallen (HSG) and has completed executive education programs at IMD in Lausanne, INSEAD and HEC Paris. He has served as Region Head of Holcim Group for Latin America since March 2026. Previously, in April 2024, he was appointed Region Head for Central and Eastern Europe. Prior to that, he held the positions of Chief Executive Officer of Holcim Switzerland, Italy, Southern Germany and Upper Rhine, and Commercial Director of Holcim Switzerland, Italy and Spain. Mr. Kronenberg was born in 1980.


Santiago Maria Ojea Quintana. Mr. Ojea serves as Strategy and Mergers and Acquisitions Director for Latin America at Holcim. With more than 20 years of professional experience across various industries, Mr. Ojea joined Holcim Argentina in 2016 as Legal and Compliance Director, and in 2021 he was appointed Regional Legal and Compliance Director for Latin America. During his tenure, he has promoted a culture of integrity and regulatory compliance, while also leading the design and execution of legal strategy in high-profile matters. He has also actively contributed to Holcim’s regional growth strategy, including the company’s expansion in Guatemala and its entry into the Peruvian market. Mr. Ojea holds a Master’s degree in Business Law from the Pontifical Catholic University of Argentina and a Master’s degree in International Law from the SMU Dedman School of Law. He currently serves as Chairman of the Board of Holcim Argentina and as a member of the Board of Directors of Holcim Ecuador. Mr. Ojea was born in 1951.


Executive Officers


Our executive officers oversee our business and are responsible for the execution of the decisions of the board of directors. The following table presents information concerning our executive officers and their respective positions as of December 31, 2025:


Name   Position   Year of
Birth
  Year of Appointment
Humberto Reynaldo Nadal Del Carpio   Chief Executive Officer   1964   2008
Diego Arispe Silva   Director of People and Community Relations   1981   2021
Aldo Bertoli Estrella   Commercial Director   1969   2016
Ibrahim Chahuan Riveros   Building Solutions Director   1988   2021
Ely Adriana Hayashi Hirahoka(1)   Chief Financial Officer   1982   2021
Diego Reyes Pazos   Supply Chain and Risks Management Director/Compliance Officer   1977   2013
Inés Roggero Cilloniz   Innovation and Digital Transformation  Director   1981   2022
Julio Oropeza Reyes   Director of Operations   1978   2022
Gabriela Dañino Sinclair(2)   Legal Director/General Counsel   1982   2025


(1)On April 1, 2025, Ms. Hayashi took over as our Chief Financial Officer, following Mr. Manuel Bartolomé Ferreyros Peña decision to retire, effective as of March 31, 2025, as part of an orderly succession plan.
(2)On December 4, 2025, Ms. Dañino took over as our Legal Vice – President/General Counsel, following Mr. Jorge Javier Durand Planas decision to retire, effective as of December 3, 2025, as part of an orderly succession plan.


108


The following sets forth selected biographical information for each of our executive officers:


Humberto Reynaldo Nadal Del Carpio. See the information set forth under “―Board of Directors


Diego Arispe Silva. Mr. Arispe has been the Director of People and Community Relations since 2025. He previously served as Corporate Social Responsibility Managing Director since June 2019 and as Corporate Social Responsibility Officer since January 2022. He holds a law degree from the Pontificia Universidad Católica del Perú (PUCP) and an MBA from Columbia Business School (United States). He has worked in the company for more than 15 years, having held various positions in the areas of Human Management, Social Responsibility, and Legal, and was part of the team in charge of the implementation of our cement plant in Piura, as Project Controller.


Aldo Bertoli Estrella. Mr. Bertoli has been the Commercial Director since May 2025 and previously served as Commercial Managing Director since 2016. He holds a degree in Business Administration from the Universidad del Pacífico and a master’s degree in Business Administration from the Universidad de Piura. Before joining our company, Mr. Bertoli worked for five years as Peru-Ecuador-Bolivia Sales Manager at Pepsico Inc. Previously, he spent 12 years at Procter & Gamble in various commercial positions, including four years in Bolivia as Country Manager.


Ibrahim Chahuan Riveros. Mr. Chahuan has been Building Solutions Director since 2025 and previously served as Building Solutions Managing Director since 2022. He holds a bachelor’s degree in Business Administration from Universidad del Pacífico and an Executive MBA from Northwestern University - Kellogg School of Management. Mr. Chahuan has 11 years of experience with Cementos Pacasmayo, having held various positions mainly in the marketing, finance and operations area. He participated in key corporate finance projects for the Company’s development, including the issuance of US$300 million in bonds, and for nearly seven years has been responsible for driving and developing the Company’s building solutions.


Ely Adriana Hayashi Hirahoka. Ms. Hayashi was Finance and Cybersecurity Director since 2025 and  previously served as Finance Managing Director since 2022. She is currently the Company’s CFO. She is a member of the Board of Directors of Fosfatos del Pacífico S.A. and FOSSAL S.A.A. since April 2025. She holds a Bachelor’s degree in Business Administration from Universidad del Pacífico and a Master’s degree in Business Administration (MBA) from IE Business School in Madrid, Spain. Ms. Hayashi joined Cementos Pacasmayo in 2006 and has held various positions in operational and financial areas throughout her nearly 20 years with the company.


Diego Reyes Pazos. Mr. Reyes serves as Supply Chain and Risk Director and Compliance Officer since 2025. He previously served as Supply Chain Manager since 2013 and, in subsequent years, also assumed responsibility for Administration and Risk Management. He has solid experience in supply chain, project development, system/process design and implementation, and financial analysis. He holds a bachelor’s degree in Business Administration from the Universidad de Lima and a master’s degree in Business Administration from the Universidad de Piura. Before joining Cementos Pacasmayo, Mr. Reyes worked as Operations and Finance Manager at Belcorp, as senior business process expert for Latin America at SAB Miller, Project Manager in the Supply Chain Vice-Presidency at UCP Backus & Johnston, among others.


Inés Roggero Cilloniz. Mrs. Roggero has been the Innovation and Digital Transformation Director since June 2025 and previously served as Innovation and Digital Transformation Managing Director since 2022. In 2023, she was assigned the leadership of the Data and Analytics tribe. Before joining Cementos Pacasmayo, she was the Corporate Innovation Manager at Alicorp, where she was in charge of identifying process improvement initiatives, new analog and digital products. In addition, Mrs. Roggero has more than 17 years of experience in mass marketing in companies such as Johnson & Johnson and Coca-Cola company. During this time, she won more than 10 marketing awards and successfully launched more than 10 new products on the market. She holds a Master’s degree in Design Management from IED Barcelona.


109


Julio Oropeza Reyes. Mr. Oropeza has been Director of Operations since 2025 and previously served as Cement Operations Managing Director since November 2022. He is also in charge of the company’s Climate Change and R&D Committees. He has 24 years of experience in the cement industry, holding different positions and functions in Venezuela, Ecuador, Chile, Argentina and Peru. His areas of expertise include: production, process optimization, quality control, KPI and cost optimization, high performance team building, environmental management, safety, innovation, project development and plant management. He holds a degree in Chemical Engineering from Universidad Nacional Experimental Francisco de Miranda (Venezuela, 2002), certified as Process Engineer (Holcim, 2012) and an MBA in Integrated Management System: Quality, Environment and Safety from Universidad de Viña del Mar (Chile, 2015).


Gabriela Dañino Sinclair. Mrs. Daniño has served as General Counsel since 2025. She holds a law degree from the Pontificia Universidad Católica del Peru and a Master of Laws degree from Harvard Law School in the United States. Throughout her career, she has worked at renowned law firms such as Skadden, Arps, Slate, Meagher & Flom LLP in New York, and built a solid track record as an attorney at Miranda & Amado Abogados. Her expertise focuses on financial, corporate, commercial, and civil law, having advised national and international companies across various industries. At Cementos Pacasmayo, she leads the organization’s legal strategy, fostering a culture committed to ethics, integrity, and sustainability, aligned with the company’s values.


B.Compensation


For the year ended December 31, 2025, the total short-term compensation amounted to S/29,493,000 (compared to S/27,704,000 in 2024 and to S/28,922,000 in 2023) and the total long-term compensations expense amounted to S/4,925,000 (compared to S/7,167,000 in 2024 and to S/7,632,000 in 2023), and there were no post-employment or contract termination benefits or share-based payments.


Likewise, the expenses associated with Holcim’s acquisition presented in note 21 to our Consolidated Financial Statements, included in this annual report on Form 20-F, correspond primarily to bonuses awarded to key management (See ―Components of Executive Compensation).


Since 2011, we have paid each of our board members a yearly compensation of US$200,000 (US$400,000 in the case of our Chairman). In addition, compensation paid to certain of our board members for serving on board committees will be, in aggregate per year, not higher than the total amount paid to our board members for serving on our board. Our 2025 board member compensation was approved at our annual shareholders’ meeting.


Neither we nor any of our subsidiaries have entered into any agreement that provides for any benefit or compensation to any director or executive officer after expiration of his or her term.


Executive Compensation Plan


Our business operates in a competitive environment where highly trained professionals and executives are in demand. Continued expansion of the Peruvian economy over the past several years has created new opportunities resulting in additional competition for local talent. As a result, we have in place compensation plan to retain our key executives and attract new executives with the skills and experience required to achieve our strategic objectives and create long-term value for our shareholders. We believe that executive compensation should reward individual performance and the achievement of our strategic objectives.


Our executive compensation plan has been designed to achieve the following primary objectives:


●recruit, retain and incentivize highly talented and dedicated executives with the skills and experience required to manage and operate our business and create long-term value for our shareholders;


●provide our executive officers with compensation opportunities that are fair, reasonable and competitive in the market;


110


●compensate based on our performance and individual performance;


●promote transparency by using clear and straightforward compensation metrics; and


●align the interests of our executive officers with the interests of our shareholders, both in the short-term and long-term.


Our executive compensation plan is in addition to workers’ profit sharing requirements applicable to all of our employees, including our executive officers, under Peruvian labor laws.


Our compensation plan has been designed to compensate our executives through a combination of base salary, a cash bonus incentive and other benefits that we believe are fair and equitable to us and our shareholders and competitive in the market. We believe that the combination of salary, cash bonus incentive and other benefits help distinguish us from other companies in the cement industry in Peru and serve as an important retention tool as we compete for executive talent. We also believe that it will provide an appropriate compensation structure to retain our executives, reward them for individual performance, and induce them to contribute to the creation of long-term value. For more information about our Compensation Plan please see note 19 to our consolidated financial statements included in this annual report on Form 20-F.


Components of Executive Compensation


The key components of our executive compensation plan are:


●base salary;


●short-term cash bonus incentives; and


●long-term cash bonus incentives.


We believe that the use of few and straightforward compensation components promotes the effectiveness and transparency of our executive compensation plan and enables us to be competitive. No formula or specific weightings or relationships are used to allocate the various components in our executive compensation plan. Each component has an important role in implementing our executive compensation philosophy and in meeting the executive compensation objectives described above.


Additionally, during 2025, the Company granted and paid: (i) a one-time remunerative performance bonus to the company’s CEO, and (ii) a one-time incentive bonus to the company’s top management. Such bonuses were non-recurring payments and are not part of our current executive compensation components. See “Item 4. Information of the company—B. Business Overview.”


Base Salary


We compensate our executive officers and other employees with a base salary to compensate them for services rendered on a day-to-day basis during the fiscal year. Base salaries provide stable compensation to executives, allow us to recruit and retain highly talented and dedicated executives and, through periodic merit increases, provide a basis upon which executives may be rewarded for individual performance.


Short-Term Cash Bonus Incentives


As a key component of our compensation plan, we currently provide our executive officers the opportunity to earn annual cash bonuses based on the achievement of our short-term business objectives. As additional cash compensation that is contingent on achieving our business objectives, cash incentives augment the base salary component while being tied directly to corporate and individual performance objectives.


111


Long-Term Cash Bonus Incentives


In addition, as a tool to promote retention of our executive officers, we have implemented a deferred cash incentive program that we believe aligns compensation with corporate performance, allows us to recruit and retain competent executive talent, and rewards for superior performance measured over the long-term. Our plan provides for the payment of bonuses in addition to the annual bonuses that are paid to our executive officers.


Our long-term bonus incentive program features the following key components:


●available to senior executives who have been employed by our company at this level for at least four years;


●at the end of each year, the cash bonus will be accrued in a “personal virtual account” for the benefit of the relevant executive;


●at the beginning of the sixth year the relevant executive will receive the amount accrued during the first four years;


●additional annual bonuses will be accrued for the following four years and a final payout will be made at the end of the eighth year from the creation or beginning of the plan; and


●if the employee decides to voluntarily leave the company before a scheduled distribution, he will not receive this compensation.


Our plan provides that the executive must meet the following eligibility criteria:


●must be no older than 58 years at the time his or her participation in the incentive program begins;


●must have at least four years as senior executives with either our company, or our subsidiaries or affiliates;


●is a professional who is deemed to have characteristics that are attractive to the market; and


●the executive’s departure is deemed by the board of directors or a committee thereof to have an adverse effect on our performance.


C.Board Practices


For information about the date of expiration of the current term of office and the period during which each director has served in such office, see “Item 6. Directors, Senior Management and Employees—A. Directors and Senior Management.”


Benefits upon Termination of Employment


There are no contracts providing for benefits to directors upon termination of employment.


Board Committees


We have four board committees composed by members of our board of directors, which are described below. The members of these committees were elected at the Board meeting held on April 6, 2026, for a three year period.


Executive Committee


Our by-laws permit us to delegate an executive committee composed of three to five members of the board of directors. Mr. Simon Rolf Kronenberg (chairman), Mr. Raimundo Morales Dasso and Mr. Humberto Reynaldo Nadal Del Carpio are currently members of our executive committee. Our executive committee is mainly responsible for (i) supervising and supporting our management in executing the resolutions passed by our board of directors, (ii) executing the strategy approved by our board of directors, (iii) meeting short-term and medium-term goals, as well as designing action plans to meet such goals in accordance with the long-term strategy and goals approved by our board of directors, (iv) approving agreements or transactions involving amounts greater than US$3 million but less than US$20 million, (v) monitoring compliance with the annual budget and approving any significant deviations from approved levels of working capital, (vi) making strategic decisions that do not rise to the level of a full board approval, and (vii) approving and executing new projects in amounts up to US$20 million.


112


Our executive committee also performs the functions of a compensation committee which includes the determination of the compensation, retention and bonification plans for the main executives.


Antitrust Best Practices Committee


The antitrust best practices committee is composed of three members: Mr. Raimundo Morales Dasso, Mr. Humberto Reynaldo Nadal Del Carpio and Mr. Santiago María Ojea Quintana. The antitrust best practices committee is responsible for informing our employees about our competition best practices and for monitoring compliance with such practices, including compliance with antitrust regulations.


Audit Committee


Our audit committee is composed of three directors: Mr. Esteban Chong León, who is the chairman of the audit committee, Mr. Venkat Krishnamurthy and Mrs. Ana María Botella Serrano. All of the members of the audit committee qualify as independent in accordance with the SEC rules applicable to foreign private issuers Mr. Esteban Chong León also qualifies as a financial expert under SEC rules. The audit committee is responsible for (i) reviewing our financial statements; (ii) evaluating our internal controls and procedures, and identifying deficiencies; (iii) the appointment, compensation, retention; and (iv) oversight of our external auditors. Additionally, it is responsible for informing our board of directors regarding any issues that arise with respect to the quality or integrity of our financial statements, our compliance with legal or regulatory requirements, the performance and independence of the external auditors, or the performance of the internal audit function; and overseeing measures adopted as a result of any observations made by our shareholders, directors, executive officers, employees or any third parties with respect to accounting, internal controls and internal and external audit, as well as any complaints regarding management irregularities, including anonymous and confidential methods for addressing concerns raised by employees.


Good Corporate Governance Committee


Our good corporate governance committee is composed of three directors. The current members are Mr. Santiago María Ojea Quintana (chairman), Mr. Raimundo Morales Dasso and Mr. Humberto Reynaldo Nadal Del Carpio. The good corporate governance committee is responsible for overseeing director nomination and committee assignments, and board and CEO successions. Similarly, it is responsible for assisting in the implementation of committee and board self-assessment surveys and the review of governance principles.


Sustainability Committee


Our sustainability committee is composed of three directors. The current members are Mrs. Ana María Botella Serrano (chairman), Mr. Santiago María Ojea Quintana and Mr. Humberto Reynaldo Nadal Del Carpio. The sustainability Committee is responsible for approving our sustainability strategy, overseeing its implementation, and monitoring key ESG indicators.


D.Employees


As of December 31, 2025, we had a total of 1,975 permanent employees. The following table sets forth a breakdown of our employees by category as of the periods indicated.


   As of December 31, 
   2025   2024   2023 
Senior Management   50    53    50 
Administrative personnel   1,106    1,086    988 
Plant workers (cement)   346    334    331 
Plant workers (concrete)   473    503    403 
Total(1)   1,975    1,976    1,772 


(1)Workers from our social venture Acuícola Los Paiches S.A.C. are excluded from these calculations.


113


As of December 31, 2025, approximately 17.9% of our employees were members of labor unions (Sindicato Único de Trabajadores de Cementos Pacasmayo S.A.A, Sindicato de Trabajadores de Distribuidora Norte Pacamasyo S.R.L., Sindicato Único de Trabajadores de la Empresa Distribuidora Norte Pacasmayo S.R.L.-Dino) that represents its members in collective bargaining negotiations. Our management and administrative personnel are not members of a labor union. Labor relations for unionized and non-unionized employees in our production facilities, including compensation and benefits, are governed by collective bargaining agreements that are renewed every three years. In May 2025, three-year Union Agreements were signed with our largest unions.


Under Peruvian law, it is illegal to lay off employees without cause or without following certain formal procedures. In addition, employees who are laid off are entitled to severance payments upon termination of their employment in an amount equal to one and a half month’s salary for each full year of work performed with a maximum payment equal to 12 monthly salaries provided they are indefinite term employees. In case of fixed term employment relationship the severance payment is equal to 1.5 monthly salaries for each month, until the completion of the contract, with a maximum of 12 monthly salaries.


Our employees are enrolled in either the national public pension fund or a privately managed pension fund. In both cases the applicable payment (approximately 13%) is withheld by the employer from the employees’ monthly salary. As of December 31, 2025, approximately 9.1% of our employees were enrolled with the national public pension fund and 90.1% with a private social pension plan.


We seek to build a company with a high level of engagement with collaborators, with the aim of achieving a sense of belonging for our people and, therefore, their happiness in the organization. Our engagement strategy seeks to measure the following components:


●Engagement - It measures the employee’s strong connection with their work (a psychological state of energy, dedication and total involvement in their work).


●Leadership - It measures the leadership style adapted to the individual needs of its employees and that focuses on helping them grow and succeed.


This involvement and identification will allow us to consolidate ourselves as a committed team, that shares the same objectives and values, that co-creates the success of the company and at the same time focuses on growing and improving their personal well-being. The resources we use for our engagement strategy consist of two large measurements that are carried out in July and November, which are complemented with periodic measurements (pulses) to know the feeling and think about a specific dimension and/or situation. Our goal for 2025 was to have an Engagement Index of 87.71%, and thanks to the joint work of leaders, promoters and teams in general, we achieved an index of 88.71%.


We believe we have a good relationship with our employees. In the past, we have not experienced any material strikes, work stoppages or any other significant disruptions.


E.Share Ownership


As of March 31, 2026, people who are currently members of our board of directors and our executive officers (Mr. Humberto Nadal and Mr. Raimundo Morales) held as a group 1,441,485 of our common shares and no non-voting investment shares. This amount represented less than 1% of our outstanding share capital as of March 31, 2026.


F.Disclosure of a Registrant’s Action to Recover Erroneously Awarded Compensation


On November 17, 2023, we adopted an incentive compensation clawback policy providing for the recovery of erroneously awarded incentive-based compensation received by current and former executive officers in connection with a financial restatement, regardless of fault or misconduct. Please see Exhibit No. 97 to our annual report on Form 20-F for the year ended December 31, 2023.


We have not been required to prepare an accounting restatement at any time during or after our last completed fiscal year and no recovery of awarded compensation is required pursuant to our Clawback policy.


114


Item 7.MAJOR SHAREHOLDERS AND RELATED PARTY TRANSACTIONS


A.Major Shareholders


Change in Control of the Company


On March 30, 2026, Holcim Ltd (“Holcim”) completed the acquisition of 99.99% of the capital stock of Inversiones Aspi S.A. (“ASPI”). Prior to this transaction, ASPI was the majority shareholder of Cementos Pacasmayo S.A.A. (the “Company”), holding 50.01% of the Company’s outstanding common shares. As a result of the acquisition of ASPI, Holcim has become the indirect beneficial owner of the 50.01% interest in the Company previously held by ASPI, resulting in a change of control.


Pursuant to Peruvian securities regulations, Holcim has announced its intention to conduct a mandatory public tender offer (the “Tender Offer”) to acquire additional outstanding shares. For further information, see “Item 4. Information on the Company—A. History and Development of the Company—Recent Developments.”


As of March 31, 2026, our issued and outstanding share capital was composed of 423,868,449 common shares. In addition, as of March 31, 2026, we had 40,278,894 non-voting investment shares outstanding, 36,040,497 of which were held in treasury.


The number of common shares and non-voting investment shares beneficially owned by each entity, person, executive officer or director is determined in accordance with the rules of the SEC, and the information is not necessarily indicative of beneficial ownership for any other purpose. Under such rules, beneficial ownership includes any shares over which the individual has sole or shared voting power or investment power as well as any shares that the individual has the right to acquire within 60 days through the exercise of any option, warrant or other right. Except as otherwise indicated, and subject to applicable community property laws, the persons named in the table have sole voting and investment power with respect to all common shares held by that person.


The following table sets forth the beneficial ownership of our common shares and non-voting investment shares as of March 31, 2026. We are not aware of any other shareholder that beneficially owns more than 5% of our common shares or non-voting investment shares.


    As of March 31, 2026  
    Common shares     Non-voting Investment
shares
    Total  
Shareholder   Number of
shares
beneficially
owned
    Percentage
of shares
beneficially
owned
    Number of
shares
beneficially
owned
    Percentage
of shares
beneficially
owned
    Number of
shares
beneficially
owned
    Percentage
of shares
beneficially
owned
 
Inversiones ASPI S.A.(1)     211,985,547       50.0 %     —       —       211,985,547       45.7 %
Cementos Pacasmayo (treasury shares)     —       —       36,040,497       89.5 %     36,040,497       7.8 %
Carlos De Ferrari Brignole     38,324,373       9.0 %     —       —       38,324,373       8.3 %
AFP Habitat     24,246,791       5.7 %     —       —       24,246,791       5.2 %
AFP Integra     20,998,479       5.0 %     —       —       20,998,479       4.5 %
AFP Prima     19,715,228       4.7 %     —       —       19,715,228       4.2 %
Directors and officers as a group(2)     1,441,485       0.3 %     —       —       2,170,540       0.3 %
American Depositary Share Program     36,566,921       8.6 %     —       —       36,566,921       7.9 %
Other shareholders     70,589,625       16.7 %     4,238,397       10.5 %     74,098,967       16.1 %
Total     423,868,449       100.0 %     40,278,894       100.0 %     464,147,343       100.0 %


(1)This information is based solely on the Schedule 13D filed with the SEC on April 6, 2026 (“Schedule 13D”) on behalf of (i) Inversiones ASPI S.A., a Peruvian sociedad anonima (“ASPI”), and (ii) Holcim Ltd, a Swiss limited company (“Holcim”) and the ultimate parent entity of the Holcim Group, the principal business of which is the manufacture of construction and building materials, listed on the SIX Swiss Exchange (ticker: HOLN). The Schedule 13D was filed by ASPI and Holcim regarding 211,985,547 common shares held of record by ASPI. Since March 30, 2026, Holcim holds 99.99% of the issued and outstanding shares of common stock of ASPI. For further information, see “Item 4. Information on the Company—A. History and Development of the Company—Recent Developments.” As a result, since March 30, 2026, Holcim may be deemed to have beneficial ownership of the common shares held of record by ASPI. Holcim disclaims ownership of the common shares except to the extent it has a pecuniary interest therein. The principal business and office address of ASPI is Calle La Colonia, No. 150, Urb. El Vivero, Surco, Lima 33, Peru. The principal business and office address of Holcim is Grafenauweg 10, 6300 Zug, Switzerland.
(2)See “Item 6. Directors, Senior Management and Employees—Share Ownership” for information regarding shares of our common stock owned by members of our board of directors and executive officers. The number of common shares held by directors and executive officers excludes any shares that may be deemed to be beneficially owned by Mr. Eduardo Hochschild through ASPI.


115


Changes in Ownership


The following sets forth the composition of ownership from December 31, 2021 to December 31, 2025, including common share and non-voting investment shares.


   As of December 31, 
Shareholder  2025   2024   2023   2022   2021 
ASPI   45.7%   45.7%   45.7%   45.7%   45.7%
Carlos De Ferrari Brignole   8.3%   6.5%   2.8%   1.3%   0.8%
Cementos Pacasmayo (treasury shares)   7.8%   7.8%   7.8%   7.8%   7.8%
AFP Habitat   5.2%   3.1%   3.2%   2.4%   1.3%
AFP Integra   4.7%   6.6%   7.0%   8.0%   8.6%
AFP Prima   4.3%   6.3%   9.3%   9.6%   9.7%
Profuturo AFP   2.4%   5.7%   4.8%   7.3%   9.2%
American Depositary Receipt Program   8.3%   7.3%   7.7%   7.3%   7.4%
Other shareholders   13.5%   11.0%   11.8%   7.9%   9.7%
Total   100.0%   100.0%   100.0%   100.0%   100.0%


Differences in Voting Rights


Our major shareholders do not have different voting rights.


Securities Held in the Host Country


On February 7, 2012, we completed our initial public offering of 20,000,000 ADSs, each representing five common shares, in the United States. On March 2, 2012, we sold an additional 2,296,800 ADSs pursuant to an over-allotment option granted to the underwriters in that offering. The ADSs are listed on the New York Stock Exchange. As of March 31, 2026, we estimate that there were 7,313,384 ADSs outstanding, which represented 8.6% of our common shares outstanding as of such date.


Arrangements for Change in Control


We are not aware of any arrangements that may, when in force, result in a change in control. On March 30, 2026, as reported to us by our shareholder Inversiones ASPI S.A., Holcim has acquired 99.99% of the shares representing the capital stock of Inversiones ASPI S.A., which in turn is the holder of 50.01% of the capital stock of Cementos Pacasmayo S.A.A. For further information, see “Item 3. Key Information―D. Risk Factors―Risks Relating to our Business and Industry―A change of control of our company occurred in March 2026, which could lead to shifts in our strategy, management, and corporate governance.” and “Item 4. Information on the Company—A. History and Development of the Company—Recent Developments.”


116


B.Related Party Transactions


Peruvian Law Concerning Related Party Transactions


Under Peruvian law, board members and executive officers of a publicly held company may not (i) engage in transactions with the company or any related party of the company, except for transactions entered into in the ordinary course of business and on an arm’s length basis, (ii) appropriate for their own benefit a business opportunity that belongs to the company, or (iii) participate in any transaction or decision that presents a conflict of interest with the company.


Peruvian law sets forth certain restrictions and limitations on transactions with certain related parties.


For instance, from a tax standpoint, the value of those transactions must be equal to the fair market value assessed under transfer pricing rules (i.e., the value agreed to by unrelated parties under the same or similar circumstances). Similarly, companies with securities registered in the Peruvian Public Registry of Securities (Registro Público del Mercado de Valores), such as us, are required to comply with the following rules:


●The directors and managers of the company cannot, without the prior authorization of the board of directors, (i) receive in the form of a loan money or assets of the company; or (ii) use, for their own benefit or for the benefit of related parties, assets, services or credits of the company.


●The execution of agreements that involve at least 5% of the assets of the company with persons or entities related to directors, managers or shareholders that own, directly or indirectly, 10% of the share capital, requires the prior authorization of the board of directors (with no participation of the director involved in the transaction, if any).


●The execution of agreements with a party controlled by the company’s controlling shareholder requires the prior authorization of the board of directors and an evaluation of the terms of the transaction by an external independent company (audit companies or other to be determined by the Peruvian Securities Commission).


The external independent company that reviews the transaction should not be related to the parties involved therein, nor to directors, managers or shareholders that own at least 10% of the share capital of the company.


Related Party Transactions


As a general policy, we do not enter into transactions with related parties, including our board members and officers, on terms more favorable than what we would offer third parties. Any related party transaction we have entered into in the past has been in the ordinary course of business and on an arm’s length basis.


As of December 31, 2025, we had no accounts payable balance with ASPI, our controlling shareholder.


The following transactions have been entered into by us with related parties:


●We lease a plot of land adjacent to our headquarters to our affiliate, Compañía Minera Ares S.A.C., a subsidiary of Hochschild Mining plc. We received rental payments of S/1,150,000 in 2023, S/1,224,000 in 2024 and S/1,151,000 in 2025.


●We provide back office management and administrative services to ASPI, Fossal and Fosfatos del Pacifico, for which we received S/275,000 in 2023, S/276,000 in 2024 and S/509,000 in 2025.


●We receive a reimbursement of security services from our affiliate Compañía Minera Ares S.A.C., a subsidiary of Hochschild Mining plc. We paid a total of S/1,940,000 in 2023, S/2,570,000 in 2024 and S/3,023,000 in 2025 for these services.


As of December 31, 2025, ASPI and Hochschild Mining plc were majority-owned and controlled, directly and indirectly, by Mr. Eduardo Hochschild. On March 30, 2026, Holcim Ltd (“Holcim”) completed the acquisition of 99.99% of the capital stock of Inversiones Aspi S.A. (“ASPI”). Prior to this transaction, Eduardo Hochschild, owned this 99.99% of ASPI. As a result of this transaction, through ASPI, Holcim now directly and indirectly, owns and controls 50.01% of Cementos Pacasmayo S.A.A. (the “Company”), which resulted in a change of control. Pursuant to Peruvian securities regulations, Holcim has announced its intention to conduct a mandatory public tender offer (the “Tender Offer”) to acquire additional outstanding shares. For further information, see “Item 4. Information on the Company—A. History and Development of the Company—Recent Developments.”


117


For more information about our related-party transactions please see note 23 to our consolidated financial statements included in this annual report on Form 20-F.


C.Interests of Experts and Counsel


Not applicable.


Item 8.FINANCIAL INFORMATION


A.Consolidated Statements and Other Financial Information.


See “Item 19. Exhibits.”


Legal and Administrative Proceedings


From time to time, we may become subject to various legal and administrative proceedings that are incidental to the ordinary conduct of our business. We are currently not party to any material legal or administrative proceedings. Notwithstanding the above, the SMV has requested information related to certain expenses recorded by the company in its audited financial statements for the 2025 fiscal year, which were incurred associated with the Holcim acquisition. While the company maintains that these costs represent legitimate, pre-existing obligations, the SMV is reviewing the adequacy of their assumption, disclosure and recording, and their direct relevance to corporate activities. This inquiry may lead to the beginning of formal administrative proceedings and shareholder disputes. See “Item 3. Key Information―D. Risk Factors―Risks Relating to our Business and Industry—Regulatory information requests regarding certain transaction-related expenses recorded in 2025 may result in administrative proceedings”.


Dividends and Dividend Policy


Our ability to pay dividends is subject to our results of operations for each year. Holders of our common shares and non-voting investment shares are entitled to receive dividends on a pro rata basis in accordance with their respective number of shares held.


Under our dividend policy, shareholders must take the following factors into consideration prior to declaring dividends: our financial and economic condition, including committed and budgeted expenses and obligations, and previously approved investments. In addition, our dividend policy states that (a) our board of directors may declare advanced dividends based on either the net income resulting from financial statements prepared for such purpose or the cumulative net income corresponding to previous years, provided that shareholders delegated such authority to the board of directors, and (b) holders of common shares representing no less than 20% of our total share capital may request the distribution of dividends up to 50% of the net income corresponding to the previous year, net of any legal reserve requirements. Our board of directors makes a recommendation at the annual shareholders’ meeting with respect to the amount and timing of dividend payments, if any, to be made on our common shares and non-voting investment shares.


Under Peruvian law, companies may distribute up to 100% of their profit (after payment of income tax) subject to a 10% legal reserve until the legal reserve equals 20% of shareholders’ equity. According to Article 40 of the Peruvian Corporate Law, in order to distribute dividends, profits must be determined in accordance with the individual financial statements of the company.


Payment of Dividends


Dividends are paid to holders of our common shares and non-voting investment shares, as of a record date determined by us. In order to allow for the settlement of securities, under the rules of the Peruvian Securities Commission, investors who purchase shares of a publicly held company three business days prior to a dividend payment date do not have the right to receive such dividend payment. Dividends on issued and outstanding common shares and non-voting investment shares are distributed pro rata.


118


Holders of common shares and non-voting investment shares are not entitled to interest on accrued dividends. In addition, under Article 232 of the Peruvian Corporate Law, the right to collect accrued dividends declared by a publicly held company expires 10 years from the original dividend payment date.


Previous Dividend Payments


The following table sets forth the amounts of cash dividends declared and paid from 2012 through the date hereof for our common shares and our non-voting investment shares.


For the Year ended December 31, Total
Dividends
paid
    Dividends
paid per
share
 
    (in S/)     (in S/)  
2025     190,300,411       0.41000  
2024     190,300,411       0.41000  
2023     190,300,411       0.41000  
2022     194,941,884       0.42000  
2021     366,676,401       0.79000  
2020     106,753,888       0.23000  
2019     167,093,043       0.36000  
2018     174,983,548       0.37700  
2017     162,451,570       0.35000  
2016     165,859,911       0.28500  


At the annual shareholders’ meeting held on March 24, 2026, the shareholders of the Company approved the financial statements for fiscal year 2025 including the net income for such year and delegated to the Board of Directors the authority to decide the distribution of dividends from the retained earnings account and fiscal year 2025 operating results.


B.Significant Changes


We are not aware of any changes bearing upon our financial condition since the date of the financial statements included in this annual report on Form 20-F.


Item 9.THE OFFER AND LISTING


A.Offer and Listing Details


Market Price of Our Common Shares and ADSs


The principal trading market for our Common Shares and Investment Shares is the Lima Stock Exchange (Bolsa de Valores de Lima or “BVL”). Our Common Shares have been listed on the BVL since 1995 under the symbol “CPACASC1,” and our Investment Shares are listed under the symbol “CPACASI1.”


Common Shares vs. Investment Shares


As of December 31, 2025, our capital stock is represented by Common Shares and Investment Shares, which differ primarily in terms of voting rights. Each Common Share entitles the holder to one vote at our shareholders’ meetings. These shares represent the voting equity of the Company. Investment Shares are non-voting securities that were originally created under Peruvian law as “labor shares.” While they do not grant voting rights or the right to participate in shareholders’ meetings (except in very limited circumstances mandated by law), they grant their holders the same rights as common shareholders regarding the distribution of dividends and the distribution of assets upon liquidation, in proportion to their share of the total capital.


119


Market Liquidity and Trading History


Our securities trade on the BVL, which is a regulated, organized secondary market in Peru. There have been no significant trading suspensions of our Common Shares or Investment Shares on the Lima Stock Exchange during the three years ended December 31, 2025, nor through the date of this annual report.


We believe our securities are regularly traded in an organized market. While the trading volume on the BVL is generally lower than that of major U.S. exchanges, our Common Shares and Investment Shares have maintained consistent liquidity levels that allowed for orderly trading. During the last three fiscal years, we have not experienced a significant lack of liquidity that would prevent investors from executing transactions in the ordinary course of business.


On April 6, 2026, Holcim filed a Schedule 13D with the SEC, in which it stated its intention to, once the Mandatory Tender Offer (OPA) is completed, (i) delist our common shares (traded in the form of American Depositary Shares) from the New York Stock Exchange (NYSE) and (ii) deregister our common shares under the Exchange Act. As of the date of this annual report on Form 20-F, such communication has been made exclusively by Holcim as our new controlling shareholder and constitutes only an intention manifested by said shareholder, without representing a decision adopted by the Company nor a definitive fact.


ADSs


On February 7, 2012, we completed our initial public offering of 20,000,000 ADSs, each representing five common shares, in the United States. On March 2, 2012, we sold an additional 2,296,800 ADSs pursuant to an over-allotment option granted to the underwriters in that offering.


The ADSs are listed on the New York Stock Exchange under the symbol “CPAC.”


B.Plan of Distribution


Not applicable.


C.Markets


Trading in the Peruvian Securities Market


The Lima Stock Exchange


As of December 31, 2024, there were 339 companies with securities listed on the Lima Stock Exchange. Established in 1970, the Lima Stock Exchange is Peru’s only securities exchange. On November 19, 2003, the members of the Lima Stock Exchange approved to convert its corporate status to a publicly held corporation effective as of January 1, 2003. As of December 31, 2024, The Lima Stock Exchange had a share capital of S/132,893,960 divided into 182,092,340 shares with a par value S/0.73 each, fully subscribed and paid. As of December 31, 2023, the Lima Stock Exchange had 124 shareholders.


Trading on the Lima Stock Exchange is primarily done on an electronic trading system that became operational in August 1995. From the first Monday of November through the second Sunday of March of each year, trading hours are Monday through Friday (except holidays) as follows: 8:20 a.m.-8:30 a.m. (pre-market ordering); 8:30 a.m.-2:55 p.m. (trading); 2:55 p.m.-3:00 p.m. (after-market sales); and 3:00 p.m.-3:10 p.m. (after-market trading). At all other times, trading hours are from Monday to Friday (except holidays) as follows: 9:00 a.m.-9:30 a.m. (pre-market ordering); 9:30 a.m.-3:55 p.m. (trading); 3:55 p.m.-4:00 p.m. (after-market sales); and 4:00 p.m.-4:10 p.m. (after-market trading).


Transactions during the electronic sessions are executed through brokerage firms and stock brokers on behalf of their clients. Brokers submit orders in the order in which they are received. The orders must specify the type of security as well as the amount and price of the proposed sale or purchase. In order to control price volatility, for Peruvian companies there are volatility auctions for variations of +/- 7% during trading session and +/- 4% during the last half-hour of continuous trading, when a stock reaches the 15% limit there is an auction and a consequent price formation. For non-Peruvian companies there is no limit because it is the price in the foreign market the main reference.


120


Regulation of the Peruvian Securities Market


The Securities Market Law regulates certain securities matters, such as transparency and disclosure, corporate takeovers, capital market instruments and operations, the securities markets and broker-dealers, and credit-rating agencies. In 1996, the Peruvian Securities Commission (Superintendencia del Mercado de Valores, or “SMV”), formerly known as the National Supervisory Commission for Securities and Companies (Comisión Nacional Supervisora de Empresas y Valores, or “CONASEV”), was given additional responsibilities relating to the supervision, regulation and development of the securities market, while the Lima Stock Exchange was granted the status of a self-regulatory organization. Additionally, a unified system of guarantees and capital requirements was established for the Lima Stock Exchange.


Pursuant to Law No. 29782, published in the Peruvian Official Gazette, El Peruano, on July 28, 2011, the Peruvian Securities Commission is a governmental entity reporting to Peru’s Ministry of Economy and Finance with functional, administrative, economic, technical and budgetary autonomy.


The Peruvian Securities Commission is governed by the Superintendent and a five board-members confirmed by the Superintendent (who acts as President of the board) and four members appointed by the Peruvian Executive Power (one suggested by the Ministry of Economy and Finance, one suggested by the BCRP, one suggested by the Peruvian Superintendence of Banking, Insurance and Private Pension Funds and one independent member). The Peruvian Securities Commission has broad regulatory powers, including reviewing, promoting, and making rules regarding the securities market, supervising its participants, and approving the registration of public offerings of securities.


The Peruvian Securities Commission supervises the securities markets and the dissemination of information to investors. It also (i) governs the operations of the Public Registry of Securities, (ii) regulates mutual funds, publicly placed investment funds and their respective management companies and broker-dealers, (iii) monitors compliance with accounting regulations by companies under its supervision as well as the accuracy of financial statements and (iv) registers and supervises auditors who provide accounting services to those companies registered with the Peruvian Securities Commission.


Pursuant to the Securities Market Law, broker-dealers must maintain a guarantee fund. This guarantee fund must be managed by an entity supervised by the Peruvian Securities Commission. Contributions to the guarantee fund must be made by the 25 broker-dealers that are members of the Lima Stock Exchange and are based on the volume traded over the exchange. In addition to the guarantee fund managed, each broker-dealer is required to maintain a guarantee in favor of the Peruvian Securities Commission to guarantee any liability that broker-dealers may have with respect to their clients. Such guarantees are generally established through letters of credit issued by local banks.


Disclosure Obligations


Issuers of securities registered with the Peruvian Securities Commission are required to disclose material information relating to the issuer. Pursuant to the Securities Market Law and relevant regulations enacted thereunder, all material information in connection with the issuer of registered securities (such as our common shares and non-voting investment shares), its activities or securities issued or secured by such issuer which may influence the liquidity or price of such securities must be disclosed. Accordingly, issuers must file with the Peruvian Securities Commission mainly two types of information: (a) financial information, including interim unaudited financial statements on a quarterly basis (which are not required to be subject to limited review), and annual audited consolidated financial statements on an annual basis, and (b) material information relating to the issuer and its activities that may significantly affect the price, offering or negotiation of the issued securities, and in general, all the information that may be relevant for investors to be able to make investment decisions.


In order to comply with the foregoing disclosure obligations, issuers must disclose reaffirmation to the Peruvian Securities Commission and, if the securities are listed, with the Lima Stock Exchange as soon as practicable but not later than one business day after having become aware of such information.


D.Selling Shareholders


Not applicable.


E.Dilution


Not applicable.


121


F.Expenses of the Issue


Not applicable.


Item 10.ADDITIONAL INFORMATION


A.Share Capital


Not applicable.


B.Memorandum and Articles of Association


Set forth below is certain information relating to our share capital, including brief summaries of the material provisions of our by-laws, Peruvian corporate law and certain related laws and regulations of Peru, all as in effect as of the date hereof.


General


We are a publicly held corporation under Peruvian Corporate law registered with the Public Registry of Corporations in Lima. We are currently listed on the Lima Stock Exchange.


The second article of our by-laws provides that our principal corporate purpose is mining and the production and sale of cement, quicklime and other construction materials in Peru and internationally.


We have common shares and non-voting investment shares.


See “Item 6. Directors, Senior Management and Employees—A. Directors and Senior Management” for information regarding our Board of Directors.


Common Shares


Common shares represent 100% of our voting shares. As of March 31, 2026, 423,868,449 of our common shares were outstanding. As of March 31, 2026, there were 34,114 owners of record of our common shares (considering the ADSs listed in the New York Stock Exchange are held by one registered owner). Our common shares have a par value of S/1.00 per share and have been fully subscribed and are fully paid. Our common shares are registered in the Securities Public Registry of the Peruvian Securities Commission and are listed on the Lima Stock Exchange.


Non-voting Investment Shares


As of March 31, 2026, 4,238,397 of our non-voting investment shares were outstanding excluding 36,040,497 non-voting investment shares that were held in treasury. Our investment shares have no voting rights and are not, under Peruvian law and accounting regulations, characterized as share capital. However, non-voting investment shares are still considered part of a company’s equity. As of March 31, 2026, there were 530 owners of record of our non-voting investment shares. Our non-voting investment shares have a par value of S/1.00 per share and have been fully subscribed and are fully paid. Our non-voting investment shares are registered in the Securities Public Registry of the Peruvian Securities Commission and are listed on the Lima Stock Exchange.


Shareholders’ Liability


Under Peruvian Corporate Law, holders of our common shares cannot vote on matters with respect to which they have a conflict of interest.


Under Article 133 of the Peruvian Corporate Law, a shareholder must abstain from voting if such shareholder has a conflict of interest. A resolution approved in disregard of this provision may be challenged under Article 139 of the Peruvian Corporate Law and any shareholder that participated in the determination in breach of this provision, if such shareholder’s vote was key in attaining the required majority, may be held liable individually, or jointly with any other shareholder voting in breach of the provision.


122


Redemption and Rights of Withdrawal


Under Article 200 of the Peruvian Corporate Law, holders of our common shares have redemption rights if: (i) we change our corporate purpose; (ii) a change occurs in the place of organization to a foreign country; or (iii) any transformation, merger or significant spin-off occurs with respect to our company.


Preemptive and Accretion Rights


If we increase our share capital, holders of our common shares and non-voting investment shares have the right to subscribe to new common shares and non-voting investment shares, respectively, on a pro rata basis. Holders of common shares have preemptive rights in order to maintain their share interest in our share capital, unless the capital increase (i) results from a conversion of debt to common shares; (ii) is approved by shareholders representing at least 40% of the subscribed voting shares provided that the capital increase does not favor, directly or indirectly, certain shareholders to the detriment of others; and (iii) results from a corporate reorganization. Holders of non-voting investment shares have preemptive rights to maintain their proportional ownership in our share capital.


Shareholders who are in default of any payments relating to a capital call may not exercise their preemptive rights.


Preemptive rights are exercised in two rounds. During the first round, shareholders may subscribe to the new shares on a pro rata basis. During the second round, shareholders who participated in the first round may subscribe to any remaining shares on a pro rata basis up to the amount of shares such shareholders subscribed for in the first round. The first round must remain open for at least 15 business days. The second round must remain open for at least three business days.


Voting Rights and Dividends


Common Shares


Holders of common shares are entitled to one vote per share, with the exception of the election of the board of directors, where each holder is entitled to one vote per share per nominee. Each holder’s votes may be cast for a single nominee or distributed among the nominees at the holder’s discretion. To that effect, each of our common shares gives the holder the rights to as many votes as there are directors to be elected. Shareholders may pool votes in favor of one person or distribute them among various persons. Those candidates for the board who receive the most votes are elected directors. Holders of common shares may attend and vote at shareholders’ meetings either in person or through a proxy.


Holders of common shares have the right to participate in the distribution of dividends and shareholder equity resulting from liquidation. Our by-laws do not establish a maximum time limit for the payment of the dividends. However, according to Article 232 of the Peruvian Corporate law, the right to collect past-due dividends in the case of companies that are publicly held companies, such as ours, expires 10 years after the date on which the dividend payment was due.


Our share capital may be increased by a decision of holders of common shares at a shareholders’ meeting. Capital reductions may be voluntary or mandatory and must be approved by holders of common shares at a shareholders’ meeting. Capital reductions are mandatory when accumulated losses exceed 50% of the capital and to the extent such accumulated losses are not offset by accumulated earnings and capital increases within the following fiscal year. Capital increases and reductions must be communicated to the Peruvian Securities Commission, the Lima Stock Exchange and the SUNAT. Voluntary capital reductions must also be published in the official gazette El Peruano and in a widely circulated newspaper in the city in which we are located.


123


Non-voting Investment Shares


Under Peruvian Corporate Law, investment shares do not represent share capital. Accordingly, our balance sheet reflects the non-voting investment shares as a separate account from our share capital. Holders of non-voting investment shares are neither entitled neither to vote nor to participate in shareholders’ meetings. However, non-voting investment shares confer upon the holders thereof the right to participate in the dividends distributed according to their par value, in the same manner as common shares. Non-voting investment shares also confer to the holders thereof the preemptive right to (i) maintain the current proportion of the non-voting investment shares in the case of a capital increase through new contributions; (ii) increase the number of non-voting investment shares upon capitalization of retained earnings, revaluation surplus or other reserves that do not represent cash contributions; (iii) participate in the distribution of assets resulting from a liquidation in the same manner as common shares; and, (iv) redeem the non-voting investment shares in case of a merger and/or change of business activity.


Liquidation Rights


If we are liquidated, our shareholders have the right to receive net assets resulting from the liquidation, after we comply with our obligation to pay all our creditors and after discounting any existing dividend liabilities. For this reason, we cannot assure that we will be able to reimburse 100% of the book value of the common shares and non-voting investment shares in case of bankruptcy or liquidation.


Ordinary and Extraordinary Meetings


Pursuant to Peruvian Corporate Law and our by-laws, the annual shareholders’ meeting must be held during the three-month period after the end of each fiscal year. Additional shareholders’ meetings may be held during the year. Because we are a publicly held corporation, we are subject to the special control of the Peruvian Securities Commission, as provided in Article 253 of the Peruvian Corporate Law. If we do not hold the annual shareholders’ meeting during the three-month period after the end of each fiscal year or any other shareholders’ meeting required by our by-laws, a public notary or a competent judge shall call for such a meeting at the request of at least one shareholder of the common shares. Such meeting will take place within a reasonable period of time.


Other shareholders’ meetings are convened by the board of directors when deemed convenient by our company or when it is requested by the holders of at least 20% of our common shares. If, at the request of holders of 20% of the common shares, the shareholders’ meeting is not convened by the board of directors within 15 business days of the receipt of such request, or the board expressly or implicitly refuses to convene the shareholders’ meeting, a public notary or a competent judge will call pursuant to Law No. 29560 for such meeting at the request of holders of at least 20% of our common shares. If a public notary or competent judge calls for a shareholders’ meeting, the place, time and hour of the meeting, the agenda and the person who will preside shall be indicated on the meeting notice. If the meeting called is other than the annual shareholders’ meeting or a shareholders’ meeting required by the Peruvian Corporate Law or the by-laws, the agenda will contain those matters requested by the shareholders who requested the meeting.


Holders of non-voting investment shares have no right to request the board to call a shareholders’ meeting.


Notices of Meetings


Since we are a publicly held corporation, notice of shareholders’ meetings must be given by publication of a notice. The publication shall occur at least 25 days prior to any shareholders’ meeting in the Peruvian Official Gazette, El Peruano, and in a widely circulated newspaper in the city in which we are located. The notice requirement may be waived at the shareholders’ meeting by agreement of the holders of 100% of the outstanding common shares.


Quorum and Voting Requirements


According to Article 25 of our by-laws and Article 257 of the Peruvian Corporate Law, shareholders’ meetings called for the purpose of considering a capital increase or decrease, the issuance of obligations, a change in the by-laws, the sale in a single act of assets with an accounting value that exceeds 50% of our share capital, a merger, division, reorganization, transformation or dissolution, are subject to a first, second and third quorum call, each of the second and third quorum call to occur upon the failure of the preceding one. A quorum for the first call requires the presence of shareholders holding 50% of our total common shares. For the second call, the presence of shareholders holding at least 25% of our total common shares is adequate, while for the third call there is no quorum requirement. These decisions require the approval of the majority of the common shares represented at the shareholders’ meeting. Shareholders’ meetings convened to consider all other matters are subject to a first and second quorum call, the second quorum call to occur upon the failure of the first quorum.


In accordance with Peruvian Corporate Law, only those holders of common shares whose names are registered in our stock ledger not less than 10 days in advance of a meeting will be entitled to attend the shareholders’ meeting and to exercise their rights.


124


Limitations on the Rights of Non-residents or Foreign Shareholders


There are no limitations under our by-laws or Peruvian Corporate Law on the rights of nonresidents or foreign shareholders to own securities or exercise voting rights with respect to our securities.


Disclosure of Shareholdings and Tender Offer Regulations


Disclosure of Shareholdings


There are no provisions in our by-laws governing the ownership threshold above which share ownership must be disclosed.


However, according to SMV Resolution No. 019-1015-SMV-01, as amended, we disclose through the Stock Market Superintendency (Superintendencia del Mercado de Valores - SMV) our holders of common shares owning more than 4% share interest. Also, according to SMV Resolution No. 019-2015-SMV.01, as amended, we must inform the SMV of the members of our economic group and a list of our holders of common shares owning more than a 0.5% share interest, as well as any change to such information.


Tender Offer Regulations


Peruvian security regulations include mandatory takeover rules applicable to the acquisition of control of a listed company.


Subject to certain conditions, such regulations generally establish the obligation to make a tender offer when a person or group of persons acquires a relevant interest in a listed company. According to Peruvian law, a person acquires a relevant interest in a listed company when such person (a) holds or has the power to exercise directly or indirectly 25%, 50% or 60% of the voting rights in a listed company, or (b) has the power to appoint or remove the majority of the board members or to amend its by-laws.


In general, the tender offer must be launched prior to the acquisition of the relevant interest. The tender offer may be launched after the “relevant interest” is acquired if it is acquired (a) by means of an indirect transaction, (b) as a consequence of a public sale offer, or (c) in no more than four transactions within a three-year period.


This mandatory procedure has the effect of alerting other shareholders and the market that an individual or financial group has acquired a significant percentage of a company’s voting shares, and gives other shareholders the opportunity to sell their shares at the price offered by the purchaser. The purchaser is required to launch a tender offer unless: (a) shareholders representing 100% of the voting rights consent in writing, (b) voting shares are acquired by a depositary in order to subsequently issue ADSs, or (c) voting shares are acquired pursuant to the exercise of preemptive rights.


Changes in Capital


Our by-laws do not establish special conditions to increase or reduce our share capital beyond what is required under Peruvian Corporate Law.


Anti-Takeover Provisions


Our by-laws do not contain any provision that would have the effect of delaying, deferring or preventing a change of control. However, acquisitions of shares of our capital stock that involve a change of control may be subject to Peruvian securities and exchange regulations (Ley de Mercado de Valores y Reglamento de Oferta Pública de Adquisición y de Compra de Valores por Exclusión) applicable to tender offers.


125


Form and Transfer


Common shares and non-voting investment shares may be either physical share certificates in registered form or book-entry securities in the CAVALI S.A. ICLV book-entry settlement system, also in registered form.


Furthermore, the Peruvian Corporate Law forbids publicly held corporations, such as us, from including in their by-laws stipulations limiting the transfer of their shares or restraining their trading in other ways. In addition, pursuant to our by-laws, we cannot recognize a shareholders’ agreement that contemplates limitations, restrictions or preferential rights on the transfer of shares, even if such an agreement is recorded in our stock ledger (matrícula de acciones) or in CAVALI S.A. ICLV.


C.Material Contracts


On December 31, 2007, we entered into a contract for the general management and provision of services with ASPI, pursuant to which we provide legal and corporate services to it. See “Item 7. Major Shareholders and Related Party Transactions—A. Related Party Transactions.”


On February 1, 2008, we entered into a surface rights agreement with Compañía Minera Ares S.A.C., pursuant to which we lease a plot of land adjacent to our headquarters to our affiliate, Compañía Minera Ares S.A.C., a subsidiary of Hochschild Mining plc. See “Item 7. Major Shareholders and Related Party Transactions—A. Related Party Transactions.”


On June 30, 2008, we entered into a property lease agreement with ASPI pursuant to which we lease part of our headquarters as office space to ASPI. See “Item 7. Major Shareholders and Related Party Transactions—A. Related Party Transactions.”


On June 3, 2010, we entered into a long-term electricity supply agreement with Electroperú, a government-owned company, which was set to expire in July 2020, to serve the electricity requirements of our Pacasmayo facility. Electroperú has agreed to provide us with sufficient energy to operate our Pacasmayo facility (later expanded to include our Piura facility) at pre-determined maximum amounts during the term of the contract. Payments for electricity are based on a formula that takes into consideration our energy consumption and certain market variables, such as the U.S. purchase price index, the global price of oil, the local price of natural gas and the import price of bituminous coal. We entered into an addendum to this agreement, effective February 1, 2016, which extended the term of the agreement until December 31, 2025, reduced the prices for the 2016-2020 period and established new prices for the 2020-2026 period. We subsequently entered into another addendum to extend this agreement until May 31, 2026. Beginning in June 2026, we have an electricity supply contract with Orygen Perú S.A.A. to supply electricity to our Pacasmayo and Piura facilities through May 2031. See “Item 4. Information on the Company—A. History and Development of the Company—Raw Materials and Energy Sources.”


On January 31, 2019, we issued an aggregate principal amount of S/570,000,000 of debt securities in the local market in two issuances. One in the aggregate principal amount of S/260 million bearing interest at a rate of 6.68750% for a term of 10 years, and the other in the aggregate principal amount of S/310 million bearing interest at a rate of 6.84375% for a term of 15 years. The proceeds were used to purchase a portion of our 4.50% Senior Notes due 2023.


On August 6, 2021, we established the conditions of a medium-term corporate loan in the form of a “Club Deal” with Banco de Crédito del Perú S.A. and Scotiabank Perú S.A.A. The loan amounted to S/860,000,000 that will allow the payment of all the financial obligations that the Company maintains with maturity until February 2023 and will be disbursed based on the maturity of each of them.


D.Exchange Controls


Since August 1990, there have been no exchange controls in Peru and all foreign exchange transactions are based on free market exchange rates. Prior to August 1990, the Peruvian foreign exchange market consisted of several alternative exchange rates. Additionally, during the 1990s, the Peruvian currency experienced a significant number of large devaluations, and Peru has consequently adopted, and operated under, various exchange rate control practices and exchange rate determination policies, ranging from strict control over exchange rates to market determination of rates. Current Peruvian regulations on foreign investment allow the foreign holders of equity shares of Peruvian companies to receive and repatriate 100 percent of the cash dividends distributed by such companies. Such investors are allowed to purchase foreign exchange at free market currency rates through any member of the Peruvian banking system and transfer such foreign currency outside Peru without restriction.


126


E.Taxation


The following summary contains a description of certain Peruvian and United States federal income tax consequences of the acquisition, ownership and disposition of common shares or ADSs, but it does not purport to be a comprehensive description of all the tax considerations that may be relevant to a decision to purchase common shares or ADSs. The summary is based upon the tax laws of Peru and regulations thereunder and on the tax laws of the United States and regulations thereunder as in effect on the date hereof, which are subject to change.


Prospective holders of common shares or ADSs should consult their own tax advisors as to the tax consequences of the acquisition, ownership and disposition of common shares or ADSs in their particular circumstances.


Peruvian Tax Considerations


The following are the principal tax consequences of ownership of common shares or ADSs by non-resident individuals or entities (“Non-Peruvian Holders”) as of the date hereof. Legislative, judicial or administrative changes or interpretations may, however, be forthcoming. Any such changes or interpretations could affect the tax consequences to holders of common shares or ADSs and could alter or modify the conclusions set forth herein. This summary is not intended to be a comprehensive description of all the tax consequences of acquisition, ownership and disposition of common shares or ADSs and does not describe any tax consequences arising under the laws of any taxing jurisdiction other than Peru or applicable to a resident of Peru or to a person with a permanent establishment in Peru.


For purposes of Peruvian taxation:


●individuals are residents of Peru, if they are Peruvian nationals who have established their principal place of residence in Peru or if they are foreign nationals with a permanence in Peru of 183 days in any 12-month period (the condition of Peruvian resident can only be acquired as of the 1st of January of the year following the fulfillment of residence conditions); and


●legal entities are residents of Peru if they are established or incorporated in Peru.


Peruvian Income Tax Rate


The Peruvian income tax rate is 29.5%.


Cash Dividends and Other Distributions


Cash dividends paid with respect to common shares and amounts distributed with respect to ADSs are currently subject to a Peruvian withholding tax, at a rate of 5.0% of the dividend paid. As a general rule, the distribution of additional common shares representing profits, distribution of shares which differ from the distribution of earnings or profits, as well as the distribution of preemptive rights with respect to common shares, which are carried out as part of a pro rata distribution to shareholders, will not be subject to Peruvian tax or withholding taxes.


Capital Gains


Pursuant to Article 6 of the Peruvian income tax law, individuals and entities resident in Peru are subject to Peruvian income tax on their worldwide income while Non-Peruvian Holders are subject to Peruvian income tax on Peruvian source income only.


The general rule of the Law of Income Tax in Peru provides that income derived from the disposal of securities issued by Peruvian entities is considered Peruvian source income and is therefore subject to income tax. Peruvian income tax law also provides that capital gains resulting from the disposal of ADSs that represent shares issued by Peruvian entities are considered Peruvian source income and therefore also subject to Peruvian income tax. Peruvian income tax law also provides that taxable income resulting from the disposal of securities is determined by the difference between the sale price of the securities at market value and the tax basis.


127


Notwithstanding the foregoing, capital gains resulting from the disposal of ADSs or beneficial interest in ADSs that represent shares issued by a Peruvian entity are not considered Peruvian source income as long as the ADSs issued by the foreign depositary are held in the name of a nominee and such ADSs are not transferred to a third party as a result of the disposal of the ADSs.


In the event ADSs are exchanged into common shares and such common shares are disposed of, capital gains resulting therefrom will be subject to an income tax rate of either 5% or 30%, depending on where the transaction takes place. If the transaction is consummated in Peru, the income tax rate is 5%; if the transaction is consummated outside of Peru, capital gains are taxed at a rate of 30%. Peruvian income tax law regulations have stated that transactions are deemed to be consummated in Peru if the common shares are transferred through the Lima Stock Exchange. Any gain resulting from the conversion of ADSs into common shares or common shares into ADSs will not be subject to taxation in Peru.


Any Non-Peruvian Holder who acquires common shares will have the following tax basis: (i) for common shares purchased by the transferor, the acquisition price paid for the shares; (ii) for common shares received by the transferor as a result of a share capital increase because of a capitalization of net profits, the face or nominal value of such common shares; (iii) for other common shares received free of any payment, the stock market value of such shares if listed on the Lima Stock Exchange or, if not, the face or nominal value of such common shares and (iv) for common shares of the same type acquired at different opportunities and at different values, the tax basis will be the weighted average cost. In cases where common shares are sold by Non-Peruvian Holders outside the Lima Stock Exchange, the tax basis must be certified by the Peruvian tax administration prior to the time payment is made to the transferor; otherwise it would not be possible to deduct the tax basis and a 30% Peruvian income tax would apply to the total sale price. Under Peruvian income tax law, tax basis certification is granted by the tax authorities within 30 days from the date of the application (which application must contain supporting evidence with respect to the tax basis) is made by the transferor. If the tax authorities do not respond within such a 30 day period, the tax basis presented for approval by the transferor is deemed automatically approved.


On December 31, 2010, Law No. 29645 was enacted and took effect from January 1, 2011. This law states that in transactions relating to Peruvian securities through the Lima Stock Exchange, CAVALI S.A. ICLV (the Peruvian clearing house) will act as withholding agent to the extent that such transactions are settled in cash through CAVALI’s account (liquidación en efectivo). The implementing regulations of Law No. 29645 enacted on July 9, 2011 provide that CAVALI began acting as a withholding agent as from November 1, 2011. As a result, while such regulations do not apply to securities transferred though the Lima Stock Exchange by a Non-Peruvian Holder, such transferor must still self-assess and pay its income tax liability directly to Peruvian tax authorities within the first 12 working days following the month in which Peruvian source income was earned. With respect to transactions of Peruvian securities conducted through the Lima Stock Exchange that are settled directly without CAVALI’s intervention (liquidación directa), Non-Peruvian Holders are required to self-assess and pay income taxes directly to the Peruvian tax authorities within the first 12 working days following the month in which income from a Peruvian source was earned. Finally, if the purchaser is resident in Peru and the sale is not performed through the Lima Stock Exchange, the purchaser will act as withholding agent.


Other Considerations


No Peruvian estate or gift taxes are imposed on the gratuitous transfer of ADSs or common shares. No stamp, transfer or similar tax applies to any transfer of ADSs or common shares, except for commissions payable by seller and buyer to the Lima Stock Exchange (0.15% of value sold), fees payable to the Peruvian Securities Commission (0.05% of value sold), brokers’ fees (about 0.05% to 1% of value sold) and Value Added Tax (at the rate of 18%) on commissions and fees. Any investor who sells its common shares on the Lima Stock Exchange will incur these fees and taxes upon purchase and sale of the common shares.


128


United States Federal Income Tax Considerations


The following are the material United States federal income tax consequences as of the date hereof to a United States Holder (as defined below) of the ownership and disposition of ADSs and our common shares. This summary deals only with ADSs and common shares held as capital assets (generally, property held for investment). As used herein, the term “United States Holder” means a beneficial owner of ADSs or common shares that is for United States federal income tax purposes:


●an individual who is a citizen or resident of the United States;


●a corporation (or other entity treated as a corporation for United States federal income tax purposes) created or organized in or under the laws of the United States, any state thereof or the District of Columbia;


●an estate the income of which is subject to United States federal income taxation regardless of its source; or


●a trust if it (1) is subject to the primary supervision of a court within the United States and one or more United States persons have the authority to control all substantial decisions of the trust, or (2) has a valid election in effect under applicable United States Treasury regulations to be treated as a United States person.


This summary does not represent a detailed description of the United States federal income tax consequences applicable to you if you are subject to special treatment under the United States federal income tax laws, including if you are:


●a dealer or broker in securities or currencies;


●a financial institution;


●a regulated investment company;


●a real estate investment trust;


●an insurance company;


●a tax-exempt organization;


●a person holding ADSs or our common shares as part of a hedging, integrated or conversion transaction, a constructive sale or a straddle;


●a trader in securities that has elected the mark-to-market method of accounting for your securities;


●a person liable for alternative minimum tax;


●a person who owns or is deemed to own 10% or more of our stock (by vote or value);


●a partnership or other pass-through entity for United States federal income tax purposes;


●a person required to accelerate the recognition of any item of gross income with respect to ADSs or our common shares as a result of such income being recognized on an applicable financial statement; or


●a person whose “functional currency” is not the U.S. Dollar.


The discussion below is based upon the provisions of the U.S. Internal Revenue Code of 1986, as amended (the “Code”), and regulations, rulings and judicial decisions thereunder as of the date hereof, and such authorities may be replaced, revoked or modified so as to result in United States federal income tax consequences different from those discussed below. There is currently no income tax treaty between the United States and Peru that would provide for United States federal income tax consequences different from those discussed below. In addition, this summary assumes that the deposit agreement, and all other related agreements, will be performed in accordance with their terms.


129


If a partnership (or other entity or arrangement treated as a partnership for United States federal income tax purposes) holds ADSs or our common shares, the tax treatment of a partner in the partnership will generally depend upon the status of the partner and the activities of the partnership. If you are a partnership or a partner of a partnership holding ADSs or our common shares, you should consult your tax advisors.


This summary does not contain a detailed description of all the United States federal income tax consequences to you in light of your particular circumstances and does not address the Medicare tax on net investment income, United States federal estate and gift taxes or the effects of any state, local or non-United States tax laws. If you are considering the acquisition of ADSs or our common shares, you should consult your own tax advisors concerning the United States federal income tax consequences to you in light of your particular situation as well as any consequences arising under other United States federal tax laws and the laws of any other taxing jurisdiction.


ADSs


If you hold ADSs, for United States federal income tax purposes, you generally will be treated as the owner of the underlying common shares that are represented by such ADSs. Accordingly, deposits or withdrawals of common shares for ADSs will not be subject to United States federal income tax.


Taxation of Dividends


The gross amount of distributions on the ADSs or common shares (including amounts withheld to reflect Peruvian withholding taxes) will be taxable as dividends, to the extent paid out of our current or accumulated earnings and profits, as determined under United States federal income tax principles.


To the extent that the amount of any distribution (including amounts withheld to reflect Peruvian withholding taxes) exceeds our current and accumulated earnings and profits for a taxable year, as determined under United States federal income tax principles, the distribution will first be treated as a tax-free return of capital, causing a reduction in the adjusted basis of the ADSs or common shares, and the balance in excess of adjusted basis will be taxed as capital gain recognized on a sale or exchange. However, we do not expect to keep earnings and profits in accordance with United States federal income tax principles. Therefore, you should expect that a distribution will generally be reported as a dividend. Such dividends (including withheld taxes) will be includable in your gross income as ordinary income on the day actually or constructively received by you, in the case of the common shares, or by the depositary, in the case of ADSs. Such dividends will not be eligible for the dividends received deduction generally allowed to corporations under the Code.


Subject to applicable limitations (including a minimum holding period requirement), dividends received by non-corporate United States Holders from a qualified foreign corporation may be treated as “qualified dividend income” that is subject to reduced rates of taxation. A non-United States corporation is generally treated as a qualified foreign corporation with respect to dividends paid by that corporation on common shares (or ADSs backed by such shares) that are readily tradable on an established securities market in the United States. United States Treasury Department guidance indicates that the ADSs, which are listed on the New York Stock Exchange, but not our common shares, are readily tradable on an established securities market in the United States. Thus, we believe that dividends we pay on our common shares that are represented by ADSs, but not our common shares that are not so represented, will be eligible for the reduced tax rates. There can be no assurance, however, that the ADSs will be considered readily tradable on an established securities market in the United States in later years. You should consult your own tax advisors regarding the application of these rules given your circumstances.


The amount of any dividend paid in Soles will equal the U.S. Dollar value of the Soles received, calculated by reference to the exchange rate in effect on the date the dividend is actually or constructively received by you, in the case of the common shares, or by the depositary, in the case of ADSs, regardless of whether the Soles are converted into U.S. Dollars at that time. If the Soles received as a dividend are converted into U.S. Dollars on the date they are received, you generally will not be required to recognize foreign currency gain or loss in respect of the dividend income. If the Soles received as a dividend are not converted into U.S. Dollars on the date of receipt, you will have a tax basis in the Soles equal to their U.S. Dollar value on the date of receipt. Any gain or loss realized on a subsequent conversion or other disposition of the Soles will be treated as United States source ordinary income or loss.


130


Subject to certain conditions and limitations (including a minimum holding period requirement), Peruvian withholding taxes on dividends may be treated as foreign taxes eligible for credit against your United States federal income tax liability. For purposes of calculating the foreign tax credit, dividends paid on the ADSs or common shares will be treated as foreign source income and will generally constitute passive category income. However, Treasury regulations addressing foreign tax credits (the “Foreign Tax Credit Regulations”) impose additional requirements for foreign taxes to be eligible for a foreign tax credit, and there can be no assurance that those requirements will be satisfied. The United States Treasury Department and the Internal Revenue Service (the “IRS”) are considering proposing amendments to the Foreign Tax Credit Regulations. In addition, recent notices from the IRS provide temporary relief by allowing taxpayers that comply with applicable requirements to apply many aspects of the foreign tax credit regulations as they previously existed (before the release of the current Foreign Tax Credit Regulations) for taxable years ending before the date that a notice or other guidance withdrawing or modifying the temporary relief is issued (or any later date specified in such notice or other guidance). Instead of claiming a foreign tax credit, you may be able to deduct Peruvian withholding taxes on dividends in computing your taxable income, subject to generally applicable limitations under United States law (including that a United States Holder is not eligible for a deduction for otherwise creditable foreign income taxes paid or accrued in a taxable year if such United States Holder claims a foreign tax credit for any foreign income taxes paid or accrued in the same taxable year). The rules governing the foreign tax credit and deductions for foreign taxes are complex. You are urged to consult your tax advisors regarding the availability of a foreign tax credit or a deduction under your particular circumstances.


Distributions of ADSs, common shares or rights to subscribe for ADSs or common shares that are received as part of a pro rata distribution to all of our shareholders generally will not be subject to United States federal income tax.


Taxation of Capital Gains


For United States federal income tax purposes, you will recognize taxable gain or loss on any sale, exchange or other taxable disposition of ADSs or common shares in an amount equal to the difference between the amount realized for the ADSs or common shares and your tax basis in the ADSs or common shares, both as determined in U.S. Dollars. Such gain or loss will generally be capital gain or loss. Capital gains of non-corporate United States Holders derived with respect to capital assets held for more than one year are eligible for reduced rates of taxation. The deductibility of capital losses is subject to limitations.


If Peruvian income tax is withheld on the sale, exchange or other taxable disposition of ADSs or our common shares, your amount realized will include the gross amount of the proceeds of that disposition before deduction of the Peruvian income tax. Any gain or loss recognized by you will generally be treated as United States source gain or loss. Consequently, in the case of gain from the disposition of ADSs or common shares that is subject to Peruvian income tax, you may not be able to benefit from a foreign tax credit for that Peruvian income tax (i.e., because the gain from the disposition would be United States source), unless you can apply the credit (subject to applicable limitations) against United States federal income tax payable on other income from foreign sources. However, pursuant to the Foreign Tax Credit Regulations, any such Peruvian income tax would generally not be a foreign income tax eligible for a foreign tax credit (regardless of any other income that you may have that is from foreign sources). In such case, the non-creditable Peruvian income tax may reduce the amount realized on the sale, exchange or other taxable disposition of the ADSs or common shares. As discussed above, however, recent notices from the IRS provide temporary relief by allowing taxpayers that comply with applicable requirements to apply many aspects of the foreign tax credit regulations as they previously existed (before the release of the current Foreign Tax Credit Regulations) for taxable years ending before the date that a notice or other guidance withdrawing or modifying the temporary relief is issued (or any later date specified in such notice or other guidance). If a Peruvian income tax is imposed on the sale, exchange or other taxable disposition of the ADSs or common shares and you apply such temporary relief, such Peruvian income tax may be eligible for a foreign tax credit or deduction, subject to the applicable conditions and limitations. You are urged to consult your tax advisors regarding the tax consequences if Peruvian income tax is imposed on a disposition of ADSs or common shares, including the availability of a foreign tax credit or a deduction under your particular circumstances.


Passive Foreign Investment Company


We do not believe that we are, for United States federal income tax purposes, a passive foreign investment company (“PFIC”), and we expect to operate in such a manner so as not to become a PFIC. If, however, we are or become a PFIC, you could be subject to additional United States federal income taxes on gain recognized with respect to the ADSs or common shares and on certain distributions, plus an interest charge on certain taxes treated as having been deferred under the PFIC rules. Non-corporate United States Holders will not be eligible for reduced rates of taxation on any dividends received from us (as discussed above under “—Taxation of Dividends”) if we are a PFIC in the taxable year in which such dividends are paid or in the preceding taxable year.


131


Information Reporting and Backup Withholding


In general, information reporting will apply to dividends in respect of ADSs or our common shares and the proceeds from the sale, exchange or other taxable disposition of ADSs or our common shares that are paid to you within the United States (and in certain cases, outside the United States), unless you establish that you are an exempt recipient. Backup withholding may apply to such payments if you fail to provide a taxpayer identification number and a certification that you are not subject to backup withholding or if you fail to report in full dividend and interest income.


Backup withholding is not an additional tax. Any amounts withheld under the backup withholding rules will be allowed as a refund or a credit against your United States federal income tax liability provided the required information is furnished to the IRS in a timely manner.


The above description is not intended to constitute a complete analysis of all tax consequences relating to the ownership or disposition of ADSs or our common shares. You should consult your own tax advisors concerning the overall tax consequences to you, including the consequences under laws other than United States federal income tax laws, of an investment in ADSs or our common shares.


F.Dividends and Paying Agents


Not applicable.


G.Statement by Experts


Not applicable.


H.Documents on Display


We make our filings in electronic form under the EDGAR filing system of the SEC. Our filings are available through the EDGAR system at www.sec.gov. In addition, our filings are available to the public over our website www.cementospacasmayo.com.pe. Such filings and other information on our website are not incorporated by reference in this annual report on Form 20-F. You may request a copy of this filing, and any other report, at no cost, by writing to us at the following address or telephoning us:


Investor Relations Department
Calle La Colonia 150,
Urbanización El Vivero, Surco,
Lima, Peru
Tel.: + (511) 317-6000
E-mail: cbustamante@cpsaa.com.pe


I.Subsidiary Information


See note 1 to our consolidated financial statements included in this annual report on Form 20-F for a description of our subsidiaries.


J.Annual Report to Security Holders


If we are required to provide an annual report to security holders in response to the requirements of Form 6-K, we will submit the annual report to security holders in electronic format in accordance with the EDGAR Filer Manual.


132


Item 11.QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK


We are exposed to market risks in the ordinary course of our business, primarily foreign currency risk and, to a lesser extent, interest rate risk. Our foreign currency risk arises mainly from operating activities when income or expenses are denominated in a currency other than our functional currency. As of December 31, 2025, a reasonably possible appreciation of the U.S. dollar of 5% or 10% against the sol would have increased our consolidated profit before income tax by approximately S/812 thousand and S/1,625 thousand, respectively, while a reasonably possible depreciation of the U.S. dollar of 5% or 10% against the sol would have had an equal and opposite effect. As of December 31, 2025, all of our borrowings bore fixed rates of interest and, accordingly, management determined that an interest rate sensitivity analysis was not relevant. For additional information relating to quantitative and qualitative disclosures about these market risks, see note 26 to our consolidated financial statements included in this annual report on Form 20-F.


Item 12.DESCRIPTION OF SECURITIES OTHER THAN EQUITY SECURITIES


A.Debt Securities


Not applicable.


B.Warrants and Rights


Not applicable.


C.Other Securities


Not applicable.


D.American Depositary Shares


Our American Depositary Shares are evidenced by American Depositary Receipts and each American Depositary Share represents five common shares, par value S/1.00 per share (the “ADSs”). On February 7, 2012, we completed our initial public offering of 20,000,000 ADSs in the United States. On March 2, 2012, we sold an additional 2,296,800 ADSs pursuant to an over-allotment option granted to the underwriters in that offering.


The ADSs are listed on the New York Stock Exchange under the symbol “CPAC.” As of March 31, 2026, we estimate that there were 7,313,384 ADSs outstanding, which represented 8.6% of our common shares outstanding as of such date.


JPMorgan Chase Bank, N.A. acts as our depositary (the “Depositary”), pursuant to our Deposit Agreement, dated as of February 7, 2012, and the amendment dated December 4, 2020 (as so amended the “Deposit Agreement”), The address of the Depositary’s principal executive office is 270 Park Avenue, Floor 08, New York, NY 10017.


Fees and expenses


Pursuant to the Deposit Agreement, the Depositary may charge each person to whom ADSs are issued, including, without limitation, issuances against deposits of common shares, issuances in respect of common share distributions, rights and other distributions, issuances pursuant to a stock dividend or stock split declared by us or issuances pursuant to a merger, exchange of securities or any other transaction or event affecting the ADSs or deposited securities, and each person surrendering ADSs for withdrawal of deposited securities or whose ADSs or American Depositary Receipts representing ADSs (“ADRs”) are cancelled or reduced for any other reason, US$5.00 for each 100 ADSs (or any portion thereof) issued, delivered, reduced, cancelled or surrendered, as the case may be. The depositary may sell (by public or private sale) sufficient securities and property received in respect of a common share distribution, rights and/or other distribution prior to such deposit to pay such charge.


The following additional charges shall be incurred by the ADR holders, by any party depositing or withdrawing common shares or by any party surrendering ADSs or to whom ADSs are issued (including, without limitation, issuance pursuant to a stock dividend or stock split declared by us or an exchange of stock regarding the ADRs or the deposited securities or a distribution of ADSs), whichever is applicable:


●a fee of US$1.50 per ADR or ADRs for transfers of certificated or direct registration ADRs;


●a fee of US$0.05 or less per ADS for any cash distribution made pursuant to the deposit agreement;


133


●a fee of US$0.05 or less per ADS per calendar year (or portion thereof) for services performed by the depositary in administering the ADRs (which fee may be charged on a periodic basis during each calendar year and shall be assessed against holders of ADRs as of the record date or record dates set by the depositary during each calendar year and shall be payable in the manner described in the next succeeding provision);


●reimbursement of such fees, charges and expenses as are incurred by the depositary and/or any of the depositary’s agents (including, without limitation, the custodian and expenses incurred on behalf of holders in connection with compliance with foreign exchange control regulations or any law or regulation relating to foreign investment) in connection with the servicing of the common shares or other deposited securities, the delivery of deposited securities or otherwise in connection with the depositary’s or its custodian’s compliance with applicable law, rule or regulation (which charge shall be assessed on a proportionate basis against holders as of the record date or dates set by the depositary and shall be payable at the sole discretion of the depositary by billing such holders or by deducting such charge from one or more cash dividends or other cash distributions);


●a fee for the distribution of securities (or the sale of securities in connection with a distribution), such fee being in an amount equal to US$0.05 per ADS issuance fee for the execution and delivery of ADSs which would have been charged as a result of the deposit of such securities (treating all such securities as if they were common shares) but which securities or the net cash proceeds from the sale thereof are instead distributed by the depositary to those holders entitled thereto;


●stock transfer or other taxes and other governmental charges;


●cable and facsimile transmission and delivery charges incurred at your request in connection with the deposit or delivery of common shares;


●transfer or registration fees for the registration of transfer of deposited securities on any applicable register in connection with the deposit or withdrawal of deposited securities; and


●expenses of the depositary in connection with the conversion of foreign currency into U.S. Dollars.


We will pay all other charges and expenses of the depositary and any agent of the depositary (except the custodian) pursuant to agreements from time to time between us and the depositary. The charges described above may be amended from time to time by agreement between us and the depositary.


Our depositary has agreed to reimburse us for certain expenses we incur that are related to establishment and maintenance of the ADR program, including investor relations expenses and exchange application and listing fees. In 2025, the Depositary made direct payments and reimbursements to us in the gross amount of U.S.$ 67,355.40. The amounts of reimbursements available to us are not based upon the amounts of fees the depositary collects from investors. The depositary collects its fees for issuance and cancellation of ADSs directly from investors depositing common shares or surrendering ADSs for the purpose of withdrawal or from intermediaries acting on their behalf. The depositary collects fees for making distributions to investors by deducting those fees from the amounts distributed or by selling a portion of distributable property to pay the fees. The depositary may collect its annual fee for depositary services by deduction from cash distributions, or by directly billing investors, or by charging the book-entry system accounts of participants acting for them. The depositary will generally set off the amounts owing from distributions made to holders of ADSs. If, however, no distribution exists and payment owing is not timely received by the depositary, the depositary may refuse to provide any further services to holders that have not paid those fees and expenses owing until such fees and expenses have been paid. At the discretion of the depositary, all fees and charges owing under the deposit agreement are due in advance and/or when declared owing by the depositary.


The Deposit Agreement is incorporated by reference as Exhibit 2.2 to this annual report on Form 20-F, and Amendment No. 1 thereto is incorporated by reference in this annual report on Form 20-F as Exhibit 2.2A, and Amendment No. 2 thereto is incorporated by reference in this annual report on Form 20-F as Exhibit 2.2B. We encourage you to review these documents carefully if you are a holder of ADRs.


134


Part II


Item 13.DEFAULTS, DIVIDEND ARREARAGES AND DELINQUENCIES


Not applicable.


Item 14.MATERIAL MODIFICATIONS TO THE RIGHTS OF SECURITY HOLDERS AND USE OF PROCEEDS


Not applicable.


Item 15.CONTROLS AND PROCEDURES


A.Disclosure Controls and Procedures


As of the end of the period covered by this annual report, the Company’s management, with the participation of our Chief Executive Officer and Chief Financial Officer, performed an evaluation of the effectiveness of the design and operation of our disclosure controls and procedures as defined in Rules 13a-15(e) and 15d-15(e) of the U.S. Securities Exchange Act of 1934, as amended (the “Exchange Act”). There are inherent limitations to the effectiveness of any system of disclosure controls and procedures, including the possibility of human error and the circumvention or overriding of the controls and procedures. Accordingly, even effective disclosure controls and procedures can only provide reasonable assurance of achieving their control objectives. Based upon this evaluation, our Chief Executive Officer and Chief Financial Officer concluded that, as of December 31, 2025, the design and operation of our disclosure controls and procedures were effective in providing reasonable assurance that information required to be disclosed in the reports we file or submit under the Exchange Act is recorded, processed, summarized and reported within the time periods specified in the SEC’s rules and forms, and that such information is accumulated and communicated to our management, including the Chief Executive Officer and the Chief Financial Officer, as appropriate to allow timely decisions regarding required disclosures.


B.Management’s Annual Report on Internal Control Over Financial Reporting


Our management is responsible for establishing and maintaining adequate internal control over financial reporting. Our internal control over financial reporting is designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of the financial statements for external purposes in accordance with generally accepted accounting principles.


Because of its inherent limitations, internal control over financial reporting may not necessarily prevent or detect some misstatements. It can only provide reasonable assurance regarding financial statement preparation and presentation. Also, projections of any evaluation of effectiveness for future periods are subject to the risk that controls may become inadequate because of changes in conditions or because the degree of compliance with the policies or procedures may deteriorate over time.


Management assessed the effectiveness of its internal control over financial reporting for the year ended December 31, 2025. The assessment was based on criteria established in the framework “Internal Controls—Integrated Framework” issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 Framework) (COSO). Based on this assessment, our management has concluded that as of December 31, 2025, our internal control over financial reporting was effective.


The effectiveness of internal control over financial reporting as of December 31, 2025, has been audited by Tanaka, Valdivia, Arribas & Asociados SCRL, member firm of Ernst & Young Global Limited, an independent registered public accounting firm, as stated in their attestation report, which is included under “Item 15—Controls and Procedures—C. Attestation Report of Independent Registered Public Accounting Firm.”


C.Attestation Report of the Independent Registered Public Accounting Firm


Report of Independent Registered Public Accounting Firm


To the Shareholders and the Board of Directors of Cementos Pacasmayo S.A.A. and subsidiaries


Opinion on Internal Control Over Financial Reporting


We have audited Cementos Pacasmayo S.A.A. and subsidiaries’ internal control over financial reporting as of December 31, 2025, based on criteria established in Internal Control—Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria). In our opinion, Cementos Pacasmayo S.A.A. and subsidiaries (the “Company”) maintained, in all material respects, effective internal control over financial reporting as of December 31, 2025, based on the COSO criteria.


We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated statements of financial position of the Company as of December 31, 2025 and 2024, the related consolidated statements of profit or loss, other comprehensive income (loss), changes in equity, and cash flows for each of the three years in the period ended December 31, 2025, and the related notes and our report dated April 27, 2026, expressed an unqualified opinion thereon.


Basis for Opinion


The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying Management’s Annual Report on Internal Control Over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.


We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects.


135


Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.


Definition and Limitations of Internal Control Over Financial Reporting


A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.


Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.


/s/ Tanaka, Valdivia, Arribas & Asociados Sociedad Civil de Responsabilidad Limitada


A member of Ernst & Young Global Limited


Lima, Peru


April 27, 2026


D.Changes in Internal Control Over Financial Reporting


There have been no changes in our internal control over financial reporting identified in connection with the evaluation required under Rules 13a-15 or 15d-15 that occurred during the period covered by this annual report on Form 20-F that has materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.


Item 16.[RESERVED]


Item 16A.AUDIT COMMITTEE FINANCIAL EXPERT


Our Board of Directors has determined that Mr. Esteban Chong León, President of the audit committee, is a “financial expert,” as such term is defined in the SEC rules. We have determined that Ms. Ana María Botella Serrano, Mr. Venkat Krishnamurti and Mr. Esteban Chong León are independent under the standards of the New York Stock Exchange listing rules and Rule 10A-3 under the Exchange Act.


Item 16B.CODE OF ETHICS


The Company has adopted a code of ethics for the Pacasmayo Group that applies to our directors, officers and employees. Furthermore, on March 30, 2026, we adopted the code of ethics for the Holcim Group applicable to our directors, officers and employees. Both codes of ethics are available on our website http://www.cementospacasmayo.com.pe. Information on our website is not incorporated by reference in this annual report on Form 20-F.


If we make any substantive amendment to the abovementioned codes of ethics or if we grant any waivers, including any implicit waiver, from a provision of the code of ethics, we will disclose the nature of such amendment or waiver by filing a current report on a Form 6-K or in our subsequent annual report on Form 20-F to be filed with the SEC. During the year ended December 31, 2025, no such amendment was made nor did we grant any waiver to any provision of the relevant code of ethics.


Item 16C.PRINCIPAL ACCOUNTANT FEES AND SERVICES


Audit and Non-Audit Fees


The following table presents the aggregate fees for professional services and other services rendered by our independent auditors, Tanaka, Valdivia, Arribas y Asociados, SCRL, member firm of Ernst & Young Global Limited, responsible for auditing the annual consolidated financial statements included in the annual report on Form 20-F, during the fiscal years ended December 31, 2025, 2024 and 2023.


   Year Ended December 31, 
   2025   2024   2023 
   (in thousands of S/) 
Audit fees   1,483    1,247    1,190 
All other fees   0    8    117 
Tax fees   391    294    206 
Total fees   1,874    1,549    1,513 

136


Audit fees in the above table are the aggregate fees billed and billable by our independent auditors in connection with the audit of our annual consolidated financial statements and review of our quarterly financial information.


Tax fees in the above table are fees billed relating to tax compliance services.


All other fees in the above table are fees billed relating to advisory services.


Audit Committee Pre-Approval Policies and Procedures


We have adopted pre-approval policies and procedures under which our audit committee is responsible for the oversight of the independent auditors and has established pre-approval procedures for the engagement of its independent registered public accounting firm for audit and non-audit services. Such services can only be contracted if they are approved by the audit committee, they comply with the restriction provided under applicable rules and they do not jeopardize the independence of our auditors.


Item 16D.EXEMPTIONS FROM THE LISTING STANDARDS FOR AUDIT COMMITTEES


Not applicable.


Item 16E.PURCHASES OF EQUITY SECURITIES BY THE ISSUER AND AFFILIATED PURCHASERS


Neither the Company nor, to our knowledge, any affiliated purchaser has made any purchases of our registered equity securities during the fiscal years ended on December 31, 2025, 2024 and 2023.


Item 16F.CHANGE IN REGISTRANT’S CERTIFYING ACCOUNTANT


None.


Item 16G.CORPORATE GOVERNANCE


We are a “foreign private issuer” within the meaning of the New York Stock Exchange corporate governance standards. Under New York Stock Exchange rules, a foreign private issuer may elect to comply with the practices of its home country and not to comply with certain corporate governance requirements applicable to U.S. companies with securities listed on the exchange.


We currently follow certain Peruvian practices concerning corporate governance and intend to continue to do so. There are significant differences in the Peruvian corporate governance practices as compared to those followed by United States domestic companies under the New York Stock Exchange’s listing standards.


The New York Stock Exchange listing standards provide that the board of directors of a U.S. listed company must have a majority of independent directors at the time the company ceases to be a “controlled company.” Under Peruvian corporate governance practices, a Peruvian company is not required to have a majority of independent members on its board of directors.


The listing standards for the New York Stock Exchange also require that U.S. listed companies, at the time they cease to be “controlled companies,” have a nominating/corporate governance committee and a compensation committee (in addition to an audit committee). Each of these committees must consist solely of independent directors and must have a written charter that addresses certain matters specified in the listing standards. Under Peruvian law, a Peruvian company may, but is not required to, form special governance committees, which may be composed partially or entirely of non-independent directors.


In addition, New York Stock Exchange rules require the independent non-executive directors of U.S. listed companies to meet on a regular basis without management being present. There is no similar requirement under Peruvian law.


The New York Stock Exchange’s listing standards also require U.S. listed companies to adopt and disclose corporate governance guidelines. In November 2013, the Peruvian Securities Commission and a committee of regulatory agencies and associations prepared and published a list of suggested non-mandatory corporate governance guidelines called the “Good Corporate Governance Code for Peruvian Companies.” These principles are disclosed on the Peruvian Securities Commission web page at http:// http://www.smv.gob.pe/ and the Lima Stock Exchange web page at http://www.bvl.com.pe. Although we have implemented a number of these measures and are part of the Best Corporate Governance Practices Index of the Lima Stock Exchange, we are not required to comply with the referred corporate governance guidelines by law or regulation, only to disclose whether or not we are in compliance.


Item 16H.MINE SAFETY DISCLOSURE


Not applicable.

137


Item 16I.DISCLOSURE REGARDING FOREIGN JURISDICTIONS THAT PREVENT INSPECTIONS


Not applicable.


Item 16J.INSIDER TRADING POLICIES


Cementos Pacasmayo has adopted an insider trading policy governing the purchase, sale, and other dispositions of its securities by directors, senior management, and employees with access to material non-public information. This policy is outlined in our “Manual de Políticas Relacionadas con Información Material No Pública y la Prevención de la Transferencia de Valores con Información Privilegiada” (Manual of Policies Related to Non-Public Material Information and the Prevention of Insider Stock Transfers). The manual is designed to promote compliance with insider trading laws, including the Exchange Act, applicable stock exchange listing standards, and local regulations. For further information on our insider trading policy, please refer to Exhibit 11 of this annual report on Form 20-F.


Item 16K.CYBERSECURITY


Risk Management and Strategy


Cementos Pacasmayo considers risk management to be a fundamental pillar of its strategy. The Company therefore evaluates threats and vulnerabilities, identifies its critical assets and quantifies the associated risk at least twice a year or sooner if warranted. Identified risks are confirmed by senior management to determine whether, due to their importance, they should be considered strategic risks, and different restricted maximum likelihood (REML) audit was carried out to evaluate our Information Security Management System (ISMS) based on the guidelines and controls of ISO27001, as well as the respective external audit, which allowed us to obtain the ISO27001:2022 certification for our cement production and distribution process issued by AENOR, being the first cement company in Peru with remediation or mitigation mechanisms relating to such risks evaluated. For example, cybersecurity risks have been evaluated and determined to be strategic risks for the following reasons:


●economic impact due to loss of information and interruption of our operations due to attacks on our information systems and failures of our systems that support business processes and guarantee continuity; and


●economic and reputational impact due to cyberattacks (phishing, malware, etc.) due to lack of patches or inadequate patch management, lack of secure identification and authentication mechanisms (AD authentication, complex passwords, tokens, captcha, etc.), poor password management and lack of protection against new generation threats.


Our cybersecurity strategy is based on the NIST 1.1 framework. Specifically, when referring to the identification and management of cybersecurity risks and threats that could compromise the Company, we have developed a methodology for risk management of information security based on ISO/IEC 27005. This systematic method allows our management to make appropriate decisions. Based on this and as part of our focus on the continuous improvement of information security in the company, during 2024 an internal obtain this certification. In 2025, we continued to perform both internal and external audits of our Information Security Management System as part of the maintenance of that certification and our continuous improvement efforts, which support the further development of our information security maturity across the Company.


The Company identifies and oversees risks internally. The audit committee of the Company has defined what a material cybersecurity risk is, so that the occurrence of a cybersecurity incident can be reported to the SEC. In 2025, we did not identify any threats that materially affected, or were reasonably likely to materially affect, our business strategy, results of operations or financial condition. As part of our information security policies, we have established the standards for access to and use of our information systems by employees or by third parties. In addition, we have established a new policy specifically relating to the access to and use of our information systems by third parties, which sets forth the conditions any third party must comply with in order to have any access to our information systems, which are being progressively incorporated into contracts with suppliers that are subject to these guidelines.


Finally, twice a year we run ethical hacking and pen-testing to evaluate our risks and vulnerabilities, and we have engaged an ethical hacking service which runs automatically when we perform spot exercises in our information systems (in-house and third-party solutions).


138


However, despite our efforts to identify and respond to cybersecurity threats, we cannot eliminate all risks from cybersecurity threats, or provide assurances that we have not experienced an undetected cybersecurity incident. For more information about these risks, see “Item 3D. Risk Factors—Risks Relating to Our Business and Industry—Failures in our information technology systems and information security (cybersecurity) systems can adversely impact our operations and reputation.”


Governance


Role of the Board


The Board, in coordination with the Audit Committee, which is the corporate body in charge of centralizing corporate risks, oversees the Company’s risk management program, which includes risks arising from cybersecurity threats. The Audit Committee meets quarterly and reviews the corporate risk matrix in detail, including cybersecurity risks. At each regularly scheduled Board meeting, the Audit Committee Chair provides the full Board with an update on all significant matters discussed, reviewed, considered and approved by the committee since the last regularly scheduled.


Additionally, the Audit Committee is promptly apprised of any cybersecurity incident that meets established reporting thresholds, and receives ongoing updates regarding any such incident until it has been resolved. We have established a Policy for Response to Cybersecurity Incidents, and a related plan, which includes four playbooks (covering ransomware, phishing, DOS and malware) on how to respond to each type of incident and the specificities to communications matters, to our legal, compliance, risk management and audit committee. This policy and these plans are part of our Disaster Recovery Plan (DRP) which is also part of our Business Continuity Plan (BCP).


Role of Management


Senior management is highly committed to maintaining corporate cybersecurity, and is cognizant of cybersecurity risks and threats and the potential impact of the occurrence of cybersecurity incidents, which is evidenced by the review and oversight of such matters by the audit committee and the cybersecurity subcommittees, and has provided the necessary resources for the mitigation of such risks. In addition to the audit committee at the Board level, we also have two cybersecurity sub committees (IT & OT), each of which meets quarterly, with the presence of the Company’s senior executive officers. All participants in the subcommittee meetings receive a copy of the presentation for each meeting, which sets forth the applicable subcommittee’s role, strategy, project status (culture, risks, IT/OT and policies) and relevant information (our key performance metrics and POCs on cybersecurity technology, cybersecurity lab results, etc.), and meeting minutes, which include a summary of the information to be discussed and the principal action points.


In 2024, the Information Security Department was established as an independent Information Technology department, reporting directly to the Chief Financial Officer (CFO), with the goal of providing it with the autonomy and strategic position it deserves.


The Chief Information Security Office (CISO) is primarily responsible for overseeing, maintaining, and improving our cybersecurity strategy. He also leads our two cybersecurity subcommittees (IT and OT) and works closely with the Technology, Human Resources, Legal and Compliance, Operations departments, among others. He also has over eight years of experience managing and leading cybersecurity projects and holds the following certifications:


●Certiprof - Lead Cybersecurity Professional Certificate - January 2023


●ESAN Graduate School of Business (Lima, Peru) - International Diploma in Cybersecurity and Privacy Management - July 2020


●Ramon Llull University (Barcelona, Spain) - Master in Information Technology Management - August 2015


All of Cementos Pacasmayo’s senior executive officers have been trained in cybersecurity matters and are the main promoters of our corporate cybersecurity culture and compliance with the established internal framework, which includes policies, guidelines and cybersecurity standards, among others.


139


Part III


Item 17.FINANCIAL STATEMENTS


We have responded to Item 18 in lieu of this item.


Item 18.FINANCIAL STATEMENTS


See our consolidated financial statements beginning at page F-1 of this annual report on Form 20-F. Our financial statements have been prepared in accordance with IFRS as issued by the IASB.


Item 19.EXHIBITS


The agreements and other documents filed as exhibits to this Annual Report on Form 20-F are not intended to provide factual information or other disclosure other than with respect to the terms of the agreements or other documents themselves, and you should not rely on them for that purpose. In particular, any representations and warranties made by us in these agreements or other documents were made solely within the specific context of the relevant agreement or document and for the benefit of the other parties to the agreements and they may not describe the actual state of affairs as of the date they were made or at any other time.


The following documents are filed as part of this Annual Report on Form 20-F or incorporated by reference herein.


Exhibit
Number
  Description of Document
1.1   Amended and Restated By-laws of the Registrant, as currently in effect, incorporated by reference to Exhibit 1.1 of the Registrant’s Annual Report on Form 20-F filed with the SEC on May 1, 2017 (File No. 001-35401).
2(d)   Description of securities registered under Section 12(d) of the Exchange Act incorporated by reference to Exhibit 2(d) of the Registrant’s Annual Report on Form 20-F filed with the SEC on April 29, 2024 (File No. 001-35401).
2.1   Registrant’s Form of American Depositary Receipt, incorporated by reference to Exhibit 4.1 to the Registrant’s Registration Statement on Form F-1 filed with the SEC on January 6, 2012 (File No. 333-178922).
2.2   Deposit Agreement dated January 19, 2012 among the Registrant, J.P. Morgan Chase N.A., as depositary, and the holders from time to time of American depositary shares issued thereunder, incorporated by reference to Exhibit 4.2 to the Registrant’s Registration Statement on Form F-1 filed with the SEC on January 6, 2012 (File No. 333-178922).
2.2A   Amendment No. 1, dated as of February 21, 2017, to the Deposit Agreement dated as of February 7, 2012, among the Registrant, J.P. Morgan Chase Bank, N.A., as depositary, and all holders from time to time of American depositary receipts issued thereunder, incorporated by reference to the Registrant’s Registration Statement on Form F-6 filed with the SEC on February 21, 2017 (File No. 333-216152).
2.2B   Amendment No. 2, dated as of December 4, 2020, to the Deposit Agreement dated as of February 7, 2012, among the Registrant, J.P. Morgan Chase Bank, N.A., as depositary, and all holders from time to time of American depositary receipts issued thereunder, incorporated by reference to the Registrant’s Registration Statement on Form F-6 filed with the SEC on December 4, 2020 (File No. 333-216152).
2.3   English Summary of Principle terms of Medium-term loan agreement entered into by Banco de Crédito del Perú and Scotiabank Perú S.A.A. with the intervention of Cementos Pacasmayo S.A.A.
2.4   Local bond issuance agreement (Contrato Marco de Emisión de Bonos Corporativos correspondiente al Segundo Programa de Bonos Corporativos de Cementos Pacasmayo S.A.A.) dated January 8, 2019, between Scotiabank Perú S.A.A. as administrative agent and Cementos Pacasmayo S.A.A. as issuer (English summary of principal terms), providing for the issuance of up to S/1,000,000,000 in one or more series, and related issuances of series 1 in an aggregate principal amount of S/260,000,000 and series 2 in an aggregate principal amount of S/310 million, incorporated by reference to Exhibit 2.4 of the Registrant’s Annual Report on Form 20-F filed with the SEC on April 30, 2019 (File No. 001-35401).
4.1   Power Supply Agreement, dated June 3, 2010, between the Registrant and Electroperú S.A., incorporated by reference to Exhibit 4.1 of the Registrant’s Annual Report on Form 20-F filed with the SEC on April 30, 2012 (File No. 001-35401).
4.2   Contract of General Management and Provision of Services, dated December 31, 2007, between the Registrant and Inversiones ASPI S.A. (formerly Inversiones Pacasmayo S.A.), incorporated by reference to Exhibit 4.2 of the Registrant’s Annual Report on Form 20-F filed with the SEC on April 30, 2012 (File No. 001-35401).
4.3   Property Lease Agreement, dated June 30, 2008, between the Registrant and Inversiones ASPI S.A. (formerly Inversiones Pacasmayo S.A.), incorporated by reference to Exhibit 4.3 of the Registrant’s Annual Report on Form 20-F filed with the SEC on April 30, 2012 (File No. 001-35401).
4.4   Surface Rights Agreement, dated February 1, 2008, between the Registrant and Compañía Minera Ares S.A.C., incorporated by reference to Exhibit 4.4 of the Registrant’s Annual Report on Form 20-F filed with the SEC on April 30, 2012 (File No. 001-35401).
4.5   Addendum, effective February 1, 2020, to the Power Supply Agreement, dated June 3, 2010, between the Registrant and Electroperú S.A., incorporated by reference to Exhibit 4.5 of the Registrant’s Annual Report on Form 20-F filed with the SEC on May 1, 2020 (File No. 001-35401).
4.8*   English Summary of Principal Terms for the Power Supply Agreement, dated December 11, 2023 between the Registrant and Orygen Perú S.A.A.
8.1*   List of Subsidiaries.
11   Insider Trading Policy, incorporated by reference to Exhibit 11 of the Registrant’s Annual Report on Form 20-F filed with the SEC on April 29, 2025 (File No. 001-35401).
12.1*   Certification of the Chief Executive Officer pursuant to Section 302 of the Sarbanes-Oxley Act of 2002.
12.2*   Certification of the Chief Financial Officer pursuant to Section 302 of the Sarbanes-Oxley Act of 2002.
13.1*†   Certification pursuant to 18 U.S.C. 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002 for Chief Executive Officer.
13.2*†   Certification pursuant to 18 U.S.C. 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002 for Chief Financial Officer.
96.1   Technical Report Summary (TRS), Tembladera Quarry and Pacasmayo Cement Plant 20-F 229.601 (Item 601)
96.2   Technical Report Summary (TRS), Virrilá Quarry and Piura Cement Plant 20-F 229.601 (Item 601)
96.3   Technical Report Summary (TRS), Tioyacu Quarry and Rioja Cement Plant 20-F 229.601 (Item 601)
97.1   Compensation Recovery Policy incorporated by reference to Exhibit 97 of the Registrant’s Annual Report on Form 20-F filed with the SEC on April 29, 2024 (File No. 001-35401).
101.INS*   Inline XBRL Instance Document.
101.SCH*   Inline XBRL Taxonomy Extension Schema Document.
101.CAL*   Inline XBRL Taxonomy Extension Calculation Linkbase Document.
101.DEF*   Inline XBRL Taxonomy Extension Definition Linkbase Document.
101.LAB*   Inline XBRL Taxonomy Extension Label Linkbase Document.
101.PRE*   Inline XBRL Taxonomy Extension Presentation Linkbase Document.
104*   Cover Page Interactive Data File (the cover page XBRL tags are embedded within the inline XBRL document).


*Filed with this Annual Report on Form 20-F.
†This certification will not be deemed “filed” for purposes of Section 18 of the Exchange Act (15 U.S.C. 78r), or otherwise subject to the liability of that section. Such certification will not be deemed to be incorporated by reference into any filing under the Securities Act or the Exchange Act, except to the extent that the Registrant specifically incorporates it by reference.


140


SIGNATURES


The registrant hereby certifies that it meets all of the requirements for filing on Form 20-F and that it has duly caused and authorized the undersigned to sign this annual report on Form 20-F on its behalf.


    CEMENTOS PACASMAYO S.A.A.
     
  By: /s/ Humberto Reynaldo Nadal Del Carpio
    Humberto Reynaldo Nadal Del Carpio
Chief Executive Officer
     
  By: /s/ Ely Adriana Hayashi Hirahoka
    Ely Adriana Hayashi Hirahoka
Chief Financial Officer


Date: April 27, 2026


141


INDEX TO CONSOLIDATED FINANCIAL STATEMENTS


  Page
Report of Independent Registered Public Accounting Firm (PCAOB ID No. 01315) F-4
Audited Consolidated Financial Statements—Cementos Pacasmayo S.A.A.  
Consolidated Statement of Financial Position as of December 31, 2025 and 2024 F-5
Consolidated Income Statement for the years ended December 31, 2025, 2024 and 2023 F-6
Consolidated Statement of Comprehensive Income for the years ended December 31, 2025, 2024 and 2023 F-7
Consolidated Statement of Changes in Equity for the years ended December 31, 2025, 2024 and 2023 F-8
Consolidated Statement of Cash Flows for the years ended December 31, 2025, 2024 and 2023 F-9
Notes to the Consolidated Financial Statements as of December 31, 2025 and 2024 and for the years ended December 31, 2025, 2024 and 2023 F-11


F-1


Cementos Pacasmayo S.A.A. and Subsidiaries


Consolidated financial statements as of December 31, 2025 and 2024, together with the Report of Independent Registered Accounting Firm


F-2


Cementos Pacasmayo S.A.A. and Subsidiaries


Consolidated financial statements as of December 31, 2025 and 2024, together with the Report of Independent Registered Accounting Firm


Contents


Report of Independent Registered Accounting Firm F-4
 
Consolidated financial statements
 
Consolidated statement of financial position F-5
Consolidated statement of profit or loss F-6
Consolidated statement of other comprehensive income (loss) F-7
Consolidated statement of changes in equity F-8
Consolidated statement of cash flows F-9
Notes to the consolidated financial statements F-11


F-3


Report of Independent Registered Public Accounting Firm


To the Board of Directors and Shareholders of Cementos Pacasmayo S.A.A. and Subsidiaries


Opinion on the Financial Statements


We have audited the accompanying consolidated statements of financial position of Cementos Pacasmayo S.A.A. and subsidiaries (the Company) as of December 31, 2025 and 2024, and the related consolidated statements of profit or loss, other comprehensive income (loss), changes in equity and cash flows for each of the three years in the period ended December 31, 2025, and the related notes (collectively referred to as the “consolidated financial statements”). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company as of December 31, 2025 and 2024, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2025, in conformity with IFRS Accounting standards as issued by the International Accounting Standards Board (“IASB”) (“IFRS Accounting Standards”).


We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB) the Company’s internal control over financial reporting as of December 31, 2025, based on criteria established in Internal Control - Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) and our report dated April 27, 2026, expressed an unqualified opinion thereon.


Basis for opinion


These consolidated financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s consolidated financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.


We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. We believe that our audits provide a reasonable basis for our opinion.


Critical audit matter


Critical audit matters are those matters that, in our professional judgment, were of most significance in our audit of the consolidated financial statements of the current period. We have determined that there are no critical audit matters to communicate in our report.


/s/ Tanaka, Valdivia, Arribas & Asociados Sociedad Civil de Responsabilidad Limitada

A member of Ernst & Young Global Limited


We have served as the Company’s auditor since 2002.


PCAOB ID No. 01315


Lima, Peru

April 27, 2026


F-4


Cementos Pacasmayo S.A.A. and Subsidiaries


Consolidated statement of financial position

As of December 31, 2025 and 2024


   Note   2025   2024 
         S/(000)    S/(000) 
Assets               
Current assets               
Cash and cash equivalents   6    53,571    72,723 
Trade and other receivables, net   7    146,674    131,168 
Income tax prepayments        24,857    7,736 
Inventories   8    707,143    773,997 
Prepayments        17,503    6,872 
Total current assets        949,748    992,496 
Non-current assets               
Trade and other receivables, net   7    28,450    43,224 
Financial investments designated at fair value through other comprehensive income        163    239 
Property, plant and equipment, net   9    2,005,714    2,031,139 
Intangible assets, net   10    62,800    63,596 
Goodwill        4,459    4,459 
Deferred income tax assets   14    34,994    21,816 
Right of use assets        16,988    9,023 
Other assets        50    51 
Total non-current assets        2,153,618    2,173,547 
Total assets        3,103,366    3,166,043 
Liabilities and equity               
Current liabilities               
Trade and other payables   11    283,907    242,051 
Financial obligations   13    532,346    458,346 
Lease liabilities        4,879    2,958 
Income tax payable        3,784    17,937 
Provisions   12    47,689    44,263 
Total current liabilities        872,605    765,555 
Non-current liabilities               
Financial obligations   13    879,809    1,034,845 
Lease liabilities        11,350    6,462 
Provisions   12    29,005    28,146 
Deferred income tax liabilities   14    119,232    117,937 
Total non-current liabilities        1,039,396    1,187,390 
Total liabilities        1,912,001    1,952,945 
Equity   15           
Capital stock        423,868    423,868 
Investment shares        40,279    40,279 
Investment shares held in treasury        (121,258)   (121,258)
Additional paid-in capital        432,779    432,779 
Legal reserve        168,636    168,636 
Other accumulated comprehensive loss        (16,966)   (16,551)
Retained earnings        264,027    285,345 
Total equity        1,191,365    1,213,098 
Total liabilities and equity        3,103,366    3,166,043 


The accompanying notes are an integral part of these consolidated financial statements.


F-5


Cementos Pacasmayo S.A.A. and Subsidiaries


Consolidated statement of profit or loss

For the years ended December 31, 2025, 2024 and 2023


   Note  2025   2024   2023 
       S/(000)     S/(000)     S/(000)  
                   
Sales of goods  16   2,116,883    1,978,071    1,950,075 
Cost of sales  17   (1,310,017)   (1,249,545)   (1,260,623)
Gross profit      806,866    728,526    689,452 
                   
Operating expenses                  
Administrative expenses  18   (291,538)   (253,383)   (231,967)
Selling and distribution expenses  19   (92,785)   (81,410)   (69,569)
Other operating expenses, net  21   (75,442)   (2,700)   (13,810)
Impairment to retirement of property, plant and equipment  9(g)   
-
    
-
    (36,551)
Total operating expenses, net      (459,765)   (337,493)   (351,897)
Operating profit      347,101    391,033    337,555 
                   
Other income (expenses)                  
Finance income      11,291    6,298    7,246 
Finance costs  22   (93,036)   (100,308)   (104,045)
Net gain on derivative financial instruments recognized at fair value through profit or loss      
-
    
-
    19 
Gain (loss) from exchange difference, net  5   2,619    (836)   4,933 
Total other expenses, net      (79,126)   (94,846)   (91,847)
Profit before income tax      267,975    296,187    245,708 
Income tax expense  14   (113,770)   (97,312)   (76,808)
Profit for the year      154,205    198,875    168,900 
                   
Earnings per share                  
Basic income attributable to holders of common and investment shares of Cementos Pacasmayo S.A.A. (S/per share)  24   0.36    0.46    0.39 


The accompanying notes are an integral part of these consolidated financial statements.


F-6


Cementos Pacasmayo S.A.A. and Subsidiaries


Consolidated statement of other comprehensive income (loss)

For the years ended December 31, 2025, 2024 and 2023


   Note   2025   2024   2023 
         S/(000)    S/(000)    S/(000) 
                     
Profit for the year        154,205    198,875    168,900 
Other comprehensive (loss) income                    
Other comprehensive (loss) income that will not be reclassified to profit or loss in subsequent years:                    
Change in fair value of financial instruments designated at fair value through other comprehensive loss        (588)   (370)   (25)
Deferred income tax   14    173    109    7 
Other comprehensive (loss) income to be reclassified to profit or loss in subsequent years:                    
Net gain on cash flows hedges        
-
    
-
    2,154 
Deferred income tax        
-
    
-
    (634)
Other comprehensive (loss) income for the year, net of income tax        (415)   (261)   1,502 
Total other comprehensive income for the year, net of income tax        153,790    198,614    170,402 


The accompanying notes are an integral part of these consolidated financial statements.


F-7


Cementos Pacasmayo S.A.A. and Subsidiaries


Consolidated statement of changes in equity

For the years ended December 31, 2025, 2024 and 2023


   Capital
stock
   Investment
shares
   Treasury
shares
   Additional
paid-in
capital
   Legal
reserve
   Unrealized
net loss on
financial
instruments
designated at
fair value
   Unrealized
gain (loss)
on cash
flow hedge
   Retained
earnings
   Total 
    S/(000)    S/(000)    S/(000)    S/(000)    S/(000)   S/(000)   S/(000)    S/(000)    S/(000)
                                              
Balance as of January 1, 2023   423,868    40,279    (121,258)   432,779    168,636    (16,267)   (1,520)   268,618    1,195,135 
Profit for the year   
-
    
-
    
-
    
-
    
-
    
-
    
-
    168,900    168,900 
Other comprehensive income   
-
    
-
    
-
    
-
    
-
    (18)   1,520    
-
    1,502 
Total comprehensive income   
-
    
-
    
-
    
-
    
-
    (18)   1,520    168,900    170,402 
Dividends, note 15(g)   
-
    
-
    
-
    
-
    
-
    
-
    
-
    (175,524)   (175,524)
Others   
-
    
-
    
-
    
-
    
-
    (5)   
-
    
-
    (5)
Balance as of December 31, 2023   423,868    40,279    (121,258)   432,779    168,636    (16,290)   
-
    261,994    1,190,008 
Profit for the year   
-
    
-
    
-
    
-
    
-
    
-
    
-
    198,875    198,875 
Other comprehensive income   
-
    
-
    
-
    
-
    
-
    (261)   
-
    
-
    (261)
Total comprehensive income   
-
    
-
    
-
    
-
    
-
    (261)   
-
    198,875    198,614 
Dividends, note 15(g)   
-
    
-
    
-
    
-
    
-
    
-
    
-
    (175,524)   (175,524)
Balance as of December 31, 2024 (note 15)   423,868    40,279    (121,258)   432,779    168,636    (16,551)   
-
    285,345    1,213,098 
Profit for the year   
-
    
-
    
-
    
-
    
-
    
-
    
-
    154,205    154,205 
Other comprehensive income   
-
    
-
    
-
    
-
    
-
    (415)   
-
    
-
    (415)
Total comprehensive income   
-
    
-
    
-
    
-
    
-
    (415)   
-
    154,205    153,790 
Dividends, note 15(g)   
-
    
-
    
-
    
-
    
-
    
-
    
-
    (175,524)   (175,524)
Others   
-
    
-
    
-
    
-
    
-
    
-
    
-
    1    1 
Balance as of December 31, 2025 (note 15)   423,868    40,279    (121,258)   432,779    168,636    (16,966)   
-
    264,027    1,191,365 


The accompanying notes are an integral part of these consolidated financial statements.


F-8


Cementos Pacasmayo S.A.A. and Subsidiaries


Consolidated statement of cash flows

For the years ended December 31, 2025, 2024 and 2023


   Note  2025   2024   2023 
      S/(000)   S/(000)   S/(000) 
                
Operating activities                   
Profit before income tax       267,975    296,187    245,708 
Non-cash adjustments to reconcile profit before income tax to net cash flows from operating activities                   
Depreciation and amortization       159,481    158,246    144,195 
Finance costs   22   93,036    100,308    104,045 
Long-term incentive plan   12(c) y 20   4,925    7,167    7,632 
Allowance for expected credit losses   7(e)   3,467    2,751    1,707 
Provision for inventory obsolescence   8(b)   1,469    6,696    2,956 
Finance income       (11,291)   (6,298)   (7,246)
Reversal by arrangement of obsolescence of inventory, net   8(b)   (7,819)   (341)   (336)
Net gain on disposal of property, plant and equipment and intangible assets       (2,028)   (3,642)   (813)
Exchange difference related to monetary transactions       (44)   1,048    (973)
Impairment related to retirement of property, plant and equipment   9(g)   
-
    
-
    36,551 
Net gain on derivative financial instruments recognized at fair value through profit or loss       
-
    
-
    (19)
Other items that do not generate operating flows, net       2,928    7,347    18,021 
Working capital adjustments                   
Increase in trade and other receivables       (3,608)   (34,194)   (1,870)
Decrease in inventories       68,634    5,967    90,917 
(Increase) decrease in prepayments       (11,268)   (951)   13,210 
Increase (decrease) in trade and other payables       31,588    (14,894)   (48,680)
        597,445    525,397    605,005 
Interest received       11,833    6,422    7,315 
Interest paid       (91,898)   (99,678)   (96,907)
Income tax paid       (156,753)   (111,000)   (103,090)
Net cash flows from operating activities       360,627    321,141    412,323 


F-9


Consolidated statement of cash flows (continued)


   Note  2025   2024   2023 
       S/(000)    S/(000)    S/(000) 
Investing activities                  
Purchase of property, plant and equipment      (102,833)   (64,318)   (272,600)
Purchase of intangible assets      (15,893)   (16,563)   (16,707)
Purchase of investments available for sale      (512)   (360)   
-
 
Loans granted      (462)   (97)   (1,679)
Cash flow proceeds from sale of property, plant and equipment      3,258    4,403    1,392 
Proceeds from loans      1,000    326    150 
Opening of term deposits with original maturity greater than 90 days      
-
    (32,782)   (10,000)
Redemption of term deposits with original maturity greater than 90 days      
-
    32,782    10,000 
Net cash flows used in investing activities      (115,442)   (76,609)   (289,444)
Financing activities                  
Payment of bank loans  26   (474,564)   (384,364)   (661,520)
Dividends paid  26   (175,458)   (175,046)   (175,431)
Lease payments      (7,244)   (5,426)   (3,564)
Bank loans received  26   392,200    303,200    639,000 
Dividends returned  26   660    297    465 
Payment of bank overdraft      
-
    
-
    (85,333)
Payment for hedging instrument      
-
    
-
    (7,708)
Cash flow from settlement of derivative financial instruments      
-
    
-
    93,323 
Proceeds from bank overdraft      
-
    
-
    85,333 
Net cash flows used in financing activities      (264,406)   (261,339)   (115,435)
Net (decrease) increase in cash and cash equivalents      (19,221)   (16,807)   7,444 
Net foreign exchange difference      69    (663)   976 
Cash and cash equivalents as of January 1  6   72,723    90,193    81,773 
Cash and cash equivalents as of December 31  6   53,571    72,723    90,193 
                   
Transactions with no effect on cash flows:                  
Unrealized exchange difference related to monetary transactions      (44)   1,048    (973)
Outstanding accounts payable related to acquisition of property, plant and equipment  9(e)   (26,754)   (17,122)   (9,379)
Addition of right-of-use assets and lease liabilities      13,272    
-
    6,915 
Additions of quarry rehabilitation costs      2,087    1,465    4,458 


The accompanying notes are an integral part of this consolidated statement.


F-10


Cementos Pacasmayo S.A.A. and Subsidiaries


Notes to the consolidated financial statements

As of December 31, 2025, 2024 and 2023


1.Corporate information


Cementos Pacasmayo S.A.A. (hereinafter “the Company”) was incorporated in 1957 and, under the Peruvian General Corporation Law, is an open stock corporation, its shares are listed in the Lima and New York Stock Exchange. The Company is a subsidiary of Inversiones ASPI S.A., which holds 50.01 percent of the Company’s common shares as of December 31, 2025, 2024 and 2023.


The Company’s registered address is Calle La Colonia No.150, Urbanización El Vivero, Santiago de Surco, Lima, Peru. All the subsidiaries are domiciled and operate in Peru.


The Company and its subsidiaries’ main activity is the production and marketing of cement, concrete, precast and other minors in northern of Peru.


The issuance of the consolidated financial statements of the Company and its subsidiaries (hereinafter “the Group”) for the year ended December 31, 2025 were approved by the Annual General Shareholders’Meeting of Shareholders, on March 24, 2026. The consolidated financial statements as of December 31, 2024 and for the year then ended were approved by the General Shareholders’ Meeting on March 24, 2025.


The Group has prepared the consolidated financial statements on the basis that it will continue to operate as a going concern.


For the years ended December 31, 2025, 2024 and 2023, the consolidated financial statements comprise the financial statements of the Company and its subsidiaries: Cementos Selva S.A.C. and subsidiaries, Distribuidora Norte Pacasmayo S.R.L. and subsidiary, Empresa de Transmisión Guadalupe S.A.C., Salmueras Sudamericanas S.A., Soluciones Crealo 150 S.A.C , Soluciones Takay S.A.C., 150Krea Inc, Vanguardia Constructora del Perú S.A.C. and Corporación Materiales Piura S.A.C. As of these dates, the Company maintained a 100 percent interest in all its subsidiaries.


The main activities of the subsidiaries incorporated in the consolidated financial statements are described as follows:


-Cementos Selva S.A.C. is engaged in production and marketing of cement and other construction materials in the northeast region of Peru. Also, it holds 100 percent of the shares in Dinoselva Iquitos S.A.C. (a cement and construction materials distributor in the north of Peru, which also produces and sells precast, cement bricks and ready-mix concrete) and in Acuícola Los Paiches S.A.C. (a fish farm entity).


F-11


Notes to the consolidated financial statements (continued)


-Distribuidora Norte Pacasmayo S.R.L. is mainly engaged in selling cement produced by the Company. Additionally, it produces and sells precast, cement bricks and ready-mix concrete. It is the main partner of the Consorcio Constructor Norte del Peru, an entity established for the execution of the work “Mejoramiento del Sistema de Pistas y Cerco Perimétrico del Aeropuerto de Piura”.


-Empresa de Transmisión Guadalupe S.A.C. is mainly engaged in providing electric energy transmission services to the Company.


-Salmueras Sudamericanas S.A.(“Salmueras”) In December 2017, the Company decided not to continue with the activities related to this project of Salmueras.


-Soluciones Takay S.A.C., entity constituted on March 29, 2019 whose corporate purpose is to provide advisory services and information, promotion, acquisition and intermediation services for the management and development of real estate projects by natural and/or legal persons.


-150Krea Inc., entity constituted on June 3, 2021 whose corporate purpose is the lease of intangible assets.


-Corporación Materiales Piura S.A.C., entity acquired on January 4, 2023 whose corporate purpose is the extraction of stone, sand and clay.


-Soluciones Créalo 150 S.A.C., an entity established on June 21, 2024, under the trade name Makers150, is mainly dedicated to the research and development of digital solutions for companies in the construction sector in Latin America.


-Vanguardia Constructora del Perú S.A.C., an entity established on June 21, 2024, whose corporate purpose is the performance of all construction activities, engineering services and management consulting.


On December 15, 2025, the majority shareholders of Inversiones ASPI S.A. and Holcim Ltd entered into a Share Purchase Agreement, subject to certain conditions precedent, for the sale of 99.99 percent of the shares of Inversiones ASPI S.A. under the terms and conditions set forth in said agreement.


The execution and closing of this transaction were subject to obtaining the relevant regulatory approvals, as well as the fulfillment of certain conditions precedent established in the share purchase agreement, among them, prior authorization from the National Institute for the Defense of Competition and Protection of Intellectual Property (INDECOPI), in accordance with the provisions of Law No. 31112 and its regulations. As of December 31, 2025, the transfer of ownership of the shares representing the capital stock of Inversiones ASPI S.A. to the Holcim Group or any of its affiliates had not taken place.


F-12


Notes to the consolidated financial statements (continued)


2.Significant accounting policies


2.1Basis of preparation –


The consolidated financial statements of the Group have been prepared in accordance with International Financial Reporting Standards (IFRS), as issued by the International Accounting Standards Board (IASB).


The consolidated financial statements have been prepared on a historical cost basis, except for financial instruments designated at fair value through other comprehensive income (OCI) that have been measured at fair value. The consolidated financial statements are presented in Soles and all values are rounded to the nearest thousand S/(000), except when otherwise indicated.


The consolidated financial statements provide comparative information in respect of the previous period or periods. There are certain standards and amendments applied for the first time by the Group during 2025, that did not require the restatement of previous financial statements, as explained in note 2.3.17.


The Company classifies costs and expenses by function in the consolidated statement of income, in accordance with industry practices.


The consolidated statement of cash flows is presented using the indirect method.


2.2Basis of consolidation -


The consolidated financial statements comprise the financial statements of the Company and its subsidiaries as of December 31, 2025 and 2024 and for the years ended December 31, 2025, 2024 and 2023. Control is achieved when the Group is exposed, or has rights, to variable returns from its involvement with the investee and has the ability to affect those returns through its power over the investee. Specifically, the Group controls an investee if and only if it has: (i) power over the investee (i.e. existing rights that give it the current ability to direct the relevant activities of the investee), (ii) exposure, or rights, to variable returns from its involvement with the investee, and (iii) the ability to use its power over the investee to affect its returns.


Consolidation of a subsidiary begins when the Group obtains control over the subsidiary and ceases when the Group loses control of the subsidiary. Assets, liabilities, income and expenses of a subsidiary acquired or disposed of during the year are included in the consolidated financial statements from the date the Group gains control until the date the Group ceases to control the subsidiary.


The accounting policies are in line with the Group´s accounting policies. All intra-group assets and liabilities, equity, income, expenses and cash flows relating to transactions between members of the Group are eliminated on consolidation.


A change in the ownership interest of a subsidiary, without a loss of control, is accounted for as an equity transaction.


F-13


Notes to the consolidated financial statements (continued)


2.3Summary of significant accounting policies -


2.3.1Cash and cash equivalents -


Cash and cash equivalents presented in the statement of financial position comprise cash at banks and on hand and short-term deposits with an original maturity of three months or less.


2.3.2Financial instruments-initial recognition and subsequent measurement –


A financial instrument is any contract that gives rise to a financial asset of one entity and a financial liability or equity instrument of another entity.


(i)Financial assets -


Initial recognition and measurement -


Financial assets are classified at initial recognition as measured at amortized cost, fair value through OCI or fair value through profit or loss.


The Group’s financial assets include cash and cash equivalents, trade and other receivables and other financial investments at fair value through OCI.


Subsequent measurement -


For purposes of subsequent measurement, financial assets are classified into the following categories:


-Financial assets at amortized cost (debt instruments).


-Financial assets at fair value through OCI with recycling of cumulative gains and losses (debt instruments).


-Financial assets designated at fair value through OCI without recycling of cumulative gains and losses upon derecognition (equity instruments).


The classification depends on the business model of the Group and the contractual terms of the cash flows.


Financial assets at amortized cost (debt instruments) -


The Group measures financial assets at amortized cost if both of the following conditions are met:


-The financial asset is held within a business model with the objective to collect contractual cash flows and not sale or trade it, and,


-The contractual terms of the financial asset give rise on specified dates to cash flows that are solely payments of principal and interest on the principal amount outstanding


Financial assets at amortized cost are subsequently measured using the effective interest (EIR) method and are subject to impairment. Gains and losses are recognized in profit or loss when the asset is derecognized, modified or impaired.


Financial assets are not reclassified after their initial recognition, except if the Group changes its business model for its management.


As of December 31, 2025 and 2024, the Group held trade and other receivables in this category; because they meet the conditions described above.


F-14


Notes to the consolidated financial statements (continued)


Financial assets at fair value through OCI (equity instruments) -


Upon initial recognition, the Group can elect to irrevocably classify its equity investments as equity instruments designated at fair value through OCI when they meet the definition of equity and are not held for trading. The classification is determined on an instrument-by-instrument basis.


Gains and losses on these financial assets are never recycled to profit or loss. Dividends are recognized as other income in the statement of profit or loss when the right of payment has been established, except when the Group benefits from such proceeds as a recovery of part of the cost of the financial asset, in which case, such gains are recorded in OCI. Equity instruments designated at fair value through OCI are not subject to impairment assessment.


As of December 31, 2025 and 2024, the Group elected to classify irrevocably its listed equity investments in Fossal S.A.A. under this category.


(ii)Impairment of financial assets -


The Group recognizes an allowance for expected credit losses (ECLs) for all debt instruments not held at fair value through profit or loss. ECLs are based on the difference between the contractual cash flows due in accordance with the contract and all the cash flows that the Group expects to receive, discounted at an approximation of the original effective interest rate. The expected cash flows will include cash flows from the sale of collateral held or other credit enhancements that are integral to the contractual terms.


ECLs are recognized in two stages. For credit exposures for which there has not been a significant increase in credit risk since initial recognition, ECLs are provided for credit losses that result from default events that are possible within the next 12-months (a 12-month ECL). For those credit exposures for which there has been a significant increase in credit risk since initial recognition, a loss allowance is required for credit losses expected over the remaining life of the exposure, irrespective of the timing of the default (a lifetime ECL).


For trade receivables, the Group applies a simplified approach in calculating ECLs. Therefore, the Group does not track changes in credit risk, but instead recognizes a loss allowance based on lifetime ECLs at each reporting date. The Group has established a provision matrix that is based on its historical credit loss experience, adjusted for forward-looking factors specific to the debtors and the economic environment.

The Group considers a financial asset in default when contractual payments are 360 days past due. However, in certain cases, the Group may also consider a financial asset to be in default when internal or external information indicates that the Group is unlikely to receive the outstanding contractual amounts in full before taking into account any credit enhancements held by the Group. A financial asset is written off when there is no reasonable expectation of recovering the contractual cash flows.


(iii)Financial liabilities -


Initial recognition and measurement -


Financial liabilities are classified at initial recognition as financial liabilities at fair value through profit or loss, loans and borrowings, payables, as appropriate.


All financial liabilities are recognized initially at fair value and, in the case of loans and borrowings and payables, net of directly attributable transaction costs.


The Group’s financial liabilities include trade and other payables, interest-bearing loans and borrowings.


F-15


Notes to the consolidated financial statements (continued)


Subsequent measurement -


The subsequent measurement of financial liabilities depends on their classification, the Group maintains Loans and Borrowings, which accounting treatment is explained below:


After their initial recognition, interest-bearing loans and borrowings are subsequently measured at amortized cost using the EIR method. Gains and losses are recognized in the consolidated statement of profit or loss when the liabilities are derecognized as well as through the EIR amortization process.


Amortized cost is calculated by considering any discount or premium on acquisition and fees or costs that are an integral part of the EIR. The EIR amortization is included as finance costs in the consolidated statement of profit or loss.


As of December 31, 2025 and 2024, the Group included trade and other payables and financial liabilities in this category, for more information refer to notes 11 and 13.


Derecognition -


A financial liability is derecognized when the obligation under the liability is discharged or cancelled or expired. When an existing financial liability is replaced by another from the same lender on substantially different terms, or the terms of an existing liability are substantially modified, such an exchange or modification is treated as a derecognition of the original liability and the recognition of a new liability. The difference in the respective carrying amount is recognized in the consolidated statement of profit or loss.


(iv)Fair value measurement -


The Group measures financial instruments such as equity investments, at fair value at each period end.


Fair value is the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. The fair value measurement is based on the presumption that the transaction to sell the asset or transfer the liability takes place either:


-In the principal market for the asset or liability, or


-In the absence of a principal market, in the most advantageous market for the asset or liability.


The principal or the most advantageous market must be accessible by the Group.


The fair value of an asset or a liability is measured using the assumptions that market participants would use when pricing the asset or liability, assuming that market participants act in their economic best interest.


A fair value measurement of a non-financial asset takes into account a market participant’s ability to generate economic benefits by using the asset in its highest and best use or by selling it to another market participant that would use the asset in its highest and best use.


The Group uses valuation techniques that are appropriate in the circumstances and for which sufficient data are available to measure fair value, maximizing the use of relevant observable inputs and minimizing the use of unobservable inputs.


F-16


Notes to the consolidated financial statements (continued)


All assets and liabilities for which fair value is measured or disclosed in the financial statements are categorized within the fair value accounting hierarchy, described as follows, based on the lowest level input that is significant to the fair value measurement as a whole:


-Level 1 — Quoted (unadjusted) market prices in active markets for identical assets or liabilities.


-Level 2 — Valuation techniques for which the lowest level input that is significant to the fair value measurement is directly or indirectly observable.


-Level 3 — Valuation techniques for which the lowest level input that is significant to the fair value measurement is unobservable.


For assets and liabilities that are recognized in the financial statements at fair value on a recurring basis, the Group determines whether transfers have occurred between levels in the hierarchy by re-assessing categorization (based on the lowest level input that is significant to the fair value measurement as a whole) at the end of each reporting period.


The Group’s management determines the policies and procedures for recurring and non-recurring fair value measurements.


At each reporting date, the Financial Management analyzes the changes in the values of the assets and liabilities that must be measured or determined on a recurring and non-recurring basis according to the Group’s accounting policies. For this analysis, Management contrasts the main variables used in the latest assessments made with updated information available from valuations included in contracts and other relevant documents.


Management also compares the changes in the fair value of each asset and liability with the relevant external sources to determine whether the change is reasonable.

For purposes of disclosure of fair value, the Group has determined classes of assets and liabilities based on the inherent nature, characteristics and risks of each asset and liability, and the level of the fair value accounting hierarchy as explained above, see note 27(a).


2.3.3Foreign currencies -


The functional and presentation currency for the consolidated financial statements of the Group is soles, which is also the functional currency for its subsidiaries.


Transactions and balances


Transactions in foreign currencies are initially recorded at their respective functional currency spot rates at the date the transaction first qualifies for recognition.


Monetary assets and liabilities denominated in foreign currencies are translated at the functional currency spot rates of exchange at the reporting date. Differences arising on settlement or translation of monetary items are recognized in the consolidated statement of profit or loss.


Non-monetary items that are measured in terms of historical cost in a foreign currency are translated using the exchange rates at the dates of the initial transactions.


F-17


Notes to the consolidated financial statements (continued)


2.3.4Inventories -


Inventories are valued at the lower of cost or net realizable value. Costs incurred in bringing each product to its present location and conditions are accounted for as follows:


Raw materials, spare part and supplies


-Initially at cost and are recorded at the lower of cost and net realizable value.


Finished goods and work in progress


-Cost of direct materials and supplies, services provided by third parties, direct labor and a proportion of manufacturing overheads is based on normal operating capacity, excluding borrowing costs and exchange currency differences.


Inventory in transit


-Cost.


Net realizable value is the estimated selling price in the ordinary course of business, less estimated cost of completion and the estimated costs of inventory necessary to make the sale.


2.3.5Borrowing costs -


Borrowing costs directly attributable to the acquisition, construction or production of an asset that necessarily takes a substantial period of time to get ready for its intended use or sale are capitalized as part of the cost of the respective asset. All other borrowing costs are recognized in the consolidated statement of profit or loss in the period in which they occur. Borrowing costs consist of interest and other costs that an entity incurs in connection with the borrowing of funds.


When the funds are used to finance a project form part of general borrowings, the amount capitalized is calculated using a weighted average of interest rates applicable to relevant general borrowings of the Group during the period. All other borrowing costs are recognized in the consolidated statement of profit or loss in the period in which they are incurred.


2.3.6Property, plant and equipment -


Property, plant and equipment is stated at acquisition cost, net of accumulated depreciation and/or accumulated impairment losses, if any. Such cost includes the cost of replacing component parts of the property, plant and equipment and borrowing costs for long-term construction projects if the recognition criteria are met, see note 2.3.5. The capitalized value of a finance lease is also included within property, plant and equipment. When significant parts of plant and equipment are required to be replaced at intervals, the Group recognizes such parts as individual assets with specific useful lives and depreciates them separately based on their specific useful lives. Likewise, when a major inspection is performed, its cost is recognized in the carrying amount of the plant and equipment as a replacement if the recognition criteria are satisfied. All other repair and maintenance costs are recognized as operation cost or expense in the consolidated statement of profit or loss as incurred.


The present value of the expected cost for the decommissioning of an asset after its use is included in the cost of the respective asset if the recognition criteria for a provision are met. Refer to significant accounting judgments, estimates and assumptions, see note 3, and quarry rehabilitation cost provisions, see note 12.


F-18


Notes to the consolidated financial statements (continued)


Depreciation of assets is determined using the straight-line method over the estimated useful lives of such assets as follows:


  Years
   
Buildings and other construction:  
Minor installations related to buildings Between 10 and 35
Administrative facilities Between 20 and 51
Main production structures Between 20 and 56
Minor production structures Between 20 and 35
Machinery and equipment:  
Mills Between 24 and 45
Horizontal and vertical furnaces, crushers and grinders Between 23 and 36
Electricity facilities and other minors Between 10 and 35
Furniture and fixtures 10
Transportation units:  
Heavy units Between 5 and 15
Light units Between 5 and 10
Computer equipment Between 3 and 10
Tools Between 5 and 10


The asset’s residual value, useful lives and methods of depreciation are reviewed at each reporting period and adjusted prospectively if appropriate.


An item of property, plant and equipment and any significant part initially recognized is derecognized upon disposal or when no future economic benefits are expected from its use or disposal. Any gain or loss arising on derecognition of the asset (calculated as the difference between the net disposal proceeds and the carrying amount of the asset) is included in the consolidated statement of profit or loss when the asset is derecognized.


2.3.7Mining concessions -


Mining concessions correspond to the exploration rights in areas of interest acquired. Mining concessions are stated at cost, net of accumulated amortization and/or accumulated impairment losses, if any, and are presented within the “Property, plant and equipment, net” caption of consolidated statement of financial position. Those mining concessions are amortized following the straight-line method. In the event the Group abandons the concession, the costs associated, see note 9(b), are written-off in the consolidated statement of profit or loss.


For the years ended December 31, 2025 and 2024, mining concessions of the Group correspond to areas that contain raw material necessary for cement production.


F-19


Notes to the consolidated financial statements (continued)


2.3.8Quarry development costs and stripping costs -


Quarry development costs -


Quarry development costs incurred are stated at cost and are the next step in development of quarries after the exploration and evaluation stage. Quarry development costs are, upon commencement of the production phase, presented net of accumulated amortization and/or accumulated impairment losses, if any, and are presented within the property, plant and equipment caption. The amortization is calculated using the straight-line method based on the useful life of the quarry to which it relates. Expenditures that significantly increase the economic life of the quarry under exploitation are capitalized.


Stripping costs -


Stripping costs incurred in the development of a mine before production commences are capitalized as part of mine development costs and subsequently amortized over the life of the mine on a units-of-production basis, using the proved reserves.


Stripping costs incurred subsequently during the production phase of its operation are recorded as part of cost of production.


2.3.9Intangible assets


Intangible assets acquired separately are measured on initial recognition at cost. Following initial recognition, intangible assets are carried at cost less any accumulated amortization and accumulated impairment losses. Internally generated intangibles, excluding capitalized development costs, are not capitalized and the related expenditure is reflected in profit or loss in the period in which the expenditure is incurred. The useful lives of intangible assets are assessed as either finite or indefinite.


Intangible assets with finite lives are amortized over the economic useful life and assessed for impairment whenever there is an indication that the intangible asset may be impaired. The amortization period and the amortization method for an intangible asset with a finite useful life are reviewed at least at the end of each reporting period. Changes in the expected useful life or the expected pattern of consumption of future economic benefits embodied in the asset are considered to modify the amortization period or method, as appropriate, and are treated as changes in accounting estimates. The amortization expense on intangible assets with finite lives is recognized in the statement of profit or loss in the cost or expense category that is consistent with the function of the intangible assets.


The Group’s intangible assets with finite useful lives are amortized over an average term between three and ten years.


Any gain or loss arising upon derecognition of the asset (calculated as the difference between the net disposal proceeds and the carrying amount of the asset) is included in the consolidated statement of profit or loss.


F-20


Notes to the consolidated financial statements (continued)


Exploration and evaluation assets -


Exploration and evaluation activity involve the search for mineral resources, the determination of technical feasibility and the assessment of commercial viability of an identified resource. Exploration and evaluation activity include:


-Researching and analyzing historical exploration data.


-Gathering exploration data through geophysical studies.


-Exploratory drilling and sampling.


-Determining and examining the volume and grade of the resource.


-Surveying transportation and infrastructure requirements.


-Conducting market and finance studies.


Once the legal right to explore has been acquired, exploration and evaluation costs are charged to the consolidated statement of profit or loss, unless management concludes that a future economic benefit is more likely than not to be realized, in which case such costs are capitalized, see note 10(b).These costs include directly attributable employee remuneration, materials and fuel used, surveying costs, drilling costs and payments made to contractors.


In evaluating if costs meet the criteria to be capitalized, several different sources of information are used, including the nature of the assets, extension of the explored area and results of sampling, among others. The information that is used to determine the probability of future benefits depends on the extent of exploration and evaluation that has been performed.


Exploration and evaluation costs are capitalized when the exploration and evaluation activity is within an area of interest for which it is expected that the costs will be recouped by future exploitation and active and significant operations in relation to the area are continuing or planned for the future.


Exploration costs are amortized based on the estimated useful life of the mining property from the moment the commercial exploitation of the reserves begins. All capitalized exploration and evaluation costs are monitored for indications of impairment. Where a potential impairment indicator is identified, an assessment is performed for each area of interest in conjunction with the group of operating assets (representing a cash generating unit) to which the exploration is attributed.


At each reporting date, the Group assesses at each reporting date whether there is an indication that exploration and evaluation assets may be impaired, see note 10(c).


F-21


Notes to the consolidated financial statements (continued)


2.3.10Ore reserve and resource estimates -


Ore reserves are estimates of the amount of ore that can be extracted legally, socially, environmentally and economically from the Group’s mining properties and concessions. The Group estimates its ore reserves and mineral resources, based on information compiled by appropriately qualified persons relating to the geological data on the size, depth and shape of the ore body, and requires complex geological judgments to interpret the data. The estimation of recoverable reserves is based upon factors such as future capital requirements, and production costs along with geological assumptions and judgments made in estimating the size and grade of the ore body. Changes in the reserve or resource estimates may impact upon the carrying value of exploration and evaluation assets, provision for quarry rehabilitation and depreciation and amortization charges.


2.3.11Provisions -


General -


Provisions are recognized when the Group has a present obligation (legal or constructive) as a result of a past event, it is probable that an outflow of resources embodying economic benefits will be required to settle the obligation and a reliable estimate can be made of the amount of the obligation. When the Group expects some or all of a provision to be reimbursed, for example under an insurance contract, the reimbursement is recognized as a separate asset but only when the reimbursement is virtually certain. The expense relating to any provision is presented in profit or loss net of any reimbursement. If the effect of the time value of money is material, provisions are discounted using a current pre-tax rate that reflects where appropriate, the risks specific to the liability. When discounting is used, the increase in the provision due to the passage of time is recognized as finance cost in the consolidated statement of profit or loss.


Quarry rehabilitation provision -


The Group records the present value of estimated costs of legal and constructive obligations required to restore operating locations in the period in which the obligation is incurred. Quarry rehabilitation costs are provided at the present value of expected costs to settle the obligation using estimated cash flows and are recognized as part of the cost of that particular asset. The cash flows are discounted at a current risk-free rate. The unwinding of the discount is expensed as incurred and recognized in the consolidated statement of profit or loss as a finance cost. The estimated future costs of quarry rehabilitation are reviewed annually and adjusted as appropriate. Changes in the estimated future costs or in the discount rate applied are added to or deducted from the cost of the asset, see note 12.


Environmental expenditures and liabilities -


Environmental expenditures that relate to current or future revenues are expensed or capitalized as appropriate. Expenditures that relate to an existing condition caused by past operations and do not contribute to current or future earnings are expensed.


Liabilities for environmental costs are recognized when a clean-up is probable, and the associated costs can be reliably estimated. Generally, the timing of recognition of these provisions coincides with the commitment to a formal plan of action or, if earlier, on divestment or on closure of inactive sites.


The amount recognized is the best estimate of the expenditure required. Where the liability will not be settled for a number of years, the amount recognized is the present value of the estimated future expenditure.


F-22


Notes to the consolidated financial statements (continued)


Onerous contracts -


If the Group has an onerous contract, the present obligations arising from it should be recognised and measured as a provision. However, before recognising a provision for an onerous contract, the Group recognises any impairment loss on the assets used to fulfil the obligations arising from that contract.


An onerous contract is one in which the unavoidable costs (i.e. the costs that the Group cannot avoid because it has the contract) of fulfilling the obligations under it exceed the economic benefits expected to be received from it. Unavoidable costs correspond to the lower of the cost of complying with the terms of the contract and the amount of payments or penalties arising from non-compliance. The cost of fulfilling a contract includes costs directly related to the contract (i.e. incremental costs and an allocation of costs that directly relate to contract activities).


2.3.12Employees benefits -


The Group has short-term obligations for employee benefits including salaries, severance contributions, legal bonuses, performance bonuses and profit sharing. These obligations are recorded monthly on an accrual basis.


Additionally, the Group has a long-term incentive plan for key management. This benefit is settled in cash, measured on the salary of each officer and upon fulfilling certain conditions such as years of experience within the Group and permanency. The Group recognizes the long-term obligation at its present value at the end of the reporting period using the projected credit unit method. To calculate the present value of these long-term obligations the Group uses a government bond discount rate at the date of the consolidated financial statements. This liability is annually reviewed on the date of the consolidated financial statements, and the accrual updates and the effect of changes in discount rates are recognized in the consolidated statement of profit or loss.


2.3.13Revenue recognition -


The Group is dedicated to the production and trading of cement, concrete, precast and other minors, as well as trade of construction supplies. These goods are sold in contracts with customers.


Revenue is measured at the fair value of the consideration received or receivable, considering contractually defined terms of payment and excluding taxes or duties.

The following specific recognition criteria must also be met before revenue is recognized:


Sales of goods -


Revenue from sale of goods is recognized at the point in time when control of the asset is transferred to the customer, generally on delivery of the goods.


The Group considers whether there are other terms in the contract that are separate performance obligations to which a portion of the transaction price needs to be allocated. In determining the transaction price for the sale of goods, the Group considers the effects of variable consideration, the existence of significant financing components, noncash consideration, and consideration payable to the customer (if any).


Rendering of services –


Transport services


In the business segments cement, concrete, precast and construction supplies, the Group provides transportation services. These services are sold together with the sale of the goods to the customer.


Transportation services are satisfied when the transport service is concluded, which coincides with the moment of delivery of the goods to the customers.


Paving services


In the paving business, to satisfy performance obligations over time, the Group shall recognize revenue by measuring progress as progress is made (transferring control of the services) in accordance with the relevant contract.


To measure the progress of the paving service, the Group uses the resource method, which states that revenue should be recognized on the basis of the efforts or resources incurred to satisfy the performance obligation (for example, resources consumed, labour hours expended, costs incurred, elapsed time or machinery hours used) in relation to the total resources expected to satisfy the performance obligation.


The Group shall present the right or obligation it holds for the delivery of the transferred services to a customer as a contract asset or a contract liability in its statement of financial position when that right or obligation is conditioned by something other than the passage of time.


F-23


Notes to the consolidated financial statements (continued)


2.3.14Taxes -


Current income tax -


Current income tax assets and liabilities are measured at the amount expected to be recovered from or paid to the tax authorities. The tax rates and tax laws used to compute the amount are those that are enacted or substantively enacted, at the reporting date in Peru, where the Group operates and generates taxable income.


Deferred tax -


Deferred tax is determinated on temporary differences between the tax bases of assets and liabilities and their carrying amounts for financial reporting purposes at the reporting date.


Deferred tax liabilities are recognized for all taxable temporary differences, except in respect of taxable temporary differences associated with investments in subsidiaries, associates and interests in joint arrangements, when the timing of the reversal of the temporary differences can be controlled and it is probable that the temporary differences will not reverse in the foreseeable future.


Deferred tax assets are recognized for all deductible temporary differences, and for the future offset of unused tax credits and carryforward tax losses, provided they are considered recoverable.


The carrying amount of deferred tax assets is reviewed at each reporting date and reduced to the extent that it is no longer probable that sufficient taxable profit will be available to allow all or part of the deferred tax asset to be utilized. Unrecognized deferred tax assets are re-assessed at each reporting date and are recognized to the extent that it has become probable that future taxable profits will allow the deferred tax asset to be recovered.


Deferred tax assets and liabilities are measured at the tax rates that are expected to apply in the year when the asset is realized or the liability is settled, based on tax rates (and tax laws) that have been enacted or substantively enacted at the reporting date.


Deferred tax related to items recognized outside profit or loss are recognized outside the consolidated statement of profit or loss. Deferred tax items are recognized in correlation to the underlying transaction either in OCI or directly in equity.


2.3.15Treasury shares -


Own equity instruments which are reacquired (treasury shares) are recognized at cost and deducted from equity. No gain or loss is recognized in the consolidated statement of profit or loss on the purchase, sale, issue or cancellation of the Group’s own equity instruments.


2.3.16Impairment of non-financial assets -


The Group assesses, at each reporting date, whether there is an indication that an asset may be impaired. If any indication exists, or when annual impairment testing for an asset is required (goodwill and Intangible assets with indefinite useful lives), the Group estimates the asset’s recoverable amount. An asset’s recoverable amount is the higher of an asset’s or cash-generating unit’s (CGU) fair value less costs of disposal and its value in use and is determined for an individual asset, unless the asset does not generate cash inflows that are largely independent of those from other assets or groups of assets. Where the carrying amount of an asset or CGU exceeds its recoverable amount, the asset is considered impaired and is written down to its recoverable amount.

In assessing value in use, the estimated future cash flows are discounted to their present value using a pre-tax discount rate that reflects current market assessments of the time value of money and the risks specific to the asset. In determining fair value less costs of disposal, recent market transactions are considered. If no such transactions can be identified, an appropriate valuation model is used. These calculations are corroborated by valuation multiples, quoted share prices for publicly traded companies or other available fair value indicators.


The Group supports its impairment calculation by using detailed budgets and forecast calculations, which are prepared separately for each of the Group´s CGUs to which the individual assets are allocated.


Impairment losses related to continuing operations, including impairment on inventories, are recognized in the consolidated statement of profit or loss in expense categories consistent with the function of the impaired asset.


In addition, an assessment is made at each reporting date to determine whether there is any indication that previously recognized impairment losses may no longer exist or have decreased. If such an indication exists, the Group estimates the asset’s or CGU’s recoverable amount. A previously recognized impairment loss is reversed only if there has been a change in the assumptions used to determine the asset’s recoverable amount since the last impairment loss was recognized. The reversal is limited so that the carrying amount of the asset does not exceed its recoverable amount, nor exceed the carrying amount that would have been determined, net of depreciation, had no impairment loss been recognized for the asset in prior years. Such reversal is recognized in the consolidated statement of profit or loss.


Exploration and evaluation assets are tested for impairment annually as of December 31, either individually or at the cash-generating unit level, as appropriate, and when circumstances indicate that the carrying value may be impaired.


As of December 31, 2025 and 2024 there were no indications of impairment for long-lived assets.


2.3.17New amended standards and interpretations -


The Group applied for the first-time certain standards and amendments, which are effective for annual periods beginning on or after January 1, 2025. The Group has not early adopted any other standard, interpretation or amendment that has been issued but is not yet effective.


F-24


Notes to the consolidated financial statements (continued)


Lack of exchangeability – Amendments to IAS 21


The amendments to IAS 21 The Effects of Changes in Foreign Exchange Rates specify how an entity should assess whether a currency is exchangeable and how it should determine a spot exchange rate when exchangeability is lacking. The amendments also require disclosure of information that enables users of its financial statements to understand how the currency not being exchangeable into the other currency affects, or is expected to affect, the entity’s financial performance, financial position and cash flows.


The amendments are effective for annual reporting periods beginning on or after 1 January 2025. When applying the amendments, an entity cannot restate comparative information.


The amendments had no impact on the Group’s consolidated financial statements.


3.Significant accounting judgments, estimates and assumptions


The preparation of the Group’s consolidated financial statements requires management to make judgments, estimates and assumptions that affect the reported amounts of revenues, expenses, assets and liabilities, and the accompanying disclosures. Uncertainty about these assumptions and estimates could result in outcomes that require a material adjustment to the carrying amount of assets or liabilities affected in future periods.


If signs of impairment are identified, the most significant estimate considered by the Company’s Management will correspond to the evaluation of the impairment of long-lived assets. As of December 31, 2025 and 2024, Management has not identified signs of impairment for long-lived assets, which is why it considers that there are no significant estimates for those dates.


4.Standards issued but not yet effective


The standards and interpretations relevant to the Group, that will have effect at January 1, 2026 are below:


Amendments to the Classification and Measurement of Financial Instruments—Amendments to IFRS 9 and IFRS 7


In May 2024, the IASB issued Amendments to IFRS 9 and IFRS 7, Amendments to the Classification and Measurement of Financial Instruments (the Amendments). The Amendments include:


-A clarification that a financial liability is derecognized on the ’settlement date’ and the introduction of an accounting policy choice (if specific conditions are met) to derecognize financial liabilities settled using an electronic payment system before the settlement date.


-Additional guidance on how the contractual cash flows for financial assets with environmental, social and corporate governance (ESG) and similar features should be assessed.


-Clarifications on what constitute ‘non-recourse features’ and what are the characteristics of contractually linked instruments.


-The introduction of disclosures for financial instruments with contingent features and additional disclosure requirements for equity instruments classified at fair value through other comprehensive income (OCI).


Annual Improvements to IFRS Accounting Standards - Volume 11


In July 2024, the IASB issued nine narrow scope amendments as part of its periodic maintenance of IFRS accounting standards. The amendments include clarifications, simplifications, corrections or changes to improve consistency in IFRS 1 First-time Adoption of International Financial Reporting Standards, IFRS 7 Financial instruments: Disclosure and its accompanying Guidance on implementing IFRS 7, IFRS 9 Financial Instruments, IFRS 10 Consolidated Financial Statements and IAS 7 Statements of Cash Flows.


Contracts Referencing Nature-dependent Electricity – Amendments to IFRS 9 and IFRS 7


In December 2024, the IASB issued Amendments to IFRS 9 and IFRS 7 - Contracts Referencing Nature1dependent Electricity. The amendments apply only to contracts that reference nature-dependent electricity; the amendments:


-Clarify the application of the ‘own-use’ requirements for in-scope contracts


-Amend the designation requirements for a hedged item in a cash flow hedging relationship for in-scope contracts


-Add new disclosure requirements to enable investors to understand the effect of these contracts on a company’s financial performance and cash flows.


F-25


Notes to the consolidated financial statements (continued)


The amendments will take effect for annual reporting periods starting on or after 1 January 2026. Early adoption is allowed, but it must be disclosed. The amendments concerning the own-use exception are to be applied retrospectively, while the hedge accounting amendments should be applied prospectively to new hedging relationships designated from the initial application date. Additionally, the IFRS 7 disclosure amendments must be implemented alongside the IFRS 9 amendments. If an entity does not restate comparative information, it cannot present comparative disclosures.


The adoption of these new regulations is not expected to have a material impact on the Group’s consolidated financial statements.


5.Transactions in foreign currency


Transactions in foreign currency take place at the open-market exchange rates published by the Superintendence of Banks, Insurance and Pension Funds Administration. As of December 31, 2025 the exchange rates for transactions in United States dollars, published by this institution, were S/3.358 for purchase and S/3.368 for sale (S/3.758 for purchase and S/3.770 for sale as of December 31, 2024).


As of December 31, 2025 and 2024, the Group had the following assets and liabilities in United States dollars:


   2025   2024 
   US$(000)   US$(000) 
         
Assets        
Cash and cash equivalents   6,508    6,690 
Trade and other receivables, net   9,578    4,800 
    16,086    11,490 
           
Liabilities          
Trade and other payables   (11,262)   (14,636)
    (11,262)   (14,636)
           
Net monetary position   4,824    (3,146)


During 2025, the net gain originated by the exchange difference was approximately S/2,619,000 (the net loss from exchange difference amounted to S/836,000 during 2024). All these results are presented in the heading “Gain (loss) from exchange difference, net” in the consolidated statement of income.


6.Cash and cash equivalents


(a)This caption was made up as follows:


   2025   2024 
   S/(000)   S/(000) 
Cash on hand   167    155 
Cash at banks (b)   37,904    48,568 
Short-term deposits (c)   15,500    24,000 
           
    53,571    72,723 


(b)Cash at banks is denominated in local and foreign currency, are deposited in local and foreign bank and are freely available. The demand deposits interest yield is based on daily bank deposit rates.


(c)The short-term deposits held in domestic banks were freely available and earned interest at the respective short-term market rates and original maturity less than three months.


F-26


Notes to the consolidated financial statements (continued)


7.Trade and other receivables


(a)This caption was made up as follows:


   Current   Non-current 
   2025   2024   2025   2024 
   S/(000)   S/(000)   S/(000)   S/(000) 
                 
Trade receivables (b)   107,496    95,419    
-
    
-
 
Contract asset (c)   26,263    26,701    
-
    
-
 
Other accounts receivable   10,269    8,613    
-
    
-
 
Funds restricted to tax payments   4,022    393    
-
    
-
 
Accounts receivable from Parent and affiliates, note 23   2,633    1,969    
-
    
-
 
Loans granted   2,130    
-
    
-
    
-
 
Loans to employees   776    910    
-
    
-
 
Interest receivable   568    963    
-
    
-
 
Other receivables from sale of fixed assets   24    139    
-
    
-
 
Allowance for expected credit losses (e) and (f)   (14,099)   (11,486)   
-
    
-
 
Financial assets classified as receivables (f)   140,082    123,621    
-
    
-
 
Other accounts receivable   
-
    
-
    16,439    13,022 
Claim to the SUNAT (d)   
-
    
-
    11,118    29,559 
Value-added tax credit   6,592    7,547    893    643 
Tax refund receivable   
-
    
-
    9,034    9,034 
Allowance for expected credit losses (e)   
-
    
-
    (9,034)   (9,034)
Non-financial assets classified as receivables   6,592    7,547    28,450    43,224 
    146,674    131,168    28,450    43,224 


(b)Trade account receivables presented net of discounts and bonuses, have current maturity (30 to 90 days) and those overdue bear interest.


(c)It corresponds mainly to paving services whose recognition is carried out according to the provisions of note 2.3.13.


(d)On March 22, 2021, the Company received Tax Court Resolution N° 00905-4-21 that declares the calculation of Mining Royalty should be based on gross sale of the final product (cement) for the years 2008 and 2009. This is an opposite position to what is established by the Constitutional Court in the STC Exp. N° 1043-2013-PA/TC that declares founded the writ of protection presented by the Company recognizing our right to calculate mining royalties exclusively based on the value of the mining component, without considering in any way the value of the final products derived from industrial and manufacturing processes.


Pursuant to this, the Company initiated two legal proceedings: (i) a constitutional process to denounce the repression of homogeneous harmful acts, filed on March 31, 2021; and, (ii) a contentious-administrative claim filed before the ordinary court, the object of which was the annulment and return of securities, filed on June 22, 2021.


To date, both processes have culminated with resolutions favorable to the Company’s claims. In this regard, the ruling issued by the Constitutional Court in the proceedings for the complaint of repression of homogeneous harmful acts, dated December 16, 2024, declares the constitutional grievance appeal well-founded and consequently the respective RTF void, ordering the Tax Court to comply with the issuance of new resolutions complying with the judgment issued in STC 1043-2013-PA/TC in the sense that the method for calculating mining royalties established therein also applies to the 2008 and 2009 fiscal years and not only from 2011 onwards, as argued by the Tax Court and the National Superintendency of Tax Administration (SUNAT).


As a consequence of said ruling, it is appropriate for the National Superintendency of Tax Administration (SUNAT), either directly or through enforcement, to proceed with the return of the amounts paid by the Company amounting to S/29,559,000, since this constitutes a direct effect of the execution of the mandate ordered by the Constitutional Court.


As of August 20, 2025, The National Superintendency of Tax Administration (SUNAT) made a partial refund of accounts receivable for mining royalties in the amount of S/18,441,000, leaving an outstanding balance of S/11,118,000 to be collected as of December 31, 2025. In the opinion of Management and its external legal advisors, there is a very high probability of obtaining a favorable outcome.


(e)The movement of the allowance for expected credit losses is as follows:


   2025   2024   2023 
   S/(000)   S/(000)   S/(000) 
             
Opening balance   20,520    18,048    16,467 
Additions, note 19   3,467    2,751    1,707 
Recoveries   (854)   (279)   (126)
                
Ending balance   23,133    20,520    18,048 


As of December 31, 2025, the additions include S/3,467,000 related to the provision for expected credit losses for trade receivables (S/2,751,000 as of December 31, 2024), which are presented in the caption “selling and distribution expenses” on the consolidated statement of profit and loss, see note 19.


F-27


Notes to the consolidated financial statements (continued)


(f)The aging analysis of trade and other accounts receivable, classified as financial assets, as of December 31, 2025 and 2024, is as follows:


           Past due but not impaired
As of December 31, 2025  Total   Neither past due nor impaired   <30 days  30-60 days   61-90 days   91-120 days   >120 days 
    S/(000)     S/(000)    S/(000)   S/(000)     S/(000)     S/(000)     S/(000)  
                                  
Expected credit loss rate   9.1%   0.4%  2.7%   7.5%   22.9%   21.2%   61.1%
Carrying amount 2025   154,181    113,149   13,522   2,889    2,741    2,362    19,518 
Expected credit loss   14,099    463   363   218    628    501    11,926 


           Past due but not impaired 
As of December 31, 2024  Total   Neither past due nor impaired   <30 days   30-60 days   61-90 days   91-120 days   >120 days 
    S/(000)     S/(000)     S/(000)     S/(000)     S/(000)     S/(000)     S/(000)  
                                    
Expected credit loss rate   8.5%   0.2%   2.0%   2.8%   2.6%   8.6%   82.5%
Carrying amount 2024   135,107    100,349    11,138    5,109    4,326    1,275    12,910 
Expected credit loss   11,486    244    228    145    114    110    10,645 


8.Inventories


(a)This caption is made up as follows:


   2025   2024 
   S/(000)   S/(000) 
         
Goods and finished products   13,214    18,234 
Work in progress   205,321    221,837 
Raw materials   209,023    254,141 
Packages and packing   4,236    3,441 
Fuel   3,894    3,552 
Spare parts and supplies   264,450    259,601 
Inventory in transit   7,005    13,191 
    707,143    773,997 


(b)Movement in the provision for inventory obsolescence value is set forth below:


   2025   2024   2023 
   S/(000)   S/(000)   S/(000) 
             
Opening balance   33,880    27,525    24,905 
Additions   1,469    6,696    2,956 
Reversal by arrangement   (7,819)   (341)   (336)
Final balance   27,530    33,880    27,525 


F-28


Notes to the consolidated financial statements (continued)


9.Property, plant and equipment


(a)The composition and movement of the item as of the date of the consolidated statement of financial position is presented below:


   Mining
concessions (b)
   Mine
development
costs
   Land   Buildings
and other
construction
   Machinery,
equipment
and related
spare parts
   Furniture
and
accessories
   Transportation
units
   Computer
equipment
and tools
   Quarry
rehabilitation
costs
   Capitalized
interest (f)
   Work in
progress
(d) and units
in transit
   Total 
    S/(000)     S/(000)     S/(000)     S/(000)     S/(000)     S/(000)     S/(000)     S/(000)     S/(000)     S/(000)     S/(000)     S/(000)  
                                                             
Cost                                                            
                                                             
As of January 1, 2024   112,098    71,090    258,584    822,229    1,883,083    11,079    105,383    45,187    16,233    74,297    46,081    3,445,344 
Additions   
-
    1,023    1,827    
-
    20,710    872    2,472    4,164    1,465    
-
    40,788    73,321 
Sales and/or retirement   (1,668)   (247)   (268)   
-
    (1,056)   (136)   (4,825)   (227)   
-
    
-
    (1,149)   (9,576)
Transfers   
-
    (8,077)   
-
    214,297    (162,491)   149    2,063    1,603    
-
    
-
    (47,778)   (234)
As of December 31, 2024   110,430    63,789    260,143    1,036,526    1,740,246    11,964    105,093    50,727    17,698    74,297    37,942    3,508,855 
                                                             
Additions   157    1,280    4,528    
-
    29,266    167    20,347    5,050    2,087    
-
    52,272    115,154 
Sales and/or retirement   (146)   (58)   (1,009)   (201)   (2,215)   (15)   (2,565)   (91)   
-
    
-
    (820)   (7,120)
Transfers   210    (136)   
-
    16,691    20,557    164    1,599    598    
-
    
-
    (39,755)   (72)
As of December 31, 2025   110,651    64,875    263,662    1,053,016    1,787,854    12,280    124,474    56,284    19,785    74,297    49,639    3,616,817 
                                                             
Accumulated depreciation                                                            
As of January 1, 2024   12,472    11,234    
-
    198,656    857,790    8,771    83,335    28,834    2,650    12,167    
-
    1,215,909 
Additions   72    424    
-
    21,858    104,237    484    5,300    4,184    167    1,646    
-
    138,372 
Sales and/or retirement   (259)   
-
    
-
    
-
    (760)   (124)   (4,339)   (207)   
-
    
-
    
-
    (5,689)
Transfers   
-
    (171)   
-
    86,734    (86,431)   
-
    
-
    
-
    
-
    
-
    
-
    132 
As of December 31, 2024   12,285    11,487    
-
    307,248    874,836    9,131    84,296    32,811    2,817    13,813    
-
    1,348,724 
                                                             
Additions   
-
    602    
-
    29,309    95,891    552    5,045    4,302    265    1,646    
-
    137,612 
Sales and/or retirement   (69)   
-
    
-
    (111)   (1,514)   (13)   (2,292)   (77)   
-
    
-
    
-
    (4,076)
As of December 31, 2025   12,216    12,089    
-
    336,446    969,213    9,670    87,049    37,036    3,082    15,459    
-
    1,482,260 
                                                             
Impairment (g)                                                            
As of January 1, 2024   52,056    24,573    3,985    31,038    12,918    200    26    454    
-
    1,413    3,421    130,084 
Lows   (1,092)   
-
    
-
    
-
    
-
    
-
    
-
    
-
    
-
    
-
    
-
    (1,092)
As of December 31, 2024   50,964    24,573    3,985    31,038    12,918    200    26    454    
-
    1,413    3,421    128,992 
                                                             
Lows   
-
    
-
    (146)   
-
    
-
    
-
    
-
    (3)   
-
    
-
    
-
    (149)
As of December 31, 2025   50,964    24,573    3,839    31,038    12,918    200    26    451    
-
    1,413    3,421    128,843 
Net book value                                                            
As of December 31, 2024   47,181    27,729    256,158    698,240    852,492    2,633    20,771    17,462    14,881    59,071    34,521    2,031,139 
                                                             
As of December 31, 2025   47,471    28,213    259,823    685,532    805,723    2,410    37,399    18,797    16,703    57,425    46,218    2,005,714 


F-29


Notes to the consolidated financial statements (continued)


(b)Mining concessions mainly include acquisitions costs related to coal concessions acquired in previous years and the cost of certain concessions acquired in January 2023 for exploration activities in areas of interest to the cement business, through the purchase of the company Corporación Materiales Piura S.A.C.


(c)The Group has assessed the recoverable value of its remaining property, plant and equipment and, except as specifically mentioned in (g), has not identified indications of impairment losses for these assets as of December 31, 2025 and 2024.


(d)Work in progress included in property, plant and equipment as of December 31, 2025 and 2024 is mainly related to complementary facilities of the cement plants.


(e)As of December 31, 2025, the Group maintains accounts payable related to the acquisition of property, plant and equipment for S/26,754,000 (S/17,122,000 as of December 31, 2024), see note 11.


(f)The borrowing costs are mainly related to the construction of the cement plant located in Piura and to a lesser extent to the construction of the Clinker Lines Optimization Project – Kiln 4 in the city of Pacasmayo. Both plants are already in operation.


(g)In previous years management recognized a full impairment related to the total net book value of a closed zinc mining unit which included concession costs, development costs and related facilities and equipment.


At the end of 2023, Management recognized a specific impairment to retirement for the net value of the assets of the vertical clinker kilns located at the Pacasmayo cement plant. This deterioration estimate was carried out as a consequence of replacing the old technology of these kilns due to the entry into operation of the Clinker Lines Optimization Project – Kiln 4 in said plant, which is more efficient and produces fewer emissions. This amount was recorded in the impairment of property, plant and equipment item in the consolidated statement of profit or loss.


Likewise, in that year, Management recognized an impairment to retirement of the value of the coal concessions (northern zone).


F-30


Notes to the consolidated financial statements (continued)


10.Intangibles assets, net


(a)The composition and movement of this caption as of the date of the consolidated statement of financial position is presented below:


   IT
applications
   Finite life
intangible
   Indefinite
life
intangible
   Exploration
cost and
mining
evaluation (b)
   Total 
   S/(000)   S/(000)   S/(000)   S/(000)   S/(000) 
Cost                    
                     
As of January 1, 2024   71,207    24,543    1,975    52,846    150,571 
Additions   15,357    
-
    
-
    1,412    16,769 
Sales and/or retirement   (158)   
-
    
-
    (887)   (1,045)
Transfers and reclassifications   805    
-
    
-
    (571)   234 
As of December 31, 2024   87,211    24,543    1,975    52,800    166,529 
                          
Additions   15,304    
-
    
-
    543    15,847 
Sales and/or retirement   (160)   
-
    
-
    (155)   (315)
Transfers and reclassifications   72    
-
    
-
    
-
    72 
As of December 31, 2025   102,427    24,543    1,975    53,188    182,133 
                          
Accumulated amortization                         
As of January 1, 2024   30,243    13,073    71    9,887    53,274 
Additions   12,620    2,454    
-
    340    15,414 
Transfers   
-
    
-
    
-
    (132)   (132)
As of December 31, 2024   42,863    15,527    71    10,095    68,556 
                          
Additions   14,020    2,454    
-
    76    16,550 
Sales and/or retirement   
-
    
-
    
-
    (150)   (150)
As of December 31, 2025   56,883    17,981    71    10,021    84,956 
                          
Impairment (c)                         
                          
As of January 1, 2024   456    
-
    
-
    33,921    34,377 
                          
As of December 31, 2024   456    
-
    
-
    33,921    34,377 
                          
As of December 31, 2025   456    
-
    
-
    33,921    34,377 
                          
Net Carrying Value                         
As of December 31, 2024   43,892    9,016    1,904    8,784    63,596 
                          
As of December 31, 2025   45,088    6,562    1,904    9,246    62,800 


(b)As of December 31, 2025 and 2024, the exploration cost and mining evaluation include mainly capital expenditures related to the coal project and to other minor projects related to the cement business.


(c)As of December 31, 2025 and 2024, the Group evaluated the conditions of use of the projects related to the exploration and mining evaluation costs and its other intangibles, not finding any indicators of impairment in said assets.


F-31


Notes to the consolidated financial statements (continued)


11.Trade and other payables


(a)This balance is made up as follows:


   2025   2024 
    S/(000)     S/(000)  
           
Trade payables (b)   94,657    96,549 
Taxes and contributions   54,393    18,747 
Remuneration payable   28,757    36,405 
Interest payable (d)   26,954    28,280 
Accounts payable related to the acquisition of property, plant and equipment, note 9(e)   26,754    17,122 
Advances from customers   12,118    10,380 
Dividends payable, note 15(g)   11,823    11,097 
Board of Directors’ fees   4,790    5,243 
Guarantee deposits   3,741    3,242 
Accounts payable to the principal and affiliates, note 23   
-
    23 
Other accounts payable   19,920    14,963 
    283,907    242,051 


(b)Trade accounts payable result from the purchases of material, services and supplies for the Group’s operations, and mainly correspond to invoices payable to domestic suppliers. Trade payables are non-interest bearing and are normally settled within 60 to 120 days term.


(c)Other payables are non-interest bearing and have an average term of 3 months.


(d)Interest payable is normally settled semiannually throughout the financial year.


F-32


Notes to the consolidated financial statements (continued)


12.Provisions


(a)This balance is made up as follows:


   Workers’
profit-sharing
(b)
   Long-term incentive plan
(c)
   Quarry
Rehabilitation
provision
(d)
   Provision of legal
contingencies
   Total 
   S/(000)   S/(000)   S/(000)   S/(000)   S/(000) 
                     
At January 1, 2024   34,328    29,683    17,676    2,276    83,963 
Additions (b) and note 20   39,223    7,167    
-
    
-
    46,390 
Exchange difference   
-
    
-
    234    
-
    234 
Unwinding of discounts, note 22   
-
    431    125    
-
    556 
Change in estimate   
-
    
-
    1,250    
-
    1,250 
Payments and advances   (35,288)   (23,343)   (280)   (1,073)   (59,984)
At December 31, 2024   38,263    13,938    19,005    1,203    72,409 
                          
Current portion   38,263    6,000    
-
    
-
    44,263 
Non-current portion   
-
    7,938    19,005    1,203    28,146 
    38,263    13,938    19,005    1,203    72,409 
                          
At January 1, 2025   38,263    13,938    19,005    1,203    72,409 
Additions (b) and note 20   45,352    4,925    
-
    
-
    50,277 
Exchange difference   
-
    
-
    (1,827)   
-
    (1,827)
Unwinding of discounts, note 22   
-
    860    152    
-
    1,012 
Change in estimate   
-
    
-
    2,267    
-
    2,267 
Payments and advances   (39,251)   (7,190)   (1,003)   
-
    (47,444)
At December 31, 2025   44,364    12,533    18,594    1,203    76,694 
                          
Current portion   44,364    3,325    
-
    
-
    47,689 
Non-current portion   
-
    9,208    18,594    1,203    29,005 
    44,364    12,533    18,594    1,203    76,694 


F-33


Notes to the consolidated financial statements (continued)


(b)Workers’ profit sharing -


In accordance with Peruvian legislation, the Group is obliged to pay its employees profit sharing of between 8% and 10% of annual taxable income. Distributions to employees under the plan are based 50% on the number of days that each employee worked during the preceding year and 50% on proportionate annual salary levels.


The workers’ profit sharing is recognized in the following line items:


   2025   2024   2023 
   S/(000)   S/(000)   S/(000) 
             
Cost of sales, note 20   21,094    19,334    15,244 
Administrative expenses, note 20   20,891    15,669    15,210 
Selling and distribution expenses, note 20   3,270    4,139    3,804 
Investment   97    81    1,000 
                
    45,352    39,223    35,258 


(c)Long-term incentive plan -


In 2011, the Group implemented a compensation plan for its key management. This long-term benefit is payable in cash, based on the salary of each officer and depends on the years of service of each officer in the Group. According to the latest plan update, the executive would receive the equivalent of an annual salary for each year of service beginning to accrue from 2019. This benefit accrues and accumulates for each officer and is payable in two installments: the first payment will be made on the sixth year after the creation of this bonus plan, and the last payment will be made on the ninth year from the creation of the plan. If the executive decides to voluntarily leave the Group before a scheduled distribution, they will not receive this compensation. The Group used the Projected Unit Credit Method to determine the present value of this deferred obligation and the related current deferred cost, considering the expected increases in salary base and the corresponding current government bond discount rate (risk-free rate).


(d)Quarry Rehabilitation provision -


As of December 31, 2025 and 2024, it corresponds to the provision for the future costs of rehabilitating the quarries exploited in Group operations. The provision has been created based on studies made by internal specialists. Management believes that the assumptions used, based on current economic environment, are a reasonable basis upon which to estimate the future liability. These estimates are reviewed regularly to consider any material change to the assumptions. However, actual quarry rehabilitation costs will ultimately depend upon future market prices for the necessary decommissioning works required to reflect future economic conditions.


Future cash flows have been estimated based on financial budgets approved by Management. The range of the risk-free discount rate in dollars used in the calculation of the provision as of December 31, 2025 was from 0.49 to 4.84 percent (from 0.53 to 4.86 percent as of December 31, 2024).


Management expects to incur a significant part of this obligation in the medium and long-term. The Group estimates that this liability is sufficient according to the current environmental protection laws approved by the Ministry of Energy and Mines of Peru.


F-34


Notes to the consolidated financial statements (continued)


13.Financial obligations


(a)This caption is made up as follows:


   Currency  Nominal
interest rate
   Maturity  2025   2024 
             S/(000)   S/(000) 
                   
Short -term promissory notes                  
Banco GNB Perú  S/   5.00%  January 8, 2026   19,000    
-
 
Interbank  S/   5.07%  January 8, 2026   57,000    
-
 
Interbank  S/   4.92%  February 15, 2026   38,000    
-
 
Scotiabank  S/   4.70%  March 5, 2026   37,200    
-
 
Banco de Crédito del Perú  S/   4.82%  May 22, 2026   36,000    
-
 
Banco de Crédito del Perú  S/   4.72%  November 12, 2026   38,000    
-
 
BBVA Perú  S/   4.64%  November 24, 2026   38,000    
-
 
Banco de Crédito del Perú  S/   4.58%  November 26, 2026   38,000    
-
 
Banco de Crédito del Perú  S/   4.53%  November 30, 2026   76,000    
-
 
Banco de Crédito del Perú  S/   6.51%  January 13, 2025   
-
    38,000 
Banco de Crédito del Perú  S/   6.51%  January 16, 2025   
-
    38,000 
Banco de Crédito del Perú  S/   6.35%  February 21, 2025   
-
    38,000 
Scotiabank  S/   5.94%  March 10, 2025   
-
    37,200 
Banco GNB Perú  S/   4.88%  November 17, 2025   
-
    38,000 
Banco de Crédito del Perú  S/   4.85%  November 24, 2025   
-
    38,000 
Banco de Crédito del Perú  S/   4.85%  December 5, 2025   
-
    76,000 
               377,200    303,200 
                      
Senior Notes (b)                     
Principal, net of issuance costs  S/   6.69%  February 1, 2029   259,810    259,748 
Principal, net of issuance costs  S/   6.84%  February 1, 2034   309,604    309,555 
               569,414    569,303 
                      
Short and long-term Corporate Loan under “Club deal” (c)                     
Banco de Crédito del Perú  S/   5.82%  December 1,2028   232,771    310,344 
Scotiabank  S/   5.82%  December 1,2028   232,770    310,344 
               465,541    620,688 
               1,412,155    1,493,191 
Maturity                     
Current              532,346    458,346 
Non-current              879,809    1,034,845 
               1,412,155    1,493,191 


F-35


Notes to the consolidated financial statements (continued)


(b)Senior Notes-


(b.1)Senior Notes


On January 31, 2019, senior notes were issued in soles for S/260,000,000 at a rate of 6.688 percent per year and maturity of 10 years and; 15 years bonds for S/310,000,000 at a rate of 6.844 percent per year.


The Senior Notes in soles issued in 2019 are guaranteed by the following Company’s subsidiaries: Cementos Selva S.A.C., Distribuidora Norte Pacasmayo S.R.L., Empresa de Transmisión Guadalupe S.A.C. and Dinoselva Iquitos S.A.C.


(b.2)Financial covenants


The corporate bond contracts have the following covenants to limiting the incurring of indebtedness for the Company and its collateral subsidiaries, which are measured prior to the following transactions: issuance of debt or equity instruments, merger with another company or disposition or rental of significant assets. The covenants are the following:


-A fixed charge covenant ratio of at least 2.5 to 1.


-A consolidated debt-to-EBITDA ratio of no greater than 3.5 to 1.


As of December 31, 2025 and 2024, these covenants have not been activated because no situation has occurred that requires their measurement, as indicated in the previous paragraph.


For the years ended December 31, 2025, 2024 and 2023, senior notes generated interest that have been recognized in the consolidated statement of profit or loss for S/38,603,000, S/38,603,000 and S/38,690,000, respectively, see note 22.


(c)Medium-term Corporate Loan under “Club Deal” modality:


On August 6, 2021, the Company established the conditions of a medium-term corporate loan under “Club Deal” modality with Banco de Crédito del Perú S.A. and Scotiabank Perú S.A.A. The loan amounts to S/860,000,000 that allowed the payment of all the financial obligations that the Company maintains with a maturity until February 2023. The loan conditions include a grace/availability period of 18 months from August 6 and a payment term of 7 years from the last disbursement, which was in February 2023. Since that date, the loan will be paid in 22 equal quarterly installments and has an annual interest rate of 5.82 percent.


As part of the loan conditions, the Company assumed the following obligations:


I.Comply with the following financial covenants:


a.Debt Ratio (Financial Debt / EBITDA) <= 3.50x


b.Debt Service Coverage Ratio (CFDS / DS) >= 1.15x


c.Debt Service Coverage Ratio (EBITDA / DS) >= 1.50x


These financial safeguards are calculated and verified at the end of each calendar quarter, considering the information of the consolidated financial statements of the Company for the last 12 months, prepared in accordance with IFRS.


As of December 31, 2025 and 2024, the Company complies with the ratios contained in the conditions of the Club Deal and corporate bonds and have certain do’s and don’ts obligations that have been complying with to date.


F-36


Notes to the consolidated financial statements (continued)


14.Deferred income tax assets and liabilities


The following is the composition of the caption according to the items that originated it:


   As of
January 1,
2024
   Effect on
profit or
loss
   Effect on
OCI
   Quarry
rehabilitation
provision
   As of
December 31,
2024
   Effect on
profit or
loss
   Effect on
OCI
   Additions
about
IFRS 16
   As of
December 31,
2025
 
   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000) 
                                     
Movement of deferred income tax assets:                                    
Deferred income tax assets                                             
Impairment of investments in subsidiary   
-
    7,375    
-
    
-
    7,375    10,325    
-
    
-
    17,700 
Provision of discounts and bonuses to customers   1,864    827    
-
    
-
    2,691    1,930    
-
    
-
    4,621 
Provision for expected credit losses on trade accounts receivable   2,561    730    
-
    
-
    3,291    770    
-
    
-
    4,061 
Provision for vacations   2,215    243    
-
    
-
    2,458    269    
-
    
-
    2,727 
Effect of differences between book and tax bases of inventories   55    808    
-
    
-
    863    489    
-
    
-
    1,352 
Lease liability   441    (297)   
-
    
-
    144    (443)   
-
    1,558    1,259 
Effect of differences between book and tax bases of fixed assets   1,276    2    
-
    
-
    1,278    (124)   
-
    
-
    1,154 
Legal claim contingency   461    (148)   
-
    
-
    313    
-
    
-
    
-
    313 
Estimate for devaluation of spare parts and supplies   422    177    
-
    
-
    599    (343)   
-
    
-
    256 
Others   2,431    417    
-
    
-
    2,848    (55)   
-
    
-
    2,793 
    11,726    10,134    
-
    
-
    21,860    12,818    
-
    1,558    36,236 
Deferred income tax liabilities                                             
Right of use assets   (315)   254    
-
    
-
    (61)   360    
-
    (1,558)   (1,259)
Others   17    
-
    
-
    
-
    17    
-
    
-
    
-
    17 
    (298)   254    
         -
    
        -
    (44)   360    
     -
    (1,558)   (1,242)
Total deferred income tax liabilities, net   11,428    10,388    
-
    
-
    21,816    13,178    
-
    
-
    34,994 


F-37


Notes to the consolidated financial statements (continued)


   As of
January 1,
2024
   Effect on
profit
or loss
   Effect
on OCI
   Quarry
rehabilitation
provision
   As of
December 31,
2024
   Effect on
profit
or loss
   Effect
on OCI
   Quarry
rehabilitation
provision /
Additions
about IFRS 16
   As of
December 31,
2025
 
   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000) 
                                     
Movement of deferred income tax liabilities:                                    
Deferred income tax assets                                             
Project deterioration Salmueras   18,245    192    
-
    
-
    18,437    261    
-
    
-
    18,698 
Impairment of fixed assets   8,928    (322)   
-
    
         -
    8,606    (365)   
-
    
-
    8,241 
Financial instrument at fair value with changes in other comprehensive income   6,814    
-
    109    
-
    6,923    
-
    173    
-
    7,096 
Estimate for depreciation of spare parts and supplies   6,683    1,725    
-
    
-
    8,408    (1,531)   
-
    
-
    6,877 
Estimation for impairment of mining assets   7,380    (295)   
-
    
-
    7,085    (491)   
-
    
-
    6,594 
Provision for quarry closure   5,738    (532)   
-
    439    5,645    235    
-
    615    6,495 
Provision for vacations   4,220    176    
-
    
-
    4,396    398    
-
    
-
    4,794 
Provision for compensation to officials   8,756    (4,645)   
-
    
-
    4,111    (415)   
-
    
-
    3,696 
Lease liability   1,226    708    
-
    
-
    1,934    (1,468)   
-
    2,357    2,823 
Provision for expected credit losses on trade accounts receivable   1,107    (69)   
-
    
-
    1,038    (937)   
-
    
-
    101 
Legal claim contingency   210    (169)   
-
    
-
    41    
-
    
-
    
-
    41 
Others   1,446    1,500    
-
    
-
    2,946    (2,357)   
-
    
-
    589 
    70,753    (1,731)   109    439    69,570    (6,670)   173    2,972    66,045 
Deferred income tax liabilities                                             
Effect of the difference between accounting and tax bases of fixed assets and the difference in depreciation rates   (188,410)   4,867    
-
    (439)   (183,982)   3,616    
-
    (615)   (180,981)
Right of use assets   (1,197)   (698)   
-
    
-
    (1,895)   1,211    
-
    (2,357)   (3,041)
Effect of costs incurred from bond issuance   (1,980)   392    
-
    
-
    (1,588)   392    
-
    
-
    (1,196)
Others   (42)   
-
    
-
    
-
    (42)   (17)   
-
    
-
    (59)
    (191,629)   4,561    
-
    (439)   (187,507)   5,202    
-
    (2,972)   (185,277)
Total deferred income tax liabilities, net   (120,876)   2,830    109    
-
    (117,937)   (1,468)   173    
 
    (119,232)
         13,218    109              11,710    173           


F-38


Notes to the consolidated financial statements (continued)


The Group offsets tax assets and liabilities if and only if it has a legally enforceable right to set off current tax assets and current tax liabilities, and the tax assets and deferred tax liabilities relate to income taxes levied by the same tax authority. The legal right is defined for each individual determination of the income tax of the Company and its Subsidiaries.


A reconciliation between tax expense and the product of the accounting profit multiplied by Peruvian tax rate for the years ended December 31, 2025, 2024 and 2023 are as follows:


   2025   2024   2023 
   S/(000)   S/(000)   S/(000) 
                
Profit before income tax   267,975    296,187    245,708 
Income tax expense calculated at the statutory income tax rate of 29.5%   (79,053)   (87,375)   (72,484)
                
Permanent differences               
Non-deductible expenses, net   (29,824)   (3,114)   (2,369)
Effect of tax-loss carry forward not recognized   (4,893)   (6,823)   (1,955)
Total income tax   (113,770)   (97,312)   (76,808)


The components of the deferred income tax related to the items recognized in the consolidated statements of profit or loss during the years ended December 31, 2025, 2024 and 2023, are as follow:


   2025   2024   2023 
   S/(000)   S/(000)   S/(000) 
             
Consolidated statement of profit or loss               
Current   (125,480)   (110,530)   (100,617)
Deferred   11,710    13,218    23,809 
                
    (113,770)   (97,312)   (76,808)


As of December 31, 2025, 2024 and 2023, the Group had not recognized a deferred tax liability for taxes that would be payable on the unremitted earnings of the Group’s subsidiaries. The Group has determined that the timing differences will be reversed by means of dividends to be received in the future that, according to the current tax rules in effect in Peru, are not subject to income tax.


As of December 31, 2025, certain subsidiaries of the Group had tax loss carryforwards of S/128,609,000 (2024 S/92,998,000). These tax loss carryforwards do not expire, are related to subsidiaries that have a history of losses for some time and cannot be used to offset future taxable profits of other Group subsidiaries. No deferred tax assets have been recognized in relation to these tax loss carryforwards, since there are no possibilities of tax planning opportunities or other evidence of recovery in the near future.


For information purposes, in the year 2025, the temporary difference associated with investments in subsidiaries, would generate an aggregate deferred tax liability amounting to S/89,541,000 (2024: S/102,730,000), which should not be recognized in the consolidated financial statements as it is not expected to reverse in the foreseeable future and the Company is in control of such reversal.


F-39


Notes to the consolidated financial statements (continued)


15.Equity


(a)Capital stock -


As of December 31, 2025 and 2024, share capital was represented by 423,868,449 authorized common shares subscribed and fully paid, with a nominal value of one Soles per share. As of December 31, 2025, the total outstanding common shares were as follows; 35,458,546 were listed on the New York Stock Exchange and 388,409,903 were listed on the Lima Stock Exchange. As of December 31, 2024, the total outstanding common shares were as follows; 34,103,766 were listed on the New York Stock Exchange and 389,764,683 were listed on the Lima Stock Exchange


(b)Investment shares -


Investment shares do not have voting rights or participate in shareholder’s meetings or the appointment of directors. Investment shares confer upon the holders thereof the right to participate in dividends distributed according to their nominal value, in the same manner as common shares. Investment shares also confer the holders thereof the right to:


(i)maintain the current proportion of the investment shares in the case of capital increase by new contributions;


(ii)increase the number of investment shares upon capitalization of retained earnings, revaluation surplus or other reserves that do not represent cash contributions;


(iii)participate in the distribution of the assets resulting from liquidation of the Company in the same manner as common shares; and,


(iv)redeem the investment shares in case of a merger and/or change of business activity of the Company.


As of December 31, 2025 and 2024, the Company had 40,278,894 investment shares subscribed and fully paid, with a nominal value of one Sol per share.


(c)Treasury shares -


As of December 31, 2025 and 2024, the Company maintains 36,040,497 investment shares held in treasury amounting to S/121,258,000.


(d)Additional paid-in capital -


As of December 31, 2025 and 2024, the additional capital amounted to S/432,779,000 and arises mainly as a result of the excess of total proceeds obtained versus par value in the issuance of 111,484,000 common shares and 927,783 investment shares corresponding to a public offering of American Depositary Shares (ADS) registered with the New York Stock Exchange and Lima Stock Exchange.


(e)Legal reserve -


The General Corporation Law require that a minimum of 10 per cent of the distributable earnings for each period, after deducting the income tax, be transferred to a legal reserve until such is equal to 20 per cent of the capital. This legal reserve can offset losses or can be capitalized, and in both cases, there is the obligation to replenish it.


(f)Other accumulated comprehensive results -


This reserve records changes in the fair value of financial instruments at fair value through OCI.


(g)Distributions made and proposed –


   2025   2024   2023 
Common stock dividends               
Approval date by Board of Directors   October 21, 2025    October 28, 2024    November 7, 2023 
                
Declared dividends per share to be paid in cash S/.   0.41000    0.41000    0.41000 
Declared dividends S/(000):   175,524    175,524    175,524 


As of December 31, 2025 and 2024, dividends payable amounted to S/11,823,000 and S/11,097,000, respectively, see note 11.


F-40


Notes to the consolidated financial statements (continued)


16.Sales of goods
  
 This caption is made up as follows:


   For the year ended of December 31, 2025 
   Cement   Concrete,
pavement and
mortar
   Precast   Construction
supplies
   Other   Total 
   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000) 
Segments                        
Sale of cement, concrete, pavement, mortar and precast  1,745,234   288,420   31,020  
-
  
-
   2,064,674 
Sale of construction supplies 
-
  
-
  
-
   41,745  
-
   41,745 
Sale of other 
-
  
-
  
-
  
-
   10,464   10,464 
                         
   1,745,234   288,420   31,020   41,745   10,464   2,116,883 
                         
Timing of revenue recognition                        
Goods and services transferred at a point in time  1,745,234   254,090   31,020   41,745   9,954   2,082,043 
Services transferred over time 
-
   34,330  
-
  
-
   510   34,840 
Total revenues from contracts with customers  1,745,234   288,420   31,020   41,745   10,464   2,116,883 


   For the year ended of December 31, 2024 
   Cement   Concrete,
pavement and
mortar
   Precast   Construction
supplies
   Other   Total 
   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000) 
Segments                        
Sale of cement, concrete, pavement, mortar and precast  1,605,472   271,276   30,101  
-
  
-
   1,906,849 
Sale of construction supplies 
-
  
-
  
-
   56,873  
-
   56,873 
Sale of other 
-
  
-
  
-
  
-
   14,349   14,349 
                         
   1,605,472   271,276   30,101   56,873   14,349   1,978,071 
                         
Timing of revenue recognition                        
Goods and services transferred at a point in time  1,605,472   183,686   30,101   56,873   14,349   1,890,481 
Services transferred over time 
-
   87,590  
-
  
-
  
-
   87,590 
Total revenues from contracts with customers  1,605,472   271,276   30,101   56,873   14,349   1,978,071 


   For the year ended of December 31, 2023 
   Cement   Concrete,
pavement and
mortar
   Precast   Construction
supplies
   Other   Total 
   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000) 
Segments                        
Sale of cement, concrete, pavement, mortar and precast  1,642,420   182,278   25,540  
-
  
-
   1,850,238 
Sale of construction supplies 
-
  
-
  
-
   74,096  
-
   74,096 
Sale of other 
-
  
-
  
-
  
-
   25,741   25,741 
                         
   1,642,420   182,278   25,540   74,096   25,741   1,950,075 
                         
Timing of revenue recognition                        
Goods and services transferred at a point in time  1,642,420   161,222   25,540   74,096   25,741   1,929,019 
Services transferred over time 
-
   21,056  
-
  
-
  
-
   21,056 
Total revenues from contracts with customers  1,642,420   182,278   25,540   74,096   25,741   1,950,075 


For all segments the terms of payment are usually between 30 and 90 days from the date of dispatch.


For all segments, the amounts presented as sales of the different products are already net of discounts and bonuses.


F-41


Notes to the consolidated financial statements (continued)


17.Cost of sales
  
 This caption is made up as follows:


   2025   2024   2023 
   S/(000)   S/(000)   S/(000) 
Beginning balance of goods and finished products   19,916    16,916    20,037 
Beginning balance of work in progress   222,492    174,224    186,937 
Consumption of miscellaneous supplies   338,964    395,718    429,069 
Maintenance and third-party services   273,814    282,045    244,722 
Shipping costs   184,307    166,134    177,393 
Depreciation and amortization   136,301    134,322    125,494 
Personnel expenses, note 20(b)   188,685    158,103    125,318 
Costs of packaging   55,745    54,889    66,456 
Other manufacturing expenses   110,501    109,602    76,337 
Ending balance of goods and finished products   (14,732)   (19,916)   (16,916)
Ending balance of work in progress   (205,976)   (222,492)   (174,224)
    1,310,017    1,249,545    1,260,623 


18.Administrative expenses
  
 This caption is made up as follows:


   2025   2024   2023 
   S/(000)   S/(000)   S/(000) 
Personnel expenses, note 20(b)   164,987    136,776    125,072 
Third-party services   81,838    74,127    67,187 
Depreciation and amortization   17,450    17,107    15,258 
Donations   7,533    8,598    9,028 
Board of Directors compensation   5,389    6,032    5,941 
Consumption of supplies   1,862    1,526    1,551 
Other   12,479    9,217    7,930 
    291,538    253,383    231,967 


F-42


Notes to the consolidated financial statements (continued)


19.Selling and distribution expenses
  
 This caption is made up as follows:


   2025   2024   2023 
   S/(000)   S/(000)   S/(000) 
Personnel expenses, note 20(b)   49,030    43,700    41,642 
Third-party services   18,623    19,705    15,720 
Advertising and promotion   15,590    9,140    7,548 
Depreciation   5,715    5,953    2,744 
Allowance for expected credit losses, note 7(e)   3,467    2,751    1,707 
Other   360    161    208 
    92,785    81,410    69,569 


20.Employee benefits expenses
  
 (a) Employee benefits expenses are made up as follow:


   2025   2024   2023 
   S/(000)   S/(000)   S/(000) 
Wages and salaries   234,296    186,293    162,252 
Social contributions   47,517    39,241    33,868 
Workers ‘profit sharing, note 12(b)   45,255    39,142    34,258 
Legal bonuses   29,120    27,205    23,013 
Vacations   26,186    23,567    22,226 
Cessation payments   10,182    12,513    6,308 
Long-term incentive plan, note 12   4,925    7,167    7,632 
Training   3,447    2,297    1,332 
Other   1,993    1,496    1,143 
    402,921    338,921    292,032 


(b)Employee benefits expenses are allocated as follows:


   2025   2024   2023 
   S/(000)   S/(000)   S/(000) 
Cost of sales, note 17   188,685    158,103    125,318 
Administrative expenses, note 18   164,987    136,776    125,072 
Selling and distribution expenses, note 19   49,030    43,700    41,642 
Miscellaneous expenses   219    342    
-
 
    402,921    338,921    292,032 


F-43


Notes to the consolidated financial statements (continued)


21.Other operating expenses, net
  
 This caption is made up as follows:


   2025   2024   2023 
   S/(000)   S/(000)   S/(000) 
Expenses associated with the acquisition of Holcim   (77,625)   
-
    
-
 
Impairment to retirement of the value of the coal concessions (northern zone), note 9(g)   
-
    
-
    (11,393)
Others income (loss)   2,183    (2,700)   (2,417)
    (75,442)   (2,700)   (13,810)


22.Finance costs
  

This caption is made up as follows:


   2025   2024   2023 
   S/(000)   S/(000)   S/(000) 
Interest on Club Deal promissory note and loan, note 13(c)   48,471    59,077    59,643 
Interest on senior notes, note 13 (b.2)   38,603    38,603    38,690 
Tax interest   2,143    11    166 
Amortization of issuance costs of senior notes   1,328    1,328    1,249 
Interest on lease liabilities   1,141    730    573 
Financial cost of cash flow hedging instruments   
-
    
-
    1,730 
Counterparty credit risk in cross currency swaps   
-
    
-
    12 
Interest for bank overdraft   
-
    
-
    31 
Other   338    3    127 
                
Total interest expense   92,024    99,752    102,221 
Unwinding of discount of provisions, note 12   1,012    556    1,824 
    93,036    100,308    104,045 


F-44


Notes to the consolidated financial statements (continued)


23.Related parties
  
 Transactions with related entities -
  
 During 2025, 2024 and 2023, the Group carried out the following transactions with its parent company Inversiones ASPI S.A. and its other related parties:


   2025   2024   2023 
   S/(000)   S/(000)   S/(000) 
Income            
Parent            
Inversiones ASPI S.A. (ASPI)               
Fees for management and administrative services   158    88    88 
Income from office lease   15    16    16 
                
Other related parties               
Compañía Minera Ares S.A.C. (Ares)               
Income from land lease, note 25   1,151    1,224    1,150 
Income from parking leases   398    357    259 
                
Fosfatos del Pacífico S.A. (Fospac)               
Fees for management and administrative services   287    144    143 
Income from office lease   15    16    16 
                
Fossal S.A.A.(Fossal)               
Fees for management and administrative services   64    44    44 
Income from office lease   15    16    16 
                
Asociación Sumac Tarpuy               
Income from office lease   15    16    16 
Fees for management and administrative services   11    
-
    
-
 
                
Inversiones Moray S.A.C               
Fees for management and administrative services   20    
-
    
-
 
Income from office lease   13    
-
    
-
 
                
Expense               
Other related parties               
Security services provided by Compañía Minera Ares S.A.C.   (3,023)   (2,570)   (1,940)


F-45


Notes to the consolidated financial statements (continued)


As a result of these transactions, the Group had the following rights and obligations as of December 31, 2025 and 2024:


   2025   2024 
   Accounts
receivable
   Accounts
payable
   Accounts
receivable
   Accounts
payable
 
   S/(000)   S/(000)   S/(000)   S/(000) 
Parent                   
Inversiones ASPI S.A.   
-
  
-
    115    
-
 
    
-
  
-
    115    
-
 
                    
Other related parties                   
Fosfatos del Pacífico S.A.   1,885  
-
    1,409    23 
Compañía Minera Ares S.A.C.   350  
-
    231    
-
 
Fossal S.A.A.   227  
-
    126    
-
 
Other   171  
-
    88    
-
 
    2,633  
-
    1,854    23 
    2,633  
-
    1,969    23 


Terms and conditions of transactions with related parties - Sales and purchases with related parties are made under market conditions equivalent to those applied to transactions between independent parties. Outstanding balances with related parties at the year-end are unsecured and interest free and settlement occurs in cash. For the years ended December 31, 2025, 2024 and 2023, the Group had not recorded an allowance for expected credit losses relating to amounts owed by related parties. This assessment is undertaken each financial year through examining the financial position of the related party and the market in which the related party operates. Lease transactions with related parties are described in note 25.


Compensation of key management personnel of the Group – The compensation paid to key management personnel of the Group includes expenses for profit-sharing, compensation and other concepts for members of the Board of Directors and the key management. For the year ended December 31, 2025, the total short-term compensation amounted to S/29,493,000 (2024 S/27,704,000 and 2023: S/28,922,000) and the total long-term compensations expense amounted to S/4,925,000 (2024 S/7,167,000 and 2023: S/7,632,000), and there were no post-employment or contract termination benefits or share-based payments.


Likewise, the expenses associated with Holcim´s acquisition presented in note 21, correspond primarily to bonuses awarded to key management.


F-46


Notes to the consolidated financial statements (continued)


24.Earnings per share (EPS)


Basic earnings per share amounts are calculated by dividing the profit for the year by the weighted average number of common shares and investment shares outstanding during the year.


The Group does not have potential common shares with a dilutive effect as of December 31, 2025, 2024 and 2023.


The calculation of basic earnings per share is shown below:


   2025   2024   2023 
   S/(000)   S/(000)   S/(000) 
Numerator            
Net profit attributable to the owners of the Holding Company  154,205   198,875   168,900 
Denominator            
Weighted average number of common and investment shares (thousands)  428,107   428,107   428,107 
Basic profit for common and investment shares  0.36   0.46   0.39 


There have been no other transactions involving common shares or investment shares between the reporting date and the date of the authorization of these consolidated financial statements.


25.Commitments and contingencies


Operating lease commitments – Group as lessor


As of December 31, 2025 and 2024, the Group, as lessor, has a land lease with Compañía Minera Ares S.A.C. a related party of Inversiones ASPI S.A. This lease is renewable annually, and provided an annual rent expense for the years ended December 31, 2025, 2024 and 2023 of S/1,151,000, S/1,224,000, and S/1,150,000, respectively; see note 23.


Consortium contract –


On December 19, 2022, Distribuidora Norte Pacasmayo S.R.L., subsidiary of the Group, subscribed a collaboration contract, with the purpose to participate in the project “Mejoramiento del Sistema de Pistas y Cerco Perimétrico del Aeropuerto de Piura”. As of December 31, 2025, the project has been completed.


Capital commitments


As of December 31, 2025 and 2024, the Group had no significant capital commitments.


F-47


Notes to the consolidated financial statements (continued)


Usufruct Concessions


In December 2013, the Company signed an agreement with a third party, related to the use of the Virrilá concession, to carry out other non-metallic mining activities related to cement production. This agreement has a term of 30 years, with fixed annual payments of US$600,000 for the first three years and variable payments for the rest of the contract. The related expense for the years 2025, 2024 and 2023 amounted to S/5,627,000, S/5,546,000 and S/5,273,000 respectively, and was recognized as part of cost of inventory production. As part of this agreement, the Company is required to pay an equivalent amount of S/4.5 for each metric ton of calcareous extracted that is indexed by inflation after the first year of exploitation; the annual royalty may not be less than the equivalent to 850,000 metric tons after the beginning of the fourth year of production.


The Company signed an agreement with two third parties in October 2007, related to usufruct of the Bayovar 4 concession for an indefinite period to extract seashells and other minerals. As consequence, the Group made payments amounting to US$250,000 for each third party for the first five years and variable payments for the rest of the contract. The related expense as of December 31, 2025 and 2024 amounted to S/1,419,000 and S/1,553,000, respectively, and were recognized as part of the cost of inventory production. As part of this agreement, the Company is required to pay an equivalent amount of US$5.1 to each third party for every metric ton of calcareous extracted, with the minimum production level for the calculation of 20,000 metric tons every six months following the beginning of the sixth year of production.


Mining royalty


According with the Royalty Mining Law in force since October 1, 2011, the royalty for the exploitation of metallic and nonmetallic resources is payable on a quarterly basis in an amount equal to the greater of: (i) an amount determined in accordance with a statutory scale of rates based on operating profit margin that is applied to the quarterly operating profit, adjusted by certain items, and (ii) 1% of net sales, in each case during the applicable quarter. These amounts are estimated based on the separated financial statements of Cementos Pacasmayo S.A.A. and each of the subsidiaries affected by this mining royalty, prepared in accordance with IFRS. Mining royalty payments will be deductible for income tax purposes in the fiscal year in which such payments are made.


Mining royalty expense paid to the Peruvian Government for 2025, 2024 and 2023 amounted to S/1,497,000, S/1,266,000 and S/983,000, respectively, and is recognized as part of the cost of inventory production.


F-48


Notes to the consolidated financial statements (continued)


Tax situation


The Company and its subsidiaries are subject to Peruvian tax law. As of December 31, 2025, 2024 and 2023, the income tax rate is 29.5 percent of the taxable profit after deducting employee participation, which is calculated at a rate of 8 to 10 percent of the taxable income.


For purposes of determining income tax, transfer pricing for transactions with related companies and companies resident in territories with low or no taxation, must be supported with documentation including information on the valuation methods used and the criteria considered for determination. Based on the operations of the Group, Management and its legal advisors believe that as a result of the application of these standards will not result in significant contingencies for the Group as of December 31, 2025 and 2024.


The tax authority has the power to review and, if applicable, adjust the income tax calculated by each company in the four years subsequent after the year of filing the tax return.


The statements of income tax and value added tax corresponding to the years indicated in the attached table are subject to review by the tax authorities:


   Years open to review by Tax Authority
Entity  Income tax  Value-added tax
Cementos Pacasmayo S.A.A.  2022– 2025  Dec.2021-Dec.2025
Cementos Selva S.A.C.  2021 – 2025  Dec.2021-Dec.2025
Distribuidora Norte Pacasmayo S.R.L.  2021 – 2025  Dec.2021-Dec.2025
Empresa de Transmisión Guadalupe S.A.C.  2021 – 2025  Dec.2021-Dec.2025
Salmueras Sudamericanas S.A.  2021 – 2025  Dec.2021-Dec.2025
Calizas del Norte S.A.C. (liquidated during 2022)  2021 – 2022  Dec.2021-Dec.2022
Soluciones Takay S.A.C.  2021 – 2025  Dec.2021-Dec.2025
Corporación Materiales Piura S.A.C.  2021 – 2025  Dec.2021-Dec.2025
Soluciones Crealo 150 S.A.C.  2024 – 2025  Sep.2024.-Dec 2025
Vanguardia Constructora del Perú S.A.C.  2024 – 2025  Oct.2024-Dec. 2025


Due to possible interpretations that the tax authority may give to legislation in effect, it is not possible to determine whether or not any of the tax audits will result in increased liabilities for the Group. For that reason, tax or surcharge that could arise from future tax audits would be applied to the income of the period in which it is determined. However, in management’s opinion and that of its legal advisors, any possible additional payment of taxes would not have a material effect on the consolidated financial statements as of December 31, 2025 and 2024.


F-49


Notes to the consolidated financial statements (continued)


Environmental matters


The Group’s exploration and mining activities are subject to compliance with the environmental obligations defined by the competent authorities and environmental protection regulations.


Environmental remediation -


Law No. 28271 which regulates the environmental liabilities in mining activities, aims to regulate the identification of mining activity’s environmental liabilities and financing the remediation of the affected areas. According to this law, environmental liabilities refer to the impact caused to the environment by abandoned or inactive mining operations.


In compliance with the above-mentioned laws, the Group presented environmental impact studies (EIS), declaration of environmental studies (DES) and Environmental Adaptation and Management Programs (EAMP), as well as the respective closure plans for its operating units.


The Peruvian authorities approved the EAMP and EIS submitted by the Group for its mining units and exploration projects, as presented below:


Project unit  Resource  Resolution
Number
  Year of
approval
   Program
approved
  Operating year expense 
                 2025    2024    2023 
                 S/(000)    S/(000)    S/(000) 
Rioja  Limestone  RD186-2014-PRODUCE/DVMYPE-I/DIGGAM   2014   EIS  665    851    879 
Tembladera  Limestone  RD304-18-PRODUCE/DVMYPE-I/DIGGAM   2018   EAMP  322    329    320 
                 987    1,180    1,199 


As of December 31, 2025 and 2024, the Group had no liabilities related to environmental remediation expenses because all were paid before the end of the year.


Quarry rehabilitation provision -


The Law No. 28090 regulates the obligations and procedures that must be met by the holders of mining activities for the preparation, filing and implementation of Quarry Closure Plans, as well as the establishment of the corresponding environmental guarantees to secure fulfillment of the investments that this includes, subject to the principles of protection, preservation and recovery of the environment. In connection with this obligation, as of December 31, 2025 and 2024, the Group maintained a provision for the closing of the quarries exploited by its operations amounting to S/18,594,000 and S/19,005,000, respectively. The Group believes that this liability is adequate to meet the current environmental protection laws approved by the Ministry of Energy and Mines, refer to note 12.


F-50


Notes to the consolidated financial statements (continued)


Legal claim contingency


As of December 31, 2025, the Group had received claims from third parties in relation with its operations which in aggregate represent S/2,956,000 that corresponded to labor claims from former employees.


Management expects that these claims will be resolved within the next five years based on prior experience; however, the Group cannot assure that these claims will be resolved within this period because the authorities do not have a maximum term to resolve cases.


The Group has been advised by its legal counsel that it is only possible, but not probable, that these actions will succeed. Accordingly, no provision for any liability has been made in these consolidated financial statements.


Works for taxes –


As of December 31, 2025 and 2024, the Company had commitments to execute projects under the works for taxes modality for amounts totaling S/387,437,000 and S/79,018,000, respectively. The execution of the projects committed as of December 31, 2025, will be carried out as planned for S/ 274,388,000 in 2026 and S/113,005,000 in 2027.


26.Financial risk management, objectives and policies


The Group’s main financial liabilities comprise loans and borrowings, trade payables and other payables. The main purpose of these financial liabilities is to finance the Group’s operations. The Group´s main financial assets include cash and short-term deposits and trade and other receivables that derive directly from its operations.


The Group is exposed to market risk, credit risk and liquidity risk. The Group’s senior management oversees the management of these risks. The Group’s senior management is supported by Financial Management that advises on financial risks and the appropriate financial risk governance framework for the Group. The financial management provides assurance to the Group’s senior management that the Group’s financial risk-taking activities are governed by appropriate policies and procedures and that financial risks are identified, measured and managed in accordance with the Group´s policies and risk objectives.


Management reviews and implements policies for managing each of these risks, which are summarized below.


Market risk -


Market risk is the risk that the fair value or future cash flows of a financial instrument will fluctuate because of changes in market prices. Market risk comprise three types of risk: interest rate risk, foreign currency risk and other price risk (such as equity price risk and commodity risk).


The sensitivity analyses shown in the following sections relate to the Group’s consolidated position as of December 31, 2025 and 2024.


F-51


Notes to the consolidated financial statements (continued)


Interest rate risk -


Interest rate risk is the risk that the fair value or future cash flows of a financial instrument will fluctuate because of changes in market interest rates.


As of December 31, 2025 and 2024, all of the Group’s borrowings are at a fixed rate of interest; consequently, the management evaluated that it is not relevant to do an interest rate sensitivity analysis.


Foreign currency risk -


Foreign exchange risk is the risk that the fair value or future cash flows of a financial instrument will fluctuate due to changes in foreign currency exchange rates. The Group’s exposure to foreign exchange risk relates primarily to the Group’s operating activities (when income or expenses are denominated in a currency other than the Group’s functional currency).


Foreign currency sensitivity


The following table demonstrates the sensitivity to a reasonably possible change in the US dollar exchange rate, with all other variables held constant. The impact on the Group’s profit before income tax is due to changes in the fair value of monetary assets and liabilities.


2025   Change in
US$ rate
   Effect on
consolidated profit
before tax
 
U.S. Dollar    %    S/(000) 
            
     +5    812 
     +10    1,625 
     -5    (812)
     -10    (1,625)


2024   Change in
US$ rate
   Effect on
consolidated profit
before tax
 
U.S. Dollar    %    S/(000) 
            
     +5    (593)
     +10    (1,186)
     -5    593 
     -10    1,186 


Credit risk -


Credit risk is the risk that counterparty will not meet its obligations under a financial instrument or customer contract, leading to a financial loss. The Group is exposed to a credit risk from its operating activities (primarily for trade receivables) and from its financing activities, including deposits with banks and financial institutions, foreign exchange transactions and other financial instruments.


Trade receivables


Customer credit risk is managed by each business unit subject to the Group’s established policy, procedures and control relating to customer credit risk management. Credit quality of the customer is assessed, and individual credit limits are defined in accordance with this assessment. Outstanding customer receivables are regularly monitored and any shipments to major customers are generally covered by letters of credit. As of December 31, 2025 and 2024, the Group had 9 and 8 customers, respectively, that owed the Group more than S/3,000,000 each accounting for approximately 55% and 34% of all trade receivables outstanding, respectively. There were 26 and 22 customers with balances greater than S/700,000 and less than S/3,000,000, which accounted for approximately 28% and 23% of the total trade receivables, respectively. The evaluation for allowance for expected credit losses is updated at the date of the consolidated financial statements and individually for the main customers. This calculation is based on actual historical data incurred.


The maximum exposure to credit risk at the reporting date is the carrying value of each class of financial assets disclosed in note 7. The Group does not maintain credit insurance for its accounts receivable.


F-52


Notes to the consolidated financial statements (continued)


Cash deposits


Credit risk from balances with banks and financial institutions is managed by the Group’s treasury department in accordance with the Group’s policy. Investments of surplus funds are made only with approved counterparties of first level. The limits are set to minimize the concentration of risks and therefore mitigate financial loss through potential counterparty’s failure to make payments. As of December 31, 2025 and 2024, the Group’s maximum exposure to credit risk for the components of carrying amounts is showed in note 6.


Liquidity risk -


The Group monitors its risk of shortage of funds using a recurring liquidity planning tool.


The Group’s objective is to maintain a balance between continuity of funding and flexibility through the use of bank loans and long term debentures. Access to sources of funding is sufficiently available and debt maturing within 12 months can be rolled over under the same conditions with existing lenders, if is necessary.


The table below summarizes the maturity profile of the Group’s financial liabilities based on contractual undiscounted payments:


   Less than 3
months
   3 to 12 months   1 to 5 years   More than 5
years
   Total 
   S/(000)   S/(000)   S/(000)   S/(000)   S/(000) 
As of December 31, 2025                         
Financial obligations   190,292    343,272    665,727    217,000    1,416,291 
Interest   26,674    44,729    145,449    29,703    246,555 
Trade and other payables   157,001    60,395    
-
    
-
    217,396 
Lease liabilities   1,278    3,601    10,849    501    16,229 
                          
As of December 31, 2024                         
Financial obligations   190,292    269,272    729,091    310,000    1,498,655 
Interest   29,255    49,887    189,657    47,735    316,534 
Trade and other payables   155,556    57,368    
-
    
-
    212,924 
Lease liabilities   758    2,200    5,819    643    9,420 


The changes in liabilities arising from financing activities are presented below:


   Balance as of
January 1,
   Distribution of
dividends
   Cash
inflow
   Cash
outflow
   Amortization of
costs of issuance of
senior notes
   Balance as of
December 31
 
   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000) 
2025                              
Dividends payable   11,097    175,524    660    (175,458)   
-
    11,823 
Financial obligations   1,493,191    
-
    392,200    (474,564)   1,328    1,412,155 
                               
2024                              
Dividends payable   10,322    175,524    297    (175,046)   
-
    11,097 
Financial obligations   1,573,026    
-
    303,200    (384,364)   1,329    1,493,191 


F-53


Notes to the consolidated financial statements (continued)


Capital management -


For the purpose of the Group’s capital management, capital includes capital stock, investment shares, additional paid-in capital and all other equity reserves attributable to the equity holders of the Company. The primary objective of the Group’s capital management is to maximize the shareholders’ value.


In order to achieve this overall objective, the Group’s capital management, among other things, aims to ensure that it meets financial covenants attached to the interest-bearing loans and borrowings that define capital structure requirements. Breaches in meeting the financial covenants would permit the creditors to immediately call the senior notes. There have been no breaches in the financial covenants of Senior Notes in any of the years presented.


The Group manages its capital structure and adjusts it in light of changes in economic conditions and the requirements of the financial covenants. To maintain or adjust the capital structure, the Group may adjust the dividend payment to shareholders, return capital to shareholders or issue new shares.


No changes were made in the objectives, policies or processes for managing capital during the years ended December 31, 2025 and 2024.


27.Fair value of financial assets and liabilities


Financial assets -


Except for derivative financial instruments and financial instruments designated at fair value through OCI, all financial assets which included trade and other receivables are classified in the category of loans and receivables, which are non-derivative financial assets carried at amortized cost, held to maturity, and generate a fixed or variable interest income for the Group. The carrying value may be affected by changes in the credit risk of the counterparties.


Financial liabilities -


All financial liabilities of the Group including trade and other payables financial obligations are classified as loans and borrowings and are carried at amortized cost.


F-54


Notes to the consolidated financial statements (continued)


(a)Fair values and fair value accounting hierarchy -


Set out below is a comparison of the carrying amounts and fair values of financial instruments of the Group as of December 31, 2025 and 2024, as well as the fair value accounting hierarchy. The dates of valuations at fair value were as of December 31, 2025 and 2024, respectively.


   Carrying amount   Fair value   Fair value
hierarchy
 
   2025    2024   2025    2024   2025/2024
   S/(000)    S/(000)   S/(000)    S/(000)     
Financial assets                      
Cash and cash equivalents  53,571    72,723   53,571    72,723   Level 1 
Trade and other receivables  175,124    174,392   175,124    174,392   Level 2 
Financial investments designated at fair value through other comprehensive income  163    239   163    239   Level 3 
Total financial assets  228,858    247,354   228,858    247,354     
                       
Financial liabilities                      
 Trade and other payables  283,907    242,051   283,907    242,051   Level 2 
 Senior notes  569,414    569,303   541,619    541,508   Level 1 
 Fixed rate notes and loans  842,741    923,888   834,838    916,415   Level 2 
Total financial liabilities  1,696,062    1,735,242   1,660,364    1,699,974     


All financial instruments for which fair value is recognized or disclosed are categorized within the fair value hierarchy, based on the lowest level input that is significant to the fair value measurement as a whole. The fair value hierarchies are those described in note 2.3.2 (iv).


For assets and liabilities that are recognized at fair value on a recurring basis, the Group determines whether transfers have occurred between levels in the hierarchy. As of December 31, 2025 and 2024, there were no transfers between the fair value hierarchies.


Management assessed that cash and cash equivalents; trade and other receivables and other current liabilities approximate their carrying amounts largely due to the short-term maturities of these instruments.


The following methods and assumptions were used to estimate the fair values:


-The fair value of quoted corporate bonds is based on the current value of the notes in the market as of the reporting date.


-The fair value of the fixed rate promissory note it is calculated using the results of cash flow discounted at the average indebtedness rates effective as of the reporting date.


-The fair value of financial instruments at fair value with changes in OCI has been determined through the percentage of the Company’s shareholding in the equity of Fossal S.A.A.


F-55


Notes to the consolidated financial statements (continued)


28.Segment information


For management purposes, the Group is organized into business units based on their products and activities and have two reportable segments as follows:


-Production and sales of cement, concrete, pavement, mortar and precast in the northern region of Peru.
   
-Sale of construction supplies in the northern region of Peru.


No other operating segments have been aggregated to form the above reportable operating segments.


Management monitors the profit before income tax of each business units separately for the purpose of making decisions about resource allocation and performance assessment. Segment performance is evaluated based on profit before income tax and is measured consistently with profit before income tax in the consolidated statement of profit and loss.


Transfer prices between operating segments are on an arm’s length basis in a similar manner to transactions with third parties.


   2025   2024   2023 
   Cement,
concrete,
pavement,
mortar and
precast
   Construction
supplies
   Others (*)   Total
consolidated
   Cement,
concrete,
pavement,
mortar and
precast
   Construction
supplies
   Others (*)   Total
consolidated
   Cement,
concrete,
pavement,
mortar and
precast
   Construction
supplies
   Others (*)   Total
consolidated
 
   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000)   S/(000) 
Revenues from external customers  2,064,674   41,745    10,464   2,116,883   1,906,849   56,873    14,349   1,978,071   1,850,238   74,096   25,741   1,950,075 
Gross profit  817,310   656    (11,100)  806,866   728,850   2,006    (2,330)  728,526   687,727   723   1,002   689,452 
Administrative expenses  (285,527)  (3,222)   (2,789)  (291,538)  (248,047)  (2,848)   (2,488)  (253,383)  (227,459)  (2,692)  (1,816)  (231,967)
Selling and distribution expenses  (90,873)  (1,025)   (887)  (92,785)  (79,696)  (915)   (799)  (81,410)  (68,286)  (766)  (517)  (69,569)
Other operating (expenses) income, net  2,169   (4)   (77,607)  (75,442)  (2,805)  33    72   (2,700)  (13,813)  3   -   (13,810)
Finance income  11,238   13    40   11,291   6,201   33    64   6,298   7,160   9   77   7,246 
Finance cost  (93,029)  -    (7)  (93,036)  (100,302)  -    (6)  (100,308)  (104,045)  -   -   (104,045)
Net gain on settlement of derivative financial instruments  -   -    -   -   -   -    -   -   19   -   -   19 
Impairment of assets  -   -    -   -   -   -    -   -   (36,551)  -   -   (36,551)
Gain (loss) from exchange difference, net  2,679   (18)   (42)  2,619   (828)  (7)   (1)  (836)  4,932   (6)  7   4,933 
Profit (loss) before income tax  363,967   (3,600)   (92,392)  267,975   303,373   (1,698)   (5,488)  296,187   249,684   (2,729)  (1,247)  245,708 
Income tax expense  (154,524)  1,530    39,224   (113,770)  (99,673)  558    1,803   (97,312)  (78,050)  853   389   (76,808)
Profit (loss) for the year  209,443   (2,070)   (53,168)  154,205   203,700   (1,140)   (3,685)  198,875   171,634   (1,876)  (858)  168,900 


(*) The “other” segment includes activities that do not meet the threshold for disclosure under IFRS 8.13 and represent non-material operations of the Group (including brine projects). In 2025, the caption Other operating (expenses) income, net, includes expenses associated with the acquisition of Holcim amounting to S/77,625,000.


F-56


Notes to the consolidated financial statements (continued)


  2025  2024  2023 
  Cement,
concrete,
pavement,
mortar and
precast
  Construction
supplies
  Others (*)  Consolidated  Cement,
concrete,
pavement,
mortar and
precast
  Construction
supplies
  Others (*)  Consolidated  Cement,
concrete,
pavement,
mortar and
precast
  Construction
supplies
  Others (*)  Consolidated 
  S/(000)  S/(000)  S/(000)  S/(000)  S/(000)  S/(000)  S/(000)  S/(000)  S/(000)  S/(000)  S/(000)  S/(000) 
Segment assets  2,976,370   31,337   95,496   3,103,203   3,021,210   40,583   104,011   3,165,804   3,074,279   46,941   100,266   3,221,486 
Other assets (*)  -   -   163   163   -   -   239   239   -   -   249   249 
Total assets  2,976,370   31,337   95,659   3,103,366   3,021,210   40,583   104,250   3,166,043   3,074,279   46,941   100,515   3,221,735 
Operating liabilities  1,825,277   83,586   3,138   1,912,001   1,879,580   71,901   1,464   1,952,945   1,968,133   62,907   687   2,031,727 
Capital expenditure (**)  144,276   -   -   144,276   96,912   -   -   96,912   299,326   -   -   299,326 
Depreciation and amortization  (154,164)  (1,033)  (4,284)  (159,481)  (152,584)  (1,189)  (4,473)  (158,246)  (137,968)  (1,468)  (4,759)  (144,195)
Provision of inventory net realizable value and obsolescence  (1,469)  -   -   (1,469)  (6,418)  -   -   (6,418)  (2,956)  -   -   (2,956)


(*)As of December 31, 2025 and 2024, it corresponds to the financial investment at fair value with changes in OCI for S/ 163,000 and S/239,000, respectively.
  
(**)Capital investments amounting to S/144,276,000, S/96,912,000 and S/299,326,000 for the years 2025, 2024 and 2023, respectively, correspond to additions of property, plant and equipment, intangibles and other minor non-current assets.


Geographic information


As of December 31, 2025 and 2024, all non-current assets are located in Peru and all revenues are from clients located in the north region of the country.


29.Subsequent event


Since February 27, 2026, in connection with Note 1 and the expenses detailed in Note 21 as ‘Expenses associated with the Holcim acquisition,’ the Peruvian Securities Commission (Superintendencia del Mercado de Valores, or the ’SMV’) has submitted a series of information requests to the Company regarding the nature of such expenses, their appropriate disclosure, and their connection with the Company’s activities. All such requests had been addressed by Company’s management.


Furthermore, management, with the support of external legal counsel, believes that these expenses constitute legitimate and existing liabilities of the Company associated with Holcim Ltd’s acquisition of a controlling interest in the Company. These expenses and their tax impacts were properly recognized, disclosed and reflected in the enclosed financial statements.


On March 30, 2026, Holcim Ltd, a limited liability company incorporated under Swiss law, acquired 99.99% of the shares representing the share capital of Inversiones ASPI S.A., which owns 50.01% of the share capital of Cementos Pacasmayo S.A.A.


F-57
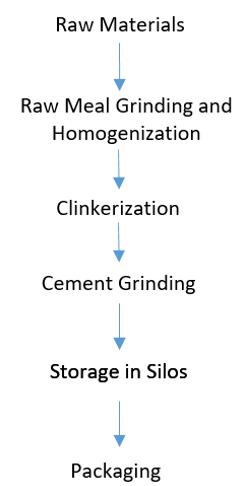
 

CEMENTOS PACASMAYO SAA +51 1-317-6000 International Financial Reporting Standards 1315 On March 22, 2021, the Company received Tax Court Resolution N° 00905-4-21 that declares the calculation of Mining Royalty should be based on gross sale of the final product (cement) for the years 2008 and 2009. This is an opposite position to what is established by the Constitutional Court in the STC Exp. N° 1043-2013-PA/TC that declares founded the writ of protection presented by the Company recognizing our right to calculate mining royalties exclusively based on the value of the mining component, without considering in any way the value of the final products derived from industrial and manufacturing processes. Pursuant to this, the Company initiated two legal proceedings: (i) a constitutional process to denounce the repression of homogeneous harmful acts, filed on March 31, 2021; and, (ii) a contentious-administrative claim filed before the ordinary court, the object of which was the annulment and return of securities, filed on June 22, 2021. To date, both processes have culminated with resolutions favorable to the Company’s claims. In this regard, the ruling issued by the Constitutional Court in the proceedings for the complaint of repression of homogeneous harmful acts, dated December 16, 2024, declares the constitutional grievance appeal well-founded and consequently the respective RTF void, ordering the Tax Court to comply with the issuance of new resolutions complying with the judgment issued in STC 1043-2013-PA/TC in the sense that the method for calculating mining royalties established therein also applies to the 2008 and 2009 fiscal years and not only from 2011 onwards, as argued by the Tax Court and the National Superintendency of Tax Administration (SUNAT). As a consequence of said ruling, it is appropriate for the National Superintendency of Tax Administration (SUNAT), either directly or through enforcement, to proceed with the return of the amounts paid by the Company amounting to S/29,559,000, since this constitutes a direct effect of the execution of the mandate ordered by the Constitutional Court. As of August 20, 2025, The National Superintendency of Tax Administration (SUNAT) made a partial refund of accounts receivable for mining royalties in the amount of S/18,441,000, leaving an outstanding balance of S/11,118,000 to be collected as of December 31, 2025. In the opinion of Management and its external legal advisors, there is a very high probability of obtaining a favorable outcome. In previous years management recognized a full impairment related to the total net book value of a closed zinc mining unit which included concession costs, development costs and related facilities and equipment. At the end of 2023, Management recognized a specific impairment to retirement for the net value of the assets of the vertical clinker kilns located at the Pacasmayo cement plant. This deterioration estimate was carried out as a consequence of replacing the old technology of these kilns due to the entry into operation of the Clinker Lines Optimization Project – Kiln 4 in said plant, which is more efficient and produces fewer emissions. This amount was recorded in the impairment of property, plant and equipment item in the consolidated statement of profit or loss. Likewise, in that year, Management recognized an impairment to retirement of the value of the coal concessions (northern zone). Workers’ profit sharing - In accordance with Peruvian legislation, the Group is obliged to pay its employees profit sharing of between 8% and 10% of annual taxable income. Distributions to employees under the plan are based 50% on the number of days that each employee worked during the preceding year and 50% on proportionate annual salary levels. Long-term incentive plan - In 2011, the Group implemented a compensation plan for its key management. This long-term benefit is payable in cash, based on the salary of each officer and depends on the years of service of each officer in the Group. According to the latest plan update, the executive would receive the equivalent of an annual salary for each year of service beginning to accrue from 2019. This benefit accrues and accumulates for each officer and is payable in two installments: the first payment will be made on the sixth year after the creation of this bonus plan, and the last payment will be made on the ninth year from the creation of the plan. If the executive decides to voluntarily leave the Group before a scheduled distribution, they will not receive this compensation. The Group used the Projected Unit Credit Method to determine the present value of this deferred obligation and the related current deferred cost, considering the expected increases in salary base and the corresponding current government bond discount rate (risk-free rate). Quarry Rehabilitation provision - As of December 31, 2025 and 2024, it corresponds to the provision for the future costs of rehabilitating the quarries exploited in Group operations. The provision has been created based on studies made by internal specialists. Management believes that the assumptions used, based on current economic environment, are a reasonable basis upon which to estimate the future liability. These estimates are reviewed regularly to consider any material change to the assumptions. However, actual quarry rehabilitation costs will ultimately depend upon future market prices for the necessary decommissioning works required to reflect future economic conditions. Future cash flows have been estimated based on financial budgets approved by Management. The range of the risk-free discount rate in dollars used in the calculation of the provision as of December 31, 2025 was from 0.49 to 4.84 percent (from 0.53 to 4.86 percent as of December 31, 2024). Management expects to incur a significant part of this obligation in the medium and long-term. The Group estimates that this liability is sufficient according to the current environmental protection laws approved by the Ministry of Energy and Mines of Peru. Senior Notes- (b.1) Senior Notes On January 31, 2019, senior notes were issued in soles for S/260,000,000 at a rate of 6.688 percent per year and maturity of 10 years and; 15 years bonds for S/310,000,000 at a rate of 6.844 percent per year. The Senior Notes in soles issued in 2019 are guaranteed by the following Company’s subsidiaries: Cementos Selva S.A.C., Distribuidora Norte Pacasmayo S.R.L., Empresa de Transmisión Guadalupe S.A.C. and Dinoselva Iquitos S.A.C. (b.2) Financial covenants The corporate bond contracts have the following covenants to limiting the incurring of indebtedness for the Company and its collateral subsidiaries, which are measured prior to the following transactions: issuance of debt or equity instruments, merger with another company or disposition or rental of significant assets. The covenants are the following: - A fixed charge covenant ratio of at least 2.5 to 1. - A consolidated debt-to-EBITDA ratio of no greater than 3.5 to 1. As of December 31, 2025 and 2024, these covenants have not been activated because no situation has occurred that requires their measurement, as indicated in the previous paragraph. For the years ended December 31, 2025, 2024 and 2023, senior notes generated interest that have been recognized in the consolidated statement of profit or loss for S/38,603,000, S/38,603,000 and S/38,690,000, respectively, see note 22. Medium-term Corporate Loan under “Club Deal” modality: On August 6, 2021, the Company established the conditions of a medium-term corporate loan under “Club Deal” modality with Banco de Crédito del Perú S.A. and Scotiabank Perú S.A.A. The loan amounts to S/860,000,000 that allowed the payment of all the financial obligations that the Company maintains with a maturity until February 2023. The loan conditions include a grace/availability period of 18 months from August 6 and a payment term of 7 years from the last disbursement, which was in February 2023. Since that date, the loan will be paid in 22 equal quarterly installments and has an annual interest rate of 5.82 percent. As part of the loan conditions, the Company assumed the following obligations: I. Comply with the following financial covenants: a. Debt Ratio (Financial Debt / EBITDA) <= 3.50x b. Debt Service Coverage Ratio (CFDS / DS) >= 1.15x c. Debt Service Coverage Ratio (EBITDA / DS) >= 1.50x These financial safeguards are calculated and verified at the end of each calendar quarter, considering the information of the consolidated financial statements of the Company for the last 12 months, prepared in accordance with IFRS. As of December 31, 2025 and 2024, the Company complies with the ratios contained in the conditions of the Club Deal and corporate bonds and have certain do’s and don’ts obligations that have been complying with to date. 0001221029 false FY 00000 00000 0001221029 2025-01-01 2025-12-31 0001221029 dei:BusinessContactMember 2025-01-01 2025-12-31 0001221029 cpac:AmericanDepositarySharesEvidencedByAmericanDepositaryReceiptsEachAmericanDepositaryShareRepresentingFiveCommonSharesOfTheRegistrantParValueS100PerShareADSsMember 2025-01-01 2025-12-31 0001221029 cpac:CommonSharesParValueS100PerShareMember 2025-01-01 2025-12-31 0001221029 2025-12-31 0001221029 2024-12-31 0001221029 2024-01-01 2024-12-31 0001221029 2023-01-01 2023-12-31 0001221029 cpac:CapitalStockMember 2022-12-31 0001221029 cpac:InvestmentSharesMember 2022-12-31 0001221029 ifrs-full:TreasurySharesMember 2022-12-31 0001221029 ifrs-full:AdditionalPaidinCapitalMember 2022-12-31 0001221029 cpac:LegalReserve1Member 2022-12-31 0001221029 cpac:UnrealizedLossOnFinancialInstrumentsDesignatedAtFairValueMember 2022-12-31 0001221029 cpac:UnrealizedGainlossOnCashFlowHedgeMember 2022-12-31 0001221029 ifrs-full:RetainedEarningsMember 2022-12-31 0001221029 2022-12-31 0001221029 cpac:CapitalStockMember 2023-01-01 2023-12-31 0001221029 cpac:InvestmentSharesMember 2023-01-01 2023-12-31 0001221029 ifrs-full:TreasurySharesMember 2023-01-01 2023-12-31 0001221029 ifrs-full:AdditionalPaidinCapitalMember 2023-01-01 2023-12-31 0001221029 cpac:LegalReserve1Member 2023-01-01 2023-12-31 0001221029 cpac:UnrealizedLossOnFinancialInstrumentsDesignatedAtFairValueMember 2023-01-01 2023-12-31 0001221029 cpac:UnrealizedGainlossOnCashFlowHedgeMember 2023-01-01 2023-12-31 0001221029 ifrs-full:RetainedEarningsMember 2023-01-01 2023-12-31 0001221029 cpac:CapitalStockMember 2023-12-31 0001221029 cpac:InvestmentSharesMember 2023-12-31 0001221029 ifrs-full:TreasurySharesMember 2023-12-31 0001221029 ifrs-full:AdditionalPaidinCapitalMember 2023-12-31 0001221029 cpac:LegalReserve1Member 2023-12-31 0001221029 cpac:UnrealizedLossOnFinancialInstrumentsDesignatedAtFairValueMember 2023-12-31 0001221029 cpac:UnrealizedGainlossOnCashFlowHedgeMember 2023-12-31 0001221029 ifrs-full:RetainedEarningsMember 2023-12-31 0001221029 2023-12-31 0001221029 cpac:CapitalStockMember 2024-01-01 2024-12-31 0001221029 cpac:InvestmentSharesMember 2024-01-01 2024-12-31 0001221029 ifrs-full:TreasurySharesMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AdditionalPaidinCapitalMember 2024-01-01 2024-12-31 0001221029 cpac:LegalReserve1Member 2024-01-01 2024-12-31 0001221029 cpac:UnrealizedLossOnFinancialInstrumentsDesignatedAtFairValueMember 2024-01-01 2024-12-31 0001221029 cpac:UnrealizedGainlossOnCashFlowHedgeMember 2024-01-01 2024-12-31 0001221029 ifrs-full:RetainedEarningsMember 2024-01-01 2024-12-31 0001221029 cpac:CapitalStockMember 2024-12-31 0001221029 cpac:InvestmentSharesMember 2024-12-31 0001221029 ifrs-full:TreasurySharesMember 2024-12-31 0001221029 ifrs-full:AdditionalPaidinCapitalMember 2024-12-31 0001221029 cpac:LegalReserve1Member 2024-12-31 0001221029 cpac:UnrealizedLossOnFinancialInstrumentsDesignatedAtFairValueMember 2024-12-31 0001221029 cpac:UnrealizedGainlossOnCashFlowHedgeMember 2024-12-31 0001221029 ifrs-full:RetainedEarningsMember 2024-12-31 0001221029 cpac:CapitalStockMember 2025-01-01 2025-12-31 0001221029 cpac:InvestmentSharesMember 2025-01-01 2025-12-31 0001221029 ifrs-full:TreasurySharesMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AdditionalPaidinCapitalMember 2025-01-01 2025-12-31 0001221029 cpac:LegalReserve1Member 2025-01-01 2025-12-31 0001221029 cpac:UnrealizedLossOnFinancialInstrumentsDesignatedAtFairValueMember 2025-01-01 2025-12-31 0001221029 cpac:UnrealizedGainlossOnCashFlowHedgeMember 2025-01-01 2025-12-31 0001221029 ifrs-full:RetainedEarningsMember 2025-01-01 2025-12-31 0001221029 cpac:CapitalStockMember 2025-12-31 0001221029 cpac:InvestmentSharesMember 2025-12-31 0001221029 ifrs-full:TreasurySharesMember 2025-12-31 0001221029 ifrs-full:AdditionalPaidinCapitalMember 2025-12-31 0001221029 cpac:LegalReserve1Member 2025-12-31 0001221029 cpac:UnrealizedLossOnFinancialInstrumentsDesignatedAtFairValueMember 2025-12-31 0001221029 cpac:UnrealizedGainlossOnCashFlowHedgeMember 2025-12-31 0001221029 ifrs-full:RetainedEarningsMember 2025-12-31 0001221029 cpac:InversionesASPISAMember 2025-01-01 2025-12-31 0001221029 cpac:InversionesASPISAMember 2024-01-01 2024-12-31 0001221029 cpac:InversionesASPISAMember 2023-01-01 2023-12-31 0001221029 cpac:InversionesASPISAMember 2025-12-15 2025-12-15 0001221029 srt:MinimumMember cpac:MinorInstallationsRelatedToBuildingsMember 2025-01-01 2025-12-31 0001221029 cpac:MinorInstallationsRelatedToBuildingsMember 2025-01-01 2025-12-31 0001221029 srt:MinimumMember cpac:AdministrativeFacilitiesMember 2025-01-01 2025-12-31 0001221029 cpac:AdministrativeFacilitiesMember 2025-01-01 2025-12-31 0001221029 srt:MinimumMember cpac:MainProductionStructuresMember 2025-01-01 2025-12-31 0001221029 cpac:MainProductionStructuresMember 2025-01-01 2025-12-31 0001221029 srt:MinimumMember cpac:MinorProductionStructuresMember 2025-01-01 2025-12-31 0001221029 cpac:MinorProductionStructuresMember 2025-01-01 2025-12-31 0001221029 srt:MinimumMember cpac:MillsMember 2025-01-01 2025-12-31 0001221029 cpac:MillsMember 2025-01-01 2025-12-31 0001221029 srt:MinimumMember cpac:HorizontalAndVerticalFurnacesCrushersAndGrindersMember 2025-01-01 2025-12-31 0001221029 cpac:HorizontalAndVerticalFurnacesCrushersAndGrindersMember 2025-01-01 2025-12-31 0001221029 srt:MinimumMember cpac:ElectricityFacilitiesAndOtherMinorsMember 2025-01-01 2025-12-31 0001221029 cpac:ElectricityFacilitiesAndOtherMinorsMember 2025-01-01 2025-12-31 0001221029 cpac:FurnitureAndFixtureMember 2025-01-01 2025-12-31 0001221029 srt:MinimumMember cpac:HeavyUnitsMember 2025-01-01 2025-12-31 0001221029 cpac:HeavyUnitsMember 2025-01-01 2025-12-31 0001221029 srt:MinimumMember cpac:LightUnitsMember 2025-01-01 2025-12-31 0001221029 cpac:LightUnitsMember 2025-01-01 2025-12-31 0001221029 srt:MinimumMember ifrs-full:ComputerEquipmentMember 2025-01-01 2025-12-31 0001221029 ifrs-full:ComputerEquipmentMember 2025-01-01 2025-12-31 0001221029 srt:MinimumMember cpac:ToolsMember 2025-01-01 2025-12-31 0001221029 cpac:ToolsMember 2025-01-01 2025-12-31 0001221029 cpac:USDMember 2025-12-31 0001221029 cpac:USDMember 2024-12-31 0001221029 ifrs-full:BottomOfRangeMember 2025-01-01 2025-12-31 0001221029 ifrs-full:TopOfRangeMember 2025-01-01 2025-12-31 0001221029 2025-08-20 0001221029 ifrs-full:TradeReceivablesMember 2025-12-31 0001221029 ifrs-full:TradeReceivablesMember 2024-12-31 0001221029 ifrs-full:ContractAssetsMember 2025-12-31 0001221029 ifrs-full:ContractAssetsMember 2024-12-31 0001221029 cpac:OtherAccountsReceivableMember 2025-12-31 0001221029 cpac:OtherAccountsReceivableMember 2024-12-31 0001221029 cpac:FundsRestrictedToTaxPaymentsMember 2025-12-31 0001221029 cpac:FundsRestrictedToTaxPaymentsMember 2024-12-31 0001221029 cpac:AccountsReceivableFromParentCompanyAndAffiliatesMember 2025-12-31 0001221029 cpac:AccountsReceivableFromParentCompanyAndAffiliatesMember 2024-12-31 0001221029 cpac:LoansGrantedMember 2025-12-31 0001221029 cpac:LoansGrantedMember 2024-12-31 0001221029 cpac:LoansToEmployeesMember 2025-12-31 0001221029 cpac:LoansToEmployeesMember 2024-12-31 0001221029 cpac:InterestsReceivablesMember 2025-12-31 0001221029 cpac:InterestsReceivablesMember 2024-12-31 0001221029 cpac:OtherReceivablesFromSaleOfFixedAssetsMember 2025-12-31 0001221029 cpac:OtherReceivablesFromSaleOfFixedAssetsMember 2024-12-31 0001221029 cpac:AllowanceForExpectedCreditLossesForOtherReceivablesMember 2025-12-31 0001221029 cpac:AllowanceForExpectedCreditLossesForOtherReceivablesMember 2024-12-31 0001221029 cpac:FinancialAssetsClassifiedAsReceivablesMember 2025-12-31 0001221029 cpac:FinancialAssetsClassifiedAsReceivablesMember 2024-12-31 0001221029 cpac:OtherAccountsReceivableNetMember 2025-12-31 0001221029 cpac:OtherAccountsReceivableNetMember 2024-12-31 0001221029 cpac:ClaimToTheSUNATMember 2025-12-31 0001221029 cpac:ClaimToTheSUNATMember 2024-12-31 0001221029 cpac:ValueaddedTaxCreditMember 2025-12-31 0001221029 cpac:ValueaddedTaxCreditMember 2024-12-31 0001221029 cpac:TaxRefundReceivableMember 2025-12-31 0001221029 cpac:TaxRefundReceivableMember 2024-12-31 0001221029 cpac:AllowanceForExpectedCreditLossesMember 2025-12-31 0001221029 cpac:AllowanceForExpectedCreditLossesMember 2024-12-31 0001221029 cpac:NonfinancialAssetsClassifiedAsReceivablesMember 2025-12-31 0001221029 cpac:NonfinancialAssetsClassifiedAsReceivablesMember 2024-12-31 0001221029 cpac:TotalMember 2025-12-31 0001221029 cpac:TotalMember 2024-12-31 0001221029 ifrs-full:FinancialAssetsNeitherPastDueNorImpairedMember 2025-12-31 0001221029 ifrs-full:FinancialAssetsPastDueButNotImpairedMember cpac:LessThanOneMonthMember 2025-12-31 0001221029 ifrs-full:FinancialAssetsPastDueButNotImpairedMember ifrs-full:LaterThanOneMonthAndNotLaterThanTwoMonthsMember 2025-12-31 0001221029 ifrs-full:FinancialAssetsPastDueButNotImpairedMember ifrs-full:LaterThanTwoMonthsAndNotLaterThanThreeMonthsMember 2025-12-31 0001221029 ifrs-full:FinancialAssetsPastDueButNotImpairedMember ifrs-full:LaterThanThreeMonthsMember 2025-12-31 0001221029 ifrs-full:FinancialAssetsPastDueButNotImpairedMember cpac:LaterThanFourMonthMember 2025-12-31 0001221029 ifrs-full:FinancialAssetsNeitherPastDueNorImpairedMember 2024-12-31 0001221029 ifrs-full:FinancialAssetsPastDueButNotImpairedMember cpac:LessThanOneMonthMember 2024-12-31 0001221029 ifrs-full:FinancialAssetsPastDueButNotImpairedMember ifrs-full:LaterThanOneMonthAndNotLaterThanTwoMonthsMember 2024-12-31 0001221029 ifrs-full:FinancialAssetsPastDueButNotImpairedMember ifrs-full:LaterThanTwoMonthsAndNotLaterThanThreeMonthsMember 2024-12-31 0001221029 ifrs-full:FinancialAssetsPastDueButNotImpairedMember ifrs-full:LaterThanThreeMonthsMember 2024-12-31 0001221029 ifrs-full:FinancialAssetsPastDueButNotImpairedMember cpac:LaterThanFourMonthMember 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MiningConcessionsMember 2023-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MineDevelopmentsMember 2023-12-31 0001221029 ifrs-full:GrossCarryingAmountMember ifrs-full:LandMember 2023-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:BuildingsAndOtherConstructionMember 2023-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2023-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:FurnitureAndAccessoriesMember 2023-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:TransportationUnitsMember 2023-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:ComputerEquipmentAndToolsMember 2023-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:QuarryRehabilitationCostsMember 2023-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:CapitalizedInterestMember 2023-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:WorksInProgressAndUnitsInTransitMember 2023-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:TotalMember 2023-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MiningConcessionsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MineDevelopmentsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember ifrs-full:LandMember 2024-01-01 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:BuildingsAndOtherConstructionMember 2024-01-01 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:FurnitureAndAccessoriesMember 2024-01-01 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:TransportationUnitsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:ComputerEquipmentAndToolsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:QuarryRehabilitationCostsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:CapitalizedInterestMember 2024-01-01 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:WorksInProgressAndUnitsInTransitMember 2024-01-01 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:TotalMember 2024-01-01 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MiningConcessionsMember 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MineDevelopmentsMember 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember ifrs-full:LandMember 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:BuildingsAndOtherConstructionMember 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:FurnitureAndAccessoriesMember 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:TransportationUnitsMember 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:ComputerEquipmentAndToolsMember 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:QuarryRehabilitationCostsMember 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:CapitalizedInterestMember 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:WorksInProgressAndUnitsInTransitMember 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:TotalMember 2024-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MiningConcessionsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MineDevelopmentsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember ifrs-full:LandMember 2025-01-01 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:BuildingsAndOtherConstructionMember 2025-01-01 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:FurnitureAndAccessoriesMember 2025-01-01 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:TransportationUnitsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:ComputerEquipmentAndToolsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:QuarryRehabilitationCostsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:CapitalizedInterestMember 2025-01-01 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:WorksInProgressAndUnitsInTransitMember 2025-01-01 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:TotalMember 2025-01-01 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MiningConcessionsMember 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MineDevelopmentsMember 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember ifrs-full:LandMember 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:BuildingsAndOtherConstructionMember 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:FurnitureAndAccessoriesMember 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:TransportationUnitsMember 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:ComputerEquipmentAndToolsMember 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:QuarryRehabilitationCostsMember 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:CapitalizedInterestMember 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:WorksInProgressAndUnitsInTransitMember 2025-12-31 0001221029 ifrs-full:GrossCarryingAmountMember cpac:TotalMember 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MiningConcessionsMember 2023-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MineDevelopmentsMember 2023-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember ifrs-full:LandMember 2023-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:BuildingsAndOtherConstructionMember 2023-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2023-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:FurnitureAndAccessoriesMember 2023-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:TransportationUnitsMember 2023-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:ComputerEquipmentAndToolsMember 2023-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:QuarryRehabilitationCostsMember 2023-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:CapitalizedInterestMember 2023-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:WorksInProgressAndUnitsInTransitMember 2023-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:TotalMember 2023-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MiningConcessionsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MineDevelopmentsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember ifrs-full:LandMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:BuildingsAndOtherConstructionMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:FurnitureAndAccessoriesMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:TransportationUnitsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:ComputerEquipmentAndToolsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:QuarryRehabilitationCostsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:CapitalizedInterestMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:WorksInProgressAndUnitsInTransitMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:TotalMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MiningConcessionsMember 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MineDevelopmentsMember 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember ifrs-full:LandMember 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:BuildingsAndOtherConstructionMember 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:FurnitureAndAccessoriesMember 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:TransportationUnitsMember 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:ComputerEquipmentAndToolsMember 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:QuarryRehabilitationCostsMember 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:CapitalizedInterestMember 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:WorksInProgressAndUnitsInTransitMember 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:TotalMember 2024-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MiningConcessionsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MineDevelopmentsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember ifrs-full:LandMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:BuildingsAndOtherConstructionMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:FurnitureAndAccessoriesMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:TransportationUnitsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:ComputerEquipmentAndToolsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:QuarryRehabilitationCostsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:CapitalizedInterestMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:WorksInProgressAndUnitsInTransitMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:TotalMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MiningConcessionsMember 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MineDevelopmentsMember 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember ifrs-full:LandMember 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:BuildingsAndOtherConstructionMember 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:FurnitureAndAccessoriesMember 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:TransportationUnitsMember 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:ComputerEquipmentAndToolsMember 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:QuarryRehabilitationCostsMember 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:CapitalizedInterestMember 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:WorksInProgressAndUnitsInTransitMember 2025-12-31 0001221029 ifrs-full:AccumulatedDepreciationAndAmortisationMember cpac:TotalMember 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MiningConcessionsMember 2023-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MineDevelopmentsMember 2023-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember ifrs-full:LandMember 2023-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:BuildingsAndOtherConstructionMember 2023-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2023-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:FurnitureAndAccessoriesMember 2023-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:TransportationUnitsMember 2023-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:ComputerEquipmentAndToolsMember 2023-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:QuarryRehabilitationCostsMember 2023-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:CapitalizedInterestMember 2023-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:WorksInProgressAndUnitsInTransitMember 2023-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:TotalMember 2023-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MiningConcessionsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MineDevelopmentsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember ifrs-full:LandMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:BuildingsAndOtherConstructionMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:FurnitureAndAccessoriesMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:TransportationUnitsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:ComputerEquipmentAndToolsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:QuarryRehabilitationCostsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:CapitalizedInterestMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:WorksInProgressAndUnitsInTransitMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:TotalMember 2024-01-01 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MiningConcessionsMember 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MineDevelopmentsMember 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember ifrs-full:LandMember 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:BuildingsAndOtherConstructionMember 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:FurnitureAndAccessoriesMember 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:TransportationUnitsMember 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:ComputerEquipmentAndToolsMember 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:QuarryRehabilitationCostsMember 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:CapitalizedInterestMember 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:WorksInProgressAndUnitsInTransitMember 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:TotalMember 2024-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MiningConcessionsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MineDevelopmentsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember ifrs-full:LandMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:BuildingsAndOtherConstructionMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:FurnitureAndAccessoriesMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:TransportationUnitsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:ComputerEquipmentAndToolsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:QuarryRehabilitationCostsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:CapitalizedInterestMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:WorksInProgressAndUnitsInTransitMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:TotalMember 2025-01-01 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MiningConcessionsMember 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MineDevelopmentsMember 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember ifrs-full:LandMember 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:BuildingsAndOtherConstructionMember 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:FurnitureAndAccessoriesMember 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:TransportationUnitsMember 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:ComputerEquipmentAndToolsMember 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:QuarryRehabilitationCostsMember 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:CapitalizedInterestMember 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:WorksInProgressAndUnitsInTransitMember 2025-12-31 0001221029 ifrs-full:AccumulatedImpairmentMember cpac:TotalMember 2025-12-31 0001221029 cpac:NetBookValueMember cpac:MiningConcessionsMember 2024-12-31 0001221029 cpac:NetBookValueMember cpac:MineDevelopmentsMember 2024-12-31 0001221029 cpac:NetBookValueMember ifrs-full:LandMember 2024-12-31 0001221029 cpac:NetBookValueMember cpac:BuildingsAndOtherConstructionMember 2024-12-31 0001221029 cpac:NetBookValueMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2024-12-31 0001221029 cpac:NetBookValueMember cpac:FurnitureAndAccessoriesMember 2024-12-31 0001221029 cpac:NetBookValueMember cpac:TransportationUnitsMember 2024-12-31 0001221029 cpac:NetBookValueMember cpac:ComputerEquipmentAndToolsMember 2024-12-31 0001221029 cpac:NetBookValueMember cpac:QuarryRehabilitationCostsMember 2024-12-31 0001221029 cpac:NetBookValueMember cpac:CapitalizedInterestMember 2024-12-31 0001221029 cpac:NetBookValueMember cpac:WorksInProgressAndUnitsInTransitMember 2024-12-31 0001221029 cpac:NetBookValueMember cpac:TotalMember 2024-12-31 0001221029 cpac:NetBookValueMember cpac:MiningConcessionsMember 2025-12-31 0001221029 cpac:NetBookValueMember cpac:MineDevelopmentsMember 2025-12-31 0001221029 cpac:NetBookValueMember ifrs-full:LandMember 2025-12-31 0001221029 cpac:NetBookValueMember cpac:BuildingsAndOtherConstructionMember 2025-12-31 0001221029 cpac:NetBookValueMember cpac:MachineryEquipmentAndRelatedSparePartsMember 2025-12-31 0001221029 cpac:NetBookValueMember cpac:FurnitureAndAccessoriesMember 2025-12-31 0001221029 cpac:NetBookValueMember cpac:TransportationUnitsMember 2025-12-31 0001221029 cpac:NetBookValueMember cpac:ComputerEquipmentAndToolsMember 2025-12-31 0001221029 cpac:NetBookValueMember cpac:QuarryRehabilitationCostsMember 2025-12-31 0001221029 cpac:NetBookValueMember cpac:CapitalizedInterestMember 2025-12-31 0001221029 cpac:NetBookValueMember cpac:WorksInProgressAndUnitsInTransitMember 2025-12-31 0001221029 cpac:NetBookValueMember cpac:TotalMember 2025-12-31 0001221029 cpac:CostMember cpac:ITApplicationsMember 2023-12-31 0001221029 cpac:CostMember cpac:FiniteLifeIntangibleMember 2023-12-31 0001221029 cpac:CostMember cpac:IndefiniteLifeIntangibleMember 2023-12-31 0001221029 cpac:CostMember cpac:ExplorationCostAndMiningEvaluationMember 2023-12-31 0001221029 cpac:CostMember cpac:IntangibleAssetMember 2023-12-31 0001221029 cpac:CostMember cpac:ITApplicationsMember 2024-01-01 2024-12-31 0001221029 cpac:CostMember cpac:FiniteLifeIntangibleMember 2024-01-01 2024-12-31 0001221029 cpac:CostMember cpac:IndefiniteLifeIntangibleMember 2024-01-01 2024-12-31 0001221029 cpac:CostMember cpac:ExplorationCostAndMiningEvaluationMember 2024-01-01 2024-12-31 0001221029 cpac:CostMember cpac:IntangibleAssetMember 2024-01-01 2024-12-31 0001221029 cpac:CostMember cpac:ITApplicationsMember 2024-12-31 0001221029 cpac:CostMember cpac:FiniteLifeIntangibleMember 2024-12-31 0001221029 cpac:CostMember cpac:IndefiniteLifeIntangibleMember 2024-12-31 0001221029 cpac:CostMember cpac:ExplorationCostAndMiningEvaluationMember 2024-12-31 0001221029 cpac:CostMember cpac:IntangibleAssetMember 2024-12-31 0001221029 cpac:CostMember cpac:ITApplicationsMember 2025-01-01 2025-12-31 0001221029 cpac:CostMember cpac:FiniteLifeIntangibleMember 2025-01-01 2025-12-31 0001221029 cpac:CostMember cpac:IndefiniteLifeIntangibleMember 2025-01-01 2025-12-31 0001221029 cpac:CostMember cpac:ExplorationCostAndMiningEvaluationMember 2025-01-01 2025-12-31 0001221029 cpac:CostMember cpac:IntangibleAssetMember 2025-01-01 2025-12-31 0001221029 cpac:CostMember cpac:ITApplicationsMember 2025-12-31 0001221029 cpac:CostMember cpac:FiniteLifeIntangibleMember 2025-12-31 0001221029 cpac:CostMember cpac:IndefiniteLifeIntangibleMember 2025-12-31 0001221029 cpac:CostMember cpac:ExplorationCostAndMiningEvaluationMember 2025-12-31 0001221029 cpac:CostMember cpac:IntangibleAssetMember 2025-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:ITApplicationsMember 2023-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:FiniteLifeIntangibleMember 2023-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:IndefiniteLifeIntangibleMember 2023-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:ExplorationCostAndMiningEvaluationMember 2023-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:IntangibleAssetMember 2023-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:ITApplicationsMember 2024-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:FiniteLifeIntangibleMember 2024-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:IndefiniteLifeIntangibleMember 2024-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:ExplorationCostAndMiningEvaluationMember 2024-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:IntangibleAssetMember 2024-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:ITApplicationsMember 2025-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:FiniteLifeIntangibleMember 2025-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:IndefiniteLifeIntangibleMember 2025-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:ExplorationCostAndMiningEvaluationMember 2025-12-31 0001221029 cpac:AccumulatedAmortization1Member cpac:IntangibleAssetMember 2025-12-31 0001221029 cpac:ImpairmentMember cpac:ITApplicationsMember 2023-12-31 0001221029 cpac:ImpairmentMember cpac:FiniteLifeIntangibleMember 2023-12-31 0001221029 cpac:ImpairmentMember cpac:IndefiniteLifeIntangibleMember 2023-12-31 0001221029 cpac:ImpairmentMember cpac:ExplorationCostAndMiningEvaluationMember 2023-12-31 0001221029 cpac:ImpairmentMember cpac:IntangibleAssetMember 2023-12-31 0001221029 cpac:ImpairmentMember cpac:ITApplicationsMember 2024-12-31 0001221029 cpac:ImpairmentMember cpac:FiniteLifeIntangibleMember 2024-12-31 0001221029 cpac:ImpairmentMember cpac:IndefiniteLifeIntangibleMember 2024-12-31 0001221029 cpac:ImpairmentMember cpac:ExplorationCostAndMiningEvaluationMember 2024-12-31 0001221029 cpac:ImpairmentMember cpac:IntangibleAssetMember 2024-12-31 0001221029 cpac:ImpairmentMember cpac:ITApplicationsMember 2025-12-31 0001221029 cpac:ImpairmentMember cpac:FiniteLifeIntangibleMember 2025-12-31 0001221029 cpac:ImpairmentMember cpac:IndefiniteLifeIntangibleMember 2025-12-31 0001221029 cpac:ImpairmentMember cpac:ExplorationCostAndMiningEvaluationMember 2025-12-31 0001221029 cpac:ImpairmentMember cpac:IntangibleAssetMember 2025-12-31 0001221029 cpac:NetCarryingValueMember cpac:ITApplicationsMember 2024-12-31 0001221029 cpac:NetCarryingValueMember cpac:FiniteLifeIntangibleMember 2024-12-31 0001221029 cpac:NetCarryingValueMember cpac:IndefiniteLifeIntangibleMember 2024-12-31 0001221029 cpac:NetCarryingValueMember cpac:ExplorationCostAndMiningEvaluationMember 2024-12-31 0001221029 cpac:NetCarryingValueMember cpac:IntangibleAssetMember 2024-12-31 0001221029 cpac:NetCarryingValueMember cpac:ITApplicationsMember 2025-12-31 0001221029 cpac:NetCarryingValueMember cpac:FiniteLifeIntangibleMember 2025-12-31 0001221029 cpac:NetCarryingValueMember cpac:IndefiniteLifeIntangibleMember 2025-12-31 0001221029 cpac:NetCarryingValueMember cpac:ExplorationCostAndMiningEvaluationMember 2025-12-31 0001221029 cpac:NetCarryingValueMember cpac:IntangibleAssetMember 2025-12-31 0001221029 cpac:ProvisionForWorkersProfitSharingMember ifrs-full:BottomOfRangeMember 2025-12-31 0001221029 cpac:ProvisionForWorkersProfitSharingMember ifrs-full:TopOfRangeMember 2025-12-31 0001221029 cpac:ProvisionForWorkersProfitSharingMember 2025-12-31 0001221029 cpac:ProvisionForWorkersProfitSharingMember 2024-12-31 0001221029 cpac:ProvisionForDecommissioningRestorationAndRehabilitationCostMember ifrs-full:BottomOfRangeMember 2025-12-31 0001221029 cpac:ProvisionForDecommissioningRestorationAndRehabilitationCostMember ifrs-full:TopOfRangeMember 2025-12-31 0001221029 cpac:ProvisionForDecommissioningRestorationAndRehabilitationCostMember ifrs-full:BottomOfRangeMember 2024-12-31 0001221029 cpac:ProvisionForDecommissioningRestorationAndRehabilitationCostMember ifrs-full:TopOfRangeMember 2024-12-31 0001221029 cpac:ProvisionForWorkersProfitSharingMember ifrs-full:BottomOfRangeMember 2024-12-31 0001221029 cpac:ProvisionForWorkersProfitSharingMember ifrs-full:TopOfRangeMember 2024-12-31 0001221029 cpac:ProvisionForWorkersProfitSharingMember 2023-12-31 0001221029 cpac:ProvisionForLongTermIncentivePlanMember 2023-12-31 0001221029 cpac:QuarryRehabilitationProvisionMember 2023-12-31 0001221029 cpac:ProvisionOfLegalContingenciesMember 2023-12-31 0001221029 cpac:ProvisionForWorkersProfitSharingMember 2024-01-01 2024-12-31 0001221029 cpac:ProvisionForLongTermIncentivePlanMember 2024-01-01 2024-12-31 0001221029 cpac:QuarryRehabilitationProvisionMember 2024-01-01 2024-12-31 0001221029 cpac:ProvisionOfLegalContingenciesMember 2024-01-01 2024-12-31 0001221029 cpac:ProvisionForLongTermIncentivePlanMember 2024-12-31 0001221029 cpac:QuarryRehabilitationProvisionMember 2024-12-31 0001221029 cpac:ProvisionOfLegalContingenciesMember 2024-12-31 0001221029 cpac:ProvisionForWorkersProfitSharingMember 2025-01-01 2025-12-31 0001221029 cpac:ProvisionForLongTermIncentivePlanMember 2025-01-01 2025-12-31 0001221029 cpac:QuarryRehabilitationProvisionMember 2025-01-01 2025-12-31 0001221029 cpac:ProvisionOfLegalContingenciesMember 2025-01-01 2025-12-31 0001221029 cpac:ProvisionForLongTermIncentivePlanMember 2025-12-31 0001221029 cpac:QuarryRehabilitationProvisionMember 2025-12-31 0001221029 cpac:ProvisionOfLegalContingenciesMember 2025-12-31 0001221029 cpac:SeniorNotesInSolesMember 2019-01-31 2019-01-31 0001221029 ifrs-full:FinancialGuaranteeContractsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:FinancialGuaranteeContractsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:FinancialGuaranteeContractsMember 2023-01-01 2023-12-31 0001221029 2021-08-06 2021-08-06 0001221029 cpac:FinancialDebtEBITDAMember 2025-01-01 2025-12-31 0001221029 cpac:FCSDSDMember 2025-01-01 2025-12-31 0001221029 cpac:EBITDASDMember 2025-01-01 2025-12-31 0001221029 cpac:January82026Member cpac:BancoGNBPerMember 2025-01-01 2025-12-31 0001221029 cpac:January82026Member cpac:BancoGNBPerMember 2025-12-31 0001221029 cpac:January82026Member cpac:BancoGNBPerMember 2024-12-31 0001221029 cpac:January82026Member cpac:InterbankMember 2025-01-01 2025-12-31 0001221029 cpac:January82026Member cpac:InterbankMember 2025-12-31 0001221029 cpac:January82026Member cpac:InterbankMember 2024-12-31 0001221029 cpac:February152026Member cpac:InterbankMember 2025-01-01 2025-12-31 0001221029 cpac:February152026Member cpac:InterbankMember 2025-12-31 0001221029 cpac:February152026Member cpac:InterbankMember 2024-12-31 0001221029 cpac:March52026Member cpac:ScotiabankMember 2025-01-01 2025-12-31 0001221029 cpac:March52026Member cpac:ScotiabankMember 2025-12-31 0001221029 cpac:March52026Member cpac:ScotiabankMember 2024-12-31 0001221029 cpac:May222026Member cpac:BancoDeCrditoDelPerMember 2025-01-01 2025-12-31 0001221029 cpac:May222026Member cpac:BancoDeCrditoDelPerMember 2025-12-31 0001221029 cpac:May222026Member cpac:BancoDeCrditoDelPerMember 2024-12-31 0001221029 cpac:November122026Member cpac:BancoDeCrditoDelPerMember 2025-01-01 2025-12-31 0001221029 cpac:November122026Member cpac:BancoDeCrditoDelPerMember 2025-12-31 0001221029 cpac:November122026Member cpac:BancoDeCrditoDelPerMember 2024-12-31 0001221029 cpac:November242026Member cpac:BBVAPeruMember 2025-01-01 2025-12-31 0001221029 cpac:November242026Member cpac:BBVAPeruMember 2025-12-31 0001221029 cpac:November242026Member cpac:BBVAPeruMember 2024-12-31 0001221029 cpac:November262026Member cpac:BancoDeCrditoDelPerMember 2025-01-01 2025-12-31 0001221029 cpac:November262026Member cpac:BancoDeCrditoDelPerMember 2025-12-31 0001221029 cpac:November262026Member cpac:BancoDeCrditoDelPerMember 2024-12-31 0001221029 cpac:November302026Member cpac:BancoDeCrditoDelPerMember 2025-01-01 2025-12-31 0001221029 cpac:November302026Member cpac:BancoDeCrditoDelPerMember 2025-12-31 0001221029 cpac:November302026Member cpac:BancoDeCrditoDelPerMember 2024-12-31 0001221029 cpac:January132025Member cpac:BancoDeCrditoDelPerMember 2025-01-01 2025-12-31 0001221029 cpac:January132025Member cpac:BancoDeCrditoDelPerMember 2025-12-31 0001221029 cpac:January132025Member cpac:BancoDeCrditoDelPerMember 2024-12-31 0001221029 cpac:January162025Member cpac:BancoDeCrditoDelPerMember 2025-01-01 2025-12-31 0001221029 cpac:January162025Member cpac:BancoDeCrditoDelPerMember 2025-12-31 0001221029 cpac:January162025Member cpac:BancoDeCrditoDelPerMember 2024-12-31 0001221029 cpac:February212025Member cpac:BancoDeCrditoDelPerMember 2025-01-01 2025-12-31 0001221029 cpac:February212025Member cpac:BancoDeCrditoDelPerMember 2025-12-31 0001221029 cpac:February212025Member cpac:BancoDeCrditoDelPerMember 2024-12-31 0001221029 cpac:March102025Member cpac:ScotiabankMember 2025-01-01 2025-12-31 0001221029 cpac:March102025Member cpac:ScotiabankMember 2025-12-31 0001221029 cpac:March102025Member cpac:ScotiabankMember 2024-12-31 0001221029 cpac:November172025Member cpac:BancoGNBPerMember 2025-01-01 2025-12-31 0001221029 cpac:November172025Member cpac:BancoGNBPerMember 2025-12-31 0001221029 cpac:November172025Member cpac:BancoGNBPerMember 2024-12-31 0001221029 cpac:November242025Member cpac:BancoDeCrditoDelPerMember 2025-01-01 2025-12-31 0001221029 cpac:November242025Member cpac:BancoDeCrditoDelPerMember 2025-12-31 0001221029 cpac:November242025Member cpac:BancoDeCrditoDelPerMember 2024-12-31 0001221029 cpac:December52025Member cpac:BancoDeCrditoDelPerMember 2025-01-01 2025-12-31 0001221029 cpac:December52025Member cpac:BancoDeCrditoDelPerMember 2025-12-31 0001221029 cpac:December52025Member cpac:BancoDeCrditoDelPerMember 2024-12-31 0001221029 cpac:ShorttermPromissoryNotesMember 2025-12-31 0001221029 cpac:ShorttermPromissoryNotesMember 2024-12-31 0001221029 cpac:February12029Member cpac:SeniorNoteMember 2025-01-01 2025-12-31 0001221029 cpac:February12029Member cpac:SeniorNoteMember 2025-12-31 0001221029 cpac:February12029Member cpac:SeniorNoteMember 2024-12-31 0001221029 cpac:February12034Member cpac:SeniorNoteMember 2025-01-01 2025-12-31 0001221029 cpac:February12034Member cpac:SeniorNoteMember 2025-12-31 0001221029 cpac:February12034Member cpac:SeniorNoteMember 2024-12-31 0001221029 cpac:SeniorNoteMember 2025-12-31 0001221029 cpac:SeniorNoteMember 2024-12-31 0001221029 cpac:December12028Member cpac:ShortAndLongtermCorporateLoanMember cpac:BancoDeCrditoDelPerMember 2025-01-01 2025-12-31 0001221029 cpac:December12028Member cpac:ShortAndLongtermCorporateLoanMember cpac:BancoDeCrditoDelPerMember 2025-12-31 0001221029 cpac:December12028Member cpac:ShortAndLongtermCorporateLoanMember cpac:BancoDeCrditoDelPerMember 2024-12-31 0001221029 cpac:December12028Member cpac:ShortAndLongtermCorporateLoanMember cpac:ScotiabankMember 2025-01-01 2025-12-31 0001221029 cpac:December12028Member cpac:ShortAndLongtermCorporateLoanMember cpac:ScotiabankMember 2025-12-31 0001221029 cpac:December12028Member cpac:ShortAndLongtermCorporateLoanMember cpac:ScotiabankMember 2024-12-31 0001221029 cpac:ShortAndLongtermCorporateLoanMember 2025-12-31 0001221029 cpac:ShortAndLongtermCorporateLoanMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ImpairmentOfInvestmentsInSubsidiaryMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ImpairmentOfInvestmentsInSubsidiaryMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ImpairmentOfInvestmentsInSubsidiaryMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ImpairmentOfInvestmentsInSubsidiaryMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ImpairmentOfInvestmentsInSubsidiaryMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionOfDiscountsAndBonusesToCustomersMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionOfDiscountsAndBonusesToCustomersMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionOfDiscountsAndBonusesToCustomersMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionOfDiscountsAndBonusesToCustomersMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionOfDiscountsAndBonusesToCustomersMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionForExpectedCreditLossesOnTradeAccountsReceivableMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionForExpectedCreditLossesOnTradeAccountsReceivableMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionForExpectedCreditLossesOnTradeAccountsReceivableMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionForExpectedCreditLossesOnTradeAccountsReceivableMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionForExpectedCreditLossesOnTradeAccountsReceivableMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionForVacationsMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionForVacationsMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionForVacationsMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionForVacationsMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:ProvisionForVacationsMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EffectOfDifferencesBetweenBookAndTaxBasesOfInventoriesMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EffectOfDifferencesBetweenBookAndTaxBasesOfInventoriesMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EffectOfDifferencesBetweenBookAndTaxBasesOfInventoriesMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EffectOfDifferencesBetweenBookAndTaxBasesOfInventoriesMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EffectOfDifferencesBetweenBookAndTaxBasesOfInventoriesMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember ifrs-full:LeaseLiabilitiesMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember ifrs-full:LeaseLiabilitiesMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember ifrs-full:LeaseLiabilitiesMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember ifrs-full:LeaseLiabilitiesMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember ifrs-full:LeaseLiabilitiesMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EffectOfDifferencesBetweenBookAndTaxBasesOfFixedAssetsMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EffectOfDifferencesBetweenBookAndTaxBasesOfFixedAssetsMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EffectOfDifferencesBetweenBookAndTaxBasesOfFixedAssetsMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EffectOfDifferencesBetweenBookAndTaxBasesOfFixedAssetsMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EffectOfDifferencesBetweenBookAndTaxBasesOfFixedAssetsMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:LegalClaimContingencyMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:LegalClaimContingencyMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:LegalClaimContingencyMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:LegalClaimContingencyMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:LegalClaimContingencyMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EstimateForDevaluationOfSparePartsAndSuppliesMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EstimateForDevaluationOfSparePartsAndSuppliesMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EstimateForDevaluationOfSparePartsAndSuppliesMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EstimateForDevaluationOfSparePartsAndSuppliesMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:EstimateForDevaluationOfSparePartsAndSuppliesMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:OtherDeferredIncomeTaxAssetsMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:OtherDeferredIncomeTaxAssetsMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:OtherDeferredIncomeTaxAssetsMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:OtherDeferredIncomeTaxAssetsMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:OtherDeferredIncomeTaxAssetsMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:TotalDeferredIncomeTaxAssetsMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:TotalDeferredIncomeTaxAssetsMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:TotalDeferredIncomeTaxAssetsMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:TotalDeferredIncomeTaxAssetsMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxAssetsMember cpac:TotalDeferredIncomeTaxAssetsMember 2025-12-31 0001221029 cpac:DeferredIncomeTaxLiabilitiesMember ifrs-full:RightofuseAssetsMember 2023-12-31 0001221029 cpac:DeferredIncomeTaxLiabilitiesMember ifrs-full:RightofuseAssetsMember 2024-01-01 2024-12-31 0001221029 cpac:DeferredIncomeTaxLiabilitiesMember ifrs-full:RightofuseAssetsMember 2024-12-31 0001221029 cpac:DeferredIncomeTaxLiabilitiesMember ifrs-full:RightofuseAssetsMember 2025-01-01 2025-12-31 0001221029 cpac:DeferredIncomeTaxLiabilitiesMember ifrs-full:RightofuseAssetsMember 2025-12-31 0001221029 cpac:DeferredIncomeTaxLiabilitiesMember cpac:OtherDeferredIncomeTaxAssetsOneMember 2023-12-31 0001221029 cpac:DeferredIncomeTaxLiabilitiesMember cpac:OtherDeferredIncomeTaxAssetsOneMember 2024-01-01 2024-12-31 0001221029 cpac:DeferredIncomeTaxLiabilitiesMember cpac:OtherDeferredIncomeTaxAssetsOneMember 2024-12-31 0001221029 cpac:DeferredIncomeTaxLiabilitiesMember cpac:OtherDeferredIncomeTaxAssetsOneMember 2025-01-01 2025-12-31 0001221029 cpac:DeferredIncomeTaxLiabilitiesMember cpac:OtherDeferredIncomeTaxAssetsOneMember 2025-12-31 0001221029 cpac:TotalDeferredIncomeTaxLiabilitiesThreeMember 2023-12-31 0001221029 cpac:TotalDeferredIncomeTaxLiabilitiesThreeMember 2024-01-01 2024-12-31 0001221029 cpac:TotalDeferredIncomeTaxLiabilitiesThreeMember 2024-12-31 0001221029 cpac:TotalDeferredIncomeTaxLiabilitiesThreeMember 2025-01-01 2025-12-31 0001221029 cpac:TotalDeferredIncomeTaxLiabilitiesThreeMember 2025-12-31 0001221029 cpac:TotalDeferredIncomeTaxLiabilitiesNetMember 2023-12-31 0001221029 cpac:TotalDeferredIncomeTaxLiabilitiesNetMember 2024-01-01 2024-12-31 0001221029 cpac:TotalDeferredIncomeTaxLiabilitiesNetMember 2024-12-31 0001221029 cpac:TotalDeferredIncomeTaxLiabilitiesNetMember 2025-01-01 2025-12-31 0001221029 cpac:TotalDeferredIncomeTaxLiabilitiesNetMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProjectDeteriorationSalmuerasMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProjectDeteriorationSalmuerasMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProjectDeteriorationSalmuerasMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProjectDeteriorationSalmuerasMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProjectDeteriorationSalmuerasMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ImpairmentOfFixedAssetsMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ImpairmentOfFixedAssetsMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ImpairmentOfFixedAssetsMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ImpairmentOfFixedAssetsMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ImpairmentOfFixedAssetsMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:FinancialInstrumentAtFairValueWithChangesInOtherComprehensiveIncomeMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:FinancialInstrumentAtFairValueWithChangesInOtherComprehensiveIncomeMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:FinancialInstrumentAtFairValueWithChangesInOtherComprehensiveIncomeMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:FinancialInstrumentAtFairValueWithChangesInOtherComprehensiveIncomeMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:FinancialInstrumentAtFairValueWithChangesInOtherComprehensiveIncomeMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EstimateForDepreciationOfSparePartsAndSuppliesMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EstimateForDepreciationOfSparePartsAndSuppliesMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EstimateForDepreciationOfSparePartsAndSuppliesMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EstimateForDepreciationOfSparePartsAndSuppliesMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EstimateForDepreciationOfSparePartsAndSuppliesMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EstimationForImpairmentOfMiningAssetsMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EstimationForImpairmentOfMiningAssetsMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EstimationForImpairmentOfMiningAssetsMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EstimationForImpairmentOfMiningAssetsMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EstimationForImpairmentOfMiningAssetsMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForQuarryClosureMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForQuarryClosureMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForQuarryClosureMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForQuarryClosureMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForQuarryClosureMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForVacationsMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForVacationsMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForVacationsMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForVacationsMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForVacationsMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForCompensationToOfficialsMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForCompensationToOfficialsMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForCompensationToOfficialsMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForCompensationToOfficialsMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForCompensationToOfficialsMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember ifrs-full:LeaseLiabilitiesMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember ifrs-full:LeaseLiabilitiesMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember ifrs-full:LeaseLiabilitiesMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember ifrs-full:LeaseLiabilitiesMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember ifrs-full:LeaseLiabilitiesMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForExpectedCreditLossesOnTradeAccountsReceivableMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForExpectedCreditLossesOnTradeAccountsReceivableMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForExpectedCreditLossesOnTradeAccountsReceivableMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForExpectedCreditLossesOnTradeAccountsReceivableMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:ProvisionForExpectedCreditLossesOnTradeAccountsReceivableMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:LegalClaimContingencyMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:LegalClaimContingencyMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:LegalClaimContingencyMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:LegalClaimContingencyMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:LegalClaimContingencyMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:OtherDeferredIncomeTaxAssetsTwoMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:OtherDeferredIncomeTaxAssetsTwoMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:OtherDeferredIncomeTaxAssetsTwoMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:OtherDeferredIncomeTaxAssetsTwoMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:OtherDeferredIncomeTaxAssetsTwoMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxAssetsOneMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxAssetsOneMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxAssetsOneMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxAssetsOneMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxAssetsOneMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EffectOfTheDifferenceBetweenAccountingAndTaxBasesOfFixedAssetsAndTheDifferenceInDepreciationRatesMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EffectOfTheDifferenceBetweenAccountingAndTaxBasesOfFixedAssetsAndTheDifferenceInDepreciationRatesMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EffectOfTheDifferenceBetweenAccountingAndTaxBasesOfFixedAssetsAndTheDifferenceInDepreciationRatesMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EffectOfTheDifferenceBetweenAccountingAndTaxBasesOfFixedAssetsAndTheDifferenceInDepreciationRatesMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EffectOfTheDifferenceBetweenAccountingAndTaxBasesOfFixedAssetsAndTheDifferenceInDepreciationRatesMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember ifrs-full:RightofuseAssetsMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember ifrs-full:RightofuseAssetsMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember ifrs-full:RightofuseAssetsMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember ifrs-full:RightofuseAssetsMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember ifrs-full:RightofuseAssetsMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EffectOfCostsIncurredFromBondIssuanceMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EffectOfCostsIncurredFromBondIssuanceMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EffectOfCostsIncurredFromBondIssuanceMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EffectOfCostsIncurredFromBondIssuanceMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:EffectOfCostsIncurredFromBondIssuanceMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:OtherMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:OtherMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:OtherMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:OtherMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:OtherMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxLiabilitiesMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxLiabilitiesMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxLiabilitiesMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxLiabilitiesMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxLiabilitiesMember 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxLiabilitiesNetMember 2023-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxLiabilitiesNetMember 2024-01-01 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxLiabilitiesNetMember 2024-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxLiabilitiesNetMember 2025-01-01 2025-12-31 0001221029 cpac:MovementOfDeferredIncomeTaxLiabilitiesMember cpac:TotalDeferredIncomeTaxLiabilitiesNetMember 2025-12-31 0001221029 cpac:TotalDeferredIncomeTaxLiabilitiesMember 2024-01-01 2024-12-31 0001221029 cpac:TotalDeferredIncomeTaxLiabilitiesMember 2025-01-01 2025-12-31 0001221029 cpac:NewYorkStockExchangeMember 2025-12-31 0001221029 cpac:LimaStockExchangeMember 2025-12-31 0001221029 cpac:NewYorkStockExchangeMember 2024-12-31 0001221029 cpac:LimaStockExchangeMember 2024-12-31 0001221029 cpac:InvestmentSharesMember 2025-12-31 0001221029 cpac:InvestmentSharesMember 2024-12-31 0001221029 cpac:CementMember 2025-01-01 2025-12-31 0001221029 cpac:ConcretePavementAndMortarMember 2025-01-01 2025-12-31 0001221029 cpac:PrecastMember 2025-01-01 2025-12-31 0001221029 cpac:ConstructionSuppliesMember 2025-01-01 2025-12-31 0001221029 cpac:OtherMember 2025-01-01 2025-12-31 0001221029 cpac:CementMember 2024-01-01 2024-12-31 0001221029 cpac:ConcretePavementAndMortarMember 2024-01-01 2024-12-31 0001221029 cpac:PrecastMember 2024-01-01 2024-12-31 0001221029 cpac:ConstructionSuppliesMember 2024-01-01 2024-12-31 0001221029 cpac:OtherMember 2024-01-01 2024-12-31 0001221029 cpac:CementMember 2023-01-01 2023-12-31 0001221029 cpac:ConcretePavementAndMortarMember 2023-01-01 2023-12-31 0001221029 cpac:PrecastMember 2023-01-01 2023-12-31 0001221029 cpac:ConstructionSuppliesMember 2023-01-01 2023-12-31 0001221029 cpac:OtherMember 2023-01-01 2023-12-31 0001221029 cpac:InversionesASPIMember 2025-01-01 2025-12-31 0001221029 cpac:InversionesASPIMember 2024-01-01 2024-12-31 0001221029 cpac:InversionesASPIMember 2023-01-01 2023-12-31 0001221029 cpac:CompaaMineraAresSACMember 2025-01-01 2025-12-31 0001221029 cpac:CompaaMineraAresSACMember 2024-01-01 2024-12-31 0001221029 cpac:CompaaMineraAresSACMember 2023-01-01 2023-12-31 0001221029 cpac:FosfatosDelPacficoSAMember 2025-01-01 2025-12-31 0001221029 cpac:FosfatosDelPacficoSAMember 2024-01-01 2024-12-31 0001221029 cpac:FosfatosDelPacficoSAMember 2023-01-01 2023-12-31 0001221029 cpac:FossalSAAMember 2025-01-01 2025-12-31 0001221029 cpac:FossalSAAMember 2024-01-01 2024-12-31 0001221029 cpac:FossalSAAMember 2023-01-01 2023-12-31 0001221029 cpac:AsociacinSumacTarpuyMember 2025-01-01 2025-12-31 0001221029 cpac:AsociacinSumacTarpuyMember 2024-01-01 2024-12-31 0001221029 cpac:AsociacinSumacTarpuyMember 2023-01-01 2023-12-31 0001221029 cpac:InversionesMoraySACMember 2025-01-01 2025-12-31 0001221029 cpac:InversionesMoraySACMember 2024-01-01 2024-12-31 0001221029 cpac:InversionesMoraySACMember 2023-01-01 2023-12-31 0001221029 cpac:SecurityServicesProvidedByCompaaMineraAresSACMember 2025-01-01 2025-12-31 0001221029 cpac:SecurityServicesProvidedByCompaaMineraAresSACMember 2024-01-01 2024-12-31 0001221029 cpac:SecurityServicesProvidedByCompaaMineraAresSACMember 2023-01-01 2023-12-31 0001221029 cpac:InversionesASPISAMember 2025-12-31 0001221029 cpac:InversionesASPISAMember 2024-12-31 0001221029 cpac:FosfatosDelPacficoSAMember 2025-12-31 0001221029 cpac:FosfatosDelPacficoSAMember 2024-12-31 0001221029 cpac:CompaniaMineraAresSACMember 2025-12-31 0001221029 cpac:CompaniaMineraAresSACMember 2024-12-31 0001221029 cpac:FossalSAMember 2025-12-31 0001221029 cpac:FossalSAMember 2024-12-31 0001221029 cpac:OtherMember 2025-12-31 0001221029 cpac:OtherMember 2024-12-31 0001221029 ifrs-full:OtherRelatedPartiesMember 2025-12-31 0001221029 ifrs-full:OtherRelatedPartiesMember 2024-12-31 0001221029 2013-01-01 2013-12-31 0001221029 ifrs-full:ContingentLiabilityArisingFromPostemploymentBenefitObligationsMember 2025-01-01 2025-12-31 0001221029 cpac:PeruvianGovernmentMember 2025-01-01 2025-12-31 0001221029 ifrs-full:BottomOfRangeMember 2024-01-01 2024-12-31 0001221029 ifrs-full:BottomOfRangeMember 2023-01-01 2023-12-31 0001221029 ifrs-full:TopOfRangeMember 2024-01-01 2024-12-31 0001221029 ifrs-full:TopOfRangeMember 2023-01-01 2023-12-31 0001221029 cpac:RehabilitationProvisionMember 2025-12-31 0001221029 cpac:RehabilitationProvisionMember 2024-12-31 0001221029 cpac:TwoThousandTwentySixPlanMember 2025-01-01 2025-12-31 0001221029 cpac:TwoThousandTwentySevenPlanMember 2025-01-01 2025-12-31 0001221029 cpac:CementosPacasmayoSAAMember 2025-01-01 2025-12-31 0001221029 cpac:CementosSelvaSACMember 2025-01-01 2025-12-31 0001221029 cpac:DistribuidoraNortePacasmayoSRLMember 2025-01-01 2025-12-31 0001221029 cpac:EmpresaDeTransmisinGuadalupeSACMember 2025-01-01 2025-12-31 0001221029 cpac:SalmuerasSudamericanasSAMember 2025-01-01 2025-12-31 0001221029 cpac:CalizasDelNorteSACMember 2025-01-01 2025-12-31 0001221029 cpac:SolucionesTakaySACMember 2025-01-01 2025-12-31 0001221029 cpac:CorporacinMaterialesPiuraSACMember 2025-01-01 2025-12-31 0001221029 cpac:SolucionesCrealo150SACMember 2025-01-01 2025-12-31 0001221029 cpac:VanguardiaConstructoraDelPerSACMember 2025-01-01 2025-12-31 0001221029 cpac:RiojaProjectUnitMember 2025-01-01 2025-12-31 0001221029 cpac:RiojaProjectUnitMember 2024-01-01 2024-12-31 0001221029 cpac:RiojaProjectUnitMember 2023-01-01 2023-12-31 0001221029 cpac:TembladeraMember 2025-01-01 2025-12-31 0001221029 cpac:TembladeraMember 2024-01-01 2024-12-31 0001221029 cpac:TembladeraMember 2023-01-01 2023-12-31 0001221029 ifrs-full:TradeReceivablesMember 2025-01-01 2025-12-31 0001221029 ifrs-full:TradeReceivablesMember 2024-01-01 2024-12-31 0001221029 ifrs-full:TopOfRangeMember 2025-12-31 0001221029 ifrs-full:BottomOfRangeMember 2025-12-31 0001221029 ifrs-full:TradeReceivablesMember cpac:CustomersTwentySixMember 2025-01-01 2025-12-31 0001221029 ifrs-full:TradeReceivablesMember cpac:CustomersTwentyTwoMember 2024-01-01 2024-12-31 0001221029 ifrs-full:TopOfRangeMember 2024-12-31 0001221029 ifrs-full:BottomOfRangeMember 2024-12-31 0001221029 cpac:ChangesInExchangeRatePlusFiveMember cpac:ForeignCurrencyRiskMember 2025-01-01 2025-12-31 0001221029 cpac:ChangeInExchangeRatePlusTenMember cpac:ForeignCurrencyRiskMember 2025-01-01 2025-12-31 0001221029 cpac:ChangeInExchangeRateMinusFiveMember cpac:ForeignCurrencyRiskMember 2025-01-01 2025-12-31 0001221029 cpac:ChangeInExchangeRateMinusTenMember cpac:ForeignCurrencyRiskMember 2025-01-01 2025-12-31 0001221029 cpac:ChangesInExchangeRatePlusFiveMember cpac:ForeignCurrencyRiskMember 2024-01-01 2024-12-31 0001221029 cpac:ChangeInExchangeRatePlusTenMember cpac:ForeignCurrencyRiskMember 2024-01-01 2024-12-31 0001221029 cpac:ChangeInExchangeRateMinusFiveMember cpac:ForeignCurrencyRiskMember 2024-01-01 2024-12-31 0001221029 cpac:ChangeInExchangeRateMinusTenMember cpac:ForeignCurrencyRiskMember 2024-01-01 2024-12-31 0001221029 ifrs-full:NotLaterThanThreeMonthsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:LaterThanThreeMonthsAndNotLaterThanOneYearMember 2025-01-01 2025-12-31 0001221029 ifrs-full:LaterThanOneYearAndNotLaterThanFiveYearsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:LaterThanFiveYearsMember 2025-01-01 2025-12-31 0001221029 ifrs-full:NotLaterThanThreeMonthsMember 2025-12-31 0001221029 ifrs-full:LaterThanThreeMonthsAndNotLaterThanOneYearMember 2025-12-31 0001221029 ifrs-full:LaterThanOneYearAndNotLaterThanFiveYearsMember 2025-12-31 0001221029 ifrs-full:LaterThanFiveYearsMember 2025-12-31 0001221029 ifrs-full:NotLaterThanThreeMonthsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:LaterThanThreeMonthsAndNotLaterThanOneYearMember 2024-01-01 2024-12-31 0001221029 ifrs-full:LaterThanOneYearAndNotLaterThanFiveYearsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:LaterThanFiveYearsMember 2024-01-01 2024-12-31 0001221029 ifrs-full:NotLaterThanThreeMonthsMember 2024-12-31 0001221029 ifrs-full:LaterThanThreeMonthsAndNotLaterThanOneYearMember 2024-12-31 0001221029 ifrs-full:LaterThanOneYearAndNotLaterThanFiveYearsMember 2024-12-31 0001221029 ifrs-full:LaterThanFiveYearsMember 2024-12-31 0001221029 cpac:DividendsPayableMember 2024-12-31 0001221029 cpac:DividendsPayableMember 2025-01-01 2025-12-31 0001221029 cpac:DividendsPayableMember 2025-12-31 0001221029 cpac:FinancialObligationsMember 2024-12-31 0001221029 cpac:FinancialObligationsMember 2025-01-01 2025-12-31 0001221029 cpac:FinancialObligationsMember 2025-12-31 0001221029 cpac:DividendsPayableMember 2023-12-31 0001221029 cpac:DividendsPayableMember 2024-01-01 2024-12-31 0001221029 cpac:FinancialObligationsMember 2023-12-31 0001221029 cpac:FinancialObligationsMember 2024-01-01 2024-12-31 0001221029 cpac:CashEquivalentMember ifrs-full:Level1OfFairValueHierarchyMember 2025-12-31 0001221029 cpac:CashEquivalentMember ifrs-full:Level1OfFairValueHierarchyMember 2024-12-31 0001221029 cpac:TradeAndOtherReceivablesMember ifrs-full:Level2OfFairValueHierarchyMember 2025-12-31 0001221029 cpac:TradeAndOtherReceivablesMember ifrs-full:Level2OfFairValueHierarchyMember 2024-12-31 0001221029 cpac:DerivativesFinancialAssetsCrossCurrencySwapsMember ifrs-full:Level3OfFairValueHierarchyMember 2025-12-31 0001221029 cpac:DerivativesFinancialAssetsCrossCurrencySwapsMember ifrs-full:Level3OfFairValueHierarchyMember 2024-12-31 0001221029 cpac:TradeAndOtherPayablesMember ifrs-full:Level2OfFairValueHierarchyMember 2025-12-31 0001221029 cpac:TradeAndOtherPayablesMember ifrs-full:Level2OfFairValueHierarchyMember 2024-12-31 0001221029 cpac:SeniorNoteMember ifrs-full:Level1OfFairValueHierarchyMember 2025-12-31 0001221029 cpac:SeniorNoteMember ifrs-full:Level1OfFairValueHierarchyMember 2024-12-31 0001221029 cpac:FixedRateNotesAndLoansMember ifrs-full:Level2OfFairValueHierarchyMember 2025-12-31 0001221029 cpac:FixedRateNotesAndLoansMember ifrs-full:Level2OfFairValueHierarchyMember 2024-12-31 0001221029 cpac:CementConcretePavementMortarAndPrecastMember 2025-01-01 2025-12-31 0001221029 cpac:TotalConsolidatedMember 2025-01-01 2025-12-31 0001221029 cpac:CementConcretePavementMortarAndPrecastMember 2024-01-01 2024-12-31 0001221029 cpac:TotalConsolidatedMember 2024-01-01 2024-12-31 0001221029 cpac:CementConcretePavementMortarAndPrecastMember 2023-01-01 2023-12-31 0001221029 cpac:TotalConsolidatedMember 2023-01-01 2023-12-31 0001221029 cpac:CementConcretePavementMortarAndPrecastMember 2025-12-31 0001221029 cpac:ConstructionSuppliesMember 2025-12-31 0001221029 cpac:OtherMember 2025-12-31 0001221029 cpac:TotalConsolidatedMember 2025-12-31 0001221029 cpac:CementConcretePavementMortarAndPrecastMember 2024-12-31 0001221029 cpac:ConstructionSuppliesMember 2024-12-31 0001221029 cpac:OtherMember 2024-12-31 0001221029 cpac:TotalConsolidatedMember 2024-12-31 0001221029 cpac:CementConcretePavementMortarAndPrecastMember 2023-12-31 0001221029 cpac:ConstructionSuppliesMember 2023-12-31 0001221029 cpac:OtherMember 2023-12-31 0001221029 cpac:TotalConsolidatedMember 2023-12-31 0001221029 cpac:InversionesASPISAMember cpac:NonadjustingEventsMember 2026-03-30 2026-03-30 0001221029 cpac:CementosPacasmayoSAAMember cpac:NonadjustingEventsMember 2026-03-30 2026-03-30 xbrli:shares iso4217:PEN iso4217:PEN xbrli:shares xbrli:pure iso4217:USD

Exhibit 2(d)


Description of Securities Registered under Section 12(b) of the Exchange Act


As of December 31, 2025, Cementos Pacasmayo S.A.A. (the “Company,” “we,” “us” or “our”) had one class of securities registered under Section 12(b) of the U.S. Securities Exchange Act of 1934, as amended – American Depositary Shares (“ADS”), each representing five common shares issued by the Company, each of which has a par value of 1.00 Peruvian Sol per share.


The following is a summary of the terms of our ADS and our common shares, and certain material provisions of our by-laws. We have filed copies of our by-laws as exhibit 1.1 to our annual report on Form 20-F filed on April 28, 2022. As well, our by-laws are available in our website (www.cementospacasmayo.com.pe).


Description of American Depositary Shares


General


The depositary for the ADSs is JPMorgan Chase Bank, N.A. Each ADS represents an ownership interest in five common shares which have been deposited with the custodian, Citibank del Perú S.A., as agent of the depositary, under the deposit agreement among us, the depositary and all registered holders from time to time of ADSs issued under the deposit agreement. In the future, each ADS will also represent any securities, cash or other property deposited with the depositary but which they have not distributed directly to holders of ADSs. Unless specifically requested by an ADS holder, all ADSs will be issued on the books of our depositary in book-entry form and periodic statements will be mailed to ADS holders which reflect such holders’ ownership interest in such ADSs.


The depositary’s offices are located at 270 Park Avenue, Floor 08, New York NY 10017. ADSs may be held either directly or indirectly through brokers or other financial institutions. If a holder holds ADSs directly, by having an ADS registered in such holder’s name on the books of the depositary, such person is a holder of American Depositary Receipts (“ADRs”). This description assumes that ADSs are held directly. If a holder holds ADSs through its broker or financial institution nominee, such holder must rely on the procedures of such broker or financial institution to assert the rights of an ADR holder described in this section. Holders should consult with their brokers or financial institutions to find out what those procedures are.


ADR holders have no direct ownership interest in our common shares and only have the rights of an ADR holder specified in the deposit agreement. Such rights derive from the terms of the deposit agreement to be entered into among us, the depositary and all registered holders from time to time of ADSs issued under the deposit agreement. The obligations of the depositary and its agents are also set out in the deposit agreement. Because the depositary or its nominee will actually be the registered owner of the common shares, a holder of ADSs must rely on the depositary or its nominee to exercise the rights of a shareholder on behalf of such holder. The deposit agreement and the ADSs are governed by New York State law. However, our obligations to the holders of common shares represented by the ADSs will continue to be governed by the laws of Peru, which may be different from the laws of the State of New York.


The following is a summary of what we believe to be the material terms of the deposit agreement. This summary is qualified in its entirety by reference to, and should be read in conjunction with, the entire deposit agreement and the form of ADR which contains the complete terms of the ADSs. You can read a copy of the deposit agreement, which was filed as exhibit 4.2 to our Form f-1 filed on January 6, 2012, as well as Amendment 1, filed on Form F-6 on February 21, 2017 and Amendment 2, filed as Form F-6 on December 4, 2020. We encourage you to review these documents carefully if you are a holder of ADRs. You may obtain information on the operation of the Public Reference Room by calling the SEC at 1-800-732-0330. You may also find our annual reports on Form 20-F and the deposit agreement on the SEC’s website at http://www.sec.gov.


Dividends and Other Distributions


We may make various types of distributions with respect to our securities. The depositary has agreed that, to the extent practicable, it will pay to holders of ADSs the cash dividends or other distributions it or the custodian receives on common shares or other deposited securities, after converting any cash received into U.S. dollars and, in all cases, making any necessary deductions provided for in the deposit agreement. Each ADS holder will receive these distributions in proportion to the number of underlying securities that such holder’s ADSs represent.


Except as stated below, the depositary will deliver such distributions to ADR holders in proportion to their interests in the following manner:


Distribution of cash. The depositary will distribute any U.S. dollars available to it resulting from a cash dividend or other cash distribution or the net proceeds of sales of any other distribution or portion thereof (to the extent applicable), on an averaged or other practicable basis, subject to (i) appropriate adjustments for taxes withheld, (ii) such distribution being impermissible or impracticable with respect to certain registered ADR holders, and (iii) deduction of the depositary’s expenses in (1) converting any foreign currency to U.S. dollars to the extent that it determines that such conversion may be made on a reasonable basis, (2) transferring foreign currency or U.S. dollars to the United States by such means as the depositary may determine to the extent that it determines that such transfer may be made on a reasonable basis, (3) obtaining any approval or license of any governmental authority required for such conversion or transfer, which is obtainable at a reasonable cost and within a reasonable time and (4) making any sale by public or private means in any commercially reasonable manner. If exchange rates fluctuate during a time when the depositary cannot convert a foreign currency, a holder may lose some or all of the value of the distribution.


Distribution of common shares. In the case of a distribution of common shares, the depositary will issue additional ADRs to evidence the number of ADSs representing such common shares. Only whole ADSs will be issued. Any common shares which would result in fractional ADSs will be sold and the net proceeds will be distributed in the same manner as cash to the ADR holders entitled thereto.


No distribution of ADRs as described above will be made if it violates U.S. securities laws, or any other law, or if it is not operationally practicable. If the depositary does not distribute new ADRs as described above, it will use its best efforts to sell the common shares received and distribute the proceeds of the sale in the same manner as a cash distribution.


Rights to receive additional common shares. In the case of a distribution of rights to subscribe for additional common shares or other rights, if we provide evidence satisfactory to the depositary that it may lawfully distribute such rights, the depositary will distribute warrants or other instruments in the discretion of the depositary representing such rights. If we do not furnish such evidence, the depositary may:


●sell such rights if practicable and distribute the net proceeds in the same manner as cash distributions to the ADR holders entitled thereto; or


●if it is not reasonably practicable to sell such rights, do nothing and allow such rights to lapse, in which case ADR holders will receive nothing


We have no obligation to file a registration statement under the Securities Act in order to make any rights available to ADR holders.


Other Distributions. In the case of a distribution of securities or property other than those described above, the depositary may either (i) distribute such securities or property in any manner it deems equitable and practicable or (ii) to the extent the depositary deems distribution of such securities or property not to be equitable and practicable, sell such securities or property and distribute any net proceeds in the same manner it distributes cash.


2


If the depositary determines that any distribution described above is not practicable with respect to any specific registered ADR holder, the depositary may choose any method of distribution that it deems practicable for such ADR holder, including the distribution of foreign currency, securities or property, or it may retain such items, without paying interest on or investing them, on behalf of the ADR holder as deposited securities, in which case the ADSs will also represent the retained items.


U.S. dollars will be distributed by checks drawn on a bank in the United States for whole U.S. dollars and cents. Fractional cents will be withheld without liability and dealt with by the depositary in accordance with its then current practices.


The depositary is not responsible if it decides that it is unlawful or impractical to make a distribution available to any ADR holders.


There can be no assurance that the depositary will be able to convert any currency at a specified exchange rate or sell any property, rights, common shares or other securities at a specified price, nor that any of such transactions can be completed within a specified time period.


Issuance of ADSs upon Deposit of Common Shares


The depositary will issue ADSs if an ADS holder or such holder’s broker deposits common shares or evidence of rights to receive common shares with the custodian and pays the fees and expenses owing to the depositary in connection with such issuance.


Common shares deposited in the future with the custodian must be accompanied by certain delivery documentation and shall, at the time of such deposit, be registered in the name of the depositary for the benefit of holders of ADRs or in such other name as the depositary shall direct.


The custodian will hold all deposited common shares for the account of the depositary. ADR holders thus have no direct ownership interest in our common shares and only have such rights as are contained in the deposit agreement. The custodian will also hold any additional securities, property and cash received on or in substitution for the deposited common shares. The deposited common shares and any such additional items are referred to as “deposited securities.”


Upon each deposit of common shares, receipt of related delivery documentation and compliance with the other provisions of the deposit agreement, including the payment of the fees and charges of the depositary and any taxes or other fees or charges owing, the depositary will issue an ADR or ADRs in the name or upon the order of the person entitled thereto evidencing the number of ADSs to which such person is entitled. All of the ADSs issued will, unless specifically requested to the contrary, be part of the depositary’s direct registration system, and a registered holder will receive periodic statements from the depositary which will show the number of ADSs registered in such holder’s name. An ADR holder can request that the ADSs not be held through the depositary’s direct registration system and that a certificated ADR be issued.


The term “common shares” in this description of the ADSs also refers to preliminary stock certificates (certificados provisionales), which are subsequently converted to common shares once the applicable capital increase is registered with the Peruvian public registry and new common shares are listed on the Lima Stock Exchange and registered in the book-entry settlement system of CAVALI S.A. ICLV.


Withdrawal of Common Shares upon Cancellation of ADSs


When a holder turns in its ADR certificate at the depositary’s office, or when a holder provides proper instructions and documentation in the case of direct registration ADSs, the depositary will, upon payment of certain applicable fees, charges and taxes, deliver the underlying common shares to such holder upon such holder’s written order. At such holder’s risk, expense and request, the depositary may deliver deposited securities at such other place as such holder may request.


3


The depositary may only restrict the withdrawal of deposited securities in connection with:


●temporary delays caused by closing our transfer books or those of the depositary or the deposit of common shares in connection with voting at a shareholders’ meeting, or the payment of dividends;


  ● the payment of fees, taxes and similar charges; or


  ● compliance with any Peruvian, U.S. or other foreign laws or governmental regulations relating to the ADRs or to the withdrawal of deposited securities.


Notwithstanding the foregoing, no withdrawal of deposited securities in the form of preliminary stock certificates (certificados provisionales) will be permitted until such preliminary stock certificates have been converted into common shares once the applicable capital increase has been recorded with the Peruvian public registry.


This right of withdrawal may not be limited by any other provision of the deposit agreement.


Record Dates


The depositary may, after consultation with us if practicable, fix record dates for the determination of the registered ADR holders who will be entitled (or obligated, as the case may be):


  ● to receive any distribution on or in respect of common shares;


  ● to give instructions for the exercise of voting rights at a meeting of holders of common shares;


  ● to pay the fee assessed by the depositary for administration of the ADR program and for any expenses as provided for in the ADR; or


  ● to receive any notice or to act in respect of any other matter,


in each case, subject to the provisions of the deposit agreement.


Voting Rights


A holder of an ADR representing common shares will generally have the right under the deposit agreement to instruct the depositary to exercise the voting rights for the underlying common shares represented by such ADRs. The voting rights of holders of common shares are described under “Description of Our By-laws and Shares—Voting Rights and Dividends” in this exhibit to our annual report on Form 20-F.


If the depositary asks an ADR holder to provide it with voting instructions, such holder may instruct the depositary how to exercise the voting rights for the common shares which underlie such holder’s ADSs. As soon as practicable after receiving notice of any meeting or solicitation of consents or proxies from us, the depositary will distribute to the registered ADR holders a notice stating such information as is contained in the voting materials received by the depositary and describing how holders may instruct the depositary to exercise the voting rights for the common shares which underlie such holders’ ADSs, including instructions for giving a discretionary proxy to a person designated by us. For instructions to be valid, the depositary must receive them in the manner and on or before the date specified. The depositary will try, as far as is practical, subject to the provisions of and governing the underlying common shares or other deposited securities, to vote or to have its agents vote the common shares or other deposited securities as holders instruct. The depositary will only vote or attempt to vote as instructed by holders. The depositary will not itself exercise any voting discretion. Furthermore, neither the depositary, nor its agents, are responsible for any failure to carry out any voting instructions, for the manner in which any vote is cast or for the effect of any vote, other than for failure caused directly by gross negligence, bad faith or willful misconduct on the part of the depositary or its agents. Notwithstanding anything contained in the deposit agreement or any ADR, the depositary may, to the extent not prohibited by law or applicable regulations, or by the requirements of the stock exchange on which the ADSs are listed, in lieu of distribution of the materials provided to the depositary in connection with any meeting of, or solicitation of consents or proxies from, holders of deposited securities, distribute to the registered holders of ADRs a notice that provides such holders with, or otherwise publicizes to such holders, instructions on how to retrieve such materials or receive such materials upon request (i.e., by reference to a website containing the materials for retrieval or a contact for requesting copies of the materials).


4


There is no assurance that holders will receive voting materials in time to instruct the depositary to vote and it is possible that holders, or persons who hold their ADSs through brokers, dealers or other third parties, will not have the opportunity to exercise a right to vote.


Reports and Other Communications


The depositary will make available for inspection by ADR holders at the offices of the depositary and the custodian the deposit agreement, the provisions of or governing deposited securities, and any written communications from us which are both received by the custodian or its nominee as a holder of deposited securities and made generally available to the holders of deposited securities.


Additionally, if we make any written communications generally available to holders of our common shares, and we furnish copies thereof (or English translations or summaries) to the depositary, it will distribute the same to registered ADR holders.


Fees and Expenses


The depositary may charge each person to whom ADSs are issued, including, without limitation, issuances against deposits of common shares, issuances in respect of common share distributions, rights and other distributions, issuances pursuant to a stock dividend or stock split declared by us or issuances pursuant to a merger, exchange of securities or any other transaction or event affecting the ADSs or deposited securities, and each person surrendering ADSs for withdrawal of deposited securities or whose ADRs are cancelled or reduced for any other reason, US$5.00 for each 100 ADSs (or any portion thereof) issued, delivered, reduced, cancelled or surrendered, as the case may be. The depositary may sell (by public or private sale) sufficient securities and property received in respect of a common share distribution, rights and/or other distribution prior to such deposit to pay such charge.


The following additional charges shall be incurred by the ADR holders, by any party depositing or withdrawing common shares or by any party surrendering ADSs or to whom ADSs are issued (including, without limitation, issuance pursuant to a stock dividend or stock split declared by us or an exchange of stock regarding the ADRs or the deposited securities or a distribution of ADSs), whichever is applicable:


  ● a fee of US$1.50 per ADR or ADRs for transfers of certificated or direct registration ADRs;


  ● a fee of US$0.05 or less per ADS for any cash distribution made pursuant to the deposit agreement;


●a fee of US$0.05 or less per ADS per calendar year (or portion thereof) for services performed by the depositary in administering the ADRs (which fee may be charged on a periodic basis during each calendar year and shall be assessed against holders of ADRs as of the record date or record dates set by the depositary during each calendar year and shall be payable in the manner described in the next succeeding provision);


●reimbursement of such fees, charges and expenses as are incurred by the depositary and/or any of the depositary’s agents (including, without limitation, the custodian and expenses incurred on behalf of holders in connection with compliance with foreign exchange control regulations or any law or regulation relating to foreign investment) in connection with the servicing of the common shares or other deposited securities, the delivery of deposited securities or otherwise in connection with the depositary’s or its custodian’s compliance with applicable law, rule or regulation (which charge shall be assessed on a proportionate basis against holders as of the record date or dates set by the depositary and shall be payable at the sole discretion of the depositary by billing such holders or by deducting such charge from one or more cash dividends or other cash distributions);


●a fee for the distribution of securities (or the sale of securities in connection with a distribution), such fee being in an amount equal to US$0.05 per ADS issuance fee for the execution and delivery of ADSs which would have been charged as a result of the deposit of such securities (treating all such securities as if they were common shares) but which securities or the net cash proceeds from the sale thereof are instead distributed by the depositary to those holders entitled thereto;


  ● stock transfer or other taxes and other governmental charges;


●cable and facsimile transmission and delivery charges incurred at the request of a holder in connection with the deposit or delivery of common shares;


●transfer or registration fees for the registration of transfer of deposited securities on any applicable register in connection with the deposit or withdrawal of deposited securities; and


  ● expenses of the depositary in connection with the conversion of foreign currency into U.S. dollars.


We will pay all other charges and expenses of the depositary and any agent of the depositary (except the custodian) pursuant to agreements from time to time between us and the depositary. The charges described above may be amended from time to time by agreement between us and the depositary.


5


Our depositary has agreed to reimburse us for certain expenses we incur that are related to establishment and maintenance of the ADR program, including investor relations expenses and exchange application and listing fees. The amounts of reimbursements available to us are not based upon the amounts of fees the depositary collects from investors. The depositary collects its fees for issuance and cancellation of ADSs directly from investors depositing common shares or surrendering ADSs for the purpose of withdrawal or from intermediaries acting on their behalf. The depositary collects fees for making distributions to investors by deducting those fees from the amounts distributed or by selling a portion of distributable property to pay the fees. The depositary may collect its annual fee for depositary services by deduction from cash distributions, or by directly billing investors, or by charging the book-entry system accounts of participants acting for them. The depositary will generally set off the amounts owing from distributions made to holders of ADSs. If, however, no distribution exists and payment owing is not timely received by the depositary, the depositary may refuse to provide any further services to holders that have not paid those fees and expenses owing until such fees and expenses have been paid. At the discretion of the depositary, all fees and charges owing under the deposit agreement are due in advance and/or when declared owing by the depositary.


Payment of Taxes


ADS holders or ADR holders, as the case may be, must pay any tax or other governmental charge payable by the custodian or the depositary on any ADS or ADR, deposited security or distribution. If an ADS holder or ADR holder, as the case may be, owes any tax or other governmental charge, the depositary may (i) deduct the amount thereof from any cash distributions, or (ii) sell deposited securities (by public or private sale) and deduct the amount owing from the net proceeds of such sale. In either case the ADS holder or ADR holder, as the case may be, remains liable for any shortfall. Additionally, if any taxes or other governmental charges (including any penalties and/or interest) shall become payable by or on behalf of the custodian or the depositary with respect to any ADR, any deposited securities represented by the ADSs evidenced thereby or any distribution thereon, such tax or other governmental charge shall be paid by the holder thereof to the depositary. By holding or having held an ADS or an ADR, as the case may be, a holder agrees to indemnify, defend and save harmless each of the depositary, its agents and us in respect thereof. If any tax or governmental charge is unpaid, the depositary may also refuse to effect any registration, registration of transfer, split up or combination of deposited securities or withdrawal of deposited securities until such payment is made. If any tax or governmental charge is required to be withheld on any cash distribution, the depositary may deduct the amount required to be withheld from any cash distribution or, in the case of a non-cash distribution, sell the distributed property or securities (by public or private sale) to pay such taxes and distribute any remaining net proceeds to the ADS holders or the ADR holders entitled thereto.


By holding an ADR or an ADS, as the case may be, or an interest therein, holders agree to indemnify us, the depositary, its custodian and any of our or their respective directors, employees, agents and affiliates against, and hold each of them harmless from, any claims by any governmental authority with respect to taxes, additions to tax, penalties or interest arising out of any refund of taxes, reduced rate of withholding at source or other tax benefit obtained.


Reclassifications, Recapitalizations and Mergers


If we take certain actions that affect the deposited securities, including (i) any change in par value, split up, consolidation, cancellation or other reclassification of deposited securities or (ii) any distributions not made to holders of ADRs or (iii) any recapitalization, reorganization, merger, consolidation, liquidation, receivership, bankruptcy or sale of all or substantially all of our assets, then the depositary may choose to:


  ● amend the form of ADR;


  ● distribute additional or amended ADRs;


  ● distribute cash, securities or other property it has received in connection with such actions;


  ● sell any securities or property received and distribute the proceeds as cash; or


  ● none of the above.


If the depositary does not choose any of the above options, any of the cash, securities or other property it receives will constitute part of the deposited securities and each ADS will then represent a proportionate interest in such property.


6


Amendment and Termination


We may agree with the depositary to amend the deposit agreement and the ADSs without the consent of holders for any reason. ADR holders must be given at least 30 days’ notice of any amendment that imposes or increases any fees or charges (other than stock transfer or other taxes and other governmental charges, transfer or registration fees, cable, telex or facsimile transmission costs, delivery costs or other such expenses), or otherwise prejudices any substantial existing right of ADR holders. Such notice need not describe in detail the specific amendments effectuated thereby, but must give ADR holders a means to access the text of such amendment. If an ADR holder continues to hold an ADR or ADRs after being so notified, such ADR holder is deemed to agree to such amendment and to be bound by the deposit agreement as so amended. Notwithstanding the foregoing, if any governmental body or regulatory body should adopt new laws, rules or regulations which would require amendment or supplement of the deposit agreement or the form of ADR to ensure compliance therewith, we and the depositary may amend or supplement the deposit agreement and the ADR at any time in accordance with such changed laws, rules or regulations, which amendment or supplement may take effect before a notice is given or within any other period of time as required for compliance. No amendment, however, will impair the right of a holder to surrender its ADSs and receive the underlying securities, except in order to comply with mandatory provisions of applicable law.


The depositary may, and shall at our written direction, terminate the deposit agreement and the ADRs by mailing notice of such termination to the registered holders of ADRs at least 30 days prior to the date fixed in such notice for such termination; provided, however, if the depositary shall have (i) resigned as depositary under the deposit agreement, notice of such termination by the depositary shall not be provided to registered holders unless a successor depositary shall not be operating under the deposit agreement within 60 days of the date of such resignation, and (ii) been removed as depositary under the deposit agreement, notice of such termination by the depositary shall not be provided to registered holders of ADRs unless a successor depositary shall not be operating under the deposit agreement on the 60th day after our notice of removal was first provided to the depositary. After termination, the depositary’s only responsibility will be (i) to deliver deposited securities to ADR holders who surrender their ADRs, and (ii) to hold or sell distributions received on deposited securities. As soon as practicable after the expiration of six months from the termination date, the depositary will sell the deposited securities which remain and hold the net proceeds of such sales (as long as it may lawfully do so), without liability for interest, in trust for the ADR holders who have not yet surrendered their ADRs. After making such sale, the depositary shall have no obligations except to account for such proceeds and other cash.


Limitations on Obligations and Liability


Prior to the issue, registration, registration of transfer, split-up, combination, or cancellation of any ADRs, or the delivery of any distribution in respect thereof, and from time to time, we or the depositary or its custodian may require:


●payment with respect thereto of (i) any stock transfer or other tax or other governmental charge, (ii) any stock transfer or registration fees in effect for the registration of transfers of common shares or other deposited securities upon any applicable register and (iii) any applicable fees and expenses described in the deposit agreement;


●the production of proof satisfactory to it of (i) the identity of any signatory and genuineness of any signature and (ii) such other information, including, without limitation, information as to citizenship, residence, exchange control approval, beneficial ownership of any securities, compliance with applicable law, regulations, provisions of or governing deposited securities and terms of the deposit agreement and the ADRs, as it may deem necessary or proper; and


  ● compliance with such regulations as the depositary may establish consistent with the deposit agreement.


The issuance of ADRs, the acceptance of deposits of common shares, the registration, registration of transfer, split-up or combination of ADRs or the withdrawal of common shares, may be suspended, generally or in particular instances, when the ADR register or any register for deposited securities is closed or when any such action is deemed advisable by the depositary or when reasonably requested by us in order to enable us to comply with applicable law; provided that the ability to withdraw common shares may only be limited under the following circumstances: (i) temporary delays caused by closing transfer books of the depositary or our transfer books or the deposit of common shares in connection with voting at a shareholders’ meeting, or the payment of dividends, (ii) the payment of fees, taxes, and similar charges, and (iii) compliance with any laws or governmental regulations relating to ADRs or to the withdrawal of deposited securities.


7


The deposit agreement expressly limits the obligations and liability of the depositary, ourselves and our respective agents. Neither we nor the depositary nor any such agent will be liable if:


●any present or future law, rule, regulation, fiat, order or decree of the United States, Peru or any other country, or of any governmental or regulatory authority or securities exchange or market or automated quotation system, the provisions of or governing any deposited securities, any present or future provision of our charter, any act of God, war, terrorism or other circumstance beyond our, the depositary’s or our respective agents’ control shall prevent or delay, or shall cause any of them to be subject to any civil or criminal penalty in connection with, any act which the deposit agreement or the ADRs provide shall be done or performed by us, the depositary or our respective agents (including, without limitation, voting);


  ● it exercises or fails to exercise discretion under the deposit agreement or the ADRs issued thereunder;


●it performs its obligations under the deposit agreement and ADRs issued thereunder without gross negligence or bad faith;


●it takes any action or refrains from taking any action in reliance upon the advice of or information from legal counsel, accountants, any person presenting common shares for deposit, any registered holder of ADRs, or any other person believed by it to be competent to give such advice or information; or


●it relies upon any written notice, request, direction or other document believed by it to be genuine and to have been signed or presented by the proper party or parties.


Neither the depositary nor its agents have any obligation to appear in, prosecute or defend any action, suit or other proceeding in respect of any deposited securities or the ADRs. We and our agents shall only be obligated to appear in, prosecute or defend any action, suit or other proceeding in respect of any deposited securities or the ADRs, which in our opinion may involve us in expense or liability, if indemnity satisfactory to us against all expense (including fees and disbursements of counsel) and liability is furnished as often as may be required. The depositary and its agents may fully respond to any and all demands or requests for information maintained by or on its behalf in connection with the deposit agreement, any registered holder or holders of ADRs, any ADRs or otherwise related to the deposit agreement or ADRs to the extent such information is requested or required by or pursuant to any lawful authority, including, without limitation, laws, rules, regulations, administrative or judicial processes, banking, securities or other regulators. The depositary shall not be liable for the acts or omissions made by any securities depository, clearing agency or settlement system in connection with or arising out of book-entry settlement of deposited securities or otherwise. Furthermore, the depositary shall not be responsible for, and shall incur no liability in connection with or arising from, the insolvency of any custodian that is not a branch or affiliate of JPMorgan Chase Bank, N.A. The depositary and the custodian(s) may use third party delivery services and providers of information regarding matters such as pricing, proxy voting, corporate actions, class action litigation and other services in connection with the ADRs and the deposit agreement, and use local agents to provide extraordinary services such as attendance at annual meetings of issuers of securities.


The depositary shall be under no obligation to inform holders of ADSs regarding the requirements of Peruvian law, rules or regulations or any changes therein or thereunder.


Additionally, none of us, the depositary or the custodian shall be liable for the failure by any registered holder of ADRs or beneficial owner therein to obtain the benefits of credits on the basis of non-U.S. tax paid against such holder’s or beneficial owner’s income tax liability. Neither we nor the depositary shall incur any liability for any tax consequences that may be incurred by holders or beneficial owners on account of their ownership of ADRs or ADSs.


Neither the depositary nor its agents will be responsible for any failure to carry out any instructions to vote any of the deposited securities, for the manner in which any such vote is cast or for the effect of any such vote. None of us, the depositary, or our agents shall be liable to registered holders of ADRs or beneficial owners of interests in ADSs for any indirect, special, punitive or consequential damages (including, without limitation, lost profits) of any form incurred by any person or entity, whether or not foreseeable and regardless of the type of action in which such a claim may be brought.


The depositary may own and deal in any class of our securities and in ADSs.


Disclosure of Interest in ADSs


To the extent that the provisions of, or governing, any deposited securities may require disclosure of or impose limits on beneficial or other ownership of deposited securities, other common shares and other securities and may provide for blocking transfer, voting or other rights to enforce such disclosure or limits, each holder agrees to comply with all such disclosure requirements and ownership limitations and to comply with any reasonable instructions we may provide in respect thereof. We reserve the right to instruct each holder to deliver such holder’s ADSs for cancellation and withdrawal of the deposited securities so as to permit us to deal with such holder directly as a holder of common shares and, by holding an ADS or an interest therein, each holder agrees to comply with such instructions.


8


Books of Depositary


The depositary or its agent will maintain a register for the registration, registration of transfer, combination and split-up of ADRs, which register shall include the depositary’s direct registration system. Registered holders of ADRs may inspect such records at the depositary’s office at all reasonable times, but solely for the purpose of communicating with other holders in the interest of the business of our company or a matter relating to the deposit agreement. Such register may be closed from time to time, when deemed expedient by the depositary.


The depositary will maintain facilities for the delivery and receipt of ADRs.


Pre-release of ADSs


In its capacity as depositary, the depositary shall not lend common shares or ADSs; provided, however, that the depositary may (i) issue ADSs prior to the receipt of common shares and (ii) deliver common shares prior to the receipt of ADSs for withdrawal of deposited securities, including ADSs which were issued under (i) above but for which common shares may not have been received (each such transaction a “pre-release”). The depositary may receive ADSs in lieu of common shares under (i) above (which ADSs will promptly be canceled by the depositary upon receipt by the depositary) and receive common shares in lieu of ADSs under (ii) above. Each such pre-release will be subject to a written agreement whereby the person or entity (the “applicant”) to whom ADSs or common shares are to be delivered (a) represents that at the time of the pre-release the applicant or its customer owns the common shares or ADSs that are to be delivered by the applicant under such pre-release, (b) agrees to indicate the depositary as owner of such common shares or ADSs in its records and to hold such common shares or ADSs in trust for the depositary until such common shares or ADSs are delivered to the depositary or the custodian, (c) unconditionally guarantees to deliver to the depositary or the custodian, as applicable, such common shares or ADSs, and (d) agrees to any additional restrictions or requirements that the depositary deems appropriate. Each such pre-release will be at all times fully collateralized with cash, U.S. government securities or such other collateral as the depositary deems appropriate, terminable by the depositary on not more than five business days’ notice and subject to such further indemnities and credit regulations as the depositary deems appropriate. The depositary will normally limit the number of ADSs and common shares involved in such pre-release at any one time to 30% of the ADSs outstanding (without giving effect to ADSs outstanding under (i) above), provided, however, that the depositary reserves the right to change or disregard such limit from time to time as it deems appropriate. The depositary may also set limits with respect to the number of ADSs and common shares involved in pre-release with any one person on a case-by-case basis as it deems appropriate. The depositary may retain for its own account any compensation received by it in conjunction with the foregoing. Collateral provided in connection with pre-release transactions, but not the earnings thereon, shall be held for the benefit of the registered holders of ADRs (other than the applicant).


Appointment


In the deposit agreement, each registered holder of ADRs and each person holding an interest in ADSs, upon acceptance of any ADSs (or any interest therein) issued in accordance with the terms and conditions of the deposit agreement will be deemed for all purposes to:


  ● be a party to and bound by the terms of the deposit agreement and the applicable ADR or ADRs; and


●appoint the depositary as its attorney-in-fact, with full power to delegate, to act on its behalf and to take any and all actions contemplated in the deposit agreement and the applicable ADR or ADRs, to adopt any and all procedures necessary to comply with applicable laws and to take such action as the depositary in its sole discretion may deem necessary or appropriate to carry out the purposes of the deposit agreement and the applicable ADR and ADRs, the taking of such actions to be the conclusive determinant of the necessity and appropriateness thereof.


Governing Law


The deposit agreement and the ADRs shall be governed by and construed in accordance with the laws of the State of New York. In the deposit agreement, we have submitted to the jurisdiction of the courts of the State of New York and appointed an agent for service of process on our behalf.


9


Description of Our By-laws and Shares


Set forth below is certain information relating to our share capital, including brief summaries of the material provisions of our by-laws, Peruvian corporate law and certain related laws and regulations of Peru, all as in effect as of the date of the annual report on Form 20-F to which this summary is an exhibit. 


General


We are a publicly held corporation under Peruvian Law No. 26887 (the “Peruvian Corporate Law”) registered with the Public Registry of Corporations in Lima. We are currently listed on the Lima Stock Exchange.


The second article of our by-laws provides that our principal corporate purpose is mining and the production and sale of cement, quicklime and other construction materials in Peru and internationally.


We have common shares and investment shares. 


Common Shares


Common shares represent 100% of our voting shares. As of March 31, 2020, 423,868,449 of our common shares were outstanding. As of March 31, 2026, there were 9,030 owners of record of our common shares (considering the ADSs listed in the New York Stock Exchange are held by one registered owner). Our common shares have a par value of S/1.00 per share and have been fully subscribed and are fully paid. Our common shares are registered in the Securities Public Registry of the Peruvian Securities Commission and are listed on the Lima Stock Exchange.


Investment Shares


As of March 31, 2026, 4,238,397 of our investment shares were outstanding excluding 36,040,497 investment shares that were held in treasury. Investment shares have no voting rights and are not, under Peruvian law and accounting regulations, characterized as share capital. However, investment shares are still considered part of a company’s equity. As of March 31, 2026, there were 600 owners of record of our investment shares. Our investment shares have a par value of S/1.00 per share and have been fully subscribed and are fully paid. Our investment shares are registered in the Securities Public Registry of the Peruvian Securities Commission and are listed on the Lima Stock Exchange.


Shareholders’ Liability


Under Peruvian Corporate Law, holders of our common shares cannot vote on matters with respect to which they have a conflict of interest.


Under Article 133 of the Peruvian Corporate Law, a shareholder must abstain from voting if such shareholder has a conflict of interest. A resolution approved in disregard of this provision may be challenged under Article 139 of the Peruvian Corporate Law and any shareholder that participated in the determination in breach of this provision, if such shareholder’s vote was key in attaining the required majority, may be held liable individually, or jointly with any other shareholder voting in breach of the provision.


10


Redemption and Rights of Withdrawal


Under Article 200 of the Peruvian Corporate Law, holders of our common shares have redemption rights if: (i) we change our corporate purpose; (ii) a change occurs in the place of organization to a foreign country; or (iii) any transformation, merger or significant spin-off occurs with respect to our company.


Preemptive and Accretion Rights


If we increase our share capital, holders of our common shares and investment shares have the right to subscribe to new common shares and investment shares, respectively, on a pro rata basis. Holders of common shares have preemptive rights in order to maintain their share interest in our share capital, unless the capital increase (i) results from a conversion of debt to common shares; (ii) is approved by shareholders representing at least 40% of the subscribed voting shares provided that the capital increase does not favor, directly or indirectly, certain shareholders to the detriment of others; and (iii) results from a corporate reorganization. Holders of investment shares have preemptive rights to maintain their proportional ownership in our share capital.


Shareholders who are in default of any payments relating to a capital call may not exercise their preemptive rights.


Preemptive rights are exercised in two rounds. During the first round, shareholders may subscribe to the new shares on a pro rata basis. During the second round, shareholders who participated in the first round may subscribe to any remaining shares on a pro rata basis up to the amount of shares such shareholders subscribed for in the first round. The first round must remain open for at least 15 business days. The second round must remain open for at least three business days. 


Voting Rights and Dividends


Common Shares


Holders of common shares are entitled to one vote per share, with the exception of the election of the board of directors, where each holder is entitled to one vote per share per nominee. Each holder’s votes may be cast for a single nominee or distributed among the nominees at the holder’s discretion. To that effect, each of our common shares gives the holder the rights to as many votes as there are directors to be elected. Shareholders may pool votes in favor of one person or distribute them among various persons. Those candidates for the board who receive the most votes are elected directors. Holders of common shares may attend and vote at shareholders’ meetings either in person or through a proxy.


Holders of common shares have the right to participate in the distribution of dividends and shareholder equity resulting from liquidation. Our by-laws do not establish a maximum time limit for the payment of the dividends. However, according to Article 232 of the Peruvian Corporate Law, the right to collect past-due dividends in the case of companies that are publicly held companies, such as ours, expires 10 years after the date on which the dividend payment was due.


Our share capital may be increased by a decision of holders of common shares at a shareholders’ meeting. Capital reductions may be voluntary or mandatory and must be approved by holders of common shares at a shareholders’ meeting. Capital reductions are mandatory when accumulated losses exceed 50% of the capital and to the extent such accumulated losses are not offset by accumulated earnings and capital increases within the following fiscal year. Capital increases and reductions must be communicated to the Peruvian Securities Commission, the Lima Stock Exchange and the Peruvian Tax Superintendence (Superintendencia Nacional de Administración Tributaria). Voluntary capital reductions must also be published in the official gazette El Peruano and in a widely circulated newspaper in the city in which we are located.


11


Investment Shares


Under Peruvian Corporate Law, investment shares do not represent share capital. Accordingly, our balance sheet reflects the investment shares as a separate account from our share capital. Holders of investment shares are neither entitled neither to vote nor to participate in shareholders’ meetings. However, investment shares confer upon the holders thereof the right to participate in the dividends distributed according to their par value, in the same manner as common shares. Investment shares also confer to the holders thereof the preemptive right to (i) maintain the current proportion of the investment shares in the case of a capital increase through new contributions; (ii) increase the number of investment shares upon capitalization of retained earnings, revaluation surplus or other reserves that do not represent cash contributions; (iii) participate in the distribution of assets resulting from a liquidation in the same manner as common shares; and, (iv) redeem the investment shares in case of a merger and/or change of business activity.


Liquidation Rights


If we are liquidated, our shareholders have the right to receive net assets resulting from the liquidation, after we comply with our obligation to pay all our creditors and after discounting any existing dividend liabilities. For this reason, we cannot assure that we will be able to reimburse 100% of the book value of the common shares and investment shares in case of bankruptcy or liquidation.


Ordinary and Extraordinary Meetings


Pursuant to Peruvian Corporate Law and our by-laws, the annual shareholders’ meeting must be held during the three-month period after the end of each fiscal year. Because we are a publicly-held corporation, we are subject to the special control of the Peruvian Securities Commission, as provided in Article 253 of the Peruvian Corporate Law. If we do not hold the annual shareholders’ meeting during the three-month period after the end of each fiscal year or any other shareholders’ meeting required by our by-laws, a public notary or a competent judge shall call for such a meeting at the request of at least one shareholder of the common shares. Such meeting will take place within a reasonable period of time.


Other shareholders’ meetings are convened by the board of directors when deemed convenient by our company or when it is requested by the holders of at least 20% of our common shares. If, at the request of holders of 20% of the common shares, the shareholders’ meeting is not convened by the board of directors within 15 business days of the receipt of such request, or the board expressly or implicitly refuses to convene the shareholders’ meeting, a public notary or a competent judge will call pursuant to Law No. 29560 for such meeting at the request of holders of at least 20% of our common shares. If a public notary or competent judge calls for a shareholders’ meeting, the place, time and hour of the meeting, the agenda and the person who will preside shall be indicated on the meeting notice. If the meeting called is other than the annual shareholders’ meeting or a shareholders’ meeting required by the Peruvian Corporate Law or the by-laws, the agenda will contain those matters requested by the shareholders who requested the meeting. 


Holders of investment shares have no right to request the board to call a shareholders’ meeting.


12


Notices of Meetings


Since we are a publicly held corporation, notice of shareholders’ meetings must be given by publication of a notice. The publication shall occur at least 25 days prior to any shareholders’ meeting in the Peruvian Official Gazette, El Peruano, and in a widely circulated newspaper in the city in which we are located. The notice requirement may be waived at the shareholders’ meeting by agreement of the holders of 100% of the outstanding common shares.


Quorum and Voting Requirements


According to Article 25 of our by-laws and Article 257 of the Peruvian Corporate Law, shareholders’ meetings called for the purpose of considering a capital increase or decrease, the issuance of obligations, a change in the by-laws, the sale in a single act of assets with an accounting value that exceeds 50% of our share capital, a merger, division, reorganization, transformation or dissolution, are subject to a first, second and third quorum call, each of the second and third quorum call to occur upon the failure of the preceding one. A quorum for the first call requires the presence of shareholders holding 50% of our total common shares. For the second call, the presence of shareholders holding at least 25% of our total common shares is adequate, while for the third call there is no quorum requirement. These decisions require the approval of the majority of the common shares represented at the shareholders’ meeting. Shareholders’ meetings convened to consider all other matters are subject to a first and second quorum call, the second quorum call to occur upon the failure of the first quorum.


In accordance with Peruvian Corporate Law, only those holders of common shares whose names are registered in our stock ledger not less than 10 days in advance of a meeting will be entitled to attend the shareholders’ meeting and to exercise their rights.


Limitations on the Rights of Non-residents or Foreign Shareholders


There are no limitations under our by-laws or Peruvian Corporate Law on the rights of nonresidents or foreign shareholders to own securities or exercise voting rights with respect to our securities.


Disclosure of Shareholdings and Tender Offer Regulations


Disclosure of Shareholdings


There are no provisions in our by-laws governing the ownership threshold above which share ownership must be disclosed.


However, according to CONASEV Resolution No. 079-1997-EF/94.10, as amended, we disclose through the Stock Market Superintendency (Superintendencia del Mercado de Valores - SMV) our holders of common shares owning more than 4% share interest. A well, according to SMV Resolution No. 019-2015-SMV.01, as amended, we must inform the SMV of the members of our economic group and a list of our holders of common shares owning more than a 0.5% share interest, as well as any change to such information.


Tender Offer Regulations


Peruvian security regulations include mandatory takeover rules applicable to the acquisition of control of a listed company.


13


Subject to certain conditions, such regulations generally establish the obligation to make a tender offer when a person or group of persons acquires a relevant interest in a listed company. According to Peruvian law, a person acquires a relevant interest in a listed company when such person (a) holds or has the power to exercise directly or indirectly 25%, 50% or 60% of the voting rights in a listed company, or (b) has the power to appoint or remove the majority of the board members or to amend its by-laws. 


In general, the tender offer must be launched prior to the acquisition of the relevant interest. The tender offer may be launched after the “relevant interest” is acquired if it is acquired (a) by means of an indirect transaction, (b) as a consequence of a public sale offer, or (c) in no more than four transactions within a three-year period.


This mandatory procedure has the effect of alerting other shareholders and the market that an individual or financial group has acquired a significant percentage of a company’s voting shares, and gives other shareholders the opportunity to sell their shares at the price offered by the purchaser. The purchaser is required to launch a tender offer unless: (a) shareholders representing 100% of the voting rights consent in writing, (b) voting shares are acquired by a depositary in order to subsequently issue ADSs, or (c) voting shares are acquired pursuant to the exercise of preemptive rights.


Changes in Capital


Our by-laws do not establish special conditions to increase or reduce our share capital beyond what is required under Peruvian Corporate Law.


Anti-Takeover Provisions


Our by-laws do not contain any provision that would have the effect of delaying, deferring or preventing a change of control. However, acquisitions of shares of our capital stock that involve a change of control may be subject to Peruvian securities and exchange regulations (Ley de Mercado de Valores y Reglamento de Oferta Pública de Adquisición y de Compra de Valores por Exclusión) applicable to tender offers.


Form and Transfer


Common shares and investment shares may be either physical share certificates in registered form or book-entry securities in the CAVALI S.A. ICLV book-entry settlement system, also in registered form.


Furthermore, the Peruvian Corporate Law forbids publicly held corporations, such as us, from including in their by-laws stipulations limiting the transfer of their shares or restraining their trading in other ways. In addition, pursuant to our by-laws, we cannot recognize a shareholders’ agreement that contemplates limitations, restrictions or preferential rights on the transfer of shares, even if such an agreement is recorded in our stock ledger (matrícula de acciones) or in CAVALI S.A. ICLV.


14


Exhibit 2.3


ENGLISH SUMMARY OF PRINCIPAL TERMS

OF THE

MEDIUM-TERM LOAN AGREEMENT ENTERED INTO BY BANCO DE CRÉDITO DEL
PERÚ AND SCOTIABANK PERÚ S.A.A. WITH THE INTERVENTION OF CEMENTOS PACASMAYO S.A.A.


The summary below contains an abridged description of the principal terms of the agreement originally executed in Spanish language by the parties referred to herein (the “Agreement”).


Date of Execution: November 29, 2021.


By means of a public deed dated November 29, 2021, a loan agreement was entered into with Banco de Crédito del Perú and Scotiabank Perú S.A.A. for an amount of up to S/860,000,000.00 (Eight Hundred Sixty Million and 00/100 Peruvian Soles), with each lender participating for an amount of up to S/430,000,000.00 (Four Hundred Thirty Million and 00/100 Peruvian Soles). Credicorp Capital Servicios Financieros S.A. acted as the arranger, under the following terms and conditions:


Term: 7 years from the closing date.


Interest Rate: Annual Effective Rate (TEA) of 5.82%.


Commitment Fee: 0.30% (waived for the first 90 days).


Structuring Fee: 0.85%.


Grace/Availability Period: 18 months from the closing date.


Amortization Structure: 22 quarterly installments.


Prepayment Fee: 1.5% for each remaining year, capped at 3.0%.

Exhibit 4.8


ENGLISH SUMMARY OF PRINCIPAL TERMS

POWER SUPPLY AGREEMENT BETWEEN ORYGEN PERÚ S.A.A.
(formerly Enel Generación Perú S.A.A.) AND CEMENTO PACASMAYO S.A.A.


The summary below contains an abridged description of the principal terms of the agreement originally executed in Spanish language by the parties referred to herein (the “Agreement”).


Date of Execution: December 11, 2023


Term: June 1, 2026, at 12:00 a.m. through May 31, 2031, at 12:00 a.m.


Contracted capacities:


Lot Adress Supply Point Contracted
Capacity
HP
(MW)
Contracted
Capacity
HFP
(MW)
1 Carretera
Panamericana
Norte km. 665
Pacasmayo – La
Libertad
Supply No.: N.A.
Voltage: 60 kV
BRG: Guadalupe 60 KV
Concessionaire: Electroperú S.A.
28.00 44.00
2 Carretera Piura –
Paita km. 3
Veintiséis de
Octubre - Piura
Supply No.: N.A.
Voltage: 220 Kv
BRG: Piura Oeste 220 KV
Concessionaire: Electroperú S.A.
16.00 22.00


Capacity increase: The CLIENT may request increases of up to 5% of the initial contracted capacity, subject to the terms of the contract and the execution of the corresponding amendment.


Minimum capacities (purchase obligation): Equivalent to 0% of the contracted capacity at each Supply Point.


Exclusivity: During the term of the contract and up to the limit of the Contracted Capacity, the CLIENT may not acquire Energy from any supplier other than the GENERATOR for the Supply Points, unless the GENERATOR is unable to fully or partially comply with supplying the required Capacity and Associated Energy up to such limits.


Price: From June 1, 2026 to May 31, 2031


Generation Reference
Busbar (BRG)
Associated Energy
US$/MWh
Capacity Soles/kW-
month
Peak Hours
(PEPo)
Off-Peak Hours
(PEFo)
(PPO)
Piura Oeste 220 kV and
Guadalupe 60 kV
32.20 32.20 Busbar Tariff
(PPM)


Additionally, the CLIENT shall bear the tolls and other current or future charges, costs and/or items directly linked to the supply covered by this Agreement, to the extent that: (i) such tolls, charges, costs and/or items may be passed through to the CLIENT under the Applicable Laws, and (ii) they entail costs for the GENERATOR that would not exist if this Agreement were not in force. Tolls, compensations, regulated charges and taxes, as well as their calculation methodology, payment timing, billing currency and updating formulas, shall be those established by OSINERGMIN or the competent Government Authority.


The Prices set forth in numeral 1 of Annex 1 shall be adjusted in accordance with the indexation formulas provided therein. The capacity price (PPM) is the Generation-Level Capacity Price, expressed in S//kW- month, at the BRG associated with the relevant Supply Point, in force during the relevant billing period, and corresponds to the basic Capacity price determined, published and updated by OSINERGMIN, pursuant to the applicable regulation. The base prices for Associated Energy during Peak Hours (PEPO) and Off-Peak Hours (PEFO) at the Supply Point shall be adjusted monthly by the FAEi in force at that time.


Tariff Periods:


-Peak Hours: The hours between 6:00 p.m. and 11:00 p.m. on all Days of the year, except Sundays and holidays.


-Peak Hours: The hours of the day not included within Peak Hours.


Excess capacity: If the Coincident Monthly Demand at any of the Supply Points exceeds 105% of the relevant Contracted Capacity, the CLIENT shall be deemed to have incurred excess Capacity. In such cases, the GENERATOR shall bill such excess with a 2% surcharge over the applicable Capacity price. The Energy associated with the excess Capacity shall be billed at the higher of the contractual price and 102% of the Short-Term Marginal Cost (CMG).


Supply Point: Each of the delivery and metering points within the premises agreed by the GENERATOR and the CLIENT. Currently, pursuant to Annex 3, they are


●Carretera Panamericana Norte km. 665, Pacasmayo – La Libertad; tensión 60 kV; BRG Guadalupe 60 kV.


●Carretera Piura – Paita km. 3, Veintiséis de Octubre – Piura; tensión 220 kV; BRG Piura Oeste 220 kV.


Termination: Except for the grounds set forth in numeral 16.2, in the event of breach, the aggrieved Party may require the breaching Party, by notarial letter, to remedy the relevant breach within a period of not less than twenty (20) Days, under warning that, otherwise, the Agreement shall be terminated. Likewise, either Party shall have the right to terminate the Agreement by operation of law upon the grounds set forth in numeral 16.2.1, including insolvency, dissolution or liquidation, disregard or non-compliance with arbitral awards or interim measures, force majeure for more than three (3) consecutive months, and unauthorized assignment of contractual position. In the cases provided in items (c) and (e) of numeral 16.2.1, the Party that gave rise to the termination event shall pay the other Party, as a penalty, an amount equal to 12 (twelve) times the average amount of the last 12 (twelve) Capacity and Energy invoices.


Liability and indemnification: The Agreement contains certain provisions relating to the parties’ liabilities and indemnification obligations for damages, loss of profit and other events, including certain exceptions for acts of God and force majeure under Peruvian law.


Governing law and forum: The Agreement is governed by Peruvian law, and any dispute under the Agreement shall be resolved by the courts of the city of Lima, Peru.


Exhibit 8.1


LIST OF SUBSIDIARIES


Subsidiary*   Jurisdiction
of
Incorporation
  Name Under
Which the
Subsidiary Does
Business
Cementos Selva S.A.C.   Perú    
Distribuidora Norte Pacasmayo S.R.L.   Perú   Dino
Dinoselva Iquitos S.A.C.   Perú   Dino Selva
Empresa de Transmisión Guadalupe S.A.C.   Perú    
Salmueras Sudamericanas S.A.   Perú    
Acuícola Los Paiches S.A.C.   Perú    
Soluciones Takay S.A.C.   Perú    
150Krea   United States    
Corporación Materiales Piura S.A.C   Perú    
Soluciones Crealo 150 S.A.C.   Perú    


*All subsidiaries are wholly owned, directly or indirectly, by Cementos Pacasmayo S.A.A.


Exhibit 12.1


CERTIFICATION PURSUANT TO

SECTION 302 OF THE SARBANES-OXLEY ACT OF 2002


I, Humberto Reynaldo Nadal Del Carpio, certify that:


1.I have reviewed this annual report on Form 20-F of Cementos Pacasmayo S.A.A.;


2.Based on my knowledge, this report does not contain any untrue statement of a material fact or omit to state a material fact necessary to make the statements made, in light of the circumstances under which such statements were made, not misleading with respect to the period covered by this report;


3.Based on my knowledge, the financial statements, and other financial information included in this report, fairly present in all material respects the financial condition, results of operations and cash flows of the company as of, and for, the periods presented in this report;


4.The company’s other certifying officer(s) and I are responsible for establishing and maintaining disclosure controls and procedures (as defined in Exchange Act Rules 13a-15(e) and 15d-15(e)) and internal control over financial reporting (as defined in Exchange Act Rules 13a-15(f) and 15d-15(f)) for the company and have:


(a)Designed such disclosure controls and procedures, or caused such disclosure controls and procedures to be designed under our supervision, to ensure that material information relating to the company, including its consolidated subsidiaries, is made known to us by others within those entities, particularly during the period in which this report is being prepared;


(b)Designed such internal control over financial reporting, or caused such internal control over financial reporting to be designed under our supervision, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles;


(c)Evaluated the effectiveness of the company’s disclosure controls and procedures and presented in this report our conclusions about the effectiveness of the disclosure controls and procedures, as of the end of the period covered by this report based on such evaluation; and


(d)Disclosed in this report any change in the company’s internal control over financial reporting that occurred during the period covered by the annual report that has materially affected, or is reasonably likely to materially affect, the company’s internal control over financial reporting; and


5.The company’s other certifying officer(s) and I have disclosed, based on our most recent evaluation of internal control over financial reporting, to the company’s auditors and the audit committee of the company’s board of directors (or persons performing the equivalent functions):


(a)All significant deficiencies and material weaknesses in the design or operation of internal control over financial reporting which are reasonably likely to adversely affect the company’s ability to record, process, summarize and report financial information; and


(b)Any fraud, whether or not material, that involves management or other employees who have a significant role in the company’s internal control over financial reporting.


Date: April 27, 2026  
   
  /s/ Humberto Reynaldo Nadal Del Carpio
  Humberto Reynaldo Nadal Del Carpio
  Chief Executive Officer


Exhibit 12.2


CERTIFICATION PURSUANT TO

SECTION 302 OF THE SARBANES-OXLEY ACT OF 2002


I, Ely Adriana Hayashi Hirahoka, certify that:


1.I have reviewed this annual report on Form 20-F of Cementos Pacasmayo S.A.A.;


2.Based on my knowledge, this report does not contain any untrue statement of a material fact or omit to state a material fact necessary to make the statements made, in light of the circumstances under which such statements were made, not misleading with respect to the period covered by this report;


3.Based on my knowledge, the financial statements, and other financial information included in this report, fairly present in all material respects the financial condition, results of operations and cash flows of the company as of, and for, the periods presented in this report;


4.The company’s other certifying officer(s) and I are responsible for establishing and maintaining disclosure controls and procedures (as defined in Exchange Act Rules 13a-15(e) and 15d-15(e)) and internal control over financial reporting (as defined in Exchange Act Rules 13a-15(f) and 15d-15(f)) for the company and have:


(a)Designed such disclosure controls and procedures, or caused such disclosure controls and procedures to be designed under our supervision, to ensure that material information relating to the company, including its consolidated subsidiaries, is made known to us by others within those entities, particularly during the period in which this report is being prepared;


(b)Designed such internal control over financial reporting, or caused such internal control over financial reporting to be designed under our supervision, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles;


(c)Evaluated the effectiveness of the company’s disclosure controls and procedures and presented in this report our conclusions about the effectiveness of the disclosure controls and procedures, as of the end of the period covered by this report based on such evaluation; and


(d)Disclosed in this report any change in the company’s internal control over financial reporting that occurred during the period covered by the annual report that has materially affected, or is reasonably likely to materially affect, the company’s internal control over financial reporting; and


5.The company’s other certifying officer(s) and I have disclosed, based on our most recent evaluation of internal control over financial reporting, to the company’s auditors and the audit committee of the company’s board of directors (or persons performing the equivalent functions):


(a)All significant deficiencies and material weaknesses in the design or operation of internal control over financial reporting which are reasonably likely to adversely affect the company’s ability to record, process, summarize and report financial information; and


(b)Any fraud, whether or not material, that involves management or other employees who have a significant role in the company’s internal control over financial reporting.


Date: April 27, 2026  
   
  /s/ Ely Adriana Hayashi Hirahoka
  Ely Adriana Hayashi Hirahoka
  Chief Financial Officer

Exhibit 13.1


CERTIFICATION PURSUANT TO 18 U.S.C. SECTION 1350,

AS ADOPTED PURSUANT TO

SECTION 906 OF THE U.S. SARBANES-OXLEY ACT OF 2002


Pursuant to section 906 of the Sarbanes-Oxley Act of 2002 (subsections (a) and (b) of Section 1350, Chapter 63 of Title 18, United States Code), the undersigned officer of Cementos Pacasmayo S.A.A. (“the Company”), hereby certifies, to such officer’s knowledge, that:


The Annual Report on Form 20-F for the year ended December 31, 2025 (the “Report”) of the Company to which this statement is provided as an exhibit fully complies with the requirements of section 13(a) or 15(d) of the Securities Exchange Act of 1934 and all information contained in the Report fairly presents, in all material respects, the financial condition and results of operations of the Company.


Date: April 27, 2026  
   
  /s/ Humberto Reynaldo Nadal Del Carpio
  Humberto Reynaldo Nadal Del Carpio
  Chief Executive Officer


Exhibit 13.2


CERTIFICATION PURSUANT TO 18 U.S.C. SECTION 1350,

AS ADOPTED PURSUANT TO

SECTION 906 OF THE U.S. SARBANES-OXLEY ACT OF 2002


Pursuant to section 906 of the Sarbanes-Oxley Act of 2002 (subsections (a) and (b) of Section 1350, Chapter 63 of Title 18, United States Code), the undersigned officer of Cementos Pacasmayo S.A.A. (“the Company”), hereby certifies, to such officer’s knowledge, that:


The Annual Report on Form 20-F for the year ended December 31, 2025 (the “Report”) of the Company to which this statement is provided as an exhibit fully complies with the requirements of section 13(a) or 15(d) of the Securities Exchange Act of 1934 and all information contained in the Report fairly presents, in all material respects, the financial condition and results of operations of the Company.


Date: April 27, 2026  
   
  /s/ Ely Adriana Hayashi Hirahoka
  Ely Adriana Hayashi Hirahoka
  Chief Financial Officer


Exhibit 96.1


CEMENTOS PACASMAYO S.A.A.

Technical Report Summary (TRS)

Tembladera Quarry

and

Pacasmayo Cement Plant

20-F 229.601 (Item 601)


January 2025


Index


1. Executive Summary 1
  1.1. Location and access 1
  1.2. Climate 1
  1.3. History 1
  1.4. Geological environment and mineralization 2
  1.5. Exploration 2
  1.6. Sample preparation, analysis and security 2
  1.7. Data verification 3
  1.8. Mineral processing and metallurgical tests 3
  1.9. Estimation of Resources and Mineral Reserves 3
  1.10. Mining Methods 4
  1.11. Processing Plant & Infrastructure 5
  1.12. Market studies 6
  1.13. Capital and operating costs & Economic Analysis 7
  1.14. Adjacent properties 10
  1.15. Interpretation and conclusions 11
  1.16. Recommendations 12
2. Introduction 12
  2.1. Participants 12
  2.2. Terms of Reference 12
  2.3. Conventions 14
  2.4. Previous Work and Sources of Information 14
  2.5. Details of QP Personal Inspection 14
  2.6. Previously Filed Technical Report Summary 14
3. Property description 15
  3.1. Tembladera quarry 15
  3.2. Pacasmayo Industrial Cement Plant 16
4. Accessibility, climate, local Resources, infrastructure and physiography 17
  4.1. Tembladera quarry 17
  4.2. Pacasmayo cement plant 18
5. History 20
  5.1. Tembladera quarry 20
  5.2. Pacasmayo Plant 20
6. Geological setting, mineralization, and deposit 21
  6.1. Regional geology 21
  6.2. Local Geology 22
  6.3. Characteristics of the deposit 23


i


7. Exploration 24
  7.1. Drilling 24
  7.2. Hydrogeology 24
  7.3. Geotechnical studies 25
8. Sample preparation, analyses, and security 25
  8.1. Geology and quarry 25
    8.1.1. Preparation of samples, procedures, assays and laboratories 25
    8.1.2. Quality Assurance Procedures 25
    8.1.3. Sample security 26
    8.1.4. Chain of custody 26
    8.1.5. Qualified person’s opinion on quarry QAQC 26
  8.2. Pacasmayo plant 27
    8.2.1. Samples preparation, procedures, assays and laboratories 27
    8.2.2. Quality Assurance Actions 27
    8.2.3. Security of the samples 28
    8.2.4. Qualified Person’s Opinion on cement plant QAQC 28
9. Data verification 28
  9.1. Geology and quarry 28
    9.1.1. Data Verification procedure 28
    9.1.2. Data collection 28
    9.1.3. Management and Validation of Database 29
    9.1.4. Tracking Data 29
    9.1.5. Validation of Data 29
    9.1.6. Qualified Person’s Opinion Geologic Data 30
  9.2. Pacasmayo plant 30
    9.2.1. Data verification procedures 30
    9.2.2.  Data validation 30
    9.2.3. Qualified Person’s Opinion on cement plant 31
10. Mineral proccessing and metallurgical testing 31
  10.1. Nature of Testing Program 31
  10.2. Cement Manufacturing Test Results 32
  10.3. Qualified Person’s Opinion of the Adequacy of the Test Data 32
11. Mineral Resources estimates 32
  11.1. Data base 34
  11.2. Density 34
  11.3. Compositing 34
  11.4. Basic statistics of the data (Assay – Composites) 35
  11.5. Extreme values 35


ii


  11.6. Variogram Analysis 35
  11.7. Interpolation 36
  11.8. Resources estimation 38
    11.8.1.  Cut-off 38
     11.8.2. Reasonable Prospects of Economic Extraction 38
     11.8.3. Mineral Resource classification 39
  11.9. Qualified Person’s Opinion 40
12. Mineral Reserves estimates 40
  12.1. Criteria for Mineral Reserves determination 41
    12.1.1. Run of Mine (ROM) determination criteria 41
     12.1.2 Cement plant recovery 41
  12.2. Reserves estimation methodology 41
  12.3. Mineral Reserve estimates 42
13. Mining methods 43
  13.1. Mining Methods and Equipment 43
  13.2. Geotechnical models 46
  13.3. Hydrological models 47
  13.4. Other Mine Design and Planning Parameters 47
  13.5. Annual Production Rate 47
  13.6. Mining Plan 47
  13.7. Life of Mine 49
  13.8. Staff 49
14. Processing and recovery methods 50
  14.1. Process plant 50
  14.2. Raw materials for the cement production 50
  14.3. Flow sheet 52
  14.4. Main equipment 52
  14.5. Material balance cement plant 53
    14.5.1.  Material balance 53
  14.6. Process losses 53
  14.7. Water consumption 53
  14.8. Fossil fuel consumption 54
  14.9. Electric power consumption 54
  14.10. Maintenance Plan 54
  14.11. Staff 54
15. Infrastructure 55
  15.1. Tembladera quarry 55
  15.2. Pacasmayo plant 56


iii


16. Market Studies 57
  16.1. The cement market in Peru 57
  16.2. Industry and Macroeconomic Analysis 58
  16.3. The North Region Market 60
  16.4. Cement price 61
  16.5. Current and future demand 61
17. Environmental studies, permitting, and plans, negotiations, or agreements with local individuals or groups. 64
  17.1. Environmental Aspects 64
     17.1.1. Tembladera quarry 64
    17.1.2. Cement plant in Pacasmayo 65
  17.2. Solid waste disposal 66
  17.3. Qualified Person’s Opinion 66
18. Capital and operations costs 67
  18.1. Basis for operating and capital cost for the quarry and plant 67
  18.2. Capital and Operating Cost Estimates 68
  18.3. Capital and Operating Cost Estimation Risks 69
19. Economic analysis 70
  19.1. Methodology: Discounted Cash flow (Free) 70
  19.2. Assumptions 70
    19.2.1. General and Macroeconomic Assumptions 70
    19.2.2.  Income and Cost Assumptions 71
  19.3. Results of financial model 71
  19.4. Sensitivity Analysis 74
20. Adjacent properties 76
21. Other relevant data and information 77
22. Interpretation and conclusions 77
23. Recommendations 78
24. References 78
25. Reliance on information provided by the registrant. 79
Signature Page 80


iv


Index of tables


Table 1 Mineral Resources (exclusive of Reserves) of Tembladera quarry 4
Table 2 Mineral Reserves of Tembladera quarry 4
Table 3 Projection of demand and price for the next 30 years 7
Table 4 Free Cash Flow and valuation 9
Table 5 Resource Categorization (exclusive of Reserves) at the Tembladera quarry 11
Table 6 Mineral Reserves expressed in millions of tonnes 11
Table 7 List of Cementos Pacasmayo S.A.A. QPs 13
Table 8 QP’s field visit 14
Table 9 Central coordinates of the Acumulación Tembladera property 15
Table 10 Central coordinates of the Pacasmayo cement plant 16
Table 11 Regional stratigraphic column 21
Table 12 Local stratigraphic column of the Tembladera quarry 23
Table 13 Characteristics of the Tembladera deposit 23
Table 14 Drilling campaigns in Tembladera quarry 24
Table 15 Quality Plan of the Tembladera quarry 26
Table 16 Tests and frequency for each stage of the process 27
Table 17 Quality Plan of Pacasmayo cement plant 27
Table 18 Lithologic units of the Tembladera quarry geological model 32
Table 19 Pacasmayo plant material restrictions 33
Table 20 Characteristics of the block model 33
Table 21 Limestone Cal statistics 35
Table 22 Variogram modeling parameters 36
Table 23 Estimation Parameters Secondary Variables 36
Table 24 Estimation Parameters CaO 37
Table 25 Resource estimates (exclusive of Reserves) at the Tembladera quarry 38
Table 26 Mineral Reserves expressed in millions of tonnes 42
Table 27 Main equipment of the Tembladera quarry 45
Table 28 Auxiliary equipment of the Tembladera quarry 46
Table 29 Parameters of design according to geotechnical zonification 46
Table 30 Reviewed Safety Factor 2021 47
Table 31 Summary of Tembladera quarry design parameters 47
Table 32 Mining plan for the next years 48
Table 33 Main equipment in Pacasmayo plant 52
Table 34 Balance for raw meal production 53
Table 35 Balance for clinker production 53
Table 36 Balance for cement production 53
Table 37 Fuel consumption in Pacasmayo plant 54
Table 38 Tembladera quarry Facilities* 56
Table 39 Cement shipments at domestic level (in thousands of tonnes) 58
Table 40 Types of products of Pacasmayo Cement plant 60
Table 41 Forecast of future demand for Pacasmayo cement plant 63
Table 42 Cost structure of Tembladera quarry and Pacasmayo plant 67
Table 43 Operating costs forecast of quarry and plant 68
Table 44 Investment forecast in quarry and plant 69
Table 45 Profit and Loss Statement 72
Table 46 Free Cash Flow and valuation 73
Table 47 Sensitivity analysis of the Net Present Value (expressed as %) 74
Table 48 Sensitivity analysis of EBITDA (expressed as %) 74
Table 49 Resource Categorization (exclusive of Reserves) at the Tembladera quarry 77
Table 50 Mineral Reserves expressed in millions of tonnes 77
Table 51 List of Cementos Pacasmayo S.A.A. information. 79


v


Index of figures


Figure 1 Tembladera quarry mining sequence 4
Figure 2 Pacasmayo plant process block diagram 5
Figure 3 Graph of slopes of the variables on the Economic Value (expressed as %) 10
Figure 4 Sensitivity of EBITDA (expressed as %) 10
Figure 5 Acumulación Tembladera Concession 15
Figure 6 Pacasmayo Industrial Plant map 16
Figure 7 Geological Section of the Tembladera quarry 23
Figure 8 Water level at the Tembladera quarry 24
Figure 9 Tembladera quarry mining sequence 44
Figure 10 Tembladera quarry final pit 49
Figure 11 Pacasmayo plant process block diagram 52
Figure 12 Mining Facilities 56
Figure 13 Segmentation of the cement market in Peru 57
Figure 14 Global GDP and Construction sector GDP MoM variation (%) 59
Figure 15 Historic prices of cement in Peru 61
Figure 16 Evolution of the national demand of cement 62
Figure 17 Sensitivity of Net Present Value 74
Figure 18 Sensitivity of EBITDA 75
Figure 19 Concession Acumulación Tembladera and adjacent concessions 76


vi


1.Executive Summary


Cementos Pacasmayo S.A.A (CPSAA) is a Peruvian company, whose corporate purpose is the production of cement and other products associated with the construction sector. This Technical Report Summary summarizes a Pre-feasibility study of the Tembladera quarry located in the Cajamarca Region and the cement plant located in La Libertad Regional, both owned by CPSAA. Cementos Pacasmayo’s qualified persons (QPs) prepared this Report to support disclosure of limestone Resources and Reserves.


1.1.Location and access


The Tembladera quarry contains limestone, which is the main raw material for cement production. This quarry is located in the Yonan district of Contumaza province in Cajamarca Region. There is an access road to this quarry from Lima to Trujillo. The Cementos Pacasmayo plant is located at Kilometer 666 of the Panamericana Norte highway in the district and province of Pacasmayo in the region of La Libertad. The cement manufacturing plant is located 60 kilometers away from the Tembladera Quarry and 120 kilometers from the city of Trujillo.


1.2.Climate


The quarry is in the semi-arid climate of the region of the Andean lower level of northern Peru. Precipitation ranges from minimum values of 0 mm from June to September, to a maximum value of 26.3 mm in March. Temperatures throughout the year vary between 20°C from July to August, and 25°C in March. The maximum temperature is 27°C on average, but it can go up to 29°C (January - April). Minimum temperatures are around 15-17°C (July - September).


In the cement plant in Pacasmayo, the annual average temperature varies between 16.5 and 25.0°C. The monthly average temperature varies between 19 and 25°C. The annual relative humidity averages 85%.


1.3.History


Tembladera quarry is a limestone deposit, which is used to produce different types of cement for construction. The deposit is owned by Cementos Pacasmayo S.A.A.


In 2002, the National Institute of Cadastre and Mining Claims gave to Cementos Pacasmayo S.A.A., the title of non-metallic concession called “Acumulación Tembladera”, which goes back in time to the date of the oldest claim “North N° 1” granted by the Mining Regional Office of Cajamarca by Ministerial Resolution N° 267, dated June 30, 1950, in favor of Cementos Portland del Norte S.A., starting operations as Cementos Pacasmayo S.A.A. from 1957 to 2013.


The Calizas del Norte S.A.C. company (CALNOR) operated the mine from January 2014 to May 2016. The Tembladera quarry did not operate from June to September 2016. Afterwards, Cementos Pacasmayo hired San Martin Contratistas Generales S.A. to operate the mine, which they have done since October 2016.


CPSAA conducted a major exploration project in March 2007, which consisted of a drilling campaign. MINTEC, a consulting company, was hired to create the 3D model of the deposit and estimate Mineral Resources.


In 2019, another campaign of eight diamond drill holes was carried out, to confirm the Mineral Resources and the Reserves in the eastern part of the deposit. Interpretation of the information obtained was used to prepare a new geological model. Cementos Pacasmayo oversaw the interpretation.


In December 2022, Cementos Pacasmayo started a diamond drilling campaign of eight (8) drill holes to confirm Mineral Resources and Reserves. Drilling activities continue during the first month of 2023.


Between October and December 2025, the Tembladera quarry did not dispatch material to the Pacasmayo plant due to corrective maintenance works on internal components of the primary crusher, during that period, limestone was consumed from strategic stocks. However, waste removal activities continued during October and November, and the construction of a safety wall in the pit was completed in December.


1 


1.4.Geological environment and mineralization


The deposit is contained within the so-called Cajamarca Formation, which belongs to the Upper Cretaceous (Turonian floor, around 90 MA). This formation overlies the Quilquiñan Group and underlies the Celendín Formation.


Sedimentary rocks corresponding to the Cajamarca Formation and the Upper Cretaceous Celendín Formation outcrop in the area.


On the other hand, the Cajamarca Formation is composed of thin limestones, well stratified, in strata of thin layers, with a coloration that goes from dark to light gray. It has a thickness of 230 meters.


1.5.Exploration


Exploration activities at the Tembladera quarry were carried out in 2007 and 2019. The first diamond drilling campaign, in 2007, drilled 31 drill holes. In 2007, DCR Ingenieros S.R. Ltd determined the geotechnical guidelines of the Tembladera quarry and grouped them into seven (7) geotechnical zones. In 2019, the second diamond drilling campaign was carried out with eight (8) drill holes. In the same year, Walsh Peru S.A. carried out a hydrogeological study of the Tembladera quarry.


During 2021, Cementos Pacasmayo update of Hydrogeological studies in the Tembladera quarry was made; however, the works were office work. Likewise, the update of geotechnical studies on the stability of the pit slope and the waste disposal in the quarry. Those works involved sample collection and sample analysis to determine the rock strength, density, and other properties.


From December 2022 to early 2023, Cementos Pacasmayo drilled eight (8) more holes at the Tembladera quarry in order to confirm the Mineral Reserves.


1.6.Sample preparation, analysis and security


Cementos Pacasmayo has implemented procedures for sample preparation, tests and security of the information on its operations. The cement plants and operations have been complying with ISO 9001 standards since 2015. The certification under this standard is renewed annually by means of an external audit.


With respect to the geology, CPSAA uses XRF characterization and other analytical methods to analyze the main chemical components in the limestone. In the cement plant, the raw materials for the production of clinker and cement are analyzed using methods specified in the ASTM. and Peruvian Technical Standards for cement testing. The laboratory in the cement plant has properly calibrated equipment and a periodic maintenance plan.


At the Pacasmayo plant, the sampling and data verification plan applies to the processes of receiving raw materials, crushing of raw materials, coal grinding, crude grinding, clinkerization and cement grinding. Additionally, it is applied to the lime production, lime grinding and lime dispatch.


Cementos Pacasmayo S.A.A. had implemented quality assurance, quality control (QAQC) protocols for the development of the exploration and production activities in the Tembladera quarry and in the Pacasmayo plant to ensure the quality of the information that is used in the estimation of Mineral Resources and Reserves.


2 


1.7.Data verification


Concerning geological activities, CPSAA has a data verification unit for the geological database. This unit has as its main function, the verification of data to be used in the estimation of Mineral Resources and Reserves. For the appropriate administration of information, internal protocols have been implemented that are subject to internal verification. The geologic data verification activities include data collection, administration and validation received from internal and external laboratories, data tracking through the confirmation of custody chains and finally, validation of data in the database. CPSAA staff use verified data in developing the Mineral Resources and Reserves model.


The qualified persons followed the defined processes for information flows to support Mineral Resource and Reserve estimation. The qualified person followed the same process as a means of verifying and validating the geologic data. They found that the validated information is congruent in the interpretations of the same, with which the fundamental base geological models were generated for the estimation of the Mineral Resources.


No findings have been found that could invalidate the estimation of the Resources and Reserves of the deposit.


For data verification activities at the cement plant, uses the Plan, Do, Check and Act (PDCA) methodology. This is applied to the technical information received from the company’s internal and external customers. The quality control laboratory compares the results with national and international laboratories as part of the verification procedures.


1.8.Mineral processing and metallurgical tests


Cementos Pacasmayo has procedures for the development of products at the laboratory level and its scaling at the industrial level, as well as its own procedures for the preparation, review, issuance and control of laboratory test reports. Cementos Pacasmayo has a research and development laboratory located in the Pacasmayo plant to evaluate technical aspects of cement plant and quarry operations.


To have a representative sample of its raw materials and cement at the Pacasmayo plant, Cementos Pacasmayo performs the analysis of its samples in its internal Research and Development Laboratory located at the plant.


A significant percentage of Research and Development activities are focused on evaluating different ratios between clinker-mineral additions providing the best functional characteristics to our products and at the same time balancing the benefits generated for the company. Another objective is to identify other additions that can substitute for clinker: slag, pozzolana, fly ash, calcined clays, etc., to reduce its environmental footprint and the cost of cement production. Based on this work, the laboratory has determined (and confirmed with production estimates) that 1 tonne of limestone yields 0.74 tonnes of clinker and the clinker/cement factor of the main cements with additions is 0.71.


The Research Laboratory issues technical reports to the operations department following international standards. The operations department evaluates the convenience of implementing the tests industrially and validates what is reported at the laboratory level.


1.9.Estimation of Resources and Mineral Reserves


Qualified person (QP) has estimated limestone Resources and Reserves contained in this technical report summary (TRS). The evaluation uses, the information from exploration activities from previous years has been used, and is the database for the Resources and Reserves model.


The limestone Resources are presented in Table 1. The Resource estimation considered the quality restrictions of limestone received in Pacasmayo cement plant, limits of the concessions, accessibility to the Resources and legal restrictions of the mining concessions, and economic factors and modifying factors.


3 


The minimum quality accepted is 48.6% CaO to be used as raw material for production and considering the sale prices of cement at the Pacasmayo plant, the economic evaluation used for Reserve evaluation is shown in Chapter 19 and considers the same criteria used for the estimation of Reserves.


Table 1 Mineral Resources (exclusive of Reserves) of Tembladera quarry


Resources Tonnes
M
CaO
(%)
MgO
(%)
Al2O3
(%)
SO3
(%)
Limestone Measured 135.1 49.85 1.79 1.63 0.29
Indicated 39.2 50.58 1.56 1.39 0.17
Measured + Indicated 174.3 50.01 1.74 1.58 0.26
Inferred 41.5 50.61 1.56 1.38 0.17


For Reserve estimation, the Mineral Resources and the quality criteria, modifying factors and limestone production costs were considered. The mining method used is open pit. The economic results are shown in Chapter 19.


Table 2 Mineral Reserves of Tembladera quarry


Reserves Tonnes
M
CaO
(%)
MgO
(%)
Al2O3
(%)
SO3
(%)
Limestone Proven 67.8 49.83 1.49 1.51 0.35
Probable 5.1 50.56 1.28 1.39 0.19
Total 72.9 49.88 1.48 1.50 0.33


1.10.Mining Methods


Cementos Pacasmayo S.A.A. is the current owner of the Tembladera quarry, which has outsourced its production to a specialized contractor. The limestone mining at the Tembladera quarry includes drilling, blasting, loading, hauling, and crushing.


Figure 1 Tembladera quarry mining sequence


4 


The major equipment used for the production of limestone at the Tembladera quarry is a track drill, primary crusher, secondary crusher, excavator, tractor, front loader, and dump truck. Also, auxiliary equipment is necessary, including pickups, lubricator trucks, ambulance, and other equipment.


The mining plan of the Tembladera quarry considers an average annual production of 2.4 million tonnes of limestone for the next 30 years and a stripping rate of 0.20.


Based on the plant requirements and sales projection for the next 30 years, the pit design parameters for the Tembladera quarry are inter-ramp slope angle, bench slope, bench height, safety bench, width of ramps, safety berm height and ramp gradient.


1.11.Processing Plant & Infrastructure


Cement production considers the stages of raw material extraction, grinding and homogenization, clinkerization, cement grinding, silo storage and packaging, loading and transportation. Cement is moved through conveyor belts to packing systems to be packed in bags and then loaded onto trucks operated by third parties for distribution.


Figure 2 Pacasmayo plant process block diagram


The raw materials and additions are considered for cement production at Pacasmayo plant. The raw materials for cement production are limestone, sand, iron, clay and coal. The mixture of these raw materials is crude which is fed to the calcination kiln to produce clinker. The limestone represents 81% by weight of the raw material.


5 


Clinker and additional materials are used to produce cement. The additions used in cement production are slag, pozzolana, gypsum and limestone. Currently, the cement plant in Pacasmayo has a Clinker/Cement factor of 0.71.


The Pacasmayo plant has an electrical substation with a capacity of 105 MVA, the electric power is supplied from the national grid.


Cementos Pacasmayo has implemented a preventive and corrective maintenance plan to keep cement production uninterrupted.


Cementos Pacasmayo maintains operational efficiency to control costs and operating margins, and makes efforts to diversify energy sources and ensure supply when possible.


1.12.Market studies


The Peruvian Cement Market is geographically segmented by regions: northern, central and southern region and every region is served by different companies, most of which are cement producers.


The main companies that supply the cement market in Peru are Cementos Pacasmayo S.A.A., UNACEM, Cemento Yura, and Cementos Selva S.A.C. There are also companies that import cement or clinker, such as Cemento Inka, Cemento Nacional, Cemex, Holcim Perú S.A, among others.


The companies that commercialized cement in Peru follow the Peruvian Technical Standards associated with - technical specifications for cement.


Portland Cement is subdivided into Type I and Type V. Portland Cement is subdivided into Type ICO, Type IL, Type 1P and Type 1 (PM); and finally, Hydraulic Cements specified by performance are Type GU, Type MS (MH), Type HS, Type HE, Type MH and Type LH.


Cementos Pacasmayo, being the leading company in the production and sale of cement in the Northern Region, has a market share in the following cities: Cajamarca, Chiclayo, Chimbote, Jaen, Pacasmayo, Piura, Rioja, Tarapoto, Trujillo, Tumbes, Yurimaguas and Iquitos. Cementos Pacasmayo also has a Market Share above 91.8% in the northern region of the country.


Annual cement shipments at the national scale for the year 2025 reached a total of 12.9 million tonnes, while total cement shipments at the Pacasmayo plant for 2025 were 1,822.0 thousand tonnes. Pacasmayo plant meets almost 54.8% of the cement demand in the Northern Region of the country and its cement shipments represent 59.8% of the three cement plant’s overall shipments.


Figure 3 shows the projected demand and price per ton of cement for the next 30 years.


6 


Table 3 Projection of demand and price for the next 30 years


   Shipments
(tonnes)
   Revenue
S/ x t
 
         
2026P   1,851,309    475.4 
2027P   1,888,335    484.9 
2028P   1,926,102    494.6 
2029P   1,964,624    504.5 
2030P   2,003,916    514.6 
2031P   2,043,995    524.9 
2032P   2,084,875    535.4 
2033P   2,126,572    546.1 
2034P   2,169,104    557.1 
2035P   2,212,486    568.2 
2036P   2,256,735    579.6 
2037P   2,301,870    591.2 
2038P   2,347,907    603.0 
2039P   2,394,866    615.0 
2040P   2,442,763    627.3 
2041P   2,491,618    639.9 
2042P   2,541,451    652.7 
2043P   2,592,280    665.7 
2044P   2,644,125    679.0 
2045P   2,697,008    692.6 
2046P   2,750,948    706.5 
2047P   2,805,967    720.6 
2048P   2,862,086    735.0 
2049P   2,900,000    749.7 
2050P   2,900,000    764.7 
2051P   2,900,000    780.0 
2052P   2,900,000    795.6 
2053P   2,900,000    811.5 
2054P   2,900,000    827.8 
2055P   2,900,000    844.3 


1.13.Capital and operating costs & Economic Analysis


This document presents the cash flow analysis and an economic evaluation of the project based on the current operating costs of the cement plant in Pacasmayo and using limestone production information for the Tembladera quarry. For the Mineral Reserves evaluation, the general and macroeconomic assumptions used for the projection of the free/economic cash flows and for the valuation are:


-Projection horizon: 30 years (2026 to 2055) according to the estimated quarry life.


-Annual inflation rate, 2.90%, based on Banco Central de Reserva del Perú as of projection 2026: applies equally to sales price, costs and expenses.


7 


-Capital cost projections were determined using a historical ratio of annual investments and maintenance costs which also considers the increase in production volume.


-The company’s capital structure is considered in the discount rate (WACC) of 10.91%.


-Income tax rate: effective rate of actual (historical) business results, 29% - 30%.


-Workers’ Profit Sharing: 10%.


-Exchange rate: exchange rate is assumed to remain at 3.80 (USD/PEN).


The economic analysis uses the economic assumptions listed in Chapter 19. The main variables considered in the economic model for the sensitivity analysis were cement price, production cost and CapEx.


For the economic analysis of Reserves, the free cash flow is constructed, which does not incorporate the financing structure, since the latter is considered in the weighted average cost of capital of the company (WACC) for discounting future cash flows. The following financial parameters were calculated:


●30-year mine life


●Average plant throughput for cement production: 2.5 million tonnes per year over the 30-year projection.


●Average sales price: 642.9 soles per ton of cement, an average of the 30-year projection, at nominal values.


●Revenues: 1,618 million soles annual, an average of the 30-year projection.


●Average production cost: 406 soles per ton of cement, an average of the 30-year projection, at nominal values.


The cash flow of the project is presented in Table 4 below. The NPV at a discount rate of 10.91% is 2,248 million Soles.


8 


Table 4 Free Cash Flow and valuation


   FCF - Valuation (Thousand S/) 
   (-) Taxes (EBIT*t)   (-) CapEx   EBITDA Planta
Pacasmayo
   Free Cash
Flow
 
                     
2026P   -112,737    -51,237    344,731    180,757 
2027P   -125,048    -52,723    383,244    205,474 
2028P   -134,700    -54,252    415,218    226,266 
2029P   -133,972    -55,825    417,085    227,288 
2030P   -142,757    -57,444    442,471    242,270 
2031P   -141,143    -59,110    440,013    239,760 
2032P   -142,228    -60,824    444,161    241,110 
2033P   -149,871    -62,588    465,407    252,948 
2034P   -156,382    -64,403    484,455    263,670 
2035P   -157,372    -66,271    489,862    266,219 
2036P   -163,702    -68,193    507,976    276,081 
2037P   -169,733    -70,170    523,877    283,974 
2038P   -170,455    -72,205    523,962    281,302 
2039P   -176,821    -74,299    541,606    290,486 
2040P   -182,633    -76,454    558,216    299,130 
2041P   -173,942    -78,671    533,288    280,675 
2042P   -178,208    -80,952    545,414    286,253 
2043P   -181,718    -83,300    555,576    290,558 
2044P   -140,511    -85,716    435,890    209,663 
2045P   -138,134    -88,201    429,123    202,788 
2046P   -134,796    -90,759    419,543    193,987 
2047P   -123,409    -93,391    392,489    175,688 
2048P   -118,397    -96,100    379,455    164,959 
2049P   -112,725    -98,887    365,481    153,870 
2050P   -101,491    -101,754    336,108    132,863 
2051P   -95,719    -104,705    322,699    122,274 
2052P   -89,280    -107,742    307,359    110,338 
2053P   -76,617    -110,866    274,799    87,316 
2054P   -69,580    -114,081    258,172    74,511 
2055P   -66,327    -117,390    250,686    66,970 


WACC   10.91%
Economic NPV (Thousand S/)   2,248,101 


9 


Figure 3 and Figure 4 show the sensitivity analysis, which shows the influence of changes in prices, OpEx, CapEx on NPV and EBITDA, respectively.


Figure 3 Graph of slopes of the variables on the Economic Value (expressed as %)


Figure 4 Sensitivity of EBITDA (expressed as %)


1.14.Adjacent properties


The Acumulación Tembladera property shares borders with private properties. No mining activities are being performed on these properties. The mining concession (EAGLE 1) overlaps with the Acumulación Tembladera property by 46.43 hectares; however, Cementos Pacasmayo owns the surface property; consequently, this concession does not restrict the Cementos Pacasmayo’s activities in the current exploitation areas. Eagle 1 does not interfere with Cementos Pacasmayo S.A.A.’s operations, Resources or Reserve estimates. Also Julissa A and Ana Paula 2805 concessions do not interfere with the area of the mining rights in the Cementos Pacasmayo S.A.A. concession.


10 


1.15.Interpretation and conclusions


●From a legal point of view, Cementos Pacasmayo S.A.A. has ownership of the mining properties for the exploration, development and production of limestone to supply the cement plants for normal production during the life of the quarry.


●Cementos Pacasmayo S.A.A. has been complying with international ISO-9001 (Quality) standards since 2015 and has implemented Quality Assurance and Quality Control (QAQC). The controls are applied for the construction of the geological Model, and for estimating the Mineral Resources and Reserves.


●Cementos Pacasmayo S.A.A. has a robust quality assurance system in its operations that includes sample preparation methods, procedures, analysis and result validation which comply with the best practices in the industry.


●The information verification and validation processes are carried out following the procedures indicated in the information flows. The validated information is congruent with the one that generated the geological models, which are the fundamental basis for the estimation of Resources.


●The geological modeling of the limestone deposit considers the updated data from the last diamond drilling campaigns.


●The Mineral Resource and Reserve estimation consider the geologic characteristics and modifying factors as well as due consideration of risk: geologic and associated with evaluation of modifying factors. The main quality variable is the CaO content, which is very stable in the deposit, also there are along with other secondary variables that determine the quality of the Reserves.


●In the process of estimating Mineral Reserves and in the production plans of the quarry, these variables have been adequately considered in the mining plan, properly sequenced and with blending processes. There are sufficient proven and probable Reserves for the next 30 years.


●Table 5 and Table 6 show the Mineral Resources and Reserves of the Tembladera quarry, respectively.


Table 5 Resource Categorization (exclusive of Reserves) at the Tembladera quarry


Resources Tonnes
M
CaO
(%)
MgO
(%)
Al2O3
(%)
SO3
(%)
Limestone Measured 135.1 49.85 1.79 1.63 0.29
Indicated 39.2 50.58 1.56 1.39 0.17
Measured + Indicated 174.3 50.01 1.74 1.58 0.26
Inferred 41.5 50.61 1.56 1.38 0.17


Table 6 Mineral Reserves expressed in millions of tonnes


Reserves Tonnes
M
CaO
(%)
MgO
(%)
Al2O3
(%)
SO3
(%)
Limestone Proven 67.8 49.83 1.49 1.51 0.35
Probable 5.1 50.56 1.28 1.39 0.19
Total 72.9 49.88 1.48 1.50 0.33


11 


●The cement plant located in Pacasmayo has equipment and facilities available for cement production using limestone from the Tembladera quarry and other necessary materials.


●The Health, Safety and Environment department is in charge of supervising compliance with the Company’s corporate policies and the various legal requirements of the national regulatory bodies by all company areas.


●Through its Social Responsibility area, Cementos Pacasmayo S.A.A. has generated relationships of trust with the communities surrounding its operations, which have a solid relationship with our communities, identifying their primary needs in health, education, urban development, and local development.


●The operation in Tembladera quarry and Pacasmayo plant, with regards to infrastructure, is technically and economically feasible due to the life of the quarry.


●The sensitivity analysis shows that the operation is economically robust.


1.16.Recommendations


●Maintain the QAQC program for exploration, development and production activities associated with cement production.


●Continue geotechnical monitoring of the quarry components to ensure their physical stability.


●Conduct limestone density testing in upcoming studies at the Tembladera quarry.


●Continue diamond drilling campaigns aimed at recategorizing inferred resources and confirming reserves to the SE of the Tembladera quarry.


●Geologically define the continuity of the main NW-SE oriented dike in the quarry’s operating area to more accurately quantify its volume (waste).


2.Introduction


2.1.Participants


This Technical Report Summary (TRS) was prepared for Cementos Pacasmayo S.A.A. by a team of Qualified Persons (QPs), including professionals from Cementos Pacasmayo and an independent Qualified Person from C&O Project LLC. Each QP contributed to the preparation of specific sections of this report in accordance with their respective expertise and professional experience and is responsible for the content of those sections.


In preparing this report, the QPs utilized information provided by Cementos Pacasmayo, including internal data, information validated and approved by the competent authorities in Peru, and publicly available sources. Such information was relied upon within the scope of each QP’s responsibilities.


Mr. Marco Carrasco, Project Manager of C&O Project LLC, participated as an independent Qualified Person and contributed to the sections specifically assigned to him. In addition, he provided support in the overall coordination and integration of the report.


His role was primarily focused on the organization and presentation of the document and did not include independent technical verification of information prepared by other Qualified Persons. Accordingly, the content of those sections remains the responsibility of their respective authors.


Mr. Carrasco is a Chemical Engineer and a member in good standing of the Peruvian Engineers Association (Colegio de Ingenieros del Perú), identified with CIP Number 100531, and He is qualified to practice my profession. He is also a member of the Mining and Metallurgical Society of America (MMSA), a United States based professional organization, identified under Qualified Person number QP1485.


Table 7 identifies the Qualified Persons who prepared this report, together with the sections under their respective responsibility.


1.1.Terms of Reference


This technical report summary was prepared as an exhibit to support disclosure of Mineral Resources and Reserves by Cementos Pacasmayo. This report summarizes the results of the Prefeasibility study of the “Acumulación Tembladera” property for the production of limestone using open pit mining methods. The report is effective December 31, 2025.


The limestone extracted from the Acumulación Tembladera property supplies raw material for the Pacasmayo plant where cement is produced. The annual limestone production is 2.4 million tonnes per year (Mtpy). Actual operating costs have been considered for the estimates and used as a basis for economic projections within the economic analysis. This technical report summary estimates Mineral Resources and Reserves according to the regulations published in Securities Exchange Commission (SEC) Form 20-F and under subpart 1300 of Regulation S-K.


The report was prepared by the qualified persons listed in Table 7 using available studies and, in some cases (see Chapter 25), relying on information provided by Cementos Pacasmayo, the registrant.


12 


Table 7 List of Qualified Persons


Item   Chapter   First and Last Names   Company   Job Position   Profession
0   Coordination and Integration   Marco Carrasco (*)   C&O Projects LLC   Project Manager   Chemical Engineer
1   Executive summary   All QPs (**)            
2   Introduction   All QPs (**)            
3   Property description   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
4   Accessibility, climate, local Resources, infrastructure and physiography   Marco Carrasco   C&O Projects LLC   Project Manager   Chemical Engineer
5   History   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
6   Geological setting, mineralization, and deposit   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
7   Exploration   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
8   Sample preparation, analyses, and security   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
8   Sample preparation, analyses, and security   Dennis Rodas   Cementos Pacasmayo S.A.A   Quality Assurance Superintendent   Chemical Engineer
9   Data verification   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
9   Data verification   Dennis Rodas   Cementos Pacasmayo S.A.A   Quality Assurance Superintendent   Chemical Engineer
10   Mineral processing and metallurgical testing   Dennis Rodas   Cementos Pacasmayo S.A.A   Quality Assurance Superintendent   Chemical Engineer
11   Mineral resource estimates   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
12   Mineral reserve estimates   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
13   Mining methods   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
14   Processing and recovery methods   Dennis Rodas   Cementos Pacasmayo S.A.A   Quality Assurance Superintendent   Chemical Engineer
15   Infrastructure   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
16   Market studies   Marco Carrasco   C&O Projects LLC   Project Manager   Chemical Engineer
17   Environmental studies, permitting, and plans, negotiations, or agreements with local individuals or groups   Marco Carrasco   C&O Projects LLC   Project Manager   Chemical Engineer
18   Capital and operating costs   Marco Carrasco   C&O Projects LLC   Project Manager   Chemical Engineer
19   Economic analysis   Marco Carrasco   C&O Projects LLC   Project Manager   Chemical Engineer
20   Adjacent properties   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
21   Other relevant data and information   All QPs (**)            
22   Interpretation and conclusions   All QPs (**)            
23   Recommendations  

Jason Gamio

Dennis Rodas

  Cementos Pacasmayo S.A.A        
24   References   All QPs (**)            
25   Reliance on information provided by the registrant   All QPs (**)            


(*)

Marco Carrasco served as Project Manager for Cementos Pacasmayo S.A.A. until March 2026 and thereafter participated as Project Manager of C&O Project LLC. In this capacity, he compiled and integrated the information provided by the Qualified Persons responsible for each chapter to prepare a consolidated report. Each Qualified Person is solely responsible for the content of the sections they prepared. Mr. Carrasco’s role in the compilation process was limited to the organization and integration of such information and did not include independent technical verification or validation of the data, analyses, or conclusions provided by other Qualified Persons.


(**)Marco Carrasco, Dennis Rodas and Jason Gamio


13 


1.2.Conventions


Unless otherwise indicated in the report, all currencies are in soles and all measurements and units are in the metric system. The Tembladera Accumulation property is represented by Universal Transverse Mercator (UTM) coordinates. All coordinates referenced in this report and in the accompanying figures, tables, maps and sections are provided in the WGS84 coordinate system, UTM 17S zone, unless otherwise indicated.


1.3.Previous Work and Sources of Information


The information used is sufficient to allow this TRS to be completed with the level of detail required by Regulation S-K subpart 1300. The information used included exploration results from all the drilling campaigns, actual information from Cementos Pacasmayo’s operations, information submitted to and approved by the corresponding authorities and public information in organizations specialized in the cement industry. The list of sources of information is presented in Chapter 24 of this report.


1.4.Details of QP Personal Inspection


The QPs who developed this document visited the Tembladera quarry and Pacasmayo plant as part of their activities for 2025.


Table 8 Qualified Persons field visit


Item   First and Last Names   Company   Job Position   Profession   Field visit
1   Dennis Rodas   Cementos Pacasmayo S.A.A   Quality Assurance Superintendent   Chemical Engineer   Pacasmayo plant, all year as part of his duties in the quality control department.
2   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer   Mr. Gamio has visited the Tembladera quarry and Pacasmayo plant regularly. The last visit to the Tembladera quarry and Pacasmayo plant was in October 2025, visiting core facilities, discussing grade control, geological mapping, exploration, and delineation drill practices, diamond drill core logging, quality assurance, and quality control (QA/QC), raw material storage and mineral reserve estimation practices.
3   Marco Carrasco   C&O Projects LLC   Project Manager   Chemical Engineer   In September 2025, Mr. Carrasco visited the Pacasmayo plant and Tembladera quarry; He coordinated remotely with operational staff. His visit emphasized the operational cement process and equipment conditions (kilns, mills, storages (raw material and sub-products and products, etc.) and in Tembladera quarry He visited the Coreshack and the operations.


1.5.Previously Filed Technical Report Summary


This Technical Report Summary (TRS) updates the previously filed technical report summary for the property. The previously filed TRS is the “Technical Report Summary (TRS), Tembladera Quarry and Pacasmayo Cement Plant 20-F 229.601”, which was filed as Exhibit 96.1 of the CPSAA’s Annual Report on Form 20-F filed with the SEC on April 29, 2025 (File No. 001-35401).


14 


3.Property description


3.1.Tembladera quarry


We refer to the non-metallic mining concession called Acumulación Tembladera. The mentioned mining property is located in the area of Tembladera, in the district of Yonan, province of Contumaza, Cajamarca region.


The quarry is located 60 km from the Pacasmayo district, Pacasmayo province, La Libertad region, where the cement plant is located. Consider the UTM coordinate of the center of the circle of the Acumulación Tembladera as follows:


Table 9 Central coordinates of the Acumulación Tembladera property


North  East  Radius  Zone
 706744.79  9198636.74  5,000.00  17


The area of the property is 3,390.97 hectares and is shown in Figure 5. The mining rights (the mining concession title) are granted by INGEMMET (Geological Mining and Metallurgic Institute) of the Energy and Quarries Sector by means of a Presidential Resolution. In the particular case of the Acumulación Tembladera, the Director’s Resolution N° 01989-2002-INACC/J the State Organization that granted that title was the National Institute of Concessions and Mining Cadastre (Instituto Nacional de Concesiones y Catastro). Cementos Pacasmayo S.A.A has surface rights for the operation area in the Tembladera quarry.


The mineral rights were issued based on the General Mining Law (DS-014-92-EM) and its Regulation D.L 020-2020-EM.


The property is in the name of Cementos Pacasmayo S.A.A., is also registered with the name Acumulación Tembladera, and with type of substance NON-METALLIC.


Cementos Pacasmayo S.A.A. pays the right of validity for the concession of Acumulación Tembladera with unique code 010001801L. These payments must be made from the first business day of January to June 30 of every year. Cementos Pacasmayo S.A.A. pays royalties to the State according to regulations established by the Authority in Law N° 28258 and its amendment N° 29788, for the property called Acumulación Tembladera.


Figure 5 Acumulación Tembladera Concession


15 


3.2.Pacasmayo Industrial Cement Plant


The cement plant property is located in the Pacasmayo District, Pacasmayo Province, La Libertad Region. It is located at Kilometer 666 of the Panamericana Norte.


The property is shown in the Figure 6 and Table 10 shows the UTM coordinates of the center of the circle of the Pacasmayo plant:


Table 10 Central coordinates of the Pacasmayo cement plant


North  East  Radius  Zone
659953.76  9180941.32  700.00  17


The area of the property is 132.8 hectares. The property is registered in the National Superintendence of Public Registries (Superintendencia Nacional de los Registros Públicos – SUNARP) under the registration number 11026568 in registry zone No. V TRUJILLO, Registry Office San Pedro de Lloc.


Cementos Pacasmayo S.A.A. pays taxes to the State according to that established by the Municipal Authority, for the Pacasmayo plant.


Figure 6 Pacasmayo Industrial Plant map


16 


4.Accessibility, climate, local Resources, infrastructure and physiography


4.1.Tembladera quarry


This chapter describes the accessibility, climate, local resources and infrastructure for the Tembladera quarry and Pacasmayo plant. The chapter uses information obtained from technical and environmental studies prepared by specialized companies and approved by the authorities.


Topography


Tembladera is located between 500 and 1000 masl. The topography shows steep surfaces and abrupt slopes. Drainage is dendritic and controlled by structural features; all the streams are tributaries of the Jequetepeque River.


Access


The main access is by land. The journey from the city of Lima to the Tembladera quarry is as follows: Lima – Pacasmayo (666 km), Pacasmayo – Ciudad de Dios (14.3 km), Ciudad de Dios – Tembladera (50 km) and Tembladera – Checkpoint (0.8 km), for a total of 747.1 km.


By air route is as follows: Lima – Trujillo in 1 hour flight, and from Trujillo to Tembladera quarry by land route for a journey of 2 hours.


Another alternative by air route is as follows: Lima – Chiclayo, in approx. 1:15 hrs flight, and from Chiclayo to Tembladera by land route with a journey of 2.5 hrs.


Climate


The Tembladera quarry is in an area, that is entirely classified as an arid climate E and temperate thermal efficiency B’, with humidity deficiency throughout the year under normal conditions.


Meteorological information is administered by the National Service of Meteorology and Hydrology, SENAMHI. The precipitation data from the Monte Grande Meteorological Station has minimum values 0 mm from June to September and maximum values of 26.3 mm in March, corresponding to the dry and wet periods of the year. The total annual precipitation averages 64.6 mm.


17 


Temperature


The average annual temperature is 22.7 °C. From June to September, the lowest temperatures are recorded on average, while the rest of the year sees higher temperatures, reaching up to 25.0 °C in March. The average annual maximum temperature is 28.3 °C, and the month with the highest maximum temperature is February, at 30.4 °C. The lowest average temperatures were recorded during the months of June to September, with the greatest temperature drop of 15 °C occurring in August.


Physiography


The quarry area is located in northern Peru between the transition of the coast and the mountain range, a region characterized by hilly mountainous relief, cut by rivers and streams creating cultivated valleys and watercourses, where the current morpho-dynamic processes show a moderate to low activity, except during periods of the El Niño Phenomenon. The property groups physiographic units into three morphological classes: plains, mountains and hills and one class originated by human activity.


Local resources and infrastructure


The personnel of the quarry are divided into Cementos Pacasmayo S.A.A. and contractor personnel. Additionally, the quarry is located 5 kilometers from the Tembladera town, where there are local resources for a population such as housing, schools, hotels, electrical infrastructure, water supply, internet access, etc. The contractor accesses the Tembladera quarry by pickup trucks and buses.


The national electricity grid is the source of energy for the Tembladera quarry. A water channel supplies the Tembladera quarry with water, which is authorized by the National Water Authority (ANA).


4.2.Pacasmayo cement plant


Topography


The area is located in the alluvial pampas, with elevations between 25 and 100 masl., consisting of extensive variety of conglomerate material that represent ancient dejection cones of the Cupisnique, Jequetepeque, Las Viejas, Zaña and Reque rivers. In general, these pampas are desert-like and are practically free of crops; they are equal to the high terraces created by the rivers in the area.


The continuity of these pampas is interrupted by the trenches eroded by the modern rivers. It is common to find minor terraces on the flanks of the valleys, especially in the inland sectors, such as the Jequetepeque valley.


The coastal morphology consists of an almost continuous line of ravines, interrupted only by the narrow valleys of the main rivers. The ravines are 20 to 50 meters high, almost vertical, consisting of conglomerate material belonging to the ancient dejection cones. The beaches are very narrow.


18 


Access


The main access is by land. The journey from the city of Lima to Pacasmayo (682km). By air route is as follows. Lima – Trujillo, 1 hour flight, and by land route 1.5 hours from Trujillo to Pacasmayo. Another alternative by air route is Lima – Chiclayo, 1 hour flight and from Chiclayo to Pacasmayo 1.5 hours by land route.


Climate


Temperature: This coastal zone has average annual temperatures between 17.7 and 27.83 ºC. The average monthly temperature ranges from 19 to 25 °C, based on data from the Meteorological Station of Talla.


Precipitation: The area has very low precipitation for the most of the year, having an annual average of less than 10 mm.


The annual average Relative Humidity is 77%.


Atmospheric Pressure: The atmospheric pressure fluctuates from 1017 hPa to 1013 hPa in the period of November 2006, with a daily average of 1009 hPa. These pressure values are related to the influence of the South Pacific Anticyclone.


Sunshine is high at midday in summer, with an average of 7 hours of solar rays per day. In the winter, the sunshine decreases to 3.5 hours of solar rays, although it is worth noting that there are clouds that allow the diffuse radiation to pass through.


Local resources and infrastructure


The personnel of the plant are divided into Cementos Pacasmayo S.A.A. and contractor personnel. The cement plant is located next to Pacasmayo town where most of the personnel live. They are taken from Pacasmayo to the cement plant in buses provided by Cementos Pacasmayo.


Electricity is supplied by the national grid and there is a contract with Electro Perú, which supplies energy through a 60 KV transmission line.


Water supply at the Pacasmayo plant is provided by a groundwater well.


19 


5.History


5.1.Tembladera quarry


Tembladera quarry is a limestone quarry mining limestone that is suitable for different types of cement. The quarry and deposit are owned by Cementos Pacasmayo S.A.A. By means of Director’s Resolution No. 01989-2002-INACC/J dated on November 4, 2002, the National Institute of Cadastre and Mining Concessions granted to Cementos Pacasmayo S.A.A., the title of the non-metallic accumulation concession called “Acumulación Tembladera” with code No. 01-00018-01-L, whose antiquity goes back to the date of its oldest integral concession: “Norte No. 1” granted by the Regional Mining Headquarters of Cajamarca by Ministerial Resolution No. 267 of June 30, 1950, in favor of Cementos Portland del Norte S.A., starting operations as Cementos Pacasmayo S.A. from 1957 to 2013, the year in which Calizas del Norte S.AC.(CALNOR) was constituted. CALNOR started activities from January 2014 to May 2016. San Martin Contratistas Generales S.A. started activities from October 2016 to the present.


In March 2007, MINTEC Consulting Company was hired by Cementos Pacasmayo to perform the 3D modeling of the deposit and a preliminary estimation of the Mineral Resources. The geological information was obtained from 31 diamond drill holes. The samples obtained were analyzed in internal and external laboratories to obtain the content of CaO, MgO, Al2O3, SiO2, Fe2O3, SO3, Cl and CO3.


With the information generated, the geological interpretation was made and the structures which control or dominate the deposit were defined. The geological model was completed by Cementos Pacasmayo’s QPs in the MineSight software from vertical sections.


In 2019, a campaign of eight (8) diamond drill holes was carried out to confirm the Mineral Resources and Reserves of the east area of the deposit. With the interpretation of information obtained, a new geological model was prepared. Cementos Pacasmayo oversaw the interpretation and the geologic modeling.


In December 2022, Cementos Pacasmayo started a diamond drilling campaign of eight (8) additional drill holes to confirm Mineral Resources and Reserves. Drilling activities continued during the first month of 2023.


Between October and December 2025, the Tembladera quarry did not dispatch material to the Pacasmayo plant due to corrective maintenance works on internal components of the primary crusher, during that period, limestone was consumed from strategic stocks. However, waste removal activities continued during October and November, and the construction of a safety wall in the pit was completed in December.


5.2.Pacasmayo Plant


In 1957, Compañia Cementos Pacasmayo S.A. began operations in the Pacasmayo plant by installing the first clinker line, which had an installed production capacity of approximately 110,000 metric tons per year.


In 1966, CPSAA added a second clinker line of 150,000 metric tons per year, increasing the installed clinker production capacity.


In 1974, Cementos Norte Pacasmayo S.A. (CNP) was created to transfer gradually the shares to the Peruvian State.


In 1976, a third clinker line was added, increasing the installed clinker production capacity to 540,000 metric tons per year.


In 1994, CPSAA installed a new computerized process control and optimization system in the Pacasmayo plant, and the Management approved the expansion of the practical clinker production capacity from 540,000 metric tons per year to 690,000 metric tons per year. In 1995, CNP upgraded the third kiln technologically, allowing it to increase its capacity to 840,000 metric tons per year of clinker.


On December 10, 1998, a significant milestone was reached in our company’s history. Cementos Pacasmayo S.A.A. was born due to the merger between Cementos Norte Pacasmayo, Cementos Selva (formerly Cementos Rioja), and Cordasa. This strategic move not only solidified our position in the market but also paved the way for our continued growth and success.


In 2023, we completed a significant investment in a more efficient kiln for our Pacasmayo plant. This strategic move underscores our unwavering belief in our country’s future growth and, more importantly, our steadfast commitment to environmental sustainability. The new kiln, designed to significantly lower our emissions, is a testament to our dedication to carbon neutrality.


20 


6.Geological setting, mineralization, and deposit


6.1.Regional geology


The strata of the district of Yonan, province of Contumaza, Cajamarca region consists of Cretaceous Age sedimentary strata of the Quilquiñan Group, Cajamarca Formation, Celendín Formation, and Recent Quaternary Deposits (Table 11).


Table 11 Regional stratigraphic column


Quilquiñán Group (Ks-q).


The Quilquiñán Group is composed of the Romirón and Coñor formations which together are represented by 100 to 200 m. of shales and marls with some calcareous intercalations.


The Quilquiñán Group overlies the Pulluicana Group and underlies the Cajamarca Formation. Both contacts are concordant. It varies from a thickness of 120 m., in the Chongoyape quadrangle, to a known maximum of 281 m. in the Tembladera area (Cerro de Chepen).  The group consists of dark gray friable shales and bluish marls in thin layers weathering to dark brown or reddish brown. The Quilquiñán Group is fossiliferous and contains a varied fauna of ammonites, lamellibranchs and echinoidea. BENAVIDES V., (1956) dated it to the Late Cenomanian-Early Turonian interval because of its ammonite content.


Cajamarca Formation (Ks-c).


The Cajamarca Formation is composed of 100 to 400 m. of limestone whose main outcrops are located in the Cutervo, Chota and Celendín quadrangles. The Cajamarca Formation is characterized by regular and uniform stratification and grayish or whitish colors.


The formation is limited by concordant contacts with the Celendín Formation in the upper part and with the Quilquiñán Group at the base. In both cases these are sharp contacts with abrupt lithology changes. The Cajamarca Formation has a fairly uniform lithology throughout the region. It consists of a thin, pure, light brown limestone weathering to whitish or light gray. The limestone is well stratified in thin to medium layers.


A nearly complete section at Tembladera (Cerro de Chepén) is 111 m thick. (BENAVIDES V., 1956). The Cajamarca Formation is characterized by the content of Coilopoceras newelli BENAVIDES, from the late Turonian (BENAVIDES, V. 1956); therefore it correlates with the upper part of the Jumasha Formation, from other parts of northern and central Peru.


21 


Celendín Formation (Ks-ce).


The Celendín Formation outcrops only in the Cutervo, Chota and Celendín quadrangles generating a relief of hollows and low terrains characterized by yellowish and brownish tones produced by weathering. The formation concordantly overlies the Cajamarca Formation. The Celendín Formation is composed of thin layers of clayey nodular limestone, intercalated with marls and shales. In general, the marls and shales predominate over the limestones. The ammonites contained in the Celendín Formation indicate that the unit belongs to the Coniacian and early Santonian (BENAVIDES, B. 1956). The Celendín Formation correlates with other outcrops of the same unit in the north and center of the country and with the top of the Chota Formation in the Selva region.


Recent Quaternary Deposits.


Along the coastal strip and the Andean foothills, there are abundant alluvial and fluvial deposits made up of conglomerates, gravels, sands, silts, etc. forming the floors of the valleys and ravines located between San Pedro de Lloc, and Motupe, where the main population centers and farming areas of the area are located. (Source: Bulletin No. 38 Series A. National Geological Chart by John Wilson - 1,984).


6.2.Local Geology


The Tembladera quarry hosts a limestone deposit with a grade suitable for cement production. The deposit is contained within the so-called Cajamarca Formation, belonging to the Upper Cretaceous (Turonian floor, around 90 MA). This formation overlies the Quilquiñan Group and underlies the Celendín Formation.


Sedimentary rocks corresponding to the Cajamarca Formation and the Upper Cretaceous Celendín Formation outcrop in the area as described below. This formation overlies the Quilquiñan Group, and underlies the Celendín Formation.


Mesozoic


Quilquiñán Group (Ks-q).


Composed by a thin stratification of marly shales, thin layers of marly limestones, and marl nodules in thin layers, dark brown in color, it is not mineable. This formation is the limit of the Cajamarca Fm. limestones. Which represents the oldest rocks in the area, they are found outcropping in the northern part of the area of the quarry.


Cajamarca formation (Ks-c)


Composed of thin limestones, well stratified, in strata of thin layers, with a color ranging from dark to light gray, these limestones are mined for cement production because they meet quality standards. This formation lies concordant with the Quilquiñan group. The average strike of these strata is N 75° W and dip varies from sub-horizontal to 50º. It has a thickness or power of 230 meters.


Celendín formation (Ks-ce)


It presents an interstratification of thin layers of light gray limestones, cream to dark brown nodular marly limestones and shales. This formation outcrops on the south-central side of the quarry, in a reduced area, with a thickness of 35 meters, which underlies concordant to the Cajamarca Fm. These types of limestones were considered as waste rock for not complying with the quality standards.


Cenozoic


In the quarry, intrusions of andesitic dikes of plutonic formation can be found, which intrude longitudinally in very localized areas of the limestone deposit rock mass. These dykes present aphanitic to porphyritic texture, with some plagioclase crystals visible in greenish gray to whitish matrix, showing moderate to high alteration, moderate poly directional fracturing degree.


Quaternary Deposits


Along the Andean foothills there are abundant alluvial and fluvial deposits made up of conglomerates, gravels, silty sands, etc. In the Tembladera quarry area, these deposits are restricted to the Jequetepeque riverbeds, stream mouths and some terraces.


22 


Table 12 Local stratigraphic column of the Tembladera quarry


System

Series Stratigraphic Unit Intrusive rocks Lithologic Description
Quaternary Recent Fluvial Deposit Qr-fl     Fluvial origin
Alluvial Deposit Qr-al     Alluvial origin
Tertiary Lower     Andesite T-an Intrusion of andesitic dykes longitudinally into the deposit rock mass.
Cretaceous Upper Celendin Formation Ks-ce     Thin layers of clayey nodular limestone, interbedded with marls and lutites.
Cajamarca Formation Ks-c     Limestone of marine origin of whitish to light gray color.
Quilquiñan Group Ks-q     Lutites and marls with some calcareous intercalations.


6.3.Characteristics of the deposit


Table 13 shows the main characteristics of the deposit.


Table 13 Characteristics of the Tembladera deposit


Quarry

Average Width

(m)

Total
Length
(m)
Thickness
(m)
Average depth (m) Continuity
Top Elevation Lower elevation
Tembladera 800 1900 230 720 420 It is a sedimentary deposit whose continuity is controlled by a folded structure (syncline) whose limits are marked by its flanks.


Figure 7 Geological Section of the Tembladera quarry


23 


7.Exploration


7.1.Drilling


Cementos Pascamayo’s exploration activities at the Tembladera quarry property involve diamond drilling to adequately characterize the geology. The holes range in depth from 80 to 150, with an average depth of 120.


Table 14 Drilling campaigns in Tembladera quarry


Drilling Campaign Date N° of holes Hole Type Holes dimeter N° of
samples
Type of sampling Objective
1 2007 31 Diamond Drilling HQ 2515 Core sampling Exploration
2 2019 8 Diamond Drilling HQ 858 Core sampling Exploration
3 2022 - 2023 8 Diamond Drilling HQ 956 Core sampling Resources and Reserves Confirmation


7.2.Hydrogeology


In 2025, Cementos Pacasmayo did not conduct further hydrogeological studies. The last hydrogeological studies were conducted in 2021 and the information was presented in the previously filed TRS titled “Technical Report Summary (TRS), Tembladera Quarry and Pacasmayo Cement Plant 20-F 229.601”, which was filed as Exhibit 96.1 of the CPSAA’s Annual Report on Form 20-F filed with the SEC on April 28, 2022 (File No. 001-35401).


As stated in the previous TRS, Cementos Pacasmayo hired Magma Consulting S.A.C. in 2021 to update its previous hydrogeological surveys. The hydrogeological study included the evaluation of 5 piezometers. Magma Consulting S.A.C. concluded that the groundwater is 300 m above the current topographic elevation. Figure 8 shows the water table relative to ground surface (Magma Consulting S.A.C. 2021).


Figure 8 Water level at the Tembladera quarry


As per the previous TRS, CPSAA hired Walsh Perú S.A. to define the hydrogeological characteristics of the quarry. Their study (Walsh Perú S.A., 2009), which included evaluation of EC, TDS, S, pH, and T from 13 monitoring points. The evaluation concluded there is no water contamination from the current mining practices.


24 


7.3.Geotechnical studies


Cementos Pacasmayo did not conduct further geotechnical studies in 2025. The update studies were conducted in 2021 and the information was presented in the previously filed TRS titled “Technical Report Summary (TRS), Tembladera Quarry and Pacasmayo Cement Plant 20-F 229.601”, which was filed as Exhibit 96.1 of the CPSAA’s Annual Report on Form 20-F filed with the SEC on April 28, 2022 (File No. 001-35401).


As per the previously filed TRS, the geotechnical studies concluded, based on the geotechnical test work that the current slopes at the Tembladera quarry are stable for static and pseudo-static loading conditions, with safety factors above the minimum recommended for operating conditions. The studies also recommended geotechnical design criteria including a single bench height of 10 m, inter-ramp angles between 35° and 45°, with berm widths ranging from 5.04 m to 6.40 m. The recommended bank angles is between 47° and 70° and bench angles is between 47° and 70°.


8.Sample preparation, analyses, and security


This Chapter describes the preparation, analysis and security of the samples used for the geology, quarry and cement plant operations.


8.1.Geology and quarry


Cementos Pacasmayo S.A.A. has implemented international standards in all its operations such as quarries and plants. The ISO 9001 standard has been implemented and certified since 2015. The certification is renewed annually through an external audit.


The SSOMASIG department (Security, Occupational Health, Environment and Management Systems), is part of the team that determines and gives the necessary support for the maintenance of the ISO 9001 (Quality) and the scope is in all the company’s activities.


The Geology department has protocols for the activities of sample preparation methods, quality control procedures, security and other activities.


8.1.1.Preparation of samples, procedures, assays and laboratories


Samples obtained from the drill holes are placed in holders to be duly coded, cut, bagged and sent to the laboratory at the Pacasmayo plant and are occasionally sent to an external laboratory following the company’s procedures.


Certimin S.A. is used as an external laboratory for chemical analysis. Certimin S.A. is a Peruvian laboratory that is certified in ISO 9001, ISO 14001, ISO 45001, NTP-ISO/IEC 17025 Accreditation and has a membership in ASTM. This laboratory has modern facilities for the development of mining services associated with the cement industry and technical support in the geochemical field for national and international companies.


For the limestone samples, the laboratory analyses evaluate CaO, MgO, Al2O3, SiO2, Fe2O3, SO3 and Cl. Once received in the laboratory, the properties of the limestone to be used in cement production are analyzed.


8.1.2.Quality Assurance Procedures


Cementos Pacasmayo S.A.A. has developed quality assurance procedures, which guarantees the accuracy of the results in the sampling, in the preparation and analysis of the samples.


Cementos Pacasmayo S.A.A. has implemented QAQC protocols for the development of exploration and production activities in the Tembladera quarry to ensure the quality of the information that allows the estimation of Mineral Resources and Reserves of the deposit.


25 


Based on the information and samples from the 2019 drilling campaign where limestone samples were obtained, Cementos Pacasmayo S.A.A. performed an audit for the validation of results as part of the quality assurance and quality control (QAQC) activities. For this purpose, it hired the Wiracocha Mining Services S.R.L., who conducted a re-sampling of a group of drill holes executed in Tembladera quarry in the past. Also, the work included the revision of the QAQC program. The samples and controls of this program were analyzed at Certimin S.A., an external laboratory.


The analysis of the results obtained for the different samples and controls inserted show a confidence level, with an acceptable bias that are within the standards of the sampling theory, which guarantees the accuracy of the results in the initial sampling, so it is concluded that both the preparation and analysis of the samples obtained initially in the laboratory of Cementos Pacasmayo S.A.A., has reliable processes and procedures.


The quality plan implemented by Cementos Pacasmayo for the quarries includes the insertion of blanks, duplicates and standards, in order to control the precision, accuracy and contamination in the samples (Table 15).


Table 15 Quality Plan of the Tembladera quarry


Blanks Duplicates Standards Remark
1 control sample for each batch of 20 samples. 2 control sample for each batch of 20 samples. 1 control sample for each batch of 20 samples. Cementos Pacasmayo protocol
¨OM-GL-PRT-0023-R0¨.


8.1.3.Sample security


Cementos Pacasmayo S.A.A. has implemented QAQC protocols for the development of exploration and production activities in the Tembladera quarry in order to ensure the quality of the information that allows the estimation of Resources and Reserves of the deposit.


Cementos Pacasmayo S.A.A has a specific area for the storage of the samples obtained during the drilling campaigns; the samples are properly stored to preserve their quality.


The necessary materials for storage and transport of the samples were implemented. Sampling cards were also implemented with information on the name of the project, name of the borehole to be sampled, date of sampling, sampling interval, sampling manager, sampling and type of sample or control sample.


All samples were labeled, and a photographic record is available. The photographic record of each sampling bag is made together with the weighing of the sample.


8.1.4.Chain of custody


Cementos Pacasmayo has implemented actions to ensure the physical security of samples, data, and associated records. The traceability of the sample from its generation to its analysis and subsequent conservation of rejects and pulps. At the Tembladera quarry, core samples are duly stored in the core shack.


8.1.5.Qualified person’s opinion on quarry QAQC


In the author’s opinion, Cementos Pacasmayo has been complying with the international standards of ISO-9001 (Quality) since 2015 and implemented Quality Assurance and Quality Control (QAQC). Cementos Pacasmayo S.A.A. has used a QAQC check program comprising blank, standard and duplicate samples. The QAQC shipping rate used complies with accepted industry standards for insertion rates, as well; the actual sample storage areas and procedures are consistent with industry standards.


26 


Protocols in the different exploration and production processes are strictly complied with. There is information on sample preparation methods, quality control measures, sample security, and these results are accurate and free of significant error. The information in this report is adequate for use in the construction of the Geological Model, Resource Estimation and Reserve Estimation.


8.2.Pacasmayo plant


8.2.1.Samples preparation, procedures, assays and laboratories


Cementos Pacasmayo S.A.A. has a quality control plan for each of its operations that is part of the quality system.


As part of the quality control plan (P-CC-D-03 VE 05 Quality control - cement and lime), samples of raw materials such as limestone, sand, clay and iron are evaluated in the laboratory at the Pacasmayo plant, where they are analyzed to determine the chemical composition of each material for cement production.


The procedures applied are the chemical analysis of raw materials and raw meal, sampling of clinker, slag and pozzolana, physical testing of cement, chemical analysis by wet route for clinker and cement, preparation of coal samples, physical testing for additions, analyses and operating procedures in the X-ray area, which are based on ASTM, NTP (Peruvian Technical Standard) and ISO standards.


8.2.1.1.Raw materials sample preparation


For preparation of samples, it is considered the collection and preparation of samples procedure, which consists of primary and secondary crushing, and reduction of the sample by the quartering method, then the sample is pulverized in the ring mill.


8.2.1.2.Analysis of Laboratory


The laboratory at Pacasmayo plant has implemented the ISO 9001 standard; also, it has calibrated equipment, with a calibration and maintenance program established by the laboratory area. The main equipment in the laboratory at Pacasmayo plant are the XRF fluorescence equipment and the compressive strength press, which are maintained annually.


The tests for air content, fineness, autoclave expansion, compressive strength and setting time and vicat are made for all types of cements. The autoclave contraction, 14-days mortar expansion, 6-months sulfates expansion, SO3, MgO, loss on ignition, insoluble residue and C3A and 2 C3A+ C4AF tests only apply to some specific cements.


8.2.2.Quality Assurance Actions


Table 16 describes the sampling plan and frequency of tests and data verification (P-CC-D-04 VE 11) for the processes of raw material reception, raw material crushing, coal milling, raw meal milling, clinkerization, cement milling, lime production, lime milling and lime dispatch.


Table 16 Tests and frequency for each stage of the process


Stage Tests Frequency
Receiving raw materials Chemical analysis by X-ray, granulometry and humidity. 1 samples per 2 hour up to Once per day.
Crushing raw materials Chemical analysis by X-ray. 2 samples by shift or depending on the material.
Coal grinding Chemical analysis by X-ray, humidity, calorific value and proximate analysis. 1 samples per 2 hour up to Once per day.
Raw meal grinding Chemical analysis for X-ray, Humidity, R70 and R170. Each 1 hour up to 2 hours.
Clinkerization Chemical analysis by X-ray. Each hour up to 2 hours.
Cement and other grinding Chemical analysis by X-ray, pozzolana, IAP pozzolana, IAP Slag, Blaine, R325, R450, loss on ignition, insoluble residue and chemical/physical tests. Each hour up to 2 hours, silo composting and daily composite
Packaging of cement Chemical analysis by X-ray, Blaine, R325, R450, loss on ignition, insoluble residue and chemical/physical tests. 2 samples per shift and depending on the type of cement and daily and weekly composite


The quality plan implemented by Cementos Pacasmayo for the cement plants includes the insertion of blanks, duplicates and standards, in order to control the precision, accuracy and pollution in the samples. Table 17 shows the QAQC plan for the Pacasmayo plant.


Table 17 Quality Plan of Pacasmayo cement plant


Blanks Duplicates Standard Comment
03 1500 18 Blanks only apply by performing spot checks by Classical methods.


27 


In 2025, CPSAA evaluated 03 blank samples, 1500 duplicate samples, and 18 standard samples in the Pacasmayo Plant. The results show the precision and accuracy are below the error limits. As part of the quality plan, the laboratory evaluates its performance through external interlaboratory; in this sense, the laboratory participates in 02 interlaboratory:


●CCRL: Compliance greater than 94% in qualification Z Score > 4


●XAMTEC: Qualification greater than 98%.


Likewise, quality assurance procedures include control of finished products, control of non-conforming products, validation of silos, density analysis, QAQC program, quality plan and Quality control parameters for raw materials received at the Pacasmayo plant.


8.2.3.Security of the samples


Cementos Pacasmayo S.A.A. has implemented QAQC protocols for the development of cement production activities at the Pacasmayo plant, to ensure the quality of the information that allows the estimation of the Mineral Resources and Reserves of the deposit.


Sample preparation methods are sample collection and preparation, clinker, slag and pozzolana sampling and coal sample preparation.


The testing procedures are: Chemical analysis of raw meal and raw materials, analysis by X-ray equipment, X-ray laboratory operation, physical tests for additions, physical chemical analysis for coal samples, physical tests for cement, wet testing of clinker and cement and quality plan.


Likewise, the control parameters are raw material parameters, pozzolana, slag, mineral reception parameters, clinker production parameters, raw material parameters for raw meal, raw meal feed parameters, raw meal milling parameters, coal milling parameters and cement milling parameters.


8.2.4.Qualified Person’s Opinion on cement plant QAQC


Cementos Pacasmayo S.A.A. has a Quality Assurance, Research and Development area that ensures compliance with the requirements for finished products specified in Peruvian Technical Standards, which are traceable to the standards of the American Society for Testing and Materials (ASTM).


For quality assurance, the control parameters have been defined from the raw materials, products in process and finished products. Compliance with the requirements based on indicators of the quality assurance management system for the 2025 period is 0% of nonconforming products in the market. This is evaluated under the specification of Standards NTP 334.009, NTP 334.090, and NTP 334.082 (similar to ASTM C150 and ASTM C1157). Likewise, the level of customer satisfaction (D-COM-P-01 VE10 Customer satisfaction) is 91.59%.


In this sense, in the author’s opinion, the quality assurance system at the Pacasmayo plant, which includes preparation methods, procedures, analysis and security, complies with the best practices in the industry, thus ensuring that the final customer has confidence in the quality level of the products marketed by Cementos Pacasmayo. The QAQC is adequate for Mineral Reserves estimation.


9.Data verification


This Chapter shows the data verification activities for the geology, quarry and cement plant areas.


9.1.Geology and quarry


9.1.1.Data Verification procedure


CPSAA has a unit specialized in the compilation, standardization and verification of information to be loaded into the geological database. Its main function is the administration and validation of the data to be used in the estimation of mineral Resources and Reserves. For the proper management of the information of the database, internal protocols have been implemented, which are subject to internal audits.


9.1.2.Data collection


The data collection applies to exploration activities and quarry operations.


For diamond drilling, the process flow for planning and executing drilling, survey methods for reporting drill collars and ddh / verification of the quality of information and recovery process of the core information. In addition, for geological sampling activities, the processes flowsheet, validation and consistency of sample information, sample preparation and testing, density, registration process and digital photographic storage are used.


28 


For quarry operations, it applies to the sampling of detritus from the blast holes and rock chips.


9.1.3.Management and Validation of Database


The stages for management and validation of database are the recovery, processing and storage of the database. The database validation includes database development process flow, information standardization and integration process, information storage strategy, appropriate database technology, structure and practicality of the database system that allows a fast and flexible access and input of information and validation of chemical results.


9.1.4.Tracking Data


The consistency between the database records and the original registry was verified by the QPs in 2025. No differences were detected between the database and the log files. A digital copy of all records is kept as a pdf file. Digital certificates support the chemical analysis data.


The collection of the information considered the following: drill collars, survey, lithology, photographic record, samples and assays.


9.1.5.Validation of Data


Collar, Survey, Lithology and chemical analysis data were imported and processed with MX-Deposit software (By Seequent).


The results indicated that the database had adequate integrity for Resource estimation. This software verifies that the data entered from each sample or reported by the external laboratory is correct for input into the Resource model.


The team followed the defined processes for information flows to support Resource and Reserve estimation. The qualified person followed the same process as a means of verifying and validating. It has been found that the validated information is congruent in the interpretations of the same, with which the fundamental base geological models were generated for the estimation of the Resources.


No findings have been found that could invalidate the estimation of the Resources and Reserves of the unit.


Data for each hole was individually checked in the database to confirm accuracy.


The reviews included:


●Drill hole lithology database comparison to geophysical logs


●Sample quality database comparison to quality certificates


●Survey sheets


●Collar sheets


●Core photographic record


Typical errors may impact reserve and resource estimation related to discrepancies in original data entry. These errors may include:


●Incorrect drill hole coordinates (including elevation)


●Mislabeled drill hole lithology


●Unnoticed erroneous quality analyses where duplicate analyses were not requested


●Unrecorded drill hole core loss


Data validation follows the field operational procedures that collect information from the source (collar, survey, lithology, samples, and assays). Finally, when the information is transmitted and uploaded to the mining software for geological modeling and estimation, it is double-checked to eliminate any additional errors.


29 


9.1.6.Qualified Person’s Opinion Geologic Data


The qualified persons followed the defined processes for information flows to support Resource and Reserve estimation. The qualified person followed the same process as a means of verifying and validating the geologic data. They found that the validated information is congruent in the interpretations of the same, with which the fundamental base geological models were generated for the estimation of the Resources.


No findings have been found that could invalidate the estimation of the Resources and Reserves of the unit.


9.2.Pacasmayo plant


The Quality Control Plan consists of the following: PDCA cycle, customer, person in charge, activities, risks, control methods, monitoring, measurement, analysis, evaluation and documentary evidence.


The PDCA cycle is:


●Plan, during this stage the following activities are considered: determination of characteristics of raw materials, product in process and finished product, elaboration of control and arrays parameters and determination of activities and results assurance program.


●Do, during this stage the following activities are considered: verification and compliance with the requirements and matrices, sampling and preparation.


●Check, during this stage the following activities are considered: chemical analysis by XRF, chemical analysis, physical analyses, recording of results, taking action on non-conformities.


●Act, during this stage the following activity is considered, acting to improve.


The Quality Assurance Plan is applied to the following customers: production, quarry, provisions chain and external customer.


9.2.1.Data verification procedures


The XRF analysis, chemical analysis and physical analysis are made to verify the results of the samples, as part of the Quality Control Plan.


The data resulting from these three types of analysis are recorded and evaluated - to determine whether or not they comply with the technical specifications.


Data verification procedures include internal verification, check lists, statistical tables, reports, validation of data, certificates, interlaboratory test reports and compliance with quality protocols.


9.2.2.Data validation


Cementos Pacasmayo S.A.A. through its quality assurance and control unit participates in evaluations with international laboratories such as CCRL/ASTM (Concrete and Cement Reference Laboratory), which is an international reference laboratory for construction materials, and Xamtec of Colombia, an international interlaboratory, in order to report reliable data.


30 


The Quality Control laboratories endorse their analysis methods by participating in interlaboratory analysis programs, which compare the results with national and foreign laboratories. The methods of analysis compared are X-ray fluorescence (XRF) and the physical cement tests, which are the methods used to control cement quality. In all the results of these interlaboratory programs, the companies always obtain the best results for each test.


9.2.3.Qualified Person’s Opinion on cement plant


In the author’s opinion, the methodologies used for collecting and processing data at the cement plant are accurate and free of important errors. The information can be used within the models’ construction and estimates for cement production. Considering that the analyses of the main chemical components and physical properties of the raw materials and final products are made in external laboratories, the quality of the information is adequate for preparing mineral Resource and Reserve Estimates.


10.Mineral processing and metallurgical testing


10.1.Nature of Testing Program


Cementos Pacasmayo S.A.A. has a Quality Assurance and Research and Development department. The objective of the department is to develop, evaluate and research procedures for the development of products at laboratory level and their scaling up to industrial level. Another objective is to identify supplementary cementitious materials (SCM) that can substitute for clinker: slag, pozzolana, fly ash, calcined clays, etc., to reduce their environmental footprint and the cost of cement production.


They have also implemented their own procedures for the preparation, review, issuance and control of test reports associated with cement production.


Cementos Pacasmayo has implemented the ISO 9001 standard since 2015. The Research and Development laboratory, located at the Pacasmayo plant, is responsible for technical aspects of cement plant and quarry operations.


Cementos Pacasmayo applies the procedures:


●P-ID-P-04 Preparation of raw materials.


●P-ID-P-05 Sampling of cement and raw materials.


●P-ID-P-13 Input, storage and disposal of samples.


A permanent control is carried out with other laboratories to give greater reliability to the results. Likewise, interlaboratory reports are obtained from external laboratories such as CCRL (Cement and Concrete Reference Laboratory), which is an international reference laboratory for construction materials, and Xamtec from Colombia, an internal interlaboratory.


Cementos Pacasmayo S.A.A. has also obtained the certification that certifies compliance with Supreme Decree No. 001-2022, which validates compliance with the Technical Regulation on Hydraulic Cement used in Buildings and General Construction.


Cementos Pacasmayo SAA opted for the highest and most rigorous certification model (Type 5) granted by ICONTEC, which has extensive experience in the certification of products and services.


A significant percentage of Research and Development activities are focused on evaluating different ratios between clinker-mineral additions that provide the best functional characteristics to our products and at the same time keep balance with the benefits generated for the company. Whether it is a requirement or an internal initiative oriented to supply any previously identified need, the laboratory tests are developed with the objective to generate an operational advantage to the company. Based on this work, the laboratory has determined (and confirmed with production estimates) that 1 tonne of limestone yields 0.74 tonnes of clinker and the clinker/cement factor with additions is 0.71.


31 


The R&D Laboratory located at the Pacasmayo plant provides analysis and research services to all of the company’s cement plants.


10.2.Cement Manufacturing Test Results


At the Pacasmayo plant, the studies conducted in the Research and Development Laboratory and the Quality Control department include: reduction of the clinker/cement factor, substitution of slag for pozzolan, and substitution of fossil fuels for rice husks, the latter at the Rioja plant. The clinker/cement factor of the main cements with additions is 0.71.


The substitution of slag from blast furnace by natural pozzolanic materials was also analyzed, with the objective of improving the company’s carbon footprint and reducing operating costs. The main test was the analysis of pozzolanic activity at laboratory level and subsequently at industrial level. By 2026, the objective is to further reduce slag consumption and further reduce CO2.


10.3.Qualified Person’s Opinion of the Adequacy of the Test Data


The Research Laboratory issues technical reports in compliance with international standards to support the Operations area. These reports ensure the identification of reliable data and the establishment of applicable requirements, which may vary but typically encompass accuracy, consistency, and validity. This process is supported by systematic data evaluation, the implementation of corrective and improvement actions, and the subsequent validation of data adequacy.


The Operations area assesses the feasibility of implementing the tests at an industrial scale and validates the results reported by the laboratory. The integrity and adequacy of the data generated and reported by the area are underpinned by the technical expertise of its personnel, as well as by consistently high performance in external interlaboratory comparison programs conducted by recognized organizations such as XAMTEC and CCRL.


11.Mineral Resources estimates


The geological model was developed and structured using Leapfrog software. The model solids were generated considering the lithology of the deposit based on the geological characteristics and its quality.


Due to the nature of the deposit and its stratified nature and occurrence, the geological model was interpreted with the help of 56 E-W cross sections and 82 N-S sections, spaced every 20 meters.


Additionally, in the interpretation with the sectioning, a structural analysis has been considered defining a main NE-SW fault system whose effect on the terrain has been reflected in the displacement of blocks related to fault jumps of normal and inverse nature.


The geochemical analysis of the samples from the diamond drilling campaigns was performed by the geologists of Cementos Pacasmayo S.A.A., which has allowed grouping the calcareous stratigraphic sequence into 15 lithological groups or domains, establishing the following sequence to be considered in the geological modeling.


The lithological units have been grouped by assigning a numerical code to each, in the mining software, to simplify the modeling. Table 18 shows the lithological units with their respective Mine Sight code and numerical code.


Table 18 Lithologic units of the Tembladera quarry geological model


Lithologic Units Mine Sight Code
ITEM (USO)
Numeric Code
(CUSO)
01_CALIZA MARGOSA CMG 1
02_CALIZA IMPURA MARGOSA A CIMA 2
03_MARGA DE ARENISCA MGAR 3
04_CALIZA IMPURA MARGOSA B CIMB 4
05_CALIZA TIPO I CTI 5
06_CALIZA TIPO I CTI 6
07_CALIZA CAL CAL 7
08_CALIZA TIPO I CTI 8
09_CALIZA ADICION CADI 9
10_CALIZA TIPO I CTI 10
11_CALIZA ADICIÓN CADI 11
12_CALIZA TIPO I CTI 12
13_CALIZA CAL CAL 13
14_CALIZA TIPO I CTI 14
15_CALIZA ADICION CADI 15
16_DIQUES DQ 16
00_SOBRECARGA SU, DES 20


*CALIZA means limestone.


32 


The main criteria used for geological modeling are the lithological and quality aspects.


The lithological criteria are based on the macroscopic physical characteristics, such as color, texture, hardness, etc., of the calcareous rocks.


In relation to the quality criteria, the main reference is the content of calcium oxide (CaO) as the main oxide, and of economic interest, as well as the concentration of oxides and secondary elements and/or contaminants were also considered in classifying the type of rocks oriented to the final product.


In the Tembladera quarry, the reference cut off of the content of oxides that determine the classification of the final products of calcareous rock is shown in Table 19.


Table 19 Pacasmayo plant material restrictions


  Limestone
Type I
Limestone
Type V
Limestone
Type Cal
Limestone
Type Addition
Al2O3 (%) Min. 0 0 0 0
Max. 2.50 1.30 0 0
Target 1.50 0.80 0 0
CaO (%) Min. 48.60 50.50 51.10 41.00
Max. 0 0 0 0
Target 50.20 52.00 52.50 44.00
MgO (%) Min. 0 0 0 0
Max. 2.50 2.50 0 2.50
Target 1.50 1.50 0 1.50
SO3 (%) Min. 0 0 0 0
Max. 0.35 0.35 0 1.10
Target 0.25 0.25 0 0.50
SiO2 (%) Min. 0 0 0 0
Max. 0 0 2.00 0
Target 0 0 1.50 0


The block model was configured based on the dimensions and spatial distribution of the bodies containing the material of economic interest. Table 20 shows the extents of and dimensions of blocks in the block model (coordinates in UTM units).


Table 20 Characteristics of the block model


Minimum (m) Maximum (m) Size (m) Number
X 706700 708700 10 200
Y 9197800 9199200 10 140
Z 350 900 10 55


33 


11.1.Data base


A total of 890 samples from 47 diamond drill holes were used for the Resource estimation.


The data is managed in a database. From there, it is extracted and loaded into MineSight (by Hexagon) and used for resource estimation.


11.2.Density


The density data for the estimation of the limestone Resources of the Tembladera quarry as of December 2025, were taken from the historical data of sampling results carried out in the first drilling campaigns, the density varies between 2.69 and 2.72 t/m3.


11.3.Compositing


In general, each geological unit is estimated from the information of the composites belonging to that unit, the composites should not cross “hard” boundaries between different geological units, and in this case units were established according to the quality.


The objective of compositing is to have uniform grades in each initial core, to reconstitute the grade profile of each drill hole. This means that when compositing we must be careful that the composites preserve the original nature of the sample. The calculated values considered in the compositing were for the SiO2, Al2O3, CaO, MgO and SO3.


Composites were made at different lengths to determine the optimum compositing size. The optimum value was 10 m. This size, which best fits the nature of the original sample, was included in the resource estimation process.


In addition, the length of the composites is considered based on an exact multiple of the height of the blocks used to model the deposit and is also matched to the bench height to be processed.


34 


11.4.Basic statistics of the data (Assay – Composites)


Table 21 shows the results of the basic statistics of the main oxides as CaO, SiO2, MgO, Al2O3 and SO3 content for the original data and for the composited data. The statistical analysis was performed for each defined body with the interpretation of deposit quality, which were also taken as criteria for modeling and estimation.


Table 21 shows the statistics for “Limestone Cal” as this is the one of greatest economic interest due to its CaO content and the main one in the estimation of Resources and Reserves.


Table 21 Limestone Cal statistics


Components

Origen Valid Rejected Minimum Maximum Mean Std. Devn. Variance Co. Of Variation
CaO Assay 1112 0 42.99 55.17 52.48 1.39 1.93 0.03
Composito 208 0 48.03 54.85 52.41 0.88 0.77 0.02
SiO2 Assay 1112 0 0 11.35 1.65 1.20 1.44 0.73
Composito 208 0 0.11 6.16 1.59 0.80 0.64 0.50
MgO Assay 1112 0 0.19 6.29 1.46 0.79 0.63 0.54
Composito 208 0 0.34 3.68 1.45 0.54 0.29 0.37
Al2O3 Assay 1112 0 0 3.99 0.61 0.43 0.18 0.69
Composito 208 0 0.09 2.31 0.59 0.29 0.08 0.49
SO3 Assay 1090 22 0 1.64 0.18 0.14 0.02 0.77
Composito 201 7 0.01 0.50 0.18 0.11 0.01 0.64


11.5.Extreme values


Extreme values are those analysis results that are not representative of the unit being studied and are those that are above the mean plus twice the standard deviation.


In the analysis of the extreme values from the laboratory results for the calcareous lithologic units being estimated, no significant deviations were found that would alter the estimation results; the results are consistent and representative considering the geological nature of the horizons to which they correspond.


11.6.Variogram Analysis


The variographic analysis considered the composited data for each level corresponding to each body of economic interest of the Tembladera quarry; the variographic structures found indicate preferential directions in the correlation of the results, which allows us to analyze the spatial behavior of the variables, mainly of the CaO variable.


35 


This has allowed us to obtain resulting experimental variographic structures that reflect the maximum distance or maximum range and the way in which one point has influence on another point at different distances.


Table 22 Variogram modeling parameters


Type of Variogram Model Spherical
Nugget effect 0.3
Total Sill 1
Range 150 and 510


11.7.Interpolation


The Ordinary Kriging Interpolation (OK) method was used for the main CaO variable, of Inverse Distance (ID2) for the secondary variables (Oxides, see Table 25) and Nearest Neighbor (NN) for validations, defining parameters for each estimator. Table 23 and Table 24 show the main parameters used to define the interpolations of the main CaO variable of the CAL limestone layer and of the secondary variables, respectively.


The interpolations were performed in 3 consecutive processes.


-The first with a search radius of 1/3 the range of the variogram.


-The second with a search radius of 2/3 the range of the variogram.


-Finally, the third one considering the maximum range of the variogram.


Regarding the number of composites, we used a minimum of 2 per block and 5 as maximum, for the first interpolation and a minimum of 1 per block for the second and third pass with 3 and 5 as maximum, respectively.


Additionally, a maximum of 02 composites were considered for each borehole taken in the interpolation.


Table 23 Estimation Parameters Secondary Variables


Comment Pass 1 Pass 2 Pass 3
Search dist. Block on Model -X 150 300 750
Search dist. Block on Model -Y 120 240 750
Search dist. Block on Model -Z 70 80 80
Max distance accept data 150 300 900
Min # comps per Block 2 1 1
Max # comps per Block 5 3 5
Min # comps per hole 2 2 2
Variable Model SI13 SI13 SI13
Variable comp SIO2 SIO2 SIO2
Pass PASS1 PASS2 PASS3
Distance along major 30 60 90
Distance along minor 175 350 525
Distance along vert 85 170 260
ROT 0 0 0
DIPN 75 75 75
DIPE 45 45 45
Limiting Variable model RT13 RT13 RT13
Code model 13 13 13
Limiting Variable composite CUSO CUSO CUSO


36 


Table 24 Estimation Parameters CaO


Comment Pass 01 Pass 02 Pass 03
Search dis. Block on Model -X 150 300 750
Search dis. Block on Model -Y 120 240 750
Search dis. Block on Model -Z 70 80 80
Max distance accept data 150 300 900
Min # comps a Block 2 1 1
Max # comps a Block 5 3 5
Min # comps per hole 2 2 2
Variable Model CA13 CA13 CA13
Variable comp CAO CAO CAO
Variable Pass PSC13 PSC13 PSC13
Pass 1 PASS1 PASS2 PASS3
Store Distance DIC13 DIC13 DIC13
Store max # comp NCC13 NCC13 NCC13
Store max # drillholes NDC13 NDC13 NDC13
Store kriging variance SDC13 SDC13 SDC13
Distance along major 30 60 90
Distance along minor 175 350 525
Distance along vert 85 170 260
ROT 0 0 0
DIPN 75 75 75
DIPE 45 45 45
Limiting Variable model RT13 RT13 RT13
Codigo model 13 13 13
Limiting Variable composite CUSO CUSO CUSO
File variogram allvar. var allvar. var allvar. var


The geological modeling of the limestone deposit of the Tembladera quarry has been modeled considering the quality and geological characteristics of the calcareous horizons, such interpretation was made based on the diamond drill holes carried out in the drilling campaigns, the relationship between the information and the geological model is consistent.


37 


11.8.Resources estimation


Mineral Resource estimates are effective December 31, 2025. The point of reference for all Mineral Resources estimates is as quantities at delivered to the cement plant. For the estimation of Mineral Resources, the content of CaO was considered, in addition to the content of impurities. The impurities are restrictions determined by the cement production plant. Table 25 shows the quantity of Resources and the average values of their quality.


Table 25 Resource estimates (exclusive of Reserves) at the Tembladera quarry


Resources Tonnes
M
CaO
(%)
MgO
(%)
Al2O3
(%)
SO3
(%)
Limestone Measured 135.1 49.85 1.79 1.63 0.29
Indicated 39.2 50.58 1.56 1.39 0.17
Measured + Indicated 174.3 50.01 1.74 1.58 0.26
Inferred 41.5 50.61 1.56 1.38 0.17


11.8.1.Cut-off


For the determination of Resources, the costs of extraction, transportation, cement processing and cement dispatch were considered to determine the Resources. The cost estimate considers the increase in distances, which vary from 5.6 kilometers to 5.9 kilometers from the quarry to the plant and operating costs in the open pit during the 30 years of evaluation. Since the stripping or overburdens is 0.2 and is consider in the economic model.


The costs are based on real sources of current operations of Cementos Pacasmayo S.A.A. and the selling price of cement during 2026 (475.4 S/. x t). Chapter 18 and 19 shows the costs and prices for the determination of Mineral Resources. The main factor for the determination of Resources is quality. The Tembladera quarry is a sedimentary deposit in that sense the model for the estimation of Resources has considered the Tembladera quarry as a unit, whose limestone production is carried out by 10 m banks.


11.8.2.Reasonable Prospects of Economic Extraction


The evaluation of mineral resources has considered other modifying factors such as limestone production costs, cement sales prices and the environmental and social viability of our operations.


38 


From an environmental and social point of view, Cementos Pacasmayo has been carrying out activities in Peru for more than 60 years and is recognized as a Peruvian company with a high reputation. Therefore, environmental and social viability is expected to continue.


The inclusion of a new diamond drilling campaign in the eastern part of the pit (in production) is allowing us to identify the resources, understand the geology of the deposit associated with the andesitic dike structures and has also allowed us to reclassify the Indicated Resources to Measured Resources and the Inferred Resources found in that area of the deposit to resources of greater certainty.


It is important to complete the geological evaluation of the deposit in order to define the resources globally.


11.8.3.Mineral Resource classification


The parameters for Resource classification used by Cementos Pacasmayo S.A.A. were obtained from the experience of calculating the optimum drilling grid for sampling by geostatistical methods. Additionally, the variographic analysis was considered taking as reference the variogram range. After considering all these, resource classification was based on the following criteria:


-Measured Resource: 1/3 of the distance of the variogram range.


-Indicated Resource: 2/3 of the distance of the variogram range.


-Inferred Resource: The total distance of the variogram range.


From this basic configuration, several configurations have been defined, taking into account the number of holes and the average search distance. Other factors used for Mineral Resource estimation are the maximum number of composites used per block and the number of drill holes for each block, as shown in Table 23.


39 


11.9.Qualified Person’s Opinion


The geological modeling of the limestone deposit at the Tembladera quarry has been based on the quality and geological characteristics of the calcareous horizons. This interpretation was carried out based on the diamond drilling carried out during the drilling campaigns. The relationship between the information and the geological data of the model is consistent.


The revision of the model for this report has been based on the geological update of the calcareous horizons, taking into account data related to production progress and the updated production topographic base. During the review period, no diamond drilling was carried out, nor were any geological studies or assessments performed that could substantially modify the presented model.


No fundamental changes have been considered in the estimation plans or strategies, such as interpolation ranges or distances that could considerably modify the resource model.


The resource estimate of the Tembladera quarry has been developed following the best standards and modeling and estimation techniques of the mining industry.


12.Mineral Reserves estimates


The total estimated Mineral Reserves in the Tembladera quarry are 72.9 M tonnes which are detailed in Table 26 in their different classes.


In the periodic update of the Reserves of the Tembladera quarry, the Reserves produced within the update of the Resources and Reserves models are taken into account, along with any changes to assumptions about “modifying factors” or the change and entry of any new information if it had been generated.


The quality metric used in the Mineral Resources and Reserves estimation is the calcium oxide (CaO) content. It is a stable variable in the deposit, which develops in specific ranges depending on the lithological domain, and are characterized according to the strata or horizons as they were deposited, with varying degrees of concentration.


Based on the revised Mineral Resources model, the Mineral Reserves model was also updated with which the new design of the production pit was made and elaborated.


The Mineral Reserves estimated in the limestone deposit was 67.8 M of proven Reserves with 49.83% of CaO and 5.1 M of probable Reserves with 50.56% of CaO for a total of 72.9 M of Reserves that support the mining plans for its production and the supply to Cementos Pacasmayo S.A.A. plants.


A LOM of 30 years has been calculated for the quarry. This based on the estimated Reserves and the plant’s limestone consumption projection for the following years, provided by the management and financial control area, and is incremental until 2049 and fixed consumption thereafter.


40 


12.1.Criteria for Mineral Reserves determination


The criteria used for the determination of Mineral Reserves are described below.


12.1.1.Run of Mine (ROM) determination criteria


ROM is all material produced in the quarry that complies with the specifications and will be sent to the plant for cement production. For determining ROM tonnage, dilution is considered negligible. The recovery in the quarry was assumed to be 100%.


12.1.2.Cement plant recovery


The limestone received at the Pacasmayo plant is properly stored and then mixed with other raw materials to obtain the raw meal feed (kiln feed). The use of limestone in the formulation of the raw meal is an average of 81%. After the crude is obtained, it is fed to the calcination kiln to obtain clinker. Finally, the clinker is mixed with additions to obtain cement.


12.2.Reserves estimation methodology


For the determination of the Mineral Reserves, the costs of extraction, transportation and cement processing, including the quality restrictions of the raw material, were considered. The costs are based on actual sources from the current operations of Cementos Pacasmayo S.A.A. in Tembladera quarry and Pacasmayo plant. Chapter 18 shows the costs to determine the Mineral Reserves.


●Proven and Probable Reserves are derived from Measured and Indicated Resources, respectively.


●Proven and Probable Reserves consists of Indicated and Measured Resources, respectively, that are within the designed pit the Tembladera quarry.


●Reserves are those for which economic viability has been demonstrated by discounted cash flow analysis based on estimated capital and operating costs.


●Cementos Pacasmayo S.A.A. has permits for limestone production at the Tembladera quarry. All material considered to be Mineral Reserves are material for which CPSAA has mining permits.


●The effective date of the Reserve estimate is December 31, 2025.


●The Reserve estimate is the final product placed in the Pacasmayo plant.


41 


12.3.Mineral Reserve estimates


The quality restrictions for limestone at the Pacasmayo cement plant are Al2O3, CaO, MgO, SO3 and SiO2. These restrictions are used for Limestone Type I, Limestone Type V, Limestone Type Cal and Limestone Type Adición.


From the quality point of view, the cut-off grade for limestone is 48.6% CaO and from the economic point of view, the results are shown in Chapter 19.


The economic analysis for the estimation of Mineral Resources and Reserves is presented in Chapter 19. Reserves are expressed in millions of tonnes and are shown in Table 26.


Table 26 Mineral Reserves expressed in millions of tonnes


  Reserves Tonnes
M
CaO
(%)
MgO
(%)
Al2O3
(%)
SO3
(%)
Limestone Proven 67.8 49.83 1.49 1.51 0.35
Probable 5.1 50.56 1.28 1.39 0.19
Total 72.9 49.88 1.48 1.50 0.33


The Reserves calculated for the quarry from the Mineral Resources consider the risk factors and modifying factors within which the quality factors are considered as the most sensitive ones that by their nature can affect the Reserves. Although the main variable is CaO, which is very stable in the deposit, there are others that determine the quality of the Reserves and could even affect the process if they are not adequately controlled, such as the SO3 content.


In the process of calculating Reserves, and in the quarry production plans, these variables have been adequately considered in the mining plan; properly sequenced, and with blending processes.


In addition to quality factors, ore reserves could change from operating performance-controlled production costs, allowing for maximization of the use of resources in the extractive processes for the use of resources in the extractive processes for the industrialists, guaranteeing the LOM of the quarry.


42 


13.Mining methods


Cementos Pacasmayo S.A.A. is the current owner of the Tembladera quarry. The production of the quarry has been outsourced to a specialized contractor, San Martin Contratistas Generales S.A., who conducts limestone mining activities. Cementos Pacasmayo S.A.A. supervises the quarry to verify the activities and production according to the requirements of the Cement plant.


13.1.Mining Methods and Equipment


The mining method is open pit mining, which consists of mining in a series of benches with pit expansion possible both vertically and laterally. At Tembladera, mining generally proceeds top-down with a bench height of 10 meters and no more than 3 working benches open simultaneously.


The transported material passes through the primary crusher, which reduces the fragments to a size of less than 4” for the cement production. The crushed limestone is accumulated in 2 piles to be dispatched to the cement plant.


For the production of lime is necessary a secondary crushing operation, which is generally carried out for limestone lime-type, bringing the granulometry of that limestone to less than 45 mm.


The secondary crusher only processes limestone destined for lime production, after which the product is screened using meshes of size 24 mm, 12 mm and 8 mm. The two coarse products are used for lime and the fine product is used as raw material as a quality enhancer. As a request of Pacasmayo cement plant, the secondary crusher is processing Type I limestone (Size <1/2”).


43 


Figure 9 Tembladera quarry mining sequence


The mining of limestone at the Tembladera quarry includes the following unit operations:


●Drilling


Drilling is mainly done with 1 hydraulic drill. The work is done in two 12-hour shifts with 20 effective hours and 4.0 hours of operational and non-operational delays.


●Blasting


The Blasting fragments the rock to a suitable size for efficient loading, hauling and crushing operations. The operation mainly uses ANFO and Booster as the blasting agent, and non-electric detonators are used to mitigate vibration and sound.


●Loading and hauling


After blasting, the Quality Control staff delimits the zones according to the results of blast hole sampling to define the material destinations. The excavators then load the material into trucks, which transport it to the assigned destination (waste dump or crusher).


44 


●Crushing


The purpose of crushing is to reduce the size of the rock as a result of blasting to the size required by the plant. The quarry has 2 types of crushers:


Primary Crusher


The Primary crusher, which is an Allis Chalmers 7”, is used to reduce the ROM limestone to sizes less than 4” at an average crushing rate of 700 tonnes/hour. After the primary crushing, the material is separated in two hoppers depending on the type of material and its granulometry.


Secondary Crusher


The secondary crusher, which is a Symons 5 1/2, reduces limestone sizes further to less than 45 mm at an average of 130 tonnes per hour. The limestone then passes through screens and is classified into 3 sizes of 45mm-25mm, 25mm-12.5mm and 12.5mm-8mm. As a request of Pacasmayo cement plant, the secondary crusher is processing Type I limestone (Size <1/2”).


The main equipment used to carry out mining activities at the Tembladera quarry are shown in Table 27 and Table 28 shows the auxiliary equipment.


Table 27 Main equipment of the Tembladera quarry


Equipment Quantity Function Description
Track Drill (15 m max hole depth, single boom) 1 Drilling This machine is used to drill holes for blasting.
Primary Crusher 1 Material Crushing This equipment allows to reduce the particulate size from 12” to 4”.
Secondary Crusher 1 Material Crushing This equipment allows to reduce the particulate size from 4” to 12.5mm and also to classify it by size.
Caterpillar tractor 1 Material Loading and Stacking Equipment used to move the fragmented material resulting from blasting.
Front Loader and Excavator 5 Material Loading and Stacking Material handling equipment.
Dump truck (20 m3 capacity) 10 Material hauling Equipment for conveying material from the production areas to the primary crusher.


45 


Table 28 Auxiliary equipment of the Tembladera quarry


Equipment Quantity Function Description
Pickup van and Bus 4 Personnel Transportation Personnel and material transport units.
Tanker truck, Lighting tower, Lubricator truck, Mobile crane, Compressor, Welding machine, Ambulance and Fuel Tanker Truck. 11 Auxiliary equipment Auxiliary equipment to ensure the operability of quarry equipment and personnel.
Motor grader, Compactor 2 Track maintenance Equipment used for track maintenance.
Hydraulic Hammer 1 Breaking banks Equipment used to reduce the fragment size greater than 12” in the primary crusher.


13.2.Geotechnical models


The stability study prepared by DCR Ingenieros S.R. Ltd in 2007 was used until 2020. The slope stability study established 10 zones within the deposit. For the period from 2021 and onwards, the update made by Magma Consulting S.A.C. shown in Table 29 and Table 30 will be applied.


Table 29 Parameters of design according to geotechnical zonification


Domain Bench
height (m)
Design Berm width (m) Slope azimuth range
BFA
(°)
IRA
(°)
Domain 01 10 47 35 5.16 80-140
Domain 02 10 50 36 5.37 NA
Domain 03 10 47 35 5.04 80-130
10 65 43 6.10 <80  and 130<
Domain 04 10 65 43 6.10 <105 and 170<
10 48 35 5.27 105-170
Domain 05 10 70 45 6.40 NA
Domain 06 10 70 45 6.40 NA
Domain 07 10 70 45 6.40 NA
Domain 08 10 70 45 6.40 NA
Domain 09 10 58 41 5.30 NA
Domain 10 10 65 41 6.84 <10 and 50<
Domain 11 10 65 41 6.84 NA


*Note:


BFA:Slope angle


IRA:Inter ramp angle


It is recommended to have a bench for each 150 m of slope, this bench should be at least 10.5m wide and for blocks 1, 2, 3 and 4 it should be at 602 m above sea level.


46 


Table 30 Reviewed Safety Factor 2021


Section Description Safety factor
Static Pseudo-static
K=0.147g
S-1 Global Fault 4.23 3.29
S-2 Global Fault 3.49 2.72
S-3 Global Fault 2.92 2.30
S-4 Global Fault 2.90 2.29
S-5 Global Fault 3.14 2.52
S-6 Global Fault 3.42 2.77
S-7 Global Fault 3.33 2.69
S-8 Global Fault 4.90 3.97
S-9 Global Fault 6.21 4.78
S-10 Global Fault 5.00 4.06
S-11 Global Fault 5.02 3.91
S-12 Global Fault 3.04 2.43


13.3.Hydrological models


In 2021 the hydrogeological study was conducted by Magma Consulting S.A. and based on the hydrogeological interpretation, basin morphology, lithology, piezometric levels, recharge and discharge zones, and piezometry, groundwater is at a depth of 300 m with respect to the topographic elevation of the Tembladera quarry.


13.4.Other Mine Design and Planning Parameters


The limestone production achieved as of December 2025 is 1,618,832 tonnes and 392,328 tonnes of waste rock was removed, which gives a stripping ratio of 0.24. Based on the plant requirements and sales projection for the next 30 years, the pit design parameters for the Tembladera quarry are presented in Table 31.


Table 31 Summary of Tembladera quarry design parameters


Description Value
Inter-ramp slope angle variable between 35° and 45°
Bench slope angle in situ variable between 47° and 70°
Bench height 10 meters
Safety bench 5.04 to 6.40 meters
Width of ramps 12.0 meters (including safety berm and curb and gutter
Safety berm height 1.30m
Ramp gradient 10% to 12%


13.5.Annual Production Rate


Considering that the cement plant demands an average annual production of 2.4 million tonnes per year of limestone, the plan for the following 30 years is shown in Table 32.


13.6.Mining Plan


The proposed mining plan for the next 30 years is presented in Table 32.


47 


Table 32 Mining plan for the next years


Year  Year  Tonnes (t)  CaO  MgO  SO3  Al2O3
1  2026  2,400,000  50.49  1.36  0.18  1.32
2  2027  2,192,306  50.70  1.30  0.17  1.31
3  2028  2,198,913  50.86  1.26  0.14  1.30
4  2029  2,205,652  50.37  1.24  0.20  1.50
5  2030  2,359,294  50.72  1.28  0.21  1.31
6  2031  2,366,680  50.03  1.37  0.31  1.47
7  2032  2,374,214  50.27  1.41  0.25  1.42
8  2033  2,381,898  50.18  1.35  0.32  1.50
9  2034  2,389,736  49.66  1.28  0.29  1.57
10  2035  2,397,730  49.44  1.31  0.37  1.46
11  2036  2,405,885  49.90  1.38  0.39  1.37
12  2037  2,414,203  50.03  1.43  0.39  1.33
13  2038  2,422,687  50.02  1.48  0.42  1.31
14  2039  2,431,340  49.63  1.52  0.41  1.57
15  2040  2,440,167  49.98  1.47  0.40  1.34
16  2041  2,449,171  49.81  1.44  0.39  1.54
17  2042  2,458,354  49.24  1.63  0.38  1.70
18  2043  2,467,721  49.29  1.62  0.41  1.65
19  2044  2,477,275  49.26  1.64  0.36  1.76
20  2045  2,487,021  49.77  1.51  0.40  1.47
21  2046  2,496,961  49.89  1.54  0.38  1.53
22  2047  2,507,100  49.91  1.54  0.34  1.44
23  2048  2,517,442  49.64  1.49  0.38  1.72
24  2049  2,524,429  49.61  1.67  0.35  1.52
25  2050  2,524,429  49.74  1.53  0.35  1.64
26  2051  2,524,429  49.70  1.60  0.33  1.60
27  2052  2,524,429  50.20  1.60  0.33  1.41
28  2053  2,524,429  49.49  1.61  0.38  1.58
29  2054  2,524,429  49.53  1.71  0.36  1.63
30  2055  2,524,429  49.32  1.72  0.37  1.74
Total general     72,912,757  49.88  1.48  0.33  1.50


In the same period of 30 years, the removal of waste rock will be a stripping average of 0.20 tonnes of waste rock/limestone, according to the mine plan.


48 


Figure 10 Tembladera quarry final pit


13.7.Life of Mine


The life of the Tembladera quarry is 30 years.


13.8.Staff


Cementos Pacasmayo personnel develop its operations at the Tembladera quarry with its staff and contractors.


49 


14.Processing and recovery methods


14.1.Process plant


The cement production involves the following stages:


Receiving raw materials: the limestone is produced from the Tembladera quarry, as described in Chapter 13. The other raw materials are obtained from third party companies and in the case of clay; it is obtained from our own quarry on the Señor de los Milagros de Pacasmayo property.


Grinding and homogenization: once the limestone is received at the plant, it is mixed with clay, sand and iron. The mixture must comply with the quality standards to be sent to a storage silo from where it is fed the preheater of the clinker kiln.


Clinkerization: the blend is heated at a temperature of approximately 1,450 Celsius degrees in rotary kilns whose product is clinker. The clinker is then cooled at a temperature of approximately 200 Celsius degrees and is stored in a silo or in an open-air yard.


Cement grinding: after cooling, the clinker, together with the additions, is entered into a mill to obtain a fine powder called cement.


Storage in silos: after passing through the mills, the cement is transferred on conveyor belts and stored in concrete silos to preserve its quality until distribution.


Packaging, loading and transportation: the cement is moved through conveyor belts and pneumatic conveyors to bagging systems to be packed into bags and then loaded to the trucks for distribution.


14.2.Raw materials for the cement production


At the Pacasmayo plant, the following raw materials and additions are used in the production of cement.


50 


Raw materials


Limestone: a material composed largely of calcium carbonate, is used as raw material and also as additive in the production of cement.


Sand: inert material composed basically of crystalline silica, aluminum and alkalis, such as potassium and sodium.


Iron: inert material composed basically of iron oxide (Fe2O3).


Clay: inert material composed basically of silicon, aluminum and a low proportion of alkalis such as potassium and sodium.


Coal: a solid, black or dark brown mineral that contains essentially carbon, as well as small amounts of hydrogen, oxygen and nitrogen.


Raw meal: the artificial mixture of limestone, clay, sand and iron, which is used to produce clinker.


Clinker: product obtained during the calcination of the mixture of limestone, sand, clays and iron.


Fossil fuel


Bunker oil: fuel used as an energy source in the calcining kiln.


Additions


Slag: artificial pozzolanic material that can set in contact with water and can develop compressive strength.


Pozzolan: materials containing silica and/or alumina, which can be of natural or artificial origin.


Gypsum: material composed of calcium sulfate hydrates. When gypsum is mixed with the clinker, it allows for better control of the setting time when the cement initiates the hydration reactions. The mineral gypsum may contain crystalline silica.


51 


14.3.Flow sheet


Figure 11 shows the flow sheet for the cement production at the cement plant.


Figure 11 Pacasmayo plant process block diagram


14.4.Main equipment


Table 33 below shows the design and production capacities for clinker and cement.


Table 33 Main equipment in Pacasmayo plant


Equipment

Product Capacity of production* Unit

Raw meal Mill 1

Raw meal Mill 2

Raw meal Mill 3

Raw meal

594,000

1,425,600

633,600

tonnes/year

Miag 1

Miag 2

Coal

95,040

126,720

tonnes/year

Kiln 2

Kiln 3

Kiln 4

Clinker I-V

264,000

831,600

660,000

tonnes/year

Cement Mill 4

Cement Mill 6

Cement Mill 7

Cement Type I-V

498,960

1,211,760

1,211,760

tonnes/year

Bagging system 3

Bagging system 4

Bagging system 5

Bagging system 6

Cement

1,080,000

1,500,000

1,500,000

1,440,000

bags/month


*The equipment capacities consider 330 days of production.


52 


14.5.Material balance cement plant


The following section presents information on the material balance at Pacasmayo plant for cement production.


14.5.1.Material balance


Table 34 shows the balance of raw meal production. Table 35 shows the balance for cement production considering the additions used for the mixture with clinker and consequently, cement production.


Table 34 Balance for raw meal production


Raw material  Annual
quantity
(tonnes/year)
   Dosage 
Limestone   1,617,924    81%
Others   390,849    19%
Raw meal Type I and Raw meal Type V*   2,008,773    100%


*Raw meal includes coal.


Table 35 Balance for clinker production


Raw material  Annual
quantity
(tonnes/year)
 
Raw meal   2,008,773 
Clinker   1,254,363 


Table 36 Balance for cement production


Cement  Annual
quantity
(tonnes/year)
   Dosage 
Clinker**   1,298,658    71%
Additions***   526,462    19%
Cement   1,825,120    100%


**Consumption of clinker imported during 2025 amounted to 44,295 tonnes.
***The amount of limestone used as an addition was 318,193 tonnes.


14.6.Process losses


Losses in the cement production process associated with the raw material (limestone) are 0.57% due to handling and transport of the material during the production process.


14.7.Water consumption


Pacasmayo plant has a water treatment plant (PETAT) for the kiln cooling system during clinker production. The cooling water is used in the clinker and cement grinding processes. It is also used to irrigate green areas and accesses. 396,947 m3 of water was consumed at the Pacasmayo Plant during its operations in 2025.


53 


14.8.Fossil fuel consumption


Liquid fuels are used for the various engines in the operation. Table 37 shows the consumption of liquid fuels used at the Pacasmayo plant.


Table 37 Fuel consumption in Pacasmayo plant


Fuel Consumption Description
Diesel 205,279 (gal/year) P. Cal 41.2 Gj/t
Oil 6 373,541 (gal/year) P. Cal 43.7 Gj/t


14.9.Electric power consumption


The Pacasmayo plant has an electrical substation with a capacity of 105 MVA, which is supplied by the national grid 683,655 GJ of energy was consumed at the Pacasmayo plant during its operations in 2025.


14.10. Maintenance Plan


Cementos Pacasmayo has implemented a preventive and corrective maintenance plan with the purpose of not interrupting cement production.


Cementos Pacasmayo maintains the operational efficiency to control costs and operating margins. Cementos Pacasmayo has initiatives to diversify the energy sources and secure the supply when possible.


14.11. Staff


Cementos Pacasmayo personnel develop its operations at the Pacasmayo plant with its staff and contractors.


54 


15.Infrastructure


15.1.Tembladera quarry


The quarry consumes electrical energy supplied by the national electricity system through Hidrandina S.A. company. The supply is aerial with medium voltage of 2.3 KV. The Tembladera quarry has electricity sub-stations located in coordinates UTM 707345 E and 9197947 N, it occupies a surface area of 1,062 m2.


The supply of liquid fuels to the Tembladera quarry is through a contractor.


The water is used to water the roads, limestone in loads, demolition, vegetation, consumption and sanitary facilities.


The Tembladera quarry has the following facilities:


-DME 01 waste dump


-DME 05A-6 waste dump


-Low grade stockpile


DME 01 Dump


The current elevation of the upper platform of the DME-1 dump is 535 meters above sea level. To ensure the physical stability of this dump and increase its storage volume, it has been designed to reach an upper platform elevation of 545 meters above sea level at a slope of 2.5H:1V.


DME 05A-6 Deposit


To ensure the physical stability of this future dump, it has been deemed convenient to maintain the upper platform at 790 masl at a slope of 1.5H:1V.


Low grade stockpile


The design has a low-grade stockpile with a slope angle of 35° and a berm width of 10m with a minimum elevation of 532 masl and a maximum elevation of 580 masl, reaching a capacity of 1 M m3.


55 


The auxiliary facilities at the Tembladera quarry are administrative offices, explosives storage, key yard, power house, crushers and the auxiliary service facilities are interconnected to the electrical system of the Central-North system for power supply.


There are also additional facilities at the Tembladera quarry, as described in Table 38.


Table 38 Tembladera quarry Facilities*


Facility Area m2
Offices 972
Explosives warehouse 2/3/5 156
Truck Scale N°2 65
Loading Tunnel 78
Ore Belt N°4, 5 and 6 195
Meteorological Station 17
Septic Well 8
Recreational Complex 4,362


*Source, EIA (Environmental Impact Study)


Figure 12 Mining Facilities


15.2.Pacasmayo plant


Electricity is supplied by the national grid and there is a contract with Electro Perú, which supplies energy through two 60 KV transmission line. There is also a sub-station with three power transformers of 30, 37.5 and 37.5 MVA at ONAF, equivalent to 28.8 MW, 36 MW and 36 MW of active power, respectively.


The Pacasmayo plant is supplied with fuel by a contractor and has a fuel tank for regular vehicle fueling.


Water supply at the Pacasmayo plant is provided by a groundwater well, Cementos Pacasmayo is allow to draw 561,932 m3 per year.


56 


16.Market Studies


Cementos Pacasmayo is a leading company in the cement production and other construction materials in the north of Peru. This chapter describes the cement market as well as the macro and microeconomic factors that define it.


For the description of the cement market in Peru, public information has been collected from different sources, such as the Central Reserve Bank of Peru (BCRP), National Institute of Statistics and Informatics (INEI), Association of Cement Producers (ASOCEM), Ministry of Housing, Construction and Sanitation, Superintendency of Tax Administration and the Peruvian Construction Chamber. In addition to this information, this chapter also relies on statistics provided by the company, CPSAA, to provide a better understanding of its specific market.


16.1.The cement market in Peru


The Peruvian cement market is geographically segmented by regions: north region, central region and south region. Diverse companies supply each region. Figure 13 is an illustration of the Peruvian map and of its 3 regions, according to the segmentation of cement market, where each region is the main area of influence of domestic cement companies.


Figure 13 Segmentation of the cement market in Peru


The main companies which deal with the cement market in Peru are: Cementos Pacasmayo S.A.A., UNION Andina de Cementos S.A.A., Yura S.A. and Cementos Selva S.A.C. Additionally, there are companies that import cement or clinker, such as Caliza Cemento Inca S.A., Distribuidora Cemento Nacional S.A.C., CEMEX Perú S.A., Cal & Cemento Sur S.A., Holcim Perú S.A., amongst others.


57 


Table 39 shows the cement shipments at domestic level (in thousands of tonnes):


Table 39 Cement shipments at domestic level (in thousands of tonnes)


   2023   2024   2025 
National cement shipments   12,175.7    12,001.8    12,936.0 
Overall cement shipments (CPSAA/CSSAC, 3 plants)   2,936.6    2,835.1    3,049.2 
Pacasmayo plant shipments   1,634.8    1,674.9    1,822.0 


Sources: ASOCEM and CPSAA/CSSAC.


The types of cement produced by the main cement companies of the country are Type I, Type V, Type ICO, Type IL, Type GU, Type MS (MH), Type HS, Type HE and Type MH.


It is important to mention that, according to the main requirement standards, Peruvian Technical Standards, cements are divided into five types:


●NTP 334.009 2013. Cements Portland. Requirement. (ASTM C 150).


●NTP 334.090 2013. Cements Portland Added. Requirements. (ASTM C595).


●NTP 334.082 2011. Cements Portland. Performance Specification. (ASTM C1157).


●NTP 334.050 2004. Cements Portland White. Requirements. (ASTM C150).


●NTP 334.069 2007. Building Cements. Requirements. (ASTM C091).


Cementos Pacasmayo only produces cement that meets the first three NTP standards.


16.2.Industry and Macroeconomic Analysis


Producer and trading companies of cement compete mainly within the limits of their area of influence, which is determined by the geographical location of their plants, giving rise to segmentation of the national market. However, the north region presents a high demand potential because of the infrastructure gap, the housing deficit and a higher capillarity in terms of important adjacent cities with an urbanization level lower than in the central and south region.


On the other hand, it highlights the importance of transportation in the structure of cement costs; composed primarily of raw materials, fuels and transport.


The cement market and the industry in Peru have the following characteristics:


●Base of consumers highly segmented, informal and of low Resources.


●Low costs of energy and raw materials.


58 


●Zone of influence / distribution determined by geographical location of the plant.


●High correlation level between public and private investment, and self-construction.


The construction sector and cement industry have a behavior directly related to the Gross Domestic Product (GDP) and Private Consumption. Figure 14 shows how the GDP of the construction sector (variation % monthly) accompanies the cyclic behavior of the Global GDP (variation % monthly), showing variations of lower significance than those of the Global GDP, but in the same direction. It is also noted that, in May 2020, the GDP of the construction sector had a positive variation of more than 200% (with regards to the previous month), whilst the Global GDP was only 10%. This was due to the confinement measures given by the Government to counter the Covid-19 pandemic. This reactivation was motivated primarily by the private-construction sector consumption. Under the uncertainty conditions caused by the sanitation and economic crisis in 2020, consumers showed savings behaviors, which meant that people preferred consumption of goods for home improvement, amongst them, cement. This trend was maintained throughout 2021. However, in 2023 there was a decrease in demand for public and private investment due to the political and social situation. As a result, cement volumes are returning to pre-covid levels.


Figure 14 Global GDP and Construction sector GDP MoM variation (%)


Source: BCRP 2025


The cement industry is also motivated by housing sector growth, public and private investment in infrastructure, mining projects, shopping centers, construction of transportation systems, etc. Thus, one of the variables with more impact on cement industry and future demand is the infrastructure gap which remains high in the country.


In 2025, the cement market grew by 7.8% compared to 2024. Given greater stability in the sector, a moderate growth of 2% in cement shipments is expected in 2026.


59 


16.3.The North Region Market


Cementos Pacasmayo, a leading company in the production and sales of cement in the North Region, has market presence in the following cities: Cajamarca, Chiclayo, Chimbote, Jaén, Pacasmayo, Piura, Rioja, Tarapoto, Trujillo, Tumbes, Yurimaguas and Iquitos. The company has a Market share of 91.8% in the north region of the country.


Overall shipments of Pacasmayo plant for 2025 were 1,822.0 thousand tonnes. Pacasmayo plant supplies almost 54.8% of the cement demand of the North Region.


Other companies with lower presence in the cement market of the North Region are:


●Quisqueya - Cemex


●Cemento Nacional


●Cemento Inka


●Holcim Perú


These companies are competitors of Pacasmayo plant.


Cementos Pacasmayo S.A.A in its Pacasmayo plant produces different types of cement and it has in the National Market, different trademarks to deal with diverse segments of the market. Table 40 shows the products in Pacasmayo plant.


Table 40 Types of products of Pacasmayo Cement plant


Business Name  Use  Comment
Cemento Portland      
Cement Type I  Cement for general use.  The average result of resistance to compression is higher than the minimum requirement set forth in the technical standard NTP 334.009 / ASTM C150.
Cement Type V  For works, structures exposed to soils with high sulphate (salt residue).  The average result of resistance to compression is higher than the minimum requirement set forth in the technical standard NTP 334.009 / ASTM C150.
Qhuna Type I  For use in construction Works in general, manufacturing of bricks, sewage systems, paving stones, to lay bricks, plaster with cement, to cover with majolica, preparation of concretes in foundations, over foundations, brake shoes, beams, columns and building roofs.  Complies with the requirements of technical standards NTP 334.009 and ASTM C 150.
Cemento Portland Added      
Cement Fortimax  Ideal for Works which require moderate h heat, for Works exposed to sulphate action and for Works near to large water sources (sea, lakes, rivers, etc.)  The average result of resistance to compression is higher than the minimum requirement set forth in technical standard NTP 334.082 / ASTM C1157.
Cement Extra Forte  Ideal for the execution of structural Works, repairs, remodeling, home applications, floors, leveling, grouts, tips, prefabricated elements of small and medium size and concrete elements which require special characteristics.  The average result of resistance to compression is higher than the minimum requirement set forth in technical standard NTP 334.090.
Cement Ultra Armado  Ideal for the execution of structural Works, elaboration of mortars for floors, leveling, grouts and tips and production of prefabricated elements of small and medium size.  The average result of resistance to compression is higher than the minimum requirement set forth in technical standard NTP 334.090 / ASTM C595.
Cement Type HE      
Cements for Prefabrications  For construction elements.  The average result of resistance to compression is higher than the minimum requirement set forth in technical standard NTP 334.009 / ASTM C150.
Qhuna Structural      
Hydraulic Cements specified by performance      
Line Mochica MS  For structures in contact with environments and humid and salty soils.   
Line Mochica GU  Cement of general use.   
Qhuna MS  Structural elements and non-structural which are exposed to environments and humid salty soils.  Complies with the requirements set forth in standard ASTM C 1157 and NTP 334.082.


60 


16.4.Cement price


The prices of cement in the Peruvian market vary pursuant to their type and their geographical location. The price difference of each type is explained primarily by the dosifications of raw materials and additions, whilst the variations for geographical location are caused by the freights for the distribution to the points of sale.


At domestic level, the cement price in 2025 was, on average, 717.41 S/ x t. Figure 15 shows the historic prices of cement in Peru.


Figure 15 Historic prices of cement in Peru


Source: Ministerio de Vivienda, Construcción y Saneamiento (November 2025).


16.5.Current and future demand


Cement demand at the national level is met by local shipments (local production), for the most part, and by imports. In 2025, 12.94 M tonnes were shipped locally; 7.8% more than in the same period of 2024 (12.00 M). Imports amounted to 0.49 M tonnes during 2025; 81.5% more than 2024 (0.27 M).


61 


Figure 16 shows the evolution of the national demand of cement, expressed in thousands of tonnes, since 2019.


Figure 16 Evolution of the national demand of cement


Source: ASOCEM


It is noted that domestic demand has been growing, on average, at a rate of 3% per year, with the exception of 2020, which is considered an atypical year due to the adverse effects of the pandemic and the confinement measures, to then take a historic leap in 2021 with an annual increase of 38%. During 2024, shipments decreased by 1.9% compared to 2023 as a result of the political and social situation in the country. In 2025, dispatches grew by 7.8% due to the recovery of private investment (real estate, mining, and infrastructure projects) and the dynamism of self-construction, supported by higher employment and incomes, as well as increased execution of public works and the momentum of concession-based projects.


According to our internal information, in terms of regional distribution, the Northern Region accounts for approximately 25.7% of domestic cement demand, the Central Region for 53.1%, and the Southern Region for 21.1%.


Cementos Pacasmayo’s cement shipments (3 plants) reached 3,049.0 thousand tonnes in 2025, constituting a 23.6% share of total shipments in Peru and 91.8% in the Northern Region. This is 7% more than in 2024 (2,835.1 thousand tonnes).


62 


Table 41 shows the projection of future demand or shipments of cement for Pacasmayo plant. These projections are based on the 2026 shipments.


Table 41 Forecast of future demand for Pacasmayo cement plant


Year  Cement
Shipments
(Tonnes)
   Variation
(%)
 
2026   1,851,309      
2027   1,888,335    2%
2028   1,926,102    2%
2029   1,964,624    2%
2030   2,003,916    2%
2031   2,043,995    2%
2032   2,084,875    2%
2033   2,126,572    2%
2034   2,169,104    2%
2035   2,212,486    2%
2036   2,256,735    2%
2037   2,301,870    2%
2038   2,347,907    2%
2039   2,394,866    2%
2040   2,442,763    2%
2041   2,491,618    2%
2042   2,541,451    2%
2043   2,592,280    2%
2044   2,644,125    2%
2045   2,697,008    2%
2046   2,750,948    2%
2047   2,805,967    2%
2048   2,862,086    2%
2049   2,900,000    1%
2050   2,900,000    0%
2051   2,900,000    0%
2052   2,900,000    0%
2053   2,900,000    0%
2054   2,900,000    0%
2055   2,900,000    0%


63 


17.Environmental studies, permitting, and plans, negotiations, or agreements with local individuals or groups.


17.1.Environmental Aspects


Cementos Pacasmayo S.A.A holds Corporate Policies, which are applied to the operations of quarries and cement plants. Relevant policies include Safety Occupational Health Policy, Quality Policy and Environmental Policy.


Cementos Pacasmayo S.A.A. carries out activities in Tembladera quarry and Pacasmayo plant, in that sense, according to the environmental legislation. It has an environmental authority in the industrial sector and another authority (Ministry of Energy and Mines) that issues an opinion for the Closure of quarries.


Likewise, Cementos Pacasmayo S.A.A. complies with the provisions of the Regulation with Supreme Decree No. 006-2025-EM - Regulation of the Mine Closure Law.


17.1.1.Tembladera quarry


Tembladera quarry holds the environmental permit authorized by the Ministry of Production, dated November 08, 2018, through Directorate Resolution N° 304-2018-PRODUCE/DVMYPE-I/DGAAMI. It approved the updating of the Environmental Management Plan of the Adequation Program and Environmental Management (PAMA per its acronym in Spanish) of Tembladera quarry, this, pursuant to the Technical-Legal Report NO 979-2018-PRODUCE/DVMYPE-I/DGAAMI-DEAM and its annexes. Likewise, on April 17, 2024, through Directorial Resolution No. 326-2024-PRODUCE/DGAAMI, the modification of the environmental monitoring program with respect to the biological component was approved, considering that from the date of approval it will be carried out annually, rather than semiannual, because no significant changes in the biological environment were identified.


On April 10, 2025, through Directorial Resolution 252-2025-PRODUCE/DGAAMI, the Supporting Technical Report (ITS) “Expansion of DME 5A-DME 6 and Auxiliary Component”, was approved by Ministry of Production.


Likewise, 0n October 10, 2025, through Directorial Resolution 688-2025-PRODUCE/DGAAMI, the Supporting Technical Report (ITS) “Confirmation of Mineral Reserves at Tembladera quarry”, was approved by Ministry of Production.


The updating of the Environmental Management Plan of the PAMA included the identification of potential environmental impacts for which, there were preventive, corrective and/or mitigation measures.


Additionally, it includes the environmental monitoring program taking into consideration the components of air quality, environmental noise and biological monitoring. There are 4 monitoring stations for air quality, 4 monitoring stations for environmental noise and 9 stations for biological monitoring.


In the Tembladera quarry, measurements of air quality and particulate matter parameters were considered. The results obtained in 2025 are under the environmental quality standard limit, ECA in compliance with the established Supreme Decree No. 003-2017-MINAM.


The environmental noise monitoring results obtained in 2025 are below the standards of the environmental quality standard, ECA, complying with the provisions of Supreme Decree N°085-2003-PCM.


Cementos Pacasmayo S.A.A complies with Peruvian legislation on Closure Plans, which under current legislation is the Regulation of Environmental Management of the Manufacturing Industry and Domestic Trade, Supreme Decree No. 017-2015-PRODUCE. This standard establishes the environmental management of the activities covered by Ministerial Resolution No. 157-2011-MINAM, table of the first update of the list of inclusion of investment projects subject to the National System of Environmental Impact Assessment (SEIA).


For the Tembladera quarry, Directorial Resolution Number 723-2025-PRODUCE/DGAAMI approved the Modification of the Detailed Closure Plan for the Tembladera quarry mining unit of Cementos Pacasmayo S.A.A.


The Closure Plan submitted by Cementos Pacasmayo S.A.A. has included the necessary measures to ensure effectiveness or consistency with the requirements necessary for the protection of public health and the environment. The initial strategy has continued with the Closure of the components of Tembladera quarry mining unit, establishing temporary, progressive, final and post-Closure activities at the end and/or closure of operations.


64 


Final closure activities have included physical stability in the mine, geochemical stability, water management facilities, dismantling for the removal of equipment and machinery. Also included are infrastructure demolition, reclamation, waste disposal, landform establishment, habitat rehabilitation, revegetation and social programs.


Post-closure activities such as physical maintenance, hydrological maintenance, and social monitoring will be carried out, and post-closure monitoring activities include physical stability monitoring, geochemical stability monitoring, water management monitoring and social monitoring.


It is important to mention that the approval of the Modification of the Mine Closure Plan involves the constitution of guarantees to ensure that the owner of the mining activity complies with the obligations derived from the Mine Closure Plan, in accordance with environmental protection regulations.


Cementos Pacasmayo S.A.A has a provided financial assurance for the mine closure plan for the Tembladera quarry consistent with the approved and updated mine closure plan for an amount of 439,719.53 USD.


Cementos Pacasmayo has a strong relationship with our communities and has identified their main needs such as health, education, urban development and local development. In this regard, we have a social investment program, which contributes to dealing with their necessities, based on good dialog and the compliance with our commitments.


The communities are a priority for Cementos Pacasmayo. For this reason, we promote periodic meetings with their representatives and create opportunities for dialog to know their expectations. In addition, we have established public and private alliances for development projects and programs, to contribute to a better quality of life, and to strengthen our relations. During 2025, we worked in partnership with the district authorities of Pacasmayo and Tembladera.


CPSAA has no commitments for local procurement and hiring although it does its best to hire local talent and do business with local businesses.


17.1.2.Cement plant in Pacasmayo


On November 05, 2025 by Directorial Resolution No. 0752-2025-PRODUCE/DGAAMI, the Supporting Technical Reports (ITS) of the project, “Separate grindings”, was approved by Ministry of Production.


Cementos Pacasmayo S.A.A. in compliance with current environmental regulations, it has been carrying out environmental monitoring through an accredited laboratory, the results are reported to the Environmental Evaluation Agency - OEFA, competent authority for environmental supervision and control activities, responsible for reviewing and validating the information presented by the industrial owner.


In the Pacasmayo plant, the measurements of air quality parameters and particulate air material were considered. The results obtained in 2025 are below the environmental quality standard limit (ECA) complying with that established in the Supreme Decree No. 003-2017-MINAM.


In the environmental noise monitoring, the results obtained in 2025 are below the limit of the environmental quality standard (ECA) in compliance with that established in the Supreme Decree N°085-2003-PCM.


Regarding atmospheric emissions at the source of emissions, the results obtained in 2025 are below the maximum permissible limit (LMP) in compliance with that established in Supreme Decree N°001-2020-MINAM.


Finally, in accordance with Environmental Management Regulation of the Manufacturing Industry and Domestic Trade, approved with Supreme Decree N° 017-2015-PRODUCE and its amendments, companies that produce cement are required to submit Closure plans at the time before the execution of the closure. Cementos Pacasmayo S.A.A. in compliance with Peruvian legislation will submit the Closure Plan in a timely manner.


65 


17.2.Solid waste disposal


Cementos Pacasmayo S.A.A. has a Solid Waste Minimization and Disposal Plan for our production activities at the Pacasmayo plant and Tembladera quarry. Annually, our company declares the generation, storage, collection, and final disposal of hazardous and non-hazardous solid waste in compliance with environmental legislation.


In our solid waste minimization plan for 2025, Cementos Pacasmayo S.A.A declared 25.2 tonnes of hazardous waste and 57.8 tonnes of non-hazardous waste for the Tembladera quarry. Likewise, for the Pacasmayo plant we declared 106.7 tonnes of hazardous waste and 548 tonnes of non-hazardous waste, which were disposed of in accordance with environmental legislation.


17.3.Qualified Person’s Opinion


Cementos Pacasmayo S.A.A. complies with national environmental standards applicable to the development of industrial activity and for the exploitation of non-metallic minerals carried out in the Tembladera quarry where limestone, the main material for the manufacture of cement, is produced.


The company has been complying with the provisions of the Environmental Management Regulation for the Manufacturing Industry and Internal Trade approved with Supreme Decree No. 017-2015-PRODUCE, which regulates the environmental management of the activities indicated in Ministerial Resolution No. 157- 2011-MINAM and investment projects subject to the National Environmental Impact Assessment System (SEIA) and its modifications.


Cementos Pacasmayo S.A.A. reports the environmental commitments periodically to the Environmental Evaluation Agency - OEFA. The monitoring is carried out by external laboratories that provide comprehensive services using testing methods accredited by the National Institute of Quality (INACAL) or, failing that, by bodies accredited by a member entity of the International Laboratory Accreditation Cooperation (ILAC).


Cementos Pacasmayo S.A.A. strictly complies with the protocols in the different processes in compliance with environmental legislation and reporting to the OEFA.


Qualified personnel consider that CPSAA’s current management plans and strategies are adequate to prevent, mitigate and control the potential environmental impacts that may be generated by the development of activities, which were evaluated and approved by the competent authority. In addition, the qualified person considers that CPSAA has a good relationship with the local communities and that its social investment plans are adequate for reducing any social risks to the project.


66 


18.Capital and operations costs


18.1.Basis for operating and capital cost for the quarry and plant


This section presents, in a tabular manner, the operating costs of Tembladera quarry for the extraction of limestone, the main raw material used in cement production at the Pacasmayo plant. The section also contains the operating costs for the cement plant where the whole industrial process to convert the raw material to cement takes place. The costs are mainly based on real historic costs which are the basis for estimating forecasted costs.


Similarly, this section reports the detail of the capital investments made in the quarry and plant, and the forecasted plan of investments, required to sustain all the activities in the quarry and plant, and to assure the supply of limestone Reserves for the production levels required to support forecasted cement sales of Pacasmayo plant.


Table 42 depicts the main components of the cost structure of Tembladera quarry and Pacasmayo plant and the sources used in their forecasts.


Table 42 Cost structure of Tembladera quarry and Pacasmayo plant


Cost category   Description   Source
Quarry Operating Cost   Mineral Production, processing, fuel, Materials (Explosives), Maintenance, Insurances and Services  

●   Real, historic costs

●   Suppliers´ quotes

         
Quarry Operating Cost   Royalties   ●   Contract of mining royalty payment
      with regional/state entities
         
Quarry Operating Cost   Energy  

●   Historic, real costs

●   Supply Contract

●   Suppliers´quote

         
Plant Operating Cost   Fuel, Materials, Maintenance, Wages and Insurances  

●   Historic, real costs

●   Suppliers´quote

         
Plant Operating Cost   Energy  

●   Historic, real costs

●   Supply Contract

●   Suppliers´quote


67 


Being an ongoing operation, actual historical costs are the primary basis of information to estimate forecasted costs. These actual costs in some cases are maintained, and in other cases are appropriately adjusted to account for factors specific to the quarry operation, conditions and obligations stipulated in supply and concession contracts, and other macroeconomic factors that could have an indirect impact on future operating costs, such as inflation and devaluation of the local currency against the US dollar.


18.2.Capital and Operating Cost Estimates


Table 43 details the operating costs of quarry and plant for the year 2025, and 30 years of forecast.


Table 43 Operating costs forecast of quarry and plant


   Production Data         
   Extracted
Mineral
tonnes
’000
   Cement
Production
tonnes
’000
   Total
Operating
Cost
S/ ’000
   Cost per
tonne of product
S/ x tonne
 
                 
2025   1,609    1,825    442,088    242.22 
2026   2,101    1,851    433,656    234.24 
2027   2,171    1,888    439,836    232.92 
2028   2,177    1,926    444,741    230.90 
2029   2,184    1,965    473,782    241.16 
2030   2,336    2,004    487,441    243.24 
2031   2,343    2,044    530,528    259.55 
2032   2,351    2,085    564,251    270.64 
2033   2,358    2,127    589,382    277.15 
2034   2,366    2,169    617,039    284.47 
2035   2,374    2,212    656,081    296.54 
2036   2,382    2,257    686,699    304.29 
2037   2,390    2,302    720,350    312.94 
2038   2,399    2,348    765,981    326.24 
2039   2,407    2,395    803,091    335.34 
2040   2,416    2,443    843,581    345.34 
2041   2,425    2,492    921,438    369.82 
2042   2,434    2,541    971,484    382.26 
2043   2,443    2,592    1,025,811    395.72 
2044   2,453    2,644    1,206,209    456.18 
2045   2,462    2,697    1,280,513    474.79 
2046   2,472    2,751    1,360,339    494.50 
2047   2,482    2,806    1,455,212    518.61 
2048   2,493    2,862    1,543,828    539.41 
2049   2,499    2,900    1,623,658    559.88 
2050   2,499    2,900    1,687,206    581.80 
2051   2,499    2,900    1,741,161    600.40 
2052   2,499    2,900    1,798,182    620.06 
2053   2,499    2,900    1,867,907    644.11 
2054   2,499    2,900    1,929,125    665.22 
2055   2,499    2,900    1,980,719    683.01 


Table 43 shows the capital cost projection for the next 30 years, according to the production plan for 30 years of Reserves. Costs are adjusted annually by applying 2.90% inflation rate to the cost/tonne.


68 


Table 44 shows the detail of capital investments in the quarry and plant, by type of investment, for 1 year of historical result (2025) and 30 years of projection.


Table 44 Investment forecast in quarry and plant


   Total
Investments
S/ ’000
 
     
2025   19,875 
2026   22,276 
2027   22,276 
2028   23,249 
2029   23,924 
2030   24,617 
2031   25,331 
2032   26,066 
2033   26,822 
2034   27,600 
2035   28,400 
2036   29,224 
2037   30,071 
2038   30,943 
2039   31,841 
2040   32,764 
2041   33,714 
2042   34,692 
2043   35,698 
2044   36,733 
2045   37,798 
2046   38,895 
2047   40,022 
2048   41,183 
2049   42,377 
2050   43,606 
2051   44,871 
2052   46,172 
2053   47,511 
2054   48,889 
2055   50,307 


In recent years, there have been no significant variations in investments related to maintenance and replacement of equipment in the quarry and plant to sustain operations.


The costs described in this chapter are applied to estimate the Mineral Resources and Reserves of the Tembladera quarry as part of the analysis.


18.3.Capital and Operating Cost Estimation Risks


Considering that mine production and cement plant will continue in the same geological deposit and using the same mining and industrial methods, there is little risk associated with the specific engineering estimation methods used for capital and production costs. An assessment of accuracy of estimation methods is reflected in the sensitivity analysis in Section 19.


For purposes of the Preliminary Feasibility Study completed relative to the Tembladera quarry and Pacasmayo plant, both capital and operating costs are estimated to an accuracy of +/- 25%.


69 


19.Economic analysis


19.1.Methodology: Discounted Cash flow (Free)


The Economic Analysis chapter describes the assumptions, parameters and methodology used to demonstrate the economic viability or profitability of extracting the mineral Reserves and Resources. That is, the Pre-feasibility level support for the determination of mineral Resources and Reserves, by means of a business valuation through the Discounted (Free or Economic) Cash Flow method.


In the economic the same evaluation criteria were considered for the estimation of Mineral Resources and Reserves.


For the cash flow projection, the forecast horizon is consistent with the life of the quarry, which is calculated based on the total declared Reserves and the annual production of the quarry. The cash flow for each period is approximated indirectly from the EBITDA (the latter is constructed in the Profit and Loss Statement), and the corresponding adjustments are made for taxes and capital costs (CapEx).


Finally, for this economic analysis we work with the free cash flow, since it does not incorporate the capital structure, and we apply the weighted average cost of capital (WACC) for discounting future cash flows.


19.2.Assumptions


19.2.1.General and Macroeconomic Assumptions


For the Reserves evaluation, the general and macroeconomic assumptions used for the projection of the free/economic cash flows and for the valuation are:


-Projection horizon: 30 years (2026 to 2055) according to the estimated years of quarry life.


-Annual inflation rate, 2.90%, based on Banco Central de Reserva del Perú as of projection 2026: applies equally to sales price, costs and expenses.


-Capital cost projections were determined using a historical ratio of annual investments and maintenance costs which also considers the increase in production volume.


70 


-The company’s capital structure is being considered in the discount rate (WACC) of 10.91%.


-Income tax rate: effective rate of actual (historical) business results, 29% - 30%.


-Workers’ Profit Sharing: 10%.


-Exchange rate: exchange rate is assumed to remain at 3.80 (USD/PEN).


19.2.2.Income and Cost Assumptions


●The sales price of cement, expressed as S/ x t, is the sales price from Pacasmayo plant to Distribuidora Norte Pacasmayo, FOB at Pacasmayo plant; and this is lower than the sales price to the final customer in the market. This difference is explained by the distribution freight to the multiple points of sale and by the selling expenses associated with distribution and promotion in the different commercial channels.


●The base price used in the projection is an estimate for the year 2026 (475.4 S/ x t), which has been determined based on current market conditions and cement demand for 2026, among other factors.


●Starting in 2027 (year 2 of the projection), an annual price escalation rate of 2.90% is applied the sales prices.


●The cost of cement production, expressed as S/ x t, has been estimated for the year 2026 based on actual operating costs, the market situation of local inputs and services, plant demand for imported clinker and other factors. Cost of production for year 2026 is 234.2 S/ x t.


●Starting in 2027, an annual cost escalation rate of 2.90% is applied to the costs.


●The initial stock of products in the quarry and plant is assumed to be zero.


19.3.Results of financial model


For the Mineral Reserves evaluation, the following financial parameters were calculated:


●NPV of 2,248 million soles at a discount rate of 10.91%.


●30-year mine life.


●Average plant throughput for cement production: 2.5 million tonnes per year over the 30-year projection.


71 


●Average sales price: 642.9 soles per ton of cement, an average of the 30-year projection, at nominal values.


●Revenues: 1,618 million soles annual, an average of the 30-year projection.


●Average production cost: 406 soles per ton of cement, an average of the 30-year projection, at nominal values.


The Table 45 shows the forecast of the Profit and Loss Statement of the operation of Tembladera quarry and Pacasmayo plant.


Table 45 Profit and Loss Statement


   Shipments (tonnes)   Revenue
S/ x t
   Gross Profit
S/ ’000
   Gross Margin
S/ x t
   Gross
Mg
%
   Operating Profit   (+) Depreciation   EBITDA Pacasmayo Plant   EBITDA
Mg %
 
                                     
2026P   1,851,309    475.4    415,803    224.6    47%   268,520    43,360    311,880    35%
2027P   1,888,335    484.9    445,401    235.9    49%   289,056    57,699    346,756    38%
2028P   1,926,102    494.6    476,123    247.2    50%   316,422    59,627    376,048    39%
2029P   1,964,624    504.5    483,804    246.3    49%   317,361    60,055    377,416    38%
2030P   2,003,916    514.6    508,761    253.9    49%   338,952    61,032    399,984    39%
2031P   2,043,995    524.9    507,504    248.3    47%   334,723    63,293    398,016    37%
2032P   2,084,875    535.4    515,372    247.2    46%   334,353    67,395    401,748    36%
2033P   2,126,572    546.1    534,298    251.2    46%   349,428    71,692    421,120    36%
2034P   2,169,104    557.1    552,467    254.7    46%   363,458    74,937    438,395    36%
2035P   2,212,486    568.2    560,421    253.3    45%   362,796    80,593    443,390    35%
2036P   2,256,735    579.6    579,540    256.8    44%   378,615    81,179    459,794    35%
2037P   2,301,870    591.2    597,399    259.5    44%   392,419    81,258    473,677    35%
2038P   2,347,907    603.0    604,446    257.4    43%   391,015    81,588    472,604    33%
2039P   2,394,866    615.0    623,162    260.2    42%   405,912    82,226    488,138    33%
2040P   2,442,763    627.3    640,759    262.3    42%   419,008    83,766    502,774    33%
2041P   2,491,618    639.9    623,677    250.3    39%   394,002    84,976    478,978    30%
2042P   2,541,451    652.7    636,756    250.5    38%   402,933    86,465    489,398    30%
2043P   2,592,280    665.7    648,132    250.0    38%   409,661    88,387    498,049    29%
2044P   2,644,125    679.0    539,851    204.2    30%   295,838    90,067    385,906    21%
2045P   2,697,008    692.6    537,232    199.2    29%   289,275    89,297    378,572    20%
2046P   2,750,948    706.5    532,083    193.4    27%   279,708    89,071    368,779    19%
2047P   2,805,967    720.6    516,364    184.0    26%   256,181    89,755    345,936    17%
2048P   2,862,086    735.0    509,295    177.9    24%   245,331    88,624    333,955    16%
2049P   2,900,000    749.7    500,007    172.4    23%   231,667    89,683    321,350    15%
2050P   2,900,000    764.7    480,256    165.6    22%   202,743    91,998    294,741    13%
2051P   2,900,000    780.0    471,091    162.4    21%   188,449    94,451    282,900    13%
2052P   2,900,000    795.6    459,671    158.5    20%   172,058    97,104    269,162    12%
2053P   2,900,000    811.5    436,711    150.6    19%   139,905    99,838    239,744    10%
2054P   2,900,000    827.8    423,028    145.9    18%   122,306    102,608    224,914    9%
2055P   2,900,000    844.3    418,954    144.5    17%   112,245    105,428    217,674    9%


Cement sales at Pacasmayo Plant are on average S/ 1,618 million per year (for the period 2026-2055) and the average EBITDA margin for the same period is 27%.


The EBITDA margin remains relatively stable in the 30-year projection. The slight variations in the margin are mainly explained by the cost of remunerations, which has a behavior with peaks every three years due to union negotiations, the distribution of demand among plants and the consumption of imported clinker when reaching the maximum production capacity of the company’s own clinker.


72 


Table 46 shows the Free Cash Flow projection and the valuation of the cement business of Pacasmayo plant:


Table 46 Free Cash Flow and valuation


   FCF - Valuation (Thousand S/) 
   (-) Taxes
(EBIT*t)
   (-)
CapEx
   EBITDA
Pacasmayo
Plant
   Free Cash
Flow
 
                 
2026P   -112,737    -51,237    344,731    180,757 
2027P   -125,048    -52,723    383,244    205,474 
2028P   -134,700    -54,252    415,218    226,266 
2029P   -133,972    -55,825    417,085    227,288 
2030P   -142,757    -57,444    442,471    242,270 
2031P   -141,143    -59,110    440,013    239,760 
2032P   -142,228    -60,824    444,161    241,110 
2033P   -149,871    -62,588    465,407    252,948 
2034P   -156,382    -64,403    484,455    263,670 
2035P   -157,372    -66,271    489,862    266,219 
2036P   -163,702    -68,193    507,976    276,081 
2037P   -169,733    -70,170    523,877    283,974 
2038P   -170,455    -72,205    523,962    281,302 
2039P   -176,821    -74,299    541,606    290,486 
2040P   -182,633    -76,454    558,216    299,130 
2041P   -173,942    -78,671    533,288    280,675 
2042P   -178,208    -80,952    545,414    286,253 
2043P   -181,718    -83,300    555,576    290,558 
2044P   -140,511    -85,716    435,890    209,663 
2045P   -138,134    -88,201    429,123    202,788 
2046P   -134,796    -90,759    419,543    193,987 
2047P   -123,409    -93,391    392,489    175,688 
2048P   -118,397    -96,100    379,455    164,959 
2049P   -112,725    -98,887    365,481    153,870 
2050P   -101,491    -101,754    336,108    132,863 
2051P   -95,719    -104,705    322,699    122,274 
2052P   -89,280    -107,742    307,359    110,338 
2053P   -76,617    -110,866    274,799    87,316 
2054P   -69,580    -114,081    258,172    74,511 
2055P   -66,327    -117,390    250,686    66,970 


WACC   10.91%
Economic NPV (Thousand S/)   2,248,101 


The net present value (NPV) of Pacasmayo Plant cement business amounts to more than S/ 2,248 million at a discount rate of 10.91% and it is made up of the sum of the discounted cash flows of each period, for the 30-year projection.


For discounting of the cash flows, the weighted average cost of capital of the company (WACC for its acronym in English) was applied.


73 


19.4.Sensitivity Analysis


The sensitivity analysis considers a variation of +/- 5 and 10% in the variables that have the greatest impact on the NPV and EBITDA. These variables are the cement sales price, operating cost and CapEx.


Table 47 and Table 48 detail the sensitivity of the EBITDA and NPV to each variable, respectively, when the variables are varied independently. Figure 17 and Figure 18 show the results of the sensitivity of NPV and EBITDA, respectively, to the three variables.


Table 47 Sensitivity analysis of the Net Present Value (expressed as %)


Variable / Variation   -10%    -5%    0%    +5%    +10% 
Price   -32.7    -16.3    0    16.3    32.7 
Cost   24.3    12.1    0    -12.1    -24.3 
CapEx   1.2    0.6    0    -0.6    -1.2 


Table 48 Sensitivity analysis of EBITDA (expressed as %)


Variable / Variation   -10%    -5%    0%    +5%    +10% 
Price   -38.8    -19.4    0    19.4    38.8 
Cost   30.7    15.3    0    -15.3    -30.7 
CapEx   -1.3    -0.7    0    0.7    1.3 


Figure 17 Sensitivity of Net Present Value


74 


Figure 18 Sensitivity of EBITDA


Based on these results, the NPV is most sensitive to cement price, followed by operating cost, and least sensitive to the CapEx. The EBITDA, on the other hand, is as sensitive to cement price as to the cost, and shows no sensitivity towards variations to the CapEx.


75 


20.Adjacent properties


The information in this chapter was obtained from the competent authority Instituto Geológico, Minero Metalúrgico (INGEMMET) according to the document “Resumen del Derecho Minero Acumulación Tembladera”. Figure 19 shows adjacent mineral concessions. The Eagle 1 concession overlaps with the Cementos Pacasmayo S.A.A. concession by 46.43 hectares. The Julissa A and Ana Paula 2805 concessions do not interfere with the area of the mining rights in the Cementos Pacasmayo S.A.A. concession. Eagle 1 does not interfere with Cementos Pacasmayo S.A.A.’s operations or Reserve estimates.


Figure 19 Concession Acumulación Tembladera and adjacent concessions.


76 


21.Other relevant data and information


Not applicable


22.Interpretation and conclusions


●From a legal point of view, Cementos Pacasmayo S.A.A. has the ownership of the mining properties for the exploration, development and production of limestone to supply the cement plants for normal production during the life of the quarry.


●Cementos Pacasmayo S.A.A. has been complying with international ISO-9001 (Quality) standards since 2015 and has implemented Quality Assurance and Quality Control (QAQC). The controls are applied for the construction of the Geological Model, Resource Estimation and Reserves Estimation.


●Cementos Pacasmayo S.A.A. has a robust quality assurance system in its operations that includes sample preparation methods, procedures, analysis and result validation which comply with the best practices in the industry.


●The information verification and validation processes are carried out following the procedures indicated in the information flows. The validated information is congruent with the one that generated the geological models, which are the fundamental basis for the estimation of Resources.


●The geological modeling of the limestone deposit considers the update with the last diamond drilling campaigns, being consistent with the relationship between the information and the geological model.


●The Mineral Resources and Reserves estimation consider the geologic characteristics and modifying factors as well as due consideration of risk: geologic and associated with evaluation of modifying factors. The main quality variable is the CaO content, which is very stable in the deposit, also there are along with other secondary variables that determine the quality of the Reserves.


●In the process of estimating Mineral Reserves and in the production plans of the quarry, these variables have been adequately considered in the mining plan, properly sequenced and with blending processes. There are sufficient proven and probable Reserves for the next 30 years.


●Table 49 shows the Mineral Resources of the Tembladera quarry and the results of Mineral Resource classification. Likewise, the Mineral Reserves and the results of Mineral Reserve classification are shown in Table 50.


Table 49 Resource Categorization (exclusive of Reserves) at the Tembladera quarry


    Resources Tonnes
M
CaO
(%)
MgO
(%)
Al2O3
(%)
SO3
(%)
Limestone Measured 135.1 49.85 1.79 1.63 0.29
Indicated 39.2 50.58 1.56 1.39 0.17
Measured + Indicated 174.3 50.01 1.74 1.58 0.26
Inferred 41.5 50.61 1.56 1.38 0.17


Table 50 Mineral Reserves expressed in millions of tonnes


    Reserves Tonnes
M
CaO
(%)
MgO
(%)
Al2O3
(%)
SO3
(%)
Limestone Proven 67.8 49.83 1.49 1.51 0.35
Probable 5.1 50.56 1.28 1.39 0.19
Total 72.9 49.88 1.48 1.50 0.33


77 


●The cement plant located in Pacasmayo has equipment and facilities available for cement production using limestone from the Tembladera quarry and other necessary materials.


●The Health, Safety and Environment department is in charge of supervising compliance with the Company’s corporate policies and the various legal requirements of the national regulatory bodies by all company areas.


●Through its Social Responsibility area, Cementos Pacasmayo S.A.A. has generated relationships of trust with the communities surrounding its operations, which have a solid relationship with our communities, identifying their primary needs in health, education, urban development, and local development.


●The operation in Tembladera quarry and Pacasmayo plant, with regards to infrastructure, is technically and economically feasible due to the life of the quarry.


●The sensitivity analysis shows that the operation is economically robust.


23.Recommendations


●Maintain the QAQC program for exploration, development and production activities associated with cement production.


●Continue geotechnical monitoring of the quarry components to ensure their physical stability.


●Conduct limestone density testing in upcoming studies at the Tembladera quarry.


●Continue diamond drilling campaigns aimed at recategorizing inferred resources and confirming reserves to the SE of the Tembladera quarry.


●Geologically define the continuity of the main NW-SE oriented dike in the quarry’s operating area to more accurately quantify its volume (waste).


24.References


BISA Ingeniería de Proyectos S.A.(2017). Actualización del Plan de Manejo Ambiental del Programa de Adecuación y Manejo Ambiental – PAMA de la Cantera Tembladera


Servicios Generales de Seguridad y Ecología S.A. (2011). Declaración de Impacto Ambiental Instalación de 02 Hornos Verticales nº 5 y 6.


Servicios Generales de Seguridad y Ecología S.A. (2007). Estudio de Impacto Ambiental Incremento de la Producción de Clinker en la Planta de Cemento.


BISA Ingeniería de Proyectos S.A. (2017). Actualización del Plan de Manejo Ambiental del Programa de Adecuación y Manejo Ambiental – PAMA de la Cantera Tembladera – Volumen I


Magma Consulting S.A.C. (2021). Estudio Geomecánico Geotécnico Cantera Tembladera.


Magma Consulting S.A.C. (2021). Anexo 4: Estudio Hidrogeológico Cantera Tembladera.


Walsh Perú S.A. (2016). Actualización del Plan de Cierre de la Cantera Tembladera.


Magma Consulting S.A.C (2023). Ingeniería de Factibilidad para la Ampliación del Depósito de Material Estéril 5A y Depósito de Material Estéril 6


78 


25.Reliance on information provided by the registrant.


In preparing this report, the qualified persons relied upon data, written reports and statements provided by the registrant in accordance with 17 CFR § 229.1302(f). After careful review of the information provided, the QPs have no reason to believe that any material facts have been withheld or misstated. Cementos Pacasmayo provided the information as summarized in Table 51.


Table 51 List of Cementos Pacasmayo S.A.A. information.


Chapter Chapter name Information provided by CPSAA
3 Property description Legal matters related to property rights and the authority “Instituto Geológico, Minero y Metalúrgico INGEMMET”
16 Market studies Marketing information, ASOCEM, INEI, MEF and BCRP
17 Environmental studies, permitting, and plans, negotiations, or agreements with local individuals or groups Environmental studies and information, Community Relations and information about agreements with stakeholders
18 Capital and operating costs Historical data about cost, price and investments.
19 Economic analysis The International Monetary Fund Economic model, Macroeconomic trends, data, assumptions, and interest rates
20 Adjacent properties Legal matters related to property rights and the authority “Instituto Geológico, Minero y Metalúrgico “INGEMMET”


79 


Responsibility and Reliance Statement – Marco Carrasco


Mr. Marco Carrasco, in his capacity as Project Manager of C&O Project LLC and compiler of this Technical Report Summary, has coordinated and integrated the information prepared by the respective Qualified Persons responsible for each section of this report.


Each Qualified Person assumes full responsibility for the accuracy, completeness, and validity of the technical content, analyses, and conclusions contained within the sections they have prepared. Mr. Carrasco has not independently verified all underlying data, interpretations, or conclusions provided by other Qualified Persons and has reasonably relied on their expertise, professional judgment, and compliance with applicable industry standards and regulatory requirements, including SEC Regulation S-K Subpart 1300.


Mr. Carrasco contributed as Qualified Person to Chapters 4, 16, 17, 18, and 19 of this report. In the preparation of these chapters, he relied on information provided by Cementos Pacasmayo S.A.A., including internal data and information validated by the competent authorities in Peru. Such information constituted the basis for his review and analysis, which was carried out in coordination with personnel from Cementos Pacasmayo.


Accordingly, Mr. Carrasco’s responsibility is limited to the compilation, organization, and overall presentation of this report, as well as to the specific chapters identified above. His role in the compilation process did not include independent technical verification or validation of the data, analyses, or conclusions prepared by other Qualified Persons, and his responsibility does not extend to the technical accuracy or completeness of such sections.


To the best of his knowledge, no material inconsistencies were identified during the compilation process or within the chapters under his responsibility; however, Mr. Carrasco assumes no responsibility for any errors or omissions that fall outside the scope of his assigned chapters or that arise from information provided by Cementos Pacasmayo or other Qualified Persons.


80


Signature Page


This report titled “Technical Report Summary Tembladera Quarry and Pacasmayo Cement Plant” with an effective date of December 31, 2025 was prepared, compiled, and signed by the following qualified professionals, as indicated in the respective sections of this document.


Dated at Lima, Peru  
April 27, 2026  
   
/s/ Marco Carrasco  
(*) Marco Carrasco, P. Eng., RM-MMSA  
Project Manager   
C&O Projects LLC (USA)  
   
/s/ Jason Gamio  
Jason Gamio, P. Eng.  
Planning and Evaluation of Resources and Reserves Superintendent  Cementos Pacasmayo S.A.A.  
   
   
/s/ Dennis Rodas  
Dennis Rodas, P. Eng.  
Quality Assurance Superintendent  
Cementos Pacasmayo S.A.A.   


Note:


(*)Marco Carrasco served as Project Manager for Cementos Pacasmayo S.A.A. until March 2026 and thereafter participated as Project Manager of C&O Project LLC. In this capacity, he compiled and integrated the information provided by the Qualified Persons responsible for each chapter to prepare a consolidated report. Each Qualified Person is solely responsible for the content of the sections they prepared. Mr. Carrasco’s role in the compilation process was limited to the organization and integration of such information and did not include independent technical verification or validation of the data, analyses, or conclusions provided by other Qualified Persons.


81 


82 


83 


84 


Exhibit 96.2


CEMENTOS PACASMAYO S.A.A.

Technical Report Summary (TRS)

Virrila Quarry

and

Piura Cement Plant

20-F 229.601 (Item 601)


January 2025


Index


1.  Executive summary 1
  1.1. Location and access 1
  1.2. Climate 1
  1.3. History 1
  1.4. Geological environment and mineralization 2
  1.5. Exploration 3
  1.6. Sample preparation, analysis and security 3
  1.7. Data Verification 4
  1.8. Mineral processing and metallurgical test 5
  1.9. Estimation of Resources and Mineral Reserves 6
  1.10. Mining Methods 7
  1.11. Processing Plant and Infrastructure 8
  1.12. Market studies 9
  1.13. Capital and operating costs and Economic Analysis 10
  1.14. Adjacent properties 13
  1.15. Conclusions 14
  1.16. Recommendations 15
2. Introduction 16
  2.1. Participants 16
  2.2. Terms of Reference 16
  2.3. Conventions 18
  2.4. Previous Work and Sources of Information 18
  2.5. Details of QP Personal Inspection 18
  2.6. Previously Filed Technical Report Summary 18
3. Property description 19
  3.1. Virrila quarry 19
  3.2. Piura Industrial Cement Plant 22
4. Accesibility, climate, local resources, infrastructure and physiography 24
  4.1. Virrila quarry 24
  4.2. Piura industrial cement plant 26
5. History 27
6. Geological setting, mineralization, and deposit 28
  6.1. Regional geology 28
  6.2. Local geology 29
  6.3. Characteristics of the deposit 30


i


7. Exploration 32
  7.1. Drilling 32
  7.2. Hydrogeology 33
  7.3. Geotechnical studies 33
8. Sample preparation, analysis and security 34
  8.1. Geology and Quarry 34
    8.1.1. Preparation of samples, procedures, assays and laboratories 34
    8.1.2. Quality Assurance Procedures 35
    8.1.3. Sample security 35
    8.1.4. Chain custody 36
    8.1.5. Qualified Person’s Opinion on Cement Plant QAQC 36
  8.2. Piura Plant 36
    8.2.1.Samples preparation, procedures, assays and laboratories 36
      8.2.1.1.  Raw materials sample preparation 37
      8.2.1.2.  Laboratory analysis 37
    8.2.2. Quality Assurance Procedures 38
    8.2.3. Security of the samples 39
    8.2.4. Qualified Person’s Opinion on cement plant QAQC 39
9. Data verification 40
  9.1. Geology and quarry 40
  9.1.1. Data Verification procedure 40
  9.1.2. Data collection 40
  9.1.3. Management and Validation of Database 40
  9.1.4. Tracking Data 40
  9.1.5. Validation of Data 41
  9.1.6. Qualified Person’s Opinion Geologic Data 42
  9.2. Piura plant 42
  9.2.1. Data verification procedures 43
  9.2.2. Data validation 43
  9.2.3. Qualified Person’s Opinion on cement plant 43
10. Mineral processing and metallurgical testing 44
  10.1. Nature of testing program 44
  10.2. Cement Manufacturing Test Results 45
  10.3. Qualified Peron Opinion of the Adequacy of the Test Data 45


ii


11. Mineral Resources Estimates 46
  11.1. Database 47
  11.2. Density 48
  11.3. Compositing 48
  11.4. Basic statistics of the data (Assay – Composites) 48
  11.5. Extreme values 49
  11.6. Variogram Analysis 49
  11.7. Interpolation 50
  11.8. Resources estimation 51
    11.8.1. Cut-off 51
    11.8.2. Reasonable prospects of economic extraction 52
  11.9. Mineral Resources classification 53
  11.10. Qualified person’s opinion 53
12. Mineral Reserves estimates 54
  12.1. Criteria for Mineral Reserves determination 54
    12.1.1.  Run of Mine (ROM) determination criteria 54
    12.1.2.  Cement plant recovery 55
  12.2. Reserves estimation methodology 55
  12.3. Mineral Reserve estimates 56
13. Mining methods 57
  13.1. Mining methods and Equipment 57
  13.2. Geotechnical models 58
  13.3. Hydrological models 60
  13.4. Other mine design and planning parameters 61
  13.5. Annual production rate 61
  13.6. Mining plan 62
  13.7. Life of Mine 63
  13.8. Staff 63
14. Processing and recovery methods 64
  14.1. Process Plant 64
  14.2. Raw materials for the cement production 65
  14.3. Flow sheet 66
  14.4. Main equipment 67
  14.5. Cement Plant Mass balance 67
  14.6. Process losses 68


iii


  14.7. Water consumption 68
  14.8. Fossil fuel consumption 68
  14.9. Electric power consumption 69
  14.10. Maintenance Plan 69
  14.11. Staff 69
15. Infrastructure 70
  15.1. Virrila quarry 70
  15.2. Piura plant 70
16. Market Studies 71
  16.1. The cement market in Peru 71
  16.2. Industry and Macroeconomic Analysis 72
  16.3. The North Region Market 74
  16.4. Cement price 75
  16.5. Current and future demand 76
17. Environmental studies, permitting, and plans, negotiations, or agreements with local individual or groups. 79
  17.1. Environmental Aspects 79
    17.1.1.  Virrila quarry 79
    17.1.2.  Piura plant 81
  17.2. Solid waste disposal 82
  17.3. Qualified Person’s Opinion 82
18. Capital and operating costs 83
  18.1. Basis for operating and capital cost for the quarry and plant 83
  18.2. Capital and Operating Cost Estimates 84
  18.3. Capital and Operating cost estimation risks 86
19. Economic analysis 87
  19.1. Methodology: for Discounted Cash flow (Free) 87
  19.2. Assumptions 87
    19.2.1.  General and Macroeconomic Assumptions 87
    19.2.2.  Income and Cost Assumptions 88
  19.3. Results of financial model 88
  19.4. Sensitivity Analysis 91
20. Adjacent properties 93
21. Other relevant data and information 94
22. Interpretation and conclusions 94
23. Recommendations 96
24. References 96
25. Reliance on information provided by the registrant 97
Signature Page 98


iv


Index of tables


Table 1 Mineral Resources (exclusive of Reserves) in the Virrila quarry 6
Table 2 Ore Reserves in the Virrila quarry 7
Table 3 Projection of demand and price for the next 30 years 10
Table 4 Free Cash Flow and valuation 12
Table 5 Resources at the Virrila quarry in millions of tonnes (exclusive of Reserves) 15
Table 6 Mineral Reserves expressed in millions of tonnes 15
Table 7 List of Cementos Pacasmayo S.A.A. QPs 17
Table 8 QP’s field visit 18
Table 9 UEA Virrila Concessions 19
Table 10 Central coordinates of the UEA Virrila property 20
Table 11 Central coordinates of the Piura cement plant 22
Table 12 Regional stratigraphic column 28
Table 13 Local stratigraphic column of the Virrila quarry 30
Table 14 Characteristics of the Virrila deposit 30
Table 15 Quality Plan of the Virrila quarry 35
Table 16 Tests and frequency for each stage of the process 38
Table 17 Lithologic units of the Virrila quarry geological model 46
Table 18 Quality Parameters for Dome and Additive coquina 47
Table 19 Characteristics of the block models 47
Table 20 Basic data statistics os Zone 3 and Zone 2 49
Table 21 Estimation Parameters Secondary Variables 50
Table 22 Resource estimates (exclusive of Reserves) at the Virrila quarry 51
Table 23 Ore Reserves expressed in million tons 56
Table 24 Mining equipment at the Virrila Quarry 58
Table 25 Virrila quarry physical stability analysis summary 59
Table 26 Geotechnical properties of materials 60
Table 27 Mine design parameters 61
Table 28 Minning plan forecast 62
Table 29 Main equipment in Piura plant 67
Table 30 Balance for raw meal production 67
Table 31 Balance for clinker production 68
Table 32 Balance for cement production 68
Table 33 Fuel Consumption for Cementos Pacasmayo S.A.A – Piura Plant 68
Table 34 Cement shipments at domestic level (in thousands of tonnes) 72
Table 35 Cement at Piura plant 75
Table 36 Forecast of future demand for Piura cement plant 78
Table 37 Cost structure of Virrila quarry and Piura plant 83
Table 38 Operating costs forecast of quarry and plant 84
Table 39 Investment forecast in quarry and plant 85
Table 40 Profit and Loss Statement 89
Table 41 Free Cash Flow and valuation 90
Table 42 Sensitivity analysis of the Net Present Value 91
Table 43 Sensitivity analysis of EBITDA 91
Table 44 Resources at the Virrila quarry in millions of tonnes (exclusive of Reserves) 95
Table 45 Mineral Reserves expressed in millions of tonnes 95
Table 46 List of Cementos Pacasmayo S.A.A. information. 97


v


Index of figures


Figure 1 Mining sequence of Virrila quarry 7
Figure 2 Piura plant process block diagram 8
Figure 3 Sensitivity of Net Present Value (expressed as %) 13
Figure 4 Sensitivity of EBITDA (expressed as %) 13
Figure 5 UEA Virrila map 21
Figure 6 Piura plant perimeter 23
Figure 7 Geological section of the Virrila quarry 31
Figure 8 Map of the location of drill holes in the Virrila quarry. 33
Figure 9 Mining sequence of Virrila quarry 57
Figure 10 Virrila quarry final pit 63
Figure 11 Piura plant process block diagram 66
Figure 12 Virrila quarry facilities 70
Figure 13 Segmentation of the cement market in Peru 71
Figure 14 Global GDP and Construction sector GDP MoM variation (%) 73
Figure 15 Historic prices of cement in Peru 76
Figure 16 Evolution of the national demand of cement 77
Figure 17 Sensitivity of Net Present Value (expressed as %) 92
Figure 18 Sensitivity of EBITDA (expressed as %) 92
Figure 19 Adjacent properties map 93


vi


1.Executive summary


Cementos Pacasmayo S.A.A (CPSAA) is a Peruvian company whose corporate purpose is the production of cement and other products associated with the construction sector. This Technical Report Summary summarizes a Pre-feasibility study of the Virrila quarry and Cement Plant located in the Piura Region, both owned by CPSAA. Cementos Pacasmayo´s qualified persons (QPs) prepared this Report to support disclosure of coquina Resources and Reserves.


1.1.Location and access


The Virrila quarry contains coquina, the main raw material for cement production. This quarry is located in the Sechura district, of Sechura Province, in the Piura Region. There is an access road to this quarry from Lima to Piura. The Piura plant is located in Piura city, and is 192 km from Virrila quarry and 950 Km from Lima.


1.2.Climate


The quarry is in a temperate and humid climate, with little rainfall, mostly between February and April. Average annual temperatures vary between 17.8 °C and 29.5 °C. The highest temperatures were recorded in January, February, and March, and the lowest in August and September.


In the Piura plant, the climate is predominantly arid and warm, with no rain for most of the year. The average maximum temperature is 31.2 °C, and the minimum is 17.7 °C. When the El Niño phenomenon occurs, there is rainfall, especially between December and June.


1.3.History


The Virrila quarry is a production stage operation on a non-metallic deposit of calcareous material from marine shells that supply raw material to the cement plant in Piura. Cementos Pacasmayo S.A.A owns the mineral deposit.


The Virrila quarry started operations on September 17, 2015. The mining contractor San Martin Contratistas Generales S.A. was in charge of the production from the start of operations until March 14, 2020. The mining contractor Posada Perú S.A.C started operations at the Virrila quarry on September 14, 2020, until December 30, 2021. On January 3, 2022, the mining contractor San Martin Contratistas Generales S.A. was hired for the production of the coquina. The transport the coquina from the Virrila quarry to the Piura plant in in charge of other companies.


1


During the 2023 period, two mining contractors worked at the Virrilá quarry operations from January to April with San Martin Contratistas Generales S.A. and from October to December with Sechura Ingenieria y Contrucción E.I.R.L.


From May to September 2023, Cantera Virrila stopped operations due to the closure of the road caused by the overflow of the La Niña lagoon provoked by cyclone Yaku. Likewise, the Piura plant stopped its clinker production operations (raw meal milling, coal milling and reception of raw materials) from July to September was to avoid exceeding the strategic inventories (clinker). The cement grinding, receiving (cement additions), packaging and dispatching processes remained active to cover the cement demand. Virrila quarry restarted operations in October.


From January to April 2024, Virrila quarry shipped coquina from its stockpiles to the Piura Plant, the company in charge of loading the material was Peruvian Master. From May to October, Sechura Ingenieria y Contrucción E.I.R.L. was in charge of operations of the quarry. After October the quarry stopped operations according to the 2024 mining plan. Likewise, the Piura plant stopped its clinker production operations (raw meal milling, coal milling and reception of raw materials) from March to May and from November to December was to avoid exceeding the strategic inventories (clinker). The cement grinding, receiving (cement additions), packaging and dispatching processes remained active to cover the cement demand.


During the month of January, operations remained suspended in accordance with the 2025 Mining Plan. From February to December 2025, the Virrila Quarry dispatched coquina material to the Piura Plant, both from the operational area and from existing stockpiles. The company responsible for the material loading activities was Inversiones y Servicios Felicitas S.R.L. Likewise, the Piura plant stopped its clinker production operations (raw meal milling, coal milling and reception of raw materials) from Enero y de Septiembre to December was to avoid exceeding the strategic inventories (clinker). The cement grinding, receiving (cement additions), packaging and dispatching processes remained active to cover the cement demand


1.4.Geological environment and mineralization


Geologically, the study area is in the desert zone of Sechura and has sedimentary rocks from the Recent Quaternary.


It is composed of silty sand deposits with intercalations of medium to fine-grained sands and coquina horizons. Below the recent deposits, there are diagenetic eolian deposits in the sandy matrix with calcareous cement. Below these, there are intercalations of conglomerates with gray diatomites, intercalated with white reef sandstones, corresponding to the Talara Bedrock and the upper levels of the Zapallal Formation.


2


The Virrila quarry deposit is comprised of coquina portions of the Talara Tablazo that undergo lateral variations in thickness and composition of calcareous remains.


1.5.Exploration


In 2007 and 2008 exploration activities were performed to obtain geological information from the Virrila quarry that would allow the production of coquina.


In 2013, exploration activities were carried out by means of test pits in the best areas of the mining concession.


In 2019, activities and sampling in the operation area were developed to validate the Mineral Reserves in the area of operation and update the inventory.


In 2021, drilling was conducted to confirm Reserves within the operations and to know in more detail the characteristics of the deposit.


In 2022, drilling was conducted to confirm Reserves in the same area that the 2021 campaign.


In 2023, from May to June Cementos Pacasmayo carry out a drilling campaign in order to confirm mineral Reserves of Virrila deposit.


1.6.Sample preparation, analysis and security


Cementos Pacasmayo S.A.A., through its quality control group, performed quality assurance activities for the samples obtained at the Virrila deposit, applying the quality control plan, protocols, and measures necessary to get information on the coquina samples. Laboratory analyses were performed at the chemical laboratory of Piura plant and were applied for the estimation of Resources and Reserves of the deposit.


The Piura plant’s Quality Assurance and Control Department has implemented a sampling and data verification plan for the following processes: raw material reception, raw mill scale, raw mill grinding, kiln feed, coal scale, coal grinding, preheater, kiln filter, clinkerization, cement grinding, mill scale, cement grinding, cement composting, packaging control, packaging-composting and by-pass.


3


Likewise, Cementos Pacasmayo S.A.A. has implemented quality assurance, quality control (QAQC) protocols to develop exploration and production activities in the Virrila quarry and in the Piura plant to ensure the quality of the information that is used in the estimation of Mineral Resources and Reserves.


Cementos Pacasmayo has procedures for sample preparation, testing, and information security in its operations. The cement plants and operations have implemented the ISO 9001 standard since 2015. Certification is renewed annually through an external audit.


1.7.Data Verification


Concerning geological activities, CPSAA has a data verification unit for the geological database. The main function of this department is the verification of data to be used in the estimation of Mineral Resources and Reserves. For the appropriate administration of information, internal protocols have been implemented that are subject to internal verification. The geologic data verification activities include data collection, administration and validation received from internal and external laboratories, data tracking through the confirmation of custody chains and finally, validation of data in the database. CPSAA staff use verified data in developing the Mineral Resources and Reserves model.


The qualified persons followed the defined processes for information flows to support Mineral Resource and Reserve estimation. The qualified person followed the same process as a means of verifying and validating the geologic data. They found that the validated information is congruent in the interpretations of the same, with which the fundamental base geological models were generated for the estimation of the Mineral Resources.


No findings have been found that could invalidate the estimation of the Resources and Reserves of the deposit.


4


For data verification activities at the cement plant, CPSAA uses the Plan, Do, Check and Act (PDCA) methodology. This is applied to the technical information received from the company’s internal and external customers. The quality control laboratory compares the results with national and international laboratories as part of the verification procedures.


1.8.Mineral processing and metallurgical test


Cementos Pacasmayo has procedures for developing products at the laboratory level and scaling at the industrial level: its guidelines for preparing, reviewing, insurance, and controlling laboratory test reports. Cementos Pacasmayo has a research and development laboratory located in the Pacasmayo plant to evaluate the technical operations of cement plant and quarry operations.


In order for its operations at the Piura plant to have a representative sample of its raw materials and cement, Cementos Pacasmayo performs the analysis of its samples in its internal Research and Development Laboratory located at the Pacasmayo plant.


A significant percentage of Research and Development activities are focused on evaluating different ratios between clinker-mineral additions providing the best functional characteristics to our products, and balancing the benefits generated for the company. Another objective is to identify other additions that can substitute for clinker: slag, pozzolana, fly ash, calcined clays, etc., to reduce our environmental footprint and the cost of cement production. Based on this work, the laboratory has determined (and confirmed with production estimates) that 1 tonne of coquina yields 0.77 tonnes of clinker and the clinker/cement factor of the main cements with additions is 0.71.


5


The clinker/cement factor of the cement with additions: ICO and MS (MH) were investigated.


For ICO cement, the clinker/cement factor was reduced by 0.68 (2023), 0.66 (2024) and 0.68 (2025). For MS (MH) cement the clinker/cement factor was 0.70 (2023), 0.65 (2024) and 0.62 (2025).


The Research Laboratory issues technical reports to the operations department following international standards. The operations department evaluates the convenience of implementing the tests industrially and validates what is reported at the laboratory level.


1.9.Estimation of Resources and Mineral Reserves


The qualified persons (QPs) developed the estimates coquina Resources and Reserves contained in this technical report summary (TRS). The information from exploration in the previous years has been used for the evaluation, and is the database for the Resources and Reserves model.


The coquina Resources are presented in Table 1. The Resource estimation considered the quality restrictions of coquina received in the Piura plant, limits of the concessions, accessibility to the Resources and legal limits of the mining concessions, relevant economic factors, and modifying factors.


The minimum quality accepted is 48.5% CaO to be used as raw material for cement production. Considering the sales prices of cement at the Piura plant, the economic evaluation used for Resource evaluation is shown in Chapter 19 and uses the same criteria used to estimate Reserves.


Table 1 Mineral Resources (exclusive of Reserves) in the Virrila quarry


  Resources Tonnes
M
CaO
(%)
SO3
(%)
MgO
(%)
Na2O
(%)
K2O
(%)
Cl
(ppm)
Coquina Measured 21.8 49.80 0.54 0.62 0.22 0.19 0.07
Indicated 26.8 48.98 1.06 1.18 0.21 0.22 0.07
Measured + Indicated 48.6 49.35 0.83 0.93 0.21 0.21 0.07
Inferred 4.4 46.70 2.11 1.54 0.24 0.25 0.06


6


For Reserve estimation, the Resources and the quality criteria, modifying factors, and coquina production costs were considered. The economic results are shown in Chapter 19. The mining method used is open pit mining.


Table 2 Ore Reserves in the Virrila quarry


Reserves Tonnes
M
CaO
(%)
MgO
(%)
SO3
(%)
Na2O
(%)
K2O
(%)
Cl 
(ppm)
Coquina Proven 39.9 51.86 0.71 0.36 0.29 0.15 0.03
Probable 0.9 49.83 0.84 0.64 0.32 0.23 0.03
Total 40.8 51.82 0.71 0.36 0.29 0.16 0.03


1.10.Mining Methods


Cementos Pacasmayo S.A.A. is the current owner of the Virrila quarry and is in charge of the coquina´s production. The loading and transport of coquina has been outsourced to contractors, Cementos Pacasmayo S.A.A. supervises the quarry to verify the activities and output according to the requirements of the Cement Plant.


The mining of coquina at the Virrila quarry consider the activities of Stripping, surface mining, stacking, loading for dispatch, weighing and dispatch.


Figure 1 Mining sequence of Virrila quarry


The main equipment used for the production of coquina in the Virrila quarry is a surface miner, front loader and dump truck. Also auxiliary equipment is necessary, including pickup van, tanker truck and other equipment.


The mining plan of the Virrila quarry consider an average annual production of 1.36 million tonnes of coquina for the next 30 years and a stripping rate of 0.38.


Based on the plant requirements and sales projection for the next 30 years, the pit design parameters for the Virrila quarry are maximum pit height, maximum bench height and pit bank slope.


7


1.11.Processing Plant and Infrastructure


Cement production considers the stages of raw material extraction, raw material grinding and homogenization, clinkerization, cement grinding, silo storage and packaging, loading, and transportation. Cement is moved through pneumatic conveyors to bagging systems to be packed in bags and then loaded onto trucks operated by third parties for distribution.


Figure 2 Piura plant process block diagram


The raw materials for cement production are coquina, sand, iron, clay, and coal. The mixture of these raw materials is the ground material called raw meal, which is fed to the calcining kiln to produce clinker. Coquina represents 78% by weight of the raw meal.


Clinker and additions are used to produce cement. The additions used in cement production are slag, pozzolana, shale, and gypsum.


Currently, the Piura cement plant has a clinker/cement ratio of 0.69.


8


The Piura plant has an electrical substation of 37.50 MW and uses electricity supplied from the national grid.


Cementos Pacasmayo has implemented a preventive and corrective maintenance plan to prevent interruptions in cement production.


Cementos Pacasmayo maintains operating efficiency to control costs and operating margins, and has initiatives to diversify energy sources and secure supply when possible.


1.12.Market studies


The Peruvian cement market is geographically segmented by region: northern region, central region, and southern region, and each area is served by several companies, most of which are cement producers.


The main companies that supply the Peruvian cement market are Cementos Pacasmayo, UNACEM, and Cemento Yura. Some companies import cement or clinker, such as Cemento Inka, Cemento Nacional and Cemex, Holcim Perú S.A, among others.


Companies that market cement in Peru follow the Peruvian Technical Standards associated with cement technical specifications.


Portland cement is subdivided into Type I and Type V cement. Portland Cement is subdivided into Type ICO, Type IL, Type IP, and Type I (PM); and finally, Hydraulic Cements specified by performance are Type GU, Type MS (MH), Type HS, Type HE, Type MH, and Type LH.


Cementos Pacasmayo, being the leading company in the production and sale of cement in the Northern Region, has a market share in the following cities: Cajamarca, Chiclayo, Chimbote, Jaén, Pacasmayo, Piura, Rioja, Tarapoto, Trujillo, Tumbes, Yurimaguas and Iquitos. Cementos Pacasmayo also has a market share of 92.1% in the country’s northern region.


Annual cement deliveries nationwide for the year 2025 reached 12.9 million tons, while total cement deliveries of Piura plant for 2025 were 0.9 million tons. The Piura plant serves 29.1% of the cement demand in the country’s Northern Region, and its cement dispatches represent almost 26.7% of the three cement plant’s overall shipments. Table 3 shows the projected demand and price per ton of cement for the next 30 years.


9


Table 3 Projection of demand and price for the next 30 years


   Shipments (tonnes)   Revenue
S/ x t
 
           
2026P   944,677    524.0 
2027P   963,571    534.5 
2028P   982,842    545.2 
2029P   1,002,499    556.1 
2030P   1,022,549    567.2 
2031P   1,043,000    578.5 
2032P   1,063,860    590.1 
2033P   1,085,137    601.9 
2034P   1,106,840    613.9 
2035P   1,128,976    626.2 
2036P   1,151,556    638.7 
2037P   1,174,587    651.5 
2038P   1,198,079    664.6 
2039P   1,229,989    677.8 
2040P   1,263,389    691.4 
2041P   1,297,457    705.2 
2042P   1,332,206    719.3 
2043P   1,367,650    733.7 
2044P   1,403,803    748.4 
2045P   1,440,679    763.4 
2046P   1,478,293    778.6 
2047P   1,516,659    794.2 
2048P   1,555,792    810.1 
2049P   1,595,708    826.3 
2050P   1,600,000    842.8 
2051P   1,600,000    859.7 
2052P   1,600,000    876.9 
2053P   1,600,000    894.4 
2054P   1,600,000    912.3 
2055P   1,600,000    930.5 


1.13.Capital and operating costs and Economic Analysis


This document presents the cash flow analysis and an economic evaluation of the project based on the current operating costs of the cement plant in Piura. It uses the information on the Virrila quarry for coquina production.


For the Reserves evaluation, the general and macroeconomic assumptions used for the projection of the free/economic cash flows and for the valuation are:


-Projection horizon: 30 years (2026 to 2055) according to the estimated years of quarry life.


10


-Annual inflation rate, 2.90%, based on Banco Central de Reserva del Perú as of projection 2026: applies equally to sales price, costs and expenses.


-Capital cost projections were determined using a historical ratio of annual investments and maintenance costs which also considers the increase in production volume.


-The company’s capital structure is considered in the discount rate (WACC) of 10.91%.


-Income tax rate: effective rate of actual (historical) business results, 29% - 30%.


-Workers’ Profit Sharing: 10%.


-Exchange rate: exchange rate is assumed to remain at 3.80 (USD/PEN).


The economic analysis uses the economic assumptions listed in Chapter 19. The main variables considered in the economic model for the sensitivity analysis were cement price, production cost, and Capex. Some of these main assumptions are listed below here.


The free cash flow is constructed for the economic analysis, which does not incorporate the financing structure. The latter is considered in the weighted average cost of capital (WACC) to discount future cash flows. The following financial parameters were calculated:


●NPV of 1,983 million soles at a discount rate of 10.91%.


●30-year mine life


●Average plant throughput for cement production: 1.3 million tonnes per year over the 30-year projection. 


●Average sales price: 708.6 soles per ton of cement, an average of the 30-year projection, at nominal values.


●Revenues: 948 million soles, an average of the 30-year projection. 


●Average production cost: 400.5 soles per ton of cement, an average of the 30-year projection, at nominal values.


11


Table 4 presents the cash flow of the project. The net present value at a discount rate of 10.91% is 1,983 million Soles.


Table 4 Free Cash Flow and valuation


   FCF - Valuation (Thousand S/) 
   (-) Taxes (EBIT*t)   (-) CapEx  

EBITDA

Pacasmayo

plant

   Free Cash Flow 
                 
2026P   -66,445    -12,700    230,180    151,036 
2027P   -76,849    -13,068    261,271    171,353 
2028P   -80,197    -13,447    271,310    177,666 
2029P   -81,327    -13,837    276,522    181,358 
2030P   -87,588    -14,239    291,905    190,078 
2031P   -89,036    -14,651    292,441    188,753 
2032P   -90,977    -15,076    297,835    191,781 
2033P   -95,022    -15,514    309,317    198,781 
2034P   -98,876    -15,963    320,423    205,584 
2035P   -100,438    -16,426    326,225    209,361 
2036P   -104,708    -16,903    334,836    213,226 
2037P   -110,199    -17,393    349,662    222,071 
2038P   -114,623    -17,897    363,920    231,399 
2039P   -119,640    -18,416    378,798    240,742 
2040P   -125,893    -18,950    393,594    248,750 
2041P   -128,759    -19,500    402,244    253,985 
2042P   -134,547    -20,065    417,615    263,002 
2043P   -139,482    -20,647    432,453    272,323 
2044P   -139,540    -21,246    441,789    281,002 
2045P   -144,590    -21,862    456,920    290,468 
2046P   -148,550    -22,496    470,138    299,092 
2047P   -136,573    -23,149    435,114    275,392 
2048P   -135,170    -23,820    432,236    273,246 
2049P   -133,204    -24,511    427,707    269,992 
2050P   -129,213    -25,222    418,095    263,660 
2051P   -126,584    -25,953    411,488    258,951 
2052P   -124,375    -26,706    406,396    255,315 
2053P   -119,931    -27,480    394,921    247,510 
2054P   -118,134    -28,277    388,355    241,944 
2055P   -120,047    -29,097    395,556    246,412 


WACC   10.91%
Economic NPV (Thousand S/)   1,983,147 


12


Figure 3 and Figure 4 show the sensitivity analysis, which shows the influence of changes in prices, OpEx and CapEx on NPV and EIBTDA, respectively.


Figure 3 Sensitivity of Net Present Value (expressed as %)


Figure 4 Sensitivity of EBITDA (expressed as %)


1.14.Adjacent properties


To the north of the Cementos Pacasmayo S.A.A. concession is the Bayovar N° 7 concession owned by Americas Potash Peru S.A. To the east of CPSAA’s concession are concessions Virrila 12, Virrila 19, and Virrila 23 owned by Cementos Pacasmayo S.A.A. To the west are concessions Virrila 6, Virrila 9 and Virrila 14 owned by Cementos Pacasmayo S.A.A. and to the north is concession Virrila 16 owned by Cementos Pacasmayo S.A.A.


13


1.15.Conclusions


●From a legal viewpoint, Cementos Pacasmayo S.A.A. has mining rights for the areas of exploration, development, and production of coquina to supply the cement plants for normal production during the quarry’s life. It also has an agreement with Fundación Comunal San Martín de Sechura for the right of usufruct, surface and easement for the area of operations at the Virrila quarry.


●Cementos Pacasmayo S.A.A. has been complying with ISO-9001 (Quality) standards since 2015 and has implemented Quality Assurance and Quality Control (QAQC). The controls are applied for the construction of the geological Model and for estimating the Mineral Resources and Reserves.


●Cementos Pacasmayo S.A.A. has a quality assurance system in its operations that includes sample preparation methods, procedures, analysis and security, which comply with the best practices in the industry.


●The information verification and validation processes are carried out following the procedures indicated in the information flows. The validated information is congruent with the one that generated the geologic models, which are the fundamental basis for the estimation of Mineral Resources.


●The geological modeling of the coquina deposit considers the updated data from the last diamond drilling campaigns.


●The Mineral Resources and Reserves estimation consider the geologic characteristics and modifying factors as well as due consideration of risk: geologic and associated with evaluation of modifying factors. The main quality variable is the CaO content which is very stable in the deposit, also present are other secondary variables that determine the quality of the Reserves.


●In the process of estimating Mineral Reserves and in the production plans of the quarry these variables have been adequately considered in the mining plan, properly sequenced and with blending processes. There are sufficient proven and probable Reserves for the next 30 years.


14


●Table 5 and Table 6 show the Mineral Resources and Reserves of the Virrila quarry, respectively.


Table 5 Resources at the Virrila quarry in millions of tonnes (exclusive of Reserves)


  Resources Tonnes
M
CaO
(%)
SO3
(%)
MgO
(%)
Na2O
(%)
K2O
(%)
Cl
(ppm)
Coquina Measured 21.8 49.80 0.54 0.62 0.22 0.19 0.07
Indicated 26.8 48.98 1.06 1.18 0.21 0.22 0.07
Measured + Indicated 48.6 49.35 0.83 0.93 0.21 0.21 0.07
Inferred 4.4 46.70 2.11 1.54 0.24 0.25 0.06


Table 6 Mineral Reserves expressed in millions of tonnes


  Reserves Tonnes
M
CaO
(%)
MgO
(%)
SO3
(%)
Na2O
(%)
K2O
(%)
Cl
(ppm)
Coquina Proven 39.9 51.86 0.71 0.36 0.29 0.15 0.03
Probable 0.9 49.83 0.84 0.64 0.32 0.23 0.03
Total 40.8 51.82 0.71 0.36 0.29 0.16 0.03


●The cement plant located in Piura has all the equipment and facilities available to produce cement, using coquina from the Virrila quarry and other necessary materials.


●Cementos Pacasmayo S.A.A. has the Safety, Health and Environment department, which manage the environmental aspects for quarry and cement operations in compliance with current environmental legislation and in accordance with the company’s corporate policies.


●Through its Social Responsibility unit, Cementos Pacasmayo S.A.A. has generated relationships of trust with the communities surrounding its operations, which have translated into a solid relationship with our communities, identifying their primary needs in health, education, urban development, and local development.


●Infrastructure-wise, the operation at the Virrila quarry and Piura plant is technically and economically feasible due to the quarry’s life. The sensitivity analysis shows that the operation is economically robust.


1.16.Recommendations


●Maintain the QAQC program for exploration, development and production activities associated with cement production.


●It is recommended to complete the diamond drilling campaign initiated in Zone 4, in order to update and implement the corresponding new model, which will provide greater stability and support for resources and reserves.


15


●Optimize the extraction plan in terms of the waste rock removal ratio during operation to achieve a reduction in production costs.


●Conduct density tests of the coquina rock to update the information in zones 2 and 3, also in the upcoming studies at the Virrila quarry.


2.Introduction


2.1.Participants


This technical summary report (TRS) was prepared for Cementos Pacasmayo by qualified persons (QPs), including professionals from Cementos Pacasmayo and an independent Qualified Person from C&O Project LLC. Each QP contributed to the preparation of specific sections of this report in accordance with their respective expertise and professional experience and is responsible for the content of those sections.


In preparing this report, the QPs utilized information provided by Cementos Pacasmayo, including internal data, information validated and approved by the competent authorities in Peru, and publicly available sources. Such information was relied upon within the scope of each QP’s responsibilities.


Mr. Marco Carrasco, Project Manager of C&O Project LLC, participated as an independent Qualified Person and contributed to the sections specifically assigned to him. In addition, he provided support in the overall coordination and integration of the report.


His role was primarily focused on the organization and presentation of the document and did not include independent technical verification of information prepared by other Qualified Persons. Accordingly, the content of those sections remains the responsibility of their respective authors.


Mr. Carrasco is a Chemical Engineer and a member in good standing of the Peruvian Engineers Association (Colegio de Ingenieros del Perú), identified with CIP Number 100531, and He is qualified to practice my profession. He is also a member of the Mining and Metallurgical Society of America (MMSA), a United States based professional organization, identified under Qualified Person number QP1485.


Table 7 identifies the Qualified Persons who prepared this report, together with the sections under their respective responsibility.


1.1.Terms of Reference


This report summarizes the Pre-feasibility study results of the “UEA Virrila” property for the production of coquina using open-pit mining methods. This technical report summary was prepared as an exhibit to support disclosure of Mineral Resources and Reserves by Cementos Pacasmayo. The information is effective December 31, 2025.


The coquina was produced from the UEA Virrila property located in the Sechura district. This property supplies raw material for the Piura plant where cement is produced. The annual limestone production is 1.3 million tonnes per year (Mtpy). This technical report summary estimates Mineral Resources and Reserves according to the regulations published in Securities Exchange Commission (SEC) Form 20-F and under subpart 1300 of Regulation S-K. Actual operating costs have been considered for the estimates and used as a basis for economic projections within the financial analysis.


The report was prepared by the qualified persons listed in Table 7 using available studies and, in some cases (see Chapter 25), relying on information provided by Cementos Pacasmayo, the registrant.


16


Table 7 List os Qualified Persons


Item   Chapter   First and Last Names   Company   Job Position   Profession
0   Coordination and Integration   Marco Carrasco (*)   C&O Projects LLC   Project Manager   Chemical Engineer
1   Executive summary   All QPs (**)            
2   Introduction   All QPs (**)            
3   Property description   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
4   Accessibility, climate, local Resources, infrastructure and physiography   Marco Carrasco   C&O Projects LLC   Project Manager   Chemical Engineer
5   History   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
6   Geological setting, mineralization, and deposit   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
7   Exploration   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
8   Sample preparation, analyses, and security   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
8   Sample preparation, analyses, and security   Dennis Rodas   Cementos Pacasmayo S.A.A   Quality Control Superintendent   Chemical Engineer
9   Data verification   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
9   Data verification   Dennis Rodas   Cementos Pacasmayo S.A.A   Quality Control Superintendent   Chemical Engineer
10   Mineral processing and metallurgical testing   Dennis Rodas   Cementos Pacasmayo S.A.A   Quality Control Superintendent   Chemical Engineer
11   Mineral resource estimates   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
12   Mineral reserve estimates   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
13   Mining methods   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
14   Processing and recovery methods   Dennis Rodas   Cementos Pacasmayo S.A.A   Quality Control Superintendent   Chemical Engineer
15   Infrastructure   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
16   Market studies   Marco Carrasco   C&O Projects LLC   Project Manager   Chemical Engineer
17   Environmental studies, permitting, and plans, negotiations, or agreements with local individuals or groups   Marco Carrasco   C&O Projects LLC   Project Manager   Chemical Engineer
18   Capital and operating costs   Marco Carrasco   C&O Projects LLC   Project Manager   Chemical Engineer
19   Economic analysis   Marco Carrasco   C&O Projects LLC   Project Manager   Chemical Engineer
20   Adjacent properties   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
21   Other relevant data and information   All QPs (**)            
22   Interpretation and conclusions   All QPs (**)            
23   Recommendations  

Jason Gamio

Dennis Rodas

  Cementos Pacasmayo S.A.A        
24   References   All QPs (**)            
25   Reliance on information provided by the registrant   All QPs (**)            


(*)

Marco Carrasco served as Project Manager for Cementos Pacasmayo S.A.A. until March 2026 and thereafter participated as Project Manager of C&O Project LLC. In this capacity, he compiled and integrated the information provided by the Qualified Persons responsible for each chapter to prepare a consolidated report. Each Qualified Person is solely responsible for the content of the sections they prepared. Mr. Carrasco’s role in the compilation process was limited to the organization and integration of such information and did not include independent technical verification or validation of the data, analyses, or conclusions provided by other Qualified Persons.


(**)

Marco Carrasco, Dennis Rodas and Jason Gamio


17


1.2.Conventions


Unless otherwise indicated in the report, all currencies are in soles and all measurements and units are in the metric system. The UEA Virrila property is represented by Universal Transverse Mercator (UTM) coordinates. Unless otherwise indicated, all coordinates referenced in this report and the accompanying figures, tables, maps, and sections are provided in the WGS84 coordinate system, UTM 17S zone.


1.3.Previous Work and Sources of Information


The information used is sufficient to allow this TRS to be completed with the level of detail required by Regulation S-K subpart 1300. The information used included exploration results from the various drilling campaigns, actual information from Cementos Pacasmayo’s operations, information submitted to and approved by the corresponding authorities and public information in organizations specialized in the cement industry. The list of sources of information is presented in Chapter 24 of this report.


1.4.Details of QP Personal Inspection


The QP’s who developed this document visited the Virrila quarry and the Piura plant as part of their activities for 2025.


Table 8 Qualified Persons field visit


Item   First and Last Names   Company   Job Position   Profession   Field visit
1   Dennis Rodas   Cementos Pacasmayo S.A.A   Quality Control Superintendent   Chemical Engineer   Piura Plant, all year as part of his duties in the quality control department.
2   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and evaluation of resources and reserves Superintendent   Geological Engineer   Mr. Gamio has visited the Virrila quarry and Piura plant regularly. The last visit to the Virrila quarry and Piura plant was in October 2025, visiting core facilities, discussing grade control, geological mapping, exploration, and delineation drill practices, diamond drill core logging, quality assurance, and quality control (QA/QC), raw material storage and mineral reserve estimation practices.
3   Marco Carrasco   C&O Projects LLC   Project Manager   Chemical Engineer   In May 2025, Mr. Carrasco visited the Piura plant and Virrila. His visit emphasized the operational cement process and equipment conditions (kilns, mills, storages (raw material and sub-products and products, etc.) and in Virrila quarry He visited the operations areas.


1.5.Previously Filed Technical Report Summary


This Technical Report Summary (TRS) updates the previously filed technical report summary for the property. The previously filed TRS is the “Technical Report Summary (TRS), Virrila Quarry and Piura Cement Plant 20-F 229.601”, which was filed as Exhibit 96.2 of the CPSAA’s Annual Report on Form 20-F filed with the SEC on April 29, 2025 (File No. 001-35401).


18


3.Property description


3.1.Virrila quarry


The quarry is located in Sechura District, Sechura Province, Piura Region. It is located 192 Km from Cementos Pacasmayo S.A.A.’s Piura plant.


The Peruvian State granted the mining right to Cementos Pacasmayo S.A.A. to carry out exploration and production activities that allow non-metallic minerals found in the subsurface through mining concessions.


The mining rights registered with the authority, Instituto Geológico Minero y Metalúrgico (INGEMMET) are as follows Virrila 3, Virrila 4, Virrila 6, Virrila 7, Virrila 8, Virrila 9, Virrila 10, Virrila 11, Virrila 12, Virrila 13, Virrila 14, Virrila 15, Virrila 16, Virrila 17, Virrila 18, Virrila 19, Virrila 20, Virrila 21, Virrila 22, Virrila 23 y Bayovar N° 4. The area of the mining property is 38,226.00 Hectares.


The mining rights (the mining concession title) are granted by INGEMMET of the Energy and Mines Sector through a Presidential Resolution. It is determined to include the mining rights in the Virrila Economic-Administrative Unit (UEA).


On March 31, 2016, by Presidential Resolution No. 0147-2016-INGEMMET/PCD/PM, the competent authority granted to CPSAA the Virrila Economic-Administrative Unit (UEA), with code No. 01-00011-00-U of Cementos Pacasmayo S.A.A. These mining rights included 21 mining concessions.


Table 9 UEA Virrila Concessions


N°

Code Name Hectares Material
1 010221599 Virrila 3 600.00 Non Metallic
2 010221699 Virrila 4 400.00 Non Metallic
3 010531406 Virrila 6 600.00 Non Metallic
4 010531306 Virrila 7 700.00 Non Metallic
5 010089707 Virrila 8 500.00 Non Metallic
6 010089807 Virrila 9 1000.00 Non Metallic
7 010089907 Virrila 10 1000.00 Non Metallic
8 010090007 Virrila 11 900.00 Non Metallic
9 010090107 Virrila 12 700.00 Non Metallic
10 010090207 Virrila 13 800.00 Non Metallic
11 010090307 Virrila 14 900.00 Non Metallic
12 010090407 Virrila 15 600.00 Non Metallic
13 010090507 Virrila 16 1000.00 Non Metallic

14 010090607 Virrila 17 1000.00 Non Metallic
15 010090707 Virrila 18 1000.00 Non Metallic
16 010090807 Virrila 19 1000.00 Non Metallic
17 010090907 Virrila 20 1000.00 Non Metallic
18 010091007 Virrila 21 1000.00 Non Metallic
19 010091107 Virrila 22 1000.00 Non Metallic
20 010479607 Virrila 23 200.00 Non Metallic
21 12000440Y01 Bayovar N° 4 22326.00 Non Metallic


19


The properties described above were granted by the authority (INGEMMET) from 2000 to 2008. Table 10 shows the UTM central coordinates of the Virrila Economic Administrative Unit (UEA).


Table 10 Central coordinates of the UEA Virrila property


North   East   Radius   Zone 
 9,350,000    526,000    20,000    17 


In accordance with this, the Virrila UEA includes twenty-one (21) non-metallic mining rights covering 38,226.00 hectares, in favor of Cementos Pacasmayo S.A.A., owner of said rights; located in the district of Sechura, province of Sechura and department of Piura.


Cementos Pacasmayo S.A.A. complies annually with the payments for the rights to the Virrila concessions.


These payments must be made from the first business day of January to June 30 of each year, CPSAA provides the financial entities in charge of receiving the payments with the SINGLE CODE (see Table 9) of its mining rights, to comply with its obligation.


In the case of Virrila concessions, the payment is equivalent to US$3 per hectare.


Likewise, Cementos Pacasmayo S.A.A. pays royalties to the State as established by the Authority in Law N° 28258 and its amendment N° 29788.


Cementos Pacasmayo S.A.A currently has an agreement with the Fundacion Comunal San Martin de Sechura for the use of the surface land associated with the production area of the Virrila quarry. The area of usufruct, surface and easement rights held by Fundación Comunal San Martín de Sechura is 14,842.800 hectares. Superintendencia Nacional de los Registros Públicos (SUNARP).


20


Figure 5 UEA Virrila map


21


3.2.Piura Industrial Cement Plant


The cement plant property is located in the Veintiséis de Octubre District, Piura Province, Piura Region. The Piura plant is located at kilometer 3 of the Piura highway.


The property is shown in Figure 6, and Table 11 shows the UTM coordinates of the center of the circle of the Piura plant:


Table 11 Central coordinates of the Piura cement plant


North   East   Radius   Zone 
 531293.65    9429098.05    650.00    17 


The area of the property is 42.28 hectares. The property is registered in the National Superintendence of Public Registries (SUNARP) under the registration numbers 11161659 and 11164329 in the registry zone No. I SEDE PIURA, Piura Registry Office.


Cementos Pacasmayo S.A.A. pays taxes to the government as established by the Municipal Authority in the case of the Piura plant.


22


Figure 6 Piura plant perimeter


23


4.Accessibility, climate, local resources, infrastructure and physiography


This chapter describes the accessibility, climate, local resources and infrastructure for the Virrila quarry and Piura plant. Information obtained from technical and environmental studies.


4.1.Virrila quarry


Topography


The topography of the study area is homogeneous, comprising a flat relief made up of a large plain belonging to the Sechura desert.


Access


There is an access road to this quarry from Lima to Piura. The Piura plant is located in Piura city, and it is located 192 km from Virrila quarry and 950 Km from Lima.


The main access is by land. The journey from Lima to the Virrila quarry is as follows: Lima - Sechura (950 km) for a total of 15 hours.


By air, the route is as follows: Lima - Piura in 1.5 hours flight and an additional 1 hour drive on the Panamerican Highway north.


Climate


The quarry has a temperate and wet climate, with little rainfall, mainly between February and April. Meteorological information was taken at the SENAMHI Chusis station, the closest to the quarry. According to the data from this station, the predominant wind direction is from the S and SE.


From the analysis of the information from 2010-2014, it is evident that there is rainfall in the area in March and April. The months with less precipitation are June, July, August, and September. The month of March has the highest rainfall in the years analyzed, with a monthly total of 54.11 mm.


24


Temperature


The highest temperature values were recorded in January, February, and March, and the lowest in August and September. Reported temperatures for 2010-2014 were evaluated, showing temperature variations between 17.8 °C and 29.5 °C on average.


Physiography


The quarry area is located in a basin where sedimentation was interrupted by tectonic movements with changes in accumulation styles until the Pliocene.


The lithostratigraphy of the area consists of Cenozoic sedimentary units corresponding to the Tertiary period that are not exposed on the surface and Quaternary deposits (Tablezo Lobitos, Quaternary deposits of ancient alluvial, recent alluvial, coastal, lacustrine, beach and eolian origin).


Other geomorphological units outside the quarry area were identified as the estuary and floodplain.


The degree of slope of the predominant land surface is flat to slightly sloping. According to its formation and dominant material type, the plain landscape is Aeolian and Marine Plain.


Floods and tsunamis form external geodynamics. Earthquakes form internal geodynamics.


Local resources and infrastructure


The quarry personnel is divided into Cementos Pacasmayo S.A.A. personnel and contractor personnel.


The quarry is located 61.7 kilometers from the town of Sechura, which has the resources of a town. Contractor personnel is transported by bus and pickup trucks for supervision personnel.


A powerhouse provides a power supply with a generator set installed.


25


4.2.Piura industrial cement plant


The Piura plant is located in the province of Piura and region of the same name. The plant is located 192 km from the Virrila quarry.


Topography


The Piura plant area is located on the left bank of the Piura to Paita highway, 3 km from the city of Piura, and has a coastal plain topography, with thick banks of semi-compacted and compacted sands at an average depth of 0.50 m.


Climate


The dry season is from May to December, and the rainy season is from January to April. The highest rainfall occurs in March, reaching a value of 448.4 mm.


The average annual relative humidity has 69.9%; the lowest value of 66.5% was recorded in February and the highest value of 74.4% in June.


Regarding wind speed data, the month with the lowest wind speed is March with 1.9 m/sec, and the month with the highest wind speed is September with 3.3 m/sec. Regarding the data on wind direction, the wind direction is predominantly from south to north.


Physiography


In the study area, the slope of the land is slightly inclined because it is covered by eolian materials made up of light gray silty sands and sands, with loose sands resulting from the transfer of alluvial and fluvial materials by the wind; these are accumulations of sands of variable thickness. It is possible to identify within the plains anthropic areas of recent works. Likewise, it is possible to distinguish the slope phase from flat to slightly inclined (0 - 4 %).


Geomorphology


The geomorphology of the Piura Region is the result of a succession of events related to processes of uplift, subsidence, erosion, sedimentation, and deformation of the materials deposited in the sedimentary basins. This scenario has identified the following geoforms: Ardisols Sands, Tablezos, Coastal Plain, Aeolian Sand Mantos.


Local resources and infrastructure


Personnel at the Piura plant are divided into Cementos Pacasmayo S.A.A. and contractors. Most of the personnel live in the city of Piura and travel to the cement plant in company buses or their own vehicles.


Power is supplied through the national grid. Cementos Pacasmayo has a contract with ENOSA (Electric Company), which provides power through a 60 KV transmission line.


A deep well supplies water to the Piura plant.


26


5.History


Virrila quarry is a coquina quarry mining coquina that is suitable for different types of construction cement; Cementos Pacasmayo S.A.A owns the mineral deposit.


The Virrila quarry started operations on September 17, 2015. Cementos Pacasmayo hired San Martin Contratistas Generales S.A. to be the contractor in charge of production from the start of operations until March 14, 2020.


Due to the Covid-19 pandemic, operations at the Virrila quarry were suspended from March until September 2020.


After the suspension, the mining contractor Posada Perú S.A.C started operations at the Virrila quarry on September 14, 2020, until December 30, 2021.


January 3, 2022, the mining contractor San Martin Contratistas Generales S.A. was hired for the production of the coquina. The transport the coquina from the Virrila quarry to the Piura plant is in charge of TRC and Induamerica companies.


During the 2023 period, two mining contractors worked at the Virrilá quarry operations from January to April with San Martin Contratistas Generales S.A. and from October to December with Sechura Ingenieria y Contrucción E.I.R.L.


In 2023, from May to June Cementos Pacasmayo carry out a drilling campaign in order to confirm Reserves in the zona 2 and zone 4.


From May to September 2023, Virrila quarry stopped operations due to the closure of the road caused by the overflow of the La Niña lagoon provoked by cyclone Yaku. Likewise, the Piura plant stopped its clinker production operations (raw meal milling, coal milling and reception of raw materials) from July to September was to avoid exceeding the strategic inventories (clinker). The cement grinding, receiving (cement additions), packaging and dispatching processes remained active to cover the cement demand. Virrila quarry and Piura plant restarted operations.


From January to April 2024, Virrila quarry shipped coquina from its stockpiles to the Piura Plant, the company in charge of loading the material was Peruvian Master. From May to October, Sechura Ingenieria y Contrucción E.I.R.L. was in charge of operations of the quarry. After October the quarry stopped operations according to the 2024 mining plan. Likewise, the Piura plant stopped its clinker production operations (raw meal milling, coal milling and reception of raw materials) from March to May and from November to December was to avoid exceeding the strategic inventories (clinker). The cement grinding, receiving (cement additions), packaging and dispatching processes remained active to cover the cement demand.


During the month of January, operations remained suspended in accordance with the 2025 Mining Plan. From February to December 2025, the Virrila Quarry dispatched coquina material to the Piura Plant, both from the operational area and from existing stockpiles. The company responsible for the material loading activities was Inversiones y Servicios Felicitas S.R.L. Likewise, the Piura plant stopped its clinker production operations (raw meal milling, coal milling and reception of raw materials) January and September to December was to avoid exceeding the strategic inventories (clinker). The cement grinding, receiving (cement additions), packaging and dispatching processes remained active to cover the cement demand.


27


6.Geological setting, mineralization, and deposit


6.1.Regional geology


The strata of the district of Sechura, province of Sechura, Piura region, consists of Cenozoic Age sedimentary strata of the Tablazo Talara deposit, Tablazo Lobitos deposit, Eolian deposits, Alluvial deposits and Recent deposits.


The lithostratigraphic units found in the area correspond to Quaternary-Pleistocene deposits (2.58 to 0.129 Ma). Within this category are first the tablazos, then the eolian deposits and old alluvial deposits with little diagenesis. The tablazos were first described by T.O. BOSWORTH (1922) in the Talara - Mancora region and finally followed by the recent deposits.


Table 12 Regional stratigraphic column


28


6.2.Local geology


Geologically, the study area corresponds to the desert zone of Sechura and is represented by sedimentary materials from the Recent Quaternary.


It is made up of silty sand deposits with intercalations of medium to fine-grained sands and coquina horizons.


Below the recent deposits, there are diagenetic eolian deposits in a sandy matrix with calcareous cement. And underneath these are intercalations of conglomerates with gray diatomites, intercalated with white reef sandstones, corresponding to the Tablazo of Talara and the upper levels of the Zapallal Formation.


Cenozoic - Tertiary (Miocene)


Zapallal Formation (Tm-zas)


This lithostratigraphic unit is an outcrop only in its upper member in the southern and northeastern part of the quarry area. It comprises compact fine sand, coquina with fragments of reef shells, and conglomerate levels of diverse lithology with gravels smaller than 2” in a sandy matrix with little cement.


It is covered by light brown eolian sand, plant remains, and some very scarce remains of calcareous fragments due to erosion of its upper levels.


Cenozoic - Quaternary (Pleistocene)


Talara Tablazo (Qp - tt)


It is a Pleistocene-raised marine terrace. It has a significant extension in the region and constitutes 95% of the total area of the quarry. Its relief is essentially flat, with slight undulations due to wind action and the crossing of small streams, which are activated only during rainy periods. Topographically, this unit develops at an average elevation of 80 meters above sea level, with a slight inclination to the SE. The calcareous deposit of the Virrila quarry is formed by coquina portions of the Tablazo Talara that undergo lateral variations in thickness and composition of calcareous remains.


Cenozoic - Quaternary (Recent)


Aeolian Deposits (Qr - e)


29


These deposits are accumulations of fine to medium-grained sands transported from their sources of origin by the wind. They occur as small layers or stacks of 1 to 2 meters thick, and are composed of brown silty sand with fragments of reef shells, gravels and remains of roots at the deepest level. At the top, there are gray to dark brown eolian sands with few fragments of shells, reefs, gravels, and roots.


Table 13 Local stratigraphic column of the Virrila quarry


Era

System Series Lithostratigraphic units Lithologic Description
Cenozoic


Quaternary

Recent Eolic deposits SU Gray to dark brown eolian sand, few fragments of coquina, gravels, remains of vegetation.
Pleistocene Tablazo Talara CT Earthy calcareous in beige to brown sandy matrix. Remnants of coquina, reefs, not very compact or loose and with some gravels.
B1S Fragments of bivalves, gray color, with remains of shells and presence of gravel.
LM Sandy silt with traces of calcareous, gray to beige color, medium dense, mostly occurring as large lenses within the CT, B1S and A1 layer.
A1 Calcareous of fine matrix of beige to gray color, with presence of fragments of shells and reefs somewhat preserved of beige to gray color, friable or somewhat compact due to the presence of sulfates.
A2-A Semi-compact calcareous, with presence of coral reef and some sand.
A2 Coral reef fragments of heterogeneous size and somewhat preserved, creamy beige to pinkish color, sometimes accompanied by a fine white calcareous matrix, friable and somewhat compact in contact with the A2-B layer.
A2-B Semi-compact coral reef fragments, with some gravel.
A2-C Fragments of coral reef, with some gravel.
A3 Dark beige calcareous fine compact matrix with presence of voids and high magnesium, weak reaction to HCl.
ARE Silty sand with traces of calcareous minerals
B1 Fine matrix calcareous, beige color with preserved coquina fragments of heterogeneous size and traces of gravels.
B2 Sandy calcareous with remains of fragmented whitish gray shells and with presence of gravels.
GRV Conglomerate of sandy matrix, medium to coarse-grained, gray color, compact.
Tertiary Miocene Zapallal Formation DIA Diatomite massive green color, semi compact.


6.3.Characteristics of the deposit


Table 14 shows the characteristics of the deposit.


Table 14 Characteristics of the Virrila deposit


Quarry

Average
Width
(m)

Average
Length
(m)

Average
Thickness
(m)
Average depth (m) Continuity
Top
Elevation
Lower
Elevation
Virrila  950-2000 3100-4000 7-20 37 20 Calcareous sedimentary deposit whose zones are controlled by the continuity of the quality of the strata.


30


Figure 7 Geological section of the Virrila quarry


31


7.Exploration


7.1.Drilling


During 2007 and 2008, exploration activities were performed to collect geological information from the Virrila quarry.


In 2013, exploration activities were carried out using test pits in the best areas of the concession.


In 2019, activities and sampling in the operation area were developed to validate the reserves in the area of operation and update the inventory.


During 2021, drilling was conducted to confirm Reserves within the operations. The work performed during 2021 aimed to:


●Obtain representative samples of drill core.


●Identify and recognize the lithological strata.


●Perform chemical tests to determine the qualities of the material.


●Reconfirm the volume and tonnage of the Reserves. 


The drilling work was supervised by Cementos Pacasmayo S.A.A. personnel and executed by Ram Peru S.A.C. 


Ram Peru S.A.C. executed the diamond drill holes of 10 m depth. The drill holes had a vertical orientation (-90°), and HQ pipe (63, 5 mm) was used.


In 2022, drilling was conducted to confirm Reserves in the same area that the 2021 campaign.


In 2023, drilling campaign was conducted to confirm Reserves in the zone 2 and zone 4. The drilling work was supervised by Cementos Pacasmayo S.A.A. personnel and executed by Ram Peru S.A.C. 


32


Figure 8 Map of the location of drill holes in the Virrila quarry.


7.2.Hydrogeology


In 2025, Cementos Pacasmayo did not conduct further hydrogeological studies. The last hydrogeological studies were conducted in 2012 and the information was presented in the previously filed TRS titled “Technical Report Summary (TRS), Virrila Quarry and Piura Cement Plant 20-F 229.601”, which was filed as Exhibit 96.2 of the CPSAA’s Annual Report on Form 20-F filed with the SEC on April 28, 2022 (File No. 001-35401).


As stated in the previous TRS, Cementos Pacasmayo hired IENDESA S.A.C to perform a hydrogeological study at the Virrila quarry. The hydrogeological study included the evaluation of 07 Electro Vertical Soundings (SEV).


The results showed that the yields oscillate between 13 to 17 l/s, and the depths range from 134.4 to 271.45 m, indicating the nappe is semi-confined in the Tertiary age sedimentary rocks.


7.3.Geotechnical studies


Cementos Pacasmayo did not conduct further geotechnical studies in 2025, The last geotechnical study was conducted 2013 and the information was presented in the previously filed TRS titled “Technical Report Summary (TRS), Virrila Quarry and Piura Cement Plant 20-F 229.601”, which was filed as Exhibit 96.2 of the CPSAA’s Annual Report on Form 20-F filed with the SEC on April 28, 2022 (File No. 001-35401).


As per the previously filed TRS, the geotechnical studies concluded, based on the geotechnical test work that the current slopes at the Virrila quarry are stable for static and pseudo-static loading conditions, with safety factors above the minimum recommended for operating conditions.


33


8.Sample preparation, analysis and security


This Chapter describes the preparation, analysis and security of the samples used for the geology, quarry and cement plant operations.


8.1.Geology and Quarry


Cementos Pacasmayo S.A.A. has implemented international standards in all its operations, such as quarries and plants. The ISO 9001 standard has been implemented and certified since 2015. The certification is renewed annually through an external audit.


The SSOMASIG department (Security, Occupational Health, Environment and Management Systems) is part of the team that determines and gives the necessary support for maintaining the ISO 9001 (Quality). The scope is in all the company’s activities.


The Geology department has protocols for the activities of sample preparation methods, quality control procedures, security and other activities.


8.1.1.Preparation of samples, procedures, assays and laboratories


Samples obtained from the drill holes are placed in holders to be duly coded, cut, bagged and sent to the laboratory at the Piura plant and are occasionally sent to an external laboratory following the company’s procedures.


Certimin S.A. is used as an external laboratory for chemical analysis. This laboratory has modern facilities for developing mining services associated with the cement industry and technical support in the geochemical field for national and international companies. Certimin S.A. is a Peruvian laboratory certified in ISO 9001, ISO 14001, ISO 45001, NTP-ISO/IEC 17025 Accreditation and membership in ASTM.


For the coquina samples, the laboratory analyses evaluate CaO, MgO, AlO3, SiO2, Fe2O3 and SO3. Once received in the laboratory, the properties of the coquina to be used in cement production are analyzed.


34


8.1.2.Quality Assurance Procedures


Cementos Pacasmayo S.A.A., through its Quality Control unit, performed quality assurance procedures for the samples obtained in the Virrila deposit, applying the quality plan, procedures and measures necessary to obtain information from the coquina samples. The laboratory analyses were performed in the chemical laboratory of the Piura plant. The results were used for the estimation of Resources and Reserves of the deposit.


Cementos Pacasmayo S.A.A. has implemented QAQC protocols to develop exploration and production activities in the Virrila quarry to ensure the quality of the information that allows the estimation of Mineral Resources and Reserves in the deposit.


The quality plan implemented by Cementos Pacasmayo for the quarries includes the insertion of blanks, duplicates and standards to control the precision, accuracy, and contamination in the samples (Table 15).


Table 15 Quality Plan of the Virrila quarry


Blanks

Duplicates Standards Remark
1 control sample for each batch of 20 samples. 2 control sample for each batch of 20 samples. 1 control sample for each batch of 20 samples. Cementos Pacasmayo protocol ¨OM-GL-PRT-0023-R0¨.


8.1.3.Sample security


Cementos Pacasmayo S.A.A. has implemented QAQC protocols to develop exploration and production activities in the Virrila quarry to ensure the quality of the information that allows the estimation of Resources and Reserves in the deposit.


During the drilling campaigns, Cementos Pacasmayo S.A.A. had built a core shack where the samples are correctly stored to preserve their quality.


CPSAA provided the necessary materials for the storage and transport of the samples. CPSAA also implemented sampling cards with information on the name of the project, name of the borehole to be sampled, date of sampling, sampling interval, sampling manager, sampling, and type of sample or control sample.


35


All samples were labeled and a photographic record is available. The photographic record of each sampling bag is made together with the weighing of the sample.


8.1.4.Chain custody


CPSAA implemented chain-of-custody systems to guarantee the physical security of the samples, data and associated records. The traceability of the sample from its generation to its analysis and subsequent conservation of rejects and pulps. At the Virrila quarry, core samples are duly stored in the coreshack.


8.1.5.Qualified Person’s Opinion on Cement Plant QAQC


In the qualified person’s opinion, Cementos Pacasmayo has been complying with the international standards of ISO-9001 (Quality) since 2015 and has implemented Quality Assurance and Quality Control (QAQC). Cementos Pacasmayo S.A.A. has used a QAQC check program comprising blank, standard, and duplicate samples. The actual sample storage areas and procedures are consistent with industry standards.


There is information on sample preparation methods, quality control measures and sample security. These results are accurate and free of significant error. The protocols in the different exploration and production processes strictly comply with local and international best practices.


The sample preparation, security, and analytical procedures used to acquire the data in this report are adequate for use in the construction of the Geological Model, Resource Estimation, and Reserve Estimation.


8.2.Piura Plant


8.2.1.Samples preparation, procedures, assays and laboratories


Cementos Pacasmayo S.A.A. has a quality control plan for each of its operations as part of the corporate quality system.


36


The quality control plan (PI-CC-D-01 VE 06) describes the evaluation methods used in the Piura Plant’s quality control laboratory, applied to samples of raw materials such as coquina, sand, clays, and iron ore; in-process products: raw meal, clinker, and cement; active additions: gypsum mineral, pozzolana, slag, and coquina; and finished products such as MS, ICO and Type I packaged cement.


Different analytical methods are applied for the physical and chemical characterization of raw materials, products in-process, and finished products, such as classical tests, X-ray fluorescence tests, X-ray diffractometry tests, potentiometry, among other analytical techniques supported by equipment designed for such specific purposes.


The analytical methods are based on guidelines described in ASTM, NTP (Peruvian Technical Standard), and ISO standards.


8.2.1.1.Raw materials sample preparation


The sample preparation consists of the collection and preparation of samples. The sample preparation procedure consists of primary crushing, pulverization and reduction of the sample by the quartering method. The sample is pulverized in the ring mill.


8.2.1.2.Laboratory analysis


The Piura plant laboratory has implemented the ISO 9001 standard; it has different instrumental equipment. The annual maintenance and calibration program is applied to ensure the reliability and traceability of the measurements performed.


The major equipment is X-ray fluorescence (XRF), which is used for chemical control of the different plant processes, such as:


●Reception and entry of raw materials.


●Grinding of raw meal and coal.


●Production of clinker.


●Grinding and packaging of cement.


Also, the hydraulic press is used to determine and analyze the compressive strength of the different types of cement produced in the plant.


37


For all types of cement, different physical characterization tests are performed, such as air content test, Blaine fineness, autoclave expansion, compressive strength and setting time using the Vicat needle method. 


Other complementary tests are autoclave shrinkage test, expansion in the mortar at 14 days, expansion by sulfates at six months, chemical tests by the classical method to determine loss on ignition and insoluble residue.


8.2.2.Quality Assurance Procedures


Table 16 describes the sampling and data verification plan (PI-CC-D-01 VE 27) for the processes for receiving of raw materials, raw mill scale, raw meal milling, kiln feeding, coal scale, coal milling, preheater, kiln filter, clinkerization, cement mill scale, cement grinding, composite cement grinding, packaging control and packaging – composite.


Table 16 Tests and frequency for each stage of the process


Stage

Tests Frequency
Reception of raw materials XRF pellets, XRF beads, moisture, RM-3in, calorific power and Cl by potentiometry Every 5 to 10 trucks
Raw mill scale XRF pellets, XRF beads and Cl by potentiometry Once per shift
Crude milling XRF pellets, RM 170 and loss on ignition. Every hour or up to Once per shift.
Kiln feeding XRF pellets, RM 170 and loss on ignition. Every 2 hours
Coal scale XRF pellets, calorific power and moisture. Every 4 hours
Coal milling XRF pellets, RM 63 um, calorific power and fine moisture. Every 4 hours
Preheater XRF beads, loss to fire, calcination and volatilization. Every 2 hours
Kiln filter Loss on ignition, XRF beads and Cl by potentiometry. One sample per shift
Clinkerization XRF pellets Every hour
Cement Mill scale XRF pellets, XRF beads for daily composting and XRF bead for daily composting One sample per shift
Cement grinding XRF pellets, Rm 325, RM 450, loss on ignition, Blaine and cal libre Every 15 min or Once per shift
Composite cement grinding XRF pellets, loss on ignition, insoluble residue (Type I), cal libre, Blaine, Rm 325, RM 450, compressive strength, setting, autoclave expansion and setting time using the Vicat needle method. One sample per day
Packaging control RM 1/2in, RM8 and XRF pellets every 4 hours, every 100 big bags, every 5 trucks
Packaging – Composite XRF pellets, loss on ignition, insoluble residue (Type I), cal libre, Blaine, Rm 325, RM 450, compressive strength, setting, autoclave expansion, setting time using the Vicat needle method, density, 14-day mortar bar expansion, sulfate resistance and heat of hydration (In Pacasmayo Cement Plant). One sample per day


38


The quality plan implemented by Cementos Pacasmayo for the cement plants includes the insertion of standards to control the accuracy in the samples. As part of the quality plan, the laboratory evaluates its performance through external interlaboratory; in this sense, the laboratory participates in 02 interlaboratory:


●CCRL: Compliance greater than 95%


●XAMTEC: Qualification greater than 99%.


Quality assurance procedures include control of finished products, control of non-conforming products, validation of silos, density analysis, QAQC program, quality plan and quality control parameters for raw materials received at the Piura plant.


8.2.3.Security of the samples


Cementos Pacasmayo S.A.A has implemented QAQC protocols to develop cement production activities at the Piura plant to ensure the quality of the information that allows the Estimation of the Mineral Resources and Reserves of the deposit.


Sampling of raw materials, raw meal and cement during the cement production process at the Piura plant is carried out by the contractor Bureau Veritas.


Sample preparation consists of sample collection and preparation for raw material, raw meal, coal, clinker and cement.


The testing procedures are physical testing for cement, wet chemical analysis and operation of XRF equipment.


Likewise, the control parameters are raw material parameters, pozzolana, slag, mineral reception parameters, clinker production parameters, raw material parameters for raw meal, raw meal feed parameters, raw meal milling parameters, coal milling parameter and cement milling parameters.


8.2.4.Qualified Person’s Opinion on cement plant QAQC


Cementos Pacasmayo S.A.A. has a Quality Assurance, Research and Development area that ensures compliance with the requirements for finished products specified in Peruvian Technical Standards, which are traceable to the standards of the American Society for Testing and Materials (ASTM).


The Research and Development area is located at the Pacasmayo plant, and its scope includes operations at the Piura plant.


Compliance with the requirements based on the quality assurance management system, the indicator was 0% of nonconforming products in the market. This evaluated under the specification of Standards NTP 334.009, NTP 334.090 and NTP 334.082 (similar to ASTM C150 and ASTM C1157). Likewise, the level of customer satisfaction (G-GH-F-03) is 91.59%.


Based on the above, in the qualified person’s opinion, the quality assurance system at the Piura plant, which includes preparation methods, procedures, analysis and security, complies with the best practices in the industry, thus ensuring that the end customer has confidence in the level of quality of the products marketed by Cementos Pacasmayo. The QAQC is adequate for Mineral Reserves estimation.


39


9.Data verification


This Chapter shows the data verification activities for the geology, quarry, and cement plant areas.


9.1.Geology and quarry


9.1.1.Data Verification procedure


CPSAA has an unit specialized in the compilation, verification and standardization of information for the geological database. It’s main function is the validation of the data to be used in the estimation of mineral Resources and Reserves. For the proper management of the information, internal protocols have been implemented, which are subject to internal audits.


9.1.2.Data collection


The data collection applies to exploration activities. For diamond drilling, the process flow for planning and executing drilling, survey methods for reporting drill collars and ddh / verification of the quality of information and recovery process of the core information. In addition, for geological sampling activities, the processes flowsheet, validation and consistency of sample information, sample preparation and testing, density, registration process and digital photographic storage are used.


9.1.3.Management and Validation of Database


The stages for management and validation of database are the recovery, processing and storage of the database. The database validation includes database development process flow, information standardization and integration process, information storage strategy, appropriate database technology, structure and practicality of the database system that allows a fast and flexible access and input of information and validation of chemical results, which includes the QAQC report.


9.1.4.Tracking Data


The consistency between the database records and the original registry was verified by the QPs in 2025. No differences were detected between the database and the log files. A digital copy of all records is kept as a pdf file. Digital certificates support the chemical analysis data.


40


The collection of the information considered the following: drill collars, survey, lithology, samples and assays.


9.1.5.Validation of Data


Collar, Survey, Lithology and chemical analysis data were imported and processed with MX-Deposit software (By Seequent).


The results indicated that the database had adequate integrity for Resource estimation. This software verifies that the data entered from each sample or reported by the external laboratory is correct for input into the Resource model.


The team followed the defined processes for information flows to support Resource and Reserve estimation. The qualified person followed the same process as a means of verifying and validating. It has been found that the validated information is congruent in the interpretations of the same, with which the fundamental base geological models were generated for the estimation of the Resources.


No findings have been found that could invalidate the estimation of the Resources and Reserves of the unit.


Data for each hole was individually checked in the database to confirm accuracy.


The reviews included:


●Drillhole lithology database comparison to geophysical logs


●Sample quality database comparison to quality certificates


●Survey sheets


●Collar sheets


●Core photographic record


41


Typical errors may impact reserve and resource estimation related to discrepancies in original data entry. These errors may include:


●Incorrect drillhole coordinates (including elevation)


●Mislabeled drillhole lithology


●Unnoticed erroneous quality analyses where duplicate analyses were not requested


●Unrecorded drillhole core loss


Data validation follows the field operational procedures that collect information from the source (collar, survey, lithology, samples, and assays). Finally, when the information is transmitted and uploaded to the mining software for geological modeling and estimation, it is double-checked to eliminate any additional errors.


9.1.6.Qualified Person’s Opinion Geologic Data


The qualified persons followed the defined processes for information flows to support Resource and Reserve estimation. The qualified person followed the same process as a means of verifying and validating the geologic data. They found that the validated information is congruent in the interpretations of the same, with which the fundamental base geological models were generated for the estimation of the Resources.


No findings have been found that could invalidate the estimation of the Resources and Reserves of the unit.


9.2.Piura plant


The Quality Control Plan consists of the following: PDCA cycle, customer, a person in charge, activities, risks, control methods, monitoring, measurement, analysis, evaluation and documentary evidence.


The PDCA cycle is:


●Plan; during this stage, the following activities are considered: determination of characteristics of raw materials, product in-process and finished product, elaboration of control and matrices parameters, and determination of actions and results in assurance program.


42


●Do; during this stage, the following activities are considered: verification and compliance with the requirements and matrices, sampling, and preparation.


●Check: during this stage, the following activities are considered: chemical analysis by XRF, chemical analysis, physical analyses, recording of results, taking action on non-conformities.


●Act, during this stage, the following activity is considered, acting to improve.


●The Quality Assurance Plan is applied to the following customers: production, quarry, provisions chain, and external customer.


9.2.1.Data verification procedures


The XRF analysis, chemical analysis, and physical analysis are made to verify the results of the samples as part of the Quality Control Plan.


The data resulting from these three types of analysis are recorded and evaluated to determine whether they comply with the technical specifications.


Data verification procedures include internal audits, checklists, statistical tables, reports, data validation, certificates, interlaboratory test reports, and compliance with quality protocols.


9.2.2.Data validation


Cementos Pacasmayo S.A.A. through its quality assurance and control unit participates in evaluations with international laboratories such as CCRL/ASTM (Concrete and Cement Reference Laboratory), which is an international reference laboratory for construction materials, and Xamtec of Colombia, an international interlaboratory, in order to report reliable data.


The Quality Control laboratories endorse their analysis methods by participating in interlaboratory analysis programs, which compare the results with national and foreign laboratories. The methods of analysis compared are X-ray fluorescence (XRF) and the physical cement tests, which are the methods used to control cement quality. In all the results of these interlaboratory programs, the companies always obtain the best results for each test.


9.2.3.Qualified Person’s Opinion on cement plant


In the author’s opinion, the methodologies applied for data collection and processing at the cement plant are appropriate, reliable, and free from material errors. Accordingly, the data are suitable for use in the construction of the model and for estimating cement production.


Given that the analyses of the main chemical components and physical properties of both raw materials and final products are performed by external laboratories, the quality of the information is considered adequate for the preparation of Mineral Resource and Mineral Reserve estimates.


43


10.Mineral processing and metallurgical testing


10.1.Nature of testing program


Cementos Pacasmayo S.A.A. has a Quality Assurance and Control and a Research and Development department. The objective of the department is to develop, evaluate and research procedures for developing products at the laboratory level and they are scaling up to the industrial level. Another objective is to identify other additions that can substitute for clinker: slag, pozzolana, fly ash, calcined clays, etc., to reduce their environmental footprint and the cost of cement production.


They have also implemented procedures for preparing, reviewing, issuing, and controlling test reports associated with cement production in the Pacasmayo and Piura plants.


Cementos Pacasmayo has implemented the ISO 9001 standard since 2015. The Research and Development laboratory, located at the Pacasmayo plant, is responsible for technical aspects of cement plant and quarry operations (including the Virrila quarry).


A permanent control is carried out with other laboratories to further the results. Likewise, interlaboratory reports are obtained from external laboratories such as CCRL (Cement and Concrete Reference Laboratory), which is an international reference laboratory for construction materials, and Xamtec from Colombia, an internal interlaboratory.


Cementos Pacasmayo S.A.A. has also obtained the certification that certifies compliance with Supreme Decree No. 001-2022, which validates compliance with the Technical Regulation on Hydraulic Cement used in Buildings and General Construction.


Cementos Pacasmayo SAA opted for the highest and most rigorous certification model (Type 5) granted by ICONTEC, which has extensive experience in the certification of products and services.


44


A significant percentage of Research and Development activities are focused on evaluating different ratios between clinker-mineral additions that provide the best functional characteristics to our products and at the same time keep balance with the benefits generated for the company. Whether it is a requirement or an own initiative oriented to supply any previously identified need, the laboratory tests are developed to continuously generate an operational advantage for the company. Based on this work, the laboratory has determined (and confirmed with production estimates) that 1 tonne of coquina yields 0.78 tonnes of clinker and the clinker/cement factor with additions is 0.70.


The R&D Laboratory located at the Pacasmayo plant provides analysis and research services to all of the company’s cement plants.


10.2.Cement Manufacturing Test Results


At the Pacasmayo plant, the studies conducted in the Research and Development Laboratory and the Quality Control area include reducing the clinker/cement factor and substituting slag for pozzolan at the Piura plant. The clinker/cement factor of the cement is 0.70.


10.3.Qualified Peron Opinion of the Adequacy of the Test Data


The Research Laboratory issues technical reports following international standards for the operations area, identifying the correct data, defining the requirements that may vary but include accuracy, consistency, and validity through an evaluation of the data and implementation of solutions and finally, validating the adequacy of the data.


The operations area then evaluates the convenience of industrially implementing the tests and validating what is reported at the laboratory level. The integrity and adequacy of the data reported by the area is based not only on the technical competencies of the collaborators as well as on the high scores obtained in the external interlaboratory of recognized entities such as XAMTEC and CCRL in their different programs.


45


11.Mineral Resources Estimates


The geological model was developed and structured using Leapfrog software. The QP generated the model solids, taking into account the lithology of the deposit based on the geological characteristics and its quality.


Due to the nature of the deposit in its stratified nature and occurrence, the qualified persons interpreted the geological model with the help of a set of sections parallel to the two main directions of the deposit shape, spaced every 140 meters.


Considering the conceptual model of the project and based on the fieldwork carried out by Cementos Pacasmayo’s geologists, the lithological descriptions were grouped into ten horizons (Table 17).


Table 17 Lithologic units of the Virrila quarry geological model


Lithologic Units Zone 3 Zone 2

Mine Sight Code

ITEM (TLITO)

Numeric Code

ITEM (CODEM) 

Mine Sight Code

ITEM (TLITO) 

Numeric Code

ITEM (CODEM)

Aeolian sand, brown to brownish color, with coquina remains. SU 1 SU 1
Earthy calcareous, creamy beige color, scarce coquina and reefs. CT 2 CT 2
Calcareous with compact shell debris A1 3 A1 3
Coquina with presence of shells and beige corals A2-A,A2,A2-B,A2-C 4,5,6,7 A2 5
Massive compact beige coquina and beige corals A3 8 A3 8
Green clayey silt with intercalation of calcareous levels. LM 9 LM 9
Beige calcareous compact massive fine matrix. B1S 10 - -
Gray sand, with traces of calcareous, gravel. ARE 11 ARE 11
Calcareous with remains of coquina and sand with some gravels. B1 12 B1 7
Gray sand, fine grain, friable. GRV 13 B2 12
Green diatomite DIA 14 GRV 13


The main criterion for the geological model is the quality, supported and associated with the lithological aspect.


The lithological criteria are based on the macroscopic physical characteristics of the shell horizons and the percentage of important elements in their composition (oxides).


This analysis uses a quality cut-off of 48.5% of CaO based cement manufacturing technical specifications. In addition, other quality parameters were considered according to the technical specifications. All criteria together allowed the identification of good quality horizons, which were assigned the following codes in the CAPA item.


Table 18 shows the quality parameters for Domo coquina and Addition coquina.


46


Table 18 Quality Parameters for Dome and Additive coquina


  Domo Coquina Addition Coquina
 CaO (%) Min. 48.50 NA
Max. - NA
Target 50.00 NA
MgO (%) Min. - -
Max. 2.00 2.00
Target 1.50 1.50
SO3 Min. - -
Max. 0.85 2.50
Target 0.80 2.00
Cl Min. - -
Max. 0.035 0.035
Target 0.030 0.030
Na2O (%) Min. - -
Max. 0.300 0.30
Target 0.250 0.25
K2O (%) Min. - -
Max. 0.200 0.20
Target 0.150 0.15


The block model was configured based on the dimensions and spatial distribution of the formations containing the material of economic interest.


Table 19 shows the extents of and dimensions of block in the model. (Coordinates in UTM units).


Table 19 Characteristics of the block models


Zone 3  Minimum (m)   Maximum (m)   Size (m)   Number 
X   528,430    533,170    10    474 
Y   9,341,860    9,345,360    10    350 
Z   20    45    0.5    90 


Zone 2  Minimum (m)   Maximum (m)   Size (m)   Number 
X   524,700    528,900    10    420 
Y   9,341,100    9,344,300    10    320 
Z   10    50    0.5    80 


11.1.Database


The Geological Model used 3,678 samples obtained from 536 diamond drill holes in Zone 3 and 2,550 samples obtained from 478 diamond drill holes in Zone 2, in the current production areas for resource estimation. The data is managed in a database. From there, it is extracted and loaded into MineSight (by Hexagon) and used for resource estimation


47


11.2.Density


The density data for the estimation of the coquina Resources of the Virrila quarry as of December 2025, were taken from the historical data of sampling results carried out in the first drilling campaigns. The density ranges between 1.51 and 1.89 t/m3.


11.3.Compositing


In general, each geological unit is estimated from the composite data (the composites were restricted to not cross “hard” boundaries between different geological units).


The objective of composting is to create a distribution of grades of equal support (volumes) from the initial samples in the drill hole. Thus, when compositing, one must be careful that the composites preserve the original nature of the sample. The calculated values considered in the compositing were for the SiO2, Al2O3, CaO, MgO, and SO3.


Composites were made at different lengths to determine the optimum compositing length, resulting in compositing at 1 m as the length that best fits the nature of the original sample and is included in the resource estimation process.


In addition, the length of the deposits is considered based on an exact multiple of the height of the blocks used to model the deposit and is also matched to the bench height to be operated.


11.4.Basic statistics of the data (Assay – Composites)


Table 20 shows the results of the basic statistics of the principal oxides as CaO, SiO2, MgO, Al2O3 and SO3 contents for the original data and the composited data.


QP performed the statistical analysis for each defined body with the interpretation of deposit quality, which were also taken as criteria for modeling and estimation.


48


Table 20 shows the statistics for “Horizon A2” as this is the main horizon for estimating the Reserves.


Table 20 Basic data statistics of Zone 3 and Zone 2


Zone 3
Components Origen Valid Rejected Minimum Maximum Mean Std. Devn. Variance Co. Of Variation
SiO2 Assay 1,769 3 0.46 99.58 5.718 4.394 19.310 0.769
Composito 1,835 1 0.46 60.73 5.568 3.526 12.435 0.633
CaO Assay 1,769 3 0.12 55.65 51.503 2.918 8.514 0.057
Composito 1,835 1 21.25 55.59 51.630 2.353 5.535 0.046
MgO Assay 1,768 4 0.28 1.76 0.725 0.131 0.017 0.181
Composito 1,835 1 0.18 1.76 0.709 0.121 0.015 0.171
Na2O Assay 1,768 4 0.02 0.95 0.302 0.072 0.005 0.238
Composito 1,834 2 0.02 0.89 0.298 0.068 0.005 0.229
K2O Assay 1,769 3 0.04 0.97 0.166 0.074 0.005 0.445
Composito 1,835 1 0.05 0.95 0.159 0.060 0.004 0.377
SO3 Assay 1,759 13 0.01 2.47 0.306 0.243 0.059 0.794
Composito 1,829 7 0.01 1.97 0.300 0.218 0.047 0.726
Cl Assay 1,743 29 0.01 0.38 0.033 0.040 0.002 1.227
Composito 1,814 22 0.01 0.37 0.033 0.037 0.001 1.121


Zone 2
Components Origen Valid Rejected Minimum Maximum Mean Std. Devn. Variance Co. Of Variation
SiO2 Assay 1,982 1260 0.01 99.37 12.807 11.972 143.317 0.935
Composito 2,025 819 0.13 99.37 13.138 11.608 134.737 0.884
CaO Assay 1,982 1260 0.13 54.97 46.001 7.763 60.265 0.169
Composito 2,025 819 0.13 54.94 45.720 7.576 57.389 0.166
MgO Assay 1,980 1262 0.23 15.7 0.952 1.819 3.310 1.912
Composito 2,023 821 0.23 14.56 1.011 1.923 3.697 1.903
Na2O Assay 1,982 1260 0.05 1.32 0.260 0.110 0.012 0.423
Composito 2,025 819 0.05 1.32 0.263 0.110 0.012 0.418
K2O Assay 1,884 1358 0.01 0.85 0.184 0.126 0.016 0.686
Composito 1,970 874 0.01 0.85 0.188 0.123 0.015 0.653
SO3 Assay 1,982 1260 0.04 9.62 0.600 0.673 0.452 1.120
Composito 2,025 819 0.04 9.62 0.600 0.640 0.410 1.066
Cl Assay 1,981 1261 0.00 0.463 0.022 0.024 0.001 1.073
Composito 2,024 820 0.00 0.463 0.022 0.025 0.001 1.132


11.5.Extreme values


Extreme values are considered to be those analysis results that are not representative of the unit being studied and are above the mean plus twice the standard deviation.


In the analysis of the extreme values from the laboratory results for the calcareous lithologic units being estimated, no significant deviations were found that would alter the estimation results; the results are consistent and representative considering the geological nature of the horizons to which they correspond.


11.6.Variogram Analysis


In the variogram analysis of the composited data for each level corresponding to each body of economic interest at the Virrila quarry, the variogram structures found do not show any preferential direction in the correlation. With the variogram is not possible experimental reflects the maximum distance or range and how a point influences another point at different lengths. In this sense, for the Virrila quarry, the inverse of the distance method was applied.


49


11.7.Interpolation


The Inverse Distance (ID2) method was used for all variables and Nearest Neighbor (NN) for validations, defining parameters for each estimator. Table 21 shows the main parameters used to define the interpolations of the main CaO variable of the A2 layer and of the secondary variables, respectively.


The interpolations were performed in 3 consecutive processes.


-The first with a search radius of 2 times the drilling grid.


-The second with a search radius of 1.5 times the drilling grid and


-Finally, the range corresponding to 1.0 times the drilling grid.


Regarding the number of composites, we used a minimum of 1 per block and 2 as maximum, for the first interpolation and a minimum of 2 per block and 3 as maximum for the second and a minimum of 3 per block and 4 as maximum, for the third interpolation.


Additionally, a maximum of 1 composite were considered for each borehole taken in the interpolation.


Table 21 Estimation Parameters Secondary Variables


Comment Zone 3 Zone 2
Pass 1 Pass 2 Pass 3 Pass 1 Pass 2 Pass 3
Distance in X direction 200 200 200 200 200 200
Distance in Y Direction 200 200 200 200 200 200
Distance in Z directions 200 200 200 200 200 200
3D Distance 200 200 200 200 200 200
Min # Comp 1 2 3 1 2 3
Max # Comp 2 3 4 2 3 4
Max # Comp DDH 1 1 1 1 1 1
Element Model IDW  CA4  CA4  CA4  CA5  CA5  CA5
Element MComp IDW  CACA  CACA  CACA  CACA  CACA  CACA
Pass in Model  PSCA4  PSCA4  PSCA4  PSCA5  PSCA5  PSCA5
Pass in comp  PASS3  PASS2  PASS1  PASS3  PASS2  PASS1
Dist comp  DICA4  DICA4  DICA4  DICA5  DICA5  DICA5
# comp for Block  NCCA4  NCCA4  NCCA4  NCCA5  NCCA5  NCCA5
# comp for DHH  NDCA4  NDCA4  NDCA4  NDCA5  NDCA5  NDCA5
Local error  SDCA4  SDCA4  SDCA4  SDCA5  SDCA5  SDCA5
Major Axis 300 200 150 300 200 150
Minor Axis 200 150 100 200 150 100
Vertical Axis 20 20 20 20 20 20
ROT 320 320 320 285 285 285
DIPN 0 0 0 0 0 0
DIPE 0 0 0 0 0 0
Body  RT4  RT4  RT4  RT5  RT5  RT5
Body code 5 5 5 5 5 5
ORE comp  CODEM  CODEM  CODEM  CODEM  CODEM  CODEM
Run extension 1 2 3 1 2 3
Archive 09 vi309.dat vi309.dat vi309.dat vi209.dat vi209.dat vi209.dat


50


11.8.Resources estimation


Mineral Resource estimates are effective December 31, 2025. The point of reference for all Mineral Resources estimates is as quantities at delivered to the cement plant. For the estimation of Mineral Resources, the analysis considered the CaO content as well as the content of impurities. The impurities are restrictions determined by the cement production plant. Table 22 shows the quantity of Resources and the average values of their quality.


Table 22 Resource estimates (exclusive of Reserves) at the Virrila quarry


  Resources Tonnes   Mt CaO
(%)
SO3
(%)
MgO
(%)
Na2O
(%)
K2O
(%)
Cl
(ppm)
Coquina Measured 21.8 49.80 0.54 0.62 0.22 0.19 0.07
Indicated 26.8 48.98 1.06 1.18 0.21 0.22 0.07
Measured + Indicated 48.6 49.35 0.83 0.93 0.21 0.21 0.07
Inferred 4.4 46.70 2.11 1.54 0.24 0.25 0.06


11.8.1.Cut-off


For the determination of Resources, the costs of extraction, transportation, cement processing and cement dispatch were considered to determine the Resources. The cost estimate considers the increase in distances, which vary from 4.6 kilometers to 7.5 kilometers from the quarry to the plant and operating costs in the open pit during the 30 years of evaluation. Since the stripping or overburdens is 0.39 and is consider in the economic model


The costs are based on real sources of current operations of Cementos Pacasmayo S.A.A. and the selling price of cement in 524.0 S/ x t during 2026 (at cement plant). Chapter 18 and 19 shows the costs and prices for the determination of Mineral Resources. The main factor for the determination of Resources is quality. The cut off can be seen in Table 18, the Virrila quarry is a sedimentary deposit and, thus, the model for the estimation of Resources considered the Virrila quarry as a unit, whose coquina production is carried out by 12 m benches.


51


11.8.2.Reasonable prospects of economic extraction


The Mineral Resource estimation considers the Virrila deposit as a set of layers integrated into a single body, defined by the continuity of quality.


The definition of waste is based on the quality (CaO) as the main parameter. The waste is variable in thickness and quality throughout the deposit.


The area associated with the resource estimation is located in the central part of the UEA Virrila and away from the mining property boundaries.


On the other hand, the public road to Bayovar Bay, the transmission line owned by a third party company, and an oil supply pipeline that ends at the port of Petro Peru pass through our mining concessions. It is important to mention that these components do not interfere with the operations in the Virrila quarry nor with the estimation of coquina resources reported in this report.


The Mineral Resource evaluation has considered relevant technical and economic factors such as coquina production costs, cement sales prices, environmental and social viability at our operations.


From the environmental and social point of view, Cementos Pacasmayo has been developing activities in Peru for more than 60 years and is recognized as a Peruvian company with a high reputation, therefore, it is expected that the environmental and social viability will continue.


The economic analysis that shows the economic viability of Mineral Resources is presented in Chapter 19.


The information that supports the estimation of the quarry’s Resources is consistent, which allows obtaining a robust Resource model.


52


11.9.Mineral Resources classification


The parameters for Resource classification used by Cementos Pacasmayo S.A.A. were obtained from the experience of calculating the optimum drilling grid for sampling by geostatistical methods. Additionally, the variographic analysis was considered taking as reference the variogram range. After considering all these, resource classification was based on the following criteria:


●Measured Resource: One regular drilling grid.


●Indicated Resource: 2 regular perforation grids.


●Inferred Resource: up to 3 grids.


Several configurations have been defined from this basic configuration, taking into account the number of drill holes and the average search distance.


11.10.Qualified person’s opinion


The geological modeling of the Virrila quarry deposit has been developed considering four zones.


Currently, the production has migrated and is centered 90% in zone 3, the quality and geological characteristics of the calcareous horizons were considered as a basis for the interpretation and development of the model, taking into account the diamond drilling of the different drilling campaigns. The relationship between drill hole information and the geological model is consistent.


The process of production in zone 1 is in its final phase, a gradual migration process to zone 3 should be initiated.


The latest diamond drilling campaign in Zone 2 has allowed for the standardization of geological interpretation criteria, similar to those used in Zones 1 and 3. With this standardization of information, the geological, resource, and reserve model has been updated. The update of the Zone 4.


The information that supports the estimation of the quarry’s Resources is consistent, allowing obtaining a robust resource model.


53


12.Mineral Reserves estimates


The total estimated Mineral Reserves in the Virrila quarry are 40.8 million tonnes which are detailed in Table 23 in their different classes.


In the periodic update of the Reserves of the Virrila quarry, the Reserves produced within the update of the Resource and Reserves models are taken into account. Also taken into account were any changes to assumptions about “modifying factors” (which should be evaluated), or the change and entry of any new data.


The quality metric used in the Mineral Resources and Reserves estimation is the calcium oxide (CaO) content, which is a stable variable in the deposit. Its specific values depend on the lithological domain with its concentration higher in some lithologies than in others.


Based on the revised Mineral Resources model, the Mineral Reserves were estimated as the indicated and measured resources in the life of mine pit that supports the mining plans for production and supply of coquina to the Cementos Pacasmayo S.A.A. plants.


The QPs estimated life of mine consumption of coquina over the 30 years of mine life is based on the estimated Reserves and the projection of plant needs provided by CPSAA management and finance control department. The projected consumption increases gradually each year.


12.1.Criteria for Mineral Reserves determination


The criteria used for the determination of Mineral Reserves are described below.


12.1.1.Run of Mine (ROM) determination criteria


ROM is considered to be all material produced in the quarry that complies with the specifications and will be sent to the plant for cement production. For determining ROM tonnage, dilution was considered to be negligible. The recovery in the quarry was assumed to be 100%.


54


12.1.2.Cement plant recovery


The coquina received at the Piura plant is properly stored and then mixed with other raw materials to obtain the raw meal feed (kiln feed). On average, the raw meal contains 78% coquina. After the raw meal is obtained, it is fed to the calcination kiln to obtain clinker. Finally, the clinker is mixed with additives to obtain cement.


12.2.Reserves estimation methodology


For the determination of the mineral Reserves, the costs of production, transportation, cement processing, and the quality restrictions of the raw material, were considered. The costs are based on actual sources from the current operations of Cementos Pacasmayo S.A.A. in Virrila quarry and Piura plant. Chapter 19 shows the economic analysis to determine the Mineral Reserves.


●Reserves meet the quality restrictions for coquina at the Piura plant (Table 23).


●Proven and Probable Reserves consists of Indicated and Measured Resources, respectively, that are within the designed pit the Virrila quarry.


●Proven and Probable Reserves are within the life-of-mine pit designed for the Virrila quarry.


●Reserves are those for which economic viability has been demonstrated by discounted cash flow analysis based on estimated capital and operating costs.


●Cementos Pacasmayo S.A.A. has an agreement with the San Martin de Sechura Community associated with the Virrila concession. The agreement allows Cementos Pacasmayo to produce coquina from year 2010 to year 2040.


●The effective date of the Reserve estimate is December 31, 2025.


●The point of reference is at the point of delivery to the Piura plant.


The economic analysis that shows the economic viability of Mineral Resources and Reserves is presented in Chapter 19.


55


12.3.Mineral Reserve estimates


Table 23 shows the Mineral Reserves at the Virrila quarry.


Table 23 Ore Reserves expressed in million tons


  Reserves Tonnes M CaO
(%)
MgO
(%)
SO3
(%)
Na2O
(%)
K2O
(%)
Cl  (ppm)
Coquina Proven 39.9 51.86 0.71 0.36 0.29 0.15 0.03
Probable 0.9 49.83 0.84 0.64 0.32 0.23 0.03
Total 40.8 51.82 0.71 0.36 0.29 0.16 0.03


The Reserves calculated for Virrila quarry from the Mineral Resources consider the risk factors and modifying factors. The quality factors are considered the most sensitive factors that, by their nature, can affect the Reserve estimates. Although the main variable is considered to be CaO, which is very stable in the deposit, there are others that determine the quality of the Reserves and could even affect the process if they are not adequately controlled, such as the Chlorine and SO3 content.


However, in certain conditions the increase of SO3 is acceptable, considering that its genesis, according to its geological nature, comes from gypsum. This is important because it allows a better balance in the cycle of alkalis (Na2O, K2O) considered in the sulfate module.


In the process of calculating Reserves and in the quarry production plans, these variables have been adequately considered in the mining plan by proper production sequencing with blending processes.


In addition to quality factors, ore reserves could change from operating performance-controlled production costs, allowing for maximization of the use of resources in the extractive processes for the use of resources in the extractive processes for the industrialists, guaranteeing the LOM of the quarry.


56


13.Mining methods


Cementos Pacasmayo S.A.A. is the current owner of the Virrila quarry and is in charge of the coquina´s production. The loading and transport of coquina has been outsourced to contractors, Cementos Pacasmayo S.A.A. supervises the quarry to verify the activities and output according to the requirements of the Cement Plant.


In 2013, Cementos Pacasmayo S.A.A. performed a geotechnical study at the Virrila quarry to understand the rock mass.


In 2015, Cementos Pacasmayo S.A.A. carried out hydrogeological studies at the Virrila quarry to understand hydrology.


13.1.Mining methods and Equipment


The mining method is open-pit mining with benches, ramps, and access roads. The main production unit is a Surface Miner. The quarry does not require explosives. Figure 9 shows the overall production process. The main production activities are:


1.Production with a surface miner;


2.Stacking;


3.Loading for dispatch; and


4.Weighing and transport.


Figure 9 Mining sequence of Virrila quarry


●Production with surface miner


The surface miner is used in horizontal layers of 0.25 meters deep by 3.8 meters wide. Subsequently, it is sampled to assess the quality of the coquina. The sand over the coquina is used in progressive clousure plan.


57


●Stockpiles


The material is stacked using a front-end loader. The stockpiles consider the angle of repose of the material and form slopes of 37°, maximum height of 3 m, and a maximum volume of 25,000 m3 per stockpile.


●Loading, Weighing and transport


Loading and transportation is conducted with dump trucks, which are weighed on an 80 tonnes capacity platform scale. The material is transported from Virrila quarry to Piura plant.


Table 24 shows the main equipment used to conduct production activities at the Virrila quarry.


Table 24 Mining equipment at the Virrila Quarry


Equipment

Quantity Function Description
Pickup van 04 Personnel Transportation Personnel and material transport units.
Surface Miner 02 Continuous mining Coquina production
Front Loader (3.5 m³ bucket capacity) 04 Material Loading and Stacking Material handling equipment.
Tanker truck 02 track watering Auxiliary equipment to ensure the operability of quarry equipment and personnel.
Dump truck (15 m3 capacity) 04 Material hauling Equipment for conveying material from the production areas to the primary crusher. Their capacity is 15 m3.


13.2.Geotechnical models


In 2013, Cementos Pacasmayo hired DCR Ingenieros S.A.C. to conduct geotechnical studies of the Virrila quarry. This serves as the basis of geotechnical assumptions used at the quarry to date. The main results are presented below.


During the study, DCR Ingenieros S.A.C noted that the lithological profile is stable when cut. With slopes between 75° to 80° of inclination, no slides or landslides occur. The stability analyses determine these conditions.


58


Table 25 Virrila quarry physical stability analysis summary


Typical section

Typical section Cutting slope angle (°) Safety factor
Static Pseudo-Static
Section A-A’ 7 80 2.077 1.713
Section A-A’ 8 75 2.323 1.827
Section B-B’ 12 75 1.897 1.490
Section B-B’ 16 75 2.477 1.920


Analysis methodology


Stability analyses were performed using the Rocscience SLIDE software, version 5.014, which allows the user to perform limit equilibrium calculations.


The software used allowed engineers to search for the most critical failure surface with the lowest safety factor for a given geometry and materials.


The analysis considered the Morgenstern-Price and Spencer limit equilibrium methods, which satisfy the equilibrium of forces and moments.


It also considered that the material is homogeneous and isotropic and that plastic collapse would occur due to the progressive failure mechanism along the slip surface.


Factors of Safety


The safety factors recommended for the stability analyses are based on the recommendations of the Environmental Guide for Slope Stability of Solid Waste Deposit Slopes of the Ministry of Energy and Mines, the United States Society of Dam (USSD), and the United States Bureau of Reclamation (USBR).


According to the guidelines mentioned above, the following safety factors are considered:


-Minimum factor of safety in static conditions is 1.5.


-Minimum factor of safety in the pseudo-static condition is 1.0


59


Geotechnical Parameters


The geotechnical parameters used for the physical stability analysis were obtained from geotechnical field and laboratory investigations and based on a geomechanical evaluation using the RocLab program (Rocscience).


Table 26 summarizes the geotechnical parameters used in the static and pseudo-static stability analysis.


Table 26 Geotechnical properties of materials


Materials

Specific gravity

(kN/m3)

Angle of friction (ɸ°) Cohesion  (c) (kPa)
Geotechnical unit UG-I (Quaternary deposit) 16 30 0
Geotechnical unit UG-II (Very weak to weak coquina) 20 24 23
Geotechnical unit UG-III (Weak to moderately weak sandstone) 22 40 61


Due to the characteristics of the calcareous material (cemented coquina) present in the Virrila quarry, as well as the depth at which the calcareous material to be produced is present, the physical stability of the quarry’s production cuts has been analyzed, considering the following typical cutting geometry:


Cutting slopes: 75° - 85°.


The geotechnical aspects are those currently used in the Virrila quarry.


13.3.Hydrological models


Based on the study that DRC Ingenieros S.A.C conducted in 2013, Ram Perú S.A.C drilled two piezometers in the Virrila quarry to obtain information associated with the hydraulic tests being applied to date. The main results are presented below.


Topographically, this unit is developed at a maximum elevation of 80 meters above sea level, being slightly inclined to the SE. The quarry is located on a raised Pleistocene marine terrace, higher than 60 meters above sea level; Its relief is essentially flat, with slight undulations due to wind action. Though, it is under the influence of the Piura river basin; the quarry is not at risk of flooding.


60


13.4.Other mine design and planning parameters


The coquina production achieved during the year 2025 is 0.9 million tonnes of coquina, and 0.40 million tonnes of waste rock, which gives a stripping ratio of 0.44.


Based on the plant requirements and sales projection for the next 30 years, the pit design parameters for the Virrila quarry are presented in Table 27.


Table 27 Mine design parameters


Description

Value
Maximum pit height 12 meters
Maximum bench height 6 meters
Pit bank slope 75° to 80°
Production (t/h) 500
Net production hours 10
Surface miner production (t/d)  4,400
Number of workdays per month 25
Production per month (t.) 109,000
Number of working months per year 12
Estimated annual production (t) 1,311,000


13.5.Annual production rate


Considering that the cement plant demands an average annual production of 1.36 million tonnes per year of coquina, the plan for the following 30 years is shown in Table 28.


61


13.6.Mining plan
 

The forecasted mining plan for the next 30 years is presented in Table 28.


Table 28 Minning plan forecast


Year  Tonnes (t)   CaO   MgO   SO3   Cl   Na2O   K2O 
2026   909,000    51.95    0.72    0.28    0.02    0.27    0.15 
2027   1,052,075    53.12    0.70    0.35    0.02    0.25    0.13 
2028   1,054,696    53.06    0.72    0.33    0.02    0.28    0.13 
2029   1,057,369    52.60    0.70    0.24    0.02    0.29    0.14 
2030   1,178,792    53.09    0.74    0.25    0.03    0.28    0.13 
2031   1,181,574    52.64    0.73    0.27    0.03    0.29    0.14 
2032   1,184,411    52.39    0.74    0.24    0.03    0.30    0.15 
2033   1,187,304    52.39    0.73    0.34    0.03    0.31    0.15 
2034   1,190,256    52.97    0.71    0.31    0.02    0.29    0.13 
2035   1,193,267    52.52    0.71    0.32    0.03    0.29    0.14 
2036   1,196,338    51.07    0.73    0.30    0.02    0.31    0.18 
2037   1,318,166    51.47    0.75    0.53    0.02    0.31    0.17 
2038   1,468,599    50.79    0.73    0.33    0.03    0.32    0.19 
2039   1,472,938    52.32    0.74    0.34    0.02    0.31    0.15 
2040   1,477,481    51.55    0.72    0.28    0.03    0.32    0.17 
2041   1,482,114    51.71    0.72    0.32    0.03    0.31    0.16 
2042   1,486,840    51.53    0.76    0.30    0.02    0.33    0.17 
2043   1,491,661    51.74    0.75    0.38    0.02    0.31    0.15 
2044   1,496,578    51.73    0.71    0.36    0.03    0.28    0.16 
2045   1,501,593    50.37    0.79    0.34    0.02    0.32    0.20 
2046   1,506,708    52.00    0.67    0.35    0.03    0.27    0.15 
2047   1,511,926    51.31    0.78    0.46    0.03    0.32    0.17 
2048   1,517,248    51.07    0.83    0.49    0.03    0.33    0.17 
2049   1,522,677    51.96    0.71    0.33    0.03    0.29    0.16 
2050   1,523,261    50.96    0.68    0.27    0.03    0.30    0.17 
2051   1,523,261    52.26    0.69    0.36    0.03    0.30    0.14 
2052   1,523,261    50.74    0.70    0.29    0.03    0.30    0.18 
2053   1,523,261    51.03    0.70    0.64    0.03    0.26    0.12 
2054   1,523,261    51.82    0.54    0.52    0.03    0.23    0.09 
2055   1,523,261    52.25    0.52    0.61    0.03    0.21    0.09 
Total   40,779,175    51.82    0.71    0.36    0.03    0.29    0.15 


In the same 30-year period, the removal of waste rock will have a stripping of 0.38 tonnes of waste rock/coquina.


62


Figure 10 Virrila quarry final pit


13.7.Life of Mine


The life of the Virrila quarry is 30 years.


13.8.Staff


The Cementos Pacasmayo personnel develop its operations at the Virrila quarry with its staff and contractors.


63


14.Processing and recovery methods


14.1.Process Plant


The cement production process includes different stages: quarry production, reception of raw materials, raw material grinding, clinkerization, cement grinding, cement packaging and cement dispatch.


The process begins with the reception and storage of raw materials; then, the material is fed to the raw milling stage, where the raw materials (coquina, clay, bauxite, gypsum, sand and iron ore) are mixed in specific quantities to obtain a material known as “raw meal.”


Piura plant has a vertical mill for the raw material grinding stage. This equipment allows pulverizing all raw materials to obtain an average fineness of less than 15% measured on a 170 µm mesh.


The raw meal obtained is transported to a homogenizing silo, where it is stored before feeding it to the kiln.


This stage aims to reduce the variability of the raw material mix and guarantees the uniformity of the quality of production in the clinkerization stage.


The homogenized raw material is fed into the rotary kiln. The temperature of the clinkering process reaches approximately 1,450°C; the resulting product is called “clinker.”


The clinker obtained is then pulverized in a vertical mill, with small amounts of gypsum and other mineral additions (such as slag, pozzolana and coquina). Combining different proportions of these minerals makes it possible to obtain the different types of cement marketed.


The Piura plant has two silos for special cement and one silo for Type I cement for cement storage.


64


There is also finished product storage (APT) for storing cement packaged in bags and big bags.


Before shipment, the quality control laboratory evaluates the cement produced for all the physical and chemical characteristics required by current technical standards. After the validation process, the Quality Assurance unit approves the cement for bulk or 42.50 kg bags.


14.2.Raw materials for the cement production


At the Piura plant, the following raw materials and additions are used to produce cement.


Raw materials 


Coquina domo: Material composed mainly of calcium carbonate, used as raw material and as additive in cement production.


Sand: Inert material composed basically of crystalline silica, aluminum and alkalis such as potassium and sodium.


Iron: Inert material composed basically of iron oxide (Fe2O3).


Clay: Inert material composed of silicon, aluminum and a low proportion of alkalis such as potassium and sodium.


Bauxite: Material used as a source of alumina. Its primary function is an alumina corrector and melting effect in the clinkerization process.


Gypsum: Material composed of calcium sulfate hydrates. The mineral gypsum may contain crystalline silica. When gypsum is mixed with the clinker, it controls the setting time when the cement initiates the hydration reactions.


Coal: Solid, black, or dark brown mineral that contains carbon and small amounts of hydrogen, oxygen, and nitrogen for the most part.


Raw meal: Artificial mixture of coquina, clay, sand and iron used to produce clinker.


65


Clinker: Product obtained during the calcination of the mixture of coquina, sand, clays, and iron.


Fossil fuel


For the heating process of the rotary kiln, it is necessary to use fossil fuels that are easy to burn since this process starts at low temperatures. For this purpose, the Piura plant has systems that can use natural gas and DB5 diesel as complementary fuels for the clinker production process. 


Mineral components (MIC)


Slag: Artificial pozzolanic material that can be set in contact with water and develop compressive strength.


Pozzolan: Materials containing silica and/or alumina of natural or artificial origin.


Gypsum: Material composed of calcium sulfate hydrates. The mineral gypsum may contain crystalline silica. When gypsum is mixed with the clinker, it controls the setting time when the cement initiates the hydration reactions.


Process additions: bypass filter dust is used such as a process additive in cement grinding.


14.3.Flow sheet


Figure 11 shows the flow sheet for the cement production at the cement plant.


Figure 11 Piura plant process block diagram


66


14.4.Main equipment


Table 29 below shows the design capacities for clinker and cement production.


Table 29 Main equipment in Piura plant


Equipment

Product Capacity of production* Unit
Raw meal Mill 1 Raw meal 1,980,000 tonnes/year
Miag 1 Pulverized Coal 182,160 tonnes/year
Kiln 1 Clinker 990,000 tonnes/year
Mill 1 Cement 1,639,440 tonnes/year
Bagging system 1 Cement 1,009,800 tonnes/year
Bagging system 2 Cement 1,009,800 tonnes/year


*The capacities of each equipment consider a production of 330 days.


14.5.Cement Plant Mass balance


Table 30 shows the balance of raw meal production. In addition, Table 32 also shows the balance for cement production considering the additions used for the mixture with clinker and, consequently, cement production.


Table 30 Balance for raw meal production


Raw meal  Annual quantity (tonnes/year)   Dosage 
Coquina   799,365    78%
Others   222,612    22%
Raw meal   1,021,977    100%


*Raw meal includes coal.


67


The raw meal is fed to the rotary kiln. The production of 1 ton of clinker requires 1.66 tons of raw meal.


Table 31 Balance for clinker production


Raw material  Annual quantity (tonnes/year) 
Raw meal   1,021,977 
Clinker   616,400 


Table 32 Balance for cement production


Cement  Annual quantity (tonnes/year)   Dosage 
Clinker   616,400    69%
Additions**   270,668    31%
Cement   887,068    100%


**The amount of coquina used as an addition was 126,790 tonnes.


14.6.Process losses


Losses in the cement production process associated with the raw material (coquina) are 1.68% due to natural humidity.


14.7.Water consumption


The Piura plant has a reverse osmosis plant for the water supply system for clinker production, which is used in the clinker and cement grinding processes. It is also used to irrigate green areas and access roads. 59,128 m3 of water was consumed at the Piura Plant during its operations in 2025.


14.8.Fossil fuel consumption


Liquid fuels and eventually natural gas (depending on availability) are used to generate the hot gases required in the production process. Table 33 shows the consumption of liquid fuels used in Cementos Pacasmayo S.A.A. - Piura plant, based on the volumes consumed during 2025.


Table 33 Fuel Consumption for Cementos Pacasmayo S.A.A – Piura Plant


Fuel Consumption Description
Natural Gas 234,451 m3 PC: 37.8 GJ/Nm3
Diesel B5 156,572 Gal PC 41.20 GJ/t


68


14.9.Electric power consumption


Cementos Pacasmayo S.A.A. - Piura plant has an electrical substation with a nominal capacity of 37.50 MW, the energy is supplied by the national interconnected network. 299,630 GJ of energy was consumed at the Piura plant during its operations in 2025.


14.10.Maintenance Plan


Cementos Pacasmayo S.A.A. has initiatives to diversify energy sources and secure supply when possible. Cementos Pacasmayo has implemented a preventive and corrective maintenance plan to maintain the cement production. Cementos Pacasmayo controls operating efficiency to assure costs and operating margins. The equipment is in good condition and operational.


14.11.Staff


The Cementos Pacasmayo personnel develop its operations at the Piura plant with its staff and contractors.


69


15.Infrastructure


15.1.Virrila quarry


Electricity consumption during the operation stage is 100 kW-h, and a powerhouse provides the power supply with a 100 kW generator set.


The fuel is supplied by a contractor using diesel oil trucks.


Water consumption in quarry operations is for human consumption and industrial use.


The quarry has offices and workshops for minor maintenance. No explosives is required, no crushers are used, and there is a scale for the dispatch of coquina trucks located in an area adjacent to the offices.


Figure 12 Virrila quarry facilities


15.2.Piura plant


The Piura plant has an installed power substation of 25 MW for use in electric motors and lighting of the plant.


Power is supplied through a 60 KV transmission line from ENOSA’s Piura Oeste sub-station to the plant’s substation. The plant’s substation is equipped with voltage transformers, protection, and energy metering equipment.


70


About the fuel infrastructure, there is a pipeline system for liquid fuels and natural gas.


The water supply comes from a deep well; the water is for industrial use, irrigation, and sanitary services. Drinking water which is supplied in drums, is used for human consumption.


16.Market Studies


Cementos Pacasmayo is a leading company in cement production and other construction materials in the north of Peru. This chapter describes the cement market and the macro and microeconomic factors that define it.


For the description of the cement market in Peru, public information has been collected from different sources, such as the Central Reserve Bank of Peru (BCRP), National Institute of Statistics and Informatics (INEI), Association of Cement Producers (ASOCEM), Ministry of Housing, Construction and Sanitation, Superintendency of Tax Administration and the Peruvian Construction Chamber. In addition to this information, this chapter also relies on statistics provided by the company (CPSAA) to understand its specific market better.


16.1.The cement market in Peru


The Peruvian cement market is geographically segmented by north, central, and south regions. Diverse companies supply each area. Figure 13 illustrates the Peruvian map and its three regions, according to the segmentation of the cement market, where each part is the area of influence of domestic cement companies.


Figure 13 Segmentation of the cement market in Peru


The main companies that supply Peru’s cement market are Cementos Pacasmayo S.A.A., UNION Andina de Cementos S.A.A., Yura S.A., and Cementos Selva S.A.C. Some companies import cement or clinker, such as Caliza Cemento Inca S.A., Distribuidora Cemento Nacional S.A.C., CEMEX Perú S.A., Cal & Cemento Sur S.A., Holcim Perú S.A., amongst others.


71


Table 34 shows the cement shipments at the domestic level (in thousands of tonnes):


Table 34 Cement shipments at domestic level (in thousands of tonnes)


   2023   2024   2025 
National cement shipments   12,175.7    12,001.8    12,936.0 
Overall cement shipments (CPSAA/CSSAC, 3 plants)   2,936.6    2,835.1    3,049.2 
Piura cement plant shipments   1,044.7    841.9    886,6 


Sources: ASOCEM and CPSAA/CSSAC.


The cement produced by the main cement companies of the country is Type I, Type V, Type ICO, Type IL, Type GU, Type MS (MH), Type HS, Type HE, Type MH.


It is important to mention that, according to the main requirement standards, Peruvian Technical Standards, there are five cement types:  


●NTP 334. 009 2013. Cements Portland. Requirement. (ASTM C 150).


●NTP 334. 090 2013. Cements Portland Added. Requirements. (ASTM C595).


●NTP 334. 082 2011. Cements Portland. Performance Specification. (ASTM C1157).


●NTP 334. 050 2004. Cements Portland White. Requirements. (ASTM C150).


●NTP 334. 069 2007. Building Cements. Requirements. (ASTM C091).


Cementos Pacasmayo only produces cement that meets the first three NTP standards.


16.2.Industry and Macroeconomic Analysis


Producers and trading companies of cement compete mainly within the limits of their area of influence, which is determined by the geographical location of their plants, giving rise to segmentation of the national market. However, the north region presents a high demand potential because of the infrastructure gap, the housing deficit, and a higher capillarity in terms of essential cities adjacent to one another, and with an urbanization level lower than in the central and south regions. 


On the other hand, one should underline the importance of transportation in the structure of cement costs, which are composed primarily of raw materials, fuels, and transportation.


The cement market and the industry in Peru have the following characteristics: 


●The base of consumers is highly segmented, informal, and of low resources. 


●Low costs of energy and raw materials. 


72


●Zone of influence/distribution determined by the geographical location of the plant. 


●High correlation between public and private investment and self-construction.


●The construction sector and cement industry are directly related to the Gross Domestic Product (GDP) and Private Consumption. 


Figure 14 shows how the Global of the construction sector (variation % monthly) accompanies the cyclic behavior of the Global GDP (variation % monthly), indicating variations of lower significance than those of the Global GDP, but in the same direction. It is also noted that, in May 2020, the GDP of the construction sector had a positive variation of more than 200% (compared to the previous month), while the Global GDP was only 10%. This situation was due to the confinement measures given by the Government to counter the Covid-19 pandemic. This reactivation was motivated primarily by the private-construction sector’s consumption. Under the uncertain conditions caused by the health and economic crisis in 2020, consumers showed savings behaviors, which meant that people preferred consumption of goods for home improvement, including cement. This trend was maintained throughout 2021. However, in 2023 there was a decrease in demand for public and private investment due to the political and social situation. As a result, cement volumes are returning to pre-covid levels.


Figure 14 Global GDP and Construction sector GDP MoM variation (%)


Source: BCR 2025


The cement industry is also driven by housing sector growth, public and private investment in infrastructure, mining projects, shopping centers, construction of transportation systems, etc. Thus, one of the variables with more impact on the cement industry and future demand is the infrastructure gap which remains high in the country.


73


In 2025, the cement market grew by 7.8% compared to 2024. Given greater stability in the sector, a moderate growth of 2% in cement shipments is expected in 2026.


16.3.The North Region Market


Cementos Pacasmayo, a leading company in the production and sales of cement in the North Region, has market presence in the following cities: Cajamarca, Chiclayo, Chimbote, Jaén, Pacasmayo, Piura, Rioja, Tarapoto, Trujillo, Tumbes, Yurimaguas and Iquitos. CPSAA has a Market share of over 91.8% in the country’s north region.


Piura plant supplies 26.7% of the cement demand of the country’s North Region. Overall shipments of the Piura plant for 2025 were 886.6 thousand tonnes.


Other companies with lower presence in the cement market of the North Region are: 


●Quisqueya - Cemex


●Cemento Nacional


●Cemento Inka


●Holcim Perú


74


These companies are competitors of the Piura plant.


Cementos Pacasmayo S.A.A Piura plant produces different types of cement. It has placed in the National Market other trademark products to meet the needs of diverse segments of the market. Table 35 shows the products in the Piura plant.


Table 35 Cement at Piura plant


Business Name

Use Comment
Cemento Portland    
Cement Type I Cement of general use. The average result of resistance to compression is higher than the minimum requirement set forth in the technical standard NTP 334.009 / ASTM C150.
Cemento Portland Added    
Cement Fortimax Ideal for Works which require moderate hydratation heat, for Works exposed to sulphate action and for Works near to large water sources (sea, lakes, rivers, etc.) The average result of resistance to compression is higher than the minimum requirement set forth in technical standard NTP 334.082 / ASTM C1157.
Cement Extra Forte Ideal for the execution of structural Works, repairs, remodelings, home applications, floors, levelings, grouts, tips, prefabricated elements of small and medium size and concrete elements which require special characteristics. The average result of resistance to compression is higher than the minimum requirement set forth in technical standard NTP 334.090.
Hydraulic Cements specified by performance    
Line Mochica MS For structures in contact with environment and humid and salty soils.  


16.4.Cement price


The sale prices of cement in the Peruvian market vary according to their type and geographical location. The price difference of each type is explained primarily by the dosifications of raw materials and additives. The variations for geographical location are caused by the freights for the distribution to the points of sale.


At the domestic level, the cement price in 2025 was, on average, 717.41 S/ x t. Figure 15 shows the historical prices of cement in Peru.


75


Figure 15 Historic prices of cement in Peru


Source: Ministerio de Vivienda, Construcción y Saneamiento (November 2025).


16.5.Current and future demand


Cement demand at the national level is met by local shipments (local production), for the most part, and by imports. In 2025, 12.94 M tonnes were shipped locally; 7.8% more than in the same period of 2024 (12.00 M). Imports amounted to 0.49 M tonnes during 2025; 81.5% more than 2024 (0.27 M).


Figure 16 shows the evolution of the national demand of cement, expressed in thousand of tonnes, since 2019.


76


Figure 16 Evolution of the national demand of cement


Source: ASOCEM


It is noted that domestic demand has been growing, on average, at a rate of 3% per year, with the exception of 2020, which is considered an atypical year due to the adverse effects of the pandemic and the confinement measures, to then take a historic leap in 2021 with an annual increase of 38%. During 2024, shipments decreased by 1.9% compared to 2023 as a result of the political and social situation in the country. In 2025, dispatches grew by 7.8% due to the recovery of private investment (real estate, mining, and infrastructure projects) and the dynamism of self-construction, supported by higher employment and incomes, as well as increased execution of public works and the momentum of concession-based projects.


According to our internal information, in terms of regional distribution, the Northern Region accounts for approximately 25.7% of domestic cement demand, the Central Region for 53.1%, and the Southern Region for 21.1%.


Cementos Pacasmayo’s cement shipments (3 plants) reached 3,049.0 thousand tonnes in 2025, constituting a 23.6% share of total shipments in Peru and 91.8% in the Northern Region. This is 7% more than in 2024 (2,835.1 thousand tonnes).


77


Table 36 shows the projection of future demand or shipments of cement for the Piura plant. These projections are based on the 2026 shipments.


Table 36 Forecast of future demand for Piura cement plant


Year  Cement
Shipments
(Tonnes)
   Variation
(%)
 
2026   944,677      
2027   963,571    2.0%
2028   982,842    2.0%
2029   1,002,499    2.0%
2030   1,022,549    2.0%
2031   1,043,000    2.0%
2032   1,063,860    2.0%
2033   1,085,137    2.0%
2034   1,106,840    2.0%
2035   1,128,976    2.0%
2036   1,151,556    2.0%
2037   1,174,587    2.0%
2038   1,198,079    2.0%
2039   1,229,989    2.7%
2040   1,263,389    2.7%
2041   1,297,457    2.7%
2042   1,332,206    2.7%
2043   1,367,650    2.7%
2044   1,403,803    2.6%
2045   1,440,679    2.6%
2046   1,478,293    2.6%
2047   1,516,659    2.6%
2048   1,555,792    2.6%
2049   1,595,708    2.6%
2050   1,600,000    0.3%
2051   1,600,000    0.0%
2052   1,600,000    0.0%
2053   1,600,000    0.0%
2054   1,600,000    0.0%
2055   1,600,000    0.0%


78


17.Environmental studies, permitting, and plans, negotiations, or agreements with local individual or groups.


17.1.Environmental Aspects


Cementos Pacasmayo S.A.A has corporate policies applied to the operations of quarries and cement plants. Relevant policies include Safety Occupational Health Policy, Quality Policy, and Environmental Policy.


Cementos Pacasmayo S.A.A. carries out activities in Virrila quarry and Piura plant according to the environmental legislation. It has an environmental authority in the industrial sector and another authority (Ministry of Energy and Mines) that issues an opinion for the Closure of quarries.


Likewise, Cementos Pacasmayo complies with the provisions of the Regulation with Supreme Decree No. 006-2025-EM - Regulation of the Mine Closure Law.


17.1.1.Virrila quarry


According to current legislation, there is the Regulation of Environmental Management of the Manufacturing Industry and Internal Trade, approved with Supreme Decree No. 017-2015-PRODUCE. This standard establishes the environmental management of the activities contemplated in Ministerial Resolution No. 157- 2011-MINAM, table of the first update of the list of inclusion of investment projects subject to the National Environmental Impact Assessment System (SEIA) and its amendments.


The Directorial Resolution Number 548-2015-PRODUCE/DVMYPE-I/DIGGAM approved the Closure Plan of the mining unit Virrila quarry.


79


Regarding water management, it is essential to mention that Virrila quarry does not have generate effluent discharges. The small water consumption is only for green area irrigation and road maintenance.


The Closure Plan submitted by Cementos Pacasmayo S.A.A included the necessary measures to ensure effectiveness or consistency with the requirements required to protect public health and the environment. The initial strategy has continued with the components of the Virrila quarry, establishing temporary, progressive, final, and post-Closure activities at the end and/or closure of operations.


Environmental closure activities include measures to ensure physical stability at the quarry, geochemical stability, decommissioning for the removal of equipment and machinery, demolition of infrastructure, reclamation, disposal of waste, the establishment of geographical features, habitat rehabilitation and social and revegetation programs.


Cementos Pacasmayo S.A.A. will carry out Post-closure activities such as physical, and biological maintenance. Post-closure monitoring activities include physical stability monitoring, air quality monitoring and biological monitoring.


Considering that the land use before mining production was a barren area typical of the coastal geography of the Piura Region, forestation activities with native species have been considered part of the post-closure activities. Likewise, Cementos Pacasmayo S.A.A. will fulfill the commitments included in the Closure Plan approved by the above authority.


The approval of the Mine Closure Plan involves the constitution of guarantees to ensure that the owner of the mining activity complies with the obligations derived from the Mine Closure Plan by environmental protection regulations. Cementos Pacasmayo S.A.A. has provided financial assurance for the mine closure plan for the Virrila quarry consistent with the approved and updated mine closure plan for an amount of 68,824.24 USD.


Cementos Pacasmayo S.A.A has a strong relationship with our communities and has identified their main needs such as health, education, urban development and local development.


80


In this regard, we have a social investment program that contributes to dealing with their necessities based on good dialog and compliance with our commitments.


The communities are a priority for Cementos Pacasmayo S.A.A. For this reason, we promote periodic meetings with their representatives, and we create opportunities for dialog to know their expectations. Also, we have established public and private alliances for development projects and programs to contribute to better life quality and strengthen our relations. In 2025, CPSAA worked in partnership with the district governments of Piura and Sechura.


CPSAA has no commitments for local procurement and hiring although it does its best to hire local talent and do business with local businesses.


17.1.2.Piura plant


On July 03, 2025, through Directorial Resolution No. 438-2025-PRODUCE/DGAAMI, the Ministry of Production approved the Supporting Technical Reports (ITS) of the project “Auxiliary component enablement”.


Regarding water management, it is essential to mention that Piura plant does not have any discharges. The domestic wastewater is treated and reused for irrigation of green areas.


The Environmental Management regulation of the Manufacturing Industry and Domestic Trade, approved by Supreme Decree N° 017-2015-PRODUCE, companies that produce cement are required to submit Closure Plans in the case of definitive closure of the facilities. Cementos Pacasmayo S.A.A in compliance with Peruvian legislation will submit the Closure Plan on time.


81


17.2.Solid waste disposal


Cementos Pacasmayo S.A.A. has a Solid Waste Minimization and Disposal Plan for our production activities at the Piura plant and Virrila quarry. Annually, our company declares the generation, storage, collection, and final disposal of hazardous and non-hazardous solid waste in compliance with environmental legislation.


As part of the solid waste minimization plan (2025), Cementos Pacasmayo S.A.A. declared 2.4 tons of hazardous waste and 92.7 tonnes of non-hazardous waste for the Virrila quarry.


Likewise, Cementos Pacasmayo S.A.A. declared 13.9 tonnes of hazardous waste for the Piura plant and 388.3 tonnes of non-hazardous waste disposed of in accordance with environmental legislation.


17.3.Qualified Person’s Opinion


Cementos Pacasmayo S.A.A. complies with national environmental standards in the industrial sector. In the Virrila quarry, coquina is produced, a raw material used for the manufacture of cement.


For the industrial and mining sector, our company complies with the Environmental Management Standards for the Manufacturing Industry and Internal Trade approved with Supreme Decree No. 017-2015-PRODUCE and its amendments that regulate the environmental management of the activities indicated in the Resolution Ministerial No. 157-2011-MINAM and investment projects subject to the National Environmental Impact Assessment System (SEIA), considered in Annex II of the Regulation of Law No. 27446, approved by Supreme Decree No. 019-2009- MINAM.


Cementos Pacasmayo S.A.A. semiannually reports the environmental commitments assumed in its Environmental Management Plan and its monitoring program to the Environmental Assessment Body - OEFA. The monitoring is carried out by external laboratories that provide comprehensive services using testing methods accredited by the National Institute of Quality (INACAL) or, failing that, by bodies accredited by a member entity of the International Laboratory Accreditation Cooperation (ILAC).


Cementos Pacasmayo S.A.A. strictly complies with the different protocols in compliance with environmental legislation and are reported to the OEFA, according to the frequency established in its approved Environmental Instruments.


The qualified person considers that CPSAA’s current plans and management strategies are adequate to prevent, mitigate and control the potential environmental impacts that may be generated by the development of activities, obtaining approval of their respective environmental studies. In addition, the qualified person considers that CPSAA has a good relationship with the local communities and that its social investment plans are adequate for reducing any social risks to the project.


82


18.Capital and operating costs


18.1.Basis for operating and capital cost for the quarry and plant


This section presents the operating costs of the Virrila quarry for the production of coquina, the primary raw material used in cement production at the Piura plant. It also exhibits the plant’s operating costs, for the whole industrial process, from the reception of raw material to its conversion to the final product (cement). The operating cost forecast is mainly based on actual historical costs.


Similarly, this section reports the detail of the capital investments made in the quarry and plant and the forecasted plan of assets required to sustain all the activities in the quarry and plant to assure the supply of coquina Reserves for the necessary products to support forecasted cement shipments of the Piura plant.


Table 37 depicts the main components of the cost structure of the Virrila quarry and Piura plant and the sources used in their forecasts.


Table 37 Cost structure of Virrila quarry and Piura plant


Cost category Description Source
Quarry Operating Cost Mineral Production, processing, fuel, Materials (Explosives), Maintenance, Insurances and Services

●   Real, historic costs

●   Suppliers quotes

Quarry Operating Cost Royalties ●   Contract of mining royalty
     payment with regional/state  entities
Quarry Operating Cost Energy

●   Historic, real costs

●   Supply Contract

●   Suppliers´quote

Plant Operating Cost Fuel, Materials, Maintenance, Wages and Insurances

●   Historic, real costs

●   Suppliers´quote

Plant Operating Cost Energy

●   Historic, real costs

●   Supply Contract

●   Suppliers´quote


Considering that the Virrila quarry and the Piura plant are currently operating, the historical costs are the principal basis for estimating forecasted costs.


83


Thus, the actual costs in some cases are maintained, and in other cases, are appropriately adjusted for factors specific to the quarry and plant operating, conditions, and obligations stipulated in supply and concession contracts.


On the other hand, macroeconomic factors such as inflation and devaluation of the local currency against the US dollar could indirectly impact future operating costs estimation.


18.2.Capital and Operating Cost Estimates


Table 38 show the operating costs of quarry and plant for the year 2025, and 30 years of forecast:


Table 38 Operating costs forecast of quarry and plant


  Production Data   Total   Cost per
  Extracted
Mineral
   Cement
Production
   Operating
Cost
   tonne of
product
  tonnes ’000   tonnes ’000   S/ ’000   S/ x tonne
             
2025   905    888    233,011   262.53
2026   900    945    240,350   254.43
2027   1,042    964    235,865   244.78
2028   1,044    983    246,263   250.56
2029   1,047    1,002    259,478   258.83
2030   1,167    1,023    267,560   261.66
2031   1,170    1,043    292,239   280.19
2032   1,173    1,064    307,889   289.41
2033   1,176    1,085    321,479   296.26
2034   1,178    1,107    336,162   303.71
2035   1,181    1,129    354,357   313.87
2036   1,184    1,152    373,891   324.68
2037   1,305    1,175    391,434   333.25
2038   1,454    1,198    409,003   341.38
2039   1,458    1,230    431,124   350.51
2040   1,463    1,263    455,226   360.32
2041   1,467    1,297    484,335   373.30
2042   1,472    1,332    511,555   383.99
2043   1,477    1,368    540,865   395.47
2044   1,482    1,404    574,760   409.43
2045   1,487    1,441    607,921   421.97
2046   1,492    1,478    644,793   436.17
2047   1,497    1,517    729,239   480.82
2048   1,502    1,556    786,861   505.76
2049   1,508    1,596    848,202   531.55
2050   1,508    1,600    883,543   552.21
2051   1,508    1,600    915,878   572.42
2052   1,508    1,600    946,903   591.81
2053   1,508    1,600    981,973   613.73
2054   1,508    1,600    1,015,705   634.82
2055   1,508    1,600    1,035,902   647.44


Table 38 shows the forecast for the next 30 years, according to the production plan for 30 years of Reserves. Costs are adjusted annually by applying a 2.90% inflation rate to the cost/tonne.


84


Costs described in this chapter are applied to estimate the Mineral Resources and Reserves of the Virrila quarry as part of the analysis.


Table 39 shows the detail of capital investments in the quarry and plant, by type of investment, for one year of historical result (2025) and 30 years of projection:


Table 39 Investment forecast in quarry and plant


   Total Investments 
   S/ ’000 
      
2025   13,173 
2026   14,011 
2027   13,068 
2028   13,447 
2029   13,837 
2030   14,239 
2031   14,651 
2032   15,076 
2033   15,514 
2034   15,963 
2035   16,426 
2036   16,903 
2037   17,393 
2038   17,897 
2039   18,416 
2040   18,950 
2041   19,500 
2042   20,065 
2043   20,647 
2044   21,246 
2045   21,862 
2046   22,496 
2047   23,149 
2048   23,820 
2049   24,511 
2050   25,222 
2051   25,953 
2052   26,706 
2053   27,480 
2054   28,277 
2055   29,097 


85


In recent years, there have been no significant variations in capital investment, mainly for maintenance and replacement of equipment in the quarry and plant to sustain operations.


The Company´s investment plan does not consider any unusual or expansion activity. The sole plan is to perform the necessary replacement for quarry support and the maintenance of operations in the plant. The investments are kept at levels similar to those registered in the last years


18.3.Capital and Operating cost estimation risks


There is a low risk associated with capital and production costs because mine production and cement plant will continue in the same geological deposit, using the same mining and industrial methods.


An assessment of the accuracy of estimation methods is reflected in the sensitivity analysis in Section 19.


For purposes of the Preliminary Feasibility Study completed relative to the Virrila quarry and Piura plant, capital and operating costs are estimated to an accuracy of +/- 25%.


86


19.Economic analysis


19.1.Methodology: for Discounted Cash flow (Free)


The Economic Analysis chapter describes the assumptions, parameters and methodology used to demonstrate the economic viability or profitability of extracting the Mineral Reserves and Resources. The economic analysis at the Pre-feasibility level supports the determination of Mineral Resources and Reserves through a business valuation through the Discounted (Free or Economic) Cash Flow method.


For the cash flow projection, the forecast horizon is considered to be consistent with the quarry’s life, which is calculated based on the total declared Reserves and the annual production of the quarry. The cash flow for each period is approximated indirectly from the EBITDA (the latter is constructed in the Profit and Loss Statement), and the corresponding adjustments are made for taxes and capital costs (CapEx).


Finally, we work with the free cash flow for this economic analysis since it does not incorporate the financing structure. We apply the weighted average cost of capital (WACC) to discount said future cash flows.


The economic analysis considered the same evaluation criteria for Resource and Reserves estimation.


19.2.Assumptions


19.2.1.General and Macroeconomic Assumptions


The general and macroeconomic assumptions used for the projection of economic cash flows and the valuation are:


●Projection horizon: 30 years (2026 to 2055), according to the estimated years of quarry life. 


●Annual inflation rate, 2.90%, based on Banco Central de Reserva del Perú as of projection 2026: applies equally to sales price, costs and expenses.


87


●Capital cost projections were determined using a historical ratio of annual investments and maintenance costs, which also considers the increase in production volume.


●The company’s capital structure is being considered in the discount rate (WACC); 10.91%.


●Income tax rate: effective rate of actual (historical) business results, 29% - 30%.
   
●Workers’ Profit Sharing: 10%.
   
●Exchange rate: exchange rate is assumed to remain at 3.80 (USD/PEN)


19.2.2.Income and Cost Assumptions


●The sales price of cement, expressed as S/ x t, is the sales price of Piura plant to Distribuidora Norte Pacasmayo, FOB at Piura plant; and it is lower than the sales price to the final customer in the market. The distribution freight explains this difference to the multiple points of sale and the selling expenses associated with distribution and promotion in the different commercial channels.


●The base price used in the projection is an estimate for the year 2026 (524.0 S/ x t), which has been determined based on current market conditions and cement demand for 2026, among other factors.


●Starting in 2027 (year 2 of the projection), an annual price escalation rate of 2.9% is applied to the sales price.


●The cost of cement production, expressed as S/ x t, has been estimated for 2026 based on actual operating costs, the market situation of local materials and services, plant demand for imported clinker, and other factors. The cost of production for the year 2026 is 254.4 S/ x t.


●Starting in 2027, an annual cost escalation rate of 2.9% is applied to the cost.


●The initial stock of products in the quarry and plant is assumed to be zero.


19.3.Results of financial model


The following financial parameters were calculated:


●NPV of 1,983 million soles at a discount rate of 10.91%.


●30-year mine life


88


●Average plant throughput for cement production: 1.3 million tonnes per year over the 30-year projection. 


●Average sales price: 708.6 soles per ton of cement, an average of the 30-year projection, at nominal values.


●Revenues: 948 million soles, an average of the 30-year projection. 


●Average production cost: 400.5 soles per ton of cement, an average of the 30-year projection, at nominal values.


Table 40 shows the forecast of the Profit and Loss Statement of the operation of Virrila quarry and Piura plant:


Table 40 Profit and Loss Statement


   Shipments (tonnes)   Revenue
S/ x t
   Gross Profit
S/ ’000
   Gross Margin
S/ x t
   Gross
Mg %
   Operating Profit   (+) Depreciation   EBITDA Piura Plant   EBITDA
Mg %
 
                                     
2026P   944,677    524.0    230,914    244.4    47%   172,830    49,307    222,137    45%
2027P   963,571    534.5    261,787    271.7    51%   201,460    50,648    252,108    49%
2028P   982,842    545.2    272,195    276.9    51%   210,437    50,851    261,288    49%
2029P   1,002,499    556.1    280,628    279.9    50%   216,048    50,899    266,947    48%
2030P   1,022,549    567.2    298,448    291.9    51%   232,722    48,690    281,412    49%
2031P   1,043,000    578.5    297,200    284.9    49%   230,724    51,168    281,892    47%
2032P   1,063,860    590.1    305,927    287.6    49%   236,477    51,261    287,738    46%
2033P   1,085,137    601.9    317,700    292.8    49%   247,028    51,525    298,553    46%
2034P   1,106,840    613.9    329,405    297.6    48%   257,282    51,776    309,058    45%
2035P   1,128,976    626.2    338,663    300.0    48%   263,249    52,062    315,311    45%
2036P   1,151,556    638.7    347,692    301.9    47%   270,929    52,377    323,305    44%
2037P   1,174,587    651.5    363,245    309.3    47%   284,783    52,702    337,485    44%
2038P   1,198,079    664.6    383,355    320.0    48%   301,490    50,524    352,014    44%
2039P   1,229,989    677.8    398,789    324.2    48%   315,570    50,620    366,190    44%
2040P   1,263,389    691.4    414,454    328.0    47%   329,645    50,717    380,361    44%
2041P   1,297,457    705.2    426,841    329.0    47%   339,008    50,802    389,810    43%
2042P   1,332,206    719.3    442,917    332.5    46%   353,686    50,906    404,592    42%
2043P   1,367,650    733.7    458,779    335.5    46%   367,918    51,016    418,933    42%
2044P   1,403,803    748.4    472,011    336.2    45%   379,435    51,047    430,482    41%
2045P   1,440,679    763.4    488,011    338.7    44%   394,180    51,146    445,326    40%
2046P   1,478,293    778.6    502,422    339.9    44%   407,122    51,261    458,383    40%
2047P   1,516,659    794.2    471,467    310.9    39%   373,345    51,359    424,704    35%
2048P   1,555,792    810.1    469,637    301.9    37%   370,448    51,486    421,934    33%
2049P   1,595,708    826.3    466,484    292.3    35%   366,013    51,616    417,629    32%
2050P   1,600,000    842.8    461,131    288.2    34%   357,197    51,750    408,947    30%
2051P   1,600,000    859.7    455,766    284.9    33%   350,699    51,887    402,587    29%
2052P   1,600,000    876.9    452,251    282.7    32%   345,758    52,029    397,787    28%
2053P   1,600,000    894.4    445,241    278.3    31%   335,075    52,175    387,249    27%
2054P   1,600,000    912.3    440,130    275.1    30%   328,678    52,325    381,003    26%
2055P   1,600,000    930.5    449,126    280.7    30%   335,729    52,479    388,208    26%


89


Cement sales at the Piura plant are, on average, S/ 948 million per year (for the period 2026-2055), and the average EBITDA margin for the same period is 39%.


The EBITDA margin remains relatively stable in the 30-year projection. The slight variations in the margin are mainly explained by the cost of remunerations, which has a behavior with peaks every three years due to union negotiations.


Table 41 shows the Free Cash Flow projection and the valuation of the cement business of the Piura plant:


Table 41 Free Cash Flow and valuation


   FCF - Valuation (Thousand S/) 
   (-) Taxes (EBIT*t)   (-) CapEx  

EBITDA

Pacasmayo

plant

   Free Cash Flow 
                 
2026P   -66,445    -12,700    230,180    151,036 
2027P   -76,849    -13,068    261,271    171,353 
2028P   -80,197    -13,447    271,310    177,666 
2029P   -81,327    -13,837    276,522    181,358 
2030P   -87,588    -14,239    291,905    190,078 
2031P   -89,036    -14,651    292,441    188,753 
2032P   -90,977    -15,076    297,835    191,781 
2033P   -95,022    -15,514    309,317    198,781 
2034P   -98,876    -15,963    320,423    205,584 
2035P   -100,438    -16,426    326,225    209,361 
2036P   -104,708    -16,903    334,836    213,226 
2037P   -110,199    -17,393    349,662    222,071 
2038P   -114,623    -17,897    363,920    231,399 
2039P   -119,640    -18,416    378,798    240,742 
2040P   -125,893    -18,950    393,594    248,750 
2041P   -128,759    -19,500    402,244    253,985 
2042P   -134,547    -20,065    417,615    263,002 
2043P   -139,482    -20,647    432,453    272,323 
2044P   -139,540    -21,246    441,789    281,002 
2045P   -144,590    -21,862    456,920    290,468 
2046P   -148,550    -22,496    470,138    299,092 
2047P   -136,573    -23,149    435,114    275,392 
2048P   -135,170    -23,820    432,236    273,246 
2049P   -133,204    -24,511    427,707    269,992 
2050P   -129,213    -25,222    418,095    263,660 
2051P   -126,584    -25,953    411,488    258,951 
2052P   -124,375    -26,706    406,396    255,315 
2053P   -119,931    -27,480    394,921    247,510 
2054P   -118,134    -28,277    388,355    241,944 
2055P   -120,047    -29,097    395,556    246,412 


WACC   10.91%
Economic NPV (Thousand S/)   1,983,147 


90


The net present value (NPV) of Piura plant cement business amounts to more than S/ 1,983 million at a discount rate of 10.91% and is made up of the sum of the discounted cash flows of each period, for the 30-year projection. For the discount rate of the cash flows, the QPs applied the weighted average cost of capital (WACC) of the company.


19.4.Sensitivity Analysis


The sensitivity analysis considers a variation of +/- 5 and 10% in the variables that have the greatest impact on the NPV and EBITDA. These variables are the cement sales price, operating cost, and CapEx.


Table 42 and Table 43 detail the sensitivity of the EBITDA and NPV to each variable, respectively. Figure 17 and Figure 18 show the results of the sensitivity of NPV and EBITDA, respectively, to the three variables.


Table 42 Sensitivity analysis of the Net Present Value


Variable / Variation -10% -5% 0% +5% +10%
Price -22 -11 0 11 22
Cost 14.4 7.2 0 -7.2 -14.4
CapEx 1.2 0.6 0 -0.6 -1.2


Table 43 Sensitivity analysis of EBITDA


Variable / Variation -10% -5% 0% +5% +10%
Price -26 -13 0 13 26
Cost 17.4 8.7 0 -8.7 -17.4
CapEx 0 0 0 0 0


91


Figure 17 Sensitivity of Net Present Value (expressed as %)


Figure 18 Sensitivity of EBITDA (expressed as %)


Based on these results, the NPV is most sensitive to cement price, followed by operating cost, and least susceptible to the CapEx. EBITDA has a similar sensitivity to NPV, being most exposed to cement price, followed by operating cost but shows no sensitivity towards variations to the CapEx.


92


20.Adjacent properties


The information in this chapter was obtained from the competent authority Instituto Geológico, Minero Metalúrgico (INGEMMET). Figure 19 shows adjacent mineral concessions. To the north of the Cementos Pacasmayo S.A.A., concession is the Bayovar N° 7 concession owned by Activos Mineros S.A.C. To the east of the concession are concessions Virrila 12 and Virrila 23, owned by Cementos Pacasmayo S.A.A. and Bayovar N° 8 and Bayovar N° 12 owned by Activos Mineros S.A.C. To the west are concessions Virrila 6, Virrila 9 and Virrila 14 owned by Cementos Pacasmayo S.A.A. and to the north is the Virrila 16 and Virrila 20 concession owned by Cementos Pacasmayo S.A.A.


Figure 19 Adjacent properties map


93


21.Other relevant data and information


Not applicable.


22.Interpretation and conclusions


●From a legal viewpoint, Cementos Pacasmayo S.A.A. has mining rights for the areas of exploration, development, and production of coquina to supply the cement plants for normal production during the quarry’s life. It also has an agreement with Fundación Comunal San Martín de Sechura for the right of usufruct, surface and easement for the area of operations at the Virrila quarry.


●Cementos Pacasmayo S.A.A. has been complying with ISO-9001 (Quality) standards since 2015 and has implemented Quality Assurance and Quality Control (QAQC). The controls are applied for the construction of the Geological Model, Resource Estimation and Reserves Estimation.


●Cementos Pacasmayo S.A.A. has a quality assurance system in its operations that includes sample preparation methods, procedures, analysis and security, which comply with the best practices in the industry.


●The information verification and validation processes are carried out following the procedures indicated in the information flows. The validated information is congruent with the one that generated the geological models, which are the fundamental basis for the estimation of Resources.


●The geological modeling of the coquina deposit considers its update with the last diamond drilling campaigns, being consistent with the relationship between the information and the geological model.


●The Mineral Resources and Reserves estimation consider the geologic characteristics and modifying factors as well as due consideration of risk: geologic and associated with evaluation of modifying factors. The main quality variable is the CaO content which is very stable in the deposit, also present are other secondary variables that determine the quality of the Reserves.


94


●In the process of estimating Mineral Reserves and in the production plans of the quarry these variables have been adequately considered in the mining plan, properly sequenced and with blending processes. There are sufficient proven and probable Reserves for the next 30 years.


●Table 44 shows the Mineral Resources of the Virrila quarry and the results of Mineral Resource classification. Likewise, the Mineral Reserves and the results of Mineral Reserves classification are shown in Table 45.


Table 44 Resources at the Virrila quarry in millions of tonnes (exclusive of Reserves)


  Resources Tonnes
M
CaO
(%)
SO3
(%)
MgO
(%)
Na2O
(%)
K2O
(%)
Cl
(ppm)
Coquina Measured 21.8 49.80 0.54 0.62 0.22 0.19 0.07
Indicated 26.8 48.98 1.06 1.18 0.21 0.22 0.07
Measured + Indicated 48.6 49.35 0.83 0.93 0.21 0.21 0.07
Inferred 4.4 46.70 2.11 1.54 0.24 0.25 0.06


Table 45 Mineral Reserves expressed in millions of tonnes


  Reserves Tonnes
M
CaO
(%)
MgO
(%)
SO3
(%)
Na2O
(%)
K2O
(%)
Cl
(ppm)
Coquina Proven 39.9 51.86 0.71 0.36 0.29 0.15 0.03
Probable 0.9 49.83 0.84 0.64 0.32 0.23 0.03
Total 40.8 51.82 0.71 0.36 0.29 0.16 0.03


●The cement plant located in Piura has all the equipment and facilities available to produce cement, using coquina from the Virrila quarry and other necessary materials.


●Cementos Pacasmayo S.A.A. has the Safety, Health and Environment department, which manage the environmental aspects for quarry and cement operations in compliance with current environmental legislation and in accordance with the company’s corporate policies.


●Through its Social Responsibility unit, Cementos Pacasmayo S.A.A. has generated relationships of trust with the communities surrounding its operations, which have translated into a solid relationship with our communities, identifying their primary needs in health, education, urban development, and local development.


●Infrastructure-wise, the operation at the Virrila quarry and Piura plant is technically and economically feasible due to the quarry’s life. The sensitivity analysis shows that the operation is economically robust.


95


23.Recommendations


●Maintain the QAQC program for exploration, development and production activities associated with cement production.


●It is recommended to complete the diamond drilling campaign initiated in Zone 4, in order to update and implement the corresponding new model, which will provide greater stability and support for resources and reserves.


●Optimize the extraction plan in terms of the waste rock removal ratio during operation to achieve a reduction in production costs.


●Conduct density tests of the coquina rock to update the information in zones 2 and 3, also in the upcoming studies at the Virrila quarry.


24.References


Empresa de Ingeniería y Desarrollo S.A.C. (2012). Estudio Hidrogeológico para Abastecimiento de Agua a la Cantera Virrila – CPSAA


Geoservice Ingenieria S.A.C. (2012). Estudio de Impacto ambiental de la Planta de fabricación de Cementos Piura.


Umbrella EcoConsulting S.A.C (2012). DIA del Proyecto de Exploración de Calcáreos.


DCR Ingenieros S.R.Ltda. (2013). Estudio De Ingenieria para la Estabilidad Fisica de la Cantera Calcarea Virrila – Sechura – Piura


Ram Perú S.A.C. (2015). Investigaciones Hidrogeologicas en la Perforacion de 02 Piezometros para Abastecimiento de Agua para la Actividad Extractiva en la “Cantera Virrila”


Tecnología XXI S.A. (2016). Informe Técnico Sustentatorio para la modificación del proyecto de explotación Cantera de Virrila.


Consorcio Andes Group S.A.C. (2019). Segundo Informe Técnico Sustentatorio del Proyecto modificación del proyecto de explotación Cantera de Virrila.


96


25.Reliance on information provided by the registrant


In preparing this report, the qualified persons relied upon the registrant’s data, written reports, and statements in accordance with 17 CFR § 229.1302(f). After carefully reviewing the information provided, the QPs have no reason to believe that any material facts have been withheld or misstated. Cementos Pacasmayo provided the information as summarized in Table 46.


Table 46 List of Cementos Pacasmayo S.A.A. information.


Chapter

Chapter name Information provided by CPSAA
3 Property description Legal matters related to property rights and the authority “Instituto Geológico, Minero y Metalúrgico INGEMMET”
16 Market studies Marketing information, ASOCEM, INEI and BCRP
17 Environmental studies, permitting, and plans, negotiations, or agreements with local individuals or groups Community Relations and information about agreements with stakeholders
18 Capital and operating costs Historical data about cost, price and investments
19 Economic analysis The International Monetary Fund Economic model, Macroeconomic trends, data, and assumptions, and interest rates
20 Adjacent properties Legal matters related to property rights and the authority “Instituto Geológico, Minero y Metalúrgico “INGEMMET”


97


Signature Page


This report titled “Technical Report Summary Virrila Quarry and Piura Cement Plant” with an effective date of December 31, 2025, was prepared, compiled, and signed by the following qualified professionals, as indicated in the respective sections of this document.


Dated at Lima, Peru

April 27, 2026


/s/ Marco Carrasco  
(*) Marco Carrasco, P. Eng., RM-MMSA
Project Manager
 
C&O Projects LLC (USA)  
   
/s/ Jason Gamio  
Jason Gamio, P. Eng.  
Planning and Evaluation of Resources and Reserves Superintendent Cementos Pacasmayo S.A.A.  
   
/s/ Dennis Rodas  
Dennis Rodas, P. Eng.  
Quality Assurance Superintendent   
Cementos Pacasmayo S.A.A.  


Note:


(*)Marco Carrasco served as Project Manager for Cementos Pacasmayo S.A.A. until March 2026 and thereafter participated as Project Manager of C&O Project LLC. In this capacity, he compiled and integrated the information provided by the Qualified Persons responsible for each chapter to prepare a consolidated report. Each Qualified Person is solely responsible for the content of the sections they prepared. Mr. Carrasco’s role in the compilation process was limited to the organization and integration of such information and did not include independent technical verification or validation of the data, analyses, or conclusions provided by other Qualified Persons.


98


99


100


101


Exhibit 96.3


CEMENTOS SELVA S.A.C.

Technical Report Summary (TRS)

Tioyacu Quarry

and

Rioja Cement Plant

20-F 229.601 (Item 601)


Index    
       
1. Executive Summary 1
  1.1. Location and access 1
  1.2. Climate 1
  1.3. History 1
  1.4. Geological environment and mineralization 3
  1.5. Exploration 3
  1.6. Preparation of samples, analysis and security 3
  1.7. Data verification 4
  1.8. Mineral processing and metallurgical test 4
  1.9. Mineral Resources and Reserves 5
  1.10. Mining Methods 6
  1.11. Processing Plant and Infrastructure 7
  1.12. Market studies 7
  1.13. Capital, Operating costs and Economic Analysis 9
  1.14. Adjacent properties 11
  1.15. Conclusions 11
  1.16. Recommendations 13
2. Introduction 14
  2.1. Participants 14
  2.2. Terms of Reference 14
  2.3. Conventions 16
  2.4. Previous Work and Sources of Information 16
  2.5. Details of QP Personal Inspection 16
  2.6. Previously Filed Technical Report Summary 16
3. Property description 17
  3.1. Tioyacu quarry 17
  3.2. Rioja plant 20
4. Accessibility, climate, local resources, infrastructure and physiography 22
  4.1. Tioyacu quarry and Rioja plant 22
5. History 24
6. Geological setting, mineralization, and deposit 25
  6.1. Regional geology 25
  6.2. Local geology 25
  6.3. Characteristics of the deposit 26


i


7. Exploration 28
  7.1. Drilling 28
  7.2. Hydrogeology 28
  7.3. Geotechnical studies 29
8. Sample preparation, analysis, and security 30
  8.1. Geology and quarry 30
  8.1.1. Preparation of samples, procedures, assays and laboratories 30
  8.1.2. Quality Assurance Procedures 31
  8.1.3. Sample security 31
  8.1.4. Chain custody 32
  8.1.5. Qualified person’s opinion on quarry QAQC 32
  8.2. Rioja plant 33
  8.2.1. Sample preparation, procedures, assays and laboratories 33
    8.2.1.1. Raw materials sample preparation 33
    8.2.1.2. Laboratory Analysis 33
  8.2.2. Quality Assurance Procedures 34
  8.2.3. Sample security 35
  8.2.4. Qualified Person’s Opinion on cement plant QAQC 35
9. Data verification 36
  9.1. Geology and quarry 36
  9.1.1. Data Verification procedure 36
  9.1.2. Data collection 36
  9.1.3. Management and Validation of Database 36
  9.1.4. Tracking Data 36
  9.1.5. Validation of Data 37
  9.1.6. Qualified Person’s Opinion Geologic Data 38
  9.2. Rioja plant 38
  9.2.1. Data verification procedures 39
  9.2.2. Data validation 39
  9.2.3. Qualified Person’s Opinion on cement plant 39
10. Mineral processing and metallurgical testing 40
  10.1. Nature of Testing Program 40
  10.2. Cement Manufacturing Test Results 41
  10.3. Qualified Person’s Opinion of the Adequacy of the Test Data 41
11. Mineral Resources estimates 42
  11.1. Database 43
  11.2. Density 44


ii


  11.3. Compositing 44
  11.4. Basic statistics of the data (Assay – Composites) 44
  11.5. Extreme values 45
  11.6. Variogram Analysis 45
  11.7. Interpolation 46
  11.8. Resource estimation 47
  11.8.1. Cut-off 47
  11.8.2. Reasonable Prospects of Economic Extraction 48
  11.8.3. Mineral Resource classification 48
  11.9. Qualified Person’s Opinion 49
12. Mineral Reserves estimates 50
  12.1. Criteria for Mineral Reserves estimation 50
  12.1.1. Run of Mine (ROM) determination criteria 50
  12.1.2. Cement Plant recovery 51
  12.2. Reserves estimation methodology 51
  12.3. Mineral Reserve estimate 51
  12.4. QP’s Opinion on Risk Factors affecting Reserve Estimates 52
13. Mining methods 53
  13.1. Mining methods and equipment 53
  13.2. Geotechnical models 54
  13.3. Hydrological models 55
  13.4. Other Mine Design and Planning Parameters 55
  13.5. Annual production rate 56
  13.6. Mining plan 56
  13.7. Life of Mine 57
  13.8. Staff 57
14. Processing and recovery methods 58
  14.1. Process Plant 58
  14.2. Raw materials for the cement production 59
  14.3. Flow sheet 60
  14.4. Main equipment 60
  14.5. Material balance cement plant 61
  14.5.1. Material balance 61
  14.6. Process losses 61
  14.7. Water consumption 61
  14.8. Fossil fuel consumption 62


iii


  14.9. Electric power consumption 62
  14.10. Maintenance Plan 62
  14.11. Staff 62
15. Infrastructure 63
  15.1. Tioyacu quarry 63
  15.2. Rioja Plant 63
16. Market Studies 64
  16.1. The cement market in Peru 64
  16.2. Industry and Macroeconomic Analysis 65
  16.3. The North Region Market 67
  16.4. Cement price 68
  16.5. Current and future demand 69
17. Environmental studies, permitting, and plans, negotiations, or agreements with local individuals or groups. 72
  17.1. Environmental Aspects 72
  17.1.1. Tioyacu quarry 72
  17.1.2. Rioja plant 75
  17.2. Solid waste disposal 75
  17.3. Qualified Person’s Opinion 76
18. Capital and operating costs 77
  18.1. Basis for operating and capital costs for the quarry and plant 77
  18.2. Capital and Operating Cost Estimates 78
  18.3. Capital and Operating Cost Estimation Risks 79
19. Economic Analysis 80
  19.1. Methodology: Discounted Cash Flow (Free) 80
  19.2. Assumptions 80
  19.2.1. General and Macroeconomic Assumptions 80
  19.2.2. Income and Cost Assumptions 81
  19.3. Financial Model Results 81
  19.4. Sensitivity Analysis 84
20. Adjacent properties 86
21. Other relevant data and information 86
22. Interpretation and conclusions 87
23. Recommendations 89
24. References 90
25. Reliance on information provided by registrant 91


iv


Index of tables  
   
Table 1 Mineral Resources (exclusive of Reserves) of Tioyacu quarry 5
Table 2 Mineral Reserves of Tioyacu quarry 6
Table 3 Projection of demand and price for the next 26 years 8
Table 4 Free Cash Flow and valuation 10
Table 5 Mineral Resources (exclusive of Reserves) of Tioyacu quarry 12
Table 6 Mineral Reserves of Tioyacu quarry 13
Table 7 List of Cementos Pacasmayo S.A.A. QPs 15
Table 8 QP’s field visit 16
Table 9 UEA Rioja Concessions 17
Table 10 UEA Rioja Concessions 18
Table 11 Central coordinates of the UEA Rioja property 18
Table 12 Central coordinates of the Rioja plant 20
Table 13 Characteristics of Tioyacu quarry 26
Table 14 Drilling campaigns in Tioyacu quarry 28
Table 15 Quality Plan of the Tioyacu quarry 31
Table 16 Tests and frequency for each stage of the process 34
Table 17 Quality Plan of Rioja plant 34
Table 18 Lithologic units of the Tioyacu quarry geological model 42
Table 19 Rioja plant material restrictions 43
Table 20 Characteristics of the block model 43
Table 21 Limestone density per horizon 44
Table 22 Basic statistics of the limestone horizon data 45
Table 23 Basic statistics of the data of the marly limestone horizon. 45
Table 24 Variogram modeling parameters 46
Table 25 Ordinary Kriging Estimation Parameters CaO 46
Table 26 Resource estimates (exclusive of Reserves) at the Tioyacu quarry 47
Table 27 Criteria for Resource classification 49
Table 28 Mineral Reserves expressed in millions of tonnes 51
Table 29 Equipment of the Tioyacu quarry 54
Table 30 Tioyacu quarry design criteria 54
Table 31 Stability Analysis 55
Table 32 2021 piezometric data 55
Table 33 Summary of Tioyacu quarry design parameters 55
Table 34 Mining plan for the next 26 years 56
Table 35 Main equipment in Rioja plant 60
Table 36 Balance for raw meal production 61
Table 37 Balance for clinker production 61
Table 38 Balance for cement production 61
Table 38 Fuel consumption in Rioja plant 62
Table 39 Cement shipments at domestic level (in thousands of tonnes) 65
Table 40 Types of products of Rioja plant 68
Table 41 Forecast of future demand for Rioja cement plant 71
Table 42 Cost structure of Tioyacu quarry and Rioja plant 77
Table 43 Operating costs forecast of quarry and plant 78
Table 44 Investment forecast in quarry and plant 79
Table 45 Profit and Loss Statement 82
Table 46 Free Cash Flow and valuation 83
Table 47 Sensitivity analysis of the Net Present Value 84
Table 48 Sensitivity analysis of the EBITDA 84
Table 49 Mineral Resources (exclusive of Reserves) of Tioyacu quarry 88
Table 50 Mineral Reserves of Tioyacu quarry 88
Table 51 List of Cementos Selva S.A.C. information. 91


v


Index of figures  
   
Figure 1 Tioyacu quarry mining sequence 6
Figure 2 Sensitivity of Net Present Value (expressed as %) 11
Figure 3 Sensitivity of EBITDA (expressed as %) 11
Figure 4 UEA Rioja map 19
Figure 5 Rioja plant map 21
Figure 6 Regional stratigraphic column 25
Figure 7 Local stratigraphic column of the Tioyacu quarry. 26
Figure 8 Geological Section of the Tioyacu quarry 27
Figure 9 Tioyacu quarry mining sequence 53
Figure 10 Tioyacu quarry final pit 57
Figure 11 Rioja plant process block diagram 60
Figure 12 Segmentation of the cement market in Peru 64
Figure 13 Global GDP and Construction sector GDP MoM variation (%) 66
Figure 14 Historic prices of cement in Peru 69
Figure 15 Evolution of the national demand of cement 70
Figure 16 Sensitivity of Net Present Value (expressed as %) 84
Figure 17 Sensitivity of EBITDA (expressed as %) 85
Figure 18 Concession Calizas Tioyacu and adjacent concessions. 86


vi


1.Executive Summary


Cementos Selva S.A.C. (CSSAC), a wholly-owned subsidiary of Cementos Pacasmayo S. A.A., is a Peruvian company whose corporate purpose is the production of cement and other products associated with the construction sector. This Technical Report Summary summarizes the Pre-feasibility study of the Tioyacu quarry located in the San Martin Region and the Rioja plant located in the same region, both owned by CSAAC. Qualified persons (QPs) from Cementos Pacasmayo have prepared the report to support the Resources and Reserves Estimates.


1.1.Location and access


The Tioyacu quarry contains limestone, a non-metallic mineral that is primarily used as raw material in cement production. This quarry is located in the district of Elías Soplin Vargas, Rioja Province, San Martin Region. The access route to this quarry is by land through the Fernando Belaunde Terry highway. The cement plant located in the city of Rioja is adjacent to the Tioyacu quarry.


1.2.Climate


The vegetation is evergreen with lianas and vines, many of which are covered by epiphytes of the Bromeliaceae family. The forests have a very heterogeneous floristic composition.


The climate in this Amazon region in northern Peru is mainly influenced by the following factors: the Intertropical Convergence Zone (ITCZ), the presence of the Eastern Cordillera of the Andes and the Extratropical Fronts.


1.3.History


On February 6, 1998, the public auction of the Rioja Cement Plant was held, and Consorcio Pacasmayo was awarded the contract. To comply with the terms of the auction, Consorcio incorporated and subsequently transferred ownership of the plant to Cementos Rioja S.A. The award mentioned above included, by public deed dated April 8, 1998, the non-metallic mining concession “Calizas Tioyacu.” The Tioyacu quarry began operations as Cementos Rioja S.A. in 2000.


1


As historical information about the quarry, a campaign of 460 meters of drilling was carried out in 05 drill holes located in the eastern flank of the “Tioyacu” limestone-dolomitic massif executed by the company Andes Diamantina S.R.L., at the end of 1982 into early 1983. The objective was to determine the feasibility of a new cement Portland plant in the region of San Martin. The exploration study identified significant limestone material suitable for cement manufacturing.


In 2015, Cementos Selva S.A. commissioned Geosym Consultores S.A.C. to carry out prospecting work through drilling. A total of 6 mixed drill holes were drilled, conveniently located and distributed along the Tioyacu quarry: 2 drill holes in the southern sector, 03 drill holes in the central area, and 1 drill hole in the northern sector, to geologically evaluate the deposit and know its conditions at depth. These 6 drill holes drilled during that campaign in conjunction with blast hole information and geological evaluation work allowed the CSSAC to update its Mineral Resources and Reserves.


From 2018 to the present, Cementos Selva S.A., with the help and support of mining software such as Leapfrog and MineSight, has developed the updated estimates of its Mineral Resources and Reserves at the Tioyacu quarry.


On March 1, 2022, Cementos Selva S.A. changed its corporate name to Cementos Selva S.A.C. (CSSAC).


From October to November, 2023, the Rioja plant stopped its operations because of a general power outage in the area.


In December 2023, Cementos Selva started a diamond drilling campaign of 6 drill holes to confirm Resources and Reserves.


On 2024, no blasting activities were carried out from May to September in the Tioyacu quarry due to delays from the authority for permits. In November 2024 CSSAC carried out diamond drilling at the Tioyacu quarry in order to update the quarry’s mineral resources and reserves.


2


1.4.Geological environment and mineralization


The strata of the district of Elias Soplin Vargas, province of Rioja, San Martin region consists of Paleozoic/Mesozoic Age sedimentary formations of the Mitu Group, Pucara Group, Chambara Formation, Celendín Formation, Aramachay Formation, Condorsinga Formation, Ipururo Formation, and Quaternary Deposits.


1.5.Exploration


Cementos Selva S.A.C. did not carry out any exploration activities at the Tioyacu quarry during the current year. The exploration activities described in section 1.3 describe the exploration work at the Tioyacu quarry till date.


In 2024, Cementos Selva carried out a drilling campaign at the Tioyacu quarry in order to confirm Mineral Resources and Reserves.


1.6.Preparation of samples, analysis and security


Cementos Selva S.A.C. has implemented international standards in all its operations such as quarries and plants. The ISO 9001 standards has been implemented and certified since 2015. The certification is renewed annually through an external audit.


The SSOMASIG (Security, Occupational Health, Environment and Management Systems) department, is part of the team that determines and gives the necessary support for the maintenance of the ISO 9001 and the scope is in all the company’s activities.


Cementos Selva S.A.C. has implemented QAQC protocols to develop exploration and production activities in the Tioyacu quarry and Rioja plant to ensure the quality of the information used for estimation of limestone Resources and Reserves.


With respect to the geology, CSSAC uses XRF characterization and other analytical methods to analyze the main chemical components in the limestone. In the cement plant, the raw materials for the production of clinker and cement are analyzed using methods specified in the ASTM and Peruvian Technical Standards for cement testing. The laboratory in the cement plant has properly calibrated equipment and a periodic maintenance plan.


On the other hand, the Rioja plant, through its Quality Assurance and Control department, has implemented a sampling and data verification plan, which applies to the processes of receiving minerals, crushing of materials, drying of raw materials, grinding of raw meal, clinkerization, grinding of cement and cement packaging


3


1.7.Data verification


Concerning geological activities, CPSAA has a data verification department for the geological database. The main function of this department is the verification of data to be used in the estimation of Mineral Resources and Reserves. For the appropriate administration of information, internal protocols have been implemented that are subject to internal verification. The geologic data verification activities include data collection, administration and validation received from internal and external laboratories, data tracking through the confirmation of custody chains and finally, validation of data in the database. CPSAA (and CCSAC) staff use verified data in developing the Mineral Resources and Reserves model.


For data verification activities at the cement plant, CCSAC uses the Plan, Do, Check and Act (PDCA) methodology. This is applied to the technical information received from the company’s internal and external customers. The quality control laboratory compares the results with national and international laboratories as part of the verification procedures.


1.8.Mineral processing and metallurgical test


Cementos Pacasmayo has procedures for developing products at the laboratory level and scaling at the industrial level (including at Cementos Selva S.A.C. operations). It has guidelines for preparing, reviewing, insurance, and controlling laboratory test reports. Cemento Pacasmayo has a research and development laboratory located in the Pacasmayo plant to evaluate the technical aspects of cement plants and quarry operations.


At the Pacasmayo plant, the studies conducted in the Research and Development laboratory and the Quality Control department include the substitution of fossil fuels for rice husks at the Rioja plant. The main objective of the substitution of fossil fuels is the reduction of CO2 or greenhouse gas emissions. In 2024, CSSAC used 3,272 t of alternative fuel (measured as coal equivalent) in the Rioja plant. This result represented 7.10% of the 8,853 t of CO2.


4


A significant percentage of Research and Development activities are focused on evaluating different ratios between clinker-mineral additions providing the best functional characteristics to our products and at the same time balancing the benefits generated for the company. Another objective is to identify other additions that can substitute for clinker: slag, pozzolana, fly ash, calcined clays, etc., to reduce its environmental footprint and the cost of cement production. Based on this work, the laboratory has determined (and confirmed with production estimates) that 1 tonne of limestone yields 0.77 tonnes of clinker and the clinker/cement factor of the main cements with additions is 0.74.


The Research Laboratory issues technical reports to the operations department following international standards. The operations department evaluates the convenience of implementing the tests industrially and validates what is reported at the laboratory level.


1.9.Mineral Resources and Reserves


Cementos Pacasmayo’s QPs developed the estimates of limestone Resources and Reserves contained in this technical report summary (TRS). The evaluation uses information from exploration activities carried out until 2024.


Table 1 shows the limestone Resources. The result of the estimation of Resources considered the quality restrictions of limestone received at Rioja plant, accessibility to the Resources and legal limits inherent to the mining concessions, and relevant economic and technical factors.


The minimum quality accepted is 51% CaO to be used as raw material for production. Considering the selling prices of cement at the Rioja plant, the economic evaluation used for the estimates of Resources and Reserves is shown in Chapter 19.


Table 1 Mineral Resources (exclusive of Reserves) of Tioyacu quarry


  Resources Tonnes M CaO (%) MgO (%) SiO2 (%) K2O (%)
Limestone Measured 25.8 49.52 1.26 6.88 0.25
Indicated 4.8 48.29 1.66 7.92 0.26
Measured + Indicated 30.6 49.33 1.32 7.04 0.25
Inferred 7.2 49.11 3.44 1.70 0.11


5


The Reserves calculation considered the Mineral Resource estimates and the quality criteria, relevant modifying factors, and limestone extraction costs.


The mining method used is open pit mining. The financial results are shown in Chapter 19. Table 2 presents the Mineral Reserve estimates.


Table 2 Mineral Reserves of Tioyacu quarry


  Reserves Tonnes M CaO (%) MgO (%) SiO2 (%) K2O (%)
Limestone Proven 10.3 51.20 1.70 3.21 0.18
Probable 1.3 49.31 1.79 5.40 0.17
Total 11.6 50.99 1.71 3.46 0.18


1.10.Mining Methods


Cementos Selva S.A.C., a wholly-owned subsidiary of Cementos Pacasmayo S.A.A, is the current owner of the Tioyacu quarry. Cementos Selva S.A.C. carries out the planning, production, supervision and quality control of the quarry to verify the activities and production according to the requirements of Rioja plant.


Figure 1 Tioyacu quarry mining sequence


The major equipment used for the production of limestone at the Tioyacu quarry is a track drill, excavator, front loader, and dump truck. Also, auxiliary equipment is necessary, including pickups, lubricator trucks, and other equipment.


The mining plan of the Tioyacu quarry considers an average annual production of 0.4 million tonnes of limestone for the next 26 years.


Based on the plant requirements and sales projection for the next 26 years, the pit design parameters for the Tioyacu quarry are inter-ramp bench slope angle, bench height, safety bench and width of ramps.


6


1.11.Processing Plant and Infrastructure


Cement production considers the stages of raw material extraction, grinding, homogenization, clinkerization, cement grinding, silo storage and packaging, loading, and transportation. Cement is moved through conveyor belts to bagging systems to be packed in bags and then loaded onto trucks operated by third parties for distribution.


The raw materials for cement production are Limestone, Sand, Iron, Clay, Coal. The mixture of these raw materials is raw meal and is fed to the calcination kiln to produce clinker.


Limestone represents 75% by weight of the raw meal. Anthracite coal is also used as part of the raw material for the production of clinker. Clinker and additions are used to produce cement. The additions used in cement production are slag, pozzolana, and gypsum. Currently, the cement plant in Rioja has a clinker/cement factor of 0.75.


The Rioja plant has an electrical substation with a capacity of 12 MVA. Rioja plant uses electric power, which is supplied from the national grid.


Cementos Selva has implemented a preventive and corrective maintenance plan for equipment to prevent interruptions to cement production. Additionally, operating efficiency controls costs and operating margins.


1.12.Market studies


The Peruvian cement market is geographically segmented by regions: north region, central region and south region. Diverse companies supply each region.


The main companies that comprise the cement market in Peru are: Cementos Pacasmayo S.A.A., UNION Andina de Cementos S.A.A., Yura S.A. and Cementos Selva S.A.C. Additionally, there are companies that import cement or clinker, such as Caliza Cemento Inca S.A., Distribuidora Cemento Nacional S.A.C., CEMEX Perú S.A., and Cal & Cemento Sur S.A., Holcim Perú S.A, amongst others.


Companies that market cement in Peru follow the Peruvian Technical Standards associated with cement technical specifications.


7


The types of cement produced by the main cement companies of the country are Type I, Type V, Type ICO, Type IL, Type GU, Type MS (MH), Type HS, Type HE, Type MH.


Cementos Pacasmayo, a leading company in the production and sales of cement in the North Region, has market presence in the following cities: Cajamarca, Chiclayo, Chimbote, Jaén, Pacasmayo, Piura, Rioja, Tarapoto, Trujillo, Tumbes, Yurimaguas and Iquitos. The company has a Market share of over 91.8% in the north region of the country.


For Cementos Selva S.A.C. the overall shipments of the Rioja plant for 2024 were 318 thousand tonnes. It supplied 10.2% of the country’s North Region cement demand, and its cement sales represented 11.2% of the three cement plant’s overall shipments.


Table 3 shows the projected demand and price per ton of cement for the next 26 years.


Table 3 Projection of demand and price for the next 26 years


   Shipments (tonnes)   Revenue
S/ x t
 
         
2026P   346,279    582.2 
2027P   353,205    593.9 
2028P   360,269    605.7 
2029P   367,474    617.8 
2030P   374,824    630.2 
2031P   382,320    642.8 
2032P   389,966    655.7 
2033P   397,766    668.8 
2034P   405,721    682.1 
2035P   413,835    695.8 
2036P   422,112    709.7 
2037P   430,554    723.9 
2038P   439,166    738.4 
2039P   440,000    753.1 
2040P   440,000    768.2 
2041P   440,000    783.6 
2042P   440,000    799.2 
2043P   440,000    815.2 
2044P   440,000    831.5 
2045P   440,000    848.2 
2046P   440,000    865.1 
2047P   440,000    882.4 
2048P   440,000    900.1 
2049P   440,000    918.1 
2050P   440,000    936.4 
2051P   440,000    955.2 


8


1.13.Capital, Operating costs and Economic Analysis


This document presents the cash flow analysis and an economic evaluation of the project based on the current operating costs of the Rioja plant and using limestone production information for the Tioyacu quarry. For the Mineral Reserves evaluation, the general and macroeconomic assumptions used for the projection of the free/economic cash flows and for the valuation are:


  ● Projection horizon: 26 years (2026 to 2051) according to the estimated quarry life.


  ● Annual inflation rate, 2.90%, based on Banco Central de Reserva del Perú as of projection 2026: applies equally to sales price, costs and expenses.


  ● Capital cost projections were determined using a historical ratio of annual investments and maintenance costs, which also considers the increase in production volume.


  ● The company’s financing structure is considered in the discount rate (WACC), which is 10.91%, not in the cash flows.


  ● Income tax rate: effective rate of actual (historical) business results, 29% - 30%.


  ● Workers’ Profit Sharing: 10%.


  ● Exchange rate: exchange rate is assumed to remain at 3.80 (USD/PEN).


The economic analysis considers the same evaluation criteria for estimating Resources and Reserves, considering that the Tioyacu quarry is one location using the same infrastructure and mining methods. The main variables considered in the economic model for the sensitivity analysis were cement price, production cost, and CAPEX. The free cash flow is constructed for the economic analysis, which does not incorporate the financing structure. The latter is considered in the weighted average cost of capital of the company (WACC) to discount future cash flows. The following financial parameters were calculated:


  ● 26-year mine life


  ● Average plant throughput of 0.4 million tonnes per year over the 26-year projection.


  ● Average sales price of 754 soles per ton of cement, on average for the 26-year projection, at nominal values.


9


  ● Revenues of 316 million soles, on average for the 26-year projection.


  ● Average production cost of 497.6 soles per ton of cement, on average for the 26-year projection, at nominal values.


Table 4 presents the cash flow of the project. The NPV at a discount rate of 10.91%, is 599 million soles.


Table 4 Free Cash Flow and valuation


   FCF - Valuation (Thousand S/) 
   (-) Taxes
(EBIT*t)
   (-)
CapEx
   EBITDA
Rioja Plant
   Free
Cash Flow
 
                 
2026P   -29,086    -1,072    89,267    59,109 
2027P   -29,290    -1,103    89,385    58,991 
2028P   -29,195    -1,135    88,007    57,677 
2029P   -31,330    -1,168    93,195    60,697 
2030P   -33,341    -1,202    97,821    63,277 
2031P   -32,393    -1,237    95,034    61,405 
2032P   -34,431    -1,273    100,375    64,671 
2033P   -36,265    -1,309    105,099    67,525 
2034P   -35,344    -1,347    102,195    65,503 
2035P   -37,373    -1,387    107,684    68,924 
2036P   -39,141    -1,427    112,518    71,950 
2037P   -38,564    -1,468    109,467    69,434 
2038P   -39,594    -1,511    111,228    70,123 
2039P   -40,318    -1,554    113,237    71,365 
2040P   -38,372    -1,600    107,819    67,847 
2041P   -39,367    -1,646    110,538    69,524 
2042P   -40,198    -1,694    112,513    70,621 
2043P   -38,273    -1,743    106,882    66,866 
2044P   -39,190    -1,793    109,378    68,394 
2045P   -39,787    -1,845    111,080    69,448 
2046P   -37,569    -1,899    105,110    65,642 
2047P   -33,826    -1,954    94,954    59,174 
2048P   -34,316    -2,011    96,332    60,005 
2049P   -32,074    -2,069    90,254    56,111 
2050P   -32,912    -2,129    92,167    57,126 
2051P   -32,912    -2,191    6,155    -28,948 


WACC   10.91%
Economic NPV (Thousand S/)   598,817 


10


Figure 2 and Figure 3 show the sensitivity analysis, which shows the influence of changes in prices, operating costs, and capital costs on NPV and EBITDA, respectively.


Figure 2 Sensitivity of Net Present Value (expressed as %)


Figure 3 Sensitivity of EBITDA (expressed as %)


1.14.Adjacent properties


The Calizas Tioyacu borders to the north of the Cementos Selva S.A.C concession is the Rioja 2 concession owned by Cementos Selva S.A.C; to the east of the mining concession is the Rioja 4 concession owned by Cementos Selva S.A.C, to the southwest is the Rioja 3 concession owned by Cementos Selva S.A.C


1.15.Conclusions


●From a legal point of view, Cementos Selva S.A.C. has ownership of the mining properties for the exploration, development, and production of limestone to supply the cement plants for normal production during the life of the quarry.


11


●Cementos Selva S.A.C. has been complying with international ISO-9001 standards since 2015 and has implemented Quality Assurance and Quality Control (QAQC). The controls are applied for the construction of the geological Model and for estimating the Mineral Resources and Reserves.


●Cementos Selva S.A.C. has a quality assurance system in its operations that includes sample preparation methods, procedures, analysis and security, which comply with the best practices in the industry.


●The information verification and validation processes are carried out following the procedures indicated in the information flows. The validated information is congruent with the one that generated the geologic models, which is the fundamental basis for the estimation of Mineral Resources.


  ● The geological modeling of the limestone deposit considers the updated data from the 2024 drilling campaign.


●The Mineral Resource and Reserve estimation considers the geologic characteristics and modifying factors as well as due consideration of risk: geologic and associated with evaluation of modifying factors. The main quality variable is the CaO content which is very stable in the deposit. There are other secondary variables that determine the quality of the Reserves.


●In the process of estimating Mineral Reserves and in the production plans of the quarry these variables have been adequately considered in the mining plan, properly sequenced, and with blending processes. There are sufficient proven and probable Reserves for the next 26 years.


  ● Table 5 and Table 6 show the Mineral Resources and Reserves of the Tioyacu quarry, respectively.


Table 5 Mineral Resources (exclusive of Reserves) of Tioyacu quarry


  Resources Tonnes M CaO (%) MgO (%) SiO2 (%) K2O (%)
Limestone Measured 25.8 49.52 1.26 6.88 0.25
Indicated 4.8 48.29 1.66 7.92 0.26
Measured + Indicated 30.6 49.33 1.32 7.04 0.25
Inferred 7.2 49.11 3.44 1.70 0.11


12


Table 6 Mineral Reserves of Tioyacu quarry


  Reserves Tonnes M CaO (%) Al2O3 (%) SiO2 (%) K2O (%)
Limestone Proven 10.3 51.20  0.43 3.21 0.18
Probable 1.3 49.31  0.48 5.40 0.17
Total 11.6 50.99  0.43 3.46 0.18


●The cement plant located in Rioja has equipment and facilities available for cement production, using limestone from the Tioyacu quarry and other necessary materials.


●The Health, Safety and Environment department is in charge of supervising and ensuring compliance with the Company’s corporate policies and the various legal requirements of the national regulatory bodies by all company departments.


●Through its Social Responsibility department, Cementos Selva S.A.C. has built relationships of trust with the communities surrounding its operations, identifying their primary needs in health, education, urban development and local development.


●Infrastructure-wise, the operation in Tioyacu quarry and Rioja plant, in relation to infrastructure, is technically and economically feasible due to the life of the quarry.


●The sensitivity analysis shows that the operation is economically robust.


1.16.Recommendations


●Maintain the QAQC program for exploration, development and production activities associated with cement production.


●Include QAQC plans and density control for the subsequent diamond drilling campaigns.


  ● It is recommended to continue evaluating the SiO2 and MgO variables to optimize extraction plans in terms of the waste rock removal ratio during operation to achieve a reduction in production costs.


  ● It is recommended to continue the geological evaluation of the deposit towards the southeast, to incorporate it into the Resources and Reserves model, which will provide greater robustness and support for said model.


●Maintain a permanent monitoring of the installed piezometers both for water levels and water quality, to evaluate the evolution of levels during the production of the Tioyacu quarry.


13


2.Introduction


2.1.Participants


This Technical Summary Report (TRS) was prepared for Cementos Selva by qualified persons (QP’s), including professionals from Cementos Pacasmayo and an independent Qualified Person from C&O Project LLC. Each QP contributed to the preparation of specific sections of this report in accordance with their respective expertise and professional experience and is responsible for the content of those sections.


In preparing this report, the QPs utilized information provided by Cementos Pacasmayo, including internal data, information validated and approved by the competent authorities in Peru, and publicly available sources. Such information was relied upon within the scope of each QP’s responsibilities.


Mr. Marco Carrasco, Project Manager of C&O Project LLC, participated as an independent Qualified Person and contributed to the sections specifically assigned to him. In addition, he provided support in the overall coordination and integration of the report.


His role was primarily focused on the organization and presentation of the document and did not include independent technical verification of information prepared by other Qualified Persons. Accordingly, the content of those sections remains the responsibility of their respective authors.


Mr. Carrasco is a Chemical Engineer and a member in good standing of the Peruvian Engineers Association (Colegio de Ingenieros del Perú), identified with CIP Number 100531, and He is qualified to practice my profession. He is also a member of the Mining and Metallurgical Society of America (MMSA), a United States based professional organization, identified under Qualified Person number QP1485.


Table 7 identifies the Qualified Persons who prepared this report, together with the sections under their respective responsibility.


1.1.Terms of Reference


This technical report summary was prepared as an exhibit to support disclosure of Mineral Resources and Reserves by Cementos Selva, a wholly-owned subsidiary of Cementos Pacasmayo SAA. This report summarizes the results of the Pre-feasibility study of the “Calizas Tioyacu” property for the production of limestone using open pit mining methods. The report is effective December 31, 2025.


The limestone produced from the Calizas Tioyacu property supplies raw material for the Rioja plant, located in the city of the same name, Cementos Selva produces cement. The annual limestone production is 0.4 million tonnes per year (mtpy). Actual operating costs have been considered for the estimates and used as a basis for economic projections within the economic analysis. This technical report summary estimates Mineral Resources and Reserves according to the regulations published in Securities Exchange Commission (SEC) Form 20-F and under subpart 1300 of Regulation S-K.


The report was prepared by the qualified persons listed in Table 7 using available studies and, in some cases (see Chapter 25), relying on information provided by Cementos Pacasmayo, the registrant.


14


Table 7 List of Qualified Persons


Item   Chapter   First and Last Names   Company   Job Position   Profession
0   Coordination and Integration   Marco Carrasco (*)   C&O Projects LLC   Project Manager   Chemical Engineer
1   Executive summary   All QPs (**)            
2   Introduction   All QPs(**)            
3   Property description   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
4   Accessibility, climate, local Resources, infrastructure and physiography   Marco Carrasco   C&O Projects LLC   Project Manager   Chemical Engineer
5   History   Marco Alarcón   Cementos Selva S.A.C   Quarry Superintendent   Mining Engineering
6   Geological setting, mineralization, and deposit   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
7   Exploration   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
8   Sample preparation, analyses, and security   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
8   Sample preparation, analyses, and security   Marco Alarcón   Cementos Selva S.A.C   Quarry Superintendent   Mining Engineering
9   Data verification   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
9   Data verification   Marco Alarcón   Cementos Selva S.A.C   Quarry Superintendent   Mining Engineering
10   Mineral processing and metallurgical testing   Marco Alarcón   Cementos Selva S.A.C   Quarry Superintendent   Mining Engineering
11   Mineral resource estimates   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
12   Mineral reserve estimates   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
13   Mining methods   Marco Alarcón   Cementos Selva S.A.C   Quarry Superintendent   Mining Engineering
14   Processing and recovery methods   Marco Alarcón   Cementos Selva S.A.C   Quarry Superintendent   Mining Engineering
15   Infrastructure   Marco Alarcón   Cementos Selva S.A.C   Quarry Superintendent   Mining Engineering
16   Market studies   Marco Carrasco (*)   C&O Projects LLC   Project Manager   Chemical Engineer
17   Environmental studies, permitting, and plans, negotiations, or agreements with local individuals or groups   Marco Carrasco (*)   C&O Projects LLC   Project Manager   Chemical Engineer
18   Capital and operating costs   Marco Carrasco (*)   C&O Projects LLC   Project Manager   Chemical Engineer
19   Economic analysis   Marco Carrasco (*)   C&O Projects LLC   Project Manager   Chemical Engineer
20   Adjacent properties   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer
21   Other relevant data and information   All QPs (**)            
22   Interpretation and conclusions   All QPs (**)            
23   Recommendations  

Jason Gamio

Marco Alarcón

           
24   References   All QPs (**)            
25   Reliance on information provided by the registrant   All QPs (**)            


(*)

Marco Carrasco served as Project Manager for Cementos Pacasmayo S.A.A. until March 2026 and thereafter participated as Project Manager of C&O Project LLC. In this capacity, he compiled and integrated the information provided by the Qualified Persons responsible for each chapter to prepare a consolidated report. Each Qualified Person is solely responsible for the content of the sections they prepared. Mr. Carrasco’s role in the compilation process was limited to the organization and integration of such information and did not include independent technical verification or validation of the data, analyses, or conclusions provided by other Qualified Persons.


(**)  

Marco Alarcón and Jason Gamio.


15


1.2.Conventions


Unless otherwise indicated in the report, all currencies are in soles and all measurements and units are in the metric system. The Tioyacu quarry is located within the boundaries of the WGS84 two-dimensional geographic coordinate reference system, in the UTM 18S (Universal Transverse Mercator) zone. All coordinates referenced in this report and in the accompanying figures, tables, maps and sections are provided in the WGS84 coordinate system, UTM 18S zone, unless otherwise indicated.


1.3.Previous Work and Sources of Information


The information used is sufficient to allow this TRS to be completed with the level of detail required by Regulation S-K subpart 1300. The information used included exploration results from the various drilling campaigns with the exception of the 2024 campaign, actual information from Cementos Selva’s operations, information submitted to and approved by the corresponding authorities, and public information in organizations specialized in the cement industry. The list of sources of information is presented in Chapter 24 of this report.


1.4.Details of QP Personal Inspection


The QP’s who developed this document visited the Tioyacu quarry and the Rioja plant as part of their activities for 2025.


Table 8 Qualified Persons field visit


Item   First and Last Names   Company   Job Position   Profession   Field visit
1   Marco Alarcon   Cementos Pacasmayo S.A.A   Quarry’s Superintendent   Mining Engineering   Rioja plant and Tioyacu quarry, all year as part of his duties.
2   Jason Gamio   Cementos Pacasmayo S.A.A   Planning and Evaluation of Resources and Reserves Superintendent   Geological Engineer   Mr. Gamio has regularly visited the Tioyacu quarry and Rioja plant, most recently in October 2024, but during 2025, he coordinated remotely with operational staff.  His visit emphasized core facilities, discussing grade control, geological mapping, exploration, and delineation drill practices, diamond drill core logging, quality assurance, and quality control (QA/QC), raw material storage and mineral reserve estimation practices.
3   Marco Carrasco   C&O Projects LLC   Project Manager   Chemical Engineer   Mr. Carrasco visited the Rioja plant multiple times. His last visit to the Tioyacu quarry and Rioja plant was in 2022, but during 2025, he coordinated remotely with operational staff. His visit emphasized the operational cement process and equipment conditions (kilns, mills, storages (raw material and sub-products and products, etc.).


1.5.Previously Filed Technical Report Summary


This Technical Report Summary (TRS) updates the previously filed technical report summary for the property. The previously filed TRS is the “Technical Report Summary (TRS), Tioyacu Quarry and Rioja Cement Plant 20-F 229.601”, which was filed as Exhibit 96.3 of the CPSAA’s Annual Report on Form 20-F filed with the SEC on April 29, 2025 (File No. 001-35401).


16


3.Property description


3.1.Tioyacu quarry


The quarry is located in Elías Soplin Vargas District, Rioja Province, San Martin Region close to the Rioja plant.


The Peruvian State granted the mining right to Cementos Selva S.A.C. to carry out exploration and production activities that allow non-metallic minerals found in the subsurface through the granting of mining concessions. The mining rights registered with the authority, Instituto Geológico Minero y Metalúrgico (INGEMMET) are as follows Moyobamba 98, Pajonal 2, Rioja 1, Rioja 2, Rioja 3, Rioja 5, Rioja 6, Rioja 7, Rioja 8, Rioja 9, Calizas Tioyacu, Arcillas el Pajonal, Pajonal 3 and Pajonal 4. The area of the mining property is 9,600 hectares.


The mining rights (the mining concession title) are granted by INGEMMET of the Energy and Mines Sector through a Presidential Resolution. It is determined to include the mining rights in the Rioja Economic-Administrative Unit (UEA).


On March 15, 2016, by Presidential Resolution No. 0140-2016-INGEMMET/PCD/PM, the competent authority granted to Cementos Selva S.A.C the Rioja Economic-Administrative Unit (UEA), with code No. 01-00005-04-U of Cementos Selva S.A.C. These mining rights included 15 mining concessions.


Table 9 UEA Rioja Concessions


N°

Code Name Hectares Material
1 10912695 ARCILLAS EL PAJONAL 200 Non Metallic
2 10912495 CALIZAS TIOYACU 400 Non Metallic
3 10062498 MOYOBAMBA 98 100 Non Metallic
4 10133998 PAJONAL 2 400 Non Metallic
5 10073705 PAJONAL 3 800 Non Metallic
6 10073605 PAJONAL 4 300 Non Metallic
7 10157996 RIOJA 1 1,000 Non Metallic
8 10158096 RIOJA 2 1,000 Non Metallic
9 10158196 RIOJA 3 1,000 Non Metallic
10 10158296 RIOJA 4 800 Non Metallic
11 10158396 RIOJA 5 1,000 Non Metallic
12 10158496 RIOJA 6 400 Non Metallic
13 10158596 RIOJA 7 1,000 Non Metallic
14 10158696 RIOJA 8 1,000 Non Metallic
15 10158796 RIOJA 9 1,000 Non Metallic


17


On February 09, 2022, by Report No. 1003-2022-INGEMMET/DCM/UTM, the competent authority has notified the exclusion of the Rioja 4 concession with code 10158296 from the Rioja UEA with code No. 01-00005-04-U.


The UEA Rioja is conformed by the following concessions:


Table 10 UEA Rioja Concessions


N°

Code Name Hectares Material
1 10912695 ARCILLAS EL PAJONAL 200 Non Metallic
2 10912495 CALIZAS TIOYACU 400 Non Metallic
3 10062498 MOYOBAMBA 98 100 Non Metallic
4 10133998 PAJONAL 2 400 Non Metallic
5 10073705 PAJONAL 3 800 Non Metallic
6 10073605 PAJONAL 4 300 Non Metallic
7 10157996 RIOJA 1 1,000 Non Metallic
8 10158096 RIOJA 2 1,000 Non Metallic
9 10158196 RIOJA 3 1,000 Non Metallic
10 10158396 RIOJA 5 1,000 Non Metallic
11 10158496 RIOJA 6 400 Non Metallic
12 10158596 RIOJA 7 1,000 Non Metallic
13 10158696 RIOJA 8 1,000 Non Metallic
14 10158796 RIOJA 9  1,000 Non Metallic


Table 11 shows the UTM central coordinates of the Rioja Economic Administrative Unit (UEA).


Table 11 Central coordinates of the UEA Rioja property


North

  East  Radius  Zone
9,340,000  246,000  20,000  18


In accordance with this, the Rioja UEA includes fourteen (14) non-metallic mining rights covering 9,600.00 hectares, in favor of Cementos Selva S.A.C., owner of said rights; located in the Districts of Rioja / Awajun / Elias Soplin Vargas / Nueva Cajamarca / Posic, Province of Rioja and department of San Martin.


Cementos Selva S.A.C. complies annually with the payments for the rights to the UEA Rioja concessions. These payments must be made from the first business day of January to June 30 of each year; CSSAC provides the financial entities in charge of receiving the payments with the SINGLE CODE (see Table 10) of its mining rights, to comply with its obligation.


18


In the case of Rioja concessions, the payment is equivalent to US$3 per hectare. Likewise, Cementos Selva S.A.C. pays royalties to the State as established by the Authority in Law N° 28258 and its amendment N° 29788.


Figure 4 UEA Rioja map


19


3.2.Rioja plant


The Rioja plant is located in the district of Elías Soplin Vargas, province of Rioja, San Martin region; on land owned by the Company that occupies a total area of 28.16 hectares, duly registered in File No. 4273, Electronic Record No. 05004085 of the Land Registry of Moyobamba, Registry Zone No. III, Moyobamba Headquarters. Table 12 shows the UTM coordinate of the centroid of the Rioja plant.


Table 12 Central coordinates of the Rioja plant


North  East  Radius  Zone
248338.19  9336658.96  200.00  18


According to the Organic Law of Municipalities (Law 27972), Cementos Selva S.A.C. must pay the annual property tax for the property described above.

20


Figure 5 Rioja plant map


21


4.Accessibility, climate, local resources, infrastructure and physiography


4.1.Tioyacu quarry and Rioja plant


Cementos Selva S.A.C. is an industrial company dedicated to the production of cement. Its Tioyacu quarry provides limestone as raw material for cement production.


The Tioyacu quarry and the Rioja cement plant are located in the district of Elías Soplín Vargas, province of Rioja, department of San Martín, approximately 14.46 km from the city of Rioja.


Topography


The study area consists mainly of hillsides with slopes ranging from 25% to more than 75%, terraces of alluvial origin, with slopes of less than 8% and slightly undulating, and small hillsides. The Tioyacu quarry has an average altitude of 900 meters above sea level.


Vegetation


The vegetation is evergreen with lianas and vines, many of which are covered by epiphytes of the Bromeliaceae family. The forests present a very heterogeneous flora composition.


Access


By air is from Lima – Tarapoto in a 1.5 hour flight, and by land from Tarapoto to Tioyacu quarry for a journey of 3 hours.


Access to the Tioyacu quarry is via the Fernando Belaunde Terry highway, which crosses the district of Elías Soplin Vargas from south to north.


22


Climate


The climate in this Amazon region in northern Peru is mainly influenced by the following factors: the Intertropical Convergence Zone (ITCZ), the presence of the Eastern Cordillera of the Andes and the Extratropical Fronts.


Physiography


The study area has landforms that have been generally classified as large plains landscape and mountainous landscape (mountain slopes).


Local Resources


The Tioyacu quarry is operated by Cementos Selva S.A.C personnel. The quarry is located 13.7 kilometers from the town of Rioja, which has the resources of a city.


Power is supplied by the 60 kV Rioja - Nueva Cajamarca transmission line owned by Electro Oriente.


The company has a water use license for industrial purposes, with its water catchment point located in the Tioyacu River. The National Water Authority issued the authorization R.A. Nº 100-2010-ANA-ALA ALTOMAYO.


23


5.History


On February 6, 1998, the public auction of the Rioja plant was held, and Consorcio Pacasmayo was awarded the contract. To comply with the terms of the auction, Consorcio incorporated and subsequently transferred ownership of the plant to Cementos Rioja S.A. The award mentioned above included, by public deed dated April 8, 1998, the non-metallic mining concession “Calizas Tioyacu.” The Tioyacu quarry began operations as Cementos Rioja S.A. in 2000.


At the end of 1982 and beginning of 1983 a campaign of 460 meters of drilling was carried out in 05 drill holes located in the eastern flank of the “Tioyacu” limestone-dolomitic massif executed by Andes Diamantina S.R.L. The objective was to determine the feasibility of a new cement Portland plant in the department of San Martin. The exploration study identified limestone suitable for cement manufacturing.


In 2015, Cementos Selva S.A.C. commissioned Geosym Consultores S.A.C. to carry out prospecting work through drilling. A total of 06 drill holes were drilled, conveniently located and distributed along the Tioyacu quarry (02 holes in the southern sector, 03 holes in the central area, and 01 hole in the northern sector) to geologically evaluate the deposit and know its characteristics at depth. These 06 drillings together with blast holes information and geological evaluation work allowed Cementos Pacasmayo to update the inventory of Mineral Resources and Reserves.


From 2018 to the present, Cementos Selva S.A.C., with the help and support of mining software such as Leapfrog and MineSight has updated its Resources and Reserves at the Tioyacu quarry. On March 1, 2022, Cementos Selva S.A. changed its corporate name to Cementos Selva S.A.C. (CSSAC).


From October to November 2023, the Rioja plant stopped operations because there was general power outage in the area. During 2023, Cementos Selva performed a drilling campaign in the Tioyacu quarry in order to confirm Mineral Reserves. In 2024, no blasting activities were carried out from May to September in the Tioyacu quarry due to delays from the authority for permits. During the month of November diamond drilling was carried out at the Tioyacu quarry in order to update the quarry’s Mineral Resources and Reserves.


24


6.Geological setting, mineralization, and deposit


6.1.Regional geology


The strata of the district of Elias Soplin Vargas, province of Rioja, San Martin region consists of Paleozoic/Mesozoic Age sedimentary strata of the Mitu Group, Pucara Group, Chambara Formation, Aramachay Formation, Condorsinga Formation, Ipururo Formation, and Quaternary Deposits.


Figure 6 Regional stratigraphic column


6.2.Local geology


A lithological series of continental marine facies of limestones, marls, and dolomites have been identified in the quarry area. The classification of carbonate rocks based on the percentage of magnesium carbonate and clays, proposed by J.R.V Brooks (1896) and modified by J.A. Martinez-Alvarez, was used.


25


In the Tioyacu quarry, ten types of rocks were classified, corresponding to a sequence of limestones, magnesian limestones, dolomitic limestones, dolomitic marly limestones, marly limestones, marls, calcareous marls, clayey marls, dolomites, and calcareous dolomites. Overlying this formation are recent Quaternary deposits, consisting mainly of alluvial deposits comprised of colluvium and terraces with blocks and gravels in a sandy clay matrix.


Figure 7 Local stratigraphic column of the Tioyacu quarry.


6.3.Characteristics of the deposit


Table 13 shows the main characteristics of the deposit.


Table 13 Characteristics of Tioyacu quarry


Quarry

Average Width (m) Total Length (m) Thickness (m) Average depth (m) Continuity
Top
Elevation
Lower elevation
Tioyacu 450 1200 150 1000 820 It is a sedimentary limestone deposit whose continuity is controlled longitudinally by the limestone outcrop, laterally by fault structures and at depth by the water table.


26


Figure 8 Geological Section of the Tioyacu quarry


27


7.Exploration


7.1.Drilling


Cementos Selva’s exploration activities at the Tioyacu quarry property involve drilling to characterize the geology adequately.


Table 14 Drilling campaigns in Tioyacu quarry


Drilling
Campaign
Date N° of holes Hole diameter Type of sampling Objective
1 1983 5 HQ Core sampling Exploration
2 2015 6 HQ Core sampling Exploration
3 2023 6 HQ Core sampling Resources and Reserves Confirmation
4 2024 6 HQ Core sampling Resources and Reserves Confirmation


7.2.Hydrogeology


In 2025, Cementos Selva did not conduct further hydrogeological studies. The last hydrogeological studies were conducted in 2015 and the information was presented in the previously filed TRS titled “Technical Report Summary (TRS), Tioyacu Quarry and Rioja Cement Plant 20-F 229.601”, which was filed as Exhibit 96.3 of the CPSAA’s Annual Report on Form 20-F filed with the SEC on April 28, 2022 (File No. 001-35401).


As stated in the previous TRS, Cementos Selva hired Geosym Consultores S.A.C (2015) to conduct hydrogeological investigations through 04 borings with piezometers, 19 Lefranc and Lugeon permeability tests, 01 Slug Test, and 02 Air Lift tests, physical-chemical parameter readings, gauging with use of current meter and groundwater sampling. The hydrogeological study included the evaluation of 04 piezometers. Geosym Consultores S.A.C concluded that the groundwater is above the current topographic elevation. The results of the hydrogeological study conducted in 2015 and the information was presented in the previously filed TRS titled “Technical Report Summary (TRS), Tioyacu Quarry and Rioja Cement Plant 20-F 229.601”, which was filed as Exhibit 96.3 of the CPSAA’s Annual Report on Form 20-F filed with the SEC on April 28, 2022 (File No. 001-35401).


As per the previous TRS, CSSAC hired Consultora Minera Minconsult S.R.L to define the hydrogeological characteristics of the quarry.


28


7.3.Geotechnical studies


Cementos Pacasmayo did not conduct further geotechnical studies in 2025. The last geotechnical studies were conducted in 2015 and the information was presented in the previously filed TRS titled “Technical Report Summary (TRS), Tioyacu Quarry and Rioja Cement Plant 20-F 229.601”, which was filed as Exhibit 96.3 of the CPSAA’s Annual Report on Form 20-F filed with the SEC on April 28, 2022 (File No. 001-35401).


As per the previously filed TRS, the geotechnical studies concluded, based on the geotechnical test work that the current slopes at the Tioyacu quarry are stable for static and pseudo-static loading conditions, with safety factors above the minimum recommended for operating conditions. The studies also recommended geotechnical design criteria including a single bench height between 4 and 6 m, inter-ramp angles between 35° and 44°. The recommended bank angles and bench angles are 65°.


29


8.Sample preparation, analysis, and security


This Chapter describes the preparation, analysis and security of the samples used for the geology, quarry and cement plant operations.


8.1.Geology and quarry


Cementos Selva S.A.C. has implemented international standards in all its operations such as quarries and plants. The ISO 9001 standard has been implemented and certified since 2015. The certification is renewed annually through an external audit.


The SSOMASIG department (Security, Occupational Health, Environment and Management Systems), is part of the team that determines and gives the necessary support for the maintenance of the ISO 9001 and the scope is in all the company’s activities.


The Geology department has protocols for the activities of sample preparation methods, quality control procedures, security and other activities.


8.1.1.Preparation of samples, procedures, assays and laboratories


Samples obtained from the drill holes are placed in holders to be duly coded, cut, bagged and sent to the laboratory at the Rioja plant and are occasionally sent to an external laboratory following the company’s procedures.


Certimin S.A. is used as an external laboratory for chemical analysis. Certimin S.A. is a Peruvian laboratory that is certified in ISO 9001, ISO 14001, ISO 45001, NTP-ISO/IEC 17025 Accreditation, and has a membership in ASTM. This laboratory has modern facilities for the development of mining services associated with the cement industry and technical support in the geochemical field for national and international companies.


For the limestone samples, the laboratory analyses evaluate CaO, MgO, Al2O3, SiO2, Fe2O3, SO3 and Cl. Once received in the laboratory, the properties of the limestone to be used in cement production are analyzed.


30


8.1.2.Quality Assurance Procedures


Cementos Selva S.A.C has developed quality assurance procedures, which guarantee the accuracy of the results in the sampling, in the preparation and analysis of the samples.


Cementos Selva S.A.C. has implemented QAQC protocols for the development of exploration and production activities in the Tioyacu quarry in order to ensure the quality of the information used in the estimation of Resources and Reserves.


Based on the information and samples from the 2015 drilling campaign were re-analyzed to re-evaluate the deposit. The quality plan implemented by Cementos Selva for the quarries includes the insertion of blanks, duplicates and standards, in order to control the precision, accuracy and contamination in the samples (Table 15).


Table 15 Quality Plan of the Tioyacu quarry


Blanks Duplicates Standards Remark
1 control sample for each batch of 20 samples. 2 control sample for each batch of 20 samples. 1 control sample for each batch of 20 samples. Cementos Pacasmayo protocol ¨OM-GL-PRT-0023-R0¨.


As part of the procedure, twin and duplicate samples were inserted at an insertion rate of 5.16% and 10.32%, respectively. Calcium (CaO), which is the main component of the limestone for cement production, was analyzed. The quality control (CaO) results showed that the Twin samples had an error of 3.08%, which is within the acceptable range (30%). The percentage of good samples was 100%. On the other hand, the quality control results of the duplicate samples showed an error of 0.94% (Coarse Duplicate) and 1.72% (Fine Duplicate), which is below the allowable error of 20%. The percentage of acceptable samples was 100%.


8.1.3.Sample security


Cementos Selva S.A.C. has implemented QAQC protocols for the development of exploration and production activities in the Tioyacu quarry in order to ensure the quality of the information that allows the estimation of Resources and Reserves.


31


Cementos Selva S.A.C. has a specific area for the storage of the samples obtained during the drilling campaigns; the samples are properly stored in order to preserve their quality.


The necessary materials for storage and transport of the samples were provided. Sampling cards were also implemented with information on the name of the project, name of the borehole to be sampled, date of sampling, sampling interval, sampling management, sampling and type of sample or control sample.


All samples were labeled and a photographic record is available. The photographic record of each sampling bag is made together with the weighing of the sample.


8.1.4.Chain custody


Cementos Selva S.A.C has implemented actions to ensure the physical security of samples, data and associated records; the traceability of the sample from its generation to its analysis and subsequent conservation of rejects and pulps. At the Tioyacu quarry, core samples are duly stored in the Coreshack.


8.1.5.Qualified person’s opinion on quarry QAQC


In the authors’ opinion, Cementos Selva S.A.C. has been complying with the international standards of ISO-9001 since 2015 and implemented Quality Assurance and Quality Control (QAQC). Cementos Selva S.A.C. has used a QAQC check program comprising blank, standard and duplicate samples. The QAQC shipping rate used complies with accepted industry standards for insertion rates, as well as the actual sample storage areas and procedures are consistent with industry standards.


Protocols in the different exploration and production processes are strictly complied with. There is information on sample preparation methods, quality control measures, sample security and these results are accurate and free of significant error. The information in this report is adequate for use in the construction of the Geological Model, Resource estimation and Reserve estimation.


32


8.2.Rioja plant


8.2.1.Sample preparation, procedures, assays and laboratories


Cementos Selva S.A.C. has a quality plan for each of its operations, part of the corporate quality system.


Within the quality plan (S-CC-D-05 - Quality Plan), samples of raw materials such as limestone, clay, iron and coal are evaluated in the Rioja plant laboratory, where they are analyzed to determine the chemical composition of each material for the production of cement.


The procedures applied are wet chemical analysis of clinker and cement, wet physical and chemical analysis of raw meal and raw materials, general XRF procedures, physical-chemical analysis for coal samples, and physical tests for cements based on ASTM, NTP (Peruvian Technical Standard) and ISO standards.


8.2.1.1.Raw materials sample preparation


For preparation of samples, staff follow the sample collection and preparation procedure, which consists of primary and secondary crushing, and reduction of the sample size by coning and quartering followed by pulverizing the sample in a ring mill.


8.2.1.2.Laboratory Analysis


The laboratory at Rioja plant has implemented the ISO 9001 standard; also, it has calibrated equipment, with a calibration and maintenance program established by the laboratory area. The main equipment in the laboratory at Rioja plant are the XRF fluorescence equipment and the compressive strength press, which are maintained annually and have inter-daily verification.


The tests for air content, fineness, autoclave expansion, compressive strength and setting time, and Vicat are made for all types of cements. The autoclave expansion, 14-day mortar expansion, SO3, MgO, loss on ignition, insoluble residue, and C3A and 2 C3A+ C4AF tests only apply to some specific cements.


33


8.2.2.Quality Assurance Procedures


Table 16 describes the sampling plan, frequency of tests and data verification for the processes for receiving raw materials, crushing of materials, drying of raw materials, grinding of raw materials, clinkerization, grinding of cement and packaging of cement.


Table 16 Tests and frequency for each stage of the process


Stage Tests Frequency
Reception of raw materials X-ray Chemical Analysis, Moisture, Sulfur / Total Moisture, Ash, Calorific power, Chemical Analysis by XRF, R.I. (weekly). Daily 1 time.
Crushing raw materials Chemical Analysis by XRF, Moisture (every 2 hours), P.F (8 hours composite). Every hour.
Drying raw materials Moisture Every 2 hours.
Raw meal grinding XRF Chemical Analysis, Moisture (Every 2 hours), P.F, RM-170. Each 2 hour up to 8 hours.
Clinkerization Chemical Analysis by XRF, P.F, f-CaO / Liter Weight. Every 2 hours.
Cement grinding Chemical Analysis by XRF, P.F, f-CaO, Blaine, R.I., RM 325, RM 450, Setting time, Autoclave Expansion, Compressive Strength. Every 2 hours up to Once per Silo.
Cement packing Chemical Analysis by FRX, P.F, f-CaO, R.I. (in type I) / Blaine, RM 325, Setting, Autoclave Expansion, Compressive Strength, Air Content, Density and Expansion of the Mortar Bar (only in type GU). Once per day per type of cement.


The quality plan implemented by Cementos Selva for the cement plants includes the insertion of blanks, duplicates and standards, in order to control the precision, accuracy and pollution in the samples. Table 17 shows the QAQC plan for the Rioja plant.


Table 17 Quality Plan of Rioja plant


Blanks Duplicate Standard Comment
50 250

11 for cement (NIST)

01 for coal (LeCo)

Blanks only apply when spot-checks are performed by Classical methods


In 2025, CSSAC evaluated 50 blank samples, 250 duplicate samples, and 16 standard samples. The results show the precision and accuracy are below the error limits. As part of the quality plan, the laboratory evaluates its performance through external interlaboratory; in this sense, the laboratory participates in 02 interlaboratory:


  ● CCRL: Compliance greater than 6% in qualification Z Score > 4


  ● XAMTEC: Qualification greater than 98%.


34


Likewise, quality procedures include control of finished products, control on non-conforming products, validation of silos, density analysis, QAQC program, quality plan and quality control parameters for raw materials received at the Rioja Plant.


8.2.3.Sample security


Cementos Selva S.A.C. has implemented QAQC protocols for the development of cement production activities at the Rioja plant, in order to ensure the quality of the information that allows the estimation of the Mineral Resources and Reserves of the deposit.


Sample preparation methods are sampling and preparation of raw meal, clinker, and cement samples, sampling and preparation of raw material samples, and preparation of coal samples for laboratory analysis.


The testing procedures are wet chemical analysis of clinker and cement, general XRF procedures, wet physical and chemical analysis of raw meal and raw materials, physical-chemical analysis for coal samples, physical tests for cements and quality plan.


Likewise, the control parameters are for raw material input, raw meal production, clinker production, cement grinding, sampling plan, frequency of tests for raw materials and sampling plan and frequency of tests for cement.


8.2.4.Qualified Person’s Opinion on cement plant QAQC


Cementos Selva S.A.C. has a Quality Assurance unit, which ensures compliance with the requirements for finished products specified in the technical product standards, based on Peruvian technical standards and traceable to the American Society for Testing and Materials (ASTM).


In the author’s opinion, the quality assurance system at the Rioja plant, which includes preparation methods, procedures, analysis and security, complies with the best practices in the industry, thus ensuring that the final customer has confidence in the quality level of the products marketed by Cementos Selva S.A.C. The QAQC is adequate for Mineral Reserves estimation.


35


9.Data verification


This Chapter shows the data verification activities for the geology, quarry and cement plant.


9.1.Geology and quarry


9.1.1.Data Verification procedure


CSSAC has a unit specialized in the compilation, verification and standardization of information for the geological database. Its main function is the validation of the data to be used in the estimation of Mineral Resources and Reserves. For the proper management of the information, internal protocols have been implemented which are subject to internal audits.


9.1.2.Data collection


The Data collection applies to exploration activities. For diamond drilling, the process flow for planning and execution of drillings, survey methods for reporting drill collars and ddh / verification of the quality of information and recovery process of the core information. In addition, for geological sampling activities, the processes flowsheet, validation and consistency of sample information, sample preparation and testing, density, registration process and digital photographic storage are used.


9.1.3.Management and Validation of Database


The stages for management and validation of database are the recovery, processing and storage of the database. The database validation includes database development process flow, information standardization and integration process, information storage strategy, appropriate database technology, structure and practicality of the database system that allows a fast and flexible access and input of information, and validation of chemical results, which includes the QAQC report.


9.1.4.Tracking Data


The consistency between the database records and the original registry was verified by the QPs 2024. No differences were detected between the database and the log files. A digital copy of all records is kept as pdf files. Digital certificates support the chemical analysis data.


36


The collection of the information considered the following: drill collars, survey, lithology, samples and assays.


9.1.5.Validation of Data


Collar, Survey, Lithology and chemical analysis data were imported and processed with MX-Deposit software (By Seequent).


The results indicated that the database had adequate integrity for Resource estimation. This software verifies that the data entered from each sample or reported by the external laboratory is correct for input into the Resource model.


The team followed the defined processes for information flows to support Resource and Reserve estimation. The qualified person followed the same process as a means of verifying and validating. It has been found that the validated information is congruent in the interpretations of the same, with which the fundamental base geological models were generated for the estimation of the Resources.


No findings have been found that could invalidate the estimation of the Resources and Reserves of the unit.


Data for each hole was individually checked in the database to confirm accuracy.


The reviews included:


●Drillhole lithology database comparison to geophysical logs


●Sample quality database comparison to quality certificates


●Survey sheets


●Collar sheets


●Core photographic record


Typical errors may impact reserve and resource estimation related to discrepancies in original data entry. These errors may include:


●Incorrect drillhole coordinates (including elevation).


37


●Mislabeled drillhole lithology.


●Unnoticed erroneous quality analyses where duplicate analyses were not requested.


●Unrecorded drillhole core loss.


Data validation follows the field operational procedures that collect information from the source (collar, survey, lithology, samples, and assays). Finally, when the information is transmitted and uploaded to the mining software for geological modeling and estimation, it is double-checked to eliminate any additional errors.


9.1.6.Qualified Person’s Opinion Geologic Data


The qualified persons followed the defined processes for information flows to support Resource and Reserve estimation. The qualified person followed the same process as a means of verifying and validating the geologic data. They found that the validated information is congruent in the interpretations of the same, with which the fundamental base geological models were generated for the estimation of the Resources.


No findings have been found that could invalidate the estimation of the Resources and Reserves of the unit.


9.2.Rioja plant


The Quality Control Plan consists of the following: PDCA cycle, customer, person in charge, activities, risks, control methods, monitoring, measurement, analysis, evaluation and documentary evidence.


The PDCA cycle is:


-Plan; during this stage the following activities are considered: determination of characteristics of raw materials, product in process and finished product, elaboration of control and matrices parameters and determination of activities and results assurance program.


-Do; during this stage the following activities are considered: verification and compliance with the requirements and matrices, sampling and preparation.


-Check: during this stage the following activities are considered: chemical analysis by XRF, chemical analysis, physical analyses, recording of results, taking action on non-conformities.


38


-Act, during this stage the following activity is considered, acting to improve.


-The Quality Assurance Plan is applied to the following customers: production, quarry, provisions chain and external customer.


9.2.1.Data verification procedures


The XRF analysis, chemical analysis and physical analysis are made to verify the results of the samples, as part of the Quality Control Plan.


The data resulting from these three types of analysis are recorded and evaluated in order to determine whether or not they comply with the technical specifications.


Data verification procedures include internal audits, check lists, statistical tables, reports, validation of data, certificates, interlaboratory test reports and compliance with quality protocols.


9.2.2.Data validation


Cementos Pacasmayo S.A.A. (Included Cementos Selva S.A.C.) through its quality assurance and control area participates in evaluations with international laboratories such as CCRL/ASTM (Concrete and Cement Reference Laboratory), which is an international reference laboratory for construction materials, and Xamtec of Colombia, an international interlaboratory, in order to report reliable data.


The Quality Control laboratories endorse their analysis methods by participating in interlaboratory analysis programs, which compare the results with national and foreign laboratories. The methods of analysis compared are X-ray fluorescence (XRF) and the physical cement tests, which are the methods used to control cement quality. In all the results of these interlaboratory programs, the companies always obtain the best results for each test.


9.2.3.Qualified Person’s Opinion on cement plant


In the author’s opinion, the methodologies used for collection and processing data at the cement plant are accurate and free of significant errors. The information can be used for model construction and estimates for cement production. Considering that the analyses of the main chemical components and physical properties of the raw materials and final products are completed by external laboratories, the quality of the information is adequate for preparing Mineral Resource and Reserve estimates.


39


10.Mineral processing and metallurgical testing


10.1.Nature of Testing Program


Cementos Pacasmayo S.A.A. (including Cementos Selva S.A.C) has Quality Assurance, Research and Development department. The objective of these departments is to develop, evaluate and research procedures for the development of products at laboratory scale and their scaling up to industrial scale. Another objective is to identify evaluations of fuel substitutes to reduce energy costs.


Cementos Pacasmayo S.A.A has also implemented their own procedures for the preparation, review, issuance and control of test reports associated with cement production.


The laboratory at Pacasmayo plant has implemented the ISO 9001 standard since 2015. The Research and Development laboratory located at the Pacasmayo plant is responsible for technical aspects of cement plant and quarry operations (including Tioyacu quarry and Rioja Plant).


Cementos Pacasmayo applies the procedures:


●P-ID-P-04 Preparation of raw materials.


●P-ID-P-05 Sampling of cement and raw materials.


●P-ID-P-13 Input, storage and disposal of samples.


A permanent control is carried out with other laboratories to give greater reliability to the results. Likewise, interlaboratory reports are obtained from external laboratories such as CCRL (Cement and Concrete Reference Laboratory), which is an international reference laboratory for construction materials, and Xamtec from Colombia, an internal interlaboratory.


Cementos Pacasmayo S.A.A. has also obtained the certification that certifies compliance with Supreme Decree No. 001-2022, which validates compliance with the Technical Regulation on Hydraulic Cement used in Buildings and General Construction.


40


Cementos Pacasmayo SAA opted for the highest and most rigorous certification model (Type 5) granted by ICONTEC, which has extensive experience in the certification of products and services.


A significant percentage of R&D activities are focused on the evaluation of alternative fuels such as rice husks. Laboratory tests are developed to continuously generate operational advantage for the company. Based on this work, the laboratory has determined (and confirmed with production estimates) that 1 tonne of limestone yields 0.77 tonnes of clinker and the clinker/cement factor with additions is 0.75.


The R&D Laboratory located at the Pacasmayo plant provides analysis and research services to all of the company’s cement plants.


10.2.Cement Manufacturing Test Results


To determine the cement design, which includes the clinker/cement factor, CPSAA uses the tests outlined in national technical standards such as NTP 334.009, NTP 334.090, and NTP 334.082. The cement design is modified when some of the chemical or physical requirements present a trend that could lead to non-compliance (non-conforming product). For the clinker/cement factor, priority is given to the compressive strength test at all ages (1, 3, 7, and 28 days). If the compressive strength shows a negative trend, even after modifying the operating variables to correct it, the clinker/cement factor is modified.


At the Pacasmayo plant, the studies conducted in the Research and Development laboratory and the Quality Control units include the substitution of fossil fuels for rice husks at the Rioja plant.


The main objective of the substitution of fossil fuels is the reduction of CO2 or greenhouse gas emissions.


In 2025, CSSAC used 3,372 t of Alternative Fuel (rice husk measured as coal equivalent) in the Rioja plant. This result represented 7.10% of the total fuels used by the plant for cement production and a reduction in emissions of 8,853 t of CO2.


10.3.Qualified Person’s Opinion of the Adequacy of the Test Data


The Research Laboratory issues technical reports following international standards for the operations area, identifying the correct data, defining the requirements that may vary but include accuracy, consistency, and validity through an evaluation of the data and implementation of solutions, and finally, validating the adequacy of the data.


The operations area then evaluates the convenience of industrially implementing the tests and validating what is reported at the laboratory level. The integrity and adequacy of the data reported by the area is based on the technical competencies of the collaborators as well as the high scores obtained in the external interlaboratory of recognized entities such as XAMTEC and CCRL in their different programs.


41


11.Mineral Resources estimates


The geological model was developed and structured using Leapfrog software; the solids were generated considering the quality of the lithology based on the results of the analysis of the samples taken.


Because the deposit is a sedimentary one, the qualified persons interpreted the geological model with the help of a set of regularly-spaced sections parallel to and perpendicular to strike of the deposit shape.


According to the lithological characteristics and descriptions, eleven lithological horizons were recognized.


The lithological units have been grouped by assigning a numerical code in the mining software to simplify the modeling. Table 18 shows the lithological units with their respective numerical codes.


Table 18 Lithologic units of the Tioyacu quarry geological model


Lithologic Units Lithology Code
Limestone 1
Marly limestone 2
Magnesian limestone 3
Marly dolomitic limestone 4
Dolomitic limestone 5
Calcareous dolomite 7
Dolomite 6
Calcareous marl 8
Marl 9
Clay loam 10
Clay 11


The main criteria for geological modeling is the quality, such as the content of oxides in limestones.


The lithological criteria is based on the macroscopic physical characteristics of the limestone horizons and the percentage of essential elements in its composition (oxides) that determine the quality of the limestones. Based on the quality and specifications of the cement plant, the qualified persons used a cut off 51% of CaO.


42


Table 19 shows the reference cut-off of the content of oxides that determine the classification of the final limestone rock products.


Table 19 Rioja plant material restrictions


    Limestone Type I
CaO (%) Min. 51.0
Max. -
SiO2 (%) Min. -
Max. 3.8
MgO (%) Min. -
Max. 1.6
K2O (%) Min. -
Max. 0.4


The qualified persons built a block model based on the dimensions and spatial distribution of the deposits containing the material of economic interest. Table 20 shows the characteristics of the model.


Table 20 Characteristics of the block model


  Minimum (m) Maximum (m) Size (m) Number
X 246,789 247,637 4 212
Y 9,335,804 9,337,080 4 319
Z 720 1,048 4 82


11.1.Database


A total of 1,672 samples from 23 drill holes and 227 samples from 30 reverse circulation drills were used for resource estimation. Additionally, 7,855 blast hole control samples were used to strengthen the variogram analysis of the primary variable CaO.


The data is managed in a database. From there, it is extracted and loaded into MineSight (by Hexagon) and used for resource estimation.


43


11.2.Density


For the bulk density of the rocks, diamond drilling samples were collected at the Tioyacu quarry, from which the bulk densities were determined by the wax method using the ASTM standard. The results of this determination and the bulk densities by lithological domain are shown in Table 21.


Table 21 Limestone density per horizon


Lithology Density (g/cm3)
Limestone 2.71
Marly limestone 2.73
Magnesian limestone 2.69
Marly dolomitic limestone 2.69
Dolomitic limestone 2.73
Calcareous dolomite 2.70
Dolomite 2.64
Calcareous marl 2.61
Marl 2.62
Clay loam 2.10
Clay 2.50


11.3.Compositing


The compositing was performed using control of the GEO Item. In general, each geological unit is estimated from the information of the composites belonging to that unit. The composites should not cross “hard” boundaries between different geological units.


For compositing, the QPs assumed each initial core section has uniform grades in order to composite the grade profile of each borehole. During compositing, the goal was to preserve the original nature (variability) of the samples.


The calculated values considered in the compositing were for CaO, MgO, SO3, SiO2, Fe2O3, Al2O3, and K2O.


Composites were made at different lengths to determine the optimum compositing length. The 4 m composite is the size that best fits the nature of the original sample and so was used in resource estimation.


In addition, the modeling considered the length of the composites based on an exact multiple of the block height, which coincided with the bench height.


11.4.Basic statistics of the data (Assay – Composites)


Table 22 and Table 23 show the results of the basic statistics of the CaO, SiO2, MgO, SO3, K2O, Na2O, and Cl contents for the original and composite data. The statistical analysis was done separately for each defined orebody (limestone horizon).


44


Table 22 and Table 23 show the statistics of the limestone and marly limestone horizons as these are the main ones for the estimation of the Resources and Reserves.


Table 22 Basic statistics of the limestone horizon data


Components Origin Valid Rejected Minimum Maximum Mean Std. Devn. Variance Co. Of Variation
SiO2 Assay 863 9 0.18 12.54 2.12 1.69 2.84 0.80
Composite 343 0 0.46 7.70 2.19 1.45 2.09 0.66
Al2O3 Assay 863 9 0.02 3.54 0.38 0.29 0.09 0.78
Composite 343 0 0.04 2.64 0.43 0.31 0.10 0.74
CaO Assay 863 9 36.45 55.68 52.50 1.88 3.54 0.04
Composite 343 0 47.12 55.03 52.51 1.52 2.30 0.03
K2O Assay 863 9 0.00 1.12 0.14 0.12 0.01 0.86
Composite 343 0 0.01 0.73 0.15 0.11 0.01 0.74
MgO Assay 863 9 0.24 16.02 1.66 1.45 2.10 0.87
Composite 343 0 0.25 6.84 1.59 1.12 1.26 0.71


Table 23 Basic statistics of the data of the marly limestone horizon.


Components Origin Valid Rejected Minimum Maximum Mean Std. Devn. Variance Co. Of Variation
SiO2 Assay 416 11 0.60 29.92 10.07 3.99 15.89 0.40
Composite 179 5 1.96 19.04 10.05 3.01 9.09 0.30
Al2O3 Assay 416 11 0.04 6.06 1.10 0.76 0.57 0.69
Composite 179 5 0.32 4.10 1.22 0.73 0.53 0.60
CaO Assay 416 11 30.68 53.30 47.68 2.30 5.31 0.05
Composite 179 5 40.15 52.64 47.61 1.83 3.35 0.04
K2O Assay 416 11 0.06 3.54 0.43 0.35 0.13 0.83
Composite 179 5 0.09 2.28 0.47 0.34 0.12 0.72
MgO Assay 416 11 0.30 4.51 0.83 0.57 0.32 0.68
Composite 179 5 0.34 3.51 0.84 0.44 0.19 0.52


11.5.Extreme values


Extreme values are considered to be those analysis results that are not representative of the unit being studied and are defined in this work to be those that are above the mean plus twice the standard deviation.


In the analysis of the extreme values from the laboratory results for the calcareous lithologic units being estimated, no significant deviations were found that would alter the estimation results; the results are consistent and representative considering the geological nature of the horizons to which they correspond.


11.6.Variogram Analysis


In the variogram analysis of the composited data, each level corresponded to a body of economic interest at the Tioyacu quarry. From the variogram analysis, it was concluded that acceptable experimental variograms could only be obtained in two lithologies due to the amount of data.


The QPs considered an experimental variogram to be acceptable if the number of pairs used to estimate the semi-variances are greater than or equal to 200. The variogram modeling consisted of fitting the experimental variograms to valid variogram models in MineSight. Of these models, the most representative was the spherical model, present in 85% of the structures, followed by the Gaussian model. Table 24 shows the results of variogram modeling.


45


Table 24 Variogram modeling parameters


Type of Variogram Model Spherical
Nugget effect 0.87
Total Sill 1.16
Range 82


11.7.Interpolation


The Ordinary Kriging Interpolation (OK) method was used for the primary CaO variable, Inverse of the Distance (ID2) for the secondary variables (MgO, SO3, SiO2, Fe2O3, Al2O3, and K2O), and Nearest Neighbor (NN) for validations. Table 25 shows the main parameters used to determine the interpolations of the primary CaO variable of the Limestone and Magnesian Limestone horizons.


-The interpolations were performed in two consecutive passes.


-The first with a search radius of twice the variogram range.


-The second with a search radius equal to the range.


During interpolation, a minimum of two and a maximum of 20 composites were used to estimate block qualities. Additionally, the QPs restricted the interpolation to using a maximum of two composites from each drill hole in all the passes.


Table 25 Ordinary Kriging Estimation Parameters CaO


Comment PASS 1 PASS 2 PASS 3
Search dis. Block on Model -X 90     135     180    
Search dis. Block on Model -Y 90     135     180    
Search dis. Block on Model -Z 90     135     180    
Max distance accept data 90     135     180    
Min # comps a Block 4     3     2    
Max # comps a Block 10     20     20    
Max # comps per hole 2     2     1    
Variable Model  CA1      CA1      CA1    
Variable comp  CAO      CAO      CAO    
Variable pasada PSCA1     PSCA1     PSCA1    
Pasada PASS1     PASS2     PASS3    
Store distance  DICA1      DICA1      DICA1    
Store max # comp NCCA1     NCCA1     NCCA1    
Store max # drillholes NDCA1     NDCA1     NDCA1    
Store kriging variance SDCA1     SDCA1     SDCA1    
Model type variogram SPH SPH  SPH  SPH  SPH  SPH  SPH  SPH  SPH
Nugget effect 0.293     0.293     0.293    
Sill 0.038 0.278 0.391 0.038 0.278 0.391 0.038 0.278 0.391
Range along major axis 82 22 10 82 22 10 82 22 10
Range along minor axis 82 22 10 82 22 10 82 22 10
Range along vertical axis 16 6 2 16 6 2 16 6 2
Direction major axis 10 38 82 10 38 82 10 38 82
Plunge mayor axis -4 -8 -16 -4 -8 -16 -4 -8 -16
Dip 25 46 82 25 46 82 25 46 82
Distance along major 90     135     180    
Distance along minor 90     135     180    
Distance along vert 12     16     32    
ROT 157.66     157.66     157.66    
DIPN -7.22     -7.22     -7.22    
DIPE 32.29     32.29     32.29    
Limiting Variable model  RT1      RT1      RT1    
Code limiting variable 1     1     1    
Code matching comp vs model  GEO      GEO      GEO    


46


11.8.Resource estimation


Mineral Resource estimates are effective December 31, 2025. The point of reference for all Mineral Resources estimates is as quantities at delivered to the cement plant. For the estimation of Mineral Resources, the CaO content was considered and the impurity content. The impurities are restrictions determined by the cement production plant. Table 26 shows the Resources and the average values of their quality.


Table 26 Resource estimates (exclusive of Reserves) at the Tioyacu quarry


  Resources Tonnes M CaO (%) Al2O3 (%) MgO (%) Si2O (%) K2O (%)
Limestone Measured 25.8 49.52 0.69 1.26 6.88 0.25
Indicated 4.8 48.29 0.76 1.66 7.92 0.26
Measured + Indicated 30.6 49.33 0.70 1.32 7.04 0.25
Inferred 7.2 49.11 0.25 3.44 1.70 0.11


11.8.1.Cut-off


The main factor for the determination of Resources is quality. The costs of production, transportation, cement processing and cement dispatch were considered to determine the Resources. The cost estimate considers the increase in distances, which vary from 0.95 kilometers to 3 kilometers from the quarry to the plant and operating costs in the open pit during the 26 years of evaluation. Since there is no stripping or overburden, the stripping ratio is 0.


47


The costs are based on real sources of the current operations of Cementos Selva S.A.C. Chapter 19 shows the economic analysis for determining the mineral Resources.


11.8.2.Reasonable Prospects of Economic Extraction


The Mineral Resource evaluation has considered relevant economic and technical factors such as limestone production costs, cement sales prices, environmental and social viability at our operations.


The area associated with the Resource estimate is located at the lower boundary of the mining concession. Complement the geological information towards the S-SW zone of the quarry, considering future production activities. The resource estimate considers the Tioyacu deposit with a thickness of 90 m, defined by its continuity associated with the water table of the deposit.


The material produced in the Tioyacu quarry is blended to be sent to the plant. The quality of this material is analyzed in the Rioja plant laboratory before blending.


The information that supports the estimation of the quarry’s Resources is consistent, supported by diamond drilling campaigns such as the one carried out in 2023 and 2024, which allows for a robust resource model.


From the environmental and social point of view, Cementos Pacasmayo (included Cementos Selva) has been developing activities in Peru for more than 60 years and is recognized as a Peruvian company with a high reputation, therefore, it is expected that the environmental and social viability will continue.


11.8.3.Mineral Resource classification


Cementos Selva S.A.C. obtained the parameters for classifying Resources based on staff´s experience designing the optimal drilling grid for sampling by geostatistical methods. Additionally, the variogram analysis was used as reference. Based on these criteria, Resource classes were defined.


48


In addition to the variogram distance criteria, the number of composites valued by each block and the number of composites per drillhole were also taken into account for categorization, as shown in Table 27.


Table 27 Criteria for Resource classification


  Measured Indicate Inferred
Minimum number of composites 2 2 1
Maximum number of composites 20 20 20
Number of composites drillhole 2 2 1
Range of Variogram (m) 60 120 180


-Measured Resource: 1/3 of the distance of the variogram range, 2 a 20 composites y 2 composites for drillhole.


-Indicated Resource: 2/3 of the distance of the variogram range. 2 a 20 composites y 2 composites for drillhole.


-Inferred Resource: The total distance of the variogram range, 1 a 20 composites y 1 composites for drillhole.


11.9.Qualified Person’s Opinion


After a detailed review of the technical information, procedures, and methodologies used, the database, primarily from diamond drilling, is considered to have been evaluated and meets appropriate quality control (QA/QC) standards.


No significant deficiencies have been identified that compromise the reliability of the data used. As a producing mine, most of the relevant technical and economic factors have been resolved.


The geological interpretation and block model construction are consistent with the available information; the estimation technique used (OK and ID) is appropriate for the type of deposit and reasonably reflects the distribution of mineralization in the limestone rocks.


The categorization of the resources into Measured, Indicated, and Inferred is considered appropriate based on the geological, geostatistical, and spatial criteria used. No regulatory noncompliance has been identified that would affect the validity of the results. The new diamond drill holes included in the model have made it more robust, providing greater support to the geological and resource models, improving the estimation of the most important variables and allowing the recategorization of resources.


Based on the review, the mineral resource estimate presented in the report is considered technically sound and reasonably represents the quarry’s mineralized potential. No significant deficiencies have been identified that invalidate the reported results.


49


12.Mineral Reserves estimates


Total Mineral Reserves estimated at the Tioyacu quarry are 11.6 million tonnes, as detailed in Table 28 in their different classes.


Additionally, the periodic update of the Mineral Reserves of the Tioyacu quarry takes into account the Reserves extracted when updating the Mineral Resources and Reserves models, any new “modifying factors”, or the change and entry of any new data.


The calcium oxide (CaO) content is the primary variable in the Mineral Resources and Reserves estimation. Its specific values depend on the lithological domain, with its concentration higher in some lithologies than in others.


The calculated Reserves in the limestone deposit was 10.3 M mt. of Proven Reserves with 51.2% CaO and 1.3 M mt. of Probable Reserves with 49.3% CaO for a total of 11.6 M mt. of Reserves with 51.0% CaO that support the mining plans for production and supply to the Cementos Selva S.A.C. plant.


Based on the estimated Reserves and the plant’s projected limestone consumption, the QPs estimate a life of mine of 26 years for the quarry.


12.1.Criteria for Mineral Reserves estimation


The criteria used for the determination of Mineral Reserves are described below.


12.1.1.Run of Mine (ROM) determination criteria


ROM is considered to be all material produced in the quarry that complies with the specifications and will be sent to the plant for cement production. For determining ROM tonnage, dilution was considered to be negligible. The recovery in the quarry was assumed to be 100%.


50


12.1.2.Cement Plant recovery


The limestone received at the Rioja plant is properly stored and then mixed with other raw materials to obtain the raw meal feed (kiln feed). The raw meal contains 75% limestone. After the raw meal is obtained, it is fed to the calcination kiln to obtain clinker. Finally, the clinker is mixed with additives to obtain cement.


12.2.Reserves estimation methodology


The Mineral Reserve estimation considers the costs of production, transportation, cement processing, and the quality restrictions of the raw material. The costs are based on actual costs from the current operations of Cementos Selva S.A.C. at the Tioyacu quarry and Rioja plant. Chapter 19 shows the economic analysis used to determine the Mineral Reserves.


●Proven and Probable Reserves consists of Measured and Indicated Resources, respectively that are within the designed pit the Tioyacu quarry.


●Reserves are those for which economic viability has been demonstrated by discounted cash flow analysis based on estimated capital and operating costs.


●Cementos Selva S.A.C. has permits for limestone production at the Tioyacu quarry. All material considered to be Mineral Reserves are material for which CSSAC has mining permits.


●The effective date of the Reserve estimate is December 31, 2025.


●The Reserve estimate is the final product placed in the Rioja plant.


12.3.Mineral Reserve estimate


Table 28 shows the Mineral Reserves at the Tioyacu quarry.


Table 28 Mineral Reserves expressed in millions of tonnes


  Reserves Tonnes M CaO (%) MgO (%) SiO2 (%) K2O (%)
Limestone Proven 10.3 51.2 1.70 3.21 0.18
Probable 1.3 49.3 1.79 5.40 0.17
Total 11.6 51.0 1.71 3.46 0.18


51


12.4.QP’s Opinion on Risk Factors affecting Reserve Estimates


In the QP’s opinion, the Reserves estimated for the quarry from the Resources consider the relevant risk factors and modifying factors which affect the tonnage and quality estimates. The primary variable is considered to be CaO, which is very stable in the deposit. SiO2 is viewed as a secondary variable that, without adequate control, can have an inverse effect on the CaO content in the Reserves. The primary variable is CaO, which is very stable in the reservoir. SiO₂ is considered a secondary variable that, without proper control, can have an inverse effect on the CaO content in the reserves. MgO is a secondary control variable that is also taken into account when defining reserves; with the updated reserve model considered in the current report, its average is observed to be at the maximum level of the recommended margin, which is manageable with an efficient blending process.


In estimating Reserves and the production plans for the quarry, these variables have been adequately considered with production sequencing and blending processes.


Because Cementos Selva has been operating the Tioyacu quarry for 26 years and the deposit is relatively stable in the main quality metrics, the QP is of the opinion that the risks associated with the Reserve estimate is low.


In addition to quality factors, ore reserves could change from operating performance-controlled production costs, allowing for maximization of the use of resources in the extractive processes for the use of resources in the extractive processes for the industrialists, guaranteeing the LOM of the quarry.


52


13.Mining methods


Cementos Selva S.A.C., a wholly-owned subsidiary of Cementos Pacasmayo S.A.A, is the current owner of the Tioyacu quarry. Cementos Selva S.A.C. carries out the planning, production, supervision and quality control of the quarry to verify the activities and production according to the requirements of Rioja plant.


13.1.Mining methods and equipment


The production of the deposit begins with the drilling and blasting. The fragmented material is loaded with an excavator or front loader into dump trucks. The material is transported to the cement plant.


The quarry activities allow the production of fragmented limestone smaller than 12” in diameter, with carbonate grades according to the plant’s needs.


The sequence of limestone extraction is by benches, which are produced sequentially according to the annual requirement of the plant.


Figure 9 Tioyacu quarry mining sequence


Limestone mining at the Tioyacu quarry comprises the following unit operations:


●Drilling


Drilling activities at Tioyacu quarry are carried out with one diesel-powered drilling rig and one as stand-by.


●Blasting


Blasting allows the rock to be fragmented to a size suitable for loading, hauling, and crushing unit operations. Non-electric detonators and connectors are used to avoid vibration and sound.


●Loading and Transportation


Loading and transportation is conducted with 04 Volvo dump trucks of 14 m3 capacity, 01 excavator Hyundai and 01 front loader Volvo L150G.


53


The main equipment used to carry out mining activities at the Tioyacu quarry are shown in Table 29.


Table 29 Equipment of the Tioyacu quarry


Equipment Quantity Function Description
Track Drill and Rock Drill (9 m max hole depth with a drill bit of 4.5”, single boom) 02 Drilling These machines are used to drill holes for blasting.
Excavator (1.44 – 1.9 m3 bucket capacity) 01 Material Loading and Stacking Material handling equipment.
Dump truck (14 m3 capacity) 04 Material hauling Equipment for conveying material from the production areas to the primary crusher.


13.2.Geotechnical models


In 2022, Cementos Selva SAC hired Magma Consulting S.A.C, to carry out hydrological, hydrogeological, geotechnical and seismic risk of the Tioyacu quarry.


The study determined the maximum and minimum bank slope angles and inter-ramp angles based on stability analysis and kinematic analysis.


As a result of the study, seven structural domains were defined. The Table 30 shows the design criteria in each geotechnical domain of the quarry.


Table 30 Tioyacu quarry design criteria


Domain Bench height (m) Design Berm width
(m)
BFA
(°)
IRA
(°)
Domain 01 8 65 43 4.84
Domain 02 8 65 43 4.84
Domain 03 Clay 8 60 35 7
Rock 8 65 43 4.84
Domain 04 8 65 47 4.54
Domain 05 8 70 47 4.54
Domain 06 8 65 44 4.55
Domain 07 8 65 43 4.84


*Note:


BFA: Face slope angle


IRA: Inter ramp angle


54


Magma Consulting S.A.C (2022), performed stability analyses, the results are shown in Table 31.


Table 31 Stability Analysis


Section Description Bench face angle
Static Pseudo-static K=0.078g
S-1 Global Fault 2.85 2.54
S-2 Global Fault 2.67 2.37
S-3 Global Fault 2.58 2.32
S-4 Global Fault 2.67 2.35
S-5 Global Fault 2.08 1.87
S-6 Global Fault 2.80 2.52
S-7 Global Fault 4.01 3.64
S-8 Global Fault 4.35 3.96
S-9 Global Fault 5.02 4.55


13.3.Hydrological models


In 2021 the hydrogeological study was conducted by Magma Consulting S.A.C. The objectives of the hydrogeological study was to track the installed piezometric levels and evaluate the variations until the end of 2021.


Table 32 2021 piezometric data


Code Water level (masl) Date Type
DH-02 834.75 16/10/2021 Piezometer
DH-03 825.25 16/10/2021 Piezometer
DH-06 836.30 16/10/2021 Piezometer


13.4.Other Mine Design and Planning Parameters


The limestone production reached by December 2025 is 398,766 tonnes, and no waste rock was removed. Based on the plant requirements and sales projection for the next 26 years, the pit design parameters for the Tioyacu quarry are presented in Table 33.


Table 33 Summary of Tioyacu quarry design parameters


Description Value
Safety bench Rock 4.54 - 4.84 m
Rock and clay 7 m
Bench slope angle 60° - 70°
Bench height 8 m
Width of ramps 12 m


55


13.5.Annual production rate


Considering that the cement plant demands an average of 0.4 million tonnes per year of limestone, the plan for the next 26 years is shown in Table 34.


13.6.Mining plan


The proposed mining plan for the next 26 years is presented in Table 34.


Table 34 Mining plan for the next 26 years


Year  Tonnes   CaO   SiO2   MgO   Al2O3   K2O 
2026   444,541    51.0    4.55    1.43    0.40    0.21 
2027   443,040    51.0    3.43    1.70    0.59    0.24 
2028   444,508    51.0    4.45    1.39    0.45    0.17 
2029   446,005    51.0    3.92    1.58    0.54    0.20 
2030   447,533    51.0    4.44    1.38    0.59    0.21 
2031   449,090    51.0    3.62    1.70    0.49    0.19 
2032   450,679    51.0    4.01    1.54    0.47    0.19 
2033   452,300    51.0    2.84    2.05    0.34    0.15 
2034   453,953    51.0    2.44    2.12    0.36    0.17 
2035   455,639    51.0    3.12    1.85    0.47    0.20 
2036   457,359    51.0    3.64    1.80    0.39    0.15 
2037   459,113    51.0    4.73    1.15    0.52    0.20 
2038   460,902    51.0    3.41    1.72    0.37    0.14 
2039   461,076    51.0    4.22    1.40    0.52    0.24 
2040   461,076    51.0    4.85    1.15    0.52    0.20 
2041   461,076    51.0    4.09    1.38    0.54    0.24 
2042   461,076    51.0    4.52    1.28    0.50    0.21 
2043   461,076    51.0    3.14    1.92    0.35    0.16 
2044   461,076    51.0    2.48    2.16    0.33    0.15 
2045   461,076    51.0    2.41    2.10    0.34    0.15 
2046   461,076    51.0    2.18    2.15    0.29    0.12 
2047   461,076    51.0    2.98    1.80    0.43    0.20 
2048   461,076    51.0    2.15    2.07    0.33    0.14 
2049   461,076    51.0    2.24    2.11    0.30    0.13 
2050   461,076    51.0    3.02    1.73    0.45    0.21 
2051   204,178    51.3    2.62    1.67    0.43    0.19 
Total   11,601,748    51.0    3.46    1.71    0.43    0.18 


56


Figure 10 Tioyacu quarry final pit


13.7.Life of Mine


The life of the Tioyacu quarry is 26 years.


13.8.Staff


Cementos Selva S.A.C. personnel develop its operations at the Tioyacu quarry with its staff and contractors.


57


14.Processing and recovery methods


14.1.Process Plant


Cement production involves the following stages:


Production of raw materials. Limestone is produced from the Tioyacu quarry, as described in Chapter 13.


Milling and homogenization. Once the limestone is received at the plant, it is dosed to the raw mill with clay, iron and coal. The mixture must meet the quality standards to be sent to a storage silo from where it is fed to the raw meal storage silo. The raw meal is fed to the kiln for clinker production.


Clinkerization. The mixture is pelletized and then enters the vertical kiln where it reaches a temperature of approximately 1,450 degrees Celsius, the product of which is clinker. The clinker is then cooled to about 200 degrees Celsius and stored in silos or storage bins.


Cement grinding. After cooling, the clinker, together with gypsum and some additives, is fed into a mill to obtain cement.


Storage in silos. After passing through the mills, the cement is transferred to conveyor channels and stored in concrete silos to preserve its quality until distribution.


Packing, loading, and transportation. Cement is transferred through chutes from the silo to be packed into 42.5 kilogram bags in bagging machines, and then stored or loaded onto trucks operated by third parties for distribution. Bulk cement is transported by trucks.


58


14.2.Raw materials for the cement production


The following raw materials and additives are used in the Rioja plant to produce cement.


Raw Materials


Limestone, is composed mainly of calcium carbonate and is used as raw material and an additive in cement production.


Iron, is inert material composed basically of iron oxide (Fe2O3).


Clay, is inert material composed of silicon, aluminum and a low proportion of alkalis such as potassium and sodium.


Coal, is a solid, black, or dark brown mineral that is essentially carbon with small amounts of hydrogen, oxygen and nitrogen.


Gypsum. It is a material composed of calcium sulfate hydrates. When gypsum is mixed with the clinker, it controls the setting time when the cement initiates the hydration reactions.


Raw meal, is an artificial mixture of limestone, clay, iron, and coal used to produce clinker.


Clinker is a product obtained from limestone, clay, iron, and coal.


Additives


Limestone. It is a material composed mainly of calcium carbonate, which, when finely ground, is used as an additive in cement production.


Gypsum. It is a material composed of calcium sulfate hydrates. When gypsum is mixed with the clinker, it controls the setting time when the cement initiates the hydration reactions.


59


14.3.Flow sheet


The following is the block diagram of the cement plant for raw material processing, clinker and cement production.


Figure 11 Rioja plant process block diagram


14.4.Main equipment


Table 35 shows the design and production capacities for clinker and cement.


Table 35 Main equipment in Rioja plant


Equipment Product Capacity of production* Unit
Crusher Limestone Iron Gypsum 792,000 tonnes/year
Dryer 1 Limestone Clay 792,000 tonnes/year
Dryer 2 396,000 tonnes/year
Raw meal mill 1 Raw meal 198,000 440,000 tonnes/year
Raw meal mill 2 Raw meal 475,200 tonnes/year
Kiln 1 Clinker 43,560 tonnes/year
Kiln 2 Clinker 79,200 tonnes/year
Kiln 3 Clinker 83,160 tonnes/year
Kiln 4 Clinker 83,160 tonnes/year
Cement mill 1 Cement 55,440 tonnes/year
Cement mill 2 Cement 118,800 tonnes/year
Cement mill 3 Cement 265,760 tonnes/year
Bagging system 1 Cement 8,316,000 Bags/year
Bagging system 2 Cement 8,316,000 Bags/year


*The equipment capacities consider 330 days of production.


60


  14.5. Material balance cement plant


The following section presents information on the material balance at Rioja plant for cement production.


14.5.1.Material balance


Below is the clinker production balance at the Rioja plant, considering the use of limestone obtained from the Tioyacu quarry, clay, iron, and coal as part of the raw material for clinker production. Likewise, the balance for cement production is presented considering the additives used for the mixture with clinker and consequently cement production for the year 2025.


Table 36 Balance for raw meal production


Raw material Annual quantity (tonnes/year) Dosage
Limestone 321,647 75%
Others 106,586 25%
Raw meal* 428,233 100%


*Raw meal includes coal.


Raw meal is fed to the vertical kiln. The production of 1 ton of clinker requires 1.67 tons of raw meal.


Table 37 Balance for clinker production


Raw material Annual quantity (tonnes/year)
Raw meal 428,233
Clinker 256,194


Table 38 Balance for cement production.


Raw Material Annual quantity (tonnes/year) Dosage
Clinker 256,194 75%
Additions** 84,062 25%
Cement 340,256 100%


**The amount of limestone used as an addition was 66,179 tonnes.


14.6.Process losses


Losses in the cement production process associated with the raw material (limestone) are 1.55% due to the humidity of the limestone that is typical of the region (constant rainfall).


14.7.Water consumption


Water is mainly used for cooling in the milling processes and for the pelletizing process of the raw meal before it enters the vertical kilns. It is also used for watering green areas and accesses and restrooms. It is also used to irrigate green areas and accesses. 100,730 m3 of water was consumed at the Rioja Plant during its operations in 2025.


61


14.8.Fossil fuel consumption


The cement production process consumes liquid fuels for heavy equipment within the operation. Biomass is used as energy in the raw material drying process.


Table 39 Fuel consumption in Rioja plant


Fuel Consumption (tonnes/year) Description
Diesel 287.48 P.Cal 9845 Kcal/kg


14.9.Electric power consumption


The Rioja plant has an electrical substation with a capacity of 12 MVA, which uses electrical energy supplied from the national grid, 171,248 GJ of energy was consumed at the Rioja plant during its operations in 2025.


14.10.Maintenance Plan


Cementos Selva S.A.C. has implemented a preventive and corrective maintenance plan to prevent interruptions to the cement production process. Cementos Selva S.A.C. maintains operating efficiency to control costs and operating margins. Cementos Selva S.A.C. has initiatives to diversify energy sources and secure supply when possible. The equipment is in good condition and operational.


14.11.Staff


Cementos Selva S.A.C. personnel develop its operations at the Rioja plant with its staff and contractors.


62


15.Infrastructure


15.1.Tioyacu quarry


The Tioyacu quarry uses the infrastructure of the Rioja plant, such as administrative offices, workshops, utilities and other services. The quarry is located adjacent to the cement plant.


Explosive storage: Cementos Selva S.A.C. has built explosive storage facilities for the storage of explosives and accessories necessary for the quarry’s production activities. They are located in the El Pajonal quarry owned by Cementos Selva S.A.C.


15.2.Rioja Plant


The use of electrical energy is required; there is a high voltage electrical energy supply system of 60 Kv, 60 Hz transmission for the industrial facilities of Cementos Selva S.A.C.


There is a derivation from the 60 kV Rioja - Nueva Cajamarca transmission line owned by Electro Oriente, which runs in front of CSSAC’s facilities at a distance of 345.8 m.


The company has a license to use water for industrial purposes. The National Water Authority issued the Alto Mayo Local Water Administration (R.A. Nº 100-2010-ANA-ALA ALTOMAYO).


Water supply at the Rioja plant is provided by a groundwater well, Cementos Selva is allow to draw 567,648 m3 per year.


The construction of a new finished products warehouse with a capacity of 40,000 cement bags was completed in 2023.


63


16.Market Studies


Cementos Selva S.A.C is a subsidiary of Cementos Pacasmayo. Cementos Pacasmayo is a leading company in the cement production and other construction materials in the north of Peru. This chapter describes the cement market, as well as the macro and microeconomic factors that define it.


For the description of the cement market in Peru, public information has been collected from different sources, such as the Central Reserve Bank of Peru (BCRP), National Institute of Statistics and Informatics (INEI), Association of Cement Producers (ASOCEM), Ministry of Housing, Construction and Sanitation, Superintendence of Tax Administration and the Peruvian Construction Chamber. In addition to this information, this chapter also relies on statistics provided by the company (CPSAA) to provide a better understanding of its specific market.


16.1.The cement market in Peru


The Peruvian cement market is geographically segmented by regions: north, central and south. Diverse companies supply each region. Figure 12 is an illustration of the Peruvian map and of its 3 regions, according to the segmentation of the cement market, where each region is the main area of influence of domestic cement companies.


Figure 12 Segmentation of the cement market in Peru


The main companies that comprise the cement market in Peru are: Cementos Pacasmayo S.A.A., UNION Andina de Cementos S.A.A., Yura S.A. and Cementos Selva S.A.C. Additionally, there are companies that import cement or clinker, such as Caliza Cemento Inca S.A., Distribuidora Cemento Nacional S.A.C., CEMEX Perú S.A., Cal & Cemento Sur S.A., Holcim Perú S.A., amongst others.


64


Table 40 shows the domestic cement shipments (in thousands of tonnes):


Table 40 Cement shipments at domestic level (in thousands of tonnes)


   2023   2024   2025 
National cement shipments   12,175.7    12,001.8    12,936.0 
Overall cement shipments (CPSAA/CSSAC 3 plants)   2,936.6    2,835.1    3,049.2 
Rioja plant shipments   257.1    318.3    340.6 


Sources: ASOCEM, CPSAA/CSSAC


The types of cement produced by the main cement companies in the country are Type I, Type V, Type ICO, Type IL, Type GU, Type MS (MH), Type HS, Type HE, Type MH.


It is important to mention that, according to the main requirement standards, Peruvian Technical Standards, cements are divided into five types:


●NTP 334. 009 2013. Cements Portland. Requirement. (ASTM C 150).


●NTP 334. 090 2013. Cements Portland Added. Requirements. (ASTM C595).


●NTP 334. 082 2011. Cements Portland. Performance Specification. (ASTM C1157).


●NTP 334. 050 2004. Cements Portland White. Requirements. (ASTM C150).


●NTP 334. 069 2007. Building Cements. Requirements. (ASTM C091).


For Cementos Selva’s cement products, only the first 3 NTP standards apply.


16.2.Industry and Macroeconomic Analysis


Producers and trading companies of cement compete mainly within the limits of their area of influence, which is determined by the geographical location of their plants, giving rise to segmentation of the national market. However, the northern region presents a high demand potential because of the infrastructure gap, the housing deficit and a higher capillarity in terms of important cities adjacent to one another and with an urbanization level lower than in the central and southern region. On the other hand, it is important to note the importance of transportation in the structure of cement costs, which are composed primarily of raw materials, fuels and transportation.


The cement market and industry in Peru have the following characteristics:


●Base of consumers highly segmented, informal and of low resources.


●Low costs of energy and raw materials.


65


●Zone of influence / distribution determined by geographical location of the plant.


●High correlation between public and private investment, and self-construction.


The construction sector and cement industry have a behavior directly related to the Gross Domestic Product (GDP) and Private Consumption. Figure 13 shows how the GDP of the construction sector (monthly variation %) tracks the cyclic behavior of the Global GDP (monthly variation %), showing variations of lower significance than those of the Global GDP, but in the same direction. It is also noted that, in May 2020, the GDP of the construction sector had a positive variation of more than 200% (compared to the previous month), whilst Global GDP went up only 10%. This was due to the reactivation of economic activity and consumption once the confinement measures given by the Government to counter the Covid-19 pandemic were loosened. This reactivation was motivated primarily by private-construction sector consumption. In the face of the uncertainty caused by the health and economic crisis in 2020, consumers showed savings behaviors, which meant that people preferred consumption of goods for home improvement, amongst them, cement. This trend was maintained throughout 2021. However, in 2023 there was a decrease in demand for public and private investment due to the political and social situation. As a result, cement volumes are returning to pre-covid levels.


Figure 13 Global GDP and Construction sector GDP MoM variation (%)


Source: BCRP 2025


66


The cement industry is also motivated by housing sector growth, public and private investment in infrastructure, mining projects, shopping centers, construction of transportation systems, etc. Thus, one of the variables with more impact on cement industry and future demand is the infrastructure gap which remains high in the country.


For the 2016 – 2025 period, the infrastructure gap is estimated to be US$ 160 billion and this is present in the main economic sectors and services of public supply, that is: Transportation (36%), Energy (19%), Telecommunications (17%), Health (12%), Sewage System (8%), Irrigation (5%) and Education (3%). The 90% of the roads not included in the large national road network still remain without pavement. Only 40% of schools have access to basic services such as water, electricity and sewage system. There are only 15 hospital beds for every 10,000 individuals compared to 27 beds recommended by the WHO.


In 2025, the cement market grew by 7.8% compared to 2024, while in 2019 (before the pandemic) it grew by 20%. Given greater stability in the sector, a moderate growth of 2% in cement shipments is expected in 2026.


16.3.The North Region Market


Cementos Pacasmayo, a leading company in the production and sales of cement in the North Region, has market presence in the following cities: Cajamarca, Chiclayo, Chimbote, Jaén, Pacasmayo, Piura, Rioja, Tarapoto, Trujillo, Tumbes, Yurimaguas and Iquitos. The company has a Market share of over 91.8% in the northern region of the country.


Cementos Selva S.A.C.’s overall shipments from the Rioja plant were 340.6 tonnes. It supplied 10.2% of the country’s North Region cement demand, and its cement sales represented 11.2% of the Company’s overall shipments.


67


Other companies with lower presence in the cement market of the North Region are:


●Quisqueya - Cemex


●Cemento Nacional


●Cemento Inka


●Cemento Tayka


These companies are competitors of the Rioja plant.


Cementos Selva S.A.C.’s Rioja plant produces different types of cement and it has placed in the National Market different trademark products to meet the needs of diverse segments of the market. Table 41 shows the products in Rioja plant.


Table 41 Types of products of Rioja plant


Cement type Use Comment
Cemento Portland    
Cement Type I Cement of general use. The average result of resistance to compression is higher than the minimum requirement set forth in the technical standard NTP 334.009 / ASTM C150.
Cemento Portland with additives    
Cement Extra Forte Ideal for the execution of structural Works, repairs, remodelings, home applications, floors, levelings, grouts, tips, prefabricated elements of small and medium size and concrete elements which require special characteristics. The average result of resistance to compression is higher than the minimum requirement set forth in technical standard NTP 334.090.
Hydraulic Cements specified by performance    
Mochica GU Line For structures in contact with environment and humid and salty soils.    
Amazonico GU Line Cement for general purpose.  


16.4.Cement price


The sale prices of cement in the Peruvian market vary pursuant to their type and their geographical location. The price difference between each type is explained primarily by the dosifications of raw materials and additives, whilst the variations for geographical location are caused by the freights for the distribution to the points of sale.


68


At domestic level, the cement price in 2025 was, on average, 717.41 S/ x t Figure 14 shows the historical prices of cement in Peru.


Figure 14 Historic prices of cement in Peru


Source: Ministerio de Vivienda, Construcción y Saneamiento (November 2025).


16.5.Current and future demand


Cement demand at the national level is met by local shipments (local production), for the most part, and by imports. In 2025, 12.94 M tonnes were shipped locally; 7.8% more than in the same period of 2024 (12.00 M). Imports amounted to 0.49 M tonnes during 2025; 81.5% more than 2024 (0.27 M).


Figure 15 shows the evolution of the national demand of cement, expressed in thousands of tonnes, since 2019.


69


Figure 15 Evolution of the national demand of cement


Source: ASOCEM


It is noted that domestic demand has been growing, on average, at a rate of 3% per year, with the exception of 2020, which is considered an atypical year due to the adverse effects of the pandemic and the confinement measures, to then take a historic leap in 2021 with an annual increase of 38%. During 2024, shipments decreased by 1.9% compared to 2023 as a result of the political and social situation in the country. In 2025, dispatches grew by 7.8% due to the recovery of private investment (real estate, mining, and infrastructure projects) and the dynamism of self-construction, supported by higher employment and incomes, as well as increased execution of public works and the momentum of concession-based projects.


According to our internal information, in terms of regional distribution, the Northern Region accounts for approximately 25.7% of domestic cement demand, the Central Region for 53.1%, and the Southern Region for 21.1%.


Cementos Pacasmayo’s cement shipments (3 plants) reached 3,049.0 thousand tonnes in 2025, constituting a 23.6% share of total shipments in Peru and 91.8% in the Northern Region. This is 7% more than in 2024 (2,835.1 thousand tonnes).


70


Table 42 shows the projection of future demand or cement shipments for Cementos Selva S.A.C (Rioja plant). These projections are based on the 2026 estimated shipments.


Table 42 Forecast of future demand for Rioja cement plant


Year  Cement
Shipments
(Tonnes)
   Variation
(%)
 
2026   346,279      
2027   353,205    2.0%
2028   360,269    2.0%
2029   367,474    2.0%
2030   374,824    2.0%
2031   382,320    2.0%
2032   389,966    2.0%
2033   397,766    2.0%
2034   405,721    2.0%
2035   413,835    2.0%
2036   422,112    2.0%
2037   430,554    2.0%
2038   439,166    2.0%
2039   440,000    0.2%
2040   440,000    0.0%
2041   440,000    0.0%
2042   440,000    0.0%
2043   440,000    0.0%
2044   440,000    0.0%
2045   440,000    0.0%
2046   440,000    0.0%
2047   440,000    0.0%
2048   440,000    0.0%
2049   440,000    0.0%
2050   440,000    0.0%
2051   440,000    0.0%


71


17.Environmental studies, permitting, and plans, negotiations, or agreements with local individuals or groups.


17.1.Environmental Aspects


Cementos Pacasmayo S.A.A. has Corporate Policies that apply to the operations of quarries and cement plants. Relevant policies include Safety Occupational Health Policy, Quality Policy, and Environmental Policy.


17.1.1.Tioyacu quarry


On January 06, 2025, through Directorial Resolution No. 013-2025-PRODUCE/DGAAMI, the Ministry of Production approved the Update of the Detailed Environmental Impact Study of “Tioyacu quarry limestone”, which approve the modification of the environmental management plan.


In 2025, CSSAC carried out environmental monitoring through the Laboratory Environmental Testing Laboratory S.A.C. - Envirotest, a company with accreditation before the International Accreditation Service (IAS) and the National Quality Institute (INACAL), both signatories of the ILAC-MRA International Mutual Recognition Agreement.


Envirotest was in charge of collecting and analyzing the samples, and presenting the results through reports to the Environmental Assessment and Enforcement Agency - OEFA, an institution of the Peruvian State in charge of reviewing and validating the information presented by the owner. At the Tioyacu quarry, particulate matter parameters for air quality were measured annually. The 2025 results are below the threshold values established in the Environmental Quality Standard (ECA) for air approved by Supreme Decree No. 003-2017-MINAM.


The results obtained from the environmental noise measurement activities in 2025 are below the Environmental Quality Standard Limit (ECA) in compliance with the provisions of Supreme Decree N°085-2003-PCM.


72


Biological monitoring in the Tioyacu quarry was carried out by the company Consulting Biogroup S.R.L. The objective was to characterize the Vegetation, Herpetofauna, Avifauna and Mastofauna. The results showed an abundance of birdlife, a species typical of this type of vegetation where forest predominates.


Regarding water management, it is essential to mention that Tioyacu quarry does not have any discharges. The small water consumption is only for green area irrigation and road maintenance.


The Environmental Management of the Manufacturing Industry and Domestic Trade, Supreme Decree No. 017-2015-PRODUCE, establishes the environmental management procedures covered by Ministerial Resolution No. 157-2011-MINAM for investment projects subject to the National System of Environmental Impact Assessment (SEIA) and its amendments.


Law No. 28090 and its Regulation approved by Supreme Decree No. 033-2005-EM establishes the closure measures for non-metallic quarries.  Directorial Resolution No. 178-2016-MEM-DGAAM, the Update of the Closure Plan of the Tioyacu quarry mining unit was approved, which establishes measures at the end of the useful life of the quarry.


The Closure Plan submitted by Cementos Selva S.A.C. included the necessary measures to ensure effectiveness or consistency with the requirements necessary for the protection of public health and the environment. The initial strategy has continued with the Closure of the components of Tioyacu quarry mining unit, establishing temporary, progressive, final and post-Closure activities at the end and/or closure of operations.


73


Environmental closure activities have included physical stability in the mine, geochemical stability, water management facilities, decommissioning for the removal of equipment and machinery. Also infrastructure demolition, reclamation, waste disposal, landform establishment, habitat rehabilitation, revegetation and social programs.


Post-closure activities such as physical maintenance, geochemical maintenance, hydrological maintenance, and biological maintenance will be carried out, and post-closure monitoring activities include physical stability monitoring, geochemical stability monitoring, water management monitoring, biological monitoring, and social monitoring.


Considering that the land use before mining production was a secondary forest which was affected by other activities, forestation activities with native species have been considered part of the post-closure activities. Likewise, CSSAC will fulfill the commitments included in the Closure Plan approved by the above authority.


It is important to mention that the approval of the Mine Closure Plan involves the constitution of guarantees to ensure that the owner of the mining activity complies with the obligations derived from the Mine Closure Plan, in accordance with environmental protection regulations.


Cementos Selva S.A.C has provided financial assurance for the mine closure plan for the Tioyacu quarry consistent with the approved and updated mine closure plan for an amount of 492,010.00 USD.


We have a solid relationship with our communities and we have identified its main needs in health, education, urban development and local development.


We have a social investment program which contributes to dealing with their needs, based on good dialog and our compliance to our commitments to our communities.


74


The communities are a priority for Cementos Selva S.A.C. For this reason, we promote periodic meetings with their representatives and we create opportunities for dialog to know their expectations. Also, we have established public and private alliances for development projects and programs to contribute to a better quality of life and to strengthen our relationship. In 2025, CSSAC worked in partnership with the district governments of Elias Soplin Vargas and Rioja.


CSSAC has no commitments for local procurement and hiring although it does its best to hire local talent and do business with local businesses.


17.1.2.Rioja plant


Regarding water management, it is essential to mention that Rioja plant does not have any discharges. The small water consumption is only for green area irrigation.


In accordance with environmental regulations and according to the Regulation of Environmental Management of the Manufacturing Industry and Domestic Trade, Supreme Decree N° 017-2015-PRODUCE, companies that produce cement are required to submit Closure Plans before executing closure activities. To meet that requirement, Cementos Selva S.A.C. in compliance with Peruvian legislation will submit the Closure Plan in a timely manner.


17.2.Solid waste disposal


Cementos Selva S.A.C. has a Solid Waste Minimization and Disposal Plan for our production activities at the Rioja plant and Tioyacu quarry. Annually, our company declares the generation, storage, collection, and final disposal of hazardous and non-hazardous solid waste in compliance with environmental legislation.


75


As part of the solid waste minimization plan (2025), we declared 0 tonnes of hazardous waste and 5.2 tonnes of non-hazardous waste for the Tioyacu quarry. Likewise, for the Rioja plant we declared 34.3 tonnes of hazardous waste and 889.2 tonnes of non-hazardous waste, which were disposed of in accordance with environmental legislation.


17.3.Qualified Person’s Opinion


Cementos Selva S.A.C. complies with national environmental standards in the industrial sector and to the International Standard Industrial Classification - ISIC 2694 for the non-metallic production of the limestone material for the manufacture of cement.


For the industrial and mining sector, the company specifically complies with the Environmental Management Regulations for the Manufacturing Industry and Domestic Trade, Supreme Decree No. 017-2015-PRODUCE, which is the rule that regulates the environmental management of the activities indicated in Ministerial Resolution No. 157-2011-MINAM and investment projects subject to the National System of Environmental Impact Assessment (SEIA), considered in Annex II of the Regulations of Law No. 27446, approved by Supreme Decree No. 019-2009-MINAM.


The company reports the environmental commitments, semiannually to the Environmental Evaluation Agency - OEFA. The monitoring is carried out through external laboratories that provide comprehensive monitoring and analysis services and have double accreditation, by the international IAS (International Accreditation Service) and the national INACAL (National Institute of Quality), both signatories of the ILAC-MRA international Mutual Recognition Agreement.


Cementos Selva S.A.C. strictly complies with the protocols in the different processes in compliance with environmental legislation and reporting to the OEFA.


The qualified person believes that CSSAC’s current plans and management strategies are adequate for addressing any issues related to environmental compliance and maintaining its environmental permits. In addition, the qualified person believes that CSSAC has a good relationship with the local communities and that its social investment plans are adequate for reducing any social risks to the project.


76


18.Capital and operating costs


18.1.Basis for operating and capital costs for the quarry and plant


In a tabular manner, this section presents the operating costs of Tioyacu quarry for the production of limestone - the primary raw material used for cement production at the Rioja plant. It also exhibits the plant’s operating costs, for the whole industrial process; from the reception of raw material, to its conversion to the final product (cement). The operating cost forecast is mainly based on actual historical costs.


Similarly, this section reports the detail of the capital investments made in the quarry and plant, and the forecasted investment plan required to sustain all the activities in the quarry and plant and to assure the supply of limestone Reserves necessary to achieve the production levels according to the forecasted cement shipments of the Rioja plant.


Table 43 depicts the main components of the cost structure of Tioyacu quarry and Rioja plant and the sources used in their forecasts:


Table 43 Cost structure of Tioyacu quarry and Rioja plant


Cost category Description Source
Quarry Operating Cost Mineral Extraction /Exploitation, Processing, Fuel, Materials (Explosives), Maintenance, Insurance and Services ● Real, historic costs
● Suppliers´ quotes
Quarry Operating Cost Royalties ● Contract of mining royalty payment with
regional/state entities
Quarry Operating Cost Energy ● Historic, real costs
● Supply Contract
●
Suppliers’ quote
Plant Operating Cost Fuel, Materials, Maintenance, Wages and Insurance ● Historic, real costs
● Suppliers’ quote
Plant Operating Cost Energy ● Historic, real costs
● Supply Contract
●
Suppliers’ quote


Considering that the Tioyacu quarry and the Rioja plant are in operation, the historical costs are the principal basis for estimating forecasted costs.


77


Thus, the actual costs in some cases are maintained, and in other cases, are appropriately adjusted for factors specific to the quarry and plant operating, conditions, and obligations stipulated in supply and concession contracts.


On the other hand, macroeconomic factors such as inflation and devaluation of the local currency against the US dollar could indirectly impact future operating costs estimation.


18.2.Capital and Operating Cost Estimates


Table 44 details the operating costs of quarry and plant for the year 2025, and 26 years of forecast:


Table 44 Operating costs forecast of quarry and plant


   Production Data   Total   Cost per 
   Extracted
Mineral
   Cement
Production
   Operating
Cost
   tonne of
product
 
   tonnes ’000   tonnes ’000   S/ ’000   S/ x tonne 
                 
2025   399    340    108,461    318.76 
2026   440    346    110,609    319.42 
2027   439    353    116,138    328.81 
2028   440    360    125,729    348.99 
2029   442    367    129,091    351.29 
2030   443    375    133,363    355.80 
2031   445    382    145,410    380.34 
2032   446    390    149,706    383.90 
2033   448    398    155,012    389.71 
2034   449    406    168,356    414.95 
2035   451    414    173,731    419.81 
2036   453    422    180,203    426.91 
2037   455    431    195,022    452.95 
2038   456    439    205,506    467.95 
2039   457    440    210,255    477.85 
2040   457    440    221,936    504.40 
2041   457    440    225,601    512.73 
2042   457    440    230,134    523.03 
2043   457    440    242,400    550.91 
2044   457    440    246,667    560.61 
2045   457    440    251,860    572.41 
2046   457    440    264,861    601.96 
2047   457    440    282,183    641.32 
2048   457    440    288,110    654.80 
2049   457    440    301,635    685.53 
2050   457    440    307,314    698.44 
2051   457    440    401,066    911.51 


78


Table 45 shows the capital cost projection for the next 26 years, according to the production plan for 26 years of Reserves. Costs are adjusted annually by applying a 2.90% inflation rate to the cost/tonne.


Costs described in this chapter are applied to estimate the Mineral Resources and Reserves of the Tioyacu quarry as part of the analysis.


Table 45 shows the detail of capital investments in the quarry and plant, by type of investment, for one year of historical result (2025), and 26 years of projection:


Table 45 Investment forecast in quarry and plant


   Total
Investments
 
   S/ ’000 
     
2025   2,383 
2026   5,087 
2027   1,051 
2028   1,081 
2029   1,113 
2030   1,145 
2031   1,178 
2032   1,212 
2033   1,248 
2034   1,284 
2035   1,321 
2036   1,359 
2037   1,399 
2038   1,439 
2039   1,481 
2040   1,524 
2041   1,568 
2042   1,614 
2043   1,660 
2044   1,709 
2045   1,758 
2046   1,809 
2047   1,862 
2048   1,916 
2049   1,971 
2050   2,028 
2051   2,087 


In recent years, there have been no significant variations in capital investment, which correspond mainly to maintenance and replacement of equipment in the quarry and plant to sustain operations. The Company´s investment plan does not consider any unusual or expansion activity. It is solely planned to perform the necessary replacement for the quarry support and the maintenance of operations in the plant. The investments are kept at levels similar to those registered in the last few years.


18.3.Capital and Operating Cost Estimation Risks


There is a low risk associated with capital and production costs because mine production and cement plant operation will continue in the same geological deposit and using the same mining and industrial methods.


An assessment of the accuracy of estimation methods is reflected in the sensitivity analysis in Section 19.


For purposes of the Preliminary Feasibility Study completed relative to the Tioyacu quarry and Rioja plant, capital and operating costs are estimated to an accuracy of +/- 25%.


79


19.Economic Analysis


19.1.Methodology: Discounted Cash Flow (Free)


The Economic Analysis chapter describes the assumptions, parameters and methodology used to demonstrate the economic viability or profitability of extracting the mineral Reserves. That is, the pre-feasibility level support for the determination of mineral Resources and Reserves, by means of a business valuation through the Discounted (Free or Economic) Cash Flow method.


The horizon of the cash flow projection is consistent with the life of the quarry, which is calculated based on the total declared Reserves and the annual production at the quarry. Each period’s cash flow is approximated indirectly from the EBITDA (the latter is constructed in the Profit and Loss Statement), and the corresponding adjustments are made for taxes and capital costs (CapEx).


Finally, for this economic analysis we use the free cash flow, since it does not incorporate the company’s capital structure, and we apply the weighted average cost of capital (WACC) for discounting future cash flows.


19.2.Assumptions


19.2.1.General and Macroeconomic Assumptions


The general and macroeconomic assumptions used for the projection of economic cash flows and the valuation are:


●Projection horizon: 26 years (2026 to 2051) according to the estimated years of quarry life. 


●Annual inflation rate, 2.90%, based on Banco Central de Reserva del Perú as of projection 2025: applies equally to sales price, costs and expenses.


●Capital cost projections were determined using a historical ratio of annual investments and maintenance costs, which also considers the increase in production volume.


  ● The company’s financing structure is being considered in the discount rate (WACC), which is 10.91%.


80


●Income tax rate: effective rate of actual (historical) business results, 29% - 30%.


●Workers’ Profit Sharing: 10%.


●Exchange rate: exchange rate is assumed to remain at 3.80 (USD/PEN).


19.2.2.Income and Cost Assumptions


●The sales price of cement, expressed as S/ x t, is the sales price of the Rioja plant to Dino Selva Iquitos, FOB at Rioja plant; which is lower than the sales price to the final customer in the market. The distribution freight explains this difference to the multiple points of sale and the selling expenses associated with distribution and promotion in the different commercial channels.


●The base price used in the projection is an estimate for the year 2026 (582.2 S/ x t), which has been determined based on current market conditions and cement demand for 2025, among other factors.


●Starting in 2027 (year 2 of the projection), an annual price escalation rate of 2.9% is applied the sales prices.


●The cost of cement production, expressed as S/ x t, has been estimated for 2026 based on actual operating expenses, the market situation of local materials and services, plant demand for imported clinker, and other factors. The cost of production for year 2026 is 319.4 S/ x t.


●Starting in 2027, an annual cost escalation rate of 2.9% is applied to the cost.


●The initial stock of products in the quarry and plant is assumed to be zero.


19.3.Financial Model Results


The following financial parameters were calculated:


●NPV of 599 million Soles at a discount rate of 10.91%.


  ● 26-year mine life.


●Average plant throughput of 0.4 million tonnes per year over the 26-year projection.


●Average sales price of 754 Soles per ton of cement, on average for the 26-year projection, at nominal values.


81


●Revenues of 316 million Soles, on average for the 26-year projection.


  ● Average production cost of 497.6 Soles per ton of cement, on average for the 26-year projection, at nominal values.


Table 46 shows the forecasted Profit and Loss Statement for the Tioyacu quarry and Rioja plant operation:


Table 46 Profit and Loss Statement


   Shipments
(tonnes)
   Revenue
S/ x t
   Gross
Profit
S/ ’000
   Gross
Margin
S/ x t
   Gross Mg
%
   Operating
Profit
   (+) Depreciation   EBITDA
Rioja
Plant
   EBITDA
Mg %
 
                                     
2026P   346,279    582.2    82,239    237.5    41%   73,110    9,048    82,158    41%
2027P   353,205    593.9    84,659    239.7    40%   75,129    6,951    82,080    39%
2028P   360,269    605.7    83,659    232.2    38%   73,917    6,903    80,820    37%
2029P   367,474    617.8    88,643    241.2    39%   78,768    6,768    85,536    38%
2030P   374,824    630.2    93,127    248.5    39%   83,039    6,707    89,746    38%
2031P   382,320    642.8    90,870    237.7    37%   80,509    6,697    87,206    35%
2032P   389,966    655.7    96,029    246.3    38%   85,366    6,709    92,074    36%
2033P   397,766    668.8    100,636    253.0    38%   89,653    6,729    96,382    36%
2034P   405,721    682.1    98,298    242.3    36%   86,994    6,742    93,736    34%
2035P   413,835    695.8    103,620    250.4    36%   91,978    6,763    98,740    34%
2036P   422,112    709.7    108,353    256.7    36%   96,377    6,770    103,147    34%
2037P   430,554    723.9    105,908    246.0    34%   93,589    6,778    100,367    32%
2038P   439,166    738.4    107,860    245.6    33%   95,189    6,783    101,973    31%
2039P   440,000    753.1    110,047    250.1    33%   97,016    6,788    103,804    31%
2040P   440,000    768.2    105,475    239.7    31%   92,077    6,790    98,866    29%
2041P   440,000    783.6    108,329    246.2    31%   94,550    6,794    101,344    29%
2042P   440,000    799.2    110,517    251.2    31%   96,347    6,798    103,145    29%
2043P   440,000    815.2    105,783    240.4    29%   91,221    6,791    98,012    27%
2044P   440,000    831.5    108,468    246.5    30%   93,499    6,788    100,287    27%
2045P   440,000    848.2    110,442    251.0    30%   95,043    6,797    101,839    27%
2046P   440,000    865.1    105,436    239.6    28%   89,595    6,803    96,398    25%
2047P   440,000    882.4    96,627    219.6    25%   80,331    6,812    87,143    22%
2048P   440,000    900.1    98,344    223.5    25%   81,579    6,821    88,400    22%
2049P   440,000    918.1    93,279    212.0    23%   76,029    6,832    82,862    21%
2050P   440,000    936.4    95,511    217.1    23%   77,763    6,844    84,606    21%
2051P   440,000    955.2    9,999    22.7    2%   -8,261    6,855    -1,406    0%


Cement sales at Rioja plant are, on average, S/ 316 million per year (for the period 2026-2051), and the average EBITDA margin for the same period is 30%. Due to the increase in cement shipments, the installed capacity of clinker is exceeded, and it is necessary to start importing a minimum quantity from year 2047 until year 2051.


82


Table 47 shows the Free Cash Flow projection and the valuation of the cement business of Rioja plant:


Table 47 Free Cash Flow and valuation


   FCF - Valuation (Thousand S/) 
   (-) Taxes (EBIT*t)   (-)
CapEx
   EBITDA Rioja Plant   Free Cash Flow 
                 
2026P   -29,086    -1,072    89,267    59,109 
2027P   -29,290    -1,103    89,385    58,991 
2028P   -29,195    -1,135    88,007    57,677 
2029P   -31,330    -1,168    93,195    60,697 
2030P   -33,341    -1,202    97,821    63,277 
2031P   -32,393    -1,237    95,034    61,405 
2032P   -34,431    -1,273    100,375    64,671 
2033P   -36,265    -1,309    105,099    67,525 
2034P   -35,344    -1,347    102,195    65,503 
2035P   -37,373    -1,387    107,684    68,924 
2036P   -39,141    -1,427    112,518    71,950 
2037P   -38,564    -1,468    109,467    69,434 
2038P   -39,594    -1,511    111,228    70,123 
2039P   -40,318    -1,554    113,237    71,365 
2040P   -38,372    -1,600    107,819    67,847 
2041P   -39,367    -1,646    110,538    69,524 
2042P   -40,198    -1,694    112,513    70,621 
2043P   -38,273    -1,743    106,882    66,866 
2044P   -39,190    -1,793    109,378    68,394 
2045P   -39,787    -1,845    111,080    69,448 
2046P   -37,569    -1,899    105,110    65,642 
2047P   -33,826    -1,954    94,954    59,174 
2048P   -34,316    -2,011    96,332    60,005 
2049P   -32,074    -2,069    90,254    56,111 
2050P   -32,912    -2,129    92,167    57,126 
2051P   -32,912    -2,191    6,155    -28,948 


WACC   10.91%
Economic NPV (Thousand S/)   598,817 


The net present value (NPV) of Rioja plant cement business amounts to almost S/ 599 million and it is made up of the sum of the discounted cash flows of each period, for the 26-year projection.


For discounting of the cash flows, the weighted average cost of capital of the company (WACC for its acronym in English) was applied.


83


19.4.Sensitivity Analysis


The sensitivity analysis considers a variation of +/- 5 and 10% in the variables that have the greatest impact on the NPV and EBITDA. These variables are the cement sales price, operating cost and CapEx.


Table 48 and Table 49 detail the sensitivity of the NPV and EBITDA to each variable, respectively, when the variables are varied independently. Figure 16 and Figure 17 show the results of the sensitivity of NPV and EBITDA, respectively, to the three variables:


Table 48 Sensitivity analysis of the Net Present Value


Variable / Variation -10% -5% 0% +5% +10%
Price -26.6 -13.3 0 13.3 26.6
Cost 16.4 8.2 0 -8.2 -16.4
CapEx 0.2 0.1 0 -0.1 -0.2


Table 49 Sensitivity analysis of the EBITDA


Variable / Variation -10% -5% 0% +5% +10%
Price -30.4 -15.2 0 15.2 30.4
Cost 19.9 10.0 0 -10.0 -19.9
CapEx 0 0 0 0 0


Figure 16 Sensitivity of Net Present Value (expressed as %)


84


Figure 17 Sensitivity of EBITDA (expressed as %)


Based on these results, the NPV is most sensitive to cement price, followed by operating cost, and least susceptible to the CapEx. EBITDA has a similar sensitivity to NPV, being most exposed to cement price, followed by operating cost, but shows no sensitivity towards variations to the CapEx.


85


20.Adjacent properties


The information in this chapter was obtained from the competent authority: Instituto Geológico, Minero Metalúrgico (INGEMMET). The only public information obtained is shown in the Figure below.


To the north of the Cementos Selva S.A.C. concession is the Rioja 2 concession owned by Cementos Selva S.A.C.; to the east of the mining concession is the Rioja 4 concession owned by Cementos Selva S.A.C., and to the southwest is the Rioja 3 concession owned by Cementos Selva S.A.C.


Figure 18 Concession Calizas Tioyacu and adjacent concessions.


21.Other relevant data and information


Not applicable.


86


22.Interpretation and conclusions


●From a legal point of view, Cementos Selva S.A.C. has the ownership of the mining properties for the exploration, development and production of limestone to supply the cement plants for normal production during the life of the quarry.


●Cementos Selva S.A.C. has been complying with international ISO-9001 standards since 2015 and has implemented Quality Assurance and Quality Control (QAQC). The controls are applied for the construction of the Geological Model, Resource estimation and Reserves estimation.


●Cementos Selva S.A.C. has a quality assurance system in its operations that includes sample preparation methods, procedures, analysis and security, which comply with the best practices in the industry.


●The information verification and validation processes are carried out following the procedures indicated in the information flows. The validated information is congruent with the one that generated the geological models, which is the fundamental basis for the estimation of Resources.


●The geological modeling of the limestone deposit considers its update with the drilling campaign developed during the 2024, being consistent with the relationship between the information and the geological model.


●The Mineral Resource and Reserves estimation considers the geologic characteristic and modifying factors as well as due consideration of risk: geologic and associated with evaluation of modifying factors. The main quality variable is the CaO content which is very stable in the deposit. There are other secondary variables that determine the quality of the Reserves.


●In the process of estimating Mineral Reserves and in the production plans of the quarry these variables have been adequately considered in the mining plan, properly sequenced, and with blending processes. There are sufficient proven and probable Reserves for the next 26 years.


87


  ● Table 50 shows the Mineral Resources of the Tioyacu quarry the results of Mineral Resource classification. Likewise, the Mineral Reserves and the results of Mineral Reserve classification are shown in Table 51.


Table 50 Mineral Resources (exclusive of Reserves) of Tioyacu quarry


  Resources Tonnes
M
CaO
(%)
Al2O3
(%)
MgO
(%)
SiO2
(%)
K2O
(%)
Limestone Measured 25.8 49.52 0.69 1.26 6.88 0.25
Indicated 4.8 48.29 0.76 1.66 7.92 0.26
Measured + Indicated 30.6 49.33 0.70 1.32 7.04 0.25
Inferred 7.2 49.11 0.25 3.44 1.70 0.11


Table 51 Mineral Reserves of Tioyacu quarry


  Reserves Tonnes
M
CaO
(%)
Al2O3
(%)
MgO
(%)
SiO2
(%)
K2O
(%)
Limestone Proven 10.3 51.20  0.43 1.70 3.21 0.18
Probable 1.3 49.31  0.48 1.79 5.40 0.17
Total 11.6 50.99  0.43 1.71 3.46 0.18


●The cement plant located in Rioja has equipment and facilities available for cement production, using limestone from the Tioyacu quarry and other necessary materials.


●The Health, Safety and Environment department is in charge of supervising and ensuring compliance with the Company’s corporate policies and the various legal requirements of the national regulatory bodies by all company departments.


●Through its Social Responsibility department, Cementos Selva S.A.C. has built relationships of trust with the communities surrounding its operations, identifying their primary needs in health, education, urban development and local development.


●Infrastructure-wise, the operation in Tioyacu quarry and Rioja plant, in relation to infrastructure, is technically and economically feasible due to the life of the quarry.


●The sensitivity analysis shows that the operation is economically robust.


88


23.Recommendations


●Maintain the QAQC program for exploration, development and production activities associated with cement production.


●Include QAQC plans and density control for the subsequent diamond drilling campaigns.


●It is recommended to continue evaluating the SiO2 and MgO variables to optimize extraction plans in terms of the waste rock removal ratio during operation to achieve a reduction in production costs.


●It is recommended to continue the geological evaluation of the deposit towards the southeast, to incorporate it into the Resources and Reserves model, which will provide greater robustness and support for said model.


●Maintain a permanent monitoring of the installed piezometers both for water levels and water quality, to evaluate the evolution of levels during the production of the Tioyacu quarry.


89


24.References


SEGECO S.A. (1998). Estudio de Impacto Ambiental De La Cantera de Calizas “Tioyacu” de Cementos Selva S.A.C.


Walsh Perú S.A. (2000). Diagnóstico Ambiental Preliminar (DAP) de la Planta Industrial Rioja.


SEGECO S.A. (2011). Estudio de Impacto Ambiental “Ampliación de Producción Línea 3 – Cementos Selva”.


SEGECO S.A. (2012). Estudio de Impacto Ambiental “Ampliación de Explotación de la Cantera Tioyacu”.


MINCONSULT S.R.Ltda, (2012). Plan de Minado.


Environmental Hygiene & Safety S.R.L. (2104). “Almacen de Materias Primas en Exteriores de Planta de Fabricación de Cementos – Rioja”.


GEOSYM CONSULTORES S.A.C (2016). Estudio Geológico, Geotécnico, Hidrológicos e Hidrogeológicos de La Cantera “Tioyacu” – Volumen I: Estudio Geológico.


GEOSYM CONSULTORES S.A.C (2016). Estudio Geológico, Geotécnico, Hidrológicos e Hidrogeológicos de La Cantera “Tioyacu” – Volumen II: Estudio Hidrogeológico.


GEOSYM CONSULTORES S.A.C (2016). Estudio Geológico, Geotécnico, Hidrológicos e Hidrogeológicos de La Cantera “Tioyacu” – Volumen III: Estudio Geotécnico.


GEOSYM CONSULTORES S.A.C (2016). Estudio Geológico, Geotécnico, Hidrológicos e Hidrogeológicos de La Cantera “Tioyacu” – Volumen IV: Estudio Hidrológico.


90


25.Reliance on information provided by registrant


In preparing this report, the qualified persons relied upon data, written reports and statements provided by the registrant in accordance with 17 CFR § 229.1302(f). After careful review of the information provided, the QPs have no reason to believe that any material facts have been withheld or misstated. Cementos Selva provided the information as summarized in Table 52.


Table 52 List of Cementos Selva S.A.C. information.


Chapter Chapter name Information provided by CPSAA
3 Property description Legal matters related to property rights and the authority “Instituto Geológico, Minero y Metalúrgico INGEMMET”
16 Market studies Marketing information, CPSAA information, CSSA information, ASOCEM, INEI and BCRP
17 Environmental studies, permitting, and plans, negotiations, or agreements with local individuals or groups Community Relations and information about agreements with stakeholders
18 Capital and operating costs Historical data about cost, price and investments
19 Economic analysis The International Monetary Fund Economic model, Macroeconomic trends, data, assumptions, and interest rates
20 Adjacent properties Legal matters related to property rights and the authority “Instituto Geológico, Minero y Metalúrgico “INGEMMET”


 91


Signature Page


This report titled “Technical Report Summary Tioyacu Quarry and Rioja Cement Plant” with an effective date of December 31, 2025, was prepared, compiled, and signed by the following qualified professionals, as indicated in the respective sections of this document.


Dated at Lima, Peru

April 27, 2026


/s/ Marco Carrasco  
Marco Carrasco, P. Eng., RM-MMSA  
Project Manager
 
C&O Projects LLC  
   
/s/ Jason Gamio  
Jason Gamio, P. Eng.  
Planning and Evaluation of Resources and Reserves Superintendent
Cementos Pacasmayo S.A.A
 
   
/s/ Marco Alarcón  
Marco Alarcón, P. Eng.  
Quarry Superintendent  
Cementos Pacasmayo S.A.A  


Note:


(*)Marco Carrasco served as Project Manager for Cementos Pacasmayo S.A.A. until March 2026 and thereafter participated as Project Manager of C&O Project LLC. In this capacity, he compiled and integrated the information provided by the Qualified Persons responsible for each chapter to prepare a consolidated report. Each Qualified Person is solely responsible for the content of the sections they prepared. Mr. Carrasco’s role in the compilation process was limited to the organization and integration of such information and did not include independent technical verification or validation of the data, analyses, or conclusions provided by other Qualified Persons.


 92


 93


 94


 95