Exhibit 99.1
| FOR IMMEDIATE RELEASE | |||||||||||
| Investor Contact: | Ian Tanaka | Media Contact: | Dean Kawamura | ||||||||
| VP, Treasury Manager | VP, Community Development Manager | ||||||||||
| (808) 544-3646 | (808) 544-3642 | ||||||||||
| [email protected] | [email protected] | ||||||||||
NEWS RELEASE
CENTRAL PACIFIC FINANCIAL CORP. REPORTS RESULTS FOR SECOND QUARTER 2020
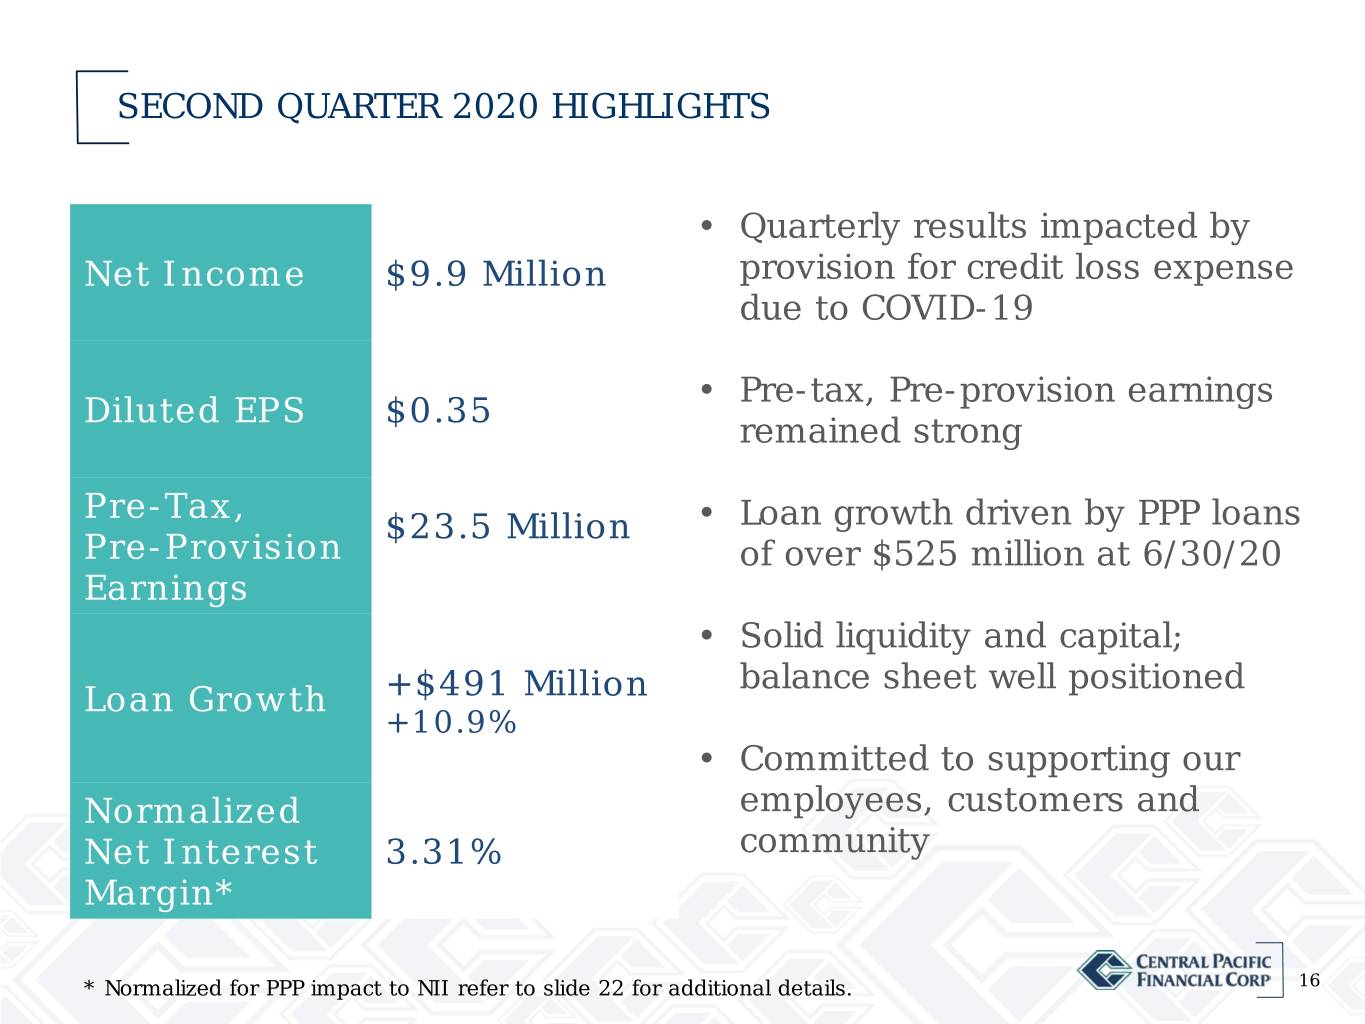
•Net income of $9.9 million, or fully diluted EPS of $0.35 for the second quarter, compared to net income of $8.3 million, or fully diluted EPS of $0.29 for the first quarter.
•Strong pre-tax pre-provision earnings of $23.5 million for the second quarter, compared to $19.4 million in the year-ago quarter and $20.5 million in the first quarter.
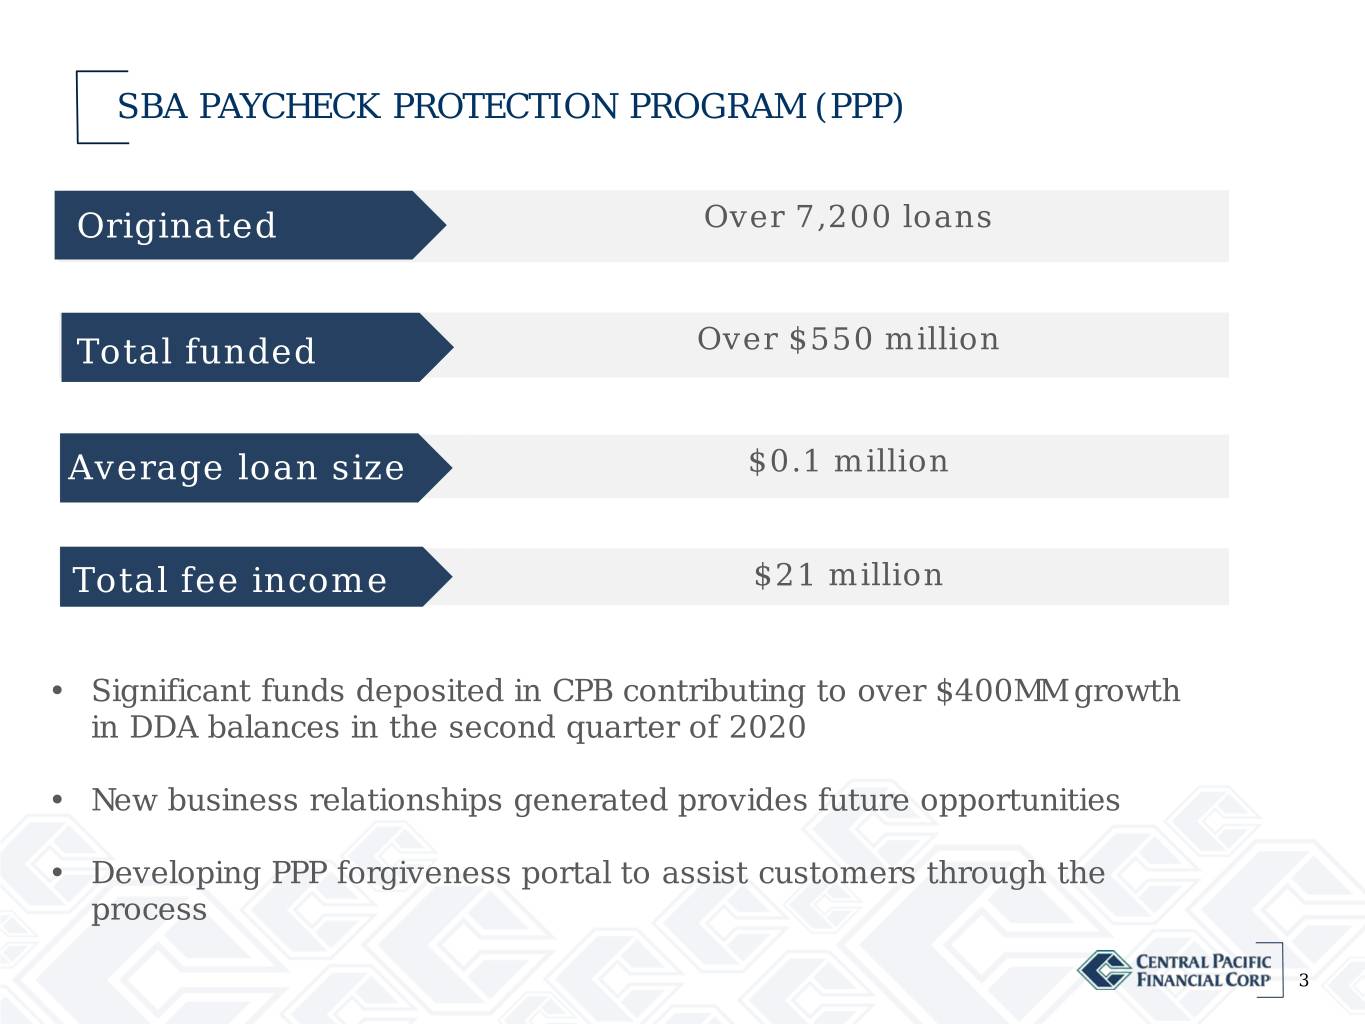
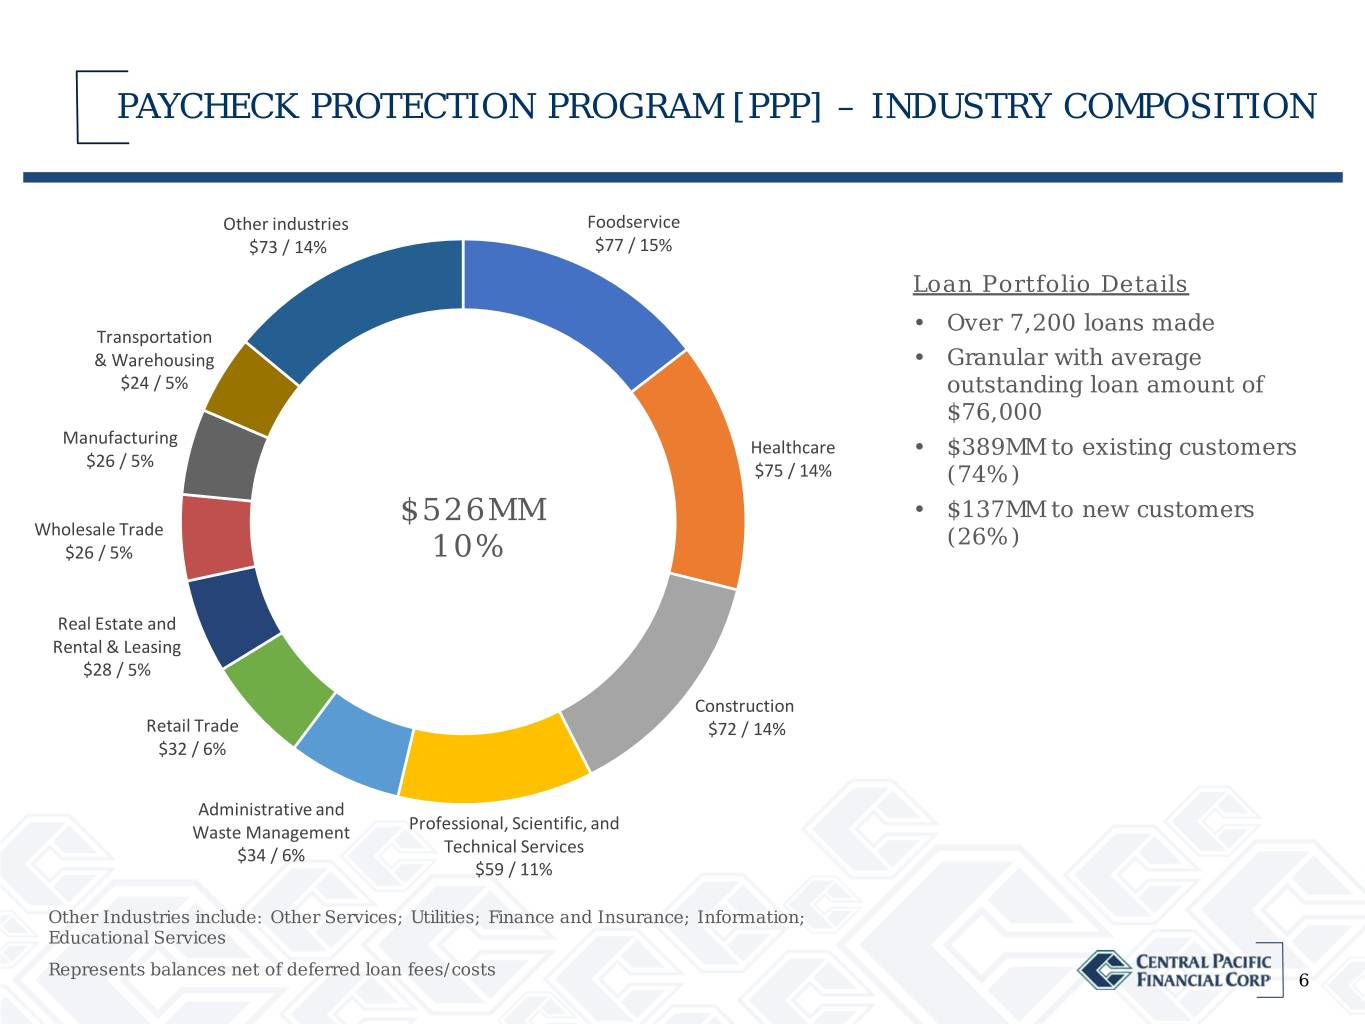
•Supported over 7,200 small businesses with SBA Paycheck Protection Program ("PPP") loan originations totaling $556.9 million, which largely contributed to the increase in total loans of $491.4 million, or 10.9% sequentially, and $756.3 million, or 17.8% year-over-year.
•Core deposits increased by $719.3 million, or 16.7% sequentially, and $925.2 million, or 22.6% year-over-year. The deposit of PPP funds into both new and existing deposit accounts largely contributed to the increase in core deposits.
•Cost of average total deposits of 0.20% in the second quarter declined by 16 basis points from the first quarter.
•We continue to execute on our RISE2020 initiative while navigating the challenging current landscape.
•Board of Directors declared a quarterly cash dividend of $0.23 per share.
HONOLULU, HI, July 29, 2020 – Central Pacific Financial Corp. (NYSE: CPF) (the "Company"), parent company of Central Pacific Bank, today reported net income in the second quarter of 2020 of $9.9 million, or fully diluted earnings per share ("EPS") of $0.35, compared to net income in the second quarter of 2019 of $13.5 million, or EPS of $0.47, and net income in the first quarter of 2020 of $8.3 million, or EPS of $0.29. Our operating results continue to be impacted by a higher provision for credit loss expense due to deteriorating economic conditions brought on by the current COVID-19 pandemic. During the second quarter of 2020, the Company recorded a provision for credit loss expense of $10.6 million, compared to $1.4 million in the second quarter of 2019 and $9.3 million in the first quarter of 2020.
Central Pacific Financial Corp. Reports Results for Second Quarter 2020
Page 2
"Central Pacific is strong and well-positioned to manage through the challenging operating environment. Our credit quality, capital and liquidity are solid, which enables us to support our customers and the community during this time of great need," said Paul Yonamine, Chairman and Chief Executive Officer.
"Through the Paycheck Protection Program, we’ve been able to help save thousands of local jobs in our community. We are proud of our employees that stepped up during this tremendous effort and continue to work diligently to help our customers navigate the current challenges," said Catherine Ngo, President.
On July 28, 2020, the Company's Board of Directors declared a quarterly cash dividend of $0.23 per share on its outstanding common shares. The dividend will be payable on September 15, 2020 to shareholders of record at the close of business on August 31, 2020.
Earnings Highlights
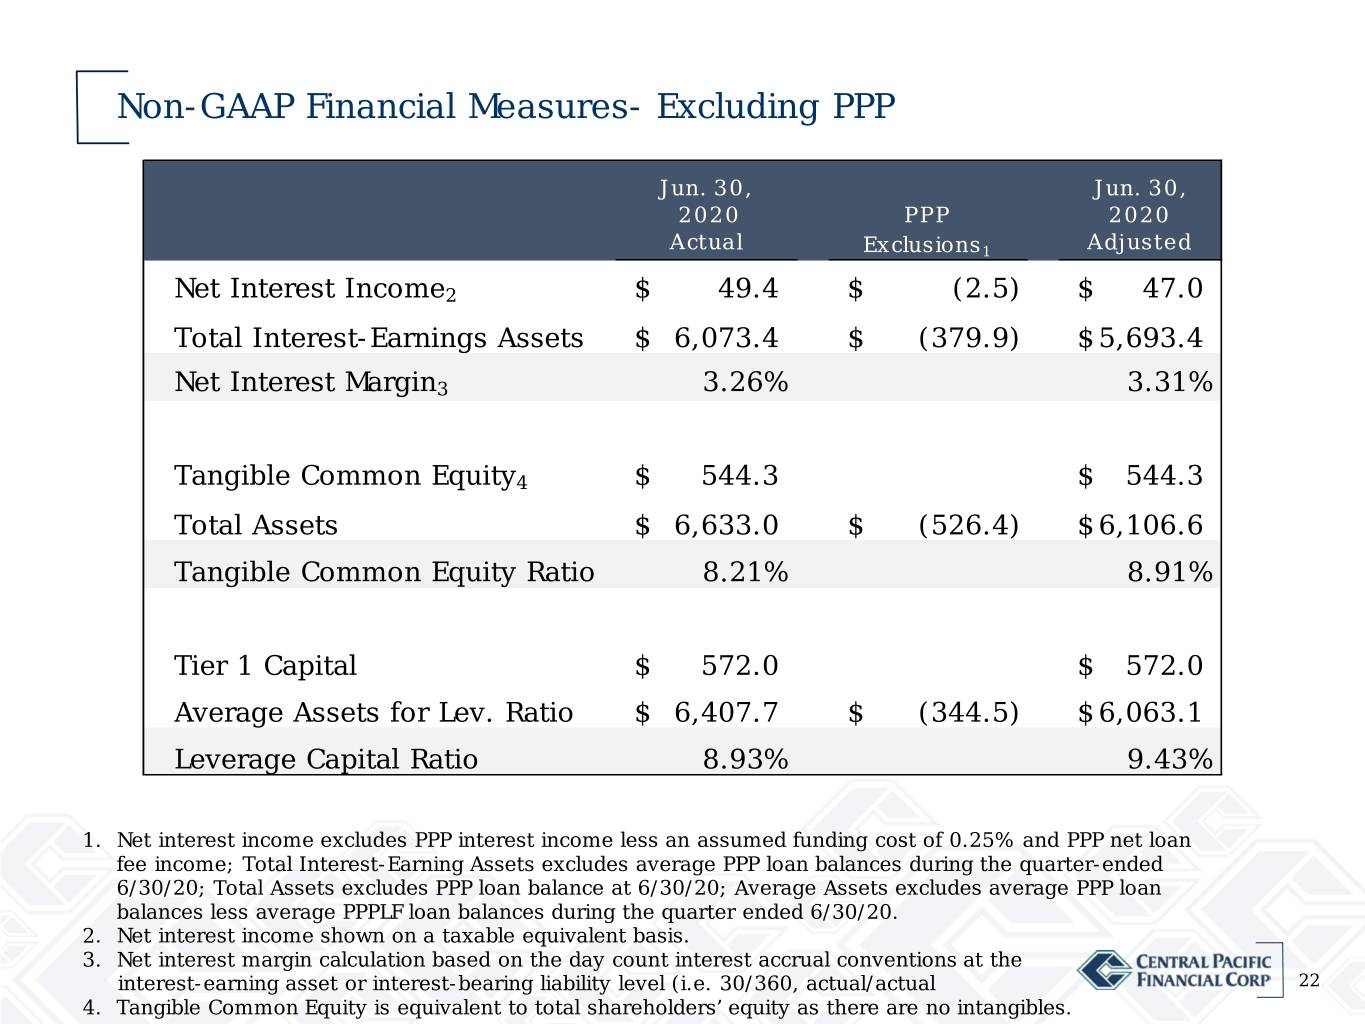
Net interest income for the second quarter of 2020 was $49.3 million, compared to $45.4 million in the year-ago quarter and $47.8 million in the previous quarter. Net interest margin for the second quarter of 2020 was 3.26%, compared to 3.33% in the year-ago quarter and 3.43% in the previous quarter. The increases in net interest income from the year-ago and sequential quarters were due to growth in the loan portfolio, primarily attributable to loans originated under the Paycheck Protection Program ("PPP"), combined with lower rates paid on interest-bearing liabilities, partially offset by lower yields earned on the loan and investment securities portfolios. Net interest income for the second quarter of 2020 included $2.5 million in PPP net interest income and net loan fees, which are accreted into income over the term of the loans and accelerated when the loans are forgiven or paid-off. The declines in net interest margin, yields earned on the loans and investment securities portfolios and rates paid on interest-bearing liabilities from the year-ago and sequential quarters is primarily attributable to the five rate cuts by the Federal Reserve from August 2019 through March 2020. During the quarter, the Company had an average PPP loan balance of $379.9 million, which earned approximately 2.61% in net interest income and net loan fees.
Other operating income for the second quarter of 2020 totaled $10.7 million, compared to $10.1 million in the year-ago quarter and $8.9 million in the previous quarter. The increase in other operating income from the year-ago quarter was primarily due to higher mortgage banking income of $1.9 million and higher income from bank-owned life insurance of $0.5 million. These increases were partially offset by lower other service charges and fees of $1.0 million and lower service charges on deposit accounts of $0.9 million as certain service charges were suspended during the quarter to support our customers through the pandemic. In addition, there was less transactional activity due to the pandemic. The increase in other operating income from the previous quarter was primarily due to higher mortgage banking income of $3.2 million, combined with higher income from bank-owned life insurance of $1.4 million, partially offset by lower other service charges and fees of $2.0 million and lower service charges on deposit accounts of $0.9 million. The lower other charges and fees was primarily due to $1.3 million in income related to an interest rate swap recognized in the previous quarter, combined with the aforementioned suspension of service charges and lower transaction activity. The higher mortgage banking income compared to the year-ago and sequential quarters was primarily due to higher gains on sales of residential mortgage loans of $3.6 million and $3.8 million, respectively, partially offset by higher amortization of mortgage servicing rights of $1.1 million and $0.1 million, respectively, and lower net servicing fees of $0.6 million and $0.2 million, respectively. The higher amortization of mortgage servicing rights was primarily attributable to the recent decline in market interest rates. The higher income from bank-owned life insurance compared to the year-ago and sequential quarters was primarily attributable to current quarter gains in the equity markets.
Other operating expense for the second quarter of 2020 totaled $36.4 million, which increased from $36.1 million in the year-ago quarter and increased from $36.2 million in the previous quarter. The increase from the year-ago quarter was primarily due to higher legal and professional services of $0.5 million and higher computer software expense of $0.5 million, partially offset by lower entertainment and promotions of $0.9 million (included in other). The lower entertainment and promotions was primarily due to expenses related to a core deposit gathering campaign in the year-ago quarter. The increase from the previous quarter was primarily due to higher salaries and employee benefits of $0.3 million and higher legal and professional services of $0.2 million, partially offset by lower advertising expense of $0.2 million.
The efficiency ratio for the second quarter of 2020 was 60.76%, compared to 65.09% in the year-ago quarter and 63.90% in the previous quarter.
In the second quarter of 2020, the Company recorded income tax expense of $3.0 million, compared to $4.4 million in the year-ago quarter and $2.8 million in the previous quarter. The effective tax rate for the second quarter of 2020 was 23.0%, compared to 24.6% in the year-ago quarter and 25.3% in the previous quarter. The decrease in the effective tax rate was primarily due to higher tax-exempt bank-owned life insurance income in the current quarter, compared to the year-ago and sequential quarters.
Central Pacific Financial Corp. Reports Results for Second Quarter 2020
Page 3
Balance Sheet Highlights
Total assets at June 30, 2020 of $6.63 billion increased by $713.0 million, or 12.0% from June 30, 2019, and increased by $524.4 million, or 8.6% from March 31, 2020.
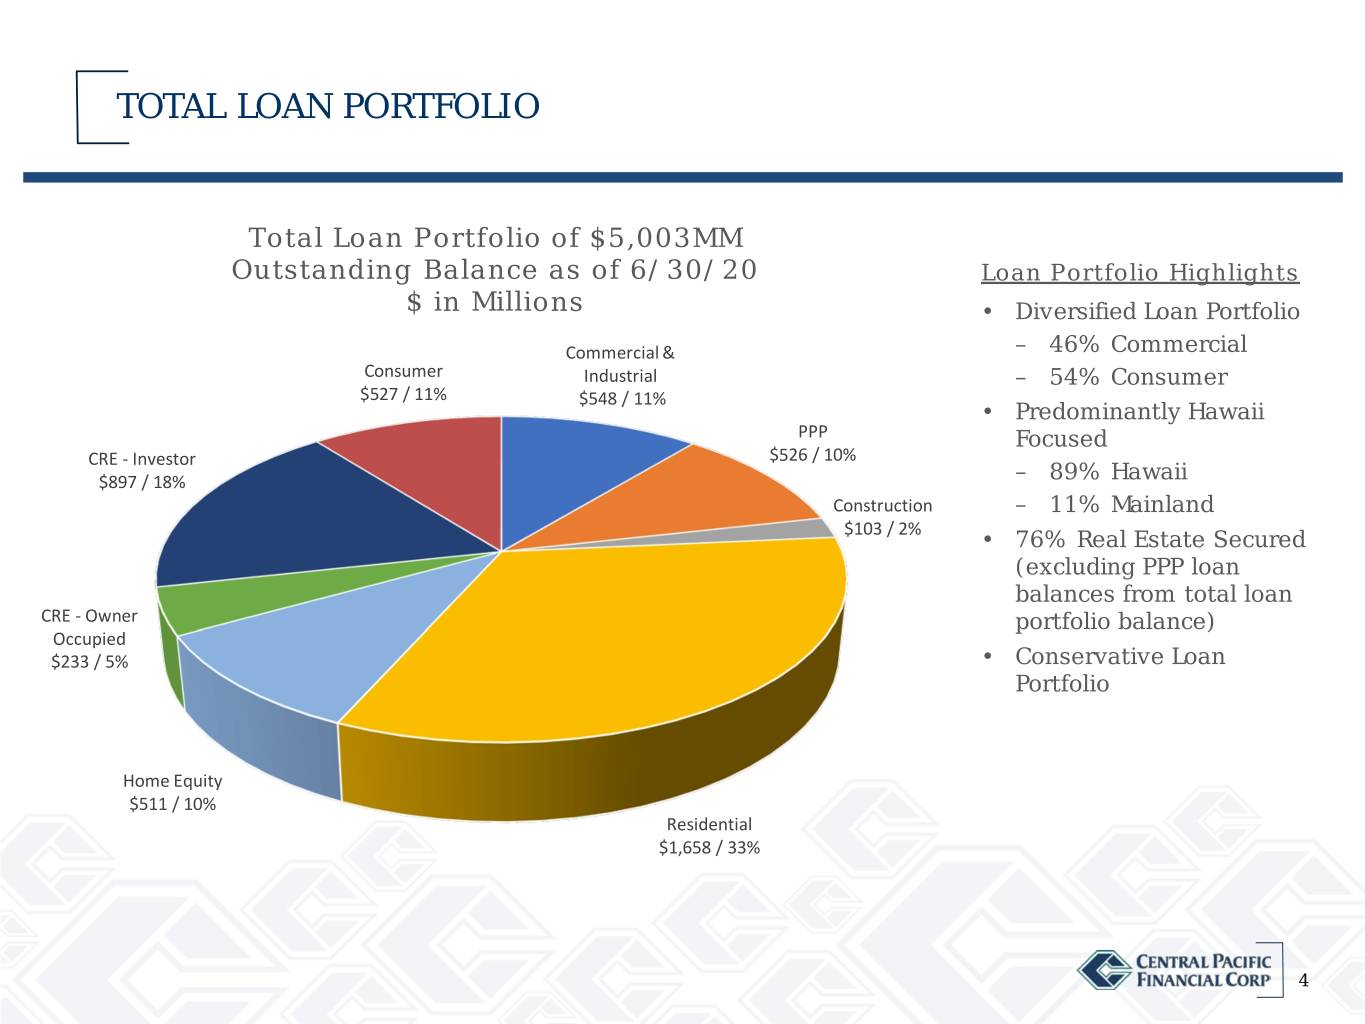
Total loans at June 30, 2020 of $5.00 billion increased by $756.3 million, or 17.8%, and $491.4 million, or 10.9% from June 30, 2019 and March 31, 2020, respectively. The year-over-year increase in total loans was driven by the origination of PPP loans totaling $526.4 million, net of deferred fees and costs, combined with broad-based growth in almost all other loan categories. The sequential quarter increase in total loans was primarily due to PPP loans and an increase in residential mortgage loans of $25.0 million, partially offset by decreases in other commercial and consumer loans.
Total deposits at June 30, 2020 of $5.79 billion increased by $817.8 million, or 16.4% from June 30, 2019, and increased by $658.6 million, or 12.8% from March 31, 2020. The sequential quarter increase in total deposits was primarily attributable to the increases in noninterest-bearing demand deposits of $420.5 million, savings and money market deposits of $252.5 million and interest-bearing demand deposits of $49.0 million. This increase was offset by a decrease in total time deposits of $63.3 million. Core deposits, which include demand deposits, savings and money market deposits, and time deposits less than $100,000, totaled $5.02 billion at June 30, 2020. This represents an increase of $925.2 million, or 22.6% from June 30, 2019, and $719.3 million, or 16.7% from March 31, 2020. The deposit of PPP funds into both new and existing deposit accounts largely contributed to the increase in core deposits. The Company's loan-to-deposit ratio was 86.4% at June 30, 2020, compared to 85.3% at June 30, 2019 and 87.9% at March 31, 2020.
Asset Quality
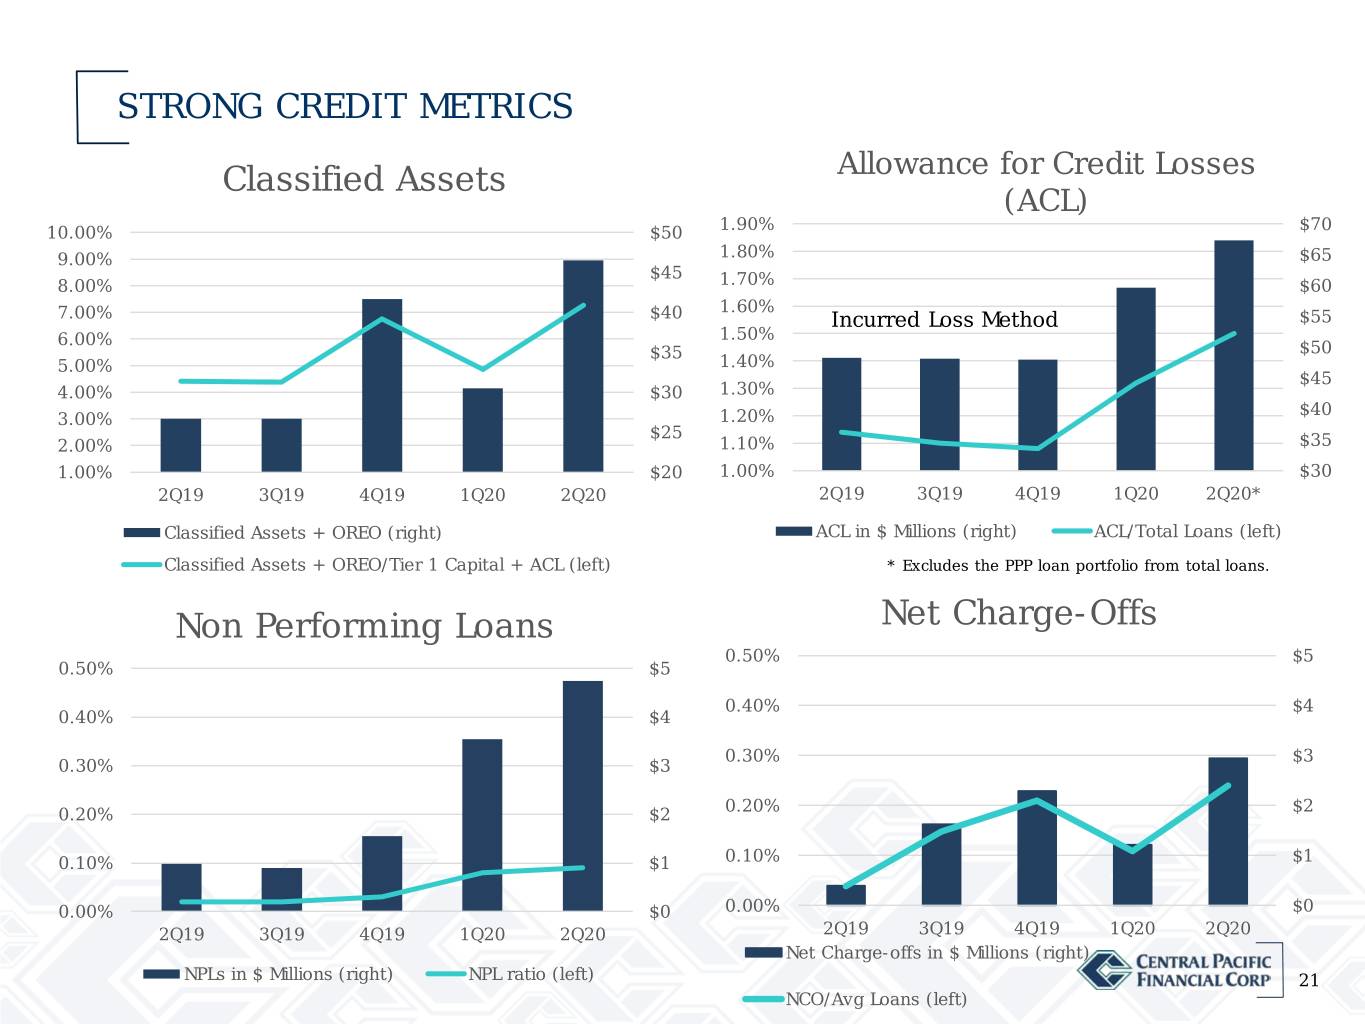
Nonperforming assets at June 30, 2020 totaled $4.7 million, or 0.07% of total assets, compared to $1.3 million, or 0.02% of total assets at June 30, 2019, and $3.6 million, or 0.06% of total assets at March 31, 2020. During the second quarter of 2020, the Company had $1.8 million in additions to nonperforming loans.
Loans delinquent for 90 days or more still accruing interest totaled $1.2 million at June 30, 2020, compared to $0.3 million and $1.6 million at June 30, 2019 and March 31, 2020, respectively.
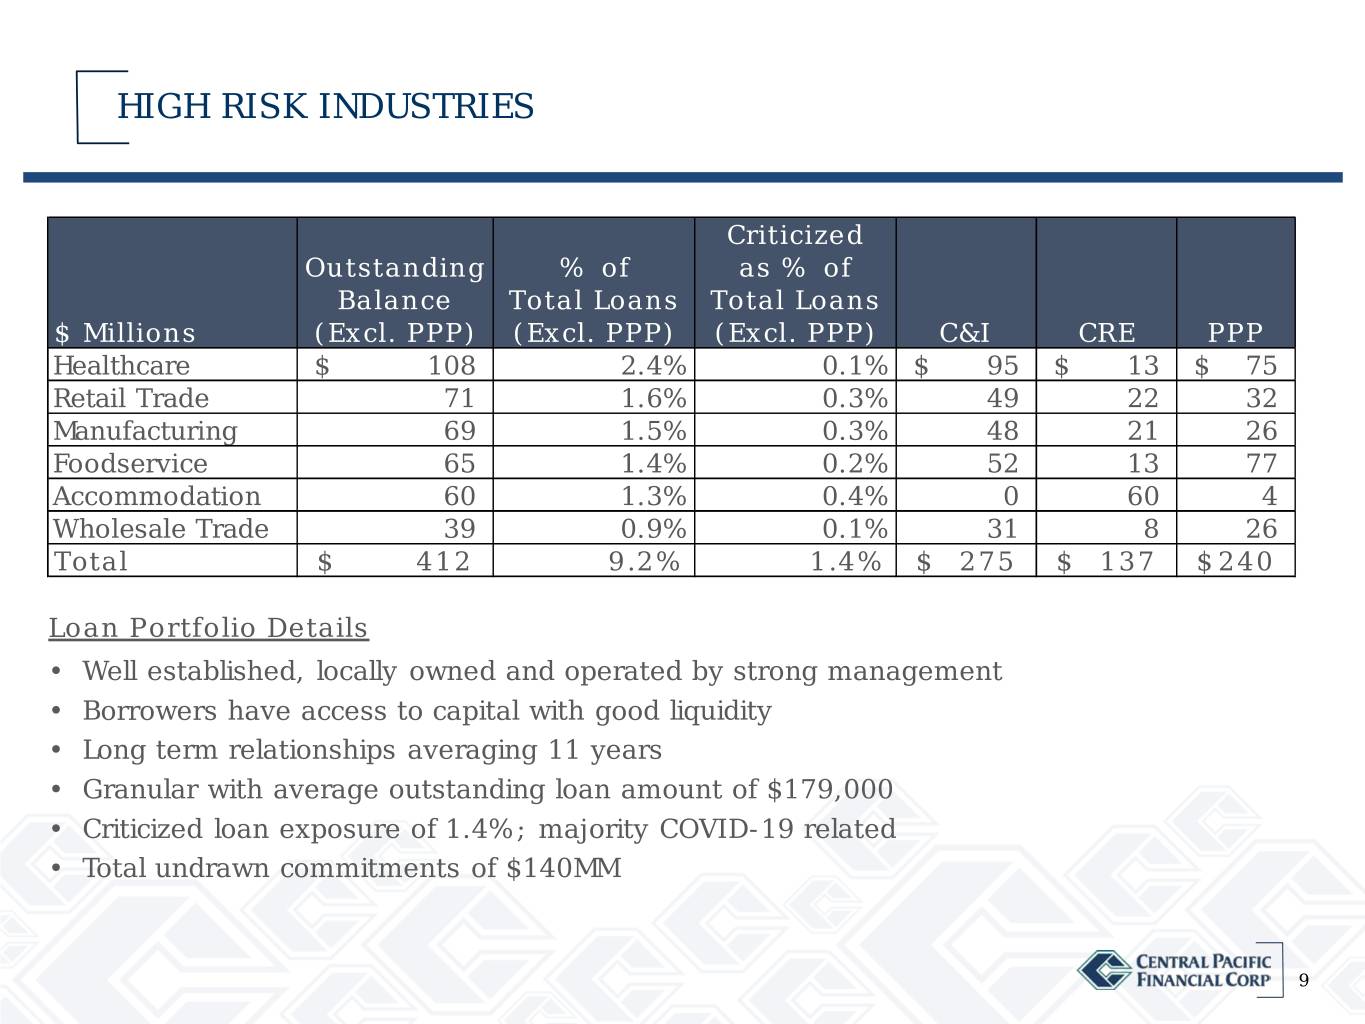
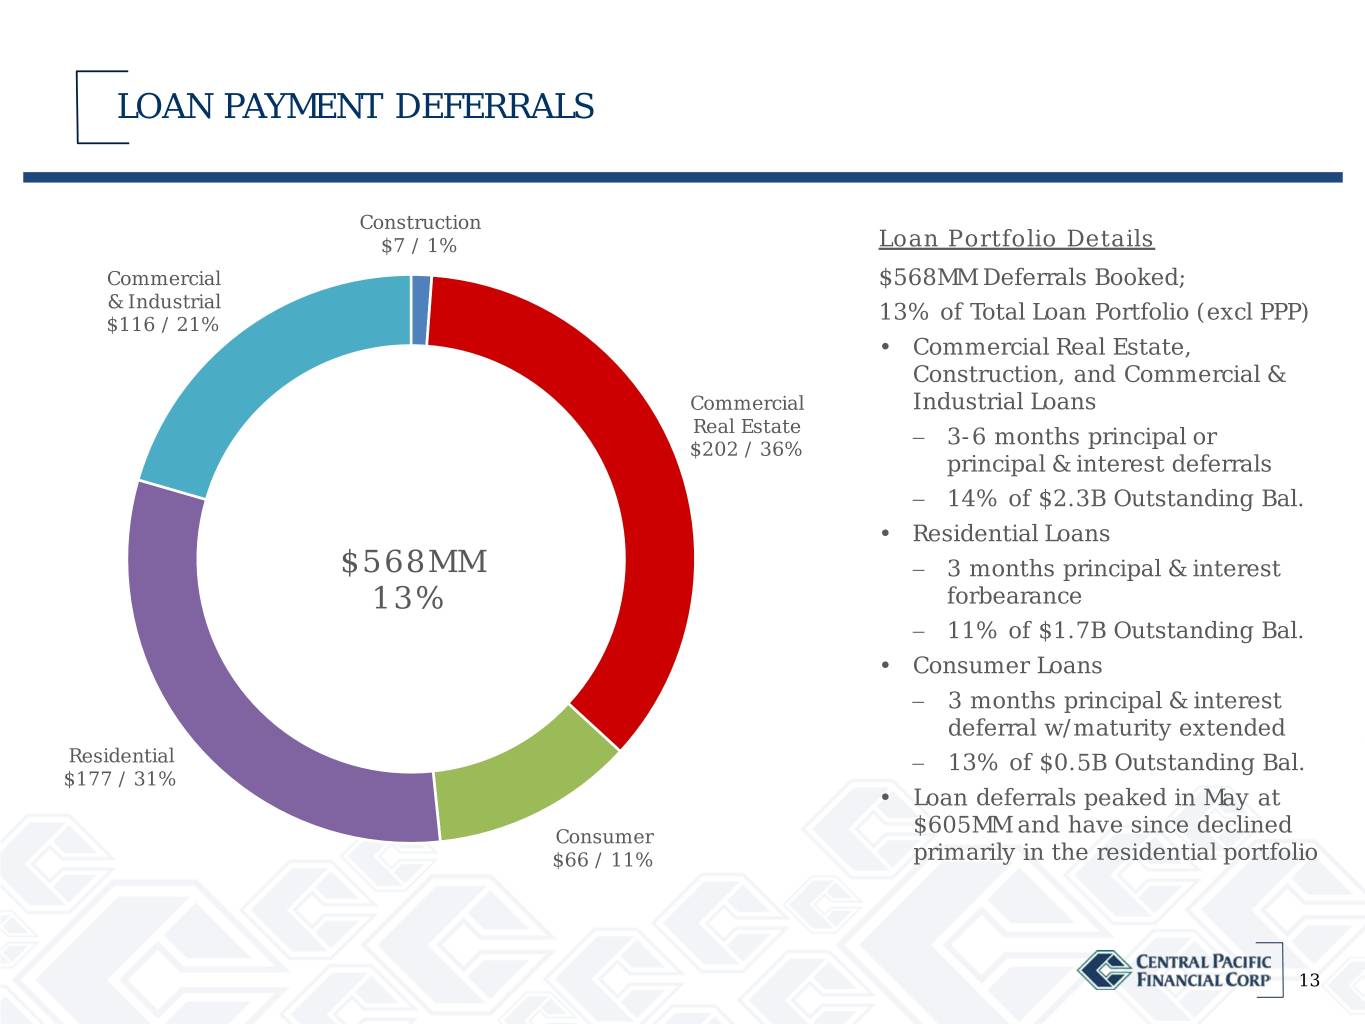
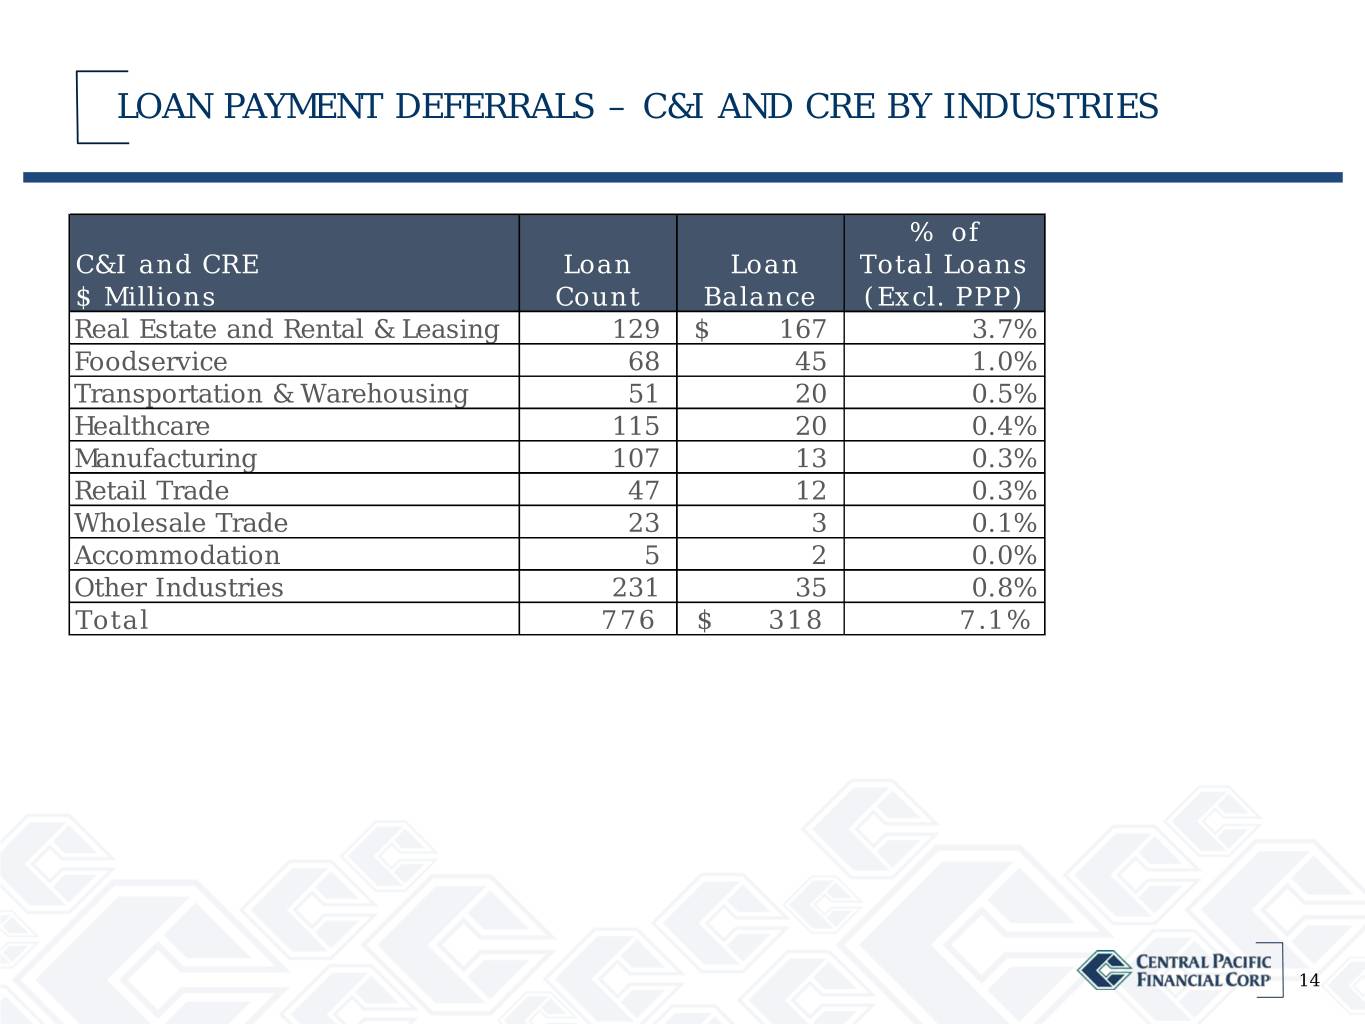
Loan payment forbearances or deferrals were made for borrowers impacted by the COVID-19 pandemic with loan balances totaling $567.9 million or 12.7% of the total loan portfolio, excluding PPP loans, as of June 30, 2020.
Net charge-offs in the second quarter of 2020 totaled $2.9 million, compared to net charge-offs of $0.4 million in the year-ago quarter, and net charge-offs of $1.2 million in the previous quarter.
In the second quarter of 2020, the Company recorded a provision for credit losses on loans of $10.6 million, compared to a provision of $1.4 million in the year-ago quarter and a provision of $9.3 million in the previous quarter. In addition, the Company recorded a provision for off-balance sheet credit exposures (included in other operating expense) of $0.6 million, compared to a provision of $0.5 million in the year-ago quarter and a provision of $1.8 million in the previous quarter. The increase in the provision for credit losses from the year-ago and sequential quarters was primarily due to negative economic conditions brought on by the COVID-19 pandemic. The allowance for credit losses, as a percentage of total loans at June 30, 2020 was 1.35%, compared to 1.14% at June 30, 2019 and 1.32% at March 31, 2020. Excluding the PPP loans, the allowance for credit losses, as a percentage of total loans at June 30, 2020 was 1.50%.
Capital
Total shareholders' equity was $544.3 million at June 30, 2020, compared to $515.7 million and $533.8 million at June 30, 2019 and March 31, 2020, respectively.
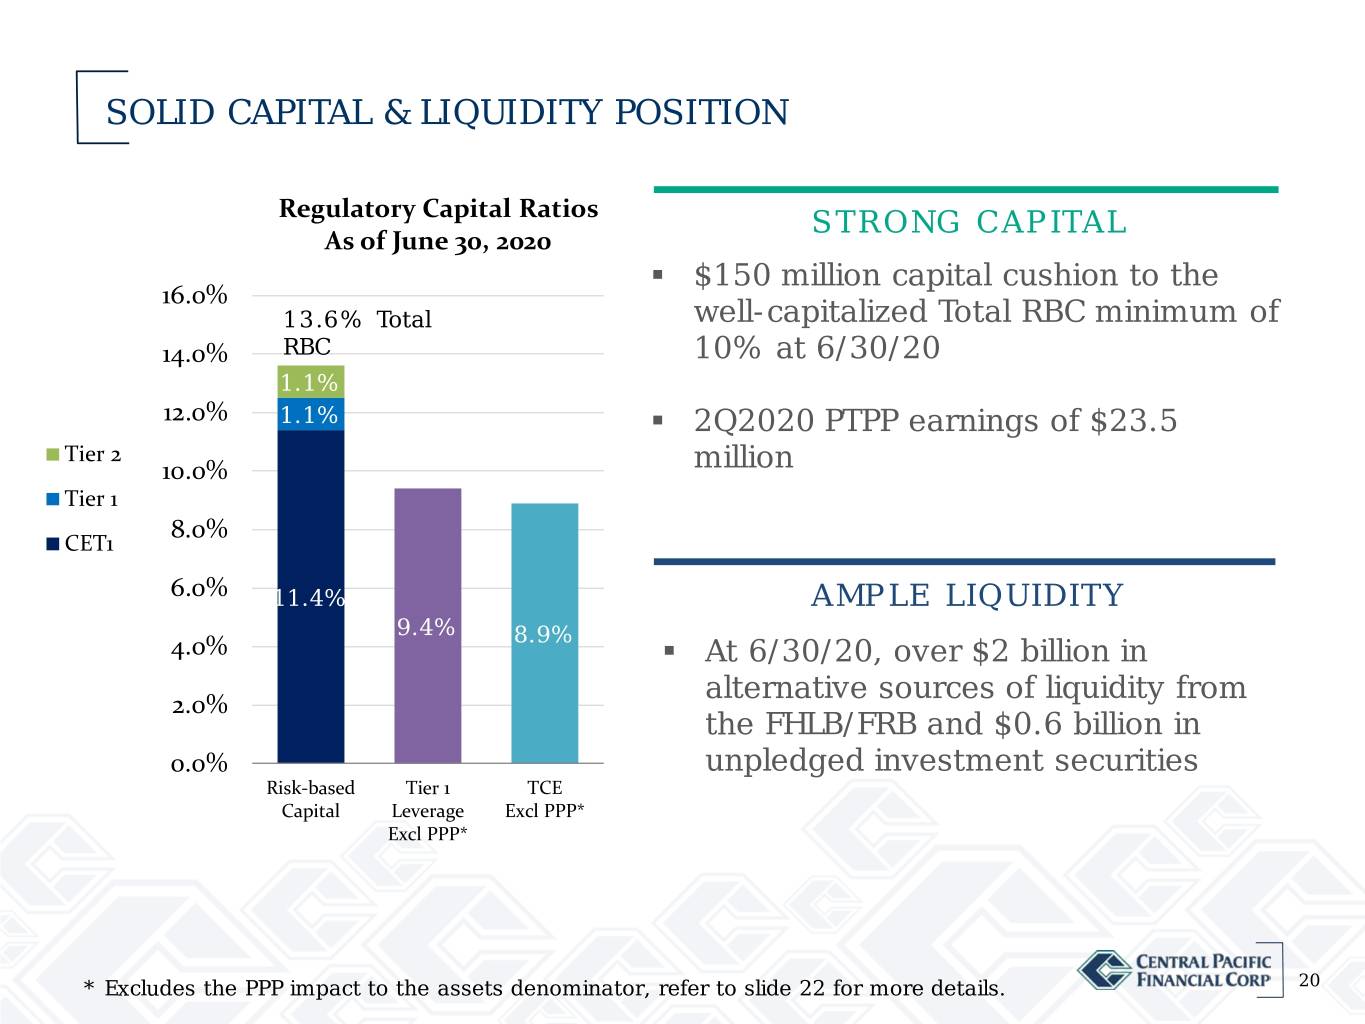
The Company maintained its strong capital position and its capital ratios continue to exceed the levels required to be considered a "well-capitalized" institution for regulatory purposes under Basel III. At June 30, 2020, the Company's leverage capital, tier 1 risk-based capital, total risk-based capital, and common equity tier 1 ratios were 8.9%, 12.5%, 13.6%, and 11.4%, respectively, compared to 9.5%, 12.3%, 13.4%, and 11.3%, respectively, at March 31, 2020.
Central Pacific Financial Corp. Reports Results for Second Quarter 2020
Page 4
Conference Call
The Company's management will host a conference call today at 1:00 p.m. Eastern Time (7:00 a.m. Hawaii Time) to discuss the quarterly results. Individuals are encouraged to listen to the live webcast of the presentation by visiting the investor relations page of the Company's website at http://ir.centralpacificbank.com. Alternatively, investors may participate in the live call by dialing 1-877-505-7644. A playback of the call will be available through August 29, 2020 by dialing 1-877-344-7529 (passcode: 10146483) and on the Company's website. Information which may be discussed in the conference call is provided in an earnings supplement presentation on the Company's website at http://ir.centralpacificbank.com.
About Central Pacific Financial Corp.
Central Pacific Financial Corp. is a Hawaii-based bank holding company with approximately $6.6 billion in assets. Central Pacific Bank, its primary subsidiary, operates 35 branches (nine of which are temporarily closed to protect the health and well-being of the Company's employees and customers from COVID-19) and 76 ATMs in the state of Hawaii, as of June 30, 2020. For additional information, please visit the Company's website at http://www.cpb.bank.
**********
Central Pacific Financial Corp. Reports Results for Second Quarter 2020
Page 5
Forward-Looking Statements
This document may contain forward-looking statements concerning: projections of revenues, expenses, income or loss, earnings or loss per share, capital expenditures, the payment or nonpayment of dividends, capital position, credit losses, net interest margin or other financial items; statements of plans, objectives and expectations of Central Pacific Financial Corp. or its management or Board of Directors, including those relating to business plans, use of capital resources, products or services and regulatory developments and regulatory actions; statements of future economic performance including anticipated performance results from our RISE2020 initiative; or any statements of the assumptions underlying or relating to any of the foregoing. Words such as "believes," "plans," "anticipates," "expects," "intends," "forecasts," "hopes," "targeting," "continue," "remain," "will," "should," "estimates," "may" and other similar expressions are intended to identify forward-looking statements but are not the exclusive means of identifying such statements.
While we believe that our forward-looking statements and the assumptions underlying them are reasonably based, such statements and assumptions are by their nature subject to risks and uncertainties, and thus could later prove to be inaccurate or incorrect. Accordingly, actual results could differ materially from those statements or projections for a variety of reasons, including, but not limited to: the adverse effects of the COVID-19 pandemic virus on local, national and international economies, including, but not limited to, the adverse impact on tourism and construction in the State of Hawaii, our borrowers, customers, third-party contractors, vendors and employees as well as the effects of government programs and initiatives in response to COVID-19; the increase in inventory or adverse conditions in the real estate market and deterioration in the construction industry; adverse changes in the financial performance and/or condition of our borrowers and, as a result, increased loan delinquency rates, deterioration in asset quality, and losses in our loan portfolio; our ability to successfully implement our RISE2020 initiative; the impact of local, national, and international economies and events (including natural disasters such as wildfires, volcanic eruptions, hurricanes, tsunamis, storms, earthquakes and pandemic virus and disease, including COVID-19) on the Company's business and operations and on tourism, the military, and other major industries operating within the Hawaii market and any other markets in which the Company does business; deterioration or malaise in domestic economic conditions, including any destabilization in the financial industry and deterioration of the real estate market, as well as the impact of declining levels of consumer and business confidence in the state of the economy in general and in financial institutions in particular; changes in estimates of future reserve requirements based upon the periodic review thereof under relevant regulatory and accounting requirements; the impact of the Dodd-Frank Wall Street Reform and Consumer Protection Act (the "Dodd-Frank Act"), changes in capital standards, other regulatory reform and federal and state legislation, including but not limited to regulations promulgated by the Consumer Financial Protection Bureau (the "CFPB"), government-sponsored enterprise reform, and any related rules and regulations which affect our business operations and competitiveness; the costs and effects of legal and regulatory developments, including legal proceedings or regulatory or other governmental inquiries and proceedings and the resolution thereof, the results of regulatory examinations or reviews and the effect of, and our ability to comply with, any regulatory orders or actions we are or may become subject to; ability to successfully implement our initiatives to lower our efficiency ratio; the effects of and changes in trade, monetary and fiscal policies and laws, including the interest rate policies of the Board of Governors of the Federal Reserve System (the "FRB" or the "Federal Reserve"); inflation, interest rate, securities market and monetary fluctuations, including the anticipated replacement of the London Interbank Offered Rate ("LIBOR") Index and the impact on our loans and debt which are tied to that index; negative trends in our market capitalization and adverse changes in the price of the Company's common stock; political instability; acts of war or terrorism; pandemic virus and disease, including COVID-19; changes in consumer spending, borrowings and savings habits; failure to maintain effective internal control over financial reporting or disclosure controls and procedures; cybersecurity and data privacy breaches and the consequence therefrom; the ability to address deficiencies in our internal controls over financial reporting or disclosure controls and procedures; technological changes and developments; changes in the competitive environment among financial holding companies and other financial service providers; the effect of changes in accounting policies and practices, as may be adopted by the regulatory agencies, as well as the Public Company Accounting Oversight Board, the Financial Accounting Standards Board ("FASB") and other accounting standard setters and the cost and resources required to implement such changes; our ability to attract and retain key personnel; changes in our organization, compensation and benefit plans; and our success at managing the risks involved in the foregoing items.
For further information with respect to factors that could cause actual results to materially differ from the expectations or projections stated in the forward-looking statements, please see the Company's publicly available Securities and Exchange Commission filings, including the Company's Form 10-K for the last fiscal year and, in particular, the discussion of "Risk Factors" set forth therein. We urge investors to consider all of these factors carefully in evaluating the forward-looking statements contained in this Form 8-K. Forward-looking statements speak only as of the date on which such statements are made. We undertake no obligation to update any forward-looking statements to reflect events or circumstances after the date on which such statements are made, or to reflect the occurrence of unanticipated events except as required by law.
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Financial Highlights | |||||
| (Unaudited) | TABLE 1 | ||||
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, | June 30, | March 31, | December 31, | September 30, | June 30, | June 30, | ||||||||||||||||||||||||||||||||||||||
| except for per share amounts) | 2020 | 2020 | 2019 | 2019 | 2019 | 2020 | 2019 | |||||||||||||||||||||||||||||||||||||
| CONDENSED INCOME STATEMENT | ||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 49,259 | $ | 47,830 | $ | 47,934 | $ | 45,649 | $ | 45,378 | $ | 97,089 | $ | 90,491 | ||||||||||||||||||||||||||||||
| Provision for credit losses [1] | 10,640 | 9,329 | 2,098 | 1,532 | 1,404 | 19,969 | 2,687 | |||||||||||||||||||||||||||||||||||||
| Net interest income after provision for credit losses [1] | 38,619 | 38,501 | 45,836 | 44,117 | 43,974 | 77,120 | 87,804 | |||||||||||||||||||||||||||||||||||||
| Total other operating income | 10,692 | 8,886 | 9,768 | 10,266 | 10,094 | 19,578 | 21,767 | |||||||||||||||||||||||||||||||||||||
| Total other operating expense | 36,427 | 36,240 | 36,242 | 34,934 | 36,107 | 72,667 | 70,455 | |||||||||||||||||||||||||||||||||||||
| Income before taxes | 12,884 | 11,147 | 19,362 | 19,449 | 17,961 | 24,031 | 39,116 | |||||||||||||||||||||||||||||||||||||
| Income tax expense | 2,967 | 2,821 | 5,165 | 4,895 | 4,427 | 5,788 | 9,545 | |||||||||||||||||||||||||||||||||||||
| Net income | 9,917 | 8,326 | 14,197 | 14,554 | 13,534 | 18,243 | 29,571 | |||||||||||||||||||||||||||||||||||||
| Basic earnings per common share | $ | 0.35 | $ | 0.30 | $ | 0.50 | $ | 0.51 | $ | 0.47 | $ | 0.65 | $ | 1.03 | ||||||||||||||||||||||||||||||
| Diluted earnings per common share | 0.35 | 0.29 | 0.50 | 0.51 | 0.47 | 0.65 | 1.03 | |||||||||||||||||||||||||||||||||||||
| Dividends declared per common share | 0.23 | 0.23 | 0.23 | 0.23 | 0.23 | 0.46 | 0.44 | |||||||||||||||||||||||||||||||||||||
| PERFORMANCE RATIOS | ||||||||||||||||||||||||||||||||||||||||||||
| Return on average assets (ROA) [2] | 0.61 | % | 0.55 | % | 0.95 | % | 0.99 | % | 0.92 | % | 0.58 | % | 1.01 | % | ||||||||||||||||||||||||||||||
| Return on average shareholders’ equity (ROE) [2] | 7.34 | 6.21 | 10.70 | 11.11 | 10.73 | 6.77 | 11.84 | |||||||||||||||||||||||||||||||||||||
| Average shareholders’ equity to average assets | 8.36 | 8.93 | 8.87 | 8.87 | 8.62 | 8.64 | 8.57 | |||||||||||||||||||||||||||||||||||||
| Efficiency ratio [1] [3] | 60.76 | 63.90 | 62.81 | 62.48 | 65.09 | 62.29 | 62.76 | |||||||||||||||||||||||||||||||||||||
| Net interest margin (NIM) [2] | 3.26 | 3.43 | 3.43 | 3.30 | 3.33 | 3.34 | 3.33 | |||||||||||||||||||||||||||||||||||||
| Dividend payout ratio [4] | 65.71 | 79.31 | 46.00 | 45.10 | 48.94 | 70.77 | 42.72 | |||||||||||||||||||||||||||||||||||||
| SELECTED AVERAGE BALANCES | ||||||||||||||||||||||||||||||||||||||||||||
| Average loans, including loans held for sale | $ | 4,902,905 | $ | 4,462,347 | $ | 4,412,247 | $ | 4,293,455 | $ | 4,171,558 | $ | 4,682,626 | $ | 4,127,917 | ||||||||||||||||||||||||||||||
| Average interest-earning assets | 6,073,361 | 5,621,043 | 5,595,142 | 5,527,532 | 5,485,977 | 5,847,202 | 5,475,237 | |||||||||||||||||||||||||||||||||||||
| Average assets | 6,468,129 | 6,007,237 | 5,978,797 | 5,907,207 | 5,856,465 | 6,237,592 | 5,833,326 | |||||||||||||||||||||||||||||||||||||
| Average deposits | 5,614,595 | 5,121,696 | 4,998,897 | 4,987,414 | 4,977,781 | 5,368,056 | 4,978,124 | |||||||||||||||||||||||||||||||||||||
| Average interest-bearing liabilities | 4,082,699 | 3,917,332 | 3,947,924 | 3,920,304 | 3,897,619 | 4,000,016 | 3,859,784 | |||||||||||||||||||||||||||||||||||||
| Average shareholders’ equity | 540,802 | 536,721 | 530,464 | 524,083 | 504,749 | 538,762 | 499,720 | |||||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Financial Highlights | |||||
| (Unaudited) | TABLE 1 (CONTINUED) | ||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| (dollars in thousands) | 2020 | 2020 | 2019 | 2019 | 2019 | |||||||||||||||||||||||||||
| REGULATORY CAPITAL | ||||||||||||||||||||||||||||||||
| Central Pacific Financial Corp. | ||||||||||||||||||||||||||||||||
| Leverage capital | $ | 571,976 | $ | 567,947 | $ | 568,529 | $ | 561,478 | $ | 556,403 | ||||||||||||||||||||||
| Tier 1 risk-based capital | 571,976 | 567,947 | 568,529 | 561,478 | 556,403 | |||||||||||||||||||||||||||
| Total risk-based capital | 622,393 | 618,504 | 617,772 | 611,076 | 606,567 | |||||||||||||||||||||||||||
| Common equity tier 1 capital | 521,976 | 517,947 | 518,529 | 511,478 | 506,403 | |||||||||||||||||||||||||||
| Central Pacific Bank | ||||||||||||||||||||||||||||||||
| Leverage capital | 559,461 | 556,895 | 556,077 | 550,913 | 544,480 | |||||||||||||||||||||||||||
| Tier 1 risk-based capital | 559,461 | 556,895 | 556,077 | 550,913 | 544,480 | |||||||||||||||||||||||||||
| Total risk-based capital | 609,811 | 607,402 | 605,320 | 600,511 | 594,644 | |||||||||||||||||||||||||||
| Common equity tier 1 capital | 559,461 | 556,895 | 556,077 | 550,913 | 544,480 | |||||||||||||||||||||||||||
| REGULATORY CAPITAL RATIOS | ||||||||||||||||||||||||||||||||
| Central Pacific Financial Corp. | ||||||||||||||||||||||||||||||||
| Leverage capital ratio | 8.9 | % | 9.5 | % | 9.5 | % | 9.5 | % | 9.5 | % | ||||||||||||||||||||||
| Tier 1 risk-based capital ratio | 12.5 | 12.3 | 12.6 | 12.6 | 12.7 | |||||||||||||||||||||||||||
| Total risk-based capital ratio | 13.6 | 13.4 | 13.6 | 13.7 | 13.9 | |||||||||||||||||||||||||||
| Common equity tier 1 capital ratio | 11.4 | 11.3 | 11.5 | 11.5 | 11.6 | |||||||||||||||||||||||||||
| Central Pacific Bank | ||||||||||||||||||||||||||||||||
| Leverage capital ratio | 8.7 | 9.3 | 9.3 | 9.4 | 9.3 | |||||||||||||||||||||||||||
| Tier 1 risk-based capital ratio | 12.2 | 12.1 | 12.3 | 12.4 | 12.5 | |||||||||||||||||||||||||||
| Total risk-based capital ratio | 13.3 | 13.2 | 13.4 | 13.5 | 13.6 | |||||||||||||||||||||||||||
| Common equity tier 1 capital ratio | 12.2 | 12.1 | 12.3 | 12.4 | 12.5 | |||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| (dollars in thousands, except for per share amounts) | 2020 | 2020 | 2019 | 2019 | 2019 | |||||||||||||||||||||||||||
| BALANCE SHEET | ||||||||||||||||||||||||||||||||
| Total loans, net of deferred fees and costs | $ | 5,003,438 | $ | 4,511,998 | $ | 4,449,540 | $ | 4,367,862 | $ | 4,247,113 | ||||||||||||||||||||||
| Total assets | 6,632,972 | 6,108,548 | 6,012,672 | 5,976,716 | 5,920,006 | |||||||||||||||||||||||||||
| Total deposits | 5,794,685 | 5,136,069 | 5,120,023 | 5,037,659 | 4,976,849 | |||||||||||||||||||||||||||
| Long-term debt | 167,491 | 101,547 | 101,547 | 101,547 | 101,547 | |||||||||||||||||||||||||||
| Total shareholders’ equity | 544,271 | 533,781 | 528,520 | 525,227 | 515,695 | |||||||||||||||||||||||||||
| Total shareholders’ equity to total assets | 8.21 | % | 8.74 | % | 8.79 | % | 8.79 | % | 8.71 | % | ||||||||||||||||||||||
| ASSET QUALITY | ||||||||||||||||||||||||||||||||
| Allowance for credit losses ("ACL") [1] | $ | 67,339 | $ | 59,645 | $ | 47,971 | $ | 48,167 | $ | 48,267 | ||||||||||||||||||||||
| Non-performing assets | 4,741 | 3,647 | 1,719 | 1,360 | 1,258 | |||||||||||||||||||||||||||
| ACL to total loans [1] | 1.35 | % | 1.32 | % | 1.08 | % | 1.10 | % | 1.14 | % | ||||||||||||||||||||||
| ACL to total loans, excluding PPP loans [1] | 1.50 | % | 1.32 | % | 1.08 | % | 1.10 | % | 1.14 | % | ||||||||||||||||||||||
| ACL to non-performing assets [1] | 1,420.35 | % | 1,635.45 | % | 2,790.63 | % | 3,541.69 | % | 3,836.80 | % | ||||||||||||||||||||||
| PER SHARE OF COMMON STOCK OUTSTANDING | ||||||||||||||||||||||||||||||||
| Book value per common share | $ | 19.33 | $ | 18.99 | $ | 18.68 | $ | 18.47 | $ | 18.05 | ||||||||||||||||||||||
| [1] The Company adopted ASU 2016-13, "Financial Instruments-Credit Losses" ("CECL"), effective January 1, 2020 using the modified retrospective approach. Results for the reporting periods beginning after January 1, 2020 are presented under CECL, while prior period amounts continue to be reported under previous GAAP. | ||||||||||||||||||||||||||||||||
| [2] ROA, ROE and ROTE are annualized based on a 30/360 day convention. Annualized net interest income and expense in the NIM calculation are based on the day count interest payment conventions at the interest-earning asset or interest-bearing liability level (i.e. 30/360, actual/actual). | ||||||||||||||||||||||||||||||||
| [3] Efficiency ratio is defined as total operating expense divided by total revenue (net interest income and total other operating income). | ||||||||||||||||||||||||||||||||
| [4] Dividend payout ratio is defined as dividends declared per share divided by diluted earnings per share. | ||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Consolidated Balance Sheets | |||||
| (Unaudited) | TABLE 2 | ||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| (Dollars in thousands, except share data) | 2020 | 2020 | 2019 | 2019 | 2019 | |||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||
| Cash and due from financial institutions | $ | 102,132 | $ | 81,972 | $ | 78,418 | $ | 87,395 | $ | 83,534 | ||||||||||||||||||||||
| Interest-bearing deposits in other financial institutions | 41,201 | 11,021 | 24,554 | 7,803 | 15,173 | |||||||||||||||||||||||||||
| Investment securities: | ||||||||||||||||||||||||||||||||
| Available-for-sale debt securities, at fair value | 1,168,594 | 1,184,023 | 1,126,983 | 1,186,875 | 1,254,743 | |||||||||||||||||||||||||||
| Equity securities, at fair value | 1,209 | 1,002 | 1,127 | 1,058 | 1,034 | |||||||||||||||||||||||||||
| Total investment securities | 1,169,803 | 1,185,025 | 1,128,110 | 1,187,933 | 1,255,777 | |||||||||||||||||||||||||||
| Loans held for sale | 10,443 | 3,910 | 9,083 | 7,016 | 6,848 | |||||||||||||||||||||||||||
| Loans, net of deferred fees and costs | 5,003,438 | 4,511,998 | 4,449,540 | 4,367,862 | 4,247,113 | |||||||||||||||||||||||||||
| Less allowance for credit losses [1] | 67,339 | 59,645 | 47,971 | 48,167 | 48,267 | |||||||||||||||||||||||||||
| Loans, net of allowance for credit losses | 4,936,099 | 4,452,353 | 4,401,569 | 4,319,695 | 4,198,846 | |||||||||||||||||||||||||||
| Premises and equipment, net | 55,032 | 50,447 | 46,343 | 44,095 | 43,600 | |||||||||||||||||||||||||||
| Accrued interest receivable | 19,590 | 16,851 | 16,500 | 16,220 | 17,260 | |||||||||||||||||||||||||||
| Investment in unconsolidated subsidiaries | 16,428 | 16,721 | 17,115 | 17,001 | 17,247 | |||||||||||||||||||||||||||
| Other real estate owned | — | 100 | 164 | 466 | 276 | |||||||||||||||||||||||||||
| Mortgage servicing rights | 12,771 | 13,345 | 14,718 | 15,058 | 15,266 | |||||||||||||||||||||||||||
| Bank-owned life insurance | 161,758 | 159,637 | 159,656 | 158,939 | 158,294 | |||||||||||||||||||||||||||
| Federal Home Loan Bank ("FHLB") stock | 9,229 | 18,109 | 14,983 | 17,183 | 17,824 | |||||||||||||||||||||||||||
| Right of use lease asset | 50,039 | 51,198 | 52,348 | 52,588 | 53,678 | |||||||||||||||||||||||||||
| Other assets | 48,447 | 47,859 | 49,111 | 45,324 | 36,383 | |||||||||||||||||||||||||||
| Total assets | $ | 6,632,972 | $ | 6,108,548 | $ | 6,012,672 | $ | 5,976,716 | $ | 5,920,006 | ||||||||||||||||||||||
| LIABILITIES AND SHAREHOLDERS' EQUITY | ||||||||||||||||||||||||||||||||
| Deposits: | ||||||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 1,851,012 | $ | 1,430,540 | $ | 1,450,532 | $ | 1,399,200 | $ | 1,351,190 | ||||||||||||||||||||||
| Interest-bearing demand | 1,067,483 | 1,018,508 | 1,043,010 | 998,037 | 1,002,706 | |||||||||||||||||||||||||||
| Savings and money market | 1,945,744 | 1,693,280 | 1,600,028 | 1,593,738 | 1,573,805 | |||||||||||||||||||||||||||
| Time | 930,446 | 993,741 | 1,026,453 | 1,046,684 | 1,049,148 | |||||||||||||||||||||||||||
| Total deposits | 5,794,685 | 5,136,069 | 5,120,023 | 5,037,659 | 4,976,849 | |||||||||||||||||||||||||||
| FHLB advances and other short-term borrowings | — | 222,000 | 150,000 | 205,000 | 221,000 | |||||||||||||||||||||||||||
| Long-term debt | 167,491 | 101,547 | 101,547 | 101,547 | 101,547 | |||||||||||||||||||||||||||
| Lease liability | 50,440 | 51,541 | 52,632 | 52,807 | 53,829 | |||||||||||||||||||||||||||
| Other liabilities | 76,050 | 63,561 | 59,950 | 54,476 | 51,086 | |||||||||||||||||||||||||||
| Total liabilities | 6,088,666 | 5,574,718 | 5,484,152 | 5,451,489 | 5,404,311 | |||||||||||||||||||||||||||
| Shareholders' equity: | ||||||||||||||||||||||||||||||||
| Preferred stock, no par value, authorized 1,000,000 shares; issued and outstanding: none at June 30, 2020, March 31, 2020, December 31, 2019, September 30, 2019, and June 30, 2019 | — | — | — | — | — | |||||||||||||||||||||||||||
| Common stock, no par value, authorized 185,000,000 shares; issued and outstanding: 28,154,159 at June 30, 2020, 28,115,353 at March 31, 2020, 28,289,257 at December 31, 2019, 28,441,341 at September 30, 2019, and 28,567,777 at June 30, 2019 | 442,699 | 442,853 | 447,602 | 452,278 | 456,293 | |||||||||||||||||||||||||||
| Additional paid-in capital | 93,007 | 92,284 | 91,611 | 90,604 | 89,724 | |||||||||||||||||||||||||||
| Accumulated deficit [1] | (16,986) | (20,428) | (19,102) | (26,782) | (34,780) | |||||||||||||||||||||||||||
| Accumulated other comprehensive income (loss) | 25,551 | 19,072 | 8,409 | 9,127 | 4,458 | |||||||||||||||||||||||||||
| Total shareholders' equity | 544,271 | 533,781 | 528,520 | 525,227 | 515,695 | |||||||||||||||||||||||||||
| Non-controlling interest | 35 | 49 | — | — | — | |||||||||||||||||||||||||||
| Total equity | 544,306 | 533,830 | 528,520 | 525,227 | 515,695 | |||||||||||||||||||||||||||
| Total liabilities and shareholders' equity | $ | 6,632,972 | $ | 6,108,548 | $ | 6,012,672 | $ | 5,976,716 | $ | 5,920,006 | ||||||||||||||||||||||
| [1] The Company adopted ASU 2016-13, "Financial Instruments-Credit Losses" ("CECL"), effective January 1, 2020 using the modified retrospective approach. Results for the reporting periods beginning after January 1, 2020 are presented under CECL, while prior period amounts continue to be reported under previous GAAP. | ||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Consolidated Statements of Income | |||||
| (Unaudited) | TABLE 3 | ||||
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | June 30, | |||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | 2020 | 2020 | 2019 | 2019 | 2019 | 2020 | 2019 | |||||||||||||||||||||||||||||||||||||
| Interest income: | ||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 45,915 | $ | 46,204 | $ | 47,488 | $ | 45,861 | $ | 45,540 | $ | 92,119 | $ | 89,308 | ||||||||||||||||||||||||||||||
| Interest and dividends on investment securities: | ||||||||||||||||||||||||||||||||||||||||||||
| Taxable investment securities | 6,310 | 6,757 | 6,486 | 7,178 | 7,530 | 13,067 | 15,790 | |||||||||||||||||||||||||||||||||||||
| Tax-exempt investment securities | 599 | 668 | 656 | 708 | 814 | 1,267 | 1,680 | |||||||||||||||||||||||||||||||||||||
| Dividend income on investment securities | 17 | 17 | 17 | 14 | 14 | 34 | 32 | |||||||||||||||||||||||||||||||||||||
| Interest on deposits in other financial institutions | 3 | 36 | 54 | 33 | 46 | 39 | 114 | |||||||||||||||||||||||||||||||||||||
| Dividend income on FHLB stock | 106 | 132 | 456 | 186 | 161 | 238 | 322 | |||||||||||||||||||||||||||||||||||||
| Total interest income | 52,950 | 53,814 | 55,157 | 53,980 | 54,105 | 106,764 | 107,246 | |||||||||||||||||||||||||||||||||||||
| Interest expense: | ||||||||||||||||||||||||||||||||||||||||||||
| Interest on deposits: | ||||||||||||||||||||||||||||||||||||||||||||
| Demand | 114 | 176 | 202 | 207 | 199 | 290 | 391 | |||||||||||||||||||||||||||||||||||||
| Savings and money market | 567 | 1,118 | 1,253 | 1,549 | 1,507 | 1,685 | 2,298 | |||||||||||||||||||||||||||||||||||||
| Time | 2,124 | 3,268 | 3,653 | 4,432 | 4,867 | 5,392 | 9,959 | |||||||||||||||||||||||||||||||||||||
| Interest on short-term borrowings | 74 | 508 | 1,139 | 1,130 | 1,123 | 582 | 2,016 | |||||||||||||||||||||||||||||||||||||
| Interest on long-term debt | 812 | 914 | 976 | 1,013 | 1,031 | 1,726 | 2,091 | |||||||||||||||||||||||||||||||||||||
| Total interest expense | 3,691 | 5,984 | 7,223 | 8,331 | 8,727 | 9,675 | 16,755 | |||||||||||||||||||||||||||||||||||||
| Net interest income | 49,259 | 47,830 | 47,934 | 45,649 | 45,378 | 97,089 | 90,491 | |||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 10,640 | 9,329 | 2,098 | 1,532 | 1,404 | 19,969 | 2,687 | |||||||||||||||||||||||||||||||||||||
| Net interest income after provision for credit losses | 38,619 | 38,501 | 45,836 | 44,117 | 43,974 | 77,120 | 87,804 | |||||||||||||||||||||||||||||||||||||
| Other operating income: | ||||||||||||||||||||||||||||||||||||||||||||
| Mortgage banking income | 3,566 | 337 | 1,410 | 1,994 | 1,708 | 3,903 | 3,281 | |||||||||||||||||||||||||||||||||||||
| Service charges on deposit accounts | 1,149 | 2,050 | 2,159 | 2,125 | 2,041 | 3,199 | 4,122 | |||||||||||||||||||||||||||||||||||||
| Other service charges and fees | 2,916 | 4,897 | 4,095 | 3,894 | 3,909 | 7,813 | 7,124 | |||||||||||||||||||||||||||||||||||||
| Income from fiduciary activities | 1,270 | 1,297 | 1,175 | 1,126 | 1,129 | 2,567 | 2,094 | |||||||||||||||||||||||||||||||||||||
| Equity in earnings of unconsolidated subsidiaries | 104 | 26 | 92 | 86 | 71 | 130 | 79 | |||||||||||||||||||||||||||||||||||||
| Net gain (loss) on sales of investment securities | — | — | — | 36 | — | — | — | |||||||||||||||||||||||||||||||||||||
| Income from bank-owned life insurance | 1,424 | (19) | 594 | 645 | 914 | 1,405 | 1,866 | |||||||||||||||||||||||||||||||||||||
| Net gain (loss) on sales of foreclosed assets | (6) | — | (162) | 17 | — | (6) | — | |||||||||||||||||||||||||||||||||||||
| Other (refer to Table 4) | 269 | 298 | 405 | 343 | 322 | 567 | 3,201 | |||||||||||||||||||||||||||||||||||||
| Total other operating income | 10,692 | 8,886 | 9,768 | 10,266 | 10,094 | 19,578 | 21,767 | |||||||||||||||||||||||||||||||||||||
| Other operating expense: | ||||||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 20,622 | 20,347 | 21,207 | 20,631 | 20,563 | 40,969 | 40,452 | |||||||||||||||||||||||||||||||||||||
| Net occupancy | 3,645 | 3,672 | 3,619 | 3,697 | 3,525 | 7,317 | 6,983 | |||||||||||||||||||||||||||||||||||||
| Equipment | 1,043 | 1,097 | 1,142 | 1,067 | 1,138 | 2,140 | 2,144 | |||||||||||||||||||||||||||||||||||||
| Communication expense | 774 | 837 | 906 | 1,008 | 903 | 1,611 | 1,637 | |||||||||||||||||||||||||||||||||||||
| Legal and professional services | 2,238 | 2,028 | 2,123 | 1,933 | 1,728 | 4,266 | 3,298 | |||||||||||||||||||||||||||||||||||||
| Computer software expense | 3,035 | 2,943 | 2,942 | 2,713 | 2,560 | 5,978 | 5,157 | |||||||||||||||||||||||||||||||||||||
| Advertising expense | 923 | 1,092 | 527 | 711 | 712 | 2,015 | 1,423 | |||||||||||||||||||||||||||||||||||||
| Foreclosed asset expense | — | 67 | 28 | 15 | 49 | 67 | 208 | |||||||||||||||||||||||||||||||||||||
| Other (refer to Table 4) | 4,147 | 4,157 | 3,748 | 3,159 | 4,929 | 8,304 | 9,153 | |||||||||||||||||||||||||||||||||||||
| Total other operating expense | 36,427 | 36,240 | 36,242 | 34,934 | 36,107 | 72,667 | 70,455 | |||||||||||||||||||||||||||||||||||||
| Income before income taxes | 12,884 | 11,147 | 19,362 | 19,449 | 17,961 | 24,031 | 39,116 | |||||||||||||||||||||||||||||||||||||
| Income tax expense | 2,967 | 2,821 | 5,165 | 4,895 | 4,427 | 5,788 | 9,545 | |||||||||||||||||||||||||||||||||||||
| Net income | $ | 9,917 | $ | 8,326 | $ | 14,197 | $ | 14,554 | $ | 13,534 | $ | 18,243 | $ | 29,571 | ||||||||||||||||||||||||||||||
| Per common share data: | ||||||||||||||||||||||||||||||||||||||||||||
| Basic earnings per share | $ | 0.35 | $ | 0.30 | $ | 0.50 | $ | 0.51 | $ | 0.47 | $ | 0.65 | $ | 1.03 | ||||||||||||||||||||||||||||||
| Diluted earnings per share | 0.35 | 0.29 | 0.50 | 0.51 | 0.47 | 0.65 | 1.03 | |||||||||||||||||||||||||||||||||||||
| Cash dividends declared | 0.23 | 0.23 | 0.23 | 0.23 | 0.23 | 0.46 | 0.44 | |||||||||||||||||||||||||||||||||||||
| Basic weighted average shares outstanding | 28,040,802 | 28,126,400 | 28,259,294 | 28,424,898 | 28,546,564 | 28,083,602 | 28,651,852 | |||||||||||||||||||||||||||||||||||||
| Diluted weighted average shares outstanding | 28,095,230 | 28,277,753 | 28,448,243 | 28,602,338 | 28,729,510 | 28,190,132 | 28,847,786 | |||||||||||||||||||||||||||||||||||||
| Note: Certain amounts in the prior period financial statements have been reclassified to conform to the presentation of the current period. | ||||||||||||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Other Operating Income and Other Operating Expense - Detail | |||||
| (Unaudited) | TABLE 4 | ||||
The following table sets forth the components of other operating income - other for the periods indicated:
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | June 30, | |||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | 2020 | 2020 | 2019 | 2019 | 2019 | 2020 | 2019 | |||||||||||||||||||||||||||||||||||||
| Other operating income - other: | ||||||||||||||||||||||||||||||||||||||||||||
| Income recovered on nonaccrual loans previously charged-off | $ | 37 | $ | 23 | $ | 80 | $ | 73 | $ | 85 | $ | 60 | $ | 167 | ||||||||||||||||||||||||||||||
| Other recoveries | 26 | 40 | 36 | 42 | 26 | 66 | 52 | |||||||||||||||||||||||||||||||||||||
| Commissions on sale of checks | 56 | 81 | 75 | 75 | 79 | 137 | 159 | |||||||||||||||||||||||||||||||||||||
| Gain on sale of MasterCard stock | — | — | — | — | — | — | 2,555 | |||||||||||||||||||||||||||||||||||||
| Other | 150 | 154 | 214 | 153 | 132 | 304 | 268 | |||||||||||||||||||||||||||||||||||||
| Total other operating income - other | $ | 269 | $ | 298 | $ | 405 | $ | 343 | $ | 322 | $ | 567 | $ | 3,201 | ||||||||||||||||||||||||||||||
The following table sets forth the components of other operating expense - other for the periods indicated:
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | June 30, | |||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | 2020 | 2020 | 2019 | 2019 | 2019 | 2020 | 2019 | |||||||||||||||||||||||||||||||||||||
| Other operating expense - other: | ||||||||||||||||||||||||||||||||||||||||||||
| Charitable contributions | $ | 10 | $ | 187 | $ | 122 | $ | 230 | $ | 175 | $ | 197 | $ | 329 | ||||||||||||||||||||||||||||||
| FDIC insurance assessment | 475 | — | — | 5 | 362 | 475 | 863 | |||||||||||||||||||||||||||||||||||||
| Miscellaneous loan expenses | 399 | 300 | 361 | 274 | 317 | 699 | 611 | |||||||||||||||||||||||||||||||||||||
| ATM and debit card expenses | 584 | 634 | 672 | 660 | 620 | 1,218 | 1,270 | |||||||||||||||||||||||||||||||||||||
| Armored car expenses | 229 | 294 | 186 | 220 | 211 | 523 | 409 | |||||||||||||||||||||||||||||||||||||
| Entertainment and promotions | 165 | 280 | 495 | 323 | 1,023 | 445 | 1,253 | |||||||||||||||||||||||||||||||||||||
| Stationery and supplies | 220 | 248 | 305 | 240 | 279 | 468 | 504 | |||||||||||||||||||||||||||||||||||||
| Directors’ fees and expenses | 196 | 241 | 246 | 242 | 238 | 437 | 480 | |||||||||||||||||||||||||||||||||||||
| Directors' deferred compensation plan expense | 103 | (1,483) | 148 | (155) | 133 | (1,380) | 568 | |||||||||||||||||||||||||||||||||||||
| Provision (credit) for residential mortgage loan repurchase losses | — | — | — | — | (403) | — | (403) | |||||||||||||||||||||||||||||||||||||
| Provision for off-balance sheet credit exposures | 573 | 1,798 | (160) | (465) | 487 | 2,371 | 654 | |||||||||||||||||||||||||||||||||||||
| Other | 1,193 | 1,658 | 1,373 | 1,585 | 1,487 | 2,851 | 2,615 | |||||||||||||||||||||||||||||||||||||
| Total other operating expense - other | $ | 4,147 | $ | 4,157 | $ | 3,748 | $ | 3,159 | $ | 4,929 | $ | 8,304 | $ | 9,153 | ||||||||||||||||||||||||||||||
| Note: Certain amounts in the prior period financial statements have been reclassified to conform to the presentation of the current period. | ||||||||||||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Average Balances, Interest Income & Expense, Yields and Rates (Taxable Equivalent) | |||||
| (Unaudited) | TABLE 5 | ||||
| Three Months Ended | Three Months Ended | Three Months Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| June 30, 2020 | March 31, 2020 | June 30, 2019 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average | Average | Average | Average | Average | Average | |||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | Balance | Yield/Rate | Interest | Balance | Yield/Rate | Interest | Balance | Yield/Rate | Interest | |||||||||||||||||||||||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning assets: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in other financial institutions | $ | 15,777 | 0.10 | % | $ | 3 | $ | 11,082 | 1.29 | % | $ | 36 | $ | 8,002 | 2.34 | % | $ | 46 | ||||||||||||||||||||||||||||||||||||||
| Investment securities, excluding valuation allowance: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Taxable | 1,042,441 | 2.43 | 6,327 | 1,027,695 | 2.64 | 6,774 | 1,147,759 | 2.63 | 7,544 | |||||||||||||||||||||||||||||||||||||||||||||||
| Tax-exempt | 100,485 | 3.02 | 758 | 105,330 | 3.21 | 845 | 142,660 | 2.89 | 1,030 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total investment securities | 1,142,926 | 2.48 | 7,085 | 1,133,025 | 2.69 | 7,619 | 1,290,419 | 2.66 | 8,574 | |||||||||||||||||||||||||||||||||||||||||||||||
| Loans, including loans held for sale | 4,902,905 | 3.76 | 45,915 | 4,462,347 | 4.16 | 46,204 | 4,171,558 | 4.37 | 45,540 | |||||||||||||||||||||||||||||||||||||||||||||||
| Federal Home Loan Bank stock | 11,753 | 3.62 | 106 | 14,589 | 3.61 | 132 | 15,998 | 4.02 | 161 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-earning assets | 6,073,361 | 3.51 | 53,109 | 5,621,043 | 3.85 | 53,991 | 5,485,977 | 3.97 | 54,321 | |||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-earning assets | 394,768 | 386,194 | 370,488 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 6,468,129 | $ | 6,007,237 | $ | 5,856,465 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| LIABILITIES AND EQUITY | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing demand deposits | $ | 1,056,885 | 0.04 | % | $ | 114 | $ | 1,013,795 | 0.07 | % | $ | 176 | $ | 962,402 | 0.08 | % | $ | 199 | ||||||||||||||||||||||||||||||||||||||
| Savings and money market deposits | 1,856,621 | 0.12 | 567 | 1,651,751 | 0.27 | 1,118 | 1,577,437 | 0.38 | 1,507 | |||||||||||||||||||||||||||||||||||||||||||||||
| Time deposits under $100,000 | 161,874 | 0.65 | 261 | 164,274 | 0.70 | 284 | 173,556 | 0.70 | 305 | |||||||||||||||||||||||||||||||||||||||||||||||
| Time deposits $100,000 and over | 807,276 | 0.93 | 1,863 | 846,152 | 1.42 | 2,984 | 907,330 | 2.02 | 4,562 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 3,882,656 | 0.29 | 2,805 | 3,675,972 | 0.50 | 4,562 | 3,620,725 | 0.73 | 6,573 | |||||||||||||||||||||||||||||||||||||||||||||||
| Federal Home Loan Bank advances and other short-term borrowings | 63,104 | 0.48 | 74 | 139,813 | 1.46 | 508 | 175,347 | 2.57 | 1,123 | |||||||||||||||||||||||||||||||||||||||||||||||
| Long-term debt | 136,939 | 2.38 | 812 | 101,547 | 3.62 | 914 | 101,547 | 4.07 | 1,031 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 4,082,699 | 0.36 | 3,691 | 3,917,332 | 0.61 | 5,984 | 3,897,619 | 0.90 | 8,727 | |||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 1,731,939 | 1,445,724 | 1,357,056 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other liabilities | 112,687 | 107,458 | 97,041 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities | 5,927,325 | 5,470,514 | 5,351,716 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | 540,802 | 536,721 | 504,749 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-controlling interest | 2 | 2 | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total equity | 540,804 | 536,723 | 504,749 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 6,468,129 | $ | 6,007,237 | $ | 5,856,465 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 49,418 | $ | 48,007 | $ | 45,594 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest rate spread | 3.15 | % | 3.24 | % | 3.07 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest margin | 3.26 | % | 3.43 | % | 3.33 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Average Balances, Interest Income & Expense, Yields and Rates (Taxable Equivalent) | |||||
| (Unaudited) | TABLE 6 | ||||
| Six Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||
| June 30, 2020 | June 30, 2019 | |||||||||||||||||||||||||||||||||||||
| Average | Average | Average | Average | |||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | Balance | Yield/Rate | Interest | Balance | Yield/Rate | Interest | ||||||||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||||||||
| Interest-earning assets: | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in other financial institutions | $ | 13,430 | 0.59 | % | $ | 39 | $ | 9,682 | 2.38 | % | $ | 114 | ||||||||||||||||||||||||||
| Investment securities, excluding valuation allowance: | ||||||||||||||||||||||||||||||||||||||
| Taxable | 1,035,068 | 2.53 | 13,101 | 1,174,596 | 2.69 | 15,822 | ||||||||||||||||||||||||||||||||
| Tax-exempt | 102,907 | 3.12 | 1,604 | 147,899 | 2.88 | 2,127 | ||||||||||||||||||||||||||||||||
| Total investment securities | 1,137,975 | 2.58 | 14,705 | 1,322,495 | 2.71 | 17,949 | ||||||||||||||||||||||||||||||||
| Loans, including loans held for sale | 4,682,626 | 3.95 | 92,119 | 4,127,917 | 4.35 | 89,308 | ||||||||||||||||||||||||||||||||
| Federal Home Loan Bank stock | 13,171 | 3.61 | 238 | 15,143 | 4.26 | 322 | ||||||||||||||||||||||||||||||||
| Total interest-earning assets | 5,847,202 | 3.67 | 107,101 | 5,475,237 | 3.95 | 107,693 | ||||||||||||||||||||||||||||||||
| Noninterest-earning assets | 390,390 | 358,089 | ||||||||||||||||||||||||||||||||||||
| Total assets | $ | 6,237,592 | $ | 5,833,326 | ||||||||||||||||||||||||||||||||||
| LIABILITIES AND EQUITY | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing demand deposits | $ | 1,035,340 | 0.06 | % | $ | 290 | $ | 956,783 | 0.08 | % | $ | 391 | ||||||||||||||||||||||||||
| Savings and money market deposits | 1,754,186 | 0.19 | 1,685 | 1,525,425 | 0.30 | 2,298 | ||||||||||||||||||||||||||||||||
| Time deposits under $100,000 | 163,074 | 0.67 | 546 | 174,683 | 0.68 | 592 | ||||||||||||||||||||||||||||||||
| Time deposits $100,000 and over | 826,714 | 1.18 | 4,846 | 944,796 | 2.00 | 9,367 | ||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 3,779,314 | 0.39 | 7,367 | 3,601,687 | 0.71 | 12,648 | ||||||||||||||||||||||||||||||||
| Federal Home Loan Bank advances and other short-term borrowings | 101,459 | 1.15 | 582 | 156,550 | 2.60 | 2,016 | ||||||||||||||||||||||||||||||||
| Long-term debt | 119,243 | 2.91 | 1,726 | 101,547 | 4.15 | 2,091 | ||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 4,000,016 | 0.49 | 9,675 | 3,859,784 | 0.88 | 16,755 | ||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 1,588,742 | 1,376,437 | ||||||||||||||||||||||||||||||||||||
| Other liabilities | 110,070 | 97,385 | ||||||||||||||||||||||||||||||||||||
| Total liabilities | 5,698,828 | 5,333,606 | ||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | 538,762 | 499,720 | ||||||||||||||||||||||||||||||||||||
| Non-controlling interest | 2 | — | ||||||||||||||||||||||||||||||||||||
| Total equity | 538,764 | 499,720 | ||||||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 6,237,592 | $ | 5,833,326 | ||||||||||||||||||||||||||||||||||
| Net interest income | $ | 97,426 | $ | 90,938 | ||||||||||||||||||||||||||||||||||
| Interest rate spread | 3.18 | % | 3.07 | % | ||||||||||||||||||||||||||||||||||
| Net interest margin | 3.34 | % | 3.33 | % | ||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Loans by Geographic Distribution | |||||
| (Unaudited) | TABLE 7 | ||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| (Dollars in thousands) | 2020 | 2020 | 2019 | 2019 | 2019 | |||||||||||||||||||||||||||
| HAWAII: | ||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural: | ||||||||||||||||||||||||||||||||
| SBA Paycheck Protection Program | $ | 483,827 | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||
| Other | 431,887 | 454,817 | 454,582 | 439,296 | 435,353 | |||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Construction | 103,518 | 100,617 | 95,854 | 96,661 | 72,427 | |||||||||||||||||||||||||||
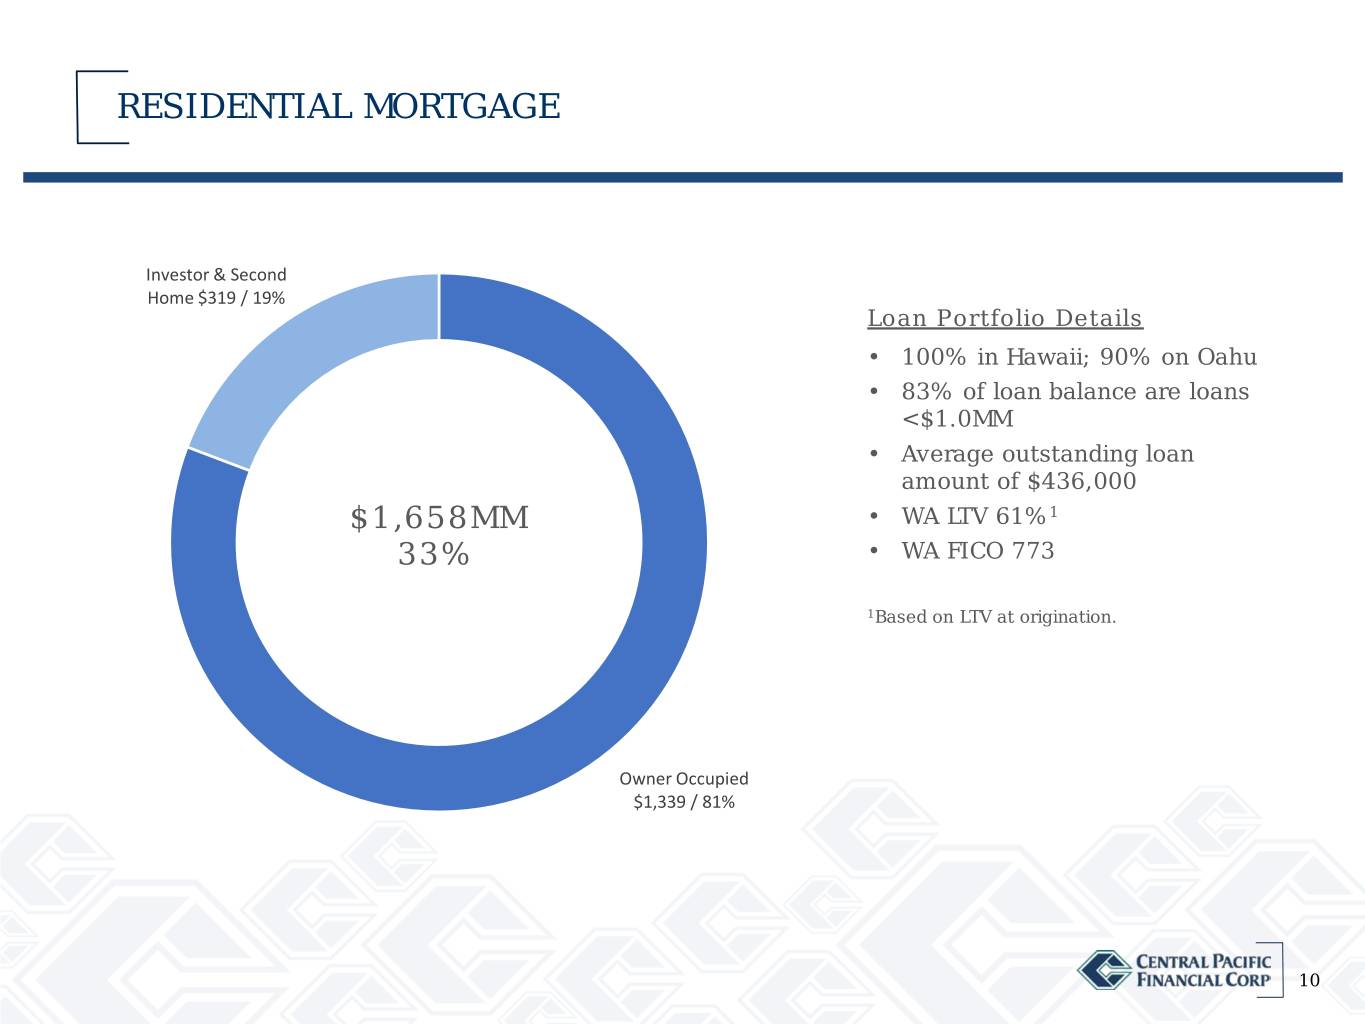
| Residential mortgage | 1,657,558 | 1,632,536 | 1,599,801 | 1,558,735 | 1,516,936 | |||||||||||||||||||||||||||
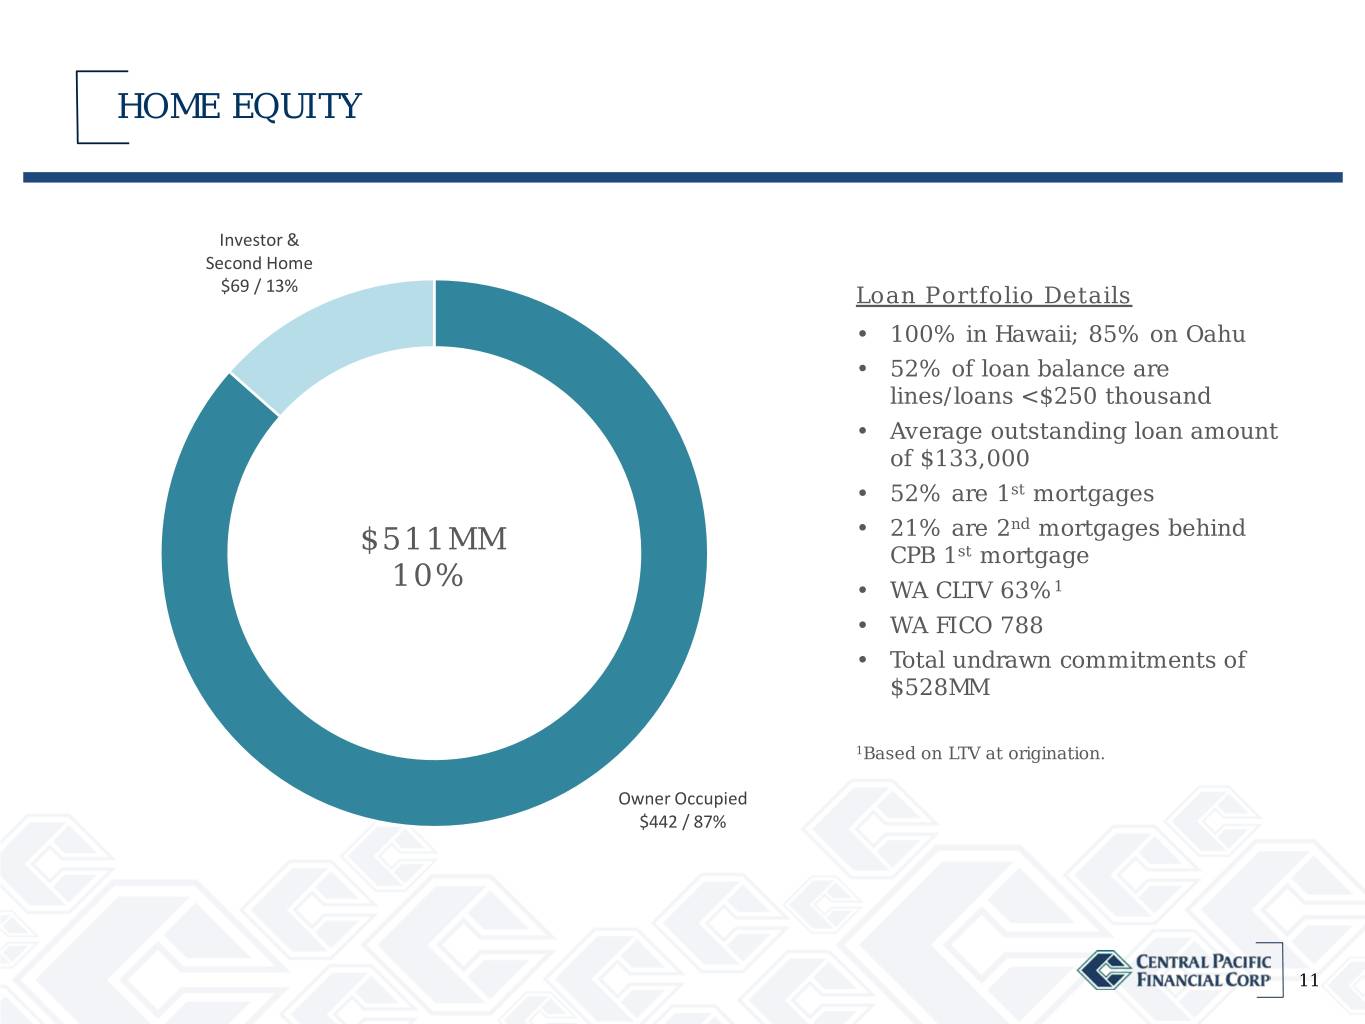
| Home equity | 510,962 | 504,686 | 490,734 | 475,565 | 473,151 | |||||||||||||||||||||||||||
| Commercial mortgage | 912,422 | 917,886 | 909,798 | 909,987 | 905,479 | |||||||||||||||||||||||||||
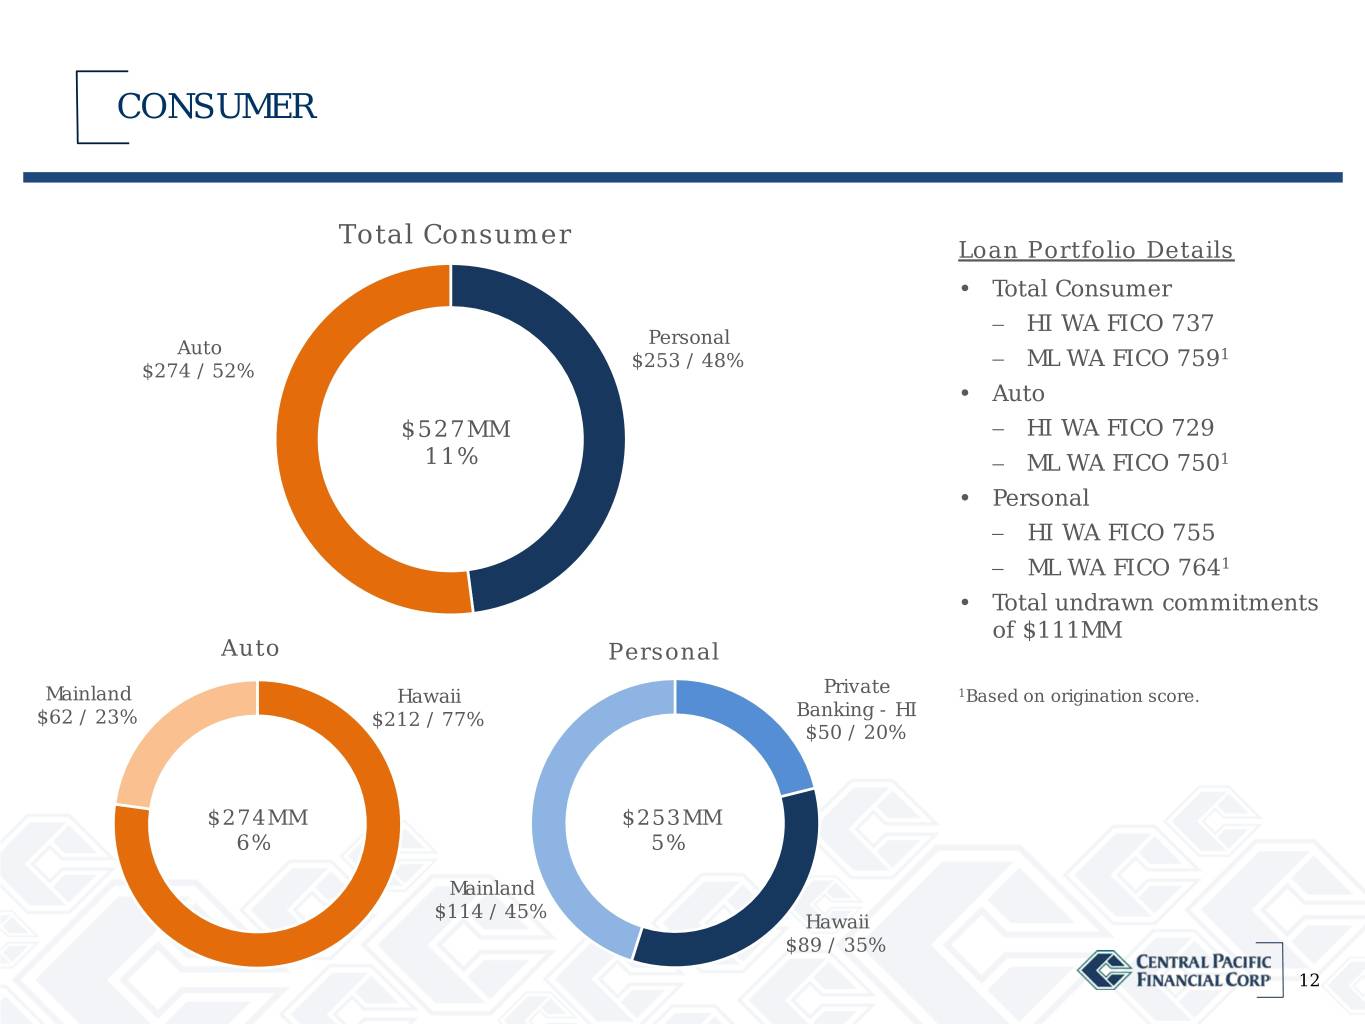
| Consumer | 350,414 | 367,960 | 373,451 | 369,511 | 353,282 | |||||||||||||||||||||||||||
| Leases | — | — | — | 31 | 52 | |||||||||||||||||||||||||||
| Total loans, net of deferred fees and costs | 4,450,588 | 3,978,502 | 3,924,220 | 3,849,786 | 3,756,680 | |||||||||||||||||||||||||||
| Allowance for credit losses | (59,765) | (51,646) | (42,592) | (42,286) | (42,414) | |||||||||||||||||||||||||||
| Loans, net of allowance for credit losses | $ | 4,390,823 | $ | 3,926,856 | $ | 3,881,628 | $ | 3,807,500 | $ | 3,714,266 | ||||||||||||||||||||||
| U.S. MAINLAND: [1] | ||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural: | ||||||||||||||||||||||||||||||||
| SBA Paycheck Protection Program | $ | 42,581 | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||
| Other | 115,971 | 120,507 | 115,722 | 137,316 | 155,130 | |||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Construction | — | — | — | — | — | |||||||||||||||||||||||||||
| Residential mortgage | — | — | — | — | — | |||||||||||||||||||||||||||
| Home equity | — | — | — | — | — | |||||||||||||||||||||||||||
| Commercial mortgage | 217,747 | 221,251 | 213,617 | 223,925 | 187,379 | |||||||||||||||||||||||||||
| Consumer | 176,551 | 191,738 | 195,981 | 156,835 | 147,924 | |||||||||||||||||||||||||||
| Leases | — | — | — | — | — | |||||||||||||||||||||||||||
| Total loans, net of deferred fees and costs | 552,850 | 533,496 | 525,320 | 518,076 | 490,433 | |||||||||||||||||||||||||||
| Allowance for credit losses | (7,574) | (7,999) | (5,379) | (5,881) | (5,853) | |||||||||||||||||||||||||||
| Loans, net of allowance for credit losses | $ | 545,276 | $ | 525,497 | $ | 519,941 | $ | 512,195 | $ | 484,580 | ||||||||||||||||||||||
| TOTAL: | ||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural: | ||||||||||||||||||||||||||||||||
| SBA Paycheck Protection Program | $ | 526,408 | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||
| Other | 547,858 | 575,324 | 570,304 | 576,612 | 590,483 | |||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Construction | 103,518 | 100,617 | 95,854 | 96,661 | 72,427 | |||||||||||||||||||||||||||
| Residential mortgage | 1,657,558 | 1,632,536 | 1,599,801 | 1,558,735 | 1,516,936 | |||||||||||||||||||||||||||
| Home equity | 510,962 | 504,686 | 490,734 | 475,565 | 473,151 | |||||||||||||||||||||||||||
| Commercial mortgage | 1,130,169 | 1,139,137 | 1,123,415 | 1,133,912 | 1,092,858 | |||||||||||||||||||||||||||
| Consumer | 526,965 | 559,698 | 569,432 | 526,346 | 501,206 | |||||||||||||||||||||||||||
| Leases | — | — | — | 31 | 52 | |||||||||||||||||||||||||||
| Total loans, net of deferred fees and costs | 5,003,438 | 4,511,998 | 4,449,540 | 4,367,862 | 4,247,113 | |||||||||||||||||||||||||||
| Allowance for credit losses | (67,339) | (59,645) | (47,971) | (48,167) | (48,267) | |||||||||||||||||||||||||||
| Loans, net of allowance for credit losses | $ | 4,936,099 | $ | 4,452,353 | $ | 4,401,569 | $ | 4,319,695 | $ | 4,198,846 | ||||||||||||||||||||||
| [1] U.S. Mainland includes territories of the United States. | ||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Deposits | |||||
| (Unaudited) | TABLE 8 | ||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| (Dollars in thousands) | 2020 | 2020 | 2019 | 2019 | 2019 | |||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 1,851,012 | $ | 1,430,540 | $ | 1,450,532 | $ | 1,399,200 | $ | 1,351,190 | ||||||||||||||||||||||
| Interest-bearing demand | 1,067,483 | 1,018,508 | 1,043,010 | 998,037 | 1,002,706 | |||||||||||||||||||||||||||
| Savings and money market | 1,945,744 | 1,693,280 | 1,600,028 | 1,593,738 | 1,573,805 | |||||||||||||||||||||||||||
| Time deposits less than $100,000 | 159,739 | 162,399 | 165,755 | 165,687 | 171,106 | |||||||||||||||||||||||||||
| Core deposits | 5,023,978 | 4,304,727 | 4,259,325 | 4,156,662 | 4,098,807 | |||||||||||||||||||||||||||
| Government time deposits | 509,927 | 523,343 | 533,088 | 552,470 | 574,825 | |||||||||||||||||||||||||||
| Other time deposits $100,000 to $250,000 | 96,633 | 100,047 | 107,550 | 103,959 | 105,382 | |||||||||||||||||||||||||||
| Other time deposits greater than $250,000 | 164,147 | 207,952 | 220,060 | 224,568 | 197,835 | |||||||||||||||||||||||||||
| Total time deposits $100,000 and over | 770,707 | 831,342 | 860,698 | 880,997 | 878,042 | |||||||||||||||||||||||||||
| Total deposits | $ | 5,794,685 | $ | 5,136,069 | $ | 5,120,023 | $ | 5,037,659 | $ | 4,976,849 | ||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Nonperforming Assets, Past Due and Restructured Loans | |||||
| (Unaudited) | TABLE 9 | ||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| (Dollars in thousands) | 2020 | 2020 | 2019 | 2019 | 2019 | |||||||||||||||||||||||||||
| Nonaccrual loans (including loans held for sale): [1] | ||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural | $ | 934 | $ | 667 | $ | 467 | $ | — | $ | — | ||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Residential mortgage | 3,215 | 2,287 | 979 | 799 | 738 | |||||||||||||||||||||||||||
| Home equity | 538 | 545 | 92 | 95 | 244 | |||||||||||||||||||||||||||
| Consumer | 54 | 48 | 17 | — | — | |||||||||||||||||||||||||||
| Total nonaccrual loans | 4,741 | 3,547 | 1,555 | 894 | 982 | |||||||||||||||||||||||||||
| Other real estate owned ("OREO"): | ||||||||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Residential mortgage | — | — | — | 302 | 276 | |||||||||||||||||||||||||||
| Home equity | — | 100 | 164 | 164 | — | |||||||||||||||||||||||||||
| Total OREO | — | 100 | 164 | 466 | 276 | |||||||||||||||||||||||||||
| Total nonperforming assets ("NPAs") | 4,741 | 3,647 | 1,719 | 1,360 | 1,258 | |||||||||||||||||||||||||||
| Loans delinquent for 90 days or more still accruing interest: [1] | ||||||||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Residential mortgage | 726 | 1,221 | 724 | — | — | |||||||||||||||||||||||||||
| Consumer | 444 | 352 | 286 | 235 | 267 | |||||||||||||||||||||||||||
| Total loans delinquent for 90 days or more still accruing interest | 1,170 | 1,573 | 1,010 | 235 | 267 | |||||||||||||||||||||||||||
| Restructured loans still accruing interest: [1] | ||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural | 172 | 113 | 135 | 157 | 178 | |||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Residential mortgage | 5,290 | 5,431 | 5,502 | 6,717 | 6,831 | |||||||||||||||||||||||||||
| Commercial mortgage | 1,888 | 1,709 | 1,839 | 1,985 | 2,097 | |||||||||||||||||||||||||||
| Consumer | 145 | — | — | — | — | |||||||||||||||||||||||||||
| Total restructured loans still accruing interest | 7,495 | 7,253 | 7,476 | 8,859 | 9,106 | |||||||||||||||||||||||||||
| Total NPAs and loans delinquent for 90 days or more and restructured loans still accruing interest | $ | 13,406 | $ | 12,473 | $ | 10,205 | $ | 10,454 | $ | 10,631 | ||||||||||||||||||||||
| Total nonaccrual loans as a percentage of total loans | 0.09 | % | 0.08 | % | 0.03 | % | 0.02 | % | 0.02 | % | ||||||||||||||||||||||
| Total NPAs as a percentage of total loans and OREO | 0.09 | % | 0.08 | % | 0.04 | % | 0.03 | % | 0.03 | % | ||||||||||||||||||||||
| Total NPAs and loans delinquent for 90 days or more still accruing interest as a percentage of total loans and OREO | 0.12 | % | 0.12 | % | 0.06 | % | 0.04 | % | 0.04 | % | ||||||||||||||||||||||
| Total NPAs and loans delinquent for 90 days or more and restructured loans still accruing interest as a percentage of total loans and OREO | 0.27 | % | 0.28 | % | 0.23 | % | 0.24 | % | 0.25 | % | ||||||||||||||||||||||
| Quarter-to-quarter changes in NPAs: | ||||||||||||||||||||||||||||||||
| Balance at beginning of quarter | $ | 3,647 | $ | 1,719 | $ | 1,360 | $ | 1,258 | $ | 3,338 | ||||||||||||||||||||||
| Additions | 1,771 | 2,056 | 695 | 112 | — | |||||||||||||||||||||||||||
| Reductions: | ||||||||||||||||||||||||||||||||
| Payments | (367) | (60) | (34) | (51) | (2,055) | |||||||||||||||||||||||||||
| Return to accrual status | (123) | — | — | (2) | (25) | |||||||||||||||||||||||||||
| Sales of NPAs | (94) | — | (302) | — | — | |||||||||||||||||||||||||||
| Charge-offs, valuation and other adjustments | (93) | (68) | — | 43 | — | |||||||||||||||||||||||||||
| Total reductions | (677) | (128) | (336) | (10) | (2,080) | |||||||||||||||||||||||||||
| Balance at end of quarter | $ | 4,741 | $ | 3,647 | $ | 1,719 | $ | 1,360 | $ | 1,258 | ||||||||||||||||||||||
| [1] Section 4013 of the CARES Act and the revised Interagency Statement are being applied to loan modfications related to the COVID-19 pandemic as eligible and applicable. These loan modifications are not included in the delinquent, nonaccrual or restructured loan balances presented above. | ||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Allowance for Credit Losses on Loans | |||||
| (Unaudited) | TABLE 10 | ||||
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | June 30, | |||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | 2020 | 2020 | 2019 | 2019 | 2019 | 2020 | 2019 | |||||||||||||||||||||||||||||||||||||
| Allowance for credit losses ("ACL"): | ||||||||||||||||||||||||||||||||||||||||||||
| ACL at beginning of period | $ | 59,645 | $ | 47,971 | $ | 48,167 | $ | 48,267 | $ | 47,267 | $ | 47,971 | $ | 47,916 | ||||||||||||||||||||||||||||||
| Adoption of ASU 2016-13 | — | 3,566 | — | — | — | 3,566 | — | |||||||||||||||||||||||||||||||||||||
| Adjusted ACL at beginning of period | 59,645 | 51,537 | 48,167 | 48,267 | 47,267 | 51,537 | 47,916 | |||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 10,640 | 9,329 | 2,098 | 1,532 | 1,404 | 19,969 | 2,687 | |||||||||||||||||||||||||||||||||||||
| Charge-offs: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural | 1,103 | 437 | 379 | 797 | 839 | 1,540 | 1,302 | |||||||||||||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage | 52 | — | — | — | — | 52 | — | |||||||||||||||||||||||||||||||||||||
| Home equity | — | — | — | 5 | — | — | — | |||||||||||||||||||||||||||||||||||||
| Consumer | 2,626 | 2,217 | 2,723 | 1,832 | 1,459 | 4,843 | 3,710 | |||||||||||||||||||||||||||||||||||||
| Total charge-offs | 3,781 | 2,654 | 3,102 | 2,634 | 2,298 | 6,435 | 5,012 | |||||||||||||||||||||||||||||||||||||
| Recoveries: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural | 305 | 342 | 264 | 362 | 315 | 647 | 548 | |||||||||||||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||||||||||||||
| Construction | — | 131 | 6 | 6 | 592 | 131 | 598 | |||||||||||||||||||||||||||||||||||||
| Residential mortgage | 20 | 181 | 26 | 104 | 372 | 201 | 394 | |||||||||||||||||||||||||||||||||||||
| Home equity | — | 31 | — | 24 | 9 | 31 | 18 | |||||||||||||||||||||||||||||||||||||
| Commercial mortgage | 1 | 2 | — | — | 25 | 3 | 25 | |||||||||||||||||||||||||||||||||||||
| Consumer | 509 | 746 | 512 | 506 | 581 | 1,255 | 1,093 | |||||||||||||||||||||||||||||||||||||
| Total recoveries | 835 | 1,433 | 808 | 1,002 | 1,894 | 2,268 | 2,676 | |||||||||||||||||||||||||||||||||||||
| Net charge-offs (recoveries) | 2,946 | 1,221 | 2,294 | 1,632 | 404 | 4,167 | 2,336 | |||||||||||||||||||||||||||||||||||||
| ACL at end of period | $ | 67,339 | $ | 59,645 | $ | 47,971 | $ | 48,167 | $ | 48,267 | $ | 67,339 | $ | 48,267 | ||||||||||||||||||||||||||||||
| Average loans, net of deferred fees and costs | $ | 4,902,905 | $ | 4,462,347 | $ | 4,412,247 | $ | 4,293,455 | $ | 4,171,558 | $ | 4,682,626 | $ | 4,127,917 | ||||||||||||||||||||||||||||||
| Annualized ratio of net charge-offs to average loans | 0.24 | % | 0.11 | % | 0.21 | % | 0.15 | % | 0.04 | % | 0.18 | % | 0.11 | % | ||||||||||||||||||||||||||||||
| Ratio of ACL to total loans | 1.35 | % | 1.32 | % | 1.08 | % | 1.10 | % | 1.14 | % | 1.35 | % | 1.14 | % | ||||||||||||||||||||||||||||||
| Ratio of ACL to total loans, excluding PPP loans | 1.50 | % | 1.32 | % | 1.08 | % | 1.10 | % | 1.14 | % | 1.50 | % | 1.14 | % | ||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Reconciliation of Non-GAAP Financial Measures | |||||
| (Unaudited) | TABLE 11 | ||||
The Company believes that pre-tax, pre-provision earnings, a non-GAAP financial measure, is useful as a tool to help evaluate the ability to provide for credit costs through operations. The following table sets forth a reconciliation of our pre-tax pre-provision earnings for each of the dates indicated:
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | June 30, | |||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | 2020 | 2020 | 2019 | 2019 | 2019 | 2020 | 2019 | |||||||||||||||||||||||||||||||||||||
| Net income | $ | 9,917 | $ | 8,326 | $ | 14,197 | $ | 14,554 | $ | 13,534 | $ | 18,243 | $ | 29,571 | ||||||||||||||||||||||||||||||
| Add: Income tax expense | 2,967 | 2,821 | 5,165 | 4,895 | 4,427 | 5,788 | 9,545 | |||||||||||||||||||||||||||||||||||||
| Income before taxes | 12,884 | 11,147 | 19,362 | 19,449 | 17,961 | 24,031 | 39,116 | |||||||||||||||||||||||||||||||||||||
| Add: Provision for credit losses | 10,640 | 9,329 | 2,098 | 1,532 | 1,404 | 19,969 | 2,687 | |||||||||||||||||||||||||||||||||||||
| Pre-tax pre-provision earnings | $ | 23,524 | $ | 20,476 | $ | 21,460 | $ | 20,981 | $ | 19,365 | $ | 44,000 | $ | 41,803 | ||||||||||||||||||||||||||||||
The following table sets forth a reconciliation of the ratios of our allowance for credit losses to total loans and total loans, excluding PPP loans, for each of the dates indicated:
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| (Dollars in thousands) | 2020 | 2020 | 2019 | 2019 | 2019 | |||||||||||||||||||||||||||
| Allowance for credit losses ("ACL") | $ | 67,339 | $ | 59,645 | $ | 47,971 | $ | 48,167 | $ | 48,267 | ||||||||||||||||||||||
| Total loans | $ | 5,003,438 | $ | 4,511,998 | $ | 4,449,540 | $ | 4,367,862 | $ | 4,247,113 | ||||||||||||||||||||||
| SBA Paycheck Protection Program ("PPP loans") | 526,408 | — | — | — | — | |||||||||||||||||||||||||||
| Total loans, excluding PPP loans | $ | 4,477,030 | $ | 4,511,998 | 4,449,540 | 4,367,862 | $ | 4,247,113 | ||||||||||||||||||||||||
| Ratio of ACL to total loans | 1.35 | % | 1.32 | % | 1.08 | % | 1.10 | % | 1.14 | % | ||||||||||||||||||||||
| Ratio of ACL to total loans, excluding PPP loans | 1.50 | % | 1.32 | % | 1.08 | % | 1.10 | % | 1.14 | % | ||||||||||||||||||||||