Exhibit 99.1
Equity Bancshares, Inc.
 PRESS RELEASE - 04/20/2021
Equity Bancshares, Inc. Reports First-Quarter Net Income
of $15.1 million and $1.02 Earnings Per Diluted Share
Company experienced 7.6% of annualized loan growth not including Paycheck Protection Program; originated $233 million of new Paycheck Protection Program loans
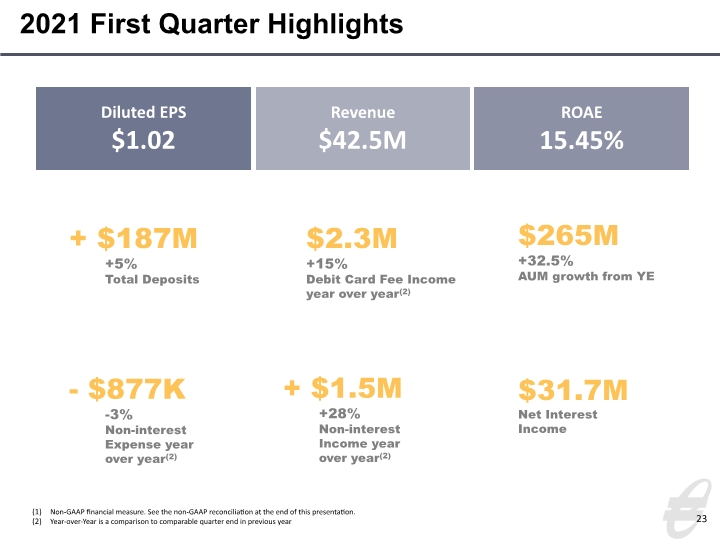
WICHITA, Kansas, April 20, 2021 (GLOBE NEWSWIRE) – Equity Bancshares, Inc. (NASDAQ: EQBK), (“Equity”, “the Company”, “we”, “us”, “our”), the Wichita-based holding company of Equity Bank, reported net income of $15.1 million and $1.02 per diluted share, including $0.65 of core earnings per diluted share the first quarter ended March 31, 2021.
Core earnings of $0.65 per diluted share for the quarter were driven by non-Paycheck Protection Program (“PPP”) loan growth of $43.7 million, representing growth of 1.9%, or 7.6% annualized growth from December 31, 2020. Further driving results this quarter was the recognition of origination fee income from the successful forgiveness of PPP loans by the SBA; improved operating performance with many of our fee-based initiatives such as wealth management and trust business lines, and debit card and commercial credit card interchange income. Expense control remained a focus with non-interest expenses, excluding merger related expenses, down from the linked-and-comparable-quarters in 2020.
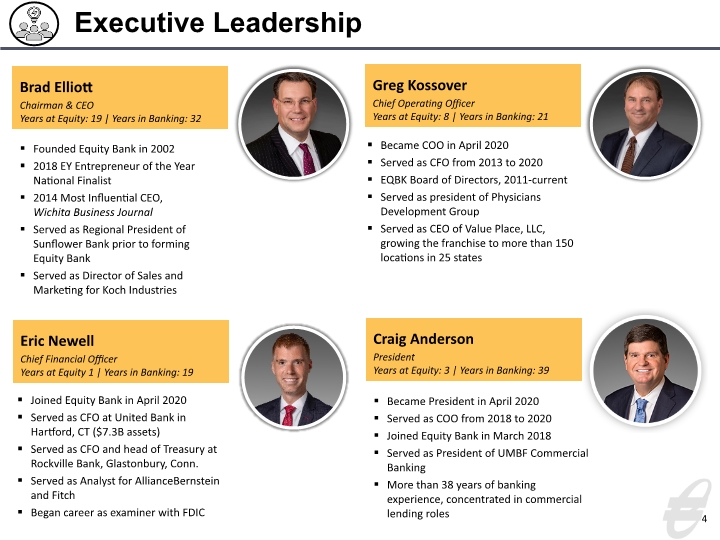
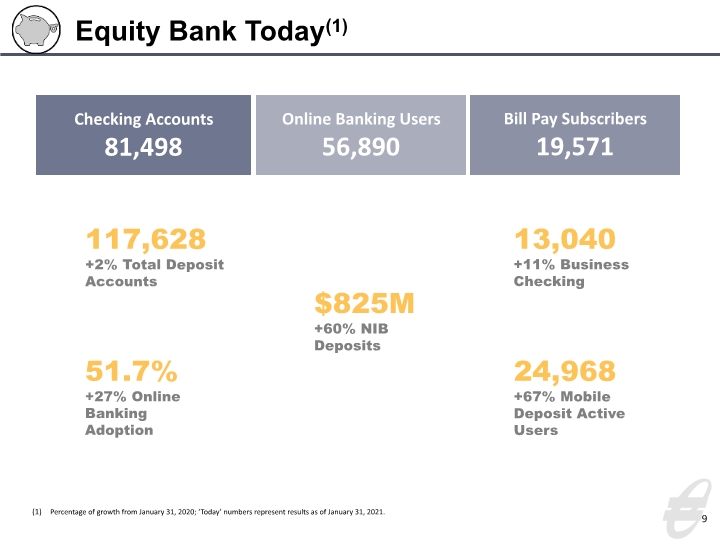
“I’m very proud of the collaboration and entrepreneurial spirit of our Equity teams. Our lending, operations, and customer service teams have worked together to create innovative processes and efficiencies that benefit our customers” said Brad S. Elliott, Chairman and CEO of Equity. “Our teams have worked to onboard new core deposit customers, and we have seen sustained increases in usage of our digital products, including online banking, mobile deposit, and bill pay – while continuing to service customers from fully opened lobbies. Entrepreneurial spirit is one of our core values, and we believe business, commercial, and retail customers continue to choose Equity Bank for our approach.”
“Throughout our footprint, our Equity Bank teams worked incredibly hard on behalf of our customers to secure PPP funds and help our customers maintain their businesses and livelihoods,” said Mr. Elliott. “A community bank prioritizes its customers and delivers dependable, innovative and round the clock service when our customers need it. We’ve remained open, ready and available to our customers to serve loan and business growth needs in all facets.”
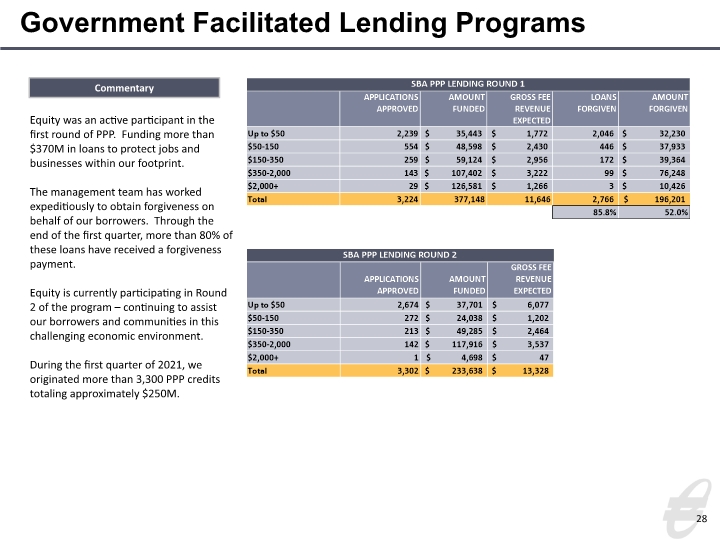
In the quarter ended March 31, 2021, Equity originated $233.6 million in total PPP loans, and Equity’s total outstanding PPP loans were $414.1 million at the end of the quarter. The Company’s customers successfully had $99.7 million of PPP loans forgiven during the quarter, resulting in the recognition of fee income totaling $2.3 million in the three-month period ended March 31, 2021. At March 31, 2021, the total unrecognized fee income associated with PPP loans was $12.7 million. Through two rounds of PPP, Equity originated more than $610 million in PPP loans.
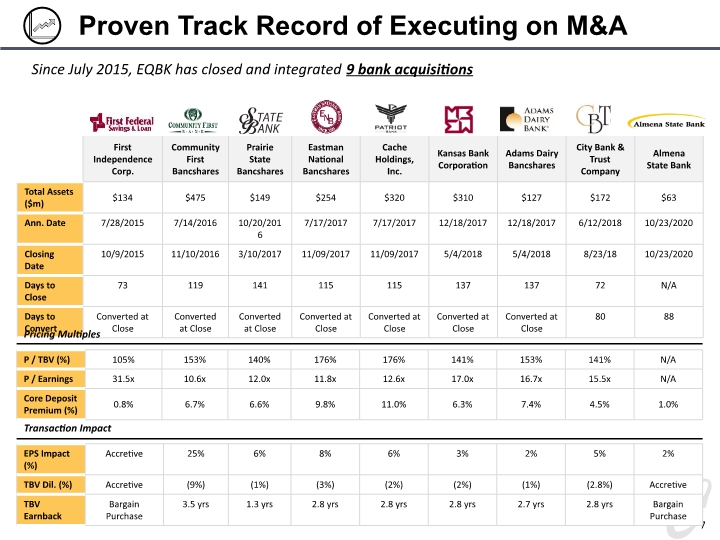
The results in the quarter ended December 31, 2020, reflect the Company’s purchase of assets and deposit liabilities of Almena State Bank. Equity completed the data system conversion of Almena State Bank on January 16, 2021, following the acquisition of Almena State Bank branches from the Federal Deposit Insurance Corporation (“FDIC”) in October 2020. Results also reflect Equity customers’ obtaining forgiveness of Paycheck Protection Program (“PPP”) loans from the Small Business Administration (“SBA”) totaling $102.8 million resulting in a recognition of $3.8 million of fee income.
Equity Bancshares, Inc.
PRESS RELEASE - 04/20/2021
Notable Items:
|
|
• |
The Company authorized a second stock repurchase program in the third quarter of 2020 totaling 800,000 shares. During the quarter ended March 31, 2021, the Company repurchased 233,012 shares at a weighted average cost of $25.35 per share, totaling $5.9 million. At the end of the quarter, capacity of 253,757 shares remained under the current repurchase program. |
|
|
• |
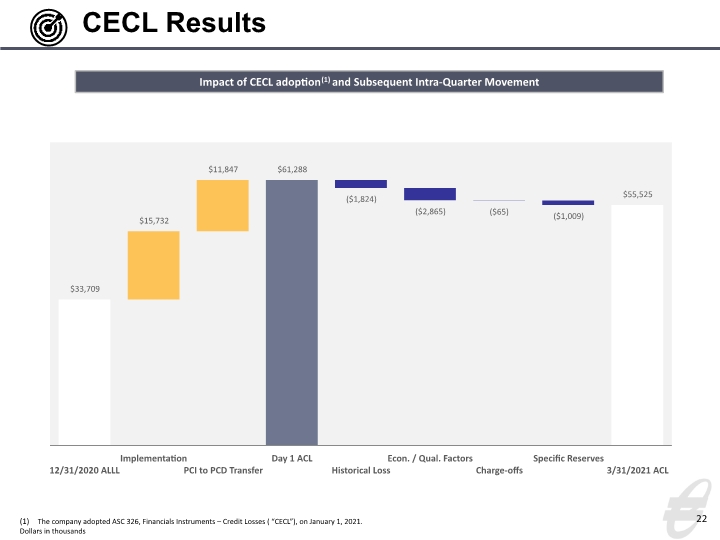
The Company adopted ASU 2016-13, also known as Current Expected Credit Losses (“CECL”) at January 1, 2021. Upon implementation, the Company recognized a day one after tax $12.4 million reduction in stockholders’ equity and transferred $11.8 million of purchase credit impaired (“PCI”) marks to the allowance for credit losses (“ACL”) as purchase credit deteriorated (“PCD”) reserves. On implementation, the allowance for credit losses, including reserve on unfunded commitments, increased to $62.1 million from $33.7 million at December 31, 2020. |
|
|
• |
During the quarter ended March 31, 2021, there was a release of reserve for credit losses of $5.8 million as compared to a $1.0 million provision for loan losses in the quarter ended December 31, 2020. |
Equity’s Balance Sheet Highlights:
|
|
• |
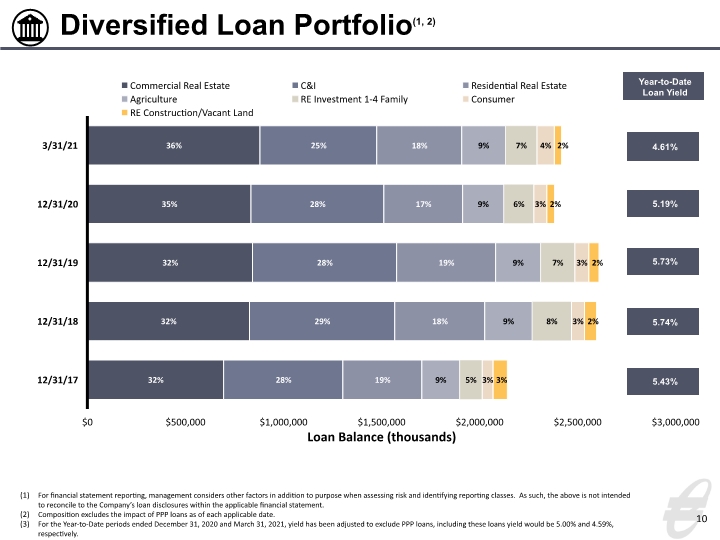
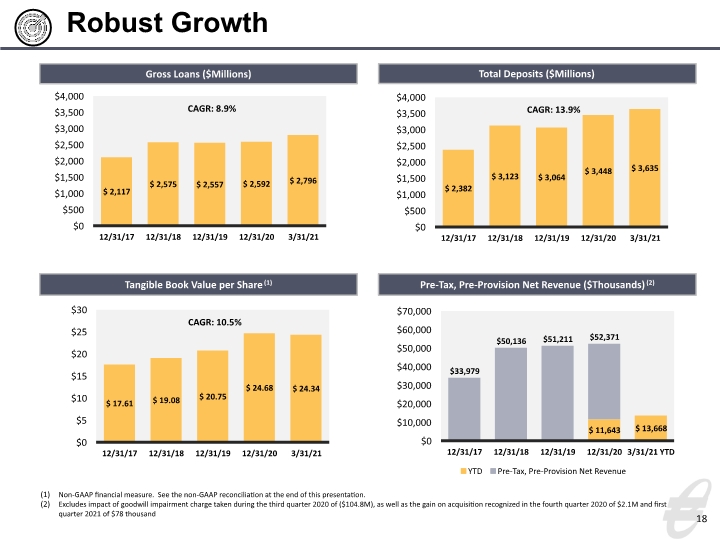
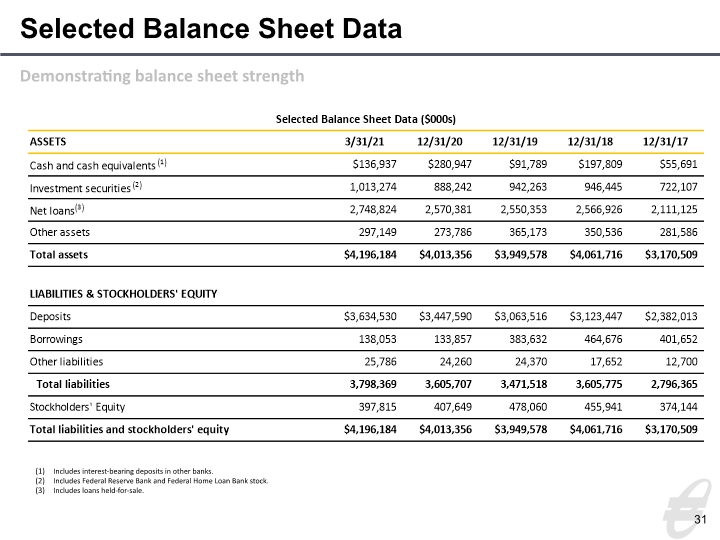
Total loans held for investment of $2.80 billion at March 31, 2021, as compared to total loans held for investment of $2.59 billion at December 31, 2020. |
|
|
• |
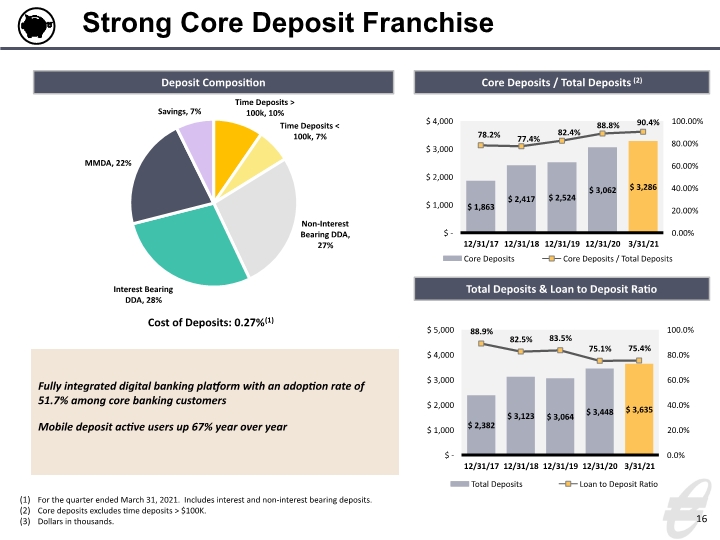
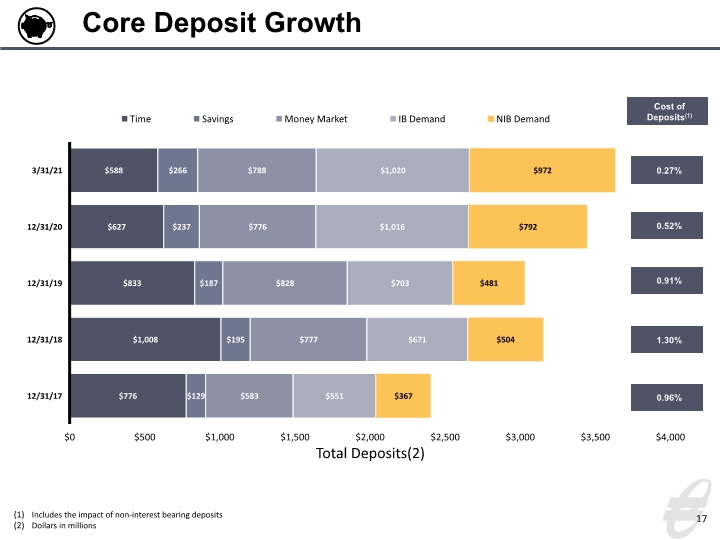
Total deposits of $3.63 billion at March 31, 2021, as compared to $3.45 billion at December 31, 2020. Signature deposits, including core deposits comprised of checking, savings and money market accounts, were $3.05 billion at March 31, 2021, relative to $2.82 billion at December 31, 2020. Included in this signature deposit growth was a $180.7 million increase in non-interest-bearing deposits, from $791.6 million at December 31, 2020, to $972.4 million at March 31, 2021. |
|
|
• |
Total assets were $4.20 billion at March 31, 2021, as compared to $4.01 billion at December 31, 2020. |
Financial Results for the Quarter Ended March 31, 2021
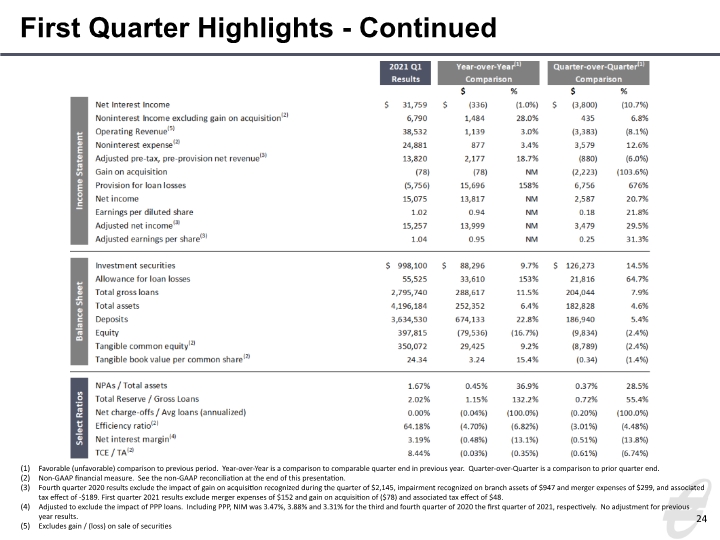
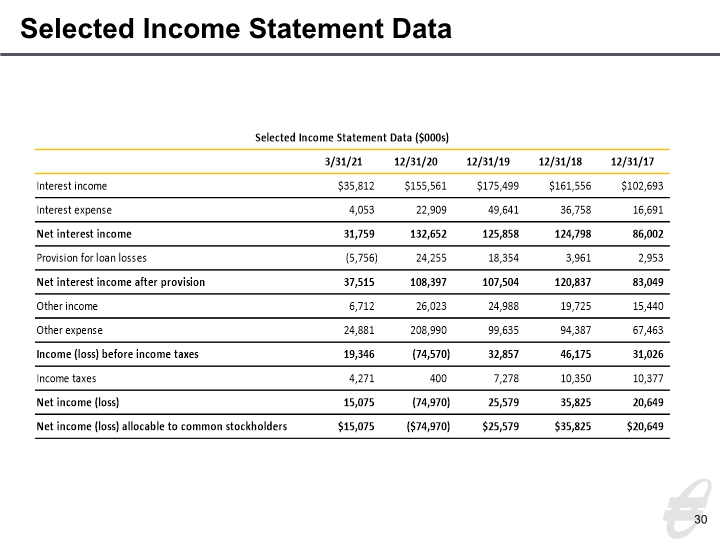
Net income allocable to common stockholders was $15.1 million, or $1.02 per diluted share, for the three months ended March 31, 2021, as compared to $12.5 million, or $0.84 per diluted share, for the three months ended December 31, 2020, an increase of $2.6 million. This increase was attributable to a release of reserve for credit losses of $5.8 million during the quarter as compared to a provision for loan losses of $1.0 million during the fourth quarter of 2020. This $6.8 million provision improvement as well as the decrease in non-interest expense of $3.6 million and increase in non-interest income, exclusive of gain on acquisition, of $435 thousand were partially offset by a $3.8 million decrease in net interest income, a $2.2 million increase in provision for income taxes and a $2.2 million reduction in gain on acquisition.
Net Interest Income
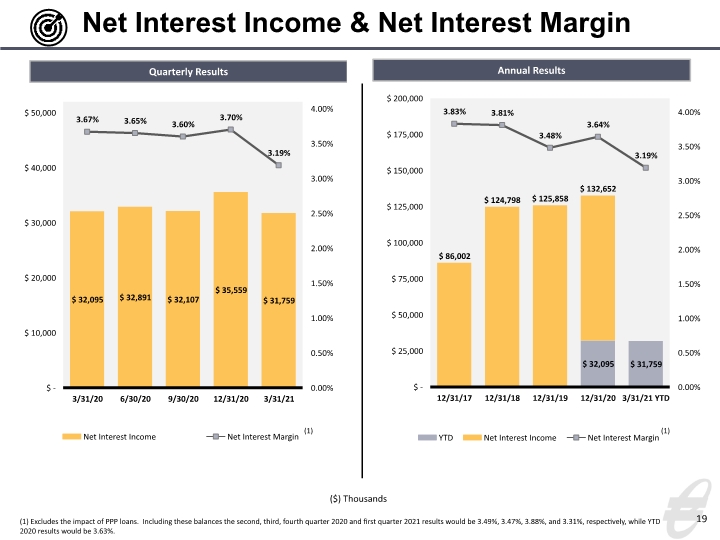
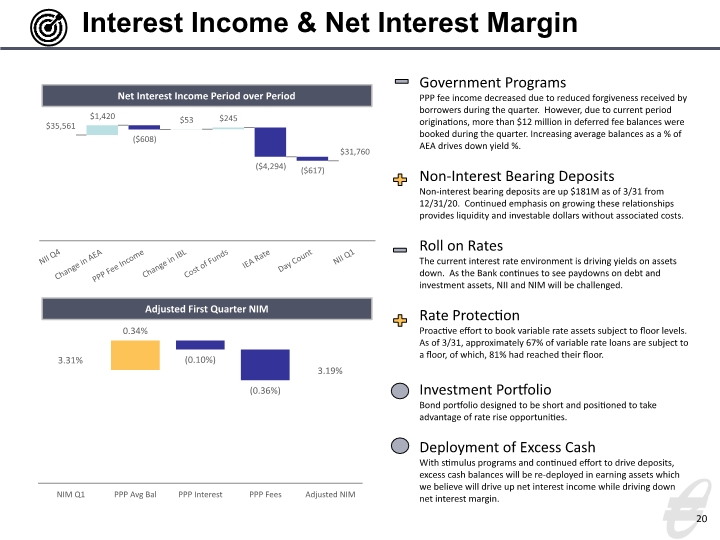
Net interest income was $31.8 million for the three months ended March 31, 2021, as compared to $35.6 million for the three months ended December 31, 2020, a decrease of $3.8 million, or 10.7%. The decrease in net interest income was primarily driven by a 63-basis point decrease in average rate earned on interest-earning assets, to 3.73% for the quarter ended March 31, 2021, from 4.36% for the quarter ended December 31, 2020. The decline in yield on earning assets was driven, in part, by the success of our forgiveness program with regard to the first round of PPP funding during the fourth quarter of 2020 resulting in a comparative reduction in interest income of $651 thousand; the success of the special assets team in processing program assets in the fourth quarter of 2020 resulting in a comparable decline of $1.1 million; and a reduction in the loan fee recognition. The cost of interest-bearing liabilities declined to 0.58% or seven basis points for the quarter ended March 31, 2021 from 0.65% in the quarter ended December 31, 2020. The cost of interest-bearing deposits declined by seven basis points to 0.36% for the three months ended March 31, 2021 from 0.43% in the previous quarter primarily attributed to the reduction in the cost of time deposits, that slipped to 16 basis points between the quarters.
Equity Bancshares, Inc.
PRESS RELEASE - 04/20/2021
Provision for Credit Losses
During the three months ended March 31, 2021, there was a reversal of $5.8 million in the allowance for credit losses recognized through the provision for credit losses as compared to a $1.0 million provision for loan losses for the three months ended December 31, 2020. For the three months ended March 31, 2021, we had net charge-offs of $65 thousand as compared to $1.4 million for the three months ended December 31, 2020. The reversal is attributed primarily to improved economic inputs into the CECL model and, to a lesser extent, an improvement in historical loss experience and associated impact on the allowance for credit losses.
Non-Interest Income
Total non-interest income was $6.7 million for the three months ended March 31, 2021, as compared to $8.5 million for the three months ended December 31, 2020, or $6.4 million excluding the $2.1 million net gain on the purchase and assumption of Almena State Bank. Other non-interest income was $1.3 million, an increase of $439 thousand, or 51.5%, from the quarter ended December 31, 2020. The largest contributor was a $197 thousand increase from derivative transactions. The first quarter increase in value of bank-owned life insurance was $601 thousand, as compared to $489 thousand during the fourth quarter of 2020.
Non-Interest Expense
Total non-interest expense for the quarter ended March 31, 2021, was $24.9 million as compared to $28.5 million for the quarter ended December 31, 2020. The $3.6 million reduction is attributed to $1.6 million less in other real estate owned expense and a $1.3 million decline in salaries and employee benefits. The most significant contributor to the decrease in other real estate owned expense was a $947 thousand valuation adjustment during the fourth quarter of 2020 on two facilities that were closed in May 2020.
Asset Quality
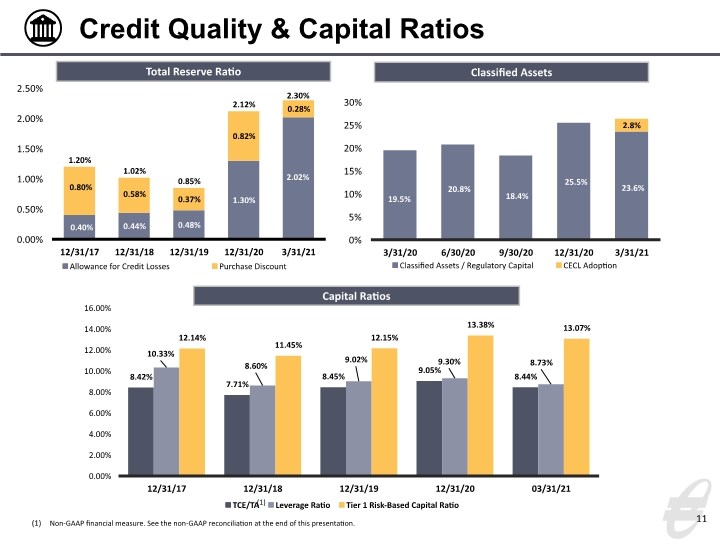
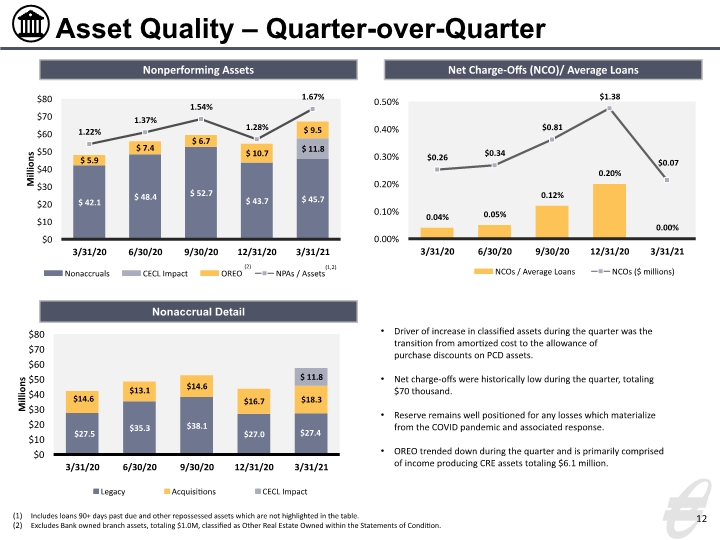
As of March 31, 2021, Equity’s allowance for credit losses, plus reserve for unfunded commitments, to total loans was 2.02%, as compared to 1.30% at December 31, 2020. Total reserves to total loans were approximately 2.30% as of March 31, 2021, as compared to 2.12% at December 31, 2020. Nonperforming assets were $70.1 million as of March 31, 2021, or 1.67% of total assets. Nonperforming assets were $54.6 million at December 31, 2020, or 1.36% of total assets. Total other real estate owned declined to $10.6 million at March 31, 2021 from $11.7 million in the linked quarter. The increase of non-performing assets is attributed to the Company’s adoption of ASC 326 on January 1, 2021, and consequently transferring $11.8 million of PCI loan marks to PCD which is included in the ACL. The PCI marks, primarily attributed to acquired loans associated with Almena State Bank, previously reduced the amortized cost basis of the acquired loans before the January 1, 2021 CECL implementation.
Regulatory Capital
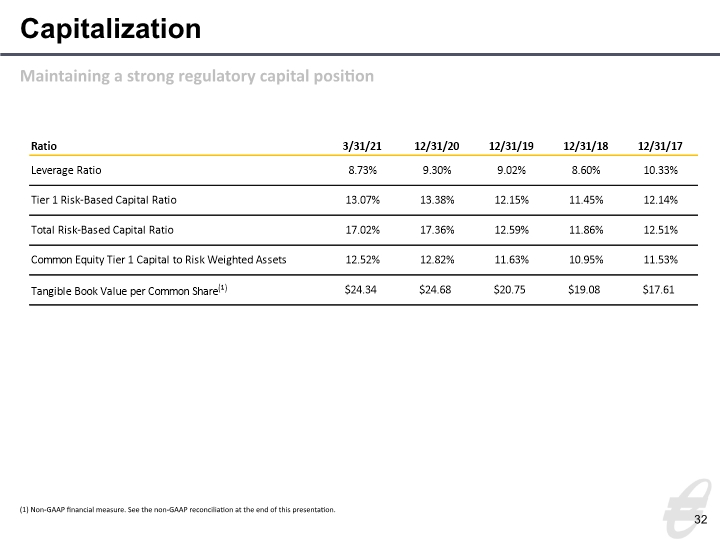
The Company’s ratio of common equity tier 1 capital to risk-weighted assets was 12.5%, the total capital to risk-weighted assets was 17.0% and the total leverage ratio was 8.7% at March 31, 2021. At December 31, 2020, the Company’s common equity tier 1 capital to risk-weighted assets ratio was 12.8%, the total capital to risk-weighted assets ratio was 17.4% and the total leverage ratio was 9.3%. The Company’s subsidiary, Equity Bank, had a ratio of common equity tier 1 capital to risk-weighted assets of 14.4%, a ratio of total capital to risk-weighted assets of 15.7% and a total leverage ratio of 9.6% at March 31, 2021. At December 31, 2020, Equity Bank’s ratio of common equity tier 1 capital to risk-weighted assets was 14.5%, the ratio of total capital to risk-weighted assets was 15.7% and the total leverage ratio was 10.1%.
Equity Bancshares, Inc.
PRESS RELEASE - 04/20/2021
Non-GAAP Financial Measures
In addition to evaluating the Company’s results of operations in accordance with accounting principles generally accepted in the United States of America (“GAAP”), management periodically supplements this evaluation with an analysis of certain non-GAAP financial measures that are intended to provide the reader with additional perspectives on operating results, financial condition and performance trends, while facilitating comparisons with the performance of other financial institutions. Non-GAAP financial measures are not a substitute for GAAP measures, rather, they should be read and used in conjunction with the Company’s GAAP financial information.
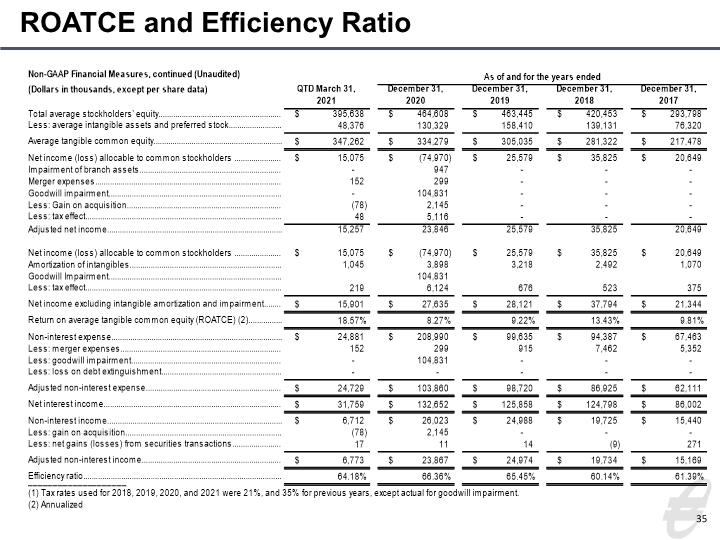
The efficiency ratio is used as a common measure by banks as a comparable metric to understand the Company’s expense structure relative to its total revenue; in other words, for every dollar of total revenue recognized, how much of that dollar is expended. To improve the comparability of the ratio to our peers, non-core items are excluded. To improve transparency and acknowledging that banks are not consistent in their definition of the efficiency ratio, we include our calculation of this non-GAAP measure.
Return on average assets before income tax provision, provision for loan losses and goodwill impairment is a measure that the Company uses to understand fundamental operating performance before these expenses. Used as a ratio relative to average assets, we believe it demonstrates the “core” performance and can be viewed as an alternative measure of how efficiently the Company services its asset base. Used as a ratio relative to average equity, it can function as an alternative measure of the Company’s earnings performance in relationship to its equity.
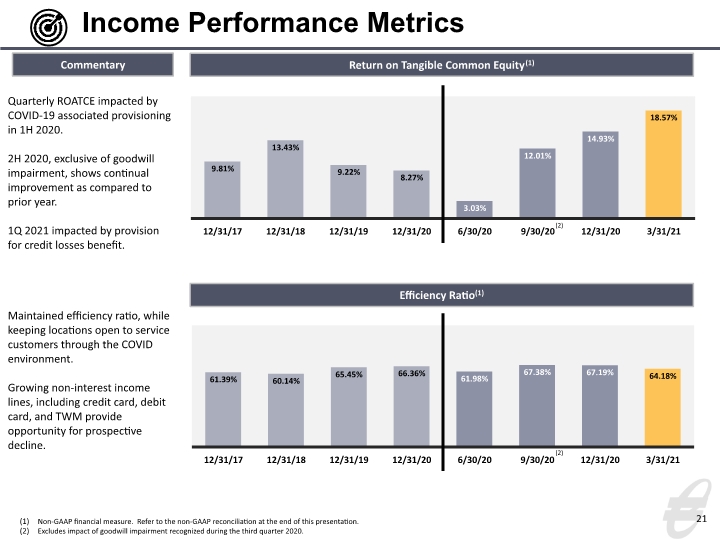
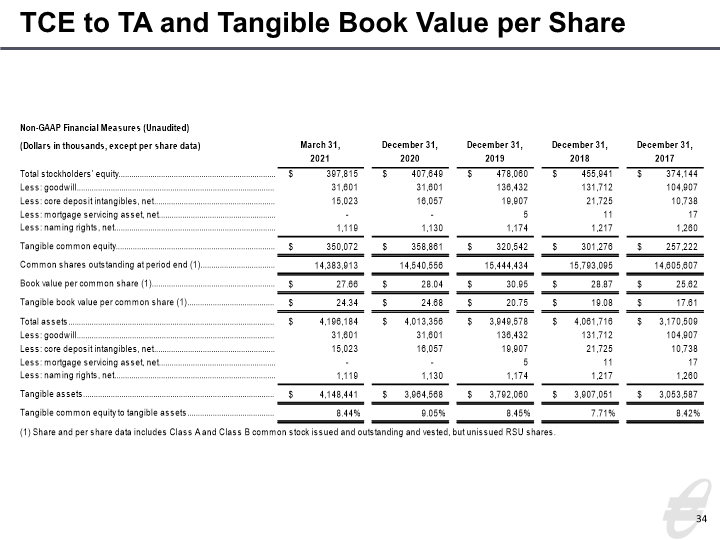
Tangible common equity and related measures are non-GAAP financial measures that exclude the impact of intangible assets, net of deferred taxes, and their related amortization. These financial measures are useful for evaluating the performance of a business consistently, whether acquired or developed internally. Return on average tangible common equity is used by management and readers of our financial statements to understand how efficiently the Company is deploying its common equity. Companies that are able to demonstrate more efficient use of common equity are more likely to be viewed favorably by current and prospective investors.
The Company believes that disclosing these non-GAAP financial measures is both useful internally and is expected by our investors and analysts in order to understand the overall performance of the Company. Other companies may calculate and define their non-GAAP financial measures and supplemental data differently. A reconciliation of GAAP financial measures to non-GAAP measures and other performance ratios, as adjusted, are included in Table 8 in the following press release tables.
Conference Call and Webcast
Equity Chairman and Chief Executive Officer, Brad Elliott, and Executive Vice President and Chief Financial Officer, Eric Newell, will hold a conference call and webcast to discuss the 2021 first quarter results on Wednesday, April 21, 2021, at 10:00 a.m. eastern time, 9:00 a.m. central time.
Investors, news media and other participants should register for the call or audio webcast at investor.equitybank.com. On Wednesday, April 21, 2021, participants may also dial into the call toll-free at (844) 534-7311 from anywhere in the U.S. or (574) 990-1419 internationally, using conference ID no. 9542529.
Participants are encouraged to dial into the call or access the webcast approximately 10 minutes prior to the start time. Presentation slides to pair with the call or webcast will be posted one hour prior to the call at investor.equitybank.com.
A replay of the call and webcast will be available two hours following the close of the call until April 28, 2021, accessible at (855) 859-2056 with conference ID no. 9542529 at investor.equitybank.com.
Equity Bancshares, Inc.
PRESS RELEASE - 04/20/2021
About Equity Bancshares, Inc.
Equity Bancshares, Inc. is the holding company for Equity Bank, offering a full range of financial solutions, including commercial loans, consumer banking, mortgage loans, trust and wealth management services and treasury management services, while delivering the high-quality, relationship-based customer service of a community bank. Equity’s common stock is traded on the NASDAQ Global Select Market under the symbol “EQBK.” Learn more at www.equitybank.com.
Special Note Concerning Forward-Looking Statements
This press release contains “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. These forward-looking statements reflect the current views of Equity’s management with respect to, among other things, future events and Equity’s financial performance. These statements are often, but not always, made through the use of words or phrases such as “may,” “should,” “could,” “predict,” “potential,” “believe,” “will likely result,” “expect,” “continue,” “will,” “anticipate,” “seek,” “estimate,” “intend,” “plan,” “project,” “forecast,” “goal,” “target,” “would” and “outlook,” or the negative variations of those words or other comparable words of a future or forward-looking nature. These forward-looking statements are not historical facts, and are based on current expectations, estimates and projections about Equity’s industry, management’s beliefs and certain assumptions made by management, many of which, by their nature, are inherently uncertain and beyond Equity’s control. Accordingly, Equity cautions you that any such forward-looking statements are not guarantees of future performance and are subject to risks, assumptions and uncertainties that are difficult to predict. Although Equity believes that the expectations reflected in these forward-looking statements are reasonable as of the date made, actual results may prove to be materially different from the results expressed or implied by the forward-looking statements. Factors that could cause actual results to differ materially from Equity’s expectations include COVID-19 related impacts; competition from other financial institutions and bank holding companies; the effects of and changes in trade, monetary and fiscal policies and laws, including interest rate policies of the Federal Reserve Board; changes in the demand for loans; fluctuations in value of collateral and loan reserves; inflation, interest rate, market and monetary fluctuations; changes in consumer spending, borrowing and savings habits; and acquisitions and integration of acquired businesses; and similar variables. The foregoing list of factors is not exhaustive.
For discussion of these and other risks that may cause actual results to differ from expectations, please refer to “Cautionary Note Regarding Forward-Looking Statements” and “Risk Factors” in Equity’s Annual Report on Form 10-K filed with the Securities and Exchange Commission on March 9, 2021, and any updates to those risk factors set forth in Equity’s subsequent Quarterly Reports on Form 10-Q or Current Reports on Form 8-K. If one or more events related to these or other risks or uncertainties materialize, or if Equity’s underlying assumptions prove to be incorrect, actual results may differ materially from what Equity anticipates. Accordingly, you should not place undue reliance on any such forward-looking statements. Any forward-looking statement speaks only as of the date on which it is made, and Equity does not undertake any obligation to publicly update or review any forward-looking statement, whether as a result of new information, future developments or otherwise. New risks and uncertainties arise from time to time, such as COVID-19, and it is not possible for us to predict those events or how they may affect us. In addition, Equity cannot assess the impact of each factor on Equity’s business or the extent to which any factor, or combination of factors, may cause actual results to differ materially from those contained in any forward-looking statements. All forward-looking statements, expressed or implied, included in this press release are expressly qualified in their entirety by this cautionary statement. This cautionary statement should also be considered in connection with any subsequent written or oral forward-looking statements that Equity or persons acting on Equity’s behalf may issue.
Investor Contact:
Chris Navratil
SVP, Finance
Equity Bancshares, Inc.
(316) 612-6014
Equity Bancshares, Inc.
PRESS RELEASE - 04/20/2021
Media Contact:
John J. Hanley
SVP, Senior Director of Marketing
Equity Bancshares, Inc.
(816) 505-4063
Unaudited Financial Tables
|
|
• |
Table 1. Quarterly Consolidated Statements of Operations |
|
|
• |
Table 2. Consolidated Balance Sheets |
|
|
• |
Table 3. Selected Financial Highlights |
|
|
• |
Table 4. Quarter-to-Date Net Interest Income Analysis |
|
|
• |
Table 5. Quarter-Over-Quarter Net Interest Income Analysis |
|
|
• |
Table 6. Non-GAAP Financial Measures |
Equity Bancshares, Inc.
PRESS RELEASE - 04/20/2021
TABLE 1. QUARTERLY CONSOLIDATED STATEMENTS OF OPERATIONS (Unaudited)
(Dollars in thousands, except per share data)
|
|
|
As of and for the three months ended |
|
|||||||||||||||||
|
|
|
March 31, 2021 |
|
|
December 31, 2020 |
|
|
September 30, 2020 |
|
|
June 30, 2020 |
|
|
March 31, 2020 |
|
|||||
|
Interest and dividend income |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Loans, including fees |
|
$ |
31,001 |
|
|
$ |
35,383 |
|
|
$ |
32,278 |
|
|
$ |
32,627 |
|
|
$ |
34,376 |
|
|
Securities, taxable |
|
|
3,799 |
|
|
|
3,408 |
|
|
|
3,476 |
|
|
|
4,017 |
|
|
|
4,620 |
|
|
Securities, nontaxable |
|
|
724 |
|
|
|
913 |
|
|
|
923 |
|
|
|
880 |
|
|
|
966 |
|
|
Federal funds sold and other |
|
|
288 |
|
|
|
285 |
|
|
|
405 |
|
|
|
409 |
|
|
|
595 |
|
|
Total interest and dividend income |
|
|
35,812 |
|
|
|
39,989 |
|
|
|
37,082 |
|
|
|
37,933 |
|
|
|
40,557 |
|
|
Interest expense |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Deposits |
|
|
2,410 |
|
|
|
2,755 |
|
|
|
3,064 |
|
|
|
3,899 |
|
|
|
6,864 |
|
|
Federal funds purchased and retail repurchase agreements |
|
|
22 |
|
|
|
25 |
|
|
|
25 |
|
|
|
24 |
|
|
|
31 |
|
|
Federal Home Loan Bank advances |
|
|
65 |
|
|
|
94 |
|
|
|
471 |
|
|
|
552 |
|
|
|
1,175 |
|
|
Federal Reserve Bank discount window |
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
6 |
|
|
|
— |
|
|
Bank stock loan |
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
306 |
|
|
|
109 |
|
|
Subordinated debentures |
|
|
1,556 |
|
|
|
1,556 |
|
|
|
1,415 |
|
|
|
255 |
|
|
|
283 |
|
|
Total interest expense |
|
|
4,053 |
|
|
|
4,430 |
|
|
|
4,975 |
|
|
|
5,042 |
|
|
|
8,462 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Net interest income |
|
|
31,759 |
|
|
|
35,559 |
|
|
|
32,107 |
|
|
|
32,891 |
|
|
|
32,095 |
|
|
Provision for credit losses |
|
|
(5,756 |
) |
|
|
1,000 |
|
|
|
815 |
|
|
|
12,500 |
|
|
|
9,940 |
|
|
Net interest income after provision for credit losses |
|
|
37,515 |
|
|
|
34,559 |
|
|
|
31,292 |
|
|
|
20,391 |
|
|
|
22,155 |
|
|
Non-interest income |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Service charges and fees |
|
|
1,596 |
|
|
|
1,759 |
|
|
|
1,706 |
|
|
|
1,365 |
|
|
|
2,026 |
|
|
Debit card income |
|
|
2,350 |
|
|
|
2,401 |
|
|
|
2,491 |
|
|
|
2,201 |
|
|
|
2,043 |
|
|
Mortgage banking |
|
|
935 |
|
|
|
855 |
|
|
|
877 |
|
|
|
831 |
|
|
|
590 |
|
|
Increase in value of bank-owned life insurance |
|
|
601 |
|
|
|
489 |
|
|
|
489 |
|
|
|
481 |
|
|
|
482 |
|
|
Net gain on acquisition |
|
|
(78 |
) |
|
|
2,145 |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
Net gains (losses) from securities transactions |
|
|
17 |
|
|
|
(1 |
) |
|
|
— |
|
|
|
4 |
|
|
|
8 |
|
|
Other |
|
|
1,291 |
|
|
|
852 |
|
|
|
922 |
|
|
|
850 |
|
|
|
157 |
|
|
Total non-interest income |
|
|
6,712 |
|
|
|
8,500 |
|
|
|
6,485 |
|
|
|
5,732 |
|
|
|
5,306 |
|
|
Non-interest expense |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Salaries and employee benefits |
|
|
12,722 |
|
|
|
14,053 |
|
|
|
13,877 |
|
|
|
12,695 |
|
|
|
13,504 |
|
|
Net occupancy and equipment |
|
|
2,368 |
|
|
|
2,206 |
|
|
|
2,224 |
|
|
|
2,119 |
|
|
|
2,235 |
|
|
Data processing |
|
|
2,663 |
|
|
|
2,748 |
|
|
|
2,817 |
|
|
|
2,763 |
|
|
|
2,663 |
|
|
Professional fees |
|
|
1,073 |
|
|
|
1,095 |
|
|
|
877 |
|
|
|
943 |
|
|
|
1,367 |
|
|
Advertising and business development |
|
|
682 |
|
|
|
801 |
|
|
|
598 |
|
|
|
403 |
|
|
|
696 |
|
|
Telecommunications |
|
|
580 |
|
|
|
510 |
|
|
|
486 |
|
|
|
390 |
|
|
|
487 |
|
|
FDIC insurance |
|
|
415 |
|
|
|
797 |
|
|
|
360 |
|
|
|
414 |
|
|
|
517 |
|
|
Courier and postage |
|
|
369 |
|
|
|
338 |
|
|
|
366 |
|
|
|
353 |
|
|
|
384 |
|
|
Free nationwide ATM cost |
|
|
472 |
|
|
|
423 |
|
|
|
439 |
|
|
|
327 |
|
|
|
420 |
|
|
Amortization of core deposit intangibles |
|
|
1,034 |
|
|
|
1,044 |
|
|
|
1,030 |
|
|
|
974 |
|
|
|
802 |
|
|
Loan expense |
|
|
238 |
|
|
|
161 |
|
|
|
107 |
|
|
|
287 |
|
|
|
234 |
|
|
Other real estate owned |
|
|
5 |
|
|
|
1,600 |
|
|
|
133 |
|
|
|
269 |
|
|
|
308 |
|
|
Merger expenses |
|
|
152 |
|
|
|
299 |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
Goodwill impairment |
|
|
— |
|
|
|
— |
|
|
|
104,831 |
|
|
|
— |
|
|
|
— |
|
|
Other |
|
|
2,108 |
|
|
|
2,385 |
|
|
|
2,690 |
|
|
|
2,000 |
|
|
|
2,141 |
|
|
Total non-interest expense |
|
|
24,881 |
|
|
|
28,460 |
|
|
|
130,835 |
|
|
|
23,937 |
|
|
|
25,758 |
|
|
Income (loss) before income tax |
|
|
19,346 |
|
|
|
14,599 |
|
|
|
(93,058 |
) |
|
|
2,186 |
|
|
|
1,703 |
|
|
Provision for income taxes (benefit) |
|
|
4,271 |
|
|
|
2,111 |
|
|
|
(2,653 |
) |
|
|
497 |
|
|
|
445 |
|
|
Net income (loss) and net income (loss) allocable to common stockholders |
|
$ |
15,075 |
|
|
$ |
12,488 |
|
|
$ |
(90,405 |
) |
|
$ |
1,689 |
|
|
$ |
1,258 |
|
|
Basic earnings (loss) per share |
|
$ |
1.04 |
|
|
$ |
0.85 |
|
|
$ |
(6.01 |
) |
|
$ |
0.11 |
|
|
$ |
0.08 |
|
Equity Bancshares, Inc.
PRESS RELEASE - 04/20/2021
|
Diluted earnings (loss) per share |
|
$ |
1.02 |
|
|
$ |
0.84 |
|
|
$ |
(6.01 |
) |
|
$ |
0.11 |
|
|
$ |
0.08 |
|
|
Weighted average common shares |
|
|
14,464,291 |
|
|
|
14,760,810 |
|
|
|
15,040,407 |
|
|
|
15,209,483 |
|
|
|
15,387,697 |
|
|
Weighted average diluted common shares |
|
|
14,734,083 |
|
|
|
14,934,058 |
|
|
|
15,040,407 |
|
|
|
15,304,009 |
|
|
|
15,595,024 |
|
Equity Bancshares, Inc.
PRESS RELEASE - 04/20/2021
TABLE 2. CONSOLIDATED BALANCE SHEETS (Unaudited)
(Dollars in thousands)
|
|
|
March 31, 2021 |
|
|
December 31, 2020 |
|
|
September 30, 2020 |
|
|
June 30, 2020 |
|
|
March 31, 2020 |
|
|||||
|
ASSETS |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Cash and due from banks |
|
$ |
136,190 |
|
|
$ |
280,150 |
|
|
$ |
65,534 |
|
|
$ |
178,045 |
|
|
$ |
141,989 |
|
|
Federal funds sold |
|
|
498 |
|
|
|
548 |
|
|
|
305 |
|
|
|
245 |
|
|
|
263 |
|
|
Cash and cash equivalents |
|
|
136,688 |
|
|
|
280,698 |
|
|
|
65,839 |
|
|
|
178,290 |
|
|
|
142,252 |
|
|
Interest-bearing time deposits in other banks |
|
|
249 |
|
|
|
249 |
|
|
|
499 |
|
|
|
2,248 |
|
|
|
2,498 |
|
|
Available-for-sale securities |
|
|
998,100 |
|
|
|
871,827 |
|
|
|
798,576 |
|
|
|
177,228 |
|
|
|
187,812 |
|
|
Held-to-maturity securities(1) |
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
662,522 |
|
|
|
721,992 |
|
|
Loans held for sale |
|
|
8,609 |
|
|
|
12,394 |
|
|
|
9,053 |
|
|
|
4,802 |
|
|
|
6,494 |
|
|
Loans, net of allowance for credit losses(2) |
|
|
2,740,215 |
|
|
|
2,557,987 |
|
|
|
2,691,626 |
|
|
|
2,772,256 |
|
|
|
2,485,208 |
|
|
Other real estate owned, net |
|
|
10,559 |
|
|
|
11,733 |
|
|
|
8,727 |
|
|
|
7,374 |
|
|
|
5,870 |
|
|
Premises and equipment, net |
|
|
90,322 |
|
|
|
89,412 |
|
|
|
86,087 |
|
|
|
87,055 |
|
|
|
84,732 |
|
|
Bank-owned life insurance |
|
|
102,645 |
|
|
|
77,044 |
|
|
|
76,555 |
|
|
|
76,066 |
|
|
|
75,585 |
|
|
Federal Reserve Bank and Federal Home Loan Bank stock |
|
|
15,174 |
|
|
|
16,415 |
|
|
|
32,545 |
|
|
|
31,832 |
|
|
|
31,662 |
|
|
Interest receivable |
|
|
16,655 |
|
|
|
15,831 |
|
|
|
18,110 |
|
|
|
19,598 |
|
|
|
15,549 |
|
|
Goodwill |
|
|
31,601 |
|
|
|
31,601 |
|
|
|
31,601 |
|
|
|
136,432 |
|
|
|
136,432 |
|
|
Core deposit intangibles, net |
|
|
15,023 |
|
|
|
16,057 |
|
|
|
17,101 |
|
|
|
18,131 |
|
|
|
19,105 |
|
|
Other |
|
|
30,344 |
|
|
|
32,108 |
|
|
|
29,252 |
|
|
|
31,435 |
|
|
|
28,641 |
|
|
Total assets |
|
$ |
4,196,184 |
|
|
$ |
4,013,356 |
|
|
$ |
3,865,571 |
|
|
$ |
4,205,269 |
|
|
$ |
3,943,832 |
|
|
LIABILITIES AND STOCKHOLDERS’ EQUITY |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Deposits |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Demand |
|
$ |
972,364 |
|
|
$ |
791,639 |
|
|
$ |
693,967 |
|
|
$ |
756,613 |
|
|
$ |
508,441 |
|
|
Total non-interest-bearing deposits |
|
|
972,364 |
|
|
|
791,639 |
|
|
|
693,967 |
|
|
|
756,613 |
|
|
|
508,441 |
|
|
Savings, NOW and money market |
|
|
2,074,261 |
|
|
|
2,029,097 |
|
|
|
1,816,307 |
|
|
|
1,800,132 |
|
|
|
1,668,145 |
|
|
Time |
|
|
587,905 |
|
|
|
626,854 |
|
|
|
623,344 |
|
|
|
690,522 |
|
|
|
783,811 |
|
|
Total interest-bearing deposits |
|
|
2,662,166 |
|
|
|
2,655,951 |
|
|
|
2,439,651 |
|
|
|
2,490,654 |
|
|
|
2,451,956 |
|
|
Total deposits |
|
|
3,634,530 |
|
|
|
3,447,590 |
|
|
|
3,133,618 |
|
|
|
3,247,267 |
|
|
|
2,960,397 |
|
|
Federal funds purchased and retail repurchase agreements |
|
|
40,339 |
|
|
|
36,029 |
|
|
|
46,295 |
|
|
|
51,557 |
|
|
|
37,113 |
|
|
Federal Home Loan Bank advances |
|
|
9,926 |
|
|
|
10,144 |
|
|
|
167,862 |
|
|
|
344,900 |
|
|
|
389,620 |
|
|
Bank stock loan |
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
|
40,000 |
|
|
Subordinated debentures |
|
|
87,788 |
|
|
|
87,684 |
|
|
|
87,537 |
|
|
|
55,575 |
|
|
|
14,638 |
|
|
Contractual obligations |
|
|
4,856 |
|
|
|
5,189 |
|
|
|
5,478 |
|
|
|
5,571 |
|
|
|
5,781 |
|
|
Interest payable and other liabilities |
|
|
20,930 |
|
|
|
19,071 |
|
|
|
22,609 |
|
|
|
20,633 |
|
|
|
18,932 |
|
|
Total liabilities |
|
|
3,798,369 |
|
|
|
3,605,707 |
|
|
|
3,463,399 |
|
|
|
3,725,503 |
|
|
|
3,466,481 |
|
|
Commitments and contingent liabilities |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Stockholders’ equity |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Common stock |
|
|
175 |
|
|
|
174 |
|
|
|
174 |
|
|
|
174 |
|
|
|
174 |
|
|
Additional paid-in capital |
|
|
387,939 |
|
|
|
386,820 |
|
|
|
386,017 |
|
|
|
384,955 |
|
|
|
383,850 |
|
|
Retained earnings |
|
|
53,459 |
|
|
|
50,787 |
|
|
|
38,299 |
|
|
|
128,704 |
|
|
|
127,015 |
|
|
Accumulated other comprehensive income (loss) |
|
|
12,019 |
|
|
|
19,781 |
|
|
|
21,074 |
|
|
|
3,390 |
|
|
|
3,769 |
|
|
Employee stock loans |
|
|
— |
|
|
|
(43 |
) |
|
|
(43 |
) |
|
|
(43 |
) |
|
|
(43 |
) |
|
Treasury stock |
|
|
(55,777 |
) |
|
|
(49,870 |
) |
|
|
(43,349 |
) |
|
|
(37,414 |
) |
|
|
(37,414 |
) |
|
Total stockholders’ equity |
|
|
397,815 |
|
|
|
407,649 |
|
|
|
402,172 |
|
|
|
479,766 |
|
|
|
477,351 |
|
|
Total liabilities and stockholders’ equity |
|
$ |
4,196,184 |
|
|
$ |
4,013,356 |
|
|
$ |
3,865,571 |
|
|
$ |
4,205,269 |
|
|
$ |
3,943,832 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
(1) Fair market value of held-to-maturity securities |
|
$ |
— |
|
|
$ |
— |
|
|
$ |
— |
|
|
$ |
689,206 |
|
|
$ |
750,900 |
|
|
(2) Allowance for credit losses |
|
|
55,525 |
|
|
|
33,709 |
|
|
|
34,087 |
|
|
|
34,078 |
|
|
|
21,915 |
|
Equity Bancshares, Inc.
PRESS RELEASE - 04/20/2021
TABLE 3. SELECTED FINANCIAL HIGHLIGHTS (Unaudited)
(Dollars in thousands, except per share data)
|
|
|
As of and for the three months ended |
|
|||||||||||||||||
|
|
|
March 31, |
|
|
December 31, |
|
|
September 30, |
|
|
June 30, |
|
|
March 31, |
|
|||||
|
|
|
2021 |
|
|
2020 |
|
|
2020 |
|
|
2020 |
|
|
2020 |
|
|||||
|
Loans Held-For-Investment by Type |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Commercial real estate |
|
$ |
1,218,545 |
|
|
$ |
1,188,696 |
|
|
$ |
1,188,329 |
|
|
$ |
1,191,336 |
|
|
$ |
1,200,762 |
|
|
Commercial and industrial |
|
|
820,728 |
|
|
|
734,495 |
|
|
|
857,244 |
|
|
|
883,355 |
|
|
|
542,571 |
|
|
Residential real estate |
|
|
438,503 |
|
|
|
381,958 |
|
|
|
402,242 |
|
|
|
442,486 |
|
|
|
480,603 |
|
|
Agricultural real estate |
|
|
134,944 |
|
|
|
133,693 |
|
|
|
127,349 |
|
|
|
129,080 |
|
|
|
130,795 |
|
|
Consumer |
|
|
89,256 |
|
|
|
58,532 |
|
|
|
67,465 |
|
|
|
71,037 |
|
|
|
64,799 |
|
|
Agricultural |
|
|
93,764 |
|
|
|
94,322 |
|
|
|
83,084 |
|
|
|
89,040 |
|
|
|
87,593 |
|
|
Total loans held-for-investment |
|
|
2,795,740 |
|
|
|
2,591,696 |
|
|
|
2,725,713 |
|
|
|
2,806,334 |
|
|
|
2,507,123 |
|
|
Allowance for credit losses |
|
|
(55,525 |
) |
|
|
(33,709 |
) |
|
|
(34,087 |
) |
|
|
(34,078 |
) |
|
|
(21,915 |
) |
|
Net loans held-for-investment |
|
$ |
2,740,215 |
|
|
$ |
2,557,987 |
|
|
$ |
2,691,626 |
|
|
$ |
2,772,256 |
|
|
$ |
2,485,208 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Asset Quality Ratios |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Allowance for credit losses on loans and unfunded commitments to total loans |
|
|
2.02 |
% |
|
|
1.30 |
% |
|
|
1.25 |
% |
|
|
1.21 |
% |
|
|
0.87 |
% |
|
Past due or nonaccrual loans to total loans |
|
|
2.58 |
% |
|
|
1.99 |
% |
|
|
2.12 |
% |
|
|
1.88 |
% |
|
|
2.47 |
% |
|
Nonperforming assets to total assets |
|
|
1.67 |
% |
|
|
1.36 |
% |
|
|
1.55 |
% |
|
|
1.37 |
% |
|
|
1.22 |
% |
|
Nonperforming assets to total loans plus other real estate owned |
|
|
2.50 |
% |
|
|
2.10 |
% |
|
|
2.19 |
% |
|
|
2.05 |
% |
|
|
1.92 |
% |
|
Classified assets to bank total regulatory capital |
|
|
26.45 |
% |
|
|
25.50 |
% |
|
|
18.35 |
% |
|
|
20.81 |
% |
|
|
19.50 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Selected Average Balance Sheet Data (QTD Average) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Investment securities |
|
$ |
947,453 |
|
|
$ |
814,114 |
|
|
$ |
802,525 |
|
|
$ |
877,308 |
|
|
$ |
907,910 |
|
|
Total gross loans receivable |
|
|
2,736,918 |
|
|
|
2,692,223 |
|
|
|
2,758,680 |
|
|
|
2,806,865 |
|
|
|
2,525,344 |
|
|
Interest-earning assets |
|
|
3,891,140 |
|
|
|
3,647,730 |
|
|
|
3,679,168 |
|
|
|
3,786,629 |
|
|
|
3,519,267 |
|
|
Total assets |
|
|
4,143,752 |
|
|
|
3,910,628 |
|
|
|
4,041,187 |
|
|
|
4,159,336 |
|
|
|
3,888,205 |
|
|
Interest-bearing deposits |
|
|
2,690,159 |
|
|
|
2,551,219 |
|
|
|
2,430,407 |
|
|
|
2,487,187 |
|
|
|
2,531,508 |
|
|
Borrowings |
|
|
139,360 |
|
|
|
172,730 |
|
|
|
377,158 |
|
|
|
384,727 |
|
|
|
355,303 |
|
|
Total interest-bearing liabilities |
|
|
2,829,519 |
|
|
|
2,723,949 |
|
|
|
2,807,565 |
|
|
|
2,871,914 |
|
|
|
2,886,811 |
|
|
Total deposits |
|
|
3,577,625 |
|
|
|
2,960,791 |
|
|
|
3,145,810 |
|
|
|
3,257,631 |
|
|
|
3,021,181 |
|
|
Total liabilities |
|
|
3,748,114 |
|
|
|
3,501,056 |
|
|
|
3,558,099 |
|
|
|
3,675,731 |
|
|
|
3,405,638 |
|
|
Total stockholders' equity |
|
|
395,638 |
|
|
|
409,572 |
|
|
|
483,088 |
|
|
|
483,605 |
|
|
|
482,567 |
|
|
Tangible common equity* |
|
|
347,262 |
|
|
|
355,025 |
|
|
|
329,039 |
|
|
|
327,411 |
|
|
|
325,470 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Performance ratios |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Return on average assets (ROAA) annualized |
|
|
1.48 |
% |
|
|
1.27 |
% |
|
|
(8.90 |
)% |
|
|
0.16 |
% |
|
|
0.13 |
% |
|
Return on average assets before income tax, provision for loan losses and goodwill impairment* |
|
|
1.33 |
% |
|
|
1.59 |
% |
|
|
1.24 |
% |
|
|
1.42 |
% |
|
|
1.20 |
% |
|
Return on average equity (ROAE) annualized |
|
|
15.45 |
% |
|
|
12.13 |
% |
|
|
(74.45 |
)% |
|
|
1.40 |
% |
|
|
1.05 |
% |
|
Return on average equity before income tax, provision for loan losses and goodwill impairment* |
|
|
13.93 |
% |
|
|
15.15 |
% |
|
|
10.37 |
% |
|
|
12.21 |
% |
|
|
9.70 |
% |
|
Return on average tangible common equity (ROATCE) annualized* |
|
|
18.57 |
% |
|
|
14.93 |
% |
|
|
(108.31 |
)% |
|
|
3.03 |
% |
|
|
2.35 |
% |
|
Return on average tangible common equity adjusted for goodwill impairment* |
|
|
18.57 |
% |
|
|
14.93 |
% |
|
|
12.01 |
% |
|
|
3.03 |
% |
|
|
2.35 |
% |
|
Yield on loans annualized |
|
|
4.59 |
% |
|
|
5.23 |
% |
|
|
4.65 |
% |
|
|
4.68 |
% |
|
|
5.47 |
% |
|
Cost of interest-bearing deposits annualized |
|
|
0.36 |
% |
|
|
0.43 |
% |
|
|
0.50 |
% |
|
|
0.63 |
% |
|
|
1.09 |
% |
|
Cost of total deposits annualized |
|
|
0.27 |
% |
|
|
0.37 |
% |
|
|
0.39 |
% |
|
|
0.48 |
% |
|
|
0.91 |
% |
|
Net interest margin annualized |
|
|
3.31 |
% |
|
|
3.88 |
% |
|
|
3.47 |
% |
|
|
3.49 |
% |
|
|
3.67 |
% |
|
Efficiency ratio* |
|
|
64.18 |
% |
|
|
67.19 |
% |
|
|
67.38 |
% |
|
|
61.98 |
% |
|
|
68.88 |
% |
|
Non-interest income / average assets |
|
|
0.66 |
% |
|
|
0.86 |
% |
|
|
0.64 |
% |
|
|
0.55 |
% |
|
|
0.55 |
% |
|
Non-interest expense / average assets |
|
|
2.44 |
% |
|
|
2.90 |
% |
|
|
12.88 |
% |
|
|
2.31 |
% |
|
|
2.66 |
% |
Equity Bancshares, Inc.
PRESS RELEASE - 04/20/2021
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Capital Ratios |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Tier 1 Leverage Ratio |
|
|
8.73 |
% |
|
|
9.30 |
% |
|
|
8.76 |
% |
|
|
8.52 |
% |
|
|
9.02 |
% |
|
Common Equity Tier 1 Capital Ratio |
|
|
12.52 |
% |
|
|
12.82 |
% |
|
|
12.76 |
% |
|
|
12.02 |
% |
|
|
11.67 |
% |
|
Tier 1 Risk Based Capital Ratio |
|
|
13.07 |
% |
|
|
13.37 |
% |
|
|
13.32 |
% |
|
|
12.57 |
% |
|
|
12.20 |
% |
|
Total Risk Based Capital Ratio |
|
|
17.02 |
% |
|
|
17.35 |
% |
|
|
17.35 |
% |
|
|
15.33 |
% |
|
|
13.00 |
% |
|
Total stockholders' equity to total assets |
|
|
9.48 |
% |
|
|
10.16 |
% |
|
|
10.40 |
% |
|
|
11.41 |
% |
|
|
12.10 |
% |
|
Tangible common equity to tangible assets* |
|
|
8.44 |
% |
|
|
9.05 |
% |
|
|
9.23 |
% |
|
|
8.00 |
% |
|
|
8.47 |
% |
|
Book value per common share |
|
$ |
27.66 |
|
|
$ |
28.04 |
|
|
$ |
27.08 |
|
|
$ |
31.53 |
|
|
$ |
31.41 |
|
|
Tangible book value per common share* |
|
$ |
24.34 |
|
|
$ |
24.68 |
|
|
$ |
23.72 |
|
|
$ |
21.29 |
|
|
$ |
21.10 |
|
|
Tangible book value per diluted common share* |
|
$ |
23.87 |
|
|
$ |
24.32 |
|
|
$ |
23.57 |
|
|
$ |
21.13 |
|
|
$ |
20.96 |
|
* The value noted is considered a Non-GAAP financial measure. For a reconciliation of Non-GAAP financial measures, see Table 6. Non-GAAP Financial Measures
Equity Bancshares, Inc.
PRESS RELEASE - 04/20/2021
TABLE 4. QUARTER-TO-DATE NET INTEREST INCOME ANALYSIS (Unaudited)
(Dollars in thousands)
|
|
For the three months ended |
|
|
For the three months ended |
|
||||||||||||||||||
|
|
March 31, 2021 |
|
|
March 31, 2020 |
|
||||||||||||||||||
|
|
Average Outstanding Balance |
|
|
Interest Income/ Expense |
|
|
Average Yield/Rate(3)(4) |
|
|
Average Outstanding Balance |
|
|
Interest Income/ Expense |
|
|
Average Yield/Rate(3)(4) |
|
||||||
|
Interest-earning assets |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Loans (1) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Commercial and industrial |
$ |
803,012 |
|
|
$ |
9,234 |
|
|
|
4.66 |
% |
|
$ |
555,927 |
|
|
$ |
7,881 |
|
|
|
5.70 |
% |
|
Commercial real estate |
|
971,825 |
|
|
|
11,441 |
|
|
|
4.77 |
% |
|
|
913,065 |
|
|
|
12,942 |
|
|
|
5.70 |
% |
|
Real estate construction |
|
255,677 |
|
|
|
2,178 |
|
|
|
3.45 |
% |
|
|
267,388 |
|
|
|
3,575 |
|
|
|
5.38 |
% |
|
Residential real estate |
|
394,329 |
|
|
|
4,452 |
|
|
|
4.58 |
% |
|
|
496,186 |
|
|
|
5,302 |
|
|
|
4.30 |
% |
|
Agricultural real estate |
|
140,875 |
|
|
|
1,696 |
|
|
|
4.88 |
% |
|
|
137,664 |
|
|
|
2,091 |
|
|
|
6.11 |
% |
|
Consumer |
|
76,413 |
|
|
|
963 |
|
|
|
5.11 |
% |
|
|
67,160 |
|
|
|
1,275 |
|
|
|
7.64 |
% |
|
Agricultural |
|
94,787 |
|
|
|
1,037 |
|
|
|
4.44 |
% |
|
|
87,954 |
|
|
|
1,310 |
|
|
|
5.99 |
% |
|
Total loans |
|
2,736,918 |
|
|
|
31,001 |
|
|
|
4.59 |
% |
|
|
2,525,344 |
|
|
|
34,376 |
|
|
|
5.47 |
% |
|
Securities |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Taxable securities |
|
839,349 |
|
|
|
3,799 |
|
|
|
1.84 |
% |
|
|
774,653 |
|
|
|
4,620 |
|
|
|
2.40 |
% |
|
Nontaxable securities |
|
108,104 |
|
|
|
724 |
|
|
|
2.72 |
% |
|
|
133,257 |
|
|
|
966 |
|
|
|
2.92 |
% |
|
Total securities |
|
947,453 |
|
|
|
4,523 |
|
|
|
1.94 |
% |
|
|
907,910 |
|
|
|
5,586 |
|
|
|
2.47 |
% |
|
Federal funds sold and other |
|
206,769 |
|
|
|
288 |
|
|
|
0.56 |
% |
|
|
86,013 |
|
|
|
595 |
|
|
|
2.78 |
% |
|
Total interest-earning assets |
$ |
3,891,140 |
|
|
|
35,812 |
|
|
|
3.73 |
% |
|
$ |
3,519,267 |
|
|
|
40,557 |
|
|
|
4.64 |
% |
|
Interest-bearing liabilities |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Savings, NOW and money market deposits |
$ |
2,079,057 |
|
|
|
971 |
|
|
|
0.19 |
% |
|
$ |
1,724,774 |
|
|
|
3,125 |
|
|
|
0.73 |
% |
|
Time deposits |
|
611,102 |
|
|
|
1,439 |
|
|
|
0.96 |
% |
|
|
806,734 |
|
|
|
3,739 |
|
|
|
1.86 |
% |
|
Total interest-bearing deposits |
|
2,690,159 |
|
|
|
2,410 |
|
|
|
0.36 |
% |
|
|
2,531,508 |
|
|
|
6,864 |
|
|
|
1.09 |
% |
|
FHLB advances |
|
10,013 |
|
|
|
65 |
|
|
|
2.63 |
% |
|
|
295,677 |
|
|
|
1,175 |
|
|
|
1.60 |
% |
|
Other borrowings |
|
129,347 |
|
|
|
1,578 |
|
|
|
4.95 |
% |
|
|
59,626 |
|
|
|
423 |
|
|
|
2.85 |
% |
|
Total interest-bearing liabilities |
$ |
2,829,519 |
|
|
|
4,053 |
|
|
|
0.58 |
% |
|
$ |
2,886,811 |
|
|
|
8,462 |
|
|
|
1.18 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Net interest income |
|
|
|
|
$ |
31,759 |
|
|
|
|
|
|
|
|
|
|
$ |
32,095 |
|
|
|
|
|
|
Interest rate spread |
|
|
|
|
|
|
|
|
|
3.15 |
% |
|
|
|
|
|
|
|
|
|
|
3.46 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Net interest margin (2) |
|
|
|
|
|
|
|
|
|
3.31 |
% |
|
|
|
|
|
|
|
|
|
|
3.67 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
(1) Average loan balances include nonaccrual loans. |
|
||||||||||||||||||||||
|
(2) Net interest margin is calculated by dividing annualized net interest income by average interest-earning assets for the period. |
|
||||||||||||||||||||||
|
(3) Tax exempt income is not included in the above table on a tax-equivalent basis. |
|
||||||||||||||||||||||
Equity Bancshares, Inc.
PRESS RELEASE - 04/20/2021
TABLE 5. QUARTER-OVER-QUARTER NET INTEREST INCOME ANALYSIS (Unaudited)
(Dollars in thousands)
|
|
For the three months ended |
|
|
For the three months ended |
|
||||||||||||||||||
|
|
March 31, 2021 |
|
|
December 31, 2020 |
|
||||||||||||||||||
|
|
Average Outstanding Balance |
|
|
Interest Income/ Expense |
|
|
Average Yield/Rate(3)(4) |
|
|
Average Outstanding Balance |
|
|
Interest Income/ Expense |
|
|
Average Yield/Rate(3)(4) |
|
||||||
|
Interest-earning assets |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Loans (1) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Commercial and industrial |
$ |
803,012 |
|
|
$ |
9,234 |
|
|
|
4.66 |
% |
|
$ |
782,433 |
|
|
$ |
10,943 |
|
|
|
5.56 |
% |
|
Commercial real estate |
|
971,825 |
|
|
|
11,441 |
|
|
|
4.77 |
% |
|
|
980,686 |
|
|
|
12,647 |
|
|
|
5.13 |
% |
|
Real estate construction |
|
255,677 |
|
|
|
2,178 |
|
|
|
3.45 |
% |
|
|
216,714 |
|
|
|
2,301 |
|
|
|
4.22 |
% |
|
Residential real estate |
|
394,329 |
|
|
|
4,452 |
|
|
|
4.58 |
% |
|
|
406,450 |
|
|
|
5,005 |
|
|
|
4.90 |
% |
|
Agricultural real estate |
|
140,875 |
|
|
|
1,696 |
|
|
|
4.88 |
% |
|
|
135,337 |
|
|
|
2,244 |
|
|
|
6.60 |
% |
|
Consumer |
|
76,413 |
|
|
|
963 |
|
|
|
5.11 |
% |
|
|
78,430 |
|
|
|
1,080 |
|
|
|
5.48 |
% |
|
Agricultural |
|
94,787 |
|
|
|
1,037 |
|
|
|
4.44 |
% |
|
|
92,173 |
|
|
|
1,163 |
|
|
|
5.02 |
% |
|
Total loans |
|
2,736,918 |
|
|
|
31,001 |
|
|
|
4.59 |
% |
|
|
2,692,223 |
|
|
|
35,383 |
|
|
|
5.23 |
% |
|
Securities |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Taxable securities |
|
839,349 |
|
|
|
3,799 |
|
|
|
1.84 |
% |
|
|
698,985 |
|
|
|
3,408 |
|
|
|
1.94 |
% |
|
Nontaxable securities |
|
108,104 |
|
|
|
724 |
|
|
|
2.72 |
% |
|
|
115,129 |
|
|
|
913 |
|
|
|
3.15 |
% |
|
Total securities |
|
947,453 |
|
|
|
4,523 |
|
|
|
1.94 |
% |
|
|
814,114 |
|
|
|
4,321 |
|
|
|
2.11 |
% |
|
Federal funds sold and other |
|
206,769 |
|
|
|
288 |
|
|
|
0.56 |
% |
|
|
141,393 |
|
|
|
285 |
|
|
|
0.80 |
% |
|
Total interest-earning assets |
$ |
3,891,140 |
|
|
|
35,812 |
|
|
|
3.73 |
% |
|
$ |
3,647,730 |
|
|
|
39,989 |
|
|
|
4.36 |
% |
|
Interest-bearing liabilities |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Savings, NOW and money market deposits |
$ |
2,079,057 |
|
|
|
971 |
|
|
|
0.19 |
% |
|
$ |
1,915,280 |
|
|
|
970 |
|
|
|
0.20 |
% |
|
Time deposits |
|
611,102 |
|
|
|
1,439 |
|
|
|
0.96 |
% |
|
|
635,939 |
|
|
|
1,785 |
|
|
|
1.12 |
% |
|
Total interest-bearing deposits |
|
2,690,159 |
|
|
|
2,410 |
|
|
|
0.36 |
% |
|
|
2,551,219 |
|
|
|
2,755 |
|
|
|
0.43 |
% |
|
FHLB advances |
|
10,013 |
|
|
|
65 |
|
|
|
2.63 |
% |
|
|
39,245 |
|
|
|
94 |
|
|
|
0.95 |
% |
|
Other borrowings |
|
129,347 |
|
|
|
1,578 |
|
|
|
4.95 |
% |
|
|
133,485 |
|
|
|
1,581 |
|
|
|
4.71 |
% |
|
Total interest-bearing liabilities |
$ |
2,829,519 |
|
|
|
4,053 |
|
|
|
0.58 |
% |
|
$ |
2,723,949 |
|
|
|
4,430 |
|
|
|
0.65 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Net interest income |
|
|
|
|
$ |
31,759 |
|
|
|
|
|
|
|
|
|
|
$ |
35,559 |
|
|
|
|
|
|
Interest rate spread |
|
|
|
|
|
|
|
|
|
3.15 |
% |
|
|
|
|
|
|
|
|
|
|
3.71 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Net interest margin (2) |
|
|
|
|
|
|
|
|
|
3.31 |
% |
|
|
|
|
|
|
|
|
|
|
3.88 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
(1) Average loan balances include nonaccrual loans. |
|
||||||||||||||||||||||
|
(2) Net interest margin is calculated by dividing annualized net interest income by average interest-earning assets for the period. |
|
||||||||||||||||||||||
|
(3) Tax exempt income is not included in the above table on a tax-equivalent basis. |
|
||||||||||||||||||||||
Equity Bancshares, Inc.
PRESS RELEASE - 04/20/2021
TABLE 6. NON-GAAP FINANCIAL MEASURES (Unaudited)
(Dollars in thousands, except per share data)
|
|
|
As of and for the three months ended |
|
|||||||||||||||||
|
|
|
March 31, |
|
|
December 31, |
|
|
September 30, |
|
|
June 30, |
|
|
March 31, |
|
|||||
|
|
|
2021 |
|
|
2020 |
|
|
2020 |
|
|
2020 |
|
|
2020 |
|
|||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Income before income taxes |
|
$ |
19,346 |
|
|
$ |
14,599 |
|
|
$ |
(93,058 |
) |
|
$ |
2,186 |
|
|
$ |
1,703 |
|
|
Add: goodwill impairment |
|
|
— |
|
|
|
— |
|
|
|
104,831 |
|
|
|
— |
|
|
|
— |
|
|
Less: tax effect |
|
|
4,271 |
|
|
|
2,111 |
|
|
|
2,652 |
|
|
|
497 |
|
|
|
445 |
|
|
Adjusted income |
|
$ |
15,075 |
|
|
$ |
12,488 |
|
|
$ |
9,121 |
|
|
$ |
1,689 |
|
|
$ |
1,258 |
|
|
Weighted average common shares outstanding |
|
|
14,464,291 |
|
|
|
14,760,810 |
|
|
|
15,040,407 |
|
|
|
15,209,483 |
|
|
|
15,387,697 |
|
|
Effect of weighted average dilutive shares assuming positive net income |
|
|
269,792 |
|
|
|
173,248 |
|
|
|
82,804 |
|
|
|
94,526 |
|
|
|
207,327 |
|
|
Weighted average diluted shares |
|
|
14,734,083 |
|
|
|
14,934,058 |
|
|
|
15,123,211 |
|
|
|
15,304,009 |
|
|
|
15,595,024 |
|
|
Diluted earnings per share adjusted for goodwill impairment |
|
$ |
1.02 |
|
|
$ |
0.84 |
|
|
$ |
0.60 |
|
|
$ |
0.11 |
|
|
$ |
0.08 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Total stockholders' equity |
|
$ |
397,815 |
|
|
$ |
407,649 |
|
|
$ |
402,172 |
|
|
$ |
479,766 |
|
|
$ |
477,351 |
|
|
Less: goodwill |
|
|
31,601 |
|
|
|
31,601 |
|
|
|
31,601 |
|
|
|
136,432 |
|
|
|
136,432 |
|
|
Less: core deposit intangibles, net |
|
|
15,023 |
|
|
|
16,057 |
|
|
|
17,101 |
|
|
|
18,131 |
|
|
|
19,105 |
|
|
Less: mortgage servicing asset, net |
|
|
— |
|
|
|
— |
|
|
|
1 |
|
|
|
2 |
|
|
|
4 |
|
|
Less: naming rights, net |
|
|
1,119 |
|
|
|
1,130 |
|
|
|
1,141 |
|
|
|
1,152 |
|
|
|
1,163 |
|
|
Tangible common equity |
|
$ |
350,072 |
|
|
$ |
358,861 |
|
|
$ |
352,328 |
|
|
$ |
324,049 |
|
|
$ |
320,647 |
|
|
Common shares issued at period end |
|
|
14,383,913 |
|
|
|
14,540,556 |
|
|
|
14,853,487 |
|
|
|
15,218,301 |
|
|
|
15,198,986 |
|
|
Diluted common shares outstanding at period end |
|
|
14,668,287 |
|
|
|
14,756,378 |
|
|
|
14,945,282 |
|
|
|
15,333,977 |
|
|
|
15,297,319 |
|
|
Book value per common share |
|
$ |
27.66 |
|
|
$ |
28.04 |
|
|
$ |
27.08 |
|
|
$ |
31.53 |
|
|
$ |
31.41 |
|
|
Tangible book value per common share |
|
$ |
24.34 |
|
|
$ |
24.68 |
|
|
$ |
23.72 |
|
|
$ |
21.29 |
|
|
$ |
21.10 |
|
|
Tangible book value per diluted common share |
|
$ |
23.87 |
|
|
$ |
24.32 |
|
|
$ |
23.57 |
|
|
$ |
21.13 |
|
|
$ |
20.96 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Total assets |
|
$ |
4,196,184 |
|
|
$ |
4,013,356 |
|
|
$ |
3,865,571 |
|
|
$ |
4,205,269 |
|
|
$ |
3,943,832 |
|
|
Less: goodwill |
|
|
31,601 |
|
|
|
31,601 |
|
|
|
31,601 |
|
|
|
136,432 |
|
|
|
136,432 |
|
|
Less: core deposit intangibles, net |
|
|
15,023 |
|
|
|
16,057 |
|
|
|
17,101 |
|
|
|
18,131 |
|
|
|
19,105 |
|
|
Less: mortgage servicing asset, net |
|
|
— |
|
|
|
— |
|
|
|
1 |
|
|
|
2 |
|
|
|
4 |
|
|
Less: naming rights, net |
|
|
1,119 |
|
|
|
1,130 |
|
|
|
1,141 |
|
|
|
1,152 |
|
|
|
1,163 |
|
|
Tangible assets |
|
$ |
4,148,441 |
|
|
$ |
3,964,568 |
|
|
$ |
3,815,727 |
|
|
$ |
4,049,552 |
|
|
$ |
3,787,128 |
|
|
Total stockholders' equity to total assets |
|
|
9.48 |
% |
|
|
10.16 |
% |
|
|
10.40 |
% |
|
|
11.41 |
% |
|
|
12.10 |
% |
|
Tangible common equity to tangible assets |
|
|
8.44 |
% |
|
|
9.05 |
% |
|
|
9.23 |
% |
|
|
8.00 |
% |
|
|
8.47 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Total average stockholders' equity |
|
$ |
395,638 |
|
|
$ |
409,572 |
|
|
$ |
483,088 |
|
|
$ |
483,605 |
|
|
$ |
482,567 |
|
|
Less: average intangible assets |
|
|
48,376 |
|
|
|
54,547 |
|
|
|
154,049 |
|
|
|
156,194 |
|
|
|
157,097 |
|
|
Average tangible common equity |
|
$ |
347,262 |
|
|
$ |
355,025 |
|
|
$ |
329,039 |
|
|
$ |
327,411 |
|
|
$ |
325,470 |
|
|
Net income (loss) allocable to common stockholders |
|
$ |
15,075 |
|
|
$ |
12,488 |
|
|
$ |
(90,405 |
) |
|
$ |
1,689 |
|
|
$ |
1,258 |
|
|
Add: goodwill impairment |
|
|
— |
|
|
|
— |
|
|
|
104,831 |
|
|
|
— |
|
|
|
— |
|
|
Less: tax effect of goodwill impairment |
|
|
— |
|
|
|
— |
|
|
|
5,305 |
|
|
|
— |
|
|
|
— |
|
|
Adjusted net income (loss) plus goodwill impairment |
|
|
15,075 |
|
|
|
12,488 |
|
|
|
9,121 |
|
|
|
1,689 |
|
|
|
1,258 |
|
|
Amortization of intangible assets |
|
|
1,045 |
|
|
|
1,055 |
|
|
|
1,043 |
|
|
|
986 |
|
|
|
814 |
|
|
Less: tax effect of intangible assets amortization |
|
|
219 |
|
|
|
222 |
|
|
|
234 |
|
|
|
207 |
|
|
|
171 |
|
|
Adjusted net income (loss) allocable to common stockholders |
|
$ |
15,901 |
|
|
$ |
13,321 |
|
|
$ |
9,930 |
|
|
$ |
2,468 |
|
|
$ |
1,901 |
|
|
Return on total average stockholders' equity (ROAE) annualized |
|
|
15.45 |
% |
|
|
12.13 |
% |
|
|
(74.45 |
)% |
|
|
1.40 |
% |
|
|
1.05 |
% |
|
Return on average tangible common equity (ROATCE) annualized |
|
|
18.57 |
% |
|
|
14.93 |
% |
|
|
(108.31 |
)% |
|
|
3.03 |
% |
|
|
2.35 |
% |
|
Adjusted return on average tangible common equity |
|
|
18.57 |
% |
|
|
14.93 |
% |
|
|
12.01 |
% |
|
|
3.03 |
% |
|
|
2.35 |
% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Equity Bancshares, Inc.
PRESS RELEASE - 04/20/2021
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Non-interest expense |
|
$ |
24,881 |
|
|
$ |
28,460 |
|
|
$ |
130,835 |
|
|
$ |
23,937 |
|
|
$ |
25,758 |
|
|
Less: merger expense |
|
|
152 |
|
|
|
299 |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
Less: goodwill impairment |
|
|
— |
|
|
|
— |
|
|
|
104,831 |
|
|
|
— |
|
|
|
— |
|
|
Non-interest expense, excluding merger expense and goodwill impairment |
|
$ |
24,729 |
|
|
$ |
28,161 |
|
|
$ |
26,004 |
|
|
$ |
23,937 |
|
|
$ |
25,758 |
|
|
Net interest income |
|
$ |
31,759 |
|
|
$ |
35,559 |
|
|
$ |
32,107 |
|
|
$ |
32,891 |
|
|
$ |
32,095 |
|
|
Non-interest income |
|
|
6,712 |
|
|
|
8,500 |
|
|
|
6,485 |
|
|
|
5,732 |
|
|
|
5,306 |
|
|
Less: net gain on acquisition |
|
|
(78 |
) |
|
|
2,145 |
|
|
|
— |
|
|
|
— |
|
|
|
— |
|
|
Less: net gains (losses) from securities transactions |
|
|
17 |
|
|
|
(1 |
) |
|
|
— |
|
|
|
4 |
|
|
|
8 |
|
|
Non-interest income, excluding gains (losses) from securities transactions |
|
$ |
6,773 |
|
|
$ |
6,356 |
|
|
$ |
6,485 |
|
|
$ |
5,728 |
|
|
$ |
5,298 |
|
|
Net interest income plus non-interest income, excluding net gains (losses) from securities transactions |
|
$ |
38,532 |
|
|
$ |
41,915 |
|
|
$ |
38,592 |
|
|
$ |
38,619 |
|
|
$ |
37,393 |
|
|
Non-interest expense to net interest income plus non-interest income |
|
|
64.67 |
% |
|
|
64.60 |
% |
|
|
339.02 |
% |
|
|
61.98 |
% |
|
|
68.87 |
% |
|
Efficiency ratio |
|
|
64.18 |
% |
|
|
67.19 |
% |
|
|
67.38 |
% |
|
|
61.98 |
% |
|
|
68.88 |
% |
|
Net income (loss) allocable to common stockholders |
|
$ |
15,075 |
|
|
$ |
12,488 |
|
|
$ |
(90,405 |
) |
|
$ |
1,689 |
|
|
$ |
1,258 |
|
|
Add: income tax provision |
|
|
4,271 |
|
|
|
2,111 |
|
|
|
(2,653 |
) |
|
|
497 |
|
|
|
445 |
|
|
Add: provision for loan losses |
|
|
(5,756 |
) |
|
|
1,000 |
|
|
|
815 |
|
|
|
12,500 |
|
|
|
9,940 |
|
|
Add: goodwill impairment |
|
|
— |
|
|
|
— |
|
|
|
104,831 |
|
|
|
— |
|
|
|
— |
|
|
Adjusted net income |
|
$ |
13,590 |
|
|
$ |
15,599 |
|
|
$ |
12,588 |
|
|
$ |
14,686 |
|
|
$ |
11,643 |
|
|
Total average assets |
|
$ |
4,143,752 |
|
|
$ |
3,910,628 |
|
|
$ |
4,041,187 |
|
|
$ |
4,159,336 |
|
|
$ |
3,888,205 |
|
|
Total average stockholders' equity |
|
$ |
395,638 |
|
|
$ |
409,572 |
|
|
$ |
483,088 |
|
|
$ |
483,605 |
|
|
$ |
482,567 |
|
|
Return on average assets (ROAA) annualized |
|
|
1.48 |
% |
|
|
1.27 |
% |
|
|
(8.90 |
)% |
|
|
0.16 |
% |
|
|
0.13 |
% |
|
Adjusted return on average assets |
|
|
1.33 |
% |
|
|
1.59 |
% |
|
|
1.24 |
% |
|
|
1.42 |
% |
|
|
1.20 |
% |
|
Adjusted return on average equity |
|
|
13.93 |
% |
|
|
15.15 |
% |
|
|
10.37 |
% |
|
|
12.21 |
% |
|
|
9.70 |
% |