Fifth Third Announces Third Quarter 2020 Results
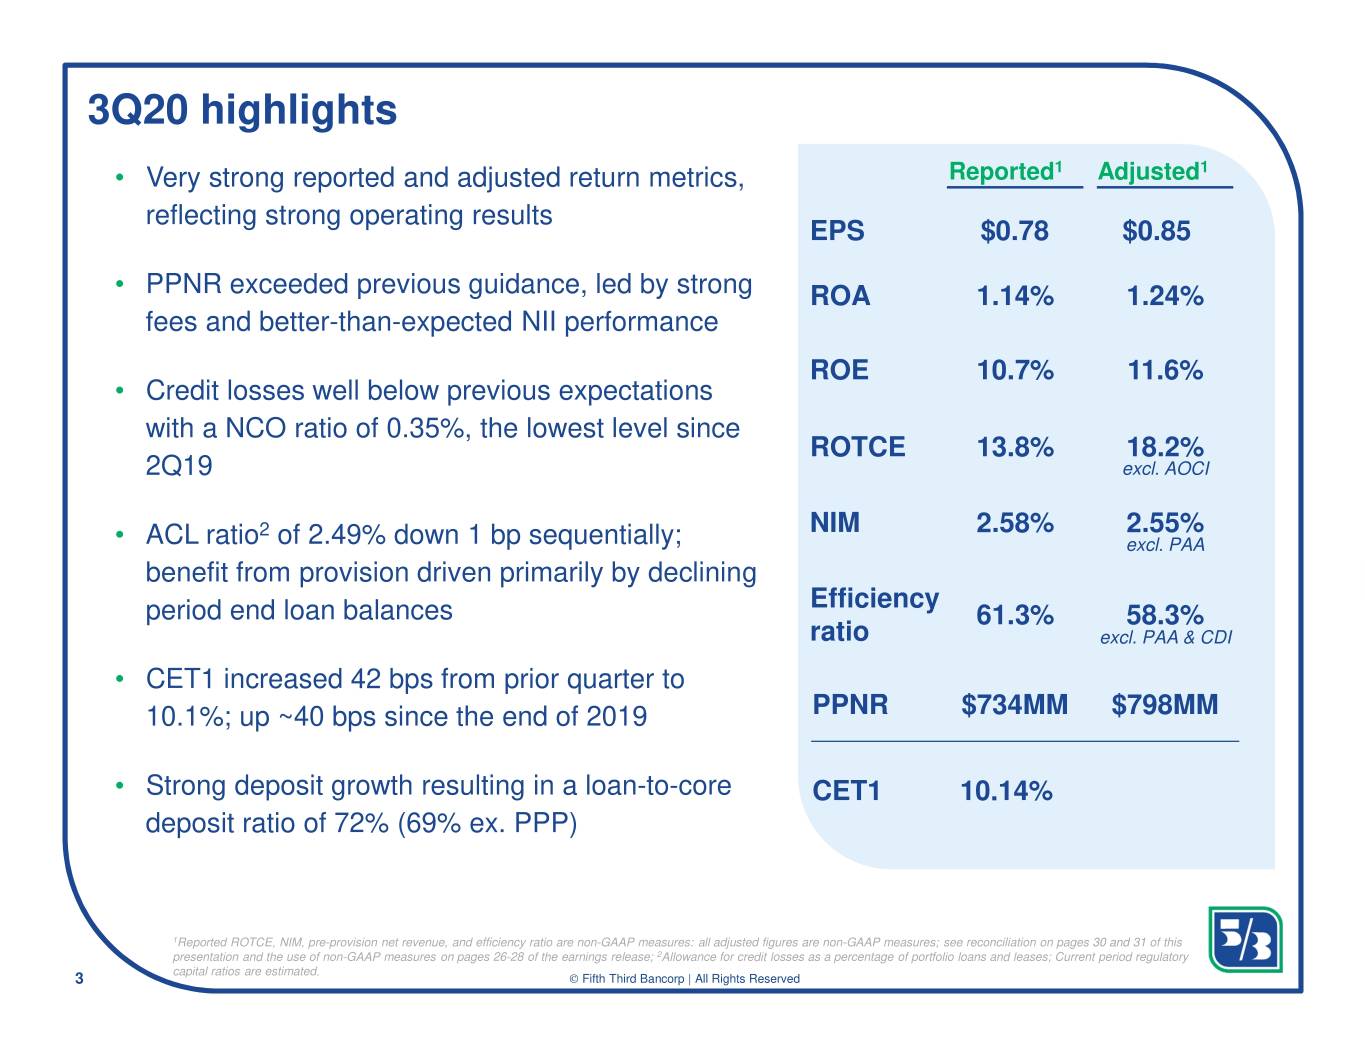
Reported diluted earnings per share of $0.78
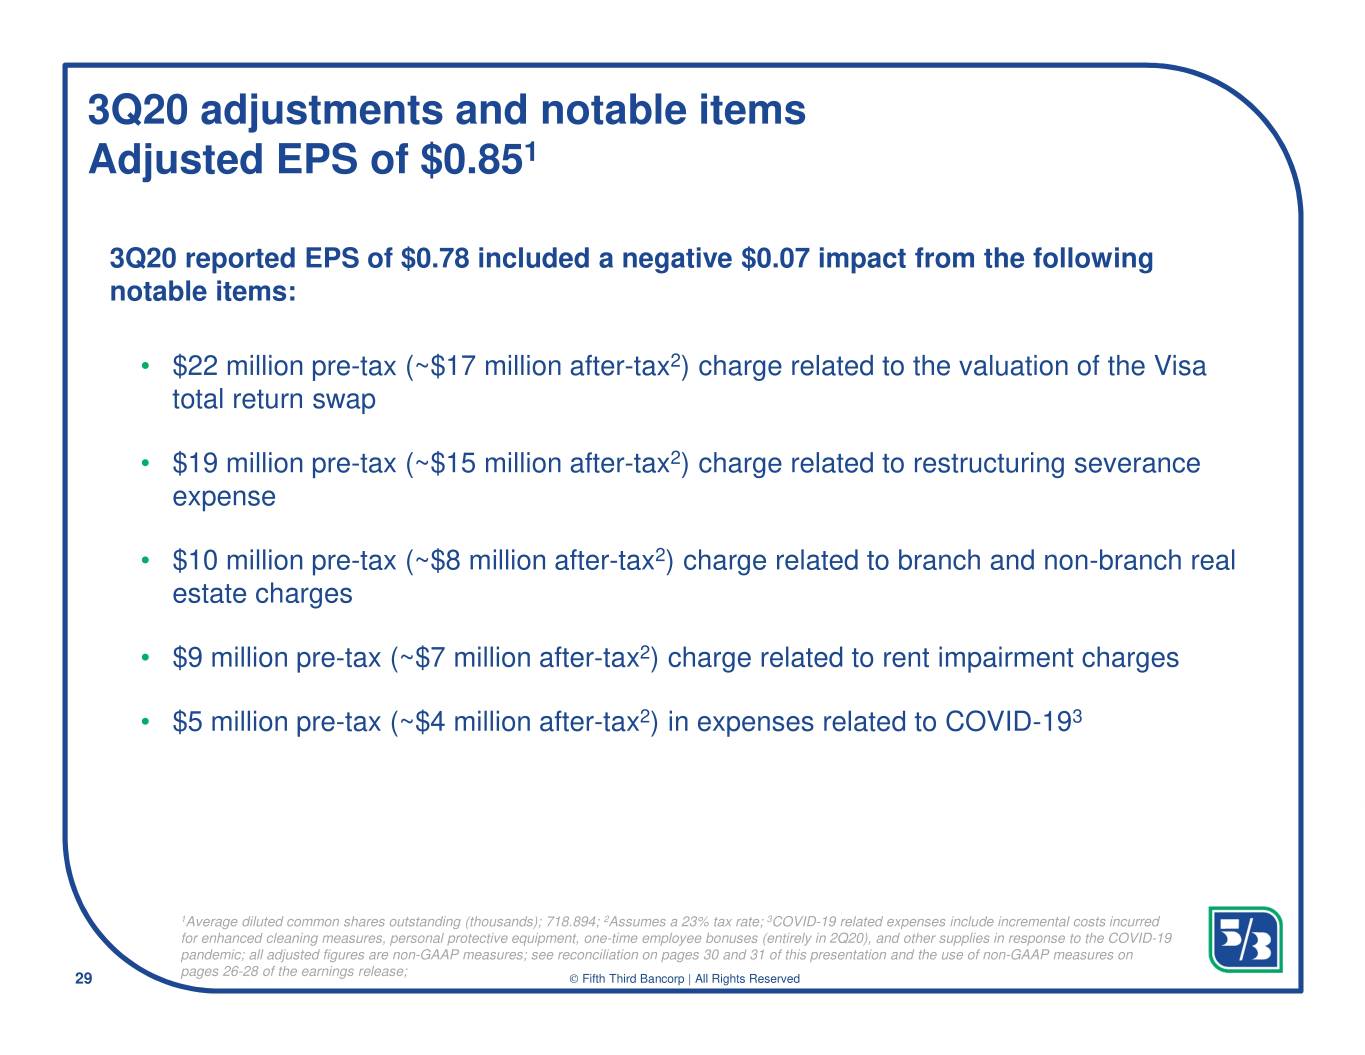
Reported results included a negative $0.07 impact from certain items on page 2
| | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | |
| Key Financial Data | | | | | | | Key Highlights |
| | | | | | | | |
| $ millions for all balance sheet and income statement items | | | | | | | |
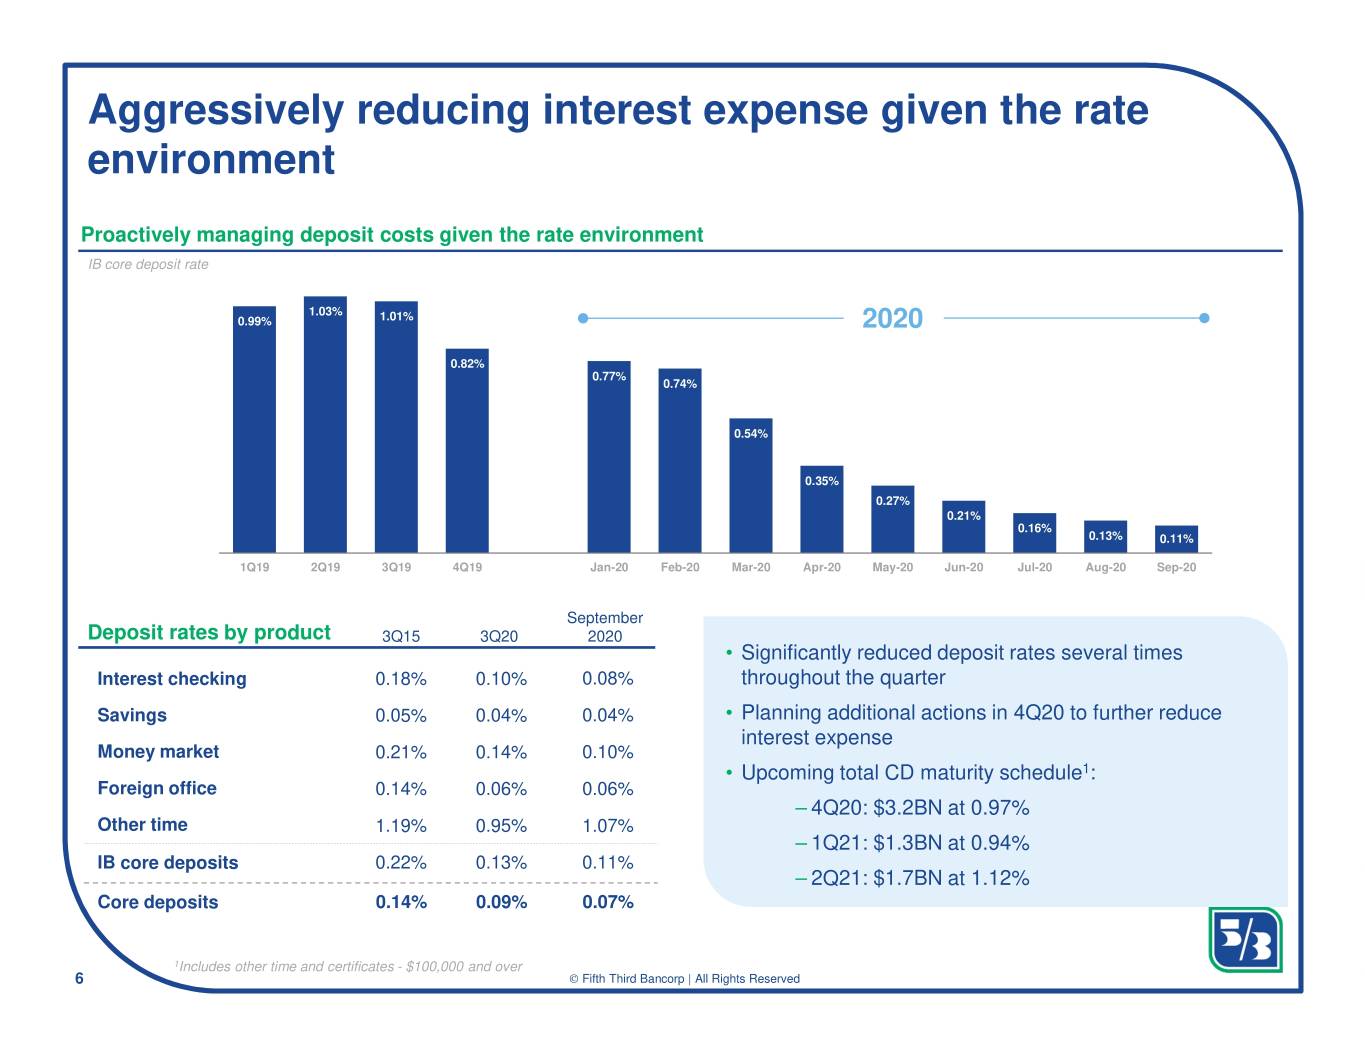
| | 3Q20 | | 2Q20 | | 3Q19 | | –Very strong reported and adjusted return metrics, reflecting strong operating results –Credit losses well below previous expectations with a NCO ratio of 0.35%, the lowest level since 2Q19 –PPNR(a) exceeded previous guidance, led by strong fees and better-than-expected NII performance (interest-bearing core deposit costs down 14 bps, more than previous guidance) –3Q20 NIM was negatively impacted ~48 bps due to excess liquidity and Paycheck Protection Program (PPP) loans –Strong balance sheet; CET1 ratio of 10.14% well above target range, with record balance sheet liquidity –Grew tangible book value per share for six consecutive quarters |
| | | | | | | | |
| Income Statement Data | | | | | | | |
| Net income available to common shareholders | $562 | | $163 | | $530 | | |
| Net interest income (U.S. GAAP) | 1,170 | | 1,200 | | 1,242 | | |
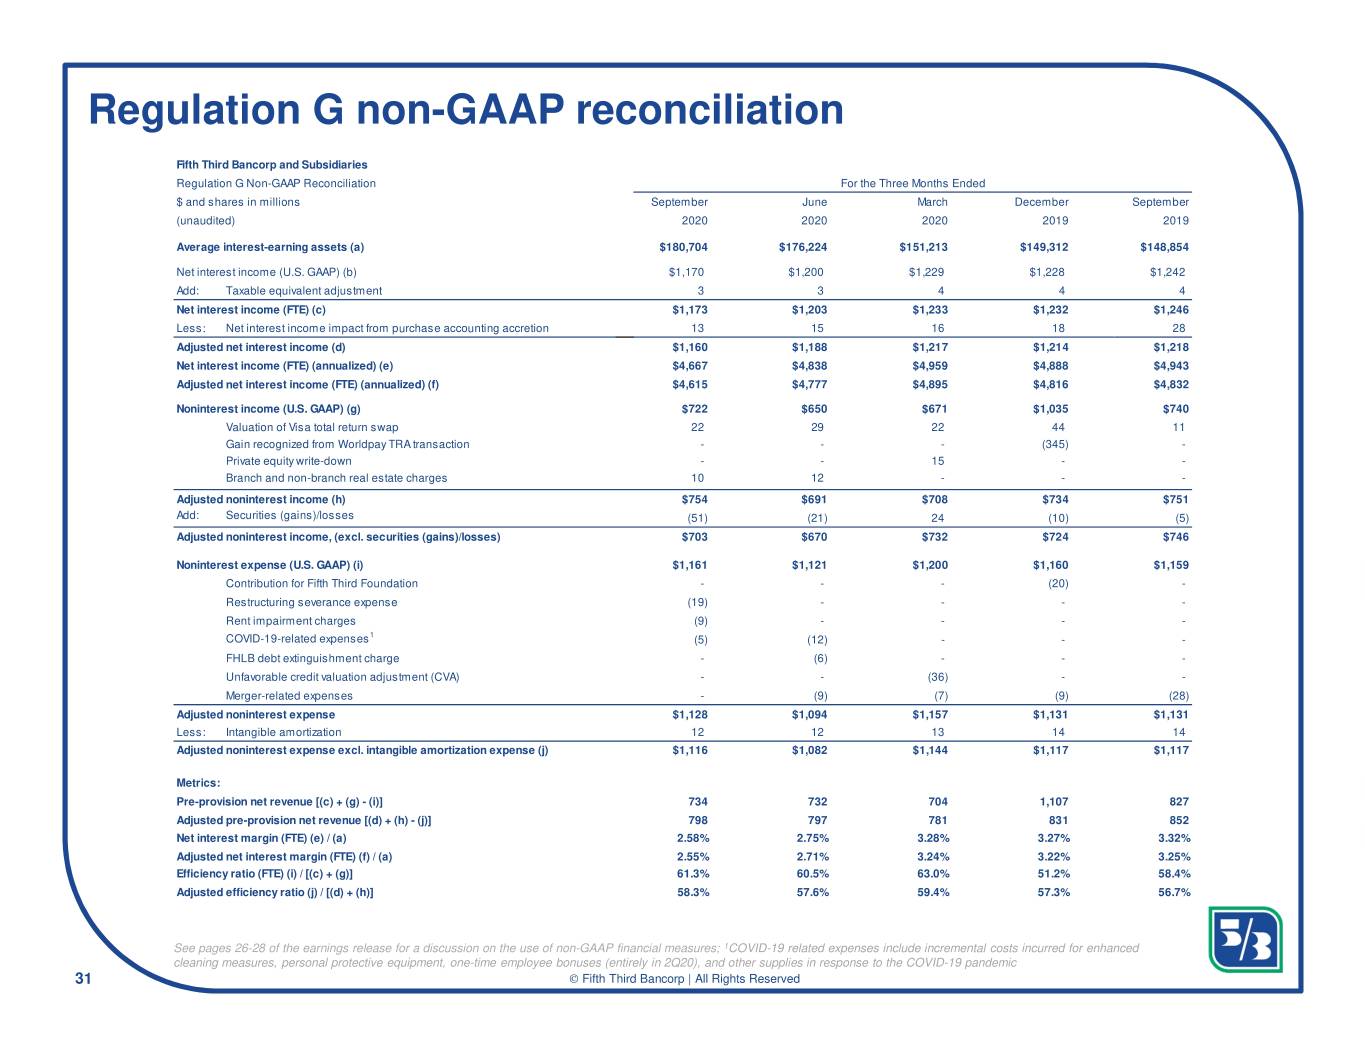
| Net interest income (FTE)(a) | 1,173 | | 1,203 | | 1,246 | | |
| Noninterest income | 722 | | 650 | | 740 | | |
| Noninterest expense | 1,161 | | 1,121 | | 1,159 | | |
| | | | | | | | |
| Per Share Data | | | | | | | |
| Earnings per share, basic | $0.78 | | $0.23 | | $0.72 | | |
| Earnings per share, diluted | 0.78 | | 0.23 | | 0.71 | | |
| Book value per share | 29.25 | | 28.88 | | 27.32 | | |
| Tangible book value per share(a) | 23.06 | | 22.66 | | 21.06 | | |
| | | | | | | | |
| Balance Sheet & Credit Quality | | | | | | | |
| Average portfolio loans and leases | $113,362 | | $118,506 | | $109,541 | | |
| Average deposits | 155,911 | | 150,598 | | 125,206 | | |
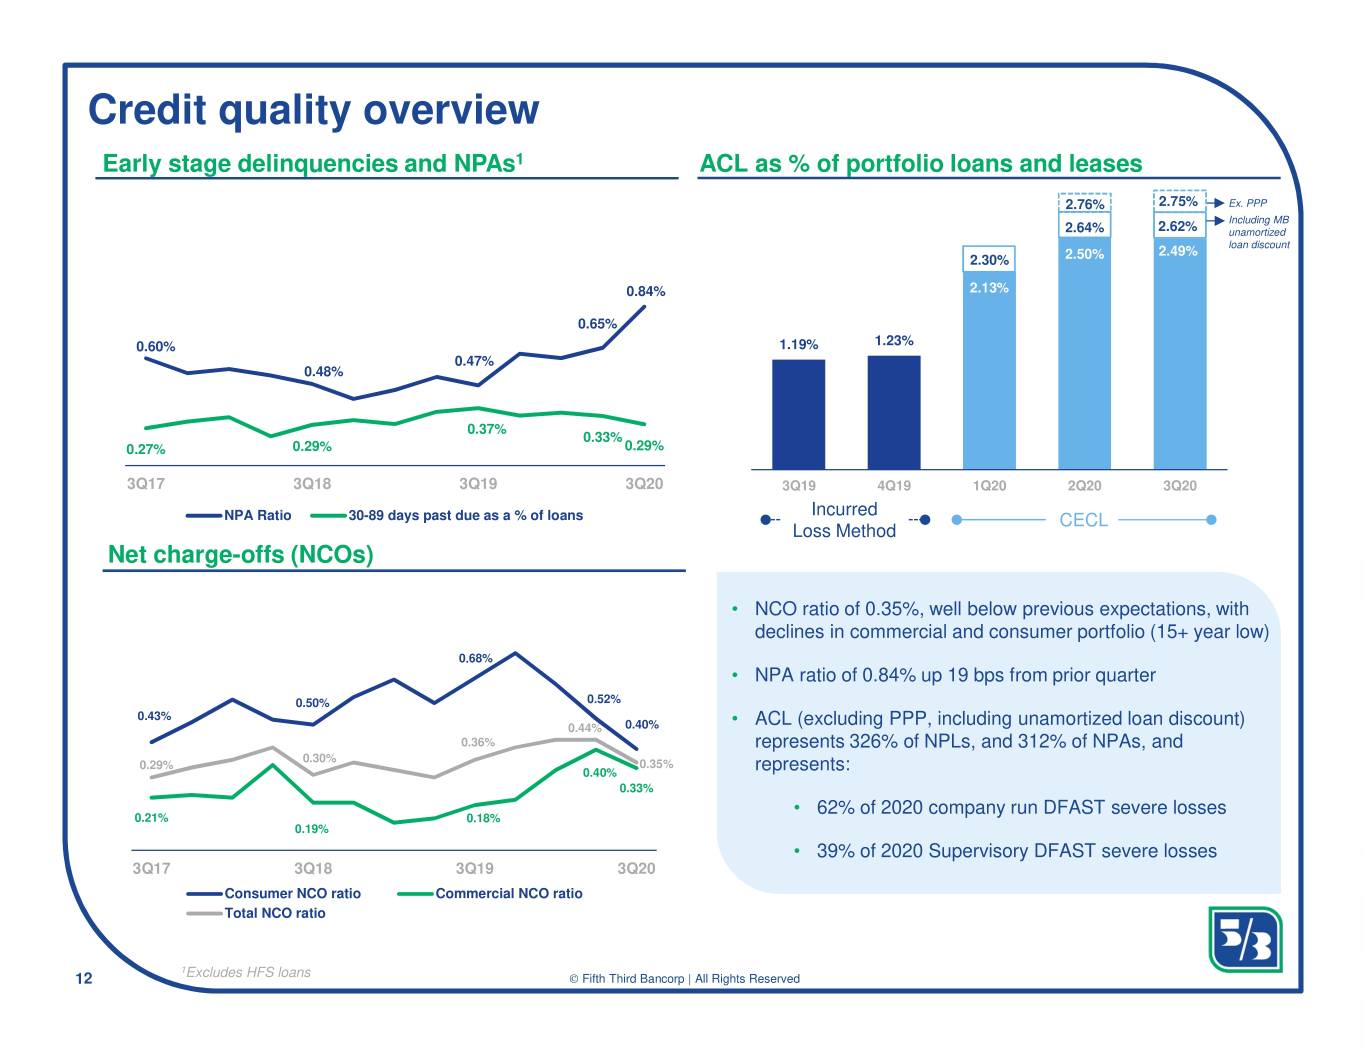
| Net charge-off ratio(b) | 0.35 | % | 0.44 | % | 0.36 | % | |
| Nonperforming asset ratio(c) | 0.84 | | 0.65 | | 0.47 | | |
| | | | | | | | |
| Financial Ratios | | | | | | | |
| Return on average assets | 1.14 | % | 0.40 | % | 1.28 | % | |
| Return on average common equity | 10.7 | | 3.2 | | 10.7 | | |
| Return on average tangible common equity(a) | 13.8 | | 4.3 | | 14.2 | | |
| CET1 capital(d)(e) | 10.14 | | 9.72 | | 9.56 | | |
| Net interest margin(a) | 2.58 | | 2.75 | | 3.32 | | |
| Efficiency(a) | 61.3 | | 60.5 | | 58.4 | | |
| Other than the Quarterly Financial Review tables beginning on page 13, commentary is on a fully taxable-equivalent (FTE) basis unless otherwise noted. Consistent with SEC guidance in Industry Guide 3 that contemplates the calculation of tax-exempt income on a taxable-equivalent basis, net interest income, net interest margin, net interest rate spread, total revenue and the efficiency ratio are provided on an FTE basis. | | | | | | | |
| | | | | | | | |
| | | | | | | | |
"Our third quarter results were very strong despite the challenging operating dynamics. We remain intently focused on taking appropriate actions for our customers, our employees, and our communities during these uncertain times. I am very proud of the way our employees have responded to support our customers and each other.
Our financial performance once again highlighted the strength of our franchise and our ability to navigate the current environment. Our already strong capital and liquidity levels further improved this quarter, and our credit performance was better than previous expectations, indicative of our balance sheet strength which will serve us well throughout this challenging environment.
We have consistently communicated our through-the-cycle principles of disciplined client selection, conservative underwriting, and an overall balance sheet management approach focused on long-term performance. We have also executed numerous strategic actions over the last several years in anticipation of an eventual downturn in the economy.
Given the anticipated revenue headwinds, we are very focused on optimizing our expense base to maintain healthy levels of returns. To that end, we took proactive measures during the quarter to ensure Fifth Third continues to generate sustainable, long-term value for shareholders. We continue to believe we are well-positioned to emerge from the pandemic as a top performing regional bank."
-Greg D. Carmichael, Chairman, President and CEO
Investor contact: Chris Doll (513) 534-2345 | Media contact: Ed Loyd (513) 534-6397 October 22, 2020
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Income Statement Highlights | | | | | | | | | | | | | |
| ($ in millions, except per share data) | For the Three Months Ended | | | | | | | | | % Change | | | |
| | September | | | June | | | September | | | | | | |
| | 2020 | | | 2020 | | | 2019 | | | Seq | | Yr/Yr | |
| Condensed Statements of Income | | | | | | | | | | | | | |
| Net interest income (NII)(a) | $1,173 | | | $1,203 | | | $1,246 | | | (2)% | | (6)% | |
| (Benefit from) provision for credit losses | (15) | | | 485 | | | 134 | | | NM | | NM | |
| Noninterest income | 722 | | | 650 | | | 740 | | | 11% | | (2)% | |
| Noninterest expense | 1,161 | | | 1,121 | | | 1,159 | | | 4% | | — | |
| Income before income taxes(a) | $749 | | | $247 | | | $693 | | | 203% | | 8% | |
| | | | | | | | | | | | | | |
| Taxable equivalent adjustment | $3 | | | $3 | | | $4 | | | — | | (25)% | |
| Applicable income tax expense | 165 | | | 49 | | | 140 | | | 237% | | 18% | |
| Net income | $581 | | | $195 | | | $549 | | | 198% | | 6% | |
| Dividends on preferred stock | 19 | | | 32 | | | 19 | | | (41)% | | — | |
| Net income available to common shareholders | $562 | | | $163 | | | $530 | | | 245% | | 6% | |
| Earnings per share, diluted | $0.78 | | | $0.23 | | | $0.71 | | | 239% | | 10% | |
| | | | | | | | | | | | | | |
Fifth Third Bancorp (NASDAQ®: FITB) today reported third quarter 2020 net income of $581 million compared to net income of $195 million in the prior quarter and $549 million in the year-ago quarter. Net income available to common shareholders in the current quarter was $562 million, or $0.78 per diluted share, compared to $163 million, or $0.23 per diluted share, in the prior quarter and $530 million, or $0.71 per diluted share, in the year-ago quarter.
| | | | | | | | | | | | | | | | | |
| | | | | |
| | Diluted earnings per share impact of certain items - 3Q20 | | | |
| | | | | |
| | (after-tax impacts(f); $ in millions, except per share data) | | | |
| | | | | |
| | Valuation of Visa total return swap within other noninterest income | $(17) | | |
| | Restructuring charges: | | | |
| | Severance expense within compensation and benefits expense | (15) | | |
| | Branch and non-branch real estate charges within other noninterest income | (8) | | |
| | Rent impairment charges within net occupancy expense | (7) | | |
| | COVID-19-related expenses(g) | (4) | | |
| | After-tax impact(f) of certain items | $(51) | | |
| | | | | |
| | Diluted earnings per share impact of certain items | $(0.07) | | |
| | | | | |
| | Diluted earnings per share impact reflect 718.894 million average diluted shares outstanding | | | |
| | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Net Interest Income | | | | | | | | | | | | | |
| (FTE; $ in millions)(a) | For the Three Months Ended | | | | | | | | | % Change | | | |
| | September | | | June | | | September | | | | | | |
| | 2020 | | | 2020 | | | 2019 | | | Seq | | Yr/Yr | |
| Interest Income | | | | | | | | | | | | | |
| Interest income | $1,332 | | | $1,406 | | | $1,629 | | | (5)% | | (18)% | |
| Interest expense | 159 | | | 203 | | | 383 | | | (22)% | | (58)% | |
| Net interest income (NII) | $1,173 | | | $1,203 | | | $1,246 | | | (2)% | | (6)% | |
| Adjusted NII(a) | $1,160 | | | $1,188 | | | $1,218 | | | (2)% | | (5)% | |
| | | | | | | | | | | | | | |
| Average Yield/Rate Analysis | | | | | | | | | | bps Change | | | |
| Yield on interest-earning assets | 2.93 | % | | | 3.21 | % | | | 4.34 | % | | | (28) | | (141) | |
| Rate paid on interest-bearing liabilities | 0.51 | % | | | 0.66 | % | | | 1.41 | % | | | (15) | | (90) | |
| | | | | | | | | | | | | | |
| Ratios | | | | | | | | | | | | | |
| Net interest rate spread | 2.42 | % | | | 2.55 | % | | | 2.93 | % | | | (13) | | (51) | |
| Net interest margin (NIM) | 2.58 | % | | | 2.75 | % | | | 3.32 | % | | | (17) | | (74) | |
| Adjusted NIM(a) | 2.55 | % | | | 2.71 | % | | | 3.25 | % | | | (16) | | (70) | |
| | | | | | | | | | | | | | |
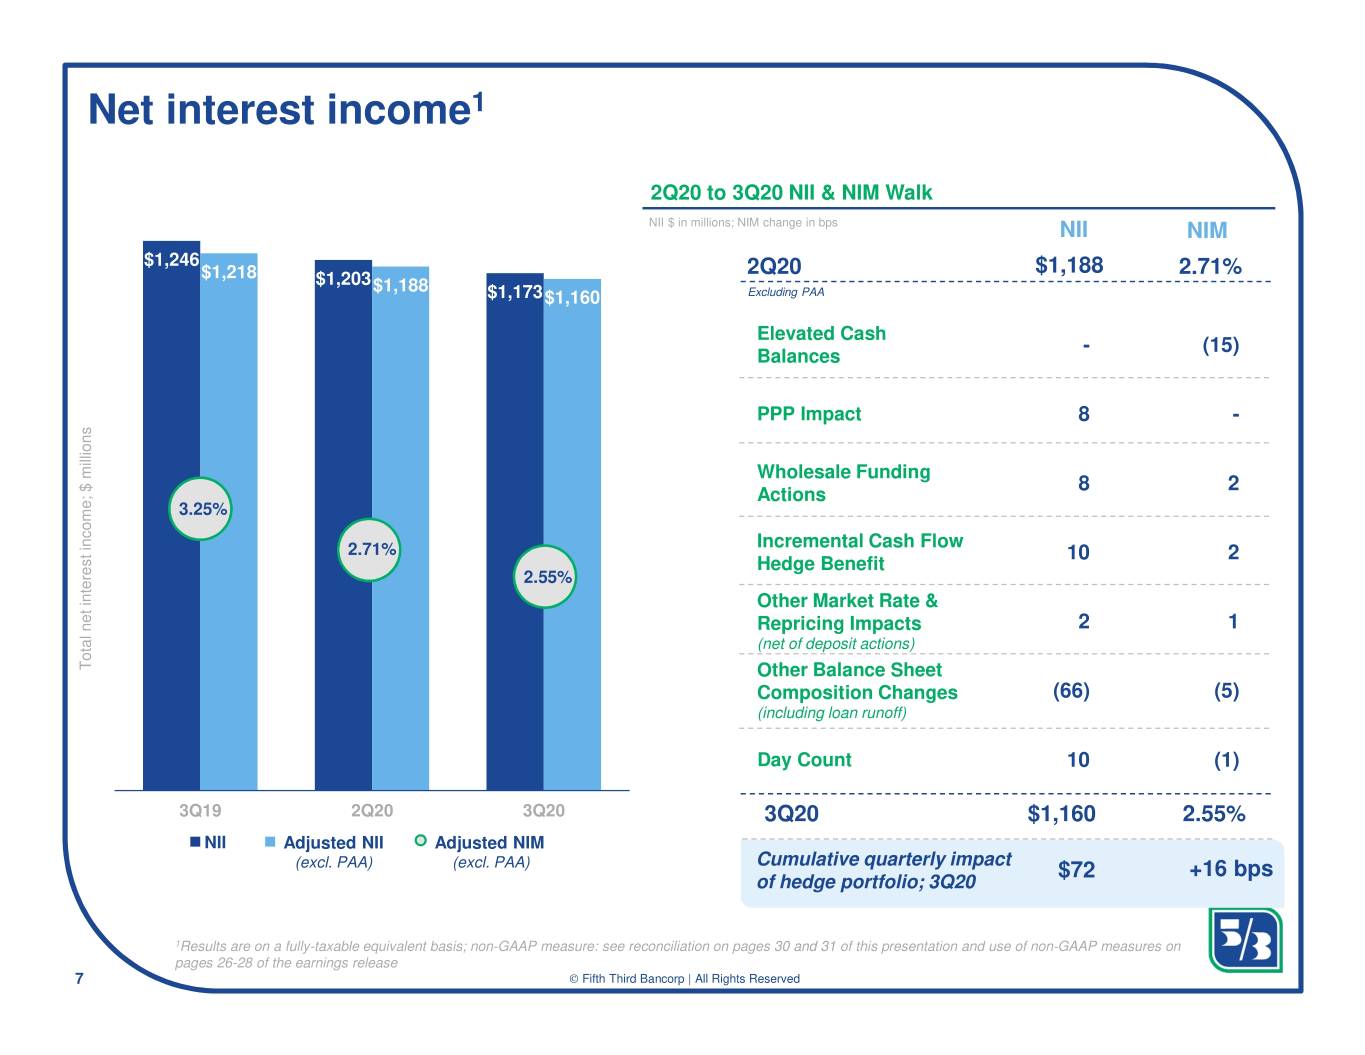
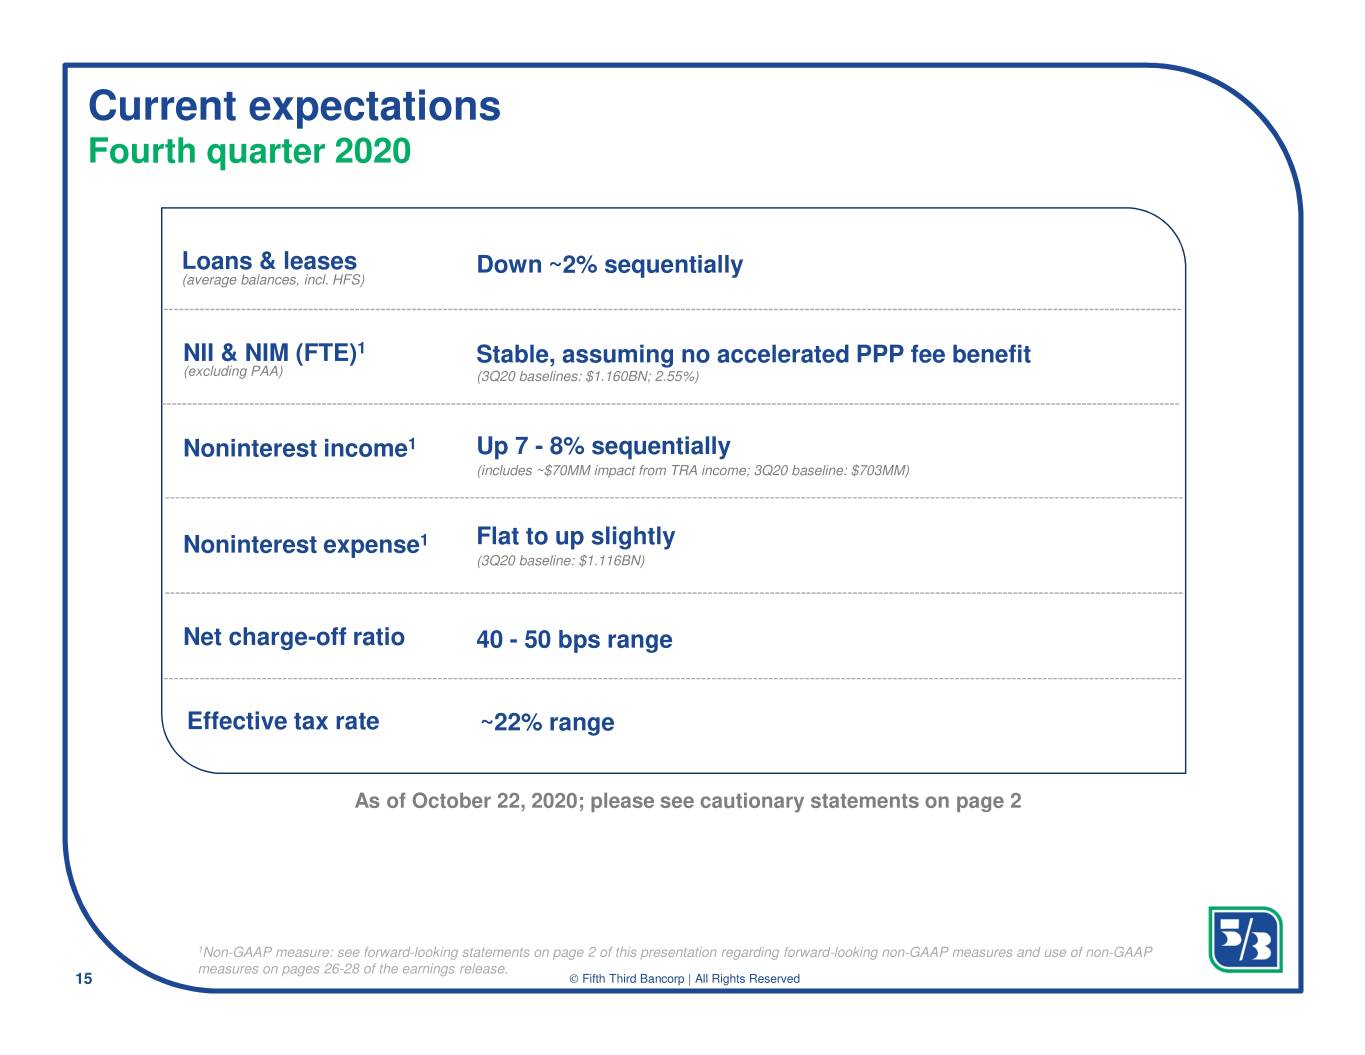
Compared to the prior quarter, reported NII decreased $30 million, or 2%. Excluding purchase accounting accretion of $13 million in the current quarter and $15 million in the prior quarter, adjusted NII decreased $28 million, or 2%. The decrease was primarily attributable to a decline in commercial and industrial (C&I) loans and the impact of lower market rates. These impacts were partially offset by the actions taken to reduce deposit costs, the full-quarter impact of PPP loans, the favorable impact of previously executed cash flow hedges, and day count. Compared to the prior quarter, reported and adjusted NIM decreased 17 bps and 16 bps, respectively, driven by the unfavorable impacts from elevated cash balances (approximately 15 bps drag on NIM compared to the prior quarter), lower market rates, and lower C&I loan balances, partially offset by benefits from lower deposit costs and previously executed cash flow hedges. NIM was negatively impacted approximately 48 bps due to PPP loans and excess liquidity compared to historical balances.
Compared to the year-ago quarter, reported NII decreased $73 million, or 6%. Excluding purchase accounting accretion, adjusted NII decreased $58 million, or 5%, primarily reflecting lower market rates and lower commercial loan balances, partially offset by reduced deposit costs and the favorable impact of previously executed cash flow hedges, as well as growth in both the indirect secured consumer (predominantly indirect automobile) and lower-yielding PPP portfolios. Compared to the year-ago quarter, reported NIM decreased 74 bps. Adjusted NIM, which excludes purchase accounting accretion, decreased 70 bps, primarily reflecting the impact of elevated cash balances and lower market rates, partially offset by benefits from lower deposit costs and previously executed cash flow hedges.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Noninterest Income | | | | | | | | | | |
| ($ in millions) | For the Three Months Ended | | | | | | % Change | | | |
| | September | | June | | September | | | | | |
| | 2020 | | 2020 | | 2019 | | Seq | | Yr/Yr | |
| Noninterest Income | | | | | | | | | | |
| Service charges on deposits | $144 | | $122 | | $143 | | 18% | | 1% | |
| Commercial banking revenue | 125 | | 137 | | 123 | | (9)% | | 2% | |
| Mortgage banking net revenue | 76 | | 99 | | 95 | | (23)% | | (20)% | |
| Wealth and asset management revenue | 132 | | 120 | | 124 | | 10% | | 6% | |
| Card and processing revenue | 92 | | 82 | | 94 | | 12% | | (2)% | |
| Leasing business revenue | 77 | | 57 | | 92 | | 35% | | (16)% | |
| Other noninterest income | 26 | | 12 | | 64 | | 117% | | (59)% | |
| Securities gains, net | 51 | | 21 | | 5 | | 143% | | 920% | |
| Securities losses, net - non-qualifying hedges | | | | | | | | | | |
| on mortgage servicing rights | (1) | | — | | — | | NM | | NM | |
| Total noninterest income | $722 | | $650 | | $740 | | 11% | | (2)% | |
| | | | | | | | | | | |
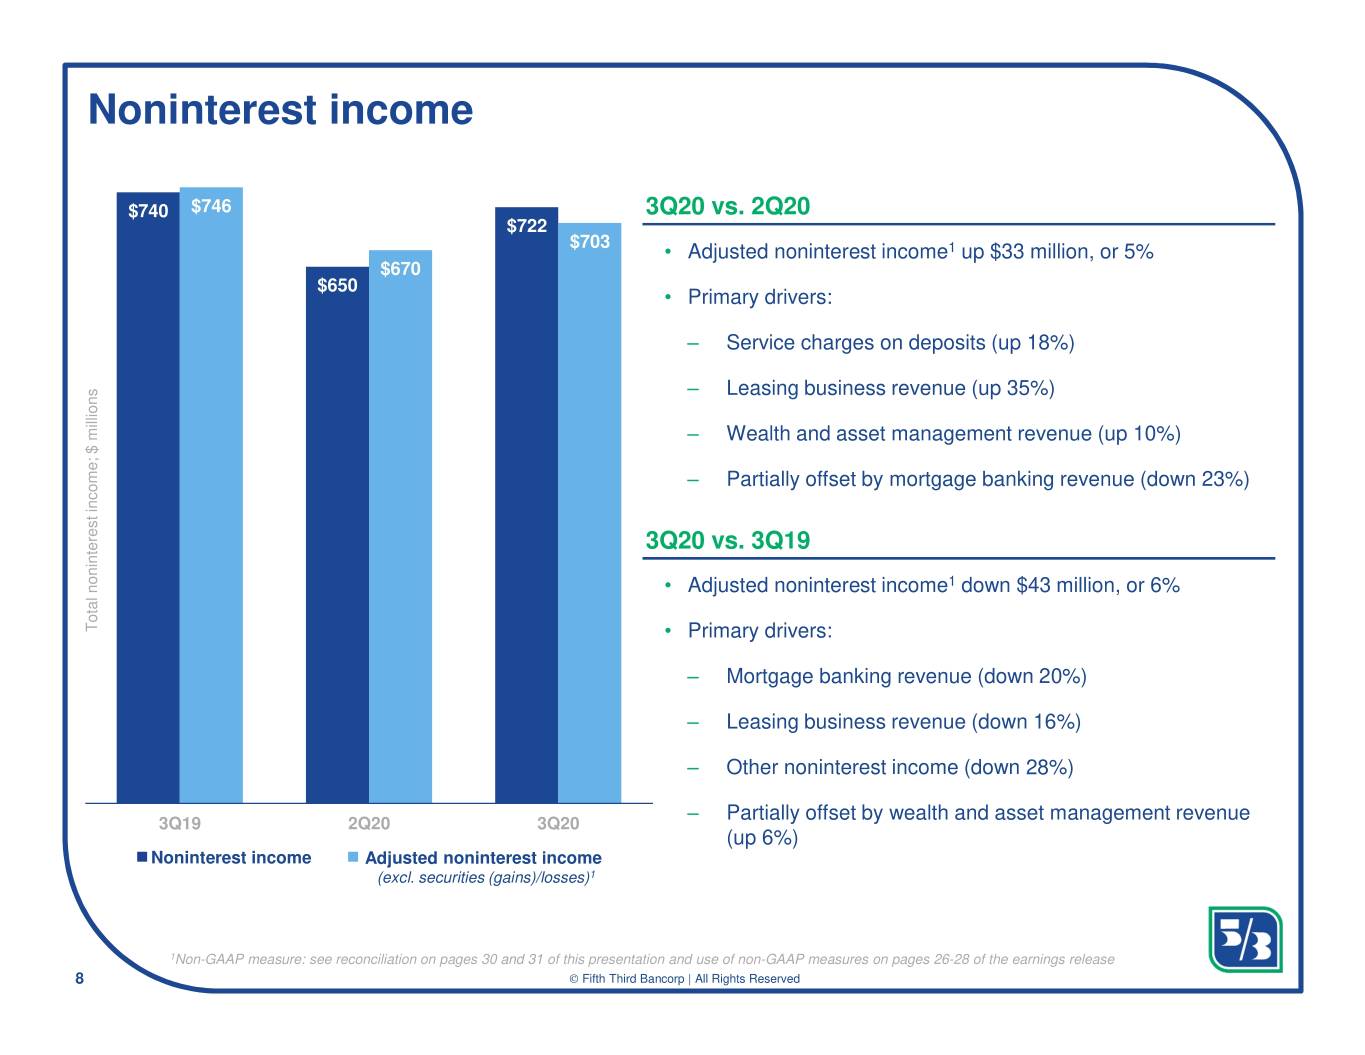
Reported noninterest income increased $72 million, or 11%, from the prior quarter, and decreased $18 million, or 2%, from the year-ago quarter. The reported results reflect the impact of certain items in the table below. Reported results in the current quarter include securities gains, including approximately $5 million attributable to mark-to-market impacts related to non-qualified deferred compensation assets, which were offset in noninterest expense, resulting in an immaterial impact to pre-tax income.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Noninterest Income excluding certain items | | | | | | | | |
| ($ in millions) | For the Three Months Ended | | | | | | | |
| | September | | | June | | | September | |
| | 2020 | | | 2020 | | | 2019 | |
| Noninterest Income excluding certain items | | | | | | | | |
| Noninterest income (U.S. GAAP) | $722 | | | $650 | | | $740 | |
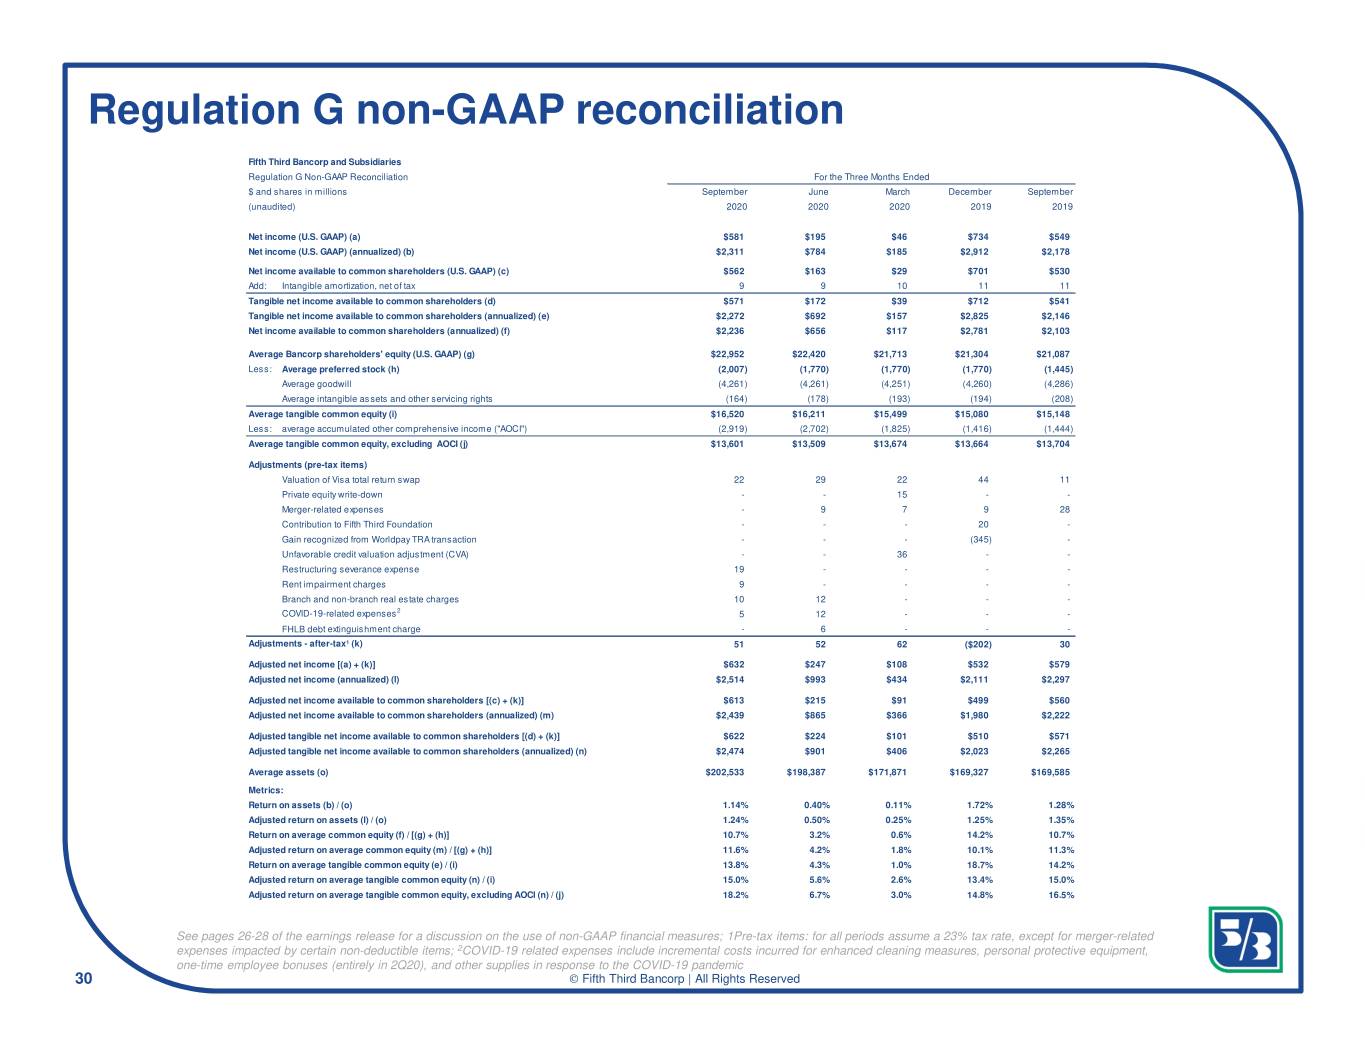
| Valuation of Visa total return swap | 22 | | | 29 | | | 11 | |
| Branch and non-branch real estate charges | 10 | | | 12 | | | — | |
| Securities gains, net | (51) | | | (21) | | | (5) | |
| Noninterest income excluding certain items(a) | $703 | | | $670 | | | $746 | |
| | | | | | | | | |
Compared to the prior quarter, noninterest income excluding certain items increased $33 million, or 5%. Compared to the year-ago quarter, noninterest income excluding certain items decreased $43 million, or 6%.
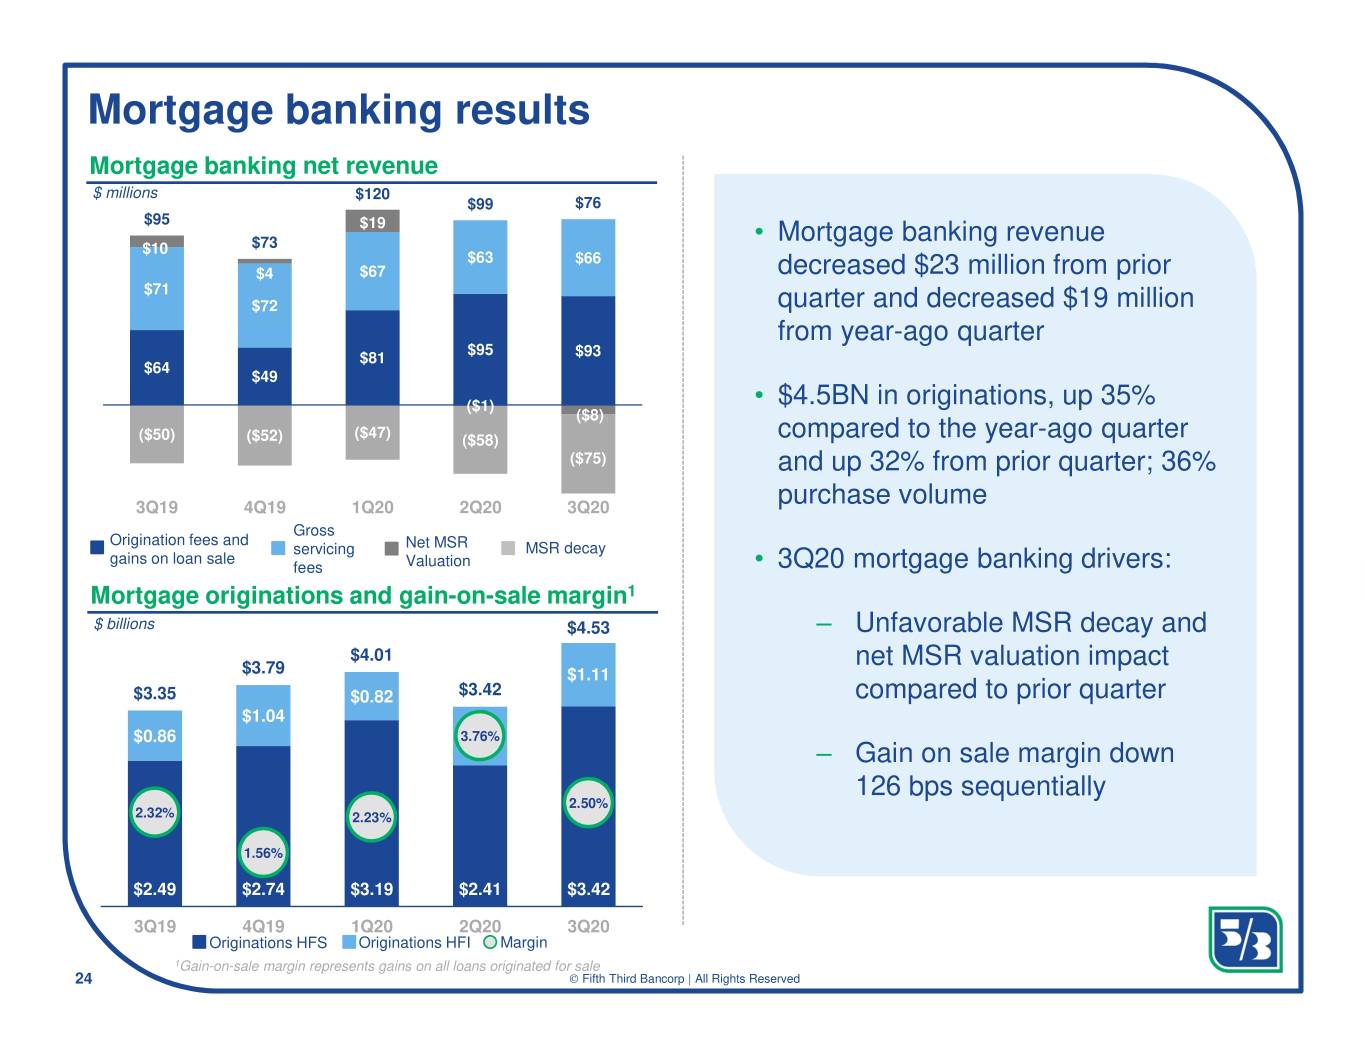
Compared to the prior quarter, service charges on deposits increased $22 million, or 18%, with improving commercial deposit fees reflecting a partial normalization of treasury management service volumes and lower earnings credits, as well as elevated consumer deposit fees compared to the prior quarter which included hardship-related fee waivers. Commercial banking revenue decreased $12 million, or 9%, primarily reflecting a decrease from the record high capital markets revenue in the prior quarter. Mortgage banking net revenue decreased $23 million, or 23%, primarily driven by an unfavorable MSR net valuation adjustment and an increase in MSR decay resulting from higher prepayment speeds. Current quarter mortgage originations of $4.5 billion increased 32% compared to the prior quarter. Wealth and asset management revenue increased $12 million, or 10%, primarily driven by higher personal asset management revenue and brokerage fees. Card and processing revenue increased $10 million, or 12%, reflecting increases in credit and debit transaction volumes. Leasing business revenue increased $20 million, or 35%, primarily driven by an increase in business solutions revenue.
Compared to the year-ago quarter, service charges on deposits increased $1 million, or 1%, as increased commercial deposit fees were partially offset by a decline in consumer deposit fees. Commercial banking revenue increased $2 million, or 2%, reflecting increases in both debt and equity capital markets revenue, partially offset by lower M&A advisory fees and financial risk management revenue. Mortgage banking net revenue decreased $19 million, or 20%, primarily driven by an unfavorable MSR net valuation adjustment and an increase in MSR decay resulting from higher prepayment speeds, partially offset by improved gain on sale margin and higher mortgage originations. Wealth and asset management revenue increased $8 million, or 6%, primarily driven by higher personal asset management revenue and brokerage fees. Card and processing revenue decreased by $2 million, or 2%, primarily reflecting lower commercial card transaction volumes, partially offset by elevated debit transaction volumes and lower rewards. Leasing business revenue decreased $15 million, or 16% primarily reflecting lower lease remarketing revenue.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Noninterest Expense | | | | | | | | | | | | | |
| ($ in millions) | For the Three Months Ended | | | | | | | | | % Change | | | |
| | September | | | June | | | September | | | | | | |
| | 2020 | | | 2020 | | | 2019 | | | Seq | | Yr/Yr | |
| Noninterest Expense | | | | | | | | | | | | | |
| Compensation and benefits | $637 | | | $627 | | | $584 | | | 2% | | 9% | |
| Net occupancy expense | 90 | | | 82 | | | 84 | | | 10% | | 7% | |
| Technology and communications | 89 | | | 90 | | | 100 | | | (1)% | | (11)% | |
| Equipment expense | 33 | | | 32 | | | 33 | | | 3% | | — | |
| Card and processing expense | 29 | | | 29 | | | 33 | | | — | | (12)% | |
| Leasing business expense | 35 | | | 33 | | | 40 | | | 6% | | (13)% | |
| Marketing expense | 23 | | | 20 | | | 40 | | | 15% | | (43)% | |
| Intangible amortization expense | 12 | | | 12 | | | 14 | | | — | | (14)% | |
| Other noninterest expense | 213 | | | 196 | | | 231 | | | 9% | | (8)% | |
| Total noninterest expense | $1,161 | | | $1,121 | | | $1,159 | | | 4% | | — | |
| | | | | | | | | | | | | | |
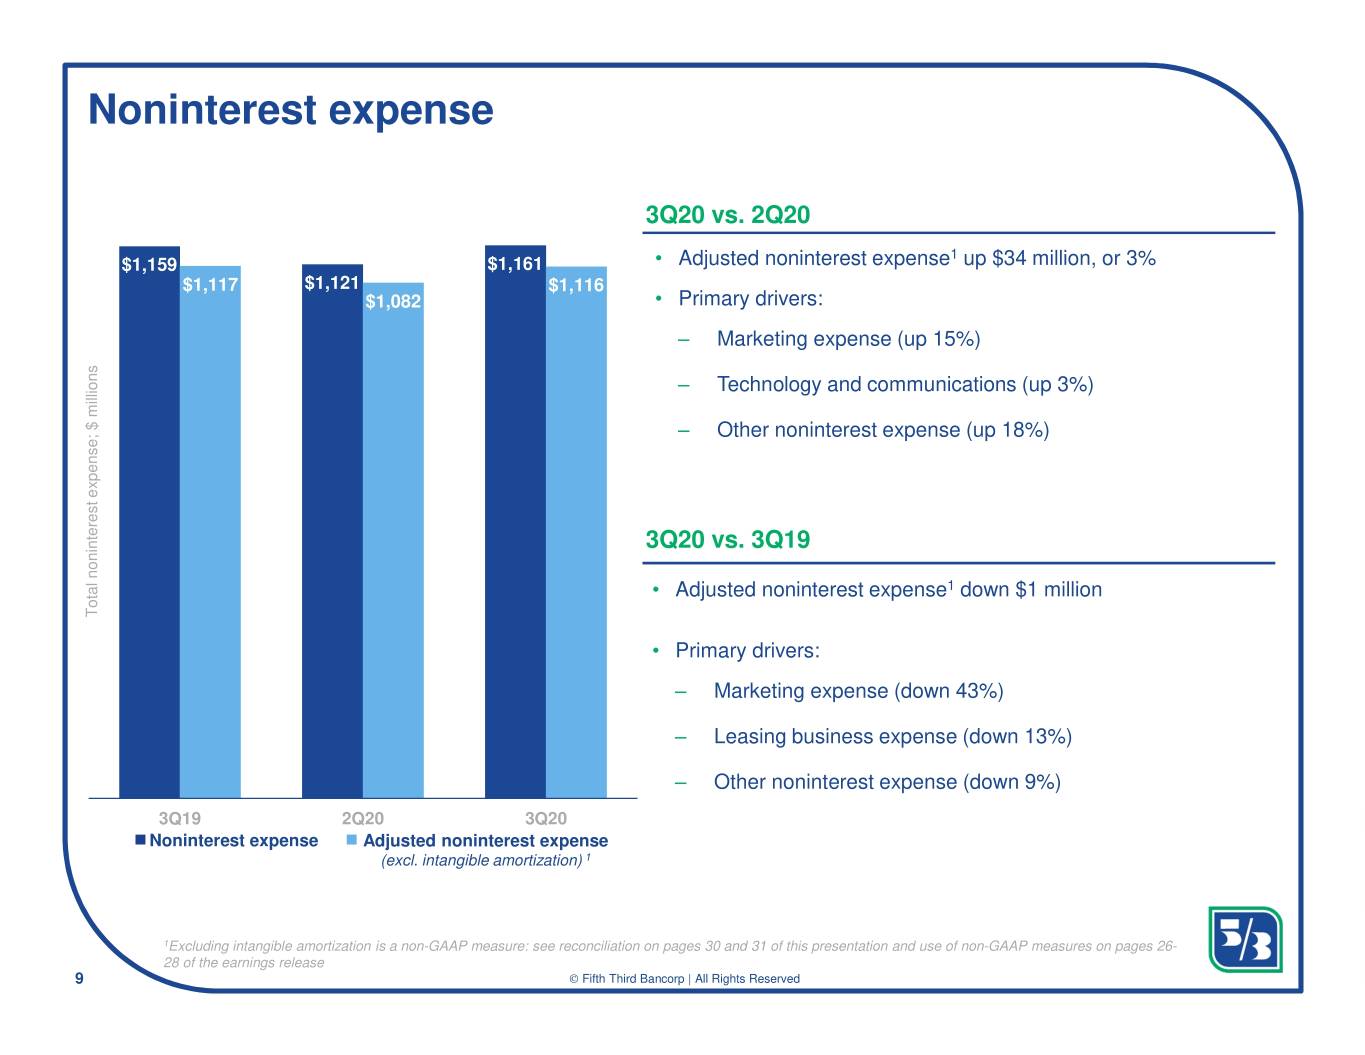
Reported noninterest expense increased $40 million, or 4%, from the prior quarter, and increased $2 million from the year-ago quarter. The reported results reflect the impact of certain items in the table below.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Noninterest Expense excluding certain items | | | | | | | | |
| ($ in millions) | For the Three Months Ended | | | | | | | |
| | September | | | June | | | September | |
| | 2020 | | | 2020 | | | 2019 | |
| Noninterest Expense excluding certain items | | | | | | | | |
| Noninterest expense (U.S. GAAP) | $1,161 | | | $1,121 | | | $1,159 | |
| Restructuring severance expense | (19) | | | — | | | — | |
| Intangible amortization expense | (12) | | | (12) | | | (14) | |
| Rent impairment charges | (9) | | | — | | | — | |
| COVID-19 related expenses(g) | (5) | | | (12) | | | — | |
| Merger-related expenses | — | | | (9) | | | (28) | |
| FHLB debt extinguishment charge | — | | | (6) | | | — | |
| Noninterest expense excluding certain items(a) | $1,116 | | | $1,082 | | | $1,117 | |
| | | | | | | | | |
Compared to the prior quarter, noninterest expense excluding certain items increased $34 million, or 3%, primarily reflecting an increase in other noninterest expense and marketing expense, partially offset by lower compensation and benefits expense (which included approximately $7 million in non-qualified deferred compensation expense in the current quarter compared to a $22 million expense in the prior quarter). Compared to the year-ago quarter, noninterest expense excluding certain items decreased $1 million, primarily reflecting lower marketing expense and other noninterest expense, partially offset by an increase in compensation and benefits expense.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Average Interest-Earning Assets | | | | | | | | | | | | | |
| ($ in millions) | For the Three Months Ended | | | | | | | | | % Change | | | |
| | September | | | June | | | September | | | | | | |
| | 2020 | | | 2020 | | | 2019 | | | Seq | | Yr/Yr | |
| Average Portfolio Loans and Leases | | | | | | | | | | | | | |
| Commercial loans and leases: | | | | | | | | | | | | | |
| Commercial and industrial loans | $54,004 | | | $59,040 | | | $51,241 | | | (9)% | | 5% | |
| Commercial mortgage loans | 11,069 | | | 11,222 | | | 10,692 | | | (1)% | | 4% | |
| Commercial construction loans | 5,534 | | | 5,548 | | | 5,267 | | | — | | 5% | |
| Commercial leases | 2,966 | | | 3,056 | | | 3,562 | | | (3)% | | (17)% | |
| Total commercial loans and leases | $73,573 | | | $78,866 | | | $70,762 | | | (7)% | | 4% | |
| Consumer loans: | | | | | | | | | | | | | |
| Residential mortgage loans | $16,618 | | | $16,561 | | | $16,736 | | | — | | (1)% | |
| Home equity | 5,581 | | | 5,820 | | | 6,267 | | | (4)% | | (11)% | |
| Indirect secured consumer loans | 12,599 | | | 12,124 | | | 10,707 | | | 4% | | 18% | |
| Credit card | 2,134 | | | 2,248 | | | 2,448 | | | (5)% | | (13)% | |
| Other consumer loans | 2,857 | | | 2,887 | | | 2,621 | | | (1)% | | 9% | |
| Total consumer loans | $39,789 | | | $39,640 | | | $38,779 | | | — | | 3% | |
| Total average portfolio loans and leases | $113,362 | | | $118,506 | | | $109,541 | | | (4)% | | 3% | |
| | | | | | | | | | | | | | |
| Average Loans and Leases Held for Sale | | | | | | | | | | | | | |
| Commercial loans and leases held for sale | $55 | | | $68 | | | $127 | | | (19)% | | (57)% | |
| Consumer loans held for sale | 1,196 | | | 844 | | | 998 | | | 42% | | 20% | |
| Total average loans and leases held for sale | $1,251 | | | $912 | | | $1,125 | | | 37% | | 11% | |
| | | | | | | | | | | | | | |
| Securities and other short-term investments | $66,091 | | | $56,806 | | | $38,188 | | | 16% | | 73% | |
| Total average interest-earning assets | $180,704 | | | $176,224 | | | $148,854 | | | 3% | | 21% | |
| | | | | | | | | | | | | | |
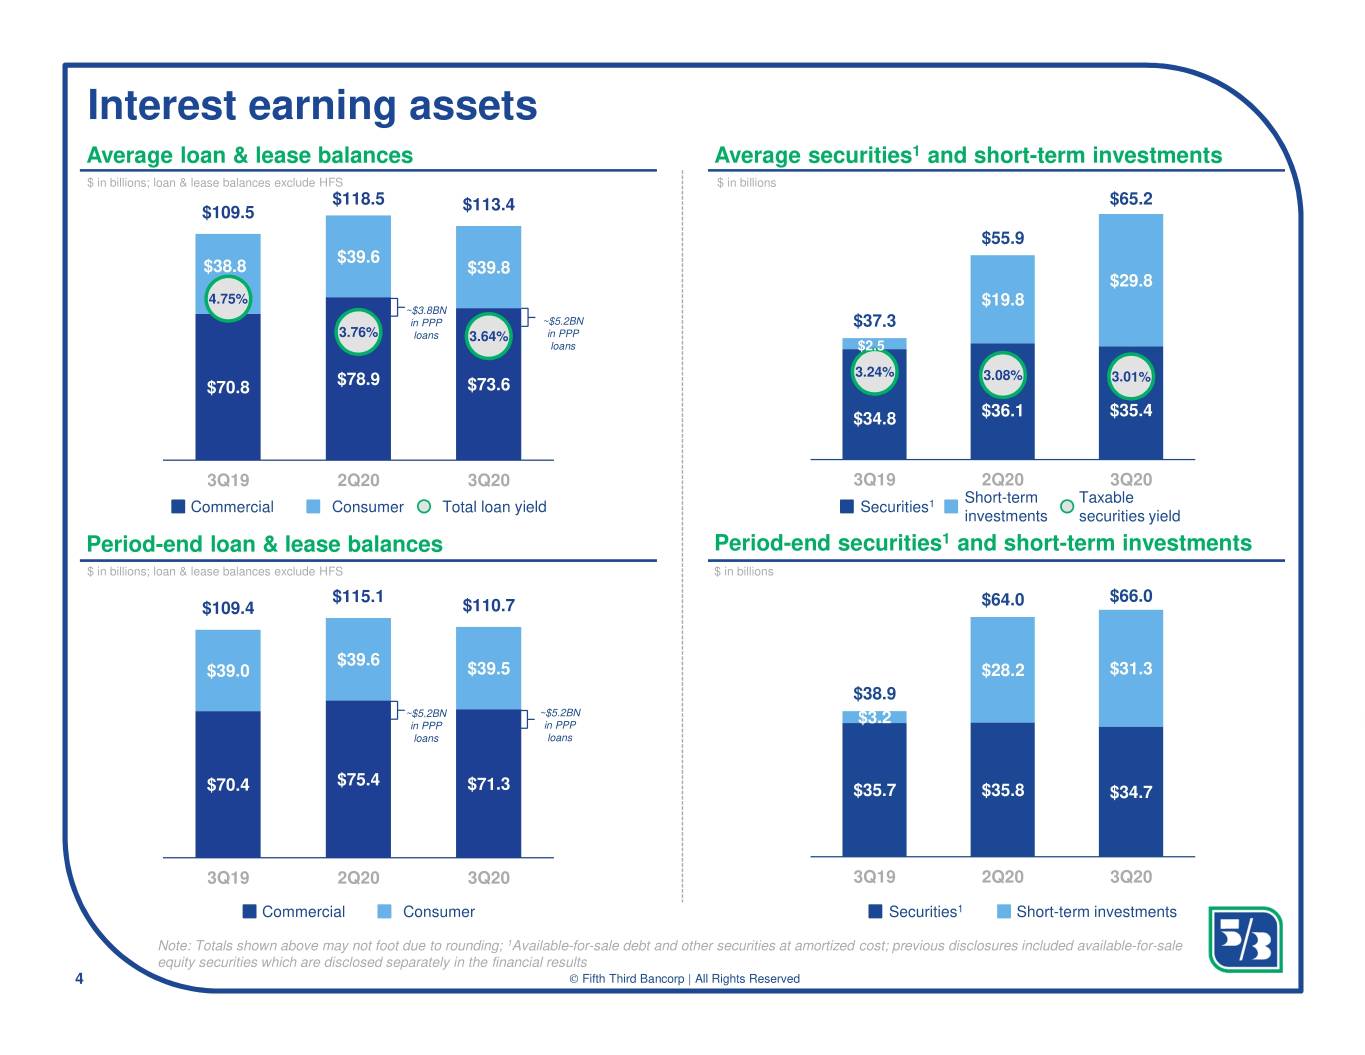
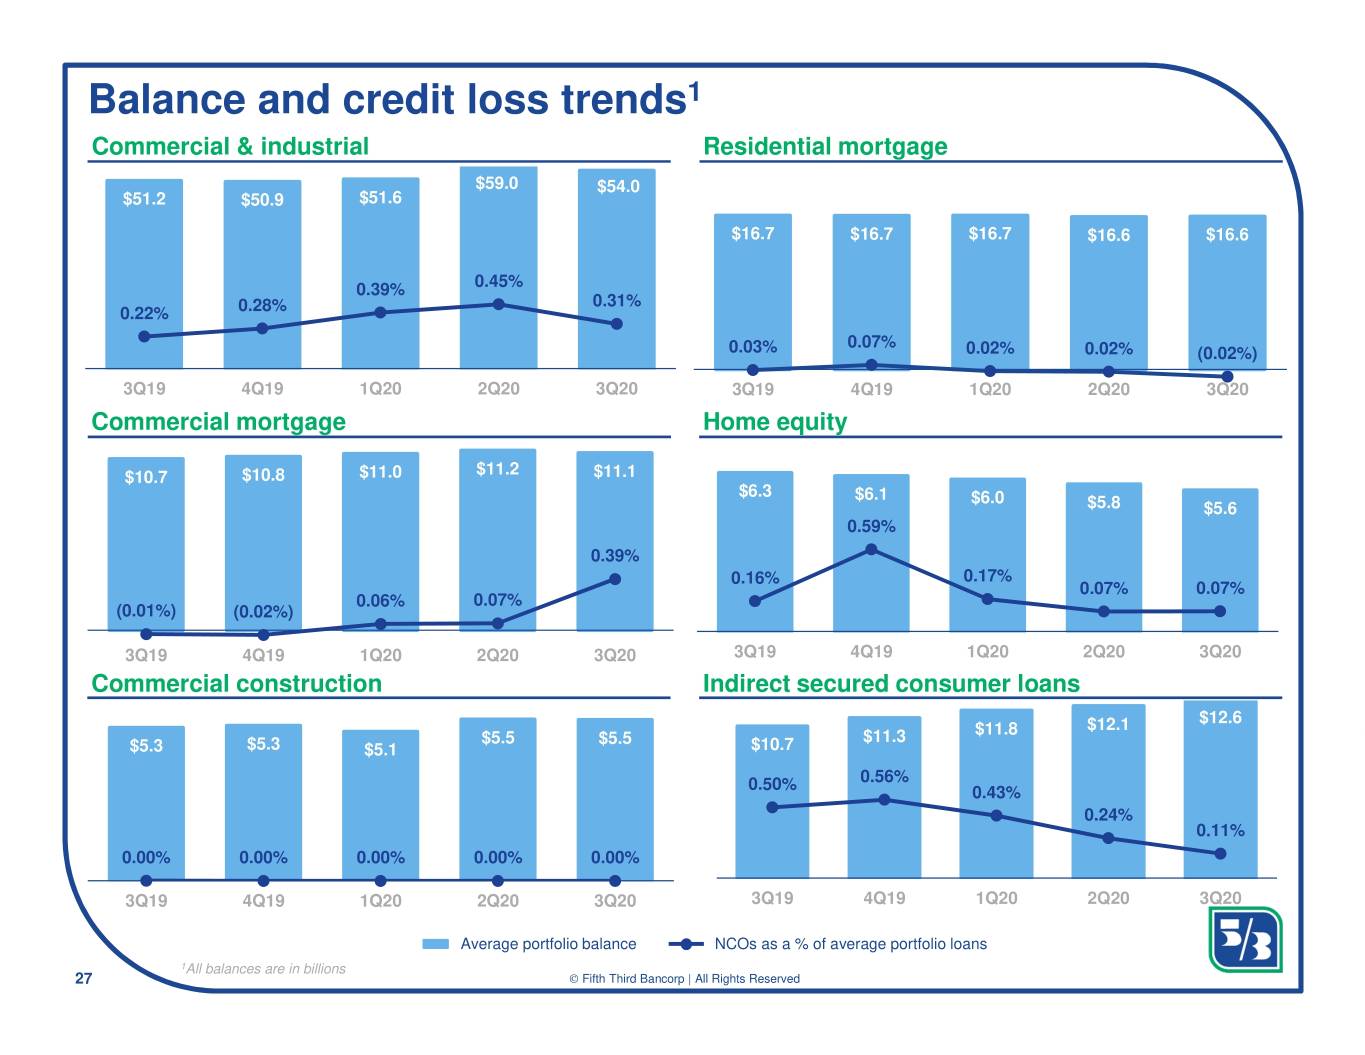
Compared to the prior quarter, total average portfolio loans and leases decreased 4%, primarily driven by a decline in C&I loans, partially offset by an increase in indirect secured consumer loans (predominantly indirect automobile). Average commercial portfolio loans and leases decreased 7%, reflecting lower C&I revolving line of credit utilization and a decline in commercial mortgage loans, partially offset by the full-quarter impact of PPP loans. Average consumer portfolio loans were flat, as higher indirect secured consumer loans were offset by lower home equity and credit card balances.
Compared to the year-ago quarter, total average portfolio loans and leases increased 3%, reflecting growth in C&I loans as well as continued growth in indirect secured consumer loans. Average commercial portfolio loans and leases increased 4%, reflecting elevated C&I balances predominantly from PPP loans and growth in commercial mortgage loans, partially offset by the expected decline in commercial leases. Average consumer portfolio loans increased 3%, as higher indirect secured consumer loans were partially offset by lower home equity and credit card balances.
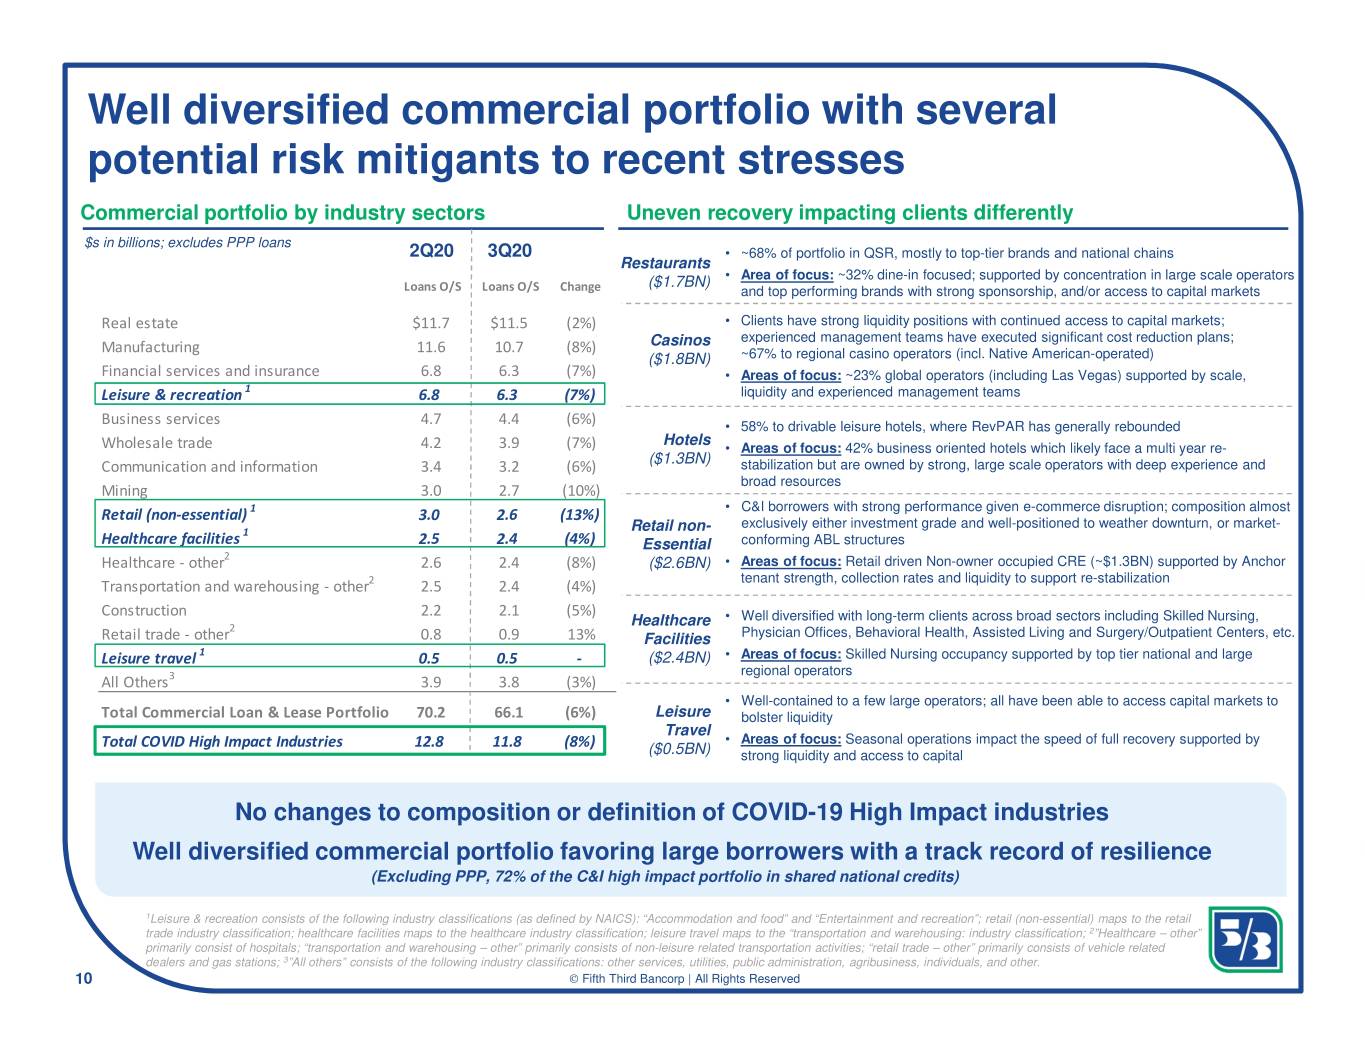
Total period-end commercial portfolio loans and leases of $71 billion (including $5.2 billion in PPP loan balances) decreased $4 billion, or 6%, from the prior quarter, and increased $1 billion, or 1%, from the year-ago quarter. The sequential decline reflected lower revolving line utilization throughout the current quarter. Period-end commercial revolving line utilization was 33%, compared to 38% in the prior quarter and 36% in the year-ago quarter.
Average available-for-sale debt and other securities of $35.4 billion (amortized cost) decreased 2% compared to the prior quarter and increased 2% compared to the year-ago quarter. Average other short-term investments (which includes interest-bearing cash) of $29.8 billion increased $10 billion compared to the prior quarter and increased $27.3 billion compared to the year-ago quarter.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Average Deposits | | | | | | | | | | | | | | |
| ($ in millions) | For the Three Months Ended | | | | | | | | | % Change | | | |
| | September | | | June | | | September | | | | | | |
| | 2020 | | | 2020 | | | 2019 | | | Seq | | Yr/Yr | |
| Average Deposits | | | | | | | | | | | | | |
| Demand | $50,414 | | | $45,761 | | | $35,223 | | | 10% | | 43% | |
| Interest checking | 49,800 | | | 49,760 | | | 37,729 | | | — | | 32% | |
| Savings | 17,013 | | | 16,354 | | | 14,405 | | | 4% | | 18% | |
| Money market | 31,151 | | | 30,022 | | | 26,962 | | | 4% | | 16% | |
| Foreign office(h) | 189 | | | 182 | | | 222 | | | 4% | | (15)% | |
| Total transaction deposits | $148,567 | | | $142,079 | | | $114,541 | | | 5% | | 30% | |
| Other time | 3,711 | | | 4,421 | | | 5,823 | | | (16)% | | (36)% | |
| Total core deposits | $152,278 | | | $146,500 | | | $120,364 | | | 4% | | 27% | |
| Certificates - $100,000 and over | 3,633 | | | 4,067 | | | 4,795 | | | (11)% | | (24)% | |
| Other deposits | — | | | 31 | | | 47 | | | (100)% | | (100)% | |
| Total average deposits | $155,911 | | | $150,598 | | | $125,206 | | | 4% | | 25% | |
| | | | | | | | | | | | | | |
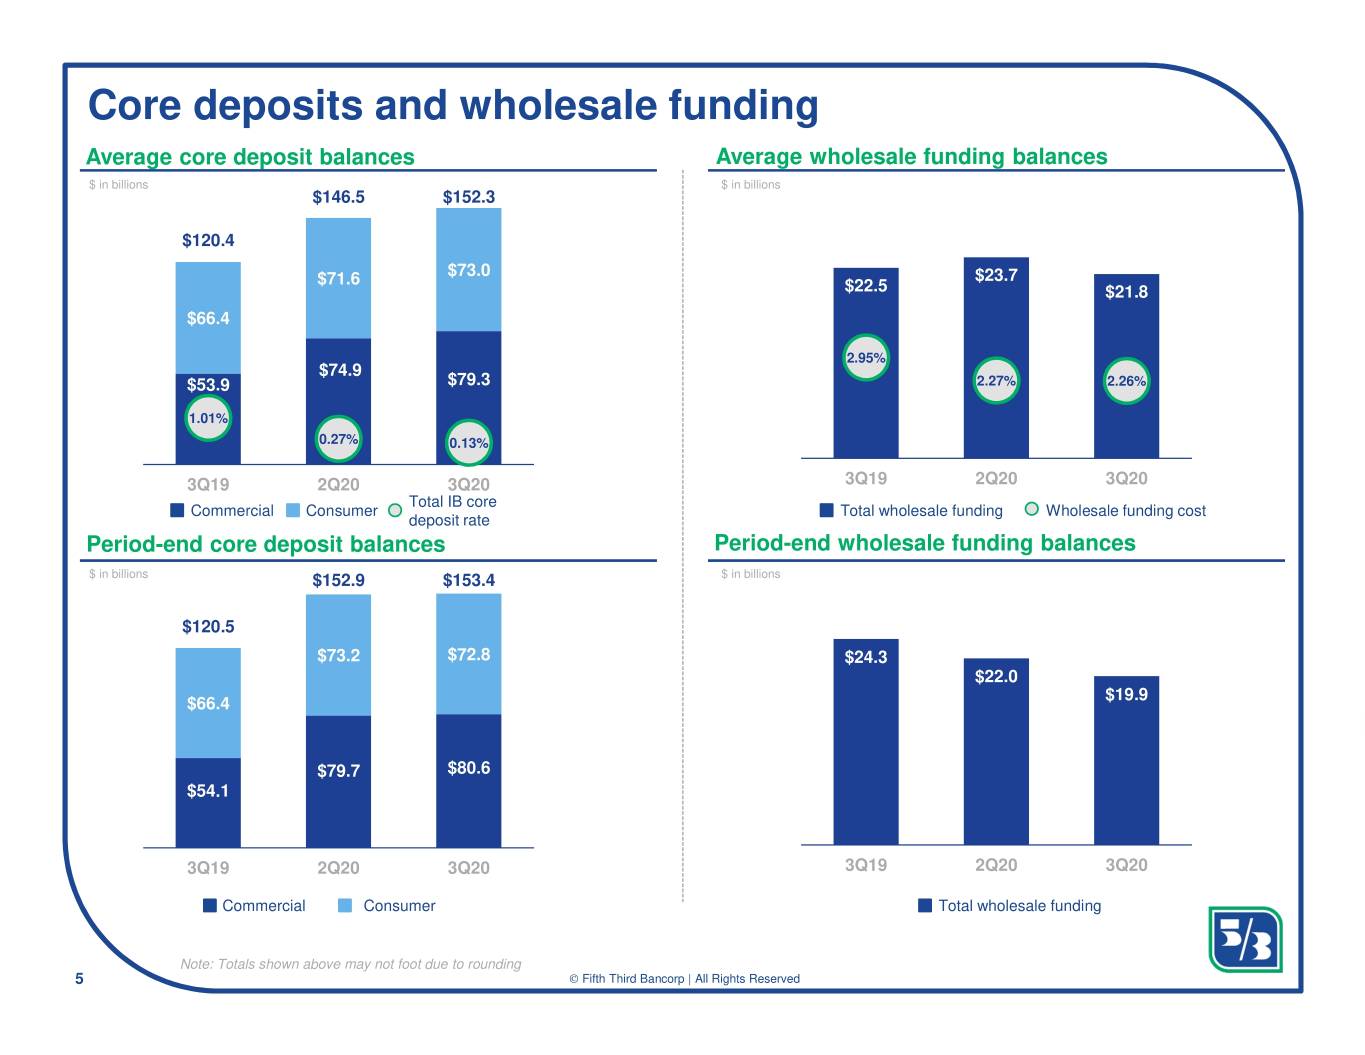
Compared to the prior quarter, average core deposits increased 4%, with growth in all deposit captions except other time deposits. Average demand deposits represented 33% of total core deposits in the current quarter compared to 31% in the prior quarter. Average commercial transaction deposits increased 6% and average consumer transaction deposits increased 3%.
Compared to the year-ago quarter, average core deposits increased 27%, reflecting double-digit growth in all deposit captions except other time and foreign office deposits. Average commercial transaction deposits increased 47% and average consumer transaction deposits increased 14%.
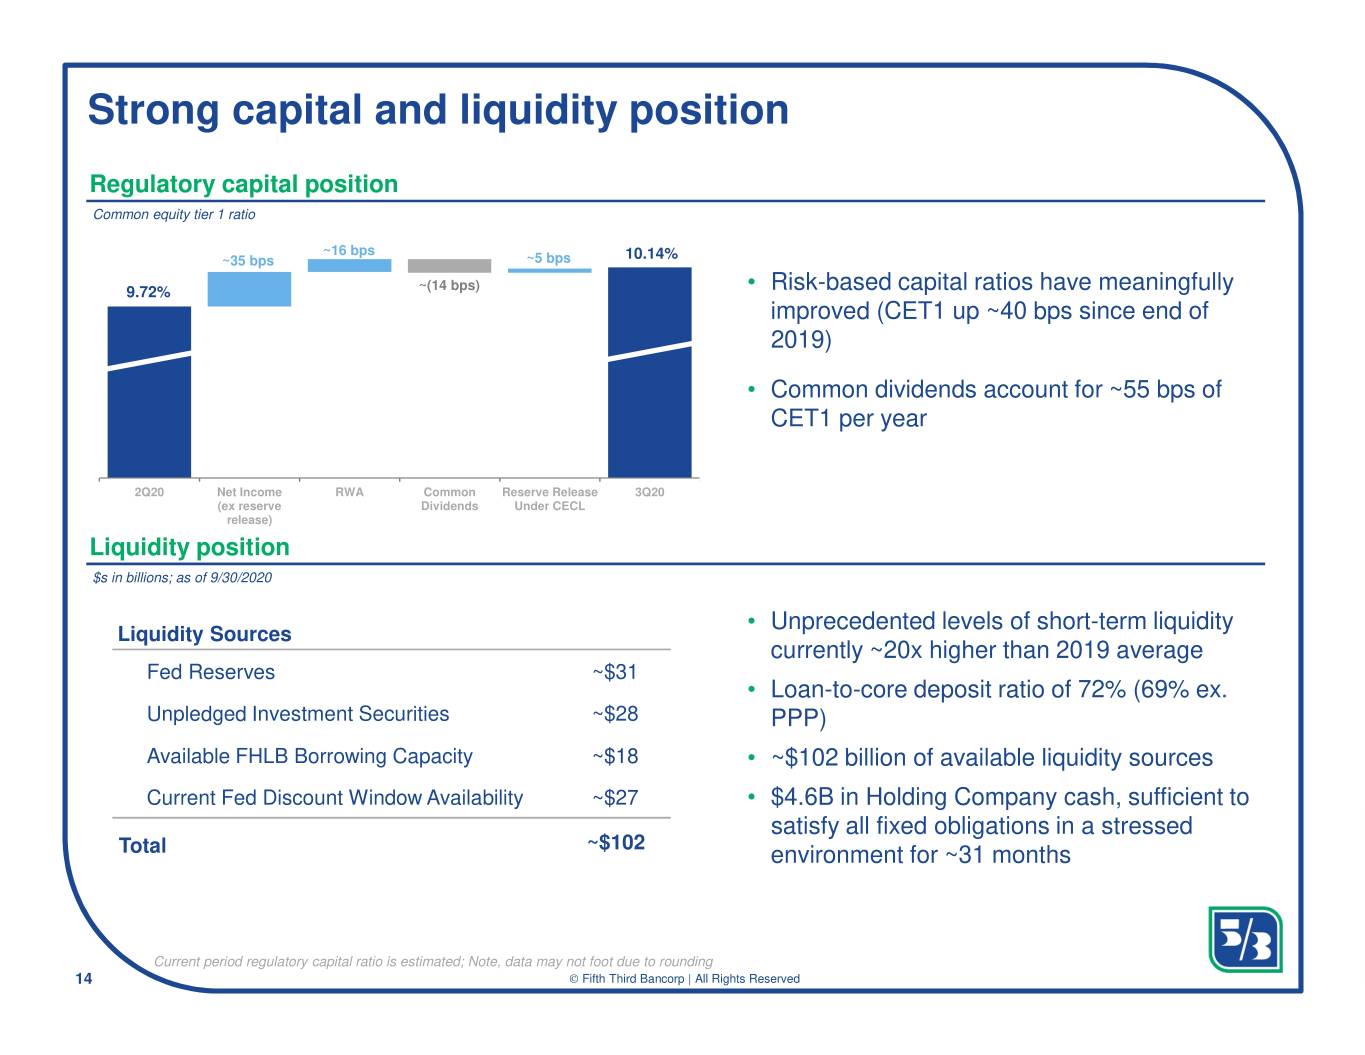
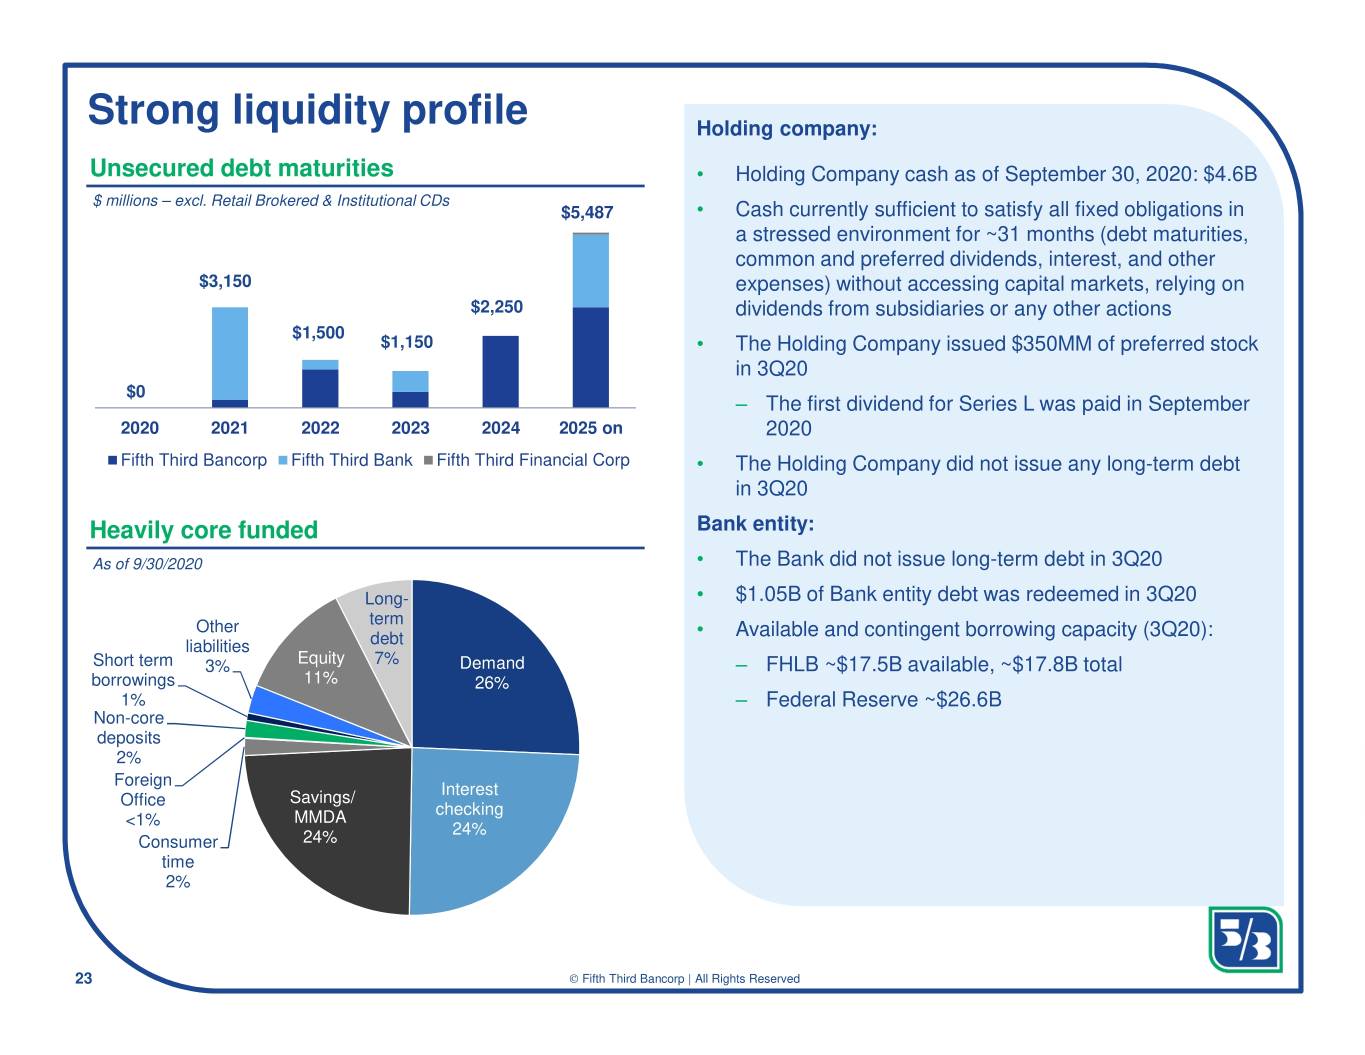
The period end loan-to-core deposit ratio was 72% in the current quarter, compared to 75% in the prior quarter and 91% in the year-ago quarter. Excluding PPP loans, the period end loan-to-core deposit ratio was 69% in the current quarter, compared to 72% in the prior quarter.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Average Wholesale Funding | | | | | | | | | | | | | | |
| ($ in millions) | For the Three Months Ended | | | | | | | | | % Change | | | |
| | September | | | June | | | September | | | | | | |
| | 2020 | | | 2020 | | | 2019 | | | Seq | | Yr/Yr | |
| Average Wholesale Funding | | | | | | | | | | | | | |
| Certificates - $100,000 and over | $3,633 | | | $4,067 | | | $4,795 | | | (11)% | | (24)% | |
| Other deposits | — | | | 31 | | | 47 | | | (100)% | | (100)% | |
| Federal funds purchased | 273 | | | 309 | | | 739 | | | (12)% | | (63)% | |
| Other short-term borrowings | 1,626 | | | 2,377 | | | 1,278 | | | (32)% | | 27% | |
| Long-term debt | 16,230 | | | 16,955 | | | 15,633 | | | (4)% | | 4% | |
| Total average wholesale funding | $21,762 | | | $23,739 | | | $22,492 | | | (8)% | | (3)% | |
| | | | | | | | | | | | | | |
Compared to the prior quarter, average wholesale funding decreased 8%, driven by a reduction in other short-term borrowings reflecting lower FHLB advances, lower jumbo CD balances, as well as the full-quarter impact of a debt redemption that occurred at the end of the second quarter. Compared to the year-ago quarter, average wholesale funding decreased 3%, reflecting decreases in jumbo CD balances, federal funds borrowings and other deposits, partially offset by increases in long-term debt and other short-term borrowings.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Credit Quality Summary | | | | | | | | | | | | | | |
| ($ in millions) | As of and For the Three Months Ended | | | | | | | | | | | | | |
| September | | | June | | | March | | | December | | | September | |
| 2020 | | | 2020 | | | 2020 | | | 2019 | | | 2019 | |
| | | | | | | | | | | | | | |
| Total nonaccrual portfolio loans and leases (NPLs) | $891 | | | $700 | | | $647 | | | $618 | | | $482 | |
| Repossessed property | 7 | | | 4 | | | 10 | | | 10 | | | 9 | |
| OREO | 33 | | | 43 | | | 52 | | | 52 | | | 28 | |
| Total nonperforming portfolio loans and leases and OREO (NPAs) | $931 | | | $747 | | | $709 | | | $680 | | | $519 | |
| | | | | | | | | | | | | | |
NPL ratio(i) | 0.80 | % | | | 0.61 | % | | | 0.55 | % | | | 0.56 | % | | | 0.44 | % | |
NPA ratio(c) | 0.84 | % | | | 0.65 | % | | | 0.60 | % | | | 0.62 | % | | | 0.47 | % | |
| | | | | | | | | | | | | | |
| Total loans and leases 30-89 days past due (accrual) | $323 | | | $381 | | | $409 | | | $364 | | | $402 | |
| Total loans and leases 90 days past due (accrual) | 139 | | | 136 | | | 151 | | | 130 | | | 132 | |
| | | | | | | | | | | | | | |
| Allowance for loan and lease losses (ALLL), beginning | $2,696 | | | $2,348 | | | $1,202 | | | $1,143 | | | $1,115 | |
| Impact of CECL adoption | — | | | — | | | 643 | | | — | | | — | |
| Total net losses charged-off | (101) | | | (130) | | | (122) | | | (113) | | | (99) | |
| (Benefit from) provision for loan and lease losses | (21) | | | 478 | | | 625 | | | 172 | | | 127 | |
| ALLL, ending | $2,574 | | | $2,696 | | | $2,348 | | | $1,202 | | | $1,143 | |
| | | | | | | | | | | | | | |
| Reserve for unfunded commitments, beginning | $176 | | | $169 | | | $144 | | | $154 | | | $147 | |
| Impact of CECL adoption | — | | | — | | | 10 | | | — | | | — | |
| Provision for (benefit from) the reserve for unfunded commitments | 6 | | | 7 | | | 15 | | | (10) | | | 7 | |
| Reserve for unfunded commitments, ending | $182 | | | $176 | | | $169 | | | $144 | | | $154 | |
| | | | | | | | | | | | | | |
| Total allowance for credit losses (ACL) | $2,756 | | | $2,872 | | | $2,517 | | | $1,346 | | | $1,297 | |
| | | | | | | | | | | | | | |
| ACL ratios: | | | | | | | | | | | | | | |
| As a % of portfolio loans and leases | 2.49 | % | | | 2.50 | % | | | 2.13 | % | | | 1.23 | % | | | 1.19 | % | |
| As a % of nonperforming portfolio loans and leases | 309 | % | | | 410 | % | | | 389 | % | | | 218 | % | | | 269 | % | |
| As a % of nonperforming portfolio assets | 296 | % | | | 385 | % | | | 355 | % | | | 198 | % | | | 250 | % | |
| | | | | | | | | | | | | | |
| ALLL as a % of portfolio loans and leases | 2.32 | % | | | 2.34 | % | | | 1.99 | % | | | 1.10 | % | | | 1.04 | % | |
| | | | | | | | | | | | | | |
| Total losses charged-off | $(135) | | | $(163) | | | $(159) | | | $(152) | | | $(130) | |
| Total recoveries of losses previously charged-off | 34 | | | 33 | | | 37 | | | 39 | | | 31 | |
| Total net losses charged-off | $(101) | | | $(130) | | | $(122) | | | $(113) | | | $(99) | |
| | | | | | | | | | | | | | |
Net charge-off ratio (NCO ratio)(b) | 0.35 | % | | | 0.44 | % | | | 0.44 | % | | | 0.41 | % | | | 0.36 | % | |
| Commercial NCO ratio | 0.33 | % | | | 0.40 | % | | | 0.32 | % | | | 0.20 | % | | | 0.18 | % | |
| Consumer NCO ratio | 0.40 | % | | | 0.52 | % | | | 0.66 | % | | | 0.78 | % | | | 0.68 | % | |
| | | | | | | | | | | | | | |
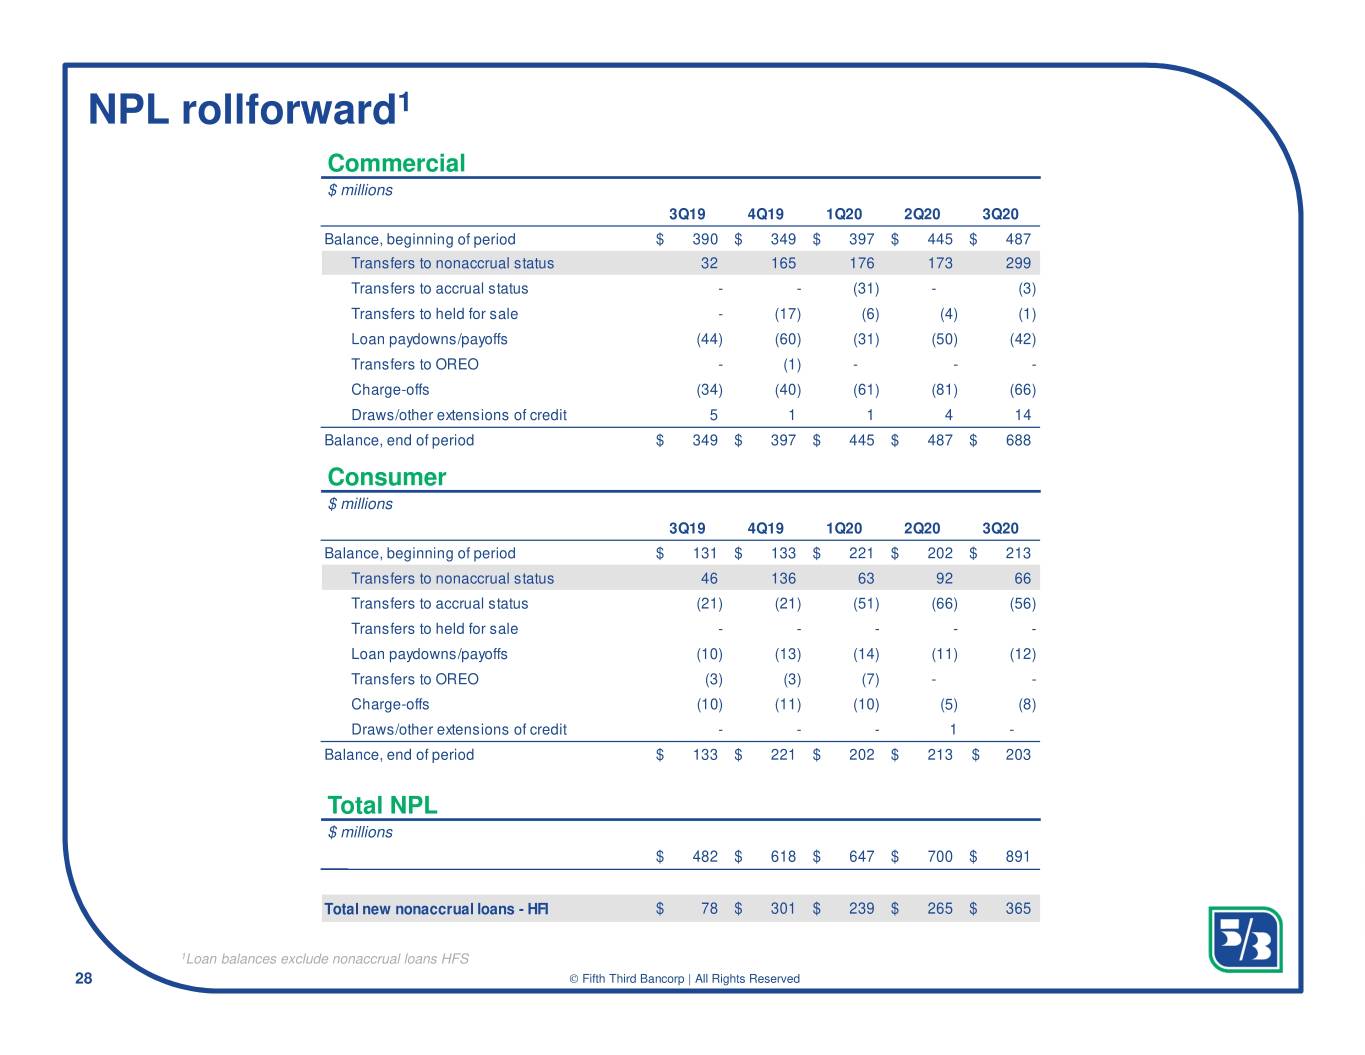
Nonperforming portfolio loans and leases were $891 million in the current quarter, with the resulting NPL ratio of 0.80%. Compared to the prior quarter, NPLs increased $191 million with the NPL ratio increasing 19 bps. Compared to the year-ago quarter, NPLs increased $409 million with the NPL ratio increasing 36 bps.
Nonperforming portfolio assets were $931 million in the current quarter, with the resulting NPA ratio of 0.84%. Compared to the prior quarter, NPAs increased $184 million with the NPA ratio increasing 19 bps. Compared to the year-ago quarter, NPAs increased $412 million with the NPA ratio increasing 37 bps.
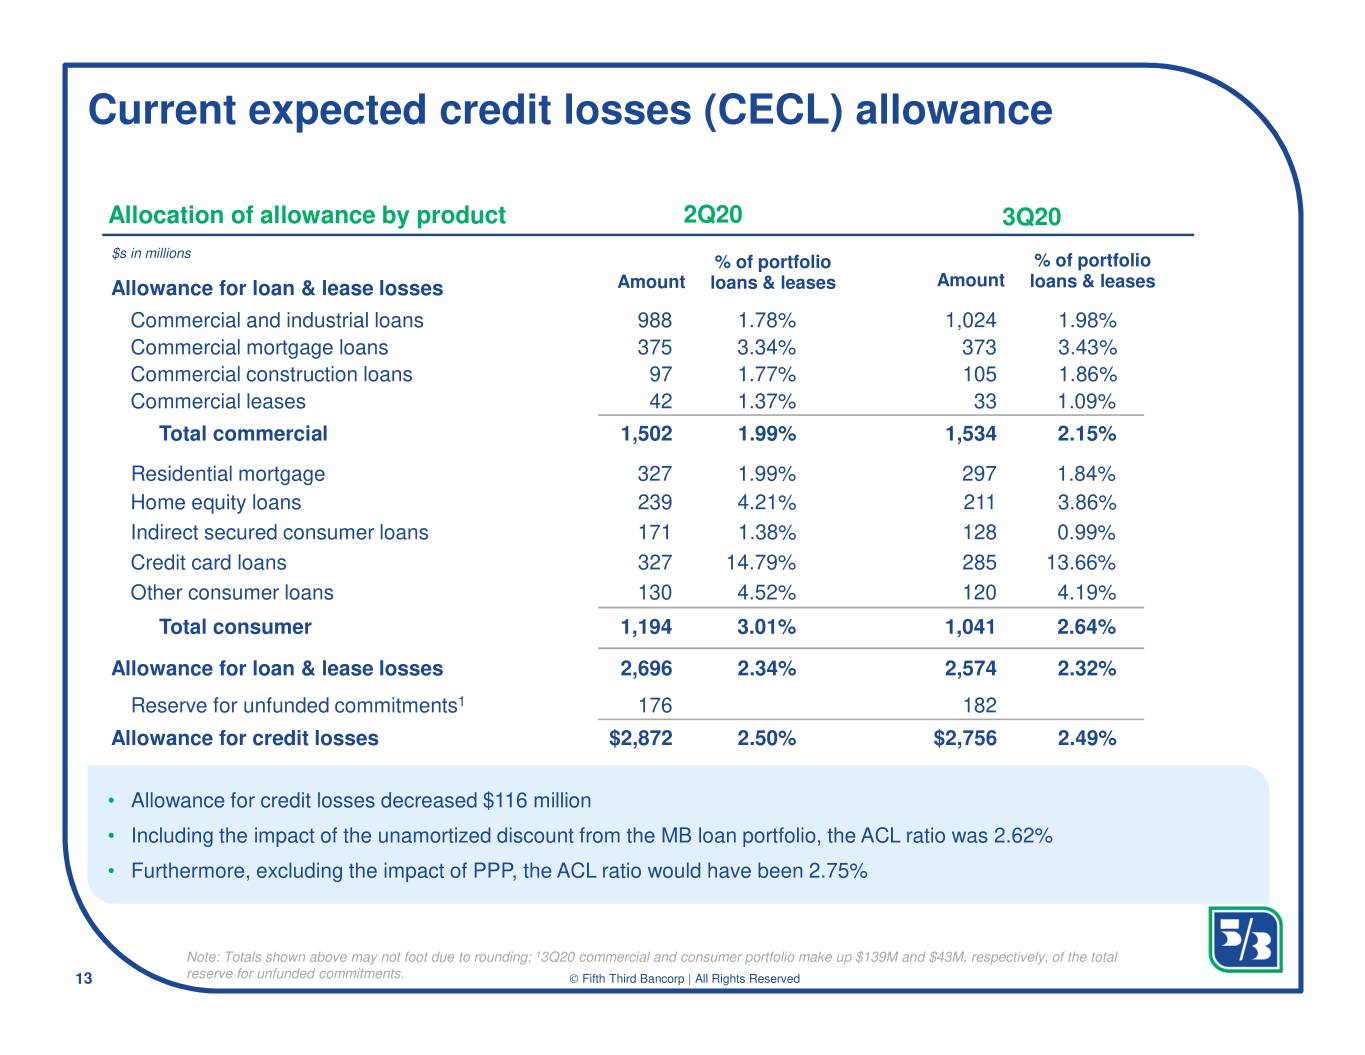
The benefit from credit losses totaled $15 million in the current quarter. The allowance for credit loss ratio represented 2.49% of total portfolio loans and leases in the current quarter, compared with 2.50% in the prior quarter and 1.19% in the year-ago quarter (under the incurred loss methodology). In the current quarter, the allowance for credit losses represented 309% of nonperforming portfolio loans and leases and 296% of nonperforming portfolio assets. The allowance for loan and lease losses ratio represented 2.32% of total portfolio loans and leases in the current quarter.
Net charge-offs were $101 million in the current quarter, with the resulting NCO ratio of 0.35%. Compared to the prior quarter, net charge-offs decreased $29 million and the NCO ratio decreased 9 bps. Compared to the year-ago quarter, net charge-offs increased $2 million and the NCO ratio decreased 1 bp.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Capital Position | | | | | | | | | | | | | | | |
| | | | As of and For the Three Months Ended | | | | | | | | | | | | |
| | | | September | | | June | | | March | | | December | | September | |
| | | | 2020 | | | 2020 | | | 2020 | | | 2019 | | 2019 | |
| Capital Position | | | | | | | | | | | | | | | |
| Average total Bancorp shareholders' equity as a % of average assets | | | 11.33 | % | | | 11.30 | % | | | 12.63% | | | 12.58% | | 12.43 | % | |
| Tangible equity(a) | | | 8.09 | % | | | 7.68 | % | | | 8.41% | | | 9.52% | | 9.29 | % | |
| Tangible common equity (excluding AOCI)(a) | | | 6.99 | % | | | 6.77 | % | | | 7.41% | | | 8.44% | | 8.21 | % | |
| Tangible common equity (including AOCI)(a) | | | 8.31 | % | | | 8.13 | % | | | 8.65% | | | 9.08% | | 9.09 | % | |
| | | | | | | | | | | | | | | | |
| Regulatory Capital Ratios(e) | | | | | | | | | | | | | | | |
| CET1 capital(d) | | | 10.14 | % | | | 9.72 | % | | | 9.37% | | | 9.75% | | 9.56 | % | |
| Tier I risk-based capital(d) | | | 11.64 | % | | | 10.96 | % | | | 10.56% | | | 10.99% | | 10.81 | % | |
| Total risk-based capital(d) | | | 14.93 | % | | | 14.24 | % | | | 13.59% | | | 13.84% | | 13.68 | % | |
| Tier I leverage | | | 8.37 | % | | | 8.16 | % | | | 9.37% | | | 9.54% | | 9.36 | % | |
| | | | | | | | | | | | | | | | |
Capital ratios remained strong and grew during the quarter. The CET1 capital ratio was 10.14%, the tangible common equity to tangible assets ratio was 6.99% excluding AOCI, and 8.31% including AOCI. The Tier I risk-based capital ratio was 11.64%, the Total risk-based capital ratio was 14.93%, and the Tier I leverage ratio was 8.37%. Certain capital ratios, including the Tier I leverage ratio, continued to be impacted by the increase in assets since the onset of the pandemic, predominantly from growth in 0% risk-weighted assets resulting from an increase in interest-bearing cash as well as PPP loans.
On September 17, 2020, the Federal Reserve released its hypothetical scenarios for its second round of stress tests under the Comprehensive Capital Analysis and Review (CCAR) process due to continued uncertainty from COVID-19. Fifth Third will be resubmitting its own base and stress scenario projections to the Federal Reserve by November 2, 2020. Additionally, on September 30, 2020, the Federal Reserve announced it has extended for an additional quarter several measures to ensure that large banks such as Fifth Third maintain a high level of capital resilience, including prohibiting share repurchases through at least the fourth quarter of 2020, as well as capping dividend payments tied to a formula based on recent income.
Tax Rate
The effective tax rate was 22.1% compared with 19.9% in the prior quarter and 20.2% in the year-ago quarter.
Conference Call
Fifth Third will host a conference call to discuss these financial results at 9:00 a.m. (Eastern Time) today. This conference call will be webcast live and may be accessed through the Fifth Third Investor Relations website at www.53.com (click on “About Us” then “Investor Relations”).
Those unable to listen to the live webcast may access a webcast replay through the Fifth Third Investor Relations website at the same web address.
Corporate Profile
Fifth Third Bancorp is a diversified financial services company headquartered in Cincinnati, Ohio, and the indirect parent company of Fifth Third Bank, National Association, a federally chartered institution. As of September 30, 2020, the Company had $202 billion in assets and operates 1,122 full-service Banking Centers, and 2,414 Fifth Third branded ATMs in Ohio, Kentucky, Indiana, Michigan, Illinois, Florida, Tennessee, West Virginia, Georgia, North Carolina and South Carolina. In total, Fifth Third provides its customers with access to approximately 52,000 fee-free ATMs across the United States. Fifth Third operates four main businesses: Commercial Banking, Branch Banking, Consumer Lending, and Wealth & Asset Management. Fifth Third is among the largest money managers in the Midwest and, as of September 30, 2020, had $422 billion in assets under care, of which it managed $53 billion for individuals, corporations and not-for-profit organizations through its Trust and Registered Investment Advisory businesses. Investor information and press releases can be viewed at www.53.com. Fifth Third’s common stock is traded on the NASDAQ® Global Select Market under the symbol “FITB.”
Earnings Release End Notes
(a)Non-GAAP measure; see discussion of non-GAAP and Reg. G reconciliation beginning on page 26.
(b)Net losses charged-off as a percent of average portfolio loans and leases.
(c)Nonperforming portfolio assets as a percent of portfolio loans and leases and OREO.
(d)Under the U.S. banking agencies' Basel III Final Rule, assets and credit equivalent amounts of off-balance sheet exposures are calculated according to the standardized approach for risk-weighted assets. The resulting values are added together resulting in the Bancorp’s total risk-weighted assets.
(e)Current period regulatory capital ratios are estimated.
(f)Assumes a 23% tax rate.
(g)COVID-19 related expenses include incremental costs incurred for enhanced cleaning measures, personal protective equipment, one-time employee bonuses (entirely in 2Q20), and other supplies in response to the COVID-19 pandemic
(h)Includes commercial customer Eurodollar sweep balances for which the Bank pays rates comparable to other commercial deposit accounts.
(i)Nonperforming portfolio loans and leases as a percent of portfolio loans and leases and OREO.
FORWARD-LOOKING STATEMENTS
This release contains statements that we believe are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Rule 175 promulgated thereunder, and Section 21E of the Securities Exchange Act of 1934, as amended, and Rule 3b-6 promulgated thereunder. These statements relate to our financial condition, results of operations, plans, objectives, future performance or business. They usually can be identified by the use of forward-looking language such as “will likely result,” “may,” “are expected to,” “is anticipated,” “potential,” “estimate,” “forecast,” “projected,” “intends to,” or may include other similar words or phrases such as “believes,” “plans,” “trend,” “objective,” “continue,” “remain,” or similar expressions, or future or conditional verbs such as “will,” “would,” “should,” “could,” “might,” “can,” or similar verbs. You should not place undue reliance on these statements, as they are subject to risks and uncertainties, including but not limited to the risk factors set forth in our most recent Annual Report on Form 10-K as updated by our filings with the U.S. Securities and Exchange Commission (“SEC”). When considering these forward-looking statements, you should keep in mind these risks and uncertainties, as well as any cautionary statements we may make. Moreover, you should treat these statements as speaking only as of the date they are made and based only on information then actually known to us. We undertake no obligation to release revisions to these forward-looking statements or reflect events or circumstances after the date of this document.
There are a number of important factors that could cause future results to differ materially from historical performance and these forward-looking statements. Factors that might cause such a difference include, but are not limited to: (1) effects of the global COVID-19 pandemic; (2) deteriorating credit quality; (3) loan concentration by location or industry of borrowers or collateral; (4) problems encountered by other financial institutions; (5) inadequate sources of funding or liquidity; (6) unfavorable actions of rating agencies; (7) inability to maintain or grow deposits; (8) limitations on the ability to receive dividends from subsidiaries; (9) cyber-security risks; (10) Fifth Third’s ability to secure confidential information and deliver products and services through the use of computer systems and telecommunications networks; (11) failures by third-party service providers; (12) inability to manage strategic initiatives and/or organizational changes; (13) inability to implement technology system enhancements; (14) failure of internal controls and other risk management systems; (15) losses related to fraud, theft or violence; (16) inability to attract and retain skilled personnel; (17) adverse impacts of government regulation; (18) governmental or regulatory changes or other actions; (19) failures to meet applicable capital requirements; (20) regulatory objections to Fifth Third’s capital plan; (21) regulation of Fifth Third’s derivatives activities; (22) deposit insurance premiums; (23) assessments for the orderly liquidation fund; (24) replacement of LIBOR; (25) weakness in the national or local economies; (26) global political and economic uncertainty or negative actions; (27) changes in interest rates; (28) changes and trends in capital markets; (29) fluctuation of Fifth Third’s stock price; (30) volatility in mortgage banking revenue; (31) litigation, investigations, and enforcement proceedings by governmental authorities; (32) breaches of contractual covenants, representations and warranties; (33) competition and changes in the financial services industry; (34) changing retail distribution strategies, customer preferences and behavior; (35) difficulties in identifying, acquiring or integrating suitable strategic partnerships, investments or acquisitions; (36) potential dilution from future acquisitions; (37) loss of income and/or difficulties encountered in the sale and separation of businesses, investments or other assets; (38) results of investments or acquired entities; (39) changes in accounting standards or interpretation or declines in the value of Fifth Third’s goodwill or other intangible assets; (40) inaccuracies or other failures from the use of models; (41) effects of critical accounting policies and judgments or the use of inaccurate estimates; (42) weather-related events, other natural disasters, or health emergencies; and (43) the impact of reputational risk created by these or other developments on such matters as business generation and retention, funding and liquidity.
You should refer to our periodic and current reports filed with the Securities and Exchange Commission, or “SEC,” for further information on other factors, which could cause actual results to be significantly different from those expressed or implied by these forward-looking statements.
# # #
Quarterly Financial Review for September 30, 2020
Table of Contents
| | | | | | | | | | | |
| | | |
| | | |
| Financial Highlights | 13-14 | |
| Consolidated Statements of Income | 15-16 | |
| Consolidated Balance Sheets | 17-18 | |
| Consolidated Statements of Changes in Equity | 19 | |
| Average Balance Sheet and Yield Analysis | 20-21 | |
| Summary of Loans and Leases | 22 | |
| Regulatory Capital | 23 | |
| Summary of Credit Loss Experience | 24 | |
| Asset Quality | 25 | |
| Regulation G Non-GAAP Reconciliation | 26-28 | |
| Segment Presentation | 29 | |
| | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | | | | | |
| Financial Highlights | | | | | % / bps | | | | % / bps |
| $ in millions, except per share data | | For the Three Months Ended | | | Change | | Year to Date | | Change |
| (unaudited) | | September | June | September | | | September | September | |
| | 2020 | 2020 | 2019 | Seq | Yr/Yr | 2020 | 2019 | Yr/Yr |
| Income Statement Data | | | | | | | | | |
| Net interest income | | $1,170 | $1,200 | $1,242 | (3%) | (6%) | $3,600 | $3,569 | 1% |
Net interest income (FTE)(a) | | 1,173 | 1,203 | 1,246 | (2%) | (6%) | 3,610 | 3,582 | 1% |
| Noninterest income | | 722 | 650 | 740 | 11% | (2%) | 2,043 | 2,501 | (18%) |
| Total revenue (FTE)(a) | 1,895 | 1,853 | 1,986 | 2% | (5%) | 5,653 | 6,083 | (7%) |
| Provision for (benefit from) credit losses | | (15) | 485 | 134 | NM | NM | 1,110 | 310 | 258% |
| Noninterest expense | | 1,161 | 1,121 | 1,159 | 4% | — | 3,482 | 3,499 | — |
| Net income | | 581 | 195 | 549 | 198% | 6% | 823 | 1,778 | (54%) |
| Net income available to common shareholders | | 562 | 163 | 530 | 245% | 6% | 754 | 1,718 | (56%) |
| | | | | | | | | |
| Earnings Per Share Data | | | | | | | | | |
| Net income allocated to common shareholders | | $560 | $162 | $526 | 246% | 6% | $751 | $1,702 | (56%) |
| Average common shares outstanding (in thousands): | | | | | | | | | |
| Basic | 715,102 | 714,767 | 726,716 | — | (2%) | 714,477 | 708,849 | 1% |
| Diluted | 718,894 | 717,572 | 736,086 | — | (2%) | 718,943 | 718,413 | — |
| Earnings per share, basic | | $0.78 | $0.23 | $0.72 | 239% | 8% | $1.05 | $2.40 | (56%) |
| Earnings per share, diluted | | 0.78 | 0.23 | 0.71 | 239% | 10% | 1.04 | 2.37 | (56%) |
| | | | | | | | | |
| Common Share Data | | | | | | | | | |
| Cash dividends per common share | | $0.27 | $0.27 | $0.24 | — | 13% | $0.81 | $0.70 | 16% |
| Book value per share | | 29.25 | 28.88 | 27.32 | 1% | 7% | 29.25 | 27.32 | 7% |
| Market price per share | | 21.32 | 19.28 | 27.38 | 11% | (22%) | 21.32 | 27.38 | (22%) |
| Common shares outstanding (in thousands) | | 712,328 | 712,202 | 718,583 | — | (1%) | 712,328 | 718,583 | (1%) |
| Market capitalization | | $15,187 | $13,731 | $19,675 | 11% | (23%) | $15,187 | $19,675 | (23%) |
| | | | | | | | | |
| Financial Ratios | | | | | | | | | |
| Return on average assets | | 1.14 | % | 0.40 | % | 1.28 | % | 74 | (14) | 0.58 | % | 1.47 | % | (89) |
| Return on average common equity | | 10.7 | % | 3.2 | % | 10.7 | % | 750 | — | 4.9 | % | 12.7 | % | (780) |
Return on average tangible common equity(a) | | 13.8 | % | 4.3 | % | 14.2 | % | 950 | (40) | 6.5 | % | 16.5 | % | (1,000) |
Noninterest income as a percent of total revenue(a) | | 38 | % | 35 | % | 37 | % | 300 | 100 | 36 | % | 41 | % | (500) |
| Dividend payout | | 34.6% | 117.4% | 33.3% | (8,280) | 130 | 77.1% | 29.2% | 4,790 |
| Average total Bancorp shareholders' equity as a percent of average assets | | 11.33 | % | 11.30 | % | 12.43 | % | 3 | (110) | 11.71 | % | 11.99 | % | (28) |
Tangible common equity(a) | | 6.99 | % | 6.77 | % | 8.21 | % | 22 | (122) | 6.99 | % | 8.21 | % | (122) |
Net interest margin (FTE)(a) | | 2.58 | % | 2.75 | % | 3.32 | % | (17) | (74) | 2.85 | % | 3.32 | % | (47) |
Efficiency (FTE)(a) | | 61.3 | % | 60.5 | % | 58.4 | % | 80 | 290 | 61.6 | % | 57.5 | % | 410 |
| Effective tax rate | | 22.1 | % | 19.9 | % | 20.2 | % | 220 | 190 | 21.6 | % | 21.4 | % | 20 |
| | | | | | | | | |
| Credit Quality | | | | | | | | | |
| Net losses charged-off | | $101 | $130 | $99 | (22 | %) | 2 | % | $353 | $256 | 38 | % |
| Net losses charged-off as a percent of average portfolio loans and leases | | 0.35 | % | 0.44 | % | 0.36 | % | (9) | (1) | 0.41 | % | 0.32 | % | 9 |
| ALLL as a percent of portfolio loans and leases | | 2.32 | % | 2.34 | % | 1.04 | % | (2) | 128 | 2.32 | % | 1.04 | % | 128 |
ACL as a percent of portfolio loans and leases(g) | | 2.49 | % | 2.50 | % | 1.19 | % | (1) | 130 | 2.49 | % | 1.19 | % | 130 |
| Nonperforming portfolio assets as a percent of portfolio loans and leases and OREO | | 0.84 | % | 0.65 | % | 0.47 | % | 19 | 37 | 0.84 | % | 0.47 | % | 37 |
| | | | | | | | | |
| Average Balances | | | | | | | | | |
| Loans and leases, including held for sale | | $114,613 | $119,418 | $110,666 | (4%) | 4% | $115,401 | $106,719 | 8% |
| Securities and other short-term investments | | 66,091 | 56,806 | 38,188 | 16% | 73% | 54,021 | 37,369 | 45% |
| Assets | | 202,533 | 198,387 | 169,585 | 2% | 19% | 190,973 | 162,119 | 18% |
Transaction deposits(b) | | 148,567 | 142,079 | 114,541 | 5% | 30% | 136,293 | 109,396 | 25% |
Core deposits(c) | | 152,278 | 146,500 | 120,364 | 4% | 27% | 140,695 | 114,853 | 23% |
Wholesale funding(d) | | 21,762 | 23,739 | 22,492 | (8%) | (3%) | 22,441 | 22,772 | (1%) |
| Bancorp shareholders' equity | | 22,952 | 22,420 | 21,087 | 2% | 9% | 22,364 | 19,430 | 15% |
| | | | | | | | | |
Regulatory Capital Ratios(e) | | | | | | | | | |
CET1 capital(f) | | 10.14 | % | 9.72 | % | 9.56 | % | 42 | 58 | 10.14 | % | 9.56 | % | 58 |
Tier I risk-based capital(f) | | 11.64 | % | 10.96 | % | 10.81 | % | 68 | 83 | 11.64 | % | 10.81 | % | 83 |
Total risk-based capital(f) | | 14.93 | % | 14.24 | % | 13.68 | % | 69 | 125 | 14.93 | % | 13.68 | % | 125 |
| Tier I leverage | | 8.37 | % | 8.16 | % | 9.36 | % | 21 | (99) | 8.37 | % | 9.36 | % | (99) |
| | | | | | | | | |
| Operations | | | | | | | | | |
| Banking centers | | 1,122 | 1,122 | 1,143 | — | (2%) | 1,122 | 1,143 | (2%) |
| ATMs | | 2,414 | 2,456 | 2,487 | (2%) | (3%) | 2,414 | 2,487 | (3%) |
| Full-time equivalent employees | | 20,283 | 20,340 | 19,478 | — | 4% | 20,283 | 19,478 | 4% |
(a)Non-GAAP measure; see discussion of non-GAAP and Reg. G reconciliation beginning on page 26.
(b)Includes demand, interest checking, savings, money market and foreign office deposits of commercial customers.
(c)Includes transaction deposits plus other time deposits.
(d)Includes certificates $100,000 and over, other deposits, federal funds purchased, other short-term borrowings and long-term debt.
(e)Current period regulatory capital ratios are estimates.
(f)Under the U.S. banking agencies' Basel III Final Rule, assets and credit equivalent amounts of off-balance sheet exposures are calculated according to the standardized approach for risk-weighted assets. The resulting values are added together resulting in the Bancorp’s total risk-weighted assets.
(g)The allowance for credit losses is the sum of the ALLL and the reserve for unfunded commitments.
| | | | | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | | |
| Financial Highlights | | | | | | |
| $ in millions, except per share data | | For the Three Months Ended | | | | |
| (unaudited) | | September | June | March | December | September |
| | 2020 | 2020 | 2020 | 2019 | 2019 |
| Income Statement Data | | | | | | |
| Net interest income | | $1,170 | $1,200 | $1,229 | $1,228 | $1,242 |
Net interest income (FTE)(a) | | 1,173 | 1,203 | 1,233 | 1,232 | 1,246 |
| Noninterest income | | 722 | 650 | 671 | 1,035 | 740 |
| Total revenue (FTE)(a) | 1,895 | 1,853 | 1,904 | 2,267 | 1,986 |
| (Benefit from) provision for credit losses | | (15) | 485 | 640 | 162 | 134 |
| Noninterest expense | | 1,161 | 1,121 | 1,200 | 1,160 | 1,159 |
| Net income | | 581 | 195 | 46 | 734 | 549 |
| Net income available to common shareholders | | 562 | 163 | 29 | 701 | 530 |
| | | | | | |
| Earnings Per Share Data | | | | | | |
| Net income allocated to common shareholders | | $560 | $162 | $28 | $696 | $526 |
| Average common shares outstanding (in thousands): | | | | | | |
| Basic | 715,102 | 714,767 | 713,556 | 715,137 | 726,716 |
| Diluted | 718,894 | 717,572 | 720,363 | 724,968 | 736,086 |
| Earnings per share, basic | | $0.78 | $0.23 | $0.04 | $0.97 | $0.72 |
| Earnings per share, diluted | | 0.78 | 0.23 | 0.04 | 0.96 | 0.71 |
| | | | | | |
| Common Share Data | | | | | | |
| Cash dividends per common share | | $0.27 | $0.27 | $0.27 | $0.24 | $0.24 |
| Book value per share | | 29.25 | 28.88 | 28.26 | 27.41 | 27.32 |
| Market value per share | | 21.32 | 19.28 | 14.85 | 30.74 | 27.38 |
| Common shares outstanding (in thousands) | | 712,328 | 712,202 | 711,306 | 708,916 | 718,583 |
| Market capitalization | | $15,187 | $13,731 | $10,563 | $21,792 | $19,675 |
| | | | | | |
| Financial Ratios | | | | | | |
| Return on average assets | | 1.14 | % | 0.40 | % | 0.11 | % | 1.72 | % | 1.28 | % |
| Return on average common equity | | 10.7 | % | 3.2 | % | 0.6 | % | 14.2 | % | 10.7 | % |
Return on average tangible common equity(a) | | 13.8 | % | 4.3 | % | 1.0 | % | 18.7 | % | 14.2 | % |
Noninterest income as a percent of total revenue(a) | | 38 | % | 35 | % | 35 | % | 46 | % | 37 | % |
| Dividend payout | | 34.6% | 117.4% | 675.0% | 24.7% | 33.3% |
| Average total Bancorp shareholders' equity as a percent of average assets | | 11.33 | % | 11.30 | % | 12.63 | % | 12.58 | % | 12.43 | % |
Tangible common equity(a) | | 6.99 | % | 6.77 | % | 7.41 | % | 8.44 | % | 8.21 | % |
Net interest margin (FTE)(a) | | 2.58 | % | 2.75 | % | 3.28 | % | 3.27 | % | 3.32 | % |
Efficiency (FTE)(a) | | 61.3 | % | 60.5 | % | 63.0 | % | 51.2 | % | 58.4 | % |
| Effective tax rate | | 22.1 | % | 19.9 | % | 22.6 | % | 22.0 | % | 20.2 | % |
| | | | | | |
| Credit Quality | | | | | | |
| Net losses charged-off | | $101 | $130 | $122 | $113 | $99 |
| Net losses charged-off as a percent of average portfolio loans and leases | | 0.35 | % | 0.44 | % | 0.44 | % | 0.41 | % | 0.36 | % |
| ALLL as a percent of portfolio loans and leases | | 2.32 | % | 2.34 | % | 1.99 | % | 1.10 | % | 1.04 | % |
ACL as a percent of portfolio loans and leases(g) | | 2.49 | % | 2.50 | % | 2.13 | % | 1.23 | % | 1.19 | % |
| Nonperforming portfolio assets as a percent of portfolio loans and leases and OREO | | 0.84 | % | 0.65 | % | 0.60 | % | 0.62 | % | 0.47 | % |
| | | | | | |
| Average Balances | | | | | | |
| Loans and leases, including held for sale | | $114,613 | $119,418 | $112,180 | $110,986 | $110,666 |
| Securities and other short-term investments | | 66,091 | 56,806 | 39,033 | 38,326 | 38,188 |
| Assets | | 202,533 | 198,387 | 171,871 | 169,327 | 169,585 |
Transaction deposits(b) | | 148,567 | 142,079 | 118,096 | 116,285 | 114,541 |
Core deposits(c) | | 152,278 | 146,500 | 123,177 | 121,792 | 120,364 |
Wholesale funding(d) | | 21,762 | 23,739 | 21,832 | 21,491 | 22,492 |
| Bancorp shareholders' equity | | 22,952 | 22,420 | 21,713 | 21,304 | 21,087 |
| | | | | | |
Regulatory Capital Ratios(e) | | | | | | |
CET1 capital(f) | | 10.14 | % | 9.72 | % | 9.37 | % | 9.75 | % | 9.56 | % |
Tier I risk-based capital(f) | | 11.64 | % | 10.96 | % | 10.56 | % | 10.99 | % | 10.81 | % |
Total risk-based capital(f) | | 14.93 | % | 14.24 | % | 13.59 | % | 13.84 | % | 13.68 | % |
| Tier I leverage | | 8.37 | % | 8.16 | % | 9.37 | % | 9.54 | % | 9.36 | % |
| | | | | | |
| Operations | | | | | | |
| Banking centers | | 1,122 | 1,122 | 1,123 | 1,149 | 1,143 |
| ATMs | | 2,414 | 2,456 | 2,464 | 2,481 | 2,487 |
| Full-time equivalent employees | | 20,283 | 20,340 | 20,182 | 19,869 | 19,478 |
(a)Non-GAAP measure; see discussion of non-GAAP and Reg. G reconciliation beginning on page 26.
(b)Includes demand, interest checking, savings, money market and foreign office deposits of commercial customers.
(c)Includes transaction deposits plus other time deposits.
(d)Includes certificates $100,000 and over, other deposits, federal funds purchased, other short-term borrowings and long-term debt.
(e)Current period regulatory capital ratios are estimates.
(f)Under the U.S. banking agencies' Basel III Final Rule, assets and credit equivalent amounts of off-balance sheet exposures are calculated according to the standardized approach for risk-weighted assets. The resulting values are added together resulting in the Bancorp’s total risk-weighted assets.
(g)The allowance for credit losses is the sum of the ALLL and the reserve for unfunded commitments.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | | | | | |
| Consolidated Statements of Income | | | | | | | | | |
| $ in millions | For the Three Months Ended | | | % Change | | | Year to Date | | % Change |
| (unaudited) | September | June | September | | | | September | September | |
| 2020 | 2020 | 2019 | Seq | Yr/Yr | | 2020 | 2019 | Yr/Yr |
| Interest Income | | | | | | | | | |
| Interest and fees on loans and leases | $1,047 | $1,115 | $1,320 | (6%) | (21%) | | $3,397 | $3,799 | (11%) |
| Interest on securities | 274 | 283 | 291 | (3%) | (6%) | | 840 | 862 | (3%) |
| Interest on other short-term investments | 8 | 5 | 14 | 60% | (43%) | | 20 | 33 | (39%) |
| Total interest income | 1,329 | 1,403 | 1,625 | (5%) | (18%) | | 4,257 | 4,694 | (9%) |
| | | | | | | | | |
| Interest Expense | | | | | | | | | |
| Interest on deposits | 46 | 83 | 243 | (45%) | (81%) | | 295 | 692 | (57%) |
| Interest on federal funds purchased | — | — | 4 | NM | (100%) | | 2 | 23 | (91%) |
| Interest on other short-term borrowings | 5 | 2 | 8 | 150% | (38%) | | 13 | 23 | (43%) |
| Interest on long-term debt | 108 | 118 | 128 | (8%) | (16%) | | 347 | 387 | (10%) |
| Total interest expense | 159 | 203 | 383 | (22%) | (58%) | | 657 | 1,125 | (42%) |
| | | | | | | | | |
| Net Interest Income | 1,170 | 1,200 | 1,242 | (3%) | (6%) | | 3,600 | 3,569 | 1% |
| | | | | | | | | |
| Provision for (benefit from) credit losses | (15) | 485 | 134 | NM | NM | | 1,110 | 310 | 258% |
| Net Interest Income After Provision for Credit Losses | 1,185 | 715 | 1,108 | 66% | 7% | | 2,490 | 3,259 | (24%) |
| | | | | | | | | |
| Noninterest Income | | | | | | | | | |
| Service charges on deposits | 144 | 122 | 143 | 18% | 1% | | 414 | 417 | (1%) |
| Commercial banking revenue | 125 | 137 | 123 | (9%) | 2% | | 387 | 333 | 16% |
| Mortgage banking net revenue | 76 | 99 | 95 | (23%) | (20%) | | 295 | 214 | 38% |
| Wealth and asset management revenue | 132 | 120 | 124 | 10% | 6% | | 387 | 358 | 8% |
| Card and processing revenue | 92 | 82 | 94 | 12% | (2%) | | 260 | 266 | (2%) |
| Leasing business revenue | 77 | 57 | 92 | 35% | (16%) | | 207 | 199 | 4% |
| Other noninterest income | 26 | 12 | 64 | 117% | (59%) | | 42 | 679 | (94%) |
| Securities gains, net | 51 | 21 | 5 | 143% | 920% | | 48 | 30 | 60% |
| Securities gains (losses), net - non-qualifying hedges on mortgage servicing rights | (1) | — | — | NM | NM | | 3 | 5 | (40%) |
| Total noninterest income | 722 | 650 | 740 | 11% | (2%) | | 2,043 | 2,501 | (18%) |
| | | | | | | | | |
| Noninterest Expense | | | | | | | | | |
| Compensation and benefits | 637 | 627 | 584 | 2% | 9% | | 1,911 | 1,843 | 4% |
| Net occupancy expense | 90 | 82 | 84 | 10% | 7% | | 254 | 248 | 2% |
| Technology and communications | 89 | 90 | 100 | (1%) | (11%) | | 272 | 319 | (15%) |
| Equipment expense | 33 | 32 | 33 | 3% | — | | 97 | 96 | 1% |
| Card and processing expense | 29 | 29 | 33 | — | (12%) | | 89 | 98 | (9%) |
| Leasing business expense | 35 | 33 | 40 | 6% | (13%) | | 103 | 97 | 6% |
| Marketing expense | 23 | 20 | 40 | 15% | (43%) | | 74 | 117 | (37%) |
| Other noninterest expense | 225 | 208 | 245 | 8% | (8%) | | 682 | 681 | — |
| Total noninterest expense | 1,161 | 1,121 | 1,159 | 4% | — | | 3,482 | 3,499 | — |
| Income Before Income Taxes | 746 | 244 | 689 | 206% | 8% | | 1,051 | 2,261 | (54%) |
| Applicable income tax expense | 165 | 49 | 140 | 237% | 18% | | 228 | 483 | (53%) |
| Net Income | 581 | 195 | 549 | 198% | 6% | | 823 | 1,778 | (54%) |
| Dividends on preferred stock | 19 | 32 | 19 | (41%) | — | | 69 | 60 | 15% |
| Net Income Available to Common Shareholders | $562 | $163 | $530 | 245% | 6% | | $754 | $1,718 | (56%) |
| | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | |
| Consolidated Statements of Income | | | | | |
| $ in millions | For the Three Months Ended | | | | |
| (unaudited) | September | June | March | December | September |
| 2020 | 2020 | 2020 | 2019 | 2019 |
| Interest Income | | | | | |
| Interest and fees on loans and leases | $1,047 | $1,115 | $1,235 | $1,252 | $1,320 |
| Interest on securities | 274 | 283 | 283 | 299 | 291 |
| Interest on other short-term investments | 8 | 5 | 7 | 8 | 14 |
| Total interest income | 1,329 | 1,403 | 1,525 | 1,559 | 1,625 |
| | | | | |
| Interest Expense | | | | | |
| Interest on deposits | 46 | 83 | 166 | 201 | 243 |
| Interest on federal funds purchased | — | — | 2 | 5 | 4 |
| Interest on other short-term borrowings | 5 | 2 | 6 | 5 | 8 |
| Interest on long-term debt | 108 | 118 | 122 | 120 | 128 |
| Total interest expense | 159 | 203 | 296 | 331 | 383 |
| | | | | |
| Net Interest Income | 1,170 | 1,200 | 1,229 | 1,228 | 1,242 |
| | | | | |
| (Benefit from) provision for credit losses | (15) | 485 | 640 | 162 | 134 |
| Net Interest Income After Provision for Credit Losses | 1,185 | 715 | 589 | 1,066 | 1,108 |
| | | | | |
| Noninterest Income | | | | | |
| Service charges on deposits | 144 | 122 | 148 | 149 | 143 |
| Commercial banking revenue | 125 | 137 | 124 | 127 | 123 |
| Mortgage banking net revenue | 76 | 99 | 120 | 73 | 95 |
| Wealth and asset management revenue | 132 | 120 | 134 | 129 | 124 |
| Card and processing revenue | 92 | 82 | 86 | 95 | 94 |
| Leasing business revenue | 77 | 57 | 73 | 71 | 92 |
| Other noninterest income | 26 | 12 | 7 | 382 | 64 |
| Securities gains (losses), net | 51 | 21 | (24) | 10 | 5 |
| Securities (losses) gains, net - non-qualifying hedges on mortgage servicing rights | (1) | — | 3 | (1) | — |
| Total noninterest income | 722 | 650 | 671 | 1,035 | 740 |
| | | | | |
| Noninterest Expense | | | | | |
| Compensation and benefits | 637 | 627 | 647 | 576 | 584 |
| Net occupancy expense | 90 | 82 | 82 | 84 | 84 |
| Technology and communications | 89 | 90 | 93 | 103 | 100 |
| Equipment expense | 33 | 32 | 32 | 33 | 33 |
| Card and processing expense | 29 | 29 | 31 | 33 | 33 |
| Leasing business expense | 35 | 33 | 35 | 36 | 40 |
| Marketing expense | 23 | 20 | 31 | 44 | 40 |
| Other noninterest expense | 225 | 208 | 249 | 251 | 245 |
| Total noninterest expense | 1,161 | 1,121 | 1,200 | 1,160 | 1,159 |
| Income Before Income Taxes | 746 | 244 | 60 | 941 | 689 |
| Applicable income tax expense | 165 | 49 | 14 | 207 | 140 |
| Net Income | 581 | 195 | 46 | 734 | 549 |
| Dividends on preferred stock | 19 | 32 | 17 | 33 | 19 |
| Net Income Available to Common Shareholders | $562 | $163 | $29 | $701 | $530 |
| | | | | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | | |
| Consolidated Balance Sheets | | | | | | |
| $ in millions, except per share data | As of | | | % Change | | |
| (unaudited) | September | June | September | | | |
| 2020 | 2020 | 2019 | Seq | Yr/Yr | |
| Assets | | | | | | |
| Cash and due from banks | $2,996 | $3,221 | $3,261 | (7%) | (8%) | |
| Other short-term investments | 31,285 | 28,243 | 3,235 | 11% | 867% | |
Available-for-sale debt and other securities(a) | 37,425 | 38,599 | 37,178 | (3%) | 1% | |
Held-to-maturity securities(b) | 15 | 16 | 18 | (6%) | (17%) | |
| Trading debt securities | 704 | 526 | 297 | 34% | 137% | |
| Equity securities | 277 | 273 | 459 | 1% | (40%) | |
| Loans and leases held for sale | 2,323 | 912 | 1,223 | 155% | 90% | |
| Portfolio loans and leases: | | | | | | |
| Commercial and industrial loans | 51,695 | 55,661 | 50,768 | (7%) | 2% | |
| Commercial mortgage loans | 10,878 | 11,233 | 10,822 | (3%) | 1% | |
| Commercial construction loans | 5,656 | 5,479 | 5,281 | 3% | 7% | |
| Commercial leases | 3,021 | 3,061 | 3,495 | (1%) | (14%) | |
| Total commercial loans and leases | 71,250 | 75,434 | 70,366 | (6%) | 1% | |
| Residential mortgage loans | 16,158 | 16,457 | 16,675 | (2%) | (3%) | |
| Home equity | 5,455 | 5,681 | 6,218 | (4%) | (12%) | |
| Indirect secured consumer loans | 12,925 | 12,395 | 11,026 | 4% | 17% | |
| Credit card | 2,087 | 2,211 | 2,467 | (6%) | (15%) | |
| Other consumer loans | 2,856 | 2,875 | 2,657 | (1%) | 7% | |
| Total consumer loans | 39,481 | 39,619 | 39,043 | — | 1% | |
| Portfolio loans and leases | 110,731 | 115,053 | 109,409 | (4%) | 1% | |
| Allowance for loan and lease losses | (2,574) | (2,696) | (1,143) | (5%) | 125% | |
| Portfolio loans and leases, net | 108,157 | 112,357 | 108,266 | (4%) | — | |
| Bank premises and equipment | 2,090 | 2,053 | 2,053 | 2% | 2% | |
| Operating lease equipment | 818 | 809 | 869 | 1% | (6%) | |
| Goodwill | 4,261 | 4,261 | 4,290 | — | (1%) | |
| Intangible assets | 157 | 171 | 201 | (8%) | (22%) | |
| Servicing rights | 660 | 676 | 910 | (2%) | (27%) | |
| Other assets | 10,828 | 10,789 | 8,819 | — | 23% | |
| Total Assets | $201,996 | $202,906 | $171,079 | — | 18% | |
| | | | | | |
| Liabilities | | | | | | |
| Deposits: | | | | | | |
| Demand | $51,896 | $49,359 | $35,893 | 5% | 45% | |
| Interest checking | 49,566 | 51,586 | 36,965 | (4%) | 34% | |
| Savings | 17,221 | 16,896 | 14,354 | 2% | 20% | |
| Money market | 31,192 | 30,881 | 27,370 | 1% | 14% | |
| Foreign office | 160 | 191 | 226 | (16%) | (29%) | |
| Other time | 3,337 | 3,913 | 5,662 | (15%) | (41%) | |
| Certificates $100,000 and over | 3,311 | 4,120 | 4,377 | (20%) | (24%) | |
| Other deposits | — | — | 500 | NM | (100%) | |
| Total deposits | 156,683 | 156,946 | 125,347 | — | 25% | |
| Federal funds purchased | 251 | 262 | 876 | (4%) | (71%) | |
| Other short-term borrowings | 1,196 | 1,285 | 4,046 | (7%) | (70%) | |
| Accrued taxes, interest and expenses | 2,500 | 2,582 | 2,507 | (3%) | — | |
| Other liabilities | 3,292 | 3,169 | 2,425 | 4% | 36% | |
| Long-term debt | 15,123 | 16,327 | 14,474 | (7%) | 4% | |
| Total Liabilities | 179,045 | 180,571 | 149,675 | (1%) | 20% | |
| Equity | | | | | | |
Common stock(c) | 2,051 | 2,051 | 2,051 | — | — | |
| Preferred stock | 2,116 | 1,770 | 1,770 | 20% | 20% | |
| Capital surplus | 3,624 | 3,603 | 3,589 | 1% | 1% | |
| Retained earnings | 18,010 | 17,643 | 17,786 | 2% | 1% | |
| Accumulated other comprehensive income | 2,831 | 2,951 | 1,635 | (4%) | 73% | |
| Treasury stock | (5,681) | (5,683) | (5,427) | — | 5% | |
| Total Equity | 22,951 | 22,335 | 21,404 | 3% | 7% | |
| Total Liabilities and Equity | 201,996 | 202,906 | 171,079 | — | 18% | |
| (a) Amortized cost | 34,693 | 35,780 | 35,662 | (3%) | (3%) | |
| (b) Market values | 15 | | 16 | | 18 | | (6%) | (17%) | |
| (c) Common shares, stated value $2.22 per share (in thousands): | | | | | | |
| Authorized | 2,000,000 | 2,000,000 | 2,000,000 | — | | — | | |
| Outstanding, excluding treasury | 712,328 | 712,202 | 718,583 | — | | (1 | %) | |
| Treasury | 211,565 | 211,690 | 205,309 | — | | 3 | % | |
| | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | |
| Consolidated Balance Sheets | | | | | |
| $ in millions, except per share data | As of | | | | |
| (unaudited) | September | June | March | December | September |
| 2020 | 2020 | 2020 | 2019 | 2019 |
| Assets | | | | | |
| Cash and due from banks | $2,996 | $3,221 | $3,282 | $3,278 | $3,261 |
| Other short-term investments | 31,285 | 28,243 | 6,319 | 1,950 | 3,235 |
Available-for-sale debt and other securities(a) | 37,425 | 38,599 | 38,645 | 36,028 | 37,178 |
Held-to-maturity securities(b) | 15 | 16 | 17 | 17 | 18 |
| Trading debt securities | 704 | 526 | 433 | 297 | 297 |
| Equity securities | 277 | 273 | 459 | 564 | 459 |
| Loans and leases held for sale | 2,323 | 912 | 1,630 | 1,400 | 1,223 |
| Portfolio loans and leases: | | | | | |
| Commercial and industrial loans | 51,695 | 55,661 | 58,250 | 50,542 | 50,768 |
| Commercial mortgage loans | 10,878 | 11,233 | 11,160 | 10,963 | 10,822 |
| Commercial construction loans | 5,656 | 5,479 | 5,462 | 5,090 | 5,281 |
| Commercial leases | 3,021 | 3,061 | 3,123 | 3,363 | 3,495 |
| Total commercial loans and leases | 71,250 | 75,434 | 77,995 | 69,958 | 70,366 |
| Residential mortgage loans | 16,158 | 16,457 | 16,701 | 16,724 | 16,675 |
| Home equity | 5,455 | 5,681 | 5,963 | 6,083 | 6,218 |
| Indirect secured consumer loans | 12,925 | 12,395 | 12,050 | 11,538 | 11,026 |
| Credit card | 2,087 | 2,211 | 2,417 | 2,532 | 2,467 |
| Other consumer loans | 2,856 | 2,875 | 2,911 | 2,723 | 2,657 |
| Total consumer loans | 39,481 | 39,619 | 40,042 | 39,600 | 39,043 |
| Portfolio loans and leases | 110,731 | 115,053 | 118,037 | 109,558 | 109,409 |
| Allowance for loan and lease losses | (2,574) | (2,696) | (2,348) | (1,202) | (1,143) |
| Portfolio loans and leases, net | 108,157 | 112,357 | 115,689 | 108,356 | 108,266 |
| Bank premises and equipment | 2,090 | 2,053 | 2,009 | 1,995 | 2,053 |
| Operating lease equipment | 818 | 809 | 819 | 848 | 869 |
| Goodwill | 4,261 | 4,261 | 4,261 | 4,252 | 4,290 |
| Intangible assets | 157 | 171 | 184 | 201 | 201 |
| Servicing rights | 660 | 676 | 685 | 993 | 910 |
| Other assets | 10,828 | 10,789 | 10,959 | 9,190 | 8,819 |
| Total Assets | $201,996 | $202,906 | $185,391 | $169,369 | $171,079 |
| | | | | |
| Liabilities | | | | | |
| Deposits: | | | | | |
| Demand | $51,896 | $49,359 | $39,533 | $35,968 | $35,893 |
| Interest checking | 49,566 | 51,586 | 44,520 | 40,409 | 36,965 |
| Savings | 17,221 | 16,896 | 15,557 | 14,248 | 14,354 |
| Money market | 31,192 | 30,881 | 27,775 | 27,277 | 27,370 |
| Foreign office | 160 | 191 | 177 | 221 | 226 |
| Other time | 3,337 | 3,913 | 4,683 | 5,237 | 5,662 |
| Certificates $100,000 and over | 3,311 | 4,120 | 2,816 | 3,702 | 4,377 |
| Other deposits | — | — | — | — | 500 |
| Total deposits | 156,683 | 156,946 | 135,061 | 127,062 | 125,347 |
| Federal funds purchased | 251 | 262 | 1,625 | 260 | 876 |
| Other short-term borrowings | 1,196 | 1,285 | 4,542 | 1,011 | 4,046 |
| Accrued taxes, interest and expenses | 2,500 | 2,582 | 2,432 | 2,441 | 2,507 |
| Other liabilities | 3,292 | 3,169 | 3,576 | 2,422 | 2,425 |
| Long-term debt | 15,123 | 16,327 | 16,282 | 14,970 | 14,474 |
| Total Liabilities | 179,045 | 180,571 | 163,518 | 148,166 | 149,675 |
| Equity | | | | | |
Common stock(c) | 2,051 | 2,051 | 2,051 | 2,051 | 2,051 |
| Preferred stock | 2,116 | 1,770 | 1,770 | 1,770 | 1,770 |
| Capital surplus | 3,624 | 3,603 | 3,597 | 3,599 | 3,589 |
| Retained earnings | 18,010 | 17,643 | 17,677 | 18,315 | 17,786 |
| Accumulated other comprehensive income | 2,831 | 2,951 | 2,477 | 1,192 | 1,635 |
| Treasury stock | (5,681) | (5,683) | (5,699) | (5,724) | (5,427) |
| Total Equity | 22,951 | 22,335 | 21,873 | 21,203 | 21,404 |
| Total Liabilities and Equity | $201,996 | $202,906 | $185,391 | $169,369 | $171,079 |
| (a) Amortized cost | $34,693 | $35,780 | $36,428 | $34,966 | $35,662 |
| (b) Market values | 15 | 16 | 17 | 17 | 18 |
| (c) Common shares, stated value $2.22 per share (in thousands): | | | | | |
| Authorized | 2,000,000 | 2,000,000 | 2,000,000 | 2,000,000 | 2,000,000 |
| Outstanding, excluding treasury | 712,328 | 712,202 | 711,306 | 708,916 | 718,583 |
| Treasury | 211,565 | 211,690 | 212,586 | 214,977 | 205,309 |
| | | | | | | | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | | | |
| Consolidated Statements of Changes in Equity | | | | | | | |
| $ in millions | | | | | | | |
| (unaudited) | | | | | | | |
| | | For the Three Months Ended | | | Year to Date | |
| | | September | September | | September | September |
| | | 2020 | 2019 | | 2020 | 2019 |
| Total Equity, Beginning | | | $22,335 | $20,671 | | $21,203 | $16,250 |
| Net income | | | 581 | 549 | | 823 | 1,778 |
| Other comprehensive income, net of tax: | | | | | | | |
| Change in unrealized gains (losses): | | | | | | |
| | Available-for-sale debt securities | (66) | 377 | | 1,272 | 1,385 |
| | Qualifying cash flow hedges | (55) | 79 | | 364 | 359 |
| Change in accumulated other comprehensive income related to employee benefit plans | | 1 | 1 | | 3 | 3 |
| Comprehensive income | | | 461 | 1,006 | | 2,462 | 3,525 |
| Cash dividends declared: | | | | | | | |
| Common stock | | (195) | (175) | | (585) | (518) |
| Preferred stock | | (19) | (19) | | (69) | (60) |
| Issuance of preferred stock | | | 346 | 439 | | 346 | 439 |
| Impact of stock transactions under stock compensation plans, net | | | 23 | 24 | | 66 | 59 |
| Shares acquired for treasury | | | — | (350) | | — | (1,463) |
| Impact of acquisition | | | — | — | | — | 3,159 |
| Noncontrolling interest | | | — | (197) | | — | — |
| Other | | | — | 5 | | — | 3 |
| Impact of cumulative effect of change in accounting principles | | | — | — | | (472) | 10 |
| Total Equity, Ending | | | $22,951 | $21,404 | | $22,951 | $21,404 |
| | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | | | | |
| Average Balance Sheet and Yield/Rate Analysis | | | | | | | | |
| $ in millions | For the Three Months Ended | | | % Change | | Year to Date | | % Change |
| (unaudited) | September | June | September | | | September | September | |
| 2020 | 2020 | 2019 | Seq | Yr/Yr | 2020 | 2019 | Yr/Yr |
| Assets | | | | | | | | |
| Interest-earning assets: | | | | | | | | |
| Commercial and industrial loans | $54,056 | $59,106 | $51,364 | (9%) | 5% | $54,948 | $49,895 | 10% |
| Commercial mortgage loans | 11,071 | 11,224 | 10,695 | (1%) | 4% | 11,105 | 9,593 | 16% |
| Commercial construction loans | 5,534 | 5,548 | 5,267 | — | 5% | 5,405 | 5,119 | 6% |
| Commercial leases | 2,966 | 3,056 | 3,563 | (3%) | (17%) | 3,074 | 3,643 | (16%) |
| Total commercial loans and leases | 73,627 | 78,934 | 70,889 | (7%) | 4% | 74,532 | 68,250 | 9% |
| Residential mortgage loans | 17,814 | 17,405 | 17,733 | 2% | — | 17,748 | 17,163 | 3% |
| Home equity | 5,581 | 5,820 | 6,267 | (4%) | (11%) | 5,802 | 6,333 | (8%) |
| Indirect secured consumer loans | 12,599 | 12,124 | 10,707 | 4% | 18% | 12,179 | 10,030 | 21% |
| Credit card | 2,134 | 2,248 | 2,448 | (5%) | (13%) | 2,293 | 2,418 | (5%) |
| Other consumer loans | 2,858 | 2,887 | 2,622 | (1%) | 9% | 2,847 | 2,525 | 13% |
| Total consumer loans | 40,986 | 40,484 | 39,777 | 1% | 3% | 40,869 | 38,469 | 6% |
| Taxable securities | 36,147 | 36,817 | 35,653 | (2%) | 1% | 36,312 | 35,151 | 3% |
| Tax exempt securities | 153 | 156 | 38 | (2%) | 303% | 157 | 35 | 349% |
| Other short-term investments | 29,791 | 19,833 | 2,497 | 50% | 1,093% | 17,552 | 2,183 | 704% |
| Total interest-earning assets | 180,704 | 176,224 | 148,854 | 3% | 21% | 169,422 | 144,088 | 18% |
| Cash and due from banks | 2,944 | 3,121 | 2,769 | (6%) | 6% | 2,981 | 2,641 | 13% |
| Other assets | 21,583 | 21,394 | 19,077 | 1% | 13% | 20,870 | 16,501 | 26% |
| Allowance for loan and lease losses | (2,698) | (2,352) | (1,115) | 15% | 142% | (2,300) | (1,111) | 107% |
| Total Assets | $202,533 | $198,387 | $169,585 | 2% | 19% | $190,973 | $162,119 | 18% |
| | | | | | | | |
| Liabilities | | | | | | | | |
| Interest-bearing liabilities: | | | | | | | | |
| Interest checking deposits | $49,800 | $49,760 | $37,729 | — | 32% | $46,631 | $35,995 | 30% |
| Savings deposits | 17,013 | 16,354 | 14,405 | 4% | 18% | 16,031 | 13,963 | 15% |
| Money market deposits | 31,151 | 30,022 | 26,962 | 4% | 16% | 29,434 | 25,357 | 16% |
| Foreign office deposits | 189 | 182 | 222 | 4% | (15%) | 193 | 198 | (3%) |
| Other time deposits | 3,711 | 4,421 | 5,823 | (16%) | (36%) | 4,402 | 5,457 | (19%) |
| Total interest-bearing core deposits | 101,864 | 100,739 | 85,141 | 1% | 20% | 96,691 | 80,970 | 19% |
| Certificates $100,000 and over | 3,633 | 4,067 | 4,795 | (11%) | (24%) | 3,685 | 4,650 | (21%) |
| Other deposits | — | 31 | 47 | (100%) | (100%) | 95 | 269 | (65%) |
| Federal funds purchased | 273 | 309 | 739 | (12%) | (63%) | 412 | 1,298 | (68%) |
| Other short-term borrowings | 1,626 | 2,377 | 1,278 | (32%) | 27% | 1,916 | 1,017 | 88% |
| Long-term debt | 16,230 | 16,955 | 15,633 | (4%) | 4% | 16,333 | 15,538 | 5% |
| Total interest-bearing liabilities | 123,626 | 124,478 | 107,633 | (1%) | 15% | 119,132 | 103,742 | 15% |
| Demand deposits | 50,414 | 45,761 | 35,223 | 10% | 43% | 44,004 | 33,883 | 30% |
| Other liabilities | 5,541 | 5,727 | 5,522 | (3%) | — | 5,473 | 4,950 | 11% |
| Total Liabilities | 179,581 | 175,966 | 148,378 | 2% | 21% | 168,609 | 142,575 | 18% |
| Total Equity | 22,952 | 22,421 | 21,207 | 2% | 8% | 22,364 | 19,544 | 14% |
| Total Liabilities and Equity | $202,533 | $198,387 | $169,585 | 2% | 19% | $190,973 | $162,119 | 18% |
| | | | | | | | |
| For the Three Months Ended | | | bps Change | | Year to Date | | bps Change |
| September | June | September | | | September | September | |
| Yield/Rate Analysis | 2020 | 2020 | 2019 | Seq | Yr/Yr | 2020 | 2019 | Yr/Yr |
| Interest-earning assets: | | | | | | | | |
Commercial and industrial loans(a) | 3.35 | % | 3.47 | % | 4.66 | % | (12) | | (131) | | 3.67 | % | 4.71 | % | (104) | |
Commercial mortgage loans(a) | 3.12 | % | 3.44 | % | 4.86 | % | (32) | | (174) | | 3.66 | % | 4.94 | % | (128) | |
Commercial construction loans(a) | 3.18 | % | 3.53 | % | 5.39 | % | (35) | | (221) | | 3.82 | % | 5.55 | % | (173) | |
Commercial leases(a) | 3.44 | % | 3.47 | % | 3.34 | % | (3) | | 10 | | 3.46 | % | 3.31 | % | 15 | |
| Total commercial loans and leases | 3.30 | % | 3.47 | % | 4.68 | % | (17) | | (138) | | 3.67 | % | 4.73 | % | (106) | |
| Residential mortgage loans | 3.48 | % | 3.53 | % | 3.67 | % | (5) | | (19) | | 3.55 | % | 3.69 | % | (14) | |
| Home equity | 3.59 | % | 3.60 | % | 5.20 | % | (1) | | (161) | | 3.98 | % | 5.28 | % | (130) | |
| Indirect secured consumer loans | 3.93 | % | 4.04 | % | 4.22 | % | (11) | | (29) | | 4.02 | % | 4.05 | % | (3) | |
| Credit card | 11.37 | % | 11.28 | % | 12.57 | % | 9 | | (120) | | 11.61 | % | 12.52 | % | (91) | |
| Other consumer loans | 6.46 | % | 6.50 | % | 7.69 | % | (4) | | (123) | | 6.88 | % | 7.59 | % | (71) | |
| Total consumer loans | 4.25 | % | 4.34 | % | 4.87 | % | (9) | | (62) | | 4.43 | % | 4.86 | % | (43) | |
| Total loans and leases | 3.64 | % | 3.76 | % | 4.75 | % | (12) | | (111) | | 3.94 | % | 4.78 | % | (84) | |
| Taxable securities | 3.01 | % | 3.08 | % | 3.24 | % | (7) | | (23) | | 3.08 | % | 3.28 | % | (20) | |
Tax exempt securities(a) | 2.99 | % | 2.96 | % | 3.18 | % | 3 | | (19) | | 3.00 | % | 3.72 | % | (72) | |
| Other short-term investments | 0.10 | % | 0.11 | % | 2.18 | % | (1) | | (208) | | 0.15 | % | 1.99 | % | (184) | |
| Total interest-earning assets | 2.93 | % | 3.21 | % | 4.34 | % | (28) | | (141) | | 3.36 | % | 4.37 | % | (101) | |
| | | | | | | | |
| Interest-bearing liabilities: | | | | | | | | |
| Interest checking deposits | 0.10 | % | 0.24 | % | 1.12 | % | (14) | | (102) | | 0.33 | % | 1.15 | % | (82) | |
| Savings deposits | 0.04 | % | 0.06 | % | 0.18 | % | (2) | | (14) | | 0.07 | % | 0.17 | % | (10) | |
| Money market deposits | 0.14 | % | 0.32 | % | 1.13 | % | (18) | | (99) | | 0.38 | % | 1.11 | % | (73) | |
| Foreign office deposits | 0.06 | % | 0.09 | % | 0.37 | % | (3) | | (31) | | 0.25 | % | 0.49 | % | (24) | |
| Other time deposits | 0.95 | % | 1.21 | % | 1.79 | % | (26) | | (84) | | 1.27 | % | 1.81 | % | (54) | |
| Total interest-bearing core deposits | 0.13 | % | 0.27 | % | 1.01 | % | (14) | | (88) | | 0.35 | % | 1.01 | % | (66) | |
| Certificates $100,000 and over | 1.26 | % | 1.40 | % | 2.20 | % | (14) | | (94) | | 1.56 | % | 2.14 | % | (58) | |
| Other deposits | — | | 0.04 | % | 1.97 | % | (4) | | (197) | | 0.76 | % | 2.43 | % | (167) | |
| Federal funds purchased | 0.20 | % | 0.16 | % | 2.06 | % | 4 | | (186) | | 0.68 | % | 2.42 | % | (174) | |
| Other short-term borrowings | 1.28 | % | 0.32 | % | 2.55 | % | 96 | | (127) | | 0.90 | % | 2.97 | % | (207) | |
| Long-term debt | 2.62 | % | 2.80 | % | 3.26 | % | (18) | | (64) | | 2.84 | % | 3.33 | % | (49) | |
| Total interest-bearing liabilities | 0.51 | % | 0.66 | % | 1.41 | % | (15) | | (90) | | 0.74 | % | 1.45 | % | (71) | |
| (a) Presented on an FTE basis. | | | | | | | | |
| | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | |
| Average Balance Sheet and Yield/Rate Analysis | | | | | |
| $ in millions | For the Three Months Ended | | | | |
| (unaudited) | September | June | March | December | September |
| 2020 | 2020 | 2020 | 2019 | 2019 |
| Assets | | | | | |
| Interest-earning assets: | | | | | |
| Commercial and industrial loans | $54,056 | $59,106 | $51,693 | $50,980 | $51,364 |
| Commercial mortgage loans | 11,071 | 11,224 | 11,020 | 10,832 | 10,695 |
| Commercial construction loans | 5,534 | 5,548 | 5,132 | 5,334 | 5,267 |
| Commercial leases | 2,966 | 3,056 | 3,201 | 3,384 | 3,563 |
| Total commercial loans and leases | 73,627 | 78,934 | 71,046 | 70,530 | 70,889 |
| Residential mortgage loans | 17,814 | 17,405 | 18,024 | 17,853 | 17,733 |
| Home equity | 5,581 | 5,820 | 6,006 | 6,147 | 6,267 |
| Indirect secured consumer loans | 12,599 | 12,124 | 11,809 | 11,281 | 10,707 |
| Credit card | 2,134 | 2,248 | 2,498 | 2,496 | 2,448 |
| Other consumer loans | 2,858 | 2,887 | 2,797 | 2,679 | 2,622 |
| Total consumer loans | 40,986 | 40,484 | 41,134 | 40,456 | 39,777 |
| Taxable securities | 36,147 | 36,817 | 35,973 | 36,255 | 35,653 |
| Tax exempt securities | 153 | 156 | 162 | 57 | 38 |
| Other short-term investments | 29,791 | 19,833 | 2,898 | 2,014 | 2,497 |
| Total interest-earning assets | 180,704 | 176,224 | 151,213 | 149,312 | 148,854 |
| Cash and due from banks | 2,944 | 3,121 | 2,880 | 3,063 | 2,769 |
| Other assets | 21,583 | 21,394 | 19,623 | 18,096 | 19,077 |
| Allowance for loan and lease losses | (2,698) | (2,352) | (1,845) | (1,144) | (1,115) |
| Total Assets | $202,533 | $198,387 | $171,871 | $169,327 | $169,585 |
| Liabilities | | | | | |
| Interest-bearing liabilities: | | | | | |
| Interest checking deposits | $49,800 | $49,760 | $40,298 | $38,628 | $37,729 |
| Savings deposits | 17,013 | 16,354 | 14,715 | 14,274 | 14,405 |
| Money market deposits | 31,151 | 30,022 | 27,109 | 27,429 | 26,962 |
| Foreign office deposits | 189 | 182 | 209 | 244 | 222 |
| Other time deposits | 3,711 | 4,421 | 5,081 | 5,507 | 5,823 |
| Total interest-bearing core deposits | 101,864 | 100,739 | 87,412 | 86,082 | 85,141 |
| Certificates $100,000 and over | 3,633 | 4,067 | 3,355 | 4,072 | 4,795 |
| Other deposits | — | 31 | 257 | 252 | 47 |
| Federal funds purchased | 273 | 309 | 654 | 1,174 | 739 |
| Other short-term borrowings | 1,626 | 2,377 | 1,750 | 1,133 | 1,278 |
| Long-term debt | 16,230 | 16,955 | 15,816 | 14,860 | 15,633 |
| Total interest-bearing liabilities | 123,626 | 124,478 | 109,244 | 107,573 | 107,633 |
| Demand deposits | 50,414 | 45,761 | 35,765 | 35,710 | 35,223 |
| Other liabilities | 5,541 | 5,727 | 5,149 | 4,740 | 5,522 |
| Total Liabilities | 179,581 | 175,966 | 150,158 | 148,023 | 148,378 |
| Total Equity | 22,952 | 22,421 | 21,713 | 21,304 | 21,207 |
| Total Liabilities and Equity | $202,533 | $198,387 | $171,871 | $169,327 | $169,585 |
| Yield/Rate Analysis | | | | | |
| Interest-earning assets: | | | | | |
Commercial and industrial loans(a) | 3.35 | % | 3.47 | % | 4.25 | % | 4.32 | % | 4.66 | % |
Commercial mortgage loans(a) | 3.12 | % | 3.44 | % | 4.44 | % | 4.48 | % | 4.86 | % |
Commercial construction loans(a) | 3.18 | % | 3.53 | % | 4.82 | % | 4.88 | % | 5.39 | % |
Commercial leases(a) | 3.44 | % | 3.47 | % | 3.46 | % | 3.30 | % | 3.34 | % |
| Total commercial loans and leases | 3.30 | % | 3.47 | % | 4.28 | % | 4.34 | % | 4.68 | % |
| Residential mortgage loans | 3.48 | % | 3.53 | % | 3.63 | % | 3.57 | % | 3.67 | % |
| Home equity | 3.59 | % | 3.60 | % | 4.71 | % | 4.80 | % | 5.20 | % |
| Indirect secured consumer loans | 3.93 | % | 4.04 | % | 4.09 | % | 4.16 | % | 4.22 | % |
| Credit card | 11.37 | % | 11.28 | % | 12.13 | % | 12.37 | % | 12.57 | % |
| Other consumer loans | 6.46 | % | 6.50 | % | 7.71 | % | 7.75 | % | 7.69 | % |
| Total consumer loans | 4.25 | % | 4.34 | % | 4.71 | % | 4.74 | % | 4.87 | % |
| Total loans and leases | 3.64 | % | 3.76 | % | 4.44 | % | 4.49 | % | 4.75 | % |
| Taxable securities | 3.01 | % | 3.08 | % | 3.15 | % | 3.27 | % | 3.24 | % |
Tax exempt securities(a) | 2.99 | % | 2.96 | % | 3.04 | % | 4.44 | % | 3.18 | % |
| Other short-term investments | 0.10 | % | 0.11 | % | 0.97 | % | 1.65 | % | 2.18 | % |
| Total interest-earning assets | 2.93 | % | 3.21 | % | 4.07 | % | 4.15 | % | 4.34 | % |
| Interest-bearing liabilities: | | | | | |
| Interest checking deposits | 0.10 | % | 0.24 | % | 0.75 | % | 0.88 | % | 1.12 | % |
| Savings deposits | 0.04 | % | 0.06 | % | 0.13 | % | 0.14 | % | 0.18 | % |
| Money market deposits | 0.14 | % | 0.32 | % | 0.72 | % | 0.89 | % | 1.13 | % |
| Foreign office deposits | 0.06 | % | 0.09 | % | 0.57 | % | 0.95 | % | 0.37 | % |
| Other time deposits | 0.95 | % | 1.21 | % | 1.56 | % | 1.75 | % | 1.79 | % |
| Total interest-bearing core deposits | 0.13 | % | 0.27 | % | 0.68 | % | 0.82 | % | 1.01 | % |
| Certificates $100,000 and over | 1.26 | % | 1.40 | % | 2.09 | % | 2.14 | % | 2.20 | % |
| Other deposits | — | | 0.04 | % | 0.85 | % | 1.75 | % | 1.97 | % |
| Federal funds purchased | 0.20 | % | 0.16 | % | 1.13 | % | 1.74 | % | 2.06 | % |
| Other short-term borrowings | 1.28 | % | 0.32 | % | 1.32 | % | 1.89 | % | 2.55 | % |
| Long-term debt | 2.62 | % | 2.80 | % | 3.12 | % | 3.22 | % | 3.26 | % |
| Total interest-bearing liabilities | 0.51 | % | 0.66 | % | 1.09 | % | 1.22 | % | 1.41 | % |
| Ratios: | | | | | |
Net interest margin (FTE)(b) | 2.58 | % | 2.75 | % | 3.28 | % | 3.27 | % | 3.32 | % |
Net interest rate spread (FTE)(b) | 2.42 | % | 2.55 | % | 2.98 | % | 2.93 | % | 2.93 | % |
| Interest-bearing liabilities to interest-earning assets | 68.41 | % | 70.64 | % | 72.24 | % | 72.05 | % | 72.31 | % |
| (a) Presented on an FTE basis. | | | | | |
| (b) Non-GAAP measure; see discussion of non-GAAP and Reg. G reconciliation beginning on page 26. | | | | | |
| | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | |
| Summary of Loans and Leases | | | | | |
| $ in millions | For the Three Months Ended | | | | |
| (unaudited) | September | June | March | December | September |
| 2020 | 2020 | 2020 | 2019 | 2019 |
| Average Portfolio Loans and Leases | | | | | |
| Commercial loans and leases: | | | | | |
| Commercial and industrial loans | $54,004 | $59,040 | $51,586 | $50,938 | $51,241 |
| Commercial mortgage loans | 11,069 | 11,222 | 11,019 | 10,831 | 10,692 |
| Commercial construction loans | 5,534 | 5,548 | 5,132 | 5,334 | 5,267 |
| Commercial leases | 2,966 | 3,056 | 3,201 | 3,384 | 3,562 |
| Total commercial loans and leases | 73,573 | 78,866 | 70,938 | 70,487 | 70,762 |
| Consumer loans: | | | | | |
| Residential mortgage loans | 16,618 | 16,561 | 16,732 | 16,697 | 16,736 |
| Home equity | 5,581 | 5,820 | 6,006 | 6,147 | 6,267 |
| Indirect secured consumer loans | 12,599 | 12,124 | 11,809 | 11,281 | 10,707 |
| Credit card | 2,134 | 2,248 | 2,498 | 2,496 | 2,448 |
| Other consumer loans | 2,857 | 2,887 | 2,796 | 2,679 | 2,621 |
| Total consumer loans | 39,789 | 39,640 | 39,841 | 39,300 | 38,779 |
| Total average portfolio loans and leases | $113,362 | $118,506 | $110,779 | $109,787 | $109,541 |
| | | | | |
| Average Loans and Leases Held for Sale | | | | | |
| Average commercial loans and leases held for sale | $55 | $68 | $108 | $43 | $127 |
| Average consumer loans held for sale | 1,196 | 844 | 1,293 | 1,156 | 998 |
| Average loans and leases held for sale | $1,251 | $912 | $1,401 | $1,199 | $1,125 |
| | | | | |
| End of Period Portfolio Loans and Leases | | | | | |
| Commercial loans and leases: | | | | | |
| Commercial and industrial loans | $51,695 | $55,661 | $58,250 | $50,542 | $50,768 |
| Commercial mortgage loans | 10,878 | 11,233 | 11,160 | 10,963 | 10,822 |
| Commercial construction loans | 5,656 | 5,479 | 5,462 | 5,090 | 5,281 |
| Commercial leases | 3,021 | 3,061 | 3,123 | 3,363 | 3,495 |
| Total commercial loans and leases | 71,250 | 75,434 | 77,995 | 69,958 | 70,366 |
| Consumer loans: | | | | | |
| Residential mortgage loans | 16,158 | 16,457 | 16,701 | 16,724 | 16,675 |
| Home equity | 5,455 | 5,681 | 5,963 | 6,083 | 6,218 |
| Indirect secured consumer loans | 12,925 | 12,395 | 12,050 | 11,538 | 11,026 |
| Credit card | 2,087 | 2,211 | 2,417 | 2,532 | 2,467 |
| Other consumer loans | 2,856 | 2,875 | 2,911 | 2,723 | 2,657 |
| Total consumer loans | 39,481 | 39,619 | 40,042 | 39,600 | 39,043 |
| Total portfolio loans and leases | $110,731 | $115,053 | $118,037 | $109,558 | $109,409 |
| | | | | |
End of Period Loans and Leases Held for Sale | | | | | |
| Commercial loans and leases held for sale | $59 | $72 | $65 | $136 | $86 |
| Consumer loans held for sale | 2,264 | 840 | 1,565 | 1,264 | 1,137 |
| Loans and leases held for sale | $2,323 | $912 | $1,630 | $1,400 | $1,223 |
| | | | | |
| Operating lease equipment | $818 | $809 | $819 | $848 | $869 |
| | | | | |
Loans and Leases Serviced for Others(a) | | | | | |
| Commercial and industrial loans | $903 | $967 | $947 | $922 | $916 |
| Commercial mortgage loans | 585 | 592 | 545 | 454 | 446 |
| Commercial construction loans | 623 | 536 | 462 | 397 | 392 |
| Commercial leases | 584 | 582 | 302 | 322 | 345 |
| Residential mortgage loans | 73,521 | 78,804 | 81,901 | 80,734 | 82,702 |
| Other consumer loans | 50 | 50 | 50 | 50 | 50 |
| Total loans and leases serviced for others | 76,266 | 81,531 | 84,207 | 82,879 | 84,851 |
| Total loans and leases serviced | $190,138 | $198,305 | $204,693 | $194,685 | $196,352 |
| (a) Fifth Third sells certain loans and leases and obtains servicing responsibilities. | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | | | |
| Regulatory Capital | | | | | | | |
| $ in millions | | | As of | | | | |
| (unaudited) | | | September | June | March | December | September |
| | | 2020(a) | 2020 | 2020 | 2019 | 2019 |
| Regulatory Capital | | | | | | | |
| CET1 capital | | | $14,306 | $13,935 | $13,840 | $13,847 | $13,568 |
| Additional tier I capital | | | 2,115 | 1,769 | 1,769 | 1,769 | 1,769 |
| Tier I capital | | | 16,421 | 15,704 | 15,609 | 15,616 | 15,337 |
| Tier II capital | | | 4,645 | 4,703 | 4,472 | 4,045 | 4,076 |
| Total regulatory capital | | | $21,066 | $20,407 | $20,081 | $19,661 | $19,413 |
Risk-weighted assets(b) | | | $141,065 | $143,322 | $147,756 | $142,065 | $141,880 |
| | | | | | | |
| Ratios | | | | | | | |
| Average total Bancorp shareholders' equity as a percent of average assets | | | 11.33 | % | 11.30 | % | 12.63 | % | 12.58 | % | 12.43 | % |
| | | | | | | |
| Regulatory Capital Ratios | | | | | | | |
| Fifth Third Bancorp | | | | | | | |
| CET1 capital(b) | | 10.14 | % | 9.72 | % | 9.37 | % | 9.75 | % | 9.56 | % |
| Tier I risk-based capital(b) | | 11.64 | % | 10.96 | % | 10.56 | % | 10.99 | % | 10.81 | % |
| Total risk-based capital(b) | | 14.93 | % | 14.24 | % | 13.59 | % | 13.84 | % | 13.68 | % |
| Tier I leverage | | 8.37 | % | 8.16 | % | 9.37 | % | 9.54 | % | 9.36 | % |
| | | | | | | |
| Fifth Third Bank | | | | | | | |
| Tier I risk-based capital(b) | | 12.25 | % | 11.76 | % | 11.36 | % | 11.86 | % | 11.79 | % |
| Total risk-based capital(b) | | 14.15 | % | 13.65 | % | 13.17 | % | 13.46 | % | 13.37 | % |
| Tier I leverage | | 8.85 | % | 8.80 | % | 10.16 | % | 10.36 | % | 10.26 | % |
(a)Current period regulatory capital data and ratios are estimated.
(b)Under the U.S. banking agencies' Basel III Final Rule, assets and credit equivalent amounts of off-balance sheet exposures are calculated according to the standardized approach for risk-weighted assets. The resulting values are added together resulting in the Bancorp’s total risk-weighted assets.
| | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | |
| Summary of Credit Loss Experience | | | | | |
| $ in millions | For the Three Months Ended | | | | |
| (unaudited) | September | June | March | December | September |
| 2020 | 2020 | 2020 | 2019 | 2019 |
| Average portfolio loans and leases: | | | | | |
| Commercial and industrial loans | $54,004 | $59,040 | $51,586 | $50,938 | $51,241 |
| Commercial mortgage loans | 11,069 | 11,222 | 11,019 | 10,831 | 10,692 |
| Commercial construction loans | 5,534 | 5,548 | 5,132 | 5,334 | 5,267 |
| Commercial leases | 2,966 | 3,056 | 3,201 | 3,384 | 3,562 |
| Total commercial loans and leases | 73,573 | 78,866 | 70,938 | 70,487 | 70,762 |
| Residential mortgage loans | 16,618 | 16,561 | 16,732 | 16,697 | 16,736 |
| Home equity | 5,581 | 5,820 | 6,006 | 6,147 | 6,267 |
| Indirect secured consumer loans | 12,599 | 12,124 | 11,809 | 11,281 | 10,707 |
| Credit card | 2,134 | 2,248 | 2,498 | 2,496 | 2,448 |
| Other consumer loans | 2,857 | 2,887 | 2,796 | 2,679 | 2,621 |
| Total consumer loans | 39,789 | 39,640 | 39,841 | 39,300 | 38,779 |
| Total average portfolio loans and leases | $113,362 | $118,506 | $110,779 | $109,787 | $109,541 |
| | | | | |
| Losses charged-off: | | | | | |
| Commercial and industrial loans | ($45) | ($68) | ($54) | ($40) | ($30) |
| Commercial mortgage loans | (11) | (2) | (2) | — | — |
| Commercial leases | (10) | (11) | (5) | — | (4) |
| Total commercial loans and leases | (66) | (81) | (61) | (40) | (34) |
| Residential mortgage loans | (1) | (2) | (2) | (4) | (2) |
| Home equity | (4) | (3) | (5) | (12) | (5) |
| Indirect secured consumer loans | (11) | (15) | (21) | (24) | (21) |
| Credit card | (34) | (40) | (42) | (40) | (38) |
| Other consumer loans | (19) | (22) | (28) | (32) | (30) |
| Total consumer loans | (69) | (82) | (98) | (112) | (96) |
| Total losses charged-off | ($135) | ($163) | ($159) | ($152) | ($130) |
| | | | | |
| Recoveries of losses previously charged-off: | | | | | |
| Commercial and industrial loans | $3 | $3 | $4 | $4 | $1 |
| Commercial mortgage loans | — | — | — | — | — |
| Commercial leases | 2 | — | — | — | — |
| Total commercial loans and leases | 5 | 3 | 4 | 4 | 1 |
| Residential mortgage loans | 2 | 1 | 1 | 1 | 1 |
| Home equity | 3 | 2 | 2 | 3 | 3 |
| Indirect secured consumer loans | 8 | 8 | 9 | 8 | 8 |
| Credit card | 5 | 6 | 6 | 7 | 5 |
| Other consumer loans | 11 | 13 | 15 | 16 | 13 |
| Total consumer loans | 29 | 30 | 33 | 35 | 30 |
| Total recoveries of losses previously charged-off | $34 | $33 | $37 | $39 | $31 |
| | | | | |
| Net losses charged-off: | | | | | |
| Commercial and industrial loans | ($42) | ($65) | ($50) | ($36) | ($29) |
| Commercial mortgage loans | (11) | (2) | (2) | — | — |
| Commercial leases | (8) | (11) | (5) | — | (4) |
| Total commercial loans and leases | (61) | (78) | (57) | (36) | (33) |
| Residential mortgage loans | 1 | (1) | (1) | (3) | (1) |
| Home equity | (1) | (1) | (3) | (9) | (2) |
| Indirect secured consumer loans | (3) | (7) | (12) | (16) | (13) |
| Credit card | (29) | (34) | (36) | (33) | (33) |
| Other consumer loans | (8) | (9) | (13) | (16) | (17) |
| Total consumer loans | (40) | (52) | (65) | (77) | (66) |
| Total net losses charged-off | ($101) | ($130) | ($122) | ($113) | ($99) |
| | | | | |
| Net losses charged-off as a percent of average portfolio loans and leases: | | | | | |
| Commercial and industrial loans | 0.31 | % | 0.45 | % | 0.39 | % | 0.28 | % | 0.22 | % |
| Commercial mortgage loans | 0.39 | % | 0.07 | % | 0.06 | % | (0.02 | %) | (0.01 | %) |
| Commercial leases | 1.09 | % | 1.47 | % | 0.60 | % | 0.06 | % | 0.41 | % |
| Total commercial loans and leases | 0.33 | % | 0.40 | % | 0.32 | % | 0.20 | % | 0.18 | % |
| Residential mortgage loans | (0.02 | %) | 0.02 | % | 0.02 | % | 0.07 | % | 0.03 | % |
| Home equity | 0.07 | % | 0.07 | % | 0.17 | % | 0.59 | % | 0.16 | % |
| Indirect secured consumer loans | 0.11 | % | 0.24 | % | 0.43 | % | 0.56 | % | 0.50 | % |
| Credit card | 5.44 | % | 6.17 | % | 5.87 | % | 5.21 | % | 5.41 | % |
| Other consumer loans | 1.05 | % | 1.17 | % | 1.87 | % | 2.51 | % | 2.47 | % |
| Total consumer loans | 0.40 | % | 0.52 | % | 0.66 | % | 0.78 | % | 0.68 | % |
| Total net losses charged-off as a percent of average portfolio loans and leases | 0.35 | % | 0.44 | % | 0.44 | % | 0.41 | % | 0.36 | % |
| | | | | | | | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | | | |
| Asset Quality | | | | | | | |
| $ in millions | | For the Three Months Ended | | | | | |
| (unaudited) | | September | | June | March | December | September |
| | 2020 | | 2020 | 2020 | 2019 | 2019 |
| Allowance for Credit Losses | | | | | | | |
| Allowance for loan and lease losses, beginning | | $2,696 | | $2,348 | $1,202 | $1,143 | $1,115 |
| Impact of CECL adoption | | — | | — | 643 | — | — |
| Total net losses charged-off | | (101) | | (130) | (122) | (113) | (99) |
| (Benefit from) provision for loan and lease losses | | (21) | | 478 | 625 | 172 | 127 |
| Allowance for loan and lease losses, ending | | $2,574 | | $2,696 | $2,348 | $1,202 | $1,143 |
| | | | | | | |
| Reserve for unfunded commitments, beginning | | $176 | | $169 | $144 | $154 | $147 |
| Impact of CECL adoption | | — | | — | 10 | — | — |
| Provision for (benefit from) the reserve for unfunded commitments | | 6 | | 7 | 15 | (10) | 7 |
| Reserve for unfunded commitments, ending | | $182 | | $176 | $169 | $144 | $154 |
| | | | | | | |
| Components of allowance for credit losses: | | | | | | | |
| Allowance for loan and lease losses | | $2,574 | | $2,696 | $2,348 | $1,202 | $1,143 |
| Reserve for unfunded commitments | | 182 | | 176 | 169 | 144 | 154 |
| Total allowance for credit losses | | $2,756 | | $2,872 | $2,517 | $1,346 | $1,297 |
| | | | | | | |
| | As of | | | | | |
| | September | | June | March | December | September |
| | 2020 | | 2020 | 2020 | 2019 | 2019 |
| Nonperforming Assets and Delinquent Loans | | | | | | | |
| Nonaccrual portfolio loans and leases: | | | | | | | |
| Commercial and industrial loans | | $266 | | $94 | $100 | $118 | $70 |
| Commercial mortgage loans | | 99 | | 89 | 83 | 21 | 17 |
| Commercial construction loans | | — | | — | 1 | 1 | — |
| Commercial leases | | 16 | | 22 | 18 | 26 | 27 |
| Residential mortgage loans | | 30 | | 14 | 12 | 13 | 12 |
| Home equity | | 50 | | 52 | 54 | 54 | 63 |
| Indirect secured consumer loans | | 8 | | 5 | 1 | 1 | 1 |
| Other consumer loans | | 3 | | 2 | 2 | 2 | 2 |
| Total nonaccrual portfolio loans and leases (excludes restructured loans) | | 472 | | 278 | 271 | 236 | 192 |
| Nonaccrual restructured portfolio commercial loans and leases | | 307 | | 282 | 243 | 231 | 235 |
| Nonaccrual restructured portfolio consumer loans and leases | | 112 | (c) | 140 | 133 | 151 | 55 |
| Total nonaccrual portfolio loans and leases | | 891 | | 700 | 647 | 618 | 482 |
| Repossessed property | | 7 | | 4 | 10 | 10 | 9 |
| OREO | | 33 | | 43 | 52 | 52 | 28 |
| Total nonperforming portfolio loans and leases and OREO | | 931 | | 747 | 709 | 680 | 519 |
| Nonaccrual loans held for sale | | 10 | | 1 | — | — | — |
| Nonaccrual restructured loans held for sale | | 1 | | 1 | 1 | 7 | 13 |
| Total nonperforming assets | | $942 | | $749 | $710 | $687 | $532 |
| | | | | | | |
| Restructured portfolio consumer loans and leases (accrual) | | $818 | (d) | $963 | $976 | $965 | $958 |
| Restructured portfolio commercial loans and leases (accrual) | | $123 | | $119 | $63 | $23 | $34 |
| | | | | | | |
| Loans and leases 90 days past due (accrual): | | | | | | | |
| Commercial and industrial loans | | $4 | | $10 | $13 | $11 | $15 |
| Commercial mortgage loans | | 26 | | 23 | 20 | 15 | 18 |
| Commercial construction loans | | — | | — | — | — | 1 |
| Commercial leases | | 2 | | — | 10 | — | 1 |
| Total commercial loans and leases | | 32 | | 33 | 43 | 26 | 35 |
| Residential mortgage loans | | 67 | | 54 | 54 | 50 | 48 |
| Home equity | | 2 | | — | — | 1 | — |
| Indirect secured consumer loans | | 10 | | 12 | 11 | 10 | 10 |
| Credit card | | 27 | | 36 | 42 | 42 | 38 |
| Other consumer loans | | 1 | | 1 | 1 | 1 | 1 |
| Total consumer loans | | 107 | | 103 | 108 | 104 | 97 |
Total loans and leases 90 days past due (accrual)(b) | | $139 | | $136 | $151 | $130 | $132 |
| Ratios | | | | | | | |
| Net losses charged-off as a percent of average portfolio loans and leases | | 0.35 | % | | 0.44 | % | 0.44 | % | 0.41 | % | 0.36 | % |
| Allowance for credit losses: | | | | | | | |
| As a percent of portfolio loans and leases | | 2.49 | % | | 2.50 | % | 2.13 | % | 1.23 | % | 1.19 | % |
As a percent of nonperforming portfolio loans and leases(a) | | 309 | % | | 410 | % | 389 | % | 218 | % | 269 | % |
As a percent of nonperforming portfolio assets(a) | | 296 | % | | 385 | % | 355 | % | 198 | % | 250 | % |
Nonperforming portfolio loans and leases as a percent of portfolio loans and leases and OREO(a) | | 0.80 | % | | 0.61 | % | 0.55 | % | 0.56 | % | 0.44 | % |
Nonperforming portfolio assets as a percent of portfolio loans and leases and OREO(a) | | 0.84 | % | | 0.65 | % | 0.60 | % | 0.62 | % | 0.47 | % |
| Nonperforming assets as a percent of total loans and leases, OREO, and repossessed property | | 0.83 | % | | 0.65 | % | 0.59 | % | 0.62 | % | 0.48 | % |
| (a) Excludes nonaccrual loans held for sale. | | | | | | | |
| (b) Excludes loans held for sale. | | | | | | | |
(c) Excludes approximately $12 of residential mortgage loans that were modified prior to repurchase. | | | | | | | |
(d) Excludes approximately $125 of residential mortgage loans that were modified prior to repurchase. | | | | | | | |
Use of Non-GAAP Financial Measures
In addition to GAAP measures, management considers various non-GAAP measures when evaluating the performance of the business, including: “net interest income (FTE),” “interest income (FTE),” “net interest margin (FTE),” “net interest rate spread (FTE),” “income before income taxes (FTE),” “tangible net income available to common shareholders,” “average tangible common equity,” “return on average tangible common equity,” “tangible common equity (excluding AOCI),” “tangible common equity (including AOCI),” “tangible equity,” “tangible book value per share,” “adjusted noninterest income,” “noninterest income excluding certain items,” “adjusted noninterest expense,” “noninterest expense excluding certain items,” “pre-provision net revenue,” “adjusted efficiency ratio,” “adjusted return on average common equity,” “adjusted return on average tangible common equity,” “adjusted return on average tangible common equity, excluding accumulated other comprehensive income,” “adjusted net interest margin,” “adjusted pre-provision net revenue,” “adjusted return on average assets,” “efficiency ratio (FTE),” “total revenue (FTE),” and certain ratios derived from these measures. The Bancorp believes these non-GAAP measures provide useful information to investors because these are among the measures used by the Fifth Third management team to evaluate operating performance and to make day-to-day operating decisions.
The FTE basis adjusts for the tax-favored status of income from certain loans and securities held by the Bancorp that are not taxable for federal income tax purposes. The Bancorp believes this presentation to be the preferred industry measurement of net interest income and net interest margin as it provides a relevant comparison between taxable and non-taxable amounts.
The Bancorp believes tangible net income available to common shareholders, average tangible common equity, tangible common equity (excluding AOCI), tangible common equity (including AOCI), tangible equity, tangible book value per share and return on average tangible common equity are important measures for evaluating the performance of the business without the impacts of intangible items, whether acquired or created internally, in a manner comparable to other companies in the industry who present similar measures.
The Bancorp believes noninterest income, noninterest expense, net interest income, net interest margin, pre-provision net revenue, efficiency ratio, return on average common equity, return on average tangible common equity, and return on average assets are important measures that adjust for significant, unusual, or large transactions that may occur in a reporting period which management does not consider indicative of ongoing financial performance and enhances comparability of results with prior periods.
The Bancorp believes noninterest income excluding certain items and noninterest expense excluding certain items are important measures that adjust for certain components that are prone to significant period-to-period changes in order to facilitate the explanation of variances in the noninterest income and noninterest expense line items.
Management considers various measures when evaluating capital utilization and adequacy, including the tangible equity and tangible common equity (including and excluding AOCI), in addition to capital ratios defined by U.S. banking agencies. These calculations are intended to complement the capital ratios defined by U.S. banking agencies for both absolute and comparative purposes. These ratios are not formally defined by U.S. GAAP or codified in the federal banking regulations and, therefore, are considered to be non-GAAP financial measures. Management believes that providing the tangible common equity ratio excluding AOCI on certain assets and liabilities enables investors and others to assess the Bancorp’s use of equity without the effects of changes in AOCI, some of which are uncertain; providing the tangible common equity ratio including AOCI enables investors and others to assess the Bancorp’s use of equity if components of AOCI, such as unrealized gains or losses, were to be monetized.
Please note that although non-GAAP financial measures provide useful insight, they should not be considered in isolation or relied upon as a substitute for analysis using GAAP measures.
Please see Reg. G reconciliations of all historical non-GAAP measures used in this release to the most directly comparable GAAP measures, beginning on the following page.
| | | | | | | | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | | |
| Regulation G Non-GAAP Reconciliation | | | | | | |
| $ and shares in millions | | As of and For the Three Months Ended | | | | |
| (unaudited) | | September | June | March | December | September |
| | | 2020 | 2020 | 2020 | 2019 | 2019 |
| Net interest income | | $1,170 | $1,200 | $1,229 | $1,228 | $1,242 |
| Add: Taxable equivalent adjustment | | 3 | 3 | 4 | 4 | 4 |
| Net interest income (FTE) (a) | | 1,173 | 1,203 | 1,233 | 1,232 | 1,246 |
| | | | | | | |
| Net interest income (annualized) (b) | | 4,655 | 4,826 | 4,943 | 4,872 | 4,928 |
| Net interest income (FTE) (annualized) (c) | | 4,667 | 4,838 | 4,959 | 4,888 | 4,943 |
| | | | | | | |
| Net interest income (FTE) | | 1,173 | 1,203 | 1,233 | 1,232 | 1,246 |
| Less: Net interest income impact from purchase accounting accretion | | 13 | 15 | 16 | 18 | 28 |
| Adjusted net interest income (FTE) (d) | | 1,160 | 1,188 | 1,217 | 1,214 | 1,218 |
| Adjusted net interest income (FTE) (annualized) (e) | | 4,615 | 4,777 | 4,895 | 4,816 | 4,832 |
| | | | | | | |
| Interest income | | 1,329 | 1,403 | 1,525 | 1,559 | 1,625 |
| Add: Taxable equivalent adjustment | | 3 | 3 | 4 | 4 | 4 |
| Interest income (FTE) | | 1,332 | 1,406 | 1,529 | 1,563 | 1,629 |
| Interest income (FTE) (annualized) (f) | | 5,299 | 5,655 | 6,150 | 6,201 | 6,463 |
| | | | | | | |
| Interest expense (annualized) (g) | | 633 | 816 | 1,191 | 1,313 | 1,520 |
| Average interest-earning assets (h) | | 180,704 | 176,224 | 151,213 | 149,312 | 148,854 |
| Average interest-bearing liabilities (i) | | 123,626 | 124,478 | 109,244 | 107,573 | 107,633 |
| | | | | | | |
| Net interest margin (b) / (h) | | 2.58 | % | 2.74 | % | 3.27 | % | 3.26 | % | 3.31 | % |
| Net interest margin (FTE) (c) / (h) | | 2.58 | % | 2.75 | % | 3.28 | % | 3.27 | % | 3.32 | % |
| Adjusted net interest margin (e) / (h) | | 2.55 | % | 2.71 | % | 3.24 | % | 3.22 | % | 3.25 | % |
| Net interest rate spread (FTE) (f) / (h) - (g) / (i) | | 2.42 | % | 2.55 | % | 2.98 | % | 2.93 | % | 2.93 | % |
| | | | | | | |
| Income before income taxes | | $746 | $244 | $60 | $941 | $689 |
| Add: Taxable equivalent adjustment | | 3 | 3 | 4 | 4 | 4 |
| Income before income taxes (FTE) | | $749 | $247 | $64 | $945 | $693 |
| | | | | | | |
| Net income available to common shareholders | | $562 | $163 | $29 | $701 | $530 |
| Add: Intangible amortization, net of tax | | 9 | 9 | 10 | 11 | 11 |
| Tangible net income available to common shareholders (j) | | 571 | 172 | 39 | 712 | 541 |
| Tangible net income available to common shareholders (annualized) (k) | | 2,272 | 692 | 157 | 2,825 | 2,146 |
| | | | | | | |
| Average Bancorp shareholders' equity | | 22,952 | 22,420 | 21,713 | 21,304 | 21,087 |
| Less: | Average preferred stock | (2,007) | (1,770) | (1,770) | (1,770) | (1,445) |
| | Average goodwill | (4,261) | (4,261) | (4,251) | (4,260) | (4,286) |
| | Average intangible assets | (164) | (178) | (193) | (194) | (208) |
| Average tangible common equity, including AOCI (l) | | 16,520 | 16,211 | 15,499 | 15,080 | 15,148 |
| Less: | Average AOCI | (2,919) | (2,702) | (1,825) | (1,416) | (1,444) |
| Average tangible common equity, excluding AOCI (m) | | 13,601 | 13,509 | 13,674 | 13,664 | 13,704 |
| | | | | | | |
| Total Bancorp shareholders' equity | | 22,951 | 22,335 | 21,873 | 21,203 | 21,404 |
| Less: | Preferred stock | (2,116) | (1,770) | (1,770) | (1,770) | (1,770) |
| | Goodwill | (4,261) | (4,261) | (4,261) | (4,252) | (4,290) |
| | Intangible assets | (157) | (171) | (184) | (201) | (201) |
| Tangible common equity, including AOCI (n) | | 16,417 | 16,133 | 15,658 | 14,980 | 15,143 |
| Less: | AOCI | (2,831) | (2,951) | (2,477) | (1,192) | (1,635) |
| Tangible common equity, excluding AOCI (o) | | 13,586 | 13,182 | 13,181 | 13,788 | 13,508 |
| Add: | Preferred stock | 2,116 | 1,770 | 1,770 | 1,770 | 1,770 |
| Tangible equity (p) | | 15,702 | 14,952 | 14,951 | 15,558 | 15,278 |
| | | | | | | |
| Total assets | | 201,996 | 202,906 | 185,391 | 169,369 | 171,079 |
| Less: | Goodwill | (4,261) | (4,261) | (4,261) | (4,252) | (4,290) |
| | Intangible assets | (157) | (171) | (184) | (201) | (201) |
| Tangible assets, including AOCI (q) | | 197,578 | 198,474 | 180,946 | 164,916 | 166,588 |
| Less: | AOCI, before tax | (3,584) | (3,735) | (3,135) | (1,509) | (2,070) |
| Tangible assets, excluding AOCI (r) | | $193,994 | $194,739 | $177,811 | $163,407 | $164,518 |
| | | | | | | |
| Common shares outstanding (s) | | 712 | 712 | 711 | 709 | 719 |
| | | | | | | |
| Tangible equity (p) / (r) | | 8.09 | % | 7.68 | % | 8.41 | % | 9.52 | % | 9.29 | % |
| Tangible common equity (excluding AOCI) (o) / (r) | | 6.99 | % | 6.77 | % | 7.41 | % | 8.44 | % | 8.21 | % |
| Tangible common equity (including AOCI) (n) / (q) | | 8.31 | % | 8.13 | % | 8.65 | % | 9.08 | % | 9.09 | % |
| Tangible book value per share (n) / (s) | | $23.06 | $22.66 | $22.02 | $21.13 | $21.06 |
| | | | | | | | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | | |
| Regulation G Non-GAAP Reconciliation | | | | | | |
| $ in millions | | For the Three Months Ended | | | | |
| (unaudited) | | September | | June | | September |
| | | 2020 | | 2020 | | 2019 |
| Net income (t) | | $581 | | $195 | | $549 |
| Net income (annualized) (u) | | 2,311 | | 784 | | 2,178 |
| | | | | | | |
| Adjustments (pre-tax items)(a) | | | | | | |
| | Valuation of Visa total return swap | 22 | | 29 | | 11 |
| | Restructuring severance expense | 19 | | - | | - |
| | Branch and non-branch real estate charges | 10 | | 12 | | - |
| | Rent impairment charges | 9 | | - | | - |
| | COVID-19-related expenses(b) | 5 | | 12 | | - |
| | Merger-related expenses | - | | 9 | | 28 |
| | FHLB debt extinguishment charge | - | | 6 | | - |
| Adjustments, after-tax (v)(a) | | 51 | | 52 | | 30 |
| | | | | | | |
| Noninterest income (w) | | 722 | | 650 | | 740 |
| | Valuation of Visa total return swap | 22 | | 29 | | 11 |
| | Branch and non-branch real estate charges | 10 | | 12 | | - |
| Adjusted noninterest income (x) | | 754 | | 691 | | 751 |
| | | | | | | |
| Noninterest expense (y) | | 1,161 | | 1,121 | | 1,159 |
| | Restructuring severance expense | (19) | | - | | - |
| | Rent impairment charges | (9) | | - | | - |
| | COVID-19-related expenses(b) | (5) | | (12) | | - |
| | Merger-related expenses | - | | (9) | | (28) |
| | FHLB debt extinguishment charge | - | | (6) | | - |
| Adjusted noninterest expense (z) | | 1,128 | | 1,094 | | 1,131 |
| | Intangible amortization expense | 12 | | 12 | | 14 |
| Adjusted noninterest expense excluding intangible amortization expense (aa) | | 1,116 | | 1,082 | | 1,117 |
| | | | | | | |
| Adjusted net income (t) + (v) | | 632 | | 247 | | 579 |
| Adjusted net income (annualized) (ab) | | 2,514 | | 993 | | 2,297 |
| | | | | | | |
| Adjusted tangible net income available to common shareholders (j) + (v) | | 622 | | 224 | | 571 |
| Adjusted tangible net income available to common shareholders (annualized) (ac) | | 2,474 | | 901 | | 2,265 |
| | | | | | | |
| Average assets (ad) | | $202,533 | | $198,387 | | $169,585 |
| | | | | | | |
| Return on average tangible common equity (k) / (l) | | 13.8 | % | | 4.3 | % | | 14.2 | % |
| Adjusted return on average tangible common equity, including AOCI (ac) / (l) | | 15.0 | % | | 5.6 | % | | 15.0 | % |
| Adjusted return on average tangible common equity, excluding AOCI (ac) / (m) | | 18.2 | % | | 6.7 | % | | 16.5 | % |
| | | | | | | |
| Return on average assets (u) / (ad) | | 1.14 | % | | 0.40 | % | | 1.28 | % |
| Adjusted return on average assets (ab) / (ad) | | 1.24 | % | | 0.50 | % | | 1.35 | % |
| Efficiency ratio (y) / [(a) + (w)] | | 61.3 | % | | 60.5 | % | | 58.4 | % |
| Adjusted efficiency ratio (aa) / [(d) + (x)] | | 58.3 | % | | 57.6 | % | | 56.7 | % |
| Total revenue (FTE) (a) + (w) | | $1,895 | | $1,853 | | $1,986 |
| Pre-provision net revenue (PPNR) (a) + (w) - (y) | | $734 | | $732 | | $827 |
| Adjusted pre-provision net revenue (PPNR) (d) + (x) - (aa) | | $798 | | $797 | | $852 |
| (a) Assumes a 23% tax rate, except for merger-related expenses impacted by certain non-deductible items; (b) COVID-19 related expenses include incremental costs incurred for | | | | | | |
| enhanced cleaning measures, personal protective equipment, one-teim employee bonuses (entirely in 2Q20), and other supplies in response to the COVID-19 pandemic | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | |
| Fifth Third Bancorp and Subsidiaries | | | | | | | |
| Segment Presentation | | | | | | | |
| $ in millions | | | | | | | |
| (unaudited) | | | | | | | |
| | | | | | | |
For the three months ended September 30, 2020 | Commercial Banking | Branch Banking(b) | Consumer Lending(c) | Wealth and Asset Management | Other/ Eliminations | Total | |
| | | | | | | |
Net interest income (FTE)(a) | $435 | $355 | $98 | $28 | $257 | $1,173 | |
| Benefit from (provision for) credit losses | (337) | (68) | (2) | — | 422 | 15 | |
| Net interest income after benefit from (provision for) credit losses | 98 | 287 | 96 | 28 | 679 | 1,188 | |
| Noninterest income | 318 | 192 | 73 | 132 | 7 | 722 | |
| Noninterest expense | (411) | (460) | (137) | (133) | (20) | (1,161) | |
| Income before income taxes | 5 | 19 | 32 | 27 | 666 | 749 | |
Applicable income tax (expense) benefit(a) | 7 | (4) | (7) | (6) | (158) | (168) | |
| Net income | $12 | $15 | $25 | $21 | $508 | $581 | |
| | | | | | | |
For the three months ended June 30, 2020 | Commercial Banking | Branch Banking(b) | Consumer Lending(c) | Wealth and Asset Management | Other/ Eliminations | Total | |
| | | | | | | |
Net interest income (FTE)(a) | $573 | $513 | $92 | $51 | $(26) | $1,203 | |
| (Provision for) benefit from credit losses | (457) | (52) | (10) | 1 | 33 | (485) | |
| Net interest income after (provision for) benefit from credit losses | 116 | 461 | 82 | 52 | 7 | 718 | |
| Noninterest income | 294 | 167 | 98 | 121 | (30) | 650 | |
| Noninterest expense | (405) | (454) | (120) | (122) | (20) | (1,121) | |
| Income (loss) before income taxes | 5 | 174 | 60 | 51 | (43) | 247 | |
Applicable income tax (expense) benefit(a) | 7 | (36) | (12) | (11) | — | (52) | |
| Net income (loss) | $12 | $138 | $48 | $40 | $(43) | $195 | |
| | | | | | | |
For the three months ended March 31, 2020 | Commercial Banking | Branch Banking(b) | Consumer Lending(c) | Wealth and Asset Management | Other/ Eliminations | Total | |
| | | | | | | |
Net interest income (FTE)(a) | $511 | $505 | $89 | $37 | $91 | $1,233 | |
| Provision for credit losses | (45) | (62) | (13) | (1) | (519) | (640) | |
| Net interest income after provision for credit losses | 466 | 443 | 76 | 36 | (428) | 593 | |
| Noninterest income | 287 | 198 | 124 | 135 | (73) | 671 | |
| Noninterest expense | (480) | (488) | (122) | (143) | 33 | (1,200) | |
| Income (loss) before income taxes | 273 | 153 | 78 | 28 | (468) | 64 | |
Applicable income tax (expense) benefit(a) | (49) | (32) | (17) | (6) | 86 | (18) | |
| Net income (loss) | $224 | $121 | $61 | $22 | $(382) | $46 | |
| | | | | | | |
For the three months ended December 31, 2019 | Commercial Banking | Branch Banking(b) | Consumer Lending(c) | Wealth and Asset Management | Other/ Eliminations | Total | |
| | | | | | | |
Net interest income (FTE)(a) | $603 | $569 | $91 | $41 | $(72) | $1,232 | |
| Provision for credit losses | (83) | (60) | (15) | — | (4) | (162) | |
| Net interest income after provision for credit losses | 520 | 509 | 76 | 41 | (76) | 1,070 | |
| Noninterest income | 324 | 214 | 74 | 129 | 294 | 1,035 | |
| Noninterest expense | (422) | (485) | (123) | (131) | 1 | (1,160) | |
| Income before income taxes | 422 | 238 | 27 | 39 | 219 | 945 | |
Applicable income tax expense(a) | (81) | (50) | (6) | (8) | (66) | (211) | |
| Net income | $341 | $188 | $21 | $31 | $153 | $734 | |
| | | | | | | |
For the three months ended September 30, 2019 | Commercial Banking | Branch Banking(b) | Consumer Lending(c) | Wealth and Asset Management | Other/ Eliminations | Total | |
| | | | | | | |
Net interest income (FTE)(a) | $627 | $598 | $88 | $44 | $(111) | $1,246 | |
| Provision for credit losses | (54) | (58) | (14) | — | (8) | (134) | |
| Net interest income after provision for credit losses | 573 | 540 | 74 | 44 | (119) | 1,112 | |
| Noninterest income | 335 | 204 | 96 | 125 | (20) | 740 | |
| Noninterest expense | (425) | (469) | (114) | (129) | (22) | (1,159) | |
| Income (loss) before income taxes | 483 | 275 | 56 | 40 | (161) | 693 | |
Applicable income tax (expense) benefit(a) | (90) | (58) | (12) | (8) | 24 | (144) | |
| Net income (loss) | $393 | $217 | $44 | $32 | $(137) | $549 | |
(a) Includes taxable equivalent adjustments of $3 million, $3 million, $4 million, $4 million and $4 million for the three months ended September 30, 2020, June 30, 2020, March 31, 2020, December 31, 2019 and September 30, 2019, respectively. | | | | | | | |
| (b) Branch Banking provides a full range of deposit and loan and lease products to individuals and small businesses through full-service banking centers. | | | | | | | |
| (c) Consumer Lending includes the Bancorp's residential mortgage, home equity, automobile and other indirect lending activities. | | | | | | | |