 |  | |
Exhibit 99.1
Freddie Mac Reports Net Income of $0.2 Billion and
Comprehensive Income of $0.6 Billion for First Quarter 2020
The Company Takes Extraordinary Steps to Support the Market During the Pandemic
“Freddie Mac’s first quarter was marked by unprecedented challenges to our country, our business and our markets - and I am very proud of how we have responded. We are offering relief to millions of homeowners and renters, supporting our customers in new and vital ways, and serving as a stabilizing force for the housing finance system. Through these efforts, we are continuing to fully serve our mission.” |
David M. Brickman Chief Executive Officer |
First Quarter 2020 Financial Results(1)
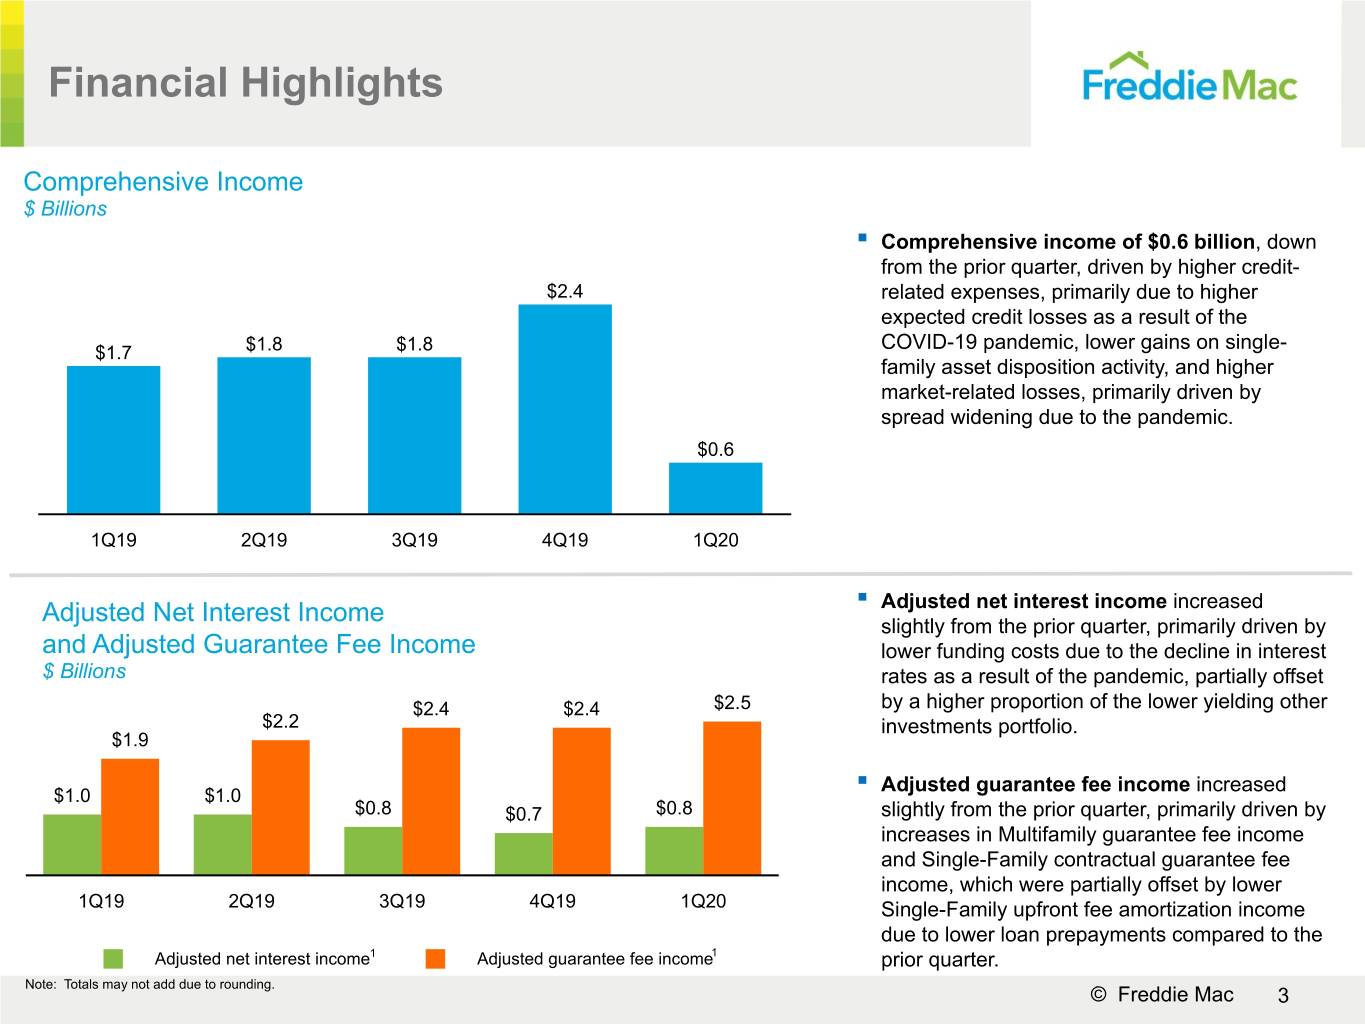
• | Comprehensive income of $0.6 billion, down $1.8 billion from the prior quarter, driven by: |
▪ | Higher credit-related expense of $1.1 billion, or $0.9 billion, after-tax, primarily due to higher expected credit losses as a result of the COVID-19 pandemic; |
▪ | Lower gains on single-family asset disposition activity of $0.6 billion, or $0.5 billion, after-tax; and |
▪ | Higher market-related losses of $0.3 billion, after-tax, primarily driven by spread widening due to the pandemic. |
• | Total equity/net worth(2) increased to $9.5 billion at March 31, 2020, from $9.1 billion at December 31, 2019. |
COVID-19 Pandemic Response Efforts(1)
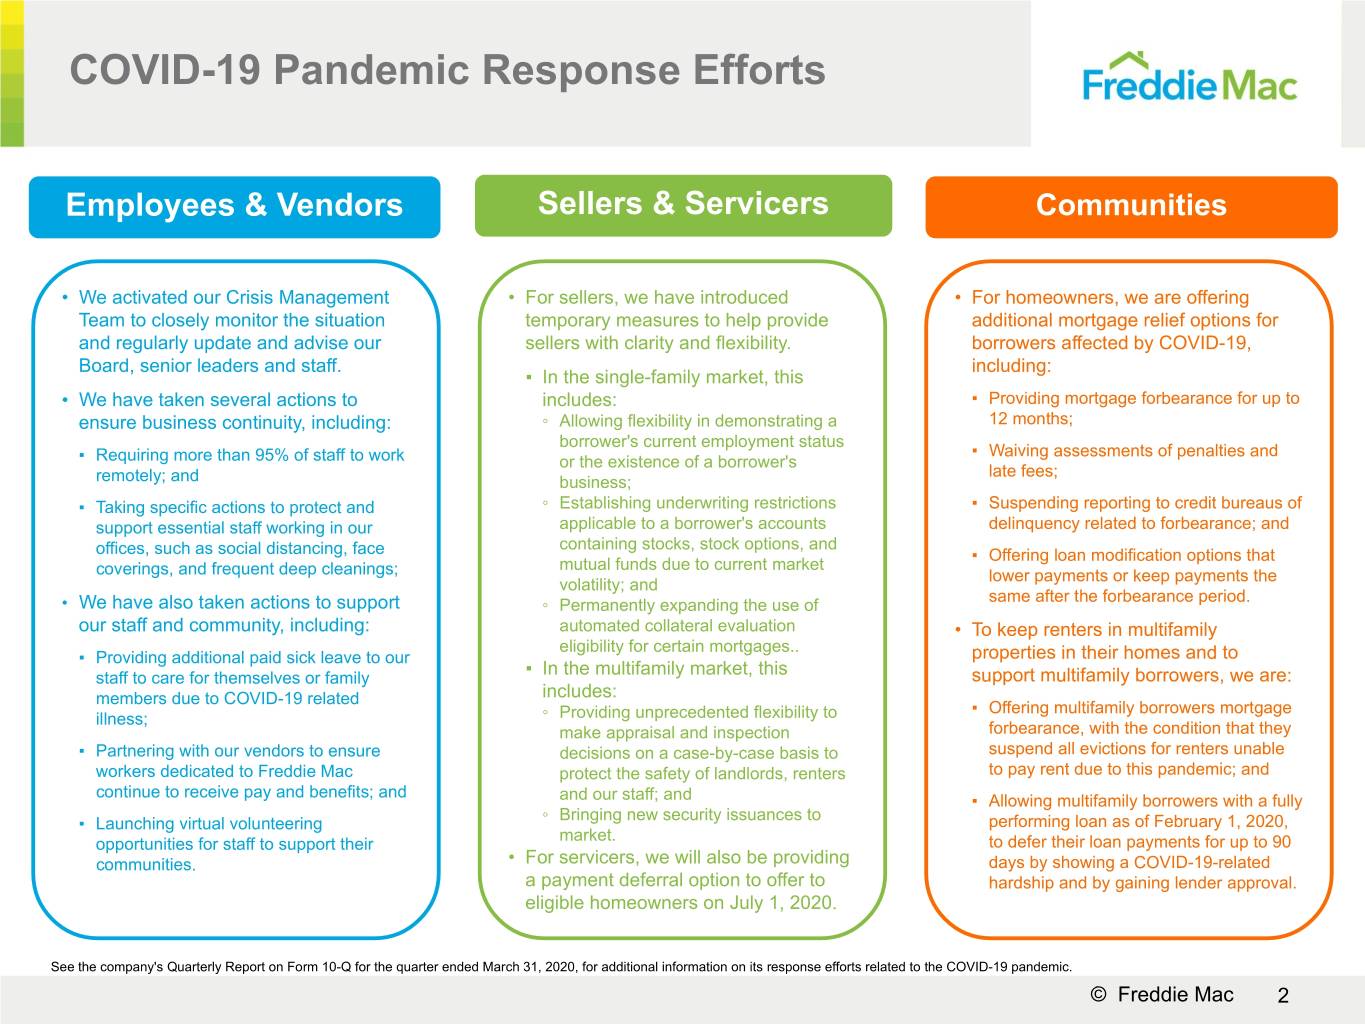
• | Actions To Support Homeowners and Renters — In March 2020, working with the Federal Housing Finance Agency (FHFA), the company took steps to provide relief to homeowners, renters, and multifamily property owners with Freddie Mac-backed loans, including mortgage forbearance and eviction protection. |
• | Actions To Support Lenders — Also working with FHFA, the company introduced temporary measures to provide sellers with clarity and flexibility to help them continue to support borrowers. |
Open for Business
• | Freddie Mac demonstrated its business resiliency and importance to the housing markets by continuing to serve its critical mission during the pandemic. |
▪ | New business activity was $138 billion for Single-Family and $10 billion for Multifamily in the first quarter of 2020. The Single-Family and Multifamily guarantee portfolios grew 6% and 13%, respectively, year over year. |
▪ | Credit enhancement coverage of the Single-Family credit guarantee portfolio increased to 58% in the first quarter of 2020 from 56% in the prior quarter; credit enhancement coverage of the Multifamily mortgage portfolio remained at 89%. |
• | As of March 31, 2020, the company maintained sufficient liquidity to meet its contractual obligations and continued to actively access the debt markets. |
• | The company has not experienced any significant operational or technological issues associated with its pandemic response efforts despite more than 95% of its workforce working remotely. |
• | In addition, the company continued to engage with its customers and third parties to ensure continuity of critical business activities. |
(1) See the company's Quarterly Report on Form 10-Q for the quarter ended March 31, 2020, for additional information on its response efforts related to the COVID-19 pandemic and its outlook for 2020.
(2) See page 12 for additional information about the company's net worth and the September 2019 Letter Agreement.
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 2
McLean, VA — Freddie Mac (OTCQB: FMCC) today reported net income of $0.2 billion for the first quarter of 2020, compared to net income of $2.6 billion for the fourth quarter of 2019. The company also reported comprehensive income of $0.6 billion for the first quarter of 2020, compared to comprehensive income of $2.4 billion for the fourth quarter of 2019.
• | Comprehensive income decreased $1.8 billion from the prior quarter, mainly due to: |
▪ | Higher credit-related expense of $1.1 billion primarily driven by higher expected credit losses on loans as a result of the pandemic, partially offset by the related expected recoveries from credit enhancements, such as STACR and ACIS, on the corresponding loans; |
▪ | Losses on single-family loans held in inventory due to effects from the pandemic, combined with lower gains on single-family reperforming and nonperforming loan sales due to a lower volume of dispositions; |
▪ | Higher market-related losses primarily driven by spread widening, resulting in higher Multifamily spread-related fair value losses, partially offset by higher fair value gains on certain Single-Family credit risk transfer (CRT) transactions, both due to the effects of the pandemic; |
◦ | Although certain interest rates, such as the 10-year Treasury, reached all-time lows during the quarter, interest rate-related impacts on comprehensive income were minimal due to the company's effective use of hedge accounting; and |
▪ | Lower net amortization income driven by the timing differences in amortization related to prepayments between the debt of consolidated trusts and the underlying mortgage loans, as loan prepayments increased significantly in March 2020. |
Summary of Consolidated Statements of Comprehensive Income (Loss)
(Dollars in millions) | 1Q 2020 | 4Q 2019 | Change | 1Q 2019 | Change | |||||||
Net interest income | $2,785 | $3,358 | $(573) | $3,153 | $(368) | |||||||
Guarantee fee income | 377 | 239 | 138 | 290 | 87 | |||||||
Investment gains (losses), net | (835) | 901 | (1,736) | (513 | ) | (322) | ||||||
Other income (loss) | 95 | 75 | 20 | (17 | ) | 112 | ||||||
Net revenues | 2,422 | 4,573 | (2,151) | 2,913 | (491) | |||||||
Benefit (provision) for credit losses | (1,233) | 272 | (1,505) | 135 | (1,368) | |||||||
Credit enhancement (expense) benefit, net | 236 | (214 | ) | 450 | (158 | ) | 394 | |||||
Real estate owned (REO) operations expense | (85) | (57 | ) | (28) | (33 | ) | (52) | |||||
Credit-related expense | (1,082) | 1 | (1,083) | (56 | ) | (1,026) | ||||||
Administrative expense | (587) | (747 | ) | 160 | (578 | ) | (9) | |||||
Temporary Payroll Tax Cut Continuation Act of 2011 expense | (432) | (420 | ) | (12) | (390 | ) | (42) | |||||
Other expense | (103) | (157 | ) | 54 | (124 | ) | 21 | |||||
Operating expense | (1,122) | (1,324 | ) | 202 | (1,092 | ) | (30) | |||||
Income (loss) before income tax (expense) benefit | 218 | 3,250 | (3,032) | 1,765 | (1,547) | |||||||
Income tax (expense) benefit | (45) | (658 | ) | 613 | (358 | ) | 313 | |||||
Net income (loss) | 173 | 2,592 | (2,419) | 1,407 | (1,234) | |||||||
Total other comprehensive income (loss), net of taxes and reclassification adjustments | 449 | (144 | ) | 593 | 258 | 191 | ||||||
Comprehensive income (loss) | $622 | $2,448 | $(1,826) | $1,665 | $(1,043) | |||||||
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 3
Selected Financial Measures
Net Interest Income and Net Interest Yield
(Dollars in billions)
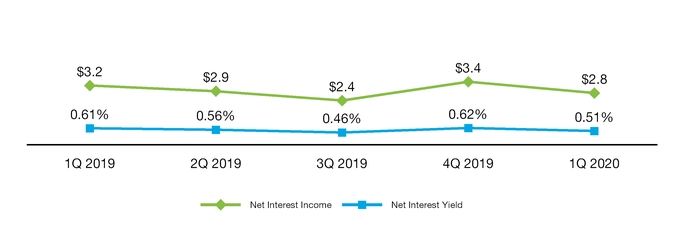
• | Net interest income and net interest yield decreased from the prior quarter, primarily driven by a less favorable hedge accounting mismatch and lower amortization income due to the timing difference in amortization related to prepayments between the debt of consolidated trusts and the underlying mortgage loans, partially offset by increased contractual net interest income from the Single-Family guarantee portfolio. |
Guarantee Fee Income(1) and
Multifamily Guarantee Portfolio
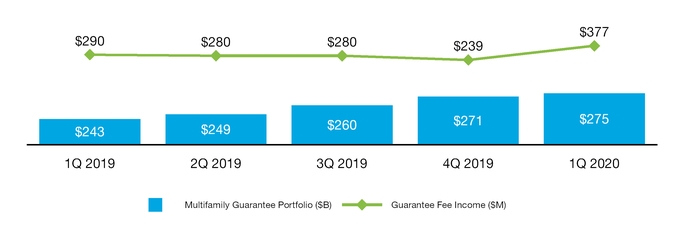
(1) Guarantee fee income on a GAAP basis is primarily from the company’s multifamily business.
• | The company’s guarantee business remained strong in the first quarter of 2020 as evidenced by continued high contractual guarantee fee income. Improvements in the fair value of multifamily guarantee assets due to declines in interest rates resulted in an increase in guarantee fee income in the quarter. |
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 4
Credit-Related Expense(1)(2)
(Dollars in billions)
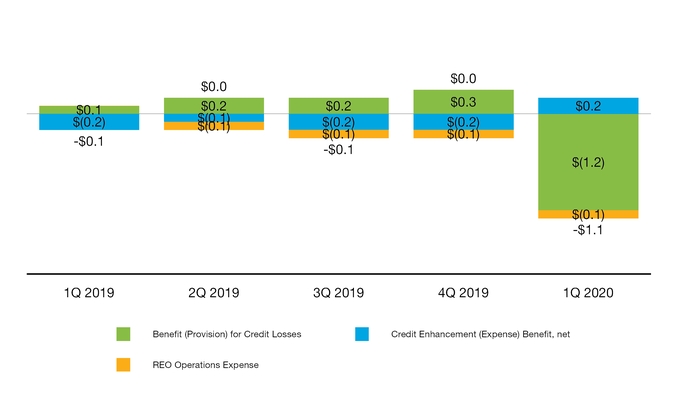
(1) Excludes interest expense related to single-family CRT debt included in GAAP net interest income.
(2) The company adopted the Current Expected Credit Losses (CECL) impairment model on January 1, 2020. See the company's Quarterly Report on Form 10-Q for the quarter ended March 31, 2020, for additional information.
• | Credit-related expense increased from the prior quarter, primarily due to: |
▪ | A shift from a benefit for credit losses to a provision to incorporate the forecasts of higher expected credit losses on loans as a result of the pandemic; partially offset by |
▪ | A shift from a credit enhancement expense to a benefit due to an increase in expected recoveries from certain credit enhancements, such as STACR and ACIS transactions, as a result of the corresponding increase in expected credit losses on the covered loans. |
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 5
Non-GAAP Financial Measure Highlights
In addition to analyzing the company’s results on a GAAP basis, management reviews net interest income and guarantee fee income on an “adjusted,” or non-GAAP, basis. These adjusted financial measures are calculated by reclassifying certain credit guarantee-related activities and investment-related activities between various line items on the company’s GAAP consolidated statements of comprehensive income. The company also presents one additional non-GAAP financial measure, adjusted net interest yield, that is calculated based on adjusted net interest income. Management believes that this non-GAAP financial measure is useful because it more clearly reflects the company’s sources of revenue and return.
For additional information about the company's non-GAAP financial measures and reconciliations to the comparable amounts under GAAP, see pages 16 - 17 of this press release.
Adjusted Net Interest Income(1), Adjusted Net Interest Yield(1), and
Investments Portfolio
(Dollars in billions)
(1) | Non-GAAP financial measure. For reconciliations to the comparable amounts under GAAP, see page 16 of this press release. |
Amounts may not add due to rounding.
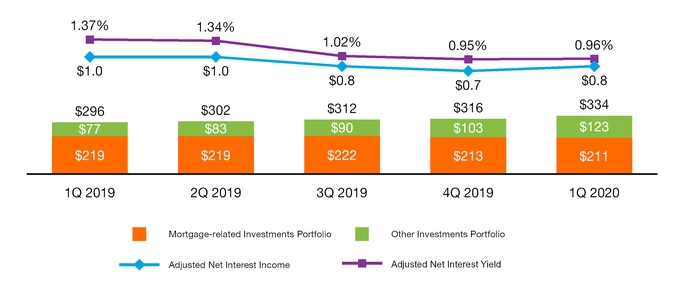
• | Adjusted net interest income and adjusted net interest yield increased slightly from the prior quarter, primarily driven by lower funding costs due to the decline in interest rates as a result of the pandemic, partially offset by a higher proportion of the lower yielding other investments portfolio. |
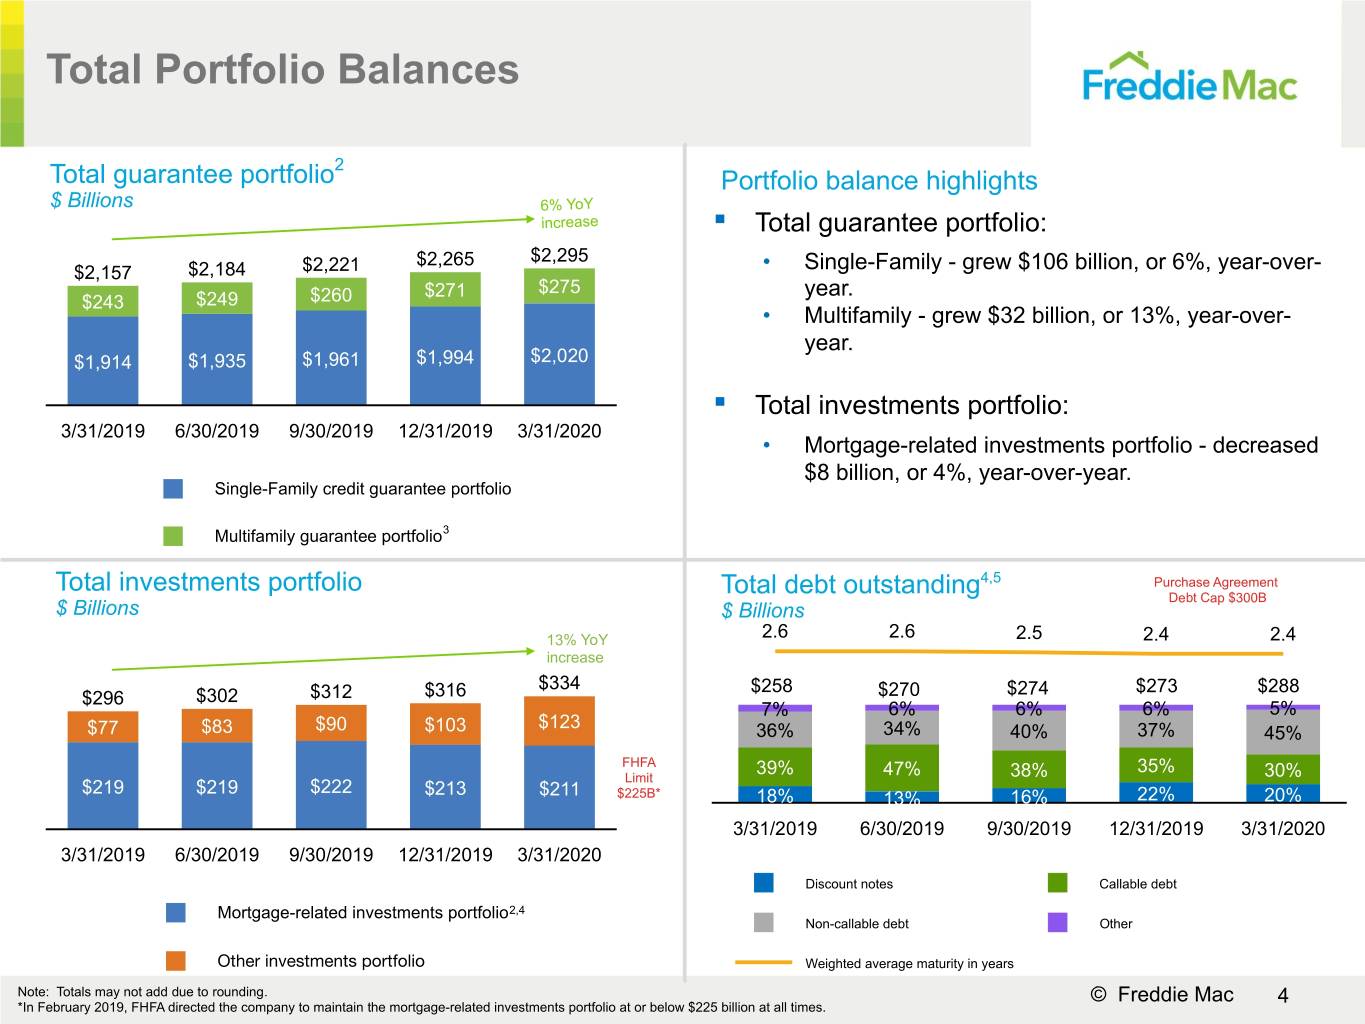
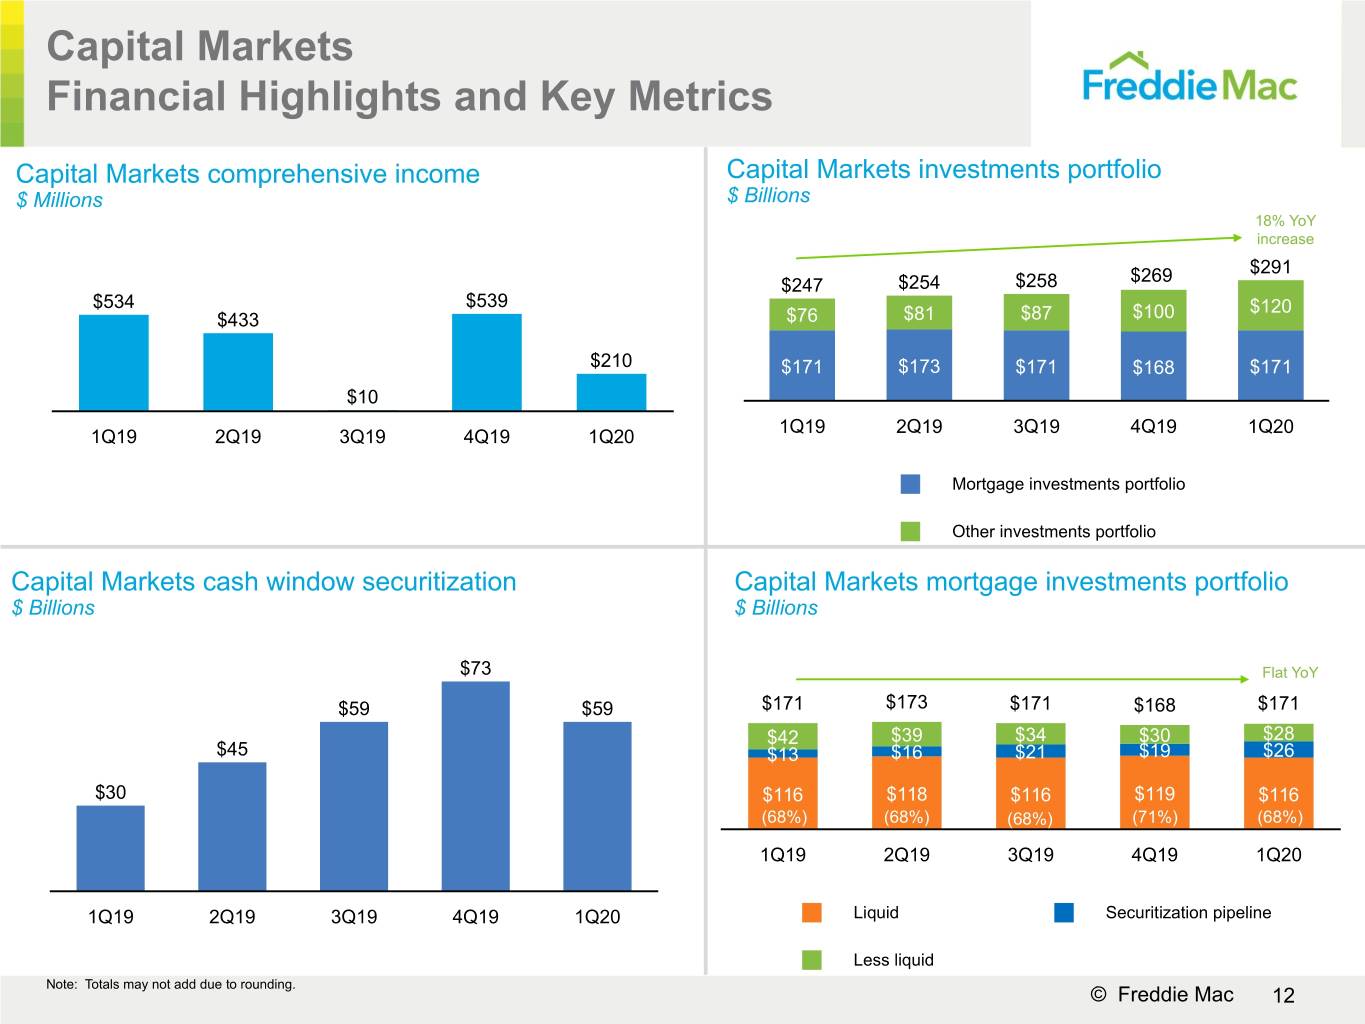
• | The mortgage-related investments portfolio was $211 billion, down more than $1 billion, or 1%, from the prior quarter and $8 billion, or 4%, from the prior year. In February 2019, FHFA directed the company to maintain the mortgage-related investments portfolio at or below $225 billion at all times. |
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 6
Adjusted Guarantee Fee Income(1) and
Total Guarantee Portfolio
(Dollars in billions)
(1) | Non-GAAP financial measure. For reconciliations to the comparable amounts under GAAP, see page 16 of this press release. |
Amounts may not add due to rounding.
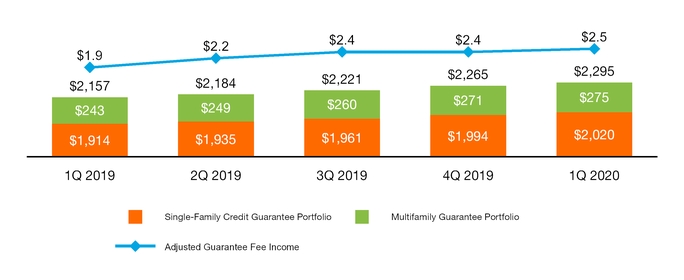
• | Adjusted guarantee fee income remained strong, increasing slightly from the prior quarter. Increases in Multifamily guarantee fee income and Single-Family contractual guarantee fee income were partially offset by lower Single-Family upfront fee amortization income due to lower loan prepayments compared to the prior quarter. |
• | The total guarantee portfolio grew $30 billion, or 1%, from the prior quarter and $138 billion, or 6%, from the prior year, driven by increases in both the Single-Family and Multifamily guarantee portfolios. |
Return on Conservatorship Capital (ROCC)
The table below provides the ROCC, calculated as (1) annualized comprehensive income for the period divided by (2) average conservatorship capital during the period.
ROCC is not based on the company's total equity and does not reflect actual returns on total equity. The company does not believe that returns on total equity are meaningful because of the net worth limit imposed since 2012 under the Purchase Agreement. In addition, the company believes that returns post-conservatorship would most likely be lower than the levels calculated below, assuming the same portfolio of risk assets, as it expects that it would hold capital above the minimum required regulatory capital levels and that it would likely be required to pay fees for federal government support, thereby reducing its total comprehensive income.
The Conservatorship Capital Framework (CCF) has been and may be further revised by FHFA from time to time, including in connection with FHFA’s consideration and adoption of a final Enterprise Capital Rule, which could possibly result in material changes in the company's conservatorship capital and, thus, its returns on conservatorship capital. FHFA has announced that it plans to re-propose the Enterprise Capital Rule in 2020.
Return on Conservatorship Capital
(Dollars in billions) | 1Q 2020 | 4Q 2019 | Change | 1Q 2019 | Change | ||||||||||
Comprehensive income | $0.6 | $2.4 | $(1.8) | $1.7 | $(1.1) | ||||||||||
Conservatorship capital (average during the period)(1)(2) | $50.5 | $51.5 | $(1.0) | $52.4 | $(1.9) | ||||||||||
ROCC, based on comprehensive income | 4.9 | % | 19.0 | % | (14.1 | )% | 12.7 | % | (7.8 | )% | |||||
(1) Average conservatorship capital and ROCC for 1Q 2020 are preliminary and subject to change until official submission to FHFA.
(2) Average conservatorship capital for each period is based on the CCF in effect during that period. The CCF in effect as of March 31, 2020 was largely unchanged from the CCF as of December 31, 2019.
Amounts may not add due to rounding.
ROCC decreased compared to the prior quarter, primarily driven by the decrease in comprehensive income in the first quarter of 2020.
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 7
For additional information on the CCF and ROCC, see the company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2020.
Segment Financial Results and Business Highlights
Freddie Mac’s operations consist of three reportable segments, which are based on the types of business activities they perform – Single-Family Guarantee, Multifamily, and Capital Markets. The company presents Segment Earnings for each reportable segment by reclassifying certain credit guarantee-related activities and investment-related activities between various line items on its GAAP consolidated statements of comprehensive income and allocating certain revenues and expenses, including funding costs and administrative expenses, to its three reportable segments.
For more information about Segment Earnings, see Note 13 to the financial statements included in the company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2020.
Single-Family Guarantee Segment
Providing liquidity to the market while transforming U.S. housing finance
Financial Results(1)
(Dollars in millions) | 1Q 2020 | 4Q 2019 | Change | 1Q 2019 | Change | |||||
Guarantee fee income | $2,093 | $2,199 | $(106) | $1,635 | $458 | |||||
Investment gains (losses), net | 437 | 325 | 112 | 6 | 431 | |||||
Other income (loss) | 15 | 167 | (152) | 112 | (97) | |||||
Net revenues | 2,545 | 2,691 | (146) | 1,753 | 792 | |||||
Benefit (provision) for credit losses | (1,222) | 177 | (1,399) | 71 | (1,293) | |||||
Credit enhancement (expense) benefit, net | 28 | (393) | 421 | (316) | 344 | |||||
REO operations expense | (87) | (60) | (27) | (38) | (49) | |||||
Credit-related expense | (1,281) | (276) | (1,005) | (283) | (998) | |||||
Administrative expense | (372) | (474) | 102 | (374) | 2 | |||||
Other expense | (151) | (161) | 10 | (168) | 17 | |||||
Operating expense | (523) | (635) | 112 | (542) | 19 | |||||
Segment Earnings (Losses) before income tax (expense) benefit | 741 | 1,780 | (1,039) | 928 | (187) | |||||
Income tax (expense) benefit | (153) | (360) | 207 | (188) | 35 | |||||
Segment Earnings (Losses), net of taxes | 588 | 1,420 | (832) | 740 | (152) | |||||
Total other comprehensive income (loss), net of tax | (2) | (13) | 11 | (4) | 2 | |||||
Total comprehensive income (loss) | $586 | $1,407 | $(821) | $736 | $(150) | |||||
(1) | The financial performance of the company’s Single-Family Guarantee segment is measured based on its contribution to GAAP net income (loss). |
Key Drivers
Comprehensive income decreased from the prior quarter, primarily due to:
• | Higher credit-related expense primarily driven by higher expected credit losses on loans as a result of the pandemic, partially offset by the related expected recoveries from credit enhancements, such as STACR and ACIS, on the corresponding covered loans; |
• | Lower guarantee fee income due to a decline in upfront fee amortization resulting from lower loan prepayments in the current quarter as compared to the prior quarter; and |
• | Higher investment gains due to higher fair value gains on certain CRT transactions resulting from significant spread widening in the first quarter, partially offset by valuation losses on single-family loans held in inventory, both driven by the impact of the pandemic. Gains were lower on reperforming and nonperforming loan sales due to a lower volume of dispositions. |
Business Highlights
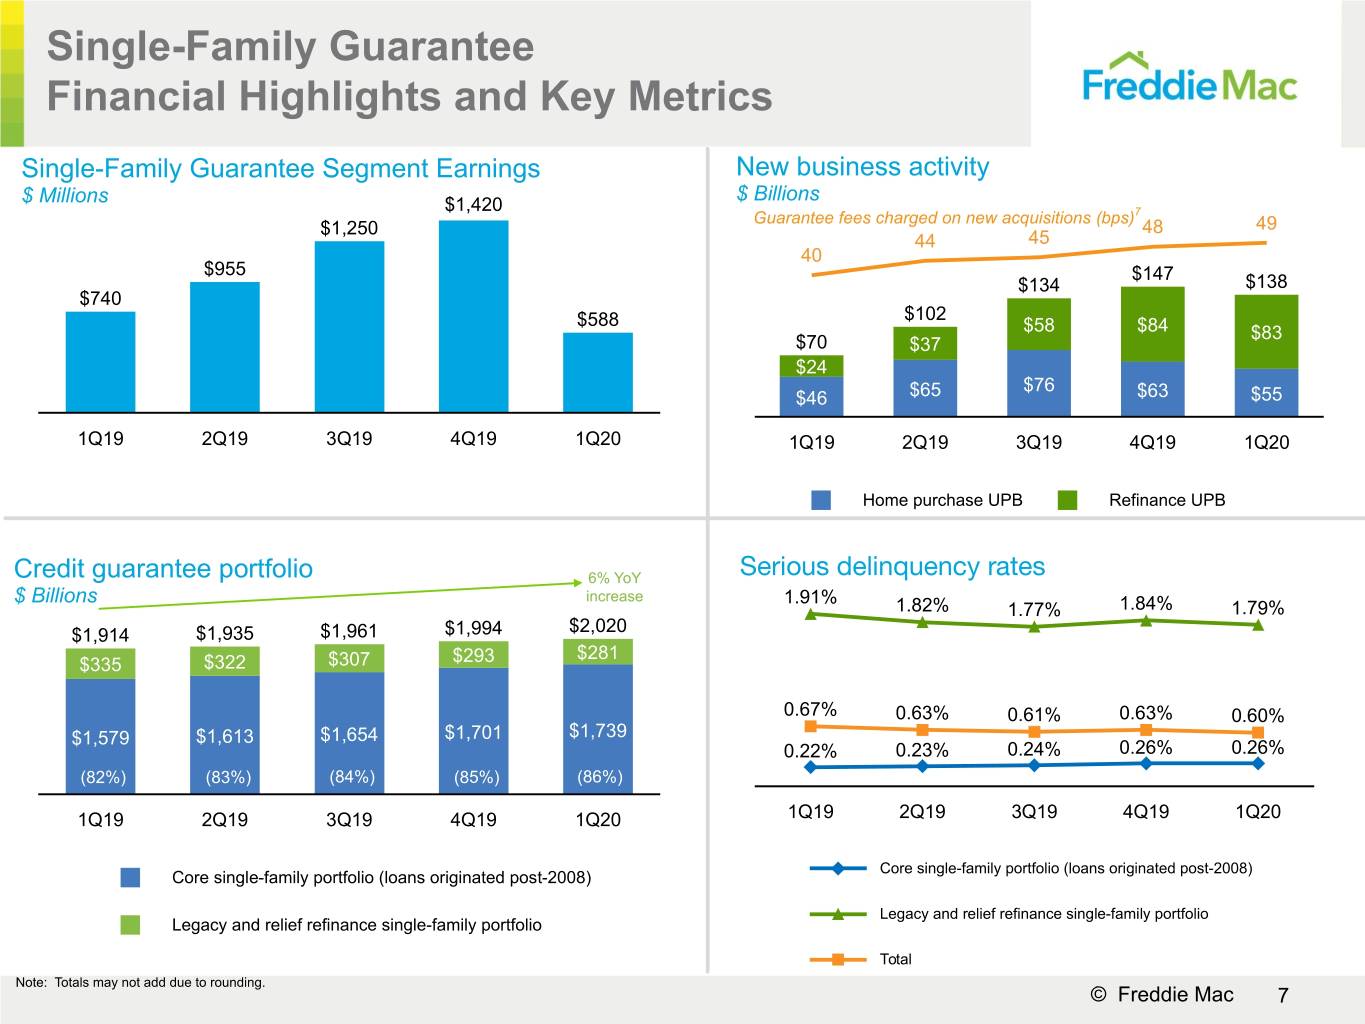
• | New business activity was $138 billion, a decrease of $9 billion, or 6%, from the prior quarter, primarily resulting from a decrease in purchase volume. |
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 8
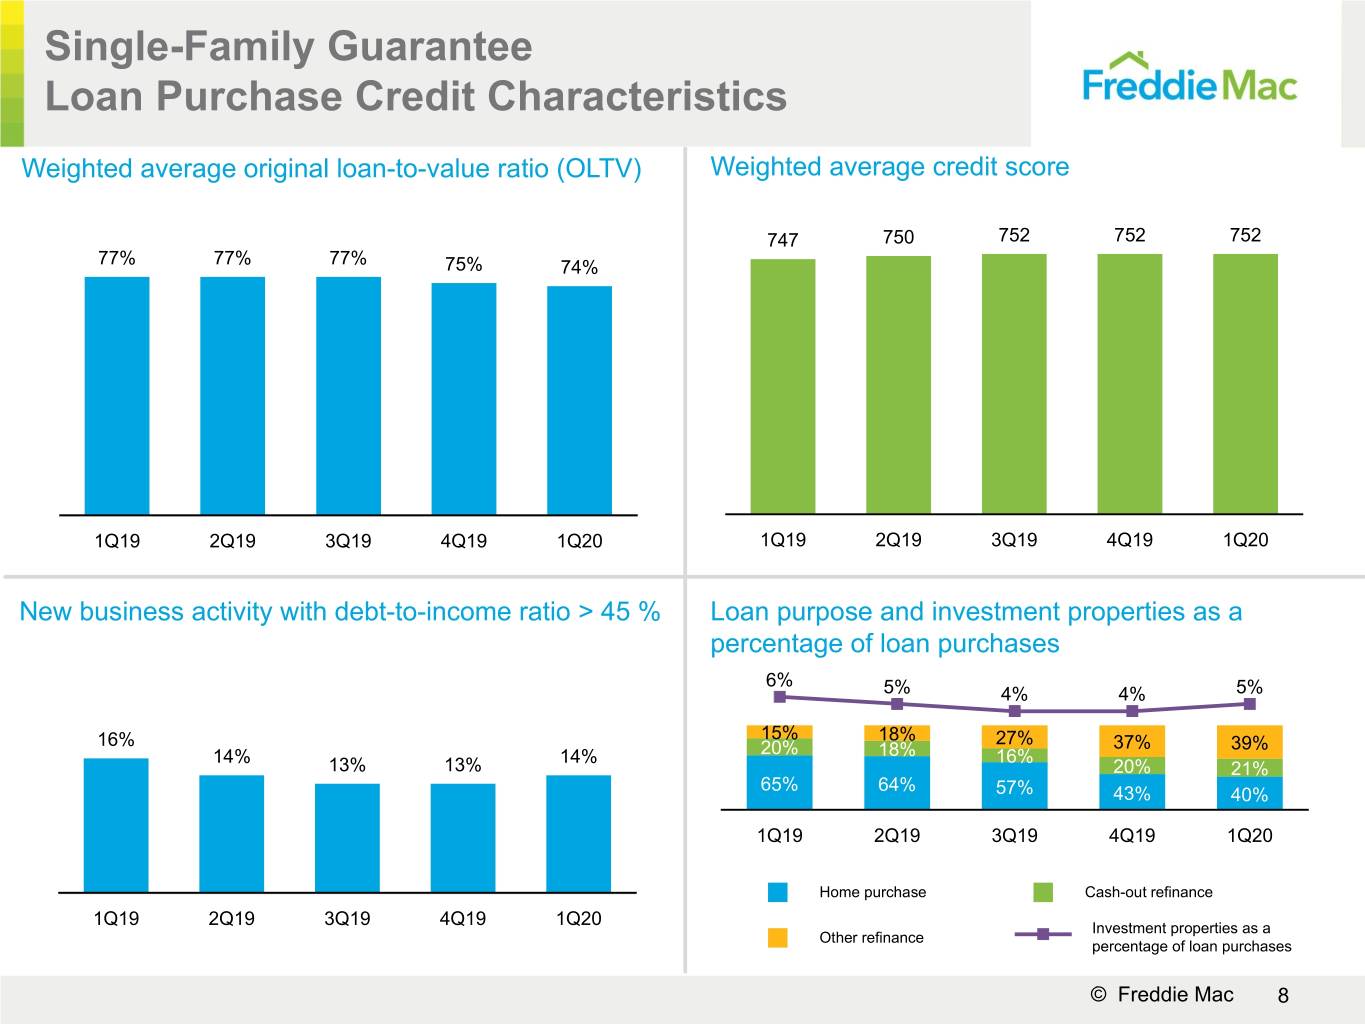
▪ | The weighted average original loan-to-value (LTV) ratio of new business activity was 74% for the first quarter of 2020, down from 75% for the prior quarter, while the weighted average original credit score was 752, unchanged from the prior quarter. |
▪ | The average guarantee fee rate charged on new acquisitions was 49 basis points, up from 48 basis points for the prior quarter. |
▪ | First-time homebuyers represented 47% of new single-family purchase loans in the first quarter of 2020. |
▪ | The company provided funding for 526,000 single-family homes, nearly 309,000 of which were refinance loans. |
• | The Single-Family credit guarantee portfolio increased 6% from March 31, 2019, to $2,020 billion at March 31, 2020, driven by an increase in U.S. single-family mortgage debt outstanding as a result of home price appreciation. |
▪ | The average guarantee fee rate on the Single-Family credit guarantee portfolio was 42 basis points, down from 45 basis points for the prior quarter. |
◦ | The rate decreased in the first quarter of 2020 due to the decreased amortization of single-family upfront fees, net of hedging, driven by a lower prepayment rate, partially offset by an increase in contractual guarantee fees as older vintages were replaced by acquisitions of new loans with higher contractual guarantee fees. |
• | The Single-Family serious delinquency rate declined to 0.60%, from 0.63% at the end of the prior year. |
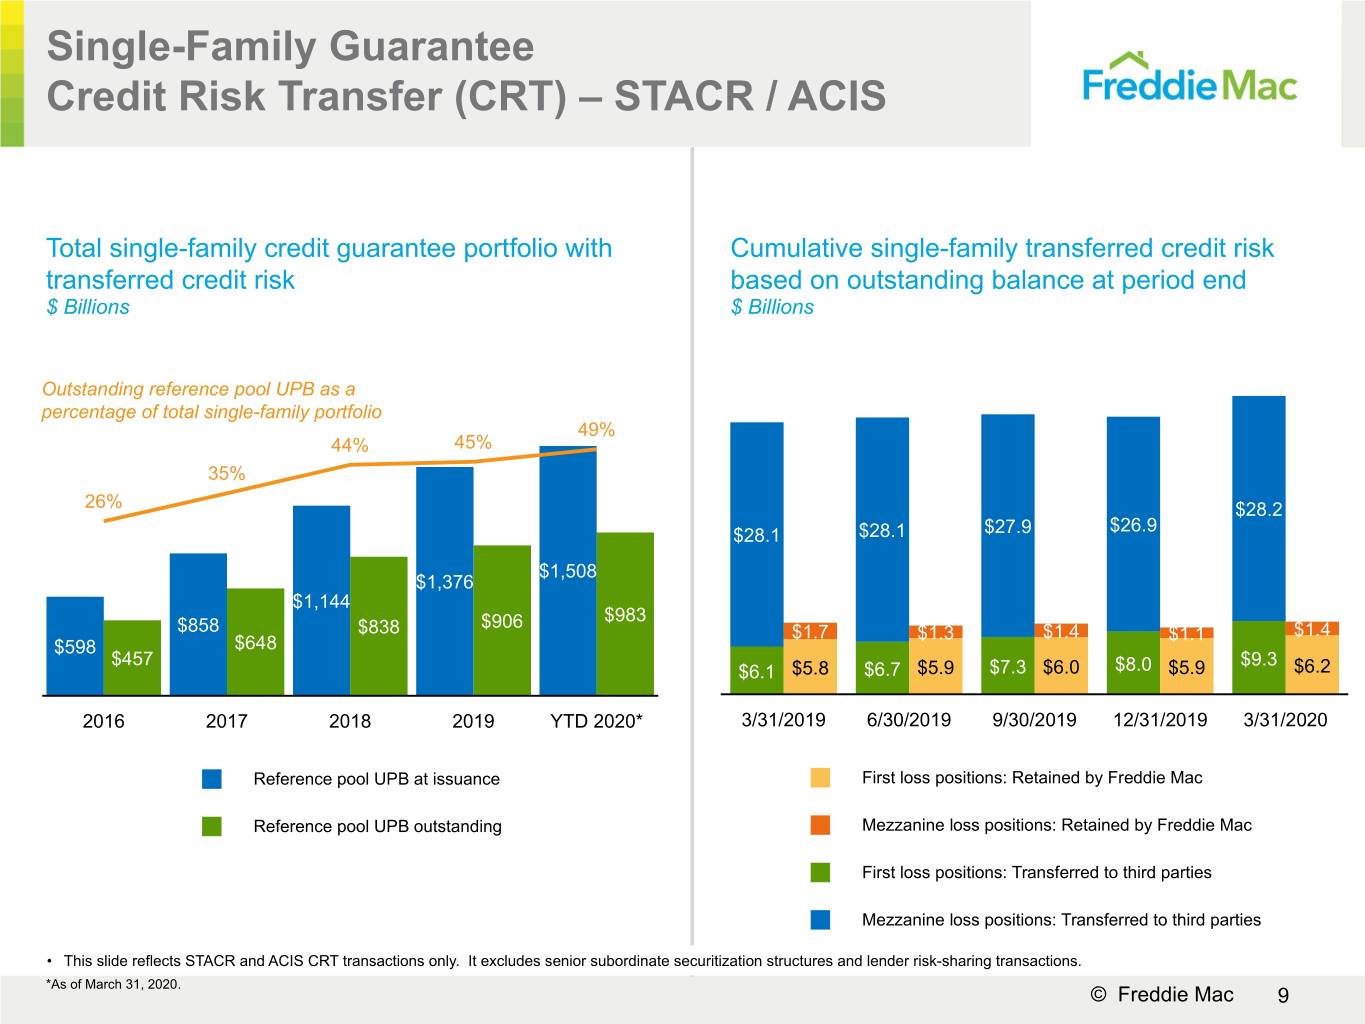
• | The company reduces the amount of conservatorship capital needed for credit risk by shifting the risk of credit losses from Freddie Mac to third-party investors through its CRT transactions, primarily STACR and ACIS transactions. |
▪ | As of March 31, 2020, 51% of the Single-Family credit guarantee portfolio was covered by certain CRT transactions (including STACR, ACIS, certain senior subordination securitization structures, and certain lender risk-sharing transactions), and conservatorship capital needed for credit risk on this population was reduced by approximately 75% through these CRT transactions based on prescribed CCF guidelines. |
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 9
Multifamily Segment
Leading through innovation
Financial Results(1)
(Dollars in millions) | 1Q 2020 | 4Q 2019 | Change | 1Q 2019 | Change | ||||||
Net interest income | $269 | $264 | $5 | $247 | $22 | ||||||
Guarantee fee income | 413 | 227 | 186 | 287 | 126 | ||||||
Investment gains (losses), net | (851) | 317 | (1,168) | (26 | ) | (825) | |||||
Other income (loss) | 37 | 22 | 15 | 29 | 8 | ||||||
Net revenues | (132) | 830 | (962) | 537 | (669) | ||||||
Credit-related expense | (43) | (2) | (41) | (5 | ) | (38) | |||||
Administrative expense | (120) | (146) | 26 | (112 | ) | (8) | |||||
Other expense | (5) | (14) | 9 | (6 | ) | 1 | |||||
Operating expense | (125) | (160) | 35 | (118 | ) | (7) | |||||
Segment Earnings (Losses) before income tax (expense) benefit | (300) | 668 | (968) | 414 | (714) | ||||||
Income tax (expense) benefit | 62 | (135) | 197 | (84 | ) | 146 | |||||
Segment Earnings (Losses), net of taxes | (238) | 533 | (771) | 330 | (568) | ||||||
Total other comprehensive income (loss), net of tax | 64 | (31) | 95 | 65 | (1) | ||||||
Total comprehensive income (loss) | $(174) | $502 | $(676) | $395 | $(569) | ||||||
(1) | The financial performance of the company’s Multifamily segment is measured based on its contribution to GAAP comprehensive income (loss). |
Key Drivers
Comprehensive income decreased from the prior quarter, primarily due to:
• | Investment losses (net of other comprehensive income), primarily driven by increased spread-related fair value losses due to spread widening in the first quarter of 2020, combined with losses on derivatives used to economically hedge index lock commitments due to interest rate declines as a result of the market volatility caused by the pandemic; |
▪ | Economic hedging losses will be mostly offset in the second quarter of 2020 as the index locks become loan purchase commitments that are measured at fair value; and |
• | Higher guarantee fee income, driven by improvements in the fair value of guarantee assets due to declines in interest rates. |
Business Highlights
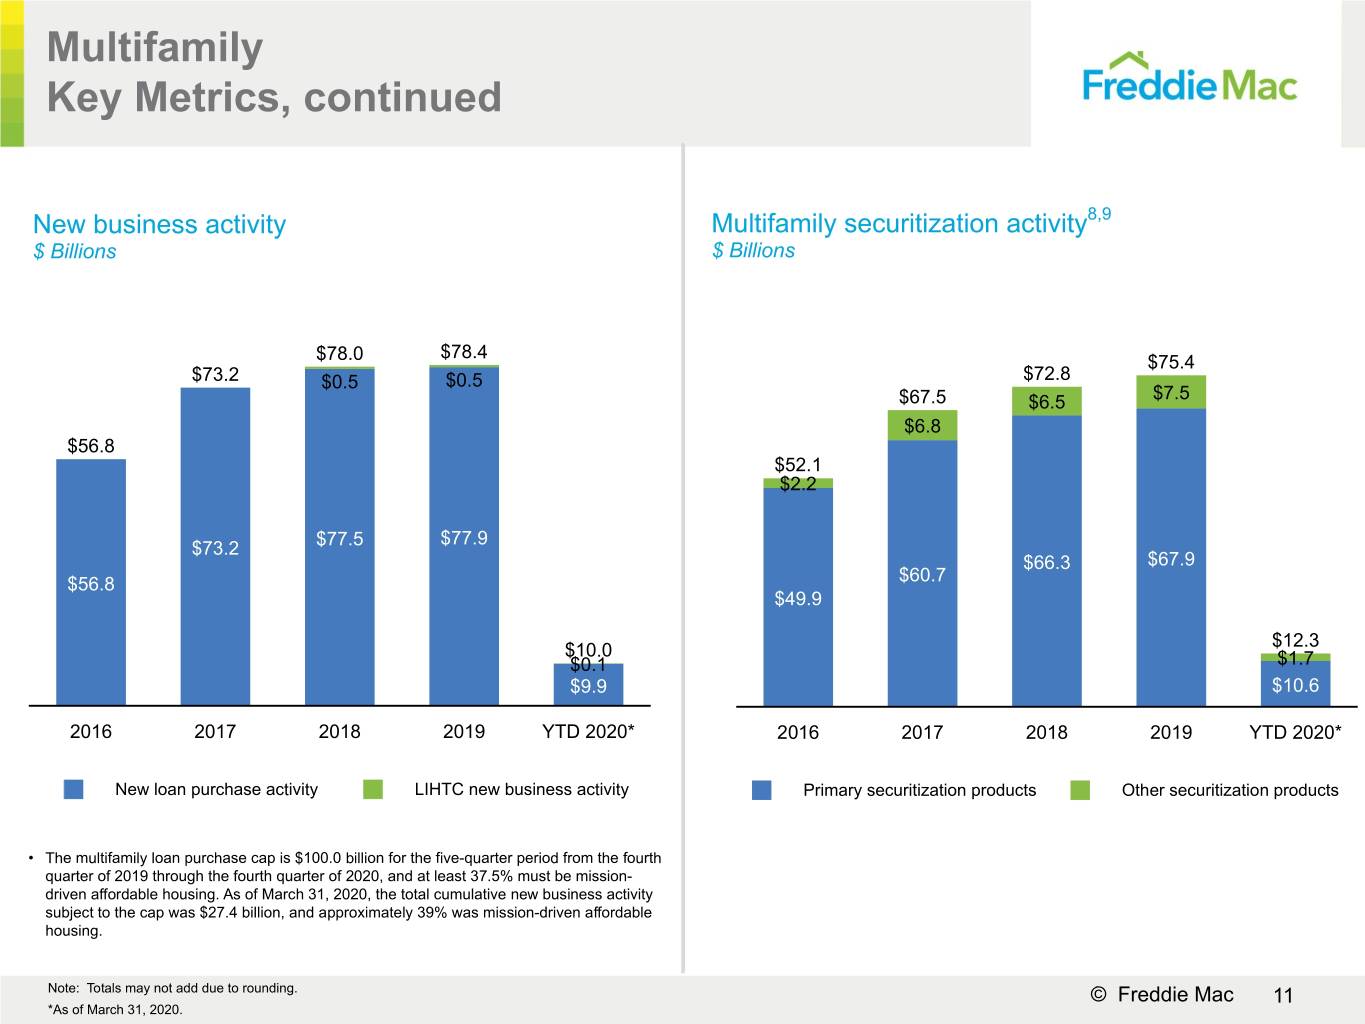
• | New business activity was $10.0 billion, a 44% decrease from the prior quarter, as funding activity is typically higher at year-end. |
▪ | In September 2019, FHFA announced a revised loan purchase cap structure for the multifamily business. The loan purchase cap is $100.0 billion for the five-quarter period from the fourth quarter of 2019 through the fourth quarter of 2020 and at least 37.5% of the new multifamily business must be mission-driven, affordable housing over the same five-quarter period. |
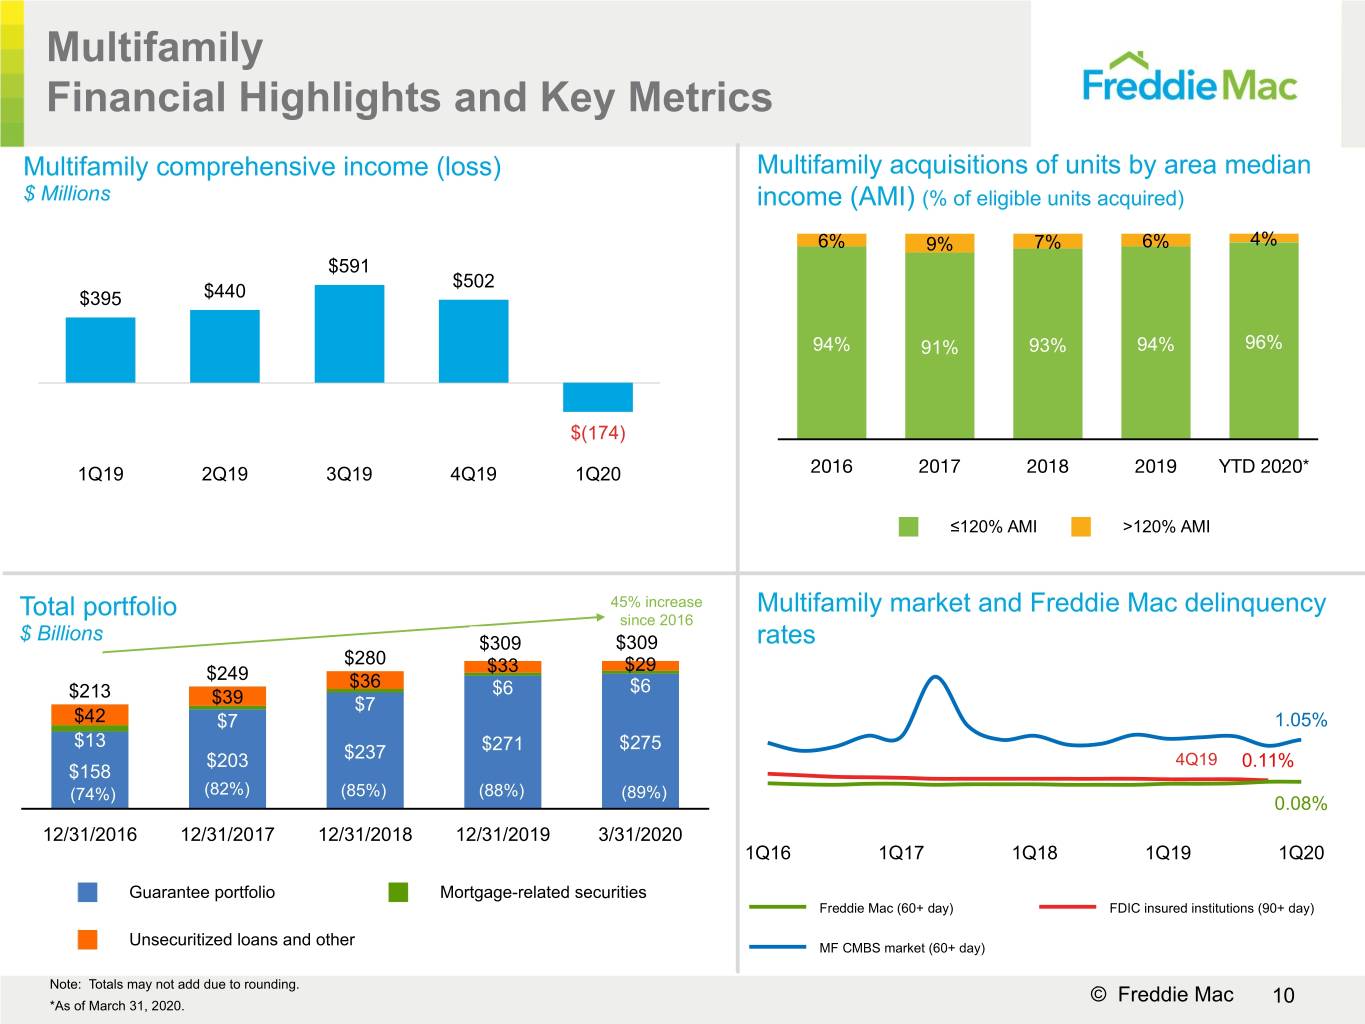
◦ | As of March 31, 2020, the total cumulative new business activity subject to the cap was $27.4 billion. Approximately 39% of this activity was mission-driven, affordable housing. |
▪ | The weighted average original LTV ratio of new business activity was 69% for the first quarter of 2020, substantially unchanged from the prior quarter. |
▪ | The company provided financing for more than 111,000 rental units. |
▪ | 96% of the eligible multifamily rental units financed in the first quarter of 2020 were affordable to families earning at or below 120% of area median incomes. |
• | The Multifamily guarantee portfolio increased to $275 billion, driven by new securitization activity. |
• | The Multifamily delinquency rate remained low at 0.08%. |
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 10
• | As of March 31, 2020, the company had cumulatively transferred the large majority of expected and stress credit risk on the Multifamily guarantee portfolio, primarily through subordination in its securitizations. |
▪ | In addition, nearly all of the company's securitization activities shifted substantially all the interest-rate and liquidity risk associated with the underlying collateral away from Freddie Mac to third-party investors. |
Capital Markets Segment
Innovating the distribution of loans and securities into the mortgage market and actively reducing risk for taxpayers
Financial Results(1)
(Dollars in millions) | 1Q 2020 | 4Q 2019 | Change | 1Q 2019 | Change | |||||
Net interest income | $509 | $484 | $25 | $758 | $(249) | |||||
Investment gains (losses), net | (427) | 552 | (979) | (36) | (391) | |||||
Other income (loss) | (201) | (62) | (139) | (206) | 5 | |||||
Net revenues | (119) | 974 | (1,093) | 516 | (635) | |||||
Administrative expense | (95) | (127) | 32 | (92) | (3) | |||||
Other expense | (9) | (45) | 36 | (1) | (8) | |||||
Operating expense | (104) | (172) | 68 | (93) | (11) | |||||
Segment Earnings (Losses) before income tax (expense) benefit | (223) | 802 | (1,025) | 423 | (646) | |||||
Income tax (expense) benefit | 46 | (163) | 209 | (86) | 132 | |||||
Segment Earnings (Losses), net of taxes | (177) | 639 | (816) | 337 | (514) | |||||
Total other comprehensive income (loss), net of tax | 387 | (100) | 487 | 197 | 190 | |||||
Total comprehensive income (loss) | $210 | $539 | $(329) | $534 | $(324) | |||||
(1) | The financial performance of the company’s Capital Markets segment is measured based on its contribution to GAAP comprehensive income (loss). |
Key Drivers
• | Comprehensive income decreased from the prior quarter, primarily due to: |
▪ | Higher fair value losses on investments (some of which are recorded in other comprehensive income) due to spread widening, partially offset by fair value gains due to lower interest rates, combined with losses from derivatives due to lower interest rates, most of which were deferred due to the company’s effective use of hedge accounting. Spread changes and lower interest rates were both driven by significant market volatility caused by the pandemic; |
▪ | Lower gains on reperforming loan sales due to a lower volume of dispositions; and |
▪ | Higher amortization expense in other income (loss) due to the timing difference in amortization related to prepayments between the debt of consolidated trusts and the underlying mortgage loans; partially offset by |
▪ | Increased net interest income driven by lower amortization expense due to a decrease in loan prepayments. |
Business Highlights
• | Freddie Mac continued to maintain a presence in the agency mortgage-related securities market to strategically support the guarantee business. |
• | While the company continued to actively reduce its holdings of less liquid assets during the first quarter of 2020, the effect of the pandemic on market conditions negatively affected the overall liquidity of the company's portfolios. In addition, although FHFA has instructed the company to maintain loans in COVID-19 payment forbearance plans in mortgage-backed security pools for at least the duration of the forbearance plan, its less liquid assets are likely to increase in future periods as the company will likely purchase a higher amount of delinquent and modified loans out of Freddie Mac mortgage-backed security pools. Its less liquid assets are likely to increase in future periods as the company expects its ability to continue to sell less liquid assets at acceptable prices may be negatively affected by the market volatility caused by the pandemic. |
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 11
Housing Market Support
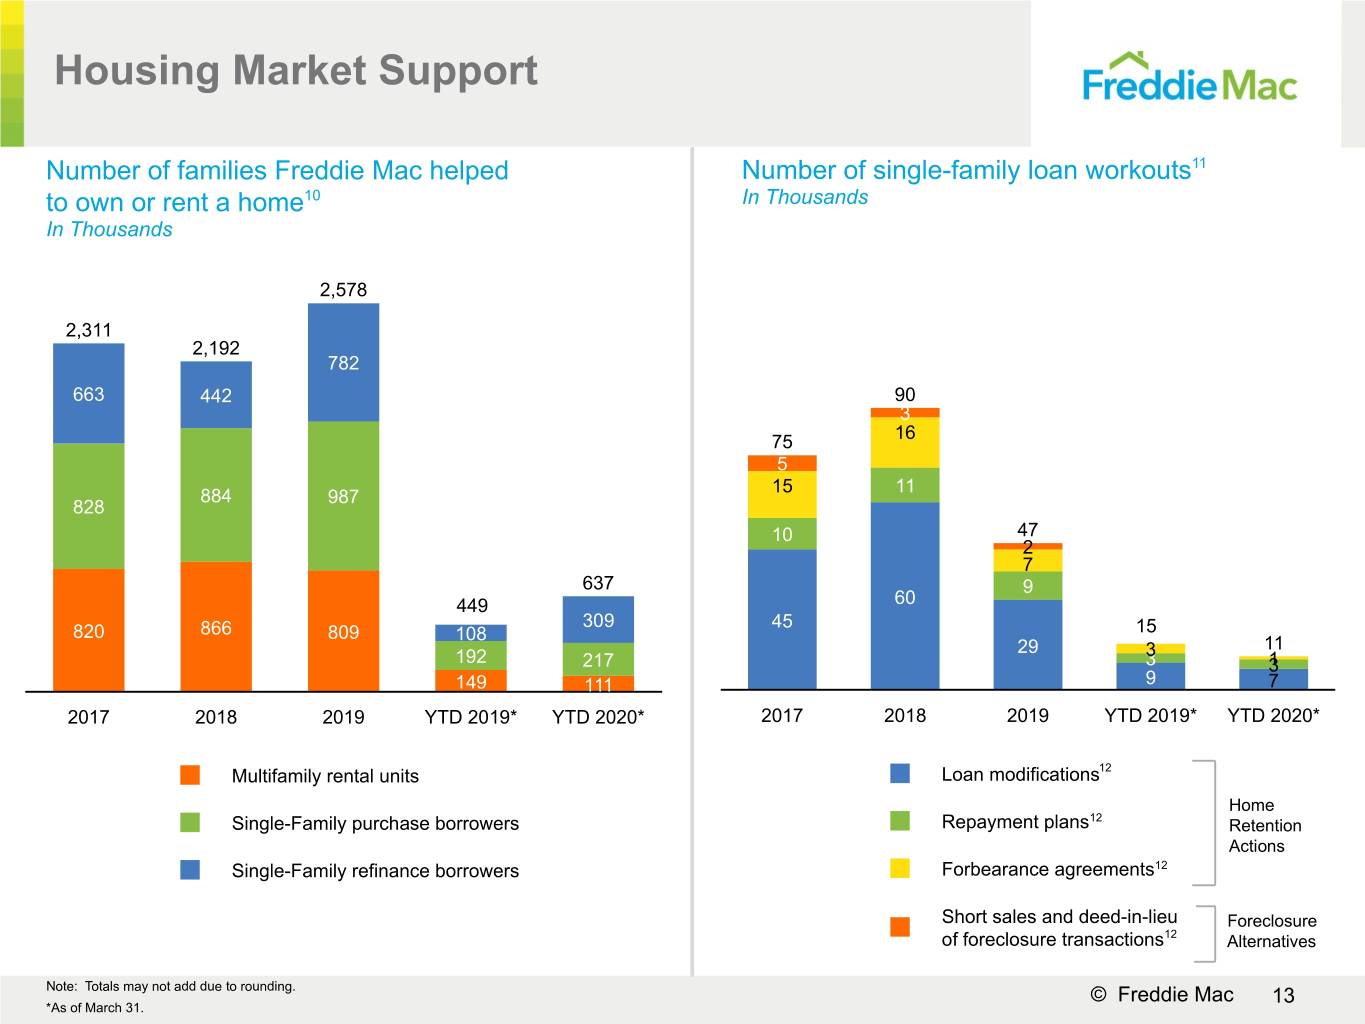
Freddie Mac supports the U.S. housing market by executing its Charter Mission to ensure credit availability for new and refinanced single-family mortgages as well as for rental housing, and by helping struggling homeowners avoid foreclosure. Despite the significant challenges presented by the pandemic, the company remains open for business.
Mortgage Funding – Freddie Mac provided approximately $152 billion in liquidity to the market in the three months ended March 31, 2020, funding:
• | Nearly 526,000 single-family homes, approximately 309,000 of which were refinance loans; and |
• | More than 111,000 multifamily rental units. |
Number of Families Helped to Own or Rent a Home
(In Thousands)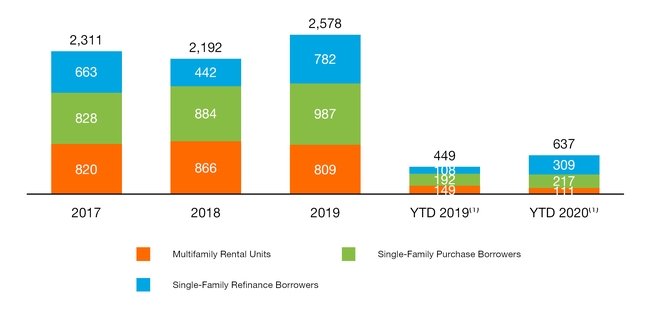
(1) As of March 31.
Amounts may not add due to rounding.
Preventing Foreclosures – Freddie Mac continued to help struggling borrowers retain their homes or otherwise
avoid foreclosure, completing nearly 11,000 single-family loan workouts in the three months ended March 31, 2020 compared to approximately 15,000 in the three months ended March 31, 2019.
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 12
About Freddie Mac’s Conservatorship
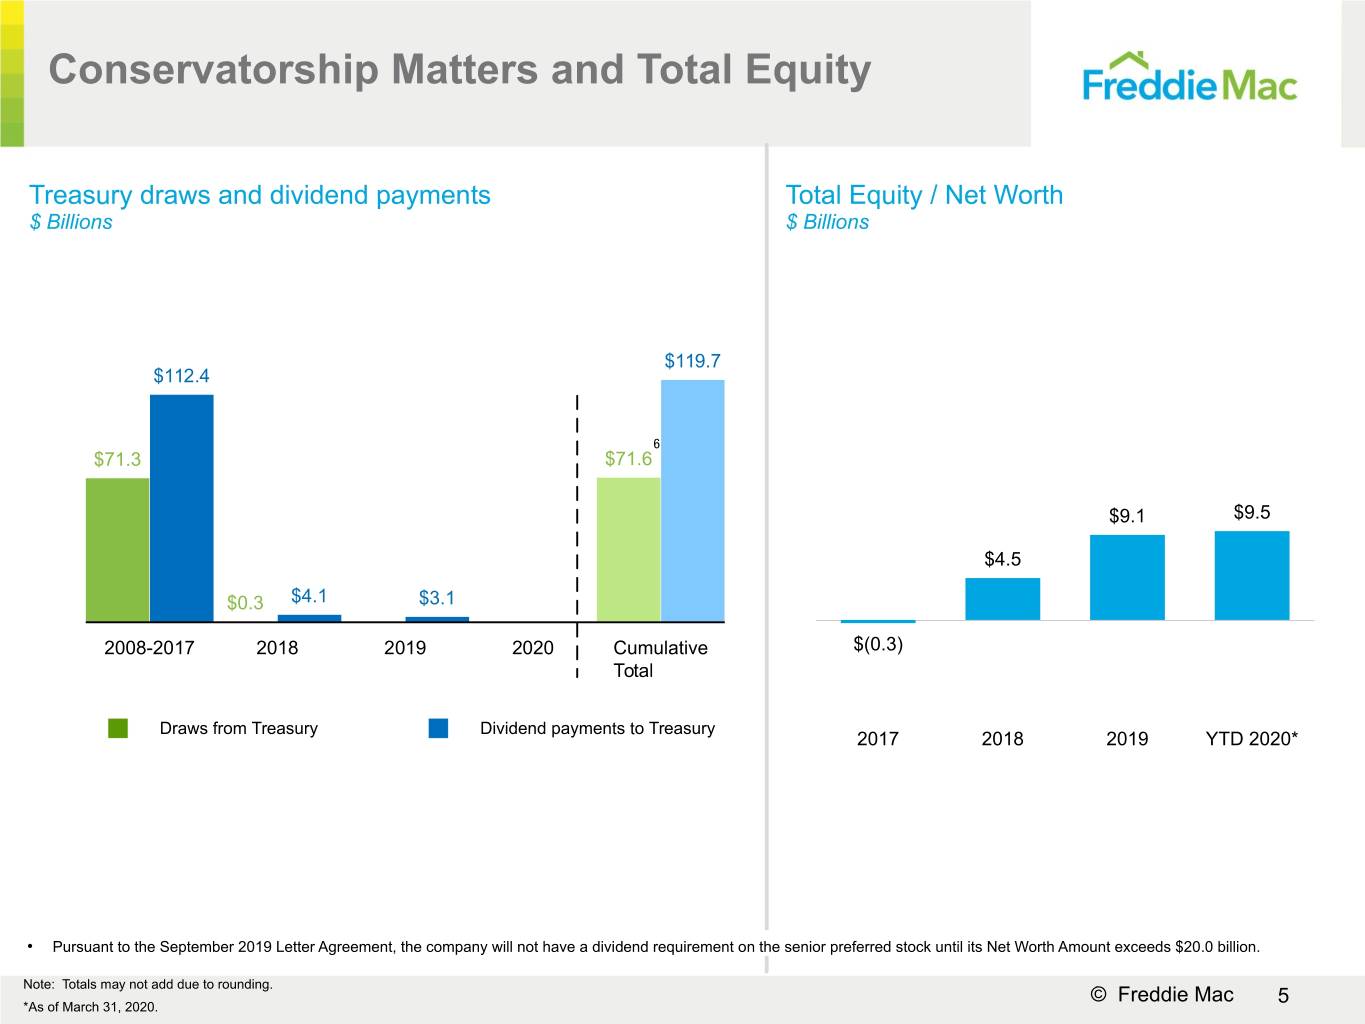
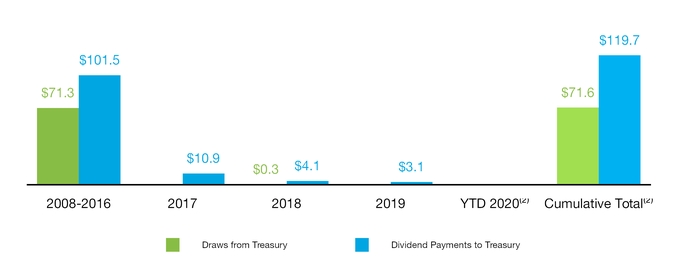
Since September 2008, Freddie Mac has been operating under conservatorship with FHFA as Conservator. The support provided by Treasury pursuant to the Purchase Agreement enables the company to maintain access to the debt markets and have adequate liquidity to conduct its normal business operations.
Treasury Draws(1) and Dividend Payments
(Dollars in billions)
(1) | Excludes the initial $1 billion liquidation preference of senior preferred stock issued to Treasury in September 2008 as consideration for Treasury’s funding commitment, and the increases in the aggregate liquidation preference of the senior preferred stock pursuant to the December 2017 and September 2019 Letter Agreements. The company received no cash proceeds in connection with the initial $1 billion liquidation preference of senior preferred stock or the $3 billion, $1.8 billion, $1.8 billion, and $2.4 billion increases on December 31, 2017, September 30, 2019, December 31, 2019, and March 31, 2020, respectively. |
(2) | As of March 31, 2020. |
• | As a result of the increase in the Capital Reserve Amount pursuant to the September 2019 Letter Agreement, the company did not have a dividend requirement to Treasury on the senior preferred stock in March 2020, and it will not be required to pay a dividend on the senior preferred stock to Treasury until its Net Worth Amount exceeds $20.0 billion. |
▪ | Pursuant to the September 2019 Letter Agreement, the liquidation preference of the senior preferred stock increased from $79.3 billion to $81.8 billion on March 31, 2020 based on the $2.4 billion increase in the Net Worth Amount during the fourth quarter of 2019. |
◦ | The liquidation preference will increase to $82.2 billion on June 30, 2020 based on the $0.4 billion increase in the Net Worth Amount during the first quarter of 2020. The variance between the company's $0.6 billion comprehensive income and the increase in the liquidation preference is due to an adjustment to retained earnings made on January 1, 2020, related to the adoption of CECL, which totaled $0.2 billion, net of income taxes. |
• | The amount of funding available to Freddie Mac under the Purchase Agreement remained $140.2 billion at March 31, 2020. |
Amounts may not add due to rounding.
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 13
Additional Information
For more information, including information related to Freddie Mac’s financial results, conservatorship, and related matters, see the company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2020 and the company’s Financial Results Supplement. These documents are available on the Investor Relations page of the company’s website at www.FreddieMac.com/investors.
Additional information about Freddie Mac and its business is also set forth in the company’s other filings with the SEC, which are available on the Investor Relations page of the company’s website at www.FreddieMac.com/investors and the SEC’s website at www.sec.gov. Freddie Mac encourages all investors and interested members of the public to review these materials for a more complete understanding of the company’s financial results and related disclosures.
Webcast Announcement
Management will host a conference call at 9 a.m. Eastern Time on April 30, 2020 to discuss the company’s results with the media. The conference call will be concurrently webcast. To access the live audio webcast, use the following link: https://edge.media-server.com/mmc/p/x3m5nirr. The replay will be available on the company’s website at www.FreddieMac.com/investors for approximately 30 days. All materials related to the call will be available on the Investor Relations page of the company’s website at www.FreddieMac.com/investors.
Media Contact: Frederick Solomon (703) 903-3861 | Investor Contact: Laurie Garthune (571) 382-4732 |
* * * *
This press release contains forward-looking statements, which may include statements pertaining to the conservatorship, the company’s current expectations and objectives for its Single-Family Guarantee, Multifamily, and Capital Markets segments, its efforts to assist the housing market, liquidity and capital management, economic and market conditions and trends, the effects of the COVID-19 pandemic and actions taken in response thereto on its business, financial condition, and liquidity, its market share, the effect of legislative and regulatory developments and new accounting guidance, credit quality of loans the company owns or guarantees, the costs and benefits of the company’s CRT transactions, and results of operations and financial condition on a GAAP, Segment Earnings, non-GAAP, and fair value basis. Forward-looking statements involve known and unknown risks and uncertainties, some of which are beyond the company’s control. Management’s expectations for the company’s future necessarily involve a number of assumptions, judgments, and estimates, and various factors, including changes in market conditions, liquidity, mortgage spreads, credit outlook, uncertainty about the duration and severity, and effects of, the COVID-19 pandemic and actions taken in response thereto, actions by the U.S. government (including FHFA, Treasury, Congress, and state and local governments), and the impacts of legislation or regulations and new or amended accounting guidance, could cause actual results to differ materially from these expectations. These assumptions, judgments, estimates, and factors are discussed in the company’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2020, which is available on the Investor Relations page of the company’s website at www.FreddieMac.com/investors and the SEC’s website at www.sec.gov. The company undertakes no obligation to update forward-looking statements it makes to reflect events or circumstances occurring after the date of this press release.
Freddie Mac makes home possible for millions of families and individuals by providing mortgage capital to lenders. Since its creation by Congress in 1970, the company has made housing more accessible and affordable for homebuyers and renters in communities nationwide. The company is building a better housing finance system for homebuyers, renters, lenders, and taxpayers. Learn more at FreddieMac.com, Twitter @FreddieMac and Freddie Mac’s blog FreddieMac.com/blog.
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 14
FREDDIE MAC
Condensed Consolidated Statements of Comprehensive Income (Loss) (Unaudited)
(In millions, except share-related amounts) | 1Q 2020 | 4Q 2019 | 1Q 2019 | ||||||
Interest income | |||||||||
Mortgage loans | $16,632 | $16,851 | $17,946 | ||||||
Investment securities | 652 | 678 | 689 | ||||||
Other | 308 | 378 | 351 | ||||||
Total interest income | 17,592 | 17,907 | 18,986 | ||||||
Interest expense | (14,807 | ) | (14,549 | ) | (15,833 | ) | |||
Net interest income | 2,785 | 3,358 | 3,153 | ||||||
Non-interest income (loss) | |||||||||
Guarantee fee income | 377 | 239 | 290 | ||||||
Investment gains (losses), net | (835 | ) | 901 | (513 | ) | ||||
Other income (loss) | 95 | 75 | (17 | ) | |||||
Non-interest income (loss) | (363 | ) | 1,215 | (240 | ) | ||||
Net revenues | 2,422 | 4,573 | 2,913 | ||||||
Benefit (provision) for credit losses | (1,233 | ) | 272 | 135 | |||||
Non-interest expense | |||||||||
Salaries and employee benefits | (341 | ) | (451 | ) | (322 | ) | |||
Professional services | (76 | ) | (103 | ) | (105 | ) | |||
Other administrative expense | (170 | ) | (193 | ) | (151 | ) | |||
Total administrative expense | (587 | ) | (747 | ) | (578 | ) | |||
Credit enhancement (expense) benefit, net | 236 | (214 | ) | (158 | ) | ||||
REO operations expense | (85 | ) | (57 | ) | (33 | ) | |||
Temporary Payroll Tax Cut Continuation Act of 2011 expense | (432 | ) | (420 | ) | (390 | ) | |||
Other expense | (103 | ) | (157 | ) | (124 | ) | |||
Non-interest expense | (971 | ) | (1,595 | ) | (1,283 | ) | |||
Income (loss) before income tax (expense) benefit | 218 | 3,250 | 1,765 | ||||||
Income tax (expense) benefit | (45 | ) | (658 | ) | (358 | ) | |||
Net income (loss) | 173 | 2,592 | 1,407 | ||||||
Other comprehensive income (loss), net of taxes and reclassification adjustments | |||||||||
Changes in unrealized gains (losses) related to available-for-sale securities | 438 | (139 | ) | 246 | |||||
Changes in unrealized gains (losses) related to cash flow hedge relationships | 13 | 14 | 18 | ||||||
Changes in defined benefit plans | (2 | ) | (19 | ) | (6 | ) | |||
Total other comprehensive income (loss), net of taxes and reclassification adjustments | 449 | (144 | ) | 258 | |||||
Comprehensive income (loss) | $622 | $2,448 | $1,665 | ||||||
Net income (loss) | $173 | $2,592 | $1,407 | ||||||
Undistributed net worth sweep, senior preferred stock dividends, or future increase in senior preferred stock liquidation preference | (382) | (2,448) | (1,665) | ||||||
Net income (loss) attributable to common stockholders | $(209) | $144 | $(258) | ||||||
Net income (loss) per common share — basic and diluted | $(0.06) | $0.04 | $(0.08) | ||||||
Weighted average common shares outstanding (in millions) — basic and diluted | 3,234 | 3,234 | 3,234 | ||||||
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 15
FREDDIE MAC
Condensed Consolidated Balance Sheets (Unaudited)
March 31 | December 31, | |||||
(In millions, except share-related amounts) | 2020 | 2019 | ||||
Assets | ||||||
Cash and cash equivalents (includes $17,920 and $991 of restricted cash and cash equivalents) | $24,324 | $5,189 | ||||
Securities purchased under agreements to resell | 45,968 | 56,271 | ||||
Investment securities, at fair value | 79,189 | 75,711 | ||||
Mortgage loans held-for-sale (includes $13,518 and $15,035 at fair value) | 32,502 | 35,288 | ||||
Mortgage loans held-for-investment (net of allowance for credit losses of $6,121 and $4,234) | 2,014,155 | 1,984,912 | ||||
Accrued interest receivable | 6,841 | 6,848 | ||||
Derivative assets, net | 2,815 | 844 | ||||
Deferred tax assets, net | 4,629 | 5,918 | ||||
Other assets (includes $4,914 and $4,627 at fair value) | 31,561 | 22,799 | ||||
Total assets | $2,241,984 | $2,193,780 | ||||
Liabilities and equity | ||||||
Liabilities | ||||||
Accrued interest payable | $6,271 | $6,559 | ||||
Debt (includes $3,214 and $3,938 at fair value) | 2,216,135 | 2,169,685 | ||||
Derivative liabilities, net | 2,226 | 372 | ||||
Other liabilities | 7,848 | 8,042 | ||||
Total liabilities | 2,232,480 | 2,184,658 | ||||
Commitments and contingencies | ||||||
Equity | ||||||
Senior preferred stock (liquidation preference of $81,770 and $79,322) | 72,648 | 72,648 | ||||
Preferred stock, at redemption value | 14,109 | 14,109 | ||||
Common stock, $0.00 par value, 4,000,000,000 shares authorized, 725,863,886 shares issued and 650,059,033 shares outstanding | — | — | ||||
Additional paid-in capital | — | — | ||||
Retained earnings (accumulated deficit) | (74,255 | ) | (74,188 | ) | ||
AOCI, net of taxes, related to: | ||||||
Available-for-sale securities | 1,056 | 618 | ||||
Cash flow hedge relationships | (231 | ) | (244 | ) | ||
Defined benefit plans | 62 | 64 | ||||
Total AOCI, net of taxes | 887 | 438 | ||||
Treasury stock, at cost, 75,804,853 shares | (3,885 | ) | (3,885 | ) | ||
Total equity | 9,504 | 9,122 | ||||
Total liabilities and equity | $2,241,984 | $2,193,780 | ||||
The table below presents the carrying value and classification of the assets and liabilities of consolidated variable interest entities (VIEs) on the company's condensed consolidated balance sheets. | ||||||
March 31 | December 31, | |||||
(In millions) | 2020 | 2019 | ||||
Condensed Consolidated Balance Sheet Line Item | ||||||
Assets: | ||||||
Mortgage loans held-for-investment | $1,963,630 | $1,940,523 | ||||
All other assets | 53,415 | 40,598 | ||||
Total assets of consolidated VIEs | $2,017,045 | $1,981,121 | ||||
Liabilities: | ||||||
Debt | $1,930,005 | $1,898,355 | ||||
All other liabilities | 5,551 | 5,537 | ||||
Total liabilities of consolidated VIEs | $1,935,556 | $1,903,892 | ||||
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 16
FREDDIE MAC
Non-GAAP Reconciliations
The company’s GAAP net interest income includes the spread earned on its investment activities plus the guarantee fees earned by its single-family business. Adjusted net interest income is the net spread earned on the company’s investment activities, including the cost of funds associated with using derivatives. Net interest yield, GAAP and adjusted, is calculated as annualized quarterly GAAP or adjusted net interest income divided by the average balance of the underlying assets and liabilities. | |||||||||||||||
Reconciliation of GAAP Net Interest Income to Adjusted Net Interest Income (pre-tax) | |||||||||||||||
(Dollars in millions) | 1Q 2019 | 2Q 2019 | 3Q 2019 | 4Q 2019 | 1Q 2020 | ||||||||||
GAAP net interest income | $3,153 | $2,927 | $2,410 | $3,358 | $2,785 | ||||||||||
Reclassifications: | |||||||||||||||
Guarantee fee income reclassified to adjusted guarantee fee income (1)(2) | (2,022 | ) | (2,287 | ) | (2,486 | ) | (2,607 | ) | (2,561 | ) | |||||
Accrual of periodic cash settlements reclassified from derivative gain (loss) (3) | (54 | ) | (42 | ) | (47 | ) | (129 | ) | (176 | ) | |||||
Hedge accounting impact (4) | (267 | ) | 13 | 517 | (11 | ) | 350 | ||||||||
Other reclassifications (5) | 195 | 402 | 395 | 137 | 380 | ||||||||||
Total reclassifications | (2,148 | ) | (1,914 | ) | (1,621 | ) | (2,610 | ) | (2,007 | ) | |||||
Adjusted net interest income | $1,005 | $1,013 | $789 | $748 | $778 | ||||||||||
Average balance of assets and liabilities, GAAP (in billions) | $2,062 | $2,089 | $2,120 | $2,162 | $2,205 | ||||||||||
Average balance of assets and liabilities, adjusted (in billions) | $293 | $303 | $311 | $319 | $324 | ||||||||||
The company's GAAP guarantee fees are primarily those generated by the company's multifamily business. Adjusted guarantee fee income consists of the revenues from guarantee fees from both the single-family and multifamily businesses, net of the 10 basis point guarantee fee remitted to Treasury as part of the Temporary Payroll Tax Cut Continuation Act of 2011. | |||||||||||||||
Reconciliation of GAAP Guarantee Fee Income to Adjusted Guarantee Fee Income (pre-tax) | |||||||||||||||
(Dollars in millions) | 1Q 2019 | 2Q 2019 | 3Q 2019 | 4Q 2019 | 1Q 2020 | ||||||||||
GAAP guarantee fee income | $290 | $280 | $280 | $239 | $377 | ||||||||||
Reclassifications: | |||||||||||||||
Guarantee fee income reclassified from net interest income (1)(2) | 2,022 | 2,287 | 2,486 | 2,607 | 2,561 | ||||||||||
Temporary Payroll Tax Cut Continuation Act of 2011 expense reclassified from other non-interest expense (6) | (390 | ) | (399 | ) | (408 | ) | (420 | ) | (432 | ) | |||||
Total reclassifications | 1,632 | 1,888 | 2,078 | 2,187 | 2,129 | ||||||||||
Adjusted guarantee fee income | $1,922 | $2,168 | $2,358 | $2,426 | $2,506 | ||||||||||
Columns may not add due to rounding.
For notes on reclassifications, see page 17 of this press release.
Freddie Mac First Quarter 2020 Financial Results
April 30, 2020
Page 17
Notes on Significant Reclassifications
(1) Net guarantee fees, including upfront fees and related hedge amortization and implied guarantee fee income related to unsecuritized loans held in the mortgage-related investments portfolio, are reclassified from GAAP net interest income to adjusted guarantee fee income.
(2) Short-term returns on cash received related to certain upfront fees on single-family loans are reclassified from GAAP net interest income to adjusted guarantee fee income.
(3) The accrual of periodic cash settlements of derivatives is reclassified from GAAP investment gains (losses) to adjusted net interest income to fully reflect the periodic cost associated with the protection provided by these contracts.
(4) Hedge accounting impact consists of removing the effects of hedge accounting including deferred gains and losses on closed cash flow hedges related to forecasted debt issuances.
(5) Other reclassifications primarily relate to items reclassified out of GAAP net interest income, including the amortization related to derivative commitment basis adjustments associated with mortgage-related and non-mortgage-related securities, amortization related to accretion of other-than-temporary impairments on available-for-sale securities, amortization of discounts on loans purchased with deteriorated credit quality that are on accrual status, amortization related to premiums and discounts, including non-cash premiums and discounts, on single-family loans in trusts and on the associated consolidated securities, amortization related to premiums and discounts associated with securities issued by consolidated trusts that were previously held and subsequently transferred to third parties, costs associated with STACR debt note expenses, and internally allocated costs associated with the refinancing of debt related to Multifamily segment held-for-investment loans which were securitized.
(6) The expense related to the Temporary Payroll Tax Cut Continuation Act of 2011 is reclassified from GAAP other non-interest expense to adjusted guarantee fee income. As a result of the reclassification, the revenue and expense related to the legislated 10 basis point increase are netted within adjusted guarantee fee income.