Document
false0001020569 0001020569 2020-08-06 2020-08-06


UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, DC 20549

FORM 8-K

CURRENT REPORT PURSUANT
TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934

Date of report (Date of earliest event reported): August 6, 2020

IRON MOUNTAIN INCORPORATED
(Exact Name of Registrant as Specified in Its Charter)

Delaware
(State or Other Jurisdiction of Incorporation)

1-13045
 
23-2588479
(Commission File Number)
 
(IRS Employer Identification No.)

One Federal Street, Boston, Massachusetts
(Address of Principal Executive Offices)
 
2110
(Zip Code)

(617) 535-4766
(Registrant’s Telephone Number, Including Area Code)

Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:

☐
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425)

☐
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12)

☐
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))

☐
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))


Securities Registered Pursuant to Section 12(b) of the Act:
Title of Each Class
 
Trading Symbol(s)
 
Name Of Each Exchange On Which Registered
Common Stock, $.01 par value per share
 
IRM
 
New York Stock Exchange

Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐

Item 2.02.    Results of Operations and Financial Condition.
On August 6, 2020, Iron Mountain Incorporated, or the Company, issued an earnings press release and supplemental financial information for the quarter ended June 30, 2020. In addition, the Company will be using a slide presentation during its earnings conference call. Copies of the earnings press release, slide presentation and supplemental financial information are furnished as Exhibits 99.1, 99.2 and 99.3, respectively, hereto and posted on the Company’s website, www.ironmountain.com, under “Investors.”
Item 9.01.    Financial Statements and Exhibits.
(d) Exhibits
99.1
99.2
99.3
The information in this report, including Exhibits 99.1, 99.2 and 99.3 is furnished in accordance with SEC Release No. 33-8216 and shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934 (the “Exchange Act”) or otherwise subject to the liabilities of that section, nor shall it be deemed incorporated by reference in any filing under the Securities Act of 1933 or the Exchange Act, regardless of any general incorporation language in such filing.


SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
                    
IRON MOUNTAIN INCORPORATED
 
By:
/s/ Barry Hytinen
Name:
Barry Hytinen
Title:
Executive Vice President and Chief Financial Officer


Date: August 6, 2020


q22020earningspressre_image1.jpg

FOR IMMEDIATE RELEASE

Iron Mountain Reports Second Quarter 2020 Results

BOSTON – August 6, 2020 – Iron Mountain Incorporated (NYSE: IRM), the storage and information management services company, announces financial and operating results for the second quarter of 2020. The conference call / webcast details, earnings call presentation and supplemental financial information, which includes definitions of certain capitalized terms used in this release, are available on Iron Mountain’s Investor Relations website. Reconciliations of non-GAAP measures to the appropriate GAAP measures are included herein.
“I am proud of the way our organization quickly adapted to the challenges presented by the COVID-19 pandemic and is navigating the environment ever since,” said William L. Meaney, president and CEO of Iron Mountain. "A crisis such as COVID tests us on many levels and we are pleased that from the beginning of this crisis, we have taken decisive, yet thoughtful, action to help keep our Mountaineers, their families, and our customers safe all whilst meeting our customers' business needs around the world. At the same time, we took purposeful steps to further strengthen our financial position and liquidity, enhancing our flexibility to continue to invest in our business for the long term, and reward our shareholders with a sustainable dividend. On a less positive front, we found through reflection after the murder of George Floyd, that whilst we have made progress living up to our stated value around building diverse and inclusive teams, we have fallen well short of our intended - and necessary - objectives. For Iron Mountain, Diversity and Inclusion is about social justice as well as a business imperative. It is only by achieving a truly diverse and inclusive workplace, that we will be assured to have both the best talent as well as the level of creativity to continue to serve our customers in the best possible ways. We have recommitted ourselves to this value and are making the necessary changes to make better and faster progress in this area."

Meaney commented on the second-quarter results, “Although our business faced unprecedented challenges and added complexity as a result of the COVID-19 pandemic, our team performed very well during the second quarter, and our results demonstrated the durability and resiliency of our core Storage business. In our Service business, we experienced improvements in our activity levels in June as compared to April and May, across our various product lines.

The early benefits of Project Summit are evident in our results, with $65 million of Adjusted EBITDA benefits realized in the first half from our transformation initiatives. We delivered constant currency Adjusted EBITDA in line with the year-ago level, despite a $58 million revenue decline, resulting in 200 basis points of margin expansion. Our Global Data Center business continues to perform exceptionally well, with strong commercial successes and a growing pipeline. Whilst a high degree of uncertainty remains as we look to the back half of the year, we are confident that the value of Iron Mountain’s new, as well as existing offerings, are even more relevant to our customers today. We remain committed to delivering solutions which address our customers’ needs both today and well into the future."

Financial Performance Highlights for the Second Quarter and Year-to-Date 2020

•
Total reported Revenues for the second quarter were $982.2 million, compared with $1.1 billion in the second quarter of 2019, a decline of 7.9%. Excluding the impact of foreign exchange (FX), total reported Revenues declined 5.6% compared to the prior year, driven by a 21.3% decline in Service revenue, partially offset by a 3.7% increase in Storage revenue. Year to date, total reported Revenues decreased 3.3%, or 1.2%, excluding the impact of FX.
•
Loss from Continuing Operations for the second quarter was $7.1 million, compared with Income from Continuing Operations of $92.3 million in the second quarter of 2019. Loss from Continuing Operations in the second quarter of 2020 included Restructuring Charges of $39.3 million associated with Project Summit and a debt extinguishment charge of $17.0 million related to the early extinguishment of the Company's 43/8% Senior Notes due 2021 and the 6% Senior Notes due 2023. Income from Continuing Operations in the second quarter of 2019 included $1.9 million of Significant Acquisition Costs. Year to date, Income from Continuing Operations was $57.8 million, compared with $122.8 million in 2019. Income from Continuing Operations in 2020 included Restructuring Charges of $80.3 million and Income from Continuing Operations in 2019 included Significant Acquisition Costs of $4.6 million.
•
Adjusted EBITDA for the second quarter was $342.9 million, compared with $350.9 million in the second quarter of 2019. On a constant currency basis, Adjusted EBITDA decreased by 0.1%, driven in part by the aforementioned decline in Service revenue, partially offset by the benefits of Project Summit and the flow through from revenue management, leading to 200 basis points of Adjusted EBITDA margin expansion compared to the second quarter of 2019. Year to date, Adjusted EBITDA was $706.0 million, compared with $675.4 million in 2019, and increased 6.6%, excluding the impact of FX.
•
Reported EPS - Fully Diluted from Continuing Operations for the second quarter was $(0.02), compared with $0.32 in the second quarter of 2019. Year to date, Reported EPS - Fully Diluted from Continuing Operations was $0.20, compared with $0.42 in 2019.
•
Adjusted EPS for the second quarter was $0.22, compared with $0.23 in the second quarter of 2019. Year to date, Adjusted EPS was $0.49, compared with $0.40 in 2019. The structural tax rate was 17.1% in the second quarter of 2020, compared with 17.7% in the second quarter of 2019.
•
Net Loss for the second quarter was $7.1 million compared with Net Income of $92.5 million in the second quarter of 2019. Net Loss in the second quarter of 2020 included the aforementioned Restructuring Charges related to Project Summit and debt extinguishment charge. Year to date, Net Income was $57.8 million compared with $122.9 million in 2019.
•
FFO (Normalized) per share was $0.53 for the second quarter, compared with $0.54 in the second quarter of 2019, or a decrease of 1.9%. Year to date, FFO (Normalized) per share was $1.12, compared with $1.02 in 2019.
•
AFFO was $249.5 million for the second quarter, compared with $209.6 million in the second quarter of 2019, an increase of 19.0%. As compared to Adjusted EBITDA, the increase in AFFO was primarily driven by a tax refund. Year to date, AFFO was $480.7 million, compared with $403.0 million in 2019.
Dividend
On August 5, 2020, Iron Mountain's board of directors declared a quarterly cash dividend of $0.6185 per share for the third quarter. The third-quarter 2020 dividend is payable on October 2, 2020, for shareholders of record on September 15, 2020.

About Iron Mountain
Iron Mountain Incorporated (NYSE: IRM), founded in 1951, is the global leader for storage and information management services. Trusted by more than 225,000 organizations around the world, and with a real estate network of more than 90 million square feet across more than 1,480 facilities in approximately 50 countries, Iron Mountain stores and protects billions of valued assets, including critical business information, highly sensitive data, and cultural and historical artifacts. Providing solutions that include secure records storage, information management, digital transformation, secure destruction, as well as data centers, cloud services and art storage and logistics, Iron Mountain helps customers lower cost and risk, comply with regulations, recover from disaster, and enable a more digital way of working. Visit www.ironmountain.com for more information.
Investor Relations Contacts: 
 
 
Greer Aviv
 
Nathan McCurren
Senior Vice President, Investor Relations
 
Director, Investor Relations


Forward Looking Statements
Safe Harbor Statement Under the Private Securities Litigation Reform Act of 1995: This release contains certain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 and other securities laws and is subject to the safe-harbor created by such Act. Forward-looking statements include, but are not, limited to statements concerning our operations, economic performance, financial condition, goals, beliefs, future growth strategies, plans and current expectations, such as statements about: (i) expectations for the remainder of 2020, (ii) the expected impact of COVID-19 on our operations and financial conditions, (iii) new service offerings, (iv) expected benefits, costs and actions related to Project Summit; (v) planned 2020 capital expenditures, M&A and other investments; (vi) stabilization of our data center developments and expectation as to data center leasing activity for 2020; (vii) expectations with respect to change in volume of records stored with us; (viii) expectations related to our revenue management programs and continuous improvement initiatives, (ix) the durability of our core storage business, (x) our expected leverage; (xi) our dividend policy and targeted dividend payments; and (xii) longer term capital allocation, strategy and other goals. When we use words such as "believes," "expects," "anticipates," "estimates" or similar expressions, we are making forward-looking statements. Although we believe that our forward looking statements are based on reasonable assumptions, our expected results may not be achieved, and actual results may differ materially from our expectations.

These forward-looking statements are subject to various known and unknown risks, uncertainties and other factors. Important factors that could cause actual results to differ from expectations include the (i) impact of COVID-19 on our operations, (ii) our ability to remain qualified for taxation as a real estate investment trust for U.S. federal income tax purposes; (iii) the adoption of alternative technologies and shifts by our customers to storage of data through non-paper based technologies; (iv) changes in customer preferences and demand for our storage and information management services; (v) the cost and our ability to comply with laws, regulations and customer demands relating to data security and privacy issues, as well as fire and safety standards; (vi) our ability or inability to execute our strategic growth plan, expand internationally, complete acquisitions on satisfactory terms, and to integrate acquired companies efficiently; (vii) changes in the amount of our growth and recurring capital expenditures and our ability to raise capital and invest according to plan; (viii) the impact of litigation or disputes that may arise in connection with incidents in which we fail to protect our customers' information or our internal records or IT systems and the impact of such incidents on our reputation and ability to compete; (ix) our ability to execute on Project Summit and the potential impacts of Project Summit on our ability to retain and recruit employees and execute on our strategy (x) changes in the price for our storage and information management services relative to the cost of providing such storage and information management services; (xi) changes in the political and economic environments in the countries in which our international subsidiaries operate and changes in the global political climate; (xii) the impact of executing on our growth strategy through joint ventures; (xiii) our ability to comply with our existing debt obligations and restrictions in our debt instruments or to obtain additional financing to meet our working capital needs; (xiv) the impact of service interruptions or equipment damage and the cost of power on our data center operations; (xv) changes in the cost of our debt; (xvi) the impact of alternative, more attractive investments on dividends; (xvii) the cost or potential liabilities associated with real estate necessary for our business; (xviii) the performance of business partners upon whom we depend for technical assistance or management expertise; (xix) other trends in competitive or economic conditions affecting our financial condition or results of operations not presently contemplated; and (xx) other risks described more fully in our filings with the Securities and Exchange Commission, including under the caption “Risk Factors” in our periodic reports or incorporated therein. You should not rely upon forward-looking statements except as statements of our present intentions and of our present expectations, which may or may not occur. Except as required by law, we undertake no obligation to release publicly the result of any revision to these forward-looking statements that may be made to reflect events or circumstances after the date hereof or to reflect the occurrence of unanticipated events.

Reconciliation of Non-GAAP Measures:

Throughout this release, Iron Mountain discusses (1) Adjusted EBITDA, (2) Adjusted Earnings per Share (“Adjusted EPS”), (3) Funds from Operations (“FFO Nareit”), (4) FFO (Normalized) and (5) Adjusted Funds from Operations (“AFFO”). These measures do not conform to accounting principles generally accepted in the United States (“GAAP”). These non-GAAP measures are supplemental metrics designed to enhance our disclosure and to provide additional information that we believe to be important for investors to consider in addition to, but not as a substitute for, other measures of financial performance reported in accordance with GAAP, such as operating income, income (loss) from continuing operations, net income (loss) attributable to Iron Mountain Incorporated or cash flows from operating activities from continuing operations (as determined in accordance with GAAP). The reconciliation of these measures to the appropriate GAAP measure, as required by Regulation G under the Securities Exchange Act of 1934, as amended, and their definitions are included later in this release.


Consolidated Balance Sheets
(Unaudited; dollars in thousands)
 
 
6/30/2020
 
 
12/31/2019
 
ASSETS


Current Assets:


Cash and Cash Equivalents
 
$
907,180
 
 
$
193,555
 
Accounts Receivable, Net
 
805,901
 
 
850,701
 
Other Current Assets
 
184,292
 
 
192,083
 
Total Current Assets
 
$
1,897,373
 
 
$
1,236,339
 
Property, Plant and Equipment:


Property, Plant and Equipment
 
$
8,074,520
 
 
$
8,048,906
 
Less: Accumulated Depreciation
 
(3,538,792
)
 
(3,425,869
)
Property, Plant and Equipment, Net
 
$
4,535,728
 
 
$
4,623,037
 
Other Assets, Net:


Goodwill
 
$
4,421,062
 
 
$
4,485,209
 
Customer Relationships, Customer Inducements and Data Center Lease-Based Intangibles
 
1,346,282
 
 
1,393,183
 
Operating Lease Right-of-use Assets
 
1,947,665
 
 
1,869,101
 
Other
 
219,443
 
 
209,947
 
Total Other Assets, Net
 
$
7,934,452
 
 
$
7,957,440
 
Total Assets
 
$
14,367,553
 
 
$
13,816,816


LIABILITIES AND EQUITY


Current Liabilities:


Current Portion of Long-term Debt
 
$
880,212
 
 
$
389,013
 
Accounts Payable
 
296,629
 
 
324,708
 
Accrued Expenses and Other Current Liabilities
 
954,396
 
 
961,752
 
Deferred Revenue
 
252,034
 
 
274,036
 
Total Current Liabilities
 
$
2,383,271
 
 
$
1,949,509
 
Long-term Debt, Net of Current Portion
 
8,750,116
 
 
8,275,566
 
Long-term Operating Lease Liabilities
 
1,802,494
 
 
1,728,686
 
Other Long-term Liabilities (1)
 
407,341
 
 
398,828
 
Total Long-term Liabilities
 
$
10,959,951
 
 
$
10,403,080
 
Total Liabilities
 
$
13,343,222
 
 
$
12,352,589
 
Equity


Total Stockholders' Equity
 
$
1,024,300
 
 
$
1,463,962
 
Noncontrolling Interests
 
31
 
 
265
 
Total Equity
 
$
1,024,331
 
 
$
1,464,227
 
Total Liabilities and Equity
 
$
14,367,553
 
 
$
13,816,816
 
(1) Includes redeemable noncontrolling interests of $63.5M and $67.7M as of June 30, 2020 and December 31, 2019, respectively.


Consolidated Statements of Operations
(Unaudited; dollars in thousands, except per-share data)
 
Q2 2020
 
Q2 2019
 
% Change
 
 
YTD 2020
 
YTD 2019
 
% Change
Revenues:


Storage Rental
$
676,956
 
 
$
669,288
 
 
1.1
%
 
 
$
1,360,503
 
 
$
1,332,262
 
 
2.1
%
Service
305,283
 
 
397,619
 
 
(23.2
)%
 
 
690,467
 
 
788,508
 
 
(12.4
)%
Total Revenues
$
982,239
 
 
$
1,066,907
 
 
(7.9
)%
 
 
$
2,050,970
 
 
$
2,120,770
 
 
(3.3
)%


Operating Expenses:


Cost of Sales (excluding Depreciation and Amortization) (1)
$
406,693
 
 
$
463,809
 
 
(12.3
)%
 
 
$
873,614
 
 
$
924,455
 
 
(5.5
)%
Selling, General and Administrative (2)
241,947
 
 
252,156
 
 
(4.0
)%
 
 
480,680
 
 
520,867
 
 
(7.7
)%
Depreciation and Amortization
163,850
 
 
164,331
 
 
(0.3
)%
 
 
326,434
 
 
326,814
 
 
(0.1
)%
Significant Acquisition Costs
—


1,901
 
 
n/a
 
 
—


4,647
 
 
n/a
Restructuring Charges
39,298
 
 
—


n/a
 
 
80,344
 
 
—


n/a
Intangible Impairments
—


—


n/a
 
 
23,000
 
 
—


n/a
(Gain) Loss on Disposal/Write-Down of PP&E, Net
(1,275

)
 
(8,405

)
 
(84.8
)%
 
 
(2,330

)
 
(7,803

)
 
(70.1
)%
Total Operating Expenses
$
850,513
 
 
$
873,792
 
 
(2.7
)%
 
 
$
1,781,742
 
 
$
1,768,980
 
 
0.7
%


Operating Income (Loss)
$
131,726
 
 
$
193,115
 
 
(31.8
)%
 
 
$
269,228
 
 
$
351,790
 
 
(23.5
)%
Interest Expense, Net
103,456
 
 
105,314
 
 
(1.8
)%
 
 
209,105
 
 
207,750
 
 
0.7
%
Foreign Currency Transaction Loss / (Gain)
1,471
 
 
(19,331)
 
 
n/a
 
 
(35,928)
 
 
(1,634)
 
 
n/a
Debt Extinguishment Expense
17,040
 
 
—


n/a
 
 
17,040
 
 
—


n/a
Other Expense (Income), Net
7,189


4,139


73.7
%
 
 
1,862


1,652


12.7
%
Income (Loss) before Provision (Benefit) for Income Taxes
$
2,570
 
 
$
102,993
 
 
(97.5
)%
 
 
$
77,149
 
 
$
144,022
 
 
(46.4
)%
Provision (Benefit) for Income Taxes
9,683


10,646


(9.0
)%
 
 
19,370


21,199


(8.6
)%
(Loss) Income from Continuing Operations
$(7,113)
 
 
$
92,347
 
 
(107.7
)%
 
 
$
57,779
 
 
$
122,823
 
 
(53.0
)%
(Loss) Income from Discontinued Operations, Net of Tax
—


128


n/a
 
 
—


104


n/a
Net (Loss) Income
$(7,113)
 
 
$
92,475
 
 
(107.7
)%
 
 
$
57,779
 
 
$
122,927
 
 
(53.0
)%
Less: Net (Loss) Income Attributable to Noncontrolling Interests
(27

)
 
34


n/a
 
 
890


925


(3.7
)%
Net (Loss) Income Attributable to Iron Mountain Incorporated
$(7,086)
 
 
$
92,441
 
 
(107.7
)%
 
 
$
56,889
 
 
$
122,002
 
 
(53.4
)%


(Losses) Earnings per Share - Basic:


(Loss) Income from Continuing Operations
$(0.020)
 
 
$
0.32
 
 
(106.3
)%
 
 
$
0.20
 
 
$
0.43
 
 
(53.5
)%
Total Income (Loss) from Discontinued Operations
—


—


n/a
 
 
—


—


n/a
Net (Loss) Income Attributable to Iron Mountain Incorporated
$(0.020)
 
 
$
0.32
 
 
(106.3
)%
 
 
$
0.20
 
 
$
0.43
 
 
(53.5
)%


(Losses) Earnings per Share - Diluted:


(Loss) Income from Continuing Operations
$(0.020)
 
 
$
0.32
 
 
(106.3
)%
 
 
$
0.20
 
 
$
0.42
 
 
(52.4
)%
Total Income (Loss) from Discontinued Operations
—


—


n/a
 
 
—


—


n/a
Net (Loss) Income Attributable to Iron Mountain Incorporated
$(0.020)
 
 
$
0.32
 
 
(106.3
)%
 
 
$
0.20
 
 
$
0.42
 
 
(52.4
)%


Weighted Average Common Shares Outstanding - Basic
288,071
 
 
286,925
 
 
0.4
%
 
 
287,955
 
 
286,727
 
 
0.4
%
Weighted Average Common Shares Outstanding - Diluted
288,071
 
 
287,481
 
 
0.2
%
 
 
288,301
 
 
287,487
 
 
0.3
%

(1) Includes $7.6M of direct and incremental costs related to COVID-19 in Q2 and YTD 2020.
(2) Includes $1.6M of direct and incremental costs related to COVID-19 in Q2 and YTD 2020.


Reconciliation of Income from Continuing Operations to Adjusted EBITDA
(Dollars in thousands)
 
Q2 2020
 
Q2 2019
 
% Change
 
 
YTD 2020
 
YTD 2019
 
% Change


(Loss) Income from Continuing Operations
$(7,113)
 
 
$
92,347
 
 
(107.7
)%
 
 
$
57,779
 
 
$
122,823
 
 
(53.0
)%


Add / (Deduct):


Intangible Impairments
—


—


n/a
 
 
23,000
 
 
—


n/a
Provision (Benefit) for Income Taxes
9,683
 
 
10,646
 
 
(9.0
)%
 
 
19,370
 
 
21,199
 
 
(8.6
)%
Foreign Currency Transaction Loss / (Gain)
1,471
 
 
(19,331)
 
 
n/a
 
 
(35,928)
 
 
(1,634)
 
 
n/a
Other Expense (Income), Net
7,189
 
 
4,139
 
 
73.7
%
 
 
1,862
 
 
1,652
 
 
12.7
%
Debt Extinguishment Expense
17,040
 
 
—


n/a
 
 
17,040
 
 
—


n/a
Interest Expense, Net
103,456
 
 
105,314
 
 
(1.8
)%
 
 
209,105
 
 
207,750
 
 
0.7
%
(Gain) Loss on Disposal/Write-Down of PP&E, Net
(1,275

)
 
(8,405)
 
 
(84.8
)%
 
 
(2,330)
 
 
(7,803)
 
 
(70.1
)%
Depreciation and Amortization
163,850


164,331


(0.3
)%
 
 
326,434
 
 
326,814
 
 
(0.1
)%
Significant Acquisition Costs
—


1,901


n/a
 
 
—


4,647


n/a
Restructuring Charges
39,298
 
 
—


n/a
 
 
80,344
 
 
—


n/a
COVID-19 Costs
9,285


—


n/a
 
 
9,285
 
 
—


n/a
Adjusted EBITDA
$
342,884
 
 
$
350,942
 
 
(2.3
)%
 
 
$
705,961
 
 
$
675,448
 
 
4.5
%

Adjusted EBITDA
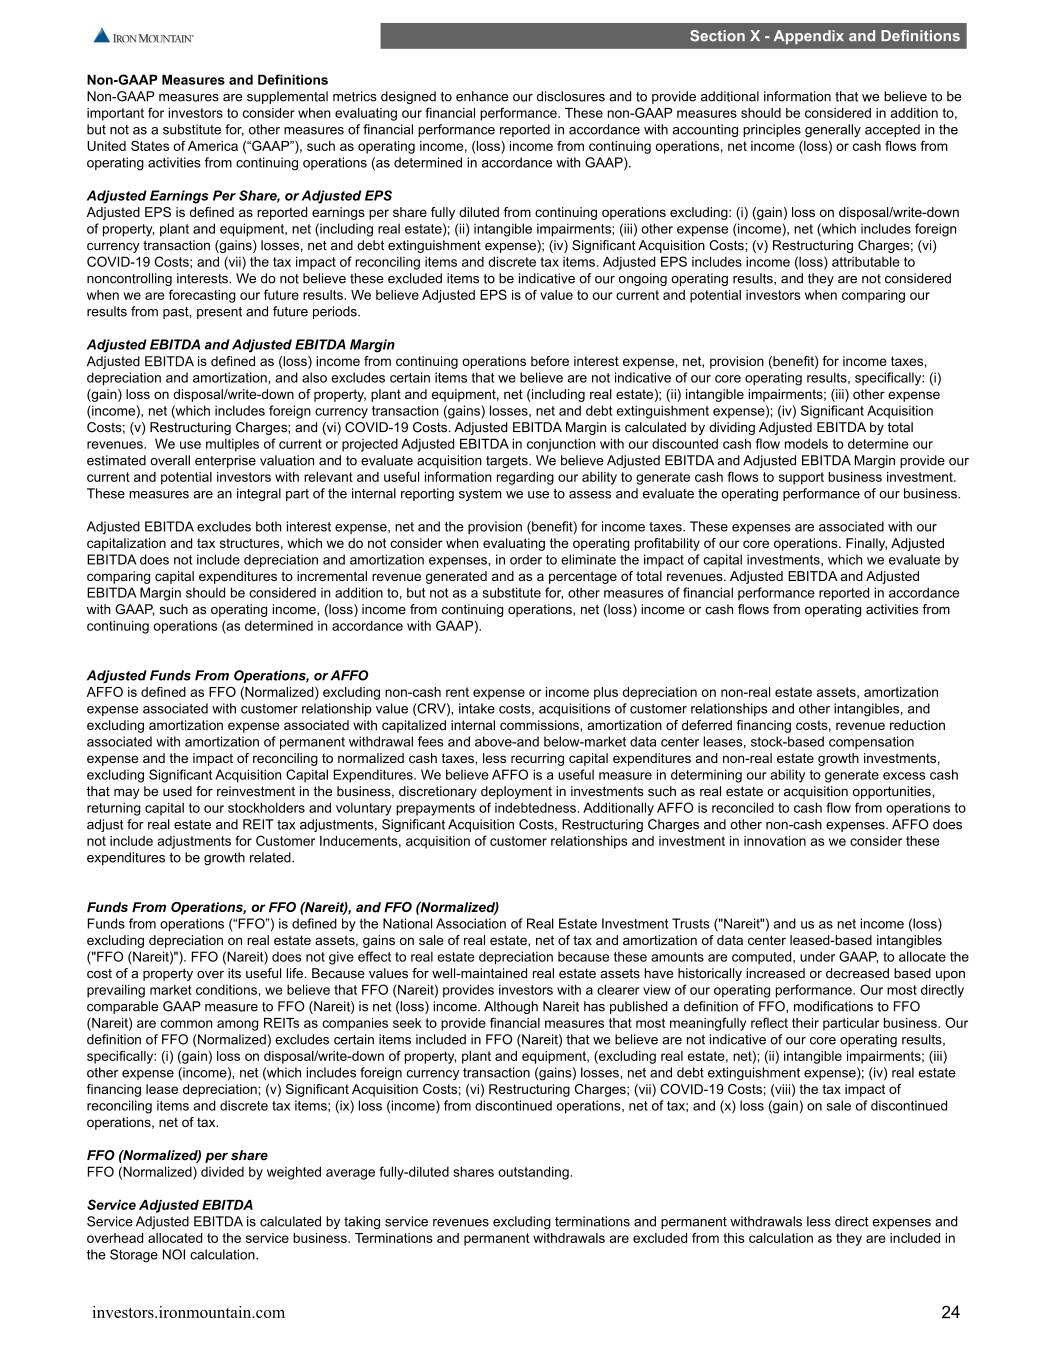
Adjusted EBITDA is defined as (loss) income from continuing operations before interest expense, net, provision (benefit) for income taxes, depreciation and amortization, and also excludes certain items that we believe are not indicative of our core operating results, specifically: (i) (gain) loss on disposal/write-down of property, plant and equipment, net (including real estate); (ii) intangible impairments; (iii) other expense (income), net (which includes foreign currency transaction (gains) losses, net, and debt extinguishment expense); (iv) Significant Acquisition Costs; (v) Restructuring Charges; and (vi) COVID-19 Costs. Adjusted EBITDA Margin is calculated by dividing Adjusted EBITDA by total revenues. We use multiples of current or projected Adjusted EBITDA in conjunction with our discounted cash flow models to determine our estimated overall enterprise valuation and to evaluate acquisition targets. We believe Adjusted EBITDA and Adjusted EBITDA Margin provide our current and potential investors with relevant and useful information regarding our ability to generate cash flows to support business investment. These measures are an integral part of the internal reporting system we use to assess and evaluate the operating performance of our business.
Adjusted EBITDA excludes both interest expense, net and the provision (benefit) for income taxes. These expenses are associated with our capitalization and tax structures, which we do not consider when evaluating the operating profitability of our core operations. Finally, Adjusted EBITDA does not include depreciation and amortization expenses, in order to eliminate the impact of capital investments, which we evaluate by comparing capital expenditures to incremental revenue generated and as a percentage of total revenues. Adjusted EBITDA and Adjusted EBITDA Margin should be considered in addition to, but not as a substitute for, other measures of financial performance reported in accordance with GAAP, such as operating income, (loss) income from continuing operations, net (loss) income or cash flows from operating activities from continuing operations (as determined in accordance with GAAP).

Reconciliation of Reported Earnings per Share to Adjusted Earnings per Share
 
Q2 2020
 
Q2 2019
 
% Change
 
 
YTD 2020
 
YTD 2019
 
% Change


Reported EPS - Fully Diluted from Continuing Operations
$(0.020)
 
 
$
0.32
 
 
(106.3
)%
 
 
$
0.20
 
 
$
0.42
 
 
(52.4
)%


Add / (Deduct):


Intangible Impairments
—


—


0.08


—


Other Expense (Income), Net
0.09


(0.05

)


(0.06

)
 
—


(Gain) Loss on Disposal/Write-Down of PP&E, Net
—


(0.03

)


(0.01

)
 
(0.03

)
 
 
Significant Acquisition Costs
—


0.01


—


0.02


Restructuring Charges
0.14


—


0.28


—


COVID-19 Costs
0.03


—


0.03


—


Tax Impact of Reconciling Items and Discrete Tax Items (1)
(0.01

)
 
(0.01

)


(0.03

)
 
(0.01

)
 
 
Adjusted EPS - Fully Diluted from Continuing Operations
$
0.22
 
 
$
0.23
 
 
(4.30)
%
 
 
$
0.49
 
 
$
0.40
 
 
22.5
%
(1) The difference between our effective tax rates and our structural tax rate (or adjusted effective tax rates) for the quarters ended June 30, 2020 and 2019, is primarily due to (i) the reconciling items above, which impact our reported income (loss) from continuing operations before provision (benefit) for income taxes but have an insignificant impact on our reported provision (benefit) for income taxes and (ii) other discrete tax items. Our structural tax rate for purposes of the calculation of Adjusted EPS for the three and six months ended June 30 2020 and 2019 was 17.1% and 17.7%, respectively. The Tax Impact of Reconciling Items and Discrete Tax Items is calculated using the current quarter’s estimate of the annual structural tax rate for the full year. This may result in the current period adjustment plus prior reported quarterly adjustments to not sum to the full year adjustment.

Adjusted Earnings Per Share, or Adjusted EPS
Adjusted EPS is defined as reported earnings per share fully diluted from continuing operations excluding: (i) (gain) loss on disposal/write-down of property, plant and equipment, net (including real estate); (ii) intangible impairments; (iii) other expense (income), net (which includes foreign currency transaction (gains) losses, net, and debt extinguishment expense); (iv) Significant Acquisition Costs; (v) Restructuring Charges; (vi) COVID-19 Costs; and (vii) the tax impact of reconciling items and discrete tax items. Adjusted EPS includes income (loss) attributable to noncontrolling interests. We do not believe these excluded items to be indicative of our ongoing operating results, and they are not considered when we are forecasting our future results. We believe Adjusted EPS is of value to our current and potential investors when comparing our results from past, present and future periods.


Reconciliation of Net Income Attributable to IRM to FFO and AFFO

(Dollars in thousands, except per-share data)
 
Q2 2020
 
Q2 2019
 
% Change
 
 
YTD 2020
 
YTD 2019
 
% Change


Net Income
$(7,113)
 
 
$
92,475
 
 
(107.7
)%
 
 
$
57,779
 
 
$
122,927
 
 
(53.0
)%
Add / (Deduct):


Real Estate Depreciation (1)
75,719
 
 
74,161
 
 
2.1
%
 
 
152,306
 
 
147,240
 
 
3.4
%
(Gain) Loss on Sale of Real Estate, Net of Tax
(1,089)
 
 
(30,512

)
 
(96.4
)%
 
 
(1,581)
 
 
(30,512)
 
 
(94.8
)%
Data Center Lease-Based Intangible Asset Amortization (2)
10,379
 
 
11,372
 
 
(8.7
)%
 
 
21,732
 
 
23,981
 
 
(9.4
)%


FFO (NAREIT)
$
77,896
 
 
$
147,496
 
 
(47.2
)%
 
 
$
230,236
 
 
$
263,636
 
 
(12.7
)%
Add / (Deduct):


(Gain) Loss on Disposal/Write-Down of PP&E, Net
(155)
 
 
27,587
 
 
n/a
 
 
(399)
 
 
28,189
 
 
n/a
Foreign Currency Transaction Loss / (Gain)
1,471
 
 
(19,331)
 
 
n/a
 
 
(35,928)
 
 
(1,634)
 
 
n/a
Debt Extinguishment Expense
17,040
 
 
—


17,040
 
 
—


Other Expense (Income) , Net
7,189
 
 
4,139
 
 
73.7
%
 
 
1,862
 
 
1,652
 
 
12.7
%
Intangible Impairments
—


—


(10,144)
 
 
(15,008)


Tax Impact of Reconciling Items and Discrete Tax Items (3)
(3,241)
 
 
(10,168)
 
 
(68.1
)%
 
 
(10,053

)
 
(10,144)
 
 
(0.9
)%
(Income) Loss from Discontinued Operations, Net of Tax
—


(128)
 
 
n/a
 
 
—


(104)
 
 
n/a
Real Estate Financing Lease Depreciation
3,431


3,113
 
 
10.2
%
 
 
6,594
 
 
6,617
 
 
(0.3
)%
Significant Acquisition Costs
—


1,901
 
 
n/a
 
 
—


4,647
 
 
n/a
Restructuring Charges
39,298
 
 
—


n/a
 
 
80,344
 
 
—


n/a
COVID-19 Costs
9,285
 
 
—


n/a
 
 
9,285
 
 
—


n/a
FFO (Normalized)
$
152,214
 
 
$
154,609
 
 
(1.5
)%
 
 
$
321,981
 
 
$
292,859
 
 
9.9
%


Per Share Amounts (Fully Diluted Shares)


FFO (Nareit)
$
0.27
 
 
$
0.51
 
 
(47.1
)%
 
 
$
0.80
 
 
$
0.92
 
 
(13.0
)%
FFO (Normalized)
$
0.53
 
 
$
0.54
 
 
(1.9
)%
 
 
$
1.12
 
 
$
1.02
 
 
9.8
%


Weighted Average Common Shares Outstanding - Basic
288,071
 
 
286,925
 
 
0.4
%
 
 
287,955
 
 
286,727
 
 
0.4
%
Weighted Average Common Shares Outstanding - Diluted
288,071
 
 
287,481
 
 
0.2
%
 
 
288,301
 
 
287,487
 
 
0.3
%
(1) Includes depreciation expense related to owned real estate assets (land improvements, buildings, building improvements, leasehold improvements and racking), excluding depreciation related to financing leases.
(2) Includes amortization expense for Data Center In-Place Lease Intangible Assets and Data Center Tenant Relationship Intangible Assets.
(3) Represents the tax impact of (i) the reconciling items above, which impact our reported income (loss) from continuing operations before provision (benefit) for income taxes but have an insignificant impact on our reported provision (benefit) from income taxes and (ii) other discrete tax items.

Funds From Operations, or FFO (Nareit), and FFO (Normalized)
Funds from operations (“FFO”) is defined by the National Association of Real Estate Investment Trusts ("Nareit") and us as net (loss) income excluding depreciation on real estate assets, gains on sale of real estate, net of tax and amortization of data center leased-based intangibles ("FFO (Nareit)"). FFO (Nareit) does not give effect to real estate depreciation because these amounts are computed, under GAAP, to allocate the cost of a property over its useful life. Because values for well-maintained real estate assets have historically increased or decreased based upon prevailing market conditions, we believe that FFO (Nareit) provides investors with a clearer view of our operating performance. Our most directly comparable GAAP measure to FFO (Nareit) is net (loss) income. Although Nareit has published a definition of FFO, modifications to FFO (Nareit) are common among REITs as companies seek to provide financial measures that most meaningfully reflect their particular business. Our definition of FFO (Normalized) excludes certain items included in FFO (Nareit) that we believe are not indicative of our core operating results, specifically: (i) (gain) loss on disposal/write-down of property, plant and equipment (excluding real estate), net; (ii) intangible impairments; (iii) other expense (income), net (which includes foreign currency transaction (gains) losses, net, and debt extinguishment expense); (iv) real estate financing lease depreciation; (v) Significant Acquisition Costs; (vi) Restructuring Charges; (vii) COVID-19 Costs; (viii) the tax impact of reconciling items and discrete tax items; (ix) loss (income) from discontinued operations, net of tax; and (x) loss (gain) on sale of discontinued operations, net of tax.
FFO (Normalized) per share
FFO (Normalized) divided by weighted average fully-diluted shares outstanding.
Reconciliation of Net Income Attributable to IRM to FFO and AFFO (continued)

(Dollars in thousands)
 
Q2 2020
 
Q2 2019
 
% Change
 
YTD 2020
 
YTD 2019
 
% Change


FFO (Normalized)
$
152,214
 
 
$
154,609
 
 
(1.5
)%
 
$
321,981
 
 
$
292,859
 
 
9.9
%
Add / (Deduct):


Non-Real Estate Depreciation
33,779
 
 
36,447
 
 
(7.3
)%
 
67,728
 
 
74,475
 
 
(9.1
)%
Amortization Expense (1)
34,526
 
 
33,303
 
 
3.7
%
 
66,433
 
 
64,620
 
 
2.8
%
Amortization of Deferred Financing Costs
4,488
 
 
4,100
 
 
9.5
%
 
9,001
 
 
8,208
 
 
9.7
%
Revenue Reduction Associated with Amortization of Permanent Withdrawal Fees and Above - and Below-Market Leases
2,566
 
 
3,534
 
 
(27.4
)%
 
5,248
 
 
7,179
 
 
(26.9
)%
Non-Cash Rent Expense (Income)
2,952
 
 
2,632
 
 
12.2
%
 
5,497
 
 
2,015
 
 
n/a
Stock-based Compensation Expense
18,857
 
 
12,501
 
 
50.8
%
 
23,943
 
 
21,020
 
 
13.9
%
Reconciliation to Normalized Cash Taxes
27,050
 
 
(6,252)
 
 
n/a
 
29,226
 
 
(10,864)
 
 
n/a
Less:


Non-Real Estate Growth Investment (2)
11,764
 
 
3,687
 
 
n/a
 
20,142
 
 
13,094
 
 
53.8
%
Real Estate, Data Center and Non-Real Estate Recurring CapEx
15,203
 
 
27,563
 
 
(44.8
)%
 
28,207
 
 
43,397
 
 
(35.0
)%
AFFO
$
249,465
 
 
$
209,624
 
 
19.0
%
 
$
480,708
 
 
$
403,022
 
 
19.3
%

(1) Includes Customer Relationship Value, intake costs, acquisition of customer relationships, and other intangibles. Excludes amortization of capitalized commissions of $6.0M and $5.9M in Q2 2020 and Q2 2019, respectively, and $11.6M and $9.9M in YTD 2020 and YTD 2019, respectively.
(2) Non-Real Estate Growth Investment CapEx excludes CapEx associated with Project Summit of $2.0M and $2.0M in Q2 2020 and YTD 2020, respectively.

Adjusted Funds From Operations, or AFFO
AFFO is defined as FFO (Normalized) excluding non-cash rent expense or income plus depreciation on non-real estate assets, amortization expense associated with customer relationship value (CRV), intake costs, acquisitions of customer relationships and other intangibles, and excluding amortization expense associated with capitalized internal commissions, amortization of deferred financing costs, revenue reduction associated with amortization of permanent withdrawal fees and above-and below-market data center leases, stock-based compensation expense and the impact of reconciling to normalized cash taxes, less recurring capital expenditures and non-real estate growth investments, excluding Significant Acquisition Capital Expenditures. We believe AFFO is a useful measure in determining our ability to generate excess cash that may be used for reinvestment in the business, discretionary deployment in investments such as real estate or acquisition opportunities, returning capital to our stockholders and voluntary prepayments of indebtedness. Additionally AFFO is reconciled to cash flow from operations to adjust for real estate and REIT tax adjustments, Significant Acquisition Costs, Restructuring Charges, and other non-cash expenses. AFFO does not include adjustments for customer inducements, acquisition of customer relationships and investment in innovation as we consider these expenditures to be growth related.


1
Q2 2020 Earnings Call August 6, 2020


Forward Looking Statements 2 Safe Harbor Statement Under the Private Securities Litigation Reform Act of 1995: This presentation contains certain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 and other securities laws and is subject to the safe-harbor created by such Act. Forward-looking statements include, but are not, limited to statements concerning our operations, economic performance, financial condition, goals, beliefs, future growth strategies, plans and current expectations, such as statements about: (i) expectations for the remainder of 2020, (ii) the expected impact of COVID-19 on our operations and financial conditions, (iii) new service offerings, (iv) expected benefits, costs and actions related to Project Summit; (v) planned 2020 capital expenditures, M&A and other investments; (vi) stabilization of our data center developments and expectation as to data center leasing activity for 2020; (vii) expectations with respect to change in volume of records stored with us; (viii) expectations related to our revenue management programs and continuous improvement initiatives, (ix) the durability of our core storage business, (x) our expected leverage; (xi) our dividend policy and targeted dividend payments; and (xii) longer term capital allocation, strategy and other goals. When we use words such as "believes," "expects," "anticipates," "estimates" or similar expressions, we are making forward-looking statements. Although we believe that our forward looking statements are based on reasonable assumptions, our expected results may not be achieved, and actual results may differ materially from our expectations. These forward-looking statements are subject to various known and unknown risks, uncertainties and other factors. Important factors that could cause actual results to differ from expectations include the (i) impact of COVID-19 on our operations, (ii) our ability to remain qualified for taxation as a real estate investment trust for U.S. federal income tax purposes; (iii) the adoption of alternative technologies and shifts by our customers to storage of data through non-paper based technologies; (iv) changes in customer preferences and demand for our storage and information management services; (v) the cost and our ability to comply with laws, regulations and customer demands relating to data security and privacy issues, as well as fire and safety standards; (vi) our ability or inability to execute our strategic growth plan, expand internationally, complete acquisitions on satisfactory terms, and to integrate acquired companies efficiently; (vii) changes in the amount of our growth and recurring capital expenditures and our ability to raise capital and invest according to plan; (viii) the impact of litigation or disputes that may arise in connection with incidents in which we fail to protect our customers' information or our internal records or IT systems and the impact of such incidents on our reputation and ability to compete; (ix) our ability to execute on Project Summit and the potential impacts of Project Summit on our ability to retain and recruit employees and execute on our strategy (x) changes in the price for our storage and information management services relative to the cost of providing such storage and information management services; (xi) changes in the political and economic environments in the countries in which our international subsidiaries operate and changes in the global political climate; (xii) the impact of executing on our growth strategy through joint ventures; (xiii) our ability to comply with our existing debt obligations and restrictions in our debt instruments or to obtain additional financing to meet our working capital needs; (xiv) the impact of service interruptions or equipment damage and the cost of power on our data center operations; (xv) changes in the cost of our debt; (xvi) the impact of alternative, more attractive investments on dividends; (xvii) the cost or potential liabilities associated with real estate necessary for our business; (xviii) the performance of business partners upon whom we depend for technical assistance or management expertise; (xix) other trends in competitive or economic conditions affecting our financial condition or results of operations not presently contemplated; and (xx) other risks described more fully in our filings with the Securities and Exchange Commission, including under the caption “Risk Factors” in our periodic reports or incorporated therein. You should not rely upon forward-looking statements except as statements of our present intentions and of our present expectations, which may or may not occur. Except as required by law, we undertake no obligation to release publicly the result of any revision to these forward-looking statements that may be made to reflect events or circumstances after the date hereof or to reflect the occurrence of unanticipated events. "Reconciliation of Non-GAAP Measures: Throughout this presentation, Iron Mountain will discuss (1) Adjusted EBITDA, (2) Adjusted Earnings per Share (“Adjusted EPS”), (3) Funds from Operations (“FFO Nareit”), (4) FFO (Normalized) and (5) Adjusted Funds from Operations (“AFFO”). These measures do not conform to accounting principles generally accepted in the United States (“GAAP”). These non-GAAP measures are supplemental metrics designed to enhance our disclosure and to provide additional information that we believe to be important for investors to consider in addition to, but not as a substitute for, other measures of financial performance reported in accordance with GAAP, such as operating income, income (loss) from continuing operations, net income (loss) attributable to Iron Mountain Incorporated or cash flows from operating activities from continuing operations (as determined in accordance with GAAP). The reconciliation of these measures to the appropriate GAAP measure, as required by Regulation G under the Securities Exchange Act of 1934, as amended, and their definitions are included in the Supplemental Reporting Information.


3 COVID-19 Update Community ● Committed to the health, safety and well-being of employees, customers, vendors, and communities ○ Heightened hygiene and sanitation practices; social distancing and safety protocols ● Maximizing flexible and remote work arrangements ● Bringing Mountaineers back from furlough as service activity levels resume ● Increased communication with employees and customers ● Recommitting to building diverse and inclusive environment Operations ● Iron Mountain facilities are operating as “essential businesses” focused on serving customers ○ 100% of Records Management facilities now open and operating around the globe ● Service activity levels improved in June compared to April/May, though still well below year-ago levels ● Providing new and innovative customer solutions around storage and distribution, document scanning, and the secure remote access and application of artificial intelligence through the InSight platform, assisting customers with remote workforces ● Global Data Center leasing accelerated significantly in Q2; signed 32+ MW of new and expansion leases Financial ● Iron Mountain is operating from a solid financial position ● Committed to sustainable dividend ● Significant liquidity to fund business needs ● Project Summit transformation well on track; creating a more dynamic, agile and customer-focused organization ● Reduced expenses and taken steps to preserve cash in the near term ○ Managing variable costs well


Q2 Performance 4 Solid performance in a challenging environment • Delivered constant-currency Adjusted EBITDA in line with last year, despite $58 million revenue decline • Adjusted EBITDA margin expanded 200 bps Y/Y - benefits from Project Summit, revenue management, and mix • Drove cash cycle improvement of nearly 4 days Y/Y, with benefits coming from both DPO and DSO Core Storage business highly durable • Continue to benefit from deep and long-lasting customer relationships • Global organic storage rental revenue growth of 2.3% supported by strong revenue management • Global organic storage volume declined 1.8M cubic feet; Consumer and Other grew 2.2M cubic feet Global Data Center momentum accelerated • 32.3 megawatts of new and expansion leases executed in Q2; first half leasing of approximately 39 megawatts • Expect to execute an additional 10+ megawatts of leasing in the back half • Expect full-year leasing of 45-50 megawatts relative to original full-year 2020 guidance of 15-20 megawatts


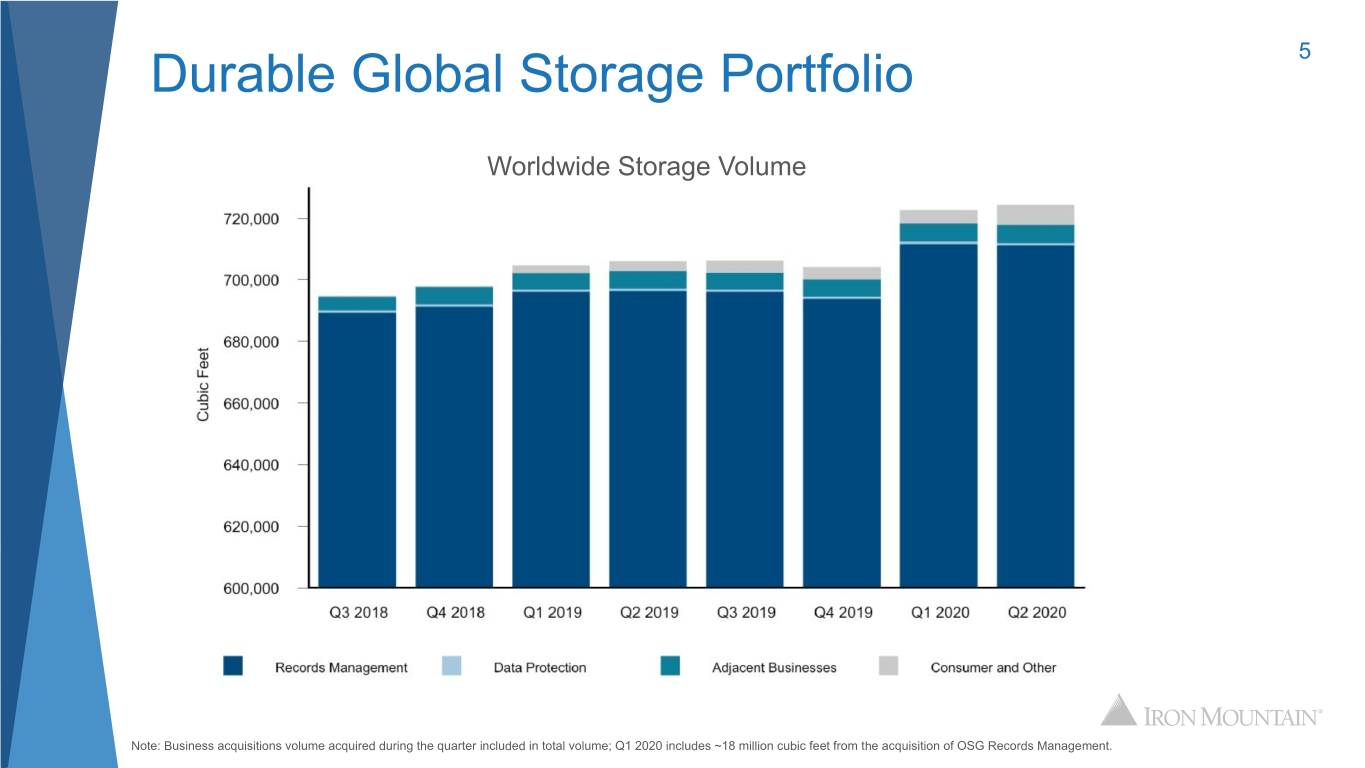
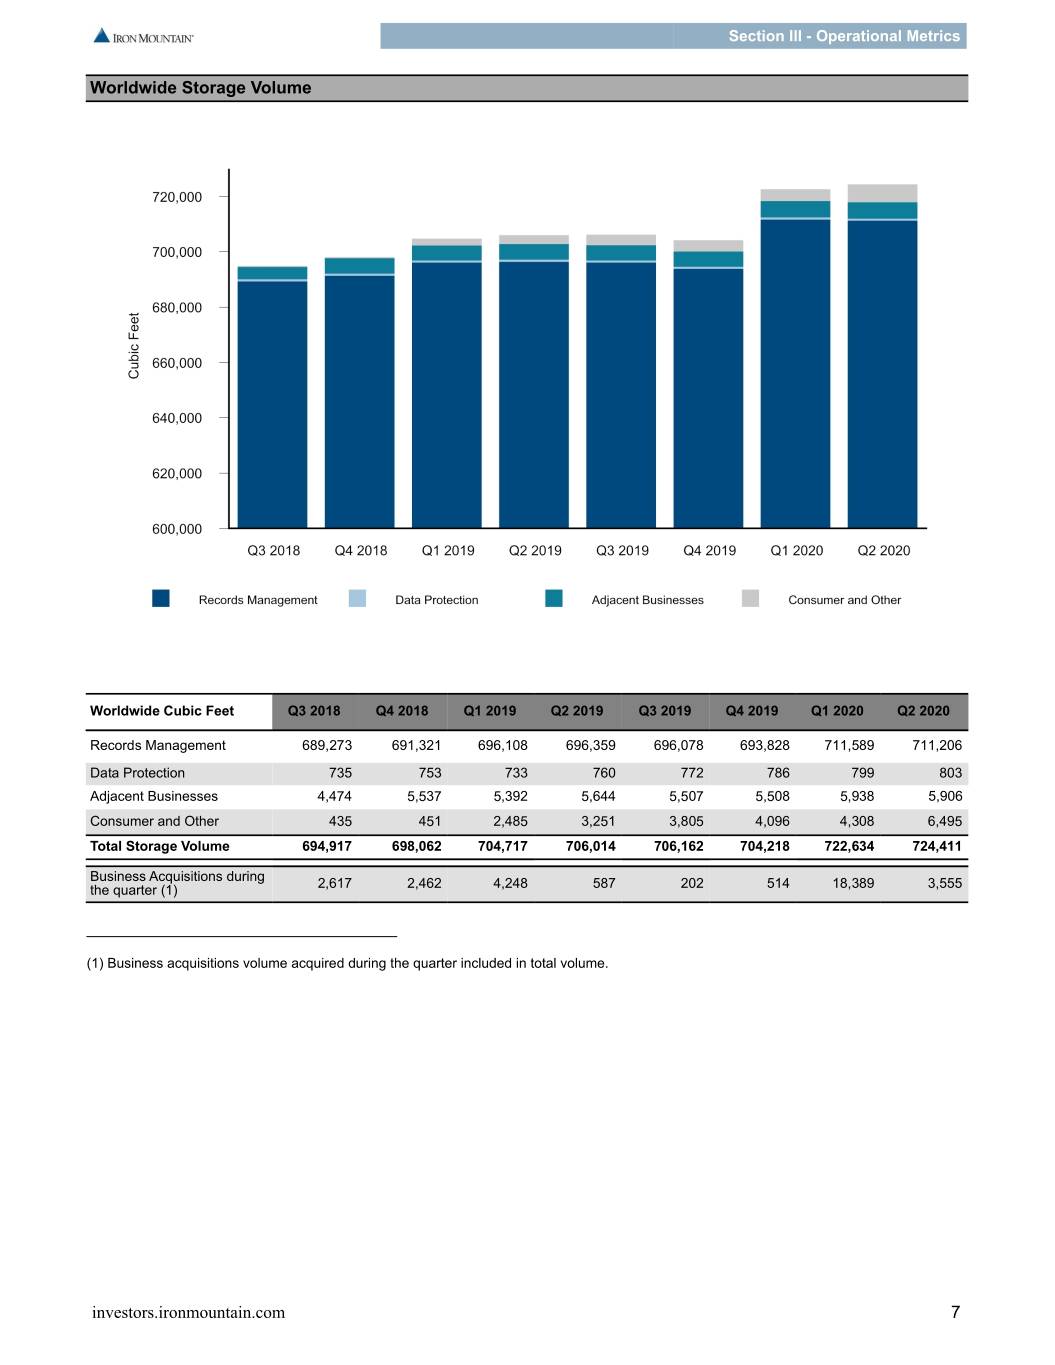
Durable Global Storage Portfolio 5 Worldwide Storage Volume Note: Business acquisitions volume acquired during the quarter included in total volume; Q1 2020 includes ~18 million cubic feet from the acquisition of OSG Records Management.


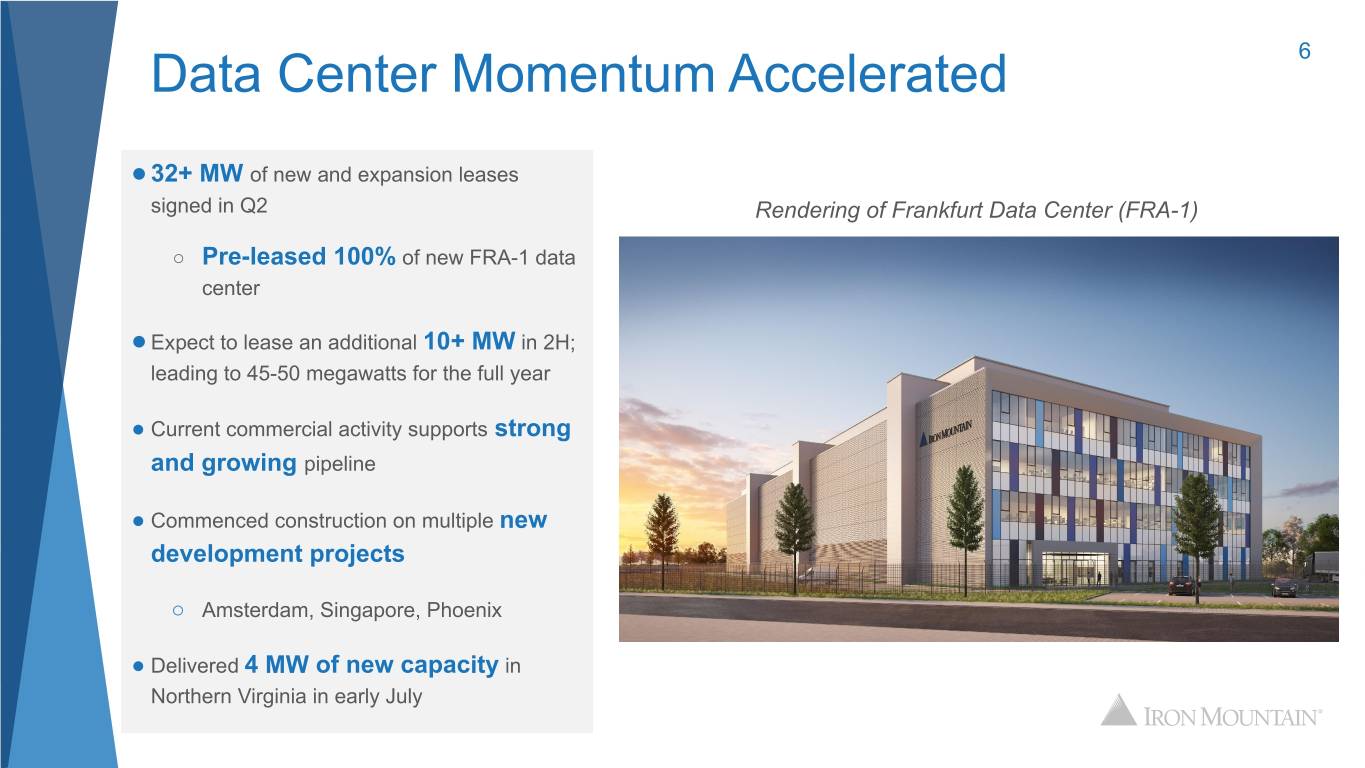
Data Center Momentum Accelerated 6 ● 32+ MW of new and expansion leases signed in Q2 Rendering of Frankfurt Data Center (FRA-1) ○ Pre-leased 100% of new FRA-1 data center ● Expect to lease an additional 10+ MW in 2H; leading to 45-50 megawatts for the full year ● Current commercial activity supports strong and growing pipeline ● Commenced construction on multiple new development projects ○ Amsterdam, Singapore, Phoenix ● Delivered 4 MW of new capacity in Northern Virginia in early July


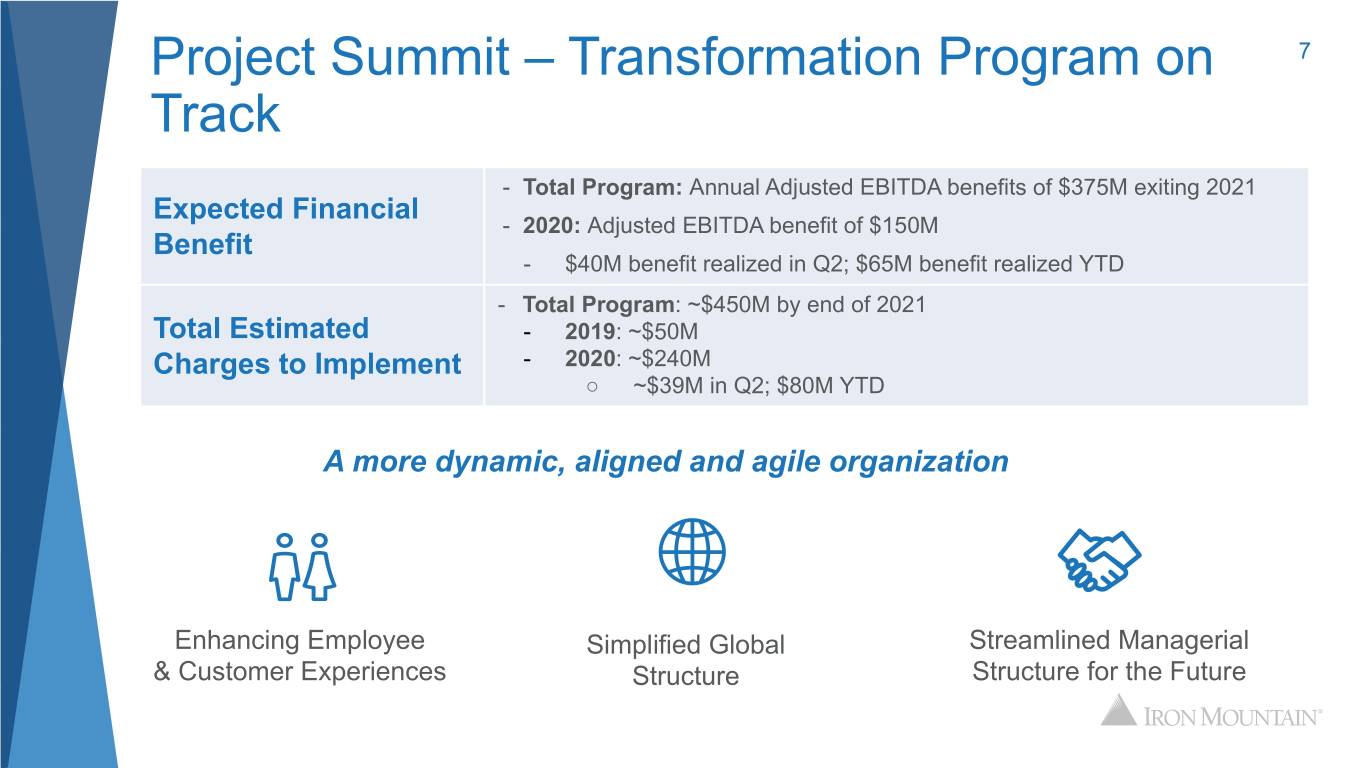
Project Summit – Transformation Program on 7 Track - Total Program: Annual Adjusted EBITDA benefits of $375M exiting 2021 Expected Financial - 2020: Adjusted EBITDA benefit of $150M Benefit - $40M benefit realized in Q2; $65M benefit realized YTD - Total Program: ~$450M by end of 2021 Total Estimated - 2019: ~$50M Charges to Implement - 2020: ~$240M ○ ~$39M in Q2; $80M YTD A more dynamic, aligned and agile organization Enhancing Employee Simplified Global Streamlined Managerial & Customer Experiences Structure Structure for the Future


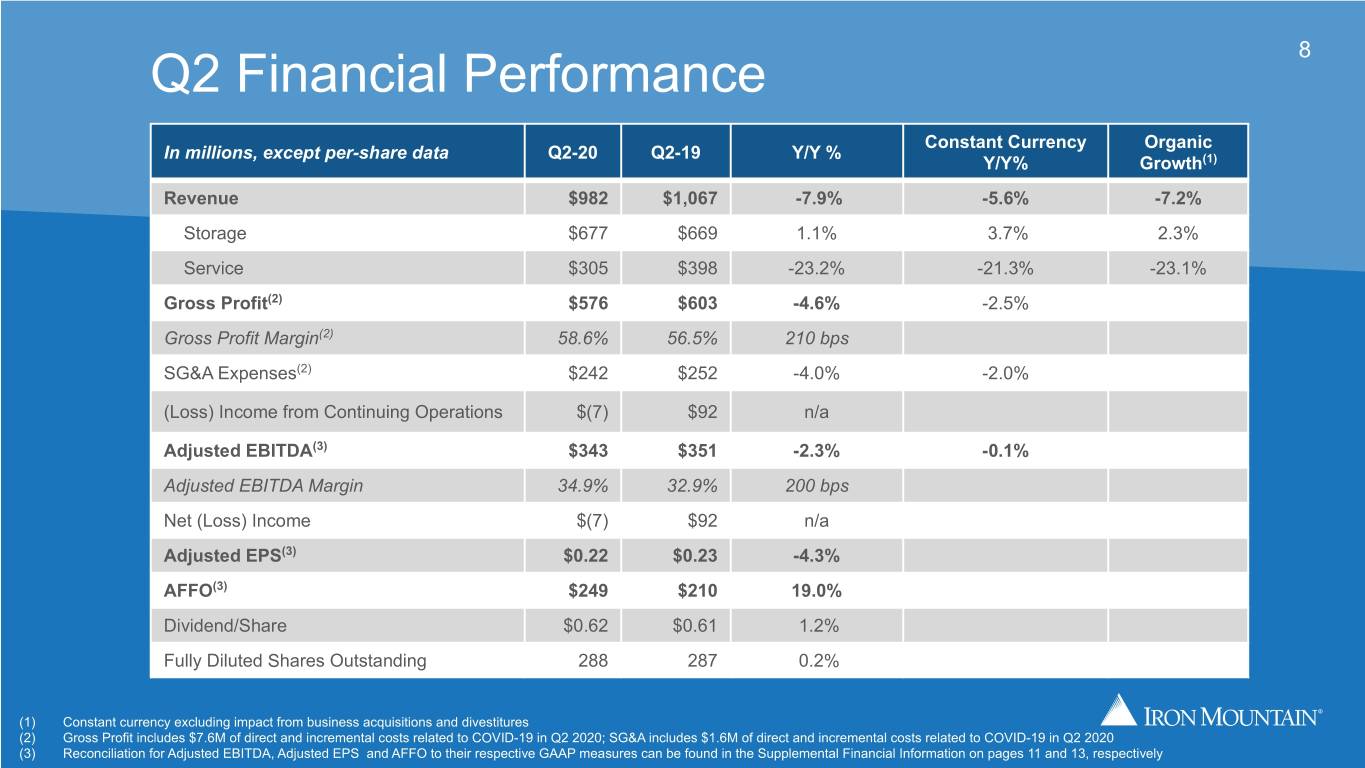
Q2 Financial Performance 8 Constant Currency Organic In millions, except per-share data Q2-20 Q2-19 Y/Y % Y/Y% Growth(1) Revenue $982 $1,067 -7.9% -5.6% -7.2% Storage $677 $669 1.1% 3.7% 2.3% Service $305 $398 -23.2% -21.3% -23.1% Gross Profit(2) $576 $603 -4.6% -2.5% Gross Profit Margin(2) 58.6% 56.5% 210 bps SG&A Expenses(2) $242 $252 -4.0% -2.0% (Loss) Income from Continuing Operations $(7) $92 n/a Adjusted EBITDA(3) $343 $351 -2.3% -0.1% Adjusted EBITDA Margin 34.9% 32.9% 200 bps Net (Loss) Income $(7) $92 n/a Adjusted EPS(3) $0.22 $0.23 -4.3% AFFO(3) $249 $210 19.0% Dividend/Share $0.62 $0.61 1.2% Fully Diluted Shares Outstanding 288 287 0.2% (1) Constant currency excluding impact from business acquisitions and divestitures (2) Gross Profit includes $7.6M of direct and incremental costs related to COVID-19 in Q2 2020; SG&A includes $1.6M of direct and incremental costs related to COVID-19 in Q2 2020 (3) Reconciliation for Adjusted EBITDA, Adjusted EPS and AFFO to their respective GAAP measures can be found in the Supplemental Financial Information on pages 11 and 13, respectively


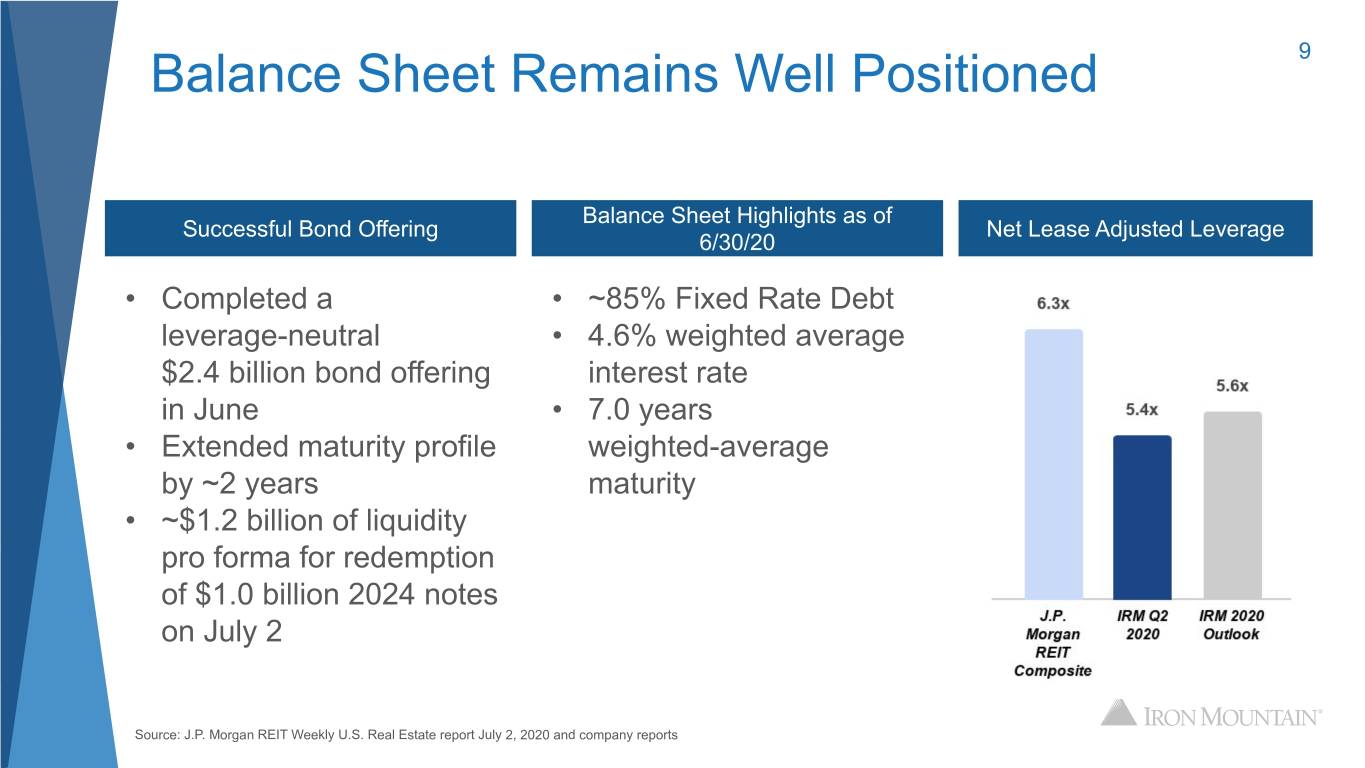
Balance Sheet Remains Well Positioned 9 Balance Sheet Highlights as of Successful Bond Offering Net Lease Adjusted Leverage 6/30/20 • Completed a • ~85% Fixed Rate Debt leverage-neutral • 4.6% weighted average $2.4 billion bond offering interest rate in June • 7.0 years • Extended maturity profile weighted-average by ~2 years maturity • ~$1.2 billion of liquidity pro forma for redemption of $1.0 billion 2024 notes on July 2 Source: J.P. Morgan REIT Weekly U.S. Real Estate report July 2, 2020 and company reports


Capital Allocation Strategy Has Not Changed 10 • Sustain the dividend at current level • Long-term target leverage ratio of 4.5x – 5.5x • Reinvest in the business through growth Capital Expenditures • Invest in accretive M&A • Capital recycling + alternative sources of funding


Key Takeaways 11 Strong Q2 financial performance; core storage business remains durable Service activity levels improved in June compared to April/May Strong balance sheet and liquidity position as we execute on our strategic initiatives in a challenging economic environment Extensive portfolio of new and existing solutions across our leading global footprint positioning us well for further opportunity during the recovery Recommitting ourselves to our long-stated value around Diversity and Inclusion, which is just, fair, and instrumental in continuing to develop new solutions for our customers


Supplemental Financial Information Second Quarter 2020 investors.ironmountain.com


Safe Harbor Statement Under the Private Securities Litigation Reform Act of 1995: Safe Harbor Statement Under the Private Securities Litigation Reform Act of 1995: This release contains certain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 and other securities laws and is subject to the safe-harbor created by such Act. Forward-looking statements include, but are not, limited to statements concerning our operations, economic performance, financial condition, goals, beliefs, future growth strategies, plans and current expectations, such as statements about: (i) expectations for the remainder of 2020, (ii) the expected impact of COVID-19 on our operations and financial conditions, (iii) new service offerings, (iv) expected benefits, costs and actions related to Project Summit; (v) planned 2020 capital expenditures, M&A and other investments; (vi) stabilization of our data center developments and expectation as to data center leasing activity for 2020; (vii) expectations with respect to change in volume of records stored with us; (viii) expectations related to our revenue management programs and continuous improvement initiatives,(ix) the durability of our core storage business, (x) our expected leverage; (xi) our dividend policy and targeted dividend payments; and (xii) longer term capital allocation, strategy and other goals. When we use words such as "believes," "expects," "anticipates," "estimates" or similar expressions, we are making forward-looking statements. Although we believe that our forward looking statements are based on reasonable assumptions, our expected results may not be achieved, and actual results may differ materially from our expectations. These forward-looking statements are subject to various known and unknown risks, uncertainties and other factors. Important factors that could cause actual results to differ from expectations include the (i) impact of COVID-19 on our operations, (ii) our ability to remain qualified for taxation as a real estate investment trust for U.S. federal income tax purposes; (iii) the adoption of alternative technologies and shifts by our customers to storage of data through non-paper based technologies; (iv) changes in customer preferences and demand for our storage and information management services; (v) the cost and our ability to comply with laws, regulations and customer demands relating to data security and privacy issues, as well as fire and safety standards; (vi) our ability or inability to execute our strategic growth plan, expand internationally, complete acquisitions on satisfactory terms, and to integrate acquired companies efficiently; (vii) changes in the amount of our growth and recurring capital expenditures and our ability to raise capital and invest according to plan; (viii) the impact of litigation or disputes that may arise in connection with incidents in which we fail to protect our customers' information or our internal records or IT systems and the impact of such incidents on our reputation and ability to compete; (ix) our ability to execute on Project Summit and the potential impacts of Project Summit on our ability to retain and recruit employees and execute on our strategy (x) changes in the price for our storage and information management services relative to the cost of providing such storage and information management services; (xi) changes in the political and economic environments in the countries in which our international subsidiaries operate and changes in the global political climate; (xii) the impact of executing on our growth strategy through joint ventures; (xiii) our ability to comply with our existing debt obligations and restrictions in our debt instruments or to obtain additional financing to meet our working capital needs; (xiv) the impact of service interruptions or equipment damage and the cost of power on our data center operations; (xv) changes in the cost of our debt; (xvi) the impact of alternative, more attractive investments on dividends; (xvii) the cost or potential liabilities associated with real estate necessary for our business; (xviii) the performance of business partners upon whom we depend for technical assistance or management expertise; (xix) other trends in competitive or economic conditions affecting our financial condition or results of operations not presently contemplated; and (xx) other risks described more fully in our filings with the Securities and Exchange Commission, including under the caption “Risk Factors” in our periodic reports or incorporated therein. You should not rely upon forward-looking statements except as statements of our present intentions and of our present expectations, which may or may not occur. Except as required by law, we undertake no obligation to release publicly the result of any revision to these forward-looking statements that may be made to reflect events or circumstances after the date hereof or to reflect the occurrence of unanticipated events. Reconciliation of Non-GAAP Measures: Throughout this presentation, Iron Mountain will discuss (1) Adjusted EBITDA, (2) Adjusted Earnings per Share (“Adjusted EPS”), (3) Funds from Operations (“FFO Nareit”), (4) FFO (Normalized) and (5) Adjusted Funds from Operations (“AFFO”). These measures do not conform to accounting principles generally accepted in the United States (“GAAP”). These non-GAAP measures are supplemental metrics designed to enhance our disclosure and to provide additional information that we believe to be important for investors to consider in addition to, but not as a substitute for, other measures of financial performance reported in accordance with GAAP, such as operating income, income (loss) from continuing operations, net income (loss) attributable to Iron Mountain Incorporated or cash flows from operating activities from continuing operations (as determined in accordance with GAAP). The reconciliation of these measures to the appropriate GAAP measure, as required by Regulation G under the Securities Exchange Act of 1934, as amended, and their definitions are included later in this document (see Table of Contents). Investor Relations Contacts: Greer Aviv, 617-535-2887 Nathan McCurren, 617-535-2997 Senior Vice President, Investor Relations Director, Investor Relations [email protected] [email protected] investors.ironmountain.com 2


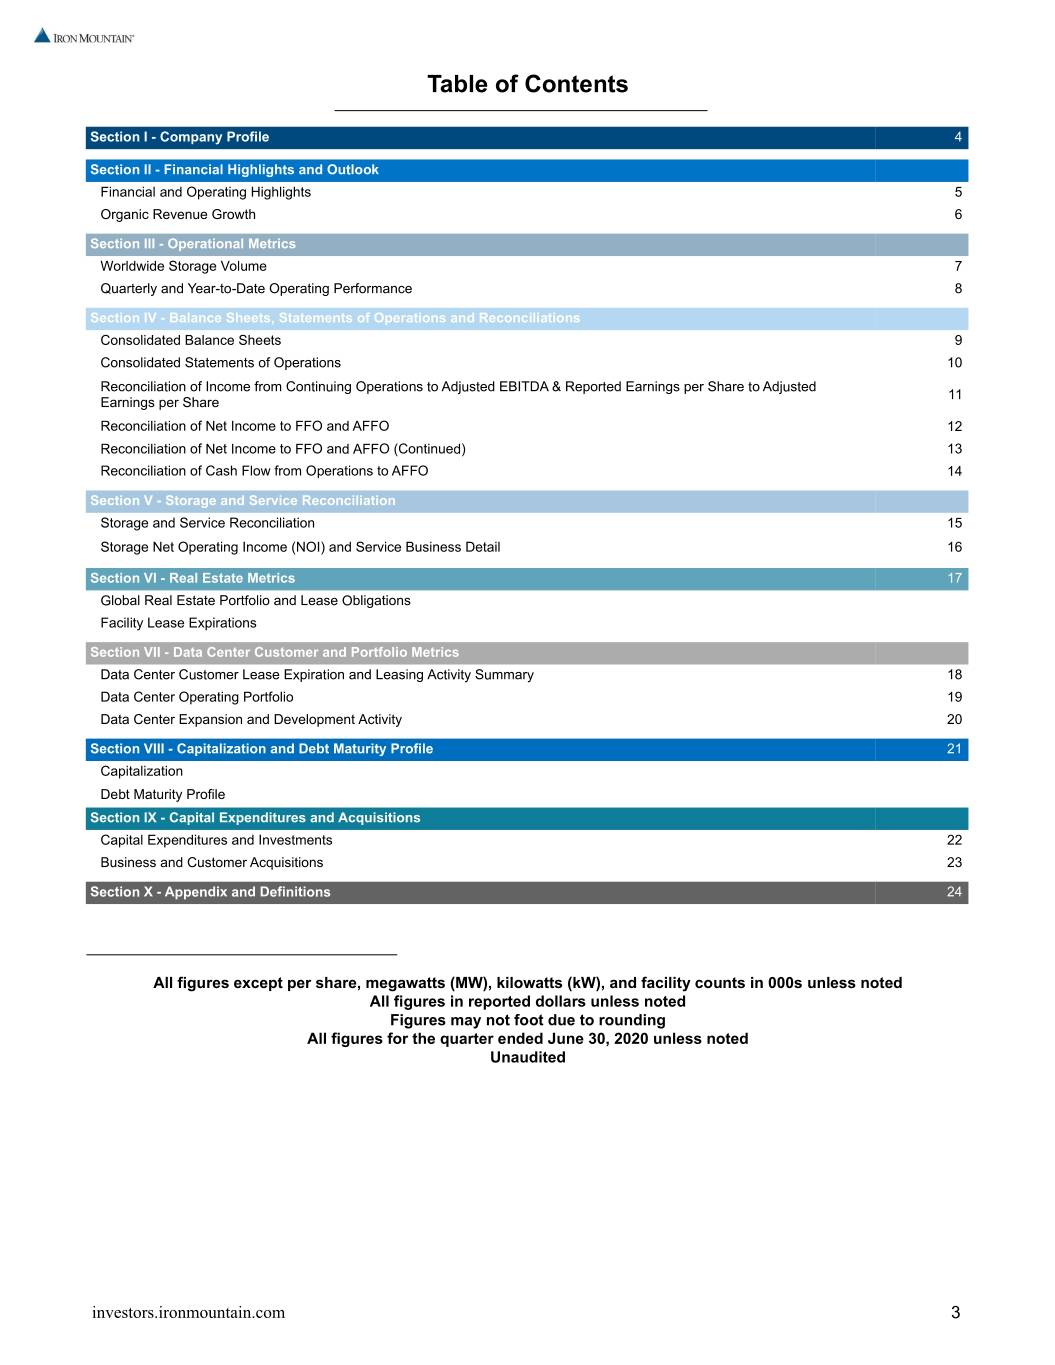
Table of Contents Section I - Company Profile 4 Section II - Financial Highlights and Outlook Financial and Operating Highlights 5 Organic Revenue Growth 6 Section III - Operational Metrics Worldwide Storage Volume 7 Quarterly and Year-to-Date Operating Performance 8 Section IV - Balance Sheets, Statements of Operations and Reconciliations Consolidated Balance Sheets 9 Consolidated Statements of Operations 10 Reconciliation of Income from Continuing Operations to Adjusted EBITDA & Reported Earnings per Share to Adjusted 11 Earnings per Share Reconciliation of Net Income to FFO and AFFO 12 Reconciliation of Net Income to FFO and AFFO (Continued) 13 Reconciliation of Cash Flow from Operations to AFFO 14 Section V - Storage and Service Reconciliation Storage and Service Reconciliation 15 Storage Net Operating Income (NOI) and Service Business Detail 16 Section VI - Real Estate Metrics 17 Global Real Estate Portfolio and Lease Obligations Facility Lease Expirations Section VII - Data Center Customer and Portfolio Metrics Data Center Customer Lease Expiration and Leasing Activity Summary 18 Data Center Operating Portfolio 19 Data Center Expansion and Development Activity 20 Section VIII - Capitalization and Debt Maturity Profile 21 Capitalization Debt Maturity Profile Section IX - Capital Expenditures and Acquisitions Capital Expenditures and Investments 22 Business and Customer Acquisitions 23 Section X - Appendix and Definitions 24 All figures except per share, megawatts (MW), kilowatts (kW), and facility counts in 000s unless noted All figures in reported dollars unless noted Figures may not foot due to rounding All figures for the quarter ended June 30, 2020 unless noted Unaudited investors.ironmountain.com 3


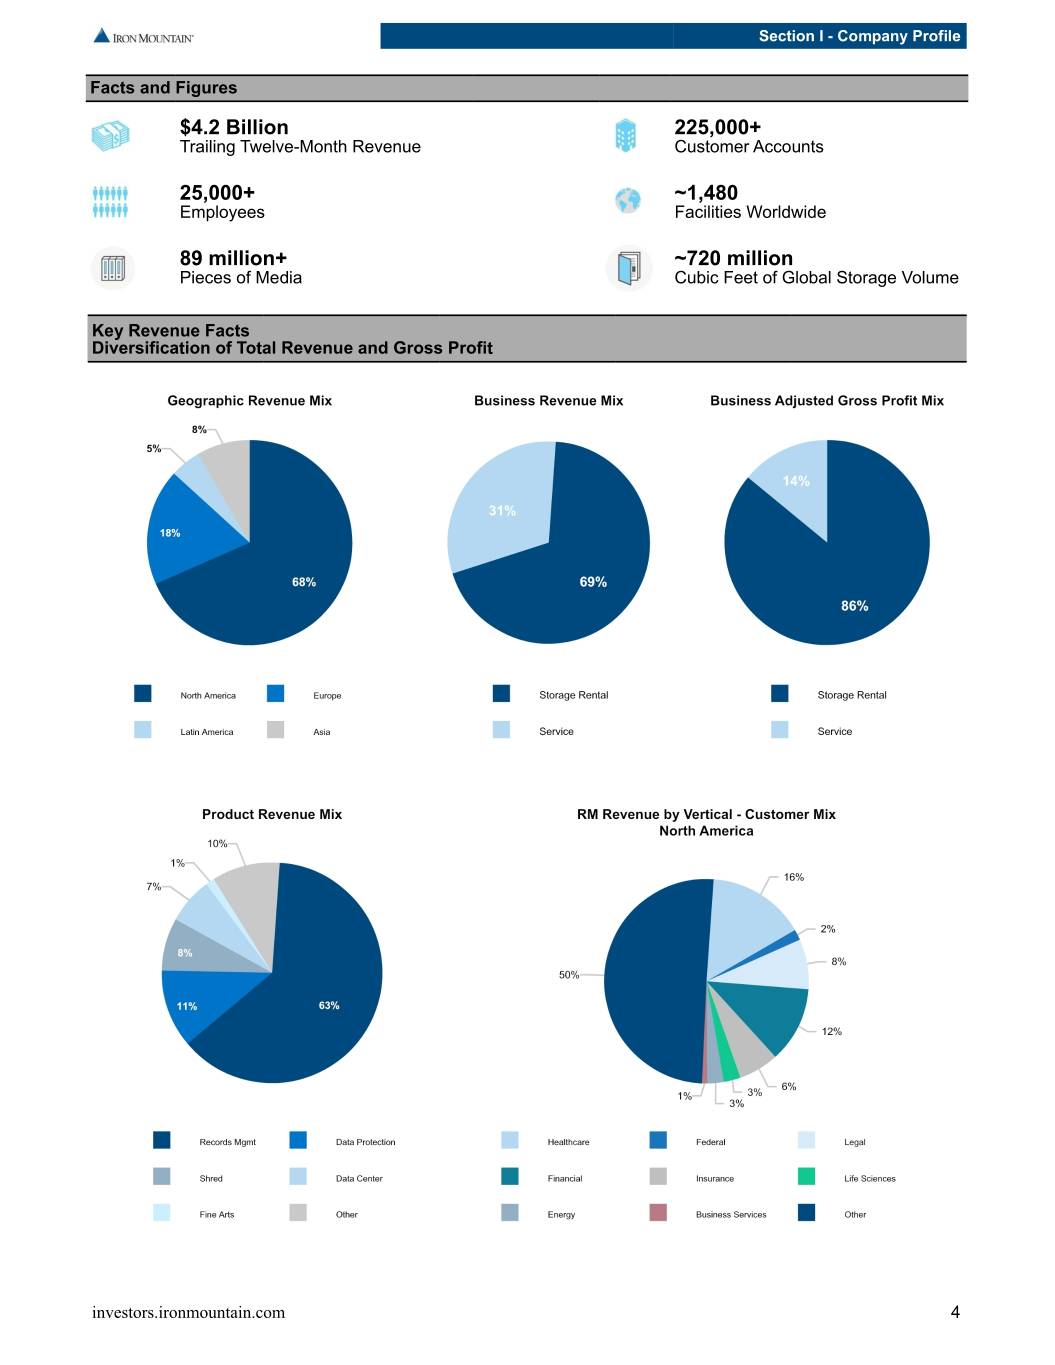
Section I - Company Profile Facts and Figures $4.2 Billion 225,000+ Trailing Twelve-Month Revenue Customer Accounts 25,000+ ~1,480 Employees Facilities Worldwide 89 million+ ~720 million Pieces of Media Cubic Feet of Global Storage Volume Key Revenue Facts Diversification of Total Revenue and Gross Profit investors.ironmountain.com 4


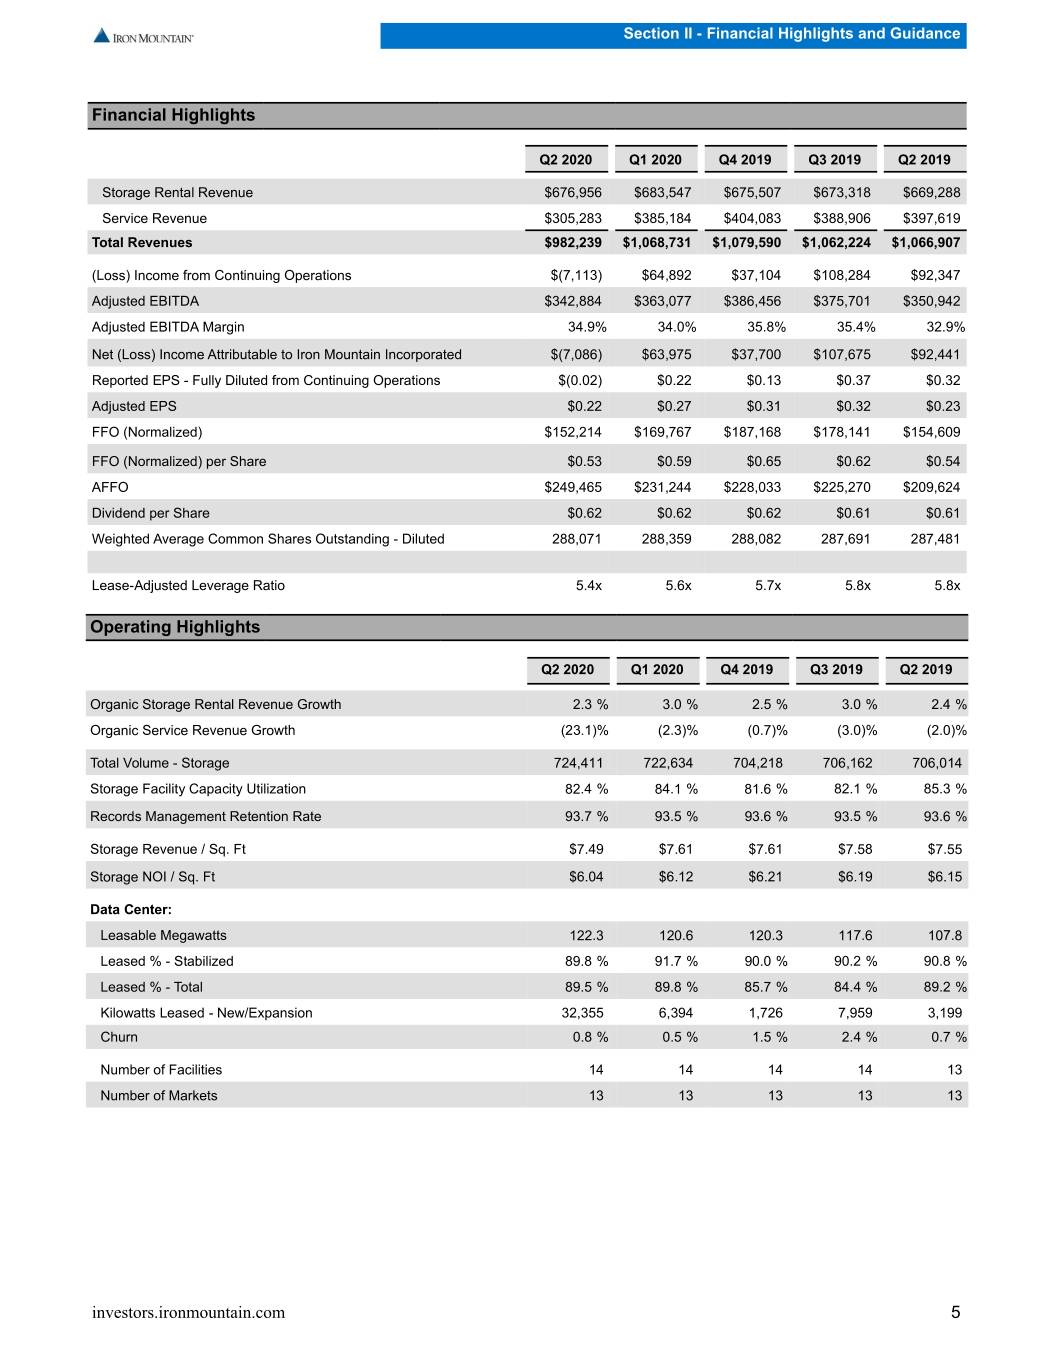
Section II - Financial Highlights and Guidance Financial Highlights Q2 2020 Q1 2020 Q4 2019 Q3 2019 Q2 2019 Storage Rental Revenue $676,956 $683,547 $675,507 $673,318 $669,288 Service Revenue $305,283 $385,184 $404,083 $388,906 $397,619 Total Revenues $982,239 $1,068,731 $1,079,590 $1,062,224 $1,066,907 (Loss) Income from Continuing Operations $(7,113) $64,892 $37,104 $108,284 $92,347 Adjusted EBITDA $342,884 $363,077 $386,456 $375,701 $350,942 Adjusted EBITDA Margin 34.9% 34.0% 35.8% 35.4% 32.9% Net (Loss) Income Attributable to Iron Mountain Incorporated $(7,086) $63,975 $37,700 $107,675 $92,441 Reported EPS - Fully Diluted from Continuing Operations $(0.02) $0.22 $0.13 $0.37 $0.32 Adjusted EPS $0.22 $0.27 $0.31 $0.32 $0.23 FFO (Normalized) $152,214 $169,767 $187,168 $178,141 $154,609 FFO (Normalized) per Share $0.53 $0.59 $0.65 $0.62 $0.54 AFFO $249,465 $231,244 $228,033 $225,270 $209,624 Dividend per Share $0.62 $0.62 $0.62 $0.61 $0.61 Weighted Average Common Shares Outstanding - Diluted 288,071 288,359 288,082 287,691 287,481 Lease-Adjusted Leverage Ratio 5.4x 5.6x 5.7x 5.8x 5.8x Operating Highlights Q2 2020 Q1 2020 Q4 2019 Q3 2019 Q2 2019 Organic Storage Rental Revenue Growth 2.3 % 3.0 % 2.5 % 3.0 % 2.4 % Organic Service Revenue Growth (23.1)% (2.3)% (0.7)% (3.0)% (2.0)% Total Volume - Storage 724,411 722,634 704,218 706,162 706,014 Storage Facility Capacity Utilization 82.4 % 84.1 % 81.6 % 82.1 % 85.3 % Records Management Retention Rate 93.7 % 93.5 % 93.6 % 93.5 % 93.6 % Storage Revenue / Sq. Ft $7.49 $7.61 $7.61 $7.58 $7.55 Storage NOI / Sq. Ft $6.04 $6.12 $6.21 $6.19 $6.15 Data Center: Leasable Megawatts 122.3 120.6 120.3 117.6 107.8 Leased % - Stabilized 89.8 % 91.7 % 90.0 % 90.2 % 90.8 % Leased % - Total 89.5 % 89.8 % 85.7 % 84.4 % 89.2 % Kilowatts Leased - New/Expansion 32,355 6,394 1,726 7,959 3,199 Churn 0.8 % 0.5 % 1.5 % 2.4 % 0.7 % Number of Facilities 14 14 14 14 13 Number of Markets 13 13 13 13 13 investors.ironmountain.com 5


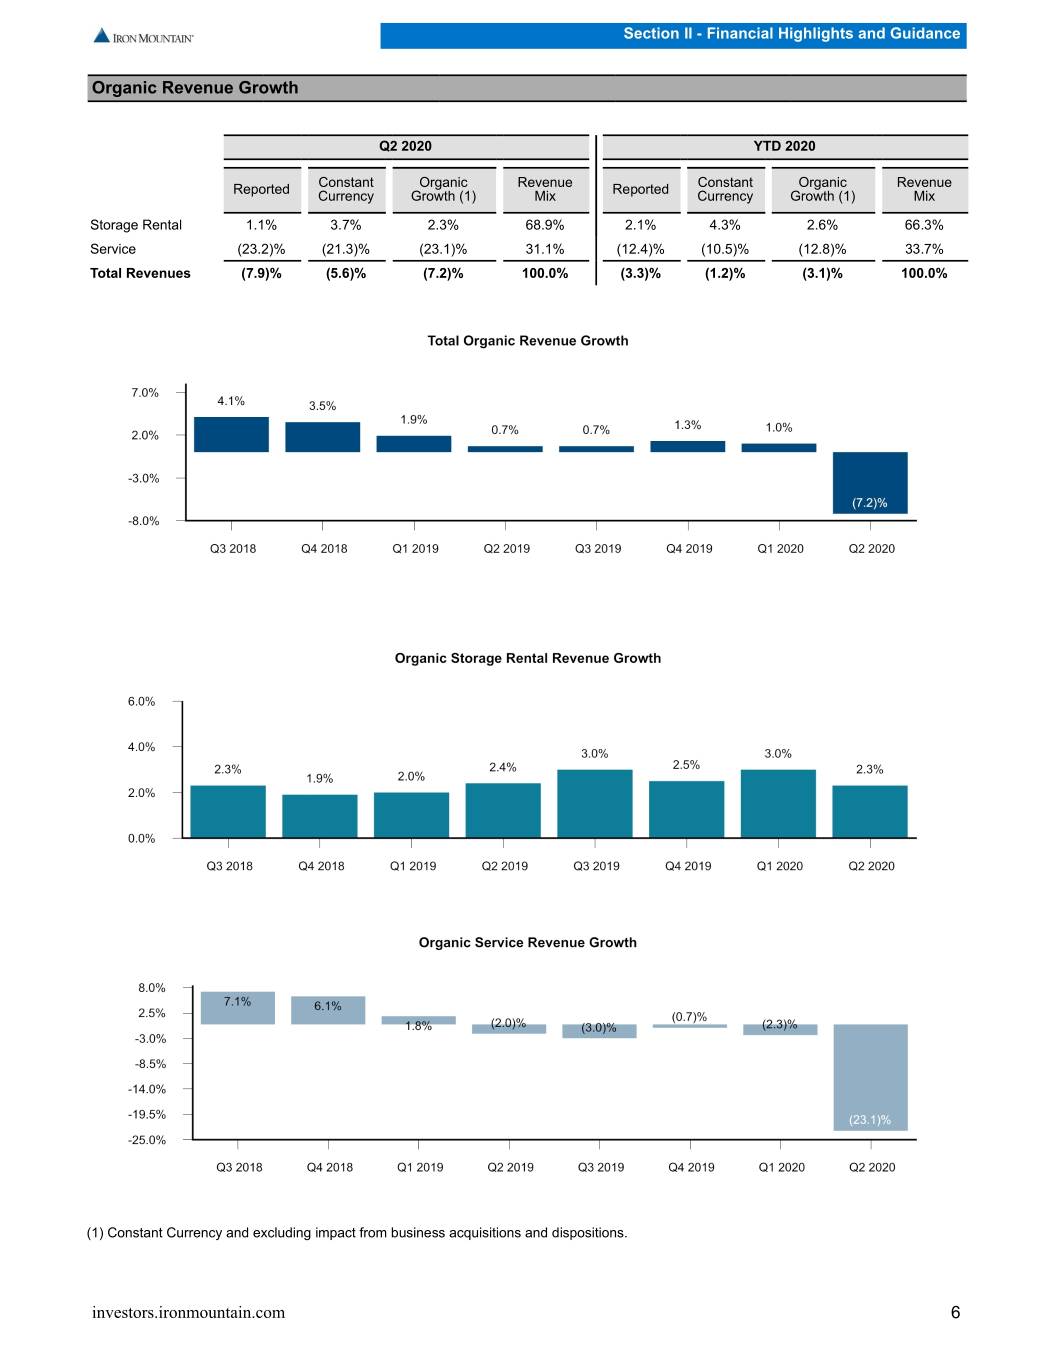
Section II - Financial Highlights and Guidance Organic Revenue Growth Q2 2020 YTD 2020 Constant Organic Revenue Constant Organic Revenue Reported Currency Growth (1) Mix Reported Currency Growth (1) Mix Storage Rental 1.1% 3.7% 2.3% 68.9% 2.1% 4.3% 2.6% 66.3% Service (23.2)% (21.3)% (23.1)% 31.1% (12.4)% (10.5)% (12.8)% 33.7% Total Revenues (7.9)% (5.6)% (7.2)% 100.0% (3.3)% (1.2)% (3.1)% 100.0% (1) Constant Currency and excluding impact from business acquisitions and dispositions. investors.ironmountain.com 6


Section III - Operational Metrics Worldwide Storage Volume Worldwide Cubic Feet Q3 2018 Q4 2018 Q1 2019 Q2 2019 Q3 2019 Q4 2019 Q1 2020 Q2 2020 Records Management 689,273 691,321 696,108 696,359 696,078 693,828 711,589 711,206 Data Protection 735 753 733 760 772 786 799 803 Adjacent Businesses 4,474 5,537 5,392 5,644 5,507 5,508 5,938 5,906 Consumer and Other 435 451 2,485 3,251 3,805 4,096 4,308 6,495 Total Storage Volume 694,917 698,062 704,717 706,014 706,162 704,218 722,634 724,411 Business Acquisitions during the quarter (1) 2,617 2,462 4,248 587 202 514 18,389 3,555 (1) Business acquisitions volume acquired during the quarter included in total volume. investors.ironmountain.com 7


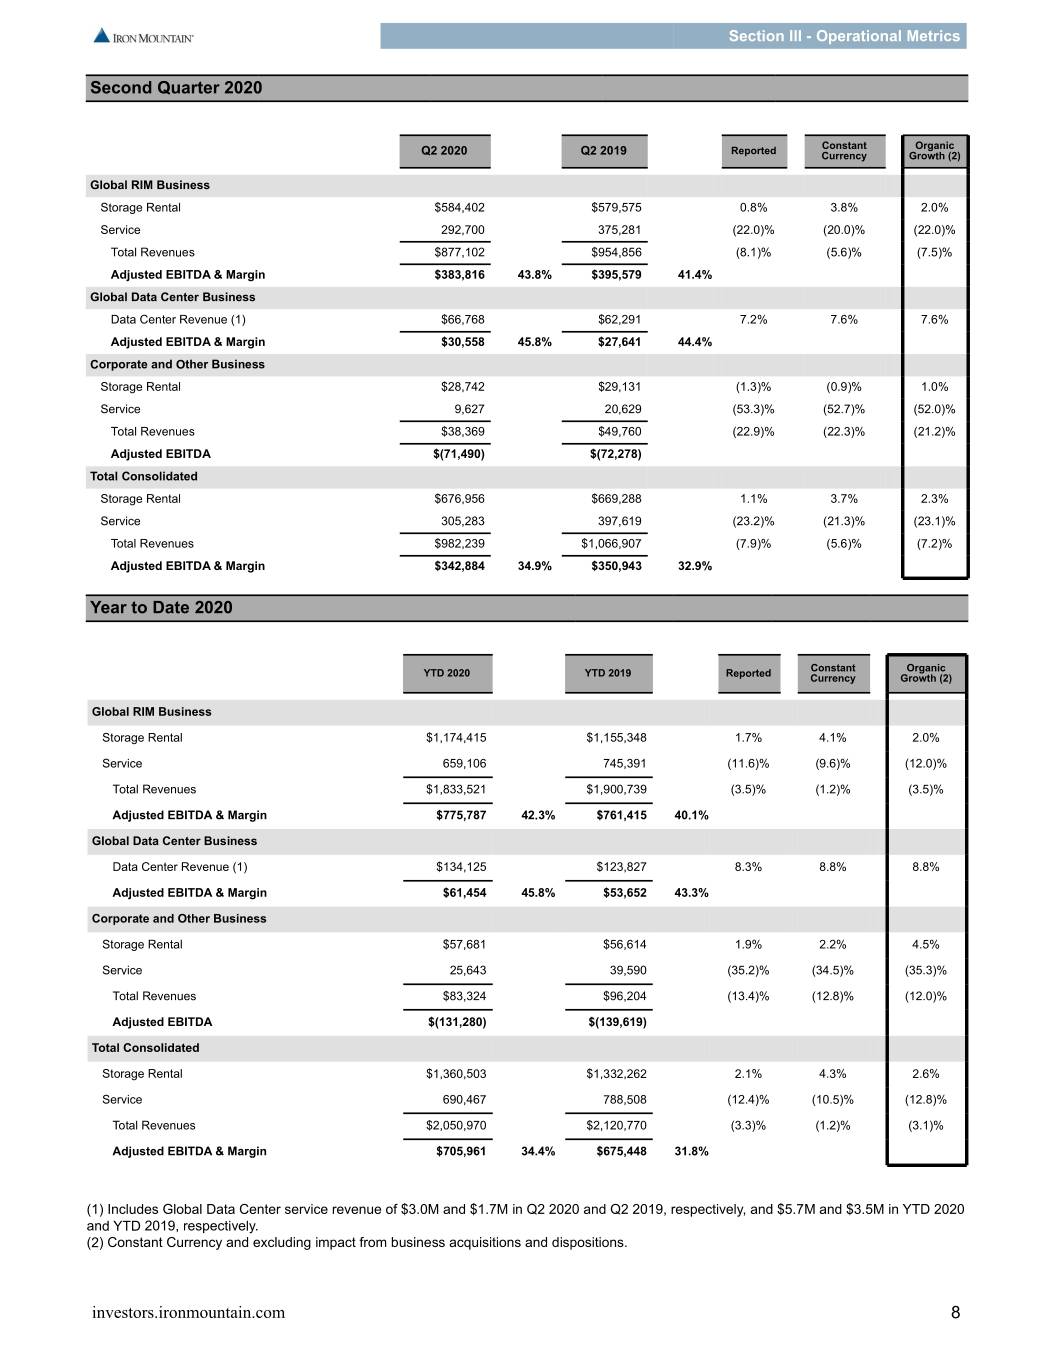
Section III - Operational Metrics Second Quarter 2020 Constant Organic Q2 2020 Q2 2019 Reported Currency Growth (2) Global RIM Business Storage Rental $584,402 $579,575 0.8% 3.8% 2.0% Service 292,700 375,281 (22.0)% (20.0)% (22.0)% Total Revenues $877,102 $954,856 (8.1)% (5.6)% (7.5)% Adjusted EBITDA & Margin $383,816 43.8% $395,579 41.4% Global Data Center Business Data Center Revenue (1) $66,768 $62,291 7.2% 7.6% 7.6% Adjusted EBITDA & Margin $30,558 45.8% $27,641 44.4% Corporate and Other Business Storage Rental $28,742 $29,131 (1.3)% (0.9)% 1.0% Service 9,627 20,629 (53.3)% (52.7)% (52.0)% Total Revenues $38,369 $49,760 (22.9)% (22.3)% (21.2)% Adjusted EBITDA $(71,490) $(72,278) Total Consolidated Storage Rental $676,956 $669,288 1.1% 3.7% 2.3% Service 305,283 397,619 (23.2)% (21.3)% (23.1)% Total Revenues $982,239 $1,066,907 (7.9)% (5.6)% (7.2)% Adjusted EBITDA & Margin $342,884 34.9% $350,943 32.9% Year to Date 2020 Constant Organic YTD 2020 YTD 2019 Reported Currency Growth (2) Global RIM Business Storage Rental $1,174,415 $1,155,348 1.7% 4.1% 2.0% Service 659,106 745,391 (11.6)% (9.6)% (12.0)% Total Revenues $1,833,521 $1,900,739 (3.5)% (1.2)% (3.5)% Adjusted EBITDA & Margin $775,787 42.3% $761,415 40.1% Global Data Center Business Data Center Revenue (1) $134,125 $123,827 8.3% 8.8% 8.8% Adjusted EBITDA & Margin $61,454 45.8% $53,652 43.3% Corporate and Other Business Storage Rental $57,681 $56,614 1.9% 2.2% 4.5% Service 25,643 39,590 (35.2)% (34.5)% (35.3)% Total Revenues $83,324 $96,204 (13.4)% (12.8)% (12.0)% Adjusted EBITDA $(131,280) $(139,619) Total Consolidated Storage Rental $1,360,503 $1,332,262 2.1% 4.3% 2.6% Service 690,467 788,508 (12.4)% (10.5)% (12.8)% Total Revenues $2,050,970 $2,120,770 (3.3)% (1.2)% (3.1)% Adjusted EBITDA & Margin $705,961 34.4% $675,448 31.8% (1) Includes Global Data Center service revenue of $3.0M and $1.7M in Q2 2020 and Q2 2019, respectively, and $5.7M and $3.5M in YTD 2020 and YTD 2019, respectively. (2) Constant Currency and excluding impact from business acquisitions and dispositions. investors.ironmountain.com 8


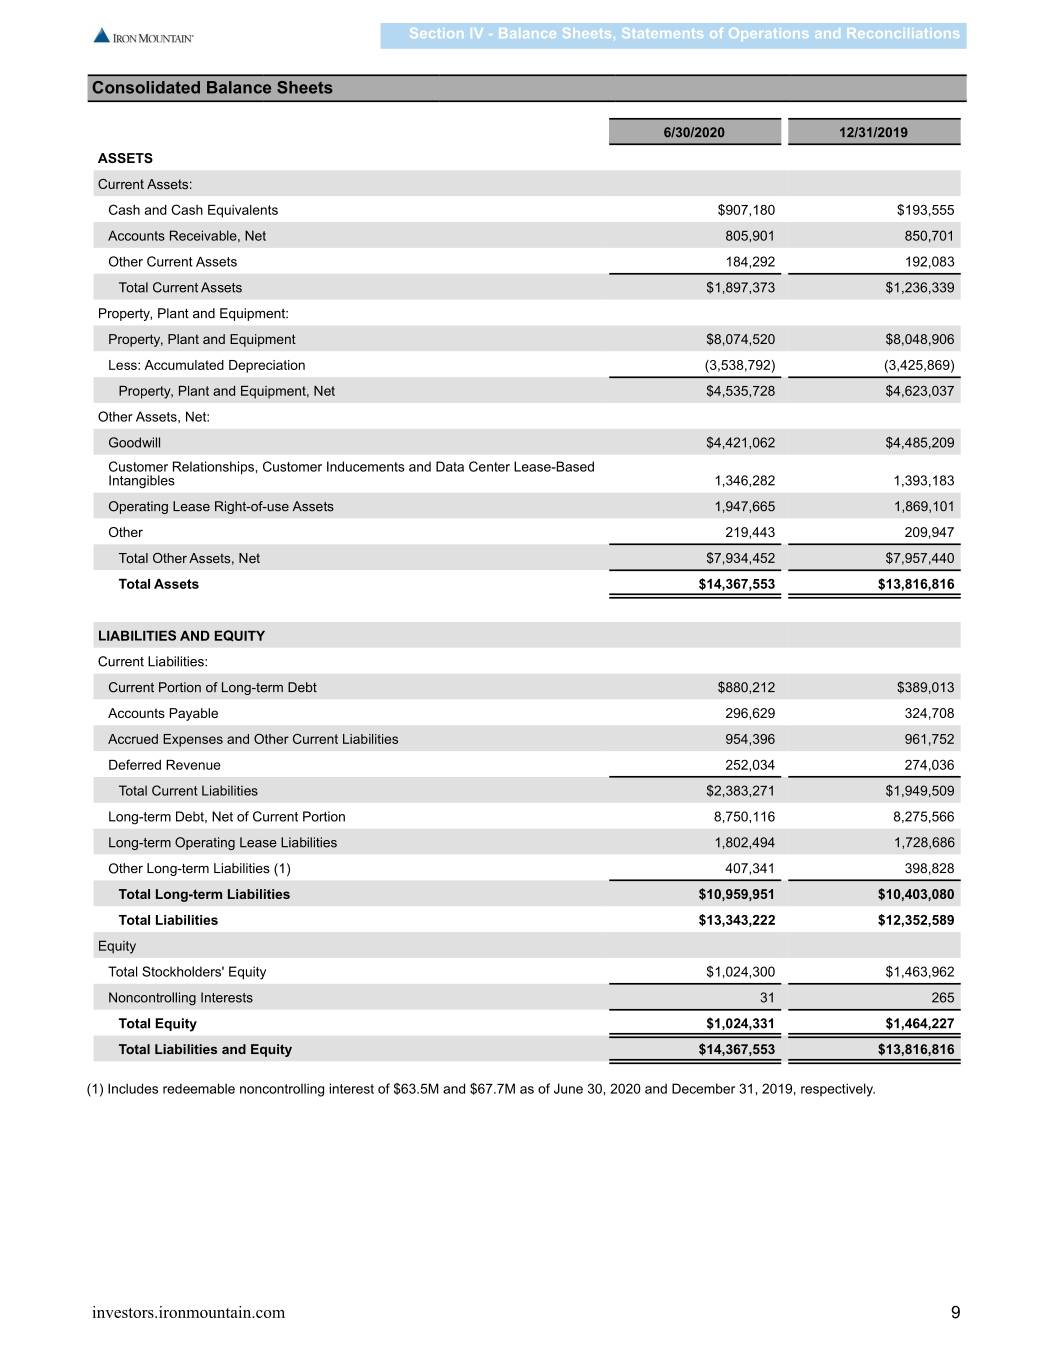
Section IV - Balance Sheets, Statements of Operations and Reconciliations Consolidated Balance Sheets 6/30/2020 12/31/2019 ASSETS Current Assets: Cash and Cash Equivalents $907,180 $193,555 Accounts Receivable, Net 805,901 850,701 Other Current Assets 184,292 192,083 Total Current Assets $1,897,373 $1,236,339 Property, Plant and Equipment: Property, Plant and Equipment $8,074,520 $8,048,906 Less: Accumulated Depreciation (3,538,792) (3,425,869) Property, Plant and Equipment, Net $4,535,728 $4,623,037 Other Assets, Net: Goodwill $4,421,062 $4,485,209 Customer Relationships, Customer Inducements and Data Center Lease-Based Intangibles 1,346,282 1,393,183 Operating Lease Right-of-use Assets 1,947,665 1,869,101 Other 219,443 209,947 Total Other Assets, Net $7,934,452 $7,957,440 Total Assets $14,367,553 $13,816,816 LIABILITIES AND EQUITY Current Liabilities: Current Portion of Long-term Debt $880,212 $389,013 Accounts Payable 296,629 324,708 Accrued Expenses and Other Current Liabilities 954,396 961,752 Deferred Revenue 252,034 274,036 Total Current Liabilities $2,383,271 $1,949,509 Long-term Debt, Net of Current Portion 8,750,116 8,275,566 Long-term Operating Lease Liabilities 1,802,494 1,728,686 Other Long-term Liabilities (1) 407,341 398,828 Total Long-term Liabilities $10,959,951 $10,403,080 Total Liabilities $13,343,222 $12,352,589 Equity Total Stockholders' Equity $1,024,300 $1,463,962 Noncontrolling Interests 31 265 Total Equity $1,024,331 $1,464,227 Total Liabilities and Equity $14,367,553 $13,816,816 (1) Includes redeemable noncontrolling interest of $63.5M and $67.7M as of June 30, 2020 and December 31, 2019, respectively. investors.ironmountain.com 9


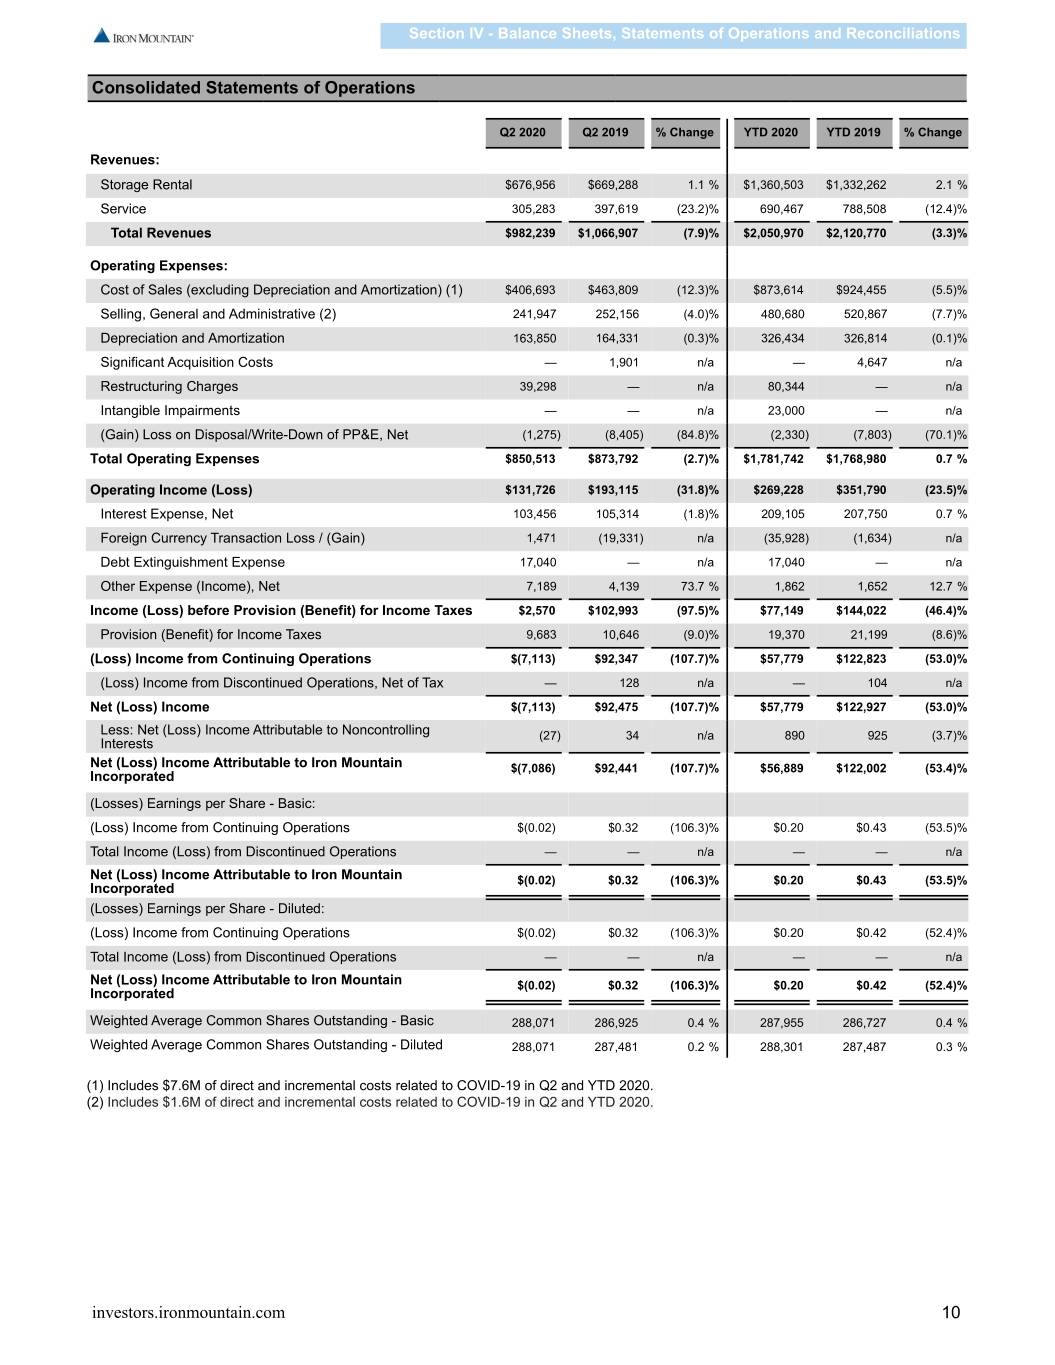
Section IV - Balance Sheets, Statements of Operations and Reconciliations Consolidated Statements of Operations Q2 2020 Q2 2019 % Change YTD 2020 YTD 2019 % Change Revenues: Storage Rental $676,956 $669,288 1.1 % $1,360,503 $1,332,262 2.1 % Service 305,283 397,619 (23.2)% 690,467 788,508 (12.4)% Total Revenues $982,239 $1,066,907 (7.9)% $2,050,970 $2,120,770 (3.3)% Operating Expenses: Cost of Sales (excluding Depreciation and Amortization) (1) $406,693 $463,809 (12.3)% $873,614 $924,455 (5.5)% Selling, General and Administrative (2) 241,947 252,156 (4.0)% 480,680 520,867 (7.7)% Depreciation and Amortization 163,850 164,331 (0.3)% 326,434 326,814 (0.1)% Significant Acquisition Costs — 1,901 n/a — 4,647 n/a Restructuring Charges 39,298 — n/a 80,344 — n/a Intangible Impairments — — n/a 23,000 — n/a (Gain) Loss on Disposal/Write-Down of PP&E, Net (1,275) (8,405) (84.8)% (2,330) (7,803) (70.1)% Total Operating Expenses $850,513 $873,792 (2.7)% $1,781,742 $1,768,980 0.7 % Operating Income (Loss) $131,726 $193,115 (31.8)% $269,228 $351,790 (23.5)% Interest Expense, Net 103,456 105,314 (1.8)% 209,105 207,750 0.7 % Foreign Currency Transaction Loss / (Gain) 1,471 (19,331) n/a (35,928) (1,634) n/a Debt Extinguishment Expense 17,040 — n/a 17,040 — n/a Other Expense (Income), Net 7,189 4,139 73.7 % 1,862 1,652 12.7 % Income (Loss) before Provision (Benefit) for Income Taxes $2,570 $102,993 (97.5)% $77,149 $144,022 (46.4)% Provision (Benefit) for Income Taxes 9,683 10,646 (9.0)% 19,370 21,199 (8.6)% (Loss) Income from Continuing Operations $(7,113) $92,347 (107.7)% $57,779 $122,823 (53.0)% (Loss) Income from Discontinued Operations, Net of Tax — 128 n/a — 104 n/a Net (Loss) Income $(7,113) $92,475 (107.7)% $57,779 $122,927 (53.0)% Less: Net (Loss) Income Attributable to Noncontrolling (27) 34 n/a 890 925 (3.7)% Interests Net (Loss) Income Attributable to Iron Mountain $(7,086) $92,441 (107.7)% $56,889 $122,002 (53.4)% Incorporated (Losses) Earnings per Share - Basic: (Loss) Income from Continuing Operations $(0.02) $0.32 (106.3)% $0.20 $0.43 (53.5)% Total Income (Loss) from Discontinued Operations — — n/a — — n/a Net (Loss) Income Attributable to Iron Mountain $(0.02) $0.32 (106.3)% $0.20 $0.43 (53.5)% Incorporated (Losses) Earnings per Share - Diluted: (Loss) Income from Continuing Operations $(0.02) $0.32 (106.3)% $0.20 $0.42 (52.4)% Total Income (Loss) from Discontinued Operations — — n/a — — n/a Net (Loss) Income Attributable to Iron Mountain $(0.02) $0.32 (106.3)% $0.20 $0.42 (52.4)% Incorporated Weighted Average Common Shares Outstanding - Basic 288,071 286,925 0.4 % 287,955 286,727 0.4 % Weighted Average Common Shares Outstanding - Diluted 288,071 287,481 0.2 % 288,301 287,487 0.3 % (1) Includes $7.6M of direct and incremental costs related to COVID-19 in Q2 and YTD 2020. (2) Includes $1.6M of direct and incremental costs related to COVID-19 in Q2 and YTD 2020. investors.ironmountain.com 10


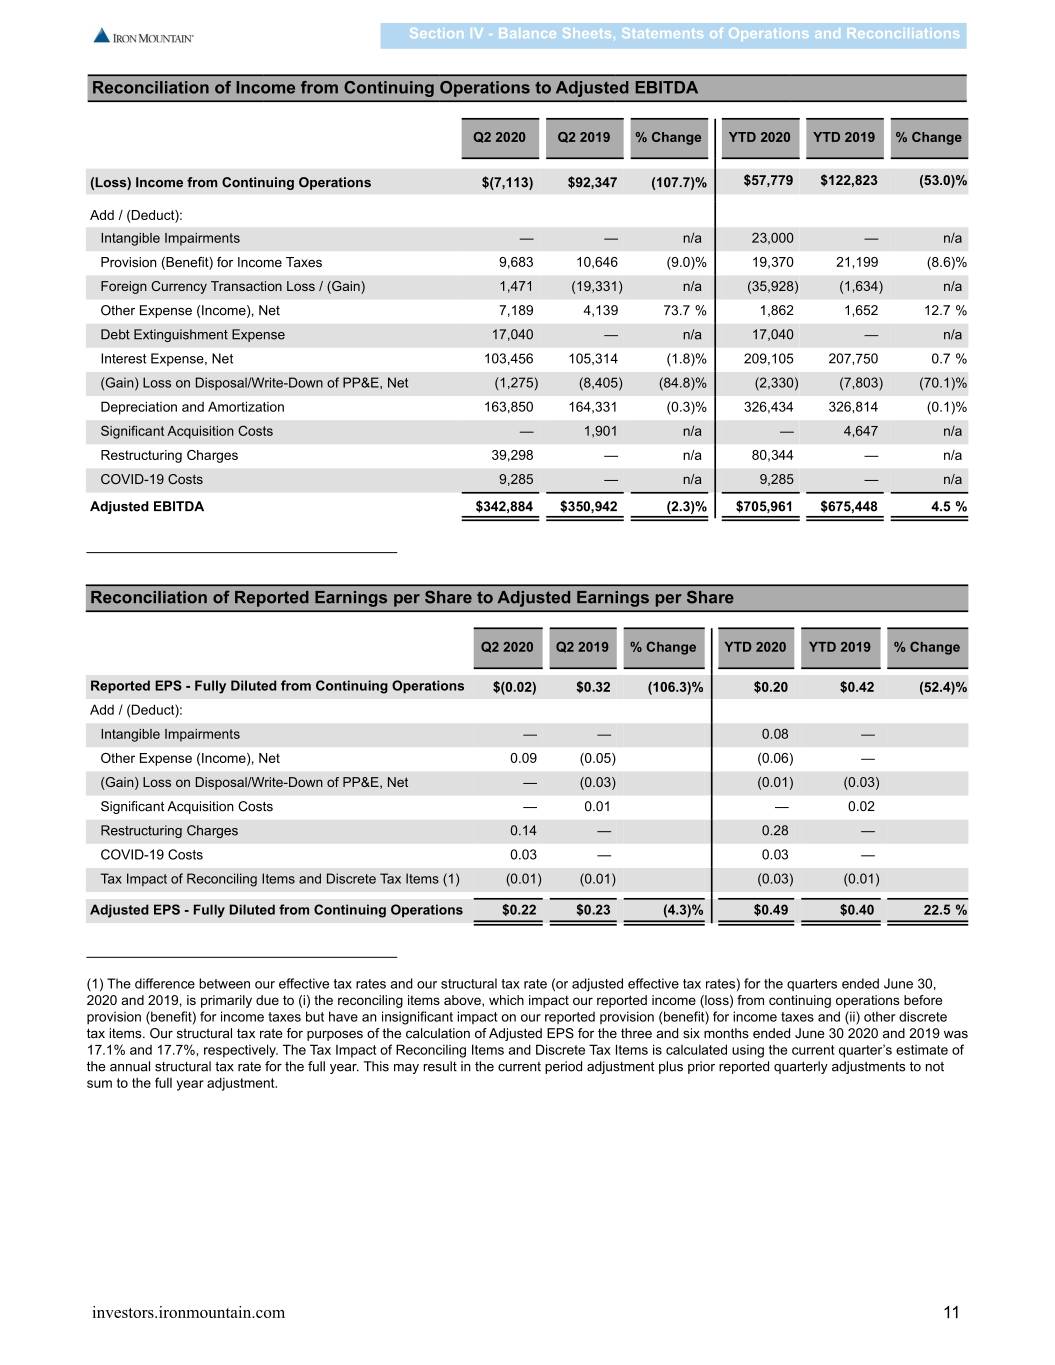
Section IV - Balance Sheets, Statements of Operations and Reconciliations Reconciliation of Income from Continuing Operations to Adjusted EBITDA Q2 2020 Q2 2019 % Change YTD 2020 YTD 2019 % Change (Loss) Income from Continuing Operations $(7,113) $92,347 (107.7)% $57,779 $122,823 (53.0)% Add / (Deduct): Intangible Impairments — — n/a 23,000 — n/a Provision (Benefit) for Income Taxes 9,683 10,646 (9.0)% 19,370 21,199 (8.6)% Foreign Currency Transaction Loss / (Gain) 1,471 (19,331) n/a (35,928) (1,634) n/a Other Expense (Income), Net 7,189 4,139 73.7 % 1,862 1,652 12.7 % Debt Extinguishment Expense 17,040 — n/a 17,040 — n/a Interest Expense, Net 103,456 105,314 (1.8)% 209,105 207,750 0.7 % (Gain) Loss on Disposal/Write-Down of PP&E, Net (1,275) (8,405) (84.8)% (2,330) (7,803) (70.1)% Depreciation and Amortization 163,850 164,331 (0.3)% 326,434 326,814 (0.1)% Significant Acquisition Costs — 1,901 n/a — 4,647 n/a Restructuring Charges 39,298 — n/a 80,344 — n/a COVID-19 Costs 9,285 — n/a 9,285 — n/a Adjusted EBITDA $342,884 $350,942 (2.3)% $705,961 $675,448 4.5 % Reconciliation of Reported Earnings per Share to Adjusted Earnings per Share Q2 2020 Q2 2019 % Change YTD 2020 YTD 2019 % Change Reported EPS - Fully Diluted from Continuing Operations $(0.02) $0.32 (106.3)% $0.20 $0.42 (52.4)% Add / (Deduct): Intangible Impairments — — 0.08 — Other Expense (Income), Net 0.09 (0.05) (0.06) — (Gain) Loss on Disposal/Write-Down of PP&E, Net — (0.03) (0.01) (0.03) Significant Acquisition Costs — 0.01 — 0.02 Restructuring Charges 0.14 — 0.28 — COVID-19 Costs 0.03 — 0.03 — Tax Impact of Reconciling Items and Discrete Tax Items (1) (0.01) (0.01) (0.03) (0.01) Adjusted EPS - Fully Diluted from Continuing Operations $0.22 $0.23 (4.3)% $0.49 $0.40 22.5 % (1) The difference between our effective tax rates and our structural tax rate (or adjusted effective tax rates) for the quarters ended June 30, 2020 and 2019, is primarily due to (i) the reconciling items above, which impact our reported income (loss) from continuing operations before provision (benefit) for income taxes but have an insignificant impact on our reported provision (benefit) for income taxes and (ii) other discrete tax items. Our structural tax rate for purposes of the calculation of Adjusted EPS for the three and six months ended June 30 2020 and 2019 was 17.1% and 17.7%, respectively. The Tax Impact of Reconciling Items and Discrete Tax Items is calculated using the current quarter’s estimate of the annual structural tax rate for the full year. This may result in the current period adjustment plus prior reported quarterly adjustments to not sum to the full year adjustment. investors.ironmountain.com 11


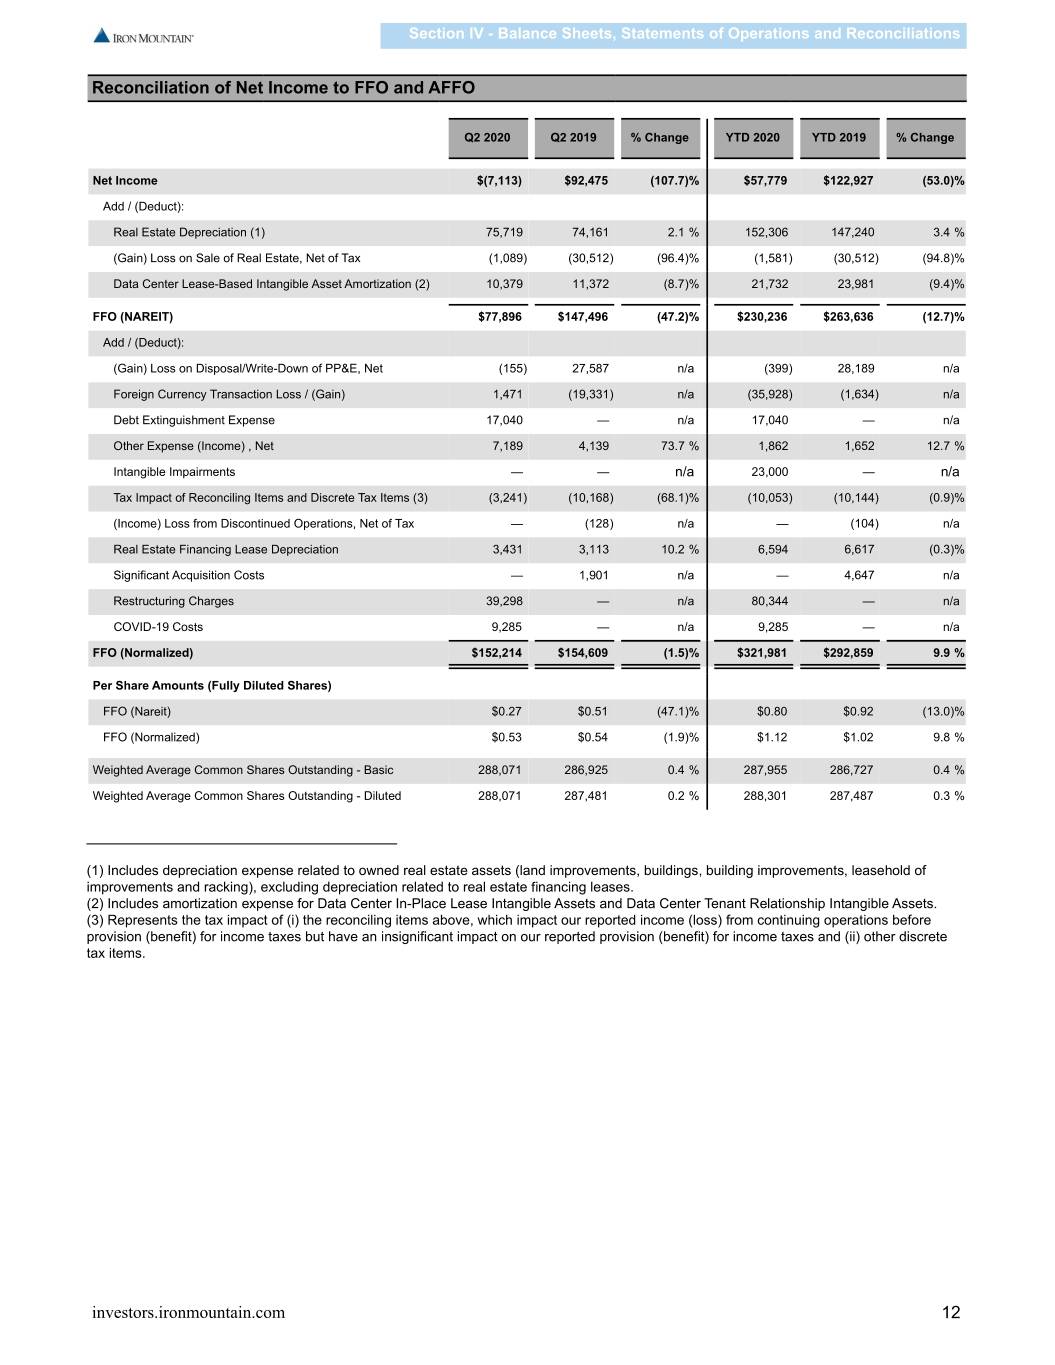
Section IV - Balance Sheets, Statements of Operations and Reconciliations Reconciliation of Net Income to FFO and AFFO Q2 2020 Q2 2019 % Change YTD 2020 YTD 2019 % Change Net Income $(7,113) $92,475 (107.7)% $57,779 $122,927 (53.0)% Add / (Deduct): Real Estate Depreciation (1) 75,719 74,161 2.1 % 152,306 147,240 3.4 % (Gain) Loss on Sale of Real Estate, Net of Tax (1,089) (30,512) (96.4)% (1,581) (30,512) (94.8)% Data Center Lease-Based Intangible Asset Amortization (2) 10,379 11,372 (8.7)% 21,732 23,981 (9.4)% FFO (NAREIT) $77,896 $147,496 (47.2)% $230,236 $263,636 (12.7)% Add / (Deduct): (Gain) Loss on Disposal/Write-Down of PP&E, Net (155) 27,587 n/a (399) 28,189 n/a Foreign Currency Transaction Loss / (Gain) 1,471 (19,331) n/a (35,928) (1,634) n/a Debt Extinguishment Expense 17,040 — n/a 17,040 — n/a Other Expense (Income) , Net 7,189 4,139 73.7 % 1,862 1,652 12.7 % Intangible Impairments — — n/a 23,000 — n/a Tax Impact of Reconciling Items and Discrete Tax Items (3) (3,241) (10,168) (68.1)% (10,053) (10,144) (0.9)% (Income) Loss from Discontinued Operations, Net of Tax — (128) n/a — (104) n/a Real Estate Financing Lease Depreciation 3,431 3,113 10.2 % 6,594 6,617 (0.3)% Significant Acquisition Costs — 1,901 n/a — 4,647 n/a Restructuring Charges 39,298 — n/a 80,344 — n/a COVID-19 Costs 9,285 — n/a 9,285 — n/a FFO (Normalized) $152,214 $154,609 (1.5)% $321,981 $292,859 9.9 % Per Share Amounts (Fully Diluted Shares) FFO (Nareit) $0.27 $0.51 (47.1)% $0.80 $0.92 (13.0)% FFO (Normalized) $0.53 $0.54 (1.9)% $1.12 $1.02 9.8 % Weighted Average Common Shares Outstanding - Basic 288,071 286,925 0.4 % 287,955 286,727 0.4 % Weighted Average Common Shares Outstanding - Diluted 288,071 287,481 0.2 % 288,301 287,487 0.3 % (1) Includes depreciation expense related to owned real estate assets (land improvements, buildings, building improvements, leasehold of improvements and racking), excluding depreciation related to real estate financing leases. (2) Includes amortization expense for Data Center In-Place Lease Intangible Assets and Data Center Tenant Relationship Intangible Assets. (3) Represents the tax impact of (i) the reconciling items above, which impact our reported income (loss) from continuing operations before provision (benefit) for income taxes but have an insignificant impact on our reported provision (benefit) for income taxes and (ii) other discrete tax items. investors.ironmountain.com 12


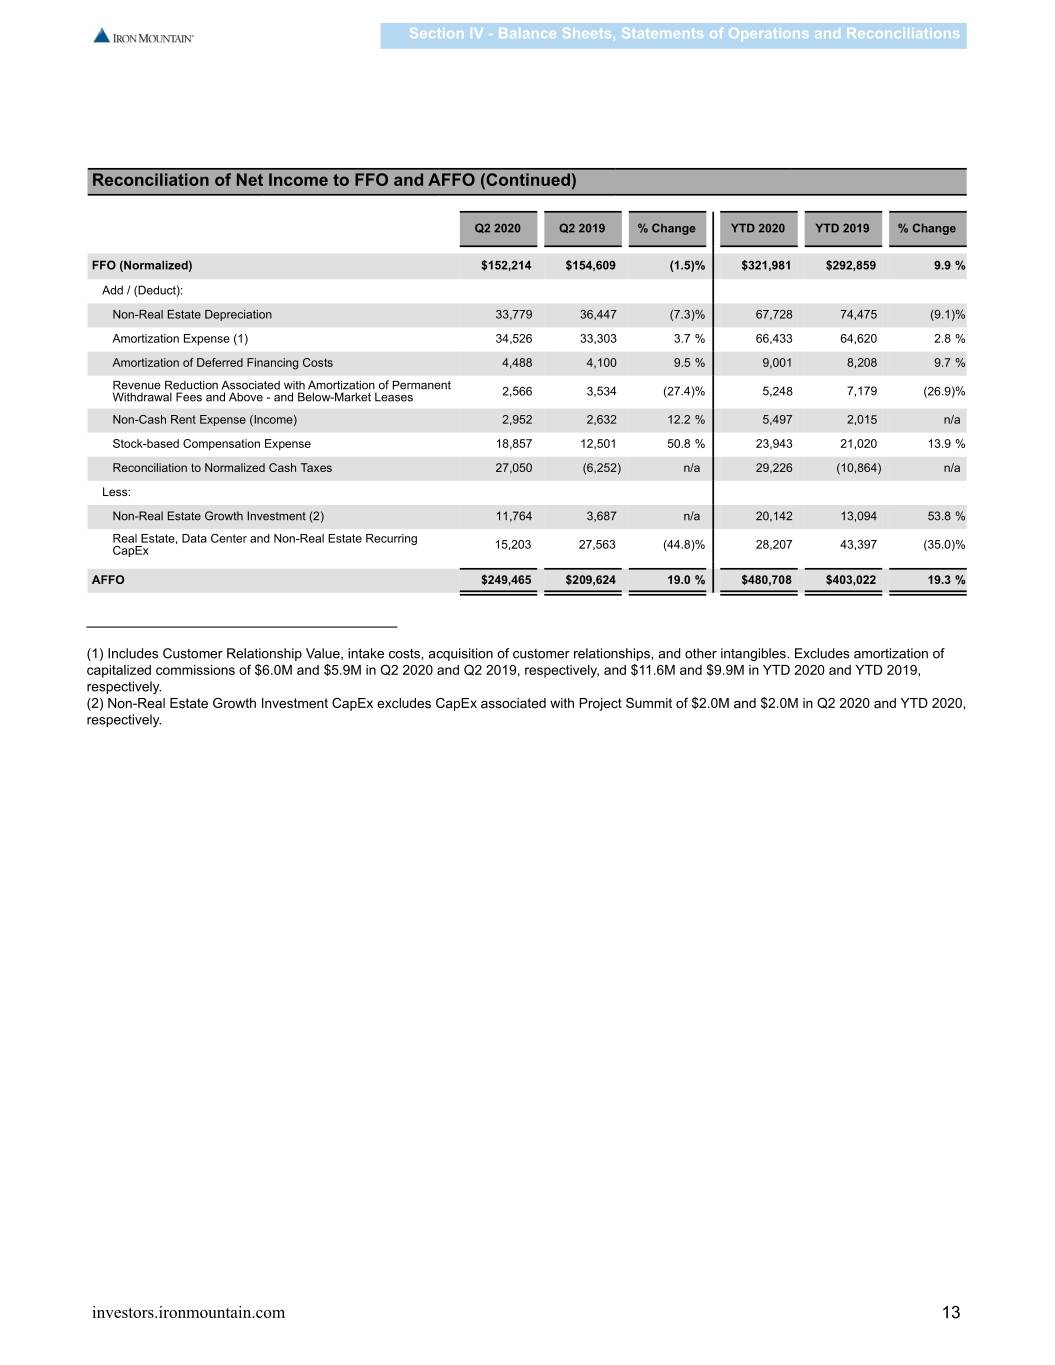
Section IV - Balance Sheets, Statements of Operations and Reconciliations Reconciliation of Net Income to FFO and AFFO (Continued) Q2 2020 Q2 2019 % Change YTD 2020 YTD 2019 % Change FFO (Normalized) $152,214 $154,609 (1.5)% $321,981 $292,859 9.9 % Add / (Deduct): Non-Real Estate Depreciation 33,779 36,447 (7.3)% 67,728 74,475 (9.1)% Amortization Expense (1) 34,526 33,303 3.7 % 66,433 64,620 2.8 % Amortization of Deferred Financing Costs 4,488 4,100 9.5 % 9,001 8,208 9.7 % Revenue Reduction Associated with Amortization of Permanent 7,179 Withdrawal Fees and Above - and Below-Market Leases 2,566 3,534 (27.4)% 5,248 (26.9)% Non-Cash Rent Expense (Income) 2,952 2,632 12.2 % 5,497 2,015 n/a Stock-based Compensation Expense 18,857 12,501 50.8 % 23,943 21,020 13.9 % Reconciliation to Normalized Cash Taxes 27,050 (6,252) n/a 29,226 (10,864) n/a Less: Non-Real Estate Growth Investment (2) 11,764 3,687 n/a 20,142 13,094 53.8 % Real Estate, Data Center and Non-Real Estate Recurring CapEx 15,203 27,563 (44.8)% 28,207 43,397 (35.0)% AFFO $249,465 $209,624 19.0 % $480,708 $403,022 19.3 % (1) Includes Customer Relationship Value, intake costs, acquisition of customer relationships, and other intangibles. Excludes amortization of capitalized commissions of $6.0M and $5.9M in Q2 2020 and Q2 2019, respectively, and $11.6M and $9.9M in YTD 2020 and YTD 2019, respectively. (2) Non-Real Estate Growth Investment CapEx excludes CapEx associated with Project Summit of $2.0M and $2.0M in Q2 2020 and YTD 2020, respectively. investors.ironmountain.com 13


Section IV - Balance Sheets, Statements of Operations and Reconciliations Reconciliation of Cash Flow from Operations to AFFO Q2 2020 Q2 2019 % Change YTD 2020 YTD 2019 % Change Cash Flow from Operating Activities-Continuing Operations $313,659 $312,664 0.3 % $439,074 $429,731 2.2 % Adjust for: Tax on Gain from Disposition of Real Estate 31 5,484 (99.4)% 350 5,481 (93.6)% Tax Impact of Reconciling Items and Discrete Tax Items Net of Deferred Tax (935) (11,498) (91.9)% (7,640) (12,897) (40.8)% Reconciliation to Normalized Cash Taxes 27,050 (6,252) n/a 29,226 (10,864) n/a Significant Acquisition Costs — 1,901 n/a — 4,647 n/a Restructuring Charges 39,298 — n/a 80,344 — n/a COVID-19 Costs 9,285 — n/a 9,285 — n/a Working Capital Adjustments (1) (101,969) (62,139) 64.1 % (9,197) 43,756 n/a Non-Real Estate Growth Investment CapEx (2) (11,764) (3,687) n/a (20,142) (13,094) 53.8 % Real Estate, Data Center and Non-Real Estate Recurring CapEx (15,203) (27,563) (44.8)% (28,207) (43,397) (35.0)% Amortization of Capitalized Commissions (6,017) (5,935) 1.4 % (11,642) (9,881) 17.8 % Other and FX (3,970) 6,649 n/a (743) 9,539 n/a AFFO $249,465 $209,624 19.0 % $480,708 $403,022 19.3 % (1) Working capital adjustments in Q2 2020 are driven primarily by changes in accruals for interest payable and accrued expense. (2) Non-Real Estate Growth CapEx excludes Summit CapEx included in the Summit Transformation project of $2.0M and $2.0M in Q2 2020 and YTD 2020, respectively. investors.ironmountain.com 14


Section V - Storage and Service Reconciliation Storage and Service Reconciliation Q2 2020 Q2 2019 % Change YTD 2020 YTD 2019 % Change Total Storage Rental Revenue $676,956 $669,288 1.1 % $1,360,503 $1,332,262 2.1 % Add: Permanent Withdrawal Fees 4,585 6,063 (24.4)% 10,024 12,555 (20.2)% Adjusted Storage Rental Revenue $681,541 $675,351 0.9 % $1,370,527 $1,344,817 1.9 % Total Service Revenue $305,283 $397,619 (23.2)% $690,467 $788,508 (12.4)% Less: Permanent Withdrawal Fees 4,585 6,063 (24.4)% 10,024 12,555 (20.2)% Adjusted Service Revenue $300,698 $391,556 (23.2)% $680,443 $775,953 (12.3)% Storage Cost of Sales (COS) Storage COS Excluding Rent 92,050 $94,940 (3.0)% 193,690 $193,464 0.1 % Storage Rent 88,128 85,569 3.0 % 178,879 168,746 6.0 % Total Storage COS $180,178 $180,509 (0.2)% $372,569 $362,210 2.9 % Service Cost of Sales (COS) Service COS Excluding Rent 216,050 $280,088 (22.9)% 487,278 $555,879 (12.3)% Service Rent 2,816 3,211 (12.3)% 6,120 6,365 (3.8)% Total Service COS $218,866 $283,299 (22.7)% $493,398 $562,244 (12.2)% COVID-19 Costs 7,648 — n/a 7,648 — n/a Total COS $406,693 $463,809 (12.3)% $873,614 $924,455 (5.5)% SG&A Costs Storage Overhead $43,616 $35,126 24.2 % $81,453 $78,481 3.8 % Service Overhead 22,455 24,455 (8.2)% 47,540 52,304 (9.1)% Corporate Overhead 121,855 130,039 (6.3)% 238,206 261,375 (8.9)% Sales and Marketing 52,385 62,536 (16.2)% 111,844 128,706 (13.1)% COVID-19 Costs 1,637 — n/a 1,637 — n/a Total SG&A $241,947 $252,156 (4.0)% $480,680 $520,867 (7.7)% Adjusted EBITDA Total Storage Adjusted EBITDA $457,747 $459,716 (0.4)% $916,505 $904,126 1.4 % Total Service Adjusted EBITDA 59,377 83,802 (29.1)% 139,505 161,405 (13.6)% Less: Corporate Overhead and Sales and Marketing (174,240) (192,576) (9.5)% (350,049) (390,083) (10.3)% Total Adjusted EBITDA $342,884 $350,942 (2.3)% $705,961 $675,448 4.5 % investors.ironmountain.com 15


Section V - Storage and Service Reconciliation Storage Net Operating Income (NOI) Q2 2020 Q2 2019 % Change YTD 2020 YTD 2019 % Change Total Storage Rental Revenue $676,956 $669,288 1.1 % $1,360,503 $1,332,262 2.1 % Terminations/Permanent Withdrawal Fees 4,585 6,063 (24.4)% 10,024 12,555 (20.2)% Total Revenue from Adjusted Storage Rental Activities $681,541 $675,351 0.9 % $1,370,527 $1,344,817 1.9 % Less: Storage Rental Expenses Facility Costs $164,543 $164,242 0.2 % $339,713 $332,800 2.1 % Storage Rental Labor 5,879 5,821 1.0 % 11,699 13,030 (10.2)% Other Storage Rental Expenses 9,756 10,446 (6.6)% 21,157 16,380 29.2 % Storage Cost of Sales $180,178 $180,509 (0.2)% $372,569 $362,210 2.9 % Allocated Overhead 43,616 35,126 24.2 % 81,453 78,481 3.8 % Total Storage Rental Expenses $223,794 $215,635 3.8 % $454,022 $440,691 3.0 % Storage Gross Profit $501,363 $494,842 1.3 % $997,958 $982,607 1.6 % Storage Gross Margin 73.6% 73.3% 30 bps 72.8% 73.1% -30 bps Total Storage Adjusted EBITDA $457,747 $459,716 (0.4)% $916,505 $904,126 1.4 % Total Storage Adjusted EBITDA Margin 67.2% 68.1% -85 bps 66.9% 67.2% -40 bps Storage Rent 88,128 85,569 3.0 % 178,879 168,746 6.0 % Storage Net Operating Income $545,875 $545,285 0.1 % $1,095,384 $1,072,872 2.1 % Storage Net Operating Income Margin 80.1% 80.7% -60 bps 79.9% 79.8% 10 bps Service Business Detail Q2 2020 Q2 2019 % Change YTD 2020 YTD 2019 % Change Total Service Revenue $305,283 $397,619 (23.2)% $690,467 $788,508 (12.4)% Less: Terminations/Permanent Withdrawal Fees 4,585 6,063 (24.4)% 10,024 12,555 (20.2)% Adjusted Service Revenue $300,698 $391,556 (23.2)% $680,443 $775,953 (12.3)% Less: Service Expenses Facility Costs $9,074 $8,956 1.3 % $18,438 $18,875 (2.3)% Service Labor 158,792 200,801 (20.9) 356,818 398,883 (10.5)% Other Service Expenses 51,000 73,542 (30.7)% 118,142 144,486 (18.2)% Service Cost of Sales $218,866 $283,299 (22.7)% $493,398 $562,244 (12.2)% Allocated Overhead 22,455 24,455 (8.2)% 47,540 52,304 (9.1)% Total Service Expenses $241,321 $307,754 (21.6)% $540,938 $614,548 (12.0)% Total Service Gross Profit $81,832 $108,257 (24.4)% $187,045 $213,709 (12.5)% Total Service Gross Margin 27.2% 27.6% -40 bps 27.5% 27.5% -10 bps Total Service Adjusted EBITDA $59,377 $83,802 (29.1)% $139,505 $161,405 (13.6)% Total Service Adjusted EBITDA Margin 19.7% 21.4% -170 bps 20.5% 20.8% -30 bps Service Rent 2,816 3,211 (12.3)% 6,120 6,365 (3.8)% Total Service Adjusted EBITDAR $62,193 $87,013 (28.5)% $145,625 $167,770 (13.2)% Total Service Adjusted EBITDAR Margin 20.7% 22.2% -150 bps 21.4% 21.6% -20 bps investors.ironmountain.com 16


Section VI - Real Estate Metrics Global Real Estate Portfolio and Lease Obligations Global Real Estate Portfolio (1) Owned Facilities Leased Facilities (2) Total Buildings Sq. Ft. Buildings Sq. Ft. Buildings Sq. Ft. Total as of 3/31/2020 (3) 298 28,314 1,189 64,655 1,487 92,968 Additions & Expansions 3 118 12 637 15 755 Dispositions & Move Outs — — (29) (693) (29) (693) Total as of 6/30/2020 (4) 301 28,432 1,172 64,599 1,473 93,031 Total % 20.4% 30.6% 79.6% 69.3% Top Five Markets Owned, United States (in Sq. Ft.) Top Five Markets Owned, International (in Sq. Ft.) Northern New Jersey 2,086 Paris, France 807 Boston 1,428 Montreal, Canada 552 Chicago 1,282 London, UK 474 Dallas 1,023 Bueños Aires, Argentina 470 Los Angeles 1,012 Mexico City, Mexico 452 Facility Lease Expirations (5) (% of total square feet subject to lease) Weighted-Average Remaining Operating Lease Obligation: 12.0 Years (1) Includes real estate held in consolidated joint ventures. (2) Out of the 12 leased building additions and expansions, none were the result of acquiring leases in business acquisitions and leased buildings related to acquisitions of customer relationships. (3) Reflects adjustments to previous periods due to refinements to real estate basis. (4) Includes 9 owned data center facilities and 5 leased data center facilities with 2.3M Sq.Ft. and 0.6M Sq. Ft., respectively. (5) Includes financing and operating lease obligations. investors.ironmountain.com 17


Section VII - Data Center Customer and Portfolio Metrics Data Center Customer Lease Expiration Number of Leases Percentage of Total Annualized GAAP Percentage of TCV Year Expiring Total MW Expiring MW TCV Rent Expiring Annualized Rent 2020 251 14.5 10.3% $30,490 10.5% 2021 534 19.4 13.8% 61,546 21.3% 2022 267 13.6 9.7% 40,155 13.9% 2023 189 12.8 9.1% 38,848 13.4% 2024 45 7.0 5.0% 17,743 6.1% 2025 33 11.2 7.9% 23,649 8.2% 2026 5 6.3 4.5% 12,119 4.2% Thereafter 20 55.6 39.7% 64,864 22.4% Total 1,344 140.5 100.0% $289,414 100.0% WALE: 4.0 years Data Center Leasing Activity Summary Q2 2020 YTD 2020 Transaction GAAP kW $ / kW / Transaction GAAP kW $ / kW / Count MRR Month Count MRR Month New/expansion leases signed 63 $2,614 32,355 $81 117 $3,109 (1) 38,749 $85 (1) Commenced leases 104 706 5,198 136 189 977 6,409 152 Renewed leases 104 2,076 10,733 193 178 2,854 14,060 203 Churn 0.8% 1.3% Cash Mark to Market (9.3)% (7.2)% GAAP Mark to Market (6.3)% (4.7)% Rendering of Frankfurt (FRA-1) Data Center (1) GAAP MRR includes contractual payments related to reserved dedicated expansion space, which is excluded from the rate. investors.ironmountain.com 18


Section VII - Data Center Customer and Portfolio Metrics Data Center Operating Portfolio Stabilized Pre-Stabilized Total Leasable MW Leased % by MW Leasable MW Leased % by MW Leasable MW Leased % by MW Boyers and Other WPA-1 and Other 14.2 85.8 % — — 14.2 85.8 % Phoenix AZP-1 41.0 93.3 % — — 41.0 93.3 % AZP-2 4.0 100.0 % — — 4.0 100.0 % AZS-1 5.7 66.2 % — — 5.7 66.2 % Total Phoenix 50.7 90.7 % — — 50.7 90.7 % Denver DEN-1 11.3 63.9 % — — 11.3 63.9 % New Jersey NJE-1 15.1 100.0 % — — 15.1 100.0 % Northern Virginia VA-1 10.9 100.0 % — — 10.9 100.0 % Amsterdam AMS-1 12.4 89.8 % — — 12.4 89.8 % London LON-1 3.2 100.0 % 1.9 71.7 % 5.1 89.4 % Singapore SIN-1 2.6 91.3 % — — 2.6 91.3 % Total Data Center Properties 120.4 89.8 % 1.9 71.7 % 122.3 89.5 % Total Potential Capacity - Megawatts Q2 2020 Q2 2019 Operating 122.3 107.8 Under Construction 28.7 11.3 Held for Development 207.0 236.4 Total Data Center Portfolio 358.0 355.5 investors.ironmountain.com 19


Section VII - Data Center Customer and Portfolio Metrics Data Center Expansion and Development Activity Total Project / MW Under MW Pre- % Investment in Cumulative Expected Expected Expected MW Held for Facilities Construction leased Pre- Q2 2020 ($M) Investment Investment Completion Stabilization Development Leased ($M) ($M) Data Center Expansion Amsterdam AMS-1 Phase 2b 0.3 — — $1.0 $1.7 $2.6 Q3 2020 Q4 2020 — AMS-1 Phase 3 1.1 — — $0.1 $1.0 $17.8 Q4 2020 Q2 2021 — AMS-1 Phase 4 4.8 — — $0.1 $0.1 $45.0 Q4 2021 Q4 2023 4.8 London LON-1 Phase 2 2.0 — — $1.6 $2.1 $14.6 Q4 2020 Q2 2022 2.0 New Jersey NJE-1 Phase 3b 0.2 — — — $1.3 $6.4 Q3 2020 Q4 2020 — NJE-1 Phase 4 1.0 — — $0.1 $0.2 $4.5 Q4 2020 Q2 2021 9.3 Northern Virginia VA-1 Phase 4b 1.5 1.5 100.0% $2.5 $3.9 $5.6 Q3 2020 Q3 2020 — Phoenix AZP-2 Phase 2 2.0 1.0 50.0% $0.2 $0.3 $12.0 Q4 2020 Q1 2021 42.0 Singapore SIN-1 Phase 2 2.8 2.0 72.7% $0.1 $0.3 $19.8 Q4 2020 Q1 2021 1.5 All Other Facilities 14.3 Total Expansion 15.7 4.5 28.7% $5.8 $10.9 $128.3 73.9 New Development Amsterdam AMS-2 — — — — — — 10.6 Chicago CHI-2 — — — — — — 36.0 Frankfurt FRA-1 Phase 1 9.0 9.0 100.0% $14.6 $31.1 $141.0 Q2 2021 Q2 2021 18.0 London LON-2 — — — — — — 25.0 Northern Virginia VA-2 Phase 1 4.0 0.8 20.3% $19.3 $96.8 $96.8 Q3 2020 Q1 2021 20.0 VA Future Phases — — — — — — 23.6 Total New 13.0 9.8 75.5% $33.9 $127.9 $237.8 133.2 Development Total Development 28.7 14.3 49.9% $39.7 $138.8 $366.1 207.0 investors.ironmountain.com 20

 
Section VIII - Capitalization and Debt Maturity Profile Capitalization Senior Credit Facility Total Market Capitalization Capacity $1,971,875 # of Shares Outstanding 288,143 Outstanding $583,981 Share Price as of 6/30/2020 $26.10 Letters of Credit $3,197 Total Market Capitalization $7,520,532 Remaining Capacity $1,384,697 Net Debt(1) $8,823,931 Interest Rate Spread (Prime) 0.75% Total Enterprise Value $16,344,463 Interest Rate Spread (LIBOR) 1.75% Net Debt to Total Enterprise Value 54% Weighted Average Interest Rate 1.9% Adjusted EBITDA to Interest Expense 3.5x Maturity Date 6/3/2023 Fixed-Charge Coverage Ratio 2.3x Lease-Adjusted Leverage Ratio 5.4x Total Enterprise Value to Adjusted EBITDA (2) 11.1x Credit Ratings S&P Moody's Corporate BB- Ba3 Senior Credit Facility BB Ba3 Outlook Negative Stable Latest Update 5/13/2020 7/1/2020 Total Debt Weighted Average Rates Weighted Average Interest 4.6% Weighted Average Maturity 7.0 Years USD Denominated 82.6% Debt Maturity Profile ($ in Millions) (3) (1) Net debt is calculated as current portion of long-term debt of $880.2M plus long-term debt net of current portion of $8,750.1M plus deferred financing costs of $100.8M less cash and cash equivalents of $907.2M. (2) Total Enterprise Value to Adjusted EBITDA is calculated on a trailing twelve-month basis. (3) Excludes Deferred Financing Costs, Financing Leases, Notes Payable and Other. (4) 2024 notes redeemed on 07/02/2020. investors.ironmountain.com 21


Section IX - Capital Expenditures and Acquisitions Capital Expenditures and Investments Q2 2020 Q2 2019 % Change YTD 2020 YTD 2019 % Change Capital Expenditures Growth Investment: Real Estate (1) $11,193 $25,623 (56.3)% $28,624 $40,459 (29.3)% Non-Real Estate (2) 11,173 10,167 9.9 % 17,912 18,993 (5.7)% Data Center (3) 54,879 100,166 (45.2)% 91,831 235,170 (61.0)% Innovation 402 5,899 (93.2)% 501 10,680 (95.3)% $77,647 $141,855 (45.3)% $138,868 $305,302 (54.5)% Recurring Real Estate $9,859 $16,864 (41.5)% $17,294 $27,563 (37.3)% Non-Real Estate 2,546 7,764 (67.2)% 6,666 12,260 (45.6)% Data Center 2,798 2,945 (5.0)% 4,247 3,607 17.7 % $15,203 $27,573 (44.9)% $28,207 $43,430 (35.1)% Total Growth Investment and Recurring Capital $92,850 $169,428 (45.2)% $167,075 $348,732 (52.1)% Expenditures Net Change in Prepaid and Accrued Capital 10,164 12,938 (21.4)% 33,083 18,399 79.8 % Expenditures and Financing Leases Total Cash Paid for Growth Investment and Recurring Capital Expenditures $103,014 $182,366 (43.5)% $200,158 $367,131 (45.5)% Capital Expenditures Outlook Total Capital Expenditures expected to be ~$525M in 2020; reflecting increased Data Center Growth Investment and increased Recurring Capital Expenditures. (1) Includes land, buildings improvements, and racking structures. (2) Non-Real Estate Growth CapEx includes Summit CapEx included in the Summit Transformation project of $2.0M and $2.0M in Q2 2020 and YTD 2020, respectively. (3) Includes Non-Real Estate Growth Investment associated with our Global Data Center Business segment of $2.6M and $6.5M in Q2 2020 and 2019, respectively, and $4.2M and $7.1M in YTD 2020 and 2019, respectively. investors.ironmountain.com 22


Section IX - Capital Expenditures and Acquisitions Business Acquisitions Q2 2020 Q2 2019 % Change YTD 2020 YTD 2019 % Change Business Acquisitions Business Acquisitions — $5,777 n/a $118,496 $27,307 n/a Change in Business Acquisition Accruals and 443 (549) n/a 16 17,344 (99.9)% Cash Acquired Cash Paid for Acquisitions, Net of Cash Acquired $443 $5,228 (91.5)% $118,512 $44,651 n/a Customer Acquisitions Q2 2020 Q2 2019 % Change YTD 2020 YTD 2019 % Change Customer Acquisitions Acquisition of Customer Relationships (1) $1,151 $9,020 (87.2)% $2,885 $42,882 (93.3)% Customer Inducements 2,642 3,024 (12.6)% 6,970 5,841 19.3 % Contract Fulfillment Costs (2) 7,596 10,185 (25.4)% 18,738 51,346 (63.5)% Total Acquisition of Customer Relationships, Customer Inducements, and Contract Fulfillment $11,389 $22,229 (48.8)% $28,593 $100,069 (71.4)% Costs Change in Customer Acquisition Accruals — 421 n/a — (9,507) n/a Total Cash Paid for Acquisition of Customer Relationships, Customer Inducements, and Contract $11,389 $22,650 (49.7)% $28,593 $90,562 (68.4)% Fulfillment Costs (1) Acquisition of customer relationships contributed 0.1% to Organic Storage Rental Revenue and 0.3% to Organic Service Revenue in Q2 2020. (2) Includes $30.9M associated with the execution of customer contracts in Q1 2019 following the closing of IO Data Centers, LLC. investors.ironmountain.com 23


Section X - Appendix and Definitions Non-GAAP Measures and Definitions Non-GAAP measures are supplemental metrics designed to enhance our disclosures and to provide additional information that we believe to be important for investors to consider when evaluating our financial performance. These non-GAAP measures should be considered in addition to, but not as a substitute for, other measures of financial performance reported in accordance with accounting principles generally accepted in the United States of America (“GAAP”), such as operating income, (loss) income from continuing operations, net income (loss) or cash flows from operating activities from continuing operations (as determined in accordance with GAAP). Adjusted Earnings Per Share, or Adjusted EPS Adjusted EPS is defined as reported earnings per share fully diluted from continuing operations excluding: (i) (gain) loss on disposal/write-down of property, plant and equipment, net (including real estate); (ii) intangible impairments; (iii) other expense (income), net (which includes foreign currency transaction (gains) losses, net and debt extinguishment expense); (iv) Significant Acquisition Costs; (v) Restructuring Charges; (vi) COVID-19 Costs; and (vii) the tax impact of reconciling items and discrete tax items. Adjusted EPS includes income (loss) attributable to noncontrolling interests. We do not believe these excluded items to be indicative of our ongoing operating results, and they are not considered when we are forecasting our future results. We believe Adjusted EPS is of value to our current and potential investors when comparing our results from past, present and future periods. Adjusted EBITDA and Adjusted EBITDA Margin Adjusted EBITDA is defined as (loss) income from continuing operations before interest expense, net, provision (benefit) for income taxes, depreciation and amortization, and also excludes certain items that we believe are not indicative of our core operating results, specifically: (i) (gain) loss on disposal/write-down of property, plant and equipment, net (including real estate); (ii) intangible impairments; (iii) other expense (income), net (which includes foreign currency transaction (gains) losses, net and debt extinguishment expense); (iv) Significant Acquisition Costs; (v) Restructuring Charges; and (vi) COVID-19 Costs. Adjusted EBITDA Margin is calculated by dividing Adjusted EBITDA by total revenues. We use multiples of current or projected Adjusted EBITDA in conjunction with our discounted cash flow models to determine our estimated overall enterprise valuation and to evaluate acquisition targets. We believe Adjusted EBITDA and Adjusted EBITDA Margin provide our current and potential investors with relevant and useful information regarding our ability to generate cash flows to support business investment. These measures are an integral part of the internal reporting system we use to assess and evaluate the operating performance of our business. Adjusted EBITDA excludes both interest expense, net and the provision (benefit) for income taxes. These expenses are associated with our capitalization and tax structures, which we do not consider when evaluating the operating profitability of our core operations. Finally, Adjusted EBITDA does not include depreciation and amortization expenses, in order to eliminate the impact of capital investments, which we evaluate by comparing capital expenditures to incremental revenue generated and as a percentage of total revenues. Adjusted EBITDA and Adjusted EBITDA Margin should be considered in addition to, but not as a substitute for, other measures of financial performance reported in accordance with GAAP, such as operating income, (loss) income from continuing operations, net (loss) income or cash flows from operating activities from continuing operations (as determined in accordance with GAAP). Adjusted Funds From Operations, or AFFO AFFO is defined as FFO (Normalized) excluding non-cash rent expense or income plus depreciation on non-real estate assets, amortization expense associated with customer relationship value (CRV), intake costs, acquisitions of customer relationships and other intangibles, and excluding amortization expense associated with capitalized internal commissions, amortization of deferred financing costs, revenue reduction associated with amortization of permanent withdrawal fees and above-and below-market data center leases, stock-based compensation expense and the impact of reconciling to normalized cash taxes, less recurring capital expenditures and non-real estate growth investments, excluding Significant Acquisition Capital Expenditures. We believe AFFO is a useful measure in determining our ability to generate excess cash that may be used for reinvestment in the business, discretionary deployment in investments such as real estate or acquisition opportunities, returning capital to our stockholders and voluntary prepayments of indebtedness. Additionally AFFO is reconciled to cash flow from operations to adjust for real estate and REIT tax adjustments, Significant Acquisition Costs, Restructuring Charges and other non-cash expenses. AFFO does not include adjustments for Customer Inducements, acquisition of customer relationships and investment in innovation as we consider these expenditures to be growth related. Funds From Operations, or FFO (Nareit), and FFO (Normalized) Funds from operations (“FFO”) is defined by the National Association of Real Estate Investment Trusts ("Nareit") and us as net income (loss) excluding depreciation on real estate assets, gains on sale of real estate, net of tax and amortization of data center leased-based intangibles ("FFO (Nareit)"). FFO (Nareit) does not give effect to real estate depreciation because these amounts are computed, under GAAP, to allocate the cost of a property over its useful life. Because values for well-maintained real estate assets have historically increased or decreased based upon prevailing market conditions, we believe that FFO (Nareit) provides investors with a clearer view of our operating performance. Our most directly comparable GAAP measure to FFO (Nareit) is net (loss) income. Although Nareit has published a definition of FFO, modifications to FFO (Nareit) are common among REITs as companies seek to provide financial measures that most meaningfully reflect their particular business. Our definition of FFO (Normalized) excludes certain items included in FFO (Nareit) that we believe are not indicative of our core operating results, specifically: (i) (gain) loss on disposal/write-down of property, plant and equipment, (excluding real estate, net); (ii) intangible impairments; (iii) other expense (income), net (which includes foreign currency transaction (gains) losses, net and debt extinguishment expense); (iv) real estate financing lease depreciation; (v) Significant Acquisition Costs; (vi) Restructuring Charges; (vii) COVID-19 Costs; (viii) the tax impact of reconciling items and discrete tax items; (ix) loss (income) from discontinued operations, net of tax; and (x) loss (gain) on sale of discontinued operations, net of tax. FFO (Normalized) per share FFO (Normalized) divided by weighted average fully-diluted shares outstanding. Service Adjusted EBITDA Service Adjusted EBITDA is calculated by taking service revenues excluding terminations and permanent withdrawals less direct expenses and overhead allocated to the service business. Terminations and permanent withdrawals are excluded from this calculation as they are included in the Storage NOI calculation. investors.ironmountain.com 24


Section X - Appendix and Definitions Service Adjusted EBITDAR Service Adjusted EBITDA as defined above, excluding rent expense associated with the service business. This is provided to enable valuation of Service Adjusted EBITDA irrespective of whether the company’s properties are leased or owned. Storage Adjusted EBITDA Storage Adjusted EBITDA is calculated by taking storage revenues including terminations and permanent withdrawal fees less direct expenses and overhead allocated to the storage business. Constant Currency Adjusts results for normalized FX impacts in prior period. Other Definitions Business Segments Global Record and Information Management ("Global RIM") Business: provides (i) storage of physical records, including media such as microfilm and microfiche, film, X-rays and blueprints, including healthcare information services, vital records services, service and courier operations, and the collection, handling and disposal of sensitive documents for customers in approximately 50 countries ("Records Management"), (ii) storage and rotation of backup computer media as part of corporate disaster recovery plans, including service and courier operations (“Data Protection & Recovery”); server and computer backup services; and related services offerings, (collectively, "Data Management"), (iii) Information Governance and Digital Solutions, which develops, implements and supports comprehensive storage and information management solutions for the complete lifecycle of our customers' information, including the management of physical records, document conversion and digital storage in the United States and Canada, (iv) the shredding of sensitive documents for customers that, in many cases, store their records with us ("Secure Shredding") and the subsequent sale of shredded paper for recycling, and (v) on-demand, valet storage for consumers across 24 markets in North America through the MakeSpace JV. Global Data Center Business: provides enterprise-class data center facilities to protect mission-critical assets and ensure the continued operation of our customers’ IT infrastructure, with secure and reliable data center options. As of December 31, 2019, our Global Data Center Business footprint spanned nine markets in the United States: Denver, Colorado; Kansas City, Missouri; Boston, Massachusetts; Boyers, Pennsylvania; Manassas, Virginia; Edison, New Jersey; Columbus, Ohio; and Phoenix and Scottsdale, Arizona and four international markets: Amsterdam, London, and Singapore, with land held for development in Frankfurt. Corporate and Other Business: consists primarily of Adjacent Businesses and other corporate items. Our Adjacent Businesses is comprised of (i) helping entertainment and media industry clients store, safeguard and deliver physical media of all types, and provides digital content repository systems that house, distribute, and archive key media assets, throughout the United States, Canada, France, China - Hong Kong S.A.R., the Netherlands and the United Kingdom ("Entertainment Services") and (ii) technical expertise in the handling, installation and storing of art in the United States, Canada and Europe ("Fine Arts"). Additionally, our Corporate and Other Business segment includes costs related to executive and staff functions, including finance, human resources and IT, which benefit the enterprise as a whole, and stock-based employee compensation expense associated with all stock options, restricted stock units, performance units and shares of stock issued under our employee stock purchase plan. Additionally, our Corporate and Other Business segment includes our technology escrow services business in the United States. Capital Expenditures and Investments – Our business requires capital expenditures to support our expected storage rental revenue and service revenue growth and ongoing operations, new products and services and increased profitability. The majority of our capital goes to support business line growth and our ongoing operations. Additionally, we invest capital to acquire or construct real estate. We also expend capital to support the development and improvement of products and services and projects designed to increase our profitability. These expenditures are generally relatively small and discretionary in nature. We categorize our capital expenditures as follows: Growth Investment: Real Estate – Expenditures primarily related to investments in land, buildings, building improvements, leasehold improvements and racking structures to grow our revenues or achieve operational efficiencies. Non-Real Estate - Expenditures that support the growth of our business, and/or increase our profitability, such as customer-inventory technology systems, security upgrades or system enhancements. Data Center - Expenditures primarily related to investments in new construction of data center facilities (including the acquisition of land and development of facilities) or capacity expansion in existing buildings. Innovation - Discretionary capital expenditures in significant new products and services in new, existing or AB opportunities. Recurring: Real Estate – Expenditures primarily related to the replacement of components of real estate assets such as buildings, building improvements, leasehold improvements and racking structures. Non-Real Estate – Expenditures primarily related to the replacement of customer-facing assets such as containers and shred bins, warehouse equipment, fixtures, computer hardware, or third-party or internally-developed software assets. Data Center – Expenditures related to the upgrade or re-configuration of existing data center assets. Components of Overhead Allocated Overhead – Includes overhead expenses directly associated with storage and service business operations allocated as follows: Field Operation Costs – Allocated to storage and service operations based on percent of revenue. Bad Debt Expenses – Allocated to storage and service operations based on percent of revenue. Transportation Costs – Allocated fully to service operations. investors.ironmountain.com 25


Section X - Appendix and Definitions Corporate Overhead – Includes all other overhead expenses associated with business support functions, including: Executive, Legal, Real Estate/Facilities, Accounting, Financial Performance & Analysis, Treasury, Tax, Internal Audit, M&A, Security, Procurement, HR, REIT, Other G&A, Integration Costs, IT, Product Engineering and Product Management. Customer Turnover Overhead – Overhead associated with customer acquisition and retention including Sales, Marketing and Account Management expenses. COVID-19 Costs: Costs that are incremental and directly attributable to the COVID-19 pandemic which are not expected to reoccur once the pandemic ends. Customer Inducements – Represents Free Move Costs and Permanent Withdrawal Fees. Data Center Business Definitions Leasable MW – Represents the amount of critical power capacity available for customer use, measured in megawatts. Leased % Calculation – Calculated as the megawatts under contract divided by the leasable megawatts. Monthly Recurring Revenue (MRR) - defined as recurring contractual revenue under existing commenced customer leases, including rent, power, and other recurring data center services. Pre-leased - A lease on data center capacity that is signed before construction has completed. Pre-Stabilized - A building recently placed in service which has not yet reached 85% leased or 24 months in service. Rental Churn Rate - represents data center leases which are not renewed or are terminated during the period. Rental churn is calculated based on the MRR terminated in the period, compared with total MRR at the beginning of the period. TCV – “Total Contract Value” represents total revenue contracted for active contracts through the contract term, not including renewals or extensions, but including fixed power charges. Total potential MW - Total amount of existing and planned critical power capacity at full build-out, measured in megawatts. WALE – “Weighted Average Lease Expiry” (in years) is calculated on a revenue basis, using annual GAAP revenue of all in-place contracts, excluding utility reimbursements. Fixed-Charges Coverage Ratio - The Credit Facility Fixed-Charges Coverage Ratio is calculated by LTM Adjusted EBITDA plus rent expenses divided by scheduled amortization, interest expense related to outstanding debt and preferred equity, if any, and rent expenses. Lease-Adjusted Leverage Ratio - The calculation for this ratio is net debt including the capitalized value of lease obligations plus six times rent expenses divided by EBITDA plus rent expenses. Organic Revenue Growth - Our organic revenue growth rate, which is a non-GAAP measure, represents the year-over-year growth rate of our revenues excluding the impact of business acquisitions, divestitures and foreign currency exchange rate fluctuations. Our organic revenue growth rates includes the impact of acquisitions of customer relationships. Records Management Retention Rate – One minus the result of dividing the total number of cubic feet of records removed from inventory due to customer terminations and destructions in a one-year period by the total number of cubic feet of records in storage at the beginning of the period. Restructuring Charges - Operating expenditures associated with Project Summit, our transformation program announced in Q4 2019 which is designed to accelerate execution of Iron Mountain's Strategy. Storage Rev/NOI per Sq.Ft. - Storage revenue (or storage NOI) divided by the quarterly building sq ft average for storage products. Significant Acquisition Capital Expenditures – Represents capitalized expenditures associated with the May 2, 2016 acquisition of Recall Holdings Limited ("Recall") pursuant to the Scheme Implementation Deed, as amended with Recall (the "Recall Transaction") and the acquisition of IO Data Centers, LLC. Significant Acquisition Costs – Represents operating expenditures associated with (1) our acquisition of Recall including: (i) advisory and professional fees to complete the Recall Transaction; (ii) costs associated with the divestments required in connection with receipt of regulatory approvals in connection with the Recall Transaction (including transitional services); and (iii) costs to integrate Recall with our existing operations, including moving, severance, facility upgrade, REIT integration and system upgrade costs, as well as certain costs associated with our shared service center initiative for our finance, human resources and information technology functions; and (2) the advisory and professional fees to complete the acquisition of IO Data Centers, LLC. Service Profit and Margin – The Gross Profit and Margin attributable to the worldwide service business. Calculated as follows: Services Adjusted EBITDA + Allocated Overhead Expenses + Termination and Permanent Withdrawal Fees = Service Profit ($) / Total Service Revenues (including Termination and Permanent Withdrawal Fees) = Service Margin (%) Storage Net Operating Income, or Storage NOI Storage NOI is defined as revenue from rental activities (storage rental revenue, termination fees and permanent withdrawal fees) less storage rental costs. Storage rental costs include facility costs (excluding rent), storage rental labor, other storage costs and allocated overhead. Storage NOI is commonly used in the REIT industry and enables investors to understand and value the income generated from the company’s real estate. Storage Profit and Margin – The Gross Profit and Margin attributable to the worldwide storage business. Calculated as follows: Storage Net Operating Income investors.ironmountain.com 26


Section X - Appendix and Definitions + Allocated Overhead Expenses - Storage Rent - Termination and Permanent Withdrawal Fees = Storage Profit ($) / Total Storage Revenues (excluding Termination and Permanent Withdrawal Fees) = Storage Margin (%) Tax Rates Effective Tax Rate – GAAP tax rate for the period calculated as tax expense or benefit for the quarter (total of current and deferred tax provisions), including discrete items, and divided by profit before tax for the period. Structural Tax Rate – Estimated tax rate for the full fiscal year based on forecasted ordinary income and forecasted tax expense/ benefit excluding any significant unusual or infrequently occurring items (i.e., discrete items) and items recognized net of tax on the financials (i.e., discontinued operations). Total Physical Storage Volume - Comprised of Iron Mountain’s comprehensive portfolio of physical storage, including Records Management hardcopy records, data protection tapes, Consumer and Other, and Adjacent Businesses (Fine Art and Entertainment Services), measured on an absolute basis in cubic feet. investors.ironmountain.com 27