UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
______________________
FORM 10-K
______________________
(Mark One)
| ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 | |||||
For the fiscal year ended December 31 , 2025
OR
TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 FOR THE TRANSITION PERIOD FROM TO | |||||
Commission File Number 001-42878
______________________
(Exact name of Registrant as specified in its Charter)
______________________
(State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | ||||
| (Address of principal executive offices) | (Zip Code) | ||||
Registrant’s telephone number, including area code: (727 ) 202-4815
______________________
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the Registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☐ No ☒
Indicate by check mark if the Registrant is not required to file reports pursuant to Section 13 or 15(d) of the Act. Yes☐ No ☒
Indicate by check mark whether the Registrant: (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the Registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the Registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the Registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☐ | Accelerated filer | ☐ | |||||||||||||||||
| ☒ | Smaller reporting company | |||||||||||||||||||
| Emerging growth company | ||||||||||||||||||||
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☐
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements. ☐
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive officers during the relevant recovery period pursuant to § 240.10D-1(b). ☐
Indicate by check mark whether the Registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ☐ No ☒
The registrant was not a public company as of June 30, 2025, the last business day of its most recently completed second fiscal quarter and, therefore, cannot calculate the aggregate market value of its voting and non-voting common equity held by non-affiliates as of such date. The registrant’s Class A common stock began trading on the New York Stock Exchange on October 1, 2025.
As of February 24, 2026, the registrant had outstanding 94,718,530 shares of Class A common stock and 43,435,000 shares of Class B common stock, each with a par value of $0.00001.
DOCUMENTS INCORPORATED BY REFERENCE
Portions of the registrant’s Definitive Proxy Statement to be filed with the Securities and Exchange Commission no later than 120 days after the end of the registrant’s fiscal year ended December 31, 2025, are incorporated by reference in Part III of this Annual Report on Form 10-K.
SPECIAL NOTE REGARDING FORWARD-LOOKING STATEMENTS
This Annual Report on Form-10-K (this “Annual Report”) contains forward-looking statements. All statements contained in this Annual Report other than statements of historical fact, including statements regarding our future results of operations, financial position, market size and opportunity, our business strategy and plans, the factors affecting our performance and our objectives for future operations, are forward-looking statements. The words “believe,” “may,” “will,” “estimate,” “continue,” “anticipate,” “intend,” “could,” “would,” “expect,” “objective,” “plan,” “potential,” “seek,” “grow,” “target,” “if” and similar expressions are intended to identify forward-looking statements. We have based these forward-looking statements largely on our current expectations and projections about future events and trends that we believe may affect our financial condition, results of operations, business strategy, short-term and long-term business operations and objectives and financial needs. These forward-looking statements are subject to a number of risks, uncertainties and assumptions, including those described in the “Risk Factors.” Moreover, we operate in a very competitive and rapidly changing environment. New risks emerge from time to time. It is not possible for our management to predict all risks, nor can we assess the impact of all factors on our business or the extent to which any factor, or combination of factors, may cause actual results to differ materially from those contained in any forward-looking statements we may make. In light of these risks, uncertainties and assumptions, the future events and trends discussed in this Annual Report may not occur and actual results could differ materially and adversely from those anticipated or implied in the forward-looking statements. Forward-looking statements contained in this Annual Report include, but are not limited to, statements about:
•our ability to protect and enforce our intellectual property;
•our ability to effectively manage and sustain our rapid growth, which may place significant demands on our resources, systems, and personnel;
•adverse NFIP developments that create challenges for private insurers;
•the impact of slower housing market activity, especially in areas needing flood coverage, due to various general economic and other factors;
•our ability to attract and retain talent, including highly skilled engineers, data scientists, and other technical professionals;
•our reliance on third parties for critical functions such as processing policyholder payments and mailing policy documents and notices;
•the highly competitive industry in which we operate;
•our reliance on the accuracy and performance of our AI-powered Triton platform for underwriting and data modeling;
•developments and projections relating to advancements in AI, our competitors, and our industry;
•our ability to successfully launch additional products or expand our product offerings, including into new domestic and international markets;
•our ability to apply technology effectively in driving value for our policyholders through technology-based solutions;
•the impact of current and future laws and regulations, especially those related to insurance regulations;
•potential cybersecurity risks with respect to our or our vendors’ information processing systems;
•the development of a market for our common stock; and
•other risks and uncertainties, including those listed under the caption “Risk Factors.”
We caution you that the foregoing list may not contain all of the forward-looking statements made in this Annual Report.
You should not rely upon forward-looking statements as predictions of future events. The events and circumstances reflected in the forward-looking statements may not be achieved or occur. Although we believe that the expectations reflected in the forward-looking statements are reasonable, we cannot guarantee future results, levels of activity, performance, or achievements. Important factors that could cause actual results to differ materially from our expectations, or cautionary statements, are disclosed under the sections titled “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in this Annual Report. All written and oral forward-looking statements attributable to us, or persons acting on our behalf, are expressly qualified in their entirety by these cautionary statements as well as other cautionary statements that are made from time to time in our other SEC filings and public communications. You should evaluate all forward-looking statements made in this Annual Report in the context of these risks and uncertainties. The forward-looking statements included in this Annual Report are made only as of the date hereof. Except as required by law, we do not intend to update any of these forward-looking statements after the date of this Annual Report or to conform these statements to actual results or revised expectations.
You should read this Annual Report and the documents that we reference in this Annual Report and have filed with the SEC as exhibits to this Annual Report with the understanding that our actual future results, levels of activity, performance and events and circumstances may be materially different from what we expect.
SUMMARY OF RISK FACTORS
Our business is subject to numerous risks and uncertainties and this summary provides an overview of such risks. You should read this risk factor summary together with the more detailed discussion of risks and uncertainties covered under Item 1A “Risk Factors.”
• Our business may be harmed if one or more of our relationships with capacity providers are terminated or are reduced, if we fail to maintain good relationships with such capacity providers, if we become dependent upon a limited number of capacity providers, or if we fail to develop new capacity provider relationships.
• Our distribution model depends on third-party agents and brokers, and any failure by those agents and brokers to consistently promote our products or the loss of any key agent or broker relationships could adversely affect our business.
• Rapid advancements in AI, including the development of AGI and ML technologies, could increase competition and disrupt our business model.
• Errors in underwriting or data modeling could harm our reputation, competitive position, and financial results.
• Reliance on cloud computing exposes us to technological disruptions and potential risks.
• We are highly dependent on the services of our senior management team, including our Chief Executive Officer.
• Our business is dependent upon information processing systems. Cybersecurity events, data breaches, cyberattacks, or other similar incidents, as well as defects, interruptions, or other failures, with respect to our or our vendors’ information processing systems and data may hurt our business, damage our reputation, negatively impact policyholder retention and capacity provider relationships, and expose us to financial and legal liabilities.
• Failure to seek, obtain, maintain, protect, defend, or enforce our intellectual property rights, or allegations that we have infringed, misappropriated, or otherwise violated the intellectual property rights of others, could harm our reputation, ability to compete effectively, financial condition, and business.
• The insurance business is extensively regulated, and changes in regulation may reduce our profitability and limit our growth.
• Compliance with insurance licensing requirements for MGAs and E&S lines agencies and individual producers is critical to our operations, and any failure to maintain required licenses could disrupt our business.
• We are subject to evolving laws and regulations on data privacy, data protection, and cybersecurity, which can be complex and conflicting. We may face investigations, fines, and sanctions as a result of our or our service providers’ or partners’ actual or perceived failure to comply with such laws and regulations and incur increased operational costs in order to ensure future compliance.
• Changes in accounting principles and financial reporting requirements could impact our consolidated results of operations and financial condition.
• We have debt outstanding that could adversely affect our financial flexibility and subjects us to restrictions and limitations that could significantly impact our ability to operate our business.
• The concentration of our share ownership with those stockholders who held our stock prior to our IPO, including our executive officers, directors, and holders of more than 5% of our capital stock, may limit our investor's ability to influence corporate matters.
• We are a “controlled company” within the meaning of the NYSE rules and, as a result, qualify for, and have chosen to rely on, exemptions from certain corporate governance requirements that provide protection to the stockholders of companies that are subject to such corporate governance requirements.
• We are a holding company, and our only material asset is our equity interest in Neptune Flood. As a result, we depend on the ability of our subsidiaries to pay dividends and make other payments and distributions to us in order to meet our obligations.
• The dual class structure of our common stock has the effect of concentrating voting control with our Chief Executive Officer; this will limit or preclude your ability to influence corporate matters.
• Some provisions of Delaware law and our amended and restated certificate of incorporation and bylaws may deter third parties from acquiring us and diminish the value of our Class A common stock.
COMMONLY USED DEFINED TERMS
The following terms have the following meanings throughout this Annual Report unless the context indicates or requires otherwise:
“2025 Amended and Restated Credit Agreement” means the Amended and Restated Credit Agreement, dated as of April 10, 2025, by and among Neptune Holdings, Neptune Flood, the other loan parties thereto from time to time, the lenders party thereto from time to time, and JPMorgan Chase Bank, N.A., as administrative agent.
“AGI” means artificial general intelligence.
“API” means application programming interface.
“Amended Credit Agreement” means the 2025 Amended and Restated Credit Agreement, as amended by the First Amendment.
“CCPA” means the California Consumer Privacy Act, as amended by the California Privacy Rights Act.
“Commission” means the United States Securities and Exchange Commission.
“DGCL” means Delaware General Corporation Law.
“EBITDA” means earnings before interest, taxes, depreciation and amortization.
“EGC” means emerging growth company, as defined in the JOBS Act.
“Exchange Act” means the Securities Act of 1934, as amended.
"FDPA" means the Flood Disaster Protection Act of 1973.
“FEMA” means Federal Emergency Management Agency.
“First Amendment” means Amendment No. 1 to the 2025 Amended and Restated Credit Agreement, dated as of November 10, 2025.
“FTC” means the United States Federal Trade Commission.
"GAAP" means U.S. generally accepted accounting principles.
“GLBA” means the Gramm-Leach-Bliley Act.
“IPO” means the initial public offering of Neptune Insurance Holdings Inc., completed on October 2, 2025.
“JOBS Act” means the Jumpstart Our Business Startups Act of 2012.
“ML” means machine learning.
“NYSE” means New York Stock Exchange.
“Plan” means the Neptune Flood Incorporated 2019 Stock Plan.
“Securities Act” means the Securities Act of 1933, as amended.
“SFHA” means Special Flood Hazard Area, as designated by FEMA.
“we,” “us,” “our,” the “Company,” and “Neptune” refer to Neptune Insurance Holdings Inc. and its subsidiaries, taken as a whole; “Neptune Holdings” refers only to Neptune Insurance Holdings Inc.; and “Neptune Flood” refers only to Neptune Flood Incorporated.
TRADEMARKS, TRADE NAMES, AND SERVICE MARKS
“Neptune,” “Neptune Flood,” “Triton,” the Neptune stylized design logo, and our other registered or common law trademarks, trade names, and service marks appearing in this Annual Report are our property. Solely for convenience, our trademarks, trade names, and service marks referred to in this Annual Report appear without the ®, ™ and ℠ symbols, but those references are not intended to indicate, in any way, that we will not assert, to the fullest extent under applicable law, our rights to these trademarks and trade names. This Annual Report may contain additional trademarks, trade names, and service marks of other companies that are the property of their respective owners.
NON-GAAP FINANCIAL MEASURES AND KEY PERFORMANCE INDICATORS
This Annual Report contains certain financial measures, including Adjusted EBITDA, Adjusted EBITDA margin, Adjusted net income and Adjusted earnings (basic and diluted) per share that are not required by, or prepared in accordance with, U.S. generally accepted accounting principles. We refer to these measures as “non-GAAP” financial measures. See “Item 7—Management’s Discussion and Analysis of Financial Condition and Results of Operations — Non-GAAP Financial Measures” for our definitions of these non-GAAP measures, information about how and why we use these non-GAAP measures and a reconciliation of each of these non-GAAP measures to its most directly comparable financial measure calculated in accordance with GAAP.
This Annual Report also includes certain key performance indicators, including revenue per employee, Adjusted EBITDA per employee, premium in force, policies in force, policy retention rate, premium retention rate, revenue retention rate, organic revenue, organic revenue growth, and written premium, that Neptune’s management regularly reviews in managing its business to evaluate its business and operations, guide decision-making, measure progress and understand growth and retention, and ultimately help drive profitability. Organic revenue and organic revenue growth are common non-GAAP financial measures reported by others in the insurance industry. We use “organic revenue” and “organic revenue growth” in this Annual Report to facilitate investors’ understanding of our operating performance and comparison with our peers. However, as of the date of this Annual Report and for the relevant periods presented herein, we have not completed any relevant acquisitions or divestitures, therefore our organic revenue and organic revenue growth reflect our total revenue and total revenue growth, respectively, as determined in accordance with GAAP. For definitions of these key performance indicators, see “Item 7—Management’s Discussion and Analysis of Financial Condition and Results of Operations — Key Performance Indicators.”
Table of Contents
| Page | ||||||||
Item 1C. | Cybersecurity | 55 | ||||||
[Reserved] | ||||||||
| 81 | ||||||||
| 106 | ||||||||
| 106 | ||||||||
| 106 | ||||||||
| 106 | ||||||||
i
PART I
Item 1. Business.
Company Overview
Neptune is a leading, high-growth, highly profitable, data-driven MGA that is revolutionizing the way homeowners and businesses protect against the growing risks of flooding. We offer a range of easy-to-purchase residential and commercial insurance products - including primary flood insurance, excess flood insurance, and parametric earthquake insurance - distributed through a nationwide network of agencies. Neptune does not take any balance sheet insurance risk or have claims handling responsibility relating to the policies we sell. We underwrite and administer the issuance of insurance policies on behalf of a diverse panel of insurance and reinsurance companies, whom we refer to as capacity providers, that manage both this risk and the associated claims handling. From day one, we have built our business on a foundation of advanced data science and AI, leveraging proprietary ML algorithms, which has led to superior underwriting results, outsized growth, recurring revenue, and robust margins, including delivering a lifetime written loss ratio of just 24.7% to our capacity providers from our inception through June 30, 2025. In addition, for the year ended December 31, 2025, we achieved 33.7% organic revenue growth, 23.4% net income margin and 59.5% Adjusted EBITDA margin.
Neptune was founded to solve the inefficiencies and poor product-market fit we saw in the traditional flood insurance market, which we believe represents a significant and underpenetrated opportunity. According to the American Housing Survey and the Energy Information Administration, there are over 100 million residential and commercial buildings in the U.S., many of which face flood risk, yet only a small fraction are covered by flood insurance. Today, the largest provider of flood insurance in the United States - and the holder of the majority market share - is the NFIP, a U.S. government-run entity and our main competitor. We believe purchasing insurance from the NFIP is relatively burdensome and time-consuming for policyholders and agents, and that its limited product offerings often fail to meet policyholder needs. In addition, the NFIP has historically received substantial government subsidies that have enabled it to limit premiums to rates that have been challenging for private flood insurance providers to compete with, a dynamic that is shifting with the NFIP’s 2021 introduction of its “Risk Rating 2.0” pricing model, discussed in more detail below. Private market participation has also historically been constrained by regulatory barriers, a lack of innovation expertise, and limited access to sufficient claims and performance data to optimize pricing and underwriting decisions. We believe that Neptune’s position as the first scaled private flood platform, including the years of claims and performance data we have generated through our operations, provides a key early-mover advantage in addressing all of these challenges and disrupting the industry.
With Neptune’s use of AI, our technology platform, and our data-driven approach, we believe we have delivered the promise of disrupting the insurance industry. Not only have our innovation efforts delivered vastly improved policyholder and agent experiences through the ease-of-use of our proprietary underwriting (Triton) and policy management (Poseidon) platforms, we have also demonstrated superior risk selection and underwriting through our top-tier financial performance and sustained growth. Utilizing AI and ML algorithms with no human underwriters, Neptune has redefined how flood insurance can be underwritten, creating value for policyholders and agents while producing consistent, long-term positive returns for our insurance and reinsurance partners. Further, as the NFIP moves away from its historical subsidized pricing model, we believe our Triton platform, backed by years of proprietary data derived from our business operations, positions us to optimize pricing determinations and compete for existing NFIP policyholders in a way that would be challenging for a new entrant to replicate until it is able to generate, or otherwise gain access to, comparable claims and performance data.
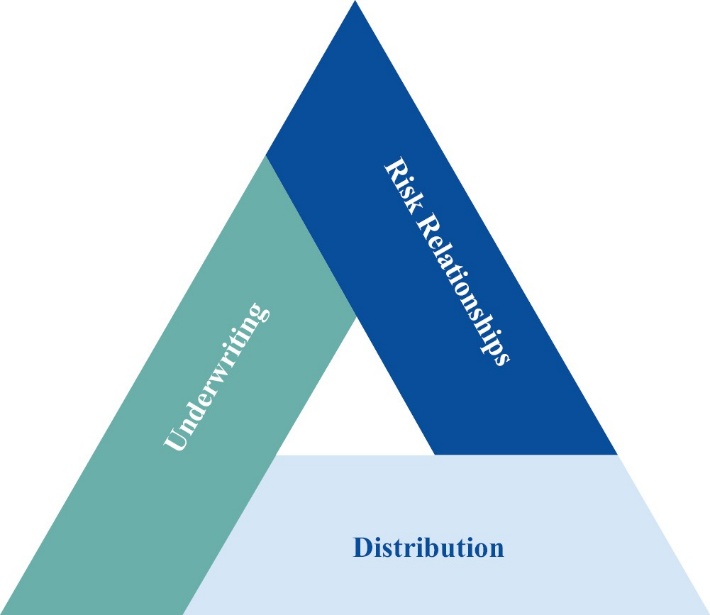
Technology and data science are the foundation of Neptune’s business model, driving our three core pillars:
•Our Underwriting Engine: Our entirely digital underwriting engine, Triton, uses advanced technology, including proprietary AI and ML models, without any human underwriters, to assess risk with speed and precision. Powered by predictive analytics and loss estimation, Triton has enabled Neptune’s policies to consistently outperform the NFIP in written loss ratio despite 21 landfall hurricanes - including 4 of the 10 largest flood events in U.S. history - taking place since Neptune’s founding.
•Our Risk Relationships: Our risk relationships are built on performance and trust, and we currently have 40 capacity providers, including 32 reinsurance providers, backing 8 distinct insurance programs to help minimize concentration risk while delivering consistent returns. In turn, the accuracy of our risk assessment and our precision pricing have delivered hundreds of millions of dollars of underwriting profit for our capacity providers since inception, leading to high rates of capacity renewals and increases in committed capacity.
1
•Our Distribution: Our distribution strategy is primarily focused on deep partnerships across agencies with tens of thousands of agents who benefit from the ease-of-use of our automated underwriting platform, seamless API integrations, instantaneous bindable quotes, and proprietary Agent Portal. We believe this is a meaningful departure from industry norms and makes our approach to distribution attractive to the agents we work with.
The three pillars above interlock, creating a powerful and reinforcing loop. Unlike traditional insurance underwriting that historically relied on humans, static models, and infrequent adjustments, we leverage an iterative approach that allows us to consistently and rapidly integrate new data and models into our underwriting engine, thereby refining our processes and adapting to evolving market and environmental conditions. As our models constantly evolve and improve, they are able to deliver superior results that minimize losses for our capacity providers, which in turn grant us additional underwriting capacity. With more capacity available, we can offer coverages our policyholders want, enhancing the ability for our agency partners to easily sell policies while expanding our distribution and reach. The resulting increase in quoted and bound policies provides us with access to more data, enhancing the predictive capabilities of our underlying models.
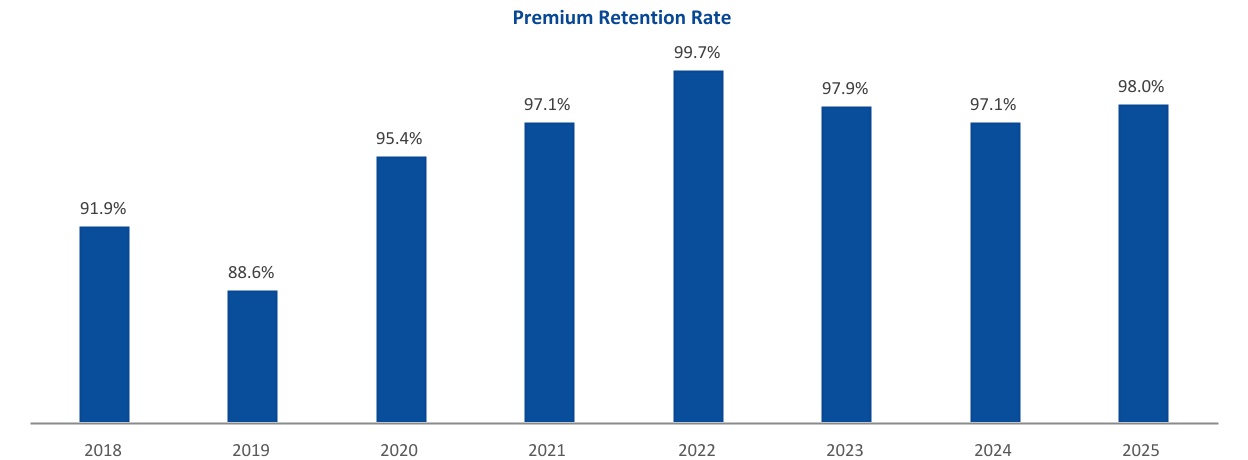
We operate as an MGA, with a highly profitable, recurring, fee-based revenue model derived from two primary sources: commissions paid by capacity providers, and fees paid by policyholders. Commissions are calculated as a negotiated percentage of premium for each policy. For the year ended December 31, 2025, our average commission rates have increased by more than 4.5% since 2018, as capacity providers continue to recognize our superior underwriting performance. Given our strong policy and premium retention rates to date, we believe that we have a high degree of visibility into our future revenue streams. For example, for the year ended December 31, 2025, our eligible policy and premium retention rates at renewal were 86.1% and 98.0%, respectively.
As of December 31, 2018, the end of our first full year of operations, we had $4.4 million of premium in force with one insurance program. As of December 31, 2025, we have achieved remarkable growth. Since 2018, our premium in force has increased at a CAGR of 88.3% to $370.2 million as of December 31, 2025. For the year ended December 31, 2025, we generated $159.6 million in revenue, $37.4 million in net income, and $95.0 million in Adjusted EBITDA. This translates to $2.8 million in revenue per employee and $1.6 million in Adjusted EBITDA per employee, a 23.4% net income margin and a 59.5% Adjusted EBITDA margin. Our Adjusted EBITDA margin has consistently exceeded 55.0% over the past four years, thanks to the operational leverage inherent in our technology-first business model. Notably, our organic revenue for the year ended December 31, 2025, increased by $40.3 million, or 33.7%, year-over-year. For the year ended December 31, 2025, we also generated net cash provided by operating activities of $51.7 million. As of December 31, 2025, we had negative book value per share due to our history of paying dividends to our stockholders, which have been financed through a combination of debt and redeemable, convertible preferred stock financings, and cash flows generated from our business operations. Since inception, we have made dividend payments to our stockholders totaling approximately $605.0 million.
2
Organic Revenue
($MM)
| YoY Organic Revenue Growth % | 382 | 171 | 98 | 62 | 42 | 41 | 34 | ||||||||||||||||||||||||||||||||||||||||
Net Income
($MM)
| Net Income Margin% | 10 | 32 | 34 | 29 | 21 | 29 | 26 | ||||||||||||||||||||||||||||||||||||||||
Premium in Force
($MM)
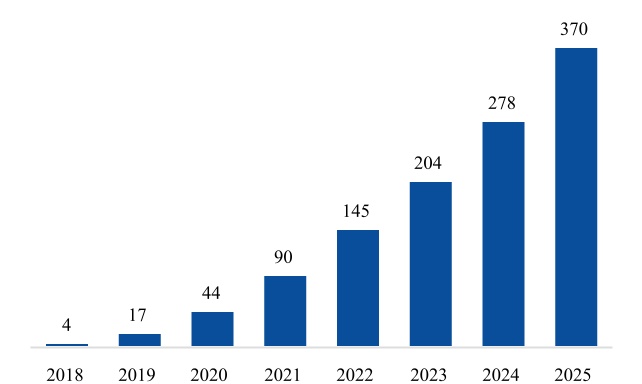
| YoY Premium in Force Growth % | 287 | 156 | 105 | 61 | 41 | 36 | 33 | ||||||||||||||||||||||||||||||||||||||||
Adjusted EBITDA
($MM)
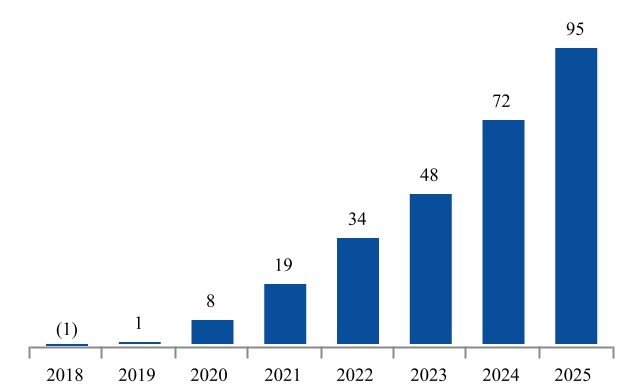
| Adjusted EBITDA Margin% | 15 | 45 | 51 | 55 | 57 | 60 | 59 | ||||||||||||||||||||||||||||||||||||||||
Our Unique, Data-Driven Approach
Data science is our guiding principle, driving innovation that we believe enables us to deliver fast and accurate insurance solutions that are policyholder-centric and more efficient for our agents, and that deliver consistent underwriting profits for our capacity providers.
Our internally-developed and proprietary technology platforms include Triton, our underwriting engine, and Poseidon, our policy management system, which are closely integrated and easy to use. The key features of our data science approach that underpin our platforms include:
•Precise Pricing Models: Our models leverage advanced ML and data analysis to evaluate flood risks at the individual property level. By incorporating real-time data, including from geospatial mapping as well as predictive analytics, we deliver competitive, risk-adjusted pricing that reflects the unique risk of each property. The precision of this data-driven approach empowers us to offer instant underwriting decisions and bindable quotes at scale, with a level of intention and sophistication in our risk selection that we believe sets us apart in the industry and that results in a high degree of predictability in our business outcomes.
•Automation and Efficiency: We operate with the mantra of “automating everything.” We constantly focus on reducing manual processes across our operations and enabling our team to concentrate on more complex and high-value tasks.
•Scalability: Our emphasis on automation in our technology infrastructure allows us to process tens of thousands of quotes daily, providing the scale necessary for rapid growth and market expansion without a proportional increase in headcount.
3
•Agility: Our platform has demonstrated a great degree of flexibility, seamlessly incorporating new perils and geographies over time in response to the evolving needs of policyholders and agency partners.
•Ease of Use: Our platforms are designed with a focus on simplicity and accessibility. Agents and policyholders can obtain quotes, purchase policies, and manage policyholder coverage in just minutes through our streamlined online interface. In many cases, the creation of a Neptune quote is automatic and instantaneous for agents via our API, allowing seamless cross-sell opportunities alongside standard home and business insurance quotes. We believe this ease of use and quote-to-issue process differentiates Neptune from traditional insurance providers and has been a key driver of our success.
Triton and Poseidon were built entirely in-house by our Neptune Engineering Group. These platforms are powered by ML models centered around our vast proprietary datasets, which are developed and maintained by the in-house Neptune Data Science Group and are generated from data collected through the operation of our business, including quote requests, the policies we have bound, and the losses incurred on the policies we have sold. Triton processes over 20,000 quotes on a typical day. As of December 31, 2025, Triton has provided approximately 32.7 million quotes, underwritten 12.8 million properties, and bound 1.3 million policies across the U.S. since inception, providing Neptune with what we believe is the largest flood insurance sales and claims database outside of the NFIP.
Our systems continually update and constantly learn and improve from the expansive datasets generated by our daily operations, helping us stay ahead of the curve in understanding flood risk. In December 2025, we released the 546th product version of our underwriting model, demonstrating our commitment to continued improvements.
From a risk selection perspective, we believe our focus on data science has allowed us to provide a more accurate estimate of likelihood of loss across our portfolio compared to the industry. This has allowed us to deliver superior written loss ratios for our capacity providers. Despite navigating some of the largest flood disasters in U.S. history, our Triton underwriting platform has delivered a lifetime written loss ratio of just 24.7% from our inception through June 30, 2025. For example, in 2024, Hurricane Helene devastated parts of Florida and North Carolina as the fourth most expensive flooding event in NFIP history. The written loss ratio on that storm for policies sold by Neptune was 17.0% while the NFIP produced a written loss ratio of 169.6%. At the time of the storm, we had approximately 74,000 policies in force in the affected states of Florida, North Carolina, and Tennessee.
In 2024, we also implemented a ML-driven renewal optimization model, which has had a measurable impact on policy retention rates. This model enabled more precise identification of policyholders at risk of non-renewal and allowed for targeted engagement strategies, driving an increase in policy retention from 84.0% for the year ended December 31, 2024, to 86.1% for the year ended December 31, 2025.
Altogether, our data science capabilities underpin the visibility of our earnings to date, driving a premium retention rate of our policies that are extended upon renewal that has exceeded 97.0% for each of the last 5 years. As our business grows, this strong retention rate has resulted in an increasing share of our portfolio consisting of tenured policyholders. As of December 31, 2025, 68.9% of our premium in force was associated with policies in a renewal term, and for the full year 2025, our revenue retention rate was 91.8% reflecting the percentage of revenue recognized in 2024 that was recognized again under the renewal terms of those same policies in 2025.
4
Our Industry
Our Market Opportunity
We operate in the large and growing flood insurance market. According to FEMA, flooding is the most common and costly natural disaster in the U.S., causing damages that exceed $40 billion annually according to the Congressional Budget Office, and is expected to continue to grow with progressing climate change. Despite the growing risk, flood insurance penetration remains low.
In the U.S., there are more than 100 million residential and commercial buildings, and we believe more of these buildings are likely to be at risk of flooding than is currently identified by FEMA. According to First Street’s First National Flood Risk Assessment, in 2020 there were approximately 22 million buildings at risk of flooding and over 14 million buildings at risk of substantial flooding over the following 30 years. However, only approximately 9 million buildings are identified by FEMA as being within SFHAs - regions with 1% or higher annual probability of flooding. Properties in SFHAs with federally backed mortgages are required by the FDPA and related regulations to have flood insurance. Yet FEMA has noted that flood maps that underlie the SFHA designations are outdated and require extensive updates, as they do not currently take into account key types of precipitation. This was highlighted during Hurricane Harvey (2017) when, despite lower flood insurance penetration rates than in SFHAs, 68% of reported claims in Harris County were outside SFHAs according to Harris County Flood Control District.
Outside SFHAs, we estimate that flood insurance uptake in general is inadequate, with only approximately 2% of properties being covered by flood insurance, representing vast underinsurance and what we believe is a significant and untapped addressable market for our products. Even in high-risk states such as Florida, Texas, and Louisiana, combined residential penetration is just 11% according to NFIP Residential Penetration Rates as of December 12, 2025. We believe this gap in flood insurance coverage, together with the limited designation of SFHAs, creates significant financial vulnerabilities for millions of American home and business owners and lenders and presents a substantial opportunity for innovative private-sector insurance solutions like Neptune.
NFIP Challenges and Developments
Historically, the flood insurance market offered limited options, as regulated lending institutions were required to accept only policies underwritten by the NFIP to satisfy mortgage requirements. In 2012, however, Congress passed the Biggert-Waters Act, mandating that lenders also accept private flood insurance policies if written on an NFIP-equivalent form. Despite this regulatory opening, to date, the NFIP has continued to dominate the market, as private insurers have lacked the expertise, innovation, and access to historical claims data necessary to profitably underwrite flood risk. In addition, the NFIP historically received substantial government subsidies that enabled it to limit premiums to rates that were challenging for private flood insurance providers to compete with, a dynamic that is shifting with the NFIP’s introduction of “Risk Rating 2.0,” discussed in more detail below.
As of December 31, 2025, the NFIP insured approximately 3.6 million properties and collected approximately $5.5 billion in total policy cost, with an average annual policy cost of $1,546 per policy, according to FEMA. We believe the NFIP falls short in meeting the evolving needs of homeowners and businesses. For decades, its policies have provided low coverage limits that often fail to address the true costs of rebuilding. Moreover, the process of purchasing NFIP coverage can be slow and cumbersome for both policyholders and agents, in contrast to the instantaneous and accessible Neptune quote-to-issue process.
Operational and financial challenges have also persisted throughout the NFIP’s history. We believe these issues stem from its subsidized and rudimentary pricing methodology, which has frequently failed to accurately reflect the underlying risk of policies. As a result, the NFIP has accumulated substantial financial losses, currently owing $22.525 billion to the U.S. Treasury and accruing approximately $2 million in daily interest, according to FEMA and the Congressional Research Service.
In 2021, the NFIP launched Risk Rating 2.0, a new pricing methodology aimed at better aligning premiums with the risk profile of a given property. Under Risk Rating 2.0, most policyholders will experience annual rate increases of up to 18%, the maximum allowed under congressional caps, until their premiums reach full risk-based levels. The U.S. Government Accountability Office estimates that approximately $27 billion in additional subsidies will be required for the NFIP portfolio between 2022 and 2037 due to these price caps. While this subsidized pricing model historically allowed the NFIP to price policies at rates that limited our ability to compete for those policies, as subsidies phase out under Risk Rating 2.0, we expect the gap between NFIP rates and actual risk costs to narrow, positioning Neptune to offer more
5
affordable coverage to approximately 50-60% of current NFIP policyholders, representing approximately 50-70% of the NFIP’s premium base.
We believe the NFIP’s legacy pricing model, cumbersome processes, and limited coverage have created significant market dislocation and inefficiencies, resulting in a compelling opportunity for private flood insurers like Neptune to capture market share.
Industry Tailwinds
We believe there are several additional structural shifts that will continue to drive opportunities in the flood insurance market broadly and for private providers such as Neptune, including:
•Increased Demand Driven by Growing Natural Disaster and Flood Damage: As climate change intensifies, areas with low perceived flood risk today (e.g., non-coastal regions) could face increased frequency and intensity of flooding due to additional rainfalls and storms. As climate change continues to intensify, associated with increasing severity of storms and resulting losses, we expect the demand for flood insurance to increase. Additionally, more areas with severe inland flooding could be designated as mandatory flood insurance zones for policyholders with federally-backed mortgages.
•Underlying Housing Market Backdrop: The housing market significantly influences property and flood insurance sales, as a substantial portion of policies are purchased during home acquisitions or refinancings. If housing market activity were to increase, a revitalized housing market would likely also stimulate growth in the property and flood insurance sector, presenting opportunities for insurers to expand their policyholder base and enhance market share. At the same time, with housing prices increasing above the rate of inflation, the NFIP coverage limit of $250,000 - which was first implemented in 1994 and has remained static since - grows more outdated each year, prompting policyholders to look to the private market for excess or replacement coverage. We believe that Neptune, with its advanced technology, policyholder and agent-first approach, coverage limit of over $7,000,000 for residential properties, and innovative products, can be at the forefront of capitalizing on this potential growth, were it to materialize, and closing the insurance gap.
Our Business Model
Our team’s energy is focused, every day, on advancing the three pillars of our business: underwriting, risk relationships, and distribution.
6
Underwriting
Our automated underwriting engine, Triton, is at the core of everything we do. Our use of the latest ML technology, advanced data science, AI, and behavioral economics allows us to execute key underwriting tasks - including risk selection, accurate risk pricing, aggregation management, and carrier assignment - in less than two seconds. This combination of speed and precision provides robust scalability and enables us to process high volumes of quotes and policies efficiently while maintaining industry-leading performance. We have no human underwriters and 100% of our underwriting is performed instantaneously by our Triton engine.
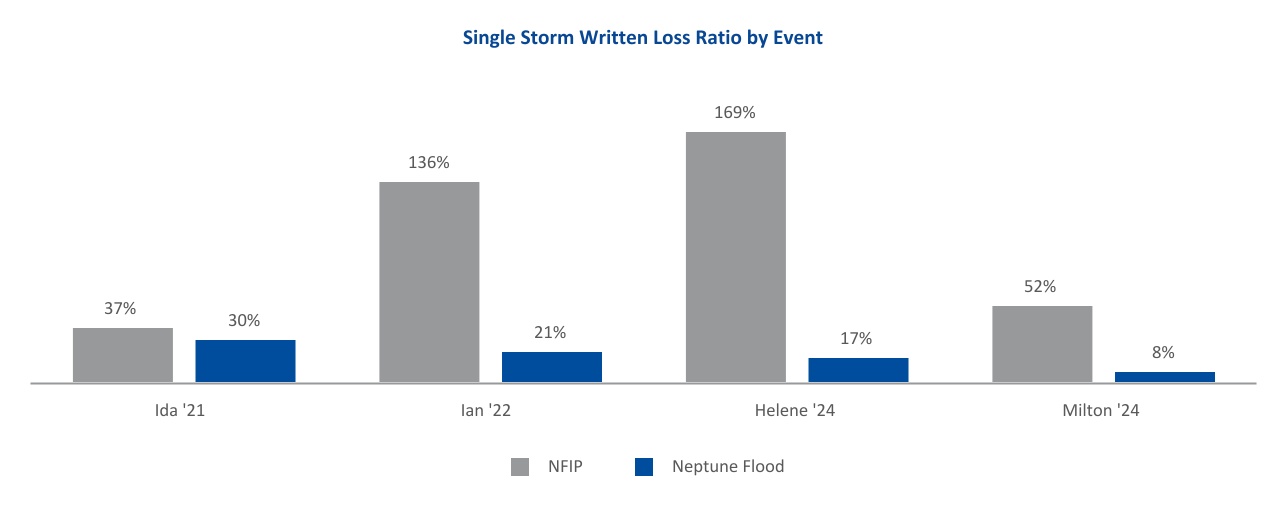
(1)We had 27,021 policies in force in states with flood insurance claims related to Hurricane Ida.
(2)We had 51,562 policies in force in states with flood insurance claims related to Hurricane Ian.
(3)We had 102,426 policies in force in states with flood insurance claims related to Hurricane Helene.
(4)We had 80,266 policies in force in states with flood insurance claims related to Hurricane Milton.
Our underwriting engine has delivered positive results, including a lifetime written loss ratio of just 24.7% from our inception through June 30, 2025. This performance has spanned some of the largest flooding disasters in U.S. history - including four of the ten largest flooding events in U.S. history, as measured by NFIP insured loss: Hurricane Ida (2021), Hurricane Ian (2022), Hurricane Helene (2024), and Hurricane Milton (2024). By contrast, from 2018 to 2024, the NFIP delivered an 86% written loss ratio, according to FEMA, and the U.S. property and casualty industry in general has seen an average written loss ratio of 54%, according to NAIC statutory data.
Our underwriting philosophy is generally built around three fundamental principles:
•Risk Selection: Our approach to risk selection is driven by data science and informed by what we believe is the most comprehensive claims dataset in the private flood insurance market, generated predominantly from our operations to date. With over a quarter billion dollars in paid claims across our portfolio since inception, and our extensive analysis of industry claims and performance data, we have developed deep insights into identifying and managing properties with the highest probability of flood losses.
We believe we can evaluate property-specific risks with exceptional accuracy. Our proprietary models identify the characteristics and factors most likely to contribute to large-scale losses, allowing us to focus on selecting risks that align with the risk tolerances of our capacity providers. This granular approach helps us avoid adverse selection and has allowed us to deliver consistent, positive underwriting results. It has also allowed us to provide quotes for 95% of all submissions, optimizing the identification of properties with the highest probability of flood losses.
Through ongoing analysis of claims data and continuous refinement of our underwriting models, we ensure that our risk selection process remains sophisticated and nimble. By focusing on selecting the right risks, we aim to deliver value to both our capacity providers and our policyholders while maintaining a sustainable and profitable portfolio.
•Pricing: Our pricing is a sophisticated, data-driven process that incorporates advanced ML and behavioral economics to ensure accuracy and market competitiveness. Rather than relying on static or simplistic pricing
7
models, we use a proprietary technology-driven framework to evaluate the unique characteristics of each property and its risk profile. Our pricing methodology is informed by a combination of flood risk data, customer behavior, and market dynamics. Behavioral economics plays a crucial role in determining how customers perceive and value coverage, and incorporating customer behavioral factors into our methodology enables us to tailor pricing to increase adoption while maintaining underwriting integrity. By understanding not only the risk, but also the behavior of customers, we believe we can optimize premium structures to drive growth and retention.
Unlike traditional insurance underwriting, our pricing does not depend on manual adjustments or broad risk groupings. Instead, it is dynamically informed by hundreds of data points to assess factors such as property characteristics, geographic exposure, and historical loss data. This property-specific, data-first approach allows us to quickly offer fair and competitive pricing while aligning with the risk tolerance of our capacity providers and continuously improving the accuracy of our Triton underwriting system.
•Aggregation Management (Disaggregation): Our approach to aggregation management is a key differentiator that sets us apart from industry norms. Traditional underwriting and risk assessment methods often rely on generalized risk aggregation based on administrative boundaries, such as states or counties, which serve as crude proxies for exposure to catastrophic events. In contrast, we have developed a patented technology that enables us to manage maximum loss scenarios at the individual property level through an analysis that uses radial circles to assess policy concentration in any given area in real time. This advanced methodology, which we refer to as “disaggregation,” allows us to optimize risk exposure in real time and align each policy with the specific risk appetite of our capacity providers.
By moving beyond man-made legacy geographic boundaries, we can more effectively distribute exposure to minimize concentration risk while focusing on the actual drivers of loss, such as property-specific vulnerability to flood. This precision also allows us to confidently underwrite in high-cost insurance markets, including hurricane-prone areas, while continuously informing and refining our pricing models to remain both responsive and data-driven.
Our disaggregation framework also leverages real-time data to adjust exposure dynamically as policies are written. This sophisticated approach enables us to manage risk with precision, which we believe maintains our capacity providers’ confidence in our ability to deliver consistent, positive underwriting performance. Through our patented technology and innovative methodology, we not only provide accurate risk management for our capacity providers but also ensure long-term scalability and sustainability for our business.
Risk Relationships
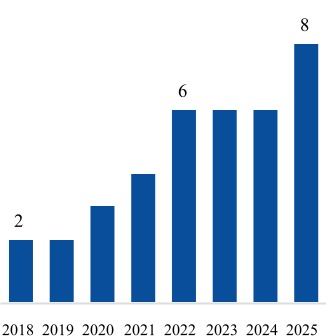
Neptune does not take any balance sheet insurance risk or have claims handling responsibility relating to the policies we sell. We currently contract with 8 distinct insurance programs, which are supported by 32 reinsurance providers, all of whom collectively provide underwriting capacity for the policies we sell. We refer to this panel of global insurers and reinsurers as our “capacity providers,” who bear all of the balance sheet insurance risk associated with our underwriting. Although we do not directly contract with the reinsurance providers who support our insurance programs, we engage and cultivate relationships with them, and believe that the superior written loss ratios and underwriting results we are able to deliver on the policies we sell incentivizes these reinsurance providers to provide underwriting capacity in support of our insurance programs.
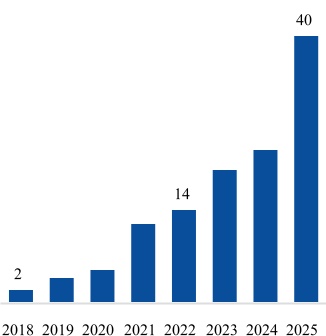
Over the past 8 years, we have built and expanded a panel of 40 capacity providers, including some of the largest insurance and reinsurance companies in the world. The strength and reputation of our capacity providers underscores the market’s confidence in our ability to deliver consistent results and manage risk effectively. Our insurance carriers are high-quality international insurers with A.M. Best ratings of A- or higher and our 32 reinsurance providers, supporting 8 distinct insurance programs, diversify our risk across both program structures and ultimate risk takers. As of December 31, 2025, our largest capacity provider accounted for 15.9% of our dollar-one premium risk. In addition, all of our insurance programs are eligible to write policies in all 50 states and Washington D.C. This approach mitigates concentration risk on both a financial and geographic basis, provides stability for both our business and our capacity providers, and ensures our portfolios remain resilient with access to ample future capacity to continue to grow our business.
The relationships we have cultivated with our capacity providers are built on transparency, trust, and our unwavering commitment to delivering value. A key driver of our success is the availability of detailed data and insights, paired with our ability to deliver results with speed and efficiency. We provide real-time access to performance metrics,
8
maintain an open and continuous dialogue with our capacity providers, and consistently exceed expectations with profitable underwriting results.
We have also delivered consistent and substantial premium growth for our capacity providers and our proven performance has been instrumental in driving partner confidence and growth and engagement with additional reinsurers who may wish to provide underwriting capacity for our insurance programs. Through the exceptional written loss ratios experienced by our capacity providers on policies sold by Neptune, driven by the dynamic, risk-adjusted pricing and coverage decisions made by our Triton platform, we have been able to deliver superior returns, even through some of the largest flooding events in U.S. history. As a result, we have delivered hundreds of millions of dollars of underwriting profits for our capacity providers since inception and have delivered underwriting profitability to every capacity provider in every contract year. These outcomes are a testament to our platform capabilities and our success has led to an increase in the average commission paid to us by our capacity providers of more than 4.5% between 2018 and 2025.
These results, combined with our ability to provide actionable insights, have attracted new capacity providers and strengthened relationships with existing ones. Our proven underwriting results have also generated meaningful goodwill with our existing capacity providers, allowing us to enhance and develop our product offerings efficiently to respond to agent and policyholder needs.
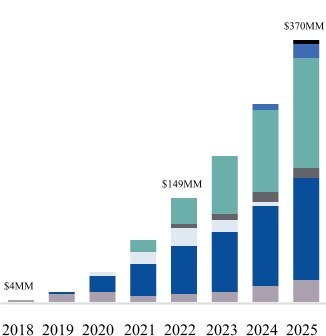
The following information showcases the expansion of our capacity relationships since inception.
Premium in Force by Program
($MM, colors represent each of the respective insurance programs)
Capacity Providers
(#)
Programs
(#)
Distribution
Our distribution strategy is built to maximize market reach and provide seamless access to our innovative flood insurance products with diversification across distribution partnerships. Leveraging a hybrid distribution model, we utilize strong agency partnerships across the insurance industry and complement those with direct-to-customer sales to drive efficiency, reach, and scale.
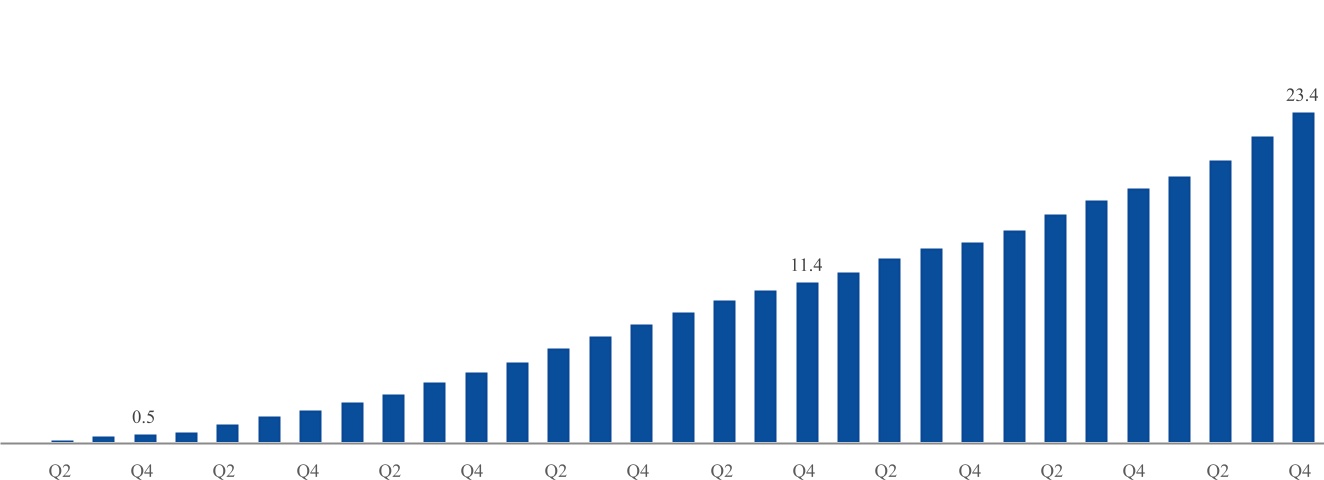
Agent and Broker Partnerships: The cornerstone of our distribution network is our deep relationships with insurance agents and brokers. As of December 31, 2025, over 96.7% of our policies in force are driven by these partnerships, which include more than 23,000 unique agency codes that have bound a policy through Neptune and over 99,000 unique agency codes that have run a quote through our Triton platform. Since inception, we have been able to grow our distribution network tremendously and uninterruptedly.
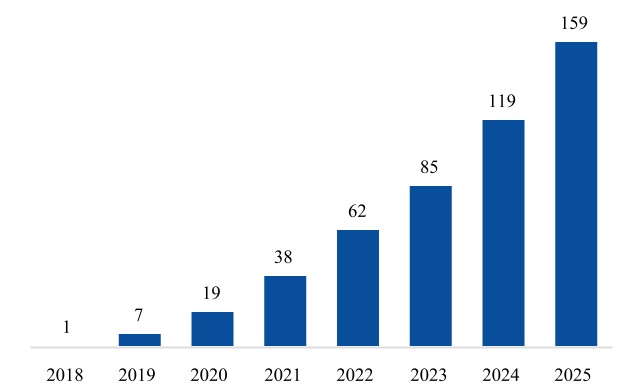
As of December 31, 2025, 23,412 cumulative agency codes have bound a policy with Neptune, an increase of 29.6% from 18,060 as of December 31, 2024.
Unique Agency Codes with Policy Bind
(thousands)
9
| 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 | 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Annual Growth: | 332% | 118% | 70% | 35% | 26% | 26% | 30% | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
We believe that Neptune delivers significant value to agents through a combination of ease of use, a superior product-market fit, high availability - made possible by our quoting of 95% of all submissions - and our ability to deepen agents’ relationships with policyholders. Historically, agents have had to undergo NFIP training and engage in the cumbersome NFIP quoting process to sell flood insurance policies. With Neptune, agents can leverage our user-friendly Agent Portal to quickly enter customer data and receive instantaneous quotes, which they can relay in real-time, thereby democratizing the sale of flood insurance. To further enhance the agent experience, we have developed deep technology integrations with many of our agency partners through API links directly into their quoting systems, allowing them to quickly quote and bind flood policies alongside homeowner policies and provide comprehensive solutions for their customers. In addition, our Agent Portal provides our agents with up to date, data-driven insights about flood risk in the geographies where a quote is being sought, empowering our agents to drive further demand for our products at the time of each quote. Through these innovations, our platform enables agents to grow their business by enhancing the overall value of the policyholder relationship, while offering a product that seamlessly fits the needs of both agents and policyholders. This in turn drives increasing adoption and higher conversion rates.
We believe our deep relationships with high quality agencies are critical in maintaining our early-mover advantage. Our agency partners include carriers with large captive agent forces, wholesalers, agency networks, flood specialists, and small, independent, family-owned agencies. Our ability to offer an alternative product that better fits many customers’ needs has resonated with our agents and has been essential to driving over 60.0% of our new policy sales in “non-mandatory flood zones” over the last three years. Furthermore, our policies in force are highly diversified across a network of high-quality agents, without any material concentration risk or reliance on individual agencies or agents. As of December 31, 2025, our largest agency partner contributed approximately 8.7% of our total policyholder base. We maintain a robust pipeline of potential agencies interested in partnering with Neptune, while our in-house sales team continually nurtures existing relationships, supporting strong alignment with our agency partners and mutual growth. Our agency relationships are deeply entrenched at the agent level and play an active role in both converting NFIP policyholders to Neptune and winning new customers to the flood insurance market to enable our continued expansion.
Neptune Internal Agency: 2.1% of our policies in force as of December 31, 2025, were attributed to our in- house agency, with a team of licensed agents managing a growing number of quotes from our website and a select few of our distribution partners. These agents are also licensed to distribute NFIP policies in certain rare cases where policies do not meet Triton’s underwriting criteria.
Direct-to-Customer Sales: 1.1% of our policies in force as of December 31, 2025, were attributed to our direct-to-customer channel. Our easy-to-use online interface allows prospective customers in select states to quote, bind, and manage policies directly. This option complements our agency partnerships and provides ease of access for all property owners seeking flood insurance solutions. We support our online interface with our third-party agencies and in-house agency able to assist when required or to otherwise finalize the sales process.
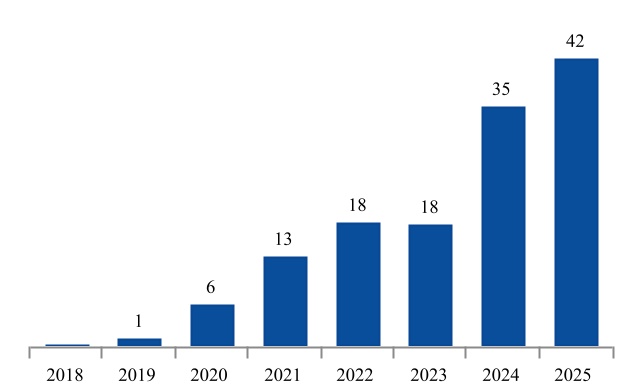
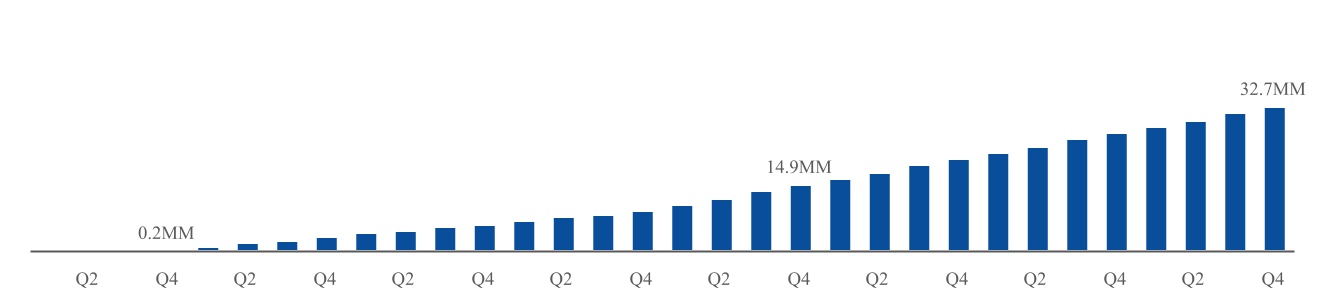
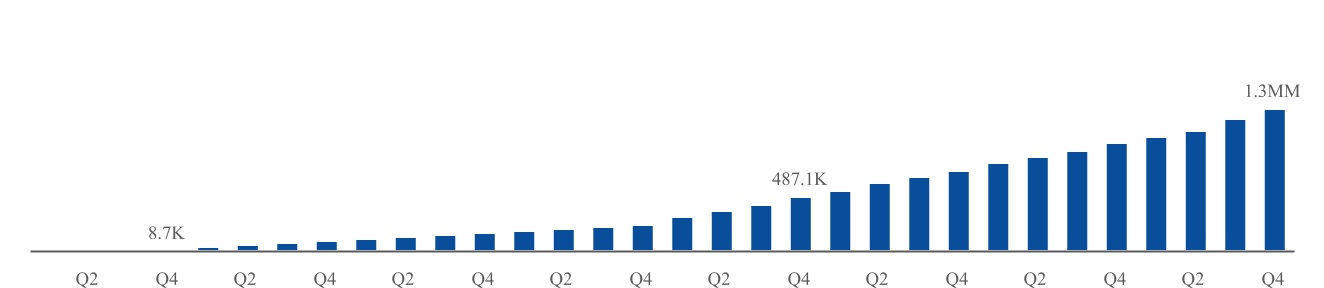
In addition to driving scalability and flexibility, as we rapidly expand into new markets and introduce additional products, our distribution infrastructure is critical in reinforcing our data advantage. Our distribution and referral partners submit over 20,000 quotes to Triton on a typical day, with approximately 32.7 million lifetime quotes and 1.3 million binds
10
from inception through December 31, 2025. All these quotes (whether or not they lead to binds) and binds fold into and grow our proprietary dataset, allowing us to continually build the competitive advantage provided by our platform.
The following information illustrates the cumulative quotes and binds on our Triton and Poseidon systems since inception in 2018.
Cumulative Triton Quotes
Proprietary Underwriting System
| 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 | 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Cumulative Poseidon Binds
Proprietary Policy Management System
| 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 | 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
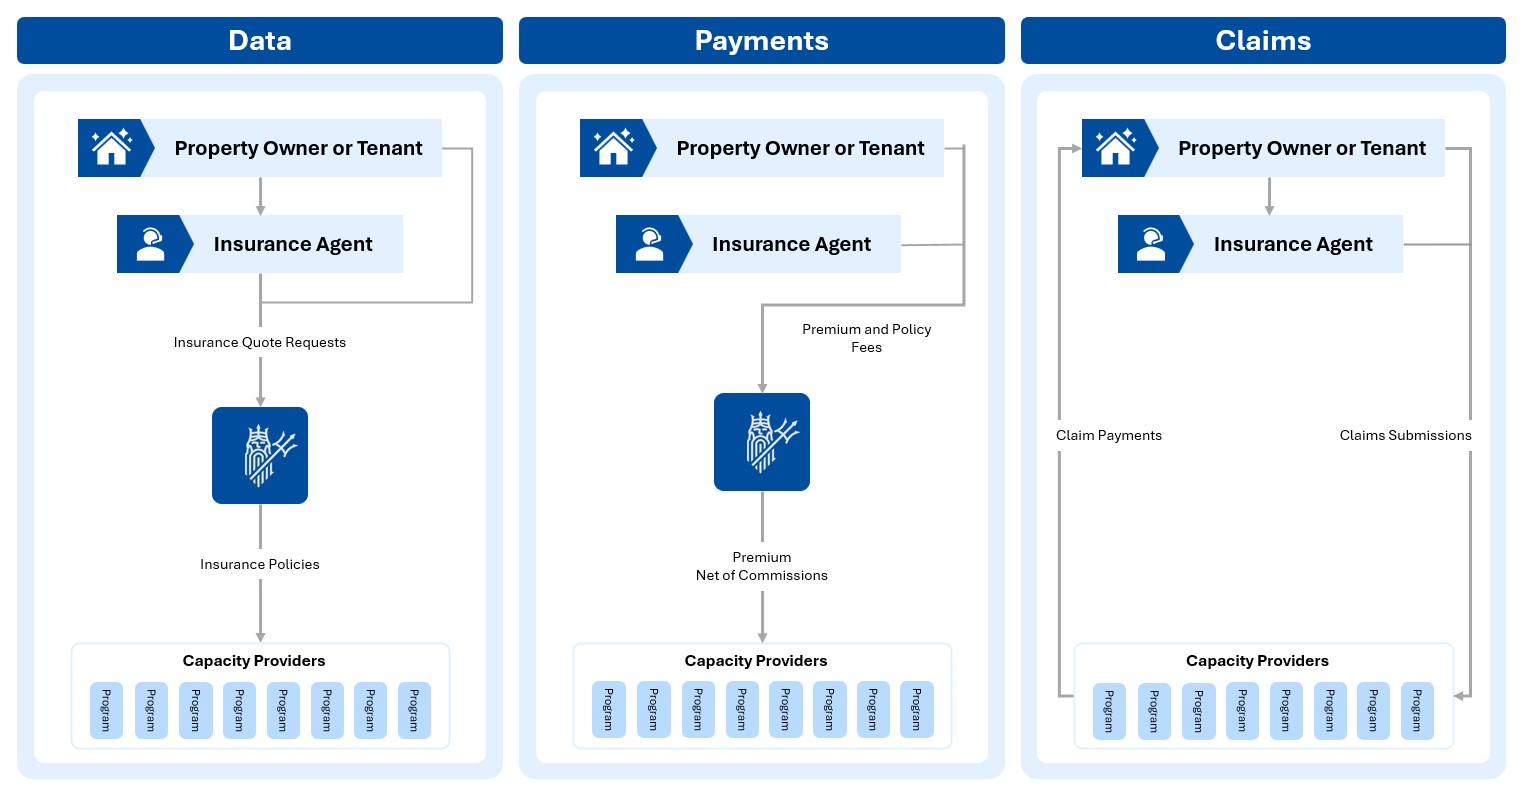
The following chart illustrates the roles we, our capacity providers, and our distribution partners play in the flow of data and payments, and the role our capacity providers and distribution partners play in the flow of claims from policyholders:
11
Our Products
We offer a range of innovative insurance products designed to address the needs of residential and commercial property owners facing flood and other natural disaster risks. As of December 31, 2025, across all of our insurance product offerings, residential properties accounted for 88.0% of our premium in force and commercial properties accounted for the remaining 12.0%. Our flagship primary residential flood insurance product accounted for 85.7% of our premium in force as of December 31, 2025. In addition to the base policy, we offer enhanced protection through expanded coverage options, which we believe make our flood insurance product a superior coverage alternative to the NFIP. We also offer an excess flood insurance product, which we introduced in 2024. This product, which is available to both residential and commercial property owners, represented 2.9% of our premium in force as of December 31, 2025. Both our primary and excess flood insurance products are structured around the NFIP form and can be used to supplement or fully replace existing NFIP coverage, as needed. In addition to our flood insurance products, we offer a parametric earthquake insurance product, launched following our acquisition of Jumpstart in September 2021, and in December 2025 we launched a beta test of an indemnity earthquake product to a small group of agencies within the state of California. While currently less than 1% of our portfolio, these earthquake insurance products allow us to collect data and expertise that we believe will allow us to eventually diversify into other perils and address additional unmet insurance needs.
Primary Flood Insurance: Our primary flood insurance products for both residential and commercial property owners accounted for 97.0% of our premium in force as of December 31, 2025. In addition to the base policy, we offer enhanced protection through expanded coverage options, which we believe make our flood insurance product a superior coverage alternative to the NFIP.
Excess Flood Insurance: In February 2024, we introduced our excess flood insurance product, to meet the needs of a significant portion of NFIP policyholders for whom transition to the private market is not economical due to continued substantial subsidies that currently support their NFIP policy premiums. This product, which is available to both residential and commercial property owners, allows policyholders to supplement their existing NFIP coverage, providing more comprehensive protection for their homes, businesses and families. The introduction of our excess insurance product has been well received in the market. Premium in force was $10.8 million as of December 31, 2025, and the product made up 2.9% of our premium in force as of December 31, 2025. By addressing critical gaps in NFIP flood insurance, this product expands our ability to protect a broader set of property owners from significant financial risks.
Both our primary and excess flood insurance products are structured around the NFIP form and can be used to supplement or fully replace existing NFIP coverage, as needed.
Parametric Earthquake Insurance: In addition to our flood insurance products, we offer a parametric earthquake insurance product, launched following our acquisition of Jumpstart in September 2021. This innovative product provides predetermined payouts based on the intensity of an earthquake, ensuring fast and straightforward claims processing. While currently less than 1% of our portfolio, these earthquake insurance products allow us to collect data and
12
expertise that we believe will allow us to eventually diversify into other perils and address additional unmet insurance needs.
Indemnity Earthquake Insurance: In December 2025, we launched a beta test of an indemnity earthquake product to a small group of agencies within the state of California. This innovative product provides benefits to policyholders based on the intensity of an earthquake.
Our Geographic Presence
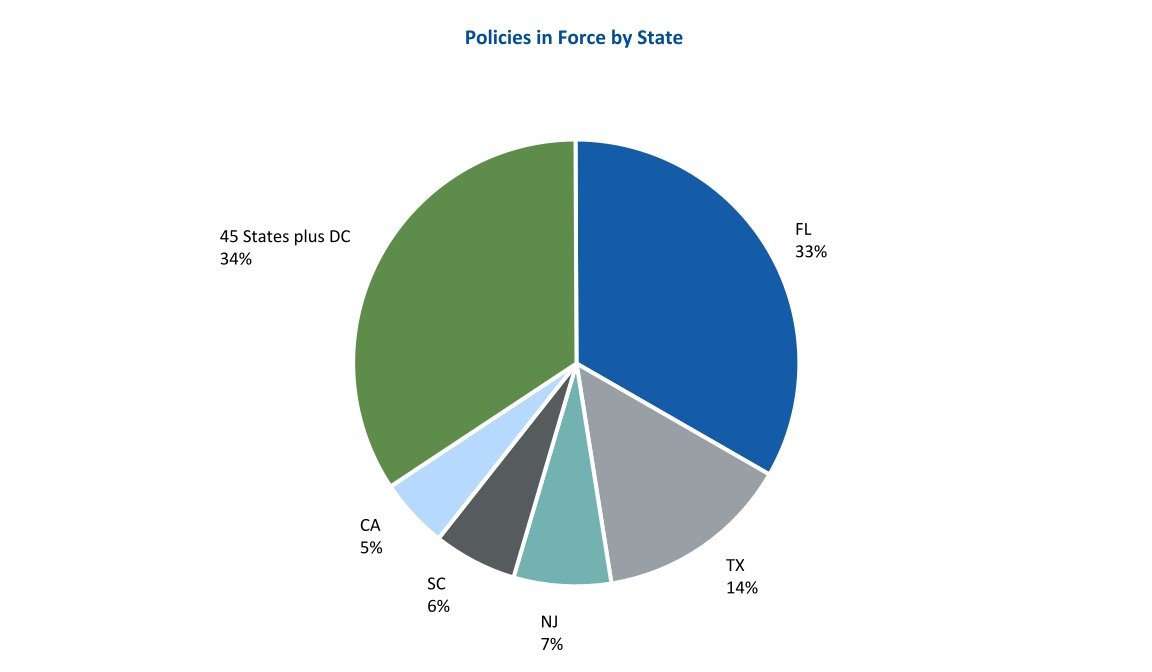
We operate nationwide and actively mitigate our concentration risk by expanding and diversifying our portfolio across the country. As of December 31, 2025, Florida, Texas, and Louisiana accounted for only 48.9% of our policies in force, compared to a much heavier exposure of 59.6% for the NFIP, according to the NFIP.
The Neptune Advantage
We believe that Neptune’s competitive advantage is driven by the three core pillars of our business model (underwriting engine, risk relationships, and distribution) and is extended by the following:
•Technology and Data-First Culture: Technology is at the heart of our capabilities and success, enabling us to deliver innovative, efficient, and optimized insurance solutions in a simple and accessible way. As of December 31, 2025, 40% of our 62 employees were on our technology development team, with our proprietary and internally-developed underwriting and policy management systems forming the backbone of our operations.
•Our technology infrastructure is built to support rapid expansion into new markets and product lines. Whether adapting to regulatory changes, adding capacity relationships, or launching new offerings like our excess flood product, our systems are designed to support growth without compromising speed or reliability. We operate on a fully digital, cloud-based computing infrastructure. Leveraging cloud computing allows us to rapidly scale our underwriting, policy management, and analytics capabilities in response to market demand. This infrastructure provides seamless remote access for our distributed workforce, enhancing system reliability, and ensuring that our data science and ML models can process vast amounts of information with minimal latency.
•Our technology ecosystem is strengthened by our ML models and predictive analytics developed by the Neptune Data Science Group. These models use vast datasets from our operations, as well as geospatial mapping and real-time risk assessments, along with our proprietary data from the high volumes of transactions effected on our systems, to evaluate flood risks at the individual property level
13
with precision. This enables us to provide instant underwriting decisions and dynamic, risk-adjusted pricing for both residential and commercial properties, allowing us to provide coverage with exceptional accuracy that incumbents and other players struggle to do.
•We are committed to continuously refining and expanding our technology capabilities. Through constant innovation, we ensure our platforms remain at the cutting edge of the insurance industry, empowering us to stay ahead of market trends and deliver value to our capacity providers, agents and policyholders.
•Early-Mover Advantage in a Large, Evolving Market Dominated by the NFIP: As the first entrant in the private flood insurance market with substantial scale and geographic presence, we have accumulated proprietary datasets through our operations that continuously improve our predictive technology, designed innovative products that we believe better suit evolving customer demand, and developed an extensive distribution network with trusted relationships that ensures broad reach across the market. We believe this measurable competitive edge positions us to capture greater market share as the industry evolves following anticipated long-term structural shifts driven by NFIP risk re-rating, climate change, and growing housing demand.
•Trusted Relationships with Capacity Providers: Through eight challenging storm seasons, we have delivered underwriting profit to each of our capacity providers every year. This has enabled our capacity providers to deliver consistent and predictable capacity to support our current and expected growth. Additionally, as a result of our performance, our capacity providers have awarded us greater flexibility to underwrite and bind policies, a contrast to industry norms where binding authority is typically set on stricter negotiated limits and criteria. This flexibility allows us to control product design, risk aggregation, and capacity allocation, and allows us to respond to opportunities and needs from agents and our policyholders in an agile manner, continuing to reinforce our competitive advantage.
•Robust Track Record of Financial Performance with Strong Visibility into Future Earnings: We have consistently outperformed our internal expectations, demonstrating a disciplined and reliable approach to growth. Through 21 landfall hurricanes, we have delivered positive underwriting results and maintained strong loss performance. This operational consistency has translated into substantial revenue and Adjusted EBITDA growth since inception. Our business is supported by a high degree of recurring revenue and predictable renewal patterns, providing strong visibility into revenue growth and profitability. For the twelve months ended December 31, 2025, 67.9% of our revenue was derived from renewal business.
•Disciplined Leadership Team: We are a founder-led organization, with a unified strategic vision, focused on delivering superior outcomes for our stakeholders. Our disciplined approach to risk management and optimization has led to us being profitable since our second year of operation. Our lean organizational footprint of 62 employees as of December 31, 2025, allows us to prioritize efficiency, scalability, and flexibility in our operations, driving industry-leading profitability per employee.
Our Growth Strategy
The opportunities for growth in the Neptune portfolio are both broad and deep. We believe we will continue to maintain strong revenue growth based on:
•Growth Across Existing Products and Geographies: We believe the U.S. primary and excess flood insurance markets present immense growth opportunities for Neptune. Despite our significant achievements and expanding scale to date, based on data from NAIC and NFIP, we estimate that as of December 31, 2025, we accounted for just 8.2% of the U.S. primary residential flood insurance market, with an even smaller share of both the excess flood market, which we entered in 2024, and the commercial flood market. This leaves substantial room for growth given the current insurance gap, increased market awareness of flood risk, and evolving market conditions, particularly around anticipated developments related to the NFIP’s implementation of Risk Rating 2.0. In addition, we believe our distribution strategy, which is primarily focused on deep partnerships across agencies with tens of thousands of agents, facilitates increased awareness of both our products and flood risk among our agents and prospective policyholders, through the ease-of-use of our automated underwriting platform, seamless API integrations, instantaneous bindable quotes, and proprietary Agent Portal. In many cases, the creation of a Neptune quote is automatic and instantaneous for agents via our API, facilitating easy cross-sell opportunities alongside standard home and business insurance quotes. In addition, our Agent Portal provides our agents with up to date, data-driven
14
insights they can share with prospective policyholders about flood risk in the geographies where a quote is being sought, empowering our agents to drive further demand for our products at the time of each quote. Through these innovations, we believe our platform enables agents to grow their business by delivering added value to the policyholders, while creating further awareness in support of our growth strategy.
•Ability to Scale with Limited Incremental Cost: Our technology infrastructure is built to support rapid expansion, allowing us to scale our business using the same cost structure without requiring us to incur material additional capital expenditures. We operate on a fully digital, cloud-based computing infrastructure, which we can leverage to rapidly scale our underwriting, policy management, and analytics capabilities in response to market demand. This infrastructure provides seamless remote access for our distributed workforce, enhancing system reliability and ensuring that our data science and ML models can process vast amounts of information with minimal latency. Further, because our entirely digital underwriting engine, Triton, uses advanced algorithms, without any human underwriters, to assess risk with speed and precision, we are able to price, quote, and bind additional policies at scale without any significant expansions to our employee base. As a result, while many of our G&A costs are expected to scale with the size of our business (for example, as the number of policyholders increases, customer support and cloud hosting costs may rise), we do not believe that growing our business or the number of policies we sell will require any material changes to our cost structure. We intend to continue to implement new technology from time to time, which we intend to build and maintain using our existing technology development team, including our Neptune Engineering Group and Neptune Data Science Group, to further improve efficiency and scalability.
•Expansion of Product Offerings: We have continued to innovate and broaden our product offerings to capitalize on market trends and growth opportunities. In 2024, we launched an excess flood insurance product designed to address a critical gap in coverage for policyholders who remain with the NFIP. Many NFIP policyholders are unable to transition fully into the private market due to the economic benefit provided by substantial government subsidies that limit their premiums. Our excess flood product allows these policyholders to maintain their NFIP coverage while purchasing additional protection from Neptune, providing more comprehensive protection for their homes and families. Growth within this market represents a meaningful opportunity. With our innovative primary flood product and rapidly growing excess flood offering, we are well-equipped to serve both residential and commercial property owners, providing them with comprehensive and affordable coverage. As climate change likely continues to increase the frequency and severity of flooding events, including in areas that have not historically been considered flood prone, we believe increased awareness of flood risk among the general public can drive further demand for Neptune products. As a result, we remain focused on leveraging technology and delivering tailored solutions to meet the evolving needs of our policyholders. These market dynamics play directly to Neptune’s strengths and reinforce our ability to grow market share. Additionally, as part of our commitment to addressing long-standing market gaps and expanding our product portfolio, we are actively exploring opportunities in additional perils beyond flood. In December 2025, we launched a beta test of a new indemnity earthquake product in California, where there is a material insurance gap for earthquake coverage, with approximately 89% of buildings uninsured. We believe the indemnity earthquake product will provide true value to policyholders by addressing shortcomings in the options currently available on the market, including long-term affordability and ease of purchase. The development of an indemnity earthquake product builds on the expertise gained from our acquisition of Jumpstart and would respond to the growing demand from both policyholders and our agency partners for comprehensive earthquake protection. By leveraging our proprietary technology platform and underwriting capabilities, we believe we are well-positioned to develop new insurance solutions that deliver value to policyholders and close protection gaps in underserved markets.
•International Expansion: Flooding is a pervasive and growing global challenge, yet the flood peril remains inadequately understood and underinsured in many countries around the world. Across the globe, millions of residential and commercial properties face significant and rising flood risks, often without sufficient insurance coverage to protect property owners from financial loss. In most international markets, flood insurance penetration is minimal, with many regions relying on outdated risk models, government-backed programs, or ad hoc relief efforts to address flooding events. These approaches often leave property owners exposed to significant financial vulnerabilities, particularly as climate change likely exacerbates the frequency and severity of flood events globally. This underinsurance may create an opportunity for Neptune to expand into international markets and provide innovative, data-driven flood insurance solutions to property owners in need. Leveraging our proprietary technology platform, advanced underwriting capabilities, and experience in the U.S. market, we believe we are uniquely positioned in the coming years
15
to enter international markets and address the gaps left by traditional insurance providers. We expect our scalable technology infrastructure, built for rapid deployment, would enable us to adapt quickly to the regulatory requirements and unique risk profiles of different countries.
•Inorganic Growth Opportunities: From time to time, we may supplement our long-term organic growth with strategic acquisitions, focused on gaining expertise or expanding and complementing our existing portfolio. In recent years, we have completed a notable intellectual capital focused acquisition of Jumpstart, a leading parametric insurance company, and expanded our expertise through the strategic hiring of the employees of Charles River Data, a Boston-based data science consulting firm.
Potential Challenges
There are also a number of factors that we believe could present challenges to our strategic plans or limit our ability to grow our business, including:
•Adverse NFIP Developments: The flood insurance market is highly concentrated, with the NFIP holding approximately 80% of the market share. As the dominant provider, the NFIP benefits from strong federal backing and widespread consumer recognition. Its significant market presence and subsidized pricing in certain areas create challenges for private insurers, including Neptune, to compete effectively. If the NFIP’s implementation of Risk Rating 2.0 is tolled or delayed or the Congress elects to continue to subsidize the NFIP consistent with historic levels, it could limit our potential growth opportunities relating to existing NFIP policyholders. In addition, adjustments to the NFIP’s pricing, coverage options, or underwriting guidelines could also significantly alter the competitive landscape. Although we believe purchasing insurance from the NFIP is relatively burdensome and time-consuming for policyholders and agents, and that its limited product offerings often fail to meet policyholder needs, if the NFIP were to lower premiums, simplify its processes, or increase its coverage options, we could face increased difficulty in retaining or growing our policyholder base.
•Continued Weakness in the Housing Market: Our performance and ability to issue new policies and retain existing policies is closely tied to home sales, economic activity, construction costs, household income, and employment levels, as well as commercial property markets. Elevated mortgage rates and declining affordability have strained the housing market in recent years, leading to a decrease in first-time homebuyers and overall housing market activity. Rising interest rates from 2022 to mid-2025 contributed to a decline in home sales and elevated mortgage rates, together with higher home prices, can create affordability challenges, particularly for first-time buyers. For example, the National Association of Home Builders estimates that in 2023, when mortgage rates on a 30-year fixed mortgage rose from 6.25% to 6.5%, nearly 1.3 million households were priced out of the market for a median-priced home. While mortgage rates experienced some decrease in late 2025, continued weakness or a further decrease in housing market activity, particularly in areas where flood coverage is needed, due to adverse economic conditions or other factors, could result in a decline in the home insurance industry and reduction in the sale of our policies, reduced renewal rates, and increased cancellations of existing policies, as many flood insurance purchases are driven by mortgage requirements and a substantial portion of our flood insurance policies are purchased during home acquisitions or refinancing.
•Access to Top Talent: Our success depends, in large part, on our ability to attract and retain talent, which may be difficult due to the intense competition in our industry and the technology industry generally for key employees with demonstrated ability. We rely on a team of highly skilled engineers, data scientists, and other technical professionals who are responsible for the development, enhancement, and maintenance of our proprietary technology. This team’s expertise in ML, geospatial analysis, and data modeling is vital to ensuring our ongoing success and our ability to remain competitive. The financial services and technology industries are highly competitive, and the demand for talented professionals in fields such as data science and ML often exceeds supply. The loss of key technical talent or critical members of our engineering and data science team, or any inability to hire additional talent as the needs of our business may require, could impair our ability to refine our risk assessment capabilities, address evolving market needs, or respond effectively to competitive pressures.
16
M&A
Jumpstart
In September 2021, we acquired Jumpstart, a leading parametric insurance company providing parametric earthquake coverage in California, Oregon, and Washington. This acquisition allowed us to introduce a parametric earthquake insurance product, positioning us for expansion into the indemnity earthquake insurance market. The expertise and technology gained through Jumpstart served as the foundation for our beta launch of an indemnity earthquake product, targeted at further addressing the significant insurance gap in the U.S. earthquake market. This innovative approach aligns with our mission to simplify and expedite the insurance process for property owners.
Charles River Data
In May 2024, we hired all of the employees of Charles River Data, a Boston-based data science consulting firm renowned for its expertise in advanced analytics and ML, which had previously consulted on the enhancement of our AI-driven underwriting platform, Triton. The onboarding of all the employees of Charles River Data led to the formation of our Neptune Data Science Group, which is dedicated to further enhancing Triton. By integrating Charles River Data’s capabilities, we have improved the precision and speed of our flood risk assessments, further solidifying our position as a technology leader in the insurance industry.
This integration demonstrated our ability to execute and our commitment to leveraging cutting-edge technology and innovative insurance solutions to meet the evolving needs of our policyholders while driving growth and market leadership.
Competition
The flood insurance market is competitive, with participants ranging from government programs to private insurers. While the NFIP remains the predominant provider by far, its challenges - such as substantial debt, inadequate coverage limits, and rising premiums under Risk Rating 2.0 - create opportunities for us to compete in the future. However, to date, the U.S. government subsidization of the NFIP and resulting lower premiums have discouraged most policyholders from considering private market alternatives. Competition in the insurance business is largely based upon innovation, knowledge, terms and condition of coverage, quality of service, and price.
In the private flood insurance sector, we face competition from other MGAs, established carriers, and startups. Certain established carriers and other MGAs may have substantially greater resources and market presence than us. However, unlike these carriers and other MGAs, we believe we have successfully leveraged advanced data analytics and risk modeling, via our Triton platform, to offer competitively priced policies with comprehensive coverage options at sustainable written loss ratios, addressing the complex nature of flood risk assessment. Established carriers often do not directly originate flood insurance due to the perceived unpredictability, data gaps, and potential for catastrophic losses with traditional aggregation approaches, preferring to focus on their core risk offerings. In contrast, we have focused on solving the barriers to entry in flood insurance by using technology to drive scale, streamline underwriting processes, enhance policyholder and agent experience, and improve underwriting results through appropriate pricing and risk disaggregation.
Startup companies in the flood insurance space often struggle with brand recognition and trust, areas where we believe we have built a strong reputation and confidence among agents, policyholders, and capacity providers. Ultimately, our proprietary technology platform enables us to provide precise, scalable solutions that meet the needs of property owners. Additionally, our partnership approach and tech-enabled integrations with agencies makes us a provider of choice. Based on our analysis of State-by-State data on the private flood insurance market published by the NAIC, we believe that we currently hold more than one third of the primary residential private flood insurance market, and that our leading market share continues to grow. This leadership position reflects our early-mover advantage and our ability to outperform competitors by offering innovative products, efficient processes, and a proven track record of underwriting success. We believe our substantial market share, carrier capacity, and deep data advantages support our positioning to scale more rapidly and efficiently than competitors.
As we continue to expand across our current products and footprint, and into new insurance markets, we expect new entrants and established players to emerge. However, we believe that our commitment to technology, data science, and policyholder value will enable us to maintain and grow our competitive and early-mover advantage.
17
Branding and Marketing
Our branding and marketing efforts are central to building Neptune’s reputation as a trusted, innovative leader in insurance. From our headquarters in St. Petersburg, Florida, we manage all branding and marketing activities with a sharp focus on data-driven strategies that deliver measurable results.
Our marketing initiatives are primarily online, leveraging a diverse range of digital channels, including targeted advertising, social media, and agent promotions. This digital-first approach allows us to engage directly with consumers and efficiently drive demand for our products. We prioritize campaigns that we believe deliver immediate and measurable growth, ensuring our marketing efforts are accretive to financial performance.
In 2024, we underwent a comprehensive rebranding effort to prepare Neptune for its next phase of growth. This included a significant investment in updating our logo, website, and overall brand aesthetic. Our new branding reflects our commitment to innovation and excellence, resonating with stakeholders across the industry.
We believe that our brand recognition and reputation have been instrumental in driving growth through both direct-to-consumer channels and partnerships with agents and brokers. It is our view that the Neptune brand has not only attracted distribution relationships but also enhances our appeal to risk-taking partners, helping to build strong alliances that further our business objectives.
In addition to traditional branding and marketing efforts, we launched the Neptune Research Group in 2024. This initiative produces and publishes research reports aimed at increasing awareness of flood risk and fostering industry-wide discussions about flood insurance. These reports have received extensive coverage across the insurance sector for their insight and depth, further establishing Neptune as a thought leader in flood risk mitigation.
Our marketing and branding efforts are tightly aligned with our mission to simplify flood insurance and close the protection gap for homeowners and businesses. By combining innovative design, strategic messaging, and data-driven tactics, we expect to continue to strengthen our position as a leading provider of private flood insurance.
Intellectual Property
Our intellectual property is a cornerstone of our competitive advantage, enabling us to deliver innovative solutions and maintain our position as one of the market leaders in private flood insurance. We have developed a portfolio of proprietary technologies, algorithms, and data models that are critical to our operations and growth strategy. We rely on intellectual property laws, as well as restrictions on our employees, consultants, contractors, and other third parties, including through confidentiality, invention assignment and nondisclosure agreements, license agreements, policies and procedures, and other contractual obligations, to protect our intellectual property rights, proprietary technologies and commercially valuable confidential information, and data used in our business. The success of our business depends in part on our ability to obtain, use, maintain, defend, and enforce our intellectual property in the operation of our business.
Proprietary Technology and Platforms: Our underwriting engine, Triton, our policy management system, Poseidon, and other core technologies have been developed entirely in-house by our Neptune Engineering Group. These platforms incorporate patented features and proprietary algorithms that enable us to evaluate flood risk with precision and efficiency.
Machine Learning Models and Data Science Capabilities: Developed by our Neptune Data Science Group, our advanced ML models and predictive analytics tools are essential to our ability to provide instant, accurate underwriting decisions and competitive pricing. These models are built and maintained exclusively within Neptune, ensuring we maintain full control over their development and evolution.
Patents and Trade Secrets: We actively protect our intellectual property through patents, trade secrets, and other intellectual property laws and legal safeguards. In the United States, we have obtained one issued patent on our disaggregation technology, an advancement in aggregation management that is a key component to the creation of efficient
18
and attractive portfolios for our risk-taking partners. We also rely on trade secrets to protect aspects of our business that are not amenable to, or that we do not consider appropriate for, patent protection. We have measures in place designed to protect our proprietary algorithms, dynamic pricing models, and other technological innovations and to ensure they cannot be replicated by competitors, securing our unique position in the market. However, trade secrets can be difficult to protect. While we have confidence in the measures we take to protect and preserve our trade secrets, such measures can be breached, and we may not have adequate remedies for any such breach. In addition, our trade secrets may otherwise become known or be independently discovered by competitors.
Brand and Trademarks: The Neptune brand, including our name, logo, and other trademarks, is a valuable asset that reinforces our reputation as an industry leader. We have registered trademarks that protect the Neptune brand identity against unauthorized use by others. In the United States, we have obtained five trademark registrations. In addition, we have registered the <neptuneflood.com> domain name, which we use in connection with our platform.
Continuous Innovation: We are committed to ongoing investment in R&D to expand our intellectual property portfolio. This includes enhancements to existing technologies, the creation of new products, and the exploration of additional applications for our proprietary tools.
Our intellectual property is not only a key differentiator but also a critical driver of our ability to scale efficiently, expand into new markets, and deliver unmatched value to our policyholders and partners. We have procedures in place to monitor for potential infringement, misappropriation, or other violation of our intellectual property or proprietary rights, and it is our policy to take appropriate action to defend and enforce our intellectual property, taking into account the strength of our claim, likelihood of success, cost, and overall business priorities. However, the steps we take may not be adequate and could harm our reputation and could adversely affect our competitive position, financial condition, or results of operations. See “Risk Factors - Risks Relating to Data, Intellectual Property, and Cybersecurity.” By taking steps to safeguard and continually advance our innovations, we look to ensure Neptune remains at the forefront of the insurance industry.
Regulatory Matters
As an MGA, we operate within a highly regulated industry, subject to state and federal laws governing various aspects of our business. Unlike traditional admitted carriers, we operate on an Excess and Surplus (“E&S”) lines basis, which provides greater flexibility in underwriting, pricing, and product offerings. This flexibility allows us to innovate and respond quickly to market demands without requiring the filing of rates and forms for state approval.
Operating on E&S lines requires compliance with specific regulatory frameworks, including maintaining proper licensure, adhering to E&S lines reporting requirements, and ensuring compliance with applicable E&S lines laws, and the payment of E&S lines taxes, in each jurisdiction where we write business. Our dedication to regulatory compliance ensures we meet these obligations while enabling us to maintain operational agility. In addition, all of our insurance programs are eligible to write policies in all 50 states and Washington D.C., facilitating the operation of our business throughout the United States. In addition to E&S regulations, we are subject to data privacy and cybersecurity laws relating to the policyholder data and other personal information we collect and must comply with stringent privacy standards, including state-level privacy laws in the United States and international data protection regulations, where applicable. However, the personally identifiable information we collect and store with respect to policyholders is limited and basic and does not include payment information, credit status, social security numbers, or dates of birth, which we believe limits our exposure to such laws and regulations, and any potential changes thereto. We strive to maintain systems and processes to safeguard policyholder information that are designed to ensure compliance with evolving legal requirements. See also “Risk Factors - Risks Relating to Regulatory and Legal Matters - We are subject to evolving laws and regulations on data privacy, data protection, and cybersecurity, which can be complex and conflicting. We may face investigations, fines, and sanctions as a result of our or our service providers’ or partners’ actual or perceived failure to comply with such laws and regulations and incur increased operational costs in order to ensure future compliance” and “Risk Factors - Risks Relating to Regulatory and Legal Matters - We rely on the efficient, uninterrupted, and secure operation of complex information technology systems and networks to operate our business. Any significant system or network disruption due to an actual or perceived breach in the security of our or our vendors’ information technology systems could have a negative impact on our reputation, regulatory compliance status, operations, sales, and operating results.”
Through our use of AI, we may also from time to time be subject to laws and regulations relating to AI, automated decision-making, and similar technologies, or may be impacted if existing or future laws and regulations are interpreted in ways that would affect or extend to the types of “machine learning models” utilized by Neptune, which use AI-driven, complex algorithms to analyze data inputs. Our models, however, predominantly use proprietary data derived from our
19
business operations, and are generally not trained on external or other third-party data. See also “Risk Factors - The regulatory framework for AI technologies is rapidly evolving as many federal, state, and foreign government bodies and agencies have introduced or are currently considering additional laws and regulations; to the extent any such laws or regulations apply to our business, or existing laws and regulations are interpreted in ways that would affect the use of AI in our business, we may need to implement additional standards or practices to remain compliant and the operation of our business could be adversely affected.”
While our regulatory environment is complex, we view compliance as essential to maintaining trust with policyholders, partners, and stakeholders. By staying proactive and adaptive in our approach, we are well-positioned to navigate the evolving regulatory landscape and support the continued growth of our business.
Human Capital Management
Our employees are our most valuable asset, driving innovation, growth, and operational excellence. With a lean yet highly efficient workforce of 62 employees as of December 31, 2025, most of whom work remotely, we have built a company culture focused on talent, efficiency, and automation.
Our hiring process is rigorous, incorporating both personality and capability testing to ensure that every employee not only has the skills required to excel in their role but also aligns with our values and mission. This approach has allowed us to assemble a team of exceptionally talented individuals who are passionate about solving complex challenges and delivering value to our policyholders and partners.
Neptune was founded on the principle of automating everything. By leveraging advanced technology and data science, we have created a business model that allows our team to focus on high-value, complex tasks rather than routine operations. This mantra continues to shape our approach to innovation and efficiency, ensuring that our workforce is able to drive maximum impact with minimal resource requirements.
Forty percent of our employees are dedicated entirely to the development of our proprietary technology, including our underwriting platform, ML models, and policy management systems. This investment in technology development not only enables us to stay at the forefront of the industry but also allows us to operate at a level of efficiency and scalability that is unmatched in the insurance market.
Our remote-first workforce model provides flexibility and access to a broader talent pool, enabling us to attract and retain top talent regardless of location. We support our employees with the tools and resources they need to succeed, fostering a collaborative and innovative environment that drives both individual and company success.
By focusing on talent, efficiency, and automation, we have built a human capital management strategy that supports our mission to revolutionize flood insurance and ensures our ability to scale effectively as we continue to grow.
20
Item 1A. Risk Factors.
A description of the risks and uncertainties associated with our business is set forth below. You should carefully consider the risks and uncertainties described below, together with the other information in this Annual Report, including our consolidated financial statements and the related notes and “Management’s Discussion and Analysis of Financial Condition and Results of Operations.” The occurrence of any of the events or developments described below could materially and adversely affect our business, financial condition, results of operations, and growth prospects. In such an event, the market price of our Class A common stock could decline, and you may lose all or part of your investment. Additional risks and uncertainties not presently known to us or that we currently believe are not material may also impair our business, financial condition, results of operations, and growth prospects.
Risks Relating to our Business and Industry
Our business may be harmed if one or more of our relationships with capacity providers are terminated or are reduced, if we fail to maintain good relationships with such capacity providers, if we become dependent upon a limited number of capacity providers, or if we fail to develop new capacity provider relationships.
Neptune does not assume any balance sheet insurance risk or claims handling responsibility relating to the policies we sell, and our business depends on a carefully selected network of capacity providers that assume such balance sheet insurance risk for those policies. This risk-taking structure is fundamental to our business model and operational efficiency. Our ability to offer competitive insurance products and maintain our market position is also contingent upon the relationships with these capacity providers. Any adverse impact on these relationships or the overall financial health of our network of capacity providers could reduce our overall insurance capacity and could have an adverse effect on our financial condition and results of operations. Our contractual relationships are sometimes unique to us, but they are typically non-exclusive and terminable on short notice by either party for any reason. In many cases, capacity providers can also amend the terms of our agreements unilaterally on short notice. If we are unable to maintain profitable portfolios for our capacity providers or if our relationship with them is undermined for any reason, capacity providers may be unwilling to provide insurance capacity to us, or may seek to amend our agreements with them. This could happen for various reasons, including for competitive or regulatory reasons, because of an insurance carrier’s reluctance to distribute their products through our platform, because they decide to rely on their own internal flood insurance providers or products or elect not to insure or reinsure flood risk generally, or because they decide not to distribute insurance products in individual markets, in certain geographies, or altogether. Conditions in the broader insurance and reinsurance markets can also influence the capacity of our providers. If our capacity providers were to experience liquidity problems or other financial difficulties, we may not be able to sell additional policies or renew existing ones and could encounter significant adverse impacts on our financial condition and results of operations. If any of our key capacity providers decide to terminate or reduce their relationship with us, we may face difficulties in securing alternative insurance capacity from other providers on similar terms, which could negatively impact our ability to offer insurance products and retain policyholders. Similarly, our business could be harmed if we fail to develop new capacity provider relationships to ensure a diversified portfolio of capacity providers that support our business.
In the future, whether as a result of the termination of capacity provider relationships, capacity provider consolidation or otherwise, it may become necessary for us to partner with and derive a greater portion of our revenues from a reduced and more concentrated number of capacity providers if and as our business and the flood and general insurance industry evolve, which would increase our dependence on a smaller number of capacity providers. As a result, we may become more vulnerable to adverse changes in our relationships with such capacity providers. This could reduce the volume of policies we are able to underwrite. The termination, amendment, or consolidation of our relationships with our capacity providers could harm our business, financial condition, and results of operations.
The overall financial health of our network of capacity providers is important to our success. Widespread, catastrophic flood events, such as hurricanes or severe inland flooding, could strain the financial resources of our capacity providers, reducing their ability to meet claim obligations or remain profitable. This, in turn, could lead capacity providers to reduce the capacity they allocate to flood insurance or could cause them to demand higher premiums, pay lower commissions, impose stricter underwriting criteria, or exit the flood insurance market as they choose to prioritize more profitable or less risky lines of insurance. This could result in reduced capacity or support for our flood insurance products, potentially limiting our ability to underwrite new policies or renew existing ones. Any such changes could impact our ability to offer competitive policies and secure adequate coverage for policyholders, which could expose us to reputational harm, increased regulatory scrutiny, and operational disruption and which may have a material and adverse effect on our business.
21
The termination or reduction of any of these key relationships could lead to a significant loss of sales and adversely affect our financial performance. It could also disrupt our operations and require us to invest additional resources in finding and establishing new partnerships; replacement capacity for our capacity providers may not be immediately available or could come at less favorable terms, leading to increased costs and reduced competitiveness. If we are not able to effectively manage our relationships with our capacity providers, resulting in the loss of one or more key capacity providers or a significant reduction in their capacity, our business, financial condition, results of operations, growth potential, reputation in the market, and ability to sustain our business could be materially and adversely impacted.
Our distribution model depends on third-party agents and brokers, and any failure by those agents and brokers to consistently promote our products or the loss of any key agent or broker relationships could adversely affect our business.
The third-party agents who generate the majority of our policy sales operate within a diverse network that includes independent agents, brokers, and referral partners. Our insurance agent and broker partners drive over 96% of our policy sales, supported by our in-house sales team and technology integrations. This distribution model exposes us to meaningful third-party risks relating to agent prioritization, agent attrition and sales productivity, and competition within distribution channels, as well as regulatory and reputational risks. Third-party agents have discretion over which flood insurance products they recommend to customers. If our agents choose to prioritize offerings from the NFIP or other flood insurance providers due to familiarity, perceived reliability, or regulatory incentives, or shift their focus to competing private flood insurance providers based on superior pricing, more attractive commission structures, enhanced coverage options, or for any other reason, our ability to generate new policies may be adversely affected. Similarly, a decline in agent productivity, whether due to reduced customer activity, economic factors, or lack of engagement with our products could materially reduce our revenue, and insufficient training or support for agents could result in fewer policies sold or misrepresentation of our offerings. Agents who fail to comply with regulatory standards, whether by misrepresenting policy terms or engaging in unethical practices, could also expose us to legal liabilities and reputational harm, and increased regulatory scrutiny resulting from third-party agent misconduct could lead to fines, operational disruptions, or a loss of market credibility.
Finally, high turnover among independent agents or changes in agent affiliations can lead to disruptions in our distribution network. Our ability to compete effectively depends on maintaining strong relationships with the agents distributing our products and providing them with compelling reasons to prioritize Neptune products, such as delivering a strong agent and policyholder-focused experience. Furthermore, our ability to retain and attract new agents to distribute our products to new customers may be influenced by our existing agent and policyholder relationships. We cannot be certain that any loss of a significant agent or broker relationship or the loss of business from any significant group of policyholders would be replaced by relationships with or other business from other agency partners or policyholders, existing or new. If a substantial number of agents cease to represent Neptune or choose to represent alternative MGAs due to more competitive commissions, technology, responsive support, or any other factor, our ability to generate new policies and maintain policyholder relationships would be adversely impacted. Any significant disruption in these relationships could materially and adversely affect our business, financial condition, results of operations, and growth prospects.
Rapid advancements in AI, including the development of AGI, and ML technologies could increase competition and disrupt our business model.
Neptune relies on proprietary AI-driven technology, including our Triton platform, to assess risk, underwrite policies, and maintain a competitive advantage in the flood insurance market. In addition, we rely on AI for certain business uses, including, for example, to help generate code and code tests. Rapid advancements in AI, including the development of AGI, could present significant challenges to our business model.
For example, AGI - if developed - and other advancements in AI could accelerate the pace of innovation, requiring us to make continuous and costly upgrades to our proprietary systems and technologies to maintain our competitiveness. AI (and possibly future AGI) technologies can also democratize access to advanced ML tools, enabling competitors to rapidly develop capabilities similar to ours. This could reduce the effectiveness of our intellectual property protections and diminish our ability to differentiate in the market. Such advancements could also lower the barriers to entry in the flood insurance market, allowing competitors to leverage new AI and AGI technologies to replicate or surpass the capabilities of our proprietary technology, potentially offering more accurate risk assessments, lower prices, or enhanced customer experiences, which could erode our competitive advantage and reduce our market share. The development of AGI could also fundamentally alter the flood insurance industry by enabling unprecedented levels of automation, personalization, and predictive accuracy. If AGI-driven solutions redefine customer expectations or market standards, our existing technology and business model could become outdated or obsolete. Further, the widespread
22
adoption of AGI may introduce unforeseen challenges in integrating new technologies, adapting workflows, or managing compliance with evolving regulations. These disruptions could negatively affect our operations, policyholder relationships, and financial performance. The rapid and unpredictable development of further advancements in AI, AGI, and related technologies and any failure to adapt to these advancements could materially and adversely impact our competitive position, business, financial condition and results of operations. See also “- The regulatory framework for AI technologies is rapidly evolving as many federal, state, and foreign government bodies and agencies have introduced or are currently considering additional laws and regulations; to the extent any such laws or regulations apply to our business, or existing laws and regulations are interpreted in ways that would affect the use of AI in our business, we may need to implement additional standards or practices to remain compliant and the operation of our business could be adversely affected.”
The regulatory framework for AI technologies is rapidly evolving as many federal, state, and foreign government bodies and agencies have introduced or are currently considering additional laws and regulations; to the extent any such laws or regulations apply to our business, or existing laws and regulations are interpreted in ways that would affect the use of AI in our business, we may need to implement additional standards or practices to remain compliant and the operation of our business could be adversely affected.
The regulatory framework for AI and similar technologies and automated decision-making is changing rapidly. It is possible that new laws and regulations will be adopted in the United States and in non-United States jurisdictions, or that existing laws and regulations may be interpreted in ways that would affect the operation of our products and solutions and the way in which we use AI and similar technologies. We may not be able to adequately anticipate or respond to these evolving laws and regulations, and, to the extent we expand our business to more jurisdictions, we may need to expend additional resources to adjust our offerings in certain jurisdictions if applicable legal frameworks are inconsistent across jurisdictions. Moreover, because these technologies are themselves highly complex and rapidly developing, it is not possible to predict all of the legal or regulatory risks that may arise relating to our current or future use of AI and such technologies. Further, the cost to comply with such laws or regulations could be significant and would increase our operating expenses, which could adversely affect our business, financial condition, and results of operations.
As the use of AI becomes more prevalent, we anticipate that it will continue to present new or unanticipated ethical, reputational, technical, operational, legal, competitive, and regulatory issues, among others. In addition, public and regulatory focus on ethical use and data privacy concerns regarding AI could lead to reputational damage if we fail, or are perceived to fail, to align with societal expectations or regulatory standards relating to the use of AI. Such scrutiny may result in financial or other penalties and may also erode customer trust, which is crucial for our brand and long-term success. As such, we expect that our incorporation of AI in our business will require additional resources, including the incurrence of additional costs, to develop and maintain our products and features to minimize potentially harmful or unintended consequences, to comply with applicable and emerging laws and regulations, to maintain or extend our competitive position, and to address any ethical, reputational, technical, operational, legal, competitive, or regulatory issues that may arise as a result of any of the foregoing.
Further, a number of aspects of intellectual property protection in the field of AI are currently under development and there is uncertainty and ongoing litigation in different jurisdictions as to the degree and extent of protection warranted for AI and relevant system input and outputs. If we fail to obtain protection for our intellectual property rights within our AI technologies, or later have our intellectual property rights invalidated or otherwise diminished, our competitors may be able to take advantage of our research and development efforts to develop competing products that could adversely affect our business, reputation and financial condition. See also “- We utilize AI in a significant manner, which could expose us to liability or adversely affect our business.”
Errors in underwriting or data modeling could harm our reputation, competitive position, and financial results.
Our underwriting success relies heavily on the accuracy and performance of our AI-powered Triton platform. Triton’s performance is inherently dependent on the quality of the data it processes and the algorithms driving its decision-making.
Triton’s advanced modeling relies in part on data from external sources. Inaccuracies, delays, disruptions, or other inadequacies in these data sources could lead to flawed risk assessments or mispriced policies. In addition, errors in the Triton ML model’s training process, biases in its underlying data, or flaws in the algorithm’s design could result in systemic inaccuracies. For example, “overfitting” of our model (i.e., where the model focuses on the specific details it was trained on but is unable to perform well with new data), or underestimating rare but severe events could lead to suboptimal pricing or coverage decisions, and errors or inefficiencies in Triton’s risk selection could result in us offering policies that
23
are less attractive than those of our competitors. If policyholders perceive that our pricing or coverage is inferior, it could lead to lower renewal rates and diminished market share.
Further, as an AI-driven system, Triton’s complex algorithms may lack transparency, making it challenging to identify or correct errors before they cause significant issues. This opacity could complicate efforts to explain or defend pricing and coverage decisions to regulators, insurers, reinsurers, or policyholders, potentially leading to legal or reputational challenges. Additionally, if our cloud computing or third-party data providers change their terms of service, restrict access, or cease operations, it could impact Triton’s ability to function effectively. See also “- We utilize AI in a significant manner, which could expose us to liability or adversely affect our business.”; “- We rely on the efficient, uninterrupted, and secure operation of complex information technology systems and networks to operate our business. Any significant system or network disruption due to an actual or perceived breach in the security of our or our vendors’ information technology systems could have a negative impact on our reputation, regulatory compliance status, operations, sales, and operating results.”; “- Reliance on cloud computing exposes us to technological disruptions and potential risks.”; and “- Reliance on third-party service providers for critical operations, such as payments and mailing, exposes us to operational and reputational risks.”
Triton’s ability to evaluate flood risks and set pricing is critical to our ability to compete with the NFIP and private flood insurance providers. If Triton’s effectiveness were impaired and our policies were to generate higher-than-expected losses, it could negatively impact our relationships with our capacity providers and could result in a reduction in insurance capacity and damage to our reputation as a reliable MGA. This, in turn, could lead to significant operational and financial consequences for us and result in a material and adverse effect on our business, financial condition and results of operations.
Any such significant issues with Triton or our other products could harm our relationships with partners and standing in the marketplace and have a material and adverse effect on our business, financial condition, and results of operations.
We utilize AI in a significant manner, which could expose us to liability or adversely affect our business.
We rely on AI to make decisions in connection with the generation of insurance policies. Our significant use of AI exposes us to various risks, such as damage to our reputation, competitive position, and business, legal, and regulatory risks and additional costs. For example, AI has been known to produce false or “hallucinatory” inferences or output, and certain AI uses ML and predictive analytics, which can create inaccurate, incomplete, or misleading content, unintended biases and other discriminatory or unexpected results, errors, or inadequacies, any of which may not be easily detectable by us or any of our related service providers. Accordingly, while AI and ML systems may help us generate more tailored pricing and underwriting determinations with respect to a given policyholder, if the content, analyses, or recommendations produced by the AI and ML systems used in our Triton and Poseidon platforms are, or are perceived to be, deficient, inaccurate, biased, unethical, or otherwise flawed, our reputation, competitive position, and business may be materially and adversely affected. For further information on how these risks apply to our Triton platform, see “- Errors in underwriting or data modeling could harm our reputation, competitive position, and financial results.”
Additionally, if any of our employees, contractors, consultants, vendors, or service providers use any third-party AI-powered software in connection with our business or the services they provide to us, it may lead to the inadvertent disclosure or incorporation of our confidential information into publicly available training sets, which may impact our ability to realize the benefit of, or adequately maintain, protect, and enforce our intellectual property or confidential information, harming our competitive position and business. Any output created by us using AI tools may not be subject to copyright protection, which may adversely affect our intellectual property rights in, or our ability to commercialize or use, any such content. In the United States, a number of civil lawsuits have been initiated related to the foregoing and other concerns, any one of which may, among other things, require us to limit the ways in which our AI systems are trained and may affect our ability to continue to develop our AI-powered platforms. To the extent that we do not have sufficient rights to use any of the data or other material or content used in or produced by the AI tools we employ, or if we experience cybersecurity incidents in connection with our use of AI, it could adversely affect our reputation and expose us to legal liability or regulatory risk, including with respect to third-party intellectual property, privacy, data protection and cybersecurity, publicity, contractual, or other rights. Further, our competitors or other third parties may incorporate AI into their products, offerings or underwriting assessment more quickly or more successfully than us, which could impair our ability to compete effectively.
24
Reliance on cloud computing exposes us to technological disruptions and potential risks.
Our reliance on cloud computing infrastructure introduces several key risks that could impact our operations and competitive advantage. Any disruption, outage, or degradation in cloud computing performance - whether due to cyberattacks, technical failures, natural disasters, or other unforeseen events - could impair our ability to operate. Such incidents could result in operational delays, policyholder dissatisfaction, and reputational harm.
Our ability to handle growing volumes of policy data and transactions also depends on the reliability and capacity of cloud computing providers. If they fail to meet our evolving performance requirements, we may experience slow response times, decreased efficiency, or service interruptions, potentially affecting policyholder satisfaction and agent productivity. Our reliance on third-party cloud computing providers also means we have limited control over their operations, pricing, and service terms. Changes in pricing structure or contractual terms could increase our costs, while any service degradation or failure on their part could disrupt our operations. Transitioning to an alternative cloud provider, if required, could involve significant time, cost, and operational risk.
Any such disruption in our platform’s performance due to cloud-related limitations, or failure to maintain our technological edge, could adversely impact our ability to compete effectively as rapid advancements in AI and insurance technology solutions enable our competitors to develop similar or alternative platforms or services. See also “- Rapid advancements in AI, including the development of AGI, and ML technologies could increase competition and disrupt our business model.”
Any significant issues with our cloud infrastructure could materially and adversely affect our business, financial condition, and results of operations. See also “- We rely on the efficient, uninterrupted, and secure operation of complex information technology systems and networks to operate our business. Any significant system or network disruption due to an actual or perceived breach in the security of our or our vendors’ information technology systems could have a negative impact on our reputation, regulatory compliance status, operations, sales, and operating results.”
Reliance on third-party service providers for critical operations, such as payments and mailing, exposes us to operational and reputational risks.
We depend on third-party service providers for critical functions such as processing policyholder payments and mailing policy documents and notices. Technical failures, cyberattacks, or financial instability affecting our third-party vendors could interrupt their ability to provide services. Delays or errors in payment processing could harm policyholder trust, while issues with mailing policy documents could result in missed policyholder notifications. Failures by third-party vendors to meet service expectations or comply with regulatory standards could also be attributed to Neptune, resulting in reputational harm, regulatory scrutiny, or financial penalties. In the event of any such issues, identifying and transitioning to alternative providers, if necessary, would require significant time, cost, resources, operational risk, and could lead to temporary disruptions. Any disruption, failure, or performance issues involving these third-party providers could adversely affect our ability to operate efficiently, maintain policyholder satisfaction, and comply with regulatory requirements, which could have a material and adverse effect on our business, financial condition, and results of operations.
Claims handling by third parties, including insurance carriers and third-party administrators (“TPAs”), could negatively impact our reputation and result in litigation risks.
As an MGA, we neither assume insurance risk nor have claims-handling authority. Instead, the responsibility for adjudicating claims lies with the insurance carriers that underwrite the policies we sell. These carriers frequently rely on TPAs to process and manage claims on their behalf. While this model allows us to focus on policy issuance and distribution, it exposes us to reputational and operational risks tied to claims handling.
The timeliness and fairness of claims processing are critical to maintaining policyholder trust. Policyholders may not fully understand that Neptune does not handle claims directly, leading to confusion or misplaced blame when issues arise. Similarly, any operational issues at the TPAs delivering claims services for our insurance carriers, such as insufficient staffing, inadequate training, or technical failures, could impact the speed and quality of claims resolution, and any misaligned priorities between the TPAs and our insurance carriers could also exacerbate delays or disputes, further eroding policyholder trust. If a TPA or our insurance carriers deny claims, process them slowly, or fail to meet policyholder expectations, policyholders may associate claims dissatisfaction with Neptune, regardless of our lack of direct involvement in the claims process, and we may face reputational harm which can, among other things, reduce policyholder retention and deter new policy sales. In addition, disputes over claims decisions can result in lawsuits involving policyholders, insurance carriers, TPAs, and, indirectly, Neptune as an MGA. We are not responsible for claims adjudication and are indemnified by our insurance carriers for claims-related litigation matters, but our association with the policies sold can
25
result in legal costs, regulatory scrutiny, and reputational damage. These risks are exacerbated during catastrophic events, which often lead to heightened claims activity and increased likelihood of litigation. While we actively collaborate with our insurance carriers and their TPAs to ensure high standards in claims handling, we cannot guarantee that all claims will be processed in a manner consistent with the expectations of our policyholders and negative experiences or lawsuits related to claims handling could materially and adversely affect our business, financial condition, and results of operations.
An overall decline in the housing market or general economic conditions could have a material adverse effect on the financial condition and results of operations of our business.
Our performance and ability to issue new policies and retain existing policies is closely tied to home sales, economic activity, construction costs, household income, and employment levels, as well as commercial property markets. The demand for flood insurance generally rises as the overall level of household income increases and generally falls as household income decreases, affecting both premium volume and policy count, which would impact our revenue and financial condition. In addition, home and business owners often purchase flood insurance at the time of the purchase of a home or commercial property, and major slowdowns in the residential or commercial housing market could impact our ability to generate new business.
Elevated mortgage rates and declining affordability have recently strained the housing market, leading to a decrease in first-time homebuyers and overall housing market activity. Rising interest rates from 2022 to mid-2025 contributed to a decline in home sales and elevated mortgage rates, together with higher home prices, can create affordability challenges, particularly for first-time buyers. For example, the National Association of Home Builders estimates that in 2023, when mortgage rates on a 30-year fixed mortgage rose from 6.25% to 6.5%, nearly 1.3 million households were priced out of the market for a median-priced home. A decrease in housing market activity, particularly in areas where flood coverage is needed, due to adverse economic conditions - caused by inflation, tariffs, rising interest rates, geopolitical tensions, recessionary pressures, or other factors - could result in a decline in the home insurance industry and reduction in the sale of our policies, reduced renewal rates, and increased cancellations of existing policies, as many flood insurance purchases are driven by mortgage requirements (homeowners with a mortgage in FEMA designated high-risk SFHAs must obtain coverage) and a substantial portion of our flood insurance policies are purchased during home acquisitions or refinancing.
Economic downturns can also impact our existing policyholder base. Economic conditions influence consumer behavior and spending patterns. During periods of economic uncertainty or recession, consumers may prioritize other expenses over purchasing or renewing flood insurance or other E&S lines. This shift in consumer priorities can lead to a decrease in demand for our products, further impacting our sales and revenue. Homeowners facing financial difficulties may choose to cancel existing insurance policies, modify their coverage, or not renew the policies they hold with us, leading to lower renewal rates. Economic stress can also result in lower property values, which in turn can reduce the premiums we collect on existing policies. This reduction in premium income could adversely affect our revenue and profitability. Additionally, financially stressed homeowners may be more likely to file claims, and the cost of claims may rise if economic conditions, including impacts from recent tariffs, lead to increased repair and rebuilding costs. As we rely on our carrier partners to provide insurance capacity and assume the associated risk, if the incurred losses exceed any carrier’s loss tolerance, we risk their reduction or withdrawal as a risk-taking partner to Neptune.
In addition, economic downturns can strain our distribution network and affect the operations and financial health of our partners, potentially leading to a reduction in their productivity or even their exit from the flood insurance market. Agents may also experience reduced customer activity, limiting their ability to sell Neptune products. This would limit our ability to reach new policyholders and maintain existing ones, thereby affecting our overall sales. Any prolonged economic downturn and long-term loss could strain our financial resources, requiring us to invest additional capital to maintain operations and support our distribution network. This could lead to increased borrowing and higher interest expenses. As a result, any extended decline in the housing market or any overall economic downturn could materially and adversely affect our business, financial condition, and results of operations.
We may be negatively affected by the cyclicality of the markets and industry in which we operate.
The insurance market in which we operate has historically been cyclical based on the underwriting capacity of the insurance carriers, general economic conditions, state regulatory responses to market conditions, the timing of hurricane and storm season and other natural disasters, and other social, economic, and business factors. In a period of decreasing insurance capacity or higher than typical written loss ratios across an insurance segment or segments, insurance carriers may raise premium rates. This type of market frequently is referred to as a “hard” market. In a period of increasing insurance capacity or lower than typical written loss ratios across an insurance segment or segments, insurance carriers may
26
reduce premium rates, and business might migrate away from the E&S lines market and into the admitted market. This type of market frequently is referred to as a “soft” market. Our results of operations are affected by this cyclicality of the market.
The frequency and severity of natural disasters and timing of significant flood risks, other catastrophic events (such as hurricanes), social inflation, and reductions or increases in insurance capacity can affect the timing, duration, and extent of industry cycles for the product lines we distribute. For example, increasing high-profile flood events, including Hurricane Ida (2021), Hurricane Ian (2022), Hurricane Helene (2024), and Hurricane Milton (2024), tend to raise consumer awareness of flood risk and can increase demand for flood insurance in areas that have, or are believed to have, higher risk of flooding. However, significant increases in insured losses due to increasing frequency and intensity of storms could cause our capacity providers to exit from, or reduce their exposure to, significant flood events and other natural disasters. These catastrophic events can lead to significant losses for capacity providers, prompting them to adjust their risk tolerances. Such conditions can adversely affect our relationships with our capacity providers and could result in a reduction in insurance capacity which could lead to significant operational and financial consequences for us. In contrast, while slower than expected storm seasons can result in lower insured losses experienced by capacity providers, they can also limit demand for flood insurance policies, potentially decreasing our policy sales and, as a result, our commissions and fees and revenues in subsequent periods.
The unpredictability of severity, timing, or duration of these cycles makes it challenging to predict the related responses of insurance carriers and regulators and forecast their impact on our business operations and financial performance. In addition, if our capacity providers experience liquidity problems, insolvency, or other financial difficulties, or do not timely provide required information to us, we could encounter the loss of capacity provider partners, which could lead to reduced capacity and a reduction in our ability to sell our insurance products to our policyholders. These conditions may adversely affect our revenue and make it difficult for us to accurately predict our future results, which could harm our business, financial condition, and results of our operations.
Because the revenue we earn on the sale of certain insurance products is based on premiums and commission rates set by capacity providers, any reductions, volatility, or adverse trends in these premiums or commission rates could adversely impact our revenue and profitability.
The majority of our revenue is derived from commissions set by the capacity providers that underwrite the policies we sell. These commissions are typically calculated as a fixed percentage of the premiums charged to policyholders, making our financial performance sensitive to changes in commission rates year-over-year. As a result, any decline in commission rates, whether driven by market conditions, carrier profitability, or regulatory changes, could materially and adversely affect our business. Capacity providers may face financial challenges stemming from increased claims activity, catastrophic events, rising reinsurance costs, or regulatory changes and, in response, may look to reduce commission rates to manage expenses or may reassess their underwriting profitability, which could also lead to pricing adjustments, tighter underwriting criteria, or reductions in commissions. In addition, economic downturns that result in downward pressure on policy premiums may decrease our commission-based revenue.
Because commissions represent a key source of our income, any reduction in the amounts of these commissions could require us to identify alternative revenue streams, reduce operating expenses, or accept diminished profitability. In addition, failure to effectively adapt to changes in commission structures could hinder our ability to execute our growth strategy and maintain our competitive position in the flood insurance market. Any such impacts could have a material adverse effect on our business, financial condition, and results of operations.
Competition in our industry may be intense, including from the NFIP, and if we are unable to compete effectively, then our ability to grow and maintain market share and financial results may be negatively affected.
The flood insurance market is highly concentrated, with the NFIP holding approximately 80% of the market share. As the dominant provider, the NFIP benefits from strong federal backing and widespread consumer recognition. Its significant market presence and subsidized pricing in certain areas create challenges for private insurers, including Neptune, to compete effectively. In addition, the private flood insurance market is becoming increasingly competitive, with new entrants and existing players seeking to capture market share. If capacity providers adjust their commission structures to align with competitive pressures or incentivize other MGAs or distributors, we may face reduced commission rates or less favorable terms. Changes in federal or state regulations governing insurance commissions could also cap or reduce allowable commission rates. The NFIP and private competitors could expand market share more rapidly or compete more effectively through innovation, pricing strategies, or expanded distribution networks. Some of these competitors may have greater financial resources, established reputations, or strategic partnerships, which could enable them to attract
27
policyholders or agents at our expense. Competition in this market is driven by, among other things, pricing, technology and regulatory changes, reputation, coverage options, agent preference, and innovation. For example, the NFIP’s subsidized premiums in certain areas and the potential for competitors to undercut prices can limit our ability to compete solely on cost. Alternatively, customers may perceive the NFIP as a safer or more affordable option, even in cases where private insurance offers superior coverage. Adjustments to the NFIP’s pricing, coverage options, or underwriting guidelines could also significantly alter the competitive landscape. If the NFIP were to lower premiums or simplify its processes, private insurers, including Neptune, may face increased difficulty in retaining or growing their policyholder base. In addition, our competitors could differentiate themselves by offering unique or expanded policy features, which could appeal to customers seeking more tailored solutions. If other private insurers utilize advanced technologies or data-driven approaches to provide faster, more accurate risk assessments or enhanced customer experiences, such competitors could challenge our position as a leader in providing private flood insurance, and any inability to match or exceed such offerings could reduce our competitiveness. Finally, independent agents and brokers who distribute Neptune’s policies also represent other insurers, including the NFIP and private competitors. Agents may prioritize insurers that offer higher commissions, simpler processes, or perceived customer benefits, impacting Neptune’s ability to maintain its distribution network. See also “- Our distribution model depends on third-party agents and brokers, and any failure by those agents and brokers to consistently promote our products or the loss of any key agent or broker relationships could adversely affect our business.” The highly competitive nature of the flood insurance market could result in pricing pressures, reduced policy retention, increased marketing cost, or difficulty acquiring new policyholders. If we are unable to effectively compete with the NFIP or other private insurers, our market share, revenue growth, financial condition, and results of operations could be materially and adversely affected.
Increased commission requirements from our distribution partners could have an adverse impact on our profits.
The majority of our policy sales are generated through third-party distribution agents and brokers, who play an important role in generating sales and expanding our market reach. Most of our revenue is a function of premium volume (policy sales) and commission rates. If our distribution partners increased their commission requirements for any reason, our financial performance could be adversely affected. Several factors could lead to an increase in such commission expenses, including competitive pressures in the market, market conditions, and regulatory changes. Agents and brokers have the flexibility to promote multiple insurance providers, including both private insurers and the NFIP. To remain competitive, we may need to increase commission rates, bonuses, or incentives to retain and attract high-performing third-party partners. In addition, economic downturns or reductions in consumer demand for flood insurance could prompt agents and brokers to negotiate higher commissions to offset lower policy volumes. Finally, future regulations or industry standards could require insurers to adjust commission structures, which may lead to higher payout obligations. Any increase in commission expenses would have an adverse effect on our margins and, if we are unable to offset higher commission costs through pricing adjustments or operational efficiencies, our business, financial condition, and results of operations could be materially and adversely impacted.
We are highly dependent on the services of our senior management team, including our Chief Executive Officer.
The continued success of our business is highly dependent on the expertise and leadership of our senior management team, including Trevor Burgess, our Chief Executive Officer, Chairman of our board of directors, and our largest stockholder, who has been the driving force behind our success since Neptune’s inception. Mr. Burgess has played, and continues to play, a critical role in shaping our strategic direction, fostering key relationships with capacity providers and distribution and agency partners, and driving innovation within our business and the flood insurance industry. Mr. Burgess and our senior management team’s extensive experience in finance, insurance, and technology has been instrumental in our growth and market differentiation. The unexpected loss of Mr. Burgess or other members of our senior management team could disrupt our operations and impact our ability to continue executing our business strategy with the same level of effectiveness. Finding a successor with a comparable vision and capability to maintain the momentum and direction that Mr. Burgess and our senior management team have established for us would present a substantial challenge. Furthermore, Mr. Burgess’ departure could lead to instability within Neptune, potentially affecting the morale and productivity of our team, which has been crucial in our rapid growth and innovation. The potential uncertainty surrounding such a leadership transition could also undermine confidence among our policyholders, partners, and investors as well as other stakeholders who are integral to our continued success and expansion, and any perceived weakening of our leadership could be exploited by our competitors. As a result of their instrumental role in our business, if Mr. Burgess or other members of our senior management team were to discontinue their service to Neptune due to death, disability, or for any other reason, our business, financial condition, results of operations, and growth prospects could be adversely affected.
28
We may not be able to attract and retain the key employees and highly skilled people we need to support our business.
Our success depends, in large part, on our ability to attract and retain talent, which may be difficult due to the intense competition in our industry and the technology industry generally for key employees with demonstrated ability. We rely on a team of highly skilled engineers, data scientists, and other technical professionals who are responsible for the development, enhancement, and maintenance of our proprietary technology. This team’s expertise in ML, geospatial analysis, and data modeling is vital to ensuring our ongoing success and our ability to remain competitive. The loss of key technical talent or critical members of our engineering and data science team could impair our ability to refine our risk assessment capabilities, address evolving market needs, or respond effectively to competitive pressures and could disrupt operations, delay strategic initiatives, and undermine our relationships with capacity providers, agents, and policyholders. Replacing such individuals may require substantial time and resources, and there is no assurance that we could identify suitable candidates with comparable expertise. We also rely on employees with specific licenses. The departure of key licensed individuals could immediately impact our ability to place new business or service existing policies in affected states until we can obtain new individual licenses.
The financial services and technology industries are highly competitive, and the demand for talented professionals in fields such as data science and AI development often exceeds supply. To attract and retain top talent, we must offer competitive compensation, benefits, and growth opportunities or we could be required to replace certain critical employees or hire contractors to fill highly skilled roles while vacant. Rising costs in these areas could increase our operating expenses, while failure to maintain a strong leadership team or technical workforce could impede growth and innovation. Any disruption to our talent pool of key personnel or failure to attract and retain key employees could materially and adversely affect our business, financial condition, results of operations, and growth prospects.
Reliance on the Neptune brand is critical to our success, and any failure to maintain or enhance our brand or damage to our reputation could adversely impact our business.
Our brand is a cornerstone of our business, and our reputation is a key factor in attracting policyholders, capacity providers, agents, and other partners. Maintaining a strong and trusted brand is essential to our competitive positioning and long-term success. A weakened brand or damage to our reputation could result in reduced demand for our products, decreased agent engagement, less favorable terms from capacity providers or less desire by capacity providers to partner with us, or challenges in partnering with other key service providers. A decline in brand recognition or policyholder trust could also hinder our ability to stand out in the marketplace and make us less attractive to current and prospective employees relative to our competitors, particularly given the intensely competitive market for highly skilled employees.
Negative publicity and unfavorable opinions or reviews from policyholders, whether related to claims handling, policy terms, policyholder service, underwriting practices, data security breaches, the use of our technology for illegal or objectionable applications (including AI and ML applications that present ethical, regulatory, or other issues), or any other factors could erode trust in the Neptune brand. Also, while we do not have any claims-handling authority, negative experiences related to claims handling or policyholder service could also result in complaints, reduced policyholder retention, or unfavorable online reviews. Delays, denials, or disputes in claims adjudication by TPAs or reinsurers could also be attributed to us, harming our relationships and public image. In addition, issues such as system outages, data breaches, or errors in underwriting and pricing could undermine trust in our brand and products, and any investigations, fines, or lawsuits could damage our reputation with existing policyholders, capacity providers, agents, and other stakeholders as well as our ability to obtain new policyholders, capacity providers, and agents. Further, media coverage of any perceived shortcomings, such as allegations of unethical practices, discrimination, or unfair pricing, could erode confidence in our company. Any such adverse impacts on our brand or reputation could lead to decreased policyholder loyalty, reduced policy sales, and challenges in retaining agent and capacity provider relationships.
Moreover, repairing our brand and reputation in the case of any adverse event may be difficult, time-consuming, and expensive. Our failure to quickly respond to and address, or the appearance of our failure to respond to and address, corporate crises and other issues that give rise to reputational risk could significantly harm our brand and reputation, which could result in loss of trust from our policyholders, third-party partners, and employees and could lead to an increase in litigation claims and asserted damages or subject us to regulatory actions or restrictions.
Maintaining and enhancing our brand also requires ongoing investment in marketing, technology, and policyholder experience. If these efforts fail to produce the desired results or if competitors outperform us in brand perception, it could limit our growth opportunities. The loss of confidence in, or any failure to maintain or enhance, the Neptune brand or our reputation could materially and adversely affect our ability to attract and retain policyholders, agents, and partners, thereby negatively impacting our business, financial condition, results of operations, and growth prospects.
29
In addition, third parties’ use of trademarks and branding similar to ours could materially harm our business or result in litigation or other expenses. We may not be able to adequately prevent such practices, which could harm the value of our business, result in the abandonment, dilution, or invalidity of trademarks associated with our business and adversely affect our results of operations or our financial condition. Heightened competitive pressures that result in a loss of policyholders or a reduction in revenues or revenue growth rates, or failure to successfully maintain, defend, enforce, and enhance our brand and substantial expenses in attempts to maintain, defend, enforce, and enhance our brand, could have a material adverse effect on our business, financial condition, and results of operations. See also “- Failure to seek, obtain, maintain, protect, defend, or enforce our intellectual property rights, or allegations that we have infringed, misappropriated, or otherwise violated the intellectual property rights of others, could harm our reputation, ability to compete effectively, financial condition, and business.”
Our rapid growth may place significant demands on our resources, systems, and personnel, which could adversely impact our business.
We have experienced rapid growth since our inaugural full year of operations in 2018. Our continued success depends on our ability to effectively manage and sustain this growth and our efforts to expand our operations, policyholder base, and geographic reach can place significant demands on our resources, systems, and personnel.
For example, rapid growth may outpace our existing technical infrastructure, technology, and processes, leading to inefficiencies, delays, or operational disruptions. Inadequate systems to manage policy issuance or agent or policyholder support could harm our reputation and policyholder satisfaction. Growth may also require attracting, hiring, and retaining skilled employees, including engineers, data scientists, and policyholder service representatives, and increased competition for talent in the technology and financial services industries may make it challenging to expand our workforce if needed to support our expansion. See also “- We may not be able to attract and retain the key employees and highly skilled people we need to support our business.”
Further, if we expand into new markets, the complexity of complying with diverse regulatory requirements and managing relationships with agents, capacity providers, and third-party vendors in those markets will increase. Failure to adequately scale operations to address these complexities could limit our ability to grow effectively. If we are unable to manage the demands of our growth effectively, it could result in operational inefficiencies, policyholder dissatisfaction, and financial challenges, which could materially and adversely impact our business, financial condition, results of operations, and growth prospects.
If we cannot maintain our corporate culture as we grow, our business may be harmed.
We believe that our culture, including our management philosophy, has been a critical component to our success and that our culture creates an environment that drives and perpetuates our overall business strategy, innovation, efficiency, and employee satisfaction. We have invested substantial time and resources in building our team and we expect to continue to hire as our business expands. As we grow and mature, we may find it difficult to maintain the valuable aspects of our culture. Rapid growth can lead to changes in organizational structure, increased complexity in operations, geographical dispersion, and the need to integrate new employees who may not be familiar with our cultural values. If we are unable to effectively communicate and instill our culture in new hires, or if the pressures of growth lead to a dilution of our cultural principles, our business may suffer.
Any failure to preserve our culture could harm our future success, including our ability to retain and recruit personnel, innovate and operate effectively, achieve efficiency, and execute on our business strategy. If we are unsuccessful in recruiting, hiring, training, managing, and integrating new employees, or retaining our existing employees, or if we fail to preserve the valuable aspects of our culture, it could materially impair our ability to attract and support new capacity providers, agent and broker partners, and policyholders, all of which would materially and adversely affect our business, financial condition, and results of operations.
If we are unable to successfully launch additional products or expand our product offerings, including into new domestic and international markets, it may impact our ability to continue to grow revenue.
In the future, we may choose to expand our product offerings, including into international markets. Introducing new insurance products and new or existing product offerings into new markets would allow us to diversify our revenues, attract a broader policyholder base, and increase policyholder retention. Our ability to successfully develop and launch such initiatives is subject to several risks and challenges, including market demand and adoption, regulatory approvals and compliance, competition, operational and technical challenges, and reinsurance and capital constraints.
30
The success of any new initiative depends on policyholder demand, agent adoption, and overall market conditions. If our new initiatives fail to attract sufficient policyholders or fail to gain traction among distribution partners, they may not generate the revenue we expect. Expanding into new insurance products and new geographies may require approval from state, federal, or other applicable regulators in such geographies, which can be a lengthy and complex process. In addition, established insurers and new market entrants may already offer similar products or introduce competing solutions, making it more difficult for us to differentiate our offerings and gain market share, and any delays, denials, or regulatory changes could also hinder our ability to bring new products to market.
Developing and launching new products and new or existing product offerings into new markets may also require enhancements to our proprietary technology, underwriting models, and policyholder service capabilities. Any shortcomings in these areas could limit the effectiveness of new offerings. New insurance products would also require support from new or existing insurance and reinsurance partners, and if we are unable to secure such additional support or new partnerships on favorable terms or at all, our ability to introduce new products or to enter into new geographies may be limited.
Additionally, if we look to expand our business internationally, we may encounter different regulatory regimes and heightened competition, whether from governmental or other private insurers, that could increase pricing pressures or inhibit our ability to implement our initiatives. As a result, we may not be able to adapt quickly enough to foreign regulatory requirements, certain markets may offer uniquely different risk profiles that we have not previously encountered, local insurers, distribution channels, and regulatory bodies may be unwilling to partner with us, and our experience in the U.S. market may not translate to allow us to effectively compete in international markets. See also “- Changes to the E&S lines regulatory landscape, or a requirement for Neptune to file admitted rates, could have a detrimental impact to our sales, innovation, and ability to grow.”
If we are unable to successfully develop, launch, and scale new products or to expand into new geographies, our ability to generate additional revenue and sustain growth and our business, financial conditions, and results of operations may be materially and adversely affected.
Business or asset acquisitions and dispositions may expose us to certain risks.
We have made acquisitions in the past and may pursue further acquisitions or other strategic transactions, including dispositions and joint ventures, in the future. The completion of any business or asset acquisition or disposition is subject to certain risks, including those relating to the receipt and terms and conditions of required regulatory approvals, including any financial accommodations required by regulators, our ability to satisfy such terms, conditions, and accommodations, the occurrence of any event, change, or other circumstances that could give rise to the termination of a transaction, and the risk that parties may not be willing or able to satisfy the conditions to a transaction. As a result, there can be no assurance that any business or asset acquisition or disposition will be completed as contemplated, or at all, and no assurance regarding the expected timing of the completion of the acquisition or disposition.
Once we complete acquisitions or dispositions, there can be no assurance that we will realize the anticipated economic, strategic, or other benefits of any transaction. For example, the integration of businesses or employees we acquire may not be as successful as we anticipate, or there may be undisclosed risks present in such businesses. Acquisitions involve a number of risks, including operational, strategic, financial, accounting, legal, compliance, and tax risks, including difficulties in assimilating and retaining employees and intermediaries, difficulties in retaining the existing policyholders of the acquired entities, difficulties in integrating acquired technologies or systems, unforeseen liabilities that arise in connection with the acquired businesses, or unfavorable market conditions that could negatively impact our expectations for the acquired businesses, as well as difficulties in integrating and realizing the projected results of acquisitions and managing the litigation and regulatory matters to which acquired entities are party. Such difficulties in integrating an acquired business may result in the acquired business performing differently than we expected (including through the loss of policyholders) or in our failure to realize anticipated expense-related efficiencies. Risks resulting from future acquisitions may have a material adverse effect on our results of operations and financial condition.
Similarly, dispositions of a business also involve a number of risks, including operational and technology risks of data loss, loss of talent, and stranded costs, which could potentially have a negative impact on our business, results of operations, financial condition, and liquidity. In connection with a business or asset disposition, we may also acquire a concentrated position in securities of the acquirer as part of the consideration, which would subject us to risks related to the price of equity securities and our ability to monetize such securities. In addition, with respect to certain dispositions, we could be subject to restrictions on our use of proceeds. If we fail to realize the benefits of any disposition, our business, financial condition, and results of operations may be adversely affected.
31
Our inability to successfully recover should we experience a disaster or other business continuity problem could cause material financial loss, loss of human capital, reputational harm, or legal liability.
Our operations are dependent upon our ability to protect our personnel and technology infrastructure against damage from business continuity events that could have a significant disruptive effect on our operations. Should we experience a local or regional disaster or other business continuity problem, such as an earthquake, hurricane, terrorist attack, pandemic, protest or riot, security breach, cyberattack or other similar incident, power loss, telecommunications failure, or other natural or man-made disaster, our continued success will depend, in part, on the availability of our personnel and the proper functioning of computer, telecommunication, and other related systems and operations. We could potentially lose key executives, personnel, and policyholder data, or experience material adverse interruptions to our operations or delivery of services in a disaster recovery scenario. Such disruption could also result in significant financial losses arising from the inability to process new policies or renew existing ones in a timely manner. Our inability to successfully recover should we experience a disaster or other business continuity problem, could materially interrupt our business operations and cause material financial loss, loss of human capital, regulatory actions, reputational harm, damaged policyholder relationships, or legal liability.
Risks Relating to Data, Intellectual Property, and Cybersecurity
We rely on data, technology, and intellectual property, as applicable, from third parties for our pricing models, underwriting engine, and other products, the unavailability or inaccuracy of which could limit the functionality of our products and disrupt our business, and which may also impose limitations on our ability to commercialize our products.
We use data, technology, and intellectual property licensed from unaffiliated third parties in certain of our products and we may license additional third-party data, technology, and intellectual property in the future. Any errors, delays, or defects in this third-party data, technology, and intellectual property could result in errors that could harm our brand and business. In addition, licensed data, technology, and intellectual property may not continue to be available on commercially reasonable terms, or at all. If data providers were to terminate their relationship with us, reduce the quality or quantity of data provided, or experience operational disruptions, our ability to accurately underwrite policies could be compromised, which may lead to increased insurance risk, higher written loss ratios, and reduced profitability. Also, should any third party refuse to license its proprietary information to us on the same terms that it offers to our competitors or enter into exclusive contracts with our competitors, we could be placed at a significant competitive disadvantage. Disputes may arise between us and our licensors regarding the data, technology, and intellectual property licensed to us under any license agreement, including disputes related to:
•the scope of rights granted under the license agreement and other interpretation-related issues;
•our compliance with reporting, financial, or other obligations under the license agreement;
•the amounts of royalties or other payments due under the license agreement;
•whether and the extent to which we infringe, misappropriate, or otherwise violate intellectual property rights of the licensor that are not subject to the license agreement;
•our right to sublicense applicable rights to third parties;
•our right to transfer or assign the license; and
•the ownership of intellectual property and know-how resulting from the joint creation or use of intellectual property by our licensors and us and our partners.
In addition, if regulatory bodies impose stringent requirements on the use and validation of third-party data in underwriting processes and the data provided by our vendors do not meet regulatory standards, we could face fines, penalties, or other regulatory actions. Any changes in regulations that affect the use of third-party data could require us to modify our underwriting models and processes, potentially increasing our operational costs and impacting our profitability.
Further, the loss of our right to use any of this data, technology, and intellectual property, whether due to such third parties failing, being acquired, pivoting their product offerings, or other circumstances, could result in delays in producing or delivering affected products until equivalent data, technology, or intellectual property is identified, licensed, or otherwise procured and integrated. Our business would be disrupted if any data, technology, and intellectual property we license from others were either no longer available to us or no longer offered to us on commercially reasonable terms. In
32
either case, we would be required to either attempt to redesign our products to function with data, technology, and intellectual property available from other parties or to develop these components ourselves, which would result in increased costs and could result in delays in product sales and the release of new product offerings. Alternatively, we might be forced to limit the features available in affected products. Any of these results could harm our business, results of operations, and financial condition.
Our business is dependent upon information processing systems. Cybersecurity events, data breaches, cyberattacks, or other similar incidents, as well as defects, interruptions, or other failures, with respect to our or our vendors’ information processing systems and data may hurt our business, damage our reputation, negatively impact policyholder retention and capacity provider relationships, and expose us to financial and legal liabilities.
Our business is highly dependent upon the effective operation of our information processing systems. We also rely on these systems throughout our business for a variety of functions, including collecting, processing, and storing sensitive personal, financial, and policyholder data. Despite the implementation of security and back-up measures, our computer systems and those of our partners and third-party service providers may in the future be vulnerable to system failures, physical or electronic intrusions, computer viruses, social engineering, phishing, software bugs, ransomware, malware, infiltration by unauthorized persons, fraud, usage errors by their respective professionals, theft or misuse, break-ins or other attacks, programming errors, and similar disruptive problems. This is, in part, due to the increased sophistication of such cyberattacks and cyber incidents, the introduction of new technologies, and the continued expansion of the use of internet and telecommunications technologies (including mobile devices) to conduct financial and other business transactions. The failure of these systems for any reason could cause significant interruptions to our operations, which could result in a material adverse effect on our business, results of operations, and financial condition. See also “- We rely on the efficient, uninterrupted and secure operation of complex information technology systems and networks to operate our business. Any significant system or network disruption due to an actual or perceived breach in the security of our or our vendors’ information technology systems could have a negative impact on our reputation, regulatory compliance status, operations, sales, and operating results.”
We also have arrangements in place with our partners and other third-party service providers through which we share and receive information. Our reliance on our vendors and other third-party service providers increases our exposure to cybersecurity risks outside of our direct control, which could also expose us to risk of loss, litigation, and potential liability. For example, we may have limited insight into the data privacy or cybersecurity practices of third-party vendors and providers, including as it relates to our AI algorithms. Also, even if our own security measures remain intact, cyberattacks, data breaches, security incidents, malicious internet-based activities, or other incidents or failures at one of our vendors or third-party service providers could compromise our systems and data. Further, in such a circumstance, we may not receive timely notice of, or sufficient information about, the breach or other incident or failure, or be able to exert any meaningful control of or influence over how and when the breach or other incident or failure is addressed. Any theft, loss, or misappropriation of, or access to, policyholders’ or other proprietary data, or other breach of our third-party service providers’ and vendors’ information technology systems, could disrupt our operations, damage our reputation, result in fines, legal claims, or proceedings, including regulatory investigations and actions, liability for failure to comply with privacy and information security laws, or otherwise result in loss of revenue, fraudulent transactions, loss of policyholders, transaction errors, processing inefficiencies, service reliability, and increased costs, including costs to deploy additional personnel and protection technologies, train employees, and engage third-party experts and consultants. Further, the costs of mitigating cybersecurity risks may be significant, including, but not limited to, retaining the services of cybersecurity providers; compliance costs arising out of existing and future cybersecurity, data protection and privacy laws and regulations; and costs related to maintaining redundant networks, data backups, and other damage-mitigation measures. Moreover, the mere perception of a security breach involving us or any part of the insurance services industry, whether or not true, could also damage our business, operations, or reputation or otherwise expose us to potential liability.
Technology continues to expand and plays an ever-increasing role in our business. While it is our goal to safeguard information assets from physical theft and cybersecurity threats, there can be no assurance that our information security will detect and protect information assets from these ever-increasing risks. Information assets include both information itself in the form of computer data, written materials, knowledge, and supporting processes, and the information technology systems, networks, other electronic devices, and storage media used to store, process, retrieve, and transmit that information. As more information is used and shared by our employees, partners and policyholders, both within and outside our company, cybersecurity threats, such as ransomware, phishing, or distributed denial-of-service attacks, become expansive in nature. A cybersecurity event could occur that would cause damage to our reputation with our policyholders and other stakeholders and could have a material adverse effect on our business, results of operations, and financial condition. Such cyberattacks could disrupt our proprietary technology or other critical systems. This could hinder our ability to underwrite policies or support our partners, policyholders, and agents, leading to financial losses and
33
operational downtime. Confidentiality, integrity, and availability of information are essential to maintaining our reputation, legal position, and ability to conduct our operations. Furthermore, as a company subject to privacy and data protection regulations such as the California Consumer Privacy Act, as amended by the CCPA and the GLBA, any cybersecurity incident could also result in noncompliance penalties, regulatory scrutiny, and lawsuits. See also “- We are subject to evolving laws and regulations on data privacy, data protection, and cybersecurity, which can be complex and conflicting. We may face investigations, fines, and sanctions as a result of our or our service providers’ or partners’ actual or perceived failure to comply with such laws and regulations and incur increased operational costs in order to ensure future compliance” and “- Improper disclosure of confidential, personal, or proprietary data, whether due to human error, misuse of information by employees or vendors, or as a result of security breaches, cyberattacks, or other similar incidents with respect to our or our vendors’ systems, could result in regulatory scrutiny, legal liability, or reputational harm and could have an adverse effect on our business or operations.” Our cyber liability insurance may not be sufficient to protect against all losses we may incur if we suffer significant or multiple attacks. Similarly, while in some cases a service provider may have agreed to indemnify us for certain costs, such indemnifying service provider may refuse or be unable to uphold its contractual obligations.
We rely on technologies to provide services to our policyholders. Policyholders require us to issue our policies in a secure manner, either electronically through our internet website or through direct electronic data transmissions. Accordingly, we invest resources in establishing and maintaining electronic connectivity with policyholders and, more generally, in technological advancements. If our information technology systems are inferior to our competitors’, existing and potential policyholders may choose our competitors’ products over ours. Our business would be negatively impacted if we are unable to enhance our platform when necessary to support our primary business functions, including to match or exceed the technological capabilities of our competitors. We cannot predict with certainty the cost of maintaining and improving our platform, but failure to make necessary improvements and any significant shortfall in any technology enhancements or negative variance in the timeline in which system enhancements are delivered could have an adverse effect on our business, results of operations, and financial condition. In addition, a natural or man-made disaster or a pandemic could disrupt public and private infrastructure, including our information technology systems. See also “- Our inability to successfully recover should we experience a disaster or other business continuity problem could cause material financial loss, loss of human capital, reputational harm, or legal liability.”
We rely on the efficient, uninterrupted, and secure operation of complex information technology systems and networks to operate our business. Any significant system or network disruption due to an actual or perceived breach in the security of our or our vendors’ information technology systems could have a negative impact on our reputation, regulatory compliance status, operations, sales, and operating results.
While we manage some of our information technology systems and some are outsourced to third parties, all information technology systems are potentially vulnerable to damage, breakdown, or interruption from a variety of sources, including but not limited to cyberattacks, ransomware, malware, security breaches, theft or misuse, unauthorized access or improper actions by insiders or employees, sophisticated nation-state and nation-state-supported actors, natural disasters, terrorism, war, telecommunication and electrical failures, or other compromise. We are at risk of attack by a growing list of adversaries through increasingly sophisticated methods. Because the techniques used to infiltrate or sabotage systems change frequently, we may be unable to anticipate these techniques or implement adequate preventative measures.
We can make no assurances that we will not experience cyberattack or that we will be successful at protecting Neptune from cyberattacks. Any such incident or resulting or other misuse of data could harm our reputation, lead to legal exposure, divert management attention and resources, increase our operating expenses due to the employment of consultants and third-party experts and the purchase of additional security infrastructure, and/or subject us to liability, resulting in increased costs and loss of revenue. Further, our reliance on cloud computing infrastructure introduces several key risks that could impact our operations and competitive advantage. In particular, our ability to handle growing volumes of policy data and transactions depends on the reliability and capacity of cloud computing providers. Any disruption, outage, or degradation in cloud computing performance - whether due to cyberattacks, technical failures, natural disasters, catastrophic events, terrorism, or other unforeseen events - could impair our ability to operate. Such incidents could result in operational delays, policyholder dissatisfaction, and reputational harm. In addition, if our cloud computing providers fail to meet our evolving performance requirements, we may experience slow response times, decreased efficiency, or service interruptions, potentially affecting policyholder satisfaction and agent productivity. Any such disruption in our platform’s performance due to cloud-related limitations, or failure to maintain our technological edge, could adversely impact our ability to compete effectively. See also “- Reliance on cloud computing exposes us to technological disruptions and potential risks.” In addition, any remediation efforts we undertake may not be successful. The perception that we do not adequately protect the privacy of information of our employees, partners, or policyholders could inhibit our growth and damage our reputation.
34
If we are unable to maintain and upgrade our system safeguards, we may incur unexpected costs and certain aspects of our systems may become more vulnerable to unauthorized access. Cyberattacks and security breaches that affect our partners and policyholders could adversely affect our ability to deliver our products and otherwise conduct our business and could put our systems at risk.
We have implemented various measures to manage our risks related to system and network security and disruptions, but a security breach or a significant and extended disruption in the functioning of our information technology systems could damage our reputation and cause us to lose policyholders, adversely impact our operations and operating results, and require us to incur significant expense to address and remediate or otherwise resolve such issues. In order to maintain the level of security, service, compliance, and reliability that our policyholders and applicable laws require, we may be required to make significant additional investments in our information technology systems on an ongoing basis.
Infringement, misappropriation, dilution, or other violations of our intellectual property or other proprietary information by third parties could harm our business.
We believe our intellectual property has significant value and is critical to our competitive advantage and market position. Our underwriting engine, Triton, and our policy management system, Poseidon, were built entirely in-house and form the backbone of our operations. Our Triton platform incorporates patented features. Both platforms’ proprietary algorithms enable us to evaluate flood risk with precision and efficiency. Similarly, our advanced ML models and predictive analytics tools, developed entirely in-house, are essential to our ability to provide instant, accurate underwriting decisions and competitive pricing. These models are built and maintained exclusively within Neptune, ensuring we maintain full control over their development and evolution. If third parties were to infringe upon, misappropriate, or otherwise violate these systems and models, or if our proprietary technology or processes were compromised or became publicly accessible, it could compromise our ability to offer differentiated products and services in the flood insurance market, diminish the value of our brand, undermine our competitive position, reduce our market shares, and adversely affect our business, particularly against well-funded competitors or emerging flood insurance companies.
The effectiveness of intellectual property protections, such as patents, trademarks, and copyrights, depends on the legal systems of the jurisdictions where we operate. If we expand our operations into additional jurisdictions, including internationally, certain regions may have limited or inconsistent enforcement, or otherwise fail to provide the same level of protection of our proprietary and confidential information as do the laws of the United States, increasing the risk of unauthorized use or disclosure, infringement, misappropriation, or other violation of our intellectual property, even if contractual restrictions exist surrounding use of our intellectual property. Additionally, we cannot guarantee that future patent, copyright, trademark, or service mark registrations for any pending or future applications will issue, or that any registered patents, copyrights, trademarks, or service marks will be valid, enforceable, sufficiently broad in scope, or provide adequate protection of our intellectual property and other proprietary rights. The United States Patent and Trademark Office requires compliance with a number of procedural, documentary, fee payment, and other similar provisions during the patent and trademark registration process and after a registration has issued. For example, there are situations in which noncompliance can result in abandonment or cancellation of a trademark filing, resulting in partial or complete loss of trademark rights in the relevant jurisdiction. If this occurs, our competitors might be able to enter the market under or acquire identical or similar brands, trademarks, service marks, or other intellectual property or other proprietary rights, or otherwise violate or diminish the value of our trademarks and our other intellectual property and proprietary rights. Failure to adequately protect our intellectual property rights could damage our brand and impair our ability to compete effectively.
Even where we have effectively secured statutory protection for our trademarks and other intellectual property, our competitors and other third parties may infringe on, misappropriate, or otherwise violate our intellectual property, which could weaken our competitive position and erode our market share. Detecting and addressing intellectual property infringement may require costly litigation or enforcement actions, with no guarantee of favorable outcomes, and, in the course of litigation, such competitors and other third parties may attempt to challenge the breadth of our rights or ability to prevent others from using similar marks or designs or invalidate our intellectual property. If such challenges were to be successful, having less ability to prevent others from using similar marks or designs may ultimately result in a reduced distinctiveness of our brand in the minds of consumers. Defending or enforcing our trademark rights, branding practices and other intellectual property could result in the expenditure of significant resources and divert the attention of management, which in turn may materially and adversely affect our business and operating results, even if such defense or enforcement is ultimately successful. Even though competitors occasionally may attempt to challenge our ability to prevent infringers from using our marks, we are not aware of any challenges to our right to use.
35
Furthermore, as we continue to innovate and expand, there is a risk that third parties may assert claims that our proprietary technology or other aspects of our business infringe on their intellectual property rights. Defending against such claims, even if unfounded, could result in costly litigation, operational disruptions, or the need to modify or cease using certain technologies. An unfavorable ruling could lead to monetary damages or licensing fees, negatively impacting our financial position.
Failure to seek, obtain, maintain, protect, defend, or enforce our intellectual property rights, or allegations that we have infringed, misappropriated, or otherwise violated the intellectual property rights of others, could harm our reputation, ability to compete effectively, financial condition, and business.
Our success and ability to compete depends in part on our ability to seek, obtain, maintain, protect, defend, and enforce our intellectual property rights, including with respect to our proprietary technology and our brand. To protect our intellectual property rights, we rely on a combination of trademark laws, copyright laws, patent protection, trade secret protection, confidentiality agreements, and other contractual arrangements with our affiliates, employees, policyholders, strategic partners, and others. It is our policy to enter into agreements containing obligations of confidentiality with each party that has or may have had access to proprietary information, know-how or trade secrets owned or held by us, including confidentiality and invention assignment agreements with our employees, consultants, and contractors. Such protective steps may be ineffective or inadequate to deter infringement, misappropriation, or other violations of our proprietary information or other intellectual property. For example, our competitors and other third parties may design around our intellectual property, independently develop similar or superior intellectual property, or otherwise duplicate or mimic our platform or products in a manner that does not violate our intellectual property rights, such that we would not be able to successfully assert our intellectual property rights or other proprietary rights against them. In addition, we may be unable to detect the unauthorized use of, or take appropriate steps to enforce, our intellectual property rights. Policing unauthorized use of our intellectual property is difficult, expensive, and time-consuming, and we may be required to spend significant resources to monitor and protect our intellectual property rights. Failure to protect our intellectual property adequately could harm our reputation and affect our ability to compete effectively.
In addition, even if we initiate litigation against third parties such as suits alleging infringement, misappropriation, or other violations of our intellectual property, we may not prevail. Litigation brought to protect and enforce our intellectual property rights could be costly, time-consuming, and distracting to management. Our efforts to enforce our intellectual property rights may be met with defenses, counterclaims, and countersuits attacking the validity and enforceability of our intellectual property rights. Additionally, because of the substantial amount of discovery required in connection with intellectual property litigation, there is a risk that some of our confidential information could be compromised by disclosure during this type of litigation. An adverse determination of any litigation proceedings could put our intellectual property at risk of being invalidated or interpreted narrowly and could put our related intellectual property at risk of not issuing or being canceled. There could also be public announcements of the results of hearings, motions, or other interim proceedings or developments. If securities analysts or investors perceive these results to be negative, it could have a material adverse effect on the price of our common stock. Any of the foregoing could adversely affect our business, financial condition, and results of operations. See also “- Infringement, misappropriation, dilution, or other violations of our intellectual property or other proprietary information by third parties could harm our business.”
Our trademarks are valuable assets that support our brand and perception of our platform and products and distinguish our platform and products from those of our competitors. We have registered or applied to register many of these trademarks. Third parties may also oppose our trademark applications or otherwise challenge our use of such trademarks, and our trademarks may be circumvented or declared generic. Further, there can be no assurance that competitors will not infringe our trademarks or that we will have adequate resources to enforce our trademarks. Third parties may file for registration of trademarks similar or identical to our trademarks, thereby impeding our ability to build brand identity and possibly leading to market confusion. Moreover, third parties may file first for our trademarks in certain countries. If they succeed in registering or developing common law rights in such trademarks, and if we are not successful in challenging such third-party rights, we may not be able to use these trademarks to develop brand recognition in those jurisdictions. If we are unable to protect our trademarks as well as our internet domain names in the United States or in other jurisdictions in which we may ultimately seek to operate, our brand recognition and reputation would suffer, we would incur significant re-branding expenses, and our results of operations could be adversely impacted.
Moreover, third parties may challenge, invalidate, or circumvent our intellectual property and other proprietary rights, or otherwise assert rights therein or ownership thereof, including through administrative processes or litigation, and we may be unable to successfully resolve any such conflicts in our favor or to our satisfaction. Litigation brought to protect and enforce our intellectual property rights could be costly, time-consuming, and distracting to management. Furthermore, third parties may assert intellectual property-related claims against us, including claims of infringement, misappropriation,
36
or other violation of their intellectual property, which may be costly to defend, could require the payment of damages, legal fees, settlement payments, royalty payments, and other costs or damages, including treble damages if we are found to have willfully infringed certain types of intellectual property, and could limit our ability to use or offer certain technologies, products, or other intellectual property. Any intellectual property claims, with or without merit, could be expensive, take significant time, and divert management’s resources, time, and attention from other business concerns. There could also be public announcements of the results of hearings, motions, or other interim proceedings or developments. If securities analysts or investors perceive these results to be negative, it could have a material adverse effect on the price of our common stock. Any of the foregoing could adversely affect our business, financial condition, and results of operations. Furthermore, successful challenges against us could require us to modify or discontinue our use of technology or business processes where such use is found to infringe, misappropriate, or otherwise violate the rights of others, or require us to purchase licenses from third parties, which may not be available on commercially reasonable terms, or at all. Even if a license is available to us, it could be non-exclusive, thereby giving our competitors and other third parties access to the same technologies licensed to us, or we may be required to pay significant licensing payments or royalties, which would increase our operating expenses, or require us to redesign our platform or other products, or functionality therein, any of which could adversely affect our business, financial condition, and results of operations.
Improper disclosure of confidential, personal, or proprietary data, whether due to human error, misuse of information by employees or vendors, or as a result of security breaches, cyberattacks, or other similar incidents with respect to our or our vendors’ systems, could result in regulatory scrutiny, legal liability, or reputational harm and could have an adverse effect on our business or operations.
We maintain confidential, personal, and proprietary information relating to policyholders and agents, including their names, addresses, phone numbers, and emails. We are subject to laws and regulations relating to the collection, use, retention, security, and transfer of this information. These laws apply to transfers of information among our affiliates, as well as to transactions we enter into with third-party vendors. Any improper disclosure, data breach, or failure to comply with privacy and data protection laws could expose us to significant risks, including regulatory penalties, legal liabilities, and reputational damage. Cybersecurity breaches, such as computer viruses, unauthorized parties gaining access to our information technology systems, and similar incidents could disrupt the security of our internal systems and business applications, impair our ability to provide our products to our policyholders and protect the privacy of their data, compromise confidential business information, or result in intellectual property or other confidential or proprietary information being lost or stolen, including partner, policyholder, employee, or company data, which could harm our competitive position or otherwise adversely affect our business. Cyber threats are constantly evolving, which makes it more difficult to detect cybersecurity incidents, assess their severity or impact in a timely manner, and successfully defend against them.
We maintain policies, procedures, and technical safeguards designed to protect the security and privacy of confidential, personal, and proprietary information. Nonetheless, we cannot eliminate the risk of human error or guarantee our safeguards against employee, vendor, or third-party malfeasance. It is possible that the steps we follow, including our security controls over personal data and training of employees on data security, may not prevent improper access to, disclosure of, or misuse of confidential, personal, or proprietary information. Policyholders, agents, and partners trust us to protect their data. Moreover, while we strive to publish and prominently display privacy policies that are accurate, comprehensive, and compliant with applicable laws, rules, regulations, and industry standards, we cannot ensure that our privacy policies and other statements regarding our practices will be sufficient to protect us from claims, proceedings, liability, or adverse publicity. If our public statements about our use, collection, disclosure, and other processing of personal information - whether made through our privacy policies, information provided on our website, press statements, or otherwise - are alleged to be deceptive, unfair, or misrepresentative of our actual practices, we may be subject to potential government investigations and enforcement actions, including by the FTC or relevant state attorneys general. Any incident involving improper disclosure or misuse of confidential, personal, or proprietary information - whether due to cyberattacks, internal errors, or third-party service provider failures - could erode confidence in our brand, create legal exposure, subject us to legal liability, reduce policyholder retention, and attract negative media attention. See also “- Our business is dependent upon information processing systems. Cybersecurity events, data breaches, cyberattacks, or other similar incidents, as well as defects, interruptions, or other failures, with respect to our or our vendors’ information processing systems and data may hurt our business, damage our reputation, negatively impact policyholder retention and capacity provider relationships, and expose us to financial and legal liabilities” and “- We rely on the efficient, uninterrupted, and secure operation of complex information technology systems and networks to operate our business. Any significant system or network disruption due to an actual or perceived breach in the security of our or our vendors’ information technology systems could have a negative impact on our reputation, regulatory compliance status, operations, sales, and operating results.”
37
Data privacy is subject to frequently changing laws, rules, and regulations in the various jurisdictions in which we operate. We are subject to an evolving, and sometimes conflicting, landscape of privacy regulations, including the CCPA and the GLBA, which impose stringent requirements on data handling or other processing, security, and transparency. Noncompliance with these laws, and other laws, rules, and regulations to which we are subject, could result in fines, penalties, enforcement actions, or costly litigation. Additionally, legislators in the U.S. are proposing new and more robust cybersecurity legislation in light of the recent broad-based cyberattacks at a number of companies. Continuing to maintain compliance with evolving privacy and data protection laws and regulations requires significant time, resources, and expense, as will the effort to monitor whether additional changes to our business practices and our backend configuration are needed, all of which may increase operating costs, or limit our ability to operate or expand our business. Our actual or perceived failure to adhere to, or successfully implement processes in response to, changing legal or regulatory requirements in this area could result in financial losses, legal liability, or damage to our reputation in the marketplace. See also “- We are subject to evolving laws and regulations on data privacy, data protection, and cybersecurity, which can be complex and conflicting. We may face investigations, fines, and sanctions as a result of our or our service providers’ or partners’ actual or perceived failure to comply with such laws and regulations and incur increased operational costs in order to ensure future compliance.”
Finally, because the interpretation and application of many privacy and data protection laws, commercial frameworks, and standards are uncertain, it is possible that these laws, frameworks, and standards may be interpreted and applied in a manner that is inconsistent with our existing data management practices or the features of our products. If so, in addition to the possibility of fines, lawsuits, breach of contract claims, criminal penalties, and other claims and penalties, we could be required to fundamentally change our business activities and practices or modify our products and features, which could have an adverse effect on our business. Furthermore, we may also be required to disclose personal information pursuant to demands from individuals, regulators, government authorities, and law enforcement agencies in a variety of jurisdictions with conflicting laws and regulations. Such disclosure may result in adverse media coverage and harm our brand and reputation, leading to loss of policyholders, which can result in adverse impact on our business, financial condition, and share price.
The confidentiality and invention assignment agreements that we enter into with our employees, consultants, and contractors involved in the development of intellectual property may not provide meaningful protection for our trade secrets or other confidential information, and if we are unable to protect the confidentiality of our trade secrets or other confidential information, the value of our platform and products and our business and competitive position could be materially adversely affected.
We rely heavily on trade secret laws and confidentiality agreements to protect our unpatented know-how, technology, and other proprietary information, including our platform and products and to maintain our competitive position. With respect to our platform and products, we consider trade secrets and know-how to be one of our primary sources of intellectual property. Trade secrets and know-how can be difficult to protect. We seek to protect these trade secrets and other confidential information in part by entering into non-disclosure and confidentiality agreements with parties who have access to them, such as our employees, outside contractors, advisors, and other third parties. We also enter into confidentiality and invention assignment agreements with our employees, contractors, consultants, and other third parties who develop intellectual property on our behalf or who may have access to our proprietary information, know-how, or trade secrets. These confidentiality agreements are designed to protect our proprietary information and, in the case of agreements or clauses containing invention assignment, to grant us ownership of technologies that are developed through a relationship with employees or third parties. These agreements may not be self-executing or otherwise sufficient and may not provide meaningful protection against the unauthorized use or disclosure of our trade secrets or other confidential information, and adequate remedies may not exist if unauthorized use or disclosure were to occur, or we may not have executed, or may in the future fail to execute, invention assignment agreements with employees, contractors, consultants, and third parties who may be involved in the development of our intellectual property. The exposure of our trade secrets and other proprietary information would impair our competitive advantages and could have a material adverse effect on our business, results of operations, and financial condition. In particular, a failure to protect our confidential information may allow competitors to copy our technology, which could adversely affect our pricing and market share. Further, other parties may independently develop substantially equivalent know-how and technology.
Furthermore, individuals executing agreements with us may have preexisting or competing obligations to third parties, and thus an agreement with us may be ineffective in perfecting ownership of intellectual property developed by those individuals. We may in the future become subject to claims that we or our employees have inadvertently or otherwise used or disclosed trade secrets or other proprietary information of former employers. Litigation may be necessary to defend against these claims. If we fail in defending such claims, we may be forced to pay monetary damages or be enjoined from
38
using certain technology, aspects of our platforms, aspects of our programs, or knowledge. Even if we are successful in defending against these claims, litigation could result in substantial costs and demand on management resources.
In addition to contractual measures, we seek to protect the confidential nature of our proprietary information using commonly accepted physical and technological security measures. Such measures may not, for example, in the case of misappropriation of a trade secret by an employee, consultant, or other third party with authorized access, provide adequate protection for our proprietary information. Our security measures may not prevent an employee, consultant, contractor, or other third party from misappropriating our trade secrets and providing them to a competitor, and the recourse we take against such misconduct may not provide an adequate remedy to protect our interests fully. Monitoring unauthorized uses and disclosures is difficult, and we do not know whether the steps we have taken to protect our intellectual property, trade secrets, or confidential information will be effective. Unauthorized parties may also attempt to copy or reverse engineer certain aspects of our platform and programs that we consider proprietary. Enforcing a claim that a party illegally disclosed or misappropriated a trade secret can be difficult, expensive, and time-consuming, and the outcome is unpredictable. Trade secret violations are often a matter of state law, and the criteria for protection of trade secrets can vary among different jurisdictions. In addition, trade secrets may otherwise become known or be independently developed by others, including our competitors, in a manner that could prevent legal recourse by us.
Our platform contains third-party open-source software components, which may entail greater operational risks than use of third-party commercial software.
Our platform contains software modules licensed by third-party providers and authors under “open-source” licenses. Use and distribution of open-source software may entail greater risks than use of third-party commercial software, as open source licensors generally do not provide support, warranties, indemnification, or other contractual protections regarding infringement claims or the quality of the code. In addition, the public availability of such software may make it easier for others to compromise our platform, leading to greater cybersecurity risks.
Some open-source licenses contain requirements that the licensee makes available source code for modifications or derivative works we create based upon the type of open-source software we use or grant other licenses to our intellectual property. If we combine our proprietary software with open-source software in a certain manner, we could, under certain open-source licenses, be required to release the source code of our proprietary software to the public. This would allow our competitors to create similar products with lower development effort and time and ultimately could result in a loss of our competitive advantages. Alternatively, to avoid the public release of the affected portions of our source code, we could be required to expend substantial time and resources to re-engineer some or all of our software.
We expect that we will monitor our use of open-source software to avoid subjecting our platform to conditions we do not intend, but we cannot provide assurance that our processes for controlling our use of open-source software will be effective. If we are held to have breached or failed to fully comply with all the terms and conditions of an open source software license, we could face litigation, infringement, or other liability, or be required to seek costly licenses from third-parties to continue providing our offerings on terms that are not economically feasible, to re-engineer our platform, to discontinue or delay the provision of our offerings if re-engineering could not be accomplished on a timely basis, or to make generally available, in source code form, our proprietary code, any of which could adversely affect our business and operations. Moreover, the terms of many open-source licenses have not been interpreted by U.S. or foreign courts. As a result, there is a risk that these licenses could be construed in a way that could impose unanticipated conditions or restrictions on our ability to operate our platform. From time to time, there have been claims challenging the ownership of open-source software against companies that incorporate open-source software into their solutions. As a result, we could be subject to lawsuits by parties claiming ownership of what we believe to be open-source software. The risks associated with our use of open-source software described above can result in adverse impact on our reputation, business, and operations.
Intellectual property rights do not necessarily address all potential threats.
The degree of future protection afforded by our intellectual property and other proprietary rights is uncertain because intellectual property rights have limitations and may not adequately protect our business or permit us to maintain our competitive advantage. For example:
•others may be able to develop a platform or other technology that is similar to our Triton platform, but that is not covered by the claims of our issued patent;
•others may independently develop similar or alternative technologies or otherwise circumvent any of our technologies without infringing our intellectual property rights;
39
•we might not have been the first to invent the inventions covered by our issued patent;
•we might not have been the first to file the patent application covering our issued patent or future patents;
•it is possible that any patent applications we may file in the future will not lead to issued patents;
•others may have access to the same intellectual property rights licensed to us on a non-exclusive basis in the future;
•our issued patent or any future patents we own may not provide us with any competitive advantage, or may be held invalid or unenforceable as a result of legal challenges by our competitors;
•our competitors might conduct research and development (“R&D”) activities in countries where we do not have patent rights, or in countries where R&D safe harbor laws exist, and then use the information learned from such activities to develop competitive products for sale in our major commercial markets;
•ownership, validity, or enforceability of our issued patent may be challenged by third parties;
•patent enforcement is expensive and time-consuming and difficult to predict, thus we may not be able to enforce our issued patent or future patents against a competitor;
•we may choose not to file a patent for certain inventions, instead choosing to rely on trade secret protection or know-how, and a third party may subsequently file a patent covering such intellectual property; and
•the patents of third parties or pending or future applications of third parties, if issued, may have an adverse effect on our business.
Should any of these events occur, it could significantly harm our business, financial condition, and results of operations.
Risks Relating to Regulatory and Legal Matters
The insurance business is extensively regulated, and changes in regulation may reduce our profitability and limit our growth.
We operate in a highly regulated industry, subject to regulatory oversight in the 50 states and Washington, D.C., where we are qualified to do business, and regulatory factors at the federal and state level may impact our ability to sell insurance policies. This extensive regulatory framework governs consumer protections and data security, exposing our business to significant litigation and compliance risks. Any failure to meet these requirements as a result of our or our service providers’ or partners’ actual or perceived failure to comply with such laws and regulations or allegations of noncompliance can result in fines, penalties, or operational restrictions. Regulators and members of other governmental agencies or instrumentalities may scrutinize the underwriting and pricing decisions made by our proprietary Triton platform, potentially raising concerns about transparency, accuracy, or adherence to applicable laws. For example, we have in the past, and may in the future, receive inquiries from regulators and members of the U.S. Congress relating to our business model, use of technology and other business practices and activities. Failure to comply with applicable regulations or to obtain or maintain appropriate authorizations or exemptions under any applicable laws, and any investigations, inquiries or examinations by regulators or other governmental agencies or instrumentalities, could result in adverse publicity, restrictions on our ability to conduct business or engage in activities regulated in one or more jurisdictions in which we operate and could subject us to reputational damage, fines, injunctions, or other sanctions that could have a material adverse effect on our business, results of operations, and financial condition. In addition, the nature and extent of regulation could materially change, which may result in additional costs associated with compliance with any such changes, or changes to our operations that may be necessary to comply, any of which may have a material adverse effect on our business. State insurance regulatory authorities have broad administrative powers, which at times are coordinated and communicated across regulatory bodies. These administrative powers include, but are not limited to:
•licensing companies and agents to transact business;
•regulating certain premium rates;
•reviewing and approving policy forms;
•regulating discrimination in pricing, coverage terms, and unfair trade and claims practices, including payment of inducements;
40
•establishing and revising statutory capital and reserve requirements and solvency standards;
•evaluating enterprise risk to an insurance company;
•approving changes in control of insurance companies;
•restricting the payment of dividends and other transactions between affiliates;
•regulating the types, amounts, and valuation of investments; and
•restricting, pursuant to state monoline restrictions, the types of insurance products that may be offered.
State insurance regulators and the National Association of Insurance Commissioners regularly re-examine existing laws and regulations, which may lead to modifications to statutory accounting principles, interpretations of existing laws, and the development of new laws and regulations applicable to insurance companies and their products. Changes in regulations or heightened scrutiny of underwriting practices or E&S lines could materially and adversely affect our business, financial condition, results of operations, and growth prospects.
Litigation often arises from claims activity. Even though we do not directly handle or adjudicate claims, legal disputes related to denied or delayed claims under policies sold through our platform may incorrectly name us as a party, resulting in reputational damage and legal expenses. Litigation may also involve underwriting decisions, where Triton’s algorithms could be challenged for perceived inaccuracies, discrimination, or noncompliance with regulatory standards. Such disputes can lead to court-mandated changes to our processes, financial liabilities, and reputational harm. The scale and reach of our business can also expose us to the risk of class-action lawsuits or consumer protection claims alleging unfair practices or misleading disclosures. Legal proceedings tied to these allegations, whether substantiated or not, can result in significant financial liabilities, disruption to operations, and erosion of policyholder trust.
While we operate as a private flood insurer, changes in NFIP regulations can impact our business. For example, the implementation of Risk Rating 2.0 by the NFIP aims to align premiums more closely with actuarial accuracy by increasing rates for most policyholders. Similar changes could affect the competitive landscape and influence policyholder behavior, potentially impacting our market share and profitability.
As a provider of flood insurance, we are particularly sensitive to regulations related to climate change and natural disasters. Due to the frequency and intensity of the natural disasters related to climate change, government and regulatory bodies may introduce new regulations aimed at mitigating the impact of natural disasters. These regulations could include stricter building codes, mandatory insurance requirements, or incentives for risk mitigation measures. Such regulations could increase our service providers’ or partners’ compliance costs and operational complexity. Further, a substantial legal liability or a significant regulatory action against us could have a material adverse effect on our business, results of operations, and financial condition. It is possible that we could become subject to future investigations, regulatory actions, lawsuits, or enforcement actions, which could cause us to incur legal costs and, if we were found to have violated any laws or regulations, require us to pay fines and damages, perhaps in material amounts, and result in injunctions and other sanctions. Increased regulatory scrutiny and any resulting investigations or legal proceedings could result in new legal precedents and industry-wide regulations or practices that could have a material adverse effect on our business, results of operations, and financial condition. Moreover, even if we ultimately prevail in such litigation, regulatory action, or investigation, we could suffer significant reputational harm and incur significant legal expenses, which could have a material adverse effect on our business, results of operations, and financial condition. We cannot predict the ultimate outcomes of any future investigations, regulatory actions, or legal proceedings. Additionally, our carrier partners are regulated by state insurance departments for solvency issues and are subject to reserve requirements. We cannot guarantee that all carriers with which we do business comply with regulations instituted by state insurance departments. For example, if our carrier partners are perceived as unstable or financially weak, they may face increased regulatory scrutiny, which could result in restrictions on their operations or additional compliance requirements. This could further impact their ability to support our business and lead to operational disruptions. If our carriers are unable to adapt to these regulatory changes, it could lead to a reduction in their capacity or willingness to partner with us, thereby affecting our ability to operate and expand our business and maintain existing policies. We may need to expend resources to address questions or concerns regarding our relationships with these insurers, diverting management resources away from operating our business, which could have an adverse impact on our business.
41
Reform or repeal of the Biggert-Waters Act could materially reduce sales.
The Biggert-Waters Act of 2012 defined “private flood insurance” as an insurance policy that meets certain criteria and mandated that the NFIP establish actuarially sound premium rates; following its adoption, the NFIP’s premium rates increased. Thereafter, as part of the Consolidated Appropriations Act of 2014, Congress prohibited FEMA from implementing section 207 of the Biggert-Waters Act, effectively stopping certain rate increases while new law was developed to address concerns about increased rates. In 2014, Congress passed the Homeowner Flood Insurance Affordability Act of 2014, which repealed certain provisions of the Biggert-Waters Act, thereby restoring certain subsidies and “grandfathering” of certain properties, and also implemented limits on certain NFIP rate increases, implemented an annual surcharge on all policyholders, and mandated FEMA conduct an affordability study to explore ways to make flood insurance more affordable for policyholders. In addition to the mandates relating to NFIP rates, the Biggert-Waters Act and the related regulations required federally-regulated lending institutions to accept private flood insurance policies that meet certain criteria in satisfaction of flood regulations governing a federally-related mortgage loan secured by a building located in an SFHA.
Subsequently, in 2021, FEMA continued to modify NFIP’s approach to pricing by launching Risk Rating 2.0, a pricing methodology aimed at better aligning premiums with the risk profile of a given property. Under Risk Rating 2.0, NFIP policyholders became subject to limits on annual rate increases of up to 18%, the maximum allowed under congressional caps, until their premiums reach full risk-based levels. In addition, certain executive orders have been adopted in 2025 that have rescinded the Federal Flood Risk Management Standard Policy and established a bipartisan FEMA Review Council tasked with reforming and streamlining the U.S. emergency management and disaster response system. To date, these developments have not had any impact on the provisions of the Biggert-Waters Act that established the private flood insurance market, but a weakening or repeal of, or future legislation or executive action addressing, the mandatory acceptance provisions included in the Biggert-Waters Act or the related regulations could result in fewer sales if lending institutions subsequently choose not to accept private flood policies in satisfaction of the regulation. Further, if NFIP’s implementation of Risk Rating 2.0 is tolled or delayed or Congress elects to continue to subsidize the NFIP consistent with historic levels, it could limit our potential growth opportunities relating to existing NFIP policyholders. In addition, adjustments to NFIP’s pricing, coverage options, or underwriting guidelines, whether through amendments or modifications to the Biggert-Waters-Act or otherwise, could also significantly alter the competitive landscape. If any of such developments occur, it could materially and adversely affect our business, financial condition, and results of operations.
Changes to the E&S lines regulatory landscape, or a requirement for Neptune to file admitted rates, could have a detrimental impact to our sales, innovation, and ability to grow.
We operate in the E&S lines market, which allows for greater flexibility in underwriting, pricing, and product innovation compared to the admitted insurance market. E&S insurers are not required to file rates and forms with state regulators in the same manner as admitted carriers, enabling us to adapt quickly to market conditions and policyholder needs.
Regulatory changes affecting the E&S market or the imposition of admitted-market requirements on Neptune could have a material and adverse impact on our business. If we are required to file and receive approval for our rates and policy forms in certain states, it could significantly slow our ability to adjust pricing based on evolving risk factors and our proprietary models and technology platform. This would limit our flexibility and responsiveness to competitive and climate-related changes and could require us to make changes to our pricing structure. In addition, the E&S market’s ability to rapidly introduce new coverage options and adjust terms is a key advantage. If regulatory changes require us to comply with admitted-market filing processes, our product development cycles could be delayed, reducing our ability to respond to emerging policyholder needs. Further, many of our competitors and potential competitors operate within the admitted insurance market and have already built compliance frameworks for rate and form filings. If we are required to transition to an admitted structure, we may face increased operational costs and administrative burdens that could reduce our competitive advantage. Some states may also introduce new regulations limiting the use of E&S carriers or requiring E&S lines insurers to meet additional compliance thresholds. If states impose restrictions that force more policies into the admitted market, our ability to underwrite and sell flood insurance through the E&S structure could be limited. Changes in E&S regulations may also affect how insurance and reinsurance partners evaluate risk-taking arrangements. Stricter regulatory oversight could lead to increased capital requirements or changes in reinsurance terms, impacting our ability to secure or grow risk-taking partnerships. If regulatory changes restrict the advantages of the E&S market or require Neptune to file admitted rates, it could hinder our ability to innovate, slow our sales growth, and impose additional costs that could materially and adversely affect our business, financial condition, and results of operations.
42
Compliance with insurance licensing requirements for MGAs and E&S lines agencies and individual producers is critical to our operations, and any failure to maintain required licenses could disrupt our business.
As an MGA, we are subject to licensing requirements and must maintain insurance licenses in each of the jurisdictions in which we operate. These licenses are subject to periodic renewal and compliance with jurisdiction-specific regulations, including recordkeeping, tax reporting, and E&S lines filing requirements. Any failure to meet these obligations could result in fines, penalties, or suspension of our licenses, which would impair our ability to operate in affected jurisdictions.
Our operations as both an MGA and E&S lines broker subject us to complex, overlapping licensing requirements that could have an adverse impact on our business if not maintained. This dual role subjects us to distinct but overlapping regulatory frameworks, increasing both compliance complexity and operational risk. Some states require separate licenses for MGA and E&S lines activities, while others may combine these authorities under different licensing structures.
Additionally, certain employees who provide customer service or interact with policyholders are required to obtain and maintain individual insurance producer licenses in compliance with state regulations. These licenses require passing state examinations, completing continuing education courses, and adhering to ethical standards. Many states also restrict E&S lines broker licenses to individuals rather than agencies. Our ability to operate in these jurisdictions depends entirely on maintaining employed individuals who hold these personal licenses. The departure of key licensed individuals could immediately impact our ability to place new business or service existing policies in affected states until we can obtain new individual licenses. This creates operational risk, as the process of obtaining new individual licenses can be time-consuming, potentially creating business interruptions. As a result, failure by any of our licensed employees to meet these requirements could limit our ability to provide customer service or result in regulatory action.
The variation in licensing requirements across states increases administrative complexity and costs. Monitoring and managing compliance for both agency and individual licenses requires significant investment in resources and systems. Any oversight, such as missed renewal deadlines or failure to meet state-specific reporting requirements, could result in lapses or disciplinary action. Loss or suspension of licenses in key markets could significantly impact our revenue and growth prospects, particularly in states that represent a substantial portion of our business. Additionally, lapses in individual licensing could expose Neptune to liability if unlicensed employees inadvertently engage in regulated activities.
The regulatory landscape governing insurance licensing is continually evolving, and new or modified requirements could impose additional compliance burdens or restrict our ability to operate in certain jurisdictions. Maintaining licensing compliance requires significant ongoing investment in personnel, training, and systems, and these costs may increase as regulations evolve or our business expands. We also depend on third-party service providers to assist with certain aspects of our licensing compliance and any failures by these providers could result in inadvertent non-compliance with licensing requirements. In addition, as we expand into new markets or offer new products, we may face additional licensing requirements or heightened regulatory scrutiny, which could impede our growth strategies.
Finally, as an MGA, we must verify that our third-party agent and brokers maintain required licenses and comply with the conditions of our delegated binding authorities. Failure to oversee the license status of these agents and brokers could result in termination of carrier relationships and/or increased regulatory risk.
These licensing requirements are complex, vary by state, and impose ongoing obligations that are critical to maintaining our ability to conduct business. While we strive to maintain all required licenses, we cannot ensure that we will be able to maintain them in the future or obtain additional licenses as needed, and any such failure or lapses in compliance could materially and adversely affect our business, financial condition, results of operations, and growth prospects.
Our role in collecting and paying E&S lines taxes exposes us to financial, operational, and regulatory risks.
As an E&S lines broker, we are responsible for collecting and remitting E&S lines taxes on behalf of our policyholders to various state authorities. This process requires strict compliance with state-specific tax laws, accurate recordkeeping, and timely payments.
Any errors, delays, or omissions in the collection or payment of E&S lines taxes could result in penalties, fines, or interest charges. State regulators may also audit our tax compliance practices, and any findings of noncompliance could lead to further penalties or reputational harm. E&S lines tax requirements also vary by state, adding complexity to our operations. Misinterpretation of state laws, calculation errors, or failures in tracking transactions across jurisdictions could result in underpayment or overpayment of taxes, disrupting cash flow and increasing administrative burdens.
43
Our role in handling funds for E&S lines taxes could make us liable for any unpaid taxes. Disputes with policyholders or state authorities over tax amounts or remittance could result in financial losses and damage to our reputation. Proper management of E&S lines taxes is critical to maintaining compliance and avoiding financial and operational disruptions. Any failure to do so could materially and adversely affect our business, financial condition, and results of operations.
Regulatory and licensing requirement changes could disrupt operations or increase compliance costs and restrict our ability to conduct our business.
The flood insurance industry operates within a complex and evolving regulatory environment, encompassing federal, state, and local laws. Changes to these regulations could significantly impact our business model, operational costs, and competitive position.
Dramatic policy changes to the NFIP are possible. Any modifications to the NFIP’s pricing structure, underwriting guidelines, or subsidy programs could alter the competitive landscape in which we operate. For example, if the administration were to implement measures to lower NFIP premiums or expand coverage options, private flood insurance providers like Neptune could face heightened competitive pressures. Conversely, reductions in NFIP subsidies could drive more customers to seek private market solutions, creating both opportunities and operational challenges.
Regulatory changes at the federal level, including those affecting floodplain mapping, risk assessment standards, and lender requirements, could also create uncertainty for private insurers. For example, changes to FEMA’s flood zone designations or its risk rating methodologies could affect how we evaluate and price flood risk, necessitating costly updates to our proprietary technology. Additionally, prolonged regulatory uncertainty could discourage banks or other lenders from accepting private flood insurance policies, further limiting market growth. Changes to Standard Flood Insurance Policy forms or requirements could also necessitate swift adjustments to our processes and systems, potentially increasing compliance costs and operational risks. These dependencies make our business sensitive to potential federal policy shifts. Further, while federal policies dominate the flood insurance market, state regulators also play a significant role in governing private insurers. Variability in state-level requirements for rate filings, consumer protections, and policy approvals can add complexity and cost to our operations.
Additionally, we are subject to licensing requirements and must maintain insurance licenses in each of the jurisdictions where we operate. These licenses are subject to periodic renewal and compliance with state-and jurisdiction-specific regulations, including recordkeeping, tax reporting, and E&S lines filing requirements. For example, a significant portion of our business is concentrated in Florida, Texas, and Louisiana, collectively representing 48.9% of our policies in force as of December 31, 2025. The insurance business is primarily a state-regulated industry, and therefore, state legislatures may enact laws that adversely affect the insurance industry. Because our business is concentrated in these states, we face greater exposure to unfavorable changes in regulatory conditions in Florida, Texas, and Louisiana than insurance intermediaries whose operations are more diversified through a greater number of states. Unfavorable changes to regulatory conditions in Florida, Texas, and Louisiana could harm our business, financial condition, and results of operations. See also “- Compliance with insurance licensing requirements for MGAs and E&S lines agencies and individual producers is critical to our operations, and any failure to maintain required licenses could disrupt our business” for further discussion.
As a result, any significant shifts in federal or state regulations - particularly those related to the NFIP - could materially and adversely affect our business, financial condition, and results of operations.
Changes in federal and state tax laws, or interpretations thereof, could materially and adversely affect our financial performance.
Neptune is subject to federal and state income taxes, including in Florida where our headquarters are located and in numerous other states where we sell policies. The complexity and variability of tax regulations, combined with the potential for legislative or administrative changes, expose our business to significant tax-related risks.
Federal and state governments periodically enact changes to income tax rates, tax deductions, credits, and other provisions. Increases in corporate income tax rates or reductions in available deductions could materially increase our tax obligations. For example, legislative proposals to raise federal corporate tax rates or broaden the tax base could significantly impact our profitability.
In addition, as we operate in multiple states, Neptune is subject to varying tax regimes and reporting requirements. States may impose additional taxes, which could increase our compliance burden and tax liabilities. Changes in Florida’s
44
tax laws or in other key states where we sell policies could disproportionately affect our financial results. Differences in state tax laws and interpretations can also result in disputes with tax authorities, audits, and potential assessments for unpaid taxes, penalties, or interest. Additionally, changes in enforcement practices or increased scrutiny from federal or state tax agencies could lead to greater compliance costs and risks of financial penalties. Further, changes to tax laws or regulations may be enacted with retroactive effect, resulting in unexpected liabilities. Similarly, unanticipated changes in tax policy could disrupt our financial planning and operational strategies, potentially impacting cash flow and investment decisions.
The need to comply with diverse tax laws across multiple jurisdictions adds administrative complexity and costs and we must allocate resources to ensure compliance with filing requirements, tax payments, and reporting standards, diverting attention and resources from core business activities. The dynamic and often unpredictable nature of tax regulation increases the risk of adverse impacts, particularly as we continue to look to expand our operations into additional jurisdictions. As a result, tax policy changes or increased tax liabilities could materially and adversely affect our business, financial condition, and results of operations.
We are subject to evolving laws and regulations on data privacy, data protection, and cybersecurity, which can be complex and conflicting. We may face investigations, fines, and sanctions as a result of our or our service providers’ or partners’ actual or perceived failure to comply with such laws and regulations and incur increased operational costs in order to ensure future compliance.
Our collection, use, retention, protection, disclosure, transfer, and other processing of personal data subject us to laws and regulations on data protection in multiple jurisdictions, which are often evolving and sometimes conflicting. There is uncertainty and inconsistency in how these data protection and privacy laws and regulations are interpreted and applied, and they continue to evolve in ways that could adversely impact our business. These laws have a substantial impact on our operations in the United States. Further, we are subject to certain federal, state, and international regulations related to cybersecurity, including the NYDFS 23 NYCRR Part 500 Cybersecurity Requirements for Financial Services Companies.
We may also be considered a financial institution under the GLBA. The GLBA regulates, among other things, the use of personal information (“non-public personal information” under the GLBA) in the context of the provision of financial services, including by banks and other financial institutions. The GLBA includes both a “Privacy Rule,” which imposes obligations on financial institutions relating to the use or disclosure of non-public personal information, and a “Safeguards Rule,” which imposes obligations on financial institutions and, indirectly, their service providers, to implement and maintain physical, administrative, and technological measures to protect the security of non-public personal information.
Furthermore, in the United States, federal and state lawmakers and regulatory authorities have increased their attention to the collection and use of consumer data. For example, certain states in the United States have enacted stringent privacy and data protection legislation and regulations, such as the CCPA, which gives California residents the right to access and request deletion of their personal data, opt out of the sale of personal data, and receive detailed information about how their personal data is processed, and which provides a private right of action for certain data breaches involving the loss of personal data. The California Privacy Rights Act modified the CCPA by expanding consumers’ rights with respect to certain personal data and creating a new state agency to oversee implementation and enforcement efforts. Another example is the Virginia Consumer Data Protection Act, which regulates how businesses collect and share personal information. Several other states have passed comprehensive privacy laws similar to the CCPA. Like the CCPA, these laws create obligations related to the processing of personal information, as well as special obligations for the processing of “sensitive” data. Some of the provisions of these laws may apply to our business activities. Additionally, state laws are changing rapidly and there is discussion in Congress of a new comprehensive federal data privacy law to which we may become subject, if enacted, which may add additional complexity, conflicting requirements, additional restrictions, and potential legal risk. The existence of comprehensive privacy laws in various jurisdictions will make our compliance obligations more complex and costly and may increase the likelihood that we may be subject to enforcement actions or otherwise incur liability for noncompliance.
We also send marketing messages via email and are subject to the Controlling the Assault of Non-Solicited Pornography And Marketing Act (the “CAN-SPAM Act”). The CAN-SPAM Act imposes certain obligations regarding the content of emails and providing opt-outs (with the corresponding requirement to honor such opt-outs promptly). While we strive to ensure that all of our marketing communications comply with the requirements set forth in the CAN-SPAM Act, any violations could result in the FTC and/or state regulators and attorneys general seeking civil penalties against us.
45
Additionally, depending on the nature of the information compromised, in the event of a data breach or other unauthorized access to our policyholder data, we may also have obligations to notify policyholders and regulators about the incident, and we may need to provide some form of remedy, such as a subscription to credit monitoring services, pay significant fines to one or more regulators, or pay compensation in connection with a class action settlement. Furthermore, we may be required to disclose personal data pursuant to demands from individuals, regulators, government agencies, and law enforcement agencies in various jurisdictions with conflicting privacy and security laws, which could result in a breach of privacy and data protection policies, notices, laws, rules, court orders, and regulations. Although we may have contractual protections with our vendors, any actual or perceived security breach, incident, or compromise could harm our reputation and brand, expose us to potential liability, or require us to expend significant resources on cybersecurity and in responding to any such actual or perceived breach, incident, or compromise. Any contractual protections we may have from our vendors may not be sufficient to adequately protect us from any such liabilities and losses, and we may be unable to enforce any such contractual protections. Moreover, changes in the laws and regulations that govern our collection, use, and disclosure of policyholder data and offering of products to new jurisdictions could impose additional requirements with respect to the retention and security of policyholder data and could limit marketing activities. Complying with these obligations could cause us to incur substantial costs and could increase negative publicity surrounding any incident that compromises policyholder data. Our failure to comply with data protection laws or the improper disclosure of our own confidential business information or sensitive policyholder information could have an adverse effect on our reputation, business, operating results, financial condition, and share price.
Our business is subject to risks related to legal, governmental, and regulatory proceedings.
In the normal course of business, we may be subject to regulatory and governmental investigations and civil actions, litigation, and other forms of dispute resolution. In addition, we may become involved in litigation and arbitration concerning our rights and obligations under insurance policies issued by our capacity providers to third parties. Additionally, from time to time, various regulatory and governmental agencies may review our transactions and practices in connection with industry-wide and other inquiries. Such investigations, inquiries, or examinations could in the future develop into administrative, civil, or criminal proceedings or enforcement actions, in which remedies could include fines, penalties, restitution, or alterations in our business practices, and could result in additional expenses, limitations on certain business activities, and reputational damage.
We and our officers and directors may also become subject to a variety of additional types of legal disputes brought by holders of our securities, policyholders, employees and others, alleging, among other things, breach of contractual or fiduciary duties, bad faith, indemnification, and violations of federal and state statutes and regulations. Certain of these matters may also involve potentially significant risk of loss due to the possibility of significant jury awards and settlements, punitive damages, or other penalties. These matters could be highly complex and seek recovery on behalf of a class or similarly large number of plaintiffs. It is therefore inherently difficult to predict the size or scope of potential future losses arising from them, and developments in these matters could have a material adverse effect on our financial condition or results of operations.
Risks Related to Financial and Accounting Matters
We will incur significant costs and management resources as a result of operating as a public company.
As a public company, we are subject to the information and reporting requirements of the Securities Act, the Exchange Act, and other federal securities laws, rules and regulations related thereto, including compliance with the Sarbanes-Oxley Act and the Dodd-Frank Act. In addition, the NYSE listing requirements and other applicable securities rules and regulations impose various requirements on public companies. Our management and other personnel will need to devote a substantial amount of time to these compliance initiatives. Moreover, these rules and regulations have significantly increased our legal and financial compliance costs and made some activities more time-consuming and costly. Among other things, as a public company we are required to:
•maintain and evaluate a system of internal controls over financial reporting in compliance with the requirements of Section 404 of the Sarbanes-Oxley Act and the related rules and regulations of the Commission and the Public Company Accounting Oversight Board;
•maintain policies relating to disclosure controls and procedures;
•prepare and distribute periodic reports in compliance with our obligations under federal securities laws;
•institute a comprehensive compliance function, including with respect to corporate governance; and
46
•involve, to a greater degree, our outside legal counsel and accountants in the above activities.
The costs of preparing and filing annual and quarterly reports, proxy statements, and other information with the Commission and furnishing audited reports to stockholders is expensive and much greater than that of a privately-held company. Compliance with these rules and regulations will require us to hire additional financial reporting, internal controls, and other finance personnel, and has involved a material increase in regulatory, legal, and accounting expenses and the attention of our board of directors and management. In addition, being a public company makes it more expensive for us to obtain and maintain director and officer liability insurance. These factors could also make it more difficult for us to attract and retain qualified executives and members of our board of directors. We expect a substantial increase in legal, accounting, insurance, and certain other expenses incurred to comply with these additional regulatory and other requirements in the future, which will negatively impact our business, results of operations, and financial condition.
Changes in accounting principles and financial reporting requirements could impact our consolidated results of operations and financial condition.
Our financial statements are prepared in accordance with GAAP, which are periodically revised. Changes in accounting principles and financial reporting requirements could significantly impact our consolidated results of operations and financial condition. From time to time, we are required to adopt new or revised accounting standards issued by the Financial Accounting Standards Board, which may require us to modify our accounting policies, procedures, and systems. These changes could result in significant variations in our reported financial results and may affect our financial condition. See Note 2, “Significant Accounting Policies,” to our audited financial statements included elsewhere in this Annual Report for a discussion of any accounting developments that have been issued but not yet implemented.
We could be subject to additional tax liabilities.
We are subject to U.S. federal, state, and local income taxes, sales, and other taxes in the United States. Significant judgment is required in evaluating our tax positions, and the ultimate tax outcome may be uncertain. In addition, our provision for income taxes is subject to volatility and could be adversely affected by many factors, including, among other things, changes to our operating or holding structure, changes in the amounts of earnings in jurisdictions with differing statutory tax rates, and changes in the valuation of deferred tax assets and liabilities. In addition, our future income tax obligations could be adversely affected by changes in, or interpretations of, tax laws in the United States. Tax authorities may disagree with our calculation of R&D tax credits, cross-jurisdictional transfer pricing, or other matters and assess additional taxes, interest, or penalties. While we regularly assess the likely outcomes of these examinations to determine the adequacy of our provision for income taxes and we believe that our financial statements reflect adequate reserves to cover any such contingencies, there can be no assurance that the outcomes of such examinations will not have a material impact on our results of operations and cash flows. If tax authorities change applicable tax laws, our overall taxes could increase, and our financial condition or results of operations may be adversely impacted.
If our estimates or judgments relating to our critical accounting policies are based on assumptions that change or prove to be incorrect, our results of operations could fall below expectations of securities analysts and investors, resulting in a decline in the market price of our stock.
We prepare our consolidated financial statements in accordance with GAAP. These accounting principles require us to make estimates and assumptions that affect the reported amounts of assets and liabilities, revenue, and expenses, as well as the disclosure of contingent assets and liabilities at the date of our financial statements. We base our estimates on historical experience and various assumptions that we believe to be reasonable based on specific circumstances, the results of which form the basis for making judgments about the carrying values of assets, liabilities, equity, revenue, and expenses that are not readily apparent from other sources. If our assumptions change or actual circumstances differ from those in our assumptions, our results could differ from these estimates, which could materially affect our consolidated financial statements. This could cause our results of operations to fall below expectations of securities analysts and investors, and result in a decline in the market price of our common stock. Future changes in accounting standards or accounting guidance generally could also have an adverse impact on our results of operations and financial condition. Further, the design and effectiveness of our disclosure controls and procedures and internal control over financial reporting may not prevent all errors, misstatements, or misrepresentations.
We are exposed to the risk of failure by banks where we hold uninsured deposits exceeding Federal Deposit Insurance Corporation (“FDIC”) limits.
We currently maintain cash deposits at JPMorgan Chase Bank, N.A., with balances that often exceed the $250,000 per-depositor limit insured by the FDIC. Any failure of a bank where we hold deposits above this insured threshold could
47
result in the loss of uninsured funds, leading to financial losses, liquidity constraints, and operational disruptions. For example, in early 2023, substantially all of our cash and cash equivalents were held in accounts with Silicon Valley Bank (“SVB”) at the time it was closed by state regulators, and the FDIC was appointed as its receiver. As a result, we were unable to access funds needed for working capital and operating expenses during the suspension of SVB’s banking services. While the FDIC eventually created a successor bridge bank for SVB and all of our funds held at SVB were subsequently transferred to the bridge bank under a systemic risk exception approved by the U.S. Treasury, the Federal Reserve, and the FDIC, there can be no guarantee that we would be able to recover our uninsured deposits from any other banking institution with which we hold funds if such institution were to fail.
Economic instability, financial market volatility, or stress in the banking sector could increase the likelihood of bank failures. If a bank holding our uninsured deposits fails and we are unable to recover those funds, it could materially and adversely affect our financial condition, liquidity, results of operations, and ability to execute our business strategy.
Risks Relating to our Indebtedness
We have debt outstanding that could adversely affect our financial flexibility and subjects us to restrictions and limitations that could significantly impact our ability to operate our business.
As of December 31, 2025, we had total consolidated debt outstanding with a principal balance of $240.0 million. Our outstanding debt is collateralized by substantially all of our assets. For the year ended December 31, 2025, we incurred debt servicing costs of $18.2 million, all of which were attributable to interest expense. The level of debt we have outstanding during any period could adversely affect our financial flexibility. We also bear risk at the time our debt matures and related to the floating nature of the interest rate on our debt. Our ability to make interest and principal payments, to refinance our debt obligations, and to fund any planned capital expenditures will depend on our ability to generate cash from operations. Our ability to generate cash from operations is, to a certain extent, subject to general economic, financial, competitive, legislative, regulatory, and other factors that are beyond our control, such as an environment of rising interest rates. The need to service our indebtedness will also reduce our ability to use cash for other purposes, including working capital, dividends to stockholders, acquisitions, capital expenditures, share repurchases, and general corporate purposes. If we cannot service our indebtedness, we may have to take actions such as selling assets, seeking additional equity, or reducing or delaying capital expenditures, strategic acquisitions, and investments, any of which could impede the implementation of our business strategy or prevent us from entering into transactions that would otherwise benefit our business. Additionally, we may not be able to effect such actions, if necessary, on favorable terms, or at all. We may not be able to refinance any of our indebtedness on favorable terms, or at all.
The Amended Credit Agreement governing our debt contains covenants that, among other things, restrict our ability to make certain restricted payments, incur additional debt, engage in certain asset sales, mergers, acquisitions, or similar transactions, create liens on assets, engage in certain transactions with affiliates, change our business, or make investments, and require us to comply with certain financial covenants. The restrictions in the Amended Credit Agreement governing our debt may prevent us from taking actions that we believe would be in the best interest of our business and our stockholders and may make it difficult for us to execute our business strategy successfully or effectively compete with companies that are not similarly restricted. We may also incur future debt obligations that might subject us to additional or more restrictive covenants that could affect our financial and operational flexibility, including our ability to pay dividends. We cannot make any assurances that we will be able to refinance our debt or obtain additional financing on terms acceptable to us, or at all. A failure to comply with the restrictions under the Amended Credit Agreement could result in a default under the financing obligations or could require us to obtain waivers from our lenders for failure to comply with these restrictions. If we were unable to make payments or refinance our debt or obtain new financing under these circumstances, we would have to consider other options, such as sales of assets, sales of equity, or negotiations to restructure the debt. The occurrence of a default that remains uncured or the inability to secure a necessary consent or waiver could cause our obligations with respect to our debt to be accelerated and have a material adverse effect on our business, financial condition, and results of operations.
We may seek additional debt financing in the future, which may not be available or may be available only on unfavorable terms.
We may need to raise additional funds through debt financings or access funds through new or existing credit facilities, including the Amended Credit Agreement. Any debt financing or refinancing, if available at all, may be on terms that are not favorable to us. Our access to additional funds under the Amended Credit Agreement is dependent on the ability of the banks that are parties to the Amended Credit Agreement to meet their funding commitments. If we cannot
48
obtain adequate capital or sources of credit on favorable terms, or at all, our business, results of operations, and financial condition could be adversely affected.
Our business, and therefore our results of operations and financial condition, may be adversely affected by further changes in the U.S.-based credit markets.
We utilize the credit markets to finance our operations and support our growth initiatives. For example, in 2023, we undertook a recapitalization that significantly increased our debt levels, in June 2024, we refinanced our long-term debt, in April 2025, we undertook another recapitalization through our entry into the 2025 Amended and Restated Credit Agreement that further increased our debt levels and in November 2025, we entered into the First Amendment and drew funds under our amended revolving credit facility to repay in full the previously outstanding term loans under the 2025 Amended and Restated Credit Agreement. These transactions were dependent on favorable credit market conditions. If the credit markets were to deteriorate, it could become more difficult or expensive for us to obtain financing on favorable terms. This could limit our ability to invest in technology, expand our operations, or pursue strategic initiatives, thereby impacting our growth and profitability. Tightening conditions in the credit markets could adversely affect the availability and terms of future borrowings or renewals or refinancing.
Risks Relating to our Organizational Structure
The concentration of our share ownership with those stockholders who held our stock prior to our IPO, including our executive officers, directors, and holders of more than 5% of our capital stock, may limit your ability to influence corporate matters.
Stockholders who held our stock prior to our IPO, including our executive officers, directors, and holders of more than 5% of our capital stock, beneficially owned at least 84.7% of our outstanding common stock, including 96.5% of the voting power of our outstanding common stock, after the IPO. As a result, stockholders who held our stock prior to our IPO control all matters requiring a stockholder vote, including: the election of directors; mergers, consolidations and acquisitions; the sale of all or substantially all of our assets and other decisions affecting our capital structure; the amendment of our amended and restated certificate of incorporation and our amended and restated bylaws; and our winding up and dissolution. This concentration of ownership may delay, deter, or prevent acts that would be favored by our other stockholders. The interests of stockholders who held our stock prior to our IPO may not always coincide with our interests or the interests of our other stockholders. This concentration of ownership may also have the effect of delaying, preventing, or deterring a change in control of our company. Also, stockholders who held our stock prior to our IPO may seek to cause us to take courses of action that, in their judgment, could enhance their investment in us, but which might involve risks to our other stockholders or adversely affect us or our other stockholders. As a result, the market price of our Class A common stock could decline or stockholders might not receive a premium over the then-current market price of our Class A common stock upon a change in control. In addition, this concentration of share ownership may adversely affect the trading price of our Class A common stock because investors may perceive disadvantages in owning shares in a company with significant stockholders.
We are a “controlled company” within the meaning of the NYSE rules and, as a result, qualify for, and rely on, exemptions from certain corporate governance requirements that provide protection to the stockholders of companies that are subject to such corporate governance requirements.
We are a “controlled company” as defined under the NYSE corporate governance rules. A “controlled company” is one in which more than 50% of the voting power is held by a single entity or a group of entities acting together. As a result, we qualify for, and have chosen to rely on, exemptions from certain corporate governance requirements, including:
•Independent Board Requirements: We are not required to have a majority of independent directors on our board of directors.
•Independent Committees: We are exempt from requirements to have a fully independent nominating and corporate governance committee, or a fully independent compensation committee.
•Governance Oversight: The exemptions may reduce the level of oversight typically provided by independent directors over management decisions, executive compensation, and director nominations.
While we believe that our governance structure and the composition of our board of directors serves the best interests of Neptune and its stockholders, reliance on these exemptions means that minority stockholders may have limited
49
influence over corporate governance matters. This could result in decisions that favor the interests of our controlling stockholder(s) at the expense of other stockholders.
The implications of being a controlled company could materially and adversely affect the perception of our corporate governance practices, stockholder confidence, and the market value of our common stock.
We are a holding company, and our only material asset is our equity interest in Neptune Flood. As a result, we depend on the ability of our subsidiaries to pay dividends and make other payments and distributions to us in order to meet our obligations.
Neptune Holdings was incorporated in Delaware on March 20, 2025, to implement a holding company organizational structure for Neptune Flood. Neptune Holdings currently has no material assets other than ownership of the outstanding equity of Neptune Flood. As such, Neptune Holdings has no independent means of generating revenue or cash flow, and its ability to pay taxes and operating expenses or declare and pay dividends in the future, if any, will be dependent upon the results of operations and cash flows of Neptune Flood and its subsidiaries. Its direct and indirect subsidiaries may not generate sufficient cash flow to distribute funds to Neptune Holdings and applicable law and contractual restrictions, such as negative covenants in any debt instruments, such as the Amended Credit Agreement, may not permit such distributions. In addition, in the event that the board of directors and stockholders of Neptune Holdings were to approve a sale of all of the equity in its direct or indirect subsidiaries, your shares of Class A common stock would be in a holding company with no material assets other than those assets and other consideration received in such transaction.
Risks Relating to Ownership of our Common Stock
Our failure to maintain proper and effective internal controls over financial reporting could result in material weaknesses, impact investor confidence in us, and adversely affect the value of our common stock.
As a public company, we are required to design, implement, and maintain internal controls over financial reporting to comply with the requirements of the Sarbanes-Oxley Act, including Section 404. This process requires us to document and test our internal control procedures, remediate any deficiencies identified, and undergo an annual audit of these controls by our independent registered public accounting firm.
Developing and maintaining proper and effective internal controls has and may continue to involve substantial costs, significant management time and resources, and potential disruption to our financial reporting processes. We may encounter challenges in completing our assessment of internal controls over financial reporting in a timely manner, or we may identify material weaknesses or significant deficiencies that require remediation.
If we fail to maintain adequate internal controls or if our auditors identify material weaknesses, it could result in:
•Inaccurate Financial Reporting: Ineffective internal controls could lead to errors or inaccuracies in our financial statements, potentially requiring restatements or impairing investor confidence.
•Regulatory Noncompliance: Failure to comply with Section 404 could result in regulatory scrutiny, fines, or penalties, further impacting our business and reputation.
•Loss of Investor Confidence: Material weaknesses or perceived weaknesses in our internal controls may reduce investor confidence in our financial reporting, adversely affecting the market price of our common stock.
•Operational Disruptions: Addressing control deficiencies could divert management’s attention and resources from other strategic priorities, negatively impacting our operations and growth.
Ensuring ongoing compliance with Section 404 of the Sarbanes-Oxley Act is critical to maintaining the integrity of our financial reporting and investor confidence. Any failure to establish or maintain effective internal controls could materially and adversely affect our business, financial condition, and the value of our common stock.
The dual class structure of our common stock has the effect of concentrating voting control with our Chief Executive Officer; this will limit or preclude your ability to influence corporate matters.
Our Class B common stock has ten votes per share, and our Class A common stock has one vote per share. Our Chief Executive Officer and Chairman of our board of directors, Mr. Burgess, beneficially owns all of our outstanding shares of Class B common stock, constituting approximately 82.1% of the voting power of our outstanding capital stock
50
following our IPO. In addition, we and Mr. Burgess are party to an equity exchange right agreement (the “Class B Equity Exchange Agreement”), which gives Mr. Burgess a right (but not an obligation) to require us to exchange any shares of Class A common stock received by Mr. Burgess upon the exercise, vesting, and/or settlement of certain equity awards held by Mr. Burgess for an equivalent number of shares of Class B common stock. If Mr. Burgess exercises his rights under the Class B Equity Exchange Agreement with respect to all equity awards subject to such agreement as of the completion of our IPO, Mr. Burgess will have approximately 84.5% of the voting power of our outstanding capital stock. Because of the ten-to-one voting ratio between our Class B common stock and Class A common stock, Mr. Burgess controls, and will continue to control, a majority of the combined voting power of our common stock and therefore is able to control all matters submitted to our stockholders for approval so long as the shares of Class B common stock represent approximately at least 9.1% of all outstanding shares of our Class A common stock and Class B common stock. Mr. Burgess may have conflicting interests with holders of shares of our Class A common stock. Mr. Burgess’ concentrated control will limit or preclude your ability to influence corporate matters for the foreseeable future. For example, during such period of time, Mr. Burgess will have significant influence with respect to our management, business plans, and policies, including the appointment and removal of our officers, decisions on whether to raise future capital, and whether to amend our charter and bylaws, which govern the rights attached to our common stock. In particular, for so long as Mr. Burgess continues to own a significant percentage of our common stock, Mr. Burgess will be able to cause or prevent a change of control of Neptune or a change in the composition of our board of directors and could preclude any unsolicited acquisition of us. The concentration of ownership could deprive you of an opportunity to receive a premium for your shares of Class A common stock as part of a sale of us and ultimately might affect the market price of our Class A common stock.
Each outstanding share of Class B common stock is convertible at any time at the option of the holder into one share of Class A common stock. In addition, each share of Class B common stock will convert automatically into one share of Class A common stock upon any transfer, whether or not for value, except for certain permitted transfers, as further described in our amended and restated certificate of incorporation. In addition, each share of Class B common stock will convert automatically into one share of Class A common stock upon the earlier of (i) twelve months following the death or disability of Mr. Burgess or (ii) upon the first trading day on or after such date that the outstanding shares of Class B common stock represent less than 5% of the then-outstanding Class A and Class B common stock, which, in either instance, may be extended to 18 months upon affirmative approval of a majority of our independent directors. The conversion of Class B common stock to Class A common stock will have the effect, over time, of increasing the relative voting power of the remaining outstanding shares of Class B common stock.
Some provisions of Delaware law and our amended and restated certificate of incorporation and amended and restated bylaws may deter third parties from acquiring us and diminish the value of our Class A common stock.
Our amended and restated certificate of incorporation and our amended and restated bylaws contain provisions that could delay or prevent a change in control of our company. These provisions could also make it difficult for stockholders to elect directors who are not nominated by current members of our board of directors or take other corporate actions, including effecting changes in our management. These provisions:
•establish a classified board of directors so that not all members of our board of directors are elected at one time;
•permit only the board of directors to establish the number of directors and fill vacancies on the board;
•provide that directors may only be removed “for cause” and only with the approval of two-thirds of our stockholders;
•following the first date after the date on which the outstanding shares of our Class B common stock represent less than a majority of the combined voting power of our then-outstanding Class A common stock and Class B common stock entitled to vote generally in the election of directors (the “Voting Threshold Date”), require super-majority voting to amend some provisions in our amended and restated certificate of incorporation and amended and restated bylaws;
•authorize the issuance of “blank check” preferred stock that our board of directors could use to implement a stockholder rights plan;
•prohibit cumulative voting;
•following the Voting Threshold Date, provide that our stockholders will only be able to take action at a meeting of stockholders and not by written consent;
51
•provide that only the chairperson of our board of directors, the chief executive officer, or our board of directors acting pursuant to a resolution adopted by a majority of the whole board of directors will be authorized to call a special meeting of stockholders; and
•establish advance notice requirements for nominations for election to our board of directors or for proposing matters that can be acted upon by stockholders at annual stockholder meetings.
These and other provisions in our amended and restated certificate of incorporation, our amended and restated bylaws, and Delaware law could make it more difficult for stockholders or potential acquirers to obtain control of our board of directors or initiate actions that are opposed by our then-current board of directors, including actions to delay or impede a merger, tender offer, or proxy contest involving Neptune. The existence of these provisions could negatively affect the price of our Class A common stock and limit opportunities for you to realize value in a corporate transaction.
In addition, until the Voting Threshold Date, we have opted out of Section 203 of the DGCL, which prohibits a publicly held Delaware corporation from engaging in a business combination transaction with an interested stockholder for a period of three years after the interested stockholder became such unless the transaction fits within an applicable exemption, such as board approval of the business combination or the transaction which resulted in such stockholder becoming an interested stockholder.
Our certificate of incorporation designates the Court of Chancery of the State of Delaware as the exclusive forum for certain litigation that may be initiated by our stockholders and the federal district courts of the U.S. as the exclusive forum for litigation arising under the Securities Act, which could limit our stockholders’ ability to obtain a favorable judicial forum for disputes with us.
Our amended and restated certificate of incorporation provides that the Court of Chancery of the State of Delaware is the exclusive forum (or, if, and only if, the Court of Chancery of the State of Delaware lacks subject matter jurisdiction, any state court located within the State of Delaware or, if, and only if, all such state courts lack subject matter jurisdiction, the federal district court for the District of Delaware) for the following types of actions or proceedings under Delaware statutory or common law: any derivative action, suit, or proceeding brought on our behalf; any action, suit, or proceeding asserting a breach of a fiduciary duty; any action, suit, or proceeding asserting a claim against us arising pursuant to the DGCL, our amended and restated certificate of incorporation, or bylaws; any action, suit, or proceeding as to which the DGCL confers jurisdiction; or any action, suit, or proceeding asserting a claim against us that is governed by the internal affairs doctrine. The provisions would not apply to suits brought to enforce a duty or liability created by the Securities Act, the Exchange Act, or any other claim for which the U.S. federal courts have exclusive jurisdiction. Furthermore, Section 22 of the Securities Act creates concurrent jurisdiction for federal and state courts over all such Securities Act actions. Accordingly, both state and federal courts have jurisdiction to entertain such claims. To prevent having to litigate claims in multiple jurisdictions and the threat of inconsistent or contrary rulings by different courts, among other considerations, our amended and restated certificate of incorporation provides that the federal district courts of the United States of America will be the exclusive forum for resolving any complaint asserting a cause of action arising under the Securities Act. Investors cannot waive compliance with the federal securities laws and the rules and regulations thereunder. Accordingly, given the provision in Section 22 of the Securities Act for concurrent jurisdiction by federal and state courts, there is uncertainty as to whether a court would enforce this forum selection provision with respect to claims arising under the Securities Act.
We believe these provisions may benefit us by providing increased consistency in the application of Delaware law and federal securities laws by chancellors and judges, as applicable, who are particularly experienced in resolving corporate disputes, efficient administration of cases on a more expedited schedule relative to other forums and protection against the burdens of multi-forum litigation. These choice of forum provisions may limit a stockholder’s ability to bring a claim in a judicial forum that it finds favorable for disputes with us or our directors, officers, or other employees. While the Delaware courts have determined that such choice of forum provisions are facially valid, a stockholder may nevertheless seek to bring such a claim arising under the Securities Act against us, our directors, officers, or other employees in a venue other than in the federal district courts of the United States of America. In such instance, we would expect to vigorously assert the validity and enforceability of the exclusive forum provisions of our amended and restated certificate of incorporation. This may require significant additional costs associated with resolving such action in other jurisdictions, and there can be no assurance that the provisions will be enforced by a court in those other jurisdictions.
52
If a substantial number of shares become available for sale and are sold in a short period of time, the market price of our Class A common stock could decline.
Following our IPO, we had 94,600,000 shares of Class A common stock outstanding, and 13,080,678 shares of Class A common stock issuable upon exercise of outstanding equity awards. Of these shares, 21,184,210 shares of our Class A common stock sold in the IPO are freely tradable without further restriction or registration under the Securities Act.
The 43,435,000 outstanding shares of our Class B common stock and the remaining 73,415,790 outstanding shares of our Class A common stock are deemed “restricted securities,” as that term is defined under Rule 144 of the Securities Act. In connection with our IPO, stockholders owning substantially all of our common stock entered into lock-up agreements with the underwriters under which they agreed, subject to specific exceptions, not to sell any of their stock for at least an initial 180-day lock-up period following our IPO. In addition, we are party to agreements with holders of substantially all of our outstanding options that contain market standoff provisions imposing restrictions on the ability of such security holders to offer, sell, or transfer our equity securities issuable upon the exercise thereof for a period of 180 days following the date of our Final Prospectus, which we have agreed to enforce during the lock-up period.
Following the expiration of the lock-up period, all of the shares of our common stock that are restricted securities will be eligible for sale in the public market, subject to compliance with Rule 144 under the Securities Act. Sales under Rule 144 by our affiliates or persons selling shares on behalf of our affiliates are subject to certain manner of sale, volume limitation, and notice provisions, and to the availability of current public information about us. See the section titled “Shares Eligible for Future Sale” in our Final Prospectus for additional information regarding shares of our common stock that are eligible for resale after our IPO.
Further, pursuant to our registration rights agreement, dated October 2, 2025, certain holders of our Class A common stock can, following the expiration of the lock-up and subject to certain conditions, require us to file registration statements for the public resale of shares of our Class A common stock or to include such shares in registration statements that we may file for us or other stockholders. See the section titled “Description of Capital Stock - Registration Rights” in our Final Prospectus for additional information regarding these registration rights.
Sales of a substantial number of shares of our common stock upon the expiration of lock-up restrictions or pursuant to the exercise of registration rights, or the perception that such sales may occur, could cause the market price of our Class A common stock to decline or make it more difficult for you to sell your Class A common stock at a time and price that you deem appropriate.
If our institutional or other investors continue holding the shares they acquired in our IPO, it may reduce the liquidity and adversely affect the trading price of our Class A common stock.
A portion of the shares of our Class A common stock sold in the IPO were acquired by certain institutional and other large investors. If these or any other investors elect not to sell the shares they acquired in our IPO, it could reduce the number of shares of our Class A common stock available for trading in the public market. A limited public float and lower trading volumes can make it more difficult for investors to buy or sell shares without materially affecting the market price of our shares, may result in price volatility, and could impair the liquidity of our Class A common stock.
Lower liquidity and heightened volatility may also reduce our Class A common stock’s attractiveness to certain investors. These factors could adversely affect the trading price of our Class A common stock, independent of our operating performance, and could negatively impact our ability to raise additional equity capital on acceptable terms. In addition, if these investors later elect to sell significant amounts of our Class A common stock, or are perceived as likely to do so, the trading price of our Class A common stock could also decline. See also “- If a substantial number of shares become available for sale and are sold in a short period of time, the market price of our Class A common stock could decline.”
If securities analysts cease to publish research or reports about our business or if they publish negative evaluations of our common stock, the price of our Class A common stock could decline.
The trading market for our Class A common stock will depend in part on the research and reports that securities or industry analysts publish about us or our business, as well as the way analysts and investors interpret our financial information and other disclosures. Securities and industry analysts may cease to publish research on our business. If few or no securities or industry analysts cover us, our stock price could be negatively affected. If securities or industry analysts downgrade our common stock, or publish negative reports about our business, our stock price would likely decline. If one
53
or more of these analysts cease coverage of us or fail to publish reports on us regularly, demand for our Class A common stock could decrease, which might cause our stock price to decline and could decrease the trading volume of our Class A common stock.
We may issue shares of preferred stock in the future, which could make it difficult for another company to acquire us or could otherwise adversely affect holders of our common stock, which could depress the price of our common stock.
Our amended and restated certificate of incorporation authorizes us to issue one or more series of preferred stock. Our board of directors has the authority to determine the preferences, limitations, and relative rights of the shares of preferred stock and to fix the number of shares constituting any series and the designation of such series, without any further vote or action by our stockholders. Our preferred stock could be issued with voting, liquidation, dividend, and other rights superior to the rights of our Class A common stock. The potential issuance of preferred stock may delay or prevent a change in control of us, discouraging bids for our Class A common stock at a premium to the market price, and materially adversely affect the market price and the voting and other rights of the holders of our Class A common stock.
For as long as we are an emerging growth company, we will not be required to comply with certain reporting requirements, including those relating to accounting standards and disclosure about our executive compensation, that apply to other public companies, which may make our Class A common stock less attractive to investors.
We are an emerging growth company, as defined in the JOBS Act, and, for as long as we continue to be an EGC, we may choose to take advantage of exemptions from various reporting requirements applicable to other public companies but not to EGCs, including:
•not being required to have our independent registered public accounting firm audit our internal control over financial reporting under Section 404 of the Sarbanes-Oxley Act;
•reduced disclosure obligations regarding executive compensation in our periodic reports and annual report on Form 10-K; and
•exemptions from the requirements to obtain nonbinding advisory votes on executive compensation and stockholder approval of any golden parachute payments not previously approved.
Our status as an EGC will end as soon as any of the following takes place:
•the last day of the fiscal year in which we have more than $1.235 billion in annual revenues;
•the date we qualify as a “large accelerated filer,” with at least $700 million of equity securities held by non-affiliates;
•the date on which we have issued, in any three-year period, more than $1.00 billion in non-convertible debt securities; or
•the end of the fiscal year following the fifth anniversary of the completion of our IPO.
We cannot predict if investors will find our Class A common stock less attractive if we rely on the exemptions afforded EGCs. If some investors find our Class A common stock less attractive because we rely on any of these exemptions, there may be a less active trading market for our Class A common stock and the market price of our Class A common stock may be more volatile.
Under the JOBS Act, EGCs can also delay adopting new or revised accounting standards until such time as those standards apply to private companies. We have elected to avail ourselves of this provision of the JOBS Act. As a result, we will not be subject to new or revised accounting standards at the same time as other public companies that are not EGCs. Therefore, our consolidated financial statements may not be comparable to those of companies that comply with new or revised accounting pronouncements as of public company effective dates.
We do not intend to pay dividends on our common stock and, consequently, your ability to achieve a return on your investment will depend on appreciation in the price of our Class A common stock.
While we have paid dividends in the past, we do not currently intend to pay any cash dividends for the foreseeable future. We expect to retain future earnings, if any, to repay debt and to fund the development and growth of our business.
54
As a result, you may only receive a return on your investment in our Class A common stock if the market price of our Class A common stock increases.
Item 1B. Unresolved Staff Comments.
None.
Item 1C. Cybersecurity.
Cybersecurity Risk Management
Protecting the sensitive data of our policyholders, partners, and organization is a top priority. As a technology-first company, we recognize that maintaining cybersecurity practices and safeguards is essential to ensuring the integrity of our systems and the trust of our stakeholders.
1.Comprehensive Security Framework: We employ a multi-layered cybersecurity framework that includes firewalls, intrusion detection systems, endpoint protection, and encryption protocols to safeguard data and systems. Our infrastructure is regularly updated to ensure alignment with the latest security standards and regulatory requirements.
2.Cybersecurity Oversight: The board of directors has delegated oversight responsibility for cybersecurity risks to the Audit Committee . As established in the Audit Committee charter, the Audit Committee periodically receives information from management regarding cybersecurity matters. Our management, including our Chief Technology Officer and Chief Information Security Officer (CTO/CISO), a role held by a single executive, is responsible for day-to-day cybersecurity risk management, including oversight of third-party service providers and responding to potential cybersecurity incidents. Our CTO/CISO, who reports to our Chief Executive Officer, has 15 years of experience in various cybersecurity related roles.
3.Data Protection: Policyholder and partner data is stored securely within our systems, with access strictly controlled and monitored. Sensitive information is encrypted both in transit and at rest, ensuring protection against unauthorized access.
4.Proactive Threat Monitoring and Response: We utilize threat monitoring tools to identify and mitigate potential vulnerabilities in real time. Our dedicated cybersecurity team conducts regular audits, vulnerability assessments, and penetration testing to proactively address risks.
5.Employee Awareness and Training: Cybersecurity is a shared responsibility across our organization. We provide regular training to employees on identifying and mitigating cybersecurity risks, ensuring that our team is equipped to recognize phishing, social engineering, and other common attack vectors.
6.Incident Response Plan: In the event of a cybersecurity incident, we have a detailed incident response plan in place to contain, investigate, and resolve the issue promptly. Our team conducts post-incident reviews to continuously improve our defenses and reduce the likelihood of future occurrences.
7.Third-Party Risk Management : As part of our commitment to cybersecurity, we carefully vet all third-party vendors and partners to ensure they meet our security standards. We maintain contractual agreements and conduct periodic assessments to confirm compliance.
8.Regulatory Compliance: We have policies and procedures in place designed to adhere to all applicable data privacy and security regulations, including state, federal, and international standards, where applicable. Compliance is regularly reviewed to ensure our practices remain current with evolving regulatory landscapes.
55
Item 2. Properties.
Our corporate headquarters is located in St. Petersburg, Florida, where we currently lease approximately 2,000 square feet of office space on a month-to-month basis. This facility serves as the central hub for our operations, supporting key functions such as technology development, sales, and corporate administration.
As a remote-first company, the majority of our workforce operates remotely, leveraging our advanced technology infrastructure to collaborate seamlessly across locations. This model enables us to attract top talent from a broad geographic pool while maintaining operational flexibility and efficiency.
In 2027, we plan to transition to a new corporate headquarters, also located in St. Petersburg, Florida. This new facility is designed to support our continued growth. We believe that our facilities, combined with our remote-first workforce strategy, provide the resources and flexibility needed to support our business objectives as we scale.
Item 3. Legal Proceedings.
From time to time, we may be involved in various legal proceedings and subject to claims that arise in the ordinary course of business. Although the results of litigation and claims are inherently unpredictable and uncertain, we are not presently a party to any litigation the outcome of which, we believe, if determined adversely to us, would individually or taken together have a material adverse effect on our business, operating results, cash flows, or financial condition.
Item 4. Mine Safety Disclosures.
Not applicable
56
PART II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
Market Information and Holders
Our Class A common stock is listed on the New York Stock Exchange under the symbol “NP.” Our Class B common stock is not listed nor traded on any stock exchange.
On February 24, 2026, there were 16 stockholders of record of our Class A common stock and 3 stockholders of record of our Class B common stock. The number of record holders does not include persons who held shares of our Class A common stock in nominee or “street name” accounts through brokers.
Dividends
While we have paid dividends in the past, we do not currently intend to pay any cash dividends for the foreseeable future and we currently expect to retain future earnings, if any, to repay debt and to fund the development and growth of our business. Any future determination to pay dividends on our common stock will be at the discretion of our board of directors and will depend upon, among other factors, our financial condition, operating results, earnings, current and anticipated liquidity and capital requirements, plans for expansion, level of indebtedness, contractual restrictions with respect to payment of dividends, restrictions imposed by Delaware law, general business conditions, and other factors that our board of directors may deem relevant in making such a determination.
Recent Sales of Unregistered Securities
Set forth below is information regarding shares of capital stock issued by us since January 1, 2025, that were not registered under the Securities Act. Also included is the consideration, if any, received by us for such shares and information relating to the sections of the Securities Act or Commission rule under which exemption from registration was claimed. All information below has been adjusted for the 10-for-1 stock split of our capital stock that was effected on September 9, 2025.
•On April 10, 2025, pursuant to our corporate reorganization, Neptune Holdings issued 93,350,000 shares of its common stock and 41,850,000 shares of its convertible preferred stock to the prior holders of shares of common stock and convertible preferred stock, respectively, of Neptune Flood. Pursuant to the reorganization, (i) each issued and outstanding share of common stock of Neptune Flood was converted into one share of common stock of Neptune Holdings, (ii) each issued and outstanding share of convertible preferred stock of Neptune Flood was converted into one share of convertible preferred stock of Neptune Holdings, and (iii) the issued, outstanding and unexercised portions, whether or not vested or exercisable, of all options to purchase Neptune Flood common stock granted under the Neptune Flood stock plan were assumed by Neptune Holdings and therefore became exercisable for the same number of shares of common stock of Neptune Holdings.
•From August 28, 2025, through August 29, 2025, the Company issued an aggregate of 2,835,000 shares of its common stock to certain employees, officers, and directors upon the exercise of stock options at an exercise price of $5.495 per share, for aggregate consideration of approximately $15.6 million.
None of the foregoing transactions involved any underwriters, underwriting discounts or commissions, or any public offering. The sales of the above securities were deemed to be exempt from registration under the Securities Act in reliance upon Section 4(a)(2) of the Securities Act (or of Regulation D promulgated thereunder) or pursuant to benefit plans and contracts relating to compensation as provided under Rule 701.
Use of Proceeds
On October 2, 2025, we closed our initial public offering, in which our selling stockholders sold 21,184,210 shares of our Class A common stock, including 2,763,157 shares of Class A common stock sold pursuant to the underwriters’ full exercise of their 30-day option, at a public offering price of $20.00 per share. The offer and sale of all of the shares in the IPO were registered under the Securities Act pursuant to our Registration Statement.
57
We did not receive any proceeds from the sale of our Class A common stock by the selling stockholders in our initial public offering. The selling stockholders received all of the proceeds from the sale of shares of our Class A common stock by such selling stockholders. The selling stockholders reimbursed us for certain of our expenses relating to our initial public offering, in an aggregate amount not to exceed 2% of the gross proceeds of our IPO received by the selling stockholders.
Item 6. [Reserved]
58
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
The following is a discussion and analysis of our financial condition and results of operations as of, and for, the periods presented. The following discussion and analysis should be read in conjunction with the sections entitled “Risk Factors” and “Special Note Regarding Forward-Looking Statements” included in this Annual Report and in our other reports filed with the Commission, and with the consolidated financial statements and accompanying notes included in Item 8 hereto. Certain information contained in this discussion and analysis includes forward-looking statements that involve risks and uncertainties. Our actual results may differ materially from those anticipated in these forward-looking statements as a result of many factors. For information identifying important factors that could cause actual results to differ materially from those anticipated in the forward-looking statements, please refer to the sections entitled “Risk Factors” and “Special Note Regarding Forward-Looking Statements” included in this Annual Report.
Our historical results are not necessarily indicative of the results that may be expected for any period in the future.
Overview
Neptune is a leading, high-growth, highly profitable, data-driven MGA that is revolutionizing the way homeowners and businesses protect against the growing risks of flooding. We offer a range of easy-to-purchase residential and commercial insurance products - including primary flood insurance, excess flood insurance, and parametric earthquake insurance - distributed through a nationwide network of agencies. Neptune does not take any balance sheet insurance risk or have claims handling responsibility relating to the policies we sell. We underwrite and administer the issuance of insurance policies on behalf of a diverse panel of insurance and reinsurance companies, whom we refer to as capacity providers, that manage both this risk and the associated claims handling. From day one, we have built our business on a foundation of advanced data science and AI, leveraging proprietary ML algorithms, which has led to superior underwriting results, outsized growth, recurring revenue, and robust margins.
Technology and data science are the foundation of Neptune’s business model, driving our three core pillars:
•Our Underwriting Engine: Our entirely digital underwriting engine, Triton, uses advanced technology, including proprietary AI and ML models, without any human underwriters, to assess risk with speed and precision. Powered by predictive analytics and loss estimation, Triton has enabled our policies to consistently outperform the NFIP in written loss ratio despite 21 landfall hurricanes - including 4 of the 10 largest flood events in U.S. history - taking place since Neptune’s founding.
•Our Risk Relationships: Our risk relationships are built on performance and trust, and as of December 31, 2025, we had 40 capacity providers, including 32 reinsurance providers, backing 8 distinct insurance programs to help minimize concentration risk while delivering consistent returns. In turn, the accuracy of our risk assessment and our precision pricing have delivered hundreds of millions of dollars of underwriting profit for our capacity providers since inception, leading to high rates of capacity renewals and increases in committed capacity.
•Our Distribution: Our distribution strategy is primarily focused on deep partnerships across agencies with tens of thousands of agents who benefit from the ease-of-use of our automated underwriting platform, seamless API integrations, instantaneous bindable quotes, and proprietary Agent Portal. We believe this is a meaningful departure from industry norms and makes our approach to distribution attractive to the agents with whom we work.
The three pillars above interlock, creating a powerful and reinforcing loop. Unlike traditional insurance underwriting that historically relied on humans, static models, and infrequent adjustments, we leverage an iterative approach that allows us to consistently and rapidly integrate new data and models into our underwriting engine, thereby refining our processes and adapting to evolving market and environmental conditions. As our models constantly evolve and improve, they are able to deliver superior results that minimize losses for our capacity providers, which in turn grant us additional underwriting capacity. With more capacity available, we can offer coverages our policyholders want, enhancing the ability for our agency partners to easily sell policies while expanding our distribution and reach. The resulting increase in quoted and bound policies provides us with access to more data, enhancing the predictive capabilities of our underlying models.
We operate as an MGA, with a highly attractive, recurring, fee-based revenue model derived from two primary sources: commissions paid by capacity providers, and fees paid by policyholders. Commissions are calculated as a negotiated percentage of premium for each policy. Given our high retention rates to date, we believe that we have a high
59
degree of visibility into our future revenue streams. For the year ended December 31, 2025, our eligible policy rates at renewal were 86%, and premium retention rates at renewal were 98%. The difference between policy and premium retention rates reflects increases to the rates charged to renewing policyholders.
We are organized as a single operating and reportable segment.
Factors Affecting Our Results of Operations
Our financial results and operating performance are influenced by a number of macroeconomic, industry-specific, and company-specific factors, the most significant of which we believe include:
Reliance on Relationships with Capacity Providers, Third-Party Agents and Brokers
We do not bear the balance sheet insurance risk or claims handling responsibility relating to the policies sold and, as a result, our ability to support and service the policies we provide is dependent on the capacity and appetite of our capacity providers to assume flood risk. If we are unable to maintain profitable portfolios for our capacity providers or if our relationship with them is undermined for any reason, capacity providers may be unwilling to provide insurance capacity to us, or our insurance carriers may seek to amend our agreements with them. This could happen for various reasons, including for competitive or regulatory reasons, because of an insurance carrier’s reluctance to distribute their products through our platform, because they decide to rely on their own internal flood insurance providers or products or elect not to insure or reinsure flood risk generally, or because they decide not to distribute insurance products in individual markets in certain geographies or altogether. Additionally, conditions in the broader insurance and reinsurance markets may influence the ability or willingness of our capacity providers to underwrite flood insurance risk and in turn impact the capacity we receive or the commissions and other terms we are able to negotiate with our capacity providers. For example, in 2023, significant insured losses and increasing demand for reinsurance led the property catastrophe reinsurance market to experience price increases, heightened “attachment points” where primary insurers became responsible for a greater portion of initial losses before reinsurance coverage became available to them, and stricter terms and conditions for reinsurance coverage. These changes were driven by factors such as significant insured losses and increased demand for reinsurance, leading to fewer participants in the property catastrophe reinsurance market. Although this development did not impact the underwriting capacity we were able to secure from our capacity providers in the flood insurance market, industry-wide constraints could limit our growth in the future if capacity providers elect to exit the flood insurance market, limit the capacity they provide, or become more selective in providing insurance or reinsurance coverage. See “Risk Factors - An overall decline in the housing market or general economic conditions could have a material adverse effect on the financial condition and results of operations of our business.” Our results benefit from stable, long-term relationships with our capacity providers - currently, we place our policies through a panel of highly rated insurers and reinsurers who have committed significant capital to our program. If we are not able to effectively manage our relationships with our key capacity providers, if one of our key capacity providers were to reduce its desired exposure or if reinsurance costs spike dramatically or we were to otherwise lose one or more of our key capacity providers or were to experience a significant reduction in such provider’s capacity, it might require us to shift business to alternative capacity providers, if any are available, or potentially accept lower commission rates to maintain coverage availability or might otherwise materially and adversely impact our business, financial condition, results of operations, growth potential, reputation in the market, and our ability to sustain our business. See “Risk Factors - Our business may be harmed if one or more of our relationships with capacity providers are terminated or are reduced, if we fail to maintain good relationships with such capacity providers, if we become dependent upon a limited number of capacity providers, or if we fail to develop new capacity provider relationships.” We mitigate this risk by diversifying our capacity provider panel and through our ability to continually demonstrate profitable results through our data-driven underwriting. In addition, we have expanded our panel of capacity providers from 2 capacity providers as of December 31, 2018, to 40 capacity providers as of the date of this Annual Report.
Additionally, our ability to distribute the policies we offer is dependent on our distribution model, which relies on third-party agents and brokers. As of December 31, 2025, our insurance agent and broker partners drove over 96% of our policy sales, supported by our in-house sales team and technology integrations. This distribution model exposes us to meaningful third-party risks. Any failure by our agents and brokers to consistently promote our products or the loss of any key agent or broker relationships could adversely affect our business. See “Risk Factors - Our distribution model depends on third-party agents and brokers, and any failure by those agents and brokers to consistently promote our products or the loss of any key agent or broker relationships could adversely affect our business.” We mitigate this risk by diversifying the third-party agents and brokers that we use in our distribution model.
60
Impact of Climate and Catastrophic Events on Demand for Flood Insurance
Our growth and success are dependent on property owners and tenants continuing to purchase flood insurance from us, in turn increasing the revenue we generate from commissions and policy fees. High-profile flood events, including Hurricane Ida (2021), Hurricane Ian (2022), Hurricane Helene (2024), and Hurricane Milton (2024), tend to raise consumer awareness and demand for flood insurance, potentially increasing our policy sales and, as a result, our commissions and fees in subsequent periods. Increases in flood risk, or the perception of increases in flood risk, in areas believed to have lower flood risk today (e.g., non-coastal regions that have not historically been considered to be flood-prone) could also increase demand for flood insurance in those areas. Alternatively, significant increases in insured losses due to increasing frequency and intensity of storms could result in additional governmental regulation aimed at mitigating the impact of natural disasters, including stricter building codes or incentives for risk mitigation measures, that could change the dynamics of the housing markets in which we provide flood insurance or incentives for homeowners to seek private flood insurance coverage, or could cause our capacity providers to exit from, or reduce their exposure to, significant flood events and other natural disasters. In contrast, slower than expected storm seasons can limit demand for new flood insurance policies, potentially decreasing our policy sales and, as a result, our commissions and fees and revenues in subsequent periods. However, slower than expected storm seasons are also likely to result in lower insured losses experienced by our capacity providers, which would allow us to deliver further improved written loss ratios for our capacity providers. See also “- Reliance on Capacity Relationships.”
Economic Environment Impact on Demand for Flood Insurance
Macroeconomic conditions that affect the housing market influence our policy sales. Many flood insurance purchases are driven by mortgage requirements (e.g., homeowners with a government-backed mortgage in FEMA designated SFHAs are required to obtain flood insurance coverage). As a result, a high volume of home sales or new housing starts in coastal and flood-prone areas can lead to more policies written by Neptune. If rising interest rates, economic downturns, or a persistent inflationary environment slow home purchase or construction activity, particularly in areas where flood coverage is required, the growth of our new policy sales could slow. Conversely, lower home sales may lead to fewer mid-term cancellations as policy holders stay in their current home longer and could result in a positive impact to renewal rates. We also monitor property value inflation and construction cost trends, as these can increase insured values and premiums (and, thereby, our commission income) on existing policies at renewal. Alternatively, if homeowners experience higher prices generally, whether due to inflationary pressure, tariffs, or other macroeconomic factors, it may lead to a decrease in our renewal acceptance rates as homeowners seek lower cost alternatives, such as the NFIP, or elect not to maintain flood insurance in areas where it is not federally required. See “Risk Factors - Risks Relating to our Business and Industry - An overall decline in the housing market or general economic conditions could have a material adverse effect on the financial condition and results of operations of our business.”
Seasonality of Our Business
Our business is seasonal, as hurricanes typically occur during the period from June 1 through November 30 each year. Hurricane season drives sales awareness of the need for flood insurance. This has historically resulted in an increase in total sales in our second and third quarters of each fiscal year, as compared to the first and fourth quarters.
Competition from the National Flood Insurance Program and Private Market (Including New Entrants)
The flood insurance market is dominated by the U.S. government’s NFIP, which historically has provided the vast majority of flood insurance policies for American properties. Changes in NFIP policies or pricing can affect our growth. For instance, the implementation of NFIP’s Risk Rating 2.0, a new pricing methodology that could lead to regular premium increases for NFIP policyholders, may drive price-sensitive policyholders to seek private alternatives like Neptune. Conversely, if the NFIP were to reduce rates or expand coverage limits, it could potentially attract policyholders back to the NFIP program and away from private alternatives like Neptune.
Additionally, periodic lapses or uncertainties in the NFIP’s federal authorization could boost demand for private flood insurance. For example, for 43 days beginning on October 1, 2025, the U.S. federal government experienced a lapse in appropriations. During the shutdown, the NFIP was not authorized to issue new policies or renew existing policies until reauthorization by Congress, leaving the private flood insurance market as the sole source for new flood insurance policies. However, concurrently with the start of the shutdown, the federal financial institution regulatory agencies reminded lenders that, during a period when the NFIP is unavailable, lenders may continue to make loans subject to the federal flood insurance statutes without requiring federal flood insurance, while continuing to meet other regulatory obligations. This pronouncement had the effect of mitigating any prospective increase in demand for private flood insurance driven by the shutdown.
61
Further, we also face competition from other private insurers and MGAs in the flood market. Increased competition in the private flood insurance market could put pressure on, and require us to increase, the commission rates we pay to agents that distribute our products or require higher marketing spend in order for us to maintain market share.
Underwriting Profitable Portfolios
We rely on our capacity providers to provide insurance capacity and to assume the associated balance sheet insurance risk of the flood insurance policies we sell to policyholders. While higher claims frequency or severity bears no direct risk to our financial results, given we do not bear the insurance risk associated with claims, if incurred losses exceed any capacity partner’s loss tolerance, we face the risk of their reduction or withdrawal as a risk-taking partner to Neptune and as a result may need to seek additional capacity from other capacity providers, or new capacity providers, in order to support our continued growth. See “Risk Factors - Risks Relating to our Business and Industry - Our business may be harmed if one or more of our relationships with capacity providers are terminated or are reduced, if we fail to maintain good relationships with such capacity providers, if we become dependent upon a limited number of capacity providers, or if we fail to develop new capacity provider relationships.” Historically, we have been able to produce portfolios that perform exceptionally well for our capacity providers, and we believe our investments into our Triton system will help deliver continued outperformance versus our peers. If we continue to outperform through large scale flood events, this could lead to increased access to insurance capacity or improvement in ceding commissions, which could positively impact our economics and ability to grow.
Investments in Technology
Our success is due in large part to our data science-driven approach to our underwriting technology platform. Our results of operations are favorably impacted by automation in policy quoting, binding, and administration, which allows us to handle a growing book of business with relatively low incremental operating expense. Continued investment in our platform, including the integration of our recently acquired data science capabilities, is important to maintain the efficiency edge we see as a key competitive advantage. However, these investments also lead to higher amortization expense over time as we capitalize software development costs. We expect to continue balancing operating expense growth with revenue growth, and periods of heavy investment in technology or hiring can increase our cost base.
Regulatory Changes
We operate in a highly regulated industry, subject to regulatory oversight in the 50 states and Washington, D.C., where we are qualified to do business, and regulatory factors at the federal and state level may impact our ability to sell insurance policies. This extensive regulatory framework governs consumer protections and data security, exposing our business to significant litigation and compliance risks. See “Risk Factors - Risks Relating to Regulatory and Legal Matters - The insurance business is extensively regulated, and changes in regulation may reduce our profitability and limit our growth.” In addition, as an MGA, we are subject to licensing requirements and must maintain insurance licenses in each of the jurisdictions in which we operate. These licenses are subject to periodic renewal and compliance with jurisdiction-specific regulations, including recordkeeping, tax reporting, and E&S lines filing requirements. Any failure to meet these obligations could result in fines, penalties, or suspension of our licenses, which would impair our ability to operate in affected jurisdictions. We must also verify that our third-party agents and brokers maintain required licenses and comply with the conditions of our delegated binding authorities. Failure to monitor and verify the licensing status of these agents and brokers could result in the termination of carrier binding authorities and/or increased regulatory risk. See “Risk Factors - Risks Relating to Regulatory and Legal Matters - Compliance with insurance licensing requirements for MGAs and E&S lines agencies and individual producers is critical to our operations, and any failure to maintain required licenses could disrupt our business” and “Risk Factors - Risks Relating to Regulatory and Legal Matters - Regulatory and licensing requirement changes could disrupt operations or increase compliance costs and restrict our ability to conduct our business.”
Regulatory changes at the federal and state levels, including those affecting floodplain mapping, risk assessment standards, and lender requirements, could also impact private insurers like Neptune. For example, changes to FEMA’s flood zone designations or its risk rating methodologies could affect how we evaluate and price flood risk, necessitating costly updates to our proprietary technology. Prolonged uncertainty about potential regulatory changes could also discourage banks or other lenders from accepting private flood insurance policies, further limiting market growth. However, regulatory changes can also have a positive impact on our business. For example, state insurance regulations related to the placement of E&S policies can influence our ability to sell private flood products within a particular state; in 2021, Florida removed the requirement for insurance agents to complete a diligent search of the admitted market prior to placing personal lines flood insurance policies with surplus lines insurers. This change simplified the sales process for
62
agents distributing our products by no longer requiring them to seek admitted insurance options before completing a Neptune sale. Although recent updates to state insurance regulations have generally supported the growth of the private flood insurance market, there can be no assurance that future federal or state regulatory changes would be similarly favorable. Any unfavorable changes could materially restrict our ability to place private flood insurance policies and could have a material adverse effect on our business, results of operations, and/or financial condition. We closely monitor policymaking efforts that may expand or inhibit the further development of the private flood and E&S markets
Cost of Being a Public Company
As a public company, we are required to continue to implement changes in certain aspects of our business and develop, manage, and train management-level and other employees to comply with ongoing public company requirements. We will continue to incur new expenses as a public company, including those relating to public reporting obligations, proxy statements, stockholder meetings, stock exchange fees, transfer agent fees, Commission and FINRA filing fees, and expenses associated with any public offering we may engage in from time to time.
Certain Income Statement Line Items
The following is an overview of certain key income statement items which management believes are important to an understanding of our results of operations in accordance with GAAP.
Revenue
Our revenue is primarily comprised of commission income and fee income, discussed in more detail below.
Commission Income
The largest component of our revenue is commission income, which is derived from the placement of insurance contracts between our insurance carriers and policyholders who acquire our flood insurance policies. Our commissions are established by the carrier agreement between Neptune and the insurance carrier and are calculated as a negotiated percentage of premiums for the underlying insurance contract. Commission rates and terms vary across insurance carriers.
Our main performance obligation under our agreements with our insurance carriers is selecting, pricing, and placing policyholders’ insurance contracts with our carrier partners. Each underlying insurance contract is a separate and distinct contract between the policyholder and the insurance carrier. We recognize commission income at a point in time upon the effective date of the insurance policy we have placed with the insurance carrier, at which point we have satisfied our performance obligation.
Each policyholder’s insurance contract is for a period of one year and can only be canceled by the policyholder prior to expiration for a limited set of reasons, most often in conjunction with the sale of the underlying insured property. Prior to the expiration of the insurance contract, the risk is re-underwritten using the then-current version of Triton. If the risk still qualifies for an insurance contract, we present the policyholder with a renewal offer. For the year ended December 31, 2025, 86% of the eligible renewal offers presented to policyholders were accepted, respectively, and the policyholder began a new one-year insurance contract. Upon the effective date of the renewal policy, commission is recognized. As Neptune receives its commission for the full policy year up front, we estimate a cancellation reserve for commissions for those policies that are expected to cancel during the term.
The majority of our commission income is the base commissions on premium described above. Although there is a small component of revenue share commission paid by our carriers’ reinsurance broker, this additional revenue share commission is similar to the base commissions, in that it is a set percentage of the premium paid by the policyholder.
We also maintain a small internal agency which sells Neptune’s policies to direct inbound policyholders sourced via our website. Along with Neptune’s policies, the internal agency is appointed to sell NFIP policies when a risk does not meet the underwriting criteria for Neptune. We collect the agent commission that is paid by the NFIP for any NFIP policies sold by our internal agency.
Fee Income
In addition to commission income on premium, we earn fee income directly from our policyholders. This fee, which represents the administrative and operational costs associated with Neptune’s issuance of the policy, is retained 100% by Neptune.
63
Fees can vary by product type, underlying risk, and location of the insured property. The fee is non-refundable should the policy be canceled due to mid-term home sale or any other type of acceptable mid-term cancellation reason, therefore, fee income is treated as fully earned once a policy has become effective. Similar to the commission income described above, fees are recognized at a point in time upon the effective date of bound insurance coverage, at which point the performance obligation has been met as no performance obligation exists after coverage is bound.
Operating Expenses
Agent Commissions
Agent commission is our largest expense. We pay agent commissions to our distribution partners, such as independent agents, brokers, or referral partners, for bringing business to Neptune. It is a variable cost directly linked to premium placed with our insurance carriers via our distribution partners.
Employee Compensation and Benefits and Share-based Compensation
Employee compensation and benefits consist of salaries, benefits, bonuses, and payroll taxes for our employees, as well as share-based compensation expense. We expense share-based compensation over the vesting period based on the grant-date fair value of the awards.
General and Administrative
G&A expenses include all other operating costs - e.g., marketing and advertising, technology infrastructure and cloud services, office lease expenses, professional fees (legal, accounting, consulting), licensing and regulatory fees, travel, and other overhead. This category also includes certain one-time costs, such as transaction-related expenses. While many G&A costs scale with the size of our business (for example, as the number of policyholders increases, customer support and cloud hosting costs may rise), we implement new technology from time to time to improve efficiency.
Amortization Expense
Our amortization expense primarily relates to capitalized software development costs for our proprietary technology platform. We capitalize the direct labor and software costs for developing new features or capabilities of our platform and amortize those costs, typically over a three-year useful life. Amortization expense has increased in recent years as we have continued to invest in our software, with significant additions in 2024 and 2025. These expenses will likely continue to grow modestly as we deploy new technology enhancements.
Transaction Costs
Transaction costs include professional fees and other expenses related to the IPO, which was completed in October 2025.
Consolidated Results of Operations
The following is a discussion of our consolidated results of operations for the periods presented. This information is derived from our accompanying consolidated financial statements prepared in accordance with GAAP.
Comparison of the Year Ended December 31, 2025 and 2024
For a discussion of our 2023 financial results and a comparison of financial results for the years ended December 31, 2024 to 2023, refer to Management’s Discussion and Analysis of Financial Condition and Results of Operations included in our Registration Statement on Form S-1/A filed with the SEC on September 26, 2025.
The following discussion and analysis of our financial condition and results of operations should be read in conjunction with our financial statements as of December 31, 2025 and 2024, and for the years ended December 31, 2025, 2024, and 2023, and the related notes and other financial information included in Item 8. Financial Statements and Supplementary Data of this Annual Report on Form 10-K.
In addition to historical financial information, the following discussion and analysis contains forward-looking statements that involve risks, uncertainties, and assumptions. Our actual results and timing of selected events may differ materially from those anticipated in these forward-looking statements as a result of many factors, including those discussed under Item 1A. Risk Factors.
64
The following table provides an overview of our consolidated results of operations for the years ended December 31, 2025 and 2024:
| ($ in thousands) | Years Ended December 31, | |||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||
| Revenues: | ||||||||||||||||||||
| Commissions and fees | $ | 159,551 | $ | 119,299 | ||||||||||||||||
| Operating expenses: | ||||||||||||||||||||
| Agent commissions | $ | 49,065 | $ | 35,317 | ||||||||||||||||
| Employee compensation and benefits | $ | 5,462 | $ | 4,456 | ||||||||||||||||
| Share-based compensation | $ | 11,420 | $ | 296 | ||||||||||||||||
| General and administrative | $ | 10,023 | $ | 7,757 | ||||||||||||||||
| Amortization expense | $ | 3,713 | $ | 3,027 | ||||||||||||||||
| Transaction costs | $ | 8,913 | $ | — | ||||||||||||||||
| Total operating expenses | $ | 88,596 | $ | 50,853 | ||||||||||||||||
| Income from operations | $ | 70,955 | $ | 68,446 | ||||||||||||||||
| Other income (expense): | ||||||||||||||||||||
| Interest income | $ | 923 | $ | 880 | ||||||||||||||||
| Interest expense | $ | (18,243) | $ | (17,520) | ||||||||||||||||
| Loss on extinguishment of debt | $ | — | $ | (5,426) | ||||||||||||||||
| Income tax expense | $ | 16,222 | $ | 11,788 | ||||||||||||||||
| Net income | $ | 37,413 | $ | 34,592 | ||||||||||||||||
Revenues
| Years Ended December 31, | Change | |||||||||||||||||||||||||||||||
| ($ in thousands) | 2025 | 2024 | Amount | Percentage | ||||||||||||||||||||||||||||
| Revenues: | ||||||||||||||||||||||||||||||||
| Commission income | $ | 122,003 | $ | 90,098 | $ | 31,905 | 35.4 | % | ||||||||||||||||||||||||
| Fee income | $ | 37,548 | $ | 29,201 | $ | 8,347 | 28.6 | % | ||||||||||||||||||||||||
| Total revenues | $ | 159,551 | $ | 119,299 | $ | 40,252 | 33.7 | % | ||||||||||||||||||||||||
Revenue increased to $159.6 million for the year ended December 31, 2025, from $119.3 million for the year ended December 31, 2024, representing an increase of $40.3 million, or 33.7%. The increase was primarily driven by higher policy counts and premium volume, supported by policy renewals and new policy sales.
Commission income was $122.0 million for the year ended December 31, 2025, compared to $90.1 million for the year ended December 31, 2024, representing an increase of 35.4%. The increase was primarily due to growth in written premium.
Fee income was $37.5 million for the year ended December 31, 2025, compared to $29.2 million for the year ended December 31, 2024, representing an increase of 28.6%. Although the average policy fee remained relatively stable, increased volumes of new business and higher renewal acceptance rates drove overall growth in fee income.
Of the total revenue recognized on policies during the year ended December 31, 2024, 91.7% was recognized under the renewal terms of those same policies during the year ended December 31, 2025. Of the total revenue recognized on policies during the year ended December 31, 2023, 90.7% was recognized under the renewal terms of those same policies during the year ended December 31, 2024. We believe this improvement reflects the impact of ML models we have deployed to optimize renewal offers for revenue retention.
65
Operating Expenses
| Years Ended December 31, | Change | |||||||||||||||||||||||||
| ($ in thousands) | 2025 | 2024 | Amount | Percentage | ||||||||||||||||||||||
| Operating expenses: | ||||||||||||||||||||||||||
| Agent commissions | $ | 49,065 | $ | 35,317 | $ | 13,748 | 38.9 | % | ||||||||||||||||||
| Employee compensation and benefits | $ | 5,462 | $ | 4,456 | $ | 1,006 | 22.6 | % | ||||||||||||||||||
| Share-based compensation | $ | 11,420 | $ | 296 | $ | 11,124 | NM | |||||||||||||||||||
| General and administrative | $ | 10,023 | $ | 7,757 | $ | 2,266 | 29.2 | % | ||||||||||||||||||
| Amortization expense | $ | 3,713 | $ | 3,027 | $ | 686 | 22.7 | % | ||||||||||||||||||
| IPO transaction costs | $ | 8,913 | $ | — | $ | 8,913 | NM | |||||||||||||||||||
| Total operating expenses | $ | 88,596 | $ | 50,853 | $ | 37,743 | 74.2 | % | ||||||||||||||||||
NM - not meaningful
Total operating expenses were $88.6 million for the year ended December 31, 2025, compared to $50.9 million for the year ended December 31, 2024, representing an increase of 74.2%. The primary drivers of these increases were higher agent commission costs, which are directly correlated with growth in our policy portfolio, higher share-based compensation costs, and elevated professional fees incurred in preparation for our IPO, a substantial portion of which were reimbursed by the selling stockholders in our IPO upon the consummation of our IPO on October 2, 2025.
Agent commission expenses were $49.1 million for the year ended December 31, 2025, compared to $35.3 million for the year ended December 31, 2024, representing an increase of 38.9%. The increase in commission expenses for the year ended December 31, 2025, was primarily volume-driven, resulting from higher policy sales. Commission rates remained consistent year-over-year, and the increase aligns with our overall revenue growth.
Employee compensation and benefits expenses were $5.5 million for the year ended December 31, 2025, compared to $4.5 million for the year ended December 31, 2024, representing an increase of 22.6%. The increase was primarily attributable to a full year of compensation for employees hired from Charles River Data, compared to a partial year in the prior period. For the year ended December 31, 2025, share-based compensation expense increased to $11.4 million, compared to $0.3 million for the year ended December 31, 2024.
General and administrative expenses were $10.0 million for the year ended December 31, 2025, compared to $7.8 million for the year ended December 31, 2024, representing an increase of 29.2%. These increases were primarily driven by year-over-year increases in our professional fees, due to increased costs relating to accounting and legal expenses in preparation for our IPO.
Amortization expense was $3.7 million for the year ended December 31, 2025, compared to $3.0 million for the year ended December 31, 2024, representing an increase of 22.7%. The increase is attributable to higher amortization of capitalized software development costs, reflecting continued investment in our proprietary technology platform.
IPO transaction costs recorded during the year ended December 31, 2025, reflect professional fees and other expenses incurred in connection with our initial public offering, which was completed on October 2, 2025. No IPO-related activities or costs were incurred during the year ended December 31, 2024.
Interest Income (Expense) and Other
| Years Ended December 31, | Change | |||||||||||||||||||||||||
| ($ in thousands) | 2025 | 2024 | Amount | Percentage | ||||||||||||||||||||||
| Other income (expense): | ||||||||||||||||||||||||||
| Interest income | $ | 923 | $ | 880 | $ | 43 | 4.9 | % | ||||||||||||||||||
| Interest expense | $ | (18,243) | $ | (17,520) | $ | (723) | 4.1 | % | ||||||||||||||||||
| Loss on extinguishment of debt | $ | — | $ | (5,426) | $ | 5,426 | (100.0) | % | ||||||||||||||||||
Interest income was $0.9 million for both the years ended December 31, 2025 and 2024. Interest expense increased to $18.2 million for the year ended December 31, 2025, from $17.5 million for the year ended December 31,
66
2024. The increase was due to higher average debt outstanding during 2025, partially offset by lower average interest rates. For the year ended December 31, 2024, the refinancing of our debt facilities resulted in a $5.4 million loss on extinguishment of debt, attributed to the write-off of unamortized capitalized loan costs and a prepayment penalty.
Income Tax Expense
Income tax expense was $16.2 million for the year ended December 31, 2025, compared to $11.8 million for the year ended December 31, 2024, representing an increase of 37.6%. The increase in income tax expense was primarily attributable to higher pre-tax income for the period. To a lesser extent, the increase was also driven by a higher effective tax rate of 30.2% for the year ended December 31, 2025, compared to 25.4% in the same period of 2024. The increase in the effective tax rate was due to the impact of non-deductible executive compensation and IPO transaction costs, partially offset by share-based compensation.
Key Performance Indicators
In managing our business, our management regularly reviews certain KPIs, to evaluate our operations, guide decision-making, and measure progress. We utilize a variety of operational metrics to understand growth and retention and ultimately to drive profitability.
•Premium in force is the annualized premium of all active policies at a given date. Premium in force is an insurance industry indication of scale and a leading indicator of future renewal commissions.
•Policies in force is the number of active policies at a given point in time. This is monitored to gauge scale and penetration and is a strong indicator of future renewal opportunities and their related revenue.
•Policy Retention Rate is a key performance indicator defined as the percentage of our policyholders who receive renewal offers that accept the offered renewal term. We monitor the acceptance of renewal offers as an early indicator of price elasticity.
•Premium Retention Rate is a key performance indicator defined as the premium associated with those accepted renewal offers, as a percentage of the total premium from expiring policies for which renewal offers were made.
•Revenue Retention Rate is the percentage of revenue recognized on policies in a given period that is recognized under the renewal terms of those same policies in the subsequent period. We monitor this metric as a comprehensive indicator of renewal performance and the long-term stability of our revenue base, as it reflects the combined effect of policy retention, premium changes, and policy fee income.
•Written Premium is the total premium we placed with insurance programs during a reporting period, less “return premiums” refunded to policyholders due to cancellations, endorsement of policies, or otherwise. We believe written premium is an appropriate measure of operating performance because it is the primary driver of our commission revenue.
•Average number of employees is the daily weighted average number of full-time equivalent employees during the trailing four quarters.
•Revenue per Employee is a key performance indicator defined as revenue for the trailing four quarters, determined in accordance with GAAP, divided by the average number of our employees during the trailing four quarters. We monitor this as a metric of scaling growth and believe it to be a leading indicator of sustained profitability and efficiency.
•Adjusted EBITDA per Employee is a key performance indicator defined as Adjusted EBITDA, a non-GAAP metric, for the trailing four quarters divided by the average number of our employees during the trailing four quarters. We monitor this as a metric of scaling growth and believe it to be a leading indicator of sustained profitability and efficiency. For further discussion on our calculation of Adjusted EBITDA, see “Non-GAAP Financial Measures” below.
•Organic revenue and organic revenue growth: We define organic revenue as total revenue determined in accordance with GAAP, adjusted to remove the impact of any acquisitions or divestitures. We define organic revenue growth as the year-over-year growth in our organic revenue. However, as of the date of this Annual Report and for the relevant periods presented herein, we have not completed any relevant acquisitions or
67
divestitures, therefore our organic revenue and organic revenue growth reflect our total revenue and total revenue growth, respectively, as determined in accordance with GAAP. Organic revenue and organic revenue growth are also non-GAAP financial measures which are commonly reported by others in the insurance industry. We use “organic revenue” and “organic revenue growth” in this Annual Report to facilitate investors’ understanding of our operating performance and comparison with our peers.
The tables below compare certain of our KPIs as of and for the three months and years ended December 31, 2025 and 2024:
| ($ in thousands) | Three Months Ended December 31, | Change %/pp | Years Ended December 31, | Change %/pp | |||||||||||||||||||||||||||||||
| 2025 | 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||
Premium in force (year-end) | $ | 370,210 | $ | 277,595 | 33.4 | % | $ | 370,210 | $ | 277,595 | 33.4 | % | |||||||||||||||||||||||
Policies in force (year-end) | 280,200 | 220,964 | 26.8 | % | 280,200 | 220,964 | 26.8 | % | |||||||||||||||||||||||||||
Policy retention rate (1) | 86.0 | % | 86.0 | % | — | 86.1% | 84.3% | 1.8 | |||||||||||||||||||||||||||
Premium retention rate (1) | 96.3 | % | 97.4 | % | (1.1) | 98.0% | 97.1% | 0.9 | |||||||||||||||||||||||||||
Revenue retention rate (1) | 90.2 | % | 93.7 | % | (3.5) | 91.8% | 90.7% | 1.1 | |||||||||||||||||||||||||||
Written Premium | $ | 100,304 | $ | 70,993 | 41.3 | % | $ | 367,309 | $ | 273,917 | 34.1 | % | |||||||||||||||||||||||
Organic revenue | $ | 43,767 | $ | 31,503 | 38.9 | % | $ | 159,551 | $ | 119,299 | 33.7 | % | |||||||||||||||||||||||
Organic revenue growth (1) | 38.9 | % | 41.0 | % | (2.1) | 33.7% | 40.6% | (6.9) | |||||||||||||||||||||||||||
(1)Year-over-year changes in percentages are reported in percentage points (pp).
Non-GAAP Financial Measures
To supplement our consolidated financial statements, which are prepared in conformity with GAAP, we use certain financial measures, including Adjusted EBITDA and Adjusted EBITDA margin, Adjusted net income and Adjusted earnings (basic and diluted) per share, which are not required by, or prepared in accordance with, GAAP. We refer to these measures as “non-GAAP” financial measures. We use these non-GAAP financial measures when planning, monitoring, and evaluating our performance. We consider these non-GAAP financial measures to be useful metrics for management and investors to facilitate operating performance comparisons from period to period and to assess our financial and operating performance. These non-GAAP financial measures should not be considered as substitutes for, or superior to, the financial statements and financial information prepared in accordance with GAAP. In addition, the non-GAAP financial information presented below may be determined or calculated differently by other companies and may not be directly comparable to that of other companies. See below for a description of these non-GAAP financial measures, as well as for more information about the limitations of these non-GAAP financial measures and for reconciliations to their most directly comparable measure reported under GAAP.
Adjusted EBITDA and Adjusted EBITDA margin: We define Adjusted EBITDA as net income (the most directly comparable GAAP measure) adjusted to exclude interest expense (net of interest income), income taxes, depreciation and amortization, and further adjusted for other non-cash or non-recurring items, including share-based compensation. By removing these expenses, we believe Adjusted EBITDA provides a clearer representation of operating performance.
We regard Adjusted EBITDA as an important measure for several reasons:
•It excludes the impact of financing decisions (debt vs. equity) by adding back interest, thus focusing on the performance of the underlying operations.
•It excludes loss on extinguishment of debt, which we do not consider indicative of our core operating performance.
•It excludes non-cash charges like amortization and share-based compensation (which depends on equity grant timing and valuation assumptions).
•It removes any other non-recurring, one-time expenses, most often related to corporate finance activities such as the debt refinancing we conducted in 2024 and expenses associated with our IPO in 2025.
•This measure is also useful for management and investors to compare our performance with that of other insurance technology or MGA companies that may have differing depreciation or financing structures.
68
In conjunction with Adjusted EBITDA, we also calculate Adjusted EBITDA margin, or Adjusted EBITDA as a percentage of total revenue. We believe that Adjusted EBITDA margin is a useful measurement of operating profitability for the same reasons we find Adjusted EBITDA useful and also because it provides a period-to-period comparison of our operating performance. Below is a reconciliation of Adjusted EBITDA to net income (the most directly comparable GAAP measure), as well as our Adjusted EBITDA margin to net income margin (the most directly comparable GAAP measure), for the years ended December 31, 2025 and 2024:
| Years Ended December 31, | ||||||||||||||||||||
| ($ in thousands) | 2025 | 2024 | Change %/pp | |||||||||||||||||
| Total revenues | $ | 159,551 | $ | 119,299 | 33.7% | |||||||||||||||
| Net income | $ | 37,413 | $ | 34,592 | 8.2% | |||||||||||||||
| Interest expense (net of interest income) | $ | 17,320 | $ | 16,640 | 4.1% | |||||||||||||||
| Income tax expense | $ | 16,222 | $ | 11,788 | 37.6% | |||||||||||||||
| Loss on extinguishment of debt | $ | — | $ | 5,426 | (100.0%) | |||||||||||||||
| Amortization expense | $ | 3,713 | $ | 3,027 | 22.7% | |||||||||||||||
| Share-based compensation | $ | 11,420 | $ | 296 | 3758.1% | |||||||||||||||
Corporate transaction related(1) | $ | 8,913 | $ | 100 | 8813.0% | |||||||||||||||
One-time expenses(2) | $ | — | $ | 230 | (100.0%) | |||||||||||||||
| Adjusted EBITDA | $ | 95,001 | $ | 72,099 | 31.8% | |||||||||||||||
Net income margin(3) | 23.4 | % | 29.0 | % | (5.6) | |||||||||||||||
Adjusted EBITDA margin(3) | 59.5 | % | 60.4 | % | (0.9) | |||||||||||||||
(1)Corporate transaction expenses during the year ended December 31, 2025, were comprised of accounting and legal fees and other expenses related to the preparation for and execution of our IPO. Corporate transaction expenses during the year ended December 31, 2024, were related to an administrative fee incurred in connection with the refinancing and extinguishment of our prior credit facility.
(2)One-time expenses during the year ended December 31, 2024, were entirely related to the corporate rebrand that was completed in that period.
(3)Year-over-year changes in percentages are reported in percentage points (pp).
Adjusted EBITDA was $95.0 million for the year ended December 31, 2025, an increase of $22.9 million, or 31.8%, from $72.1 million for the year ended December 31, 2024. Adjusted EBITDA margin for the year ended December 31, 2025 was 59.5%, compared to 60.4% for the year ended December 31, 2024.
| Years Ended December 31, | Change | ||||||||||||||||||||||
| ($ in thousands) | 2025 | 2024 | Amount | Change %/pp | |||||||||||||||||||
| Average number of employees | 58.0 | 51.2 | 6.8 | 13.2 | % | ||||||||||||||||||
| Total revenues | $ | 159,551 | $ | 119,299 | $ | 40,252 | 33.7 | % | |||||||||||||||
| Revenue per employee | $ | 2,750 | $ | 2,328 | $ | 422 | 18.1 | % | |||||||||||||||
| Adjusted EBITDA | $ | 95,001 | $ | 72,099 | $ | 22,902 | 31.8 | % | |||||||||||||||
| Adjusted EBITDA per employee | $ | 1,638 | $ | 1,407 | $ | 230 | 16.3 | % | |||||||||||||||
| Adjusted EBITDA margin | 59.5 | % | 60.4 | % | (0.9) | (0.9) | |||||||||||||||||
While our revenue and Adjusted EBITDA grew 33.7% and 31.8%, respectively, for the year ended December 31, 2025 compared to the year ended December 31, 2024, our headcount increased by approximately 13.2% over the same period. The accelerated growth in revenue and Adjusted EBITDA relative to our growth in employees illustrates the scalability of our existing platform and emphasis on efficient growth.
Adjusted Net Income and Adjusted Earnings (Basic and Diluted) Per Share:
We define Adjusted net income as net income (the most directly comparable GAAP measure), adjusted to exclude loss on extinguishment of debt, amortization expense, share-based compensation, corporate transaction related expenses, and other one-time expenses, and the related tax effect of those adjustments. By removing these expenses, we believe Adjusted net income provides a clearer representation of operating performance.
69
We regard Adjusted net income as an important measure for several reasons:
•It excludes loss on extinguishment of debt, which we do not consider indicative of our core operating performance.
•It excludes non-cash charges like amortization and share-based compensation (which depends on equity grant timing and valuation assumptions)
•It removes any other non-recurring, one-time expenses, most often related to corporate finance activities such as the debt refinancing we conducted in 2024 and expenses associated with our IPO in 2025.
We define Adjusted diluted earnings per share as Adjusted net income divided by diluted weighted average shares outstanding, assuming the full conversion of all outstanding shares of Redeemable Convertible Preferred Stock into an equivalent number of shares of common stock, which occurred upon the consummation of our IPO. Similarly, we define Adjusted basic earnings per share as Adjusted net income divided by basic weighted average shares outstanding, also assuming the conversion of all outstanding Redeemable Convertible Preferred Stock into an equivalent number of shares of common stock, which occurred upon the consummation of our IPO. We believe that Adjusted earnings per share (basic and diluted) is a useful measurement for the same reasons we find Adjusted net income useful and also because, by implementing the conversion of the Redeemable Convertible Preferred Stock, we believe Adjusted earnings (basic and diluted) per share provides a clearer representation of operating performance. The most directly comparable GAAP measures are diluted earnings per share and basic earnings per share, respectively.
The table below presents a reconciliation of Adjusted net income to net income (the most directly comparable GAAP measure), as well as our Adjusted earnings (basic and diluted) per share to basic earnings (loss) and diluted earnings
70
(loss) per share of common stock, respectively (the most directly comparable GAAP measure), for each of the years ended December 31, 2025 and 2024.
Years ended December 31, | ||||||||||||||||||||
| (In thousands, except share and per share data) | 2025 | 2024 | Change % | |||||||||||||||||
Adjusted diluted and basic earnings per share | ||||||||||||||||||||
Net income | 37,413 | 34,592 | 8.2 | % | ||||||||||||||||
Income tax expense | 16,222 | 11,788 | ||||||||||||||||||
Loss on extinguishment of debt | - | 5,426 | ||||||||||||||||||
Amortization expense | 3,713 | 3,027 | ||||||||||||||||||
Share-based compensation | 11,420 | 296 | ||||||||||||||||||
Corporate transaction related | 8,913 | 100 | ||||||||||||||||||
One-time expenses (1) | - | 230 | ||||||||||||||||||
Adjusted Income before income tax expense | $ | 77,681 | $ | 55,459 | 40.1 | % | ||||||||||||||
Adjusted income taxes (2) | $ | (20,749) | $ | (14,096) | ||||||||||||||||
Adjusted net income | $ | 56,932 | $ | 41,363 | 37.6 | % | ||||||||||||||
Weighted average Common Stock outstanding - Basic | 104,502,838 | 93,350,000 | ||||||||||||||||||
Plus: Impact of conversion of redeemable, convertible preferred stock (3) | 31,330,328 | 41,850,000 | ||||||||||||||||||
Adjusted Weighted average Common Stock outstanding - Basic | 135,833,166 | 135,200,000 | ||||||||||||||||||
Basic earnings (loss) per share | $ | (0.26) | $ | 0.16 | ||||||||||||||||
Effect of conversion of redeemable,convertible preferred stock and net loss attributable to preferred stock holders(4) | 0.66 | 0.18 | ||||||||||||||||||
Other adjustments to earnings (loss) per share(6) | 0.18 | 0.07 | ||||||||||||||||||
Adjusted income taxes per share | (0.15) | (0.10) | ||||||||||||||||||
Adjusted basic earnings per share | $ | 0.42 | $ | 0.31 | 35.5 | % | ||||||||||||||
Weighted average Common Stock outstanding - Diluted | 104,502,838 | 93,350,000 | ||||||||||||||||||
Plus: Impact of dilutive RSUs and stock options(5) | 4,208,597 | - | ||||||||||||||||||
Plus: Impact of conversion of redeemable, convertible preferred stock(2) | 31,330,328 | 41,850,000 | ||||||||||||||||||
Adjusted weighted average Common Stock outstanding - Diluted | 140,041,763 | 135,200,000 | ||||||||||||||||||
Diluted earnings (loss) per share | $ | (0.26) | $ | 0.16 | ||||||||||||||||
Effect of conversion of redeemable,convertible preferred stock (4) | 0.65 | 0.18 | ||||||||||||||||||
Other adjustments to earnings (loss) per share(6) | 0.17 | 0.07 | ||||||||||||||||||
Adjusted income taxes per share | (0.15) | (0.10) | ||||||||||||||||||
Adjusted diluted earnings per share | $ | 0.41 | $ | 0.31 | 32.3 | % | ||||||||||||||
(1)One-time expenses during the year ended December 31, 2024, were entirely related to the corporate rebrand that was completed in that period.
(2)This represents the tax impact using effective tax rates of 30.2% and 25.4% for the years ended December 31, 2025 and 2024, respectively, excluding items that are non‑deductible/non-taxable or subject to a specific tax treatment.
(3)Assumes the conversion of all shares of Redeemable Convertible Preferred Stock into an equivalent number of shares of common stock.
(4)For comparability purposes, this calculation reflects net income that would be distributable to holders of common stock, assuming all redeemable preferred shares had been converted and therefore no longer impacted the numerator. For the year ended December 31, 2025, $10.4 million of accretion adjustments and $54.2 million of cash dividends paid on redeemable preferred stock were added back, totaling $64.6 million. For the year ended December 31, 2024, $13.3 million of accretion and $6.6 million of allocations to participating preferred stock were added back, totaling
71
$19.9 million. These adjustments were divided by the weighted-average shares outstanding for the year ended December 31, 2025 and December 31, 2024 to calculate Adjusted earnings (basic and diluted) per share.
(5)Represents the impact of 3,531,938 stock options and 676,659 RSUs that were considered anti-dilutive in the GAAP diluted weighted-average common stock outstanding calculation but are included for purposes of Adjusted diluted earnings per share, for the year ended December 31, 2025.
(6)Other adjustments to earnings (loss) represent loss on extinguishment of debt, amortization expense, share-based compensation, corporate transaction related expenses, and one-time expenses.
72
Summary of Changes in Outstanding Shares and Equity Awards in Connection with the IPO
The following table presents a summary of our outstanding equity interests as of December 31, 2025, and the cumulative changes since September 30, 2025, to illustrate the impact of our IPO on October 2, 2025 and subsequent activity through year end. This table is provided to illustrate the impact of the IPO-related events, including the conversion of preferred stock and the vesting of equity awards, on our post-IPO share capitalization.
| Pre-IPO | Post-IPO | ||||||||||||||||||||||||||||
Date | Preferred | Common | Preferred | Class A Common | Class B Common | Shares issued and outstanding | |||||||||||||||||||||||
| Beginning shares outstanding (Common) | 9/30/2025 | 41,850,000 | 93,350,000 | - | - | - | 135,200,000 | ||||||||||||||||||||||
| Add: Vesting of early exercised options at IPO | 10/2/2025 | - | 2,835,000 | - | - | - | 138,035,000 | ||||||||||||||||||||||
| Add: Conversion of preferred stock to common (1:1) | 10/2/2025 | (41,850,000) | 41,850,000 | - | - | - | 138,035,000 | ||||||||||||||||||||||
| Reclassification to Class A common | 10/2/2025 | - | (138,035,000) | - | 138,035,000 | - | 138,035,000 | ||||||||||||||||||||||
| Exchange of Class A to Class B (1-for-1) | 10/2/2025 | - | - | - | (43,435,000) | 43,435,000 | 138,035,000 | ||||||||||||||||||||||
| Add: Exercise of options | Multiple dates (1) | - | - | - | 118,530 | - | 138,153,530 | ||||||||||||||||||||||
| Ending shares outstanding | 12/31/2025 | - | - | - | 94,718,530 | 43,435,000 | 138,153,530 | ||||||||||||||||||||||
| Pre-IPO | Post-IPO | ||||||||||||||||||||||||||||
Date | Preferred | Common | Preferred | Class A Common | Class B Common | Dilutive awards outstanding | |||||||||||||||||||||||
| Beginning unvested options, net of forfeitures | 9/30/2025 | - | 17,640,000 | - | - | - | 17,640,000 | ||||||||||||||||||||||
| Restricted Stock Unit grants | 9/30/2025 | - | 4,155,678 | - | - | - | 21,795,678 | ||||||||||||||||||||||
| Less: Cancellation of unvested options at IPO | 10/2/2025 | - | (5,880,000) | - | - | - | 15,915,678 | ||||||||||||||||||||||
| Less: Vesting of early exercised options at IPO | 10/2/2025 | - | (2,835,000) | - | - | - | 13,080,678 | ||||||||||||||||||||||
| Reclassification to Class A and Class B common RSU | 10/2/2025 | - | (4,155,678) | - | 2,172,714 | 1,982,964 | 13,080,678 | ||||||||||||||||||||||
| Reclassification to Class A and Class B common option | 10/2/2025 | - | (8,925,000) | - | 2,765,000 | 6,160,000 | 13,080,678 | ||||||||||||||||||||||
| Less: Exercise of options | Multiple dates (1) | - | - | - | (146,615) | - | 12,934,063 | ||||||||||||||||||||||
| Plus: Restricted Stock Unit grants | 12/22/2025 | - | - | - | 21,810 | - | 12,955,873 | ||||||||||||||||||||||
| Ending awards outstanding | 12/31/2025 | - | - | - | 4,812,909 | 8,142,964 | 12,955,873 | ||||||||||||||||||||||
(1) Represents the total number of options exercised during the fourth quarter of 2025, which occurred over multiple days during the period.
73
Limitations of Non-GAAP Financial Measures
Non-GAAP financial measures have limitations as analytical tools and should not be considered in isolation or as substitutes for financial information presented under GAAP. There are a number of limitations related to the use of non-GAAP financial measures versus comparable financial measures determined under GAAP. For example, the non-GAAP financial information presented above may be determined or calculated differently by other companies and may not be directly comparable to that of other companies.
In addition, while we find Adjusted EBITDA, Adjusted EBITDA margin, Adjusted EBITDA per share, Adjusted net income and Adjusted earnings (basic and diluted) per share to be useful measures, they have limitations. Adjusted EBITDA, Adjusted EBITDA margin, Adjusted EBITDA per share, Adjusted net income, and Adjusted earnings (basic and diluted) per share do not reflect cash needs for capital expenditures. They also do not reflect changes in working capital. Therefore, they should not be considered in isolation or as a substitute for net income or cash flow metrics.
All of these limitations could reduce the usefulness of these non-GAAP financial measures as analytical tools. Investors are encouraged to review the related GAAP financial measures and the reconciliations of these non-GAAP financial measures to their most directly comparable GAAP financial measures and to not rely on any single financial measure to evaluate our business. We provide this non-GAAP measure as supplemental information and encourage review of the reconciliation to understand the adjustments made.
Liquidity and Capital Resources
Liquidity and Capital Resources
Liquidity is a measure of a company’s ability to generate cash flows sufficient to meet the short-term and long-term cash requirements of its business operations. Our principal sources of liquidity are cash generated from operating activities and available borrowing capacity under our credit facilities. Our principal liquidity requirements include operating expenses, debt service obligations (interest and scheduled principal repayments), capital expenditures (primarily capitalized software development), and working capital.
As of December 31, 2025, and December 31, 2024, we had $40.5 million and $28.1 million of cash and cash equivalents and fiduciary cash on the balance sheet, respectively. This consisted of $8.0 million and $7.1 million of cash and cash equivalents, respectively, and $32.5 million and $21.0 million of fiduciary cash, respectively. In our capacity as an insurance agent, we typically collect premiums from policyholders and, after deducting the authorized commissions, remit the net premiums to the appropriate insurance company or companies. Accordingly, premiums receivable from policyholders are reported as fiduciary receivables and premiums payable to insurance companies are reported as insurance company payables. Unremitted net insurance premiums are held in a fiduciary capacity until we distribute them. Net insurance premiums payable to insurance companies, together with premium deposits received from policyholders, are held as fiduciary cash on the balance sheet. Cash and cash equivalents held in excess of the amounts required to meet our fiduciary obligations are recognized as cash and cash equivalents. We had operating cash flows of $51.7 million and $49.9 million for the year ended December 31, 2025 and 2024, respectively. We have historically used our cash provided by operations to pre-pay portions of the principal amount of our then-outstanding loans, while retaining sufficient liquidity for working capital needs.
As of December 31, 2025, the Company was allowed to borrow up to $20.0 million under our $260.0 million revolving credit facility effected pursuant to our Amended Credit Agreement.
As of December 31, 2024, the Company was allowed to borrow up to $10.0 million under a then undrawn revolving credit facility, which was effected under that certain Credit Agreement, dated as of June 13, 2024 (the “2024 Credit Agreement”). On April 10, 2025, in connection with our corporate reorganization, the 2024 Credit Agreement was amended and restated in its entirety in the form of the 2025 Amended and Restated Credit Agreement to, among other things, increase the aggregate principal amount of term loans outstanding under the facility to $301.0 million, including $170.0 million in principal amount of new term loans, and extend the maturity date of all outstanding loans under the facility to April 10, 2030. We also maintained a revolving credit facility of up to $10.0 million as part of the 2025 Amended and Restated Credit Agreement.
On November 10, 2025, we entered into the First Amendment to the 2025 Amended and Restated Credit Agreement which, among other things, (i) increased the “Revolving Commitments” (as defined in the 2025 Amended and Restated Credit Agreement) from $10.0 million to $260.0 million, (ii) extended the maturity date of the revolving credit facility from April 10, 2030, to November 10, 2030, and (iii) lowered the applicable margin for interest accruing on
74
borrowings under the Revolving Credit Facility by 0.50% per annum. At the closing of the First Amendment, Neptune Flood borrowed $251.0 million of the increased Revolving Commitments and used the proceeds to repay in full the term loans outstanding under the 2025 Amended and Restated Credit Agreement immediately prior to the First Amendment.
As of December 31, 2025, $240.0 million in revolving loans were outstanding under our $260.0 million revolving credit facility pursuant to the Amended Credit Agreement, leaving $20.0 million available for future borrowing. The remaining undrawn portion of our revolving credit facility provides flexibility for short-term funding needs or working capital requirements.
We believe our current cash and cash equivalents and the undrawn amounts available under our Amended Credit Agreement will be sufficient to meet our working capital and capital expenditure requirements for at least the next twelve months and beyond. Over the longer term, we may explore additional refinancing options to reduce interest costs or raise equity to accelerate growth or reduce leverage and, depending on interest rates and market conditions, may from time to time consider distributing dividends or engaging in stock repurchases.
Cash Flows
Comparison of the Year Ended December 31, 2025 and 2024
The following table shows a summary of our cash flows for the periods presented:
| ($ in thousands) | Years Ended December 31, | |||||||||||||
| 2025 | 2024 | |||||||||||||
Net cash provided by operating activities | $ | 51,670 | $ | 49,926 | ||||||||||
Net cash used in investing activities | $ | (3,977) | $ | (3,713) | ||||||||||
Net cash used in financing activities | $ | (35,210) | $ | (42,468) | ||||||||||
Operating Activities
For the year ended December 31, 2025, net cash provided by operating activities was $51.7 million, primarily consisting of our net income of $37.4 million, adjusted for share-based compensation of $11.4 million, amortization of intangible assets of $3.7 million, and amortization of deferred financing costs of $0.6 million. These amounts were partially offset by a $3.5 million increase in operating assets and $2.0 million decrease in deferred tax assets. Accounts payable and accrued expenses grew as the Company’s operations expanded, contributing to cash flow.
For the year ended December 31, 2024, net cash provided by operating activities was $49.9 million, primarily consisting of our net income of $34.6 million, adjusted for amortization of intangible assets of $3.0 million, amortization of deferred financing costs of $0.9 million, loss on the extinguishment of debt of $5.4 million, $0.3 million in share-based compensation, and an increase in operating liabilities of $7.4 million. These amounts were partially offset by a $1.1 million increase in operating assets and a $0.6 million decrease in deferred tax assets.
Investing Activities
For the year ended December 31, 2025, net cash used in investing activities was $4.0 million, compared to $3.7 million for the year ended December 31, 2024. For both years, the cash used in investing activities all related to capital expenditures for internally developed software. The increase in year-over-year net cash used in investing activities for the year ended December 31, 2025, was primarily driven by the increase in the capitalization of software development cost, reflecting additions to headcount in the technology and data science teams. We expect to continue investing in software development at a similar or slightly greater pace in the future, which is a use of cash that we believe yields high returns in terms of functionality and accretion to future growth.
Financing Activities
For the year ended December 31, 2025, net cash used in financing activities was $35.2 million, which was primarily due to cash dividends paid of $175.0 million, $436.0 million of repayments of our long-term debt, $0.9 million of deferred financing fees and prepayment penalty, and a $1.3 million change in fiduciary receivables, partially offset by the refinancing of our then-existing debt facility through our entry into the 2025 Amended and Restated Credit Agreement, which resulted in proceeds to us of $301.0 million, a $12.8 million change in fiduciary liabilities, $251.0 million in proceeds from the revolving credit facility in connection with our entry into the First Amendment in connection with our
75
entry into the First Amendment. $8.5 million in Contributed capital, stockholder reimbursement of IPO transaction costs, and $15.7 million in proceeds from the exercise of stock options.
For the year ended December 31, 2024, net cash used in financing activities was $42.5 million, which was primarily due to $214.5 million of repayments of our long-term debt, a $3.7 million payment of deferred financing fees, and a $0.6 million change in fiduciary receivables. This was partially offset by proceeds of $171.0 million from the issuance of long-term debt and a $5.4 million change in fiduciary liabilities.
Contractual Obligations and Commitments
As of December 31, 2025, we did not have, and we do not currently have, any off-balance sheet financing arrangements or any relationships with unconsolidated entities or financial partnerships, including entities sometimes referred to as structured finance or special purpose entities, established for the purpose of facilitating off-balance sheet arrangements or other contractually narrow or limited purposes.
As of December 31, 2025, we were party to the 2025 Amended and Restated Credit Agreement, as amended by the First Amendment. At the closing of the First Amendment, we borrowed $251.0 million under the revolving credit facility and used the proceeds to repay in full the term loans outstanding under the 2025 Amended and Restated Credit Agreement immediately prior to the First Amendment. From November 10, 2025, through December 31, 2025, our outstanding revolving loans bore interest at the Term SOFR Rate plus 2.50%; thereafter subject to our election to convert the borrowing to an ABR Loan, interest accrues at the Term SOFR Rate (subject to a 1.00% floor) plus an applicable margin ranging from 1.75% to 3.00%, depending on our Total Net Leverage Ratio (as defined in the Amended Credit Agreement) for the prior fiscal quarter.
Neptune Flood is also required to pay an unused commitment fee, which accrues at a per annum rate ranging from 0.20% to 0.40%, depending on the Company's Total Net Leverage Ratio for the prior fiscal quarter, on the daily amount of any undrawn portion of the increased Revolving Commitments.
As of December 31, 2025, $240.0 million was outstanding under our $260.0 million revolving credit facility, leaving $20.0 million available for future borrowing. The remaining undrawn portion of our revolving credit facility provides flexibility for short-term funding needs or working capital requirements. The foregoing description of the First Amendment and the Amended Credit Agreement is qualified in its entirety by reference to the complete text of the First Amendment, a copy of which is filed as Exhibit 10.8 hereto and is incorporated herein by reference.
The Amended Credit Agreement contains covenants that, among other things, restrict our ability to make certain restricted payments, incur additional debt, engage in certain asset sales, mergers, acquisitions or similar transactions, create liens on assets, engage in certain transactions with affiliates, change our business or make investments, and require us to comply with certain financial covenants. We are currently in compliance with the Amended Credit Agreement and were in compliance with the 2025 Amended and Restated Credit Agreement covenants as of December 31, 2025.
Quarterly Results of Operations
The following table sets forth our unaudited quarterly consolidated results of operations for each of the quarterly periods for the years ended December 31, 2025 and 2024. These unaudited quarterly results of operations have been prepared on the same basis as our audited consolidated financial statements included elsewhere in this Annual Report on Form 10-K. In the opinion of management, the financial information set forth in the table below reflects all normal recurring adjustments necessary for the fair statement of results of operations for these periods. Our historical results are not necessarily indicative of the results that may be expected in the future, and the results of a particular quarter or other interim period are not necessarily indicative of the results for a full year. You should read the following unaudited quarterly consolidated results of operations in conjunction with our consolidated financial statements and related notes included elsewhere in this Annual Report on Form 10-K.
76
| Three months ended | ||||||||||||||||||||||||||||||||||||||||||||||||||
| March 31, | June 30, | September 30, | December 31, | March 31, | June 30, | September 30, | December 31, | |||||||||||||||||||||||||||||||||||||||||||
| (In thousands) | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||||||||||||||||||||
| Revenues: | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Commission income | $ | 16,204 | $ | 24,208 | $ | 25,549 | $ | 24,137 | $ | 22,707 | $ | 32,062 | $ | 33,916 | $ | 33,318 | ||||||||||||||||||||||||||||||||||
| Fee income | 5,362 | 8,202 | 8,271 | 7,366 | 6,646 | 10,004 | 10,449 | 10,449 | ||||||||||||||||||||||||||||||||||||||||||
| Total commissions and fees | $ | 21,566 | $ | 32,410 | $ | 33,820 | $ | 31,503 | $ | 29,353 | $ | 42,066 | $ | 44,365 | $ | 43,767 | ||||||||||||||||||||||||||||||||||
| Operating expenses: | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Agent commissions | 6,511 | 9,646 | 10,014 | 9,146 | 8,940 | 12,736 | 13,840 | 13,549 | ||||||||||||||||||||||||||||||||||||||||||
| Employee compensation and benefits | 1,121 | 1,154 | 1,210 | 971 | 1,321 | 1,424 | 1,662 | 1,055 | ||||||||||||||||||||||||||||||||||||||||||
| General and administrative | 1,633 | 2,096 | 1,931 | 2,097 | 1,976 | 2,657 | 2,138 | 3,252 | ||||||||||||||||||||||||||||||||||||||||||
| Share-based compensation expense | 71 | 72 | 74 | 79 | 84 | 104 | 111 | 11,121 | ||||||||||||||||||||||||||||||||||||||||||
| IPO transaction costs | — | — | — | — | 531 | 2,943 | 4,966 | 473 | ||||||||||||||||||||||||||||||||||||||||||
| Amortization expense | 688 | 737 | 782 | 820 | 874 | 912 | 948 | 979 | ||||||||||||||||||||||||||||||||||||||||||
| Total operating expenses | $ | 10,024 | $ | 13,705 | $ | 14,011 | $ | 13,113 | $ | 13,726 | $ | 20,776 | $ | 23,665 | $ | 30,429 | ||||||||||||||||||||||||||||||||||
| Income from operations | 11,542 | $ | 18,705 | $ | 19,809 | $ | 18,390 | $ | 15,627 | $ | 21,290 | $ | 20,700 | $ | 13,338 | |||||||||||||||||||||||||||||||||||
| Other income (expense): | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest income | 168 | 255 | 256 | 201 | 169 | 247 | 281 | 226 | ||||||||||||||||||||||||||||||||||||||||||
| Interest expense | (5,518) | (5,114) | (3,771) | (3,117) | (2,401) | (5,868) | (5,518) | (4,456) | ||||||||||||||||||||||||||||||||||||||||||
| Loss on extinguishment of debt | — | (5,426) | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||
| Other income | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||
| Income before income tax expense | 6,192 | $ | 8,420 | $ | 16,294 | $ | 15,474 | $ | 13,395 | $ | 15,669 | $ | 15,463 | $ | 9,108 | |||||||||||||||||||||||||||||||||||
| Income tax expense | 1,578 | 2,147 | 4,201 | 3,862 | 3,456 | 4,049 | 3,952 | 4,765 | ||||||||||||||||||||||||||||||||||||||||||
| Net income | $ | 4,614 | $ | 6,273 | $ | 12,093 | $ | 11,612 | $ | 9,939 | $ | 11,620 | $ | 11,511 | $ | 4,343 | ||||||||||||||||||||||||||||||||||
| Accretion adjustment to redeemable preferred stock | (3,230) | (3,276) | (3,360) | (3,408) | (3,381) | (3,467) | (3,555) | (34) | ||||||||||||||||||||||||||||||||||||||||||
| Allocation to participating preferred stock | (428) | (928) | (2,703) | (2,540) | (2,030) | — | (2,463) | (14) | ||||||||||||||||||||||||||||||||||||||||||
| Cash dividend paid on redeemable preferred stock | — | — | — | — | — | (54,170) | — | — | ||||||||||||||||||||||||||||||||||||||||||
| Net income available to common stockholders | $ | 956 | $ | 2,069 | $ | 6,030 | $ | 5,664 | $ | 4,528 | $ | (46,017) | $ | 5,493 | $ | 4,295 | ||||||||||||||||||||||||||||||||||
77
| Three months ended | ||||||||||||||||||||||||||||||||||||||||||||||||||
| March 31, | June 30, | September 30, | December 31, | March 31, | June 30, | September 30, | December 31, | |||||||||||||||||||||||||||||||||||||||||||
| (In thousands) | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||||||||||||||||||||
| Net income | $ | 4,614 | $ | 6,273 | $ | 12,093 | $ | 11,612 | $ | 9,939 | $ | 11,620 | $ | 11,511 | $ | 4,343 | ||||||||||||||||||||||||||||||||||
Interest expense (net of interest income) | 5,350 | 4,859 | 3,515 | 2,916 | 2,232 | 5,621 | 5,237 | 4,230 | ||||||||||||||||||||||||||||||||||||||||||
Income tax expense | 1,578 | 2,147 | 4,201 | 3,862 | 3,456 | 4,049 | 3,952 | 4,765 | ||||||||||||||||||||||||||||||||||||||||||
Loss on extinguishment of debt | — | 5,426 | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||
Amortization expense | 688 | 737 | 782 | 820 | 874 | 912 | 948 | 979 | ||||||||||||||||||||||||||||||||||||||||||
Share-based compensation | 71 | 72 | 74 | 79 | 84 | 104 | 111 | 11,121 | ||||||||||||||||||||||||||||||||||||||||||
Corporate transaction related | — | 100 | — | — | 531 | 2,943 | 4,966 | 473 | ||||||||||||||||||||||||||||||||||||||||||
One-time expenses | — | 115 | 115 | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||
Adjusted EBITDA | $ | 12,301 | $ | 19,729 | $ | 20,780 | $ | 19,289 | $ | 17,116 | $ | 25,249 | $ | 26,725 | $ | 25,911 | ||||||||||||||||||||||||||||||||||
Net income margin | 21.4 | % | 19.4 | % | 35.8 | % | 36.9 | % | 33.9 | % | 27.6 | % | 25.9 | % | 9.9 | % | ||||||||||||||||||||||||||||||||||
Adjusted EBITDA margin | 57.0 | % | 60.9 | % | 61.4 | % | 61.2 | % | 58.3 | % | 60.0 | % | 60.2 | % | 59.2 | % | ||||||||||||||||||||||||||||||||||
Adjusted Net Income and Adjusted Earnings (Basic and Diluted) Per Share:
The table below presents a reconciliation of Adjusted net income to net income (the most directly comparable GAAP measure), as well as our Adjusted earnings (basic and diluted) per share to basic earnings (loss) and diluted earnings (loss) per share of common stock, respectively (the most directly comparable GAAP measure), for each of the quarterly periods for the years ended December 31, 2025 and 2024.
| Three months ended | ||||||||||||||||||||||||||||||||||||||||||||||||||
| March 31, | June 30, | September 30, | December 31, | March 31, | June 30, | September 30, | December 31, | |||||||||||||||||||||||||||||||||||||||||||
| (In thousands, except share and per share data) | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||||||||||||||||||||
Adjusted diluted and basic earnings per share | ||||||||||||||||||||||||||||||||||||||||||||||||||
Net income | 4,614 | 6,273 | 12,093 | 11,612 | 9,939 | 11,620 | 11,511 | 4,343 | ||||||||||||||||||||||||||||||||||||||||||
Income tax expense | 1,578 | 2,147 | 4,201 | 3,862 | 3,456 | 4,049 | 3,952 | 4,765 | ||||||||||||||||||||||||||||||||||||||||||
Loss on extinguishment of debt | - | 5,426 | - | - | - | - | - | - | ||||||||||||||||||||||||||||||||||||||||||
Amortization expense | 688 | 737 | 782 | 820 | 874 | 912 | 948 | 979 | ||||||||||||||||||||||||||||||||||||||||||
Share-based compensation | 71 | 72 | 74 | 79 | 84 | 104 | 111 | 11,121 | ||||||||||||||||||||||||||||||||||||||||||
Corporate transaction related expenses | - | 100 | - | - | 531 | 2,943 | 4,966 | 473 | ||||||||||||||||||||||||||||||||||||||||||
One-time expenses | - | 115 | 115 | - | - | - | - | - | ||||||||||||||||||||||||||||||||||||||||||
Adjusted Income before income tax expense | $ | 6,951 | $ | 14,870 | $ | 17,265 | $ | 16,373 | $ | 14,884 | $ | 19,628 | $ | 21,488 | $ | 21,681 | ||||||||||||||||||||||||||||||||||
Adjusted income taxes (1) | $ | (1,771) | $ | (3,792) | $ | (4,451) | $ | (4,087) | $ | (3,840) | $ | (5,072) | $ | (5,492) | $ | (6,346) | ||||||||||||||||||||||||||||||||||
Adjusted net income | $ | 5,180 | $ | 11,078 | $ | 12,814 | $ | 12,286 | $ | 11,044 | $ | 14,556 | $ | 15,996 | $ | 15,335 | ||||||||||||||||||||||||||||||||||
Weighted average Common Stock outstanding - Basic | 93,350,000 | 93,350,000 | 93,350,000 | 93,350,000 | 93,350,000 | 93,350,000 | 93,350,000 | 138,069,793 | ||||||||||||||||||||||||||||||||||||||||||
78
Plus: Impact of conversion of redeemable, convertible preferred stock (2) | 41,850,000 | 41,850,000 | 41,850,000 | 41,850,000 | 41,850,000 | 41,850,000 | 41,850,000 | 454,891 | ||||||||||||||||||||||||||||||||||||||||||
Adjusted Weighted average Common Stock outstanding - Basic | 135,200,000 | 135,200,000 | 135,200,000 | 135,200,000 | 135,200,000 | 135,200,000 | 135,200,000 | 138,524,684 | ||||||||||||||||||||||||||||||||||||||||||
Basic earnings (loss) per share | $ | 0.01 | $ | 0.02 | $ | 0.06 | $ | 0.06 | $ | 0.05 | $ | (0.49) | $ | 0.06 | $ | 0.03 | ||||||||||||||||||||||||||||||||||
Effect of conversion of redeemable, convertible preferred stock and net loss attributable to preferred stock holders(3) | 0.04 | 0.04 | 0.05 | 0.05 | 0.05 | 0.61 | 0.05 | 0.04 | ||||||||||||||||||||||||||||||||||||||||||
Other adjustments to earnings (loss) per share (4) | 0.01 | 0.05 | 0.01 | 0.01 | 0.01 | 0.03 | 0.04 | 0.09 | ||||||||||||||||||||||||||||||||||||||||||
Adjusted income taxes per share | (0.01) | (0.03) | (0.03) | (0.03) | (0.03) | (0.04) | (0.04) | (0.05) | ||||||||||||||||||||||||||||||||||||||||||
Adjusted basic earnings per share | $ | 0.04 | $ | 0.08 | $ | 0.09 | $ | 0.09 | $ | 0.08 | $ | 0.11 | $ | 0.12 | $ | 0.11 | ||||||||||||||||||||||||||||||||||
Weighted average Common Stock outstanding - Diluted | 93,350,000 | 93,350,000 | 93,350,000 | 93,350,000 | 93,350,000 | 93,350,000 | 97,262,548 | 147,676,485 | ||||||||||||||||||||||||||||||||||||||||||
Plus: Impact of conversion of redeemable, convertible preferred stock(2) | 41,850,000 | 41,850,000 | 41,850,000 | 41,850,000 | 41,850,000 | 41,850,000 | 41,850,000 | 454,891 | ||||||||||||||||||||||||||||||||||||||||||
Adjusted weighted average Common Stock outstanding - Diluted | 135,200,000 | 135,200,000 | 135,200,000 | 135,200,000 | 135,200,000 | 135,200,000 | 139,112,548 | 148,131,376 | ||||||||||||||||||||||||||||||||||||||||||
Diluted earnings (loss) per share | $ | 0.01 | $ | 0.02 | $ | 0.06 | $ | 0.06 | $ | 0.05 | $ | (0.49) | $ | 0.06 | $ | 0.03 | ||||||||||||||||||||||||||||||||||
Effect of conversion of redeemable, convertible preferred stock (3) | 0.04 | 0.04 | 0.05 | 0.05 | 0.05 | 0.61 | 0.05 | 0.03 | ||||||||||||||||||||||||||||||||||||||||||
Other adjustments to earnings (loss) per share (4) | 0.01 | 0.05 | 0.01 | 0.01 | 0.01 | 0.03 | 0.04 | 0.08 | ||||||||||||||||||||||||||||||||||||||||||
Adjusted income taxes per share | (0.01) | (0.03) | (0.03) | (0.03) | (0.03) | (0.04) | (0.04) | (0.04) | ||||||||||||||||||||||||||||||||||||||||||
Adjusted diluted earnings per share | $ | 0.04 | $ | 0.08 | $ | 0.09 | $ | 0.09 | $ | 0.08 | $ | 0.11 | $ | 0.11 | $ | 0.10 | ||||||||||||||||||||||||||||||||||
(1)This represents the tax impact using the applicable effective tax rates for each respective period presented, excluding items that are non‑deductible/non-taxable or subject to a specific tax treatment.
(2)Assumes the conversion of all shares of Redeemable Convertible Preferred Stock into an equivalent number of shares of common stock.
(3)For comparability purposes, this calculation reflects net income that would be distributable to holders of common stock assuming all redeemable preferred shares had been converted and therefore no longer impacted the numerator. Accordingly, accretion adjustments and dividends or other allocations attributable to redeemable preferred stock have been added back to net income, as applicable for each period presented. These adjustments were divided by the weighted-average shares outstanding for each respective period to calculate adjusted earnings (basic and diluted) per share.
(4)Other adjustments to earnings (loss) represent loss on extinguishment of debt, amortization expense, share-based compensation, corporate transaction related expenses, and one-time expenses.
79
Critical Accounting Estimates
Our consolidated financial statements are prepared in accordance with GAAP, which require management to make estimates and assumptions that affect the reported amounts of assets, liabilities, revenue, and expenses. Management regularly evaluates these estimates, which are based on historical experience and other factors, including expectations of future events that are believed to be reasonable. Actual results may differ from these estimates. We consider an accounting estimate to be critical if it involves a significant level of estimation uncertainty and if different estimates or assumptions could reasonably have a material impact on our financial condition or results of operations. The following are the critical accounting policies and estimates that we believe are most important to understanding our financial statements:
Revenue Recognition (Commission and Fee Revenue)
We recognize revenue from commissions and fees upon the effective date of insurance coverage, with an estimate for cancellations.
Estimates for Policy Cancellations
We estimate the proportion of premiums and commissions that will not ultimately remain in force for the full policy term due to cancellations. This estimate directly reduces the revenue we recognize at policy inception. We base our estimates on historical cancellation experience by policy type and tenure and adjust for any known trends or events. The estimation period typically covers the allowable cancellation period. If our estimated cancellation rates are inaccurate, then our revenue could be materially impacted. We monitor actual cancellations and update our estimates quarterly. For instance, if cancellation rates were to rise, we might increase the constraint and recognize less revenue upfront, deferring more commission until uncertainty is resolved. For the years ended December 31, 2025 and 2024, no significant adjustments were recorded for prior estimates.
Capitalization of Internally Developed Software and Amortization
We capitalize internally developed software at cost. The critical estimates here include:
•Determining which projects meet the criteria for capitalization. We carefully evaluate each feature and project for these criteria.
•The useful life of our capitalized software. We review this estimated useful life periodically. Given the rapid innovation in our platform, three years has historically been used as our platform’s useful life. For the years ended December 31, 2025 and 2024, no changes were made to the useful life of our capitalized software. As we continue to incorporate AI and other enhancements, we will continue our periodic assessments to determine if such integrations warrant the use of a different useful life for our platform.
Recent Accounting Pronouncements
We currently qualify as an EGC under the JOBS Act. Accordingly, we are provided the option to adopt new or revised accounting guidance either (i) within the same periods as those otherwise applicable to non-emerging growth companies or (ii) within the same time periods as private companies. We are electing to use the extended transition periods available under the JOBS Act for complying with new or revised accounting standards and, as a result, we will not be required to adopt new or revised accounting standards on the relevant dates on which adoption of such standards is required for other public companies.
We will remain an EGC until the earliest to occur of: (i) the end of the first fiscal year in which our annual gross revenues are $1.235 billion or more; (ii) the end of the first fiscal year in which we are deemed to be a “large accelerated filer,” as defined in the Exchange Act; (iii) the date on which we have, during the previous three-year period, issued more than $1.0 billion in non-convertible debt securities; and (iv) the end of the fiscal year during which the fifth anniversary of the completion of our IPO.
See Note 2, “Significant Accounting Policies,” to our consolidated financial statements included in Item 8. Financial Statements and Supplementary Data of this Annual Report for disclosures regarding recently issued accounting pronouncements and the critical accounting policies related to our business.
80
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
Market risk is the potential loss arising from adverse changes in market rates and prices, such as premium amounts, interest rates, and equity prices. We are exposed to market risk through our business partners, investments, and borrowings.
The insurance market in which we operate has historically been cyclical based on the underwriting capacity of the insurance carriers and reinsurers, general economic conditions, state regulatory responses to market conditions, the timing of hurricane and storm season and other natural disasters, and other social, economic, and business factors. In a period of decreasing insurance capacity or higher than typical loss ratios across an insurance segment or segments, insurance carriers may raise premium rates. This type of market frequently is referred to as a “hard” market. In a period of increasing insurance capacity or lower than typical loss ratios across an insurance segment or segments, insurance carriers may reduce premium rates, and business might migrate away from the E&S lines market and into the admitted market. This type of market frequently is referred to as a “soft” market. Our results of operations are affected by this cyclicality of the market.
Our investments are held primarily as cash and cash equivalents. These investments are subject to interest rate risk. The fair values of cash and cash equivalents as of December 31, 2025, approximated their carrying values due to their short-term nature and therefore, such market risk is not considered to be material. We do not actively invest or trade in equity or derivative securities.
As of December 31, 2025, under our Amended Credit Agreement, we had $240.0 million of principal balance outstanding on our revolving credit facility with $20.0 million in available capacity. These borrowings accrue interest tied to SOFR and therefore interest expense under these borrowings is subject to change. An immediate hypothetical 1% change in interest rates on our borrowings would have a $2.4 million annual pre-tax effect on our consolidated financial statements.
81
Item 8. Financial Statements and Supplementary Data.
Index to consolidated financial statements
| Page | |||||
| Neptune Insurance Holdings Inc. | |||||
Annual consolidated financial statements | |||||
Report of Independent Registered Public Accounting Firm (PCAOB ID: | |||||
82
Report of Independent Registered Public Accounting Firm
To the Board of Directors and Stockholders of Neptune Insurance Holdings Inc.
Opinion on the Financial Statements
We have audited the accompanying consolidated balance sheets of Neptune Insurance Holdings Inc. and its subsidiaries (the "Company") as of December 31, 2025 and 2024, and the related consolidated statements of income, of changes in redeemable, convertible preferred stock and stockholders' deficit and of cash flows for each of the three years in the period ended December 31, 2025, including the related notes (collectively referred to as the "consolidated financial statements"). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company as of December 31, 2025 and 2024, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2025 in conformity with accounting principles generally accepted in the United States of America.
Basis for Opinion
These consolidated financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s consolidated financial statements based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits of these consolidated financial statements in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud.
Our audits included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. We believe that our audits provide a reasonable basis for our opinion.
/s/ PricewaterhouseCoopers LLP
February 25, 2026
We have served as the Company's auditor since 2025.
83
Neptune Insurance Holdings Inc. and Subsidiaries
Consolidated Balance Sheets
December 31, 2025 and 2024
(In thousands, except share and per share data)
| 2025 | 2024 | ||||||||||
| Assets | |||||||||||
| Current assets: | |||||||||||
Cash and cash equivalents | $ | $ | |||||||||
Fiduciary cash | |||||||||||
Fiduciary receivable | |||||||||||
Commissions and fees receivable | |||||||||||
Prepaid expenses and other current assets | |||||||||||
Income tax receivable | |||||||||||
Total current assets | |||||||||||
| Intangible assets, net | |||||||||||
| Internally developed software, net | |||||||||||
| Goodwill | |||||||||||
| Deferred tax assets | |||||||||||
| Deferred financing asset | |||||||||||
Total assets | $ | $ | |||||||||
| Liabilities, Redeemable Convertible Preferred Stock and Stockholders’ Deficit | |||||||||||
| Current liabilities: | |||||||||||
Accounts payable | |||||||||||
Commissions payable | |||||||||||
Insurance company payables | |||||||||||
Income tax payable | |||||||||||
Accrued expenses | |||||||||||
Premium deposits | |||||||||||
Current portion of debt | |||||||||||
Total current liabilities | |||||||||||
| Debt, less current portion | |||||||||||
| Revolving credit facility | $ | ||||||||||
Total liabilities | $ | $ | |||||||||
| Commitments and contingencies (Notes 13) | |||||||||||
Redeemable, convertible preferred stock, $ | |||||||||||
| Stockholders’ deficit: | |||||||||||
Class A common stock, $ | |||||||||||
Class B common stock, $ | |||||||||||
Accumulated deficit | ( | ( | |||||||||
Additional paid-in capital | |||||||||||
Total stockholders’ deficit | ( | ( | |||||||||
Total liabilities, redeemable, convertible preferred stock, and stockholders’ deficit | $ | $ | |||||||||
See notes to consolidated financial statements.
84
Neptune Insurance Holdings Inc. and Subsidiaries
Consolidated Statements of Income
for the years ended December 31, 2025, 2024 and 2023
(In thousands, except share and per share data)
| 2025 | 2024 | 2023 | |||||||||||||||
| Revenues: | |||||||||||||||||
Commissions and fees | $ | $ | $ | ||||||||||||||
| Operating expenses: | |||||||||||||||||
Agent commissions | |||||||||||||||||
Employee compensation and benefits | |||||||||||||||||
General and administrative | |||||||||||||||||
Amortization expense | |||||||||||||||||
| IPO transaction costs | |||||||||||||||||
Total operating expenses | |||||||||||||||||
Income from operations | |||||||||||||||||
| Other income (expense): | |||||||||||||||||
Interest income | |||||||||||||||||
Interest expense | ( | ( | ( | ||||||||||||||
Loss on extinguishment of debt | ( | ( | |||||||||||||||
Income before income tax expense | |||||||||||||||||
| Income tax expense | |||||||||||||||||
Net income | $ | $ | $ | ||||||||||||||
Accretion adjustment to redeemable preferred stock | ( | ( | ( | ||||||||||||||
Allocation to participating preferred stock | ( | ||||||||||||||||
| Cash dividend paid on redeemable preferred stock | ( | ||||||||||||||||
Net income available to common stockholders | $ | ( | $ | $ | |||||||||||||
| Net income per share of common stock: | |||||||||||||||||
| Class A and Class B Common Stock | |||||||||||||||||
Basic | $ | ( | $ | $ | |||||||||||||
Diluted | $ | ( | $ | $ | |||||||||||||
| Weighted average shares of common stock outstanding: | |||||||||||||||||
| Class A and Class B Common Stock | |||||||||||||||||
Basic | |||||||||||||||||
Diluted | |||||||||||||||||
See notes to consolidated financial statements.
85
Neptune Insurance Holdings Inc. and Subsidiaries
Consolidated Statements of Changes in Redeemable, Convertible Preferred Stock
and Stockholders’ Deficit for the years ended December 31, 2025, 2024 and 2023
and Stockholders’ Deficit for the years ended December 31, 2025, 2024 and 2023
(In thousands)
| Stockholders' Deficit | ||||||||||||||||||||||||||||||||||||||||||||
| Redeemable Convertible Preferred Stock | Class A Common Stock | Class B Common Stock | Additional Paid-in Capital | Accumulated Deficit | Total | |||||||||||||||||||||||||||||||||||||||
| Shares | Amount | Shares | Amount | Shares | Amount | |||||||||||||||||||||||||||||||||||||||
| Balance, at December 31, 2022 | ( | ( | ||||||||||||||||||||||||||||||||||||||||||
| Common stock issued | - | - | - | - | - | - | ||||||||||||||||||||||||||||||||||||||
| Rescission of common stock issued | - | - | ( | - | - | - | ( | - | ( | |||||||||||||||||||||||||||||||||||
| Redeemable, convertible preferred stock issued, net of issuance costs | - | - | - | - | - | - | - | |||||||||||||||||||||||||||||||||||||
| Accretion of redeemable, convertible preferred stock | - | - | - | - | - | - | ( | ( | ||||||||||||||||||||||||||||||||||||
| Cash dividend paid | - | - | - | - | - | - | - | ( | ( | |||||||||||||||||||||||||||||||||||
| Share-based compensation | - | - | - | - | - | - | - | |||||||||||||||||||||||||||||||||||||
| Net income | - | - | - | - | - | - | - | |||||||||||||||||||||||||||||||||||||
| Balance, at December 31, 2023 | $ | $ | $ | $ | ( | $ | ( | |||||||||||||||||||||||||||||||||||||
| Accretion of redeemable, convertible preferred | - | - | - | - | - | - | ( | ( | ||||||||||||||||||||||||||||||||||||
| Share-based compensation | - | - | - | - | - | - | - | |||||||||||||||||||||||||||||||||||||
| Net income | - | - | - | - | - | - | - | |||||||||||||||||||||||||||||||||||||
| Balance at December 31, 2024 | $ | $ | $ | $ | ( | $ | ( | |||||||||||||||||||||||||||||||||||||
| Accretion of redeemable, convertible preferred | ( | ( | ||||||||||||||||||||||||||||||||||||||||||
| Share-based compensation | - | - | - | - | - | - | - | |||||||||||||||||||||||||||||||||||||
| Contributed capital, stockholder reimbursement of IPO transaction costs | - | - | - | - | - | - | - | |||||||||||||||||||||||||||||||||||||
| Exercise of options | - | - | - | - | - | - | ||||||||||||||||||||||||||||||||||||||
| Redemption of preferred stock for Class A common stock | ( | ( | - | - | - | - | ||||||||||||||||||||||||||||||||||||||
| Redemption of Class A common stock for Class B common stock | - | - | ( | - | - | - | - | - | ||||||||||||||||||||||||||||||||||||
| Cash dividend paid | - | - | - | - | - | - | - | ( | ( | |||||||||||||||||||||||||||||||||||
| Net income | - | - | - | - | - | - | - | |||||||||||||||||||||||||||||||||||||
| Balance at December 31, 2025 | $ | $ | $ | ( | $ | ( | ||||||||||||||||||||||||||||||||||||||
See notes to consolidated financial statements.
86
Neptune Insurance Holdings Inc. and Subsidiaries
Consolidated Statements of Cash Flows
for the years ended December 31, 2025, 2024 and 2023
(In thousands)
| 2025 | 2024 | 2023 | |||||||||||||||
| Cash flows from operating activities: | |||||||||||||||||
Net income | $ | $ | $ | ||||||||||||||
Adjustments to reconcile net income to cash provided by operating activities: | |||||||||||||||||
Amortization expense | |||||||||||||||||
Amortization of deferred financing costs | |||||||||||||||||
Loss on extinguishment of debt | |||||||||||||||||
Share-based compensation | |||||||||||||||||
Deferred income taxes | ( | ( | |||||||||||||||
(Increase) decrease in operating assets: | |||||||||||||||||
Commissions and fees receivable | ( | ( | ( | ||||||||||||||
Income tax receivable | ( | ( | |||||||||||||||
Prepaid expenses and other current assets | ( | ( | |||||||||||||||
Deferred financing asset | ( | ( | |||||||||||||||
Increase (decrease) in operating liabilities: | |||||||||||||||||
Accounts payable | |||||||||||||||||
Commissions payable | |||||||||||||||||
Income tax payable | ( | ( | |||||||||||||||
Accrued expenses | ( | ||||||||||||||||
Net cash provided by operating activities | |||||||||||||||||
| Cash flows from investing activities: | |||||||||||||||||
Internal developed software | ( | ( | ( | ||||||||||||||
Purchase of intangible assets | ( | ||||||||||||||||
Net cash used in investing activities | ( | ( | ( | ||||||||||||||
| Cash flows from financing activities: | |||||||||||||||||
Change in fiduciary receivables | ( | ( | ( | ||||||||||||||
Change in fiduciary liabilities | |||||||||||||||||
Repayments of 2021 Term Loan | ( | ||||||||||||||||
Proceeds from 2023 Term Loan | |||||||||||||||||
Repayments of 2023 Term Loan | ( | ( | |||||||||||||||
Proceeds from 2024 Term Loan | |||||||||||||||||
Repayments of 2024 Term Loan | ( | ( | |||||||||||||||
Proceeds from 2025 Term Loan | |||||||||||||||||
Repayments of 2025 Term Loan | ( | ||||||||||||||||
Payment of deferred financing fees and prepayment penalty | ( | ( | ( | ||||||||||||||
| Issuance of common stock | |||||||||||||||||
| Rescission of common stock | ( | ||||||||||||||||
| Issuance of redeemable, convertible preferred stock, net of issuance costs | |||||||||||||||||
Proceeds from revolving credit facility | |||||||||||||||||
Repayments of revolving credit facility | ( | ||||||||||||||||
Proceeds from exercise of stock options | |||||||||||||||||
Contributed capital, stockholder reimbursement of IPO transaction costs | |||||||||||||||||
Cash dividend paid | ( | ( | |||||||||||||||
Net cash used in financing activities | ( | ( | ( | ||||||||||||||
Net increase in cash and cash equivalents and fiduciary cash | |||||||||||||||||
| Cash and cash equivalents and fiduciary cash: | |||||||||||||||||
Beginning of year | |||||||||||||||||
End of year | $ | $ | $ | ||||||||||||||
| Cash and cash equivalents | $ | $ | $ | ||||||||||||||
| Fiduciary cash | |||||||||||||||||
Total cash and cash equivalents and fiduciary cash | $ | $ | $ | ||||||||||||||
87
| Cash paid for: | |||||||||||||||||
Interest | $ | $ | $ | ||||||||||||||
Income taxes | $ | $ | $ | ||||||||||||||
| Supplemental disclosure of non-cash financing activities: | |||||||||||||||||
| Reclassification of unamortized deferred financing fees to deferred financing asset | $ | $ | $ | ||||||||||||||
See notes to consolidated financial statements.
88
Neptune Insurance Holdings Inc.
Notes to Audited Consolidated Financial Statements
Note 1. Nature of Business and Basis of Presentation
Neptune Insurance Holdings Inc. (“Neptune Holdings” or the “Company”) was incorporated in Delaware on March 20, 2025, to serve as the holding company for Neptune Flood Incorporated (“Neptune Flood”).
Neptune Flood, incorporated in Delaware on February 10, 2017, is an insurance agency engaged in the business of selling residential and commercial flood insurance policies on behalf of insurance carrier partners throughout the United States.
On April 10, 2025, Neptune Holdings completed a corporate restructuring through a reverse triangular merger (the “Reorganization”) to implement a holding company structure. In connection with the Reorganization, Neptune Insurance Merger Sub Inc. (“Merger Sub”), a wholly-owned subsidiary of Neptune Holdings, merged with and into Neptune Flood, with Neptune Flood continuing as the surviving entity. Each issued and outstanding share of common and preferred stock of Neptune Flood was converted into an equivalent share of common and preferred stock of Neptune Holdings. The outstanding shares of Neptune Holdings previously owned by Neptune Flood were canceled and retired. As a result, Neptune Holdings became the parent holding company, and Neptune Flood became its wholly-owned operating subsidiary. In connection with the Reorganization, the Company filed an amendment to its Articles of Incorporation, effective April 10, 2025, which did not include any material changes other than those necessary to give effect to the new holding company structure. In connection with the Reorganization, Neptune Holdings assumed the Amended and Restated 2019 Stock Plan and amended and restated it in its entirety. The Amended and Restated 2019 Stock Plan, as so amended and restated in connection with the Reorganization, shall be referred to as the Pre-IPO 2025 Plan. Neptune Holdings also assumed Neptune Flood’s obligations under the Pre-IPO Stockholders Agreement that was entered into in connection with the convertible preferred stock financing of Neptune Flood in May 2023 as well as certain common stock and restricted stock purchase agreements and certain indemnification agreements.
The Reorganization was accounted for as a combination of entities under common control in accordance with subsections of Accounting Standards Codification (“ASC”) Topic 805-50, Business Combinations (“ASC 805-50”). Consequently, Neptune Flood was contributed to Neptune Holdings and the Reorganization was recorded at historical carrying amounts and the Company’s consolidated financial statements prior to the Reorganization have been adjusted to reflect the retrospective combination of the entities for all periods presented.
Initial Public Offering: On October 2, 2025, the Company completed its IPO, in which certain stockholders of the Company sold 21,184,210 shares of its Class A common stock at a public offering price of $20.00 per share. The Company received no proceeds from the sale of Class A common stock by the selling stockholders in the offering. The Company incurred IPO transaction costs for the year ended December 31, 2025, of $8,913 , excluding the underwriting discount, which were expensed as incurred, as the Company received no proceeds from the IPO. These transaction costs are recorded within IPO transaction costs in the accompanying consolidated statements of income.
In connection with the IPO, all 41,850,000 shares of the Company’s convertible preferred stock converted into 41,850,000 shares of common stock. Additionally, all 138,035,000 shares of common stock (including shares of common stock issued upon the automatic conversion of our outstanding convertible preferred stock) were reclassified into 138,035,000 shares of Class A common stock, of which 43,435,000 shares were then exchanged for Class B common stock on a one -for-one basis, resulting in 94,600,000 shares of Class A common stock and 43,435,000 shares of Class B common stock outstanding at the time of the IPO. Class A and Class B common stock are identical in their economic rights.
In connection with the IPO, the selling stockholders agreed to reimburse the Company for certain IPO offering costs, in an aggregate amount not to exceed 2 % of the gross IPO proceeds to be received by the selling stockholders. On October 2, 2025, the Company received the full reimbursement amount due from the selling stockholders.
Basis of Presentation: The consolidated financial statements have been prepared in accordance with accounting principles generally accepted in the United States of America (“US GAAP”). The consolidated financial statements are presented in U.S. Dollars. All amounts are presented in thousands, except per share data and where otherwise noted.
Emerging Growth Company: Section 102(b)(1) of the Jumpstart Our Business Startups Act (“JOBS Act”) exempts emerging growth companies (“EGC”) from being required to comply with new or revised financial accounting standards until private companies are required to. For the purpose of this section, a private company is one that has not had a Securities Act registration statement declared effective or does not have a class of securities registered under the
89
Securities Exchange Act of 1934, as amended. The JOBS Act provides that a company can elect to opt out of the extended transition period and comply with the requirements that apply to non-emerging growth companies but any such election to opt out is irrevocable. The Company qualifies as an EGC and has elected not to opt out of such extended transition period which means that when a standard is issued or revised and it has different application dates for Public Business Entities (“PBEs”) and Non-PBEs, the Company, as an EGC, can adopt the new or revised standard at the time private companies adopt the new or revised standard, until such time the Company is no longer considered to be an EGC. At times, the Company may elect to early adopt a new or revised standard.
Principles of Consolidation: The accompanying consolidated financial statements include the accounts of the Company and its wholly owned subsidiaries. All significant intercompany account balances and transactions have been eliminated in the consolidated financial statements.
Stock Split: On September 9, 2025, the Company effected a ten -for-one stock split of its common stock and redeemable, convertible preferred stock. All share and per share information has been retroactively adjusted to reflect the stock split for all periods presented. The shares of common stock and redeemable, convertible preferred stock retain a par value of $0.00001 per share.
Use of Estimates: The preparation of consolidated financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities, disclosures of contingent assets and liabilities at the date of the consolidated financial statements, and the reported amounts of revenue and expenses during the reporting period. These estimates, judgments, and assumptions are continually evaluated based on available information and experience. Because of the use of estimates inherent in the financial reporting process, actual results could differ from those estimates. The Company’s most significant estimates and judgments involve the valuation of share-based compensation, including the fair value of common stock, accounting for capitalized internal-use software, including the related estimated useful life, as well as the estimates for policy cancellations.
Note 2. Significant Accounting Policies
Revenue Recognition: The Company recognizes revenue for the transfer of such promised products or services to customers in an amount that reflects the consideration to which the Company expects to be entitled to in exchange for those products or services. Under ASC Topic 606, Revenue from Contracts with Customers (“ASC 606”), revenue is recognized when or as the transfer of control of the underlying performance obligations occurs. ASC 606 provides a five-step model for recognizing revenue from contracts with customers as follows:
•Identify the contract with a customer
•Identify the performance obligations in the contract
•Determine the transaction price
•Allocate the transaction price to the performance obligations in the contract
•Recognize revenue when or as the performance obligations are satisfied
Concentrations of Credit Risk: Financial instruments that potentially subject the Company to concentrations of credit risk are primarily comprised of cash and cash equivalents and fiduciary cash. Cash deposits may, at times, exceed amounts insured by the Federal Deposit Insurance Corporation and the Securities Investor Protection Corporation. However, the Company’s exposure to credit risk in the event of default by the financial institutions is limited to the excess of the amounts recorded on the consolidated balance sheets over the insured amounts. The Company has not experienced any losses on its deposits of cash and cash equivalents or fiduciary cash to date.
Fiduciary Cash and Fiduciary Receivable: In its capacity as a managing general agency (“MGA”), the Company typically collects premiums from insureds and, after deducting the authorized commissions, remits the net premiums to the appropriate insurance company or companies. Accordingly, premiums receivable from insureds are reported as fiduciary receivable and premiums payable to insurance companies are reported as insurance company payables in the accompanying consolidated balance sheets. Unremitted net insurance premiums are held in a fiduciary capacity until
90
the Company disburses them. Net insurance premiums payable to insurance companies together with premium deposits received from customers are held as fiduciary cash on the accompanying consolidated balance sheets. Insurance company payables together with premium deposits are considered fiduciary liabilities. Cash and cash equivalents held in excess of the amount required to meet the Company’s fiduciary obligations are recognized as cash and cash equivalents on the consolidated balance sheets.
Commissions and Fees Receivable: Commissions receivable reflect commissions due from insurance carrier partners. Fees receivable represent fees due from policyholders.
The Company assesses collectability by reviewing accounts receivable on a collective basis where similar characteristics exist and on an individual basis when the Company identifies specific customers with known disputes or collectability issues. In determining the amount of the allowance for expected credit losses, the Company considers historical collectability based on past due status and makes judgments about the creditworthiness of customers based on ongoing credit evaluations. The Company also considers customer-specific information, current market conditions, and reasonable and supportable forecasts of future economic conditions to inform adjustments to historical loss data. The allowance for expected credit losses is not material as of December 31, 2025 and 2024. Non-payments are accrued for as part of the Company’s estimate for policy cancellations.
Intangible Assets, Net: Intangible assets are stated at cost, which includes the fair value of intangible assets acquired in business acquisitions, less accumulated amortization, and consist of acquired customer relationships and trade names. Acquired relationships and trade names are amortized on a straight-line basis over estimated useful lives of 10 years.
91
Goodwill: Goodwill totaled $3,793
Goodwill represents the excess of the purchase price over the fair value of assets acquired and liabilities assumed in a business combination. Goodwill has an indefinite useful life and is not amortized. The Company reviews its goodwill for impairment at least annually or whenever events or changes in circumstances indicate that the carrying value of the Company’s reporting unit may exceed its fair value. The Company first assesses qualitative factors to determine whether it is more likely than not that the fair value of the Company’s reporting unit is less than its carrying amount, including goodwill. If that is the case, the Company performs a quantitative impairment test, and, if the carrying amount of the Company’s reporting unit exceeds its fair value, then the Company will recognize an impairment charge for the amount by which its carrying amount exceeds its fair value, not to exceed the carrying amount of the goodwill.
The Company performed a qualitative assessment of goodwill for each of the years ended December 31, 2025, 2024 and 2023, determined that the fair value of its reporting unit exceeded its carrying value, and thus concluded that the carrying value of goodwill was not impaired as of each goodwill impairment test date, which is December 31. Accordingly, no further analysis was required or performed.
Premium Deposits: Premium deposits consist of payments received from the policyholder in advance of performance under the insurance policy contract with the policyholder.
Deferred Financing Fees: The Company capitalizes financing fees incurred in connection with its debt arrangements. For term loans, deferred financing costs are presented as a direct deduction from the carrying amount of the related debt and are amortized using the effective interest method over the term of the loan. For revolving credit facilities, deferred financing costs are recorded as a deferred asset and amortized on a straight-line basis over the availability period of the facility.
Leases: The Company accounts for leases under ASC Topic 842, Leases. A lease is an agreement between two or more parties that creates enforceable rights and obligations that conveys the right to control the use of an identified asset for a period of time in exchange for consideration. ASC Topic 842, Leases requires an entity to determine whether a contract is a lease or contains a lease at the inception of the contract, considering all relevant facts and circumstances.
As of December 31, 2025, the Company’s only lease arrangement is a month-to-month office space lease, which qualifies as a short-term lease under ASC Topic 842, Leases. The office space is leased from a related party. Refer to Note 10 – Related Party Transactions for additional details. The Company elected to not recognize a lease liability or right-of-use asset on the consolidated balance sheets for leases with an initial term of 12 months or less. Operating lease expenses on short-term leases are recognized on a straight-line basis over the respective lease term as a component of general and administrative expense in the consolidated statements of income.
Agent Commissions: Agent commissions are incurred in connection with the placement of residential and commercial property insurance policies by third-party agents. These commissions are expensed as incurred and are presented as agent commissions in the consolidated statements of income. Commissions payable to agents represents amounts due but not yet paid as of the reporting date. These amounts are included in commissions payable on the consolidated balance sheets.
Fair Value of Financial Instruments: Fair value accounting establishes a framework for measuring fair value, which is defined as the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date (i.e., an exit price). This framework includes a fair value hierarchy that prioritizes the inputs to the valuation technique used to measure fair value.
The classification of a financial instrument within the valuation hierarchy is based upon the transparency of inputs to the valuation of an asset or liability on the measurement date. The three levels of the hierarchy in order of priority of inputs to the valuation technique are defined as follows:
•Level 1 - Valuations are based on unadjusted quoted prices in active markets for identical financial instruments;
•Level 2 - Valuations are based on quoted market prices, other than quoted prices included in Level 1, in markets that are not active or on inputs that are observable either directly or indirectly for the full term of the financial instrument; and
92
•Level 3 - Valuations are based on pricing or valuation techniques that require inputs that are both unobservable and significant to the overall fair value measurement of the financial instrument. Such inputs may reflect management’s own judgment about the assumptions a market participant would use in pricing the financial instrument.
The level in the fair value hierarchy within which the fair value measurement is classified is determined based on the lowest level input that is significant to the fair value measure in its entirety.
The Company’s financial assets and liabilities consist of cash and cash equivalents, fiduciary cash, accounts receivable, accounts payable, commissions payable, insurance company payables, accrued expenses, and debt. The carrying value of cash and cash equivalents, accounts receivable, accounts payable, commissions payable, insurance company payables, and accrued expenses approximates fair value because of the short-term nature of those instruments. The carrying value of debt approximates fair value due to the variable rate nature of the debt.
Redeemable, Convertible Preferred Stock: The Company applies ASC Topic 480, Distinguishing Liabilities from Equity, when determining the classification of preferred stock. The Company classifies instruments that are conditionally redeemable for cash or other assets outside of permanent equity if they are redeemable (i) at a fixed or determinable price on a fixed or determinable date, (ii) at the option of the holder, or (iii) upon the occurrence of an event that is not solely within the control of the issuer.
The Company classifies redeemable, convertible preferred stock (“Redeemable Preferred Stock”) as temporary equity on the accompanying consolidated balance sheets as it is redeemable solely on the passage of time or upon an event outside the control of the Company. The Company accretes the changes in the redemption value over the period from the original issuance date until the earliest probable redemption date using the interest method. Changes in the redemption value are considered to be changes in accounting estimates.
On October 2, 2025, prior to the completion of the Company’s IPO, all outstanding shares of Redeemable Preferred Stock were automatically converted into shares of the Company’s Class A common stock on a one -for-one basis. Upon conversion, the carrying amount of the Redeemable Preferred Stock, including any accretion to redemption value, was reclassified to permanent equity.
Income Taxes: The Company accounts for income taxes pursuant to the asset and liability method, which requires the recognition of deferred income tax assets and liabilities related to the expected future tax consequences arising from temporary differences between the carrying amounts and tax bases of assets and liabilities based on enacted statutory tax rates applicable to the periods in which the temporary differences are expected to reverse. Any effects of changes in income tax rates or laws are included in income tax expense in the period of enactment.
The Company and its subsidiaries apply ASC Topic 740, Income Taxes. A component of this standard prescribes a recognition and measurement threshold of uncertain tax positions taken or expected to be taken in a tax return. For those benefits to be recognized, a tax position must be more likely than not to be sustained upon examination by taxing authorities. Management has evaluated the Company’s tax positions and concluded that the Company has taken no uncertain tax positions that require adjustment to the financial statements to comply with the provisions of this guidance.
Earnings Per Share: Basic earnings per share is computed by dividing net income attributable to common stockholders by the weighted average number of common shares outstanding during the period. The Company’s Redeemable Preferred Stock is classified as temporary equity and is considered probable of becoming redeemable. Additionally, Redeemable Preferred Stock represents participating securities, as holders of the Preferred Stock participate in dividends with holders of common stock on a pro rata basis. Accordingly, the Company used the two-class method of computing basic and diluted earnings per share for common stock. Under this method, net income applicable to holders of common stock is first reduced by the amount of accretion adjustment to the Redeemable Preferred Stock in the current period, and remaining undistributed earnings is then allocated on a pro rata basis to the holders of common stock and Redeemable Preferred Stock to the extent that each class may share income for the period; whereas undistributed net loss is allocated to common stock only because holders of Redeemable Preferred Stock are not contractually obligated to share the loss.
93
Comprehensive Income: Comprehensive income consists of net income and changes in equity during a period from transactions and other equity and circumstances generated from non-owner sources. The Company’s net income equals comprehensive income for all periods presented.
Recently Adopted Accounting Pronouncements:
Income Taxes: In December 2023, the Financial Accounting Standards Board (“FASB”) issued Accounting Standards Update (“ASU”) 2023-09, ASC Topic 740, Income Taxes - Improvements to Income Tax Disclosures. This standard requires the Company to provide further disaggregated income tax disclosures for specific categories on the effective tax rate reconciliation, as well as additional information about federal, state, local and foreign income taxes. The standard also requires the Company to annually disclose its income taxes paid (net of refunds received), disaggregated by jurisdiction. This guidance is effective for fiscal years beginning after December 15, 2024, with early adoption permitted. The standard is to be applied on a prospective basis, although optional retrospective application is permitted. The Company has adopted this standard and applied the standard retrospectively as disclosed in Note 8 – Income Taxes. The adoption of ASU 2023-09 did not have a material impact on the Company’s consolidated financial statements.
Recent Accounting Pronouncements Not Yet Adopted:
Disaggregation of Income Statement Expenses: In November 2024, the FASB issued ASU 2024-03, ASC Topic 220-40, Income Statement Reporting - Comprehensive Income - Expense Disaggregation Disclosures, Disaggregation of Income Statement Expenses (“ASU 2024-03”). The standard update improves the disclosures about a PBE’s expense by requiring more detailed information about the types of expenses (including purchases of inventory, employee compensation, depreciation and amortization) included within income statement expense captions. ASU 2024-03 will be effective for annual reporting periods beginning after December 15, 2026, and interim reporting periods beginning after December 15, 2027. Early adoption is permitted and changes are required to be applied prospectively with the option for retrospective application. The Company is currently evaluating the impact of this new guidance on its consolidated financial statements.
Note 3. Revenue
The Company’s revenue is derived from the sale of insurance policies and is primarily comprised of commission income and fee income.
Commission Income
The largest component of the Company’s revenue is commission income from the placement of insurance contracts between insurance carriers and the policyholders who acquire property insurance policies. These commissions are established by the carrier agreement between the Company and the insurance carrier partner and are calculated as a negotiated percentage of premiums for the underlying insurance contract. Commission rates and terms vary across insurance carriers. The Company’s performance obligation under its agreements with insurance carrier partners is selecting, pricing, and placing policyholders’ insurance contracts on their behalf. Each underlying insurance contract is a separate and distinct contract between the policyholder and the insurance carrier partner. The Company collects the full premium for the
94
policy from the policyholder at inception, then remits that premium, net of the commission owed to the Company, to the insurance carrier partner. Commission income is recognized at a point in time upon the effective date of bound insurance coverage, at which point the performance obligation has been met as no performance obligation exists after coverage is bound.
The transaction price is the total commission the Company expects to receive from the insurance carrier partner for the current term of the policy. The transaction date is determined by the effective date of the insurance policy. Policies may be cancelled in accordance with permitted reasons under applicable laws and the policy terms. In the event of a permitted cancellation, the Company’s commission being limited to the period that the policy was in effect. The Company estimates any expected variable consideration, or cancellations, based on historical information, and records a corresponding deduction in revenue at the time revenue is recognized. The Company bases its estimates on historical cancellation experience by policy type and tenure and adjusts for any known trends or events. The estimation period typically covers the allowable cancellation period. This variable consideration is recognized to the extent that it is probable there will not be a significant reversal of revenue.
The Company also earns small amounts of contingent income from insurance carrier partners in the form of a profit-sharing commission, which is highly variable and based on underwriting results. The Company assesses whether the underlying book of business has attained the profitability criteria set by carriers and whether enough time has passed to minimize the risk that sufficient losses will become realized that would negate the profit share. The Company closely monitors the calculations to identify if a profit-sharing commission would be earned and recognizes the profit-sharing commission as the underlying policies are placed, net of a constraint.
Contingent profit-sharing commissions represent a form of variable consideration associated with the placement and profitability of coverage, for which the Company earns base commissions. In connection with ASC 606, contingent profit-sharing commissions are estimated with a constraint applied and accrued relative to the recognition of the corresponding base commissions for the period over which the contract applies. As contingent commissions are earned in relation to policies placed by the Company with the insurance carrier partner, the timing of recognizing contingent commissions follows a similar pattern as the base commissions on premium described above, with any adjustments recognized when payments are received or as additional information that affects the estimate becomes available.
Fee Income
In addition to commissions on premium, the Company earns fee income. These fees are established by the carrier agreement between the Company and the insurance carrier partner and represent a flat charge on each underlying insurance contract. The Company’s performance obligation under its agreements with insurance carrier partners is selecting, pricing, and placing policyholders’ insurance contracts on their behalf. This fee compensates the Company for the administrative and operational costs associated with the Company's placement of the policy for the insured. The Company is entitled to the full fee for the policy year, even in the event of cancellation. At each annual renewal, the policyholder is re-assessed a flat, non-refundable policy fee, which the Company is entitled to retain.
Fees can vary by product type, underlying risk, and location of the insured property. The fee is non-refundable should the policy be canceled due to home sale or any other type of acceptable mid-term cancellation reason, therefore, fee income is treated as fully earned once a policy has become effective and is recognized as revenue at that time. Similar to the base commissions on premium described above, fees are recognized at a point in time upon the effective date of bound insurance coverage, at which point the performance obligation has been met as no performance obligation exists after coverage is bound.
The Company excludes from revenue any amounts collected from policyholders that are assessed by governmental authorities, such as sales and premium taxes, when the Company acts solely as a collecting agent.
Contract Costs
ASC Topic 340-40, Other Assets and Deferred Costs - Contracts with Customers requires the Company to review certain costs to obtain customer contracts primarily as they relate to agency commission arrangements. The Company pays agent commissions to its distribution partners, such as independent agents, brokers, or referral partners, for selling policies on behalf of the Company. The Company’s agency commission arrangements are the same for both new or renewal business. The Company has elected the practical expedient to expense these costs as incurred since the amortization period related to the resulting asset would be one year or less. The Company has no significant instances of contracts that would be amortized for a period greater than a year and therefore has no contract costs deferred for such arrangements.
95
Costs to fulfill - Due to the relatively short time period between the information gathering phase and binding insurance coverage, the Company has determined that costs to fulfill contracts are not significant. Therefore, costs to fulfill a contract are expensed as incurred.
Disaggregation of Revenue
The following table disaggregates revenue by source for the years ended December 31:
| (In thousands) | 2025 | 2024 | 2023 | ||||||||||||||
| Commission income | $ | $ | $ | ||||||||||||||
| Fee income | |||||||||||||||||
| Total revenues | $ | $ | $ | ||||||||||||||
Contract Asset and Premium Deposits
The timing of revenue recognition may not align with the right to invoice the customer. The Company records accounts receivable when it has the unconditional right to issue an invoice and receive payment, regardless of whether revenue has been recognized. Policyholder payments received in advance of commencement of the performance obligation are recorded as premium deposits. No revenue is recognized on these deposits until the performance obligation is complete.
The following table provides information about receivables and premium deposits as of December 31:
| (In thousands) | 2025 | 2024 | |||||||||
| Commissions and fees receivable | $ | $ | |||||||||
| Premium deposits | $ | $ | |||||||||
During the year ended December 31, 2025, the Company recognized revenue of $3,377 related to the premium deposits balance at December 31, 2024.
Note 4. Intangible Assets
Intangible assets consist of the following as of December 31:
| (In thousands) | Useful Life | 2025 | 2024 | ||||||||
| Customer relationships | $ | $ | |||||||||
| Trade name | |||||||||||
| Less accumulated amortization | ( | ( | |||||||||
| Net intangible assets | $ | $ | |||||||||
The weighted average amortization period of intangible assets was 6.07 , 6.75 , and 7.75 years for the years ended December 31, 2025, 2024, and 2023, respectively. Amortization expense related to intangible assets totaled $73 , $71 , and $70 for the years ended December 31, 2025, 2024, and 2023, respectively.
96
The following table summarizes the expected amortization of the intangible assets for the next five years and thereafter as of December 31, 2025:
| (In thousands) | |||||
| Years ending December 31: | |||||
| 2026 | |||||
| 2027 | |||||
| 2028 | |||||
| 2029 | |||||
| 2030 | |||||
| Thereafter | |||||
Note 5. Debt
Debt consists of the following as of December 31:
| (In thousands) | 2025 | 2024 | |||||||||
| 2024 Term Loan | $ | $ | |||||||||
| 2025 Term Loan | |||||||||||
| Total debt | |||||||||||
| Less: unamortized deferred financing fees | ( | ||||||||||
| Less current maturities of debt | ( | ||||||||||
| Debt, net | $ | $ | |||||||||
| Revolving credit facility | $ | $ | |||||||||
Amended and Restated Credit Agreement
On May 8, 2023, the Company amended and restated its prior credit agreement entered into during 2021 (“2023 Amended and Restated Credit Agreement”) in its entirety with its existing lender, increasing its borrowing base on the term loan to $190,000 (“2023 Term Loan”) and providing access to incremental loans and a revolving line of credit of $10,000 . During the year ended December 31, 2024, and prior to the refinancing on June 13, 2024, the Company made aggregate principal repayments of $4,475 .
2024 Credit Agreement
On June 13, 2024, the Company entered into a credit agreement (“2024 Credit Agreement”) comprised of a $171,000 term loan (“2024 Term Loan”) and a revolving line of credit commitment of $10,000 (“2024 Revolver”) as well as access to incremental loans. The Company used the proceeds from the 2024 Term Loan in part to pay down the remaining balance of the 2023 Term Loan under the 2023 Amended and Restated Credit Agreement. A loss on extinguishment of debt of $5,346 was recognized in the consolidated statements of income during the year ended December 31, 2024, related to the pay down of the 2023 Term Loan, consisting of the prepayment penalty of $1,741 and the write-off of unamortized deferred financing fees of $3,348 and deferred financing asset of $257 .
During the year ended December 31, 2025, and prior to the refinancing on April 10, 2025, the Company made aggregate principal repayments of $4,000 . During the year ended December 31, 2024, the Company made aggregate principal repayments of $36,000 . The Company recorded amortization expense of $111 and $556 for the years ended December 31, 2025 and 2024, respectively. Interest expense related to the 2024 Credit Agreement was $2,617 and $7,974 for the years ended December 31, 2025 and 2024, respectively.
2025 Credit Agreement
On April 10, 2025, the Company amended and restated its 2024 Credit Agreement (the “2025 Amended and Restated Credit Agreement”) with its existing lenders to, among other things, increase its borrowing base on the term loan to $301,000 (the “2025 Term Loan”) and extend the maturity date to April 30, 2030. The proceeds of the 2025 Term Loan
97
were used to repay in full all outstanding obligations under the 2024 Term Loan and to finance a dividend. The revolving loan commitment remained at $10,000 (“2025 Revolver”) and its maturity date was also extended to April 30, 2030. The Company applied modification accounting to the 2024 Credit Agreement and capitalized $477 of deferred financing fees, $36 of deferred financing asset, and recognized interest expense of $518 for third party fees related to the 2025 Amended and Restated Credit Agreement. Unamortized deferred financing fees of $1,238 related to the 2024 Term Loan continued to be amortized over the term of the 2025 Term Loan. During the year ended December 31, 2025, and prior to the refinancing on November 10, 2025, the Company made aggregate principal repayments of $50,000 .
First Amendment to the 2025 Credit Agreement
On November 10, 2025, Neptune Flood entered into the first amendment to the 2025 Amended and Restated Credit Agreement (“First Amendment”) with its existing lenders to, among other things, to increase the maximum availability of the 2024 Revolver to $260,000 (“Amended 2025 Revolver”). The Company used proceeds drawn on the Amended 2025 Revolver from the First Amendment to paydown the outstanding balance of the 2025 Term Loan. The Company applied modification accounting to the Amended 2025 Revolver and capitalized $426 of deferred financing asset related to the First Amendment. Unamortized deferred financing fees of $1,264 related to the 2025 Amended and Restated Credit Agreement were reclassified to deferred financing asset and deferred financing asset of $106 related to the 2025 Amended and Restated Credit Agreement continues to be amortized over the term of the Amended 2025 Revolver. At the Company's option, the interest rate on the Amended 2025 Revolver may be based on either ABR plus an applicable margin ranging from 0.75 % to 2.00 % or Term SOFR ranging from 1.75 % to 3.00 %, depending on the Company’s total net leverage ratio for the prior fiscal quarter. Interest is payable quarterly and the maturity date was extended to November 10, 2030, at which time any outstanding principal and accrued interest is due. As of December 31, 2025, the total amount outstanding under the revolving credit facility was $240,000 .
Incremental Loans: The Company may request up to three tranches of incremental term loans (“Incremental Term Loan”) or increases to the existing Revolver (“Additional Revolving Commitment”), subject to lender participation and agent approval. Each Incremental Term Loan request must be for a minimum principal amount of $10,000 . The total amount of Additional Revolving Commitments under all such requests shall not exceed $10,000 over the term of the agreement. Any Incremental Term Loan(s) must (a) rank pari passu in right of payment and be secured solely by the existing collateral, (b) have no obligors other than the loan parties, (c) mature no earlier than the latest maturity date of any then-outstanding term loans, and (d) not have a shorter weighted average life to maturity than the existing Term Loans. Incremental Term Loans may be priced differently but must otherwise be treated no more favorably than existing term loans, subject to exceptions for loans maturing after the latest maturity date.
Borrowings under the Amended Credit Agreement are secured by a first-priority lien on substantially all of the Company’s stock and assets and are subject to certain restrictive covenants primarily relating to net leverage ratios. Under the 2024 Credit Agreement, the Company was subject to two key financial covenants which began with the fiscal quarter ending June 30, 2024. First, the Company was required to maintain a total net leverage ratio that did not exceed 4.50 through the quarter ending September 30, 2024. This threshold tightened over time, requiring a maximum ratio of 4.25 for quarters ending from December 31, 2024 through March 31, 2025. Under the 2025 Amended and Restated Credit Agreement, the Company was required to maintain a total net leverage ratio that did not exceed 5.00 through the quarter ending September 30, 2025. This threshold will tighten to 4.50 for the quarters ending from December 31, 2025 through June 30, 2026, and further reduce to 4.00 for quarters ending on or after September 30, 2026. Second, the Company is required to maintain an interest coverage ratio of at least 2.00 for any rolling four-quarter period ending on the last day of each fiscal quarter, starting with the quarter ending June 30, 2024. The Company was in compliance with both covenants as of December 31, 2025.
The First Amendment contains a number of customary negative covenants for agreements of this type that, among other things and subject to certain exceptions, restrict the Company’s ability to: create, incur, or assume any additional indebtedness; create, incur, or assume any liens; engage in mergers, consolidations, or amalgamations; make investments, loans, or advances; pay dividends; sell assets; engage in certain transactions with affiliates; enter into restrictive agreements; enter into sale and leaseback transactions; execute amendments to organizational documents or certain other material agreements; and make certain accounting changes.
Interest expense was $18,243 , $17,520 and $21,326 for the years ended December 31, 2025, 2024, and 2023, respectively, of which $562 , $871 and $1,194 was attributable to the amortization of the debt issuance costs, respectively, and $70 , $34 and $34 was attributable to the amortization of the deferred financing asset, respectively. Accrued interest associated with the outstanding debt is included within accrued expenses on the consolidated balance sheets. As of December 31, 2025, and 2024, the Company had $932 and $451 , respectively, of accrued interest associated with the debt.
98
Note 6. Stockholders’ Deficit and Redeemable, Convertible Preferred Stock
The total number of shares of all classes of stock that the Company has authority to issue is 500,000,000 shares, consisting of 480,000,000 shares of common stock, par value $0.00001 per share (the “Common Stock”), 428,422,036 shares of which are designated as Class A Common Stock, par value $0.00001 per share (the “Class A Common Stock”) and 51,577,964 shares of which are designated as Class B Common Stock, par value $0.00001 per share (the “Class B Common Stock”), and 20,000,000 shares of Preferred Stock, par value $0.00001 per share (the “Preferred Stock”).
The following table presents a rollforward of the Company’s common stock issued and outstanding as of December 31, 2025:
| Redeemable Preferred Stock | Class A Common Stock | Class B Common Stock | |||||||||||||||
| Shares issued at December 31, 2024 | |||||||||||||||||
| Redemption of preferred stock for Class A common stock | ( | - | |||||||||||||||
| Redemption of Class A common stock for Class B common stock | - | ( | |||||||||||||||
| Exercise of options | - | ||||||||||||||||
| Shares issued at December 31, 2025 | |||||||||||||||||
On July 28, 2023, the Company amended and restated its certificate of incorporation to effect a 1,000 -for-1 forward stock split of the Company’s outstanding and authorized shares of Common Stock and Redeemable, Convertible Preferred Stock so that the par value of the issued and outstanding shares of the Company’s Common Stock and Redeemable Preferred Stock was reduced from $0.01 0.00001
Class A Common Stock
Holders of the Company’s Class A common stock are entitled to one vote per share on all matters submitted to a vote of stockholders. Holders of Class A common stock vote together with holders of Class B common stock as a single class, except as otherwise required by law. Holders of Class A common stock are entitled to receive dividends when and if declared by the Company’s board of directors out of legally available funds, on a ratable per share basis. Upon liquidation, dissolution, or winding up of the Company, and subject to the rights of any preferred stock outstanding, holders of Class A common stock are entitled to share ratably in the Company’s remaining assets available for distribution.
Class B Common Stock
On October 2, 2025, 43,435,000 shares of Class A common stock were exchanged for 43,435,000 shares of Class B common stock on a one -for-one basis, resulting 43,435,000 shares of Class B common stock outstanding as of December 31, 2025. Refer to Note 1 – Nature of Business and Basis of Presentation.
Holders of the Company’s Class B common stock are entitled to ten votes per share on all matters submitted to a vote of stockholders. Holders of Class B common stock vote together with holders of Class A common stock as a single class, except as otherwise required by law.
Holders of Class B common stock are entitled to receive dividends when and if declared by the Company’s board of directors out of legally available funds on the same basis as holders of Class A common stock. Upon liquidation, dissolution, or winding up of the Company, and subject to the rights of any preferred stock outstanding, holders of Class B common stock are entitled to share ratably in the Company’s remaining assets available for distribution.
Each share of Class B common stock is convertible at any time, at the option of the holder, into one share of Class A common stock. In addition, each share of Class B common stock will automatically convert into one share of Class A common stock upon the occurrence of certain transfer events, other than permitted transfers, or upon the occurrence of a final conversion date, as defined in the Company’s governing documents. Following the final conversion date, Class B common stock may no longer be reissued, and any outstanding shares will be retired and canceled.
99
Redeemable, Convertible Preferred Stock
Upon the consummation of an initial public offering or transaction with a special purpose acquisition company that results in a certain amount of aggregate proceeds and an offering price above a certain threshold (“Qualified IPO”) the Redeemable, Convertible Preferred Stock was to be automatically converted into such number of shares of Common Stock having a value per share equal to the amount that would have been distributed with respect to such share had the Company been sold for cash in a Liquidation for the value of the Company in a Qualified IPO implied by the price per share of Common Stock at which shares are sold to the public in a Qualified IPO.
On October 2, 2025, the Company completed its IPO which resulted in the conversion of all 41,850,000 outstanding shares of the Company’s Redeemable, Convertible Preferred Stock on a one -for-one basis into shares of the Company’s Class A Common Stock. Refer to Note 1 – Nature of Business and Basis of Presentation.
Dividends
On April 10, 2025, the Company’s board of directors approved a cash dividend in the aggregate amount of $175,000 , payable to holders of Common Stock and Redeemable, Convertible Preferred Stock of record as of April 10, 2025.
Note 7. Share-Based Compensation Plan
In 2019, the stockholders of the Company approved the Neptune Flood Incorporated 2019 Stock Plan (the “Pre-Existing Plan”), that provides for the granting of restricted stock or options to employees and consultants contingent on performance-based and/or time-based criteria and was subsequently amended and restated in May and November of 2023. On April 10, 2025, the Company adopted the Amended and Restated 2025 Stock Plan (the “Pre-IPO Plan”), which amended and restated the Pre-Existing Plan. Pursuant to an Agreement and Plan of Merger dated April 10, 2025 by and among the Company, Neptune Flood, and Neptune Insurance Merger Sub Inc., the Company assumed the Pre-Existing Plan and all awards previously granted thereunder.
The principal purpose of the Pre-IPO Plan was to attract and retain the best available personnel for positions of substantial responsibility, to provide additional incentive to employees, and to promote the success of the Company’s business. The maximum contractual term of the stock options issued under the Pre-IPO Plan was 10 years. The number of shares of stock reserved for issuance under the stock plan was 12,800,000 shares. No awards could be granted under the Pre-IPO Plan if such awards could result in the issuance of more than 11,760,000 shares pursuant to awards granted after May 8, 2023. In connection with the adoption of the 2025 Plan, the Pre-IPO Plan was terminated and no additional awards may be granted thereunder; however, awards previously granted under the Pre-IPO Plan remain outstanding in accordance with their terms.
In connection with the IPO, the Company adopted the 2025 Equity Incentive Plan (the “2025 Plan”), which became effective on September 30, 2025. The 2025 Plan provides for the grant of equity-based awards, including stock options, restricted stock, restricted stock units, stock appreciation rights, and other share-based awards. The principal purpose of the 2025 Plan is to attract and retain the best available personnel for positions of substantial responsibility, to provide additional incentive to employees, and to promote the success of the Company’s business. The maximum contractual term of the stock options issued under the 2025 Plan is 10 years. The maximum aggregate number of shares of common stock authorized for issuance under the 2025 Plan is 6,123,333 shares. In addition, the number of shares available for issuance under the 2025 Plan will automatically increase on the first day of each fiscal year beginning in fiscal year 2027 through fiscal year 2036 by an amount equal to the lesser of (i) 2% of the outstanding shares of the Company’s common stock (including both Class A and Class B common stock) on the last day of the immediately preceding fiscal year, calculated on a fully diluted and as-converted basis, (ii) 6,123,333 shares, or (iii) such smaller number of shares as determined by the Company’s board of directors. Shares subject to awards under the 2025 Plan that expire, terminate, are forfeited, or are settled without issuance of shares generally become available for future issuance under the 2025 Plan, subject to the terms of the plan.
Stock Options
Stock options issued under the Pre-IPO Plan in 2025 and 2024 consist of two 5 th anniversary date of the grant date. Upon an optionee’s death or disability, or the consummation of a liquidity event by the Company, all of the Time-Based Option will immediately vest and become exercisable. All Time-Based Options have an exercise price of $5.50 per share. Performance-Based Options contain service, performance and market conditions. Subject to the optionee’s
100
continuous service through a liquidity event, Performance-Based Options will vest upon the occurrence of a liquidity event; provided that if the return on the invested capital of preferred stockholders is less than a multiple of 3.0 (as defined in the Plan (referred to herein as the “Preferred Return Multiple”)), the exercise price for the vested options will be $10.99 per share; and if the return on the invested capital of preferred stockholders equals or is more than the Preferred Return Multiple, the exercise price for the vested options will be $5.50 per share. If a liquidity event does not occur before the 5th anniversary date of the grant date, the service condition is considered to be met once a grantee has provided continuous service for 5 years; however, the performance condition is still required to be met for the Performance-Based Options to vest.
Upon the completion of the IPO on October 2, 2025, the liquidity event performance condition was satisfied. As a result, the exercise price applicable to the vested Performance-Based Options was $5.50 per share.
A summary of stock option activity for the year ended December 31, 2025, is presented below:
| Time Based | Performance Based | ||||||||||||||||||||||||||||||||||
Options | Weighted Average Exercise Price | Weighted Average Remaining Contractual Term | Options | Weighted Average Exercise Price | Weighted Average Remaining Contractual Term | ||||||||||||||||||||||||||||||
| Outstanding as of December 31, 2024 | $ | $ | |||||||||||||||||||||||||||||||||
Granted | $ | $ | |||||||||||||||||||||||||||||||||
Exercised or converted | ( | $ | ( | $ | |||||||||||||||||||||||||||||||
Forfeited | ( | $ | ( | $ | |||||||||||||||||||||||||||||||
Expired | |||||||||||||||||||||||||||||||||||
| Outstanding as of December 31, 2025 | $ | $ | |||||||||||||||||||||||||||||||||
| Exercisable as of December 31, 2025 | |||||||||||||||||||||||||||||||||||
The weighted average grant-date fair value of the Time-Based Options issued in 2025 and 2024 is $2.96 and $0.42 , respectively. During the years ended December 31, 2025, and 2024, the Company recognized approximately $2,572 and $296 , respectively, in compensation expense related to Time-Based Options which is included in employee compensation and benefits expenses in the consolidated statements of income. There was no unrecognized compensation expenses for Time-Based Options as of December 31, 2025.
The weighted average grant-date fair value of the Performance-Based Options issued in December 31, 2025 and 2024 is $1.70 and $0.17 , respectively. During the year ended December 31, 2025, the Company recognized $1,866 of share-based compensation expense related to Performance-Based Options, representing the acceleration of previously unrecognized compensation cost as a result of the completion of the IPO. During the year ended December 31, 2024, No compensation expense was recognized for Performance-Based Options because the performance condition was not considered probable to be met. There was no unrecognized compensation expenses for Performance-Based Options as of December 31, 2025.
As of December 31, 2025, there were 1,945,845 shares of common stock available for future issuance under the 2025 Plan.
Prior to the IPO, there was no public market for the Company’s Common Stock. The estimated fair value of its Common Stock was determined by the Company’s board of directors as of the date of each equity award, with input from management, considering the Company’s most recently available third-party valuations of its Common Stock, and the board of director's assessment of additional objective and subjective factors that it believed were relevant and which may have changed from the date of the most recent valuation through the date of the grant. The fair value of the Company’s Common Stock in 2025 and 2024 was estimated using a combination of income and market approach based on the most recent transaction that provided an observable market value. A discount for lack of marketability of the Common Stock is then applied to arrive at an indication of value for the Common Stock.
The fair value of each option award is estimated on the date of grant using the Black-Scholes option-pricing model that uses the assumptions noted in the table below. Expected volatility for the Company’s Common Stock was determined based on an average of the historical volatility of a peer group of similar public companies. The expected term of options granted was calculated using the simplified method, which represents the average of the contractual term of the option and the weighted average vesting period of the option. The Company uses the simplified method because it does not have sufficient historical exercise data to provide a reasonable basis upon which to estimate the expected term. The assumed dividend yield is based upon the Company’s expectation of not paying dividends in the foreseeable future. The risk-free
101
rate is based upon the U.S. Treasury yield curve in effect at the time of grant for the period equivalent to the expected term of the option.
Below is a summary of the weighted average assumptions used for the Black-Scholes model valuation of stock options during the years ended December 31:
| Time-Based | ||||||||
| 2025 | 2024 | |||||||
| Expected term in years | ||||||||
| Expected stock price volatility | ||||||||
| Dividend yield | ||||||||
| Risk-free interest rate | % | |||||||
| Fair value of the underlying share | $ | $ | ||||||
| Performance-Based | ||||||||
| 2025 | 2024 | |||||||
| Expected term in years | ||||||||
| Expected stock price volatility | ||||||||
| Dividend yield | ||||||||
| Risk-free interest rate | % | % | ||||||
| Fair value of the underlying share | $ | $ | ||||||
Restricted Stock Units
Restricted stock units (“RSUs”) represent the right to receive shares of the Company’s Class A common stock upon vesting. Each RSU grant vests ratably in three equal installments on each of the first, second, and third anniversaries of the vesting commencement date, subject to the employee’s continued service. The grant date fair value of RSUs is based on the closing market price of the Company’s Class A common stock on the grant date. The aggregate grant date fair value of RSUs issued during the year ended December 31, 2025 was $83,728 . No 6,982 of share-based compensation expense related to RSUs, which is included in employee compensation and benefits expense in the consolidated statements of income. As of December 31, 2025, unrecognized compensation cost related to unvested RSUs was $76,746 , which is expected to be recognized over a weighted-average period of 2.8 years.
A summary of restricted stock unit activity for the year ended December 31, 2025, is presented below:
| Restricted Stock Units | |||||||||||||||||
Number of Units | Weighted Average Grant Date Fair Value | Weighted Average Remaining Service Period | |||||||||||||||
| Outstanding as of December 31, 2024 | $ | — | |||||||||||||||
Granted | |||||||||||||||||
Vested | — | ||||||||||||||||
Forfeited | — | ||||||||||||||||
| Outstanding as of December 31, 2025 | $ | ||||||||||||||||
102
Note 8. Income Taxes
Components of income tax expense include the following for the years ended December 31:
| (In thousands) | 2025 | 2024 | 2023 | ||||||||||||||
| Current: | |||||||||||||||||
| Federal | $ | $ | $ | ||||||||||||||
| State | $ | ||||||||||||||||
| Deferred: | |||||||||||||||||
| Federal | $ | ( | ( | ||||||||||||||
| State | $ | ( | ( | ||||||||||||||
| ( | ( | ||||||||||||||||
| $ | $ | $ | |||||||||||||||
A reconciliation of the statutory U.S. federal tax rate and the Company’s effective tax rates is as follows for the years ended December 31:
| 2025 | 2024 | 2023 | |||||||||||||||||||||||||||||||||
| Tax Expense | Rate | Tax Expense | Rate | Tax Expense | Rate | ||||||||||||||||||||||||||||||
| US federal statutory tax rate | $ | % | $ | % | $ | % | |||||||||||||||||||||||||||||
State and local income taxes, net of federal income tax effect (1) | % | % | % | ||||||||||||||||||||||||||||||||
| Foreign tax effects | % | % | % | ||||||||||||||||||||||||||||||||
| Effect of cross-border tax laws | % | % | % | ||||||||||||||||||||||||||||||||
| Effect of changes in tax laws or rates enacted in the current period | % | % | % | ||||||||||||||||||||||||||||||||
| Nontaxable or nondeductible items | |||||||||||||||||||||||||||||||||||
| Nondeductible executive compensation | % | % | % | ||||||||||||||||||||||||||||||||
| Stock compensation | ( | ( | % | % | % | ||||||||||||||||||||||||||||||
| IPO costs | % | % | % | ||||||||||||||||||||||||||||||||
| Other | % | % | % | ||||||||||||||||||||||||||||||||
| Tax credits | |||||||||||||||||||||||||||||||||||
| Research and development tax credit | ( | ( | % | ( | ( | % | ( | ( | % | ||||||||||||||||||||||||||
| Changes in valuation allowances | % | % | % | ||||||||||||||||||||||||||||||||
| Changes in unrecognized tax benefits | % | % | % | ||||||||||||||||||||||||||||||||
| Other items | ( | % | ( | ( | % | % | |||||||||||||||||||||||||||||
| Effective income tax rate | $ | % | $ | $ | |||||||||||||||||||||||||||||||
(1)Taxes in Florida make up the majority of the effect of the state and local tax category.
The Company paid cash taxes, net of refunds, for the year ended December 31, as follows:
103
| (In thousands) | 2025 | 2024 | 2023 | ||||||||||||||
| U.S. federal taxes | $ | $ | $ | ||||||||||||||
| State and local taxes | |||||||||||||||||
| Florida | |||||||||||||||||
| New Jersey | |||||||||||||||||
| Other states | |||||||||||||||||
| Total income taxes paid | $ | $ | $ | ||||||||||||||
The following table summarizes components of deferred income tax assets and liabilities as of December 31:
| (In thousands) | 2025 | 2024 | |||||||||
| Deferred tax assets (liabilities): | |||||||||||
| Cancellation reserves | $ | $ | |||||||||
| Acquisition intangibles | |||||||||||
| 163(j) interest expense limitations | |||||||||||
| Internally developed software | |||||||||||
| Stock compensation | |||||||||||
| Other | |||||||||||
| Deferred tax assets | $ | $ | |||||||||
| Goodwill | ( | ( | |||||||||
| Prepaid expenses | ( | ( | |||||||||
| Internally developed software | ( | ||||||||||
| Deferred tax liabilities | ( | ( | |||||||||
| Net deferred tax assets | $ | $ | |||||||||
The Company assessed the future realization of the tax benefit of its existing deferred tax assets and concluded based on projected future earnings that it is more likely than not that all of its deferred tax assets will be realized in the future. Accordingly, no valuation allowance was recorded as of December 31, 2025 or 2024.
As of December 31, 2025, the Company has not recorded a reserve for any uncertain tax positions, penalties, or interest as management has concluded that all positions meet the requirements to be recognized in the financial statements. Interest and penalties accrued by the Company are included in the General and administrative section of the consolidated statements of income. The Company’s U.S. federal and state income tax returns remain subject to examination by taxing authorities for tax years 2022 and after.
On July 4, 2025, the One Big Beautiful Bill Act (“OBBBA”) was enacted in the United States. The impacts of this legislation have been reflected in the provision for income taxes for the year ended December 31, 2025. The new legislation allows the immediate expensing of domestic research and development costs, rather than capitalizing and amortizing these costs over 60 months. Taxpayers also are given the option to accelerate the remaining unamortized domestic research and development costs over one or two years beginning in 2025. There is no change to the treatment of foreign research and development costs. The Company elected to fully expense its remaining unamortized domestic research and development costs in 2025 and immediately deducted such costs incurred during the year.
We believe the changes to tax law described above are the most material impacts to the Company and have been reflected in the provision for the year ended December 31, 2025.
104
Note 9. Defined Contribution Plan
The Company adopted the Neptune Flood Incorporated 401(k) Plan (the “401(k) Plan”) on January 1, 2020. The 401(k) Plan is a voluntary defined contribution retirement plan for eligible employees of the Company. All eligible employees become participants unless they elect not to participate. The 401(k) Plan is subject to the provisions of the Employee Retirement Income Security Act of 1974. During the years ended December 31, 2025, 2024, and 2023, the Company made nonelective contributions of $286 , $181 , and $175 , respectively, which were included in general and administrative expense in the consolidated statements of income.
Note 10. Related-Party Transactions
Rent Expense
In February 2021, the Company entered into a month-to-month operating lease agreement for office space for management and administrative services at a rate of $12 per month from an affiliate of the Company’s executive and principal stockholder. Rent expense was approximately $144
Software Development
In 2022, the Company engaged with a contractor for software development and data analytics that is an affiliate of the Company’s executive and principal stockholder. Payments made to the contractor were $194 , $585 , and $945 during the years ended December 31, 2025, 2024, and 2023, respectively, which were included in general and administrative expense in the consolidated statements of income.
Note 11. Segment Reporting
The Company has one operating segment and therefore one reportable segment relating to its business as an MGA that offers residential and commercial insurance products, including primary and excess flood insurance,, and parametric earthquake insurance, primarily through a nationwide agency network in the United States. The Company’s chief operating decision maker (“CODM”), the CEO, manages the Company’s operations on a consolidated basis as one operating segment for the purpose of evaluating financial performance and allocating resources.
The accounting policies of the Company’s segment are the same as those described in the summary of significant accounting policies. The CODM uses net income, as reported on the consolidated statements of income, to assess performance and allocate resources. The significant segment expense categories regularly provided to the CODM are the same as those included on the consolidated statements of income. The measure of segment assets is total assets as reported on the consolidated balance sheets.
The CODM uses net income to assess performance by examining period-over-period trends, benchmarking to the Company’s competitors, and monitoring budget versus actual results. The CODM uses net income to evaluate income generated from segment assets in deciding whether to reinvest profits into the segment or into other parts of the entity.
The Company does not have revenue from any one customer that is greater than 10% of consolidated revenue.
105
Note 12. Earnings Per Share
As of December 31, 2025, the Company had Class A common stock and Class B common stock. Both classes have the same rights to the Company’s earnings and neither of the shares have any preference rights to dividends to other shares. The following table sets forth the computation of basic and dilutive earnings per share:
| (In thousands, except share and per share data) | 2025 | 2024 | 2023 | ||||||||||||||
| Basic Shares: | |||||||||||||||||
| Numerator: | |||||||||||||||||
| Net income | $ | $ | $ | ||||||||||||||
| Less: accretion adjustment to redeemable preferred stock (1) | ( | ( | ( | ||||||||||||||
| Less: allocation to participating preferred stock | ( | ||||||||||||||||
Less: Cash dividend paid on redeemable preferred stock | ( | ||||||||||||||||
| Net income (loss) available to common stockholders (2) | $ | ( | $ | $ | |||||||||||||
| Denominator: | |||||||||||||||||
| Weighted average Common Stock outstanding - Basic | |||||||||||||||||
| Class A Common Stock | |||||||||||||||||
| Class B Common Stock | |||||||||||||||||
| Total Weighted average Common Stock outstanding - Basic | |||||||||||||||||
Basic earnings (loss) per share - Class A and Class B Common Stock | $ | ( | $ | $ | |||||||||||||
Weighted average Common Stock outstanding Class A and Class B Common Stock - Diluted | |||||||||||||||||
Diluted earnings (loss) per share - Class A and Class B Common Stock | $ | ( | $ | $ | |||||||||||||
The potential shares of common stock that were excluded from the computation of diluted earnings (loss) per share attributable to common stockholders for the periods presented because including them would have been anti-dilutive are as follows:
| Outstanding as of December 31, 2025 | Outstanding as of December 31, 2024 | Outstanding as of December 31, 2023 | |||||||||||||||
Time vesting options (3) | |||||||||||||||||
Performance Vesting Options (4) | |||||||||||||||||
Fully vested options (5) | |||||||||||||||||
Restricted Stock Units (6) | |||||||||||||||||
(1)Represents the accretion of the redeemable preferred stock to its redemption value and includes both the effect of cumulative undeclared dividends and the accretion of issuance costs for the applicable periods.
(2)Net income (loss) available to common stockholders for the year ended December 31, 2025 included $8,913 of IPO transaction costs which were reimbursed to the Company by the selling stockholders on October 2, 2025.
(3)The Time Vesting Options were excluded from the calculation of diluted earnings (loss) per share for the years ended December 31, 2024 and 2023, as their inclusion would have been anti-dilutive.
(4)Performance Vesting Options have a performance condition. For the years ended December 31, 2024 and 2023 the performance condition was not met and therefore, these options were excluded from the dilutive earnings (loss) per share computation.
(5)These options, including Time Vesting Options and Performance Vesting Options, were excluded from the diluted earnings (loss) per share computation for the year ended December 31, 2025, as they were anti-dilutive.
(6)The unvested Restricted Stock Units have been excluded from the calculation of diluted earnings (loss) per share for the year ended December 31, 2025, as their effect would be anti-dilutive.
Note 13. Commitments and Contingencies
The Company is, from time to time, party to various legal actions and is subject to various claims arising in the ordinary course of business from time to time. Management believes that the resolution of these matters will not have a material adverse effect on the Company’s financial position or results of operations.
106
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure.
None.
Item 9A. Controls and Procedures.
Evaluation of Disclosure Controls and Procedures
We maintain “disclosure controls and procedures,” as defined in Rule 13a-15(e) and Rule 15d-15(e) under the Exchange Act, that are designed to ensure that information we are required to disclose in the reports that we file or submit under the Exchange Act is recorded, processed, summarized, and reported within the time periods specified in the SEC’s rules and forms and that such information is accumulated and communicated to our management, including our principal executive officer and principal financial officer, or persons performing similar functions, as appropriate to allow timely decisions regarding required disclosure.
Our management, with the participation and supervision of our Chief Executive Officer (our principal executive officer) and our Chief Financial Officer (our principal financial officer), has evaluated the effectiveness of our disclosure controls and procedures as of the end of the period covered by this Annual Report. Based on such evaluation, our Chief Executive Officer and our Chief Financial Officer have concluded that as of the end of the period covered by this Annual Report, our disclosure controls and procedures were, in design and operation, effective at a reasonable assurance level.
Management’s Annual Report on Internal Control Over Financial Reporting
This Annual Report on Form 10-K does not include a report of management’s assessment regarding internal control over financial reporting or an attestation report of our independent registered public accounting firm due to a transition period established by the rules of the SEC for newly public companies.
Changes in Internal Control Over Financial Reporting
There were no changes in our internal control over financial reporting (as such term is defined in Rule 13a-15(f) and Rule 15d-15(f) under the Exchange Act) that occurred during the three months ended December 31, 2025, that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Inherent Limitations on Effectiveness of Controls
Our management, including our Chief Executive Officer and Chief Financial Officer, believes that our disclosure controls and procedures and internal control over financial reporting are designed to provide reasonable assurance of achieving their objectives and are effective at the reasonable assurance level. However, the effectiveness of any system of internal control over financial reporting, including ours, is subject to inherent limitations, including the exercise of judgment in designing, implementing, operating, and evaluating the controls and procedures, and the inability to eliminate misconduct completely. Accordingly, any system of internal control over financial reporting, including ours, no matter how well designed and operated, can only provide reasonable, not absolute, assurance that its desired control objectives will be met. In addition, the design of disclosure controls and procedures must reflect the fact that there are resource constraints and that management is required to apply its judgment in evaluating the benefits of possible controls and procedures relative to their costs. Moreover, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate. We intend to continue to monitor and upgrade our internal controls as necessary or appropriate for our business, but cannot assure you that such improvements will be sufficient to provide us with effective internal control over financial reporting.
Item 9B. Other Information.
During the year ended December 31, 2025, none of our directors or officers (as defined in Section 16 of the Exchange Act) adopted terminated
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections.
Not applicable.
107
PART III
Item 10. Directors, Executive Officers and Corporate Governance.
The information required by this item is incorporated herein by reference to the definitive Proxy Statement to be filed with the Commission pursuant to Regulation 14A within 120 days after the end of the fiscal year covered by this Annual Report.
We have adopted a Code of Business Conduct and Ethics that applies to all employees, including executive officers, and to directors. The Code of Business Conduct and Ethics is available on the Governance Overview page of our investor relations website at https://investors.neptuneflood.com/governance/governance-documents/default.aspx. Any approved amendments to, or waiver of, any provision of the Code of Business Conduct and Ethics will be posted on our investor relations website at the aforementioned address.
Item 11. Executive Compensation.
The information required by this item is incorporated herein by reference to the definitive Proxy Statement to be filed with the Commission pursuant to Regulation 14A within 120 days after the end of the fiscal year covered by this Annual Report.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
The information required by this item is incorporated herein by reference to the definitive Proxy Statement to be filed with the Commission pursuant to Regulation 14A within 120 days after the end of the fiscal year covered by this Annual Report.
Item 13. Certain Relationships and Related Transactions, and Director Independence.
The information required by this item is incorporated herein by reference to the definitive Proxy Statement to be filed with the Commission pursuant to Regulation 14A within 120 days after the end of the fiscal year covered by this Annual Report.
Item 14. Principal Accounting Fees and Services.
The information required by this item is incorporated herein by reference to the definitive Proxy Statement to be filed with the Commission pursuant to Regulation 14A within 120 days after the end of the fiscal year covered by this Annual Report.
108
PART IV
Item 15. Exhibits, Financial Statement Schedules.
The following documents are filed as part of this Annual Report.
(1)Consolidated financial statements: Refer to Item 8. Financial Statements and Supplementary Data elsewhere in this Annual Report.
(2)Consolidated financial statement schedules. All schedules are omitted for the reason that the information is included in the consolidated financial statements or the notes thereto or that they are not required or are not applicable.
(3)Exhibits: The exhibits listed in the accompanying index are filed, furnished or incorporated by reference as part of this Annual Report.
Exhibit Index
| Exhibit Number | Description | |||||||||||||
| 2.1 | ||||||||||||||
3.1* | ||||||||||||||
3.2* | ||||||||||||||
| 4.1 | ||||||||||||||
| 4.2 | ||||||||||||||
| 4.3* | ||||||||||||||
| 10.1 | ||||||||||||||
| 10.2+ | ||||||||||||||
| 10.3+ | ||||||||||||||
| 10.4+ | ||||||||||||||
| 10.5+ | ||||||||||||||
10.6⸸ | ||||||||||||||
| 10.7 | ||||||||||||||
| 10.8 | ||||||||||||||
| 10.9 | ||||||||||||||
| 14.1* | ||||||||||||||
| 19.1* | ||||||||||||||
109
| 21.1 | ||||||||||||||
| 23.2* | ||||||||||||||
| 24.1* | Power of Attorney (included in the signature page hereto). | |||||||||||||
| 31.1* | ||||||||||||||
| 31.2* | ||||||||||||||
| 32.1** | ||||||||||||||
| 32.2** | ||||||||||||||
| 97.1* | ||||||||||||||
| 101.INS | Inline XBRL Instance Document – the instance document does not appear in the Interactive Data File because XBRL tags are embedded within the Inline XBRL document. | |||||||||||||
| 101.SCH | Inline XBRL Taxonomy Extension Schema Document. | |||||||||||||
| 101.CAL | Inline XBRL Taxonomy Extension Calculation Linkbase Document. | |||||||||||||
| 101.DEF | Inline XBRL Taxonomy Extension Definition Linkbase Document. | |||||||||||||
| 101.LAB | Inline XBRL Taxonomy Extension Label Linkbase Document. | |||||||||||||
| 101.PRE | Inline XBRL Taxonomy Extension Presentation Linkbase Document. | |||||||||||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document). | |||||||||||||
* Filed herewith.
** Exhibit is furnished and shall not be deemed “filed” for purposes of Section 18 of the Exchange Act, or otherwise subject to the liabilities of that section, nor shall it be deemed incorporated by reference in any filing under the Securities Act, or the Exchange Act, except as shall be expressly set forth by specific reference in such filing.
+ Indicates a management contract or compensatory plan or arrangement.
⸸ Certain of the exhibits and schedules to this exhibit have been omitted in accordance with Regulation S-K Item 601(a)(5). The registrant agrees to furnish a copy of all omitted exhibits and schedules to the Commission upon its request.
Item 16. Form 10-K Summary
None.
110
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Exchange Act, the registrant has duly caused this Annual Report to be signed on its behalf by the undersigned, thereunto duly authorized.
Neptune Insurance Holdings Inc. | |||||||||||
Date: February 25, 2026 | By: | /s/ Trevor Burgess | |||||||||
Trevor Burgess | |||||||||||
Chief Executive Officer and Chairman of the Board of Directors | |||||||||||
(principal executive officer) | |||||||||||
Date: February 25, 2026 | By: | /s/ Jim Steiner | |||||||||
Jim Steiner | |||||||||||
Chief Financial Officer and Director | |||||||||||
(principal financial and accounting officer) | |||||||||||
POWER OF ATTORNEY
KNOW ALL PERSONS BY THESE PRESENTS, that each individual whose signature appears below constitutes and appoints Trevor Burgess and Jim Steiner, and each of them, such individual’s true and lawful attorneys-in-fact and agents with full power of substitution, for such individual and in such individual’s name, place and stead, in any and all capacities, to sign any and all amendments to this Annual Report, and to file the same, with all exhibits thereto and any and all applications and other documents in connection therewith, with the SEC, granting unto said attorneys-in-fact and agents, and each of them, full power and authority to do and perform each and every act and thing requisite and necessary to be done in and about the premises, as fully to all intents and purposes as such individual might or could do in person, hereby ratifying and confirming all that said attorneys-in-fact and agents, or any of them or their substitute or substitutes, may lawfully do or cause to be done or by virtue hereof.
Pursuant to the requirements of the Securities Act, this Annual Report has been signed by the following persons in the capacities and on the dates indicated:
| Name | Title | Date | ||||||||||||
/s/ Trevor Burgess | Chief Executive Officer and Chairman of the Board of Directors (principal executive officer) | February 25, 2026 | ||||||||||||
Trevor Burgess | ||||||||||||||
/s/ Jim Steiner | Chief Financial Officer and Director (principal financial and accounting officer) | February 25, 2026 | ||||||||||||
Jim Steiner | ||||||||||||||
/s/ Jonathan Carlon | Director | February 25, 2026 | ||||||||||||
| Jonathan Carlon | ||||||||||||||
/s/ Blair J. Greenberg | Director | February 25, 2026 | ||||||||||||
| Blair J. Greenberg | ||||||||||||||
/s/ Cristian Melej | Director | February 25, 2026 | ||||||||||||
| Cristian Melej | ||||||||||||||
/s/ Mike Vostrizansky | Director | February 25, 2026 | ||||||||||||
| Mike Vostrizansky | ||||||||||||||
111