pk-8k_20201105.htm
false 0001617406 0001617406 2020-11-05 2020-11-05


UNITED STATES

SECURITIES AND EXCHANGE COMMISSION

WASHINGTON, D.C. 20549


FORM 8-K


CURRENT REPORT

Pursuant to Section 13 or 15(d)

of the Securities Exchange Act of 1934

Date of Report (Date of earliest event reported): November 5, 2020


Park Hotels & Resorts Inc.

(Exact name of Registrant as Specified in Its Charter)


Delaware

001-37795

36-2058176

(State or Other Jurisdiction

of Incorporation)

(Commission

File Number)

(IRS Employer

Identification No.)


1775 Tysons Blvd., 7th Floor, Tysons, VA


22102

(Address of Principal Executive Offices)


(Zip Code)

(571) 302-5757

(Registrant’s Telephone Number, Including Area Code)

Not Applicable

(Former Name or Former Address, if Changed Since Last Report)


Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instructions A.2. below):


☐

Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425)

☐

Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12)

☐

Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))

☐

Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))

Securities registered pursuant to Section 12(b) of the Act:


Title of each class

Trading Symbol

Name of each exchange on which registered

Common Stock, $0.01 par value per share

PK

New York Stock Exchange

Indicate by check mark whether the registrant is an emerging growth company as defined in as defined in Rule 405 of the Securities Act of 1933 (§ 230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§ 240.12b-2 of this chapter).

Emerging growth company    ☐

If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.    ☐


Item 2.02. Results of Operations and Financial Condition.

On November 5, 2020, Park Hotels & Resorts Inc. (the “Company”) issued a press release announcing its results of operations for the third quarter ended September 30, 2020 and made available certain supplemental information concerning the portfolio and operation of the Company.  Copies of the press release and the supplemental information are furnished as Exhibits 99.1 and Exhibit 99.2, respectively, to this Current Report on Form 8-K.

In accordance with General Instructions B.2 of Form 8-K, the information included in Item 2.02 of this Current Report on Form 8-K (including Exhibits 99.1 and 99.2 hereto) shall not be deemed “filed” for the purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), or otherwise subject to the liabilities of that section, nor shall it be deemed incorporated by reference into any filing made by the Company under the Exchange Act or Securities Act of 1933, as amended, except as shall be expressly set forth by specific reference in such a filing.

Item 9.01. Financial Statements and Exhibits.

(d) Exhibits.


Exhibit

Number


Description


99.1


Press release dated November 5, 2020.

99.2


Third Quarter 2020 Supplemental Data.

104


Cover Page Interactive Data File (embedded within the Inline XBRL document).


SIGNATURES

Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned thereunto duly authorized.


Park Hotels & Resorts Inc.


Date: November 5, 2020


By:

/s/ Sean M. Dell’Orto


Sean M. Dell’Orto


Executive Vice President and Chief Financial Officer


Exhibit 99.1


Investor Contact

1775 Tysons Boulevard, 7th Floor

Ian Weissman

Tysons, VA 22102

+ 1 571 302 5591

www.pkhotelsandresorts.com


Park Hotels & Resorts Inc. Reports Third Quarter 2020 Results

TYSONS, VA (November 5, 2020) – Park Hotels & Resorts Inc. (“Park” or the “Company”) (NYSE: PK) today announced results for the third quarter ended September 30, 2020 and an operational update on COVID-19.


Third quarter financial highlights include:


•

Pro-forma RevPAR was $26.14, a decrease of 86.1% from the same period in 2019, which was an improvement from a 95.9% year-over-year decline reported last quarter;


•

Occupancy for Park’s 33 consolidated hotels open during the entirety of the third quarter was 36.4%;


•

Net loss and net loss attributable to stockholders were both $(276) million;


•

Adjusted EBITDA was $(89) million;


•

Adjusted FFO attributable to stockholders was $(149) million;


•

Diluted loss per share was $(1.17); and


•

Diluted Adjusted FFO per share was $(0.63).


Additional highlights include:


•

Reopened 16 hotels since June, increasing the total number of hotels open to 48 of 60 hotels (80%), or 64% of total room count;


•

Issued $725 million of senior secured notes due 2028 (“2028 Senior Secured Notes”) and utilized the net proceeds to fully repay its $631 million term loan due December 2021 (the “2016 Term Loan”) and $80 million of its revolving credit facility (“Revolver”);


•

Increased commitments under the Revolver by $75 million to $1.075 billion and extended the maturity date for $901 million of the aggregate commitments under the Revolver from December 2021 to December 2023, including all $75 million of the increased Revolver commitments;


•

Amended its bank credit facilities to obtain additional financial covenant relief and increase its carve out for acquisitions funded with equity proceeds from $500 million to $1 billion, among other amended provisions;


•

Continued to take proactive measures to preserve cash and improved Park’s baseline burn rate to approximately $50 million per month; and


•

Amended certain mortgage loan agreements to defer interest and principal payments for three to six months and obtained temporary suspensions from required cash reserves.


Thomas J. Baltimore, Jr., Chairman, President and Chief Executive Officer, stated, “I am extremely proud of the continued proactive efforts by our team as we navigate the severe impact that COVID-19 has had on all facets of our business. During the third quarter, we made significant improvements to our liquidity and balance sheet by reducing our monthly burn rate, completing another successful senior notes offering to pay off our 2016 Term Loan and extending our Revolver, pushing out significant debt maturities until 2023. On the operations front, we continue to make significant progress reopening hotels, and witnessed a steady increase in demand across our portfolio during the third quarter as September occupancy topped 42% for our opened hotels. Although our industry continues to face unprecedented challenges from COVID-19, I am confident that our efforts have positioned Park to get to the other side of this crisis with opportunities to create value for our stockholders.”

1


Selected Statistical and Financial Information

(unaudited, amounts in millions, except RevPAR, ADR and per share data)


Three Months Ended September 30,


Nine Months Ended September 30,


2020


2019


Change(1)


2020


2019


Change(1)


Pro-forma RevPAR


$

26.14


$

187.93


(86.1

)%


$

56.64


$

185.66


(69.5

)%


Pro-forma Occupancy


19.1

%


84.7

%


(65.6

)% pts


28.9

%


82.7

%


(53.8

)% pts


Pro-forma ADR


$

137.10


$

222.04


(38.3

)%


$

195.78


$

224.29


(12.7

)%


Pro-forma Total RevPAR


$

35.36


$

277.40


(87.3

)%


$

89.14


$

282.17


(68.4

)%


Net (loss) income


$

(276

)


$

9


NM(2)


$

(1,226

)


$

190


NM(2)


Net (loss) income attributable to stockholders


$

(276

)


$

5


NM(2)


$

(1,223

)


$

183


NM(2)


Adjusted EBITDA


$

(89

)


$

180


NM(2)


$

(129

)


$

563


NM(2)


Pro-forma Hotel Adjusted EBITDA


$

(76

)


$

217


NM(2)


$

(95

)


$

671


NM(2)


Pro-forma Hotel Adjusted EBITDA margin


(81.2

)%


28.9

%


NM(2)


(13.4

)%


29.6

%


NM(2)


Adjusted FFO attributable to stockholders


$

(149

)


$

140


NM(2)


$

(267

)


$

440


NM(2)


(Loss) earnings per share - Diluted(1)


$

(1.17

)


$

0.02


NM(2)


$

(5.19

)


$

0.90


NM(2)


Adjusted FFO per share - Diluted(1)


$

(0.63

)


$

0.68


NM(2)


$

(1.13

)


$

2.16


NM(2)


Weighted average shares outstanding - Diluted


235


207


28


236


204


32


(1)

Amounts are calculated based on unrounded numbers.

(2)

Percentage change is not meaningful.


COVID-19 Action Plan Update

The following is an update on the actions Park and its hotel managers have taken to mitigate the effects of COVID-19 on its business:


•

Continued identification of opportunities for alternative sources of revenue, including but not limited to housing for colleges and universities, medical professionals and those associated with professional sporting events.  In addition, certain hotels are providing guest rooms as work spaces;


•

Initiated permanent property-level full-time staff reductions, representing expected future annual savings of up to $70 million throughout the portfolio based on 2019 operations, continuing its efforts to remove costs from the hotel operating model;


•

Reopened 14 hotels during the third quarter, increasing total rooms by 7,278, and an additional 2 hotels thus far in the fourth quarter, increasing total rooms by another 1,466; and


•

Expects to have 50 of 60 hotels open by the end of 2020, or 74% of the total room count, with the remaining 10 suspended hotels expected to reopen in Q1 2021.

The current status of Park’s hotels as of November 5, 2020 is as follows (for a list of status by hotel please see Park’s financial supplement):


Status


Number of Hotels


Total Rooms


Consolidated Open


41


16,831


Consolidated Suspended


12


12,100


Total Consolidated


53


28,931


Unconsolidated Open


7


4,297


Total Hotels


60


33,228


2


Operational Update

Since the beginning of March, Park has experienced a significant decline in ADR, occupancy, and RevPAR associated with COVID-19 throughout its portfolio, which has resulted in a decline in Park’s operating cash flow. Changes in Pro-forma ADR, Occupancy and RevPAR for each month in 2020 compared to the same period in 2019 and Pro-Forma Occupancy for all of Park’s current 53 consolidated hotels during each month of 2020 are as follows:


Change in

Pro-forma ADR


Change in

Pro-forma Occupancy


Change in

Pro-forma RevPAR


Pro-forma Occupancy


January


(1.0

)%


1.6

%

pts


1.2

%


73.8

%

February


(0.7

)


0.9


0.4


79.2


March


(10.1

)


(49.4

)


(63.8

)


33.3


Q1


(2.5

)


(16.0

)


(22.6

)


61.7


April


(47.0

)


(80.9

)


(97.6

)


3.9


May


(54.1

)


(79.9

)


(97.3

)


4.9


June


(36.5

)


(78.5

)


(93.0

)


9.7


Q2


(43.2

)


(79.8

)


(95.9

)


6.1


July


(31.7

)


(71.3

)


(88.3

)


14.7


August


(38.1

)


(65.5

)


(85.4

)


20.3


September


(43.0

)


(59.7

)


(84.5

)


22.3


Q3


(38.3

)


(65.6

)


(86.1

)


19.1


Changes in Pro-forma ADR, Occupancy and RevPAR for each month in 2020 compared to the same period in 2019 and Pro-forma Occupancy for 2020 for consolidated hotels open during the entirety of each month are as follows:


Number of Consolidated Hotels Open


Change in Pro-forma ADR


Change in Pro-Forma Occupancy


Change in Pro-Forma RevPAR


Pro-forma Occupancy


January


53


(1.0

)%


1.6

%

pts


1.2

%


73.8

%

February


53


(0.7

)


0.9


0.4


79.2


March


25


(13.2

)


(44.9

)


(60.9

)


36.9


April


18


(41.8

)


(72.1

)


(90.3

)


14.4


May


18


(49.7

)


(65.7

)


(88.1

)


20.4


June


22


(48.6

)


(58.5

)


(82.5

)


30.2


July


33


(24.3

)


(53.4

)


(71.5

)


32.3


August


37


(28.6

)


(42.2

)


(65.8

)


38.8


September


37


(36.5

)


(37.2

)


(66.2

)


42.3


Park’s estimated hotel level break-even occupancy is 35% to 40%, assuming a 15% to 20% decrease in ADR compared to the comparable period in 2019. For the third quarter, Park had 12 hotels reach operational break-even levels.

During the third quarter, group, transient and contract revenue represented 13%, 72% and 15%, respectively, of our business compared to 27%, 67% and 6% in the third quarter of 2019. Additionally, within the transient segment, business and leisure represented 35% and 65%, respectively, compared to 43% and 57% during the third quarter of 2019. Park recognized approximately $2 million of cancellation and attrition revenue during the third quarter.

The current operating status for each of the Company’s key markets is as follows:


•

Hawaii: Hawaii reopened to tourism on October 15th and with the exclusion of the Big Island, guests may bypass the state’s 14-day quarantine period if certain protocols are followed upon arrival.  Both the Hilton Waikoloa Village and

3


Hilton Hawaiian Village remain suspended; however, Park is monitoring demand and currently expects to reopen the hotels during the fourth quarter of 2020;


•

San Francisco: Although the city allowed hotels to reopen for leisure travel in September, four of Park’s San Francisco hotels remain suspended, while the JW Marriott San Francisco Union Square and Hyatt Centric Fisherman's Wharf remained open, primarily housing medical personnel and airline crew;


•

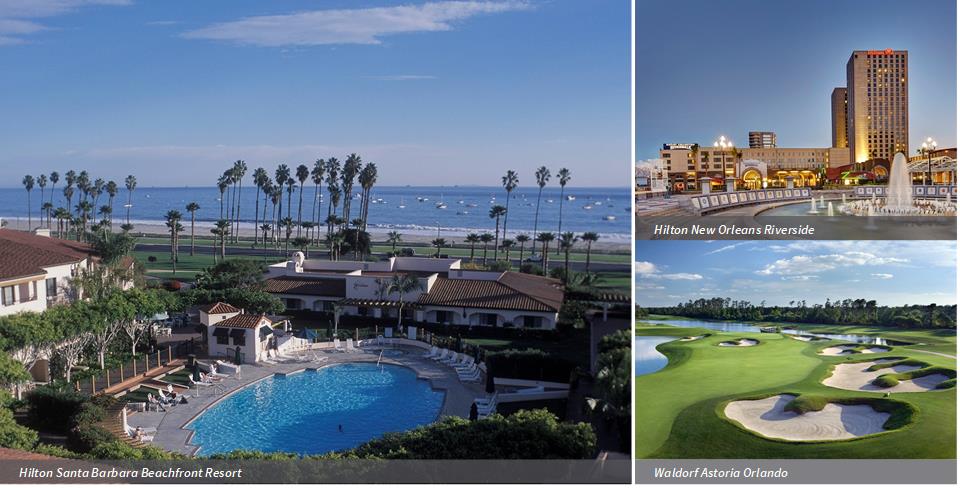
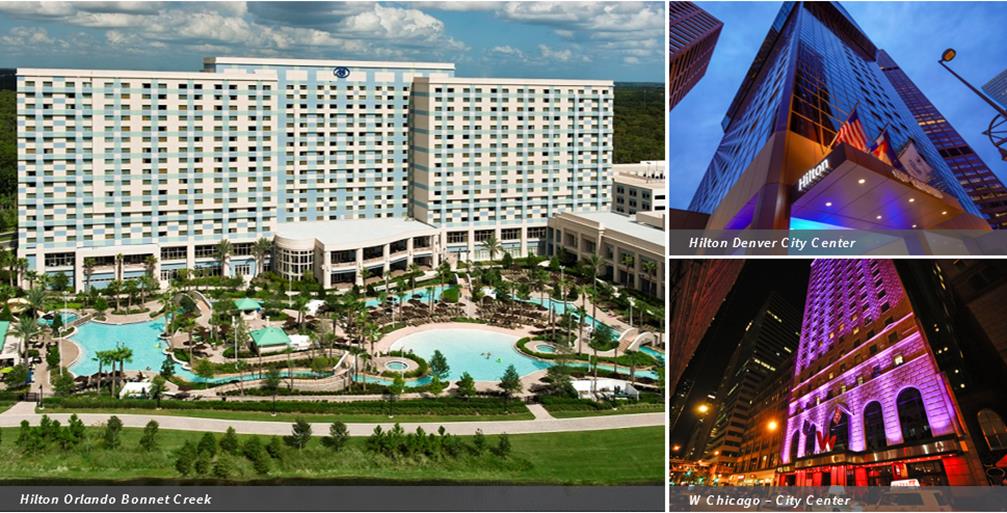
Orlando: All of Park’s Orlando hotels have reopened and the Waldorf Astoria Orlando benefited from the National Basketball Association’s events in the area with an occupancy rate of over 70% during the quarter; the Hilton Bonnet Creek successfully hosted several small group events during the third quarter utilizing Hilton’s EventReady protocols;


•

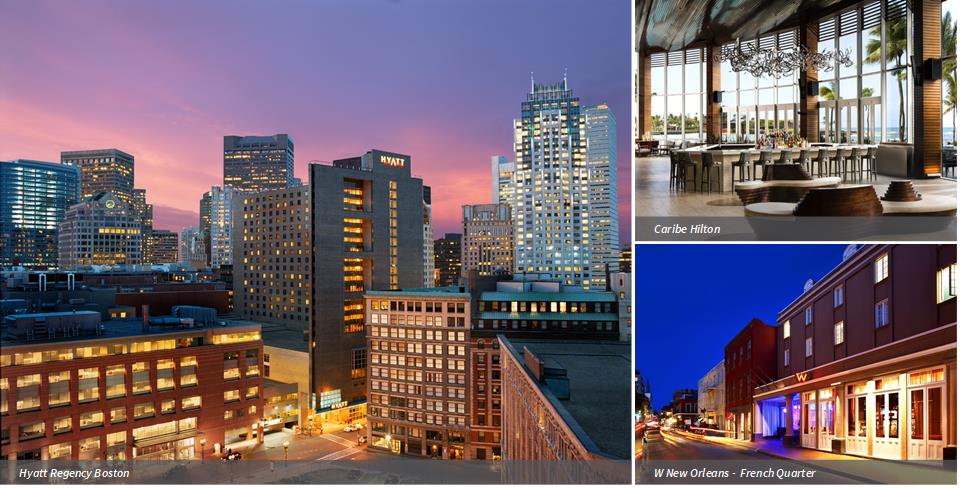
New Orleans: Both the Hilton New Orleans Riverside and the W New Orleans – French Quarter reopened during the third quarter as the city continued its phased reopening.  The Hilton New Orleans Riverside secured several non-traditional business opportunities including Hurricane Laura evacuee housing and a contract to house college students resulting in occupancy of over 40% at this hotel during the quarter;


•

Boston: All of Park’s Boston hotels are open with demand from airline crews and an increase in transient demand;


•

New York: As New York continues to have restrictions on certain out-of-state travelers and limits on gatherings, the Hilton New York’s operations remain suspended;


•

Southern California: All of Park’s hotels in Southern California have re-opened and benefited during the quarter from optimal weather conditions and being located in drive-to market destinations, resulting in an increase in occupancy of 30 percentage points from the second quarter.  Occupancy at the Hilton Santa Barbara Beachfront Resort was over 60% for the quarter;


•

Chicago: The W Chicago – Lakeshore and Hilton Chicago/Oak Brook Suites remained open primarily due to demand from airline crews and transient demand from summer leisure travelers. Both the state of Illinois and the city of Chicago have maintained travel and event restrictions, including a 14-day quarantine period for certain travelers and restrictions on large gatherings, and as a result, both the Hilton Chicago and W Chicago City Center are likely to remain suspended for the balance of the year;


•

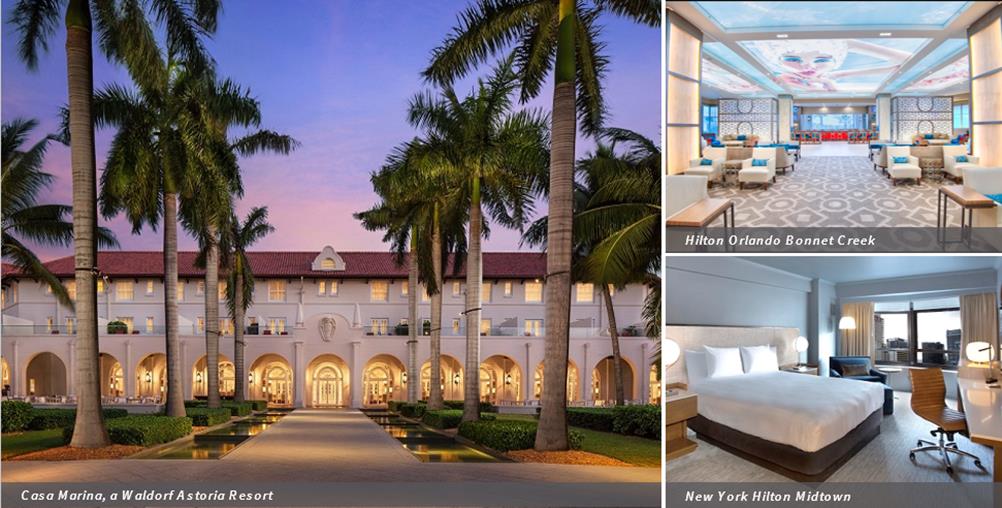
Key West: Casa Marina, A Waldorf Astoria Resort, and The Reach Key West, Curio Collection, both of which resumed operations in June, benefited from strong transient demand from leisure travelers, resulting in occupancy of nearly 60% for the quarter;


•

Denver: The Hilton Denver reopened in July as the city eased its restrictions and the hotel benefited from transient demand, resulting in occupancy of 30% for the quarter;


•

Miami: Both of Park’s Miami hotels, the Royal Palm South Beach Miami and Hilton Miami Airport, were open for the entire quarter and are benefiting from transient demand, resulting in occupancy of nearly 30% for the quarter;


•

Washington, D.C.: Although Washington, D.C. requires a 14-day quarantine period for non-essential travelers from deemed high-risk states, all of Park’s hotels are open with demand primarily from airline crews; and


•

Seattle: Two of Park’s three Seattle hotels are open based on demand from airline crews and local business transient travel, with the two airport hotels consolidating operations.


Balance Sheet and Liquidity


Park’s Net Debt as of September 30, 2020 was $4.2 billion. With total cash and cash equivalents as of September 30, 2020 of $1.2 billion, including $35 million of restricted cash, Park is maintaining higher than historical cash levels due to the continued uncertainty surrounding COVID-19.  As a result of the proactive measures taken by Park’s team and its hotel managers to dramatically reduce costs, coupled with recent capital raises, including the issuance of $650 million of 2025 Senior Secured Notes in May and $725 million of 2028 Senior Secured Notes in September, Park believes it has sufficient liquidity to satisfy its short-term liquidity obligations even though certain of the Company’s hotels are operating at limited capacity and certain hotels continue to suspend operations.


With total liquidity of $1.6 billion as of September 30, 2020, including $474 million of available capacity remaining on the Revolver, and a burn rate of approximately $50 million per month, which takes into account current operations from both open and suspended hotels and uses an accrual-based methodology, Park estimates it currently has over two and half years of liquidity available to meet its financial obligations. The estimated burn rate amount does not take into account capital expenditures (which were reduced by 75% in 2020 to approximately $4 million per month) or any possible alternative sources of revenue that may arise, any hotel property dispositions for the remainder of the year or any payment of future cash dividends, if any. Additionally, the estimated burn rate amount has not been reduced by any amount available to Park under existing or future debt facilities, or proceeds from issuance of any additional debt, equity or equity-linked securities.


Park continues to take proactive measures to reduce the near-term burn rate, including deferral of payments, hiring freezes and other cost reduction measures.


4


Additionally, in September 2020, Park further amended its credit facilities to extend the waiver period for the testing of its financial covenants to the date the financial statements are delivered for the quarter ended March 31, 2022.  As part of the amendment process, Park (i) increased commitments under the Revolver by $75 million to $1.075 billion and extended the maturity date with respect to $901 million of the aggregate commitments for two years to December 2023, including all $75 million of the increased Revolver commitments, (ii) extended the temporary periods for which certain financial covenants are adjusted once quarterly testing of financial covenants resumes, (iii) increased the mandatory repayment carve out for equity issuances from $500 million to $1 billion, so long as proceeds from the issuances are used for capital expenditures and hotel acquisitions that become part of the unencumbered pool and (iv) extended the minimum liquidity covenant and maintained the existing guarantees and pledges of equity interests in certain subsidiaries subject to specific conditions, among other amended provisions. Additionally, during the second and third quarters of 2020, Park amended certain mortgage loan agreements to defer interest and principal payments for three to six months and obtained temporary suspensions from required cash reserves.

Park had the following debt outstanding as of September 30, 2020:


(unaudited, dollars in millions)


Debt


Collateral


Interest Rate


Maturity Date


As of

September 30, 2020


Fixed Rate Debt


Mortgage loan


DoubleTree Hotel Spokane City Center


3.55%


October 2020(1)


$

12


Mortgage loan


Hilton Denver City Center


4.90%


August 2022(2)


60


Mortgage loan


Hilton Checkers Los Angeles


4.11%


March 2023


27


Mortgage loan


W Chicago - City Center


4.25%


August 2023


76


Commercial mortgage-backed

securities loan


Hilton San Francisco Union Square, Parc 55 San Francisco - a Hilton Hotel


4.11%


November 2023


725


Mortgage loan


Hyatt Regency Boston


4.25%


July 2026


140


Commercial mortgage-backed

securities loan


Hilton Hawaiian Village Beach Resort


4.20%


November 2026


1,275


Mortgage loan


Hilton Santa Barbara Beachfront Resort


4.17%


December 2026


165


2025 Senior Secured Notes


7.50%


June 2025


650


2028 Senior Secured Notes


5.88%


October 2028


725


Finance lease obligations


3.07%


2021 to 2022


1


Total Fixed Rate Debt


5.06%(3)


3,856


Variable Rate Debt


Revolving credit facility(4)(5)


Unsecured


L + 3.00%


2021 to 2023(6)


601


2016 Term Loan(7)


Unsecured


N/A


December 2021


—


Mortgage loan


DoubleTree Hotel Ontario Airport


L + 2.25%


May 2022


30


2019 Term Facility(4)(8)


Unsecured


L + 2.65%


September 2024


670


Total Variable Rate Debt


3.08%(3)


1,301


Add: unamortized premium


4


Less: unamortized deferred financing costs and discount


(40

)

Total Debt(9)


4.63%(3)


$

5,121


(1)

Park is actively negotiating a one-year maturity date extension to October 2021. The loan was not paid in full at its originally scheduled maturity date in October 2020 due to current market conditions. Failure to pay off the loan constitutes an event of default; however, Park has not received, nor does it expect to receive, notice of the lenders’ intent to foreclose.

(2)

The loan matures in August 2042 but is callable by the lender beginning August 2022.

(3)

Calculated on a weighted average basis.

(4)

In May 2020, Park amended its credit and term loan facilities, which added a LIBOR floor of 25 basis points.

(5)

During September 2020, Park repaid $80 million of the Revolver.

(6)

In September 2020, Park increased its aggregate commitments under the Revolver by $75 million to $1.075 billion and extended the maturity date with respect to $901 million of the aggregate commitments for two years to December 2023, including all $75 million of the increased Revolver commitments. The maturity date for the remaining $174 million of commitments under the Revolver is December 2021.  

(7)

The 2016 Term Loan was entered into in December 2016 with a maturity date of December 2021. Park fully repaid the 2016 Term Loan in September 2020 using the proceeds from the 2028 Senior Secured Notes.

(8)

In August 2019, the Company, Park Intermediate Holdings LLC and PK Domestic Property LLC entered into a credit agreement with Bank of America, N.A. and certain other lenders, providing a $950 million unsecured delayed draw term loan facility (the”2019 Term Facility”), with the $850 million, five-year delayed draw term loan tranche fully drawn on September 18, 2019 to fund the merger with Chesapeake Lodging Trust (“Chesapeake”).  The

5


$100 million, two-year delayed draw term loan tranche was unfunded and the commitments thereunder terminated on September 18, 2019. On December 31, 2019, Park repaid $180 million of the 2019 Term Facility.

(9)

Excludes $225 million of Park’s share of debt of its unconsolidated joint ventures.


Dividends

As a precautionary measure in light of COVID-19, Park has suspended dividend payments following the payment of its first quarter 2020 dividend until such time that Park’s Board of Directors determines a year-end dividend, if any.


Full-Year 2020 Outlook

Given the continued economic uncertainty, travel restrictions and rapidly-changing circumstances related to the COVID-19 pandemic, in March 2020, Park withdrew its previously issued 2020 guidance.  Park is not providing an updated outlook at this time.

The Company’s ability to predict future operating results is significantly impacted by the current COVID-19 pandemic. Park expects that the trends affecting the economy will continue to depress hotel operating results across the portfolio. The economic environment lacks sufficient clarity at this time to provide accurate guidance.


Supplemental Disclosures

In conjunction with this release, Park has furnished a financial supplement with additional disclosures on its website. Visit www.pkhotelsandresorts.com for more information. Park has no obligation to update any of the information provided to conform to actual results or changes in Park’s portfolio, capital structure or future expectations.

Conference Call

Park will host a conference call for investors and other interested parties to discuss third quarter 2020 results on November 6, 2020 beginning at 11 a.m. Eastern Time. Participants may listen to the live webcast by logging onto the Investors section of the website at www.pkhotelsandresorts.com. Alternatively, participants may listen to the live call by dialing (877) 451-6152 in the United States or (201) 389-0879 internationally and requesting Park Hotels & Resorts’ Third Quarter 2020 Earnings Conference Call. Participants are encouraged to dial into the call or link to the webcast at least ten minutes prior to the scheduled start time.

A replay and transcript of the webcast will be available within 24 hours after the live event on the Investors section of Park’s website.

6


Forward-Looking Statements


This press release contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements include, but are not limited to, statements related to Park’s current expectations regarding the performance of its business, financial results, liquidity and capital resources, the effects of competition and the effects of future legislation or regulations, the expected completion of anticipated dispositions, the declaration and payment of future dividends, and other non-historical statements. Forward-looking statements include all statements that are not historical facts, and in some cases, can be identified by the use of forward-looking terminology such as the words “outlook,” “believes,” “expects,” “potential,” “continues,” “may,” “will,” “should,” “could,” “seeks,” “projects,” “predicts,” “intends,” “plans,” “estimates,” “anticipates” or the negative version of these words or other comparable words. You should not rely on forward-looking statements since they involve known and unknown risks, uncertainties and other factors which are, in some cases, beyond the Company’s control and which could materially affect its results of operations, financial condition, cash flows, performance or future achievements or events. Currently, one of the most significant factors is the potential adverse effect of COVID-19, including possible resurgences, on the Company’s financial condition, results of operations, cash flows and performance, its hotel management companies and its hotels’ tenants, and the global economy and financial markets. The extent to which COVID-19 impacts the Company, its hotel managers, tenants and guests at the Company’s hotels will depend on future developments, which are highly uncertain and cannot be predicted with confidence, including the scope, severity and duration of the pandemic, the actions taken to contain the pandemic or mitigate its effect, additional closures that may be mandated or advisable even after the reopening of certain of the Company’s hotels on a limited basis, whether due to an increased number of COVID-19 cases or otherwise, and the direct and indirect economic effects of the pandemic and containment measures, among others.


Forward-looking statements involve risks, uncertainties and assumptions. Actual results may differ materially from those expressed in these forward-looking statements. You should not put undue reliance on any forward-looking statements and Park urges investors to carefully review the disclosures Park makes concerning risk and uncertainties in Item 1A: “Risk Factors” in Park’s Quarterly Reports on Form 10-Q for the quarters ended March 31, 2020 and June 30, 2020 and Annual Report on Form 10-K for the year ended December 31, 2019, as such factors may be updated from time to time in Park’s filings with the SEC, which are accessible on the SEC’s website at www.sec.gov. Except as required by law, Park undertakes no obligation to update or revise publicly any forward-looking statements, whether as a result of new information, future events or otherwise.

Non-GAAP Financial Measures

Park presents certain non-GAAP financial measures in this press release, including Nareit FFO attributable to stockholders Adjusted FFO attributable to stockholders, EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA, Hotel Adjusted EBITDA margin and Net debt. These non-GAAP financial measures should be considered along with, but not as alternatives to, net income (loss) as a measure of its operating performance. Please see the schedules included in this press release including the “Definitions” section for additional information and reconciliations of such non-GAAP financial measures.

About Park

Park is the second largest publicly traded lodging REIT with a diverse portfolio of market-leading hotels and resorts with significant underlying real estate value. Park’s portfolio currently consists of 60 premium-branded hotels and resorts with over 33,000 rooms primarily located in prime city center and resort locations. Visit www.pkhotelsandresorts.com for more information.

7


PARK HOTELS & RESORTS INC.

CONDENSED CONSOLIDATED BALANCE SHEETS

(unaudited, in millions, except share and per share data)


September 30, 2020


December 31, 2019


(unaudited)


ASSETS


Property and equipment, net


$

9,255


$

9,594


Assets held for sale, net


—


71


Investments in affiliates


17


35


Goodwill


—


607


Intangibles, net


45


46


Cash and cash equivalents


1,134


346


Restricted cash


35


40


Accounts receivable, net of allowance for doubtful accounts of $4 and $2


36


180


Prepaid expenses


43


83


Other assets


53


40


Operating lease right-of-use assets


235


248


TOTAL ASSETS (variable interest entities - $234 and $242)


$

10,853


$

11,290


LIABILITIES AND EQUITY


Liabilities


Debt


$

5,121


$

3,871


Accounts payable and accrued expenses


168


217


Due to hotel managers


102


159


Deferred income tax liabilities


34


50


Other liabilities


124


282


Operating lease liabilities


249


260


Total liabilities (variable interest entities - $217 and $219)


5,798


4,839


Stockholders' Equity


Common stock, par value $0.01 per share, 6,000,000,000 shares authorized,

    235,914,952 shares issued and 235,613,445 shares outstanding as of

    September 30, 2020 and 239,589,639 shares issued and 239,386,877

    shares outstanding as of December 31, 2019


2


2


Additional paid-in capital


4,512


4,575


Retained earnings


595


1,922


Accumulated other comprehensive loss


(5

)


(3

)

Total stockholders' equity


5,104


6,496


Noncontrolling interests


(49

)


(45

)

Total equity


5,055


6,451


TOTAL LIABILITIES AND EQUITY


$

10,853


$

11,290


8


PARK HOTELS & RESORTS INC.

CONDENSED CONSOLIDATED STATEMENTS OF OPERATIONS

(unaudited, in millions, except per share data)


Three Months Ended September 30,


Nine Months Ended September 30,


2020


2019


2020


2019


Revenues


Rooms


$

70


$

430


$

453


$

1,267


Food and beverage


10


156


174


534


Ancillary hotel


15


64


87


174


Other


3


22


25


59


Total revenues


98


672


739


2,034


Operating expenses


Rooms


30


114


162


334


Food and beverage


18


117


155


371


Other departmental and support


64


153


296


453


Other property-level


84


54


200


152


Management fees


2


32


27


101


Impairment and casualty loss, net


2


8


696


8


Depreciation and amortization


75


61


225


184


Corporate general and administrative


13


14


42


47


Acquisition costs


9


59


10


65


Other


6


23


31


61


Total expenses


303


635


1,844


1,776


(Loss) gain on sales of assets, net


(1

)


1


62


20


Operating (loss) income


(206

)


38


(1,043

)


278


Interest income


—


2


2


5


Interest expense


(59

)


(33

)


(149

)


(98

)

Equity in (losses) earnings from investments in affiliates


(7

)


3


(16

)


18


Other loss, net


(3

)


(1

)


(6

)


(1

)


(Loss) income before income taxes


(275

)


9


(1,212

)


202


Income tax expense


(1

)


—


(14

)


(12

)

Net (loss) income


(276

)


9


(1,226

)


190


Net loss (income) attributable to noncontrolling interests


—


(4

)


3


(7

)

Net (loss) income attributable to stockholders


$

(276

)


$

5


$

(1,223

)


$

183


(Loss) Earnings per share:


(Loss) Earnings per share - Basic


$

(1.17

)


$

0.02


$

(5.19

)


$

0.90


(Loss) Earnings per share - Diluted


$

(1.17

)


$

0.02


$

(5.19

)


$

0.90


Weighted average shares outstanding - Basic


235


206


236


203


Weighted average shares outstanding - Diluted


235


207


236


204


9


PARK HOTELS & RESORTS INC.

NON-GAAP FINANCIAL MEASURES RECONCILIATIONS

EBITDA AND ADJUSTED EBITDA


(unaudited, in millions)


Three Months Ended September 30,


Nine Months Ended September 30,


2020


2019


2020


2019


Net (loss) income


$

(276

)


$

9


$

(1,226

)


$

190


Depreciation and amortization expense


75


61


225


184


Interest income


—


(2

)


(2

)


(5

)

Interest expense


59


33


149


98


Income tax expense


1


—


14


12


Interest expense, income tax and depreciation and

   amortization included in equity in earnings from

   investments in affiliates


2


7


11


19


EBITDA


(139

)


108


(829

)


498


Loss (gain) on sales of assets, net


1


(1

)


(62

)


(20

)

Acquisition costs


9


59


10


65


Severance expense


24


—


26


2


Share-based compensation expense


4


4


10


12


Impairment and casualty loss, net


2


8


696


8


Other items


10


2


20


(2

)

Adjusted EBITDA


$

(89

)


$

180


$

(129

)


$

563


10


PARK HOTELS & RESORTS INC.

NON-GAAP FINANCIAL MEASURES RECONCILIATIONS

PRO-FORMA HOTEL ADJUSTED EBITDA AND

PRO-FORMA HOTEL ADJUSTED EBITDA MARGIN(1)


(unaudited, dollars in millions)


Three Months Ended


Nine Months Ended


September 30,


September 30,


2020


2019


2020


2019


Adjusted EBITDA(2)


$

(89

)


180


$

(129

)


$

563


Less: Adjusted EBITDA from investments in

   affiliates


2


(9

)


2


(31

)

Add: All other(3)


11


12


34


41


Hotel Adjusted EBITDA


(76

)


183


(93

)


573


Add:  Adjusted EBITDA from hotels acquired(1)


—


39


—


129


Less: Adjusted EBITDA from hotels disposed of


—


(5

)


(2

)


(31

)

Pro-forma Hotel Adjusted EBITDA(1)


$

(76

)


$

217


$

(95

)


$

671


Three Months Ended


Nine Months Ended


September 30,


September 30,


2020


2019


2020


2019


Total Revenues


$

98


$

672


$

739


$

2,034


Less: Other revenue


(3

)


(22

)


(25

)


(59

)

Add: Revenues from hotels acquired(1)


—


125


—


405


Less: Revenues from hotels disposed of


—


(25

)


(6

)


(116

)

Pro-forma Hotel Revenues(1)


$

95


$

750


$

708


$

2,264


Three Months Ended


Nine Months Ended


September 30,


September 30,


2020


2019


Change(4)


2020


2019


Change(4)


Pro-forma Hotel Revenues(1)


$

95


$

750


(87.5

)%


$

708


$

2,264


(68.8

)%

Pro-forma Hotel Adjusted EBITDA(1)


$

(76

)


$

217


NM(5)


$

(95

)


$

671


NM(5)


Pro-forma Hotel Adjusted EBITDA margin(1)(4)


(81.2

)%


28.9

%


NM(5)


(13.4

)%


29.6

%


NM(5)


_____________________________________________________________


(1)   Assumes hotels were acquired on January 1, 2019.


(2)   Includes EBITDA of $8 million for both the three and nine months ended September 30, 2019, for the period of ownership of the

      Chesapeake hotels between September 18, 2019 and September 30, 2019.


(3)    Includes other revenues and other expenses, non-income taxes on TRS leases included in other property-level expenses and

       corporate general and administrative expenses in the condensed consolidated statements of operations.


(4)   Percentages are calculated based on unrounded numbers.


(5)   Percentage change is not meaningful.


11


PARK HOTELS & RESORTS INC.

NON-GAAP FINANCIAL MEASURES RECONCILIATIONS

NAREIT FFO AND ADJUSTED FFO


(unaudited, in millions, except per share data)


Three Months Ended September 30,


Nine Months Ended September 30,


2020


2019


2020


2019


Net (loss) income attributable to stockholders


$

(276

)


$

5


$

(1,223

)


$

183


Depreciation and amortization expense


75


61


225


184


Depreciation and amortization expense attributable to

   noncontrolling interests


(1

)


(1

)


(3

)


(3

)

Loss (gain) on sales of assets, net


1


(1

)


(62

)


(20

)

Gain on sale of investments in affiliates(1)


—


—


(1

)


—


Impairment loss


2


—


697


—


Equity investment adjustments:


Equity in losses (earnings) from investments in affiliates


7


(3

)


16


(18

)

Pro rata FFO of investments in affiliates


(5

)


6


(9

)


27


Nareit FFO attributable to stockholders


(197

)


67


(360

)


353


Casualty loss (gain), net


—


7


(1

)


7


Acquisition costs


9


59


10


65


Severance expense


24


—


26


2


Share-based compensation expense


4


4


10


12


Other items(2)


11


3


48


1


Adjusted FFO attributable to stockholders


$

(149

)


$

140


$

(267

)


$

440


Nareit FFO per share - Diluted(3)


$

(0.84

)


$

0.33


$

(1.53

)


$

1.73


Adjusted FFO per share - Diluted(3)


$

(0.63

)


$

0.68


$

(1.13

)


$

2.16


Weighted average shares outstanding - Diluted


235


207


236


204


(1)

Included in other loss, net in the condensed consolidated statements of operations.

(2)

The nine months ended September 30, 2020, includes $30 million of tax expense recognized from hotels sold during the period.

(3)

Per share amounts are calculated based on unrounded numbers.


12


PARK HOTELS & RESORTS INC.

NON-GAAP FINANCIAL MEASURES RECONCILIATIONS

NET DEBT


(unaudited, in millions)


September 30, 2020


Debt


$

5,121


Add: unamortized deferred financing costs and discount


40


Less: unamortized premium


(4

)

Long-term debt, including current maturities and excluding

   unamortized deferred financing cost, premiums and discounts


5,157


Add: Park's share of unconsolidated affiliates debt,

   excluding unamortized deferred financing costs


225


Less: cash and cash equivalents


(1,134

)

Less: restricted cash


(35

)

Net debt


$

4,213


13


PARK HOTELS & RESORTS INC.

DEFINITIONS

Pro-forma

The Company presents certain data for its consolidated hotels on a pro-forma hotel basis as supplemental information for investors: Pro-forma Hotel Revenues, Pro-forma RevPAR, Pro-forma Total RevPAR, Pro-forma Occupancy, Pro-forma ADR, Pro-forma Hotel Adjusted EBITDA and Pro-forma Hotel Adjusted EBITDA Margin.  The Company presents pro-forma hotel results to help the Company and its investors evaluate the ongoing operating performance of its hotels. The Company’s pro-forma metrics exclude results from property dispositions and include results from property acquisitions as though such acquisitions occurred on January 1, 2019.

EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA and Hotel Adjusted EBITDA margin

Earnings (loss) before interest expense, taxes and depreciation and amortization (“EBITDA”), presented herein, reflects net income (loss) excluding depreciation and amortization, interest income, interest expense, income taxes and interest expense, income tax and depreciation and amortization included in equity in earnings (losses) from investments in affiliates.

Adjusted EBITDA, presented herein, is calculated as EBITDA, as previously defined, further adjusted to exclude:


•

Gains or losses on sales of assets for both consolidated and unconsolidated investments;


•

Costs associated with hotel acquisitions or dispositions expensed during the period;


•

Severance expense;


•

Share-based compensation expense;


•

Casualty gains or losses;


•

Impairment losses; and


•

Other items that management believes are not representative of the Company’s current or future operating performance.

Hotel Adjusted EBITDA measures hotel-level results before debt service, depreciation and corporate expenses of the Company’s consolidated hotels but excluding hotels owned by unconsolidated affiliates, and is a key measure of the Company’s profitability. The Company presents Hotel Adjusted EBITDA to help the Company and its investors evaluate the ongoing operating performance of the Company’s consolidated hotels.

EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA and Hotel Adjusted EBITDA margin are not recognized terms under United States (“U.S.”) GAAP and should not be considered as alternatives to net income (loss) or other measures of financial performance or liquidity derived in accordance with U.S. GAAP. In addition, the Company’s definitions of EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA and Hotel Adjusted EBITDA margin may not be comparable to similarly titled measures of other companies.

The Company believes that EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA and Hotel Adjusted EBITDA margin provide useful information to investors about the Company and its financial condition and results of operations for the following reasons: (i) EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA and Hotel Adjusted EBITDA margin are among the measures used by the Company’s management team to make day-to-day operating decisions and evaluate its operating performance between periods and between REITs by removing the effect of its capital structure (primarily interest expense) and asset base (primarily depreciation and amortization) from its operating results; and (ii) EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA and Hotel Adjusted EBITDA margin are frequently used by securities analysts, investors and other interested parties as a common performance measure to compare results or estimate valuations across companies in the industry.

EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA and Hotel Adjusted EBITDA margin have limitations as analytical tools and should not be considered either in isolation or as a substitute for net income (loss) or other methods of analyzing the Company’s operating performance and results as reported under U.S. GAAP.

14


Nareit FFO attributable to stockholders, Adjusted FFO attributable to stockholders Nareit FFO per share - diluted and Adjusted FFO per share - diluted

Nareit FFO attributable to stockholders and Nareit FFO per diluted share (defined as set forth below) are presented herein as non-GAAP measures of the Company’s performance. The Company calculates funds from (used in) operations (“FFO”) attributable to stockholders for a given operating period in accordance with standards established by the National Association of Real Estate Investment Trusts (“Nareit”), as net income or loss attributable to stockholders (calculated in accordance with U.S. GAAP), excluding depreciation and amortization, gains or losses on sales of assets, impairment, and the cumulative effect of changes in accounting principles, plus adjustments for unconsolidated joint ventures. Adjustments for unconsolidated joint ventures are calculated to reflect the Company’s pro rata share of the FFO of those entities on the same basis. As noted by Nareit in its December 2018 “Nareit Funds from Operations White Paper – 2018 Restatement,” since real estate values historically have risen or fallen with market conditions, many industry investors have considered presentation of operating results for real estate companies that use historical cost accounting to be insufficient by themselves. For these reasons, Nareit adopted the FFO metric in order to promote an industry-wide measure of REIT operating performance. The Company believes Nareit FFO provides useful information to investors regarding its operating performance and can facilitate comparisons of operating performance between periods and between REITs. The Company’s presentation may not be comparable to FFO reported by other REITs that do not define the terms in accordance with the current Nareit definition, or that interpret the current Nareit definition differently. The Company calculates Nareit FFO per diluted share as Nareit FFO divided by the number of fully diluted shares outstanding during a given operating period.

The Company also presents Adjusted FFO attributable to stockholders and Adjusted FFO per diluted share when evaluating its performance because management believes that the exclusion of certain additional items described below provides useful supplemental information to investors regarding the Company’s ongoing operating performance. Management historically has made the adjustments detailed below in evaluating its performance and in its annual budget process. Management believes that the presentation of Adjusted FFO provides useful supplemental information that is beneficial to an investor’s complete understanding of operating performance. The Company adjusts Nareit FFO attributable to stockholders for the following items, which may occur in any period, and refers to this measure as Adjusted FFO attributable to stockholders:


•

Costs associated with hotel acquisitions or dispositions expensed during the period;


•

Severance expense;


•

Share-based compensation expense;


•

Casualty gains or losses; and


•

Other items that management believes are not representative of the Company’s current or future operating performance.

Net Debt

Net debt, presented herein, is a non-GAAP financial measure that the Company uses to evaluate its financial leverage. Net debt is calculated as (i) long-term debt, including current maturities and excluding unamortized deferred financing costs; and (ii) the Company’s share of investments in affiliate debt, excluding unamortized deferred financing costs; reduced by (a) cash and cash equivalents; and (b) restricted cash and cash equivalents.

The Company believes Net debt provides useful information about its indebtedness to investors as it is frequently used by securities analysts, investors and other interested parties to compare the indebtedness of companies. Net debt should not be considered as a substitute to debt presented in accordance with U.S. GAAP. Net debt may not be comparable to a similarly titled measure of other companies.

Occupancy

Occupancy represents the total number of room nights sold divided by the total number of room nights available at a hotel or group of hotels. Room nights available to guests have not been adjusted for suspended or reduced operations at certain of Park’s hotels as a result of COVID-19, unless otherwise noted. Occupancy measures the utilization of the Company’s hotels’ available capacity. Management uses occupancy to gauge demand at a specific hotel or group of hotels in a given period. Occupancy levels also help management determine achievable Average Daily Rate (“ADR”) levels as demand for rooms increases or decreases.

15


Average Daily Rate

ADR represents rooms revenue divided by total number of room nights sold in a given period. ADR measures average room price attained by a hotel and ADR trends provide useful information concerning the pricing environment and the nature of the customer base of a hotel or group of hotels. ADR is a commonly used performance measure in the hotel industry, and management uses ADR to assess pricing levels that the Company is able to generate by type of customer, as changes in rates have a more pronounced effect on overall revenues and incremental profitability than changes in occupancy, as described above.

Revenue per Available Room

Revenue per Available Room (“RevPAR”) represents rooms revenue divided by the total number of room nights available to guests for a given period. Room nights available to guests have not been adjusted for suspended or reduced operations at certain of Park’s hotels as a result of COVID-19. Management considers RevPAR to be a meaningful indicator of the Company’s performance as it provides a metric correlated to two primary and key factors of operations at a hotel or group of hotels: occupancy and ADR. RevPAR is also a useful indicator in measuring performance over comparable periods.

Total RevPAR

Total RevPAR represents rooms, food and beverage and other hotel revenues divided by the total number of room nights available to guests for a given period. Room nights available to guests have not been adjusted for suspended or reduced operations at certain of Park’s hotels as a result of COVID-19. Management considers Total RevPAR to be a meaningful indicator of the Company’s performance as approximately one-third of revenues are earned from food and beverage and other hotel revenues. Total RevPAR is also a useful indicator in measuring performance over comparable periods.

References to RevPAR, Total RevPAR and ADR are presented on a currency neutral basis (prior periods are reflected using current period exchange rates), unless otherwise noted.

16


1 |


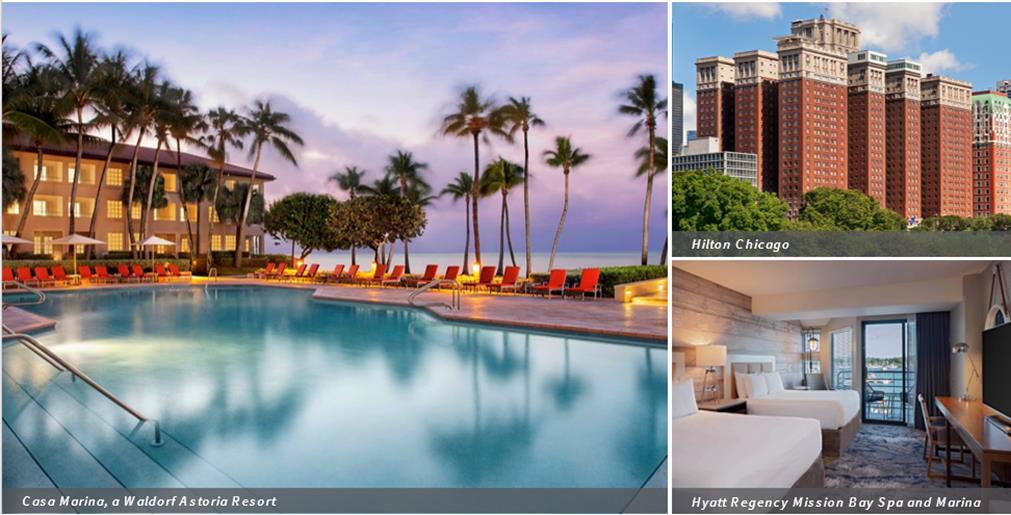
Fourth Quarter and Year End 2019 Supplemental Data December 31, 2019 Royal Palm South Beach Miami, a Tribute Portfolio Resort Parc 55 San Francisco, a Hilton Hotel Hilton Hawaiian Village Waikiki Beach Reso


About Park and Safe Harbor Disclosure


About Park Hotels & Resorts Inc.

Park (NYSE: PK) is the second largest publicly-traded lodging real estate company with a diverse portfolio of market-leading hotels and resorts with significant underlying real estate value. Park’s portfolio consists of 60 premium-branded hotels and resorts with over 33,000 rooms primarily located in prime city center and resort locations. Visit www.pkhotelsandresorts.com for more information.


Forward-Looking Statements

This supplement contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements include, but are not limited to, statements related to Park’s current expectations regarding the performance of its business, financial results, liquidity and capital resources, the effects of competition and the effects of future legislation or regulations, the expected completion of anticipated dispositions, the declaration and payment of future dividends, and other non-historical statements. Forward-looking statements include all statements that are not historical facts, and in some cases, can be identified by the use of forward-looking terminology such as the words “outlook,” “believes,” “expects,” “potential,” “continues,” “may,” “will,” “should,” “could,” “seeks,” “projects,” “predicts,” “intends,” “plans,” “estimates,” “anticipates” or the negative version of these words or other comparable words. You should not rely on forward-looking statements since they involve known and unknown risks, uncertainties and other factors which are, in some cases, beyond the Company’s control and which could materially affect its results of operations, financial condition, cash flows, performance or future achievements or events. Currently, one of the most significant factors is the potential adverse effect of COVID-19, including possible resurgences, on the Company’s financial condition, results of operations, cash flows and performance, its hotel management companies and its hotels’ tenants, and the global economy and financial markets. The extent to which COVID-19 impacts the Company, its hotel managers, tenants and guests at the Company’s hotels will depend on future developments, which are highly uncertain and cannot be predicted with confidence, including the scope, severity and duration of the pandemic, the actions taken to contain the pandemic or mitigate its effect, additional closures that may be mandated or advisable even after the reopening of certain of the Company’s hotels on a limited basis, whether due to an increased number of COVID-19 cases or otherwise, and the direct and indirect economic effects of the pandemic and containment measures, among others.


Forward-looking statements involve risks, uncertainties and assumptions. Actual results may differ materially from those expressed in these forward-looking statements. You should not put undue reliance on any forward-looking statements and Park urges investors to carefully review the disclosures Park makes concerning risk and uncertainties in Item 1A: “Risk Factors” in Park’s Annual Report on Form 10-K for the year ended December 31, 2019 and Quarterly Reports on Form 10-Q for the quarters ended March 31, 2020 and June 30, 2020, as such factors may be updated from time to time in Park’s filings with the SEC, which are accessible on the SEC’s website at www.sec.gov. Except as required by law, Park undertakes no obligation to update or revise publicly any forward-looking statements, whether as a result of new information, future events or otherwise.


Supplemental Financial Information

Park refers to certain non-generally accepted accounting principles (“GAAP”) financial measures in this presentation, including Funds from (used in) Operations (“FFO”) calculated in accordance with the guidelines of the National Association of Real Estate Investment Trusts (“Nareit”), Adjusted FFO, FFO per share, Adjusted FFO per share, Earnings (loss) before interest expense, taxes and depreciation and amortization (“EBITDA”), Adjusted EBITDA, Hotel Adjusted EBITDA, Hotel Adjusted EBITDA margin, Net debt and Net debt to Adjusted EBITDA ratio. These non-GAAP financial measures should be considered along with, but not as alternatives to, net income (loss) as a measure of its operating performance. Please see the schedules included in this presentation including the “Definitions” section for additional information and reconciliations of such non-GAAP financial measures.


2 |


Table of Contents


1. Financial Statements

4


2. Supplementary Financial Information

7


3. Portfolio and Operating Metrics

17


4. Properties Acquired & Sold

28


5. Liquidity and Capital Structure

31


6. Definitions

35


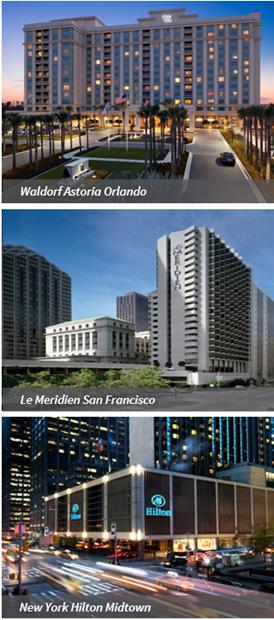
Waldorf Astoria Orlando Hilton midtown

Waldorf Astoria Orlando Le Meridien San Francisco New York Hilton Midtown


3 |


Financial Statements


4 |


Financial Statements


Condensed Consolidated Balance Sheets


(in millions, except share and per share data)


September 30, 2020


December 31, 2019


(unaudited)


ASSETS


Property and equipment, net


$

9,255


$

9,594


Assets held for sale, net


—


71


Investments in affiliates


17


35


Goodwill


—


607


Intangibles, net


45


46


Cash and cash equivalents


1,134


346


Restricted cash


35


40


Accounts receivable, net of allowance for doubtful accounts of $4 and $2


36


180


Prepaid expenses


43


83


Other assets


53


40


Operating lease right-of-use assets


235


248


TOTAL ASSETS (variable interest entities - $234 and $242)


$

10,853


$

11,290


LIABILITIES AND EQUITY


Liabilities


Debt


$

5,121


$

3,871


Accounts payable and accrued expenses


168


217


Due to hotel managers


102


159


Deferred income tax liabilities


34


50


Other liabilities


124


282


Operating lease liabilities


249


260


Total liabilities (variable interest entities - $217 and $219)


5,798


4,839


Stockholders' Equity


Common stock, par value $0.01 per share, 6,000,000,000 shares authorized,

    235,914,952 shares issued and 235,613,445 shares outstanding as of

    September 30, 2020 and 239,589,639 shares issued and 239,386,877

    shares outstanding as of December 31, 2019


2


2


Additional paid-in capital


4,512


4,575


Retained earnings


595


1,922


Accumulated other comprehensive loss


(5

)


(3

)

Total stockholders' equity


5,104


6,496


Noncontrolling interests


(49

)


(45

)

Total equity


5,055


6,451


TOTAL LIABILITIES AND EQUITY


$

10,853


$

11,290


5 |


Financial Statements (continued)


Condensed Consolidated Statements of Operations


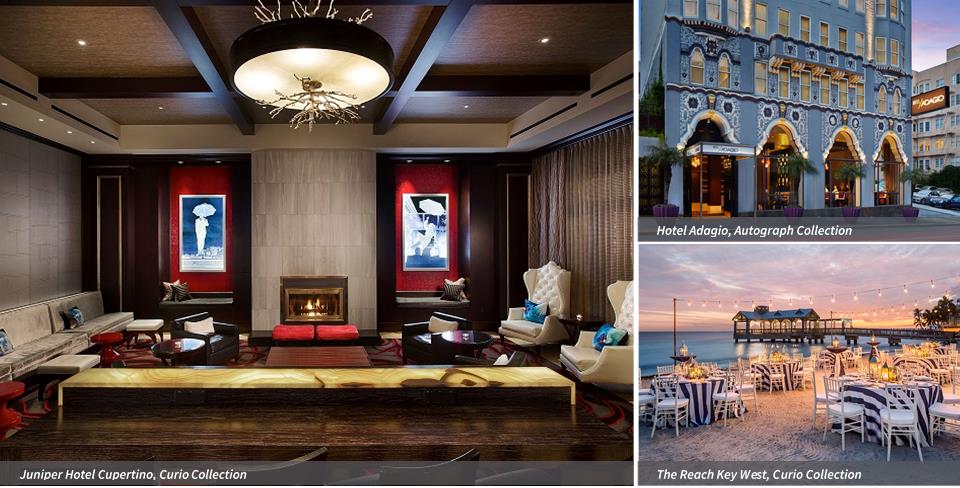
y financial information juniper hotel, curio collection hotel adagio, autograph collection the reach, Astoria resort

(unaudited, in millions, except per share data)


Three Months Ended September 30,


Nine Months Ended September 30,


2020


2019


2020


2019


Revenues


Rooms


$

70


$

430


$

453


$

1,267


Food and beverage


10


156


174


534


Ancillary hotel


15


64


87


174


Other


3


22


25


59


Total revenues


98


672


739


2,034


Operating expenses


Rooms


30


114


162


334


Food and beverage


18


117


155


371


Other departmental and support


64


153


296


453


Other property-level


84


54


200


152


Management fees


2


32


27


101


Impairment and casualty loss, net


2


8


696


8


Depreciation and amortization


75


61


225


184


Corporate general and administrative


13


14


42


47


Acquisition costs


9


59


10


65


Other


6


23


31


61


Total expenses


303


635


1,844


1,776


(Loss) gain on sales of assets, net


(1

)


1


62


20


Operating (loss) income


(206

)


38


(1,043

)


278


Interest income


—


2


2


5


Interest expense


(59

)


(33

)


(149

)


(98

)

Equity in (losses) earnings from investments in affiliates


(7

)


3


(16

)


18


Other loss, net


(3

)


(1

)


(6

)


(1

)


(Loss) income before income taxes


(275

)


9


(1,212

)


202


Income tax expense


(1

)


—


(14

)


(12

)

Net (loss) income(1)


(276

)


9


(1,226

)


190


Net loss (income) attributable to noncontrolling interests


—


(4

)


3


(7

)

Net (loss) income attributable to stockholders(1)


$

(276

)


$

5


$

(1,223

)


$

183


(Loss) Earnings per share:


(Loss) Earnings per share - Basic


$

(1.17

)


$

0.02


$

(5.19

)


$

0.90


(Loss) Earnings per share - Diluted


$

(1.17

)


$

0.02


$

(5.19

)


$

0.90


Weighted average shares outstanding - Basic


235


206


236


203


Weighted average shares outstanding - Diluted


235


207


236


204


____________________________


(1)

The nine months ended September 30, 2020 includes $607 million and $90 million of impairment losses related to goodwill and long-lived assets, respectively.


6 |


Supplementary Financial Information


7 |


Supplementary Financial Information


EBITDA and Adjusted EBITDA


(unaudited, in millions)


Three Months Ended September 30,


Nine Months Ended September 30,


2020


2019


2020


2019


Net (loss) income


$

(276

)


$

9


$

(1,226

)


$

190


Depreciation and amortization expense


75


61


225


184


Interest income


—


(2

)


(2

)


(5

)

Interest expense


59


33


149


98


Income tax expense


1


—


14


12


Interest expense, income tax and depreciation and

   amortization included in equity in earnings from

   investments in affiliates


2


7


11


19


EBITDA


(139

)


108


(829

)


498


Loss (gain) on sales of assets, net


1


(1

)


(62

)


(20

)

Acquisition costs


9


59


10


65


Severance expense


24


—


26


2


Share-based compensation expense


4


4


10


12


Impairment and casualty loss, net


2


8


696


8


Other items


10


2


20


(2

)

Adjusted EBITDA


$

(89

)


$

180


$

(129

)


$

563


8 |


Supplementary Financial Information (continued)


Pro-forma Hotel Adjusted EBITDA and Pro-forma Hotel Adjusted EBITDA Margin(1)


(unaudited, dollars in millions)


Three Months Ended


Nine Months Ended


September 30,


September 30,


2020


2019


2020


2019


Adjusted EBITDA(2)


$

(89

)


180


$

(129

)


$

563


Less: Adjusted EBITDA from investments in

   affiliates


2


(9

)


2


(31

)

Add: All other(3)


11


12


34


41


Hotel Adjusted EBITDA


(76

)


183


(93

)


573


Add:  Adjusted EBITDA from hotels acquired(1)


—


39


—


129


Less: Adjusted EBITDA from hotels disposed of


—


(5

)


(2

)


(31

)

Pro-forma Hotel Adjusted EBITDA(1)


$

(76

)


$

217


$

(95

)


$

671


Three Months Ended


Nine Months Ended


September 30,


September 30,


2020


2019


2020


2019


Total Revenues


$

98


$

672


$

739


$

2,034


Less: Other revenue


(3

)


(22

)


(25

)


(59

)

Add: Revenues from hotels acquired(1)


—


125


—


405


Less: Revenues from hotels disposed of


—


(25

)


(6

)


(116

)

Pro-forma Hotel Revenues(1)


$

95


$

750


$

708


$

2,264


Three Months Ended


Nine Months Ended


September 30,


September 30,


2020


2019


Change(4)


2020


2019


Change(4)


Pro-forma Hotel Revenues(1)


$

95


$

750


(87.5

)%


$

708


$

2,264


(68.8

)%

Pro-forma Hotel Adjusted EBITDA(1)


$

(76

)


$

217


NM(5)


$

(95

)


$

671


NM(5)


Pro-forma Hotel Adjusted EBITDA margin(1)(4)


(81.2

)%


28.9

%


NM(5)


(13.4

)%


29.6

%


NM(5)


___________________________________________


(1)   Assumes hotels were acquired on January 1, 2019.


(2)   Includes EBITDA of $8 million for both the three and nine months ended September 30, 2019, for the period of ownership of the

     Chesapeake hotels between September 18, 2019 and September 30, 2019.


(3)    Includes other revenues and other expenses, non-income taxes on TRS leases included in other property-level expenses and

     corporate general and administrative expenses in the condensed consolidated statements of operations.


(4)   Percentages are calculated based on unrounded numbers.


(5)   Percentage change is not meaningful.


9 |


Supplementary Financial Information (continued)


Nareit FFO and Adjusted FFO


(unaudited, in millions, except per share data)


Three Months Ended September 30,


Nine Months Ended September 30,


2020


2019


2020


2019


Net (loss) income attributable to stockholders


$

(276

)


$

5


$

(1,223

)


$

183


Depreciation and amortization expense


75


61


225


184


Depreciation and amortization expense attributable to

   noncontrolling interests


(1

)


(1

)


(3

)


(3

)

Loss (gain) on sales of assets, net


1


(1

)


(62

)


(20

)

Gain on sale of investments in affiliates(1)


—


—


(1

)


—


Impairment loss


2


—


697


—


Equity investment adjustments:


Equity in losses (earnings) from investments in affiliates


7


(3

)


16


(18

)

Pro rata FFO of investments in affiliates


(5

)


6


(9

)


27


Nareit FFO attributable to stockholders


(197

)


67


(360

)


353


Casualty loss (gain), net


—


7


(1

)


7


Acquisition costs


9


59


10


65


Severance expense


24


—


26


2


Share-based compensation expense


4


4


10


12


Other items(2)


11


3


48


1


Adjusted FFO attributable to stockholders


$

(149

)


$

140


$

(267

)


$

440


Nareit FFO per share - Diluted(3)


$

(0.84

)


$

0.33


$

(1.53

)


$

1.73


Adjusted FFO per share - Diluted(3)


$

(0.63

)


$

0.68


$

(1.13

)


$

2.16


Weighted average shares outstanding - Diluted


235


207


236


204


_________________________________


(1)

Included in other loss, net in the condensed consolidated statements of operations.


(2)

For the nine months ended September 30, 2020, includes $30 million of tax expense recognized from hotels sold during the period.


(3)

Per share amounts are calculated based on unrounded numbers.


10 |


Supplementary Financial Information (continued)


Historical Pro-forma Hotel Metrics


The financial information below is for the 53 consolidated hotels owned as of September 30, 2020(1).


Three Months Ended


TTM


Full Year


(unaudited)


December 31,


March 31,


June 30,


September 30,


September 30,


December 31,


2019


2020


2020


2020


2020


2019


Pro-forma RevPAR


$

177.84


$

136.27


$

7.85


$

26.14


$

87.47


$

183.69


Pro-forma Occupancy


80.8

%


61.7

%


6.1

%


19.1

%


42.1

%


82.3

%

Pro-forma ADR


$

220.20


$

220.90


$

127.65


$

137.10


$

207.69


$

223.28


Pro-forma Hotel Revenues (in millions)


$

766


$

574


$

39


$

95


$

1,474


$

3,030


Pro-forma Hotel Adjusted EBITDA (in millions)


$

223


$

90


$

(108

)


$

(76

)


$

129


$

894


Pro-forma Hotel Adjusted EBITDA margin(2)


29.2

%


15.6

%


(283.1

)%


(81.2

)%


8.8

%


29.5

%


Three Months Ended


TTM


Full Year


(unaudited)


December 31,


March 31,


June 30,


September 30,


September 30,


December 31,


2018


2019


2019


2019


2019


2018


Pro-forma RevPAR


$

173.18


$

175.97


$

192.94


$

187.93


$

182.50


$

179.14


Pro-forma Occupancy


78.2

%


77.7

%


85.9

%


84.7

%


81.6

%


81.0

%

Pro-forma ADR


$

221.59


$

226.46


$

224.59


$

222.04


$

223.64


$

221.46


Pro-forma Hotel Revenues (in millions)


$

732


$

723


$

791


$

750


$

2,996


$

2,922


Pro-forma Hotel Adjusted EBITDA (in millions)


$

212


$

206


$

248


$

217


$

883


$

870


Pro-forma Hotel Adjusted EBITDA margin(2)


29.0

%


28.4

%


31.4

%


28.9

%


29.5

%


29.8

%

_________________________________


(1)

Assumes hotels were acquired on January 1, 2018.


(2)

Percentages are calculated based on unrounded numbers.


11 |


Supplementary Financial Information (continued)


Historical Pro-forma Hotel Adjusted EBITDA – 2020 TTM


The financial information below is for the 53 consolidated hotels owned as of September 30, 2020.


Three Months Ended


TTM


Full Year


(unaudited, in millions)


December 31,


March 31,


June 30,


September 30,


September 30,


December 31,


2019


2020


2020


2020


2020


2019


Net income (loss)


$

126


$

(689

)


$

(261

)


$

(276

)


$

(1,100

)


$

316


Depreciation and amortization expense


80


75


75


75


305


264


Interest income


(1

)


(1

)


(1

)


—


(3

)


(6

)

Interest expense


42


40


50


59


191


140


Income tax expense


23


10


3


1


37


35


Interest expense, income tax and depreciation

   and amortization included in equity in earnings

   from investments in affiliates


4


5


4


2


15


23


EBITDA


274


(560

)


(130

)


(139

)


(555

)


772


Loss (gain) on sales of assets, net


1


(62

)


(1

)


1


(61

)


(19

)

Gain on sale of investments in affiliates(1)


(44

)


—


—


—


(44

)


(44

)

Acquisition costs


5


1


—


9


15


70


Severance expense


—


2


—


24


26


2


Share-based compensation expense


4


2


4


4


14


16


Casualty (gain) loss and impairment loss, net


(26

)


694


—


2


670


(18

)

Other items


9


5


5


10


29


7


Adjusted EBITDA


223


82


(122

)


(89

)


94


786


Add: Adjusted EBITDA from hotels acquired(2)


—


—


—


—


—


129


Less: Adjusted EBITDA from hotels disposed of


(6

)


(1

)


—


—


(7

)


(37

)

Less: Adjusted EBITDA from investments in

   affiliates disposed of


—


—


—


—


—


(2

)

Pro-forma Adjusted EBITDA(2)


217


81


(122

)


(89

)


87


876


Less: Adjusted EBITDA from investments in

   affiliates


(6

)


(4

)


4


2


(4

)


(35

)

Add: All other(3)


12


13


10


11


46


53


Pro-forma Hotel Adjusted EBITDA(2)


$

223


$

90


$

(108

)


$

(76

)


$

129


$

894


  __________________________________


(1)

Included in other gain (loss), net in the consolidated statement of operations.


(2)

Assumes hotels were acquired on January 1, 2018.


(3)

Includes other revenues and other expenses, non-income taxes on TRS leases included in other property-level expenses and corporate general and administrative expenses in the condensed consolidated statement of operations.


12 |


Supplementary Financial Information (continued)


Historical Pro-forma Hotel Adjusted EBITDA – 2019 TTM


The financial information below is for the 53 consolidated hotels owned as of September 30, 2020.


Three Months Ended


TTM


Full Year


(unaudited, in millions)


December 31,


March 31,


June 30,


September 30,


September 30,


December 31,


2018


2019


2019


2019


2019


2018


Net income


$

55


$

97


$

84


$

9


$

245


$

477


Depreciation and amortization expense


69


62


61


61


253


277


Interest income


(2

)


(1

)


(2

)


(2

)


(7

)


(6

)

Interest expense


33


32


33


33


131


127


Income tax expense


10


7


5


—


22


23


Interest expense, income tax and depreciation

and amortization included in equity in earnings

from investments in affiliates


6


5


7


7


25


26


EBITDA


171


202


188


108


669


924


Loss (gain) on sales of assets, net


2


(31

)


12


(1

)


(18

)


(96

)

Gain on sale of investments in affiliates(1)


—


—


—


—


—


(107

)

Acquisition costs


—


—


6


59


65


—


Transition expense


—


—


—


—


—


3


Severance expense


—


1


1


—


2


2


Share-based compensation expense


4


4


4


4


16


16


Casualty loss (gain) and impairment loss, net


—


—


—


8


8


(1

)

Other items


7


—


(4

)


2


5


13


Adjusted EBITDA


184


176


207


180


747


754


Add: Adjusted EBITDA from hotels acquired(2)


41


37


53


39


170


181


Less: Adjusted EBITDA from hotels disposed of


(15

)


(12

)


(14

)


(5

)


(46

)


(70

)

Less: Adjusted EBITDA from investments in

   affiliates disposed of


—


—


(1

)


(1

)


(2

)


(5

)

Pro-forma Adjusted EBITDA(2)


210


201


245


213


869


860


Less: Adjusted EBITDA from investments in affiliates


(11

)


(10

)


(11

)


(8

)


(40

)


(42

)

Add: All other(3)


13


15


14


12


54


52


Pro-forma Hotel Adjusted EBITDA(2)


$

212


$

206


$

248


$

217


$

883


$

870


                         __________________________________


(1)

Included in other gain (loss), net in the consolidated statement of operations.


(2)

Assumes hotels were acquired on January 1, 2018.


(3)

Includes other revenues and other expenses, non-income taxes on TRS leases included in other property-level expenses and corporate general and administrative expenses in the condensed consolidated statement of operations.


13 |


Supplementary Financial Information (continued)


Historical Pro-forma Hotel Revenues – 2020 and 2019 TTM


The financial information below is for the 53 consolidated hotels owned as of September 30, 2020.


Three Months Ended


TTM


Full Year


(unaudited, in millions)


December 31,


March 31,


June 30,


September 30,


September 30,


December 31,


2019


2020


2020


2020


2020


2019


Total Revenues


$

810


$

599


$

42


$

98


$

1,549


$

2,844


Less: Other revenue


(18

)


(19

)


(3

)


(3

)


(43

)


(77

)

Add:  Revenues from hotels acquired(1)


—


—


—


—


—


406


Less: Revenues from hotels disposed of


(26

)


(6

)


—


—


(32

)


(143

)

Pro-forma Hotel Revenues(1)


$

766


$

574


$

39


$

95


$

1,474


$

3,030


Three Months Ended


TTM


Full Year


December 31,


March 31,


June 30,


September 30,


September 30,


December 31,


2018


2019


2019


2019


2019


2018


Total Revenues


$

686


$

659


$

703


$

672


$

2,720


$

2,737


Less: Other revenue


(19

)


(18

)


(19

)


(22

)


(78

)


(72

)

Add:  Revenues from hotels acquired(1)


134


130


151


125


540


561


Less: Revenues from hotels disposed of


(69

)


(48

)


(44

)


(25

)


(186

)


(304

)

Pro-forma Hotel Revenues(1)


$

732


$

723


$

791


$

750


$

2,996


$

2,922


                   __________________________________


(1)

Assumes hotels were acquired on January 1, 2018.


14 |


Supplementary Financial Information (continued)


General and Administrative Expenses


(unaudited, in millions)


Three Months Ended


Nine Months Ended


September 30,


September 30,


2020


2019


2020


2019


Corporate general and administrative expenses


$

13


$

14


$

42


$

47


Less:


Share-based compensation expense


4


4


10


12


Disposition costs


—


—


1


1


Severance expense


—


—


2


1


G&A, excluding expenses not included in Adjusted EBITDA


$

9


$

10


$

29


$

33


15 |


Supplementary Financial Information (continued)


Net Debt and Net Debt to Pro-forma Adjusted EBITDA Ratio


(unaudited, in millions)


September 30, 2020


December 31, 2019


Debt


$

5,121


$

3,871


Add: unamortized deferred financing costs and discount


40


18


Less: unamortized premium


(4

)


(3

)

Long-term debt, including current maturities and excluding

   unamortized deferred financing cost, premiums and discounts


5,157


3,886


Add: Park's share of unconsolidated affiliates debt,

   excluding unamortized deferred financing costs


225


225


Less: cash and cash equivalents


(1,134

)


(346

)

Less: restricted cash


(35

)


(40

)

Net debt


$

4,213


$

3,725


Pro-forma Adjusted EBITDA(1)


$

87


$

876


Net debt to Pro-forma Adjusted EBITDA ratio


NM(2)


4.3x


________________________________


(1)

See slide 12 for Pro-forma Adjusted EBITDA at September 30, 2020 and December 31, 2019. Pro-forma Adjusted EBITDA excludes results from disposed hotels.


(2)

The Net debt to Pro-forma Adjusted EBITDA ratio as of September 30, 2020 is not meaningful.


16 |


Portfolio and Operating Metrics


Portfolio and Operating Metrics Hilton Santa Barbara Beachfront Resort Hilton New Orleans Riverside Waldorf Astoria Orlando GolfClub


17 |


Portfolio and Operating Metrics


Hotel Portfolio as of November 5, 2020


Hotel Name

Total Rooms


Operating Status

Reopening Date(1)

Market

Meeting Space

(square feet)


Ownership

Equity Ownership


Debt

(in millions)


Consolidated Portfolio


Hilton Hawaiian Village Waikiki Beach Resort


2,860


Suspended

12/15/2020

Hawaii


150,000


Fee Simple

100%


$

1,275


Hilton San Francisco Union Square


1,921


Suspended

Q1 2021

San Francisco


130,000


Fee Simple

100%


$

725


(2)

New York Hilton Midtown


1,878


Suspended

Q1 2021

New York


151,000


Fee Simple

100%


—


Hilton New Orleans Riverside


1,622


Reopened

7/9/2020

New Orleans


130,000


Fee Simple

100%


—


Hilton Chicago


1,544


Suspended

Q1 2021

Chicago


234,000


Fee Simple

100%


—


Parc 55 San Francisco - a Hilton Hotel


1,024


Suspended

Q1 2021

San Francisco


30,000


Fee Simple

100%


—


(2)

Hilton Orlando Bonnet Creek


1,009


Reopened

7/1/2020

Orlando


122,000


Fee Simple

100%


—


DoubleTree Hotel Seattle Airport


850


Suspended

Q1 2021

Seattle


34,000


Leasehold

100%


—


Hilton Orlando Lake Buena Vista


814


Reopened

11/2/2020

Orlando


78,000


Leasehold

100%


—


Caribe Hilton


652


Reopened

10/8/2020

Other U.S.


65,000


Fee Simple

100%


—


Hilton Waikoloa Village


647


Suspended

11/13/2020

Hawaii


235,000


Fee Simple

100%


—


DoubleTree Hotel Washington DC – Crystal City


627


Open


Washington, D.C.


31,000


Fee Simple

100%


—


Hilton Denver City Center


613


Reopened

7/1/2020

Denver


50,000


Fee Simple

100%


$

60


Hilton Boston Logan Airport


604


Open


Boston


30,000


Leasehold

100%


—


W Chicago - Lakeshore


520


Open


Chicago


21,000


Fee Simple

100%


—


Hilton Miami Airport


508


Reopened

6/4/2020

Miami


32,000


Fee Simple

100%


—


DoubleTree Hotel San Jose


505


Open


Other U.S.


48,000


Fee Simple

100%


—


Hyatt Regency Boston


502


Reopened

6/21/2020

Boston


30,000


Fee Simple

100%


$

140


Waldorf Astoria Orlando


502


Reopened

7/1/2020

Orlando


52,000


Fee Simple

100%


—


Hilton Salt Lake City Center


499


Open


Other U.S.


24,000


Leasehold

100%


—


DoubleTree Hotel Ontario Airport


482


Open


Southern California


27,000


Fee Simple

67%


$

30


Hilton McLean Tysons Corner


458


Open


Washington, D.C.


27,000


Fee Simple

100%


—


Hyatt Regency Mission Bay Spa and Marina


438


Reopened

6/25/2020

Southern California


24,000


Leasehold

100%


—


Boston Marriott Newton


430


Open


Boston


34,000


Fee Simple

100%


—


W Chicago - City Center


403


Suspended

Q1 2021

Chicago


13,000


Fee Simple

100%


$

76


Hilton Seattle Airport & Conference Center


396


Open


Seattle


40,000


Leasehold

100%


—


Royal Palm South Beach Miami, a Tribute Portfolio Resort


393


Reopened

6/1/2020

Miami


11,000


Fee Simple

100%


—


DoubleTree Hotel Spokane City Center


375


Open


Other U.S.


21,000


Fee Simple

10%


$

12


Hilton Santa Barbara Beachfront Resort


360


Open


Southern California


40,000


Fee Simple

50%


$

165


Hilton Oakland Airport


360


Open


Other U.S.


16,000


Leasehold

100%


—


Le Meridien San Francisco


360


Suspended

Q1 2021

San Francisco


13,000


Fee Simple

100%


—


JW Marriott San Francisco Union Square


344


Open


San Francisco


12,000


Leasehold

100%


—


Hyatt Centric Fisherman's Wharf


316


Open


San Francisco


19,000


Fee Simple

100%


—


Hilton Short Hills


314


Suspended

Q1 2021

Other U.S.


14,000


Fee Simple

100%


—


Casa Marina, A Waldorf Astoria Resort


311


Reopened

6/1/2020

Key West


23,000


Fee Simple

100%


—


DoubleTree Hotel San Diego – Mission Valley


300


Reopened

9/14/2020

Southern California


24,000


Leasehold

100%


—


(1) For hotels that are suspended as of November 5, 2020, the current projected reopening dates are estimated.

(2) Single $725 million CMBS loan secured by Hilton San Francisco Union Square and Parc 55 San Francisco – a Hilton Hotel.


18 |


Portfolio and Operating Metrics (continued)


Hotel Portfolio as of November 5, 2020


Hotel Name

Total Rooms


Operating Status

Reopening Date(1)

Market

Meeting Space

(square feet)


Ownership

Equity Ownership


Debt(2)

(in millions)


Consolidated Portfolio (continued)


Embassy Suites Kansas City Plaza


266


Reopened

7/16/2020

Other U.S.


11,000


Leasehold

100%


—


Embassy Suites Austin Downtown South Congress


262


Reopened

7/1/2020

Other U.S.


2,000


Leasehold

100%


—


DoubleTree Hotel Sonoma Wine Country


245


Reopened

6/4/2020

Other U.S.


50,000


Leasehold

100%


—


Juniper Hotel Cupertino, Curio Collection


224


Reopened

7/9/2020

Other U.S.


5,000


Fee Simple

100%


—


Hilton Chicago/Oak Brook Suites


211


Open


Chicago


3,000


Fee Simple

100%


—


Hotel Indigo San Diego Gaslamp Quarter


210


Reopened

6/26/2020

Southern California


6,000


Fee Simple

100%


—


Courtyard Washington Capitol Hill/Navy Yard


204


Open


Washington, D.C.


2,000


Fee Simple

100%


—


Homewood Suites by Hilton Seattle Convention Center Pike Street


195


Open


Seattle


1,000


Fee Simple

100%


—


Hilton Checkers Los Angeles


193


Reopened

7/20/2020

Southern California


3,000


Fee Simple

100%


$

27


Embassy Suites Phoenix Airport


182


Reopened

6/12/2020

Other U.S.


5,000


Leasehold

100%


—


Hotel Adagio, Autograph Collection


171


Suspended

Q1 2021

San Francisco


4,000


Fee Simple

100%


—


Hilton Garden Inn LAX/El Segundo


162


Reopened

7/1/2020

Southern California


3,000


Fee Simple

100%


—


DoubleTree Hotel Durango


159


Reopened

6/1/2020

Other U.S.


6,000


Leasehold

100%


—


The Reach Key West, Curio Collection


150


Reopened

6/1/2020

Key West


22,000


Fee Simple

100%


—


Hampton Inn & Suites Memphis – Shady Grove


131


Open


Other U.S.


1,000


Fee Simple

100%


—


Hilton Garden Inn Chicago/Oak Brook Terrace


128


Suspended

Q1/2021

Chicago


2,000


Fee Simple

100%


—


W New Orleans - French Quarter


97


Reopened

9/2/2020

New Orleans


1,000


Fee Simple

100%


—


Total Consolidated Portfolio (53 Hotels)


28,931


2,162,000


$

2,510


Unconsolidated Joint Venture Portfolio


Hilton Orlando


1,424


Open


Orlando


236,000


Fee Simple

20%


$

95


Hilton San Diego Bayfront


1,190


Reopened

8/15/2020

San Diego


165,000


Leasehold

25%


$

55


Capital Hilton


550


Reopened

8/20/2020

Washington, D.C.


30,000


Fee Simple

25%


$

25


Hilton La Jolla Torrey Pines


394


Open


Other U.S.


41,000


Leasehold

25%


$

24


Embassy Suites Alexandria Old Town


288


Reopened

7/1/2020

Washington, D.C.


7,000


Fee Simple

50%


$

26


Embassy Suites Secaucus Meadowlands


261


Open


Other U.S.


1,000


Leasehold

50%


—


DoubleTree Hotel Las Vegas Airport


190


Open


Other U.S.


3,000


Fee Simple

50%


—


Total Unconsolidated Joint Venture Portfolio


4,297


483,000


$

225


TOTAL PARK HOTELS & RESORTS PORTFOLIO (60 Hotels)


33,228


2,645,000


$

2,735


(1) For hotels that are suspended as of November 5, 2020, the current projected reopening dates are estimated.

(2)Debt related to unconsolidated joint ventures is presented on a pro-rata basis.


19 |


Portfolio and Operating Metrics (continued)


Pro-forma Hotels by Market: Q3 2020 vs. Q3 2019


(unaudited)


Pro-forma ADR(1)


Pro-forma Occupancy(1)


Pro-forma RevPAR(1)


Pro-forma Total RevPAR(1)


Hotels


Rooms


3Q20


3Q19


Change(2)


3Q20


3Q19


Change


3Q20


3Q19


Change(2)


3Q20


3Q19


Change(2)


Hawaii


2


3,507


$

—


$

274.08


(100.0

)%


—

%


92.6

%


(92.6

)%

pts


$

—


$

253.90


(100.0

)%


$

5.27


$

431.34


(98.8

)%

San Francisco


6


4,136


176.47


279.99


(37.0

)


4.5


93.6


(89.1

)


7.88


261.97


(97.0

)


11.64


323.42


(96.4

)

Orlando


3


2,325


146.89


161.62


(9.1

)


21.5


67.0


(45.5

)


31.61


108.29


(70.8

)


50.18


222.66


(77.5

)

New Orleans


2


1,719


64.58


169.21


(61.8

)


40.4


67.9


(27.5

)


26.08


114.87


(77.3

)


33.85


200.30


(83.1

)

Boston


3


1,536


132.59


251.34


(47.2

)


33.9


89.9


(56.0

)


44.93


226.01


(80.1

)


50.74


286.64


(82.3

)

New York


1


1,878


—


270.97


(100.0

)


—


95.4


(95.4

)


—


258.62


(100.0

)


2.81


380.64


(99.3

)

Southern California


7


2,145


193.99


205.44


(5.6

)


39.8


91.0


(51.2

)


77.12


186.84


(58.7

)


105.81


269.12


(60.7

)

Chicago


5


2,806


133.44


205.58


(35.1

)


6.8


83.8


(77.0

)


9.07


172.23


(94.7

)


10.99


256.94


(95.7

)

Key West


2


461


269.62


287.78


(6.3

)


57.3


58.4


(1.1

)


154.39


167.92


(8.1

)


237.76


253.08


(6.1

)

Denver


1


613


103.87


183.39


(43.4

)


30.5


94.7


(64.2

)


31.65


173.59


(81.8

)


35.89


248.71


(85.6

)

Miami


2


901


111.09


131.87


(15.8

)


28.4


84.5


(56.1

)


31.53


111.45


(71.7

)


47.56


161.10


(70.5

)

Washington, D.C.


3


1,289


113.57


166.45


(31.8

)


22.2


77.3


(55.1

)


25.17


128.61


(80.4

)


30.20


175.73


(82.8

)

Seattle


3


1,441


117.31


184.15


(36.3

)


24.1


87.0


(62.9

)


28.25


160.11


(82.4

)


33.98


201.80


(83.2

)

Other


13


4,174


125.08


179.04


(30.1

)


24.1


79.0


(54.9

)


36.96


140.29


(73.7

)


42.68


196.09


(78.2

)

All Markets


53


28,931


$

137.10


$

222.04


(38.3

)%


19.1

%


84.7

%


(65.6

)%

pts


$

26.14


$

187.93


(86.1

)%


$

35.36


$

277.40


(87.3

)%


(1)

Assumes hotels were acquired on January 1, 2019.


(2)

Calculated based on unrounded numbers.


20 |


Portfolio and Operating Metrics (continued)


Pro-forma Hotels by Market: Q3 2020 vs. Q3 2019


(unaudited, dollars in millions)


Pro-forma Hotel

Adjusted EBITDA(1)


Pro-forma Hotel Revenue(1)


Pro-forma Hotel Adjusted

EBITDA Margin(1)


Hotels


Rooms


3Q20


3Q19


Change(2)


3Q20


3Q19


Change(3)


3Q20


3Q19


Change(2)

Hawaii


2


3,507


$

(16

)

$

62


NM


$

2


$

158


(98.9

)%


(930.4

)%


39.5

%

NM

San Francisco


6


4,136


(18

)


37


NM


4


123


(96.4

)


(402.8

)


29.7


NM

Orlando


3


2,325


(4

)


8


NM


11


47


(77.5

)


(39.4

)


17.4


NM

New Orleans


2


1,719


(1

)


10


NM


5


32


(83.1

)


(27.7

)


32.0


NM

Boston


3


1,536


(2

)


15


NM


7


41


(82.3

)


(31.8

)


36.0


NM

New York


1


1,878


(17

)


9


NM


—


66


(99.3

)


(3,456.8

)


13.3


NM

Southern California


7


2,145


4


19


NM


21


53


(60.7

)


16.9


35.9


NM

Chicago


5


2,806


(9

)


17


NM


3


66


(95.7

)


(305.1

)


25.2


NM

Key West


2


461


2


2


NM


10


11


(6.1

)


15.4


14.3


NM

Denver


1


613


(1

)


5


NM


2


14


(85.6

)


(33.7

)


39.2


NM

Miami


2


901


(1

)


2


NM


4


13


(70.5

)


(26.3

)


18.3


NM

Washington, D.C.


3


1,289


(2

)


4


NM


4


21


(82.8

)


(66.3

)


20.7


NM

Seattle


3


1,441


(3

)


8


NM


5


27


(83.2

)


(57.3

)


28.9


NM

Other


13


4,174


(8

)


19


NM


17


78


(79.2

)


(66.3

)


25.0


NM

All Markets


53


28,931


$

(76

)

$

217


NM


$

95


$

750


(87.5

)%


(81.2

)%


28.9

%

NM


(1)

Assumes hotels were acquired on January 1, 2019.


(2)

Percentage change is not meaningful.


(3)

Calculated based on unrounded numbers.


21 |


Portfolio and Operating Metrics (continued)


Pro-forma Hotels by Market: YTD Q3 2020 vs. YTD Q3 2019


(unaudited)


Pro-forma ADR(1)


Pro-forma Occupancy(1)


Pro-forma RevPAR(1)


Pro-forma Total RevPAR(1)


Hotels


Rooms


2020


2019


Change(2)


2020


2019


Change


2020


2019


Change(2)


2020


2019


Change(2)


Hawaii


2


3,507


$

260.34


$

258.75


0.6

%


25.8

%


90.7

%


(64.9

)%

pts


$

67.12


$

234.70


(71.4

)%


$

122.06


$

403.40


(69.7

)%

San Francisco


6


4,136


298.65


293.40


1.8


22.9


91.7


(68.8

)


68.32


268.99


(74.6

)


95.69


342.47


(72.1

)

Orlando


3


2,325


219.00


198.13


10.5


28.5


78.0


(49.5

)


62.47


154.62


(59.6

)


130.11


321.75


(59.6

)

New Orleans


2


1,719


150.98


194.09


(22.2

)


31.7


75.1


(43.4

)


47.84


145.72


(67.2

)


82.14


249.22


(67.0

)

Boston


3


1,536


150.54


232.59


(35.3

)


36.0


85.8


(49.8

)


54.25


199.69


(72.8

)


72.55


265.66


(72.7

)

New York


1


1,878


206.31


264.74


(22.1

)


20.3


89.7


(69.4

)


41.88


237.56


(82.4

)


78.92


386.01


(79.6

)

Southern California


7


2,145


180.11


191.49


(5.9

)


39.5


87.0


(47.5

)


71.16


166.52


(57.3

)


105.85


248.42


(57.4

)

Chicago


5


2,806


139.57


193.90


(28.0

)


16.2


74.9


(58.7

)


22.63


145.24


(84.4

)


37.34


223.04


(83.3

)

Key West


2


461


379.26


383.11


(1.0

)


49.1


77.8


(28.7

)


186.35


298.13


(37.5

)


277.72


443.48


(37.4

)

Denver


1


613


138.47


178.48


(22.4

)


30.6


86.1


(55.5

)


42.32


153.67


(72.5

)


61.29


229.12


(73.2

)

Miami


2


901


198.82


177.47


12.0


37.7


88.6


(50.9

)


74.99


157.19


(52.3

)


103.94


222.06


(53.2

)

Washington, D.C.


3


1,289


135.81


175.38


(22.6

)


32.9


77.9


(45.0

)


44.74


136.77


(67.3

)


60.95


191.57


(68.2

)

Seattle


3


1,441


123.74


163.47


(24.3

)


34.9


81.4


(46.5

)


43.25


133.16


(67.5

)


60.23


177.98


(66.2

)

Other


13


4,174


154.88


181.37


(14.6

)


31.7


71.3


(39.6

)


51.68


130.27


(60.3

)


70.71


164.70


(57.1

)

All Markets


53


28,931


$

195.78


$

224.29


(12.7

)%


28.9

%


82.7

%


(53.8

)%

pts


$

56.64


$

185.66


(69.5

)%


$

89.14


$

282.17


(68.4

)%


(1)

Assumes hotels were acquired on January 1, 2019.


(2)

Calculated based on unrounded numbers.


22 |


Portfolio and Operating Metrics (continued)


Pro-forma Hotels by Market: YTD Q3 2020 vs. YTD Q3 2019


(unaudited, dollars in millions)


Pro-forma Hotel

Adjusted EBITDA(1)


Pro-forma Hotel Revenue(1)


Pro-forma Hotel Adjusted

EBITDA Margin(1)


Hotels


Rooms


2020


2019


Change(2)


2020


2019


Change(3)


2020


2019


Change(2)

Hawaii


2


3,507


$

3


$

164


NM


$

117


$

437


(73.2

)%


2.2

%


37.5

%

NM

San Francisco


6


4,136


(16

)


123


NM


108


387


(72.0

)


(14.9

)


31.9


NM

Orlando


3


2,325


10


66


NM


83


204


(59.4

)


12.0


32.1


NM

New Orleans


2


1,719


4


44


NM


39


117


(66.9

)


10.8


37.5


NM

Boston


3


1,536


(6

)


37


NM


31


111


(72.6

)


(20.3

)


33.1


NM

New York


1


1,878


(47

)


25


NM


41


198


(79.5

)


(115.7

)


12.5


NM

Southern California


7


2,145


5


47


NM


62


145


(57.2

)


8.5


32.4


NM

Chicago


5


2,806


(30

)


34


NM


29


171


(83.2

)


(105.4

)


20.2


NM

Key West


2


461


8


21


NM


35


56


(37.1

)


23.2


36.8


NM

Denver


1


613


(1

)


15


NM


10


38


(73.2

)


(8.4

)


39.8


NM

Miami


2


901


5


19


NM


26


55


(53.0

)


18.5


34.7


NM

Washington, D.C.


3


1,289


(6

)


17


NM


22


67


(68.1

)


(26.9

)


24.8


NM

Seattle


3


1,441


(6

)


16


NM


24


70


(66.0

)


(23.2

)


23.2


NM

Other


13


4,174


(18

)


43


NM


81


208


(61.0

)


(21.9

)


20.6


NM

All Markets


53


28,931


$

(95

)

$

671


NM


$

708


$

2,264


(68.8

)%


(13.4

)%


29.6

%

NM


(1)

Assumes hotels were acquired on January 1, 2019.


(2)

Percentage change is not meaningful.


(3)

Calculated based on unrounded numbers.


23 |


Portfolio and Operating Metrics (continued)


Core Hotels: Q3 2020 vs. Q3 2019


(unaudited)


ADR


Occupancy


RevPAR


Total RevPAR


3Q20


3Q19


Change(1)


3Q20


3Q19


Change


3Q20


3Q19


Change(1)


3Q20


3Q19


Change(1)


Core Hotels


1

Hilton Hawaiian Village Waikiki Beach Resort


$

—


$

280.09


(100.0

)%


—

%


95.6

%


(95.6

)%

pts


$

—


$

267.85


(100.0

)%


$

1.95


$

419.26


(99.5

)%

2

Hilton Waikoloa Village


—


256.63


(100.0

)


—


84.9


(84.9

)


—


217.95


(100.0

)


19.96


462.45


(95.7

)

3

Hilton San Francisco Union Square


—


269.14


(100.0

)


—


92.7


(92.7

)


—


249.44


(100.0

)


5.04


338.65


(98.5

)

4

Parc 55 San Francisco - a Hilton Hotel


—


272.95


(100.0

)


—


92.6


(92.6

)


—


252.65


(100.0

)


1.56


278.06


(99.4

)

5

Le Meridien San Francisco


—


302.58


(100.0

)


—


97.9


(97.9

)


—


296.11


(100.0

)


0.81


335.25


(99.8

)

6

JW Marriott San Francisco Union Square


162.57


338.49


(52.0

)


28.9


95.6


(66.7

)


47.02


323.57


(85.5

)


53.64


373.99


(85.7

)

7

Hyatt Centric Fisherman's Wharf


161.32


271.91


(40.7

)


26.9


96.8


(69.9

)


43.43


263.38


(83.5

)


56.55


329.54


(82.8

)

8

Hotel Adagio, Autograph Collection


—


288.10


(100.0

)


—


90.3


(90.3

)


—


260.10


(100.0

)


1.50


286.06


(99.5

)

9

Hilton Orlando Bonnet Creek


136.01


148.31


(8.3

)


14.0


65.3


(51.3

)


19.00


96.81


(80.4

)


46.29


221.92


(79.1

)

10

Waldorf Astoria Orlando


151.23


228.46


(33.8

)


71.6


71.0


0.6


108.28


162.27


(33.3

)


138.95


306.81


(54.7

)

11

Hilton Orlando Lake Buena Vista


—


133.84


(100.0

)


—


66.7


(66.7

)


—


89.22


(100.0

)


0.25


171.68


(99.9

)

12

Hilton New Orleans Riverside


63.60


167.90


(62.1

)


42.4


66.9


(24.5

)


26.99


112.37


(76.0

)


35.08


198.52


(82.3

)

13

Hyatt Regency Boston


118.88


281.77


(57.8

)


43.7


96.6


(52.9

)


52.01


272.28


(80.9

)


55.43


333.89


(83.4

)

14

Hilton Boston Logan Airport


148.74


260.55


(42.9

)


37.9


91.8


(53.9

)


56.43


239.36


(76.4

)


66.17


291.19


(77.3

)

15

Boston Marriott Newton


122.97


193.11


(36.3

)


16.7


79.4


(62.7

)


20.51


153.25


(86.6

)


23.60


225.09


(89.5

)

16

New York Hilton Midtown


—


270.97


(100.0

)


—


95.4


(95.4

)


—


258.62


(100.0

)


2.81


380.64


(99.3

)

17

Hilton Santa Barbara Beachfront Resort


329.24


323.88


1.7


63.3


93.0


(29.7

)


208.53


301.45


(30.8

)


267.91


450.12


(40.5

)

18

Hyatt Regency Mission Bay Spa and Marina


211.83


209.30


1.2


34.3


89.2


(54.9

)


72.73


186.75


(61.1

)


132.00


324.80


(59.4

)

19

Hotel Indigo San Diego Gaslamp Quarter


149.03


214.27


(30.4

)


53.8


92.2


(38.4

)


80.15


197.59


(59.4

)


92.34


233.21


(60.4

)

20

Hilton Checkers Los Angeles


143.08


217.56


(34.2

)


16.4


90.2


(73.8

)


23.42


196.28


(88.1

)


27.21


227.01


(88.0

)

21

Hilton Chicago


—


203.52


(100.0

)


—


84.2


(84.2

)


—


171.31


(100.0

)


0.50


284.86


(99.8

)

22

W Chicago - City Center


—


258.43


(100.0

)


—


82.8


(82.8

)


—


214.06


(100.0

)


—


262.12


(100.0

)

23

W Chicago - Lakeshore


148.09


228.39


(35.2

)


24.9


82.9


(58.0

)


36.82


189.31


(80.6

)


41.86


258.29


(83.8

)

24

Casa Marina, A Waldorf Astoria Resort


287.48


290.17


(0.9

)


55.6


73.9


(18.3

)


159.73


214.37


(25.5

)


242.39


328.98


(26.3

)

25

The Reach Key West, Curio Collection


235.76


273.76


(13.9

)


60.8


26.2


34.6


143.32


71.61


100.1


228.14


95.70


138.4


26

Hilton Denver City Center


103.87


183.39


(43.4

)


30.5


94.7


(64.2

)


31.65


173.59


(81.8

)


35.89


248.71


(85.6

)

27

Royal Palm South Beach Miami


122.96


147.40


(16.6

)


34.4


90.2


(55.8

)


42.29


132.88


(68.2

)


66.82


197.17


(66.1

)

28

DoubleTree Hotel Washington DC – Crystal City


118.56


153.60


(22.8

)


20.5


73.9


(53.4

)


24.26


113.38


(78.6

)


29.55


155.68


(81.0

)

29

DoubleTree Hotel San Jose


137.70


220.54


(37.6

)


33.5


84.5


(51.0

)


46.11


186.37


(75.3

)


54.16


257.96


(79.0

)

30

Juniper Hotel Cupertino, Curio Collection


103.65


242.05


(57.2

)


33.2


83.8


(50.6

)


34.40


202.91


(83.0

)


36.67


240.17


(84.7

)


Sub-total Core Hotels


$

147.99


$

240.59


(38.5

)%


16.3

%


85.6

%


(69.3

)%

pts


$

24.12


$

206.03


(88.3

)%


$

34.28


$

307.41


(88.9

)%


All Other Hotels


$

118.14


$

164.63


(28.2

)%


27.1

%


81.7

%


(54.6

)%

pts


$

31.96


$

134.47


(76.2

)%


$

38.50


$

188.78


(79.6

)%


Total Consolidated Portfolio(2)


$

137.10


$

222.04


(38.3

)%


19.1

%


84.7

%


(65.6

)%

pts


$

26.14


$

187.93


(86.1

)%


$

35.36


$

277.40


(87.3

)%


(1)

Calculated based on unrounded numbers.


(2)

Assumes hotels were acquired on January 1, 2019.


24 |


Portfolio and Operating Metrics (continued)


Core Hotels: Q3 2020 vs. Q3 2019


(unaudited, dollars in millions)


Hotel Adjusted EBITDA


Hotel Revenue


Hotel Adjusted EBITDA Margin


3Q20


3Q19


Change(1)


3Q20


3Q19


Change(2)


3Q20


3Q19


Change(1)


Core Hotels


1

Hilton Hawaiian Village Waikiki Beach Resort


$

(13

)

$

44


NM


$

1


$

110


(99.5

)%


(2605.1

)%


40.1

%

NM


2

Hilton Waikoloa Village


(2

)


18


NM


1


$

47


(97.5

)


(208.1

)


37.9


NM


3

Hilton San Francisco Union Square


(6

)


17


NM


1


$

60


(98.5

)


(669.8

)


28.8


NM


4

Parc 55 San Francisco - a Hilton Hotel


(4

)


8


NM


—


$

26


(99.4

)


(2,784.2

)


30.4


NM


5

Le Meridien San Francisco


(2

)


4


NM


—


$

11


(99.8

)


(8,537.6

)


35.2


NM


6

JW Marriott San Francisco Union Square


(4

)


3


NM


2


$

12


(85.7

)


(228.4

)


23.5


NM


7

Hyatt Centric Fisherman's Wharf


(1

)


3


NM


2


$

10


(82.8

)


(44.7

)


33.9


NM


8

Hotel Adagio, Autograph Collection


(1

)


1


NM


—


$

4


(99.5

)


(3,774.2

)


31.0


NM


9

Hilton Orlando Bonnet Creek


(2

)


3


NM


4


$

21


(79.1

)


(49.3

)


16.5


NM


10

Waldorf Astoria Orlando


1


3


NM


6


$

14


(54.7

)


9.5


17.6


NM


11

Hilton Orlando Lake Buena Vista


(2

)


2


NM


—


$

13


(99.9

)


(14,249.7

)


18.5


NM


12

Hilton New Orleans Riverside


(1

)


10


NM


5


$

30


(82.3

)


(18.4

)


33.7


NM


13

Hyatt Regency Boston


(1

)


7


NM


3


$

15


(83.4

)


(34.2

)


43.4


NM


14

Hilton Boston Logan Airport


(1

)


5


NM


4


$

16


(77.3

)


(17.9

)


32.6


NM


15

Boston Marriott Newton


(1

)


3


NM


1


$

9


(89.5

)


(80.0

)


29.7


NM


16

New York Hilton Midtown


(17

)


9


NM


—


$

66


(99.3

)


(3,456.8

)


13.3


NM


17

Hilton Santa Barbara Beachfront Resort


4


8


NM


9


$

15


(40.5

)


48.2


54.0


NM


18

Hyatt Regency Mission Bay Spa and Marina


—


3


NM


5


$

13


(59.4

)


5.6


25.9


NM


19

Hotel Indigo San Diego Gaslamp Quarter


—


2


NM


2


$

5


(60.4

)


10.2


40.7


NM


20

Hilton Checkers Los Angeles


(1

)


1


NM


—


$

4


(88.0

)


(146.6

)


31.8


NM


21

Hilton Chicago


(4

)


10


NM


—


$

41


(99.8

)


(6,641.5

)


23.6


NM


22

W Chicago - City Center


(2

)


3


NM


—


$

10


(100.0

)


(27,255.0

)


27.3


NM


23

W Chicago - Lakeshore


(2

)


4


NM


2


$

12


(83.8

)


(86.6

)


29.9


NM


24

Casa Marina, A Waldorf Astoria Resort


1


2


NM


7


$

9


(26.3

)


18.9


22.9


NM


25

The Reach Key West, Curio Collection


—


(1

)

NM


3


$

1


138.4


7.8


(46.9

)

NM


26

Hilton Denver City Center


(1

)


5


NM


2


$

14


(85.6

)


(33.7

)


39.2


NM


27

Royal Palm South Beach Miami


—


2


NM


2


$

7


(66.1

)


(15.8

)


22.4


NM


28

DoubleTree Hotel Washington DC – Crystal City


(1

)


2


NM


2


$

9


(81.0

)


(44.5

)


18.2


NM


29

DoubleTree Hotel San Jose


(1

)


4


NM


3


$

12


(79.0

)


(21.1

)


29.6


NM


30

Juniper Hotel Cupertino, Curio Collection


—


2


NM


1


$

5


(84.7

)


(65.9

)


34.7


NM


Sub-total Core Hotels


$

(64

)

$

187


NM


$

68


$

621


(89.1

)%


(93.5

)%


30.0

%

NM


All Other Hotels


$

(12

)

$

30


NM


$

27


$

129


(79.6

)%


(49.4

)%


23.5

%

NM


Total Consolidated Portfolio(3)


$

(76

)

$

217


NM


$

95


$

750


(87.5

)%


(81.2

)%


28.9

%

NM


(1)

Percentage change is not meaningful.


(2)

Calculated based on unrounded numbers.


(3)

Assumes hotels were acquired on January 1, 2019.


25 |


Portfolio and Operating Metrics (continued)


Core Hotels: YTD Q3 2020 vs. YTD Q3 2019


(unaudited)


ADR


Occupancy


RevPAR


Total RevPAR


2020


2019


Change(1)


2020


2019


Change


2020


2019


Change(1)


2020


2019


Change(1)


Core Hotels


1

Hilton Hawaiian Village Waikiki Beach Resort


$

258.88


$

266.28


(2.8

)%


25.6

%


94.1

%


(68.5

)%

pts


$

66.21


$

250.41


(73.6

)%


$

110.67


$

402.07


(72.5

)%


2

Hilton Waikoloa Village


266.53


236.54


12.7


26.7


82.1


(55.4

)


71.14


194.23


(63.4

)


172.41


406.83


(57.6

)


3

Hilton San Francisco Union Square


309.40


284.13


8.9


19.8


90.0


(70.2

)


61.39


255.86


(76.0

)


99.08


357.92


(72.3

)


4

Parc 55 San Francisco - a Hilton Hotel


290.76


283.27


2.6


20.1


90.6


(70.5

)


58.58


256.89


(77.2

)


70.32


291.06


(75.8

)


5

Le Meridien San Francisco


349.78


321.65


8.7


22.5


95.8


(73.3

)


78.56


308.08


(74.5

)


98.36


360.61


(72.7

)


6

JW Marriott San Francisco Union Square


316.56


362.92


(12.8

)


38.5


94.2


(55.7

)


121.84


341.88


(64.4

)


159.31


423.35


(62.4

)


7

Hyatt Centric Fisherman's Wharf


206.77


263.04


(21.4

)


34.3


97.2


(62.9

)


70.95


255.80


(72.3

)


92.91


323.56


(71.3

)


8

Hotel Adagio, Autograph Collection


325.39


309.33


5.2


21.6


91.9


(70.3

)


70.30


284.38


(75.3

)


80.99


310.87


(73.9

)


9

Hilton Orlando Bonnet Creek


214.27


187.86


14.1


25.5


76.9


(51.4

)


54.68


144.48


(62.1

)


139.09


342.86


(59.4

)


10

Waldorf Astoria Orlando


248.25


281.97


(12.0

)


43.7


76.2


(32.5

)


108.54


214.93


(49.5

)


190.68


417.45


(54.3

)


11

Hilton Orlando Lake Buena Vista


191.06


161.37


18.4


22.9


80.6


(57.7

)


43.70


130.01


(66.4

)


81.62


236.57


(65.5

)


12

Hilton New Orleans Riverside


146.23


191.92


(23.8

)


32.2


74.4


(42.2

)


47.12


142.76


(67.0

)


81.72


247.05


(66.9

)


13

Hyatt Regency Boston


142.50


250.63


(43.1

)


38.7


94.6


(55.9

)


55.13


237.07


(76.7

)


70.41


300.34


(76.6

)


14

Hilton Boston Logan Airport


157.28


244.31


(35.6

)


42.8


86.7


(43.9

)


67.39


211.89


(68.2

)


87.03


270.17


(67.8

)


15

Boston Marriott Newton


148.70


186.69


(20.4

)


23.4


74.4


(51.0

)


34.76


138.94


(75.0

)


54.71


218.85


(75.0

)


16

New York Hilton Midtown


206.31


264.74


(22.1

)


20.3


89.7


(69.4

)


41.88


237.56


(82.4

)


78.92


386.01


(79.6

)


17

Hilton Santa Barbara Beachfront Resort


272.92


281.62


(3.1

)


51.1


84.5


(33.4

)


139.33


237.79


(41.4

)


199.63


373.27


(46.5

)


18

Hyatt Regency Mission Bay Spa and Marina


185.06


189.75


(2.5

)


31.2


80.6


(49.4

)


57.69


152.79


(62.2

)


116.16


280.48


(58.6

)


19

Hotel Indigo San Diego Gaslamp Quarter


174.36


206.73


(15.7

)


43.2


90.2


(47.0

)


75.31


186.38


(59.6

)


89.72


221.83


(59.6

)


20

Hilton Checkers Los Angeles


213.16


224.02


(4.8

)


27.3


87.4


(60.1

)


58.16


195.69


(70.3

)


67.77


224.65


(69.8

)


21

Hilton Chicago


129.20


193.52


(33.2

)


12.3


75.8


(63.5

)


15.95


146.74


(89.1

)


36.67


255.40


(85.6

)


22

W Chicago - City Center


211.64


250.63


(15.6

)


15.1


73.4


(58.3

)


32.02


184.06


(82.6

)


40.32


230.31


(82.5

)


23

W Chicago - Lakeshore


143.69


206.11


(30.3

)


22.7


70.5


(47.8

)


32.65


145.36


(77.5

)


39.69


193.38


(79.5

)


24

Casa Marina, A Waldorf Astoria Resort


400.40


386.68


3.5


48.5


83.3


(34.8

)


194.32


322.26


(39.7

)


288.56


487.05


(40.8

)


25

The Reach Key West, Curio Collection


337.07


373.83


(9.8

)


50.4


66.4


(16.0

)


169.84


248.09


(31.5

)


255.23


353.14


(27.7

)


26

Hilton Denver City Center


138.47


178.48


(22.4

)


30.6


86.1


(55.5

)


42.32


153.67


(72.5

)


61.29


229.12


(73.2

)


27

Royal Palm South Beach Miami


229.87


204.01


12.7


42.0


93.9


(51.9

)


96.48


191.60


(49.6

)


135.08


266.16


(49.2

)


28

DoubleTree Hotel Washington DC – Crystal City


131.11


164.65


(20.4

)


29.8


74.5


(44.7

)


39.05


122.59


(68.1

)


48.23


166.94


(71.1

)


29

DoubleTree Hotel San Jose


174.74


229.78


(24.0

)


38.4


85.2


(46.8

)


67.11


195.81


(65.7

)


94.98


273.00


(65.2

)


30

Juniper Hotel Cupertino, Curio Collection


195.03


254.79


(23.5

)


30.3


83.7


(53.4

)


59.18


213.46


(72.3

)


70.79


252.17


(71.9

)


Sub-total Core Hotels


$

219.48


$

243.17


(9.7

)%


27.1

%


84.7

%


(57.6

)%

pts


$

59.55


$

206.06


(71.1

)%


$

96.74


$

318.03


(69.6

)%


All Other Hotels


$

141.31


$

162.92


(13.3

)%


34.1

%


77.0

%


(42.9

)%

pts


$

48.23


$

125.42


(61.5

)%


$

67.15


$

176.29


(61.9

)%


Total Consolidated Portfolio(2)


$

195.78


$

224.29


(12.7

)%


28.9

%


82.7

%


(53.8

)%

pts


$

56.64


$

185.66


(69.5

)%


$

89.14


$

282.17


(68.4

)%


(1)

Calculated based on unrounded numbers.


(2)

Assumes hotels were acquired on January 1, 2019.


26 |


Portfolio and Operating Metrics (continued)


Core Hotels: YTD Q3 2020 vs. YTD Q3 2019


(unaudited, dollars in millions)


Hotel Adjusted EBITDA


Hotel Revenue


Hotel Adjusted EBITDA Margin


2020


2019


Change(1)


2020


2019


Change(2)


2020


2019


Change(1)


Core Hotels


1

Hilton Hawaiian Village Waikiki Beach Resort


$

1


$

124


NM


$

87


$

314


(72.4

)%


1.7

%


39.6

%

NM

2

Hilton Waikoloa Village


1


40


NM


31


123


(75.2

)


3.7


32.3


NM

3

Hilton San Francisco Union Square


(4

)


58


NM


52


188


(72.2

)


(7.9

)


31.0


NM

4

Parc 55 San Francisco - a Hilton Hotel


(6

)


27


NM


20


81


(75.8

)


(28.4

)


32.6


NM

5

Le Meridien San Francisco


(1

)


13


NM


10


35


(72.6

)


(9.7

)


36.4


NM

6

JW Marriott San Francisco Union Square


(4

)


11


NM


15


40


(62.2

)


(24.7

)


28.0


NM

7

Hyatt Centric Fisherman's Wharf


(1

)


9


NM


8


28


(71.2

)


(15.5

)


32.0


NM

8

Hotel Adagio, Autograph Collection


(1

)


6


NM


4


15


(73.9

)


(14.3

)


37.5


NM

9

Hilton Orlando Bonnet Creek


7


33


NM


38


95


(59.3

)


17.9


35.2


NM

10

Waldorf Astoria Orlando


3


16


NM


26


57


(54.2

)


12.9


28.3


NM

11

Hilton Orlando Lake Buena Vista


—


16


NM


18


53


(65.4

)


(2.0

)


30.7


NM

12

Hilton New Orleans Riverside


5


43


NM


36


109


(66.8

)


13.5


39.0


NM

13

Hyatt Regency Boston


(3

)


17


NM


10


41


(76.5

)


(26.0

)


40.9


NM

14

Hilton Boston Logan Airport


(2

)


13


NM


14


44


(67.6

)


(16.3

)


28.5


NM

15

Boston Marriott Newton


(1

)


7


NM


6


26


(74.9

)


(20.6

)


28.5


NM

16

New York Hilton Midtown


(47

)


25


NM


41


198


(79.5

)


(115.7

)


12.5


NM

17

Hilton Santa Barbara Beachfront Resort


7


17


NM


20


37


(46.3

)


35.2


45.4


NM

18

Hyatt Regency Mission Bay Spa and Marina


(1

)


7


NM


14


33


(58.3

)


(7.7

)


21.6


NM

19

Hotel Indigo San Diego Gaslamp Quarter


1


5


NM


5


13


(59.4

)


11.6


41.8


NM

20

Hilton Checkers Los Angeles


(1

)


4


NM


4


12


(69.7

)


(22.6

)


32.3


NM

21

Hilton Chicago


(17

)


21


NM


16


108


(85.6

)


(118.0

)


19.2


NM

22

W Chicago - City Center


(4

)


6


NM


4


25


(82.4

)


(92.6

)


24.4


NM

23

W Chicago - Lakeshore


(7

)


5


NM


6


27


(79.4

)


(116.3

)


18.9


NM

24

Casa Marina, A Waldorf Astoria Resort


7


15


NM


25


41


(40.5

)


26.8


37.7


NM

25

The Reach Key West, Curio Collection


2


5


NM


10


14


(27.5

)


14.8


34.4


NM

26

Hilton Denver City Center


(1

)


15


NM


10


38


(73.2

)


(8.4

)


39.8


NM

27

Royal Palm South Beach Miami


4


11


NM


15


29


(49.1

)


26.9


37.7


NM

28

DoubleTree Hotel Washington DC – Crystal City


(3

)


6


NM


8


29


(71.0

)


(36.1

)


22.4


NM

29

DoubleTree Hotel San Jose


—


11


NM


13


38


(65.1

)


2.2


30.2


NM

30

Juniper Hotel Cupertino, Curio Collection


(1

)


6


NM


4


15


(71.8

)


(14.7

)


36.7


NM


Sub-total Core Hotels


$

(67

)

$

592


NM


$

570


$

1,906


(70.1

)%


(11.8

)%


31.1

%

NM


All Other Hotels


$

(28

)

$

79


NM


$

138


$

358


(61.8

)%


(19.9

)%


21.9

%

NM


Total Consolidated Portfolio(3)


$

(95

)

$

671


NM


$

708


$

2,264


(68.8

)%


(13.4

)%


29.6

%

NM


(1)

Percentage change is not meaningful.


(2)

Calculated based on unrounded numbers.


(3)

Assumes hotels were acquired on January 1, 2019.


27 |


Properties Acquired & Sold


Acquisitions & W New Orleans French Quarter


28 |


Properties Acquired and Sold


Properties Acquired


Hotel


Location


Room Count


Chesapeake Lodging Trust Acquisition (1)


Hilton Denver City Center


Denver, CO


613


W Chicago – Lakeshore


Chicago, IL


520


Hyatt Regency Boston


Boston, MA


502


Hyatt Regency Mission Bay Spa and Marina


San Diego, CA


438


Boston Marriott Newton


Newton, MA


430


Le Meridien New Orleans(2)


New Orleans, LA


410


W Chicago – City Center


Chicago, IL


403


Royal Palm South Beach Miami, a Tribute Portfolio Resort


Miami Beach, FL


393


Le Meridien San Francisco


San Francisco, CA


360


JW Marriott San Francisco Union Square


San Francisco, CA


344


Hyatt Centric Fisherman’s Wharf


San Francisco, CA


316


Hotel Indigo San Diego Gaslamp Quarter


San Diego, CA


210


Courtyard Washington Capitol Hill/Navy Yard


Washington, DC


204


Homewood Suites by Hilton Seattle Convention Center Pike Street


Seattle, WA


195


Hilton Checkers Los Angeles


Los Angeles, CA


193


Ace Hotel Downtown Los Angeles(2)


Los Angeles, CA


182


Hotel Adagio, Autograph Collection


San Francisco, CA


171


W New Orleans – French Quarter


New Orleans, LA


97


5,981


(1)

Chesapeake acquisition closed in September 2019 for total consideration of approximately $2.5 billion, including acquisition costs.


(2)

Sold in December 2019.


29 |


Properties Acquired and Sold (continued)


Properties Sold


Hotel


Location


Month Sold


Room Count


Gross Proceeds


(in millions)


2018 Sales:


Hilton Rotterdam


Rotterdam, Netherlands


January 2018


254


$

62.2


Embassy Suites Portfolio - 3 Hotels


Domestic US


February 2018


676


95.8


UK Portfolio - 7 Hotels


United Kingdom


February 2018


1,334


188.5


Hilton Durban


Durban, South Africa


February 2018


328


32.5


Hilton Berlin(1)


Berlin, Germany


May 2018


601


140.0


2018 Total


3,193


$

519.0


2019 Sales:


Pointe Hilton Squaw Peak Resort


Phoenix, Arizona


February 2019


563


$

51.4


Hilton Nuremberg


Nuremberg, Germany


March 2019


152


17.5


Hilton Atlanta Airport


Atlanta, Georgia


June 2019


507


101.0


Hilton New Orleans Airport(2)


New Orleans, Louisiana


June 2019


317


48.0


Embassy Suites Parsippany(2)


Parsippany, New Jersey


June 2019


274


17.0


591


65.0


   Conrad Dublin(3)


Dublin, Ireland


November 2019


192


61.0


   Ace Hotel Downtown Los Angeles


Los Angeles, California


December 2019


182


117.0


   Le Meridien New Orleans


New Orleans, Louisiana


December 2019


410


84.0


2019 Total


2,597


$

496.9


2020 Sales:


Hilton São Paulo Morumbi


São Paulo, Brazil


February 2020


503


$

117.5


Embassy Suites Washington DC Georgetown


Washington, D.C.


February 2020


197


90.4


2020 Total


700


$

207.9


Grand Total(4)


6,490


$

1,223.8


(1)

The unconsolidated hotel was sold for total gross proceeds of approximately $350 million, of which $140 million represents Park’s pro rata share.  


(2)

Hotels were sold as a portfolio in the same transaction.


(3)

The unconsolidated hotel was sold for total gross proceeds of approximately $128 million, of which $61 million represents Park’s pro rata share.  


(4)

To date, Park has sold a total of 23 hotels. In addition, in December 2019, Park terminated the ground lease on the Hilton Sheffield Hotel.


30 |


Liquidity and Capital Structure


Debt Summary Casa Marina, a Waldorf Astoria Resort Hilton Orlando Bonnet Creek New York Hilton Midtown


31 |


Liquidity and Capital Structure


Fixed and Variable Rate Debt


(unaudited, dollars in millions)


Debt


Collateral


Interest Rate


Maturity Date


As of

September 30, 2020


Fixed Rate Debt


Mortgage loan


DoubleTree Hotel Spokane City Center


3.55%


October 2020(1)


$

12


Mortgage loan


Hilton Denver City Center


4.90%


August 2022(2)


60


Mortgage loan


Hilton Checkers Los Angeles


4.11%


March 2023


27


Mortgage loan


W Chicago - City Center


4.25%


August 2023


76


Commercial mortgage-backed

securities loan


Hilton San Francisco Union Square, Parc 55 San Francisco - a Hilton Hotel


4.11%


November 2023


725


Mortgage loan


Hyatt Regency Boston


4.25%


July 2026


140


Commercial mortgage-backed

securities loan


Hilton Hawaiian Village Beach Resort


4.20%


November 2026


1,275


Mortgage loan


Hilton Santa Barbara Beachfront Resort


4.17%


December 2026


165


2025 Senior Secured Notes


7.50%


June 2025


650


2028 Senior Secured Notes


5.88%


October 2028


725


Finance lease obligations


3.07%


2021 to 2022


1


Total Fixed Rate Debt


5.06%(3)


3,856


Variable Rate Debt


Revolving credit facility(4)(5)


Unsecured


L + 3.00%


2021 to 2023(6)


601


2016 Term Loan(7)


Unsecured


N/A


December 2021


—


Mortgage loan


DoubleTree Hotel Ontario Airport


L + 2.25%


May 2022


30


2019 Term Facility(4)(8)


Unsecured


L + 2.65%


September 2024


670


Total Variable Rate Debt


3.08%(3)


1,301


Add: unamortized premium


4


Less: unamortized deferred financing costs and discount


(40

)

Total Debt(9)


4.63%(3)


$

5,121


(1)

Park is actively negotiating a one-year maturity date extension to October 2021. The loan was not paid in full at its originally scheduled maturity date in October 2020 due to current market conditions. Failure to pay off the loan constitutes an event of default, however, Park has not received, nor does it expect to receive, notice of the lenders’ intent to foreclose.


(2)

The loan matures in August 2042 but is callable by the lender beginning August 2022.


(3)

Calculated on a weighted average basis.


(4)

In May 2020, Park amended its credit facilities which added a LIBOR floor of 25 basis points.


(5)

During September 2020 Park repaid $80 million of the Revolver.


(6)

In September 2020, Park increased its aggregate commitments under the Revolver by $75 million to $1.075 billion and extended the maturity date with respect to $901 million of the aggregate commitments for two years to December 2023, including all $75 million of the increased Revolver commitments. The maturity date for the remaining $174 million of commitments under the Revolver is December 2021.


(7)

In September 2020, Park fully repaid the 2016 Term Loan using the proceeds from the 2028 Senior Secured Notes.


(8)

In August 2019, the Company, Park Intermediate Holdings LLC and PK Domestic entered into a credit agreement with Bank of America, N.A. and certain other lenders, providing a $950 million unsecured delayed draw term loan facility (the “2019 Term Facility”), with the $850 million, five-year delayed draw term loan tranche fully drawn on September 18, 2019 to fund the merger with Chesapeake Lodging Trust.  The $100 million, two-year delayed draw term loan tranche was unfunded and the commitments thereunder terminated on September 18, 2019. On December 31, 2019, Park repaid $180 million of the 2019 Term Facility.


(9)

Excludes $225 million of Park’s share of debt of its unconsolidated joint ventures.


32 |


Liquidity and Capital Structure


Credit Facility Amendments


•

Park further amended its credit facilities to:


▪

increase the commitments under the Revolver by $75 million to $1.075 billion


▪

extend the maturity date with respect to $901 million of the aggregate commitments for two years to December 2023, including all $75 million of the increased Revolver commitments


▪

extend the waiver period for the testing of the financial covenants to the date the financial statements are delivered for the quarter ended March 31, 2022


▪

extend the temporary periods for which certain financial covenants are adjusted once quarterly testing of financial covenants resumes


▪

increase the mandatory repayment carve out for equity issuances from $500 million to $1 billion, so long as proceeds from the issuances are used for capital expenditures and hotel acquisitions that become part of the unencumbered pool


▪

extend the minimum liquidity covenant through December 2022 and adjustment to include, through December 24, 2021, 50% of the Revolver commitments that mature in December 2021


▪

obtain the ability to pay a $0.01 per share per fiscal quarter dividend during the extended waiver period


▪

modify certain restrictions and covenants for the duration of the extended waiver period, including certain mandatory prepayments


•

Additional agreements:


▪

maintain the existing guarantees by certain Park-affiliated entities until repayment of the Revolver and 2019 Term Facility


▪

maintain existing pledges of equity interests in Park-affiliated entities owning certain unencumbered assets during the extended waiver period and until the ratio of net debt to EBITDA falls below 6.50x for two consecutive quarters  


•

Subject to various exceptions (including those listed below), additional debt covenants during the relief period restrict:


▪

stock repurchases


▪

prepayments of other indebtedness (except for certain refinancings)


▪

capital expenditures (except for certain approved budgeted amounts, and emergency, life safety and ordinary course maintenance repairs)


▪

asset dispositions and transfers (except in the case of 1031 exchanges)


▪

investments, acquisitions or mergers (except for $200 million general investments bucket)


▪

incurrence of other indebtedness (except for certain refinancings, certain capital markets transactions and up to $350 of mortgage debt)


33 |


Liquidity and Capital Structure


Cash Preservation: Estimated Burn Rate


•

Based on Park’s liquidity as of September 30, 2020 of $1.6 billion and assuming a total burn rate of roughly $50 million per month, which takes into account current operations from both open and suspended hotels and using an accrual-based methodology, Park estimates it currently has over two and a half years of liquidity available to meet its financial obligations.


•

Park continues to take proactive measures to reduce the near-term burn rate, including deferral of payments, hiring freezes and other cost reduction methods.


•

This estimate does not take into account capital expenditures (which were reduced by 75% in 2020 to approximately $4 million per month) or any possible alternative sources of revenue that may arise, any hotel property dispositions for the remainder of the year or payment of cash dividends or other distributions not already declared and paid in 2020, if any. This estimate also does not take into account the impact of the amendments to the credit facility as discussed on slide 33. The estimated burn rate has not been reduced by any amount available to Park under existing or future debt facilities, or proceeds from issuance of any additional debt, equity or equity-linked securities.


34 |


Definitions


Definitions Hilton Orlando Bonnet Creek Hilton Denver City Center W Chicago –City Center


35 |


Definitions


Pro-forma


The Company presents certain data for its consolidated hotels on a pro-forma hotel basis as supplemental information for investors: Pro-forma Hotel Revenues,  Pro-forma RevPAR, Pro-forma Total RevPAR, Pro-forma Occupancy, Pro-forma ADR, Pro-forma Adjusted EBITDA, Pro-forma Hotel Adjusted EBITDA and Pro-forma Hotel Adjusted EBITDA Margin and Net debt to Pro-forma Adjusted EBITDA ratio. The Company presents pro-forma hotel results to help the Company and its investors evaluate the ongoing operating performance of its hotels. The Company’s pro-forma metrics exclude results from property dispositions and include results from property acquisitions as though such acquisitions occurred on the earliest period presented.


EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA and Hotel Adjusted EBITDA Margin

Earnings (loss) before interest expense, taxes and depreciation and amortization (“EBITDA”), presented herein, reflects net income (loss) excluding depreciation and amortization, interest income, interest expense, income taxes and interest expense, income tax and depreciation and amortization included in equity in earnings (losses) from investments in affiliates.

Adjusted EBITDA, presented herein, is calculated as EBITDA, as previously defined, further adjusted to exclude:

•      Gains or losses on sales of assets for both consolidated and unconsolidated investments;

•      Transition expense related to the Company’s establishment as an independent, publicly-traded company;

•      Costs associated with hotel acquisitions or dispositions expensed during the period;

•      Severance expense;

•      Share-based compensation expense;

•      Casualty gains or losses;

•      Impairment losses; and

•      Other items that management believes are not representative of the Company’s current or future operating performance.

Hotel Adjusted EBITDA measures hotel-level results before debt service, depreciation and corporate expenses of the Company’s consolidated hotels but excluding hotels owned by unconsolidated affiliates and is a key measure of the Company’s profitability. The Company presents Hotel Adjusted EBITDA to help the Company and its investors evaluate the ongoing operating performance of the Company’s consolidated hotels.

Hotel Adjusted EBITDA margin is calculated as Hotel Adjusted EBITDA divided by total hotel revenue.


36 |


Definitions (continued)


EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA and Hotel Adjusted EBITDA margin are not recognized terms under United States (“U.S.”) GAAP and should not be considered as alternatives to net income (loss) or other measures of financial performance or liquidity derived in accordance with U.S. GAAP. In addition, the Company’s definitions of EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA and Hotel Adjusted EBITDA margin may not be comparable to similarly titled measures of other companies.

The Company believes that EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA and Hotel Adjusted EBITDA margin provide useful information to investors about the Company and its financial condition and results of operations for the following reasons: (i) EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA and Hotel Adjusted EBITDA margin are among the measures used by the Company’s management team to make day-to-day operating decisions and evaluate its operating performance between periods and between REITs by removing the effect of its capital structure (primarily interest expense) and asset base (primarily depreciation and amortization) from its operating results; and (ii) EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA and Hotel Adjusted EBITDA margin are frequently used by securities analysts, investors and other interested parties as a common performance measure to compare results or estimate valuations across companies in the industry.

EBITDA, Adjusted EBITDA, Hotel Adjusted EBITDA and Hotel Adjusted EBITDA margin have limitations as analytical tools and should not be considered either in isolation or as a substitute for net income (loss) or other methods of analyzing the Company’s operating performance and results as reported under U.S. GAAP.


Nareit FFO attributable to stockholders, Adjusted FFO attributable to stockholders, Nareit FFO per share – Diluted and Adjusted FFO per share – Diluted


Nareit FFO attributable to stockholders and Nareit FFO per diluted share (defined as set forth below) are presented herein as non-GAAP measures of the Company’s performance. The Company calculates funds from (used in) operations (“FFO”) attributable to stockholders for a given operating period in accordance with standards established by the National Association of Real Estate Investment Trusts (“Nareit”), as net income (loss) attributable to stockholders (calculated in accordance with U.S. GAAP), excluding depreciation and amortization, gains or losses on sales of assets, impairment, and the cumulative effect of changes in accounting principles, plus adjustments for unconsolidated joint ventures. Adjustments for unconsolidated joint ventures are calculated to reflect the Company’s pro rata share of the FFO of those entities on the same basis. As noted by Nareit in its December 2018 “Nareit Funds from Operations White Paper – 2018 Restatement,” since real estate values historically have risen or fallen with market conditions, many industry investors have considered presentation of operating results for real estate companies that use historical cost accounting to be insufficient by themselves. For these reasons, Nareit adopted the FFO metric in order to promote an industry-wide measure of REIT operating performance.  The Company believes Nareit FFO provides useful information to investors regarding its operating performance and can facilitate comparisons of operating performance between periods and between REITS.  The Company’s presentation may not be comparable to FFO reported by other REITs that do not define the terms in accordance with the current Nareit definition, or that interpret the current Nareit definition differently.  The Company calculates Nareit FFO per diluted share as Nareit FFO divided by the number of fully diluted shares outstanding during a given operating period.


37 |


Definitions (continued)


The Company also presents Adjusted FFO attributable to stockholders and Adjusted FFO per diluted share when evaluating its performance because management believes that the exclusion of certain additional items described below provides useful supplemental information to investors regarding the Company’s ongoing operating performance. Management historically has made the adjustments detailed below in evaluating its performance and in its annual budget process. Management believes that the presentation of Adjusted FFO provides useful supplemental information that is beneficial to an investor’s complete understanding of operating performance. The Company adjusts Nareit FFO attributable to stockholders for the following items, which may occur in any period, and refers to this measure as Adjusted FFO attributable to stockholders:


•      Costs associated with hotel acquisitions or dispositions expensed during the period;

•      Severance expense;

•      Share-based compensation expense;

•      Casualty gains or losses; and

•      Other items that management believes are not representative of the Company’s current or future operating performance.


Net Debt

Net debt, presented herein, is a non-GAAP financial measure that the Company uses to evaluate its financial leverage. Net debt is calculated as (i) long-term debt, including current maturities and excluding unamortized deferred financing costs; and (ii) the Company’s share of investments in affiliate debt, excluding unamortized deferred financing costs; reduced by (a) cash and cash equivalents; and (b) restricted cash and cash equivalents.

The Company believes Net debt provides useful information about its indebtedness to investors as it is frequently used by securities analysts, investors and other interested parties to compare the indebtedness of companies. Net debt should not be considered as a substitute to debt presented in accordance with U.S. GAAP. Net debt may not be comparable to a similarly titled measure of other companies.

Net Debt to Adjusted EBITDA Ratio

Net debt to Adjusted EBITDA ratio, presented herein, is a non-GAAP financial measure and is included as it is frequently used by securities analysts, investors and other interested parties to compare the financial condition of companies. Net debt to Adjusted EBITDA ratio should not be considered as an alternative to measures of financial condition derived in accordance with U.S. GAAP and it may not be comparable to a similarly titled measure of other companies.

Occupancy

Occupancy represents the total number of room nights sold divided by the total number of room nights available at a hotel or group of hotels. Room nights available to guests have not been adjusted for suspended or reduced operations at certain of Park’s hotels as a result of COVID-19. Occupancy measures the utilization of the Company’s hotels’ available capacity. Management uses occupancy to gauge demand at a specific hotel or group of hotels in a given period. Occupancy levels also help management determine achievable Average Daily Rate (“ADR”) levels as demand for hotel rooms increases or decreases.


38 |


Definitions (continued)


Average Daily Rate

ADR represents rooms revenue divided by total number of room nights sold in a given period. ADR measures average room price attained by a hotel and ADR trends provide useful information concerning the pricing environment and the nature of the customer base of a hotel or group of hotels. ADR is a commonly used performance measure in the hotel industry, and management uses ADR to assess pricing levels that the Company is able to generate by type of customer, as changes in rates have a more pronounced effect on overall revenues and incremental profitability than changes in occupancy, as described above.

Revenue per Available Room

Revenue per Available Room (“RevPAR”) represents rooms revenue divided by total number of room nights available to guests for a given period. Room nights available to guests have not been adjusted for suspended or reduced operations at certain of Park’s hotels as a result of COVID-19. Management considers RevPAR to be a meaningful indicator of the Company’s performance as it provides a metric correlated to two primary and key factors of operations at a hotel or group of hotels: occupancy and ADR. RevPAR is also a useful indicator in measuring performance over comparable periods.

Total RevPAR

Total RevPAR represents rooms, food and beverage and other hotel revenues divided by the total number of room nights available to guests for a given period.  Room nights available to guests have not been adjusted for suspended or reduced operations at certain of Park’s hotels as a result of COVID-19. Management considers Total RevPAR to be a meaningful indicator of the Company’s performance as approximately one-third of revenues are earned from food and beverage and other hotel revenues. Total RevPAR is also a useful indicator in measuring performance over comparable periods.

References to RevPAR, Total RevPAR and ADR are presented on a currency neutral basis (prior periods are reflected using current period exchange rates), unless otherwise noted.


39 |


Analyst Coverage


Analyst

Company

Phone

Email

Shaun Kelley

Bank of America

(646) 855-1005

[email protected]

Anthony Powell

Barclays

(212) 526-8768

[email protected]

Ari Klein

BMO Capital Markets

(212) 885-4103

[email protected]

Neil Malkin

Capital One Securities

(571) 633-8191

[email protected]

Smedes Rose

Citi Research

(212) 816-6243

[email protected]

Chris Woronka

Deutsche Bank

(212) 250-9376

[email protected]

Richard Hightower

Evercore ISI

(212) 752-0886

[email protected]

Stephen Grambling

Goldman Sachs

(212) 902-7832

[email protected]

Lukas Hartwich

Green Street

(949) 640-8780

[email protected]

David Katz

Jefferies

(212) 323-3355

[email protected]

Brandt Montour

JP Morgan

(212) 622-1111

[email protected]

Bill Crow

Raymond James

(727) 567-2594

[email protected]

Patrick Scholes

Truist Securities

(212) 319-3915

[email protected]

Robin Farley

UBS

(212) 713-2060

[email protected]

Dori Kesten

Wells Fargo

(617) 603-4262

[email protected]


40 |