Exhibit 99.1
PRESS RELEASE |  | |||
Investor Relations: | Media: | |||
New York: +1 (917) 663 2233 | Lausanne: +41 (0)58 242 4500 | |||
Lausanne: +41 (0)58 242 4666 | Email: [email protected] | |||
Email: [email protected] | ||||
PHILIP MORRIS INTERNATIONAL INC. REPORTS 2020 SECOND-QUARTER REPORTED DILUTED EPS OF $1.25 VERSUS $1.49 IN 2019, REFLECTING CURRENCY-NEUTRAL ADJUSTED DILUTED EPS
DECLINE OF 7.5%;
PROVIDES 2020 FULL-YEAR REPORTED DILUTED EPS FORECAST OF $4.84 TO $4.99, OR ADJUSTED DILUTED EPS OF $4.92 TO $5.07, REFLECTING LIKE-FOR-LIKE CURRENCY-NEUTRAL GROWTH OF
APPROXIMATELY 2% TO 5%
NEW YORK, July 21, 2020 – Philip Morris International Inc. (NYSE: PM) today announces its 2020 second-quarter results. Comparisons presented in this press release on a "like-for-like" basis reflect pro forma 2019 results, which have been adjusted for the deconsolidation of PMI's Canadian subsidiary, Rothmans, Benson & Hedges, Inc. (RBH), effective March 22, 2019 (the date of deconsolidation). In addition, PMI's total market share has been restated for previous periods to reflect the deconsolidation.
2020 SECOND-QUARTER & YEAR-TO-DATE HIGHLIGHTS
2020 Second-Quarter
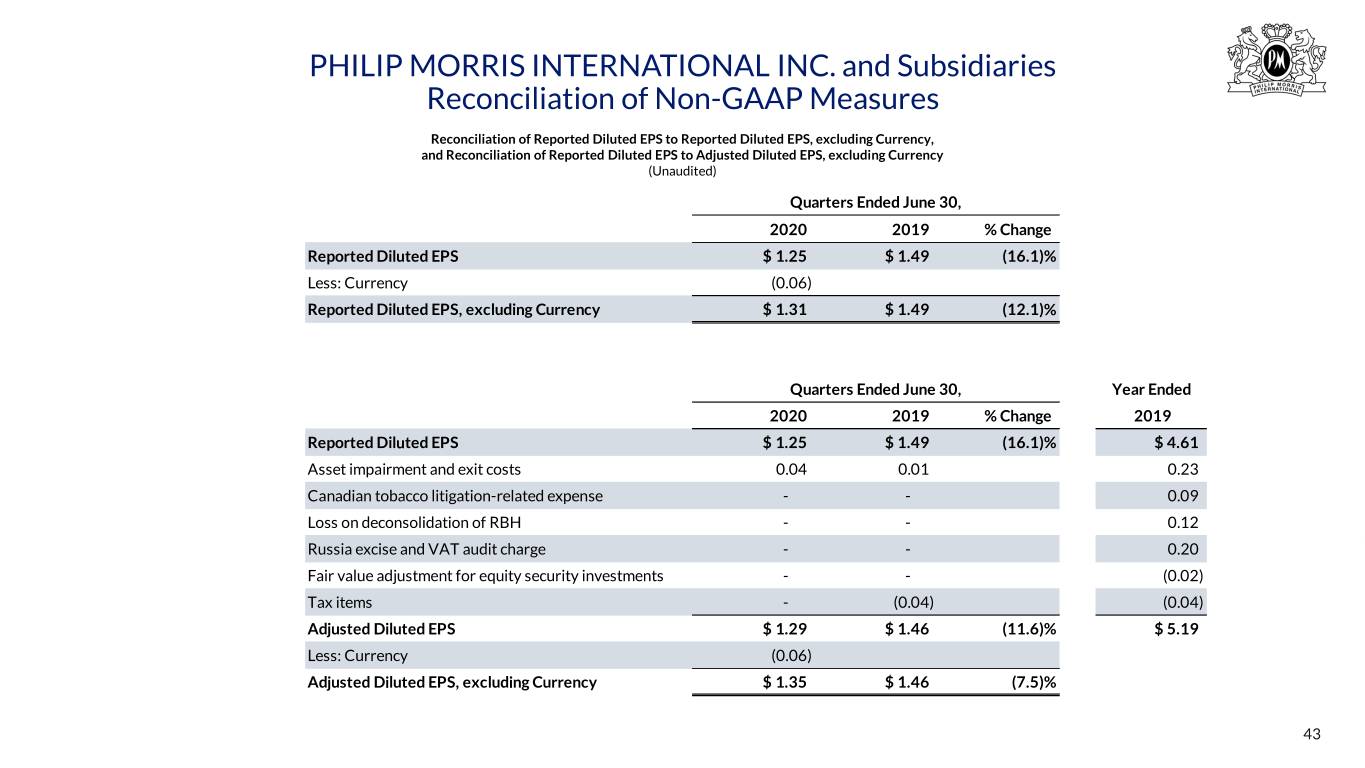
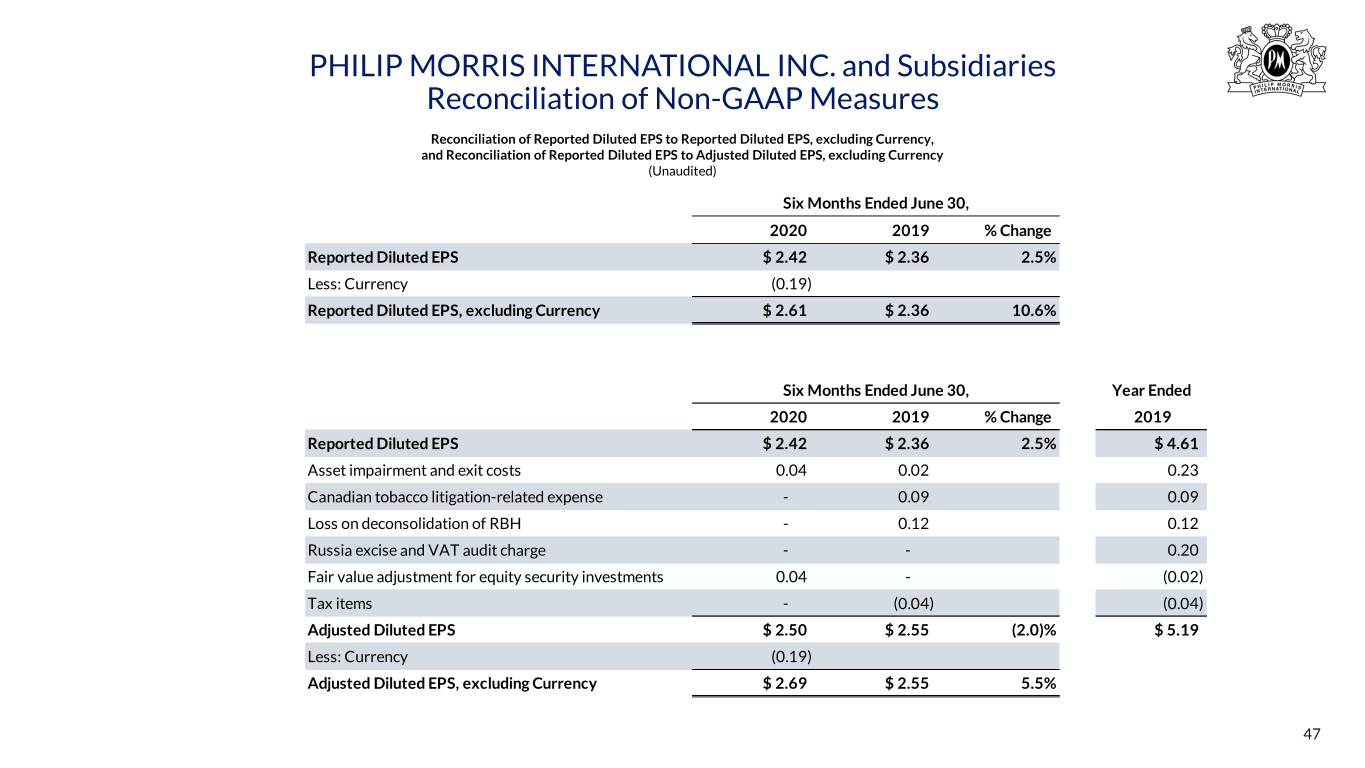
• | Reported diluted EPS of $1.25, down by 16.1%; down by 12.1%, excluding currency |
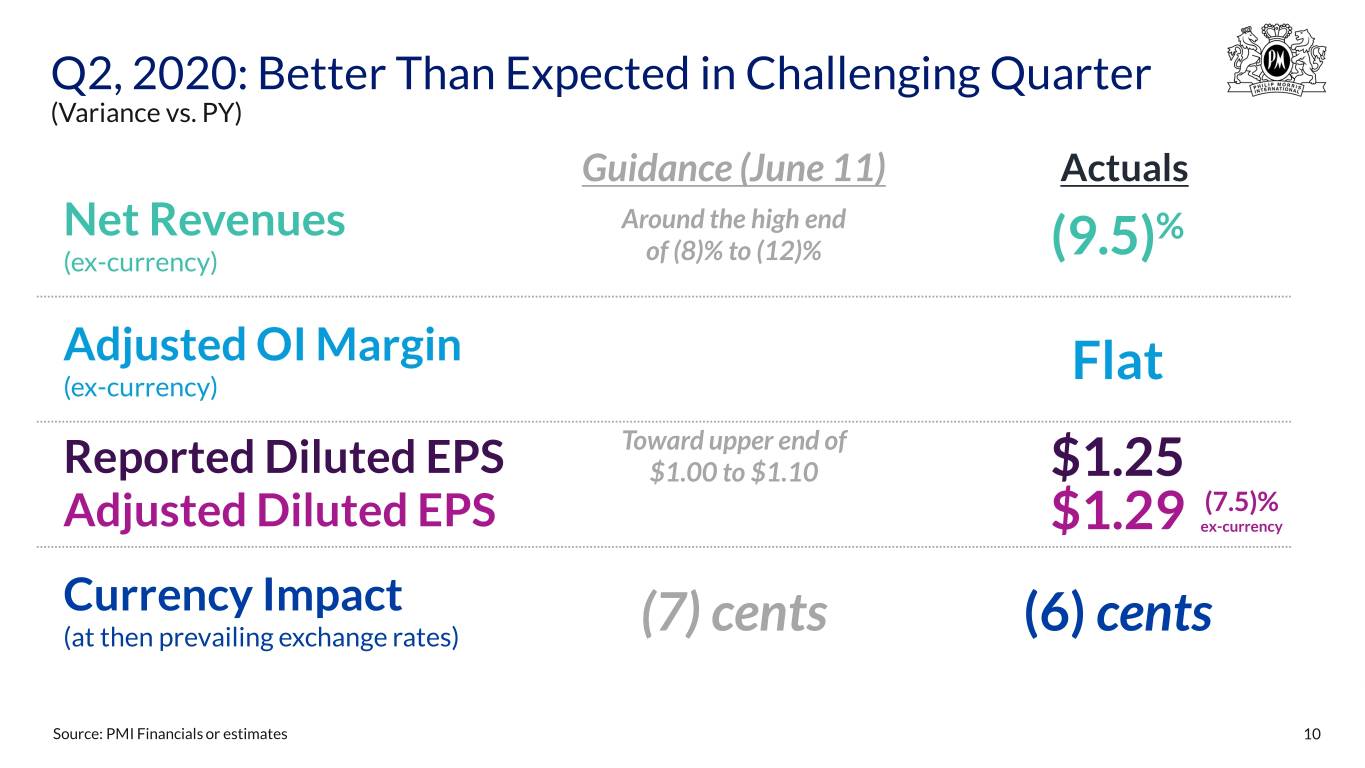
• | Adjusted diluted EPS of $1.29, down by 11.6%; down by 7.5%, excluding currency |
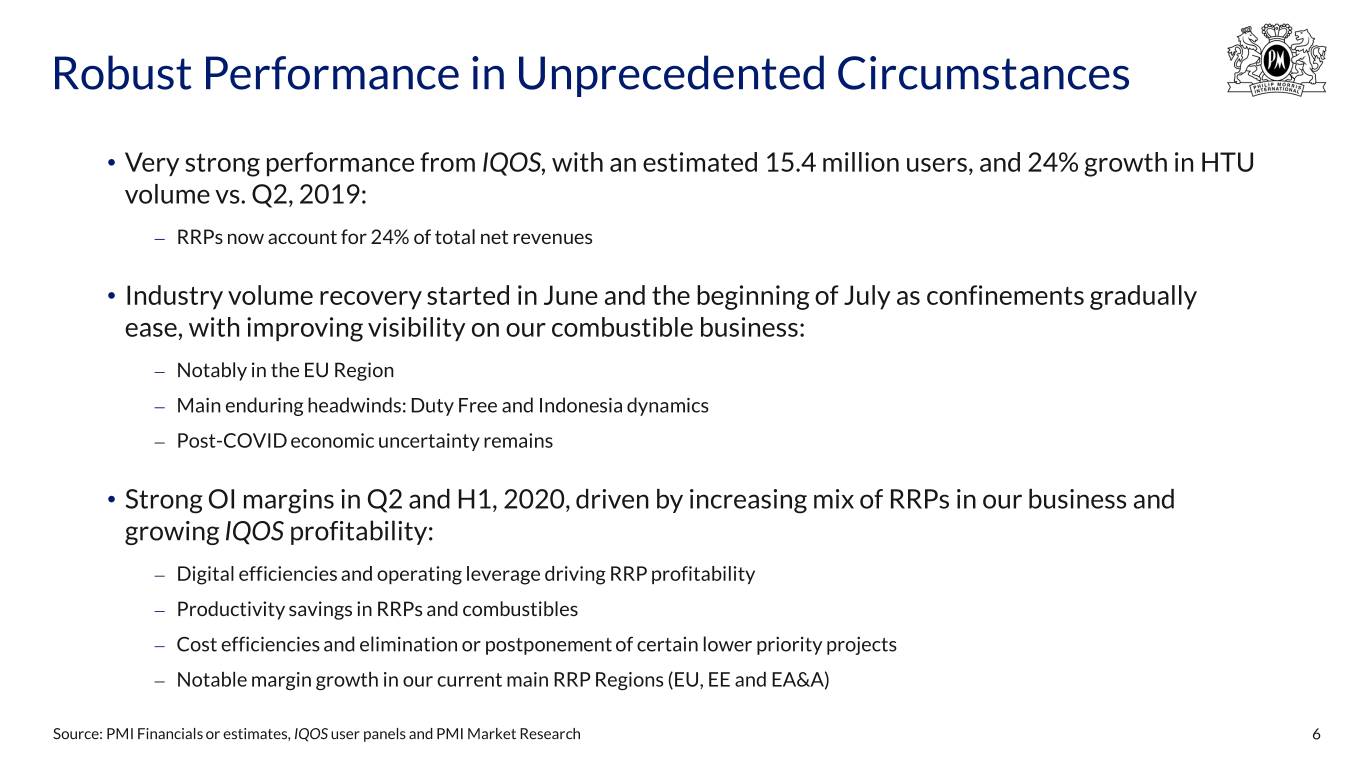
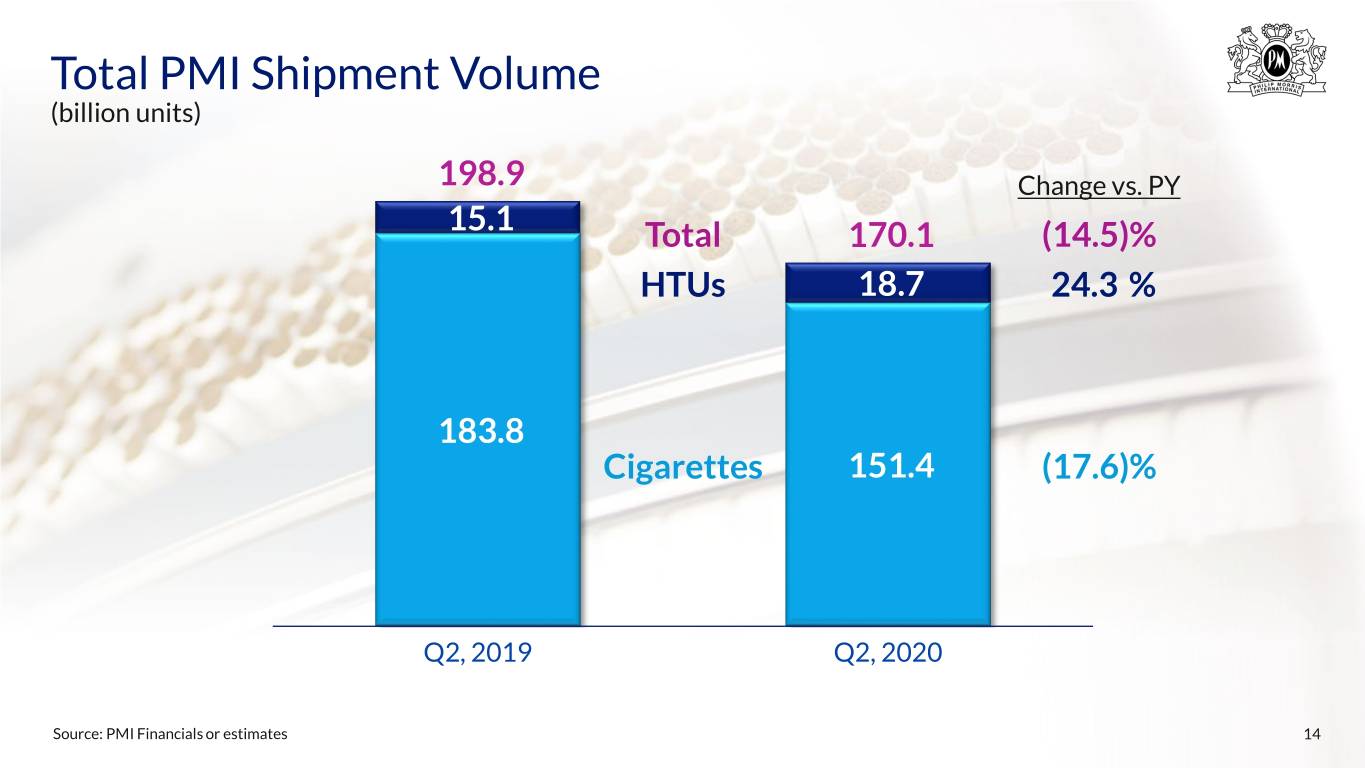
• | Cigarette and heated tobacco unit shipment volume down by 14.5% (reflecting cigarette shipment volume down by 17.6%, and heated tobacco unit shipment volume up by 24.3% to 18.7 billion units) |
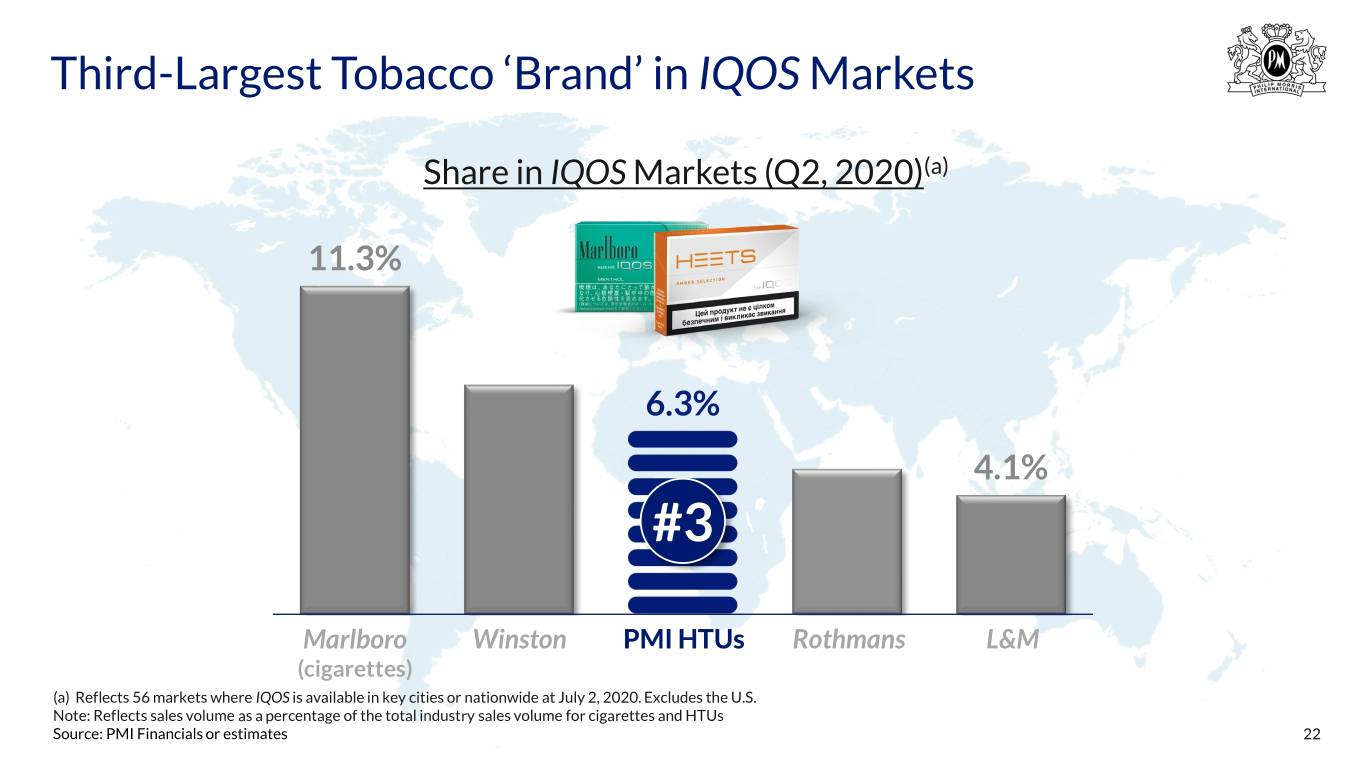
• | Market share for heated tobacco units in IQOS markets, excluding the U.S., up by 1.8 points to 6.3% |
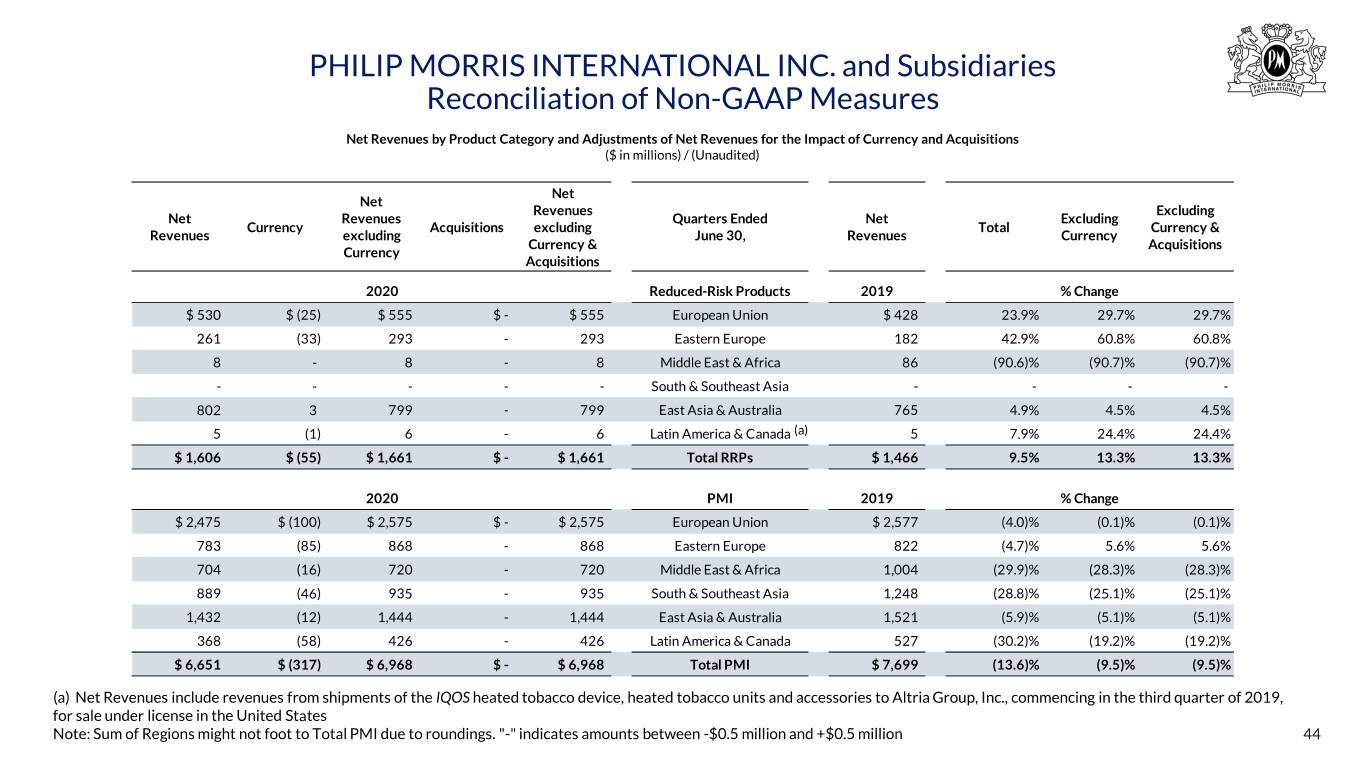
• | Net revenues down by 13.6%; down by 9.5%, excluding currency |
• | Operating income down by 14.3%; down by 11.0%, excluding currency |
• | Adjusted operating income down by 9.5%, excluding currency |
• | Adjusted operating income margin flat at 41.7%, excluding currency |
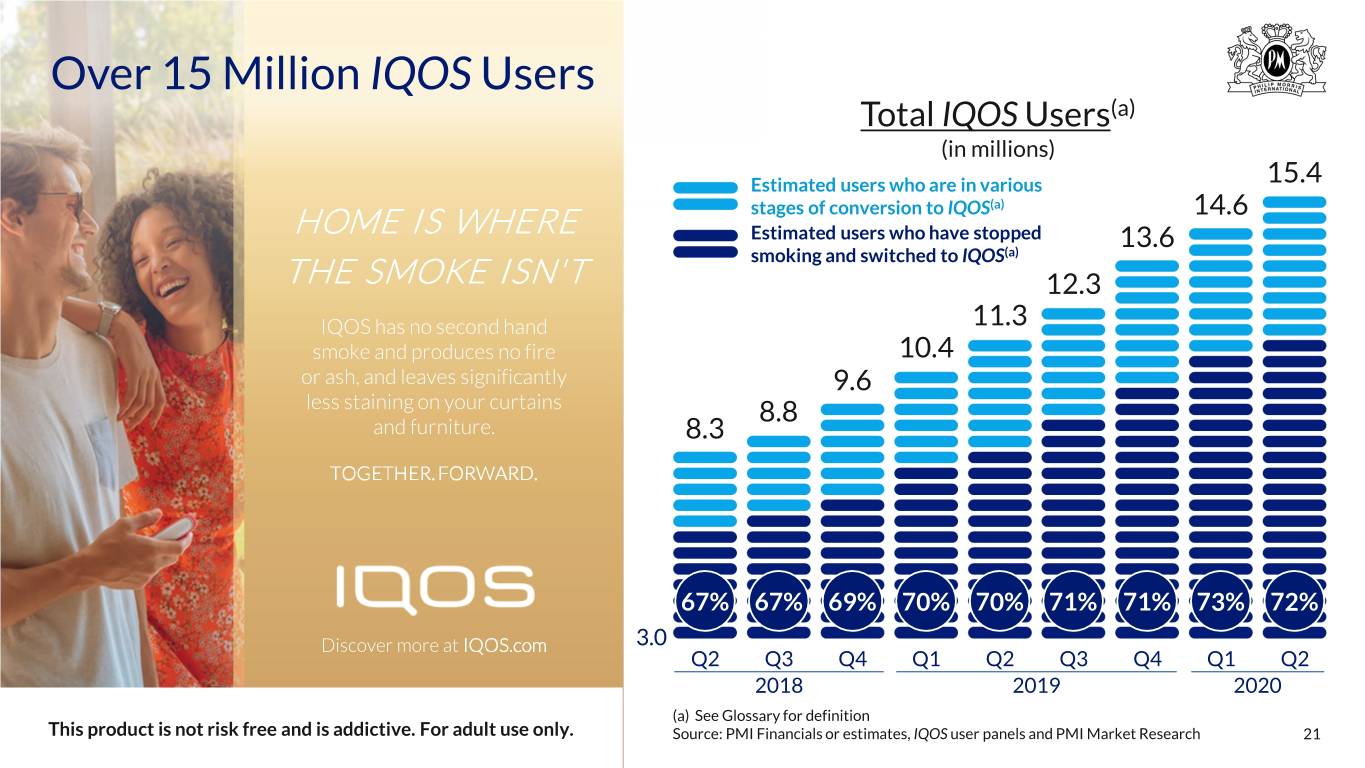
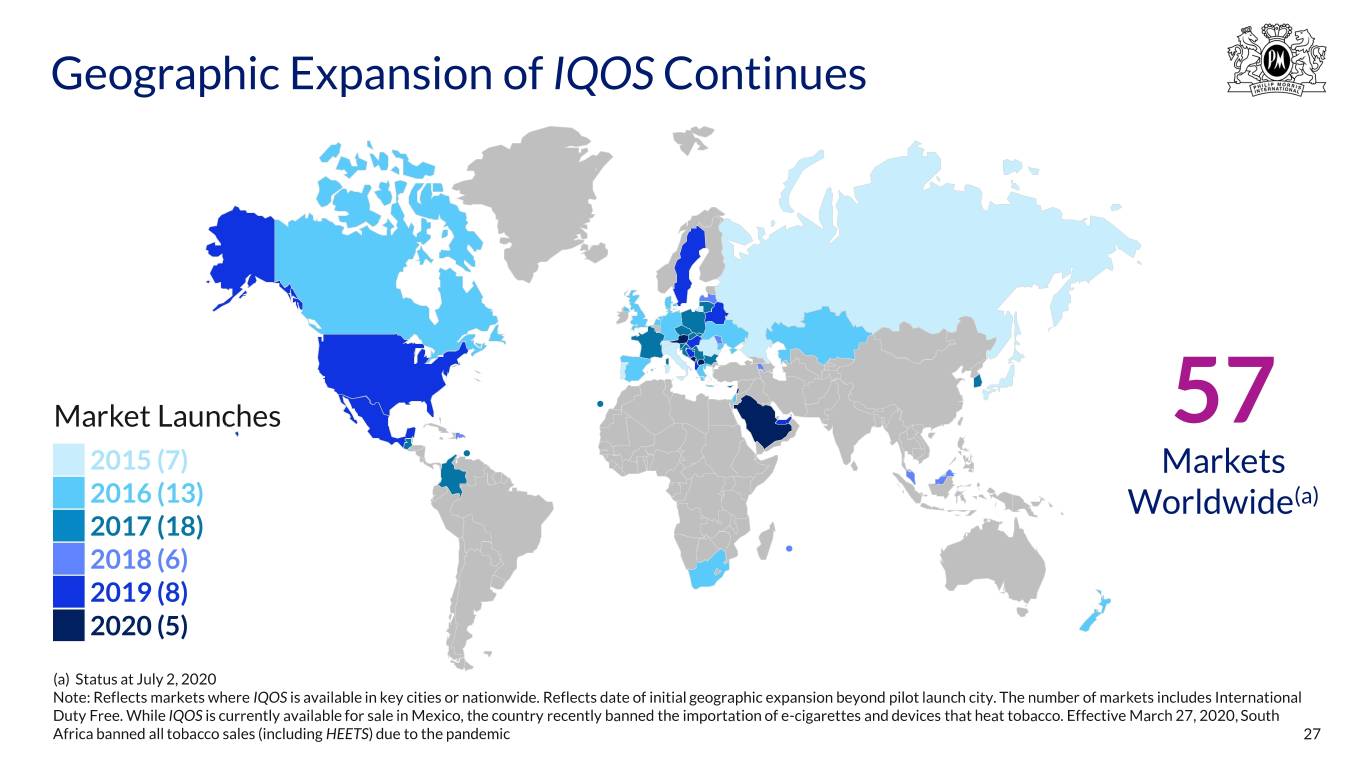
• | Total IQOS users at quarter-end estimated at approximately 15.4 million, of which approximately 11.2 million have stopped smoking and switched to IQOS |
• | During the quarter, PMI declared a regular quarterly dividend of $1.17 per common share, representing an annualized rate of $4.68 |
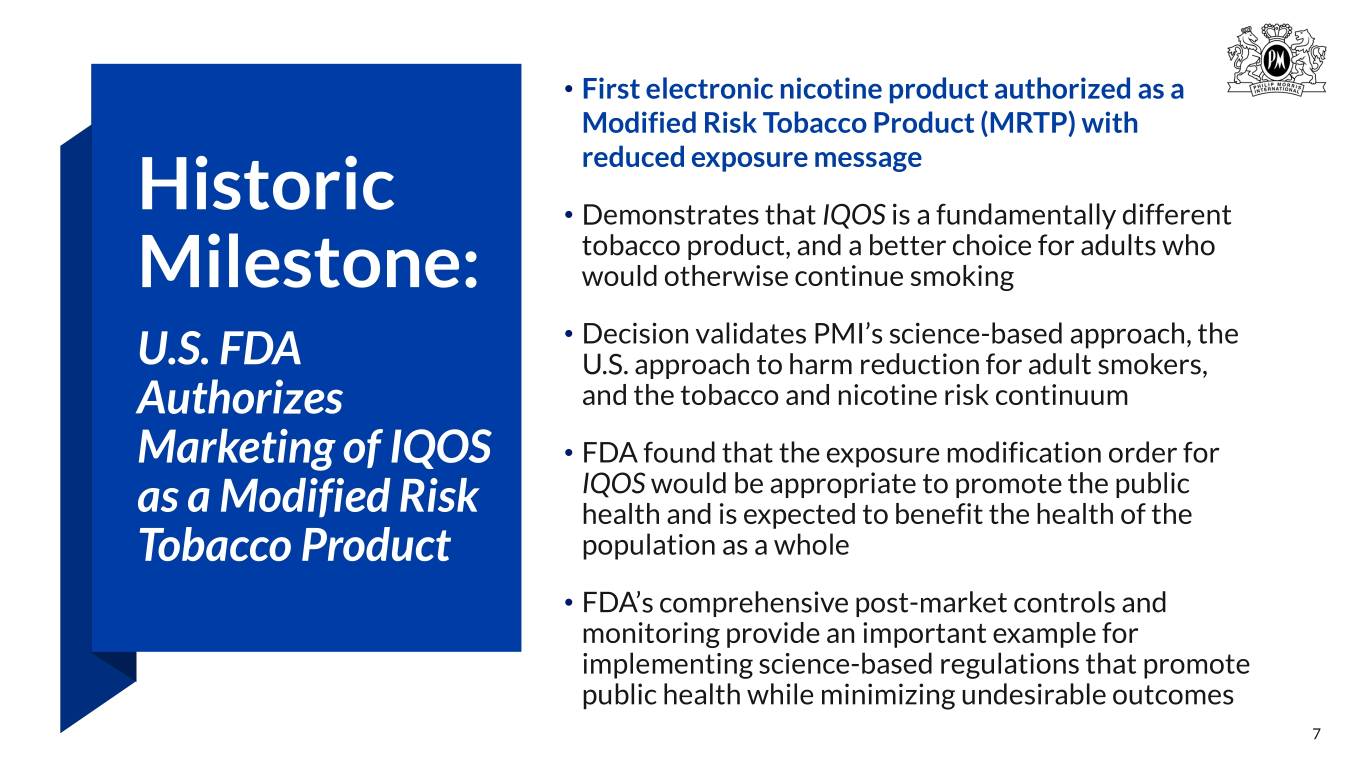
• | On July 7, 2020, the U.S. Food and Drug Administration (FDA) authorized the marketing of the IQOS tobacco heating system as a modified risk tobacco product |
2020 Six Months Year-to-Date
• | Reported diluted EPS of $2.42, up by 2.5%; up by 10.6%, excluding currency |
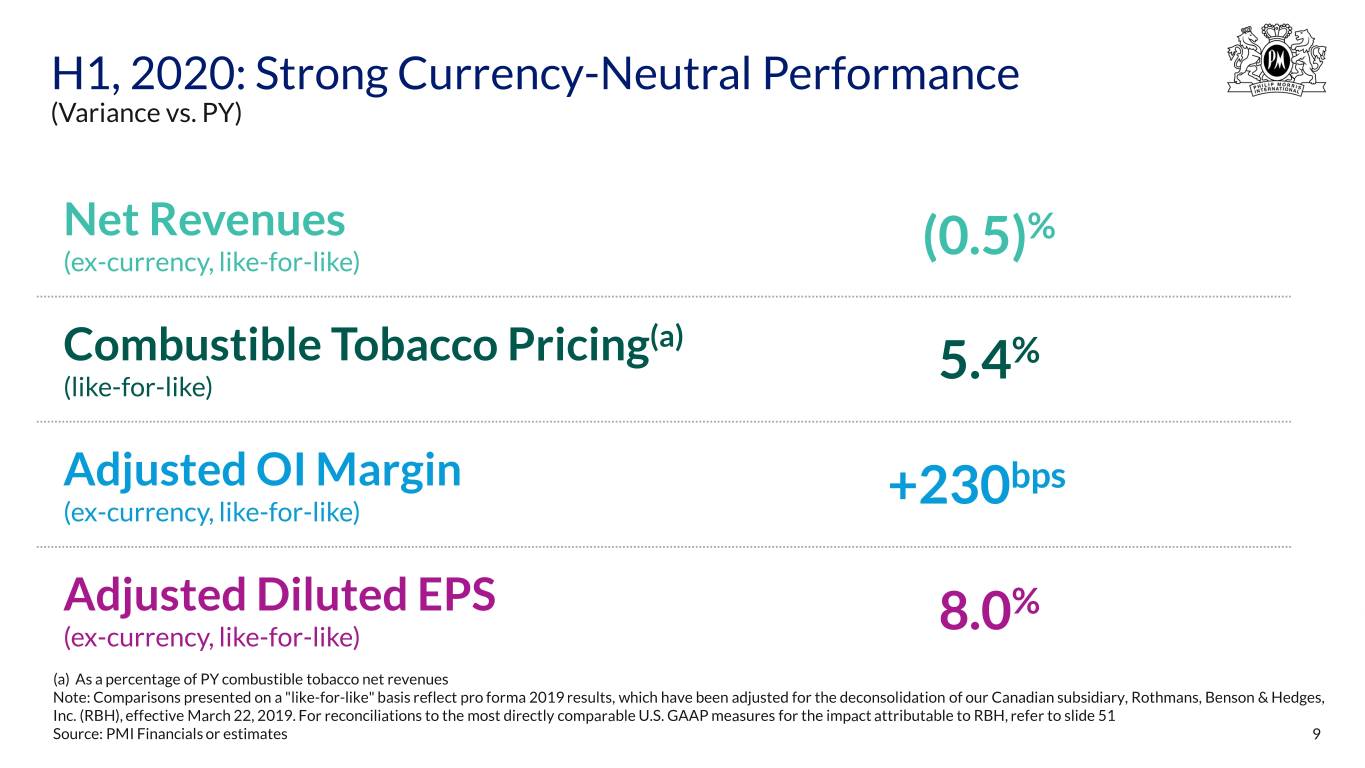
• | Adjusted diluted EPS of $2.50, down by 2.0%; up by 8.0% on a like-for-like basis, excluding currency |
• | Cigarette and heated tobacco unit shipment volume down by 8.2% (reflecting cigarette shipment volume down by 11.4%, and heated tobacco unit shipment volume up by 33.4% to 35.4 billion units); down by 8.0% on a like-for-like basis |
• | Market share for heated tobacco units in IQOS markets, excluding the U.S., up by 1.8 points to 6.3% |
• | Net revenues down by 4.5%; down by 0.5% on a like-for-like basis, excluding currency |
• | Operating income up by 5.4%; up by 11.1%, excluding currency |
• | Adjusted operating income up by 5.4% on a like-for-like basis, excluding currency |
• | Adjusted operating income margin up by 2.3 points to 41.5% on a like-for-like basis, excluding currency |
"Despite a very challenging quarter due to the pandemic, we delivered results above our previously communicated expectations for both net revenues and reported diluted EPS," said André Calantzopoulos, Chief Executive Officer.
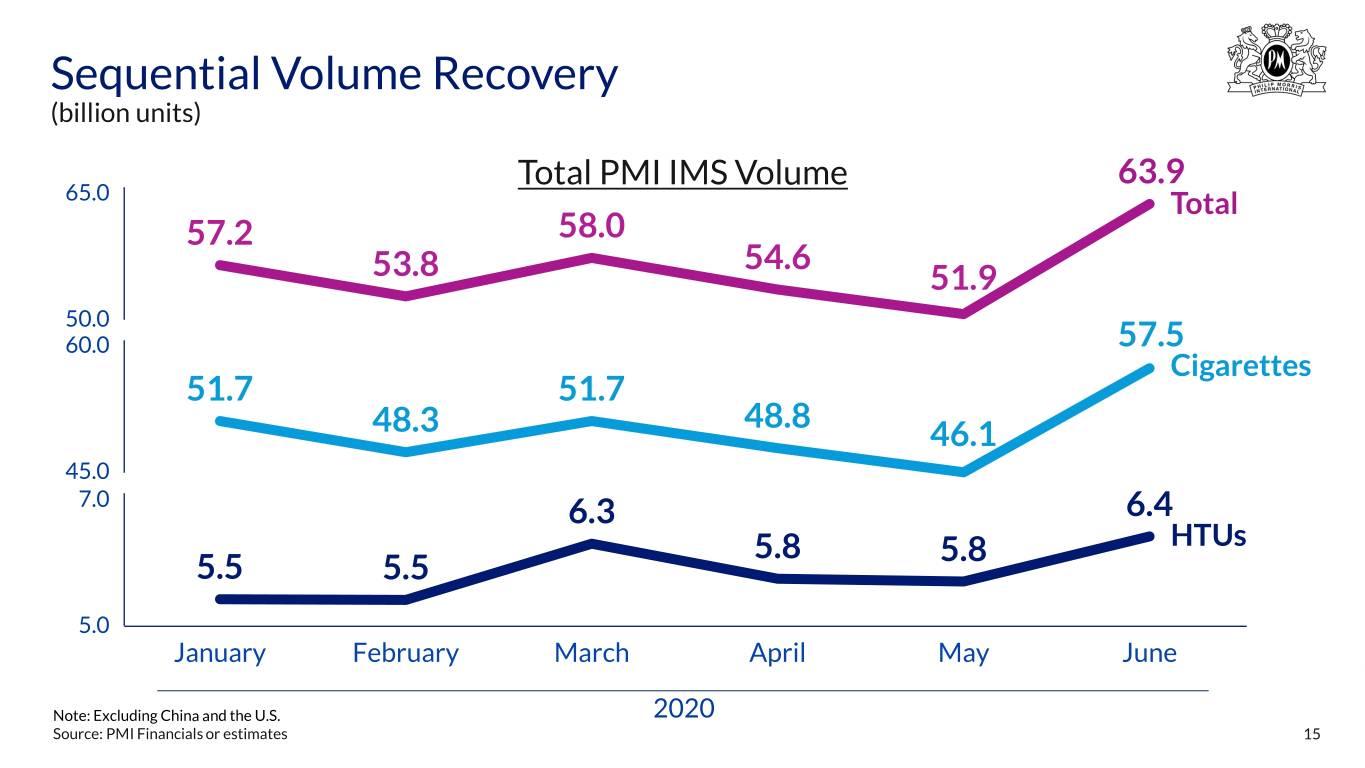
"This primarily reflected favorable sequential performance in June, with a strong industry volume recovery -- notably in the higher margin EU Region -- and substantial IQOS user acquisition growth, as well as the benefit of certain non-underlying factors, some of which we expect to reverse in the third quarter."
"We are particularly pleased by the excellent performance of IQOS, for which we continued to grow share across a broad range of markets. This is testament to the strength and agility of our commercial model, which increasingly leverages our digital assets."
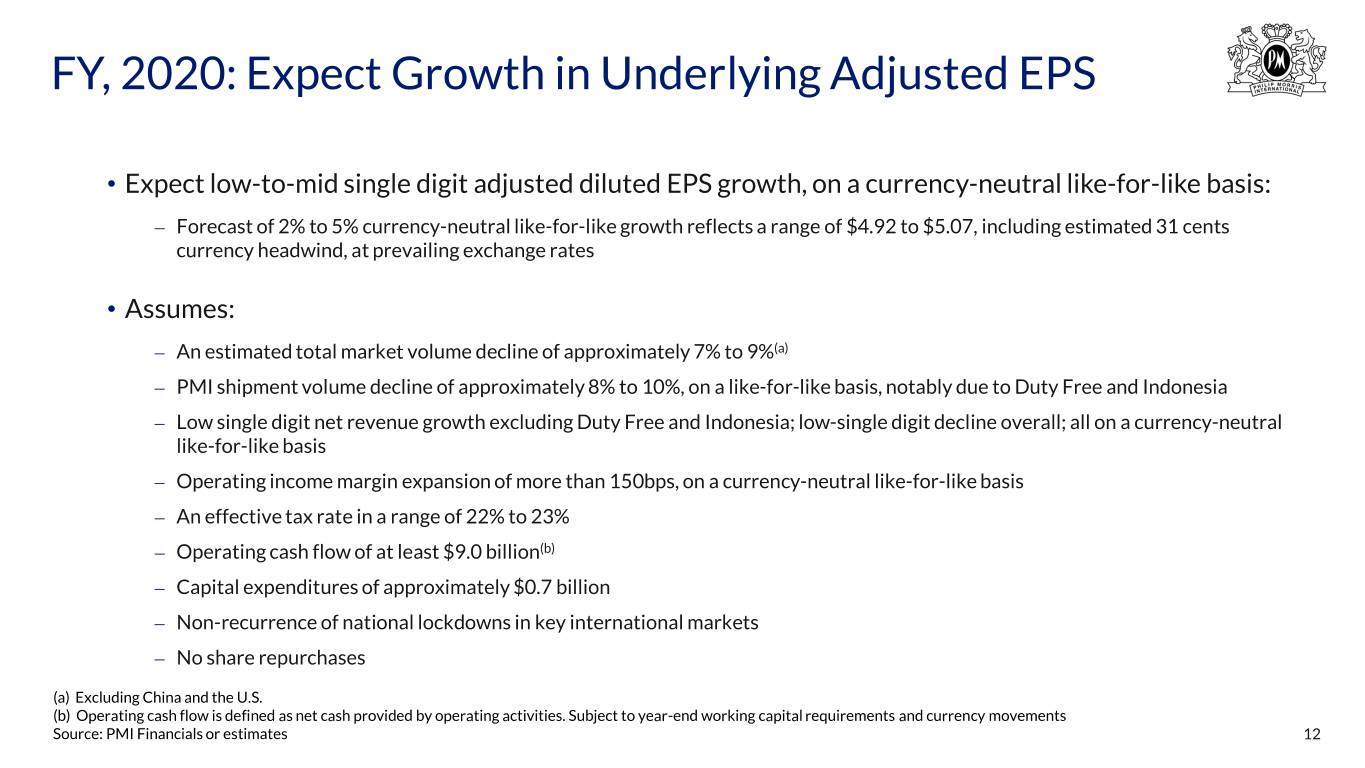
"While further volatility and restrictions are clearly possible, and the pandemic's economic impact is difficult to quantify, we have improving visibility on the trajectory of our business for the remainder of the year. We are therefore providing a full-year 2020 forecast, which reflects like-for-like currency-neutral adjusted diluted EPS growth in the low-to-mid single digits."
"Importantly, we are very pleased with the U.S. FDA’s recent authorization of IQOS as a modified risk tobacco product. This is a historic milestone for both public health and PMI, and reflects the FDA’s recognition that IQOS is a fundamentally different product than cigarettes and must be regulated differently."
COVID-19: Business Continuity Update
Since the onset of COVID-19, PMI has undertaken a number of business continuity measures to mitigate potential disruption to its operations and route-to-market in order to preserve the availability of products to its customers and adult consumers.
Currently, PMI has sufficient access to the inputs for its products and is not facing any significant business continuity issues with respect to key suppliers.
The large majority of PMI's manufacturing facilities globally are currently operational, including all heated tobacco unit factories. Certain cigarette production facilities are temporarily impacted by government-mandated shutdowns or production limitations. Such facilities account for less than 5% of PMI's total cigarette production capacity worldwide.
Based on current sales trends, there are adequate inventories of PMI finished goods across all key markets for cigarettes and across all IQOS markets for heated tobacco units and tobacco heating devices. While government-related restrictions have led to complexities in the company's route-to-market in select geographies, PMI does not currently anticipate out-of-stock situations in any major operating income markets and generally expects consumers to have adequate access to its products.
- -2 -
PMI has ample liquidity through cash on hand, the ongoing cash generation of its business, and its access to the commercial paper and debt markets. As of June 30, 2020, the company had approximately $4.2 billion of cash and cash equivalents. The company has a well laddered bond portfolio, and on May 1, 2020, issued a three-tranche bond offering totaling $2.25 billion, equally split among three, five and 10-year maturities. PMI has a $0.3 billion (equivalent) bond maturing in September 2020.
Organizational Design Optimization
As part of its transformation to a smoke-free future, PMI seeks to optimize its organizational design, which includes the elimination, relocation and outsourcing of certain activities. During the second quarter, PMI recorded pre-tax asset impairment and exit costs of $71 million related to restructuring activities in Switzerland and the outsourcing of certain activities performed in the U.S. These pre-tax charges were allocated across all segments.
2020 FULL-YEAR FORECAST
On April 21, 2020, PMI withdrew its 2020 full-year reported diluted EPS forecast of at least $5.50, originally provided on February 6, 2020. At the time, the company was unable to forecast its full-year financial results with reasonable accuracy given the uncertainty surrounding the COVID-19 pandemic and the related impact on the company's business globally.
PMI believes that it is now in a better position to provide a 2020 full-year forecast, primarily reflecting the benefit of an additional quarter of actual results, as well as improved visibility on the progression of pandemic-related government restrictions (including lockdowns) in many of its key international markets, and the impact of such restrictions on adult smoker and reduced-risk product user behavior, as well as the company's global operations.
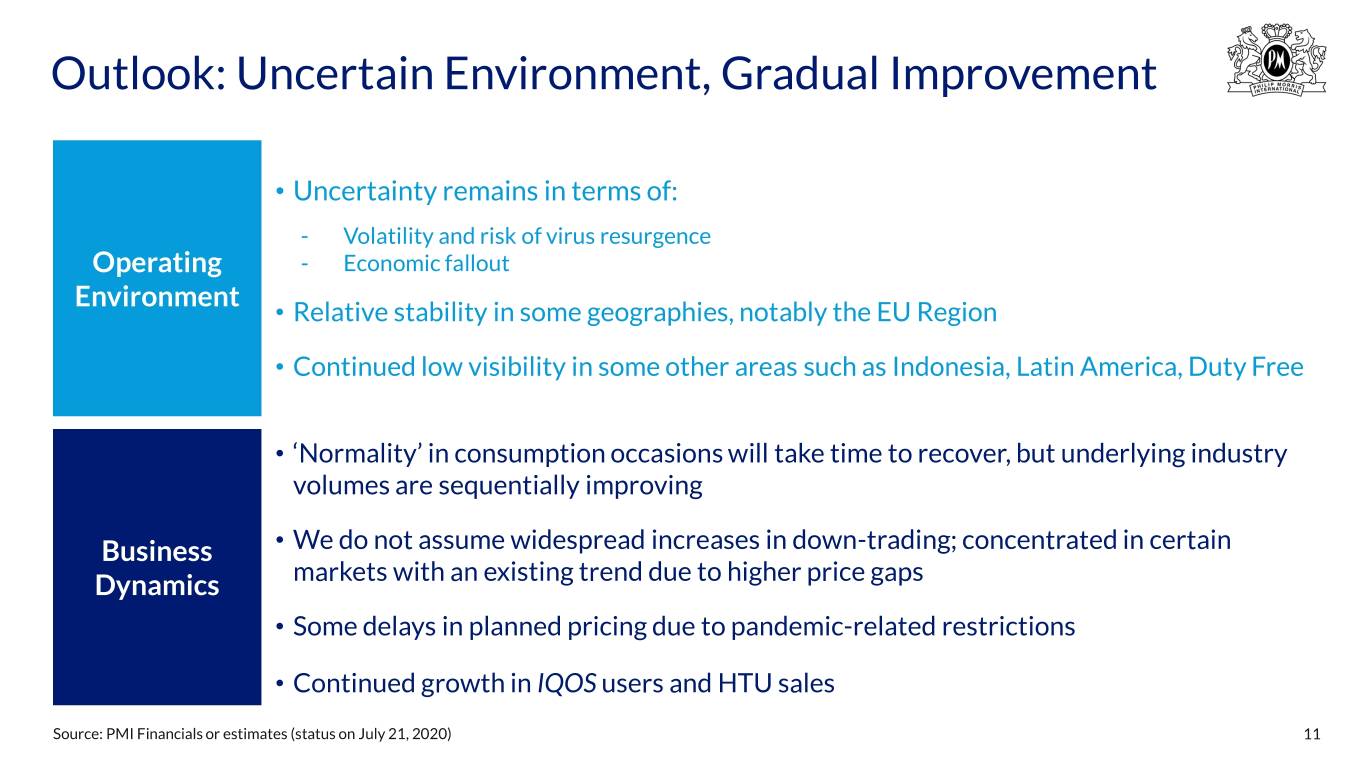
Notwithstanding this improved visibility, uncertainty remains as to the risk and magnitude of COVID-19 resurgence, as well as the economic consequences of the pandemic.
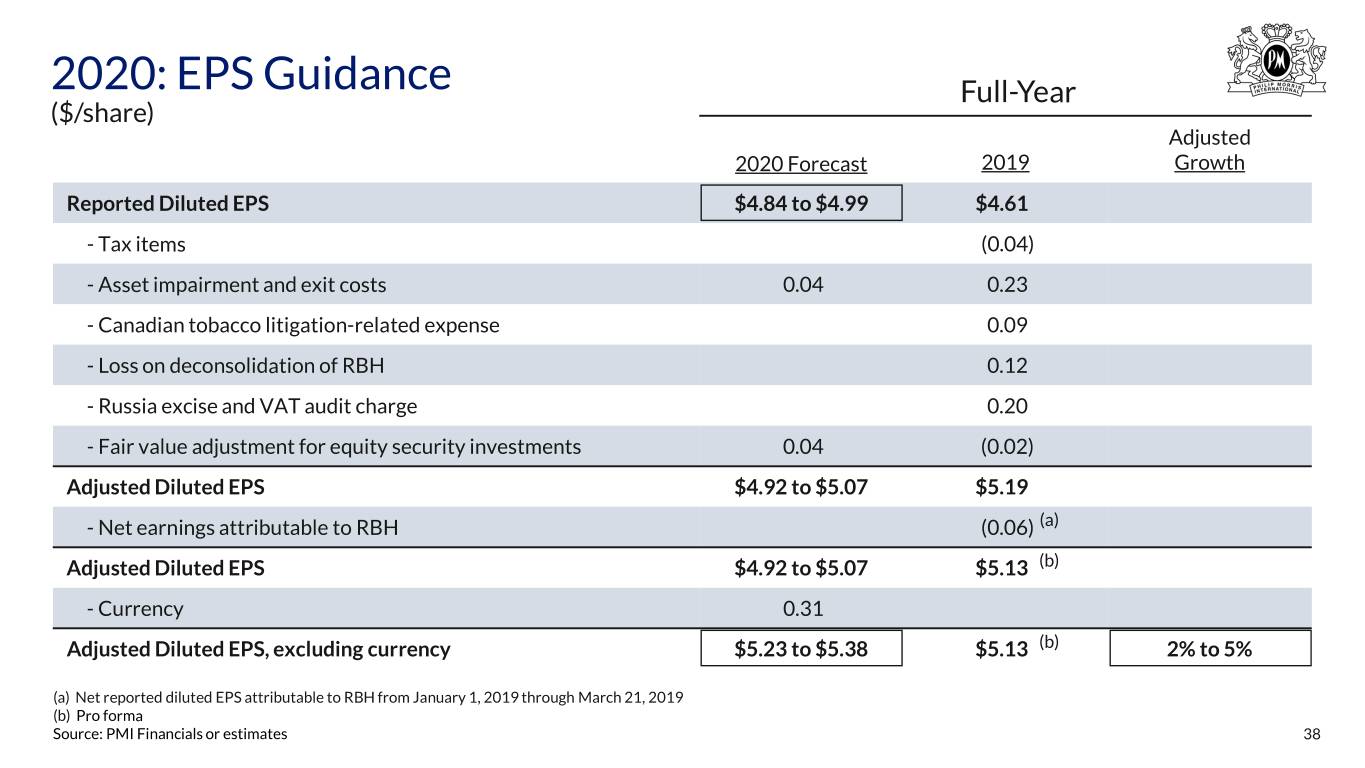
Full-Year | |||||||||||
2020 EPS Forecast | 2020 Forecast | 2019 | Adjusted Growth | ||||||||
Reported Diluted EPS | $4.84 | - | $4.99 | $4.61 | |||||||
Tax items | (0.04 | ) | |||||||||
Asset impairment and exit costs | 0.04 | 0.23 | |||||||||
Canadian tobacco litigation-related expense | 0.09 | ||||||||||
Loss on deconsolidation of RBH | 0.12 | ||||||||||
Russia excise and VAT audit charge | 0.20 | ||||||||||
Fair value adjustment for equity security investments | 0.04 | (0.02 | ) | ||||||||
Adjusted Diluted EPS | $4.92 | - | $5.07 | $5.19 | |||||||
Net earnings attributable to RBH | (0.06 | ) | (a) | ||||||||
Adjusted Diluted EPS | $4.92 | - | $5.07 | $5.13 | (b) | ||||||
Currency | 0.31 | ||||||||||
Adjusted Diluted EPS, excluding currency | $5.23 | - | $5.38 | $5.13 | (b) | 2% | - | 5% | |||
(a) Net reported diluted EPS attributable to RBH from January 1, 2019 through March 21, 2019. | |||||||||||
(b) Pro forma. | |||||||||||
Reported diluted earnings per share forecast to be in a range of $4.84 to $4.99, at prevailing exchange rates versus reported diluted earnings per share of $4.61 in 2019.
- -3 -
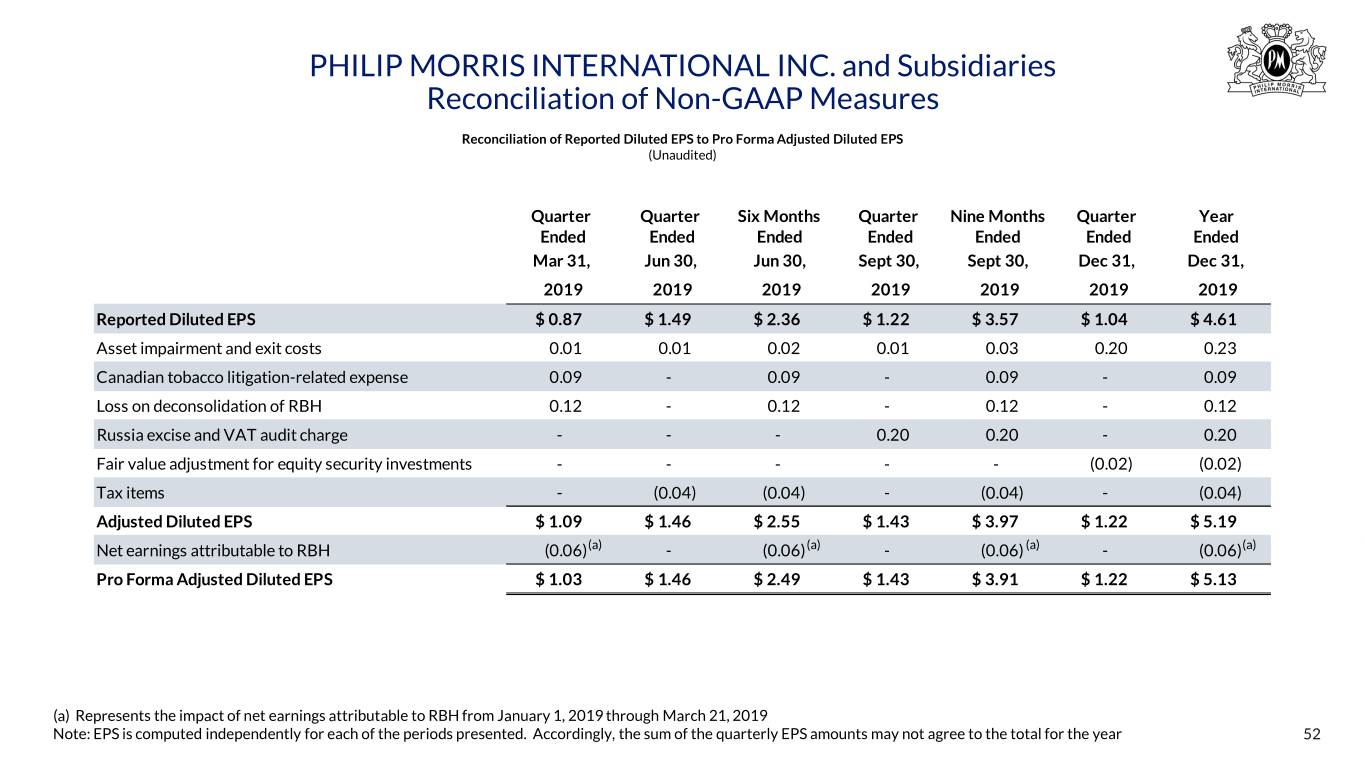
• | Excluding an unfavorable currency impact, at prevailing exchange rates, of approximately $0.31 per share, asset impairment and exit costs of $0.04 per share, and a fair value adjustment for equity security investments of $0.04 per share, this forecast represents a projected increase of approximately 2% to 5% versus pro forma adjusted diluted earnings per share of $5.13 in 2019, as detailed in the above table. |
2020 Full-Year Forecast Assumptions
This forecast assumes:
• | No recurrence of national lockdowns in PMI's key international markets during the second half of 2020; |
• | Lack of near-term recovery in PMI's duty-free business given the uncertain outlook for global travel, with current dynamics persisting at least through the third quarter; |
• | Full enforcement of minimum retail selling price requirements in Indonesia as of September 2020, at the earliest; |
• | An estimated total international industry volume decline, excluding China and the U.S., of approximately 7% to 9%; |
• | A total cigarette and heated tobacco unit shipment volume decline for PMI of approximately 8% to 10% on a like-for-like basis, notably due to Indonesia and PMI Duty Free; |
• | A full-year heated tobacco unit shipment volume that keeps PMI on-track to reach its 2021 target of 90 to 100 billion units; |
• | A currency-neutral net revenue decline in the low single digits, on a like-for-like basis. Excluding Indonesia and PMI Duty Free, this assumes currency-neutral net revenue growth in the low single digits on the same basis; |
• | An increase in currency-neutral, like-for-like adjusted operating income margin of more than 150 basis points; |
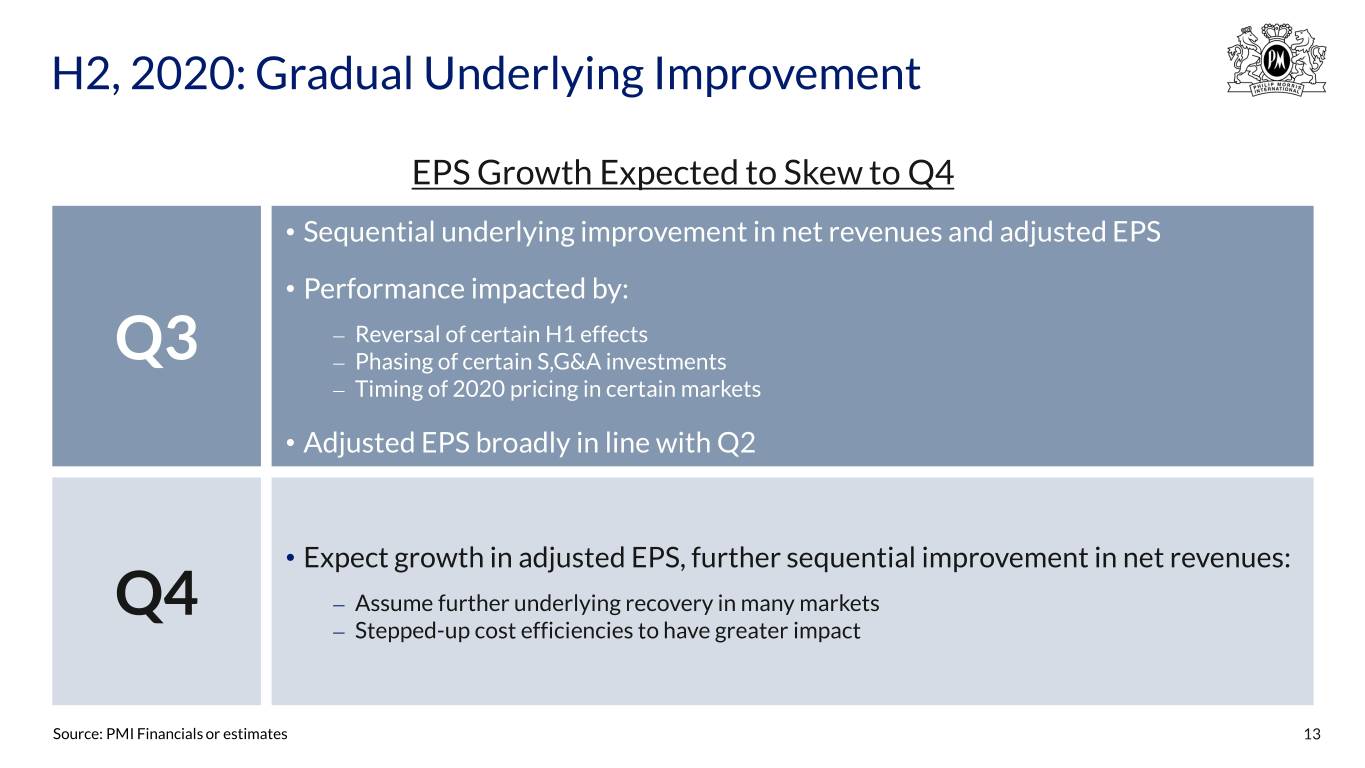
• | Reported diluted EPS in the third quarter broadly in line with the company's second-quarter 2020 EPS results, supported by a sequential improvement in reported net revenues in the quarter, offset by the unfavorable impact of the reversal of certain items from the first half and the timing of certain costs; |
• | Operating cash flow of at least $9.0 billion, subject to year-end working capital requirements and currency movements; |
• | Capital expenditures of approximately $0.7 billion; |
• | An effective tax rate of 22% to 23%, compared to approximately 23% assumed previously, notably reflecting changes in the company's earnings mix and a lower corporate tax rate in Indonesia; and |
• | No share repurchases. |
This forecast excludes the impact of any future acquisitions, unanticipated asset impairment and exit cost charges, future changes in currency exchange rates, further developments related to the U.S. Tax Cuts and Jobs Act, further developments pertaining to the judgment in the two Québec Class Action lawsuits and the Companies’ Creditors Arrangement Act (CCAA) protection granted to RBH, any unusual events, and any COVID-19-related developments different from the assumptions set forth in the company's forecast.
Factors described in the Forward-Looking and Cautionary Statements section of this release represent continuing risks to these projections.
- -4 -
FDA Authorizes Marketing of IQOS as a Modified Risk Tobacco Product
On July 7, 2020, the U.S. Food and Drug Administration (FDA) authorized the marketing of a version of IQOS, PMI’s heat-not-burn product, as a modified risk tobacco product (MRTP). In doing so, the agency found that an IQOS exposure modification order is appropriate to promote the public health. IQOS is the first and only electronic nicotine product to be granted marketing orders through the FDA’s MRTP process.
The FDA authorized the marketing of IQOS with the following information:
• | The IQOS system heats tobacco but does not burn it |
• | This significantly reduces the production of harmful and potentially harmful chemicals |
• | Scientific studies have shown that switching completely from conventional cigarettes to the IQOS system reduces your body’s exposure to harmful or potentially harmful chemicals |
The agency concluded that the available scientific evidence demonstrates that IQOS is expected to benefit the health of the population as a whole, taking into account both users of tobacco products and persons who do not currently use tobacco products.
The FDA’s decision further builds on the emerging independent international scientific consensus that IQOS is a better choice than continuing to smoke, and follows the FDA’s April 2019 decision authorizing the commercialization of a version of IQOS in the U.S.
The FDA’s decision provides an important example of how governments and public health organizations can regulate smoke-free alternatives to differentiate them from cigarettes in order to protect and promote the public health.
This decision follows a review of the extensive scientific evidence package PMI submitted to the FDA in December 2016 to support its MRTP applications.
Conference Call
A conference call, hosted by Emmanuel Babeau, Chief Financial Officer, will be webcast at 9:00 a.m., Eastern Time, on July 21, 2020. Access is at www.pmi.com/2020Q2earnings. The audio webcast may also be accessed on iOS or Android devices by downloading PMI’s free Investor Relations Mobile Application at www.pmi.com/irapp.
- -5 -
CONSOLIDATED SHIPMENT VOLUME & MARKET SHARE
PMI Shipment Volume by Region | Second-Quarter | Six Months Year-to-Date | ||||||||||||
(million units) | 2020 | 2019 | Change | 2020 | 2019 | Change | ||||||||
Cigarettes | ||||||||||||||
European Union | 40,317 | 46,367 | (13.0 | )% | 80,963 | 85,855 | (5.7 | )% | ||||||
Eastern Europe | 23,657 | 27,080 | (12.6 | )% | 45,076 | 47,400 | (4.9 | )% | ||||||
Middle East & Africa | 27,188 | 31,659 | (14.1 | )% | 57,184 | 64,963 | (12.0 | )% | ||||||
South & Southeast Asia | 33,346 | 46,376 | (28.1 | )% | 70,941 | 87,868 | (19.3 | )% | ||||||
East Asia & Australia | 12,071 | 13,845 | (12.8 | )% | 24,370 | 25,958 | (6.1 | )% | ||||||
Latin America & Canada | 14,780 | 18,472 | (20.0 | )% | 29,843 | 36,052 | (17.2 | )% | ||||||
Total PMI | 151,359 | 183,799 | (17.6 | )% | 308,377 | 348,096 | (11.4 | )% | ||||||
Heated Tobacco Units | ||||||||||||||
European Union | 4,227 | 3,043 | 38.9 | % | 8,888 | 5,336 | 66.6 | % | ||||||
Eastern Europe | 5,126 | 2,807 | 82.6 | % | 9,492 | 4,355 | +100% | |||||||
Middle East & Africa | 185 | 719 | (74.3 | )% | 655 | 1,473 | (55.5 | )% | ||||||
South & Southeast Asia | — | — | — | % | — | — | — | % | ||||||
East Asia & Australia | 9,076 | 8,428 | 7.7 | % | 16,198 | 15,277 | 6.0 | % | ||||||
Latin America & Canada (1) | 94 | 59 | 59.3 | % | 202 | 113 | 78.8 | % | ||||||
Total PMI | 18,708 | 15,056 | 24.3 | % | 35,435 | 26,554 | 33.4 | % | ||||||
Cigarettes and Heated Tobacco Units | ||||||||||||||
European Union | 44,544 | 49,410 | (9.8 | )% | 89,851 | 91,191 | (1.5 | )% | ||||||
Eastern Europe | 28,783 | 29,887 | (3.7 | )% | 54,568 | 51,755 | 5.4 | % | ||||||
Middle East & Africa | 27,373 | 32,378 | (15.5 | )% | 57,839 | 66,436 | (12.9 | )% | ||||||
South & Southeast Asia | 33,346 | 46,376 | (28.1 | )% | 70,941 | 87,868 | (19.3 | )% | ||||||
East Asia & Australia | 21,147 | 22,273 | (5.1 | )% | 40,568 | 41,235 | (1.6 | )% | ||||||
Latin America & Canada | 14,874 | 18,531 | (19.7 | )% | 30,045 | 36,165 | (16.9 | )% | ||||||
Total PMI | 170,067 | 198,855 | (14.5 | )% | 343,812 | 374,650 | (8.2 | )% | ||||||
(1) Includes shipments to Altria Group, Inc., commencing in the third quarter of 2019, for sale in the United States under license. | ||||||||||||||
Second-Quarter
PMI's total shipment volume decreased by 14.5%, principally due to:
• | the EU, reflecting lower cigarette shipment volume, notably in Italy, Poland and Spain, partly offset by higher heated tobacco unit shipment volume across most markets, notably Germany, Italy and Poland; |
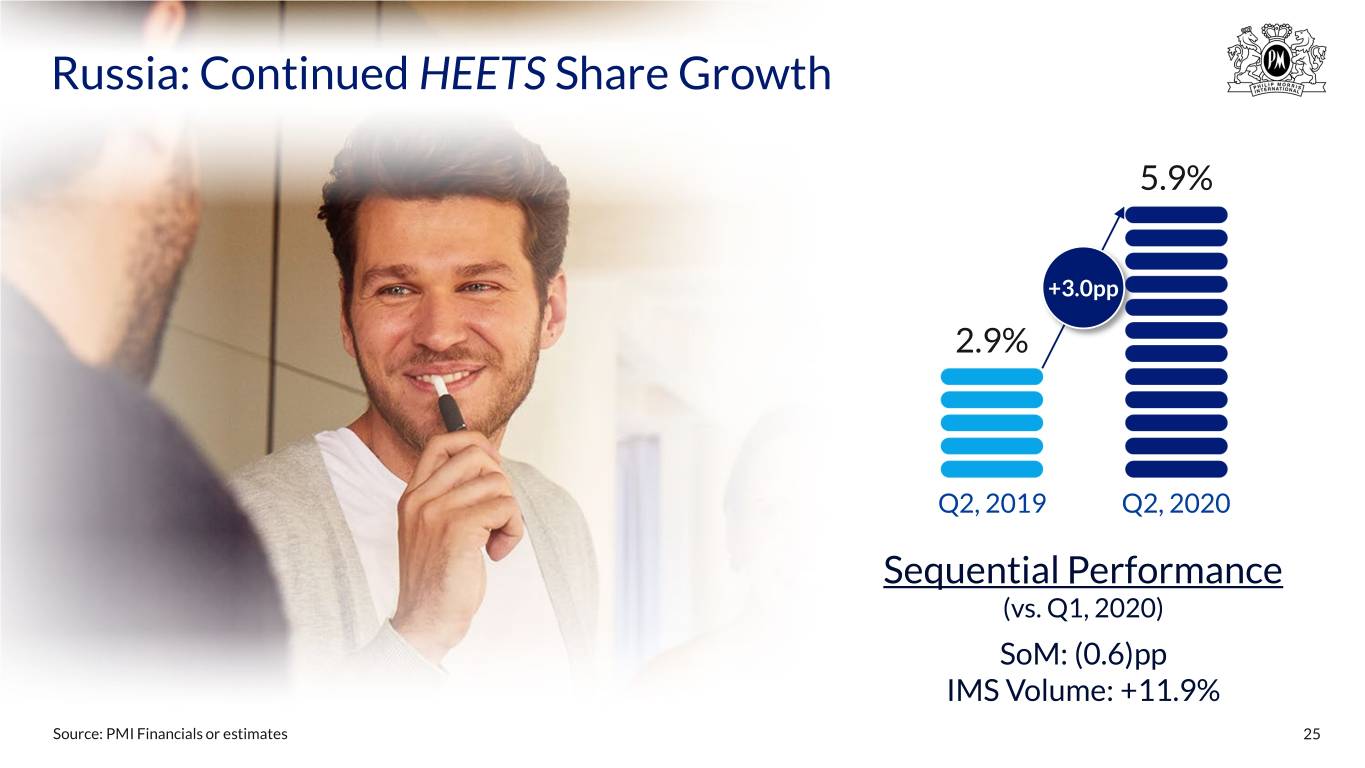
• | Eastern Europe, reflecting lower cigarette shipment volume, particularly in Russia and Ukraine, partly offset by higher heated tobacco unit shipment volume across the Region, notably in Russia; |
• | Middle East & Africa, reflecting lower cigarette shipment volume, particularly in North Africa, PMI Duty Free and Turkey, partly offset by Saudi Arabia, as well as lower heated tobacco shipment volume in PMI Duty Free; |
• | South & Southeast Asia, reflecting lower cigarette shipment volume, primarily in Indonesia, Pakistan and the Philippines; |
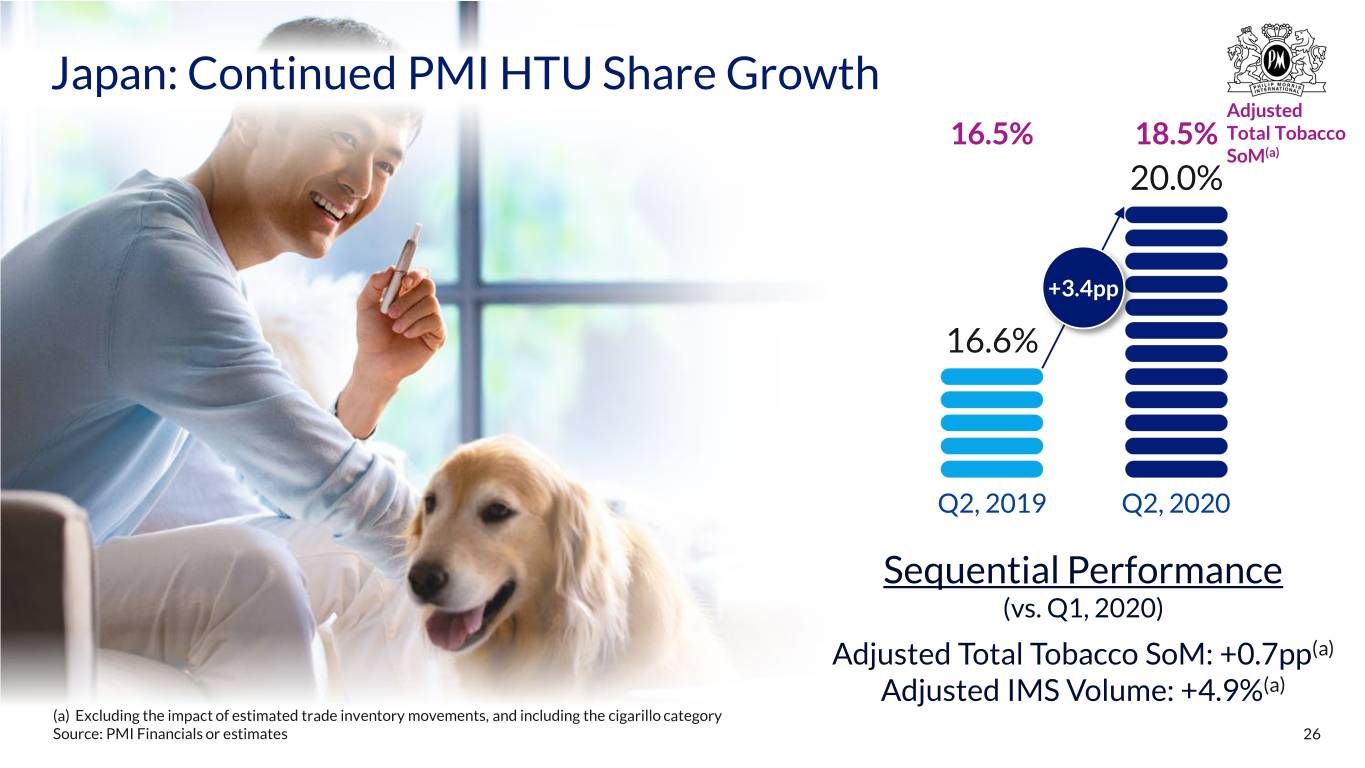
• | East Asia & Australia, reflecting lower cigarette shipment volume, mainly in Japan, partly offset by higher heated tobacco unit shipment volume in Japan; and |
• | Latin America & Canada, reflecting lower cigarette shipment volume, primarily in Argentina and Mexico. |
- -6 -
Impact of Inventory Movements
Excluding the net unfavorable impact of estimated distributor inventory movements of approximately 2.3 billion units, PMI’s total in-market sales declined by 13.4%, due to a 16.4% decline in cigarettes, partly offset by a 24.0% increase in heated tobacco units.
The net unfavorable impact of estimated distributor inventory movements of approximately 2.3 billion units reflected a net unfavorable impact of 2.5 billion cigarettes, mainly due to Italy, Japan, PMI Duty Free, Russia and Spain, partly offset by Saudi Arabia.
Six Months Year-to-Date
PMI's total shipment volume decreased by 8.2%, or by 8.0% on a like-for-like basis, due to:
• | the EU, reflecting lower cigarette shipment volume, notably in Italy, Poland and Spain, partly offset by higher heated tobacco unit shipment volume across the Region, particularly in Italy; |
• | Middle East & Africa, reflecting lower cigarette shipment volume, notably in PMI Duty Free, Saudi Arabia and Turkey, partly offset by North Africa, as well as lower heated tobacco unit shipment volume in PMI Duty Free; |
• | South & Southeast Asia, reflecting lower cigarette shipment volume, primarily in Indonesia, Pakistan and the Philippines; |
• | East Asia & Australia, reflecting lower cigarette shipment volume, mainly in Japan, partly offset by higher heated tobacco unit shipment volume in Japan; and |
• | Latin America & Canada, reflecting lower cigarette shipment volume, primarily in Argentina, Canada (due to the impact of the deconsolidation of RBH), and Mexico. On a like-for-like basis, PMI's total shipment volume in the Region decreased by 14.6%; |
partly offset by
• | Eastern Europe, reflecting higher heated tobacco unit shipment volume across the Region, notably in Russia and Ukraine, partly offset by lower cigarette shipment volume, notably in Russia and Ukraine. |
Impact of Inventory Movements
On a like-for-like basis, excluding the net favorable impact of estimated distributor inventory movements of approximately 3.0 billion units, PMI’s total in-market sales declined by 8.8%, due to an 11.8% decline in cigarettes, partly offset by a 29.5% increase in heated tobacco units.
The net favorable impact of estimated distributor inventory movements of approximately 3.0 billion units reflected:
• | a net favorable impact of 2.2 billion cigarettes, mainly driven by Japan, Kuwait and North Africa, partly offset by Saudi Arabia and Spain; and |
• | a net favorable impact of 0.8 billion heated tobacco units, mainly driven by Japan and Russia. |
- -7 -
PMI Shipment Volume by Brand
PMI Shipment Volume by Brand | Second-Quarter | Six Months Year-to-Date | ||||||||||||
(million units) | 2020 | 2019 | Change | 2020 | 2019 | Change | ||||||||
Cigarettes | ||||||||||||||
Marlboro | 54,812 | 68,060 | (19.5 | )% | 114,057 | 128,024 | (10.9 | )% | ||||||
L&M | 22,385 | 23,522 | (4.8 | )% | 45,025 | 45,337 | (0.7 | )% | ||||||
Chesterfield | 12,604 | 14,202 | (11.3 | )% | 25,507 | 28,501 | (10.5 | )% | ||||||
Philip Morris | 11,106 | 12,950 | (14.2 | )% | 22,569 | 23,673 | (4.7 | )% | ||||||
Parliament | 8,462 | 9,847 | (14.1 | )% | 16,035 | 18,677 | (14.1 | )% | ||||||
Sampoerna A | 7,254 | 9,355 | (22.5 | )% | 15,802 | 17,256 | (8.4 | )% | ||||||
Bond Street | 6,428 | 7,741 | (17.0 | )% | 12,041 | 13,412 | (10.2 | )% | ||||||
Dji Sam Soe | 5,797 | 7,839 | (26.0 | )% | 11,972 | 14,490 | (17.4 | )% | ||||||
Lark | 4,189 | 5,349 | (21.7 | )% | 8,213 | 10,619 | (22.7 | )% | ||||||
Fortune | 2,263 | 3,441 | (34.2 | )% | 4,745 | 6,487 | (26.8 | )% | ||||||
Others | 16,059 | 21,493 | (25.3 | )% | 32,411 | 41,620 | (22.1 | )% | ||||||
Total Cigarettes | 151,359 | 183,799 | (17.6 | )% | 308,377 | 348,096 | (11.4 | )% | ||||||
Heated Tobacco Units (1) | 18,708 | 15,056 | 24.3 | % | 35,435 | 26,554 | 33.4 | % | ||||||
Total PMI | 170,067 | 198,855 | (14.5 | )% | 343,812 | 374,650 | (8.2 | )% | ||||||
(1) Includes shipments to Altria Group, Inc., commencing in the third quarter of 2019, for sale in the United States under license. | ||||||||||||||
Note: Sampoerna A includes Sampoerna; Philip Morris includes Philip Morris/Dubliss; and Lark includes Lark Harmony. | ||||||||||||||
Second-Quarter
PMI's cigarette shipment volume of the following brands decreased:
• | Marlboro, mainly due to Indonesia, Italy, Japan, Mexico, the Philippines and PMI Duty Free, partially offset by the GCC; |
• | L&M, mainly due to Egypt, PMI Duty Free, Poland and Thailand, partly offset by Saudi Arabia and Turkey; |
• | Chesterfield, mainly due to Mexico, Poland, Russia and Turkey, partly offset by Brazil and Saudi Arabia; |
• | Philip Morris, primarily driven by Argentina, Indonesia and Italy; |
• | Parliament, mainly due to PMI Duty Free, Russia and Turkey; |
• | Sampoerna A in Indonesia, mainly due to premium A Mild; |
• | Bond Street, mainly due to Russia and Ukraine; |
• | Dji Sam Soe in Indonesia, mainly due to Dji Sam Soe Magnum Mild; |
• | Lark, mainly due to Japan and Turkey; |
• | Fortune in the Philippines; and |
• | "Others," notably due to: mid-price Sampoerna U in Indonesia and low-price Morven in Pakistan. |
The increase in PMI's heated tobacco unit shipment volume was mainly driven by the EU, Eastern Europe and Japan, partly offset by PMI Duty Free.
International Share of Market
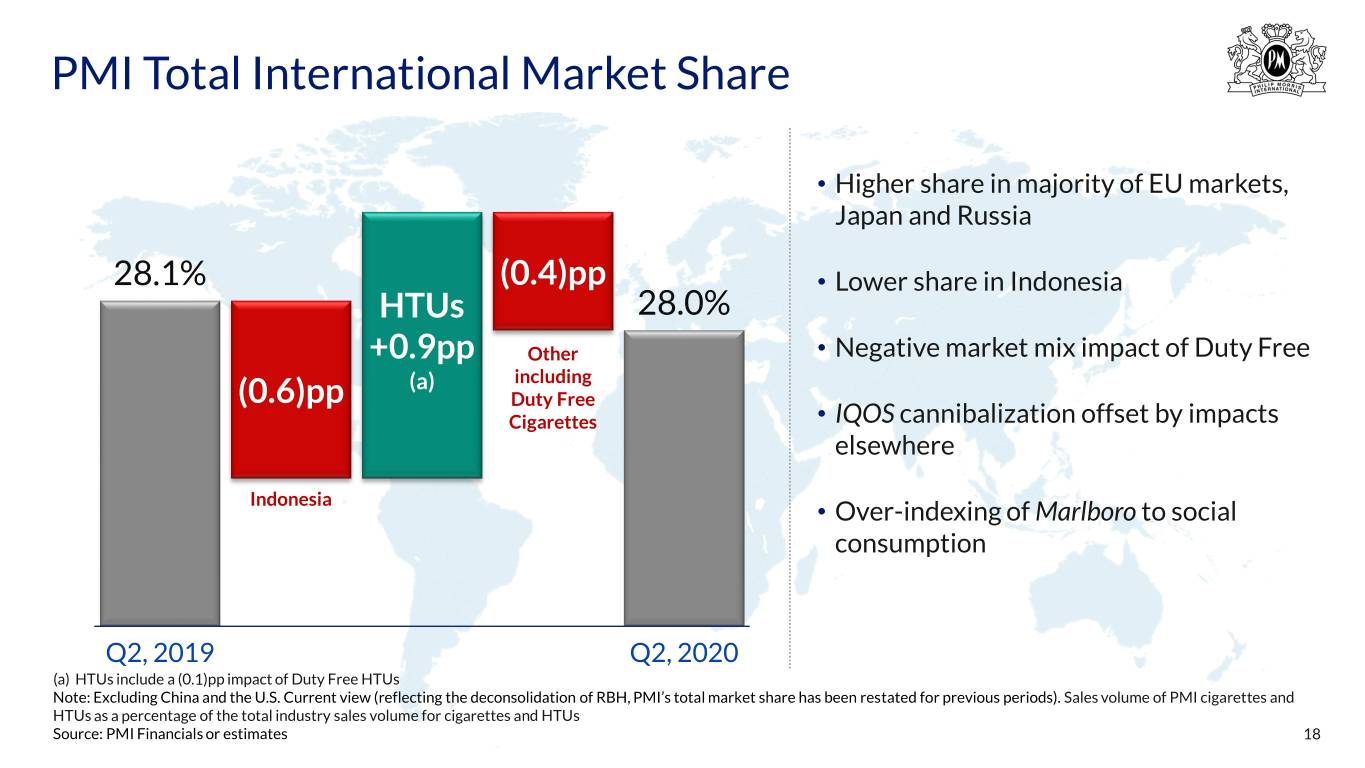
PMI's total international market share (excluding China and the U.S.), defined as PMI's cigarette and heated tobacco unit sales volume as a percentage of total industry cigarette and heated tobacco unit sales volume, decreased by 0.1 point to 28.0%, reflecting:
• | Total international market share for cigarettes of 25.0%, down by 1.0 point; and |
- -8 -
• | Total international market share for heated tobacco units of 3.0%, up by 0.9 points. |
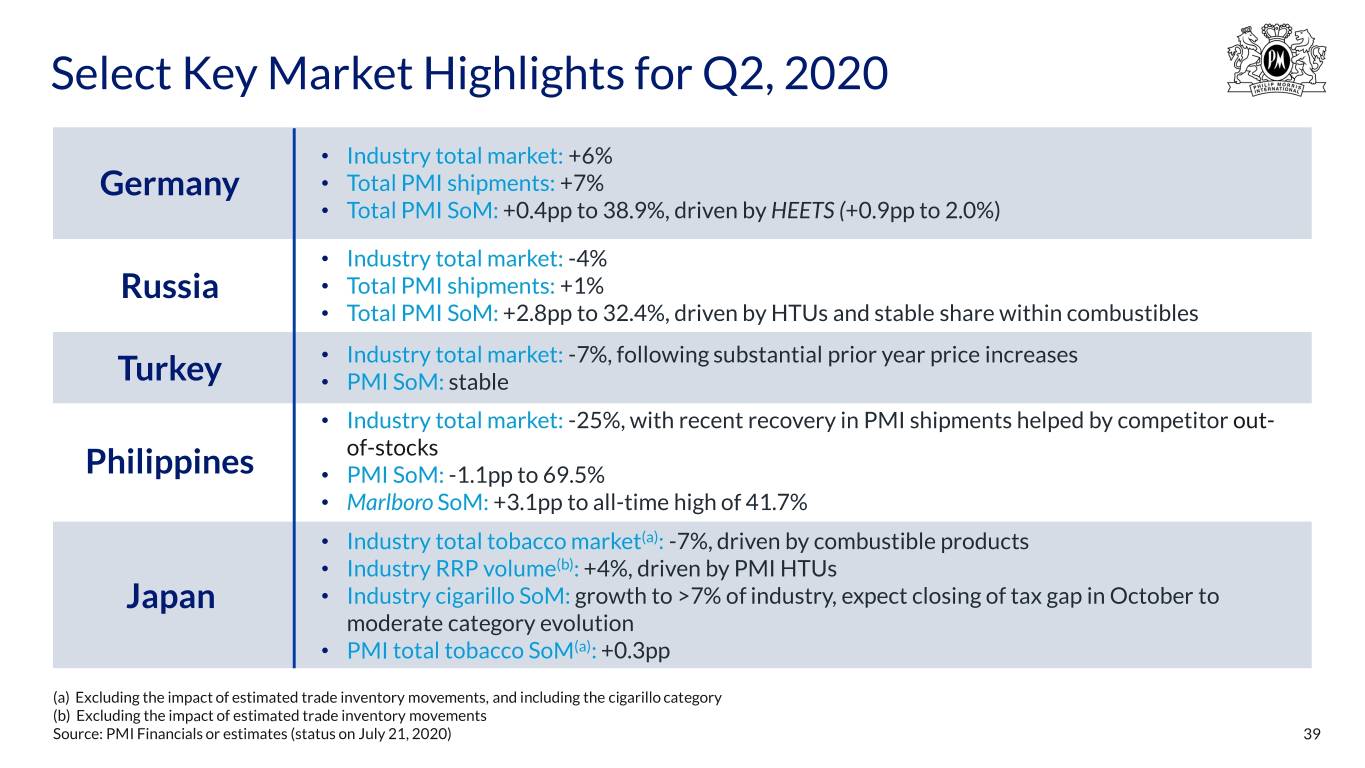
PMI's total international cigarette sales volume as a percentage of total industry cigarette sales volume was down by 0.7 points to 26.0%, mainly reflecting: out-switching to heated tobacco units, as well as lower cigarette market share and/or an unfavorable geographic mix impact, notably in Indonesia, Mexico, Pakistan, the Philippines and PMI Duty Free, partly offset by Germany, Russia and Turkey.
Six Months Year-to-Date
PMI's cigarette shipment volume of the following brands decreased:
• | Marlboro, mainly due to Indonesia, Italy, Mexico, the Philippines, PMI Duty Free, Saudi Arabia, Spain and Turkey, partially offset by Germany, Kuwait, North Africa and Russia; |
• | L&M, notably due to PMI Duty Free, Poland and Thailand, partly offset by Jordan, Mexico and Turkey; |
• | Chesterfield, notably due to Russia and Turkey, partly offset by Brazil and Saudi Arabia; |
• | Philip Morris, notably due to Argentina and Italy, partly offset by Japan, the Philippines and Russia; |
• | Parliament, mainly due to PMI Duty Free, Russia and Turkey; |
• | Sampoerna A in Indonesia, mainly due to premium A Mild; |
• | Bond Street, mainly due to Russia and Ukraine; |
• | Dji Sam Soe in Indonesia, mainly due to Dji Sam Soe Magnum Mild; |
• | Lark, mainly due to Japan and Turkey; |
• | Fortune in the Philippines; and |
• | "Others," notably due to: the impact of the deconsolidation of RBH in Canada; mid-price Sampoerna U in Indonesia and Muratti in Turkey; and low-price Baronet in Mexico and Morven in Pakistan. |
The increase in PMI's heated tobacco unit shipment volume was mainly driven by the EU (notably Italy), Eastern Europe (notably Russia and Ukraine) and Japan, partly offset by PMI Duty Free.
International Share of Market
PMI's total international market share (excluding China and the U.S.), decreased by 0.4 points to 27.7%, reflecting:
• | Total international market share for cigarettes of 24.8%, down by 1.2 points; and |
• | Total international market share for heated tobacco units of 2.9%, up by 0.8 points. |
PMI's total international cigarette sales volume as a percentage of total industry cigarette sales volume was down by 0.9 points to 25.8%, mainly reflecting: out-switching to heated tobacco units, as well as lower cigarette market share and/or an unfavorable geographic mix impact, notably in Indonesia, Mexico, Pakistan, the Philippines, PMI Duty Free and Turkey, partly offset by Germany and Russia.
- -9 -
CONSOLIDATED FINANCIAL SUMMARY
Second-Quarter
Financial Summary - Quarters Ended June 30, | Change Fav./(Unfav.) | Variance Fav./(Unfav.) | |||||||||||||||||||
2020 | 2019 | Total | Excl. Curr. | Total | Cur- rency | Price | Vol/ Mix | Cost/ Other | |||||||||||||
(in millions) | |||||||||||||||||||||
Net Revenues | $ 6,651 | $ 7,699 | (13.6 | )% | (9.5 | )% | (1,048 | ) | (317 | ) | 172 | (904 | ) | 1 | |||||||
Cost of Sales | (2,179) | (2,665) | 18.2 | % | 14.1 | % | 486 | 111 | — | 239 | 136 | ||||||||||
Marketing, Administration and Research Costs (1) | (1,722) | (1,831) | 6.0 | % | 0.4 | % | 109 | 101 | — | — | 8 | ||||||||||
Amortization of Intangibles | (19) | (16) | (18.8 | )% | (25.0 | )% | (3 | ) | 1 | — | — | (4 | ) | ||||||||
Operating Income | $ 2,731 | $ 3,187 | (14.3 | )% | (11.0 | )% | (456 | ) | (104 | ) | 172 | (665 | ) | 141 | |||||||
Asset Impairment & Exit Costs (2) | (71 | ) | (23 | ) | -(100)% | -(100)% | (48 | ) | — | — | — | (48 | ) | ||||||||
Adjusted Operating Income | $ 2,802 | $ 3,210 | (12.7 | )% | (9.5 | )% | (408 | ) | (104 | ) | 172 | (665 | ) | 189 | |||||||
Adjusted Operating Income Margin | 42.1 | % | 41.7 | % | 0.4pp | — | |||||||||||||||
(1) Favorable Cost/Other variance includes the 2019 and 2020 asset impairment and exit costs. | |||||||||||||||||||||
(2) Included in Marketing, Administration and Research Costs above. | |||||||||||||||||||||
Note: Net Revenues include revenues from shipments of Platform 1 devices, heated tobacco units and accessories to Altria Group, Inc., commencing in the third quarter of 2019, for sale under license in the United States. | |||||||||||||||||||||
Net revenues, excluding unfavorable currency, decreased by 9.5%, mainly reflecting: unfavorable volume/mix, primarily due to lower cigarette volume (mainly in Indonesia, Italy, Japan, Mexico, the Philippines, PMI Duty Free and Russia, partly offset by Saudi Arabia), partially offset by higher heated tobacco unit volume (notably in the EU, Japan and Russia, partly offset by PMI Duty Free); partially offset by a favorable pricing variance (notably driven by Germany, Mexico, the Philippines, Russia and Saudi Arabia, partly offset by Indonesia and Turkey).
Operating income, excluding unfavorable currency, decreased by 11.0%, primarily reflecting: unfavorable volume/mix, due to the same factors as for net revenues noted above; partially offset by a favorable pricing variance; lower manufacturing costs (driven by productivity gains related to combustible and reduced-risk products); and lower marketing, administration and research costs (despite pandemic-related expenses in 2020 and the unfavorable net impact of asset impairment and exit costs).
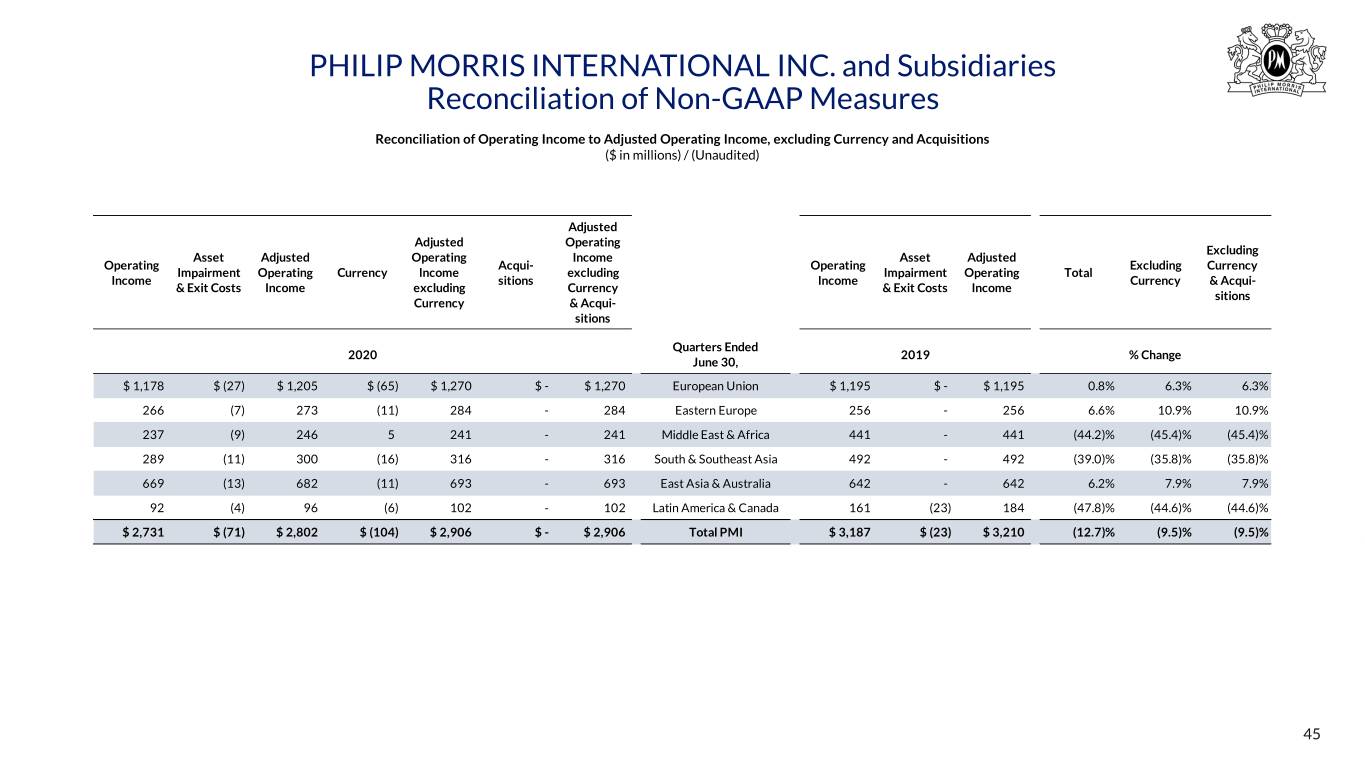
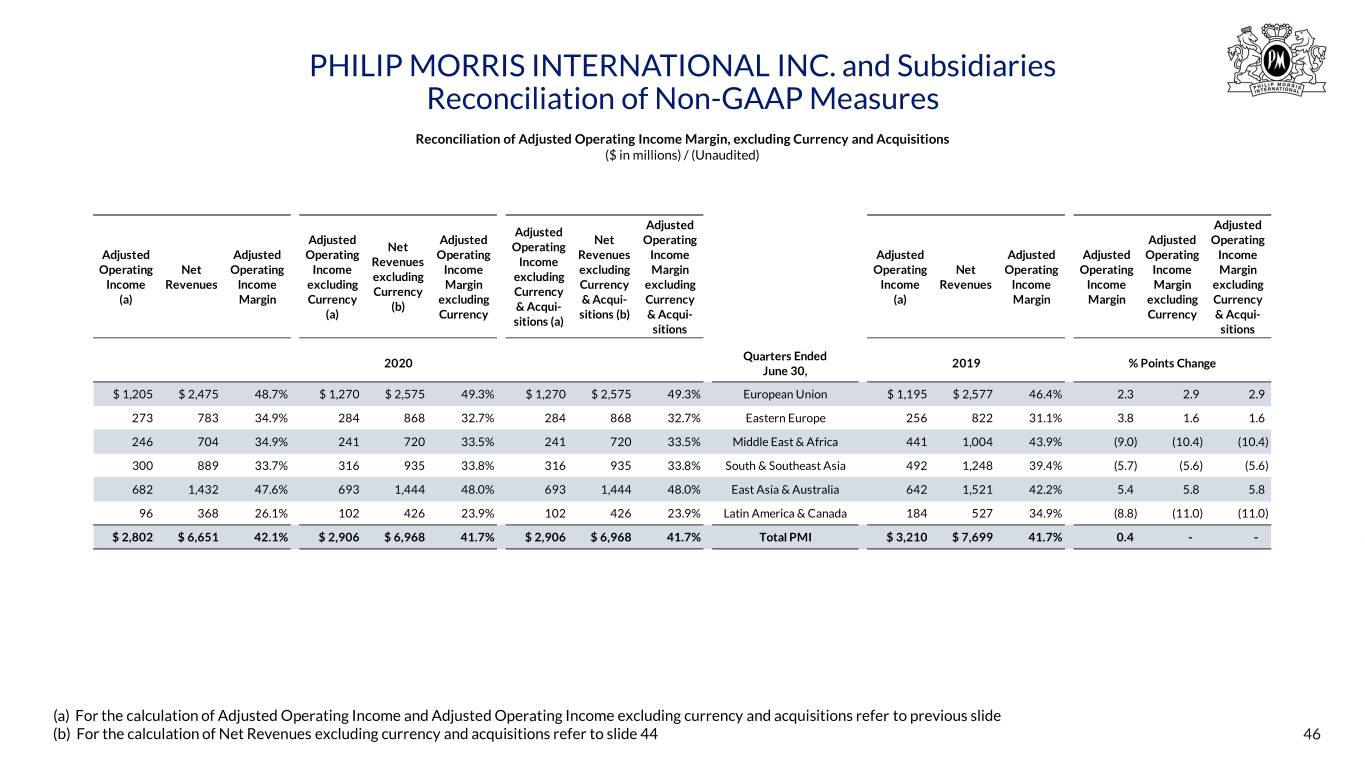
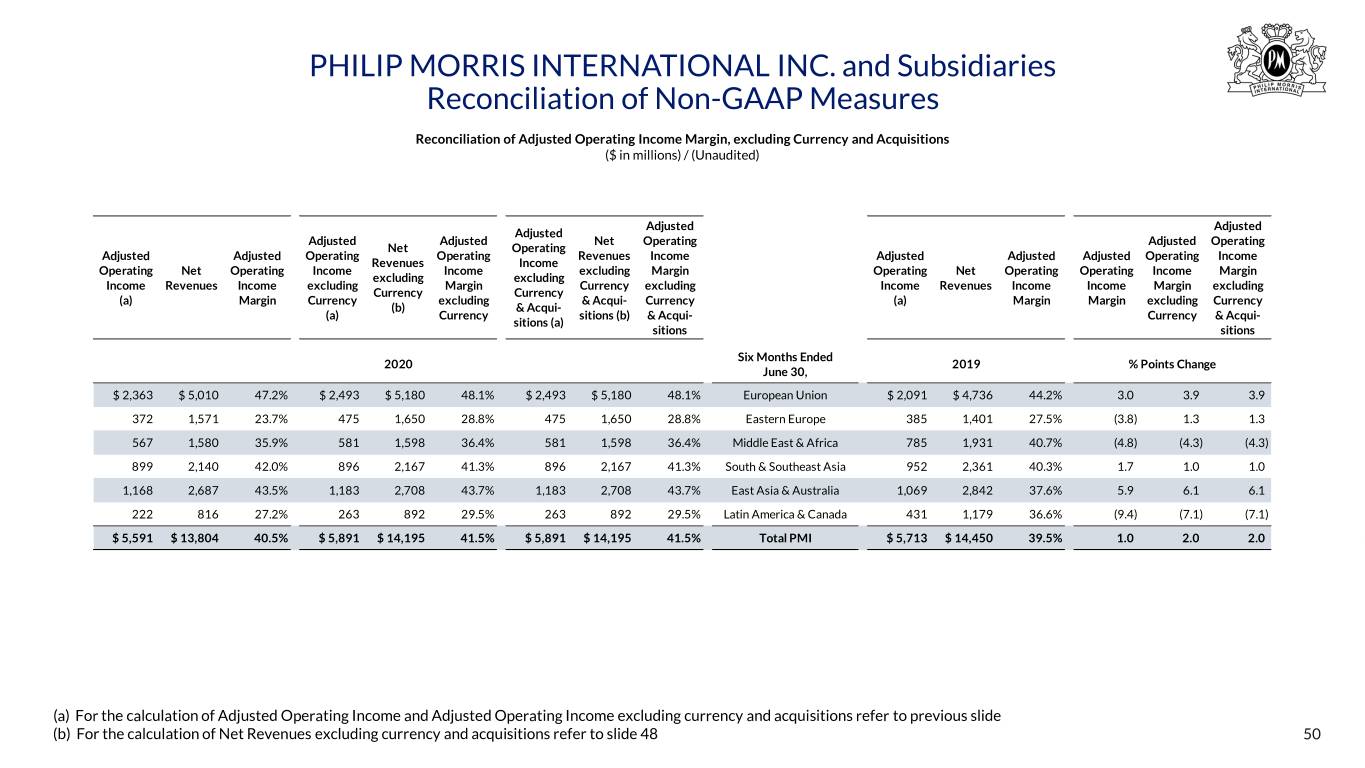
Excluding asset impairment, exit costs and unfavorable currency, adjusted operating income decreased by 9.5%. Adjusted operating income margin, excluding currency, was flat at 41.7%, as detailed in Schedule 8.
- -10 -
Six Months Year-to-Date
Financial Summary - Six Months Ended June 30, | Change Fav./(Unfav.) | Variance Fav./(Unfav.) | |||||||||||||||||||
2020 | 2019 | Total | Excl. Curr. | Total | Cur- rency | Price | Vol/ Mix | Cost/ Other(1) | |||||||||||||
(in millions) | |||||||||||||||||||||
Net Revenues | $ 13,804 | $ 14,450 | (4.5 | )% | (1.8 | )% | (646 | ) | (391 | ) | 495 | (523 | ) | (227 | ) | ||||||
Cost of Sales | (4,581 | ) | (5,130 | ) | 10.7 | % | 7.6 | % | 549 | 160 | — | 268 | 121 | ||||||||
Marketing, Administration and Research Costs (2) | (3,666 | ) | (4,048 | ) | 9.4 | % | 11.2 | % | 382 | (70 | ) | — | — | 452 | |||||||
Amortization of Intangibles | (37 | ) | (35 | ) | (5.7 | )% | (8.6 | )% | (2 | ) | 1 | — | — | (3 | ) | ||||||
Operating Income | $ 5,520 | $ 5,237 | 5.4 | % | 11.1 | % | 283 | (300 | ) | 495 | (255 | ) | 343 | ||||||||
Asset Impairment & Exit Costs (3) | (71 | ) | (43 | ) | (65.1 | )% | (65.1 | )% | (28 | ) | — | — | — | (28 | ) | ||||||
Canadian Tobacco Litigation-Related Expense (3) | — | (194 | ) | +100% | +100% | 194 | — | — | — | 194 | |||||||||||
Loss on Deconsolidation of RBH (3) | — | (239 | ) | +100% | +100% | 239 | — | — | — | 239 | |||||||||||
Adjusted Operating Income | $ 5,591 | $ 5,713 | (2.1 | )% | 3.1 | % | (122 | ) | (300 | ) | 495 | (255 | ) | (62 | ) | ||||||
Adjusted Operating Income Margin | 40.5 | % | 39.5 | % | 1.0pp | 2.0pp | |||||||||||||||
(1) Cost/Other variance includes the impact of the RBH deconsolidation. | |||||||||||||||||||||
(2) Favorable Cost/Other variance includes the 2019 Canadian tobacco litigation-related expense, the 2019 loss on deconsolidation of RBH, the 2019 and 2020 asset impairment and exit costs, and the impact of the RBH deconsolidation. | |||||||||||||||||||||
(3) Included in Marketing, Administration and Research Costs above. | |||||||||||||||||||||
Note: Net Revenues include revenues from shipments of Platform 1 devices, heated tobacco units and accessories to Altria Group, Inc., commencing in the third quarter of 2019, for sale under license in the United States. | |||||||||||||||||||||
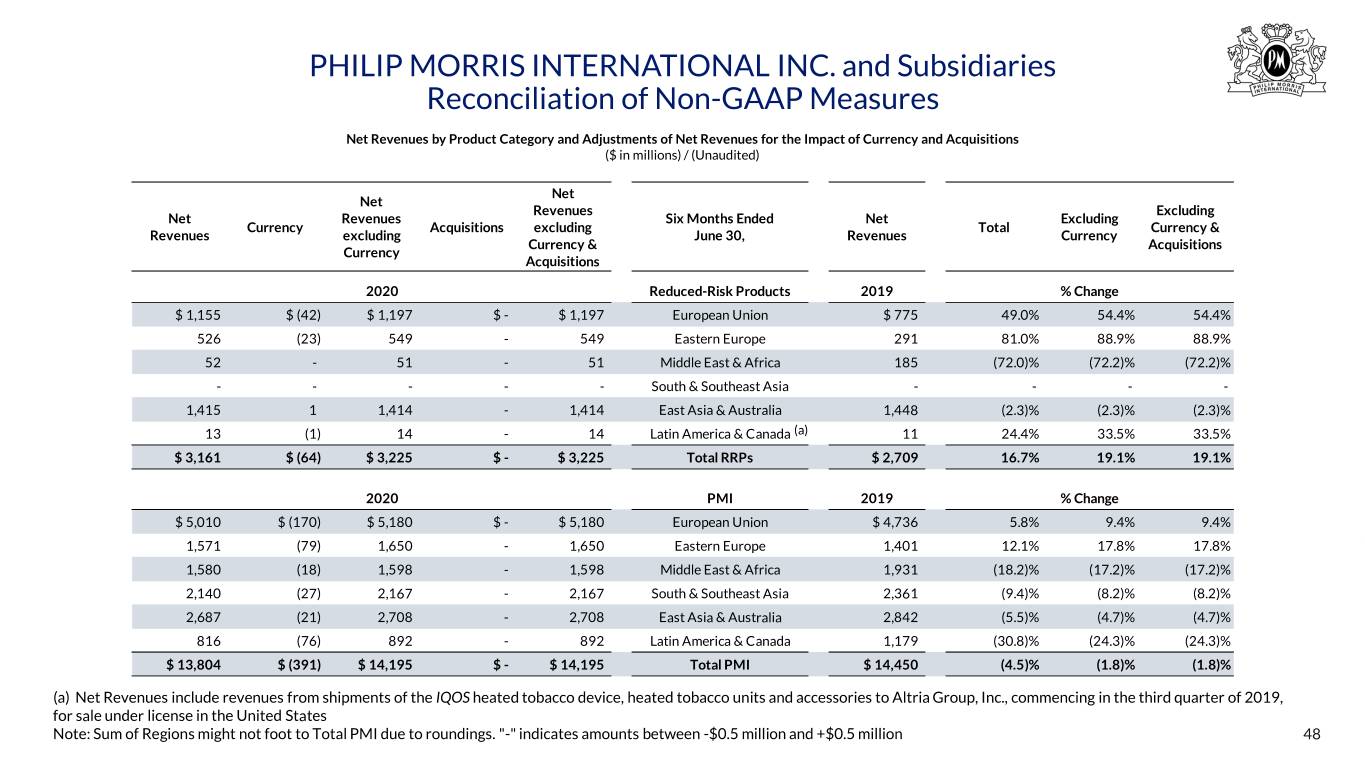
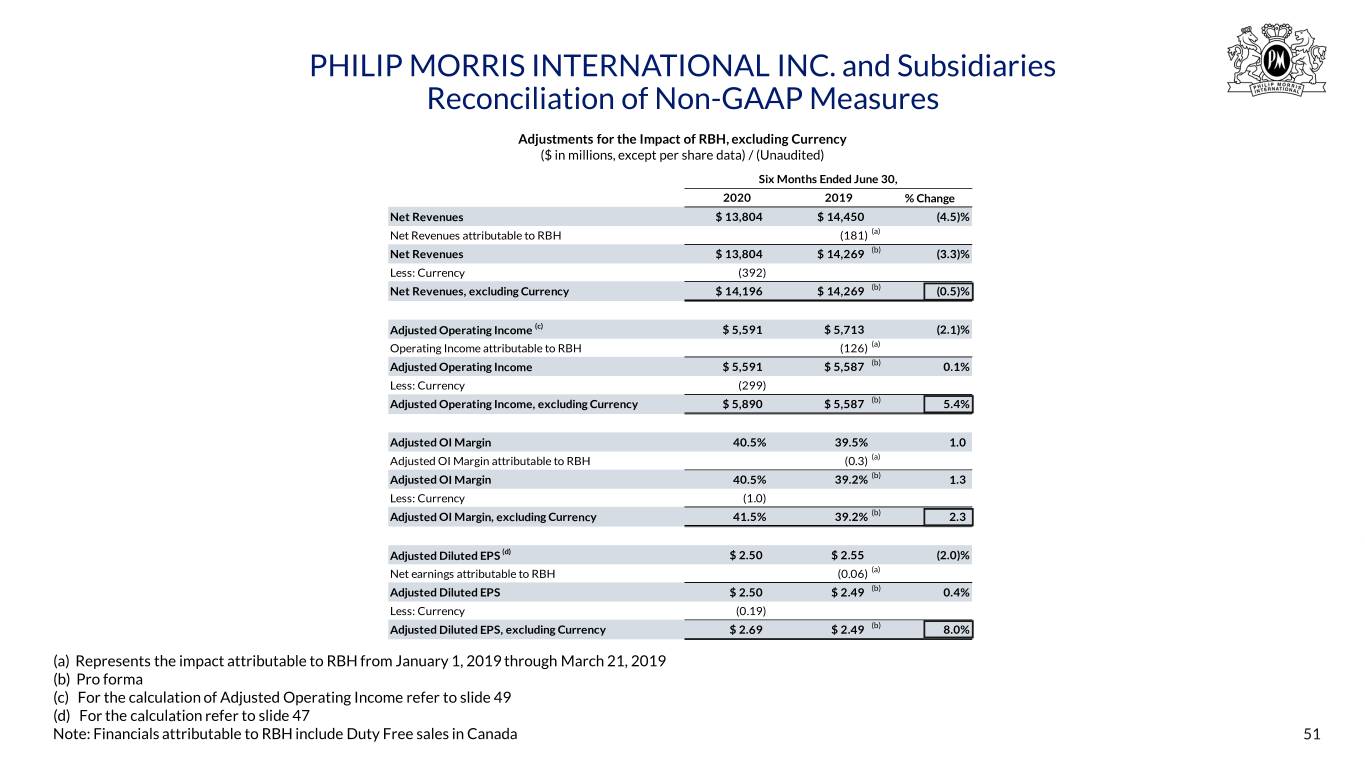
Net revenues, excluding unfavorable currency, decreased by 1.8%, reflecting: unfavorable volume/mix, primarily due to lower cigarette volume (mainly in Australia, Indonesia, Italy, Japan, Mexico, the Philippines, PMI Duty Free, Poland, Spain and Turkey, partly offset by Germany) and lower IQOS device volume (primarily in Japan), partially offset by higher heated tobacco unit volume (notably in the EU, Japan, Russia and Ukraine, partly offset by PMI Duty Free); and the unfavorable impact of $227 million, shown in "Cost/Other," mainly resulting from the deconsolidation of RBH; partly offset by a favorable pricing variance (notably driven by Australia, the GCC, Germany, Mexico, and the Philippines, partially offset by Indonesia). On a like-for-like basis, net revenues, excluding unfavorable currency, decreased by 0.5%, as detailed in Schedule 9.
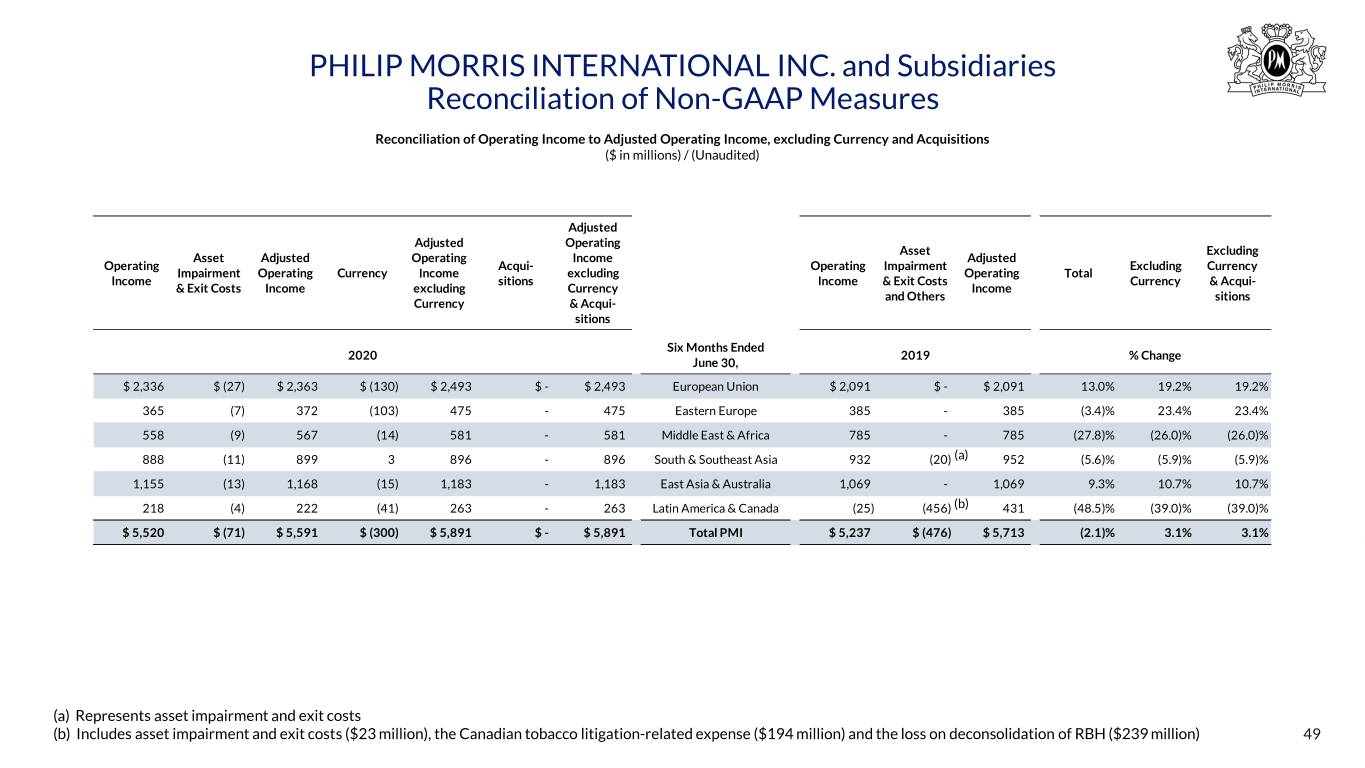
Operating income, excluding unfavorable currency, increased by 11.1%, notably reflecting a favorable comparison, shown in "Cost/Other," of charges recorded in the first half of 2020 of $71 million, related to asset impairment and exit costs associated with organizational design optimization, to charges recorded in the first half of 2019 of $476 million, related to the loss on deconsolidation of RBH, the Canadian tobacco litigation-related expense, and asset impairment and exit costs associated with plant closures in Colombia and Pakistan.
Excluding these charges and unfavorable currency, adjusted operating income increased by 3.1%, primarily reflecting: a favorable pricing variance; lower manufacturing costs (driven by productivity gains related to combustible and reduced-risk products); and lower marketing, administration and research costs (despite pandemic-related expenses in 2020); partially offset by unfavorable volume/mix, mainly due to lower cigarette volume (mainly in Australia, Indonesia, Italy, Japan, Mexico, the Philippines, PMI Duty Free, Poland and Spain, partly offset by
- -11 -
Germany), partly offset by higher heated tobacco unit volume (notably in the EU, Japan, Russia and Ukraine, partly offset by PMI Duty Free); and the net unfavorable impact resulting from the deconsolidation of RBH, included in "Cost/Other." On a like-for-like basis, adjusted operating income, excluding unfavorable currency, increased by 5.4%, as detailed in Schedule 9.
Adjusted operating income margin, excluding currency, increased by 2.0 points to 41.5%, as detailed in Schedule 8, or by 2.3 points to 41.5% on a like-for-like basis, as detailed in Schedule 9.
EUROPEAN UNION REGION
Second-Quarter
Financial Summary - Quarters Ended June 30, | Change Fav./(Unfav.) | Variance Fav./(Unfav.) | |||||||||||||||||||
2020 | 2019 | Total | Excl. Curr. | Total | Cur- rency | Price | Vol/ Mix | Cost/ Other | |||||||||||||
(in millions) | |||||||||||||||||||||
Net Revenues | $ 2,475 | $ 2,577 | (4.0 | )% | (0.1 | )% | (102 | ) | (100 | ) | 44 | (46 | ) | — | |||||||
Operating Income | $ 1,178 | $ 1,195 | (1.4 | )% | 4.0 | % | (17 | ) | (65 | ) | 44 | (2 | ) | 6 | |||||||
Asset Impairment & Exit Costs (1) | (27 | ) | — | — | % | — | % | (27 | ) | — | — | — | (27 | ) | |||||||
Adjusted Operating Income | $ 1,205 | $ 1,195 | 0.8 | % | 6.3 | % | 10 | (65 | ) | 44 | (2 | ) | 33 | ||||||||
Adjusted Operating Income Margin | 48.7 | % | 46.4 | % | 2.3pp | 2.9pp | |||||||||||||||
(1) Included in marketing, administration and research costs at the consolidated operating income level. | |||||||||||||||||||||
Net revenues, excluding unfavorable currency, decreased by 0.1%, reflecting: unfavorable volume/mix, mainly due to lower cigarette volume (notably in Italy, Poland and Spain, partly offset by Germany), partially offset by higher heated tobacco unit volume (notably in Germany, Italy and Poland); largely offset by a favorable pricing variance (driven by higher combustible pricing, notably in Germany, partly offset by lower heated tobacco unit pricing).
Operating income, excluding unfavorable currency, increased by 4.0%, mainly reflecting: a favorable pricing variance; and lower manufacturing costs (notably in Italy); partly offset by higher marketing, administration and research costs (largely related to increased investments behind reduced-risk products, as well as 2020 asset impairment and exit costs).
Excluding asset impairment, exit costs and unfavorable currency, adjusted operating income increased by 6.3%. Adjusted operating income margin, excluding currency, increased by 2.9 points to 49.3%, as detailed in Schedule 8.
- -12 -
Six Months Year-to-Date
Financial Summary - Six Months Ended June 30, | Change Fav./(Unfav.) | Variance Fav./(Unfav.) | |||||||||||||||||||
2020 | 2019 | Total | Excl. Curr. | Total | Cur- rency | Price | Vol/ Mix | Cost/ Other | |||||||||||||
(in millions) | |||||||||||||||||||||
Net Revenues | $ 5,010 | $ 4,736 | 5.8 | % | 9.4 | % | 274 | (170 | ) | 60 | 384 | — | |||||||||
Operating Income | $ 2,336 | $ 2,091 | 11.7 | % | 17.9 | % | 245 | (130 | ) | 60 | 376 | (61 | ) | ||||||||
Asset Impairment & Exit Costs (1) | (27 | ) | — | — | % | — | % | (27 | ) | — | — | — | (27 | ) | |||||||
Adjusted Operating Income | $ 2,363 | $ 2,091 | 13.0 | % | 19.2 | % | 272 | (130 | ) | 60 | 376 | (34 | ) | ||||||||
Adjusted Operating Income Margin | 47.2 | % | 44.2 | % | 3.0pp | 3.9pp | |||||||||||||||
(1) Included in marketing, administration and research costs at the consolidated operating income level. | |||||||||||||||||||||
Net revenues, excluding unfavorable currency, increased by 9.4%, reflecting: favorable volume/mix, mainly driven by higher heated tobacco unit volume across the Region (notably in Germany, Italy and Poland), partly offset by lower cigarette volume (notably in Italy, Poland and Spain, partly offset by Germany); and a favorable pricing variance (driven by higher combustible pricing across the Region, notably in Germany, partly offset by lower heated tobacco unit and IQOS device pricing).
Operating income, excluding unfavorable currency, increased by 17.9%, mainly reflecting: favorable volume/mix, driven by the same factors as for net revenues noted above; a favorable pricing variance; and lower manufacturing costs (notably in Germany and Italy); partly offset by higher marketing, administration and research costs (largely related to increased investments behind reduced-risk products, notably in Poland, as well as 2020 asset impairment and exit costs).
Excluding asset impairment, exit costs and unfavorable currency, adjusted operating income increased by 19.2%. Adjusted operating income margin, excluding currency, increased by 3.9 points to 48.1%, as detailed in Schedule 8.
- -13 -
Total Market, PMI Shipment & Market Share Commentaries
European Union Key Data | Second-Quarter | Six Months Year-to-Date | ||||||||||||
Change | Change | |||||||||||||
2020 | 2019 | % / pp | 2020 | 2019 | % / pp | |||||||||
Total Market (billion units) | 115.5 | 124.5 | (7.3 | )% | 224.6 | 231.8 | (3.1 | )% | ||||||
PMI Shipment Volume (million units) | ||||||||||||||
Cigarettes | 40,317 | 46,367 | (13.0 | )% | 80,963 | 85,855 | (5.7 | )% | ||||||
Heated Tobacco Units | 4,227 | 3,043 | 38.9 | % | 8,888 | 5,336 | 66.6 | % | ||||||
Total EU | 44,544 | 49,410 | (9.8 | )% | 89,851 | 91,191 | (1.5 | )% | ||||||
PMI Market Share | ||||||||||||||
Marlboro | 17.8 | % | 18.0 | % | (0.2 | ) | 17.7 | % | 18.1 | % | (0.4 | ) | ||
L&M | 6.5 | % | 6.9 | % | (0.4 | ) | 6.5 | % | 6.8 | % | (0.3 | ) | ||
Chesterfield | 5.6 | % | 5.8 | % | (0.2 | ) | 5.6 | % | 5.9 | % | (0.3 | ) | ||
Philip Morris | 2.6 | % | 2.7 | % | (0.1 | ) | 2.6 | % | 2.8 | % | (0.2 | ) | ||
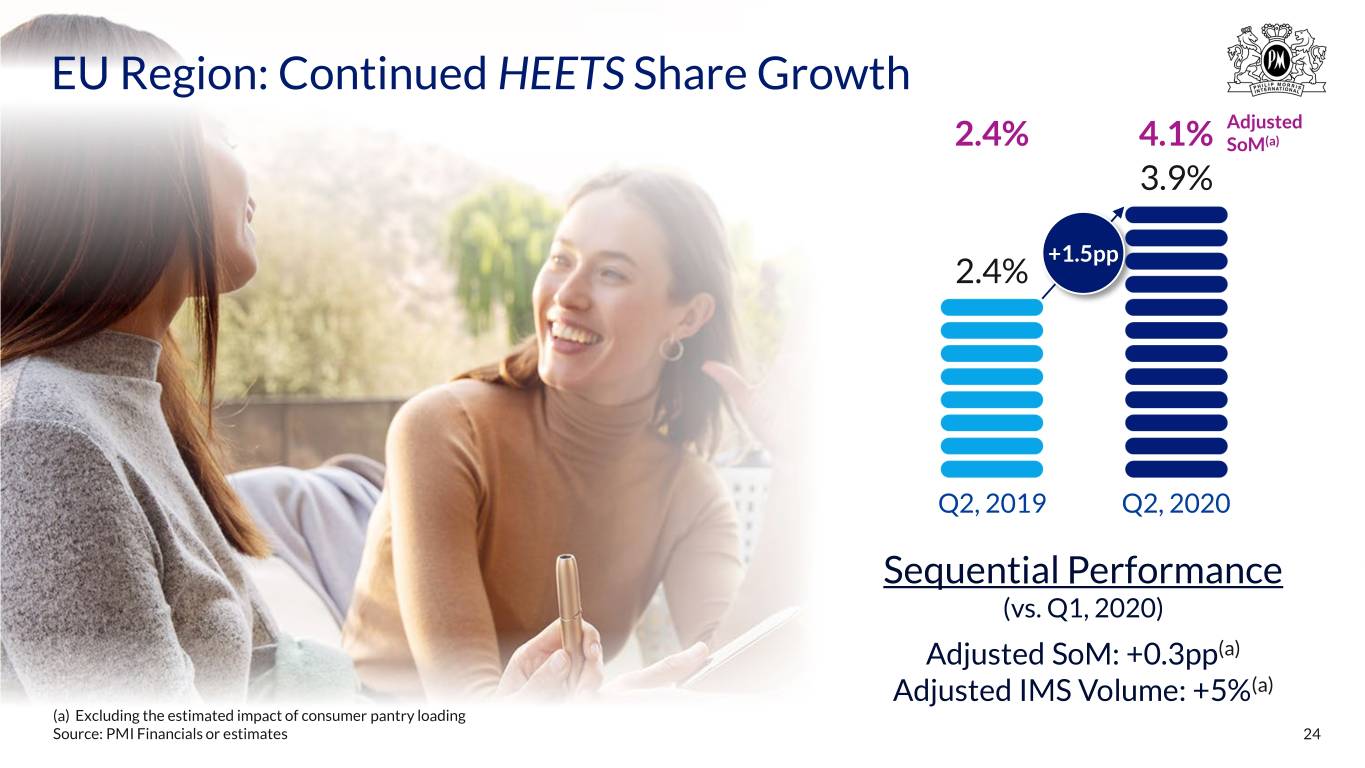
HEETS | 3.9 | % | 2.4 | % | 1.5 | 3.9 | % | 2.3 | % | 1.6 | ||||
Others | 3.0 | % | 3.0 | % | — | 3.1 | % | 3.0 | % | 0.1 | ||||
Total EU | 39.4 | % | 38.8 | % | 0.6 | 39.4 | % | 38.9 | % | 0.5 | ||||
Second-Quarter
The estimated total market in the EU decreased by 7.3% to 115.5 billion units, mainly driven by:
• | Czech Republic, down by 16.7%, mainly reflecting lower border sales due to lockdown measures; |
• | Denmark, down by 78.5%, mainly reflecting the net unfavorable impact of estimated trade inventory movements related to a significant excise tax increase on April 1, 2020. Excluding these movements, the total estimated market increased by 0.3%; |
• | Poland, down by 13.6%, notably reflecting lower border sales due to lockdown measures, as well as the impact of price increases in the first quarter of 2020; |
• | Romania, down by 16.6%, mainly reflecting the impact of lockdown measures; and |
• | Spain, down by 17.2%, mainly reflecting lower in-bound tourism and border sales due to lockdown measures; |
partly offset by
• | Germany, up by 5.9%, or by 4.2% excluding the net favorable impact of estimated trade inventory movements, primarily reflecting the favorable impact of reduced out-bound tourism and lower cross-border (non-domestic) purchases due to lockdown measures, partly offset by the impact of price increases in April and May 2020. |
PMI's total shipment volume decreased by 9.8% to 44.5 billion units, reflecting:
• | lower cigarette shipment volume, mainly due to the lower total market, lower market share (notably in Italy and Poland, partly reflecting out-switching to heated tobacco units) and the net unfavorable impact of estimated distributor inventory movements (partially due to distributor inventory decreases, following increases in the first quarter related to COVID-19, notably in Italy and Spain); |
partly offset by
- -14 -
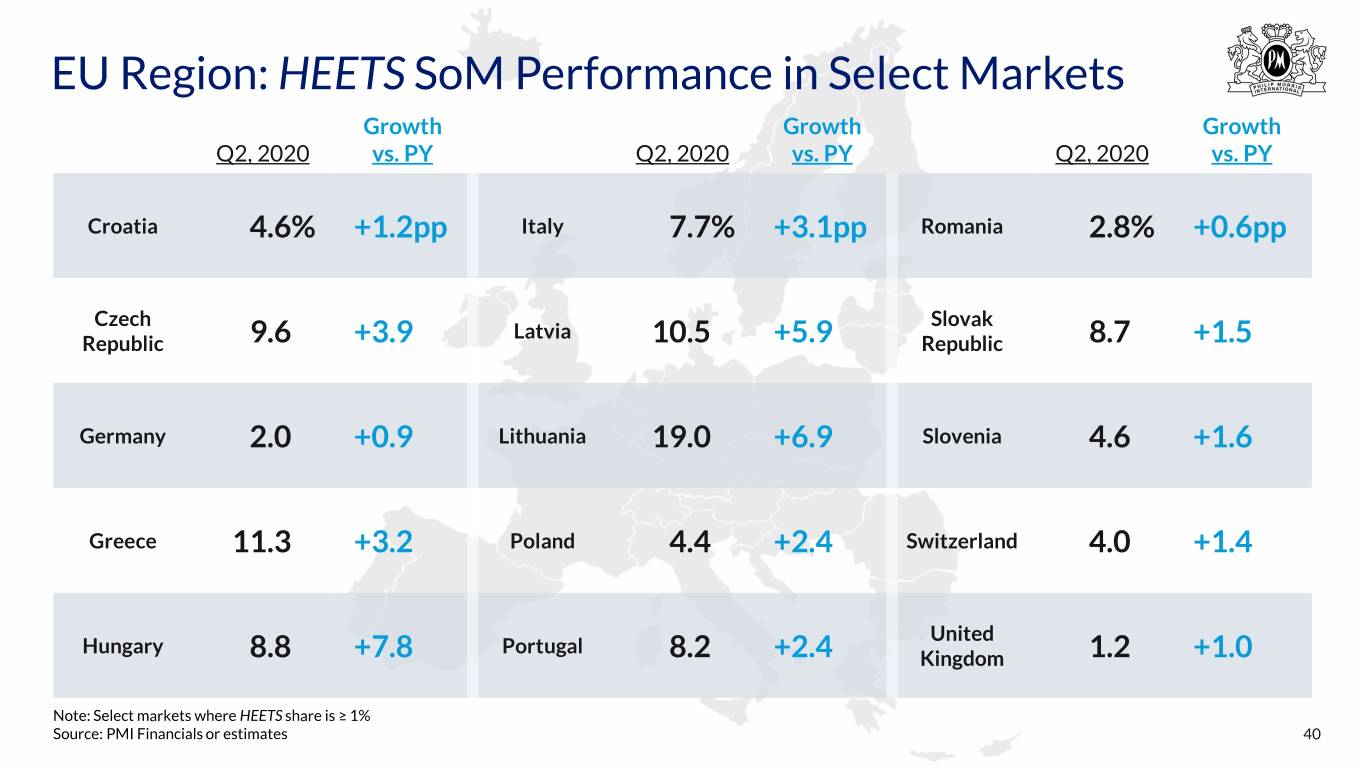
• | higher heated tobacco unit shipment volume, driven by higher market share (notably in Germany, Italy and Poland). |
Excluding the net unfavorable impact of estimated distributor inventory movements, PMI's total in-market sales in the Region decreased by 6.0%.
Six Months Year-to-Date
The estimated total market in the EU decreased by 3.1% to 224.6 billion units, notably due to:
• | Czech Republic, down by 11.5%, primarily reflecting the same factor as in the quarter; |
• | Poland, down by 6.4%, mainly reflecting the same factors as in the quarter; |
• | Romania, down by 8.7%, primarily reflecting the same factor as in the quarter; and |
• | Spain, down by 8.2%, mainly reflecting the same factors as in the quarter; |
partly offset by
• | Germany, up by 4.9%, or by 2.3% excluding the net favorable impact of estimated trade inventory movements, primarily reflecting the same factors as in the quarter. |
PMI's total shipment volume decreased by 1.5% to 89.9 billion units, reflecting:
• | lower cigarette shipment volume, mainly due to the lower total market, as well as lower cigarette market share (notably in Italy and Poland, partly reflecting out-switching to heated tobacco units); |
partly offset by
• | higher heated tobacco unit shipment volume across the Region (notably in Germany, Italy and Poland), driven by higher market share. |
EASTERN EUROPE REGION
Second-Quarter
Financial Summary - Quarters Ended June 30, | Change Fav./(Unfav.) | Variance Fav./(Unfav.) | |||||||||||||||||||
2020 | 2019 | Total | Excl. Curr. | Total | Cur- rency | Price | Vol/ Mix | Cost/ Other | |||||||||||||
(in millions) | |||||||||||||||||||||
Net Revenues | $ 783 | $ 822 | (4.7 | )% | 5.6 | % | (39 | ) | (85 | ) | 27 | 19 | — | ||||||||
Operating Income | $ 266 | $ 256 | 3.9 | % | 8.2 | % | 10 | (11 | ) | 27 | 10 | (16 | ) | ||||||||
Asset Impairment & Exit Costs (1) | (7 | ) | — | — | % | — | % | (7 | ) | — | — | — | (7 | ) | |||||||
Adjusted Operating Income | $ 273 | $ 256 | 6.6 | % | 10.9 | % | 17 | (11 | ) | 27 | 10 | (9 | ) | ||||||||
Adjusted Operating Income Margin | 34.9 | % | 31.1 | % | 3.8pp | 1.6pp | |||||||||||||||
(1) Included in marketing, administration and research costs at the consolidated operating income level. | |||||||||||||||||||||
Net revenues, excluding unfavorable currency, increased by 5.6%, reflecting: a favorable pricing variance, driven by higher combustible pricing (predominantly in Russia), partly offset by lower IQOS device pricing (mainly in Russia); and favorable volume/mix, driven by higher heated tobacco unit volume across the Region (primarily in Russia and Ukraine), partly offset by lower cigarette volume (mainly in Russia and Ukraine) and unfavorable cigarette mix in Russia.
- -15 -
Operating income, excluding unfavorable currency, increased by 8.2%, mainly reflecting: a favorable pricing variance; favorable volume/mix, reflecting the same drivers as for net revenues noted above; and lower manufacturing costs; partially offset by higher marketing, administration and research costs (largely related to increased investments behind reduced-risk products, notably in Russia).
Excluding asset impairment, exit costs and unfavorable currency, adjusted operating income increased by 10.9%. Adjusted operating income margin, excluding currency, increased by 1.6 points to 32.7%, as detailed in Schedule 8.
Six Months Year-to-Date
Financial Summary - Six Months Ended June 30, | Change Fav./(Unfav.) | Variance Fav./(Unfav.) | |||||||||||||||||||
2020 | 2019 | Total | Excl. Curr. | Total | Cur- rency | Price | Vol/ Mix | Cost/ Other | |||||||||||||
(in millions) | |||||||||||||||||||||
Net Revenues | $ 1,571 | $ 1,401 | 12.1 | % | 17.8 | % | 170 | (79 | ) | 41 | 208 | — | |||||||||
Operating Income | $ 365 | $ 385 | (5.2 | )% | 21.6 | % | (20 | ) | (103 | ) | 41 | 139 | (97 | ) | |||||||
Asset Impairment & Exit Costs (1) | (7 | ) | — | — | % | — | % | (7 | ) | — | — | — | (7 | ) | |||||||
Adjusted Operating Income | $ 372 | $ 385 | (3.4 | )% | 23.4 | % | (13 | ) | (103 | ) | 41 | 139 | (90 | ) | |||||||
Adjusted Operating Income Margin | 23.7 | % | 27.5 | % | (3.8)pp | 1.3pp | |||||||||||||||
(1) Included in marketing, administration and research costs at the consolidated operating income level. | |||||||||||||||||||||
Net revenues, excluding unfavorable currency, increased by 17.8%, reflecting: favorable volume/mix, predominantly driven by higher heated tobacco unit volume in Russia and Ukraine, partly offset by unfavorable cigarette volume/mix in Russia and lower cigarette volume in Ukraine; and a favorable pricing variance, driven by higher combustible pricing (primarily in Russia), partly offset by lower IQOS device pricing (mainly in Russia).
Operating income, excluding unfavorable currency, increased by 21.6%, mainly reflecting: favorable volume/mix, reflecting the same drivers as for net revenues noted above; and a favorable pricing variance; partly offset by higher manufacturing costs due to Russia; and higher marketing, administration and research costs (primarily related to increased investments behind reduced-risk products, notably in Russia and Ukraine).
Excluding asset impairment, exit costs and unfavorable currency, adjusted operating income increased by 23.4%. Adjusted operating income margin, excluding currency, increased by 1.3 points to 28.8%, as detailed in Schedule 8.
Total Market, PMI Shipment & Market Share Commentaries
PMI Shipment Volume | Second-Quarter | Six Months Year-to-Date | ||||||||||||
(million units) | 2020 | 2019 | Change | 2020 | 2019 | Change | ||||||||
Cigarettes | 23,657 | 27,080 | (12.6 | )% | 45,076 | 47,400 | (4.9 | )% | ||||||
Heated Tobacco Units | 5,126 | 2,807 | 82.6 | % | 9,492 | 4,355 | +100% | |||||||
Total Eastern Europe | 28,783 | 29,887 | (3.7 | )% | 54,568 | 51,755 | 5.4 | % | ||||||
- -16 -
Second-Quarter
The estimated total market in Eastern Europe decreased, notably due to:
• | Russia, down by 4.1%, or by 6.6% excluding the net favorable impact of estimated trade inventory movements, primarily reflecting the impact of price increases, partly offset by the impact of a decrease in the prevalence of illicit trade due to lockdown measures; and |
• | Ukraine, down by 15.0%, mainly reflecting the impact of excise tax-driven price increases and reduced adult smoker average daily consumption due to lockdown measures. |
PMI's total shipment volume decreased by 3.7% to 28.8 billion units, mainly due to:
• | Ukraine, down by 14.7%, or by 11.1% excluding the net unfavorable impact of estimated distributor inventory movements, mainly reflecting the lower total market, partly offset by a higher market share, driven by heated tobacco units. |
Six Months Year-to-Date
The estimated total market in Eastern Europe decreased, notably due to:
• | Russia, down by 2.1%, or by 6.4% excluding the net favorable impact of estimated trade inventory movements, primarily reflecting the same factors as in the quarter; and |
• | Ukraine, down by 10.9%, mainly reflecting the same factors as in the quarter. |
PMI's total shipment volume increased by 5.4% to 54.6 billion units, mainly due to:
• | Russia, up by 10.3%, primarily reflecting a higher market share, driven by heated tobacco units, partly offset by the lower total market; |
partly offset by
• | Ukraine, down by 5.7%, mainly due to the same factors as in the quarter. |
MIDDLE EAST & AFRICA REGION
Second-Quarter
Financial Summary - Quarters Ended June 30, | Change Fav./(Unfav.) | Variance Fav./(Unfav.) | |||||||||||||||||||
2020 | 2019 | Total | Excl. Curr. | Total | Cur- rency | Price | Vol/ Mix | Cost/ Other | |||||||||||||
(in millions) | |||||||||||||||||||||
Net Revenues | $ 704 | $ 1,004 | (29.9 | )% | (28.3 | )% | (300 | ) | (16 | ) | 45 | (335 | ) | 6 | |||||||
Operating Income | $ 237 | $ 441 | (46.3 | )% | (47.4 | )% | (204 | ) | 5 | 45 | (264 | ) | 10 | ||||||||
Asset Impairment & Exit Costs (1) | (9 | ) | — | — | % | — | % | (9 | ) | — | — | — | (9 | ) | |||||||
Adjusted Operating Income | $ 246 | $ 441 | (44.2 | )% | (45.4 | )% | (195 | ) | 5 | 45 | (264 | ) | 19 | ||||||||
Adjusted Operating Income Margin | 34.9 | % | 43.9 | % | (9.0)pp | (10.4)pp | |||||||||||||||
(1) Included in marketing, administration and research costs at the consolidated operating income level. | |||||||||||||||||||||
- -17 -
Net revenues, excluding unfavorable currency, decreased by 28.3%, primarily reflecting: unfavorable volume/mix, mainly due to lower cigarette volume (predominantly in North Africa, PMI Duty Free and South Africa, partly offset by Saudi Arabia) and lower heated tobacco unit volume in PMI Duty Free; partially offset by a favorable pricing variance, driven mainly by combustible pricing in Saudi Arabia, partly offset by Turkey.
Operating income, excluding favorable currency, decreased by 47.4%, mainly reflecting: unfavorable volume/mix, due to the same factors as for net revenues noted above; partly offset by a favorable pricing variance.
Excluding asset impairment, exit costs and favorable currency, adjusted operating income decreased by 45.4%. Adjusted operating income margin, excluding currency, decreased by 10.4 points to 33.5%, as detailed in Schedule 8.
Six Months Year-to-Date
Financial Summary - Six Months Ended June 30, | Change Fav./(Unfav.) | Variance Fav./(Unfav.) | |||||||||||||||||||
2020 | 2019 | Total | Excl. Curr. | Total | Cur- rency | Price | Vol/ Mix | Cost/ Other | |||||||||||||
(in millions) | |||||||||||||||||||||
Net Revenues | $ 1,580 | $ 1,931 | (18.2 | )% | (17.2 | )% | (351 | ) | (18 | ) | 117 | (411 | ) | (39 | ) | ||||||
Operating Income | $ 558 | $ 785 | (28.9 | )% | (27.1 | )% | (227 | ) | (14 | ) | 117 | (294 | ) | (36 | ) | ||||||
Asset Impairment & Exit Costs (1) | (9 | ) | — | — | % | — | % | (9 | ) | — | — | — | (9 | ) | |||||||
Adjusted Operating Income | $ 567 | $ 785 | (27.8 | )% | (26.0 | )% | (218 | ) | (14 | ) | 117 | (294 | ) | (27 | ) | ||||||
Adjusted Operating Income Margin | 35.9 | % | 40.7 | % | (4.8)pp | (4.3)pp | |||||||||||||||
(1) Included in marketing, administration and research costs at the consolidated operating income level. | |||||||||||||||||||||
Net revenues, excluding unfavorable currency, decreased by 17.2%, reflecting: unfavorable volume/mix, mainly due lower cigarette volume (mainly in PMI Duty Free and Turkey, partly offset by Kuwait) and lower heated tobacco unit volume in PMI Duty Free; and lower fees for certain distribution rights billed to customers in certain markets, shown in "Cost/Other"; partially offset by a favorable pricing variance, driven by combustible pricing (mainly in the GCC, particularly Saudi Arabia).
Operating income, excluding unfavorable currency, decreased by 27.1%, mainly reflecting: unfavorable volume/mix, predominantly due to lower cigarette and heated tobacco unit volume in PMI Duty Free; and unfavorable "Cost/Other," mainly due to lower fees for certain distribution rights, as noted above for net revenues; partially offset by a favorable pricing variance.
Excluding asset impairment, exit costs and unfavorable currency, adjusted operating income decreased by 26.0%. Adjusted operating income margin, excluding currency, decreased by 4.3 points to 36.4%, as detailed in Schedule 8.
- -18 -
Total Market, PMI Shipment & Market Share Commentaries
PMI Shipment Volume | Second-Quarter | Six Months Year-to-Date | ||||||||||||
(million units) | 2020 | 2019 | Change | 2020 | 2019 | Change | ||||||||
Cigarettes | 27,188 | 31,659 | (14.1 | )% | 57,184 | 64,963 | (12.0 | )% | ||||||
Heated Tobacco Units | 185 | 719 | (74.3 | )% | 655 | 1,473 | (55.5 | )% | ||||||
Total Middle East & Africa | 27,373 | 32,378 | (15.5 | )% | 57,839 | 66,436 | (12.9 | )% | ||||||
Second-Quarter
The estimated total market in the Middle East & Africa decreased, mainly due to:
• | Egypt, down by 19.6%, notably reflecting pandemic-related supply-chain shortages involving competitors' products and reductions in adult smoker average daily consumption during lockdown; |
• | International Duty Free, down by 82.9%, reflecting the impact of government travel restrictions and reduced passenger traffic due to the pandemic; |
• | South Africa, down by 100%, reflecting the impact of the pandemic-related ban on all tobacco sales effective March 27, 2020; and |
• | Turkey, down by 6.8%, or by 16.9% excluding the net favorable impact of estimated trade inventory movements, mainly reflecting the impact of lockdown measures on adult smoker average daily consumption, as well as a higher prevalence of illicit trade related to cut tobacco following significant industry-wide price increases in 2019. |
PMI's total shipment volume decreased by 15.5% to 27.4 billion units, notably due to:
• | Egypt, down by 15.6%, or by 12.1% excluding the net unfavorable impact of estimated distributor inventory movements, mainly reflecting the lower total market, partly offset by a higher market share, primarily driven by the impact of supply chain shortages for competitors' products; |
• | PMI Duty Free, down by 94.4%, or by 82.1% excluding the net unfavorable impact of estimated distributor inventory movements (driven by cigarettes), mainly reflecting the lower total market; and |
• | Turkey, down by 6.6%, mainly reflecting the lower total market; |
partly offset by
• | Saudi Arabia, up by +100%. Excluding the net favorable impact of estimated distributor inventory movements of 1.7 billion cigarettes, largely attributable to the timing of shipments in 2019, PMI's in-market sales increased by 11.2%, mainly driven by the reduced prevalence of non-domestic products and the shift from duty-free to domestic sales due to the impact of pandemic-related government travel restrictions and reduced passenger traffic. |
Six Months Year-to-Date
The estimated total market in the Middle East & Africa decreased, mainly due to:
• | Egypt, down by 6.9%, notably reflecting the same factors as in the quarter; |
• | International Duty Free, down by 57.8%, reflecting the same factors as in the quarter; |
• | South Africa, down by 50.8%, primarily reflecting the same factor as in the quarter; and |
• | Turkey, down by 9.3%, mainly reflecting the same factors as in the quarter. |
- -19 -
PMI's total shipment volume decreased by 12.9% to 57.8 billion units, notably due to:
• | PMI Duty Free, down by 55.9%, mainly reflecting the lower total market; and |
• | Turkey, down by 17.4%, mainly reflecting the lower total market and lower market share, due primarily to adult smoker down-trading following the 2019 price increases. |
SOUTH & SOUTHEAST ASIA REGION
Second-Quarter
Financial Summary - Quarters Ended June 30, | Change Fav./(Unfav.) | Variance Fav./(Unfav.) | |||||||||||||||||||
2020 | 2019 | Total | Excl. Curr. | Total | Cur- rency | Price | Vol/ Mix | Cost/ Other | |||||||||||||
(in millions) | |||||||||||||||||||||
Net Revenues | $ 889 | $ 1,248 | (28.8 | )% | (25.1 | )% | (359 | ) | (46 | ) | (15 | ) | (298 | ) | — | ||||||
Operating Income | $ 289 | $ 492 | (41.3 | )% | (38.0 | )% | (203 | ) | (16 | ) | (15 | ) | (218 | ) | 46 | ||||||
Asset Impairment & Exit Costs (1) | (11 | ) | — | — | % | — | % | (11 | ) | — | — | — | (11 | ) | |||||||
Adjusted Operating Income | $ 300 | $ 492 | (39.0 | )% | (35.8 | )% | (192 | ) | (16 | ) | (15 | ) | (218 | ) | 57 | ||||||
Adjusted Operating Income Margin | 33.7 | % | 39.4 | % | (5.7)pp | (5.6)pp | |||||||||||||||
(1) Included in marketing, administration and research costs at the consolidated operating income level. | |||||||||||||||||||||
Net revenues, excluding unfavorable currency, decreased by 25.1%, reflecting: unfavorable volume/mix, mainly due to lower cigarette volume in Indonesia and the Philippines, partly offset by favorable mix in Indonesia; and an unfavorable pricing variance, principally in Indonesia, partly offset by the Philippines.
Operating income, excluding unfavorable currency, decreased by 38.0%, primarily reflecting: unfavorable volume/mix, due to the same factors as for net revenues noted above; and an unfavorable pricing variance; partly offset by lower marketing, administration and research costs; and lower manufacturing costs (mainly in Indonesia).
Excluding asset impairment, exit costs and unfavorable currency, adjusted operating income decreased by 35.8%. Adjusted operating income margin, excluding currency, decreased by 5.6 points to 33.8%, as detailed in Schedule 8.
Six Months Year-to-Date
Financial Summary - Six Months Ended June 30, | Change Fav./(Unfav.) | Variance Fav./(Unfav.) | |||||||||||||||||||
2020 | 2019 | Total | Excl. Curr. | Total | Cur- rency | Price | Vol/ Mix | Cost/ Other | |||||||||||||
(in millions) | |||||||||||||||||||||
Net Revenues | $ 2,140 | $ 2,361 | (9.4 | )% | (8.2 | )% | (221 | ) | (27 | ) | 144 | (338 | ) | — | |||||||
Operating Income | $ 888 | $ 932 | (4.7 | )% | (5.0 | )% | (44 | ) | 3 | 144 | (236 | ) | 45 | ||||||||
Asset Impairment & Exit Costs (1) | (11 | ) | (20 | ) | 45.0 | % | 45.0 | % | 9 | — | — | — | 9 | ||||||||
Adjusted Operating Income | $ 899 | $ 952 | (5.6 | )% | (5.9 | )% | (53 | ) | 3 | 144 | (236 | ) | 36 | ||||||||
Adjusted Operating Income Margin | 42.0 | % | 40.3 | % | 1.7pp | 1.0pp | |||||||||||||||
(1) Included in marketing, administration and research costs at the consolidated operating income level. | |||||||||||||||||||||
- -20 -
Net revenues, excluding unfavorable currency, decreased by 8.2%, reflecting: unfavorable volume/mix, primarily due to lower cigarette volume in Indonesia, Pakistan and the Philippines, partly offset by favorable mix in Indonesia; partially offset by a favorable pricing variance, principally driven by the Philippines, partly offset by Indonesia.
Operating income, excluding favorable currency, decreased by 5.0%, mainly reflecting: unfavorable volume/mix, due to the same factors as for net revenues noted above; partially offset by a favorable pricing variance; lower marketing, administration and research costs; and lower manufacturing costs (notably in Indonesia).
Excluding asset impairment, exit costs and favorable currency, adjusted operating income decreased by 5.9%. Adjusted operating income margin, excluding currency, increased by 1.0 point to 41.3%, as detailed in Schedule 8.
Total Market, PMI Shipment & Market Share Commentaries
PMI Shipment Volume | Second-Quarter | Six Months Year-to-Date | ||||||||||||
(million units) | 2020 | 2019 | Change | 2020 | 2019 | Change | ||||||||
Cigarettes | 33,346 | 46,376 | (28.1 | )% | 70,941 | 87,868 | (19.3 | )% | ||||||
Heated Tobacco Units | — | — | — | % | — | — | — | % | ||||||
Total South & Southeast Asia | 33,346 | 46,376 | (28.1 | )% | 70,941 | 87,868 | (19.3 | )% | ||||||
Second-Quarter
The estimated total market in South & Southeast Asia decreased, notably due to:
• | Bangladesh, down by 29.9%, or by 5.3% excluding the net unfavorable impact of estimated trade inventory movements, primarily reflecting the impact of lockdown restrictions on tobacco product availability; |
• | India, down by 37.6%, primarily reflecting the impact of lockdown restrictions on the movement of certain products, including tobacco; |
• | Indonesia, down by 17.5%, or by 22.1% excluding the net favorable impact of estimated trade inventory movements, mainly reflecting the impact of pandemic-related measures on adult smoker average daily consumption, as well as the impact of excise tax-driven price increases; |
• | Pakistan, down by 25.8%, mainly reflecting the impact of excise tax-driven price increases in June 2019 and value brand price increases in February 2020, coupled with the impact of trade supply disruption on tobacco product availability, due to lockdown measures; and |
• | the Philippines, down by 24.6%, mainly reflecting the impact of the strict enforcement of nationwide quarantine, as well as industry-wide price increases in the third quarter of 2019. |
PMI's total shipment volume decreased by 28.1% to 33.3 billion units, notably due to:
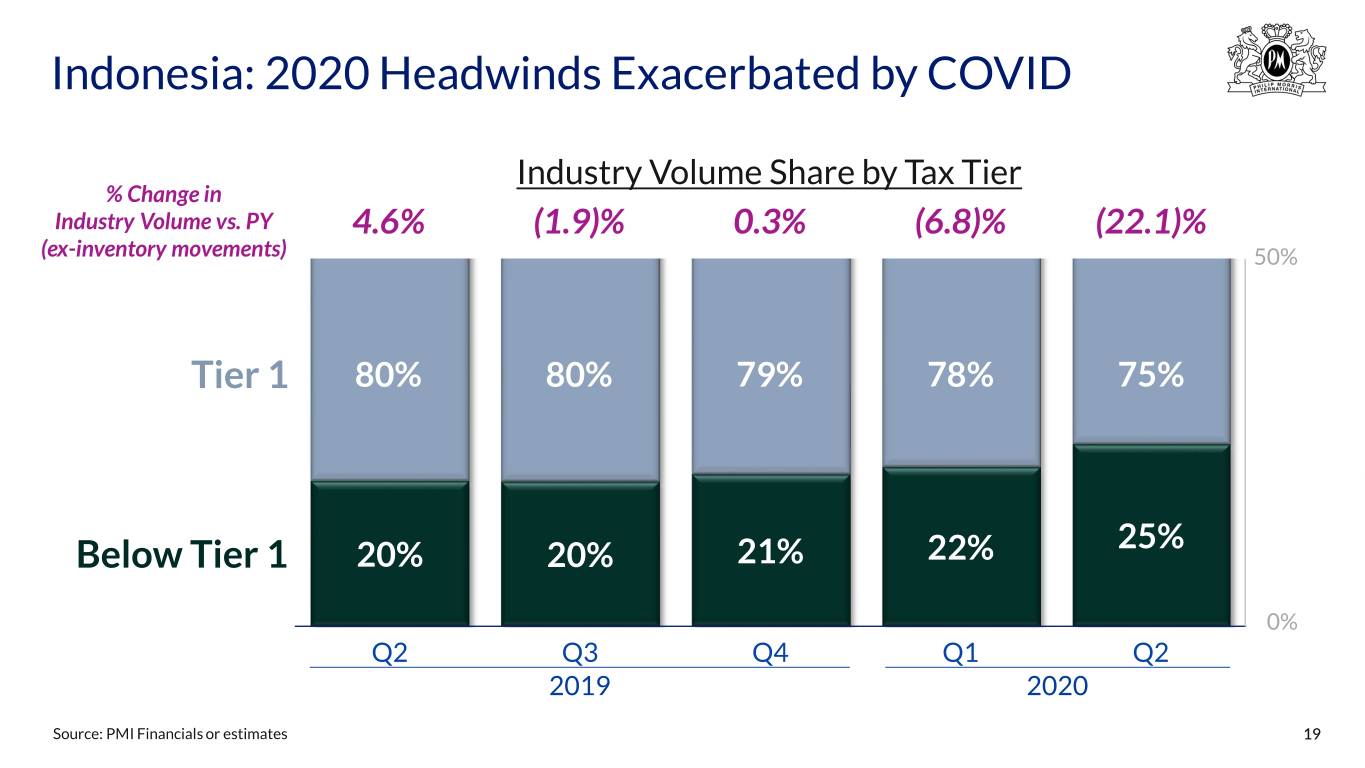
• | Indonesia, down by 27.7%, reflecting the lower total market, as well as a lower market share, mainly due to: the impact of elevated price gaps in the tier one segment (partly due to the delay in minimum price enforcement), adult smoker down-trading to the tax-advantaged 'below tier one' segment, and the disproportionate impact of stricter public mobility restrictions in urban areas, where PMI’s share is higher; |
• | Pakistan, down by 39.2%, due to the lower total market and a lower market share; and |
• | the Philippines, down by 25.7%, mainly reflecting the lower total market. |
- -21 -
Six Months Year-to-Date
The estimated total market in South & Southeast Asia decreased, notably due to:
• | Bangladesh, down by 5.6%, primarily reflecting the same factor as in the quarter; |
• | India, down by 23.5%, mainly reflecting the same factor as in the quarter; |
• | Indonesia, down by 9.5%, or by 14.8% excluding the net favorable impact of estimated trade inventory movements, primarily reflecting the same factors as in the quarter; |
• | Pakistan, down by 25.6%, mainly due to the same factors as in the quarter; and |
• | the Philippines, down by 17.1%, mainly reflecting the same factors as in the quarter. |
PMI's total shipment volume decreased by 19.3% to 70.9 billion units, notably due to:
• | Indonesia, down by 18.2%, reflecting the lower total market, as well as a lower market share, mainly due to the same factors as in the quarter; |
• | Pakistan, down by 37.4%, mainly due to the same factors as in the quarter; and |
• | the Philippines, down by 17.7%, mainly reflecting the same factor as in the quarter. |
EAST ASIA & AUSTRALIA REGION
Second-Quarter
Financial Summary - Quarters Ended June 30, | Change Fav./(Unfav.) | Variance Fav./(Unfav.) | |||||||||||||||||||
2020 | 2019 | Total | Excl. Curr. | Total | Cur- rency | Price | Vol/ Mix | Cost/ Other | |||||||||||||
(in millions) | |||||||||||||||||||||
Net Revenues | $ 1,432 | $ 1,521 | (5.9 | )% | (5.1 | )% | (89 | ) | (12 | ) | 30 | (107 | ) | — | |||||||
Operating Income | $ 669 | $ 642 | 4.2 | % | 5.9 | % | 27 | (11 | ) | 30 | (85 | ) | 93 | ||||||||
Asset Impairment & Exit Costs (1) | (13 | ) | — | — | % | — | % | (13 | ) | — | — | — | (13 | ) | |||||||
Adjusted Operating Income | $ 682 | $ 642 | 6.2 | % | 7.9 | % | 40 | (11 | ) | 30 | (85 | ) | 106 | ||||||||
Adjusted Operating Income Margin | 47.6 | % | 42.2 | % | 5.4pp | 5.8pp | |||||||||||||||
(1) Included in marketing, administration and research costs at the consolidated operating income level. | |||||||||||||||||||||
Net revenues, excluding unfavorable currency, decreased by 5.1%, reflecting: unfavorable volume/mix, mainly due to lower cigarette volume (primarily in Australia and Japan) and unfavorable heated tobacco unit mix in Japan, partly offset by higher heated tobacco unit volume in Japan; partially offset by a favorable pricing variance, mainly driven by higher heated tobacco unit pricing in Japan and higher combustible pricing in Australia, partly offset by lower IQOS device pricing in Japan.
Operating income, excluding unfavorable currency, increased by 5.9%, mainly reflecting: lower manufacturing costs (notably related to Japan and Korea); lower marketing, administration and research costs (primarily in Japan); and a favorable pricing variance; partly offset by unfavorable volume/mix, due to the same factors as for net revenues noted above.
Excluding asset impairment, exit costs and unfavorable currency, adjusted operating income increased by 7.9%. Adjusted operating income margin, excluding currency, increased by 5.8 points to 48.0%, as detailed in Schedule 8.
- -22 -
Six Months Year-to-Date
Financial Summary - Six Months Ended June 30, | Change Fav./(Unfav.) | Variance Fav./(Unfav.) | |||||||||||||||||||
2020 | 2019 | Total | Excl. Curr. | Total | Cur- rency | Price | Vol/ Mix | Cost/ Other | |||||||||||||
(in millions) | |||||||||||||||||||||
Net Revenues | $ 2,687 | $ 2,842 | (5.5 | )% | (4.7 | )% | (155 | ) | (21 | ) | 43 | (177 | ) | — | |||||||
Operating Income | $ 1,155 | $ 1,069 | 8.0 | % | 9.4 | % | 86 | (15 | ) | 43 | (96 | ) | 154 | ||||||||
Asset Impairment & Exit Costs (1) | (13 | ) | — | — | % | — | % | (13 | ) | — | — | — | (13 | ) | |||||||
Adjusted Operating Income | $ 1,168 | $ 1,069 | 9.3 | % | 10.7 | % | 99 | (15 | ) | 43 | (96 | ) | 167 | ||||||||
Adjusted Operating Income Margin | 43.5 | % | 37.6 | % | 5.9pp | 6.1pp | |||||||||||||||
(1) Included in marketing, administration and research costs at the consolidated operating income level. | |||||||||||||||||||||
Net revenues, excluding unfavorable currency, decreased by 4.7%, reflecting: unfavorable volume/mix, mainly due to lower cigarette volume in Japan, unfavorable volume/mix in Australia, lower IQOS device volume in Japan and unfavorable heated tobacco unit mix in Japan, partly offset by higher heated tobacco unit volume in Japan; partially offset by a favorable pricing variance, mainly driven by higher combustible pricing in Australia and higher heated tobacco pricing in Japan, partly offset by lower IQOS device pricing in Japan.
Operating income, excluding unfavorable currency, increased by 9.4%, mainly reflecting: lower marketing, administration and research costs (notably in Japan); lower manufacturing costs (mainly related to Japan and Korea); and a favorable pricing variance; partly offset by unfavorable volume/mix, primarily due to lower cigarette volume in Japan, unfavorable volume/mix in Australia and unfavorable heated tobacco unit mix in Japan, partly offset by higher heated tobacco unit volume in Japan.
Excluding asset impairment, exit costs and unfavorable currency, adjusted operating income increased by 10.7%. Adjusted operating income margin, excluding currency, increased by 6.1 points to 43.7%, as detailed in Schedule 8.
Total Market, PMI Shipment & Market Share Commentaries
PMI Shipment Volume | Second-Quarter | Six Months Year-to-Date | ||||||||||||
(million units) | 2020 | 2019 | Change | 2020 | 2019 | Change | ||||||||
Cigarettes | 12,071 | 13,845 | (12.8 | )% | 24,370 | 25,958 | (6.1 | )% | ||||||
Heated Tobacco Units | 9,076 | 8,428 | 7.7 | % | 16,198 | 15,277 | 6.0 | % | ||||||
Total East Asia & Australia | 21,147 | 22,273 | (5.1 | )% | 40,568 | 41,235 | (1.6 | )% | ||||||
Second-Quarter
The estimated total market in East Asia & Australia, excluding China, decreased, notably due to:
• | Japan, down by 12.7%, mainly reflecting the impact of reduced adult smoker social consumption occasions due to pandemic-related measures, as well as adult smoker out-switching from cigarettes to the cigarillo category; |
partly offset by
- -23 -
• | Korea, up by 3.9%, notably driven by the shift of adult smokers from duty-free to domestic purchases due to the pandemic-related decline in international travel. |
PMI's total shipment volume decreased by 5.1% to 21.1 billion units, notably in:
• | Japan, down by 6.4%, mainly due to the lower total market, partly offset by a higher market share driven by heated tobacco units. |
Six Months Year-to-Date
The estimated total market in East Asia & Australia, excluding China, decreased, notably due to:
• | Japan, down by 9.4%, mainly reflecting the same factors as in the quarter; |
partly offset by
• | Korea, up by 3.8%, notably due the same factor as in the quarter. |
PMI's total shipment volume decreased by 1.6% to 40.6 billion units, notably in:
• | Japan, down by 1.0%, or by 3.6% excluding the net favorable impact of estimated distributor inventory movements, mainly due to the same factors as in the quarter; and |
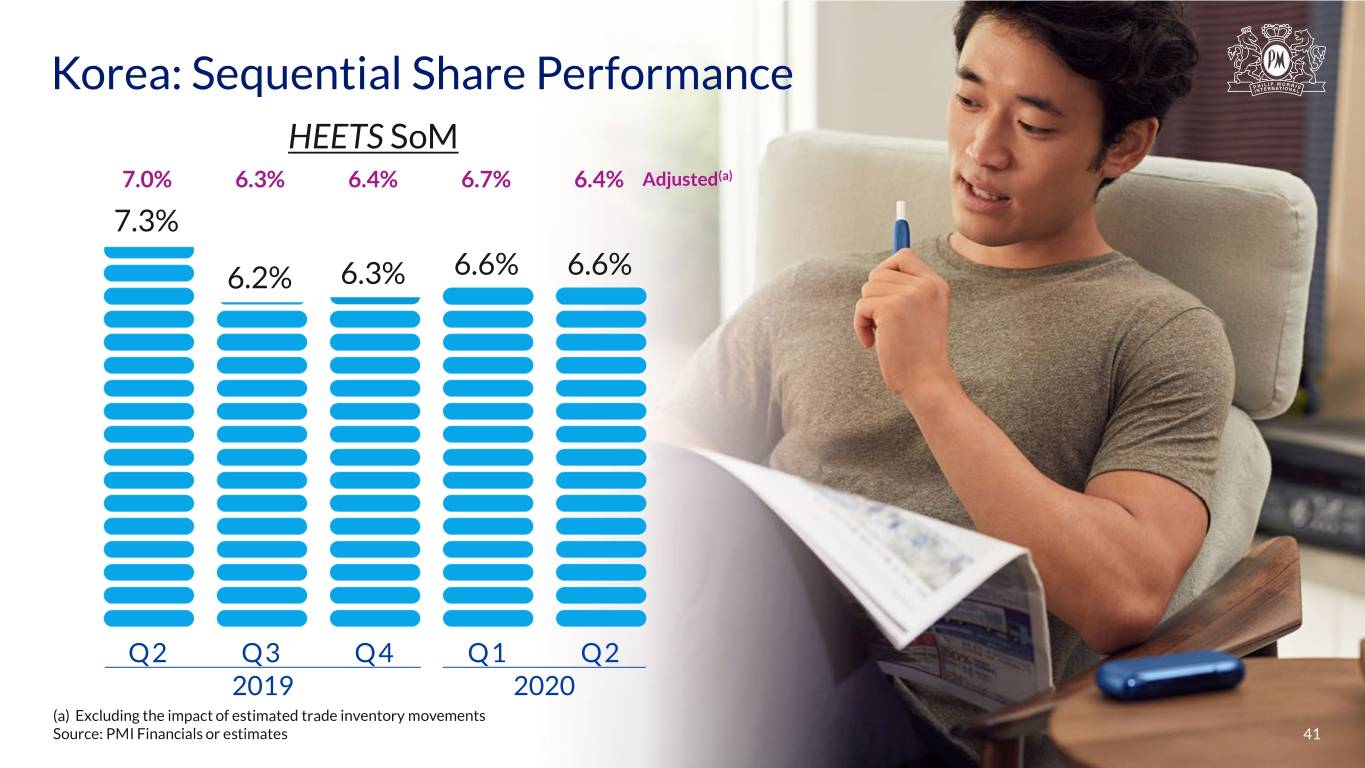
• | Korea, down by 4.6%, mainly due to a lower market share, primarily reflecting the unfavorable impact of the growth of the cigarette new taste dimension segment, in which PMI has a relatively low share, partly offset by the higher total market. |
LATIN AMERICA & CANADA REGION
Second-Quarter
Financial Summary - Quarters Ended June 30, | Change Fav./(Unfav.) | Variance Fav./(Unfav.) | |||||||||||||||||||
2020 | 2019 | Total | Excl. Curr. | Total | Cur- rency | Price | Vol/ Mix | Cost/ Other | |||||||||||||
(in millions) | |||||||||||||||||||||
Net Revenues | $ 368 | $ 527 | (30.2 | )% | (19.2 | )% | (159 | ) | (58 | ) | 41 | (137 | ) | (5 | ) | ||||||
Operating Income | $ 92 | $ 161 | (42.9 | )% | (39.1 | )% | (69 | ) | (6 | ) | 41 | (106 | ) | 2 | |||||||
Asset Impairment & Exit Costs (1) | (4 | ) | (23 | ) | 82.6 | % | 82.6 | % | 19 | — | — | — | 19 | ||||||||
Adjusted Operating Income | $ 96 | $ 184 | (47.8 | )% | (44.6 | )% | (88 | ) | (6 | ) | 41 | (106 | ) | (17 | ) | ||||||
Adjusted Operating Income Margin | 26.1 | % | 34.9 | % | (8.8)pp | (11.0)pp | |||||||||||||||
(1) Included in marketing, administration and research costs at the consolidated operating income level. | |||||||||||||||||||||
Note: Net Revenues include revenues from shipments of Platform 1 devices, heated tobacco units and accessories to Altria Group, Inc., commencing in the third quarter of 2019, for sale under license in the United States. | |||||||||||||||||||||
Net revenues, excluding unfavorable currency, decreased by 19.2%, mainly reflecting: unfavorable volume/mix, primarily due to lower cigarette volume in Argentina, Colombia and Mexico; partly offset by a favorable pricing variance, predominantly driven by higher combustible pricing in Mexico.
Operating income, excluding unfavorable currency, decreased by 39.1%, primarily reflecting: unfavorable volume/mix (mainly due to lower cigarette volume in Mexico); partly offset by a favorable pricing variance; and lower
- -24 -
marketing, administration and research costs (driven by the favorable net impact of 2019 and 2020 asset impairment and exit costs).
Excluding asset impairment, exit costs and unfavorable currency, adjusted operating income decreased by 44.6%. Adjusted operating income margin, excluding currency, decreased by 11.0 points to 23.9%, as detailed in Schedule 8.
Six Months Year-to-Date
Financial Summary - Six Months Ended June 30, | Change Fav./(Unfav.) | Variance Fav./(Unfav.) | |||||||||||||||||||
2020 | 2019 | Total | Excl. Curr. | Total | Cur- rency | Price | Vol/ Mix | Cost/ Other(1) | |||||||||||||
(in millions) | |||||||||||||||||||||
Net Revenues | $ 816 | $ 1,179 | (30.8 | )% | (24.3 | )% | (363 | ) | (76 | ) | 90 | (189 | ) | (188 | ) | ||||||
Operating Income (Loss) | $ 218 | $ (25) | +100% | +100% | 243 | (41 | ) | 90 | (144 | ) | 338 | ||||||||||
Asset Impairment & Exit Costs (2) | (4 | ) | (23 | ) | 82.6 | % | 82.6 | % | 19 | — | — | — | 19 | ||||||||
Canadian Tobacco Litigation-Related Expense (2) | — | (194 | ) | +100% | +100% | 194 | — | — | — | 194 | |||||||||||
Loss on Deconsolidation of RBH (2) | — | (239 | ) | +100% | +100% | 239 | — | — | — | 239 | |||||||||||
Adjusted Operating Income | $ 222 | $ 431 | (48.5 | )% | (39.0 | )% | (209 | ) | (41 | ) | 90 | (144 | ) | (114 | ) | ||||||
Adjusted Operating Income Margin | 27.2 | % | 36.6 | % | (9.4)pp | (7.1)pp | |||||||||||||||
(1) Cost/Other variance includes the impact of the RBH deconsolidation. | |||||||||||||||||||||
(2) Included in marketing, administration and research costs at the consolidated operating income level. | |||||||||||||||||||||
Note: Net Revenues include revenues from shipments of Platform 1 devices, heated tobacco units and accessories to Altria Group, Inc., commencing in the third quarter of 2019, for sale under license in the United States. | |||||||||||||||||||||
Net revenues, excluding unfavorable currency, decreased by 24.3%, reflecting: unfavorable volume/mix, due to lower cigarette volume, notably in Argentina and Mexico; and the unfavorable impact of the deconsolidation of RBH shown in "Cost/Other"; partly offset by a favorable pricing variance, mainly driven by higher combustible pricing in Mexico. On a like-for-like basis, net revenues, excluding unfavorable currency, decreased by 10.7%, as detailed in Schedule 10.
Operating income, excluding unfavorable currency, increased by +100%, notably reflecting a favorable comparison, shown in "Cost/Other," of charges recorded in the first half of 2020 of $4 million, related to asset impairment and exit costs associated with organizational design optimization, to charges recorded in the first half of 2019 of $456 million, related to the loss on deconsolidation of RBH, the Canadian tobacco litigation-related expense, and asset impairment and exit costs associated with a plant closure in Colombia.
Excluding these charges and unfavorable currency, adjusted operating income decreased by 39.0%, reflecting: unfavorable volume/mix, due to the same factor as for net revenues noted above; and the unfavorable impact of the deconsolidation of RBH, included in "Cost/Other"; partly offset by a favorable pricing variance. On a like-for-like basis, excluding unfavorable currency, adjusted operating income decreased by 14.7%, as detailed in Schedule 10.
Adjusted operating income margin, excluding currency, decreased by 7.1 points to 29.5%, as detailed in Schedule 8, or by 1.4 points to 29.2% on a like-for-like basis, as detailed in Schedule 10.
- -25 -
Total Market, PMI Shipment & Market Share Commentaries
PMI Shipment Volume | Second-Quarter | Six Months Year-to-Date | ||||||||||||
(million units) | 2020 | 2019 | Change | 2020 | 2019 | Change | ||||||||
Cigarettes | 14,780 | 18,472 | (20.0 | )% | 29,843 | 36,052 | (17.2 | )% | ||||||
Heated Tobacco Units | 94 | 59 | 59.3 | % | 202 | 113 | 78.8 | % | ||||||
Total Latin America & Canada | 14,874 | 18,531 | (19.7 | )% | 30,045 | 36,165 | (16.9 | )% | ||||||
Second-Quarter
The estimated total market in Latin America & Canada decreased, notably due to:
• | Argentina, down by 7.4%, mainly reflecting retail out-of-stock (particularly of PMI brands) due to temporary factory shutdowns related to the pandemic, as well as the impact of price increases, partly offset by the net favorable impact of estimated trade inventory movements; |
• | Colombia, down by 25.6%, primarily reflecting reduced product availability and adult smoker average daily consumption due to lockdown measures; and |
• | Mexico, down by 24.4%, or by 16.8% excluding the net unfavorable impact of estimated trade inventory movements (primarily related to July 2019 price increases), mainly due to the impact of excise tax-driven price increases in January 2020, as well as the impact of pandemic-related measures on adult smoker average daily consumption; |
partly offset by
• | Brazil, up by 8.7%, mainly reflecting a lower estimated prevalence of illicit trade due to: reduced price gaps with legal products and the impact of border restrictions imposed as a result of the pandemic. |
PMI's total shipment volume decreased by 19.7% to 14.9 billion units, notably due to:
• | Argentina, down by 15.2%, primarily reflecting the lower total market and a lower market share, mainly due to the impact of retail out-of-stock of PMI brands, as well as adult smoker down-trading to ultra-low-price brands produced by local manufacturers; and |
• | Mexico, down by 32.5%, mainly due to the lower total market (partly reflecting the net unfavorable impact of estimated trade inventory movements noted above) and lower market share, primarily reflecting adult smoker down-trading and the impact of the pandemic on adult smoker consumption patterns. |
Six Months Year-to-Date
The estimated total market in Latin America & Canada decreased, notably due to:
• | Argentina, down by 6.3%, mainly reflecting the same factors as in the quarter; |
• | Colombia, down by 15.3%, primarily due to the same factors as in the quarter; and |
• | Mexico, down by 18.4%, or by 13.6% excluding the net unfavorable impact of estimated trade inventory movements, mainly due to the same factors as in the quarter; |
partly offset by
• | Brazil, up by 9.5%, mainly reflecting the same factors as in the quarter. |
- -26 -
PMI's total shipment volume decreased by 16.9% to 30.0 billion units, or by 14.6% on a like-for-like basis, notably due to:
• | Argentina, down by 14.2%, primarily reflecting the same factors as in the quarter; |
• | Canada, down by 34.3%, due to the unfavorable impact of the deconsolidation of RBH; and |
• | Mexico, down by 25.0%, mainly due the same factors as in the quarter. |
- -27 -
Philip Morris International: Delivering a Smoke-Free Future
Philip Morris International (PMI) is leading a transformation in the tobacco industry to create a smoke-free future and ultimately replace cigarettes with smoke-free products to the benefit of adults who would otherwise continue to smoke, society, the company and its shareholders. PMI is a leading international tobacco company engaged in the manufacture and sale of cigarettes, as well as smoke-free products and associated electronic devices and accessories, and other nicotine-containing products in markets outside the United States. In addition, PMI ships a version of its IQOS Platform 1 device and its consumables authorized by the U.S. Food and Drug Administration to Altria Group, Inc. for sale in the U.S. under license. PMI is building a future on a new category of smoke-free products that, while not risk-free, are a much better choice than continuing to smoke. Through multidisciplinary capabilities in product development, state-of-the-art facilities and scientific substantiation, PMI aims to ensure that its smoke-free products meet adult consumer preferences and rigorous regulatory requirements. PMI's smoke-free IQOS product portfolio includes heat-not-burn and nicotine-containing vapor products. As of June 30, 2020, PMI estimates that approximately 11.2 million adult smokers around the world have already stopped smoking and switched to PMI's heat-not-burn product, available for sale in 57 markets in key cities or nationwide under the IQOS brand. For more information, please visit www.pmi.com and www.pmiscience.com.
Forward-Looking and Cautionary Statements
This press release contains projections of future results and other forward-looking statements. Achievement of future results is subject to risks, uncertainties and inaccurate assumptions. In the event that risks or uncertainties materialize, or underlying assumptions prove inaccurate, actual results could vary materially from those contained in such forward-looking statements. Pursuant to the “safe harbor” provisions of the Private Securities Litigation Reform Act of 1995, PMI is identifying important factors that, individually or in the aggregate, could cause actual results and outcomes to differ materially from those contained in any forward-looking statements made by PMI.
PMI's business risks include: excise tax increases and discriminatory tax structures; increasing marketing and regulatory restrictions that could reduce our competitiveness, eliminate our ability to communicate with adult consumers, or ban certain of our products; health concerns relating to the use of tobacco and other nicotine-containing products and exposure to environmental tobacco smoke; litigation related to tobacco use; intense competition; the effects of global and individual country economic, regulatory and political developments, natural disasters and conflicts; changes in adult smoker behavior; lost revenues as a result of counterfeiting, contraband and cross-border purchases; governmental investigations; unfavorable currency exchange rates and currency devaluations, and limitations on the ability to repatriate funds; adverse changes in applicable corporate tax laws; adverse changes in the cost and quality of tobacco and other agricultural products and raw materials; and the integrity of its information systems and effectiveness of its data privacy policies. PMI's future profitability may also be adversely affected should it be unsuccessful in its attempts to produce and commercialize reduced-risk products or if regulation or taxation do not differentiate between such products and cigarettes; if it is unable to successfully introduce new products, promote brand equity, enter new markets or improve its margins through increased prices and productivity gains; if it is unable to expand its brand portfolio internally or through acquisitions and the development of strategic business relationships; or if it is unable to attract and retain the best global talent. Future results are also subject to the lower predictability of our reduced-risk product category's performance.
The COVID-19 pandemic has created significant societal and economic disruption, and resulted in closures of stores, factories and offices, and restrictions on manufacturing, distribution and travel, all of which will adversely impact our business, results of operations, cash flows and financial position during the continuation of the pandemic.
- -28 -
Our business continuity plans and other safeguards in place may not be effective to mitigate the impact of the pandemic. Currently, significant risks include our diminished ability to convert adult smokers to our RRPs, significant volume declines in our duty-free business and certain other key markets, disruptions or delays in our manufacturing and supply chain, increased currency volatility, and delays in certain cost saving, transformation and restructuring initiatives. Our business could also be adversely impacted if key personnel or a significant number of employees or business partners become unavailable due to the COVID-19 outbreak. The significant adverse impact of COVID-19 on the economic or political conditions in markets in which we operate could result in changes to the preferences of our adult consumers and lower demand for our products, particularly for our mid-price or premium-price brands. Continuation of the pandemic could disrupt our access to the credit markets or increase our borrowing costs. Governments may temporarily be unable to focus on the development of science-based regulatory frameworks for the development and commercialization of RRPs or on the enforcement or implementation of regulations that are significant to our business. In addition, messaging about the potential negative impacts of the use of our products on COVID-19 risks may lead to increasingly restrictive regulatory measures on the sale and use of our products, negatively impact demand for our products, the willingness of adult consumers to switch to our RRPs and our efforts to advocate for the development of science-based regulatory frameworks for the development and commercialization of RRPs.
The impact of these risks also depends on factors beyond our knowledge or control, including the duration and severity of the outbreak, its recurrence in our key markets, actions taken to contain its spread and to mitigate its public health effects, and the ultimate economic consequences thereof.
PMI is further subject to other risks detailed from time to time in its publicly filed documents, including the Form 10-Q for the quarter ended March 31, 2020. PMI cautions that the foregoing list of important factors is not a complete discussion of all potential risks and uncertainties. PMI does not undertake to update any forward-looking statement that it may make from time to time, except in the normal course of its public disclosure obligations.
- -29 -
Key Terms, Definitions and Explanatory Notes
General
• | "PMI" refers to Philip Morris International Inc. and its subsidiaries. Trademarks and service marks that are the registered property of, or licensed by, the subsidiaries of PMI, are italicized. |
• | Comparisons are made to the same prior-year period unless otherwise stated. |
• | Unless otherwise stated, references to total industry, total market, PMI shipment volume and PMI market share performance reflect cigarettes and heated tobacco units. |
• | References to total international market, defined as worldwide cigarette and heated tobacco unit volume excluding the U.S., total industry, total market and market shares are PMI estimates for tax-paid products based on the latest available data from a number of internal and external sources and may, in defined instances, exclude the People's Republic of China and/or PMI's duty free business. In addition, to reflect the deconsolidation of PMI's Canadian subsidiary, Rothmans, Benson & Hedges, Inc. (RBH), effective March 22, 2019, PMI's total market share has been restated for previous periods. |
• | Estimates for second-quarter 2020 and six months year-to-date 2020 total industry volume and market share in certain geographies reflect limitations on the availability and accuracy of industry data during pandemic-related restrictions. |
• | "OTP" is defined as "other tobacco products," primarily roll-your-own and make-your-own cigarettes, pipe tobacco, cigars and cigarillos, and does not include reduced-risk products. |
• | "Combustible products" is the term PMI uses to refer to cigarettes and OTP, combined. |
• | In-market sales, or "IMS," is defined as sales to the retail channel, depending on the market and distribution model. |
• | "Total shipment volume" is defined as the combined total of cigarette shipment volume and heated tobacco unit shipment volume. |
• | "North Africa" is defined as Algeria, Egypt, Libya, Morocco and Tunisia. |
• | "The GCC" (Gulf Cooperation Council) is defined as Bahrain, Kuwait, Oman, Qatar, Saudi Arabia and the United Arab Emirates (UAE). |
• | Following the deconsolidation of PMI's Canadian subsidiary, Rothmans, Benson & Hedges, Inc. (RBH), PMI will continue to report the volume of brands sold by RBH for which other PMI subsidiaries are the trademark owner. These include HEETS, Next, Philip Morris and Rooftop. |
• | From time to time, PMI’s shipment volumes are subject to the impact of distributor inventory movements, and estimated total industry/market volumes are subject to the impact of inventory movements in various trade channels that include estimated trade inventory movements of PMI’s competitors arising from market-specific factors that significantly distort reported volume disclosures. Such factors may include changes to the manufacturing supply chain, shipment methods, consumer demand, timing of excise tax increases or other influences that may affect the timing of sales to customers. In such instances, in addition to reviewing PMI shipment volumes and certain estimated total industry/market volumes on a reported basis, management reviews these measures on an adjusted basis that excludes the impact of distributor and/or estimated trade inventory movements. Management also believes that disclosing PMI shipment volumes and estimated total industry/market volumes in such circumstances on a basis that excludes the impact of distributor and/or estimated trade inventory movements, such as on an IMS basis, improves the comparability of performance and trends for these measures over different reporting periods. |
Financial
• | Net revenues related to combustible products refer to the operating revenues generated from the sale of these products, including shipping and handling charges billed to customers, net of sales and promotion incentives, and excise taxes. PMI recognizes revenue when control is transferred to the customer, typically either upon shipment or delivery of goods. |
• | Net revenues related to RRPs represent the sale of heated tobacco units, IQOS devices and related accessories, and other nicotine-containing products, primarily e-vapor products, including shipping and handling charges billed to customers, net of sales and promotion incentives, and excise taxes. PMI recognizes revenue when control is transferred to the customer, typically either upon shipment or delivery of goods. |
• | "Cost of sales" consists principally of: tobacco leaf, non-tobacco raw materials, labor and manufacturing costs; shipping and handling costs; and the cost of IQOS devices produced by third-party electronics manufacturing |
- -30 -
service providers. Estimated costs associated with IQOS warranty programs are generally provided for in cost of sales in the period the related revenues are recognized.
• | "Marketing, administration and research costs" include the costs of marketing and selling our products, other costs generally not related to the manufacture of our products (including general corporate expenses), and costs incurred to develop new products. The most significant components of our marketing, administration and research costs are marketing and sales expenses and general and administrative expenses. |
• | "Cost/Other" in the Consolidated Financial Summary table of total PMI and the six operating segments of this release reflects the currency-neutral variances of: cost of sales (excluding the volume/mix cost component); marketing, administration and research costs (including asset impairment and exit costs, the Canadian tobacco litigation-related expense and the charge related to the deconsolidation of RBH in Canada); and amortization of intangibles. “Cost/Other” also includes the currency-neutral net revenue variance, unrelated to volume/mix and price components, attributable to fees for certain distribution rights billed to customers in certain markets in the ME&A Region, as well as the impact of the deconsolidation in RBH. |
• | "Adjusted Operating Income Margin" is calculated as adjusted operating income, divided by net revenues. |
• | "Adjusted EBITDA" is defined as earnings before interest, taxes, depreciation, amortization and equity (income)/loss in unconsolidated subsidiaries, excluding asset impairment and exit costs, and unusual items. |
• | "Net debt" is defined as total debt, less cash and cash equivalents. |
• | Management reviews net revenues, OI, OI margins, operating cash flow and earnings per share, or "EPS," on an adjusted basis, which may exclude the impact of currency and other items such as acquisitions, asset impairment and exit costs, tax items and other special items. For example, PMI’s adjusted diluted EPS and other impacted results reflect the loss on deconsolidation of RBH and the Canadian tobacco litigation-related expense, recorded in the first quarter of 2019, asset impairment and exit costs associated with plant closures in Pakistan and Colombia, recorded in the first and second quarters of 2019, respectively, and asset impairment and exit costs associated with organizational design optimization, recorded in the second quarter of 2020. PMI believes that the adjusted measures, including pro forma measures, will provide useful insight into underlying business trends and results, and will provide a more meaningful performance comparison for the period during which RBH remains under CCAA protection. For PMI's 2018 pro forma adjusted diluted EPS by quarter and year-to-date, see Schedule 3 in PMI's second-quarter 2019 earnings release. |
• | Management reviews these measures because they exclude changes in currency exchange rates and other factors that may distort underlying business trends, thereby improving the comparability of PMI’s business performance between reporting periods. Furthermore, PMI uses several of these measures in its management compensation program to promote internal fairness and a disciplined assessment of performance against company targets. PMI discloses these measures to enable investors to view the business through the eyes of management. |
• | Non-GAAP measures used in this release should neither be considered in isolation nor as a substitute for the financial measures prepared in accordance with U.S. GAAP. For a reconciliation of non-GAAP measures to the most directly comparable U.S. GAAP measures, see the relevant schedules provided with this press release. |
• | U.S. GAAP Treatment of Argentina as a Highly Inflationary Economy. Following the categorization of Argentina by the International Practices Task Force of the Center for Audit Quality as a country with a three-year cumulative inflation rate greater than 100%, the country is considered highly inflationary in accordance with U.S. GAAP. Consequently, PMI began to account for the operations of its Argentinian affiliates as highly inflationary, and to treat the U.S. dollar as the functional currency of the affiliates, effective July 1, 2018. |
• | "Fair value adjustment for equity security investments" reflects the adjustment resulting from share price movements in passive investments for publicly traded entities that are not controlled or influenced by PMI. Under U.S. GAAP, such adjustments are required, since January 1, 2018, to be reflected directly in the income statement. |
Reduced-Risk Products
• | Reduced Risk Products (“RRPs”) is the term PMI uses to refer to products that present, are likely to present, or have the potential to present less risk of harm to smokers who switch to these products versus continuing smoking. PMI has a range of RRPs in various stages of development, scientific assessment and commercialization. PMI's RRPs are smoke-free products that produce an aerosol that contains far lower quantities of harmful and potentially harmful constituents than found in cigarette smoke. |
• | "Heated tobacco units," or "HTUs," is the term PMI uses to refer to heated tobacco consumables, which include the company's HEETS, HEETS Creations, HEETS Marlboro and HEETS FROM MARLBORO, defined collectively as HEETS, as well as Marlboro HeatSticks and Parliament HeatSticks. |
- -31 -
• | Market share for HTUs is defined as the total sales volume for HTUs as a percentage of the total estimated sales volume for cigarettes and HTUs. |
• | Unless otherwise stated, all references to IQOS are to PMI's heat-not-burn products. |
• | The IQOS heat-not-burn device is a precisely controlled heating device into which a specially designed and proprietary tobacco unit is inserted and heated to generate an aerosol. |
• | “Total IQOS users” is defined as the estimated number of Legal Age (minimum 18 years) IQOS users that used PMI HTUs for at least 5% of their daily tobacco consumption over the past seven days. |
• | The estimated number of people who have "stopped smoking and switched to IQOS" is defined as: for markets where IQOS is the only heat-not-burn product, daily individual consumption of PMI HTUs represents the totality of their daily tobacco consumption in the past seven days; for markets where IQOS is one among other heat-not-burn products, daily individual consumption of HTUs represents the totality of their daily tobacco consumption in the past seven days, of which at least 70% are PMI HTUs. |
IQOS in the United States
• | On April 30, 2019, the U.S. Food and Drug Administration (FDA) announced that the marketing of a version of IQOS, PMI's heat-not-burn product, together with its heated tobacco units (the term PMI uses to refer to heated tobacco consumables), is appropriate for the protection of public health and authorized it for sale in the U.S. The FDA’s decision follows its comprehensive assessment of PMI’s premarket tobacco product applications (PMTAs) submitted to the Agency in 2017. In the third quarter of 2019, PMI brought a version of its IQOS Platform 1 device and three variants of its heated tobacco units to the U.S. through its license with Altria Group, Inc., whose subsidiary, Philip Morris USA Inc., is responsible for marketing the product and complying with the provisions set forth in the FDA's marketing order. On March 30, 2020, PMI submitted a supplemental PMTA for the IQOS 3 tobacco heating device with the FDA. |
• | On July 7, 2020, the FDA authorized the marketing of a version of IQOS, together with its heated tobacco units, as a modified risk tobacco product (MRTP). In doing so, the agency found that an IQOS exposure modification order is appropriate to promote the public health. The decision follows a review of the extensive scientific evidence package PMI submitted to the FDA in December 2016 to support its MRTP applications. |
• | Shipment volume of heated tobacco units to the U.S. is included in the heated tobacco unit shipment volume of the Latin America & Canada segment. Revenues from shipments of Platform 1 devices, heated tobacco units and accessories to Altria Group, Inc. for sale under license in the U.S. are included in Net Revenues of the Latin America & Canada segment. |
- -32 -
Appendix 1 | |||||||||||||||||||||||||||||||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | |||||||||||||||||||||||||||||||||||||||||||
Key Market Data | |||||||||||||||||||||||||||||||||||||||||||
Quarters Ended June 30, | |||||||||||||||||||||||||||||||||||||||||||
Market | Total Market, bio units | PMI Shipments, bio units | PMI Market Share, % (1) | ||||||||||||||||||||||||||||||||||||||||
Total | Cigarette | HTU | Total | HTU | |||||||||||||||||||||||||||||||||||||||
2020 | 2019 | % Change | 2020 | 2019 | % Change | 2020 | 2019 | % Change | 2020 | 2019 | % Change | 2020 | 2019 | pp Change | 2020 | 2019 | pp Change | ||||||||||||||||||||||||||
Total | 609.2 | 700.3 | (13.0 | ) | 170.1 | 198.9 | (14.5 | ) | 151.4 | 183.8 | (17.6 | ) | 18.7 | 15.1 | 24.3 | 28.0 | 28.1 | (0.1 | ) | 3.0 | 2.1 | 0.9 | |||||||||||||||||||||
European Union | |||||||||||||||||||||||||||||||||||||||||||
France | 9.8 | 9.8 | 0.7 | 4.5 | 4.5 | 0.3 | 4.4 | 4.5 | (0.4 | ) | — | — | — | 44.9 | 44.7 | 0.2 | 0.5 | 0.2 | 0.3 | ||||||||||||||||||||||||
Germany | 20.0 | 18.9 | 5.9 | 7.8 | 7.3 | 6.9 | 7.4 | 7.1 | 4.4 | 0.4 | 0.2 | 89.4 | 38.9 | 38.5 | 0.4 | 2.0 | 1.1 | 0.9 | |||||||||||||||||||||||||
Italy | 16.3 | 17.2 | (4.8 | ) | 7.9 | 9.3 | (15.5 | ) | 6.8 | 8.5 | (20.1 | ) | 1.1 | 0.8 | 32.3 | 52.1 | 51.7 | 0.4 | 7.7 | 4.6 | 3.1 | ||||||||||||||||||||||
Poland | 10.6 | 12.3 | (13.6 | ) | 4.2 | 5.0 | (16.8 | ) | 3.7 | 4.8 | (22.2 | ) | 0.5 | 0.3 | 85.9 | 39.3 | 40.8 | (1.5 | ) | 4.4 | 2.0 | 2.4 | |||||||||||||||||||||
Spain | 9.6 | 11.6 | (17.2 | ) | 2.7 | 3.9 | (29.5 | ) | 2.7 | 3.8 | (29.7 | ) | 0.1 | 0.1 | (23.9 | ) | 31.3 | 31.2 | 0.1 | 1.0 | 0.7 | 0.3 | |||||||||||||||||||||
Eastern Europe | |||||||||||||||||||||||||||||||||||||||||||
Russia | 57.2 | 59.6 | (4.1 | ) | 17.9 | 17.7 | 0.8 | 14.3 | 15.9 | (10.1 | ) | 3.6 | 1.8 | 95.5 | 32.4 | 29.6 | 2.8 | 5.9 | 2.9 | 3.0 | |||||||||||||||||||||||
Middle East & Africa | |||||||||||||||||||||||||||||||||||||||||||
Saudi Arabia | 6.0 | 5.4 | 12.0 | 2.7 | 0.8 | +100 | 2.7 | 0.8 | +100 | — | — | — | 38.6 | 38.9 | (0.3 | ) | 0.2 | — | 0.2 | ||||||||||||||||||||||||
Turkey | 29.9 | 32.1 | (6.8 | ) | 11.7 | 12.5 | (6.6 | ) | 11.7 | 12.5 | (6.6 | ) | — | — | — | 38.9 | 38.9 | — | — | — | — | ||||||||||||||||||||||
South & Southeast Asia | |||||||||||||||||||||||||||||||||||||||||||
Indonesia | 64.0 | 77.6 | (17.5 | ) | 18.0 | 24.9 | (27.7 | ) | 18.0 | 24.9 | (27.7 | ) | — | — | — | 28.2 | 32.2 | (4.0 | ) | — | — | — | |||||||||||||||||||||
Philippines | 14.0 | 18.6 | (24.6 | ) | 9.7 | 13.1 | (25.7 | ) | 9.7 | 13.1 | (25.7 | ) | — | — | — | 69.5 | 70.6 | (1.1 | ) | — | — | — | |||||||||||||||||||||
East Asia & Australia | |||||||||||||||||||||||||||||||||||||||||||
Australia | 2.6 | 2.9 | (11.2 | ) | 0.8 | 0.9 | (12.0 | ) | 0.8 | 0.9 | (12.0 | ) | — | — | — | 30.8 | 31.0 | (0.2 | ) | — | — | — | |||||||||||||||||||||
Japan | 35.4 | 40.6 | (12.7 | ) | 14.1 | 15.1 | (6.4 | ) | 6.3 | 8.0 | (20.9 | ) | 7.8 | 7.1 | 10.0 | 36.5 | 34.0 | 2.5 | 20.0 | 16.6 | 3.4 | ||||||||||||||||||||||
Korea | 18.4 | 17.7 | 3.9 | 3.8 | 4.1 | (6.2 | ) | 2.6 | 2.8 | (6.1 | ) | 1.2 | 1.3 | (6.4 | ) | 21.1 | 23.1 | (2.0 | ) | 6.6 | 7.3 | (0.7 | ) | ||||||||||||||||||||
Latin America & Canada | |||||||||||||||||||||||||||||||||||||||||||
Argentina | 7.3 | 7.8 | (7.4 | ) | 4.8 | 5.6 | (15.2 | ) | 4.8 | 5.6 | (15.2 | ) | — | — | — | 65.4 | 71.8 | (6.4 | ) | — | — | — | |||||||||||||||||||||
Mexico | 7.6 | 10.0 | (24.4 | ) | 4.7 | 7.0 | (32.5 | ) | 4.7 | 7.0 | (32.7 | ) | — | — | — | 62.1 | 69.5 | (7.4 | ) | 0.2 | — | 0.2 | |||||||||||||||||||||
(1) Market share estimates are calculated using IMS data | |||||||||||||||||||||||||||||||||||||||||||
Note: % change for Total Market and PMI shipments is computed based on millions of units; PMI Market Share estimates for previous periods are restated to reflect RBH deconsolidation and exclude RBH-owned brands. | |||||||||||||||||||||||||||||||||||||||||||
Appendix 2 | |||||||||||||||||||||||||||||||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | |||||||||||||||||||||||||||||||||||||||||||
Key Market Data | |||||||||||||||||||||||||||||||||||||||||||
Six Months Ended June 30, | |||||||||||||||||||||||||||||||||||||||||||
Market | Total Market, bio units | PMI Shipments, bio units | PMI Market Share, % (1) | ||||||||||||||||||||||||||||||||||||||||
Total | Cigarette | HTU | Total | HTU | |||||||||||||||||||||||||||||||||||||||
2020 | 2019 | % Change | 2020 | 2019 | % Change | 2020 | 2019 | % Change | 2020 | 2019 | % Change | 2020 | 2019 | pp Change | 2020 | 2019 | pp Change | ||||||||||||||||||||||||||
Total | 1,224.1 | 1,325.0 | (7.6 | ) | 343.8 | 374.7 | (8.2 | ) | 308.4 | 348.1 | (11.4 | ) | 35.4 | 26.6 | 33.4 | 27.7 | 28.1 | (0.4 | ) | 2.9 | 2.1 | 0.8 | |||||||||||||||||||||
European Union | |||||||||||||||||||||||||||||||||||||||||||
France | 18.2 | 18.9 | (3.9 | ) | 8.5 | 8.6 | (1.3 | ) | 8.4 | 8.6 | (2.1 | ) | 0.1 | — | — | 44.7 | 44.9 | (0.2 | ) | 0.4 | 0.2 | 0.2 | |||||||||||||||||||||
Germany | 36.0 | 34.3 | 4.9 | 14.5 | 13.4 | 8.7 | 13.7 | 13.0 | 5.7 | 0.8 | 0.4 | +100 | 40.4 | 38.9 | 1.5 | 2.2 | 1.1 | 1.1 | |||||||||||||||||||||||||
Italy | 32.0 | 32.8 | (2.2 | ) | 17.1 | 17.0 | 0.2 | 14.6 | 15.6 | (6.9 | ) | 2.5 | 1.4 | 78.6 | 52.0 | 51.4 | 0.6 | 7.5 | 4.2 | 3.3 | |||||||||||||||||||||||
Poland | 21.4 | 22.9 | (6.4 | ) | 8.5 | 9.2 | (8.0 | ) | 7.6 | 8.8 | (14.0 | ) | 0.9 | 0.4 | +100 | 39.7 | 40.4 | (0.7 | ) | 4.3 | 1.9 | 2.4 | |||||||||||||||||||||
Spain | 20.0 | 21.8 | (8.2 | ) | 6.4 | 7.5 | (14.4 | ) | 6.2 | 7.3 | (15.5 | ) | 0.2 | 0.1 | 39.8 | 31.1 | 31.4 | (0.3 | ) | 1.0 | 0.6 | 0.4 | |||||||||||||||||||||
Eastern Europe | |||||||||||||||||||||||||||||||||||||||||||
Russia | 104.1 | 106.3 | (2.1 | ) | 32.9 | 29.9 | 10.3 | 26.7 | 27.2 | (1.8 | ) | 6.2 | 2.7 | +100 | 32.4 | 29.1 | 3.3 | 6.2 | 3.0 | 3.2 | |||||||||||||||||||||||
Middle East & Africa | |||||||||||||||||||||||||||||||||||||||||||
Saudi Arabia | 10.3 | 10.6 | (2.9 | ) | 3.8 | 4.7 | (19.0 | ) | 3.8 | 4.7 | (19.6 | ) | — | — | — | 39.4 | 40.3 | (0.9 | ) | 0.1 | — | 0.1 | |||||||||||||||||||||
Turkey | 55.9 | 61.6 | (9.3 | ) | 21.8 | 26.4 | (17.4 | ) | 21.8 | 26.4 | (17.4 | ) | — | — | — | 38.9 | 42.9 | (4.0 | ) | — | — | — | |||||||||||||||||||||
South & Southeast Asia | |||||||||||||||||||||||||||||||||||||||||||
Indonesia | 131.4 | 145.2 | (9.5 | ) | 38.5 | 47.1 | (18.2 | ) | 38.5 | 47.1 | (18.2 | ) | — | — | — | 29.3 | 32.4 | (3.1 | ) | — | — | — | |||||||||||||||||||||
Philippines | 29.3 | 35.3 | (17.1 | ) | 20.5 | 24.9 | (17.7 | ) | 20.5 | 24.9 | (17.7 | ) | — | — | — | 69.9 | 70.4 | (0.5 | ) | — | — | — | |||||||||||||||||||||
East Asia & Australia | |||||||||||||||||||||||||||||||||||||||||||
Australia | 5.1 | 6.0 | (15.3 | ) | 1.5 | 1.7 | (9.8 | ) | 1.5 | 1.7 | (9.8 | ) | — | — | — | 29.4 | 27.6 | 1.8 | — | — | — | ||||||||||||||||||||||
Japan | 70.9 | 78.2 | (9.4 | ) | 26.9 | 27.2 | (1.0 | ) | 13.1 | 14.4 | (9.1 | ) | 13.8 | 12.7 | 8.1 | 36.4 | 34.2 | 2.2 | 19.6 | 16.8 | 2.8 | ||||||||||||||||||||||
Korea | 34.6 | 33.3 | 3.8 | 7.4 | 7.7 | (4.6 | ) | 5.1 | 5.3 | (3.8 | ) | 2.3 | 2.4 | (6.3 | ) | 21.4 | 23.2 | (1.8 | ) | 6.6 | 7.3 | (0.7 | ) | ||||||||||||||||||||
Latin America & Canada | |||||||||||||||||||||||||||||||||||||||||||
Argentina | 15.3 | 16.3 | (6.3 | ) | 10.0 | 11.7 | (14.2 | ) | 10.0 | 11.7 | (14.2 | ) | — | — | — | 65.7 | 72.1 | (6.4 | ) | — | — | — | |||||||||||||||||||||
Mexico | 14.2 | 17.4 | (18.4 | ) | 8.8 | 11.7 | (25.0 | ) | 8.7 | 11.7 | (25.2 | ) | — | — | — | 61.6 | 67.0 | (5.4 | ) | 0.2 | — | 0.2 | |||||||||||||||||||||
(1) Market share estimates are calculated using IMS data | |||||||||||||||||||||||||||||||||||||||||||
Note: % change for Total Market and PMI shipments is computed based on millions of units; PMI Market Share estimates for previous periods are restated to reflect RBH deconsolidation and exclude RBH-owned brands. | |||||||||||||||||||||||||||||||||||||||||||
Appendix 3 | ||||||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | ||||||||||||||||||
Reconciliation of Non-GAAP Measures | ||||||||||||||||||
Shipment Volume Adjusted for the Impact of RBH Deconsolidation | ||||||||||||||||||
(in million units) / (Unaudited) | ||||||||||||||||||
Total PMI | Quarters Ended June 30, | Six Months Ended June 30, | ||||||||||||||||
2020 | 2019 | % Change | 2020 | 2019 | % Change | |||||||||||||
Total Shipment Volume | 170,067 | 198,855 | (14.5 | )% | 343,812 | 374,650 | (8.2 | )% | ||||||||||
Shipment Volume for RBH-owned brands (1) | — | (1,008 | ) | (2) | ||||||||||||||
Total Shipment Volume | 170,067 | 198,855 | (14.5 | )% | 343,812 | 373,642 | (3) | (8.0 | )% | |||||||||
Total Cigarette Shipment Volume | 151,359 | 183,799 | (17.6 | )% | 308,377 | 348,096 | (11.4 | )% | ||||||||||
Shipment Volume for RBH-owned brands (1) | — | (1,008 | ) | (2) | ||||||||||||||
Total Cigarette Shipment Volume | 151,359 | 183,799 | (17.6 | )% | 308,377 | 347,088 | (3) | (11.2 | )% | |||||||||
Total HTU Shipment Volume | 18,708 | 15,056 | 24.3 | % | 35,435 | 26,554 | 33.4 | % | ||||||||||
Latin America & Canada | ||||||||||||||||||
Total Shipment Volume | 14,874 | 18,531 | (19.7 | )% | 30,045 | 36,165 | (16.9 | )% | ||||||||||
Shipment Volume for RBH-owned brands | — | (995 | ) | (2) | ||||||||||||||
Total Shipment Volume | 14,874 | 18,531 | (19.7 | )% | 30,045 | 35,170 | (3) | (14.6 | )% | |||||||||
(1) Includes Duty Free sales in Canada | ||||||||||||||||||
(2) Represents volume for RBH-owned brands from January 1, 2019 through March 21, 2019 | ||||||||||||||||||
(3) Pro forma | ||||||||||||||||||
Note: Shipment Volume includes Cigarettes and Heated Tobacco Units; following the deconsolidation of RBH, we report the volume of brands sold by RBH for which other PMI subsidiaries are the trademark owners | ||||||||||||||||||
Schedule 1 | ||||||||||||||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | ||||||||||||||||||||||||||
Diluted Earnings Per Share (EPS) | ||||||||||||||||||||||||||
($ in millions, except per share data) / (Unaudited) | ||||||||||||||||||||||||||
Quarters Ended | Diluted EPS | Six Months Ended | ||||||||||||||||||||||||
June 30, | June 30, | |||||||||||||||||||||||||
$ | 1.25 | 2020 Diluted Earnings Per Share (1) | $ | 2.42 | ||||||||||||||||||||||
$ | 1.49 | 2019 Diluted Earnings Per Share (1) | $ | 2.36 | ||||||||||||||||||||||
$ | (0.24 | ) | Change | $ | 0.06 | |||||||||||||||||||||
(16.1 | )% | % Change | 2.5 | % | ||||||||||||||||||||||
Reconciliation: | ||||||||||||||||||||||||||
$ | 1.49 | 2019 Diluted Earnings Per Share (1) | $ | 2.36 | ||||||||||||||||||||||
0.01 | 2019 Asset impairment and exit costs | 0.02 | ||||||||||||||||||||||||
— | 2019 Canadian tobacco litigation-related expense | 0.09 | ||||||||||||||||||||||||
— | 2019 Loss on deconsolidation of RBH | 0.12 | ||||||||||||||||||||||||
(0.04 | ) | 2019 Tax items | (0.04 | ) | ||||||||||||||||||||||
(0.04 | ) | 2020 Asset impairment and exit costs | (0.04 | ) | ||||||||||||||||||||||
— | 2020 Fair value adjustment for equity security investments | (0.04 | ) | |||||||||||||||||||||||
— | 2020 Tax items | — | ||||||||||||||||||||||||
(0.06 | ) | Currency | (0.19 | ) | ||||||||||||||||||||||
(0.01 | ) | Interest | — | |||||||||||||||||||||||
0.03 | Change in tax rate | 0.02 | ||||||||||||||||||||||||
(0.13 | ) | Operations (2) | 0.12 | |||||||||||||||||||||||
$ | 1.25 | 2020 Diluted Earnings Per Share (1) | $ | 2.42 | ||||||||||||||||||||||
(1) Basic and diluted EPS were calculated using the following (in millions): | ||||||||||||||||||||||||||
Quarters Ended | Six Months Ended | |||||||||||||||||||||||||
June 30, | June 30, | |||||||||||||||||||||||||
2020 | 2019 | 2020 | 2019 | |||||||||||||||||||||||
$ 1,947 | $ 2,319 | Net Earnings attributable to PMI | $ 3,773 | $ 3,673 | ||||||||||||||||||||||
5 | 5 | Less: Distributed and undistributed earnings attributable to share-based payment awards | 10 | 8 | ||||||||||||||||||||||
$ 1,942 | $ 2,314 | Net Earnings for basic and diluted EPS | $ 3,763 | $ 3,665 | ||||||||||||||||||||||
1,558 | 1,556 | Weighted-average shares for basic EPS | 1,557 | 1,556 | ||||||||||||||||||||||
— | — | Plus Contingently Issuable Performance Stock Units | — | — | ||||||||||||||||||||||
1,558 | 1,556 | Weighted-average shares for diluted EPS | 1,557 | 1,556 | ||||||||||||||||||||||
(2) Includes the impact of shares outstanding and share-based payments | ||||||||||||||||||||||||||
Schedule 2 | |||||||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | |||||||||||||||||||
Reconciliation of Non-GAAP Measures | |||||||||||||||||||
Reconciliation of Reported Diluted EPS to Reported Diluted EPS, excluding Currency, | |||||||||||||||||||
and Reconciliation of Reported Diluted EPS to Adjusted Diluted EPS, excluding Currency | |||||||||||||||||||
(Unaudited) | |||||||||||||||||||
Quarters Ended June 30, | Six Months Ended June 30, | ||||||||||||||||||
2020 | 2019 | % Change | 2020 | 2019 | % Change | ||||||||||||||
$ 1.25 | $ 1.49 | (16.1 | )% | Reported Diluted EPS | $ 2.42 | $ 2.36 | 2.5 | % | |||||||||||
(0.06 | ) | Less: Currency | (0.19 | ) | |||||||||||||||
$ 1.31 | $ 1.49 | (12.1 | )% | Reported Diluted EPS, excluding Currency | $ 2.61 | $ 2.36 | 10.6 | % | |||||||||||
Quarters Ended June 30, | Six Months Ended June 30, | Year Ended | |||||||||||||||||
2020 | 2019 | % Change | 2020 | 2019 | % Change | 2019 | |||||||||||||
$ 1.25 | $ 1.49 | (16.1 | )% | Reported Diluted EPS | $ 2.42 | $ 2.36 | 2.5 | % | $ 4.61 | ||||||||||
0.04 | 0.01 | Asset impairment and exit costs | 0.04 | 0.02 | 0.23 | ||||||||||||||
— | — | Canadian tobacco litigation-related expense | — | 0.09 | 0.09 | ||||||||||||||
— | — | Loss on deconsolidation of RBH | — | 0.12 | 0.12 | ||||||||||||||
— | — | Russia excise and VAT audit charge | — | — | 0.20 | ||||||||||||||
— | — | Fair value adjustment for equity security investments | 0.04 | — | (0.02 | ) | |||||||||||||
— | (0.04 | ) | Tax items | — | (0.04 | ) | (0.04 | ) | |||||||||||
$ 1.29 | $ 1.46 | (11.6 | )% | Adjusted Diluted EPS | $ 2.50 | $ 2.55 | (2.0 | )% | $ 5.19 | ||||||||||
(0.06 | ) | Less: Currency | (0.19 | ) | |||||||||||||||
$ 1.35 | $ 1.46 | (7.5 | )% | Adjusted Diluted EPS, excluding Currency | $ 2.69 | $ 2.55 | 5.5 | % | |||||||||||
Schedule 3 | ||||||||||||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | ||||||||||||||||||||||||
Reconciliation of Non-GAAP Measures | ||||||||||||||||||||||||
Reconciliation of Reported Diluted EPS to Pro Forma Adjusted Diluted EPS | ||||||||||||||||||||||||
(Unaudited) | ||||||||||||||||||||||||
Quarter Ended | Quarter Ended | Six Months Ended | Quarter Ended | Nine Months Ended | Quarter Ended | Year Ended | ||||||||||||||||||
March 31, | June 30, | June 30, | September 30, | September 30, | December 31, | December 31, | ||||||||||||||||||
2019 | 2019 | 2019 | 2019 | 2019 | 2019 | 2019 | ||||||||||||||||||
Reported Diluted EPS | $ 0.87 | $ 1.49 | $ 2.36 | $ 1.22 | $ 3.57 | $ 1.04 | $ | 4.61 | ||||||||||||||||
Asset impairment and exit costs | 0.01 | 0.01 | 0.02 | 0.01 | 0.03 | 0.20 | 0.23 | |||||||||||||||||
Canadian tobacco litigation-related expense | 0.09 | — | 0.09 | — | 0.09 | — | 0.09 | |||||||||||||||||
Loss on deconsolidation of RBH | 0.12 | — | 0.12 | — | 0.12 | — | 0.12 | |||||||||||||||||
Russia excise and VAT audit charge | — | — | — | 0.20 | 0.20 | — | 0.20 | |||||||||||||||||
Fair value adjustment for equity security investments | — | — | — | — | — | (0.02 | ) | (0.02 | ) | |||||||||||||||
Tax items | — | (0.04 | ) | (0.04 | ) | — | (0.04 | ) | — | (0.04 | ) | |||||||||||||
Adjusted Diluted EPS | $ 1.09 | $ 1.46 | $ 2.55 | $ 1.43 | $ 3.97 | $ 1.22 | $ 5.19 | |||||||||||||||||
Net earnings attributable to RBH | (0.06 | ) | (1) | — | (0.06 | ) | (1) | — | (0.06 | ) | (1) | — | (0.06 | ) | (1) | |||||||||
Pro Forma Adjusted Diluted EPS | $ 1.03 | $ 1.46 | $ 2.49 | $ 1.43 | $ 3.91 | $ 1.22 | $ 5.13 | |||||||||||||||||
(1) Represents the impact of net earnings attributable to RBH from January 1, 2019 through March 21, 2019 | ||||||||||||||||||||||||
Note: EPS is computed independently for each of the periods presented. Accordingly, the sum of the quarterly EPS amounts may not agree to the total for the year. | ||||||||||||||||||||||||
Schedule 4 | |||||||||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | |||||||||||||||||||||
Reconciliation of Non-GAAP Measures | |||||||||||||||||||||
Net Revenues by Product Category and Adjustments of Net Revenues for the Impact of Currency and Acquisitions | |||||||||||||||||||||
($ in millions) / (Unaudited) | |||||||||||||||||||||
Net Revenues | Currency | Net Revenues excluding Currency | Acquisitions | Net Revenues excluding Currency & Acquisitions | Quarters Ended June 30, | Net Revenues | Total | Excluding Currency | Excluding Currency & Acquisitions | ||||||||||||
2020 | Combustible Products | 2019 | % Change | ||||||||||||||||||
$ 1,945 | $ (75) | $ 2,020 | — | $ 2,020 | European Union | $ 2,149 | (9.5 | )% | (6.0 | )% | (6.0 | )% | |||||||||
522 | (52 | ) | 575 | — | 575 | Eastern Europe | 640 | (18.3 | )% | (10.1 | )% | (10.1 | )% | ||||||||
696 | (16 | ) | 712 | — | 712 | Middle East & Africa | 918 | (24.2 | )% | (22.4 | )% | (22.4 | )% | ||||||||
889 | (46 | ) | 935 | — | 935 | South & Southeast Asia | 1,248 | (28.8 | )% | (25.1 | )% | (25.1 | )% | ||||||||
630 | (15 | ) | 645 | — | 645 | East Asia & Australia | 756 | (16.7 | )% | (14.7 | )% | (14.7 | )% | ||||||||
363 | (57 | ) | 420 | — | 420 | Latin America & Canada | 522 | (30.5 | )% | (19.6 | )% | (19.6 | )% | ||||||||
$ 5,045 | $ (262) | $ 5,307 | — | $ 5,307 | Total Combustible | $ 6,233 | (19.1 | )% | (14.9 | )% | (14.9 | )% | |||||||||
2020 | Reduced-Risk Products | 2019 | % Change | ||||||||||||||||||
$ 530 | $ (25) | $ 555 | — | $ 555 | European Union | $ 428 | 23.9 | % | 29.7 | % | 29.7 | % | |||||||||
261 | (33 | ) | 293 | — | 293 | Eastern Europe | 182 | 42.9 | % | 60.8 | % | 60.8 | % | ||||||||
8 | — | 8 | — | 8 | Middle East & Africa | 86 | (90.6 | )% | (90.7 | )% | (90.7 | )% | |||||||||
— | — | — | — | — | South & Southeast Asia | — | — | % | — | % | — | % | |||||||||
802 | 3 | 799 | — | 799 | East Asia & Australia | 765 | 4.9 | % | 4.5 | % | 4.5 | % | |||||||||
5 | (1 | ) | 6 | — | 6 | Latin America & Canada(1) | 5 | 7.9 | % | 24.4 | % | 24.4 | % | ||||||||
$ 1,606 | $ (55) | $ 1,661 | — | $ 1,661 | Total RRPs | $ 1,466 | 9.5 | % | 13.3 | % | 13.3 | % | |||||||||
2020 | PMI | 2019 | % Change | ||||||||||||||||||
$ 2,475 | $ (100) | $ 2,575 | — | $ 2,575 | European Union | $ 2,577 | (4.0 | )% | (0.1 | )% | (0.1 | )% | |||||||||
783 | (85 | ) | 868 | — | 868 | Eastern Europe | 822 | (4.7 | )% | 5.6 | % | 5.6 | % | ||||||||
704 | (16 | ) | 720 | — | 720 | Middle East & Africa | 1,004 | (29.9 | )% | (28.3 | )% | (28.3 | )% | ||||||||
889 | (46 | ) | 935 | — | 935 | South & Southeast Asia | 1,248 | (28.8 | )% | (25.1 | )% | (25.1 | )% | ||||||||
1,432 | (12 | ) | 1,444 | — | 1,444 | East Asia & Australia | 1,521 | (5.9 | )% | (5.1 | )% | (5.1 | )% | ||||||||
368 | (58 | ) | 426 | — | 426 | Latin America & Canada | 527 | (30.2 | )% | (19.2 | )% | (19.2 | )% | ||||||||
$ 6,651 | $ (317) | $ 6,968 | — | $ 6,968 | Total PMI | $ 7,699 | (13.6 | )% | (9.5 | )% | (9.5 | )% | |||||||||
(1) Net Revenues include revenues from shipments of Platform 1 devices, heated tobacco units and accessories to Altria Group, Inc., commencing in the third quarter of 2019, for sale under license in the United States. | |||||||||||||||||||||
Note: Sum of product categories or Regions might not foot to Total PMI due to roundings. “-“ indicates amounts between -$0.5 million and +$0.5 million. | |||||||||||||||||||||
Schedule 5 | |||||||||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | |||||||||||||||||||||
Reconciliation of Non-GAAP Measures | |||||||||||||||||||||
Net Revenues by Product Category and Adjustments of Net Revenues for the Impact of Currency and Acquisitions | |||||||||||||||||||||
($ in millions) / (Unaudited) | |||||||||||||||||||||
Net Revenues | Currency | Net Revenues excluding Currency | Acquisitions | Net Revenues excluding Currency & Acquisitions | Six Months Ended June 30, | Net Revenues | Total | Excluding Currency | Excluding Currency & Acquisitions | ||||||||||||
2020 | Combustible Products | 2019 | % Change | ||||||||||||||||||
$ 3,855 | $ (128) | $ 3,983 | — | $ 3,983 | European Union | $ 3,961 | (2.7 | )% | 0.6 | % | 0.6 | % | |||||||||
1,045 | (56 | ) | 1,101 | — | 1,101 | Eastern Europe | 1,110 | (5.9 | )% | (0.8 | )% | (0.8 | )% | ||||||||
1,528 | (18 | ) | 1,547 | — | 1,547 | Middle East & Africa | 1,746 | (12.5 | )% | (11.4 | )% | (11.4 | )% | ||||||||
2,140 | (27 | ) | 2,167 | — | 2,167 | South & Southeast Asia | 2,361 | (9.4 | )% | (8.2 | )% | (8.2 | )% | ||||||||
1,272 | (22 | ) | 1,294 | — | 1,294 | East Asia & Australia | 1,394 | (8.8 | )% | (7.2 | )% | (7.2 | )% | ||||||||
803 | (75 | ) | 878 | — | 878 | Latin America & Canada | 1,168 | (31.3 | )% | (24.9 | )% | (24.9 | )% | ||||||||
$ 10,643 | $ (327) | $ 10,970 | — | $ 10,970 | Total Combustible | $ 11,741 | (9.4 | )% | (6.6 | )% | (6.6 | )% | |||||||||
2020 | Reduced-Risk Products | 2019 | % Change | ||||||||||||||||||
$ 1,155 | $ (42) | $ 1,197 | — | $ 1,197 | European Union | $ 775 | 49.0 | % | 54.4 | % | 54.4 | % | |||||||||
526 | (23 | ) | 549 | — | 549 | Eastern Europe | 291 | 81.0 | % | 88.9 | % | 88.9 | % | ||||||||
52 | — | 51 | — | 51 | Middle East & Africa | 185 | (72.0 | )% | (72.2 | )% | (72.2 | )% | |||||||||
— | — | — | — | — | South & Southeast Asia | — | — | % | — | % | — | % | |||||||||
1,415 | 1 | 1,414 | — | 1,414 | East Asia & Australia | 1,448 | (2.3 | )% | (2.3 | )% | (2.3 | )% | |||||||||
13 | (1 | ) | 14 | — | 14 | Latin America & Canada(1) | 11 | 24.4 | % | 33.5 | % | 33.5 | % | ||||||||
$ 3,161 | $ (64) | $ 3,225 | — | $ 3,225 | Total RRPs | $ 2,709 | 16.7 | % | 19.1 | % | 19.1 | % | |||||||||
2020 | PMI | 2019 | % Change | ||||||||||||||||||
$ 5,010 | $ (170) | $ 5,180 | — | $ 5,180 | European Union | $ 4,736 | 5.8 | % | 9.4 | % | 9.4 | % | |||||||||
1,571 | (79 | ) | 1,650 | — | 1,650 | Eastern Europe | 1,401 | 12.1 | % | 17.8 | % | 17.8 | % | ||||||||
1,580 | (18 | ) | 1,598 | — | 1,598 | Middle East & Africa | 1,931 | (18.2 | )% | (17.2 | )% | (17.2 | )% | ||||||||
2,140 | (27 | ) | 2,167 | — | 2,167 | South & Southeast Asia | 2,361 | (9.4 | )% | (8.2 | )% | (8.2 | )% | ||||||||
2,687 | (21 | ) | 2,708 | — | 2,708 | East Asia & Australia | 2,842 | (5.5 | )% | (4.7 | )% | (4.7 | )% | ||||||||
816 | (76 | ) | 892 | — | 892 | Latin America & Canada | 1,179 | (30.8 | )% | (24.3 | )% | (24.3 | )% | ||||||||
$ 13,804 | $ (391) | $ 14,195 | — | $ 14,195 | Total PMI | $ 14,450 | (4.5 | )% | (1.8 | )% | (1.8 | )% | |||||||||
(1) Net Revenues include revenues from shipments of Platform 1 devices, heated tobacco units and accessories to Altria Group, Inc., commencing in the third quarter of 2019, for sale under license in the United States. | |||||||||||||||||||||
Note: Sum of product categories or Regions might not foot to Total PMI due to roundings. “-“ indicates amounts between -$0.5 million and +$0.5 million. | |||||||||||||||||||||
Schedule 6 | |||||||||||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | |||||||||||||||||||||||
Reconciliation of Non-GAAP Measures | |||||||||||||||||||||||
Adjustments of Operating Income for the Impact of Currency and Acquisitions | |||||||||||||||||||||||
($ in millions) / (Unaudited) | |||||||||||||||||||||||
Operating Income | Currency | Operating Income excluding Currency | Acquisitions | Operating Income excluding Currency & Acquisitions | Operating Income | Total | Excluding Currency | Excluding Currency & Acquisitions | |||||||||||||||
2020 | Quarters Ended June 30, | 2019 | % Change | ||||||||||||||||||||
$ 1,178 | (1) | $ (65) | $ 1,243 | — | $ 1,243 | European Union | $ 1,195 | (1.4 | )% | 4.0 | % | 4.0 | % | ||||||||||
266 | (1) | (11 | ) | 277 | — | 277 | Eastern Europe | 256 | 3.9 | % | 8.2 | % | 8.2 | % | |||||||||
237 | (1) | 5 | 232 | — | 232 | Middle East & Africa | 441 | (46.3 | )% | (47.4 | )% | (47.4 | )% | ||||||||||
289 | (1) | (16 | ) | 305 | — | 305 | South & Southeast Asia | 492 | (41.3 | )% | (38.0 | )% | (38.0 | )% | |||||||||
669 | (1) | (11 | ) | 680 | — | 680 | East Asia & Australia | 642 | 4.2 | % | 5.9 | % | 5.9 | % | |||||||||
92 | (1) | (6 | ) | 98 | — | 98 | Latin America & Canada | 161 | (2) | (42.9 | )% | (39.1 | )% | (39.1 | )% | ||||||||
$ 2,731 | $ (104) | $ 2,835 | — | $ 2,835 | Total PMI | $ 3,187 | (14.3 | )% | (11.0 | )% | (11.0 | )% | |||||||||||
2020 | Six Months Ended June 30, | 2019 | % Change | ||||||||||||||||||||
$ 2,336 | (1) | $ (130) | $ 2,466 | — | $ 2,466 | European Union | $ 2,091 | 11.7 | % | 17.9 | % | 17.9 | % | ||||||||||
365 | (1) | (103 | ) | 468 | — | 468 | Eastern Europe | 385 | (5.2 | )% | 21.6 | % | 21.6 | % | |||||||||
558 | (1) | (14 | ) | 572 | — | 572 | Middle East & Africa | 785 | (28.9 | )% | (27.1 | )% | (27.1 | )% | |||||||||
888 | (1) | 3 | 885 | — | 885 | South & Southeast Asia | 932 | (3) | (4.7 | )% | (5.0 | )% | (5.0 | )% | |||||||||
1,155 | (1) | (15 | ) | 1,170 | — | 1,170 | East Asia & Australia | 1,069 | 8.0 | % | 9.4 | % | 9.4 | % | |||||||||
218 | (1) | (41 | ) | 259 | — | 259 | Latin America & Canada | (25 | ) | (4) | +100% | +100% | +100% | ||||||||||
$ 5,520 | $ (300) | $ 5,820 | — | $ 5,820 | Total PMI | $ 5,237 | 5.4 | % | 11.1 | % | 11.1 | % | |||||||||||
(1) Includes asset impairment and exit costs ($71 million): EU ($27 million), EE ($7 million), ME&A ($9 million), S&SA ($11 million), EA&A ($13 million) and LA&C ($4 million) | |||||||||||||||||||||||
(2) Includes asset impairment and exit costs ($23 million) | |||||||||||||||||||||||
(3) Includes asset impairment and exit costs ($20 million) | |||||||||||||||||||||||
(4) Includes asset impairment and exit costs ($23 million), the Canadian tobacco litigation-related expense ($194 million) and the loss on deconsolidation of RBH ($239 million) | |||||||||||||||||||||||
Schedule 7 | |||||||||||||||||||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | |||||||||||||||||||||||||||||||
Reconciliation of Non-GAAP Measures | |||||||||||||||||||||||||||||||
Reconciliation of Operating Income to Adjusted Operating Income, excluding Currency and Acquisitions | |||||||||||||||||||||||||||||||
($ in millions) / (Unaudited) | |||||||||||||||||||||||||||||||
Operating Income | Asset Impairment & Exit Costs and Others | Adjusted Operating Income | Currency | Adjusted Operating Income excluding Currency | Acqui-sitions | Adjusted Operating Income excluding Currency & Acqui-sitions | Operating Income | Asset Impairment & Exit Costs and Others | Adjusted Operating Income | Total | Excluding Currency | Excluding Currency & Acqui-sitions | |||||||||||||||||||
2020 | Quarters Ended June 30, | 2019 | % Change | ||||||||||||||||||||||||||||
$ 1,178 | $ (27) | (1) | $ 1,205 | $ (65) | $ 1,270 | — | $ 1,270 | European Union | $ 1,195 | — | $ 1,195 | 0.8 | % | 6.3 | % | 6.3 | % | ||||||||||||||
266 | (7 | ) | (1) | 273 | (11 | ) | 284 | — | 284 | Eastern Europe | 256 | — | 256 | 6.6 | % | 10.9 | % | 10.9 | % | ||||||||||||
237 | (9 | ) | (1) | 246 | 5 | 241 | — | 241 | Middle East & Africa | 441 | — | 441 | (44.2 | )% | (45.4 | )% | (45.4 | )% | |||||||||||||
289 | (11 | ) | (1) | 300 | (16 | ) | 316 | — | 316 | South & Southeast Asia | 492 | — | 492 | (39.0 | )% | (35.8 | )% | (35.8 | )% | ||||||||||||
669 | (13 | ) | (1) | 682 | (11 | ) | 693 | — | 693 | East Asia & Australia | 642 | — | 642 | 6.2 | % | 7.9 | % | 7.9 | % | ||||||||||||
92 | (4 | ) | (1) | 96 | (6 | ) | 102 | — | 102 | Latin America & Canada | 161 | (23 | ) | (1) | 184 | (47.8 | )% | (44.6 | )% | (44.6 | )% | ||||||||||
$ 2,731 | $ (71) | $ 2,802 | $ (104) | $ 2,906 | — | $ 2,906 | Total PMI | $ 3,187 | $ (23) | $ 3,210 | (12.7 | )% | (9.5 | )% | (9.5 | )% | |||||||||||||||
2020 | Six Months Ended June 30, | 2019 | % Change | ||||||||||||||||||||||||||||
$ 2,336 | $ (27) | (1) | $ 2,363 | $ (130) | $ 2,493 | — | $ 2,493 | European Union | $ 2,091 | — | $ 2,091 | 13.0 | % | 19.2 | % | 19.2 | % | ||||||||||||||
365 | (7 | ) | (1) | 372 | (103 | ) | 475 | — | 475 | Eastern Europe | 385 | — | 385 | (3.4 | )% | 23.4 | % | 23.4 | % | ||||||||||||
558 | (9 | ) | (1) | 567 | (14 | ) | 581 | — | 581 | Middle East & Africa | 785 | — | 785 | (27.8 | )% | (26.0 | )% | (26.0 | )% | ||||||||||||
888 | (11 | ) | (1) | 899 | 3 | 896 | — | 896 | South & Southeast Asia | 932 | (20 | ) | (1) | 952 | (5.6 | )% | (5.9 | )% | (5.9 | )% | |||||||||||
1,155 | (13 | ) | (1) | 1,168 | (15 | ) | 1,183 | — | 1,183 | East Asia & Australia | 1,069 | — | 1,069 | 9.3 | % | 10.7 | % | 10.7 | % | ||||||||||||
218 | (4 | ) | (1) | 222 | (41 | ) | 263 | — | 263 | Latin America & Canada | (25 | ) | (456 | ) | (2) | 431 | (48.5 | )% | (39.0 | )% | (39.0 | )% | |||||||||
$ 5,520 | $ (71) | $ 5,591 | $ (300) | $ 5,891 | — | $ 5,891 | Total PMI | $ 5,237 | $ (476) | $ 5,713 | (2.1 | )% | 3.1 | % | 3.1 | % | |||||||||||||||
(1) Represents asset impairment and exit costs | |||||||||||||||||||||||||||||||
(2) Includes asset impairment and exit costs ($23 million), the Canadian tobacco litigation-related expense ($194 million) and the loss on deconsolidation of RBH ($239 million) | |||||||||||||||||||||||||||||||
Schedule 8 | |||||||||||||||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | |||||||||||||||||||||||||||
Reconciliation of Non-GAAP Measures | |||||||||||||||||||||||||||
Reconciliation of Adjusted Operating Income Margin, excluding Currency and Acquisitions | |||||||||||||||||||||||||||
($ in millions) / (Unaudited) | |||||||||||||||||||||||||||
Adjusted Operating Income (1) | Net Revenues | Adjusted Operating Income Margin | Adjusted Operating Income excluding Currency (1) | Net Revenues excluding Currency (2) | Adjusted Operating Income Margin excluding Currency | Adjusted Operating Income excluding Currency & Acqui-sitions (1) | Net Revenues excluding Currency & Acqui-sitions (2) | Adjusted Operating Income Margin excluding Currency & Acqui-sitions | Adjusted Operating Income (1) | Net Revenues | Adjusted Operating Income Margin | Adjusted Operating Income Margin | Adjusted Operating Income Margin excluding Currency | Adjusted Operating Income Margin excluding Currency & Acqui-sitions | |||||||||||||
2020 | Quarters Ended June 30, | 2019 | % Points Change | ||||||||||||||||||||||||
$ 1,205 | $ 2,475 | 48.7 | % | $ 1,270 | $ 2,575 | 49.3 | % | $ 1,270 | $ 2,575 | 49.3 | % | European Union | $ 1,195 | $ 2,577 | 46.4 | % | 2.3 | 2.9 | 2.9 | ||||||||
273 | 783 | 34.9 | % | 284 | 868 | 32.7 | % | 284 | 868 | 32.7 | % | Eastern Europe | 256 | 822 | 31.1 | % | 3.8 | 1.6 | 1.6 | ||||||||
246 | 704 | 34.9 | % | 241 | 720 | 33.5 | % | 241 | 720 | 33.5 | % | Middle East & Africa | 441 | 1,004 | 43.9 | % | (9.0 | ) | (10.4 | ) | (10.4 | ) | |||||
300 | 889 | 33.7 | % | 316 | 935 | 33.8 | % | 316 | 935 | 33.8 | % | South & Southeast Asia | 492 | 1,248 | 39.4 | % | (5.7 | ) | (5.6 | ) | (5.6 | ) | |||||
682 | 1,432 | 47.6 | % | 693 | 1,444 | 48.0 | % | 693 | 1,444 | 48.0 | % | East Asia & Australia | 642 | 1,521 | 42.2 | % | 5.4 | 5.8 | 5.8 | ||||||||
96 | 368 | 26.1 | % | 102 | 426 | 23.9 | % | 102 | 426 | 23.9 | % | Latin America & Canada | 184 | 527 | 34.9 | % | (8.8 | ) | (11.0 | ) | (11.0 | ) | |||||
$ 2,802 | $ 6,651 | 42.1 | % | $ 2,906 | $ 6,968 | 41.7 | % | $ 2,906 | $ 6,968 | 41.7 | % | Total PMI | $ 3,210 | $ 7,699 | 41.7 | % | 0.4 | — | — | ||||||||
2020 | Six Months Ended June 30, | 2019 | % Points Change | ||||||||||||||||||||||||
$ 2,363 | $ 5,010 | 47.2 | % | $ 2,493 | $ 5,180 | 48.1 | % | $ 2,493 | $ 5,180 | 48.1 | % | European Union | $ 2,091 | $ 4,736 | 44.2 | % | 3.0 | 3.9 | 3.9 | ||||||||
372 | 1,571 | 23.7 | % | 475 | 1,650 | 28.8 | % | 475 | 1,650 | 28.8 | % | Eastern Europe | 385 | 1,401 | 27.5 | % | (3.8 | ) | 1.3 | 1.3 | |||||||
567 | 1,580 | 35.9 | % | 581 | 1,598 | 36.4 | % | 581 | 1,598 | 36.4 | % | Middle East & Africa | 785 | 1,931 | 40.7 | % | (4.8 | ) | (4.3 | ) | (4.3 | ) | |||||
899 | 2,140 | 42.0 | % | 896 | 2,167 | 41.3 | % | 896 | 2,167 | 41.3 | % | South & Southeast Asia | 952 | 2,361 | 40.3 | % | 1.7 | 1.0 | 1.0 | ||||||||
1,168 | 2,687 | 43.5 | % | 1,183 | 2,708 | 43.7 | % | 1,183 | 2,708 | 43.7 | % | East Asia & Australia | 1,069 | 2,842 | 37.6 | % | 5.9 | 6.1 | 6.1 | ||||||||
222 | 816 | 27.2 | % | 263 | 892 | 29.5 | % | 263 | 892 | 29.5 | % | Latin America & Canada | 431 | 1,179 | 36.6 | % | (9.4 | ) | (7.1 | ) | (7.1 | ) | |||||
$ 5,591 | $ 13,804 | 40.5 | % | $ 5,891 | $ 14,195 | 41.5 | % | $ 5,891 | $ 14,195 | 41.5 | % | Total PMI | $ 5,713 | $ 14,450 | 39.5 | % | 1.0 | 2.0 | 2.0 | ||||||||
(1) For the calculation of Adjusted Operating Income and Adjusted Operating Income excluding currency and acquisitions refer to Schedule 7 | |||||||||||||||||||||||||||
(2) For the calculation of Net Revenues excluding currency and acquisitions refer to Schedules 4 and 5 | |||||||||||||||||||||||||||
Schedule 9 | |||||||||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | |||||||||||||||||||||
Reconciliation of Non-GAAP Measures | |||||||||||||||||||||
Adjustments for the Impact of RBH, excluding Currency | |||||||||||||||||||||
($ in millions, except per share data) / (Unaudited) | |||||||||||||||||||||
Quarters Ended June 30, | Six Months Ended June 30, | ||||||||||||||||||||
2020 | 2019 | % Change | 2020 | 2019 | % Change | ||||||||||||||||
Net Revenues | $ 6,651 | $ 7,699 | (13.6 | )% | $ 13,804 | $ 14,450 | (4.5 | )% | |||||||||||||
Net Revenues attributable to RBH | — | (181 | ) | (1) | |||||||||||||||||
Net Revenues | $ 6,651 | $ 7,699 | (13.6 | )% | $ 13,804 | $ 14,269 | (2) | (3.3 | )% | ||||||||||||
Less: Currency | (317 | ) | (392 | ) | |||||||||||||||||
Net Revenues, ex. currency | $ 6,968 | $ 7,699 | (9.5 | )% | $ 14,196 | $ 14,269 | (2) | (0.5 | )% | ||||||||||||
Adjusted Operating Income (3) | $ 2,802 | $ 3,210 | (12.7 | )% | $ 5,591 | $ 5,713 | (2.1 | )% | |||||||||||||
Operating Income attributable to RBH | — | (126 | ) | (1) | |||||||||||||||||
Adjusted Operating Income | $ 2,802 | $ 3,210 | (12.7 | )% | $ 5,591 | $ 5,587 | (2) | 0.1 | % | ||||||||||||
Less: Currency | (104 | ) | (299 | ) | |||||||||||||||||
Adjusted Operating Income, ex. currency | $ 2,906 | $ 3,210 | (9.5 | )% | $ 5,890 | $ 5,587 | (2) | 5.4 | % | ||||||||||||
Adjusted OI Margin | 42.1 | % | 41.7 | % | 0.4 | 40.5 | % | 39.5 | % | 1.0 | |||||||||||
Adjusted OI Margin attributable to RBH | — | (0.3 | ) | (1) | |||||||||||||||||
Adjusted OI Margin | 42.1 | % | 41.7 | % | 0.4 | 40.5 | % | 39.2 | % | (2) | 1.3 | ||||||||||
Less: Currency | — | — | |||||||||||||||||||
Adjusted OI Margin, ex. currency | 41.7 | % | 41.7 | % | — | 41.5 | % | 39.2 | % | (2) | 2.3 | ||||||||||
Adjusted Diluted EPS (4) | $ 1.29 | $ 1.46 | (11.6 | )% | $ 2.50 | $ 2.55 | (2.0 | )% | |||||||||||||
Net earnings attributable to RBH | — | (0.06 | ) | (1) | |||||||||||||||||
Adjusted Diluted EPS | $ 1.29 | $ 1.46 | (11.6 | )% | $ 2.50 | $ 2.49 | (2) | 0.4 | % | ||||||||||||
Less: Currency | (0.06 | ) | (0.19 | ) | |||||||||||||||||
Adjusted Diluted EPS, ex. currency | $ 1.35 | $ 1.46 | (7.5 | )% | $ 2.69 | $ 2.49 | (2) | 8.0 | % | ||||||||||||
(1) Represents the impact attributable to RBH from January 1, 2019 through March 21, 2019 | |||||||||||||||||||||
(2) Pro forma | |||||||||||||||||||||
(3) For the calculation of Adjusted Operating Income, see Schedule 7 | |||||||||||||||||||||
(4) For the calculation, see Schedule 2 | |||||||||||||||||||||
Note: Financials attributable to RBH include Duty Free sales in Canada | |||||||||||||||||||||
Schedule 10 | |||||||||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | |||||||||||||||||||||
Reconciliation of Non-GAAP Measures | |||||||||||||||||||||
Adjustments for the Impact of RBH, excluding Currency | |||||||||||||||||||||
($ in millions) / (Unaudited) | |||||||||||||||||||||
Latin America & Canada | Quarters Ended June 30, | Six Months Ended June 30, | |||||||||||||||||||
2020 | 2019 | % Change | 2020 | 2019 | % Change | ||||||||||||||||
Net Revenues | $ 368 | $ 527 | (30.2 | )% | $ 816 | $ 1,179 | (30.8 | )% | |||||||||||||
Net Revenues attributable to RBH | — | (179 | ) | (1) | |||||||||||||||||
Net Revenues | $ 368 | $ 527 | (30.2 | )% | $ 816 | $ 1,000 | (2) | (18.4 | )% | ||||||||||||
Less: Currency | (58 | ) | (77 | ) | |||||||||||||||||
Net Revenues, ex. currency | $ 426 | $ 527 | (19.2 | )% | $ 893 | $ 1,000 | (2) | (10.7 | )% | ||||||||||||
Operating Income | $ 92 | $ 161 | (42.9 | )% | $ 218 | $ (25) | +100% | ||||||||||||||
Less: | |||||||||||||||||||||
Asset impairment and exit costs | (4 | ) | (23 | ) | (4 | ) | (23 | ) | |||||||||||||
Canadian tobacco litigation-related expense | — | — | — | (194 | ) | ||||||||||||||||
Loss on deconsolidation of RBH | — | — | — | (239 | ) | ||||||||||||||||
Adjusted Operating Income | $ 96 | $ 184 | (47.8 | )% | $ 222 | $ 431 | (48.5 | )% | |||||||||||||
Operating Income attributable to RBH | — | (125 | ) | (1) | |||||||||||||||||
Adjusted Operating Income | $ 96 | $ 184 | (47.8 | )% | $ 222 | $ 306 | (2) | (27.5 | )% | ||||||||||||
Less: Currency | (6 | ) | (39 | ) | |||||||||||||||||
Adjusted Operating Income, ex. currency | $ 102 | $ 184 | (44.6 | )% | $ 261 | $ 306 | (2) | (14.7 | )% | ||||||||||||
Adjusted OI Margin | 26.1 | % | 34.9 | % | (8.8 | ) | 27.2 | % | 36.6 | % | (9.4 | ) | |||||||||
Adjusted OI Margin attributable to RBH | — | (6.0 | ) | (1) | |||||||||||||||||
Adjusted OI Margin | 26.1 | % | 34.9 | % | (8.8 | ) | 27.2 | % | 30.6 | % | (2) | (3.4 | ) | ||||||||
Less: Currency | 2.2 | (2.0 | ) | ||||||||||||||||||
Adjusted OI Margin, ex. currency | 23.9 | % | 34.9 | % | (11.0 | ) | 29.2 | % | 30.6 | % | (2) | (1.4 | ) | ||||||||
(1) Represents the impact attributable to RBH from January 1, 2019 through March 21, 2019 | |||||||||||||||||||||
(2) Pro forma | |||||||||||||||||||||
Schedule 11 | |||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | |||||||||||||||
Condensed Statements of Earnings | |||||||||||||||
($ in millions, except per share data) / (Unaudited) | |||||||||||||||
Quarters Ended June 30, | Six Months Ended June 30, | ||||||||||||||
2020 | 2019 | Change Fav./(Unfav.) | 2020 | 2019 | Change Fav./(Unfav.) | ||||||||||
$ 17,819 | $ 19,987 | (10.8 | )% | Revenues including Excise Taxes | $ 36,072 | $ 37,692 | (4.3 | )% | |||||||
11,168 | 12,288 | 9.1 | % | Excise Taxes on products | 22,268 | 23,242 | 4.2 | % | |||||||
6,651 | 7,699 | (13.6 | )% | Net Revenues | 13,804 | 14,450 | (4.5 | )% | |||||||
2,179 | 2,665 | 18.2 | % | Cost of sales | 4,581 | 5,130 | 10.7 | % | |||||||
4,472 | 5,034 | (11.2 | )% | Gross profit | 9,223 | 9,320 | (1.0 | )% | |||||||
1,722 | 1,831 | 6.0 | % | Marketing, administration and research costs (1) | 3,666 | 4,048 | 9.4 | % | |||||||
19 | 16 | Amortization of intangibles | 37 | 35 | |||||||||||
2,731 | 3,187 | (14.3 | )% | Operating Income | 5,520 | 5,237 | 5.4 | % | |||||||
162 | 150 | (8.0 | )% | Interest expense, net | 291 | 302 | 3.6 | % | |||||||
22 | 20 | (10.0 | )% | Pension and other employee benefit costs | 45 | 41 | (9.8 | )% | |||||||
2,547 | 3,017 | (15.6 | )% | Earnings before income taxes | 5,184 | 4,894 | 5.9 | % | |||||||
528 | 611 | 13.6 | % | Provision for income taxes | 1,124 | 1,035 | (8.6 | )% | |||||||
(30 | ) | (30 | ) | Equity investments and securities (income)/loss, net | 24 | (41 | ) | ||||||||
2,049 | 2,436 | (15.9 | )% | Net Earnings | 4,036 | 3,900 | 3.5 | % | |||||||
102 | 117 | Net Earnings attributable to noncontrolling interests | 263 | 227 | |||||||||||
$ 1,947 | $ 2,319 | (16.0 | )% | Net Earnings attributable to PMI | $ 3,773 | $ 3,673 | 2.7 | % | |||||||
Per share data (2): | |||||||||||||||
$ 1.25 | $ 1.49 | (16.1 | )% | Basic Earnings Per Share | $ 2.42 | $ 2.36 | 2.5 | % | |||||||
$ 1.25 | $ 1.49 | (16.1 | )% | Diluted Earnings Per Share | $ 2.42 | $ 2.36 | 2.5 | % | |||||||
(1) Six months ended and quarter ended June 30, 2020 includes asset impairment and exit costs ($71 million). Six months ended June 30, 2019 includes asset impairment and exit costs ($43 million), Canadian tobacco litigation-related expense ($194 million) and the loss on deconsolidation of RBH ($239 million). Quarter ended June 30, 2019 includes asset impairment and exit costs ($23 million). | |||||||||||||||
(2) Net Earnings and weighted-average shares used in the basic and diluted Earnings Per Share computations for the quarters and for the six months ended June 30, 2020 and 2019 are shown on Schedule 1, Footnote 1. | |||||||||||||||
Schedule 12 | ||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | ||||||||||
Condensed Balance Sheets | ||||||||||
($ in millions, except ratios) / (Unaudited) | ||||||||||
June 30, | December 31, | |||||||||
2020 | 2019 | |||||||||
Assets | ||||||||||
Cash and cash equivalents | $ | 4,200 | $ | 6,861 | ||||||
All other current assets | 13,576 | 13,653 | ||||||||
Property, plant and equipment, net | 6,184 | 6,631 | ||||||||
Goodwill | 5,653 | 5,858 | ||||||||
Other intangible assets, net | 1,948 | 2,113 | ||||||||
Investments in unconsolidated subsidiaries and equity securities | 4,516 | 4,635 | ||||||||
Other assets | 3,085 | 3,124 | ||||||||
Total assets | $ | 39,162 | $ | 42,875 | ||||||
Liabilities and Stockholders' (Deficit) Equity | ||||||||||
Short-term borrowings | $ | 281 | $ | 338 | ||||||
Current portion of long-term debt | 2,304 | 4,051 | ||||||||
All other current liabilities | 13,207 | 14,444 | ||||||||
Long-term debt | 27,043 | 26,656 | ||||||||
Deferred income taxes | 775 | 908 | ||||||||
Other long-term liabilities | 5,672 | 6,077 | ||||||||
Total liabilities | 49,282 | 52,474 | ||||||||
Total PMI stockholders' deficit | (11,997 | ) | (11,577 | ) | ||||||
Noncontrolling interests | 1,877 | 1,978 | ||||||||
Total stockholders' (deficit) equity | (10,120 | ) | (9,599 | ) | ||||||
Total liabilities and stockholders' (deficit) equity | $ | 39,162 | $ | 42,875 | ||||||
Schedule 13 | ||||||||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | ||||||||||||||||||
Reconciliation of Non-GAAP Measures | ||||||||||||||||||
Calculation of Total Debt to Adjusted EBITDA and Net Debt to Adjusted EBITDA Ratios | ||||||||||||||||||
($ in millions, except ratios) / (Unaudited) | ||||||||||||||||||
Year Ended June 30, 2020 | Year Ended December 31, 2019 | |||||||||||||||||
July ~ December | January ~ June | 12 months | ||||||||||||||||
2019 | 2020 | rolling | ||||||||||||||||
Net Earnings | $ | 3,828 | $ | 4,036 | $ | 7,864 | $ | 7,728 | ||||||||||
Equity investments and securities (income)/loss, net | (108 | ) | 24 | (84 | ) | (149 | ) | |||||||||||
Provision for income taxes | 1,258 | 1,124 | 2,382 | 2,293 | ||||||||||||||
Interest expense, net | 268 | 291 | 559 | 570 | ||||||||||||||
Depreciation and amortization | 492 | 470 | 962 | 964 | ||||||||||||||
Asset impairment and exit costs and Others (1) | 753 | 71 | 824 | 1,229 | ||||||||||||||
Adjusted EBITDA | $ | 6,491 | $ | 6,016 | $ | 12,507 | $ | 12,635 | ||||||||||
June 30, | December 31, | |||||||||||||||||
2020 | 2019 | |||||||||||||||||
Short-term borrowings | $ | 281 | $ | 338 | ||||||||||||||
Current portion of long-term debt | 2,304 | 4,051 | ||||||||||||||||
Long-term debt | 27,043 | 26,656 | ||||||||||||||||
Total Debt | $ | 29,628 | $ | 31,045 | ||||||||||||||
Cash and cash equivalents | 4,200 | 6,861 | ||||||||||||||||
Net Debt | $ | 25,428 | $ | 24,184 | ||||||||||||||
Ratios: | ||||||||||||||||||
Total Debt to Adjusted EBITDA | 2.37 | 2.46 | ||||||||||||||||
Net Debt to Adjusted EBITDA | 2.03 | 1.91 | ||||||||||||||||
(1) For the period July to December 2019, Others include the Russia excise and VAT charge ($374 million). For the year ended December 31, 2019, Others include the Canadian tobacco litigation-related expense ($194 million), the loss on deconsolidation of RBH ($239 million) and the Russia excise and VAT audit charge ($374 million). | ||||||||||||||||||
Schedule 14 | ||||||||||||
PHILIP MORRIS INTERNATIONAL INC. and Subsidiaries | ||||||||||||
Reconciliation of Non-GAAP Measures | ||||||||||||
Reconciliation of Operating Cash Flow to Operating Cash Flow, excluding Currency | ||||||||||||
($ in millions) / (Unaudited) | ||||||||||||
Quarters Ended June 30, | Six Months Ended June 30, | |||||||||||
2020 | 2019 | % Change | 2020 | 2019 | % Change | |||||||
$ 1,925 | $ 3,442 | (44.1 | )% | Net cash provided by operating activities (1) | $ 3,036 | $ 4,683 | (35.2 | )% | ||||
(198 | ) | Less: Currency | (248 | ) | ||||||||
$ 2,123 | $ 3,442 | (38.3 | )% | Net cash provided by operating activities, excluding currency | $ 3,284 | $ 4,683 | (29.9 | )% | ||||
(1) Operating cash flow | ||||||||||||