EXHIBIT 99.1
ServisFirst Bancshares, Inc. Announces Results for First Quarter of 2020
BIRMINGHAM, Ala., April 20, 2020 (GLOBE NEWSWIRE) -- ServisFirst Bancshares, Inc. (NASDAQ: SFBS), today announced earnings and operating results for the quarter ended March 31, 2020.
First Quarter 2020 Highlights:
- Net income of $34.8 million for the quarter
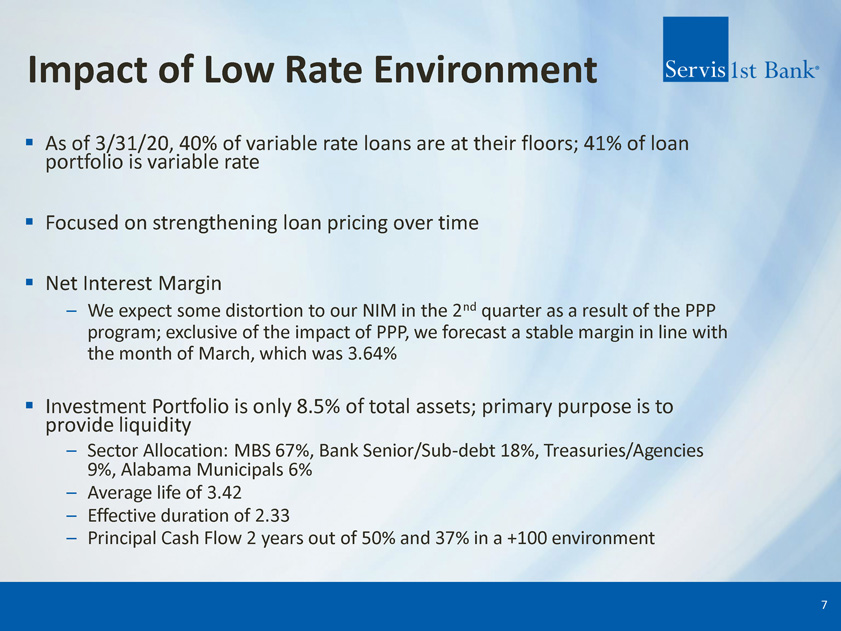
- Net interest margin increased to 3.58% compared to 3.47% in the fourth quarter of 2019
- Diluted earnings per share were $0.64 for the quarter
- Deposits grew 16% annualized during the quarter
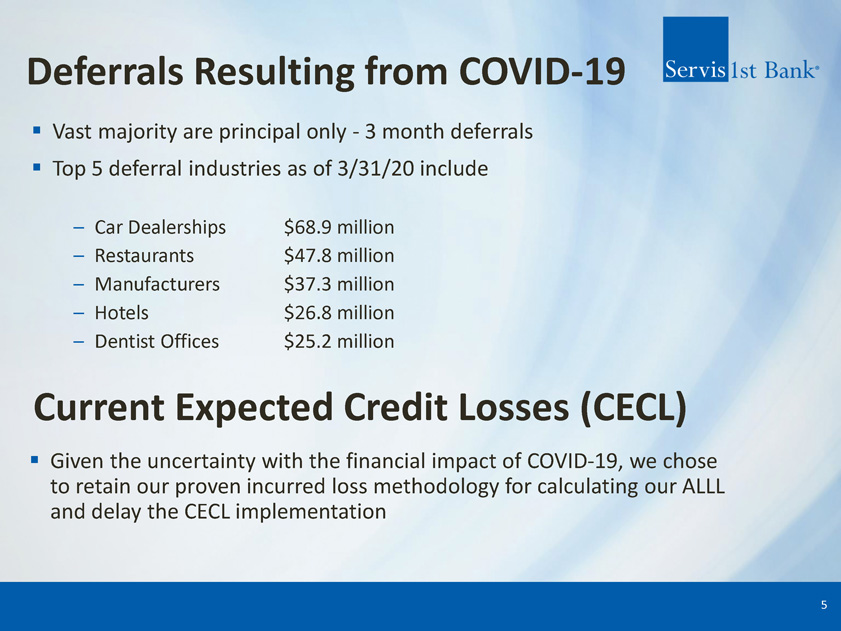
- Loan loss reserves were enhanced during the quarter in light of current economic conditions
- Non-interest income increased by $1.7 million, or 35%, year-over-year
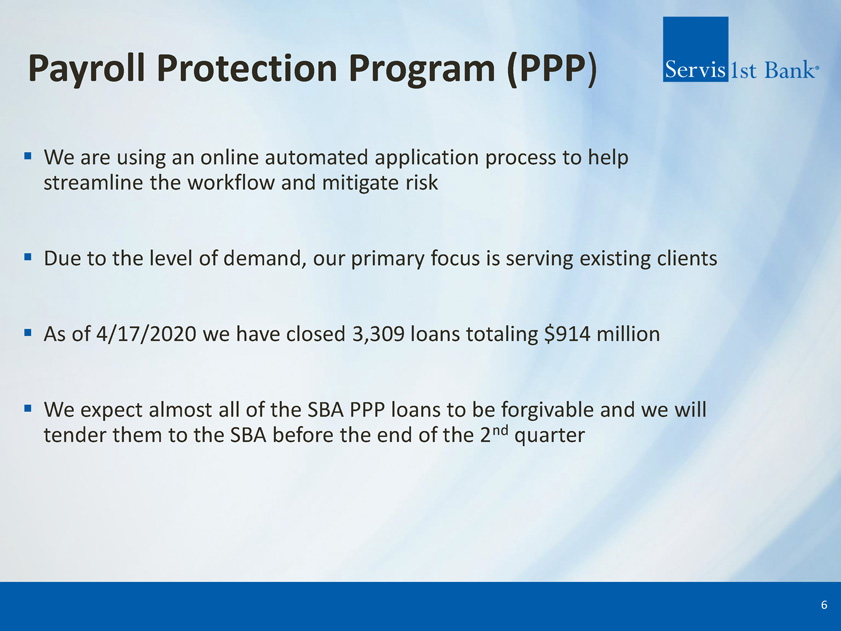
Tom Broughton, Chairman, President and CEO, said, “Our current focus is on serving our client needs during the current pandemic and our team has done an outstanding job. I could not be more proud of our hard working bankers who have gone above and beyond. They are what makes our company a standout in our industry for customer service.”
Bud Foshee, CFO, said, “We are pleased to have a strong balance sheet and solid profitability that positions us well during the current pandemic and beyond. Our return on average assets was 1.54% during the first quarter. Our pre-tax, pre-provision return on average assets was 2.49% during the first quarter, which is among the best in the banking industry.”
| FINANCIAL SUMMARY (UNAUDITED) | |||||||||||||||||||||||
| (in Thousands except share and per share amounts) | |||||||||||||||||||||||
| Period Ending March 31, 2020 | Period Ending December 31, 2019 | % Change From Period Ending December 31, 2019 to Period Ending March 31, 2020 | Period Ending March 31, 2019 | % Change From Period Ending March 31, 2019 to Period Ending March 31, 2020 | |||||||||||||||||||
| QUARTERLY OPERATING RESULTS | |||||||||||||||||||||||
| Net Income | $ | 34,778 | $ | 41,037 | (15 | ) | % | $ | 35,010 | (1 | ) | % | |||||||||||
| Net Income Available to Common Stockholders | $ | 34,778 | $ | 41,005 | (15 | ) | % | $ | 35,010 | (1 | ) | % | |||||||||||
| Diluted Earnings Per Share | $ | 0.64 | $ | 0.76 | (16 | ) | % | $ | 0.65 | (2 | ) | % | |||||||||||
| Return on Average Assets | 1.54 | % | 1.80 | % | 1.75 | % | |||||||||||||||||
| Return on Average Common Stockholders' Equity | 16.23 | % | 19.75 | % | 19.42 | % | |||||||||||||||||
| Average Diluted Shares Outstanding | 54,167,414 | 54,149,554 | 54,076,538 | ||||||||||||||||||||
| BALANCE SHEET | |||||||||||||||||||||||
| Total Assets | $ | 9,364,882 | $ | 8,947,653 | 5 | % | $ | 8,310,836 | 13 | % | |||||||||||||
| Loans | 7,568,836 | 7,261,451 | 4 | % | 6,659,908 | 14 | % | ||||||||||||||||
| Non-interest-bearing Demand Deposits | 1,925,626 | 1,749,879 | 10 | % | 1,572,703 | 22 | % | ||||||||||||||||
| Total Deposits | 7,832,655 | 7,530,433 | 4 | % | 7,083,666 | 11 | % | ||||||||||||||||
| Stockholders' Equity | 881,885 | 842,682 | 5 | % | 745,586 | 18 | % | ||||||||||||||||
DETAILED FINANCIALS
ServisFirst Bancshares, Inc. reported net income and net income available to common stockholders of $34.8 million for the quarter ended March 31, 2020, compared to net income and net income available to common stockholders of $35.0 million for the same quarter in 2019. Basic and diluted earnings per common share were $0.65 and $0.64, respectively, for the first quarter of 2020, compared to $0.65 and $0.65, respectively, for the first quarter of 2019.
Annualized return on average assets was 1.54% and annualized return on average common stockholders’ equity was 16.23% for the first quarter of 2020, compared to 1.75% and 19.42%, respectively, for the first quarter of 2019.
Net interest income was $77.6 million for the first quarter of 2020, compared to $75.8 million for the fourth quarter of 2019 and $68.8 million for the first quarter of 2019. The net interest margin in the first quarter of 2020 was 3.58% compared to 3.47% in the fourth quarter of 2019 and 3.56% in the first quarter of 2019. Linked quarter decreases in average rates paid on deposits in excess of decreases in loan yields drove a favorable rate change and increases in average balances in loans, non-interest-bearing demand deposits and equity drove favorable volume change.
Average loans for the first quarter of 2020 were $7.36 billion, an increase of $259.0 million, or 15% annualized, over average loans of $7.10 billion for the fourth quarter of 2019, and an increase of $759.7 million, or 12%, over average loans of $6.60 billion for the first quarter of 2019.
Average total deposits for the first quarter of 2020 were $7.64 billion, a decrease of $44,000, from average total deposits of $7.68 billion for the fourth quarter of 2019, and an increase of $662.7 million, or 10%, over average total deposits of $6.98 billion for the first quarter of 2019.
Non-performing assets to total assets were 0.44% for the first quarter of 2020, a decrease of six basis points compared to 0.50% for the fourth quarter of 2019 and an increase of three basis points compared to 0.41% for the first quarter of 2019. Annualized net charge-offs to average loans were 0.26%, a 10 basis point decrease compared to 0.36% for the fourth quarter of 2019 and an increase of six basis points compared to 0.20% for the first quarter of 2019. We recorded a $13.6 million provision for loan losses in the first quarter of 2020 compared to $5.9 million in the fourth quarter of 2019 and $4.9 million in the first quarter of 2019. We have added a new pandemic qualitative factor to our allowance for loan loss calculation and have increased qualitative factors related to macroeconomic conditions; these changes resulted in the need for an additional loan loss provision during the quarter. The allowance for loan loss as a percentage of total loans was 1.13% at March 31, 2020, an increase of eight basis points compared to 1.05% at December 31, 2019 and an increase of 11 basis points compared to 1.02% as of March 31, 2019. The CARES Act, passed into law on March 27, 2020 as a result of the COVID-19 outbreak, allows companies to delay their adoption of Accounting Standards Update (ASU) 2016-13, Measurement of Credit Losses on Financial Instruments (CECL), including the current expected credit losses methodology for estimating allowances for credit losses. We have elected to delay adoption of ASU 2016-13 until the date on which the national emergency concerning the COVID-19 outbreak terminates or December 31, 2020, with an effective retrospective implementation date of January 1, 2020. In management’s opinion, the allowance is adequate and was determined by consistent application of ServisFirst Bank’s methodology for calculating its allowance for loan losses.
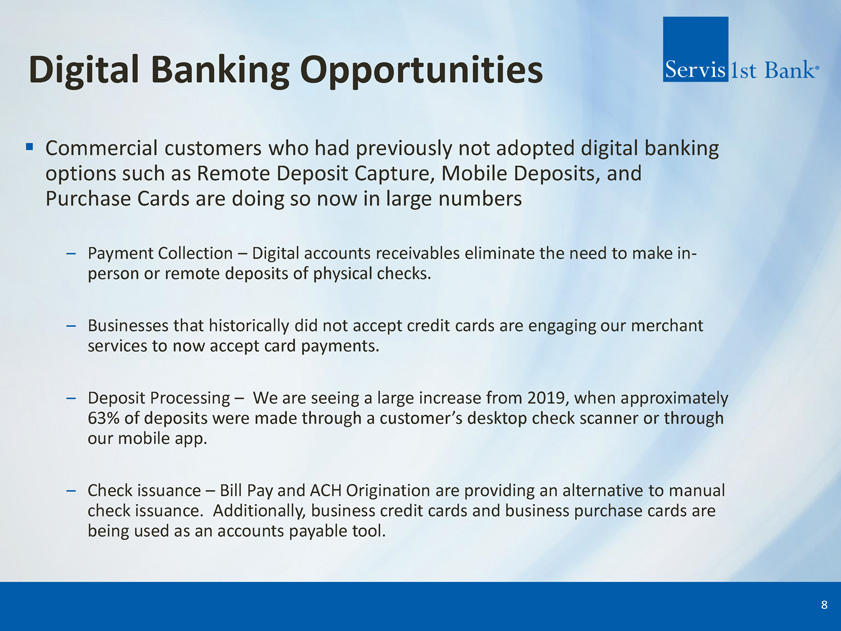
Non-interest income for the first quarter of 2020 increased $1.8 million, or 36%, to $6.7 million from $4.9 million in the first quarter of 2019. Deposit service charges increased $214,000 in the first quarter of 2020, or 13%, compared to the first quarter of 2019. Mortgage banking revenue almost doubled to $1.1 million from the first quarter of 2019 to the first quarter of 2020. Mortgage loan sales increased approximately 96% during the first quarter of 2020 when compared to the same quarter in 2019. Credit card revenue increased $189,000, or 12%, to $1.8 million during the first quarter of 2020, compared to $1.6 million during the first quarter of 2019. The number of credit card accounts increased approximately 43% and the aggregate amount of sales on all credit card accounts increased 29% during the first quarter of 2020. Cash surrender value of life insurance increased $691,000, or 91%, to $1.5 million during the first quarter of 2020, compared to $762,000 during the first quarter of 2019. We purchased $75.0 million of additional life insurance contracts during the third quarter of 2019. Other income for the first quarter of 2020 increased $140,000, or 43%, to $469,000 from $329,000 in the first quarter of 2019.
Non-interest expense for the first quarter of 2020 increased $2.6 million, or 10%, to $27.9 million from $25.3 million in the first quarter of 2019, and increased $2.3 million, or 9%, on a linked quarter basis. Salary and benefit expense for the first quarter of 2020 increased $1.4 million, or 10%, to $15.7 million from $14.3 million in the first quarter of 2019, and increased $2.0 million, or 15%, on a linked quarter basis. We adjusted accrued incentives downward by $1.0 million in December based on actual year-end production in 2019. The number of FTE employees increased from 485 at March 31, 2019 to 492 at March 31, 2020, or 1%, and decreased by eight from the end of the fourth quarter of 2019. Equipment and occupancy expense increased $141,000, or 6%, to $2.4 million in the first quarter of 2020, from $2.3 million in the first quarter of 2019, and decreased $61,000 on a linked-quarter basis. Third party processing and other services expense increased $934,000, or 39%, to $3.3 million in the first quarter of 2020, from $2.4 million in the first quarter of 2019. Professional services expense decreased $46,000, or 5%, to $948,000 in the first quarter of 2020, from $994,000 in the first quarter of 2019, and decreased $215,000 on a linked-quarter basis. FDIC and other regulatory assessments increased $313,000 to $1.3 million in the first quarter of 2020, from $1.0 million in the first quarter of 2019. Growth in our assessment base was partially offset by a decrease in our assessment rate. Expenses associated with other real estate owned increased $579,000 to $601,000 in the first quarter of 2020, from $22,000 in the first quarter of 2019. This increase was the result of write-downs in value of property based on updated appraisals related to one foreclosed loan relationship in our Nashville region. Other operating expenses for the first quarter of 2020 decreased $722,000, or 17%, to $3.6 million from $4.4 million in the first quarter of 2019, and decreased $235,000 on a linked-quarter basis. Write-downs in tax credit investments decreased significantly as our New Market Tax Credit partnerships terminated at the end of 2019. Decreases in travel and entertainment expenses also contributed to the decrease in other operating expenses. We accrued $250,000 for a pending legal matter during the first quarter of 2020. The efficiency ratio was 33.11% during the first quarter of 2020 compared to 34.36% during the first quarter of 2019 and compared to 30.83% during the fourth quarter of 2019.
Income tax expense decreased $467,000, or 6%, to $8.0 million in the first quarter of 2020, compared to $8.5 million in the first quarter of 2019. Our effective tax rate was 18.76% for the first quarter of 2020 compared to 19.53% for the first quarter of 2019. We recognized a reduction in provision for income taxes resulting from excess tax benefits from the exercise and vesting of stock options and restricted stock during the first quarters of 2020 and 2019 of $1.1 million and $772,000, respectively.
GAAP Reconciliation and Management Explanation of Non-GAAP Financial Measures
During the third quarter of 2019, we recorded a $1.7 million credit to our FDIC and other regulatory assessments expense as a result of the FDIC’s Small Bank Assessment Credit. Financial measures included in this press release that are presented adjusted for this credit are net income, net income available to common stockholders, diluted earnings per share, return on average assets and return on average common stockholders’ equity. Each of these five financial measures excludes the impact of this item, net of tax, attributable to the FDIC Small Bank Assessment Credit and are all considered non-GAAP financial measures. This press release also contains certain non-GAAP financial measures, including tangible common stockholders’ equity, total tangible assets, tangible book value per share and tangible common equity to total tangible assets, each of which excludes goodwill and core deposit intangibles associated with our acquisition of Metro Bancshares, Inc. in January 2015 and pre-tax, pre-provision return on average assets. We believe these non-GAAP financial measures provide useful information to management and investors that is supplementary to our financial condition, results of operations and cash flows computed in accordance with GAAP; however, we acknowledge that these non-GAAP financial measures have a number of limitations. As such, you should not view these disclosures as a substitute for results determined in accordance with GAAP, and they are not necessarily comparable to non-GAAP financial measures that other companies, including those in our industry, use. The following reconciliation tables provide a more detailed analysis of the non-GAAP financial measures as of and for the comparative periods presented in this press release. Dollars are in thousands, except share and per share data.
| Three Months Ended September 30, 2019 | |||||||||||||||||||||||
| Net income - GAAP | $ | 149,243 | |||||||||||||||||||||
| Adjustments: | |||||||||||||||||||||||
| FDIC Small Bank Assessment Credit | 1,669 | ||||||||||||||||||||||
| Tax on adjustment | 421 | ||||||||||||||||||||||
| Adjusted net income - non-GAAP | $ | 147,995 | |||||||||||||||||||||
| Net income available to common stockholders - GAAP | $ | 149,180 | |||||||||||||||||||||
| Adjustments: | |||||||||||||||||||||||
| FDIC Small Bank Assessment Credit | 1,669 | ||||||||||||||||||||||
| Tax on adjustment | 421 | ||||||||||||||||||||||
| Adjusted net income available to common stockholders - | |||||||||||||||||||||||
| non-GAAP | $ | 147,932 | |||||||||||||||||||||
| Diluted earnings per share - GAAP | $ | 2.76 | |||||||||||||||||||||
| Adjustments: | |||||||||||||||||||||||
| FDIC Small Bank Assessment Credit | (0.03 | ) | |||||||||||||||||||||
| Tax on adjustment | 0.01 | ||||||||||||||||||||||
| Adjusted diluted earnings per share - non-GAAP | $ | 2.74 | |||||||||||||||||||||
| Return on average assets - GAAP | 1.73 | % | |||||||||||||||||||||
| Net income - GAAP | $ | 149,243 | |||||||||||||||||||||
| Adjustments: | |||||||||||||||||||||||
| FDIC Small Bank Assessment Credit | 1,669 | ||||||||||||||||||||||
| Tax on adjustment | 421 | ||||||||||||||||||||||
| Adjusted net income - non-GAAP | $ | 147,995 | |||||||||||||||||||||
| Average assets - GAAP | $ | 8,638,604 | |||||||||||||||||||||
| Adjusted return on average assets - non-GAAP | 1.71 | % | |||||||||||||||||||||
| Return on average common stockholders' equity - GAAP | 19.15 | % | |||||||||||||||||||||
| Net income - GAAP | $ | 149,243 | |||||||||||||||||||||
| Adjustments: | |||||||||||||||||||||||
| FDIC Small Bank Assessment Credit | 1,669 | ||||||||||||||||||||||
| Tax on adjustment | 421 | ||||||||||||||||||||||
| Adjusted net income - non-GAAP | $ | 147,995 | |||||||||||||||||||||
| Average common stockholders' equity - GAAP | $ | 779,071 | |||||||||||||||||||||
| Adjusted return on average common stockholders' equity - | |||||||||||||||||||||||
| non-GAAP | 18.99 | % | |||||||||||||||||||||
| At March 31, 2020 | At December 31, 2019 | At September 30, 2019 | At June 30, 2019 | At March 31, 2019 | |||||||||||||||||||
| Book value per share - GAAP | $ | 16.38 | $ | 15.71 | $ | 15.13 | $ | 14.55 | $ | 13.94 | |||||||||||||
| Total common stockholders' equity - GAAP | 881,886 | 842,682 | 810,537 | 778,957 | 745,586 | ||||||||||||||||||
| Adjustments: | |||||||||||||||||||||||
| Adjusted for goodwill and core deposit intangible asset | 14,111 | 14,179 | 14,246 | 14,314 | 14,381 | ||||||||||||||||||
| Tangible common stockholders' equity - non-GAAP | $ | 867,775 | $ | 828,503 | $ | 796,291 | $ | 764,643 | $ | 731,205 | |||||||||||||
| Tangible book value per share - non-GAAP | $ | 16.12 | $ | 15.45 | $ | 14.86 | $ | 14.29 | $ | 13.67 | |||||||||||||
| Stockholders' equity to total assets - GAAP | 9.42 | % | 9.42 | % | 9.00 | % | 8.91 | % | 8.97 | % | |||||||||||||
| Total assets - GAAP | $ | 9,364,882 | $ | 8,947,653 | $ | 9,005,112 | $ | 8,740,237 | $ | 8,310,836 | |||||||||||||
| Adjustments: | |||||||||||||||||||||||
| Adjusted for goodwill and core deposit intangible asset | 14,111 | 14,179 | 14,246 | 14,314 | 14,381 | ||||||||||||||||||
| Total tangible assets - non-GAAP | $ | 9,350,771 | $ | 8,933,474 | $ | 8,990,866 | $ | 8,725,923 | $ | 8,296,455 | |||||||||||||
| Tangible common equity to total tangible assets - non-GAAP | 9.28 | % | 9.27 | % | 8.86 | % | 8.76 | % | 8.81 | % | |||||||||||||
| Return on average assets - GAAP | 1.54 | % | |||||||||||||||||||||
| Net income | $ | 34,778 | |||||||||||||||||||||
| Adjustments: | |||||||||||||||||||||||
| Provision for loan losses | 13,584 | ||||||||||||||||||||||
| Provision for income taxes | 8,032 | ||||||||||||||||||||||
| Net income before provision for loan losses and provision | |||||||||||||||||||||||
| for income taxes | $ | 56,394 | |||||||||||||||||||||
| Pre-tax, Pre-Provision return on average assets - non-GAAP | 2.49 | % | |||||||||||||||||||||
About ServisFirst Bancshares, Inc.
ServisFirst Bancshares, Inc. is a bank holding company based in Birmingham, Alabama. Through its subsidiary ServisFirst Bank, ServisFirst Bancshares, Inc. provides business and personal financial services from locations in Birmingham, Huntsville, Montgomery, Mobile and Dothan, Alabama, Pensacola, Sarasota and Tampa Bay, Florida, Atlanta, Georgia, Charleston, South Carolina and Nashville, Tennessee.
ServisFirst Bancshares, Inc. files periodic reports with the U.S. Securities and Exchange Commission (SEC). Copies of its filings may be obtained through the SEC’s website at www.sec.gov or at www.servisfirstbancshares.com.
Statements in this press release that are not historical facts, including, but not limited to, statements concerning future operations, results or performance, are hereby identified as "forward-looking statements" for the purpose of the safe harbor provided by Section 21E of the Securities Exchange Act of 1934 and Section 27A of the Securities Act of 1933. The words "believe," "expect," "anticipate," "project," “plan,” “intend,” “will,” “would,” “might” and similar expressions often signify forward-looking statements. Such statements involve inherent risks and uncertainties. ServisFirst Bancshares, Inc. cautions that such forward-looking statements, wherever they occur in this press release or in other statements attributable to ServisFirst Bancshares, Inc., are necessarily estimates reflecting the judgment of ServisFirst Bancshares, Inc.’s senior management and involve a number of risks and uncertainties that could cause actual results to differ materially from those suggested by the forward-looking statements. Such forward-looking statements should, therefore, be considered in light of various factors that could affect the accuracy of such forward-looking statements, including: the global health and economic crisis precipitated by the COVID-19 outbreak; general economic conditions, especially in the credit markets and in the Southeast; the performance of the capital markets; changes in interest rates, yield curves and interest rate spread relationships; changes in accounting and tax principles, policies or guidelines; changes in legislation or regulatory requirements; changes in our loan portfolio and the deposit base; economic crises and associated credit issues in industries most impacted by the COVID-19 outbreak, including the restaurant, hospitality and retail sectors; possible changes in laws and regulations and governmental monetary and fiscal policies, including, but not limited to, economic stimulus initiatives; the cost and other effects of legal and administrative cases and similar contingencies; possible changes in the creditworthiness of customers and the possible impairment of the collectability of loans and the value of collateral; the effect of natural disasters, such as hurricanes and tornados, in our geographic markets; and increased competition from both banks and non-bank financial institutions. The foregoing list of factors is not exhaustive. For discussion of these and other risks that may cause actual results to differ from expectations, please refer to “Cautionary Note Regarding Forward-looking Statements” and “Risk Factors” in our most recent Annual Report on Form 10-K and our other SEC filings. If one or more of the factors affecting our forward-looking information and statements proves incorrect, then our actual results, performance or achievements could differ materially from those expressed in, or implied by, forward-looking information and statements contained herein. Accordingly, you should not place undue reliance on any forward-looking statements, which speak only as of the date made. ServisFirst Bancshares, Inc. assumes no obligation to update or revise any forward-looking statements that are made from time to time.
More information about ServisFirst Bancshares, Inc. may be obtained over the Internet at www.servisfirstbancshares.com or by calling (205) 949-0302.
Contact: ServisFirst Bank
Davis Mange (205) 949-3420
[email protected]
| SELECTED FINANCIAL HIGHLIGHTS (Unaudited) | |||||||||||||||||||||
| (In thousands except share and per share data) | |||||||||||||||||||||
| 1st Quarter 2020 | 4th Quarter 2019 | 3rd Quarter 2019 | 2nd Quarter 2019 | 1st Quarter 2019 | |||||||||||||||||
| CONSOLIDATED STATEMENT OF INCOME | |||||||||||||||||||||
| Interest income | $ | 96,767 | $ | 98,187 | $ | 101,130 | $ | 97,787 | $ | 93,699 | |||||||||||
| Interest expense | 19,127 | 22,410 | 28,125 | 27,702 | 24,921 | ||||||||||||||||
| Net interest income | 77,640 | 75,777 | 73,005 | 70,085 | 68,778 | ||||||||||||||||
| Provision for loan losses | 13,584 | 5,884 | 6,985 | 4,884 | 4,885 | ||||||||||||||||
| Net interest income after provision for loan losses | 64,056 | 69,893 | 66,020 | 65,201 | 63,893 | ||||||||||||||||
| Non-interest income | 6,674 | 6,936 | 6,202 | 5,778 | 4,944 | ||||||||||||||||
| Non-interest expense | 27,920 | 25,503 | 25,153 | 26,022 | 25,328 | ||||||||||||||||
| Income before income tax | 42,810 | 51,326 | 47,069 | 44,957 | 43,509 | ||||||||||||||||
| Provision for income tax | 8,032 | 10,289 | 9,506 | 9,324 | 8,499 | ||||||||||||||||
| Net income | 34,778 | 41,037 | 37,563 | 35,633 | 35,010 | ||||||||||||||||
| Preferred stock dividends | - | 32 | - | 31 | - | ||||||||||||||||
| Net income available to common stockholders | $ | 34,778 | $ | 41,005 | $ | 37,563 | $ | 35,602 | $ | 35,010 | |||||||||||
| Earnings per share - basic | $ | 0.65 | $ | 0.76 | $ | 0.70 | $ | 0.66 | $ | 0.65 | |||||||||||
| Earnings per share - diluted | $ | 0.64 | $ | 0.76 | $ | 0.69 | $ | 0.66 | $ | 0.65 | |||||||||||
| Average diluted shares outstanding | 54,167,414 | 54,149,554 | 54,096,368 | 54,089,107 | 54,076,538 | ||||||||||||||||
| CONSOLIDATED BALANCE SHEET DATA | |||||||||||||||||||||
| Total assets | $ | 9,364,882 | $ | 8,947,653 | $ | 9,005,112 | $ | 8,740,237 | $ | 8,310,836 | |||||||||||
| Loans | 7,568,836 | 7,261,451 | 7,022,069 | 6,967,886 | 6,659,908 | ||||||||||||||||
| Debt securities | 827,032 | 759,649 | 688,271 | 658,221 | 631,946 | ||||||||||||||||
| Non-interest-bearing demand deposits | 1,925,626 | 1,749,879 | 1,678,672 | 1,576,959 | 1,572,703 | ||||||||||||||||
| Total deposits | 7,832,655 | 7,530,433 | 7,724,158 | 7,404,794 | 7,083,666 | ||||||||||||||||
| Borrowings | 64,707 | 64,703 | 64,693 | 64,684 | 64,675 | ||||||||||||||||
| Stockholders' equity | $ | 881,885 | $ | 842,682 | $ | 810,537 | $ | 778,957 | $ | 745,586 | |||||||||||
| Shares outstanding | 53,844,009 | 53,623,740 | 53,579,013 | 53,526,882 | 53,495,208 | ||||||||||||||||
| Book value per share | $ | 16.38 | $ | 15.71 | $ | 15.13 | $ | 14.55 | $ | 13.94 | |||||||||||
| Tangible book value per share (1) | $ | 16.12 | $ | 15.45 | $ | 14.86 | $ | 14.29 | $ | 13.67 | |||||||||||
| SELECTED FINANCIAL RATIOS (Annualized) | |||||||||||||||||||||
| Net interest margin | 3.58 | % | 3.47 | % | 3.36 | % | 3.44 | % | 3.56 | % | |||||||||||
| Return on average assets | 1.54 | % | 1.80 | % | 1.67 | % | 1.69 | % | 1.75 | % | |||||||||||
| Return on average common stockholders' equity | 16.23 | % | 19.75 | % | 18.69 | % | 18.72 | % | 19.42 | % | |||||||||||
| Efficiency ratio | 33.11 | % | 30.83 | % | 31.76 | % | 34.30 | % | 34.36 | % | |||||||||||
| Non-interest expense to average earning assets | 1.29 | % | 1.17 | % | 1.16 | % | 1.28 | % | 1.31 | % | |||||||||||
| CAPITAL RATIOS (2) | |||||||||||||||||||||
| Common equity tier 1 capital to risk-weighted assets | 10.68 | % | 10.50 | % | 10.39 | % | 10.18 | % | 10.30 | % | |||||||||||
| Tier 1 capital to risk-weighted assets | 10.68 | % | 10.50 | % | 10.39 | % | 10.19 | % | 10.30 | % | |||||||||||
| Total capital to risk-weighted assets | 12.54 | % | 12.31 | % | 12.27 | % | 12.02 | % | 12.21 | % | |||||||||||
| Tier 1 capital to average assets | 9.56 | % | 9.13 | % | 8.88 | % | 9.00 | % | 9.03 | % | |||||||||||
| Tangible common equity to total tangible assets (1) | 9.28 | % | 9.27 | % | 8.86 | % | 8.76 | % | 8.81 | % | |||||||||||
| (1) See "GAAP Reconciliation and Management Explanation of Non-GAAP Financial Measures" for a discussion of these Non-GAAP financial measures. | |||||||||||||||||||||
| (2) Regulatory capital ratios for most recent period are preliminary. | |||||||||||||||||||||
| CONSOLIDATED BALANCE SHEETS (UNAUDITED) | |||||||||||||||
| (Dollars in thousands) | |||||||||||||||
| March 31, 2020 | March 31, 2019 | % Change | |||||||||||||
| ASSETS | |||||||||||||||
| Cash and due from banks | $ | 80,461 | $ | 71,058 | 13 | % | |||||||||
| Interest-bearing balances due from depository institutions | 297,943 | 547,036 | (46 | ) | % | ||||||||||
| Federal funds sold | 306,127 | 181,435 | 69 | % | |||||||||||
| Cash and cash equivalents | 684,531 | 799,529 | (14 | ) | % | ||||||||||
| Available for sale debt securities, at fair value | 826,782 | 631,696 | 31 | % | |||||||||||
| Held to maturity debt securities (fair value of $250 at March 31, 2020 and 2019) | 250 | 250 | - | ||||||||||||
| Mortgage loans held for sale | 6,747 | 1,223 | 452 | % | |||||||||||
| Loans | 7,568,836 | 6,659,908 | 14 | % | |||||||||||
| Less allowance for loan losses | (85,414 | ) | (70,207 | ) | 22 | % | |||||||||
| Loans, net | 7,483,422 | 6,589,701 | 14 | % | |||||||||||
| Premises and equipment, net | 55,992 | 57,664 | (3 | ) | % | ||||||||||
| Goodwill and other identifiable intangible assets | 14,111 | 14,381 | (2 | ) | % | ||||||||||
| Other assets | 293,047 | 216,392 | 35 | % | |||||||||||
| Total assets | $ | 9,364,882 | $ | 8,310,836 | 13 | % | |||||||||
| LIABILITIES AND STOCKHOLDERS' EQUITY | |||||||||||||||
| Liabilities: | |||||||||||||||
| Deposits: | |||||||||||||||
| Non-interest-bearing | $ | 1,925,626 | $ | 1,572,703 | 22 | % | |||||||||
| Interest-bearing | 5,907,029 | 5,510,963 | 7 | % | |||||||||||
| Total deposits | 7,832,655 | 7,083,666 | 11 | % | |||||||||||
| Federal funds purchased | 543,623 | 373,378 | 46 | % | |||||||||||
| Other borrowings | 64,707 | 64,675 | - | % | |||||||||||
| Other liabilities | 42,012 | 43,531 | (3 | ) | % | ||||||||||
| Total liabilities | 8,482,997 | 7,565,250 | 12 | % | |||||||||||
| Stockholders' equity: | |||||||||||||||
| Preferred stock, par value $0.001 per share; 1,000,000 authorized and undesignated at | |||||||||||||||
| March 31, 2020 and March 31, 2019 | - | - | |||||||||||||
| Common stock, par value $0.001 per share; 100,000,000 shares authorized; 53,844,009 shares | |||||||||||||||
| issued and outstanding at March 31, 2020, and 53,495,208 shares issued and outstanding | |||||||||||||||
| at March 31, 2019 | 54 | 54 | - | % | |||||||||||
| Additional paid-in capital | 221,901 | 218,147 | 2 | % | |||||||||||
| Retained earnings | 641,980 | 527,853 | 22 | % | |||||||||||
| Accumulated other comprehensive income (loss) | 17,448 | (969 | ) | NM | |||||||||||
| Total stockholders' equity attributable to ServisFirst Bancshares, Inc. | 881,383 | 745,084 | 18 | % | |||||||||||
| Noncontrolling interest | 502 | 502 | - | % | |||||||||||
| Total stockholders' equity | 881,885 | 745,586 | 18 | % | |||||||||||
| Total liabilities and stockholders' equity | $ | 9,364,882 | $ | 8,310,836 | 13 | % | |||||||||
| CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED) | ||||||||
| (In thousands except per share data) | ||||||||
| Three Months Ended March 31, | ||||||||
| 2020 | 2019 | |||||||
| Interest income: | ||||||||
| Interest and fees on loans | $ | 89,385 | $ | 85,524 | ||||
| Taxable securities | 5,154 | 3,746 | ||||||
| Nontaxable securities | 233 | 446 | ||||||
| Federal funds sold | 277 | 1,219 | ||||||
| Other interest and dividends | 1,718 | 2,764 | ||||||
| Total interest income | 96,767 | 93,699 | ||||||
| Interest expense: | ||||||||
| Deposits | 16,745 | 22,145 | ||||||
| Borrowed funds | 2,382 | 2,776 | ||||||
| Total interest expense | 19,127 | 24,921 | ||||||
| Net interest income | 77,640 | 68,778 | ||||||
| Provision for loan losses | 13,584 | 4,885 | ||||||
| Net interest income after provision for loan losses | 64,056 | 63,893 | ||||||
| Non-interest income: | ||||||||
| Service charges on deposit accounts | 1,916 | 1,702 | ||||||
| Mortgage banking | 1,071 | 575 | ||||||
| Credit card income | 1,765 | 1,576 | ||||||
| Increase in cash surrender value life insurance | 1,453 | 762 | ||||||
| Other operating income | 469 | 329 | ||||||
| Total non-interest income | 6,674 | 4,944 | ||||||
| Non-interest expense: | ||||||||
| Salaries and employee benefits | 15,658 | 14,265 | ||||||
| Equipment and occupancy expense | 2,400 | 2,259 | ||||||
| Third party processing and other services | 3,345 | 2,411 | ||||||
| Professional services | 948 | 994 | ||||||
| FDIC and other regulatory assessments | 1,332 | 1,019 | ||||||
| Other real estate owned expense | 601 | 22 | ||||||
| Other operating expense | 3,636 | 4,358 | ||||||
| Total non-interest expense | 27,920 | 25,328 | ||||||
| Income before income tax | 42,810 | 43,509 | ||||||
| Provision for income tax | 8,032 | 8,499 | ||||||
| Net income | 34,778 | 35,010 | ||||||
| Dividends on preferred stock | - | - | ||||||
| Net income available to common stockholders | $ | 34,778 | $ | 35,010 | ||||
| Basic earnings per common share | $ | 0.65 | $ | 0.65 | ||||
| Diluted earnings per common share | $ | 0.64 | $ | 0.65 | ||||
| LOANS BY TYPE (UNAUDITED) | ||||||||||||||||
| (In thousands) | ||||||||||||||||
| 1st Quarter 2020 | 4th Quarter 2019 | 3rd Quarter 2019 | 2nd Quarter 2019 | 1st Quarter 2019 | ||||||||||||
| Commercial, financial and agricultural | $ | 2,771,307 | $ | 2,696,210 | $ | 2,653,934 | $ | 2,633,529 | $ | 2,522,136 | ||||||
| Real estate - construction | 548,578 | 521,392 | 550,871 | 603,779 | 556,219 | |||||||||||
| Real estate - mortgage: | ||||||||||||||||
| Owner-occupied commercial | 1,678,532 | 1,587,478 | 1,526,911 | 1,538,279 | 1,500,595 | |||||||||||
| 1-4 family mortgage | 675,870 | 644,188 | 632,346 | 630,963 | 629,285 | |||||||||||
| Other mortgage | 1,834,137 | 1,747,394 | 1,592,072 | 1,496,512 | 1,394,611 | |||||||||||
| Subtotal: Real estate - mortgage | 4,188,539 | 3,979,060 | 3,751,329 | 3,665,754 | 3,524,491 | |||||||||||
| Consumer | 60,412 | 64,789 | 65,935 | 64,824 | 57,062 | |||||||||||
| Total loans | $ | 7,568,836 | $ | 7,261,451 | $ | 7,022,069 | $ | 6,967,886 | $ | 6,659,908 | ||||||
| SUMMARY OF LOAN LOSS EXPERIENCE (UNAUDITED) | |||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||
| 1st Quarter 2020 | 4th Quarter 2019 | 3rd Quarter 2019 | 2nd Quarter 2019 | 1st Quarter 2019 | |||||||||||||||||||||||||
| Allowance for loan losses: | |||||||||||||||||||||||||||||
| Beginning balance | $ | 76,584 | $ | 77,192 | $ | 71,386 | $ | 70,207 | $ | 68,600 | |||||||||||||||||||
| Loans charged off: | |||||||||||||||||||||||||||||
| Commercial financial and agricultural | 2,640 | 4,742 | 3,626 | 3,610 | 3,037 | ||||||||||||||||||||||||
| Real estate - construction | 454 | - | - | - | - | ||||||||||||||||||||||||
| Real estate - mortgage | 1,678 | 1,689 | 4,974 | 169 | 50 | ||||||||||||||||||||||||
| Consumer | 58 | 139 | 172 | 63 | 218 | ||||||||||||||||||||||||
| Total charge offs | 4,830 | 6,570 | 8,772 | 3,842 | 3,305 | ||||||||||||||||||||||||
| Recoveries: | |||||||||||||||||||||||||||||
| Commercial financial and agricultural | 62 | 51 | 126 | 117 | 12 | ||||||||||||||||||||||||
| Real estate - construction | 1 | 1 | 1 | - | 1 | ||||||||||||||||||||||||
| Real estate - mortgage | 1 | 2 | - | 4 | 7 | ||||||||||||||||||||||||
| Consumer | 12 | 24 | 60 | 16 | 7 | ||||||||||||||||||||||||
| Total recoveries | 76 | 78 | 187 | 137 | 27 | ||||||||||||||||||||||||
| Net charge-offs | 4,754 | 6,492 | 8,585 | 3,705 | 3,278 | ||||||||||||||||||||||||
| Allocation from Loan Guarantee Program | - | - | 7,406 | - | - | ||||||||||||||||||||||||
| Provision for loan losses | 13,584 | 5,884 | 6,985 | 4,884 | 4,885 | ||||||||||||||||||||||||
| Ending balance | $ | 85,414 | $ | 76,584 | $ | 77,192 | $ | 71,386 | $ | 70,207 | |||||||||||||||||||
| Allowance for loan losses to total loans | 1.13 | % | 1.05 | % | 1.10 | % | 1.02 | % | 1.05 | % | |||||||||||||||||||
| Allowance for loan losses to total average | |||||||||||||||||||||||||||||
| loans | 1.16 | % | 1.08 | % | 1.11 | % | 1.05 | % | 1.06 | % | |||||||||||||||||||
| Net charge-offs to total average loans | 0.26 | % | 0.36 | % | 0.49 | % | 0.22 | % | 0.20 | % | |||||||||||||||||||
| Provision for loan losses to total average | |||||||||||||||||||||||||||||
| loans | 0.74 | % | 0.33 | % | 0.40 | % | 0.29 | % | 0.30 | % | |||||||||||||||||||
| Nonperforming assets: | |||||||||||||||||||||||||||||
| Nonaccrual loans | $ | 28,914 | $ | 30,091 | $ | 35,732 | $ | 21,840 | $ | 22,154 | |||||||||||||||||||
| Loans 90+ days past due and accruing | 4,954 | 6,021 | 5,317 | 10,299 | 5,021 | ||||||||||||||||||||||||
| Other real estate owned and | |||||||||||||||||||||||||||||
| repossessed assets | 7,448 | 8,178 | 5,337 | 5,649 | 5,480 | ||||||||||||||||||||||||
| Total | $ | 41,316 | $ | 44,290 | $ | 46,386 | $ | 37,788 | $ | 32,655 | |||||||||||||||||||
| Nonperforming loans to total loans | 0.45 | % | 0.50 | % | 0.58 | % | 0.46 | % | 0.41 | % | |||||||||||||||||||
| Nonperforming assets to total assets | 0.44 | % | 0.50 | % | 0.52 | % | 0.43 | % | 0.39 | % | |||||||||||||||||||
| Nonperforming assets to earning assets | 0.45 | % | 0.50 | % | 0.53 | % | 0.44 | % | 0.40 | % | |||||||||||||||||||
| Reserve for loan losses to nonaccrual loans | 295.41 | % | 254.51 | % | 216.03 | % | 326.86 | % | 316.90 | % | |||||||||||||||||||
| Restructured accruing loans | $ | 975 | $ | 625 | $ | 3,468 | $ | 2,742 | $ | 2,742 | |||||||||||||||||||
| Restructured accruing loans to total loans | 0.01 | % | 0.01 | % | 0.05 | % | 0.04 | % | 0.04 | % | |||||||||||||||||||
| TROUBLED DEBT RESTRUCTURINGS (TDRs) (UNAUDITED) | |||||||||||||||||||||||||||||
| (In thousands) | |||||||||||||||||||||||||||||
| 1st Quarter 2020 | 4th Quarter 2019 | 3rd Quarter 2019 | 2nd Quarter 2019 | 1st Quarter 2019 | |||||||||||||||||||||||||
| Beginning balance: | $ | 3,330 | $ | 11,248 | $ | 11,284 | $ | 12,289 | $ | 14,555 | |||||||||||||||||||
| Additions | 350 | 250 | - | - | - | ||||||||||||||||||||||||
| Net (paydowns) / advances | (232 | ) | (3,481 | ) | 714 | (12 | ) | (766 | ) | ||||||||||||||||||||
| Charge-offs | (1,081 | ) | (1,333 | ) | (750 | ) | (993 | ) | (1,500 | ) | |||||||||||||||||||
| Transfer to OREO | - | (3,354 | ) | - | - | - | |||||||||||||||||||||||
| $ | 2,367 | $ | 3,330 | $ | 11,248 | $ | 11,284 | $ | 12,289 | ||||||||||||||||||||
| CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED) | |||||||||||||||||||||
| (In thousands except per share data) | |||||||||||||||||||||
| 1st Quarter 2020 | 4th Quarter 2019 | 3rd Quarter 2019 | 2nd Quarter 2019 | 1st Quarter 2019 | |||||||||||||||||
| Interest income: | |||||||||||||||||||||
| Interest and fees on loans | $ | 89,385 | $ | 89,407 | $ | 90,767 | $ | 88,610 | $ | 85,524 | |||||||||||
| Taxable securities | 5,154 | 4,702 | 4,367 | 4,193 | 3,746 | ||||||||||||||||
| Nontaxable securities | 233 | 274 | 316 | 393 | 446 | ||||||||||||||||
| Federal funds sold | 277 | 1,053 | 1,768 | 1,998 | 1,219 | ||||||||||||||||
| Other interest and dividends | 1,718 | 2,751 | 3,912 | 2,593 | 2,764 | ||||||||||||||||
| Total interest income | 96,767 | 98,187 | 101,130 | 97,787 | 93,699 | ||||||||||||||||
| Interest expense: | |||||||||||||||||||||
| Deposits | 16,745 | 19,786 | 24,787 | 24,240 | 22,145 | ||||||||||||||||
| Borrowed funds | 2,382 | 2,624 | 3,338 | 3,462 | 2,776 | ||||||||||||||||
| Total interest expense | 19,127 | 22,410 | 28,125 | 27,702 | 24,921 | ||||||||||||||||
| Net interest income | 77,640 | 75,777 | 73,005 | 70,085 | 68,778 | ||||||||||||||||
| Provision for loan losses | 13,584 | 5,884 | 6,985 | 4,884 | 4,885 | ||||||||||||||||
| Net interest income after provision for loan losses | 64,056 | 69,893 | 66,020 | 65,201 | 63,893 | ||||||||||||||||
| Non-interest income: | |||||||||||||||||||||
| Service charges on deposit accounts | 1,916 | 1,806 | 1,735 | 1,786 | 1,702 | ||||||||||||||||
| Mortgage banking | 1,071 | 1,366 | 1,333 | 1,087 | 575 | ||||||||||||||||
| Credit card income | 1,765 | 1,891 | 1,868 | 1,741 | 1,576 | ||||||||||||||||
| Securities (losses) gains | - | (1 | ) | 34 | (6 | ) | - | ||||||||||||||
| Increase in cash surrender value life insurance | 1,453 | 1,419 | 787 | 778 | 762 | ||||||||||||||||
| Other operating income | 469 | 455 | 445 | 392 | 329 | ||||||||||||||||
| Total non-interest income | 6,674 | 6,936 | 6,202 | 5,778 | 4,944 | ||||||||||||||||
| Non-interest expense: | |||||||||||||||||||||
| Salaries and employee benefits | 15,658 | 13,680 | 15,499 | 14,339 | 14,265 | ||||||||||||||||
| Equipment and occupancy expense | 2,400 | 2,339 | 2,387 | 2,287 | 2,259 | ||||||||||||||||
| Third party processing and other services | 3,345 | 3,176 | 2,923 | 2,724 | 2,411 | ||||||||||||||||
| Professional services | 948 | 1,163 | 887 | 1,191 | 994 | ||||||||||||||||
| FDIC and other regulatory assessments (credits) | 1,332 | 1,171 | (296 | ) | 1,081 | 1,019 | |||||||||||||||
| Other real estate owned expense | 601 | 103 | 78 | 212 | 22 | ||||||||||||||||
| Other operating expense | 3,636 | 3,871 | 3,675 | 4,188 | 4,358 | ||||||||||||||||
| Total non-interest expense | 27,920 | 25,503 | 25,153 | 26,022 | 25,328 | ||||||||||||||||
| Income before income tax | 42,810 | 51,326 | 47,069 | 44,957 | 43,509 | ||||||||||||||||
| Provision for income tax | 8,032 | 10,289 | 9,506 | 9,324 | 8,499 | ||||||||||||||||
| Net income | 34,778 | 41,037 | 37,563 | 35,633 | 35,010 | ||||||||||||||||
| Dividends on preferred stock | - | 32 | - | 31 | - | ||||||||||||||||
| Net income available to common stockholders | $ | 34,778 | $ | 41,005 | $ | 37,563 | $ | 35,602 | $ | 35,010 | |||||||||||
| Basic earnings per common share | $ | 0.65 | $ | 0.77 | $ | 0.70 | $ | 0.67 | $ | 0.65 | |||||||||||
| Diluted earnings per common share | $ | 0.64 | $ | 0.76 | $ | 0.69 | $ | 0.66 | $ | 0.65 | |||||||||||
| AVERAGE BALANCE SHEETS AND NET INTEREST ANALYSIS (UNAUDITED) | ||||||||||||||||||||||||||||||||||||||
| ON A FULLY TAXABLE-EQUIVALENT BASIS | ||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | ||||||||||||||||||||||||||||||||||||||
| 1st Quarter 2020 | 4th Quarter 2019 | 3rd Quarter 2019 | 2nd Quarter 2019 | 1st Quarter 2019 | ||||||||||||||||||||||||||||||||||
| Average Balance | Yield / Rate | Average Balance | Yield / Rate | Average Balance | Yield / Rate | Average Balance | Yield / Rate | Average Balance | Yield / Rate | |||||||||||||||||||||||||||||
| Assets: | ||||||||||||||||||||||||||||||||||||||
| Interest-earning assets: | ||||||||||||||||||||||||||||||||||||||
| Loans, net of unearned income (1) | ||||||||||||||||||||||||||||||||||||||
| Taxable | $ | 7,328,594 | 4.89 | % | $ | 7,066,576 | 5.00 | % | $ | 6,927,075 | 5.18 | % | $ | 6,756,927 | 5.24 | % | $ | 6,570,920 | 5.26 | % | ||||||||||||||||||
| Tax-exempt (2) | 32,555 | 4.04 | 35,563 | 4.00 | 34,195 | 3.98 | 32,124 | 3.83 | 30,577 | 3.81 | ||||||||||||||||||||||||||||
| Total loans, net of | ||||||||||||||||||||||||||||||||||||||
| unearned income | 7,361,149 | 4.88 | 7,102,139 | 4.99 | 6,961,270 | 5.17 | 6,789,051 | 5.23 | 6,601,497 | 5.25 | ||||||||||||||||||||||||||||
| Mortgage loans held for sale | 4,282 | 2.16 | 6,505 | 2.44 | 6,482 | 2.45 | 5,208 | 3.85 | 1,614 | 6.53 | ||||||||||||||||||||||||||||
| Debt securities: | ||||||||||||||||||||||||||||||||||||||
| Taxable | 750,413 | 2.75 | 670,732 | 2.81 | 595,405 | 2.93 | 565,491 | 2.97 | 518,955 | 2.89 | ||||||||||||||||||||||||||||
| Tax-exempt (2) | 44,029 | 2.33 | 50,825 | 2.17 | 59,992 | 2.21 | 77,364 | 2.10 | 87,537 | 2.12 | ||||||||||||||||||||||||||||
| Total securities (3) | 794,442 | 2.72 | 721,557 | 2.76 | 655,397 | 2.87 | 642,855 | 2.86 | 606,492 | 2.78 | ||||||||||||||||||||||||||||
| Federal funds sold | 105,423 | 1.06 | 238,927 | 1.75 | 312,968 | 2.24 | 323,714 | 2.48 | 192,690 | 2.57 | ||||||||||||||||||||||||||||
| Interest-bearing balances with banks | 469,199 | 1.47 | 602,755 | 1.81 | 690,973 | 2.25 | 411,481 | 2.53 | 438,099 | 2.56 | ||||||||||||||||||||||||||||
| Total interest-earning assets | $ | 8,734,495 | 4.46 | % | $ | 8,671,883 | 4.49 | % | $ | 8,627,090 | 4.65 | % | $ | 8,172,309 | 4.80 | % | $ | 7,840,392 | 4.85 | % | ||||||||||||||||||
| Non-interest-earning assets: | ||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 66,140 | 70,381 | 71,418 | 76,988 | 74,430 | |||||||||||||||||||||||||||||||||
| Net premises and equipment | 58,066 | 57,986 | 58,243 | 58,607 | 58,852 | |||||||||||||||||||||||||||||||||
| Allowance for loan losses, accrued | ||||||||||||||||||||||||||||||||||||||
| interest and other assets | 241,479 | 233,885 | 162,654 | 156,264 | 149,941 | |||||||||||||||||||||||||||||||||
| Total assets | $ | 9,100,180 | $ | 9,034,135 | $ | 8,919,405 | $ | 8,464,168 | $ | 8,123,615 | ||||||||||||||||||||||||||||
| Interest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits: | ||||||||||||||||||||||||||||||||||||||
| Checking | $ | 956,803 | 0.57 | % | $ | 961,258 | 0.69 | % | $ | 900,754 | 0.84 | % | $ | 909,847 | 0.88 | % | $ | 942,686 | 0.86 | % | ||||||||||||||||||
| Savings | 67,380 | 0.50 | 62,311 | 0.53 | 57,431 | 0.60 | 54,391 | 0.57 | 54,086 | 0.55 | ||||||||||||||||||||||||||||
| Money market | 4,061,286 | 1.10 | 4,189,283 | 1.34 | 4,265,435 | 1.76 | 3,932,459 | 1.88 | 3,758,162 | 1.78 | ||||||||||||||||||||||||||||
| Time deposits | 805,924 | 2.09 | 712,155 | 2.15 | 703,278 | 2.20 | 694,414 | 2.16 | 698,976 | 2.06 | ||||||||||||||||||||||||||||
| Total interest-bearing deposits | 5,891,393 | 1.14 | 5,925,007 | 1.32 | 5,926,898 | 1.66 | 5,591,111 | 1.74 | 5,453,910 | 1.65 | ||||||||||||||||||||||||||||
| Federal funds purchased | 492,638 | 1.31 | 420,066 | 1.74 | 441,526 | 2.30 | 418,486 | 2.57 | 312,989 | 2.59 | ||||||||||||||||||||||||||||
| Other borrowings | 64,707 | 4.85 | 64,698 | 4.79 | 64,689 | 4.79 | 64,680 | 4.84 | 64,671 | 4.90 | ||||||||||||||||||||||||||||
| Total interest-bearing liabilities | $ | 6,448,738 | 1.19 | % | $ | 6,409,771 | 1.39 | % | $ | 6,433,113 | 1.73 | % | $ | 6,074,277 | 1.83 | % | $ | 5,831,570 | 1.73 | % | ||||||||||||||||||
| Non-interest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||
| Non-interest-bearing | ||||||||||||||||||||||||||||||||||||||
| demand deposits | 1,749,671 | 1,759,671 | 1,654,928 | 1,591,722 | 1,524,502 | |||||||||||||||||||||||||||||||||
| Other liabilities | 39,801 | 41,112 | 34,070 | 35,161 | 36,362 | |||||||||||||||||||||||||||||||||
| Stockholders' equity | 853,800 | 818,320 | 792,284 | 763,742 | 735,611 | |||||||||||||||||||||||||||||||||
| Accumulated other comprehensive | ||||||||||||||||||||||||||||||||||||||
| income (loss) | 8,170 | 5,261 | 5,010 | (734 | ) | (4,430 | ) | |||||||||||||||||||||||||||||||
| Total liabilities and | ||||||||||||||||||||||||||||||||||||||
| stockholders' equity | $ | 9,100,180 | $ | 9,034,135 | $ | 8,919,405 | $ | 8,464,168 | $ | 8,123,615 | ||||||||||||||||||||||||||||
| Net interest spread | 3.27 | % | 3.10 | % | 2.92 | % | 2.97 | % | 3.12 | % | ||||||||||||||||||||||||||||
| Net interest margin | 3.58 | % | 3.47 | % | 3.36 | % | 3.44 | % | 3.56 | % | ||||||||||||||||||||||||||||
| (1 | ) | Average loans include loans on which the accrual of interest has been discontinued. | ||||||||||||||||||||||||||||||||||||
| (2 | ) | Interest income and yields are presented on a fully taxable equivalent basis using a tax rate of 21%. | ||||||||||||||||||||||||||||||||||||
| (3 | ) | Unrealized losses on available-for-sale debt securities are excluded from the yield calculation. | ||||||||||||||||||||||||||||||||||||