UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
Form 8-K
Current Report
Pursuant to Section 13 or 15(d) of the
Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): April
30, 2020
The Bancorp, Inc.
(Exact name of registrant as specified in
its charter)
Commission File Number: 000-51018
| Delaware |
|
23-3016517 |
| (State or other jurisdiction of |
|
(IRS Employer |
| incorporation) |
|
Identification No.) |
409 Silverside Road
Wilmington, DE 19809
(Address of principal executive offices,
including zip code)
302-385-5000
(Registrant’s telephone number, including
area code)
(Former name or former address, if changed
since last report)
Check the appropriate box below if the Form 8-K filing
is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
[ ] Written communications pursuant to
Rule 425 under the Securities Act (17 CFR 230.425)
[ ] Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12)
[ ] Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))
[ ] Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))
Securities registered pursuant to Section 12(b)
of the Act:
| Title of each class |
|
Trading
Symbol(s) |
|
Name of each exchange on which registered |
| Common Stock, par value $1.00 per share |
|
TBBK |
|
Nasdaq Global Select |
Indicate by check mark whether the registrant is an emerging
growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405) or Rule 12b-2 of the Securities Exchange Act
of 1934 (§240.12b-2).
[ ] Emerging growth company
If an emerging growth company, indicate by check mark if the
registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards
provided pursuant to Section 13(a) of the Exchange Act. [ ]
Item 2.02. Results
of Operations and Financial Condition
On April 30, 2020, The Bancorp, Inc. (the
"Company") issued a press release regarding its earnings for the three months ended March 31, 2020. A copy of this press
release is furnished with this report as Exhibit 99.1.
Item 7.01. Regulation FD Disclosure.
The Company hereby furnishes the information
set forth in the presentation (the “Presentation”) attached hereto as Exhibit 99.2, which is incorporated herein
by reference.
The information being furnished pursuant
to Item 2.02 and Item 7.01 in this Current Report, including the exhibits hereto, is to be considered “furnished” pursuant
to Form 8-K and shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended,
or otherwise subject to the liabilities of that section. The information in this Current Report shall not be incorporated by reference
into any registration statement or other document pursuant to the Securities Act of 1933, as amended.
Item 9.01. Financial Statements and Exhibits
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934,
the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| Date: April 30, 2020 |
The Bancorp, Inc. |
| |
|
|
| |
By: |
/s/ Paul Frenkiel |
| |
Name: |
Paul Frenkiel |
| |
Title: |
Chief Financial and Secretary |
| |
|
|
Exhibit 99.1
The Bancorp, Inc. Reports First Quarter 2020 Financial Results
Wilmington, DE – April 30, 2020 – The Bancorp, Inc.
("The Bancorp") (NASDAQ: TBBK), a financial holding company, today reported financial results for the first quarter of
2020.
Highlights
| · | For the quarter ended March 31, 2020, The Bancorp earned net income of $13.2 million from continuing
operations, and $0.22 diluted earnings per share from combined continuing and discontinued operations. |
| · | Net interest margin increased to 3.34% for the quarter ended March 31, 2020, compared to 3.12%
for the quarter ended December 31, 2019. |
| · | Net interest income increased 26% to $42.9 million for the quarter ended March 31, 2020, compared
to $34.0 million for the quarter ended March 31, 2019. |
| · | Average loans and leases, including loans held for sale, increased 43% to $3.3 billion for the
quarter ended March 31, 2020, compared to $2.3 billion for the quarter ended March 31, 2019. |
| · | Prepaid, debit card and related fees increased 15% to $18.5 million for the quarter ended March
31, 2020, compared to $16.2 million for the quarter ended March 31, 2019. Gross dollar volume (GDV), representing total spend on
cards, increased 36%. |
| · | SBLOC (securities-backed lines of credit) and IBLOC (insurance backed lines of credit) loans
increased 46% year over year and 13% quarter over quarter to $1.2 billion at March 31, 2020. |
| · | Small Business Loans, including those held-for-sale, increased 21% year over year to $595.1 million
at March 31, 2020. |
| · | As of April 28, 2020 we have originated approximately 1250 Paycheck Protection Program
loans, totaling in excess of $200 million, which we expect will generate approximately $5.5 million of fees and interest. We
believe that income will be recognized primarily in the second quarter of 2020. The average loan size was approximately
$165,000 with 92% of the loans under $350,000. |
| · | Direct lease financing, the vast majority of which consist of vehicles, increased 16% year over
year, to $446 million. |
| · | The average rate on $4.9 billion of average deposits and interest-bearing liabilities in the
first quarter of 2020 was 0.70%. Average prepaid and debit card account deposits of $3.2 billion for first quarter 2020, reflecting
an increase of 24% over the $2.5 billion for the quarter ended March 31, 2019. |
| · | Consolidated leverage ratio was 8.90% at March 31, 2020. The Bancorp and its subsidiary, The
Bancorp Bank (the “Bank”), remain well capitalized. |
| · | Book value per common share at March 31, 2020 was $8.69 per share
compared to $7.70 a year earlier, an increase of 13%. |
The following
additional matters are notable:
| · | A
planned sale by the Bank of approximately $825 million of commercial real estate loans
scheduled for April 2020 was not consummated by the purchaser. The purchaser had
deposited $12.5 million with the Bank, which was to be forfeited should they not consummate
the purchase. We have been advised and have concluded that, under the relevant
circumstances, the Bank is entitled to retain the deposit. The Bank intends to recognize
the deposit as income in a time and manner consistent with applicable accounting rules. |
| · | We
implemented Current Expected Credit Loss (“CECL”) accounting as of January
1, 2020. As a result, we booked a $2.6 million cumulative increase to the allowance for
loan and lease losses and $569,000 to other liabilities for unfunded commitments. The
$3.2 million combined total of these items was offset through retained earnings, net
of their future tax benefit. The provision as determined through the CECL model resulted
in a $3.6 million provision for credit losses for the quarter ended March 31, 2020. |
Damian Kozlowski, The Bancorp’s
Chief Executive Officer, said, “We have continued to experience momentum in our core earnings despite the current COVID-19
developments. While the pandemic continues to be fast-developing and could be prolonged, we have evaluated the impact of lower
interest rates and potential lower business volumes on our profitability for 2020. We believe that the previously announced $1.25
minimum earnings per share guidance for 2020 is still attainable, while $1.34 earnings per share has become less likely. Accordingly,
the $1.25 earnings per share now constitutes our guidance for full year 2020. We have removed the range of earnings performance
and made $1.25 our target. We have also provided additional tables and other disclosures in this press release related to credit
exposures.”
The Bancorp reported net income of $12.6 million, or $0.22 per diluted
share, for the quarter ended March 31, 2020, compared to net income of $17.9 million, or $0.32 per diluted share, for the quarter
ended March 31, 2019. Results for 2020 reflected $5.2 million of unrealized losses on loans held for sale, which may or may not
be realized depending on future market conditions. The prior year comparable quarter reflected $10.8 million of gains on such loans,
which consisted primarily of realized gains. Pre-tax income excluding these items, which are dependent on market conditions, amounted
to $22.7 for first quarter 2020 compared to $12.7 million for first quarter 2019, or an increase of 79%. Tier one capital to assets
(leverage), tier one capital to risk-weighted assets, total capital to risk-weighted assets and common equity-tier 1 to risk-weighted
assets ratios were 8.90%, 16.99%, 17.41% and 16.99%, respectively, compared to well-capitalized minimums of 5%, 8%, 10% and 6.5%,
respectively.
Conference Call Webcast
You may access the LIVE webcast of
The Bancorp's Quarterly Earnings Conference Call at 8:00 AM ET Friday, May 1, 2020 by clicking on the webcast link on The Bancorp's
homepage at www.thebancorp.com. Or, you may dial 844.775.2543,
access code 8676348.
You may listen to the replay of the webcast following the live call on The Bancorp's investor relations website or telephonically
until Friday, May 8, 2020 by dialing 855.859.2056, access code 8676348.
The Bancorp, Inc. (NASDAQ: TBBK) is dedicated to serving the unique
needs of non-bank financial service companies, ranging from entrepreneurial start-ups to those on the Fortune 500. The company’s
only subsidiary, The Bancorp Bank (Member FDIC, Equal Housing Lender), has been repeatedly recognized in the payments industry
as the Top Issuer of Prepaid Cards (US), a top merchant sponsor bank and a top ACH originator. Specialized lending distinctions
include National Preferred SBA Lender, a leading provider of securities-backed lines of credit, and one of the few bank-owned commercial
vehicle leasing groups in the nation. For more information please visit www.thebancorp.com.
Forward-Looking Statements
Statements in this earnings release regarding The Bancorp’s
business which are not historical facts are "forward-looking statements." These statements may be identified by the use
of forward-looking terminology, including but not limited to the words “may,” “believe,” “will,”
“expect,” “look,” “anticipate,” “estimate,” “continue,” or similar
words , and are based on current expectations about important economic, political, and technological factors, among others, and
are subject to risks and uncertainties, which could cause the actual results, events or achievements to differ materially from
those set forth in or implied by the forward-looking statements and related assumptions. These risks and uncertainties include
those relating to the on-going COVID-19 pandemic, the impact it will have on our business and the industry as a whole, and the
resulting governmental and societal responses. For further discussion of the risks and uncertainties to which these forward-looking
statements may be subject, see The Bancorp’s filings with the Securities Exchange Commission, including the “Risk Factors”
and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” sections of those
filings. The forward-looking statements speak only as of the date of this press release. The Bancorp does not undertake to publicly
revise or update forward-looking statements in this press release to reflect events or circumstances that arise after the date
of this earnings release, except as may be required under applicable law.
The Bancorp, Inc. Contact
Andres Viroslav
Director, Investor Relations
215-861-7990
[email protected]
| The Bancorp, Inc. |
| Financial highlights |
| (unaudited) |
| | |
| |
| |
|
| | |
Three months ended | |
Year ended |
| | |
March 31, | |
December 31, |
| Condensed income statement | |
2020 | |
2019 | |
2019 |
| | |
(dollars in thousands except per share data) |
| | |
| |
| |
|
| Net interest income | |
$ | 42,911 | | |
$ | 34,010 | | |
$ | 141,288 | |
| Provision for loan and lease losses | |
| 3,579 | | |
| 1,700 | | |
| 4,400 | |
| Non-interest income | |
| | | |
| | | |
| | |
| Service fees on deposit accounts | |
| 10 | | |
| 47 | | |
| 75 | |
| ACH, card and other payment processing fees | |
| 1,846 | | |
| 2,303 | | |
| 9,376 | |
| Prepaid, debit card and related fees | |
| 18,540 | | |
| 16,163 | | |
| 65,141 | |
| Net realized and unrealized gains
(losses) on commercial loans originated for sale | |
| (5,156 | ) | |
| 10,763 | | |
| 24,072 | |
| Change in value of investment in unconsolidated entity | |
| (45 | ) | |
| — | | |
| — | |
| Leasing related income | |
| 833 | | |
| 695 | | |
| 3,243 | |
| Other non-interest income | |
| 571 | | |
| 394 | | |
| 2,220 | |
| Total non-interest income | |
| 16,599 | | |
| 30,365 | | |
| 104,127 | |
| Non-interest expense | |
| | | |
| | | |
| | |
| Salaries and employee benefits | |
| 22,741 | | |
| 23,840 | | |
| 94,259 | |
| Data processing expense | |
| 1,169 | | |
| 1,269 | | |
| 4,894 | |
| Legal expense | |
| 913 | | |
| 1,324 | | |
| 5,319 | |
| FDIC Insurance | |
| 2,589 | | |
| 1,929 | | |
| 7,025 | |
| Software | |
| 3,477 | | |
| 2,921 | | |
| 12,731 | |
| Civil money penalties | |
| — | | |
| — | | |
| 8,900 | |
| Lease termination expense | |
| — | | |
| — | | |
| 908 | |
| Other non-interest expense | |
| 7,529 | | |
| 7,946 | | |
| 34,485 | |
| Total non-interest expense | |
| 38,418 | | |
| 39,229 | | |
| 168,521 | |
| Income from continuing operations before income taxes | |
| 17,513 | | |
| 23,446 | | |
| 72,494 | |
| Income tax expense | |
| 4,352 | | |
| 6,035 | | |
| 21,226 | |
| Net income from continuing operations | |
| 13,161 | | |
| 17,411 | | |
| 51,268 | |
| Discontinued operations | |
| | | |
| | | |
| | |
| Income (loss) from discontinued operations before income taxes | |
| (775 | ) | |
| 805 | | |
| 510 | |
| Income tax expense (benefit) | |
| (205 | ) | |
| 286 | | |
| 219 | |
| Net income (loss) from discontinued operations, net of tax | |
| (570 | ) | |
| 519 | | |
| 291 | |
| Net income | |
$ | 12,591 | | |
$ | 17,930 | | |
$ | 51,559 | |
| | |
| | | |
| | | |
| | |
| Net income per share from continuing operations - basic | |
$ | 0.23 | | |
$ | 0.31 | | |
$ | 0.90 | |
| Net income (loss) per share from discontinued operations - basic | |
$ | (0.01 | ) | |
$ | 0.01 | | |
$ | 0.01 | |
| Net income per share - basic | |
$ | 0.22 | | |
$ | 0.32 | | |
$ | 0.91 | |
| | |
| | | |
| | | |
| | |
| Net income per share from continuing operations - diluted | |
$ | 0.23 | | |
$ | 0.31 | | |
$ | 0.89 | |
| Net income (loss) per share from discontinued operations - diluted | |
$ | (0.01 | ) | |
$ | 0.01 | | |
$ | 0.01 | |
| Net income per share - diluted | |
$ | 0.22 | | |
$ | 0.32 | | |
$ | 0.90 | |
| Weighted average shares - basic | |
| 57,220,844 | | |
| 56,522,015 | | |
| 56,765,635 | |
| Weighted average shares - diluted | |
| 57,926,785 | | |
| 56,876,662 | | |
| 57,338,985 | |
| Balance sheet | |
March 31, | |
December 31, | |
September 30, | |
March 31, |
| | |
2020 | |
2019 | |
2019 | |
2019 |
| | |
(dollars in thousands) |
| Assets: | |
| |
| |
| |
|
| Cash and cash equivalents | |
| | | |
| | | |
| | | |
| | |
| Cash and due from banks | |
$ | 13,610 | | |
$ | 19,928 | | |
$ | 24,068 | | |
$ | 11,678 | |
| Interest earning deposits at Federal Reserve Bank | |
| 105,978 | | |
| 924,544 | | |
| 932,440 | | |
| 714,514 | |
| Total cash and cash equivalents | |
| 119,588 | | |
| 944,472 | | |
| 956,508 | | |
| 726,192 | |
| | |
| | | |
| | | |
| | | |
| | |
| Investment securities, available-for-sale, at fair value | |
| 1,353,278 | | |
| 1,320,692 | | |
| 1,382,437 | | |
| 1,368,602 | |
| Investment securities, held-to-maturity, at cost | |
| — | | |
| 84,387 | | |
| 84,399 | | |
| 84,428 | |
| Commercial loans held for sale, at fair value | |
| 1,716,450 | | |
| 1,180,546 | | |
| 489,240 | | |
| 570,426 | |
| Loans, net of deferred fees and costs | |
| 1,985,755 | | |
| 1,824,245 | | |
| 1,683,377 | | |
| 1,510,395 | |
| Allowance for loan and lease losses | |
| (14,883 | ) | |
| (10,238 | ) | |
| (10,360 | ) | |
| (9,954 | ) |
| Loans, net | |
| 1,970,872 | | |
| 1,814,007 | | |
| 1,673,017 | | |
| 1,500,441 | |
| Federal Home Loan Bank & Atlantic Community Bancshares stock | |
| 1,142 | | |
| 5,342 | | |
| 4,342 | | |
| 1,113 | |
| Premises and equipment, net | |
| 17,148 | | |
| 17,538 | | |
| 17,857 | | |
| 18,056 | |
| Accrued interest receivable | |
| 15,660 | | |
| 13,619 | | |
| 13,898 | | |
| 13,907 | |
| Intangible assets, net | |
| 2,857 | | |
| 2,315 | | |
| 2,698 | | |
| 3,463 | |
| Deferred tax asset, net | |
| 12,797 | | |
| 12,538 | | |
| 13,006 | | |
| 18,423 | |
| Investment in unconsolidated entity | |
| 34,273 | | |
| 39,154 | | |
| 49,431 | | |
| 58,258 | |
| Assets held for sale from discontinued operations | |
| 134,118 | | |
| 140,657 | | |
| 162,098 | | |
| 188,025 | |
| Other assets | |
| 79,925 | | |
| 81,696 | | |
| 94,605 | | |
| 75,642 | |
| Total assets | |
$ | 5,458,108 | | |
$ | 5,656,963 | | |
$ | 4,943,536 | | |
$ | 4,626,976 | |
| | |
| | | |
| | | |
| | | |
| | |
| Liabilities: | |
| | | |
| | | |
| | | |
| | |
| Deposits | |
| | | |
| | | |
| | | |
| | |
| Demand and interest checking | |
$ | 4,512,949 | | |
$ | 4,402,740 | | |
$ | 3,844,747 | | |
$ | 3,993,828 | |
| Savings and money market | |
| 178,174 | | |
| 174,290 | | |
| 25,950 | | |
| 31,470 | |
| Time deposits | |
| — | | |
| 475,000 | | |
| 475,000 | | |
| — | |
| Total deposits | |
| 4,691,123 | | |
| 5,052,030 | | |
| 4,345,697 | | |
| 4,025,298 | |
| | |
| | | |
| | | |
| | | |
| | |
| Securities sold under agreements to repurchase | |
| 42 | | |
| 82 | | |
| 93 | | |
| 93 | |
| Short-term borrowings | |
| 140,000 | | |
| — | | |
| — | | |
| — | |
| Subordinated debenture | |
| 13,401 | | |
| 13,401 | | |
| 13,401 | | |
| 13,401 | |
| Long-term borrowings | |
| 40,813 | | |
| 40,991 | | |
| 41,166 | | |
| 41,499 | |
| Other liabilities | |
| 74,625 | | |
| 65,962 | | |
| 59,005 | | |
| 111,905 | |
| Total liabilities | |
$ | 4,960,004 | | |
$ | 5,172,466 | | |
$ | 4,459,362 | | |
$ | 4,192,196 | |
| | |
| | | |
| | | |
| | | |
| | |
| Shareholders' equity: | |
| | | |
| | | |
| | | |
| | |
| Common stock - authorized, 75,000,000 shares of $1.00 par value; 57,425,556 and 56,568,004 shares issued and outstanding at March 31, 2020 and 2019, respectively | |
| 57,426 | | |
| 56,941 | | |
| 56,911 | | |
| 56,568 | |
| Treasury stock (100,000 shares) | |
| (866 | ) | |
| (866 | ) | |
| (866 | ) | |
| (866 | ) |
| Additional paid-in capital | |
| 372,984 | | |
| 371,633 | | |
| 370,113 | | |
| 367,483 | |
| Accumulated earnings | |
| 60,960 | | |
| 50,742 | | |
| 48,888 | | |
| 17,113 | |
| Accumulated other comprehensive income (loss) | |
| 7,600 | | |
| 6,047 | | |
| 9,128 | | |
| (5,518 | ) |
| Total shareholders' equity | |
| 498,104 | | |
| 484,497 | | |
| 484,174 | | |
| 434,780 | |
| | |
| | | |
| | | |
| | | |
| | |
| Total liabilities and shareholders' equity | |
$ | 5,458,108 | | |
$ | 5,656,963 | | |
$ | 4,943,536 | | |
$ | 4,626,976 | |
| Average balance sheet and net interest income | |
Three months ended March 31, 2020 | |
Three months ended March 31, 2019 |
| | |
(dollars in thousands) |
| | |
Average | |
| |
Average | |
Average | |
| |
Average |
| Assets: | |
Balance | |
Interest | |
Rate | |
Balance | |
Interest | |
Rate |
| Interest earning assets: | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | |
| Loans net of deferred fees and costs ** | |
$ | 3,262,378 | | |
$ | 39,159 | | |
| 4.80 | % | |
$ | 2,266,834 | | |
$ | 30,161 | | |
| 5.32 | % |
| Leases - bank qualified* | |
| 10,975 | | |
| 200 | | |
| 7.29 | % | |
| 17,793 | | |
| 428 | | |
| 9.62 | % |
| Investment securities-taxable | |
| 1,395,545 | | |
| 10,495 | | |
| 3.01 | % | |
| 1,303,491 | | |
| 10,530 | | |
| 3.23 | % |
| Investment securities-nontaxable* | |
| 5,174 | | |
| 39 | | |
| 3.02 | % | |
| 7,546 | | |
| 59 | | |
| 3.13 | % |
| Interest earning deposits at Federal Reserve Bank | |
| 493,876 | | |
| 1,623 | | |
| 1.31 | % | |
| 423,024 | | |
| 2,502 | | |
| 2.37 | % |
| Net interest earning assets | |
| 5,167,948 | | |
| 51,516 | | |
| 3.99 | % | |
| 4,018,688 | | |
| 43,680 | | |
| 4.35 | % |
| | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | |
| Allowance for loan and lease losses | |
| (10,176 | ) | |
| | | |
| | | |
| (8,638 | ) | |
| | | |
| | |
| Loans held for sale from discontinued operations | |
| 137,286 | | |
| 1,275 | | |
| 3.71 | % | |
| 173,800 | | |
| 2,025 | | |
| 4.66 | % |
| Other assets | |
| 226,881 | | |
| | | |
| | | |
| 234,174 | | |
| | | |
| | |
| | |
$ | 5,521,939 | | |
| | | |
| | | |
$ | 4,418,024 | | |
| | | |
| | |
| | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | |
| Liabilities and Shareholders' Equity: | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | |
| Deposits: | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | |
| Demand and interest checking | |
$ | 4,353,690 | | |
$ | 6,695 | | |
| 0.62 | % | |
$ | 3,798,837 | | |
$ | 8,833 | | |
| 0.93 | % |
| Savings and money market | |
| 173,575 | | |
| 50 | | |
| 0.12 | % | |
| 31,392 | | |
| 37 | | |
| 0.47 | % |
| Time | |
| 319,505 | | |
| 1,483 | | |
| 1.86 | % | |
| — | | |
| — | | |
| — | |
| Total deposits | |
| 4,846,770 | | |
| 8,228 | | |
| 0.68 | % | |
| 3,830,229 | | |
| 8,870 | | |
| 0.93 | % |
| | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | |
| Short-term borrowings | |
| 56,813 | | |
| 165 | | |
| 1.16 | % | |
| 74,386 | | |
| 503 | | |
| 2.70 | % |
| Securities sold under agreements to repurchase | |
| 72 | | |
| — | | |
| 0.00 | % | |
| 90 | | |
| — | | |
| 0.00 | % |
| Subordinated debentures | |
| 13,401 | | |
| 162 | | |
| 4.84 | % | |
| 13,401 | | |
| 195 | | |
| 5.82 | % |
| Total deposits and liabilities | |
| 4,917,056 | | |
| 8,555 | | |
| 0.70 | % | |
| 3,918,106 | | |
| 9,568 | | |
| 0.98 | % |
| | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | |
| Other liabilities | |
| 113,582 | | |
| | | |
| | | |
| 79,140 | | |
| | | |
| | |
| Total liabilities | |
| 5,030,638 | | |
| | | |
| | | |
| 3,997,246 | | |
| | | |
| | |
| | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | |
| Shareholders' equity | |
| 491,301 | | |
| | | |
| | | |
| 420,778 | | |
| | | |
| | |
| | |
$ | 5,521,939 | | |
| | | |
| | | |
$ | 4,418,024 | | |
| | | |
| | |
| Net interest income on tax equivalent basis* | |
| | | |
$ | 44,236 | | |
| | | |
| | | |
$ | 36,137 | | |
| | |
| | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | |
| Tax equivalent adjustment | |
| | | |
| 50 | | |
| | | |
| | | |
| 102 | | |
| | |
| | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | |
| Net interest income | |
| | | |
$ | 44,186 | | |
| | | |
| | | |
$ | 36,035 | | |
| | |
| Net interest margin * | |
| | | |
| | | |
| 3.34 | % | |
| | | |
| | | |
| 3.41 | % |
| | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | |
| * Full taxable equivalent basis, using a statutory Federal tax rate of 21% for 2020 and 2019. | | |
| ** Includes loans held for sale. | | |
| Allowance for loan and lease losses: | |
Three months ended | |
Year ended |
| | |
March 31, | |
March 31, | |
December 31, |
| | |
2020 | |
2019 | |
2019 |
| | |
(dollars in thousands) |
| | |
| |
| |
|
| Balance in the allowance for loan and lease losses at beginning of period (1) | |
$ | 12,874 | | |
$ | 8,653 | | |
$ | 8,653 | |
| | |
| | | |
| | | |
| | |
| Loans charged-off: | |
| | | |
| | | |
| | |
| SBA non-real estate | |
| 264 | | |
| 322 | | |
| 1,362 | |
| Direct lease financing | |
| 1,194 | | |
| 106 | | |
| 529 | |
| Other consumer loans | |
| — | | |
| — | | |
| 1,102 | |
| Total | |
| 1,458 | | |
| 428 | | |
| 2,993 | |
| | |
| | | |
| | | |
| | |
| Recoveries: | |
| | | |
| | | |
| | |
| SBA non-real estate | |
| 19 | | |
| 17 | | |
| 125 | |
| Direct lease financing | |
| 84 | | |
| 12 | | |
| 51 | |
| Other consumer loans | |
| — | | |
| — | | |
| 2 | |
| Total | |
| 103 | | |
| 29 | | |
| 178 | |
| Net charge-offs | |
| 1,355 | | |
| 399 | | |
| 2,815 | |
| Provision credited to allowance, excluding commitment provision | |
| 3,364 | | |
| 1,700 | | |
| 4,400 | |
| | |
| | | |
| | | |
| | |
| Balance in allowance for loan and lease losses at end of period | |
$ | 14,883 | | |
$ | 9,954 | | |
$ | 10,238 | |
| Net charge-offs/average loans | |
| 0.04 | % | |
| 0.02 | % | |
| 0.12 | % |
| Net charge-offs/average loans (annualized) | |
| 0.17 | % | |
| 0.07 | % | |
| 0.12 | % |
| Net charge-offs/average assets | |
| 0.02 | % | |
| 0.01 | % | |
| 0.06 | % |
| (1) Excludes activity from assets held for sale from discontinued operations. |
| Loan portfolio: | |
March 31, | |
December 31, | |
September 30, | |
March 31, |
| | |
2020 | |
2019 | |
2019 | |
2019 |
| | |
(in thousands) |
| | |
| |
| |
| |
|
| SBL non-real estate | |
$ | 84,946 | | |
$ | 84,579 | | |
$ | 84,181 | | |
$ | 76,112 | |
| SBL commercial mortgage | |
| 233,220 | | |
| 218,110 | | |
| 209,008 | | |
| 179,397 | |
| SBL construction | |
| 48,823 | | |
| 45,310 | | |
| 38,116 | | |
| 23,979 | |
| Small business loans * | |
| 366,989 | | |
| 347,999 | | |
| 331,305 | | |
| 279,488 | |
| Direct lease financing | |
| 445,967 | | |
| 434,460 | | |
| 412,755 | | |
| 384,930 | |
| SBLOC / IBLOC** | |
| 1,156,433 | | |
| 1,024,420 | | |
| 920,463 | | |
| 791,986 | |
| Other specialty lending | |
| 2,711 | | |
| 3,055 | | |
| 3,167 | | |
| 34,425 | |
| Other consumer loans *** | |
| 4,023 | | |
| 4,554 | | |
| 6,388 | | |
| 9,301 | |
| | |
| 1,976,123 | | |
| 1,814,488 | | |
| 1,674,078 | | |
| 1,500,130 | |
| Unamortized loan fees and costs | |
| 9,632 | | |
| 9,757 | | |
| 9,299 | | |
| 10,265 | |
| Total loans, net of unamortized fees and costs | |
$ | 1,985,755 | | |
$ | 1,824,245 | | |
$ | 1,683,377 | | |
$ | 1,510,395 | |
| | |
| | | |
| | | |
| | | |
| | |
| Small business portfolio: | |
| March 31, | | |
| December 31, | | |
| September 30, | | |
| March 31, | |
| | |
| 2020 | | |
| 2019 | | |
| 2019 | | |
| 2019 | |
| | |
| (in thousands) | |
| | |
| | | |
| | | |
| | | |
| | |
| SBL, including unamortized fees and costs | |
| 371,072 | | |
| 352,214 | | |
| 337,440 | | |
| 286,814 | |
| SBL, included in held-for-sale | |
| 223,987 | | |
| 220,358 | | |
| 222,007 | | |
| 206,901 | |
| Total small business loans | |
$ | 595,059 | | |
$ | 572,572 | | |
$ | 559,447 | | |
$ | 493,715 | |
| * The preceding table shows small business loans and small business loans held-for-sale, which consist of the government guaranteed portion of SBA loans at the dates indicated (in thousands). |
| ** Securities Backed Lines of Credit (SBLOC) are collateralized by marketable securities, while Insurance Backed Lines of Credit (IBLOC) are collateralized by the cash surrender value of insurance policies. At March 31, 2020 and December 31, 2019, respectively, IBLOC loans amounted to $228.8 million and $144.6 million. |
| *** Included in the table above under other consumer loans are demand deposit overdrafts reclassified as loan balances totaling $455,000 and $882,000 at March 31, 2020 and December 31, 2019, respectively. Estimated overdraft charge-offs and recoveries are reflected in the allowance for loan and lease losses. |
| Small business loans as of March 31, 2020 | |
|
| | |
|
| | |
Loan principal |
| | |
| (in millions) | |
| U.S. government guaranteed portion of SBA loans (a) | |
$ | 304 | |
| Commercial mortgage SBA (b) | |
| 147 | |
| Construction SBA (c) | |
| 29 | |
| Unguaranteed portion of U.S. government guaranteed loans (d) | |
| 85 | |
| Non-SBA small business loans (e) | |
| 21 | |
| Total principal | |
$ | 586 | |
| Fair value adjustment | |
| 5 | |
| Unamortized fees | |
| 4 | |
| Total small business loans | |
$ | 595 | |
(a) This is the portion of SBA 7a loans (7a) which have been granted guarantees by the U.S. government, and therefore assumed to have no credit risk.
|
(b) Substantially all of these loans are made under the SBA 504 Fixed Asset Financing program (504) which dictates origination date loan to value percentages (LTV), generally 50-60%, to which the bank adheres.
|
(c) Of the $29 million Construction SBA loans, $21 million are 504 first mortgages with an origination date LTV of 50-60% and $8 million are SBA interim loans with an approved SBA post-construction full takeout/payoff.
|
(d) The $85 million represents the unguaranteed portion of 7a loans which are 70% or more guaranteed by the U.S. government. 7a loans are not made on the basis of real estate LTV; however, they are subject to SBA's "All Available Collateral" rule which mandates that to the extent a borrower or its 20% or greater principals have available collateral (including personal residences), the collateral must be pledged to fully collateralize the loan, after applying SBA-determined liquidation rates. In addition, all 7a and 504 loans require the personal guaranty of all 20% or greater owners.
|
(e) Of the $21 million in non-SBA loans, $2 million are bridge loans with permanent lender takeout commitments, $2 million is a secured conventional loan with an origination date LTV of 80% and $17 million consist of approximately 20 conventional coffee/doughnut/carryout franchisee note purchases. The majority of purchased notes were made to multi-unit operators and are considered seasoned and have performed as agreed. A $2 million guaranty by the seller, for an 11% first loss piece, is in place until August 2021.
|
| Additionally, the CARES Act of 2020, recently approved by Congress has provided significant support for SBA loans including funding intended to provide six months of interest payments on SBA loans, as well as other accommodations to provide for the payment of payroll and other operating expenses. |
| Type as of March 31, 2020 |
(Excludes government guaranteed portion
of SBA 7a loans) |
| | |
SBL commercial mortgage* | |
SBL
construction* | |
SBL non-real
estate | |
Total | |
% Total |
| | |
(in millions) |
| Hotels | |
$ | 62 | | |
$ | 17 | | |
$ | — | | |
$ | 79 | | |
| 28 | % |
| Professional services offices | |
| 17 | | |
| — | | |
| 5 | | |
| 22 | | |
| 8 | % |
| Full-service restaurants | |
| 15 | | |
| 1 | | |
| 5 | | |
| 21 | | |
| 8 | % |
| Child day care and youth services | |
| 18 | | |
| 1 | | |
| 1 | | |
| 20 | | |
| 7 | % |
| Bakeries | |
| 4 | | |
| — | | |
| 12 | | |
| 16 | | |
| 6 | % |
| Fitness/rec centers and instruction | |
| 8 | | |
| — | | |
| 5 | | |
| 13 | | |
| 4 | % |
| General warehousing and storage | |
| 11 | | |
| — | | |
| — | | |
| 11 | | |
| 4 | % |
| Limited-service restaurants and catering | |
| 7 | | |
| — | | |
| 3 | | |
| 10 | | |
| 4 | % |
| Elderly assisted living facilities | |
| — | | |
| 7 | | |
| 3 | | |
| 10 | | |
| 4 | % |
| Amusement and recreation industries | |
| 5 | | |
| 1 | | |
| — | | |
| 6 | | |
| 2 | % |
| Car washes | |
| 3 | | |
| 2 | | |
| — | | |
| 5 | | |
| 2 | % |
| Funeral homes | |
| 5 | | |
| — | | |
| — | | |
| 5 | | |
| 2 | % |
| New and used car dealers | |
| 4 | | |
| — | | |
| — | | |
| 4 | | |
| 1 | % |
| Automotive servicing | |
| 2 | | |
| — | | |
| 1 | | |
| 3 | | |
| 1 | % |
| Other | |
| 34 | | |
| 5 | | |
| 18 | | |
| 57 | | |
| 20 | % |
| Total | |
$ | 195 | | |
$ | 34 | | |
$ | 53 | | |
$ | 282 | | |
| 100 | % |
* Substantially all are SBA loans which had 50-60% LTV ratios at
their origination.
| State diversification as of March 31, 2020 |
| (Excludes government guaranteed portion of SBA 7a loans) |
| | |
| |
| |
| |
|
| | |
SBL commercial mortgage* | |
SBL construction* | |
SBL non-real estate | |
Total | |
% Total |
| | |
(in millions) |
| Florida | |
$ | 33 | | |
$ | 14 | | |
$ | 7 | | |
$ | 54 | | |
| 19 | % |
| Pennsylvania | |
| 29 | | |
| — | | |
| 3 | | |
| 32 | | |
| 11 | % |
| Illinois | |
| 26 | | |
| — | | |
| 5 | | |
| 31 | | |
| 11 | % |
| California | |
| 25 | | |
| 1 | | |
| 5 | | |
| 31 | | |
| 11 | % |
| North Carolina | |
| 16 | | |
| 9 | | |
| 2 | | |
| 27 | | |
| 10 | % |
| New York | |
| 13 | | |
| 1 | | |
| 5 | | |
| 19 | | |
| 7 | % |
| Texas | |
| 10 | | |
| 1 | | |
| 5 | | |
| 16 | | |
| 6 | % |
| Tennessee | |
| 8 | | |
| 5 | | |
| 1 | | |
| 14 | | |
| 5 | % |
| New Jersey | |
| 1 | | |
| 2 | | |
| 7 | | |
| 10 | | |
| 4 | % |
| Virginia | |
| 8 | | |
| 1 | | |
| 2 | | |
| 11 | | |
| 4 | % |
| Georgia | |
| 3 | | |
| — | | |
| 1 | | |
| 4 | | |
| 1 | % |
| Michigan | |
| 3 | | |
| — | | |
| 1 | | |
| 4 | | |
| 1 | % |
| Colorado | |
| 2 | | |
| — | | |
| 1 | | |
| 3 | | |
| 1 | % |
| Ohio | |
| 2 | | |
| — | | |
| 1 | | |
| 3 | | |
| 1 | % |
| Other states | |
| 16 | | |
| — | | |
| 7 | | |
| 23 | | |
| 8 | % |
| Total | |
$ | 195 | | |
$ | 34 | | |
$ | 53 | | |
$ | 282 | | |
| 100 | % |
* Substantially all are SBA loans with 50-60% LTV ratios at origination.
| Top 10 loans as of March 31, 2020 |
| | |
| |
| |
| |
|
| Type* | |
State | |
SBL commercial mortgage* | |
SBL construction* | |
Total |
| | |
(in millions) |
| Professional services office | |
CA | |
$ | 9 | | |
$ | — | | |
$ | 9 | |
| Hotel | |
FL | |
| 9 | | |
| — | | |
| 9 | |
| General warehouse | |
PA | |
| 7 | | |
| — | | |
| 7 | |
| Hotel | |
NC | |
| — | | |
| 6 | | |
| 6 | |
| Hotel | |
FL | |
| 5 | | |
| — | | |
| 5 | |
| Hotel | |
NC | |
| 5 | | |
| — | | |
| 5 | |
| Assisted living facility | |
FL | |
| — | | |
| 5 | | |
| 5 | |
| Fitness and rec center | |
PA | |
| 5 | | |
| — | | |
| 5 | |
| Hotel | |
PA | |
| 4 | | |
| — | | |
| 4 | |
| Hotel | |
NY | |
| 3 | | |
| — | | |
| 3 | |
| Total | |
| |
$ | 47 | | |
$ | 11 | | |
$ | 58 | |
* All of the top 10 loans are SBA and with the rest of the commercial
real estate portfolio are originated with an approximate loan to value ratio between 50% and 60% at origination.
Commercial real estate loans held for sale which were originated
for sale or securitization, excluding SBA loans, are as follows including LTV at origination. The vast majority of these loans
were originated in the past nine months:
| Type as of March 31, 2020 |
| Type | |
# Loans | |
Balance | |
Origination date LTV | |
Weighted average minimum interest rate |
| | |
(dollars in millions) |
| Multifamily (apartments) | |
| 175 | | |
$ | 1,364 | | |
| 77 | % | |
| 4.75 | % |
| Hospitality (hotels and lodging) * | |
| 11 | | |
| 58 | | |
| 62 | % | |
| 5.69 | % |
| Retail | |
| 7 | | |
| 51 | | |
| 72 | % | |
| 4.94 | % |
| Other | |
| 8 | | |
| 24 | | |
| 69 | % | |
| 5.18 | % |
| | |
| 201 | | |
$ | 1,497 | | |
| 76 | % | |
| 4.80 | % |
| Fair value adjustment | |
| | | |
| (4 | ) | |
| | | |
| | |
| Total | |
| | | |
$ | 1,493 | | |
| | | |
| | |
*Of the total $4 million fair value adjustment, $1.8 million was
related to hospitality loans
| State diversification as of March 31, 2020 | |
15 Largest loans (all multifamily) as of March 31, 2020 |
| | |
| |
| |
| |
| |
|
| State | |
| Balance | | |
| Origination date LTV | | |
State | |
| Balance | | |
| Origination date LTV | |
| | |
| (in millions) | | |
| | | |
| |
| (in millions) | | |
| | |
| Texas | |
$ | 375 | | |
| 77 | % | |
North Carolina | |
$ | 43 | | |
| 78 | % |
| Georgia | |
| 230 | | |
| 78 | % | |
Texas | |
| 36 | | |
| 79 | % |
| Arizona | |
| 117 | | |
| 76 | % | |
Texas | |
| 34 | | |
| 80 | % |
| North Carolina | |
| 108 | | |
| 77 | % | |
Pennsylvania | |
| 31 | | |
| 77 | % |
| Nevada | |
| 56 | | |
| 80 | % | |
Georgia | |
| 31 | | |
| 80 | % |
| Alabama | |
| 53 | | |
| 76 | % | |
Nevada | |
| 28 | | |
| 80 | % |
| Other states each <$50 million | |
| 558 | | |
| 76 | % | |
Texas | |
| 27 | | |
| 75 | % |
| Total | |
$ | 1,497 | | |
| 76 | % | |
Texas | |
| 26 | | |
| 77 | % |
| | |
| | | |
| | | |
Arizona | |
| 25 | | |
| 79 | % |
| | |
| | | |
| | | |
Mississippi | |
| 25 | | |
| 79 | % |
| | |
| | | |
| | | |
Texas | |
| 24 | | |
| 77 | % |
| | |
| | | |
| | | |
North Carolina | |
| 24 | | |
| 77 | % |
| | |
| | | |
| | | |
Texas | |
| 24 | | |
| 77 | % |
| | |
| | | |
| | | |
Georgia | |
| 23 | | |
| 79 | % |
| | |
| | | |
| | | |
Alabama | |
| 22 | | |
| 77 | % |
| | |
| | | |
| | | |
15 Largest loans | |
$ | 423 | | |
| 78 | % |
| Institutional banking loans outstanding at March 31, 2020 |
| |
| Type | |
| Principal | | |
| % of total | |
| | |
| (in millions) | | |
| | |
| Securities backed lines of credit (SBLOC) | |
$ | 927 | | |
| 80 | % |
| Insurance backed lines of credit (IBLOC) | |
| 229 | | |
| 20 | % |
| Total | |
$ | 1,156 | | |
| 100 | % |
For SBLOC, we generally lend up to 50% of the value of equities and
80% for investment grade securities. While equities have fallen in excess of 30% in recent periods, the reduction in collateral
value of brokerage accounts collateralizing SBLOCs generally has been less, for two reasons. First, many collateral accounts are
“balanced” and accordingly have a component of debt securities, which have either not decreased in value as much as
equities, or in some cases may have increased in value. Secondly, many of these accounts have the benefit of professional investment
advisors who provided some protection against market downturns, through diversification and other means. Additionally, borrowers
often utilize only a portion of collateral value, which lowers the ratio of principal to collateral. As a result, the accounts
monitored by management and related information as of March 31, 2020 were as follows:
| Assessment of SBLOC collateral market value |
| | |
Number of loans | |
Principal balances | |
Market value of collateral | |
% Principal to collateral |
| | |
(in millions) |
| 0-5% | |
| 7 | | |
$ | 4 | | |
$ | 5 | | |
| 79 | % |
| 5-10% | |
| 19 | | |
| 24 | | |
| 32 | | |
| 75 | % |
| 10-15% | |
| 40 | | |
| 26 | | |
| 36 | | |
| 71 | % |
| 15%+ | |
| 85 | | |
| 50 | | |
| 79 | | |
| 63 | % |
| Subtotal* | |
| 151 | | |
$ | 104 | | |
$ | 152 | | |
| 69 | % |
| Remaining portfolio | |
| 4,498 | | |
| 823 | | |
| 3,598 | | |
| 23 | % |
| Total | |
| 4,649 | | |
$ | 927 | | |
$ | 3,750 | | |
| 25 | % |
* Of the 4,649 SBLOC loans with principal balances of $927 million,
151 loans with principal of $104 million at March 31, 2020 were being monitored at that date, as they had exceeded the desired
threshold for the percent principal to market value of collateral. The first column reflects the percentage increase in that ratio
before additional collateral or paydown of debt would be required. As of April 23, 2020, the number of loans requiring monitoring
had decreased to 80 loans, with principal balances of $57 million.
| Top 10 SBLOC loans |
| | |
Principal amount | |
% Principal
to collateral |
| | |
(in millions) |
| | |
$ | 22 | | |
| 22 | % |
| | |
| 19 | | |
| 47 | % |
| | |
| 15 | | |
| 29 | % |
| | |
| 11 | | |
| 82 | % |
| | |
| 10 | | |
| 57 | % |
| | |
| 9 | | |
| 31 | % |
| | |
| 9 | | |
| 76 | % |
| | |
| 8 | | |
| 22 | % |
| | |
| 8 | | |
| 20 | % |
| | |
| 8 | | |
| 23 | % |
| Total | |
$ | 119 | | |
| 40 | % |
| Insurance backed lines of credit (IBLOC) |
| | |
| |
|
| IBLOC loans are backed by the cash value of life insurance policies which have been assigned to us. We lend up to 100% of such cash value. Our underwriting standards require approval of the insurance companies which carry the policies backing these loans. Currently, seven insurance companies have been approved and, as of January 21, 2020 all were rated Superior (A+ or better) by AM BEST. Moody’s ratings were at least A rated, and ranged from A3 to Aa2. |
| |
| Direct lease financing* by type as of March 31, 2020 |
| | |
|
| | |
| Principal balance | | |
| % Total | |
| | |
| (in millions) | | |
| | |
| Government agencies and public institutions** | |
$ | 79 | | |
| 18 | % |
| Construction | |
| 75 | | |
| 17 | % |
| Waste management and remediation services | |
| 62 | | |
| 14 | % |
| Real estate, rental and leasing | |
| 44 | | |
| 10 | % |
| Retail trade | |
| 40 | | |
| 9 | % |
| Transportation and warehousing | |
| 29 | | |
| 6 | % |
| Health care and social assistance | |
| 26 | | |
| 6 | % |
| Professional, scientific, and technical services | |
| 20 | | |
| 5 | % |
| Manufacturing | |
| 15 | | |
| 3 | % |
| Wholesale trade | |
| 14 | | |
| 3 | % |
| Educational services | |
| 11 | | |
| 2 | % |
| Arts, entertainment, and recreation | |
| 5 | | |
| 1 | % |
| Other | |
| 26 | | |
| 6 | % |
| Total | |
$ | 446 | | |
| 100 | % |
| * Of the total $446 million of direct lease financing, $411 million consisted of vehicle leases with the remaining balance consisting of equipment leases |
| ** Includes public universities and school districts |
| Direct lease financing by state as of March 31, 2020 |
| | |
| |
|
| State | |
Principal balance | |
% Total |
| | |
| (in millions) | | |
| | |
| Florida | |
$ | 116 | | |
| 26 | % |
| New Jersey | |
| 27 | | |
| 6 | % |
| New York | |
| 25 | | |
| 6 | % |
| Pennsylvania | |
| 27 | | |
| 6 | % |
| North Carolina | |
| 22 | | |
| 5 | % |
| Maryland | |
| 21 | | |
| 5 | % |
| California | |
| 21 | | |
| 5 | % |
| Utah | |
| 20 | | |
| 4 | % |
| Washington | |
| 16 | | |
| 4 | % |
| South Carolina | |
| 14 | | |
| 3 | % |
| Texas | |
| 14 | | |
| 3 | % |
| Georgia | |
| 13 | | |
| 3 | % |
| Alabama | |
| 12 | | |
| 3 | % |
| Connecticut | |
| 9 | | |
| 2 | % |
| Missouri | |
| 7 | | |
| 2 | % |
| Other states | |
| 82 | | |
| 18 | % |
| Total | |
$ | 446 | | |
| 100 | % |
| Capital ratios: | |
Tier 1 capital | |
Tier 1 capital | |
Total capital | |
Common equity |
| | |
to average | |
to risk-weighted | |
to risk-weighted | |
tier 1 to risk |
| | |
assets ratio | |
assets ratio | |
assets ratio | |
weighted assets |
| As of March 31, 2020 | |
| | | |
| | | |
| | | |
| | |
| The Bancorp, Inc. | |
| 8.90 | % | |
| 16.99 | % | |
| 17.50 | % | |
| 16.99 | % |
| The Bancorp Bank | |
| 8.76 | % | |
| 16.70 | % | |
| 17.22 | % | |
| 16.70 | % |
| "Well capitalized" institution (under FDIC regulations-Basel III) | |
| 5.00 | % | |
| 8.00 | % | |
| 10.00 | % | |
| 6.50 | % |
| | |
| | | |
| | | |
| | | |
| | |
| As of December 31, 2019 | |
| | | |
| | | |
| | | |
| | |
| The Bancorp, Inc. | |
| 9.63 | % | |
| 19.04 | % | |
| 19.45 | % | |
| 19.04 | % |
| The Bancorp Bank | |
| 9.46 | % | |
| 18.71 | % | |
| 19.11 | % | |
| 18.71 | % |
| "Well capitalized" institution (under FDIC regulations-Basel III) | |
| 5.00 | % | |
| 8.00 | % | |
| 10.00 | % | |
| 6.50 | % |
| |
|
Three months ended |
|
Year ended |
| |
|
March 31, |
|
December 31, |
| |
|
2020 |
|
2019 |
|
2019 |
| Selected operating ratios: |
|
|
|
|
|
|
| Return on average assets (1) |
|
0.91% |
|
1.65% |
|
1.09% |
| Return on average equity (1) |
|
10.28% |
|
17.28% |
|
11.57% |
| Net interest margin |
|
3.34% |
|
3.41% |
|
3.32% |
| (1) Annualized |
|
|
|
|
|
|
NOTE: Excluding the net of tax impact of the $5.2 million of unrealized
losses, return on assets for the quarter ended March 31, 2020 was 1.19% and return on equity was 13.35%.
| Book value per share table: | |
March 31, | |
December 31, | |
September 30, | |
March 31, |
| | |
2020 | |
2019 | |
2019 | |
2019 |
| Book value per share | |
$ | 8.69 | | |
$ | 8.52 | | |
$ | 8.52 | | |
$ | 7.70 | |
| | |
| | | |
| | | |
| | | |
| | |
| Loan quality table: | |
| March 31, | | |
| December 31, | | |
| September 30, | | |
| March 31, | |
| | |
| 2020 | | |
| 2019 | | |
| 2019 | | |
| 2019 | |
| Nonperforming loans to total loans | |
| 0.40 | % | |
| 0.50 | % | |
| 0.55 | % | |
| 0.55 | % |
| Nonperforming assets to total assets | |
| 0.14 | % | |
| 0.16 | % | |
| 0.19 | % | |
| 0.18 | % |
| Allowance for loan and lease losses to total loans | |
| 0.75 | % | |
| 0.56 | % | |
| 0.62 | % | |
| 0.66 | % |
| | |
| | | |
| | | |
| | | |
| | |
| Nonaccrual loans | |
$ | 5,645 | | |
$ | 5,796 | | |
$ | 6,420 | | |
$ | 5,863 | |
| Loans 90 days past due still accruing interest | |
| 2,245 | | |
| 3,264 | | |
| 2,788 | | |
| 2,483 | |
| Other real estate owned | |
| — | | |
| — | | |
| — | | |
| — | |
| Total nonperforming assets | |
$ | 7,890 | | |
$ | 9,060 | | |
$ | 9,208 | | |
$ | 8,346 | |
| | |
| | | |
| | | |
| | | |
| | |
| NOTE: Because SBLOC and IBLOC loans are respectively collateralized by marketable securities and the cash value of life insurance, management excludes those loans from the ratio of the allowance to total loans in its internal analysis. Accordingly, the adjusted ratio is 1.79%. | |
| | |
| Three months ended | |
| | |
| March 31, | | |
| December 31, | | |
| September 30, | | |
| March 31, | |
| | |
| 2020 | | |
| 2019 | | |
| 2019 | | |
| 2019 | |
| | |
| (in thousands) |
| Gross dollar volume (GDV) (2): | |
| | | |
| | | |
| | | |
| | |
| Prepaid and debit card GDV | |
$ | 22,982,188 | | |
$ | 19,104,327 | | |
$ | 17,264,890 | | |
$ | 16,937,325 | |
| | |
| | | |
| | | |
| | | |
| | |
| (2) Gross dollar volume represents the total dollar amount spent on prepaid and debit cards issued by The Bancorp Bank. |
| | |
| | | |
| | | |
| | | |
| | |
| Business line quarterly summary: |
| Quarter ended March 31, 2020 |
| (dollars in millions) |
| | |
| |
| |
| |
| |
| |
|
| | |
| |
Balances | |
| |
|
| | |
| |
| |
% Growth | |
| |
|
| Major business lines | |
Average approximate rates * | |
Balances ** | |
Year over year | |
Linked quarter annualized | |
| |
|
| Loans | |
| |
| |
| |
| |
| |
|
| Institutional banking *** | |
| 3.5 | % | |
$ | 1,156 | | |
| 46 | % | |
| 51 | % | |
| | | |
| | |
| SBA | |
| 5.6 | % | |
| 595 | | |
| 21 | % | |
| 16 | % | |
| | | |
| | |
| Leasing | |
| 6.3 | % | |
| 446 | | |
| 16 | % | |
| 11 | % | |
| | | |
| | |
| Commercial real estate securitization | |
| 5.0 | % | |
| 1,495 | | |
| nm | | |
| nm | | |
| | | |
| | |
| Weighted average yield | |
| 4.8 | % | |
$ | 3,692 | | |
| | | |
| | | |
| Non-interest income | |
| | |
| | | |
| | | |
| | | |
| | | |
| | | |
| % Growth | |
| Deposits | |
| | | |
| | | |
| | | |
| | | |
| Current quarter | | |
| Year over year | |
| Payment solutions (prepaid and debit card issuance) | |
| 0.5 | % | |
$ | 3,152 | | |
| 24 | % | |
| nm | | |
$ | 18.5 | | |
| 15 | % |
| Card payment and ACH processing | |
| 0.9 | % | |
| 792 | | |
| -11 | % | |
| nm | | |
| 1.8 | | |
| nm | |
| * Average rates are for the quarter ended March 31, 2020 |
| ** Loan categories are based on period end balance and deposits are based on average quarterly balances. |
| *** Comprised of Securities Backed Lines of Credit (SBLOC), collateralized by marketable securities and Insurance Backed Lines of Credit (IBLOC), collateralized by the cash surrender value of insurance policies. |
|
| Analysis of Walnut Street* marks: | |
| |
|
| | |
| |
|
| | |
Loan activity | |
Marks |
| | |
(in millions) |
| | |
| |
|
| Original Walnut Street loan balance, December 31, 2014 | |
$ | 267 | | |
| | |
| Marks through December 31, 2014 sale date | |
| (58 | ) | |
$ | (58 | ) |
| Sales price of Walnut Street | |
| 209 | | |
| | |
| Equity investment from independent investor | |
| (16 | ) | |
| | |
| December 31, 2014 Bancorp book value | |
| 193 | | |
| | |
| Additional marks 2015 - 2019 | |
| (46 | ) | |
| (46 | ) |
| 2020 Marks | |
| — | | |
| | |
| Payments received | |
| (113 | ) | |
| | |
| March 31, 2020 Bancorp book value** | |
$ | 34 | | |
| | |
| | |
| | | |
| | |
| Total marks | |
| | | |
$ | (104 | ) |
| Divided by: | |
| | | |
| | |
| Original Walnut Street loan balance | |
| | | |
$ | 267 | |
| Percentage of total mark to original balance | |
| | | |
| 39 | % |
| * Walnut Street is the investment in unconsolidated entity on the balance sheet which reflects the Bank's investment in a securitization of certain loans from the banks discontinued loan portfolio. |
| ** Approximately 32% of expected principal recoveries were from loans and properties pending liquidation or other resolution as of March 31, 2020. |
| Walnut Street portfolio composition as of March 31, 2020 | |
|
| | |
|
| Collateral type | |
% of Portfolio |
| Commercial real estate non-owner occupied | |
| | |
| Retail | |
| 58.2 | % |
| Office | |
| — | |
| Other | |
| 5.2 | % |
| Construction and land | |
| 25.2 | % |
| Commercial non real estate and industrial | |
| — | |
| First mortgage residential owner occupied | |
| 9.7 | % |
| First mortgage residential non-owner occupied | |
| 1.7 | % |
| Total | |
| 100.0 | % |
| Cumulative analysis of marks on discontinued commercial loan principal as of March 31, 2020 | |
|
| | |
| |
| |
|
| | |
Discontinued | |
Cumulative | |
% to original |
| | |
loan principal | |
marks | |
principal |
| | |
(dollars in millions) |
| | |
| |
| |
|
| Commercial loan discontinued principal before marks | |
$ | 72 | | |
| | | |
| | |
| Florida mall held in discontinued other real estate owned | |
| 42 | | |
| (27 | ) | |
| | |
| Previous mark charges | |
| 10 | | |
| (10 | ) | |
| | |
| Mark at March 31, 2020 | |
| | | |
| (4 | ) | |
| | |
| Total | |
$ | 124 | | |
$ | (41 | ) | |
| 33 | % |
Analysis of discontinued commercial loan relationships as of March
31, 2020
| | |
Performing loan principal | |
Nonperforming loan principal | |
Total loan principal | |
Performing loan marks | |
Nonperforming loan marks | |
Total marks |
| | |
(in millions) |
| | |
| |
| |
| |
| |
| |
|
| 5 loan relationships > $6 million | |
$ | 45 | | |
$ | — | | |
$ | 45 | | |
$ | (3 | ) | |
$ | — | | |
$ | (3 | ) |
| Loan relationships < $6 million | |
| 16 | | |
| 7 | | |
| 23 | | |
| (1 | ) | |
| — | | |
| (1 | ) |
| | |
$ | 61 | | |
$ | 7 | | |
$ | 68 | | |
$ | (4 | ) | |
$ | — | | |
$ | (4 | ) |
| Quarterly activity for commercial loan discontinued principal |
| | |
|
| | |
Commercial |
| | |
loan principal |
| | |
| (in millions) | |
| | |
| | |
| Commercial loan discontinued principal December 31, 2019 before marks | |
$ | 75 | |
| Quarterly paydowns and other reductions | |
| (3 | ) |
| Commercial loan discontinued principal March 31, 2020 before marks | |
$ | 72 | |
| Marks March 31, 2020 | |
| (4 | ) |
| Net commercial loan exposure March 31, 2020 | |
$ | 68 | |
| Residential mortgages | |
| 43 | |
| Net loans | |
$ | 111 | |
| Florida mall in other real estate owned | |
| 15 | |
| 10 properties in other real estate owned | |
| 8 | |
| Total discontinued assets at March 31, 2020 | |
$ | 134 | |
Discontinued commercial loan composition as of March 31, 2020
| Collateral type | |
Unpaid principal balance | |
Mark
March 31, 2020 | |
Mark as % of portfolio |
| | |
(in millions) |
| Commercial real estate - non-owner occupied: | |
| | | |
| | | |
| | |
| Retail | |
$ | 4 | | |
$ | (0.6 | ) | |
| 13 | % |
| Office | |
| 3 | | |
| — | | |
| — | |
| Other | |
| 23 | | |
| (0.3 | ) | |
| 1 | % |
| Construction and land | |
| 11 | | |
| — | | |
| — | |
| Commercial non-real estate and industrial | |
| 2 | | |
| — | | |
| — | |
| 1 to 4 family construction | |
| 11 | | |
| (2.5 | ) | |
| 23 | % |
| First mortgage residential non-owner occupied | |
| 9 | | |
| (0.2 | ) | |
| 2 | % |
| Commercial real estate owner occupied: | |
| | | |
| | | |
| | |
| Retail | |
| 7 | | |
| — | | |
| — | |
| Office | |
| — | | |
| — | | |
| — | |
| Other | |
| — | | |
| — | | |
| — | |
| Residential junior mortgage | |
| 1 | | |
| — | | |
| — | |
| Other | |
| 1 | | |
| — | | |
| — | |
| Total | |
$ | 72 | | |
| — | | |
| | |
| Less: mark | |
| (4 | ) | |
| — | | |
| | |
| Net commercial loan exposure March 31, 2020 | |
$ | 68 | | |
$ | (3.6 | ) | |
| 5 | % |
| Loan payment deferral requests as of April 23, 2020 |
| | |
| |
|
| | |
| Principal for loans with deferral requests | | |
| Total principal by loan category | | |
| % of total loan
principal with deferral requests | |
| | |
| | | |
| (in millions) | | |
| | |
| Commercial real estate loans held for sale (excluding SBA loans) | |
$ | 10 | | |
$ | 1,497 | | |
| <1 | % |
| Securities backed lines of credit & insurance backed lines of credit | |
| 10 | | |
| 1,156 | | |
| 1 | % |
| Small business lending, substantially all SBA loans | |
| 127 | | |
| 586 | | |
| 22 | % |
| Direct lease financing | |
| 80 | | |
| 446 | | |
| 18 | % |
| Discontinued operations | |
| 18 | | |
| 115 | | |
| 15 | % |
| Other consumer loans and specialty lending | |
| 1 | | |
| 7 | | |
| 17 | % |
| Total | |
$ | 246 | | |
$ | 3,807 | | |
| 6 | % |
Exhibit
99.2
December 2019* *Guidance updated April 2020
Statements in this presentation regarding The Bancorp, Inc.’s business that are not historical facts are “forward - looking statements ”. These statements may be identified by the use of forward - looking terminology, including the words “may,” “believe,” “will,” “expect,” “anticipate,” “estimate,” “intend,” “plan," or similar words, and are based on current expectations about important economic, political, and technological factors, among others, and are subject to risks and uncertainties, which could cause the actual results, events or achievements to differ materially from those set forth in or implied by the forward - looking statements and related assumptions. These risks and uncertainties include those relating to the on - going COVID - 19 pandemic, the impact it will have on our business and the industry as a whole, and the resulting governmental and societal responses . For further discussion of these risks and uncertainties, see the “risk factors” sections contained in this presentation, in The Bancorp, Inc.’s Annual Report on Form 10 - K for the year ended December 31, 2019 and in its other public filings with the SEC. In addition, these forward - looking statements are based upon assumptions with respect to future strategies and decisions that are subject to change. Actual results may differ materially from the anticipated results discussed in these forward - looking statements. The forward - looking statements speak only as of the date of this presentation. The Bancorp, Inc. does not undertake to publicly revise or update forward - looking statements in this presentation to reflect events or circumstances that arise after the date of this presentation, except as may be required under applicable law. This presentation contains information regarding financial results that is calculated and presented on the basis of methodologies other than in accordance with accounting principles generally accepted in the United States (“GAAP”). This presentation may contain statistics and other data that in some cases has been obtained from or compiled from information made available by third - party service providers. The Bancorp, Inc. makes no representation or warranty, express or implied, with respect to the accuracy, reasonableness or completeness of such information. Past performance is not indicative nor a guarantee of future results. Copies of the documents filed by The Bancorp, Inc. with the SEC are available free of charge from the website of the SEC at www.sec.gov as well as on The Bancorp, Inc.’s website at www.thebancorp.com . This document is for information purposes only and shall not constitute an offer to sell or the solicitation of an offer to buy any securities. 2 DISCLOSURES FORWARD LOOKING STATEMENTS & OTHER DISCLOSURES
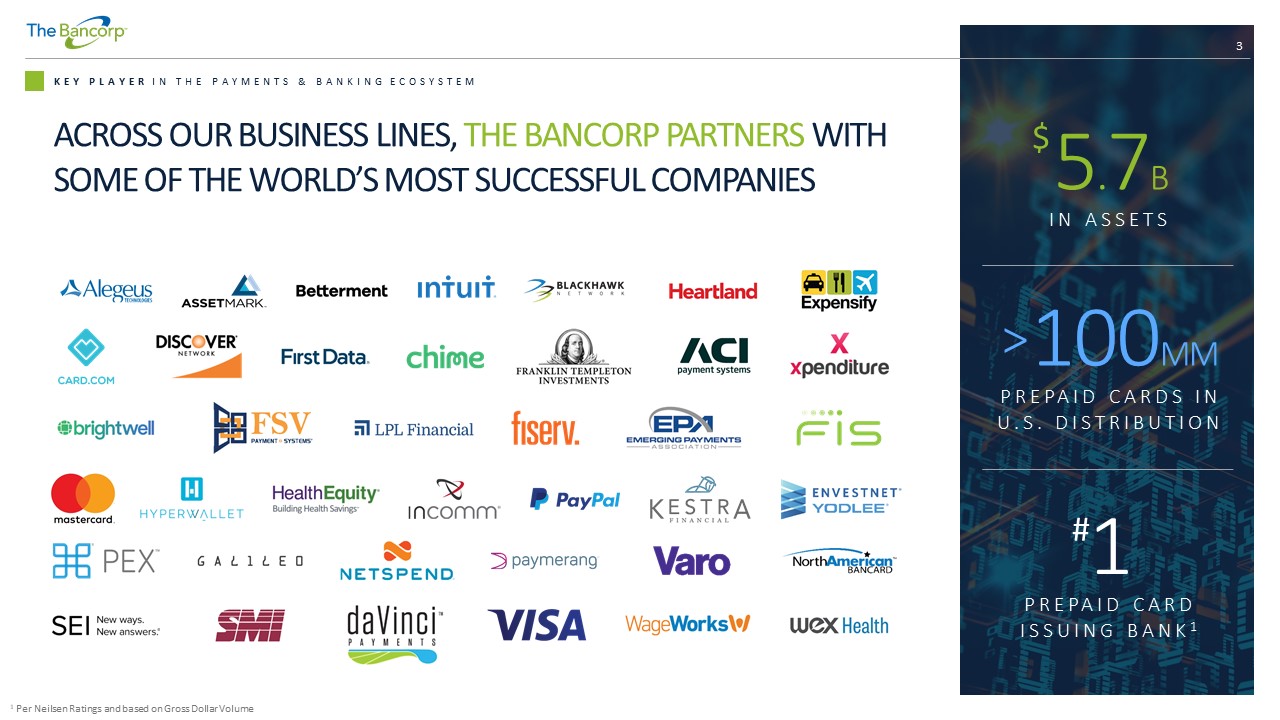
5 . 7 B $ IN ASSETS 100 MM PREPAID CARDS IN U.S. DISTRIBUTION 1 # PREPAID CARD ISSUING BANK 1 3 KEY PLAYER IN THE PAYMENTS & BANKING ECOSYSTEM 1 Per Neilsen Ratings and based on Gross Dollar Volume ACROSS OUR BUSINESS LINES, THE BANCORP PARTNERS WITH SOME OF THE WORLD’S MOST SUCCESSFUL COMPANIES >
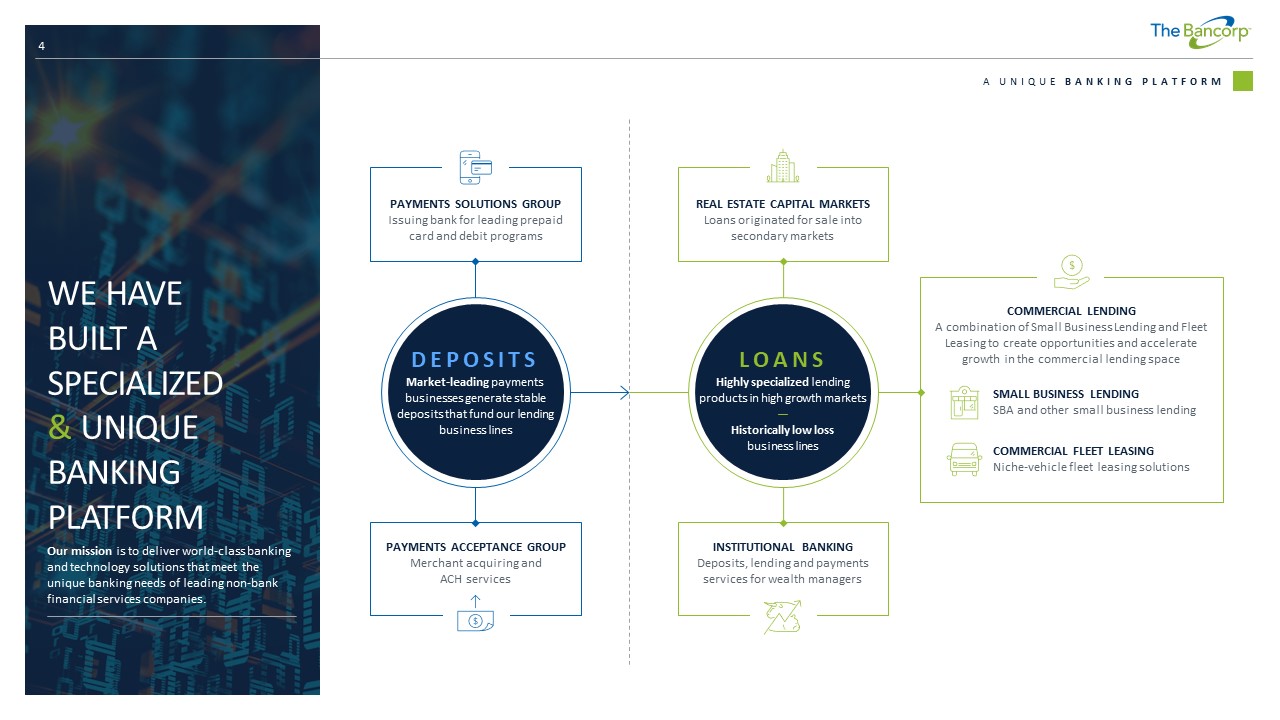
4 Our mission is to deliver world - class banking and technology solutions that meet the unique banking needs of leading non - bank financial services companies. A UNIQUE BANKING PLATFORM DEPOSITS Market - leading payments businesses generate stable deposits that fund our lending business lines LOANS Highly specialized lending products in high growth markets — Historically low loss business lines SMALL BUSINESS LENDING SBA and other small business lending COMMERCIAL FLEET LEASING Niche - vehicle fleet leasing solutions INSTITUTIONAL BANKING Deposits, lending and payments services for wealth managers PAYMENTS ACCEPTANCE GROUP Merchant acquiring and ACH services COMMERCIAL LENDING A combination of Small Business Lending and Fleet Leasing to create opportunities and accelerate growth in the commercial lending space REAL ESTATE CAPITAL MARKETS Loans originated for sale into secondary markets PAYMENTS SOLUTIONS GROUP Issuing bank for leading prepaid card and debit programs WE HAVE BUILT A SPECIALIZED & UNIQUE BANKING PLATFORM
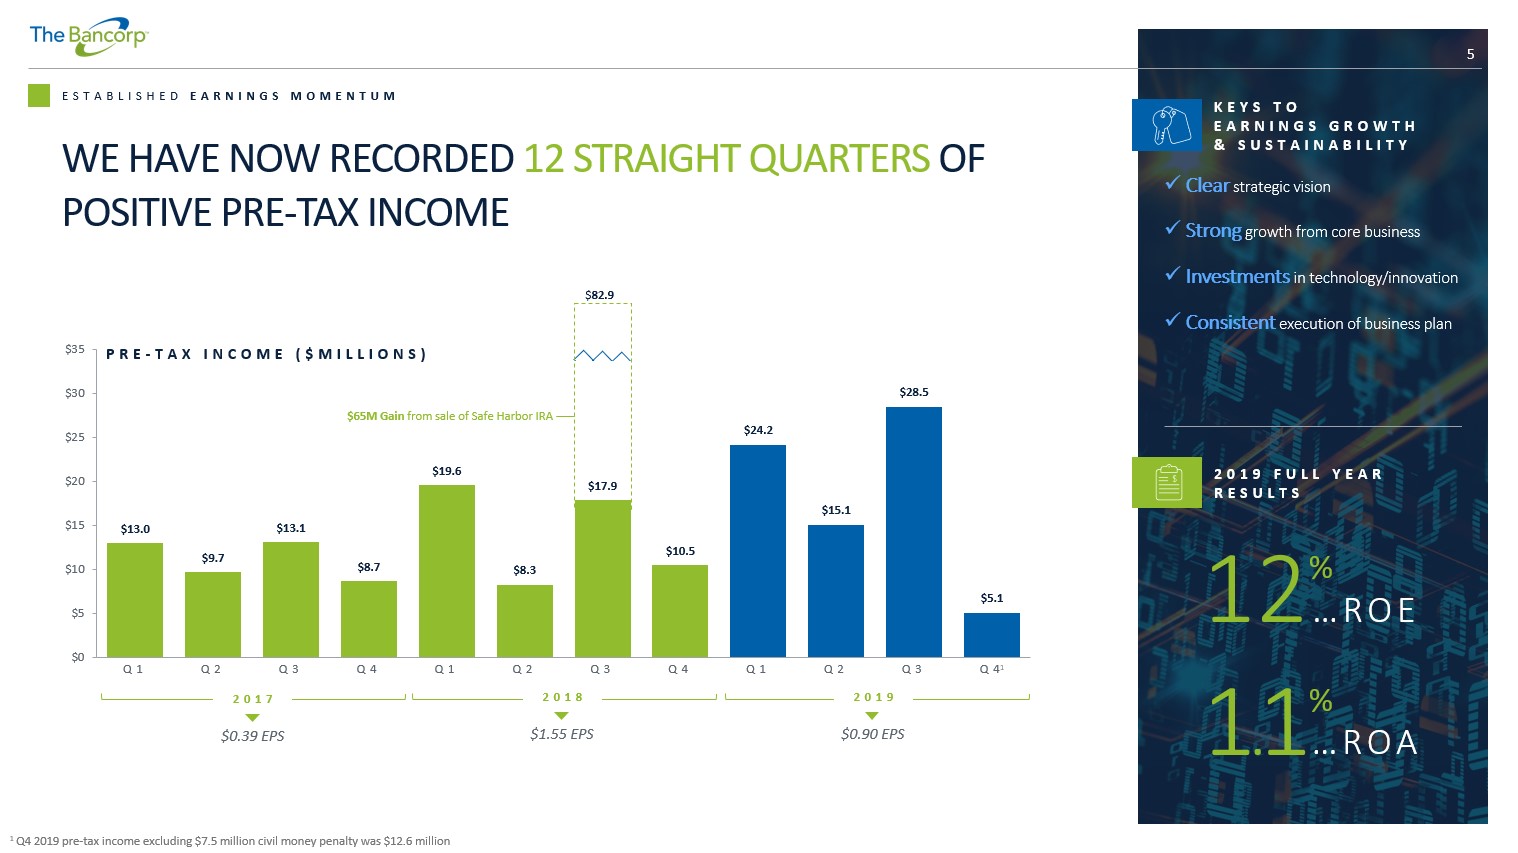
$13.0 $9.7 $13.1 $8.7 $19.6 $8.3 $17.9 $10.5 $24.2 $15.1 $28.5 $5.1 $0 $5 $10 $15 $20 $25 $30 $35 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q41 $65M Gain from sale of Safe Harbor IRA PRE - TAX INCOME ($MILLIONS) $ 82.9 2017 $0.39 EPS $1.55 EPS $ 0.90 EPS 12 % …ROE 1 . 1 % …ROA x Clear strategic vision x Strong growth from core business x Investments in technology/innovation x Consistent execution of business plan 5 ESTABLISHED EARNINGS MOMENTUM KEYS TO EARNINGS GROWTH & SUSTAINABILITY 2019 FULL YEAR RESULTS WE HAVE NOW RECORDED 12 STRAIGHT QUARTERS OF POSITIVE PRE - TAX INCOME 2018 2019 1 Q4 2019 pre-tax income excluding $7.5 million civil money penalty was $12.6 million
STRATEGIC BUSINESS PLAN
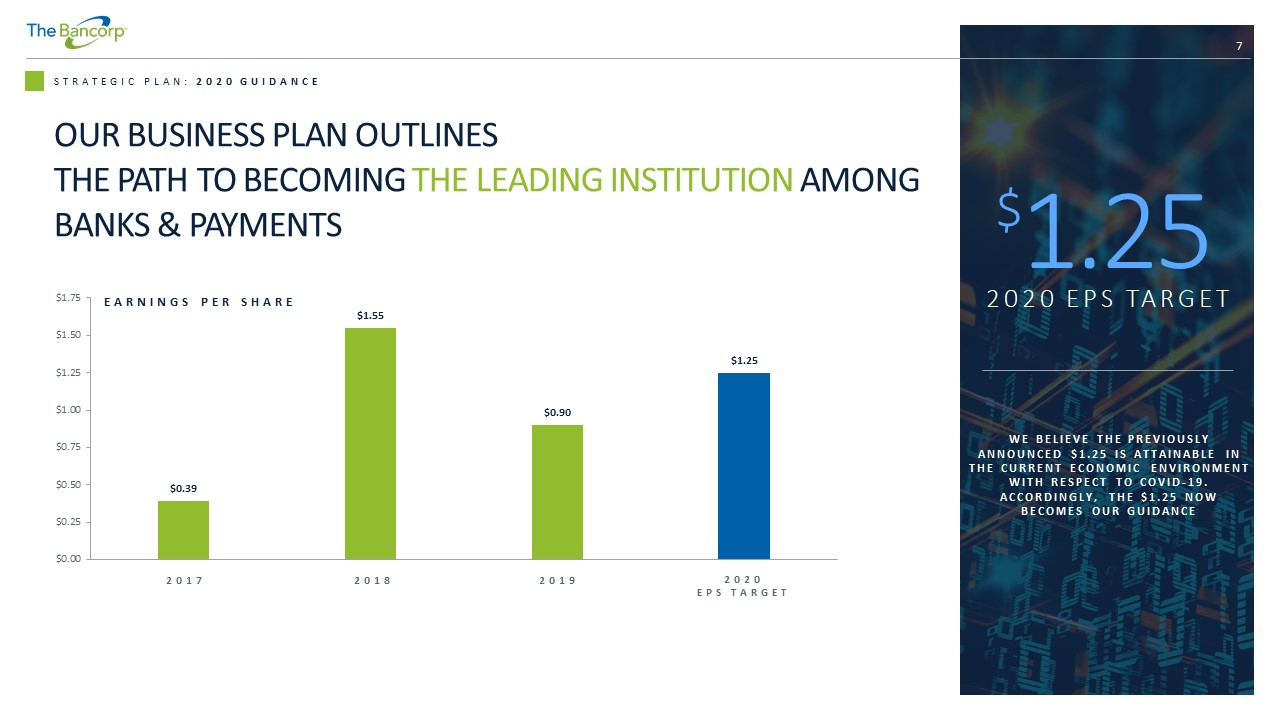
7 STRATEGIC PLAN: 2020 GUIDANCE 1.25 $ 2020 EPS TARGET $0.39 $1.55 $0.90 $1.25 $0.00 $0.25 $0.50 $0.75 $1.00 $1.25 $1.50 $1.75 2017 2018 2019 (YTD) 2020 EARNINGS PER SHARE 2020 EPS TARGET 2019 2018 2017 WE BELIEVE THE PREVIOUSLY ANNOUNCED $1.25 IS ATTAINABLE IN THE CURRENT ECONOMIC ENVIRONMENT WITH RESPECT TO COVID - 19. A CCORDINGLY, THE $1.25 NOW BECOMES OUR GUIDANCE OUR BUSINESS PLAN OUTLINES THE PATH TO BECOMING THE LEADING INSTITUTION AMONG BANKS & PAYMENTS
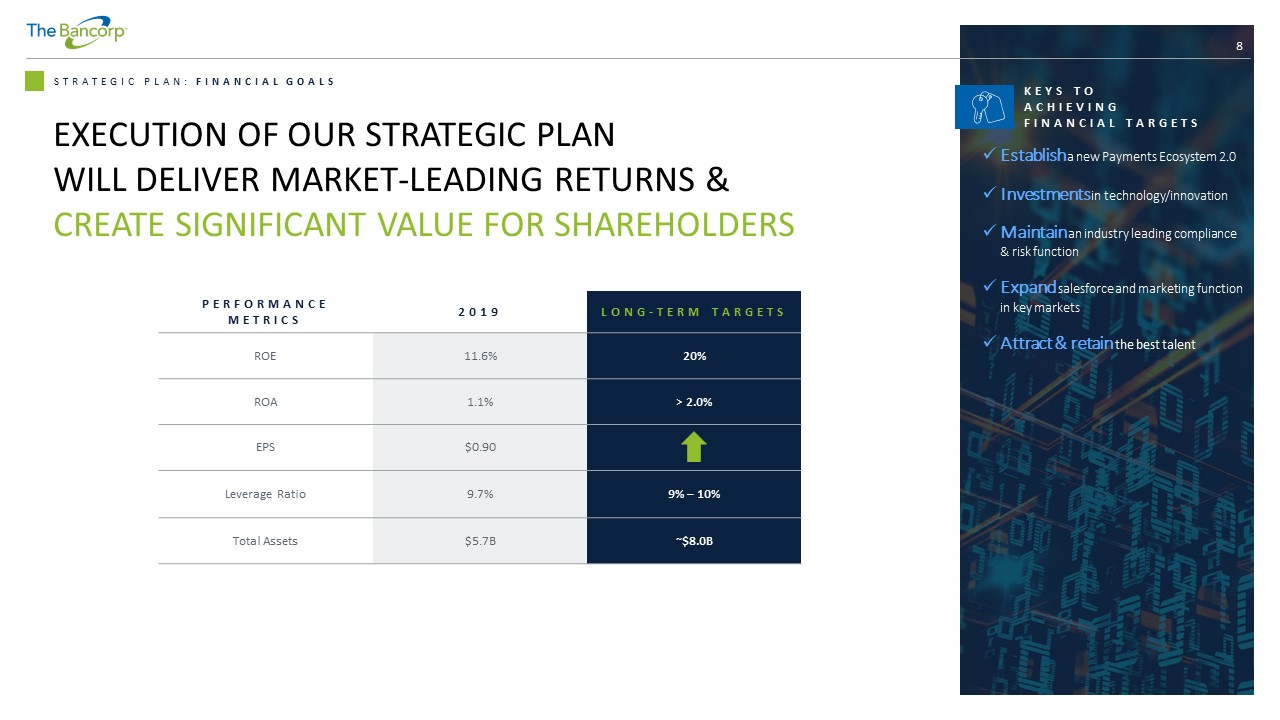
8 STRATEGIC PLAN: FINANCIAL GOALS KEYS TO ACHIEVING FINANCIAL TARGETS x Establish a new Payments Ecosystem 2.0 x Investments in technology/innovation x Maintain an industry leading compliance & risk function x Expand salesforce and marketing function in key markets x Attract & retain the best talent PERFORMANCE METRICS 2019 LONG - TERM TARGETS ROE 11.6% 20% ROA 1.1% > 2.0% EPS $ 0.90 Leverage Ratio 9.7% 9% – 10% Total Assets $ 5.7B ~$8.0B EXECUTION OF OUR STRATEGIC PLAN WILL DELIVER MARKET - LEADING RETURNS & CREATE SIGNIFICANT VALUE FOR SHAREHOLDERS
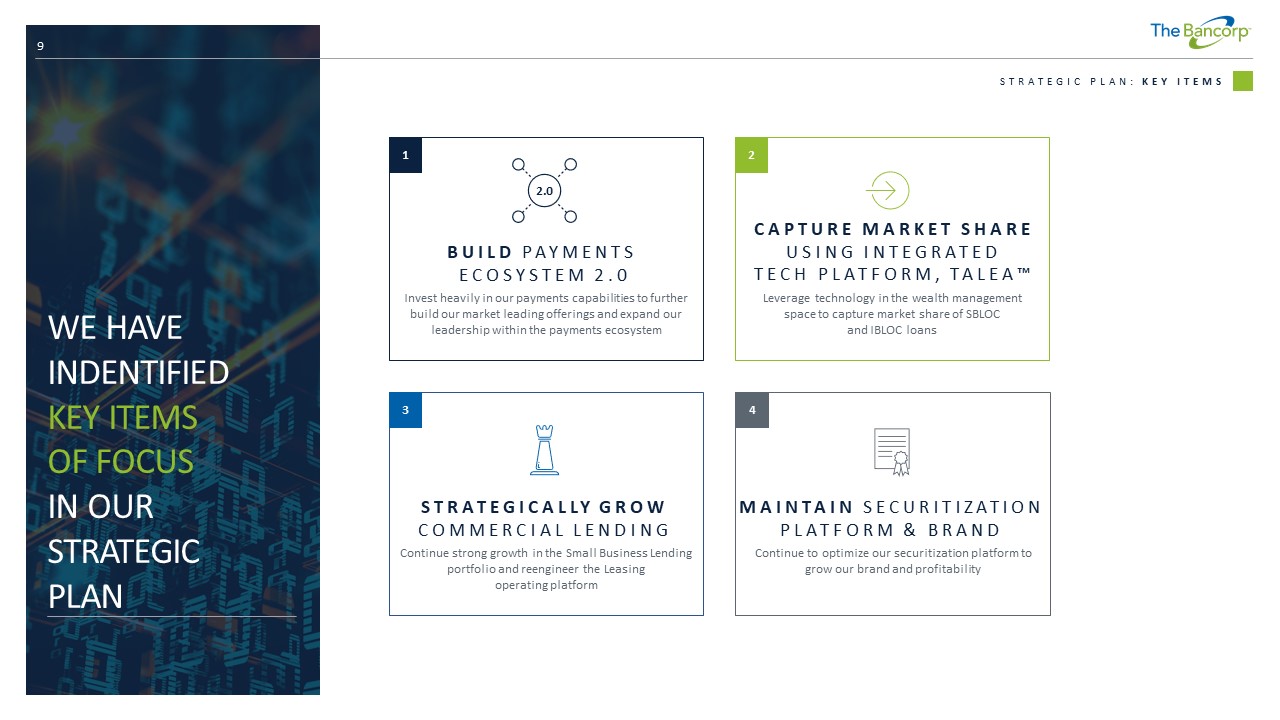
9 STRATEGIC PLAN: KEY ITEMS 1 BUILD PAYMENTS ECOSYSTEM 2.0 Invest heavily in our payments capabilities to further build our market leading offerings and expand our leadership within the payments ecosystem 2.0 CAPTURE MARKET SHARE USING INTEGRATED TECH PLATFORM, TALEA™ Leverage technology in the wealth management space to capture market share of SBLOC and IBLOC loans 2 3 STRATEGICALLY GROW COMMERCIAL LENDING Continue strong growth in the Small Business Lending portfolio and reengineer the Leasing operating platform 4 MAINTAIN SECURITIZATION PLATFORM & BRAND Continue to optimize our securitization platform to grow our brand and profitability WE HAVE INDENTIFIED KEY ITEMS OF FOCUS IN OUR STRATEGIC PLAN
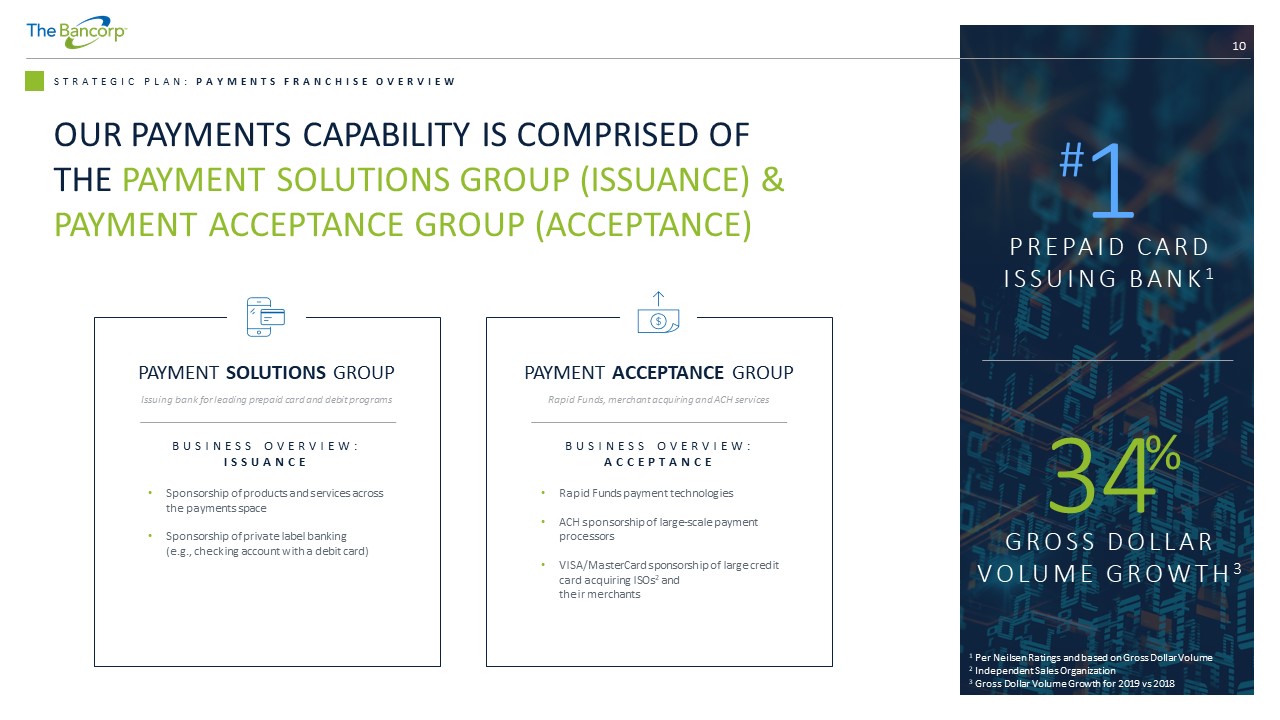
10 STRATEGIC PLAN: PAYMENTS FRANCHISE OVERVIEW PAYMENT SOLUTIONS GROUP Issuing bank for leading prepaid card and debit programs BUSINESS OVERVIEW: ISSUANCE • Sponsorship of products and services across the payments space • Sponsorship of private label banking (e.g., checking account with a debit card) PAYMENT ACCEPTANCE GROUP Rapid Funds, merchant acquiring and ACH services BUSINESS OVERVIEW: ACCEPTANCE • Rapid Funds payment technologies • ACH sponsorship of large - scale payment processors • VISA/MasterCard sponsorship of large credit card acquiring ISOs 2 and their merchants GROSS DOLLAR VOLUME GROWTH 3 1 Per Neilsen Ratings and based on Gross Dollar Volume 2 Independent Sales Organization 3 Gross Dollar Volume Growth for 2019 vs 2018 1 # 34 % OUR PAYMENTS CAPABILITY IS COMPRISED OF THE PAYMENT SOLUTIONS GROUP (ISSUANCE) & PAYMENT ACCEPTANCE GROUP (ACCEPTANCE) PREPAID CARD ISSUING BANK 1
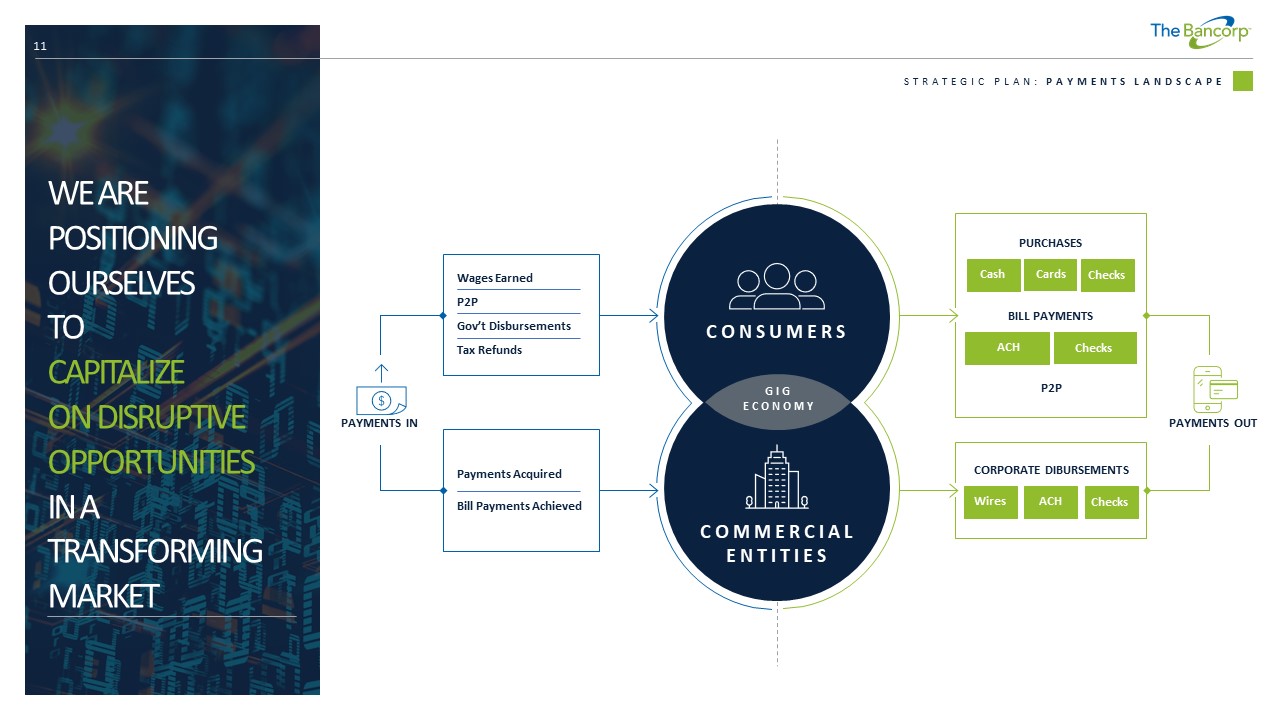
11 STRATEGIC PLAN: PAYMENTS LANDSCAPE WE ARE POSITIONING OURSELVES TO CAPITALIZE ON DISRUPTIVE OPPORTUNITIES IN A TRANSFORMING MARKET COMMERCIAL ENTITIES CONSUMERS GIG ECONOMY Wages Earned P2P Gov’t Disbursements Tax Refunds Payments Acquired Bill Payments Achieved PAYMENTS IN PURCHASES Checks Cards Cash BILL PAYMENTS Checks ACH P2P CORPORATE DIBURSEMENTS Checks ACH Wires PAYMENTS OUT
12 STRATEGIC PLAN: PAYMENTS ECOSYSTEM 2.0 THE WORLD IS CHANGING , and we have responded to create an environment to benefit our partners EVOLUTION IN CUSTOMER DEMAND HAS CREATED AN INFLECTION POINT THAT IS DISRUPTING THE STATUS QUO — NEW WINNERS ARE EMERGING
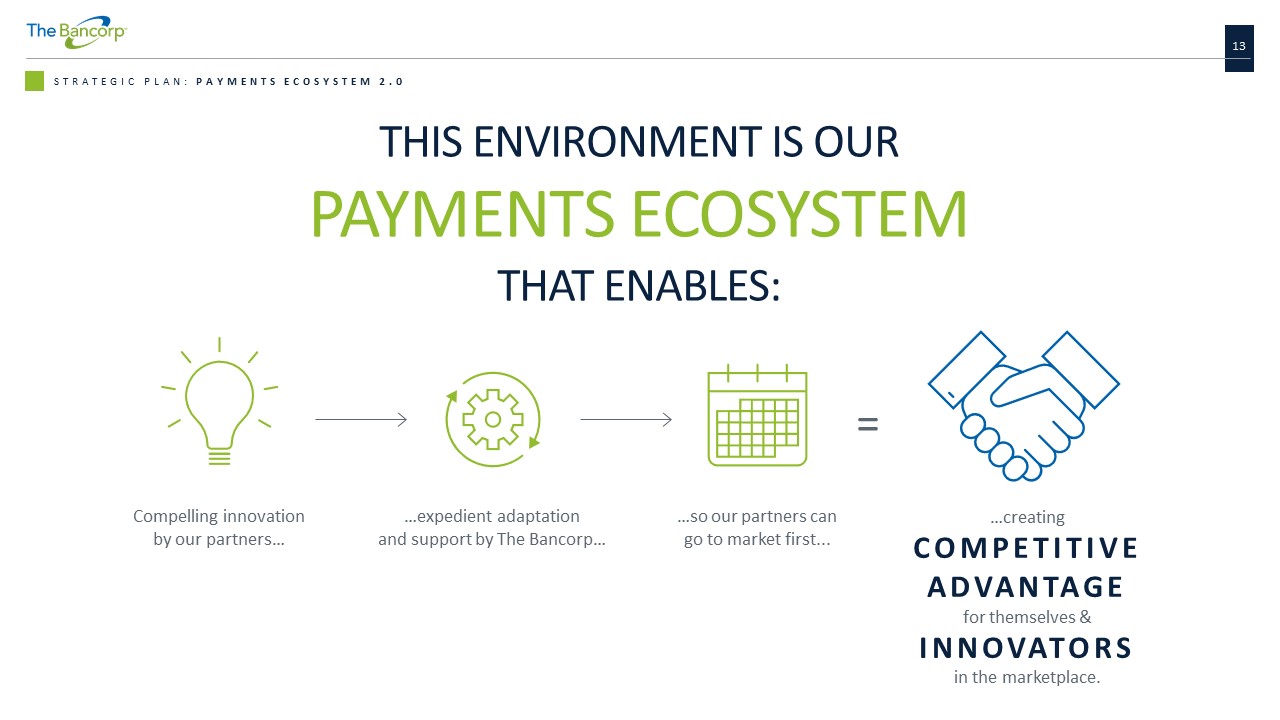
Compelling innovation by our partners… …expedient adaptation and support by The Bancorp… …so our partners can go to market first... = …creating COMPETITIVE ADVANTAGE for themselves & INNOVATORS in the marketplace. 13 STRATEGIC PLAN: PAYMENTS ECOSYSTEM 2.0 THIS ENVIRONMENT IS OUR PAYMENTS ECOSYSTEM THAT ENABLES:
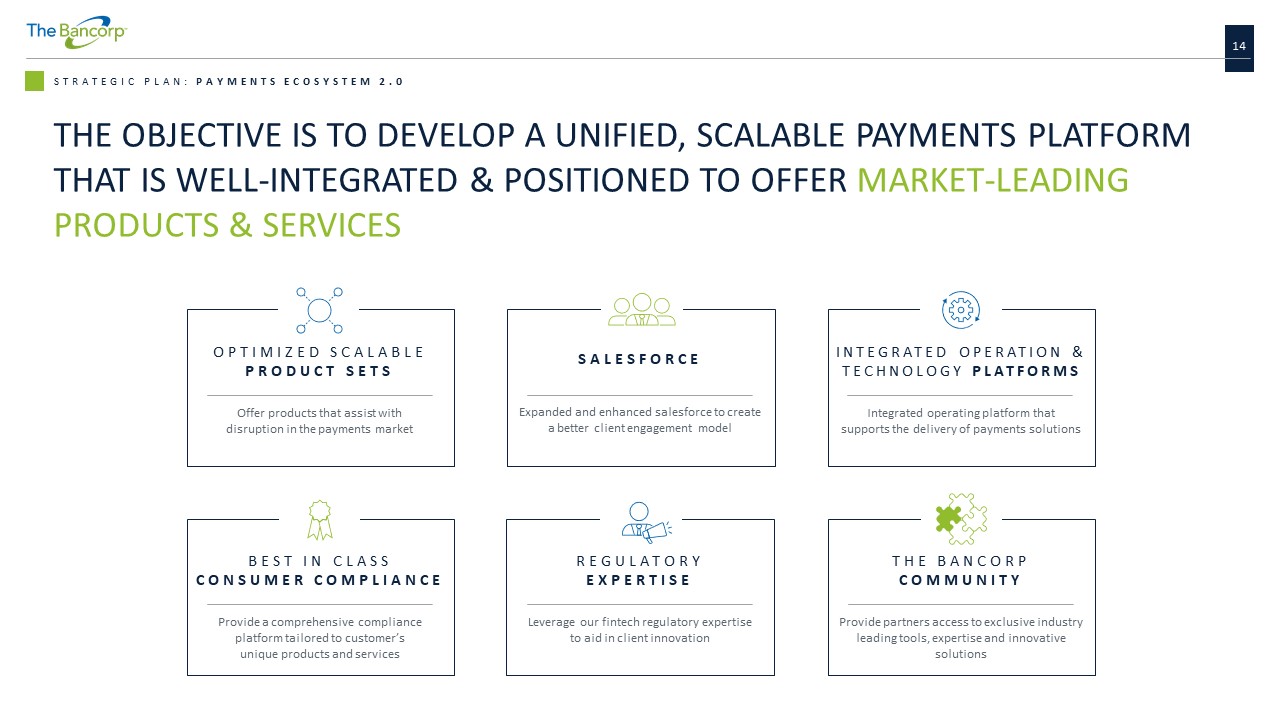
OPTIMIZED SCALABLE PRODUCT SETS Offer products that assist with disruption in the payments market SALESFORCE Expanded and enhanced salesforce to create a better client engagement model INTEGRATED OPERATION & TECHNOLOGY PLATFORMS Integrated operating platform that supports the delivery of payments solutions BEST IN CLASS CONSUMER COMPLIANCE Provide a comprehensive compliance platform tailored to customer’s unique products and services REGULATORY EXPERTISE Leverage our fintech regulatory expertise to aid in client innovation THE BANCORP COMMUNITY Provide partners access to exclusive industry leading tools, expertise and innovative solutions 14 STRATEGIC PLAN: PAYMENTS ECOSYSTEM 2.0 THE OBJECTIVE IS TO DEVELOP A UNIFIED, SCALABLE PAYMENTS PLATFORM THAT IS WELL - INTEGRATED & POSITIONED TO OFFER MARKET - LEADING PRODUCTS & SERVICES
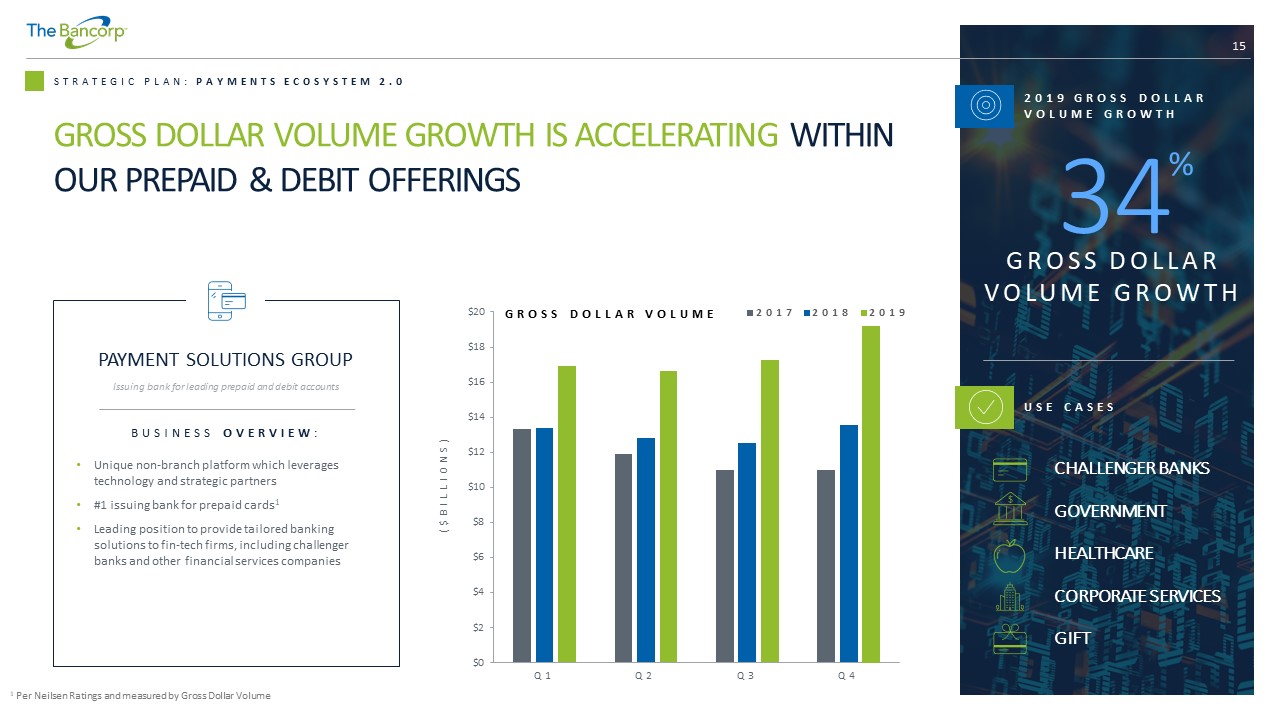
15 STRATEGIC PLAN: PAYMENTS ECOSYSTEM 2.0 ($BILLIONS) $0 $2 $4 $6 $8 $10 $12 $14 $16 $18 $20 Q1 Q2 Q3 Q4 2017 2018 2019 1 Per Neilsen Ratings and measured by Gross Dollar Volume CHALLENGER BANKS GOVERNMENT HEALTHCARE CORPORATE SERVICES GIFT GROSS DOLLAR VOLUME GROWTH IS ACCELERATING WITHIN OUR PREPAID & DEBIT OFFERINGS PAYMENT SOLUTIONS GROUP Issuing bank for leading prepaid and debit accounts BUSINESS OVERVIEW : • Unique non - branch platform which leverages technology and strategic partners • #1 issuing bank for prepaid cards 1 • Leading position to provide tailored banking solutions to fin - tech firms, including challenger banks and other financial services companies GROSS DOLLAR VOLUME 2019 GROSS DOLLAR VOLUME GROWTH 34 % GROSS DOLLAR VOLUME GROWTH USE CASES
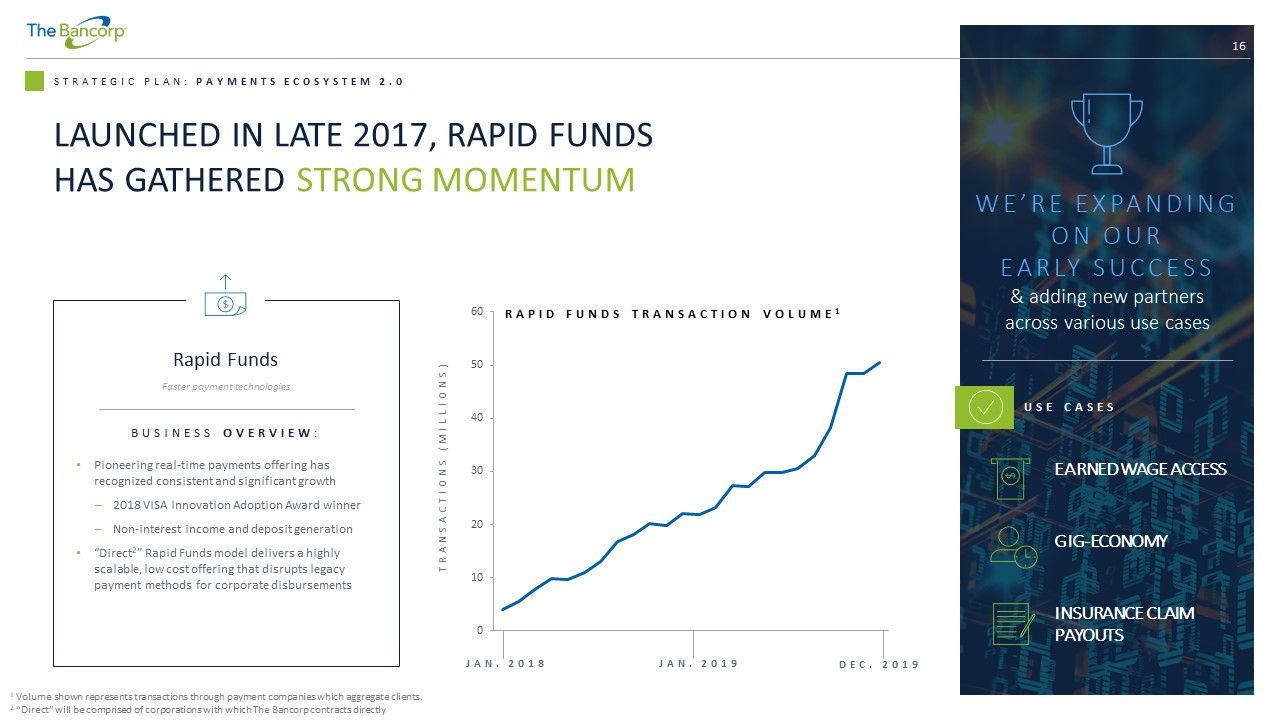
16 STRATEGIC PLAN: PAYMENTS ECOSYSTEM 2.0 WE’RE EXPANDING ON OUR EARLY SUCCESS & adding new partners across various use cases 1 Volume shown represents transactions through payment companies which aggregate clients. 2 “Direct” will be comprised of corporations with which The Bancorp contracts directly LAUNCHED IN LATE 2017, RAPID FUNDS HAS GATHERED STRONG MOMENTUM 0 10 20 30 40 50 60 JAN. 2018 JAN. 2019 DEC. 2019 TRANSACTIONS (MILLIONS) RAPID FUNDS TRANSACTION VOLUME 1 Rapid Funds Faster payment technologies BUSINESS OVERVIEW : • Pioneering real - time payments offering has recognized consistent and significant growth – 2018 VISA Innovation Adoption Award winner – Non - interest income and deposit generation • “Direct 2 ” Rapid Funds model delivers a highly scalable, low cost offering that disrupts legacy payment methods for corporate disbursements USE CASES EARNED WAGE ACCESS GIG - ECONOMY INSURANCE CLAIM PAYOUTS
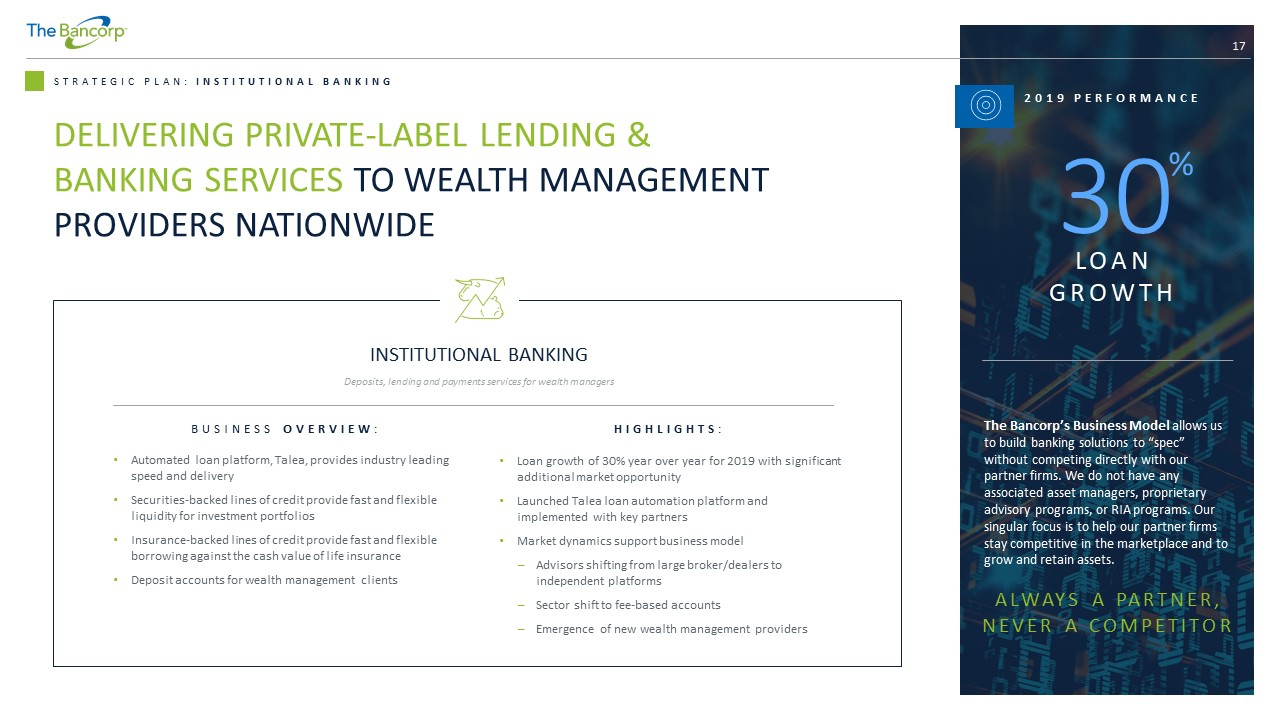
BUSINESS OVERVIEW : • Automated loan platform, Talea , provides industry leading speed and delivery • Securities - backed lines of credit provide fast and flexible liquidity for investment portfolios • Insurance - backed lines of credit provide fast and flexible borrowing against the cash value of life insurance • Deposit accounts for wealth management clients 17 STRATEGIC PLAN: INSTITUTIONAL BANKING INSTITUTIONAL BANKING Deposits, lending and payments services for wealth managers HIGHLIGHTS : • Loan growth of 30% year over year for 2019 with significant additional market opportunity • Launched Talea loan automation platform and implemented with key partners • Market dynamics support business model – Advisors shifting from large broker/dealers to independent platforms – Sector shift to fee - based accounts – Emergence of new wealth management providers The Bancorp’s Business Model allows us to build banking solutions to “spec” without competing directly with our partner firms. We do not have any associated asset managers, proprietary advisory programs, or RIA programs. Our singular focus is to help our partner firms stay competitive in the marketplace and to grow and retain assets. ALWAYS A PARTNER, NEVER A COMPETITOR DELIVERING PRIVATE - LABEL LENDING & BANKING SERVICES TO WEALTH MANAGEMENT PROVIDERS NATIONWIDE 2019 PERFORMANCE 30 % LOAN GROWTH
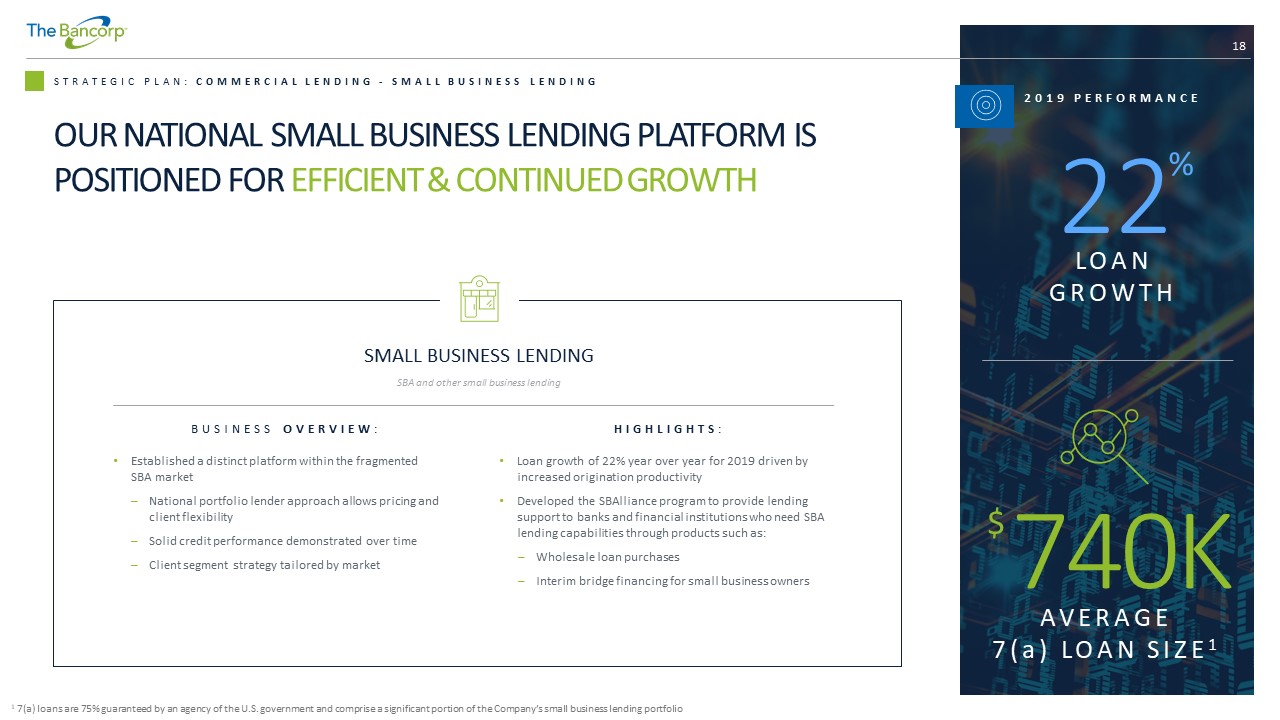
BUSINESS OVERVIEW : • Established a distinct platform within the fragmented SBA market – National portfolio lender approach allows pricing and client flexibility – Solid credit performance demonstrated over time – Client segment strategy tailored by market 18 STRATEGIC PLAN: COMMERCIAL LENDING - SMALL BUSINESS LENDING 740K AVERAGE 7(a) LOAN SIZE 1 $ SMALL BUSINESS LENDING SBA and other small business lending HIGHLIGHTS : • Loan growth of 22% year over year for 2019 driven by increased origination productivity • Developed the SBAlliance program to provide lending support to banks and financial institutions who need SBA lending capabilities through products such as: – Wholesale loan purchases – Interim bridge financing for small business owners 1 7(a) loans are 75% guaranteed by an agency of the U.S. government and comprise a significant portion of the Company’s small b us iness lending portfolio OUR NATIONAL SMALL BUSINESS LENDING PLATFORM IS POSITIONED FOR EFFICIENT & CONTINUED GROWTH 2019 PERFORMANCE 22 % LOAN GROWTH
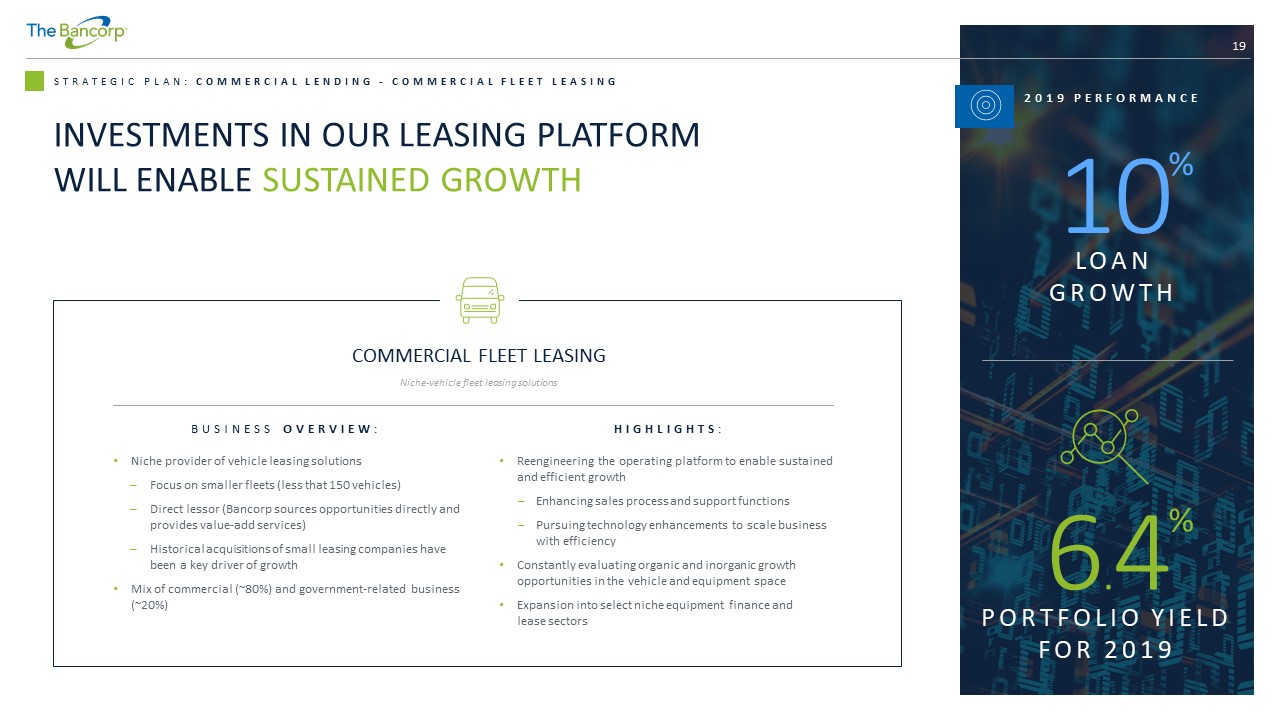
19 STRATEGIC PLAN: COMMERCIAL LENDING - COMMERCIAL FLEET LEASING BUSINESS OVERVIEW : • Niche provider of vehicle leasing solutions – Focus on smaller fleets (less that 150 vehicles) – Direct lessor (Bancorp sources opportunities directly and provides value - add services) – Historical acquisitions of small leasing companies have been a key driver of growth • Mix of commercial (~80%) and government - related business (~20%) COMMERCIAL FLEET LEASING Niche - vehicle fleet leasing solutions HIGHLIGHTS : • Reengineering the operating platform to enable sustained and efficient growth – Enhancing sales process and support functions – Pursuing technology enhancements to scale business with efficiency • Constantly evaluating organic and inorganic growth opportunities in the vehicle and equipment space • Expansion into select niche equipment finance and lease sectors INVESTMENTS IN OUR LEASING PLATFORM WILL ENABLE SUSTAINED GROWTH 2019 PERFORMANCE 10 % LOAN GROWTH 6 . 4 % PORTFOLIO YIELD FOR 2019
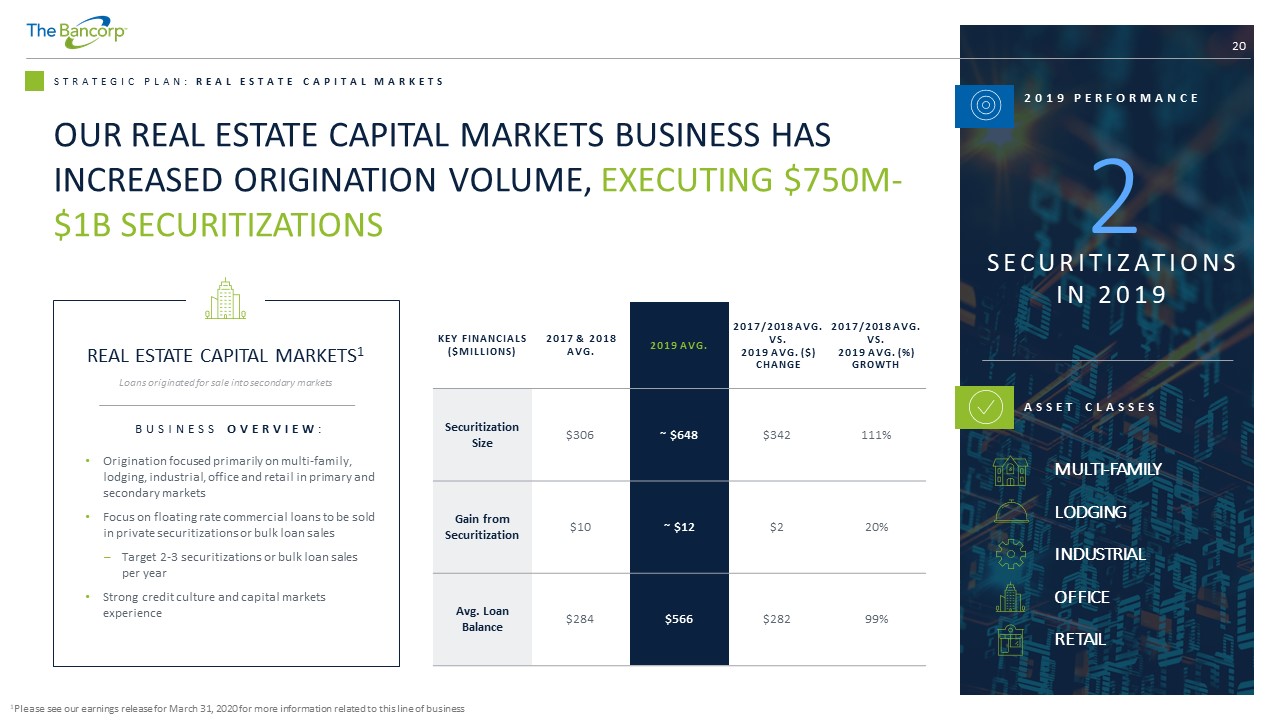
20 STRATEGIC PLAN: REAL ESTATE CAPITAL MARKETS REAL ESTATE CAPITAL MARKETS 1 Loans originated for sale into secondary markets BUSINESS OVERVIEW : • Origination focused primarily on multi - family, lodging, industrial, office and retail in primary and secondary markets • Focus on floating rate commercial loans to be sold in private securitizations or bulk loan sales – Target 2 - 3 securitizations or bulk loan sales per year • Strong credit culture and capital markets experience KEY FINANCIALS ($MILLIONS) 2017 & 2018 AVG. 2019 AVG . 2017/2018 AVG. VS. 2019 AVG. ($) CHANGE 2017/2018 AVG. VS. 2019 AVG. (%) GROWTH Securitization Size $306 ~ $648 $342 111% Gain from Securitization $10 ~ $12 $2 20% Avg . Loan Balance $284 $566 $282 99% 2019 PERFORMANCE 2 SECURITIZATIONS IN 2019 MULTI - FAMILY LODGING INDUSTRIAL OFFICE RETAIL ASSET CLASSES OUR REAL ESTATE CAPITAL MARKETS BUSINESS HAS INCREASED ORIGINATION VOLUME, EXECUTING $750M - $1B SECURITIZATIONS 1 Please see our earnings release for March 31, 2020 for more information related to this line of business
21 THE BANCORP COMMUNITY WE ARE BULDING A COMMUNITY TOGETHER TO UNLOCK THE POWER OF OUR ORGANIZATION COLLEAGUES CLIENTS INVESTORS REGULATORS PARTNERS VENDORS BOARD OF DIRECTORS
The risk factors discussed and identified in our Annual Report on Form 10 - K for the year ended December 31, 2019, and in other of our public filings with the SEC include but are not limited to the following: • changing economic and credit market conditions may have significant adverse effects on our assets and operating results, including increases in payment defaults and other credit risks, decreases in the fair value of some assets and increases in our provision for loan losses, and may result in a reduction in our capital base, reducing our ability to maintain deposits at current levels, and a reduction in our income and cash flows; • operating costs may increase; • adverse governmental or regulatory policies or actions may be promulgated; • management and other key personnel may be lost; • competition may increase; • the costs of our interest - bearing liabilities, principally deposits, may increase relative to the interest received on our interest bearing assets, principally loans, thereby decreasing our net interest income; • loan and investment yields may decrease resulting in a lower net interest margin; • possible geographic concentration could result in our loan portfolio being adversely affected by economic factors unique to the geographic area and not reflected in other regions of the country; • the market value of real estate that secures certain of our loans, principally loans we originate for sale into secondary markets, Small Business Administration loans under the 504 Fixed Asset Financing Program and our discontinued commercial loan portfolio, has been, and may continue to be, adversely affected by recent economic and market conditions, and may be affected by other conditions outside of our control such as lack of demand for real estate of the type securing our loans, natural disasters, changes in neighborhood values, competitive overbuilding, weather, casualty losses, occupancy rates and other similar factors; • we must satisfy our regulators with respect to Bank Secrecy Act, Anti - Money Laundering and other regulatory mandates to prevent additional penalties, including restrictions on adding customers; • the loans from our discontinued operations are now held for sale and were marked to fair value based on various internal and external inputs; however, the actual sales price could differ from those third - party fair values. The reinvestment rate for the proceeds of those sales in investment securities depends on future market interest rates; and • we may not be able to sustain our historical growth rate in our loan, prepaid card and other lines of business. 22 RISK FACTORS THE FOLLOWING RISK FACTORS , AMONG OTHERS, COULD CAUSE ACTUAL RESULTS TO DIFFER MATERIALLY FROM THE ANTICIPATED RESULTS OR OTHER EXPECTATIONS EXPRESSED IN THIS PRESENTATION