Exhibit 99.1
| INVESTOR CONTACT | MEDIA CONTACT | |||||||
| Jamie Britton, 214.932.6721 | Shannon Wherry, 469.399.8527 | |||||||
| [email protected] | [email protected] | |||||||
TEXAS CAPITAL BANCSHARES, INC. ANNOUNCES OPERATING RESULTS FOR Q1 2021
DALLAS - April 21, 2021 - Texas Capital Bancshares, Inc. (NASDAQ: TCBI), the parent company of Texas Capital Bank, announced operating results for the first quarter of 2021.
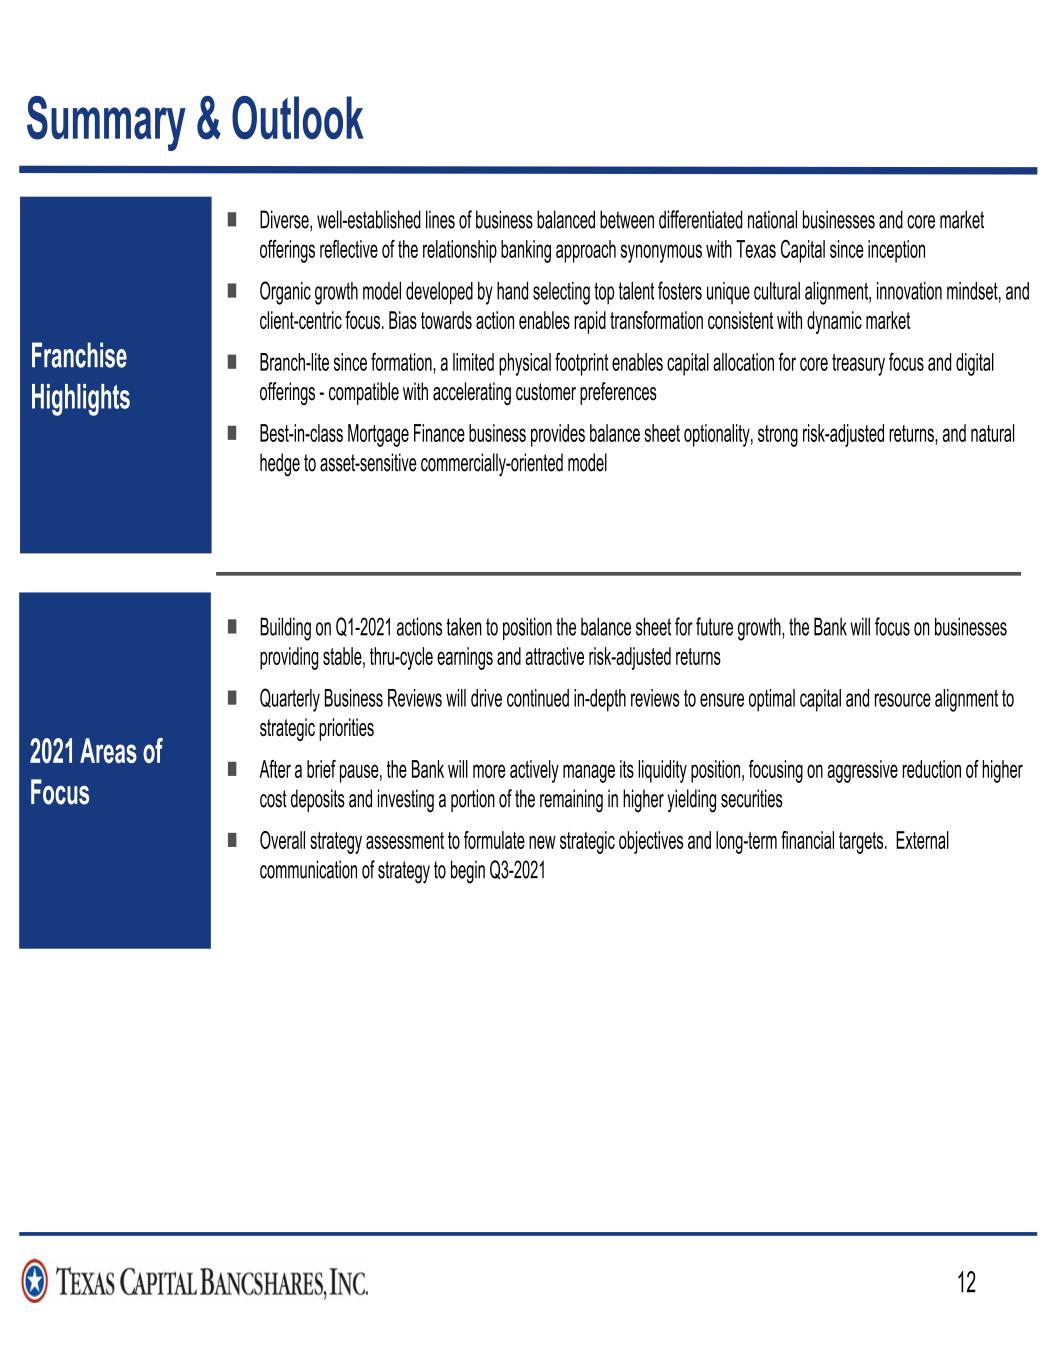
"In my first 90 days as CEO, we have achieved momentum in establishing the foundation from which we can move forward," said Rob C. Holmes, President and CEO. "In the first quarter alone, we were able to execute the largest capital raise in our history and close on our first warehouse lending credit risk transfer transaction, both of which position TCBI for future growth. Looking ahead, we will continue to supplement our workforce with new talent, take steps to drive shareholder value and develop our fulsome long-term strategy. As promised, I look forward to sharing it with you in the third quarter."
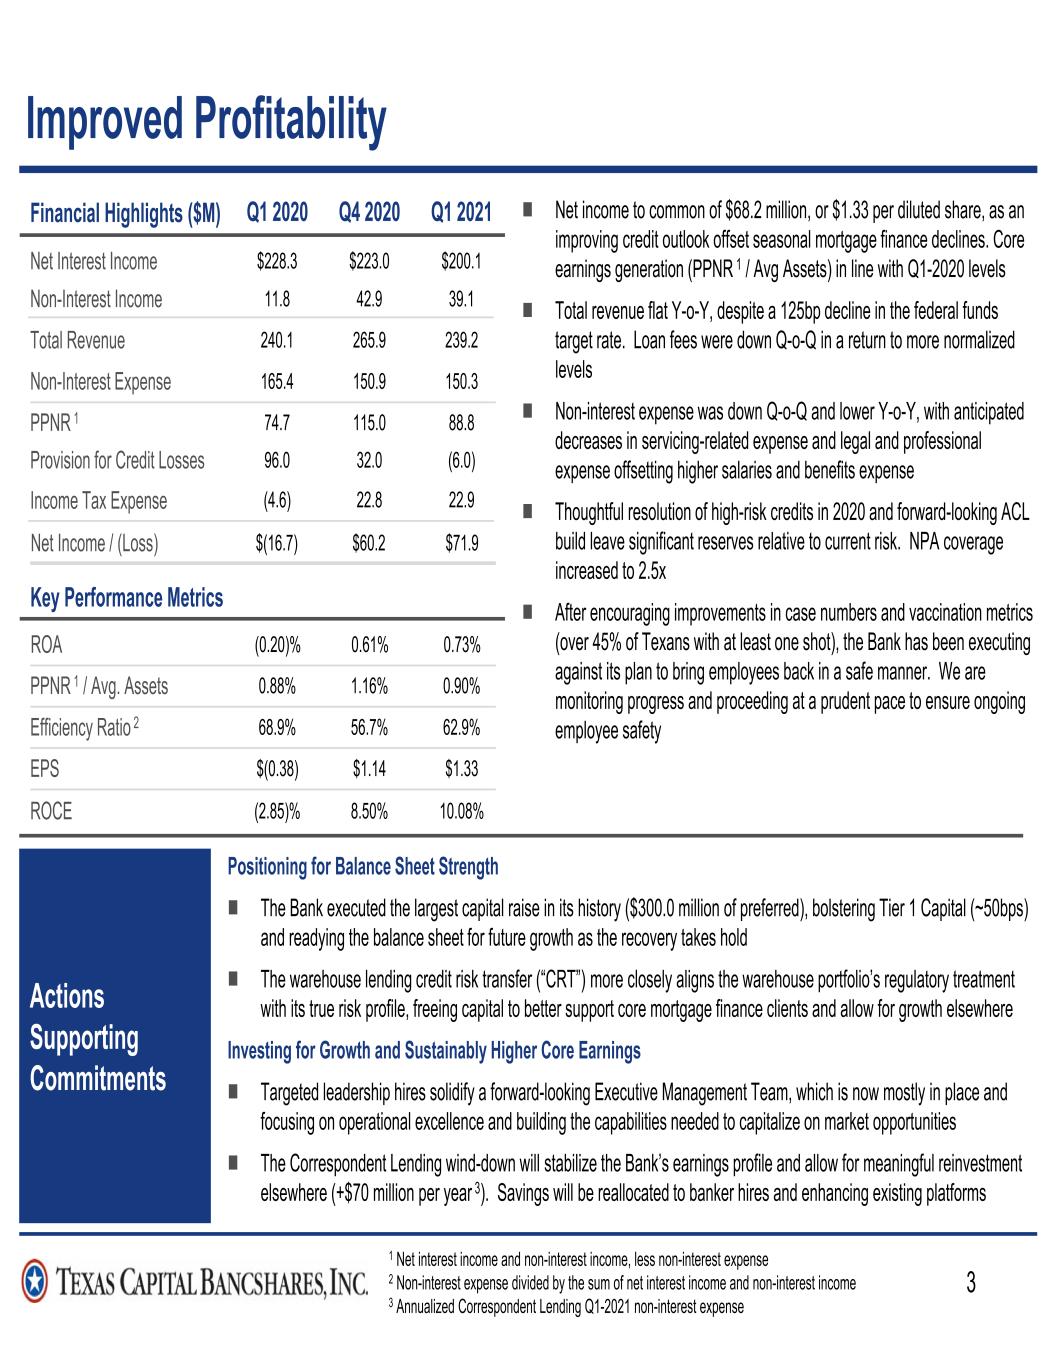
•Net income of $71.9 million ($1.33 per diluted share) reported for the first quarter of 2021, an increase of $11.8 million on a linked quarter basis and an increase of $88.6 million from the first quarter of 2020.
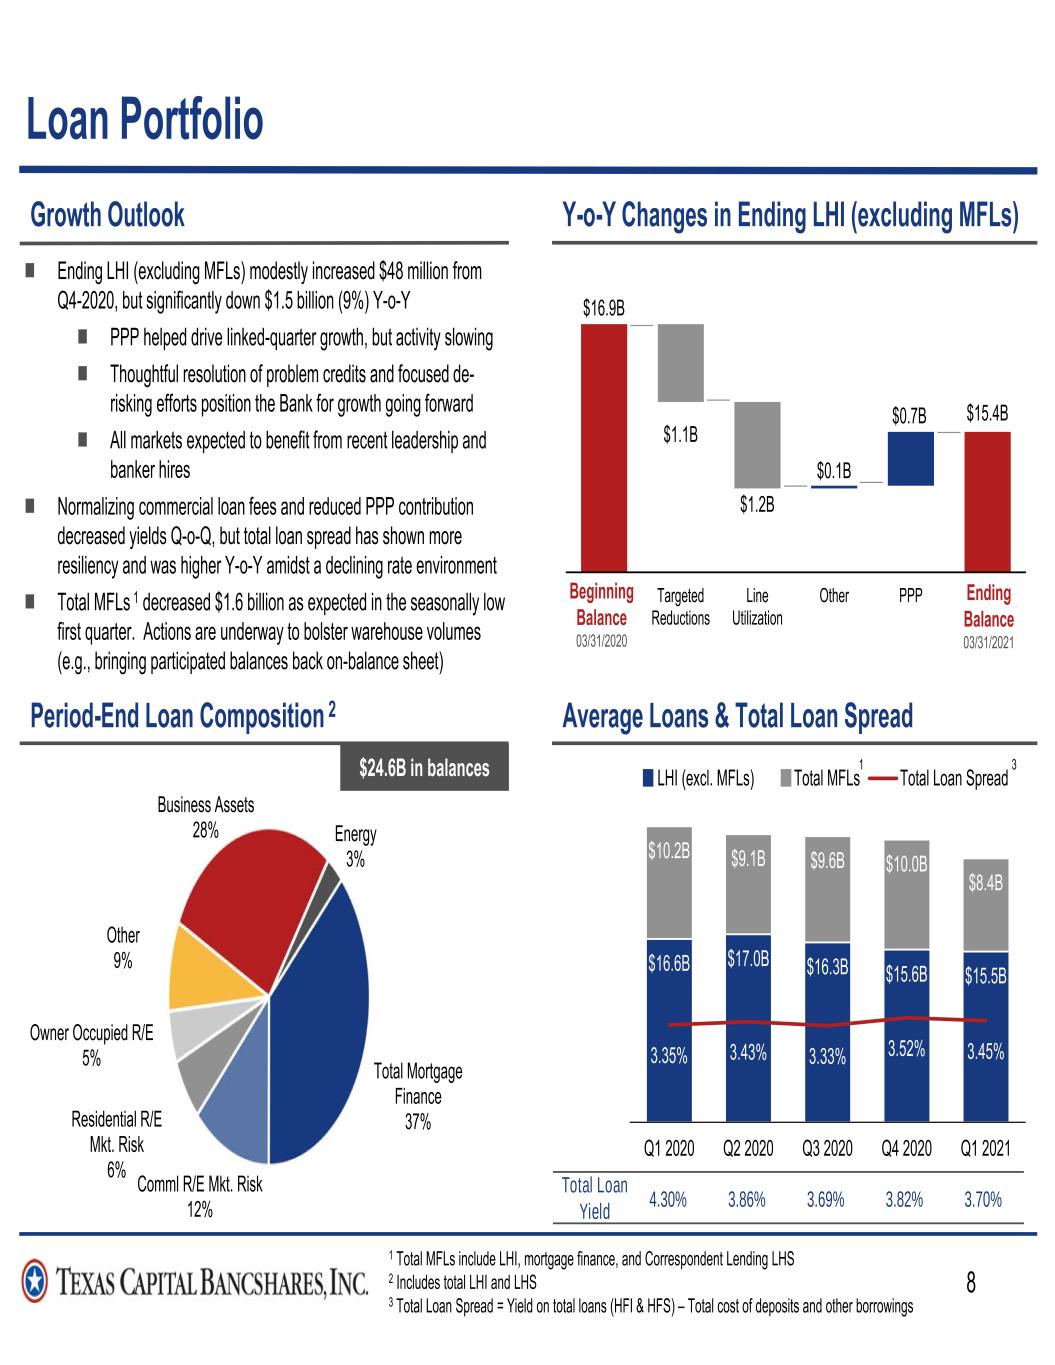
•Total mortgage finance loans, including mortgage correspondent aggregation ("MCA") loans held for sale ("LHS"), decreased 2% on a linked quarter basis (decreasing 15% on an average basis) and increased 10% from the first quarter of 2020 (decreasing 17% on an average basis).
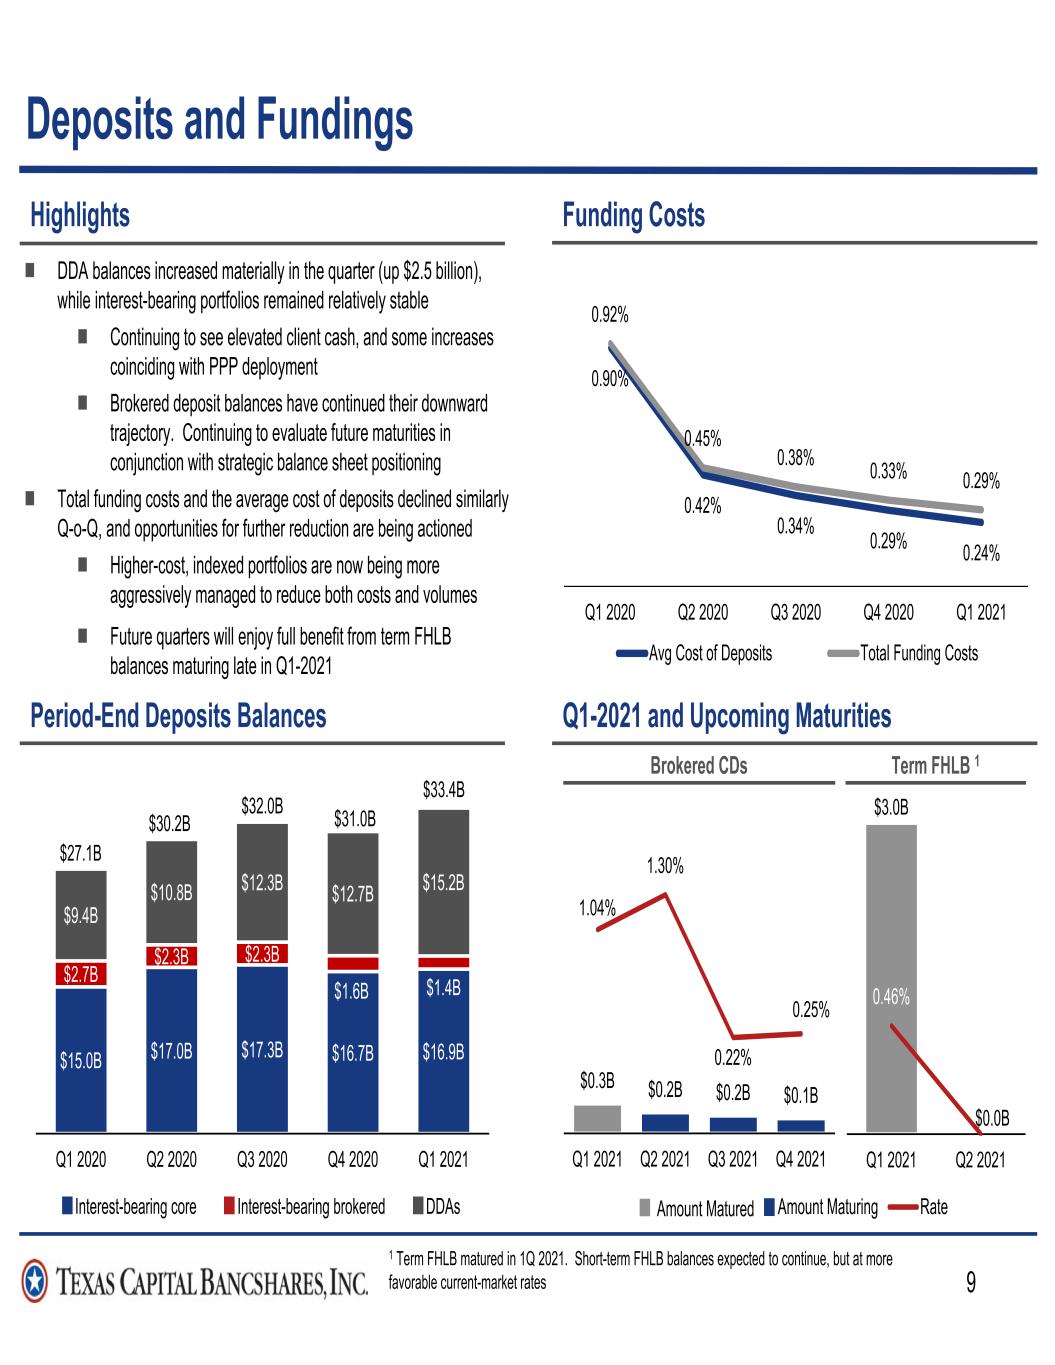
•Demand deposits increased 19% and total deposits increased 8% on a linked quarter basis (increasing 9% and 2%, respectively, on an average basis), and increased 61% and 23%, respectively, from the first quarter of 2020 (increasing 44% and 21%, respectively, on an average basis).
•Loans held for investment ("LHI"), excluding mortgage finance loans, were flat on a linked quarter basis (decreasing 1% on an average basis) and decreased 9% from the first quarter of 2020 (decreasing 7% on an average basis).
•Issuance of $300.0 million in 5.75% fixed rate non-cumulative perpetual preferred stock, completed in the first quarter of 2021, providing additional equity to be used for general corporate purchases, including funding regulatory capital infusions into the Bank. We also intend to use a portion of the net proceeds to redeem, subject to all applicable regulatory approvals, our existing 6.5% fixed rate non-cumulative perpetual preferred stock.
•Issuance of $275.0 million senior unsecured credit-linked notes in the first quarter of 2021. The net proceeds of this offering will be used to expand the Bank's warehouse lending program and better serve our clients in all market environments.
FINANCIAL SUMMARY
| (dollars and shares in thousands) | Q1 2021 | Q1 2020 | % Change | ||||||||||||||
| QUARTERLY OPERATING RESULTS | |||||||||||||||||
| Net income | $ | 71,938 | $ | (16,687) | (531) | % | |||||||||||
| Net income available to common stockholders | $ | 68,159 | $ | (19,125) | (456) | % | |||||||||||
| Diluted earnings per common share | $ | 1.33 | $ | (0.38) | (450) | % | |||||||||||
| Diluted common shares | 51,070 | 50,475 | 1 | % | |||||||||||||
| ROA | 0.73 | % | (0.20) | % | |||||||||||||
| ROE | 10.08 | % | (2.85) | % | |||||||||||||
| BALANCE SHEET | |||||||||||||||||
| LHS | $ | 176,286 | $ | 774,064 | (77) | % | |||||||||||
| LHI, mortgage finance | 9,009,081 | 7,588,803 | 19 | % | |||||||||||||
| LHI | 15,399,174 | 16,857,579 | (9) | % | |||||||||||||
| Total LHI | 24,408,255 | 24,446,382 | — | % | |||||||||||||
| Total assets | 40,054,433 | 35,879,416 | 12 | % | |||||||||||||
| Demand deposits | 15,174,642 | 9,420,303 | 61 | % | |||||||||||||
| Total deposits | 33,391,970 | 27,134,263 | 23 | % | |||||||||||||
| Stockholders’ equity | 3,159,482 | 2,772,596 | 14 | % | |||||||||||||
DETAILED FINANCIALS
For the first quarter of 2021, net income was $71.9 million, compared to net income of $60.2 million for the fourth quarter of 2020, and net loss of $16.7 million for the first quarter of 2020. On a fully diluted basis, earnings per common share were $1.33 for the quarter ended March 31, 2021, compared to earnings per common share of $1.14 for the quarter ended December 31, 2020 and loss per common share of $0.38 for the quarter ended March 31, 2020. The increase in net income for the first quarter of 2021 as compared to the fourth quarter of 2020 resulted primarily from a $38.0 million decrease in the provision for credit losses, offset by a decrease in net interest income.
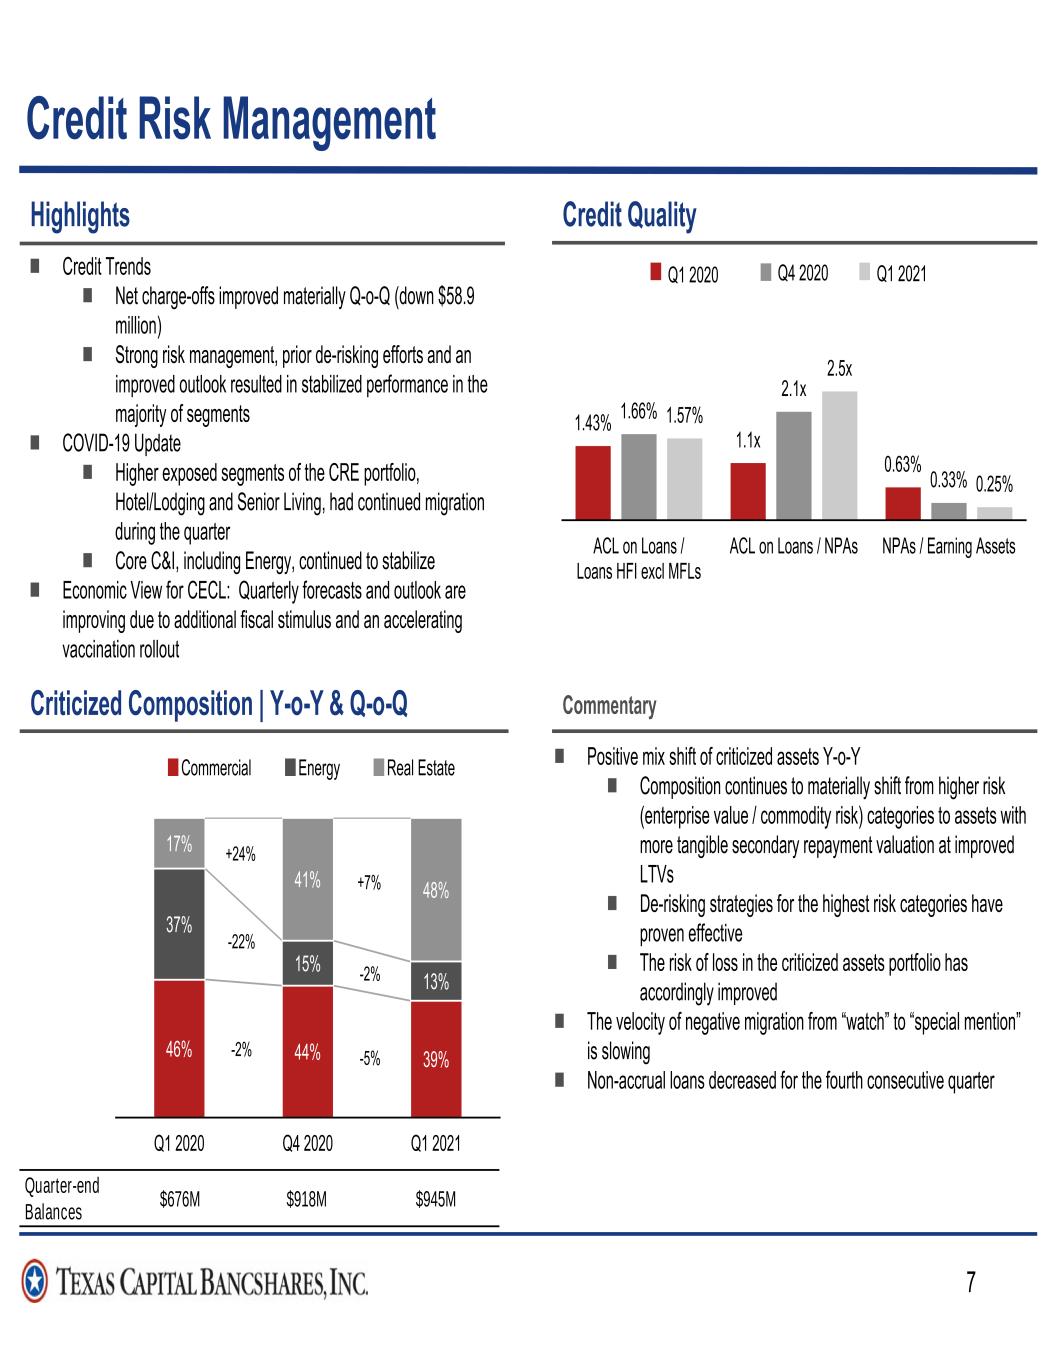
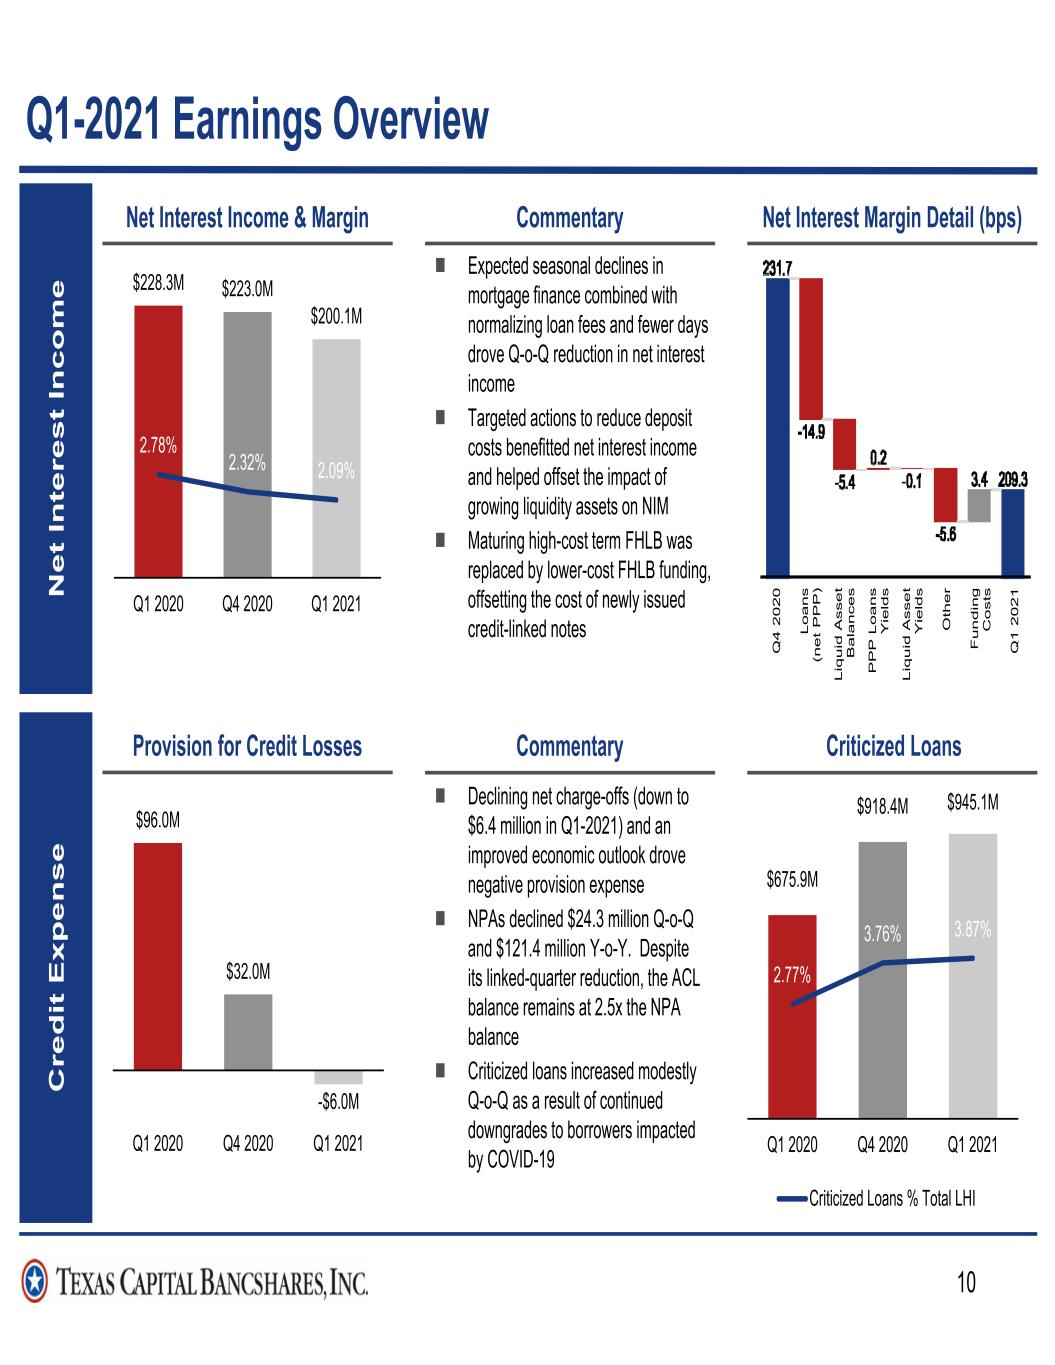
We recorded a $6.0 million negative provision for credit losses for the first quarter of 2021, compared to a $32.0 million provision for credit losses for the fourth quarter of 2020 and a $96.0 million provision for credit losses for the first quarter of 2020. The linked quarter decrease in provision for credit losses resulted primarily from a decrease in charge-offs and improvement in the economic outlook as the economy begins to recover from the impacts of the COVID-19 pandemic. We recorded $6.4 million in net charge-offs during the first quarter of 2021, including $5.0 million in energy net charge-offs on loans that had been previously identified as problem loans, compared to $65.4 million during the fourth quarter of 2020 and $57.7 million during the first quarter of 2020. Criticized loans totaled $945.1 million at March 31, 2021, compared to $918.4 million at December 31, 2020 and $675.9 million at March 31, 2020. Criticized loan levels remain elevated when compared to pre-pandemic levels due to the downgrade of loans to borrowers that have been impacted by the COVID-19 pandemic.
Non-performing assets ("NPAs") totaled $97.7 million at March 31, 2021, a decrease of $24.3 million compared to the fourth quarter of 2020 and a decrease of $121.4 million compared to the first quarter of 2020. The linked quarter change in NPAs was primarily due to a decline in non-accrual energy loans. The ratio of total LHI NPAs to total LHI plus other real estate owned ("OREO") for the first quarter of 2021 was 0.40%, compared to 0.50% for the fourth quarter of 2020 and 0.90% for the first quarter of 2020.
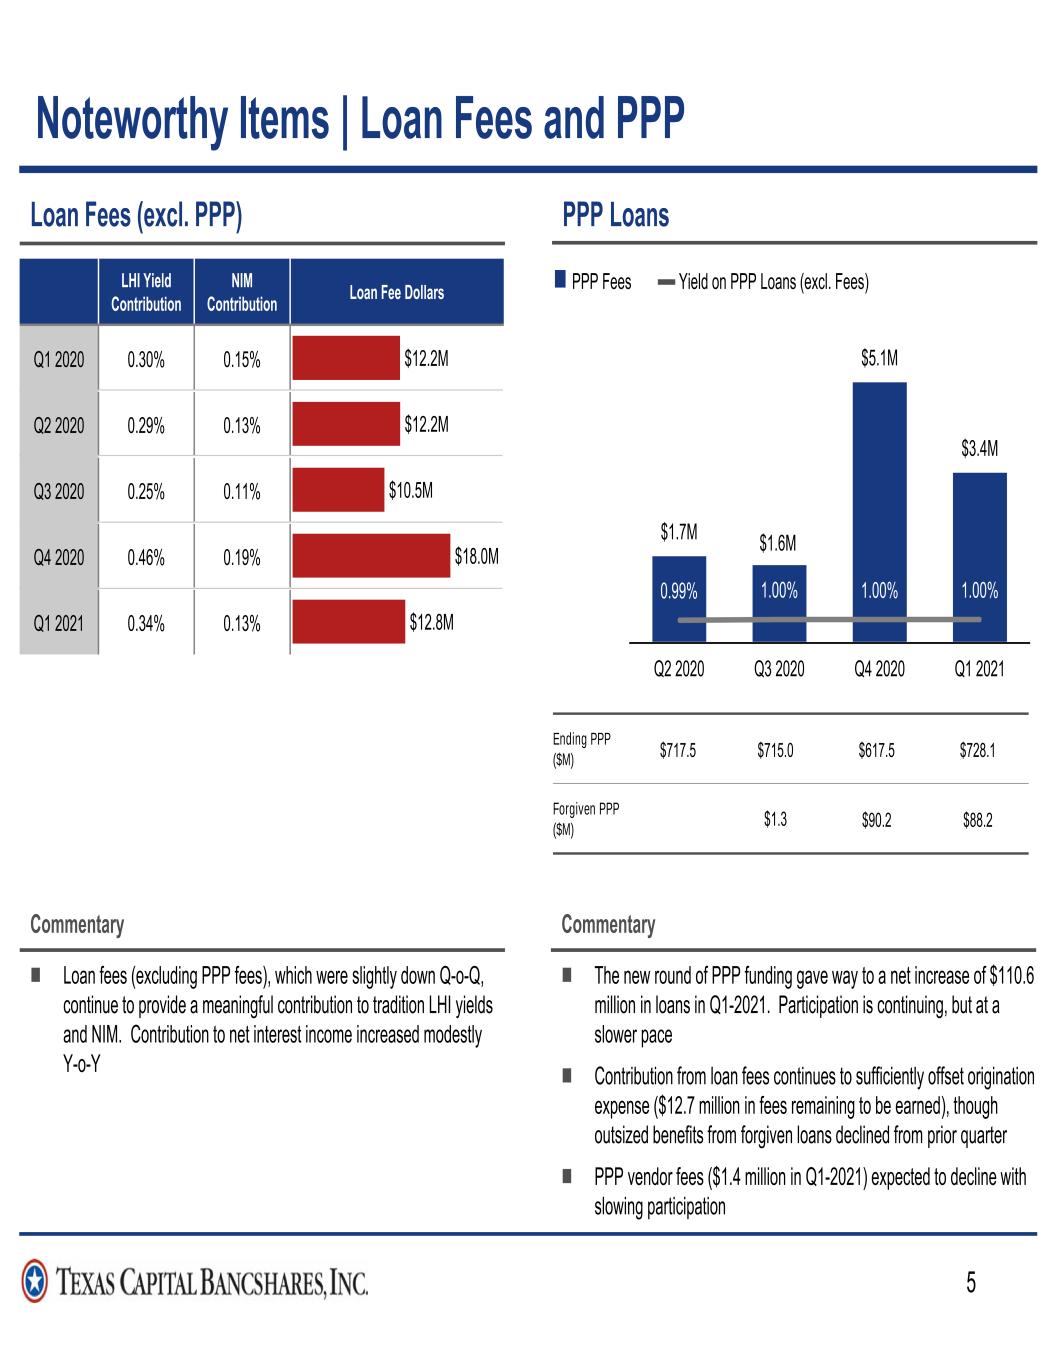
Net interest income was $200.1 million for the first quarter of 2021, compared to $223.0 million for the fourth quarter of 2020 and $228.3 million for the first quarter of 2020. Net interest margin for the first quarter of 2021 was 2.09%, a decrease of 23 basis points from the fourth quarter of 2020 and a decrease of 69 basis points from the first quarter of 2020. The shift in earning assets, primarily the increases in liquidity assets and investment securities coupled with a decrease in total average loans, contributed to the linked-quarter and year-over-year decreases in net interest margin. LHI yields, excluding mortgage finance loans, decreased 21 basis points from the fourth quarter of 2020, and decreased 98 basis points compared to the first quarter of 2020. LHI, mortgage finance yields for the first quarter of 2021 decreased 7 basis points compared to the fourth quarter of 2020, and increased 7 basis points compared to the first quarter of 2020. Additionally, total cost of deposits for the first quarter of 2021 decreased 5 basis points to 0.24% compared to 0.29% for the fourth quarter of 2020, and decreased 66 basis points from .90% for the first quarter of 2020.
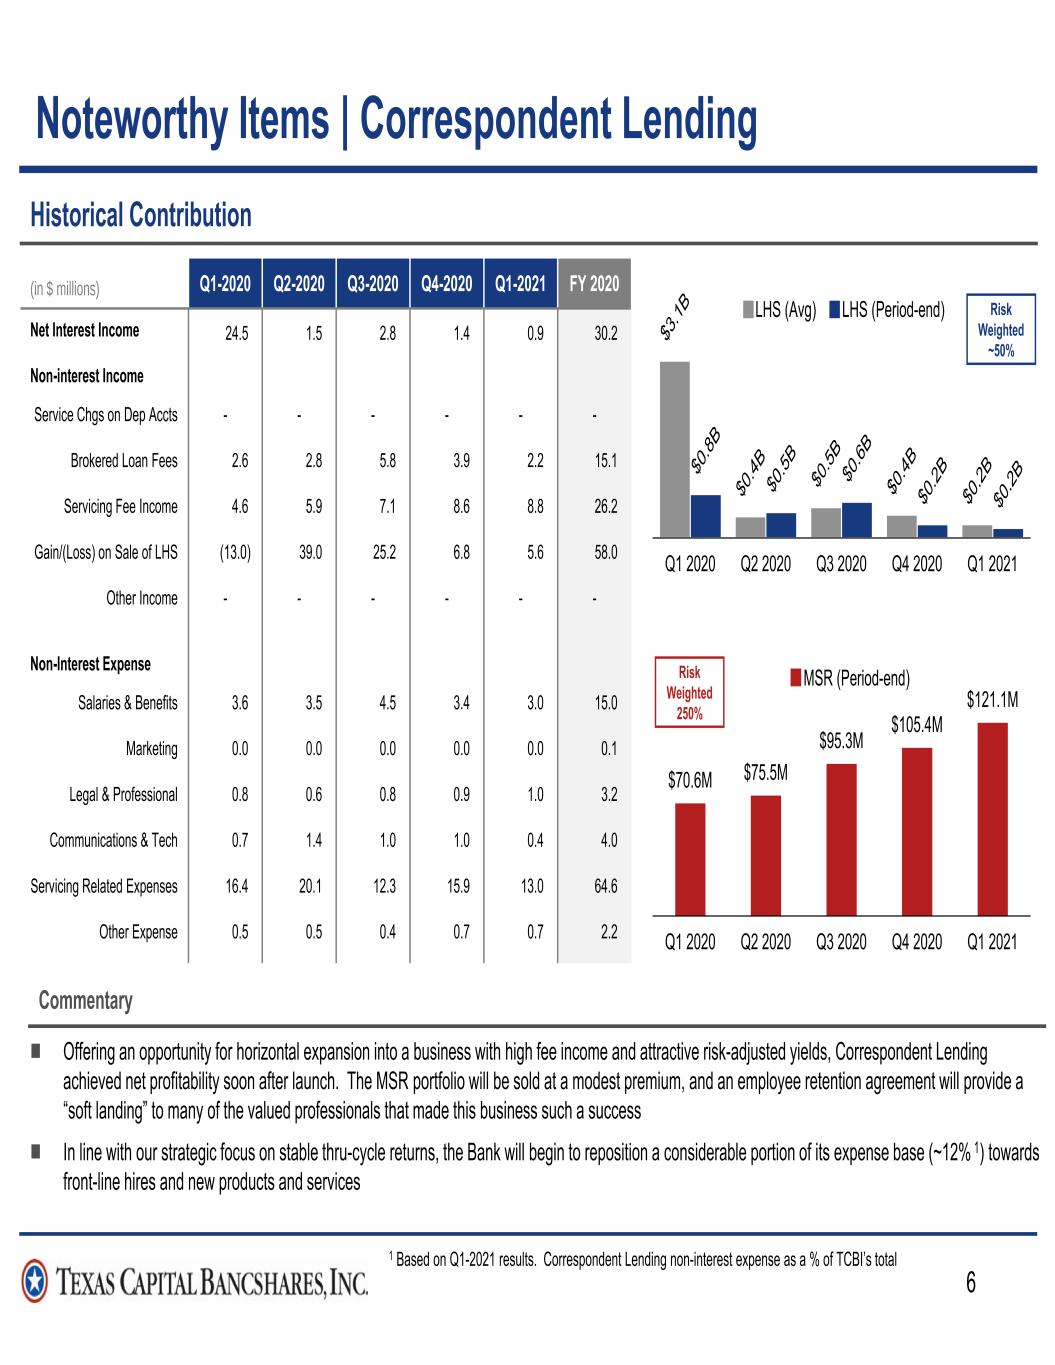
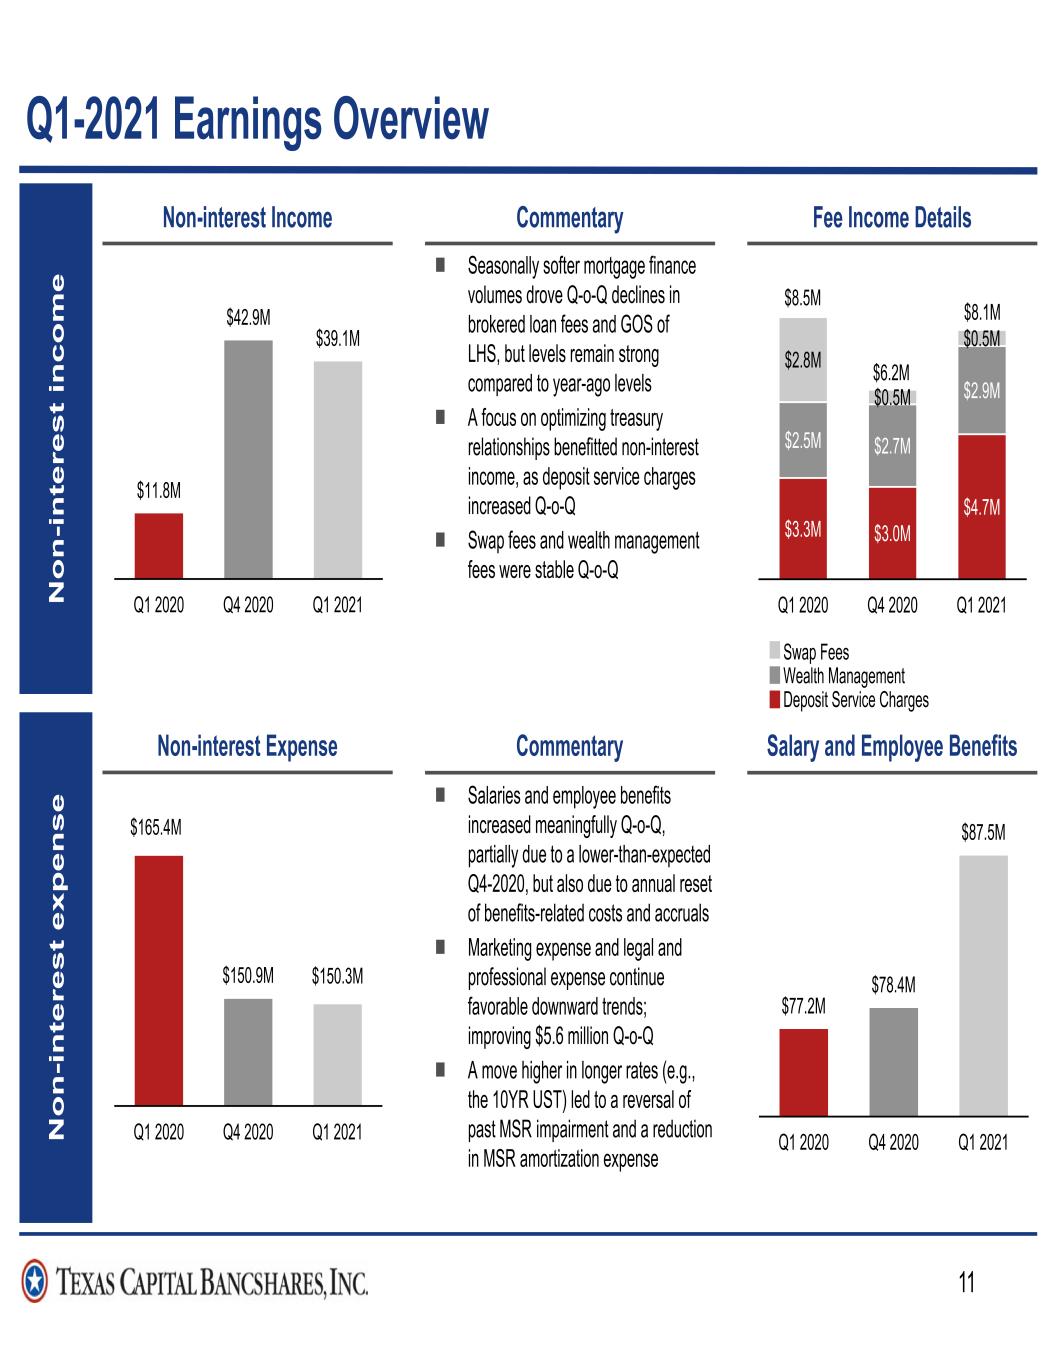
Non-interest income for the first quarter of 2021 decreased $3.8 million, or 9%, compared to the fourth quarter of 2020, and increased $27.3 million, or 232%, compared to the first quarter of 2020. The linked quarter decrease was primarily related to decreases in brokered loans fees, net gain/(loss) on sale of LHS and other non-interest income, partially offset by an increase in service charges on deposit accounts. The year-over-year increase was primarily related to increases in net gain/(loss) on sale of LHS, servicing income and other non-interest income. The linked quarter decreases in brokered loan fees and net gain/(loss) on sale of LHS were primarily due to a decrease in total mortgage finance volumes in the first quarter of 2021. The year-over-year increase in net gain/(loss) on sale of LHS was due to lower hedge costs in the first quarter of 2021 as a result of holding purchased loans for shorter durations than in prior periods, and is offset by the year-over-year decline in net interest income on LHS.
Non-interest expense for the first quarter of 2021 decreased $570,000, or less than 1 percent, compared to the fourth quarter of 2020, and decreased $15.1 million, or 9%, compared to the first quarter of 2020. The linked quarter decrease was primarily related to decreases in marketing expense, legal and professional expense and servicing-related expenses, offset by an increase in salaries and employee benefits, which is typically higher in the first quarter due to FICA and other seasonal payroll expenses that peak in the first quarter. The year-over-year decrease was primarily due to decreases in marketing expense, legal and professional expense, servicing-related expenses and merger-related expenses, offset by increases in salaries and employee benefits and communications and technology expenses.
All regulatory ratios continue to be in excess of "well-capitalized" requirements as of March 31, 2021. Our CET 1, tier 1 capital, total capital and leverage ratios were 10.2%, 12.3%, 14.0% and 8.3%, respectively, at March 31, 2021, compared to 9.4%, 10.3%, 12.1% and 7.5%, respectively, at December 31, 2020. At March 31, 2021, our ratio of tangible common equity to total tangible assets was 6.7% compared to 7.2% at December 31, 2020.
2
About Texas Capital Bancshares, Inc.
Texas Capital Bancshares, Inc. (NASDAQ®: TCBI), a member of the Russell 2000® Index and the S&P MidCap 400®, is the parent company of Texas Capital Bank, a commercial bank that delivers highly personalized financial services to businesses and entrepreneurs. Headquartered in Dallas, the bank has full-service locations in Austin, Dallas, Fort Worth, Houston and San Antonio.
Forward Looking Statements
This communication contains “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 regarding our financial condition, results of operations, business plans and future performance. These statements are not historical in nature and can generally be identified by such words as “believe,” “expect,” “estimate,” “anticipate,” “plan,” “may,” “will,” “forecast,” “could,” “should”, “projects,” “targeted,” “continue,” “intend” and similar expressions.
Because forward-looking statements relate to future results and occurrences, they are subject to inherent uncertainties, risks, and changes in circumstances that are difficult to predict. A number of factors, many of which are beyond our control, could cause actual results to differ materially from future results expressed or implied by such forward-looking statements. These factors include, but are not limited to, (1) the credit quality of our loan portfolio, (2) general economic conditions in the United States, globally and in our markets and the impact they may have on us and our customers, including the continued impact on our customers from volatility in oil and gas prices, (3) the material risks and uncertainties for the U.S. and world economies, and for our business, resulting from the COVID-19 pandemic and any other pandemic, epidemic or health related crisis, (4) expectations regarding rates of default and credit losses, (5) volatility in the mortgage industry, (6) our business strategies, (7) our expectations about future financial performance, future growth and earnings, (8) the appropriateness of our allowance for credit losses and provision for credit losses, (9) our ability to identify, employ and retain qualified employees, (10) the impact of changing regulatory requirements and legislative changes on our business, (11) increased competition, (12) interest rate risk, (13)greater than expected costs or difficulties related to the integration and development of new lines of business, new products or service offerings and new technologies, (14) technological changes, (15) the cost and effects of cyber incidents or other failures, interruptions or security breaches of our systems or those of third party providers and (16) our success at managing the risk and uncertainties involved in the foregoing factors. In addition, statements about the effects of the COVID-19 pandemic on the firm’s business, results, financial position and liquidity are subject to the risk that the actual impact may differ, possibly materially, from what is currently expected.
These and other factors that could cause results to differ materially from those described in the forward-looking statements, as well as a discussion of the risks and uncertainties that may affect our business, can be found in our Annual Report on Form 10-K, our Quarterly Reports on Form 10-Q and in other filings we make with the Securities and Exchange Commission. The information contained in this communication speaks only as of its date. Except to the extent required by applicable law or regulation, we disclaim any obligation to update such factors or to publicly announce the results of any revisions to any of the forward-looking statements included herein to reflect future events or developments.
3
| TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||||
| SELECTED FINANCIAL HIGHLIGHTS (UNAUDITED) | |||||||||||||||||
| (dollars in thousands except per share data) | |||||||||||||||||
| 1st Quarter | 4th Quarter | 3rd Quarter | 2nd Quarter | 1st Quarter | |||||||||||||
| 2021 | 2020 | 2020 | 2020 | 2020 | |||||||||||||
| CONSOLIDATED STATEMENTS OF INCOME | |||||||||||||||||
| Interest income | $ | 228,412 | $ | 255,163 | $ | 243,731 | $ | 252,010 | $ | 306,008 | |||||||
| Interest expense | 28,339 | 32,153 | 36,162 | 42,082 | 77,689 | ||||||||||||
| Net interest income | 200,073 | 223,010 | 207,569 | 209,928 | 228,319 | ||||||||||||
| Provision for credit losses | (6,000) | 32,000 | 30,000 | 100,000 | 96,000 | ||||||||||||
| Net interest income after provision for credit losses | 206,073 | 191,010 | 177,569 | 109,928 | 132,319 | ||||||||||||
| Non-interest income | 39,092 | 42,886 | 60,348 | 70,502 | 11,780 | ||||||||||||
| Non-interest expense | 150,316 | 150,886 | 165,741 | 222,352 | 165,417 | ||||||||||||
| Income/(loss) before income taxes | 94,849 | 83,010 | 72,176 | (41,922) | (21,318) | ||||||||||||
| Income tax expense/(benefit) | 22,911 | 22,834 | 15,060 | (7,606) | (4,631) | ||||||||||||
| Net income/(loss) | 71,938 | 60,176 | 57,116 | (34,316) | (16,687) | ||||||||||||
| Preferred stock dividends | 3,779 | 2,437 | 2,438 | 2,437 | 2,438 | ||||||||||||
| Net income/(loss) available to common stockholders | $ | 68,159 | $ | 57,739 | $ | 54,678 | $ | (36,753) | $ | (19,125) | |||||||
| Diluted earnings/(loss) per common share | $ | 1.33 | $ | 1.14 | $ | 1.08 | $ | (0.73) | $ | (0.38) | |||||||
| Diluted common shares | 51,069,511 | 50,794,421 | 50,573,073 | 50,416,331 | 50,474,802 | ||||||||||||
| CONSOLIDATED BALANCE SHEET DATA | |||||||||||||||||
| Total assets | $ | 40,054,433 | $ | 37,726,096 | $ | 38,432,872 | $ | 36,613,127 | $ | 35,879,416 | |||||||
| LHI | 15,399,174 | 15,351,451 | 15,789,958 | 16,552,203 | 16,857,579 | ||||||||||||
| LHI, mortgage finance | 9,009,081 | 9,079,409 | 9,378,104 | 8,972,626 | 7,588,803 | ||||||||||||
| LHS | 176,286 | 283,165 | 648,009 | 454,581 | 774,064 | ||||||||||||
Liquidity assets(1) | 11,212,276 | 9,032,807 | 10,461,544 | 9,540,044 | 9,498,189 | ||||||||||||
| Investment securities | 3,443,058 | 3,196,970 | 1,367,313 | 234,969 | 228,784 | ||||||||||||
| Demand deposits | 15,174,642 | 12,740,947 | 12,339,212 | 10,835,911 | 9,420,303 | ||||||||||||
| Total deposits | 33,391,970 | 30,996,589 | 31,959,487 | 30,187,695 | 27,134,263 | ||||||||||||
| Other borrowings | 2,515,587 | 3,111,751 | 2,908,183 | 2,895,790 | 5,195,267 | ||||||||||||
| Long-term debt | 664,968 | 395,896 | 395,806 | 395,715 | 395,625 | ||||||||||||
| Stockholders’ equity | 3,159,482 | 2,871,224 | 2,800,404 | 2,734,755 | 2,772,596 | ||||||||||||
| End of period shares outstanding | 50,557,767 | 50,470,450 | 50,455,552 | 50,435,672 | 50,407,778 | ||||||||||||
| Book value | $ | 53.59 | $ | 53.92 | $ | 52.53 | $ | 51.25 | $ | 52.03 | |||||||
Tangible book value(2) | $ | 53.24 | $ | 53.57 | $ | 52.18 | $ | 50.89 | $ | 51.67 | |||||||
| SELECTED FINANCIAL RATIOS | |||||||||||||||||
| Net interest margin | 2.09 | % | 2.32 | % | 2.22 | % | 2.30 | % | 2.78 | % | |||||||
| Return on average assets | 0.73 | % | 0.61 | % | 0.59 | % | (0.36) | % | (0.20) | % | |||||||
| Return on average common equity | 10.08 | % | 8.50 | % | 8.24 | % | (5.48) | % | (2.85) | % | |||||||
| Non-interest income to average earning assets | 0.41 | % | 0.44 | % | 0.64 | % | 0.77 | % | 0.14 | % | |||||||
Efficiency ratio(3) | 62.9 | % | 56.7 | % | 61.9 | % | 79.3 | % | 68.9 | % | |||||||
| Non-interest expense to average earning assets | 1.57 | % | 1.56 | % | 1.76 | % | 2.43 | % | 2.00 | % | |||||||
Tangible common equity to total tangible assets(4) | 6.7 | % | 7.2 | % | 6.9 | % | 7.0 | % | 7.3 | % | |||||||
| Common Equity Tier 1 | 10.2 | % | 9.4 | % | 9.1 | % | 8.8 | % | 9.3 | % | |||||||
| Tier 1 capital | 12.3 | % | 10.3 | % | 9.9 | % | 9.7 | % | 10.2 | % | |||||||
| Total capital | 14.0 | % | 12.1 | % | 11.8 | % | 11.6 | % | 12.0 | % | |||||||
| Leverage | 8.3 | % | 7.5 | % | 7.6 | % | 7.5 | % | 8.5 | % | |||||||
(1) Liquidity assets include Federal funds sold and interest-bearing deposits in other banks.
(2) Stockholders’ equity excluding preferred stock, less goodwill and intangibles, divided by shares outstanding at period end.
(3) Non-interest expense divided by the sum of net interest income and non-interest income.
(4) Stockholders’ equity excluding preferred stock, less goodwill and intangibles, divided by total assets, less goodwill and intangibles.
4
| TEXAS CAPITAL BANCSHARES, INC. | |||||||||||
| CONSOLIDATED BALANCE SHEETS (UNAUDITED) | |||||||||||
| (dollars in thousands) | |||||||||||
| March 31, 2021 | March 31, 2020 | % Change | |||||||||
| Assets | |||||||||||
| Cash and due from banks | $ | 215,835 | $ | 162,386 | 33 | % | |||||
| Interest-bearing deposits | 11,212,276 | 9,468,189 | 18 | % | |||||||
| Federal funds sold and securities purchased under resale agreements | — | 30,000 | (100) | % | |||||||
| Securities, available-for-sale | 3,443,058 | 228,784 | N/M | ||||||||
| LHS, at fair value | 176,286 | 774,064 | (77) | % | |||||||
| LHI, mortgage finance | 9,009,081 | 7,588,803 | 19 | % | |||||||
| LHI (net of unearned income) | 15,399,174 | 16,857,579 | (9) | % | |||||||
| Less: Allowance for credit losses on loans | 242,484 | 240,958 | 1 | % | |||||||
| LHI, net | 24,165,771 | 24,205,424 | — | % | |||||||
| Mortgage servicing rights, net | 121,096 | 70,619 | 71 | % | |||||||
| Premises and equipment, net | 23,346 | 29,663 | (21) | % | |||||||
| Accrued interest receivable and other assets | 679,199 | 892,305 | (24) | % | |||||||
| Goodwill and intangibles, net | 17,566 | 17,982 | (2) | % | |||||||
| Total assets | $ | 40,054,433 | $ | 35,879,416 | 12 | % | |||||
| Liabilities and Stockholders’ Equity | |||||||||||
| Liabilities: | |||||||||||
| Deposits: | |||||||||||
| Non-interest bearing | $ | 15,174,642 | $ | 9,420,303 | 61 | % | |||||
| Interest bearing | 18,217,328 | 17,713,960 | 3 | % | |||||||
| Total deposits | 33,391,970 | 27,134,263 | 23 | % | |||||||
| Accrued interest payable | 5,629 | 16,969 | (67) | % | |||||||
| Other liabilities | 316,797 | 364,696 | (13) | % | |||||||
| Federal funds purchased and repurchase agreements | 115,587 | 295,267 | (61) | % | |||||||
| Other borrowings | 2,400,000 | 4,900,000 | (51) | % | |||||||
| Long-term debt | 664,968 | 395,625 | 68 | % | |||||||
| Total liabilities | 36,894,951 | 33,106,820 | 11 | % | |||||||
| Stockholders’ equity: | |||||||||||
| Preferred stock, $.01 par value, $1,000 liquidation value: | |||||||||||
| Authorized shares - 10,000,000 | |||||||||||
| Issued shares - 6,300,000 and 6,000,000 shares issued at March 31, 2021 and 2020, respectively | 450,000 | 150,000 | 200 | % | |||||||
| Common stock, $.01 par value: | |||||||||||
| Authorized shares - 100,000,000 | |||||||||||
| Issued shares - 50,558,184 and 50,408,195 at March 31, 2021 and 2020, respectively | 505 | 504 | — | % | |||||||
| Additional paid-in capital | 984,207 | 979,939 | — | % | |||||||
| Retained earnings | 1,781,215 | 1,637,392 | 9 | % | |||||||
| Treasury stock (shares at cost: 417 at March 31, 2021 and 2020) | (8) | (8) | — | % | |||||||
| Accumulated other comprehensive income/(loss), net of taxes | (56,437) | 4,769 | N/M | ||||||||
| Total stockholders’ equity | 3,159,482 | 2,772,596 | 14 | % | |||||||
| Total liabilities and stockholders’ equity | $ | 40,054,433 | $ | 35,879,416 | 12 | % | |||||
5
| TEXAS CAPITAL BANCSHARES, INC. | ||||||||
| CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED) | ||||||||
| (dollars in thousands except per share data) | ||||||||
| Three Months Ended March 31, | ||||||||
| 2021 | 2020 | |||||||
| Interest income | ||||||||
| Interest and fees on loans | $ | 215,592 | $ | 283,625 | ||||
| Investment securities | 9,887 | 2,183 | ||||||
| Federal funds sold and securities purchased under resale agreements | 1 | 614 | ||||||
| Interest-bearing deposits in other banks | 2,932 | 19,586 | ||||||
| Total interest income | 228,412 | 306,008 | ||||||
| Interest expense | ||||||||
| Deposits | 20,004 | 62,174 | ||||||
| Federal funds purchased | 75 | 669 | ||||||
| Other borrowings | 2,517 | 9,582 | ||||||
| Long-term debt | 5,743 | 5,264 | ||||||
| Total interest expense | 28,339 | 77,689 | ||||||
| Net interest income | 200,073 | 228,319 | ||||||
| Provision for credit losses | (6,000) | 96,000 | ||||||
| Net interest income after provision for credit losses | 206,073 | 132,319 | ||||||
| Non-interest income | ||||||||
| Service charges on deposit accounts | 4,716 | 3,293 | ||||||
| Wealth management and trust fee income | 2,855 | 2,467 | ||||||
| Brokered loan fees | 9,311 | 8,015 | ||||||
| Servicing income | 9,009 | 4,746 | ||||||
| Swap fees | 526 | 2,757 | ||||||
| Net gain/(loss) on sale of LHS | 5,572 | (13,000) | ||||||
| Other | 7,103 | 3,502 | ||||||
| Total non-interest income | 39,092 | 11,780 | ||||||
| Non-interest expense | ||||||||
| Salaries and employee benefits | 87,522 | 77,193 | ||||||
| Net occupancy expense | 8,274 | 8,712 | ||||||
| Marketing | 1,697 | 8,522 | ||||||
| Legal and professional | 8,277 | 17,466 | ||||||
| Communications and technology | 15,969 | 13,791 | ||||||
| FDIC insurance assessment | 6,613 | 5,849 | ||||||
| Servicing-related expenses | 12,989 | 16,354 | ||||||
| Merger-related expenses | — | 7,270 | ||||||
| Other | 8,975 | 10,260 | ||||||
| Total non-interest expense | 150,316 | 165,417 | ||||||
| Income/(loss) before income taxes | 94,849 | (21,318) | ||||||
| Income tax expense/(benefit) | 22,911 | (4,631) | ||||||
| Net income/(loss) | 71,938 | (16,687) | ||||||
| Preferred stock dividends | 3,779 | 2,438 | ||||||
| Net income/(loss) available to common stockholders | $ | 68,159 | $ | (19,125) | ||||
| Basic earnings/(loss) per common share | $ | 1.35 | $ | (0.38) | ||||
| Diluted earnings/(loss) per common share | $ | 1.33 | $ | (0.38) | ||||
6
| TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||||
| SUMMARY OF CREDIT LOSS EXPERIENCE | |||||||||||||||||
| (dollars in thousands) | |||||||||||||||||
| 1st Quarter | 4th Quarter | 3rd Quarter | 2nd Quarter | 1st Quarter | |||||||||||||
| 2021 | 2020 | 2020 | 2020 | 2020 | |||||||||||||
| Allowance for credit losses on loans: | |||||||||||||||||
| Beginning balance | $ | 254,615 | $ | 290,165 | $ | 264,722 | $ | 240,958 | $ | 195,047 | |||||||
| Impact of CECL adoption | — | — | — | — | 8,585 | ||||||||||||
| Loans charged-off: | |||||||||||||||||
| Commercial | 2,451 | 37,984 | 2,436 | 12,287 | 20,653 | ||||||||||||
| Energy | 5,732 | 33,283 | 141 | 62,368 | 37,730 | ||||||||||||
| Real estate | — | 180 | — | — | — | ||||||||||||
| Total charge-offs | 8,183 | 71,447 | 2,577 | 74,655 | 58,383 | ||||||||||||
| Recoveries: | |||||||||||||||||
| Commercial | 1,050 | 394 | 113 | 513 | 257 | ||||||||||||
| Energy | 715 | 5,696 | 880 | — | 423 | ||||||||||||
| Total recoveries | 1,765 | 6,090 | 993 | 513 | 680 | ||||||||||||
| Net charge-offs | 6,418 | 65,357 | 1,584 | 74,142 | 57,703 | ||||||||||||
| Provision for credit losses on loans | (5,713) | 29,807 | 27,027 | 97,906 | 95,029 | ||||||||||||
| Ending balance | $ | 242,484 | $ | 254,615 | $ | 290,165 | $ | 264,722 | $ | 240,958 | |||||||
| Allowance for off-balance sheet credit losses: | |||||||||||||||||
| Beginning balance | $ | 17,434 | $ | 15,241 | $ | 12,268 | $ | 10,174 | $ | 8,640 | |||||||
| Impact of CECL adoption | — | — | — | — | 563 | ||||||||||||
| Provision for off-balance sheet credit losses | (287) | 2,193 | 2,973 | 2,094 | 971 | ||||||||||||
| Ending balance | $ | 17,147 | $ | 17,434 | $ | 15,241 | $ | 12,268 | $ | 10,174 | |||||||
| Total allowance for credit losses | $ | 259,631 | $ | 272,049 | $ | 305,406 | $ | 276,990 | $ | 251,132 | |||||||
| Total provision for credit losses | $ | (6,000) | $ | 32,000 | $ | 30,000 | $ | 100,000 | $ | 96,000 | |||||||
| Allowance for credit losses on loans to LHI | 0.99 | % | 1.04 | % | 1.15 | % | 1.04 | % | 0.99 | % | |||||||
| Allowance for credit losses on loans to average LHI | 1.03 | % | 1.01 | % | 1.14 | % | 1.03 | % | 1.02 | % | |||||||
Net charge-offs to average LHI(1) | 0.11 | % | 1.03 | % | 0.02 | % | 1.16 | % | 0.98 | % | |||||||
Net charge-offs to average LHI for last twelve months(1) | 0.59 | % | 0.80 | % | 0.59 | % | 0.73 | % | 0.53 | % | |||||||
Total provision for credit losses to average LHI(1) | (0.10) | % | 0.51 | % | 0.47 | % | 1.57 | % | 1.63 | % | |||||||
Total allowance for credit losses to LHI | 1.06 | % | 1.11 | % | 1.21 | % | 1.09 | % | 1.03 | % | |||||||
(1)Interim period ratios are annualized.
7
| TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||||
| SUMMARY OF NON-PERFORMING ASSETS AND PAST DUE LOANS | |||||||||||||||||
| (dollars in thousands) | |||||||||||||||||
| 1st Quarter | 4th Quarter | 3rd Quarter | 2nd Quarter | 1st Quarter | |||||||||||||
| 2021 | 2020 | 2020 | 2020 | 2020 | |||||||||||||
| Non-performing assets (NPAs): | |||||||||||||||||
| Non-accrual loans | $ | 97,730 | $ | 121,989 | $ | 161,946 | $ | 174,031 | $ | 219,165 | |||||||
| Other real estate owned (OREO) | — | — | — | — | — | ||||||||||||
| Total LHI NPAs | $ | 97,730 | $ | 121,989 | $ | 161,946 | $ | 174,031 | $ | 219,165 | |||||||
| Non-accrual loans to LHI | 0.40 | % | 0.50 | % | 0.64 | % | 0.68 | % | 0.90 | % | |||||||
| Total LHI NPAs to LHI plus OREO | 0.40 | % | 0.50 | % | 0.64 | % | 0.68 | % | 0.90 | % | |||||||
| Total LHI NPAs to earning assets | 0.25 | % | 0.33 | % | 0.43 | % | 0.49 | % | 0.63 | % | |||||||
| Allowance for credit losses on loans to non-accrual loans | 2.5x | 2.1x | 1.8x | 1.5x | 1.1x | ||||||||||||
LHI past due 90 days and still accruing(1) | $ | 6,187 | $ | 12,541 | $ | 15,896 | $ | 21,079 | $ | 21,274 | |||||||
| LHI past due 90 days to LHI | 0.03 | % | 0.05 | % | 0.06 | % | 0.08 | % | 0.09 | % | |||||||
LHS non-accrual(2) | $ | — | $ | 6,966 | $ | — | $ | — | $ | — | |||||||
LHS past due 90 days and still accruing(3) | $ | 16,359 | $ | 16,667 | $ | 15,631 | $ | 10,152 | $ | 9,014 | |||||||
(1)At March 31, 2021, loans past due 90 days and still accruing includes premium finance loans of $3.1 million. These loans are primarily secured by obligations of insurance carriers to refund premiums on canceled insurance policies. The refund of premiums from the insurance carriers can take 180 days or longer from the cancellation date.
(2)Includes one non-accrual loan previously reported in loans HFI that was transferred to loans HFS as of December 31, 2020 and subsequently sold at carrying value.
(3)Includes loans guaranteed by U.S. government agencies that were repurchased out of Ginnie Mae securities. Loans are recorded as LHS and carried at fair value on the balance sheet. Interest on these past due loans accrues at the debenture rate guaranteed by the U.S. government. Also includes loans that, pursuant to Ginnie Mae servicing guidelines, we have the unilateral right, but not obligation, to repurchase and thus must record as LHS on our balance sheet regardless of whether the repurchase option has been exercised.
8
| TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||||
| CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED) | |||||||||||||||||
| (dollars in thousands) | |||||||||||||||||
| 1st Quarter | 4th Quarter | 3rd Quarter | 2nd Quarter | 1st Quarter | |||||||||||||
| 2021 | 2020 | 2020 | 2020 | 2020 | |||||||||||||
| Interest income | |||||||||||||||||
| Interest and fees on loans | $ | 215,592 | $ | 242,776 | $ | 237,179 | $ | 247,595 | $ | 283,625 | |||||||
| Investment securities | 9,887 | 9,594 | 3,674 | 2,024 | 2,183 | ||||||||||||
| Federal funds sold and securities purchased under resale agreements | 1 | 1 | 1 | 77 | 614 | ||||||||||||
| Interest-bearing deposits in other banks | 2,932 | 2,792 | 2,877 | 2,314 | 19,586 | ||||||||||||
| Total interest income | 228,412 | 255,163 | 243,731 | 252,010 | 306,008 | ||||||||||||
| Interest expense | |||||||||||||||||
| Deposits | 20,004 | 23,819 | 27,830 | 32,294 | 62,174 | ||||||||||||
| Federal funds purchased | 75 | 110 | 128 | 176 | 669 | ||||||||||||
| Other borrowings | 2,517 | 3,407 | 3,365 | 4,569 | 9,582 | ||||||||||||
| Long-term debt | 5,743 | 4,817 | 4,839 | 5,043 | 5,264 | ||||||||||||
| Total interest expense | 28,339 | 32,153 | 36,162 | 42,082 | 77,689 | ||||||||||||
| Net interest income | 200,073 | 223,010 | 207,569 | 209,928 | 228,319 | ||||||||||||
| Provision for credit losses | (6,000) | 32,000 | 30,000 | 100,000 | 96,000 | ||||||||||||
| Net interest income after provision for credit losses | 206,073 | 191,010 | 177,569 | 109,928 | 132,319 | ||||||||||||
| Non-interest income | |||||||||||||||||
| Service charges on deposit accounts | 4,716 | 3,004 | 2,864 | 2,459 | 3,293 | ||||||||||||
| Wealth management and trust fee income | 2,855 | 2,681 | 2,502 | 2,348 | 2,467 | ||||||||||||
| Brokered loan fees | 9,311 | 12,610 | 15,034 | 10,764 | 8,015 | ||||||||||||
| Servicing income | 9,009 | 8,834 | 7,329 | 6,120 | 4,746 | ||||||||||||
| Swap fees | 526 | 473 | 484 | 1,468 | 2,757 | ||||||||||||
| Net gain/(loss) on sale of LHS | 5,572 | 6,761 | 25,242 | 39,023 | (13,000) | ||||||||||||
| Other | 7,103 | 8,523 | 6,893 | 8,320 | 3,502 | ||||||||||||
| Total non-interest income | 39,092 | 42,886 | 60,348 | 70,502 | 11,780 | ||||||||||||
| Non-interest expense | |||||||||||||||||
| Salaries and employee benefits | 87,522 | 78,449 | 84,096 | 100,791 | 77,193 | ||||||||||||
| Net occupancy expense | 8,274 | 8,373 | 8,736 | 9,134 | 8,712 | ||||||||||||
| Marketing | 1,697 | 3,435 | 3,636 | 7,988 | 8,522 | ||||||||||||
| Legal and professional | 8,277 | 12,129 | 11,207 | 11,330 | 17,466 | ||||||||||||
| Communications and technology | 15,969 | 15,405 | 31,098 | 42,760 | 13,791 | ||||||||||||
| FDIC insurance assessment | 6,613 | 6,592 | 6,374 | 7,140 | 5,849 | ||||||||||||
| Servicing-related expenses | 12,989 | 15,867 | 12,287 | 20,117 | 16,354 | ||||||||||||
| Merger-related expenses | — | — | — | 10,486 | 7,270 | ||||||||||||
| Other | 8,975 | 10,636 | 8,307 | 12,606 | 10,260 | ||||||||||||
| Total non-interest expense | 150,316 | 150,886 | 165,741 | 222,352 | 165,417 | ||||||||||||
| Income/(loss) before income taxes | 94,849 | 83,010 | 72,176 | (41,922) | (21,318) | ||||||||||||
| Income tax expense/(benefit) | 22,911 | 22,834 | 15,060 | (7,606) | (4,631) | ||||||||||||
| Net income/(loss) | 71,938 | 60,176 | 57,116 | (34,316) | (16,687) | ||||||||||||
| Preferred stock dividends | 3,779 | 2,437 | 2,438 | 2,437 | 2,438 | ||||||||||||
| Net income/(loss) available to common shareholders | $ | 68,159 | $ | 57,739 | $ | 54,678 | $ | (36,753) | $ | (19,125) | |||||||
9
| TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| QUARTERLY FINANCIAL SUMMARY - UNAUDITED | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Consolidated Daily Average Balances, Average Yields and Rates | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1st Quarter 2021 | 4th Quarter 2020 | 3rd Quarter 2020 | 2nd Quarter 2020 | 1st Quarter 2020 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average Balance | Revenue/ Expense | Yield/ Rate | Average Balance | Revenue/ Expense | Yield/ Rate | Average Balance | Revenue/ Expense | Yield/ Rate | Average Balance | Revenue/ Expense | Yield/ Rate | Average Balance | Revenue/ Expense | Yield/ Rate | |||||||||||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Investment securities - Taxable | $ | 3,225,786 | $ | 8,112 | 1.02 | % | $ | 2,137,481 | $ | 7,748 | 1.44 | % | $ | 525,149 | $ | 1,905 | 1.44 | % | $ | 38,829 | $ | 185 | 1.92 | % | $ | 42,799 | $ | 274 | 2.57 | % | |||||||||||||||||||||||||||||
Investment securities - Non-taxable(2) | 196,785 | 2,247 | 4.63 | % | 200,781 | 2,337 | 4.63 | % | 190,797 | 2,239 | 4.67 | % | 195,806 | 2,327 | 4.78 | % | 195,578 | 2,417 | 4.97 | % | |||||||||||||||||||||||||||||||||||||||
| Federal funds sold and securities purchased under resale agreements | 4,605 | 1 | 0.07 | % | 1,709 | 1 | 0.13 | % | 12,051 | 1 | 0.04 | % | 245,434 | 77 | 0.13 | % | 199,727 | 614 | 1.24 | % | |||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in other banks | 11,840,942 | 2,932 | 0.10 | % | 10,808,548 | 2,792 | 0.10 | % | 11,028,962 | 2,877 | 0.10 | % | 10,521,240 | 2,314 | 0.09 | % | 6,225,948 | 19,586 | 1.27 | % | |||||||||||||||||||||||||||||||||||||||
| LHS, at fair value | 243,326 | 1,595 | 2.66 | % | 410,637 | 2,475 | 2.40 | % | 543,606 | 3,867 | 2.83 | % | 380,624 | 2,547 | 2.69 | % | 3,136,381 | 27,480 | 3.52 | % | |||||||||||||||||||||||||||||||||||||||
| LHI, mortgage finance loans | 8,177,759 | 64,942 | 3.22 | % | 9,550,119 | 78,906 | 3.29 | % | 9,061,984 | 76,464 | 3.36 | % | 8,676,521 | 74,518 | 3.45 | % | 7,054,682 | 55,324 | 3.15 | % | |||||||||||||||||||||||||||||||||||||||
LHI(1)(2) | 15,457,888 | 149,196 | 3.91 | % | 15,620,410 | 161,750 | 4.12 | % | 16,286,036 | 157,230 | 3.84 | % | 17,015,041 | 170,970 | 4.04 | % | 16,598,775 | 201,781 | 4.89 | % | |||||||||||||||||||||||||||||||||||||||
Less allowance for credit losses on loans | 254,697 | — | — | 290,189 | — | — | 264,769 | — | — | 236,823 | — | — | 201,837 | — | — | ||||||||||||||||||||||||||||||||||||||||||||
| LHI, net of allowance | 23,380,950 | 214,138 | 3.71 | % | 24,880,340 | 240,656 | 3.85 | % | 25,083,251 | 233,694 | 3.71 | % | 25,454,739 | 245,488 | 3.88 | % | 23,451,620 | 257,105 | 4.41 | % | |||||||||||||||||||||||||||||||||||||||
| Total earning assets | 38,892,394 | 229,025 | 2.39 | % | 38,439,496 | 256,009 | 2.65 | % | 37,383,816 | 244,583 | 2.60 | % | 36,836,672 | 252,938 | 2.76 | % | 33,252,053 | 307,476 | 3.72 | % | |||||||||||||||||||||||||||||||||||||||
| Cash and other assets | 1,064,679 | 1,031,195 | 1,037,760 | 1,075,864 | 976,520 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 39,957,073 | $ | 39,470,691 | $ | 38,421,576 | $ | 37,912,536 | $ | 34,228,573 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities and Stockholders’ Equity | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Transaction deposits | $ | 3,991,966 | $ | 5,861 | 0.60 | % | $ | 4,384,493 | $ | 6,604 | 0.60 | % | $ | 4,275,574 | $ | 6,652 | 0.62 | % | $ | 3,923,966 | $ | 5,998 | 0.61 | % | $ | 3,773,067 | $ | 13,582 | 1.45 | % | |||||||||||||||||||||||||||||
| Savings deposits | 12,889,974 | 10,788 | 0.34 | % | 12,982,189 | 12,671 | 0.39 | % | 12,786,719 | 12,808 | 0.40 | % | 12,537,467 | 13,510 | 0.43 | % | 11,069,429 | 35,961 | 1.31 | % | |||||||||||||||||||||||||||||||||||||||
| Time deposits | 2,204,242 | 3,355 | 0.62 | % | 2,355,199 | 4,544 | 0.77 | % | 2,844,083 | 8,370 | 1.17 | % | 3,434,388 | 12,786 | 1.50 | % | 2,842,535 | 12,631 | 1.79 | % | |||||||||||||||||||||||||||||||||||||||
| Total interest bearing deposits | 19,086,182 | 20,004 | 0.43 | % | 19,721,881 | 23,819 | 0.48 | % | 19,906,376 | 27,830 | 0.56 | % | 19,895,821 | 32,294 | 0.65 | % | 17,685,031 | 62,174 | 1.41 | % | |||||||||||||||||||||||||||||||||||||||
| Other borrowings | 2,686,398 | 2,592 | 0.39 | % | 3,022,077 | 3,517 | 0.46 | % | 2,811,435 | 3,493 | 0.49 | % | 3,612,263 | 4,745 | 0.53 | % | 3,020,255 | 10,251 | 1.37 | % | |||||||||||||||||||||||||||||||||||||||
| Long-term debt | 464,731 | 5,743 | 5.01 | % | 395,841 | 4,817 | 4.84 | % | 395,749 | 4,839 | 4.87 | % | 395,658 | 5,043 | 5.13 | % | 395,571 | 5,264 | 5.35 | % | |||||||||||||||||||||||||||||||||||||||
| Total interest bearing liabilities | 22,237,311 | 28,339 | 0.52 | % | 23,139,799 | 32,153 | 0.55 | % | 23,113,560 | 36,162 | 0.62 | % | 23,903,742 | 42,082 | 0.71 | % | 21,100,857 | 77,689 | 1.48 | % | |||||||||||||||||||||||||||||||||||||||
| Demand deposits | 14,421,505 | 13,174,114 | 12,202,065 | 10,865,896 | 10,003,495 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other liabilities | 309,644 | 303,480 | 314,500 | 293,698 | 270,868 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Stockholders’ equity | 2,988,613 | 2,853,298 | 2,791,451 | 2,849,200 | 2,853,353 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 39,957,073 | $ | 39,470,691 | $ | 38,421,576 | $ | 37,912,536 | $ | 34,228,573 | |||||||||||||||||||||||||||||||||||||||||||||||||
Net interest income(2) | $ | 200,686 | $ | 223,856 | $ | 208,421 | $ | 210,856 | $ | 229,787 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest margin | 2.09 | % | 2.32 | % | 2.22 | % | 2.30 | % | 2.78 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
(1) The loan averages include loans on which the accrual of interest has been discontinued and are stated net of unearned income.
(2) Taxable equivalent rates used where applicable.