Exhibit 99.1
INVESTOR CONTACT | MEDIA CONTACT | |
Julie Anderson, 214.932.6773 | Shannon Wherry, 469.399.8527 | |
TEXAS CAPITAL BANCSHARES, INC. ANNOUNCES OPERATING RESULTS FOR Q3 2020
DALLAS - October 21, 2020 - Texas Capital Bancshares, Inc. (NASDAQ: TCBI), the parent company of Texas Capital Bank, announced operating results for the third quarter of 2020.
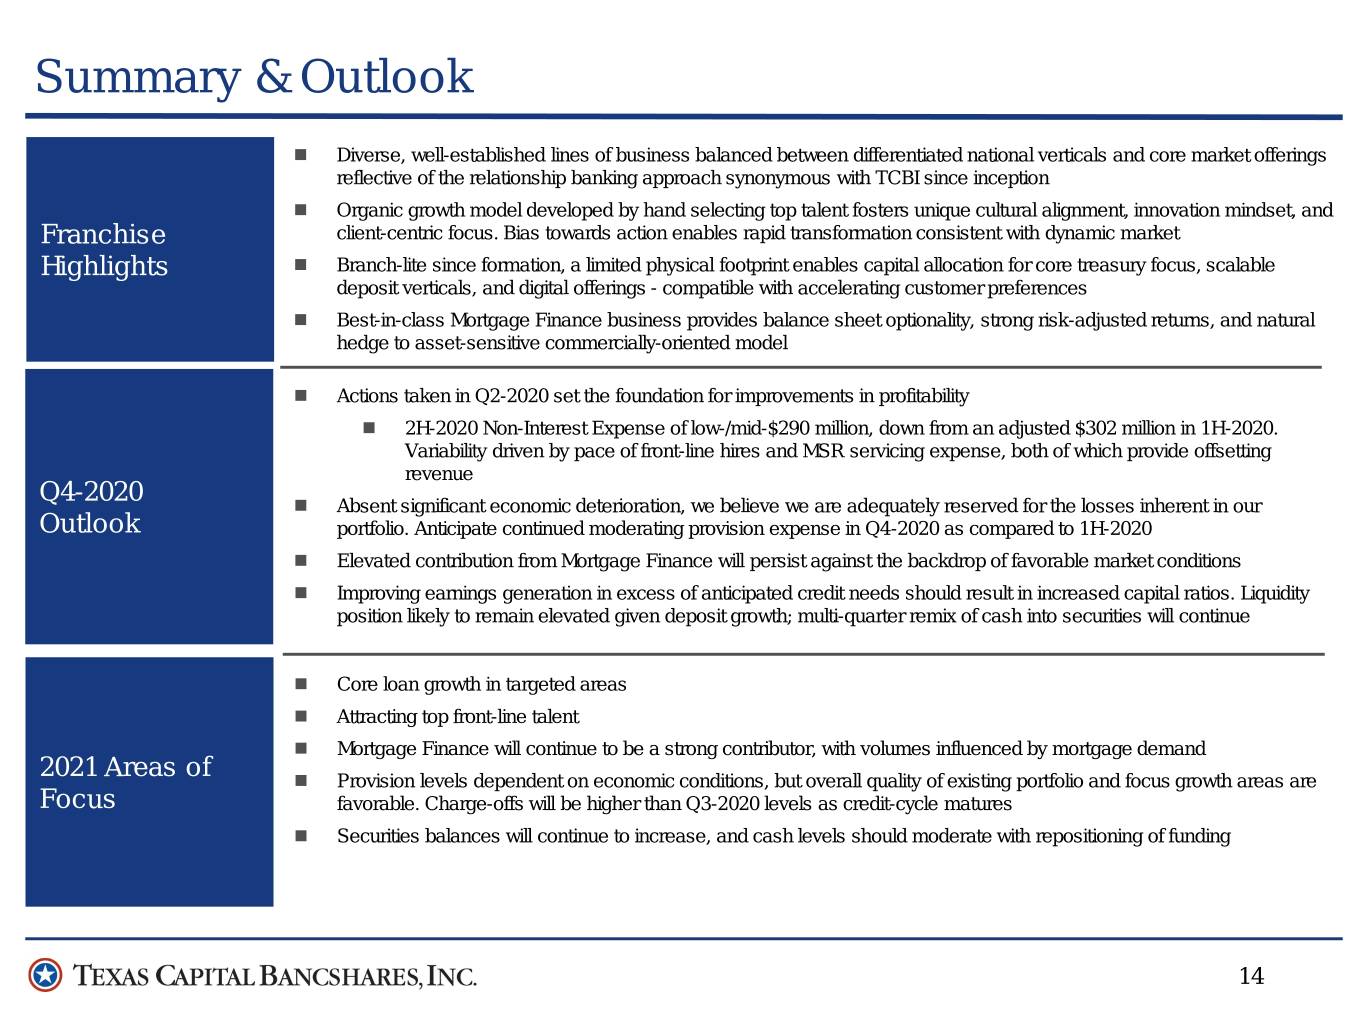
"We are pleased to report significantly improved operating results for the third quarter," said Larry Helm, Executive Chairman and CEO. "As we continue to navigate these unprecedented times I would like to thank our employees for their dedication to serving our clients and communities. We believe the actions we took during the second quarter have resulted in improvements to core operating results that will continue to serve us well as we plan for the future, and we remain committed to managing credit and taking care of our employees and clients, while continuing to recruit and develop top frontline talent and build shareholder value."
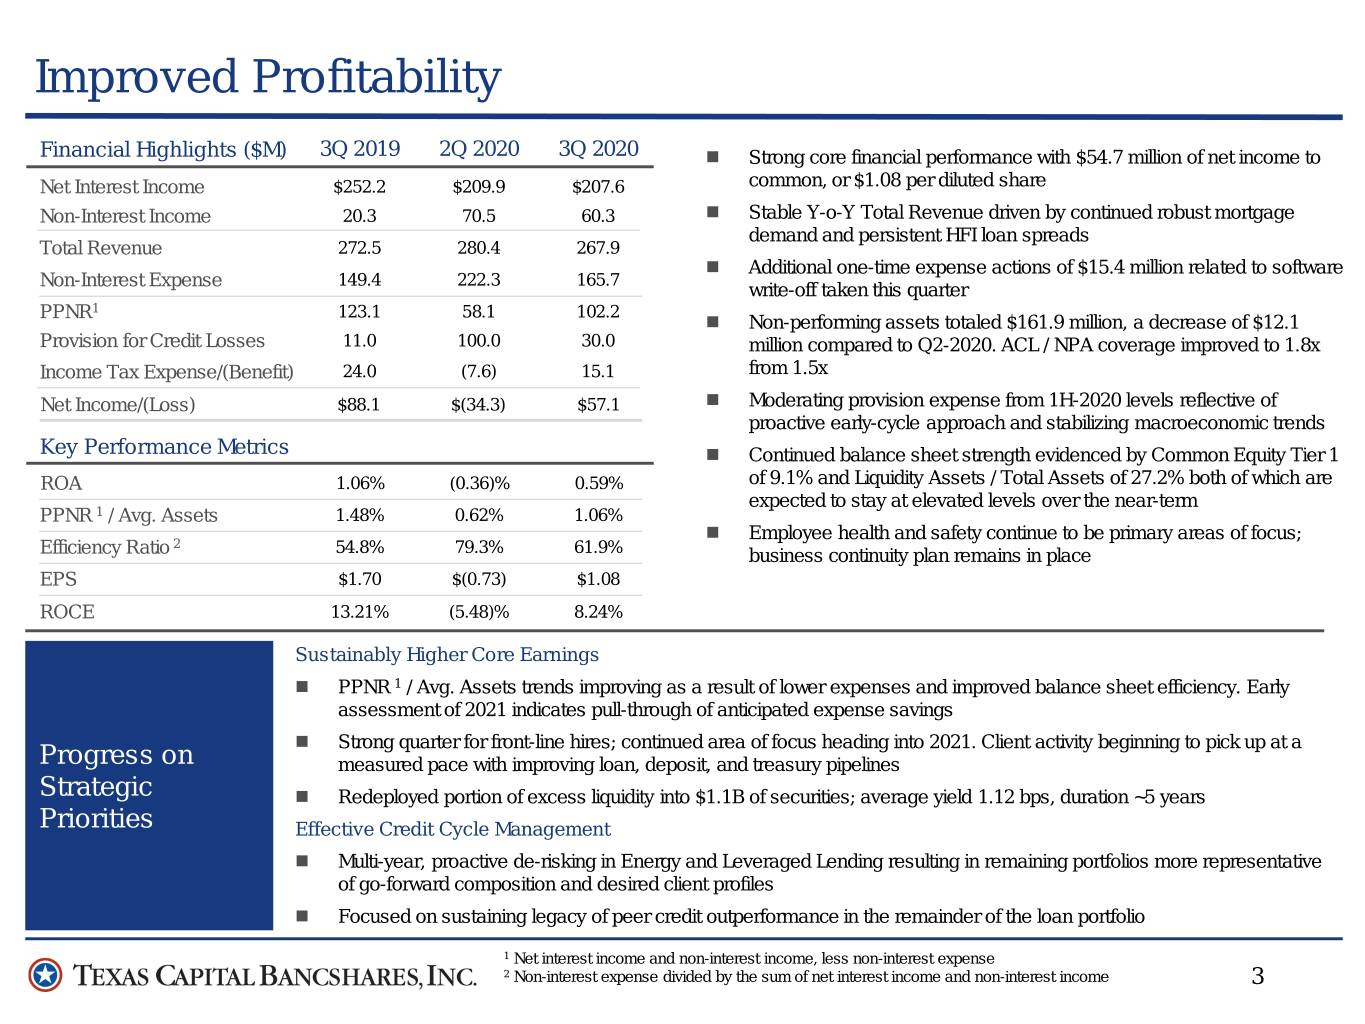
• | Net income of $57.1 million ($1.08 per share) reported for the third quarter of 2020, an increase of $91.4 million on a linked quarter basis and a decrease of $31.0 million from the third quarter of 2019. |
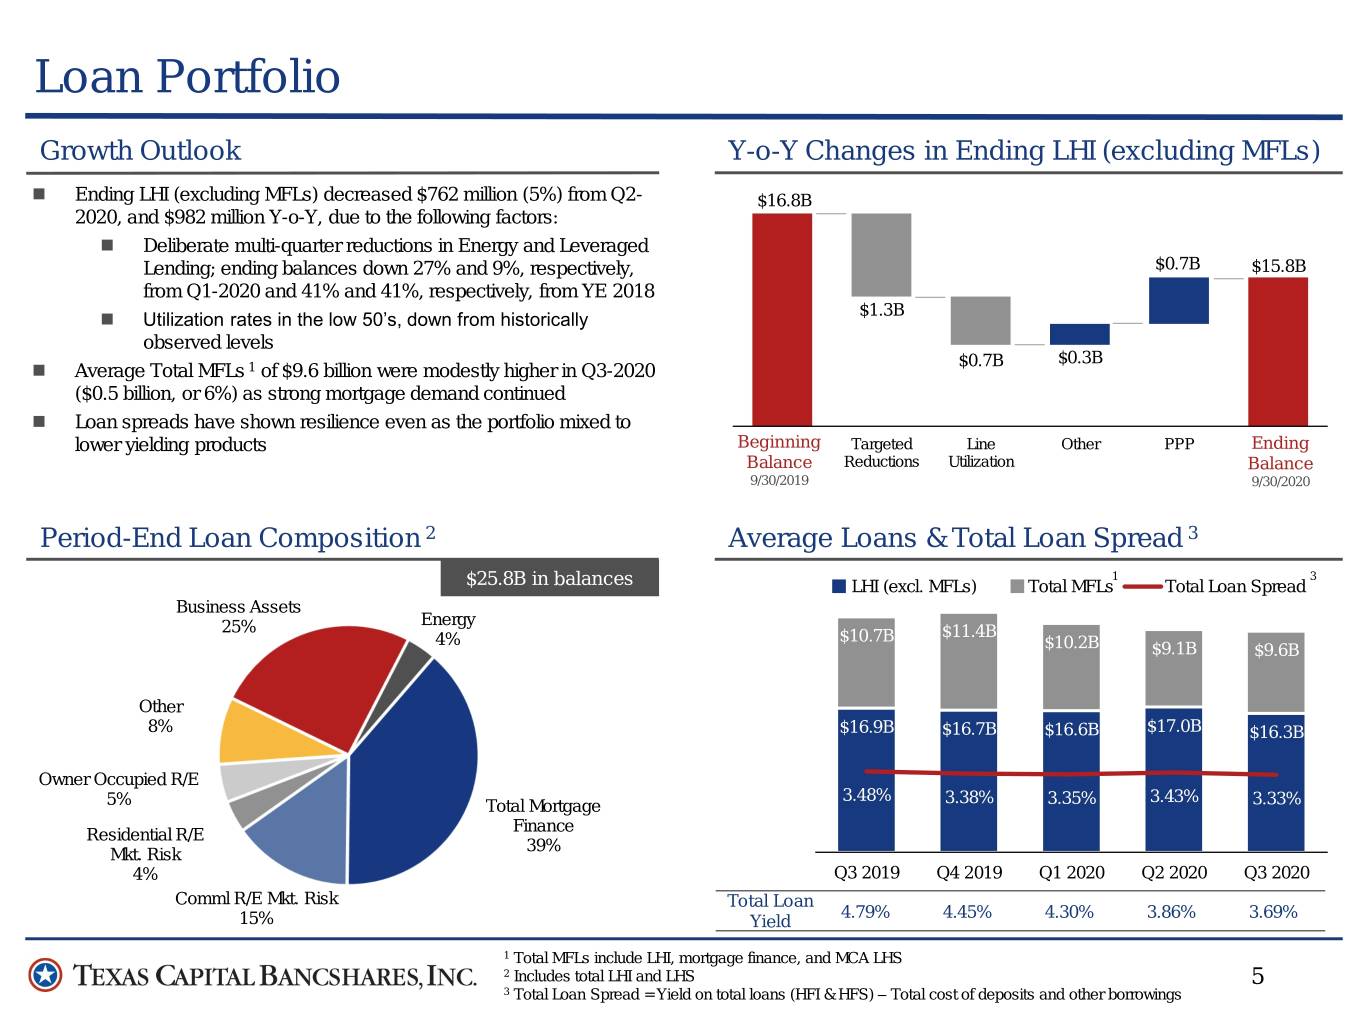
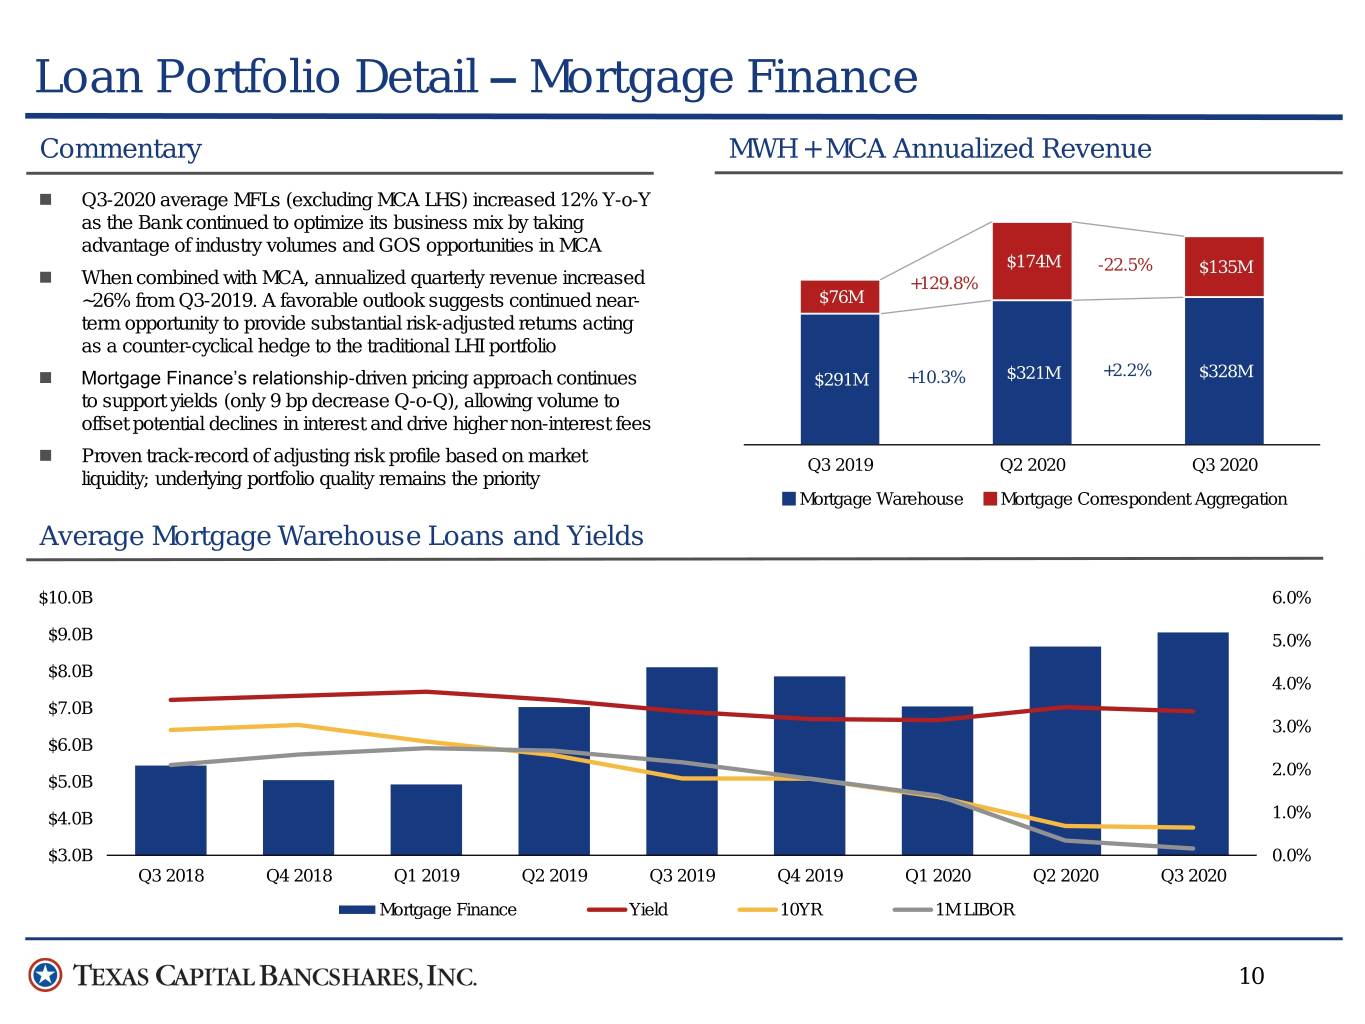
• | Total mortgage finance loans, including mortgage correspondent aggregation ("MCA") loans held for sale ("LHS"), increased 6% on a linked quarter basis (increasing 6% on an average basis) and decreased 6% from the third quarter of 2019 (decreasing 10% on an average basis). |
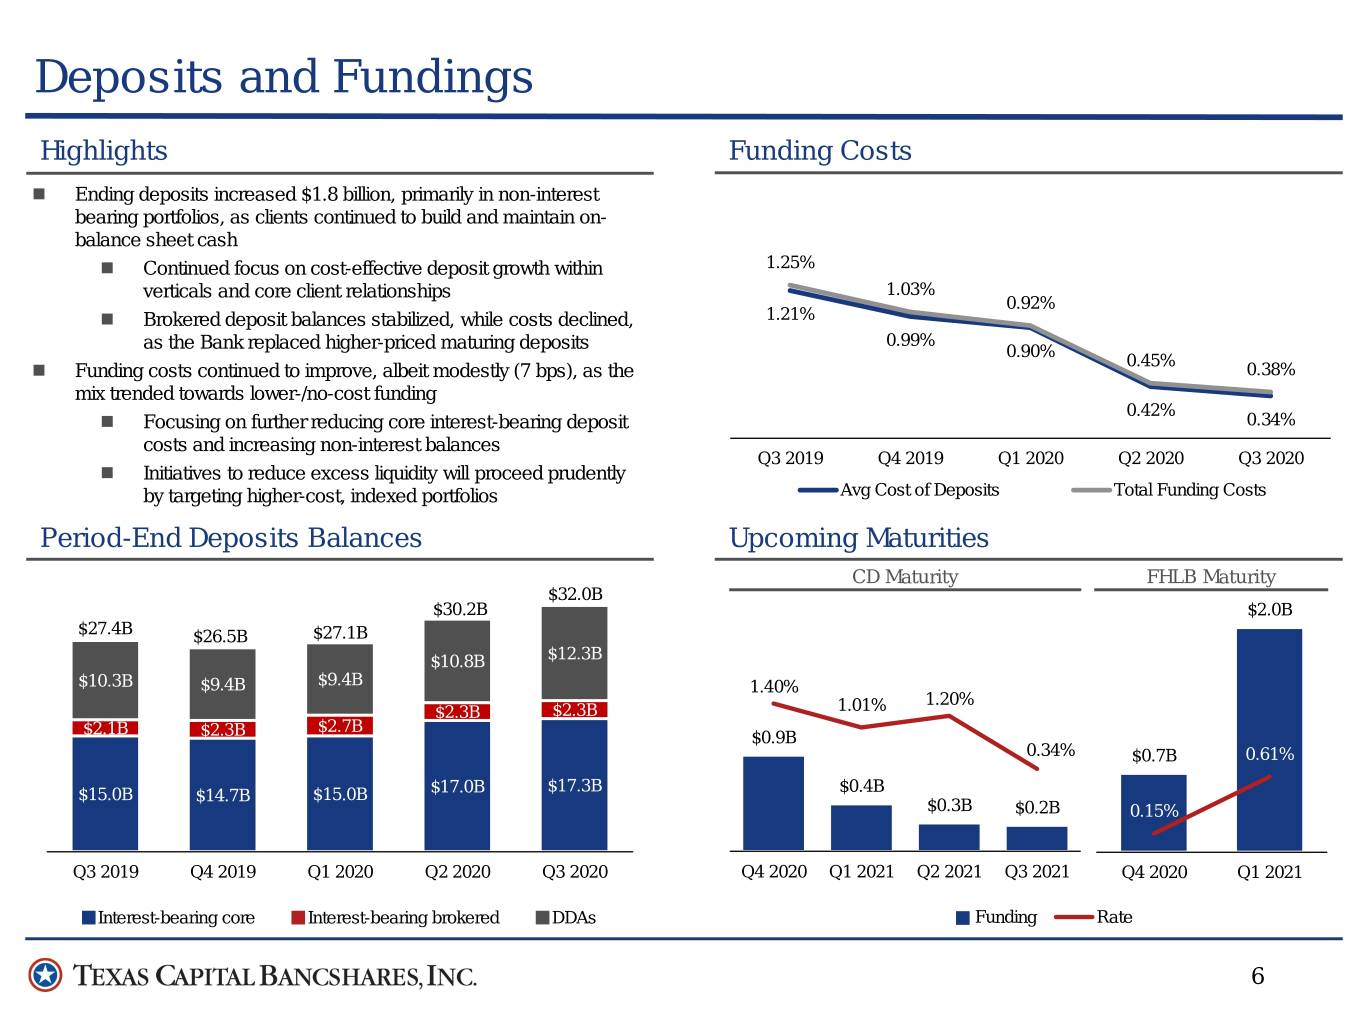
• | Demand deposits increased 14% and total deposits increased 6% on a linked quarter basis (increasing 12% and 4%, respectively, on an average basis), and increased 20% and 17%, respectively, from the third quarter of 2019 (increasing 22% and 21%, respectively, on an average basis). |
• | Loans held for investment ("LHI"), excluding mortgage finance loans, decreased 5% on a linked quarter basis (decreasing 4% on an average basis) and decreased 6% from the third quarter of 2019 (decreasing 4% on an average basis). |
FINANCIAL SUMMARY
(Dollars and shares in thousands) | Q3 2020 | Q3 2019 | % Change | |||||||
QUARTERLY OPERATING RESULTS | ||||||||||
Net income | $ | 57,116 | $ | 88,082 | (35 | )% | ||||
Net income available to common stockholders | $ | 54,678 | $ | 85,644 | (36 | )% | ||||
Diluted earnings per common share | $ | 1.08 | $ | 1.70 | (36 | )% | ||||
Diluted common shares | 50,573 | 50,416 | — | % | ||||||
ROA | 0.59 | % | 1.06 | % | ||||||
ROE | 8.24 | % | 13.21 | % | ||||||
BALANCE SHEET | ||||||||||
LHS | $ | 648,009 | $ | 2,674,225 | (76 | )% | ||||
LHI, mortgage finance | 9,378,104 | 7,951,432 | 18 | % | ||||||
LHI | 15,789,958 | 16,772,824 | (6 | )% | ||||||
Total LHI | 25,168,062 | 24,724,256 | 2 | % | ||||||
Total assets | 38,432,872 | 33,526,437 | 15 | % | ||||||
Demand deposits | 12,339,212 | 10,289,572 | 20 | % | ||||||
Total deposits | 31,959,487 | 27,413,303 | 17 | % | ||||||
Stockholders’ equity | 2,800,404 | 2,735,993 | 2 | % | ||||||
DETAILED FINANCIALS
For the third quarter of 2020, net income was $57.1 million, compared to a net loss of $34.3 million for the second quarter of 2020, and net income of $88.1 million for the third quarter of 2019. On a fully diluted basis, earnings per common share were $1.08 for the quarter ended September 30, 2020, compared to a loss per common share of $0.73 for the quarter ended June 30, 2020 and earnings per common share of $1.70 for the quarter ended September 30, 2019. The increase in net income for the third quarter of 2020 as compared to the second quarter of 2020 resulted primarily from a $70.0 million decrease in the provision for credit losses, as well as a $56.6 million decrease in non-interest expense, driven by significant non-recurring expenses incurred in the second quarter of 2020, as described below.
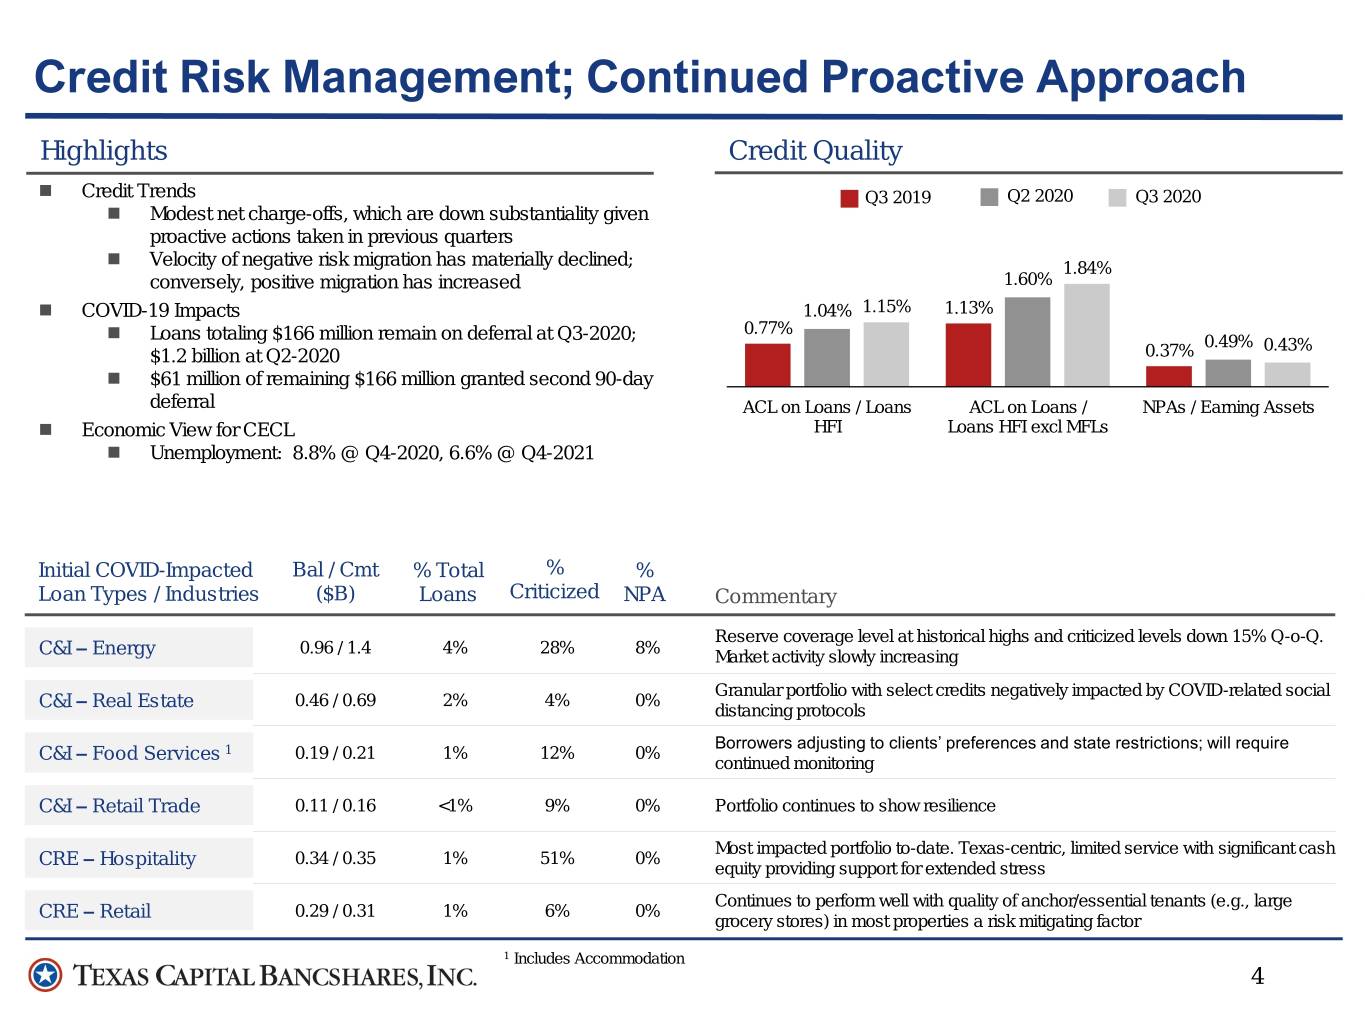
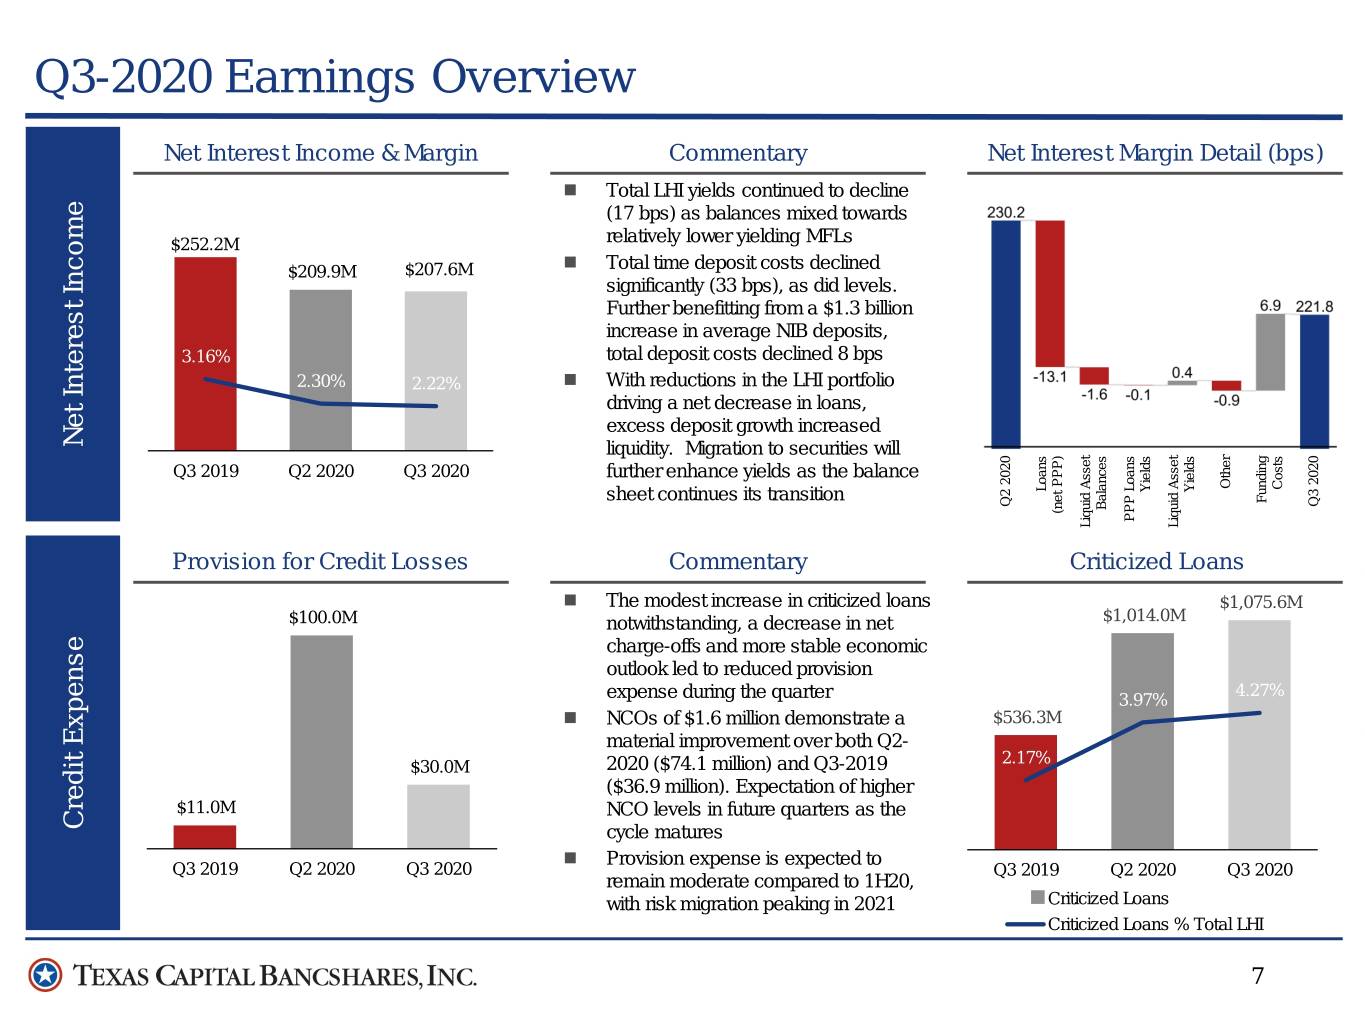
We recorded a $30.0 million provision for credit losses for the third quarter of 2020 utilizing the Current Expected Credit Loss ("CECL") methodology adopted in the first quarter of 2020, compared to $100.0 million for the second quarter of 2020 and $11.0 million for the third quarter of 2019. The linked quarter decrease in provision for credit losses resulted primarily from a decrease in charge-offs. We recorded $1.6 million in net charge-offs during the third quarter of 2020, compared to $74.1 million during the second quarter of 2020 and $36.9 million during the third quarter of 2019. Criticized loans totaled $1.1 billion at September 30, 2020, compared to $1.0 billion at June 30, 2020 and $536.4 million at September 30, 2019. Criticized loan levels remain elevated due to the downgrade of loans to borrowers that have been impacted by the COVID-19 pandemic or that are in categories that are expected to be more significantly impacted by COVID-19.
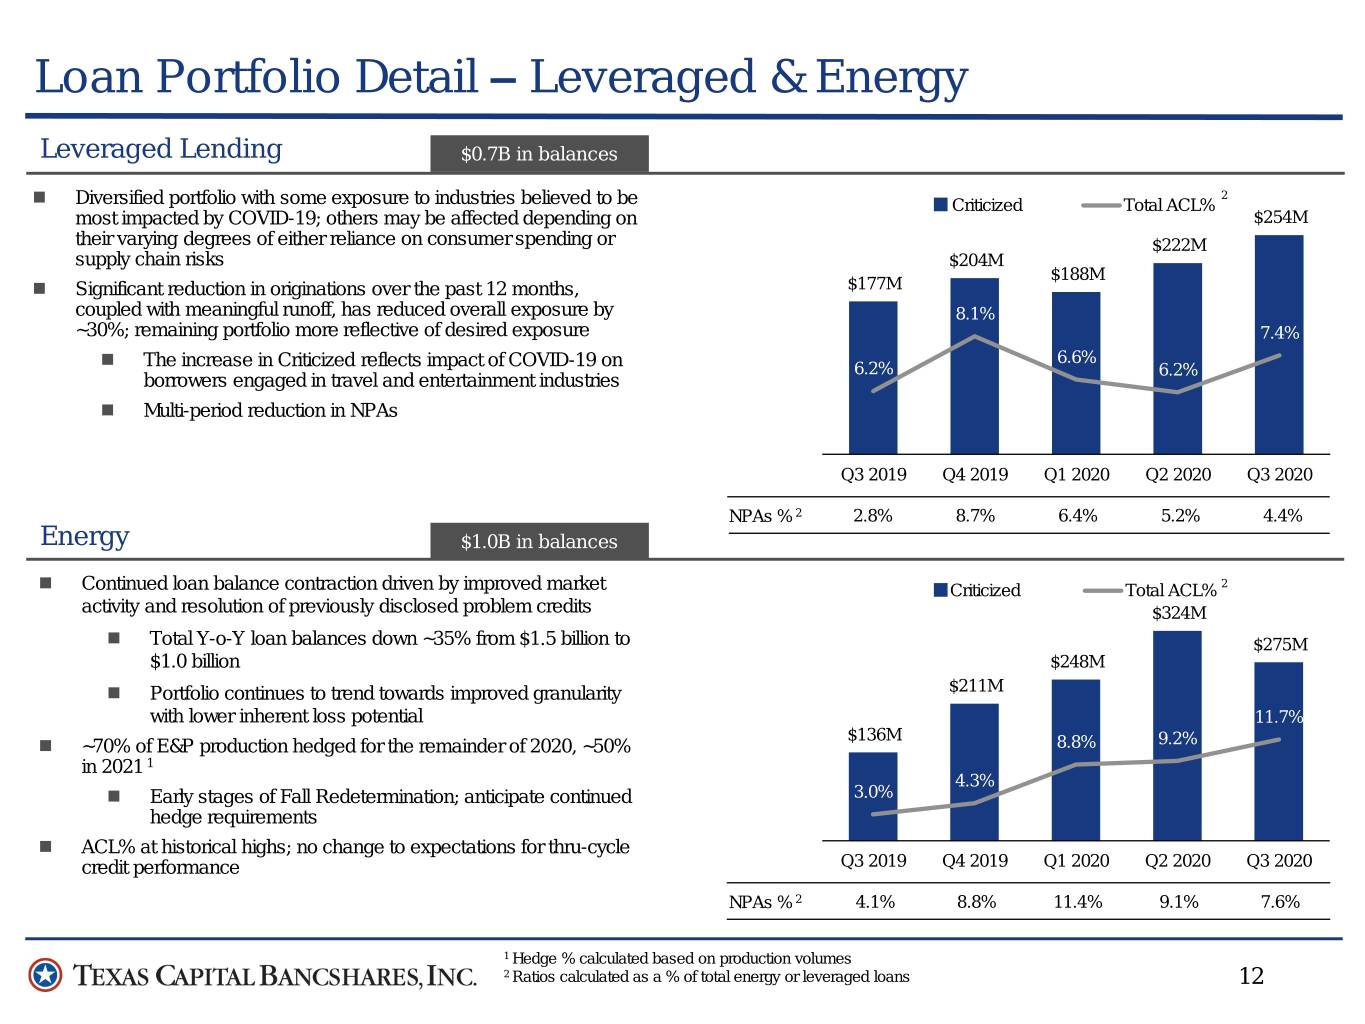
Non-performing assets ("NPAs") totaled $161.9 million at September 30, 2020, a decrease of $12.1 million compared to the second quarter of 2020 and an increase of $41.3 million compared to the third quarter of 2019. Non-accrual energy loans totaled $73.8 million (46% of total NPAs) at September 30, 2020, compared to $103.9 million (60% of total NPAs) at June 30, 2020. Non-accrual leveraged lending loans totaled $31.3 million (19% of total NPAs) at September 30, 2020, compared to $39.1 million (22% of total NPAs) at June 30, 2020. The ratio of NPAs to total LHI plus other real estate owned ("OREO") for the third quarter of 2020 was 0.64%, compared to 0.68% for the second quarter of 2020 and 0.49% for the third quarter of 2019.
Net interest income was $207.6 million for the third quarter of 2020, compared to $209.9 million for the second quarter of 2020 and $252.2 million for the third quarter of 2019. Net interest margin for the third quarter of 2020 was 2.22%, a decrease of 8 basis points from the second quarter of 2020 and a decrease of 94 basis points from the third quarter of 2019. The shift in earning assets, primarily the increases in liquidity assets and investment securities, and decrease in LHI, excluding mortgage finance, contributed to the year-over-year decrease in net interest margin. LHI yields, excluding mortgage finance loans, decreased 20 basis points from the second quarter of 2020, and decreased 169 basis points compared to the third quarter of 2019. LHI, mortgage finance yields for the third quarter of 2020 decreased 9 basis points compared to the second quarter of 2020, and were unchanged compared to the third quarter of 2019. Additionally, total cost of deposits for the third quarter of 2020 decreased 8 basis points to 0.34% compared to 0.42% for the second quarter of 2020, and decreased 87 basis points from 1.21% for the third quarter of 2019.
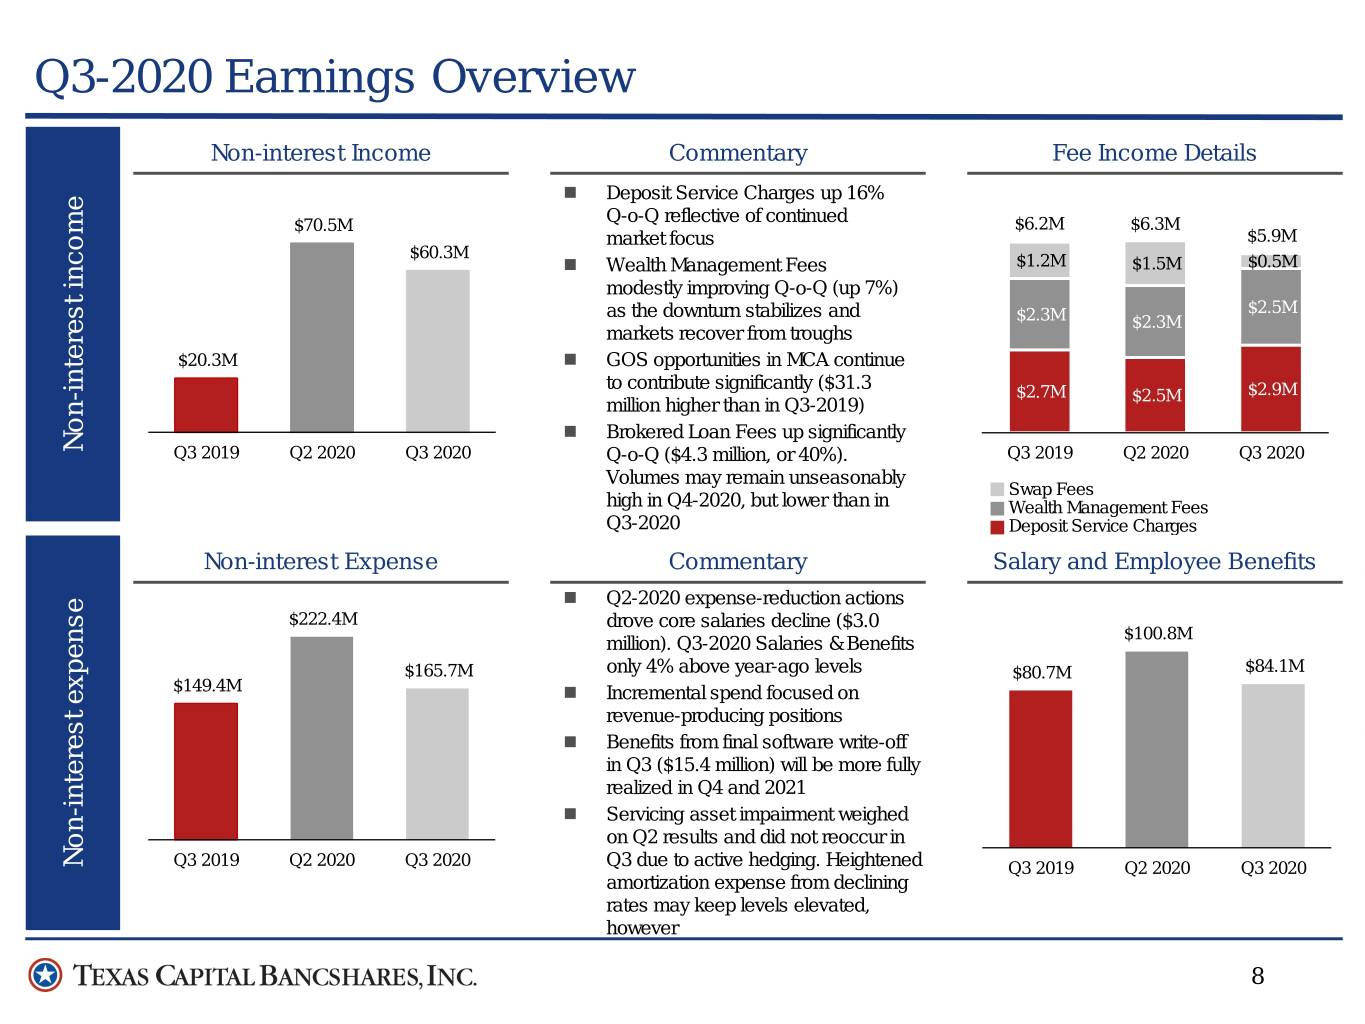
Non-interest income decreased $10.2 million, or 14%, during the third quarter of 2020 compared to the second quarter of 2020, and increased $40.0 million, or 197%, compared to the third quarter of 2019. The linked quarter decrease was primarily related to a decrease in net gain/(loss) on sale of LHS, partially offset by an increase in brokered loans fees. The year-over-year increase was primarily related to an increase in net gain/(loss) on sale of LHS and an increase in brokered loan fees. The linked quarter and year-over-year increases in brokered loan fees were due to an increase in total mortgage finance volumes in the third quarter of 2020. The year-over-year increase in net gain/(loss) on sale of LHS was due to lower hedge costs in the third quarter of 2020 as a result of holding purchased loans for shorter durations than in prior periods, and is offset by the year-over-year decline in net interest income on LHS.
Non-interest expense for the third quarter of 2020 decreased $56.6 million, or 25%, compared to the second quarter of 2020, and increased $16.3 million, or 11%, compared to the third quarter of 2019. The linked quarter decrease was primarily related to decreases in salaries and employee benefits, communications and technology expense, servicing-related expenses and merger-related expenses. The year-over-year increase was primarily due to an increase in communications and technology expense, partially offset by a decrease in marketing expense. The linked quarter decrease in salaries and employee benefits and communication and technology expense was primarily due to non-recurring severance accruals and software expenses recorded in the second quarter of 2020. We wrote-off an additional $15.4 million in software assets during the third quarter of 2020, which contributed to the year-over-year increase in communications and technology expense. The full impact on salaries and employee benefits expense from the reduction in workforce and on software amortization expense from the software write-offs in the second and third quarters of 2020 is expected to be realized in non-interest expense in the first half of 2021, with meaningful reductions in run-rate occurring in the fourth quarter of 2020. Further software write-offs are not expected in the fourth quarter of 2020. The linked-quarter decrease in servicing-related expense was primarily due to a decrease in MSR impairment expense reflecting market conditions and our hedging program.
2
All regulatory ratios continue to be in excess of "well-capitalized" requirements as of September 30, 2020. Our CET 1, tier 1 capital, total capital and leverage ratios were 9.1%, 9.9%, 11.8% and 7.6%, respectively, at September 30, 2020, compared to 8.8%, 9.7%, 11.6% and 7.5%, respectively, at June 30, 2020. At September 30, 2020, our ratio of tangible common equity to total tangible assets was 6.8% compared to 7.0% at June 30, 2020.
About Texas Capital Bancshares, Inc.
Texas Capital Bancshares, Inc. (NASDAQ®: TCBI), a member of the Russell 2000® Index and the S&P MidCap 400®, is the parent company of Texas Capital Bank, a commercial bank that delivers highly personalized financial services to businesses and entrepreneurs. Headquartered in Dallas, the bank has full-service locations in Austin, Dallas, Fort Worth, Houston and San Antonio.
Forward Looking Statements
This communication may be deemed to include “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 regarding our financial condition, results of operations, business plans and future performance. These statements are not historical in nature and can generally be identified by such words as “believe,” “expect,” “estimate,” “anticipate,” “plan,” “may,” “will,” “forecast,” “could,” “projects,” “intend” and similar expressions. Because forward-looking statements relate to future results and occurrences, they are subject to inherent uncertainties, risks, and changes in circumstances that are difficult to predict. A number of factors, many of which are beyond our control, could cause actual results to differ materially from future results expressed or implied by such forward-looking statements. These risks and uncertainties include, but are not limited to, the credit quality of our loan portfolio, general economic conditions in the United States and in our markets, including the continued impact on our customers from volatility in oil and gas prices, the material risks and uncertainties for the U.S. and world economies, and for our business, resulting from the COVID-19 pandemic, expectations regarding rates of default and credit losses, volatility in the mortgage industry, our business strategies, our expectations about future financial performance, future growth and earnings, the appropriateness of our allowance for credit losses and provision for credit losses, our ability to identify, employ and retain a successor chief executive officer, the impact of changing regulatory requirements and legislative changes on our business, increased competition, interest rate risk, new lines of business, new product or service offerings and new technologies. These and other factors that could cause results to differ materially from those described in the forward-looking statements, as well as a discussion of the risks and uncertainties that may affect our business, can be found in our Annual Report on Form 10-K, our Quarterly Reports on Form 10-Q and in other filings we make with the Securities and Exchange Commission. The information contained in this communication speaks only as of its date. Except to the extent required by applicable law or regulation, we disclaim any obligation to update such factors or to publicly announce the results of any revisions to any of the forward-looking statements included herein to reflect future events or developments.
3
TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||
SELECTED FINANCIAL HIGHLIGHTS (UNAUDITED) | |||||||||||||||
(Dollars in thousands except per share data) | |||||||||||||||
3rd Quarter | 2nd Quarter | 1st Quarter | 4th Quarter | 3rd Quarter | |||||||||||
2020 | 2020 | 2020 | 2019 | 2019 | |||||||||||
CONSOLIDATED STATEMENTS OF INCOME | |||||||||||||||
Interest income | $ | 243,731 | $ | 252,010 | $ | 306,008 | $ | 337,757 | $ | 355,101 | |||||
Interest expense | 36,162 | 42,082 | 77,689 | 89,372 | 102,933 | ||||||||||
Net interest income | 207,569 | 209,928 | 228,319 | 248,385 | 252,168 | ||||||||||
Provision for credit losses | 30,000 | 100,000 | 96,000 | 17,000 | 11,000 | ||||||||||
Net interest income after provision for credit losses | 177,569 | 109,928 | 132,319 | 231,385 | 241,168 | ||||||||||
Non-interest income | 60,348 | 70,502 | 11,780 | 17,761 | 20,301 | ||||||||||
Non-interest expense | 165,741 | 222,352 | 165,417 | 168,187 | 149,429 | ||||||||||
Income/(loss) before income taxes | 72,176 | (41,922 | ) | (21,318 | ) | 80,959 | 112,040 | ||||||||
Income tax expense/(benefit) | 15,060 | (7,606 | ) | (4,631 | ) | 16,539 | 23,958 | ||||||||
Net income/(loss) | 57,116 | (34,316 | ) | (16,687 | ) | 64,420 | 88,082 | ||||||||
Preferred stock dividends | 2,438 | 2,437 | 2,438 | 2,437 | 2,438 | ||||||||||
Net income/(loss) available to common stockholders | $ | 54,678 | $ | (36,753 | ) | $ | (19,125 | ) | $ | 61,983 | $ | 85,644 | |||
Diluted earnings/(loss) per common share | $ | 1.08 | $ | (0.73 | ) | $ | (0.38 | ) | $ | 1.23 | $ | 1.70 | |||
Diluted common shares | 50,573,073 | 50,416,331 | 50,474,802 | 50,461,723 | 50,416,402 | ||||||||||
CONSOLIDATED BALANCE SHEET DATA | |||||||||||||||
Total assets | $ | 38,432,872 | $ | 36,613,127 | $ | 35,879,416 | $ | 32,548,069 | $ | 33,526,437 | |||||
LHI | 15,789,958 | 16,552,203 | 16,857,579 | 16,476,413 | 16,772,824 | ||||||||||
LHI, mortgage finance | 9,378,104 | 8,972,626 | 7,588,803 | 8,169,849 | 7,951,432 | ||||||||||
LHS | 648,009 | 454,581 | 774,064 | 2,577,134 | 2,674,225 | ||||||||||
Liquidity assets(1) | 10,461,544 | 9,540,044 | 9,498,189 | 4,263,766 | 4,993,185 | ||||||||||
Investment securities | 1,367,313 | 234,969 | 228,784 | 239,871 | 238,022 | ||||||||||
Demand deposits | 12,339,212 | 10,835,911 | 9,420,303 | 9,438,459 | 10,289,572 | ||||||||||
Total deposits | 31,959,487 | 30,187,695 | 27,134,263 | 26,478,593 | 27,413,303 | ||||||||||
Other borrowings | 2,908,183 | 2,895,790 | 5,195,267 | 2,541,766 | 2,639,967 | ||||||||||
Subordinated notes | 282,400 | 282,309 | 282,219 | 282,129 | 282,038 | ||||||||||
Long-term debt | 113,406 | 113,406 | 113,406 | 113,406 | 113,406 | ||||||||||
Stockholders’ equity | 2,800,404 | 2,734,755 | 2,772,596 | 2,801,321 | 2,735,993 | ||||||||||
End of period shares outstanding | 50,455,552 | 50,435,672 | 50,407,778 | 50,337,741 | 50,317,654 | ||||||||||
Book value | $ | 52.53 | $ | 51.25 | $ | 52.03 | $ | 52.67 | $ | 51.39 | |||||
Tangible book value(2) | $ | 52.18 | $ | 50.89 | $ | 51.67 | $ | 52.31 | $ | 51.03 | |||||
SELECTED FINANCIAL RATIOS | |||||||||||||||
Net interest margin | 2.22 | % | 2.30 | % | 2.78 | % | 2.95 | % | 3.16 | % | |||||
Return on average assets | 0.59 | % | (0.36 | )% | (0.20 | )% | 0.74 | % | 1.06 | % | |||||
Return on average common equity | 8.24 | % | (5.48 | )% | (2.85 | )% | 9.26 | % | 13.21 | % | |||||
Non-interest income to average earning assets | 0.64 | % | 0.77 | % | 0.14 | % | 0.21 | % | 0.25 | % | |||||
Efficiency ratio(3) | 61.9 | % | 79.3 | % | 68.9 | % | 63.2 | % | 54.8 | % | |||||
Efficiency ratio, adjusted(4) | 59.8 | % | 77.5 | % | 65.8 | % | 61.4 | % | 51.3 | % | |||||
Non-interest expense to average earning assets | 1.76 | % | 2.43 | % | 2.00 | % | 1.98 | % | 1.86 | % | |||||
Tangible common equity to total tangible assets(5) | 6.8 | % | 7.0 | % | 7.3 | % | 8.1 | % | 7.6 | % | |||||
Common Equity Tier 1 | 9.1 | % | 8.8 | % | 9.3 | % | 8.9 | % | 8.6 | % | |||||
Tier 1 capital | 9.9 | % | 9.7 | % | 10.2 | % | 9.7 | % | 9.4 | % | |||||
Total capital | 11.8 | % | 11.6 | % | 12.0 | % | 11.4 | % | 11.0 | % | |||||
Leverage | 7.6 | % | 7.5 | % | 8.5 | % | 8.4 | % | 8.6 | % | |||||
(1) | Liquidity assets include Federal funds sold and interest-bearing deposits in other banks. |
(2) | Stockholders’ equity excluding preferred stock, less goodwill and intangibles, divided by shares outstanding at period end. |
(3) | Non-interest expense divided by the sum of net interest income and non-interest income. |
(4) | Non-interest expense, excluding deposit-related marketing fees and servicing related expenses, divided by the sum of net interest income and non-interest income, net of deposit-related marketing fees and servicing related expenses. Deposit-related marketing fees totaled $1.8 million, $1.7 million, $5.2 million, $9.4 million and $11.9 million for the third, second and first quarters of 2020, as well as the fourth and third quarters of 2019, respectively. |
(5) | Stockholders’ equity excluding preferred stock and accumulated other comprehensive income, less goodwill and intangibles, divided by total assets, less accumulated other comprehensive income and goodwill and intangibles. |
4
TEXAS CAPITAL BANCSHARES, INC. | ||||||||
CONSOLIDATED BALANCE SHEETS (UNAUDITED) | ||||||||
(Dollars in thousands) | ||||||||
September 30, 2020 | September 30, 2019 | % Change | ||||||
Assets | ||||||||
Cash and due from banks | $ | 185,242 | $ | 216,085 | (14 | )% | ||
Interest-bearing deposits | 10,461,544 | 4,968,185 | 111 | % | ||||
Federal funds sold and securities purchased under resale agreements | — | 25,000 | (100 | )% | ||||
Securities, available-for-sale | 1,367,313 | 238,022 | 474 | % | ||||
LHS ($639.0 million and $2,667.2 million at September 30, 2020 and 2019, respectively, at fair value) | 648,009 | 2,674,225 | (76 | )% | ||||
LHI, mortgage finance | 9,378,104 | 7,951,432 | 18 | % | ||||
LHI (net of unearned income) | 15,789,958 | 16,772,824 | (6 | )% | ||||
Less: Allowance for credit losses on loans | 290,165 | 190,138 | 53 | % | ||||
LHI, net | 24,877,897 | 24,534,118 | 1 | % | ||||
Mortgage servicing rights, net | 95,323 | 49,125 | 94 | % | ||||
Premises and equipment, net | 26,653 | 32,667 | (18 | )% | ||||
Accrued interest receivable and other assets | 753,123 | 770,793 | (2 | )% | ||||
Goodwill and intangibles, net | 17,768 | 18,217 | (2 | )% | ||||
Total assets | $ | 38,432,872 | $ | 33,526,437 | 15 | % | ||
Liabilities and Stockholders’ Equity | ||||||||
Liabilities: | ||||||||
Deposits: | ||||||||
Non-interest bearing | $ | 12,339,212 | $ | 10,289,572 | 20 | % | ||
Interest bearing | 19,620,275 | 17,123,731 | 15 | % | ||||
Total deposits | 31,959,487 | 27,413,303 | 17 | % | ||||
Accrued interest payable | 14,674 | 34,336 | (57 | )% | ||||
Other liabilities | 354,318 | 307,394 | 15 | % | ||||
Federal funds purchased and repurchase agreements | 208,183 | 139,967 | 49 | % | ||||
Other borrowings | 2,700,000 | 2,500,000 | 8 | % | ||||
Subordinated notes, net | 282,400 | 282,038 | — | % | ||||
Trust preferred subordinated debentures | 113,406 | 113,406 | — | % | ||||
Total liabilities | 35,632,468 | 30,790,444 | 16 | % | ||||
Stockholders’ equity: | ||||||||
Preferred stock, $.01 par value, $1,000 liquidation value: | ||||||||
Authorized shares - 10,000,000 | ||||||||
Issued shares - 6,000,000 shares issued at September 30, 2020 and 2019 | 150,000 | 150,000 | — | % | ||||
Common stock, $.01 par value: | ||||||||
Authorized shares - 100,000,000 | ||||||||
Issued shares - 50,455,969 and 50,318,071 at September 30, 2020 and 2019, respectively | 504 | 503 | — | % | ||||
Additional paid-in capital | 987,754 | 974,799 | 1 | % | ||||
Retained earnings | 1,655,317 | 1,601,688 | 3 | % | ||||
Treasury stock (shares at cost: 417 at September 30, 2020 and 2019) | (8 | ) | (8 | ) | — | % | ||
Accumulated other comprehensive income, net of taxes | 6,837 | 9,011 | N/M | |||||
Total stockholders’ equity | 2,800,404 | 2,735,993 | 2 | % | ||||
Total liabilities and stockholders’ equity | $ | 38,432,872 | $ | 33,526,437 | 15 | % | ||
5
TEXAS CAPITAL BANCSHARES, INC. | ||||||||||||
CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED) | ||||||||||||
(Dollars in thousands except per share data) | ||||||||||||
Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||
2020 | 2019 | 2020 | 2019 | |||||||||
Interest income | ||||||||||||
Interest and fees on loans | $ | 237,179 | $ | 329,344 | $ | 768,399 | $ | 971,889 | ||||
Investment securities | 3,674 | 2,316 | 7,881 | 6,036 | ||||||||
Federal funds sold and securities purchased under resale agreements | 1 | 554 | 692 | 1,090 | ||||||||
Interest-bearing deposits in other banks | 2,877 | 22,887 | 24,777 | 48,540 | ||||||||
Total interest income | 243,731 | 355,101 | 801,749 | 1,027,555 | ||||||||
Interest expense | ||||||||||||
Deposits | 27,830 | 80,967 | 122,298 | 222,550 | ||||||||
Federal funds purchased | 128 | 1,835 | 973 | 10,553 | ||||||||
Other borrowings | 3,365 | 14,703 | 17,516 | 46,681 | ||||||||
Subordinated notes | 4,191 | 4,191 | 12,573 | 12,573 | ||||||||
Trust preferred subordinated debentures | 648 | 1,237 | 2,573 | 3,863 | ||||||||
Total interest expense | 36,162 | 102,933 | 155,933 | 296,220 | ||||||||
Net interest income | 207,569 | 252,168 | 645,816 | 731,335 | ||||||||
Provision for credit losses | 30,000 | 11,000 | 226,000 | 58,000 | ||||||||
Net interest income after provision for credit losses | 177,569 | 241,168 | 419,816 | 673,335 | ||||||||
Non-interest income | ||||||||||||
Service charges on deposit accounts | 2,864 | 2,707 | 8,616 | 8,535 | ||||||||
Wealth management and trust fee income | 2,502 | 2,330 | 7,317 | 6,468 | ||||||||
Brokered loan fees | 15,034 | 8,691 | 33,813 | 21,093 | ||||||||
Servicing income | 7,329 | 3,549 | 18,195 | 9,409 | ||||||||
Swap fees | 484 | 1,196 | 4,709 | 2,828 | ||||||||
Net gain/(loss) on sale of LHS | 25,242 | (6,011 | ) | 51,265 | (12,502 | ) | ||||||
Other | 6,893 | 7,839 | 18,715 | 38,848 | ||||||||
Total non-interest income | 60,348 | 20,301 | 142,630 | 74,679 | ||||||||
Non-interest expense | ||||||||||||
Salaries and employee benefits | 84,096 | 80,722 | 262,080 | 238,235 | ||||||||
Net occupancy expense | 8,736 | 8,125 | 26,582 | 23,914 | ||||||||
Marketing | 3,636 | 14,753 | 20,146 | 40,548 | ||||||||
Legal and professional | 11,207 | 11,394 | 40,003 | 31,428 | ||||||||
Communications and technology | 31,098 | 10,805 | 87,649 | 31,025 | ||||||||
FDIC insurance assessment | 6,374 | 5,220 | 19,363 | 14,480 | ||||||||
Servicing-related expenses | 12,287 | 8,165 | 48,758 | 19,613 | ||||||||
Merger-related expenses | — | — | 17,756 | — | ||||||||
Other | 8,307 | 10,245 | 31,173 | 33,420 | ||||||||
Total non-interest expense | 165,741 | 149,429 | 553,510 | 432,663 | ||||||||
Income before income taxes | 72,176 | 112,040 | 8,936 | 315,351 | ||||||||
Income tax expense | 15,060 | 23,958 | 2,823 | 67,756 | ||||||||
Net income | 57,116 | 88,082 | 6,113 | 247,595 | ||||||||
Preferred stock dividends | 2,438 | 2,438 | 7,313 | 7,313 | ||||||||
Net income/(loss) available to common stockholders | $ | 54,678 | $ | 85,644 | $ | (1,200 | ) | $ | 240,282 | |||
Basic earnings/(loss) per common share | $ | 1.08 | $ | 1.70 | $ | (0.02 | ) | $ | 4.78 | |||
Diluted earnings/(loss) per common share | $ | 1.08 | $ | 1.70 | $ | (0.02 | ) | $ | 4.77 | |||
6
TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||
SUMMARY OF CREDIT LOSS EXPERIENCE | |||||||||||||||
(Dollars in thousands) | |||||||||||||||
3rd Quarter | 2nd Quarter | 1st Quarter | 4th Quarter | 3rd Quarter | |||||||||||
2020 | 2020 | 2020 | 2019 | 2019 | |||||||||||
Allowance for credit losses on loans: | |||||||||||||||
Beginning balance | $ | 264,722 | $ | 240,958 | $ | 195,047 | $ | 190,138 | $ | 214,572 | |||||
Impact of CECL adoption | — | — | 8,585 | — | — | ||||||||||
Loans charged-off: | |||||||||||||||
Commercial | 2,436 | 12,287 | 20,653 | 13,968 | 21,124 | ||||||||||
Energy | 141 | 62,368 | 37,730 | 797 | 16,655 | ||||||||||
Total charge-offs | 2,577 | 74,655 | 58,383 | 14,765 | 37,779 | ||||||||||
Recoveries: | |||||||||||||||
Commercial | 113 | 513 | 257 | 1,754 | 799 | ||||||||||
Energy | 880 | — | 423 | 209 | 107 | ||||||||||
Total recoveries | 993 | 513 | 680 | 1,963 | 906 | ||||||||||
Net charge-offs | 1,584 | 74,142 | 57,703 | 12,802 | 36,873 | ||||||||||
Provision for credit losses on loans | 27,027 | 97,906 | 95,029 | 17,711 | 12,439 | ||||||||||
Ending balance | $ | 290,165 | $ | 264,722 | $ | 240,958 | $ | 195,047 | $ | 190,138 | |||||
Allowance for off-balance sheet credit losses: | |||||||||||||||
Beginning balance | $ | 12,268 | $ | 10,174 | $ | 8,640 | $ | 9,351 | $ | 10,790 | |||||
Impact of CECL adoption | — | — | 563 | — | — | ||||||||||
Provision for off-balance sheet credit losses | 2,973 | 2,094 | 971 | (711 | ) | (1,439 | ) | ||||||||
Ending balance | $ | 15,241 | $ | 12,268 | $ | 10,174 | $ | 8,640 | $ | 9,351 | |||||
Total allowance for credit losses | $ | 305,406 | $ | 276,990 | $ | 251,132 | $ | 203,687 | $ | 199,489 | |||||
Total provision for credit losses | $ | 30,000 | $ | 100,000 | $ | 96,000 | $ | 17,000 | $ | 11,000 | |||||
Allowance for credit losses on loans to LHI | 1.15 | % | 1.04 | % | 0.99 | % | 0.79 | % | 0.77 | % | |||||
Allowance for credit losses on loans to average LHI | 1.14 | % | 1.03 | % | 1.02 | % | 0.79 | % | 0.76 | % | |||||
Net charge-offs to average LHI(1) | 0.02 | % | 1.16 | % | 0.98 | % | 0.21 | % | 0.58 | % | |||||
Net charge-offs to average LHI for last twelve months(1) | 0.59 | % | 0.73 | % | 0.53 | % | 0.31 | % | 0.41 | % | |||||
Total provision for credit losses to average LHI(1) | 0.47 | % | 1.57 | % | 1.63 | % | 0.27 | % | 0.17 | % | |||||
Total allowance for credit losses to LHI | 1.21 | % | 1.09 | % | 1.03 | % | 0.83 | % | 0.81 | % | |||||
(1) | Interim period ratios are annualized. |
7
TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||
SUMMARY OF NON-PERFORMING ASSETS AND PAST DUE LOANS | |||||||||||||||
(Dollars in thousands) | |||||||||||||||
3rd Quarter | 2nd Quarter | 1st Quarter | 4th Quarter | 3rd Quarter | |||||||||||
2020 | 2020 | 2020 | 2019 | 2019 | |||||||||||
Non-performing assets (NPAs): | |||||||||||||||
Non-accrual loans | $ | 161,946 | $ | 174,031 | $ | 219,165 | $ | 225,384 | $ | 120,686 | |||||
Other real estate owned (OREO) | — | — | — | — | — | ||||||||||
Total LHI NPAs | $ | 161,946 | $ | 174,031 | $ | 219,165 | $ | 225,384 | $ | 120,686 | |||||
Non-accrual loans to LHI | 0.64 | % | 0.68 | % | 0.90 | % | 0.91 | % | 0.49 | % | |||||
Total LHI NPAs to LHI plus OREO | 0.64 | % | 0.68 | % | 0.90 | % | 0.91 | % | 0.49 | % | |||||
Total LHI NPAs to earning assets | 0.43 | % | 0.49 | % | 0.63 | % | 0.71 | % | 0.37 | % | |||||
Allowance for credit losses on loans to non-accrual loans | 1.8x | 1.5x | 1.1x | .9x | 1.6x | ||||||||||
LHI past due 90 days and still accruing(1) | $ | 15,896 | $ | 21,079 | $ | 21,274 | $ | 17,584 | $ | 29,648 | |||||
LHI past due 90 days to LHI | 0.06 | % | 0.08 | % | 0.09 | % | 0.07 | % | 0.12 | % | |||||
LHS past due 90 days and still accruing(2) | $ | 15,631 | $ | 10,152 | $ | 9,014 | $ | 8,207 | $ | 9,187 | |||||
(1) | At September 30, 2020, loans past due 90 days and still accruing includes premium finance loans of $11.9 million. These loans are primarily secured by obligations of insurance carriers to refund premiums on canceled insurance policies. The refund of premiums from the insurance carriers can take 180 days or longer from the cancellation date. |
(2) | Includes loans guaranteed by U.S. government agencies that were repurchased out of Ginnie Mae securities. Loans are recorded as LHS and carried at fair value on the balance sheet. Interest on these past due loans accrues at the debenture rate guaranteed by the U.S. government. Also includes loans that, pursuant to Ginnie Mae servicing guidelines, we have the unilateral right, but not obligation, to repurchase and thus must record as LHS on our balance sheet regardless of whether the repurchase option has been exercised. |
8
TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||
CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED) | |||||||||||||||
(Dollars in thousands) | |||||||||||||||
3rd Quarter | 2nd Quarter | 1st Quarter | 4th Quarter | 3rd Quarter | |||||||||||
2020 | 2020 | 2019 | 2019 | 2019 | |||||||||||
Interest income | |||||||||||||||
Interest and fees on loans | $ | 237,179 | $ | 247,595 | $ | 283,625 | $ | 312,147 | $ | 329,344 | |||||
Investment securities | 3,674 | 2,024 | 2,183 | 2,618 | 2,316 | ||||||||||
Federal funds sold and securities purchased under resale agreements | 1 | 77 | 614 | 439 | 554 | ||||||||||
Interest-bearing deposits in other banks | 2,877 | 2,314 | 19,586 | 22,553 | 22,887 | ||||||||||
Total interest income | 243,731 | 252,010 | 306,008 | 337,757 | 355,101 | ||||||||||
Interest expense | |||||||||||||||
Deposits | 27,830 | 32,294 | 62,174 | 70,987 | 80,967 | ||||||||||
Federal funds purchased | 128 | 176 | 669 | 1,319 | 1,835 | ||||||||||
Other borrowings | 3,365 | 4,569 | 9,582 | 11,712 | 14,703 | ||||||||||
Subordinated notes | 4,191 | 4,191 | 4,191 | 4,191 | 4,191 | ||||||||||
Trust preferred subordinated debentures | 648 | 852 | 1,073 | 1,163 | 1,237 | ||||||||||
Total interest expense | 36,162 | 42,082 | 77,689 | 89,372 | 102,933 | ||||||||||
Net interest income | 207,569 | 209,928 | 228,319 | 248,385 | 252,168 | ||||||||||
Provision for credit losses | 30,000 | 100,000 | 96,000 | 17,000 | 11,000 | ||||||||||
Net interest income after provision for credit losses | 177,569 | 109,928 | 132,319 | 231,385 | 241,168 | ||||||||||
Non-interest income | |||||||||||||||
Service charges on deposit accounts | 2,864 | 2,459 | 3,293 | 2,785 | 2,707 | ||||||||||
Wealth management and trust fee income | 2,502 | 2,348 | 2,467 | 2,342 | 2,330 | ||||||||||
Brokered loan fees | 15,034 | 10,764 | 8,015 | 8,645 | 8,691 | ||||||||||
Servicing income | 7,329 | 6,120 | 4,746 | 4,030 | 3,549 | ||||||||||
Swap fees | 484 | 1,468 | 2,757 | 1,559 | 1,196 | ||||||||||
Net gain/(loss) on sale of LHS | 25,242 | 39,023 | (13,000 | ) | (7,757 | ) | (6,011 | ) | |||||||
Other | 6,893 | 8,320 | 3,502 | 6,157 | 7,839 | ||||||||||
Total non-interest income | 60,348 | 70,502 | 11,780 | 17,761 | 20,301 | ||||||||||
Non-interest expense | |||||||||||||||
Salaries and employee benefits | 84,096 | 100,791 | 77,193 | 90,248 | 80,722 | ||||||||||
Net occupancy expense | 8,736 | 9,134 | 8,712 | 9,075 | 8,125 | ||||||||||
Marketing | 3,636 | 7,988 | 8,522 | 12,807 | 14,753 | ||||||||||
Legal and professional | 11,207 | 11,330 | 17,466 | 21,032 | 11,394 | ||||||||||
Communications and technology | 31,098 | 42,760 | 13,791 | 13,801 | 10,805 | ||||||||||
FDIC insurance assessment | 6,374 | 7,140 | 5,849 | 5,613 | 5,220 | ||||||||||
Servicing-related expenses | 12,287 | 20,117 | 16,354 | 2,960 | 8,165 | ||||||||||
Merger-related expenses | — | 10,486 | 7,270 | 1,370 | — | ||||||||||
Other | 8,307 | 12,606 | 10,260 | 11,281 | 10,245 | ||||||||||
Total non-interest expense | 165,741 | 222,352 | 165,417 | 168,187 | 149,429 | ||||||||||
Income/(loss) before income taxes | 72,176 | (41,922 | ) | (21,318 | ) | 80,959 | 112,040 | ||||||||
Income tax expense/(benefit) | 15,060 | (7,606 | ) | (4,631 | ) | 16,539 | 23,958 | ||||||||
Net income/(loss) | 57,116 | (34,316 | ) | (16,687 | ) | 64,420 | 88,082 | ||||||||
Preferred stock dividends | 2,438 | 2,437 | 2,438 | 2,437 | 2,438 | ||||||||||
Net income/(loss) available to common shareholders | $ | 54,678 | $ | (36,753 | ) | $ | (19,125 | ) | $ | 61,983 | $ | 85,644 | |||
9
TEXAS CAPITAL BANCSHARES, INC. | ||||||||||||||||||||||||||||||||||||||||||||
QUARTERLY FINANCIAL SUMMARY - UNAUDITED | ||||||||||||||||||||||||||||||||||||||||||||
Consolidated Daily Average Balances, Average Yields and Rates | ||||||||||||||||||||||||||||||||||||||||||||
(Dollars in thousands) | ||||||||||||||||||||||||||||||||||||||||||||
3rd Quarter 2020 | 2nd Quarter 2020 | 1st Quarter 2020 | 4th Quarter 2019 | 3rd Quarter 2019 | ||||||||||||||||||||||||||||||||||||||||
Average Balance | Revenue/ Expense | Yield/ Rate | Average Balance | Revenue/ Expense | Yield/ Rate | Average Balance | Revenue/ Expense | Yield/ Rate | Average Balance | Revenue/ Expense | Yield/ Rate | Average Balance | Revenue/ Expense | Yield/ Rate | ||||||||||||||||||||||||||||||
Assets | ||||||||||||||||||||||||||||||||||||||||||||
Investment securities - Taxable | $ | 525,149 | $ | 1,905 | 1.44 | % | $ | 38,829 | $ | 185 | 1.92 | % | $ | 42,799 | $ | 274 | 2.57 | % | $ | 40,904 | $ | 693 | 6.72 | % | $ | 39,744 | $ | 357 | 3.56 | % | ||||||||||||||
Investment securities - Non-taxable(2) | 190,797 | 2,239 | 4.67 | % | 195,806 | 2,327 | 4.78 | % | 195,578 | 2,417 | 4.97 | % | 197,591 | 2,437 | 4.89 | % | 200,090 | 2,480 | 4.92 | % | ||||||||||||||||||||||||
Federal funds sold and securities purchased under resale agreements | 12,051 | 1 | 0.04 | % | 245,434 | 77 | 0.13 | % | 199,727 | 614 | 1.24 | % | 102,320 | 439 | 1.70 | % | 100,657 | 554 | 2.18 | % | ||||||||||||||||||||||||
Interest-bearing deposits in other banks | 11,028,962 | 2,877 | 0.10 | % | 10,521,240 | 2,314 | 0.09 | % | 6,225,948 | 19,586 | 1.27 | % | 5,387,000 | 22,553 | 1.66 | % | 4,184,217 | 22,887 | 2.17 | % | ||||||||||||||||||||||||
LHS, at fair value | 543,606 | 3,867 | 2.83 | % | 380,624 | 2,547 | 2.69 | % | 3,136,381 | 27,480 | 3.52 | % | 3,567,836 | 33,411 | 3.72 | % | 2,555,269 | 26,206 | 4.07 | % | ||||||||||||||||||||||||
LHI, mortgage finance loans | 9,061,984 | 76,464 | 3.36 | % | 8,676,521 | 74,518 | 3.45 | % | 7,054,682 | 55,324 | 3.15 | % | 7,870,888 | 63,114 | 3.18 | % | 8,118,025 | 68,660 | 3.36 | % | ||||||||||||||||||||||||
LHI(1)(2) | 16,286,036 | 157,230 | 3.84 | % | 17,015,041 | 170,970 | 4.04 | % | 16,598,775 | 201,781 | 4.89 | % | 16,667,259 | 216,686 | 5.16 | % | 16,901,391 | 235,557 | 5.53 | % | ||||||||||||||||||||||||
Less allowance for credit losses on loans | 264,769 | — | — | 236,823 | — | — | 201,837 | — | — | 189,353 | — | — | 212,898 | — | — | |||||||||||||||||||||||||||||
LHI, net of allowance | 25,083,251 | 233,694 | 3.71 | % | 25,454,739 | 245,488 | 3.88 | % | 23,451,620 | 257,105 | 4.41 | % | 24,348,794 | 279,800 | 4.56 | % | 24,806,518 | 304,217 | 4.87 | % | ||||||||||||||||||||||||
Total earning assets | 37,383,816 | 244,583 | 2.60 | % | 36,836,672 | 252,938 | 2.76 | % | 33,252,053 | 307,476 | 3.72 | % | 33,644,445 | 339,333 | 4.00 | % | 31,886,495 | 356,701 | 4.44 | % | ||||||||||||||||||||||||
Cash and other assets | 1,037,760 | 1,075,864 | 976,520 | 974,866 | 1,000,117 | |||||||||||||||||||||||||||||||||||||||
Total assets | $ | 38,421,576 | $ | 37,912,536 | $ | 34,228,573 | $ | 34,619,311 | $ | 32,886,612 | ||||||||||||||||||||||||||||||||||
Liabilities and Stockholders’ Equity | ||||||||||||||||||||||||||||||||||||||||||||
Transaction deposits | $ | 4,275,574 | $ | 6,652 | 0.62 | % | $ | 3,923,966 | $ | 5,998 | 0.61 | % | $ | 3,773,067 | $ | 13,582 | 1.45 | % | $ | 3,817,294 | $ | 16,428 | 1.71 | % | $ | 3,577,905 | $ | 18,442 | 2.04 | % | ||||||||||||||
Savings deposits | 12,786,719 | 12,808 | 0.40 | % | 12,537,467 | 13,510 | 0.43 | % | 11,069,429 | 35,961 | 1.31 | % | 11,111,326 | 40,603 | 1.45 | % | 10,331,078 | 45,586 | 1.75 | % | ||||||||||||||||||||||||
Time deposits | 2,844,083 | 8,370 | 1.17 | % | 3,434,388 | 12,786 | 1.50 | % | 2,842,535 | 12,631 | 1.79 | % | 2,453,655 | 13,956 | 2.26 | % | 2,706,434 | 16,939 | 2.48 | % | ||||||||||||||||||||||||
Total interest bearing deposits | 19,906,376 | 27,830 | 0.56 | % | 19,895,821 | 32,294 | 0.65 | % | 17,685,031 | 62,174 | 1.41 | % | 17,382,275 | 70,987 | 1.62 | % | 16,615,417 | 80,967 | 1.93 | % | ||||||||||||||||||||||||
Other borrowings | 2,811,435 | 3,493 | 0.49 | % | 3,612,263 | 4,745 | 0.53 | % | 3,020,255 | 10,251 | 1.37 | % | 2,822,465 | 13,031 | 1.83 | % | 2,896,477 | 16,538 | 2.27 | % | ||||||||||||||||||||||||
Subordinated notes | 282,343 | 4,191 | 5.91 | % | 282,252 | 4,191 | 5.97 | % | 282,165 | 4,191 | 5.97 | % | 282,074 | 4,191 | 5.89 | % | 281,979 | 4,191 | 5.90 | % | ||||||||||||||||||||||||
Trust preferred subordinated debentures | 113,406 | 648 | 2.28 | % | 113,406 | 852 | 3.02 | % | 113,406 | 1,073 | 3.80 | % | 113,406 | 1,163 | 4.07 | % | 113,406 | 1,237 | 4.33 | % | ||||||||||||||||||||||||
Total interest bearing liabilities | 23,113,560 | 36,162 | 0.62 | % | 23,903,742 | 42,082 | 0.71 | % | 21,100,857 | 77,689 | 1.48 | % | 20,600,220 | 89,372 | 1.72 | % | 19,907,279 | 102,933 | 2.05 | % | ||||||||||||||||||||||||
Demand deposits | 12,202,065 | 10,865,896 | 10,003,495 | 10,933,887 | 9,992,406 | |||||||||||||||||||||||||||||||||||||||
Other liabilities | 314,500 | 293,698 | 270,868 | 278,964 | 264,506 | |||||||||||||||||||||||||||||||||||||||
Stockholders’ equity | 2,791,451 | 2,849,200 | 2,853,353 | 2,806,240 | 2,722,421 | |||||||||||||||||||||||||||||||||||||||
Total liabilities and stockholders’ equity | $ | 38,421,576 | $ | 37,912,536 | $ | 34,228,573 | $ | 34,619,311 | $ | 32,886,612 | ||||||||||||||||||||||||||||||||||
Net interest income(2) | $ | 208,421 | $ | 210,856 | $ | 229,787 | $ | 249,961 | $ | 253,768 | ||||||||||||||||||||||||||||||||||
Net interest margin | 2.22 | % | 2.30 | % | 2.78 | % | 2.95 | % | 3.16 | % | ||||||||||||||||||||||||||||||||||
(1) | The loan averages include loans on which the accrual of interest has been discontinued and are stated net of unearned income. |
(2) | Taxable equivalent rates used where applicable. |
10