tfc-20201015
0000092230FALSE00000922302020-10-152020-10-150000092230us-gaap:CommonStockMember2020-10-152020-10-150000092230us-gaap:SeriesFPreferredStockMember2020-10-152020-10-150000092230us-gaap:SeriesGPreferredStockMember2020-10-152020-10-150000092230us-gaap:SeriesHPreferredStockMember2020-10-152020-10-150000092230tfc:SeriesIPreferredStockMember2020-10-152020-10-150000092230tfc:SeriesJPreferredStockMember2020-10-152020-10-150000092230tfc:SeriesOPreferredStockMember2020-10-152020-10-150000092230tfc:SeriesRPreferredStockMember2020-10-152020-10-15
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
_____________________________________________
Form 8-K
Current Report
_____________________________________________
Pursuant to Section 13 or 15(d)
of the Securities Exchange Act of 1934
October 15, 2020
Date of Report (Date of earliest event reported)
Truist Financial Corporation
(Exact name of registrant as specified in its charter)
_____________________________________________
North Carolina1-1085356-0939887
(State or other jurisdiction of incorporation)
(Commission File Number)
(I.R.S. Employer Identification No.)
  
214 North Tryon Street
Charlotte,
North Carolina
28202
(Address of principal executive offices)
(Zip Code)
(336) 733-2000
(Registrant's telephone number, including area code)
_____________________________________________
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
☐ Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425)
☐ Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12)
☐ Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))
☐ Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))
Securities registered pursuant to Section 12(b) of the Act:
Title of each classTrading SymbolName of each exchange on which registered
Common Stock, $5 par valueTFCNew York Stock Exchange
Depositary Shares each representing 1/1,000th interest in a share of Series F Non-Cumulative Perpetual Preferred StockTFC.PFNew York Stock Exchange
Depositary Shares each representing 1/1,000th interest in a share of Series G Non-Cumulative Perpetual Preferred StockTFC.PGNew York Stock Exchange
Depositary Shares each representing 1/1,000th interest in a share of Series H Non-Cumulative Perpetual Preferred StockTFC.PHNew York Stock Exchange
Depositary Shares each representing 1/4,000th interest in a share of Series I Perpetual Preferred StockTFC.PINew York Stock Exchange
5.853% Fixed-to-Floating Rate Normal Preferred Purchase Securities each representing 1/100th interest in a share of Series J Perpetual Preferred StockTFC.PJNew York Stock Exchange
Depositary Shares each representing 1/1,000th interest in a share of Series O Non-Cumulative Perpetual Preferred StockTFC.PONew York Stock Exchange
Depositary Shares each representing 1/1,000th interest in a share of Series R Non-Cumulative Perpetual Preferred StockTFC.PRNew York Stock Exchange

Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐

If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨


ITEM 2.02    Results of Operations and Financial Condition.

On October 15, 2020, Truist Financial Corporation ("Truist") issued a press release reporting third quarter 2020 results and posted on its website its third quarter 2020 Earnings Release, Quarterly Performance Summary and Earnings Release Presentation. The materials contain forward-looking statements regarding Truist and include cautionary language identifying important factors that could cause actual results to differ materially from those anticipated. The Earnings Release, Quarterly Performance Summary and Earnings Release Presentation are furnished as Exhibits 99.1, 99.2 and 99.3, respectively. Consequently, they are not deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934 or otherwise subject to the liabilities of that section. Such materials may only be incorporated by reference into another filing under the Exchange Act or Securities Act of 1933 if such subsequent filing specifically references this Form 8-K. All information in the Earnings Release, Quarterly Performance Summary and Earnings Release Presentation speaks as of the date thereof, and Truist does not assume any obligation to update such information in the future.

ITEM 9.01    Financial Statements and Exhibits.
(d)    Exhibits
Exhibit No.Description of Exhibit
Earnings Release issued October 15, 2020.
Quarterly Performance Summary issued October 15, 2020.
Earnings Release Presentation issued October 15, 2020.
104The cover page from this Current Report on Form 8-K, formatted in Inline XBRL.


SIGNATURE
 
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
 
TRUIST FINANCIAL CORPORATION
(Registrant)
By:/s/ Cynthia B. Powell
Cynthia B. Powell
Executive Vice President and Corporate Controller
(Principal Accounting Officer)
 
Date: October 15, 2020


logo-boxed11.jpg
News Release
Contact:
Investors:Ryan Richards
980.465.5000 | [email protected]
Aaron Reeves
336.733.2874 | [email protected]
Media:Shelley Miller
704.692.1518 | [email protected]

Truist Reports Third Quarter 2020 Results
Earnings of $1.1 billion, or $0.79 per diluted share

CHARLOTTE, N.C., (October 15, 2020) — Truist Financial Corporation (NYSE: TFC) today reported earnings for the third quarter of 2020.

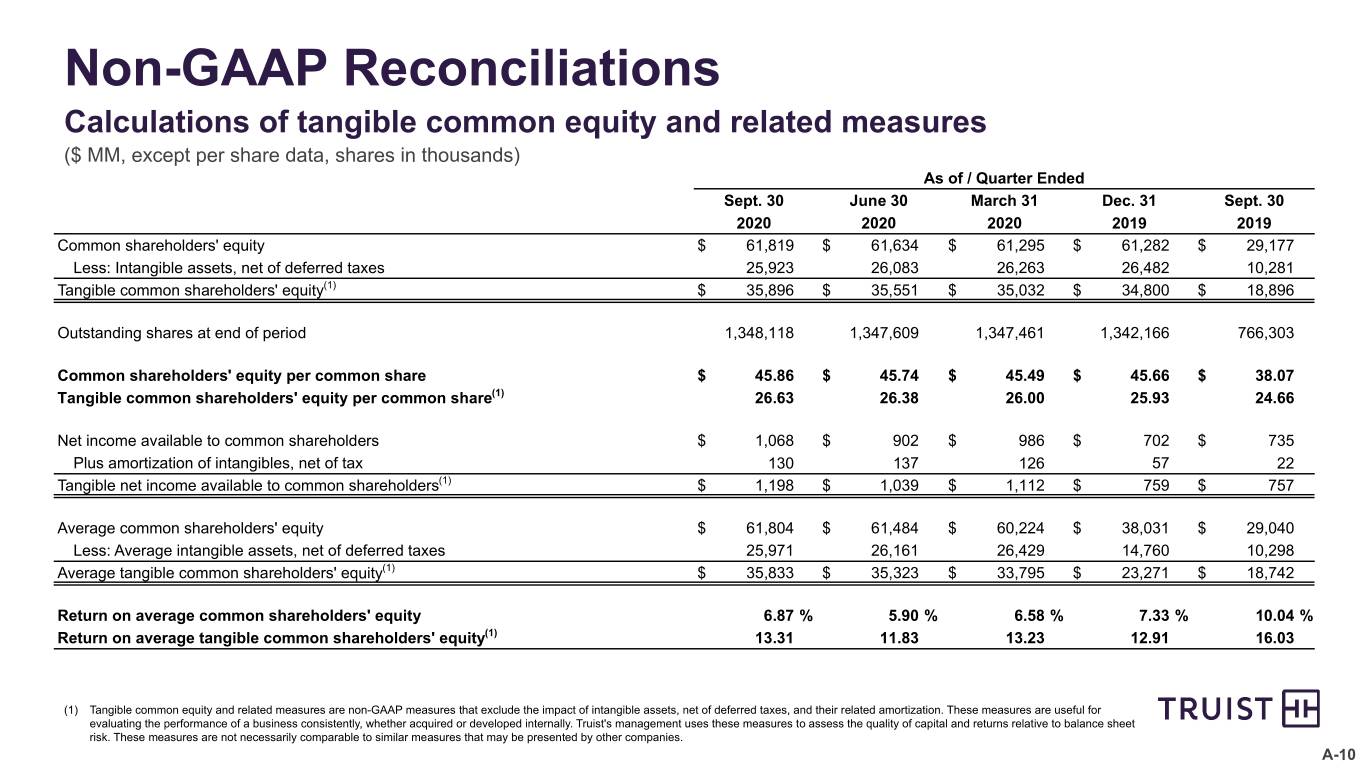
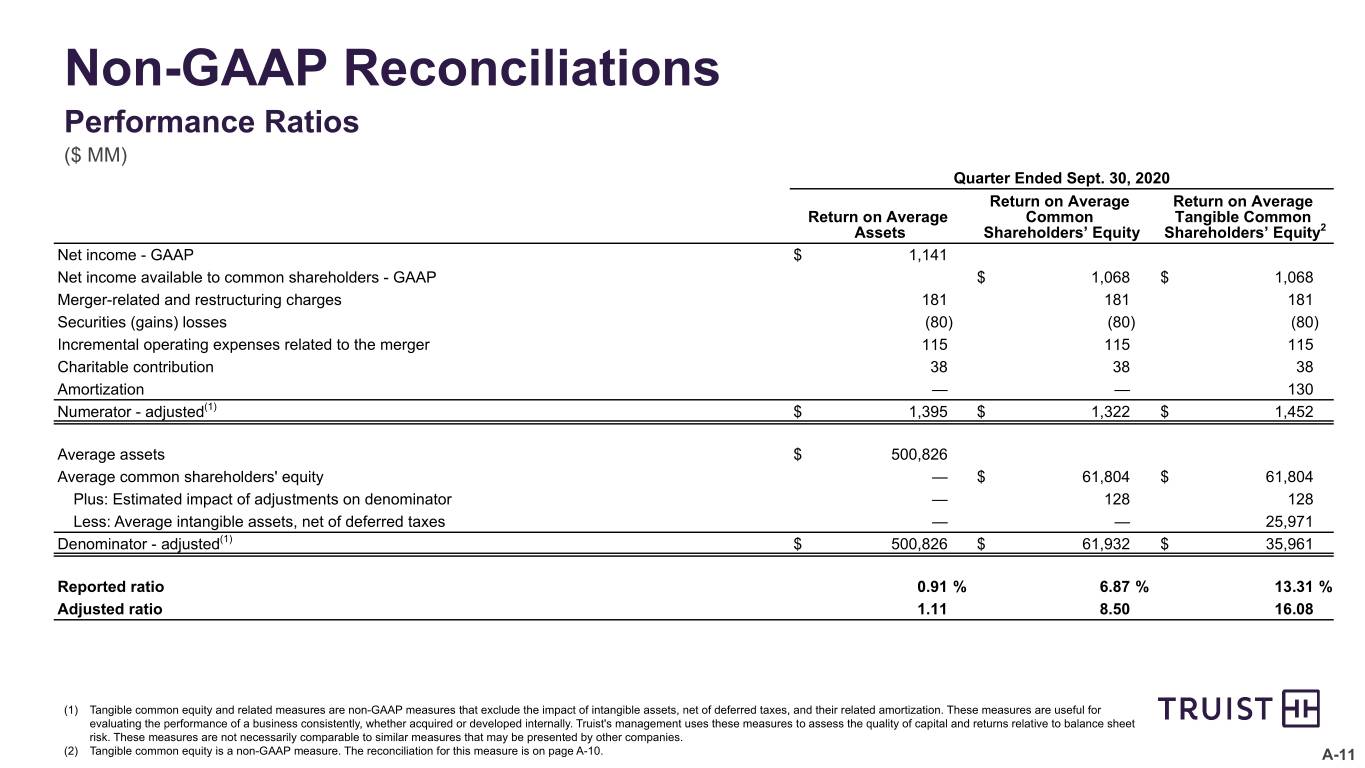
Net income available to common shareholders was $1.1 billion, up 45.3 percent, compared to the third quarter last year. Earnings per diluted common share were $0.79, a decrease of 16.8 percent compared with the same period last year. Results for the third quarter produced an annualized return on average assets (ROA) of 0.91 percent, an annualized return on average common shareholders' equity (ROCE) of 6.87 percent, and an annualized return on tangible common shareholders' equity (ROTCE) of 13.31 percent.

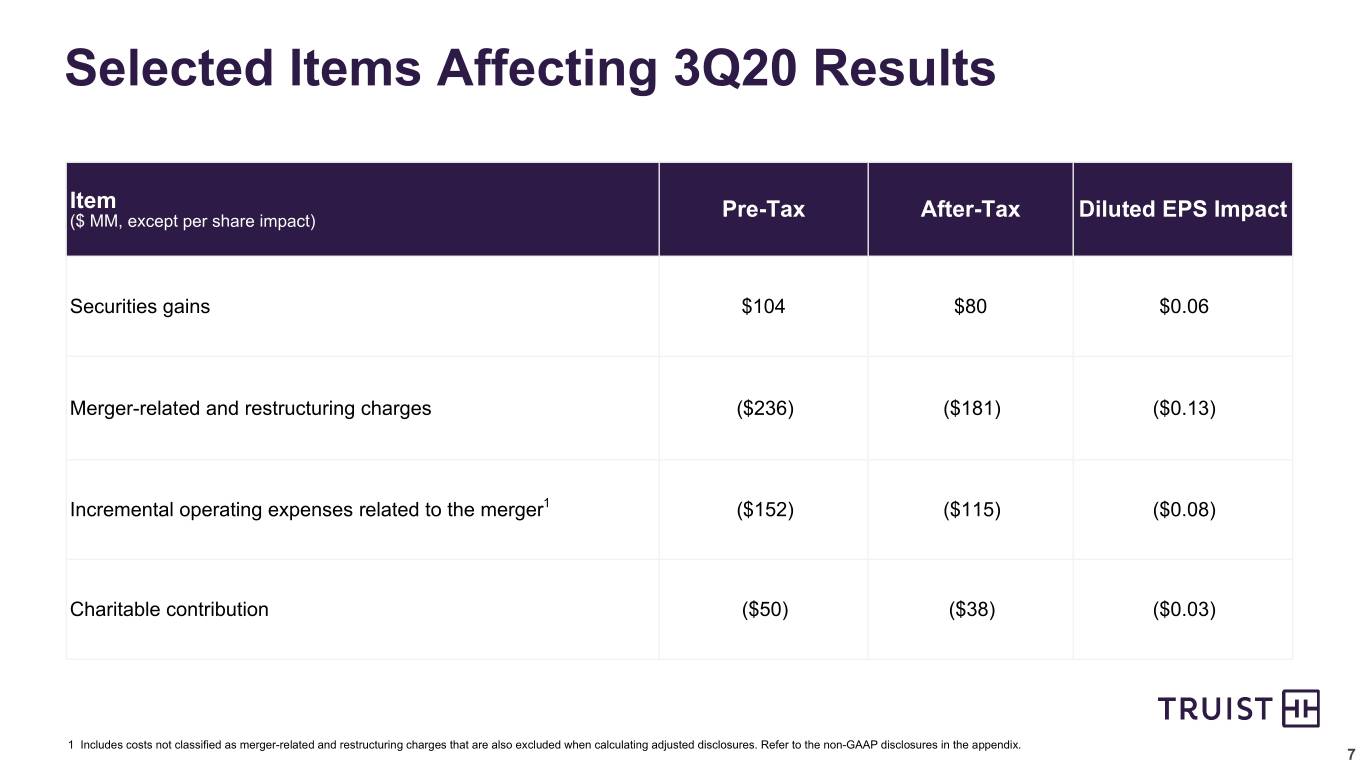
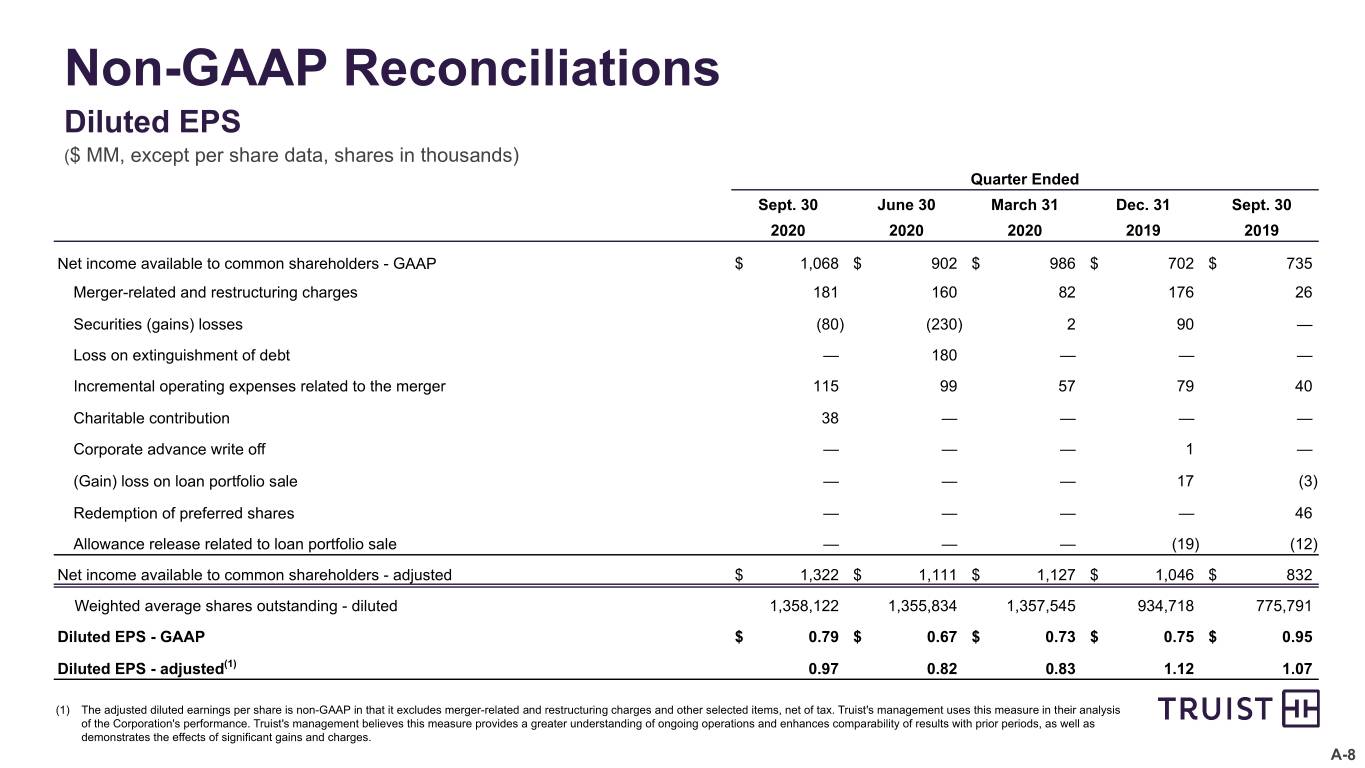
Adjusted net income available to common shareholders was $1.3 billion, or $0.97 per diluted share, excluding merger-related and restructuring charges of $236 million ($181 million after-tax), incremental operating expenses related to the merger of $152 million ($115 million after-tax), securities gains of $104 million ($80 million after-tax) and a charitable contribution of $50 million ($38 million after-tax). Adjusted diluted earnings per common share increased $0.15 compared to the second quarter of 2020. Adjusted results produced an annualized ROA of 1.11 percent, an annualized ROCE of 8.50 percent and an annualized ROTCE of 16.08 percent.

"We are pleased to report strong performance for the quarter, particularly given the challenging environment," said Chairman and Chief Executive Officer Kelly S. King. "Our earnings reflect a modest build in our allowance for loan and lease losses, benefiting from our relatively stable asset quality. We also benefited from our diverse noninterest-income generating businesses and disciplined core expense control.

"Adjusted net income was $1.3 billion, or $0.97 per share, due to strong performances from wealth management, investment banking, retail banking and insurance. We experienced growth in service charges on deposit accounts and card and payment related fees due to some waiver abatement and increased activity from clients. In addition, we are selectively investing in our insurance, investment banking, residential mortgage and wealth teams to drive more client business.

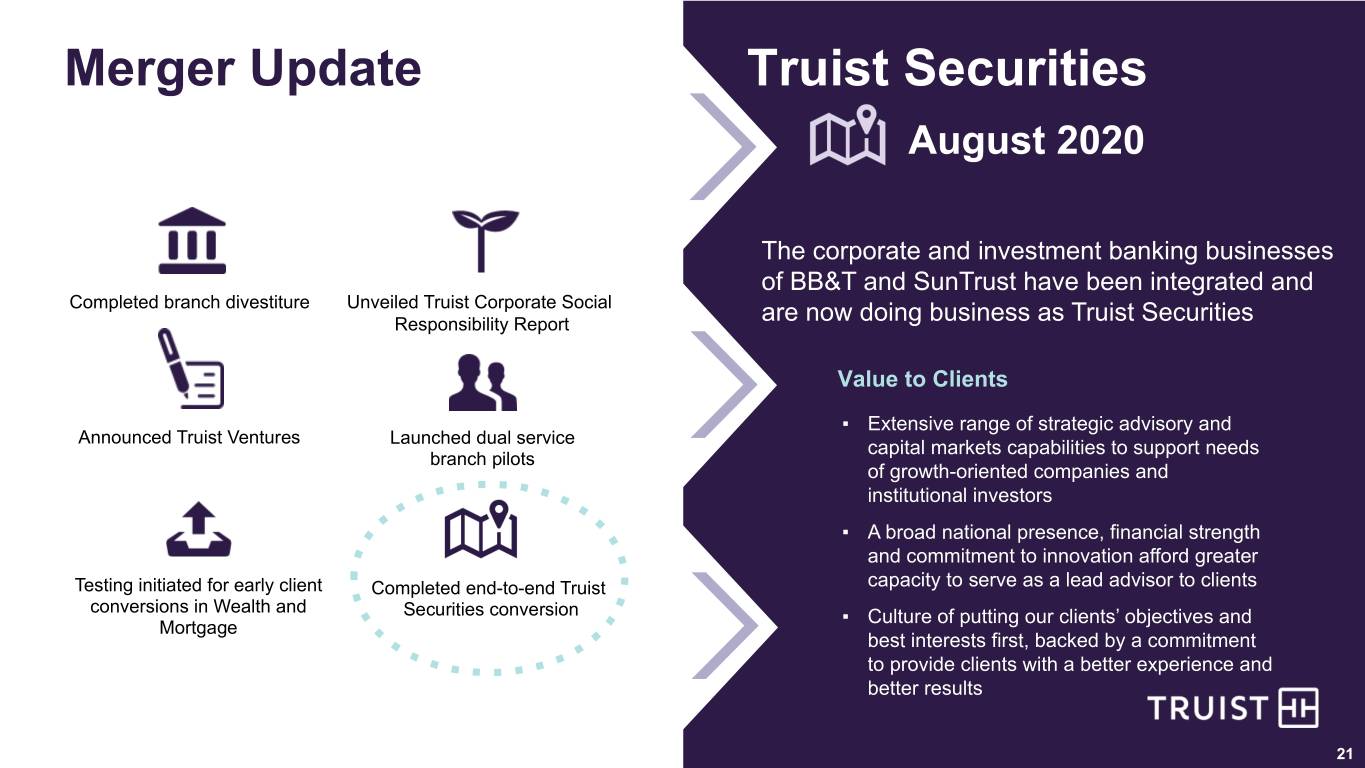
"We also made progress in terms of our systems integration as we work to build out all the capabilities of Truist. In August, we completed the conversion of Truist Securities, integrating the corporate and investment banking businesses of BB&T and SunTrust. We were pleased with this very successful major client-facing systems conversion.

- 1 -


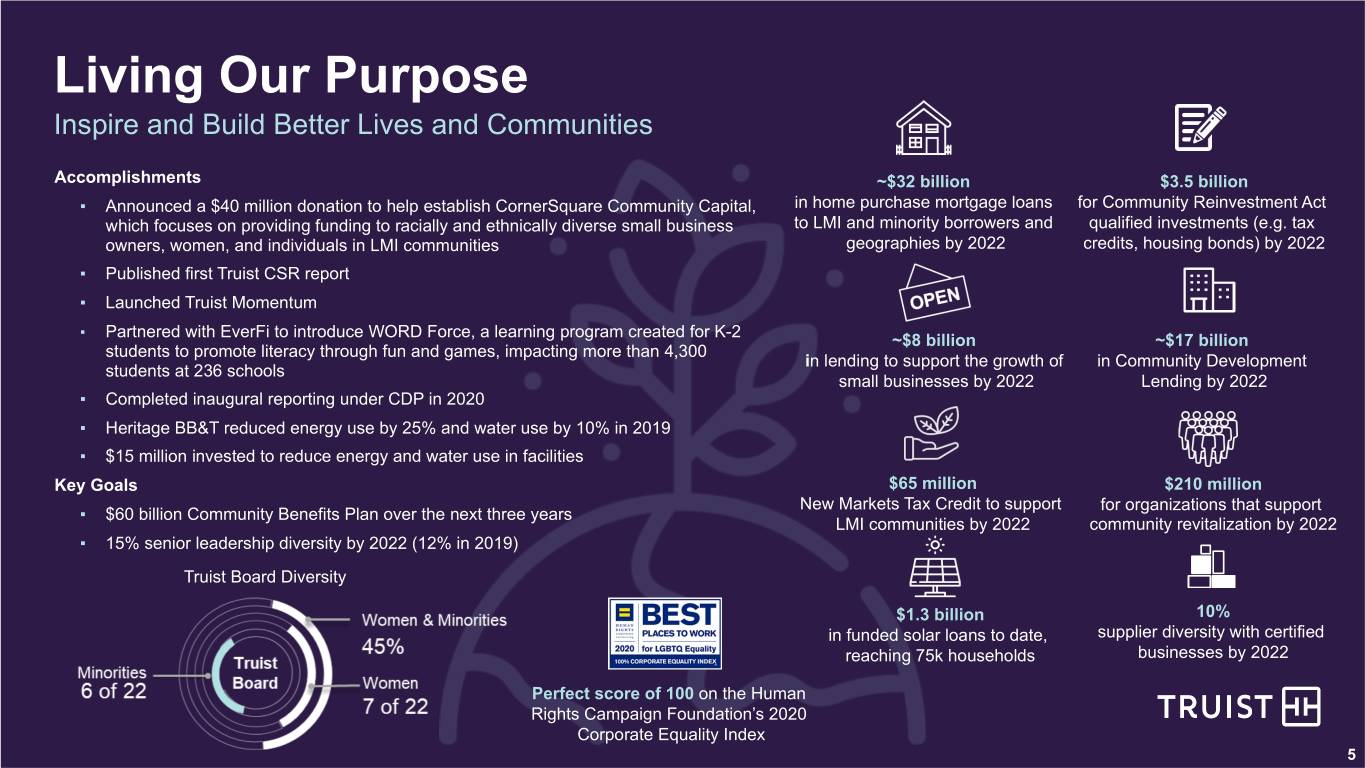
“We continue to actively support our communities during this time of need and were excited that our various foundations provided a donation of $40 million1 to help establish CornerSquare Community Capital, formed to support community development financial institutions focused on providing funding to racially and ethnically diverse small business owners, women and individuals in low- and moderate-income communities, with a particular focus on African American-owned small businesses. We also contributed $50 million to the Truist Charitable Fund to support future community giving.

"I continue to be very proud of and inspired by our teammates, who continue to live the Truist purpose and make a positive difference in the lives of their clients and in their communities."

Third Quarter 2020 Performance Highlights

•Earnings per diluted common share were $0.79
–Adjusted diluted earnings per share were $0.97
–ROA was 0.91 percent; adjusted ROA was 1.11 percent
–ROCE was 6.87 percent; adjusted ROCE was 8.50 percent
–ROTCE was 13.31 percent; adjusted ROTCE was 16.08 percent

•Taxable-equivalent revenue was $5.6 billion; includes $104 million of securities gains
–Fee income ratio was 39.7 percent, compared to 41.3 percent for second quarter 2020; excluding securities gains, fee income ratio was 38.5 percent for the current quarter
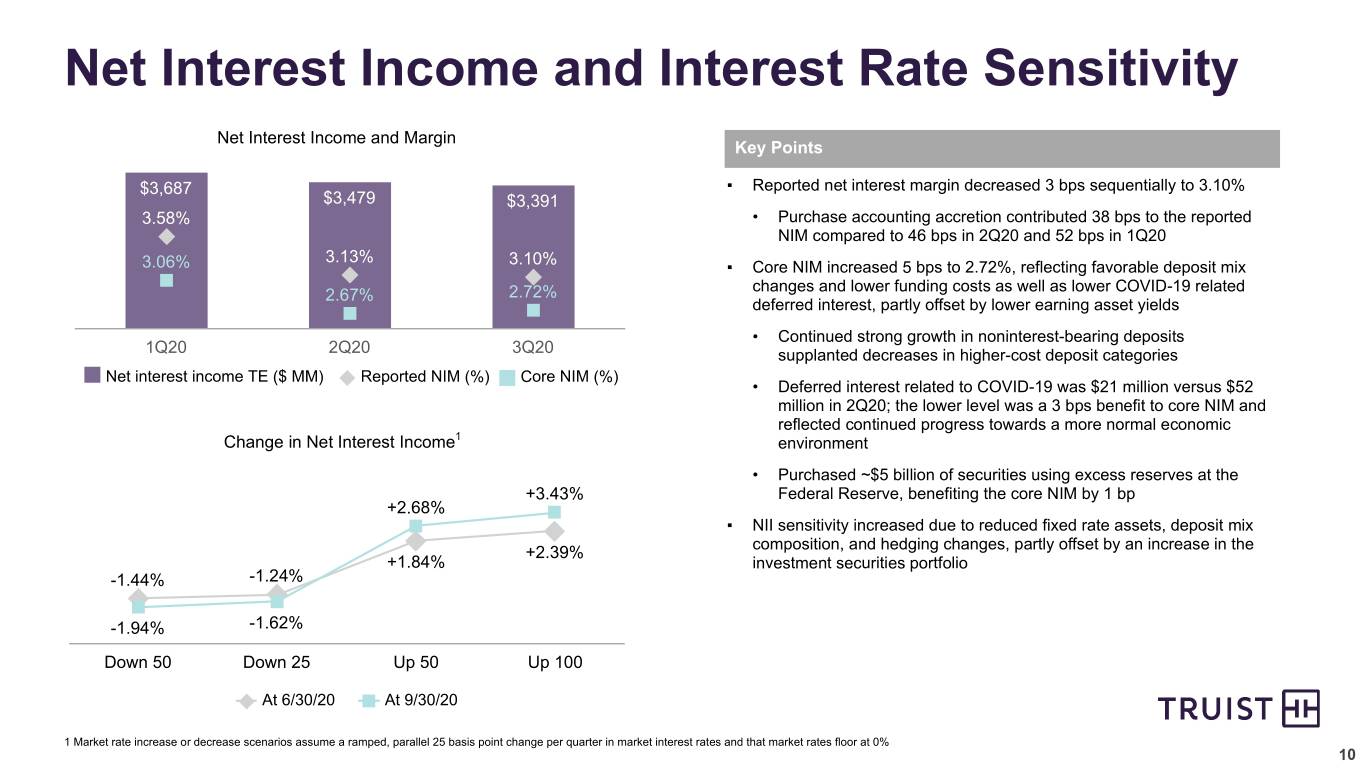
–Net interest margin was 3.10 percent, down three basis points from second quarter 2020
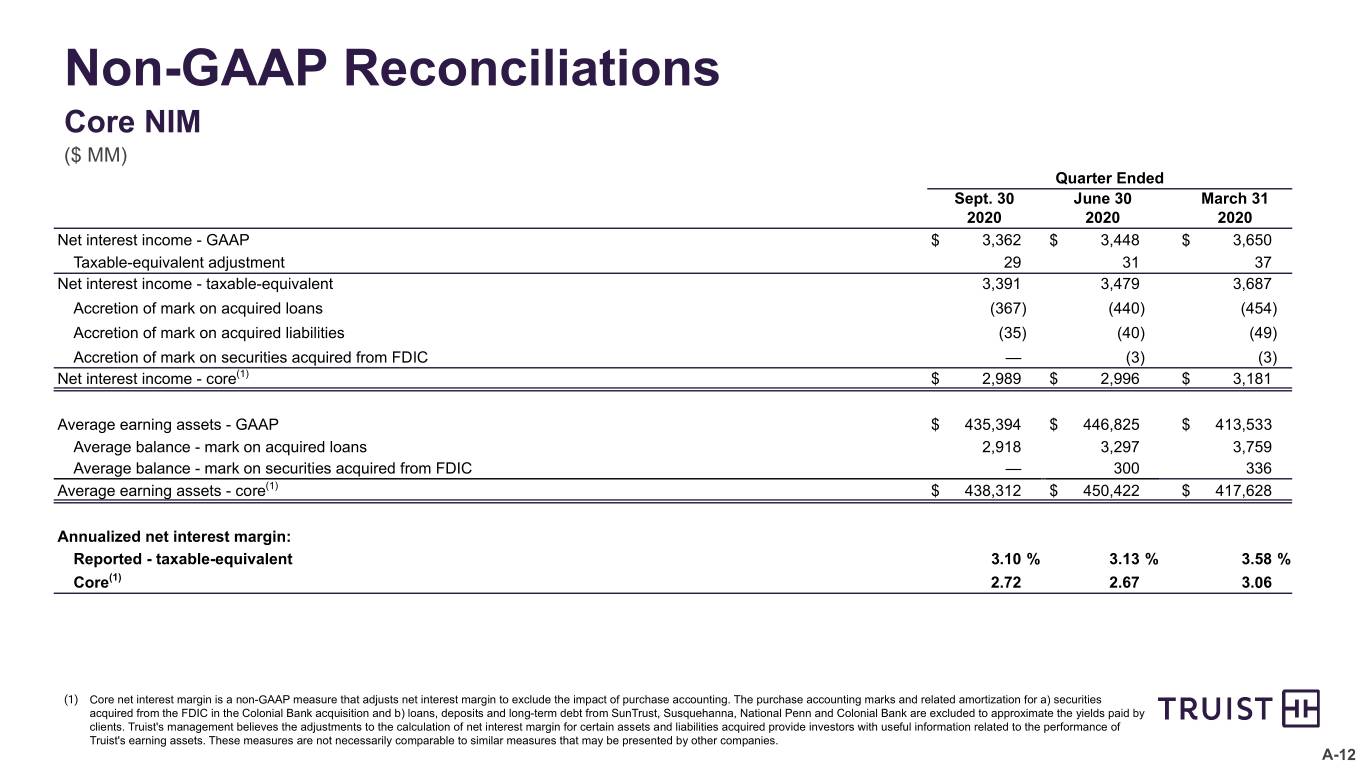
–Core net interest margin was 2.72 percent, up 5 basis points from second quarter 2020

•Noninterest expense was $3.8 billion
–Noninterest expense includes $236 million of merger-related and restructuring charges, $152 million of incremental operating expenses related to the merger, and $50 million for a charitable contribution
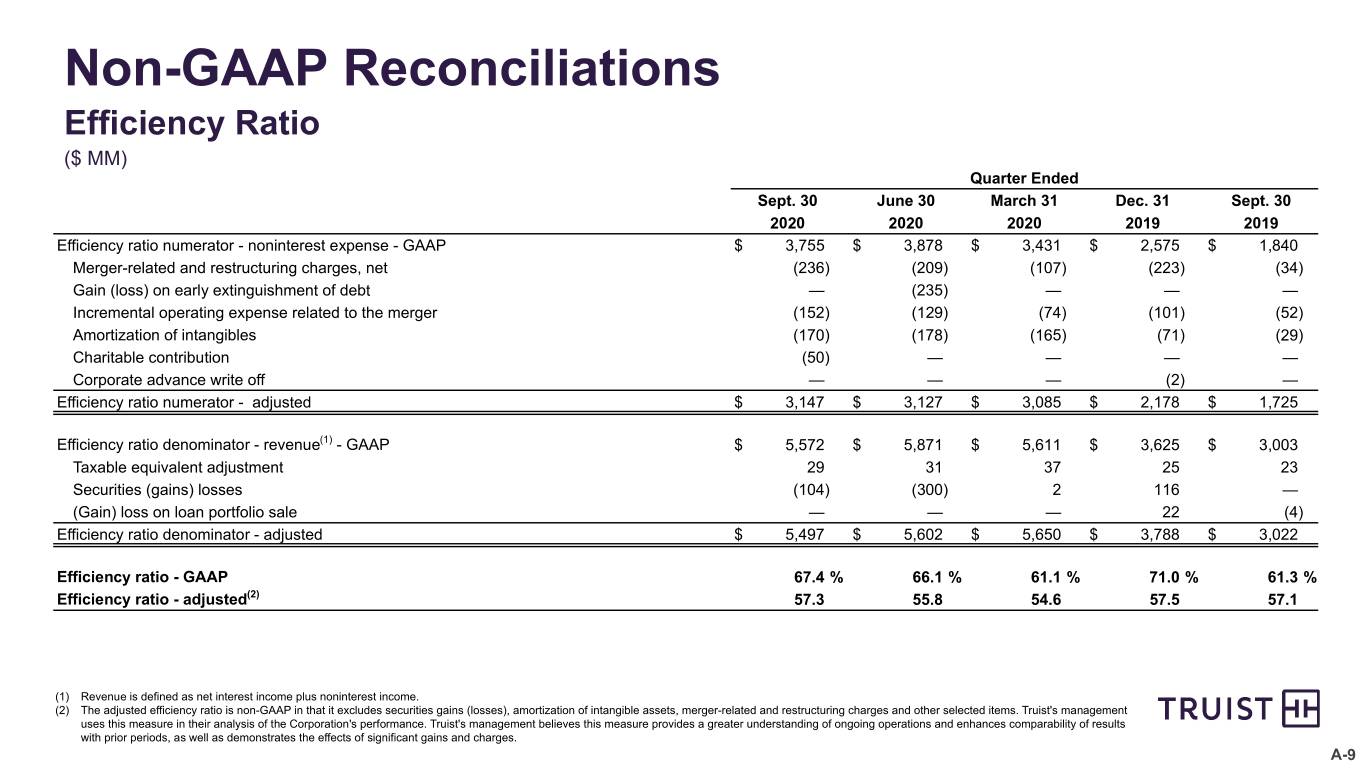
–GAAP efficiency ratio was 67.4 percent, compared to 66.1 percent for second quarter 2020
–Adjusted efficiency ratio was 57.3 percent, compared to 55.8 percent for second quarter 2020

•Asset quality ratios remain relatively stable
–Nonperforming assets were 0.26 percent of total assets, up 1 basis point from the prior quarter
–Loans 90 days or more past due and still accruing were 0.39 percent of loans held for investment, up from 0.34 percent for the prior quarter
–Excluding government guaranteed loans, loans 90 days or more past due and still accruing were 0.03 percent of loans held for investment
–Net charge-offs were 0.42 percent of average loans and leases, up three basis points compared to the prior quarter
–The allowance for loan and lease losses was 1.91 percent of loans and leases held for investment compared to 1.81 percent for second quarter 2020
–Provision for credit losses was $421 million for the third quarter of 2020, which includes a modest build in the allowance for credit losses
–The allowance for loan and lease loss coverage ratio was 5.22 times nonperforming loans and leases held for investment, versus 5.24 times in the prior quarter
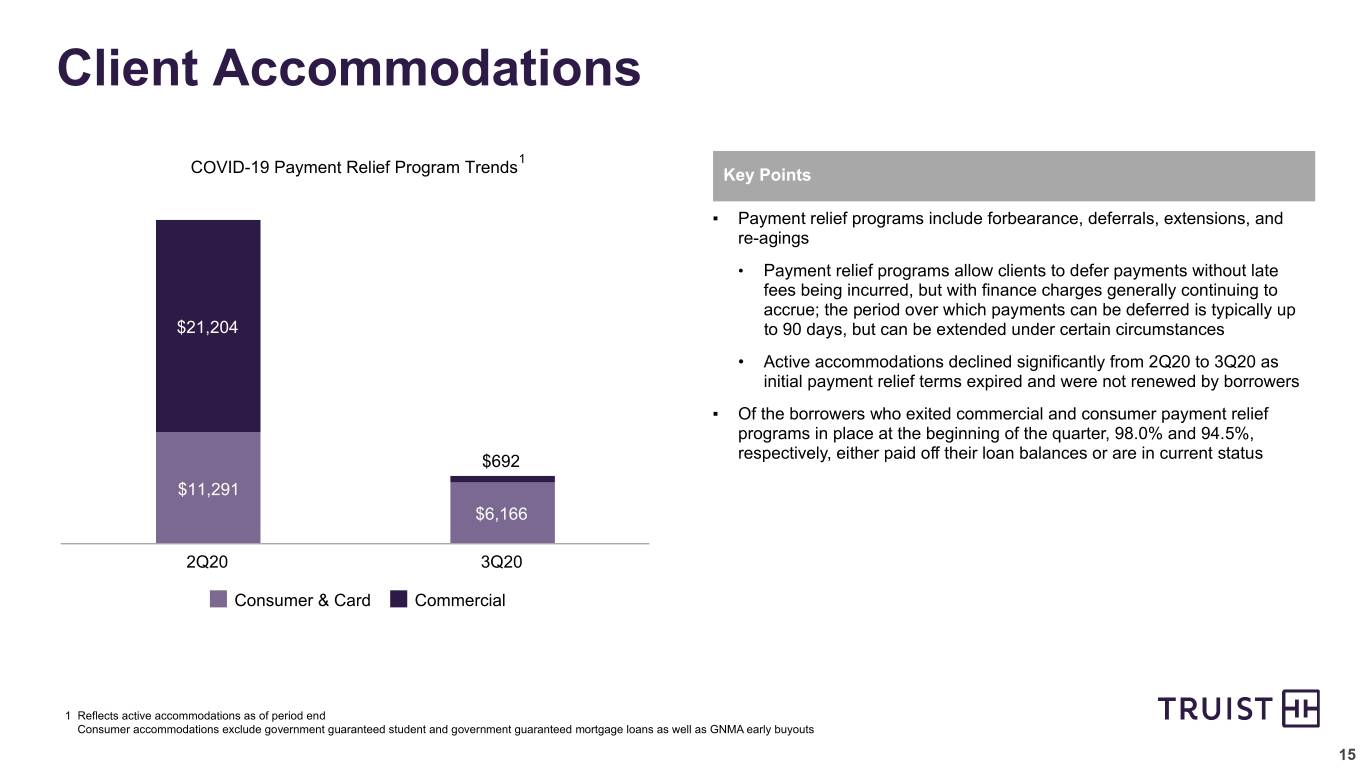
–Active client accommodations related to the CARES Act declined significantly; 98.0 percent and 94.5 percent of commercial and consumer clients, respectively, that have exited accommodation programs are current on their loans
1 The $40 million contribution to CornerSquare Community Capital consisted of two $20 million contributions made through the Truist Foundation, Inc. and the Truist Charitable Fund. These amounts did not impact Truist Financial Corporation's earnings.
- 2 -


•Capital and liquidity levels improved
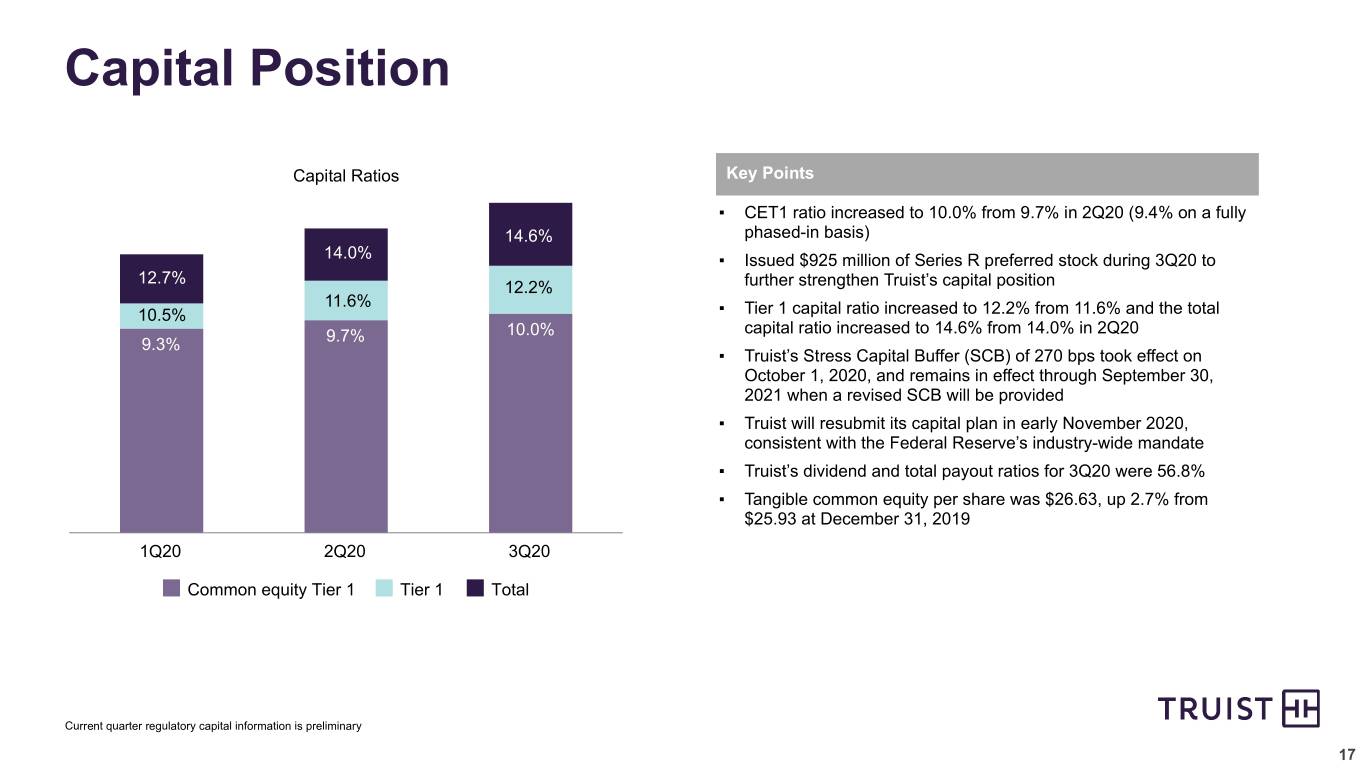
–Common equity tier 1 to risk-weighted assets was 10.0 percent
–Tier 1 risk-based capital was 12.2 percent
–Total risk-based capital was 14.6 percent
–$925 million of preferred stock was issued to further strengthen capital
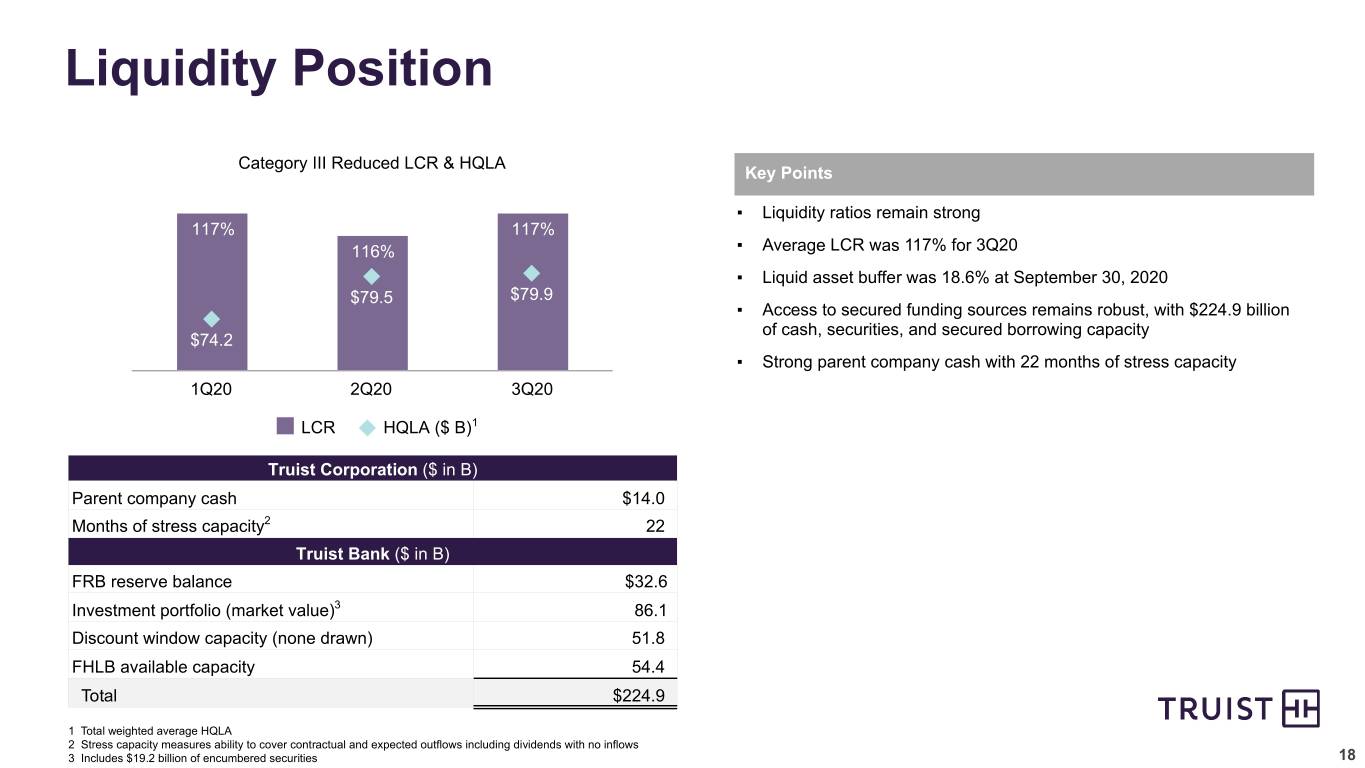
–Consolidated average LCR ratio was 117 percent

EARNINGS HIGHLIGHTSChange 3Q20 vs.
(dollars in millions, except per share data)3Q202Q203Q192Q203Q19
Net income available to common shareholders$1,068 $902 $735 $166 $333 
Diluted earnings per common share0.79 0.67 0.95 0.12 (0.16)
Net interest income - taxable equivalent$3,391 $3,479 $1,723 $(88)$1,668 
Noninterest income2,210 2,423 1,303 (213)907 
Total taxable-equivalent revenue$5,601 $5,902 $3,026 $(301)$2,575 
Less taxable-equivalent adjustment29 31 23 
Total revenue$5,572 $5,871 $3,003 
Return on average assets0.91 %0.75 %1.41 %0.16 %(0.50)%
Return on average risk-weighted assets (current quarter is preliminary)1.19 1.00 1.75 0.19 (0.56)
Return on average common shareholders' equity6.87 5.90 10.04 0.97 (3.17)
Return on average tangible common shareholders' equity (1)
13.31 11.83 16.03 1.48 (2.72)
Net interest margin - taxable equivalent3.10 3.13 3.37 (0.03)(0.27)
(1)    Excludes certain items as detailed in the non-GAAP reconciliations in the Quarterly Performance Summary.

Third Quarter 2020 compared to Second Quarter 2020

Total taxable-equivalent revenue was $5.6 billion for the third quarter of 2020, a decrease of $301 million compared to the prior quarter. This includes a decrease of $213 million in noninterest income and a decrease of $88 million in net interest income.

The net interest margin was 3.10 percent for the third quarter, down three basis points compared to the prior quarter. The decline in the net interest margin reflects lower purchase accounting accretion, lower yields on loans due to LIBOR changes and lower yield on securities due to the impact of new investments at lower rates. These decreases were partially offset by lower interest expense on deposits and borrowings primarily due to the impact of lower rates on deposits and a lower level of deferred interest on loans granted an accommodation in connection with COVID-19. Average earning assets decreased $11.4 billion, which primarily reflects a $10.7 billion decrease in average total loans and leases primarily due to paydowns on commercial and industrial revolvers. Average securities available for sale increased $4.7 billion, while average other earning assets decreased $5.7 billion as a portion of interest-earning balances were invested in higher-yield agency mortgage-backed securities. Average interest-bearing liabilities decreased $26.1 billion compared to the second quarter of 2020. Average interest-bearing deposits decreased $8.7 billion, average short-term borrowings decreased $2.8 billion and average long-term debt decreased $14.6 billion. The decline in average interest-bearing deposits was primarily in higher-cost time deposits that matured, as well as lower interest checking and money market and savings balances. The decline in long-term debt was due to the early extinguishment of certain FHLB advances in the prior quarter. These decreases were partially offset by the $10.1 billion growth in average noninterest-bearing deposits compared to the second quarter of 2020.

- 3 -


The yield on the total loan portfolio for the third quarter was 4.04 percent, down 15 basis points compared to the prior quarter primarily due to lower accretion of the fair value mark on the merged loans and the impact of lower benchmark interest rates. The yield on the average securities portfolio for the third quarter was 1.97 percent, down 40 basis points compared to the prior quarter primarily due to lower yields on new purchases and premium amortization due to higher prepayments.

The average cost of total deposits was 0.10 percent, down 12 basis points compared to the prior quarter, and the average cost of interest-bearing deposits was 0.15 percent, down 17 basis points compared to the prior quarter. The average rate on long-term debt was 1.48 percent, down four basis points compared to the prior quarter. The average rate on short-term borrowings was 0.85 percent, down 39 basis points compared to the prior quarter. The decrease in rates on deposits was attributable to deposit rate cuts and maturities of higher cost time-deposits. The decrease in the cost of short-term borrowings was a result of the maturities of higher-cost funding primarily in the second quarter of 2020.

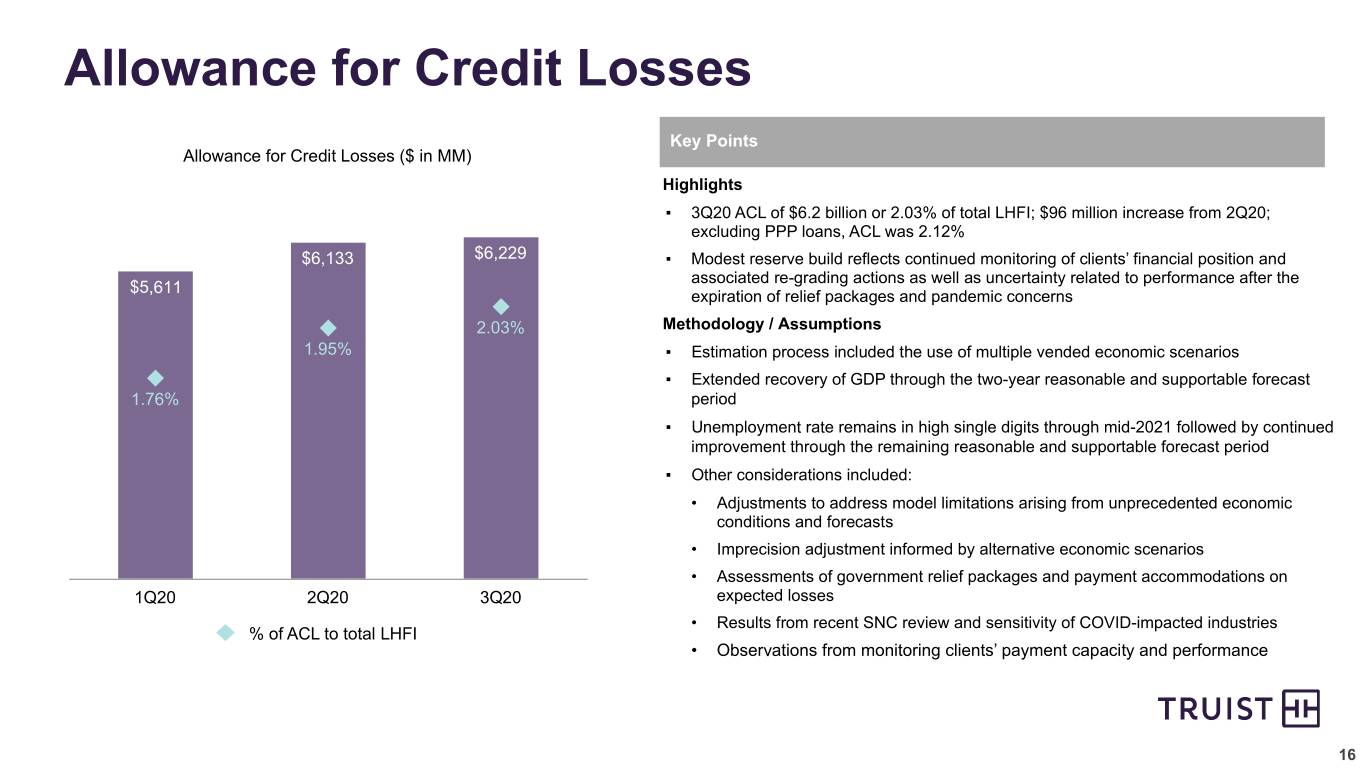
The provision for credit losses was $421 million and net charge-offs were $326 million for the third quarter, compared to $844 million and $316 million, respectively, for the prior quarter. The provision for credit losses in the third quarter reflects a modest build to the allowance for loan and lease losses primarily due to continued monitoring of clients’ financial position and associated re-grading actions as well as uncertainty related to performance after the expiration of relief packages and COVID-19.

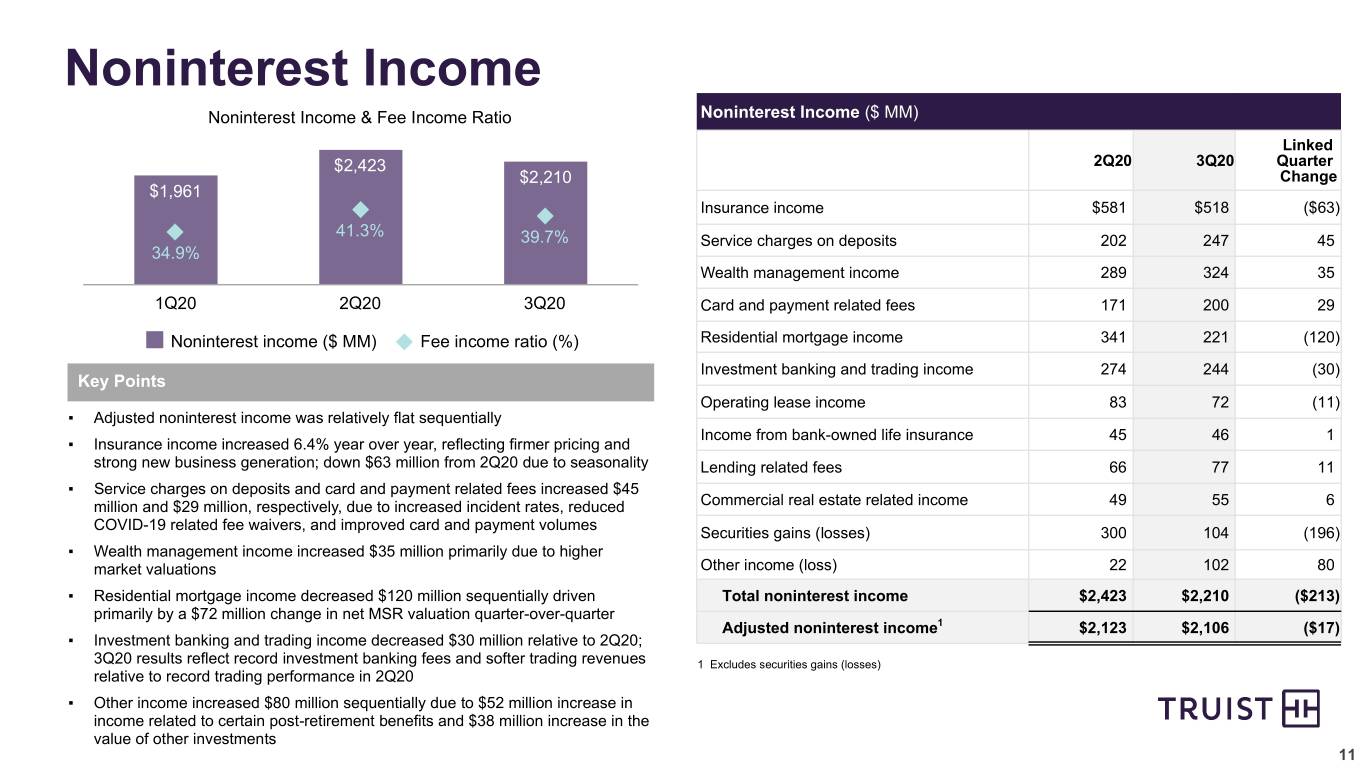
Noninterest income was $2.2 billion, a decrease of $213 million compared to the prior quarter. The current quarter includes $104 million of securities gains, whereas the prior quarter included $300 million. Excluding securities gains, noninterest income was relatively flat compared to the prior quarter. Insurance income was down $63 million primarily due to seasonality. Service charges on deposits, and card and payment related fees increased $45 million and $29 million, respectively, as volumes increased and waivers related to COVID-19 were reduced. Wealth management income increased $35 million primarily due to the market rebound that positively impacted wealth fees. Other income increased $80 million compared to the prior period primarily as a result of a $52 million increase in income from assets held for certain post-retirement benefits, which was largely offset by higher personnel expense and a $38 million increase in the value of other investments. Residential mortgage income decreased $120 million primarily due to decreases in the valuation of mortgage servicing rights. The net valuation for mortgage servicing rights was a loss of $58 million for the third quarter of 2020, compared to a gain of $14 million in the second quarter of 2020, primarily due to a third quarter change in the prepayment speed assumption resulting from the low rate environment. In addition, the realization of expected mortgage servicing rights was $36 million higher due to higher loan prepayments and the repurchase of GNMA loans. Investment banking and trading income decreased $30 million primarily due to lower trading revenues, partially offset by higher investment banking revenues.

- 4 -


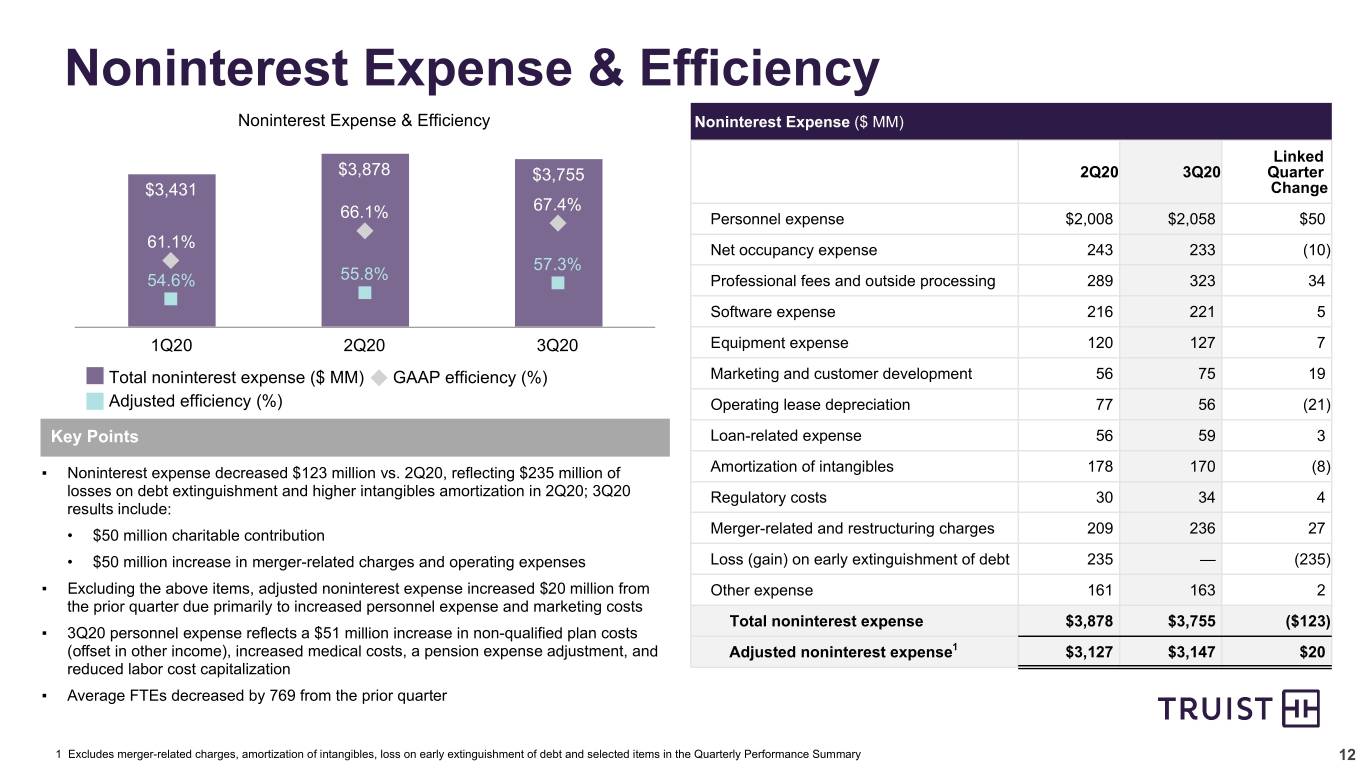
Noninterest expense was $3.8 billion for the third quarter, down $123 million compared to the prior quarter. The current quarter includes a $50 million charitable contribution to the Truist Charitable Fund. The prior quarter included $235 million of losses on the early extinguishment of long-term debt, which were part of balance sheet actions to improve net interest income, net interest margin and leverage ratios. Merger-related and restructuring charges increased $27 million primarily due to higher facilities impairments and professional services expenses, partially offset by lower severance and other personnel-related expenses. Incremental operating expenses related to the merger increased $23 million primarily due to higher professional services expenses for process and system design in connection with merger integration. Excluding the items mentioned above and changes in amortization of intangibles, adjusted noninterest expense was up $20 million primarily due to higher personnel expense. Personnel expense was higher by $50 million compared to the second quarter of 2020 primarily due to $51 million in higher costs associated with certain post-retirement benefit plans that are offset in other income. In addition, there were several items within personnel expense that were essentially offsetting in nature. Salaries and wages and related payroll taxes were lower $66 million primarily due to the elimination of on-site pay premiums, and incentive expense was lower $15 million primarily due to a higher accrual in the second quarter of 2020 related to certain incentive programs. These decreases were offset by $34 million in higher medical claims as teammates returned to more normal levels of usage, $22 million in higher defined benefit plans expense due to a change in the annual expense estimate and $30 million in reduced capitalized employee costs as the second quarter included higher deferred costs in connection with PPP loans and residential mortgage loans.

The provision for income taxes was $255 million for the third quarter, compared to $191 million for the prior quarter. The effective tax rate for the third quarter was 18.3 percent, compared to 16.6 percent for the prior quarter. The higher effective tax rate was primarily due to higher pre-tax income and a relatively stable level of permanent tax items and income tax credits.

Third Quarter 2020 compared to Third Quarter 2019

Total taxable-equivalent revenues were $5.6 billion for the third quarter of 2020, an increase of $2.6 billion compared to the earlier quarter, reflecting an increase of $1.7 billion in taxable-equivalent net interest income and an increase of $907 million in noninterest income.

Net interest margin was 3.10 percent, down 27 basis points compared to the earlier quarter. Average earning assets increased $232.0 billion. The increase in average earning assets reflects a $163.6 billion increase in average total loans and leases and a $30.9 billion increase in average securities. Average other earning assets increased $34.0 billion primarily due to higher interest-earning balances at the Federal Reserve. Average interest-bearing liabilities increased $155.0 billion compared to the earlier quarter. Average interest-bearing deposits increased $138.8 billion, average long-term debt increased $18.3 billion and average short-term borrowings decreased $2.1 billion. The significant increases in earning assets and liabilities are primarily due to the merger, as well as impacts from the COVID-19 pandemic and the resulting government stimulus programs.

The yield on the total loan portfolio for the third quarter of 2020 was 4.04 percent, down 94 basis points compared to the earlier quarter, reflecting the impact of rate decreases and deferred interest for loans granted an accommodation in connection with COVID-19, partially offset by purchase accounting accretion from merged loans. The yield on the average securities portfolio was 1.97 percent, down 63 basis points compared to the earlier quarter primarily due to lower yields on new purchases and higher premium amortization.

- 5 -


The average cost of total deposits was 0.10 percent, down 57 basis points compared to the earlier quarter, and the average cost of interest-bearing deposits was 0.15 percent, down 84 basis points compared to the earlier quarter. The average rate on short-term borrowings was 0.85 percent, down 170 basis points compared to the earlier quarter. The average rate on long-term debt was 1.48 percent, down 194 basis points compared to the earlier quarter. The lower rates on interest-bearing liabilities reflect the lower rate environment. The lower rates on long-term debt also reflect the amortization of the fair value mark on the assumed debt and the issuance of new long-term debt.

The provision for credit losses was $421 million, compared to $117 million for the earlier quarter. The increase in the provision for credit losses reflects a modest build to the allowance for credit losses primarily due to monitoring of clients’ financial position and associated re-grading actions, as well as uncertainty related to performance after the expiration of relief packages and COVID-19, the impact of the merger, and the effect of applying the CECL methodology in the current quarter compared to the incurred methodology in the earlier quarter. Net charge-offs for the third quarter of 2020 totaled $326 million compared to $153 million in the earlier quarter. Higher net charge-offs also contributed to the increase in the provision for credit losses and primarily reflect increases as a result of the merger. The net charge-off rate for the current quarter of 0.42 percent was up one basis point compared to the third quarter of 2019.

Noninterest income for the third quarter of 2020 increased $907 million compared to the earlier quarter. The current quarter includes $104 million of securities gains. Excluding the securities gains, noninterest income increased $803 million, with nearly all categories of noninterest income being impacted by the merger. In addition to the impacts from the merger, insurance income increased $31 million due to strong production and premium growth and residential mortgage banking income was up due to strong production and refinance activity driven by the declining rate environment, partially offset by lower valuations of the mortgage servicing rights. Service charges on deposits partially rebounded during the third quarter due to increased overdraft incident rates and reduced refunds and waivers to accommodate clients impacted by the COVID-19 pandemic.

Noninterest expense for the third quarter of 2020 was up $1.9 billion compared to the earlier quarter. Merger-related and restructuring charges and other incremental operating expenses related to the merger increased $202 million and $100 million, respectively. In addition, the current quarter was impacted by a $50 million charitable contribution to the Truist Charitable Fund. Excluding the items mentioned above and the impact of an increase of $141 million of amortization expense for intangibles, adjusted noninterest expense was up $1.4 billion primarily reflecting the impact of the merger. In addition to the impacts of the merger, operating costs were elevated due to COVID-19, which resulted in an additional $26 million of expenses compared to the third quarter of 2019. This was primarily related to net occupancy costs for enhanced cleaning.

The provision for income taxes was $255 million for the third quarter of 2020, compared to $218 million for the earlier quarter. This produced an effective tax rate for the third quarter of 2020 of 18.3 percent, compared to 20.8 percent for the earlier quarter. The lower effective tax rate is primarily due to higher favorable permanent tax items and income tax credits in the current year.

- 6 -


LOANS AND LEASES
(dollars in millions)
Average balances3Q202Q20Change% Change
(annualized)
Commercial:
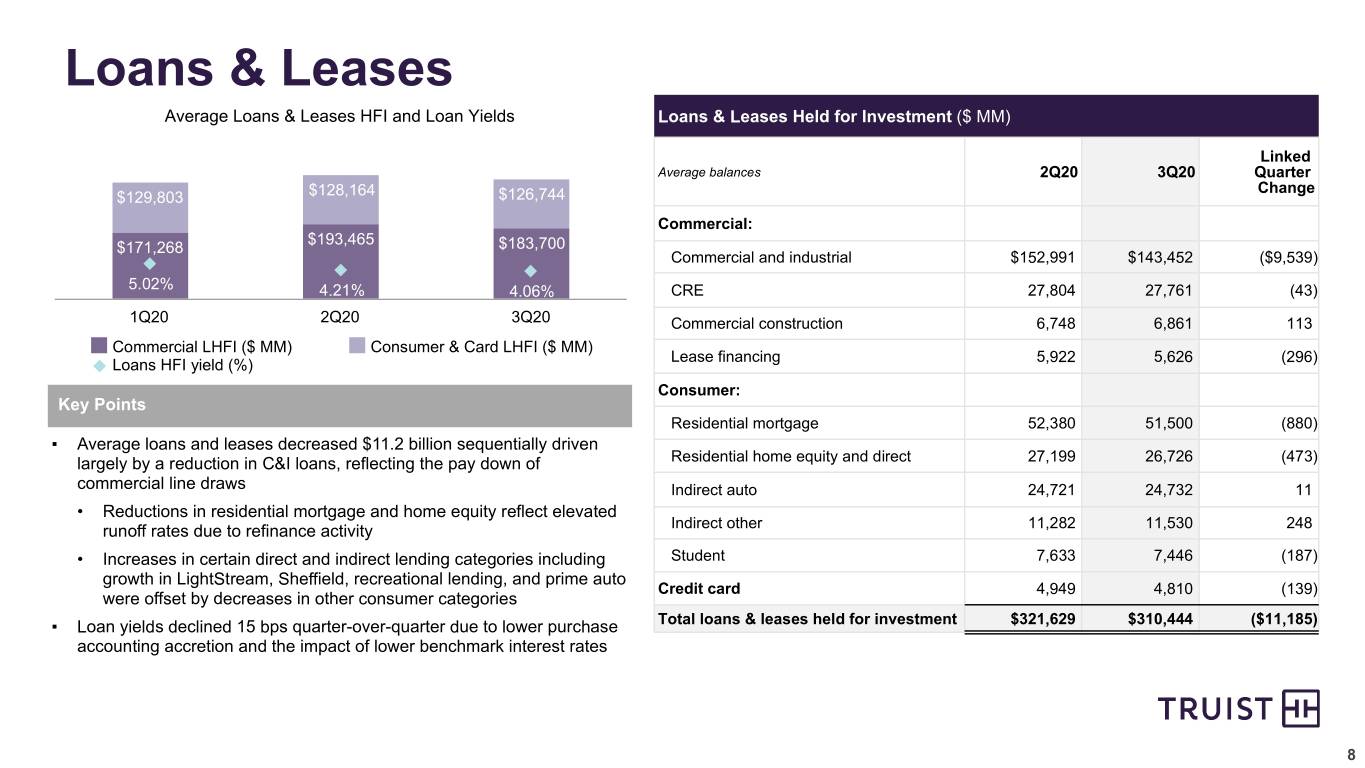
Commercial and industrial$143,452 $152,991 $(9,539)(24.8)%
CRE27,761 27,804 (43)(0.6)
Commercial construction6,861 6,748 113 6.7 
Lease financing5,626 5,922 (296)(19.9)
Total commercial183,700 193,465 (9,765)(20.1)
Consumer:
Residential mortgage51,500 52,380 (880)(6.7)
Residential home equity and direct26,726 27,199 (473)(6.9)
Indirect auto24,732 24,721 11 0.2 
Indirect other11,530 11,282 248 8.7 
Student7,446 7,633 (187)(9.7)
Total consumer121,934 123,215 (1,281)(4.1)
Credit card4,810 4,949 (139)(11.2)
Total loans and leases held for investment$310,444 $321,629 $(11,185)(13.8)

Average loans and leases held for investment for the third quarter of 2020 were $310.4 billion, down $11.2 billion compared to the second quarter of 2020 primarily due to a decline in the commercial portfolio.

The decline in the commercial portfolio was primarily in commercial and industrial loans and reflects the repayment of revolver usage. Within the commercial and industrial portfolio, Truist experienced growth in loans from mortgage warehouse lending due to the decline in rates and increased refinance activity, as well as growth in premium finance lending and equipment finance lending. Growth in these portfolios was partially offset by a decline in dealer floor plan lending.

Average consumer loans decreased $1.3 billion primarily due to refinance activity resulting in a decline in residential mortgages and residential home equity and direct loans. This was partially offset by an increase in indirect other loans due to demand for loans for recreational and power sports equipment.

DEPOSITS
(dollars in millions)
Average balances3Q202Q20Change% Change
(annualized)
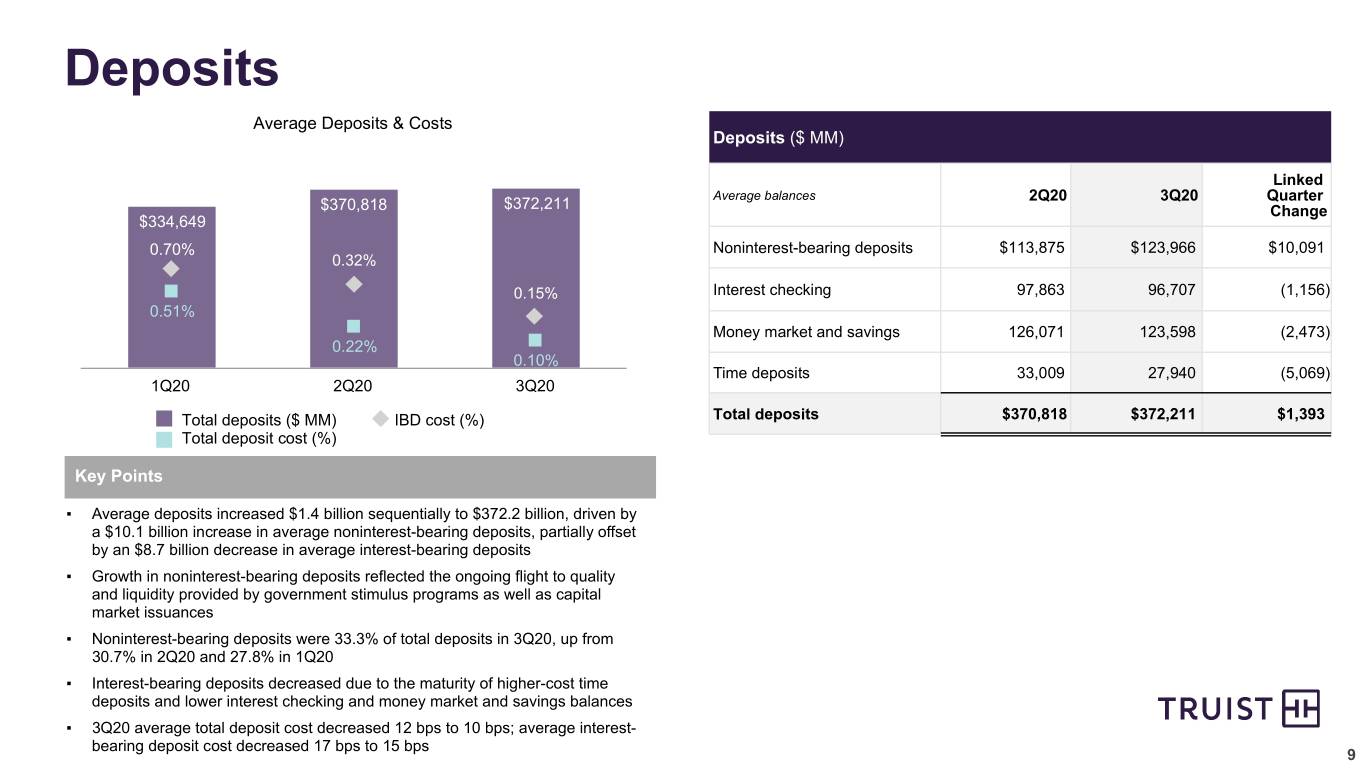
Noninterest-bearing deposits$123,966 $113,875 $10,091 35.3 %
Interest checking96,707 97,863 (1,156)(4.7)
Money market and savings123,598 126,071 (2,473)(7.8)
Time deposits27,940 33,009 (5,069)(61.1)
Total deposits$372,211 $370,818 $1,393 1.5 

Average deposits for the third quarter of 2020 were $372.2 billion, an increase of $1.4 billion compared to the prior quarter. Average noninterest-bearing deposit growth was strong for the third quarter of 2020 due to a continuation of the flight to quality and the government stimulus programs. Average time deposits decreased primarily due to maturity of wholesale negotiable certificates of deposit and higher-cost personal and business accounts.

- 7 -


Average noninterest-bearing deposits represented 33.3 percent of total deposits for the third quarter of 2020, compared to 30.7 percent for the prior quarter. The cost of average total deposits was 0.10 percent for the third quarter, down 12 basis points compared to the prior quarter. The cost of average interest-bearing deposits was 0.15 percent for the third quarter, down 17 basis points compared to the prior quarter.

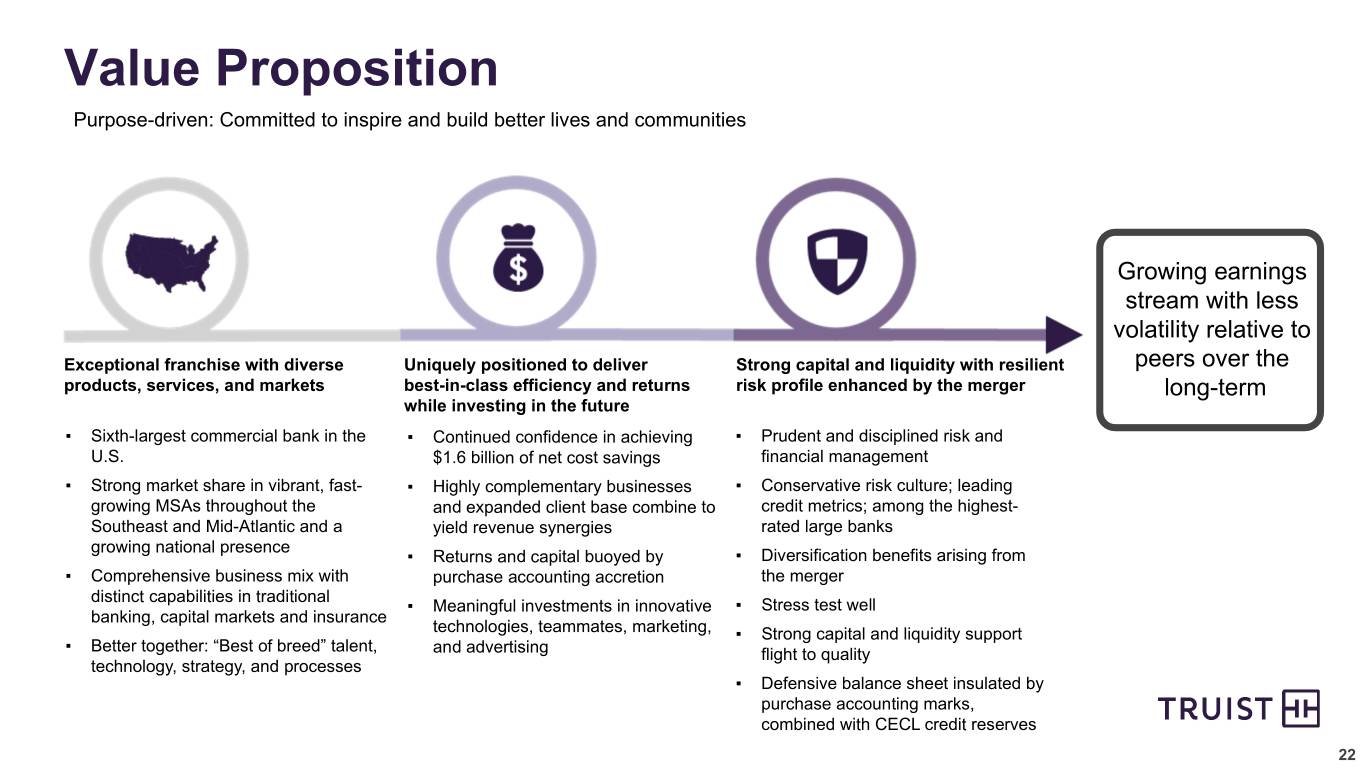
In September 2020, the FDIC published data from the Annual Summary of Deposits as of June 30, 2020. Truist is the 6th largest commercial bank in the United States based on deposits and maintained a first or second market position in thirteen of the company's Top 20 MSAs.

SEGMENT RESULTSChange 3Q20 vs.
(dollars in millions)
Segment Net Income3Q202Q203Q192Q203Q19
Consumer Banking and Wealth$817 $706 $465 $111 $352 
Corporate and Commercial Banking583 405 441 178 142 
Insurance Holdings77 126 61 (49)16 
Other, Treasury & Corporate(336)(279)(139)(57)(197)
Total net income$1,141 $958 $828 $183 $313 

Effective December 2019, operating segments were realigned in connection with the SunTrust merger. Results for prior periods have been revised to reflect the new structure.

Third Quarter 2020 compared to Second Quarter 2020

Consumer Banking and Wealth ("CB&W")

CB&W serves individuals and small business clients by offering a variety of loan and deposit products, payment services, bankcard products and other financial services by connecting clients to a wide range of financial products and services. CB&W includes Retail Community Bank, which serves retail, premier and small business clients, delivering on the banking needs of all clients through a network of branches, ATMs and contact centers. CB&W includes Dealer Retail Services, which originates loans on an indirect basis to individuals for the purchase of automobiles, boats and recreational vehicles. Additionally, CB&W includes National Consumer Finance & Payments, which provides a comprehensive set of technology-enabled lending solutions to individuals and small businesses through several national channels, as well as merchant services and payment processing solutions to business clients. CB&W also includes Mortgage Banking, which offers residential mortgage products nationally through its retail and correspondent channels, the internet and by telephone. These products are either sold in the secondary market, primarily with servicing rights retained, or held in the Company’s loan portfolio. Mortgage Banking also services loans for other investors, in addition to loans held in the Company’s loan portfolio. Mortgage Banking also includes Mortgage Warehouse Lending, which provides short-term lending solutions to finance first-lien residential mortgage LHFS by independent mortgage companies. Wealth delivers investment management, financial planning, banking, fiduciary services and related solutions to institutions, affluent and high net worth individuals and families, with financial expertise and industry-specific insights in the medical, legal, sports and entertainment industries.

- 8 -


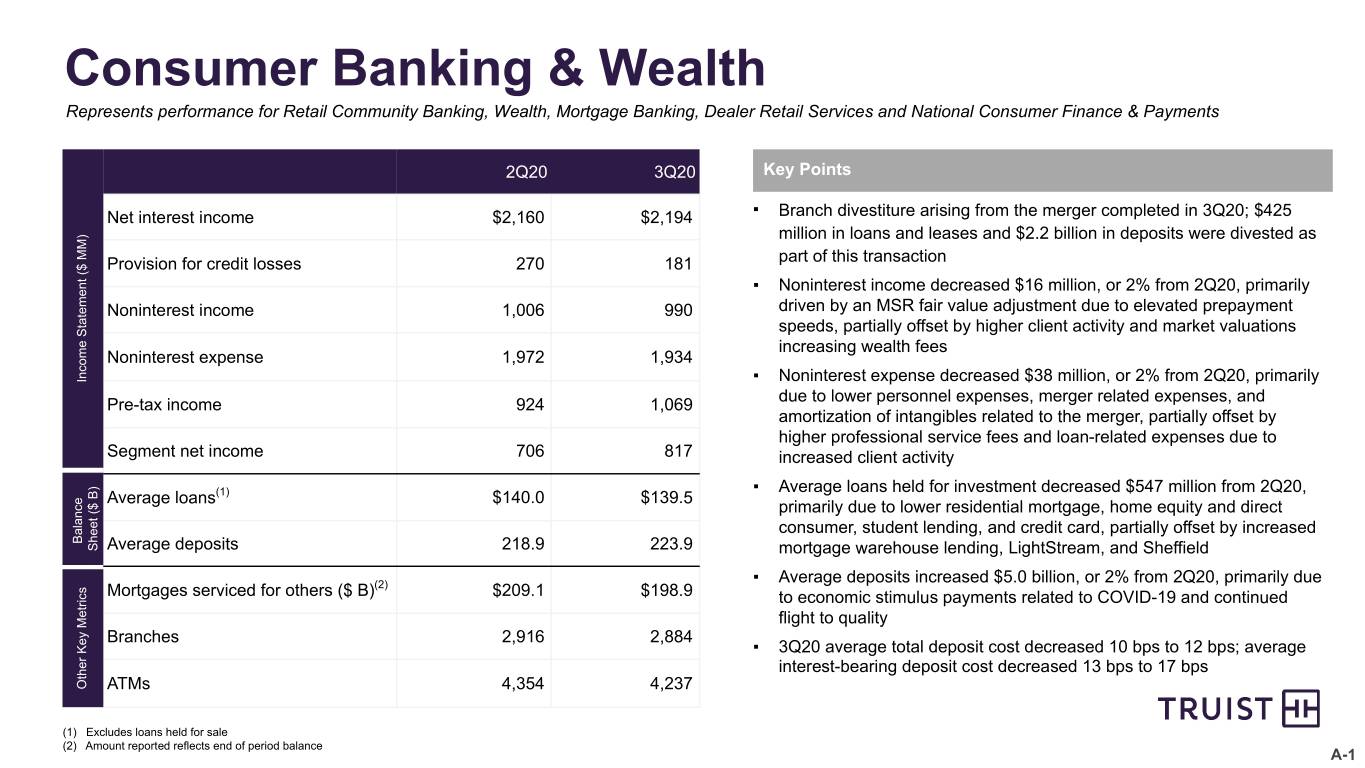
CB&W net income was $817 million for the third quarter of 2020, an increase of $111 million compared to the prior quarter. Segment net interest income increased $34 million primarily driven by day count and portfolio mix-shift. Noninterest income decreased $16 million primarily driven by an MSR fair value adjustment due to elevated prepayment speeds, partially offset by higher client activity and market valuations increasing wealth fees. The allocated provision for credit losses decreased $89 million primarily due to decreased charge-offs. Noninterest expense decreased $38 million primarily due to lower personnel expenses, merger related expenses and amortization of intangibles related to the merger, partially offset by higher professional service fees and loan-related expenses due to increased client activity.

Average loans held for investment were down $547 million compared to the prior quarter primarily due to lower residential mortgage, home equity and direct consumer, student lending and credit card, partially offset by increased mortgage warehouse lending. Average total deposits were up $5.0 billion compared to the prior quarter primarily due to economic stimulus payments related to COVID-19 and flight to quality.

Corporate and Commercial Banking ("C&CB")

C&CB serves large, medium and small business clients by offering a variety of loan and deposit products and connecting clients to the combined organization’s broad array of financial services. C&CB includes Corporate and Investment Banking (“CIB”), which delivers a comprehensive range of strategic advisory, capital raising, risk management, financing, liquidity and investment solutions to both public and private companies in the C&CB segment and Wealth. Additionally, C&CB includes Commercial Community Banking, which offers an array of traditional banking products, including lending, cash management and investment banking to commercial clients via CIB. C&CB also includes Commercial Real Estate, which provides a range of credit and deposit services as well as fee-based product offerings to privately held developers, operators, and investors in commercial real estate properties. C&CB also includes Grandbridge Real Estate Capital, which is a fully integrated commercial mortgage banking company that originates commercial and multi-family real estate loans, services loan portfolios and provides asset and portfolio management as well as real estate brokerage services. Treasury Solutions, within C&CB, provides business clients across the organization with services required to manage their payments and receipts, combined with the ability to manage and optimize their deposits across all aspects of their business.

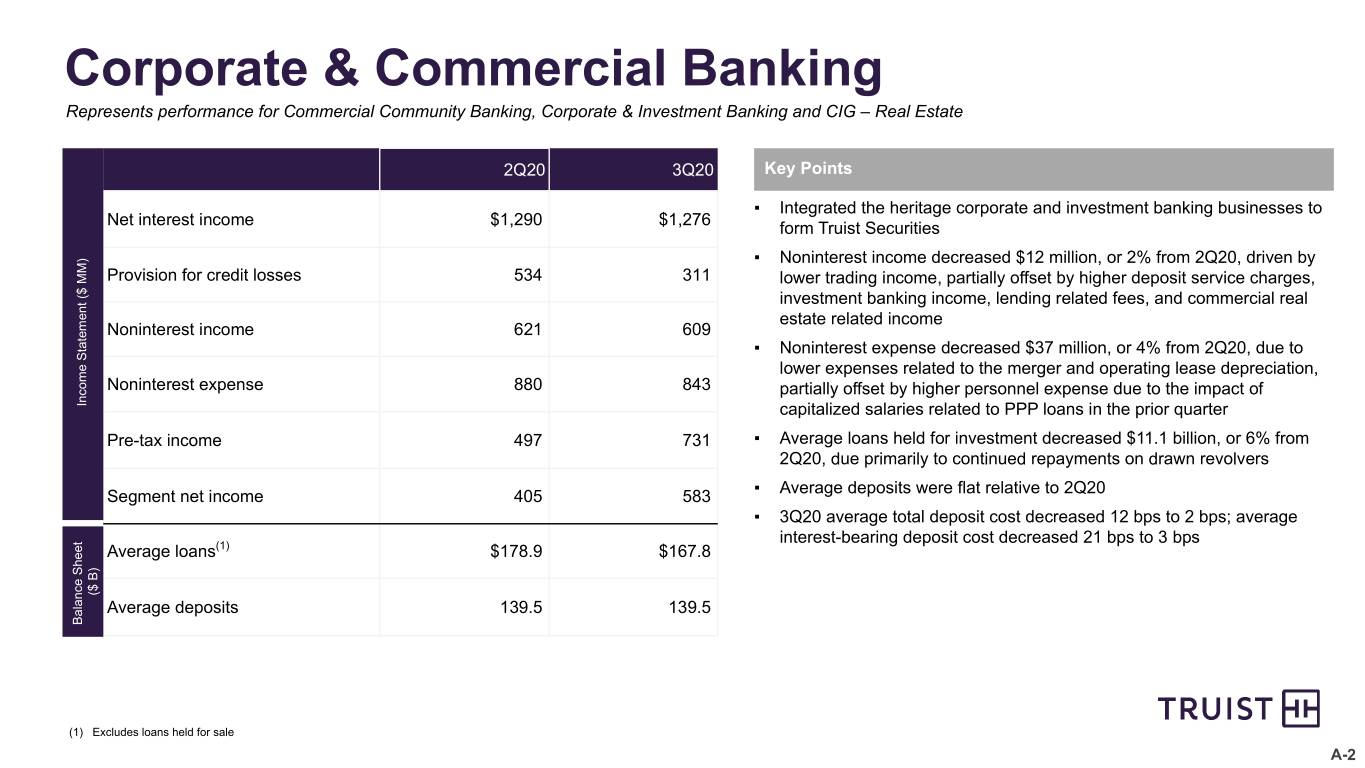
C&CB net income was $583 million for the third quarter of 2020, an increase of $178 million compared to the prior quarter. Segment net interest income decreased $14 million primarily due to the adverse interest rate environment resulting from COVID-19 impacts. Noninterest income decreased $12 million driven by lower trading income, partially offset by higher deposit service charges, investment banking income, lending related fees and commercial real estate related income. The allocated provision for credit losses decreased $223 million due to a build to the allowance in the prior quarter primarily due to risk grade updates in the commercial portfolio and qualitative considerations related to selected industries impacted by COVID-19, partially offset by increased charge-offs in the current quarter related to the implementation of CECL, which required a gross-up of loan carrying values in connection with the establishment of an allowance on PCD loans. Noninterest expense decreased $37 million primarily due to lower expenses related to the merger and operating lease depreciation, partially offset by higher personnel expense due to the impact of capitalized salaries related to PPP loans in the prior quarter.

Average loans held for investment were down $11.1 billion compared to the prior quarter due primarily to paydowns on drawn revolvers throughout the quarter. Average total deposits were flat compared to the prior quarter.

- 9 -


Insurance Holdings ("IH")

Truist’s IH segment is one of the largest insurance brokers in the world, providing property and casualty, employee benefits and life insurance to businesses and individuals. It also provides small business and corporate services, such as workers compensation and professional liability, as well as surety coverage and title insurance. In addition, IH provides premium financing for property and casualty insurance.

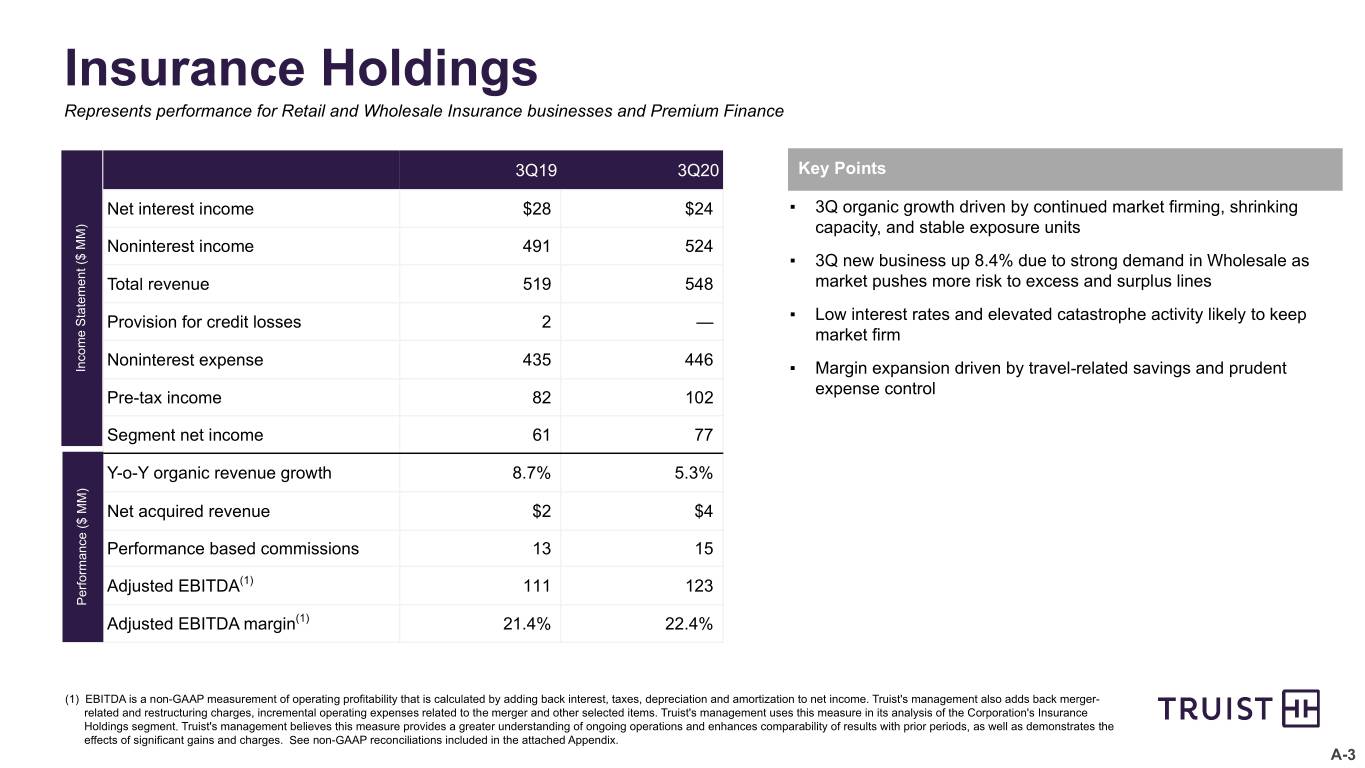
IH net income was $77 million for the third quarter of 2020, a decrease of $49 million compared to the prior quarter. Noninterest income decreased $74 million primarily due to seasonality in property and casualty and other insurance commissions. Noninterest expense decreased $2 million primarily due to seasonally lower performance-based incentives partially offset by higher operating charge-offs and restructuring charges.

Other, Treasury & Corporate ("OT&C")

Net income in OT&C can vary due to the changing needs of the Corporation, including the size of the investment portfolio, the need for wholesale funding and variability associated with derivatives used to hedge the balance sheet.

OT&C generated a net loss of $336 million for the third quarter of 2020, compared to a net loss of $279 million for the prior quarter. Segment net interest income decreased $107 million primarily due to a decline in funding charges on assets to other segments relative to the funding credit provided on liabilities. Noninterest income decreased $111 million primarily due to a decline in security gains from the prior quarter. The allocated provision for credit losses decreased $105 million due to a reduction in the reserve for unfunded commitments. Noninterest expense decreased $46 million primarily due to the loss on early extinguishment of long-term debt in the prior quarter, partially offset by higher real estate merger-related charges, higher expense related to certain post-retirement benefit plans, medical benefits and pension expenses in the current quarter. The benefit for income taxes increased $10 million primarily due to higher pre-tax losses in the current quarter.

Third Quarter 2020 compared to Third Quarter 2019

Consumer Banking and Wealth

CB&W net income was $817 million for the third quarter of 2020, an increase of $352 million compared to the earlier quarter. Segment net interest income increased $1.1 billion primarily due to the merger. Noninterest income increased $414 million due to the merger and higher residential mortgage production income as a result of the lower rate environment driving mortgage production through refinance activity, partially offset by lower residential mortgage servicing income driven by higher prepayment as a result of the lower rate environment and an MSR fair value adjustment in the current quarter. The allocated provision for credit losses increased $66 million primarily due to the merger as well as increased economic stress associated with the pandemic. Noninterest expense increased $1.0 billion primarily due to operating expenses and amortization of intangibles related to the merger.

Corporate and Commercial Banking

C&CB net income was $583 million for the third quarter of 2020, an increase of $142 million compared to the earlier quarter. Segment net interest income increased $636 million primarily due to the merger. Noninterest income increased $338 million also primarily due to the merger. The allocated provision for credit losses increased $297 million primarily due to the merger as well as increased economic stress associated with the pandemic. Noninterest expense increased $505 million primarily due to operating expenses and amortization of intangibles related to the merger in the current quarter.

- 10 -


Insurance Holdings

IH net income was $77 million for the third quarter of 2020, an increase of $16 million compared to the earlier quarter. Noninterest income increased $33 million primarily due to higher production. Noninterest expense increased $11 million primarily due to increased personnel expense, partially offset by lower travel and marketing expenses.

Other, Treasury & Corporate

OT&C generated a net loss of $336 million in the third quarter of 2020, compared to a net loss of $139 million in the earlier quarter. Segment net interest income decreased $80 million. Noninterest income increased $122 million primarily due to the gain on sale of securities in the current quarter. The allocated provision for credit losses decreased $57 million primarily due to a reduction in the provision for unfunded commitments. Noninterest expense increased $396 million primarily due to operating expenses related to the merger and higher merger-related charges in the current quarter. The benefit for income taxes increased $100 million primarily due to a higher pre-tax loss.

CAPITAL RATIOS3Q202Q201Q204Q193Q19
Risk-based:(preliminary)
Common equity Tier 110.0 %9.7 %9.3 %9.5 %10.6 %
Tier 112.2 11.6 10.5 10.8 12.2 
Total14.6 14.0 12.7 12.6 14.8 
Leverage (1)9.6 9.0 9.0 14.7 10.3 
Supplementary leverage (2)8.9 8.5 7.8 7.9 NA
(1)The leverage ratio is calculated using end of period Tier 1 capital and quarterly average tangible assets. The timing of the merger impacted the result for the fourth quarter of 2019. The estimated leverage ratio for the fourth quarter of 2019 using a full quarterly average tangible assets was 9.3 percent.
(2)Truist became subject to the supplementary leverage ratio as of January 1, 2020. The December 31, 2019 measure was an estimate based on a full quarter of average tangible assets in the denominator.

Capital ratios improved during the third quarter and remained strong compared to the regulatory levels for well capitalized banks. During the third quarter of 2020, Truist issued $925 million of preferred stock to further strengthen its capital position. Truist declared common dividends of $0.450 per share during the third quarter of 2020. The dividend and total payout ratios for the third quarter of 2020 were 56.8 percent.

In August 2020, the Federal Reserve informed Truist of its final Stress Capital Buffer ("SCB") of 270 basis points for risk-based capital ratios. This buffer, which was determined based on stress testing results developed by the Federal Reserve, is 20 basis points above the Capital Conservation Buffer. The SCB will be effective from October 1, 2020 through September 30, 2021, at which point a revised SCB will be calculated and provided to Truist. Consistent with the Federal Reserve’s mandate across the industry, Truist will update and resubmit its capital plan in early November 2020 to reflect changes in financial markets and the macroeconomic outlook.

As of January 1, 2020, Truist is subject to Category III reduced LCR. Truist's average LCR was approximately 117 percent for the three months ended September 30, 2020, compared to the regulatory minimum of 100 percent. Truist continues to maintain a strong liquidity position and is prepared to meet the funding needs of clients. In addition, the liquid asset buffer, which is defined as high quality unencumbered liquid assets as a percentage of total assets, was 18.6 percent at September 30, 2020.
- 11 -


ASSET QUALITY
(dollars in millions)3Q202Q201Q204Q193Q19
Total nonperforming assets$1,314 $1,252 $1,177 $684 $509 
Total performing TDRs1,217 1,107 1,079 980 1,057 
Total loans 90 days past due and still accruing1,197 1,072 1,748 1,994 403 
Total loans 30-89 days past due2,148 1,901 2,374 2,213 992 
Nonperforming loans and leases as a percentage of loans and leases held for investment
0.37 %0.35 %0.32 %0.15 %0.30 %
Nonperforming assets as a percentage of total assets
0.26 0.25 0.23 0.14 0.22 
Loans 30-89 days past due and still accruing as a percentage of loans and leases
0.70 0.60 0.74 0.74 0.66 
Loans 90 days or more past due and still accruing as a percentage of loans and leases
0.39 0.34 0.55 0.66 0.27 
Loans 90 days or more past due and still accruing as a percentage of loans and leases, excluding PPP, other government guaranteed and PCI0.03 0.04 0.04 0.03 0.04 
Allowance for loan and lease losses as a percentage of loans and leases held for investment
1.91 1.81 1.63 0.52 1.05 
Net charge-offs as a percentage of average loans and leases, annualized
0.42 0.39 0.36 0.40 0.41 
Ratio of allowance for loan and lease losses to net charge-offs, annualized
4.52x4.49x4.76x2.03x2.59x
Ratio of allowance for loan and lease losses to nonperforming loans and leases held for investment
5.22x5.24x5.04x3.41x3.52x

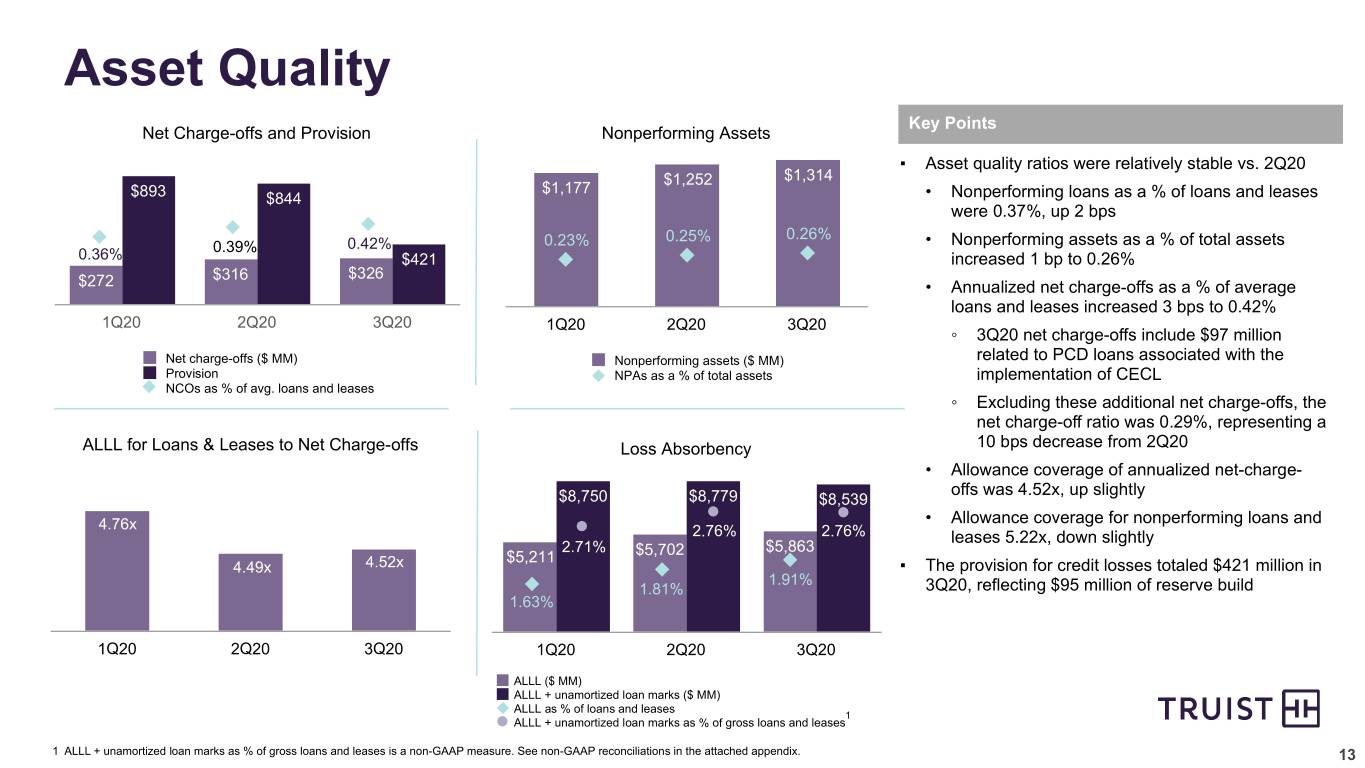
Overall asset quality ratios were relatively stable at September 30, 2020 compared to June 30, 2020.

Nonperforming assets totaled $1.3 billion at September 30, 2020, up $62 million compared to June 30, 2020. Nonperforming loans and leases held for investment represented 0.37 percent of loans and leases held for investment, up 2 basis points compared to June 30, 2020. The increase in nonperforming loans held for investment is primarily in commercial and industrial loans, which was partially offset by a decline in commercial leases due to a charge-off on a PCD loan related to the implementation of CECL. Within the consumer portfolio, indirect automobile nonaccrual loans declined as some states lifted the moratorium on repossessions. Performing TDRs were up $110 million during the third quarter primarily in residential mortgage loans.

Loans 90 days or more past due and still accruing totaled $1.2 billion at September 30, 2020, up $125 million compared to the prior quarter. The increase was primarily in government guaranteed student loans as forbearance programs in connection with the CARES Act have ended. In addition, residential mortgage loans 90 days or more past due increased primarily due to the repurchase of delinquent government guaranteed loans. The ratio of loans 90 days or more past due and still accruing as a percentage of loans and leases was 0.39 percent at September 30, 2020, up five basis points from the prior quarter. Excluding government guaranteed loans, the ratio of loans 90 days or more past due and still accruing as a percentage of loans and leases was 0.03 percent at September 30, 2020, down one basis point from June 30, 2020.

Loans 30-89 days past due and still accruing totaled $2.1 billion at September 30, 2020, up $247 million compared to the prior quarter. Student loans 30-89 days past due increased $224 million, which almost entirely relates to government guaranteed loans as forbearance programs in connection with the CARES Act have ended. In addition, residential mortgage loans and indirect automobile loans increased, while commercial and industrial loans declined. The ratio of loans 30-89 days past due and still accruing as a percentage of loans and leases was 0.70 percent at September 30, 2020, up 10 basis points from the prior quarter.

- 12 -


Net charge-offs during the third quarter totaled $326 million, up $10 million compared to the prior quarter. As a percentage of average loans and leases, annualized net charge-offs were 0.42 percent, up three basis points compared to the prior quarter. Current quarter net charge-offs includes $97 million of charge-offs related to the implementation of CECL, which required a gross-up of loan carrying values in connection with the establishment of an allowance on PCD loans. Management performed a comprehensive review of PCD assets during the third quarter and concluded in certain situations that a charge-off was required. Excluding these additional charge-offs, net charge-offs would have been an annualized 0.29 percent of average loans and leases for the third quarter of 2020, down 10 basis points compared to the prior quarter.

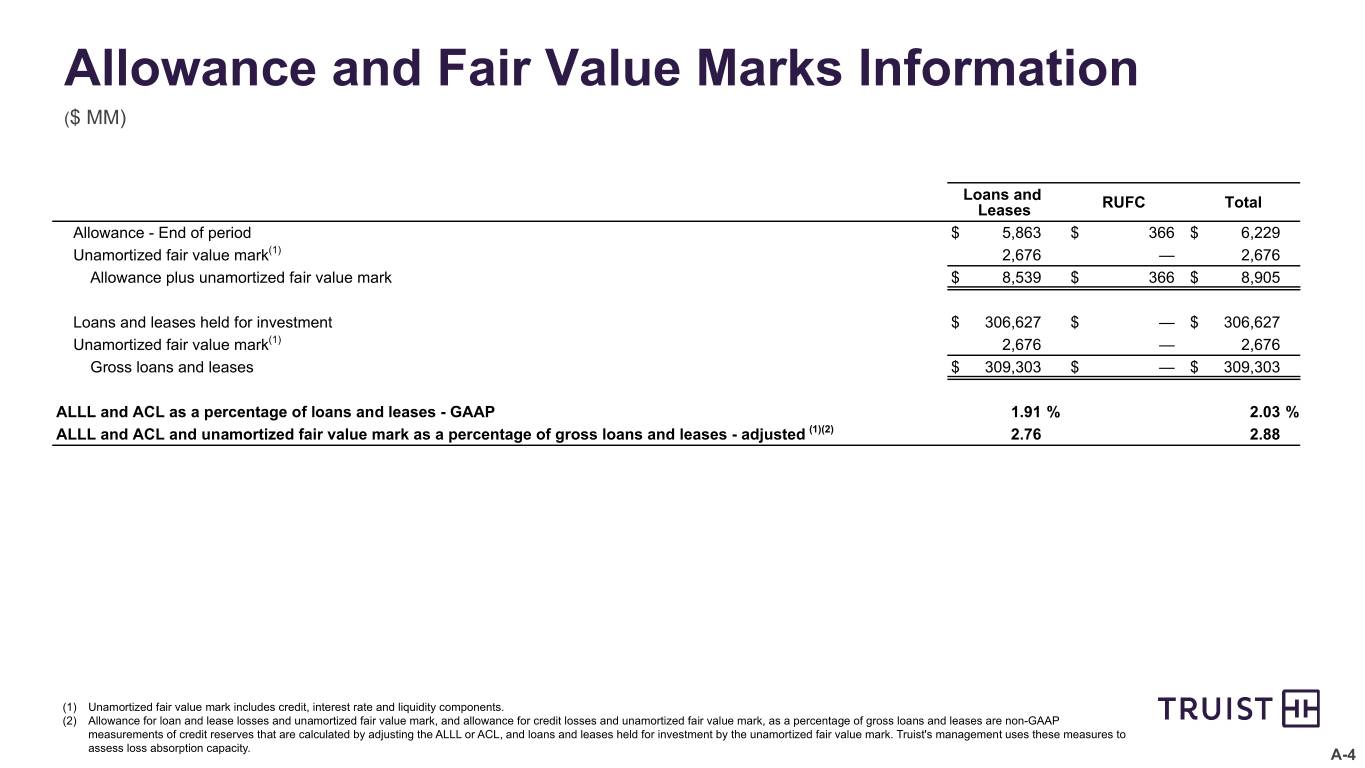
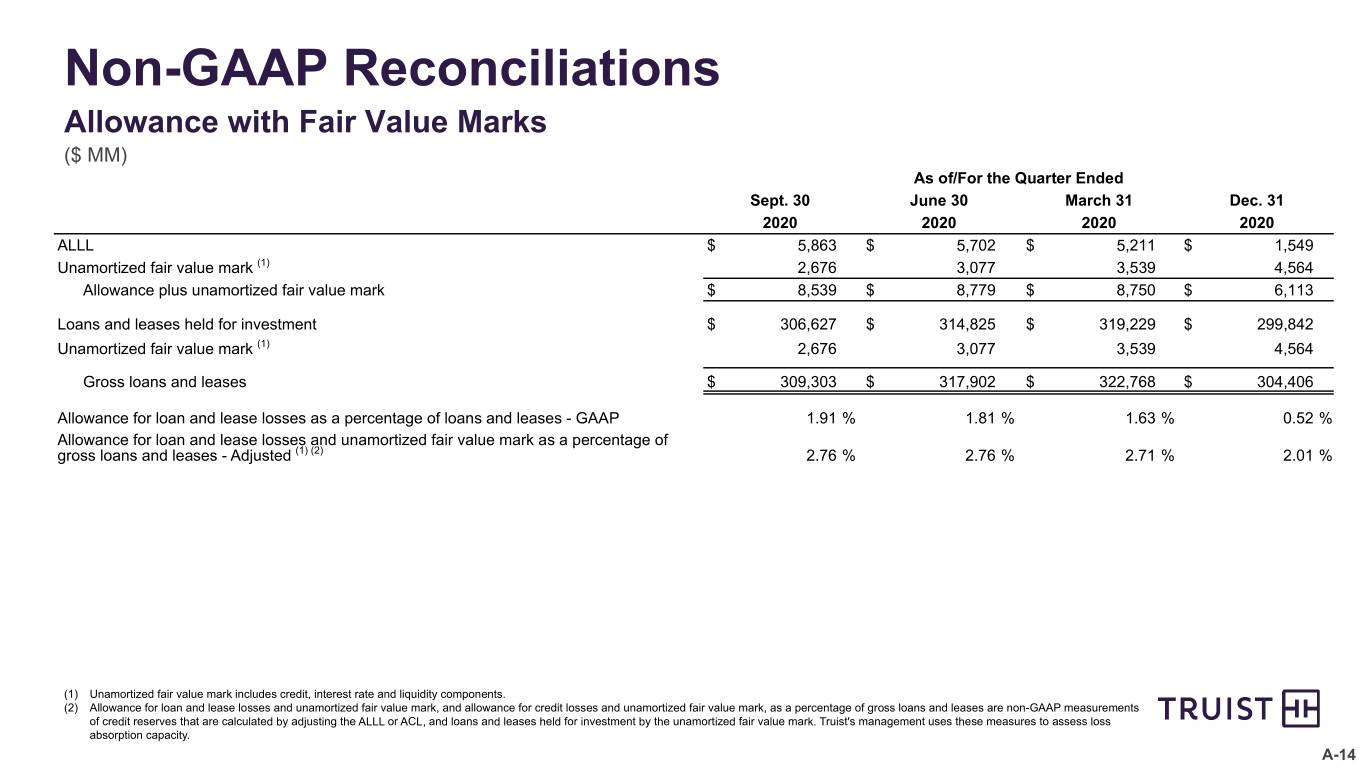
The allowance for credit losses was $6.2 billion, up $96 million compared to the prior quarter. The allowance for credit losses includes $5.9 billion for loans and leases and $366 million for the reserve for unfunded commitments. As of September 30, 2020, the allowance for loan and lease losses was 1.91 percent of loans and leases held for investment.

The allowance for loan and lease losses was 5.22 times nonperforming loans and leases held for investment, compared to 5.24 times at June 30, 2020. At September 30, 2020, the allowance for loan and lease losses was 4.52 times annualized net charge-offs, compared to 4.49 times at June 30, 2020.

Earnings Presentation and Quarterly Performance Summary

To listen to Truist's live third quarter 2020 earnings conference call at 8 a.m. ET today, please call 866-519-2796 and enter the participant code 892418. A presentation will be used during the earnings conference call and is available on our website at https://ir.truist.com/events-and-presentation. Replays of the conference call will be available for 30 days by dialing 888-203-1112 (access code 892418).

The presentation, including an appendix reconciling non-GAAP disclosures, and Truist's Third Quarter 2020 Quarterly Performance Summary, which contains detailed financial schedules, is available at https://ir.truist.com/earnings.

About Truist

Truist Financial Corporation is a purpose-driven financial services company committed to inspire and build better lives and communities. With 275 years of combined BB&T and SunTrust history, Truist has leading market share in many high-growth markets in the country. The company offers a wide range of services including retail, small business and commercial banking; asset management; capital markets; commercial real estate; corporate and institutional banking; insurance; mortgage; payments; specialized lending; and wealth management. Headquartered in Charlotte, North Carolina, Truist is the sixth-largest commercial bank in the U.S. with total assets of $499 billion as of September 30, 2020. Truist Bank, Member FDIC. Learn more at Truist.com.

#-#-#

Capital ratios and return on risk-weighted assets are preliminary.

This news release contains financial information and performance measures determined by methods other than in accordance with accounting principles generally accepted in the United States of America ("GAAP"). Truist's management uses these "non-GAAP" measures in their analysis of the Corporation's performance and the efficiency of its operations. Management believes these non-GAAP measures provide a greater understanding of ongoing operations, enhance comparability of results with prior periods and demonstrate the effects of significant items in the current period. The Corporation believes a meaningful analysis of its financial performance requires an understanding of the factors underlying that performance. Truist's management believes investors may find these non-GAAP financial measures useful. These disclosures should not be viewed as a substitute for financial measures determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. Below is a listing of the types of non-GAAP measures used in this news release:
- 13 -


•
The adjusted efficiency ratio is non-GAAP in that it excludes securities gains (losses), amortization of intangible assets, merger-related and restructuring charges and other selected items. Truist's management uses this measure in their analysis of the Corporation's performance. Truist's management believes this measure provides a greater understanding of ongoing operations and enhances comparability of results with prior periods, as well as demonstrates the effects of significant gains and charges.
•
Tangible common equity and related measures are non-GAAP measures that exclude the impact of intangible assets, net of deferred taxes, and their related amortization. These measures are useful for evaluating the performance of a business consistently, whether acquired or developed internally. Truist's management uses these measures to assess the quality of capital and returns relative to balance sheet risk.
•
Core net interest margin is a non-GAAP measure that adjusts net interest margin to exclude the impact of purchase accounting. The purchase accounting marks and related amortization for a) securities acquired from the FDIC in the Colonial Bank acquisition and b) loans, deposits and long-term debt from SunTrust, Susquehanna, National Penn and Colonial Bank are excluded to approximate the yields paid by clients. Truist's management believes the adjustments to the calculation of net interest margin for certain assets and liabilities acquired provide investors with useful information related to the performance of Truist's earning assets.
•
The adjusted diluted earnings per share is non-GAAP in that it excludes merger-related and restructuring charges and other selected items, net of tax. Truist's management uses this measure in their analysis of the Corporation's performance. Truist's management believes this measure provides a greater understanding of ongoing operations and enhances comparability of results with prior periods, as well as demonstrates the effects of significant gains and charges.
•
The adjusted performance ratios, including adjusted return on average assets, adjusted return on average common shareholders’ equity and adjusted return on average tangible common shareholders’ equity, are non-GAAP in that they exclude merger-related and restructuring charges, selected items and, in the case of return on average tangible common shareholders' equity, amortization of intangible assets. Truist's management uses these measures in their analysis of the Corporation's performance. Truist's management believes these measures provide a greater understanding of ongoing operations and enhances comparability of results with prior periods, as well as demonstrates the effects of significant gains and charges.
•
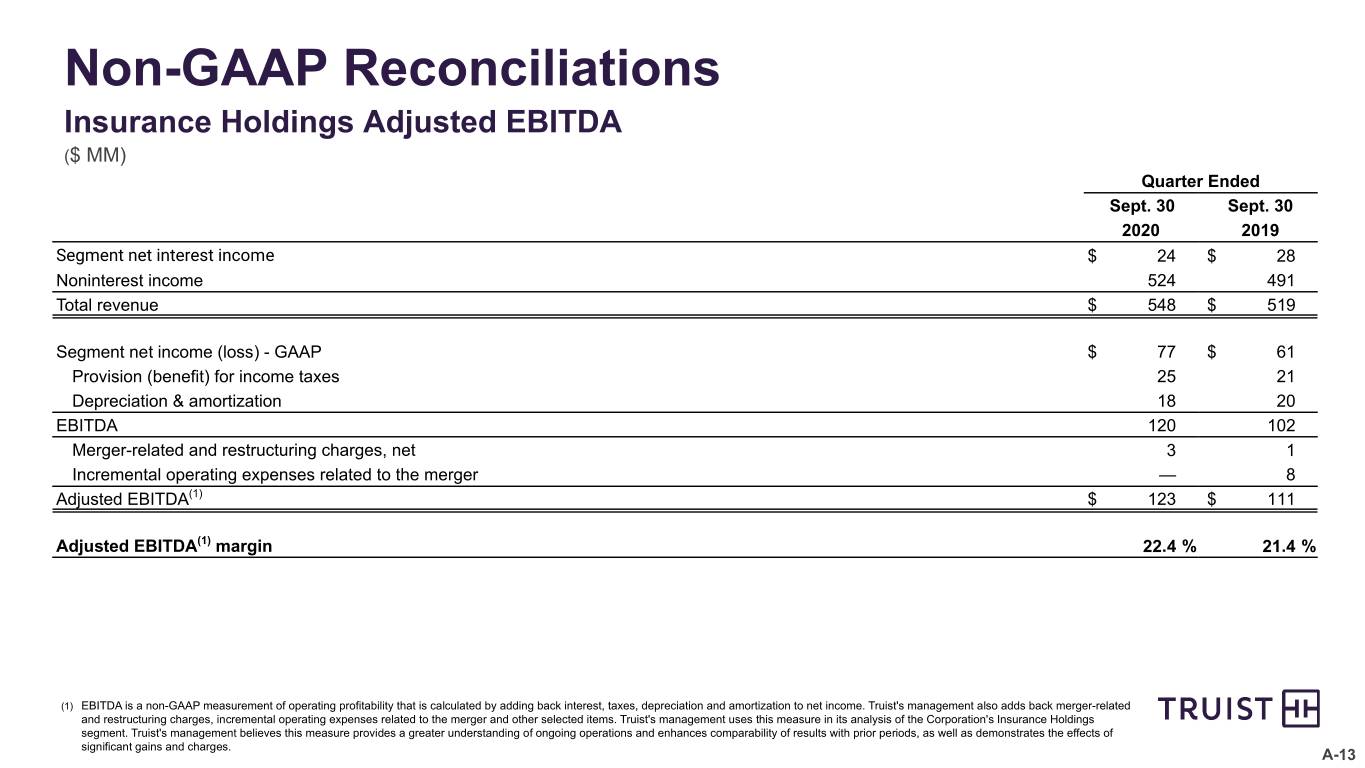
EBITDA is a non-GAAP measurement of operating profitability that is calculated by adding back interest, taxes, depreciation and amortization to net income. Truist's management also adds back merger-related and restructuring charges, incremental operating expenses related to the merger and other selected items. Truist's management uses this measure in its analysis of the Corporation's Insurance Holdings segment. Truist's management believes this measure provides a greater understanding of ongoing operations and enhances comparability of results with prior periods, as well as demonstrates the effects of significant gains and charges.
•
Allowance for loan and lease losses and unamortized fair value mark, and allowance for credit losses and unamortized fair value mark, as a percentage of gross loans and leases are non-GAAP measurements of credit reserves that are calculated by adjusting the ALLL or ACL, and loans and leases held for investment by the unamortized fair value mark. Truist's management uses these measures to assess loss absorption capacity.

A reconciliation of these non-GAAP measures to the most directly comparable GAAP measure is included in the appendix to Truist's Third Quarter 2020 Earnings Presentation, which is available at https://ir.truist.com/earnings.

This news release contains "forward-looking statements" within the meaning of the Private Securities Litigation Reform Act of 1995, regarding the financial condition, results of operations, business plans and the future performance of Truist. Words such as "anticipates," "believes," "estimates," "expects," "forecasts," "intends," "plans," "projects," "may," "will," "should," “would," "could" and other similar expressions are intended to identify these forward-looking statements.

Forward-looking statements are not based on historical facts but instead represent management's expectations and assumptions regarding Truist's business, the economy and other future conditions. Such statements involve inherent uncertainties, risks and changes in circumstances that are difficult to predict. As such, Truist’s actual results may differ materially from those contemplated by forward-looking statements. While there can be no assurance that any list of risks and uncertainties or risk factors is complete, important factors that could cause actual results to differ materially from those contemplated by forward-looking statements include the following, without limitation, as well as the risks and uncertainties more fully discussed under Item 1A-Risk Factors in our Annual Report on Form 10-K for the year ended December 31, 2019, Item 1A-Risk Factors in our Quarterly Report on Form 10-Q for the quarter ended June 30, 2020 and in Truist's subsequent filings with the Securities and Exchange Commission:
•
risks and uncertainties relating to the merger of BB&T and SunTrust ("Merger"), including the ability to successfully integrate the companies or to realize the anticipated benefits of the Merger;
•
expenses relating to the Merger and integration of heritage BB&T and heritage SunTrust;
•
deposit attrition, client loss or revenue loss following completed mergers or acquisitions may be greater than anticipated;
•
changes in the interest rate environment, including the replacement of LIBOR as an interest rate benchmark, which could adversely affect Truist’s revenue and expenses, the value of assets and obligations, and the availability and cost of capital, cash flows, and liquidity;
•
volatility in mortgage production and servicing revenues, and changes in carrying values of Truist’s servicing assets and mortgages held for sale due to changes in interest rates;
•
management’s ability to effectively manage credit risk;
•
inability to access short-term funding or liquidity;
•
loss of client deposits, which could increase Truist’s funding costs;
•
changes in Truist’s credit ratings, which could increase the cost of funding or limit access to capital markets;
•
additional capital and liquidity requirements;
- 14 -


•
regulatory matters, litigation or other legal actions, which may result in, among other things, costs, fines, penalties, restrictions on Truist’s business activities, reputational harm, or other adverse consequences;
•
risks related to originating and selling mortgages, including repurchase and indemnity demands from purchasers related to representations and warranties on loans sold, which could result in an increase in the amount of losses for loan repurchases;
•
failure to execute on strategic or operational plans, including the ability to successfully complete and/or integrate mergers and acquisitions;
•
risks relating to Truist’s role as a servicer of loans, including an increase in the scope or costs of the services Truist is required to perform without any corresponding increase in Truist’s servicing fee, or a breach of Truist’s obligations as servicer;
•
negative public opinion, which could damage Truist’s reputation;
•
increased scrutiny regarding Truist’s consumer sales practices, training practices, incentive compensation design and governance;
•
competition from new or existing competitors, including increased competition from products and services offered by non-bank financial technology companies, may reduce Truist’s client base, cause Truist to lower prices for its products and services in order to maintain market share or otherwise adversely impact Truist’s businesses or results of operations;
•
Truist’s ability to introduce new products and services in response to industry trends or developments in technology that achieve market acceptance and regulatory approval;
•
Truist’s success depends on the expertise of key personnel, and if these individuals leave or change their roles without effective replacements Truist's operations and integration activities could be adversely impacted. This could be exacerbated as Truist continues to integrate the management teams of heritage BB&T and heritage SunTrust, or if the organization is unable to hire and retain qualified personnel;
•
legislative, regulatory or accounting changes may adversely affect the businesses in which Truist is engaged;
•
evolving regulatory standards, including with respect to capital and liquidity requirements, and results of regulatory examinations, may adversely affect Truist's financial condition and results of operations;
•
accounting policies and processes require management to make estimates about matters that are uncertain;
•
general economic or business conditions, either nationally or regionally, may be less favorable than expected, resulting in, among other things, slower deposit or asset growth, a deterioration in credit quality or a reduced demand for credit, insurance or other services;
•
risk management oversight functions may not identify or address risks adequately;
•
unfavorable resolution of legal proceedings or other claims or regulatory or other governmental investigations or inquiries could result in negative publicity, protests, fines, penalties, restrictions on Truist's operations or ability to expand its business or other negative consequences, all of which could cause reputational damage and adversely impact Truist's financial condition and results of operations;
•
competitors of Truist may have greater financial resources or develop products that enable them to compete more successfully than Truist and may be subject to different regulatory standards than Truist;
•
failure to maintain or enhance Truist’s competitive position with respect to technology, whether it fails to anticipate client expectations or because its technological developments fail to perform as desired or are not rolled out in a timely manner or for other reasons, may cause Truist to lose market share or incur additional expense;
•
fraud or misconduct by internal or external parties, which Truist may not be able to prevent, detect or mitigate;
•
operational or communications systems, including systems used by vendors or other external parties, may fail or may be the subject of a breach or cyber-attack that, if successful, could adversely impact Truist's financial condition and results of operations;
•
security risks, including denial of service attacks, hacking, social engineering attacks targeting Truist’s employees and clients, malware intrusion or data corruption attempts, and identity theft could result in the disclosure of confidential information, adversely affect Truist’s business or reputation or create significant legal or financial exposure;
•
the COVID-19 pandemic has disrupted the global economy, adversely impacted Truist’s financial condition and results of operations, including through increased expenses, reduced fee income and net interest margin and increases in the allowance for credit losses, and continuation of current conditions could worsen these impacts and also adversely affect Truist’s capital and liquidity position or cost of capital, impair the ability of borrowers to repay outstanding loans, cause an outflow of deposits, and impair goodwill or other assets;
•
natural or other disasters, including acts of terrorism and pandemics, could have an adverse effect on Truist, including a material disruption of Truist's operations or the ability or willingness of clients to access Truist's products and services;
•
widespread system outages, caused by the failure of critical internal systems or critical services provided by third parties could adversely impact Truist's financial condition and results of operations; and
•
depressed market values for Truist’s stock and adverse economic conditions sustained over a period of time may require a write down to goodwill.

Readers are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date they are made. Except to the extent required by applicable law or regulation, Truist undertakes no obligation to revise or update any forward-looking statements.
- 15 -


logo-boxed21.jpg

Quarterly Performance Summary
Truist Financial Corporation
Third Quarter 2020


Table of Contents 
Quarterly Performance Summary 
Truist Financial Corporation


  Page
Financial Highlights
Financial Highlights - Five Quarter Trend
Consolidated Statements of Income
Consolidated Statements of Income - Five Quarter Trend
Segment Financial Performance - Five Quarter Trend
Consolidated Ending Balance Sheets - Five Quarter Trend
Average Balance Sheets
Average Balance Sheets - Five Quarter Trend
Average Balances and Rates - Quarters
Average Balances and Rates - Year-To-Date
Credit Quality
Capital Information - Five Quarter Trend
Selected Mortgage Banking Information & Additional Information
Selected Items
Non-GAAP Reconciliations


Financial Highlights 
Quarter Ended Year-to-Date
 September 30%September 30%
(Dollars in millions, except per share data, shares in thousands)20202019Change20202019Change
Summary Income Statement      
Interest income - taxable equivalent (1)$3,652 $2,241 63.0 %$12,034 $6,668 80.5 %
Interest expense261 518 (49.6)1,477 1,511 (2.3)
Net interest income - taxable equivalent3,391 1,723 96.8 10,557 5,157 104.7 
Less: Taxable-equivalent adjustment29 23 26.1 97 71 36.6 
Net interest income 3,362 1,700 97.8 10,460 5,086 105.7 
Provision for credit losses421 117 NM2,158 444 NM
Net interest income after provision for credit losses2,941 1,583 85.8 8,302 4,642 78.8 
Noninterest income2,210 1,303 69.6 6,594 3,857 71.0 
Noninterest expense3,755 1,840 104.1 11,064 5,359 106.5 
Income before income taxes1,396 1,046 33.5 3,832 3,140 22.0 
Provision for income taxes255 218 17.0 670 629 6.5 
Net income1,141 828 37.8 3,162 2,511 25.9 
Noncontrolling interests3 3 — 9 8 12.5 
Net income available to the bank holding company1,138 825 37.9 3,153 2,503 12.5 
Preferred stock dividends70 90 (22.2)197 177 11.3 
Net income available to common shareholders1,068 735 45.3 2,956 2,326 27.1 
Per Common Share Data
Earnings per share-basic$0.79 $0.96 (17.7)%$2.20 $3.04 (27.6)%
Earnings per share-diluted0.79 0.95 (16.8)2.18 3.00 (27.3)
Earnings per share-adjusted diluted (2)0.97 1.07 (9.3)2.62 3.25 (19.4)
Cash dividends declared0.450 0.450 — 1.350 1.260 7.1 
Common shareholders' equity45.86 38.07 20.5 45.86 38.07 20.5 
Tangible common shareholders' equity (2)26.63 24.66 8.0 26.63 24.66 8.0 
End of period shares outstanding1,348,118 766,303 75.9 1,348,118 766,303 75.9 
Weighted average shares outstanding-basic1,347,916 766,167 75.9 1,346,605 765,428 75.9 
Weighted average shares outstanding-diluted1,358,122 775,791 75.1 1,357,174 774,907 75.1 
Performance Ratios
Return on average assets0.91 %1.41 %0.85 %1.47 %
Return on average risk-weighted assets (current period is preliminary)1.19 1.75 1.10 1.81 
Return on average common shareholders' equity6.87 10.04 6.46 11.02 
Return on average tangible common shareholders' equity (2)13.31 16.03 12.79 17.90 
Net interest margin - taxable equivalent3.10 3.37 3.26 3.43 
Fee income ratio39.7 43.4 38.7 43.1 
Efficiency ratio-GAAP67.4 61.3 64.9 59.9 
Efficiency ratio-adjusted (2)57.3 57.1 55.9 56.2 
Credit Quality
Nonperforming assets as a percentage of:
Assets0.26 %0.22 %0.26 %0.22 %
Loans and leases plus foreclosed property0.39 0.34 0.39 0.34 
Net charge-offs as a percentage of average loans and leases 0.42 0.41 0.39 0.40 
Allowance for loan and lease losses as a percentage of LHFI1.91 1.05 1.91 1.05 
Ratio of allowance for loan and lease losses to nonperforming LHFI5.22x3.52x5.22x3.52x
Average Balances
Assets$500,826 $232,420 115.5 %$497,710 $229,106 117.2 %
Securities (3)79,828 48,900 63.2 76,906 47,257 62.7 
Loans and leases 315,691 152,042 107.6 316,621 150,808 109.9 
Deposits372,211 161,992 129.8 359,273 160,650 123.6 
Common shareholders' equity61,804 29,040 112.8 61,173 28,226 116.7 
Total shareholders' equity69,634 32,744 112.7 67,311 31,537 113.4 
Period-End Balances
Assets$499,183 $236,750 110.8 %$499,183 $236,750 110.8 %
Securities (3)86,132 54,765 57.3 86,132 54,765 57.3 
Loans and leases 312,149 150,855 106.9 312,149 150,855 106.9 
Deposits370,747 162,280 128.5 370,747 162,280 128.5 
Common shareholders' equity61,819 29,177 111.9 61,819 29,177 111.9 
Total shareholders' equity69,973 32,303 116.6 69,973 32,303 116.6 
Capital Ratios (current quarter is preliminary)
Common equity Tier 110.0 %10.6 %10.0 %10.6 %
Tier 112.2 12.2 12.2 12.2 
Total 14.6 14.8 14.6 14.8 
Leverage9.6 10.3 9.6 10.3 
Supplementary leverage8.9 NA8.9 NA
Applicable ratios are annualized.
NM - not meaningful
(1) Interest income includes certain fees, deferred costs and dividends.
(2) Represents a non-GAAP measure. See the calculations and management's reasons for using these measures in the Non-GAAP Reconciliations and Preliminary Capital Information - Five Quarter Trend sections of this supplement.
(3) Includes AFS and HTM securities. Average balances reflect both AFS and HTM securities at amortized cost. Period-end balances reflect AFS securities at fair value and HTM securities at amortized cost. In 4Q19, Truist transferred all HTM securities into AFS securities in response to changes in regulatory capital rules.
Truist Financial Corporation 1


Financial Highlights - Five Quarter Trend   
Quarter Ended
 Sept. 30June 30March 31Dec. 31Sept. 30
(Dollars in millions, except per share data, shares in thousands)20202020202020192019
Summary Income Statement
Interest income - taxable equivalent (1)$3,652 $3,919 $4,463 $2,837 $2,241 
Interest expense261 440 776 585 518 
Net interest income - taxable equivalent3,391 3,479 3,687 2,252 1,723 
Less: Taxable-equivalent adjustment29 31 37 25 23 
Net interest income 3,362 3,448 3,650 2,227 1,700 
Provision for credit losses421 844 893 171 117 
Net interest income after provision for credit losses2,941 2,604 2,757 2,056 1,583 
Noninterest income2,210 2,423 1,961 1,398 1,303 
Noninterest expense3,755 3,878 3,431 2,575 1,840 
Income before income taxes1,396 1,149 1,287 879 1,046 
Provision for income taxes255 191 224 153 218 
Net income1,141 958 1,063 726 828 
Noncontrolling interests3 3 3 5 3 
Net income available to the bank holding company1,138 955 1,060 721 825 
Preferred stock dividends70 53 74 19 90 
Net income available to common shareholders1,068 902 986 702 735 
Per Common Share Data
Earnings per share-basic$0.79 $0.67 $0.73 $0.76 $0.96 
Earnings per share-diluted0.79 0.67 0.73 0.75 0.95 
Earnings per share-adjusted diluted (2)0.97 0.82 0.83 1.12 1.07 
Cash dividends declared0.450 0.450 0.450 0.450 0.450 
Common shareholders' equity45.86 45.74 45.49 45.66 38.07 
Tangible common shareholders' equity (2)26.63 26.38 26.00 25.93 24.66 
End of period shares outstanding1,348,118 1,347,609 1,347,461 1,342,166 766,303 
Weighted average shares outstanding-basic1,347,916 1,347,512 1,344,372 922,840 766,167 
Weighted average shares outstanding-diluted1,358,122 1,355,834 1,357,545 934,718 775,791 
Performance Ratios
Return on average assets0.91 %0.75 %0.90 %0.95 %1.41 %
Return on average risk-weighted assets (current quarter is preliminary)1.19 1.00 1.12 1.02 1.75 
Return on average common shareholders' equity6.87 5.90 6.58 7.33 10.04 
Return on average tangible common shareholders' equity (2)13.31 11.83 13.23 12.91 16.03 
Net interest margin - taxable equivalent3.10 3.13 3.58 3.41 3.37 
Fee income ratio39.7 41.3 34.9 38.6 43.4 
Efficiency ratio-GAAP67.4 66.1 61.1 71.0 61.3 
Efficiency ratio-adjusted (2)57.3 55.8 54.6 57.5 57.1 
Credit Quality
Nonperforming assets as a percentage of:
Assets0.26 %0.25 %0.23 %0.14 %0.22 %
Loans and leases plus foreclosed property0.39 0.37 0.36 0.19 0.34 
Net charge-offs as a percentage of average loans and leases 0.42 0.39 0.36 0.40 0.41 
Allowance for loan and lease losses as a percentage of LHFI1.91 1.81 1.63 0.52 1.05 
Ratio of allowance for loan and lease losses to nonperforming LHFI5.22x5.24x5.04x3.41x3.52x
Average Balances
Assets$500,826 $514,720 $477,550 $302,059 $232,420 
Securities (3)79,828 75,159 75,701 60,699 48,900 
Loans and leases 315,691 326,435 307,748 193,641 152,042 
Deposits372,211 370,818 334,649 210,716 161,992 
Common shareholders' equity61,804 61,484 60,224 38,031 29,040 
Total shareholders' equity69,634 66,863 65,412 41,740 32,744 
Period-End Balances
Assets$499,183 $504,336 $506,229 $473,078 $236,750 
Securities (3)86,132 77,805 78,398 74,727 54,765 
Loans and leases 312,149 321,148 324,039 308,215 150,855 
Deposits370,747 376,235 350,179 334,727 162,280 
Common shareholders' equity61,819 61,634 61,295 61,282 29,177 
Total shareholders' equity69,973 68,883 66,061 66,558 32,303 
Capital Ratios (current quarter is preliminary)
Common equity Tier 110.0 %9.7 %9.3 %9.5 %10.6 %
Tier 112.2 11.6 10.5 10.8 12.2 
Total 14.6 14.0 12.7 12.6 14.8 
Leverage (4)9.6 9.0 9.0 14.7 10.3 
Supplementary leverage (5)8.9 8.5 7.8 7.9 NA
Applicable ratios are annualized.
(1) Interest income includes certain fees, deferred costs and dividends.
(2) Represents a non-GAAP measure. See the calculations and management's reasons for using these measures in the Non-GAAP Reconciliations and Preliminary Capital Information - Five Quarter Trend sections of this supplement.
(3) Includes AFS and HTM securities. Average balances reflect both AFS and HTM securities at amortized cost. Period-end balances reflect AFS securities at fair value and HTM securities at amortized cost. In 4Q19, Truist transferred all HTM securities into AFS securities in response to changes in regulatory capital rules.
(4) The leverage ratio is calculated using end of period Tier 1 capital and quarterly average tangible assets. The timing of the merger impacted the 4Q19 result.
(5) Truist became subject to the supplementary leverage ratio in 2020. The 4Q19 measure was an estimate based on a full quarter of average tangible assets.

2 Truist Financial Corporation


Q
Consolidated Statements of Income 
 Quarter EndedYear-to-Date
 Sept. 30ChangeSept. 30Change
(Dollars in millions, except per share data, shares in thousands)20202019$%20202019$%
Interest Income
Interest and fees on loans and leases$3,174 $1,886 $1,288 68.3 %$10,327 $5,611 $4,716 84.0 %
Interest on securities393 315 78 24.8 1,331 917 414 45.1 
Interest on other earning assets56 17 39 NM279 69 210 NM
Total interest income3,623 2,218 1,405 63.3 11,937 6,597 5,340 80.9 
Interest Expense
Interest on deposits96 271 (175)(64.6)718 797 (79)(9.9)
Interest on long-term debt152 193 (41)(21.2)635 578 57 9.9 
Interest on other borrowings13 54 (41)(75.9)124 136 (12)(8.8)
Total interest expense261 518 (257)(49.6)1,477 1,511 (34)(2.3)
Net Interest Income3,362 1,700 1,662 97.8 10,460 5,086 5,374 105.7 
Provision for credit losses421 117 304 NM2,158 444 1,714 NM
Net Interest Income After Provision for Credit Losses2,941 1,583 1,358 85.8 8,302 4,642 3,660 78.8 
Noninterest Income
Insurance income518 487 31 6.4 1,648 1,563 85 5.4 
Service charges on deposits247 188 59 31.4 754 540 214 39.6 
Wealth management income324 175 149 85.1 945 509 436 85.7 
Card and payment related fees200 132 68 51.5 558 399 159 39.8 
Residential mortgage income221 80 141 176.3 807 220 587 NM
Investment banking and trading income244 60 184 NM636 135 501 NM
Operating lease income72 36 36 100.0 232 106 126 118.9 
Income from bank-owned life insurance46 29 17 58.6 135 91 44 48.4 
Lending related fees77 24 53 NM210 77 133 172.7 
Commercial real estate related income55 32 23 71.9 148 68 80 117.6 
Securities gains (losses)104 — 104 NM402 — 402 NM
Other income (loss)102 60 42 70.0 119 149 (30)(20.1)
Total noninterest income2,210 1,303 907 69.6 6,594 3,857 2,737 71.0 
Noninterest Expense
Personnel expense2,058 1,161 897 77.3 6,038 3,368 2,670 79.3 
Net occupancy expense233 122 111 91.0 697 360 337 93.6 
Professional fees and outside processing323 102 221 NM859 272 587 NM
Software expense221 77 144 187.0 647 220 427 194.1 
Equipment expense127 64 63 98.4 363 197 166 84.3 
Marketing and customer development75 36 39 108.3 215 92 123 133.7 
Operating lease depreciation56 35 21 60.0 204 93 111 119.4 
Loan-related expense59 26 33 126.9 177 81 96 118.5 
Amortization of intangibles170 29 141 NM513 93 420 NM
Regulatory costs34 20 14 70.0 93 57 36 63.2 
Merger-related and restructuring charges236 34 202 NM552 137 415 NM
Loss (gain) on early extinguishment of debt— — — — 235 — 235 NM
Other expense163 134 29 21.6 471 389 82 21.1 
Total noninterest expense3,755 1,840 1,915 104.1 11,064 5,359 5,705 106.5 
Earnings
Income before income taxes1,396 1,046 350 33.5 3,832 3,140 692 22.0 
Provision for income taxes255 218 37 17.0 670 629 41 6.5 
Net income1,141 828 313 37.8 3,162 2,511 651 25.9 
Noncontrolling interests3 3 — — 9 8 1 12.5 
Net income available to the bank holding company1,138 825 313 37.9 3,153 2,503 650 26.0 
Preferred stock dividends70 90 (20)(22.2)197 177 20 11.3 
Net income available to common shareholders$1,068 $735 $333 45.3 %$2,956 $2,326 $630 27.1 %
Earnings Per Common Share
Basic$0.79 $0.96 $(0.17)(17.7)%$2.20 $3.04 $(0.84)(27.6)%
Diluted0.79 0.95 (0.16)(16.8)2.18 3.00 (0.82)(27.3)
Weighted Average Shares Outstanding
Basic1,347,916 766,167 581,749 75.9 1,346,605 765,428 581,17775.9 
Diluted1,358,122 775,791 582,331 75.1 1,357,174 774,907 582,26775.1 
NM - not meaningful

Truist Financial Corporation 3


Consolidated Statements of Income - Five Quarter Trend   
Quarter Ended
Sept. 30June 30March 31Dec. 31Sept. 30
(Dollars in millions, except per share data, shares in thousands)20202020202020192019
Interest Income
Interest and fees on loans and leases$3,174 $3,377 $3,776 $2,371 $1,886 
Interest on securities393 444 494 402 315 
Interest on other earning assets56 67 156 39 17 
Total interest income3,623 3,888 4,426 2,812 2,218 
Interest Expense
Interest on deposits96 201 421 304 271 
Interest on long-term debt152 211 272 219 193 
Interest on other borrowings13 28 83 62 54 
Total interest expense261 440 776 585 518 
Net Interest Income3,362 3,448 3,650 2,227 1,700 
Provision for credit losses421 844 893 171 117 
Net Interest Income After Provision for Credit Losses2,941 2,604 2,757 2,056 1,583 
Noninterest Income
Insurance income518 581 549 509 487 
Service charges on deposits247 202 305 222 188 
Wealth management income324 289 332 206 175 
Card and payment related fees200 171 187 156 132 
Residential mortgage income221 341 245 65 80 
Investment banking and trading income244 274 118 109 60 
Operating lease income72 83 77 47 36 
Income from bank-owned life insurance46 45 44 38 29 
Lending related fees77 66 67 47 24 
Commercial real estate related income55 49 44 48 32 
Securities gains (losses)104 300 (2)(116)— 
Other income (loss)102 22 (5)67 60 
Total noninterest income2,210 2,423 1,961 1,398 1,303 
Noninterest Expense
Personnel expense2,058 2,008 1,972 1,465 1,161 
Net occupancy expense233 243 221 147 122 
Professional fees and outside processing323 289 247 161 102 
Software expense221 216 210 118 77 
Equipment expense127 120 116 83 64 
Marketing and customer development75 56 84 45 36 
Operating lease depreciation56 77 71 43 35 
Loan-related expense59 56 62 42 26 
Amortization of intangibles170 178 165 71 29 
Regulatory costs34 30 29 24 20 
Merger-related and restructuring charges236 209 107 223 34 
Loss (gain) on early extinguishment of debt— 235 — — — 
Other expense163 161 147 153 134 
Total noninterest expense3,755 3,878 3,431 2,575 1,840 
Earnings
Income before income taxes1,396 1,149 1,287 879 1,046 
Provision for income taxes255 191 224 153 218 
Net income1,141 958 1,063 726 828 
Noncontrolling interests3 3 3 5 3 
Net income available to the bank holding company1,138 955 1,060 721 825 
Preferred stock dividends70 53 74 19 90 
Net income available to common shareholders$1,068 $902 $986 $702 $735 
Earnings Per Common Share
Basic$0.79 $0.67 $0.73 $0.76 $0.96 
Diluted0.79 0.67 0.73 0.75 0.95 
Weighted Average Shares Outstanding
Basic1,347,916 1,347,512 1,344,372 922,840 766,167 
Diluted1,358,122 1,355,834 1,357,545 934,718 775,791 

 
4 Truist Financial Corporation


Segment Financial Performance - Preliminary   
 Quarter Ended
Sept. 30June 30March 31Dec. 31Sept. 30
(Dollars in millions)20202020202020192019
Consumer Banking and Wealth
Net interest income (expense)$1,856 $1,843 $1,860 $1,114 $855 
Net intersegment interest income (expense) 338 317 394 282 229 
Segment net interest income2,194 2,160 2,254 1,396 1,084 
Allocated provision for credit losses181 270 437 145 115 
Noninterest income990 1,006 1,066 652 576 
Noninterest expense1,934 1,972 1,989 1,318 931 
Income (loss) before income taxes1,069 924 894 585 614 
Provision (benefit) for income taxes252 218 210 142 149 
Segment net income (loss)$817 $706 $684 $443 $465 
Corporate and Commercial Banking
Net interest income (expense)$1,235 $1,351 $1,534 $934 $729 
Net intersegment interest income (expense) 41 (61)(208)(99)(89)
Segment net interest income1,276 1,290 1,326 835 640 
Allocated provision for credit losses311 534 399 17 14 
Noninterest income609 621 457 412 271 
Noninterest expense843 880 883 570 338 
Income (loss) before income taxes731 497 501 660 559 
Provision (benefit) for income taxes148 92 89 142 118 
Segment net income (loss)$583 $405 $412 $518 $441 
Insurance Holdings
Net interest income (expense)$31 $33 $36 $38 $39 
Net intersegment interest income (expense) (7)(10)(11)(11)(11)
Segment net interest income24 23 25 27 28 
Allocated provision for credit losses— 6 1 2 2 
Noninterest income524 598 557 536 491 
Noninterest expense446 448 440 481 435 
Income (loss) before income taxes102 167 141 80 82 
Provision (benefit) for income taxes25 41 36 21 21 
Segment net income (loss)$77 $126 $105 $59 $61 
Other, Treasury & Corporate (1)
Net interest income (expense)$240 $221 $220 $141 $77 
Net intersegment interest income (expense) (372)(246)(175)(172)(129)
Segment net interest income(132)(25)45 (31)(52)
Allocated provision for credit losses(71)34 56 7 (14)
Noninterest income87 198 (119)(202)(35)
Noninterest expense532 578 119 206 136 
Income (loss) before income taxes(506)(439)(249)(446)(209)
Provision (benefit) for income taxes(170)(160)(111)(152)(70)
Segment net income (loss)$(336)$(279)$(138)$(294)$(139)
Total Truist Financial Corporation
Net interest income (expense)$3,362 $3,448 $3,650 $2,227 $1,700 
Net intersegment interest income (expense) — — — — — 
Segment net interest income3,362 3,448 3,650 2,227 1,700 
Allocated provision for credit losses421 844 893 171 117 
Noninterest income2,210 2,423 1,961 1,398 1,303 
Noninterest expense3,755 3,878 3,431 2,575 1,840 
Income (loss) before income taxes1,396 1,149 1,287 879 1,046 
Provision (benefit) for income taxes255 191 224 153 218 
Net income$1,141 $958 $1,063 $726 $828 
Effective December 2019, segments were realigned in connection with the SunTrust merger. Results for prior periods have been revised to reflect the new structure.
(1) Includes financial data from subsidiaries below the quantitative and qualitative thresholds requiring disclosure.

Truist Financial Corporation 5


Consolidated Ending Balance Sheets - Five Quarter Trend   
Sept. 30June 30March 31Dec. 31Sept. 30
(Dollars in millions)20202020202020192019
Assets
Cash and due from banks$4,194 $5,116 $5,312 $4,084 $2,027 
Interest-bearing deposits with banks32,914 36,081 31,036 14,981 877 
Securities borrowed or purchased under resale agreements 1,300 1,345 1,796 1,417 114 
Trading assets at fair value4,670 3,824 3,863 5,733 400 
Securities available for sale at fair value86,132 77,805 78,398 74,727 35,997 
Securities held to maturity at amortized cost— — — — 18,768 
Loans and leases:
Commercial:
Commercial and industrial140,874 147,141 149,161 130,180 64,324 
CRE27,474 27,963 27,532 26,832 17,080 
Commercial construction6,772 6,891 6,630 6,205 3,804 
Lease financing5,493 5,783 5,984 6,122 2,356 
Consumer:
Residential mortgage50,379 51,671 53,096 52,071 28,297 
Residential home equity and direct26,558 26,935 27,629 27,044 11,646 
Indirect auto25,269 24,509 25,146 24,442 11,871 
Indirect other11,527 11,592 10,980 11,100 6,590 
Student7,480 7,484 7,771 6,743 — 
Credit card4,801 4,856 5,300 5,619 3,058 
PCI— — — 3,484 387 
Total loans and leases held for investment306,627 314,825 319,229 299,842 149,413 
Loans held for sale5,522 6,323 4,810 8,373 1,442 
Total loans and leases312,149 321,148 324,039 308,215 150,855 
Allowance for loan and lease losses(5,863)(5,702)(5,211)(1,549)(1,573)
Premises and equipment3,968 4,002 3,999 3,712 2,022 
Goodwill23,869 23,882 23,927 24,154 9,832 
Core deposit and other intangible assets2,840 3,016 3,168 3,142 678 
Mortgage servicing rights1,991 2,077 2,150 2,630 929 
Other assets31,019 31,742 33,752 31,832 15,824 
Total assets$499,183 $504,336 $506,229 $473,078 $236,750 
Liabilities
Deposits:
Noninterest-bearing deposits$124,297 $122,694 $97,618 $92,405 $52,667 
Interest checking98,694 99,005 92,950 85,492 27,723 
Money market and savings121,856 123,974 124,072 120,934 64,454 
Time deposits25,900 30,562 35,539 35,896 16,526 
Foreign office deposits - interest-bearing— — — — 910 
Total deposits370,747 376,235 350,179 334,727 162,280 
Short-term borrowings6,244 5,700 12,696 18,218 10,405 
Long-term debt41,008 42,133 65,662 41,339 25,520 
Other liabilities11,211 11,385 11,631 12,236 6,242 
Total liabilities429,210 435,453 440,168 406,520 204,447 
Shareholders' Equity:
Preferred stock8,048 7,143 4,599 5,102 3,057 
Common stock6,741 6,738 6,737 6,711 3,832 
Additional paid-in capital 35,774 35,676 35,584 35,609 6,931 
Retained earnings18,834 18,373 18,076 19,806 19,440 
Accumulated other comprehensive loss470 847 898 (844)(1,026)
Noncontrolling interests106 106 167 174 69 
Total shareholders' equity69,973 68,883 66,061 66,558 32,303 
Total liabilities and shareholders' equity$499,183 $504,336 $506,229 $473,078 $236,750 
In 4Q19, Truist transferred all HTM securities into AFS securities in response to changes in regulatory capital rules.


6 Truist Financial Corporation


Average Balance Sheets  
 Quarter EndedYear-to-Date
 September 30ChangeSeptember 30Change
(Dollars in millions)20202019$%20202019$%
Assets        
Securities at amortized cost (1):
U.S. Treasury$2,218 $2,240 $(22)(1.0)%$2,243 $2,731 $(488)(17.9)%
U.S. government-sponsored entities (GSE)1,842 2,449 (607)(24.8)1,847 2,436 (589)(24.2)
Mortgage-backed securities issued by GSE75,232 43,415 31,817 73.3 72,152 41,202 30,950 75.1 
States and political subdivisions499 566 (67)(11.8)512 583 (71)(12.2)
Non-agency mortgage-backed— 198 (198)(100.0)115 271 (156)(57.6)
Other37 32 5 15.6 37 34 3 8.8 
Total securities79,828 48,900 30,928 63.2 76,906 47,257 29,649 62.7 
Loans and leases:
Commercial:
Commercial and industrial143,452 63,768 79,684 125.0 142,731 62,576 80,155 128.1 
CRE27,761 17,042 10,719 62.9 27,538 16,894 10,644 63.0 
Commercial construction6,861 3,725 3,136 84.2 6,673 3,912 2,761 70.6 
Lease financing5,626 2,260 3,366 148.9 5,872 2,135 3,737 175.0 
Consumer:
Residential mortgage51,500 28,410 23,090 81.3 52,288 30,604 21,684 70.9 
Residential home equity and direct26,726 11,650 15,076 129.4 27,161 11,673 15,488 132.7 
Indirect auto24,732 11,810 12,922 109.4 24,809 11,586 13,223 114.1 
Indirect other11,530 6,552 4,978 76.0 11,255 6,277 4,978 79.3 
Student7,446 — 7,446 NM7,622 — 7,622 NM
Credit card4,810 3,036 1,774 58.4 5,097 2,976 2,121 71.3 
PCI— 411 (411)(100.0)— 433 (433)(100.0)
Total loans and leases held for investment310,444 148,664 161,780 108.8 311,046 149,066 161,980 108.7 
Loans held for sale5,247 3,378 1,869 55.3 5,575 1,742 3,833 NM
Total loans and leases315,691 152,042 163,649 107.6 316,621 150,808 165,813 109.9 
Interest earning trading assets4,056 668 3,388 NM4,695 910 3,785 NM
Other earning assets35,819 1,798 34,021 NM33,708 1,702 32,006 NM
Total earning assets435,394 203,408 231,986 114.0 431,930 200,677 231,253 115.2 
Nonearning assets65,432 29,012 36,420 125.5 65,780 28,429 37,351 131.4 
Total assets$500,826 $232,420 $268,406 115.5 %$497,710 $229,106 $268,604 117.2 %
Liabilities and Shareholders' Equity
Deposits:
Noninterest-bearing deposits$123,966 $52,500 $71,466 136.1 %$110,375 $52,489 $57,886 110.3 %
Interest checking96,707 27,664 69,043 NM93,205 27,665 65,540 NM
Money market and savings123,598 64,920 58,678 90.4 123,536 63,885 59,651 93.4 
Time deposits27,940 16,643 11,297 67.9 32,157 16,256 15,901 97.8 
Foreign office deposits - interest-bearing— 265 (265)(100.0)— 355 (355)(100.0)
Total deposits372,211 161,992 210,219 129.8 359,273 160,650 198,623 123.6 
Short-term borrowings6,209 8,307 (2,098)(25.3)11,350 7,443 3,907 52.5 
Long-term debt40,919 22,608 18,311 81.0 47,643 23,027 24,616 106.9 
Other liabilities11,853 6,769 5,084 75.1 12,133 6,449 5,684 88.1 
Total liabilities431,192 199,676 231,516 115.9 430,399 197,569 232,830 117.8 
Shareholders' equity69,634 32,744 36,890 112.7 67,311 31,537 35,774 113.4 
Total liabilities and shareholders' equity$500,826 $232,420 $268,406 115.5 %$497,710 $229,106 $268,604 117.2 %
Average balances exclude basis adjustments for fair value hedges.
(1) Includes AFS and HTM securities.
NM - not meaningful


Truist Financial Corporation 7


Average Balance Sheets - Five Quarter Trend   
 Quarter Ended
 Sept. 30June 30March 31Dec. 31Sept. 30
(Dollars in millions)20202020202020192019
Assets     
Securities at amortized cost (1):     
U.S. Treasury$2,218 $2,237 $2,274 $2,384 $2,240 
U.S. government-sponsored entities (GSE)1,842 1,844 1,856 2,301 2,449 
Mortgage-backed securities issued by GSE75,232 70,374 70,816 55,119 43,415 
States and political subdivisions499 505 530 598 566 
Non-agency mortgage-backed— 162 185 263 198 
Other37 37 40 34 32 
Total securities79,828 75,159 75,701 60,699 48,900 
Loans and leases:
Commercial:
Commercial and industrial143,452 152,991 131,743 81,853 63,768 
CRE27,761 27,804 27,046 19,896 17,042 
Commercial construction6,861 6,748 6,409 4,506 3,725 
Lease financing5,626 5,922 6,070 3,357 2,260 
Consumer:
Residential mortgage51,500 52,380 52,993 34,824 28,410 
Residential home equity and direct26,726 27,199 27,564 15,810 11,650 
Indirect auto24,732 24,721 24,975 15,390 11,810 
Indirect other11,530 11,282 10,950 7,772 6,552 
Student7,446 7,633 7,787 1,825 — 
Credit card4,810 4,949 5,534 3,788 3,036 
PCI— — — 1,220 411 
Total loans and leases held for investment310,444 321,629 301,071 190,241 148,664 
Loans held for sale5,247 4,806 6,677 3,400 3,378 
Total loans and leases315,691 326,435 307,748 193,641 152,042 
Interest earning trading assets4,056 3,700 6,334 2,370 668 
Other earning assets35,819 41,531 23,750 6,405 1,798 
Total earning assets435,394 446,825 413,533 263,115 203,408 
Nonearning assets65,432 67,895 64,017 38,944 29,012 
Total assets$500,826 $514,720 $477,550 $302,059 $232,420 
Liabilities and Shareholders' Equity
Deposits:
Noninterest-bearing deposits$123,966 $113,875 $93,135 $64,485 $52,500 
Interest checking96,707 97,863 85,008 43,246 27,664 
Money market and savings123,598 126,071 120,936 79,903 64,920 
Time deposits27,940 33,009 35,570 23,058 16,643 
Foreign office deposits - interest-bearing— — — 24 265 
Total deposits372,211 370,818 334,649 210,716 161,992 
Short-term borrowings6,209 8,998 18,900 11,489 8,307 
Long-term debt40,919 55,537 46,547 29,888 22,608 
Other liabilities11,853 12,504 12,042 8,226 6,769 
Total liabilities431,192 447,857 412,138 260,319 199,676 
Shareholders' equity69,634 66,863 65,412 41,740 32,744 
Total liabilities and shareholders' equity$500,826 $514,720 $477,550 $302,059 $232,420 
Average balances exclude basis adjustments for fair value hedges.
(1) Includes AFS and HTM securities.


8 Truist Financial Corporation


Average Balances and Rates - Quarters   
 Quarter Ended
 September 30, 2020June 30, 2020
 (1)(2) Interest(2)(1)(2) Interest(2)
 AverageIncome/Yields/AverageIncome/Yields/
(Dollars in millions)BalancesExpenseRatesBalancesExpenseRates
Assets      
Securities at amortized cost (3):
U.S. Treasury$2,218 $10 1.78 %$2,237 $10 1.88 %
U.S. government-sponsored entities (GSE)1,842 10 2.33 1,844 12 2.33 
Mortgage-backed securities issued by GSE75,232 366 1.95 70,374 413 2.35 
States and political subdivisions499 7 5.03 505 4 3.57 
Non-agency mortgage-backed— — — 162 7 16.71 
Other37 1 1.99 37 — 2.27 
Total securities79,828 394 1.97 75,159 446 2.37 
Loans and leases:
Commercial:
Commercial and industrial143,452 1,087 3.02 152,991 1,204 3.16 
CRE27,761 203 2.88 27,804 227 3.26 
Commercial construction6,861 55 3.26 6,748 61 3.70 
Lease financing5,626 52 3.71 5,922 70 4.71 
Consumer:
Residential mortgage51,500 576 4.47 52,380 608 4.65 
Residential home equity and direct26,726 394 5.86 27,199 391 5.78 
Indirect auto24,732 405 6.51 24,721 407 6.63 
Indirect other11,530 204 7.05 11,282 201 7.18 
Student7,446 80 4.30 7,633 87 4.55 
Credit card4,810 109 9.03 4,949 114 9.27 
Total loans and leases held for investment310,444 3,165 4.06 321,629 3,370 4.21 
Loans held for sale5,247 37 2.78 4,806 36 3.04 
Total loans and leases315,691 3,202 4.04 326,435 3,406 4.19 
Interest earning trading assets4,056 32 3.23 3,700 39 4.19 
Other earning assets35,819 24 0.26 41,531 28 0.28 
Total earning assets435,394 3,652 3.34 446,825 3,919 3.52 
Nonearning assets65,432 67,895 
Total assets$500,826 $514,720 
Liabilities and Shareholders' Equity
Interest-bearing deposits:      
Interest checking$96,707 15 0.06 $97,863 55 0.23 
Money market and savings123,598 19 0.06 126,071 57 0.18 
Time deposits27,940 62 0.89 33,009 89 1.09 
Total interest-bearing deposits (4)248,245 96 0.15 256,943 201 0.32 
Short-term borrowings6,209 13 0.85 8,998 28 1.24 
Long-term debt40,919 152 1.48 55,537 211 1.52 
Total interest-bearing liabilities295,373 261 0.35 321,478 440 0.55 
Noninterest-bearing deposits (4)123,966 113,875 
Other liabilities11,853 12,504 
Shareholders' equity69,634 66,863 
Total liabilities and shareholders' equity$500,826 $514,720 
Average interest-rate spread2.99 2.97 
Net interest income/ net interest margin $3,391 3.10 %$3,479 3.13 %
Taxable-equivalent adjustment$29 $31 
Applicable ratios are annualized.
(1) Excludes basis adjustments for fair value hedges.
(2) Amounts are on a taxable-equivalent basis utilizing the federal income tax rate of 21% for the periods presented. Interest income includes certain fees, deferred costs and dividends.
(3) Includes AFS and HTM securities.
(4) Total deposit costs were 0.10% and 0.22% for the three months ended September 30, 2020 and June 30, 2020, respectively.


Truist Financial Corporation 9


Average Balances and Rates - Quarters
 Quarter Ended
 March 31, 2020December 31, 2019September 30, 2019
 (1)(2) Interest(2)(1)(2) Interest(2)(1)(2) Interest(2)
 AverageIncome/Yields/AverageIncome/Yields/AverageIncome/Yields/
(Dollars in millions)BalancesExpenseRatesBalancesExpenseRatesBalancesExpenseRates
Assets         
Securities at amortized cost (3):
U.S. Treasury$2,274 $11 1.93 %$2,384 $12 1.97 %$2,240 $11 2.04 %
U.S. government-sponsored entities (GSE)1,856 10 2.33 2,301 12 2.28 2,449 14 2.25 
Mortgage-backed securities issued by GSE70,816 461 2.60 55,119 366 2.64 43,415 279 2.57 
States and political subdivisions530 5 3.56 598 4 3.38 566 5 3.44 
Non-agency mortgage-backed185 8 16.72 263 9 13.15 198 9 18.77 
Other40 — 3.01 34 — 3.53 32 — 3.67 
Total securities75,701 495 2.62 60,699 403 2.65 48,900 318 2.60 
Loans and leases:
Commercial:
Commercial and industrial131,743 1,419 4.33 81,853 862 4.18 63,768 671 4.18 
CRE27,046 287 4.25 19,896 223 4.43 17,042 209 4.83 
Commercial construction6,409 76 4.87 4,506 57 5.17 3,725 47 5.11 
Lease financing6,070 65 4.27 3,357 32 3.79 2,260 18 3.17 
Consumer:
Residential mortgage52,993 594 4.48 34,824 361 4.15 28,410 285 4.02 
Residential home equity and direct27,564 452 6.60 15,810 242 6.04 11,650 173 5.92 
Indirect auto24,975 428 6.89 15,390 312 8.04 11,810 262 8.84 
Indirect other10,950 201 7.37 7,772 133 6.77 6,552 110 6.61 
Student7,787 104 5.38 1,825 24 5.20 — — — 
Credit card5,534 133 9.68 3,788 85 9.06 3,036 71 9.18 
PCI— — — 1,220 33 10.63 411 25 24.23 
Total loans and leases held for investment301,071 3,759 5.02 190,241 2,364 4.94 148,664 1,871 5.00 
Loans held for sale6,677 53 3.14 3,400 31 3.52 3,378 35 4.16 
Total loans and leases307,748 3,812 4.98 193,641 2,395 4.91 152,042 1,906 4.98 
Interest earning trading assets6,334 64 4.04 2,370 11 1.84 668 3 2.02 
Other earning assets23,750 92 1.55 6,405 28 1.78 1,798 14 2.92 
Total earning assets413,533 4,463 4.33 263,115 2,837 4.29 203,408 2,241 4.38 
Nonearning assets64,017 38,944 29,012 
Total assets$477,550 $302,059 $232,420 
Liabilities and Shareholders' Equity        
Interest-bearing deposits:
Interest checking$85,008 129 0.61 $43,246 65 0.60 $27,664 47 0.67 
Money market and savings120,936 178 0.59 79,903 152 0.76 64,920 156 0.95 
Time deposits35,570 114 1.29 23,058 87 1.48 16,643 67 1.62 
Foreign office deposits - interest-bearing— — — 24 — 2.19 265 1 2.13 
Total interest-bearing deposits (4)241,514 421 0.70 146,231 304 0.82 109,492 271 0.99 
Short-term borrowings18,900 83 1.76 11,489 62 2.15 8,307 54 2.55 
Long-term debt46,547 272 2.34 29,888 219 2.92 22,608 193 3.42 
Total interest-bearing liabilities306,961 776 1.02 187,608 585 1.24 140,407 518 1.47 
Noninterest-bearing deposits (4)93,135 64,485 52,500 
Other liabilities12,042 8,226 6,769 
Shareholders' equity65,412 41,740 32,744 
Total liabilities and shareholders' equity$477,550 $302,059 $232,420 
Average interest-rate spread3.31 3.05 2.91 
Net interest income/ net interest margin $3,687 3.58 %$2,252 3.41 %$1,723 3.37 %
Taxable-equivalent adjustment$37 $25 $23 
Applicable ratios are annualized.
(1) Excludes basis adjustments for fair value hedges.
(2) Amounts are on a taxable-equivalent basis utilizing the federal income tax rate of 21% for the periods presented. Interest income includes certain fees, deferred costs and dividends.
(3) Includes AFS and HTM securities.
(4) Total deposit costs were 0.51%, 0.57% and 0.67% for the three months ended March 31, 2020, December 31, 2019 and September 30, 2019, respectively.


10 Truist Financial Corporation


Average Balances and Rates - Year-To-Date   
 Year-to-Date
 September 30, 2020September 30, 2019
 (1)(2) Interest(2)(1)(2) Interest(2)
 AverageIncome/Yields/AverageIncome/Yields/
(Dollars in millions)BalancesExpenseRatesBalancesExpenseRates
Assets      
Securities at amortized cost (3):
U.S. Treasury$2,243 $31 1.86 %$2,731 $41 2.03 %
U.S. government-sponsored entities (GSE)1,847 32 2.33 2,436 41 2.25 
Mortgage-backed securities issued by GSE72,152 1,240 2.29 41,202 795 2.57 
States and political subdivisions512 16 4.04 583 17 3.85 
Non-agency mortgage-backed115 15 16.78 271 29 14.34 
Other37 1 2.44 34 1 3.83 
Total securities76,906 1,335 2.31 47,257 924 2.61 
Loans and leases:
Commercial:
Commercial and industrial142,731 3,710 3.47 62,576 2,006 4.28 
CRE27,538 717 3.46 16,894 626 4.93 
Commercial construction6,673 192 3.92 3,912 151 5.26 
Lease financing5,872 187 4.24 2,135 52 3.26 
Consumer:
Residential mortgage52,288 1,778 4.53 30,604 930 4.05 
Residential home equity and direct27,161 1,237 6.08 11,673 517 5.94 
Indirect auto24,809 1,240 6.68 11,586 756 8.73 
Indirect other11,255 606 7.19 6,277 310 6.60 
Student7,622 271 4.75 — — — 
Credit card5,097 356 9.34 2,976 203 9.05 
PCI— — — 433 69 21.20 
Total loans and leases held for investment311,046 10,294 4.42 149,066 5,620 5.04 
Loans held for sale5,575 126 3.00 1,742 54 4.17 
Total loans and leases316,621 10,420 4.39 150,808 5,674 5.03 
Interest earning trading assets4,695 135 3.85 910 15 2.20 
Other earning assets33,708 144 0.57 1,702 55 4.30 
Total earning assets431,930 12,034 3.72 200,677 6,668 4.44 
Nonearning assets65,780 28,429 
Total assets$497,710 $229,106 
Liabilities and Shareholders' Equity    
Interest-bearing deposits:
Interest checking$93,205 199 0.28 $27,665 132 0.64 
Money market and savings123,536 254 0.27 63,885 469 0.98 
Time deposits32,157 265 1.10 16,256 190 1.57 
Foreign office deposits - interest-bearing— — — 355 6 2.36 
Total interest-bearing deposits (4)248,898 718 0.39 108,161 797 0.99 
Short-term borrowings11,350 124 1.46 7,443 136 2.44 
Long-term debt47,643 635 1.78 23,027 578 3.35 
Total interest-bearing liabilities307,891 1,477 0.64 138,631 1,511 1.46 
Noninterest-bearing deposits (4)110,375 52,489 
Other liabilities12,133 6,449 
Shareholders' equity67,311 31,537 
Total liabilities and shareholders' equity$497,710 $229,106 
Average interest-rate spread3.08 2.98 
Net interest income/ net interest margin $10,557 3.26 %$5,157 3.43 %
Taxable-equivalent adjustment$97 $71 
Applicable ratios are annualized.
(1) Excludes basis adjustments for fair value hedges.
(2) Amounts are on a taxable-equivalent basis utilizing the federal income tax rate of 21% for the periods presented. Interest income includes certain fees, deferred costs and dividends.
(3) Includes AFS and HTM securities.
(4) Total deposit costs were 0.27% and 0.66% for the year ended September 30, 2020 and 2019, respectively.

Truist Financial Corporation 11


Credit Quality   
 Sept. 30June 30March 31Dec. 31Sept. 30
(Dollars in millions)20202020202020192019
Nonperforming Assets     
Nonaccrual loans and leases:     
Commercial:     
Commercial and industrial$507 $428 $443 $212 $172 
CRE52 42 18 10 27 
Commercial construction7 13 2 — 2 
Lease financing32 56 27 8 2 
Consumer:
Residential mortgage205 198 248 55 106 
Residential home equity and direct180 192 170 67 56 
Indirect auto137 155 125 100 81 
Indirect other4 3 1 2 1 
Total nonaccrual loans and leases held for investment1,124 1,087 1,034 454 447 
Loans held for sale130 102 41 107 — 
Total nonaccrual loans and leases1,254 1,189 1,075 561 447 
Foreclosed real estate30 43 63 82 33 
Other foreclosed property30 20 39 41 29 
Total nonperforming assets$1,314 $1,252 $1,177 $684 $509 
Troubled Debt Restructurings (TDRs)     
Performing TDRs:
Commercial:     
Commercial and industrial$84 $57 $65 $47 $69 
CRE36 22 7 6 6 
Commercial construction1 36 36 37 1 
Lease financing1 1 1 — — 
Consumer:
Residential mortgage640 533 513 470 570 
Residential home equity and direct71 71 66 51 54 
Indirect auto336 342 350 333 324 
Indirect other5 4 5 5 4 
Student5 4 1 — — 
Credit card38 37 35 31 29 
Total performing TDRs1,217 1,107 1,079 980 1,057 
Nonperforming TDRs140 111 121 82 115 
Total TDRs$1,357 $1,218 $1,200 $1,062 $1,172 
Loans 90 Days or More Past Due and Still Accruing
Commercial:
Commercial and industrial$6 $9 $5 $1 $— 
CRE8 3 1 — — 
Lease financing— 1 — — — 
Consumer:
Residential mortgage573 521 610 543 347 
Residential home equity and direct5 9 10 9 8 
Indirect auto8 10 11 11 9 
Indirect other3 3 2 2 — 
Student570 478 1,068 188 — 
Credit card24 38 41 22 15 
PCI— — — 1,218 24 
Total loans 90 days past due and still accruing$1,197 $1,072 $1,748 $1,994 $403 
Loans 30-89 Days Past Due
Commercial:
Commercial and industrial$155 $282 $262 $94 $34 
CRE7 6 8 5 1 
Commercial construction— 1 16 1 — 
Lease financing9 10 8 2 1 
Consumer:
Residential mortgage796 703 679 498 432 
Residential home equity and direct103 108 156 122 56 
Indirect auto321 265 521 560 380 
Indirect other52 50 74 85 43 
Student666 442 593 650 — 
Credit card39 34 57 56 29 
PCI— — — 140 16 
Total loans 30-89 days past due $2,148 $1,901 $2,374 $2,213 $992 

12 Truist Financial Corporation


As of/For the Quarter Ended
 Sept. 30June 30March 31Dec. 31Sept. 30
(Dollars in millions)20202020202020192019
Allowance for Credit Losses     
Beginning balance$6,133 $5,611 $1,889 $1,653 $1,689 
CECL adoption - impact to retained earnings before tax— — 2,762 — — 
CECL adoption - reserves on PCD assets— — 378 — — 
Provision for credit losses421 844 893 171 117 
Charge-offs:
Commercial:
Commercial and industrial(112)(123)(39)(23)(28)
CRE(44)(14)(1)(5)(2)
Commercial construction(19)— (3)— — 
Lease financing(44)(4)(2)(9)(1)
Consumer:
Residential mortgage(4)(35)(11)(8)(3)
Residential home equity and direct(52)(65)(68)(25)(24)
Indirect auto(72)(80)(142)(107)(92)
Indirect other(8)(20)(18)(19)(14)
Student(6)(6)(8)— — 
Credit card(44)(50)(53)(37)(25)
Total charge-offs(405)(397)(345)(233)(189)
Recoveries:     
Commercial:     
Commercial and industrial20 21 17 6 5 
CRE— 4 — — 3 
Commercial construction2 7 1 1 — 
Lease financing4 — — — 1 
Consumer:
Residential mortgage3 2 2 1 — 
Residential home equity and direct16 15 15 10 6 
Indirect auto22 18 23 13 12 
Indirect other4 7 7 5 3 
Student— 1 — — — 
Credit card8 6 8 5 6 
Total recoveries79 81 73 41 36 
Net charge-offs(326)(316)(272)(192)(153)
Merger related items and other1 (6)(39)257 — 
Ending balance$6,229 $6,133 $5,611 $1,889 $1,653 
Allowance for Credit Losses:     
Allowance for loan and lease losses (excluding PCD / PCI loans)$5,675 $5,408 $4,880 $1,541 $1,565 
Allowance for PCD / PCI loans188 294 331 8 8 
Reserve for unfunded lending commitments (RUFC)366 431 400 340 80 
Total$6,229 $6,133 $5,611 $1,889 $1,653 

Truist Financial Corporation 13


    As of/For the Year-to-Date
    Period Ended Sept. 30
(Dollars in millions)   20202019
Allowance for Credit Losses   
Beginning balance   $1,889 $1,651 
CECL adoption - impact to retained earnings before tax2,762 — 
CECL adoption - reserves on PCD assets378 — 
Provision for credit losses   2,158 444 
Charge-offs:   
Commercial:   
Commercial and industrial   (274)(67)
CRE   (59)(28)
Commercial construction(22)— 
Lease financing   (50)(2)
Consumer:
Residential mortgage   (50)(13)
Residential home equity and direct   (185)(68)
Indirect auto   (294)(263)
Indirect other(46)(43)
Student(20)— 
Credit card   (147)(72)
Total charge-offs   (1,147)(556)
Recoveries:     
Commercial:     
Commercial and industrial   58 19 
CRE   4 5 
Commercial construction10 2 
Lease financing   4 1 
Consumer:
Residential mortgage   7 1 
Residential home equity and direct   46 20 
Indirect auto   63 39 
Indirect other18 12 
Student1 — 
Credit card   22 15 
Total recoveries   233 114 
Net charge-offs   (914)(442)
Merger related items and other(44)— 
Ending balance   $6,229 $1,653 

As of/For the Quarter Ended
 Sept. 30June 30March 31Dec. 31Sept. 30
 20202020202020192019
Asset Quality Ratios     
Loans 30-89 days past due and still accruing as a percentage of loans and leases0.70 %0.60 %0.74 %0.74 %0.66 %
Loans 90 days or more past due and still accruing as a percentage of loans and leases0.39 0.34 0.55 0.66 0.27 
Nonperforming loans and leases as a percentage of loans and leases held for investment0.37 0.35 0.32 0.15 0.30 
Nonperforming loans and leases as a percentage of loans and leases (1)0.40 0.37 0.33 0.18 0.30 
Nonperforming assets as a percentage of:
Total assets (1)0.26 0.25 0.23 0.14 0.22 
Loans and leases plus foreclosed property0.39 0.37 0.36 0.19 0.34 
Net charge-offs as a percentage of average loans and leases (2)0.42 0.39 0.36 0.40 0.41 
Allowance for loan and lease losses as a percentage of loans and leases1.91 1.81 1.63 0.52 1.05 
Ratio of allowance for loan and lease losses to:
Net charge-offs4.52X4.49X4.76X2.03X2.59X
Nonperforming loans and leases5.22X5.24X5.04X3.41X3.52X
Asset Quality Ratios (Excluding PPP, other Government Guaranteed and PCI)
Loans 90 days or more past due and still accruing as a percentage of loans and leases0.03 %0.04 %0.04 %0.03 %0.04 %
Applicable ratios are annualized.
(1)Includes loans held for sale.
(2) The third quarter of 2020 includes $97 million of charge-offs on PCD assets directly related to the implementation of CECL.
    As of/For the Year-to-Date
    Period Ended Sept. 30
    20202019
Asset Quality Ratios     
Net charge-offs as a percentage of average loans and leases   0.39 %0.40 %
Ratio of allowance for loan and lease losses to net charge-offs   4.80X2.66X
Applicable ratios are annualized.

14 Truist Financial Corporation


 September 30, 2020
  Past Due 30-89Past Due 90+ 
(Dollars in millions)Current StatusDaysDaysTotal
Troubled Debt Restructurings
Performing TDRs: (1)      
Commercial:      
Commercial and industrial$84 100.0 %$— — %$— — %$84 
CRE36 100.0 — — — — 36 
Commercial construction1 100.0 — — — — 1 
Lease financing1 100.0 — — — — 1 
Consumer:
Residential mortgage376 58.8 114 17.8 150 23.4 640 
Residential home equity and direct68 95.8 3 4.2 — — 71 
Indirect auto306 91.1 30 8.9 — — 336 
Indirect other5 100.0 — — — — 5 
Student5 100.0 — — — — 5 
Credit card34 89.5 3 7.9 1 2.6 38 
Total performing TDRs (1)916 75.3 150 12.3 151 12.4 1,217 
Nonperforming TDRs (2)72 51.5 23 16.4 45 32.1 140 
Total TDRs (1)(2)$988 72.9 %$173 12.7 %$196 14.4 %$1,357 
(1)Past due performing TDRs are included in past due disclosures.
(2)Nonperforming TDRs are included in nonaccrual loan disclosures.
Quarter Ended
 Sept. 30June 30March 31Dec. 31Sept. 30
 20202020202020192019
Net Charge-offs as a Percentage of Average Loans and Leases:     
Commercial:     
Commercial and industrial0.25 %0.27 %0.07 %0.09 %0.14 %
CRE0.63 0.15 0.01 0.09 — 
Commercial construction1.02 (0.43)0.13 (0.09)(0.11)
Lease financing2.92 0.33 0.08 1.03 0.11 
Consumer:
Residential mortgage0.01 0.25 0.07 0.09 0.04 
Residential home equity and direct0.53 0.73 0.78 0.39 0.60 
Indirect auto0.76 1.03 1.89 2.41 2.70 
Indirect other0.21 0.41 0.47 0.72 0.60 
Student0.28 0.31 0.38 (0.01)— 
Credit card3.00 3.50 3.30 3.32 2.59 
Total loans and leases0.42 0.39 0.36 0.40 0.41 
Applicable ratios are annualized.  
 
Credit Quality - Allowance with Fair Value Marks
As of/For the Quarter Ended
Sept. 30June 30March 31Dec. 31
(Dollars in millions)2020202020202019
ALLL$5,863 $5,702 $5,211 $1,549 
Unamortized fair value mark (1)2,676 3,077 3,539 4,564 
Allowance plus unamortized fair value mark$8,539 $8,779 $8,750 $6,113 
Loans and leases held for investment$306,627 $314,825 $319,229 $299,842 
Unamortized fair value mark (1)2,676 3,077 3,539 4,564 
Gross loans and leases$309,303 $317,902 $322,768 $304,406 
Allowance for loan and lease losses as a percentage of loans and leases - GAAP1.91 %1.81 %1.63 %0.52 %
Allowance for loan and lease losses and unamortized fair value mark as a percentage of gross loans and leases - Adjusted (1) (2)2.76 2.76 2.71 2.01 
(1)Unamortized fair value mark includes credit, interest rate and liquidity components.
(2)Allowance for loan and lease losses and unamortized fair value mark, and allowance for credit losses and unamortized fair value mark, as a percentage of gross loans and leases are non-GAAP measurements of credit reserves that are calculated by adjusting the ALLL or ACL, and loans and leases held for investment by the unamortized fair value mark. Truist's management uses these measures to assess loss absorption capacity.
Truist Financial Corporation 15


Rollforward of Intangible Assets and Selected Fair Value Marks (1)
 As of/For the Quarter Ended
Sept. 30June 30March 31Dec. 31
(Dollars in millions)2020202020202019
Loans and Leases (2)
Beginning balance unamortized fair value mark$(3,077)$(3,539)$(4,564)$(221)
Additions - Merger with SunTrust— — — (4,513)
Accretion367 440 454 170 
CECL adoption - reserves on PCD assets— — 378 — 
Purchase accounting adjustments and other activity34 22 193 — 
Ending balance$(2,676)$(3,077)$(3,539)$(4,564)
Core deposit and other intangible assets
Beginning balance$3,016 $3,168 $3,142 $678 
Additions - Merger with SunTrust— — — 2,535 
Amortization of intangibles(170)(178)(165)(71)
Amortization in net occupancy expense(6)(6)(5)— 
Purchase accounting adjustments and other activity— 32 196 — 
Ending balance$2,840 $3,016 $3,168 $3,142 
Deposits (3)
Beginning balance unamortized fair value mark$(37)$(54)$(76)$— 
Additions - Merger with SunTrust— — — (83)
Amortization11 17 22 7 
Ending balance$(26)$(37)$(54)$(76)
Long-Term Debt (3)
Beginning balance unamortized fair value mark$(262)$(285)$(312)$(10)
Additions - Merger with SunTrust— — — (309)
Amortization24 23 27 7 
Ending balance$(238)$(262)$(285)$(312)
(1)Includes the merger with SunTrust, as well as other acquisitions. This summary includes only selected information and does not represent all purchase accounting adjustments.
(2)Purchase accounting marks on loans and leases includes credit, interest and liquidity components, and are generally recognized using the level-yield method over the remaining life of the individual loans or recognized in full in the event of prepayment.
(3)Purchase accounting marks on liabilities represents interest rate marks on time deposits and long-term debt and are recognized using the level-yield method over the term of the liability.
16 Truist Financial Corporation


Capital Information - Five Quarter Trend
 As of/For the Quarter Ended
 Sept. 30June 30March 31Dec. 31Sept. 30
(Dollars in millions, except per share data, shares in thousands)20202020202020192019
Selected Capital Information(preliminary)    
Risk-based capital:     
Common equity tier 1$37,881 $37,107 $36,396 $35,643 $19,905 
Tier 145,927 44,248 40,993 40,743 22,960 
Total55,031 53,436 49,395 47,511 27,666 
Risk-weighted assets377,045 382,826 390,348 376,056 187,503 
Average quarterly tangible assets476,869 490,203 454,381 276,591 223,298 
Risk-based capital ratios:
Common equity tier 110.0 %9.7 %9.3 %9.5 %10.6 %
Tier 112.2 11.6 10.5 10.8 12.2 
Total14.6 14.0 12.7 12.6 14.8 
Leverage capital ratio (1)9.6 9.0 9.0 14.7 10.3 
Supplementary leverage (2)8.9 8.5 7.8 7.9 NA
Equity as a percentage of total assets14.0 13.7 13.0 14.1 13.6 
Common equity per common share$45.86 $45.74 $45.49 $45.66 $38.07 
(1)The leverage ratio is calculated using end of period Tier 1 capital and quarterly average tangible assets. The timing of the merger impacted the 4Q19 result.
(2)Truist became subject to the supplementary leverage ratio in 2020. The 4Q19 measure was an estimate based on a full quarter of average tangible assets.
Sept. 30June 30March 31Dec. 31Sept. 30
(Dollars in millions, except per share data, shares in thousands)20202020202020192019
Calculations of Tangible Common Equity and Related Measures: (1)
Total shareholders' equity$69,973 $68,883 $66,061 $66,558 $32,303 
Less:
Preferred stock8,048 7,143 4,599 5,102 3,057 
Noncontrolling interests106 106 167 174 69 
Intangible assets, net of deferred taxes25,923 26,083 26,263 26,482 10,281 
Tangible common equity$35,896 $35,551 $35,032 $34,800 $18,896 
Outstanding shares at end of period (in thousands)1,348,118 1,347,609 1,347,461 1,342,166 766,303 
Tangible Common Equity Per Common Share$26.63 $26.38 $26.00 $25.93 $24.66 
(1)Tangible common equity and related measures are non-GAAP measures that exclude the impact of intangible assets, net of deferred taxes, and their related amortization. These measures are useful for evaluating the performance of a business consistently, whether acquired or developed internally. Truist's management uses these measures to assess the quality of capital and returns relative to balance sheet risk. These measures are not necessarily comparable to similar measures that may be presented by other companies.
Truist Financial Corporation 17


Selected Mortgage Banking Information & Additional Information
 As of/For the Quarter Ended
Sept. 30June 30March 31Dec. 31Sept. 30
(Dollars in millions, except per share data)20202020202020192019
Residential Mortgage Income
Residential mortgage production revenue$339 $344 $206 $40 $50 
Residential mortgage servicing revenue152 159 169 78 64 
Realization of expected residential MSR cash flows(212)(176)(122)(59)(36)
Residential mortgage income before MSR valuation279 327 253 59 78 
Income statement impact of mortgage servicing rights valuation:     
MSRs fair value increase (decrease) (54)(28)(503)80 (79)
MSRs hedge gains (losses) (4)42 495 (74)81 
Net MSRs valuation(58)14 (8)6 2 
Total residential mortgage income$221 $341 $245 $65 $80 
Commercial Real Estate Related Income
Commercial mortgage production revenue$49 $42 $36 $44 $26 
Commercial mortgage servicing revenue16 18 19 13 10 
Realization of expected commercial MSR cash flows(10)(8)(11)(7)(7)
Commercial real estate related income before MSR valuation55 52 44 50 29 
Income statement impact of mortgage servicing rights valuation:
MSRs fair value increase (decrease) 1 (6)(20)2 — 
MSRs hedge gains (losses) (1)3 20 (4)3 
Net MSRs valuation— (3)— (2)3 
Commercial real estate related income$55 $49 $44 $48 $32 
Other Mortgage Banking Information
Residential mortgage loan originations$15,346 $14,631 $11,708 $7,523 $5,274 
Residential mortgage servicing portfolio (1):     
Loans serviced for others198,881 209,070 219,979 219,347 87,147 
Bank-owned loans serviced54,587 56,365 56,325 60,211 29,122 
Total servicing portfolio253,468 265,435 276,304 279,558 116,269 
Weighted-average coupon rate on mortgage loans serviced for others3.92 %3.98 %4.02 %4.04 %4.09 %
Weighted-average servicing fee on mortgage loans serviced for others0.317 0.315 0.313 0.310 0.280 
Additional Information
Fair value of derivatives, net3,646 3,766 3,276 1,687 641 
Common stock prices:
High42.04 46.53 56.68 56.92 53.85 
Low33.47 26.41 24.01 50.02 44.98 
End of period38.05 37.55 30.84 56.32 53.37 
Banking offices2,884 2,916 2,957 2,958 1,789 
ATMs4,237 4,354 4,408 4,426 2,376 
FTEs (2)55,000 55,769 56,504 40,691 34,723 
(1)Amounts reported are unpaid principal balance.
(2)FTEs represents an average for the quarter. The timing of the merger impacted the 4Q19 result.
18 Truist Financial Corporation


Selected Items (1)
 Favorable (Unfavorable)
(Dollars in millions)After-Tax at
DescriptionPre-TaxMarginal Rate
Selected Items
Third Quarter 2020
Incremental operating expenses related to the merger ($99 million in professional fees and outside processing, $48 million in personnel expense, and $5 million in other expense)$(152)$(115)
Charitable contribution(50)(38)
Second Quarter 2020
Incremental operating expenses related to the merger ($64 million in professional fees and outside processing, $49 million in personnel expense, and $16 million in other expense)$(129)$(99)
First Quarter 2020
Incremental operating expenses related to the merger ($44 million in personnel expense, $20 million in professional fees and outside processing, and $10 million in other expense)$(74)$(57)
Fourth Quarter 2019
Incremental operating expenses related to the merger ($80 million in personnel expense, $12 million in professional fees and outside processing, and $9 million in other expense)$(101)$(79)
Impact of mortgage portfolio sale ($25 million in provision for credit losses, offset by $22 in residential mortgage income, and a $2 million corporate advance write off included in loan-related expense)1 1 
Third Quarter 2019
Incremental operating expenses related to the merger ($39 million in personnel expense, $12 million in professional fees and outside processing, and $1 million in other expense)$(52)$(40)
Redemption of preferred shares(46)(46)
Impact of mortgage portfolio sale ($16 million in provision for credit losses and $4 million in residential mortgage income)20 15 
Second Quarter 2019
Incremental operating expenses related to the merger ($4 million in personnel expense, and $5 million in professional fees and outside processing)$(9)$(7)
First Quarter 2019
Incremental operating expenses related to the merger ($1 million in personnel expense, and $1 million in other expense)$(2)$(1)
(1)Includes costs not classified as merger-related and restructuring charges that are excluded from adjusted disclosures.


Non-GAAP Reconciliations   
Quarter EndedYear-to-Date
 Sept. 30June 30March 31Dec. 31Sept. 30Sept. 30Sept. 30
(Dollars in millions)2020202020202019201920202019
Efficiency Ratio (1)
Efficiency Ratio Numerator - Noninterest Expense - GAAP
$3,755 $3,878 $3,431 $2,575 $1,840 $11,064 $5,359 
Merger-related and restructuring charges, net(236)(209)(107)(223)(34)(552)(137)
Gain (loss) on early extinguishment of debt— (235)— — — (235)— 
Incremental operating expense related to the merger(152)(129)(74)(101)(52)(355)(63)
Amortization of intangibles(170)(178)(165)(71)(29)(513)(93)
Charitable contribution(50)— — — — (50)— 
Corporate advance write off— — — (2)— — — 
Efficiency Ratio Numerator - Adjusted$3,147 $3,127 $3,085 $2,178 $1,725 $9,359 $5,066 
Efficiency Ratio Denominator - Revenue (2) - GAAP
$5,572 $5,871 $5,611 $3,625 $3,003 $17,054 $8,943 
Taxable equivalent adjustment29 31 37 25 23 97 71 
Securities (gains) losses(104)(300)2 116 — (402)— 
(Gain) loss on loan portfolio sale— — — 22 (4)— (4)
Efficiency Ratio Denominator - Adjusted$5,497 $5,602 $5,650 $3,788 $3,022 $16,749 $9,010 
Efficiency Ratio - GAAP67.4 %66.1 %61.1 %71.0 %61.3 %64.9 %59.9 %
Efficiency Ratio - Adjusted57.3 55.8 54.6 57.5 57.1 55.9 56.2 
(1)The adjusted efficiency ratio is non-GAAP in that it excludes securities gains (losses), amortization of intangible assets, merger-related and restructuring charges and other selected items. Truist's management uses this measure in their analysis of the Corporation's performance. Truist's management believes this measure provides a greater understanding of ongoing operations and enhances comparability of results with prior periods, as well as demonstrates the effects of significant gains and charges. These measures are not necessarily comparable to similar measures that may be presented by other companies.
(2)Revenue is defined as net interest income plus noninterest income.
Truist Financial Corporation 19


 Quarter EndedYear-to-Date
 Sept. 30June 30March 31Dec. 31Sept. 30Sept. 30Sept. 30
(Dollars in millions)2020202020202019201920202019
Return on Average Tangible Common Shareholders' Equity (1)
Net income available to common shareholders$1,068 $902 $986 $702 $735 $2,956 $2,326 
Plus: Amortization of intangibles, net of tax130 137 126 57 22 393 71 
Tangible net income available to common shareholders$1,198 $1,039 $1,112 $759 $757 $3,349 $2,397 
Average common shareholders' equity$61,804 $61,484 $60,224 $38,031 $29,040 $61,173 $28,226 
Less: Average intangible assets, net of deferred taxes25,971 26,161 26,429 14,760 10,298 26,186 10,322 
Average tangible common shareholders' equity$35,833 $35,323 $33,795 $23,271 $18,742 $34,987 $17,904 
Return on average common shareholders' equity6.87 %5.90 %6.58 %7.33 %10.04 %6.46 %11.02 %
Return on average tangible common shareholders' equity13.31 11.83 13.23 12.91 16.03 12.79 17.90 
(1)Tangible common equity and related measures are non-GAAP measures that exclude the impact of intangible assets, net of deferred taxes, and their related amortization. These measures are useful for evaluating the performance of a business consistently, whether acquired or developed internally. Truist's management uses these measures to assess the quality of capital and returns relative to balance sheet risk. These measures are not necessarily comparable to similar measures that may be presented by other companies.


 Quarter EndedYear-to-Date
 Sept. 30June 30March 31Dec. 31Sept. 30Sept. 30Sept. 30
(Dollars in millions, except per share data)2020202020202019201920202019
Diluted EPS (1)
Net income available to common shareholders - GAAP
$1,068 $902 $986 $702 $735 $2,956 $2,326 
Merger-related and restructuring charges181 160 82 176 26 423 109 
Securities (gains) losses(80)(230)2 90 — (308)— 
Loss on extinguishment of debt— 180 — — — 180 — 
Incremental operating expenses related to the merger115 99 57 79 40 271 48 
Charitable contribution38 — — — — 38 — 
Corporate advance write off— — — 1 — — — 
(Gain) loss on loan portfolio sale— — — 17 (3)— (3)
Redemption of preferred shares— — — — 46 — 46 
Allowance release related to loan portfolio sale— — — (19)(12)— (12)
Net income available to common shareholders - adjusted$1,322 $1,111 $1,127 $1,046 $832 $3,560 $2,514 
Weighted average shares outstanding - diluted
1,358,122 1,355,834 1,357,545 934,718 775,791 1,357,174 774,907 
Diluted EPS - GAAP$0.79 $0.67 $0.73 $0.75 $0.95 $2.18 $3.00 
Diluted EPS - adjusted0.97 0.82 0.83 1.12 1.07 2.62 3.25 
(1)The adjusted diluted earnings per share is non-GAAP in that it excludes merger-related and restructuring charges and other selected items, net of tax. Truist's management uses this measure in their analysis of the Corporation's performance. Truist's management believes this measure provides a greater understanding of ongoing operations and enhances comparability of results with prior periods, as well as demonstrates the effects of significant gains and charges.
20 Truist Financial Corporation
Third Quarter 2020 Earnings Conference Call Kelly King - Chairman & CEO Daryl Bible - CFO October 15, 2020


Forward-Looking Statements This presentation contains “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995, regarding the financial condition, results of operations, business plans and the future performance of Truist. Words such as “anticipates,” “believes,” “estimates,” “expects,” “forecasts,” “intends,” “plans,” “projects,” “may,” “will,” “should,” “would,” “could” and other similar expressions are intended to identify these forward-looking statements. In particular, forward looking statements include, but are not limited to, statements we make about: (i) future levels of taxable-equivalent revenue, reported net interest margin, noninterest expense and net charge-offs, (ii) Truist’s future liquidity position and access to funding sources, (iii) Truist’s projected ability to cover contractual and expected cash outflows including dividends with no cash inflows, (iv) Truist’s medium-term performance with respect to return on tangible common equity and efficiency ratios, (v) the amount of expense savings to be realized from the merger and the timing of such realization, (vi) increased investments in digital, marketing, talent and technology, (vii) projections of future dividends, and (vii) goals relating to diversity in Truist’s senior leadership, supplier diversity, CRA qualified investments, mortgage loans to LMI and minority borrowers, lending to support growth of small businesses, community development lending, New Markets Tax Credit allocations to the fuel community, and investments in a community development fund to support other CDFIs. Forward-looking statements are not based on historical facts but instead represent management’s expectations and assumptions regarding Truist’s business, the economy and other future conditions. Such statements involve inherent uncertainties, risks and changes in circumstances that are difficult to predict. As such, Truist’s actual results may differ materially from those contemplated by forward-looking statements. While there can be no assurance that any list of risks and uncertainties or risk factors is complete, important factors that could cause actual results to differ materially from those contemplated by forward-looking statements include the following, without limitation, as well as the risks and uncertainties more fully discussed under Item 1A-Risk Factors in our Annual Report on Form 10-K for the year ended December 31, 2019, Item 1A-Risk Factors in our Quarterly Report on Form 10- Q for the quarter ended June 30, 2020 and in Truist's subsequent filings with the Securities and Exchange Commission: = risks and uncertainties relating to the merger of BB&T and SunTrust ("Merger"), including the ability to successfully integrate the companies or to = legislative, regulatory or accounting changes may adversely affect the businesses in which Truist is engaged; realize the anticipated benefits of the Merger; = evolving regulatory standards, including with respect to capital and liquidity requirements, and results of regulatory examinations, may adversely = expenses relating to the Merger and integration of heritage BB&T and heritage SunTrust; affect Truist's financial condition and results of operations; = deposit attrition, client loss or revenue loss following completed mergers or acquisitions may be greater than anticipated; = accounting policies and processes require management to make estimates about matters that are uncertain; = changes in the interest rate environment, including the replacement of LIBOR as an interest rate benchmark, which could adversely affect = general economic or business conditions, either nationally or regionally, may be less favorable than expected, resulting in, among other things, Truist’s revenue and expenses, the value of assets and obligations, and the availability and cost of capital, cash flows, and liquidity; slower deposit or asset growth, a deterioration in credit quality or a reduced demand for credit, insurance or other services; = volatility in mortgage production and servicing revenues, and changes in carrying values of Truist’s servicing assets and mortgages held for sale = due to changes in interest rates; risk management oversight functions may not identify or address risks adequately; = management’s ability to effectively manage credit risk; = unfavorable resolution of legal proceedings or other claims or regulatory or other governmental investigations or inquiries could result in negative publicity, protests, fines, penalties, restrictions on Truist's operations or ability to expand its business or other negative consequences, all of = inability to access short-term funding or liquidity; which could cause reputational damage and adversely impact Truist's financial condition and results of operations; = loss of client deposits, which could increase Truist’s funding costs; = competitors of Truist may have greater financial resources or develop products that enable them to compete more successfully than Truist and may be subject to different regulatory standards than Truist; = changes in Truist’s credit ratings, which could increase the cost of funding or limit access to capital markets; = failure to maintain or enhance Truist’s competitive position with respect to technology, whether it fails to anticipate client expectations or because = additional capital and liquidity requirements; its technological developments fail to perform as desired or are not rolled out in a timely manner or for other reasons, may cause Truist to lose market share or incur additional expense; = regulatory matters, litigation or other legal actions, which may result in, among other things, costs, fines, penalties, restrictions on Truist’s business activities, reputational harm, or other adverse consequences; = fraud or misconduct by internal or external parties, which Truist may not be able to prevent, detect or mitigate; = risks related to originating and selling mortgages, including repurchase and indemnity demands from purchasers related to representations and = operational or communications systems, including systems used by vendors or other external parties, may fail or may be the subject of a breach warranties on loans sold, which could result in an increase in the amount of losses for loan repurchases; or cyber-attack that, if successful, could adversely impact Truist's financial condition and results of operations; = failure to execute on strategic or operational plans, including the ability to successfully complete and/or integrate mergers and acquisitions; = security risks, including denial of service attacks, hacking, social engineering attacks targeting Truist’s employees and clients, malware intrusion = risks relating to Truist’s role as a servicer of loans, including an increase in the scope or costs of the services Truist is required to perform without or data corruption attempts, and identity theft could result in the disclosure of confidential information, adversely affect Truist’s business or any corresponding increase in Truist’s servicing fee, or a breach of Truist’s obligations as servicer; reputation or create significant legal or financial exposure; = negative public opinion, which could damage Truist’s reputation; = the COVID-19 pandemic has disrupted the global economy, adversely impacted Truist’s financial condition and results of operations, including through increased expenses, reduced fee income and net interest margin and increases in the allowance for credit losses, and continuation of = increased scrutiny regarding Truist’s consumer sales practices, training practices, incentive compensation design and governance; current conditions could worsen these impacts and also adversely affect Truist’s capital and liquidity position or cost of capital, impair the ability of borrowers to repay outstanding loans, cause an outflow of deposits, and impair goodwill or other assets; = competition from new or existing competitors, including increased competition from products and services offered by non-bank financial technology companies, may reduce Truist’s client base, cause Truist to lower prices for its products and services in order to maintain market = natural or other disasters, including acts of terrorism and pandemics, could have an adverse effect on Truist, including a material disruption of share or otherwise adversely impact Truist’s businesses or results of operations; Truist's operations or the ability or willingness of clients to access Truist's products and services; = Truist’s ability to introduce new products and services in response to industry trends or developments in technology that achieve market = widespread system outages, caused by the failure of critical internal systems or critical services provided by third parties could adversely impact acceptance and regulatory approval; Truist's financial condition and results of operations; and = Truist’s success depends on the expertise of key personnel, and if these individuals leave or change their roles without effective replacements = depressed market values for Truist’s stock and adverse economic conditions sustained over a period of time may require a write down to Truist's operations and integration activities could be adversely impacted. This could be exacerbated as Truist continues to integrate the goodwill. management teams of heritage BB&T and heritage SunTrust, or if the organization is unable to hire and retain qualified personnel; Readers are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date they are made. Except to the extent required by applicable law or regulation, Truist undertakes no obligation to revise or update any forward-looking statements. 2


Non-GAAP Information This presentation contains financial information and performance measures determined by methods other than in accordance with accounting principles generally accepted in the United States of America ("GAAP"). Truist’s management uses these "non-GAAP" measures in their analysis of the Corporation's performance and the efficiency of its operations. Management believes these non-GAAP measures provide a greater understanding of ongoing operations, enhance comparability of results with prior periods and demonstrate the effects of significant items in the current period. The Company believes a meaningful analysis of its financial performance requires an understanding of the factors underlying that performance. Truist’s management believes investors may find these non-GAAP financial measures useful. These disclosures should not be viewed as a substitute for financial measures determined in accordance with GAAP, nor are they necessarily comparable to non- GAAP performance measures that may be presented by other companies. Below is a listing of the types of non-GAAP measures used in this presentation: Adjusted Efficiency Ratio - The adjusted efficiency ratio is non-GAAP in that it excludes securities gains (losses), amortization of intangible assets, merger-related and restructuring charges and other selected items. Truist's management uses this measure in their analysis of the Corporation's performance. Truist's management believes this measure provides a greater understanding of ongoing operations and enhances comparability of results with prior periods, as well as demonstrates the effects of significant gains and charges. Tangible Common Equity and Related Measures - Tangible common equity and related measures are non-GAAP measures that exclude the impact of intangible assets, net of deferred taxes, and their related amortization. These measures are useful for evaluating the performance of a business consistently, whether acquired or developed internally. Truist's management uses these measures to assess the quality of capital and returns relative to balance sheet risk. Core NIM - Core net interest margin is a non-GAAP measure that adjusts net interest margin to exclude the impact of purchase accounting. The purchase accounting marks and related amortization for a) securities acquired from the FDIC in the Colonial Bank acquisition and b) loans, deposits and long-term debt from SunTrust, Susquehanna, National Penn and Colonial Bank are excluded to approximate the yields paid by clients. Truist's management believes the adjustments to the calculation of net interest margin for certain assets and liabilities acquired provide investors with useful information related to the performance of Truist's earning assets. Adjusted Diluted EPS - The adjusted diluted earnings per share is non-GAAP in that it excludes merger-related and restructuring charges and other selected items, net of tax. Truist's management uses this measure in their analysis of the Corporation's performance. Truist's management believes this measure provides a greater understanding of ongoing operations and enhances comparability of results with prior periods, as well as demonstrates the effects of significant gains and charges. Performance Ratios - The adjusted performance ratios, including adjusted return on average assets, adjusted return on average common shareholders’ equity and adjusted return on average tangible common shareholders’ equity, are non-GAAP in that they exclude merger-related and restructuring charges, selected items and, in the case of return on average tangible common shareholders' equity, amortization of intangible assets. Truist's management uses these measures in their analysis of the Corporation's performance. Truist's management believes these measures provide a greater understanding of ongoing operations and enhances comparability of results with prior periods, as well as demonstrates the effects of significant gains and charges. Insurance Holdings Adjusted EBITDA - EBITDA is a non-GAAP measurement of operating profitability that is calculated by adding back interest, taxes, depreciation and amortization to net income. Truist's management also adds back merger- related and restructuring charges, incremental operating expenses related to the merger and other selected items. Truist's management uses this measure in its analysis of the Corporation's Insurance Holdings segment. Truist's management believes this measure provides a greater understanding of ongoing operations and enhances comparability of results with prior periods, as well as demonstrates the effects of significant gains and charges. Allowance for Loan and Lease Losses and Unamortized Fair Value Mark, and Allowance for Credit Losses and Unamortized Fair Value Mark, as a Percentage of Gross Loans and Leases - Allowance for loan and lease losses and unamortized fair value mark, and allowance for credit losses and unamortized fair value mark, as a percentage of gross loans and leases are non-GAAP measurements of credit reserves that are calculated by adjusting the ALLL or ACL, and loans and leases held for investment by the unamortized fair value mark. Truist's management uses these measures to assess loss absorption capacity. Selected items affecting results are included on slide 7. 3


4


Living Our Purpose Inspire and Build Better Lives and Communities Accomplishments ~$32 billion $3.5 billion ▪ Announced a $40 million donation to help establish CornerSquare Community Capital, in home purchase mortgage loans for Community Reinvestment Act which focuses on providing funding to racially and ethnically diverse small business to LMI and minority borrowers and qualified investments (e.g. tax owners, women, and individuals in LMI communities geographies by 2022 credits, housing bonds) by 2022 ▪ Published first Truist CSR report ▪ Launched Truist Momentum ▪ Partnered with EverFi to introduce WORD Force, a learning program created for K-2 ~$8 billion ~$17 billion students to promote literacy through fun and games, impacting more than 4,300 in lending to support the growth of in Community Development students at 236 schools small businesses by 2022 Lending by 2022 ▪ Completed inaugural reporting under CDP in 2020 ▪ Heritage BB&T reduced energy use by 25% and water use by 10% in 2019 ▪ $15 million invested to reduce energy and water use in facilities Key Goals $65 million $210 million New Markets Tax Credit to support for organizations that support ▪ $60 billion Community Benefits Plan over the next three years LMI communities by 2022 community revitalization by 2022 ▪ 15% senior leadership diversity by 2022 (12% in 2019) Truist Board Diversity $1.3 billion 10% in funded solar loans to date, supplier diversity with certified reaching 75k households businesses by 2022 Perfect score of 100 on the Human Rights Campaign Foundation’s 2020 Corporate Equality Index 5


3Q20 Highlights Summary Income Statement ($ MM) 3Q20 Asset Quality and Capital 3Q20 1 Total taxable-equivalent revenue $5,601 Nonperforming assets as a % of total assets 0.26% Provision for credit losses 421 Net charge-offs as a % of average loans and leases 0.42% Income before income taxes 1,396 Common equity tier 1 capital ratio (CET1)4 10.0% Net income 1,141 Key Points Net income available to common shareholders 1,068 ▪ Strong financial performance included $1.3 billion of adjusted net income or $0.97 per diluted share and adjusted ROTCE of 16.08% Adjusted net income available to common shareholders2,3 1,322 ▪ Strong noninterest-bearing deposit growth and favorable funding mix drove higher core NIM; sequential decrease in average earning assets and GAAP / 2,3 modestly lower reported NIM led to decrease in net interest income 3Q20 Performance Metrics Unadjusted Adjusted ▪ Asset quality ratios remained relatively stable; active client accommodations Diluted earnings per share $0.79 $0.97 reduced significantly ▪ Provision for credit losses was $421 million vs. $844 million in 2Q20 and Return on average assets 0.91% 1.11% included a modest build in the allowance ▪ Solid core fee income sustained by increases in service charges, card and Return on average common equity 6.87% 8.50% payment fees, wealth, and other income ▪ Maintained core expense discipline Return on average tangible common equity2 13.31% 16.08% ▪ CET1 ratio was 10.0% vs. 9.7% in 2Q20; issued $925 million of Series R preferred stock to further improve capital position Efficiency ratio 67.4% 57.3% ▪ Successfully completed first major client-facing conversion - Truist Securities 1 Composed of taxable-equivalent net interest income and noninterest income 2 See non-GAAP reconciliations in the appendix 3 Excludes merger-related and restructuring charges, incremental operating expenses related to the merger and other items noted on slide 7 4 Current quarter regulatory capital information is preliminary 6


Selected Items Affecting 3Q20 Results Item Pre-Tax After-Tax Diluted EPS Impact ($ MM, except per share impact) Securities gains $104 $80 $0.06 Merger-related and restructuring charges ($236) ($181) ($0.13) Incremental operating expenses related to the merger1 ($152) ($115) ($0.08) Charitable contribution ($50) ($38) ($0.03) 1 Includes costs not classified as merger-related and restructuring charges that are also excluded when calculating adjusted disclosures. Refer to the non-GAAP disclosures in the appendix. 7


Loans & Leases Average Loans & Leases HFI and Loan Yields Loans & Leases Held for Investment ($ MM) Linked Average balances 2Q20 3Q20 Quarter Change $129,803 $128,164 $126,744 Commercial: $193,465 $171,268 $183,700 Commercial and industrial $152,991 $143,452 ($9,539) 5.02% 4.21% 4.06% CRE 27,804 27,761 (43) 1Q20 2Q20 3Q20 Commercial construction 6,748 6,861 113 Commercial LHFI ($ MM) Consumer & Card LHFI ($ MM) Lease financing 5,922 5,626 (296) Loans HFI yield (%) Consumer: Key Points Residential mortgage 52,380 51,500 (880) ▪ Average loans and leases decreased $11.2 billion sequentially driven largely by a reduction in C&I loans, reflecting the pay down of Residential home equity and direct 27,199 26,726 (473) commercial line draws Indirect auto 24,721 24,732 11 • Reductions in residential mortgage and home equity reflect elevated runoff rates due to refinance activity Indirect other 11,282 11,530 248 • Increases in certain direct and indirect lending categories including Student 7,633 7,446 (187) growth in LightStream, Sheffield, recreational lending, and prime auto Credit card 4,949 4,810 (139) were offset by decreases in other consumer categories ▪ Loan yields declined 15 bps quarter-over-quarter due to lower purchase Total loans & leases held for investment $321,629 $310,444 ($11,185) accounting accretion and the impact of lower benchmark interest rates 8


Deposits Average Deposits & Costs Deposits ($ MM) Linked Average balances 2Q20 3Q20 Quarter $370,818 $372,211 Change $334,649 0.70% Noninterest-bearing deposits $113,875 $123,966 $10,091 0.32% 0.15% Interest checking 97,863 96,707 (1,156) 0.51% Money market and savings 126,071 123,598 (2,473) 0.22% 0.10% Time deposits 33,009 27,940 (5,069) 1Q20 2Q20 3Q20 Total deposits ($ MM) IBD cost (%) Total deposits $370,818 $372,211 $1,393 Total deposit cost (%) Key Points ▪ Average deposits increased $1.4 billion sequentially to $372.2 billion, driven by a $10.1 billion increase in average noninterest-bearing deposits, partially offset by an $8.7 billion decrease in average interest-bearing deposits ▪ Growth in noninterest-bearing deposits reflected the ongoing flight to quality and liquidity provided by government stimulus programs as well as capital market issuances ▪ Noninterest-bearing deposits were 33.3% of total deposits in 3Q20, up from 30.7% in 2Q20 and 27.8% in 1Q20 ▪ Interest-bearing deposits decreased due to the maturity of higher-cost time deposits and lower interest checking and money market and savings balances ▪ 3Q20 average total deposit cost decreased 12 bps to 10 bps; average interest- bearing deposit cost decreased 17 bps to 15 bps 9


Net Interest Income and Interest Rate Sensitivity Net Interest Income and Margin Key Points $3,687 ▪ Reported net interest margin decreased 3 bps sequentially to 3.10% $3,479 $3,391 3.58% • Purchase accounting accretion contributed 38 bps to the reported NIM compared to 46 bps in 2Q20 and 52 bps in 1Q20 3.13% 3.06% 3.10% ▪ Core NIM increased 5 bps to 2.72%, reflecting favorable deposit mix changes and lower funding costs as well as lower COVID-19 related 2.67% 2.72% deferred interest, partly offset by lower earning asset yields • Continued strong growth in noninterest-bearing deposits 1Q20 2Q20 3Q20 supplanted decreases in higher-cost deposit categories Net interest income TE ($ MM) Reported NIM (%) Core NIM (%) • Deferred interest related to COVID-19 was $21 million versus $52 million in 2Q20; the lower level was a 3 bps benefit to core NIM and reflected continued progress towards a more normal economic Change in Net Interest Income1 environment • Purchased ~$5 billion of securities using excess reserves at the +3.43% Federal Reserve, benefiting the core NIM by 1 bp +2.68% ▪ NII sensitivity increased due to reduced fixed rate assets, deposit mix +2.39% composition, and hedging changes, partly offset by an increase in the +1.84% investment securities portfolio -1.44% -1.24% -1.94% -1.62% Down 50 Down 25 Up 50 Up 100 At 6/30/20 At 9/30/20 1 Market rate increase or decrease scenarios assume a ramped, parallel 25 basis point change per quarter in market interest rates and that market rates floor at 0% 10


Noninterest Income Noninterest Income & Fee Income Ratio Noninterest Income ($ MM) Linked $2,423 2Q20 3Q20 Quarter $2,210 Change $1,961 Insurance income $581 $518 ($63) 41.3% 39.7% Service charges on deposits 202 247 45 34.9% Wealth management income 289 324 35 1Q20 2Q20 3Q20 Card and payment related fees 171 200 29 Noninterest income ($ MM) Fee income ratio (%) Residential mortgage income 341 221 (120) Investment banking and trading income 274 244 (30) Key Points Operating lease income 83 72 (11) ▪ Adjusted noninterest income was relatively flat sequentially Income from bank-owned life insurance 45 46 1 ▪ Insurance income increased 6.4% year over year, reflecting firmer pricing and strong new business generation; down $63 million from 2Q20 due to seasonality Lending related fees 66 77 11 ▪ Service charges on deposits and card and payment related fees increased $45 million and $29 million, respectively, due to increased incident rates, reduced Commercial real estate related income 49 55 6 COVID-19 related fee waivers, and improved card and payment volumes Securities gains (losses) 300 104 (196) ▪ Wealth management income increased $35 million primarily due to higher market valuations Other income (loss) 22 102 80 ▪ Residential mortgage income decreased $120 million sequentially driven Total noninterest income $2,423 $2,210 ($213) primarily by a $72 million change in net MSR valuation quarter-over-quarter Adjusted noninterest income1 $2,123 $2,106 ($17) ▪ Investment banking and trading income decreased $30 million relative to 2Q20; 3Q20 results reflect record investment banking fees and softer trading revenues 1 Excludes securities gains (losses) relative to record trading performance in 2Q20 ▪ Other income increased $80 million sequentially due to $52 million increase in income related to certain post-retirement benefits and $38 million increase in the value of other investments 11


Noninterest Expense & Efficiency Noninterest Expense & Efficiency Noninterest Expense ($ MM) Linked $3,878 $3,755 2Q20 3Q20 Quarter $3,431 Change 67.4% 66.1% Personnel expense $2,008 $2,058 $50 61.1% Net occupancy expense 243 233 (10) 57.3% 54.6% 55.8% Professional fees and outside processing 289 323 34 Software expense 216 221 5 1Q20 2Q20 3Q20 Equipment expense 120 127 7 Total noninterest expense ($ MM) GAAP efficiency (%) Marketing and customer development 56 75 19 Adjusted efficiency (%) Operating lease depreciation 77 56 (21) Key Points Loan-related expense 56 59 3 ▪ Noninterest expense decreased $123 million vs. 2Q20, reflecting $235 million of Amortization of intangibles 178 170 (8) losses on debt extinguishment and higher intangibles amortization in 2Q20; 3Q20 Regulatory costs 30 34 4 results include: • $50 million charitable contribution Merger-related and restructuring charges 209 236 27 • $50 million increase in merger-related charges and operating expenses Loss (gain) on early extinguishment of debt 235 — (235) ▪ Excluding the above items, adjusted noninterest expense increased $20 million from Other expense 161 163 2 the prior quarter due primarily to increased personnel expense and marketing costs Total noninterest expense $3,878 $3,755 ($123) ▪ 3Q20 personnel expense reflects a $51 million increase in non-qualified plan costs (offset in other income), increased medical costs, a pension expense adjustment, and Adjusted noninterest expense1 $3,127 $3,147 $20 reduced labor cost capitalization ▪ Average FTEs decreased by 769 from the prior quarter 1 Excludes merger-related charges, amortization of intangibles, loss on early extinguishment of debt and selected items in the Quarterly Performance Summary 12


Asset Quality Key Points Net Charge-offs and Provision Nonperforming Assets ▪ Asset quality ratios were relatively stable vs. 2Q20 $1,252 $1,314 $1,177 $893 $844 • Nonperforming loans as a % of loans and leases were 0.37%, up 2 bps 0.25% 0.26% 0.39% 0.42% 0.23% • Nonperforming assets as a % of total assets 0.36% $421 increased 1 bp to 0.26% $316 $326 $272 • Annualized net charge-offs as a % of average loans and leases increased 3 bps to 0.42% 1Q20 2Q20 3Q20 1Q20 2Q20 3Q20 ◦ 3Q20 net charge-offs include $97 million Net charge-offs ($ MM) Nonperforming assets ($ MM) related to PCD loans associated with the Provision NPAs as a % of total assets implementation of CECL NCOs as % of avg. loans and leases ◦ Excluding these additional net charge-offs, the net charge-off ratio was 0.29%, representing a ALLL for Loans & Leases to Net Charge-offs Loss Absorbency 10 bps decrease from 2Q20 • Allowance coverage of annualized net-charge- offs was 4.52x, up slightly $8,750 $8,779 $8,539 4.76x • Allowance coverage for nonperforming loans and 2.76% 2.76% leases 5.22x, down slightly 2.71% $5,863 $5,211 $5,702 4.49x 4.52x ▪ The provision for credit losses totaled $421 million in 1.91% 1.81% 3Q20, reflecting $95 million of reserve build 1.63% 1Q20 2Q20 3Q20 1Q20 2Q20 3Q20 ALLL ($ MM) ALLL + unamortized loan marks ($ MM) ALLL as % of loans and leases 1 ALLL + unamortized loan marks as % of gross loans and leases 1 ALLL + unamortized loan marks as % of gross loans and leases is a non-GAAP measure. See non-GAAP reconciliations in the attached appendix. 13


Selected Credit Exposures A Highly Diversified Portfolio Outstandings % of Total Key Points as of 9/30/20 ($ B) Loans HFI ▪ Loan balances for COVID-sensitive industries decreased 7.3% or $2.2 billion Hotels, Resorts & Cruise Lines* $6.8 2.2 % from 2Q20, ending at $27.9 billion Senior Care 6.0 2.0 • Total outstandings include $1.5 billion of PPP loans Oil & Gas Portfolio 5.2 1.7 ▪ Hotels, Resort & Cruise Lines reported an $894 million decrease driven by pay downs and loan sales Acute Care Facilities 4.7 1.5 ▪ Oil & Gas Portfolio outstandings were also down quarter over quarter, Restaurants 2.9 1.0 reporting an overall $671 million or 12% decrease, mainly from midstream ▪ Sensitive Retail and Restaurants loan balances decreased by 20.2% and Sensitive Retail 2.3 0.7 8.6%, respectively Total $27.9 9.1 % ▪ Leveraged Lending balances totaled $8.6 billion, reflecting a 9.5% decrease *Hotel exposures include REITs, real estate secured and Grandbridge quarter over quarter Additional exposures • $1.5 billion reflected in the COVID-sensitive industries above Outstandings % of Total as of 9/30/20 ($ B) Loans HFI ▪ Small CRE totaled $4.6 billion in outstandings; largest concentrations in retail, single family residential, and office (representing 26%, 24%, and 17%, Leveraged Lending $8.6 2.8 % respectively) Small Secured Real Estate** 4.6 1.5 • $0.2 billion reflected in COVID-sensitive industries above **Small CRE <=$2MM based on exposure Note: Industry exposures are based on systemic industry assignments (NAICS) at the borrower level 14


Client Accommodations 1 COVID-19 Payment Relief Program Trends Key Points ▪ Payment relief programs include forbearance, deferrals, extensions, and re-agings • Payment relief programs allow clients to defer payments without late fees being incurred, but with finance charges generally continuing to accrue; the period over which payments can be deferred is typically up $21,204 to 90 days, but can be extended under certain circumstances • Active accommodations declined significantly from 2Q20 to 3Q20 as initial payment relief terms expired and were not renewed by borrowers ▪ Of the borrowers who exited commercial and consumer payment relief programs in place at the beginning of the quarter, 98.0% and 94.5%, $692 respectively, either paid off their loan balances or are in current status $11,291 $6,166 2Q20 3Q20 Consumer & Card Commercial 1 Reflects active accommodations as of period end Consumer accommodations exclude government guaranteed student and government guaranteed mortgage loans as well as GNMA early buyouts 15


Allowance for Credit Losses Key Points Allowance for Credit Losses ($ in MM) Highlights ▪ 3Q20 ACL of $6.2 billion or 2.03% of total LHFI; $96 million increase from 2Q20; excluding PPP loans, ACL was 2.12% $6,133 $6,229 ▪ Modest reserve build reflects continued monitoring of clients’ financial position and associated re-grading actions as well as uncertainty related to performance after the $5,611 expiration of relief packages and pandemic concerns 2.03% Methodology / Assumptions 1.95% ▪ Estimation process included the use of multiple vended economic scenarios ▪ Extended recovery of GDP through the two-year reasonable and supportable forecast 1.76% period ▪ Unemployment rate remains in high single digits through mid-2021 followed by continued improvement through the remaining reasonable and supportable forecast period ▪ Other considerations included: • Adjustments to address model limitations arising from unprecedented economic conditions and forecasts • Imprecision adjustment informed by alternative economic scenarios • Assessments of government relief packages and payment accommodations on 1Q20 2Q20 3Q20 expected losses • Results from recent SNC review and sensitivity of COVID-impacted industries % of ACL to total LHFI • Observations from monitoring clients’ payment capacity and performance 16


Capital Position Capital Ratios Key Points ▪ CET1 ratio increased to 10.0% from 9.7% in 2Q20 (9.4% on a fully 14.6% phased-in basis) 14.0% ▪ Issued $925 million of Series R preferred stock during 3Q20 to 12.7% 12.2% further strengthen Truist’s capital position 11.6% 10.5% ▪ Tier 1 capital ratio increased to 12.2% from 11.6% and the total 10.0% capital ratio increased to 14.6% from 14.0% in 2Q20 9.3% 9.7% ▪ Truist’s Stress Capital Buffer (SCB) of 270 bps took effect on October 1, 2020, and remains in effect through September 30, 2021 when a revised SCB will be provided ▪ Truist will resubmit its capital plan in early November 2020, consistent with the Federal Reserve’s industry-wide mandate ▪ Truist’s dividend and total payout ratios for 3Q20 were 56.8% ▪ Tangible common equity per share was $26.63, up 2.7% from $25.93 at December 31, 2019 1Q20 2Q20 3Q20 Common equity Tier 1 Tier 1 Total Current quarter regulatory capital information is preliminary 17


Liquidity Position Category III Reduced LCR & HQLA Key Points ▪ Liquidity ratios remain strong 117% 117% 116% ▪ Average LCR was 117% for 3Q20 ▪ Liquid asset buffer was 18.6% at September 30, 2020 $79.5 $79.9 ▪ Access to secured funding sources remains robust, with $224.9 billion of cash, securities, and secured borrowing capacity $74.2 ▪ Strong parent company cash with 22 months of stress capacity 1Q20 2Q20 3Q20 LCR HQLA ($ B)1 Truist Corporation ($ in B) Parent company cash $14.0 Months of stress capacity2 22 Truist Bank ($ in B) FRB reserve balance $32.6 Investment portfolio (market value)3 86.1 Discount window capacity (none drawn) 51.8 FHLB available capacity 54.4 Total $224.9 1 Total weighted average HQLA 2 Stress capacity measures ability to cover contractual and expected outflows including dividends with no inflows 3 Includes $19.2 billion of encumbered securities 18


Digital Acceleration Digital Commerce Growth Active Mobile App Users Digital Accolades 474.1K Javelin’s 14th annual Mobile Banking Scorecard evaluates 25 of the top U.S. financial institutions to 390.3K 3.86MM identify the leaders in digital banking 3.58MM Aug-19 Aug-20 Aug-19 Aug-20 2020 Mobile Banking Scorecard 21% growth in digital sales 8% growth in active users BB&T was recognized as a Leader in “Ease of Use” and “Financial Fitness” Mobile Check Deposit Activity Accounts With Paperless Adoption 1,785K 8.41MM 2020 Online Banking Scorecard 1,456K BB&T was recognized as a leader in “Financial 8.00MM Fitness”; SunTrust was recognized as a leader in “Ease of Use” Aug-19 Dec-19 Apr-20 Aug-20 Aug-19 Dec-19 Apr-20 Aug-20 23% growth in transactions 5% growth in statement suppressions Results reflect combined transactions and accounts from BB&T and SunTrust Digital commerce defined as products delivered through digital applications Active users reflects clients that have logged in using the mobile app over the prior 90 days; clients using mobile app at both organizations were counted only once 19


Cost Savings Provide Investment Capacity and Performance Advantage $1.6B in net Cost saves Performance Best-in-class adjusted cost saves ROTCE and efficiency ratio over the medium term Investments Increased investments in digital, marketing, talent, and technology 20


Merger Update Truist Securities August 2020 The corporate and investment banking businesses of BB&T and SunTrust have been integrated and Completed branch divestiture Unveiled Truist Corporate Social Responsibility Report are now doing business as Truist Securities Value to Clients ▪ Extensive range of strategic advisory and Announced Truist Ventures Launched dual service capital markets capabilities to support needs branch pilots of growth-oriented companies and institutional investors ▪ A broad national presence, financial strength and commitment to innovation afford greater Testing initiated for early client Completed end-to-end Truist capacity to serve as a lead advisor to clients conversions in Wealth and Securities conversion ▪ Culture of putting our clients’ objectives and Mortgage best interests first, backed by a commitment to provide clients with a better experience and better results 2121


Value Proposition Purpose-driven: Committed to inspire and build better lives and communities Growing earnings stream with less volatility relative to Exceptional franchise with diverse Uniquely positioned to deliver Strong capital and liquidity with resilient peers over the products, services, and markets best-in-class efficiency and returns risk profile enhanced by the merger long-term while investing in the future ▪ Sixth-largest commercial bank in the ▪ Continued confidence in achieving ▪ Prudent and disciplined risk and U.S. $1.6 billion of net cost savings financial management ▪ Strong market share in vibrant, fast- ▪ Highly complementary businesses ▪ Conservative risk culture; leading growing MSAs throughout the and expanded client base combine to credit metrics; among the highest- Southeast and Mid-Atlantic and a yield revenue synergies rated large banks growing national presence ▪ Returns and capital buoyed by ▪ Diversification benefits arising from ▪ Comprehensive business mix with purchase accounting accretion the merger distinct capabilities in traditional ▪ Meaningful investments in innovative ▪ Stress test well banking, capital markets and insurance technologies, teammates, marketing, ▪ Strong capital and liquidity support ▪ Better together: “Best of breed” talent, and advertising flight to quality technology, strategy, and processes ▪ Defensive balance sheet insulated by purchase accounting marks, combined with CECL credit reserves 22


Appendix


Consumer Banking & Wealth Represents performance for Retail Community Banking, Wealth, Mortgage Banking, Dealer Retail Services and National Consumer Finance & Payments 2Q20 3Q20 Key Points Net interest income $2,160 $2,194 ▪ Branch divestiture arising from the merger completed in 3Q20; $425 million in loans and leases and $2.2 billion in deposits were divested as Provision for credit losses 270 181 part of this transaction ▪ Noninterest income decreased $16 million, or 2% from 2Q20, primarily Noninterest income 1,006 990 driven by an MSR fair value adjustment due to elevated prepayment speeds, partially offset by higher client activity and market valuations increasing wealth fees Noninterest expense 1,972 1,934 Income Statement ($ MM) ▪ Noninterest expense decreased $38 million, or 2% from 2Q20, primarily due to lower personnel expenses, merger related expenses, and Pre-tax income 924 1,069 amortization of intangibles related to the merger, partially offset by higher professional service fees and loan-related expenses due to Segment net income 706 817 increased client activity ▪ Average loans held for investment decreased $547 million from 2Q20, Average loans(1) $140.0 $139.5 primarily due to lower residential mortgage, home equity and direct consumer, student lending, and credit card, partially offset by increased Balance Sheet ($ B) Average deposits 218.9 223.9 mortgage warehouse lending, LightStream, and Sheffield (2) ▪ Average deposits increased $5.0 billion, or 2% from 2Q20, primarily due Mortgages serviced for others ($ B) $209.1 $198.9 to economic stimulus payments related to COVID-19 and continued flight to quality Branches 2,916 2,884 ▪ 3Q20 average total deposit cost decreased 10 bps to 12 bps; average interest-bearing deposit cost decreased 13 bps to 17 bps Other Key Metrics ATMs 4,354 4,237 (1) Excludes loans held for sale (2) Amount reported reflects end of period balance A-1


Corporate & Commercial Banking Represents performance for Commercial Community Banking, Corporate & Investment Banking and CIG – Real Estate 2Q20 3Q20 Key Points ▪ Integrated the heritage corporate and investment banking businesses to Net interest income $1,290 $1,276 form Truist Securities ▪ Noninterest income decreased $12 million, or 2% from 2Q20, driven by Provision for credit losses 534 311 lower trading income, partially offset by higher deposit service charges, investment banking income, lending related fees, and commercial real estate related income Noninterest income 621 609 ▪ Noninterest expense decreased $37 million, or 4% from 2Q20, due to lower expenses related to the merger and operating lease depreciation, Noninterest expense 880 843 partially offset by higher personnel expense due to the impact of Income Statement ($ MM) capitalized salaries related to PPP loans in the prior quarter Pre-tax income 497 731 ▪ Average loans held for investment decreased $11.1 billion, or 6% from 2Q20, due primarily to continued repayments on drawn revolvers ▪ Average deposits were flat relative to 2Q20 Segment net income 405 583 ▪ 3Q20 average total deposit cost decreased 12 bps to 2 bps; average interest-bearing deposit cost decreased 21 bps to 3 bps Average loans(1) $178.9 $167.8 ($ B) Average deposits 139.5 139.5 Balance Sheet (1) Excludes loans held for sale A-2


Insurance Holdings Represents performance for Retail and Wholesale Insurance businesses and Premium Finance 3Q19 3Q20 Key Points Net interest income $28 $24 ▪ 3Q organic growth driven by continued market firming, shrinking capacity, and stable exposure units Noninterest income 491 524 ▪ 3Q new business up 8.4% due to strong demand in Wholesale as Total revenue 519 548 market pushes more risk to excess and surplus lines Provision for credit losses 2 — ▪ Low interest rates and elevated catastrophe activity likely to keep market firm Noninterest expense 435 446 Income Statement ($ MM) ▪ Margin expansion driven by travel-related savings and prudent expense control Pre-tax income 82 102 Segment net income 61 77 Y-o-Y organic revenue growth 8.7% 5.3% Net acquired revenue $2 $4 Performance based commissions 13 15 Adjusted EBITDA(1) 111 123 Performance ($ MM) Adjusted EBITDA margin(1) 21.4% 22.4% (1) EBITDA is a non-GAAP measurement of operating profitability that is calculated by adding back interest, taxes, depreciation and amortization to net income. Truist's management also adds back merger- related and restructuring charges, incremental operating expenses related to the merger and other selected items. Truist's management uses this measure in its analysis of the Corporation's Insurance Holdings segment. Truist's management believes this measure provides a greater understanding of ongoing operations and enhances comparability of results with prior periods, as well as demonstrates the effects of significant gains and charges. See non-GAAP reconciliations included in the attached Appendix. A-3


Allowance and Fair Value Marks Information ($ MM) Loans and Leases RUFC Total Allowance - End of period $ 5,863 $ 366 $ 6,229 Unamortized fair value mark(1) 2,676 — 2,676 Allowance plus unamortized fair value mark $ 8,539 $ 366 $ 8,905 Loans and leases held for investment $ 306,627 $ — $ 306,627 Unamortized fair value mark(1) 2,676 — 2,676 Gross loans and leases $ 309,303 $ — $ 309,303 ALLL and ACL as a percentage of loans and leases - GAAP 1.91 % 2.03 % ALLL and ACL and unamortized fair value mark as a percentage of gross loans and leases - adjusted (1)(2) 2.76 2.88 (1) Unamortized fair value mark includes credit, interest rate and liquidity components. (2) Allowance for loan and lease losses and unamortized fair value mark, and allowance for credit losses and unamortized fair value mark, as a percentage of gross loans and leases are non-GAAP measurements of credit reserves that are calculated by adjusting the ALLL or ACL, and loans and leases held for investment by the unamortized fair value mark. Truist's management uses these measures to assess loss absorption capacity. A-4


Purchase Accounting Summary(1) ($ MM) September 30, 2020 June 30, 2020 March 31, 2020 December 31, 2019 Loans and Leases(2) Beginning balance unamortized fair value mark $ (3,077) $ (3,539) $ (4,564) $ (221) Additions - Merger with SunTrust — — — (4,513) Accretion 367 440 454 170 CECL adoption - reserves on PCD assets — — 378 — Purchase accounting adjustments and other activity 34 22 193 — Ending balance $ (2,676) $ (3,077) $ (3,539) $ (4,564) Core deposit and other intangible assets Beginning balance $ 3,016 $ 3,168 $ 3,142 $ 678 Additions - Merger with SunTrust — — — 2,535 Amortization (170) (178) (165) (71) Amortization in net occupancy expense (6) (6) (5) — Purchase accounting adjustments and other activity — 32 196 — Ending balance $ 2,840 $ 3,016 $ 3,168 $ 3,142 Deposits(3) Beginning balance unamortized fair value mark $ (37) $ (54) $ (76) $ — Additions - Merger with SunTrust — — — (83) Amortization 11 17 22 7 Ending balance $ (26) $ (37) $ (54) $ (76) Long-Term Debt(3) Beginning balance unamortized fair value mark $ (262) $ (285) $ (312) $ (10) Additions - Merger with SunTrust — — — (309) Amortization 24 23 27 7 Ending balance $ (238) $ (262) $ (285) $ (312) (1) Includes the merger with SunTrust, as well as other acquisitions. This summary includes only selected information and does not represent all purchase accounting adjustments. (2) Purchase accounting marks on loans and leases includes credit, interest and liquidity components, and are generally recognized using the level-yield method over the remaining life of the individual loans or recognized in full in the event of prepayment. (3) Purchase accounting marks on liabilities represents interest rate marks on time deposits and long-term debt and are recognized using the level-yield method over the term of the liability. A-5


4Q20 - 2Q21 Preferred Stock Projected Dividends Truist Preferred Outstandings ($ MM) 4Q20 1Q21 2Q21 Series F $450.0 $5.9 $5.9 $5.9 Series G $500.0 6.5 6.5 6.5 Series H $465.0 6.5 6.5 6.5 Series I $172.5 Greater of 3ML+0.53% or 4% Series J $101.5 Greater of 3ML+0.645% or 4% Series L $750.0 18.9 — 18.9 Series M $500.0 12.8 — 12.8 Series N $1,700.0 — 40.8 — Series O $575.0 7.5 7.5 7.5 Series P $1,000.0 24.8 — 24.8 Series Q $1,000.0 — 25.5 — Q catch-up 1Q21 only n/a 10.2 — Series R $925.0 11.0 11.0 11.0 R catch-up 4Q20 only 3.4 — — Estimated dividends based on current interest rates and amounts outstanding ($ MM) $100.1 $116.7 $96.7 3ML = 3-month LIBOR. Estimates assume an average LIBOR rate of 0.23% for 4Q20-2Q21. Actual 3ML could vary significantly causing dividend payments to differ from the estimates shown above. A-6


Non-GAAP Reconciliations


Non-GAAP Reconciliations Diluted EPS ($ MM, except per share data, shares in thousands) Quarter Ended Sept. 30 June 30 March 31 Dec. 31 Sept. 30 2020 2020 2020 2019 2019 Net income available to common shareholders - GAAP $ 1,068 $ 902 $ 986 $ 702 $ 735 Merger-related and restructuring charges 181 160 82 176 26 Securities (gains) losses (80) (230) 2 90 — Loss on extinguishment of debt — 180 — — — Incremental operating expenses related to the merger 115 99 57 79 40 Charitable contribution 38 — — — — Corporate advance write off — — — 1 — (Gain) loss on loan portfolio sale — — — 17 (3) Redemption of preferred shares — — — — 46 Allowance release related to loan portfolio sale — — — (19) (12) Net income available to common shareholders - adjusted $ 1,322 $ 1,111 $ 1,127 $ 1,046 $ 832 Weighted average shares outstanding - diluted 1,358,122 1,355,834 1,357,545 934,718 775,791 Diluted EPS - GAAP $ 0.79 $ 0.67 $ 0.73 $ 0.75 $ 0.95 Diluted EPS - adjusted(1) 0.97 0.82 0.83 1.12 1.07 (1) The adjusted diluted earnings per share is non-GAAP in that it excludes merger-related and restructuring charges and other selected items, net of tax. Truist's management uses this measure in their analysis of the Corporation's performance. Truist's management believes this measure provides a greater understanding of ongoing operations and enhances comparability of results with prior periods, as well as demonstrates the effects of significant gains and charges. A-8


Non-GAAP Reconciliations Efficiency Ratio ($ MM) Quarter Ended Sept. 30 June 30 March 31 Dec. 31 Sept. 30 2020 2020 2020 2019 2019 Efficiency ratio numerator - noninterest expense - GAAP $ 3,755 $ 3,878 $ 3,431 $ 2,575 $ 1,840 Merger-related and restructuring charges, net (236) (209) (107) (223) (34) Gain (loss) on early extinguishment of debt — (235) — — — Incremental operating expense related to the merger (152) (129) (74) (101) (52) Amortization of intangibles (170) (178) (165) (71) (29) Charitable contribution (50) — — — — Corporate advance write off — — — (2) — Efficiency ratio numerator - adjusted $ 3,147 $ 3,127 $ 3,085 $ 2,178 $ 1,725 Efficiency ratio denominator - revenue(1) - GAAP $ 5,572 $ 5,871 $ 5,611 $ 3,625 $ 3,003 Taxable equivalent adjustment 29 31 37 25 23 Securities (gains) losses (104) (300) 2 116 — (Gain) loss on loan portfolio sale — — — 22 (4) Efficiency ratio denominator - adjusted $ 5,497 $ 5,602 $ 5,650 $ 3,788 $ 3,022 Efficiency ratio - GAAP 67.4 % 66.1 % 61.1 % 71.0 % 61.3 % Efficiency ratio - adjusted(2) 57.3 55.8 54.6 57.5 57.1 (1) Revenue is defined as net interest income plus noninterest income. (2) The adjusted efficiency ratio is non-GAAP in that it excludes securities gains (losses), amortization of intangible assets, merger-related and restructuring charges and other selected items. Truist's management uses this measure in their analysis of the Corporation's performance. Truist's management believes this measure provides a greater understanding of ongoing operations and enhances comparability of results with prior periods, as well as demonstrates the effects of significant gains and charges. A-9


Non-GAAP Reconciliations Calculations of tangible common equity and related measures ($ MM, except per share data, shares in thousands) As of / Quarter Ended Sept. 30 June 30 March 31 Dec. 31 Sept. 30 2020 2020 2020 2019 2019 Common shareholders' equity $ 61,819 $ 61,634 $ 61,295 $ 61,282 $ 29,177 Less: Intangible assets, net of deferred taxes 25,923 26,083 26,263 26,482 10,281 Tangible common shareholders' equity(1) $ 35,896 $ 35,551 $ 35,032 $ 34,800 $ 18,896 Outstanding shares at end of period 1,348,118 1,347,609 1,347,461 1,342,166 766,303 Common shareholders' equity per common share $ 45.86 $ 45.74 $ 45.49 $ 45.66 $ 38.07 Tangible common shareholders' equity per common share(1) 26.63 26.38 26.00 25.93 24.66 Net income available to common shareholders $ 1,068 $ 902 $ 986 $ 702 $ 735 Plus amortization of intangibles, net of tax 130 137 126 57 22 Tangible net income available to common shareholders(1) $ 1,198 $ 1,039 $ 1,112 $ 759 $ 757 Average common shareholders' equity $ 61,804 $ 61,484 $ 60,224 $ 38,031 $ 29,040 Less: Average intangible assets, net of deferred taxes 25,971 26,161 26,429 14,760 10,298 Average tangible common shareholders' equity(1) $ 35,833 $ 35,323 $ 33,795 $ 23,271 $ 18,742 Return on average common shareholders' equity 6.87 % 5.90 % 6.58 % 7.33 % 10.04 % Return on average tangible common shareholders' equity(1) 13.31 11.83 13.23 12.91 16.03 (1) Tangible common equity and related measures are non-GAAP measures that exclude the impact of intangible assets, net of deferred taxes, and their related amortization. These measures are useful for evaluating the performance of a business consistently, whether acquired or developed internally. Truist's management uses these measures to assess the quality of capital and returns relative to balance sheet risk. These measures are not necessarily comparable to similar measures that may be presented by other companies. A-10


Non-GAAP Reconciliations Performance Ratios ($ MM) Quarter Ended Sept. 30, 2020 Return on Average Return on Average Return on Average Common Tangible Common Assets Shareholders’ Equity Shareholders’ Equity2 Net income - GAAP $ 1,141 Net income available to common shareholders - GAAP $ 1,068 $ 1,068 Merger-related and restructuring charges 181 181 181 Securities (gains) losses (80) (80) (80) Incremental operating expenses related to the merger 115 115 115 Charitable contribution 38 38 38 Amortization — — 130 Numerator - adjusted(1) $ 1,395 $ 1,322 $ 1,452 Average assets $ 500,826 Average common shareholders' equity — $ 61,804 $ 61,804 Plus: Estimated impact of adjustments on denominator — 128 128 Less: Average intangible assets, net of deferred taxes — — 25,971 Denominator - adjusted(1) $ 500,826 $ 61,932 $ 35,961 Reported ratio 0.91 % 6.87 % 13.31 % Adjusted ratio 1.11 8.50 16.08 (1) Tangible common equity and related measures are non-GAAP measures that exclude the impact of intangible assets, net of deferred taxes, and their related amortization. These measures are useful for evaluating the performance of a business consistently, whether acquired or developed internally. Truist's management uses these measures to assess the quality of capital and returns relative to balance sheet risk. These measures are not necessarily comparable to similar measures that may be presented by other companies. (2) Tangible common equity is a non-GAAP measure. The reconciliation for this measure is on page A-10. A-11


Non-GAAP Reconciliations Core NIM ($ MM) Quarter Ended Sept. 30 June 30 March 31 2020 2020 2020 Net interest income - GAAP $ 3,362 $ 3,448 $ 3,650 Taxable-equivalent adjustment 29 31 37 Net interest income - taxable-equivalent 3,391 3,479 3,687 Accretion of mark on acquired loans (367) (440) (454) Accretion of mark on acquired liabilities (35) (40) (49) Accretion of mark on securities acquired from FDIC — (3) (3) Net interest income - core(1) $ 2,989 $ 2,996 $ 3,181 Average earning assets - GAAP $ 435,394 $ 446,825 $ 413,533 Average balance - mark on acquired loans 2,918 3,297 3,759 Average balance - mark on securities acquired from FDIC — 300 336 Average earning assets - core(1) $ 438,312 $ 450,422 $ 417,628 Annualized net interest margin: Reported - taxable-equivalent 3.10 % 3.13 % 3.58 % Core(1) 2.72 2.67 3.06 (1) Core net interest margin is a non-GAAP measure that adjusts net interest margin to exclude the impact of purchase accounting. The purchase accounting marks and related amortization for a) securities acquired from the FDIC in the Colonial Bank acquisition and b) loans, deposits and long-term debt from SunTrust, Susquehanna, National Penn and Colonial Bank are excluded to approximate the yields paid by clients. Truist's management believes the adjustments to the calculation of net interest margin for certain assets and liabilities acquired provide investors with useful information related to the performance of Truist's earning assets. These measures are not necessarily comparable to similar measures that may be presented by other companies. A-12


Non-GAAP Reconciliations Insurance Holdings Adjusted EBITDA ($ MM) Quarter Ended Sept. 30 Sept. 30 2020 2019 Segment net interest income $ 24 $ 28 Noninterest income 524 491 Total revenue $ 548 $ 519 Segment net income (loss) - GAAP $ 77 $ 61 Provision (benefit) for income taxes 25 21 Depreciation & amortization 18 20 EBITDA 120 102 Merger-related and restructuring charges, net 3 1 Incremental operating expenses related to the merger — 8 Adjusted EBITDA(1) $ 123 $ 111 Adjusted EBITDA(1) margin 22.4 % 21.4 % (1) EBITDA is a non-GAAP measurement of operating profitability that is calculated by adding back interest, taxes, depreciation and amortization to net income. Truist's management also adds back merger-related and restructuring charges, incremental operating expenses related to the merger and other selected items. Truist's management uses this measure in its analysis of the Corporation's Insurance Holdings segment. Truist's management believes this measure provides a greater understanding of ongoing operations and enhances comparability of results with prior periods, as well as demonstrates the effects of significant gains and charges. A-13


Non-GAAP Reconciliations Allowance with Fair Value Marks ($ MM) As of/For the Quarter Ended Sept. 30 June 30 March 31 Dec. 31 2020 2020 2020 2020 ALLL $ 5,863 $ 5,702 $ 5,211 $ 1,549 Unamortized fair value mark (1) 2,676 3,077 3,539 4,564 Allowance plus unamortized fair value mark $ 8,539 $ 8,779 $ 8,750 $ 6,113 Loans and leases held for investment $ 306,627 $ 314,825 $ 319,229 $ 299,842 Unamortized fair value mark (1) 2,676 3,077 3,539 4,564 Gross loans and leases $ 309,303 $ 317,902 $ 322,768 $ 304,406 Allowance for loan and lease losses as a percentage of loans and leases - GAAP 1.91 % 1.81 % 1.63 % 0.52 % Allowance for loan and lease losses and unamortized fair value mark as a percentage of gross loans and leases - Adjusted (1) (2) 2.76 % 2.76 % 2.71 % 2.01 % (1) Unamortized fair value mark includes credit, interest rate and liquidity components. (2) Allowance for loan and lease losses and unamortized fair value mark, and allowance for credit losses and unamortized fair value mark, as a percentage of gross loans and leases are non-GAAP measurements of credit reserves that are calculated by adjusting the ALLL or ACL, and loans and leases held for investment by the unamortized fair value mark. Truist's management uses these measures to assess loss absorption capacity. A-14


To inspire and build better lives and communities