
USCB 8-K
Uscb Financial Holdings, Inc. (USCB)
8-K
2022-10-27
For: 2022-10-27
View Original
Added on
April 06, 2026
1
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
__________________________
FORM
__________________________
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported):
__________________________
(Exact name of Registrant as Specified in Its Charter)
(State or Other Jurisdiction
of Incorporation)
(Commission File Number)
(IRS Employer
Identification No.)
,
,
(Address of Principal Executive Offices)
(Zip Code)
Registrant’s Telephone Number, Including Area Code: (
)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under
any of the following provisions:
☐
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425)
☐
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a -12)
☐
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))
☐
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))
Securities registered pursuant to Section 12(b) of the Act:
Title of each class
Trading
Symbol(s)
Name of each exchange on which registered
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933
(§ 230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§ 240.12b -2 of this chapter).
Emerging growth company
☒
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for
complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.
☐
2
Item 2.02. Results of Operations and Financial Condition.
On October 27, 2022, USCB Financial Holdings, Inc. (the “Company”), issued a press release announcing its financial results
for the third quarter ended September 30, 2022. A copy of the press release is furnished as Exhibit 99.1 to this Current Report on Form
8-K and is incorporated herein by reference.
The information in this Item 2.02, including Exhibit 99.1, is being furnished and shall not be deemed “filed” for purposes of
Section 18 of the Securities Exchange Act of 1934 (the “Exchange Act”), or otherwise subject to the liability of that section, and shall
not be deemed to be incorporated by reference into any filing under the Securities Act of 1933 (the “Securities Act”) or the Exchange
Act.
Item 7.01. Regulation FD Disclosure.
As previously announced, at 9:00 a.m. ET on October 28, 2022, the Company will hold an earnings conference call to discuss
its financial performance for the quarter ended September 30, 2022. A copy of the slides forming the basis of the presentation is being
furnished as Exhibit 99.2 to this Current Report on Form 8-K and is incorporated herein by reference. A copy of the slides has also been
posted to the Company’s investor relations website, located at investors.uscenturybank.com.
The information in this Item 7.01, including Exhibit 99.2, is being furnished and shall not be deemed “filed” for purposes of
Section 18 of the Exchange Act, or otherwise subject to the liability of that section, and shall not be deemed to be incorporated by
reference into any filing under the Securities Act or the Exchange Act.
Item 9.01. Financial Statements and Exhibits.
(d) Exhibits.
Exhibit No.
Description
99.1
99.2
104
Cover Page Interactive Data File (embedded within the Inline XBRL document)

1
Exhibit 99.1
EARNINGS RELEASE
USCB Financial Holdings, Inc. Reports ROAA of 1.09% and ROAE of 11.90% for 3Q2022
MIAMI – October 27, 2022 – USCB Financial Holdings, Inc. (the “Company”) (NASDAQ: USCB)
, the holding company for U.S.
Century Bank (the “Bank”), reported net income of $5.6 million or $0.28 per diluted Class A share for the three months ended
September 30, 2022, compared with net income of $6.6 million or $5.11 loss and $1.02 loss per diluted share for Class A and Class B
common stock, respectively, for the same period in 2021. On December 21, 2021, the Company agreed to exchange all the outstanding
shares of Class B common stock for Class A common stock at a ratio of 1 share of Class A common stock for each 5 shares of Class B
common stock. As of December 31, 2021, the Company’s only class of securities issued and outstanding was Class A common stock.
“We are pleased to report another quarter of strong financial performance during the third quarter of 2022. Our loan and deposit activities
remain strong, with total assets and loans growing 16.1% and 21.7%, respectively, from September 30, 2021. Even with the changing
economic outlook and all the uncertainty, our ability to attract and retain clients continues to fuel outsized growth.” said Luis de la
Aguilera, President and Chief Executive Officer.
“On September 28, 2022, Hurricane Ian made landfall in Florida as a category 4 hurricane affecting some areas of the state with
significant flooding, wind damage and power outages. The Company has assessed the impact of the hurricane on our borrowers,
including the value of collateral underlying our loans and the financial condition of our borrowers impacted by the storm. Management
visited the 3 counties most impacted by the storm (Lee, Charlotte, and Collier counties) and observed negligible to no damage to our
clients’ properties. We had 9 yachts in the path of the storm and are happy to report that all owners of the vessels reported no damage.
Additionally, we have received no requests for loan modifications.”
Unless otherwise stated, all percentage comparisons in the bullet points below are calculated for the quarter ended September 30, 2022
compared to the quarter ended September 30, 2021 and annualized where appropriate.
Profitability
•
Annualized return on average assets for the quarter ended September 30, 2022 was 1.09% compared to 1.50 % for the third quarter
of 2021.
•
Annualized return on average stockholders’ equity for the quarter ended September 30, 2022 was 11.90% compared to 13.41% for
the third quarter of 2021.
•
The efficiency ratio for the quarter ended September 30, 2022 was 54.58% compared to 50.92% for the third quarter of 2021.
•
Net interest margin increased to 3.47% for the quarter ended September 30, 2022 compared to 3.19% for the third quarter of 2021.
•
Net interest income before provision for credit losses was $16.8 million for the quarter ended September 30, 2022, an increase of
$3.3 million or 24.5% compared to the third quarter of 2021.
Balance Sheet
•
Total assets were $2.0 billion at September 30, 2022, representing an increase of $282.4 million or 16.1% from September 30, 2021.
•
Total loans were $1.4 billion at September 30, 2022, representing an increase of $255.1 million or 21.7% from September 30, 2021.
•
Total deposits were $1.8 billion at September 30, 2022, representing an increase of $312.1 million or 21.0% from September 30,
2021.
•
Total stockholders’ equity was $177.4 million at September 30, 2022, representing a decrease of $24.5 million or 12.1% from
September 30, 2021.
•
Total stockholders’ equity includes unrealized security losses of $45.2 million at September 30, 2022 compared to unrealized
security gains of $1.2 million at September 30, 2021.
2
•
The Company classified $74.4 million of securities to held-to-maturity (HTM) during the quarter ended September 30, 2022 to
protect tangible book value in a rising rate environment.
Asset Quality
•
The allowance for credit losses increased by $1.7 million to $16.6 million at September 30, 2022 from $14.9 million at
September 30, 2021.
•
The allowance for credit losses represented 1.16% of total loans at September 30, 2022 compared to 1.27% at September 30, 2021.
•
Non-performing loans to total loans was 0.00% at September 30, 2022 and 2021.
Non-interest Income and Non-interest Expense
•
Non-interest income was $1.8 million for the three months ended September 30, 2022, a decrease of $2.4 million or 57.6%
compared to the same period in 2021.
•
Non-interest expense was $10.1 million for the three months ended September 30, 2022, an increase of $1.1 million or 12.5%
compared to the same period in 2021.
Capital
•
As of September 30, 2022,
total risk-based capital ratios for the Company and the Bank were 13.65% and 13.58%, respectively.
•
Tangible book value per common share of $8.87 was negatively affected by $2.26 due to unrealized security losses at September 30,
2022. At September 30, 2021, tangible book value of $10.10 was positively affected by $0.06 due to unrealized security gains.
Conference Call and Webcast
The Company will host a conference call on Friday, October 28, 2022, at 9:00 a.m. Eastern Time to discuss the Company’s unaudited
financial results for the quarter ended September 30, 2022. To access the conference call, dial (866) 652-5200 (U.S. toll-free) and ask
to join the USCB Financial Holdings Call.
Additionally, interested parties can listen to a live webcast of the call in the “Investor Relations” section of the Company’s website
at www.uscentury.com . An archived version of the webcast will be available in the same location shortly after the live call has ended.
About USCB Financial Holdings, Inc.
USCB Financial Holdings, Inc. is the bank holding company for U.S. Century Bank. Established in 2002, U.S. Century Bank is one of
the largest community banks headquartered in Miami, and one of the largest community banks in the state of Florida. U.S. Century Bank
is rated 5-Stars by BauerFinancial, the nation’s leading independent bank rating firm. U.S. Century Bank offers customers a wide range
of financial products and services and supports numerous community organizations, including the Greater Miami Chamber of
Commerce, the South Florida Hispanic Chamber of Commerce, and ChamberSouth. For more information or to find a banking center
near you, please call (305) 715-5200 or visit www.uscentury.com.
Forward-Looking Statements
This earnings release may contain statements that are not historical in nature and are intended to be, and are hereby identified as, forward-
looking statements for purposes of the safe harbor provided by Section 21E of the Securities Exchange Act of 1934, as amended. The
words “may,” “will,” “anticipate,” “should,” “would,” “believe,” “contemplate,” “expect,” “aim,” “plan,” “estimate,” “continue,” and
“intend,” as well as other similar words and expressions of the future, are intended to identify forward-looking statements. These
forward-looking statements include statements related to our projected growth, anticipated future financial performance, and
management’s long-term performance goals, as well as statements relating to the anticipated effects on results of operations and financial
condition from expected developments or events, or business and growth strategies, including anticipated internal growth.
These forward-looking statements involve significant risks and uncertainties that could cause our actual results to differ materially from
those anticipated in such statements. Potential risks and uncertainties include, but are not limited to:
•
the strength of the United States economy in general and the strength of the local economies in which we conduct operations;
•
the continuation of the COVID-19 pandemic and its impact on us, our employees, customers and third-party service providers, and
the ultimate extent of the impact of the pandemic and related government stimulus programs;
3
•
our ability to successfully manage interest rate risk, credit risk, liquidity risk, and other risks inherent to our industry;
•
the accuracy of our financial statement estimates and assumptions, including the estimates used for our credit loss reserve and
deferred tax asset valuation allowance;
•
the efficiency and effectiveness of our internal control environment;
•
our ability to comply with the extensive laws and regulations to which we are subject, including the laws for each jurisdiction where
we operate;
•
legislative or regulatory changes and changes in accounting principles, policies, practices or guidelines, including the effects of the
forthcoming implementation of the Current Expected Credit Losses (“CECL”) standard;
•
the effects of our lack of a diversified loan portfolio and concentration in the South Florida market, including the risks of geographic,
depositor, and industry concentrations, including our concentration in loans secured by real estate;
•
the concentration of ownership of our Class A common stock;
•
fluctuations in the price of our Class A common stock;
•
our ability to fund or access the capital markets at attractive rates and terms and manage our growth, both organic growth as well
as growth through other means, such as future acquisitions;
•
inflation, interest rate, unemployment rate, market, and monetary fluctuations;
•
increased competition and its effect on the pricing of our products and services as well as our margin;
•
the effectiveness of our risk management strategies, including operational risks, including, but not limited to, client, employee, or
third-party fraud and security breaches; and
•
other risks described in this earnings release and other filings we make with the Securities and Exchange Commission (“SEC”).
All forward-looking statements are necessarily only estimates of future results, and there can be no assurance that actual results will not
differ materially from expectations. Therefore, you are cautioned not to place undue reliance on any forward-looking statements. Further,
forward-looking statements included in this earnings release are made only as of the date hereof, and we undertake no obligation to
update or revise any forward-looking statement to reflect events or circumstances after the date on which the statement is made or to
reflect the occurrence of unanticipated events, unless required to do so under the federal securities laws. You should also review the risk
factors described in the reports the Company filed or will file with the SEC and, for periods prior to the completion of the bank holding
company reorganization in December 2021, the Bank filed with the FDIC.
Non-GAAP Financial Measures
This earnings release includes financial information determined by methods other than in accordance with generally accepted accounting
principles (“GAAP”). This financial information includes certain operating performance measures. Management has included these non-
GAAP measures because it believes these measures may provide useful supplemental information for evaluating the Company’s
underlying performance trends. Further, management uses these measures in managing and evaluating the Company’s business and
intends to refer to them in discussions about our operations and performance. Operating performance measures should be viewed in
addition to, and not as an alternative to or substitute for, measures determined in accordance with GAAP, and are not necessarily
comparable to non-GAAP measures that may be presented by other companies. To the extent applicable, reconciliations of these non-
GAAP measures to the most directly comparable GAAP measures can be found in the ‘Non-GAAP Reconciliation Tables’ included in
the exhibits to this earnings release.
You should assume that all numbers are unaudited unless otherwise noted.
Contacts:
Investor Relations
Media Relations
Martha Guerra-Kattou
4
USCB FINANCIAL HOLDINGS, INC.
CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED)
(Dollars in thousands, except per share data)
Three Months Ended September 30,
Nine Months Ended September 30,
2022
2021
2022
2021
Interest income:
Loans, including fees
$
15,954
$
12,538
$
42,989
$
35,944
Investment securities
2,201
1,858
7,040
5,670
Interest-bearing deposits in financial institutions
322
38
474
77
Total interest income
18,477
14,434
50,503
41,691
Interest expense:
Interest-bearing checking
19
16
52
45
Savings and money market accounts
1,141
501
2,307
1,572
Time deposits
363
306
893
1,239
FHLB advances and other borrowings
180
140
456
415
Total interest expense
1,703
963
3,708
3,271
Net interest income before provision for credit losses
16,774
13,471
46,795
38,420
Provision for credit losses
910
-
1,615
(160)
Net interest income after provision for credit losses
15,864
13,471
45,180
38,580
Non-interest income:
Service fees
934
856
2,917
2,648
Gain (loss) on sale of securities available for sale, net
(558)
(70)
(540)
179
Gain on sale of loans held for sale, net
330
532
686
1,519
Loan settlement
-
2,500
161
2,500
Other non-interest income
1,083
399
2,127
1,208
Total non-interest income
1,789
4,217
5,351
8,054
Non-interest expense:
Salaries and employee benefits
6,075
5,313
17,863
15,804
Occupancy
1,281
1,192
3,802
3,990
Regulatory assessments and fees
269
317
708
690
Consulting and legal fees
604
357
1,519
915
Network and information technology services
488
358
1,323
1,198
Other operating expense
1,415
1,470
4,080
3,761
Total non-interest expense
10,132
9,007
29,295
26,358
Net income before income tax expense
7,521
8,681
21,236
20,276
Income tax expense
1,963
2,088
5,529
4,849
Net income
5,558
6,593
15,707
15,427
Preferred stock dividend
-
542
-
2,077
Exchange and redemption of preferred shares
-
89,585
-
89,585
Net income available to common stockholders
$
5,558
$
(83,534)
$
15,707
$
(76,235)
Allocation of net income (loss) per common stock class:
(1)
Class A
$
5,558
$
(77,278)
$
15,707
$
(65,747)
Class B
$
-
$
(6,256)
$
-
$
(10,488)
Per share information:
(1)
Class A common stock
(2)
Net income (loss) per share, basic
$
0.28
$
(5.11)
$
0.79
$
(8.57)
Net income (loss) per share, diluted
$
0.28
$
(5.11)
$
0.78
$
(8.57)
Class B common stock
Net loss per share, basic
$
-
$
(1.02)
$
-
$
(1.71)
Net loss per share, diluted
$
-
$
(1.02)
$
-
$
(1.71)
Weighted average shares outstanding:
Class A common stock
(2)
Basic
20,000,753
15,121,460
19,998,841
7,674,609
Diluted
20,148,208
15,121,460
20,178,089
7,674,609
Class B common stock
Basic
-
6,121,052
-
6,121,052
Diluted
-
6,121,052
-
6,121,052
(1) For the three and nine months ended September 30, 2021, the allocation of net income available to common stockholders was based on the weighted average shares
outstanding per common share class to the total weighted average shares outstanding during the period. The income allocation is calculated using the weighted average
shares outstanding of Class B common stock on an as-converted basis (20% per share equivalent to Class A common stock).
(2) For the nine months ended September 30, 2021, the common stock outstanding, weighted average shares and net income per share for the Class A common stock
have been adjusted to reflect the 1 for 5 reverse stock split that occurred in June 2021.
5
USCB FINANCIAL HOLDINGS, INC.
SELECTED FINANCIAL DATA (UNAUDITED)
(Dollars in thousands, except per share data)
As of or For the Three Months Ended
9/30/2022
6/30/2022
3/31/2022
12/31/2021
9/30/2021
Income statement data:
Net interest income
$
16,774
$
15,642
$
14,379
$
14,076
$
13,471
Provision for credit losses
910
705
-
-
-
Net interest income after provision for credit losses
15,864
14,937
14,379
14,076
13,471
Service fees
934
1,083
900
961
856
Gain (loss) on sale of securities available for sale, net
(558)
(3)
21
35
(70)
Gain on sale of loans held for sale, net
330
22
334
107
532
Gain on sale of other assets
-
-
-
983
-
Loan settlement
-
-
161
-
2,500
Other income
1,083
515
529
558
399
Total non-interest income
1,789
1,617
1,945
2,644
4,217
Salaries and employee benefits
6,075
5,913
5,875
5,634
5,313
Occupancy
1,281
1,251
1,270
1,267
1,192
Regulatory assessments and fees
269
226
213
93
317
Consulting and legal fees
604
398
517
539
357
Network and information technology services
488
448
387
268
358
Other operating expense
1,415
1,315
1,350
1,518
1,470
Total non-interest expense
10,132
9,551
9,612
9,319
9,007
Net income before income tax expense
7,521
7,003
6,712
7,401
8,681
Income tax expense
1,963
1,708
1,858
1,751
2,088
Net income
5,558
5,295
4,854
5,650
6,593
Preferred stock dividend
-
-
-
-
542
Exchange and redemption of preferred shares
-
-
-
-
89,585
Net income (loss) available to common stockholders
$
5,558
$
5,295
$
4,854
$
5,650
$
(83,534)
Allocation of net income (loss) per common stock class:
(1)
Class A
$
5,558
$
5,295
$
4,854
$
5,650
$
(77,278)
Class B
$
-
$
-
$
-
$
-
$
(6,256)
Per share information:
Class A common stock
Net income (loss) per share, basic
$
0.28
$
0.26
$
0.24
$
0.30
$
(5.11)
Net income (loss) per share, diluted
$
0.28
$
0.26
$
0.24
$
0.30
$
(5.11)
Class B common stock
Net loss per share, basic
$
-
$
-
$
-
$
-
$
(1.02)
Net loss per share, diluted
$
-
$
-
$
-
$
-
$
(1.02)
Balance sheet data (at period-end):
Cash and cash equivalents
$
73,326
$
83,272
$
94,113
$
46,228
$
69,597
Securities available-for-sale
$
248,571
$
339,464
$
392,214
$
401,542
$
328,171
Securities held-to-maturity
$
178,865
$
116,671
$
122,361
$
122,658
$
99,866
Total securities
$
427,436
$
456,135
$
514,575
$
524,200
$
428,037
Loans held for investment
(2)
$
1,431,513
$
1,372,733
$
1,258,388
$
1,190,081
$
1,176,412
Allowance for credit losses
$
(16,604)
$
(15,786)
$
(15,074)
$
(15,057)
$
(14,900)
Total assets
$
2,037,453
$
2,016,086
$
1,967,252
$
1,853,939
$
1,755,011
Non-interest-bearing deposits
$
662,808
$
653,708
$
656,622
$
605,425
$
570,091
Interest-bearing deposits
$
1,133,834
$
1,085,012
$
1,056,672
$
984,954
$
914,498
Total deposits
$
1,796,642
$
1,738,720
$
1,713,294
$
1,590,379
$
1,484,589
FHLB advances and other borrowings
$
26,000
$
66,000
$
36,000
$
36,000
$
36,000
Total liabilities
$
1,860,036
$
1,836,018
$
1,775,213
$
1,650,042
$
1,553,093
Total stockholders' equity
$
177,417
$
180,068
$
192,039
$
203,897
$
201,918
Capital ratios:
(3)
Leverage ratio
9.48%
9.43%
9.47%
9.55%
9.69%
Common equity tier 1 capital
12.56%
12.65%
13.35%
13.70%
13.85%
Tier 1 risk-based capital
12.56%
12.65%
13.35%
13.70%
13.85%
Total risk-based capital
13.65%
13.74%
14.49%
14.92%
15.10%
(1) The allocation of net income (loss) available to common stockholders was based on the weighted average shares outstanding per common share class to the total
weighted average shares outstanding during each period. The income (loss) allocation is calculated using the weighted average shares outstanding of Class B common
stock on an as-converted basis (20% per share equivalent to Class A common stock).
(2) Loan amounts include deferred fees/costs.
(3) The Company was formed during the quarter ended December 31, 2021. As such, the capital ratios for Q3 2022, Q2 2022, Q1 2022 and Q4 2021 are for the
Company and for Q3 2021 are for the Bank. The Company, as a small bank holding company, is not subject to regulatory capital requirements.
6
USCB FINANCIAL HOLDINGS, INC.
AVERAGE BALANCES, RATIOS, AND OTHER DATA (UNAUDITED)
(Dollars in thousands)
As of or For the Three Months Ended
9/30/2022
6/30/2022
3/31/2022
12/31/2021
9/30/2021
Average balance sheet data:
Cash and cash equivalents
$
77,887
$
80,254
$
99,911
$
87,819
$
116,622
Securities available-for-sale
$
331,206
$
370,933
$
385,748
$
374,589
$
346,407
Securities held-to-maturity
$
116,733
$
120,130
$
122,381
$
114,108
$
51,238
Total securities
$
447,939
$
491,063
$
508,129
$
488,697
$
397,645
Loans held for investment
(1)
$
1,398,761
$
1,296,476
$
1,211,432
$
1,158,755
$
1,144,275
Total assets
$
2,026,791
$
1,968,381
$
1,913,484
$
1,828,037
$
1,741,423
Interest-bearing deposits
$
1,107,129
$
1,071,709
$
1,023,844
$
958,241
$
912,330
Non-interest-bearing deposits
$
655,853
$
644,975
$
626,400
$
603,735
$
564,928
Total deposits
$
1,762,982
$
1,716,684
$
1,650,244
$
1,561,976
$
1,477,258
FHLB advances and other borrowings
$
43,935
$
36,330
$
36,011
$
36,000
$
36,000
Total liabilities
$
1,841,503
$
1,781,784
$
1,711,624
$
1,625,675
$
1,546,414
Total stockholders' equity
$
185,288
$
186,597
$
201,860
$
202,362
$
195,009
Performance ratios:
Return on average assets
(2)
1.09%
1.08%
1.03%
1.23%
1.50%
Return on average equity
(2)
11.90%
11.38%
9.75%
11.08%
13.41%
Net interest margin
(2)
3.47%
3.37%
3.22%
3.19%
3.19%
Non-interest income to average assets
(2)
0.35%
0.33%
0.41%
0.57%
0.96%
Efficiency ratio
(3)
54.58%
55.34%
58.88%
55.74%
50.92%
Loans by type (at period end):
(4)
Residential real estate
$
186,551
$
203,662
$
204,317
$
201,359
$
201,124
Commercial real estate
$
928,531
$
843,445
$
782,072
$
704,988
$
693,469
Commercial and industrial
$
121,145
$
131,271
$
134,832
$
146,592
$
137,486
Foreign banks
$
94,450
$
84,770
$
63,985
$
59,491
$
58,839
Consumer and other
$
100,845
$
109,250
$
73,765
$
79,229
$
87,515
Asset quality data:
Allowance for credit losses to total loans
1.16%
1.15%
1.20%
1.27%
1.27%
Allowance for credit losses to non-performing loans
- %
- %
- %
1,265%
82,778%
Non-accrual loans less non-accrual TDRs
-
-
-
1,190
-
Non-accrual TDRs
-
-
-
-
18
Loans over 90 days past due and accruing
-
-
-
-
-
Total non-performing loans
(5)
-
-
-
1,190
18
Non-performing loans to total loans
- %
- %
- %
0.10%
0.00%
Non-performing assets to total assets
- %
- %
- %
0.06%
0.00%
Net charge-offs (recoveries of) to average loans
(2)
0.03%
(0.00)%
(0.01)%
(0.05)%
(0.02)%
Net charge-offs (recovery of) credit losses
91
(7)
(17)
(157)
(51)
Interest rates and yields:
(2)
Loans
4.53%
4.35%
4.35%
4.32%
4.29%
Investment securities
1.94%
2.04%
1.85%
1.81%
1.86%
Total interest-earning assets
3.82%
3.60%
3.43%
3.41%
3.43%
Deposits
0.34%
0.21%
0.20%
0.21%
0.22%
FHLB advances and other borrowings
1.63%
1.53%
1.54%
1.51%
1.52%
Total interest-bearing liabilities
0.59%
0.38%
0.37%
0.38%
0.40%
Other information:
Full-time equivalent employees
191
192
190
187
184
(1) Loan amounts include deferred fees/costs.
(2) Annualized.
(3) Efficiency ratio is defined as total non-interest expense divided by sum of net interest income and total non-interest income.
(4) Loan amounts exclude deferred fees/costs.
(5) The amounts for total non-performing loans and total non-performing assets are the same for the dates presented since there were no impaired investments or other
real estate owned (OREO) recorded.
7
USCB FINANCIAL HOLDINGS, INC.
NET INTEREST MARGIN (UNAUDITED)
(Dollars in thousands)
Three Months Ended September 30,
2022
2021
Average
Balance
Interest
Yield/Rate
(1)
Average
Balance
Interest
Yield/Rate
(1)
Assets
Interest-earning assets:
Loans
(2)
$
1,398,761
$
15,954
4.53%
$
1,144,275
$
12,538
4.29%
Investment securities
(3)
450,514
2,201
1.94%
399,745
1,858
1.86%
Other interest-earnings assets
70,540
322
1.81%
109,639
38
0.14%
Total interest-earning assets
1,919,815
18,477
3.82%
1,653,659
14,434
3.43%
Non-interest-earning assets
106,976
87,764
Total assets
$
2,026,791
$
1,741,423
Liabilities and stockholders' equity
Interest-bearing liabilities:
Interest-bearing checking
$
66,585
19
0.11%
$
55,621
16
0.11%
Saving and money market deposits
823,521
1,141
0.55%
627,654
501
0.32%
Time deposits
217,023
363
0.66%
229,055
306
0.53%
Total interest-bearing deposits
1,107,129
1,523
0.55%
912,330
823
0.36%
FHLB advances and other borrowings
43,935
180
1.63%
36,000
140
1.52%
Total interest-bearing liabilities
1,151,064
1,703
0.59%
948,330
963
0.40%
Non-interest-bearing demand deposits
655,853
564,928
Other non-interest-bearing liabilities
34,586
33,156
Total liabilities
1,841,503
1,546,414
Stockholders' equity
185,288
195,009
Total liabilities and stockholders' equity
$
2,026,791
$
1,741,423
Net interest income
$
16,774
$
13,471
Net interest spread
(4)
3.23%
3.03%
Net interest margin
(5)
3.47%
3.19%
(1) Annualized.
(2) Average loan balances include non-accrual loans. Interest income on loans includes accretion of deferred loan fees, net of deferred loan costs.
(3) At fair value except for securities held to maturity. This amount includes FHLB stock.
(4) Net interest spread is the average yield on total interest-earning assets minus the average rate on total interest-bearing liabilities.
(5) Net interest margin is the ratio of net interest income to total interest-earning assets.
8
USCB FINANCIAL HOLDINGS, INC.
NON-GAAP FINANCIAL MEASURES (UNAUDITED)
(Dollars in thousands)
As of or For the Three Months Ended
9/30/2022
6/30/2022
3/31/2022
12/31/2021
9/30/2021
Pre-tax pre-provision ("PTPP") income:
Net income
$
5,558
$
5,295
$
4,854
$
5,650
$
6,593
Plus: Provision for income taxes
1,963
1,708
1,858
1,751
2,088
Plus: Provision for credit losses
910
705
-
-
-
PTPP income
$
8,431
$
7,708
$
6,712
$
7,401
$
8,681
PTPP return on average assets:
PTPP income
$
8,431
$
7,708
$
6,712
$
7,401
$
8,681
Average assets
$
2,026,791
$
1,968,381
$
1,913,484
$
1,828,037
$
1,741,423
PTPP return on average assets
(1)
1.65%
1.57%
1.42%
1.61%
1.98%
Operating net income:
Net income
$
5,558
$
5,295
$
4,854
$
5,650
$
6,593
Less: Net gains (losses) on sale of securities
(558)
(3)
21
35
(70)
Less: Tax effect on sale of securities
141
1
(5)
(9)
17
Operating net income
$
5,975
$
5,297
$
4,838
$
5,624
$
6,646
Operating PTPP income:
PTPP income
$
8,431
$
7,708
$
6,712
$
7,401
$
8,681
Less: Net gains (losses) on sale of securities
(558)
(3)
21
35
(70)
Operating PTPP income
$
8,989
$
7,711
$
6,691
$
7,366
$
8,751
Operating PTPP return on average assets:
Operating PTPP income
$
8,989
$
7,711
$
6,691
$
7,366
$
8,751
Average assets
$
2,026,791
$
1,968,381
$
1,913,484
$
1,828,037
$
1,741,423
Operating PTPP return on average assets
(1)
1.76%
1.57%
1.42%
1.60%
1.99%
Operating return on average assets:
Operating net income
$
5,975
$
5,297
$
4,838
$
5,624
$
6,646
Average assets
$
2,026,791
$
1,968,381
$
1,913,484
$
1,828,037
$
1,741,423
Operating return on average assets
(1)
1.17%
1.08%
1.03%
1.22%
1.51%
(1) Annualized.
9
USCB FINANCIAL HOLDINGS, INC.
NON-GAAP FINANCIAL MEASURES (UNAUDITED)
(Dollars in thousands, except per share data)
As of or For the Three Months Ended
9/30/2022
6/30/2022
3/31/2022
12/31/2021
9/30/2021
Tangible book value per common share (at period-end):
(1)
Total stockholders' equity
$
177,417
$
180,068
$
192,039
$
203,897
$
201,918
Less: Intangible assets
-
-
-
-
-
Tangible stockholders' equity
$
177,417
$
180,068
$
192,039
$
203,897
$
201,918
Total shares issued and outstanding (at period-end):
(2)
Class A common shares
20,000,753
20,000,753
20,000,753
19,991,753
18,767,541
Class B common shares
-
-
-
-
1,224,212
Total common shares issued and outstanding
20,000,753
20,000,753
20,000,753
19,991,753
19,991,753
Tangible book value per common share
(3)
$
8.87
$
9.00
$
9.60
$
10.20
$
10.10
Operating net income available to common stockholders:
(1)
Net income
$
5,558
$
5,295
$
4,854
$
5,650
$
6,593
Less: Preferred dividends
-
-
-
-
542
Less: Exchange and redemption of preferred shares
(2)
-
-
-
-
89,585
Net income (loss) available to common stockholders
5,558
5,295
4,854
5,650
(83,534)
Add back: Exchange and redemption of preferred shares
-
-
-
-
89,585
Operating net income avail. to common stock
$
5,558
$
5,295
$
4,854
$
5,650
$
6,051
Allocation of operating net income per common stock class:
Class A common stock
$
5,558
$
5,295
$
4,854
$
5,650
$
5,598
Class B common stock
$
-
$
-
$
-
$
-
$
453
Weighted average shares outstanding:
Class A common stock
Basic
20,000,753
20,000,753
19,994,953
18,913,914
15,121,460
Diluted
20,148,208
20,171,261
20,109,783
19,023,686
15,121,460
Class B common stock
Basic
-
-
-
-
6,121,052
Diluted
-
-
-
-
6,121,052
Diluted EPS:
(4) (5)
Class A common stock
Net income (loss) per diluted share
$
0.28
$
0.26
$
0.24
$
0.30
$
(5.11)
Add back: Exchange and redemption of preferred shares
-
-
-
-
5.48
Operating net income per diluted share
$
0.28
$
0.26
$
0.24
$
0.30
$
0.37
Class B common stock
Net income (loss) per diluted share
$
-
$
-
$
-
$
-
$
(1.02)
Add back: Exchange and redemption of preferred shares
-
-
-
-
1.09
Operating net income per diluted share
$
-
$
-
$
-
$
-
$
0.07
(1) The Company believes these non-GAAP measurements are key indicators of the ongoing earnings power of the Company.
(2) During the quarter ended September 30, 2021, 47,473 shares of Class C preferred stock and 11,061,552 shares of Class D preferred stock were converted into
10,278,072 shares of Class A common stock. Additionally, the Bank closed on the initial public offering of its Class A common stock on July 27, 2021, in which it
issued 4,600,000 shares of Class A common stock. As such, the total shares issued and outstanding of Class A common stock was 18,767,541 shares at September 30,
2021.
(3) Excludes the dilutive effect, if any, of shares of common stock issuable upon exercise of outstanding stock options.
(4) During the quarter ended September 30, 2021, basic net loss per share is the same as diluted net loss per share as the inclusion of all potential common shares
outstanding would have been antidilutive.
(5) During the quarter ended December 31, 2021, the Company entered into agreements with the Class B common shareholders to exchange all outstanding Class B
non-voting common stock for Class A voting common stock at a ratio of 1 share of Class A common stock for each 5 shares of Class B non-voting common stock. In
calculating net income (loss) per diluted share for the prior quarters presented, the allocation of operating net income available to common stockholders was based on
the weighted average shares outstanding per common share class to the total weighted average shares outstanding during each period. The operating net income
allocation was calculated using the weighted average shares outstanding of Class B common stock on an as-converted basis.

Exhibit 99.2 USBC FINANCIAL HOLDINGS
Third Quarter 2022
Earnings Presentation
October 28, 2022

Forward-Looking Statements This presentation may contain statements that are not historical in nature and are intended to be, and are hereby identified as, forward-looking statements for purposes of the safe harbor provided by Section 21E of the Securities Exchange Act of 1934, as amended. The words “may,” “will,” “anticipate,” “should,” “would,” “believe,” “contemplate,” “expect ,” “aim,” “plan,” “estimate,” “continue,” and “intend,” as well as other similar words and expressions of the future, are intended to identi fy forward-looking statements. These forward-looking statements include statements related to our projected growth, anticipated future financial performance, and management’s long-term performance goals, as well as statements relating to the anticipated effects on results of operations and financial condition from expected developments or events, or business and growth strategies, including anticipated internal growth. These forward-looking statements involve significant risks and uncertainties that could cause our actual results to differ materially from those anticipated in such statements. Potential risks and uncertainties include, but are not limited to: • the strength of the United States economy in general and the strength of the local economies in which we conduct operations; • the continuation of the COVID-19 pandemic and its impact on us, our employees, customers and third-party service providers, and the ultimate extent of the impacts of the pandemic and related government stimulus programs; • our ability to successfully manage interest rate risk, credit risk, liquidity risk, and other risks inherent to our industry; • the accu racy of our financial statement estimates and assumptions, including the estimates used for our credit loss reserve and deferred tax asset valuation allowance; • the efficiency and effectiveness of our internal control environment; • our ability to comply with the
extensive laws and regulations to which we are subject, including the laws for each jurisdiction where we operate; • legislative or regulatory changes and changes in accounting principles, policies, practices or guidelines, including the effects of the forthcoming implementation of the Current Expected Credit Losses (“CECL”) standard; • the effects of our lack of a diversified loan portfolio and concentration in the South Florida market, including the risks of geographic, depositor, and industry concentrations, including our concentration in loans secured by real estate; • the concentration of ownership of our Class A common stock; • fluctuations in the price of our Class A common stock; • our ability to fund or access the capital markets at attractive rates and terms and manage our growth, both organic growth as well as growth through other means, such as future acquisitions; • inflation, interest rate, unemployment rate, market, and monetary fluctuations; • increased competition and its effect on the pricing of our products and services as well as our margin; • the effectiveness of our risk management strategies, including operational risks, including, but not limited to, client, employee, or third -party fraud and security breaches; and • other risks described in this presentation and other filings we make with the Securities and Exchange Commission (“SEC”). All forward-looking statements are necessarily only estimates of future results, and there can be no assurance that actual results will not differ materially from expectations. Therefore, you are cautioned not to place undue reliance on any forward-looking statements. Further, forward-looking statements included in this presentation are made only as of the date hereof, and we undertake no obligation to update or revise any forward-looking statement to reflect events or circumstances after the date on which the statement is made or to reflect the occurrence of
unanticipated events, unless required to do so under the federal securities laws. You should also review the risk factors described in the reports USCB Financial Holdings, Inc. filed or will file with the SEC and, for periods prior to the completion of the bank holding company reorganization in December 31, 2021, U.S Century Bank filed with the FDIC. Non-GAAP Financial Measures This presentation includes financial information determined by methods other than in accordance with generally accepted accounting principles (“GAAP”). This financial information includes certain operating performance measures. Management has included these non-GAAP measures because it believes these measures may provide useful supplemental information for evaluating the Company’s underlying performance trends. Further, management uses these measures in managing and evaluating the Company’s business and intends to refer to them in discussions about our operations and performance. Operating performance measures should be viewed in addition to, and not as an alternative to or substitute for, measures determined in accordance with GAAP, and are not necessarily comparable to non-GAAP measures that may be presented by other companies. To the extent applicable, reconciliations of these non-GAAP measures to the most directly comparable GAAP measures can be found in the ‘Non-GAAP Reconciliation Tables’ included in the presentation. You should assume that all numbers are unaudited unless otherwise noted. 2

Q3 2022 Highlights Capital/ Credit Credit metrics remain strong. There were no loans classified as nonperforming. ACL coverage ratio was 1.16%. Tangible Book Value per Share is at $8.87, down $0.13 from prior quarter primarily due to AOCI. Classified $74.4 million of securities from AFS to HTM to protect tangible book value in a rising rate environment. No shares repurchased during the quarter; Board approved repurchase program in place covering 750,000 shares of Class A common stock. Profitability Net income was $5.6 million or $0.28 per diluted share. ROAA was 1.09% and ROAE was 11.90%. Efficiency ratio was 54.58%. NIM was 3.47% and NII was $16.8 million, compared to 3.37% and $15.6 million in the second quarter 2022. Growth Average deposits increased by $285.7 million or 19.3% compared to third quarter 2021. Total average loans, excluding PPP loans, increased $113.3 million or 35.2% annualized compared to prior quarter and $321.1 million or 30.0% compared to third quarter 2021. 3

Historical Financial Data Total Loans (1) In millions $735 $1,432 2016 2017 2018 2019 2020 2021 Q1 Q2 Q3 2022 2022 2022 Total Deposits In millions $782 $1,797 2016 2017 2018 2019 2020 2021 Q1 Q2 Q3 2022 2022 2022 Total stockholders' equity In millions $86 $177 2016 2017 2018 2019 2020 2021 Q1 Q2 Q3 2022 2022 2022 ACL/Total Loans 37% 63% 2016 2017 2018 2019 2020 2021 Q1 Q2 Q3 2022 2022 2022 Net Charge offs In thousands (1019) 91 2016 2017 2018 2019 2020 2021 Q1 Q2 Q3 2022 2022 2022 Nonperforming Assets/Total Assets 1.58% 0% 2016 2017 2018 2019 2020 2021 Q1 Q2 Q3 2022 2022 2022 Total Revenue In millions $37 $63 2016 2017 2018 2019 2020 2021 Q1 Q2 Q3 2022 2022 2022 Efficiency ratio 94.15% 54.58% 2016 2017 2018 2019 2020 2021 Q1 Q2 Q3 2022 2022 2022 PTPP ROAA (2) 0.24% 1.65% 2016 2017 2018 2019 2020 2021 Q1 Q2 Q3 2022 2022 2022 (1) Loan amounts include deferred fees/costs. (2) Non-GAAP Financial Measure. Annualized for 2022 periods. * As of end of period for Balance Sheet amounts. 4

Hurricane Ian Update On September 28, 2022, Hurricane Ian made landfall in Florida as a category 4 hurricane affecting some areas of the state with significant flooding, wind damage and power outages. The Credit Department identified all potential impact zones and tracked the storms progress. 27 counties throughout the State of Florida were documented to be in the Hurricane trajectory. USCB has 94 loans totaling $173 million that were identified within the storm’s path, inclusive of properties and moored yachts. Management visited the 3 counties most impacted by the storm (Lee, Charlotte, and Collier counties) and observed negligible to no damage to our client’s properties. Yacht owners were contacted; no damage reported. To date, no loan modifications have been requested. We continue to assess any potential credit risk and most importantly we are in direct contact with our customers. 5

Financial Results In thousands (except per share data) Balance Sheet (EOP) Q3 2022 Q2 2022 Q3 2021 Income Statement Total Securities Total Loans '?) Total Assets Total Deposits Total Equity '2) Net Interest Income Non-interest Income Total Revenue Provision for Credit Losses Non-interest Expense Net Income Net Income (loss) available to common stockholders Diluted Earning (loss) Per Share (EPS) (3) Class A Common Stock Class B Common Stock $427,436 $1,431,513 $2,037,453 $1,796,642 $177,417 $16,774 $1,789 $18,563 $910 $10,132 $5,558 $5,558 $0.28 $0.00 $456,135 $1,372,733 $2,016,086 $1,738,720 $180,068 $15,642 $1,617 $17,259 $705 $9,551 $5,295 $5,295 $0.26 $0.00 $428,037 $1,176,412 $1,755,011 $1,484,589 $201,918 $13,471 $4,217 $17,688 $o $9,007 $6,593 -$83,534 $5.11 -$1.02 (1) Loan amounts include deferred fees/costs. (2) Total Equity includes unrealized security losses of $45,201 for Q3 2022, $36,860 for Q2 2022, and unrealized security gains of $1,184 for Q3 2021. (3) See footnote disclosure in the Non-GAAP reconciliation table for common stock activity (exchange of Class B common stock) which impacted diluted EPS for Q3’21. 6

Key Performance Indicators Q3 2022 Q2 2022 Q3 2021 Capital/ Credit Profitability Growth Tangible Common Equity/Tangible Assets!) Total Risk-Based Capital NCO/Avg Loans ©! NPA/Assets Allowance Credit Losses/Loans Return On Average Assets (ROAA) ) Return On Average Equity (ROAE) Net Interest Margin ! Efficiency Ratio PTPP ROAA (18) Total Assets (EOP) Total Loans (EOP) Total Deposits (EOP) Tang ible Book Value/Share ‘4! 8.71% 13.65% 0.03% 0.00% 1.16% 1.09% 11.90% 3.47% 54.58% 1.65% $2,037,453 $1,431,513 $1,796,642 $8.87 8.93% 11.51% 13.74% 15.10% 0.00% 0.02% 0.00% 0.00% 1.15% 1.27% 1.08% 1.50% 11.38% 13.41% 3.37% 3.19% 55.34% 50.92% 1.57% 1.98% In thousands (except for TBV/share) $2,016,086 $4,755,011 $1,372,733 $1,176,412 $1,738,720 $1,484,589 $9.00 $10.10 (1) Non-GAAP Financial Measures. See footnote disclosure in the Non-GAAP reconciliation table for common stock activity (exchange of Class B common stock) which impacted Q3’21. (2) The Company was established in Q4 2021. As such, the capital ratios for Q3 2022 and Q2 2022 are for the Bank Holding Company while Q3 2021 is for the Bank only. (3) Annualized. (4) Unrealized security (loss) gain effect on tangible book value per share was ($2.26) for Q3 2022, ($1.84) for Q2 2022 and $0.06 for Q2 2022. 7

Loan Portfolio Total Loans (AVG) In millions $1,400 $1,300 $1,200 $1,100 $1,000 $900 $800 $1,144 $1,159 $1,211 $1,296 $1,399 $700 $73 $51 $35 $18 $7 $600 $1,071 $1,108 $1,176 $1,278 $1,392 Q3 2021 Q4 2021 Q1 2022 Q2 2022 Q3 2022 Loans (Exd PPP) PPP Loans Loan Yields 5.00% 4.50% 4.00% 3.50% 3.00% 2.50% 2.00% 1.50% 1.00% 4.29% 4.32% 4.35% 4.35% 4.53% 0.50% 0.32% 0.33% 0.28% 1.30% 0.03% 0.00% 3.97% 3.99% 4.07% 4.22% 4.50% Q3 2021 Q4 2021 Q1 2022 Q2 2022 Q3 2022 Commentary Total average loans, excluding PPP loans, increased $113.3 million or 35.4% annualized compared to prior quarter and $321.1 million or 30.0% compared to third quarter 2021. Loan coupon increased 28 bps compared to prior quarter and 53 bps compared to third quarter 2021. Increase due to a higher interest rate environment. Loan fees decreased 10 bps from prior quarter primarily due to amortization of premium on yacht loan purchased in 2021 and subsequently paid off in 2022. Additionally, a decrease of $312 thousand in PPP loan fees. 8
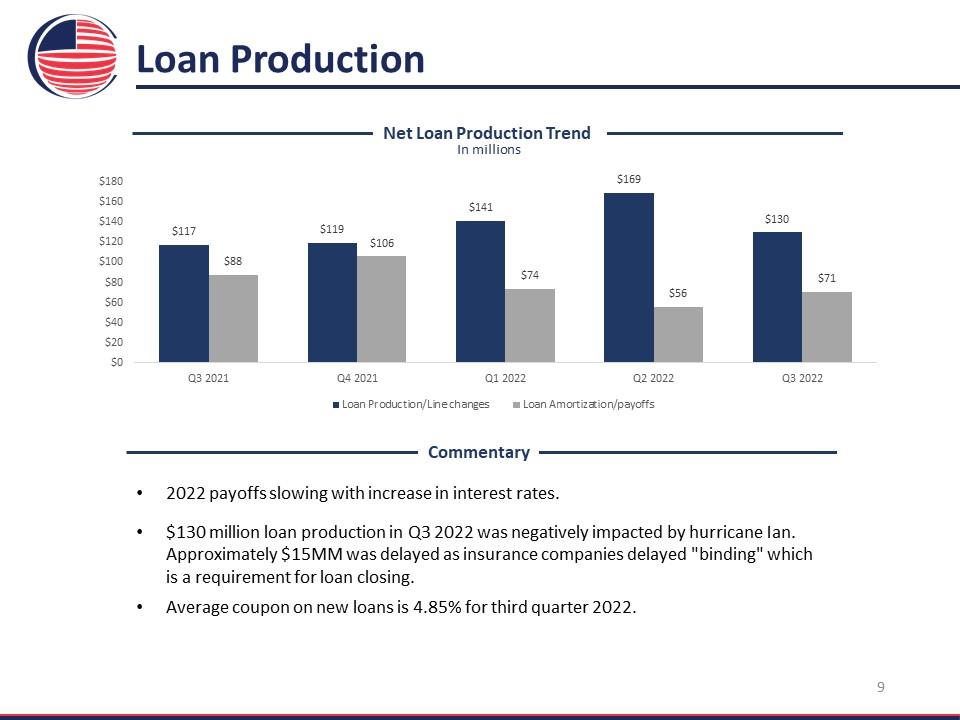
Loan Production Net Loan Production Trend In millions $180 $160 $140 $120 $100 $80 $60 $40 $20 $117 $88 $119 $106 $141 $74 $169 $56 $130 $71 $0 Q3 2021 Q4 2021 Q1 2022 Q2 2022 Q3 2022 Loan Production/Line changes Loan Amortization/payoffs Commentary 2022 payoffs slowing with increase in interest rates. $130 million loan production in Q3 2022 was negatively impacted by hurricane Ian. Approximately $15MM was delayed as insurance companies delayed "binding" which is a requirement for loan closing. Average coupon on new loans is 4.85% for third quarter 2022. 9

Paycheck Protection Program (PPP) 3 successful rounds of PPP loans, originating $168.4 million. Forgiveness of the last round of PPP loans is in process. In thousands (except for ROAA) Q3 2022 Q2 2022 Q3 2021 Pre-Tax Income $7,521 $7,003 $8,681 Net Income $5,558 $5,295 $6,593 Average Assets $2,026,791 $1,968,381 $1,741,423 ROAA (1) 1.09% 1.08% 1.50% of which PPP Income (2) $145 $484 $1,071 Unrealized PPP Fees EOP $19 $149 $2,360 PPP Balance EOP $1,362 $13,507 $57,991 PPP AVG. Balance $6,620 $17,643 $73,215 PPP Loans (1) Annualized. (2) PPP Income includes loan fees and interest income. 10

Deposit Portfolio Deposits (AVG) In millions $2,000 $1,800 $1,600 $1,400 $1,200 $1,000 $800 $1,477 $1,562 $1,650 $1,717 $1,763 $600 $229 $228 $223 $224 $217 $400 $628 $674 $736 $781 $823 $200 $55 $56 $65 $67 $67 $- $565 $604 $626 $645 $656 Q3 2021 Q4 2021 Q1 2022 Q2 2022 Q3 2022 Non-interest-bearing deposits Interest-bearing checking deposits Money amrket and savings Time deposits Deposit Cost (1) 0.70% 0.60% + 300 bps 0.50% Q3'22 vs Q4'21 0.40% 0.30% 0.20% 0.10% 0.22% 0.21% 0.20% 1.75% 3.25% 0.00% 0.25% 0.25% 5.00% 0.21% 0.34% Q3 2021 Q4 2021 Q1 2022 Q2 2022 Q3 2022 Deposit Cost Fed Funds Rate (upper bound) Commentary Average deposits increased $46.3 million or 10.7% annualized compared to prior quarter and $285.7 million or 19.3% compared to third quarter 2021. Average DDA deposits grew $10.9 million or 6.7% annualized compared to prior quarter and $90.9 million or 16.1% compared to third quarter 2021. DDA balances comprise 38.2% of total deposits at September 30, 2022. Deposit cost increased 13 bps compared to prior quarter and increased 12 bps compared to third quarter 2021. Deposit cost lagged the Fed Fund Rate increases with a 4.33% Deposit beta. (1) Annualized. 11

Net Interest Margin Net Interest Income/Margin (1) In thousands (except ratios) $18,000 $16,000 $14,000 $12,000 $10,000 $8,000 $6,000 $4,000 3.19% 3.19% 3.22% 337.00% 3.47% $2,000 3.08% 3.06% 3.05% 3.27% 3.45% $0 $13,471 $14,076 $14,379 $15,642 $16,774 Q3 2021 Q4 2021 Q1 2022 Q2 2022 Q3 2022 Net Interest Income NIM NIM excludign PPP Loans Interest-Earning Assets Mix (AVG) 100% 90% 80% 70% 60% 50% 40% 30% 6% 5% 5% 4% 4% 20% 24% 28% 28% 26% 23% 10% 5% 3% 2% 1% 0% 0% 65% 64% 65% 69% 73% Q3 2021 Q4 2021 Q1 2022 Q2 2022 Q3 2022 Total Loans (excludign PPP Loans) PPP Loans Investment Securities Cash Balances & Equivalents Commentary Net interest income increased by $1.1 million or 28.7% annualized compared to prior quarter and $3.3 million or 24.5% compared to third quarter 2021. NIM impacted by an increase in overall interest rates and growth in loans. NIM of 3.47% up 10 bps from prior quarter and up 28 bps from third quarter 2021. (1) Annualized. 12

Interest Rate Sensitivity Loan Portfolio Repricing Profile by Rate Type Hybrid ARM 6% Variable Rate 55% Fixed Rate 39% 16% 16% 68% Prime CMT LIBOR Loan Repricing Schedule Variable/Hybrid Rate Loans 31% 9% 10% 50% yrs. 1-2 yrs. 2-3 yrs. >3 yrs Static NII Simulation Year 1 & 2 $4,000 $3,500 $3,000 $2,500 $2,000 $1,500 $1,000 $500 $0 -$500 -$51 -$319 2.6% 4.4% -$1,000 0.1% 0.4% $2,032 $3,411 +100 +200 +100 +200 Net Interest Income change from base ($ in thousands and % change) As of 9/30/22 13

Non-interest Income Q3 2022 Q2 2022 Q1 2022 Q4 2021 Q3 2021 Service fees $934 $1,083 $900 $961 $856 Gain (loss) on sale of securities available for sale (558) (3) 21 35 (70) Gain on sale of loans held for sale 330 22 334 107 532 Gain on sale of other assets - - - 983 - Loan settlement - - 161 - 2,500 Other income 1,083 515 529 558 399 Total non-interest income $1,789 $1,617 $1,945 $2,644 $4,217 Average total assets $2,026,791 $1,968,381 $1,913,484 $1,828,037 $1,741,423 Non-interest income / Average assets (1) 0.35% 0.33% 0.41% 0.57% 0.96% Total revenue $18,563 $17,259 $16,324 $16,720 $17,688 Non-interest income as % of total revenue 9.64% 9.37% 11.91% 15.81% 23.85% Commentary Service fees remain substantially consistent quarter over quarter. Loss on sale of securities was offset with a $565K gain on prepayment of FHLB borrowing in “Other Income”. SBA loan sales produced $330K of gains. Fluctuation of non-interest income primarily impacted by one-time items in prior quarters. (1) Annualized. 14

Non-interest Expense In thousands (except ratios and FTE) Q3 2022 Q2 2022 Q1 2022 Q4 2021 Q3 2021 Salaries and employee benefits $6,075 $5,913 $5,875 $5,634 $5,313 Occupancy 1,281 1,251 1,270 1,267 1,192 Regulatory assessments and fees 269 226 213 93 317 Consulting and legal fees 604 398 517 539 357 Network and information technology services 488 448 387 268 358 Other operating expense 1,415 1,315 1,350 1,518 1,470 Total non-interest expenses $10,132 $9,551 $9,612 $9,319 $9,007 Efficiency ratio 54.58% 55.34% 58.88% 55.74% 50.92% Average total asset s $2,026,791 $1,968,381 $1,913,484 $1,828,037 $1,741,423 Non-interest expense / Average assets (1) 1.98% 1.95% 2.04% 2.02% 2.05% Full-time equivalent employees 191 192 190 187 184 Commentary Non-interest expense to average assets remains below 2021 levels. Salaries and employee benefits increased primarily due to 7 new FTEs (3 lenders, 1 portfolio manager, and 3 support staff) compared to third quarter 2021. Consulting fees increased due to one-time expenses for CECL, CRE related studies and tests, and placement fee for new hires. Higher revenue improved efficiency ratio to 54.58%. (1) Annualized. 15

Asset Quality Allowance for Credit Losses In thousands (except ratios) $17,000 $16,000 $15,000 $14,000 1.33% 1.31% 1.22% 1.16% 1.16% $13,000 1.27% 1.27% 1.20% 1.15% 1.16% $12,000 $14,900 $15,057 $15,074 $15,786 $16,604 Q3 2021 Q4 2021 Q1 2022 Q2 2022 Q3 2022 Allowance for credit losses ACL/Total loans ACL/Total loans excluding PPP loans Commentary ACL coverage ratio is at 1.16%. No loans classified as non-performing. No OREO. CECL modeling progressing as planned. Non-performing Loans In thousands (except ratios) 1,400 1,200 1,000 800 600 400 200 0.00% 0.10% 0.00% 0.00% 0.00% - $18 $1,190 $0 $0 $0 Q3 2021 Q4 2021 Q1 2022 Q2 2022 Q3 2022 Non-accrual loans less non-accrual TDRs Loans-over 90 days past due and accruing Non-performing loans to total loans 16

Capital Capital Ratios(1) Leverage Ratio TCE/TA (2) Tier 1 Risk Based Capital Total Risk Based Capital Q3 2022 9.48% 8.71% 12.56% 13.65% Q2 2022 9.43% 8.93% 12.65% 13.74% Q3 2021 9.69% 11.51% 13.85% 15.10% Well- Capitalized 5.00% NA 8.00% 10.00% Commentary All capital ratios remain significantly above “well capitalized” guidelines. Q3 2022 EOP shares outstanding: Class A Common Stock: 20,000,753 No shares repurchased during the quarter; Board approved repurchase program in place covering 750,000 shares of Class A common stock. (1) The Company was established in Q4 2021. As such, the capital ratios for Q3 2022 and Q2 2022 are for the Company while Q3 2021 is for the Bank only. (2) Non-GAAP. 17
Takeaways Leading Franchise Located in one of the Most Attractive Banking Markets in Florida and the U.S. Experienced and Tested Management Team Robust Organic Growth Strong Asset Quality, with Minimal Charge-offs Experienced Since Recapitalization Strong Profitability, with Pathway For Future Enhancement Identified Core Funded Deposit Base with 36.9% Non-Interest-Bearing Deposits (EOP) 18
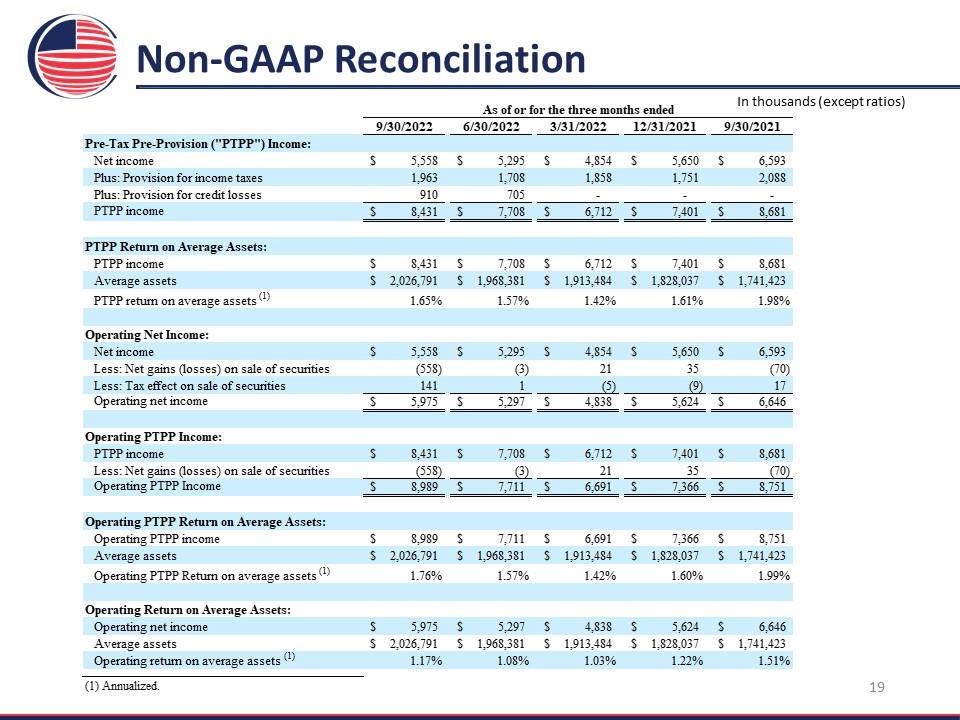
Non-GAAP Reconciliation In thousands (except ratios) Pre-TaxPre Provision ("PTPP") Income: Netincome Plus: Provision forincome taxes Plus: Provision for credit losses PIPP income PIPP Return on Average Assets: PIPP income S 34st 78 $ 6712 $ 7401 $ S681 Average assets S 2679 $ 196381 $ 191344 $ 198087 $ 1741.03 PIPP retum on average assets'"” 165% 15% 1A% 161% 198% Operating Net Income: ‘Net income Less: Net gains (losses) on sale of securities Less: Tax effect on sak of securities Operating net income Operating PTPP Income: PIPP income S84 S$ 7708 $§ «6712 $141 SRL Less: Net gains (losses) on sale of securities G3) @ 4 35 oy Operating PIPPIncome Operating PTPP Return on Average Assets: Operating PTPPincome S77 S$ 6@1 $7366 S$ 7m Average assets S 196381 $ 191344 $ 10807 $ 1741.03 Operating PTPPRetum on average assets! 15% LA% 160% 199% Operating Return on Average Assets: Operating net income S595 $ 527 $ 488 S$ Ses S$ 66m Average assets S$ 206791 S$ 196381 $ 1913484 $ 198087 $ 171.03 Operating retum on average assets"? 11% 108% 105% 12% 151% (1) Ammualized. 19

Non-GAAP Reconciliation In thousands (except per share data) As of and for the three months ended 30022 ‘63072022 3312022 12302021 9302021 ‘Tangible Book Value per Common Share (at peried-end):) Total stockholders’ equity s may $ 1006S 192039 S$ 2897S 201918, Less:Intangible assets = e - : Less: Prefered stocie - - - - ‘Tangible stockholm’ equity s ima § iw00e Ss ima maT Ss 201518 Total shares issued and onsstan ding (at period-end): ° Chass A common shares 0.000.753 20.000753, 0.000.753 18767541 Cass B common shares - 7 : 1224212 Totalcommon shares issued and ovtstanding 7201000758 20000735 20,000,753 19.99.73 ‘Tangible book valsepercommoa share") s ss 8 300 $ 20S s 10.10 Operating Net Income Available to Common Stockholders: © Net income s 5558S 5295 458s 560 658 Less: Prefemed dividends a : z as 32 Less: Exchange ané redemption of prefered shares 2 a 89,585.00 ‘Net incom (loss) avaiable to commons tockholées 485 3) Add back Exchang eand edemption of prefered shares 2 5 5 59.585, Operating net income avai. to common stock: s s s 48S 5 6051 Allocation of operating net income per common stock clas Css A conmon stock s s 5295 $ 455s 560 $ 5538 (Clas B common stock: s mans) Ey ae Sat 45 Weighted average shares outstanding Class A common stock Basie 20,000,753 20,000,753, 19.994.953, iss94 1512140 Dilotad 20,148,208 20,171.26 20,10 8,788 19,023,686 15121460 (Class B common stocks Basic . 2 : 2 6121052 Dilotad - : - : 612,052 Diluced EPS:""° Css A conmon stock Netincome (loss) per diluted share s 02s § 026 $ om $s 0x0 en Add back Exchang eand edamption of prefered shares a = : = 548 Opening netincome per diluted share s os 036. 1S om 1s 0300S 037 Class B common stocks Net income (oss) per diluted share s oan Es) a aS a0) Add back Exchanzeand demotion of prefered shares z 7 = = 109 Operating net incom per éilvted
share = ang Sas ae = 007 (1) The Company believes these non-GAAPmeasurements are key indicators of the ongoing earnings power of the Company. (2) During the quarter ended September 30, 2021, 47,473 shares of Class C preferred stock and 11,061,552 shares of Class D preferred stock were converted into 10,278,072 shares of Class A common stock. Additionally, the Bank closed on the initial public offering of ts Class A common stock on July 27, 2021, in which i issued 4,600,000 shares of Class A common stock As such, the total shares issued and outstanding of Class A common stock was 18,767,541 shares at September 30, 2021 (3) Excludes the dilutive effect, if any, of shares of common stock issuable upon exercise of outstanding stock options (4) During the quarter ended September 30, 2021, basic net loss per share is the same as diluted net loss per share as the inclusion of all potential common shares outstanding w ould have been antidilutive. (6) During the quarter ended December 31, 2021, the Corrpany entered into agreements with the Gass B common shareholders to exchange all outstanding Class B non-voting common stock for Class A voting common stock at a ratio of 1 share of Class A common stock for each 5 shares of Class B non-voting common stock. In calculating net income (loss) per diluted share for the prior quarters presented, the allocation of operating net income available to common stockholders was based on the weighted average shares outstanding per common share class to the total weighted average shares outstanding during each period. The operating net income allocation w as calculated using the weighted average shares outstanding of Class B common stock ‘onan as-converted basis. 20

Contact Information Lou de la Aguilera President, CEO & Director (305) 715-5186 [email protected] Rob Anderson Chief Financial Officer (305) 715-5393 [email protected] Investor Relations [email protected] 21