
USCB 8-K
Uscb Financial Holdings, Inc. (USCB)
8-K
2023-01-26
For: 2023-01-26
View Original
Added on
April 06, 2026
1
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
__________________________
FORM
__________________________
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported):
__________________________
(Exact name of Registrant as Specified in Its Charter)
(State or Other Jurisdiction
of Incorporation)
(Commission File Number)
(IRS Employer
Identification No.)
,
,
(Address of Principal Executive Offices)
(Zip Code)
Registrant’s Telephone Number, Including Area Code: (
)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under
any of the following provisions:
☐
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425)
☐
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a -12)
☐
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))
☐
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))
Securities registered pursuant to Section 12(b) of the Act:
Title of each class
Trading
Symbol(s)
Name of each exchange on which registered
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933
(§ 230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§ 240.12b -2 of this chapter).
Emerging growth company
☒
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for
complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.
☐
2
Item 2.02. Results of Operations and Financial Condition.
On January 26, 2023, USCB Financial Holdings, Inc. (the “Company”), issued a press release announcing its financial results
for the fourth quarter ended December 31, 2022. A copy of the press release is furnished as Exhibit 99.1 to this Current Report on Form
8-K and is incorporated herein by reference.
The information in this Item 2.02, including Exhibit 99.1, is being furnished and shall not be deemed “filed” for purposes of
Section 18 of the Securities Exchange Act of 1934 (the “Exchange Act”), or otherwise subject to the liability of that section, and shall
not be deemed to be incorporated by reference into any filing under the Securities Act of 1933 (the “Securities Act”) or the Exchange
Act.
Item 7.01. Regulation FD Disclosure.
As previously announced, at 9:00 a.m. ET on January 27, 2023, the Company will hold an earnings conference call to discuss
its financial performance for the quarter ended December 31, 2022. A copy of the slides forming the basis of the presentation is being
furnished as Exhibit 99.2 to this Current Report on Form 8-K and is incorporated herein by reference. A copy of the slides has also been
posted to the Company’s investor relations website, located at investors.uscenturybank.com.
The information in this Item 7.01, including Exhibit 99.2, is being furnished and shall not be deemed “filed” for purposes of
Section 18 of the Exchange Act, or otherwise subject to the liability of that section, and shall not be deemed to be incorporated by
reference into any filing under the Securities Act or the Exchange Act.
Item 9.01. Financial Statements and Exhibits.
(d) Exhibits.
Exhibit No.
Description
99.1
99.2
104
Cover Page Interactive Data File (embedded within the Inline XBRL document)
1
Exhibit 99.1
EARNINGS RELEASE
USCB Financial Holdings, Inc. Reports EPS of $0.22, Operating EPS of $0.29 for Q4 2022
MIAMI – January 26, 2023 – USCB Financial Holdings, Inc. (the “Company”) (NASDAQ: USCB)
, the holding company for U.S.
Century Bank (the “Bank”), reported net income of $4.4 million or $0.22 per diluted share for the three months ended December 31,
2022, compared with net income of $5.7 million or $0.30 per diluted share, for the same period in 2021.
Near quarter end, the Bank executed a portfolio restructuring strategy which resulted in a sale
of $17.0 million of its lower-yielding
available-for-sale securities for an after-tax loss of $1.5 million or $0.07 EPS in the quarter. Proceeds from the sale will be reinvested
in securities and loans currently yielding, on average, 430-460 basis points higher than the securities that were sold. The loss on sale of
securities is expected to have a nominal impact on tangible book value, as such loss was previously reflected in capital through
accumulated other comprehensive income (AOCI). Additionally, the reinvestment from the sale proceeds into higher yielding earning
assets will have a $0.03 EPS positive impact on 2023 earnings.
Excluding gain (loss) from the sale of securities, Non-GAAP Operating net income was $5.9 million or $0.29 per diluted share for the
fourth quarter ended December 31, 2022, compared to $5.6 million or $0.30 per diluted share, for the same period in 2021.
"Despite a challenging operating environment, 2022 afforded us extraordinary opportunities for growth and profitability. While a soft
landing for the economy is expected in 2023, we are taking a prudent approach with our balance sheet by limiting growth in certain
assets, maintaining appropriate capital and reserve levels, managing liquidity, and preparing for a range of economic scenarios.” said
Luis de la Aguilera, President and Chief Executive Officer.
Unless otherwise stated, all percentage comparisons in the bullet points below are calculated for the quarter ended December 31, 2022
compared to the quarter ended December 31, 2021 and annualized where appropriate.
Profitability
•
Annualized return on average assets for the quarter ended December 31, 2022 was 0.86% compared to 1.23% for the fourth quarter
of 2021. Non-GAAP Operating return on assets for the quarter ended December 31, 2022 was 1.14% compared to 1.22% for the
fourth quarter of 2021.
•
Annualized return on average stockholders’ equity for the quarter ended December 31, 2022 was 9.91% compared to 11.08 % for
the fourth quarter of 2021. Non-GAAP Operating return on equity for the quarter ended December 31, 2022 was 13.23% compared
to 11.03% for the fourth quarter of 2021.
•
The efficiency ratio for the quarter ended December 31, 2022 was 59.81% compared to 55.74% for the fourth quarter of 2021. Non-
GAAP Operating efficiency ratio for the quarter ended December 31, 2022 was 53.46% compared to 55.85% for the fourth quarter
of 2021.
•
Net interest margin increased to 3.45% for the quarter ended December 31, 2022 compared to 3.19% for the fourth quarter of 2021.
•
Net interest income before provision for credit losses was $16. 9 million for the quarter ended December 31, 2022, an increase of
$2.8 million or 19.8% compared to the fourth quarter of 2021.
Balance Sheet
•
Total assets were $2.1 billion at December 31, 2022, representing an increase of $231.9 million or 12.5% from December 31, 2021.
•
Total loans were $1.5 billion at December 31, 2022, representing an increase of $317.3 million or 26.7% from December 31, 2021.
•
Total deposits were $1.8 billion at December 31, 2022, representing an increase of $238.9 million or 15.0% from December 31,
2021.
2
•
Total stockholders’ equity was $182.4 million at December 31, 2022, representing a decrease of $21.5 million or 10.5% from
December 31, 2021. Total stockholders’ equity includes unrealized security losses of $44.8 million at December 31, 2022 compared
to unrealized security loss of $2.5 million at December 31, 2021.
Asset Quality
•
The allowance for credit losses increased by $2.4 million to $17.5 million at December 31, 2022 from $15.1 million at December 31,
2021.
•
The allowance for credit losses represented 1.16% of total loans at December 31, 2022 compared to 1.27% at December 31, 2021.
•
Non-performing loans to total loans was 0.00% at December 31, 2022 compared to 0.10% at December 31, 2021.
Non-interest Income and Non-interest Expense
•
Non-interest income was negative $0.1 million for the three months ended December 31, 2022 compared to $2.6 million for the
same period in 2021. Non-interest income was negative in the fourth quarter of 2022 due to a $2.0 million loss on the sale of
securities.
•
Non-interest expense was $10.0 million for the three months ended December 31, 2022, an increase of $0.7 million or 7.5%
compared to the same period in 2021.
Capital
•
As of December 31, 2022,
total risk-based capital ratios for the Company and the Bank were 13.65% and 13.58%, respectively.
•
Tangible book value per common share of $9.12 was negatively affected by $2.24 due to after tax unrealized security losses of
$44.8 million at December 31, 2022. At December 31, 2021, tangible book value of $10.20 was negatively affected by $0. 13 due
to $2.5 million after tax unrealized security losses.
Conference Call and Webcast
The Company will host a conference call on Friday, January 27, 2023, at 9:00 a.m. Eastern Time to discuss the Company’s unaudited
financial results for the quarter ended December 31, 2022. To access the conference call, dial (866) 652-5200 (U.S. toll-free) and ask to
join the USCB Financial Holdings Call.
Additionally, interested parties can listen to a live webcast of the call in the “Investor Relations” section of the Company’s website
at www.uscentury.com . An archived version of the webcast will be available in the same location shortly after the live call has ended.
About USCB Financial Holdings, Inc.
USCB Financial Holdings, Inc. is the bank holding company for U.S. Century Bank. Established in 2002, U.S. Century Bank is one of
the largest community banks headquartered in Miami, and one of the largest community banks in the state of Florida. U.S. Century Bank
is rated 5-Stars by BauerFinancial, the nation’s leading independent bank rating firm. U.S. Century Bank offers customers a wide range
of financial products and services and supports numerous community organizations, including the Greater Miami Chamber of
Commerce, the South Florida Hispanic Chamber of Commerce, and ChamberSouth. For more information or to find a banking center
near you, please call (305) 715-5200 or visit www.uscentury.com.
Forward-Looking Statements
This earnings release may contain statements that are not historical in nature and are intended to be, and are hereby identified as, forward-
looking statements for purposes of the safe harbor provided by Section 21E of the Securities Exchange Act of 1934, as amended. The
words “may,” “will,” “anticipate,” “should,” “would,” “believe,” “contemplate,” “expect,” “aim,” “plan,” “estimate,” “continue,” and
“intend,” as well as other similar words and expressions of the future, are intended to identify forward-looking statements. These
forward-looking statements include statements related to our projected growth, anticipated future financial performance, and
management’s long-term performance goals, as well as statements relating to the anticipated effects on results of operations and financial
condition from expected developments or events, or business and growth strategies, including anticipated internal growth and the balance
sheet restructuring.
These forward-looking statements involve significant risks and uncertainties that could cause our actual results to differ materially from
those anticipated in such statements. Potential risks and uncertainties include, but are not limited to:
3
•
the strength of the United States economy in general and the strength of the local economies in which we conduct operations;
•
the continuation of the COVID-19 pandemic and its impact on us, our employees, customers and third-party service providers, and
the ultimate extent of the impact of the pandemic and related government stimulus programs;
•
our ability to successfully manage interest rate risk, credit risk, liquidity risk, and other risks inherent to our industry;
•
the accuracy of our financial statement estimates and assumptions, including the estimates used for our credit loss reserve and
deferred tax asset valuation allowance;
•
the efficiency and effectiveness of our internal control environment;
•
our ability to comply with the extensive laws and regulations to which we are subject, including the laws for each jurisdiction where
we operate;
•
legislative or regulatory changes and changes in accounting principles, policies, practices or guidelines, including the effects of the
forthcoming implementation of the Current Expected Credit Losses (“CECL”) standard;
•
the effects of our lack of a diversified loan portfolio and concentration in the South Florida market, including the risks of geographic,
depositor, and industry concentrations, including our concentration in loans secured by real estate;
•
effects of climate change
•
the concentration of ownership of our common stock;
•
fluctuations in the price of our common stock;
•
our ability to fund or access the capital markets at attractive rates and terms and manage our growth, both organic growth as well
as growth through other means, such as future acquisitions;
•
inflation, interest rate, unemployment rate, market, and monetary fluctuations;
•
impacts of international hostilities and geopolitical events
•
increased competition and its effect on the pricing of our products and services as well as our margin;
•
the effectiveness of our risk management strategies, including operational risks, including, but not limited to, client, employee, or
third-party fraud and security breaches; and
•
other risks described in this earnings release and other filings we make with the Securities and Exchange Commission (“SEC”).
All forward-looking statements are necessarily only estimates of future results, and there can be no assurance that actual results will not
differ materially from expectations. Therefore, you are cautioned not to place undue reliance on any forward-looking statements. Further,
forward-looking statements included in this earnings release are made only as of the date hereof, and we undertake no obligation to
update or revise any forward-looking statement to reflect events or circumstances after the date on which the statement is made or to
reflect the occurrence of unanticipated events, unless required to do so under the federal securities laws. You should also review the risk
factors described in the reports the Company filed or will file with the SEC and, for periods prior to the completion of the bank holding
company reorganization in December 2021, the Bank filed with the FDIC.
Non-GAAP Financial Measures
This earnings release includes financial information determined by methods other than in accordance with generally accepted accounting
principles (“GAAP”). This financial information includes certain operating performance measures. Management has included these non-
GAAP measures because it believes these measures may provide useful supplemental information for evaluating the Company’s
underlying performance trends. Further, management uses these measures in managing and evaluating the Company’s business and
intends to refer to them in discussions about our operations and performance. Operating performance measures should be viewed in
addition to, and not as an alternative to or substitute for, measures determined in accordance with GAAP, and are not necessarily
comparable to non-GAAP measures that may be presented by other companies. To the extent applicable, reconciliations of these non-
GAAP measures to the most directly comparable GAAP measures can be found in the ‘Non-GAAP Reconciliation Tables’ included in
the exhibits to this earnings release.
All numbers included in this press release are unaudited unless otherwise noted.
Contacts:
Investor Relations
Media Relations
Martha Guerra-Kattou
4
USCB FINANCIAL HOLDINGS, INC.
CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED)
(Dollars in thousands, except per share data)
Three Months Ended December 31,
Twelve Months Ended December 31,
2022
2021
2022
2021
Interest income:
Loans, including fees
$
17,836
$
12,786
$
60,825
$
48,730
Investment securities
2,306
2,216
9,346
7,886
Interest-bearing deposits in financial institutions
455
29
929
106
Total interest income
20,597
15,031
71,100
56,722
Interest expense:
Interest-bearing checking
34
14
86
59
Savings and money market accounts
2,866
510
5,173
2,082
Time deposits
616
292
1,509
1,531
FHLB advances and other borrowings
215
139
671
554
Total interest expense
3,731
955
7,439
4,226
Net interest income before provision for credit losses
16,866
14,076
63,661
52,496
Provision for credit losses
880
-
2,495
(160)
Net interest income after provision for credit losses
15,986
14,076
61,166
52,656
Non-interest income:
Service fees
1,093
961
4,010
3,609
Gain (loss) on sale of securities available for sale, net
(1,989)
35
(2,529)
214
Gain on sale of loans held for sale, net
205
107
891
1,626
Gain on sale of other assets
-
983
-
983
Loan settlement
-
-
161
2,500
Other non-interest income
568
558
2,695
1,766
Total non-interest income
(123)
2,644
5,228
10,698
Non-interest expense:
Salaries and employee benefits
6,080
5,634
23,943
21,438
Occupancy
1,256
1,267
5,058
5,257
Regulatory assessments and fees
222
93
930
783
Consulting and legal fees
371
539
1,890
1,454
Network and information technology services
483
268
1,806
1,466
Other operating expense
1,602
1,518
5,682
5,279
Total non-interest expense
10,014
9,319
39,309
35,677
Net income before income tax expense
5,849
7,401
27,085
27,677
Income tax expense
1,415
1,751
6,944
6,600
Net income
4,434
5,650
20,141
21,077
Preferred stock dividend
-
-
-
2,077
Exchange and redemption of preferred shares
-
-
-
89,585
Net income (loss) available to common stockholders
$
4,434
$
5,650
$
20,141
$
(70,585)
Per share information:
Net income (loss) per common share, basic
$
0.22
$
0.30
$
1.01
$
(6.72)
Net income (loss) per common share, diluted
$
0.22
$
0.30
$
1.00
$
(6.72)
Weighted average shares outstanding:
Common share, basic
20,000,753
18,913,914
19,999,323
10,507,530
Common share, diluted
20,172,438
19,023,686
20,176,838
10,507,530
5
USCB FINANCIAL HOLDINGS, INC.
SELECTED FINANCIAL DATA (UNAUDITED)
(Dollars in thousands, except per share data)
As of or For the Three Months Ended
12/31/2022
9/30/2022
6/30/2022
3/31/2022
12/31/2021
Income statement data:
Net interest income
$
16,866
$
16,774
$
15,642
$
14,379
$
14,076
Provision for credit losses
880
910
705
-
-
Net interest income after provision for credit losses
15,986
15,864
14,937
14,379
14,076
Service fees
1,093
934
1,083
900
961
Gain (loss) on sale of securities available for sale, net
(1,989)
(558)
(3)
21
35
Gain on sale of loans held for sale, net
205
330
22
334
107
Gain on sale of other assets
-
-
-
-
983
Loan settlement
-
-
-
161
-
Other income
568
1,083
515
529
558
Total non-interest income
(123)
1,789
1,617
1,945
2,644
Salaries and employee benefits
6,080
6,075
5,913
5,875
5,634
Occupancy
1,256
1,281
1,251
1,270
1,267
Regulatory assessments and fees
222
269
226
213
93
Consulting and legal fees
371
604
398
517
539
Network and information technology services
483
488
448
387
268
Other operating expense
1,602
1,415
1,315
1,350
1,518
Total non-interest expense
10,014
10,132
9,551
9,612
9,319
Net income before income tax expense
5,849
7,521
7,003
6,712
7,401
Income tax expense
1,415
1,963
1,708
1,858
1,751
Net income
4,434
5,558
5,295
4,854
5,650
Preferred stock dividend
-
-
-
-
-
Net income available to common stockholders
$
4,434
$
5,558
$
5,295
$
4,854
$
5,650
Per share information:
Net income per common share, basic
$
0.22
$
0.28
$
0.26
$
0.24
$
0.30
Net income per common share, diluted
$
0.22
$
0.28
$
0.26
$
0.24
$
0.30
Balance sheet data (at period-end):
Cash and cash equivalents
$
54,168
$
73,326
$
83,272
$
94,113
$
46,228
Securities available-for-sale
$
230,140
$
248,571
$
339,464
$
392,214
$
401,542
Securities held-to-maturity
$
188,699
$
178,865
$
116,671
$
122,361
$
122,658
Total securities
$
418,839
$
427,436
$
456,135
$
514,575
$
524,200
Loans held for investment
(1)
$
1,507,338
$
1,431,513
$
1,372,733
$
1,258,388
$
1,190,081
Allowance for credit losses
$
(17,487)
$
(16,604)
$
(15,786)
$
(15,074)
$
(15,057)
Total assets
$
2,085,834
$
2,037,453
$
2,016,086
$
1,967,252
$
1,853,939
Non-interest-bearing deposits
$
629,776
$
662,808
$
653,708
$
656,622
$
605,425
Interest-bearing deposits
$
1,199,505
$
1,133,834
$
1,085,012
$
1,056,672
$
984,954
Total deposits
$
1,829,281
$
1,796,642
$
1,738,720
$
1,713,294
$
1,590,379
FHLB advances and other borrowings
$
46,000
$
26,000
$
66,000
$
36,000
$
36,000
Total liabilities
$
1,903,406
$
1,860,036
$
1,836,018
$
1,775,213
$
1,650,042
Total stockholders' equity
$
182,428
$
177,417
$
180,068
$
192,039
$
203,897
Capital ratios:
Leverage ratio
9.61%
9.48%
9.43%
9.47%
9.55%
Common equity tier 1 capital
12.53%
12.56%
12.65%
13.35%
13.70%
Tier 1 risk-based capital
12.53%
12.56%
12.65%
13.35%
13.70%
Total risk-based capital
13.65%
13.65%
13.74%
14.49%
14.92%
(1) Loan amounts include deferred fees/costs.
6
USCB FINANCIAL HOLDINGS, INC.
AVERAGE BALANCES, RATIOS, AND OTHER DATA (UNAUDITED)
(Dollars in thousands)
As of or For the Three Months Ended
12/31/2022
9/30/2022
6/30/2022
3/31/2022
12/31/2021
Average balance sheet data:
Cash and cash equivalents
$
61,892
$
77,887
$
80,254
$
99,911
$
87,819
Securities available-for-sale
$
242,144
$
331,206
$
370,933
$
385,748
$
374,589
Securities held-to-maturity
$
184,459
$
116,733
$
120,130
$
122,381
$
114,108
Total securities
$
426,603
$
447,939
$
491,063
$
508,129
$
488,697
Loans held for investment
(1)
$
1,456,780
$
1,398,761
$
1,296,476
$
1,211,432
$
1,158,755
Total assets
$
2,051,867
$
2,026,791
$
1,968,381
$
1,913,484
$
1,828,037
Interest-bearing deposits
$
1,150,049
$
1,107,129
$
1,071,709
$
1,023,844
$
958,241
Non-interest-bearing deposits
$
653,820
$
655,853
$
644,975
$
626,400
$
603,735
Total deposits
$
1,803,869
$
1,762,982
$
1,716,684
$
1,650,244
$
1,561,976
FHLB advances and other borrowings
$
37,500
$
43,935
$
36,330
$
36,011
$
36,000
Total liabilities
$
1,874,311
$
1,841,503
$
1,781,784
$
1,711,624
$
1,625,675
Total stockholders' equity
$
177,556
$
185,288
$
186,597
$
201,860
$
202,362
Performance ratios:
Return on average assets
(2)
0.86%
1.09%
1.08%
1.03%
1.23%
Return on average equity
(2)
9.91%
11.90%
11.38%
9.75%
11.08%
Net interest margin
(2)
3.45%
3.47%
3.37%
3.22%
3.19%
Non-interest income to average assets
(2)
(0.02)%
0.35%
0.33%
0.41%
0.57%
Efficiency ratio
(3)
59.81%
54.58%
55.34%
58.88%
55.74%
Loans by type (at period end):
(4)
Residential real estate
$
185,636
$
186,551
$
203,662
$
204,317
$
201,359
Commercial real estate
$
970,410
$
928,531
$
843,445
$
782,072
$
704,988
Commercial and industrial
$
126,984
$
121,145
$
131,271
$
134,832
$
146,592
Foreign banks
$
93,769
$
94,450
$
84,770
$
63,985
$
59,491
Consumer and other
$
130,429
$
100,845
$
109,250
$
73,765
$
79,229
Asset quality data:
Allowance for credit losses to total loans
1.16%
1.16%
1.15%
1.20%
1.27%
Allowance for credit losses to non-performing loans
- %
- %
- %
- %
1,265%
Non-accrual loans less non-accrual TDRs
-
-
-
-
1,190
Non-accrual TDRs
-
-
-
-
-
Loans over 90 days past due and accruing
-
-
-
-
-
Total non-performing loans
(5)
-
-
-
-
1,190
Non-performing loans to total loans
- %
- %
- %
- %
0.10%
Non-performing assets to total assets
- %
- %
- %
- %
0.06%
Net charge-offs (recoveries of) to average loans
(2)
(0.00)%
0.03%
(0.00)%
(0.01)%
(0.05)%
Net charge-offs (recovery of) credit losses
(2)
91
(7)
(17)
(157)
Interest rates and yields:
(2)
Loans
4.86%
4.53%
4.35%
4.35%
4.32%
Investment securities
2.13%
1.94%
2.04%
1.85%
1.81%
Total interest-earning assets
4.21%
3.82%
3.60%
3.43%
3.41%
Deposits
0.77%
0.34%
0.21%
0.20%
0.21%
FHLB advances and other borrowings
2.27%
1.63%
1.53%
1.54%
1.51%
Total interest-bearing liabilities
1.25%
0.59%
0.38%
0.37%
0.38%
Other information:
Full-time equivalent employees
191
191
192
190
187
(1) Loan amounts include deferred fees/costs.
(2) Annualized.
(3) Efficiency ratio is defined as total non-interest expense divided by sum of net interest income and total non-interest income.
(4) Loan amounts exclude deferred fees/costs.
(5) The amounts for total non-performing loans and total non-performing assets are the same for the dates presented since there were no impaired investments or other
real estate owned (OREO) recorded.
7
USCB FINANCIAL HOLDINGS, INC.
NET INTEREST MARGIN (UNAUDITED)
(Dollars in thousands)
Three Months Ended December 31,
2022
2021
Average
Balance
Interest
Yield/Rate
(1)
Average
Balance
Interest
Yield/Rate
(1)
Assets
Interest-earning assets:
Loans
(2)
$
1,456,780
$
17,836
4.86%
$
1,158,755
$
12,786
4.32%
Investment securities
(3)
429,020
2,306
2.13%
490,797
2,216
1.81%
Other interest-earnings assets
53,717
455
3.36%
80,170
29
0.14%
Total interest-earning assets
1,939,517
20,597
4.21%
1,729,722
15,031
3.41%
Non-interest-earning assets
112,350
98,315
Total assets
$
2,051,867
$
1,828,037
Liabilities and stockholders' equity
Interest-bearing liabilities:
Interest-bearing checking
$
61,976
34
0.22%
$
56,558
14
0.10%
Saving and money market deposits
871,269
2,866
1.31%
673,993
510
0.30%
Time deposits
216,804
616
1.13%
227,690
292
0.51%
Total interest-bearing deposits
1,150,049
3,516
1.21%
958,241
816
0.34%
FHLB advances and other borrowings
37,500
215
2.27%
36,000
139
1.51%
Total interest-bearing liabilities
1,187,549
3,731
1.25%
994,241
955
0.38%
Non-interest-bearing demand deposits
653,820
603,735
Other non-interest-bearing liabilities
32,942
27,699
Total liabilities
1,874,311
1,625,675
Stockholders' equity
177,556
202,362
Total liabilities and stockholders' equity
$
2,051,867
$
1,828,037
Net interest income
$
16,866
$
14,076
Net interest spread
(4)
2.96%
3.03%
Net interest margin
(5)
3.45%
3.19%
(1) Annualized.
(2) Average loan balances include non-accrual loans. Interest income on loans includes accretion of deferred loan fees, net of deferred loan costs.
(3) At fair value except for securities held to maturity. This amount includes FHLB stock.
(4) Net interest spread is the average yield on total interest-earning assets minus the average rate on total interest-bearing liabilities.
(5) Net interest margin is the ratio of net interest income to total interest-earning assets.
8
USCB FINANCIAL HOLDINGS, INC.
NON-GAAP FINANCIAL MEASURES (UNAUDITED)
(Dollars in thousands)
As of or For the Three Months Ended
12/31/2022
9/30/2022
6/30/2022
3/31/2022
12/31/2021
Pre-tax pre-provision ("PTPP") income:
Net income
$
4,434
$
5,558
$
5,295
$
4,854
$
5,650
Plus: Provision for income taxes
1,415
1,963
1,708
1,858
1,751
Plus: Provision for credit losses
880
910
705
-
-
PTPP income
$
6,729
$
8,431
$
7,708
$
6,712
$
7,401
PTPP return on average assets:
PTPP income
$
6,729
$
8,431
$
7,708
$
6,712
$
7,401
Average assets
$
2,051,867
$
2,026,791
$
1,968,381
$
1,913,484
$
1,828,037
PTPP return on average assets
(1)
1.30%
1.65%
1.57%
1.42%
1.61%
Operating net income:
Net income
$
4,434
$
5,558
$
5,295
$
4,854
$
5,650
Less: Net gains (losses) on sale of securities
(1,989)
(558)
(3)
21
35
Less: Tax effect on sale of securities
504
141
1
(5)
(9)
Operating net income
$
5,919
$
5,975
$
5,297
$
4,838
$
5,624
Operating PTPP income:
PTPP income
$
6,729
$
8,431
$
7,708
$
6,712
$
7,401
Less: Net gains (losses) on sale of securities
(1,989)
(558)
(3)
21
35
Operating PTPP income
$
8,718
$
8,989
$
7,711
$
6,691
$
7,366
Operating PTPP return on average assets:
Operating PTPP income
$
8,718
$
8,989
$
7,711
$
6,691
$
7,366
Average assets
$
2,051,867
$
2,026,791
$
1,968,381
$
1,913,484
$
1,828,037
Operating PTPP return on average assets
(1)
1.69%
1.76%
1.57%
1.42%
1.60%
Operating return on average assets:
Operating net income
$
5,919
$
5,975
$
5,297
$
4,838
$
5,624
Average assets
$
2,051,867
$
2,026,791
$
1,968,381
$
1,913,484
$
1,828,037
Operating return on average assets
(1)
1.14%
1.17%
1.08%
1.03%
1.22%
Operating return on average equity:
Operating net income
$
5,919
$
5,975
$
5,297
$
4,838
$
5,624
Average equity
177,556
185,288
186,597
201,860
202,362
Operating return on average equity
13.23%
12.79%
11.39%
9.72%
11.03%
Operating Revenue:
$
16,866
$
16,774
$
15,642
$
14,379
$
14,076
(123)
1,789
1,617
1,945
2,644
(1,989)
(558)
(3)
21
35
18,732
19,121
17,262
16,303
16,685
Operating Efficiency Ratio:
$
10,014
$
10,132
$
9,551
$
9,612
$
9,319
18,732
19,121
17,262
16,303
16,685
53.46%
52.99%
55.33%
58.96%
55.85%
(1) Annualized.
9
USCB FINANCIAL HOLDINGS, INC.
NON-GAAP FINANCIAL MEASURES (UNAUDITED)
(Dollars in thousands, except per share data)
As of or For the Three Months Ended
12/31/2022
9/30/2022
6/30/2022
3/31/2022
12/31/2021
Tangible book value per common share (at period-end):
(1)
Total stockholders' equity
$
182,428
$
177,417
$
180,068
$
192,039
$
203,897
Less: Intangible assets
-
-
-
-
-
Tangible stockholders' equity
$
182,428
$
177,417
$
180,068
$
192,039
$
203,897
Total shares issued and outstanding (at period-end):
Common shares
20,000,753
20,000,753
20,000,753
20,000,753
19,991,753
Total common shares issued and outstanding
20,000,753
20,000,753
20,000,753
20,000,753
19,991,753
Tangible book value per common share
(2)
$
9.12
$
8.87
$
9.00
$
9.60
$
10.20
Operating diluted net income per common share:
(1)
Operational Net Income
$
5,919
$
5,975
$
5,297
$
4,838
$
5,624
Total weighted average diluted common stock
20,172,438
20,148,208
20,171,261
20,109,783
19,023,686
Operating diluted net income per common share:
$
0.29
$
0.30
$
0.26
$
0.24
$
0.30
Tangible Common Equity/Tangible Assets
182,428
177,417
180,068
192,039
203,897
2,085,834
2,037,453
2,016,086
1,967,252
1,853,939
Tangible Common Equity/Tangible Assets
8.75%
8.71%
8.93%
9.76%
11.00%
(1) The Company believes these non-GAAP measurements are key indicators of the ongoing earnings power of the Company.
(2) Excludes the dilutive effect, if any, of shares of common stock issuable upon exercise of outstanding stock options.
Exhibit 99.2
USBC FINANCIAL HOLDINGS Fourth Quarter 2022 Earnings Presentation January 27, 2023
Forward-Looking Statements This presentation may contain statements that are not historical in nature and are intended to be, and are hereby identified as, forward-looking statements for purposes of the safe harbor provided by Section 21E of the Securities Exchange Act of 1934, as amended. The words “may,” “will,” “anticipate,” “should,” “would,” “believe,” “contemplate,” “expect,” “aim,” “plan,” “estimate,” “continue,” and “intend,” as well as other similar words and expressions of the future, are intended to identify forward-looking statements. These forward-looking statements include statements related to our projected growth, anticipated future financial performance, and management’s long-term performance goals, as well as statements relating to the anticipated effects on results of operations and financial condition from expected developments or events, or business and growth strategies, including anticipated internal growth and balance sheet restructuring. These forward-looking statements involve significant risks and uncertainties that could cause our actual results to differ materially from those anticipated in such statements. Potential risks and uncertainties include, but are not limited to: • the strength of the United States economy in general and the strength of the local economies in which we conduct operations; • the continuation of the COVID-19 pandemic and its impact on us, our employees, customers and third-party service providers, and the ultimate extent of the impacts of the pandemic and related government stimulus programs; • our ability to successfully manage interest rate risk, credit risk, liquidity risk, and other risks inherent to our industry; • the accuracy of our financial statement estimates and assumptions, including the estimates used for our credit loss reserve and deferred tax asset valuation allowance; • the efficiency and effectiveness of
our internal control environment; • our ability to comply with the extensive laws and regulations to which we are subject, including the laws for each jurisdicti on where we operate; • legislative or regulatory changes and changes in accounting principles, policies, practices or guidelines, including the effects of the forthcoming implementation of the Current Expected Credit Losses (“CECL”) standard; • the effects of our lack of a diversified loan portfolio and concentration in the South Florida market, including the risks of geographic, depositor, and industry concentrations, including our concentration in loans secured by real estate; effects of climate change • the concentration of ownership of our common stock; • fluctuations in the price of our common stock; • our ability to fund or access the capital markets at attractive rates and terms and manage our growth, both organic growth as well as growth through other means, such as future acquisitions; • inflation, interest rate, unemployment rate, market, and monetary fluctuations; impacts of international hostilities and geopolitical events • increased competition and its effect on the pricing of our products and services as well as our margin; • the effectiveness of our risk management strategies, including operational risks, including, but not limited to, client, employee, or third-party fraud and security breaches; and • other risks described in this presentation and other filings we make with the Securities and Exchange Commission (“SEC”). All forward -looking statements are necessarily only estimates of future results, and there can be no assurance that actual results will not differ materially from expectations. Therefore, you are cautioned not to place undue reliance on any forward-looking statements. Further, forward-looking statements included in this presentation are made only as of the date hereof, and we undertake no obligation
to update or revise any forward-looking statement to reflect events or circumstances after the date on which the statement is made or to reflect the occurrence of unanticipated events, unless required to do so under the federal securities laws. You should also review the risk factors described in the reports USCB Financial Holdings, Inc. filed or will file with the SEC and, for periods prior to the completion of the bank holding company reorganization in December 2021, U.S. Century Bank filed with the FDIC. Non-GAAP Financial Measures This presentation includes financial information determined by methods other than in accordance with generally accepted accounting principles (“GAAP”). This financial information includes certain operating performance measures. Management has included these non-GAAP measures because it believes these measures may provide useful supplemental information for evaluating the Company’s underlying performance trends. Further, management uses these measures in managing and evaluating the Company’s business and intends to refer to them in discussions about our operations and performance. Operating performance measures should be viewed in addition to, and not as an alternative to or substitute for, measures determined in accordance with GAAP, and are not necessarily comparable to non-GAAP measures that may be presented by other companies. To the extent applicable, reconciliations of these non-GAAP measures to the most directly comparable GAAP measures can be found in the ‘Non-GAAP Reconciliation Tables’ included in the presentation. All numbers included in this presentation are unaudited unless otherwise noted. 2
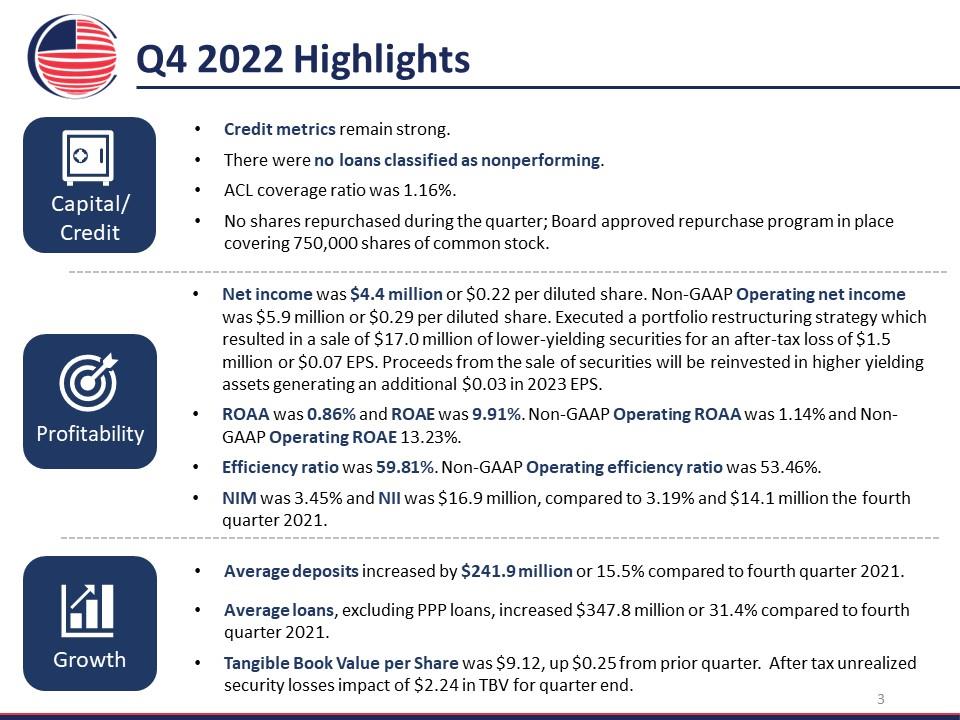
Q4 2022 Highlights Capital/ Credit Credit metrics remain strong. There were no loans classified as nonperforming. ACL coverage ratio was 1.16%. No shares repurchased during the quarter; Board approved repurchase program in place covering 750,000 shares of common stock. Profitability Net income was $4.4 million or $0.22 per diluted share. Non-GAAP Operating net income was $5.9 million or $0.29 per diluted share. Executed a portfolio restructuring strategy which resulted in a sale of $17.0 million of lower-yielding securities for an after-tax loss of $1.5 million or $0.07 EPS. Proceeds from the sale of securities will be reinvested in higher yielding assets generating an additional $0.03 in 2023 EPS. ROAA was 0.86% and ROAE was 9.91%. Non-GAAP Operating ROAA was 1.14% and Non-GAAP Operating ROAE 13.23%. Efficiency ratio was 59.81%. Non-GAAP Operating efficiency ratio was 53.46%. NIM was 3.45% and NII was $16.9 million, compared to 3.19% and $14.1 million the fourth quarter 2021. Growth Average deposits increased by $241.9 million or 15.5% compared to fourth quarter 2021. Average loans, excluding PPP loans, increased $347.8 million or 31.4% compared to fourth quarter 2021. Tangible Book Value per Share was $9.12, up $0.25 from prior quarter. After tax unrealized security losses impact of $2.24 in TBV for quarter end. 3
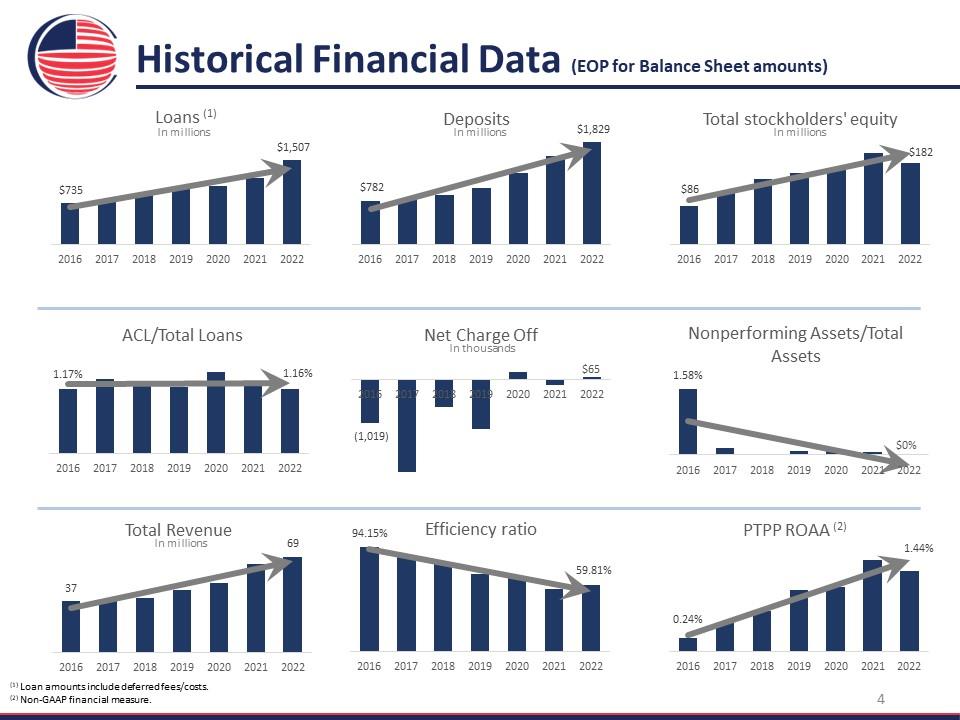
Historical Financial Data (EOP for Balance Sheet amounts) Loans (1) in millions $735 $1,507 Deposits in millions $782 $1,829 Total stockholder’s equity in millions $86 $182 ACL/Total Loans 1.17% 1.16% Net Charge Off in thousands ($1,019) $65 Nonperforming Assets/Total Assets 1.58% 0% Total Revenue in millions 37 69 Efficiency ratio 94.15% 59.81% PTPP ROAA (2) 0.24% 1.44% (1) Loan amounts include deferred fees/costs. (2) Non-GAAP financial measure. 4

Business Verticals JA/PCG(1) Deposits EOP $172 Million 33% Growth
YoY Loans EOP $9 Million 266% Growth YoY HOA(2) Deposits EOP $97 Million 42% Growth YoY Loans EOP $73 Million 59% Growth YoY Global Deposits EOP $177 Million 14% Growth YoY Loans EOP $94 Million 58% Growth YoY Yachts Loans EOP $125 Million 57% Growth YoY - $77MM in loan production in 2022 - 32% of the purchased portfolio was paid off in 2022 SBA(3) Loans EOP $38 Million - $19MM closed in SBA 7As in 2022 - $891K in gain on sale of loans in 2022 (1) JA/PCG: Jurist Advantage/Private Client Group (2) HOA: Homeowners Association (3) Does not include PPP Loans. 5
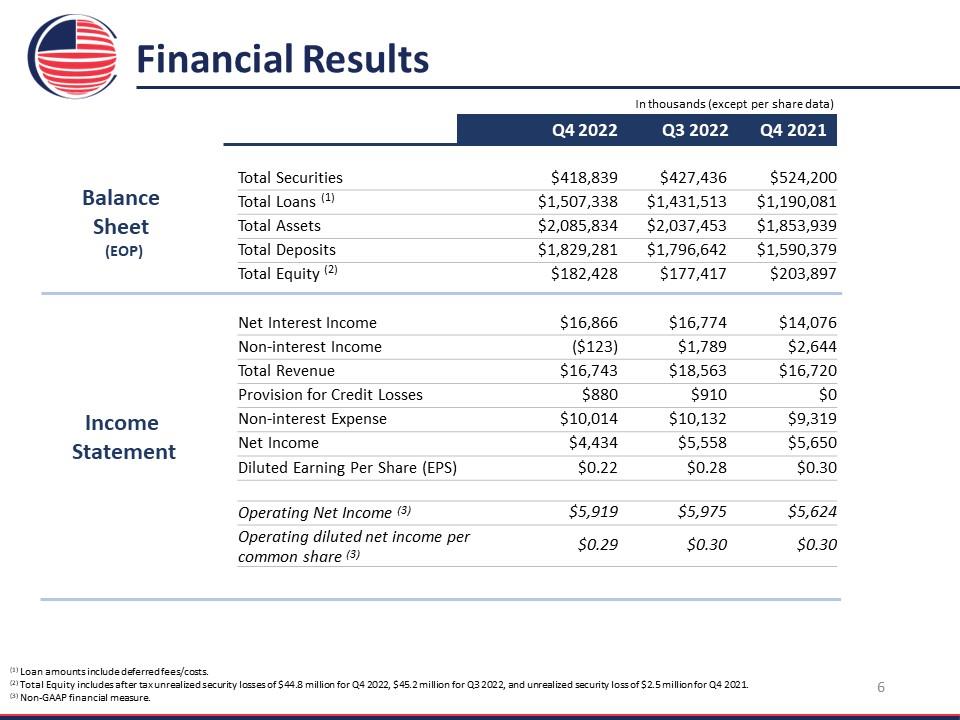
Financial Results In thousands (except per share data) Balance Sheet (EOP) Total Securities $418,839 $427,436 $524,200 Total Loans (1) $1,507,338 $1,431,513 $1,190,081 Total Assets $2,085,834 $2,037,453 $1,853,939 Total Deposits $1,829,281 $1,796,642 $1,590,379 Total Equity (2) $182,428 $177,417 $203,897 Income Statement Net Interest Income $16,866 $16,774 $14,076 Non-interest Income ($123) $1,789 $2,644 Total Revenue $16,743 $18,563 $16,720 Provision for Credit Losses $880 $910 $0 Non-interest Expense $10,014 $10,132 $9,319 Net Income $4,434 $5,558 $5,650 Diluted Earning Per Share (EPS) $0.22 $0.28 $0.30 Operating Net Income (3) $5,919 $5,975 $5,624 Operating diluted net income per common share (3) $0.29 $0.30 $0.30 (1) Loan amounts include deferred fees/costs. (2) Total Equity includes after tax unrealized security losses of $44.8 million for Q4 2022, $45.2 million for Q3 2022, and unrealized security loss of $2.5 million for Q4 2021. (3) Non-GAAP financial measure. 6
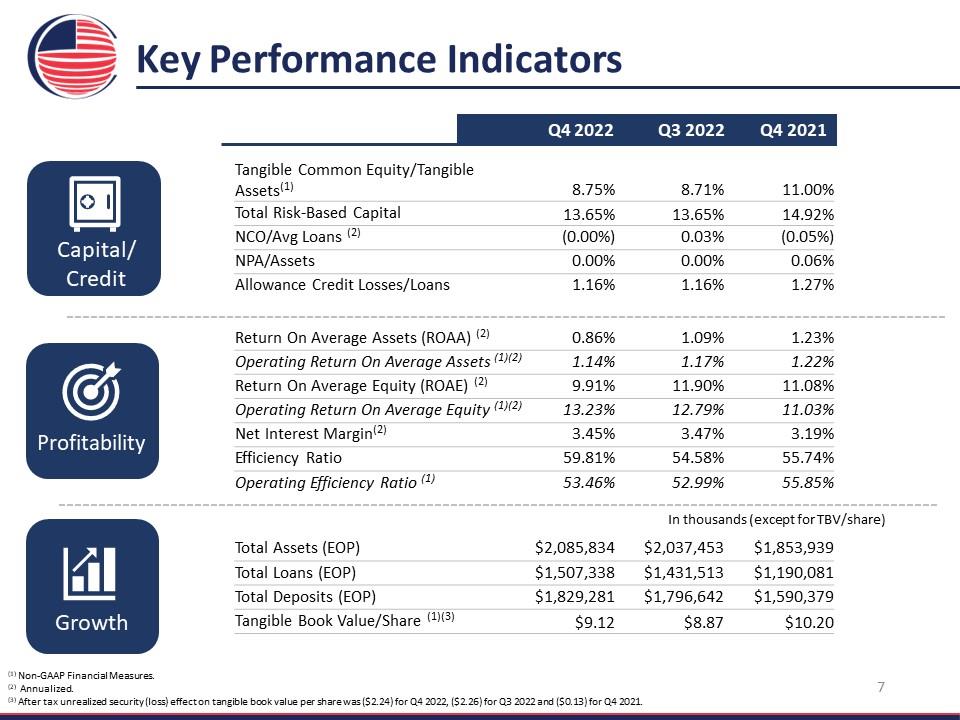
Key Performance Indicators Capital/Credit Profitability Growth Q4 2022 Q3 2022 Q4 2021 Tangible Common Equity/Tangible Assets(1) 8.75% 8.71% 11.00% Total Risk-Based Capital 13.65% 13.65% 14.92% NCO/Avg Loans (2) (0.00%) 0.03% (0.05%) NPA/Assets 0.00% 0.00% 0.06% Allowance Credit Losses/Loans 1.16% 1.16% 1.27% Return On Average Assets (ROAA) (2) 0.86% 1.09% 1.23% Operating Return On Average Assets (1)(2) 1.14% 1.17% 1.22% Return On Average Equity (ROAE) (2) 9.91% 11.90% 11.08% Operating Return On Average Equity (1)(2) 13.23% 12.79% 11.03% Net Interest Margin(2) 3.45% 3.47% 3.19% Efficiency Ratio 59.81% 54.58% 55.74% Operating Efficiency Ratio (1) 53.46% 52.99% 55.85% In thousands (except for TBV/shares) Total Assets (EOP) $2,085,834 $2,037,453 $1,853,939 Total Loans (EOP) $1,507,338 $1,431,513 $1,190,081 Total Deposits (EOP) $1,829,281 $1,796,642 $1,590,379 Tangible Book Value/Share (1)(3) $9.12 $8.87 $10.20 (1) Non-GAAP Financial Measures. (2) Annualized. (3) After tax unrealized security (loss) effect on tangible book value per share was ($2.24) for Q4 2022, ($2.26) for Q3 2022 and ($0.13) for Q4 2021. 7
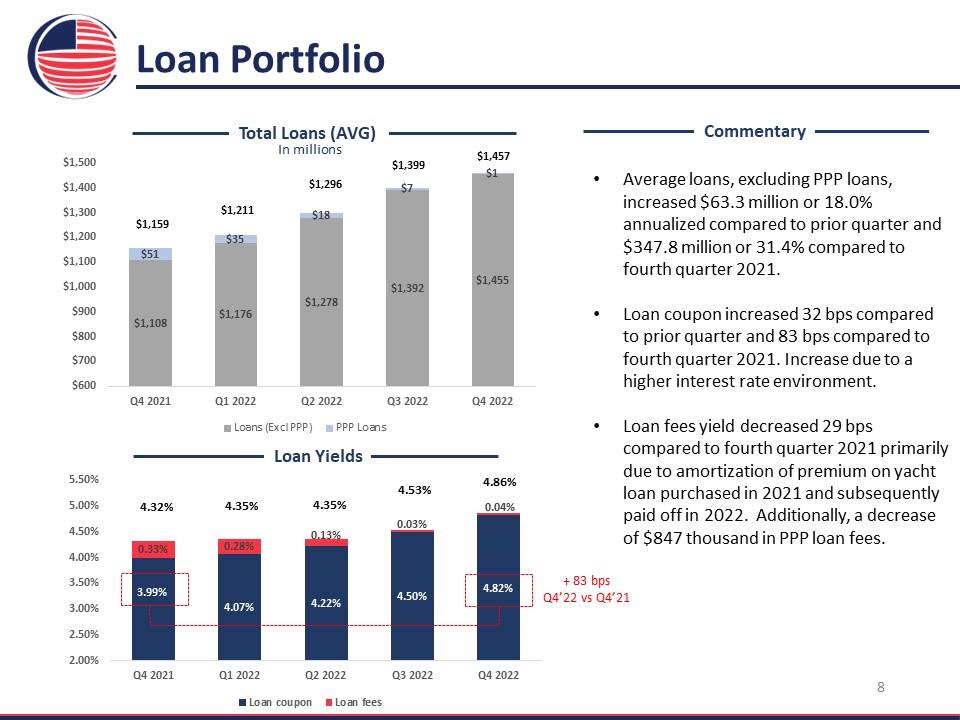
Loan Portfolio Total Loans (AVG) In millions $1,159 $1,211 $1,296 $1,399 $1,457 $51 $35 $18 $7 $1 $1,108 $1,176 $1,278 $1,392 $1,455 Loans (Exd PPP) PPP Loans Loan Yields 4.32% 4.35% 435.00% 4.53% 4.86% 0.33% 0.28% 13.00% 0.03% 0.04% 3.99% 4.07% 4.22% 4.50% 4.82% Loan coupon Loan fees + 83 bps Q4’22 vs Q4’21 Commentary Average loans, excluding PPP loans, increased $63.3 million or 18.0% annualized compared to prior quarter and $347.8 million or 31.4% compared to fourth quarter 2021. Loan coupon increased 32 bps compared to prior quarter and 83 bps compared to fourth quarter 2021. Increase due to a higher interest rate environment. Loan fees yield decreased 29 bps compared to fourth quarter 2021 primarily due to amortization of premium on yacht loan purchased in 2021 and subsequently paid off in 2022. Additionally, a decrease of $847 thousand in PPP loan fees. 8
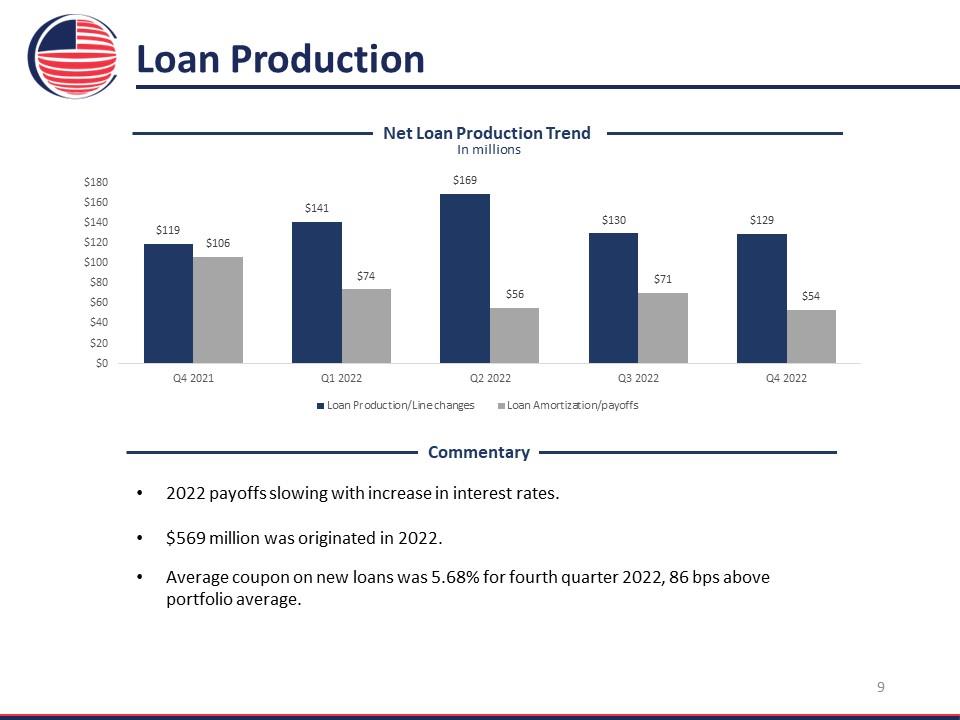
Loan Production Net Loan Production Trend In millions $119 $106 $141 $74 $169 $56 $130 $71 $129 $54 Laon Production/Line changes Loan Amortization/payoffs Commentary 2022 payoffs slowing with increase in interest rates. $569 million was originated in 2022. Average coupon on new loans was 5.68% for fourth quarter 2022, 86 bps above portfolio average. 9
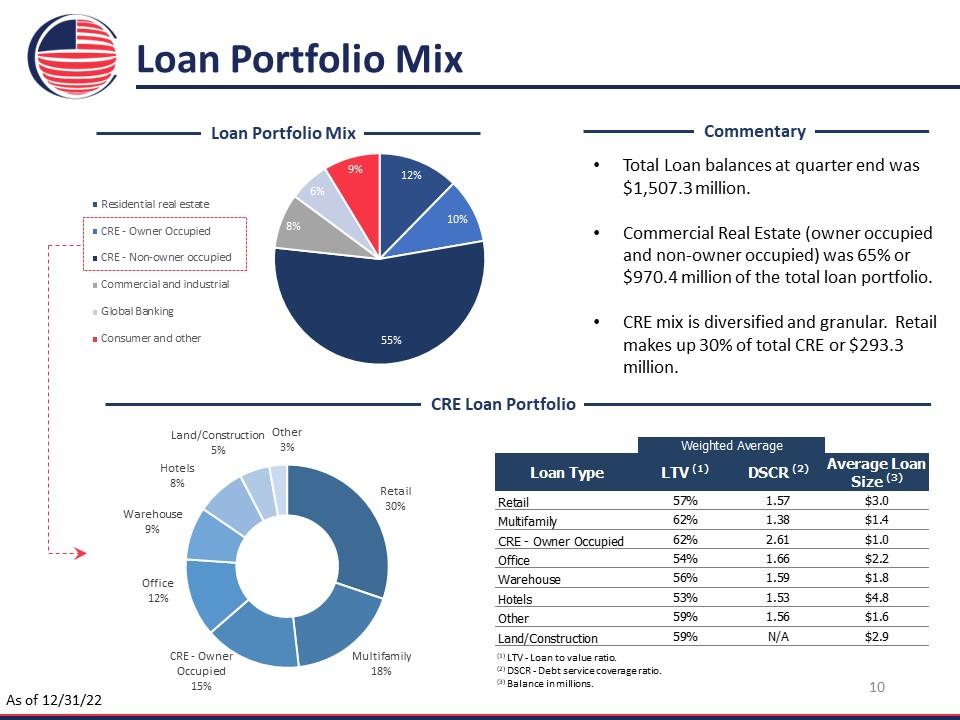
Loan Portfolio Mix Loan Portfolio Mix 9% 12% 10% 55% 8% 6% Residential real estate CRE – Owner Occupied CRE – Non-owner occupied Commercial and industrial Global Banking Consumer and other Commentary Total Loan balances at quarter end was $1,507.3 million. Commercial Real Estate (owner occupied and non-owner occupied) was 65% or $970.4 million of the total loan portfolio. CRE mix is diversified and granular. Retail makes up 30% of total CRE or $293.3 million. CRE Loan Portfolio Other 3% Retail 30% Multifamily 18% CRE - Owner Occupied 15% Office 12%’ Warehouse 9% Hotels 8% Land/Construction 5% Weighted Average Loan Type LTV(1) DSCR Average Loan Size Retail 57% 1.57 $3.0 Multifamily 62% 1.38 $1.4 CRE - Owner Occupied 62% 2.61 $1.0 Office 54% 1.66 $2.2 Warehous e 56% 1.59 $1.8 Hotels 53% 1.53 $4.8 Other 59% 1.56 $1.6 Land/Construction 59% N/A $2.9 (1) LTV - Loan to value ratio. (2) DSCR - Debt service coverage ratio. (3) Balance in millions. 10
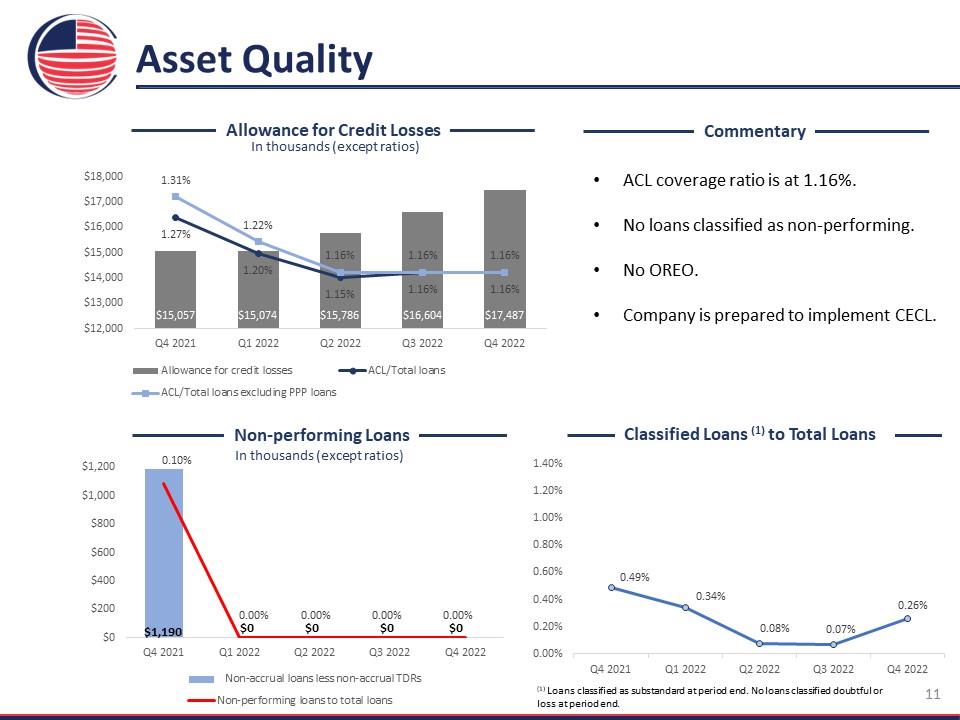
Asset Quality Allowance for Credit Losses In thousands (except ratios) 1.31% 1.22% 1.16% 1.16% 1.16% 1.27% 1.20% 1.15% 1.16% 1.16% $15,057 $15,074 $15,786 $16,604 $17,487 Allowance for credit losses ACL/Total loans ACL/Total loans excluding PPP loans Commentary ACL coverage ratio is at 1.16%. No loans classified as non-performing. No OREO. Company is prepared to implement CECL. Non-performing Loans In thousands (except ratios) 0.10% 0.00% 0.00% 0.00% 0.00% $1,190 $0 $0 $0 $0 Non-accrual loans less non-accrual TDRs Non-performing loans to total loans Classified Loans (1) to Total Loans 0.49% 0.40% 0.08% 0.07% 0.26% (1) Loans classified as substandard at period end. No loans classified doubtful or loss at period end. 11
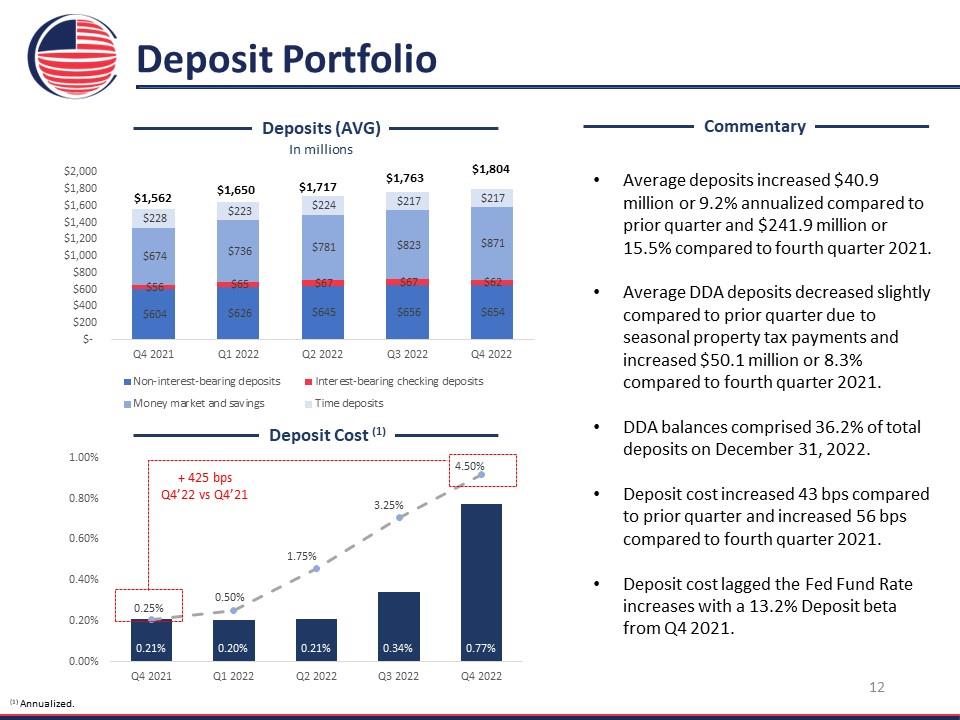
Deposit Portfolio Deposits (AVG) In millions $1,562 $1,650 $1,717 $1,763 $1,804 $228 $223 $224 $217 $217 $674 $736 $781 $823 $871 $56 $65 $67 $67 $62 $604 $626 $645 $656 $654 Non-interest-bearing deposits Money market and savings Interest-bearing checking deposits Time deposits Deposit Cost (1) 0.25% 0.50% 1.75% 3.25% 4.50% 0.21% 0.20% 2.10% 0.34% 0.77% Commentary Average deposits increased $40.9 million or 9.2% annualized compared to prior quarter and $241.9 million or 15.5% compared to fourth quarter 2021. Average DDA deposits decreased slightly compared to prior quarter due to seasonal property tax payments and increased $50.1 million or 8.3% compared to fourth quarter 2021. DDA balances comprised 36.2% of total deposits on December 31, 2022. Deposit cost increased 43 bps compared to prior quarter and increased 56 bps compared to fourth quarter 2021. Deposit cost lagged the Fed Fund Rate increases with a 13.2% Deposit beta from Q4 2021. 12
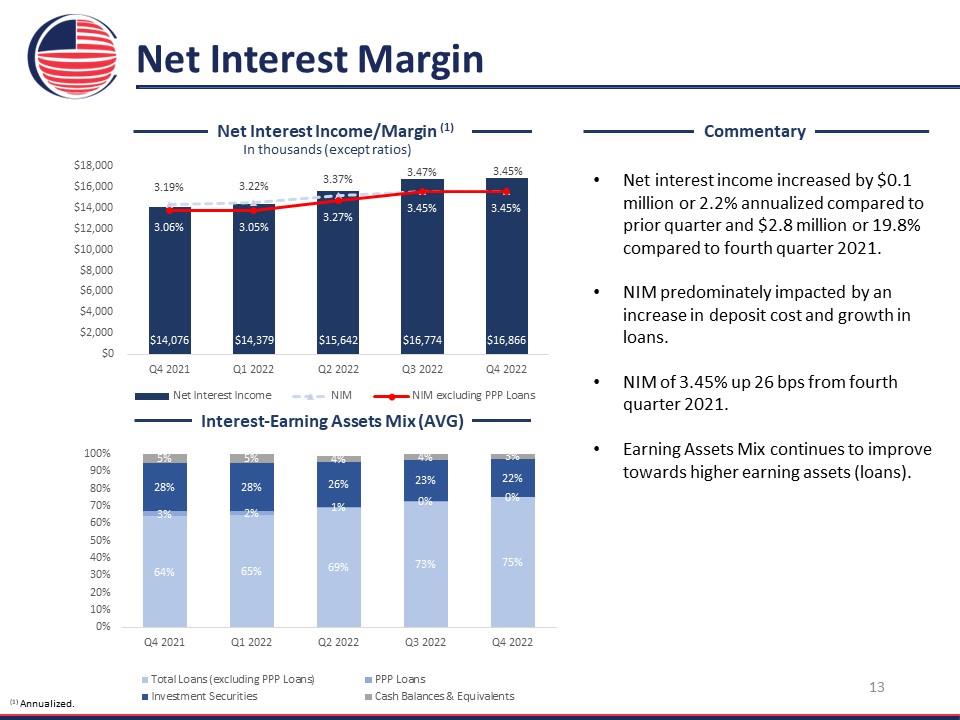
Net Interest Margin Net Interest Income/Margin (1) In thousands (except ratios) 3.19% 3.22% 3.37% 3.47% 3.45% 3.06% 3.05% 3.27% 3.45% 3.45% $14,076 $14,379 $15,642 $16,774 $16,866 Net Interest Income NIM NIM excluding PPP Loans Interest-Earning Assets Mix (AVG) 5% 5% 4% 4% 3% 28% 28% 26% 23% 22% 3% 2% 1% 0% 0% 64% 65% 69% 73% 75% Total Loans (excluding PPP Loans) Investment Securities PPP Loans Cash Balances & Equivalents Commentary Net interest income increased by $0.1 million or 2.2% annualized compared to prior quarter and $2.8 million or 19.8% compared to fourth quarter 2021. NIM predominately impacted by an increase in deposit cost and growth in loans. NIM of 3.45% up 26 bps from fourth quarter 2021. Earning Assets Mix continues to improve towards higher earning assets (loans). (1) Annualized. 13
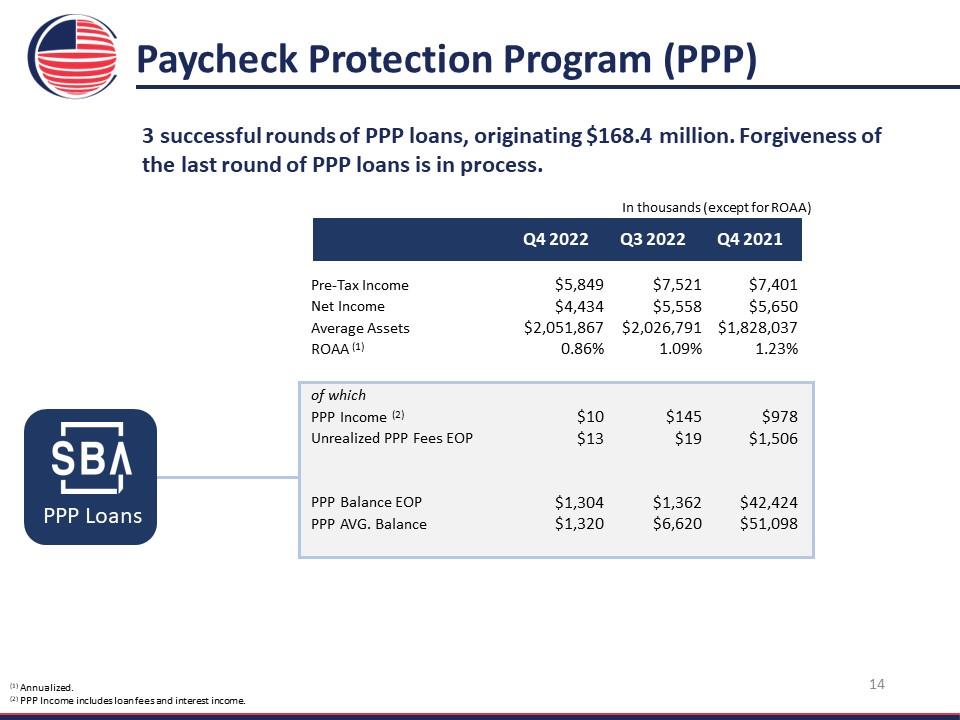
Paycheck Protection Program (PPP) 3 successful rounds of PPP loans, originating $168.4 million. Forgiveness of the last round of PPP loans is in process. In thousands (except for ROAA) Q4 2022 Q3 2022 Q4 2021 Pre-Tax Income $5,849 $7,521 $7,401 Net Income $4,434 $5,558 $5,650 Average Assets $2,051,867 $2,026,791 $1,828,037 ROAA (1) 0.86% 1.09% 1.23% of which PPP Income (2) $10 $145 $978 Unrealized PPP Fees EOP $13 $19 $1,506 PPP Balance EOP $1,304 $1,362 $42,424 PPP AVG. Balance $1,320 $6,620 $51,098 PPP Loans (1) Annualized. (2) PPP Income includes loan fees and interest income. 14
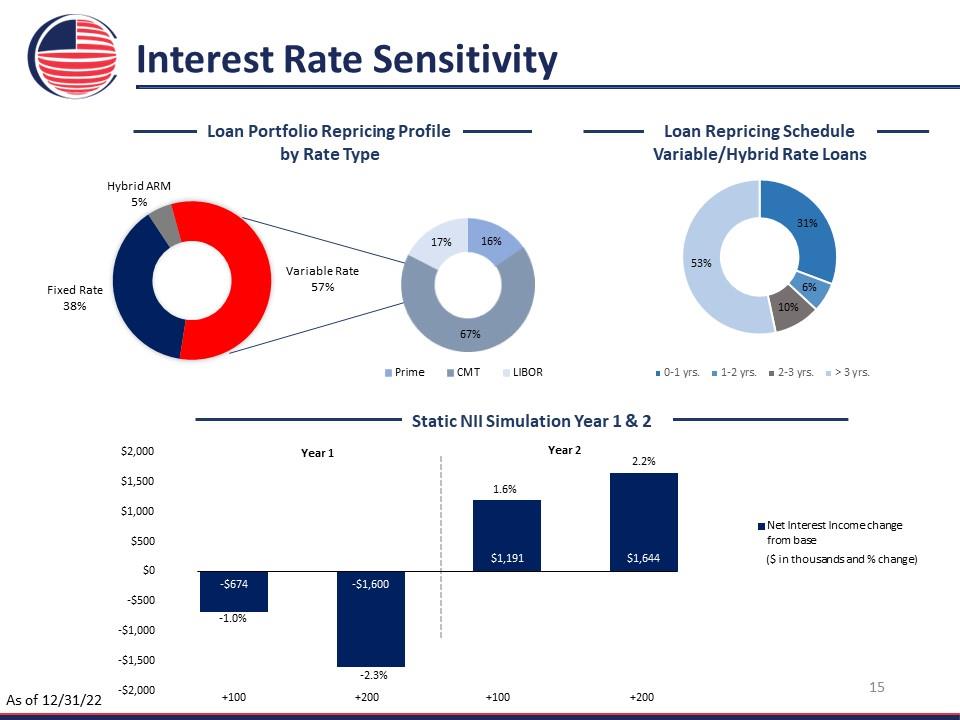
Interest Rate Sensitivity Loan Portfolio Repricing Profile by Rate Type Hybrid ARM 5% Variable Rate 57% Fixed Rate 38% 17% 16% 67% Prime CMT LIBOR 31% 6% 10%53% yrs 1-2 yrs. 2-3 yrs >3 yrs Static NII Simulation Year 1 & 2 Year 1 Years 2 -$6.74 -$16.00 $11.91 $16.44 -1.0% -2.3% 1.6% 2.2% Net Interest Income change from base ($ in thousands and % change) As of 12/31/22 15
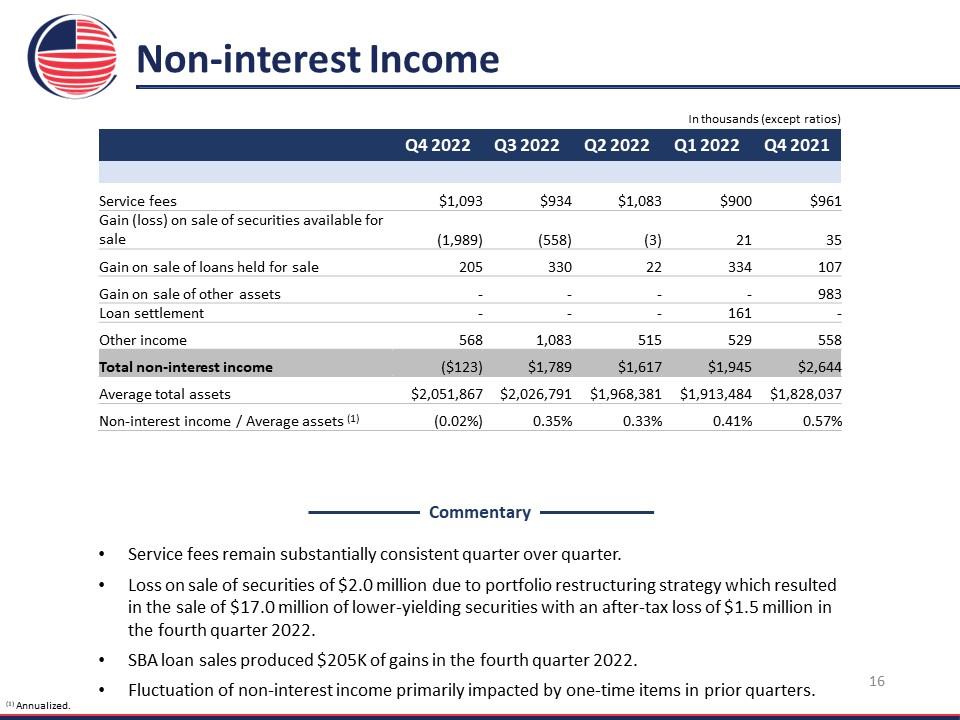
Non-interest Income In thousands (except ratios) Q4 2022 Q3 2022 Q2 2022 Q1 2022 Q4 2021 Service fees $1,093 $934 $1,083 $900 $961 Gain (loss) on sale of securities available for sale (1,989) (558) (3) 21 35 Gain on sale of loans held for sale 205 330 22 334 107 Gain on sale of other assets - - - - 983 Loan settlement - - - 161 - Other income 568 1,083 515 529 558 Total non-interest income ($123) $1,789 $1,617 $1,945 $2,644 Average total assets $2,051,867 $2,026,791 $1,968,381 $1,913,484 $1,828,037 Non-interest income / Average assets (1) (0.02%) 0.35% 0.33% 0.41% 0.57% Commentary Service fees remain substantially consistent quarter over quarter. Loss on sale of securities of $2.0 million due to portfolio restructuring strateg y which resulted in the sale of $17.0 million of lower-yielding securities with an after-tax loss of $1.5 million in the fourth quarter 2022. SBA loan sales produced $205K of gains in the fourth quarter 2022. Fluctuation of non-interest income primarily impacted by one-time items in prior quarters. (1) Annualized. 16
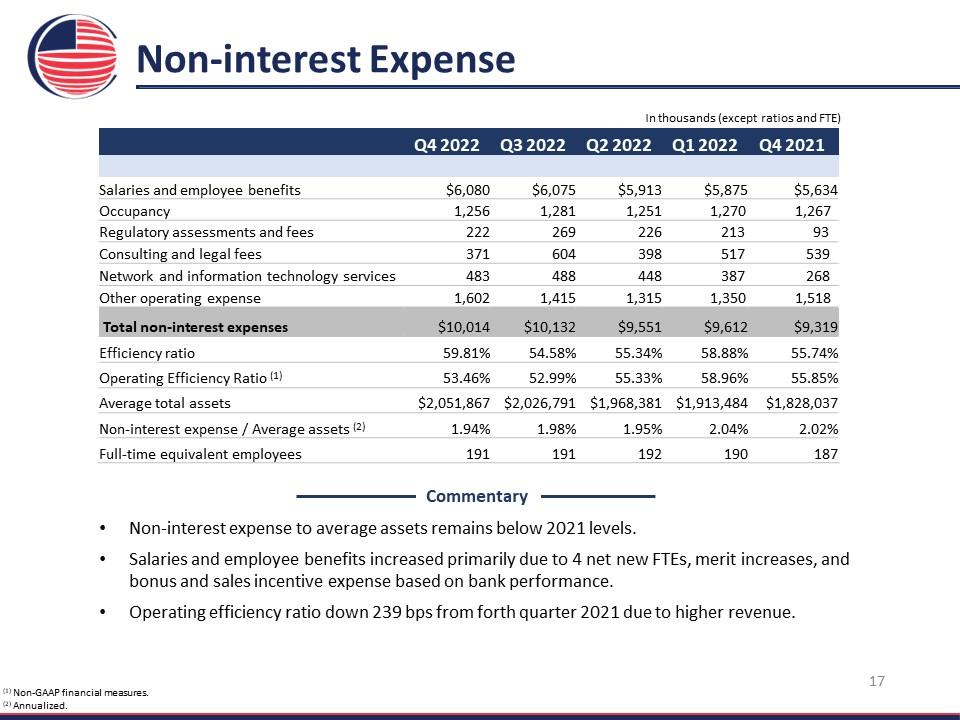
Non-interest Expense In thousands (except ratios and FTE) Q4 2022 Q3 2022 Q2 2022 Q1 2022 Q4 2021 Salaries and employee benefits $6,080 $6,075 $5,913 $5,875 $5,634 Occupancy 1,256 1,281 1,251 1,270 1,267 Regulatory assessments and fees 222 269 226 213 93 Consulting and legal fees 371 604 398 517 539 Network and information technology services 483 488 448 387 268 Other operating expense 1,602 1,415 1,315 1,350 1,518 Total non-interest expenses $10,014 $10,132 $9,551 $9,612 $9,319 Efficiency ratio 59.81% 54.58% 55.34% 58.88% 55.74% Operating Efficiency Ratio (1) 53.46% 52.99% 55.33% 58.96% 55.85% Average total assets $2,051,867 $2,026,791 $1,968,381 $1,913,484 $1,828,037 Non-interest expense / Average assets (2) 1.94% 1.98% 1.95% 2.04% 2.02% Full-time equivalent employees 191 191 192 190 187 Commentary Non-interest expense to average assets remains below 2021 levels. Salaries and employee benefits increased primarily due to 4 net new FTEs, merit increases, and bonus and sales incentive expense based on bank performance. Operating efficiency ratio down 239 bps from forth quarter 2021 due to higher revenue. (1) Non-GAAP financial measures. (2) Annualized. 17
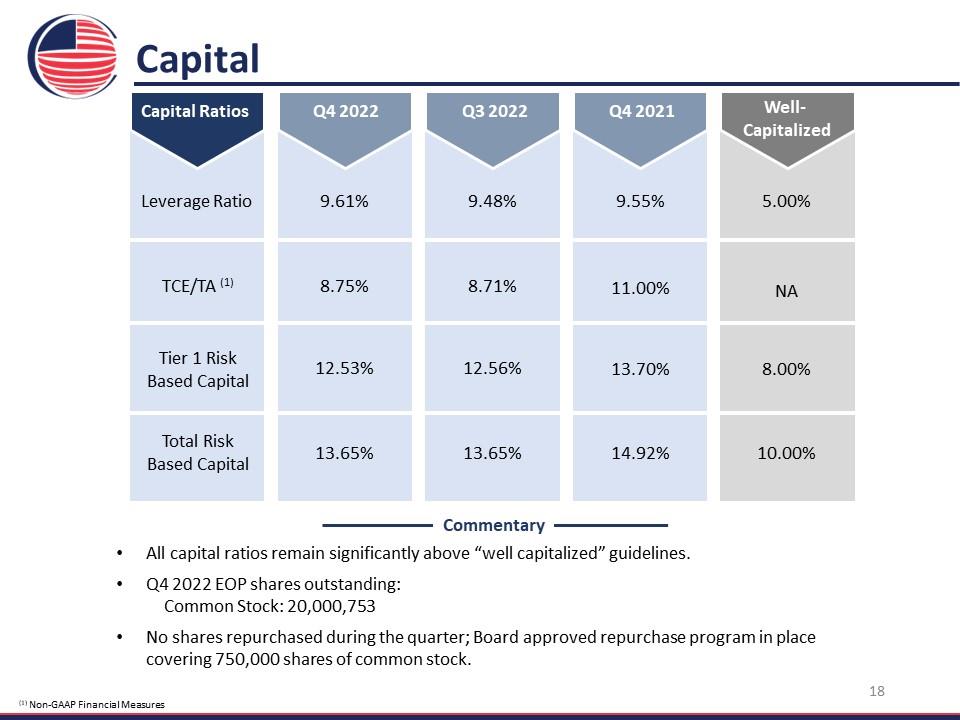
Capital Capital Ratios Q4 2022 Q3 2022 Q4 2021 Well-Capitalized Leverage Ratio 9.61% 9.48% 9.55% 5.00% TCE/TA (1) 8.75% 8.71% 11.00% NA Tier 1 Risk Based Capital 12.53% 12.56% 13.70% 8.00% Total Risk Based Capital 13.65% 13.65% 14.92% 10.00% Commentary All capital ratios remain significantly above “well capitalized” guidelines. Q4 2022 EOP shares outstanding: Common Stock: 20,000,753 No shares repurchased during the quarter; Board approved repurchase program in place covering 750,000 shares of common stock. (1) Non-GAAP Financial Measures 18
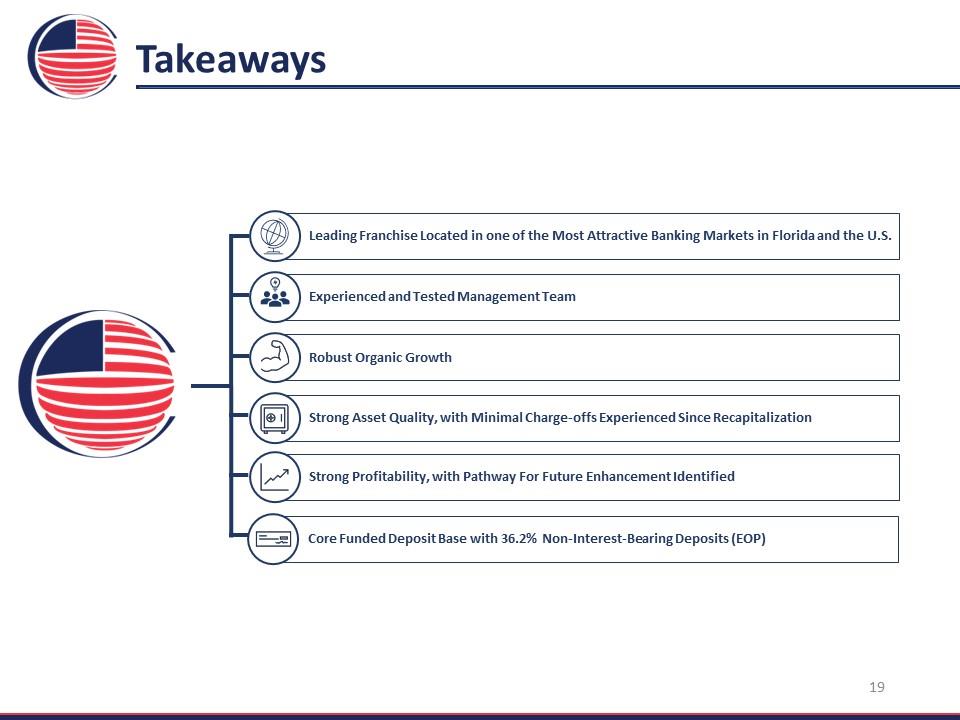
Takeaways Leading Franchise Located in one of the Most Attractive Banking Markets in Florida and the U.S. Experienced and Tested Management Team Robust Organic Growth Strong Asset Quality, with Minimal Charge-offs Experienced Since Recapitalization Strong Profitability, with Pathway For Future Enhancement Identified Core Funded Deposit Base with 36.2% Non-Interest-Bearing Deposits (EOP) 19
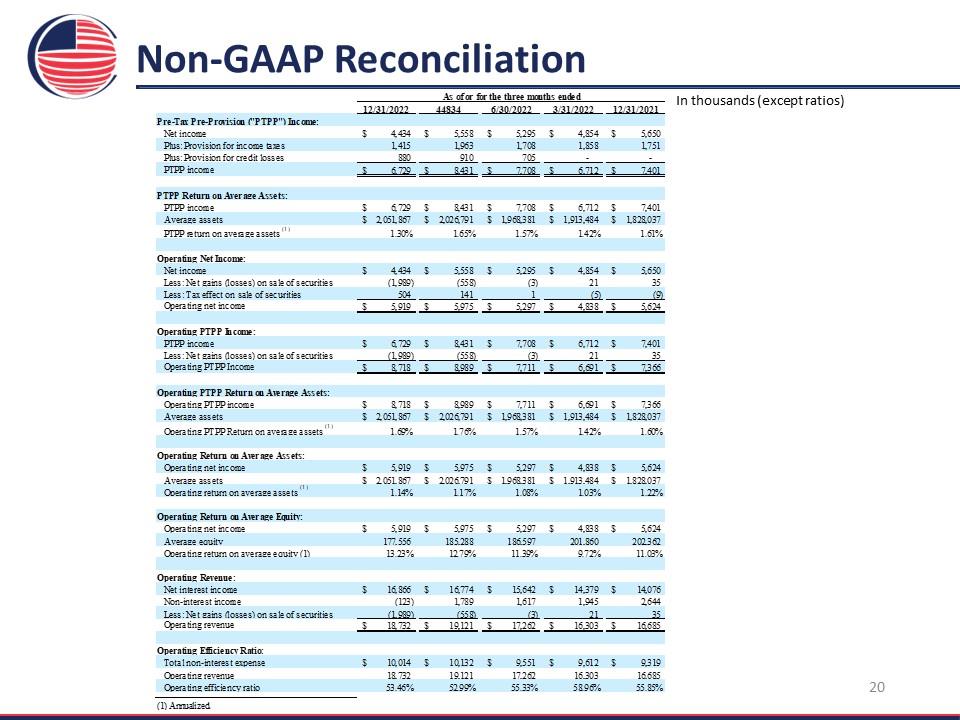
Non-GAAP Reconciliation In thousands (except ratios) 7 As of or for the three mouths ended 12/31/2022 44834 6/30/2022 3/31/2022 12/31/2021 Pre-Tax Pre-Provision ("PTPP") Income: Net income $ 4.434 $ 5.558 $ 5.295 $ 4.854 $ 5.650 Plus: Provision for income taxes 1,415 1.963 1.708 1.858 1.751 Plus: Provision for credit losses 880 910 705 - - PTPP income $ 6.729 $ 8.431 $ 7.708 $ 6.712 $ 7.401 PTPP Return on Average Assets: PTPP income $ 6.729 $ 8.431 $ 7.708 $ 6.712 $ 7.401 Average assets $ 2.051.867 $ 2.026.791 $ 1.968.381 $ 1.913.484 $ 1.828.037 PTPP return on average assets '1' 1.30% 1.65% 1.57% 1.42% 1.61% Operating Net Income: Net income $ 4.434 $ 5.558 $ 5.295 $ 4.854 $ 5.650 Less: Net gains (losses) on sale of securities (1.989) (558) (3) 21 35 Less: Tax effect on sale of securities 504 141 1 (5) (9) Operating net income $ 5.919 $ 5.975 $ 5.297 $ 4.838 $ 5.624 Operating PTPP Income: PTPP income $ 6.729 $ 8.431 $ 7.708 $ 6.712 $ 7.401 Less: Net gains (losses) on sale of securities (1.989) (558) (3) 21 35 Operating PTPP Income $ 8.718 $ 8.989 $ 7.711 $ 6.691 $ 7.366 Operating PTPP Return ou Average Assets: Operating PTPP income Average assets Operating PTPP Return on average assets 'lj $ 8.718 $ 2.051.867 1.69% Operating Return ou Average Assets: Operating net income Average assets Operating return on average assets (1) $ 5.919 $ 2.051.867 1.14% Operating Return ou Average Equity’ Operating net income Average equity Operating return on average equity (1) $ 5.919 177.556 13.23% Operating Revenue Net interest income Non-interest income Less: Net gains (losses) on sale of securities Operating revenue $ 16.866 (123) (1.989) $ 18.732 Operating Efficiency Ratio: Total non-interest expense Operating revenue Operating efficiency ratio $ 10.014 18.732 53.46% $ 8.989 $ 7.711 $ 6.691 $ 7.366 9 $ 2.026.791 $ 1.968.381 $ 1.913.484 $ 1.828.037 1.76%
1.57% 1.42% 1.60% $ 5.975 $ 5.297 $ 4.838 $ 5.624 $ 2.026.791 $ 1.968.381 $ 1.913.484 $ 1.828.037 1.17% 1.08% 1.03% 1.22% $ 5.975 $ 5.297 $ 4.838 $ 5.624 185.288 186.597 201.860 202.362 12.79% 11.39% 9.72% 11.03% $ 16.774 $ 15.642 $ 14.379 $ 14.076 1.789 1.617 1.945 2.644 (558) (3) 21 35 $ 19.121 $ 17.262 $ 16.303 $ 16.685
■
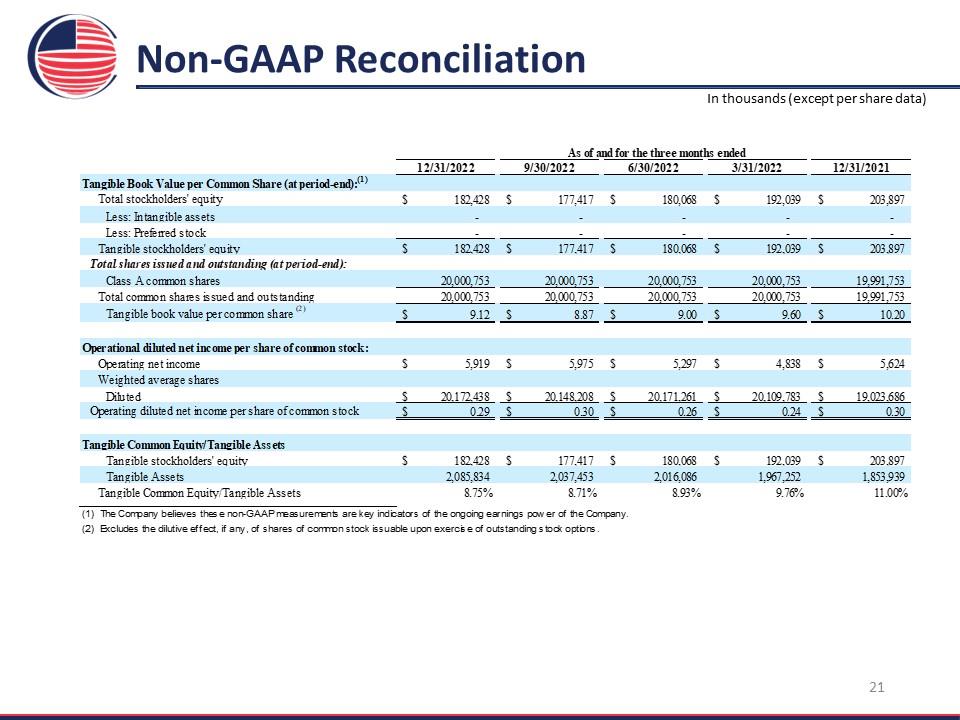
Non-GAAP Reconciliation In thousands (except per share data) As of and for the three months ended 12/31/2022 9/30/2022 6/30/2022 3/31/2022 12/31/2021 tangible Book Value per Common Share (at period-end):11 ' Total stockholders' equity S 182.428 s 177.417 s 180.06S S 192.039 S 203.897 Less: Intangible assets ..... Less: Preferred stock - - - - - Tangible stockholders' equity Total shares issued and outstanding (at period-end): s 181428 s 177.417 s 180.06S s 192.039 S 203.897 Class A common shares 20.000.753 Vi AM 1C 20.000.753 Vt /V\A If 20.000.753 yA AAA 20.(0X3.753 AA iVW If? 19.991.753 t A fWt If? total common shares issued and outstanding Tangible book value per common share ' s 2U.OOU. /5 b 9.12 s 2U.UUO. /5o 8.S7 s 2U.UW. /5b 9. CO s 2U.UUU. /5b 9.60 S i9.yyi./5b 10.20 Operational diluted net income per share of common stock: Operating net income s 5.919 s 5.975 s 5297 S 4.838 S 5.624 Weighted average shares Diluted s 20.17243S s 20.14S.20S s 20.171.261 s 20.109.7S3 s 19.023.686 Operating diluted net income per share of common stock s 029 s 030 s 0.26 s 0.24 s 0.30 fnnoihli1 fVminifin Fmiin/TmoiKlo Tangible stockholders’ equity s 181428 s 177.417 s 180.06S s 192.039 s 203.897 Tangible Assets 2.0S5.S34 1037,453 2,016,086 1,967252 LS53539 Tangible Common Equity. Tangible Assets 8.75% 8.71% 8.93% 9.76% 11.00% 1. The Carpark believes these non-GAAP treasurer 3rekey in caters of the ongoing earnings paver of the Company. 2. Precludes the dilutive effect, if any. of shares of common stock issuable upon exercise of outstanding stock options. 21
Contact Information Lou de la Aguilera President, CEO & Director (305) 715-5186 [email protected] Rob Anderson Chief Financial Officer (305) 715-5393 [email protected] Investor Relations [email protected] 22