
USCB 8-K
Uscb Financial Holdings, Inc. (USCB)
8-K
2023-04-27
For: 2023-04-27
View Original
Added on
April 06, 2026
1
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
__________________________
FORM
__________________________
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported):
__________________________
(Exact name of Registrant as Specified in Its Charter)
(State or Other Jurisdiction
of Incorporation)
(Commission File Number)
(IRS Employer
Identification No.)
,
,
(Address of Principal Executive Offices)
(Zip Code)
Registrant’s Telephone Number, Including Area Code: (
)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under
any of the following provisions:
☐
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425)
☐
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a -12)
☐
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))
☐
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))
Securities registered pursuant to Section 12(b) of the Act:
Title of each class
Trading
Symbol(s)
Name of each exchange on which registered
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933
(§ 230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§ 240.12b -2 of this chapter).
Emerging growth company
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for
complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.
2
Item 2.02. Results of Operations and Financial Condition.
On April 27, 2023, USCB Financial Holdings, Inc. (the “Company”), issued a press release announcing its financial results for
the first quarter ended March 31, 2023. A copy of the press release is furnished as Exhibit 99.1 to this Current Report on Form 8-K and
is incorporated herein by reference.
The information in this Item 2.02, including Exhibit 99.1, is being furnished and shall not be deemed “filed” for purposes of
Section 18 of the Securities Exchange Act of 1934 (the “Exchange Act”), or otherwise subject to the liability of that section, and shall
not be deemed to be incorporated by reference into any filing under the Securities Act of 1933 (the “Securities Act”) or the Exchange
Act.
Item 7.01. Regulation FD Disclosure.
As previously announced, at 11:00 a.m. ET on April 28, 2023, the Company will hold an earnings conference call to discuss
its financial performance for the quarter ended March 31, 2023. A copy of the slides forming the basis of the presentation is being
furnished as Exhibit 99.2 to this Current Report on Form 8-K and is incorporated herein by reference. A copy of the slides has also been
posted to the Company’s investor relations website, located at investors.uscenturybank.com.
The information in this Item 7.01, including Exhibit 99.2, is being furnished and shall not be deemed “filed” for purposes of
Section 18 of the Exchange Act, or otherwise subject to the liability of that section, and shall not be deemed to be incorporated by
reference into any filing under the Securities Act or the Exchange Act.
Item 9.01. Financial Statements and Exhibits.
(d) Exhibits.
Exhibit No.
Description
99.1
99.2
104
Cover Page Interactive Data File (embedded within the Inline XBRL document)
1
Exhibit 99.1
EARNINGS RELEASE
USCB Financial Holdings, Inc. Reports EPS of $0.29 and ROAA of 1.11% for Q1 2023
MIAMI, FL – April 27, 2023 – USCB Financial Holdings, Inc. (the “Company”) (NASDAQ: USCB)
, the holding company for
U.S. Century Bank (the “Bank”), reported net income of $5.8 million or $0.29 per diluted share for the three months ended March 31,
2023, compared with net income of $4.9 million or $0.24 per diluted share, for the same period in 2022.
"The beginning of 2023 was marked by significant events such as the sudden failure of three banks, prompting heightened concerns
about the safety and soundness of the banking industry, and ongoing discussions of a potential recession. Despite these challenges, we
are pleased to announce that the USCB team delivered strong performance in the first quarter of 2023, reflecting our ability to navigate
this challenging operating environment with prudent consistency. Our financial results demonstrate robust earnings, driven by strong
loan production, and disciplined credit underwriting and risk management practices” said Luis de la Aguilera, President and Chief
Executive Officer. "Our strength and stability are reinforced by our growing core customer relationships, which have enabled us to
build a granular deposit base and diversified loan portfolio, in one of the most vibrant markets in the United States.” Mr. de la Aguilera
went on to say, “ our deposits are derived primarily from our local customers and communities. We do not have any material exposure
to either crypto currencies or investments or to crypto-related business.”
Unless otherwise stated, all percentage comparisons in the bullet points below are calculated for the quarter ended March 31, 2023
compared to the quarter ended March 31, 2022 and annualized where appropriate.
Profitability
•
Annualized return on average assets for the quarter ended March 31, 2023 was 1.11% compared to 1.03% for the first quarter of
2022.
•
Annualized return on average stockholders’ equity for the quarter ended March 31, 2023 was 12.85% compared to 9.75% for the
first quarter of 2022.
•
The efficiency ratio for the quarter ended March 31, 2023 was 56.32% compared to 58.88% for the first quarter of 2022.
•
Net interest margin was 3.22% for both quarters ended March 31, 2023 and 2022.
•
Net interest income before provision for credit losses was $16.0 million for the quarter ended March 31, 2023, an increase of
$1.6 million or 11.3% compared to the first quarter of 2022.
Balance Sheet
•
Total assets were $2.2 billion at March 31, 2023, representing an increase of $196.6 million or 10.0% from March 31, 2022.
•
Total loans were $1.6 billion at March 31, 2023, representing an increase of $322.0 million or 25.6% from March 31, 2022.
•
Total deposits were $1. 8 billion at March 31, 2023, representing an increase of $117.2 million or 6.8% from March 31, 2022.
•
Total stockholders’ equity was $183.9 million at March 31, 2023, representing a decrease of $8.2 million or 4.3% from March 31,
2022. Total stockholders’ equity includes after-tax unrealized security losses of $42.1 million at March 31, 2023 compared to after-
tax unrealized security losses of $19.5 million at March 31, 2022.
Asset Quality
•
Effective January 1, 2023, the Company adopted ASU 2016-13 Current Expected Credit Losses (“CECL”) methodology for
estimating credit losses, which resulted in an increase to the allowance for credit losses of loans of $1.1 million and an increase to
the reserve for unfunded commitments of $259 thousand. This one-time cumulative adjustment resulted in an after-tax decrease of
$1.0 million in retained earnings.
2
•
The allowance for credit losses increased by $3.8 million to $18.9 million at March 31, 2023 from $15.1 million at March 31, 2022.
•
The allowance for credit losses represented 1.20% of total loans at March 31, 2023 and at March 31, 2022.
•
Non-performing loans to total loans was 0.03% at March 31, 2023 compared to 0.00% at March 31, 2022.
Non-interest Income and Non-interest Expense
•
Non-interest income was $2.1 million for the three months ended March 31, 2023, an increase of $125 thousand or 6.4% compared
to $1.9 million for the same period in 2022.
•
Non-interest expense was $10.2 million for the three months ended March 31, 2023, an increase of $564 thousand or 5.9% compared
to the same period in 2022.
Capital
•
During the quarter the Company repurchased 500,000 shares of USCB Financial Holdings Inc at a weighted average price per share
of $11.74. The aggregate purchase price for these transactions was approximately $5.9 million, including transaction costs. These
repurchases were made through open market pursuant to the Company’s publicly announced repurchase program. As of March 31,
2023, 250,000 shares remain authorized under this program.
•
As of March 31, 2023,
total risk-based capital ratios for the Company and the Bank were 13.20% and 13.12%, respectively.
•
Tangible book value per common share of $9.37 was negatively affected by $2.14 due to after tax unrealized security losses of
$42.1 million at March 31, 2023. At March 31, 2022, tangible book value of $9.60 was negatively affected by $0.97 due to $19.5
million after tax unrealized security losses.
Conference Call and Webcast
The Company will host a conference call on Friday, April 28, 2023, at 11:00 a.m. Eastern Time to discuss the Company’s unaudited
financial results for the quarter ended March 31, 2023. To access the conference call, dial (866) 652-5200 (U.S. toll-free) and ask to join
the USCB Financial Holdings Call.
Additionally, interested parties can listen to a live webcast of the call in the “Investor Relations” section of the Company’s website
at www.uscentury.com . An archived version of the webcast will be available in the same location shortly after the live call has ended.
About USCB Financial Holdings, Inc.
USCB Financial Holdings, Inc. is the bank holding company for U.S. Century Bank. Established in 2002, U.S. Century Bank is one of
the largest community banks headquartered in Miami, and one of the largest community banks in the State of Florida. U.S. Century
Bank is rated 5-Stars by BauerFinancial, the nation’s leading independent bank rating firm. U.S. Century Bank offers customers a wide
range of financial products and services and supports numerous community organizations, including the Greater Miami Chamber of
Commerce, the South Florida Hispanic Chamber of Commerce, and ChamberSouth. For more information or to find a banking center
near you, please call (305) 715-5200 or visit www.uscentury.com.
Forward-Looking Statements
This earnings release may contain statements that are not historical in nature and are intended to be, and are hereby identified as, forward-
looking statements for purposes of the safe harbor provided by Section 21E of the Securities Exchange Act of 1934, as amended.
Forward-looking statements are those that are not historical facts. The words “may,” “will,” “anticipate,” “should,” “would,” “believe,”
“contemplate,” “expect,” “aim,” “plan,” “estimate,” “continue,” and “intend,” as well as other similar words and expressions of the
future, are intended to identify forward-looking statements. These forward-looking statements include, but are not limited to, statements
related to our projected growth, anticipated future financial performance, and management’s long-term performance goals, as well as
statements relating to the anticipated effects on results of operations and financial condition from expected developments or events, or
business and growth strategies, including anticipated internal growth and balance sheet restructuring.
These forward-looking statements involve significant risks and uncertainties that could cause our actual results to differ materially from
those anticipated in such statements. Potential risks and uncertainties include, but are not limited to:
•
the strength of the United States economy in general and the strength of the local economies in which we conduct operations;
•
our ability to successfully manage interest rate risk, credit risk, liquidity risk, and other risks inherent to our industry;
3
•
the accuracy of our financial statement estimates and assumptions, including the estimates used for our credit loss reserve and
deferred tax asset valuation allowance;
•
the efficiency and effectiveness of our internal control environment;
•
our ability to comply with the extensive laws and regulations to which we are subject, including the laws for each jurisdiction where
we operate;
•
adverse changes or conditions in capital and financial markets, including actual or potential stresses in the banking industry;
•
deposit attrition and the level of our uninsured deposits;
•
legislative or regulatory changes and changes in accounting principles, policies, practices or guidelines, including the on-going
effects of the implementation of the Current Expected Credit Losses (“CECL”) standard;
•
the effects of our lack of a diversified loan portfolio and concentration in the South Florida market, including the risks of geographic,
depositor, and industry concentrations, including our concentration in loans secured by real estate;
•
effects of climate change;
•
the concentration of ownership of our common stock;
•
fluctuations in the price of our common stock;
•
our ability to fund or access the capital markets at attractive rates and terms and manage our growth, both organic growth as well
as growth through other means, such as future acquisitions;
•
inflation, interest rate, unemployment rate, market and monetary fluctuations;
•
impacts of international hostilities and geopolitical events;
•
increased competition and its effect on the pricing of our products and services as well as our margin;
•
the effectiveness of our risk management strategies, including operational risks, including, but not limited to, client, employee, or
third-party fraud and security breaches; and
•
other risks described in this earnings release and other filings we make with the Securities and Exchange Commission (“SEC”).
All forward-looking statements are necessarily only estimates of future results, and there can be no assurance that actual results will not
differ materially from expectations. Therefore, you are cautioned not to place undue reliance on any forward-looking statements. Further,
forward-looking statements included in this earnings release are made only as of the date hereof, and we undertake no obligation to
update or revise any forward-looking statement to reflect events or circumstances after the date on which the statements are made or to
reflect the occurrence of unanticipated events, unless required to do so under the federal securities laws. You should also review the risk
factors described in the reports the Company filed or will file with the SEC and, for periods prior to the completion of the bank holding
company reorganization in December 2021, the Bank filed with the FDIC.
Non-GAAP Financial Measures
This earnings release includes financial information determined by methods other than in accordance with generally accepted accounting
principles (“GAAP”). This financial information includes certain operating performance measures. Management has included these non-
GAAP measures because it believes these measures may provide useful supplemental information for evaluating the Company’s
underlying performance trends. Further, management uses these measures in managing and evaluating the Company’s business and
intends to refer to them in discussions about our operations and performance. Operating performance measures should be viewed in
addition to, and not as an alternative to or substitute for, measures determined in accordance with GAAP, and are not necessarily
comparable to non-GAAP measures that may be presented by other companies. Reconciliations of these non-GAAP measures to the
most directly comparable GAAP measures can be found in the ‘Non-GAAP Reconciliation Tables’ included in the exhibits to this
earnings release.
All numbers included in this press release are unaudited unless otherwise noted.
Contacts:
Investor Relations
Media Relations
Martha Guerra-Kattou
4
USCB FINANCIAL HOLDINGS, INC.
CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED)
(Dollars in thousands, except per share data)
Three Months Ended March 31,
2023
2022
Interest income:
Loans, including fees
$
19,711
$
12,982
Investment securities
2,286
2,329
Interest-bearing deposits in financial institutions
382
31
Total interest income
22,379
15,342
Interest expense:
Interest-bearing checking
43
16
Savings and money market accounts
4,785
551
Time deposits
1,057
259
FHLB advances and other borrowings
497
137
Total interest expense
6,382
963
Net interest income before provision for credit losses
15,997
14,379
Provision for credit losses
201
-
Net interest income after provision for credit losses
15,796
14,379
Non-interest income:
Service fees
1,205
900
Gain (loss) on sale of securities available for sale, net
(21)
21
Gain on sale of loans held for sale, net
347
334
Loan settlement
-
161
Other non-interest income
539
529
Total non-interest income
2,070
1,945
Non-interest expense:
Salaries and employee benefits
6,377
5,875
Occupancy
1,299
1,270
Regulatory assessments and fees
224
213
Consulting and legal fees
358
517
Network and information technology services
478
387
Other operating expense
1,440
1,350
Total non-interest expense
10,176
9,612
Net income before income tax expense
7,690
6,712
Income tax expense
1,881
1,858
Net income
5,809
4,854
Per share information:
Net income per common share, basic
$
0.29
$
0.24
Net income per common share, diluted
$
0.29
$
0.24
Weighted average shares outstanding:
Common shares, basic
19,855,409
19,994,953
Common shares, diluted
19,940,606
20,109,783
5
USCB FINANCIAL HOLDINGS, INC.
SELECTED FINANCIAL DATA (UNAUDITED)
(Dollars in thousands, except per share data)
As of or For the Three Months Ended
3/31/2023
12/31/2022
9/30/2022
6/30/2022
3/31/2022
Income statement data:
Net interest income
$
15,997
$
16,866
$
16,774
$
15,642
$
14,379
Provision for credit losses
201
880
910
705
-
Net interest income after provision for credit losses
15,796
15,986
15,864
14,937
14,379
Service fees
1,205
1,093
934
1,083
900
Gain (loss) on sale of securities available for sale, net
(21)
(1,989)
(558)
(3)
21
Gain on sale of loans held for sale, net
347
205
330
22
334
Loan settlement
-
-
-
-
161
Other income
539
568
1,083
515
529
Total non-interest income
2,070
(123)
1,789
1,617
1,945
Salaries and employee benefits
6,377
6,080
6,075
5,913
5,875
Occupancy
1,299
1,256
1,281
1,251
1,270
Regulatory assessments and fees
224
222
269
226
213
Consulting and legal fees
358
371
604
398
517
Network and information technology services
478
483
488
448
387
Other operating expense
1,440
1,602
1,415
1,315
1,350
Total non-interest expense
10,176
10,014
10,132
9,551
9,612
Net income before income tax expense
7,690
5,849
7,521
7,003
6,712
Income tax expense
1,881
1,415
1,963
1,708
1,858
Net income
$
5,809
$
4,434
$
5,558
$
5,295
$
4,854
Per share information:
Net income per common share, basic
$
0.29
$
0.22
$
0.28
$
0.26
$
0.24
Net income per common share, diluted
$
0.29
$
0.22
$
0.28
$
0.26
$
0.24
Balance sheet data (at period-end):
Cash and cash equivalents
$
63,251
$
54,168
$
73,326
$
83,272
$
94,113
Securities available-for-sale
$
229,409
$
230,140
$
248,571
$
339,464
$
392,214
Securities held-to-maturity
$
186,428
$
188,699
$
178,865
$
116,671
$
122,361
Total securities
$
415,837
$
418,839
$
427,436
$
456,135
$
514,575
Loans held for investment
(1)
$
1,580,394
$
1,507,338
$
1,431,513
$
1,372,733
$
1,258,388
Allowance for credit losses
$
(18,887)
$
(17,487)
$
(16,604)
$
(15,786)
$
(15,074)
Total assets
$
2,163,821
$
2,085,834
$
2,037,453
$
2,016,086
$
1,967,252
Non-interest-bearing deposits
$
633,606
$
629,776
$
662,808
$
653,708
$
656,622
Interest-bearing deposits
$
1,196,856
$
1,199,505
$
1,133,834
$
1,085,012
$
1,056,672
Total deposits
$
1,830,462
$
1,829,281
$
1,796,642
$
1,738,720
$
1,713,294
FHLB advances and other borrowings
$
120,000
$
46,000
$
26,000
$
66,000
$
36,000
Total liabilities
$
1,979,963
$
1,903,406
$
1,860,036
$
1,836,018
$
1,775,213
Total stockholders' equity
$
183,858
$
182,428
$
177,417
$
180,068
$
192,039
Capital ratios:
(2)
Leverage ratio
9.36%
9.61%
9.48%
9.43%
9.47%
Common equity tier 1 capital
12.04%
12.53%
12.56%
12.65%
13.35%
Tier 1 risk-based capital
12.04%
12.53%
12.56%
12.65%
13.35%
Total risk-based capital
13.20%
13.65%
13.65%
13.74%
14.49%
(1) Loan amounts include deferred fees/costs.
(2) Reflects the Company's capital ratios
6
USCB FINANCIAL HOLDINGS, INC.
AVERAGE BALANCES, RATIOS, AND OTHER DATA (UNAUDITED)
(Dollars in thousands)
As of or For the Three Months Ended
3/31/2023
12/31/2022
9/30/2022
6/30/2022
3/31/2022
Average balance sheet data:
Cash and cash equivalents
$
50,822
$
61,892
$
77,887
$
80,254
$
99,911
Securities available-for-sale
$
230,336
$
242,144
$
331,206
$
370,933
$
385,748
Securities held-to-maturity
$
187,826
$
184,459
$
116,733
$
120,130
$
122,381
Total securities
$
418,162
$
426,603
$
447,939
$
491,063
$
508,129
Loans held for investment
(1)
$
1,547,393
$
1,456,780
$
1,398,761
$
1,296,476
$
1,211,432
Total assets
$
2,120,218
$
2,051,867
$
2,026,791
$
1,968,381
$
1,913,484
Interest-bearing deposits
$
1,179,878
$
1,150,049
$
1,107,129
$
1,071,709
$
1,023,844
Non-interest-bearing deposits
$
664,369
$
653,820
$
655,853
$
644,975
$
626,400
Total deposits
$
1,844,247
$
1,803,869
$
1,762,982
$
1,716,684
$
1,650,244
FHLB advances and other borrowings
$
61,600
$
37,500
$
43,935
$
36,330
$
36,011
Total liabilities
$
1,936,847
$
1,874,311
$
1,841,503
$
1,781,784
$
1,711,624
Total stockholders' equity
$
183,371
$
177,556
$
185,288
$
186,597
$
201,860
Performance ratios:
Return on average assets
(2)
1.11%
0.86%
1.09%
1.08%
1.03%
Return on average equity
(2)
12.85%
9.91%
11.90%
11.38%
9.75%
Net interest margin
(2)
3.22%
3.45%
3.47%
3.37%
3.22%
Non-interest income to average assets
(2)
0.40%
(0.02)%
0.35%
0.33%
0.41%
Efficiency ratio
(3)
56.32%
59.81%
54.58%
55.34%
58.88%
Loans by type (at period end):
(4)
Residential real estate
$
184,427
$
185,636
$
186,551
$
203,662
$
204,317
Commercial real estate
$
987,757
$
970,410
$
928,531
$
843,445
$
782,072
Commercial and industrial
$
160,947
$
126,984
$
121,145
$
131,271
$
134,832
Foreign banks
$
97,405
$
93,769
$
94,450
$
84,770
$
63,985
Consumer and other
$
149,410
$
130,429
$
100,845
$
109,250
$
73,765
Asset quality data:
Allowance for credit losses to total loans
1.20%
1.16%
1.16%
1.15%
1.20%
Allowance for credit losses to non-performing loans
3,886%
- %
- %
- %
- %
Total non-performing loans
(5)
$
486
$
-
$
-
$
-
$
-
Non-performing loans to total loans
0.03%
- %
- %
- %
- %
Non-performing assets to total assets
0.02%
- %
- %
- %
- %
Net charge-offs (recoveries of) to average loans
(2)
(0.01)%
(0.00)%
0.03%
(0.00)%
(0.01)%
Net charge-offs (recovery of) credit losses
$
(49)
$
(2)
$
91
$
(7)
$
(17)
Interest rates and yields:
(2)
Loans
5.17%
4.86%
4.53%
4.35%
4.35%
Investment securities
2.20%
2.13%
1.94%
2.04%
1.85%
Total interest-earning assets
4.51%
4.21%
3.82%
3.60%
3.43%
Deposits
1.29%
0.77%
0.34%
0.21%
0.20%
FHLB advances and other borrowings
3.27%
2.27%
1.63%
1.53%
1.54%
Total interest-bearing liabilities
2.08%
1.25%
0.59%
0.38%
0.37%
Other information:
Full-time equivalent employees
196
191
191
192
190
(1) Loan amounts include deferred fees/costs.
(2) Annualized.
(3) Efficiency ratio is defined as total non-interest expense divided by sum of net interest income and total non-interest income.
(4) Loan amounts exclude deferred fees/costs.
(5) The amounts for total non-performing loans and total non-performing assets are the same at the dates presented since there were no impaired investments or other
real estate owned (OREO) recorded.
7
USCB FINANCIAL HOLDINGS, INC.
NET INTEREST MARGIN (UNAUDITED)
(Dollars in thousands)
Three Months Ended March 31,
2023
2022
Average
Balance
Interest
Yield/Rate
(1)
Average
Balance
Interest
Yield/Rate
(1)
Assets
Interest-earning assets:
Loans
(2)
$
1,547,393
$
19,711
5.17%
$
1,211,432
$
12,982
4.35%
Investment securities
(3)
421,717
2,286
2.20%
510,257
2,329
1.85%
Other interest-earnings assets
43,084
382
3.60%
90,137
31
0.14%
Total interest-earning assets
2,012,194
22,379
4.51%
1,811,826
15,342
3.43%
Non-interest-earning assets
108,024
101,658
Total assets
$
2,120,218
$
1,913,484
Liabilities and stockholders' equity
Interest-bearing liabilities:
Interest-bearing checking
$
58,087
43
0.30%
$
64,436
16
0.10%
Saving and money market deposits
897,061
4,785
2.16%
736,134
551
0.30%
Time deposits
224,730
1,057
1.91%
223,274
259
0.47%
Total interest-bearing deposits
1,179,878
5,885
2.02%
1,023,844
826
0.33%
FHLB advances and other borrowings
61,600
497
3.27%
36,011
137
1.54%
Total interest-bearing liabilities
1,241,478
6,382
2.08%
1,059,855
963
0.37%
Non-interest-bearing demand deposits
664,369
626,400
Other non-interest-bearing liabilities
31,000
25,369
Total liabilities
1,936,847
1,711,624
Stockholders' equity
183,371
201,860
Total liabilities and stockholders' equity
$
2,120,218
$
1,913,484
Net interest income
$
15,997
$
14,379
Net interest spread
(4)
2.43%
3.07%
Net interest margin
(5)
3.22%
3.22%
(1) Annualized.
(2) Average loan balances include non-accrual loans. Interest income on loans includes accretion of deferred loan fees, net of deferred loan costs.
(3) At fair value except for securities held to maturity. This amount includes FHLB stock.
(4) Net interest spread is the average yield on total interest-earning assets minus the average rate on total interest-bearing liabilities.
(5) Net interest margin is the ratio of net interest income to total interest-earning assets.
8
USCB FINANCIAL HOLDINGS, INC.
NON-GAAP FINANCIAL MEASURES (UNAUDITED)
(Dollars in thousands)
As of or For the Three Months Ended
3/31/2023
12/31/2022
9/30/2022
6/30/2022
3/31/2022
Pre-tax pre-provision ("PTPP") income:
Net income
$
5,809
$
4,434
$
5,558
$
5,295
$
4,854
Plus: Provision for income taxes
1,881
1,415
1,963
1,708
1,858
Plus: Provision for credit losses
201
880
910
705
-
PTPP income
$
7,891
$
6,729
$
8,431
$
7,708
$
6,712
PTPP return on average assets:
PTPP income
$
7,891
$
6,729
$
8,431
$
7,708
$
6,712
Average assets
$
2,120,218
$
2,051,867
$
2,026,791
$
1,968,381
$
1,913,484
PTPP return on average assets
(1)
1.51%
1.30%
1.65%
1.57%
1.42%
Operating net income:
Net income
$
5,809
$
4,434
$
5,558
$
5,295
$
4,854
Less: Net gains (losses) on sale of securities
(21)
(1,989)
(558)
(3)
21
Less: Tax effect on sale of securities
5
504
141
1
(5)
Operating net income
$
5,825
$
5,919
$
5,975
$
5,297
$
4,838
Operating PTPP income:
PTPP income
$
7,891
$
6,729
$
8,431
$
7,708
$
6,712
Less: Net gains (losses) on sale of securities
(21)
(1,989)
(558)
(3)
21
Operating PTPP income
$
7,912
$
8,718
$
8,989
$
7,711
$
6,691
Operating PTPP return on average assets:
Operating PTPP income
$
7,912
$
8,718
$
8,989
$
7,711
$
6,691
Average assets
$
2,120,218
$
2,051,867
$
2,026,791
$
1,968,381
$
1,913,484
Operating PTPP return on average assets
(1)
1.51%
1.69%
1.76%
1.57%
1.42%
Operating return on average assets:
Operating net income
$
5,825
$
5,919
$
5,975
$
5,297
$
4,838
Average assets
$
2,120,218
$
2,051,867
$
2,026,791
$
1,968,381
$
1,913,484
Operating return on average assets
(1)
1.11%
1.14%
1.17%
1.08%
1.03%
Operating return on average equity:
Operating net income
$
5,825
$
5,919
$
5,975
$
5,297
$
4,838
Average equity
$
183,371
$
177,556
$
185,288
$
186,597
$
201,860
Operating return on average equity
12.88%
13.23%
12.79%
11.39%
9.72%
Operating Revenue:
$
15,997
$
16,866
$
16,774
$
15,642
$
14,379
2,070
(123)
1,789
1,617
1,945
(21)
(1,989)
(558)
(3)
21
$
18,088
$
18,732
$
19,121
$
17,262
$
16,303
Operating Efficiency Ratio:
$
10,176
$
10,014
$
10,132
$
9,551
$
9,612
$
18,088
$
18,732
$
19,121
$
17,262
$
16,303
56.26%
53.46%
52.99%
55.33%
58.96%
(1) Annualized.
9
USCB FINANCIAL HOLDINGS, INC.
NON-GAAP FINANCIAL MEASURES (UNAUDITED)
(Dollars in thousands, except per share data)
As of or For the Three Months Ended
3/31/2023
12/31/2022
9/30/2022
6/30/2022
3/31/2022
Tangible book value per common share (at period-end):
(1)
Total stockholders' equity
$
183,858
$
182,428
$
177,417
$
180,068
$
192,039
Less: Intangible assets
-
-
-
-
-
Tangible stockholders' equity
$
183,858
$
182,428
$
177,417
$
180,068
$
192,039
Total shares issued and outstanding (at period-end):
Total common shares issued and outstanding
19,622,380
20,000,753
20,000,753
20,000,753
20,000,753
Tangible book value per common share
(2)
$
9.37
$
9.12
$
8.87
$
9.00
$
9.60
Operating diluted net income per common share:
(1)
Operating net income
$
5,825
$
5,919
$
5,975
$
5,297
$
4,838
Total weighted average diluted shares of common stock
19,940,606
20,172,438
20,148,208
20,171,261
20,109,783
Operating diluted net income per common share:
$
0.29
$
0.29
0.30
0.26
0.24
Tangible Common Equity/Tangible Assets
$
183,858
$
182,428
$
177,417
$
180,068
$
192,039
$
2,163,821
2,085,834
2,037,453
2,016,086
1,967,252
Tangible Common Equity/Tangible Assets
8.50%
8.75%
8.71%
8.93%
9.76%
(1) The Company believes these non-GAAP measurements are key indicators of the ongoing earnings power of the Company.
(2) Excludes the dilutive effect, if any, of shares of common stock issuable upon exercise of outstanding stock options.
Exhibit 99.2
Exhibit 99.2 EARNINGS PRESENTATION FIRST QUARTER 2023 NASDAQ: USCB USBC FINANCIAL HOLDINGS
FORWARD-LOOKING STATEMENTS This presentation may contain statements that are not historical in nature and are intended to be, and are hereby identified as, forward-looking statements for purposes of the safe harbor provided by Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements are those that are not historical facts. The words “may,” “will,” “anticipate,” “should,” “would,” “believe,” “contemplate,” “expect,” “aim,” “plan,” “estimate,” “continue,” and “intend,” as well as other similar words and expressions of the future, are intended to identify forward-looking statements. These forward-looking statements include, but are not limited to, statements related to our projected growth, anticipated future financial performance, and management’s long-term performance goals, as well as statements relating to the anticipated effects on results of operations and financial condition from expected developments or events, or business and growth strategies, including anticipated internal growth and balance sheet restructuring. These forward-looking statements involve significant risks and uncertainties that could cause our actual results to differ materially from those anticipated in such statements. Potential risks and uncertainties include, but are not limited to: • the strength of the United States economy in general and the strength of the local economies in which we conduct operations; • our ability to successfully manage interest rate risk, credit risk, liquidity risk, and other risks inherent to our industry; • the accuracy of our financial statement estimates and assumptions, including the estimates used for our credit loss reserve and deferred tax asset valuation allowance; • the efficiency and effectiveness of our internal control environment; • our ability to comply with the extensive laws and regulations to which we are subject, including the laws for each jurisdiction where
we operate; • adverse changes or conditions in capital and financial markets, including actual or potential stresses in the banking industry; deposit attrition and the level of our uninsured deposits; legislative or regulatory changes and changes in accounting principles, policies, practices or guidelines, including the on-going effects of the implementation of the Current Expected Credit Losses (“CECL”) standard; • the effects of our lack of a diversified loan portfolio and concentration in the South Florida market, including the risks of geographic, depositor, and industry concentrations, including our concentration in loans secured by real estate; effects of climate change; • the concentration of ownership of our common stock; • fluctuations in the price of our common stock; • our ability to fund or access the capital markets at attractive rates and terms and manage our growth, both organic growth as well as growth through other means, such as future acquisitions; • inflation, interest rate, unemployment rate, market, and monetary fluctuations; impacts of international hostilities and geopolitical events; • increased competition and its effect on the pricing of our products and services as well as our margin; • the effectiveness of our risk management strategies, including operational risks, including, but not limited to, client, employee, or third-party fraud and security breaches; and • other risks described in this presentation and other filings we make with the Securities and Exchange Commission (“SEC”). All forward -looking statements are necessarily only estimates of future results, and there can be no assurance that actual results will not differ materially from expectations. Therefore, you are cautioned not to place undue reliance on any forward-looking statements. Further, forward -looking statements included in this presentation are made only as of the date hereof, and we undertake no obligation to update or revise any
forward-looking statements to reflect events or circumstances after the date on which the statements are made or to reflect the occur rence of unanticipated events, unless required to do so under the federal securities laws. You should also review the risk factors described in the reports USCB Financial Holdings, Inc. filed or will file with the SEC and, for periods prior to the completion of the bank holding company reorganization in December 2021, U.S. Century Bank filed with the FDIC. Non-GAAP Financial Measures This presentation includes financial information determined by methods other than in accordance with generally accepted accounting principles (“GAAP”). This financial information includes certain operating performance measures. Management has included these non-GAAP measures because it believes these measures may provide useful supplemental information for evaluating the Company’s underlying performance trends. Further, management uses these measures in managing and evaluating the Company’s business and intends to refer to them in discussions about our operations and performance. Operating performance measures should be viewed in addition to, and not as an alternative to or substitute for, measures determined in accordance with GAAP, and are not necessarily comparable to non-GAAP measures that may be presented by other companies. Reconciliations of these non -GAAP measures to the most directly comparable GAAP measures can be found in the ‘Non-GAAP Reconciliation Tables’ included in the presentation. All numbers included in this presentation are unaudited unless otherwise noted. 2
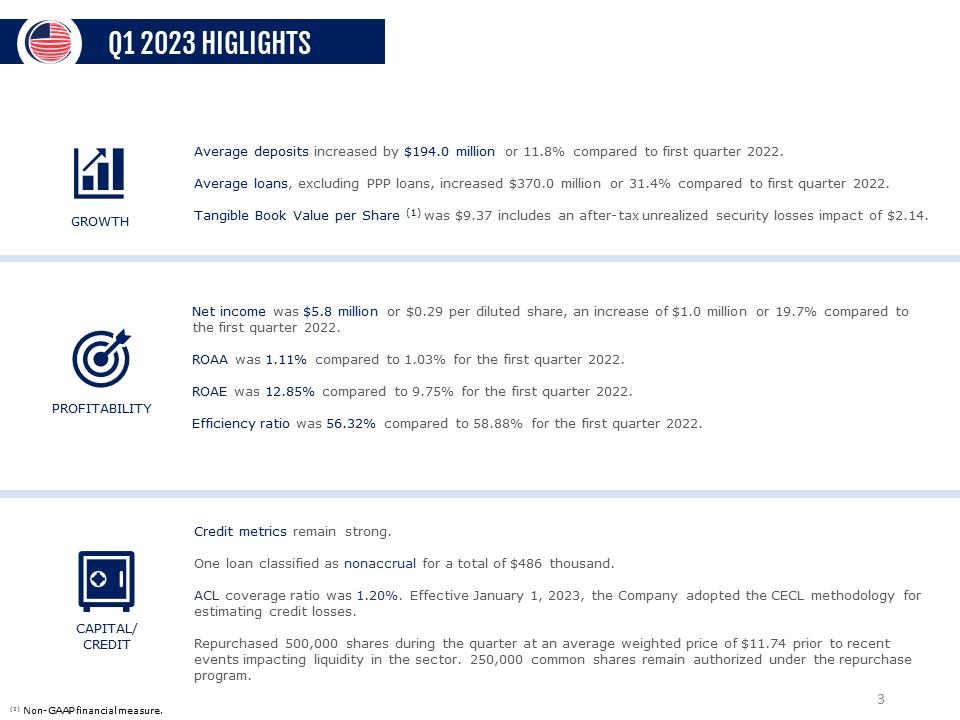
Q1 2023 HIGLIGHTS GROWTH Average deposits increased by $194.0 million or 11.8% compared to first quarter 2022. Average loans, excluding PPP loans, increased $370.0 million or 31.4% compared to first quarter 2022. Tangible Book Value per Share (1) was $9.37 includes an after-tax unrealized security losses impact of $2.14. PROFITABILITY Net income was $5.8 million or $0.29 per diluted share, an increase of $1.0 million or 19.7% compared to the first quarter 2022. ROAA was 1.11% compared to 1.03% for the first quarter 2022. ROAE was 12.85% compared to 9.75% for the first quarter 2022. Efficiency ratio was 56.32% compared to 58.88% for the first quarter 2022. CAPITAL/ CREDIT Credit metrics remain strong. One loan classified as nonaccrual for a total of $486 thousand. ACL coverage ratio was 1.20%. Effective January 1, 2023, the Company adopted the CECL methodology for estimating credit losses. Repurchased 500,000 shares during the quarter at an average weighted price of $11.74 prior to recent events impacting liquidity in the sector. 250,000 common shares remain authorized under the repurchase program. (1) Non-GAAP financial measure. 3
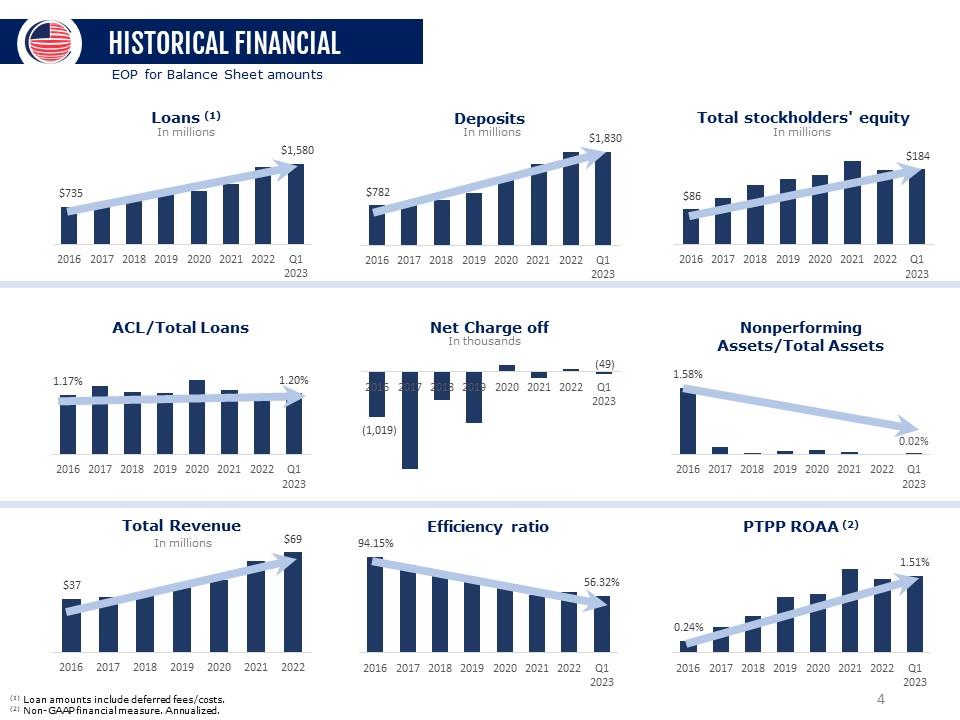
HISTORICAL FINANCIAL EOP for Balance Sheet amounts Loans (1) In millions $735 $1,580 Deposits In millions $782 $1,830 Total stockholders’ equity In millions $86 $184 ACL/Total Loans 1.17% 1.20% Net Charge off In thousands (1,019) (49) Nonperforming Assets/Total Assets 1.58% 0.02% Total Revenue In millions $37 $69 Efficiency ratio 94.15% 56.32% PTPP ROAA (2) 0.24% 1.51% (1) Loan amounts include deferred fees/costs. (2) Non-GAAP financial measure. Annualized. 4
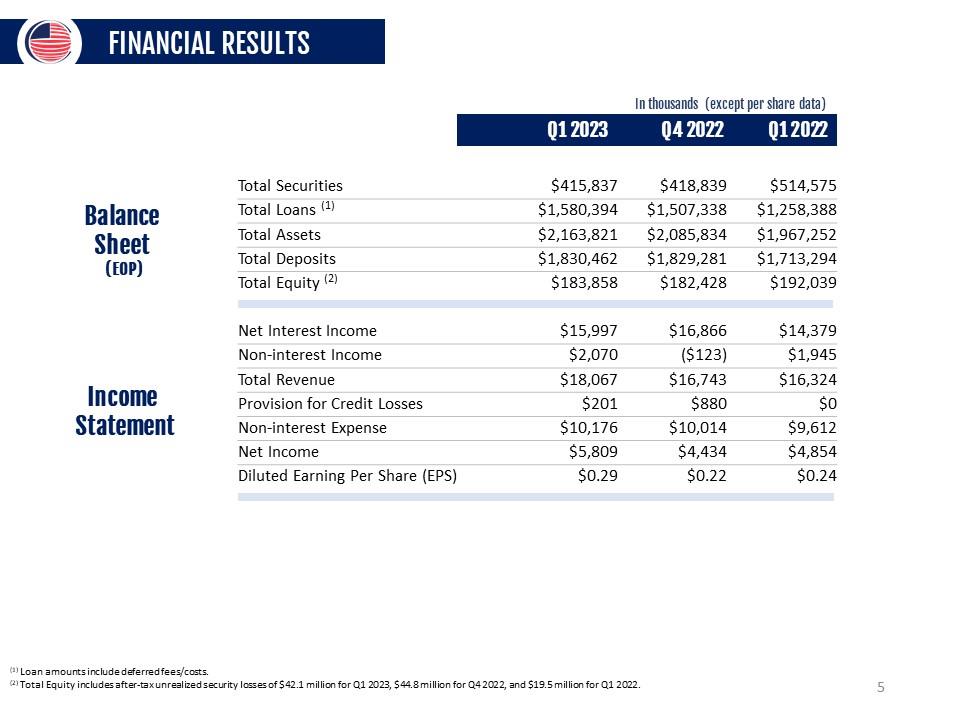
FINANCIAL RESULTS Balance Sheet (EOP) In thousands (except per share data) Q1 2023 Q4 2022 Q1 2022 Total Securities $415,837 $418,839 $514,575 Total Loans (1) $1,580,394 $1,507,338 $1,258,388 Total Assets $2,163,821 $2,085,834 $1,967,252 Total Deposits $1,830,462 $1,829,281 $1,713,294 Total Equity (2) $183,858 $182,428 $192,039 Income Statement Net Interest Income $15,997 $16,866 $14,379 Non-interest Income $2,070 ($123) $1,945 Total Revenue $18,067 $16,743 $16,324 Provision for Credit Losses $201 $880 $0 Non-interest Expense $10,176 $10,014 $9,612 Net Income $5,809 $4,434 $4,854 Diluted Earning Per Share (EPS) $0.29 $0.22 $0.24 (1) Loan amounts include deferred fees/costs. (2) Total Equity includes after-tax unrealized security losses of $42.1 million for Q1 2023, $44.8 million for Q4 2022, and $19.5 million for Q1 2022. 5
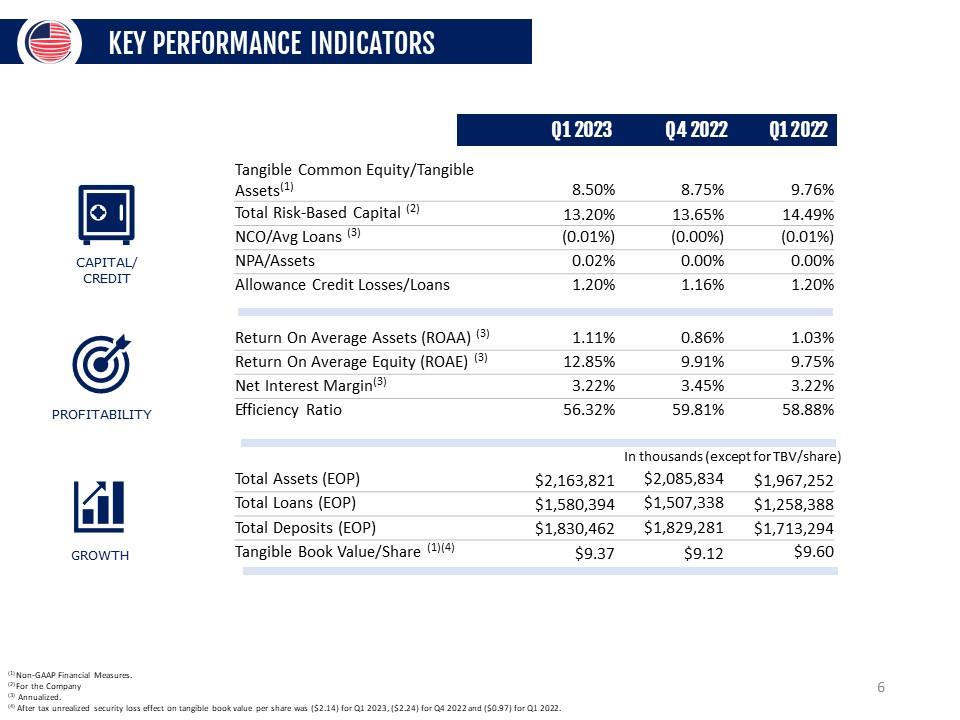
KEY PERFORMANCE INDICATORS CAPITAL/ CREDIT PROFITABILITY GROWTH Q1 2023 Q4 2022 Q1 2022 Tangible Common Equity/Tangible Assets(1) 8.50% 8.75% 9.76% Total Risk-Based Capital (2) 13.20% 13.65% 14.49% NCO/Avg Loans (3) (0.01%) (0.00%) (0.01%) NPA/Assets 0.02% 0.00% 0.00% Allowance Credit Losses/Loans 1.20% 1.16% 1.20% Return On Average Assets (ROAA) (3) 1.11% 0.86% 1.03% Return On Average Equity (ROAE) (3) 12.85% 9.91% 9.75% Net Interest Margin(3) 3.22% 3.45% 3.22% Efficiency Ratio 56.32% 59.81% 58.88% Total Assets (EOP) $2,163,821 $2,085,834 $1,967,252 Total Loans (EOP) $1,580,394 $1,507,338 $1,258,388 Total Deposits (EOP) $1,830,462 $1,829,281 $1,713,294 Tangible Book Value/Share (1)(4) $9.37 $9.12 $9.60 (1) Non-GAAP Financial Measures. (2) For the Company (3) Annualized. (4) After tax unrealized security loss effect on tangible book value per share was ($2.14) for Q1 2023, ($2.24) for Q4 2022 and ($0.97) for Q1 2022. 6
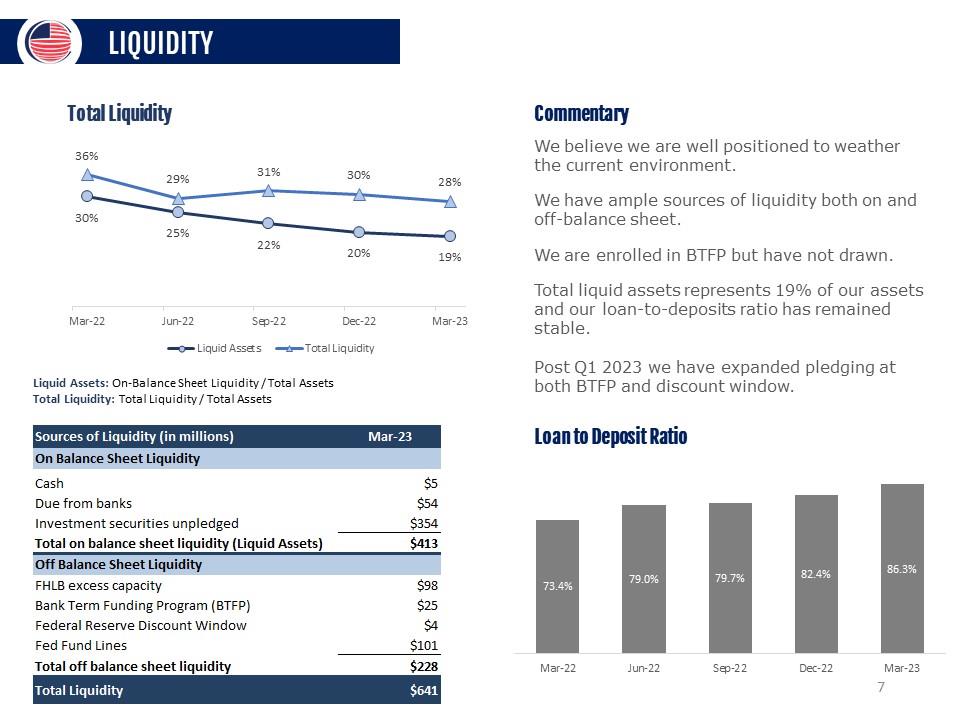
LIQUIDITY Total Liquidity 36% 29% 31% 30% 28% 30% 25% 22% 20% 19% Liquid Assets Total Liquidity Commentary We believe we are well positioned to weather the current environment. We have ample sources of liquidity both on and off-balance sheet. We are enrolled in BTFP but have not drawn. Total liquid assets represents 19% of our assets and our loan-to-deposits ratio has remained stable. Post Q1 2023 we have expanded pledging at both BTFP and discount window. Liquid Assets: On-Balance Sheet Liquidity / Total Assets Total Liquidity: Total Liquidity / Total Assets Sources of Liquidity (in millions) Mar-23 On Balance Sheet Liquidity Cash Due from banks Investment securities unpledged Total on balance sheet liquidity (Liquid Assets) Off Balance Sheet Liquidity FHLB excess capacity Bank Term Funding Program (BTFP) Federal Reserve Discount Window Fed Fund Lines Total off balance sheet liquidity $641 Total Liquidity Loan to Deposit Ratio 73.4% 79.0% 79.7% 82.4% 86.3% 7
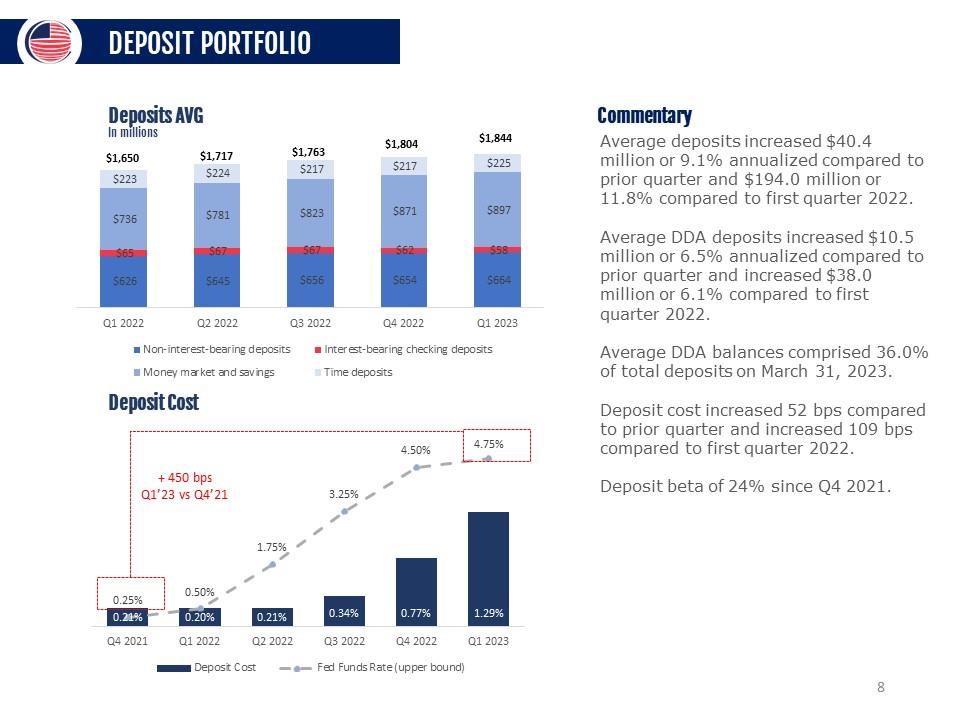
DEPOSIT PORTFOLIO Deposits AVG In millions $1,650 $1,717 $1,763 $1,804 $1,844 $223 $224 $217 $217 $225 $736 $781 $823 $871 $897 $65 $67 $67 $62 $58 $625 $645 $656 $654 $664 Q1 2022 Q2 2022 Q3 2022 Q4 2022 Q1 2023 Non-interest-bearing deposits Interest-bearing checking deposits Money market and savings Time deposits Deposit Cost 0.25% 0.50% 1.75% 3.25% 4.50% 4.75% 0.21% 0.20% 0.21% 0.34% 0.77% 1.29% Q4 2021 Q1 2022 Q2 2022 Q3 2022 Q4 2022 Q1 2023 Deposit Cost Fed Fund Rate (upper bound) Commentary Average deposits increased $40.4 million or 9.1% annualized compared to prior quarter and $194.0 million or 11.8% compared to first quarter 2022. Average DDA deposits increased $10.5 million or 6.5% annualized compared to prior quarter and increased $38.0 million or 6.1% compared to first quarter 2022. Average DDA balances comprised 36.0% of total deposits on March 31, 2023. Deposit cost increased 52 bps compared to prior quarter and increased 109 bps compared to first quarter 2022. Deposit beta of 24% since Q4 2021. 8
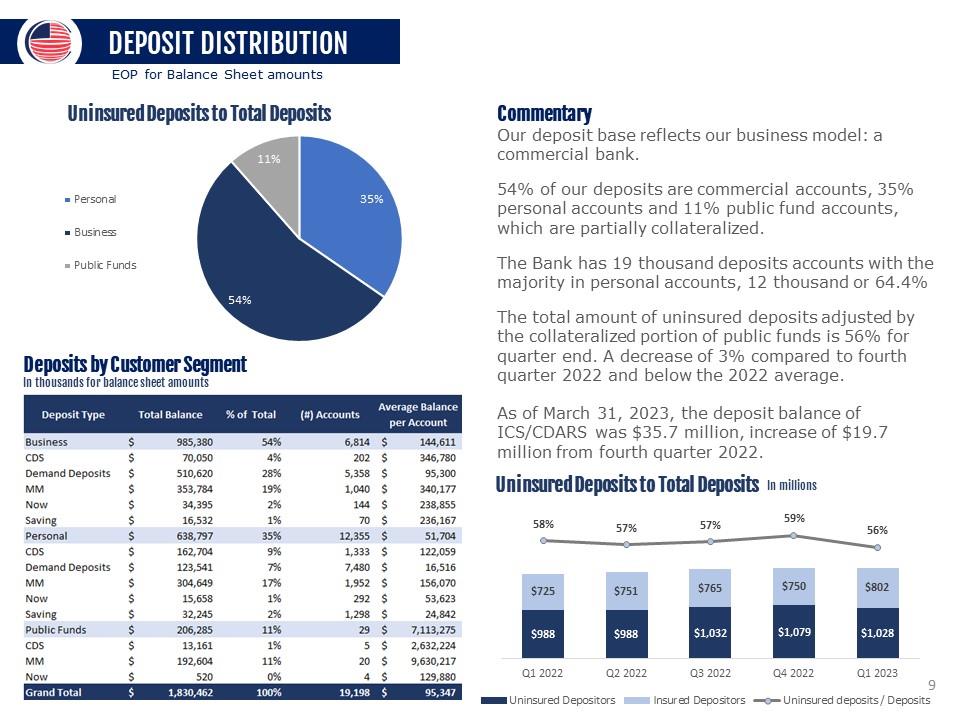
DEPOSIT DISTRIBUTION EOP for Balance Sheet amounts Uninsured Deposits to Total Deposits Personal Business Public Funds 11% 35% 54% Deposits by Customer Segment In thousands for balance sheet amounts Deposit Type Total Balance % of Total (#) Accounts Average Balance per Account Business $ 985,380 54% 6,814 $ 144,611 CDS $ 70,050 4% 202 $ 346,780 Demand Deposits $ 510,620 28% 5,358 $ 95,300 MM $ 353,784 19% 1,040 $ 340,177 Now $ 34,395 2% 144 $ 238,855 Saving $ 16,532 1% 70 $ 236,167 Personal $ 638,797 35% 12,355 $ 51,704 CDS $ 162,704 9% 1,333 $ 122,059 Demand Deposits $ 123,5 41 7% 7,480 $ 16,516 MM $ 304,649 17% 1,952 $ 156,070 Now $ 15,658 1% 292 $ 53,623 Saving $ 32,245 2% 1,298 $ 24,842 Public Funds $ 206,285 11% 29 $ 7,113,275 CDS $ 13,161 1% 5 $ 2,632,224 MM $ 192,604 11% 20 $ 9,630,217 Now $ 520 0% 4 $ 129,880 Grand Total $ 1,830,462 100% 19,198 $ 95,347 Commentary Our deposit base reflects our business model: a commercial bank. 54% of our deposits are commercial accounts, 35% personal accounts and 11% public fund accounts, which are partially collateralized. The Bank has 19 thousand deposits accounts with the majority in personal accounts, 12 thousand or 64.4% The total amount of uninsured deposits adjusted by the collateralized portion of public funds is 56% for quarter end. A decrease of 3% compared to fourth quarter 2022 and below the 2022 average. As of March 31, 2023, the deposit balance of ICS/CDARS was $35.7 million, increase of $19.7 million from fourth quarter 2022. Uninsured Deposits to Total Deposits In millions 58% 57% 57% $725 $751 $765 $988 $988 $1,032 Q1 2022 Q2 2022 Q3 2022 Uninsured Depositors Insured Depositors 59% 56% $1,079 $1,028 Q4 2022 Q1 2023 Uninsured deposits / Deposits 9
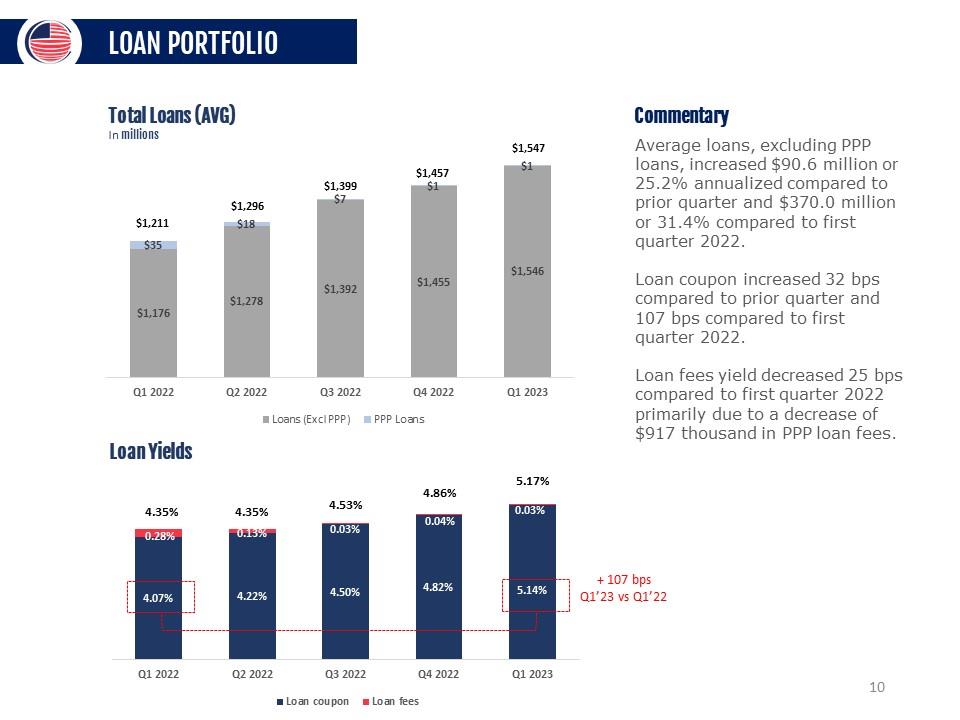
LOAN PORTFOLIO Total Loans (AVG) In millions $1,211 $1,296 $1,399 $1,457 $1,547 $35 $18 $7 $1 $1 $1,176 $1,278 $1,392 $1,455 $1,546 Q1 2022 Q2 2022 Q3 2022 Q4 2022 Q1 2023 Loans (Exd PPP) PPP Loans Loan Yields 4.35% 4.35% 4.53% 4.86% 5.17% 0.28% 0.13% 0.03% 0.04% 0.03% 4.07% 4.22% 4.50% 4.82% 4.14% Q1 2022 Q2 2022 Q3 2022 Q4 2022 Q1 2023 Loan coupon Loan fees Commentary Average loans, excluding PPP loans, increased $90.6 million or 25.2% annualized compared to prior quarter and $370.0 million or 31.4% compared to first quarter 2022. Loan coupon increased 32 bps compared to prior quarter and 107 bps compared to first quarter 2022. Loan fees yield decreased 25 bps compared to first quarter 2022 primarily due to a decrease of $917 thousand in PPP loan fees. 10
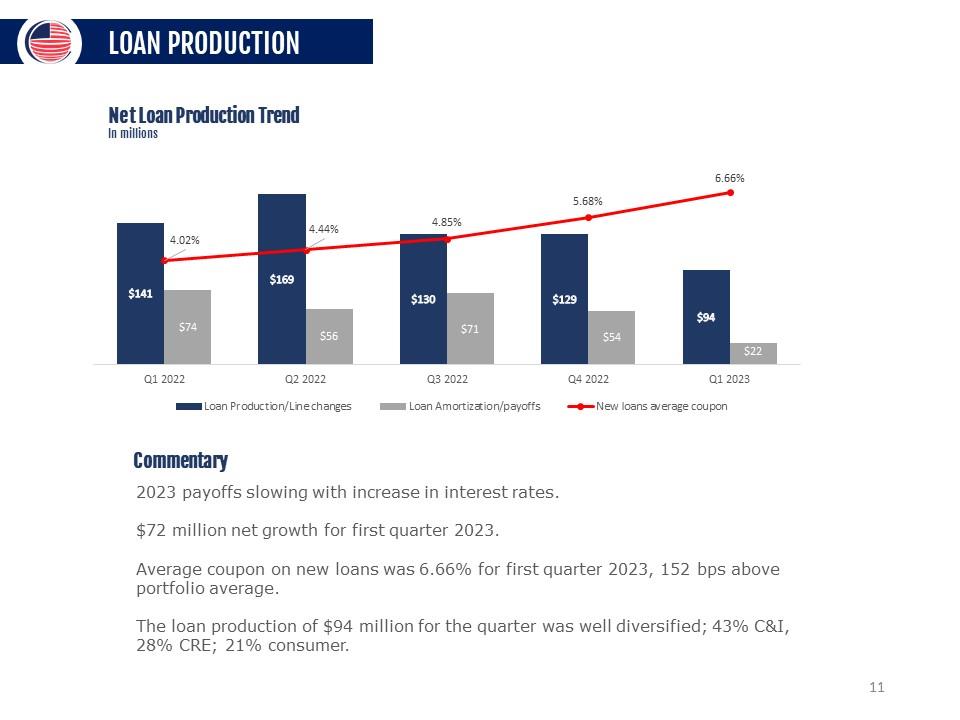
LOAN PRODUCTION Net Loan Production Trend In millions 4.02% 4.44% 4.85% 5.68% 6.66 $141 $74 $169 $56 $130 $71 $129 $54 $94 $22 Q1 2022 Q2 2022 Q3 2022 Q4 2022 Q1 2023 Loan Production/Lien changes Loan Amortization/payoffs New loans average coupon Commentary 2023 payoffs slowing with increase in interest rates. $72 million net growth for first quarter 2023. Average coupon on new loans was 6.66% for first quarter 2023, 152 bps above portfolio average. The loan production of $94 million for the quarter was well diversified; 43% C&I, 28% CRE; 21% consumer. 11
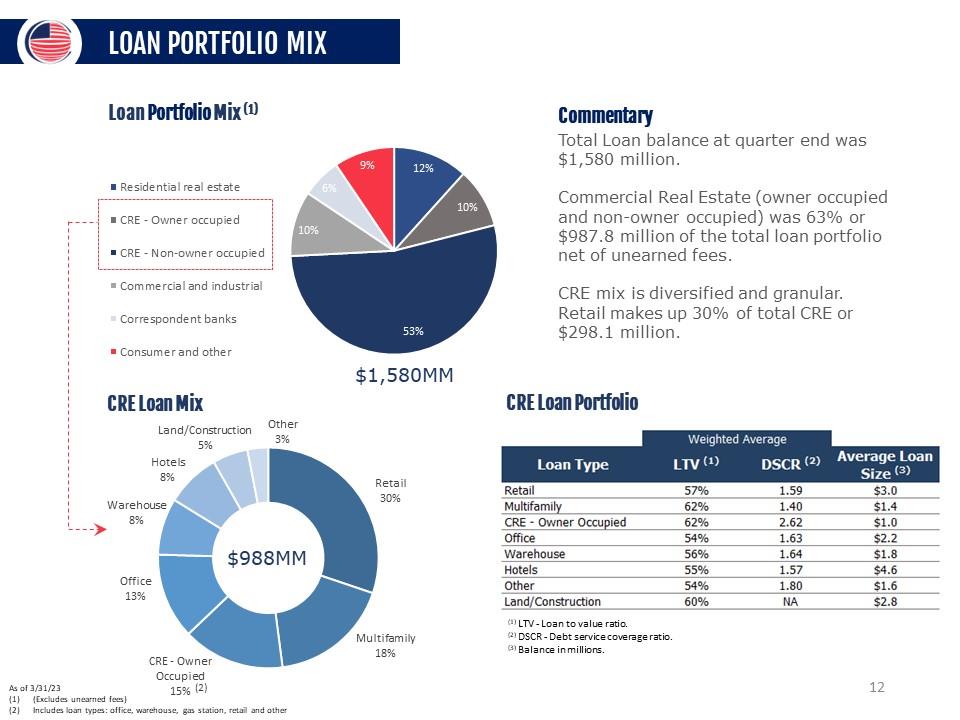
LOAN PORTFOLIO MIX Loan Portfolio Mix (1) Residential real estate -1- CRE - Owner occupied ! I ! CRE - Non-owner occupied Commercial and Industrial Correspondent banks Consumer and other 10% 6% 9% 12% 10% 53% $1,580MM Commentary Total Loan balance at quarter end was $1,580 million. Commercial Real Estate (owner occupied and non-owner occupied) was 63% or $987.8 million of the total loan portfolio net of unearned fees. CRE mix is diversified and granular. Retail makes up 30% of total CRE or $298.1 million. CRE Loan Mix Land/Construction 5% Other 3% Retail 30% Multifamily 18% CRE - Owner Occupied 15% Office 13% Warehouse 8% Hotels 8% CRE Loan Portfolio ) ► Weighted Average Loan Type LTV DSCR C2) Average Loan Size ™ Retail 57% 1.59 $3.0 Multifamily 62% 1.40 $1.4 CRE - Owner Occupied 62% 2.62 $1.0 Office 54% 1.63 $2.2 Warehouse 56% 1.64 $1.8 Hotels 55% 1.57 $4.6 Other 54% 1.80 $1.6 Land/Construction 60% NA $2.8 . : : O LTV - Loan to value ratio. '2! DSCR - Debt service coverage ratio. Balance in millions. (1) LTV - Loan to value ratio. (2) DSCR - Debt service coverage ratio. (3) Balance in millions. As of 3/31/23 (1) (Excludes unearned fees) (2) Includes loan types: office, warehouse, gas station, retail and other 12
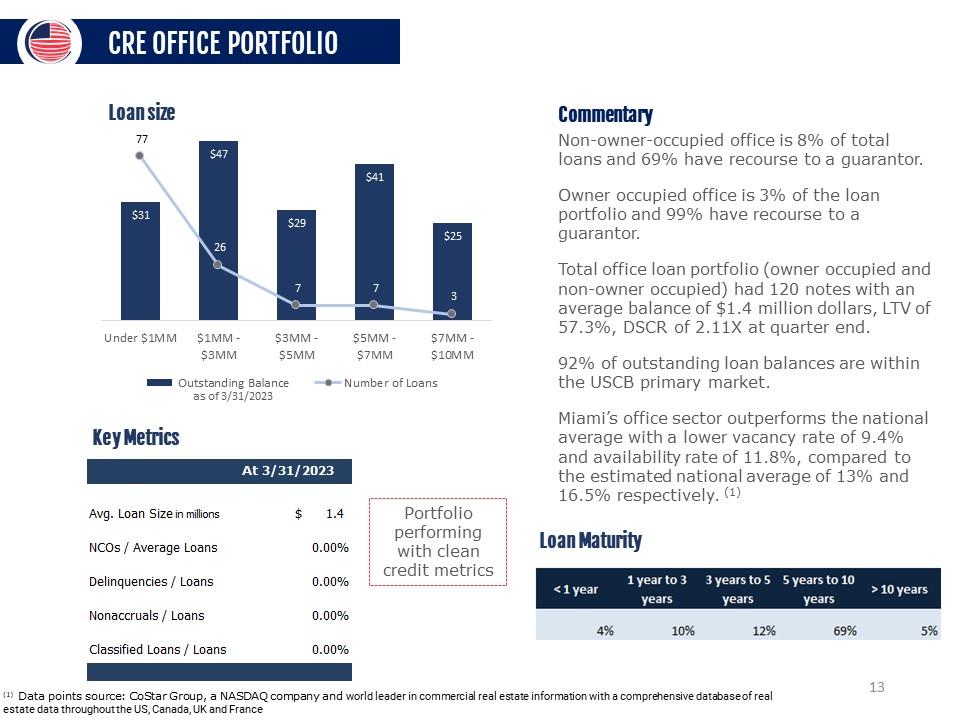
CRE OFFICE PORTFOLIO Loan size 77 $47 $31 Under SIMM SIMM - $3MM - $5MM _ $7MM - $3MM $5MM $7MM $10MM Outstanding Balance as of 3/31/2023 Number of Loans Key Metrics At 3/31/2023 Avg. Loan Size in millions $ 1.4 NCOs / Average Loans 0.00% Delinquencies / Loans 0.00% Nonaccruals / Loans 0.00% Classified Loans / Loans 0.00% Portfolio performing with clean credit metrics Commentary Non-owner-occupied office is 8% of total loans and 69% have recourse to a guarantor. Owner occupied office is 3% of the loan portfolio and 99% have recourse to a guarantor. Total office loan portfolio (owner occupied and non-owner occupied) had 120 notes with an average balance of $1.4 million dollars, LTV of 57.3%, DSCR of 2.11X at quarter end. 92% of outstanding loan balances are within the USCB primary market. Miami’s office sector outperforms the national average with a lower vacancy rate of 9.4% and availability rate of 11.8%, compared to the estimated national average of 13% and 16.5% respectively. (1) Loan Maturity < 1 year 1 year to 3 3 years to 5 5 years to 10 >10 years years years years 4% 10% 12% 69% 5% (1) Data points source: CoStar Group, a NASDAQ company and world leader in commercial real estate information with a comprehensive database of real estate data throughout the US, Canada, UK and France 13
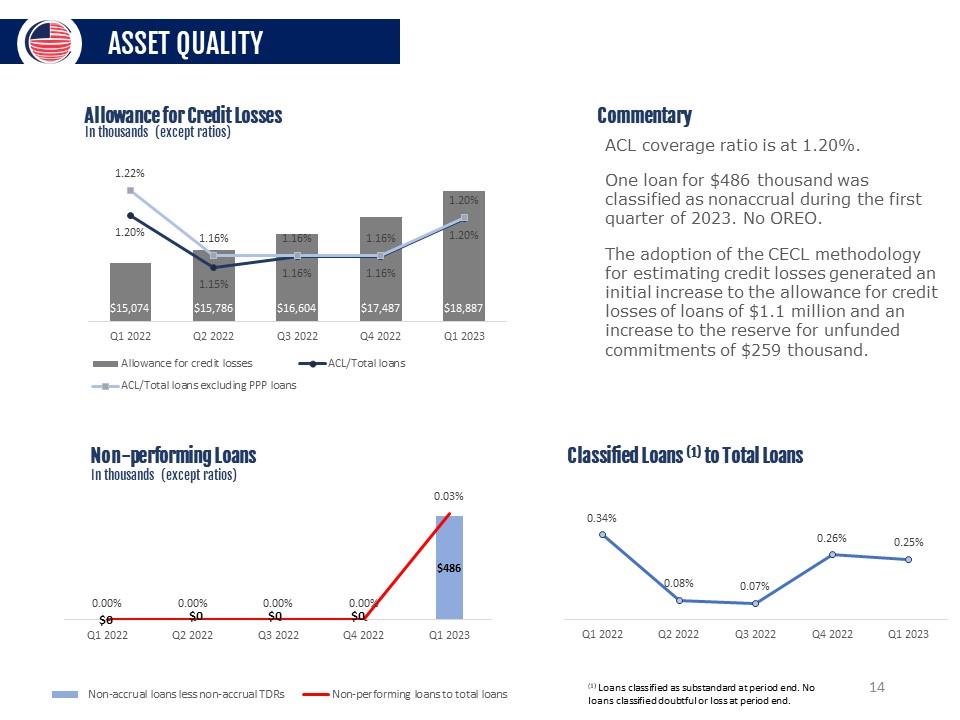
ASSET QUALITY Allowance for Credit Losses In thousands (except ratios) 1.22% 1.16% 1.16% 1.16% 1.20% 1.20% 1.15% 1.16% 1.16% 1.20% $15,074 $15,786 $16,604 $17,487 $18,887 Q1 2022 Q2 2022 Q3 2022 Q4 2022 Q1 2023 Allowance for credit losses ACL/Total loans ACL/Total loans excluding PPP loans Commentary ACL coverage ratio is at 1.20%. One loan for $486 thousand was classified as nonaccrual during the first quarter of 2023. No OREO. The adoption of the CECL methodology for estimating credit losses generated an initial increase to the allowance for credit losses of loans of $1.1 million and an increase to the reserve for unfunded commitments of $259 thousand. Non-performing Loans In th 0.00% 0.00% 0.00% 0.00% 0.03% $0 $0 $0 $0 $486 Q1 2022 Q2 2022 Q3 2022 Q4 2022 Q1 2023ousands (except ratios) Nin0accrual loans less non-accrual TDRs Non-performing loans to total loans Classified Loans M to Total Loans 0.34% 0.08% 0.07% 0.26% 0.25% Q1 2022 Q2 2022 Q3 2022 Q4 2022 Q1 2023 (1) Loans classified as substandard at period end. No loans classified doubtful or loss at period end. 14
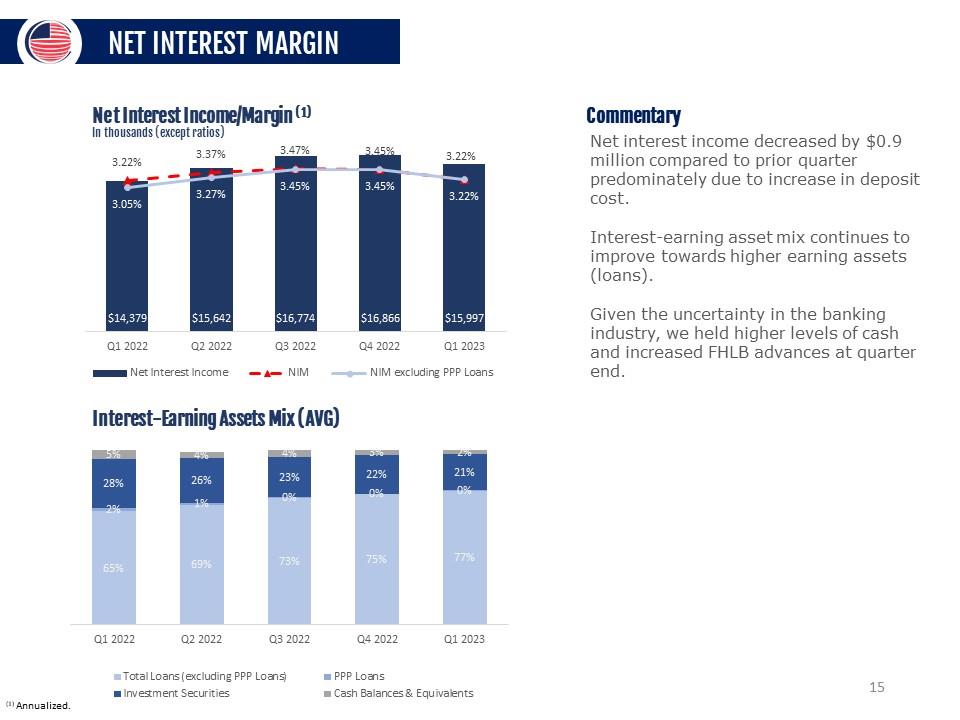
NET INTEREST MARGIN Net Interest Income/Margin (1) In thousands (except ratios) Ql 2022 Q2 2022 Q3 2022 3.22% ^,1 3.45% 3.22% $16,866 $15,997 Q4 2022 Ql 2023 Net Interest Income A— NIM NIM excluding PPP Loans Interest-Earning Assets Mix (AVG) 5% 4% 4% 3% 2% 28% 26% 23% 22% 21% 2% 1% 0% 0% 0% 65% 69% 73% 75% 77% Q1 2022 Q2 2022 Q3 2022 Q4 2022 Q1 2023 Total Loans (excluding PPP Loans) Investment Securities ■PPP Loans Cash Balances & Equivalent s Commentary Net interest income decreased by $0.9 million compared to prior quarter predominately due to increase in deposit cost. Interest -earning asset mix continues to improve towards higher earning assets (loans). Given the uncertainty in the banking industry, we held higher levels of cash and increased FHLB advances at quarter end. (1) Annualized. 15
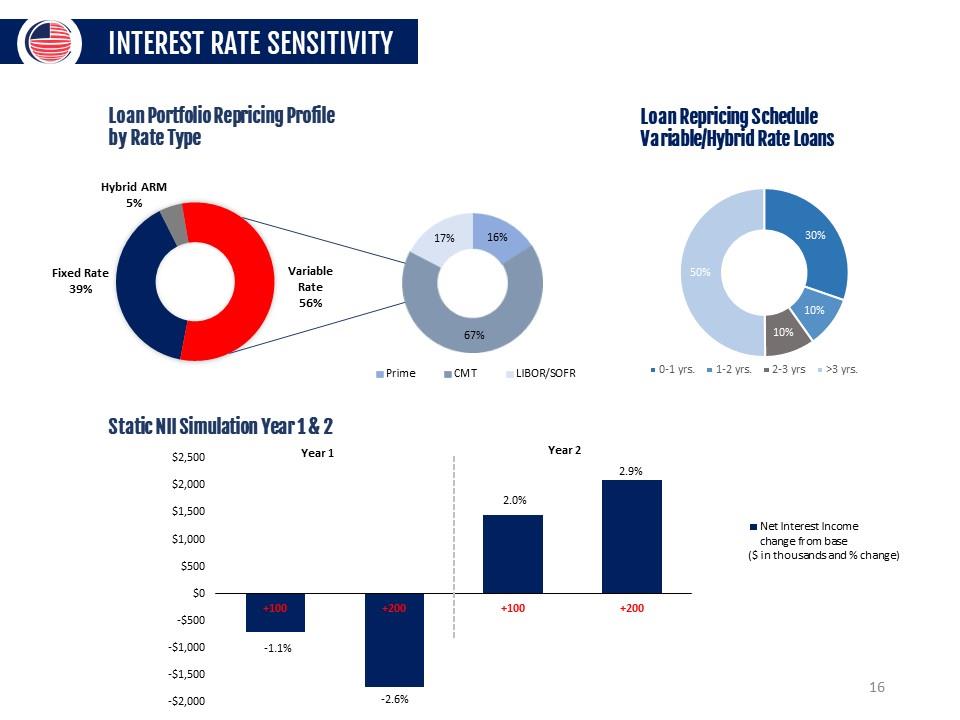
INTEREST RATE SENSITIVITY Loan Portfolio Repricing Profile by Rate Type Hybrid ARM 5% Fixed Rate 39% Variable Rate 56% 17% 16% 67% Prime CMT LIBOR/SOFRA Loan Repricing Schedule Variable/Hybrid Rate Loans 30% 10% 10% 50% yrs. 1-2 yrs. 2-3 yrs >3 yrs Static NII Simulation Year 1 & 2 100 200 100 200 -1.1% -2.6% 2.0% 2.9% Net Interest Income change from base ($ in thousands and % change) 16
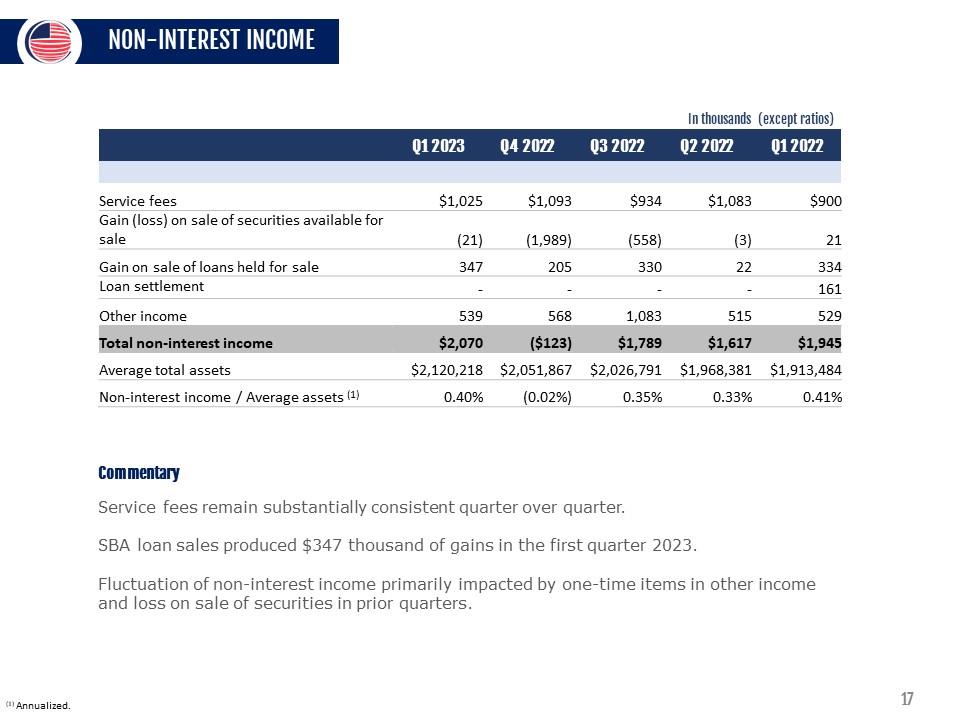
NON-INTEREST INCOME In thousands (except ratios) Q1 2023 Q4 2022 Q3 2022 Q2 2022 Q1 2022 Service fees $1,025 $1,093 $934 $1,083 $900 Gain (loss) on sale of securities available for sale (21) (1,989) (558) (3) 21 Gain on sale of loans held for sale 347 205 330 22 334 Loan settlement - - - - 161 Other income 539 568 1,083 515 529 Total non-interest income $2,070 ($123) $1,789 $1,617 $1,945 Average total assets $2,120,218 $2,051,867 $2,026,791 $1,968,381 $1,913,484 Non-interest income / Average assets (1) 0.40% (0.02%) 0.35% 0.33% 0.41% Commentary Service fees remain substantially consistent quarter over quarter. SBA loan sales produced $347 thousand of gains in the first quarter 2023. Fluctuation of non-interest income primarily impacted by one-time items in other income and loss on sale of securities in prior quarters. (1) Annualized. 17
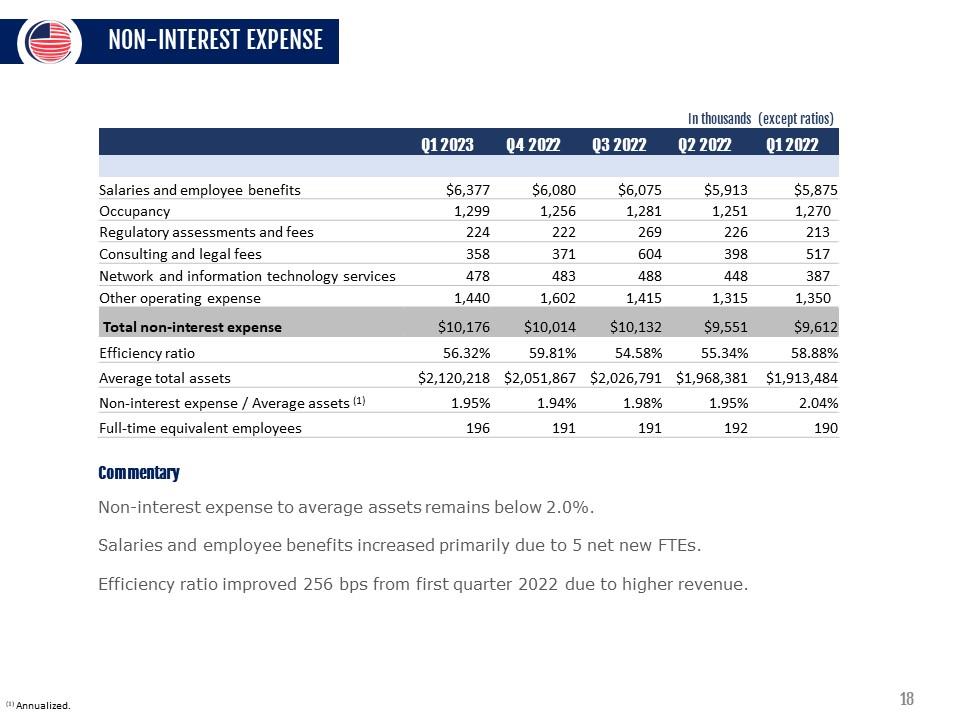
NON-INTEREST EXPENSE In thousands (except ratios) Q1 2023 Q4 2022 Q3 2022 Q2 2022 Q1 2022 Salaries and employee benefits $6,377 $6,080 $6,075 $5,913 $5,875 Occupancy 1,299 1,256 1,28 1 1,251 1,270 Regulatory assessments and fees 224 222 269 226 213 Consulting and legal fees 358 371 604 398 517 Network and information technology services 478 483 488 448 387 Other operating expense 1,440 1,602 1,415 1,315 1,350 Total non-interest expense $10,176 $10,014 $10,132 $9,551 $9,612 Efficiency ratio 56.32% 59.81% 54.58% 55.34% 58.88% Average total assets $2,120,218 $2,051,867 $2,026,791 $1,968,381 $1,913,484 Non-interest expense / Average assets (1) 1.95% 1.94% 1.98% 1.95% 2.04% Full-time equivalent employees 196 191 191 192 190 Commentary Non-interest expense to average assets remains below 2.0%. Salaries and employee benefits increased primarily due to 5 net new FTEs. Efficiency ratio improved 256 bps from first quarter 2022 due to higher revenue. (1) Annualized. 18
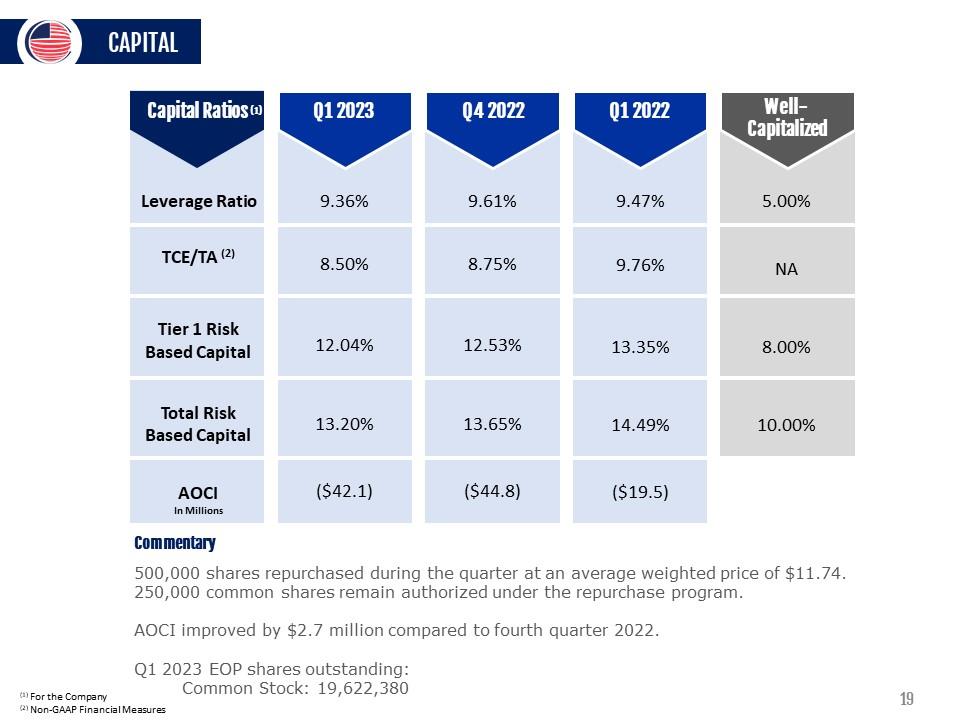
CAPITAL capital Ratios w 1 Q12023 1 Leverage Ratio 9.36% TCE/TA <2> 8.50% Tier 1 Risk Based Capital 12.04% Total Risk Based Capital 13.20% AOCI In Millions ($42.1) 042022 9.61% 8.75% 12.53% 13.65% ($44.8) WpII- IIUH Capitalized 9.47% 5.00% 9.76% NA 13.35% 8.00% 14.49% 10.00% ($19.5) Commentary 500,000 shares repurchased during the quarter at an average weighted price of $11.74. 250,000 common shares remain authorized under the repurchase program. AOCI improved by $2.7 million compared to fourth quarter 2022. Q1 2023 EOP shares outstanding: Common Stock: 19,622,380 (1) For the Company (2) Non-GAAP Financial Measures 19
TAKEAWAYS Leading franchise located in one of the most attractive Robust organic growth banking markets in Florida and the U.S. Strong asset quality, with minimal charge - offs experienced since 2015 recapitalization Experienced and tested management team Strong profitability, with pathway for future enhancement identified Core funded deposit base with 34.6% Non - Interest-Bearing Deposits (EOP) 20
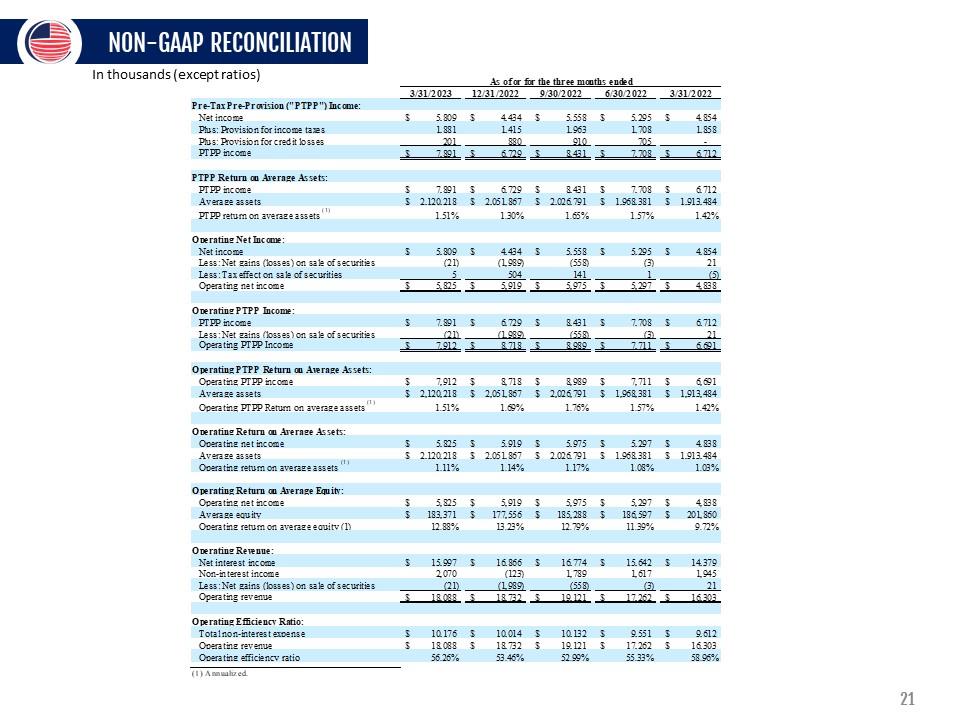
NON-GAAP RECONCILIATION In thousands (except ratios) 3/31/2023 Pre-Tax Pre-Provision (PTPP") Bicorne: Net income $ 5,809 Plus: Provision for income taxes 1,881 Plus: Provision for credit losses 201 PTPP income $ 7,891 PTPP Return ou Average Assets: PTPP income $ 7,891 Average assets $ 2,120,218 PTPP return on average assets(1) 1.51% Operating Net Income: Net income $ 5,809 Less: Net gains (losses) on sale of securities (21) Less: Tax effect on sale of securities 5_ Operating net income $ 5,825 Operating PTPP Bicorne: PTPP income $ 7,891 Less: Net gains (losses) on sale of securities (21) Operating PTPP Income $ 7,912 Operating PTPP Return on Average Assets: Operating PTPP income $ 7,912 Average assets $ 2,120,218 Operating PTPP Return on average assets(1; 1.51% As of or for the three months ended 12/31/2022 9/30/2022 6/30/2022 3/31/2022 $ 4,434 $ 5,558 $ 5295 $ 4,854 1,415 1,963 1,708 1,858 880 910 705 - $ 6,729 $ S,431 $ 7,708 $ 6,712 $ 6,729 $ 8,431 $ 7,708 $ 6,712 $ 2,051,867 $ 2,026,791 $ 1,968381 $ 1,913,484 130% 1.65% 1.57% 1.42% $ 4,434 $ 5,558 $ 5295 $ 4,854 (1,989) (558) (3) 21 504 141 1 (5)_ $ 5,919 $ 5,975 S 5297 S 4,838 $ 6,729 $ 8,431 $ 7,708 $ 6,712 (1,989) (558) ßl 21 $ 8.7 IS $ S.9S9 $ 7,711 $ 6,691 $ 8,718 $ 8,989 $ 7,711 $ 6,691 $ 2,051,867 $ 2,026,791 $ 1,968381 $ 1,913,484 1.69% 1.76% 1.57% 1.42% Oper a till 2 Return ou .Average Assets : Operating net income Average assets Operating return on average assets £ 5,825 £ 2,120,218 1.11% Operating Return on Au?rage Equity: Operating net income Average equity Operating return on average equity (1) £ 5,825 £ 183371 12.88% Operating Revenue: net interest income non-interest income Less: Net gains (losses) on sale of securities Operating revenue £ 15,997 2,070 1211 £ 18,088 Operating Efficiency Ratio: Total non-interest expense Operating revenue Operating
efficiency ratio £ 10,176 £ 18,088 56.26% $ 5,919 $ 5,975 $ 5,297 $ 4,838 $ 2,051,867 $ 2,026,791 $ 1,968381 $ 1,913,484 1.14% 1.17% 1.08% 1.03% $ 5,919 $ 5,975 $ 5,297 $ 4,838 $ 177,556 $ 185288 $ 1S6,597 $ 201,860 1323% 12.79% 1139% 9.72% $ 16,866 $ 16,774 $ 15,642 $ 14379 (123) 1,789 1,617 1,945 (1,989) (558) (31 21_ £ 1S,732 £ 19,121 S 17262 S 16303 £ 10,014 £ 10,132 £ 9,551 £ 9,612 £ 18,732 £ 19,121 £ 17262 £ 16303 53.46% 52.99% 5533% 58.96% (1) Annualized 21
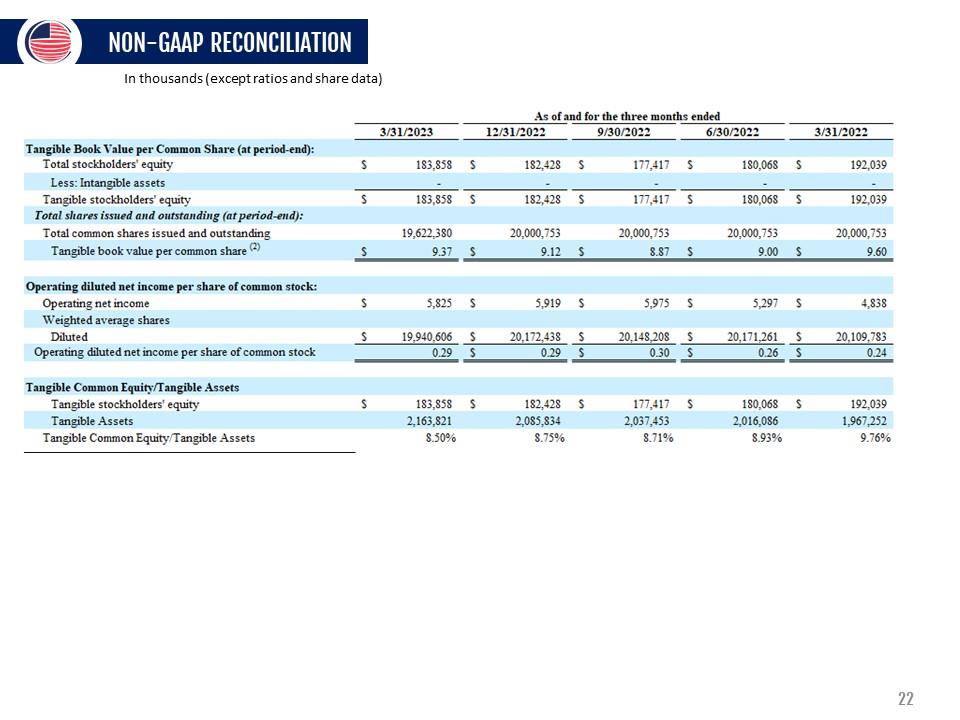
NON-GAAP RECONCILIATION In thousands (except ratios and share data) As of and for the three months ended Tangible Book Value per Common Share (at period-end): 3/31/2023 12/31/2022 9/30/2022 6/30/2022 3/31/2022 Total stockholders' equity S 1S3,S5S S 1S2,42S S 177,417 S ISO,06$ S 192,039 Less: Intangible assets _ _ _ _ _ Tangible stockholders' equity S 1S3,S5S S 1S2.428 S 177,417 S 180,06S S 192.039 Total shares issued and outstanding (at period-end): Total common shares issued and outstanding 19,622,3S0 20,000,753 20,000,753 20,000,753 20,000,753 Tangible book value per common share w s 9.37 s 9.12 s S.87 s 9.00 s 9.60 Operating diluted net income per share of common stock: Operating net income s 5.S25 s 5,919 s 5,975 s 5,297 s 4.S3S Weighted average shares Diluted S 19.940,606 S 20,172,438 S 20,148,208 S 20,171,261 S 20:109.7S3 Operating diluted net income per share of common stock 0.29 S 0.29 S 0.30 S 0.26 S 0.24 Tangible Common Equity/Tangible Assets Tangible stockholders’ equity S 1S3,S5S S 181428 S 177,417 S 180,06S S 192,039 Tangible Assets 2,163,821 2,085,834 2,037,453 2,016,0S6 1,967,252 Tangible Common Equity Tangible Assets S.50% S.75% 8.71% 8.93% 9.76% 22
CONTACT INFORMATION LOU DE LA AGUILERA President, CEO & Director (305) 715-5186 [email protected] ROB ANDERSON EVP, CHIEF FINANCIAL OFFICER (305) 715-5393 [email protected] INVESTOR RELATIONS [email protected] 23