ACIC 8-K
AMERICAN COASTAL INSURANCE Corp (ACIC)
8-K
2020-08-05
For: 2020-08-05
View Original
Added on
April 12, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of report (Date of earliest event reported): August 5, 2020
(Exact name of registrant as specified in its charter) | ||||||
(State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||
(Address of principal executive offices) | (Zip Code) | |||||
(Registrant's telephone number, including area code) | ||||||
(Former name or former address, if changed since last report.) | ||||||
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
Title of Each Class | Trading Symbol(s) | Name of Each Exchange on Which Registered |
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02. Results of Operations and Financial Condition
On August 5, 2020, United Insurance Holdings Corp. (the Company, we, our) issued a press release relating to our earnings for the second quarter ended June 30, 2020 (the Earnings Release). We have attached a copy of the Earnings Release as Exhibit 99.1.
Item 7.01: Regulation FD Disclosure.
The executive officers of the Company intend to use the materials filed herewith, in whole or in part, in one or more meetings with investors and analysts, beginning on August 5, 2020. A copy of the investor presentation is attached hereto as Exhibit 99.2.
The information furnished under this Item 2.02 and 7.01, including Exhibit 99.1 and Exhibit 99.2 attached hereto, shall not be deemed “filed” for purposes of Section 18 of the Securities Act of 1934, nor shall it be deemed incorporated by reference in any filing under the Securities Act of 1933, except as shall be expressly set forth by specific reference to such filing.
Item 9.01. Financial Statements and Exhibits
Signature
Pursuant to the requirements of the Securities Exchange Act of 1934, the Company has duly caused this report to be signed on its behalf by the undersigned thereunder duly authorized.
UNITED INSURANCE HOLDINGS CORP. | ||
August 5, 2020 | By: | /s/ B. Bradford Martz |
B. Bradford Martz, President and Chief Financial Officer (principal financial officer and principal accounting officer) | ||
Exhibit 99.1
FOR IMMEDIATE RELEASE
UNITED INSURANCE HOLDINGS CORP. REPORTS FINANCIAL RESULTS
FOR ITS SECOND QUARTER ENDED JUNE 30, 2020
Company to Host Quarterly Conference Call at 5:00 P.M. ET on August 5, 2020
The information in this press release should be read in conjunction with an investor presentation that is available on our website at investors.upcinsurance.com/Presentations.
St. Petersburg, FL - August 5, 2020: United Insurance Holdings Corp. (Nasdaq: UIHC) (UPC Insurance or the Company), a property and casualty insurance holding company, today reported its financial results for the second quarter ended June 30, 2020.
($ in thousands, except for per share data) | Three Months Ended | Six Months Ended | |||||||||||||||||||
June 30, | June 30, | ||||||||||||||||||||
2020 | 2019 | Change | 2020 | 2019 | Change | ||||||||||||||||
Gross premiums written | $ | 439,651 | $ | 449,762 | (2.2 | )% | $ | 774,834 | $ | 768,321 | 0.8 | % | |||||||||
Gross premiums earned | $ | 344,139 | $ | 330,025 | 4.3 | % | $ | 688,758 | $ | 641,838 | 7.3 | % | |||||||||
Net premiums earned | $ | 185,482 | $ | 190,404 | (2.6 | )% | $ | 377,078 | $ | 371,126 | 1.6 | % | |||||||||
Total revenues | $ | 216,397 | $ | 204,776 | 5.7 | % | $ | 392,701 | $ | 407,097 | (3.5 | )% | |||||||||
Earnings (loss) before income tax | $ | 29,482 | $ | (3,605 | ) | NM | $ | 13,678 | $ | 8,728 | 56.7 | % | |||||||||
Net income (loss) attributable to UIHC | $ | 24,274 | $ | (2,903 | ) | NM | $ | 11,551 | $ | 6,566 | 75.9 | % | |||||||||
Net income (loss) available to UIHC common stockholders per diluted share | $ | 0.56 | $ | (0.07 | ) | NM | $ | 0.27 | $ | 0.15 | 80.0 | % | |||||||||
Reconciliation of net income (loss) to core income: | |||||||||||||||||||||
Plus: Non-cash amortization of intangible assets | $ | 1,044 | $ | 1,982 | (47.3 | )% | $ | 2,181 | $ | 3,980 | (45.2 | )% | |||||||||
Less: Net realized gains (losses) on investment portfolio | $ | 59 | $ | (13 | ) | NM | $ | (9 | ) | $ | 168 | (105.4 | )% | ||||||||
Less: Unrealized gains (losses) on equity securities | $ | 20,552 | $ | 2,737 | NM | $ | (5,904 | ) | $ | 12,910 | (145.7 | )% | |||||||||
Less: Net tax impact(1) | $ | (4,109 | ) | $ | (186 | ) | NM | $ | 1,700 | $ | (2,275 | ) | 174.7 | % | |||||||
Core income (loss) (2) | $ | 8,816 | $ | (3,459 | ) | 354.9 | % | $ | 17,945 | $ | (257 | ) | NM | ||||||||
Core income (loss) per diluted share(2) | $ | 0.20 | $ | (0.08 | ) | 350.0 | % | $ | 0.42 | $ | (0.01 | ) | NM | ||||||||
Book value per share | $ | 12.27 | $ | 12.54 | (2.2 | )% | |||||||||||||||
NM = Not Meaningful
(1) In order to reconcile net income (loss) to the core income (loss) measure, we included the tax impact of all adjustments using the 21% corporate federal tax rate.
(2) Core income and core income per diluted share, measures that are not based on GAAP, are reconciled above to net income (loss) and net income (loss) per diluted share, respectively, the most directly comparable GAAP measures. Additional information regarding non-GAAP financial measures presented in this press release can be found in the "Definitions of Non-GAAP Measures" section, below.
“The second quarter saw a lot of change for me and for UIHC," said Dan Peed, CEO of UPC Insurance. "I am very excited to join the leadership team as Chairman and CEO effective July 1st. As I have been a catastrophe underwriter for over 25 years, I am very comfortable we can continue to grow our non-cat underwriting margin and optimize catastrophe exposures and reinsurance coverages. The second quarter saw continuing improvement in our underlying combined ratio as rate increases earn their way through the portfolio, and underwriting and risk
1
selection actions take effect. While the second quarter was an active non-named catastrophe quarter, in line with our peers, we were still able to generate a core income of $.20 per share and $.30 per share excluding named storms.”
“Our results for the second quarter continued to show improvement in several key metrics such as core income and the underlying combined ratio, and I’m grateful for the hard work and progress our team has made," said Brad Martz, President and CFO of UPC Insurance. "However, we are just getting started on the exciting next chapter of our Company’s evolution under Dan’s leadership and more work must be done. A hardening property insurance market provides UPC with a great opportunity to be more selective and optimize our risk portfolio for long-term profitability, so that’s what we intend to focus on.”
Return on Equity and Core Return on Equity
The calculations of the Company's return on equity and core return on equity are shown below.
($ in thousands) | Three Months Ended | Six Months Ended | |||||||||||||
June 30, | June 30, | ||||||||||||||
2020 | 2019 | 2020 | 2019 | ||||||||||||
Net income (loss) attributable to UIHC | $ | 24,274 | $ | (2,903 | ) | $ | 11,551 | $ | 6,566 | ||||||
Return on equity based on GAAP net income (loss) attributable to UIHC (1) | 18.8 | % | (2.2 | )% | 4.5 | % | 2.5 | % | |||||||
Core income (loss) | $ | 8,816 | $ | (3,459 | ) | $ | 17,945 | $ | (257 | ) | |||||
Core return on equity (1)(2) | 6.8 | % | (2.6 | )% | 6.9 | % | (0.1 | )% | |||||||
(1) Return on equity for the three and six months ended June 30, 2020 and 2019 is calculated on an annualized basis by dividing the net income (loss) or core net income (loss) for the period by the average stockholders' equity for the trailing twelve months.
(2) Core return on equity, a measure that is not based on GAAP, is calculated based on core income (loss), which is reconciled on the first page of this press release to net income (loss), the most directly comparable GAAP measure. Additional information regarding non-GAAP financial measures presented in this press release can be found in the "Definitions of Non-GAAP Measures" section, below.
Combined Ratio and Underlying Ratio
The calculations of the Company's combined ratio and underlying combined ratio are shown below.
($ in thousands) | Three Months Ended | Six Months Ended | |||||||||||||||
June 30, | June 30, | ||||||||||||||||
2020 | 2019 | Change | 2020 | 2019 | Change | ||||||||||||
Loss ratio, net(1) | 54.8 | % | 61.1 | % | (6.3 | ) pts | 54.2 | % | 59.5 | % | (5.3 | ) pts | |||||
Expense ratio, net(2) | 44.6 | % | 47.1 | % | (2.5 | ) pts | 45.0 | % | 46.5 | % | (1.5 | ) pts | |||||
Combined ratio (CR)(3) | 99.4 | % | 108.2 | % | (8.8 | ) pts | 99.2 | % | 106.0 | % | (6.8 | ) pts | |||||
Effect of current year catastrophe losses on CR | 16.1 | % | 8.3 | % | 7.8 | pts | 12.4 | % | 7.4 | % | 5.0 | pts | |||||
Effect of prior year unfavorable (favorable) development on CR | (0.4 | )% | 8.1 | % | (8.5 | ) pts | (0.5 | )% | 5.6 | % | (6.1 | ) pts | |||||
Underlying combined ratio(4) | 83.7 | % | 91.8 | % | (8.1 | ) pts | 87.3 | % | 93.0 | % | (5.7 | ) pts | |||||
(1) Loss ratio, net is calculated as losses and loss adjustment expenses (LAE), net of losses ceded to reinsurers, relative to net premiums earned.
(2) Expense ratio, net is calculated as the sum of all operating expenses less interest expense relative to net premiums earned.
(3) Combined ratio is the sum of the loss ratio, net and expense ratio, net.
(4) Underlying combined ratio, a measure that is not based on GAAP, is reconciled above to the combined ratio, the most directly comparable GAAP measure. Additional information regarding non-GAAP financial measures presented in this press release can be found in the "Definitions of Non-GAAP Measures" section, below.
Impact of Coronavirus (COVID-19), Financial Status and Outlook
The COVID-19 pandemic has resulted in governments worldwide enacting emergency measures to combat the spread of the virus. These measures, which include the implementation of travel bans and restrictions, self-imposed quarantine periods, state and local shelter-in-place orders, business and government shutdowns and social distancing, have caused and continue to cause material disruption to businesses and economies globally. In addition, global equity markets have experienced and continue to experience significant volatility and weakness.
2
The Company is committed to its employees, agents, customers and stockholders in its resolve to maintain a stable and secure business. The Company has continued to operate at nearly full capacity while taking the necessary steps to ensure the health and safety of its employees through adherence to CDC, state and local government work guidelines. In addition, the Company has converted to virtual sales processes to enable our agents to continue their activities.
The scope, severity and longevity of any potential business shutdowns or disruptions as a result of the COVID-19 outbreak is highly uncertain and cannot be predicted at this time, as new information may continue to emerge concerning the actions governments may take to contain or mitigate the spread of the virus or address its impact on individuals, businesses and the economy. The Company did not incur material claims or significant disruptions to the business for the three and six months ended June 30, 2020. The Company has not incurred any significant disruptions to its business operations, financial position, liquidity or its ability to service its policyholders as of the date of this press release, with the exceptions of fluctuations in our investment portfolios due to the volatility of the equity securities markets and an immaterial decline in new business premium generated from the Northeast region during the start of the second quarter of 2020 due to COVID-19. At this time, it is not possible to reasonably estimate the extent of the impact of the economic uncertainties on the financial results and conditions of the Company in future periods, but the Company will continue to respond to the COVID-19 pandemic and take reasonable measure to make sure customers continue to be served without interruption.
Quarterly Financial Results
Net income attributable to the Company for the second quarter of 2020 was $24.3 million, or $0.56 per diluted share, compared to net loss of $2.9 million, or $(0.07) per diluted share, for the second quarter of 2019. The increase in net income was primarily due to an increase in unrealized gains on equity securities, in conjunction with a decrease in loss and loss adjustment expenses (LAE) and a decrease in policy acquisition costs during the second quarter of 2020 compared to the second quarter of 2019. This was offset by a decline in gross written premium for the quarter as described below.
The Company's total gross written premium decreased by $10.1 million, or (2.2)%, to $439.7 million for the second quarter of 2020, from $449.8 million for the second quarter of 2019, driven by a decrease in assumed premiums which was offset by the impact of rate increases in Florida and organic policy growth in new and renewal business generated in the Gulf and Southeast regions. The breakdown of the quarter-over-quarter changes in both direct written and assumed premiums by region and gross written premium by line of business are shown in the table below.
($ in thousands) | Three Months Ended June 30, | ||||||||||||||
2020 | 2019 | Change $ | Change % | ||||||||||||
Direct Written and Assumed Premium by Region (1) | |||||||||||||||
Florida | $ | 263,108 | $ | 243,124 | $ | 19,984 | 8.2 | % | |||||||
Gulf | 74,083 | 63,723 | 10,360 | 16.3 | |||||||||||
Northeast | 55,189 | 55,814 | (625 | ) | (1.1 | ) | |||||||||
Southeast | 35,206 | 32,004 | 3,202 | 10.0 | |||||||||||
Total direct written premium by region | 427,586 | 394,665 | 32,921 | 8.3 | % | ||||||||||
Assumed premium (2) | 12,065 | 55,097 | (43,032 | ) | (78.1 | ) | |||||||||
Total gross written premium by region | $ | 439,651 | $ | 449,762 | $ | (10,111 | ) | (2.2 | )% | ||||||
Gross Written Premium by Line of Business | |||||||||||||||
Personal property | $ | 307,965 | $ | 286,106 | $ | 21,859 | 7.6 | % | |||||||
Commercial property | 131,686 | 163,656 | (31,970 | ) | (19.5 | ) | |||||||||
Total gross written premium by line of business | $ | 439,651 | $ | 449,762 | $ | (10,111 | ) | (2.2 | )% | ||||||
(1) "Gulf" is comprised of Hawaii, Louisiana and Texas; "Northeast" is comprised of Connecticut, Massachusetts, New Jersey, New York and Rhode Island; and "Southeast" is comprised of Georgia, North Carolina and South Carolina.
(2) Assumed premium written for 2020 and 2019 primarily included commercial property business assumed from unaffiliated insurers.
3
Loss and LAE decreased by $14.6 million, or 12.6%, to $101.7 million for the second quarter of 2020, from $116.3 million for the second quarter of 2019. Loss and LAE expense as a percentage of net earned premiums decreased 6.3 points to 54.8% for the second quarter of 2020, compared to 61.1% for the second quarter of 2019. Excluding catastrophe losses and reserve development, the Company's gross underlying loss and LAE ratio for the second quarter of 2020 would have been 21.1%, a decrease of 4.7 points from 25.8% during the second quarter of 2019.
Policy acquisition costs decreased by $9 million, or 14.6%, to $52.6 million for the second quarter of 2020, from $61.6 million for the second quarter of 2019 primarily due to an increase in ceding commission income, as a result of changes made to the terms of the Company's quota share reinsurance agreements.
Operating and underwriting expenses increased by $2.8 million, or 25.0%, to $14.0 million for the second quarter of 2020, from $11.2 million for the second quarter of 2019, primarily due to increased investments in technology. This was partially offset by a decrease in travel related expenses, as all business-related travel was postponed during the current quarter as a result of closures and government limitations imposed during the pandemic.
General and administrative expenses decreased by $0.7 million, or 4.2%, to $16.1 million for the second quarter of 2020, from $16.8 million for the second quarter of 2019, primarily due to a decrease in legal and consulting expenses, as well as a decrease in amortization expense as all intangible assets acquired following the 2015 acquisition of Family Security Insurance Company, Inc. (FSIC) have been fully amortized in 2020.
Combined Ratio Analysis
The calculations of the Company's loss ratios and underlying loss ratios are shown below.
($ in thousands) | Three Months Ended | Six Months Ended | |||||||||||||||||||||
June 30, | June 30, | ||||||||||||||||||||||
2020 | 2019 | Change | 2020 | 2019 | Change | ||||||||||||||||||
Loss and LAE | $ | 101,693 | $ | 116,252 | $ | (14,559 | ) | $ | 204,530 | $ | 220,799 | $ | (16,269 | ) | |||||||||
% of Gross earned premiums | 29.5 | % | 35.2 | % | (5.7 | ) pts | 29.7 | % | 34.4 | % | (4.7 | ) pts | |||||||||||
% of Net earned premiums | 54.8 | % | 61.1 | % | (6.3 | ) pts | 54.2 | % | 59.5 | % | (5.3 | ) pts | |||||||||||
Less: | |||||||||||||||||||||||
Current year catastrophe losses | $ | 29,799 | $ | 15,802 | $ | 13,997 | $ | 46,917 | $ | 27,459 | $ | 19,458 | |||||||||||
Prior year reserve unfavorable (favorable) development | (823 | ) | 15,332 | (16,155 | ) | (1,952 | ) | 20,967 | (22,919 | ) | |||||||||||||
Underlying loss and LAE (1) | $ | 72,717 | $ | 85,118 | $ | (12,401 | ) | $ | 159,565 | $ | 172,373 | $ | (12,808 | ) | |||||||||
% of Gross earned premiums | 21.1 | % | 25.8 | % | (4.7 | ) pts | 23.2 | % | 26.9 | % | (3.7 | ) pts | |||||||||||
% of Net earned premiums | 39.2 | % | 44.7 | % | (5.5 | ) pts | 42.3 | % | 46.4 | % | (4.1 | ) pts | |||||||||||
(1) Underlying loss and LAE is a non-GAAP financial measure and is reconciled above to loss and LAE, the most directly comparable GAAP measure. Additional information regarding non-GAAP financial measures presented in this press release can be found in the "Definitions of Non-GAAP Measures" section, below.
The calculations of the Company's expense ratios are shown below.
($ in thousands) | Three Months Ended | Six Months Ended | |||||||||||||||||||||
June 30, | June 30, | ||||||||||||||||||||||
2020 | 2019 | Change | 2020 | 2019 | Change | ||||||||||||||||||
Policy acquisition costs | $ | 52,573 | $ | 61,622 | $ | (9,049 | ) | $ | 111,448 | $ | 116,868 | $ | (5,420 | ) | |||||||||
Operating and underwriting | 13,977 | 11,199 | 2,778 | 23,681 | 21,410 | 2,271 | |||||||||||||||||
General and administrative | 16,121 | 16,802 | (681 | ) | 34,422 | 34,383 | 39 | ||||||||||||||||
Total Operating Expenses | $ | 82,671 | $ | 89,623 | $ | (6,952 | ) | $ | 169,551 | $ | 172,661 | $ | (3,110 | ) | |||||||||
% of Gross earned premiums | 24.0 | % | 27.2 | % | (3.2 | ) pts | 24.6 | % | 26.9 | % | (2.3 | ) pts | |||||||||||
% of Net earned premiums | 44.6 | % | 47.1 | % | (2.5 | ) pts | 45.0 | % | 46.5 | % | (1.5 | ) pts | |||||||||||
4
Reinsurance Costs as a Percentage of Gross Earned Premium
Reinsurance costs as a percentage of gross earned premium in the second quarter of 2020 and 2019 were as follows:
2020 | 2019 | ||||
Non-at-Risk | (2.6 | )% | (2.4 | )% | |
Quota Share | (13.0 | )% | (9.2 | )% | |
All Other | (30.5 | )% | (30.7 | )% | |
Total Ceding Ratio | (46.1 | )% | (42.3 | )% | |
The increase in this ratio was driven by the terms of the renewal of the Company's quota share agreement in 2019. From inception through May 2019, the quota share agreement only covered the Company's subsidiary United Property & Casualty Insurance Company at a ceding percentage of 20.0%. When the agreement was renewed on June 1, 2019, the Company modified the terms to add its subsidiary, FSIC and to increase the ceding percentage to 22.5%. This rate was effective through May 2020, and was maintained with the June 1, 2020 renewal of the quota share agreement.
Investment Portfolio Highlights
The Company's cash, restricted cash and investment holdings increased to $1.4 billion at June 30, 2020 from $1.3 billion at December 31, 2019. The Company's cash and investment holdings consist of investments in U.S. government and agency securities, corporate debt and 100% investment grade money market instruments. Fixed maturities represented approximately 87.7% of total investments at June 30, 2020, compared to 87.5% at December 31, 2019. At June 30, 2020 our fixed maturity investments had a modified duration of 3.5 years, compared to 3.4 years at December 31, 2019.
Book Value Analysis
Book value per share increased 5.0% from $11.69 at December 31, 2019, to $12.27 at June 30, 2020. Underlying book value per share increased 1.3% from $11.43 at December 31, 2019 to $11.58 at June 30, 2020. The increase in the Company's book value per share was due to an increase in the Company's retained earnings as the result of net income in the first half of 2020. As shown in the table below, removing the effect of AOCI decreases the Company's book value per share however, the Company still experienced an increase in underlying book value per share for the second quarter of 2020 as compared to year end.
($ in thousands, except for share and per share data) | June 30, 2020 | December 31, 2019 | ||||||
Book Value per Share | ||||||||
Numerator: | ||||||||
Common stockholders' equity attributable to UIHC | $ | 528,267 | $ | 503,138 | ||||
Denominator: | ||||||||
Total Shares Outstanding | 43,068,379 | 43,028,074 | ||||||
Book Value Per Common Share | $ | 12.27 | $ | 11.69 | ||||
Book Value per Share, Excluding the Impact of Accumulated Other Comprehensive Income (AOCI) | ||||||||
Numerator: | ||||||||
Common stockholders' equity attributable to UIHC | $ | 528,267 | $ | 503,138 | ||||
Less: Accumulated other comprehensive income (loss) | 29,527 | 11,319 | ||||||
Stockholders' Equity, excluding AOCI | $ | 498,740 | $ | 491,819 | ||||
Denominator: | ||||||||
Total Shares Outstanding | 43,068,379 | 43,028,074 | ||||||
Underlying Book Value Per Common Share(1) | $ | 11.58 | $ | 11.43 | ||||
5
(1) Underlying book value per common share is a non-GAAP financial measure and is reconciled above to book value per common share, the most directly comparable GAAP measure. Additional information regarding non-GAAP financial measures presented in this press release can be found in the "Definitions of Non-GAAP Measures" section, below.
Definitions of Non-GAAP Measures
The Company believes that investors' understanding of UPC Insurance's performance is enhanced by the Company's disclosure of the following non-GAAP measures. The Company's methods for calculating these measures may differ from those used by other companies and therefore comparability may be limited.
Net income excluding the effects of amortization of intangible assets, realized gains (losses) and unrealized gains (losses) on equity securities, net of tax (core income) is a non-GAAP measure which is computed by adding amortization, net of tax, to net income and subtracting realized gains (losses) on the Company's investment portfolio, net of tax, and unrealized gains (losses) on the Company's equity securities, net of tax, from net income. Amortization expense is related to the amortization of intangible assets acquired through mergers and therefore the expense does not arise through normal operations. Investment portfolio gains (losses) and unrealized equity security gains (losses) vary independent of the Company's operations. The Company believes it is useful for investors to evaluate these components separately and in the aggregate when reviewing the Company's performance. The most directly comparable GAAP measure is net income. The core income measure should not be considered a substitute for net income and does not reflect the overall profitability of the Company's business.
Core return on equity is a non-GAAP ratio calculated using non-GAAP measures. It is calculated by dividing the core income for the period by the average stockholders’ equity for the trailing twelve months (or one quarter of such average, in the case of quarterly periods). Core income is an after-tax non-GAAP measure that is calculated by excluding from net income the effect of non-cash amortization of intangible assets, unrealized gains or losses on the Company's equity security investments and net realized gains or losses on the Company's investment portfolio. In the opinion of the Company’s management, core income, core income per share and core return on equity are meaningful indicators to investors of the Company's underwriting and operating results, since the excluded items are not necessarily indicative of operating trends. Internally, the Company’s management uses core income, core income per share and core return on equity to evaluate performance against historical results and establish financial targets on a consolidated basis. The most directly comparable GAAP measure is return on equity. The core return on equity measure should not be considered a substitute for return on equity and does not reflect the overall profitability of the Company's business.
Combined ratio excluding the effects of current year catastrophe losses and prior year reserve development (underlying combined ratio) is a non-GAAP measure, which is computed by subtracting the effect of current year catastrophe losses and prior year development from the combined ratio. The Company believes that this ratio is useful to investors and it is used by management to highlight the trends in the Company's business that may be obscured by current year catastrophe losses and prior year development. Current year catastrophe losses cause the Company's loss trends to vary significantly between periods as a result of their incidence of occurrence and magnitude, and can have a significant impact on the combined ratio. Prior year development is caused by unexpected loss development on historical reserves. The Company believes it is useful for investors to evaluate these components separately and in the aggregate when reviewing the Company's performance. The most directly comparable GAAP measure is the combined ratio. The underlying combined ratio should not be considered as a substitute for the combined ratio and does not reflect the overall profitability of the Company's business.
Net loss and LAE excluding the effects of current year catastrophe losses and prior year reserve development (underlying loss and LAE) is a non-GAAP measure which is computed by subtracting the effect of current year catastrophe losses and prior year reserve development from net loss and LAE. The Company uses underlying loss and LAE figures to analyze the Company's loss trends that may be impacted by current year catastrophe losses and prior year development on the Company's reserves. As discussed previously, these two items can have a significant impact on the Company's loss trends in a given period. The Company believes it is useful for investors to evaluate these components separately and in the aggregate when reviewing the Company's performance. The most directly comparable GAAP measure is net loss and LAE. The underlying loss and LAE measure should not be considered a substitute for net loss and LAE and does not reflect the overall profitability of the Company's business.
Book value per common share, excluding the impact of accumulated other comprehensive income (underlying book value per common share), is a non-GAAP measure which is computed by dividing common stockholders' equity after excluding accumulated other comprehensive income, by total common shares outstanding plus dilutive potential common shares outstanding. The Company uses the trend in book value per common share, excluding the
6
impact of accumulated other comprehensive income, in conjunction with book value per common share to identify and analyze the change in net worth attributable to management efforts between periods. The Company believes the non-GAAP measure is useful to investors because it eliminates the effect of interest rates that can fluctuate significantly from period to period and are generally driven by economic and financial factors which are not influenced by management. Book value per common share is the most directly comparable GAAP measure. Book value per common share, excluding the impact of accumulated other comprehensive income, should not be considered a substitute for book value per common share, and does not reflect the recorded net worth of the Company's business.
Conference Call Details
Date and Time: August 5, 2020 - 5:00 P.M. ET
Participant Dial-In: (United States): 877-407-8829
(International): 201-493-6724
Webcast: | To listen to the live webcast, please go to investors.upcinsurance.com (News & Market Data - Event Calendar) and click on the conference call link, or go to: https://event.webcasts.com/starthere.jsp?ei=1346727&tp_key=3df0ca5fb6. |
An archive of the webcast will be available for a limited period of time thereafter.
Presentation: | The information in this press release should be read in conjunction with an investor presentation that is available on our website at investors.upcinsurance.com/Presentations. |
About UPC Insurance
Founded in 1999, UPC Insurance is an insurance holding company that sources, writes and services personal and commercial residential property and casualty insurance policies using a group of wholly owned insurance subsidiaries and one majority owned insurance subsidiary through a variety of distribution channels. The Company currently writes policies in Connecticut, Florida, Georgia, Hawaii, Louisiana, Massachusetts, New Jersey, New York, North Carolina, Rhode Island, South Carolina and Texas. From its headquarters in St. Petersburg, UPC Insurance's team of dedicated professionals manages a completely integrated insurance company, including sales, underwriting, customer service and claims.
Forward-Looking Statements
Statements made in this press release, or on the conference call identified above, and otherwise, that are not historical facts are “forward-looking statements” that anticipate results based on our estimates, assumptions and plans and are subject to uncertainty. These statements are made subject to the safe-harbor provisions of the Private Securities Litigation Reform Act of 1995. These forward-looking statements do not relate strictly to historical or current facts and may be identified by their use of words such as “may,” “will,” “expect,” "endeavor," "project," “believe,” "plan," “anticipate,” “intend,” “could,” “would,” “estimate” or “continue” or the negative variations thereof or comparable terminology. We believe these statements are based on reasonable estimates, assumptions and plans. However, if the estimates, assumptions or plans underlying the forward-looking statements prove inaccurate or if other risks or uncertainties arise, actual results could differ materially from those communicated in these forward-looking statements. Factors that could cause actual results to differ materially from those expressed in, or implied by, the forward-looking statements may be found in our filings with the U.S. Securities and Exchange Commission, including the “Risk Factors” section in our most recent Annual Report on Form 10-K and subsequent Quarterly Reports on Form 10-Q. Forward-looking statements speak only as of the date on which they are made, and, except as required by applicable law, we undertake no obligation to update or revise any forward-looking statement.
### #### ###
CONTACT: | OR | INVESTOR RELATIONS: | ||
United Insurance Holdings Corp. | The Equity Group | |||
Jessica Strathman | Adam Prior | |||
Director of Financial Reporting | Senior Vice-President | |||
(727) 895-7737 / [email protected] | (212) 836-9606 / [email protected] | |||
7
Consolidated Statements of Comprehensive Income
In thousands, except share and per share amounts
Three Months Ended | Six Months Ended | |||||||||||||||
June 30, | June 30, | |||||||||||||||
2020 | 2019 | 2020 | 2019 | |||||||||||||
REVENUE: | ||||||||||||||||
Gross premiums written | $ | 439,651 | $ | 449,762 | $ | 774,834 | $ | 768,321 | ||||||||
Change in gross unearned premiums | (95,512 | ) | (119,737 | ) | (86,076 | ) | (126,483 | ) | ||||||||
Gross premiums earned | 344,139 | 330,025 | 688,758 | 641,838 | ||||||||||||
Ceded premiums earned | (158,657 | ) | (139,621 | ) | (311,680 | ) | (270,712 | ) | ||||||||
Net premiums earned | 185,482 | 190,404 | 377,078 | 371,126 | ||||||||||||
Net investment income | 5,907 | 7,570 | 12,824 | 14,865 | ||||||||||||
Net realized investment gains (losses) | 59 | (13 | ) | (9 | ) | 168 | ||||||||||
Net unrealized gains (losses) on equity securities | 20,552 | 2,737 | (5,904 | ) | 12,910 | |||||||||||
Other revenue | 4,397 | 4,078 | 8,712 | 8,028 | ||||||||||||
Total revenues | $ | 216,397 | $ | 204,776 | $ | 392,701 | $ | 407,097 | ||||||||
EXPENSES: | ||||||||||||||||
Losses and loss adjustment expenses | 101,693 | 116,252 | 204,530 | 220,799 | ||||||||||||
Policy acquisition costs | 52,573 | 61,622 | 111,448 | 116,868 | ||||||||||||
Operating expenses | 13,977 | 11,199 | 23,681 | 21,410 | ||||||||||||
General and administrative expenses | 16,121 | 16,802 | 34,422 | 34,383 | ||||||||||||
Interest expense | 2,565 | 2,527 | 4,984 | 4,936 | ||||||||||||
Total expenses | 186,929 | 208,402 | 379,065 | 398,396 | ||||||||||||
Income (loss) before other income | 29,468 | (3,626 | ) | 13,636 | 8,701 | |||||||||||
Other income | 14 | 21 | 42 | 27 | ||||||||||||
Income (loss) before income taxes | 29,482 | (3,605 | ) | 13,678 | 8,728 | |||||||||||
Provision (benefit) for income taxes | 5,040 | (808 | ) | 1,752 | 1,947 | |||||||||||
Net income (loss) | $ | 24,442 | $ | (2,797 | ) | $ | 11,926 | $ | 6,781 | |||||||
Less: Net income attributable to noncontrolling interests | 168 | 106 | 375 | 215 | ||||||||||||
Net income (loss) attributable to UIHC | $ | 24,274 | $ | (2,903 | ) | $ | 11,551 | $ | 6,566 | |||||||
OTHER COMPREHENSIVE INCOME: | ||||||||||||||||
Change in net unrealized gains on investments | 28,332 | 10,633 | 24,222 | 24,955 | ||||||||||||
Reclassification adjustment for net realized investment losses (gains) | (59 | ) | 13 | 9 | (168 | ) | ||||||||||
Income tax expense related to items of other comprehensive income | (6,858 | ) | (2,429 | ) | (5,875 | ) | (5,888 | ) | ||||||||
Total comprehensive income | $ | 45,857 | $ | 5,420 | $ | 30,282 | $ | 25,680 | ||||||||
Less: Comprehensive income attributable to noncontrolling interests | 549 | 205 | 523 | 436 | ||||||||||||
Comprehensive income attributable to UIHC | $ | 45,308 | $ | 5,215 | $ | 29,759 | $ | 25,244 | ||||||||
Weighted average shares outstanding | ||||||||||||||||
Basic | 42,860,922 | 42,762,417 | 42,833,225 | 42,729,730 | ||||||||||||
Diluted | 43,055,115 | 42,762,417 | 43,041,623 | 43,097,244 | ||||||||||||
Earnings available to UIHC common stockholders per share | ||||||||||||||||
Basic | $ | 0.57 | $ | (0.07 | ) | $ | 0.27 | $ | 0.15 | |||||||
Diluted | $ | 0.56 | $ | (0.07 | ) | $ | 0.27 | $ | 0.15 | |||||||
Dividends declared per share | $ | 0.06 | $ | 0.06 | $ | 0.12 | $ | 0.12 | ||||||||
8
Consolidated Balance Sheets
In thousands, except share amounts
June 30, 2020 | December 31, 2019 | |||||||
ASSETS | ||||||||
Investments, at fair value: | ||||||||
Fixed maturities, available-for-sale | $ | 1,015,291 | $ | 884,861 | ||||
Equity securities | 131,003 | 116,610 | ||||||
Other investments | 12,010 | 10,252 | ||||||
Total investments | $ | 1,158,304 | $ | 1,011,723 | ||||
Cash and cash equivalents | 229,631 | 215,469 | ||||||
Restricted cash | 51,939 | 71,588 | ||||||
Accrued investment income | 5,815 | 5,901 | ||||||
Property and equipment, net | 37,949 | 32,728 | ||||||
Premiums receivable, net | 113,288 | 86,568 | ||||||
Reinsurance recoverable on paid and unpaid losses | 486,805 | 550,136 | ||||||
Ceded unearned premiums | 498,838 | 270,034 | ||||||
Goodwill | 73,045 | 73,045 | ||||||
Deferred policy acquisition costs | 120,182 | 104,572 | ||||||
Intangible assets, net | 23,898 | 26,079 | ||||||
Other assets | 30,738 | 19,375 | ||||||
Total Assets | $ | 2,830,432 | $ | 2,467,218 | ||||
LIABILITIES AND STOCKHOLDERS' EQUITY | ||||||||
Liabilities: | ||||||||
Unpaid losses and loss adjustment expenses | $ | 683,471 | $ | 760,357 | ||||
Unearned premiums | 760,131 | 674,055 | ||||||
Reinsurance payable on premiums | 460,807 | 166,131 | ||||||
Payments outstanding | 45,552 | 57,555 | ||||||
Accounts payable and accrued expenses | 88,061 | 78,592 | ||||||
Operating lease liability | 2,369 | 324 | ||||||
Other liabilities | 82,184 | 47,407 | ||||||
Notes payable, net | 158,340 | 158,932 | ||||||
Total Liabilities | $ | 2,280,915 | $ | 1,943,353 | ||||
Commitments and contingencies | ||||||||
Stockholders' Equity: | ||||||||
Preferred stock, $0.0001 par value; 1,000,000 authorized; none issued or outstanding | — | — | ||||||
Common stock, $0.0001 par value; 50,000,000 shares authorized; 43,216,919 and 43,056,310 issued, respectively; 43,068,379 and 43,028,074 outstanding, respectively | 4 | 4 | ||||||
Additional paid-in capital | 392,633 | 391,852 | ||||||
Treasury shares, at cost; 212,083 shares | (431 | ) | (431 | ) | ||||
Accumulated other comprehensive income | 29,527 | 11,319 | ||||||
Retained earnings | 106,534 | 100,394 | ||||||
Total stockholders' equity attributable to UIHC stockholders | $ | 528,267 | $ | 503,138 | ||||
Noncontrolling interests | 21,250 | 20,727 | ||||||
Total Stockholders' Equity | $ | 549,517 | $ | 523,865 | ||||
Total Liabilities and Stockholders' Equity | $ | 2,830,432 | $ | 2,467,218 | ||||
9
Investor Presentation Supplement to Second Quarter 2020 Results August 5, 2020 St. Petersburg, FL
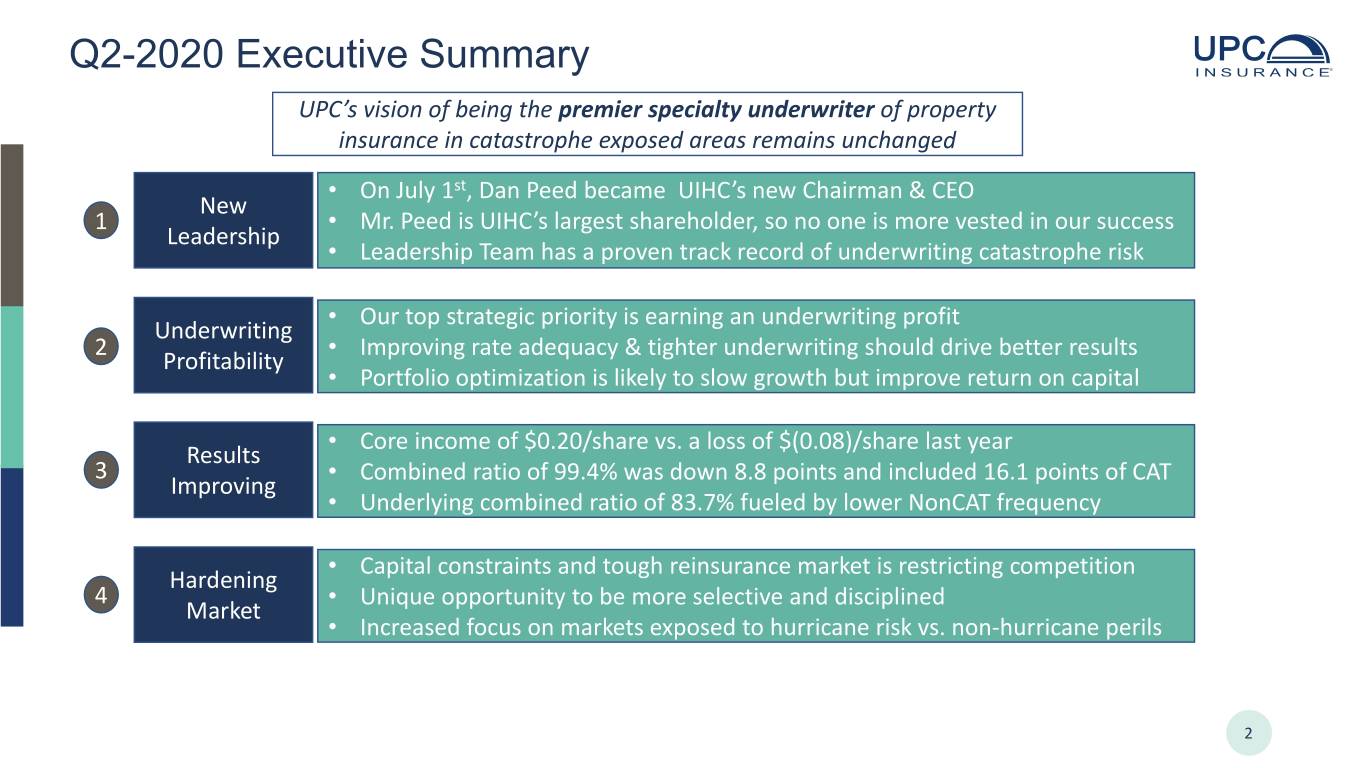
Q2-2020 Executive Summary UPC’s vision of being the premier specialty underwriter of property insurance in catastrophe exposed areas remains unchanged • On July 1st, Dan Peed became UIHC’s new Chairman & CEO New 1 • Mr. Peed is UIHC’s largest shareholder, so no one is more vested in our success Leadership • Leadership Team has a proven track record of underwriting catastrophe risk • Our top strategic priority is earning an underwriting profit Underwriting 2 • Improving rate adequacy & tighter underwriting should drive better results Profitability • Portfolio optimization is likely to slow growth but improve return on capital • Core income of $0.20/share vs. a loss of $(0.08)/share last year Results 3 • Combined ratio of 99.4% was down 8.8 points and included 16.1 points of CAT Improving • Underlying combined ratio of 83.7% fueled by lower NonCAT frequency • Capital constraints and tough reinsurance market is restricting competition Hardening 4 • Unique opportunity to be more selective and disciplined Market • Increased focus on markets exposed to hurricane risk vs. non-hurricane perils 2
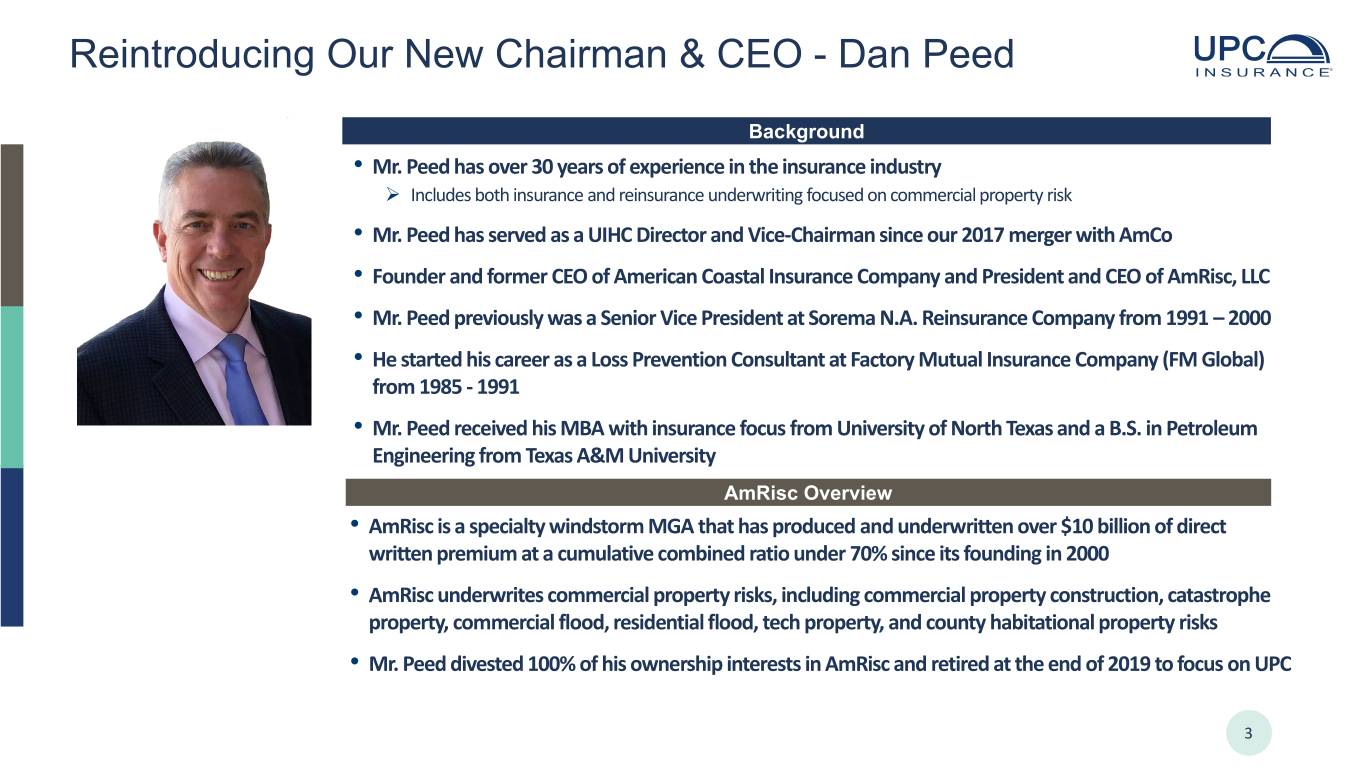
Reintroducing Our New Chairman & CEO - Dan Peed Background • Mr. Peed has over 30 years of experience in the insurance industry Includes both insurance and reinsurance underwriting focused on commercial property risk • Mr. Peed has served as a UIHC Director and Vice-Chairman since our 2017 merger with AmCo • Founder and former CEO of American Coastal Insurance Company and President and CEO of AmRisc, LLC • Mr. Peed previously was a Senior Vice President at Sorema N.A. Reinsurance Company from 1991 – 2000 • He started his career as a Loss Prevention Consultant at Factory Mutual Insurance Company (FM Global) from 1985 - 1991 • Mr. Peed received his MBA with insurance focus from University of North Texas and a B.S. in Petroleum Engineering from Texas A&M University AmRisc Overview • AmRisc is a specialty windstorm MGA that has produced and underwritten over $10 billion of direct written premium at a cumulative combined ratio under 70% since its founding in 2000 • AmRisc underwrites commercial property risks, including commercial property construction, catastrophe property, commercial flood, residential flood, tech property, and county habitational property risks • Mr. Peed divested 100% of his ownership interests in AmRisc and retired at the end of 2019 to focus on UPC 3
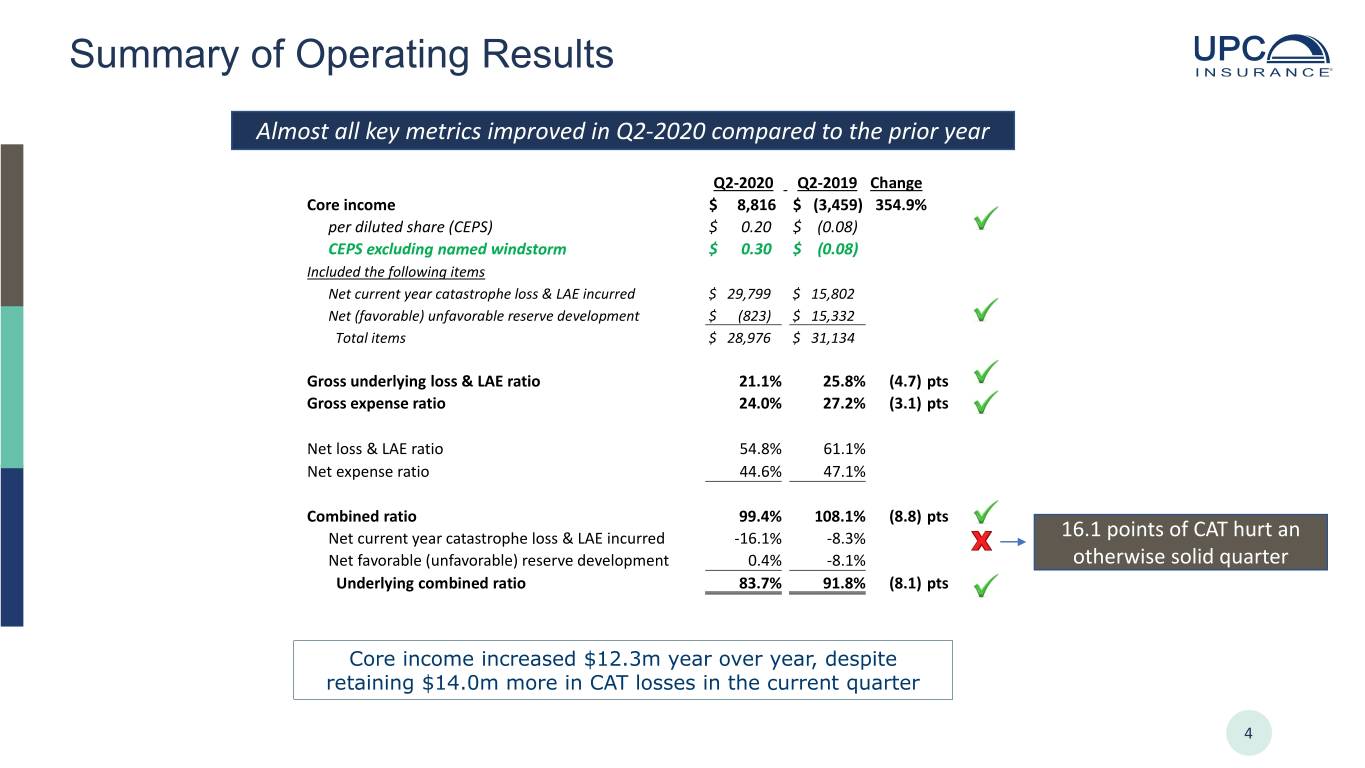
Summary of Operating Results Almost all key metrics improved in Q2-2020 compared to the prior year Q2-2020 Q2-2019 Change Core income $ 8,816 $ (3,459) 354.9% per diluted share (CEPS) $ 0.20 $ (0.08) CEPS excluding named windstorm $ 0.30 $ (0.08) Included the following items Net current year catastrophe loss & LAE incurred $ 29,799 $ 15,802 Net (favorable) unfavorable reserve development $ (823) $ 15,332 Total items $ 28,976 $ 31,134 Gross underlying loss & LAE ratio 21.1% 25.8% (4.7) pts Gross expense ratio 24.0% 27.2% (3.1) pts Net loss & LAE ratio 54.8% 61.1% Net expense ratio 44.6% 47.1% Combined ratio 99.4% 108.1% (8.8) pts Net current year catastrophe loss & LAE incurred -16.1% -8.3% 16.1 points of CAT hurt an Net favorable (unfavorable) reserve development 0.4% -8.1% otherwise solid quarter Underlying combined ratio 83.7% 91.8% (8.1) pts Core income increased $12.3m year over year, despite retaining $14.0m more in CAT losses in the current quarter 4
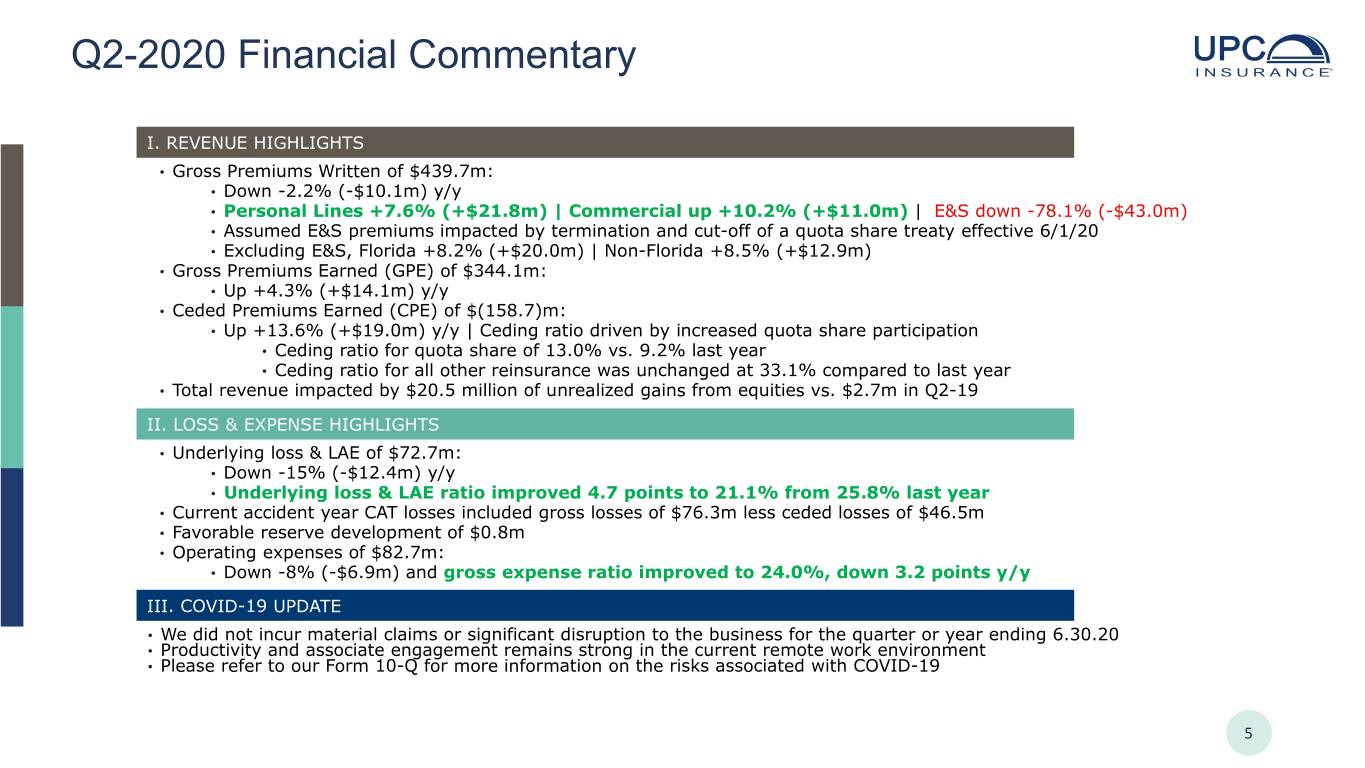
Q2-2020 Financial Commentary I. REVENUE HIGHLIGHTS • Gross Premiums Written of $439.7m: • Down -2.2% (-$10.1m) y/y • Personal Lines +7.6% (+$21.8m) | Commercial up +10.2% (+$11.0m) | E&S down -78.1% (-$43.0m) • Assumed E&S premiums impacted by termination and cut-off of a quota share treaty effective 6/1/20 • Excluding E&S, Florida +8.2% (+$20.0m) | Non-Florida +8.5% (+$12.9m) • Gross Premiums Earned (GPE) of $344.1m: • Up +4.3% (+$14.1m) y/y • Ceded Premiums Earned (CPE) of $(158.7)m: • Up +13.6% (+$19.0m) y/y | Ceding ratio driven by increased quota share participation • Ceding ratio for quota share of 13.0% vs. 9.2% last year • Ceding ratio for all other reinsurance was unchanged at 33.1% compared to last year • Total revenue impacted by $20.5 million of unrealized gains from equities vs. $2.7m in Q2-19 II. LOSS & EXPENSE HIGHLIGHTS • Underlying loss & LAE of $72.7m: • Down -15% (-$12.4m) y/y • Underlying loss & LAE ratio improved 4.7 points to 21.1% from 25.8% last year • Current accident year CAT losses included gross losses of $76.3m less ceded losses of $46.5m • Favorable reserve development of $0.8m • Operating expenses of $82.7m: • Down -8% (-$6.9m) and gross expense ratio improved to 24.0%, down 3.2 points y/y III. COVID-19 UPDATE • We did not incur material claims or significant disruption to the business for the quarter or year ending 6.30.20 • Productivity and associate engagement remains strong in the current remote work environment • Please refer to our Form 10-Q for more information on the risks associated with COVID-19 5
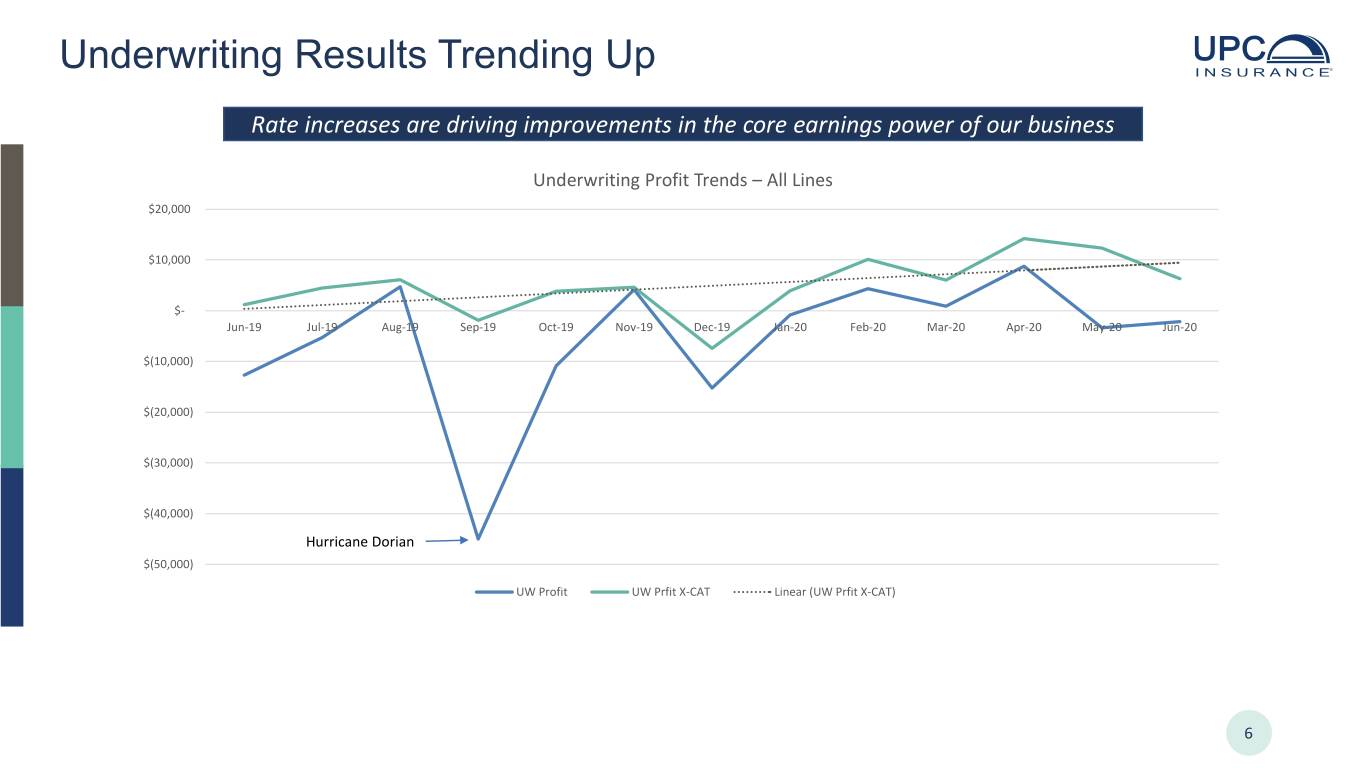
Underwriting Results Trending Up Rate increases are driving improvements in the core earnings power of our business Underwriting Profit Trends – All Lines $20,000 $10,000 $- Jun-19 Jul-19 Aug-19 Sep-19 Oct-19 Nov-19 Dec-19 Jan-20 Feb-20 Mar-20 Apr-20 May-20 Jun-20 $(10,000) $(20,000) $(30,000) $(40,000) Hurricane Dorian $(50,000) UW Profit UW Prfit X-CAT Linear (UW Prfit X-CAT) 6
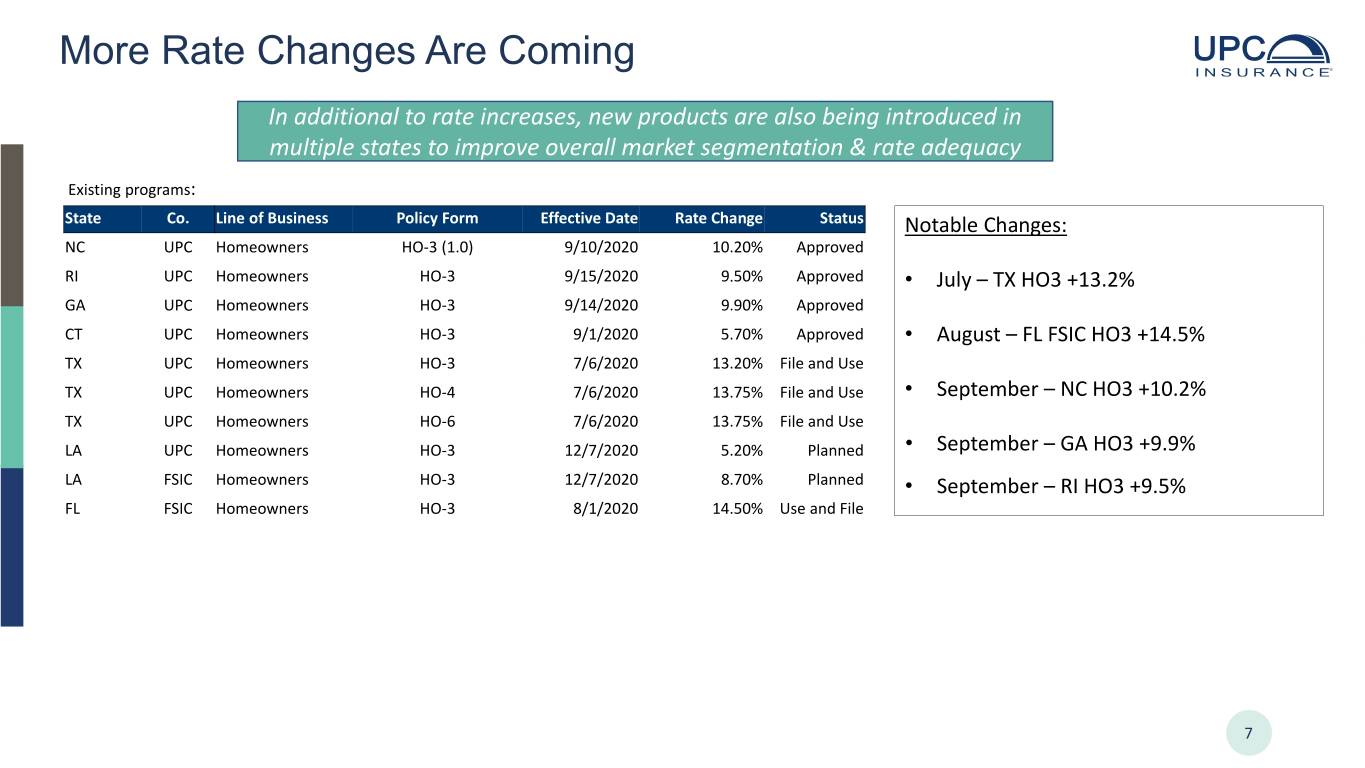
More Rate Changes Are Coming In additional to rate increases, new products are also being introduced in multiple states to improve overall market segmentation & rate adequacy Existing programs: State Co. Line of Business Policy Form Effective Date Rate Change Status Notable Changes: NC UPC Homeowners HO-3 (1.0) 9/10/2020 10.20% Approved RI UPC Homeowners HO-3 9/15/2020 9.50% Approved • July – TX HO3 +13.2% GA UPC Homeowners HO-3 9/14/2020 9.90% Approved CT UPC Homeowners HO-3 9/1/2020 5.70% Approved • August – FL FSIC HO3 +14.5% TX UPC Homeowners HO-3 7/6/2020 13.20% File and Use TX UPC Homeowners HO-4 7/6/2020 13.75% File and Use • September – NC HO3 +10.2% TX UPC Homeowners HO-6 7/6/2020 13.75% File and Use LA UPC Homeowners HO-3 12/7/2020 5.20% Planned • September – GA HO3 +9.9% LA FSIC Homeowners HO-3 12/7/2020 8.70% Planned • September – RI HO3 +9.5% FL FSIC Homeowners HO-3 8/1/2020 14.50% Use and File 7
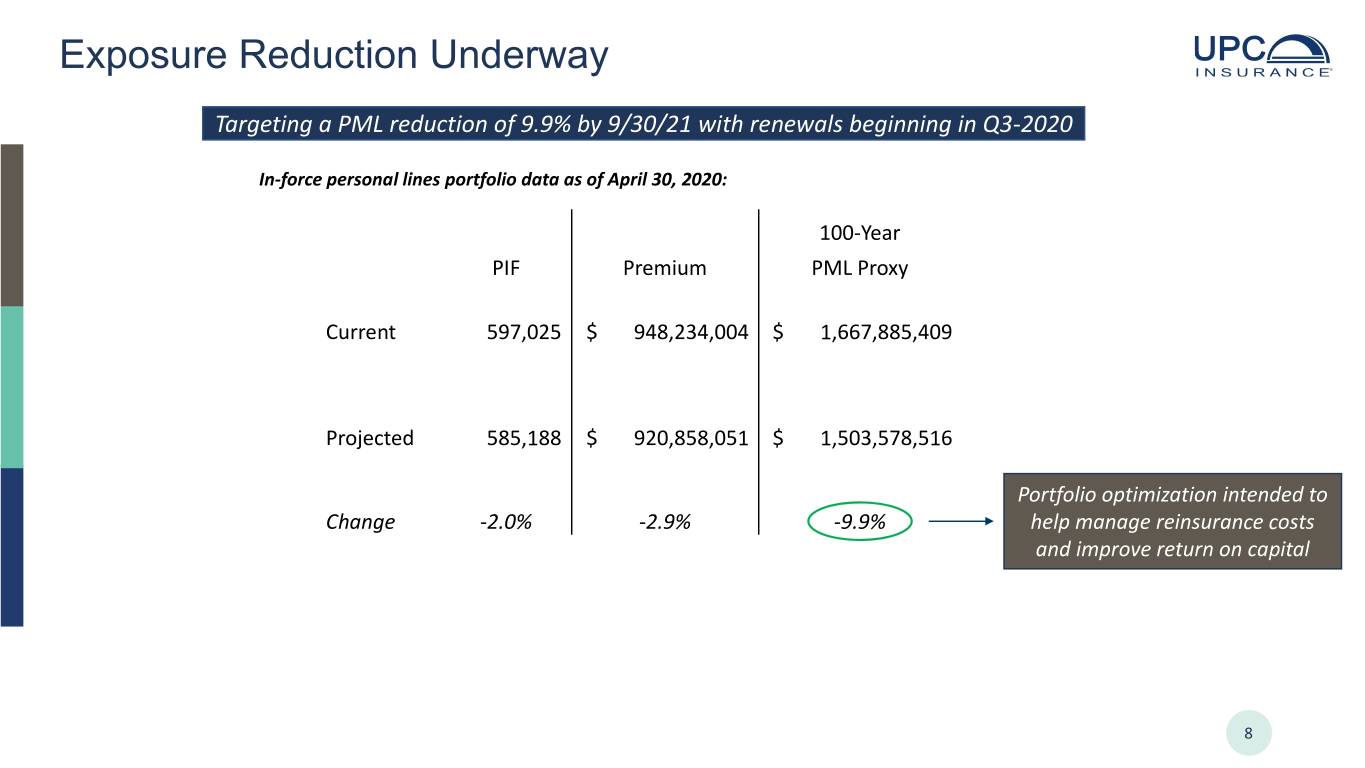
Exposure Reduction Underway Targeting a PML reduction of 9.9% by 9/30/21 with renewals beginning in Q3-2020 In-force personal lines portfolio data as of April 30, 2020: 100-Year PIF Premium PML Proxy Current 597,025 $ 948,234,004 $ 1,667,885,409 Projected 585,188 $ 920,858,051 $ 1,503,578,516 Portfolio optimization intended to Change -2.0% -2.9% -9.9% help manage reinsurance costs and improve return on capital 8
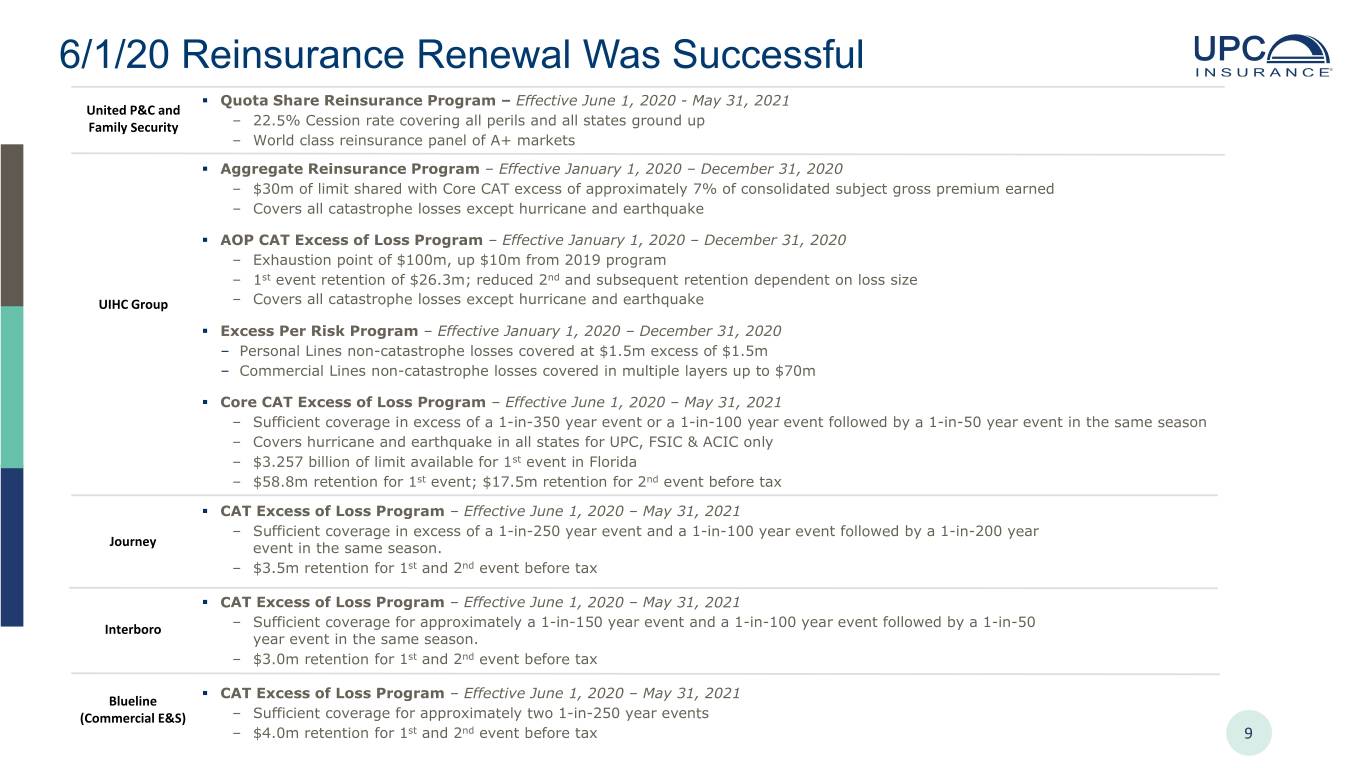
6/1/20 Reinsurance Renewal Was Successful . Quota Share Reinsurance Program – Effective June 1, 2020 - May 31, 2021 United P&C and Family Security ‒ 22.5% Cession rate covering all perils and all states ground up ‒ World class reinsurance panel of A+ markets . Aggregate Reinsurance Program – Effective January 1, 2020 – December 31, 2020 ‒ $30m of limit shared with Core CAT excess of approximately 7% of consolidated subject gross premium earned ‒ Covers all catastrophe losses except hurricane and earthquake . AOP CAT Excess of Loss Program – Effective January 1, 2020 – December 31, 2020 ‒ Exhaustion point of $100m, up $10m from 2019 program ‒ 1st event retention of $26.3m; reduced 2nd and subsequent retention dependent on loss size UIHC Group ‒ Covers all catastrophe losses except hurricane and earthquake . Excess Per Risk Program – Effective January 1, 2020 – December 31, 2020 – Personal Lines non-catastrophe losses covered at $1.5m excess of $1.5m – Commercial Lines non-catastrophe losses covered in multiple layers up to $70m . Core CAT Excess of Loss Program – Effective June 1, 2020 – May 31, 2021 ‒ Sufficient coverage in excess of a 1-in-350 year event or a 1-in-100 year event followed by a 1-in-50 year event in the same season ‒ Covers hurricane and earthquake in all states for UPC, FSIC & ACIC only ‒ $3.257 billion of limit available for 1st event in Florida ‒ $58.8m retention for 1st event; $17.5m retention for 2nd event before tax . CAT Excess of Loss Program – Effective June 1, 2020 – May 31, 2021 ‒ Sufficient coverage in excess of a 1-in-250 year event and a 1-in-100 year event followed by a 1-in-200 year Journey event in the same season. ‒ $3.5m retention for 1st and 2nd event before tax . CAT Excess of Loss Program – Effective June 1, 2020 – May 31, 2021 ‒ Sufficient coverage for approximately a 1-in-150 year event and a 1-in-100 year event followed by a 1-in-50 Interboro year event in the same season. ‒ $3.0m retention for 1st and 2nd event before tax . CAT Excess of Loss Program – Effective June 1, 2020 – May 31, 2021 Blueline (Commercial E&S) ‒ Sufficient coverage for approximately two 1-in-250 year events ‒ $4.0m retention for 1st and 2nd event before tax 9
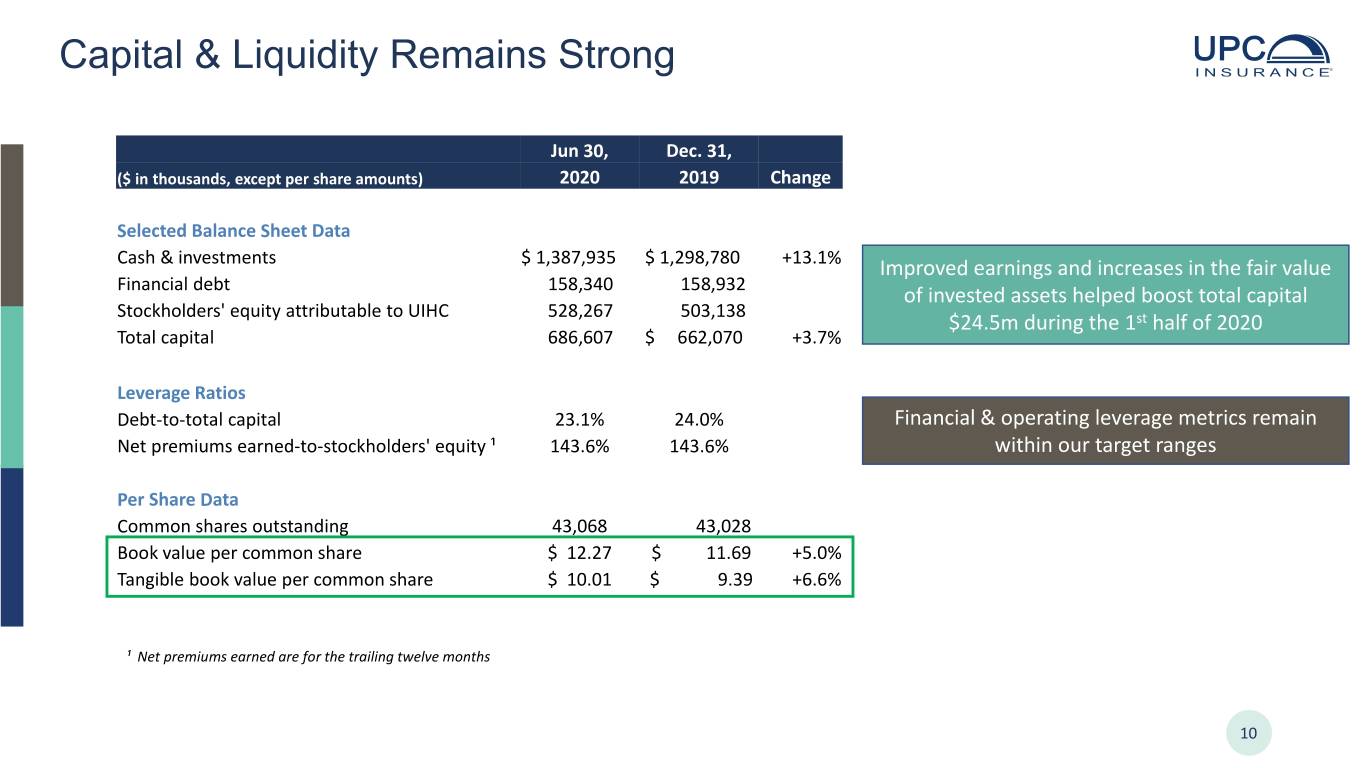
Capital & Liquidity Remains Strong Jun 30, Dec. 31, ($ in thousands, except per share amounts) 2020 2019 Change Selected Balance Sheet Data Cash & investments $ 1,387,935 $ 1,298,780 +13.1% Improved earnings and increases in the fair value Financial debt 158,340 158,932 of invested assets helped boost total capital Stockholders' equity attributable to UIHC 528,267 503,138 $24.5m during the 1st half of 2020 Total capital 686,607 $ 662,070 +3.7% Leverage Ratios Debt-to-total capital 23.1% 24.0% Financial & operating leverage metrics remain Net premiums earned-to-stockholders' equity ¹ 143.6% 143.6% within our target ranges Per Share Data Common shares outstanding 43,068 43,028 Book value per common share $ 12.27 $ 11.69 +5.0% Tangible book value per common share $ 10.01 $ 9.39 +6.6% ¹ Net premiums earned are for the trailing twelve months 10
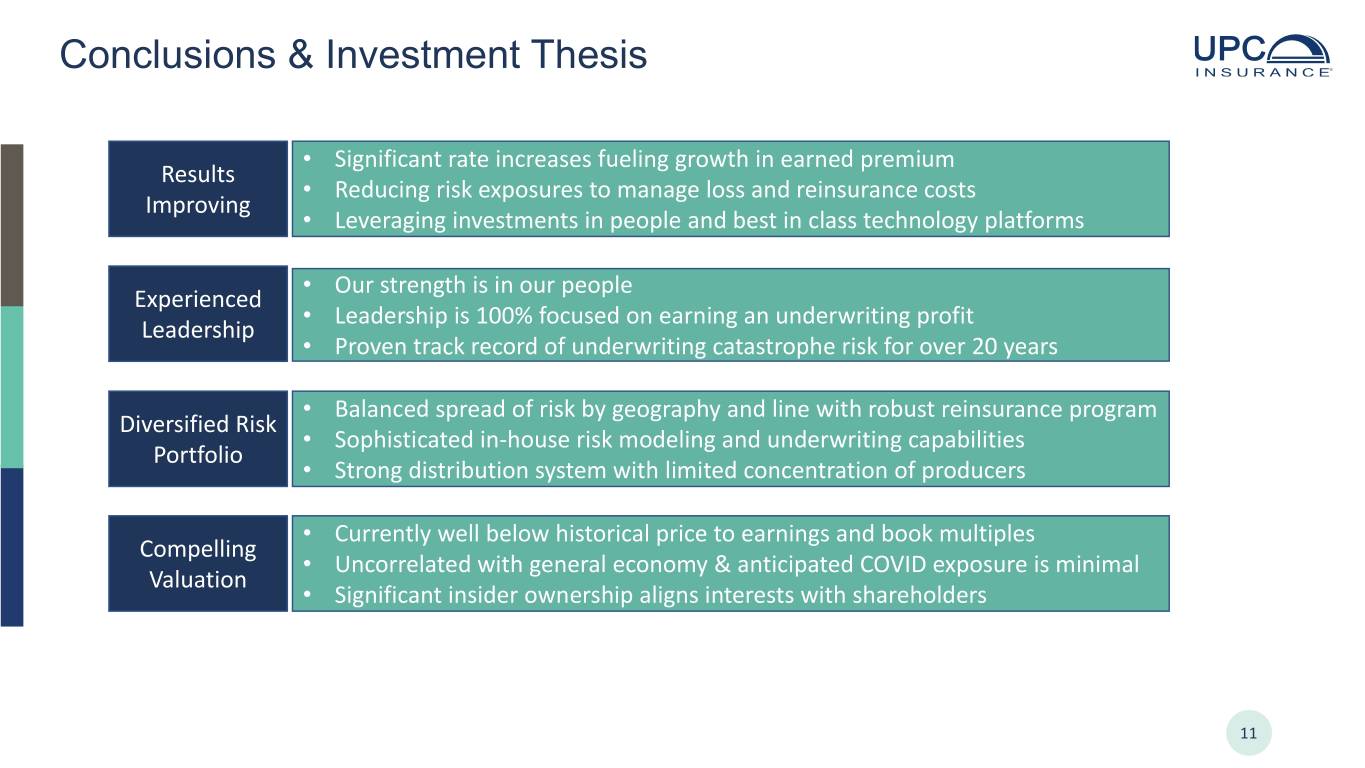
Conclusions & Investment Thesis • Significant rate increases fueling growth in earned premium Results • Reducing risk exposures to manage loss and reinsurance costs Improving • Leveraging investments in people and best in class technology platforms • Our strength is in our people Experienced • Leadership is 100% focused on earning an underwriting profit Leadership • Proven track record of underwriting catastrophe risk for over 20 years • Balanced spread of risk by geography and line with robust reinsurance program Diversified Risk • Sophisticated in-house risk modeling and underwriting capabilities Portfolio • Strong distribution system with limited concentration of producers • Currently well below historical price to earnings and book multiples Compelling • Uncorrelated with general economy & anticipated COVID exposure is minimal Valuation • Significant insider ownership aligns interests with shareholders 11
Cautionary Statements This presentation contains "forward-looking statements" within the meaning of the Private Securities Litigation Reform Act of 1995. These forward looking statements include expectations regarding our diversification, growth opportunities, retention rates, liquidity, investment returns and our ability to meet our investment objectives and to manage and mitigate market risk with respect to our investments. These statements are based on current expectations, estimates and projections about the industry and market in which we operate, and management's beliefs and assumptions. Without limiting the generality of the foregoing, words such as "may," "will," "expect," "endeavor," "project," "believe," "anticipate," "intend," "could," "would," "estimate," or "continue" or the negative variations thereof, or comparable terminology, are intended to identify forward-looking statements. Forward-looking statements are not guarantees of future performance and involve certain known and unknown risks and uncertainties that could cause actual results to differ materially from those expressed or implied by such statements. The risks and uncertainties include, without limitation: the regulatory, economic and weather conditions in the states in which we operate; the impact of new federal or state regulations that affect the property and casualty insurance market; the cost, variability and availability of reinsurance; assessments charged by various governmental agencies; pricing competition and other initiatives by competitors; our ability to attract and retain the services of senior management; the outcome of litigation pending against us, including the terms of any settlements; dependence on investment income and the composition of our investment portfolio and related market risks; our exposure to catastrophic events and severe weather conditions; downgrades in our financial strength ratings; risks and uncertainties relating to our acquisitions including our ability to successfully integrate the acquired companies; and other risks and uncertainties described in the section entitled "Risk Factors" and elsewhere in our filings with the Securities and Exchange Commission (the "SEC"), including our Annual Report in Form 10-K for the year ended December 31, 2019 and Form 10-Q for the periods ending March 31, 2020 and June 30, 2020. We caution you not to place undue reliance on these forward looking statements, which are valid only as of the date they were made. Except as may be required by applicable law, we undertake no obligation to update or revise any forward-looking statements to reflect new information, the occurrence of unanticipated events, or otherwise. This presentation contains certain non-GAAP financial measures. See the Appendix section of this presentation for further information regarding these non-GAAP financial measures. The information in this presentation is confidential. Any photocopying, disclosure, reproduction or alteration of the contents of this presentation and any forwarding of a copy of this presentation or any portion of this presentation to any person is prohibited. 12