
ASB 8-K
Associated Banc-Corp (ASB)
8-K
2022-04-21
For: 2022-04-21
View Original
Added on
April 06, 2026
| UNITED STATES SECURITIES AND EXCHANGE COMMISSION WASHINGTON, DC 20549 | |||||
| FORM | |||||
| CURRENT REPORT | |||||
| Pursuant to Section 13 OR 15(d) of the Securities Exchange Act of 1934 | |||||
| Date of Report (Date of earliest event reported) | |||||
| | ||
| (Exact name of registrant as specified in its chapter) | ||
(State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||
| (Address of principal executive offices) | (Zip code) | ||||||||||
| Registrant’s telephone number, including area code | ||||||||
| (Former name or former address, if changed since last report) | |||||
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below): | |||||
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities Registered Pursuant to Section 12(b) of the act:
| Title of each class | Trading symbol | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter). | |||||
Emerging growth company | |||||
☐ | If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. | ||||
| Item 2.02 Results of Operations and Financial Condition. | ||
| On April 21, 2022, Associated Banc-Corp announced its earnings for the quarter ended March 31, 2022. A copy of the registrant’s press release containing this information and the slide presentation discussed on the conference call for investors and analysts on April 21, 2022, are being furnished as Exhibit 99.1 and Exhibit 99.2, respectively, to this Report on Form 8-K and are incorporated herein by reference. | ||
| Item 9.01 Financial Statements and Exhibits. | ||
(d) Exhibits. | ||
The following exhibits are furnished as part of this Report on Form 8-K: | ||
| SIGNATURES | ||||||||
| Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized. | ||||||||
| Associated Banc-Corp | ||||||||
| (Registrant) | ||||||||
| Date: April 21, 2022 | By: /s/ Christopher J. Del Moral-Niles | |||||||
| Christopher J. Del Moral-Niles | ||||||||
| Chief Financial Officer | ||||||||
Exhibit 99.1
 | NEWS RELEASE Investor Contact: Ben McCarville, Vice President, Director of Investor Relations 920-491-7059 Media Contact: Jennifer Kaminski, Vice President, Public Relations Senior Manager 920-491-7576 | ||||
Associated Banc-Corp Reports First Quarter 2022 Net Income Available to Common Equity of $71 Million, or $0.47 per Common Share.
Results driven by positive margin, expense and credit trends.
GREEN BAY, Wis. -- April 21, 2022 -- Associated Banc-Corp (NYSE: ASB) ("Associated" or "Company") today reported net income available to common equity ("earnings") of $71 million, or $0.47 per common share, for the quarter ended March 31, 2022. These amounts compare to earnings of $89 million, or $0.58 per common share for the quarter ended March 31, 2021 and earnings of $74 million, or $0.49 per common share for the quarter ended December 31, 2021.
"Our first quarter results were marked by strong positive momentum in our strategic lending initiatives," said President and CEO Andy Harmening. "Commercial line utilization continues to climb, employment trends in our markets continue to reflect robust productivity and credit remains remarkably benign. Our core customers continue to borrow and grow, and we remain committed to supporting them with their financial needs. In this spirit, we also announced today that we plan to implement several changes to our overdraft program in the third quarter of this year. These changes are expected to reduce the total burden of overdrafts to our customers by approximately 30%."
"As a bank, we're in a far different place than we were a year ago," Harmening continued. "We're well-positioned to deliver expanding margins, positive operating leverage and enhanced value to all of our stakeholders as we move through 2022."
First Quarter 2022 Highlights (all comparisons to the fourth quarter of 2021)
•Average loans were up $302 million to $24.1 billion
•Excluding PPP, average Commercial & Business Lending loans were up $177 million to $9.0 billion
•Average deposits were up $245 million to $28.6 billion
•Quarterly net interest margin was up two basis points to 2.42%
•Net interest income was up $1 million to $188 million
•Noninterest income was down $7 million to $74 million
•Noninterest expense was down $9 million to $173 million
•Provision for credit losses was negative $4 million compared to negative $6 million
•Net income available to common equity was down $3 million to $71 million
Loans
First quarter 2022 average total loans of $24.1 billion were up 1%, or $302 million from the prior quarter and were down 1%, or $366 million from the same period last year. Excluding PPP, average total loans of $24.1 billion were up 2%, or $374 million from the prior quarter and were up 2%, or $397 million from the same period last year. With respect to first quarter 2022 average balances by loan category:
•Commercial and business lending (excluding PPP) increased $177 million from the prior quarter and increased $481 million compared to the same period last year to $9.0 billion.
•Commercial real estate lending increased $43 million from the prior quarter and increased $6 million from the same period last year to $6.2 billion.
•Consumer lending was $8.9 billion, up $154 million from the prior quarter and down $90 million from the same period last year.
•PPP loans decreased $71 million from the prior quarter and decreased $763 million from the same period last year to $44 million.
First quarter 2022 period-end total loans of $24.5 billion were up 1%, or $307 million from the prior quarter and were up 2%, or $370 million from the same period last year. Excluding PPP, period-end total loans of $24.5 billion were up 1%, or $355 million from the prior quarter and were up 5%, or $1.2 billion from the same period last year. With respect to first quarter 2022 period-end balances by loan category:
•Commercial and business lending (excluding PPP) decreased $51 million from the prior quarter and increased $759 million from the same period last year to $9.3 billion.
•Commercial real estate lending increased $36 million from the prior quarter and increased $86 million from the same period last year to $6.2 billion.
•Consumer lending was $9.0 billion, up $370 million from the prior quarter and up $343 million from the same period last year.
•PPP loans decreased $48 million from the prior quarter and decreased $819 million from the same period last year to $18 million.
In 2022, we expect full-year auto finance loan growth of over $1.2 billion and total commercial loan growth of $750 million to $1 billion.
Deposits
First quarter 2022 average deposits of $28.6 billion were up 1%, or $245 million compared to the prior quarter and were up 7%, or $1.8 billion from the same period last year. With respect to first quarter 2022 average balances by deposit category:
•Noninterest-bearing demand deposits decreased $100 million from the prior quarter and increased $650 million from the same period last year to $8.3 billion.
•Savings increased $163 million from the prior quarter and increased $720 million from the same period last year to $4.5 billion.
•Interest-bearing demand deposits increased $216 million from the prior quarter and increased $1.0 billion from the same period last year to $6.7 billion.
•Money market deposits increased $138 million from the prior quarter and increased $155 million from the same period last year to $7.0 billion.
•Time deposits decreased $68 million from the prior quarter and decreased $345 million from the same period last year to $1.3 billion.
•Network transaction deposits decreased $103 million from the prior quarter and decreased $345 million from the same period last year to $735 million.
First quarter 2022 period-end deposits of $28.4 billion were down $61 million compared to the prior quarter and were up 3%, or $728 million from the same period last year. Low-cost core deposits (interest-bearing demand, noninterest-bearing demand and savings) made up 68% of deposit balances as of March 31, 2022. With respect to first quarter 2022 period-end balances by deposit category:
•Noninterest-bearing demand deposits decreased $188 million from the prior quarter and decreased $180 million from the same period last year to $8.3 billion.
•Savings increased $251 million from the prior quarter and increased $628 million from the same period last year to $4.7 billion.
•Interest-bearing demand deposits decreased $403 million from the prior quarter and increased $868 million from the same period last year to $6.6 billion.
•Money market deposits increased $338 million from the prior quarter and decreased $316 million from the same period last year to $7.5 billion.
•Time deposits decreased $58 million from the prior quarter and decreased $272 million from the same period last year to $1.3 billion.
•Network transaction deposits (included in money market and interest-bearing deposits) decreased $4 million from the prior quarter and decreased $292 million from the same period last year to $763 million.
Net Interest Income and Net Interest Margin
First quarter 2022 net interest income of $188 million was up 1%, or $1 million from the prior quarter and the net interest margin increased 2 basis points from the prior quarter to 2.42%. Compared to the same period last year, net interest income increased 7%, or $12 million, and the net interest margin increased 3 basis points.
•The average yield on total loans for the first quarter of 2022 decreased 5 basis points from the prior quarter and decreased 7 basis points from the same period last year to 2.81%.
•The average cost of total interest-bearing liabilities for the first quarter of 2022 decreased 1 basis point from the prior quarter and decreased 14 basis points from the same period last year to 0.26%.
•The net free funds benefit for the first quarter of 2022 remained flat to the prior quarter and decreased 4 basis points compared to the same period last year to 0.08%.
We now expect short-term interest rates to rise following each of this year's Federal Open Market Committee meetings. Assuming rate increases of 25 basis points or more following each meeting, we now expect our 2022 net interest income to exceed $840 million.
Noninterest Income
First quarter 2022 total noninterest income of $74 million decreased $7 million from the prior quarter and decreased $21 million from the same period last year. With respect to first quarter 2022 noninterest income line items:
•Mortgage Banking, net was $8 million for the first quarter, up slightly from the prior quarter. Relative to the prior-year period, Mortgage Banking was down $16 million, driven by slowing refinance activity and higher retention of mortgages on our balance sheet.
•Service charges and deposit account fees decreased slightly from the prior quarter and increased $2 million from the same period last year.
•Card-based fees decreased $1 million from the prior quarter and increased slightly from the same period last year.
•Capital markets fees decreased $1 million from the prior quarter and increased $1 million from the same period last year.
Guided by customer feedback, we announced today that we are making several customer-friendly changes to our overdraft program in the third quarter of 2022. The planned changes are expected to reduce service charges and deposit account fees by approximately $3 million in 2022. Additional details can be found in the press release available at investor.associatedbank.com.
Given our revised outlook for higher rates in 2022, we are also modifying our noninterest income guidance. We are now expecting less mortgage banking income and lower service charge revenues for both commercial and consumer customers over the back half of the year. We now expect total noninterest income for the year of between $290 million and $300 million.
Noninterest Expense
First quarter 2022 total noninterest expense of $173 million decreased $9 million from the prior quarter and decreased $2 million compared to the same period last year. With respect to first quarter 2022 noninterest expense line items:
•Personnel expense decreased $3 million from the prior quarter and increased $1 million from the same period last year.
•Other expense decreased $7 million from the prior quarter and decreased $2 million from the same period last year, primarily driven by a reduction in pension, donation and other expenses.
We expect total noninterest expense of approximately $725 million to $740 million for 2022.
Taxes
The first quarter 2022 tax expense was $19 million compared to $15 million of tax expense in the prior quarter and $25 million of tax expense in the same period last year. The effective tax rate for first quarter of 2022 was 20.1% compared to an effective tax rate of 16.5% in the prior quarter.
We expect the annual 2022 tax rate to be between 19% and 21%, assuming no change in the statutory corporate tax rate.
Credit
The first quarter 2022 provision for credit losses was negative $4 million, compared to a negative provision of $6 million in the prior quarter and a negative provision of $23 million in the same period last year. With respect to first quarter 2022 credit quality:
•Total accruing loans 30-89 days past due of $13 million were down $3 million from the prior quarter and down $2 million from the same period last year.
•Nonaccrual loans of $143 million were up $13 million from the prior quarter and down $20 million from the same period last year. The nonaccrual loans to total loans ratio was 0.58% in the first quarter, up from 0.54% in the prior quarter and down from 0.68% in the same period last year.
•First quarter net recoveries of $2 million compared to net charge offs of $6 million in the prior quarter and net charge offs of $5 million in the same period last year.
•The allowance for credit losses on loans (ACLL) of $318 million was down $2 million from the prior quarter and down $86 million compared to the same period last year. The ACLL to total loans ratio was 1.30% in the first quarter, down from 1.32% in the prior quarter and down from 1.67% in the same period last year.
Throughout the remainder of 2022, we expect to adjust provision to reflect changes to risk grades, economic conditions, other indications of credit quality, and loan volume.
Capital
The Company’s capital position remains strong, with a CET1 capital ratio of 10.2% at March 31, 2022. The Company’s capital ratios continue to be in excess of the Basel III “well-capitalized” regulatory benchmarks on a fully phased in basis.
FIRST QUARTER 2022 EARNINGS RELEASE CONFERENCE CALL
The Company will host a conference call for investors and analysts at 4:00 p.m. Central Time (CT) today, April 21, 2022. Interested parties can access the live webcast of the call through the Investor Relations section of the Company's website, http://investor.associatedbank.com. Parties may also dial into the call at 877-407-8037 (domestic) or 201-689-8037 (international) and request the Associated Banc-Corp first quarter 2022 earnings call. The first quarter 2022 financial tables with an accompanying slide presentation will be available on the Company's website just prior to the call. An audio archive of the webcast will be available on the Company's website approximately fifteen minutes after the call is over.
ABOUT ASSOCIATED BANC-CORP
Associated Banc-Corp (NYSE: ASB) has total assets of $35 billion and is Wisconsin's largest bank holding company. Headquartered in Green Bay, Wisconsin, Associated is a leading Midwest banking franchise, offering a full range of financial products and services from more than 200 banking locations serving more than 100 communities throughout Wisconsin, Illinois and Minnesota. The company also operates loan production offices in Indiana, Michigan, Missouri, New York, Ohio and Texas. Associated Bank, N.A. is an Equal Housing Lender, Equal Opportunity Lender and Member FDIC. More information about Associated Banc-Corp is available at www.associatedbank.com.
FORWARD-LOOKING STATEMENTS
Statements made in this document which are not purely historical are forward-looking statements, as defined in the Private Securities Litigation Reform Act of 1995. This includes any statements regarding management’s plans, objectives, or goals for future operations, products or services, and forecasts of its revenues, earnings, or other measures of performance. Such forward-looking statements may be identified by the use of words such as “believe,” “expect,” “anticipate,” “plan,” “estimate,” “should,” “will,” “intend,” "target," “outlook,” "project," "guidance," or similar expressions. Forward-looking statements are based on current management expectations and, by their nature, are subject to risks and uncertainties. Actual results may differ materially from those contained in the forward-looking statements. Factors which may cause actual results to differ materially from those contained in such forward-looking statements include those identified in the Company’s most recent Form 10-K and subsequent SEC filings. Such factors are incorporated herein by reference.
NON-GAAP FINANCIAL MEASURES
This press release and related materials may contain references to measures which are not defined in generally accepted accounting principles (“GAAP”). Information concerning these non-GAAP financial measures can be found in the financial tables. Management believes these measures are meaningful because they reflect adjustments commonly made by management, investors, regulators, and analysts to evaluate the adequacy of earnings per common share, provide a greater understanding of ongoing operations and enhance comparability of results with prior periods.
# # #
| Associated Banc-Corp Consolidated Balance Sheets (Unaudited) | |||||||||||||||||||||||
| ($ in thousands) | March 31, 2022 | December 31, 2021 | Seql Qtr $ Change | September 30, 2021 | June 30, 2021 | March 31, 2021 | Comp Qtr $ Change | ||||||||||||||||
| Assets | |||||||||||||||||||||||
| Cash and due from banks | $ | 334,138 | $ | 343,831 | $ | (9,693) | $ | 378,927 | $ | 406,994 | $ | 356,285 | $ | (22,147) | |||||||||
| Interest-bearing deposits in other financial institutions | 166,929 | 681,684 | (514,755) | 1,281,916 | 1,340,385 | 1,590,494 | (1,423,565) | ||||||||||||||||
| Federal funds sold and securities purchased under agreements to resell | — | — | — | 25,000 | 25,000 | — | — | ||||||||||||||||
| Investment securities available for sale, at fair value | 2,780,803 | 4,332,015 | (1,551,212) | 3,893,379 | 3,323,346 | 3,356,949 | (576,146) | ||||||||||||||||
| Investment securities held to maturity, net, at amortized cost | 3,939,855 | 2,238,947 | 1,700,908 | 1,929,735 | 1,799,834 | 1,857,087 | 2,082,768 | ||||||||||||||||
| Equity securities | 18,560 | 18,352 | 208 | 17,939 | 17,144 | 15,673 | 2,887 | ||||||||||||||||
| Federal Home Loan Bank and Federal Reserve Bank stocks, at cost | 168,281 | 168,281 | — | 168,281 | 168,281 | 168,281 | — | ||||||||||||||||
| Residential loans held for sale | 91,582 | 136,638 | (45,056) | 158,202 | 160,547 | 153,151 | (61,569) | ||||||||||||||||
| Loans | 24,531,926 | 24,224,949 | 306,977 | 23,621,673 | 23,947,536 | 24,162,328 | 369,598 | ||||||||||||||||
| Allowance for loan losses | (279,058) | (280,015) | 957 | (290,997) | (318,811) | (352,938) | 73,880 | ||||||||||||||||
| Loans, net | 24,252,867 | 23,944,934 | 307,933 | 23,330,676 | 23,628,725 | 23,809,389 | 443,478 | ||||||||||||||||
| Tax credit and other investments | 284,561 | 293,733 | (9,172) | 301,490 | 294,220 | 303,701 | (19,140) | ||||||||||||||||
| Premises and equipment, net | 387,550 | 385,173 | 2,377 | 383,131 | 398,050 | 398,671 | (11,121) | ||||||||||||||||
| Bank and corporate owned life insurance | 679,538 | 680,021 | (483) | 683,610 | 682,709 | 680,831 | (1,293) | ||||||||||||||||
| Goodwill | 1,104,992 | 1,104,992 | — | 1,104,992 | 1,104,992 | 1,104,992 | — | ||||||||||||||||
| Other intangible assets, net | 55,890 | 58,093 | (2,203) | 60,296 | 62,498 | 64,701 | (8,811) | ||||||||||||||||
Mortgage servicing rights, net(a) | 67,015 | 54,862 | 12,153 | 50,329 | 48,335 | 49,500 | 17,515 | ||||||||||||||||
| Interest receivable | 83,120 | 80,528 | 2,592 | 79,011 | 81,797 | 86,466 | (3,346) | ||||||||||||||||
| Other assets | 540,218 | 582,168 | (41,950) | 592,753 | 609,766 | 579,084 | (38,866) | ||||||||||||||||
| Total assets | $ | 34,955,900 | $ | 35,104,253 | $ | (148,353) | $ | 34,439,666 | $ | 34,152,625 | $ | 34,575,255 | $ | 380,645 | |||||||||
| Liabilities and stockholders’ equity | |||||||||||||||||||||||
| Noninterest-bearing demand deposits | $ | 8,315,699 | $ | 8,504,077 | $ | (188,378) | $ | 8,170,105 | $ | 7,999,143 | $ | 8,496,194 | $ | (180,495) | |||||||||
| Interest-bearing deposits | 20,089,710 | 19,962,353 | 127,357 | 19,681,161 | 19,265,157 | 19,180,972 | 908,738 | ||||||||||||||||
| Total deposits | 28,405,409 | 28,466,430 | (61,021) | 27,851,266 | 27,264,299 | 27,677,166 | 728,243 | ||||||||||||||||
| Federal funds purchased and securities sold under agreements to repurchase | 368,768 | 319,532 | 49,236 | 267,943 | 170,419 | 138,507 | 230,261 | ||||||||||||||||
| Commercial paper | 30,593 | 34,730 | (4,137) | 54,553 | 55,785 | 51,171 | (20,578) | ||||||||||||||||
| FHLB advances | 1,537,948 | 1,621,047 | (83,099) | 1,620,880 | 1,619,826 | 1,629,966 | (92,018) | ||||||||||||||||
| Other long-term funding | 249,797 | 249,324 | 473 | 249,160 | 549,024 | 549,729 | (299,932) | ||||||||||||||||
| Allowance for unfunded commitments | 38,776 | 39,776 | (1,000) | 41,276 | 45,276 | 50,776 | (12,000) | ||||||||||||||||
| Accrued expenses and other liabilities | 376,322 | 348,560 | 27,762 | 359,626 | 337,942 | 350,160 | 26,162 | ||||||||||||||||
| Total liabilities | 31,007,613 | 31,079,399 | (71,786) | 30,444,705 | 30,042,573 | 30,447,474 | 560,139 | ||||||||||||||||
| Stockholders’ equity | |||||||||||||||||||||||
| Preferred equity | 193,195 | 193,195 | — | 193,195 | 290,200 | 353,512 | (160,317) | ||||||||||||||||
| Common equity | 3,755,092 | 3,831,658 | (76,566) | 3,801,766 | 3,819,852 | 3,774,268 | (19,176) | ||||||||||||||||
| Total stockholders’ equity | 3,948,287 | 4,024,853 | (76,566) | 3,994,961 | 4,110,052 | 4,127,780 | (179,493) | ||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 34,955,900 | $ | 35,104,253 | $ | (148,353) | $ | 34,439,666 | $ | 34,152,625 | $ | 34,575,255 | $ | 380,645 | |||||||||
Numbers may not sum due to rounding.
(a) On January 1, 2022, the Corporation made the irrevocable election to account for mortgage servicing rights, net at fair value. For all prior periods, mortgage servicing rights, net were carried at lower of cost or market.
1
| Associated Banc-Corp Consolidated Statements of Income (Unaudited) - Quarterly Trend | |||||||||||||||||||||||||||||
| ($ in thousands, except per share data) | Seql Qtr | Comp Qtr | |||||||||||||||||||||||||||
| 1Q22 | 4Q21 | $ Change | % Change | 3Q21 | 2Q21 | 1Q21 | $ Change | % Change | |||||||||||||||||||||
| Interest income | |||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 167,697 | $ | 170,809 | $ | (3,112) | (2) | % | $ | 174,643 | $ | 174,228 | $ | 174,049 | $ | (6,352) | (4) | % | |||||||||||
| Interest and dividends on investment securities | |||||||||||||||||||||||||||||
| Taxable | 16,472 | 13,317 | 3,155 | 24 | % | 8,745 | 8,840 | 7,014 | 9,458 | 135 | % | ||||||||||||||||||
| Tax-exempt | 16,108 | 15,569 | 539 | 3 | % | 14,613 | 14,366 | 14,162 | 1,946 | 14 | % | ||||||||||||||||||
| Other interest | 1,993 | 2,031 | (38) | (2) | % | 2,281 | 1,826 | 1,694 | 299 | 18 | % | ||||||||||||||||||
| Total interest income | 202,270 | 201,726 | 544 | — | % | 200,282 | 199,260 | 196,920 | 5,350 | 3 | % | ||||||||||||||||||
| Interest expense | |||||||||||||||||||||||||||||
| Interest on deposits | 3,571 | 3,677 | (106) | (3) | % | 4,427 | 4,609 | 5,909 | (2,338) | (40) | % | ||||||||||||||||||
| Interest on federal funds purchased and securities sold under agreements to repurchase | 38 | 40 | (2) | (5) | % | 48 | 30 | 26 | 12 | 46 | % | ||||||||||||||||||
| Interest on other short-term funding | 1 | 2 | (1) | (50) | % | 8 | 7 | 6 | (5) | (83) | % | ||||||||||||||||||
| Interest on FHLB Advances | 8,182 | 8,514 | (332) | (4) | % | 8,962 | 9,524 | 9,493 | (1,311) | (14) | % | ||||||||||||||||||
| Interest on long-term funding | 2,730 | 2,730 | — | — | % | 3,163 | 5,575 | 5,585 | (2,855) | (51) | % | ||||||||||||||||||
| Total interest expense | 14,522 | 14,963 | (441) | (3) | % | 16,607 | 19,745 | 21,018 | (6,496) | (31) | % | ||||||||||||||||||
| Net interest income | 187,747 | 186,763 | 984 | 1 | % | 183,675 | 179,515 | 175,902 | 11,845 | 7 | % | ||||||||||||||||||
| Provision for credit losses | (3,990) | (5,993) | 2,003 | (33) | % | (24,010) | (35,004) | (23,004) | 19,014 | (83) | % | ||||||||||||||||||
| Net interest income after provision for credit losses | 191,737 | 192,756 | (1,019) | (1) | % | 207,685 | 214,519 | 198,906 | (7,169) | (4) | % | ||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||
| Wealth management fees | 22,404 | 22,625 | (221) | (1) | % | 22,110 | 22,706 | 22,414 | (10) | — | % | ||||||||||||||||||
| Service charges and deposit account fees | 16,856 | 17,039 | (183) | (1) | % | 16,962 | 15,549 | 14,855 | 2,001 | 13 | % | ||||||||||||||||||
| Card-based fees | 9,926 | 11,176 | (1,250) | (11) | % | 11,113 | 10,982 | 9,743 | 183 | 2 | % | ||||||||||||||||||
| Other fee-based revenue | 3,766 | 4,316 | (550) | (13) | % | 3,929 | 4,244 | 4,596 | (830) | (18) | % | ||||||||||||||||||
| Capital markets, net | 8,646 | 9,674 | (1,028) | (11) | % | 7,114 | 5,696 | 8,118 | 528 | 7 | % | ||||||||||||||||||
| Mortgage banking, net | 8,391 | 8,041 | 350 | 4 | % | 10,657 | 8,128 | 23,925 | (15,534) | (65) | % | ||||||||||||||||||
| Bank and corporate owned life insurance | 2,071 | 4,704 | (2,633) | (56) | % | 2,760 | 3,088 | 2,702 | (631) | (23) | % | ||||||||||||||||||
| Asset gains (losses), net | 188 | 985 | (797) | (81) | % | 5,228 | (14) | 4,809 | (4,621) | (96) | % | ||||||||||||||||||
| Investment securities gains (losses), net | 21 | — | 21 | N/M | — | 24 | (39) | 60 | N/M | ||||||||||||||||||||
Gains on sale of branches, net(a) | — | — | — | N/M | — | 36 | 1,002 | (1,002) | (100) | % | |||||||||||||||||||
| Other | 2,198 | 2,941 | (743) | (25) | % | 2,205 | 3,004 | 3,216 | (1,018) | (32) | % | ||||||||||||||||||
| Total noninterest income | 74,467 | 81,502 | (7,035) | (9) | % | 82,076 | 73,443 | 95,343 | (20,876) | (22) | % | ||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||
| Personnel | 104,811 | 107,787 | (2,976) | (3) | % | 107,880 | 106,994 | 104,026 | 785 | 1 | % | ||||||||||||||||||
| Technology | 21,485 | 20,787 | 698 | 3 | % | 19,927 | 20,236 | 20,740 | 745 | 4 | % | ||||||||||||||||||
| Occupancy | 16,080 | 16,863 | (783) | (5) | % | 15,814 | 14,679 | 16,156 | (76) | — | % | ||||||||||||||||||
| Business development and advertising | 4,954 | 5,627 | (673) | (12) | % | 6,156 | 4,970 | 4,395 | 559 | 13 | % | ||||||||||||||||||
| Equipment | 4,960 | 4,905 | 55 | 1 | % | 5,200 | 5,481 | 5,518 | (558) | (10) | % | ||||||||||||||||||
| Legal and professional | 5,087 | 4,428 | 659 | 15 | % | 4,304 | 6,661 | 6,530 | (1,443) | (22) | % | ||||||||||||||||||
| Loan and foreclosure costs | 2,014 | 1,636 | 378 | 23 | % | 1,616 | 2,671 | 2,220 | (206) | (9) | % | ||||||||||||||||||
| FDIC assessment | 5,100 | 4,800 | 300 | 6 | % | 5,000 | 3,600 | 4,750 | 350 | 7 | % | ||||||||||||||||||
| Other intangible amortization | 2,203 | 2,203 | — | — | % | 2,203 | 2,203 | 2,236 | (33) | (1) | % | ||||||||||||||||||
| Other | 6,597 | 13,173 | (6,576) | (50) | % | 9,793 | 6,979 | 8,775 | (2,178) | (25) | % | ||||||||||||||||||
| Total noninterest expense | 173,292 | 182,210 | (8,918) | (5) | % | 177,892 | 174,475 | 175,347 | (2,055) | (1) | % | ||||||||||||||||||
| Income before income taxes | 92,912 | 92,048 | 864 | 1 | % | 111,870 | 113,487 | 118,903 | (25,991) | (22) | % | ||||||||||||||||||
| Income tax expense | 18,650 | 15,171 | 3,479 | 23 | % | 23,060 | 22,480 | 24,602 | (5,952) | (24) | % | ||||||||||||||||||
| Net income | 74,262 | 76,877 | (2,615) | (3) | % | 88,809 | 91,007 | 94,301 | (20,039) | (21) | % | ||||||||||||||||||
| Preferred stock dividends | 2,875 | 2,875 | — | — | % | 4,155 | 4,875 | 5,207 | (2,332) | (45) | % | ||||||||||||||||||
| Net income available to common equity | $ | 71,387 | $ | 74,002 | $ | (2,615) | (4) | % | $ | 84,655 | $ | 86,131 | $ | 89,094 | $ | (17,707) | (20) | % | |||||||||||
| Earnings per common share | |||||||||||||||||||||||||||||
| Basic | $ | 0.48 | $ | 0.49 | $ | (0.01) | (2) | % | $ | 0.56 | $ | 0.56 | $ | 0.58 | $ | (0.10) | (17) | % | |||||||||||
| Diluted | $ | 0.47 | $ | 0.49 | $ | (0.02) | (4) | % | $ | 0.56 | $ | 0.56 | $ | 0.58 | $ | (0.11) | (19) | % | |||||||||||
| Average common shares outstanding | |||||||||||||||||||||||||||||
| Basic | 148,781 | 148,697 | 84 | — | % | 150,046 | 152,042 | 152,355 | (3,574) | (2) | % | ||||||||||||||||||
| Diluted | 150,492 | 150,057 | 435 | — | % | 151,143 | 153,381 | 153,688 | (3,196) | (2) | % | ||||||||||||||||||
N/M = Not meaningful
Numbers may not sum due to rounding.
(a) Includes the deposit premium on the sale of branches net of miscellaneous costs to sell
2
| Associated Banc-Corp Selected Quarterly Information | |||||||||||||||||
| ($ in millions except per share data; shares repurchased and outstanding in thousands) | 1Q22 | 4Q21 | 3Q21 | 2Q21 | 1Q21 | ||||||||||||
| Per common share data | |||||||||||||||||
| Dividends | $ | 0.20 | $ | 0.20 | $ | 0.20 | $ | 0.18 | $ | 0.18 | |||||||
| Market value: | |||||||||||||||||
| High | 25.71 | 23.92 | 21.85 | 23.33 | 23.14 | ||||||||||||
| Low | 22.41 | 21.49 | 18.56 | 20.36 | 17.20 | ||||||||||||
| Close | 22.76 | 22.59 | 21.42 | 20.48 | 21.34 | ||||||||||||
| Book value / share | 25.03 | 25.66 | 25.35 | 24.99 | 24.56 | ||||||||||||
| Tangible book value / share | 17.29 | 17.87 | 17.58 | 17.35 | 16.95 | ||||||||||||
| Performance ratios (annualized) | |||||||||||||||||
| Return on average assets | 0.86 | % | 0.87 | % | 1.01 | % | 1.06 | % | 1.14 | % | |||||||
| Noninterest expense / average assets | 2.00 | % | 2.06 | % | 2.03 | % | 2.04 | % | 2.11 | % | |||||||
| Effective tax rate | 20.07 | % | 16.48 | % | 20.61 | % | 19.81 | % | 20.69 | % | |||||||
Dividend payout ratio(a) | 41.67 | % | 40.82 | % | 35.71 | % | 32.14 | % | 31.03 | % | |||||||
| Net interest margin | 2.42 | % | 2.40 | % | 2.38 | % | 2.37 | % | 2.39 | % | |||||||
| Selected trend information | |||||||||||||||||
Average full time equivalent employees(b) | 4,018 | 3,992 | 4,010 | 3,990 | 4,020 | ||||||||||||
| Branch count | 215 | 215 | 224 | 224 | 227 | ||||||||||||
Assets under management, at market value(c) | $ | 12,937 | $ | 13,679 | $ | 13,148 | $ | 13,141 | $ | 12,553 | |||||||
| Mortgage loans originated for sale during period | $ | 252 | $ | 404 | $ | 456 | $ | 477 | $ | 413 | |||||||
| Mortgage loan settlements during period | $ | 296 | $ | 427 | $ | 463 | $ | 484 | $ | 400 | |||||||
| Mortgage portfolio serviced for others | $ | 6,972 | $ | 6,995 | $ | 7,057 | $ | 7,150 | $ | 7,313 | |||||||
Mortgage servicing rights, net / mortgage portfolio serviced for others(d) | 0.96 | % | 0.78 | % | 0.71 | % | 0.68 | % | 0.68 | % | |||||||
Shares repurchased during period(e) | — | 1,096 | 2,919 | 1,314 | 966 | ||||||||||||
| Shares outstanding, end of period | 150,038 | 149,343 | 149,961 | 152,865 | 153,685 | ||||||||||||
| Selected quarterly ratios | |||||||||||||||||
| Loans / deposits | 86.36 | % | 85.10 | % | 84.81 | % | 87.83 | % | 87.30 | % | |||||||
| Stockholders’ equity / assets | 11.30 | % | 11.47 | % | 11.60 | % | 12.03 | % | 11.94 | % | |||||||
Risk-based capital(f)(g) | |||||||||||||||||
| Total risk-weighted assets | $ | 27,781 | $ | 27,243 | $ | 26,304 | $ | 26,073 | $ | 25,640 | |||||||
| Common equity Tier 1 | $ | 2,838 | $ | 2,808 | $ | 2,780 | $ | 2,790 | $ | 2,759 | |||||||
| Common equity Tier 1 capital ratio | 10.22 | % | 10.31 | % | 10.57 | % | 10.70 | % | 10.76 | % | |||||||
| Tier 1 capital ratio | 10.91 | % | 11.02 | % | 11.30 | % | 11.81 | % | 12.14 | % | |||||||
| Total capital ratio | 12.41 | % | 13.10 | % | 13.50 | % | 14.02 | % | 14.36 | % | |||||||
| Tier 1 leverage ratio | 8.86 | % | 8.83 | % | 8.81 | % | 9.23 | % | 9.53 | % | |||||||
| Mortgage banking, net | |||||||||||||||||
Mortgage servicing fees, net(h) | $ | 2 | $ | 1 | $ | — | $ | — | $ | (1) | |||||||
| Gains (losses) and fair value adjustments on loans held for sale | 1 | 3 | 8 | 9 | 15 | ||||||||||||
Changes in mortgage servicing rights valuation, net of economic hedge(d) | 6 | 4 | 2 | — | 11 | ||||||||||||
| Mortgage banking, net | $ | 8 | $ | 8 | $ | 11 | $ | 8 | $ | 24 | |||||||
N/M = Not meaningful
Numbers may not sum due to rounding.
(a)Ratio is based upon basic earnings per common share.
(b)Average full time equivalent employees without overtime.
(c)Excludes assets held in brokerage accounts.
(d)On January 1, 2022, the Corporation made the irrevocable election to account for mortgage servicing rights at fair value. For all prior periods, mortgage servicing rights were carried at lower of cost or market.
(e)Does not include repurchases related to tax withholding on equity compensation.
(f)The Federal Reserve establishes regulatory capital requirements, including well-capitalized standards for the Corporation. The regulatory capital requirements effective for the Corporation follow Basel III, subject to certain transition provisions.
(g)March 31, 2022 data is estimated.
(h)Includes mortgage origination and servicing fees, net of mortgage servicing rights amortization/decay.
3
| Associated Banc-Corp Selected Asset Quality Information | |||||||||||||||||||||||
| ($ in thousands) | Mar 31, 2022 | Dec 31, 2021 | Seql Qtr % Change | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Comp Qtr % Change | ||||||||||||||||
| Allowance for loan losses | |||||||||||||||||||||||
| Balance at beginning of period | $ | 280,015 | $ | 290,997 | (4) | % | $ | 318,811 | $ | 352,938 | $ | 383,702 | (27) | % | |||||||||
| Provision for loan losses | (3,000) | (4,500) | (33) | % | (20,000) | (29,500) | (26,000) | (88) | % | ||||||||||||||
| Charge offs | (2,028) | (8,869) | (77) | % | (10,929) | (7,681) | (13,174) | (85) | % | ||||||||||||||
| Recoveries | 4,072 | 2,387 | 71 | % | 3,115 | 3,054 | 8,410 | (52) | % | ||||||||||||||
| Net (charge offs) recoveries | 2,044 | (6,482) | N/M | (7,814) | (4,628) | (4,764) | N/M | ||||||||||||||||
| Balance at end of period | $ | 279,058 | $ | 280,015 | — | % | $ | 290,997 | $ | 318,811 | $ | 352,938 | (21) | % | |||||||||
| Allowance for unfunded commitments | |||||||||||||||||||||||
| Balance at beginning of period | $ | 39,776 | $ | 41,276 | (4) | % | $ | 45,276 | $ | 50,776 | $ | 47,776 | (17) | % | |||||||||
| Provision for unfunded commitments | (1,000) | (1,500) | (33) | % | (4,000) | (5,500) | 3,000 | N/M | |||||||||||||||
| Balance at end of period | $ | 38,776 | $ | 39,776 | (3) | % | $ | 41,276 | $ | 45,276 | $ | 50,776 | (24) | % | |||||||||
| Allowance for credit losses on loans (ACLL) | $ | 317,835 | $ | 319,791 | (1) | % | $ | 332,273 | $ | 364,087 | $ | 403,714 | (21) | % | |||||||||
| Provision for credit losses on loans | $ | (4,000) | $ | (6,000) | (33) | % | $ | (24,000) | $ | (35,000) | $ | (23,000) | (83) | % | |||||||||
| ($ in thousands) | Mar 31, 2022 | Dec 31, 2021 | Seql Qtr % Change | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Comp Qtr % Change | ||||||||||||||||
| Net (charge offs) recoveries | |||||||||||||||||||||||
Asset-based lending & equipment finance(a) | $ | — | $ | 27 | (100) | % | $ | 91 | $ | 261 | $ | 33 | (100) | % | |||||||||
| Commercial and industrial | 1,854 | (6,669) | N/M | (9,149) | 1,072 | 1,334 | 39 | % | |||||||||||||||
| Commercial real estate—owner occupied | 3 | 4 | (25) | % | 106 | 5 | 4 | (25) | % | ||||||||||||||
| Commercial and business lending | 1,857 | (6,638) | N/M | (8,951) | 1,338 | 1,370 | 36 | % | |||||||||||||||
| Commercial real estate—investor | — | 109 | (100) | % | 181 | (5,589) | (5,886) | (100) | % | ||||||||||||||
| Real estate construction | 32 | 52 | (38) | % | 18 | 23 | 29 | 10 | % | ||||||||||||||
| Commercial real estate lending | 32 | 162 | (80) | % | 199 | (5,566) | (5,857) | N/M | |||||||||||||||
| Total commercial | 1,889 | (6,476) | N/M | (8,752) | (4,228) | (4,487) | N/M | ||||||||||||||||
| Residential mortgage | 288 | (6) | N/M | 300 | (223) | (109) | N/M | ||||||||||||||||
| Auto finance | 4 | (11) | N/M | 8 | 3 | 9 | (56) | % | |||||||||||||||
| Home equity | 315 | 546 | (42) | % | 959 | 337 | 344 | (8) | % | ||||||||||||||
| Other consumer | (451) | (534) | (16) | % | (329) | (517) | (521) | (13) | % | ||||||||||||||
| Total consumer | 155 | (6) | N/M | 938 | (400) | (277) | N/M | ||||||||||||||||
| Total net (charge offs) recoveries | $ | 2,044 | $ | (6,482) | N/M | $ | (7,814) | $ | (4,628) | $ | (4,764) | N/M | |||||||||||
| (In basis points) | Mar 31, 2022 | Dec 31, 2021 | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | ||||||||||||||||||
| Net (charge offs) recoveries to average loans (annualized) | |||||||||||||||||||||||
Asset-based lending & equipment finance(a) | — | 9 | 36 | 87 | 10 | ||||||||||||||||||
| Commercial and industrial | 10 | (34) | (47) | 6 | 7 | ||||||||||||||||||
| Commercial real estate—owner occupied | — | — | 5 | — | — | ||||||||||||||||||
| Commercial and business lending | 8 | (29) | (40) | 6 | 6 | ||||||||||||||||||
| Commercial real estate—investor | — | 1 | 2 | (52) | (55) | ||||||||||||||||||
| Real estate construction | 1 | 1 | — | 1 | 1 | ||||||||||||||||||
| Commercial real estate lending | — | 1 | 1 | (36) | (38) | ||||||||||||||||||
| Total commercial | 5 | (17) | (23) | (11) | (12) | ||||||||||||||||||
| Residential mortgage | 2 | — | 2 | (1) | (1) | ||||||||||||||||||
| Auto finance | 1 | (9) | 43 | 15 | 37 | ||||||||||||||||||
| Home equity | 22 | 36 | 61 | 21 | 21 | ||||||||||||||||||
| Other consumer | (62) | (71) | (44) | (72) | (72) | ||||||||||||||||||
| Total consumer | 1 | — | 4 | (2) | (1) | ||||||||||||||||||
| Total net (charge offs) recoveries | 3 | (11) | (13) | (8) | (8) | ||||||||||||||||||
| ($ in thousands) | Mar 31, 2022 | Dec 31, 2021 | Seql Qtr % Change | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Comp Qtr % Change | ||||||||||||||||
| Credit Quality | |||||||||||||||||||||||
| Nonaccrual loans | $ | 143,221 | $ | 130,443 | 10 | % | $ | 135,062 | $ | 147,135 | $ | 163,292 | (12) | % | |||||||||
| Other real estate owned (OREO) | 18,194 | 29,619 | (39) | % | 33,855 | 24,000 | 24,588 | (26) | % | ||||||||||||||
| Total nonperforming assets | $ | 161,414 | $ | 160,062 | 1 | % | $ | 168,917 | $ | 171,135 | $ | 187,880 | (14) | % | |||||||||
| Loans 90 or more days past due and still accruing | $ | 1,595 | $ | 1,263 | 26 | % | $ | 1,029 | $ | 1,302 | $ | 1,675 | (5) | % | |||||||||
| Allowance for credit losses on loans to total loans | 1.30 | % | 1.32 | % | 1.41 | % | 1.52 | % | 1.67 | % | |||||||||||||
| Allowance for credit losses on loans to nonaccrual loans | 221.92 | % | 245.16 | % | 246.02 | % | 247.45 | % | 247.23 | % | |||||||||||||
| Nonaccrual loans to total loans | 0.58 | % | 0.54 | % | 0.57 | % | 0.61 | % | 0.68 | % | |||||||||||||
| Nonperforming assets to total loans plus OREO | 0.66 | % | 0.66 | % | 0.71 | % | 0.71 | % | 0.78 | % | |||||||||||||
| Nonperforming assets to total assets | 0.46 | % | 0.46 | % | 0.49 | % | 0.50 | % | 0.54 | % | |||||||||||||
| Annualized year-to-date net charge offs (recoveries) to year-to-date average loans | (0.03) | % | 0.10 | % | 0.10 | % | 0.08 | % | 0.08 | % | |||||||||||||
N/M = Not meaningful
4
| Associated Banc-Corp Selected Asset Quality Information (continued) | |||||||||||||||||||||||
| (In thousands) | Mar 31, 2022 | Dec 31, 2021 | Seql Qtr % Change | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Comp Qtr % Change | ||||||||||||||||
| Nonaccrual loans | |||||||||||||||||||||||
| PPP Loans | $ | 41 | $ | 46 | (11) | % | $ | — | $ | — | $ | — | N/M | ||||||||||
| Commercial and industrial | 225 | 6,233 | (96) | % | 8,497 | 18,380 | 33,192 | (99) | % | ||||||||||||||
| Commercial real estate—owner occupied | — | — | N/M | 7 | 7 | 7 | (100) | % | |||||||||||||||
| Commercial and business lending | 266 | 6,279 | (96) | % | 8,504 | 18,387 | 33,200 | (99) | % | ||||||||||||||
| Commercial real estate—investor | 80,886 | 60,677 | 33 | % | 61,504 | 63,003 | 58,485 | 38 | % | ||||||||||||||
| Real estate construction | 609 | 177 | N/M | 247 | 247 | 327 | 86 | % | |||||||||||||||
| Commercial real estate lending | 81,495 | 60,855 | 34 | % | 61,751 | 63,250 | 58,813 | 39 | % | ||||||||||||||
| Total commercial | 81,761 | 67,134 | 22 | % | 70,256 | 81,637 | 92,012 | (11) | % | ||||||||||||||
| Residential mortgage | 53,827 | 55,362 | (3) | % | 56,678 | 56,795 | 61,256 | (12) | % | ||||||||||||||
| Auto finance | 49 | 52 | (6) | % | 67 | 56 | 36 | 36 | % | ||||||||||||||
| Home equity | 7,490 | 7,726 | (3) | % | 7,838 | 8,517 | 9,792 | (24) | % | ||||||||||||||
| Other consumer | 95 | 170 | (44) | % | 222 | 131 | 195 | (51) | % | ||||||||||||||
| Total consumer | 61,460 | 63,309 | (3) | % | 64,806 | 65,498 | 71,280 | (14) | % | ||||||||||||||
| Total nonaccrual loans | $ | 143,221 | $ | 130,443 | 10 | % | $ | 135,062 | $ | 147,135 | $ | 163,292 | (12) | % | |||||||||
| Mar 31, 2022 | Dec 31, 2021 | Seql Qtr % Change | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Comp Qtr % Change | |||||||||||||||||
| Restructured loans (accruing) | |||||||||||||||||||||||
| Commercial and industrial | $ | 7,426 | $ | 8,687 | (15) | % | $ | 11,067 | $ | 11,569 | $ | 11,985 | (38) | % | |||||||||
| Commercial real estate—owner occupied | 473 | 967 | (51) | % | 1,031 | 1,225 | 1,488 | (68) | % | ||||||||||||||
| Commercial and business lending | 7,899 | 9,655 | (18) | % | 12,098 | 12,794 | 13,473 | (41) | % | ||||||||||||||
| Commercial real estate—investor | 2,045 | 12,866 | (84) | % | 13,236 | 13,306 | 13,627 | (85) | % | ||||||||||||||
| Real estate construction | 183 | 242 | (24) | % | 248 | 253 | 256 | (29) | % | ||||||||||||||
| Commercial real estate lending | 2,228 | 13,108 | (83) | % | 13,484 | 13,559 | 13,884 | (84) | % | ||||||||||||||
| Total commercial | 10,127 | 22,763 | (56) | % | 25,582 | 26,353 | 27,356 | (63) | % | ||||||||||||||
| Residential mortgage | 16,644 | 16,316 | 2 | % | 15,253 | 12,227 | 10,462 | 59 | % | ||||||||||||||
| Home equity | 2,486 | 2,648 | (6) | % | 2,787 | 2,451 | 1,929 | 29 | % | ||||||||||||||
| Other consumer | 747 | 803 | (7) | % | 877 | 904 | 1,073 | (30) | % | ||||||||||||||
| Total consumer | 19,876 | 19,768 | 1 | % | 18,917 | 15,582 | 13,464 | 48 | % | ||||||||||||||
| Total restructured loans (accruing) | $ | 30,003 | $ | 42,530 | (29) | % | $ | 44,499 | $ | 41,935 | $ | 40,820 | (26) | % | |||||||||
| Nonaccrual restructured loans (included in nonaccrual loans) | $ | 19,352 | $ | 17,426 | 11 | % | $ | 15,226 | $ | 17,237 | $ | 17,624 | 10 | % | |||||||||
| Mar 31, 2022 | Dec 31, 2021 | Seql Qtr % Change | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Comp Qtr % Change | |||||||||||||||||
| Accruing Loans 30-89 Days Past Due | |||||||||||||||||||||||
| PPP Loans | $ | 1 | $ | 83 | (99) | % | $ | 568 | $ | — | $ | — | N/M | ||||||||||
| Commercial and industrial | 1,085 | 632 | 72 | % | 1,229 | 258 | 526 | 106 | % | ||||||||||||||
| Commercial real estate—owner occupied | 198 | 163 | 21 | % | 30 | 47 | — | N/M | |||||||||||||||
| Commercial and business lending | 1,284 | 878 | 46 | % | 1,827 | 306 | 526 | 144 | % | ||||||||||||||
| Commercial real estate—investor | — | 616 | (100) | % | 17,021 | 391 | 5,999 | (100) | % | ||||||||||||||
| Real estate construction | — | 1,620 | (100) | % | — | 117 | 977 | (100) | % | ||||||||||||||
| Commercial real estate lending | — | 2,236 | (100) | % | 17,021 | 509 | 6,976 | (100) | % | ||||||||||||||
| Total commercial | 1,284 | 3,114 | (59) | % | 18,848 | 814 | 7,502 | (83) | % | ||||||||||||||
| Residential mortgage | 4,957 | 6,169 | (20) | % | 7,095 | 5,015 | 3,973 | 25 | % | ||||||||||||||
| Auto finance | 949 | 11 | N/M | 10 | 38 | 24 | N/M | ||||||||||||||||
| Home equity | 4,207 | 3,711 | 13 | % | 2,931 | 2,472 | 2,352 | 79 | % | ||||||||||||||
| Other consumer | 1,232 | 2,307 | (47) | % | 1,272 | 1,036 | 1,246 | (1) | % | ||||||||||||||
| Total consumer | 11,345 | 12,198 | (7) | % | 11,308 | 8,562 | 7,594 | 49 | % | ||||||||||||||
| Total accruing loans 30-89 days past due | $ | 12,629 | $ | 15,312 | (18) | % | $ | 30,156 | $ | 9,376 | $ | 15,097 | (16) | % | |||||||||
| Mar 31, 2022 | Dec 31, 2021 | Seql Qtr % Change | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Comp Qtr % Change | |||||||||||||||||
| Potential Problem Loans | |||||||||||||||||||||||
PPP Loans(b) | $ | 54 | $ | 2,000 | (97) | % | $ | 4,160 | $ | 8,695 | $ | 22,398 | (100) | % | |||||||||
Asset-based lending & equipment finance(a) | 19,057 | 17,697 | 8 | % | — | — | — | N/M | |||||||||||||||
| Commercial and industrial | 93,396 | 120,561 | (23) | % | 124,990 | 77,064 | 122,143 | (24) | % | ||||||||||||||
| Commercial real estate—owner occupied | 24,005 | 26,723 | (10) | % | 21,241 | 17,828 | 15,965 | 50 | % | ||||||||||||||
| Commercial and business lending | 136,513 | 166,981 | (18) | % | 150,391 | 103,587 | 160,506 | (15) | % | ||||||||||||||
| Commercial real estate—investor | 130,792 | 106,138 | 23 | % | 78,962 | 71,613 | 85,752 | 53 | % | ||||||||||||||
| Real estate construction | 200 | 21,408 | (99) | % | 19,187 | 16,465 | 13,977 | (99) | % | ||||||||||||||
| Commercial real estate lending | 130,992 | 127,546 | 3 | % | 98,150 | 88,078 | 99,728 | 31 | % | ||||||||||||||
| Total commercial | 267,505 | 294,527 | (9) | % | 248,541 | 191,665 | 260,234 | 3 | % | ||||||||||||||
| Residential mortgage | 3,032 | 2,214 | 37 | % | 2,374 | 3,024 | 2,524 | 20 | % | ||||||||||||||
| Home equity | 156 | 165 | (5) | % | 171 | 1,558 | 1,729 | (91) | % | ||||||||||||||
| Total consumer | 3,188 | 2,379 | 34 | % | 2,546 | 4,583 | 4,254 | (25) | % | ||||||||||||||
| Total potential problem loans | $ | 270,693 | $ | 296,905 | (9) | % | $ | 251,087 | $ | 196,248 | $ | 264,488 | 2 | % | |||||||||
N/M = Not meaningful
Numbers may not sum due to rounding.
(a) Periods prior to Mar 31, 2022 do not include equipment finance.
(b) The Corporation's policy is to assign risk ratings at the borrower level. PPP loans are 100% guaranteed by the SBA and therefore the Corporation considers these loans to have a risk profile similar to pass rated loans.
5
| Associated Banc-Corp Net Interest Income Analysis - Fully Tax-Equivalent Basis - Sequential and Comparable Quarter | |||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||
| March 31, 2022 | December 31, 2021 | March 31, 2021 | |||||||||||||||||||||||||||
| ($ in thousands) | Average Balance | Interest Income /Expense | Average Yield /Rate | Average Balance | Interest Income /Expense | Average Yield /Rate | Average Balance | Interest Income /Expense | Average Yield /Rate | ||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||
| Earning assets | |||||||||||||||||||||||||||||
Loans (a) (b) (c) | |||||||||||||||||||||||||||||
| Commercial PPP lending | $ | 43,774 | $ | 1,277 | 11.83 | % | $ | 115,074 | $ | 5,055 | 17.43 | % | $ | 806,699 | $ | 8,900 | 4.47 | % | |||||||||||
Asset-based lending (ABL) & equipment finance (d) | 202,836 | 1,449 | 2.90 | % | 125,507 | 971 | 3.07 | % | 137,862 | 1,072 | 3.15 | % | |||||||||||||||||
| Commercial and business lending (excl PPP, ABL and equipment finance) | 8,815,676 | 52,754 | 2.43 | % | 8,715,796 | 53,401 | 2.43 | % | 8,399,439 | 53,019 | 2.56 | % | |||||||||||||||||
| Commercial real estate lending | 6,177,062 | 43,886 | 2.88 | % | 6,134,049 | 45,040 | 2.91 | % | 6,171,202 | 44,315 | 2.91 | % | |||||||||||||||||
| Total commercial | 15,239,348 | 99,366 | 2.64 | % | 15,090,427 | 104,468 | 2.75 | % | 15,515,202 | 107,307 | 2.80 | % | |||||||||||||||||
| Residential mortgage | 7,671,329 | 55,403 | 2.89 | % | 7,751,337 | 54,952 | 2.84 | % | 7,962,691 | 55,504 | 2.79 | % | |||||||||||||||||
| Auto finance | 305,202 | 2,649 | 3.52 | % | 53,120 | 587 | 4.39 | % | 10,190 | 111 | 4.43 | % | |||||||||||||||||
| Other retail | 881,859 | 10,662 | 4.87 | % | 900,369 | 11,188 | 4.95 | % | 975,266 | 11,519 | 4.75 | % | |||||||||||||||||
| Total loans | 24,097,738 | 168,081 | 2.81 | % | 23,795,253 | 171,195 | 2.86 | % | 24,463,349 | 174,442 | 2.88 | % | |||||||||||||||||
| Investment securities | |||||||||||||||||||||||||||||
| Taxable | 4,363,733 | 16,472 | 1.51 | % | 4,067,612 | 13,317 | 1.31 | % | 2,976,469 | 7,014 | 0.94 | % | |||||||||||||||||
Tax-exempt(a) | 2,384,601 | 20,296 | 3.40 | % | 2,257,106 | 19,617 | 3.48 | % | 1,900,346 | 17,844 | 3.76 | % | |||||||||||||||||
| Other short-term investments | 1,154,939 | 1,993 | 0.70 | % | 1,592,840 | 2,031 | 0.51 | % | 991,844 | 1,694 | 0.69 | % | |||||||||||||||||
| Investments and other | 7,903,273 | 38,761 | 1.96 | % | 7,917,558 | 34,965 | 1.76 | % | 5,868,659 | 26,553 | 1.81 | % | |||||||||||||||||
| Total earning assets | 32,001,010 | $ | 206,842 | 2.60 | % | 31,712,810 | $ | 206,160 | 2.59 | % | 30,332,008 | $ | 200,994 | 2.67 | % | ||||||||||||||
| Other assets, net | 3,199,172 | 3,303,349 | 3,352,135 | ||||||||||||||||||||||||||
| Total assets | $ | 35,200,182 | $ | 35,016,159 | $ | 33,684,143 | |||||||||||||||||||||||
| Liabilities and stockholders' equity | |||||||||||||||||||||||||||||
| Interest-bearing liabilities | |||||||||||||||||||||||||||||
| Interest-bearing deposits | |||||||||||||||||||||||||||||
| Savings | $ | 4,529,991 | $ | 380 | 0.03 | % | $ | 4,367,233 | $ | 369 | 0.03 | % | $ | 3,810,321 | $ | 332 | 0.04 | % | |||||||||||
| Interest-bearing demand | 6,722,038 | 1,025 | 0.06 | % | 6,506,438 | 1,015 | 0.06 | % | 5,713,270 | 1,178 | 0.08 | % | |||||||||||||||||
| Money market | 7,030,945 | 965 | 0.06 | % | 6,892,803 | 927 | 0.05 | % | 6,875,730 | 1,059 | 0.06 | % | |||||||||||||||||
| Network transaction deposits | 734,895 | 265 | 0.15 | % | 838,255 | 239 | 0.11 | % | 1,080,109 | 327 | 0.12 | % | |||||||||||||||||
| Time deposits | 1,313,101 | 937 | 0.29 | % | 1,381,092 | 1,127 | 0.32 | % | 1,658,568 | 3,014 | 0.74 | % | |||||||||||||||||
| Total interest-bearing deposits | 20,330,970 | 3,571 | 0.07 | % | 19,985,821 | 3,677 | 0.07 | % | 19,137,998 | 5,909 | 0.13 | % | |||||||||||||||||
| Federal funds purchased and securities sold under agreements to repurchase | 293,915 | 38 | 0.05 | % | 293,948 | 40 | 0.05 | % | 136,144 | 26 | 0.08 | % | |||||||||||||||||
| Commercial Paper | 27,963 | 1 | 0.01 | % | 44,250 | 2 | 0.01 | % | 42,774 | 6 | 0.05 | % | |||||||||||||||||
| FHLB advances | 1,610,983 | 8,182 | 2.06 | % | 1,621,097 | 8,514 | 2.08 | % | 1,631,895 | 9,493 | 2.36 | % | |||||||||||||||||
| Long-term funding | 249,632 | 2,730 | 4.38 | % | 249,223 | 2,730 | 4.38 | % | 549,585 | 5,585 | 4.07 | % | |||||||||||||||||
| Total short and long-term funding | 2,182,492 | 10,951 | 2.03 | % | 2,208,518 | 11,286 | 2.03 | % | 2,360,397 | 15,109 | 2.58 | % | |||||||||||||||||
| Total interest-bearing liabilities | 22,513,462 | $ | 14,522 | 0.26 | % | 22,194,339 | $ | 14,963 | 0.27 | % | 21,498,395 | $ | 21,018 | 0.40 | % | ||||||||||||||
| Noninterest-bearing demand deposits | 8,316,399 | 8,416,525 | 7,666,561 | ||||||||||||||||||||||||||
| Other liabilities | 383,528 | 401,433 | 415,195 | ||||||||||||||||||||||||||
| Stockholders’ equity | 3,986,792 | 4,003,863 | 4,103,991 | ||||||||||||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 35,200,182 | $ | 35,016,159 | $ | 33,684,143 | |||||||||||||||||||||||
| Interest rate spread | 2.34 | % | 2.32 | % | 2.27 | % | |||||||||||||||||||||||
| Net free funds | 0.08 | % | 0.08 | % | 0.12 | % | |||||||||||||||||||||||
| Fully tax-equivalent net interest income and net interest margin ("NIM") | $ | 192,320 | 2.42 | % | $ | 191,197 | 2.40 | % | $ | 179,976 | 2.39 | % | |||||||||||||||||
| Fully tax-equivalent adjustment | 4,573 | 4,434 | 4,074 | ||||||||||||||||||||||||||
| Net interest income | $ | 187,747 | $ | 186,763 | $ | 175,902 | |||||||||||||||||||||||
Numbers may not sum due to rounding.
(a)The yield on tax-exempt loans and securities is computed on a fully tax-equivalent basis using a tax rate of 21% and is net of the effects of certain disallowed interest deductions.
(b)Nonaccrual loans and loans held for sale have been included in the average balances.
(c)Interest income includes amortization of net deferred loan origination costs and net accreted purchase loan discount.
(d) Periods prior to March 31, 2022 do not include equipment finance.
6
| Associated Banc-Corp Loan and Deposit Composition | |||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||
| Period end loan composition | Mar 31, 2022 | Dec 31, 2021 | Seql Qtr % Change | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Comp Qtr % Change | ||||||||||||||||
| PPP Loans | $ | 17,995 | $ | 66,070 | (73) | % | $ | 182,121 | $ | 405,482 | $ | 836,566 | (98) | % | |||||||||
Asset-based lending & equipment finance(a) | 231,040 | 178,027 | 30 | % | 111,027 | 105,726 | 137,537 | 68 | % | ||||||||||||||
| Commercial and industrial | 8,102,380 | 8,208,289 | (1) | % | 7,816,432 | 7,803,393 | 7,526,964 | 8 | % | ||||||||||||||
| Commercial real estate—owner occupied | 973,572 | 971,326 | — | % | 879,554 | 880,755 | 883,237 | 10 | % | ||||||||||||||
| Commercial and business lending | 9,324,986 | 9,423,711 | (1) | % | 8,989,133 | 9,195,355 | 9,384,303 | (1) | % | ||||||||||||||
| Commercial real estate—investor | 4,469,241 | 4,384,569 | 2 | % | 4,296,489 | 4,300,651 | 4,260,706 | 5 | % | ||||||||||||||
| Real estate construction | 1,760,076 | 1,808,976 | (3) | % | 1,834,871 | 1,880,897 | 1,882,299 | (6) | % | ||||||||||||||
| Commercial real estate lending | 6,229,317 | 6,193,545 | 1 | % | 6,131,360 | 6,181,549 | 6,143,004 | 1 | % | ||||||||||||||
| Total commercial | 15,554,303 | 15,617,256 | — | % | 15,120,493 | 15,376,904 | 15,527,307 | — | % | ||||||||||||||
| Residential mortgage | 7,609,343 | 7,567,310 | 1 | % | 7,590,895 | 7,638,372 | 7,685,218 | (1) | % | ||||||||||||||
| Auto finance | 497,523 | 143,045 | N/M | 6,739 | 7,817 | 9,165 | N/M | ||||||||||||||||
| Home equity | 580,867 | 595,615 | (2) | % | 608,566 | 631,783 | 651,647 | (11) | % | ||||||||||||||
| Other consumer | 289,889 | 301,723 | (4) | % | 294,979 | 292,660 | 288,990 | — | % | ||||||||||||||
| Total consumer | 8,977,622 | 8,607,693 | 4 | % | 8,501,180 | 8,570,632 | 8,635,020 | 4 | % | ||||||||||||||
| Total loans | $ | 24,531,926 | $ | 24,224,949 | 1 | % | $ | 23,621,673 | $ | 23,947,536 | $ | 24,162,328 | 2 | % | |||||||||
| Period end deposit and customer funding composition | Mar 31, 2022 | Dec 31, 2021 | Seql Qtr % Change | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Comp Qtr % Change | ||||||||||||||||
| Noninterest-bearing demand | $ | 8,315,699 | $ | 8,504,077 | (2) | % | $ | 8,170,105 | $ | 7,999,143 | $ | 8,496,194 | (2) | % | |||||||||
| Savings | 4,661,232 | 4,410,198 | 6 | % | 4,278,453 | 4,182,651 | 4,032,830 | 16 | % | ||||||||||||||
| Interest-bearing demand | 6,616,767 | 7,019,782 | (6) | % | 6,407,844 | 5,969,285 | 5,748,353 | 15 | % | ||||||||||||||
| Money market | 7,522,797 | 7,185,111 | 5 | % | 7,583,978 | 7,640,825 | 7,838,437 | (4) | % | ||||||||||||||
| Time deposits | 1,288,913 | 1,347,262 | (4) | % | 1,410,886 | 1,472,395 | 1,561,352 | (17) | % | ||||||||||||||
| Total deposits | 28,405,409 | 28,466,430 | — | % | 27,851,266 | 27,264,299 | 27,677,166 | 3 | % | ||||||||||||||
Customer funding(b) | 299,301 | 354,142 | (15) | % | 322,081 | 226,160 | 182,228 | 64 | % | ||||||||||||||
| Total deposits and customer funding | $ | 28,704,710 | $ | 28,820,572 | — | % | $ | 28,173,348 | $ | 27,490,459 | $ | 27,859,394 | 3 | % | |||||||||
Network transaction deposits(c) | $ | 762,680 | $ | 766,965 | (1) | % | $ | 929,174 | $ | 871,603 | $ | 1,054,634 | (28) | % | |||||||||
| Net deposits and customer funding (Total deposits and customer funding, excluding network transaction deposits) | $ | 27,942,029 | $ | 28,053,607 | — | % | $ | 27,244,174 | $ | 26,618,856 | $ | 26,804,761 | 4 | % | |||||||||
| Quarter average loan composition | Mar 31, 2022 | Dec 31, 2021 | Seql Qtr % Change | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Comp Qtr % Change | ||||||||||||||||
| PPP Loans | $ | 43,774 | $ | 115,074 | (62) | % | $ | 275,414 | $ | 701,440 | $ | 806,699 | (95) | % | |||||||||
Asset-based lending & equipment finance(a) | 202,836 | 125,507 | 62 | % | 99,463 | 121,153 | 137,862 | 47 | % | ||||||||||||||
| Commercial and industrial | 7,842,179 | 7,816,260 | — | % | 7,733,148 | 7,437,726 | 7,493,413 | 5 | % | ||||||||||||||
| Commercial real estate—owner occupied | 973,496 | 899,536 | 8 | % | 876,047 | 878,746 | 906,027 | 7 | % | ||||||||||||||
| Commercial and business lending | 9,062,286 | 8,956,378 | 1 | % | 8,984,072 | 9,139,064 | 9,344,000 | (3) | % | ||||||||||||||
| Commercial real estate—investor | 4,439,051 | 4,304,579 | 3 | % | 4,297,783 | 4,321,109 | 4,303,365 | 3 | % | ||||||||||||||
| Real estate construction | 1,738,011 | 1,829,470 | (5) | % | 1,862,458 | 1,838,619 | 1,867,836 | (7) | % | ||||||||||||||
| Commercial real estate lending | 6,177,062 | 6,134,049 | 1 | % | 6,160,241 | 6,159,728 | 6,171,202 | — | % | ||||||||||||||
| Total commercial | 15,239,348 | 15,090,427 | 1 | % | 15,144,314 | 15,298,792 | 15,515,202 | (2) | % | ||||||||||||||
| Residential mortgage | 7,671,329 | 7,751,337 | (1) | % | 7,817,737 | 7,861,139 | 7,962,691 | (4) | % | ||||||||||||||
| Auto finance | 305,202 | 53,120 | N/M | 7,144 | 8,458 | 10,190 | N/M | ||||||||||||||||
| Home equity | 588,281 | 600,963 | (2) | % | 620,601 | 641,438 | 680,738 | (14) | % | ||||||||||||||
| Other consumer | 293,578 | 299,406 | (2) | % | 294,160 | 288,786 | 294,528 | — | % | ||||||||||||||
| Total consumer | 8,858,390 | 8,704,826 | 2 | % | 8,739,643 | 8,799,822 | 8,948,147 | (1) | % | ||||||||||||||
Total loans(d) | $ | 24,097,738 | $ | 23,795,253 | 1 | % | $ | 23,883,957 | $ | 24,098,614 | $ | 24,463,349 | (1) | % | |||||||||
| Quarter average deposit composition | Mar 31, 2022 | Dec 31, 2021 | Seql Qtr % Change | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Comp Qtr % Change | ||||||||||||||||
| Noninterest-bearing demand | $ | 8,316,399 | $ | 8,416,525 | (1) | % | $ | 8,141,723 | $ | 8,069,851 | $ | 7,666,561 | 8 | % | |||||||||
| Savings | 4,529,991 | 4,367,233 | 4 | % | 4,248,493 | 4,121,553 | 3,810,321 | 19 | % | ||||||||||||||
| Interest-bearing demand | 6,722,038 | 6,506,438 | 3 | % | 6,344,504 | 5,879,173 | 5,713,270 | 18 | % | ||||||||||||||
| Money market | 7,030,945 | 6,892,803 | 2 | % | 7,011,075 | 6,981,482 | 6,875,730 | 2 | % | ||||||||||||||
| Network transaction deposits | 734,895 | 838,255 | (12) | % | 893,991 | 908,869 | 1,080,109 | (32) | % | ||||||||||||||
| Time deposits | 1,313,101 | 1,381,092 | (5) | % | 1,434,588 | 1,509,705 | 1,658,568 | (21) | % | ||||||||||||||
| Total deposits | $ | 28,647,369 | $ | 28,402,345 | 1 | % | $ | 28,074,374 | $ | 27,470,633 | $ | 26,804,559 | 7 | % | |||||||||
N/M = Not meaningful
Numbers may not sum due to rounding.
(a) Periods prior to Mar 31, 2022 do not include equipment finance.
(b) Includes repurchase agreements and commercial paper.
(c) Included above in interest-bearing demand and money market.
(d) Nonaccrual loans and loans held for sale have been included in the average balances.
7
| Associated Banc-Corp Non-GAAP Financial Measures Reconciliation | |||||||||||||||||
| ($ in millions, except per share data) | 1Q22 | 4Q21 | 3Q21 | 2Q21 | 1Q21 | ||||||||||||
Tangible common equity reconciliation(a) | |||||||||||||||||
| Common equity | $ | 3,755 | $ | 3,832 | $ | 3,802 | $ | 3,820 | $ | 3,774 | |||||||
| Goodwill and other intangible assets, net | (1,161) | (1,163) | (1,165) | (1,167) | (1,170) | ||||||||||||
| Tangible common equity | $ | 2,594 | $ | 2,669 | $ | 2,636 | $ | 2,652 | $ | 2,605 | |||||||
Tangible assets reconciliation(a) | |||||||||||||||||
| Total assets | $ | 34,956 | $ | 35,104 | $ | 34,440 | $ | 34,153 | $ | 34,575 | |||||||
| Goodwill and other intangible assets, net | (1,161) | (1,163) | (1,165) | (1,167) | (1,170) | ||||||||||||
| Tangible assets | $ | 33,795 | $ | 33,941 | $ | 33,274 | $ | 32,985 | $ | 33,406 | |||||||
Average tangible common equity and average common equity tier 1 reconciliation(a) | |||||||||||||||||
| Common equity | $ | 3,794 | $ | 3,811 | $ | 3,807 | $ | 3,788 | $ | 3,750 | |||||||
| Goodwill and other intangible assets, net | (1,162) | (1,164) | (1,167) | (1,169) | (1,175) | ||||||||||||
| Tangible common equity | 2,631 | 2,646 | 2,640 | 2,619 | 2,576 | ||||||||||||
| Modified CECL transitional amount | 67 | 91 | 97 | 106 | 116 | ||||||||||||
| Accumulated other comprehensive loss (income) | 80 | 19 | (5) | (3) | (5) | ||||||||||||
| Deferred tax assets, net | 39 | 40 | 40 | 40 | 41 | ||||||||||||
| Average common equity tier 1 | $ | 2,818 | $ | 2,795 | $ | 2,772 | $ | 2,762 | $ | 2,727 | |||||||
Average tangible assets reconciliation(a) | |||||||||||||||||
| Total assets | $ | 35,200 | $ | 35,016 | $ | 34,759 | $ | 34,380 | $ | 33,684 | |||||||
| Goodwill and other intangible assets, net | (1,162) | (1,164) | (1,167) | (1,169) | (1,175) | ||||||||||||
| Tangible assets | $ | 34,038 | $ | 33,852 | $ | 33,593 | $ | 33,211 | $ | 32,510 | |||||||
Selected trend information(b) | |||||||||||||||||
| Wealth management fees | $ | 22 | $ | 23 | $ | 22 | $ | 23 | $ | 22 | |||||||
| Service charges and deposit account fees | 17 | 17 | 17 | 16 | 15 | ||||||||||||
| Card-based fees | 10 | 11 | 11 | 11 | 10 | ||||||||||||
| Other fee-based revenue | 4 | 4 | 4 | 4 | 5 | ||||||||||||
| Fee-based revenue | 53 | 55 | 54 | 53 | 52 | ||||||||||||
| Other | 22 | 26 | 28 | 20 | 44 | ||||||||||||
| Total noninterest income | $ | 74 | $ | 82 | $ | 82 | $ | 73 | $ | 95 | |||||||
Pre-tax pre-provision income(c) | |||||||||||||||||
| Income before income taxes | $ | 93 | $ | 92 | $ | 112 | $ | 113 | $ | 119 | |||||||
| Provision for credit losses | (4) | (6) | (24) | (35) | (23) | ||||||||||||
| Pre-tax pre-provision income | $ | 89 | $ | 86 | $ | 88 | $ | 78 | $ | 96 | |||||||
Selected equity and performance ratios(a)(d) | |||||||||||||||||
| Tangible common equity / tangible assets | 7.68 | % | 7.86 | % | 7.92 | % | 8.04 | % | 7.80 | % | |||||||
| Return on average equity | 7.55 | % | 7.62 | % | 8.63 | % | 8.84 | % | 9.32 | % | |||||||
| Return on average tangible common equity | 11.00 | % | 11.09 | % | 12.72 | % | 13.19 | % | 14.03 | % | |||||||
| Return on average common equity Tier 1 | 10.27 | % | 10.50 | % | 12.11 | % | 12.51 | % | 13.25 | % | |||||||
| Return on average tangible assets | 0.88 | % | 0.90 | % | 1.05 | % | 1.10 | % | 1.18 | % | |||||||
| Average stockholders' equity / average assets | 11.33 | % | 11.43 | % | 11.74 | % | 12.01 | % | 12.18 | % | |||||||
Efficiency ratio reconciliation(e) | |||||||||||||||||
| Federal Reserve efficiency ratio | 65.71 | % | 67.36 | % | 65.43 | % | 66.81 | % | 65.74 | % | |||||||
| Fully tax-equivalent adjustment | (1.13) | % | (1.10) | % | (1.01) | % | (1.07) | % | (0.97) | % | |||||||
| Other intangible amortization | (0.84) | % | (0.82) | % | (0.83) | % | (0.87) | % | (0.82) | % | |||||||
| Fully tax-equivalent efficiency ratio | 63.76 | % | 65.46 | % | 63.61 | % | 64.88 | % | 63.96 | % | |||||||
| Provision for unfunded commitments adjustment | 0.37 | % | 0.55 | % | 1.48 | % | 2.14 | % | (1.09) | % | |||||||
| Asset gains, net adjustment | 0.05 | % | 0.24 | % | 1.29 | % | — | % | 1.12 | % | |||||||
| Acquisitions, branch sales, and initiatives | — | % | (1.43) | % | (0.91) | % | 0.01 | % | 0.22 | % | |||||||
| Adjusted efficiency ratio | 64.18 | % | 64.82 | % | 65.46 | % | 67.02 | % | 64.21 | % | |||||||
Numbers may not sum due to rounding.
(a)The ratio tangible common equity to tangible assets excludes goodwill and other intangible assets, net. This financial measure has been included as it is considered to be a critical metric with which to analyze and evaluate financial condition and capital strength.
(b)These financial measures have been included as they provide meaningful supplemental information to assess trends in the Corporation’s results of operations.
(c)Management believes these measures are meaningful because they reflect adjustments commonly made by management, investors, regulators, and analysts to evaluate the adequacy of earnings and provide greater understanding of ongoing operations and enhanced comparability of results with prior periods.
(d)These capital measurements are used by management, regulators, investors, and analysts to assess, monitor and compare the quality and composition of our capital with the capital of other financial services companies.
(e)The efficiency ratio as defined by the Federal Reserve guidance is noninterest expense (which includes the provision for unfunded commitments) divided by the sum of net interest income plus noninterest income, excluding investment securities gains / losses, net. The fully tax-equivalent efficiency ratio is noninterest expense (which includes the provision for unfunded commitments), excluding other intangible amortization, divided by the sum of fully tax-equivalent net interest income plus noninterest income, excluding investment securities gains / losses, net. The adjusted efficiency ratio is noninterest expense, which excludes the provision for unfunded commitments, other intangible amortization, acquisition related costs, and announced initiatives, divided by the sum of fully tax-equivalent net interest income plus noninterest income, excluding investment securities gains (losses), net, asset gains (losses), net, and gain on sale of branches, net. Management believes the adjusted efficiency ratio is a meaningful measure as it enhances the comparability of net interest income arising from taxable and tax-exempt sources and provides a better measure as to how the Corporation is managing its expenses by adjusting for acquisition related costs, provision for unfunded commitments, asset gains (losses), net, branch sales, and announced initiatives.
8
First Quarter 2022 Earnings Presentation APRIL 21, 2022 Exhibit 99.2
1 Forward-Looking Statements Important note regarding forward-looking statements: Statements made in this presentation which are not purely historical are forward-looking statements, as defined in the Private Securities Litigation Reform Act of 1995. This includes any statements regarding management’s plans, objectives, or goals for future operations, products or services, and forecasts of its revenues, earnings, or other measures of performance. Such forward-looking statements may be identified by the use of words such as “believe,” “expect,” “anticipate,” “plan,” “estimate,” “should,” “will,” “intend,” "target,“ “outlook,” “project,” “guidance,” or similar expressions. Forward-looking statements are based on current management expectations and, by their nature, are subject to risks and uncertainties. Actual results may differ materially from those contained in the forward-looking statements. Factors which may cause actual results to differ materially from those contained in such forward-looking statements include those identified in the Company’s most recent Form 10-K and subsequent Form 10-Qs and other SEC filings, and such factors are incorporated herein by reference. Trademarks: All trademarks, service marks, and trade names referenced in this material are official trademarks and the property of their respective owners. Presentation: Within the charts and tables presented, certain segments, columns and rows may not sum to totals shown due to rounding. Non-GAAP Measures: This presentation includes certain non-GAAP financial measures. These non-GAAP measures are provided in addition to, and not as substitutes for, measures of our financial performance determined in accordance with GAAP. Our calculation of these non-GAAP measures may not be comparable to similarly titled measures of other companies due to potential differences between companies in the method of calculation. As a result, the use of these non-GAAP measures has limitations and should not be considered superior to, in isolation from, or as a substitute for, related GAAP measures. Reconciliations of these non-GAAP financial measures to the most directly comparable GAAP financial measures can be found at the end of this presentation.
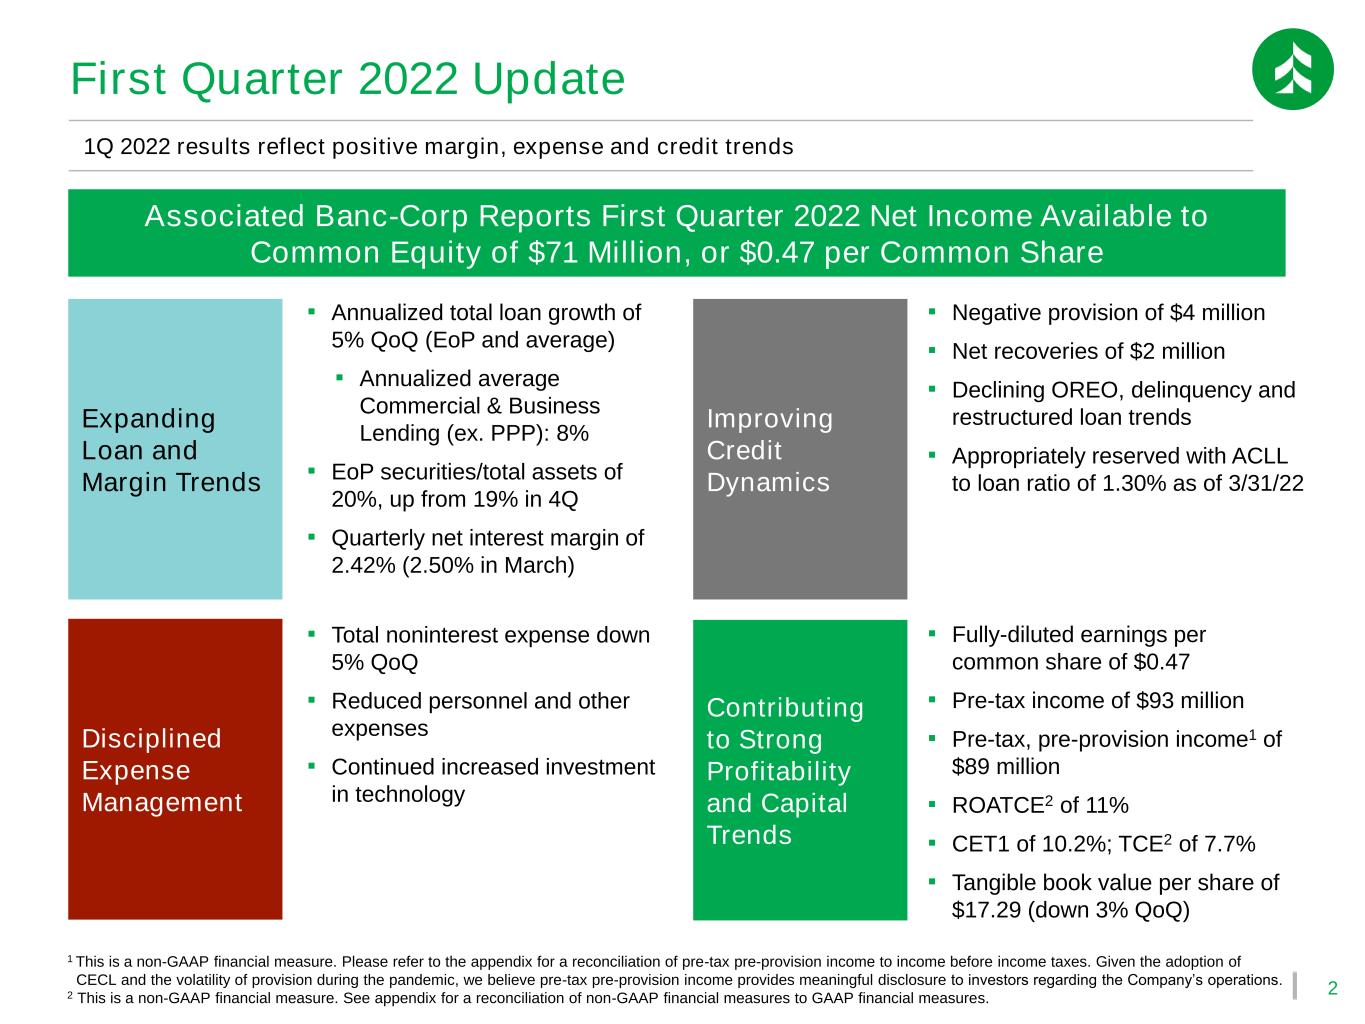
2 Expanding Loan and Margin Trends ▪ Annualized total loan growth of 5% QoQ (EoP and average) ▪ Annualized average Commercial & Business Lending (ex. PPP): 8% ▪ EoP securities/total assets of 20%, up from 19% in 4Q ▪ Quarterly net interest margin of 2.42% (2.50% in March) Contributing to Strong Profitability and Capital Trends ▪ Fully-diluted earnings per common share of $0.47 ▪ Pre-tax income of $93 million ▪ Pre-tax, pre-provision income1 of $89 million ▪ ROATCE2 of 11% ▪ CET1 of 10.2%; TCE2 of 7.7% ▪ Tangible book value per share of $17.29 (down 3% QoQ) Improving Credit Dynamics ▪ Negative provision of $4 million ▪ Net recoveries of $2 million ▪ Declining OREO, delinquency and restructured loan trends ▪ Appropriately reserved with ACLL to loan ratio of 1.30% as of 3/31/22 ▪ Total noninterest expense down 5% QoQ ▪ Reduced personnel and other expenses ▪ Continued increased investment in technology 1Q 2022 results reflect positive margin, expense and credit trends Associated Banc-Corp Reports First Quarter 2022 Net Income Available to Common Equity of $71 Million, or $0.47 per Common Share First Quarter 2022 Update Disciplined Expense Management 1 This is a non-GAAP financial measure. Please refer to the appendix for a reconciliation of pre-tax pre-provision income to income before income taxes. Given the adoption of CECL and the volatility of provision during the pandemic, we believe pre-tax pre-provision income provides meaningful disclosure to investors regarding the Company’s operations. 2 This is a non-GAAP financial measure. See appendix for a reconciliation of non-GAAP financial measures to GAAP financial measures.
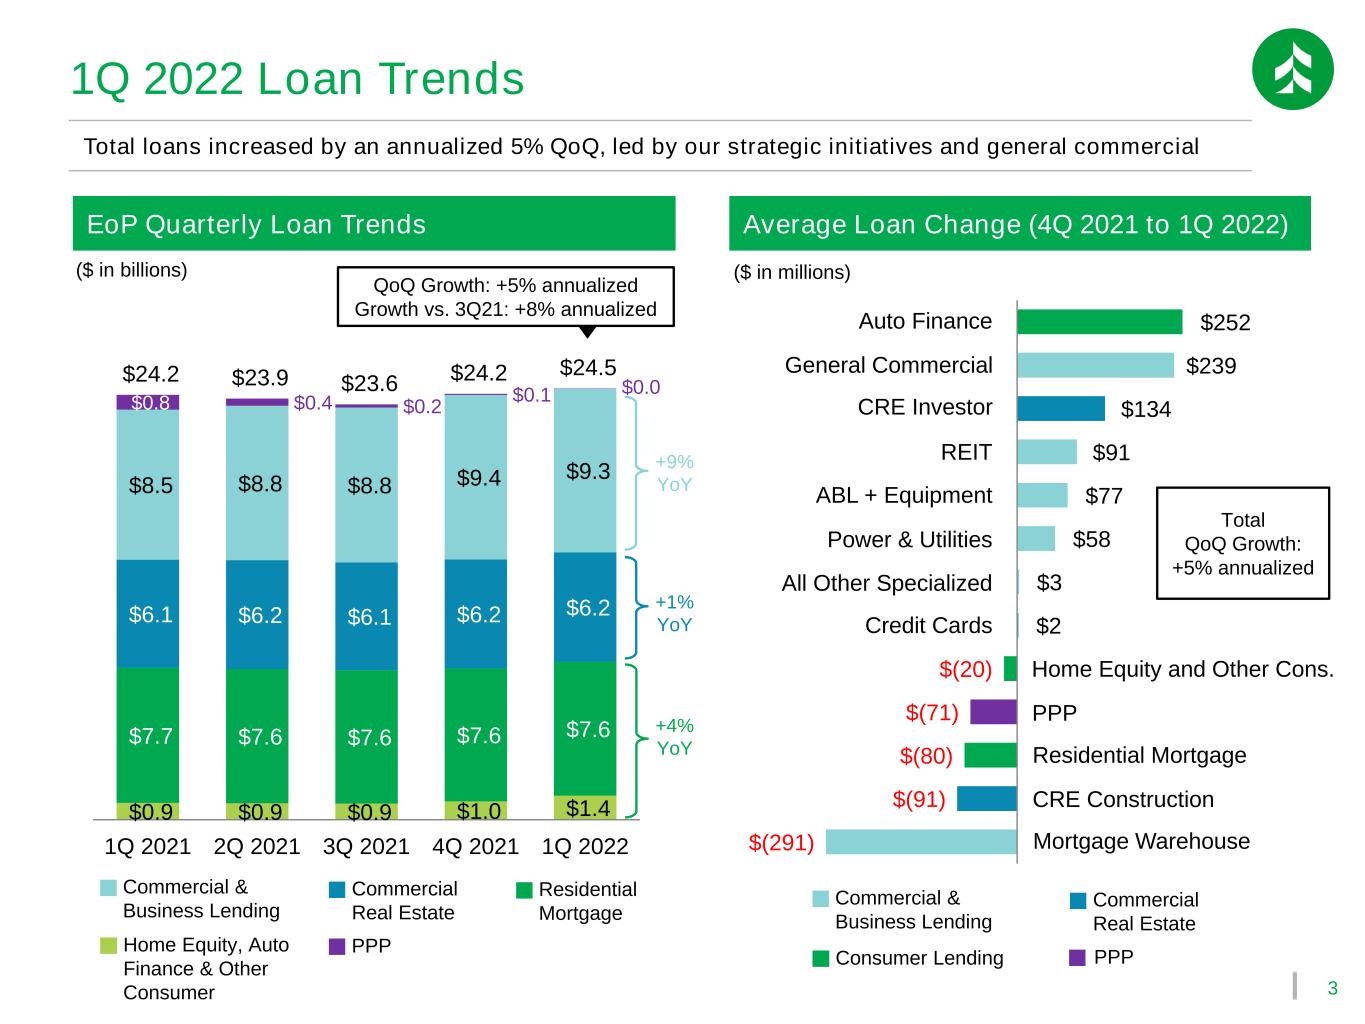
3 Total loans increased by an annualized 5% QoQ, led by our strategic initiatives and general commercial 1Q 2022 Loan Trends ($ in millions) Average Loan Change (4Q 2021 to 1Q 2022) Commercial & Business Lending Commercial Real Estate Consumer Lending PPP EoP Quarterly Loan Trends ($ in billions) Commercial & Business Lending Commercial Real Estate Residential Mortgage Home Equity, Auto Finance & Other Consumer PPP $(291) $(91) $(80) $(71) $(20) $2 $3 $58 $77 $91 $134 $239 $252 Mortgage Warehouse Home Equity and Other Cons. CRE Investor Power & Utilities General Commercial REIT PPP Credit Cards CRE Construction Auto Finance ABL + Equipment All Other Specialized Residential Mortgage $0.9 $0.9 $0.9 $1.0 $1.4 $7.7 $7.6 $7.6 $7.6 $7.6 $6.1 $6.2 $6.1 $6.2 $6.2 $8.5 $8.8 $8.8 $9.4 $9.3 $0.8 $0.4 $0.2 $0.1 $0.0 $24.2 $23.9 $23.6 $24.2 $24.5 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 +9% YoY +4% YoY +1% YoY QoQ Growth: +5% annualized Growth vs. 3Q21: +8% annualized Total QoQ Growth: +5% annualized
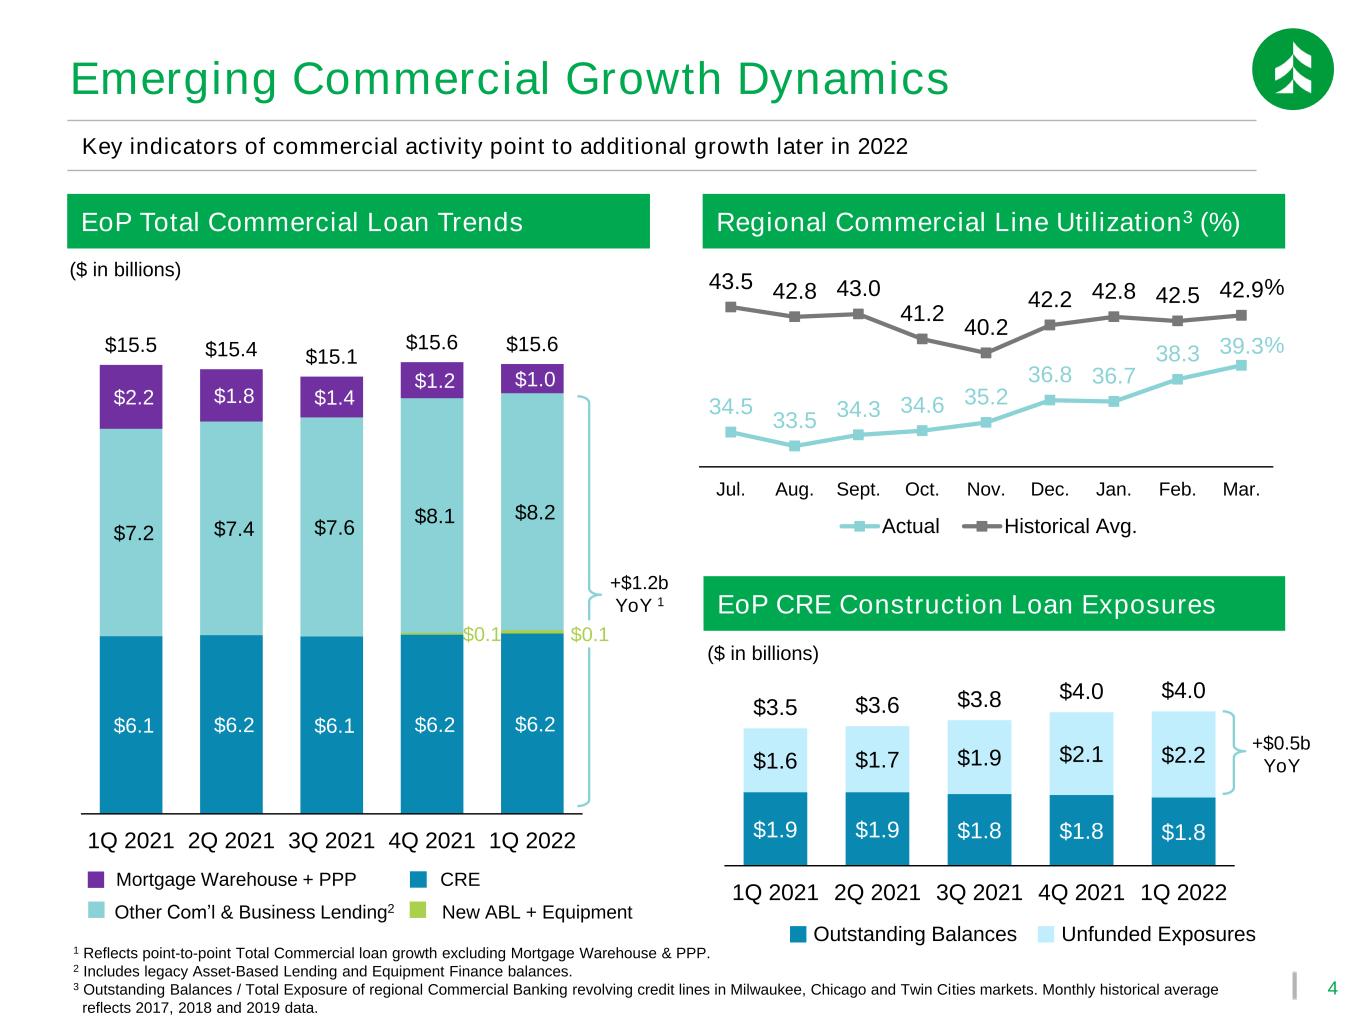
4 Mortgage Warehouse + PPP $1.9 $1.9 $1.8 $1.8 $1.8 $1.6 $1.7 $1.9 $2.1 $2.2 $3.5 $3.6 $3.8 $4.0 $4.0 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 34.5 33.5 34.3 34.6 35.2 36.8 36.7 38.3 39.3 43.5 42.8 43.0 41.2 40.2 42.2 42.8 42.5 42.9 Jul. Aug. Sept. Oct. Nov. Dec. Jan. Feb. Mar. Actual Historical Avg. Emerging Commercial Growth Dynamics Key indicators of commercial activity point to additional growth later in 2022 Regional Commercial Line Utilization3 (%) 1 Reflects point-to-point Total Commercial loan growth excluding Mortgage Warehouse & PPP. 2 Includes legacy Asset-Based Lending and Equipment Finance balances. 3 Outstanding Balances / Total Exposure of regional Commercial Banking revolving credit lines in Milwaukee, Chicago and Twin Cities markets. Monthly historical average reflects 2017, 2018 and 2019 data. EoP CRE Construction Loan Exposures ($ in billions) % % Outstanding Balances Unfunded Exposures +$0.5b YoY EoP Total Commercial Loan Trends +$1.2b YoY 1 New ABL + Equipment CRE Other Com’l & Business Lending2 ($ in billions) $6.1 $6.2 $6.1 $6.2 $6.2 $0.1 $0.1 $7.2 $7.4 $7.6 $8.1 $8.2 $2.2 $1.8 $1.4 $1.2 $1.0 $15.5 $15.4 $15.1 $15.6 $15.6 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022
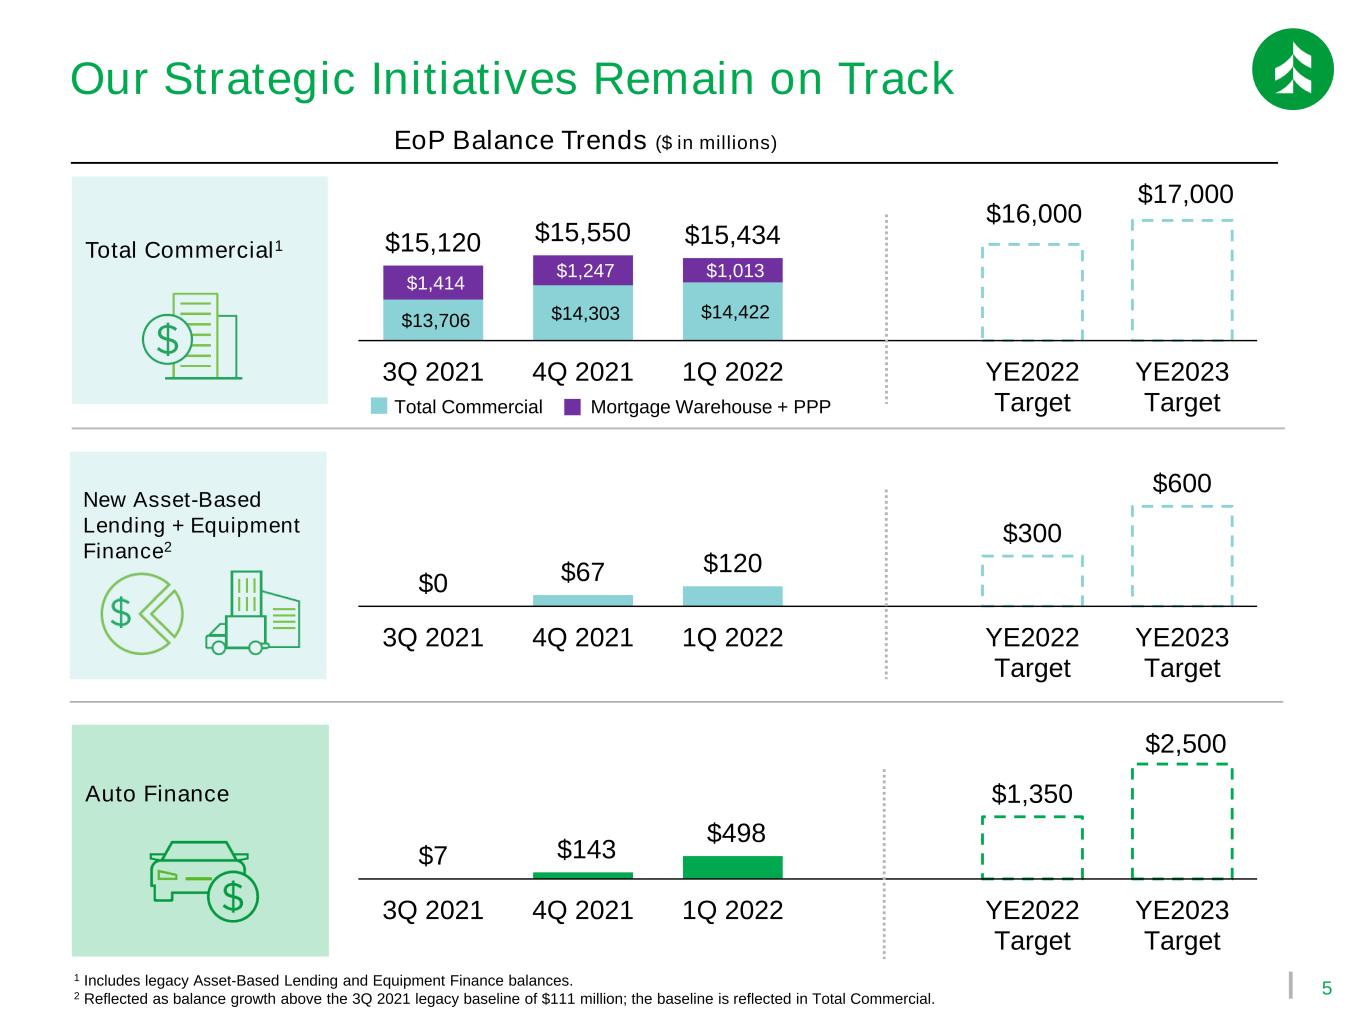
5 $13,706 $14,303 $14,422 $16,000 $17,000 $1,414 $1,247 $1,013 $15,120 $15,550 $15,434 3Q 2021 4Q 2021 1Q 2022 YE2022 Target YE2023 Target New Asset-Based Lending + Equipment Finance2 Total Commercial1 Auto Finance Our Strategic Initiatives Remain on Track $7 $143 $498 $1,350 $2,500 3Q 2021 4Q 2021 1Q 2022 YE2022 Target YE2023 Target $0 $67 $120 $300 $600 3Q 2021 4Q 2021 1Q 2022 YE2022 Target YE2023 Target EoP Balance Trends ($ in millions) Mortgage Warehouse + PPPTotal Commercial 1 Includes legacy Asset-Based Lending and Equipment Finance balances. 2 Reflected as balance growth above the 3Q 2021 legacy baseline of $111 million; the baseline is reflected in Total Commercial.
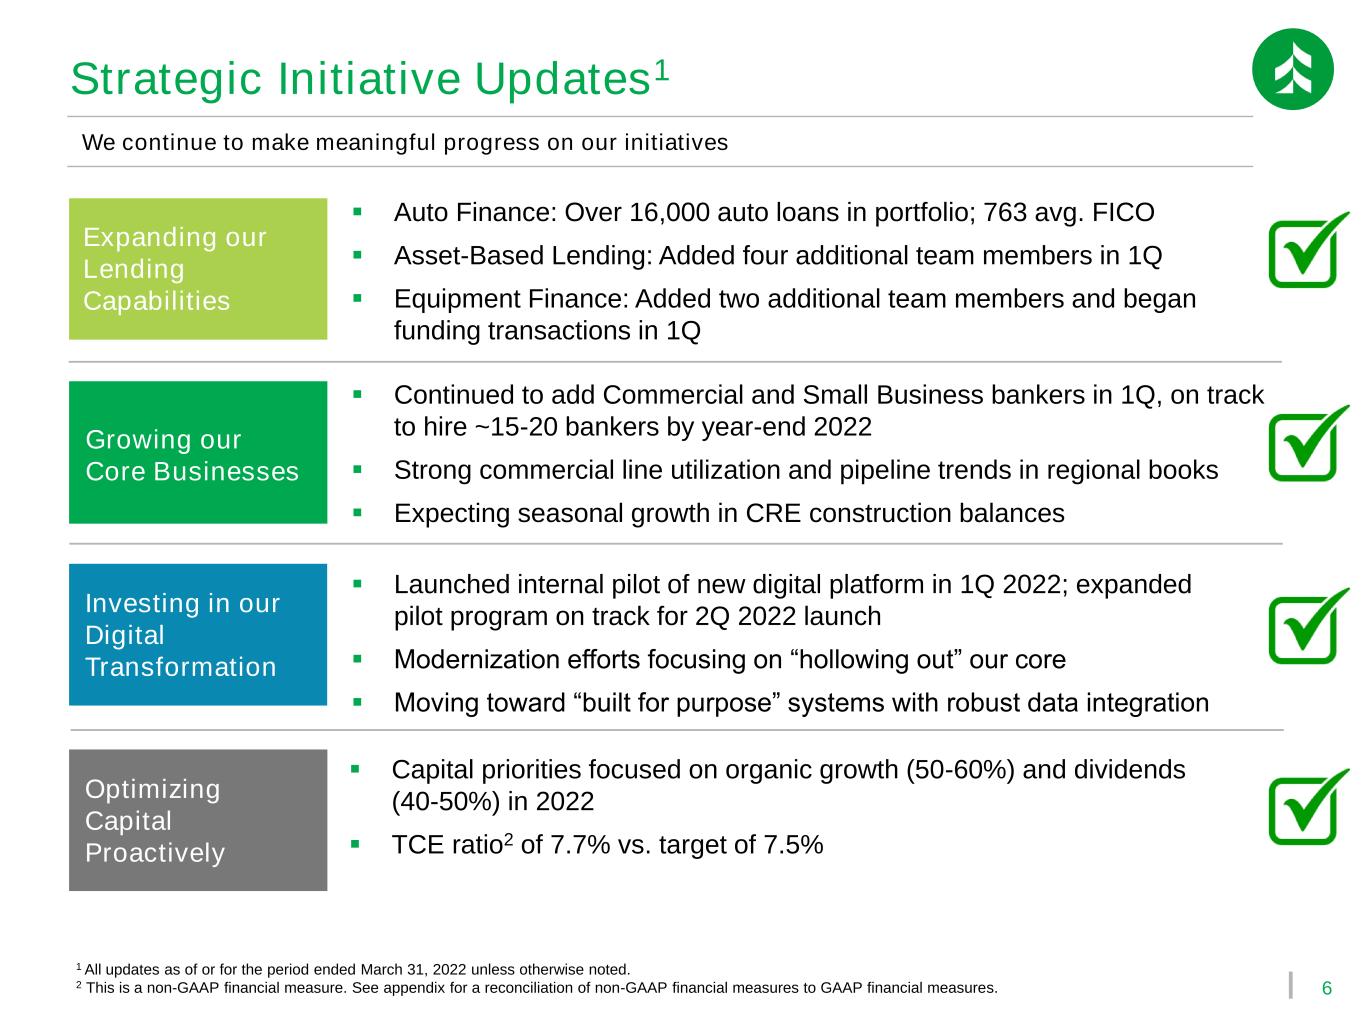
6 Strategic Initiative Updates1 We continue to make meaningful progress on our initiatives Expanding our Lending Capabilities Growing our Core Businesses Investing in our Digital Transformation ▪ Auto Finance: Over 16,000 auto loans in portfolio; 763 avg. FICO ▪ Asset-Based Lending: Added four additional team members in 1Q ▪ Equipment Finance: Added two additional team members and began funding transactions in 1Q Optimizing Capital Proactively ▪ Continued to add Commercial and Small Business bankers in 1Q, on track to hire ~15-20 bankers by year-end 2022 ▪ Strong commercial line utilization and pipeline trends in regional books ▪ Expecting seasonal growth in CRE construction balances ▪ Launched internal pilot of new digital platform in 1Q 2022; expanded pilot program on track for 2Q 2022 launch ▪ Modernization efforts focusing on “hollowing out” our core ▪ Moving toward “built for purpose” systems with robust data integration ▪ Capital priorities focused on organic growth (50-60%) and dividends (40-50%) in 2022 ▪ TCE ratio2 of 7.7% vs. target of 7.5% 1 All updates as of or for the period ended March 31, 2022 unless otherwise noted. 2 This is a non-GAAP financial measure. See appendix for a reconciliation of non-GAAP financial measures to GAAP financial measures.
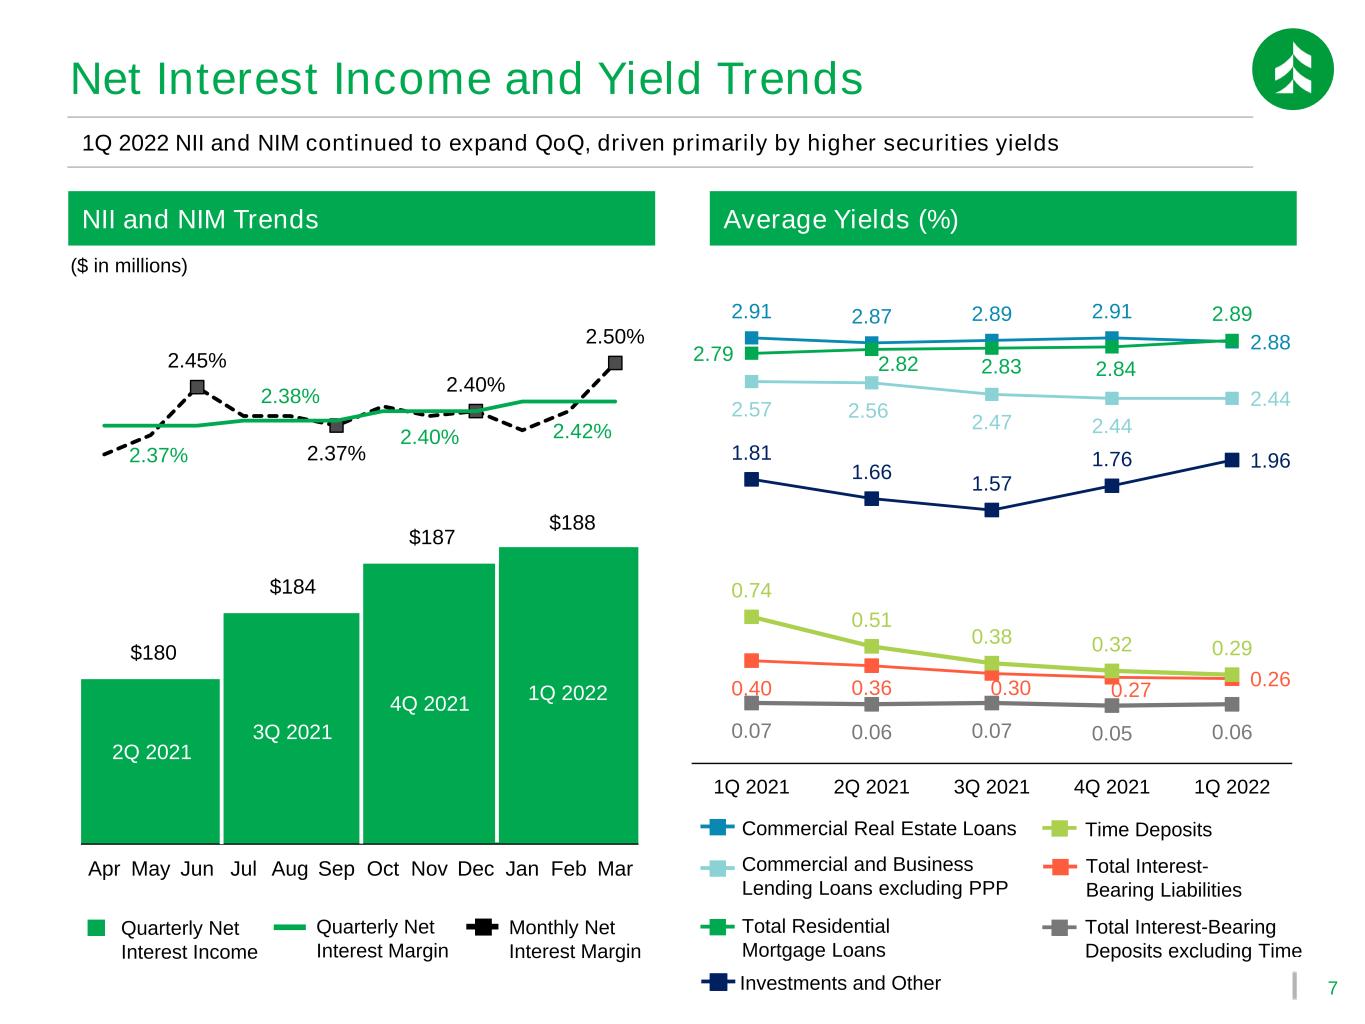
7 $180 $184 $187 $188 2.45% 2.37% 2.40% 2.50% 2.37% 2.38% 2.40% 2.42% Apr May Jun Jul Aug Sep Oct Nov Dec Jan Feb Mar Net Interest Income and Yield Trends NII and NIM Trends 2.91 2.87 2.89 2.91 2.88 2.57 2.56 2.47 2.44 2.44 2.79 2.82 2.83 2.84 2.89 1.81 1.66 1.57 1.76 1.96 0.40 0.36 0.30 0.27 0.26 0.07 0.06 0.07 0.05 0.06 0.74 0.51 0.38 0.32 0.29 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 Average Yields (%) ($ in millions) 1Q 2022 NII and NIM continued to expand QoQ, driven primarily by higher securities yields Total Residential Mortgage Loans Commercial and Business Lending Loans excluding PPP Commercial Real Estate Loans Total Interest- Bearing Liabilities Time Deposits Quarterly Net Interest Income Total Interest-Bearing Deposits excluding Time Investments and Other Quarterly Net Interest Margin 2Q 2021 3Q 2021 4Q 2021 1Q 2022 Monthly Net Interest Margin
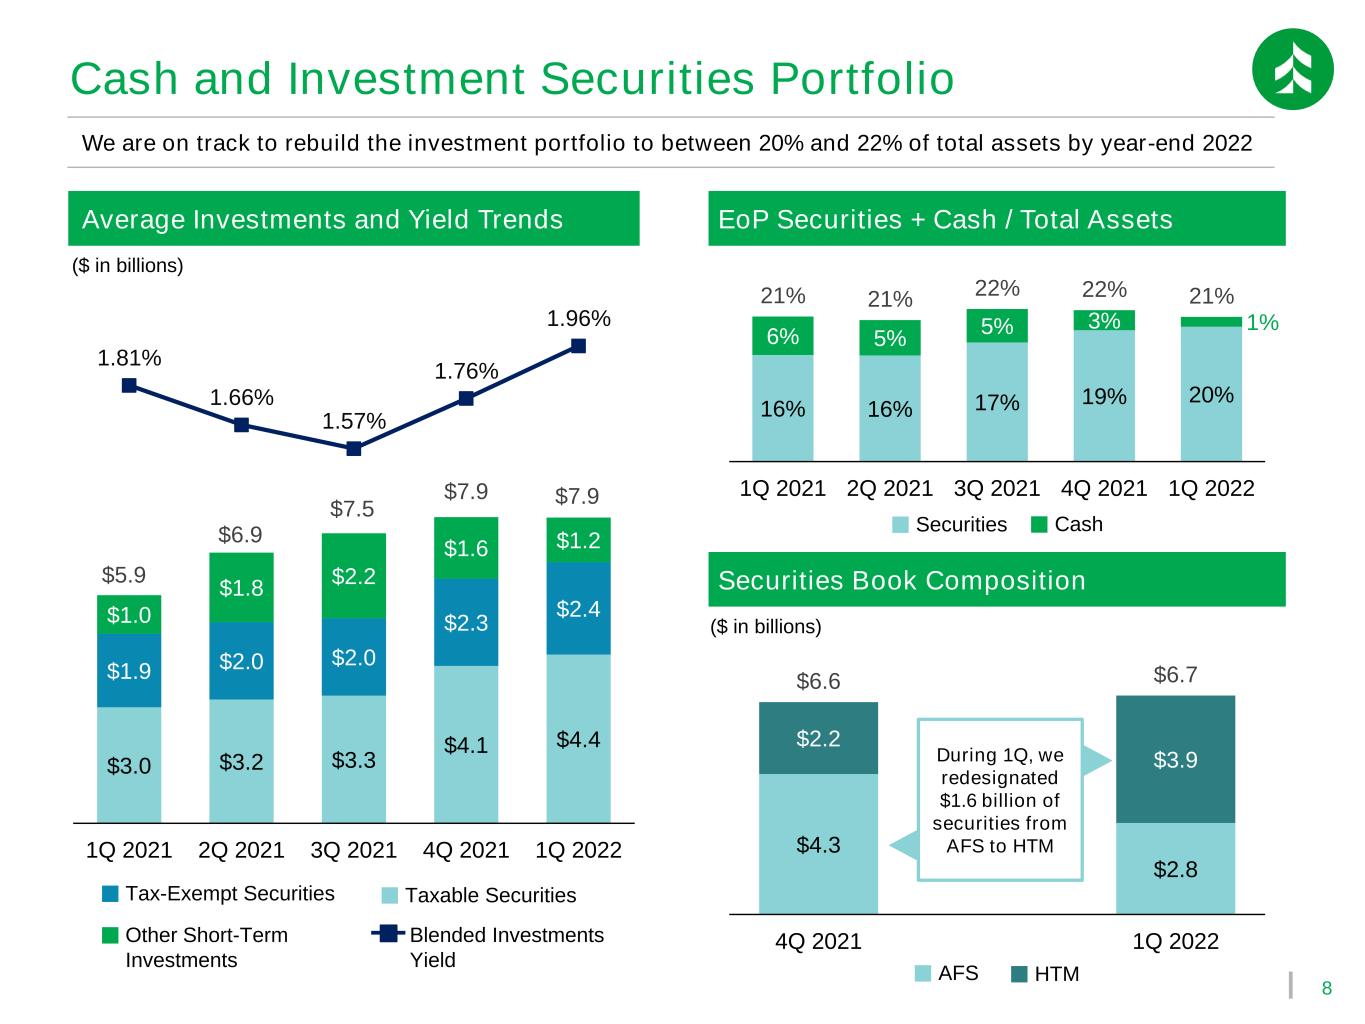
8 $3.0 $3.2 $3.3 $4.1 $4.4 $1.9 $2.0 $2.0 $2.3 $2.4 $1.0 $1.8 $2.2 $1.6 $1.2 $5.9 $6.9 $7.5 $7.9 $7.9 1.81% 1.66% 1.57% 1.76% 1.96% 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 16% 16% 17% 19% 20% 6% 5% 5% 3% 1% 21% 21% 22% 22% 21% 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 Cash and Investment Securities Portfolio Average Investments and Yield Trends EoP Securities + Cash / Total Assets We are on track to rebuild the investment portfolio to between 20% and 22% of total assets by year-end 2022 ($ in billions) Tax-Exempt Securities Taxable Securities Other Short-Term Investments Blended Investments Yield Securities Cash Securities Book Composition $4.3 $2.8 $2.2 $3.9 $6.6 $6.7 4Q 2021 1Q 2022 HTMAFS ($ in billions) During 1Q, we redesignated $1.6 billion of securities from AFS to HTM
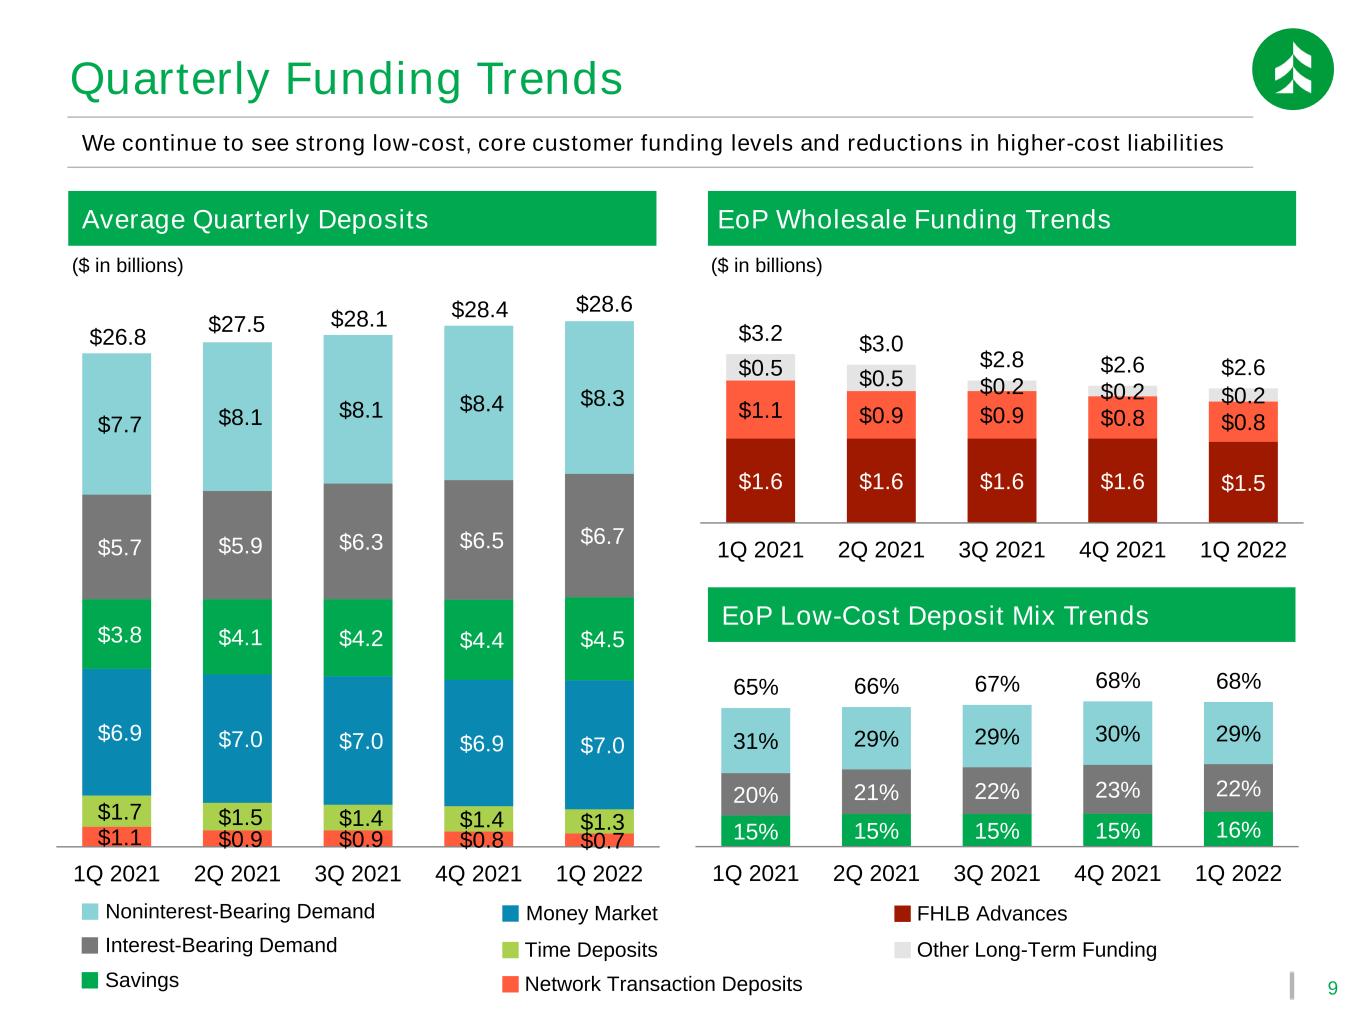
9 $1.1 $0.9 $0.9 $0.8 $0.7 $1.7 $1.5 $1.4 $1.4 $1.3 $6.9 $7.0 $7.0 $6.9 $7.0 $3.8 $4.1 $4.2 $4.4 $4.5 $5.7 $5.9 $6.3 $6.5 $6.7 $7.7 $8.1 $8.1 $8.4 $8.3 $26.8 $27.5 $28.1 $28.4 $28.6 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 Quarterly Funding Trends ($ in billions) Average Quarterly Deposits Time Deposits Savings Money Market EoP Wholesale Funding Trends Network Transaction Deposits We continue to see strong low-cost, core customer funding levels and reductions in higher-cost liabilities Noninterest-Bearing Demand Interest-Bearing Demand ($ in billions) EoP Low-Cost Deposit Mix Trends 15% 15% 15% 15% 16% 20% 21% 22% 23% 22% 31% 29% 29% 30% 29% 65% 66% 67% 68% 68% 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 FHLB Advances Other Long-Term Funding $1.6 $1.6 $1.6 $1.6 $1.5 $1.1 $0.9 $0.9 $0.8 $0.8 $0.5 $0.5 $0.2 $0.2 $0.2 $3.2 $3.0 $2.8 $2.6 $2.6 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022
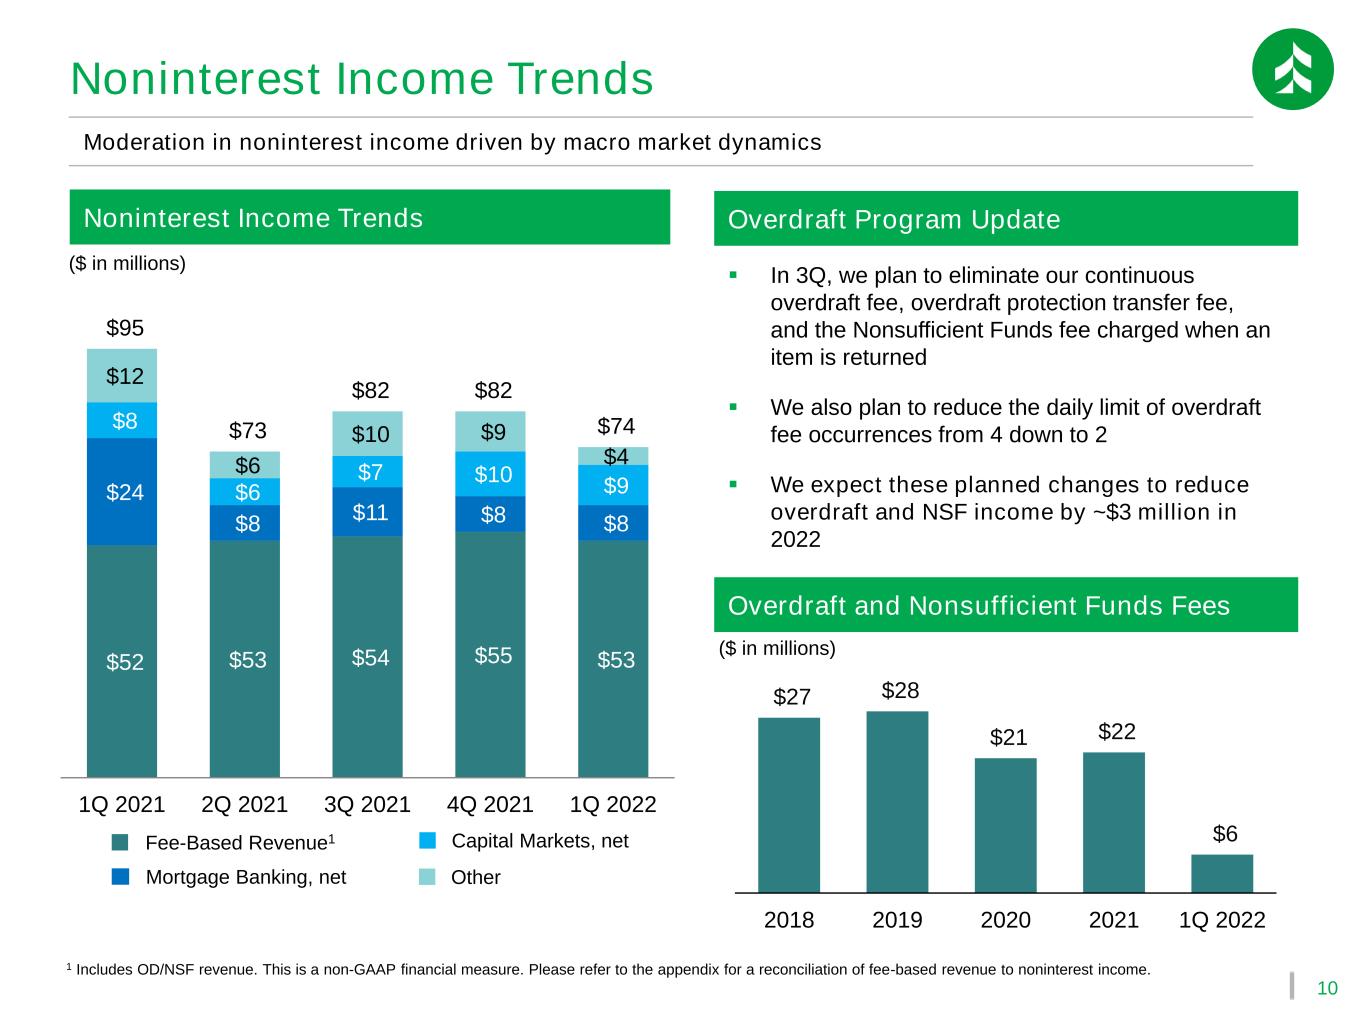
10 $52 $53 $54 $55 $53 $24 $8 $11 $8 $8 $8 $6 $7 $10 $9 $12 $6 $10 $9 $4 $95 $73 $82 $82 $74 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 Noninterest Income Trends Overdraft Program UpdateNoninterest Income Trends ($ in millions) ($ in millions) Overdraft and Nonsufficient Funds Fees Moderation in noninterest income driven by macro market dynamics Fee-Based Revenue1 Capital Markets, net Mortgage Banking, net Other 1 Includes OD/NSF revenue. This is a non-GAAP financial measure. Please refer to the appendix for a reconciliation of fee-based revenue to noninterest income. ▪ In 3Q, we plan to eliminate our continuous overdraft fee, overdraft protection transfer fee, and the Nonsufficient Funds fee charged when an item is returned ▪ We also plan to reduce the daily limit of overdraft fee occurrences from 4 down to 2 ▪ We expect these planned changes to reduce overdraft and NSF income by ~$3 million in 2022 $27 $28 $21 $22 $6 2018 2019 2020 2021 1Q 2022
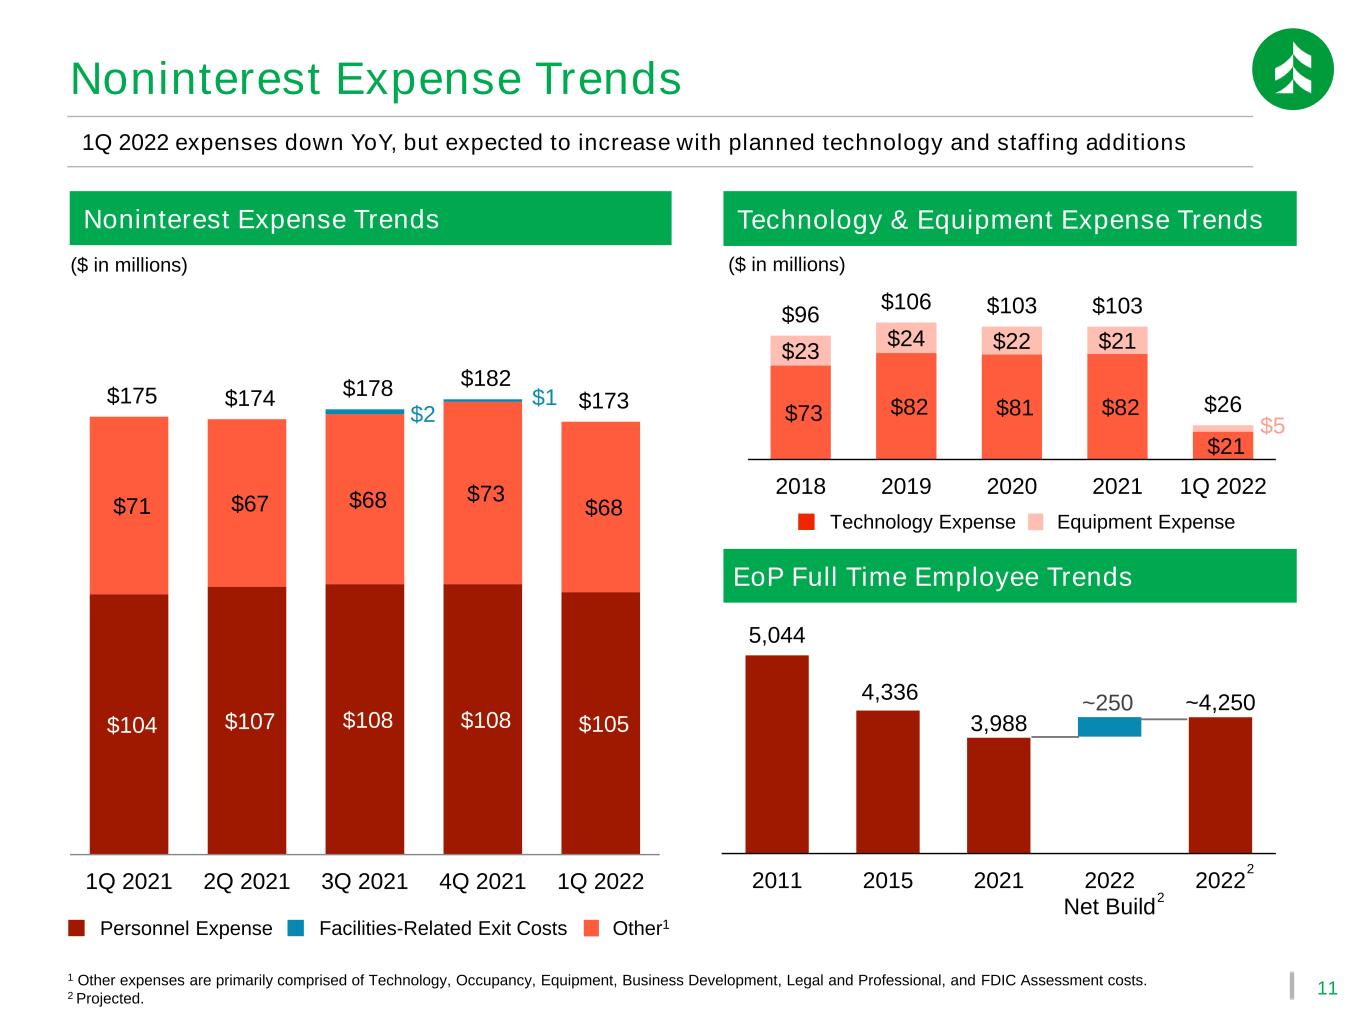
11 $104 $107 $108 $108 $105 $71 $67 $68 $73 $68 $2 $1 $175 $174 $178 $182 $173 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 Noninterest Expense Trends Technology & Equipment Expense TrendsNoninterest Expense Trends 1 Other expenses are primarily comprised of Technology, Occupancy, Equipment, Business Development, Legal and Professional, and FDIC Assessment costs. 2 Projected. ($ in millions) 1Q 2022 expenses down YoY, but expected to increase with planned technology and staffing additions Personnel Expense Other1Facilities-Related Exit Costs $73 $82 $81 $82 $21 $23 $24 $22 $21 $5 $96 $106 $103 $103 $26 2018 2019 2020 2021 1Q 2022 ($ in millions) EoP Full Time Employee Trends 5,044 4,336 3,988 ~4,250~250 2011 2015 2021 2022 Net Build 2022 2 2 Equipment ExpenseTechnology Expense
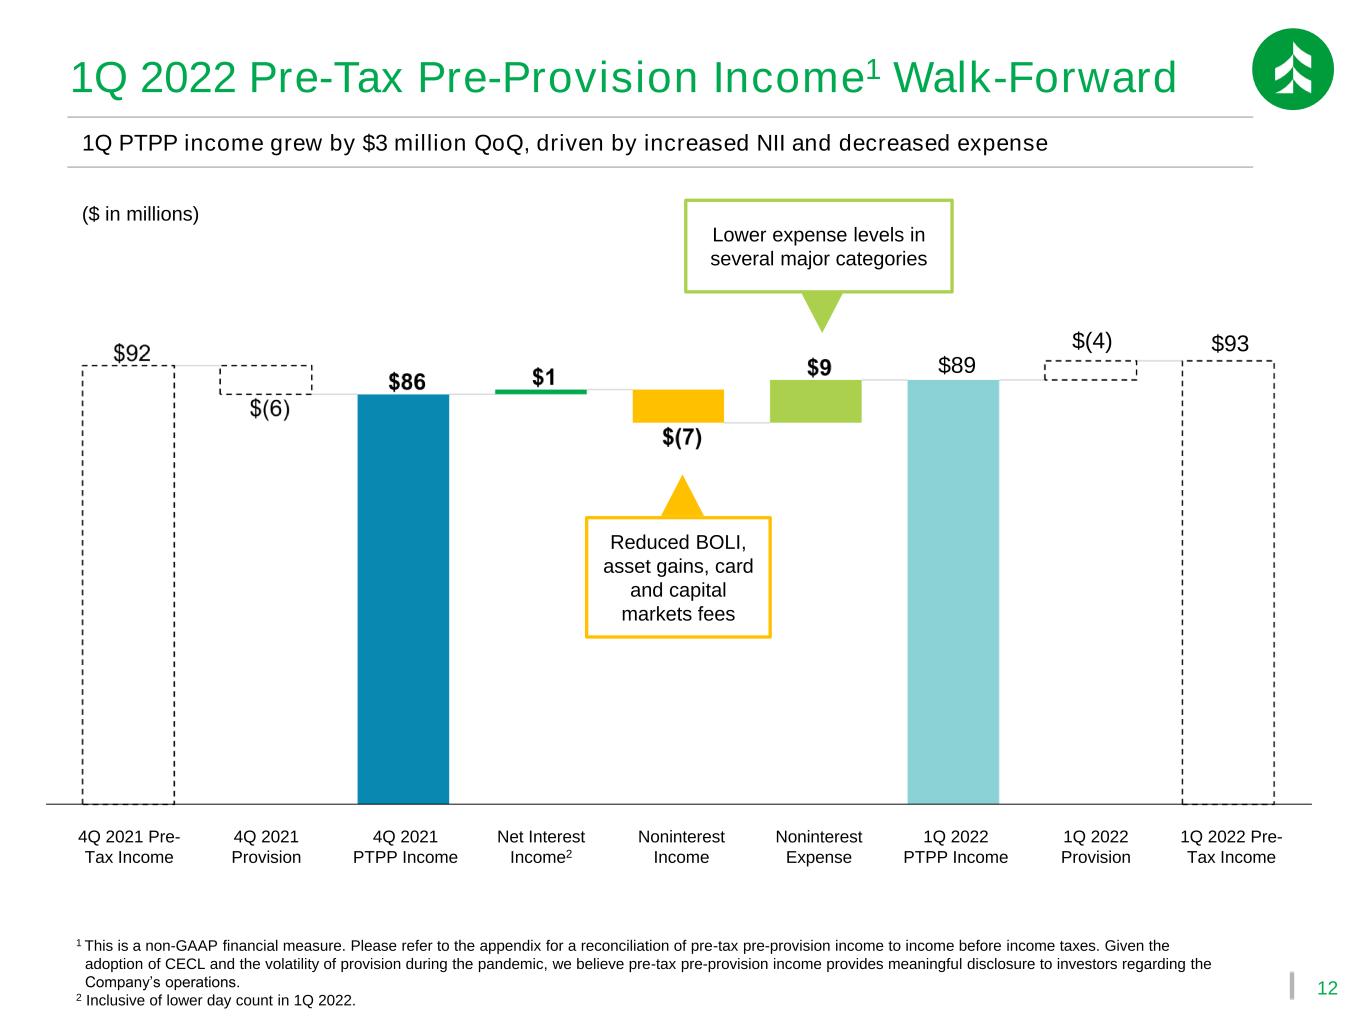
12 1Q 2022 Pre-Tax Pre-Provision Income1 Walk-Forward 1Q PTPP income grew by $3 million QoQ, driven by increased NII and decreased expense 4Q 2021 PTPP Income Net Interest Income2 Noninterest Income 1Q 2022 Pre- Tax Income ($ in millions) $89 1 This is a non-GAAP financial measure. Please refer to the appendix for a reconciliation of pre-tax pre-provision income to income before income taxes. Given the adoption of CECL and the volatility of provision during the pandemic, we believe pre-tax pre-provision income provides meaningful disclosure to investors regarding the Company’s operations. 2 Inclusive of lower day count in 1Q 2022. $(4) $93 1Q 2022 PTPP Income 1Q 2022 Provision 4Q 2021 Pre- Tax Income 4Q 2021 Provision Noninterest Expense Reduced BOLI, asset gains, card and capital markets fees Lower expense levels in several major categories
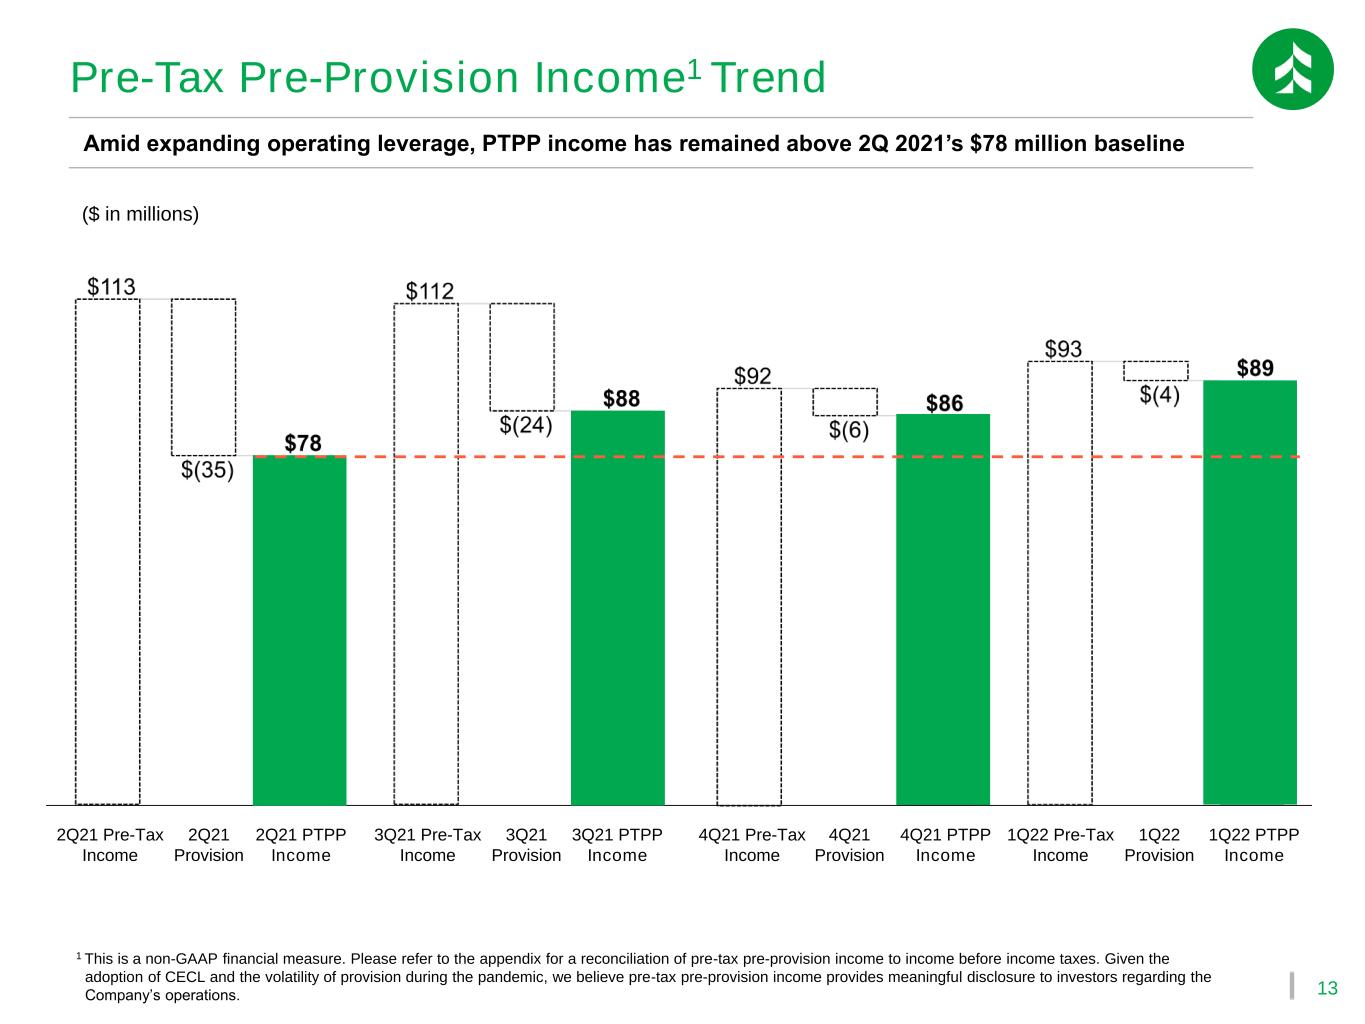
13 Pre-Tax Pre-Provision Income1 Trend Amid expanding operating leverage, PTPP income has remained above 2Q 2021’s $78 million baseline ($ in millions) 1 This is a non-GAAP financial measure. Please refer to the appendix for a reconciliation of pre-tax pre-provision income to income before income taxes. Given the adoption of CECL and the volatility of provision during the pandemic, we believe pre-tax pre-provision income provides meaningful disclosure to investors regarding the Company’s operations. 2Q21 Pre-Tax Income 2Q21 Provision 2Q21 PTPP Income 3Q21 Pre-Tax Income 3Q21 Provision 3Q21 PTPP Income 4Q21 Pre-Tax Income 4Q21 Provision 4Q21 PTPP Income 1Q22 Pre-Tax Income 1Q22 Provision 1Q22 PTPP Income
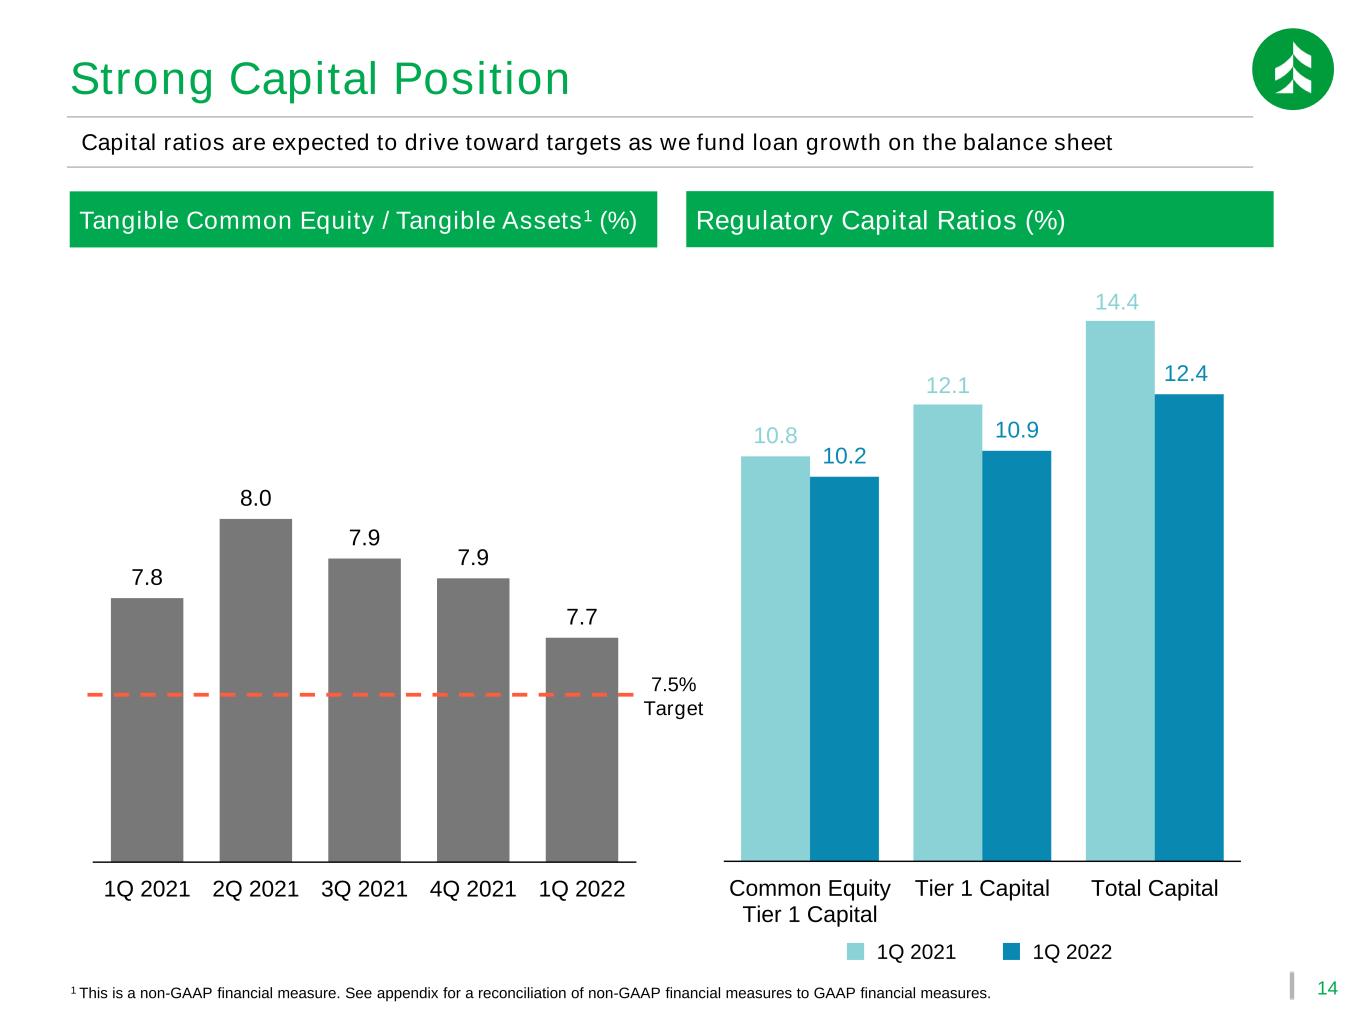
14 10.8 12.1 14.4 10.2 10.9 12.4 Common Equity Tier 1 Capital Tier 1 Capital Total Capital 1 This is a non-GAAP financial measure. See appendix for a reconciliation of non-GAAP financial measures to GAAP financial measures. Regulatory Capital Ratios (%) 1Q 2021 Capital ratios are expected to drive toward targets as we fund loan growth on the balance sheet 1Q 2022 Strong Capital Position Tangible Common Equity / Tangible Assets1 (%) 7.8 8.0 7.9 7.9 7.7 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 7.5% Target
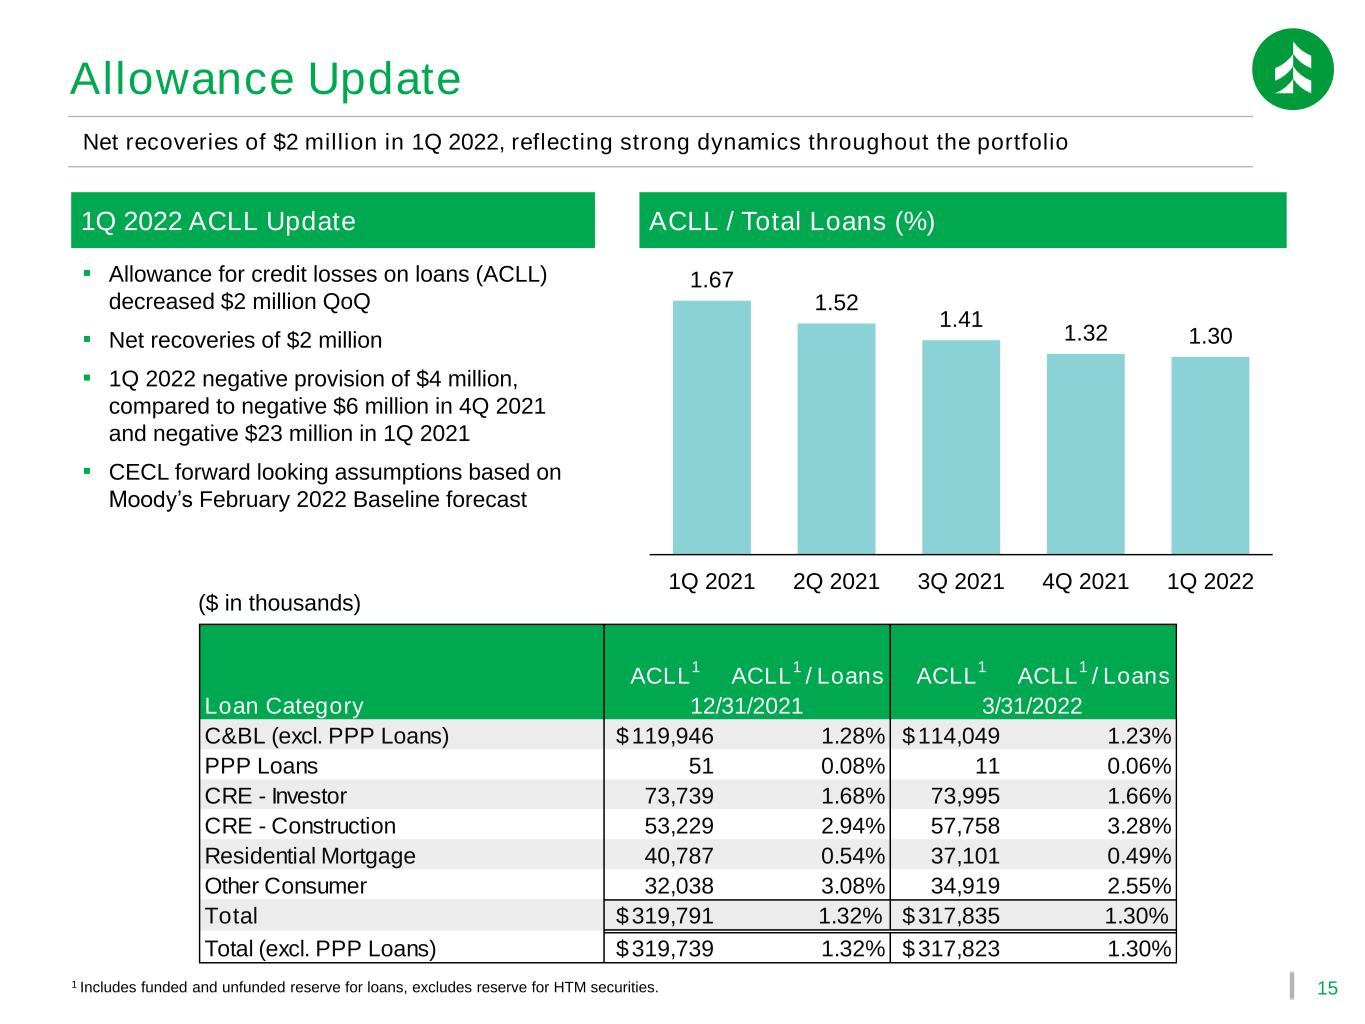
15 1Q 2022 ACLL Update ▪ Allowance for credit losses on loans (ACLL) decreased $2 million QoQ ▪ Net recoveries of $2 million ▪ 1Q 2022 negative provision of $4 million, compared to negative $6 million in 4Q 2021 and negative $23 million in 1Q 2021 ▪ CECL forward looking assumptions based on Moody’s February 2022 Baseline forecast 1 Includes funded and unfunded reserve for loans, excludes reserve for HTM securities. ($ in thousands) ACLL / Total Loans (%) Net recoveries of $2 million in 1Q 2022, reflecting strong dynamics throughout the portfolio Allowance Update 1.67 1.52 1.41 1.32 1.30 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 ACLL 1 ACLL 1 / Loans ACLL 1 ACLL 1 / Loans Loan Category C&BL (excl. PPP Loans) 119,946$ 1.28% 114,049$ 1.23% PPP Loans 51 0.08% 11 0.06% CRE - Investor 73,739 1.68% 73,995 1.66% CRE - Construction 53,229 2.94% 57,758 3.28% Residential Mortgage 40,787 0.54% 37,101 0.49% Other Consumer 32,038 3.08% 34,919 2.55% Total 319,791$ 1.32% 317,835$ 1.30% Total (excl. PPP Loans) 319,739$ 1.32% 317,823$ 1.30% 12/31/2021 3/31/2022
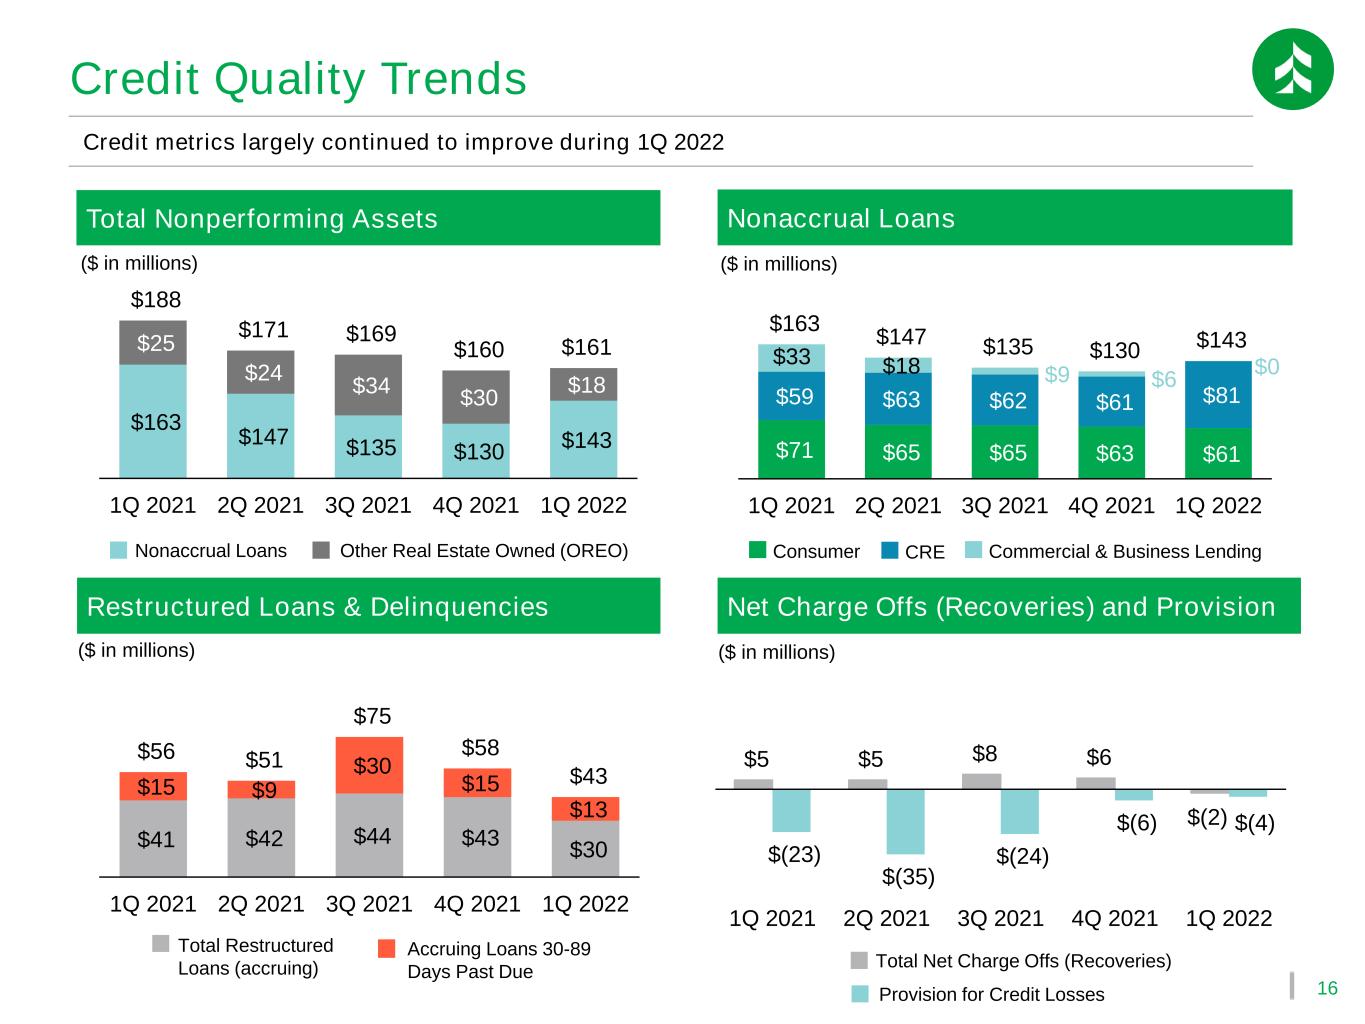
16 Credit Quality Trends $71 $65 $65 $63 $61 $59 $63 $62 $61 $81 $33 $18 $9 $6 $0 $163 $147 $135 $130 $143 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 $41 $42 $44 $43 $30 $15 $9 $30 $15 $13 $56 $51 $75 $58 $43 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 Credit metrics largely continued to improve during 1Q 2022 ($ in millions) ($ in millions) ($ in millions) Restructured Loans & Delinquencies Nonaccrual LoansTotal Nonperforming Assets Net Charge Offs (Recoveries) and Provision Total Restructured Loans (accruing) Accruing Loans 30-89 Days Past Due CREConsumer $163 $147 $135 $130 $143 $25 $24 $34 $30 $18 $188 $171 $169 $160 $161 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 ($ in millions) $5 $5 $8 $6 $(2) $(23) $(35) $(24) $(6) $(4) 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 Total Net Charge Offs (Recoveries) Provision for Credit Losses Commercial & Business LendingNonaccrual Loans Other Real Estate Owned (OREO)
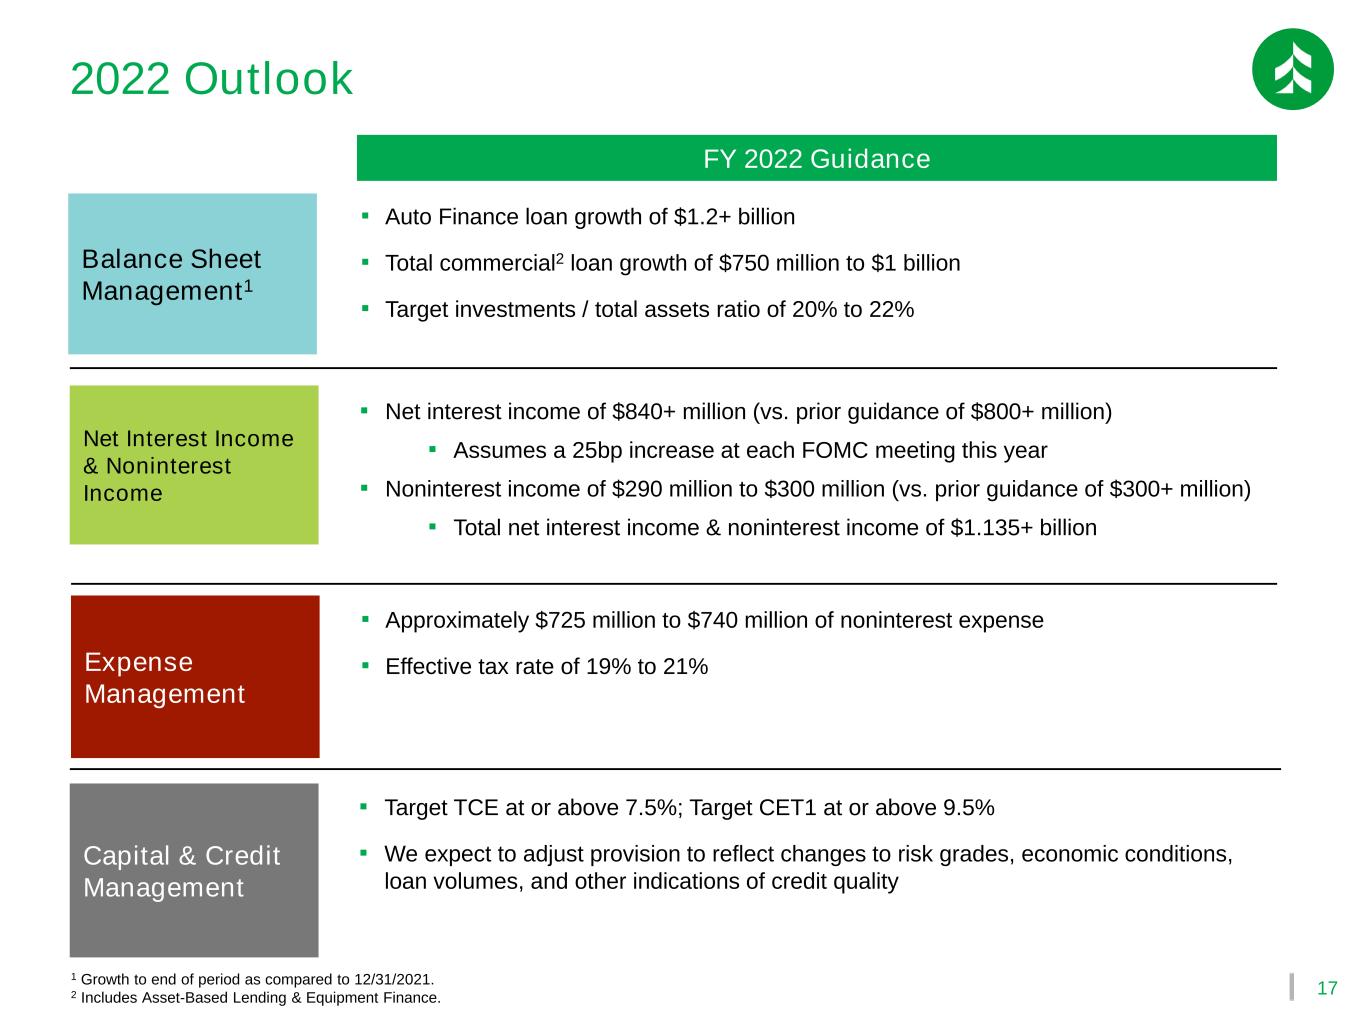
17 Balance Sheet Management1 ▪ Auto Finance loan growth of $1.2+ billion ▪ Total commercial2 loan growth of $750 million to $1 billion ▪ Target investments / total assets ratio of 20% to 22% Net Interest Income & Noninterest Income ▪ Net interest income of $840+ million (vs. prior guidance of $800+ million) ▪ Assumes a 25bp increase at each FOMC meeting this year ▪ Noninterest income of $290 million to $300 million (vs. prior guidance of $300+ million) ▪ Total net interest income & noninterest income of $1.135+ billion Expense Management ▪ Approximately $725 million to $740 million of noninterest expense ▪ Effective tax rate of 19% to 21% Capital & Credit Management ▪ Target TCE at or above 7.5%; Target CET1 at or above 9.5% ▪ We expect to adjust provision to reflect changes to risk grades, economic conditions, loan volumes, and other indications of credit quality 2022 Outlook FY 2022 Guidance 1 Growth to end of period as compared to 12/31/2021. 2 Includes Asset-Based Lending & Equipment Finance.
18
Appendix
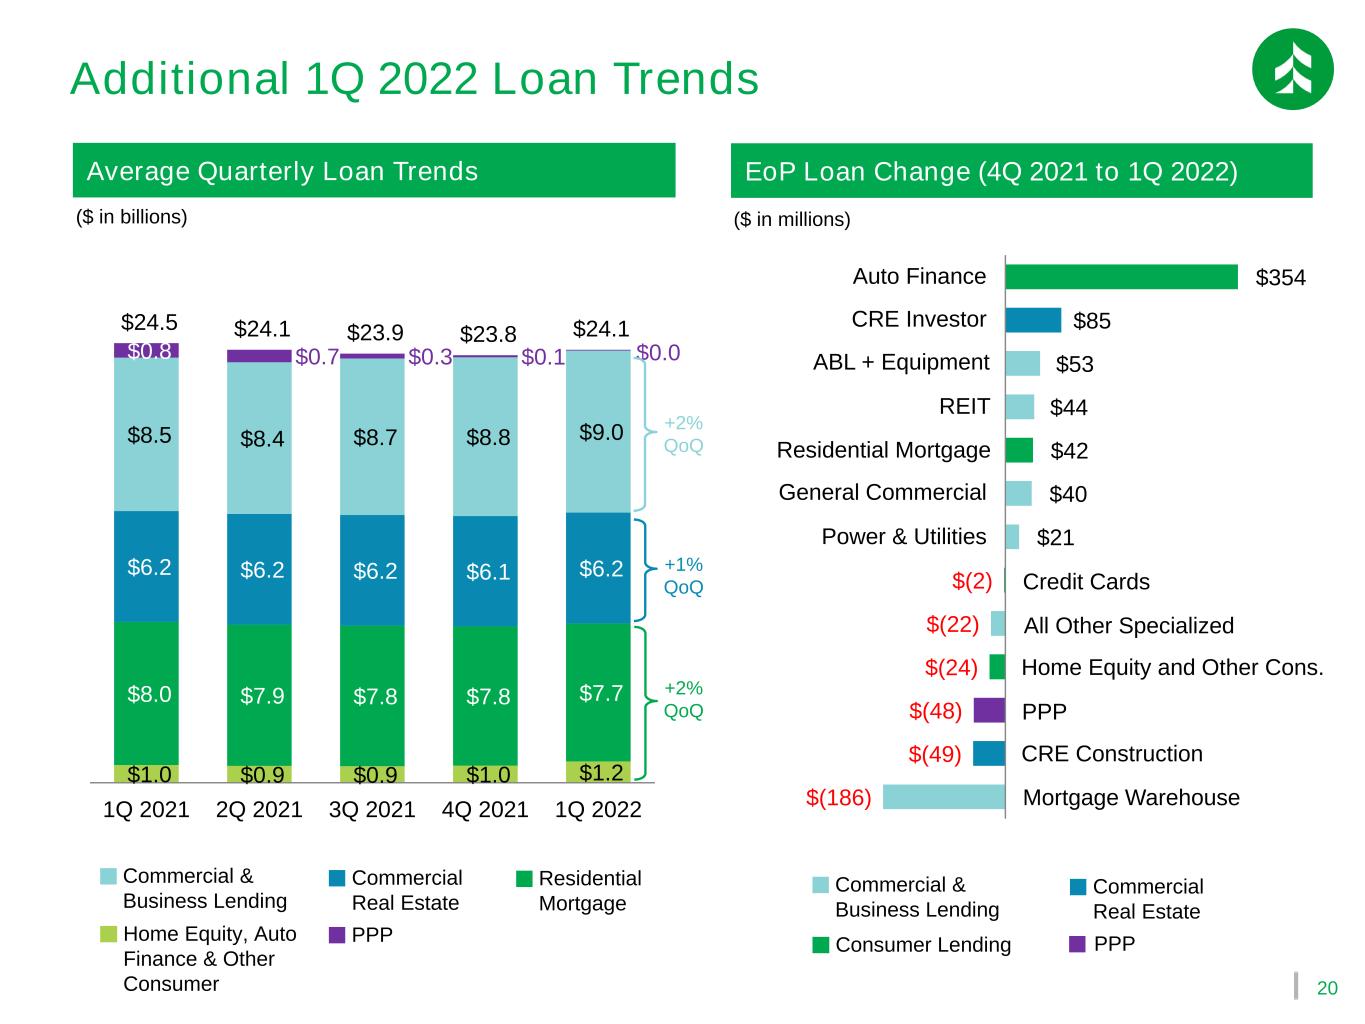
20 Additional 1Q 2022 Loan Trends $1.0 $0.9 $0.9 $1.0 $1.2 $8.0 $7.9 $7.8 $7.8 $7.7 $6.2 $6.2 $6.2 $6.1 $6.2 $8.5 $8.4 $8.7 $8.8 $9.0 $0.8 $0.7 $0.3 $0.1 $0.0 $24.5 $24.1 $23.9 $23.8 $24.1 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 Average Quarterly Loan Trends ($ in billions) Commercial & Business Lending Commercial Real Estate Residential Mortgage Home Equity, Auto Finance & Other Consumer PPP +2% QoQ +2% QoQ +1% QoQ ($ in millions) EoP Loan Change (4Q 2021 to 1Q 2022) Commercial & Business Lending Commercial Real Estate Consumer Lending PPP $(186) $(49) $(48) $(24) $(22) $(2) $21 $40 $42 $44 $53 $85 $354 Mortgage Warehouse Home Equity and Other Cons. CRE Investor Power & Utilities General Commercial REIT PPP Credit Cards CRE Construction Auto Finance ABL + Equipment All Other Specialized Residential Mortgage
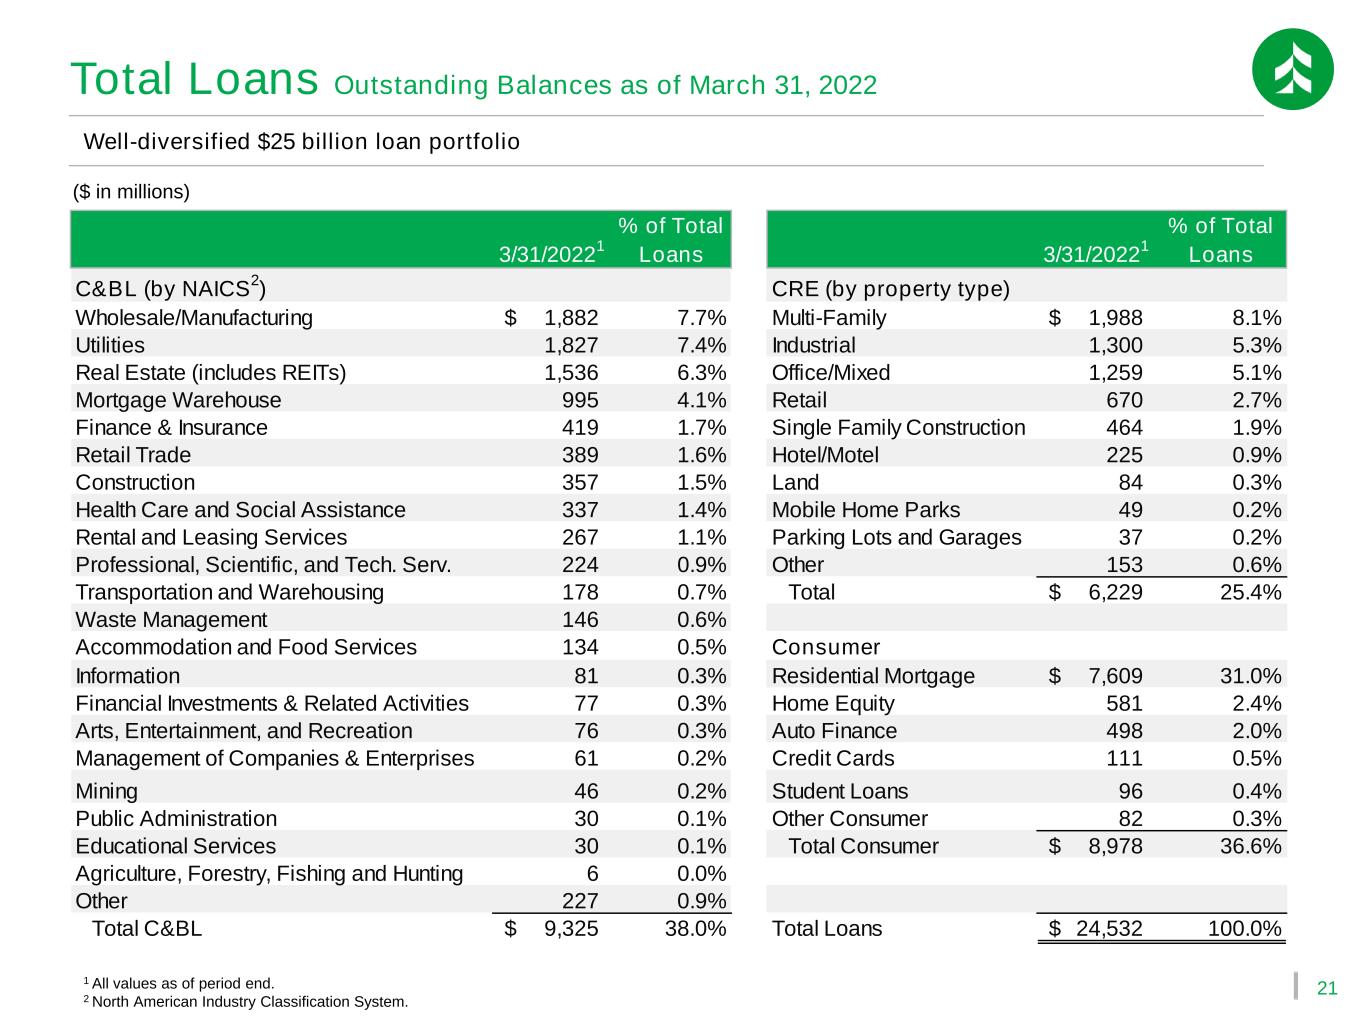
21 Total Loans Outstanding Balances as of March 31, 2022 Well-diversified $25 billion loan portfolio ($ in millions) 1 All values as of period end. 2 North American Industry Classification System. 3/31/2022 1 % of Total Loans 3/31/2022 1 % of Total Loans C&BL (by NAICS 2 ) CRE (by property type) Wholesale/Manufacturing 1,882$ 7.7% Multi-Family 1,988$ 8.1% Utilities 1,827 7.4% Industrial 1,300 5.3% Real Estate (includes REITs) 1,536 6.3% Office/Mixed 1,259 5.1% Mortgage Warehouse 995 4.1% Retail 670 2.7% Finance & Insurance 419 1.7% Single Family Construction 464 1.9% Retail Trade 389 1.6% Hotel/Motel 225 0.9% Construction 357 1.5% Land 84 0.3% Health Care and Social Assistance 337 1.4% Mobile Home Parks 49 0.2% Rental and Leasing Services 267 1.1% Parking Lots and Garages 37 0.2% Professional, Scientific, and Tech. Serv. 224 0.9% Other 153 0.6% Transportation and Warehousing 178 0.7% Total 6,229$ 25.4% Waste Management 146 0.6% Accommodation and Food Services 134 0.5% Consumer Information 81 0.3% Residential Mortgage 7,609$ 31.0% Financial Investments & Related Activities 77 0.3% Home Equity 581 2.4% Arts, Entertainment, and Recreation 76 0.3% Auto Finance 498 2.0% Management of Companies & Enterprises 61 0.2% Credit Cards 111 0.5% Mining 46 0.2% Student Loans 96 0.4% Public Administration 30 0.1% Other Consumer 82 0.3% Educational Services 30 0.1% Total Consumer 8,978$ 36.6% Agriculture, Forestry, Fishing and Hunting 6 0.0% Other 227 0.9% Total C&BL 9,325$ 38.0% Total Loans 24,532$ 100.0%
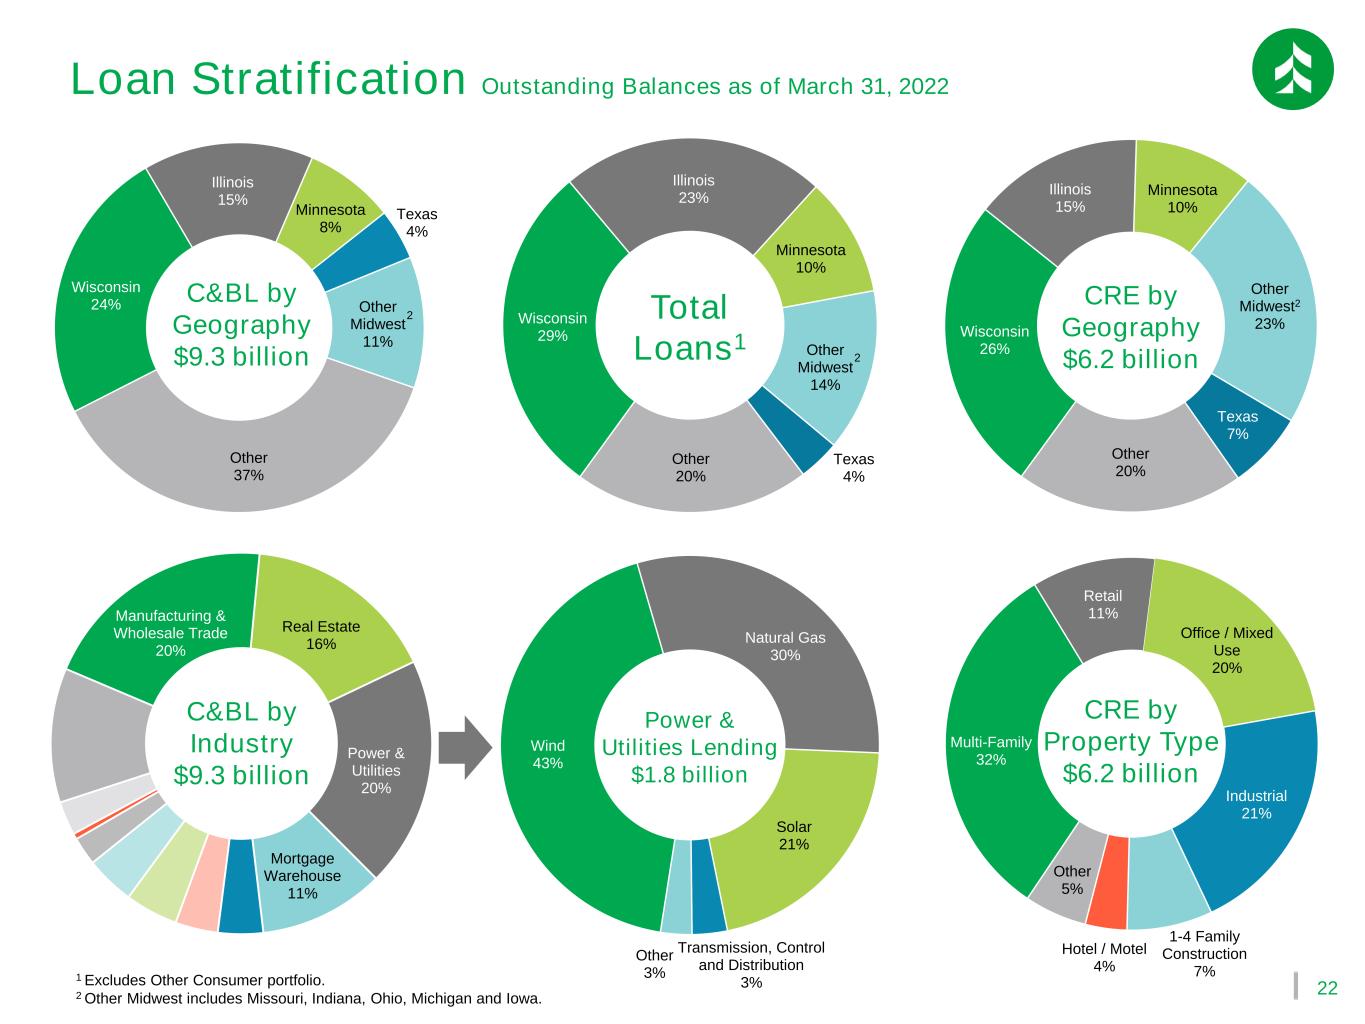
22 Wisconsin 29% Illinois 23% Minnesota 10% Other Midwest 14% Texas 4% Other 20% Manufacturing & Wholesale Trade 20% Real Estate 16% Power & Utilities 20% Mortgage Warehouse 11% 1 Excludes Other Consumer portfolio. 2 Other Midwest includes Missouri, Indiana, Ohio, Michigan and Iowa. Wind 43% Natural Gas 30% Solar 21% Transmission, Control and Distribution 3% Other 3% Wisconsin 24% Illinois 15% Minnesota 8% Texas 4% Other Midwest 11% Other 37% Wisconsin 26% Illinois 15% Minnesota 10% Other Midwest2 23% Texas 7% Other 20% 2 2 Loan Stratification Outstanding Balances as of March 31, 2022 C&BL by Geography $9.3 billion Power & Utilities Lending $1.8 billion C&BL by Industry $9.3 billion Total Loans1 CRE by Geography $6.2 billion Multi-Family 32% Retail 11% Office / Mixed Use 20% Industrial 21% 1-4 Family Construction 7% Hotel / Motel 4% Other 5% CRE by Property Type $6.2 billion
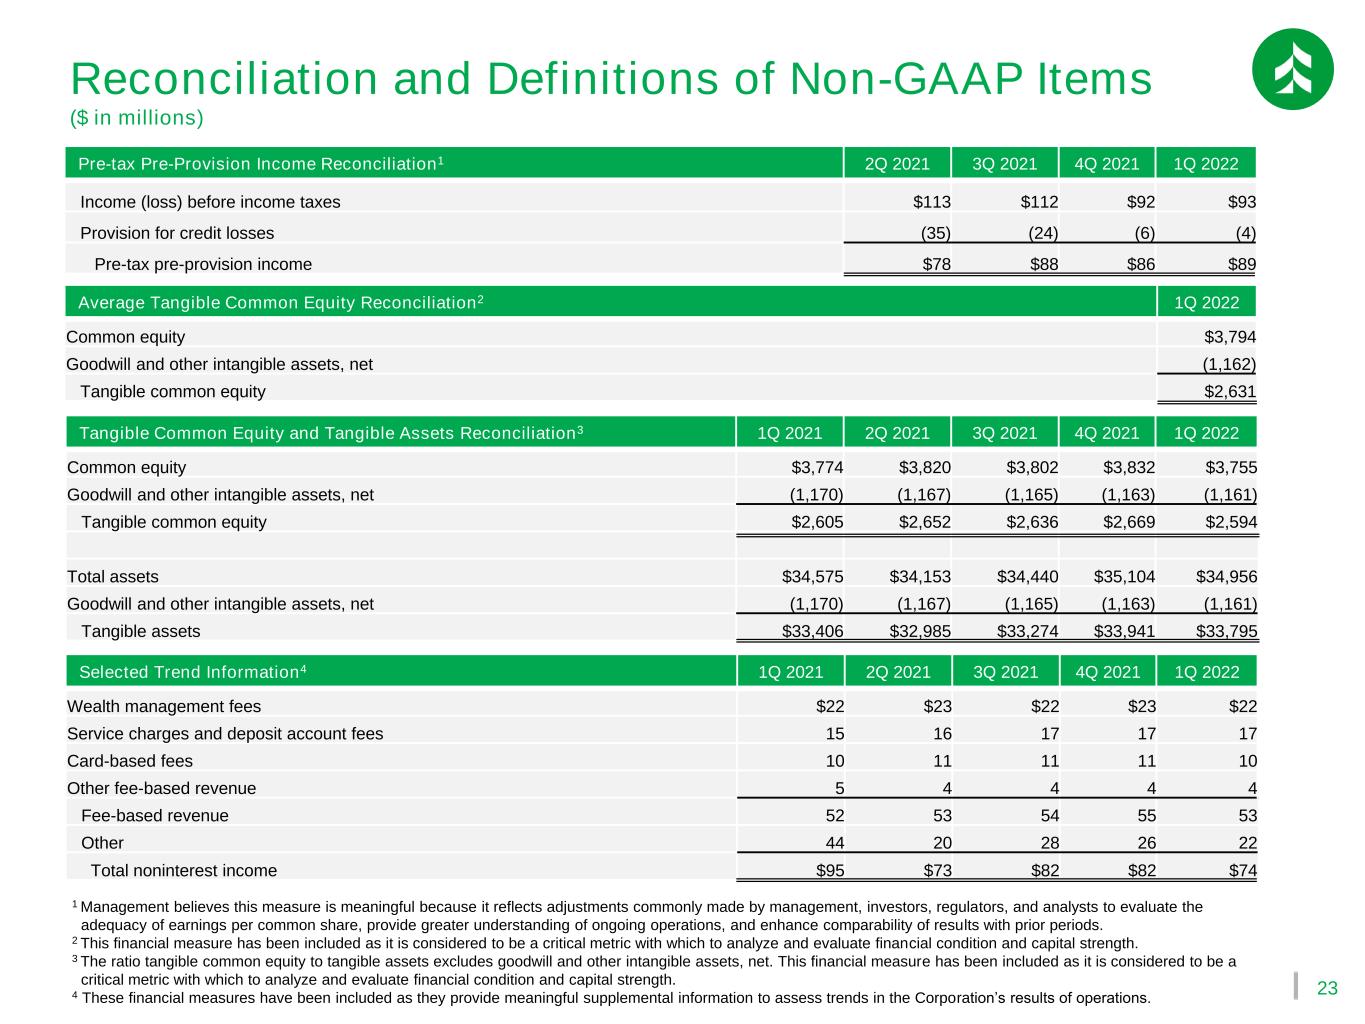
23 Reconciliation and Definitions of Non-GAAP Items ($ in millions) 1 Management believes this measure is meaningful because it reflects adjustments commonly made by management, investors, regulators, and analysts to evaluate the adequacy of earnings per common share, provide greater understanding of ongoing operations, and enhance comparability of results with prior periods. 2 This financial measure has been included as it is considered to be a critical metric with which to analyze and evaluate financial condition and capital strength. 3 The ratio tangible common equity to tangible assets excludes goodwill and other intangible assets, net. This financial measure has been included as it is considered to be a critical metric with which to analyze and evaluate financial condition and capital strength. 4 These financial measures have been included as they provide meaningful supplemental information to assess trends in the Corporation’s results of operations. Pre-tax Pre-Provision Income Reconciliation1 2Q 2021 3Q 2021 4Q 2021 1Q 2022 Income (loss) before income taxes $113 $112 $92 $93 Provision for credit losses (35) (24) (6) (4) Pre-tax pre-provision income $78 $88 $86 $89 Tangible Common Equity and Tangible Assets Reconciliation3 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 Common equity $3,774 $3,820 $3,802 $3,832 $3,755 Goodwill and other intangible assets, net (1,170) (1,167) (1,165) (1,163) (1,161) Tangible common equity $2,605 $2,652 $2,636 $2,669 $2,594 Total assets $34,575 $34,153 $34,440 $35,104 $34,956 Goodwill and other intangible assets, net (1,170) (1,167) (1,165) (1,163) (1,161) Tangible assets $33,406 $32,985 $33,274 $33,941 $33,795 Average Tangible Common Equity Reconciliation2 1Q 2022 Common equity $3,794 Goodwill and other intangible assets, net (1,162) Tangible common equity $2,631 Selected Trend Information4 1Q 2021 2Q 2021 3Q 2021 4Q 2021 1Q 2022 Wealth management fees $22 $23 $22 $23 $22 Service charges and deposit account fees 15 16 17 17 17 Card-based fees 10 11 11 11 10 Other fee-based revenue 5 4 4 4 4 Fee-based revenue 52 53 54 55 53 Other 44 20 28 26 22 Total noninterest income $95 $73 $82 $82 $74