AUB 8-K
Atlantic Union Bankshares Corp (AUB)
United States
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM
CURRENT REPORT
Pursuant to Section 13 or 15(d) of The Securities Exchange Act of 1934
Date of Report (Date of earliest event reported):
(Exact name of registrant as specified in its charter)
(State or other jurisdiction | (Commission | (I.R.S. Employer |
of incorporation) | File Number) | Identification No.) |
|
|
|
(Address of principal executive offices, including Zip Code)
Registrant’s telephone number, including area code:
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) |
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) |
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) |
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) |
Securities registered pursuant to Section 12(b) of the Act:
Title of each class |
| Trading Symbol(s) |
| Name of each exchange on which registered |
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. | ☐ |
Item 2.02 Results of Operations and Financial Condition.
On July 23, 2020, Atlantic Union Bankshares Corporation (the “Company”) issued a press release announcing its financial results for the three and six months ended June 30, 2020. A copy of the press release is being furnished as Exhibit 99.1 hereto and is incorporated herein by reference.
Attached as Exhibit 99.2 and incorporated herein by reference is a presentation that the Company will use in connection with a webcast and conference call for analysts at 9:00 a.m. Eastern Time on Thursday, July 23, 2020. This presentation is also available under the Presentations link in the Investor Relations section of the Company’s website at http://investors.atlanticunionbank.com.
The information disclosed in or incorporated by reference into this Item 2.02, including Exhibits 99.1 and 99.2, is furnished and shall not be deemed filed for purposes of Section 18 of the Securities Exchange Act of 1934.
Item 9.01 Financial Statements and Exhibits.
(d) Exhibits.
Exhibit No. |
| Description of Exhibit |
99.1 |
| Press release dated July 23, 2020 regarding second quarter results. |
99.2 | ||
104 | Cover Page Interactive Data File – the cover page iXBRL tags are embedded within the Inline XBRL document |
1
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| ATLANTIC UNION BANKSHARES CORPORATION | ||
|
|
|
|
|
|
|
|
|
|
|
|
Date: July 23, 2020 | By: | /s/ Robert M. Gorman |
|
|
| Robert M. Gorman |
|
|
| Executive Vice President and |
|
|
| Chief Financial Officer |
|
2
Exhibit 99.1
Contact: Robert M. Gorman - (804) 523-7828
Executive Vice President / Chief Financial Officer
ATLANTIC UNION BANKSHARES REPORTS SECOND QUARTER RESULTS
Richmond, Va., July 23, 2020 – Atlantic Union Bankshares Corporation (the “Company” or “Atlantic Union”) (Nasdaq: AUB) today reported net income of $30.7 million and diluted earnings per share of $0.39 for its second quarter ended June 30, 2020. Pre-tax pre-provision earnings(1) were $70.4 million, or $0.89 per share(1), in the second quarter ended June 30, 2020.
Net income was $37.8 million and earnings per share were $0.48 for the six months ended June 30, 2020. Pre-tax pre-provision earnings(1) were $138.7 million, or $1.76 per share(1), in the six months ended June 30, 2020.
“During the second quarter Atlantic Union demonstrated resilience, agility and innovation along with its willingness to make the tough decisions required to successfully navigate through the challenges of COVID-19,” said John C. Asbury, President and Chief Executive Officer of Atlantic Union. “We have remained focused on helping our customers and our communities weather the storm as exemplified by our team’s ability to process more than 11,000 loans which provided approximately $1.7 billion to businesses through the Small Business Administration’s Paycheck Protection Program during the second quarter.
“Operating under the mantra of soundness, profitability and growth – in that order of priority – we believe that Atlantic Union continues to be in a strong financial position with ample liquidity and a well-fortified capital base further enhanced by the issuance of preferred stock during the quarter. We also took action to better align our expense run rate to the revenue reality of the much lower for longer than expected interest rate environment. This includes the consolidation of 14 branches, or nearly 10% of our branch network, that is expected to close in September.”
Small Business Administration (“SBA”) Paycheck Protection Program (“PPP”)
During the second quarter of 2020, the Company continued to participate in the SBA PPP under the Coronavirus Aid, Relief, and Economic Security (“CARES”) Act, which was intended to provide economic relief to small businesses that have been adversely impacted by the COVID-19 global pandemic (“COVID-19”). The Company processed over 11,000 loans, which totaled $1.7 billion with a recorded investment of $1.6 billion as of June 30, 2020. The loans carry a 1% interest rate and the Company recorded net PPP loan origination fees of approximately $50.2 million which are being amortized over a 24-month period.
Expense Reduction Measures and Balance Sheet Repositioning
During the second quarter of 2020, the Company undertook several actions, including a planned consolidation of 14 branches expected to occur in September, to reduce expenses in light of the current and expected operating environment. These actions resulted in expenses during the second quarter of $1.8 million of severance costs and also $1.6 million related to the real estate write-downs.
In response to the current rate environment, the Company prepaid a Federal Home Loan Bank (“FHLB”) advance, which resulted in a prepayment penalty of approximately $10.3 million, and sold several securities, which resulted in a gain of approximately $10.3 million.
On June 9, 2020, the Company issued and sold 6,900,000 depositary shares, each representing a 1/400th ownership interest in a share of the Company’s 6.875% Perpetual Non-Cumulative Preferred Stock, Series A (“Series A Preferred Stock”), par value $10.00 per share of Series A Preferred Stock, with a liquidation preference of $10,000 per share of Series A Preferred Stock. The net proceeds received from the issuance of the Series A Preferred Stock were approximately $166.4 million, after deducting the underwriting discount and other offering expenses payable by the Company.
(1) These are financial measures not calculated in accordance with generally accepted accounting principles (“GAAP”). For a reconciliation of these non-GAAP financial measures, see Alternative Performance Measures (non-GAAP) section of the Key Financial Results.
NET INTEREST INCOME
For the second quarter of 2020, net interest income was $137.3 million, an increase from $135.0 million reported in the first quarter of 2020. Net interest income (FTE)(1) was $140.1 million in the second quarter of 2020, an increase of $2.3 million from the first quarter of 2020. The second quarter net interest margin decreased 26 basis points to 3.23% from 3.49% in the previous quarter, while the net interest margin (FTE)(1) decreased 27 basis points to 3.29% from 3.56% during the same period. The decreases in the net interest margin and net interest margin (FTE) were principally due to a 60 basis point decrease in the yield on earning assets (FTE)(1) offset by a 33 basis point decrease in cost of funds. The decline in the Company’s earning asset yields was driven by the impact of the lower yielding PPP loans originated during the second quarter and the full quarter impact of the lower interest rate environment. The cost of funds decline was driven by lower deposit costs and wholesale borrowing costs driven by lower market interest rates and a favorable funding mix.
The Company’s net interest margin (FTE) includes the impact of acquisition accounting fair value adjustments. During the second quarter of 2020, net accretion related to acquisition accounting decreased $3.1 million from the prior quarter to $6.3 million for the quarter ended June 30, 2020. The first and second quarters of 2020, and the remaining estimated net accretion impact are reflected in the following table (dollars in thousands):
| | | | | Deposit | | | | | | | |
| | Loan | | Accretion | | Borrowings | | | | |||
|
| Accretion |
| (Amortization) |
| Amortization |
| Total | ||||
For the quarter ended March 31, 2020 | | $ | 9,528 | | $ | 50 | | $ | (138) | | $ | 9,440 |
For the quarter ended June 30, 2020 | |
| 6,443 | |
| 34 | |
| (140) | |
| 6,337 |
For the remaining six months of 2020 (estimated) | |
| 5,400 | | | 49 | | | (355) | |
| 5,094 |
For the years ending (estimated): | |
|
| |
|
| |
|
| |
|
|
2021 | |
| 9,405 | |
| 14 | |
| (807) | |
| 8,612 |
2022 | |
| 7,569 | |
| (43) | |
| (829) | |
| 6,697 |
2023 | |
| 5,415 | |
| (32) | |
| (852) | |
| 4,531 |
2024 | |
| 4,406 | |
| (4) | |
| (877) | |
| 3,525 |
2025 | |
| 3,322 | |
| (1) | |
| (900) | |
| 2,421 |
Thereafter | |
| 14,931 | |
| — | |
| (9,873) | |
| 5,058 |
(1) These are financial measures not calculated in accordance with GAAP. For a reconciliation of these non-GAAP financial measures, see Alternative Performance Measures (non-GAAP) section of the Key Financial Results.
ASSET QUALITY
Overview
During the second quarter of 2020, the Company experienced decreases in nonperforming assets (“NPAs”) primarily due to nonaccrual loan customer payments. Past due loan levels as a percentage of total loans held for investment at June 30, 2020 were down from past due loan levels at March 31, 2020 and June 30, 2019. Net charge-off levels and the provision for loan losses decreased from the first quarter of 2020.
Loan Modifications for Borrowers Affected by COVID-19
On March 22, 2020, the five federal bank regulatory agencies and the Conference of State Bank Supervisors issued joint
guidance (subsequently revised on April 7, 2020) with respect to loan modifications for borrowers affected by COVID-19 (the “March 22 Joint Guidance”). The March 22 Joint Guidance encourages banks, savings associations, and credit unions to make loan modifications for borrowers affected by COVID-19 and, importantly, assures those financial institutions that they will not (i) receive supervisory criticism for such prudent loan modifications and (ii) be required by examiners to automatically categorize COVID-19-related loan modifications as TDRs. The federal banking regulators have confirmed with the Financial Accounting Standards Board (or FASB) that short-term loan modifications made on a
good faith basis in response to COVID-19 to borrowers who were current (i.e., less than 30 days past due on contractual payments) prior to any loan modification are not TDRs.
In addition, Section 4013 of the CARES Act provides banks, savings associations, and credit unions with the ability to make loan modifications related to COVID-19 without categorizing the loan as a TDR or conducting the analysis to make the determination, which is intended to streamline the loan modification process. Any such suspension is effective for the term of the loan modification; however, the suspension is only permitted for loan modifications made during the effective period of Section 4013 and only for those loans that were not more than thirty days past due as of December 31, 2019.
The Company has made certain loan modifications pursuant to the March 22 Joint Guidance or Section 4013 of the CARES Act and as of June 30, 2020 approximately $1.6 billion remain under their modified terms.
Nonperforming Assets
At June 30, 2020, NPAs totaled $44.0 million, a decrease of $4.4 million from March 31, 2020. NPAs as a percentage of total outstanding loans at June 30, 2020 were 0.31%, a decrease of 7 basis points from 0.38% at March 31, 2020. Excluding the impact of the PPP loans(1), NPAs as a percentage of total outstanding loans were 0.35%, a decrease of 3 basis points from March 31, 2020. The Company’s adoption of current expected credit loss (“CECL”) on January 1, 2020 resulted in a change in the accounting and reporting related to purchased credit impaired (“PCI”) loans, which are now defined as purchased credit deteriorated (“PCD”) and evaluated at the loan level instead of being evaluated in pools under PCI accounting. All prior period nonaccrual and past due loan metrics discussed herein have not been restated for CECL accounting and exclude PCI-related loan balances.
(1) These are financial measures not calculated in accordance with GAAP. For a reconciliation of these non-GAAP financial measures, see Alternative Performance Measures (non-GAAP) section of the Key Financial Results.
The following table shows a summary of nonperforming asset balances at the quarter ended (dollars in thousands):
|
| June 30, |
| March 31, |
| December 31, |
| September 30, |
| June 30, | |||||
| | 2020 | | 2020 | | 2019 | | 2019 | | 2019 | |||||
Nonaccrual loans | | $ | 39,624 | | $ | 44,022 | | $ | 28,232 | | $ | 30,032 | | $ | 27,462 |
Foreclosed properties | |
| 4,397 | |
| 4,444 | |
| 4,708 | |
| 6,385 | |
| 6,506 |
Total nonperforming assets | | $ | 44,021 | | $ | 48,466 | | $ | 32,940 | | $ | 36,417 | | $ | 33,968 |
The following table shows the activity in nonaccrual loans for the quarter ended (dollars in thousands):
|
| June 30, |
| March 31, |
| December 31, |
| September 30, |
| June 30, | |||||
| | 2020 | | 2020 | | 2019 | | 2019 | | 2019 | |||||
Beginning Balance | | $ | 44,022 | | $ | 28,232 | | $ | 30,032 | | $ | 27,462 | | $ | 24,841 |
Net customer payments | |
| (6,524) | |
| (3,451) | |
| (5,741) | |
| (3,612) | |
| (3,108) |
Additions | |
| 3,206 | |
| 6,059 | |
| 5,631 | |
| 8,327 | |
| 6,321 |
Impact of CECL adoption | | | — | | | 14,381 | | | — | | | — | | | — |
Charge-offs | |
| (1,088) | |
| (1,199) | |
| (1,690) | |
| (884) | |
| (592) |
Loans returning to accruing status | |
| 8 | |
| — | |
| — | |
| (1,103) | |
| — |
Transfers to foreclosed property | |
| — | |
| — | |
| — | |
| (158) | |
| — |
Ending Balance | | $ | 39,624 | | $ | 44,022 | | $ | 28,232 | | $ | 30,032 | | $ | 27,462 |
The following table shows the activity in foreclosed properties for the quarter ended (dollars in thousands):
|
| June 30, |
| March 31, |
| December 31, |
| September 30, |
| June 30, | |||||
| | 2020 | | 2020 | | 2019 | | 2019 | | 2019 | |||||
Beginning Balance | | $ | 4,444 | | $ | 4,708 | | $ | 6,385 | | $ | 6,506 | | $ | 7,353 |
Additions of foreclosed property | |
| — | |
| 615 | |
| 62 | |
| 645 | |
| 271 |
Valuation adjustments | |
| — | |
| (44) | |
| (375) | |
| (62) | |
| (433) |
Proceeds from sales | |
| (55) | |
| (854) | |
| (1,442) | |
| (737) | |
| (638) |
Gains (losses) from sales | |
| 8 | |
| 19 | |
| 78 | |
| 33 | |
| (47) |
Ending Balance | | $ | 4,397 | | $ | 4,444 | | $ | 4,708 | | $ | 6,385 | | $ | 6,506 |
Past Due Loans
Past due loans still accruing interest totaled $40.5 million or 0.28% of total loans held for investment at June 30, 2020, compared to $75.1 million or 0.59% of total loans held for investment at March 31, 2020, and $43.1 million or 0.35% of total loans held for investment at June 30, 2019. Excluding the impact of the PPP loans(1), past due loans still accruing interest were 0.32% of total loans held for investment at June 30, 2020. Of the total past due loans still accruing interest, $19.3 million or 0.13% of total loans held for investment were loans past due 90 days or more at June 30, 2020, compared to $12.9 million or 0.10% of total loans held for investment at March 31, 2020, and $8.8 million or 0.07% of total loans held for investment at June 30, 2019.
(1) These are financial measures not calculated in accordance with GAAP. For a reconciliation of these non-GAAP financial measures, see Alternative Performance Measures (non-GAAP) section of the Key Financial Results.
Net Charge-offs
For the second quarter of 2020, net charge-offs were $3.3 million, or 0.09% of total average loans on an annualized basis, compared to $5.0 million, or 0.16%, for the prior quarter, and $4.3 million, or 0.14%, for the second quarter last year. Excluding the impact of the PPP loans(1), net charge-offs were 0.10% of total average loans on an annualized basis. The majority of net charge-offs in the second quarter of 2020 were related to the third-party consumer loan portfolio.
(1) These are financial measures not calculated in accordance with GAAP. For a reconciliation of these non-GAAP financial measures, see Alternative Performance Measures (non-GAAP) section of the Key Financial Results.
Provision for Credit Losses
The provision for credit losses for the second quarter of 2020 was $34.2 million, a decrease of $26.0 million compared to the previous quarter. The provision for credit losses for the second quarter of 2020 consisted of $32.2 million in provision for loan losses and $2.0 million in provision for unfunded commitments.
Allowance for Credit Losses (“ACL”)
At June 30, 2020, the ACL was $181.0 million and included an allowance for loan and lease losses (“ALLL”) of $170.0 million and a reserve for unfunded commitments (“RUC”) of $11.0 million. The ACL increased $30.9 million from March 31, 2020, primarily due to the worsening economic forecast related to COVID-19.
The ALLL increased $28.9 million and the RUC increased $2.0 million from March 31, 2020, due to the worsening economic forecast related to COVID-19. The ALLL as a percentage of the total loan portfolio was 1.19% at June 30, 2020 and 1.10% at March 31, 2020, and the ACL as percentage of total loans was 1.26% at June 30, 2020. When excluding PPP loans(1), which are 100% guaranteed by the SBA, the ALLL as a percentage of adjusted loans increased 24 bps to 1.34% from the prior quarter and the ACL as a percentage of adjusted loans increased 24 bps to 1.42% from the prior quarter. The ratio of the ALLL to nonaccrual loans was 429.0% at June 30, 2020, compared to 320.4% at March 31, 2020.
(1) These are financial measures not calculated in accordance with GAAP. For a reconciliation of these non-GAAP financial measures, see Alternative Performance Measures (non-GAAP) section of the Key Financial Results.
NONINTEREST INCOME
Noninterest income increased $7.0 million to $35.9 million for the quarter ended June 30, 2020 from $28.9 million in the prior quarter primarily driven by a $10.3 million gain on sale of investment securities recorded during the quarter and an increase of $1.5 million in loan related interest rate swap income. In addition, mortgage banking income was higher by $3.8 million primarily due to increased mortgage loan refinance volumes due to the current low interest rate environment. Partially offsetting these increases was a decline in service charges on deposit accounts of $2.6 million primarily due to lower NSF and overdraft incident fees, $2.5 million in unrealized losses related to equity method investments due to the current economic environment related to COVID-19, and a decline of $469,000 in fiduciary and asset management fees.
NONINTEREST EXPENSE
Noninterest expense increased $7.2 million to $102.8 million for the quarter ended June 30, 2020 from $95.6 million in the prior quarter primarily driven by the recognition of approximately $10.3 million loss on debt extinguishment resulting from the prepayment of approximately $200.0 million in long-term FHLB advances. The increases were partially offset by a decline in marketing and advertising expense of approximately $696,000 and training and other personnel costs of approximately $695,000. Noninterest expense also included approximately $1.6 million in real estate-related branch closure costs and approximately $1.8 million in severance expenses related to the Company’s expense reduction plans. Also included in noninterest expense are costs related to the Company’s response to COVID-19 of approximately $620,000.
INCOME TAXES
The effective tax rate for the three months ended June 30, 2020 was 15.2% compared to 12.2% for the three months ended March 31, 2020. The increase in the effective tax rate was primarily due to tax benefits related to stock compensation during the first quarter of 2020 in accordance with ASU 2016-09, “Compensation - Stock Compensation (Topic 718): Improvements to Employee Share-Based Payment Accounting” as well as tax-exempt income being a higher component of pre-tax income in the first quarter of 2020 compared to the second quarter of 2020.
BALANCE SHEET
At June 30, 2020, total assets were $19.8 billion, an increase of $1.9 billion, or approximately 42.9% (annualized), from March 31, 2020, and an increase of $2.6 billion, or approximately 15.1% from June 30, 2019. The increase in assets from the prior quarter was driven by PPP loans while growth from the prior year was primarily a result of both organic and PPP loan growth.
At June 30, 2020, loans held for investment (net of deferred fees and costs) were $14.3 billion, an increase of $1.5 billion, or 48.5% (annualized), from March 31, 2020, while average loans increased $1.4 billion, or 43.6% (annualized), from the prior quarter. Excluding the effects of the PPP(2), loans held for investment (net of deferred fees and costs) declined $58.9 million, or 1.9% (annualized), while average loans increased $89.9 million, or 2.9% (annualized) during this period. Loans held for investment (net of deferred fees and costs) increased $2.1 billion, or 17.1% from June 30, 2019, while quarterly average loans increased $1.9 billion, or 15.5% from the prior year. Excluding the effects of the PPP(2), loans held for investment (net of deferred fees and costs) increased $489.4 million, or 4.0%, while quarterly average loans increased $598.9 million, or 5.0% from the prior year.
At June 30, 2020, total deposits were $15.6 billion, an increase of $2.1 billion, or approximately 60.9% (annualized), from March 31, 2020, while average deposits increased $1.6 billion, or 48.6% (annualized), from the prior quarter. Deposits increased $3.1 billion, or 24.7% from June 30, 2019, while quarterly average deposits increased $2.5 billion, or 20.1% from the prior year. The increase in deposits from the prior quarter was primarily due to the impact of PPP loan related deposits and government stimulus check deposits.
The following table shows the Company’s capital ratios at the quarters ended:
|
| June 30, |
| March 31, |
| June 30, |
|
| | 2020 | | 2020 | | 2019 |
|
Common equity Tier 1 capital ratio (1) |
| 9.81 | % | 9.74 | % | 10.53 | % |
Tier 1 capital ratio (1) |
| 10.95 | % | 9.74 | % | 10.53 | % |
Total capital ratio (1) |
| 13.71 | % | 12.37 | % | 13.00 | % |
Leverage ratio (Tier 1 capital to average assets) (1) |
| 8.82 | % | 8.44 | % | 9.00 | % |
Common equity to total assets |
| 12.41 | % | 13.59 | % | 14.64 | % |
Tangible common equity to tangible assets (2) |
| 7.74 | % | 8.43 | % | 9.28 | % |
| (1) | All ratios at June 30, 2020 are estimates and subject to change pending the Company’s filing of its FR Y9-C. All other periods are presented as filed. |
| (2) | These are financial measures not calculated in accordance with GAAP. For a reconciliation of these non-GAAP financial measures, see Alternative Performance Measures (non-GAAP) section of the Key Financial Results. |
On June 9, 2020, the Company issued and sold 6,900,000 depositary shares, each representing a 1/400th ownership interest in a share of the Company’s 6.875% Series A Preferred Stock, par value $10.00 per share of Series A Preferred Stock, with a liquidation preference of $10,000 per share of Series A Preferred Stock. The net proceeds received from the issuance of the Series A Preferred Stock was approximately $166.4 million, after deducting the underwriting discount and other offering expenses payable by the Company. The Series A Preferred Stock is included in Tier 1 capital.
During the second quarter of 2020, the Company declared and paid cash dividends of $0.25 per common share, consistent with the first quarter of 2020 and an increase of $0.02, or 8.7% compared to the second quarter of 2019. On July 10, 2019, the Company announced that its Board of Directors had authorized a share repurchase program (effective July 8, 2019) to purchase up to $150 million of the Company’s common stock through June 30, 2021 in open market transactions or privately negotiated transactions. On March 20, 2020, the Company suspended its share repurchase program, which had $20 million remaining in the authorization when it was suspended. The Company repurchased an aggregate of approximately 3.7 million shares, at an average price of $35.48 per share, under the authorization prior to the suspension.
ABOUT ATLANTIC UNION BANKSHARES CORPORATION
Headquartered in Richmond, Virginia, Atlantic Union Bankshares Corporation (Nasdaq: AUB) is the holding company for Atlantic Union Bank. Atlantic Union Bank has 149 branches and approximately 170 ATMs located throughout Virginia, and in portions of Maryland and North Carolina. Middleburg Financial is a brand name used by Atlantic Union Bank and certain affiliates when providing trust, wealth management, private banking, and investment advisory products and services. Certain non-bank affiliates of Atlantic Union Bank include: Old Dominion Capital Management, Inc., and its subsidiary, Outfitter Advisors, Ltd., Dixon, Hubard, Feinour, & Brown, Inc., and Middleburg Investment Services, LLC, which provide investment advisory and/or brokerage services; and Union Insurance Group, LLC, which offers various lines of insurance products.
SECOND QUARTER 2020 EARNINGS RELEASE CONFERENCE CALL
The Company will hold a conference call on Thursday, July 23, 2020 at 9:00 a.m. Eastern Daylight Time during which management will review the second quarter 2020 financial results and provide an update on recent activities. Interested parties may participate in the call toll-free by dialing (866) 220-4170; international callers wishing to participate may do so by dialing (864) 663-5235. The conference ID number is 6176635. Management will conduct a listen-only webcast with accompanying slides, which can be found at: https://edge.media-server.com/mmc/p/7vrpdxva.
A replay of the webcast, and the accompanying slides, will be available on the Company’s website for 90 days at: https://investors.atlanticunionbank.com/.
NON-GAAP FINANCIAL MEASURES
In reporting the results of the quarter ended June 30, 2020, the Company has provided supplemental performance measures on a tax-equivalent, tangible, operating, adjusted or pre-tax pre-provision basis. These non-GAAP financial measures are a supplement to GAAP, which is used to prepare the Company’s financial statements, and should not be considered in isolation or as a substitute for comparable measures calculated in accordance with GAAP. In addition, the Company’s non-GAAP financial measures may not be comparable to non-GAAP financial measures of other companies. The Company uses the non-GAAP financial measures discussed herein in its analysis of the Company’s performance. The Company’s management believes that these non-GAAP financial measures provide additional understanding of ongoing operations, enhance comparability of results of operations with prior periods and show the effects of significant gains and charges in the periods presented without the impact of items or events that may obscure trends in the Company’s underlying performance. For a reconciliation of these measures to their most directly comparable GAAP measures and additional information about these non-GAAP financial measures, see Alternative Performance Measures (non-GAAP) section of the Key Financial Results.
FORWARD-LOOKING STATEMENTS
Certain statements in this press release may constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Forward-looking statements, including without limitation, statements made in Mr. Asbury’s quotes, are statements that include, without limitation, projections, predictions, expectations, or beliefs about future events or results that are not statements of historical fact. Such forward-looking statements are based on various assumptions as of the time they are made, and are inherently subject to known and unknown risks, uncertainties, and other factors, some of which cannot be predicted or quantified, that may cause actual results, performance, or achievements to be materially different from those expressed or implied by such forward-looking statements. Forward-looking statements are often accompanied by words that convey projected future events or outcomes such as “expect,” “believe,” “estimate,” “plan,” “project,” “anticipate,” “intend,” “will,” “may,” “view,” “opportunity,” “potential,” or words of similar meaning or other statements concerning opinions or judgment of the Company and its management about future events. Although the Company believes that its expectations with respect to forward-looking statements are based upon reasonable assumptions within the bounds of its existing knowledge of its business and operations, there can be no assurance that actual results, performance, or achievements of, or trends affecting, the Company will not differ materially from any projected future results, performance, or achievements expressed or implied by such forward-looking statements. Actual future results, performance, achievements or trends may differ materially from historical results or those anticipated depending on a variety of factors, including, but not limited to:
| ● | changes in interest rates; |
| ● | general economic and financial market conditions, in the United States generally and particularly in the markets in which the Company operates and which its loans are concentrated, including the effects of declines in real estate values, an increase in unemployment levels and slowdowns in economic growth, including as a result of COVID-19; |
| ● | the quality or composition of the loan or investment portfolios and changes therein; |
| ● | demand for loan products and financial services in the Company’s market area; |
| ● | the Company’s ability to manage its growth or implement its growth strategy; |
| ● | planned branch consolidations; |
| ● | the introduction of new lines of business or new products and services; |
| ● | the Company’s ability to recruit and retain key employees; |
| ● | the incremental cost and/or decreased revenues associated with exceeding $10 billion in assets; |
| ● | real estate values in the Bank’s lending area; |
| ● | an insufficient ACL; |
| ● | changes in accounting principles relating to loan loss recognition (CECL); |
| ● | the Company’s liquidity and capital positions; |
| ● | concentrations of loans secured by real estate, particularly commercial real estate; |
| ● | the effectiveness of the Company’s credit processes and management of the Company’s credit risk; |
| ● | the Company’s ability to compete in the market for financial services; |
| ● | technological risks and developments, and cyber threats, attacks, or events; |
| ● | the potential adverse effects of unusual and infrequently occurring events, such as weather-related disasters, terrorist acts or public health events (such as COVID-19), and of governmental and societal responses thereto; these potential adverse effects may include, without limitation, adverse effects on the ability of the Company's borrowers to satisfy their obligations to the Company, on the value of collateral securing loans, on the demand for the Company's loans or its other products and services, on incidents of cyberattack and fraud, on the Company’s liquidity or capital positions, on risks posed by reliance on third-party service providers, on other aspects of the Company's business operations and on financial markets and economic growth; |
| ● | the effect of steps the Company takes in response to COVID-19, the severity and duration of the pandemic, including whether there is a “second wave” as a result of the loosening of governmental restrictions, the pace of recovery when the pandemic subsides and the heightened impact it has on many of the risks described herein; |
| ● | performance by the Company’s counterparties or vendors; |
| ● | deposit flows; |
| ● | the availability of financing and the terms thereof; |
| ● | the level of prepayments on loans and mortgage-backed securities; |
| ● | legislative or regulatory changes and requirements, including the impact of the CARES Act and other legislative and regulatory reactions to COVID-19; |
| ● | potential claims, damages, and fines related to litigation or government actions, including litigation or actions arising from the Company’s participation in and administration of programs related to COVID-19, including, among other things, the CARES Act; |
| ● | the effects of changes in federal, state or local tax laws and regulations; |
| ● | monetary and fiscal policies of the U.S. government, including policies of the U.S. Department of the Treasury and the Federal Reserve; |
| ● | changes to applicable accounting principles and guidelines; and |
| ● | other factors, many of which are beyond the control of the Company. |
Please refer to the “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” sections of the Company’s Annual Report on Form 10-K for the year ended December 31, 2019 and comparable “Risk Factors” sections of the Company’s Quarterly Reports on Form 10-Q and related disclosures in other filings, which have been filed with the SEC and are available on the SEC’s website at www.sec.gov. All of the forward-looking statements made in this press release are expressly qualified by the cautionary statements contained or referred to herein. The actual results or developments anticipated may not be realized or, even if substantially realized, they may not have the expected consequences to or effects on the Company or its businesses or operations. Readers are cautioned not to rely too heavily on the forward-looking statements contained in this press release. Forward-looking statements speak only as of the date they are made and the Company does not undertake any obligation to update, revise or clarify these forward-looking statements, whether as a result of new information, future events or otherwise.
ATLANTIC UNION BANKSHARES CORPORATION AND SUBSIDIARIES
KEY FINANCIAL RESULTS
(Dollars in thousands, except share data)
| | As of & For Three Months Ended |
| As of & For Six Months Ended | | |||||||||||
|
| 06/30/20 |
| 03/31/20 |
| 06/30/19 |
| 06/30/20 | | 06/30/19 | | |||||
Results of Operations | | (unaudited) | | (unaudited) | | (unaudited) |
| (unaudited) | | (unaudited) | | |||||
Interest and dividend income | | $ | 162,867 | | $ | 171,325 | | $ | 181,125 | | $ | 334,193 | | $ | 346,777 | |
Interest expense | |
| 25,562 | |
| 36,317 | |
| 42,531 | |
| 61,880 | |
| 80,636 | |
Net interest income | |
| 137,305 | |
| 135,008 | |
| 138,594 | |
| 272,313 | |
| 266,141 | |
Provision for credit losses | |
| 34,200 | |
| 60,196 | |
| 5,300 | |
| 94,396 | |
| 9,092 | |
Net interest income after provision for credit losses | |
| 103,105 | |
| 74,812 | |
| 133,294 | |
| 177,917 | |
| 257,049 | |
Noninterest income | |
| 35,932 | |
| 28,907 | |
| 30,578 | |
| 64,838 | |
| 55,515 | |
Noninterest expenses | |
| 102,814 | |
| 95,645 | |
| 105,608 | |
| 198,459 | |
| 212,335 | |
Income before income taxes | |
| 36,223 | |
| 8,074 | |
| 58,264 | |
| 44,296 | |
| 100,229 | |
Income tax expense | |
| 5,514 | |
| 985 | |
| 9,356 | |
| 6,498 | |
| 15,606 | |
Income from continuing operations | |
| 30,709 | |
| 7,089 | |
| 48,908 | |
| 37,798 | |
| 84,623 | |
Discontinued operations, net of tax | |
| — | |
| — | |
| (85) | |
| — | |
| (170) | |
Net income available to common shareholders | | $ | 30,709 | | $ | 7,089 | | $ | 48,823 | | $ | 37,798 | | $ | 84,453 | |
| | | | | | | | | | | | | | | | |
Interest earned on earning assets (FTE) (1) | | $ | 165,672 | | $ | 174,083 | | $ | 184,045 | | $ | 339,755 | | $ | 352,445 | |
Net interest income (FTE) (1) | |
| 140,110 | |
| 137,766 | |
| 141,514 | |
| 277,875 | |
| 271,809 | |
Total revenue (FTE) (1) | | | 176,042 | | | 166,673 | | | 172,092 | | | 342,713 | | | 327,324 | |
Pre-tax pre-provision earnings (8) | | | 70,423 | | | 68,270 | | | 73,862 | | | 138,692 | | | 138,064 | |
| | | | | | | | | | | | | | | | |
Key Ratios | | | | | | | | | | | | | | | | |
Earnings per common share, diluted | | $ | 0.39 | | $ | 0.09 | | $ | 0.59 | | $ | 0.48 | | $ | 1.06 | |
Return on average assets (ROA) | |
| 0.64 | % |
| 0.16 | % |
| 1.15 | % |
| 0.41 | % |
| 1.04 | % |
Return on average equity (ROE) | |
| 4.96 | % |
| 1.15 | % |
| 7.86 | % |
| 3.06 | % |
| 7.16 | % |
Efficiency ratio | |
| 59.35 | % |
| 58.35 | % |
| 62.43 | % |
| 58.86 | % |
| 66.01 | % |
Net interest margin | |
| 3.23 | % |
| 3.49 | % |
| 3.71 | % |
| 3.35 | % |
| 3.71 | % |
Net interest margin (FTE) (1) | |
| 3.29 | % |
| 3.56 | % |
| 3.78 | % |
| 3.42 | % |
| 3.79 | % |
Yields on earning assets (FTE) (1) | |
| 3.90 | % |
| 4.50 | % |
| 4.92 | % |
| 4.18 | % |
| 4.92 | % |
Cost of interest-bearing liabilities | |
| 0.84 | % |
| 1.23 | % |
| 1.50 | % |
| 1.03 | % |
| 1.46 | % |
Cost of deposits | |
| 0.53 | % |
| 0.86 | % |
| 0.93 | % |
| 0.68 | % |
| 0.90 | % |
Cost of funds | |
| 0.61 | % |
| 0.94 | % |
| 1.14 | % |
| 0.76 | % |
| 1.13 | % |
| | | | | | | | | | | | | | | | |
Operating Measures (4) | | | | | | | | | | | | | | | | |
Net operating earnings | | $ | 30,709 | | $ | 7,089 | | $ | 57,089 | | $ | 37,798 | | $ | 107,607 | |
Net operating earnings available to common shareholders | | | 30,709 | | | 7,089 | | | 57,089 | | | 37,798 | | | 107,607 | |
Operating earnings per share, diluted | | $ | 0.39 | | $ | 0.09 | | $ | 0.70 | | $ | 0.48 | | $ | 1.36 | |
Operating ROA | |
| 0.64 | % |
| 0.16 | % |
| 1.35 | % |
| 0.41 | % |
| 1.33 | % |
Operating ROE | |
| 4.96 | % |
| 1.15 | % |
| 9.20 | % | | 3.06 | % |
| 9.12 | % |
Operating ROTCE (2) (3) | |
| 9.46 | % |
| 2.87 | % |
| 16.58 | % |
| 6.13 | % |
| 16.48 | % |
Operating efficiency ratio (FTE) (1)(7) | |
| 56.00 | % |
| 54.74 | % |
| 52.46 | % |
| 55.39 | % |
| 53.24 | % |
| | | | | | | | | | | | | | | | |
Per Share Data | | | | | | | | | | | | | | | | |
Earnings per common share, basic | | $ | 0.39 | | $ | 0.09 | | $ | 0.59 | | $ | 0.48 | | $ | 1.06 | |
Earnings per common share, diluted | |
| 0.39 | |
| 0.09 | |
| 0.59 | |
| 0.48 | |
| 1.06 | |
Cash dividends paid per common share | |
| 0.25 | |
| 0.25 | |
| 0.23 | |
| 0.50 | |
| 0.46 | |
Market value per share | |
| 23.16 | |
| 21.90 | |
| 35.33 | |
| 23.16 | |
| 35.33 | |
Book value per common share | |
| 31.32 | |
| 30.99 | |
| 30.78 | |
| 31.32 | |
| 30.78 | |
Tangible book value per common share (2) | |
| 18.54 | |
| 18.15 | |
| 18.36 | |
| 18.54 | |
| 18.36 | |
Price to earnings ratio, diluted | |
| 14.77 | |
| 60.50 | |
| 14.93 | |
| 23.99 | |
| 16.37 | |
Price to book value per common share ratio | |
| 0.74 | |
| 0.71 | |
| 1.15 | |
| 0.74 | |
| 1.15 | |
Price to tangible book value per common share ratio (2) | |
| 1.25 | |
| 1.21 | |
| 1.92 | |
| 1.25 | |
| 1.92 | |
Weighted average common shares outstanding, basic | |
| 78,711,765 | |
| 79,290,352 | |
| 82,062,585 | |
| 79,001,058 | |
| 79,282,830 | |
Weighted average common shares outstanding, diluted | |
| 78,722,690 | |
| 79,317,382 | |
| 82,125,194 | |
| 79,020,036 | |
| 79,344,573 | |
Common shares outstanding at end of period | |
| 78,713,056 | |
| 78,710,448 | |
| 82,086,736 | |
| 78,713,056 | |
| 82,086,736 | |
| | As of & For Three Months Ended |
| As of & For Six Months Ended | | |||||||||||
|
| 06/30/20 |
| 03/31/20 |
| 06/30/19 |
| 06/30/20 | | 06/30/19 |
| |||||
Capital Ratios | | (unaudited) | | (unaudited) | | (unaudited) |
| (unaudited) | | (unaudited) |
| |||||
Common equity Tier 1 capital ratio (5) |
| | 9.81 | % | | 9.74 | % | | 10.53 | % | | 9.81 | % | | 10.53 | % |
Tier 1 capital ratio (5) |
| | 10.95 | % | | 9.74 | % | | 10.53 | % | | 10.95 | % | | 10.53 | % |
Total capital ratio (5) |
| | 13.71 | % | | 12.37 | % | | 13.00 | % | | 13.71 | % | | 13.00 | % |
Leverage ratio (Tier 1 capital to average assets) (5) |
| | 8.82 | % | | 8.44 | % | | 9.00 | % | | 8.82 | % | | 9.00 | % |
Common equity to total assets |
| | 12.41 | % | | 13.59 | % | | 14.64 | % | | 12.41 | % | | 14.64 | % |
Tangible common equity to tangible assets (2) |
| | 7.74 | % | | 8.43 | % | | 9.28 | % | | 7.74 | % | | 9.28 | % |
| | | | | | | | | | | | | | | | |
Financial Condition |
| |
|
| |
|
| |
| | |
|
| |
| |
Assets | | $ | 19,752,317 | | $ | 17,847,376 | | $ | 17,159,384 | | $ | 19,752,317 | | $ | 17,159,384 | |
Loans held for investment | |
| 14,308,646 | |
| 12,768,841 | |
| 12,220,514 | |
| 14,308,646 | |
| 12,220,514 | |
Securities | |
| 2,672,557 | |
| 2,655,306 | |
| 2,703,856 | |
| 2,672,557 | |
| 2,703,856 | |
Earning Assets | |
| 17,680,876 | |
| 15,813,780 | |
| 15,140,370 | |
| 17,680,876 | |
| 15,140,370 | |
Goodwill | |
| 935,560 | |
| 935,560 | |
| 930,449 | |
| 935,560 | |
| 930,449 | |
Amortizable intangibles, net | |
| 65,105 | |
| 69,298 | |
| 82,976 | |
| 65,105 | |
| 82,976 | |
Deposits | |
| 15,605,139 | |
| 13,553,035 | |
| 12,515,544 | |
| 15,605,139 | |
| 12,515,544 | |
Borrowings | |
| 1,125,030 | |
| 1,514,464 | |
| 1,909,171 | |
| 1,125,030 | |
| 1,909,171 | |
Stockholders' equity | |
| 2,618,226 | |
| 2,425,450 | |
| 2,512,295 | |
| 2,618,226 | |
| 2,512,295 | |
Tangible common equity (2) | |
| 1,451,197 | |
| 1,420,592 | |
| 1,498,870 | |
| 1,451,197 | |
| 1,498,870 | |
| | | | | | | | | | | | | | | | |
Loans held for investment, net of deferred fees and costs | |
|
| |
|
| |
|
| |
|
| |
|
| |
Construction and land development | | $ | 1,247,939 | | $ | 1,318,252 | | $ | 1,267,712 | | $ | 1,247,939 | | $ | 1,267,712 | |
Commercial real estate - owner occupied | |
| 2,067,087 | |
| 2,051,904 | |
| 1,966,776 | |
| 2,067,087 | |
| 1,966,776 | |
Commercial real estate - non-owner occupied | |
| 3,455,125 | |
| 3,328,012 | |
| 3,104,823 | |
| 3,455,125 | |
| 3,104,823 | |
Multifamily real estate | |
| 717,719 | |
| 679,390 | |
| 602,115 | |
| 717,719 | |
| 602,115 | |
Commercial & Industrial | |
| 3,555,971 | |
| 2,177,932 | |
| 2,032,799 | |
| 3,555,971 | |
| 2,032,799 | |
Residential 1-4 Family - Commercial | |
| 715,384 | |
| 721,800 | |
| 723,636 | |
| 715,384 | |
| 723,636 | |
Residential 1-4 Family - Consumer | |
| 841,051 | |
| 854,550 | |
| 928,130 | |
| 841,051 | |
| 928,130 | |
Residential 1-4 Family - Revolving | |
| 627,765 | |
| 652,135 | |
| 660,621 | |
| 627,765 | |
| 660,621 | |
Auto | |
| 380,053 | |
| 358,039 | |
| 311,858 | |
| 380,053 | |
| 311,858 | |
Consumer | |
| 311,362 | |
| 352,572 | |
| 383,653 | |
| 311,362 | |
| 383,653 | |
Other Commercial | |
| 389,190 | |
| 274,255 | |
| 238,391 | |
| 389,190 | |
| 238,391 | |
Total loans held for investment | | $ | 14,308,646 | | $ | 12,768,841 | | $ | 12,220,514 | | $ | 14,308,646 | | $ | 12,220,514 | |
| | | | | | | | | | | | | | | | |
Deposits | |
|
| |
|
| |
|
| |
|
| |
|
| |
NOW accounts | | $ | 3,618,523 | | $ | 3,180,913 | | $ | 2,552,159 | | $ | 3,618,523 | | $ | 2,552,159 | |
Money market accounts | |
| 4,158,325 | |
| 3,817,959 | |
| 3,592,523 | |
| 4,158,325 | |
| 3,592,523 | |
Savings accounts | |
| 824,164 | |
| 745,402 | |
| 749,472 | |
| 824,164 | |
| 749,472 | |
Time deposits of $250,000 and over | |
| 689,693 | |
| 696,520 | |
| 579,786 | |
| 689,693 | |
| 579,786 | |
Other time deposits | | | 1,968,474 | | | 2,044,668 | | | 2,026,708 | | | 1,968,474 | | | 2,026,708 | |
Time deposits | |
| 2,658,167 | |
| 2,741,188 | |
| 2,606,494 | |
| 2,658,167 | |
| 2,606,494 | |
Total interest-bearing deposits | | $ | 11,259,179 | | $ | 10,485,462 | | $ | 9,500,648 | | $ | 11,259,179 | | $ | 9,500,648 | |
Demand deposits | |
| 4,345,960 | |
| 3,067,573 | |
| 3,014,896 | |
| 4,345,960 | |
| 3,014,896 | |
Total deposits | | $ | 15,605,139 | | $ | 13,553,035 | | $ | 12,515,544 | | $ | 15,605,139 | | $ | 12,515,544 | |
| | | | | | | | | | | | | | | | |
Averages | |
|
| |
|
| |
|
| |
|
| |
|
| |
Assets | | $ | 19,157,238 | | $ | 17,559,921 | | $ | 16,997,531 | | $ | 18,358,579 | | $ | 16,352,222 | |
Loans held for investment | |
| 13,957,711 | |
| 12,593,923 | |
| 12,084,961 | |
| 13,275,817 | |
| 11,608,821 | |
Loans held for sale | |
| 56,846 | |
| 50,721 | |
| 47,061 | |
| 53,783 | |
| 31,119 | |
Securities | |
| 2,648,967 | |
| 2,621,437 | |
| 2,738,528 | |
| 2,635,202 | |
| 2,692,236 | |
Earning assets | |
| 17,106,132 | |
| 15,563,670 | |
| 15,002,726 | |
| 16,334,901 | |
| 14,450,057 | |
Deposits | |
| 14,960,386 | |
| 13,346,857 | |
| 12,453,702 | |
| 14,153,621 | |
| 11,964,536 | |
Time deposits | |
| 2,667,268 | |
| 2,755,500 | |
| 2,562,498 | |
| 2,711,384 | |
| 2,444,513 | |
Interest-bearing deposits | |
| 10,941,368 | |
| 10,421,419 | |
| 9,555,093 | |
| 10,681,393 | |
| 9,285,895 | |
Borrowings | |
| 1,344,994 | |
| 1,442,525 | |
| 1,847,325 | |
| 1,395,539 | |
| 1,819,147 | |
Interest-bearing liabilities | |
| 12,286,362 | |
| 11,863,944 | |
| 11,402,418 | |
| 12,076,932 | |
| 11,105,042 | |
Stockholders' equity | |
| 2,489,969 | |
| 2,485,646 | |
| 2,490,049 | |
| 2,487,807 | |
| 2,379,834 | |
Tangible common equity (2) | |
| 1,446,948 | |
| 1,478,803 | |
| 1,475,028 | |
| 1,462,875 | |
| 1,404,929 | |
| | As of & For Three Months Ended |
| As of & For Six Months Ended | | |||||||||||
|
| 06/30/20 |
| 03/31/20 |
| 06/30/19 |
| 06/30/20 | | 06/30/19 |
| |||||
Asset Quality | | (unaudited) | | (unaudited) | | (unaudited) |
| (unaudited) | | (unaudited) |
| |||||
Allowance for Credit Losses (ACL) |
| |
|
| |
|
| |
| | |
|
| |
| |
Beginning balance, Allowance for loan and lease losses (ALLL) | | $ | 141,043 | | $ | 42,294 | | $ | 40,827 | | $ | 42,294 | | $ | 41,045 | |
Add: Day 1 impact from adoption of CECL | | | — | | | 47,484 | | | — | | | 47,484 | | | — | |
Add: Recoveries | |
| 1,411 | |
| 2,160 | |
| 1,670 | |
| 3,571 | |
| 3,366 | |
Less: Charge-offs | |
| 4,677 | |
| 7,151 | |
| 5,934 | |
| 11,828 | |
| 11,873 | |
Add: Provision for loan losses | |
| 32,200 | |
| 56,256 | |
| 5,900 | |
| 88,456 | |
| 9,925 | |
Ending balance, ALLL | | $ | 169,977 | | $ | 141,043 | | $ | 42,463 | | $ | 169,977 | | $ | 42,463 | |
| | | | | | | | | | | | | | | | |
Beginning balance, Reserve for unfunded commitment (RUC) | | $ | 9,000 | | $ | 900 | | $ | 1,700 | | | 900 | | | 900 | |
Add: Day 1 impact from adoption of CECL | | | — | | | 4,160 | | | — | | | 4,160 | | | — | |
Add: Impact of acquisition accounting | | | — | | | — | | | — | | | — | | | 1,033 | |
Add: Provision for unfunded commitments | | | 2,000 | | | 3,940 | | | (600) | | | 5,940 | | | (833) | |
Ending balance, RUC | | $ | 11,000 | | $ | 9,000 | | $ | 1,100 | | | 11,000 | | | 1,100 | |
Total ACL | | $ | 180,977 | | $ | 150,043 | | $ | 43,563 | | $ | 180,977 | | $ | 43,563 | |
| | | | | | | | | | | | | | | | |
ACL / total outstanding loans | | | 1.26 | % | | 1.18 | % | | 0.36 | % | | 1.26 | % | | 0.36 | % |
ACL / total adjusted loans(9) | | | 1.42 | % | | 1.18 | % | | 0.36 | % | | 1.42 | % | | 0.36 | % |
ALLL / total outstanding loans | |
| 1.19 | % |
| 1.10 | % |
| 0.35 | % |
| 1.19 | % |
| 0.35 | % |
ALLL / total adjusted loans(9) | | | 1.34 | % | | 1.10 | % | | 0.35 | % | | 1.34 | % | | 0.35 | % |
Net charge-offs / total average loans | |
| 0.09 | % |
| 0.16 | % |
| 0.14 | % |
| 0.13 | % |
| 0.15 | % |
Net charge-offs / total adjusted average loans(9) | | | 0.10 | % | | 0.16 | % | | 0.14 | % | | 0.14 | % | | 0.15 | % |
Provision for loan losses/ total average loans | |
| 0.93 | % |
| 1.80 | % |
| 0.20 | % |
| 1.34 | % |
| 0.17 | % |
Provision for loan losses/ total adjusted average loans(9) | | | 1.02 | % | | 1.80 | % | | 0.20 | % | | 1.48 | % | | 0.17 | % |
| ` | | | | | | | | | | | | | | | |
Nonperforming Assets(6) | |
|
| |
|
| |
|
| |
|
| |
|
| |
Construction and land development | | $ | 3,977 | | $ | 3,234 | | $ | 5,619 | | $ | 3,977 | | $ | 5,619 | |
Commercial real estate - owner occupied | |
| 8,924 | |
| 11,250 | |
| 4,062 | |
| 8,924 | |
| 4,062 | |
Commercial real estate - non-owner occupied | |
| 1,877 | |
| 1,642 | |
| 1,685 | |
| 1,877 | |
| 1,685 | |
Multifamily real estate | | | 33 | | | 53 | | | — | | | 33 | | | — | |
Commercial & Industrial | |
| 2,708 | |
| 3,431 | |
| 1,183 | |
| 2,708 | |
| 1,183 | |
Residential 1-4 Family - Commercial | |
| 5,784 | |
| 7,040 | |
| 4,135 | |
| 5,784 | |
| 4,135 | |
Residential 1-4 Family - Consumer | |
| 12,029 | |
| 13,088 | |
| 8,677 | |
| 12,029 | |
| 8,677 | |
Residential 1-4 Family - Revolving | |
| 3,626 | |
| 3,547 | |
| 1,432 | |
| 3,626 | |
| 1,432 | |
Auto | |
| 584 | |
| 550 | |
| 449 | |
| 584 | |
| 449 | |
Consumer and all other | | | 82 | | | 187 | | | 220 | | | 82 | |
| 220 | |
Nonaccrual loans | | $ | 39,624 | | $ | 44,022 | | $ | 27,462 | | $ | 39,624 | | $ | 27,462 | |
Foreclosed property | |
| 4,397 | |
| 4,444 | |
| 6,506 | |
| 4,397 | |
| 6,506 | |
Total nonperforming assets (NPAs) | | $ | 44,021 | | $ | 48,466 | | $ | 33,968 | | $ | 44,021 | | $ | 33,968 | |
Construction and land development | | $ | 473 | | $ | 317 | | $ | 855 | | $ | 473 | | $ | 855 | |
Commercial real estate - owner occupied | |
| 7,851 | |
| 1,690 | |
| 2,540 | |
| 7,851 | |
| 2,540 | |
Commercial real estate - non-owner occupied | | | 878 | | | 2,037 | | | 1,489 | | | 878 | | | 1,489 | |
Multifamily real estate | | | 366 | | | 377 | | | — | | | 366 | | | — | |
Commercial & Industrial | |
| 178 | |
| 517 | |
| 295 | |
| 178 | |
| 295 | |
Residential 1-4 Family - Commercial | |
| 578 | |
| 777 | |
| 863 | |
| 578 | |
| 863 | |
Residential 1-4 Family - Consumer | |
| 5,099 | |
| 4,407 | |
| 845 | |
| 5,099 | |
| 845 | |
Residential 1-4 Family - Revolving | |
| 1,995 | |
| 2,005 | |
| 658 | |
| 1,995 | |
| 658 | |
Auto | |
| 181 | |
| 127 | |
| 122 | |
| 181 | |
| 122 | |
Consumer and all other | |
| 1,656 | |
| 622 | |
| 1,161 | |
| 1,656 | |
| 1,161 | |
Loans ≥ 90 days and still accruing | | $ | 19,255 | | $ | 12,876 | | $ | 8,828 | | $ | 19,255 | | $ | 8,828 | |
Total NPAs and loans ≥ 90 days | | $ | 63,276 | | $ | 61,342 | | $ | 42,796 | | $ | 63,276 | | $ | 42,796 | |
NPAs / total outstanding loans | |
| 0.31 | % |
| 0.38 | % |
| 0.28 | % |
| 0.31 | % |
| 0.28 | % |
NPAs / total adjusted loans(9) | | | 0.35 | % | | 0.38 | % | | 0.28 | % | | 0.35 | % | | 0.28 | % |
NPAs / total assets | |
| 0.22 | % |
| 0.27 | % |
| 0.20 | % |
| 0.22 | % |
| 0.20 | % |
ALLL / nonaccrual loans | |
| 428.97 | % |
| 320.39 | % |
| 154.62 | % |
| 428.97 | % |
| 154.62 | % |
ALLL/ nonperforming assets | |
| 386.13 | % |
| 291.01 | % |
| 125.01 | % |
| 386.13 | % |
| 125.01 | % |
Past Due Detail(6) | |
|
| |
|
| |
|
| |
|
| |
|
| |
Construction and land development | | $ | 1,683 | | $ | 2,786 | | $ | 2,327 | | $ | 1,683 | | $ | 2,327 | |
Commercial real estate - owner occupied | |
| 1,679 | |
| 10,779 | |
| 1,707 | |
| 1,679 | |
| 1,707 | |
Commercial real estate - non-owner occupied | |
| 930 | |
| 2,087 | |
| 141 | |
| 930 | |
| 141 | |
Multifamily real estate | |
| — | |
| 623 | |
| 1,218 | |
| — | |
| 1,218 | |
Commercial & Industrial | |
| 1,602 | |
| 4,893 | |
| 3,223 | |
| 1,602 | |
| 3,223 | |
Residential 1-4 Family - Commercial | |
| 480 | |
| 4,145 | |
| 1,622 | |
| 480 | |
| 1,622 | |
Residential 1-4 Family - Consumer | |
| 1,229 | |
| 15,667 | |
| 5,969 | |
| 1,229 | |
| 5,969 | |
Residential 1-4 Family - Revolving | |
| 1,924 | |
| 4,308 | |
| 4,978 | |
| 1,924 | |
| 4,978 | |
Auto | |
| 1,176 | |
| 1,967 | |
| 2,120 | |
| 1,176 | |
| 2,120 | |
Consumer and all other | | | 1,300 | | | 1,613 | | | 2,824 | | | 1,300 | | | 2,824 | |
Loans 30-59 days past due | | $ | 12,003 | | $ | 48,868 | | $ | 26,129 | | $ | 12,003 | | $ | 26,129 | |
| | As of & For Three Months Ended |
| As of & For Six Months Ended | | |||||||||||
|
| 06/30/20 |
| 03/31/20 |
| 06/30/19 |
| 06/30/20 | | 06/30/19 |
| |||||
Past Due Detail cont'd(6) | | (unaudited) | | (unaudited) | | (unaudited) |
| (unaudited) | | (unaudited) |
| |||||
Construction and land development | | $ | 294 | | $ | 316 | | $ | 318 | | $ | 294 | | $ | 318 | |
Commercial real estate - owner occupied | |
| 430 | |
| 1,444 | |
| — | |
| 430 | |
| — | |
Commercial real estate - non-owner occupied | |
| 369 | |
| 2,765 | |
| 164 | |
| 369 | |
| 164 | |
Multifamily real estate | | | — | | | 1,994 | | | — | | | — | | | — | |
Commercial & Industrial | |
| 296 | |
| 1,218 | |
| 1,175 | |
| 296 | |
| 1,175 | |
Residential 1-4 Family - Commercial | |
| 2,105 | |
| 1,066 | |
| 651 | |
| 2,105 | |
| 651 | |
Residential 1-4 Family - Consumer | |
| 3,817 | |
| 570 | |
| 2,801 | |
| 3,817 | |
| 2,801 | |
Residential 1-4 Family - Revolving | |
| 1,048 | |
| 1,286 | |
| 1,336 | |
| 1,048 | |
| 1,336 | |
Auto | |
| 290 | |
| 311 | |
| 299 | |
| 290 | |
| 299 | |
Consumer and all other | | | 561 | | | 2,362 | | | 1,423 | | | 561 | |
| 1,423 | |
Loans 60-89 days past due | | $ | 9,210 | | $ | 13,332 | | $ | 8,167 | | $ | 9,210 | | $ | 8,167 | |
| | | | | | | | | | | | | | | | |
Troubled Debt Restructurings | |
|
| |
|
| |
|
| |
|
| |
|
| |
Performing | | $ | 15,303 | | $ | 14,865 | | $ | 19,144 | | $ | 15,303 | | $ | 19,144 | |
Nonperforming | |
| 5,042 | |
| 5,491 | |
| 4,536 | |
| 5,042 | |
| 4,536 | |
Total troubled debt restructurings | | $ | 20,345 | | $ | 20,356 | | $ | 23,680 | | $ | 20,345 | | $ | 23,680 | |
| | | | | | | | | | | | | | | | |
Alternative Performance Measures (non-GAAP) | |
|
| |
|
| |
|
| |
|
| |
|
| |
Net interest income (FTE) | |
|
| |
|
| |
|
| |
|
| |
|
| |
Net interest income (GAAP) | | $ | 137,305 | | $ | 135,008 | | $ | 138,594 | | $ | 272,313 | | $ | 266,141 | |
FTE adjustment | |
| 2,805 | |
| 2,758 | |
| 2,920 | |
| 5,562 | |
| 5,668 | |
Net interest income (FTE) (non-GAAP) (1) | | $ | 140,110 | | $ | 137,766 | | $ | 141,514 | | $ | 277,875 | | $ | 271,809 | |
Noninterest income (GAAP) | | | 35,932 | | | 28,907 | | | 30,578 | | | 64,838 | | | 55,515 | |
Total revenue (FTE) (non-GAAP) (1) | | $ | 176,042 | | $ | 166,673 | | $ | 172,092 | | $ | 342,713 | | $ | 327,324 | |
| | | | | | | | | | | | | | | | |
Average earning assets | | $ | 17,106,132 | | $ | 15,563,670 | | $ | 15,002,726 | | $ | 16,334,901 | | $ | 14,450,057 | |
Net interest margin | |
| 3.23 | % |
| 3.49 | % |
| 3.71 | % |
| 3.35 | % |
| 3.71 | % |
Net interest margin (FTE) (1) | |
| 3.29 | % |
| 3.56 | % |
| 3.78 | % |
| 3.42 | % |
| 3.79 | % |
| | | | | | | | | | | | | | | | |
Tangible Assets | |
|
| |
|
| |
|
| |
|
| |
|
| |
Ending assets (GAAP) | | $ | 19,752,317 | | $ | 17,847,376 | | $ | 17,159,384 | | $ | 19,752,317 | | $ | 17,159,384 | |
Less: Ending goodwill | |
| 935,560 | |
| 935,560 | |
| 930,449 | |
| 935,560 | |
| 930,449 | |
Less: Ending amortizable intangibles | |
| 65,105 | |
| 69,298 | |
| 82,976 | |
| 65,105 | |
| 82,976 | |
Ending tangible assets (non-GAAP) | | $ | 18,751,652 | | $ | 16,842,518 | | $ | 16,145,959 | | $ | 18,751,652 | | $ | 16,145,959 | |
| | | | | | | | | | | | | | | | |
Tangible Common Equity (2) | |
|
| |
|
| |
|
| |
|
| |
|
| |
Ending equity (GAAP) | | $ | 2,618,226 | | $ | 2,425,450 | | $ | 2,512,295 | | $ | 2,618,226 | | $ | 2,512,295 | |
Less: Ending goodwill | |
| 935,560 | |
| 935,560 | |
| 930,449 | |
| 935,560 | |
| 930,449 | |
Less: Ending amortizable intangibles | |
| 65,105 | |
| 69,298 | |
| 82,976 | |
| 65,105 | |
| 82,976 | |
Less: Perpetual preferred stock | | | 166,364 | | | — | | | — | | | 166,364 | | | — | |
Ending tangible common equity (non-GAAP) | | $ | 1,451,197 | | $ | 1,420,592 | | $ | 1,498,870 | | $ | 1,451,197 | | $ | 1,498,870 | |
| | | | | | | | | | | | | | | | |
Average equity (GAAP) | | $ | 2,489,969 | | $ | 2,485,646 | | $ | 2,490,049 | | $ | 2,487,807 | | $ | 2,379,834 | |
Less: Average goodwill | |
| 935,560 | |
| 935,560 | |
| 929,455 | |
| 935,560 | |
| 894,252 | |
Less: Average amortizable intangibles | |
| 67,136 | |
| 71,283 | |
| 85,566 | |
| 69,210 | |
| 80,653 | |
Less: Average perpetual preferred stock | | | 40,325 | | | — | | | — | | | 20,162 | | | — | |
Average tangible common equity (non-GAAP) | | $ | 1,446,948 | | $ | 1,478,803 | | $ | 1,475,028 | | $ | 1,462,875 | | $ | 1,404,929 | |
| | | | | | | | | | | | | | | | |
Operating Measures (4) | |
|
| |
|
| |
|
| |
|
| |
|
| |
Net income (GAAP) | | $ | 30,709 | | $ | 7,089 | | $ | 48,823 | | $ | 37,798 | | $ | 84,453 | |
Plus: Merger and rebranding-related costs, net of tax | |
| — | | | — | |
| 8,266 | |
| — | |
| 23,154 | |
Net operating earnings (non-GAAP) | | | 30,709 | | | 7,089 | | | 57,089 | | | 37,798 | | | 107,607 | |
Less: Dividends on preferred stock | | | — | | | — | | | — | | | — | | | — | |
Net operating earnings available to common shareholders (non-GAAP) | | $ | 30,709 | | $ | 7,089 | | $ | 57,089 | | $ | 37,798 | | $ | 107,607 | |
| | | | | | | | | | | | | | | | |
Noninterest expense (GAAP) | | $ | 102,814 | | $ | 95,645 | | $ | 105,608 | | $ | 198,459 | | $ | 212,335 | |
Less: Merger Related Costs | |
| — | |
| — | |
| 6,371 | |
| — | |
| 24,493 | |
Less: Rebranding Costs | | | — | | | — | | | 4,012 | | | — | | | 4,420 | |
Less: Amortization of intangible assets | |
| 4,223 | |
| 4,401 | |
| 4,937 | |
| 8,624 | |
| 9,154 | |
Operating noninterest expense (non-GAAP) | | $ | 98,591 | | $ | 91,244 | | $ | 90,288 | | $ | 189,835 | | $ | 174,268 | |
| | | | | | | | | | | | | | | | |
Net interest income (FTE) (non-GAAP) (1) | | $ | 140,110 | | $ | 137,766 | | $ | 141,514 | | $ | 277,875 | | $ | 271,809 | |
Noninterest income (GAAP) | |
| 35,932 | |
| 28,907 | |
| 30,578 | |
| 64,838 | |
| 55,515 | |
Total revenue (FTE) (non-GAAP) (1) | | $ | 176,042 | | $ | 166,673 | | $ | 172,092 | | $ | 342,713 | | $ | 327,324 | |
| | | | | | | | | | | | | | | | |
Efficiency ratio | |
| 59.35 | % |
| 58.35 | % |
| 62.43 | % |
| 58.86 | % |
| 66.01 | % |
Operating efficiency ratio (FTE)(7) | |
| 56.00 | % |
| 54.74 | % |
| 52.46 | % |
| 55.39 | % |
| 53.24 | % |
| | As of & For Three Months Ended |
| As of & For Six Months Ended | | |||||||||||
|
| 06/30/20 |
| 03/31/20 |
| 06/30/19 |
| 06/30/20 |
| 06/30/19 |
| |||||
| | (unaudited) | | (unaudited) | | (unaudited) |
| (unaudited) | | (unaudited) |
| |||||
Operating ROTCE (2)(3) | |
|
| |
|
| |
|
| |
|
| |
|
| |
Net operating earnings available to common shareholders (non-GAAP) | | $ | 30,709 | | $ | 7,089 | | $ | 57,089 | | $ | 37,798 | | $ | 107,607 | |
Plus: Amortization of intangibles, tax effected | |
| 3,336 | |
| 3,477 | |
| 3,900 | |
| 6,813 | |
| 7,232 | |
Net operating earnings available to common shareholders before amortization of intangibles (non-GAAP) | | $ | 34,045 | | $ | 10,566 | | $ | 60,989 | | $ | 44,611 | | $ | 114,839 | |
| | | | | | | | | | | | | | | | |
Average tangible common equity (non-GAAP) | | $ | 1,446,948 | | $ | 1,478,803 | | $ | 1,475,028 | | $ | 1,462,875 | | $ | 1,404,929 | |
Operating return on average tangible common equity (non-GAAP) | |
| 9.46 | % |
| 2.87 | % |
| 16.58 | % |
| 6.13 | % |
| 16.48 | % |
| | | | | | | | | | | | | | | | |
Pre-tax pre-provision earnings (8) | | | | | | | | | | | | | | | | |
Net income (GAAP) | | $ | 30,709 | | $ | 7,089 | | $ | 48,823 | | $ | 37,798 | | $ | 84,453 | |
Plus: Provision for credit losses | | | 34,200 | | | 60,196 | | | 5,300 | | | 94,396 | | | 9,092 | |
Plus: Income tax expense | | | 5,514 | | | 985 | | | 9,356 | | | 6,498 | | | 15,606 | |
Plus: Merger and rebranding-related costs | | | — | | | — | | | 10,383 | | | — | | | 28,913 | |
Pre-tax pre-provision earnings (non-GAAP) | | $ | 70,423 | | $ | 68,270 | | $ | 73,862 | | $ | 138,692 | | $ | 138,064 | |
| | | | | | | | | | | | | | | | |
Paycheck Protection Program adjustment impact (9) | | | | | | | | | | | | | | | | |
Loans held for investment (net of deferred fees and costs)(GAAP) | | $ | 14,308,646 | | $ | 12,768,841 | | $ | 12,220,514 | | $ | 14,308,646 | | $ | 12,220,514 | |
Less: PPP adjustments | | | 1,598,718 | | | — | | | — | | | 1,598,718 | | | — | |
Loans held for investment (net of deferred fees and costs),net adjustments, excluding PPP (non-GAAP) | | $ | 12,709,928 | | $ | 12,768,841 | | $ | 12,220,514 | | $ | 12,709,928 | | $ | 12,220,514 | |
| | | | | | | | | | | | | | | | |
Average loans held for investment (GAAP) | | $ | 13,957,711 | | $ | 12,593,923 | | $ | 12,084,961 | | $ | 13,275,817 | | $ | 11,608,821 | |
Less: Average PPP adjustments | | | 1,273,883 | | | — | | | — | | | 1,273,883 | | | — | |
Average loans held for investment, net adjustments, excluding PPP (non-GAAP) | | $ | 12,683,828 | | $ | 12,593,923 | | $ | 12,084,961 | | $ | 12,001,934 | | $ | 11,608,821 | |
| | | | | | | | | | | | | | | | |
Mortgage Origination Volume | |
|
| |
|
| |
|
| |
|
| |
|
| |
Refinance Volume | | $ | 163,737 | | $ | 68,382 | | $ | 27,870 | | $ | 232,120 | | $ | 39,839 | |
Construction Volume | |
| 12,966 | |
| 7,837 | |
| 360 | |
| 20,802 | |
| 360 | |
Purchase Volume | |
| 83,248 | |
| 64,492 | |
| 84,225 | |
| 147,740 | |
| 116,332 | |
Total Mortgage loan originations | | $ | 259,951 | | $ | 140,711 | | $ | 112,455 | | $ | 400,662 | | $ | 156,531 | |
% of originations that are refinances | |
| 63.0 | % |
| 48.6 | % |
| 24.8 | % |
| 57.9 | % |
| 25.5 | % |
| | | | | | | | | | | | | | | | |
Wealth | |
|
| |
|
| |
|
| |
|
| |
|
| |
Assets under management ("AUM") | | $ | 5,271,288 | | $ | 4,783,228 | | $ | 5,332,203 | | $ | 5,271,288 | | $ | 5,332,203 | |
| | | | | | | | | | | | | | | | |
Other Data | |
|
| |
|
| |
|
| |
|
| |
|
| |
End of period full-time employees | |
| 1,973 | |
| 2,011 | |
| 1,931 | |
| 1,973 | |
| 1,931 | |
Number of full-service branches | |
| 149 | |
| 149 | |
| 153 | |
| 149 | |
| 153 | |
Number of full automatic transaction machines ("ATMs") | |
| 169 | |
| 169 | |
| 197 | |
| 169 | |
| 197 | |
| (1) | These are non-GAAP financial measures. Net interest income (FTE) and total revenue (FTE), which are used in computing net interest margin (FTE) and operating efficiency ratio (FTE), respectively, provide valuable additional insight into the net interest margin and the efficiency ratio by adjusting for differences in tax treatment of interest income sources. The entire FTE adjustment is attributable to interest income on earning assets, which is used in computing yield on earning assets. Interest expense and the related cost of interest-bearing liabilities and cost of funds ratios are not affected by the FTE components. |
| (2) | These are non-GAAP financial measures. Tangible common equity is used in the calculation of certain profitability, capital, and per share ratios. The Company believes tangible common equity and the related ratios are meaningful measures of capital adequacy because they provide a meaningful base for period-to-period and company-to-company comparisons, which the Company believes will assist investors in assessing the capital of the Company and its ability to absorb potential losses. |
| (3) | These are non-GAAP financial measures. The Company believes that ROTCE is a meaningful supplement to GAAP financial measures and useful to investors because it measures the performance of a business consistently across time without regard to whether components of the business were acquired or developed internally. |
| (4) | These are non-GAAP financial measures. Operating measures exclude merger and rebranding-related costs unrelated to the Company’s normal operations. The Company believes these measures are useful to investors as they exclude certain costs resulting from acquisition activity and allow investors to more clearly see the combined economic results of the organization’s operations. |
| (5) | All ratios at June 30, 2020 are estimates and subject to change pending the Company’s filing of its FR Y9-C. All other periods are presented as filed. |
| (6) | Amounts are not directly comparable due to the Company’s adoption of CECL on January 1, 2020. Prior to January 1, 2020, nonaccrual and past due loan information excluded PCI-related loan balances. These balances also reflect the impact of the CARES Act and the joint supervisory guidance issued by five federal bank regulatory agencies and the Conference of State Bank Supervisors (updated April 7th) which provides relief for TDR designations and also provides guidance on past due reporting for modified loans. |
| (7) | The operating efficiency ratio (FTE) excludes the amortization of intangible assets and merger-related costs. This measure is similar to the measure utilized by the Company when analyzing corporate performance and is also similar to the measure utilized for incentive compensation. The Company believes this measure is useful to investors as it excludes certain costs resulting from acquisition activity allowing for greater comparability with others in the industry and allowing investors to more clearly see the combined economic results of the organization’s operations. |
| (8) | This is a non-GAAP financial measure. Pre-tax pre-provision earnings excludes the provision for credit losses, which can fluctuate significantly from period-to-period under the recently adopted CECL methodology, merger and rebranding-related costs unrelated to the Company’s normal operations, and income tax expense. The Company believes this measure is useful to investors as it excludes certain costs resulting from acquisition activity as well as the potentially volatile provision measure, and allows for greater comparability with others in the industry and for investors to more clearly see the combined economic results of the organization’s operations. |
| (9) | These are non-GAAP financial measures. Paycheck Protection Program adjustment impact excludes the SBA guaranteed loans funded during the first half of 2020. The Company believes loans held for investment (net of deferred fees and costs), excluding PPP is useful to investors as it provides more clarity on the Company’s organic growth. The Company also believes that the related non-GAAP financial measures of past due loans still accruing interest as a percentage of total loans held for investment (net of deferred fees and costs), excluding PPP, are useful to investors as loans originated under the PPP carry an SBA guarantee. The Company believes that the ALLL as a percentage of loans held for investment (net of deferred fees and costs), excluding PPP, is useful to investors because of the size of the Company’s PPP originations and the impact of the embedded credit enhancement provided by the SBA guarantee. |
ATLANTIC UNION BANKSHARES CORPORATION AND SUBSIDIARIES
CONSOLIDATED BALANCE SHEETS
(Dollars in thousands, except share data)
| June 30, | | March 31, | | December 31, | | June 30, | ||||
| 2020 | | 2020 |
| 2019 |
| 2019 | ||||
ASSETS | | (unaudited) | | | (unaudited) | | | (audited) | | | (unaudited) |
Cash and cash equivalents: | | | | | | | | | | | |
Cash and due from banks | $ | 202,947 | | $ | 197,521 | | $ | 163,050 | | $ | 171,441 |
Interest-bearing deposits in other banks | | 636,211 | | | 292,154 | | | 234,810 | | | 146,514 |
Federal funds sold | | 2,862 | | | 15,284 | | | 38,172 | | | 2,523 |
Total cash and cash equivalents | | 842,020 | | | 504,959 | | | 436,032 | | | 320,478 |
Securities available for sale, at fair value | | 2,019,164 | | | 1,972,903 | | | 1,945,445 | | | 1,999,494 |
Securities held to maturity, at carrying value | | 547,561 | | | 552,176 | | | 555,144 | | | 558,503 |
Restricted stock, at cost | | 105,832 | | | 130,227 | | | 130,848 | | | 145,859 |
Loans held for sale, at fair value | | 55,067 | | | 76,690 | | | 55,405 | | | 62,908 |
Loans held for investment, net of deferred fees and costs | | 14,308,646 | | | 12,768,841 | | | 12,610,936 | | | 12,220,514 |
Less allowance for loan and lease losses | | 169,977 | | | 141,043 | | | 42,294 | | | 42,463 |
Total loans held for investment, net | | 14,138,669 | | | 12,627,798 | | | 12,568,642 | | | 12,178,051 |
Premises and equipment, net | | 164,321 | | | 161,139 | | | 161,073 | | | 168,514 |
Goodwill | | 935,560 | | | 935,560 | | | 935,560 | | | 930,449 |
Amortizable intangibles, net | | 65,105 | | | 69,298 | | | 73,669 | | | 82,976 |
Bank owned life insurance | | 327,075 | | | 324,980 | | | 322,917 | | | 318,734 |
Other assets | | 551,943 | | | 491,646 | | | 378,255 | | | 393,418 |
Total assets | $ | 19,752,317 | | $ | 17,847,376 | | $ | 17,562,990 | | $ | 17,159,384 |
LIABILITIES | | | | | | | | | | | |
Noninterest-bearing demand deposits | $ | 4,345,960 | | $ | 3,067,573 | | $ | 2,970,139 | | $ | 3,014,896 |
Interest-bearing deposits | | 11,259,179 | | | 10,485,462 | | | 10,334,842 | | | 9,500,648 |
Total deposits | | 15,605,139 | | | 13,553,035 | | | 13,304,981 | | | 12,515,544 |
Securities sold under agreements to repurchase | | 77,216 | | | 56,781 | | | 66,053 | | | 70,870 |
Other short-term borrowings | | — | | | 380,000 | | | 370,200 | | | 618,050 |
Long-term borrowings | | 1,047,814 | | | 1,077,683 | | | 1,077,495 | | | 1,220,251 |
Other liabilities | | 403,922 | | | 354,427 | | | 231,159 | | | 222,374 |
Total liabilities | | 17,134,091 | | | 15,421,926 | | | 15,049,888 | | | 14,647,089 |
Commitments and contingencies | | | | | | | | | | | |
STOCKHOLDERS' EQUITY | | | | | | | | | | | |
Preferred stock, $10.00 par value | | 173 | | | — | | | — | | | — |
Common stock, $1.33 par value | | 104,126 | | | 104,086 | | | 105,827 | | | 108,560 |
Additional paid-in capital | | 1,911,985 | | | 1,743,429 | | | 1,790,305 | | | 1,862,716 |
Retained earnings | | 540,638 | | | 529,606 | | | 581,395 | | | 512,952 |
Accumulated other comprehensive income (loss) | | 61,304 | | | 48,329 | | | 35,575 | | | 28,067 |
Total stockholders' equity | | 2,618,226 | | | 2,425,450 | | | 2,513,102 | | | 2,512,295 |
Total liabilities and stockholders' equity | $ | 19,752,317 | | $ | 17,847,376 | | $ | 17,562,990 | | $ | 17,159,384 |
Common shares outstanding | | 78,713,056 | | | 78,710,448 | | | 80,001,185 | | | 82,086,736 |
Common shares authorized | | 200,000,000 | | | 200,000,000 | | | 200,000,000 | | | 200,000,000 |
Preferred shares outstanding | | 17,250 | | | - | | | - | | | - |
Preferred shares authorized | | 500,000 | | | 500,000 | | | 500,000 | | | 500,000 |
ATLANTIC UNION BANKSHARES CORPORATION AND SUBSIDIARIES
CONSOLIDATED STATEMENTS OF INCOME
(Dollars in thousands, except share data)
| Three Months Ended | | Six Months Ended | |||||||||||
| June 30, | | March 31, | | June 30, | | June 30, | | June 30, | |||||
| 2020 |
| 2020 |
| 2019 |
| 2020 |
| 2019 | |||||
| (Unaudited) | | (Unaudited) | | (Unaudited) | | (Unaudited) | | (Unaudited) | |||||
Interest and dividend income: | | | | | | | | | | | | | | |
Interest and fees on loans | $ | 143,234 | | $ | 151,127 | | $ | 158,838 | | $ | 294,361 | | $ | 302,952 |
Interest on deposits in other banks | | 155 | | | 862 | | | 544 | | | 1,017 | | | 1,017 |
Interest and dividends on securities: | | | | | | | | | | | | | | |
Taxable | | 11,267 | | | 11,627 | | | 13,353 | | | 22,895 | | | 26,434 |
Nontaxable | | 8,211 | | | 7,709 | | | 8,390 | | | 15,920 | | | 16,374 |
Total interest and dividend income | | 162,867 | | | 171,325 | | | 181,125 | | | 334,193 | | | 346,777 |
Interest expense: | | | | | | | | | | | | | | |
Interest on deposits | | 19,861 | | | 28,513 | | | 28,809 | | | 48,375 | | | 53,239 |
Interest on short-term borrowings | | 186 | | | 1,340 | | | 5,563 | | | 1,526 | | | 12,114 |
Interest on long-term borrowings | | 5,515 | | | 6,464 | | | 8,159 | | | 11,979 | | | 15,283 |
Total interest expense | | 25,562 | | | 36,317 | | | 42,531 | | | 61,880 | | | 80,636 |
Net interest income | | 137,305 | | | 135,008 | | | 138,594 | | | 272,313 | | | 266,141 |
Provision for credit losses | | 34,200 | | | 60,196 | | | 5,300 | | | 94,396 | | | 9,092 |
Net interest income after provision for credit losses | | 103,105 | | | 74,812 | | | 133,294 | | | 177,917 | | | 257,049 |
Noninterest income: | | | | | | | | | | | | | | |
Service charges on deposit accounts | | 4,930 | | | 7,578 | | | 7,499 | | | 12,508 | | | 14,656 |
Other service charges, commissions and fees | | 1,354 | | | 1,624 | | | 1,702 | | | 2,978 | | | 3,367 |
Interchange fees | | 1,697 | | | 1,625 | | | 5,612 | | | 3,321 | | | 10,656 |
Fiduciary and asset management fees | | 5,515 | | | 5,984 | | | 5,698 | | | 11,499 | | | 10,752 |
Mortgage banking income | | 5,826 | | | 2,022 | | | 2,785 | | | 7,847 | | | 4,240 |
Gains (losses) on securities transactions | | 10,339 | | | 1,936 | | | 51 | | | 12,275 | | | 202 |
Bank owned life insurance income | | 2,027 | | | 2,049 | | | 2,075 | | | 4,076 | | | 4,129 |
Loan-related interest rate swap fees | | 5,484 | | | 3,948 | | | 3,716 | | | 9,432 | | | 5,176 |
Other operating income | | (1,240) | | | 2,141 | | | 1,440 | | | 902 | | | 2,337 |
Total noninterest income | | 35,932 | | | 28,907 | | | 30,578 | | | 64,838 | | | 55,515 |
Noninterest expenses: | | | | | | | | | | | | | | |
Salaries and benefits | | 49,896 | | | 50,117 | | | 50,390 | | | 100,013 | | | 98,398 |
Occupancy expenses | | 7,224 | | | 7,133 | | | 7,534 | | | 14,357 | | | 14,935 |
Furniture and equipment expenses | | 3,406 | | | 3,741 | | | 3,542 | | | 7,147 | | | 6,938 |
Printing, postage, and supplies | | 999 | | | 1,290 | | | 1,252 | | | 2,289 | | | 2,494 |
Technology and data processing | | 6,454 | | | 6,169 | | | 5,739 | | | 12,623 | | | 11,415 |
Professional services | | 2,989 | | | 3,307 | | | 2,630 | | | 6,297 | | | 5,587 |
Marketing and advertising expense | | 2,043 | | | 2,739 | | | 2,908 | | | 4,782 | | | 5,291 |
FDIC assessment premiums and other insurance | | 2,907 | | | 2,861 | | | 2,601 | | | 5,768 | | | 5,239 |
Other taxes | | 4,120 | | | 4,120 | | | 4,044 | | | 8,240 | | | 7,808 |
Loan-related expenses | | 2,501 | | | 2,697 | | | 2,396 | | | 5,198 | | | 4,685 |
OREO and credit-related expenses | | 411 | | | 688 | | | 1,473 | | | 1,099 | | | 2,157 |
Amortization of intangible assets | | 4,223 | | | 4,401 | | | 4,937 | | | 8,624 | | | 9,154 |
Training and other personnel costs | | 876 | | | 1,571 | | | 1,477 | | | 2,446 | | | 2,621 |
Merger-related costs | | — | | | — | | | 6,371 | | | — | | | 24,493 |
Rebranding expense | | — | | | — | | | 4,012 | | | — | | | 4,420 |
Loss on debt extinguishment | | 10,306 | | | — | | | — | | | 10,306 | | | — |
Other expenses | | 4,459 | | | 4,811 | | | 4,302 | | | 9,270 | | | 6,700 |
Total noninterest expenses | | 102,814 | | | 95,645 | | | 105,608 | | | 198,459 | | | 212,335 |
Income from continuing operations before income taxes | | 36,223 | | | 8,074 | | | 58,264 | | | 44,296 | | | 100,229 |
Income tax expense | | 5,514 | | | 985 | | | 9,356 | | | 6,498 | | | 15,606 |
Income from continuing operations | $ | 30,709 | | $ | 7,089 | | $ | 48,908 | | $ | 37,798 | | $ | 84,623 |
Discontinued operations: | | | | | | | | | | | | | | |
Income (loss) from operations of discontinued mortgage segment | $ | — | | $ | — | | $ | (114) | | $ | — | | $ | (229) |
Income tax expense (benefit) | | — | | | — | | | (29) | | | — | | | (59) |
Income (loss) on discontinued operations | | — | | | — | | | (85) | | | — | | | (170) |
Net income available to common shareholders | $ | 30,709 | | $ | 7,089 | | $ | 48,823 | | $ | 37,798 | | $ | 84,453 |
| | | | | | | | | | | | | | |
Basic earnings per common share | $ | 0.39 | | $ | 0.09 | | $ | 0.59 | | $ | 0.48 | | $ | 1.06 |
Diluted earnings per common share | $ | 0.39 | | $ | 0.09 | | $ | 0.59 | | $ | 0.48 | | $ | 1.06 |
AVERAGE BALANCES, INCOME AND EXPENSES, YIELDS AND RATES (TAXABLE EQUIVALENT BASIS)
| For the Quarter Ended | ||||||||||||||
| June 30, 2020 | | March 31, 2020 | ||||||||||||
| Average |
| Interest |
| Yield / |
| Average |
| Interest |
| Yield / | ||||
| (unaudited) | | | (unaudited) | |||||||||||
Assets: | | | | | | | | | | | | | | | |
Securities: | | | | | | | | | | | | | | | |
Taxable | $ | 1,626,426 | | $ | 11,267 | | 2.79% | | $ | 1,664,449 | | $ | 11,627 | | 2.81% |
Tax-exempt | | 1,022,541 | | | 10,394 | | 4.09% | | | 956,988 | | | 9,759 | | 4.10% |
Total securities | | 2,648,967 | | | 21,661 | | 3.29% | | | 2,621,437 | | | 21,386 | | 3.28% |
Loans, net (3) (4) | | 13,957,711 | | | 143,339 | | 4.13% | | | 12,593,923 | | | 151,313 | | 4.83% |
Other earning assets | | 499,454 | | | 672 | | 0.54% | | | 348,310 | | | 1,384 | | 1.60% |
Total earning assets | | 17,106,132 | | $ | 165,672 | | 3.90% | | | 15,563,670 | | $ | 174,083 | | 4.50% |
Allowance for credit losses | | (150,868) | | | | | | | | (90,141) | | | | | |
Total non-earning assets | | 2,201,974 | | | | | | | | 2,086,392 | | | | | |
Total assets | $ | 19,157,238 | | | | | | | $ | 17,559,921 | | | | | |
| | | | | | | | | | | | | | | |
Liabilities and Stockholders' Equity: | | | | | | | | | | | | | | | |
Interest-bearing deposits: | | | | | | | | | | | | | | | |
Transaction and money market accounts | $ | 7,474,210 | | $ | 7,303 | | 0.39% | | $ | 6,933,345 | | $ | 14,521 | | 0.84% |
Regular savings | | 799,890 | | | 123 | | 0.06% | | | 732,574 | | | 157 | | 0.09% |
Time deposits (5) | | 2,667,268 | | | 12,435 | | 1.88% | | | 2,755,500 | | | 13,835 | | 2.02% |
Total interest-bearing deposits | | 10,941,368 | | | 19,861 | | 0.73% | | | 10,421,419 | | | 28,513 | | 1.10% |
Other borrowings (6) | | 1,344,994 | | | 5,701 | | 1.70% | | | 1,442,525 | | | 7,804 | | 2.18% |
Total interest-bearing liabilities | | 12,286,362 | | $ | 25,562 | | 0.84% | | | 11,863,944 | | $ | 36,317 | | 1.23% |
| | | | | | | | | | | | | | | |
Noninterest-bearing liabilities: | | | | | | | | | | | | | | | |
Demand deposits | | 4,019,018 | | | | | | | | 2,925,438 | | | | | |
Other liabilities | | 361,889 | | | | | | | | 284,893 | | | | | |
Total liabilities | | 16,667,269 | | | | | | | | 15,074,275 | | | | | |
Stockholders' equity | | 2,489,969 | | | | | | | | 2,485,646 | | | | | |
Total liabilities and stockholders' equity | $ | 19,157,238 | | | | | | | $ | 17,559,921 | | | | | |
Net interest income | | | | $ | 140,110 | | | | | | | $ | 137,766 | | |
| | | | | | | | | | | | | | | |
Interest rate spread | | | | | | | 3.06% | | | | | | | | 3.27% |
Cost of funds | | | | | | | 0.61% | | | | | | | | 0.94% |
Net interest margin | | | | | | | 3.29% | | | | | | | | 3.56% |
| (1) | Income and yields are reported on a taxable equivalent basis using the statutory federal corporate tax rate of 21%. |
| (2) | Rates and yields are annualized and calculated from actual, not rounded amounts in thousands, which appear above. |
| (3) | Nonaccrual loans are included in average loans outstanding. |
| (4) | Interest income on loans includes $6.4 million and $9.5 million for the three months ended June 30, 2020 and March 31, 2020, respectively, in accretion of the fair market value adjustments related to acquisitions. |
| (5) | Interest expense on time deposits includes $34,000 and $50,000 for the three months ended June 30, 2020 and March 31, 2020, respectively, in accretion of the fair market value adjustments related to acquisitions. |
| (6) | Interest expense on borrowings includes $140,000 and $138,000 for the three months ended June 30, 2020 and March 31, 2020, in amortization of the fair market value adjustments related to acquisitions. |
Exhibit 99.2
| 2nd Quarter 2020 Earnings Presentation Nasdaq: AUB July 23, 2020 |
| Forward Looking Statements 2 Certain statements in this presentation may constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Forward-looking statements are statements that include, without limitation, projections, predictions, expectations or beliefs about future events or results that are not statements of historical fact. Such forward-looking statements are based on various assumptions as of the time they are made, and are inherently subject to known and unknown risks, uncertainties, and other factors, some of which cannot be predicted or quantified, that may cause actual results, performance or achievements to be materially different from those expressed or implied by such forward- looking statements. Forward-looking statements are often accompanied by words that convey projected future events or outcomes such as “expect,” “believe,” “estimate,” “plan,” “project,” “anticipate,” “intend,” “will,” “may,” “view,” “opportunity,” “potential,” or words of similar meaning or other statements concerning opinions or judgment of Atlantic Union Bankshares Corporation (“Atlantic Union” or the “Company”) and its management about future events. Although Atlantic Union believes that its expectations with respect to forward-looking statements are based upon reasonable assumptions within the bounds of its existing knowledge of its business and operations, there can be no assurance that actual results, performance, or achievements of, or trends affecting, the Company will not differ materially from any projected future results, performance, or achievements or trends expressed or implied by such forward-looking statements. Actual future results, performance, achievements or trends may differ materially from historical results or those anticipated depending on a variety of factors, including, but not limited to: • changes in interest rates; • general economic and financial market conditions, in the United States generally and particularly in the markets in which the Company operates and which its loans are concentrated, including the effects of declines in real estate values, an increase in unemployment levels and slowdowns in economic growth, including as a result of COVID- 19; • the quality or composition of the loan or investment portfolios and changes therein; • demand for loan products and financial services in the Company’s market area; • the Company’s ability to manage its growth or implement its growth strategy; • planned branch consolidations; • the introduction of new lines of business or new products and services; • the Company’s ability to recruit and retain key employees; • the incremental cost and/or decreased revenues associated with exceeding $10 billion in assets; • real estate values in the Bank’s lending area; • an insufficient ACL; • changes in accounting principles relating to loan loss recognition (CECL); • the Company’s liquidity and capital positions; • concentrations of loans secured by real estate, particularly commercial real estate; • the effectiveness of the Company’s credit processes and management of the Company’s credit risk; • the Company’s ability to compete in the market for financial services; • technological risks and developments, and cyber threats, attacks, or events; • the potential adverse effects of unusual and infrequently occurring events, such as weather-related disasters, terrorist acts or public health events (such as COVID-19), and of governmental and societal responses thereto; these potential adverse effects may include, without limitation, adverse effects on the ability of the Company's borrowers to satisfy their obligations to the Company, on the value of collateral securing loans, on the demand for the Company's loans or its other products and services, on incidents of cyberattack and fraud, on the Company’s liquidity or capital positions, on risks posed by reliance on third- party service providers, on other aspects of the Company's business operations and on financial markets and economic growth; • the effect of steps the Company takes in response to COVID-19, the severity and duration of the pandemic, including whether there is a “second wave” as a result of the loosening of governmental restrictions, the pace of recovery when the pandemic subsides and the heightened impact it has on many of the risks described herein; • performance by the Company’s counterparties or vendors; • deposit flows; • the availability of financing and the terms thereof; • the level of prepayments on loans and mortgage-backed securities; • legislative or regulatory changes and requirements, including the impact of the CARES Act and other legislative and regulatory reactions to COVID-19; • potential claims, damages, and fines related to litigation or government actions, including litigation or actions arising from the Company’s participation in and administration of programs related to COVID-19, including, among other things, the CARES Act; • the effects of changes in federal, state or local tax laws and regulations; • monetary and fiscal policies of the U.S. government including policies of the U.S. Department of the Treasury and the Federal Reserve; • changes to applicable accounting principles and guidelines; and • other factors, many of which are beyond the control of the Company Please refer to the “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” sections of the Company’s Annual Report on Form 10-K for the year ended December 31, 2019, comparable “Risk Factors” sections of the Company’s Quarterly Reports on Form 10-Q, and related disclosures in other filings, which have been filed with the Securities and Exchange Commission (the “SEC”), and are available on the SEC’s website at www.sec.gov. All of the forward-looking statements made in this presentation are expressly qualified by the cautionary statements contained or referred to herein. The actual results or developments anticipated may not be realized or, even if substantially realized, they may not have the expected consequences to or effects on the Company or its businesses or operations. You are cautioned not to rely too heavily on the forward-looking statements contained in this presentation. Forward-looking statements speak only as of the date they are made and the Company does not undertake any obligation to update, revise or clarify these forward-looking statements, whether as a result of new information, future events or otherwise. |
| Additional Information 3 Unaudited Pro Forma Financial Information Any unaudited pro forma financial information included in, or discussed in connection with this presentation, is presented for informational purposes only and does not necessarily reflect the financial results of the combined company had the companies actually been combined during periods presented. The adjustments included in any such unaudited pro forma financial information are preliminary and may be significantly revised and may not agree to actual amounts finally recorded by Atlantic Union. This financial information does not reflect the benefits of the Access merger’s expected cost savings and expense efficiencies, opportunities to earn additional revenue, potential impacts of current market conditions on revenues or asset dispositions, among other factors, and includes various preliminary estimates and may not necessarily be indicative of the financial position or results of operations that would have occurred if the merger had been completed on the date or at the beginning of the period indicated or which may be attained in the future. Non-GAAP Financial Measures This presentation contains certain financial information determined by methods other than in accordance with generally accepted accounting principles in the United States (“GAAP”). These non-GAAP disclosures have limitations as an analytical tool and should not be considered in isolation or as a substitute for analysis of our results as reported under GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. The Company uses the non-GAAP financial measures discussed herein in its analysis of the Company’s performance. The Company’s management believes that these non-GAAP financial measures provide additional understanding of ongoing operations, enhance comparability of results of operations with prior periods and show the effects of significant gains and charges in the periods presented without the impact of items or events that may obscure trends in the Company’s underlying performance. Please see “Reconciliation of Non-GAAP Disclosures” at the end of this presentation for a reconciliation to the nearest GAAP financial measure. No Offer or Solicitation This presentation does not constitute an offer to sell or a solicitation of an offer to buy any securities. No offer of securities shall be made except by means of a prospectus meeting the requirements of the Securities Act of 1933, as amended, and no offer to sell or solicitation of an offer to buy shall be made in any jurisdiction in which such offer, solicitation or sale would be unlawful. About Atlantic Union Bankshares Corporation Headquartered in Richmond, Virginia, Atlantic Union Bankshares Corporation (Nasdaq: AUB) is the holding company for Atlantic Union Bank. Atlantic Union Bank has 149 branches and approximately 170 ATMs located throughout Virginia, and in portions of Maryland and North Carolina. Middleburg Financial is a brand name used by Atlantic Union Bank and certain affiliates when providing trust, wealth management, private banking, and investment advisory products and services. Certain non-bank affiliates of Atlantic Union Bank include: Old Dominion Capital Management, Inc., and its subsidiary, Outfitter Advisors, Ltd., Dixon, Hubard, Feinour & Brown, Inc., and Middleburg Investment Services, LLC, which provide investment advisory and/or brokerage services; and Union Insurance Group, LLC, which offers various lines of insurance products. |
| 2020 Operating Environment – New Reality 4 Soundness Profitability Growth AUB(149) AUB LPO (3) At June 30,2020 Assets $19.8B Loans $14.3B Deposits $15.6B Managing through COVID- 19 coronavirus pandemic: • Pivoted to a new remote work and branch operating model • Focused on Teammates, clients, communities and shareholders • Mobilized SBA Paycheck Protection Program • Adapting to meet new reality AUB governing philosophy –“Soundness, Profitability, & Growth – in that order of priority” Focused on the safety, soundness and profitability of the Company: • Take care of our Teammates and clients • Mitigate credit risk • Align the expense base to the new revenue reality • Achieve and maintain top-tier financial performance Regardless of the operating environment our goal of achieving and maintaining top-tier financial performance remains the same |
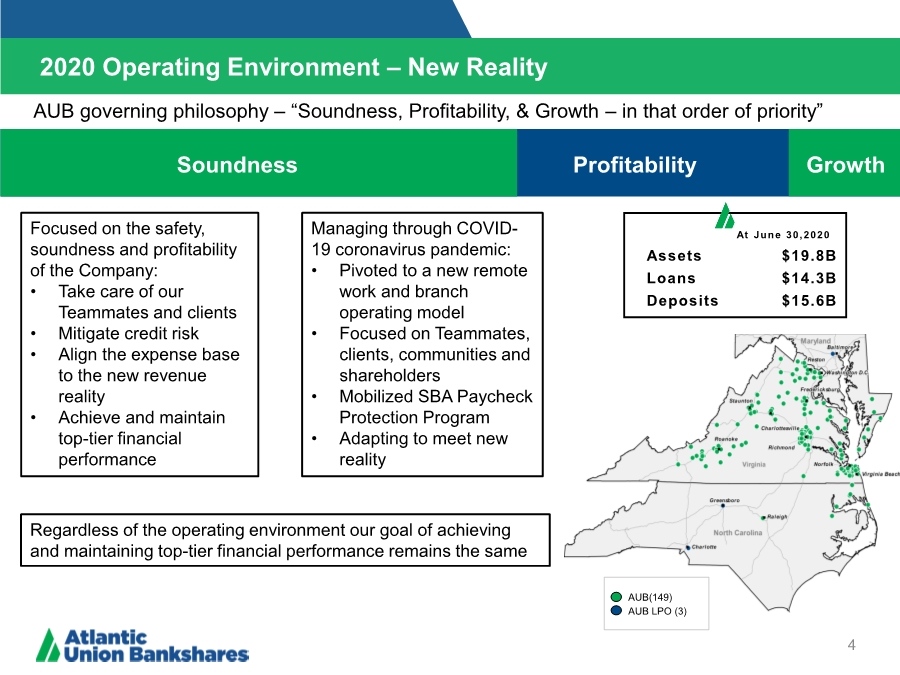
| Teammates • 90% of non-branch Teammates are working remotely • Recognition bonuses for eligible Teammates • Continuing to pay Teammates that have potential exposure • COVID-19 related testing and treatment is free under medical plans • Extra cleaning and protective measures put in place • Educate Teammates on preventative action • Comprehensive communications program Clients • Proactive outreach to Business, Wealth/Investment Services clients • Paycheck Protection Program • Customer hardship programs • Regular communications and updates • Enhancements to digital platforms • Focus on credit Shareholders • Conservative credit culture • Strong balance sheet • Strong capital base • Ample liquidity • Top tier financial performance Community • Aligned charitable giving with COVID-19 • Accelerated charitable contributions Holistic Response to Covid-19 5 |
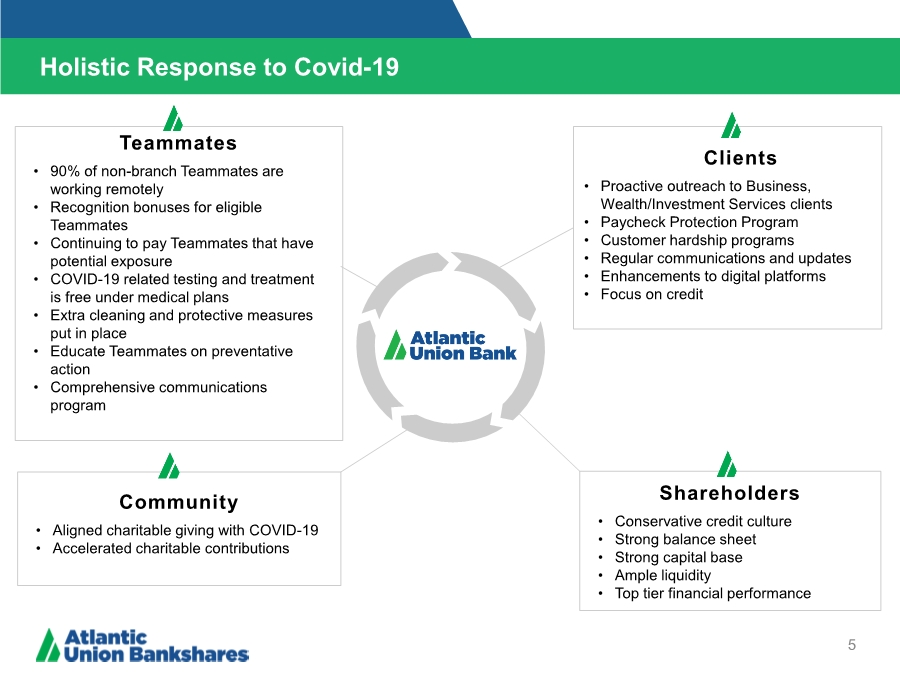
| 6 Paycheck Protection Program (PPP) • AUB had 11.1% of dollar share for VA loans, compared to deposit market share of 7% • AUB effectively shared the top spot for number of PPP loans originated in VA and was #1 among VA headquartered banks • AUB had nearly twice the count as the nearest VA headquartered bank • AUB outperformed other banks based on relative branch footprint • 9,581 loans of < $150,000 totaling $356.6 million 1) Dollars of SBA loans approved excludes $50 million in approved loans withdrawn under the safe harbor provision Deposit data as of 6/30.19 and excludes branches with deposits greater than $5 billion PPP data as of June 30, 2020. Figures may not total to 100% due to rounding 16% 12% 12% 11% 10% 10% 6% 5% 4% 3% 3% 2% 2% 2% 1% Professional, Scientific, Technical Svcs Construction Other Svcs (ex Public) Health Care & Social Assistance Accommodation & Food Svcs Retail Trade Real Estate & Rental & Leasing Waste Mgt & Remediation Education & Information Services Finance & Insurance Arts, Recreation, Entertainment Manufacturing Transportation and Warehousing Wholesale Trade Agriculture and Related Industry Distribution of PPP Loans SBA Tier # of SBA Mix $ of SBA Mix Average Median Approved Approved1 Loan Loan $2 million to $10 million 119 1% $ 409,000,000 25% $ 3,437,000 $ 3,068,000 >$350,000 to <$2 million 846 7% $ 630,000,000 38% $ 745,000 $ 600,000 Up to $350,000 10,711 92% $ 612,000,000 37% $ 57,000 $ 30,000 Total 11,676 100% $ 1,650,000,000 100% $ 141,000 $ 36,000 |
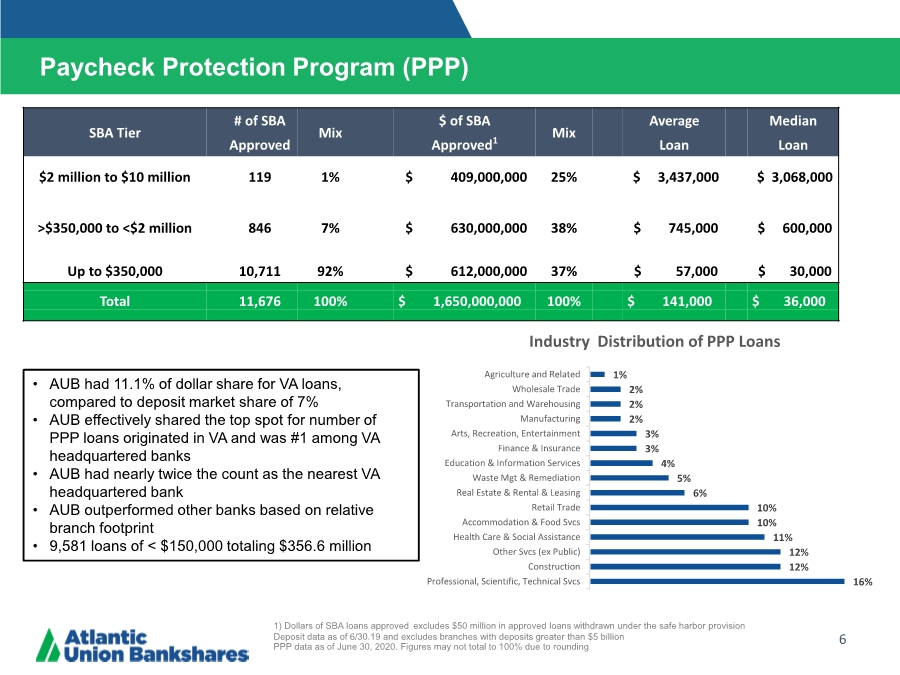
| 7 Paycheck Protection Program (PPP) Note: Virginia branches: AUB 140 Truist 445 Italics indicates a VA HQ'd Lender Rank Lender Count of Loans % of Total 1 Truist Bank 10,203 9.3% 2 Atlantic Union Bank 10,197 9.3% 3 Bank of America, National Association 8,487 7.8% 4 Wells Fargo Bank, National Association 6,247 5.7% 5 Towne Bank 5,126 4.7% 6 Celtic Bank Corporation 2,934 2.7% 7 United Bank 2,845 2.6% 8 Kabbage, Inc. 2,667 2.4% 9 Cross River Bank 2,512 2.3% 10 The First Bank and Trust Company 2,216 2.0% Top 10 Financial Institutions Lending in VA 53,434 49% All Institutions in Lending in VA 109,227 100% SBA PPP Approved Loans for Virginia Ranking of Top 10 Lenders in VA VA HQ'd Bank Rank Lender Count of Loans % of Total 1 Atlantic Union Bank 10,197 27.7% 2 Towne Bank 5,126 13.9% 3 The First Bank and Trust Company 2,216 6.0% 4 Sonabank 2,192 5.9% 5 Navy FCU 1,356 3.7% 6 Citizens and Farmers Bank 1,214 3.3% 7 Capital One, National Association 1,204 3.3% 8 The Old Point National Bank of Phoebus 1,096 3.0% 9 Burke & Herbert Bank & Trust Company 1,049 2.8% 10 Chesapeake Bank 933 2.5% Top 10 Financial Institutions Headquartered in VA 26,583 72% All Institutions Headquartered in VA 36,843 100% SBA PPP Approved Loans for Virginia Ranking of Banks Headquartered in VA |
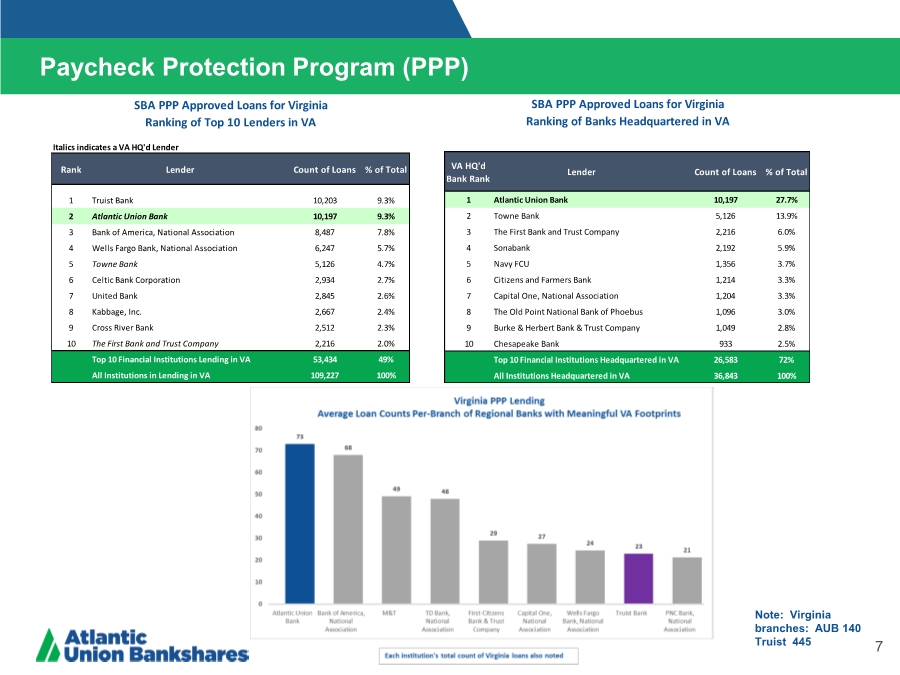
| Loan Modifications as of July 17, 2020 8 • As of July 17, ~$1.6 Billion in loans are in some form of a COVID Modification of which 93% of the balances are Commercial loans. • ~$485MM in Commercial loans rolled off their initial modification, ~$350MM made their next payment, ~$5MM rolled into a 2nd modification, ~$130MM are in their July billing cycle • ~78% of the total loan modifications as of July 17 are under a payment deferral modification and ~16% have an interest only modification Note: Figures may not total to 100% due to rounding Total COVID-19 Modifications Loan Class Count Balances % Bal. Avg. Balance Commercial & Industrial 859 472,699,576 30.3% 550,291 Commercial Real Estate 610 885,775,108 56.8% 1,452,090 Construction, Land & Development 65 86,077,972 5.5% 1,324,276 Consumer 1,968 114,309,308 7.3% 58,084 Residential 1-4 Family 174 66,701,612 4.3% 383,343 Residential 1-4 Family - Revolving 142 16,938,993 1.1% 119,289 Indirect Auto 906 18,461,049 1.2% 20,376 Other Consumer 746 12,207,655 0.8% 16,364 Total 3,502 $1,558,861,964 100.0% $445,135 COVID-19 Balance Mods as % Total Loan Portfolio 10.9% COVID-19 Balance Mods as % Total Loan Portfolio excluding PPP 12.3% |
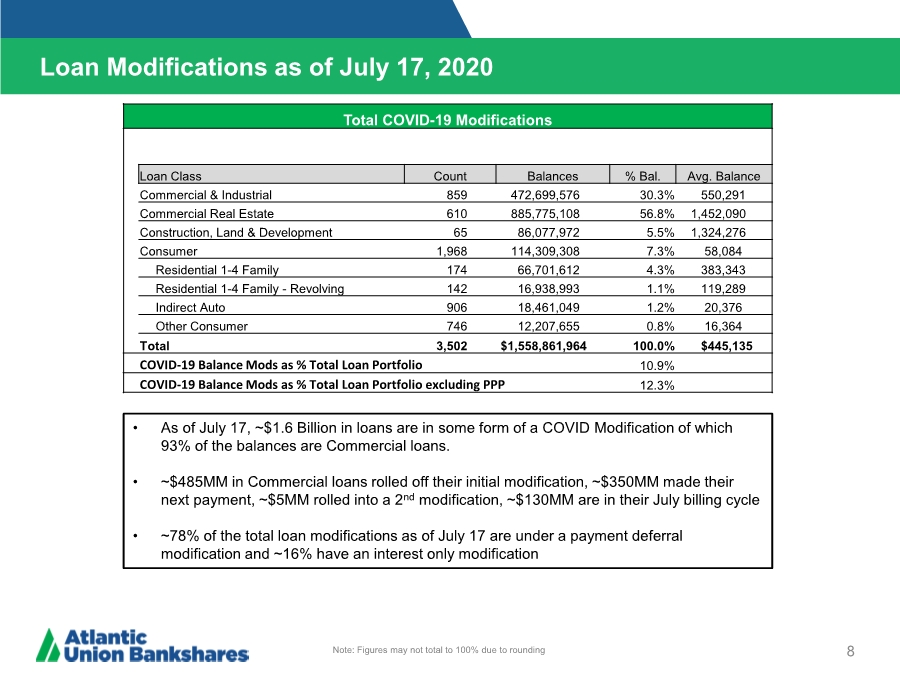
| Asset Quality – COVID-19 Sensitive Loan Segments 9 Note: Figures may not total to 100% due to rounding 1) Disrupted segment data as of June 30, 2020 Total Loan Portfolio $ 14.3 billion at June 30, 2020 Segments Disrupted by COVID-191: $2.3 Billion Portfolio Highlights No significant exposure to Energy, Cruise or Passenger Aviation sectors C&D 8.7% CRE - Owner Occupied 14.4% C&I 24.9% Non-Owner Occupied CRE 29.2% 1-4 Family 10.9% Other 2.7% Residential 1-4 family - Revolving 4.4% Consumer 4.8% Other Loans 84.1% Retail Trade 3.5% Restaurants 1.6% Hospitality, 4.8% Senior Living 2.0% Health Care 4.0% |
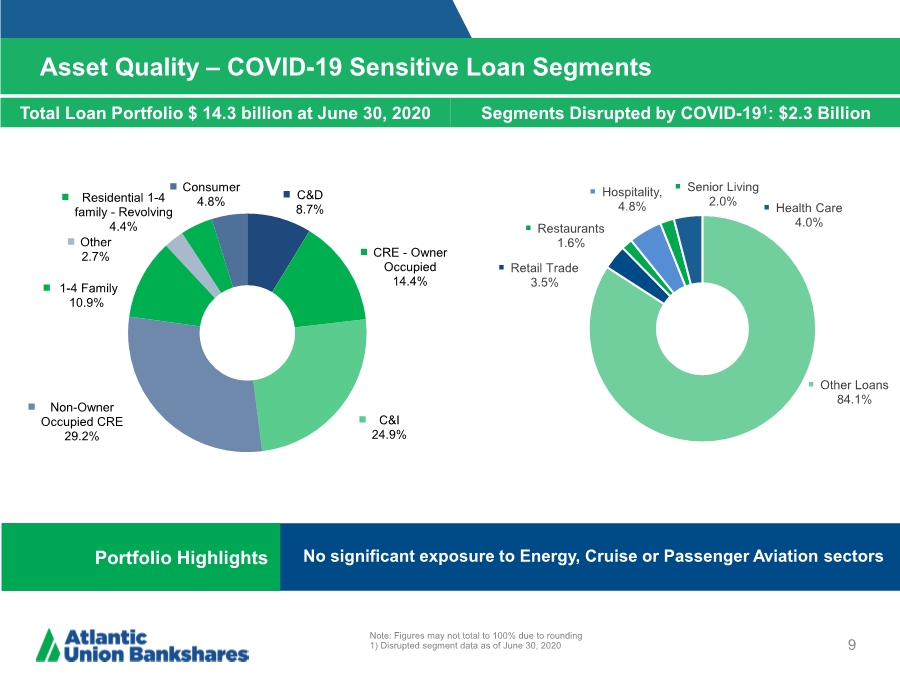
| COVID-19 Sensitive Loan Segment Details 10 Retail Trade: ~50% of exposure is convenience stores/gas or auto dealer, ~80% secured by real estate; 20% of clients in PPP Restaurants: Early modifications made; 85% secured by real estate; 25% of clients in PPP Senior Living: Significant liquidity and brand name clients; Hotel: Primarily flagged non-resort hotel properties; 36% of clients in PPP Health Care: ~80% secured by real estate; 26% of clients in PPP Note: Figures may not total to 100% due to rounding 1) Sensitive loan segment modification data as of July 17, 2020 Total Portfolio Modifications Count Balance Exposure % of Total Loans Count Balance % of Portfolio Retail Trade 1,086 $497,068,173 $553,947,990 3.5% 134 $ 81,347,261 16.4% Restaurant 595 $228,779,189 $235,949,537 1.6% 151 $ 102,509,096 44.8% Senior Living 52 $285,422,326 $310,883,822 2.0% 2 $ 5,356,044 1.9% Hotels 233 $680,981,744 $788,393,740 4.8% 108 $ 358,805,223 52.7% Health Care 1,029 $577,761,523 $643,359,344 4.0% 182 $ 158,589,975 27.4% Total Sensitive Segments 2,995 $ 2,270,012,955 $ 2,532,534,433 15.9% 577 $ 706,607,599 31.1% |
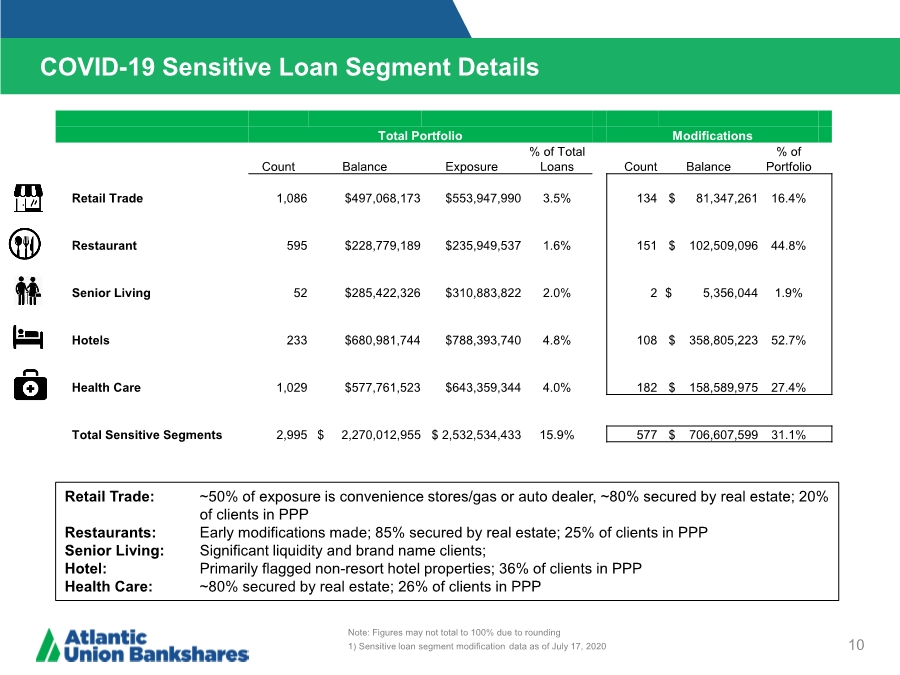
| 2020 Operating Environment – Adapting to the New Reality 11 Soundness Profitability Growth During challenging times, it is important to remember our governing philosophy –“Soundness, Profitability, & Growth – in that order of priority” ➢ This core philosophy is serving us well as we manage the Company through the current coronavirus pandemic crisis. We are managing through an unprecedented crisis that requires intense focus on the safety, soundness and profitability of the Company at this time. Growth is not our main focus. What we are doing now is: ➢ Taking care of our Teammates and clients – they will remember how we treated them during this period. ➢ Mitigating credit risk – batten down the hatches and protect the Bank working with our business and consumer clients to assist them through these tough times. ➢ Aligning the expense base to the new revenue reality – ensure sustained top tier financial performance on the other side. By effectively managing through this crisis, we will become a stronger company that is well positioned to take advantage of growth opportunities as economic activity resumes aided by government support and stimulus. |
| Q2 2020 Financial Performance At-a-Glance 12 Summarized Income Statement 2Q2020 1Q2020 Net interest income $ 137,305 $ 135,008 Provision for credit losses 34,200 60,196 Noninterest income 35,932 28,907 Noninterest expense 102,814 95,645 Taxes 5,514 985 Net income (GAAP) 30,709 7,089 + Provision for credit losses 34,200 60,196 + Taxes 5,514 985 PTPP operating earnings (non-GAAP) $ 70,423 $ 68,270 Dollars in thousands PTPP = Pre-tax Pre-provision Reported Earnings Metrics - GAAP 2Q2020 1Q2020 Net income $ 30,709 $ 7,089 EPS, diluted $ 0.39 $ 0.09 ROE 4.96% 1.15% ROA 0.64% 0.16% Efficiency ratio 59.35% 58.35% Net interest margin 3.23% 3.49% Dollars in thousands except per share amounts PTPP Operating Earnings Metrics – non-GAAP 2Q2020 1Q2020 PTPP operating net income $ 70,423 $ 68,270 PTPP operating EPS, diluted $ 0.89 $ 0.86 PTPP operating ROTCE 20.75% 19.76% PTPP operating ROA 1.48% 1.56% Operating efficiency ratio (FTE) 56.00% 54.74% Net interest margin (FTE) 3.29% 3.56% Dollars in thousands except per share amounts For non-GAAP financial measures, see reconciliation to most directly comparable GAAP measures in “Appendix – Reconciliation of Non-GAAP Disclosures” ▪ Net income for the second quarter was $30.7 million or 39 cents per share, up signficantly from $7.1 million or 9 cents per share in the first quarter primarily due to the $26.0 million decline in the provision for credit losses compared to the previous quarter. ▪ Pre-tax, pre-provision operating earnings increased $2.2 million to $70.4 million or 89 cents per share, from $68.3 million or 86 cents per share in the first quarter primarily due to higher net interest income. ▪ Second quarter net income and PTPP operating earnings include the financial impacts of strategic actions taken in the second quarter to reposition the balance sheet and to reduce the Company’s expense run rate: ▪ Non-interest income includes $10.3 million in gain on the sale of investment securities. ▪ Non-interest expense includes a $10.3 million debt extinguishment loss related to the prepayment of long-term FHLB advances; and $3.4 million in severance expenses and real estate-related write-downs related to expense reduction initiatives including the consolidation of 14 branches. |
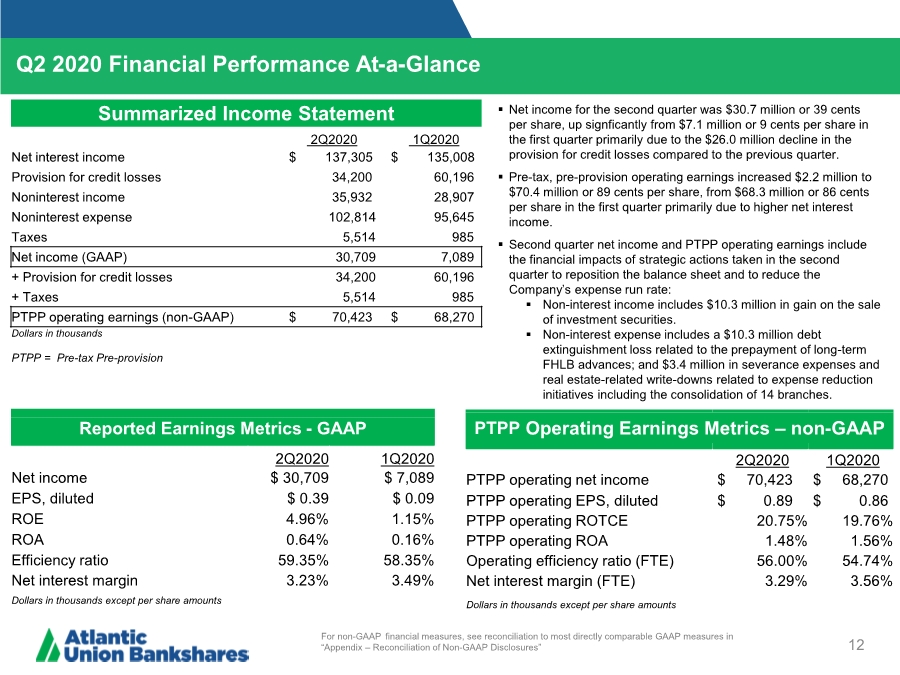
| Q2 Allowance For Credit Loss (ACL) and Provision for Credit Losses 13 Q2 Macroeconomic Forecast Q2 Additional Considerations Regulatory Capital Treatment Moody’s June Forecast • US GDP -33% in Q2; US Unemployment Rate peaks near 14% in Q2 and falls to 9.5% by Q4 2020. • Virginia Unemployment peaks at 10.4% in Q2 and stays near 7.0% for remainder of the forecast horizon • 2-year reasonable and supportable period; followed by reversion to the historical loss average over 2 years • Additional qualitative factors for COVID-19 sensitive portfolios • Model results adjusted for unprecedented government stimulus • Opted into 2 year CECL adoption capital impact delay • 25% of cumulative Day 2 impact added back to Common Equity Tier 1 capital through 2021 • 3-year regulatory CECL capital phase-in begins in 2022 1.34% Allowance for Loan Losses (excl. PPP) at 6/30/2020 represents: • ~70% of peak 2-year Great Recession1 loss rates • ~75% of forecasted 9-quarter losses in the company’s 2019 internal stress-testing scenarios 1 2-year Cumulative NCO from Q42009 through Q3 2011 NCO as percentage of Q3 2009 balance $ in millions Allowance for Loan & Lease Losses Reserve for Unfunded Commitments Allowance for Credit Losses 12/31/2019 Ending Balance/% loans $42MM ..34% $1MM < .01% $43MM ..34% Q1 2020 CECL Day 1 and Day 2 +$99MM • $48MM - Day 1 increase from consumer loans (life of loan) and “double-count” on acquired loans • $51MM - Day 2 increase attributable to COVID- 19; large increase for COVID-19 sensitive portfolios +$8MM • $4MM – Day 1 adjustment for lifetime losses • $4MM – Day 2 increase due to higher expected loss and funding rates related to COVID-19 environment +$107MM • Day 1 - $52 million Capital Cumulative Effect Adjustment of CECL Adoption • Day 2 - $60 Provision For Credit Losses including $5 million net charge-offs in Q1 3/31/2020 Ending Balance/% loans $141MM 1.10% $9MM ..08% $150MM 1.18% Q2 2020 +$29MM • Increase due to worsening economic forecast since March +$2MM • Increase due to worsening economic forecast since March +$31MM • $34 million Provision for Credit Losses including $3 million net charge-offs in Q2 6/30/2020 Ending Balance/% loans $170MM (1.19%; 1.34% excl. PPP loans) $11MM (.07%; ..08% excl. PPP loans) $181MM (1.26%; 1.42% excl. PPP loans) |
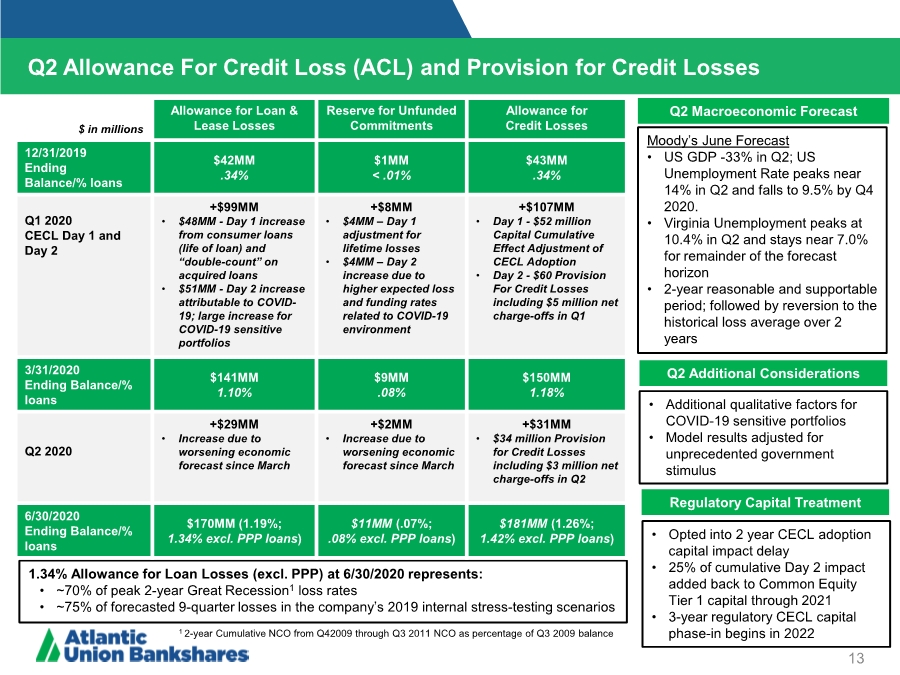
| 3.56% 3.29% 2.50% 2.70% 2.90% 3.10% 3.30% 3.50% 3.70% Quarter 1 Core NIM Core Loan Yield PPP Loans with Fees Loan Accretion Earning Asset Mix and Cash Yield Core Deposit Rate Funding Mix and Borrowing Rate Quarter 2 Core NIM Net Interest Margin: Drivers of Change 1Q2020 to 2Q2020 -43 bps -4 bps -10 bps -4 bps 25 bps 9 bps 14 Q2 2020 Net Interest Margin Market Rates 2Q2020 1Q2020 EOP Avg EOP Avg Fed funds 0.25% 0.25% 0.25% 1.41% Prime 3.25% 3.25% 3.25% 4.42% 1-month Libor 0.17% 0.35% 0.99% 1.41% 2-year Treasury 0.16% 0.19% 0.25% 1.11% 10 - year Treasury 0.66% 0.71% 0.67% 1.39% Margin Overview 2Q2020 1Q2020 Net interest margin 3.29% 3.56% Loan yield 4.13% 4.83% Investment yield 3.29% 3.28% Earning asset yield 3.90% 4.50% Cost of deposits 0.53% 0.86% Cost of borrowings 1.70% 2.18% Cost of funds 0.61% 0.94% Presented on an FTE basis Approximately 11% of the loan portfolio (ex. PPP) have floors Total Loan Yield -57 bps Loan Portfolio Pricing Mix with PPP w/o PPP Fixed 57% 51% 1 Month Libor 25% 29% Prime 10% 12% Other 8% 9% Total 100% 100% |
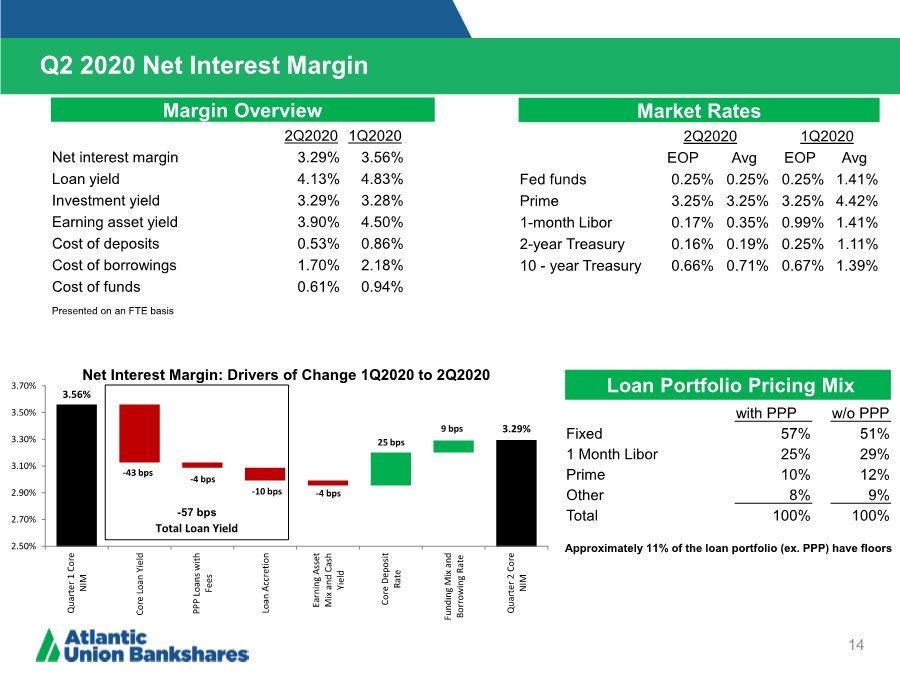
| 15 Noninterest income increased from the prior quarter to $35.9 million from $28.9 million due to: ▪ $10.3 million in gain on the sale of investment securities ▪ Higher in mortgage banking income of $3.8 million due to increased mortgage loan refinance volumes ▪ Interest rate swap income increased $1.5 million ▪ Service charges on deposit accounts declined $2.6 million due to lower overdraft volumes ▪ Other income includes $2.5 million in unrealized losses related to SBIC fund investments due to business disruptions related to COVID-19 ▪ Wealth management fees declined by $469,000 $ in thousands 2Q2020 1Q2020 Service charges on deposit accounts $ 4,930 $ 7,578 Other service charges, commissions and fees 1,354 1,624 Interchange fees 1,697 1,625 Fiduciary and asset management fees 5,515 5,984 Mortgage banking income 5,826 2,022 Gains on securities transactions 10,339 1,936 Bank owned life insurance income 2,027 2,049 Loan-related interest rate swap fees 5,484 3,948 Loss on hedge termination -(1,769) Other operating income (1,240) 3,910 Total noninterest income $ 35,932 $ 28,907 $ in thousands 2Q2020 1Q2020 Salaries and benefits $ 49,896 $ 50,117 Occupancy expenses 7,224 7,133 Furniture and equipment expenses 3,406 3,741 Printing, postage, and supplies 999 1,290 Technology and data processing 6,454 6,169 Professional services 2,989 3,307 Marketing and advertising expense 2,043 2,739 FDIC assessment premiums and other insurance 2,907 2,861 Other taxes 4,120 4,120 Loan-related expenses 2,501 2,697 OREO and credit-related expenses 411 688 Amortization of intangible assets 4,223 4,401 Training and other personnel costs 876 1,571 Loss on debt extinguishment 10,306 - Other expenses 4,459 4,811 Total noninterest expenses $ 102,814 $ 95,645 Q2 2020 Noninterest Income and Noninterest Expense Noninterest Income Noninterest Expense Noninterest expense increased from the prior quarter to $102.8 million from $95.6 million due to: ▪ $10.3 million loss on debt extinguishment resulting from the prepayment of long-term FHLB advances ▪ $3.4 million in severance expense and real estate-related write- downs related to expense reduction initiatives ▪ COVID-19 related expenses increased to $620,000 from $379,000 in the prior quarter ▪ Partially offsetting the increases were declines in most expense categories including lower marketing expenses of $696,000 and lower business travel related costs of approximately $695,000 |
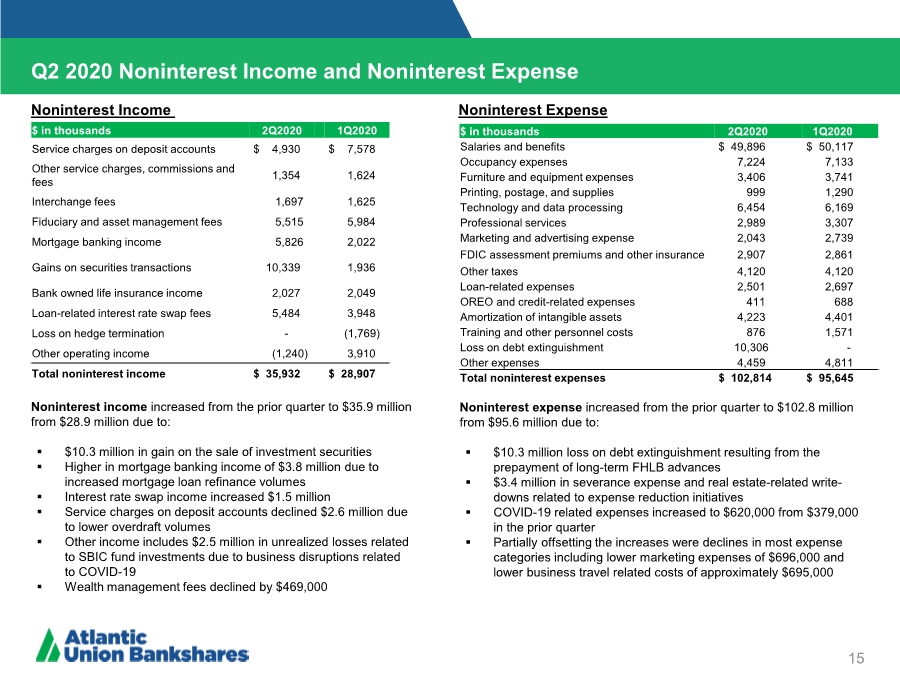
| 16 Q2 2020 Loan Growth • At quarter end, loans held for investment increased $1.5 billion, or 48.5% (annualized) from the prior quarter, driven by PPP loans • Excluding the effects of PPP, total loans declined by $58.9 million, or 1.9% (annualized), while average loans increased $89.9 million, or 2.9% (annualized) during this period • For the quarter, total commercial loans grew 60.9% on an annualized basis driven by $1.6 billion in PPP loans • Excluding PPP loans, total commercial loans were flat to first quarter balances primarily due to revolving lines of credit paydowns partially offset by growth in equipment finance and commercial real estate loans in the quarter • Consumer loans declined ~10% annualized in the quarter driven by net attrition in the mortgage and home equity line loan portfolios and third party consumer balance run-off partially offset by growth in indirect auto balances • Loan yields declined 70 basis points during the quarter due to the impact of lower yielding PPP loans originated during the second quarter and the full quarter impact of the lower interest rate environment (Dollars in thousands) 2Q2020 Less PPP 2Q2020 PPP Adjusted 1Q2020 Annualized Growth Annualized Growth ex PPP Commercial & Industrial $ 3,555,971 $1,578,373 $ 1,977,598 $ 2,177,932 254.5% -37.0% Commercial real estate - owner occupied 2,067,087 - 2,067,087 2,051,904 3.0% 3.0% Other Commercial 389,190 20,345 368,845 274,255 168.6% 138.7% Total Commercial & Industrial 6,012,248 1,598,718 4,413,530 4,504,091 134.7% -8.1% Commercial real estate - non-owner occupied 3,455,125 - 3,455,125 3,328,012 15.4% 15.4% Construction and land development 1,247,939 - 1,247,939 1,318,252 -21.5% -21.5% Multifamily real estate 717,719 - 717,719 679,390 22.7% 22.7% Residential 1-4 Family - Commercial 715,384 - 715,384 721,800 -3.6% -3.6% Total Commercial Real Estate & Construction 6,136,167 - 6,136,167 6,047,454 5.9% 5.9% Total Commercial Loans 12,148,415 1,598,718 10,549,697 10,551,545 60.9% -0.1% Residential 1-4 Family - Consumer 841,051 - 841,051 854,550 -6.4% -6.4% Residential 1-4 Family - Revolving 627,765 - 627,765 652,135 -15.0% -15.0% Auto 380,053 - 380,053 358,039 24.7% 24.7% Consumer 311,362 - 311,362 352,572 -47.0% -47.0% Total Consumer Loans 2,160,231 - 2,160,231 2,217,296 -10.4% -10.4% Total loans held for investment $14,308,646 $1,598,718 $ 12,709,928 $12,768,841 48.5% -1.9% Average loan yield 4.13% 4.83% For non-GAAP financial measures, see reconciliation to most directly comparable GAAP measures in “Appendix – Reconciliation of Non-GAAP Disclosures” |
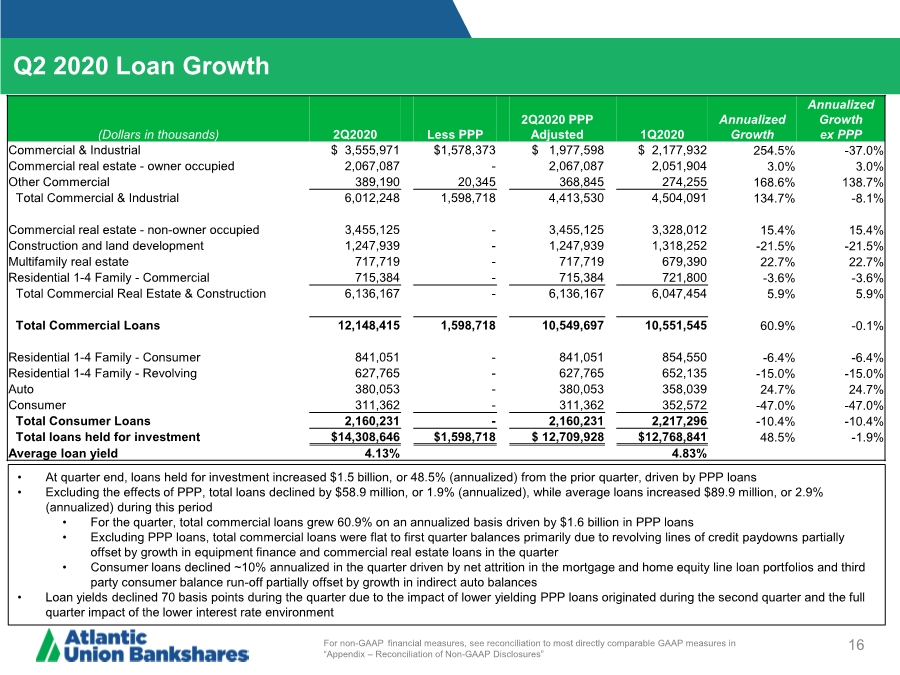
| 17 • Deposits increased $2.1 billion, or 60.9% (annualized) for the quarter, while average deposits increased $1.6 billion, or 48.6% (annualized), from the prior quarter • The deposit increase in the second quarter is primarily due to the government stimulus programs (PPP loans, stimulus checks and enhanced unemployment benefits), the deferral of tax payment deadlines and changes in customer spending and savings habits since the pandemic began •Transaction account (demand deposits and NOW accounts) balances grew $1.7 billion during the quarter partially offset by declines in retail time deposits • Low cost transaction accounts comprise ~51% of total deposits at 6/30/2020 vs. 46% of total deposits at 3/31/2020 • The cost of deposits was lower by 33 basis points during the quarter due to the positive impact from changes in the overall deposit mix between quarters as well as to the aggressive repricing of interest-bearing deposits as market interest rates trended down • The loans to deposits ratio was ~92% at quarter end, below the Company’s 95% target level Q2 2020 Deposit Growth (Dollars in thousands) 2Q2020 1Q2020 Annualized Growth (Dollars in thousands) 2Q2020 1Q2020 Annualized Growth NOW accounts $ 3,618,523 $ 3,180,913 55.3% Money market accounts 4,158,325 3,817,959 35.9% Savings accounts 824,164 745,402 42.5% Time deposits of $250,000 and over 689,693 696,520 -3.9% Other time deposits 1,968,474 2,044,668 -15.0% Time deposits 2,658,167 2,741,188 -12.2% Total interest-bearing deposits 11,259,179 10,485,462 29.7% Demand deposits 4,345,960 3,067,573 167.6% Total deposits $ 15,605,139 $13,553,035 60.9% Average cost of deposits 0.53% 0.86% Loan to deposits ratio 91.7% 94.2% |
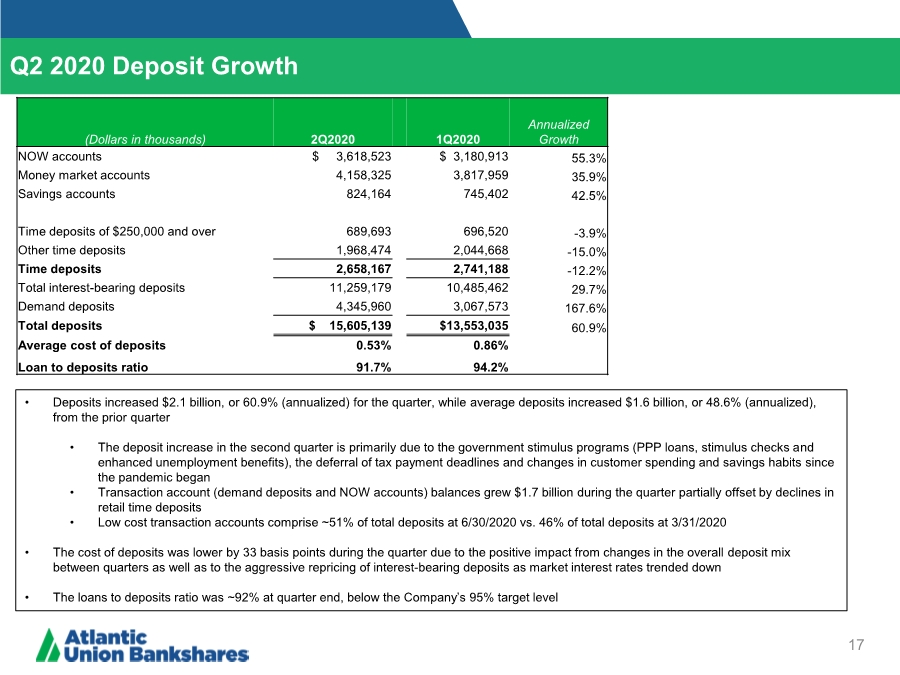
| Liquidity Position and Sources 18 • Strong liquidity metrics: ~$7.5 billion in cash, unpledged securities, and secured and unsecured borrowing capacity. Loans to Total Deposits Ratio of 92% • Paycheck Protection Program loans of approximately $1.7 billion funded using deposits, wholesale borrowings, and Federal Reserve’s Paycheck Protection Program Liquidity Facility (PPPLF) • Company has borrowed $190 million from the PPPLF as of June 30, 2020 • Holding company cash of $173.6 million with available dividend capacity (net of current year’s dividends paid) of $145 million from bank to holding company without prior regulatory approval. Liquidity Sources (June 30, 2020) Amount ($mm) Total Cash and Cash Equivalents $842 Unpledged Investment Securities (market value) $1,455 FHLB Borrowing Availability $2,486 Fed Discount Window Availability $222 PPP Liquidity Facility Availability $1,451 Fed Funds Lines $972 Line of Credit at Correspondent Bank $25 Total Liquidity Sources $7,453 |
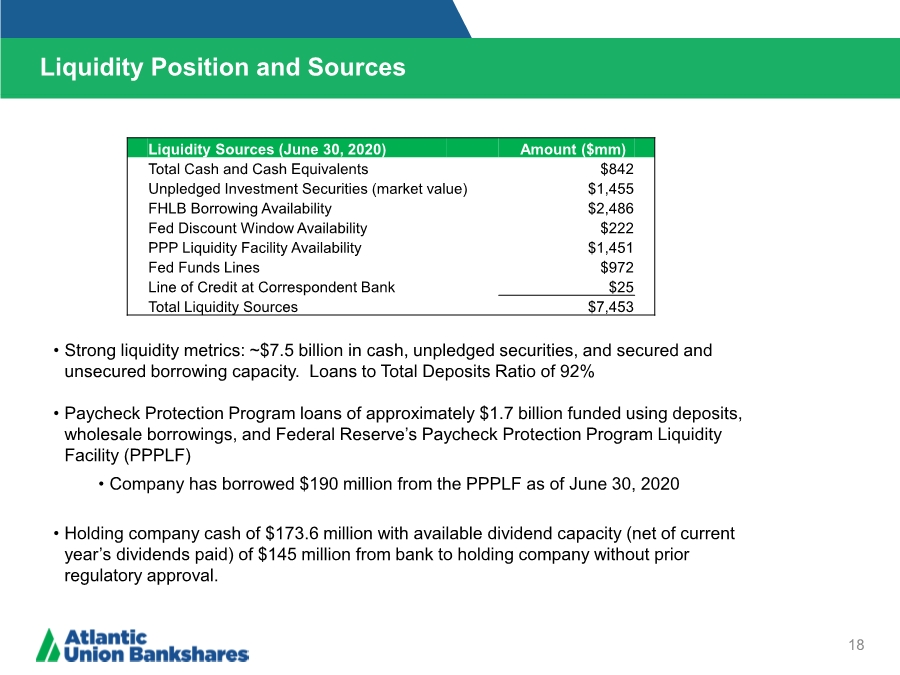
| Strong Capital Position at June 30, 2020 19 Capital Ratio Regulatory Well Capitalized Atlantic Union Bankshares* Atlantic Union Bank* Common Equity Tier 1 Ratio (CET1) 7.0% 9.8% 11.7% Tier 1 Capital Ratio 8.5% 11.0% 11.7% Total Risk Based Capital Ratio 10.5% 13.7% 12.5% Leverage Ratio 5.0% 8.8% 9.4% Tangible Common Equity Ratio (non-GAAP) - 7.7% 9.1% *Capital information presented herein is based on estimates and subject to change pending the Company’s filing of its regulatory reports Stress Testing • As a matter of sound enterprise risk management practice, the Company periodically conducts capital, credit and liquidity stress tests for scenarios such as the current operating environment • Results from these internal stress tests provides confidence that throughout the pandemic crisis AUB will remain well-capitalized and that it has the necessary liquidity and access to multiple funding sources to meet the challenges of COVID-19 Capital Management • Atlantic Union capital management objectives are to: • Maintain designation as a “well capitalized” institution • Ensure capital levels are commensurate with the Company’s risk profile, capital stress test projections, and strategic plan objectives • The Company’s capital ratio’s are well above regulatory well capitalized levels as of 6/30/2020 • During the second quarter of 2020, the Company • paid common dividends of $0.25 per common share; • further fortified the capital base for the uncertainties of Covid-19 through the issuance of $172.5 million in preferred stock increasing Tier 1 and Total Risk Based Capital by $166.4 million, net of issuance costs Quarterly Roll Forward Common Equity Tier 1 ratio Tangible Common Equity Ratio Tangible Book Value per Share At 3/31/2020 9.74% 8.43% $18.15 Pre-Provision Net Income 0.42% 0.35% 0.76 After-Tax Provision -0.20% -0.17% (0.37) CECL Transition Adjustment (1) 0.05% -- -- Common Dividends (2) -0.14% -0.12% (0.25) AOCI -- 0.08% 0.17 Other 0.06% 0.04% 0.08 Asset Growth -0.13% -0.14% -- At 6/30/2020 - Excluding PPP Balances 9.81% 8.48% $18.54 PPP Loan Balances (3) -- -0.74% -- At 6/30/2020 - Reported 9.81% 7.74% $18.54 (1) 25% of the increase in ACL as compared to the Day 1 estimate of CECL (2) 25 cents per share (3) Approximately $1.6 billion |
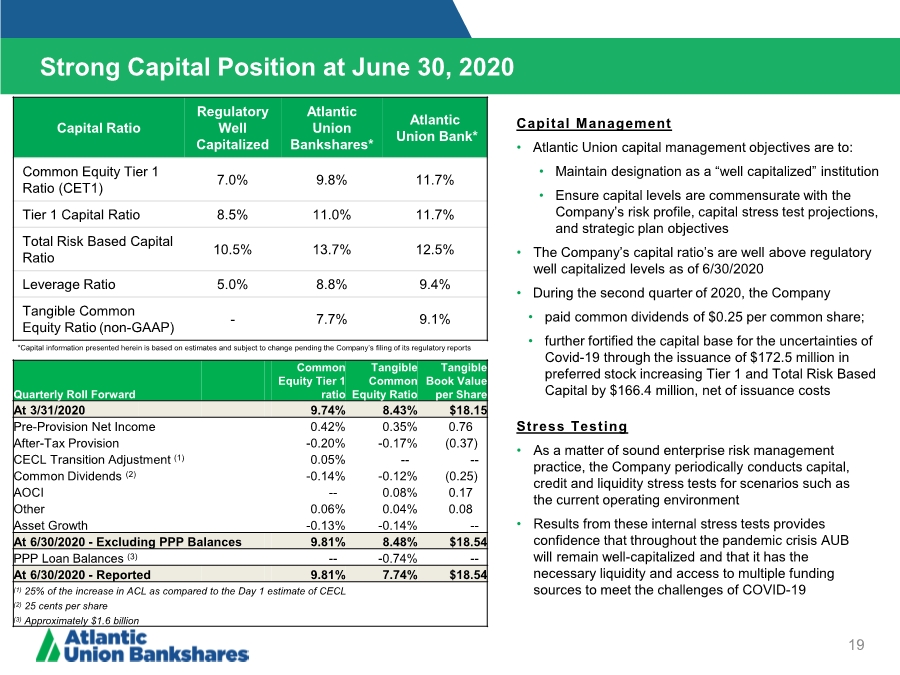
| Appendix |
| Reconciliation of Non-GAAP Disclosures 21 Operating Earnings Per Share The Company has provided supplemental performance measures on a tax-equivalent, tangible, operating, or pre- tax pre-provision basis. These non-GAAP financial measures are a supplement to GAAP, which is used to prepare the Company’s financial statements, and should not be considered in isolation or as a substitute for comparable measures calculated in accordance with GAAP. In addition, the Company’s non-GAAP financial measures may not be comparable to non-GAAP financial measures of other companies. The Company uses the non-GAAP financial measures discussed herein in its analysis of the Company’s performance. The Company’s management believes that these non-GAAP financial measures provide additional understanding of ongoing operations, enhance comparability of results of operations with prior periods and show the effects of significant gains and charges in the periods presented without the impact of items or events that may obscure trends in the Company’s underlying performance. |
| Reconciliation of Non-GAAP Disclosures 22 Operating Earnings Per Share Pre-tax pre-provision (PTPP) earnings excludes the provision for credit losses, which can fluctuate significantly from period-to-period under the recently adopted CECL methodology, merger and rebranding-related costs unrelated to the Company’s normal operations, and income tax expense. The Company believes this measure is useful to investors as it excludes certain costs resulting from acquisition activity as well as the potentially volatile provision measure, and allows for greater comparability with others in the industry and for investors to more clearly see the combined economic results of the organization’s operations. Additionally, the Company believes that return on tangible common equity (ROTCE) is a meaningful supplement to GAAP financial measures and useful to investors because it measures the performance of a business consistently across time without regard to whether components of the business were acquired or developed internally. PRE-TAX PRE-PROVISION OPERATING EARNINGS For the three months ended (Dollars in thousands, except per share amounts) 2Q2020 1Q2020 Net income Net income (GAAP) $ 30,709 $ 7,089 Plus: Provision for credit losses 34,200 60,196 Plus: Income tax expense 5,514 985 PTPP operating earnings (non-GAAP) $ 70,423 $ 68,270 Earnings per share (EPS) Weighted average common shares, diluted 78,722,690 79,317,382 EPS, diluted (GAAP) $ 0.39 $ 0.09 PPTP EPS, diluted (non-GAAP) $ 0.89 $ 0.86 Return on assets (ROA) Average assets $ 19,157,238 $ 17,559,921 ROA (GAAP) 0.64% 0.16% PTPP operating ROA (non-GAAP) 1.48% 1.56% Return on equity (ROE) PTPP operating earnings (non-GAAP) $ 70,423 $ 68,270 Plus: Amortization of intangibles 4,223 4,401 PTPP operating earnings before amortization of intangibles (non-GAAP) $ 74,646 $ 72,671 Average common equity (GAAP) $ 2,489,969 $ 2,485,646 Less: Average intangible assets 1,002,696 1,006,843 Less: Average perpetual preferred stock 40,325 - Average tangible common equity (non-GAAP) $ 1,446,948 $ 1,478,803 ROE (GAAP) 4.96% 1.15% PTPP operating ROTCE (non-GAAP) 20.75% 19.76% |
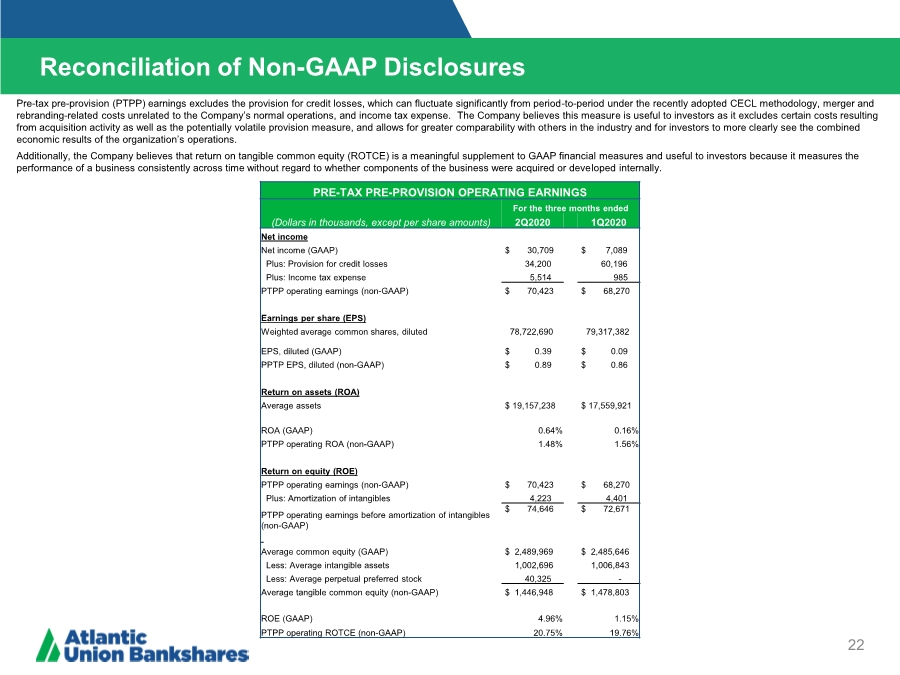
| Reconciliation of Non-GAAP Disclosures 23 Operating Earnings Per Share The operating efficiency ratio (FTE) excludes the amortization of intangible assets and merger-related costs. This measure is similar to the measure utilized by the Company when analyzing corporate performance and is also similar to the measure utilized for incentive compensation. The Company believes this measure is useful to investors as it excludes certain costs resulting from acquisition activity allowing for greater comparability with others in the industry and allowing investors to more clearly see the combined economic results of the organization’s operations. OPERATING EFFICIENCY RATIO For the three months ended (Dollars in thousands) 2Q2020 1Q2020 Noninterest expense (GAAP) $ 102,814 $ 95,645 Less: Amortization of intangible assets 4,223 4,401 Operating noninterest expense (non-GAAP) $ 98,591 $ 91,244 Net interest income (GAAP) $ 137,305 $ 135,008 Net interest income (FTE) (non-GAAP) 140,110 137,766 Noninterest income (GAAP) 35,932 28,907 Efficiency ratio (GAAP) 59.35% 58.35% Operating efficiency ratio (non-GAAP) 56.00% 54.74% |
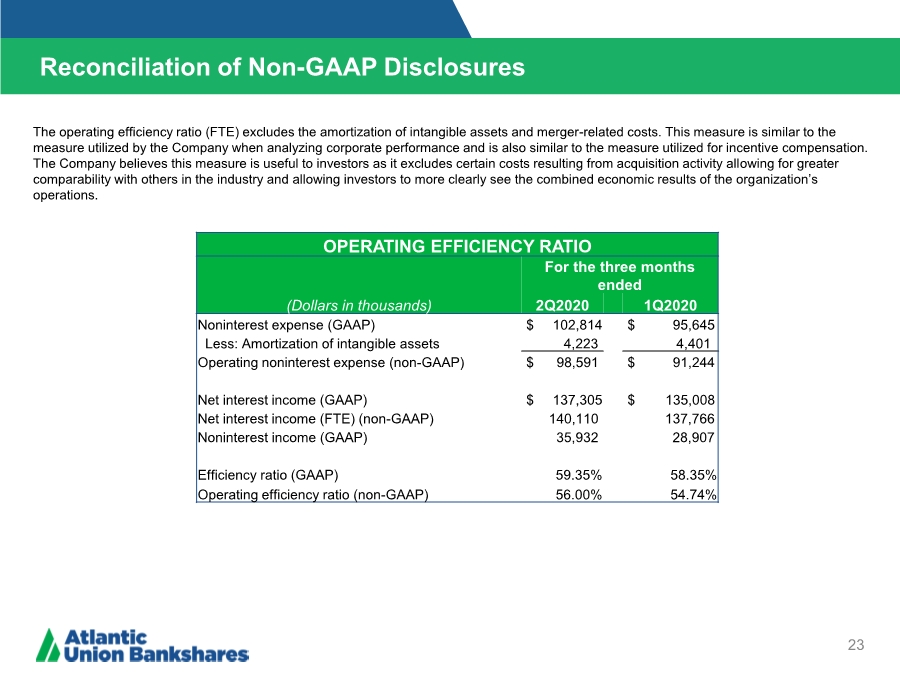
| Reconciliation of Non-GAAP Disclosures 24 Operating Earnings Per Share Net interest income (FTE), which is used in computing net interest margin (FTE), provides valuable additional insight into the net interest margin by adjusting for differences in tax treatment of interest income sources. The entire FTE adjustment is attributable to interest income on earning assets, which is used in computing yield on earning assets. Interest expense and the related cost of interest-bearing liabilities and cost of funds ratios are not affected by the FTE components. NET INTEREST MARGIN For the three months ended (Dollars in thousands) 2Q2020 1Q2020 Net interest income (GAAP) $ 137,305 $ 135,008 FTE adjustment 2,805 2,758 Net interest income (FTE) (non-GAAP) $ 140,110 $ 137,766 Average earning assets $ 17,106,132 $ 15,563,670 Net interest margin (GAAP) 3.23% 3.49% Net interest margin (FTE) 3.29% 3.56% |
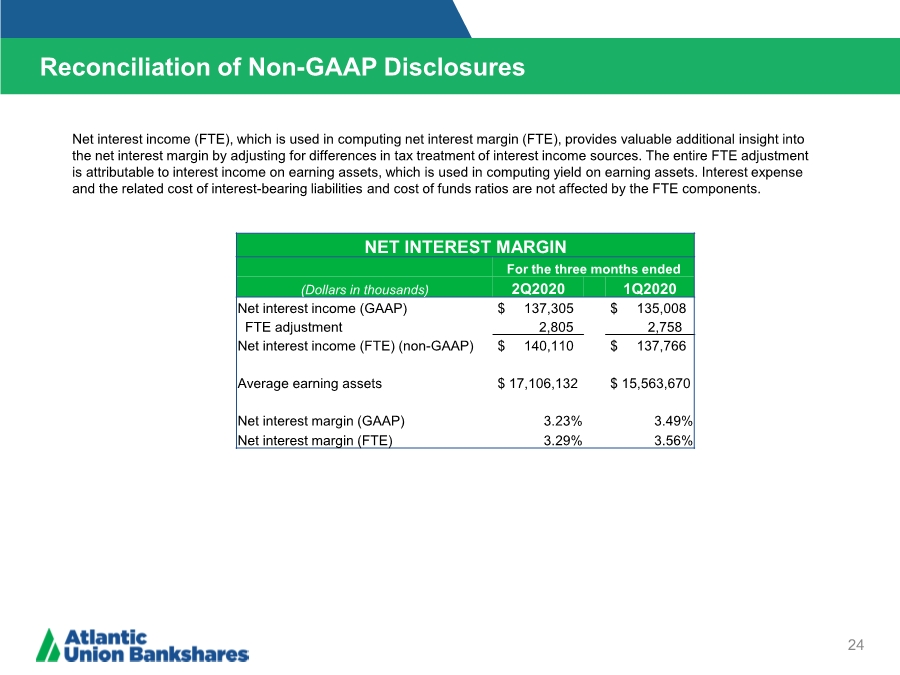
| Reconciliation of Non-GAAP Disclosures 25 Operating Earnings Per Share Tangible common equity is used in the calculation of certain profitability, capital, and per share ratios. The Company believes tangible common equity and the related ratios are meaningful measures of capital adequacy because they provide a meaningful base for period-to-period and company-to-company comparisons, which the Company believes will assist investors in assessing the capital of the Company and its ability to absorb potential losses. TANGIBLE COMMON EQUITY As of June 30, 2020 (Dollars in thousands) Atlantic Union Bankshares Atlantic Union Bank Assets (GAAP) $ 19,752,317 $ 19,706,756 Less: Intangible assets 1,000,665 1,000,665 Tangible assets (non-GAAP) $ 18,751,652 $ 18,706,091 Common equity (GAAP) $ 2,451,862 $ 2,709,865 Less: Intangible assets 1,000,665 1,000,665 Tangible common equity (non-GAAP) $ 1,451,197 $ 1,709,200 Common equity to assets (GAAP) 12.4% 13.8% Tangible common equity to tangible assets (non-GAAP) 7.7% 9.1% |
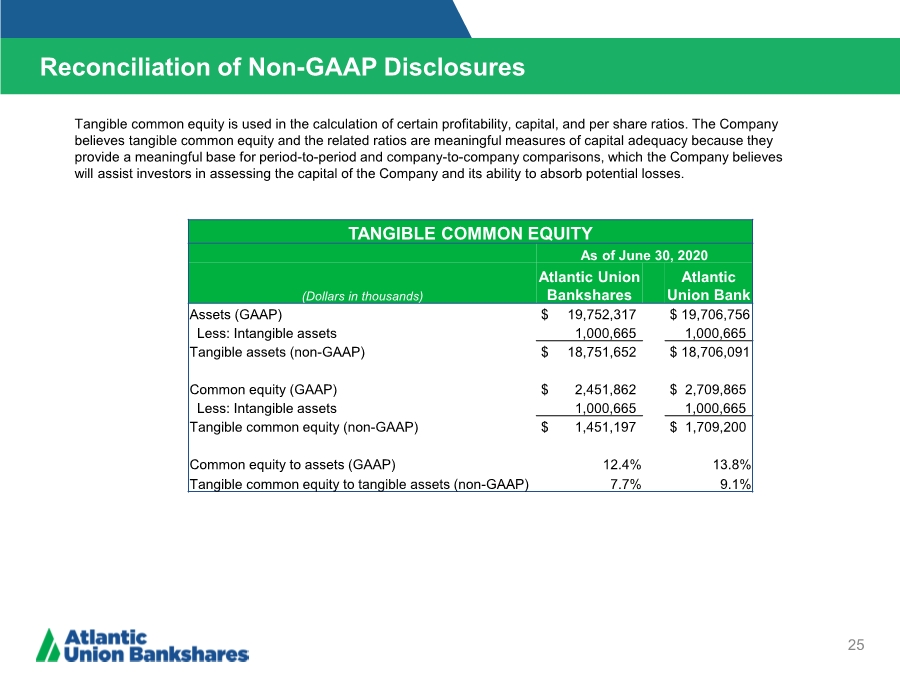
| Reconciliation of Non-GAAP Disclosures 26 ($ IN THOUSANDS) Operating Earnings Per Share The Company believes loans held for investment (net of deferred fees and costs), excluding PPP is useful to investors as it provides more clarity on the Company’s organic growth. The Company also believes that the ALLL as a percentage of loans held for investment (net of deferred fees and costs), excluding PPP, is useful to investors because of the size of the Company’s PPP organizations originations and the impact of the embedded credit enhancement provided by the SBA guarantee. ALLOWANCE FOR CREDIT LOSSES RATIO (Dollars in thousands) As of June 30, 2020 Allowance for loan losses (ALLL) $ 169,977 Reserve for unfunded commitment 11,000 Allowance for credit losses (ACL) $ 180,977 Total loans held for investment (GAAP) $ 14,308,646 Less: PPP adjustments 1,598,718 Total loans held for investment, excluding PPP (non-GAAP) $ 12,709,928 ALLL to total loans held for investment (GAAP) 1.19% ALLL to total loans held for investment, excluding PPP (non-GAAP) 1.34% ACL to total loans held for investment (GAAP) 1.26% ACL to total loans held for investment, excluding PPP (non-GAAP) 1.42% |