
AXREF 6-K
Amarc Resources Ltd (AXREF)
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM
REPORT OF FOREIGN PRIVATE ISSUER PURSUANT TO RULE 13a-16 OR 15d-16
UNDER THE SECURITIES EXCHANGE ACT OF 1934
As at July 23, 2026
Commission File Number:
(Translation of registrant's name into English) |
Canada
(Address of principal executive offices)
Indicate by check mark whether the registrant files or will file annual reports under cover Form 20-F or Form 40-F.
☒ Form 20-F ☐ Form 40-F
Indicate by check mark if the registrant is submitting the Form 6-K in paper as permitted by Regulation S-T Rule 101(b)(1): ☐
Indicate by check mark if the registrant is submitting the Form 6-K in paper as permitted by Regulation S-T Rule 101(b)(7): ☐
SUBMITTED HEREWITH
Exhibits
2 |
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
|
| Amarc Resources Ltd. (Registrant) |
|
|
|
|
|
Date: July 23, 2026 | By: | /s/ Carol Li |
|
|
| Carol Li |
|
|
| Chief Financial Officer |
|
3 |
EXHIBIT 99.1
AMARC RESOURCES LTD.
FINANCIAL STATEMENTS
FOR THE YEARS ENDED
MARCH 31, 2026, 2025 and 2024
(Expressed in Canadian Dollars)
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the Board of Directors and the Shareholders of Amarc Resources Ltd.,
Opinion on the Financial Statements
We have audited the accompanying financial statements of Amarc Resources Ltd. (the “Company”), which comprise the statements of financial position as at March 31, 2026 and 2025, and the statements of net loss and comprehensive loss, changes in (deficiency) equity and cash flows for each of the three years in the period ended March 31, 2026, and related notes and schedules (collectively referred to as the ‘financial statements’). In our opinion, the financial statements present fairly, in all material respects, the financial position of the Company as at March 31, 2026 and 2025 and its financial performance and its cash flows for each of the three years in the period ended March 31, 2026, in conformity with IFRS Accounting Standards as issued by the International Accounting Standards Board.
Going Concern
The accompanying financial statements have been prepared assuming that the Company will continue as a going concern. Without modifying our opinion, we draw attention to Note 1 in the financial statements which indicates that the Company has no current source of revenue, has incurred losses from inception and is dependent upon its ability to secure new sources of financing. These conditions, along with other matters as set forth in Note 1, indicate the existence of a material uncertainty that casts substantial doubt as to the Company's ability to continue as a going concern. Management’s plans in regard to these matters are also described in Note 1. The financial statements do not include any adjustments that might result from the outcome of this uncertainty. This issue also constitutes, from our perspective, a critical audit matter.
The critical audit matter communicated below is a matter arising from the current period audit of the financial statements that was communicated or required to be communicated to the audit committee and that: (i) relates to accounts or disclosures that are material to the financial statements; and (ii) involved, on our part, especially challenging, subjective, or complex judgements. The communication of a critical audit matter does not alter in any way our opinion on the financial statements, taken as a whole, and we are not, by communicating this critical audit matter, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.
The principal considerations for our determination that the going concern uncertainty was a critical audit matter were: (i) that the formal reporting of such uncertainty involves a significant disclosure, the absence of which could constitute a material misstatement to a financial statement reader and, (ii) that, at the same time, it involves on our part the use of a high level of subjective judgement as we are required to consider the possible impact of future events that cannot currently be known and which in all likelihood will not be directly linked to any particular current or future financial results and reporting, or the lack thereof.
Addressing this matter involved performing procedures and evaluating audit evidence in connection with forming our overall opinion on the financial statements. These procedures also included, among others, (i) obtaining and evaluating management’s assessment of the Company’s ability to remain a going concern; (ii) determining based on all other evidence available to us whether management’s assessment appeared to be fair and reasonable in the circumstances and, (iii) considering whether the resultant disclosure of these matters herein was consistent with the foregoing, in the context of the Company’s overall business activities, objectives and financial history.
Basis for Opinion
These financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s financial statements based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (‘PCAOB’) and are required to be independent with respect to the Company in accordance with U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance whether the financial statements are free of material misstatement, whether due to fraud or error. The Company is not required to have, nor were we engaged to perform, an audit of internal control over financial reporting. As part of our audits, we are required to obtain an understanding of internal control over financial reporting but not for the purpose of expressing an opinion on the effectiveness of the Company’s internal control over financial reporting. Accordingly, we express no such opinion.
Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements. We believe that our audits provide a reasonable basis for our opinion.
Critical Audit Matter
A critical audit matter was communicated above under ‘Going Concern’.
CHARTERED PROFESSIONAL ACCOUNTANTS
We have served as the Company’s auditor since 1995.
Vancouver, Canada
July 20, 2026
Amarc Resources Ltd. |
|
|
|
|
|
|
|
|
| |||
Statements of Financial Position |
|
|
|
| ||||||||
(Expressed in Canadian Dollars) |
|
|
|
|
|
|
|
|
| |||
|
|
|
|
|
|
|
|
| ||||
|
|
|
| As at March 31, 2026 |
|
| As at March 31, 2025 |
| ||||
|
| Note |
|
| ($) |
|
| ($) |
| |||
ASSETS |
|
|
|
|
|
|
|
|
| |||
Current assets |
|
|
|
|
|
|
|
|
| |||
Cash |
|
| 3 |
|
|
|
|
|
|
| ||
Amounts receivable and other assets |
|
| 6 |
|
|
|
|
|
|
| ||
Marketable securities |
|
| 4 |
|
|
|
|
|
|
| ||
|
|
|
|
|
|
|
|
|
|
| ||
Non-current assets |
|
|
|
|
|
|
|
|
|
|
|
|
Investment in Aurora Minerals Ltd. |
|
| 8 |
|
|
|
|
|
|
| ||
Restricted cash |
|
| 5 |
|
|
|
|
|
|
| ||
Right-of-use asset |
|
| 14 |
|
|
|
|
|
|
| ||
Total assets |
|
|
|
|
|
|
|
|
|
| ||
|
|
|
|
|
|
|
|
|
|
|
|
|
LIABILITIES AND SHAREHOLDERS' EQUITY |
|
|
|
|
|
|
|
|
|
|
|
|
Current liabilities |
|
|
|
|
|
|
|
|
|
|
|
|
Accounts payable and accrued liabilities |
|
| 9 |
|
|
|
|
|
|
| ||
Advanced contributions received |
|
| 7(c),8 |
|
|
|
|
|
| |||
Balances due to related parties |
|
| 12 |
|
|
|
|
|
|
| ||
Director's loan |
|
| 10 |
|
|
|
|
|
|
| ||
Lease liability |
|
| 14 |
|
|
|
|
|
|
| ||
|
|
|
|
|
|
|
|
|
|
| ||
|
|
|
|
|
|
|
|
|
|
|
|
|
Non-current liabilities |
|
|
|
|
|
|
|
|
|
|
|
|
Lease liability |
|
| 14 |
|
|
|
|
|
|
| ||
Total liabilities |
|
|
|
|
|
|
|
|
|
| ||
|
|
|
|
|
|
|
|
|
|
|
|
|
Shareholders' equity (deficiency) |
|
|
|
|
|
|
|
|
|
|
|
|
Share capital |
|
| 11 |
|
|
|
|
|
|
| ||
Reserves |
|
| 11 |
|
|
|
|
|
|
| ||
Accumulated deficit |
|
|
|
|
|
| ( | ) |
|
| ( | ) |
|
|
|
|
|
|
| ( | ) |
|
| ( | ) |
Total liabilities and shareholders' equity |
|
|
|
|
|
|
|
|
|
| ||
Nature of operations and going concern (note 1) Events after the reporting period (note 17) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
The accompanying notes are an integral part of these financial statements. |
|
|
|
|
|
|
|
|
| |||
|
|
|
|
|
|
|
|
|
|
|
|
|
/s/ Robert A. Dickinson |
| /s/ Scott D. Cousens |
|
|
|
|
|
| ||||
|
|
|
|
|
|
|
|
|
|
|
|
|
Robert A. Dickinson |
| Scott D. Cousens |
|
|
|
|
|
| ||||
Director |
| Director |
|
|
|
|
|
|
|
|
| |
| 4 | Page |
Amarc Resources Ltd.
Statements of Net Loss and Comprehensive Loss
(Expressed in Canadian Dollars, except for weighted average number of common shares)
|
|
|
| Years ended March 31 |
| |||||||||||
|
| Note |
|
| 2026 |
|
| 2025 |
|
| 2024 |
| ||||
|
|
|
| ($) |
|
| ($) |
|
| ($) |
| |||||
Expenses |
|
|
|
|
|
|
|
|
|
|
|
| ||||
Exploration and evaluation |
|
| 7,13 |
|
|
|
|
|
|
|
|
|
| |||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Administration |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
Legal, accounting and audit |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
Office and administration |
|
| 12(b),13 |
|
|
|
|
|
|
|
|
| ||||
Rent |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
Shareholder communication |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
Travel and accommodation |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
Trust and regulatory |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Equity-settled share-based compensation |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Cost recoveries |
|
| 7 |
|
|
| ( | ) |
|
| ( | ) |
|
| ( | ) |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||
Other items |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Finance income |
|
|
|
|
|
| ( | ) |
|
| ( | ) |
|
| ( | ) |
Interest expense – director's loans |
|
| 10 |
|
|
|
|
|
|
|
|
|
| |||
Accretion expense - office lease |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
Interest and penalties |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
Other fee income |
|
| 8 |
|
|
| ( | ) |
|
| ( | ) |
|
| ( | ) |
Amortization of right-of-use asset |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
Transaction cost – director's loans |
|
| 10 |
|
|
|
|
|
|
|
|
|
| |||
Flow through premium recovery |
|
|
|
|
|
|
|
|
| ( | ) |
|
|
| ||
Foreign exchange loss |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
Net loss |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Other comprehensive loss |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Items that will not be reclassified subsequently to loss (income): |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Change in value of marketable securities |
|
| 4 |
|
|
|
|
|
|
|
|
|
| |||
Total other comprehensive loss |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Basic and diluted loss per share |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Weighted average number of common |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
shares outstanding |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
The accompanying notes are integral part of these financial statements
| 5 | Page |
Amarc Resources Ltd.
Statements of Changes in (Deficiency) Equity
(Expressed in Canadian Dollars, except for share information)
|
| Share capital |
|
| Reserves |
|
|
|
|
| ||||||||||||||||||
|
| Number of shares |
|
| Amount |
|
| Share-based payments reserve |
|
| Investment revaluation reserve |
|
| Share warrants reserve |
|
| Deficit |
|
| Total |
| |||||||
|
| (#) |
|
| ($) |
|
| ($) |
|
| ($) |
|
| ($) |
|
| ($) |
|
| ($) |
| |||||||
Balance at April 1, 2023 |
|
|
|
|
|
|
|
|
|
|
| ( | ) |
|
|
|
|
| ( | ) |
|
| ( | ) | ||||
Net loss for the year |
|
| – |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ( | ) |
|
| ( | ) | ||||
Other comprehensive loss for the year |
|
| – |
|
|
|
|
|
|
|
|
| ( | ) |
|
|
|
|
|
|
|
| ( | ) | ||||
Total comprehensive loss |
|
| – |
|
|
|
|
|
|
|
|
| ( | ) |
|
|
|
|
| ( | ) |
|
| ( | ) | |||
Issuance of common shares pursuant to property agreement |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||||
Issuance of common shares pursuant to non-flow-through private placement |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||||
Issuance of common shares pursuant to a flow-through private placement |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||||
Flow-through share premium liability |
|
| – |
|
|
| ( | ) |
|
|
|
|
|
|
|
|
|
|
|
|
|
| ( | ) | ||||
Equity-settled share-based compensation |
|
| – |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||
Balance at March 31, 2024 |
|
|
|
|
|
|
|
|
|
|
| ( | ) |
|
|
|
|
| ( | ) |
|
|
| |||||
Balance at April 1, 2024 |
|
|
|
|
|
|
|
|
|
|
| ( | ) |
|
|
|
|
| ( | ) |
|
|
| |||||
Net loss for the year |
|
| – |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ( | ) |
|
| ( | ) | ||||
Other comprehensive loss for the year |
|
| – |
|
|
|
|
|
|
|
|
| ( | ) |
|
|
|
|
|
|
|
| ( | ) | ||||
Total comprehensive loss |
|
| – |
|
|
|
|
|
|
|
|
| ( | ) |
|
|
|
|
| ( | ) |
|
| ( | ) | |||
Issuance of common shares pursuant to property agreement |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||||
Shares issued through exercise of options |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||||
Fair value reversal of options exercised |
|
| – |
|
|
|
|
|
| ( | ) |
|
|
|
|
|
|
|
|
|
|
|
| |||||
Fair value reversal of warrants exercised |
|
| – |
|
|
|
|
|
| ( | ) |
|
|
|
|
|
|
|
|
|
|
|
| |||||
Shares issued through exercise of warrants |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||||
Equity-settled share-based compensation |
|
| – |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||
Balance at March 31, 2025 |
|
|
|
|
|
|
|
|
|
|
| ( | ) |
|
|
|
|
| ( | ) |
|
| ( | ) | ||||
Balance at April 1, 2025 |
|
|
|
|
|
|
|
|
|
|
| ( | ) |
|
|
|
|
| ( | ) |
|
| ( | ) | ||||
Net loss for the year |
|
| – |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ( | ) |
|
| ( | ) | ||||
Other comprehensive loss for the year |
|
| – |
|
|
|
|
|
|
|
|
| ( | ) |
|
|
|
|
|
|
|
| ( | ) | ||||
Total comprehensive loss |
|
| – |
|
|
|
|
|
|
|
|
| ( | ) |
|
|
|
|
| ( | ) |
|
| ( | ) | |||
Issuance of common shares pursuant to property agreement |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||||
Shares issued through exercise of options |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||||
Fair value reversal of options exercised |
|
| – |
|
|
|
|
|
| ( | ) |
|
|
|
|
|
|
|
|
|
|
|
| |||||
Equity-settled share-based compensation |
|
| – |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||
Balance at March 31, 2026 |
|
|
|
|
|
|
|
|
|
|
| ( | ) |
|
|
|
|
| ( | ) |
|
| ( | ) | ||||
The accompanying notes are integral part of these financial statements.
| 6 | Page |
Amarc Resources Ltd.
Statements of Cash Flows
(Expressed in Canadian Dollars)
|
|
|
| Years ended March 31 |
| |||||||||||
|
| Note |
|
| 2026 |
|
| 2025 |
|
| 2024 |
| ||||
|
|
|
| ($) |
|
| ($) |
|
| ($) |
| |||||
Operating activities |
|
|
|
|
|
|
|
|
|
|
|
| ||||
Net loss for the year |
|
|
|
|
| ( | ) |
|
| ( | ) |
|
| ( | ) | |
Adjustments for: |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |
Amortization of right-of-use asset |
|
| 14 |
|
|
|
|
|
|
|
|
|
| |||
Equity-settled share-based compensation |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
Flow through premium recovery |
|
|
|
|
|
|
|
|
| ( | ) |
|
|
| ||
Office lease accretion per IFRS 16 |
|
| 14 |
|
|
|
|
|
|
|
|
|
| |||
Office base rent recorded as lease reduction per IFRS 16 |
|
| 14 |
|
|
| ( | ) |
|
| ( | ) |
|
| ( | ) |
Property acquisition and assessments costs |
|
| 7(b) |
|
|
|
|
|
|
|
|
| ||||
Interest expense – director's loans |
|
| 10 |
|
|
|
|
|
|
|
|
|
| |||
Transaction cost – director's loans |
|
| 10 |
|
|
|
|
|
|
|
|
|
| |||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Changes in working capital items |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Amounts receivable and other assets |
|
|
|
|
|
| ( | ) |
|
|
|
|
|
| ||
Restricted cash |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
Accounts payable and accrued liabilities |
|
|
|
|
|
|
|
|
| ( | ) |
|
| ( | ) | |
Advanced contributions received |
|
| 7(c),8 |
|
| ( | ) |
|
| ( | ) |
|
|
| ||
Balances due to related parties |
|
|
|
|
|
|
|
|
|
|
|
| ( | ) | ||
Net cash provided by (used in) operating activities |
|
|
|
|
|
|
|
|
| ( | ) |
|
|
| ||
Financing activities |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Net proceeds from issuance of common shares pursuant to a private placement |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
Payment for director's loan interest |
|
| 10 |
|
|
| ( | ) |
|
| ( | ) |
|
| ( | ) |
Proceeds from exercise of share purchase warrants |
|
| 11(a) |
|
|
|
|
|
|
|
|
| ||||
Proceeds from option exercise |
|
| 11(a) |
|
|
|
|
|
|
|
|
| ||||
Net cash provided by financing activities |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Net increase (decrease) in cash |
|
|
|
|
|
|
|
|
| ( | ) |
|
|
| ||
Cash, beginning balance |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
Cash, ending balance |
|
|
|
|
|
|
|
|
|
|
|
|
| |||
The accompanying notes are an integral part of these financial statements.
| 7 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
1.NATURE AND CONTINUANCE OF OPERATIONS
Amarc Resources Ltd. (“Amarc” or the “Company”) is a company incorporated under the laws of the Province of British Columbia (“BC”). Its principal business activity is the acquisition and exploration of mineral properties. The Company’s mineral property interests are located in BC. The address of the Company’s corporate office is 14th Floor, 1040 West Georgia Street, Vancouver, BC, Canada V6E 4H1.
The Company is in the process of exploring its mineral property interests and has not yet determined whether its mineral property interests contain economically recoverable mineral reserves. The Company’s continuing operations are entirely dependent upon the existence of economically recoverable mineral reserves, the ability of the Company to obtain the necessary financing to continue the exploration and development of its mineral property interests and to obtain the permits necessary to mine, and the future profitable production from its mineral property interest or proceeds from the disposition of its mineral property interests.
These financial statements as at and for the year ended March 31, 2026 (the “Financial Statements”) have been prepared on a going concern basis, which contemplates the realization of assets and the discharge of liabilities in the normal course of business for the foreseeable future. As at March 31, 2026, the Company had cash of $
The Company will need to seek additional financing to meet its exploration and development objectives. The Company has a reasonable expectation that additional funds will be available when necessary to meet ongoing exploration and development costs. However, there can be no assurance that the Company will continue to be able to obtain additional financial resources or will achieve profitability or positive cash flows. If the Company is unable to obtain adequate additional financing, the Company will be required to re-evaluate its planned expenditures until additional funding can be raised through financing activities. These factors indicate the existence of a material uncertainty that casts significant doubt about the Company’s ability to continue as a going concern.
These Financial Statements do not include any adjustments to the recoverability and classification of recorded asset amounts and classification of liabilities that may be necessary should the Company be unable to continue as a going concern.
2. MATERIAL ACCOUNTING POLICIES
The principal accounting policies applied in the preparation of these Financial Statements are described below. These policies have been consistently applied for all years presented, unless otherwise stated.
(a) Statement of compliance
These Financial Statements have been prepared in accordance with IFRS Accounting Standards (“IFRS”), as issued by the International Accounting Standards Board.
Board of Directors of the Company authorized these Financial Statements for issuance on July 20, 2026.
(b) Basis of presentation and measurement
These Financial Statements have been prepared on a historical cost basis, except for certain financial instruments classified as fair value through other comprehensive income, which are reported at fair value. In addition, these Financial Statements have been prepared using the accrual basis of accounting, except for cash flow information.
| 8 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
Certain comparative amounts have been reclassified to conform to the presentation adopted in the current period.
These Financial Statements are presented in Canadian dollars (“CAD”), which is also the Company’s functional currency. At the transaction date, each asset, liability, revenue and expense denominated in a foreign currency is translated into CAD using the exchange rate in effect at that date. At the period-end date, unsettled monetary assets and liabilities are translated into CAD using the exchange rate in effect at the period-end date and the related translation differences are recognized in net income or loss.
(c) Significant accounting estimates and judgements
The preparation of the Financial Statements in conformity with IFRS requires management to make judgements, estimates, and assumptions that affect the application of policies and reported amounts of assets and liabilities, income and expenses. Actual results may differ from these estimates.
The impacts of such estimates are pervasive throughout the Financial Statements, and may require accounting adjustments based on future occurrences. Revisions to accounting estimates are recognized in the period in which the estimate is revised and future periods if the revision affects both current and future periods. These estimates are based on historical experience, current and future economic conditions and other factors, including expectations of future events that are believed to be reasonable under the circumstances. Specific areas where significant estimates or judgments exist are:
| · | assessment of the Company’s ability to continue as a going concern; and |
|
|
|
| · | Exploration and evaluation expenses and related cost recoveries. |
(d) Financial instruments
A financial asset (unless it is a trade receivable without a significant financing component that is initially measured at the transaction price) is initially measured at fair value plus, for an item not measured at fair value through profit or loss (“FVTPL”), transaction costs that are directly attributable to its acquisition. The directly attributable transaction costs of a financial asset classified at FVTPL are expensed in the period in which they are incurred.
Financial assets measured at amortized cost
A financial asset is measured at amortized cost if it meets both the following conditions and is not designated as at FVTPL:
| · | it is held within a business model whose objective is to hold assets to collect contractual cash flows; and, |
|
|
|
| · | its contractual terms give rise on specified dates to cash flows that are solely payments of principal and interest on the principal amount outstanding. |
These financial assets are subsequently measured at amortized cost using the effective interest method. The amortized cost is reduced by impairment losses. Interest income, foreign exchange gains and losses, and impairment losses are recognized in profit or loss. Any gain or loss on the derecognition of the financial asset is recognized in profit or loss.
| 9 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
Financial assets measured at fair value through other comprehensive income
A debt investment is measured at fair value through other comprehensive income (“FVTOCI”) if it meets both the following conditions and is not designated as at FVTPL:
| · | it is held within a business model whose objective is achieved by both collecting contractual cash flows and selling financial assets; and, |
|
|
|
| · | its contractual terms give rise on specified dates to cash flows that are solely payments of principal and interest on the principal amount outstanding. |
On the initial recognition of an equity instrument that is not held for trading, the Company may irrevocably elect to present subsequent changes in the investment’s fair value in other comprehensive income (“OCI”). This election is made on an investment-by-investment basis.
Debt investments measured at FVTOCI are subsequently measured at fair value. Interest income calculated using the effective interest method, foreign exchange gains and losses, and impairment are recognized in profit or loss. Other net gains and losses are measured in OCI. On de-recognition, gains and losses accumulated in OCI are reclassified to profit or loss.
Financial assets measured at fair value through profit or loss
All financial assets not classified as measured at amortized cost or measured at FVTOCI, as described above, are measured at FVTPL; this includes all derivative financial assets. On initial recognition, the Company may irrevocably designate a financial asset that otherwise meets the requirements to be measured at amortized cost or measured at FVTOCI as FVTPL if doing so eliminates, or significantly reduces, an accounting mismatch that would otherwise arise.
These financial assets are subsequently measured at fair value. Net gains and losses, including any interest or dividend income, are recognized in profit or loss.
Financial assets | Classification |
Cash | |
Marketable securities | |
Restricted cash | |
Amounts receivable and other assets |
Financial Liabilities | Classification |
Accounts payable and accrued liabilities | |
Balance due to related parties | |
Director’s loan |
| 10 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
(e) Exploration and evaluation expenditures
Exploration and evaluation costs are costs incurred to discover mineral resources, and to assess the technical feasibility and commercial viability of the mineral resources found.
Exploration and evaluation expenditures include:
| · | costs associated with the acquisition of licenses; |
|
|
|
| · | costs associated with the acquisition of exploration and evaluation of assets, including mineral properties; and |
|
|
|
| · | costs associated with exploration and evaluation activities. |
Exploration and evaluation costs are generally expensed as incurred until the technical feasibility and commercial viability of extracting a mineral resource has been determined and a positive decision to proceed to development has been made. However, if management concludes that future economic benefits are more likely than not to be realized, the costs of property, plant and equipment for use in the exploration and evaluation of mineral resources are capitalized.
Costs incurred before the Company has obtained the legal rights to explore an area are expensed. Costs incurred after the technical feasibility and commercial viability of extracting a mineral resource has been determined and a positive decision to proceed to development has been made are considered development costs and are capitalized.
Costs applicable to established mineral property interests where no further work is planned by the Company may, for presentation purposes only, be carried at nominal amounts.
(f) Share capital
Common shares of the Company are classified as equity. Transaction costs directly attributable to the issuance of common shares and share purchase options are recognized as a deduction from equity, net of any tax effects.
When the Company issues common shares for consideration other than cash, the transaction is measured at fair value based on the quoted market price of the Company’s common shares on the date of issuance.
(g) Loss per share
Loss per share is computed by dividing the losses attributable to common shareholders by the weighted average number of common shares outstanding during the reporting period. Diluted loss per share is determined by adjusting the losses attributable to common shareholders and the weighted average number of common shares outstanding for the effects of all dilutive potential common shares, such as options granted to employees. The dilutive effect of options assumes that the proceeds to be received on the exercise of share purchase options are applied to repurchase common shares at the average market price for the reporting period. Share purchase options are included in the calculation of dilutive earnings per share only to the extent that the market price of the common shares exceeds the exercise price of the share purchase options. The effect of anti-dilutive factors is not considered when computed diluted loss per share.
| 11 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
(h) Equity-settled share-based payments
The share purchase option plan allows employees and consultants of the Company to acquire shares of the Company. The fair value of share purchase options granted is recognized as an employee or consultant expense with a corresponding increase in the share-based payments reserve in equity. An individual is classified as an employee when the individual is an employee for legal and tax purposes (direct employee) or provides services similar to those performed by a direct employee.
For employees, fair value is measured at the grant date and each tranche is recognized on a straight-line basis over the period during which the share purchase options vest. The fair value of the share purchase options granted is measured using the Black-Scholes option pricing model taking into account the terms and conditions upon which the share purchase options were granted. At the end of each financial reporting period, the amount recognized as an expense is adjusted to reflect the actual number of share purchase options that are expected to vest.
Share-based payment transactions with non-employees are measured at the fair value of the goods and services received. However, if the fair value cannot be estimated reliably, the share-based payment transaction is measured at the fair value of the equity instrument granted at the date the entity obtains the goods or the counterparty renders the service.
(i) Income taxes
Income tax on the profit or loss for the years presented comprises of current and deferred tax. Income tax is recognized in profit or loss except to the extent that it relates to items recognized directly in equity, in which case it is recognized in equity.
Current tax expense is the expected tax payable on taxable income for the year, using tax rates enacted or substantively enacted at year end, adjusted for amendments to tax payable with regards to previous years.
Deferred tax is provided using the balance sheet liability method, providing for temporary differences between the carrying amounts of assets and liabilities for financial reporting purposes and the amounts used for taxation purposes.
The following temporary differences are not provided for:
| · | goodwill not deductible for tax purposes; |
|
|
|
| · | the initial recognition of assets or liabilities that affect neither accounting nor taxable profit; and |
|
|
|
| · | differences relating to investments in subsidiaries, associates, and joint ventures to the extent that they will probably not reverse in the foreseeable future. |
The amount of deferred tax provided is based on the expected manner of realization or settlement of the carrying amount of assets and liabilities, using tax rates enacted or substantively enacted at the financial position reporting date applicable to the period of expected realization or settlement.
A deferred tax asset is recognized only to the extent that it is probable that future taxable profits will be available against which the asset can be utilized.
Additional income taxes that arise from the distribution of dividends are recognized at the same time as the liability to pay the related dividend.
| 12 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
Deferred tax assets and liabilities are offset when there is a legally enforceable right to set off current tax assets against current tax liabilities, when they relate to income taxes levied by the same taxation authority, and the Company intends to settle its current tax assets and liabilities on a net basis.
Flow-through shares
The Company will, from time-to-time, issue flow-through common shares to finance a portion of its exploration programs. Pursuant to the terms of the flow-through share agreements, these shares transfer the tax deductibility of qualifying resource expenditures to investors. On issuance, the Company bifurcates the flow-through share into i) a flow-through share premium, equal to the estimated premium, if any, investors pay for the flow-through feature, which is recognized as a liability, and ii) share capital. Upon expenses being incurred, the Company derecognizes this liability and recognizes this premium as other income, offsetting any expense associated with the Company’s expenditure of the flow-through proceeds.
(j) Restoration, rehabilitation and environmental obligations
An obligation to incur restoration, rehabilitation and environmental costs arises when environmental disturbance is caused by the exploration or development of a mineral property interest. Such costs arising from the decommissioning of plant and other site preparation work, discounted to their net present value, are provided for and capitalized at the start of each project to the carrying amount of the asset, along with a corresponding liability at the time the obligation to incur such costs arises. The timing of the actual rehabilitation expenditure is dependent on a number of factors such as the life and nature of the project or asset, the conditions imposed by the relevant permits, and, when applicable, the jurisdiction in which the project or asset is located.
(k) Operating segments
(l) Government assistance
When the Company is entitled to receive the BC Mining Exploration Tax Credit (“BCMETC”) and other government grants, this government assistance is recognized as a cost recovery when there is reasonable assurance of recovery. Any amounts accrued or received typically remain subject to review and revision by government authorities, which may occur within a three-year look-back period. It is not possible to predict the occurrence or outcome of such actions in advance.
(m) Leases
All leases are accounted for by recognizing a right-of-use asset and a lease liability except for:
| · | Leases of low value assets; and |
|
|
|
| · | Leases with a duration of twelve months or less. |
| 13 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
Lease liabilities are measured at the present value of the contractual payments due to the lessor over the lease term, with the discount rate determined by the interest rate implicit in the lease, or if that rate cannot be readily determined, the Company’s incremental borrowing rate on commencement of the lease is used. Variable lease payments are only included in the measurement of the lease liability if they depend on an index or rate. In such cases, the initial measurement of the lease liability assumes the variable element will remain unchanged throughout the lease term. Other variable lease payments are expensed in the period to which they relate.
On initial recognition, the carrying value of the lease liability also includes:
| · | Amounts expected to be payable under any residual value guarantee; |
|
|
|
| · | The exercise price of any purchase option granted if it is reasonable certain to assess that option; and |
|
|
|
| · | Any penalties payable for terminating the lease, if the term of the lease has been estimated on the basis of termination option being exercised. |
Right-of-use assets are initially measured at the amount of the lease liability, reduced for any lease incentives received, and increased for:
| · | Lease payments made at or before commencement of the lease; |
|
|
|
| · | Initial direct costs incurred; and |
|
|
|
| · | The amount of any provision recognized where the Company is contractually required to dismantle, remove or restore the leased asset. |
Lease liabilities, on initial measurement, increase as a result of interest charged at a constant rate on the balance outstanding and are reduced for lease payments made.
Right-of-use assets are amortized on a straight-line basis over the remaining term of the lease or over the remaining economic life of the asset if this is judged to be shorter than the lease term.
When the Company revises its estimate of the term of any lease, it adjusts the carrying amount of the lease liability to reflect the payments to make over the revised term, which are discounted at the same discount rate that applied on lease commencement. The carrying value of lease liabilities is similarly revised when the variable element of future lease payments dependent on a rate or index is revised. In both cases, an equivalent adjustment is made to the carrying value.
(n) Joint Arrangements
The Company conducts exploration work jointly with other parties in joint ventures and other related legal entities in circumstances where neither party can be said to authoritatively control the entity. Such arrangements are considered, for accounting purposes, to be joint ventures when a separate legal entity exists and where the Company’s investment is substantially related only to the net assets of that entity. The Company’s interests in a joint venture are accounted for on the equity basis, reflective of the Company’s net investment at cost plus the Company’s proportionate share of the entity’s subsequent income, less its share of any losses incurred. Losses are not typically recognized to the extent that doing so would create a negative balance relative to the Company’s net investment.
Arrangements with other parties which are not typically conducted through separate legal entities are classified are joint operations and consolidated within the Company’s financial statements on a line-by-line basis and reflective of the Company’s proportionate interest in such activities.
| 14 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
(o) New and amended IFRS Accounting Standards pronouncements
IFRS 18 Presentation and Disclosures in Financial Statements
On April 9, 2024, the IASB issued IFRS 18 Presentation and Disclosures in Financial Statements. The objective of the new standard is to set out requirements for the presentation and disclosure of information in general purpose financial statements to help ensure they provide relevant information that faithfully represents an entity’s assets, liabilities, equity, income and expenses. The new standard is effective for reporting periods beginning on or after January 1, 2027. Management is currently assessing the impact of the new standard on the Company's interim and annual financial statements.
Amendments to IFRS 9 and IFRS 7
On May 30, 2024, the IASB issued amendments to the classification and measurement of financial instruments to address matters identified during the post-implementation review of the classification and measurement requirements of IFRS 9. The IASB clarified the recognition and derecognition date of certain financial assets and liabilities, and amended the requirements related to settling financial liabilities using an electronic payment system. It also clarified how to assess the contractual cash flow characteristics of financial assets in determining whether they meet the solely payments of principal and interest criterion, including financial assets that have environmental, social and corporate governance-linked features and other similar contingent features. The IASB added disclosure requirements for financial instruments with contingent features that do not relate directly to basic lending risks and costs, and amended disclosures relating to equity instruments designated at fair value through other comprehensive income. The amendments are effective for reporting periods beginning on or after January 1, 2026. Management is currently assessing the impact of the new standard on the Company's interim and annual financial statements.
3. CASH
The Company’s cash is invested in business accounts, which are available on demand by the Company. The cash balance at March 31, 2026 included $
4. MARKETABLE SECURITIES
As at March 31, 2026, the fair value of its current holdings was $
| 15 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
As at March 31, 2026, the Company held the following marketable securities:
Company |
| Shares Held |
|
| Cost |
|
| Fair Value At March 31, 2026 |
|
| Fair Value At March 31, 2025 |
|
| Change in Fair Value |
| |||||
|
| (#) |
|
| ($) |
|
| ($) |
|
| ($) |
|
| ($) |
| |||||
Carlyle Commodities Corp - Shares |
|
|
|
|
|
|
|
|
|
|
|
|
|
| ( | ) | ||||
Other |
|
|
|
|
|
|
|
|
|
|
|
|
|
| ( | ) | ||||
Total |
|
|
|
|
|
|
|
|
|
|
|
|
|
| ( | ) | ||||
5. RESTRICTED CASH
Restricted cash represents amounts held in support of exploration permits. The amounts are refundable subject to the consent of provincial regulatory authorities upon completion of any required reclamation work on the related projects.
The following tables summarize the restricted cash held by project:
|
| March 31, 2026 |
|
| March 31, 2025 |
| ||
|
| ($) |
|
| ($) |
| ||
IKE |
|
|
|
|
|
| ||
DUKE |
|
|
|
|
|
| ||
JOY |
|
|
|
|
|
| ||
Other |
|
|
|
|
|
| ||
|
|
|
|
|
|
| ||
6. AMOUNTS RECEIVABLE AND OTHER ASSETS
|
| March 31, 2026 |
|
| March 31, 2025 |
| ||
|
| ($) |
|
| ($) |
| ||
Sales tax refundable |
|
|
|
|
|
| ||
Prepaid |
|
|
|
|
|
| ||
|
|
|
|
|
|
| ||
7. EXPLORATION AND EVALUATION EXPENSES AND COST RECOVERIES
During the year ended March 31, 2026, the Company incurred $
| 16 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
|
| IKE |
|
| JOY (1) |
|
| DUKE |
|
| OTHER |
|
| TOTAL |
| |||||
Year ended March 31, 2026 |
| ($) |
|
| ($) |
|
| ($) |
|
| ($) |
|
| ($) |
| |||||
Assays and analysis |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Drilling |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Environmental |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Equipment rental |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Freight |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Geological, including geophysical |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Graphics |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Helicopter and fuel |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Operations support |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Property acquisition and assessments costs |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Socioeconomic |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Technical data |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Travel and accommodation |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
|
| IKE |
|
| JOY |
|
| DUKE |
|
| OTHER |
|
| TOTAL |
| |||||
Year ended March 31, 2025 |
| ($) |
|
| ($) |
|
| ($) |
|
| ($) |
|
| ($) |
| |||||
Assays and analysis |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Drilling |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Environmental |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Equipment rental |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Freight |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Geological, including geophysical |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Graphics |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Helicopter and fuel |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Operations support |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Property acquisition and assessments costs |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Socioeconomic |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Technical data |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
Travel and accommodation |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
| (1) | Includes expenses incurred to the date the JOY District mineral rights and title were transferred to Aurora Minerals Ltd. upon the establishment of the JOY District joint venture with Freeport (note 8). All exploration costs incurred on the JOY District subsequent to August 20, 2025 have been recorded in Aurora Minerals Ltd. and are not presented here. |
Below is a summary of the Company’s major exploration property interests, together with the material property transactions.
| 17 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
(a) IKE District
The IKE District is subject to the following royalties:
| · | A |
|
|
|
| · | A |
|
|
|
| · | The entire IKE District is subject to a |
(b) JOY District (note 8)
The JOY District is comprised of: the AuRORA Au-Cu-Ag Deposit, PINE Au-Cu Deposit, and the TWINs and CANYON Au-Cu Discoveries together with Paula Property, JOY Property, Brenda Property and PIL Property.
In November 2019, the Company entered into a purchase agreement with two prospectors to acquire
In December 2019, as per the amended PINE Property purchase agreement between Amarc and Gold Fields Toodoggone Exploration Corp. (“GFTEC”), the Company completed its acquisition of the PINE property by issuing to GFTEC
JOY District Agreement with Freeport
On May 11, 2021, the Company and Freeport-McMoRan Mineral Properties Canada Inc. (“Freeport”), a wholly-owned subsidiary of Freeport-McMoRan Inc. (NYSE:FCX) entered into a Mineral Property Earn-in Agreement (the “Agreement”) whereby Freeport may acquire up to a
| 18 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
On February 5, 2025, the Company entered into a mineral property option agreement to
During the year ended March 31, 2026, the Company recorded cost recoveries of $
The JOY District is subject to the following NSR royalties:
| · | On November 21, 2017, |
|
|
|
| · | The PINE Property is subject to a |
|
|
|
| · | |
|
|
|
| · | The Paula claim is subject to a |
(c) DUKE District
In November 2016, the Company agreed to acquire a
On July 7, 2023, the Company entered into a mineral property option agreement with an arms-length third party optionor to acquire a
| 19 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
DUKE District Agreement with Boliden
On November 22, 2022, the Company announced that it had entered into a Mineral Property Earn-in Agreement (the "EIA") with Boliden Mineral Canada Ltd. (“Boliden”), a wholly-owned subsidiary of the Boliden Group. Under the terms of the EIA, Boliden has a two-staged option to earn up to a
The Company initially records the amounts of contributions received or receivable from Boliden pursuant to the EIA as a liability (advanced contributions received) in the statements of financial position, and subsequently recognized amounts as cost recoveries in the statements of net loss and comprehensive loss as the Company incurs the related expenditures. As at March 31, 2026, the Company recorded advanced contributions balance of $
During the year ended March 31, 2026, the Company recorded cost recoveries of $
(d) Other property transactions
On May 16, 2022, the Company entered into a mineral claims option agreement with an arms-length third party optionor to acquire a
To acquire its interest, the Company paid $
8. JOINT VENTURE CORPORATION – AURORA MINERALS LTD.
On August 20, 2025, the Company and Freeport formed a private joint venture corporation, AuRORA Minerals to operate the JOY District (note 7(b)). AuRORA Minerals holds the JOY District mineral rights and titles with Freeport owning 60% and Amarc owning 40% of the common shares of AuRORA Minerals. Freeport is the operator of AuRORA Minerals and has appointed Amarc as its primary contractor to manage JOY District exploration programs under a separate services agreement. AuRORA Minerals is governed by a shareholders agreement between Amarc and Freeport.
| 20 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
AuRORA Minerals was formed by the initial contribution of each of Amarc and Freeport of their respective
The transfer of such non-monetary consideration in exchange for the joint venture equity interest was considered to lack commercial substance and accordingly no gain or loss was recorded by the Company.
Subsequent to the establishment of AuRORA Minerals,
During the year ended March 31, 2026, Amarc provided, as contractor, $
The Company’s interest in AuRORA Minerals is accounted for using the equity accounting method on the basis that it retains significant influence over its operations. Amarc reports the carrying value of its investment in AuRORA Minerals at a nominal value of $
|
| March 31, 2026 |
|
| March 31, 2025 |
| ||
Current assets |
| $ |
|
|
| N/A |
| |
Non-current assets |
| $ | nil |
|
|
| N/A |
|
Current liabilities |
| $ |
|
|
| N/A |
| |
Expenses |
| $ |
|
|
| N/A |
| |
Net loss |
| $ |
|
|
| N/A |
| |
As at March 31, 2026, the Company has a liability for advanced contributions received of $
9. ACCOUNTS PAYABLE AND ACCRUED LIABILITIES
|
| March 31, 2026 |
|
| March 31, 2025 |
| ||
|
| ($) |
|
| ($) |
| ||
Accounts payable |
|
|
|
|
|
| ||
Accrued liabilities |
|
|
|
|
|
| ||
Total |
|
|
|
|
|
| ||
10. DIRECTOR’S LOAN
In December 2019, the Company entered into a loan extension and amendment agreement (the “Loan”) with a director and significant shareholder of the Company (the “Lender”), pursuant to which a previous loan agreement with a maturity date of November 26, 2019 was extended for
| 21 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
The continuity of the Loan balance is as follows:
|
| Total |
| |
|
| ($) |
| |
Balance, March 31, 2024 |
|
|
| |
Amortization of transaction costs |
|
|
| |
Balance, March 31, 2025 |
|
|
| |
Interest expense |
|
|
| |
Amortization of transaction costs |
|
|
| |
Cash interest paid |
|
| ( | ) |
Closing balance, March 31, 2026 |
|
|
| |
Current portion |
|
|
| |
Non-current portion |
|
|
| |
Finance expenses |
| Years ended March 31, |
| |||||
|
| 2026 |
|
| 2025 |
| ||
|
| ($) |
|
| ($) |
| ||
Interest on loan |
|
|
|
|
|
| ||
Amortization of transaction costs |
|
|
|
|
|
| ||
Total |
|
|
|
|
|
| ||
11. SHARE CAPITAL AND RESERVES
(a) Authorized and outstanding share capital
The Company’s authorized share capital consists of an unlimited number of common shares without par value (“Common Shares”) and an unlimited number of preferred shares. All issued Common Shares are fully paid. No preferred shares have been issued.
On September 5, 2024,
During the year ended March 31, 2025,
During the year ended March 31, 2025,
During the year ended March 31, 2026,
On August 21, 2025, the Company issued
As at March 31, 2026, the number of total issued and outstanding common shares is
| 22 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
(b) Share purchase options
The following summarizes changes in the Company’s share purchase options:
|
| March 31, 2026 |
|
| March 31, 2025 |
| ||||||||||
|
| Weighted Average Exercise Price |
|
| Number of Options |
|
| Weighted Average Exercise Price |
|
| Number of Options |
| ||||
Beginning balance |
|
|
|
|
|
|
|
|
|
|
|
| ||||
Cancelled |
|
|
|
|
| ( | ) |
|
|
|
|
| ( | ) | ||
Exercised |
|
|
|
|
| ( | ) |
|
|
|
|
| ( | ) | ||
Expired |
| NA |
|
|
|
|
|
|
|
|
| ( | ) | |||
Granted |
|
|
|
|
|
|
|
|
|
|
|
| ||||
Ending balance |
|
|
|
|
|
|
|
|
|
|
|
| ||||
The following summarizes information on the options outstanding and exercisable as at March 31, 2026:
|
|
|
| Weighted Average |
|
| Number of |
|
| Number of |
| |||||
|
|
|
|
| Remaining Contractual |
|
| Options |
|
| Options |
| ||||
Exercise price |
|
| Expiry date |
| Life (periods) |
|
| Outstanding |
|
| Exercisable |
| ||||
|
|
|
|
|
|
|
|
|
|
|
|
| ||||
| $ |
|
| 11-Apr-26 |
|
|
|
|
|
|
|
|
| ||||
| $ |
|
| 22-Mar-29 |
|
|
|
|
|
|
|
|
| ||||
| $ |
|
| 22-Mar-27 |
|
|
|
|
|
|
|
|
| ||||
| $ |
|
| 4-Feb-30 |
|
|
|
|
|
|
|
|
| ||||
| $ |
|
| 27-Jun-30 |
|
|
|
|
|
|
|
|
| ||||
| $ |
|
| 9-Jul-27 |
|
|
|
|
|
|
|
|
| ||||
| $ |
|
| 25-Feb-31 |
|
|
|
|
|
|
|
|
| ||||
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||
During the year ended March 31, 2026, the Company granted
The Company uses the Black-Scholes option pricing model to estimate the fair value for all stock-based compensation. The expected volatility assumption inherent in the pricing model is based on the historical volatility of the Company’s shares over a term equal to the expected term of the options granted. The weighted average assumptions used in the option pricing model and the resulting weighted average fair values per option for the options granted during the year ended March 31, 2026 and 2025 were as follows:
|
| March 31, 2026 |
|
| March 31, 2025 |
| ||
Risk-free rate: |
| % |
|
| % | |||
Expected life: |
|
|
|
| ||||
Expected volatility: |
| % |
|
| % | |||
Expected dividends: |
| Nil |
|
| Nil |
| ||
Weighted average fair value per option: |
| $ |
|
| $ |
| ||
| 23 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
(c) Share purchase warrants
The following summarizes changes in the Company’s share purchase warrants:
|
| March 31, 2026 |
|
| March 31, 2025 |
| ||||||||||
|
| Weighted Average Exercise Price |
|
| Number of Warrants |
|
| Weighted Average Exercise Price |
|
| Number of Warrants |
| ||||
Beginning balance |
|
|
|
|
|
|
|
|
|
|
|
| ||||
Exercised |
| NA |
|
|
| – |
|
|
|
|
|
| ( | ) | ||
Ending balance |
|
|
|
|
|
|
|
|
|
|
|
| ||||
The following summarizes information on the warrants outstanding as at March 31, 2026:
Weighted Average | |||
Remaining Contractual | Warrants | ||
Exercise price | Expiry date | Life (periods) | Outstanding |
$ | 1-Dec-28 | ||
|
|
12. RELATED PARTY TRANSACTIONS
|
| March 31, 2026 |
|
| March 31, 2025 |
| ||
Balances due to related parties |
| ($) |
|
| ($) |
| ||
Hunter Dickinson Services Inc. |
|
|
|
|
|
| ||
United Mineral Services Ltd. |
|
|
|
|
|
| ||
High Hills Consulting Ltd. (CFO fees) |
|
|
|
|
|
| ||
Diane Nicolson (expenses reimbursement) |
|
|
|
|
|
| ||
Thomas Wilson (former-CFO fees) |
|
|
|
|
|
| ||
Total |
|
|
|
|
|
| ||
(a) Transactions with key management personnel
Key management personnel (“KMP”) are those persons that have the authority and responsibility for planning, directing, and controlling the activities of the Company, directly and indirectly, and by definition include all the directors and officers of the Company.
During the year ended March 31, 2026, the Company’s President, Chief Executive Officer and Director, and Corporate Secretary provided services to the Company under a service agreement with Hunter Dickinson Services Inc. (note 12(b)).
During the year ended March 31, 2026, the Company recorded equity settled share-based compensation expense of $
During the year ended March 31, 2026, the Company incurred fees totaling $
| 24 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
(b) Hunter Dickinson Services Inc.
Hunter Dickinson Inc. (“HDI”) and its wholly-owned subsidiary Hunter Dickinson Services Inc. (“HDSI”) are private companies established by a group of mining professionals. HDSI provides contract services for a number of mineral exploration and development companies, and also to companies that are outside of the mining and mineral development space. Amarc acquires services from a number of related and arms-length contractors, and it is at Amarc’s discretion that HDSI provides certain contract services.
The Company has one director in common with HDSI, namely Robert Dickinson. Also, the Company’s President, Chief Executive Officer and Director, and Corporate Secretary are contracted to work for the Company under an employee secondment agreement between the Company and HDSI.
Pursuant to an agreement dated July 2, 2010, HDSI provides certain technical, geological, corporate communications, regulatory compliance, and administrative and management services to the
Company, on a non-exclusive basis as needed and as requested by the Company and as available from HDSI (the “Services Agreement”).
The Company is not obligated to acquire any minimum amount of services from HDSI. The monetary amount of the services received from HDSI in a given period of time is a function of annually set and agreed charge-out rates for and the time spent by each HDSI employee engaged by the Company.
HDSI also incurs third-party costs on behalf of the Company. Such third-party costs include, for example, capital market advisory services, communication services and office supplies. Third-party costs are billed at cost, without markup.
There are no ongoing contractual or other commitments resulting from the Company’s transactions with HDSI, other than the payment for services already rendered and billed. The agreement may be terminated upon 60 days’ notice by either the Company or HDSI.
The following is a summary of transactions with HDSI that occurred during the reporting periods:
|
| Years ended March 31, |
|
|
|
| ||||||
|
| 2026 |
|
| 2025 |
|
| 2024 |
| |||
(rounded to the nearest thousand CAD) |
| ($) |
|
| ($) |
|
| ($) |
| |||
Services received from HDSI and as requested by the Company |
|
|
|
|
|
|
|
|
| |||
Information technology – infrastructure and support services |
|
|
|
|
|
|
|
|
| |||
Office rent |
|
|
|
|
|
|
|
|
| |||
Reimbursement, at cost, of third-party expenses |
|
|
|
|
|
|
|
|
|
|
|
|
incurred by HDSI on behalf of the Company |
|
|
|
|
|
|
|
|
| |||
Total |
|
|
|
|
|
|
|
|
| |||
(c) United Mineral Services Ltd.
United Mineral Services Ltd. (“UMS”) is a private company wholly-owned by one of the directors of the Company. UMS is engaged in the acquisition and exploration of mineral property interests. During the year ended March 31, 2026, the Company incurred $
| 25 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
13. SUPPLEMENTARY INFORMATION TO THE STATEMENTS OF NET LOSS AND COMPREHENSIVE LOSS
(a) Salaries, fees and benefits
Salaries, fees and benefits included in exploration and evaluation expenses and administration expenses are as follows:
|
| Years ended March 31, |
| |||||||||
|
| 2026(1) |
|
| 2025(1) |
|
| 2024(1) |
| |||
Salaries, fees and benefits |
| ($) |
|
| ($) |
|
| ($) |
| |||
Exploration and evaluation expenses |
|
|
|
|
|
|
|
|
| |||
Administration expenses (2) |
|
|
|
|
|
|
|
|
| |||
|
|
|
|
|
|
|
|
|
| |||
| (1) | rounded to the nearest whole thousand. |
|
|
|
| (2) | includes salaries and benefits included in office and administration expenses (note 13(b)) and other salaries and benefits expenses classified as administration expenses. |
(b) Office and administration expenses
Office and administration expenses include the following:
|
| Years ended March 31, |
| |||||||||
|
| 2026(1) |
|
| 2025(1) |
|
| 2024(1) |
| |||
|
| ($) |
|
| ($) |
|
| ($) |
| |||
Salaries and Benefits |
|
|
|
|
|
|
|
|
| |||
Data processing and retention |
|
|
|
|
|
|
|
|
| |||
Insurance |
|
|
|
|
|
|
|
|
| |||
Other office expenses |
|
|
|
|
|
|
|
|
| |||
|
|
|
|
|
|
|
|
|
| |||
| (1) | rounded to the nearest whole thousand. |
14. OFFICE LEASE – RIGHT OF USE ASSET AND LEASE LIABILITY
The Company subleases corporate offices in Vancouver, BC, from HDSI under a lease agreement dated May 1, 2021, and the lease expires on April 29, 2026. On May 1, 2026, the lease agreement was renewed for another 5-year term expiring on April 30, 2031.
Right-of-use asset
A summary of the changes in the right-of-use asset for the twelve months ended March 31, 2026 is as follows:
Right-of-use-asset |
| ($) |
| |
Balance at March 31, 2024 |
|
|
| |
Amortization |
|
| ( | ) |
Balance at March 31, 2025 |
|
|
| |
Amortization |
|
| ( | ) |
Balance at March 31, 2026 |
|
|
| |
| 26 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
Lease liability
On May 1, 2021, the Company entered into the lease agreement, which resulted in the lease liability of $
A summary of changes in the lease liability during the year ended March 31, 2026 are as follows:
Lease liability |
| ($) |
| |
Balance at March 31, 2025 |
|
|
| |
Lease payment – base rent portion |
|
| ( | ) |
Lease liability – accretion expense |
|
|
| |
Balance at March 31, 2026 |
|
|
| |
Current portion |
|
|
| |
Long-term portion |
|
|
| |
The following is a schedule of the Company’s future lease payments (base rent portion) under the lease obligations:
Future lease payments (base rent portion only) |
| ($) |
| |
Fiscal 2027 (April 1, 2026 to April 29, 2027) |
|
|
| |
Total undiscounted lease payments |
|
|
| |
Less: imputed interest |
|
|
| |
Lease liability as at March 31, 2026 |
|
|
| |
15. FINANCIAL RISK MANAGEMENT
(a) Capital management objectives
The Company’s primary objectives when managing capital are to safeguard the Company’s ability to continue as a going concern so that it can continue to provide returns for shareholders, and to have sufficient liquidity available to fund ongoing expenditures and suitable business opportunities as they arise.
The Company considers the components of shareholders’ equity as well as its cash as capital. The Company manages its capital structure and makes adjustments to it in light of changes in economic conditions and the risk characteristics of the underlying assets. In order to maintain or adjust the capital structure, the Company may issue equity, sell assets, or return capital to shareholders as well as issue or repay debt.
The Company’s investment policy is to invest its cash in highly liquid, short-term, interest-bearing investments having maturity dates of three months or less from the date of acquisition, which are readily convertible into known amounts of cash.
The Company is not subject to any imposed equity requirements.
There were no changes to the Company’s approach to capital management during the year ended March 31, 2026.
| 27 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
(b) Carrying amounts and fair values of financial instruments
Fair value
IFRS 7 Financial Instruments: Disclosures establishes a fair value hierarchy for financial instruments measured at fair value. Assets and liabilities are classified in their entirety based on the lowest level of input that is significant to the fair value measurement. The three levels of the fair value hierarchy are as follows:
Level 1 ‐ applies to assets or liabilities for which there are quoted prices in active markets for identical assets or liabilities.
Level 2 ‐ applies to assets or liabilities for which there are inputs other than quoted prices included in Level 1 that are observable for the asset or liability, either directly such as quoted prices for similar assets or liabilities in active markets or indirectly such as quoted prices for identical assets or liabilities in markets with insufficient volume or infrequent transactions.
Level 3 ‐ applies to assets or liabilities for which there are unobservable market data.
The Company’s recorded amounts of cash, amounts receivable, accounts payable and other liabilities approximate their respective fair values due to their short‐term nature. The carrying value of the restricted cash approximates its fair value, as it is cash-based. The Company’s marketable securities are carried at fair value based on quoted prices in active markets (level 1).
As at March 31, 2026, the carrying values of the Company’s financial assets and financial liabilities approximate their fair values.
(c) Financial instrument risk exposure and risk management
The Company is exposed in varying degrees to a variety of financial instrument-related risks. The Board of Directors approves and monitors the risk management processes, inclusive of documented treasury policies, counterparty limits, and controlling and reporting structures. The type of risk exposure and the way in which such exposure is managed is provided as follows:
Credit risk
Credit risk is the risk of potential loss to the Company if a counterparty to a financial instrument fair to meet its contractual obligations. The Company’s credit risk is primarily attributable to its liquid financial assets, including cash, and amounts receivable and other assets. The carrying values of these financial assets represent the Company’s maximum exposure to credit risk.
The Company limits the exposure to credit risk by only investing its cash in high-credit quality financial institutions in business and savings accounts, which are available on demand by the Company for its programs.
Liquidity risk
Liquidity risk is the risk that the Company will encounter difficulty in meeting the obligations associated with its financial liabilities that are settled by delivering cash or other financial assets. The Company ensures that there is sufficient cash in order to meet its short-term business requirements after taking into account the Company’s holdings of cash.
| 28 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
Liquidity risk is the risk that the Company will not be able to meet its financial obligations as they become due. In the management of liquidity risk, the Company maintains a balance between continuity of funding and the flexibility through the use of borrowings. Management closely monitors the liquidity position and expects to have adequate sources of funding to finance the Company’s projects and operations. The directors of the Company are of the opinion that, taking into account the Company's cash reserves and external financial resources, the Company has sufficient working capital for its current obligations.
Interest rate risk
The Company is subject to interest rate risk with respect to its investments in cash. The Company’s policy is to invest cash at variable rates of interest and cash reserves are to be maintained in cash in order to maintain liquidity, while achieving a satisfactory return for shareholders. Fluctuations in interest rates when cash matures impact interest income earned.
As at March 31, 2026, the Company’s exposure to interest rate risk was nominal.
Price risk
Equity price risk is defined as the potential adverse impact on the Company’s earnings due to movements in individual equity prices or general movements in the level of the stock market. The Company is subject to price risk in respect of its investments in marketable securities.
As at March 31, 2026, the Company’s exposure to price risk was not significant in relation to these Financial Statements.
16. INCOME TAXES
(a) Provision for current tax
No provision has been made for current income taxes as the Company has no taxable income.
(b) Provision for deferred tax
As future taxable profits of the Company are uncertain, no deferred tax asset has been recognized.
At March 31, 2026, the Company has unused non-capital loss carry forwards of approximately $
At March 31, 2026, the Company has resource tax pools of approximately $
| 29 | Page |
AMARC RESOURCESLTD. Notes to the Financial Statements. For the years ended March 31, 2026 and 2025 (Expressed in Canadian Dollars, unless otherwise stated) |
(c) Reconciliation of effective tax rate
|
| March 31, |
|
| March 31, |
| ||
|
| 2026 |
|
| 2025 |
| ||
|
|
|
|
|
|
| ||
Net income (loss) for the year |
|
| ( | ) |
|
| ( | ) |
Total income tax expense |
|
|
|
|
|
| ||
Net income (loss) excluding income tax |
|
| ( | ) |
|
| ( | ) |
|
|
|
|
|
|
|
|
|
Income tax expense (recovery) using the Company's tax rate |
|
| ( | ) |
|
| ( | ) |
Non-deductible expenses and other |
|
|
|
|
|
| ||
Temporary difference booked to reserve |
|
| ( | ) |
|
| ( | ) |
Deferred income tax assets not recognized |
|
| ( | ) |
|
|
| |
|
|
| - |
|
|
| - |
|
(d) Deductible temporary differences
At March 31, 2026, the Company had the following deductible temporary differences for which no deferred tax asset was recognized:
Expiry |
| Tax Losses (Capital) |
|
| Tax Losses |
|
| Resource Pools |
|
| Other |
| ||||
Within one year |
|
|
|
|
|
|
|
|
|
|
|
| ||||
One to five years |
|
|
|
|
|
|
|
|
|
|
|
| ||||
After five years |
|
|
|
|
|
|
|
|
|
|
|
| ||||
No expiry date |
|
|
|
|
|
|
|
|
|
|
|
| ||||
|
|
|
|
|
|
|
|
|
|
|
|
| ||||
17. EVENTS AFTER THE REPORTING PERIOD
(a) Exercise of Options
Subsequent to the year ended on March 31, 2026, the following options were exercised:
(b) Joint Venture Agreement with Boliden
Subsequent to the year ended on March 31, 2026, Amarc and Boliden signed a joint venture agreement to jointly operate the DUKE JV (note 7(c)).
| 30 | Page |
EXHIBIT 99.2
AMARC RESOURCES LTD.
MANAGEMENT'S DISCUSSION AND ANALYSIS
FOR THE YEAR ENDED MARCH 31, 2026
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
| DATE |
| 3 |
|
| DESCRIPTION OF THE BUSINESS |
| 4 |
|
| RECENT AND CURRENT QUARTER HIGHLIGHTS |
| 4 |
|
| MINERAL PROPERTIES |
| 7 |
|
| MARKET TRENDS |
| 17 |
|
| SELECTED ANNUAL INFORMATION |
| 18 |
|
| RESULTS OF OPERATIONS |
| 18 |
|
| LIQUIDITY |
| 22 |
|
| CAPITAL RESOURCES |
| 22 |
|
| COMMITMENTS AND FINANICAL OBLIGATIONS |
| 23 |
|
| OFF-BALANCE SHEET ARRANGEMENTS |
| 23 |
|
| TRANSACTIONS WITH RELATED PARTIES |
| 23 |
|
| PROPOSED TRANSACTIONS |
| 24 |
|
| CHANGES IN ACCOUNTING POLICIES INCLUDING INITIAL ADOPTION |
| 24 |
|
| FINANCIAL INSTRUMENTS AND RISK MANAGEMENT |
| 25 |
|
| OUTSTANDING SHARE DATA |
| 26 |
|
| DISCLOSURE CONTROLS AND PROCEDURES |
| 26 |
|
| INTERNAL CONTROLS OVER FINANCIAL REPORTING PROCEDURES |
| 26 |
|
| LIMITATIONS OF CONTROLS AND PROCEDURES |
| 27 |
|
| TECHNICAL INFORMATION |
| 27 |
|
| RISK FACTORS |
| 28 |
|
| - 2 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
This Management's Discussion and Analysis ("MD&A") should be read in conjunction with the audited financial statements (the “Annual Financial Statements”) of Amarc Resources Ltd. (“Amarc”, or the “Company”) for the year ended March 31, 2026, and the audited financial statements (the “Financial Statements”) of the Company for the year ended March 31, 2026, both of which are publicly available on SEDAR+ at www.sedarplus.ca. All monetary amounts herein are expressed in Canadian Dollars ("CAD") unless otherwise stated.
The Company reports in accordance with International Financial Reporting Standards as issued by the International Accounting Standards Board ("IASB") and interpretations of the IFRS Interpretations Committee (together known as "IFRS"). The following disclosure and associated Financial Statements are presented in accordance with IFRS.
This MD&A is prepared as of July 20, 2026.
|
Cautionary Note to Investors Concerning Forward-looking Statements
This MD&A includes certain statements that may be deemed "forward-looking statements". All such statements, other than statements of historical facts that address exploration plans and plans for enhanced relationships are forward-looking statements. Although the Company believes the expectations expressed in such forward-looking statements are based on reasonable assumptions, such statements are not guarantees of future performance and actual results or developments may differ materially from those in the forward-looking statements. Assumptions used by the Company to develop forward-looking statements include the following: Amarc's projects will obtain all required environmental and other permits and all land use and other licenses, studies and exploration of Amarc's projects will continue to be positive, and no geological or technical problems will occur. Factors that could cause actual results to differ materially from those in forward-looking statements include market prices, potential environmental issues or liabilities associated with exploration, development and mining activities, exploitation and exploration successes, continuity of mineralization, uncertainties related to the ability to obtain necessary permits, licenses and tenure and delays due to third party opposition, changes in and the effect of government policies regarding mining and natural resource exploration and exploitation, exploration and development of properties located within Aboriginal groups asserted territories may affect or be perceived to affect asserted aboriginal rights and title, which may cause permitting delays or opposition by Aboriginal groups, continued availability of capital and financing, and general economic, market or business conditions. Investors are cautioned that any such statements are not guarantees of future performance and actual results or developments may differ materially from those projected in the forward-looking statements. For more information on Amarc Resources Ltd., investors should review Amarc's annual Form 20-F filing with the United States Securities and Exchange Commission at www.sec.gov and its home jurisdiction filings that are available at www.sedarplus.ca. |
| - 3 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
DESCRIPTION OF THE BUSINESS
Amarc is a mineral exploration and development company with an experienced and successful management team focused on developing a new generation of long life, high value British Columbia (“BC”) porphyry copper-gold(“Cu-Au”) mines. By combining high demand projects, discoveries and successful management, Amarc has created a solid platform to create value from its exploration and development stage assets.
Amarc is advancing the JOY, DUKE and IKE porphyry Cu±Au districts, located in northern, central and southern BC, respectively, and in proximity to power, highways and rail infrastructure. Each District hosts one or more known Cu±Au deposits, discoveries and other deposit targets with significant potential for further discovery and the development of important-scale, porphyry Cu±Au deposits (see “Mineral Properties” for further details):
|
| · | The JOY District (or “JOY” or the “District”) is host to the new AuRORA Au-Cu-Ag Deposit, a gold-rich porphyry deposit discovered in 2024, the TWINS and CANYON Au-Cu Discoveries, the historical PINE and Brenda Au-Cu Deposits and a pipeline of other Au-Cu deposit targets; |
|
|
|
|
|
| · | The DUKE District hosts the DUKE Cu-Mo-Au-Ag Deposit and other Cu±Au deposit targets; and |
|
|
|
|
|
| · | The IKE District hosts the IKE Cu-Mo-Ag Deposit discovery, the Empress Cu-Au Deposit and multiple other Cu±Au deposit targets. |
RECENT AND CURRENT QUARTER HIGHLIGHTS
|
| · | On October 22, 2025, the Company announced completion of the 2025 AuRORA Deposit and JOY Gold-Copper District program. A total of 15,381 m of core was drilled in 35 holes across the District of which 24 holes were drilled at the AuRORA Deposit, 23 of which were Deposit expansion holes. Survey work included 64 line-km of ground Induced Polarization (“IP”) and 96 km2 of airborne magnetics geophysics, approximately 90 km2 of geological mapping and 950 grid soil, 639 rock chip and 324 silt geochemical sampling. Initial results from this program announced in November and December 2025 are included here for completeness. |
|
|
|
|
|
| · | On November 3, 2025, results from six drill holes completed on Sections 8000N and 8100N at the AuRORA Deposit were announced. The holes successfully expanded the Deposit +200 m to the north, and it remains open to further expansion to the north, east and west of Section 8000N and 8100N. Highlights include: |
|
| · | JP25089 126 m of 0.97 g/t Au, 0.32% Cu and 4.8 g/t Ag including |
|
|
| 61 m of 1.24 g/t Au, 0.47% Cu and 7.8 g/t Ag |
|
|
|
|
|
| · | JP25091 231 m of 0.83 g/t Au, 0.22% Cu and 2.3 g/t Ag including |
|
|
| 141 m of 1.11 g/t Au, 0.31% Cu and 3.0 g/t Ag |
|
|
|
|
|
| · | JP25094 154 m of 0.79 g/t Au, 0.27% Cu and 4.1 g/t Ag including |
|
|
| 60 m of 1.58 g/t Au, 0.45% Cu and 6.7 g/t Ag |
|
|
|
|
|
| · | JP25086 75 m of 0.71 g/t Au, 0.27% Cu and 2.4 g/t Ag |
|
|
|
|
|
| · | JP25100 200 m of 0.70 g/t Au, 0.24% Cu and 1.8 g/t Ag including |
|
|
| 143 m of 0.86 g/t Au, 0.28% Cu and 1.9 g/t Ag |
| - 4 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
|
| · | JP240831 204 m of 0.74 g/t Au, 0.28% Cu and 3.9 g/t Ag including |
|
|
| 51 m of 1.51 g/t Au, 0.53% Cu and 6.5 g/t Ag |
|
| · | On December 10, 2025, further results from the 2025 AuRORA Deposit drilling were announced. Two drill holes (JP25103, JP25109) located on Section 8200N expanded AuRORA a further +100 m to the north and two holes (JP25093 and JP25107) drilled on Section 7900N expanded the Deposit approximately 200 m to the east. The balance of assays from hole JP25098 drilled on Section 7600N (partially announced on September 22, 2025) were also released and expanded the Deposit approximately 300 m to the southeast. Highlights include: |
|
| · | JP25107 201 m of 1.40 g/t Au, 0.28% Cu and 2.6 g/t Ag including |
|
|
| 32 m of 1.65 g/t Au, 0.27% Cu and 2.0 g/t Ag and |
|
|
| 94 m of 2.08 g/t Au, 0.41% Cu and 3.4 g/t Ag |
|
|
|
|
|
| · | JP 25109 201 m of 1.38 g/t Au, 0.27% Cu and 1.6 g/t Ag including |
|
|
| 135 m of 1.90 g/t Au, 0.30% Cu and 1.6 g/t Ag and |
|
|
| 111 m of 2.24 g/t Au, 0.34% Cu and 1.6 g/t Ag |
|
|
|
|
|
| · | JP25103 47 m of 1.50 g/t Au, 0.44% Cu and 5.4 g/t Ag |
|
| · | On January 23, 2026, the remaining assay results from the 2025 drilling at AuRORA were announced: |
|
| · | Drill hole JP25119 on Section 8300N intersected 117 m of 0.49 g/t Au, 0.19% Cu, and 2.2 g/t Ag, including 93 m of 0.54 g/t Au, 0.20% Cu, and 2.4 g/t Ag; and 98 m of 0.52 g/t Au, 0.13% Cu, and 2.6 g/t Ag, and expanded the deposit a further +100 m to the north, for a cumulative +400 m northern extension in 2025. These intersections occur in rock with a comparatively weak magnetic signature and outside of the main core of IP chargeability responses that defines the defines the Northwest Gossan (“NWG”) Target that hosts AuRORA, opening up exciting potential for further discovery and development of a significant porphyry Au-Cu district at JOY. |
|
|
|
|
|
| · | A single large step out scout hole (JP25120) was completed +500 m to the east-northeast of hole JP25119, and which was targeted on a magnetic high within the comparatively lower contrast area of new potential within the NWG Target. It intercepted significant mineralization at depth: 33 m of 0.58 g/t Au, 0.22% Cu, and 5.4 g/t Ag with the last 36 m of the hole returning 0.29 g/t Au, 0.28% Cu, and 5.9 g/t Ag. |
|
|
|
|
|
| · | Hole JP25114, drilled 550 m south of AuRORA within the NWG Target also intercepted promising Au-Ag±Cu mineralization: 12 m of 0.40 g/t Au and 0.5 g/t Ag and 74 m of 0.92 g/t Au, 0.05% Cu, and 0.6 g/t Ag. |
|
|
|
|
|
| · | A total of 77 drill holes (33,136.7 m) were drilled JOY District in 2024-2025. Of these, 45 holes (17,722.3 m) were completed at the AuRORA Deposit and 32 holes (15,414.4 m) elsewhere across the District. |
|
|
|
|
|
| · | The AuRORA Deposit now measures 1.4 km by 0.8 km and remains open to expansion. |
_______________
1 2024 Hole previously report on February 28, 2025.
| - 5 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
|
| · | On February 5, 2026, the Company announced appointments of Gavin Titley, P.Geo, as Vice President, Exploration and Dr. Farhad Bouzari as Chief Exploration Scientist. |
|
|
|
|
|
| · | On February 19, 2026, results from 2025 drilling at the TWINS Discovery at the JOY District were announced. TWINS drillhole JP25106 stepped back and targeted underneath holes JP24051 and JP22020, intercepting, at depth, 300 m at 0.51 g/t Au and 0.23% Cu, including 243 m at 0.59 g/t Au and 0.26% Cu, 135 m at 0.86 g/t Au and 0.38% Cu and 45 m at 1.08 g/t Au and 0.47% Cu. |
|
|
|
|
|
| · | On April 2, 2026, Amarc announced that Boliden Mineral Canada Ltd. (“Boliden”), a subsidiary of Boliden Inc., would continue its participate in the exploration of the DUKE District, and effective as of April 1, 2026, a Boliden 60%/Amarc 40% Joint Venture (the “DUKE JV”) as defined by the DUKE earn in agreement dated on November 21, 2022 had commenced. Boliden completed an investment of $30 million to the end of 2025 to earn a 60% interest in the DUKE District and elected not to exercise the option to increase its interest from 60% to 70% by investing a further $60 million. Under the DUKE JV, Boliden can now invest 60% and Amarc 40% in future programs or dilute their interest in the JV. |
|
|
|
|
|
| · | On May 27, 2026, the Company announced a preliminary budget of approximately $15 million for the 2026 JOY District exploration program focused on unlocking the Tier-1 potential of the District. The program will be fully funded by Freeport-McMoRan Mineral Properties Canada Inc., a wholly-owned subsidiary of Freeport-McMoRan Inc. (“Freeport”), through AuRORA Minerals Ltd. (AuRORA Minerals”) the private joint venture corporation in which Freeport currently owns a 60% and Amarc a 40% shareholder’s interest which holds the JOY District mineral rights and titles (for further details, see “Agreement with Freeport” below). Amarc has been appointed as the primary contractor to manage the JOY exploration programs under a separate Services Agreement. |
|
|
|
|
|
| · | On June 25, 2026, the Company announced that field surveys had commenced to firm up Cu-Au deposit targets for potential drill testing later in the season at the DUKE Copper-Gold District. The $4 million 2026 DUKE District program is fully funded by Boliden as part of the DUKE JV (see above). Under the terms of the DUKE JV, Amarc has 180 days from April 30, 2026 to elect to contribute $2.66 million in funding to the program to maintain its full 40% interest in the JV. Amarc is continuing as project operator. |
|
|
|
|
|
| · | On July 2, 2026, the Company announced the commencement of the 2026 exploration program at the JOY District. Fully funded by Freeport, the 2026 program includes step out drilling to continue to assess the extent and tenure of the gold-rich AuRORA Porphyry Au-Cu-Ag Deposit as well as other studies to advance the Deposit; additional drilling at the TWINS Discovery; and geological, geochemical, and geophysical surveys across the District to refine the emerging pipeline of porphyry copper-gold deposit targets for drill testing. |
|
|
|
|
|
| · | On July 21, 2026, the Company announced a $5 million increase in funding for the 2026 JOY Copper-Gold District exploration program, adding to the initial +$15 million budget reported in the Company’s May 27, 2025 release, funded by Freeport through AuRORA Minerals. Amarc confirmed that three drill rigs were actively working with a primary focus at the AuRORA Porphyry Gold-Copper-Silver Deposit and the TWINS Gold-Copper Discovery located approximately 17 km south of AuRORA, and that extensive geological, geochemical and geophysical surveys are also underway to define potential drill sites at multiple other significant gold-copper deposit targets across the JOY District. |
| - 6 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
MINERAL PROPERTIES
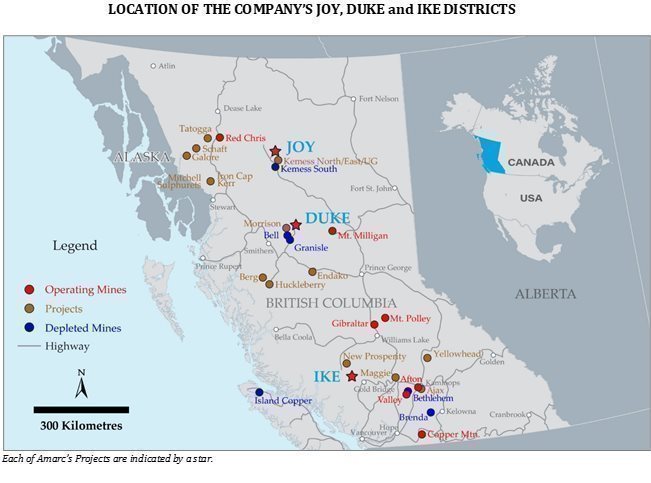
Figure 1
The JOY Au-Cu District (40% ownership)
The approximately 630 km2 JOY District is located immediately to the north of the prolific Kemess porphyry Au-Cu district (the “Kemess District”) in the Toodoggone Region (or the “Toodoggone”) of north-central BC, a geological region with high potential for important porphyry and epithermal deposits. The Toodoggone is part of BC's Golden Horseshoe trend that extends to the Golden Triangle in the west.
Three deposit discoveries have been made in the JOY District over the past four years. These include the important new AuRORA Au-Cu-Ag Deposit Discovery made in 2024, the TWINS Au-Cu Discovery made in 2024 and confirmed in 2025, and the Canyon Cu-Au Discovery made in 2022. Drilling over this time has also expanded AuRORA, TWINS and Canyon Discoveries, the historical PINE porphyry Au-Cu Deposit (the “PINE Deposit”), all of which remain open to further expansion and established a pipeline of other large, high potential, porphyry Au-Cu targets across the District (see Figure 2).
| - 7 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
LOCATION OF TARGET AREAS, DEPOSITS AND DISCOVERIES IN JOY DISTRICT
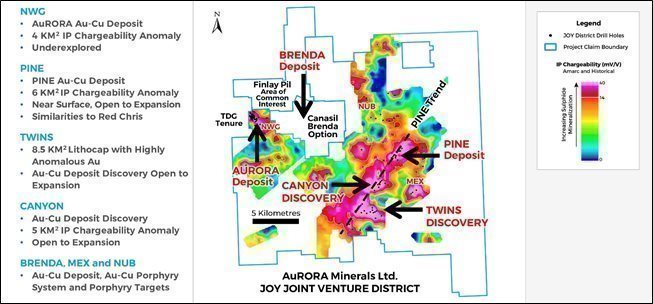
Figure 2
AuRORA Deposit
The high grade AuRORA Au-Cu-Ag Deposit represents a significant new porphyry discovery with Tier-1 potential. The discovery was made in 2024 by drilling at the 4 km2 NWG Target, a target that had not been previously drill tested. The mineralization at AuRORA begins near to the surface and is characterized by its gold-rich nature, excellent lateral and vertical continuity and its geometry.
The first hole ever drilled at AuRORA – JP24057 - intersected a new porphyry Au-Cu-Ag system hosting high and continuous Au grades. Following completion of this discovery hole, Amarc initiated systematic step out drilling with three core rigs, with a view to begin to outline the Au-Cu-Ag deposit (Amarc release January 17 and 20, 2025 and February 28, 2025). The mineralization discovered in 2024 by 20 drill holes at AuRORA extended over an area of approximately 600 m by 600 m with significant expansion potential (see Amarc release January 15, 2026).
Twenty-three step out holes and one infill hole were completed at AuRORA in 2025, successfully expanding the Deposit over an area measuring 1.4 km by 0.8 km, and which remains wide open. Table 1 summarizes key results from 2024 and 2025 at the AuRORA Deposit.
| - 8 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
Table 1
Select Results from 2024-2025 Drilling at the AuRORA Deposit
| Drill Hole | Int. 1,2,3 (m) | From (m) | Incl. | Au (g/t) | Cu (%) | Ag (g/t) |
| JP24057 | 82 | 18 |
| 1.24 | 0.38 | 2.47 |
| 42 | 58 | Incl. | 1.97 | 0.49 | 3.58 | |
| 70 | 120 |
| 2.56 | 0.42 | 5 | |
| JP24059 | 271 | 24 |
| 0.98 | 0.25 | 1.93 |
| 171 | 24 | Incl. | 1.32 | 0.34 | 2.62 | |
| 89 | 106 | and | 2.29 | 0.46 | 3.65 | |
| JP24060 | 130 | 74 |
| 2.4 | 0.61 | 5.33 |
| 81 | 104 | Incl. | 3.58 | 0.85 | 7.36 | |
| JP24063 | 132 | 70 |
| 1.01 | 0.3 | 2.8 |
| 99 | 103 | Incl. | 1.17 | 0.33 | 3.15 | |
| JP24071 | 212 | 21 |
| 1.36 | 0.4 | 3.35 |
| 108 | 104 | Incl. | 2.38 | 0.6 | 5.17 | |
| JP24075 | 266 | 34 |
| 1.24 | 0.31 | 3.42 |
| 109 | 37 | Incl. | 2.41 | 0.51 | 5.27 | |
| JP24080 | 132 | 137 |
| 1.87 | 0.63 | 5.22 |
| 90 | 167 | Incl. | 2.53 | 0.81 | 6.45 | |
| JP25087 | 66 | 162 |
| 0.65 | 0.25 | 2.7 |
| JP25088 | 106 | 194 |
| 0.62 | 0.27 | 3.1 |
| 75 | 213 | Incl. | 0.76 | 0.33 | 3.6 | |
| JP25089 | 126 | 225 |
| 0.97 | 0.32 | 4.8 |
| 61 | 225 | Incl. | 1.24 | 0.47 | 7.8 | |
| JP25091 | 231 | 132 |
| 0.83 | 0.22 | 2.3 |
| 141 | 150 | Incl. | 1.11 | 0.31 | 3.0 | |
| 90 | 192 | and | 1.42 | 0.36 | 3.4 |
| 1. | Widths reported are drill widths, such that true thicknesses are unknown. |
| 2. | All assay intervals represent length-weighted averages. |
| 3. | Some figures may not sum exactly due to rounding. |
For further results see Amarc releases January 17, 20, February 28, November 3, December 10, 2025 and January 23, 2026.
Additionally, of notable interest in the 2025 drilling at AuRORA are the areas around two drill holes, JP25114 and JP25120, which intersected promising mineralization 550 m south and 350 m to the north of the Deposit, respectively (see Amarc release January 23, 2026 and “Current Quarter and Recent Highlights” above). These holes may represent further extensions to the deposit or discoveries of new potential within the NWG Target that hosts AuRORA.
| - 9 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
TWINS and Canyon Discoveries
The highly prospective TWINS porphyry target sulphide system is defined by an 8.5 km2 IP chargeability geophysics anomaly. Several initial widely spaced and near surface reconnaissance drill holes are characterized by highly anomalous Au intercepts, including JP22020 which returned 210 m of 0.14 g/t Au, 0.03% Cu and 0.4 g/t Ag. Drill holes in 2024 and 2025 stepped back to test beneath scout hole JP22020, confirming a new porphyry Au-Cu discovery at TWINS. Hole JP24051 intercepted 124 m at 0.35 g/t Au, 0.13% Cu and 0.6 g/t Ag from 491 m and 150 m at 0.23 g/t Au, 0.08% Cu and 0.4 g/t Ag from 291 m and hole JP25106 intercepted 300 m at 0.51 g/t Au, 0.23% Cu and 0.5 g/t Ag from 819 m, including 243 m at 0.59 g/t Au, 0.26% Cu and 0.6 g/t Ag and 45 m of 1.08 g/t Au, 0.47% Cu and 1.0 g/t Ag (see Amarc release February 19, 2026).
At CANYON, very limited initial scout drilling of this expansive (5 km2) and largely covered sulphide system by Amarc in 2021 intercepted 27 m of 0.21 g/t Au, 0.06% Cu in hole JP21006 (see Amarc release March 7, 2022). Further reconnaissance drilling 2022 discovered a significant new zone of porphyry Au-Cu mineralization with hole JP22030 intersecting 96 m 0.18 g/t Au, 0.39% Cu and 2.6 g/t Ag, within 296 m of 0.14 g/t Au, 0.30% Cu and 1.7 g/t Ag and 10.5 m of 0.25 g/t Au, 0.61% Cu and 2.1 g/t Ag. In 2024, drill hole JP24046 stepped out 250 m to the east-northeast from JP22030, successfully extending the mineralization to depth and intercepting 402 m of 0.09 g/t Au, 0.16% Cu and 1.2 g/t Ag including 51 m of 0.18 g/t Au, 0.32% Cu, and 1.8 g/t Ag. The Canyon discovery remains open to expansion and requires substantial drilling to delineate the Au-Cu potential (see Amarc release March 2, 2023).
PINE Deposit
The PINE Deposit is hosted within a 6 km2 mineralized system, which remains to be fully explored. The PINE Deposit had seen several phases of historical drilling prior to initial work by Amarc which identified significant expansion potential at PINE. Prior to 2022, the historical PINE Deposit was known to extend over approximately 600 m by 900 m and be open to expansion internally and laterally as well as to depth (see Amarc release March 7, 2022). Early drilling by Amarc successfully intercepted significant mineralization that extended the footprint of the deposit over a strike length of 1,700 m within a 2,600 m mineralized footprint: for example, 204 m of 0.41 g/t Au, 0.18% Cu and 2.3 g/t Ag in hole JP22010 and 105 m of 0.47 g/t Au, 0.13% Cu and 1.8 g/t Ag in hole JP22013. Drilling also highlighted the favorable geometry of the PINE Deposit: most of the known mineralization occurs from surface to 300 m depth and locally extends to 550 m depth (see Amarc March 2, 2023 release).
Drill hole JP24058 completed in 2024 was designed to step out 250 m to the southeast from the known PINE Deposit to look for lateral extensions and high grade feeder structures. The hole was deflected off course after intersecting a fault at depth; however, it successfully intersected 182 m of 0.26 g/t Au, 0.16% Cu and 2.3 g/t Ag from 368 m, including 110 m of 0.34 g/t Au, 0.23% Cu, 3.1 g/t Ag from 440 m and 37 m of 0.51 g/t Au, 0.48% Cu and 3.7 g/t Ag from 785 m. These mineralized intersections expanded the PINE Deposit 180 m to the east and 180 m to the south (see Amarc release February 28, 2025)). Significant additional drilling is required to fully delineate the PINE Deposit and assess the Cu-Au potential within the greater PINE Target.
The JOY technical information up to and including 2020 is summarized in the Company’s National Instrument 43-101 Technical Report (“JOY Technical Report”) filed under Amarc’s profile at www.sedarplus.ca and on the Company’s website at www.amarcresources.com/projects/joy-project/technical-report. Additional details on Amarc’s exploration programs at JOY from 2021-2026 are available in previous MD&As or in new releases on the Company’s website.
| - 10 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
The JOY District is subject to the following royalties:
|
| · | On November 21, 2017, Amarc acquired 100% interest in the 7,200 hectare JOY property from a private vendor. This JOY property is subject to an underlying 3% NSR royalty from production to a former owner, which is capped at $3.5 million. |
|
|
|
|
|
| · | The PINE Property is subject to a 3% NSR on the PINE Property capped at $5 million payable from production. |
|
|
|
|
|
| · | A 2.5% net profits interest (“NPI”) on mineral claims comprising approximately 96% of the PINE Property, which are subject to the 3% NSR and a 1% NSR on the balance of the claims that are not subject to the 3% NSR. The NPI royalty can be reduced to 1.25% at any time for $2.5 million in cash or shares. The NSR royalty can be reduced to 0.5% for $2.5 million in cash or shares. |
|
|
|
|
|
| · | The Paula claim is subject to a 1% NSR royalty payable from commercial production that is capped at $500,000. |
Agreement with Freeport
In May 2021, Amarc entered into a Mineral Property Earn-In Agreement (the “EIA”) with Freeport, whereby Freeport may acquire up to a 70% ownership interest by making staged investments in the JOY District. Freeport completed the Stage 1 requirement of $35 million of expenditures, under an accelerated timeframe, and currently owns a 60% and Amarc a 40% shareholder’s interest in AuRORA Minerals Ltd. (AuRORA Minerals”) the private joint venture corporation which holds the JOY District mineral rights and titles.
On September 2, 2025, the Company announced Freeport had formally elected to proceed to Stage 2 of the EIA and to earn a further 10% interest in Aurora Minerals by spending an additional $75 million within 5 years at a rate of no less than $10 million per year, failing which the parties will proceed to fund the project pro rata on a 60:40 basis. The +$16 million 2025 program and the recently announced $20 million 2026 budget (see “Current Quarter and Recent Highlights” above) expenditures are being 100% funded by Freeport under Stage 2 and under an accelerated time frame. While Freeport is now the Operator of JOY, Aurora Minerals and Freeport have appointed Amarc as the primary contractor to manage JOY exploration programs under a separate Services Agreement.
Brenda Property
On February 11, 2025, Amarc announced that it had signed a mineral property option agreement with Canasil Resources Inc. (“Canasil”) pursuant to which it can acquire 100% interest in 22 mineral claims that are located adjacent to its JOY tenure and immediately to the east of its AuRORA Au-Cu-Ag discovery. The terms of the 5-year option to acquire 100% of the Brenda Property require annual payments of $400,000 with the option to purchase exercise price starting at $8 million if exercised in the first year and increasing on an annual basis to $12 million in year five. To March 31, 2026, $800,000 in option payments have been made. The claims are subject to a 2% NSR royalty of which 1% (or one-half) can be acquired for $5 million before commencement of commercial mining operations and $10 million after commencement of mining. The 44 km2 Brenda tenure is adjoined on three sides by the JOY District and falls largely within the area of common interest under the JOY agreement of 2021. Freeport has exercised its right to have the entire Brenda tenure included in the JOY Agreement (Amarc release July 16, 2025).
| - 11 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
The Brenda Property is underlain by the same highly prospective volcanics and transitional porphyry Au-Cu and epithermal Au-Ag geological setting as at the AuRORA and Canyon porphyry Au-Cu discoveries. Historical exploration of the Brenda Property has identified both epithermal and porphyry related rock alteration assemblages hosting Au, Cu and Ag mineralization (see Canasil 2021 Technical Report at www.sedarplus.ca).
PIL Property
In July 2025, Amarc announced that it had exercised its right to have approximately 32% of the total mineral claims area of Freeport’s option to acquire 80% of the PIL Property (see Finlay Minerals Ltd. (TSXV:FYL) release April 17, 2025) brought into the JOY District (see Amarc release July 16, 2025). The PIL Property is adjacent to the northwest of the original JOY District tenure.
Approximately 32% (42.34 km2) of the PIL mineral claims area lies within the area of common interest under the Amarc – Freeport JOY Agreement. Freeport is responsible for making any expenditures to fund the exercise of the PIL option with Finlay, and expenditures incurred within the Amarc area of common interest only will count towards Freeport’s election to spend $75 million under Stage 2 of the Agreement with Amarc. If Freeport fulfills its obligation to acquire 80% of the PIL Property, Amarc will have a maximum interest of 24% in the PIL mineral claims within the area of common interest.
Three additional claims staked by Amarc and lying adjacent to the southeast of the JOY District have also been added to the District.
The DUKE Cu-Au District (40% interest)
The DUKE District is located 80 km northeast of Smithers in the broader Babine Region (or the “Babine”), one of BC’s most prolific porphyry Cu-Au belts. The Babine is a 40 by 100 km north to northwesterly striking mineralized belt that hosts the former Bell and Granisle Cu-Au mines held by Noranda Mines which produced a total of 1.1 billion pounds of Cu, 634,000 ounces of Au and 3.5 million ounces of Ag2, and the advanced stage Morrison Cu-Au deposit that is also held by another company. Amarc’s DUKE porphyry Cu-Mo-Au-Ag Deposit (“DUKE Deposit”) is located 30 km north of the Bell Mine. Extensive infrastructure, primarily relating to the forestry industry but also dating back to previous mining activity exists in the District.
The 732 km2 DUKE District includes both the DUKE Cu-Mo-Au-Ag Deposit and a series of porphyry Cu-Au deposit targets. Systematic and extensive DUKE District programs have both substantially expanded the DUKE Deposit to an area measuring approximately 900 x 600 metres, which remains open to expansion, and revealed the potential for the development of a porphyry Cu-Au district while efficiently screening out less prospective areas (see Amarc release July 2, 2025).
__________________
2 MINFILE Number 093L 146 and 093M 001 MINFILE Production Detail Report, BC Geological Survey, Ministry of Energy and Mines, BC.
| - 12 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
DUKE Cu-Mo-Au-Ag Deposit
The DUKE Deposit lies within the 4.7 km2 DUKE Target defined by an IP geophysical anomaly indicating the presence of a mineralized system. Although explored historically, the now extensive porphyry Cu system at the DUKE discovery was not fully delineated. Amarc completed initial drill testing at DUKE in 2017 and 2018. In 2017, extensive porphyry copper-style mineralization was discovered by two holes (see Amarc release December 19, 2017). Seven of nine holes drilled by Amarc in 2018 successfully tested the geometry and grade distribution of the porphyry Cu-style mineralization in the DUKE Deposit over an area measuring approximately 400 m north-south by 600 m east-west, with mineralization extending to the depth of drilling – over 360 m deep. One other hole intersected substantial lengths of moderate to low grade Cu and Mo mineralization in the surrounding DUKE Target area (see Amarc release June 12, 2018).
Shortly after signing of the Boliden agreement in November 2022 (see “Agreement with Boliden” below), Amarc initiated delineation drilling at the DUKE Deposit, completing 11,070 m between early December 2022 and mid-March 2023. This work confirmed the DUKE Deposit extends to depths of at least 600 m and expanded the deposit footprint laterally to over 650 m north-south by 800 m east-west (see Amarc releases January 23, February 15 and June 15, 2023). Highlights include:
|
| · | 183 m of 0.43% CuEQ3 (0.31% Cu, 0.019% Mo, 0.07 g/t Au, 1.5 g/t Ag) (DK22009) |
|
| · | 217 m of 0.45% CuEQ (0.33% Cu, 0.018% Mo, 0.08 g/t Au, 1.5 g/t Ag) (DK22010) |
|
| · | 30 m of 0.47% CuEQ (0.36 % Cu, 0.015% Mo, 0.06 g/t Au, 3.2 g/t Ag) (DK23012) |
|
| · | 30 m of 0.43% CuEQ (0.31% Cu, 0.014% Mo, 0.09 g/t Au, 1.6 g/t Ag), and |
|
|
| 33 m of 0.44% CuEQ (0.20% Cu, 0.053% Mo, 0.06 g/t Au, 1.3 g/t Ag) (DK23015) |
|
| · | 83 m of 0.41% CuEQ (0.30% Cu, 0.017% Mo, 0.06 g/t Au, 1.1 g/t Ag) (DK23022) |
|
| · | 36 m of 0.47% CuEQ (0.34% Cu, 0.024% Mo, 0.06 g/t Au, 1.5 g/t Ag) (DK23024) |
|
| · | 33 m of 0.40% CuEQ (0.30% Cu, 0.017% Mo, 0.05 g/t Au, 1.5 g/t Ag) (DK23026) |
In 2024, a delineation drilling program of 4,828 m in nine holes at the DUKE Deposit further defined Cu-Mo mineralization in the central portion of the deposit and identified potentially important volumes of additional mineralization to the south and north of the main deposit (see Amarc release June 25, 2024). Highlights from drilling include:
|
| · | 72 m of 0.45% CuEQ (0.35% Cu, 0.016% Mo, 0.06 g/t Au, 1.6 g/t Ag) and |
|
|
| 104 m of 0.38% CuEQ (0.29% Cu, 0.016% Mo, 0.06 g/t Au, 1.3 g/t Ag) (DK24033) |
|
| · | 110 m of 0.38% CuEQ (0.25% Cu, 0.028% Mo, 0.04 g/t Au, 1.1 g/t Ag) and |
|
|
| 30 m of 0.39% CuEQ (0.26% Cu, 0.025% Mo, 0.05 g/t Au, 1.4 g/t Ag) (DK24034) |
|
| · | 30 m of 0.44% CuEQ (0.35% Cu, 0.013% Mo, 0.05 g/t Au, 1.5 g/t Ag) within |
|
|
| 203 m of 0.28% CuEQ (0.2% Cu, 0.015% Mo, 0.03 g/t Au, 1.0 g/t Ag) (DK24035) |
|
| · | 48 m of 0.34% CuEQ (0.26% Cu, 0.010% Mo, 0.05 g/t Au, 1.8 g/t Ag) (DK24036) |
|
| · | 15 m of 0.69% CuEQ (0.52% Cu, 0.024% Mo, 0.11 g/t Au, 2.9 g/t Ag) and |
|
|
| 29 m of 0.47% CuEQ (0.31% Cu, 0.030% Mo, 0.06 g/t Au, 1.7 g/t Ag) within |
|
|
| 209 m of 0.26% CuEQ (0.19% Cu, 0.013% Mo, 0.04 g/t Au and 1.0 g/t Ag) (DK24037) |
To the south of the main DUKE Deposit, a new and positive structural element, the South Graben Fault (“SGF”) was identified by drilling in 2024, principally from the results of drill hole DK24036. The SGF, like many other mineralized corridors in the Babine, likely has a spatial relationship to the development of significant mineralized zones with the potential to expand the DUKE deposit over a strike length of 700 m.
__________________
3 Copper equivalent (CuEQ) calculations use metal prices of: Cu US$4/lb, Au US$1800/oz., Ag US$24/oz. and Mo US$15/lb and conceptual recoveries of: Cu 85%, Mo 82%, Au 72% and 67% Ag.
| - 13 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
Additionally, drilling in 2024 to the north, holes DK24038 and DK24040 returned important Cu-Mo-Ag intercepts which, with a previously reported intercept in DK18004 (see Amarc release June 12, 2018), was found to be outlining a newly recognized volume of mineralized rock to the west of the DUKE Fault, representing an offset portion of the DUKE Deposit that was displaced some 450 to 500 m northwards (the “DUKE Offset”). The initial drilling suggests that this new target has a strike length of approximately 500 m and an estimated true width of around 120 m. It remains to be fully drill delineated.
In 2025, five drill holes were completed in the greater DUKE Deposit area; four new drill holes were completed, and one of the 2024 holes was extended.
Two holes were drilled into the DUKE Deposit area (DK25086, DK25087) within the east-west trending SGF structural corridor at the south end of the deposit, where a few short historical holes drilled in the 1970’s cut the shallowest portions of this targeted volume. In most cases the historical holes were well mineralized, for example, 70-02 returned 113 m of 0.38% CuEQ (0.29% Cu, 0.012% Mo, 0.06 g/t Au, 1.1 g/t Ag), including 12 m of 0.51% CuEQ (0.41% Cu, 0.010% Mo, 0.09 g/t Au, 1.6 g/t Ag)4. In 2025, hole DK25086 returned 211 m of 0.25% CuEQ (0.19% Cu, 0.01% Mo, 0.03 g/t Au, 1.0 g/t Ag) from 151 m, including 89 m of 0.33% CuEQ (0.24% Cu, 0.02% Mo, 0.04 g/t Au, 1.2 g/t Ag) from 273 m, and hole DK25087 returned 66 m of 0.10% CuEQ (0.08% Cu, 0.01 g/t Au, 0.4 g/t Ag) from 137 m. These newly identified mineralized volumes are open to expansion with further drilling.
Three holes in 2025 were drilled along a 440 m long east-west fence across the southern end (120 m to 150 m south of previous drilling) of the DUKE Offset and extended this deposit-area. Hole DK25085 returned 84 m at 0.16% CuEQ (0.10% Cu, 0.01% Mo, 0.02 g/t Au, 1.0 g/t Ag) from 105 m, hole DK25094 returned 12 m of 0.16% CuEQ (0.09% Cu, 0.02% Mo, 0.01 g/t Au, 0.5 g/t Ag) from 54 m, and hole DK25093 returned 31 m of 0.18% CuEQ (0.13% Cu, 0.01% Mo, 0.02 g/t Au, 0.6 g/t Ag) from 31 m, 95 m of 0.13% CuEQ (0.10% Cu, 0.02 g/t Au, 0.5 g/t Ag) from 101 m, 74 m of 0.18% CuEQ (0.11 Cu, 0.01% Mo, 0.09 g/t Au, 0.9 g/t Ag) from 219 m and 36 m of 0.20% CuEQ (0.15% Cu, 0.05 g/t Au, 1.4 g/t Ag) from 314 m. The DUKE Offset area now extends over greater than 400 m north-south, up to 450 m east-west and 250 m in depth (see Amarc release April 2, 2026).
DUKE District
Notably, the DUKE Deposit lies approximately 6 km to the southeast of American Eagle’s promising NAK Cu-Au Deposit5 along the southeast trending regional NAK–DUKE magnetic corridor (see Amarc release April 2, 2026). This corridor also hosts Amarc’s C6 and M4 DUKE District targets to the southeast of the DUKE Deposit.
Drilling in the DUKE District in 2025 focused on initial scout drilling at a number of drill-ready targets. Five holes were also completed across a 2.3 km long east-northeast trending fence on the north side of the NAK Deposit mineral tenure. A centre of anomalous porphyry-style Cu-Au mineralization was confirmed: hole DKC25074 returned 86 m of 0.13% CuEQ6 (0.10% Cu, 0.03 g/t Au, 2.3 g/t Ag) from 46 m, including 38 m at 0.22% CuEQ (0.19% Cu, 0.03 g/t Au, 2.1 g/t Ag) from 59 m. Elsewhere along this drill fence, hole DKC25071 encountered both 10 and 67 m intervals of anomalous Cu ranging from 0.08% to 0.06% Cu and 0.09 to 0.06 g/t Au (see Amarc release April 2, 2026). Other mainly short scout holes drilled at other targets did not return significant results.
______________________
4 See Amarc DUKE Project 2020 Technical Report, referenced below
5 See American Eagle Gold’s website https://americaneaglegold.ca. American Eagle Gold is a third party.
6 For CuEQ see footnote 3.
| - 14 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
Technical information from historical programs and Amarc work at DUKE to 2020 is summarized from the Company’s National Instrument 43-101 Technical Report (“DUKE Technical Report”) filed under Amarc’s profile at www.sedarplus.ca and on the Company’s website at www.amarcresources.com/projects/duke-project/technical-report. Additional details on Amarc’s exploration programs at DUKE from 2021-2026 are available in previous MD&As or in new releases on the Company’s website.
Amarc holds 100% interest in the DUKE District which is largely free of any underlying royalty.
Trail Peak Option
In September 2023, Amarc announced it had entered into an option agreement (the “Agreement”) with Richard J (Dick) Billingsley (the “Optionor”) on a group of mineral claims, covering some 2.34 km2, located internal to and near to the northern extent of the DUKE property. Under the terms of the Agreement, Amarc can acquire 100% of these claims, subject to a 2% Net Smelter Returns royalty retained by the Optionor that is capped at $10 million, by issuing 200,000 Amarc shares and making annual cash payments of $5,000 to the Optionor plus funding an annual scholarship for Indigenous students in the amount of $20,000 per year for a period of 10 years (total of 200,000 shares and $250,000 cash).
Agreement with Boliden
In November 2022, Amarc entered into a Mineral Property Earn-in Agreement (the "Agreement") with Boliden Mineral Canada Ltd. (“Boliden”), a wholly owned subsidiary of the Boliden Group. Under the terms of the Agreement, Boliden could earn up to a 70% ownership interest, by making staged exploration and development investments in the DUKE District.
Boliden sole funded $30 million of exploration expenditures though to the end of 2025 to earn a 60% interest and continues its participation in the DUKE District. As of April 1, 2026, Boliden and Amarc entered a 60:40 joint venture under which the parties must fund exploration activities on a pro rata basis or dilute their interest in the DUKE JV. The $4 million 2026 DUKE District program is fully funded by Boliden as part of the DUKE JV. Under the terms of the DUKE JV, Amarc has 180 days from April 30, 2026 to elect to contribute $2.66 million in funding to the program to maintain its full 40% interest in the JV (see Amarc release June 25, 2026). Amarc is the operator at the DUKE District.
The IKE Cu-Au District
Amarc’s 100% owned, 532 km2 IKE District is located 35 km northwest of the town of Gold Bridge in southwestern BC and near the heartland of the provinces producing porphyry Cu mines. It is proximal to industrial infrastructure including power, and also highways and rail that connect the District to Vancouver and its port facilities.
Hydrothermal alteration and mineralization, which is prospective for the discovery of porphyry Cu±Au±Mo±Ag and related deposit types occur throughout the expansive IKE District. The District occupies a highly fertile block of crust where magmatic‐hydrothermal‐structural characteristics are favorable for the formation of intrusion-related Cu±Au±Mo±Ag deposits with good grade. These characteristics are common to most porphyry districts around the world that host major, and commonly multiple, Cu±Au±Mo±Ag deposits.
| - 15 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
The greater IKE District hosts the IKE porphyry Cu-Mo-Ag deposit discovery, the high potential Greater Empress area that hosts the Empress Cu-Au-Ag Deposit and significant porphyry Cu-Au-Mo-Ag and Cu-Au-Ag replacement deposit targets, and a number of other promising porphyry Cu and Au-Ag epithermal targets. The District has the potential to develop into an important mining camp.
The IKE District is subject to the following royalties:
|
| · | A 1% net smelter return (“NSR’) on the IKE Property mineral claims capped at $2 million, which can be repurchased at any time for $2 million. An additional 2% NSR, subject to the Company retaining the right to purchase up to the entire royalty amount by the payment of up to $4 million. The Company has also agreed to make annual advance royalty payments of $50,000 to the holders of the 2% NSR royalty interest and, upon completion of a positive feasibility study, to issue to these same parties 500,000 common shares. |
|
|
|
|
|
| · | A 2% NSR on the Granite Property mineral claims which can be purchased for $2 million. In addition, there is an underlying 2.5% NSR royalty on certain mineral claims within the Granite Property, which can be purchased at any time for $1.5 million less any amount of royalty already paid. |
|
|
|
|
|
| · | The entire IKE District is subject to a 1% NSR royalty from mine production capped at a total of $5 million. |
IKE Porphyry Cu-Mo-Ag Deposit
The potential of the IKE porphyry deposit was recognized by Amarc during a review of porphyry occurrences located in underexplored mineral belts in BC. Limited historical drilling indicated the presence of a mineral system with characteristics favorable for an economically viable porphyry Cu-Mo-Ag deposit, underlying a significant area of gossanous material. Three historical drill holes, located over approximately 220 m, had intersected long continuous intercepts of chalcopyrite and molybdenite mineralization with encouraging grades, for example: Hole 11-1 returned 182 m of 0.41% CuEQ7 (0.31% Cu, 0.022% Mo, 1.9 g/t Ag and 0.01 g/t Au), including 58 m of 0.52% CuEQ (0.39% Cu, 0.031% Mo, 1.9 g/t Ag and 0.02 g/t Au); and Hole 11-2: 120 m of 0.41% CuEQ (0.31% Cu, 0.020% Mo, 3.3 g/t Ag and 0.01 g/t Au) including 32 m of 0.58% CuEQ (0.42 % Cu, 0.028% Mo, 6.3 g/t Ag and 0.02 g/t Au).
Largely co-incident magnetic, IP chargeability geophysics and geochemical talus fines anomalies, together with geological alteration mapping have defined an extensive 9 km2 hydrothermal system. Amarc has completed approximately 15,455 m of core drilling in 26 widely spaced holes from 2014-2018. This drilling has confirmed the presence of a substantial body of porphyry Cu-Mo-Ag mineralization with encouraging grades, over an area 1,200 m east-west by 1,000 m north- south, and over a vertical extent of 875 m depth, that remains open to expansion. Example intersections include 87.1 m of 0.56% CuEQ (0.36% Cu, 0.7 g/t Ag and 0.054% Mo including 36.9 m of 0.69% CuEQ (0.43% Cu, 1.2 g/t Ag and 0.068% Mo) in hole IK14005 (Amarc December 9, 2015 release), and 94.7 m of 0.47% CuEQ (0.37% Cu, 0.020 g/t Au, 2.5 g/t Ag and 0.020% Mo) including 37.4 m of 0.64% CuEQ (0.49% Cu, 0.024 g/t Au, 3.5 g/t Ag and 0.032% Mo) and 78.0 m of 0.61% CuEQ (0.44% Cu, 0.019 g/t Au, 3.0 g/t Ag and 0.038% Mo) in hole IK18025 (see Amarc release November 6, 2018).
_____________
7 For CuEQ see footnote 3.
| - 16 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
Empress Cu-Au Deposit
Historical drilling encountered significant Cu-Au-Ag replacement-style mineralization at the Empress Deposit hosted by altered volcanics, commonly occurring near the surface and predominantly within 100 m vertically above the contact of the Coast Plutonic Complex intrusive rocks with the overlying volcanics. More limited historical drilling at the Empress East Deposit Target, some 1.3 km to the east, intercepted mineralization similar in both style and grade to the Empress Deposit.
In 2024, Amarc carried out a $2.9 million, drill dominant program in the IKE District. The program focused on the potential of the higher grade historical Empress Cu-Au Deposit, where drilling by previous companies encountered replacement style mineralization with encouraging Cu and Au grades.
The 2024 program successfully confirmed high potential for the expansion of mineralization found historically at Empress and the discovery of additional higher grade intrusion-related replacement and porphyry Cu±Au±Mo±Ag deposits (see Amarc release May 14, 2025). Six of the eight drill holes collared at the Empress Deposit intercepted significant Cu-Au mineralized zones, including:
|
| · | 181 m at 0.46% CuEQ8 (0.31 g/t Au, 0.29% Cu and 0.8 g/t Ag) from 30 m |
|
|
| and 60 m at 0.90% CuEQ (0.60 g/t Au, 0.56% Cu and 1.3 g/t Ag) from 123 m in hole EM24074 |
|
| · | 68 m at 0.56% CuEQ (0.30 g/t Au, 0.38% Cu and 1.0 g/t Ag) from 123 m |
|
|
| incl. 29 m at 0.73% CuEQ (0.46 g/t Au, 0.47% Cu and 1.3 g/t Ag) from 153 m in EM24075 |
Technical information from historical work and Amarc programs to 2020 is summarized from the Company’s National Instrument 43-101 Technical Report (“IKE 2020 Technical Report”) filed under Amarc’s profile at www.sedarplus.ca and on the Company’s website at www.amarcresources.com/projects/ike-project/technical-report. Additional details on Amarc’s exploration programs at IKE from 2021-2024 are available in previous MD&As or in new releases on the Company’s website.
On May 29, 2025, the BC government announced a Pathways and Principles Document between the Province and the Tsilhqot'in First Nation to develop the Dasiqox land use plan, a portion of which falls over all of the IKE District. Amarc is in discussion with the provincial government to determine any implications of this planning processes on its IKE District.
MARKET TRENDS
Average annual prices for Cu, Mo, Au and Ag during last 5 years and year to date in calendar 2026 are shown in the following table:
|
| Average metal price (US$) | |||
| calendar year | Copper | Molybdenum | Gold | Silver |
| 2021 | 4.27/lb | 15.94/lb | 1,799/oz | 25.14/oz |
| 2022 | 3.99/lb | 18.73/lb | 1,800/oz | 21.74/oz |
| 2023 | 3.84/lb | 19.87/lb | 1,963/oz | 23.39/oz |
| 2024 | 4.16/lb | 21.30/lb | 2,386/oz | 28.27/oz |
| 2025 | 4.51/lb | 22.21/lb | 3,428/oz | 39.98/oz |
| 2026 (to the date of this document) | 5.95/lb | 28.07/lb | 4,423*/oz | 76.78/oz |
Notes:
1. Source for copper, gold and silver is Argus Media at www.metalprices.com.
_______________
8 Copper equivalent (CuEQ) calculations use metal prices of: Cu US$4.00/lb, Au US$1800/oz., and Ag US$24/oz. and conceptual recoveries of: Cu 85%, Au 72% and 67% Ag.
| - 17 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
LME Official Cash Price for copper.
LBMA PM price for gold. *YTD gold price is average year to date LME (July 20, 2026).
London PM fix for silver.
2. Source for molybdenum prices is Platts.
SELECTED ANNUAL INFORMATION
The following information is derived from the Company's annual financial statements which have been prepared in accordance with IFRS as issued by the IASB effective for the respective reporting years of the Company and are expressed in Canadian Dollars. The Company's audited financial statements are publicly available on SEDAR+ at www.sedarplus.ca.
| 2026 | 2025 | 2024 | ||
| ('$000's, except loss per share) |
| ($) | ($) | ($) |
| Total assets | 2,046 | 1,880 | 9,842 | |
| Non-current liabilities | – | 969 | 814 | |
| Net loss for the year | 930 | 3,913 | 43 | |
| Basic and diluted loss per share |
| 0.00 | 0.02 | 0.00 |
RESULTS OF OPERATIONS
Key financial results for the last eight quarters are provided in the table below:
|
| Mar 31 | Dec 31 | Sept 30 | June 30 | Mar 31 | Dec 31 | Sept 30 | June 30 |
|
| 2026 | 2025 | 2025 | 2025 | 2025 | 2024 | 2024 | 2024 |
| ('$000's) | ($) | ($) | ($) | ($) | ($) | ($) | ($) | ($) |
| Net (income) loss | 973 | 227 | (650) | 380 | 738 | 2,249 | 103 | 823 |
| Basic and diluted (earnings) loss per share | 0.00 | (0.00) | (0.00) | (0.00) | 0.00 | 0.01 | 0.02 | 0.00 |
These amounts are expressed in thousands of Canadian Dollars, except per share amounts. Minor differences are due to rounding.
The variations in net results over the fiscal quarters presented above relate to the Company’s mineral exploration and evaluation activities, which if undertaken typically ramp-up in the summer during the 3rd calendar quarter. See the following section of the MD&A for additional discussions.
Fourth quarter ended March 31, 2026
The Company recorded a net loss of $973,542 for the three months ended March 31, 2026 compared to a net loss of $738,413 for the three months ended March 31, 2025.
| - 18 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
The following table summarizes the operating results by major categories for the three months ended March 31, 2026 and 2025:
|
| Three months ended March 31, | |
|
| 2026 | 2025 |
|
| ($) | ($) |
| Exploration and evaluation assets expenditures | 491,555 | 1,857,646 |
| Administrative expenditures | 528,565 | 749,290 |
| Cost recoveries | (611,005) | (1,324,507) |
A breakdown by district and project of the Company’s exploration and evaluation expenses for the three months ended March 31, 2026 and 2025 is as follows:
|
| IKE | JOY (1) | DUKE | OTHER | TOTAL |
| Three months ended March 31, 2026 | ($) | ($) | ($) | ($) | ($) |
| Assays and analysis | 889 | – | 43,826 | 3,698 | 48,413 |
| Drilling | 141 | – | 12,244 | 2,230 | 14,615 |
| Environmental | – | – | 12,508 | – | 12,508 |
| Equipment rental | 4,050 | – | 3,671 | 142 | 7,863 |
| Freight | – | – | – | – | – |
| Geological, including geophysical | 4,031 | – | 124,976 | 100,032 | 229,039 |
| Graphics | – | – | 450 | 1,495 | 1,945 |
| Helicopter and fuel | – | – | – | (5,235) | (5,235) |
| Operations support | 6,810 | – | 60,635 | 6,296 | 73,741 |
| Property acquisition and assessments costs | 14,055 | – | 4,748 | – | 18,803 |
| Socioeconomic | 1,384 | – | 42,932 | 27,198 | 71,514 |
| Travel and accommodation | – | – | 9,312 | 9,037 | 18,349 |
|
| 31,506 | – | 315,156 | 144,893 | 491,555 |
|
| IKE | JOY | DUKE | OTHER | TOTAL |
| Three months ended March 31, 2025 | ($) | ($) | ($) | ($) | ($) |
| Assays and analysis | 72,643 | 178,719 | 28,675 | 1,900 | 281,937 |
| Drilling | – | (1,815) | (1,980) | – | (3,795) |
| Environmental | 3,239 | 15,808 | 7,079 | 492 | 26,618 |
| Equipment rental | 5,400 | 3,920 | 16,611 | – | 25,931 |
| Freight | 75 | (13,309) | (11,789) | 152 | (24,871) |
| Geological, including geophysical | 76,026 | 287,965 | 184,577 | 35,747 | 584,315 |
| Graphics | – | 3,574 | (2,610) | 563 | 1,527 |
| Helicopter and fuel | – | – | – | – | – |
| Operations support | 37,148 | 15,039 | 5,794 | 414,890 | 472,871 |
| Property acquisition and assessments costs | 77,915 | 167,844 | 98,042 | 9,549 | 353,350 |
| Socioeconomic | 1,708 | 19,854 | 67,776 | 4,343 | 93,681 |
| Technical data | 2,100 | 8,400 | 8,400 | – | 18,900 |
| Travel and accommodation | 390 | 12,535 | 7,561 | 6,696 | 27,182 |
|
| 276,644 | 698,534 | 408,136 | 474,332 | 1,857,646 |
| (1) | JOY is operating in the private joint venture corporation Aurora Minerals Ltd. (“AuRORA Minerals”) since August 20, 2026. All exploration and evaluation expenses on JOY after August 20, 2026 are in AuRORA Minerals. |
| - 19 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
The Company recorded cost recoveries for the three months ended March 31, 2026 of $611,005 compared to $1,324,507 for the three months ended March 31, 2025. The cost recoveries are related to operations at the DUKE District and JOY District (before August 20, 2025). A private joint venture corporation Aurora Minerals was set up in August 2025 to hold the JOY District mineral rights and titles. Exploration and evaluation expenses and cost recoveries for JOY District have been recorded in AuRORA Minerals since August 21, 2025.
The general and administration expenses for the three months ended March 31, 2026 were $528,525 compared to $749,290 for the three months ended March 31, 2025. The higher general and administration expenses for three months ended March 31, 2025 is mainly driven by higher Legal expenses (more corporate activities). A breakdown of general and administration expenses for the fourth quarter ended March 31, 2026 and 2025 is as follows:
|
| Three months March 31, | |
|
| 2026 | 2025 |
|
| ($) | ($) |
| Legal, accounting and audit | 22,658 | 240,801 |
| Office and administration | 190,511 | 118,402 |
| Rent | 8,192 | (13,013) |
| Shareholder communication | 177,970 | 203,027 |
| Travel and accommodation | 86,118 | 182,451 |
| Trust and regulatory | 43,116 | 17,622 |
| Total | 528,565 | 749,290 |
Year ended March 31, 2026
The Company recorded a net loss of $929,987 for the year ended March 31, 2026 compared to $3,912,888 for the year ended March 31, 2025.
The following table summarizes the operating results by major categories during year ended March 31, 2026 and 2025:
|
| Year ended March 31, | |
|
| 2026 | 2025 |
|
| ($) | ($) |
| Exploration and evaluation assets expenditures | 19,179,186 | 22,575,096 |
| Administrative expenditures | 1,819,170 | 1,597,495 |
| Cost recoveries | (18,961,755) | (18,921,430) |
| - 20 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
A breakdown by district and project of the Company’s exploration and evaluation expenses for the year ended March 31, 2026 and 2025 is as follows:
|
| IKE | JOY (1) | DUKE | OTHER | TOTAL |
| Year ended March 31, 2026 | ($) | ($) | ($) | ($) | ($) |
| Assays and analysis | 50,519 | 412,038 | 580,235 | 93,208 | 1,136,000 |
| Drilling | 6,545 | 3,023,347 | 2,903,542 | 2,230 | 5,935,664 |
| Environmental | 330 | 9,801 | 30,284 | – | 40,415 |
| Equipment rental | 16,200 | 229,129 | 228,233 | 142 | 473,704 |
| Freight | – | 322,460 | 145,736 | – | 468,196 |
| Geological, including geophysical | 74,860 | 1,087,521 | 1,451,086 | 236,788 | 2,850,255 |
| Graphics | 1,299 | 7,115 | 5,257 | 3,855 | 17,526 |
| Helicopter and fuel | – | 1,846,554 | 1,951,779 | 12,094 | 3,810,427 |
| Operations support | 19,860 | 1,000,931 | 658,803 | 70,908 | 1,750,502 |
| Property acquisition and assessments costs | 68,280 | 707,448 | 24,667 | 107,020 | 907,415 |
| Socioeconomic | 21,660 | 111,153 | 86,884 | 45,829 | 265,526 |
| Technical data | 146 | – | – | – | 146 |
| Travel and accommodation | 5,540 | 508,296 | 980,415 | 29,159 | 1,523,410 |
|
| 265,239 | 9,265,793 | 9,046,921 | 601,233 | 19,179,186 |
|
| IKE | JOY | DUKE | OTHER | TOTAL |
| Year ended March 31, 2025 | ($) | ($) | ($) | ($) | ($) |
| Assays and analysis | 293,030 | 1,009,421 | 554,906 | 4,180 | 1,861,537 |
| Drilling | 596,256 | 3,648,508 | 1,142,301 | – | 5,387,065 |
| Environmental | 16,316 | 54,459 | 24,781 | 533 | 96,089 |
| Equipment rental | 62,610 | 203,124 | 157,025 | – | 422,759 |
| Freight | 49,476 | 262,350 | 107,451 | 152 | 419,429 |
| Geological, including geophysical | 454,583 | 1,321,153 | 1,900,966 | 72,768 | 3,749,470 |
| Graphics | 2,236 | 7,310 | 17,643 | 903 | 28,092 |
| Helicopter and fuel | 1,031,806 | 2,288,980 | 1,148,199 | – | 4,468,985 |
| Operations support | 102,493 | 16,924 | 24,949 | 522,040 | 666,406 |
| Property acquisition and assessments costs | 481,900 | 2,590,722 | 1,368,652 | 28,555 | 4,469,829 |
| Socioeconomic | 91,292 | 206,574 | 189,261 | 22,068 | 509,195 |
| Technical data | 4,200 | 34,890 | 34,820 | – | 73,910 |
| Travel and accommodation | 25,018 | 200,297 | 187,924 | 9,091 | 422,330 |
|
| 3,211,216 | 11,844,712 | 6,858,878 | 660,290 | 22,575,096 |
| (2) | The JOY District mineral rights and titles were transferred to the private joint venture corporation AuRORA Minerals since August 20, 2026. All exploration and evaluation expenses on JOY after August 20, 2026 are in Aurora Minerals. |
The Company recorded cost recoveries for the year ended March 31, 2026 of $18,961,755 compared to $18,921,430 for the year ended March 31, 2025. The cost recoveries are related to operations at the DUKE District and JOY District (before August 20, 2025). AuRORA Minerals was set up in August 2025 to hold the JOY District mineral rights and titles of the JOY District. Exploration and evaluation expenses and cost recoveries for JOY District have been recorded in Aurora Minerals since August 21, 2025.
| - 21 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
The general and administration expenses for the year ended March 31, 2026 were $1,819,170 compared to $1,597,495 for the year ended March 31, 2025. The higher general and administration expenses for the current year is mainly driven by higher office and administration expenses (financial consulting expense). A breakdown of general and administration expenses for the year ended March 31, 2026 and 2025 is as follows:
|
| Year ended March 31, | |
|
| 2026 | 2025 |
|
| ($) | ($) |
| Legal, accounting and audit | 243,969 | 298,277 |
| Office and administration | 614,473 | 423,740 |
| Rent | 9,145 | 35,570 |
| Shareholder communication | 574,633 | 524,599 |
| Travel and accommodation | 298,372 | 267,551 |
| Trust and regulatory | 78,578 | 47,758 |
| Total | 1,819,170 | 1,597,495 |
LIQUIDITY
Historically, the Company's sole source of funding has been provided from the issuance of equity securities for cash, primarily through private placements to sophisticated investors and institutions, and from director loans. In addition, the Company is and has been funded by earn-in partners on certain of its exploration projects. The Company's access to financing is always uncertain. There can be no assurance of continued access to significant equity funding to finance the Company's ongoing operations.
At March 31, 2026, the Company had a cash balance of $1,414,013, of which $529,583 was advance contribution from the partners and accounts payable and accrued liabilities of $894,353.
Further advancement and development of the Company’s mineral property interests in the long run will require additional funding from a combination of the Company’s shareholders, existing or potential new partners, and debt financing. As the Company is currently in the exploration stage, it does not have any revenues from operations. Therefore, the Company relies on funding from its partners for its continuing financial liquidity and the Company relies on the equity market and debt financing as sources of funding. The Company continues to focus on preserving its cash resources while maintaining its operational activities.
CAPITAL RESOURCES
The Company has no lines of credit or other sources of financing which have been arranged or utilized. The Company has no "Purchase Obligations" defined as any agreement to purchase goods or services that is enforceable and legally binding on the Company that specifies all significant terms, including: fixed or minimum quantities to be purchased; fixed, minimum or variable price provisions; and the approximate timing of the transaction.
| - 22 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
COMMITMENTS AND FINANICAL OBLIGATIONS
As at March 31, 2026, the Company’s contractual and other obligations are as follows:
|
|
| Less than | 1-3 | 3-5 | After |
|
|
|
| 1 year | years | years | 5 years | Total |
| Accounts payable and accrued liabilities |
| 894,535 | – | – | – | 894,535 |
| Balances due to related parties |
| 311,905 | – | – | – | 311,905 |
| Director's loan |
| 1,058,846 | – | – | – | 1,058,846 |
| Minimum lease payments |
| 2,347 | – | – | – | 2,347 |
| Advanced royalties payments (1) |
| 50,000 | 100,000 | 100,000 | 275,000 | 525,000 |
| Property option payments (2) |
| 525,000 | 650,000 | 650,000 | 150,000 | 1,975,000 |
| Total |
| 2,842,633 | 750,000 | 750,000 | 425,000 | 4,767,633 |
| (1) | Advanced annual royalty payments for extension of the 1% NSR buy back option on the IKE property from December 31, 2018 to any time on or before a commercial mine production decision, which is capped at $1 million. |
| (2) | Annual property purchase option payments on the Brenda property and two other properties. |
OFF-BALANCE SHEET ARRANGEMENTS
None.
TRANSACTIONS WITH RELATED PARTIES
The required quantitative disclosure is provided in the Financial Statements, which are publicly available on SEDAR+ at www.sedarplus.ca.
Hunter Dickinson Inc.
Hunter Dickinson Inc. (“HDI”) and its wholly-owned subsidiary Hunter Dickinson Services Inc. (“HDSI”) are private companies established by a group of mining professionals. HDSI provides contract services for a number of mineral exploration and development companies, and also to companies that are outside of the mining and mineral development space. Amarc is one of the publicly-listed companies for which HDSI provides a variety of contract services.
The Company has one director in common with HDSI, namely Robert Dickinson, Executive Chair. The Company’s President, Chief Executive Officer and Director, and Corporate Secretary are employees of HDSI and work for the Company under an employee secondment arrangement between the Company and HDSI.
Pursuant to an agreement dated July 2, 2010, HDSI provides cost effective technical, geological, corporate communications, regulatory compliance, and administrative and management services to the Company, on a non-exclusive basis as needed and as requested by the Company, and as available from HDSI (the “Services Agreement”). As a result of this relationship, the Company has ready access to a range of diverse and specialized expertise on a regular basis, without having to engage or hire full-time employees or experts. The Company benefits from the economies of scale created by HDSI which itself serves several clients.
| - 23 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
The Company is not obligated to acquire any minimum amount of services from HDSI. The monetary amount of the services received from HDSI in a given period of time is a function of annually set and agreed charge-out rates for and the time spent by each HDSI employee engaged by the Company.
HDSI also incurs third-party costs on behalf of the Company. Such third party costs include, for example, capital market advisory services, communication services and office supplies. Third-party costs are billed at cost, without markup.
There are no ongoing contractual or other commitments resulting from the Company's transactions with HDSI, other than the payment for services already rendered and billed. The agreement may be terminated upon 60 days' notice by either the Company or HDSI.
The details of transactions with HDSI and the balance due to HDSI as a result of such transactions are provided in the Financial Statements, along with the details of borrowings by the Company from Mr. Dickinson, Executive Chair.
United Mineral Services Ltd.
United Mineral Services Ltd. (“UMS”) is a privately held company wholly-owned by one of the Company’s directors. UMS is engaged in the acquisition and exploration of mineral property interests. UMS does incur third party expenses on behalf of the Company from time to time.
Details of transactions with UMS and the balance due to UMS as a result of such transactions are provided in the Financial Statements.
PROPOSED TRANSACTIONS
There are no proposed transactions requiring disclosure under this section.
CHANGES IN ACCOUNTING POLICIES INCLUDING INITIAL ADOPTION
The required disclosure is provided in the Financial Statements, which are publicly available on SEDAR+ at www.sedarplus.ca.
| - 24 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
FINANCIAL INSTRUMENTS AND RISK MANAGEMENT
The carrying amounts of cash, amounts receivable, marketable securities, accounts payable and accrued liabilities, balance due to a related party, and director’s loan approximate their fair values due to their short-term nature.
Credit Risk
Financial instruments that potentially subject the Company to a concentration of credit risk consist primarily of cash and refundable deposits. The Company limits its exposure to credit loss by placing its cash and refundable deposits with high credit quality financial institutions. Substantially all of our cash held with financial institutions exceeds government-insured limits. We seek to minimize our credit risk by entering into transactions with investment grade worthy and reputable financial institutions and by monitoring the credit standing of the financial institutions with whom we transact. We seek to limit the amount of exposure with any one counterparty. The carrying amount of financial assets represents the maximum credit exposure.
Currency Risk
Foreign currency risk is the risk that a variation in exchange rates between the Canadian dollar and US dollar or other foreign currencies will affect the Company’s operations and financial results. The Company’s functional currency is the Canadian dollar and major purchases are transacted in Canadian dollars. The company’s currency risk exposure is minimal.
Interest Risk
Interest rate risk is the risk that the fair value or cash flows of a financial instrument will fluctuate because of changes in market interest rates. The Company is not exposed to significant interest rate risk.
Liquidity Risk
Liquidity risk is the risk that the Company will not be able to meet its financial obligations as they become due. The Company’s policy is to ensure that it will always have sufficient cash to allow it to meet its liabilities when they become due. The key to success in managing liquidity is the degree of certainty in the cash flow projections. If future cash flows are fairly uncertain, the liquidity risk increases.
During the year ended March 31, 2026, the Company relied on partners to fund its mineral exploration activities, and its general and administrative expenses (see “LIQUIDITY” section above).
| - 25 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
OUTSTANDING SHARE DATA
The following table details the share capital structure as of the date of this MD&A:
| Common Shares - issued and outstanding | 225,567,364 | |||
| Exercise price | Expiry Date | Shares Issuable | ||
| ($) |
| (#) | ||
| Warrants | 0.080 | December 1, 2028 | 4,807,693 | |
| 4,807,693 | ||||
| Stock options | 0.105 | March 22, 2029 | 5,100,000 | |
| 0.105 | March 22, 2027 | 282,000 | ||
| 0.670 | February 4, 2030 | 133,333 | ||
| 0.680 | June 27, 2030 | 100,000 | ||
| 0.770 | July 9, 2027 | 100,000 | ||
| 1.310 | February 25, 2031 | 400,000 | ||
|
| 6,115,333 | |||
| 236,490,390 | ||||
On August 21, 2025, the Company issued 1,000,000 common shares to Gold Fields Toodoggone Exploration Corp. as part of the contingent consideration set out in the amended PINE property purchase agreement dated on December 9, 2019 whereby consideration was an aggregate of 7,000,000 common shares of which 5,000,000 was issued in the first year and a further 2,000,000 was contingent on certain expenditure levels.
DISCLOSURE CONTROLS AND PROCEDURES
The Company has disclosure controls and procedures in place to provide reasonable assurance that any information required to be disclosed by the Company under securities legislation is recorded, processed, summarized and reported within the appropriate time periods and that required information is accumulated and communicated to the Company’s management, including the Chief Executive Officer and Chief Financial Officer, as appropriate, so that decisions can be made about the timely disclosure of that information.
INTERNAL CONTROLS OVER FINANCIAL REPORTING PROCEDURES
The Company's management, including the Chief Executive Officer and the Chief Financial Officer, is responsible for establishing and maintaining adequate internal control over financial reporting. Under the supervision of the Chief Financial Officer and Chief Executive Officer, the Company's internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with IFRS. The Company's internal control over financial reporting includes those policies and procedures that:
| - 26 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
| · | pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the Company; |
|
|
|
| · | provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with IFRS, and that receipts and expenditures of the Company are being made only in accordance with authorizations of management and directors of the company; and |
|
|
|
| · | provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use or disposition of the Company's assets that could have a material effect on the financial statements. |
|
|
|
There has been no change in the design of the Company's internal control over financial reporting that has materially affected, or is reasonably likely to materially affect, the Company's internal control over financial reporting during the period covered by this Management's Discussion and Analysis.
LIMITATIONS OF CONTROLS AND PROCEDURES
The Company's management, including its Chief Executive Officer and Chief Financial Officer, believe that any system of disclosure controls and procedures or internal control over financial reporting, no matter how well conceived and operated, can provide only reasonable, not absolute, assurance that the objectives of the control system are met. Furthermore, the design of a control system must reflect the fact that there are resource constraints and the benefits of controls must be considered relative to their costs. Because of the inherent limitations in all control systems, they cannot provide absolute assurance that all control issues and instances of fraud, if any, within the Company have been prevented or detected.
These inherent limitations include the realities that judgments in decision- making can be faulty and breakdowns can occur because of simple error or mistake. Additionally, controls can be circumvented by the individual acts of some persons, by collusion of two or more people, or by unauthorized override of controls. The design of any system of controls is also based in part upon certain assumptions about the likelihood of future events, and there can be no assurance that any design will succeed in achieving its stated goals under all potential future conditions.
Accordingly, because of the inherent limitations in a cost-effective control system, misstatements due to error or fraud may occur and not be detected.
TECHNICAL INFORMATION
The scientific and technical information contained in this MD&A has been reviewed and approved by Mark Rebagliati, P.Eng., a Qualified Person who is not independent of Amarc.
| - 27 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
RISK FACTORS
The risk factors associated with the principal business of the Company are discussed below. Briefly, these include the highly speculative nature of the mining industry characterized by the requirement for large capital investment from an early stage and a very small probability of finding economic mineral deposits.
In addition to the general risks of mining, there are country-specific risks associated with operations, including political, social, and legal risk.
Due to the nature of the Company's business and the present stage of exploration and development of its projects, the Company may be subject to significant risks. Readers should carefully consider all such risks set out in the discussion below. The Company's actual exploration and operating results may be very different from those expected as at the date of this MD&A.
Exploration and Mining Risks
Resource exploration, development, and operations are highly speculative, characterized by a number of significant risks, which even a combination of careful evaluation, experience and knowledge may not eliminate, including, among other things, unprofitable efforts resulting not only from the failure to discover mineral deposits but from finding mineral deposits which, though present, are insufficient in quantity and quality to return a profit from production. Few properties that are explored are ultimately developed into producing mines. Unusual or unexpected formations, formation pressures, fires, power outages, labour disruptions, flooding, explosions, cave-ins, landslides and the inability to obtain suitable or adequate machinery, equipment or labour are other risks involved in the operation of mines and the conduct of exploration programs. The Company will rely on consultants and others for exploration, development, construction and operating expertise. Substantial expenditures are required to establish mineral resources and mineral reserves through drilling, to develop metallurgical processes to extract the metal from mineral resources, and in the case of new properties, to develop the mining and processing facilities and infrastructure at any site chosen for mining.
No assurance can be given that minerals will be discovered in sufficient quantities to justify commercial operations or that funds required for development can be obtained on a timely basis. Whether a mineral deposit will be commercially viable depends on a number of factors, some of which are:
| · | the particular attributes of the deposit, such as size, grade and proximity to infrastructure; |
| · | metal prices, which may be volatile, and are highly cyclical; and |
| · | government regulations, including regulations relating to prices, taxes, royalties, land tenure, land use, importing and exporting of minerals, and environmental protection. |
The exact effect of these factors cannot accurately be predicted, but the combination of these factors may result in the Company not receiving an adequate return on invested capital.
The Company will carefully evaluate the political and economic environment in considering any properties for acquisition. There can be no assurance that additional significant restrictions will not be placed on the Company's projects and any other properties the Company may acquire, or its operations. Such restrictions may have a material adverse effect on the Company's business and results of operation.
| - 28 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
First Nations
Our properties are located within First Nations asserted traditional territories, and the exploration and development of these properties may affect, or be perceived to affect, asserted aboriginal rights and title, which has the potential to manifest permitting delays or opposition by First Nations communities.
The Company is working to establish positive relationships with First Nations. As part of this process the Company may enter into agreements commensurate with the stage of activity, with First Nations in relation to current and future exploration and any potential future production. This could reduce expected earnings.
Changes in Federal and Provincial Government Rules, Regulations or Agreements, or Their Application, May Negatively Affect the Company’s Ownership Rights, Its Access to or Its Ability to Advance the Exploration and Development of its Mineral Properties
The federal and provincial governments currently have in place or may in the future implement laws, regulations, policies or agreements that may negatively affect the Company’s ownership rights with respect to its mineral properties or its access to the properties. These may restrain or block the Company’s ability to advance the exploration and development of its mineral properties or significantly increase the costs and timeframe to advance the properties.
Future Profits/Losses and Production Revenues/Expenses
The Company has no history of operations and expects that its losses will continue for the foreseeable future. No deposit that has been shown to be economic has yet been found on the Company's projects. There can be no assurance that the Company will be able to acquire any additional properties. There can be no assurance that the Company will be profitable in the future. The Company's operating expenses and capital expenditures may increase in subsequent years as needed consultants, personnel and equipment associated with advancing exploration, development and commercial production of the Company's projects and any other properties the Company may acquire, are added. The amounts and timing of expenditures will depend on:
| · | the progress of ongoing exploration and development; |
| · | the results of consultants' analyses and recommendations; |
| · | the rate at which operating losses are incurred; |
| · | the execution of any joint venture agreements with strategic partners; and |
| · | the acquisition of additional properties and other factors, many of which are beyond the Company's control. |
The Company does not expect to receive revenues from operations in the foreseeable future, if at all. The Company expects to incur losses unless and until such time as the projects the Company advances, or any other properties the Company may acquire, enter into commercial production and generate sufficient revenues to fund its continuing operations.
| - 29 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
The development of mineral properties will require the commitment of substantial resources to conduct the time-consuming exploration and development of the properties. There can be no assurance that the Company will generate any revenues or achieve profitability. There can be no assurance that the underlying assumed levels of expenses will prove to be accurate.
Additional Funding Requirements
The Company has limited working capital as at the current reporting date.
Further exploration on, and development of, the Company's projects will require additional resources and funding. The Company currently does not have sufficient funds to fully develop these projects. In addition, a positive production decision, if achieved, would require significant funding for project engineering and construction. Accordingly, the continuing development of the Company's properties will depend upon the Company's ability to obtain financing through debt financing, equity financing, the joint venturing of projects, or other means.
There is no assurance that the Company will be successful in obtaining the required financing for these or other purposes, including for general working capital.
Competitors in the Mining Industry
The mining industry is competitive in all of its phases, including financing, technical resources, personnel and property acquisition. It requires significant capital, technical resources, personnel and operational experience to effectively compete in the mining industry. Because of the high costs associated with exploration, the expertise required to analyze a project's potential and the capital required to develop a mine, larger companies with significant resources may have a competitive advantage over Amarc. Amarc faces strong competition from other mining companies, some with greater financial resources, operational experience and technical capabilities than those that Amarc possesses. As a result of this competition, Amarc may be unable to maintain or acquire financing, personnel, technical resources or attractive mining properties on terms Amarc considers acceptable or at all.
Risks That Are Not Insurable
Hazards such as unusual or unexpected geological formations and other conditions are involved in mineral exploration and development. Amarc may become subject to liability for pollution, cave-ins or hazards against which it cannot insure. The payment of such liabilities could result in increases in Amarc's operating expenses which could, in turn, have a material adverse effect on Amarc's financial position and its results of operations. Although Amarc maintains liability insurance in an amount which it considers adequate, the nature of these risks is such that the liabilities might exceed policy limits, the liabilities and hazards might not be insurable against, or Amarc might elect not to insure itself against such liabilities due to high premium costs or other reasons. In these events, Amarc could incur significant liabilities and costs that could materially increase Amarc's operating expenses.
| - 30 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
Environmental Matters
All of the Company's operations will be subject to environmental regulations, which can make operations more expensive or potentially prohibit them altogether.
The Company may be subject to the risks and liabilities associated with potential pollution of the environment and the disposal of waste products that could occur as a result of its activities.
To the extent the Company is subject to environmental liabilities, the payment of such liabilities or the costs that it may incur to remedy environmental pollution would reduce funds otherwise available to it and could have a material adverse effect on the Company. If the Company is unable to fully remedy an environmental problem, it might be required to suspend operations or enter into interim compliance measures pending completion of the required remedy. The potential exposure may be significant and could have a material adverse effect on the Company.
All of the Company's activities are or will be subject to regulation under one or more environmental laws and regulations. Many of the regulations require the Company to obtain permits for its activities. The Company must update and review its permits from time to time, and is subject to environmental impact analyses and public review processes prior to approval of the additional activities. It is possible that future changes in applicable laws, regulations and permits or changes in their enforcement or regulatory interpretation could have a significant impact on some portion of the Company's business, causing those activities to become economically unattractive at that time.
Market for Securities and Volatility of Share Price
There can be no assurance that an active trading market in the Company's securities will be established or sustained. The market price for the Company's securities is subject to wide fluctuations. Factors such as announcements of exploration results, as well as market conditions in the industry, may have a significant adverse impact on the market price of the securities of the Company. Shares of the Company are suitable only for those who can afford to lose their entire investment. The stock market has from time to time experienced extreme price and volume fluctuations, which have often been unrelated to the operating performance of particular companies.
Conflicts of Interest
Certain of the Company's directors and officers may serve as directors or officers of other companies or companies providing services to the Company or they may have significant shareholdings in other companies. Situations may arise where these directors and/or officers of the Company may be in competition with the Company. Any conflicts of interest will be subject to and governed by the law applicable to directors' and officers' conflicts of interest. In the event that such a conflict of interest arises at a meeting of the Company's directors, a director who has such a conflict will abstain from voting for or against the approval of such participation or such terms. In accordance with applicable laws, the directors of the Company are required to act honestly, in good faith and in the best interests of the Company.
| - 31 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
Payment of Dividends Unlikely
There is no assurance that the Company will pay dividends on its shares in the near future. The Company will likely require all its funds to further the development of its business.
Lack of Revenues; History of Operating Losses
The Company does not have any operational history or earnings and has incurred net losses and negative cash flow from its operations since incorporation. Although the Company will hope to eventually generate revenues, significant operating losses are to be anticipated for at least the next several years and possibly longer. To the extent that such expenses do not result in the creation of appropriate revenues, the Company's business may be materially adversely affected. It is not possible to forecast how the business of the Company will develop.
General Economic Conditions
Market conditions and unexpected volatility or illiquidity in financial markets may adversely affect the prospects of the Company and the value of its shares.
Information Systems and Cyber Security
The Company’s operations depend on information technology (“IT”) systems. These IT systems include the IT systems of HDSI which provides technical, management and administrative services to the Company under the Services Agreement. These IT systems are used by us to store sensitive data in the ordinary course of our business, including personal information of our employees, as well as proprietary and confidential business information relating to ourselves and in some cases, our service providers, investors and other stakeholders. These IT systems could be subject to network disruptions caused by a variety of sources, including computer viruses, security breaches and cyber-attacks, as well as disruptions resulting from incidents such as cable cuts, damage to physical plants, natural disasters, terrorism, fire, power loss, vandalism and theft. The Company’s operations also depend on the timely maintenance, upgrade and replacement of networks, equipment, IT systems and software, as well as pre-emptive expenses to mitigate the risks of failures and to address the threat of attacks. Any of these and other events could result in information system failures, delays and/or increase in capital expenses. The failure of information systems or a component of information systems could, depending on the nature of any such failure, adversely impact the Company’s reputation and results of operations. There is a risk that the Company or HDSI may be subject to cyber-attacks or other information security breaches which could result in material loss to the Company and could severely damage our reputation, compromise our IT systems and result in a loss or escape of sensitive information, a misappropriation of assets or incidents of fraud, disrupt our normal operations, and cause us to incur additional time and expense to remediate and improve our information systems. While we employ security measures in respect of our information and data, we cannot be certain that we will be successful in securing this information and data and there may be instances where we are exposed to malware, cyber-attacks or other unauthorized access or use of our information and data. The Company’s risk and exposure to these matters cannot be fully mitigated because of, among other things, the evolving nature and sophistication of these cyber-attacks and potential security breaches. In addition, the Company is dependent on the efforts of HDSI to mitigate its IT systems from cyber-attacks and other information breaches. As a result, cyber security and the continued development and enhancement of controls, processes and practices designed to protect systems, computers, software, data and networks from attack, damage or unauthorized access remain a priority but may not ultimately defeat all potential attacks. As cyber threats continue to evolve, the Company may be required to expend additional resources to continue to modify or enhance protective measures or to investigate and remediate any security vulnerabilities.
| - 32 - |
|
| AMARC RESOURCES LTD. MANAGEMENT’S DISCUSSION AND ANALYSIS FOR THE YEAR ENDED MARCH 31, 2026 |
|
Reliance on Key Personnel
The Company will be dependent on the continued services of its senior management team, and its ability to retain other key personnel. The loss of such key personnel could have a material adverse effect on the Company. There can be no assurance that any of the Company's employees will remain with the Company or that, in the future, the employees will not organize competitive businesses or accept employment with companies competitive with the Company.
Furthermore, as part of the Company's growth strategy, it must continue to hire highly qualified individuals. There can be no assurance that the Company will be able to attract, assimilate or retain qualified personnel in the future, which would adversely affect its business.
Subsequent Events
| (a) | Exercise of Options |
|
|
|
|
| Subsequent to the year ended on March 31, 2026, the following options were exercised: 120,000 options at $0.125 per share; 50,000 options at $0.67 per share; 20,000 options at $0.105 per share. |
|
|
|
| (b) | Joint Venture Agreement with Boliden |
|
|
|
|
| Subsequent to the year ended on March 31, 2026, Amarc and Boliden signed a joint venture agreement to jointly operate DUKE District. Concurrently, the EIA was terminated and Boliden elected not to exercise the option to increase its interest from 60% to 70% by investing a further $60 million. Boliden appointed Amarc as the operator for the DUKE JV. DUKE JV is owned 60% by Boliden and 40% by Amarc. |
| - 33 - |
EXHIBIT 99.3
Form 52-109FV1
Certification of Annual Filings
Venture Issuer Basic Certificate
I, Diane S. Nicolson, Chief Executive Officer of Amarc Resources Ltd., certify the following:
| 1. | Review: I have reviewed the AIF, if any, annual financial statements and annual MD&A, including, for greater certainty, all documents and information that are incorporated by reference in the AIF (together, the “annual filings”) of Amarc Resources Ltd. (the “issuer”) for the financial year ended March 31, 2026. |
|
|
|
| 2. | No misrepresentations: Based on my knowledge, having exercised reasonable diligence, the annual filings do not contain any untrue statement of a material fact or omit to state a material fact required to be stated or that is necessary to make a statement not misleading in light of the circumstances under which it was made, for the period covered by the annual filings. |
|
|
|
| 3. | Fair presentation: Based on my knowledge, having exercised reasonable diligence, the annual financial statements together with the other financial information included in the annual filings fairly present in all material respects the financial condition, financial performance and cash flows of the issuer, as of the date of and for the periods presented in the annual filings. |
Date: July 22, 2026
/s/ Diane S. Nicolson
_______________________
Diane S. Nicolson
Chief Executive Officer
| NOTE TO READER | |
|
| |
| In contrast to the certificate required for non-venture issuers under National Instrument 52-109 Certification of Disclosure in Issuers’ Annual and Interim Filings (NI 52-109), this Venture Issuer Basic Certificate does not include representations relating to the establishment and maintenance of disclosure controls and procedures (DC&P) and internal control over financial reporting (ICFR), as defined in NI 52-109. In particular, the certifying officers filing this certificate are not making any representations relating to the establishment and maintenance of | |
|
|
|
| i) | controls and other procedures designed to provide reasonable assurance that information required to be disclosed by the issuer in its annual filings, interim filings or other reports filed or submitted under securities legislation is recorded, processed, summarized and reported within the time periods specified in securities legislation; and |
|
|
|
| ii) | a process to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with the issuer’s GAAP. |
|
|
|
| The issuer’s certifying officers are responsible for ensuring that processes are in place to provide them with sufficient knowledge to support the representations they are making in this certificate. Investors should be aware that inherent limitations on the ability of certifying officers of a venture issuer to design and implement on a cost effective basis DC&P and ICFR as defined in NI 52-109 may result in additional risks to the quality, reliability, transparency and timeliness of interim and annual filings and other reports provided under securities legislation. | |
EXHIBIT 99.4
Form 52-109FV1
Certification of Annual Filings
Venture Issuer Basic Certificate
I, Carol Li, Chief Financial Officer of Amarc Resources Ltd., certify the following:
| 1. | Review: I have reviewed the AIF, if any, annual financial statements and annual MD&A, including, for greater certainty, all documents and information that are incorporated by reference in the AIF (together, the “annual filings”) of Amarc Resources Ltd. (the “issuer”) for the financial year ended March 31, 2026. |
|
|
|
| 2. | No misrepresentations: Based on my knowledge, having exercised reasonable diligence, the annual filings do not contain any untrue statement of a material fact or omit to state a material fact required to be stated or that is necessary to make a statement not misleading in light of the circumstances under which it was made, for the period covered by the annual filings. |
|
|
|
| 3. | Fair presentation: Based on my knowledge, having exercised reasonable diligence, the annual financial statements together with the other financial information included in the annual filings fairly present in all material respects the financial condition, financial performance and cash flows of the issuer, as of the date of and for the periods presented in the annual filings. |
Date: July 22, 2026
/s/ Carol Li
_______________________
Carol Li
Chief Financial Officer
| NOTE TO READER | |
|
| |
| In contrast to the certificate required for non-venture issuers under National Instrument 52-109 Certification of Disclosure in Issuers’ Annual and Interim Filings (NI 52-109), this Venture Issuer Basic Certificate does not include representations relating to the establishment and maintenance of disclosure controls and procedures (DC&P) and internal control over financial reporting (ICFR), as defined in NI 52-109. In particular, the certifying officers filing this certificate are not making any representations relating to the establishment and maintenance of | |
|
|
|
| i) | controls and other procedures designed to provide reasonable assurance that information required to be disclosed by the issuer in its annual filings, interim filings or other reports filed or submitted under securities legislation is recorded, processed, summarized and reported within the time periods specified in securities legislation; and |
|
|
|
| ii) | a process to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with the issuer’s GAAP. |
|
|
|
| The issuer’s certifying officers are responsible for ensuring that processes are in place to provide them with sufficient knowledge to support the representations they are making in this certificate. Investors should be aware that inherent limitations on the ability of certifying officers of a venture issuer to design and implement on a cost effective basis DC&P and ICFR as defined in NI 52-109 may result in additional risks to the quality, reliability, transparency and timeliness of interim and annual filings and other reports provided under securities legislation. | |