
BOKF 8-K
Bok Financial Corp (BOKF)
8-K
2025-10-20
For: 2025-10-20
View Original
Added on
April 11, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, DC 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported):
Commission File No. 001-37811
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of Incorporation or Organization) | (IRS Employer Identification No.) | ||||||||||
| Bank of Oklahoma Tower | |||||||||||
| (Address of Principal Executive Offices) | (Zip Code) | ||||||||||
(918 ) 588-6000
(Registrant’s telephone number, including area code)
N/A
__________________________________________
(Former name or former address, if changes since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Securities registered pursuant to Section 12(b) of the Act: | ||||||||||||||
| Title of each class | Trading Symbol | Name of each exchange on which registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨
INFORMATION TO BE INCLUDED IN THE REPORT
ITEM 2.02. Results of Operations and Financial Condition.
On October 20, 2025, BOK Financial Corporation (“BOK Financial”) issued a press release announcing its financial results for the three and nine months ended September 30, 2025 (“Press Release”). The full text of the Press Release is attached as Exhibit 99.1(a) to this report and is incorporated herein by reference. On October 20, 2025, in connection with the issuance of the Press Release, BOK Financial released financial information related to the three and nine months ended September 30, 2025 (“Financial Information”), which includes certain historical financial information relating to BOK Financial. The Financial Information is attached as Exhibit 99.1(b) to this report and is incorporated herein by reference.
ITEM 7.01. Regulation FD Disclosure.
On October 20, 2025, in connection with the issuance of the Press Release, BOK Financial released financial information related to the three and nine months ended September 30, 2025 (“Financial Information”), which includes certain historical financial information relating to BOK Financial. The Financial Information is attached as Exhibit 99.2(a) to this report and is incorporated herein by reference.
ITEM 9.01. Financial Statements and Exhibits.
(d) Exhibits
99.1 Text of Press Release, dated October 20, 2025, titled "BOK Financial Corporation reports quarterly earnings of $141 million, or $2.22 per share, in the third quarter" and Financial Information for the Three and Nine Months Ended September 30, 2025.
99.2 Earnings conference call presentation, dated October 21, 2025, titled “Q3 Earnings Conference Call" for the Three and Nine Months Ended September 30, 2025.
104 Cover Page Interactive Data File (embedded within the Inline XBRL document).
Signature
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
BOK FINANCIAL CORPORATION
By: /s/ Martin E. Grunst
Martin E. Grunst
Executive Vice President
Chief Financial Officer
Date: October 20, 2025

BOK Financial Corporation reports quarterly earnings of $141 million, or $2.22 per share, in the third quarter.
Third quarter 2025 financial highlights1 | ||||||||
Net Income | Net income was $140.9 million, or $2.22 per diluted share, compared to $140.0 million, or $2.19 per diluted share. | |||||||
Net Interest Income & Margin | Net interest income totaled $337.6 million, an increase of $9.5 million. Net interest margin expanded 11 basis points to 2.91% compared to 2.80% in the prior quarter. | |||||||
Fees & Commissions Revenue | Fees and commissions revenue was $204.4 million, an increase of $7.1 million, led by growth in investment banking revenue driven by increased municipal underwriting activity. | |||||||
Operating Expense | Operating expense increased $15.3 million to $369.8 million, primarily due to higher personnel expense, including increased incentive compensation and regular compensation. Non-personnel expense was up $3.6 million, largely led by higher mortgage banking costs. | |||||||
Loans | Period end loans were $24.9 billion, growing by $573 million, driven by broad-based growth across the loan portfolio. Average outstanding loan balances were $24.8 billion, a $650 million increase. | |||||||
Credit Quality | Nonperforming assets declined to $74 million, or 0.30% of outstanding loans and repossessed assets, at September 30, 2025, from $81 million, or 0.33%, at June 30, 2025. Net charge-offs for the third quarter were $3.6 million, or 0.06% of average loans on an annualized basis. | |||||||
| Deposits | Period end deposits grew by $254 million to $38.5 billion and average deposits increased $345 million to $38.5 billion. Average interest-bearing deposits increased $408 million, while average demand deposits decreased by $64 million. The loan to deposit ratio was 65% at September 30, 2025, compared to 64% at June 30, 2025. | |||||||
| Capital | Tangible common equity ratio was 10.06% compared to 9.63% at June 30, 2025. Tier 1 capital ratio was 13.61%, common equity Tier 1 capital ratio was 13.60%, and total capital ratio was 14.48%. The company repurchased 365,547 shares of common stock at an average price paid of $111.00 per share in the third quarter of 2025. | |||||||
1 Comparisons are to prior quarter unless otherwise noted.
| p | $9.5 million | 2 bps | p | $573 million | $122.7 billion | ||||||||||||||||||||||||
| NET INTEREST INCOME | NET CHARGE-OFFS (TTM) | LOAN GROWTH | AUMA | ||||||||||||||||||||||||||
CEO Commentary
Stacy Kymes, President and CEO, stated, “I’m proud of our strong performance this quarter, highlighted by solid loan growth, improving net interest margin, and growth in Wealth assets. Loans grew an additional $573 million this quarter and nearly $1.2 billion or 10% annualized over the past two quarters following market volatility driven by first quarter tariff uncertainty. We also achieved meaningful expansion in our net interest margin with a 13 basis point increase during that same timeframe. Our fee-based businesses continued to gain momentum with a quarterly high for Investment Banking revenue and Wealth assets growing to $122.7 billion, an $8.7 billion increase in the last 6 months. We are well-positioned to build on this success in the fourth quarter and remain focused on sustaining our positive trajectory while delivering long-term value for our shareholders."
| BOK Financial Corporation quarterly earnings release | Exhibit 99.1(a) | ||||
Net Interest Income
| (Dollars in thousands) | Sep. 30, 2025 | June 30, 2025 | Change | % Change | ||||||||||||||||||||||
| Interest revenue | ||||||||||||||||||||||||||
| Interest-bearing cash and cash equivalents | $ | 5,482 | $ | 5,626 | $ | (144) | (2.6) | % | ||||||||||||||||||
| Trading securities | 72,770 | 86,488 | (13,718) | (15.9) | % | |||||||||||||||||||||
| Investment securities | 6,560 | 6,762 | (202) | (3.0) | % | |||||||||||||||||||||
| Available-for-sale securities | 133,452 | 131,360 | 2,092 | 1.6 | % | |||||||||||||||||||||
| Fair value option securities | 1,441 | 1,319 | 122 | 9.2 | % | |||||||||||||||||||||
| Restricted equity securities | 6,605 | 7,545 | (940) | (12.5) | % | |||||||||||||||||||||
| Residential mortgage loans held for sale | 1,405 | 1,346 | 59 | 4.4 | % | |||||||||||||||||||||
| Loans | 419,303 | 404,555 | 14,748 | 3.6 | % | |||||||||||||||||||||
| Total interest revenue | $ | 647,018 | $ | 645,001 | $ | 2,017 | 0.3 | % | ||||||||||||||||||
| Interest expense | ||||||||||||||||||||||||||
| Interest-bearing deposits: | ||||||||||||||||||||||||||
| Transaction | $ | 206,400 | $ | 204,216 | $ | 2,184 | 1.1 | % | ||||||||||||||||||
| Savings | 1,197 | 1,155 | 42 | 3.6 | % | |||||||||||||||||||||
| Time | 34,236 | 33,072 | 1,164 | 3.5 | % | |||||||||||||||||||||
| Total interest-bearing deposits | 241,833 | 238,443 | 3,390 | 1.4 | % | |||||||||||||||||||||
| Funds purchased and repurchase agreements | 7,250 | 6,820 | 430 | 6.3 | % | |||||||||||||||||||||
| Other borrowings | 57,724 | 67,410 | (9,686) | (14.4) | % | |||||||||||||||||||||
| Subordinated debentures | — | 1,588 | (1,588) | (100.0) | % | |||||||||||||||||||||
| Total interest expense | $ | 306,807 | $ | 314,261 | $ | (7,454) | (2.4) | % | ||||||||||||||||||
| Tax-equivalent net interest income | 340,211 | 330,740 | 9,471 | 2.9 | % | |||||||||||||||||||||
Less: Tax-equivalent adjustment | 2,565 | 2,574 | (9) | (0.3) | % | |||||||||||||||||||||
| Net interest income | $ | 337,646 | $ | 328,166 | $ | 9,480 | 2.9 | % | ||||||||||||||||||
| Net interest margin | 2.91 | % | 2.80 | % | 0.11 | % | N/A | |||||||||||||||||||
| Average earning assets | $ | 46,429,240 | $ | 46,984,071 | $ | (554,831) | (1.2) | % | ||||||||||||||||||
| Average trading securities | 5,603,200 | 6,876,788 | (1,273,588) | (18.5) | % | |||||||||||||||||||||
| Average investment securities | 1,861,565 | 1,918,969 | (57,404) | (3.0) | % | |||||||||||||||||||||
| Average available-for-sale securities | 13,386,515 | 13,218,569 | 167,946 | 1.3 | % | |||||||||||||||||||||
| Fair value option securities | 105,651 | 88,323 | 17,328 | 19.6 | % | |||||||||||||||||||||
Restricted equity securities | 337,055 | 390,191 | (53,136) | (13.6) | % | |||||||||||||||||||||
| Average loans balance | 24,826,139 | 24,176,549 | 649,590 | 2.7 | % | |||||||||||||||||||||
| Average interest-bearing deposits | 30,586,399 | 30,178,178 | 408,221 | 1.4 | % | |||||||||||||||||||||
| Funds purchased and repurchase agreements | 873,800 | 782,039 | 91,761 | 11.7 | % | |||||||||||||||||||||
| Other borrowings | 5,048,301 | 6,019,948 | (971,647) | (16.1) | % | |||||||||||||||||||||
Net interest income was $337.6 million for the third quarter of 2025, an increase of $9.5 million over the prior quarter. Net interest margin expanded to 2.91% from 2.80%. For the third quarter of 2025, our core net interest margin excluding trading activities, a non-GAAP measure, increased 4 basis points to 3.16% compared to 3.12% in the prior quarter.
Average earning assets decreased $555 million. Average trading securities decreased $1.3 billion, average investment securities decreased $57 million, and average restricted equity securities decreased $53 million. Average loan balances increased $650 million, primarily due to growth in portfolio balances for commercial real estate loans and loans to individuals. Average available-for-sale securities grew $168 million. Average interest-bearing deposits increased $408 million, primarily from growth in interest-bearing transaction accounts and time deposits. Average funds purchased and repurchase agreements increased $92 million, while average other borrowings decreased $972 million.
2
| BOK Financial Corporation quarterly earnings release | Exhibit 99.1(a) | ||||
The yield on average earning assets was 5.53%, a 6 basis point increase over the prior quarter. The yield on the available-for-sale securities portfolio increased 4 basis points to 3.93% and the yield on trading securities was up 20 basis points to 5.25%. The loan portfolio yield decreased 1 basis point to 6.70%. The yield on restricted equity securities expanded 11 basis points to 7.84%.
Funding costs were 3.33%, down 7 basis points. The cost of interest-bearing deposits decreased 3 basis points to 3.14%. The cost of funds purchased and repurchase agreements decreased 21 basis points to 3.29%, while the cost of other borrowings increased 5 basis points to 4.54%. The cost of subordinated debentures was down 638 basis points as all outstanding subordinated debentures were called during the second quarter. The benefit to net interest margin from assets funded by non-interest liabilities was 71 basis points, a decrease of 2 basis points.
Other Operating Revenue
| (Dollars in thousands) | Sep. 30, 2025 | June 30, 2025 | Change | % Change | ||||||||||||||||||||||
| Brokerage and trading revenue | $ | 43,239 | $ | 38,125 | $ | 5,114 | 13.4 | % | ||||||||||||||||||
| Transaction card revenue | 29,463 | 29,561 | (98) | (0.3) | % | |||||||||||||||||||||
| Fiduciary and asset management revenue | 63,878 | 63,964 | (86) | (0.1) | % | |||||||||||||||||||||
| Deposit service charges and fees | 31,896 | 31,319 | 577 | 1.8 | % | |||||||||||||||||||||
| Mortgage banking revenue | 19,764 | 18,993 | 771 | 4.1 | % | |||||||||||||||||||||
| Other revenue | 16,190 | 15,368 | 822 | 5.3 | % | |||||||||||||||||||||
| Total fees and commissions | 204,430 | 197,330 | 7,100 | 3.6 | % | |||||||||||||||||||||
| Other gains, net | 8,264 | 8,140 | 124 | N/A | ||||||||||||||||||||||
| Gain (loss) on derivatives, net | (453) | 5,535 | (5,988) | N/A | ||||||||||||||||||||||
Gain on fair value option securities, net | 630 | 1,112 | (482) | N/A | ||||||||||||||||||||||
| Change in fair value of mortgage servicing rights | (2,375) | (5,019) | 2,644 | N/A | ||||||||||||||||||||||
| Gain on available for sale securities, net | 213 | — | 213 | N/A | ||||||||||||||||||||||
| Total other operating revenue | $ | 210,709 | $ | 207,098 | $ | 3,611 | 1.7 | % | ||||||||||||||||||
Fees and commissions revenue totaled $204.4 million for the third quarter of 2025, growing $7.1 million over the prior quarter.
Brokerage and trading revenue increased $5.1 million to $43.2 million. Investment banking revenue grew $5.0 million driven by increased municipal underwriting activity. Trading fees and commissions revenue increased $1.1 million, largely driven by higher municipal bond trading, partially offset by a decrease in U.S. agency residential mortgage-backed securities trading volumes. Customer hedging revenue decreased $1.8 million, primarily related to lower energy derivative volumes.
Fiduciary and asset management revenue was largely unchanged from the prior quarter. The current quarter benefited from increased trust fees driven by higher market valuations and continued growth in client relationships, while the prior quarter was impacted by seasonal tax preparation fees.
3
| BOK Financial Corporation quarterly earnings release | Exhibit 99.1(a) | ||||
Operating Expenses
| (Dollars in thousands) | Sep. 30, 2025 | June 30, 2025 | Change | % Change | ||||||||||||||||||||||
| Personnel | $ | 226,347 | $ | 214,711 | $ | 11,636 | 5.4 | % | ||||||||||||||||||
| Business promotion | 9,960 | 9,139 | 821 | 9.0 | % | |||||||||||||||||||||
| Professional fees and services | 15,137 | 15,402 | (265) | (1.7) | % | |||||||||||||||||||||
| Net occupancy and equipment | 33,040 | 32,657 | 383 | 1.2 | % | |||||||||||||||||||||
| FDIC and other insurance | 7,302 | 6,439 | 863 | 13.4 | % | |||||||||||||||||||||
| FDIC special assessment | (1,209) | (523) | (686) | N/A | ||||||||||||||||||||||
| Data processing and communications | 50,062 | 49,597 | 465 | 0.9 | % | |||||||||||||||||||||
| Printing, postage, and supplies | 4,036 | 4,067 | (31) | (0.8) | % | |||||||||||||||||||||
| Amortization of intangible assets | 2,656 | 2,656 | — | — | % | |||||||||||||||||||||
| Mortgage banking costs | 10,668 | 6,711 | 3,957 | 59.0% | ||||||||||||||||||||||
| Other expense | 11,771 | 13,647 | (1,876) | (13.7) | % | |||||||||||||||||||||
| Total operating expense | $ | 369,770 | $ | 354,503 | $ | 15,267 | 4.3 | % | ||||||||||||||||||
Total operating expense was $369.8 million for the third quarter of 2025, an increase of $15.3 million compared to the prior quarter.
Personnel expense was $226.3 million, an increase of $11.6 million. Cash-based incentive compensation increased $5.4 million driven by stronger underwriting and loan origination activity. Regular compensation costs grew $3.1 million, largely reflecting transitional personnel expenses associated with aligning our talent base to future growth objectives. Deferred compensation expense was $5.8 million, an increase of $2.5 million over the prior quarter; however, this was largely offset by an increase in the value of related investments included in Other gains (losses), net.
Non-personnel expense was $143.4 million, an increase of $3.6 million. Mortgage banking costs increased $4.0 million. Expenses in the prior quarter were below typical seasonal levels, primarily due to lower mortgage servicing related costs. Other expense decreased by $1.9 million due to lower operational losses.
4
| BOK Financial Corporation quarterly earnings release | Exhibit 99.1(a) | ||||
Loans
| (Dollars in thousands) | Sep. 30, 2025 | June 30, 2025 | Change | % Change | ||||||||||||||||||||||
| Commercial: | ||||||||||||||||||||||||||
| Healthcare | $ | 3,878,543 | $ | 3,808,936 | $ | 69,607 | 1.8% | |||||||||||||||||||
| Services | 3,710,643 | 3,658,807 | 51,836 | 1.4% | ||||||||||||||||||||||
| Energy | 2,681,512 | 2,734,713 | (53,201) | (1.9)% | ||||||||||||||||||||||
| General business | 4,242,242 | 4,181,726 | 60,516 | 1.4% | ||||||||||||||||||||||
| Total commercial | 14,512,940 | 14,384,182 | 128,758 | 0.9% | ||||||||||||||||||||||
| Commercial Real Estate: | ||||||||||||||||||||||||||
| Multifamily | 2,500,323 | 2,473,365 | 26,958 | 1.1% | ||||||||||||||||||||||
| Industrial | 1,396,795 | 1,304,211 | 92,584 | 7.1% | ||||||||||||||||||||||
| Office | 811,601 | 690,086 | 121,515 | 17.6% | ||||||||||||||||||||||
| Retail | 593,835 | 592,043 | 1,792 | 0.3% | ||||||||||||||||||||||
Residential construction and land development | 122,033 | 105,701 | 16,332 | 15.5% | ||||||||||||||||||||||
| Other real estate loans | 328,020 | 356,035 | (28,015) | (7.9)% | ||||||||||||||||||||||
| Total commercial real estate | 5,752,607 | 5,521,441 | 231,166 | 4.2% | ||||||||||||||||||||||
| Loans to individuals: | ||||||||||||||||||||||||||
Residential mortgage | 2,676,366 | 2,610,681 | 65,685 | 2.5% | ||||||||||||||||||||||
| Residential mortgages guaranteed by U.S. government agencies | 151,642 | 148,453 | 3,189 | 2.1% | ||||||||||||||||||||||
| Personal | 1,771,639 | 1,627,454 | 144,185 | 8.9% | ||||||||||||||||||||||
| Total loans to individuals | 4,599,647 | 4,386,588 | 213,059 | 4.9% | ||||||||||||||||||||||
| Total loans | $ | 24,865,194 | $ | 24,292,211 | $ | 572,983 | 2.4% | |||||||||||||||||||
Outstanding loans were $24.9 billion at September 30, 2025, an increase of $573 million over June 30, 2025, driven by broad-based growth across the loan portfolio. Unfunded loan commitments grew by $530 million over the second quarter of 2025.
Outstanding commercial loan balances, which includes healthcare, services, energy, and general business loans, increased $129 million over the prior quarter.
Healthcare sector loan balances increased $70 million and totaled $3.9 billion, or 16% of total loans. Our healthcare sector loans primarily consist of $3.1 billion of senior housing and care facilities, including independent living, assisted living, and skilled nursing. Generally, we loan to borrowers with a portfolio of multiple facilities, which serves to help diversify risks specific to a single facility.
General business loans increased $61 million to $4.2 billion, or 17% of total loans. General business loans include $2.7 billion of wholesale/retail loans and $1.5 billion of loans from other commercial industries.
Services sector loan balances were up $52 million over the prior quarter to $3.7 billion, or 15% of total loans. Services loans consist of a large number of loans to a variety of businesses, including Native American tribal and state and local municipal government entities, Native American tribal casino operations, foundations and not-for-profit organizations, educational services, and specialty trade contractors.
Energy loan balances decreased $53 million to $2.7 billion, or 11% of total loans. Consolidation in the energy industry led to elevated payoff activity in recent quarters, but this payoff activity is abating and balances are stabilizing. The majority of this portfolio is first lien, senior secured, reserve-based lending to oil and gas producers, which we believe is the lowest risk form of energy lending. Approximately 71% of committed production loans are secured by properties primarily producing oil. The remaining 29% are secured by properties primarily producing natural gas. Unfunded energy loan commitments were $4.4 billion at September 30, 2025, an $89 million decrease compared to June 30, 2025.
5
| BOK Financial Corporation quarterly earnings release | Exhibit 99.1(a) | ||||
Commercial real estate loan balances increased $231 million to $5.8 billion, representing 23% of total loans. Loans secured by office facilities increased $122 million to $812 million, loans secured by industrial facilities increased $93 million to $1.4 billion, and loans secured by multifamily properties increased $27 million to $2.5 billion. The increases in these portfolios were partially offset by a $28 million decrease in other real estate loans. Unfunded commercial real estate loan commitments were $2.1 billion at September 30, 2025, an $84 million increase compared to June 30, 2025. We take a disciplined approach to managing our concentration of commercial real estate loan commitments as a percentage of capital.
Loans to individuals increased $213 million to $4.6 billion and represent 18% of total loans. Personal loans increased $144 million and residential mortgage loans increased $69 million. Personal loans consist primarily of loans to Wealth Management clients secured by the cash surrender value of insurance policies and marketable securities. Personal loans also include direct loans secured by and for the purchase of automobiles, recreational and marine equipment, as well as unsecured loans.
Period End & Average Deposits
| (Dollars in thousands) | Sep. 30, 2025 | June 30, 2025 | Change | % Change | ||||||||||||||||||||||
| Period end deposits | ||||||||||||||||||||||||||
| Demand | $ | 7,907,176 | $ | 7,998,761 | $ | (91,585) | (1.1) | % | ||||||||||||||||||
| Interest-bearing transaction | 25,983,228 | 25,843,923 | 139,305 | 0.5 | % | |||||||||||||||||||||
| Savings | 846,736 | 853,757 | (7,021) | (0.8) | % | |||||||||||||||||||||
| Time | 3,762,878 | 3,549,668 | 213,210 | 6.0 | % | |||||||||||||||||||||
| Total deposits | $ | 38,500,018 | $ | 38,246,109 | $ | 253,909 | 0.7 | % | ||||||||||||||||||
| Average deposits | ||||||||||||||||||||||||||
| Demand | $ | 7,894,847 | $ | 7,958,538 | $ | (63,691) | (0.8) | % | ||||||||||||||||||
| Interest-bearing transaction | 26,076,475 | 25,859,336 | 217,139 | 0.8 | % | |||||||||||||||||||||
| Savings | 867,939 | 853,062 | 14,877 | 1.7 | % | |||||||||||||||||||||
| Time | 3,641,985 | 3,465,780 | 176,205 | 5.1 | % | |||||||||||||||||||||
| Total average deposits | $ | 38,481,246 | $ | 38,136,716 | $ | 344,530 | 0.9 | % | ||||||||||||||||||
Our funding sources, which primarily include deposits and wholesale borrowings, provide adequate liquidity to meet our needs. The loan to deposit ratio was 65% at September 30, 2025, compared to 64% at June 30, 2025, providing significant on-balance sheet liquidity to meet future loan demand and contractual obligations.
Period end deposits totaled $38.5 billion at September 30, 2025, a $254 million increase. Time deposits increased $213 million and interest-bearing transaction accounts increased $139 million. Demand deposits decreased $92 million.
Average deposits were $38.5 billion at September 30, 2025, a $345 million increase. Average interest-bearing transaction accounts increased $217 million and average time deposits increased $176 million, while average demand deposit balances decreased $64 million.
Average Commercial Banking deposits increased $737 million to $18.2 billion, or 47% of total deposits. Our commercial deposit portfolio is highly diversified across industries and customers. The highest concentration by industry within our commercial deposit portfolio is with our energy customers representing 9% of our total deposits. Average Consumer Banking deposits increased $64 million to $8.3 billion, or 22% of total deposits. Average Wealth Management deposits decreased by $52 million to $10.7 billion, or 28% of total deposits.
6
| BOK Financial Corporation quarterly earnings release | Exhibit 99.1(a) | ||||
Capital
| Minimum Capital Requirement | Capital Conservation Buffer | Minimum Capital Requirement Including Capital Conservation Buffer | Sep. 30, 2025 | June 30, 2025 | |||||||||||||||||||||||||
| Common equity Tier 1 | 4.50 | % | 2.50 | % | 7.00 | % | 13.60 | % | 13.59 | % | |||||||||||||||||||
| Tier 1 capital | 6.00 | % | 2.50 | % | 8.50 | % | 13.61 | % | 13.60 | % | |||||||||||||||||||
| Total capital | 8.00 | % | 2.50 | % | 10.50 | % | 14.48 | % | 14.48 | % | |||||||||||||||||||
| Tier 1 leverage | 4.00 | % | N/A | 4.00 | % | 10.19 | % | 9.88 | % | ||||||||||||||||||||
Tangible common equity ratio1 | 10.06 | % | 9.63 | % | |||||||||||||||||||||||||
| Common stock repurchased (shares) | 365,547 | 663,298 | |||||||||||||||||||||||||||
| Average price per share repurchased | $ | 111.00 | $ | 93.99 | |||||||||||||||||||||||||
1 See Explanation and Reconciliation of Non-GAAP Measures following.
The company's common equity Tier 1 capital ratio was 13.60% at September 30, 2025. In addition, the company's Tier 1 capital ratio was 13.61%, total capital ratio was 14.48%, and leverage ratio was 10.19% at September 30, 2025. At June 30, 2025, the company's common equity Tier 1 capital ratio was 13.59%, Tier 1 capital ratio was 13.60%, total capital ratio was 14.48%, and leverage ratio was 9.88%.
The company's tangible common equity ratio, a non-GAAP measure, was 10.06% at September 30, 2025, and 9.63% at June 30, 2025. The tangible common equity ratio is primarily based on total shareholders' equity, which includes unrealized gains and losses on available-for-sale securities.
The company repurchased 365,547 shares of common stock at an average price paid of $111.00 per share in the third quarter of 2025. We view buybacks opportunistically, but within the context of maintaining our strong capital position.
Credit Quality
Nonperforming assets totaled $74 million, or 0.30% of outstanding loans and repossessed assets, at September 30, 2025, compared to $81 million, or 0.33%, at June 30, 2025. Excluding loans guaranteed by U.S. government agencies, nonperforming assets totaled $67 million, or 0.27% of outstanding loans and repossessed assets, at September 30, 2025, compared to $74 million, or 0.31%, at June 30, 2025.
Nonaccruing loans decreased $6.9 million compared to June 30, 2025. New nonaccruing loans identified in the third quarter totaled $6.2 million, offset by $5.9 million in payments received, $4.3 million in charge-offs, and $2.4 million in loans that returned to accrual status. Nonaccruing healthcare loans decreased $4.2 million and nonaccruing services loans decreased $3.7 million.
Net charge-offs were $3.6 million, or 0.06% of average loans on an annualized basis, in the third quarter. At September 30, 2025, net charge-offs for the trailing twelve months were $5.8 million, or 0.02% of average loans. Net charge-offs were $561 thousand, or 0.01% of average loans on an annualized basis, in the second quarter of 2025. At June 30, 2025, net charge-offs for the trailing twelve months were $2.1 million, or 0.01% of average loans.
The provision for expected credit losses of $2.0 million in the third quarter of 2025 reflects the impact of loan growth during the quarter, partially offset by a slight improvement in economic forecast scenario assumptions.
At September 30, 2025, the combined allowance for loan losses and accrual for off-balance sheet credit risk from unfunded loan commitments was $328 million, or 1.32% of outstanding loans and 505% of nonaccruing loans, excluding residential mortgage loans guaranteed by U.S. government agencies. At June 30, 2025, the combined allowance for loan losses and accrual for off-balance sheet credit risk from unfunded loan commitments was $330 million, or 1.36% of outstanding loans and 456% of nonaccruing loans.
7
| BOK Financial Corporation quarterly earnings release | Exhibit 99.1(a) | ||||
Securities & Derivatives
The fair value of the available-for-sale securities portfolio totaled $13.5 billion at September 30, 2025, a $133 million increase over June 30, 2025. At September 30, 2025, the available-for-sale securities portfolio consisted primarily of $9.4 billion of residential mortgage-backed securities fully backed by U.S. government agencies and $3.1 billion of commercial mortgage-backed securities fully backed by U.S. government agencies. At September 30, 2025, the available-for-sale securities portfolio had a net unrealized loss of $204 million, compared to $277 million at June 30, 2025.
We hold an inventory of trading securities in support of sales to a variety of customers. At September 30, 2025, the trading securities portfolio totaled $4.3 billion, compared to $5.6 billion at June 30, 2025.
The company also maintains a portfolio of residential mortgage-backed securities issued by U.S. government agencies and interest rate derivative contracts as an economic hedge of the changes in the fair value of our mortgage servicing rights. This portfolio of fair value option securities decreased $3.0 million to $105 million at September 30, 2025.
Derivative contracts are carried at fair value. At September 30, 2025, the net fair values of derivative contracts, before consideration of cash margin, reported as assets under our customer derivative programs totaled $317 million, compared to $326 million at June 30, 2025. The aggregate net fair value of derivative contracts, before consideration of cash margin, held under these programs reported as liabilities totaled $294 million at September 30, 2025, and $297 million at June 30, 2025.
The net cost of the changes in the fair value of mortgage servicing rights and related economic hedges was $2.1 million during the third quarter of 2025, including a $2.4 million decrease in the fair value of mortgage servicing rights, a $122 thousand increase in the fair value of securities and derivative contracts held as an economic hedge, and $169 thousand of related net interest income.
Third Quarter 2025 Segment Highlights
| Commercial Banking | Consumer Banking | Wealth Management | ||||||||||||||||||||||||||||||||||||
| (In thousands) | Sep. 30, 2025 | June 30, 2025 | Sep. 30, 2025 | June 30, 2025 | Sep. 30, 2025 | June 30, 2025 | ||||||||||||||||||||||||||||||||
Net interest income and fee revenue | $ | 236,734 | $ | 234,226 | $ | 96,522 | $ | 94,903 | $ | 155,142 | $ | 148,494 | ||||||||||||||||||||||||||
| Net loans charged-off (recovered) | 2,609 | 29 | 1,413 | 1,018 | (3) | (7) | ||||||||||||||||||||||||||||||||
| Personnel expense | 51,638 | 49,774 | 25,681 | 25,527 | 73,032 | 66,309 | ||||||||||||||||||||||||||||||||
| Non-personnel expense | 29,601 | 29,931 | 38,361 | 29,949 | 29,939 | 26,972 | ||||||||||||||||||||||||||||||||
| Net income before taxes | 139,817 | 141,364 | 14,490 | 24,746 | 36,606 | 40,749 | ||||||||||||||||||||||||||||||||
| Average loans | $ | 20,280,147 | $ | 19,894,391 | $ | 2,432,968 | $ | 2,304,939 | $ | 2,353,961 | $ | 2,275,378 | ||||||||||||||||||||||||||
| Average deposits | 18,161,258 | 17,424,707 | 8,330,481 | 8,266,824 | 10,731,569 | 10,783,245 | ||||||||||||||||||||||||||||||||
| Assets under management or administration | $ | 122,673,531 | $ | 117,870,970 | ||||||||||||||||||||||||||||||||||
Commercial Banking contributed $139.8 million to net income before taxes in the third quarter of 2025, a decrease of $1.5 million compared to the second quarter of 2025. Combined net interest income and fee revenue increased $2.5 million over the prior quarter. Net interest income grew $3.4 million led by higher loan balances during the quarter, which was partially offset by a decrease in loan syndication fees. Net loans charged off increased $2.6 million in the third quarter of 2025. Other operating expenses increased $1.5 million, primarily due to higher incentive compensation costs driven by increased loan origination activity during the quarter. Other gains (losses), net, declined $1.8 million related to lower gains on merchant banking activities. Corporate expense allocations decreased $1.9 million. Average loans increased $386 million, or 2% to $20.3 billion. Average deposits grew $737 million, or 4%, to $18.2 billion.
8
| BOK Financial Corporation quarterly earnings release | Exhibit 99.1(a) | ||||
Consumer Banking contributed $14.5 million to net income before taxes in the third quarter of 2025, compared to $24.7 million in the prior quarter. Combined net interest income and fee revenue totaled $96.5 million, up $1.6 million, primarily due to increased mortgage banking revenue driven by growth in mortgage production volumes. The net cost of the change in the fair value of mortgage servicing rights and the related economic hedges was $2.1 million, compared to a benefit of $1.6 million in the prior quarter. Other operating expenses increased $8.6 million. Mortgage banking costs increased $4.0 million as the prior quarter's expenses were below typical seasonal levels, primarily due to lower mortgage servicing related costs. Other expense increased $2.2 million related to operational losses and business promotion expense increased $1.9 million due to increased advertising costs. Average loans increased $128 million, or 6%, to $2.4 billion. Average deposits were consistent with prior quarter at $8.3 billion.
Wealth Management contributed $36.6 million to net income before taxes in the third quarter of 2025, a decrease of $4.1 million compared to the second quarter of 2025. Combined net interest income and fee revenue increased $6.6 million, primarily due to growth in investment banking revenue driven by the timing and volume of municipal underwriting transactions. Other operating expenses increased $9.7 million. Incentive compensation expense increased $5.7 million, reflecting stronger underwriting activity. Professional fees and services expense grew $1.1 million, largely related to ongoing projects. Average loans increased $79 million, or 3%, to $2.4 billion. Average deposits were largely unchanged at $10.7 billion. Assets under management or administration were $122.7 billion, an increase of $4.8 billion, or 4%.
Conference Call & Webcast
The company will hold a conference call at noon Central time on Tuesday, October 21, 2025, to discuss the financial results with investors. The live audio webcast and presentation slides will be available on the company’s website at bokf.com. The conference call can also be accessed by dialing 1-800-715-9871 toll free, or 1-646-307-1963, conference ID: 6617678. A webcast replay will also be available shortly after the conclusion of the live call at bokf.com or by dialing 1-800-770-2030 and referencing replay PIN: 6617678.
About BOK Financial Corporation
BOK Financial Corporation is a $50 billion regional financial services company headquartered in Tulsa, Oklahoma with $123 billion in assets under management or administration. The company's stock is publicly traded on NASDAQ under the Global Select market listings (BOKF). BOK Financial Corporation's holdings include BOKF, NA; BOK Financial Securities, Inc.; and BOK Financial Private Wealth, Inc. BOKF, NA's holdings include TransFund and Cavanal Hill Investment Management, Inc. BOKF, NA operates banking divisions across eight states as: Bank of Albuquerque; Bank of Oklahoma; Bank of Texas; and BOK Financial in Arizona, Arkansas, Colorado, Kansas and Missouri; as well as having limited purpose offices in Nebraska, Wisconsin, Connecticut, and Tennessee. Through its subsidiaries, BOK Financial Corporation provides commercial and consumer banking, brokerage trading, investment and trust services, mortgage origination and servicing, and an electronic funds transfer network. For more information, visit www.bokf.com.
The company will continue to evaluate critical assumptions and estimates, such as the appropriateness of the allowance for credit losses and asset impairment as of September 30, 2025 through the date its financial statements are filed with the Securities and Exchange Commission and will adjust amounts reported if necessary.
This news release contains forward-looking statements that are based on management's beliefs, assumptions, current expectations, estimates and projections about BOK Financial Corporation, the financial services industry and the economy generally. Words such as “anticipates,” “believes,” “estimates,” “expects,” “forecasts,” “plans,” “outlook,” “projects,” “will,” “intends,” variations of such words and similar expressions are intended to identify such forward-looking statements. Management judgments relating to and discussion of the provision and allowance for credit losses, allowance for uncertain tax positions, accruals for loss contingencies and valuation of mortgage servicing rights involve judgments as to expected events and are inherently forward-looking statements. Assessments that acquisitions and growth endeavors will be profitable are necessary statements of belief as to the outcome of future events based in part on information provided by others which BOK Financial has not independently verified. These various forward-looking statements are not guarantees of future performance and involve certain risks, uncertainties, and assumptions which are difficult to predict with regard to timing, extent, likelihood and degree of occurrence. Therefore, actual results and outcomes may materially differ from what is expected, implied or forecasted in such forward-looking statements. Internal and external factors that might cause such a difference include, but are not limited to changes in government, changes in governmental economic policy, including tariffs, changes in commodity prices, interest rates and interest rate relationships, inflation, demand for products and services, the degree of competition by traditional and nontraditional competitors, changes in banking regulations, tax laws, prices, levies and assessments, the impact of technological advances, and trends in customer behavior as well as their ability to repay loans. BOK Financial Corporation and its affiliates undertake no obligation to update, amend or clarify forward-looking statements, whether as a result of new information, future events, or otherwise.
9
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
BALANCE SHEETS – UNAUDITED
BOK FINANCIAL CORPORATION
| (In thousands) | Sep. 30, 2025 | June 30, 2025 | |||||||||
| Assets | |||||||||||
| Cash and due from banks | $ | 880,721 | $ | 1,074,130 | |||||||
| Interest-bearing cash and cash equivalents | 545,322 | 284,933 | |||||||||
| Trading securities | 4,255,732 | 5,559,417 | |||||||||
| Investment securities, net of allowance | 1,837,647 | 1,897,178 | |||||||||
| Available-for-sale securities | 13,481,030 | 13,347,821 | |||||||||
| Fair value option securities | 104,688 | 107,702 | |||||||||
| Restricted equity securities | 248,605 | 294,359 | |||||||||
| Residential mortgage loans held for sale | 100,060 | 101,437 | |||||||||
| Loans: | |||||||||||
| Commercial | 14,512,940 | 14,384,182 | |||||||||
| Commercial real estate | 5,752,607 | 5,521,441 | |||||||||
| Loans to individuals | 4,599,647 | 4,386,588 | |||||||||
| Total loans | 24,865,194 | 24,292,211 | |||||||||
| Allowance for loan losses | (277,692) | (277,049) | |||||||||
| Loans, net of allowance | 24,587,502 | 24,015,162 | |||||||||
| Premises and equipment, net | 636,256 | 637,211 | |||||||||
| Receivables | 288,140 | 299,327 | |||||||||
| Goodwill | 1,044,749 | 1,044,749 | |||||||||
| Intangible assets, net | 37,376 | 40,000 | |||||||||
| Mortgage servicing rights | 326,399 | 334,644 | |||||||||
| Real estate and other repossessed assets, net | 1,751 | 1,729 | |||||||||
| Derivative contracts, net | 299,215 | 362,908 | |||||||||
| Cash surrender value of bank-owned life insurance | 419,103 | 416,566 | |||||||||
| Receivable on unsettled securities sales | 64,515 | 76,989 | |||||||||
| Other assets | 1,034,576 | 1,101,815 | |||||||||
| Total assets | $ | 50,193,387 | $ | 50,998,077 | |||||||
| Liabilities | |||||||||||
| Deposits: | |||||||||||
| Demand | $ | 7,907,176 | $ | 7,998,761 | |||||||
| Interest-bearing transaction | 25,983,228 | 25,843,923 | |||||||||
| Savings | 846,736 | 853,757 | |||||||||
| Time | 3,762,878 | 3,549,668 | |||||||||
| Total deposits | 38,500,018 | 38,246,109 | |||||||||
| Funds purchased and repurchase agreements | 970,950 | 682,051 | |||||||||
| Other borrowings | 3,239,507 | 4,140,130 | |||||||||
| Accrued interest, taxes, and expense | 312,283 | 302,515 | |||||||||
| Due on unsettled securities purchases | 321,729 | 964,580 | |||||||||
| Derivative contracts, net | 306,796 | 285,417 | |||||||||
| Other liabilities | 517,179 | 483,919 | |||||||||
| Total liabilities | 44,168,462 | 45,104,721 | |||||||||
| Shareholders' equity | |||||||||||
| Capital, surplus and retained earnings | 6,249,199 | 6,179,898 | |||||||||
| Accumulated other comprehensive loss | (226,664) | (289,010) | |||||||||
| Total shareholders’ equity | 6,022,535 | 5,890,888 | |||||||||
| Non-controlling interests | 2,390 | 2,468 | |||||||||
| Total equity | 6,024,925 | 5,893,356 | |||||||||
| Total liabilities and equity | $ | 50,193,387 | $ | 50,998,077 | |||||||
10
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
AVERAGE BALANCE SHEETS – UNAUDITED
BOK FINANCIAL CORPORATION
| Three Months Ended | |||||||||||||||||||||||||||||
| (In thousands) | Sep. 30, 2025 | June 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | ||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||
| Interest-bearing cash and cash equivalents | $ | 495,091 | $ | 506,330 | $ | 564,014 | $ | 546,955 | $ | 531,811 | |||||||||||||||||||
| Trading securities | 5,603,200 | 6,876,788 | 5,881,997 | 5,636,949 | 5,802,448 | ||||||||||||||||||||||||
| Investment securities, net of allowance | 1,861,565 | 1,918,969 | 1,980,005 | 2,037,072 | 2,094,408 | ||||||||||||||||||||||||
| Available-for-sale securities | 13,386,515 | 13,218,569 | 12,962,830 | 12,969,630 | 12,939,422 | ||||||||||||||||||||||||
| Fair value option securities | 105,651 | 88,323 | 17,603 | 18,384 | 19,095 | ||||||||||||||||||||||||
| Restricted equity securities | 337,055 | 390,191 | 348,266 | 338,236 | 410,800 | ||||||||||||||||||||||||
| Residential mortgage loans held for sale | 91,422 | 86,543 | 63,365 | 87,353 | 95,742 | ||||||||||||||||||||||||
| Loans: | |||||||||||||||||||||||||||||
| Commercial | 14,490,145 | 14,315,695 | 14,633,090 | 14,973,929 | 15,076,308 | ||||||||||||||||||||||||
| Commercial real estate | 5,743,572 | 5,495,152 | 5,245,867 | 5,039,535 | 5,257,842 | ||||||||||||||||||||||||
| Loans to individuals | 4,592,422 | 4,365,702 | 4,189,270 | 4,011,080 | 3,970,734 | ||||||||||||||||||||||||
| Total loans | 24,826,139 | 24,176,549 | 24,068,227 | 24,024,544 | 24,304,884 | ||||||||||||||||||||||||
| Allowance for loan losses | (277,398) | (278,191) | (279,983) | (283,685) | (287,227) | ||||||||||||||||||||||||
| Loans, net of allowance | 24,548,741 | 23,898,358 | 23,788,244 | 23,740,859 | 24,017,657 | ||||||||||||||||||||||||
| Total earning assets | 46,429,240 | 46,984,071 | 45,606,324 | 45,375,438 | 45,911,383 | ||||||||||||||||||||||||
| Cash and due from banks | 960,602 | 915,487 | 995,598 | 910,894 | 884,053 | ||||||||||||||||||||||||
| Derivative contracts, net | 317,732 | 374,125 | 328,478 | 360,352 | 294,276 | ||||||||||||||||||||||||
| Cash surrender value of bank-owned life insurance | 417,261 | 419,602 | 417,797 | 414,760 | 412,945 | ||||||||||||||||||||||||
| Receivable on unsettled securities sales | 162,035 | 228,563 | 184,960 | 284,793 | 216,158 | ||||||||||||||||||||||||
| Other assets | 3,405,206 | 3,365,104 | 3,453,746 | 3,268,949 | 3,438,220 | ||||||||||||||||||||||||
| Total assets | $ | 51,692,076 | $ | 52,286,952 | $ | 50,986,903 | $ | 50,615,186 | $ | 51,157,035 | |||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||
| Demand | $ | 7,894,847 | $ | 7,958,538 | $ | 8,156,069 | $ | 8,378,558 | $ | 8,273,656 | |||||||||||||||||||
| Interest-bearing transaction | 26,076,475 | 25,859,336 | 25,859,733 | 24,992,464 | 23,986,697 | ||||||||||||||||||||||||
| Savings | 867,939 | 853,062 | 844,875 | 818,210 | 820,980 | ||||||||||||||||||||||||
| Time | 3,641,985 | 3,465,780 | 3,498,401 | 3,629,882 | 3,678,964 | ||||||||||||||||||||||||
| Total deposits | 38,481,246 | 38,136,716 | 38,359,078 | 37,819,114 | 36,760,297 | ||||||||||||||||||||||||
| Funds purchased and repurchase agreements | 873,800 | 782,039 | 935,716 | 1,076,400 | 1,016,688 | ||||||||||||||||||||||||
| Other borrowings | 5,048,301 | 6,019,948 | 4,626,402 | 4,489,870 | 6,366,046 | ||||||||||||||||||||||||
| Subordinated debentures | — | 99,846 | 131,188 | 131,185 | 131,155 | ||||||||||||||||||||||||
| Derivative contracts, net | 332,893 | 359,616 | 237,035 | 417,026 | 466,271 | ||||||||||||||||||||||||
| Due on unsettled securities purchases | 329,361 | 503,490 | 425,050 | 472,334 | 348,585 | ||||||||||||||||||||||||
| Other liabilities | 663,323 | 591,496 | 611,762 | 630,957 | 618,187 | ||||||||||||||||||||||||
| Total liabilities | 45,728,924 | 46,493,151 | 45,326,231 | 45,036,886 | 45,707,229 | ||||||||||||||||||||||||
| Total equity | 5,963,152 | 5,793,801 | 5,660,672 | 5,578,300 | 5,449,806 | ||||||||||||||||||||||||
Total liabilities and equity | $ | 51,692,076 | $ | 52,286,952 | $ | 50,986,903 | $ | 50,615,186 | $ | 51,157,035 | |||||||||||||||||||
11
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
STATEMENTS OF EARNINGS – UNAUDITED
BOK FINANCIAL CORPORATION
| Three Months Ended | Nine Months Ended | ||||||||||||||||||||||
| September 30, | September 30, | ||||||||||||||||||||||
| (In thousands, except share and per share data) | 2025 | 2024 | 2025 | 2024 | |||||||||||||||||||
| Interest revenue | $ | 644,453 | $ | 680,310 | $ | 1,905,450 | $ | 1,997,339 | |||||||||||||||
| Interest expense | 306,807 | 372,191 | 923,387 | 1,099,627 | |||||||||||||||||||
Net interest income | 337,646 | 308,119 | 982,063 | 897,712 | |||||||||||||||||||
| Provision for credit losses | 2,000 | 2,000 | 2,000 | 18,000 | |||||||||||||||||||
Net interest income after provision for credit losses | 335,646 | 306,119 | 980,063 | 879,712 | |||||||||||||||||||
| Other operating revenue: | |||||||||||||||||||||||
| Brokerage and trading revenue | 43,239 | 50,391 | 112,432 | 162,587 | |||||||||||||||||||
| Transaction card revenue | 29,463 | 28,495 | 86,116 | 81,234 | |||||||||||||||||||
| Fiduciary and asset management revenue | 63,878 | 57,384 | 188,814 | 170,265 | |||||||||||||||||||
| Deposit service charges and fees | 31,896 | 30,450 | 93,490 | 88,707 | |||||||||||||||||||
| Mortgage banking revenue | 19,764 | 18,372 | 58,572 | 55,967 | |||||||||||||||||||
| Other revenue | 16,190 | 17,402 | 46,452 | 44,325 | |||||||||||||||||||
| Total fees and commissions | 204,430 | 202,494 | 585,876 | 603,085 | |||||||||||||||||||
| Other gains, net | 8,264 | 13,087 | 15,679 | 74,731 | |||||||||||||||||||
| Gain (loss) on derivatives, net | (453) | 8,991 | 14,647 | (733) | |||||||||||||||||||
| Gain on fair value option securities, net | 630 | 764 | 2,067 | 365 | |||||||||||||||||||
| Change in fair value of mortgage servicing rights | (2,375) | (16,453) | (14,634) | (2,023) | |||||||||||||||||||
Gain (loss) on available-for-sale securities, net | 213 | (691) | 213 | (45,828) | |||||||||||||||||||
| Total other operating revenue | 210,709 | 208,192 | 603,848 | 629,597 | |||||||||||||||||||
| Other operating expense: | |||||||||||||||||||||||
| Personnel | 226,347 | 206,821 | 655,243 | 600,564 | |||||||||||||||||||
| Business promotion | 9,960 | 7,681 | 27,917 | 23,909 | |||||||||||||||||||
| Charitable contributions to BOKF Foundation | — | — | — | 13,610 | |||||||||||||||||||
| Professional fees and services | 15,137 | 13,405 | 43,808 | 38,746 | |||||||||||||||||||
| Net occupancy and equipment | 33,040 | 32,077 | 98,689 | 92,615 | |||||||||||||||||||
| FDIC and other insurance | 7,302 | 8,186 | 20,328 | 24,243 | |||||||||||||||||||
| FDIC special assessment | (1,209) | (1,437) | (1,209) | 6,207 | |||||||||||||||||||
| Data processing and communications | 50,062 | 47,554 | 147,237 | 139,249 | |||||||||||||||||||
| Printing, postage, and supplies | 4,036 | 3,594 | 11,742 | 11,380 | |||||||||||||||||||
| Amortization of intangible assets | 2,656 | 2,856 | 7,964 | 8,757 | |||||||||||||||||||
| Mortgage banking costs | 10,668 | 9,059 | 25,068 | 23,946 | |||||||||||||||||||
| Other expense | 11,771 | 11,229 | 35,015 | 34,873 | |||||||||||||||||||
| Total other operating expense | 369,770 | 341,025 | 1,071,802 | 1,018,099 | |||||||||||||||||||
| Net income before taxes | 176,585 | 173,286 | 512,109 | 491,210 | |||||||||||||||||||
| Federal and state income taxes | 35,714 | 33,313 | 111,397 | 103,811 | |||||||||||||||||||
| Net income | 140,871 | 139,973 | 400,712 | 387,399 | |||||||||||||||||||
| Net income (loss) attributable to non-controlling interests | (23) | (26) | 23 | (16) | |||||||||||||||||||
| Net income attributable to BOK Financial Corporation shareholders | $ | 140,894 | $ | 139,999 | $ | 400,689 | $ | 387,415 | |||||||||||||||
| Average shares outstanding: | |||||||||||||||||||||||
| Basic | 62,840,270 | 63,489,581 | 63,196,043 | 63,830,188 | |||||||||||||||||||
| Diluted | 62,840,270 | 63,489,581 | 63,196,043 | 63,830,188 | |||||||||||||||||||
| Net income per share: | |||||||||||||||||||||||
| Basic | $ | 2.22 | $ | 2.18 | $ | 6.27 | $ | 6.01 | |||||||||||||||
| Diluted | $ | 2.22 | $ | 2.18 | $ | 6.27 | $ | 6.01 | |||||||||||||||
12
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
QUARTERLY EARNINGS TREND – UNAUDITED
BOK FINANCIAL CORPORATION
| Three Months Ended | |||||||||||||||||||||||||||||
| (In thousands, except ratio, share, and per share data) | Sep. 30, 2025 | June 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | ||||||||||||||||||||||||
| Interest revenue | $ | 644,453 | $ | 642,427 | $ | 618,570 | $ | 639,125 | $ | 680,310 | |||||||||||||||||||
| Interest expense | 306,807 | 314,261 | 302,319 | 326,079 | 372,191 | ||||||||||||||||||||||||
Net interest income | 337,646 | 328,166 | 316,251 | 313,046 | 308,119 | ||||||||||||||||||||||||
| Provision for credit losses | 2,000 | — | — | — | 2,000 | ||||||||||||||||||||||||
Net interest income after provision for credit losses | 335,646 | 328,166 | 316,251 | 313,046 | 306,119 | ||||||||||||||||||||||||
| Other operating revenue: | |||||||||||||||||||||||||||||
| Brokerage and trading revenue | 43,239 | 38,125 | 31,068 | 55,505 | 50,391 | ||||||||||||||||||||||||
| Transaction card revenue | 29,463 | 29,561 | 27,092 | 27,631 | 28,495 | ||||||||||||||||||||||||
| Fiduciary and asset management revenue | 63,878 | 63,964 | 60,972 | 60,595 | 57,384 | ||||||||||||||||||||||||
| Deposit service charges and fees | 31,896 | 31,319 | 30,275 | 30,038 | 30,450 | ||||||||||||||||||||||||
| Mortgage banking revenue | 19,764 | 18,993 | 19,815 | 18,140 | 18,372 | ||||||||||||||||||||||||
| Other revenue | 16,190 | 15,368 | 14,894 | 15,029 | 17,402 | ||||||||||||||||||||||||
| Total fees and commissions | 204,430 | 197,330 | 184,116 | 206,938 | 202,494 | ||||||||||||||||||||||||
| Other gains (losses), net | 8,264 | 8,140 | (725) | 4,995 | 13,087 | ||||||||||||||||||||||||
| Gain (loss) on derivatives, net | (453) | 5,535 | 9,565 | (21,728) | 8,991 | ||||||||||||||||||||||||
| Gain (loss) on fair value option securities, net | 630 | 1,112 | 325 | (621) | 764 | ||||||||||||||||||||||||
| Change in fair value of mortgage servicing rights | (2,375) | (5,019) | (7,240) | 20,460 | (16,453) | ||||||||||||||||||||||||
| Gain (loss) on available-for-sale securities, net | 213 | — | — | — | (691) | ||||||||||||||||||||||||
| Total other operating revenue | 210,709 | 207,098 | 186,041 | 210,044 | 208,192 | ||||||||||||||||||||||||
| Other operating expense: | |||||||||||||||||||||||||||||
| Personnel | 226,347 | 214,711 | 214,185 | 210,675 | 206,821 | ||||||||||||||||||||||||
| Business promotion | 9,960 | 9,139 | 8,818 | 9,365 | 7,681 | ||||||||||||||||||||||||
| Professional fees and services | 15,137 | 15,402 | 13,269 | 15,175 | 13,405 | ||||||||||||||||||||||||
| Net occupancy and equipment | 33,040 | 32,657 | 32,992 | 32,713 | 32,077 | ||||||||||||||||||||||||
| FDIC and other insurance | 7,302 | 6,439 | 6,587 | 6,862 | 8,186 | ||||||||||||||||||||||||
| FDIC special assessment | (1,209) | (523) | 523 | (686) | (1,437) | ||||||||||||||||||||||||
| Data processing and communications | 50,062 | 49,597 | 47,578 | 48,024 | 47,554 | ||||||||||||||||||||||||
| Printing, postage, and supplies | 4,036 | 4,067 | 3,639 | 3,699 | 3,594 | ||||||||||||||||||||||||
| Amortization of intangible assets | 2,656 | 2,656 | 2,652 | 2,855 | 2,856 | ||||||||||||||||||||||||
| Mortgage banking costs | 10,668 | 6,711 | 7,689 | 10,692 | 9,059 | ||||||||||||||||||||||||
| Other expense | 11,771 | 13,647 | 9,597 | 8,282 | 11,229 | ||||||||||||||||||||||||
| Total other operating expense | 369,770 | 354,503 | 347,529 | 347,656 | 341,025 | ||||||||||||||||||||||||
| Net income before taxes | 176,585 | 180,761 | 154,763 | 175,434 | 173,286 | ||||||||||||||||||||||||
| Federal and state income taxes | 35,714 | 40,691 | 34,992 | 39,280 | 33,313 | ||||||||||||||||||||||||
| Net income | 140,871 | 140,070 | 119,771 | 136,154 | 139,973 | ||||||||||||||||||||||||
| Net income (loss) attributable to non-controlling interests | (23) | 52 | (6) | — | (26) | ||||||||||||||||||||||||
| Net income attributable to BOK Financial Corporation shareholders | $ | 140,894 | $ | 140,018 | $ | 119,777 | $ | 136,154 | $ | 139,999 | |||||||||||||||||||
| Average shares outstanding: | |||||||||||||||||||||||||||||
| Basic | 62,840,270 | 63,208,027 | 63,547,510 | 63,491,458 | 63,489,581 | ||||||||||||||||||||||||
| Diluted | 62,840,270 | 63,208,027 | 63,547,510 | 63,491,458 | 63,489,581 | ||||||||||||||||||||||||
| Net income per share: | |||||||||||||||||||||||||||||
| Basic | $ | 2.22 | $ | 2.19 | $ | 1.86 | $ | 2.12 | $ | 2.18 | |||||||||||||||||||
| Diluted | $ | 2.22 | $ | 2.19 | $ | 1.86 | $ | 2.12 | $ | 2.18 | |||||||||||||||||||
13
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
FINANCIAL HIGHLIGHTS – UNAUDITED
BOK FINANCIAL CORPORATION
| Three Months Ended | |||||||||||||||||||||||||||||
| (In thousands, except ratio, share, and per share data) | Sep. 30, 2025 | June 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | ||||||||||||||||||||||||
| Capital: | |||||||||||||||||||||||||||||
| Period end shareholders' equity | $ | 6,022,535 | $ | 5,890,888 | $ | 5,771,813 | $ | 5,548,353 | $ | 5,612,443 | |||||||||||||||||||
| Risk-weighted assets | $ | 38,136,467 | $ | 37,630,803 | $ | 38,062,913 | $ | 38,315,722 | $ | 38,365,133 | |||||||||||||||||||
| Risk-based capital ratios: | |||||||||||||||||||||||||||||
| Common equity Tier 1 | 13.60 | % | 13.59 | % | 13.31 | % | 13.03 | % | 12.73 | % | |||||||||||||||||||
| Tier 1 | 13.61 | % | 13.60 | % | 13.31 | % | 13.04 | % | 12.74 | % | |||||||||||||||||||
| Total capital | 14.48 | % | 14.48 | % | 14.54 | % | 14.21 | % | 13.91 | % | |||||||||||||||||||
| Leverage ratio | 10.19 | % | 9.88 | % | 10.02 | % | 9.97 | % | 9.67 | % | |||||||||||||||||||
Tangible common equity ratio1 | 10.06 | % | 9.63 | % | 9.48 | % | 9.17 | % | 9.22 | % | |||||||||||||||||||
| Common stock: | |||||||||||||||||||||||||||||
| Book value per share | $ | 95.22 | $ | 92.61 | $ | 89.82 | $ | 86.53 | $ | 87.53 | |||||||||||||||||||
| Tangible book value per share | $ | 78.11 | $ | 75.56 | $ | 72.87 | $ | 69.51 | $ | 70.44 | |||||||||||||||||||
| Market value per share: | |||||||||||||||||||||||||||||
| High | $ | 114.17 | $ | 104.15 | $ | 116.29 | $ | 121.58 | $ | 108.01 | |||||||||||||||||||
| Low | $ | 96.89 | $ | 85.08 | $ | 97.84 | $ | 99.93 | $ | 86.43 | |||||||||||||||||||
| Cash dividends paid | $ | 36,122 | $ | 36,256 | $ | 36,468 | $ | 36,421 | $ | 35,147 | |||||||||||||||||||
| Dividend payout ratio | 25.64 | % | 25.89 | % | 30.45 | % | 26.75 | % | 25.11 | % | |||||||||||||||||||
| Shares outstanding, net | 63,247,676 | 63,611,097 | 64,261,824 | 64,121,299 | 64,118,417 | ||||||||||||||||||||||||
| Stock buy-back program: | |||||||||||||||||||||||||||||
| Shares repurchased | 365,547 | 663,298 | 10,000 | — | — | ||||||||||||||||||||||||
| Amount | $ | 40,575 | $ | 62,341 | $ | 985 | $ | — | $ | — | |||||||||||||||||||
Average price paid per share2 | $ | 111.00 | $ | 93.99 | $ | 98.45 | $ | — | $ | — | |||||||||||||||||||
| Performance ratios (quarter annualized): | |||||||||||||||||||||||||||||
| Return on average assets | 1.08 | % | 1.07 | % | 0.95 | % | 1.07 | % | 1.09 | % | |||||||||||||||||||
| Return on average equity | 9.38 | % | 9.70 | % | 8.59 | % | 9.71 | % | 10.22 | % | |||||||||||||||||||
Return on average tangible common equity1 | 11.46 | % | 11.94 | % | 10.63 | % | 12.09 | % | 12.80 | % | |||||||||||||||||||
| Net interest margin | 2.91 | % | 2.80 | % | 2.78 | % | 2.75 | % | 2.68 | % | |||||||||||||||||||
Efficiency ratio1 | 66.66 | % | 65.42 | % | 68.31 | % | 65.61 | % | 65.11 | % | |||||||||||||||||||
| Other data: | |||||||||||||||||||||||||||||
| Tax-equivalent interest | $ | 2,565 | $ | 2,574 | $ | 2,542 | $ | 2,466 | $ | 2,385 | |||||||||||||||||||
| Net unrealized loss on available-for-sale securities | $ | (203,682) | $ | (276,678) | $ | (363,507) | $ | (537,335) | $ | (307,360) | |||||||||||||||||||
14
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
| Three Months Ended | |||||||||||||||||||||||||||||
| (In thousands, except ratio, share, and per share data) | Sep. 30, 2025 | June 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | ||||||||||||||||||||||||
| Mortgage banking: | |||||||||||||||||||||||||||||
| Mortgage production revenue | $ | 2,370 | $ | 1,707 | $ | 2,629 | $ | 1,282 | $ | 1,563 | |||||||||||||||||||
| Mortgage loans funded for sale | $ | 229,812 | $ | 219,154 | $ | 159,816 | $ | 208,300 | $ | 224,749 | |||||||||||||||||||
Add: Current period end outstanding commitments | 67,842 | 64,508 | 60,429 | 36,590 | 70,102 | ||||||||||||||||||||||||
| Less: Prior period end outstanding commitments | 64,508 | 60,429 | 36,590 | 70,102 | 62,960 | ||||||||||||||||||||||||
| Total mortgage production volume | $ | 233,146 | $ | 223,233 | $ | 183,655 | $ | 174,788 | $ | 231,891 | |||||||||||||||||||
| Mortgage loan refinances to mortgage loans funded for sale | 13 | % | 16 | % | 12 | % | 19 | % | 11 | % | |||||||||||||||||||
| Realized margin on funded mortgage loans | 0.96 | % | 0.66 | % | 0.91 | % | 0.87 | % | 0.93 | % | |||||||||||||||||||
| Production revenue as a percentage of production volume | 1.02 | % | 0.76 | % | 1.43 | % | 0.73 | % | 0.67 | % | |||||||||||||||||||
| Mortgage servicing revenue | $ | 17,394 | $ | 17,286 | $ | 17,186 | $ | 16,858 | $ | 16,809 | |||||||||||||||||||
| Average outstanding principal balance of mortgage loans serviced for others | $ | 22,269,300 | $ | 22,687,658 | $ | 23,089,324 | $ | 22,214,392 | $ | 22,203,787 | |||||||||||||||||||
| Average mortgage servicing revenue rates | 0.31 | % | 0.31 | % | 0.30 | % | 0.30 | % | 0.30 | % | |||||||||||||||||||
| Gain (loss) on mortgage servicing rights, net of economic hedge: | |||||||||||||||||||||||||||||
| Gain (loss) on derivatives, net | $ | (508) | $ | 5,230 | $ | 9,183 | $ | (21,917) | $ | 11,357 | |||||||||||||||||||
| Gain (loss) on fair value option securities, net | 630 | 1,112 | 325 | (621) | 764 | ||||||||||||||||||||||||
| Gain (loss) on economic hedge of mortgage servicing rights | 122 | 6,342 | 9,508 | (22,538) | 12,121 | ||||||||||||||||||||||||
| Change in fair value of mortgage servicing rights | (2,375) | (5,019) | (7,240) | 20,460 | (16,453) | ||||||||||||||||||||||||
| Gain (loss) on changes in fair value of mortgage servicing rights, net of economic hedges, included in other operating revenue | (2,253) | 1,323 | 2,268 | (2,078) | (4,332) | ||||||||||||||||||||||||
Net interest income (expense) on fair value option securities3 | 169 | 229 | (71) | (79) | (146) | ||||||||||||||||||||||||
| Total economic benefit (cost) of changes in the fair value of mortgage servicing rights, net of economic hedges | $ | (2,084) | $ | 1,552 | $ | 2,197 | $ | (2,157) | $ | (4,478) | |||||||||||||||||||
1 See Reconciliation of Non-GAAP Measures following.
2 Excludes 1% excise tax on corporate stock repurchases.
3 Actual interest earned on fair value option securities less internal transfer-priced cost of funds.
15
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
EXPLANATION AND RECONCILIATION OF NON-GAAP MEASURES – UNAUDITED
BOK FINANCIAL CORPORATION
| Three Months Ended | |||||||||||||||||||||||||||||
| (In thousands, except ratio and share data) | Sep. 30, 2025 | June 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | ||||||||||||||||||||||||
Reconciliation of tangible common equity ratio: | |||||||||||||||||||||||||||||
| Total shareholders' equity | $ | 6,022,535 | $ | 5,890,888 | $ | 5,771,813 | $ | 5,548,353 | $ | 5,612,443 | |||||||||||||||||||
| Less: Goodwill and intangible assets, net | 1,082,125 | 1,084,749 | 1,088,813 | 1,091,537 | 1,095,954 | ||||||||||||||||||||||||
| Tangible common equity | $ | 4,940,410 | $ | 4,806,139 | $ | 4,683,000 | $ | 4,456,816 | $ | 4,516,489 | |||||||||||||||||||
| Total assets | $ | 50,193,387 | $ | 50,998,077 | $ | 50,472,189 | $ | 49,685,892 | $ | 50,081,985 | |||||||||||||||||||
| Less: Goodwill and intangible assets, net | 1,082,125 | 1,084,749 | 1,088,813 | 1,091,537 | 1,095,954 | ||||||||||||||||||||||||
| Tangible assets | $ | 49,111,262 | $ | 49,913,328 | $ | 49,383,376 | $ | 48,594,355 | $ | 48,986,031 | |||||||||||||||||||
| Tangible common equity ratio | 10.06 | % | 9.63 | % | 9.48 | % | 9.17 | % | 9.22 | % | |||||||||||||||||||
| Reconciliation of return on average tangible common equity: | |||||||||||||||||||||||||||||
| Total average shareholders' equity | $ | 5,960,711 | $ | 5,791,275 | $ | 5,658,082 | $ | 5,575,583 | $ | 5,446,998 | |||||||||||||||||||
| Less: Average goodwill and intangible assets, net | 1,083,390 | 1,086,991 | 1,090,116 | 1,094,466 | 1,097,317 | ||||||||||||||||||||||||
| Average tangible common equity | $ | 4,877,321 | $ | 4,704,284 | $ | 4,567,966 | $ | 4,481,117 | $ | 4,349,681 | |||||||||||||||||||
Net income attributable to BOK Financial Corporation shareholders | $ | 140,894 | $ | 140,018 | $ | 119,777 | $ | 136,154 | $ | 139,999 | |||||||||||||||||||
| Return on average tangible common equity | 11.46 | % | 11.94 | % | 10.63 | % | 12.09 | % | 12.80 | % | |||||||||||||||||||
Calculation of efficiency ratio: | |||||||||||||||||||||||||||||
| Total other operating expense | $ | 369,770 | $ | 354,503 | $ | 347,529 | $ | 347,656 | $ | 341,025 | |||||||||||||||||||
| Less: Amortization of intangible assets | 2,656 | 2,656 | 2,652 | 2,855 | 2,856 | ||||||||||||||||||||||||
Numerator for efficiency ratio | $ | 367,114 | $ | 351,847 | $ | 344,877 | $ | 344,801 | $ | 338,169 | |||||||||||||||||||
Net interest income | $ | 337,646 | $ | 328,166 | $ | 316,251 | $ | 313,046 | $ | 308,119 | |||||||||||||||||||
Add: Tax-equivalent adjustment | 2,565 | 2,574 | 2,542 | 2,466 | 2,385 | ||||||||||||||||||||||||
Tax-equivalent net interest income | 340,211 | 330,740 | 318,793 | 315,512 | 310,504 | ||||||||||||||||||||||||
| Add: Total other operating revenue | 210,709 | 207,098 | 186,041 | 210,044 | 208,192 | ||||||||||||||||||||||||
| Less: Gain (loss) on available-for-sale securities, net | 213 | — | — | — | (691) | ||||||||||||||||||||||||
Denominator for efficiency ratio | $ | 550,707 | $ | 537,838 | $ | 504,834 | $ | 525,556 | $ | 519,387 | |||||||||||||||||||
| Efficiency ratio | 66.66 | % | 65.42 | % | 68.31 | % | 65.61 | % | 65.11 | % | |||||||||||||||||||
16
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
| Three Months Ended | |||||||||||||||||||||||||||||
| (In thousands, except ratio and share data) | Sep. 30, 2025 | June 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | ||||||||||||||||||||||||
| Reconciliation of pre-provision net revenue: | |||||||||||||||||||||||||||||
| Net income before taxes | $ | 176,585 | $ | 180,761 | $ | 154,763 | $ | 175,434 | $ | 173,286 | |||||||||||||||||||
Add: Provision for expected credit losses | 2,000 | — | — | — | 2,000 | ||||||||||||||||||||||||
Less: Net income (loss) attributable to non-controlling interests | (23) | 52 | (6) | — | (26) | ||||||||||||||||||||||||
| Pre-provision net revenue | $ | 178,608 | $ | 180,709 | $ | 154,769 | $ | 175,434 | $ | 175,312 | |||||||||||||||||||
Information on net interest income and net interest margin excluding trading activities: | |||||||||||||||||||||||||||||
Net interest income | $ | 337,646 | $ | 328,166 | $ | 316,251 | $ | 313,046 | $ | 308,119 | |||||||||||||||||||
Less: Trading activities net interest income | 14,325 | 16,138 | 15,174 | 4,648 | 3,751 | ||||||||||||||||||||||||
Net interest income excluding trading activities | 323,321 | 312,028 | 301,077 | 308,398 | 304,368 | ||||||||||||||||||||||||
Add: Tax-equivalent adjustment | 2,565 | 2,574 | 2,542 | 2,466 | 2,385 | ||||||||||||||||||||||||
Tax-equivalent net interest income excluding trading activities | $ | 325,886 | $ | 314,602 | $ | 303,619 | $ | 310,864 | $ | 306,753 | |||||||||||||||||||
| Average interest-earning assets | $ | 46,429,240 | $ | 46,984,071 | $ | 45,606,324 | $ | 45,375,438 | $ | 45,911,383 | |||||||||||||||||||
| Less: Average trading activities interest-earning assets | 5,603,200 | 6,876,788 | 5,881,997 | 5,636,949 | 5,802,448 | ||||||||||||||||||||||||
| Average interest-earning assets excluding trading activities | $ | 40,826,040 | $ | 40,107,283 | $ | 39,724,327 | $ | 39,738,489 | $ | 40,108,935 | |||||||||||||||||||
| Net interest margin on average interest-earning assets | 2.91 | % | 2.80 | % | 2.78 | % | 2.75 | % | 2.68 | % | |||||||||||||||||||
| Net interest margin on average trading activities interest-earning assets | 1.07 | % | 0.93 | % | 0.98 | % | 0.36 | % | 0.29 | % | |||||||||||||||||||
| Net interest margin on average interest-earning assets excluding trading activities | 3.16 | % | 3.12 | % | 3.05 | % | 3.09 | % | 3.02 | % | |||||||||||||||||||
The tangible common equity ratio and return on average tangible common equity are primarily based on total shareholders' equity, which includes unrealized gains and losses on available-for-sale securities, less intangible assets and equity that does not benefit common shareholders. These measures are valuable indicators of a financial institution's capital strength since they eliminate intangible assets from shareholders' equity and retain the effect of unrealized losses on securities and other components of accumulated other comprehensive income in shareholders' equity.
The efficiency ratio measures the company's ability to use its assets and manage its liabilities effectively in the current period.
Pre-provision net revenue is a measure of revenue less expenses and is calculated before provision for credit losses and income tax expense. This financial measure is frequently used by investors and analysts and enables them to assess a company's ability to generate earnings to cover credit losses through a credit cycle. It also provides an additional basis for comparing the results of operations between periods by isolating the impact of the provision for credit losses, which can vary significantly between periods.
Net interest income and net interest margin excluding trading activities removes the effect of trading activities on these metrics allowing management and investors to assess the performance of the company's core lending and deposit activities without the associated volatility from trading activities.
17
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
LOANS TREND – UNAUDITED
BOK FINANCIAL CORPORATION
| (In thousands) | Sep. 30, 2025 | June 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | ||||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||
| Healthcare | $ | 3,878,543 | $ | 3,808,936 | $ | 3,789,446 | $ | 3,967,533 | $ | 4,149,069 | |||||||||||||||||||
| Services | 3,710,643 | 3,658,807 | 3,704,834 | 3,643,203 | 3,573,670 | ||||||||||||||||||||||||
| Energy | 2,681,512 | 2,734,713 | 2,860,330 | 3,254,724 | 3,126,635 | ||||||||||||||||||||||||
| General business | 4,242,242 | 4,181,726 | 4,048,821 | 4,164,676 | 4,028,548 | ||||||||||||||||||||||||
| Total commercial | 14,512,940 | 14,384,182 | 14,403,431 | 15,030,136 | 14,877,922 | ||||||||||||||||||||||||
| Commercial real estate: | |||||||||||||||||||||||||||||
| Multifamily | 2,500,323 | 2,473,365 | 2,336,312 | 2,237,064 | 2,109,445 | ||||||||||||||||||||||||
| Industrial | 1,396,795 | 1,304,211 | 1,163,089 | 1,127,867 | 1,270,928 | ||||||||||||||||||||||||
| Office | 811,601 | 690,086 | 704,688 | 755,838 | 815,966 | ||||||||||||||||||||||||
| Retail | 593,835 | 592,043 | 497,579 | 485,926 | 521,874 | ||||||||||||||||||||||||
| Residential construction and land development | 122,033 | 105,701 | 105,190 | 109,120 | 105,048 | ||||||||||||||||||||||||
| Other commercial real estate | 328,020 | 356,035 | 356,678 | 342,637 | 365,394 | ||||||||||||||||||||||||
| Total commercial real estate | 5,752,607 | 5,521,441 | 5,163,536 | 5,058,452 | 5,188,655 | ||||||||||||||||||||||||
| Loans to individuals: | |||||||||||||||||||||||||||||
| Residential mortgage | 2,676,366 | 2,610,681 | 2,471,345 | 2,436,958 | 2,370,293 | ||||||||||||||||||||||||
| Residential mortgages guaranteed by U.S. government agencies | 151,642 | 148,453 | 133,453 | 136,649 | 127,747 | ||||||||||||||||||||||||
| Personal | 1,771,639 | 1,627,454 | 1,518,723 | 1,452,529 | 1,420,444 | ||||||||||||||||||||||||
| Total loans to individuals | 4,599,647 | 4,386,588 | 4,123,521 | 4,026,136 | 3,918,484 | ||||||||||||||||||||||||
| Total | $ | 24,865,194 | $ | 24,292,211 | $ | 23,690,488 | $ | 24,114,724 | $ | 23,985,061 | |||||||||||||||||||
18
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
LOANS MANAGED BY PRINCIPAL MARKET AREA – UNAUDITED
BOK FINANCIAL CORPORATION
| (In thousands) | Sep. 30, 2025 | June 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | ||||||||||||||||||||||||
| Texas: | |||||||||||||||||||||||||||||
| Commercial | $ | 6,800,577 | $ | 6,893,246 | $ | 6,953,714 | $ | 7,411,416 | $ | 7,437,800 | |||||||||||||||||||
| Commercial real estate | 2,107,335 | 1,997,598 | 1,864,345 | 1,731,281 | 1,816,276 | ||||||||||||||||||||||||
| Loans to individuals | 1,037,831 | 996,341 | 929,825 | 918,994 | 880,213 | ||||||||||||||||||||||||
| Total Texas | 9,945,743 | 9,887,185 | 9,747,884 | 10,061,691 | 10,134,289 | ||||||||||||||||||||||||
| Oklahoma: | |||||||||||||||||||||||||||||
| Commercial | 3,692,319 | 3,455,696 | 3,380,680 | 3,585,592 | 3,440,385 | ||||||||||||||||||||||||
| Commercial real estate | 574,126 | 512,075 | 521,992 | 513,101 | 557,025 | ||||||||||||||||||||||||
| Loans to individuals | 2,927,185 | 2,725,320 | 2,548,549 | 2,440,874 | 2,367,725 | ||||||||||||||||||||||||
| Total Oklahoma | 7,193,630 | 6,693,091 | 6,451,221 | 6,539,567 | 6,365,135 | ||||||||||||||||||||||||
| Colorado: | |||||||||||||||||||||||||||||
| Commercial | 2,132,770 | 2,185,658 | 2,246,388 | 2,188,324 | 2,175,540 | ||||||||||||||||||||||||
| Commercial real estate | 589,307 | 791,171 | 706,154 | 759,168 | 835,478 | ||||||||||||||||||||||||
| Loans to individuals | 208,323 | 217,088 | 210,531 | 213,768 | 216,938 | ||||||||||||||||||||||||
| Total Colorado | 2,930,400 | 3,193,917 | 3,163,073 | 3,161,260 | 3,227,956 | ||||||||||||||||||||||||
| Arizona: | |||||||||||||||||||||||||||||
| Commercial | 1,228,593 | 1,166,745 | 1,115,085 | 1,082,829 | 1,064,380 | ||||||||||||||||||||||||
| Commercial real estate | 1,348,838 | 1,165,927 | 1,084,967 | 1,098,174 | 1,115,928 | ||||||||||||||||||||||||
| Loans to individuals | 222,963 | 226,727 | 218,093 | 215,531 | 218,340 | ||||||||||||||||||||||||
| Total Arizona | 2,800,394 | 2,559,399 | 2,418,145 | 2,396,534 | 2,398,648 | ||||||||||||||||||||||||
| Kansas/Missouri: | |||||||||||||||||||||||||||||
| Commercial | 270,068 | 303,692 | 298,410 | 305,957 | 306,370 | ||||||||||||||||||||||||
| Commercial real estate | 618,052 | 556,390 | 533,335 | 515,511 | 438,424 | ||||||||||||||||||||||||
| Loans to individuals | 142,408 | 155,154 | 147,651 | 164,638 | 158,524 | ||||||||||||||||||||||||
| Total Kansas/Missouri | 1,030,528 | 1,015,236 | 979,396 | 986,106 | 903,318 | ||||||||||||||||||||||||
| New Mexico: | |||||||||||||||||||||||||||||
| Commercial | 282,479 | 282,918 | 324,321 | 325,246 | 324,605 | ||||||||||||||||||||||||
| Commercial real estate | 458,720 | 443,516 | 381,775 | 402,217 | 386,037 | ||||||||||||||||||||||||
| Loans to individuals | 51,056 | 55,714 | 57,926 | 60,703 | 64,511 | ||||||||||||||||||||||||
| Total New Mexico | 792,255 | 782,148 | 764,022 | 788,166 | 775,153 | ||||||||||||||||||||||||
| Arkansas: | |||||||||||||||||||||||||||||
| Commercial | 106,134 | 96,227 | 84,833 | 130,772 | 128,842 | ||||||||||||||||||||||||
| Commercial real estate | 56,229 | 54,764 | 70,968 | 39,000 | 39,487 | ||||||||||||||||||||||||
| Loans to individuals | 9,881 | 10,244 | 10,946 | 11,628 | 12,233 | ||||||||||||||||||||||||
| Total Arkansas | 172,244 | 161,235 | 166,747 | 181,400 | 180,562 | ||||||||||||||||||||||||
| Total BOK Financial | $ | 24,865,194 | $ | 24,292,211 | $ | 23,690,488 | $ | 24,114,724 | $ | 23,985,061 | |||||||||||||||||||
19
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
DEPOSITS BY PRINCIPAL MARKET AREA – UNAUDITED
BOK FINANCIAL CORPORATION
| (In thousands) | Sep. 30, 2025 | June 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | ||||||||||||||||||||||||
| Oklahoma: | |||||||||||||||||||||||||||||
| Demand | $ | 3,520,203 | $ | 3,589,146 | $ | 3,629,708 | $ | 3,618,771 | $ | 3,491,996 | |||||||||||||||||||
| Interest-bearing: | |||||||||||||||||||||||||||||
| Transaction | 13,352,070 | 13,537,068 | 13,891,707 | 13,352,732 | 12,474,626 | ||||||||||||||||||||||||
| Savings | 520,995 | 521,734 | 525,424 | 497,443 | 490,957 | ||||||||||||||||||||||||
| Time | 2,356,945 | 2,166,094 | 2,089,744 | 2,138,620 | 2,462,463 | ||||||||||||||||||||||||
| Total interest-bearing | 16,230,010 | 16,224,896 | 16,506,875 | 15,988,795 | 15,428,046 | ||||||||||||||||||||||||
| Total Oklahoma | 19,750,213 | 19,814,042 | 20,136,583 | 19,607,566 | 18,920,042 | ||||||||||||||||||||||||
| Texas: | |||||||||||||||||||||||||||||
| Demand | 2,194,177 | 2,082,652 | 2,187,903 | 2,216,393 | 2,228,690 | ||||||||||||||||||||||||
| Interest-bearing: | |||||||||||||||||||||||||||||
| Transaction | 6,427,135 | 6,203,081 | 5,925,285 | 6,205,605 | 6,191,794 | ||||||||||||||||||||||||
| Savings | 147,560 | 155,027 | 155,777 | 154,112 | 152,392 | ||||||||||||||||||||||||
| Time | 649,757 | 638,657 | 633,538 | 646,490 | 648,796 | ||||||||||||||||||||||||
| Total interest-bearing | 7,224,452 | 6,996,765 | 6,714,600 | 7,006,207 | 6,992,982 | ||||||||||||||||||||||||
| Total Texas | 9,418,629 | 9,079,417 | 8,902,503 | 9,222,600 | 9,221,672 | ||||||||||||||||||||||||
| Colorado: | |||||||||||||||||||||||||||||
| Demand | 929,383 | 1,040,223 | 1,082,304 | 1,159,076 | 1,195,637 | ||||||||||||||||||||||||
| Interest-bearing: | |||||||||||||||||||||||||||||
| Transaction | 2,204,899 | 1,989,284 | 1,988,258 | 2,089,475 | 1,935,685 | ||||||||||||||||||||||||
| Savings | 53,768 | 55,326 | 58,318 | 59,244 | 56,275 | ||||||||||||||||||||||||
| Time | 284,962 | 278,914 | 274,235 | 280,081 | 279,887 | ||||||||||||||||||||||||
| Total interest-bearing | 2,543,629 | 2,323,524 | 2,320,811 | 2,428,800 | 2,271,847 | ||||||||||||||||||||||||
| Total Colorado | 3,473,012 | 3,363,747 | 3,403,115 | 3,587,876 | 3,467,484 | ||||||||||||||||||||||||
| New Mexico: | |||||||||||||||||||||||||||||
| Demand | 591,330 | 609,205 | 631,950 | 659,234 | 628,594 | ||||||||||||||||||||||||
| Interest-bearing: | |||||||||||||||||||||||||||||
| Transaction | 1,376,694 | 1,416,741 | 1,283,998 | 1,305,044 | 1,275,502 | ||||||||||||||||||||||||
| Savings | 94,180 | 94,930 | 96,969 | 90,580 | 90,867 | ||||||||||||||||||||||||
| Time | 347,227 | 340,946 | 344,827 | 347,443 | 336,830 | ||||||||||||||||||||||||
| Total interest-bearing | 1,818,101 | 1,852,617 | 1,725,794 | 1,743,067 | 1,703,199 | ||||||||||||||||||||||||
| Total New Mexico | 2,409,431 | 2,461,822 | 2,357,744 | 2,402,301 | 2,331,793 | ||||||||||||||||||||||||
| Arizona: | |||||||||||||||||||||||||||||
| Demand | 368,432 | 385,442 | 451,085 | 418,587 | 435,553 | ||||||||||||||||||||||||
| Interest-bearing: | |||||||||||||||||||||||||||||
| Transaction | 1,406,300 | 1,467,509 | 1,312,979 | 1,277,494 | 1,237,811 | ||||||||||||||||||||||||
| Savings | 13,571 | 10,536 | 11,125 | 12,336 | 11,228 | ||||||||||||||||||||||||
| Time | 71,886 | 72,041 | 70,758 | 70,390 | 59,508 | ||||||||||||||||||||||||
| Total interest-bearing | 1,491,757 | 1,550,086 | 1,394,862 | 1,360,220 | 1,308,547 | ||||||||||||||||||||||||
| Total Arizona | 1,860,189 | 1,935,528 | 1,845,947 | 1,778,807 | 1,744,100 | ||||||||||||||||||||||||
20
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
| (In thousands) | Sep. 30, 2025 | June 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | ||||||||||||||||||||||||
| Kansas/Missouri: | |||||||||||||||||||||||||||||
| Demand | 282,235 | 269,408 | 279,808 | 277,440 | 255,950 | ||||||||||||||||||||||||
| Interest-bearing: | |||||||||||||||||||||||||||||
| Transaction | 1,151,956 | 1,169,161 | 1,202,107 | 1,169,541 | 1,134,544 | ||||||||||||||||||||||||
| Savings | 14,251 | 13,719 | 14,504 | 12,158 | 11,896 | ||||||||||||||||||||||||
| Time | 37,563 | 35,768 | 36,307 | 37,210 | 35,316 | ||||||||||||||||||||||||
| Total interest-bearing | 1,203,770 | 1,218,648 | 1,252,918 | 1,218,909 | 1,181,756 | ||||||||||||||||||||||||
| Total Kansas/Missouri | 1,486,005 | 1,488,056 | 1,532,726 | 1,496,349 | 1,437,706 | ||||||||||||||||||||||||
| Arkansas: | |||||||||||||||||||||||||||||
| Demand | 21,416 | 22,685 | 25,738 | 22,396 | 23,824 | ||||||||||||||||||||||||
| Interest-bearing: | |||||||||||||||||||||||||||||
| Transaction | 64,174 | 61,079 | 57,696 | 55,215 | 62,249 | ||||||||||||||||||||||||
| Savings | 2,411 | 2,485 | 2,602 | 2,944 | 3,092 | ||||||||||||||||||||||||
| Time | 14,538 | 17,248 | 17,019 | 15,176 | 15,156 | ||||||||||||||||||||||||
| Total interest-bearing | 81,123 | 80,812 | 77,317 | 73,335 | 80,497 | ||||||||||||||||||||||||
| Total Arkansas | 102,539 | 103,497 | 103,055 | 95,731 | 104,321 | ||||||||||||||||||||||||
| Total BOK Financial | $ | 38,500,018 | $ | 38,246,109 | $ | 38,281,673 | $ | 38,191,230 | $ | 37,227,118 | |||||||||||||||||||
21
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
NET INTEREST MARGIN TREND – UNAUDITED
BOK FINANCIAL CORPORATION
| Three Months Ended | |||||||||||||||||||||||||||||
| Sep. 30, 2025 | June 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | |||||||||||||||||||||||||
| Tax-equivalent asset yields | |||||||||||||||||||||||||||||
| Interest-bearing cash and cash equivalents | 4.39 | % | 4.46 | % | 4.48 | % | 4.60 | % | 5.33 | % | |||||||||||||||||||
| Trading securities | 5.25 | % | 5.05 | % | 5.07 | % | 4.90 | % | 5.36 | % | |||||||||||||||||||
| Investment securities, net of allowance | 1.41 | % | 1.41 | % | 1.42 | % | 1.42 | % | 1.41 | % | |||||||||||||||||||
| Available-for-sale securities | 3.93 | % | 3.89 | % | 3.82 | % | 3.82 | % | 3.76 | % | |||||||||||||||||||
| Fair value option securities | 5.45 | % | 5.90 | % | 3.72 | % | 3.70 | % | 3.69 | % | |||||||||||||||||||
| Restricted equity securities | 7.84 | % | 7.73 | % | 7.51 | % | 7.60 | % | 8.20 | % | |||||||||||||||||||
| Residential mortgage loans held for sale | 6.08 | % | 6.13 | % | 6.03 | % | 5.85 | % | 6.15 | % | |||||||||||||||||||
| Loans | 6.70 | % | 6.71 | % | 6.71 | % | 7.01 | % | 7.47 | % | |||||||||||||||||||
| Allowance for loan losses | |||||||||||||||||||||||||||||
| Loans, net of allowance | 6.78 | % | 6.79 | % | 6.79 | % | 7.10 | % | 7.55 | % | |||||||||||||||||||
| Total tax-equivalent yield on earning assets | 5.53 | % | 5.47 | % | 5.45 | % | 5.59 | % | 5.89 | % | |||||||||||||||||||
| Cost of interest-bearing liabilities: | |||||||||||||||||||||||||||||
| Interest-bearing deposits: | |||||||||||||||||||||||||||||
Transaction | 3.14 | % | 3.17 | % | 3.21 | % | 3.42 | % | 3.78 | % | |||||||||||||||||||
| Savings | 0.55 | % | 0.54 | % | 0.56 | % | 0.59 | % | 0.60 | % | |||||||||||||||||||
| Time | 3.73 | % | 3.83 | % | 4.10 | % | 4.56 | % | 4.56 | % | |||||||||||||||||||
| Total interest-bearing deposits | 3.14 | % | 3.17 | % | 3.24 | % | 3.48 | % | 3.79 | % | |||||||||||||||||||
| Funds purchased and repurchase agreements | 3.29 | % | 3.50 | % | 3.05 | % | 3.78 | % | 3.89 | % | |||||||||||||||||||
| Other borrowings | 4.54 | % | 4.49 | % | 4.57 | % | 4.95 | % | 5.55 | % | |||||||||||||||||||
| Subordinated debt | — | % | 6.38 | % | 6.44 | % | 6.80 | % | 7.15 | % | |||||||||||||||||||
| Total cost of interest-bearing liabilities | 3.33 | % | 3.40 | % | 3.42 | % | 3.69 | % | 4.11 | % | |||||||||||||||||||
Tax-equivalent net interest spread | 2.20 | % | 2.07 | % | 2.03 | % | 1.90 | % | 1.78 | % | |||||||||||||||||||
| Effect of noninterest-bearing funding sources and other | 0.71 | % | 0.73 | % | 0.75 | % | 0.85 | % | 0.90 | % | |||||||||||||||||||
| Tax-equivalent net interest margin | 2.91 | % | 2.80 | % | 2.78 | % | 2.75 | % | 2.68 | % | |||||||||||||||||||
Yield calculations are shown on a tax-equivalent basis at the statutory federal and state rates for the periods presented. The yield calculations exclude security trades that have been recorded on trade date with no corresponding interest income and the unrealized gains and losses. The yield calculation also includes average loan balances for which the accrual of interest has been discontinued and are net of unearned income. Yield/rate calculations are generally based on the conventions that determine how interest income and expense is accrued.
22
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
CREDIT QUALITY INDICATORS – UNAUDITED
BOK FINANCIAL CORPORATION
| Three Months Ended | |||||||||||||||||||||||||||||
| (In thousands, except ratios) | Sep. 30, 2025 | June 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | ||||||||||||||||||||||||
| Nonperforming assets: | |||||||||||||||||||||||||||||
| Nonaccruing loans: | |||||||||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||
| Healthcare | $ | 24,507 | $ | 28,743 | $ | 29,253 | $ | 13,717 | $ | 15,927 | |||||||||||||||||||
| Services | 7,647 | 11,329 | 13,662 | 767 | 1,425 | ||||||||||||||||||||||||
| Energy | 31 | 40 | 49 | 49 | 28,986 | ||||||||||||||||||||||||
| General business | 85 | 45 | 103 | 114 | 5,334 | ||||||||||||||||||||||||
| Total commercial | 32,270 | 40,157 | 43,067 | 14,647 | 51,672 | ||||||||||||||||||||||||
| Commercial real estate | 6,809 | 6,925 | 13,125 | 9,905 | 12,364 | ||||||||||||||||||||||||
| Loans to individuals: | |||||||||||||||||||||||||||||
| Permanent mortgage | 21,255 | 20,654 | 20,502 | 15,261 | 13,688 | ||||||||||||||||||||||||
| Permanent mortgage guaranteed by U.S. government agencies | 7,348 | 6,978 | 6,786 | 6,803 | 6,520 | ||||||||||||||||||||||||
| Personal | 4,712 | 4,613 | 40 | 109 | 71 | ||||||||||||||||||||||||
| Total loans to individuals | 33,315 | 32,245 | 27,328 | 22,173 | 20,279 | ||||||||||||||||||||||||
| Total nonaccruing loans | 72,394 | 79,327 | 83,520 | 46,725 | 84,315 | ||||||||||||||||||||||||
| Real estate and other repossessed assets | 1,751 | 1,729 | 1,769 | 2,254 | 2,625 | ||||||||||||||||||||||||
| Total nonperforming assets | $ | 74,145 | $ | 81,056 | $ | 85,289 | $ | 48,979 | $ | 86,940 | |||||||||||||||||||
| Total nonperforming assets excluding those guaranteed by U.S. government agencies | $ | 66,797 | $ | 74,078 | $ | 78,503 | $ | 42,176 | $ | 80,420 | |||||||||||||||||||
Accruing loans 90 days past due1 | $ | 1,135 | $ | 1,388 | $ | 3,258 | $ | — | $ | 597 | |||||||||||||||||||
| Gross charge-offs | $ | 4,348 | $ | 1,313 | $ | 2,291 | $ | 1,339 | $ | 2,496 | |||||||||||||||||||
| Recoveries | (721) | (752) | (1,186) | (811) | (2,550) | ||||||||||||||||||||||||
| Net charge-offs (recoveries) | $ | 3,627 | $ | 561 | $ | 1,105 | $ | 528 | $ | (54) | |||||||||||||||||||
| Provision for loan losses | $ | 4,270 | $ | (984) | $ | (336) | $ | (3,893) | $ | (3,424) | |||||||||||||||||||
| Provision for credit losses from off-balance sheet unfunded loan commitments | (2,208) | 904 | 448 | 3,874 | 5,430 | ||||||||||||||||||||||||
| Provision for expected credit losses from mortgage banking activities | (74) | 77 | (82) | 30 | 47 | ||||||||||||||||||||||||
| Provision for credit losses related to held-to-maturity (investment) securities portfolio | 12 | 3 | (30) | (11) | (53) | ||||||||||||||||||||||||
| Total provision for credit losses | $ | 2,000 | $ | — | $ | — | $ | — | $ | 2,000 | |||||||||||||||||||
23
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
| Three Months Ended | |||||||||||||||||||||||||||||
| (In thousands, except ratios) | Sep. 30, 2025 | June 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | ||||||||||||||||||||||||
| Allowance for loan losses to period end loans | 1.12 | % | 1.14 | % | 1.18 | % | 1.16 | % | 1.19 | % | |||||||||||||||||||
| Combined allowance for loan losses and accrual for off-balance sheet credit risk from unfunded loan commitments to period end loans | 1.32 | % | 1.36 | % | 1.40 | % | 1.38 | % | 1.39 | % | |||||||||||||||||||
| Nonperforming assets to period end loans and repossessed assets | 0.30 | % | 0.33 | % | 0.36 | % | 0.20 | % | 0.36 | % | |||||||||||||||||||
| Net charge-offs (annualized) to average loans | 0.06 | % | 0.01 | % | 0.02 | % | 0.01 | % | — | % | |||||||||||||||||||
Allowance for loan losses to nonaccruing loans1 | 426.92 | % | 382.93 | % | 363.06 | % | 701.46 | % | 365.65 | % | |||||||||||||||||||
Combined allowance for loan losses and accrual for off-balance sheet credit risk from unfunded loan commitments to nonaccruing loans1 | 504.99 | % | 456.18 | % | 430.95 | % | 830.81 | % | 427.05 | % | |||||||||||||||||||
1 Excludes residential mortgage loans guaranteed by agencies of the U.S. government.
24
BOK Financial Corporation Quarterly Earnings Release | Exhibit 99.1(b) | ||||
SEGMENTS – UNAUDITED
BOK FINANCIAL CORPORATION
| Three Months Ended | 3Q25 vs 2Q25 | 3Q25 vs 3Q24 | |||||||||||||||||||||||||||||||||||||||
(Dollars in thousands, except ratios) | Sep. 30, 2025 | June 30, 2025 | Sep. 30, 2024 | Change | % Change | Change | % Change | ||||||||||||||||||||||||||||||||||
| Commercial Banking: | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 179,197 | $ | 175,826 | $ | 207,610 | $ | 3,371 | 1.9 | % | $ | (28,413) | (13.7) | % | |||||||||||||||||||||||||||
| Fees and commissions revenue | 57,537 | 58,400 | 55,865 | (863) | (1.5) | % | 1,672 | 3.0 | % | ||||||||||||||||||||||||||||||||
| Combined net interest income and fee revenue | 236,734 | 234,226 | 263,475 | 2,508 | 1.1 | % | (26,741) | (10.1) | % | ||||||||||||||||||||||||||||||||
| Other operating expense | 81,239 | 79,705 | 79,230 | 1,534 | 1.9 | % | 2,009 | 2.5 | % | ||||||||||||||||||||||||||||||||
| Corporate allocations | 17,277 | 19,160 | 17,010 | (1,883) | (9.8) | % | 267 | 1.6 | % | ||||||||||||||||||||||||||||||||
| Net income before taxes | 139,817 | 141,364 | 172,181 | (1,547) | (1.1) | % | (32,364) | (18.8) | % | ||||||||||||||||||||||||||||||||
| Average assets | $ | 21,722,491 | $ | 21,318,236 | $ | 21,881,574 | $ | 404,255 | 1.9 | % | $ | (159,083) | (0.7) | % | |||||||||||||||||||||||||||
| Average loans | 20,280,147 | 19,894,391 | 20,340,512 | 385,756 | 1.9 | % | (60,365) | (0.3) | % | ||||||||||||||||||||||||||||||||
| Average deposits | 18,161,258 | 17,424,707 | 17,131,237 | 736,551 | 4.2 | % | 1,030,021 | 6.0 | % | ||||||||||||||||||||||||||||||||
| Consumer Banking: | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 58,451 | $ | 58,114 | $ | 65,263 | $ | 337 | 0.6 | % | $ | (6,812) | (10.4) | % | |||||||||||||||||||||||||||
| Fees and commissions revenue | 38,071 | 36,789 | 36,699 | 1,282 | 3.5 | % | 1,372 | 3.7 | % | ||||||||||||||||||||||||||||||||
| Combined net interest income and fee revenue | 96,522 | 94,903 | 101,962 | 1,619 | 1.7 | % | (5,440) | (5.3) | % | ||||||||||||||||||||||||||||||||
| Other operating expense | 64,042 | 55,476 | 57,779 | 8,566 | 15.4 | % | 6,263 | 10.8 | % | ||||||||||||||||||||||||||||||||
| Corporate allocations | 14,326 | 15,039 | 13,298 | (713) | (4.7) | % | 1,028 | 7.7 | % | ||||||||||||||||||||||||||||||||
| Net income before taxes | 14,490 | 24,746 | 24,774 | (10,256) | (41.4) | % | (10,284) | (41.5) | % | ||||||||||||||||||||||||||||||||
| Average assets | $ | 8,372,125 | $ | 8,310,875 | $ | 8,172,256 | $ | 61,250 | 0.7 | % | $ | 199,869 | 2.4 | % | |||||||||||||||||||||||||||
| Average loans | 2,432,968 | 2,304,939 | 2,057,870 | 128,029 | 5.6 | % | 375,098 | 18.2 | % | ||||||||||||||||||||||||||||||||
| Average deposits | 8,330,481 | 8,266,824 | 8,136,312 | 63,657 | 0.8 | % | 194,169 | 2.4 | % | ||||||||||||||||||||||||||||||||
| Wealth Management: | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 43,626 | $ | 44,844 | $ | 33,185 | $ | (1,218) | (2.7) | % | $ | 10,441 | 31.5 | % | |||||||||||||||||||||||||||
| Fees and commissions revenue | 111,516 | 103,650 | 112,457 | 7,866 | 7.6 | % | (941) | (0.8) | % | ||||||||||||||||||||||||||||||||
| Combined net interest income and fee revenue | 155,142 | 148,494 | 145,642 | 6,648 | 4.5 | % | 9,500 | 6.5 | % | ||||||||||||||||||||||||||||||||
| Other operating expense | 102,971 | 93,281 | 93,539 | 9,690 | 10.4 | % | 9,432 | 10.1 | % | ||||||||||||||||||||||||||||||||
| Corporate allocations | 15,568 | 14,471 | 13,458 | 1,097 | 7.6 | % | 2,110 | 15.7 | % | ||||||||||||||||||||||||||||||||
| Net income before taxes | 36,606 | 40,749 | 38,804 | (4,143) | (10.2) | % | (2,198) | (5.7) | % | ||||||||||||||||||||||||||||||||
| Average assets | $ | 11,265,485 | $ | 11,571,187 | $ | 10,566,503 | $ | (305,702) | (2.6) | % | $ | 698,982 | 6.6 | % | |||||||||||||||||||||||||||
| Average loans | 2,353,961 | 2,275,378 | 2,151,196 | 78,583 | 3.5 | % | 202,765 | 9.4 | % | ||||||||||||||||||||||||||||||||
| Average deposits | 10,731,569 | 10,783,245 | 9,837,888 | (51,676) | (0.5) | % | 893,681 | 9.1 | % | ||||||||||||||||||||||||||||||||
| Fiduciary assets | 73,862,296 | 71,057,135 | 63,703,618 | 2,805,161 | 3.9 | % | 10,158,678 | 15.9 | % | ||||||||||||||||||||||||||||||||
| Assets under management or administration | 122,673,531 | 117,870,970 | 110,702,612 | 4,802,561 | 4.1 | % | 11,970,919 | 10.8 | % | ||||||||||||||||||||||||||||||||
Certain prior period amounts have been reclassified to conform to current period presentation.
25
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic October 21, 2025 Q3 Earnings Conference Call
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic This presentation contains forward-looking statements that are based on management's beliefs, assumptions, current expectations, estimates and projections about BOK Financial Corporation, the financial services industry, and the economy generally. Words such as “anticipates,” “believes,” “estimates,” “expects,” “forecasts,” “plans,” "outlook," “projects,” “will,” “intends,” variations of such words and similar expressions are intended to identify such forward-looking statements. Management judgments relating to and discussion of the provision and allowance for credit losses, allowance for uncertain tax positions, accruals for loss contingencies and valuation of mortgage servicing rights involve judgments as to expected events and are inherently forward-looking statements. Assessments that acquisitions and growth endeavors will be profitable are necessary statements of belief as to the outcome of future events based in part on information provided by others which BOK Financial has not independently verified. These various forward-looking statements are not guarantees of future performance and involve certain risks, uncertainties, and assumptions which are difficult to predict with regard to timing, extent, likelihood and degree of occurrence. Therefore, actual results and outcomes may materially differ from what is expected, implied or forecasted in such forward-looking statements. Internal and external factors that might cause such a difference include, but are not limited to changes in government, changes in governmental economic policy, including tariffs, changes in commodity prices, interest rates and interest rate relationships, inflation, demand for products and services, the degree of competition by traditional and nontraditional competitors, changes in banking regulations, tax laws, prices, levies and assessments, the impact of technological advances, and trends in customer behavior as well as their ability to repay loans. For a discussion of risk factors that may cause actual results to differ from expectations, please refer to BOK Financial Corporation’s most recent annual and quarterly reports. BOK Financial Corporation and its affiliates undertake no obligation to update, amend, or clarify forward-looking statements, whether as a result of new information, future events, or otherwise. Non-GAAP Financial Measures: This presentation may refer to non-GAAP financial measures. Additional information on these financial measures is available in BOK Financial’s Form 8-K filings furnished pursuant to Item 2.02, which can be accessed at bokf.com. All data is presented as of September 30, 2025 unless otherwise noted. Legal Disclaimers 2
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Stacy Kymes Chief Executive Officer 3
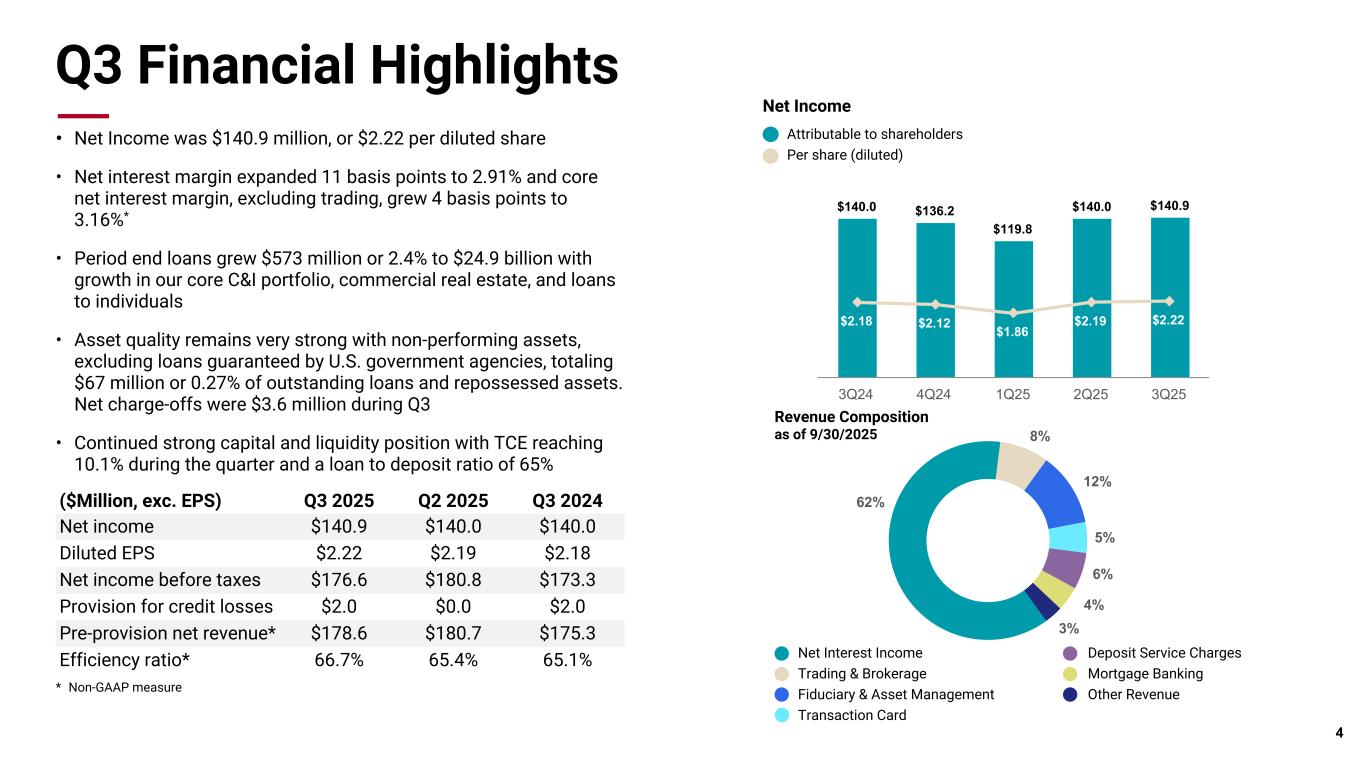
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Q3 Financial Highlights * Non-GAAP measure Attributable to shareholders Per share (diluted) Net Income • Net Income was $140.9 million, or $2.22 per diluted share • Net interest margin expanded 11 basis points to 2.91% and core net interest margin, excluding trading, grew 4 basis points to 3.16%* • Period end loans grew $573 million or 2.4% to $24.9 billion with growth in our core C&I portfolio, commercial real estate, and loans to individuals • Asset quality remains very strong with non-performing assets, excluding loans guaranteed by U.S. government agencies, totaling $67 million or 0.27% of outstanding loans and repossessed assets. Net charge-offs were $3.6 million during Q3 • Continued strong capital and liquidity position with TCE reaching 10.1% during the quarter and a loan to deposit ratio of 65% 4 $140.0 $136.2 $119.8 $140.0 $140.9 $2.18 $2.12 $1.86 $2.19 $2.22 3Q24 4Q24 1Q25 2Q25 3Q25 ($Million, exc. EPS) Q3 2025 Q2 2025 Q3 2024 Net income $140.9 $140.0 $140.0 Diluted EPS $2.22 $2.19 $2.18 Net income before taxes $176.6 $180.8 $173.3 Provision for credit losses $2.0 $0.0 $2.0 Pre-provision net revenue* $178.6 $180.7 $175.3 Efficiency ratio* 66.7% 65.4% 65.1% Revenue Composition as of 9/30/2025 62% 8% 12% 5% 6% 4% 3% Net Interest Income Trading & Brokerage Fiduciary & Asset Management Transaction Card Deposit Service Charges Mortgage Banking Other Revenue
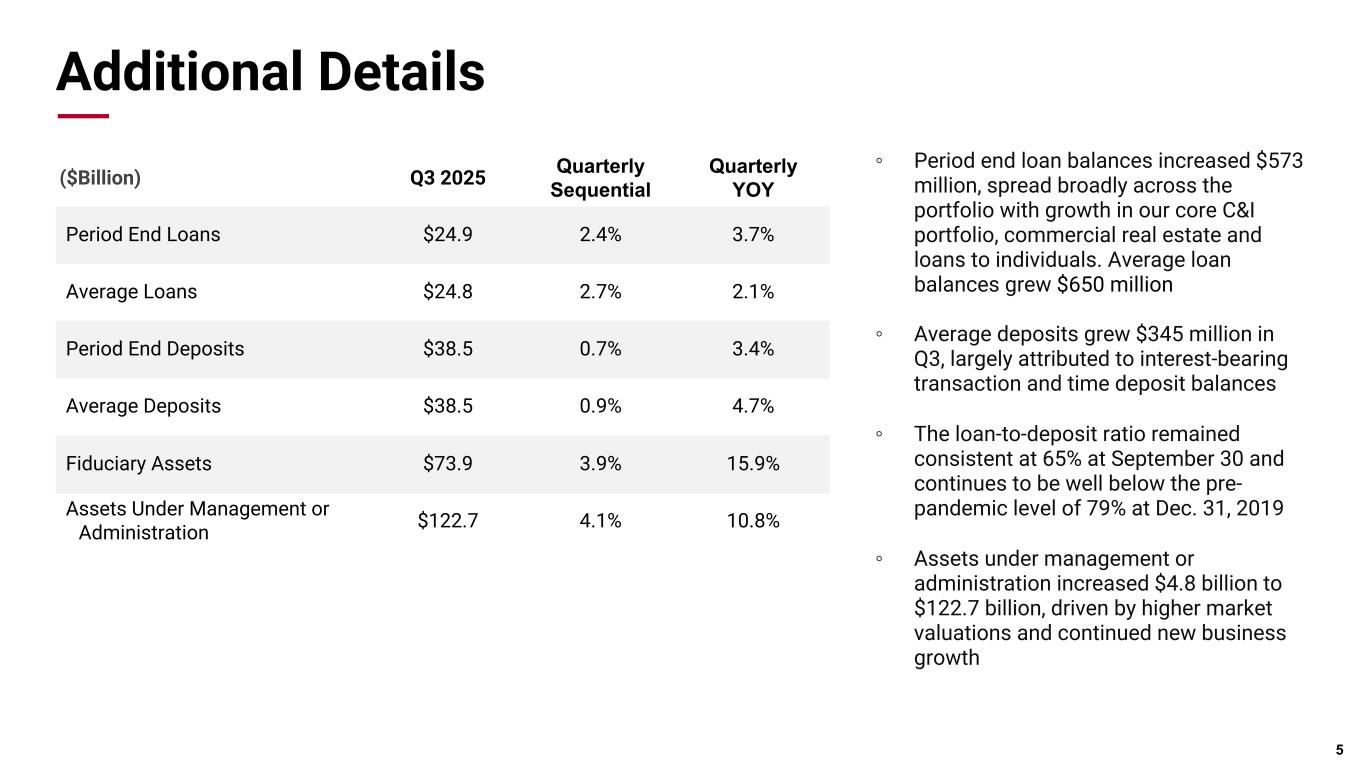
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Additional Details 5 ◦ Period end loan balances increased $573 million, spread broadly across the portfolio with growth in our core C&I portfolio, commercial real estate and loans to individuals. Average loan balances grew $650 million ◦ Average deposits grew $345 million in Q3, largely attributed to interest-bearing transaction and time deposit balances ◦ The loan-to-deposit ratio remained consistent at 65% at September 30 and continues to be well below the pre- pandemic level of 79% at Dec. 31, 2019 ◦ Assets under management or administration increased $4.8 billion to $122.7 billion, driven by higher market valuations and continued new business growth ($Billion) Q3 2025 Quarterly Sequential Quarterly YOY Period End Loans $24.9 2.4% 3.7% Average Loans $24.8 2.7% 2.1% Period End Deposits $38.5 0.7% 3.4% Average Deposits $38.5 0.9% 4.7% Fiduciary Assets $73.9 3.9% 15.9% Assets Under Management or Administration $122.7 4.1% 10.8%
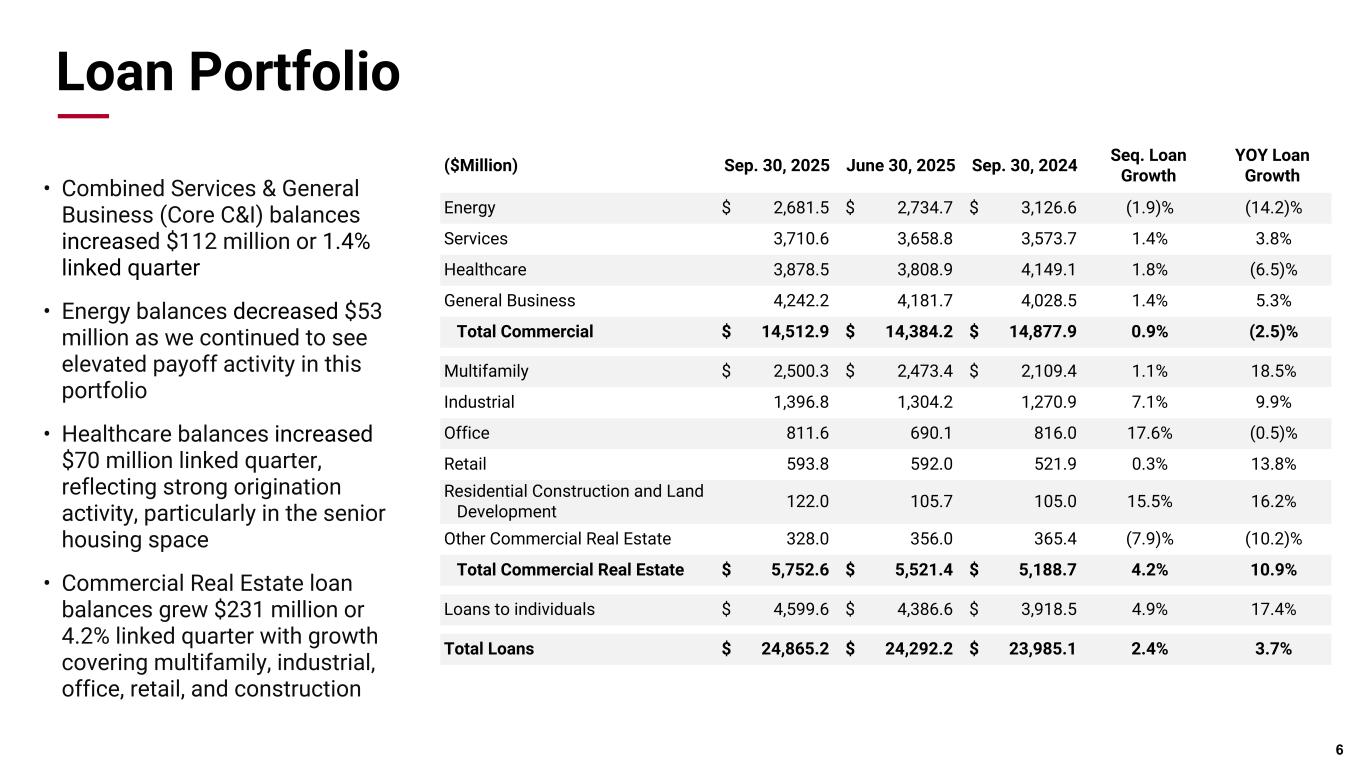
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Loan Portfolio • Combined Services & General Business (Core C&I) balances increased $112 million or 1.4% linked quarter • Energy balances decreased $53 million as we continued to see elevated payoff activity in this portfolio • Healthcare balances increased $70 million linked quarter, reflecting strong origination activity, particularly in the senior housing space • Commercial Real Estate loan balances grew $231 million or 4.2% linked quarter with growth covering multifamily, industrial, office, retail, and construction 6 ($Million) Sep. 30, 2025 June 30, 2025 Sep. 30, 2024 Seq. Loan Growth YOY Loan Growth Energy $ 2,681.5 $ 2,734.7 $ 3,126.6 (1.9)% (14.2)% Services 3,710.6 3,658.8 3,573.7 1.4% 3.8% Healthcare 3,878.5 3,808.9 4,149.1 1.8% (6.5)% General Business 4,242.2 4,181.7 4,028.5 1.4% 5.3% Total Commercial $ 14,512.9 $ 14,384.2 $ 14,877.9 0.9% (2.5)% Multifamily $ 2,500.3 $ 2,473.4 $ 2,109.4 1.1% 18.5% Industrial 1,396.8 1,304.2 1,270.9 7.1% 9.9% Office 811.6 690.1 816.0 17.6% (0.5)% Retail 593.8 592.0 521.9 0.3% 13.8% Residential Construction and Land Development 122.0 105.7 105.0 15.5% 16.2% Other Commercial Real Estate 328.0 356.0 365.4 (7.9)% (10.2)% Total Commercial Real Estate $ 5,752.6 $ 5,521.4 $ 5,188.7 4.2% 10.9% Loans to individuals $ 4,599.6 $ 4,386.6 $ 3,918.5 4.9% 17.4% Total Loans $ 24,865.2 $ 24,292.2 $ 23,985.1 2.4% 3.7%
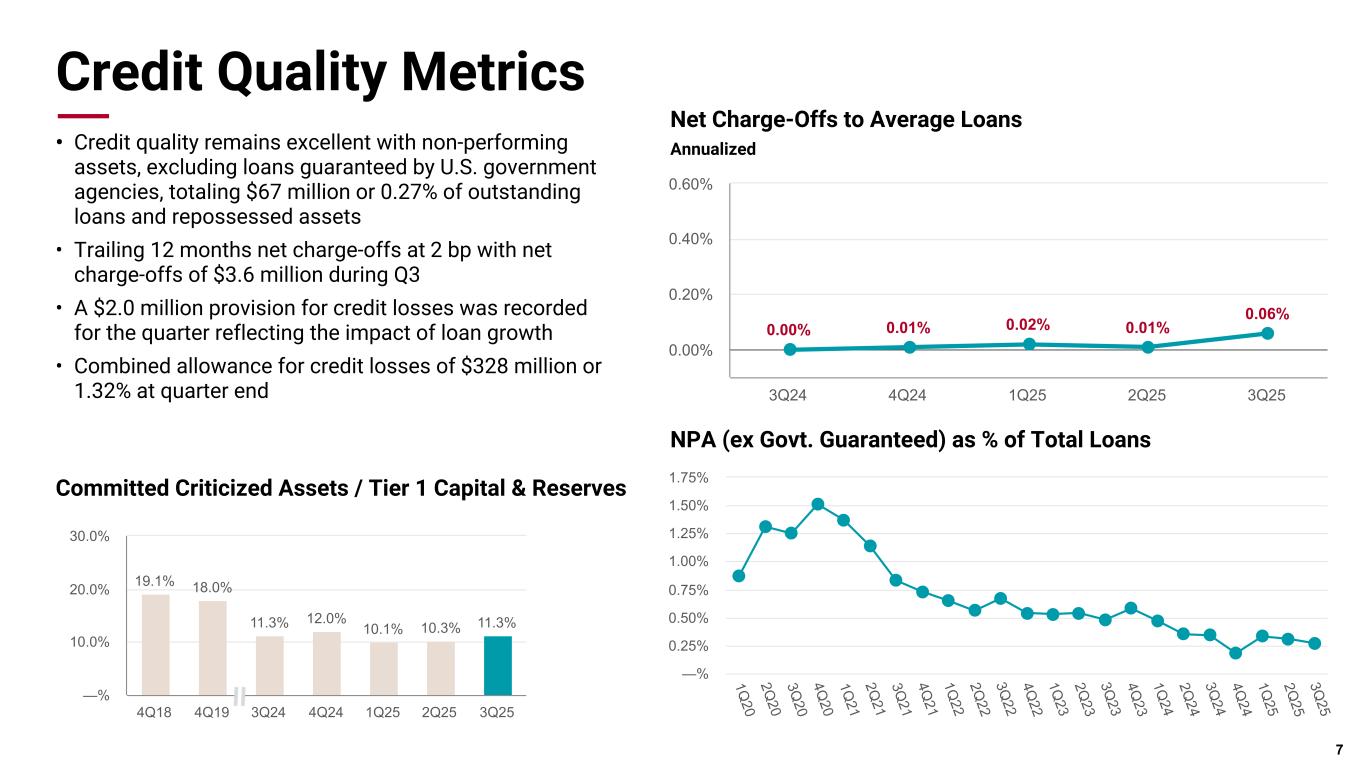
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Credit Quality Metrics • Credit quality remains excellent with non-performing assets, excluding loans guaranteed by U.S. government agencies, totaling $67 million or 0.27% of outstanding loans and repossessed assets • Trailing 12 months net charge-offs at 2 bp with net charge-offs of $3.6 million during Q3 • A $2.0 million provision for credit losses was recorded for the quarter reflecting the impact of loan growth • Combined allowance for credit losses of $328 million or 1.32% at quarter end Net Charge-Offs to Average Loans NPA (ex Govt. Guaranteed) as % of Total Loans Annualized 7 0.00% 0.01% 0.02% 0.01% 0.06% 3Q24 4Q24 1Q25 2Q25 3Q25 0.00% 0.20% 0.40% 0.60% 19.1% 18.0% 11.3% 12.0% 10.1% 10.3% 11.3% 4Q18 4Q19 3Q24 4Q24 1Q25 2Q25 3Q25 —% 10.0% 20.0% 30.0% Committed Criticized Assets / Tier 1 Capital & Reserves 1Q 20 2Q 20 3Q 20 4Q 20 1Q 21 2Q 21 3Q 21 4Q 21 1Q 22 2Q 22 3Q 22 4Q 22 1Q 23 2Q 23 3Q 23 4Q 23 1Q 24 2Q 24 3Q 24 4Q 24 1Q 25 2Q 25 3Q 25 —% 0.25% 0.50% 0.75% 1.00% 1.25% 1.50% 1.75%
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Scott Grauer EVP, Wealth Management Executive 8
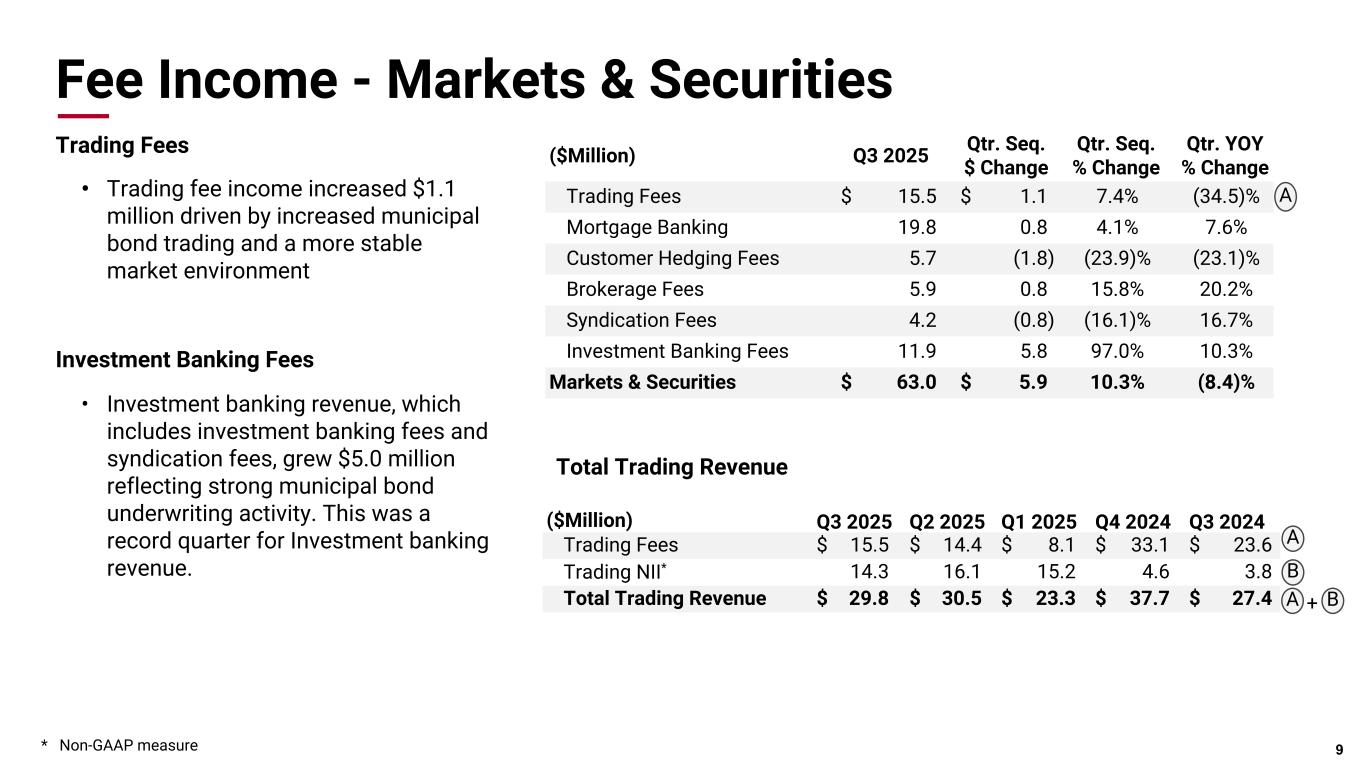
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Fee Income - Markets & Securities Trading Fees • Trading fee income increased $1.1 million driven by increased municipal bond trading and a more stable market environment Investment Banking Fees • Investment banking revenue, which includes investment banking fees and syndication fees, grew $5.0 million reflecting strong municipal bond underwriting activity. This was a record quarter for Investment banking revenue. 9 ($Million) Q3 2025 Qtr. Seq. $ Change Qtr. Seq. % Change Qtr. YOY % Change Trading Fees $ 15.5 $ 1.1 7.4% (34.5)% Mortgage Banking 19.8 0.8 4.1% 7.6% Customer Hedging Fees 5.7 (1.8) (23.9)% (23.1)% Brokerage Fees 5.9 0.8 15.8% 20.2% Syndication Fees 4.2 (0.8) (16.1)% 16.7% Investment Banking Fees 11.9 5.8 97.0% 10.3% Markets & Securities $ 63.0 $ 5.9 10.3% (8.4)% ($Million) Q3 2025 Q2 2025 Q1 2025 Q4 2024 Q3 2024 Trading Fees $ 15.5 $ 14.4 $ 8.1 $ 33.1 $ 23.6 Trading NII* 14.3 16.1 15.2 4.6 3.8 Total Trading Revenue $ 29.8 $ 30.5 $ 23.3 $ 37.7 $ 27.4 A A Total Trading Revenue A + B B * Non-GAAP measure
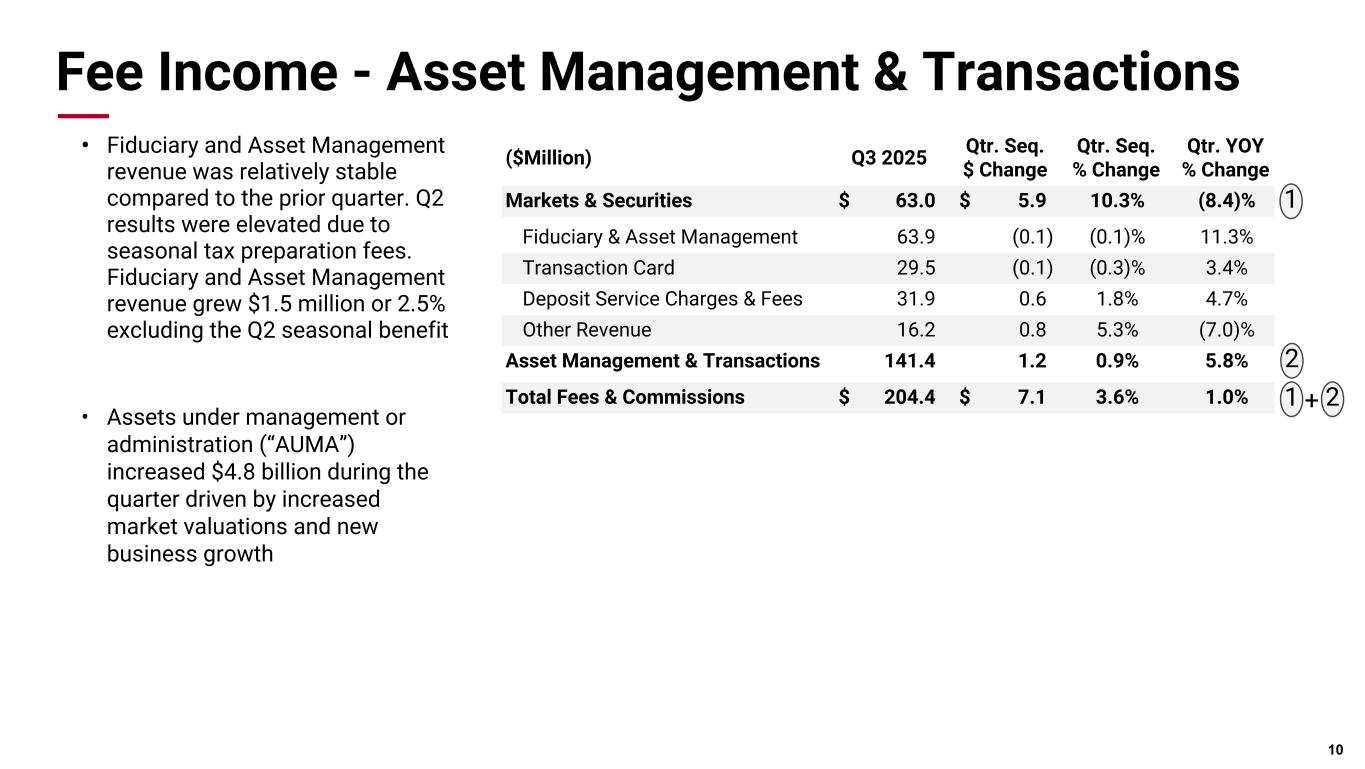
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Fee Income - Asset Management & Transactions • Fiduciary and Asset Management revenue was relatively stable compared to the prior quarter. Q2 results were elevated due to seasonal tax preparation fees. Fiduciary and Asset Management revenue grew $1.5 million or 2.5% excluding the Q2 seasonal benefit • Assets under management or administration (“AUMA”) increased $4.8 billion during the quarter driven by increased market valuations and new business growth 10 ($Million) Q3 2025 Qtr. Seq. $ Change Qtr. Seq. % Change Qtr. YOY % Change Markets & Securities $ 63.0 $ 5.9 10.3% (8.4)% Fiduciary & Asset Management 63.9 (0.1) (0.1)% 11.3% Transaction Card 29.5 (0.1) (0.3)% 3.4% Deposit Service Charges & Fees 31.9 0.6 1.8% 4.7% Other Revenue 16.2 0.8 5.3% (7.0)% Asset Management & Transactions 141.4 1.2 0.9% 5.8% Total Fees & Commissions $ 204.4 $ 7.1 3.6% 1.0% 2+1 1 2
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Marty Grunst EVP, Chief Financial Officer 11
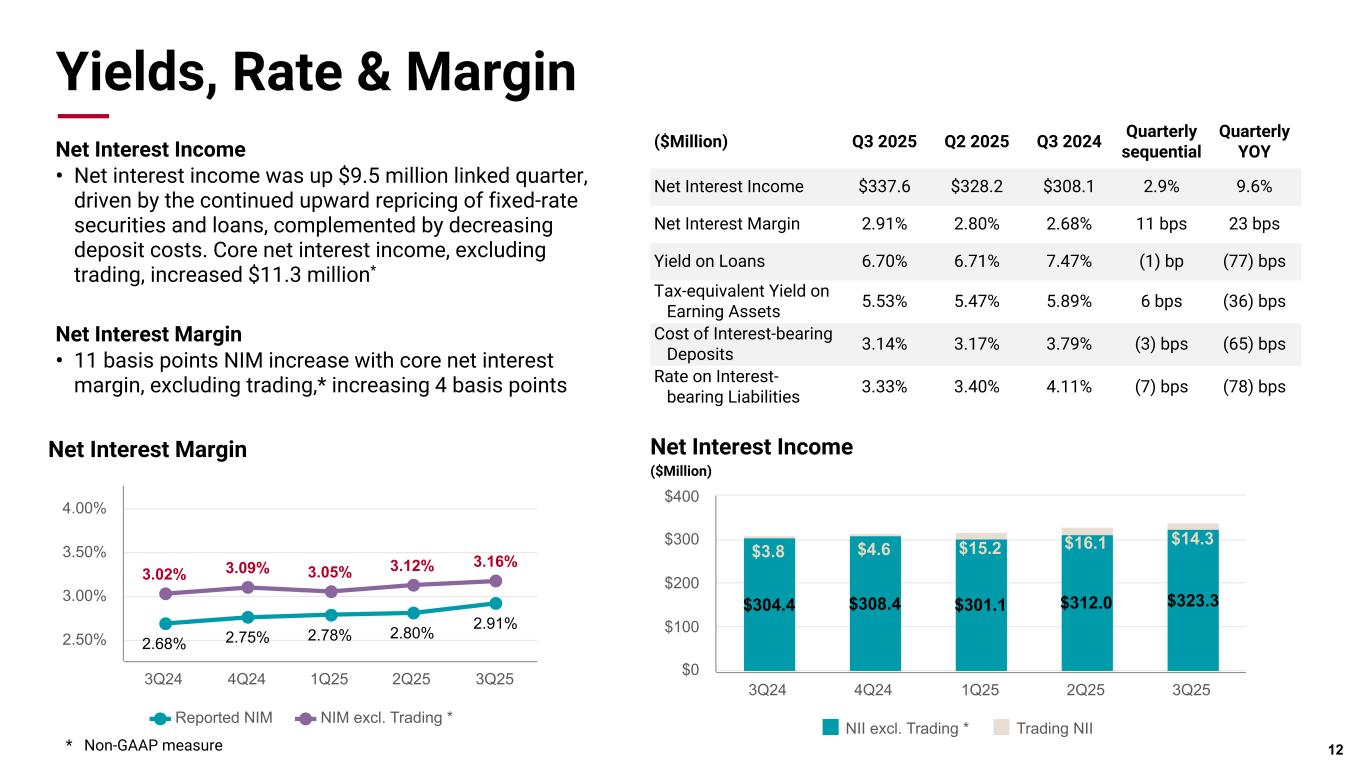
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Yields, Rate & Margin Net Interest Income • Net interest income was up $9.5 million linked quarter, driven by the continued upward repricing of fixed-rate securities and loans, complemented by decreasing deposit costs. Core net interest income, excluding trading, increased $11.3 million* Net Interest Margin • 11 basis points NIM increase with core net interest margin, excluding trading,* increasing 4 basis points 12 ($Million) Q3 2025 Q2 2025 Q3 2024 Quarterly sequential Quarterly YOY Net Interest Income $337.6 $328.2 $308.1 2.9% 9.6% Net Interest Margin 2.91% 2.80% 2.68% 11 bps 23 bps Yield on Loans 6.70% 6.71% 7.47% (1) bp (77) bps Tax-equivalent Yield on Earning Assets 5.53% 5.47% 5.89% 6 bps (36) bps Cost of Interest-bearing Deposits 3.14% 3.17% 3.79% (3) bps (65) bps Rate on Interest- bearing Liabilities 3.33% 3.40% 4.11% (7) bps (78) bps Net Interest Income ($Million) $304.4 $308.4 $301.1 $312.0 $323.3 $3.8 $4.6 $15.2 $16.1 $14.3 NII excl. Trading * Trading NII 3Q24 4Q24 1Q25 2Q25 3Q25 $0 $100 $200 $300 $400 2.68% 2.75% 2.78% 2.80% 2.91% 3.02% 3.09% 3.05% 3.12% 3.16% Reported NIM NIM excl. Trading * 3Q24 4Q24 1Q25 2Q25 3Q25 2.50% 3.00% 3.50% 4.00% Net Interest Margin * Non-GAAP measure
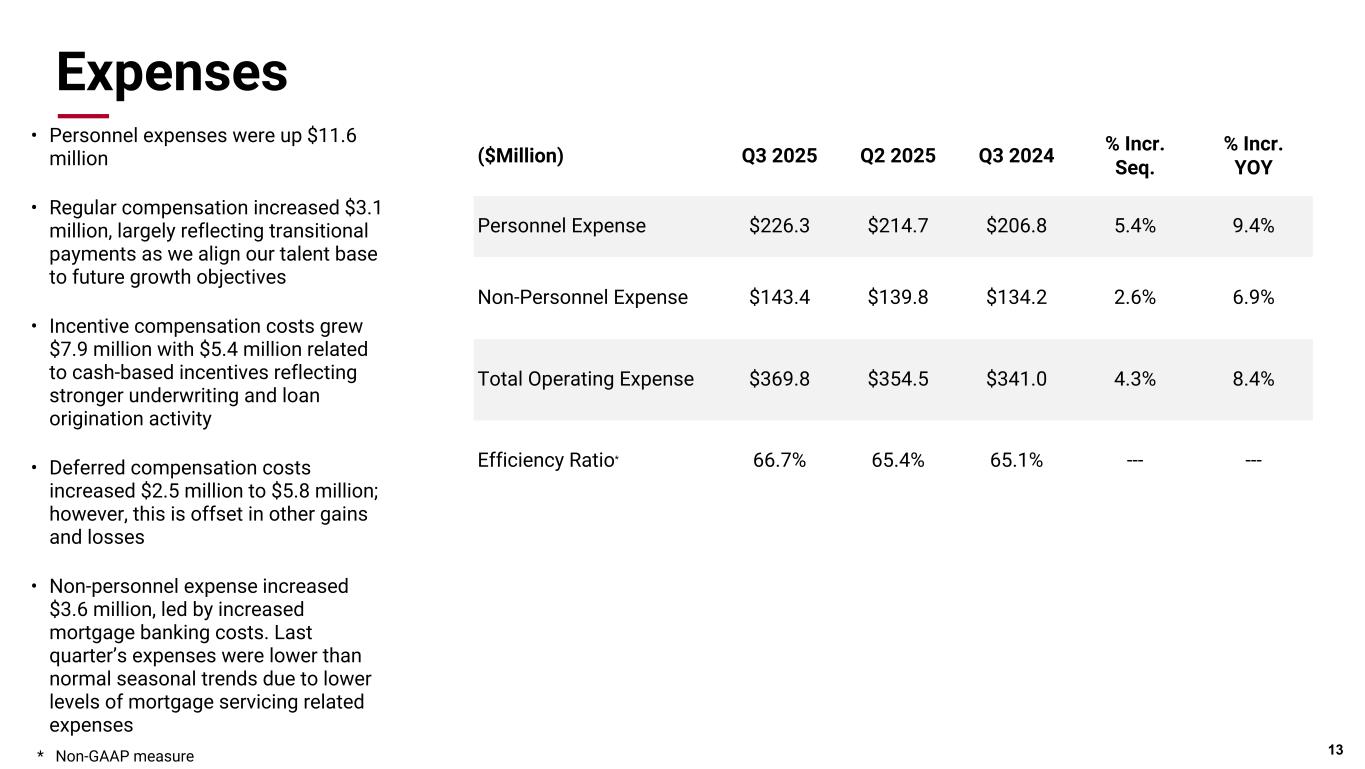
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Expenses • Personnel expenses were up $11.6 million • Regular compensation increased $3.1 million, largely reflecting transitional payments as we align our talent base to future growth objectives • Incentive compensation costs grew $7.9 million with $5.4 million related to cash-based incentives reflecting stronger underwriting and loan origination activity • Deferred compensation costs increased $2.5 million to $5.8 million; however, this is offset in other gains and losses • Non-personnel expense increased $3.6 million, led by increased mortgage banking costs. Last quarter’s expenses were lower than normal seasonal trends due to lower levels of mortgage servicing related expenses 13 ($Million) Q3 2025 Q2 2025 Q3 2024 % Incr. Seq. % Incr. YOY Personnel Expense $226.3 $214.7 $206.8 5.4% 9.4% Non-Personnel Expense $143.4 $139.8 $134.2 2.6% 6.9% Total Operating Expense $369.8 $354.5 $341.0 4.3% 8.4% Efficiency Ratio* 66.7% 65.4% 65.1% --- --- * Non-GAAP measure
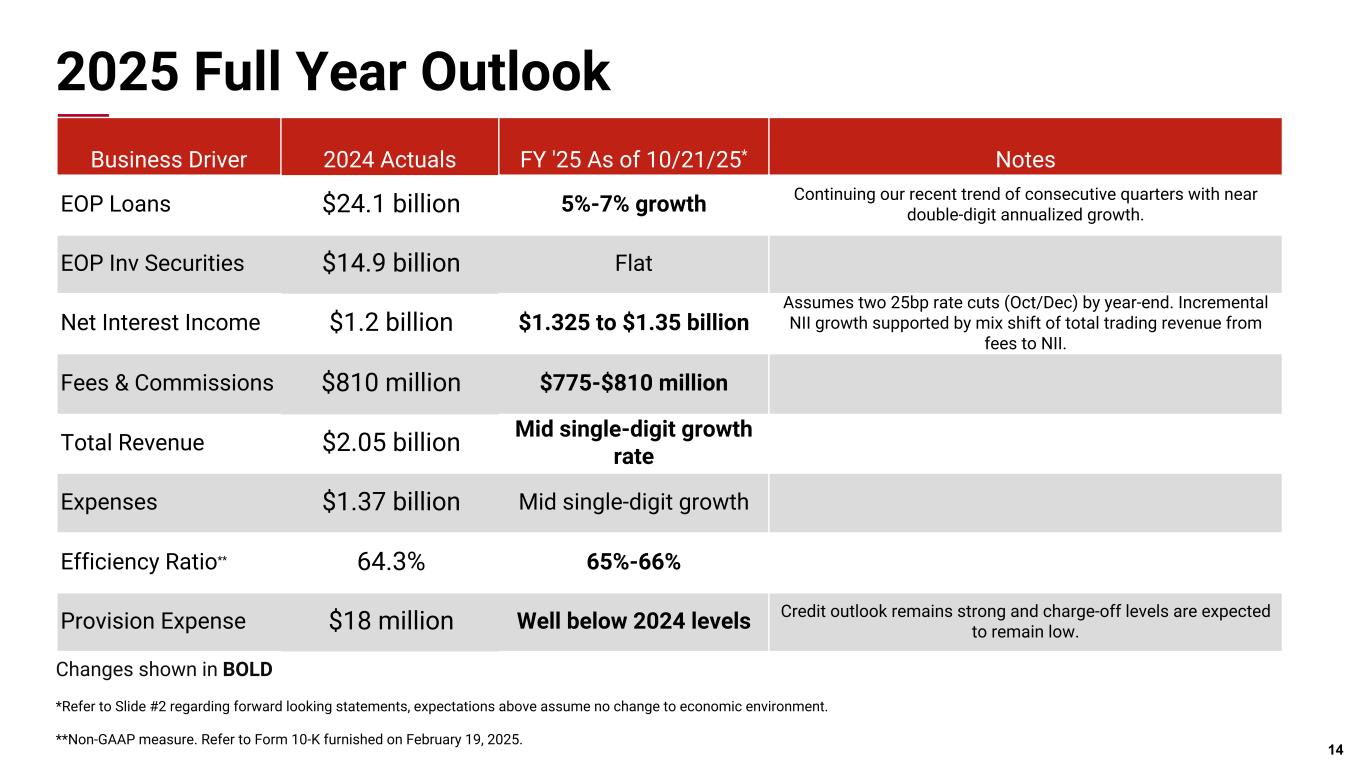
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic 2025 Full Year Outlook 14 Changes shown in BOLD *Refer to Slide #2 regarding forward looking statements, expectations above assume no change to economic environment. **Non-GAAP measure. Refer to Form 10-K furnished on February 19, 2025. Business Driver 2024 Actuals FY '25 As of 10/21/25* Notes EOP Loans $24.1 billion 5%-7% growth Continuing our recent trend of consecutive quarters with near double-digit annualized growth. EOP Inv Securities $14.9 billion Flat Net Interest Income $1.2 billion $1.325 to $1.35 billion Assumes two 25bp rate cuts (Oct/Dec) by year-end. Incremental NII growth supported by mix shift of total trading revenue from fees to NII. Fees & Commissions $810 million $775-$810 million Total Revenue $2.05 billion Mid single-digit growth rate Expenses $1.37 billion Mid single-digit growth Efficiency Ratio** 64.3% 65%-66% Provision Expense $18 million Well below 2024 levels Credit outlook remains strong and charge-off levels are expected to remain low.
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Question & Answer Session 15
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Stacy Kymes Chief Executive Officer 16
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Appendix 17
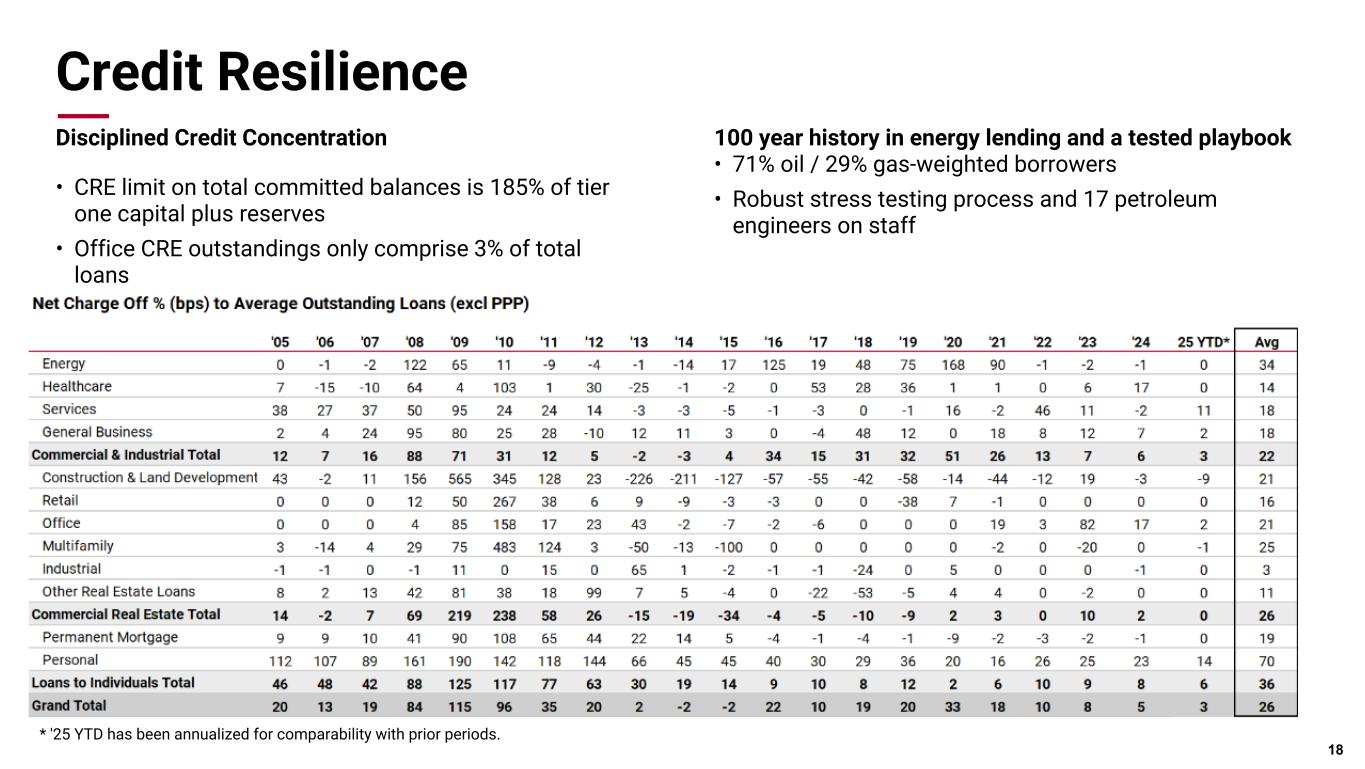
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Credit Resilience Disciplined Credit Concentration • CRE limit on total committed balances is 185% of tier one capital plus reserves • Office CRE outstandings only comprise 3% of total loans 18 100 year history in energy lending and a tested playbook • 71% oil / 29% gas-weighted borrowers • Robust stress testing process and 17 petroleum engineers on staff * '25 YTD has been annualized for comparability with prior periods.
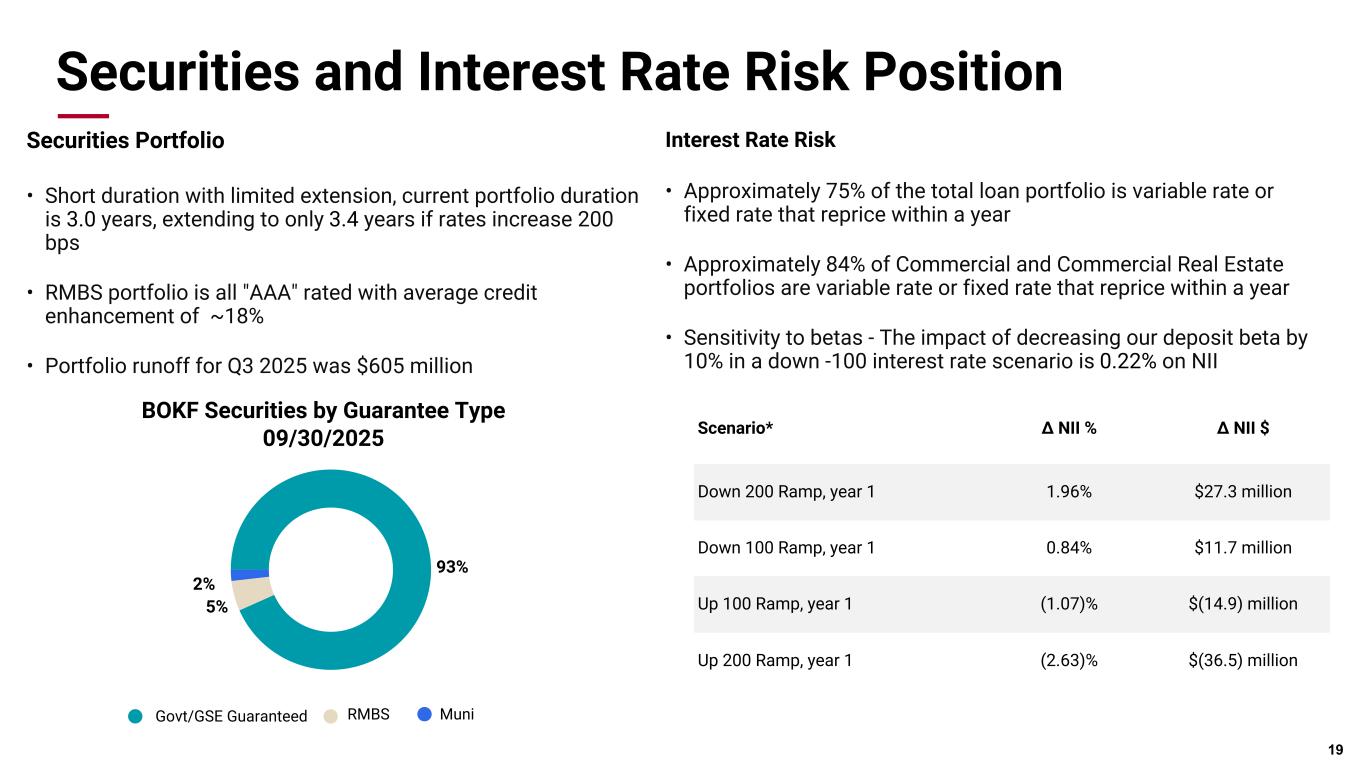
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Securities and Interest Rate Risk Position Interest Rate Risk • Approximately 75% of the total loan portfolio is variable rate or fixed rate that reprice within a year • Approximately 84% of Commercial and Commercial Real Estate portfolios are variable rate or fixed rate that reprice within a year • Sensitivity to betas - The impact of decreasing our deposit beta by 10% in a down -100 interest rate scenario is 0.22% on NII 19 Scenario* Δ NII % Δ NII $ Down 200 Ramp, year 1 1.96% $27.3 million Down 100 Ramp, year 1 0.84% $11.7 million Up 100 Ramp, year 1 (1.07)% $(14.9) million Up 200 Ramp, year 1 (2.63)% $(36.5) million Securities Portfolio • Short duration with limited extension, current portfolio duration is 3.0 years, extending to only 3.4 years if rates increase 200 bps • RMBS portfolio is all "AAA" rated with average credit enhancement of ~18% • Portfolio runoff for Q3 2025 was $605 million 93% 5% 2% Govt/GSE Guaranteed RMBS Muni BOKF Securities by Guarantee Type 09/30/2025
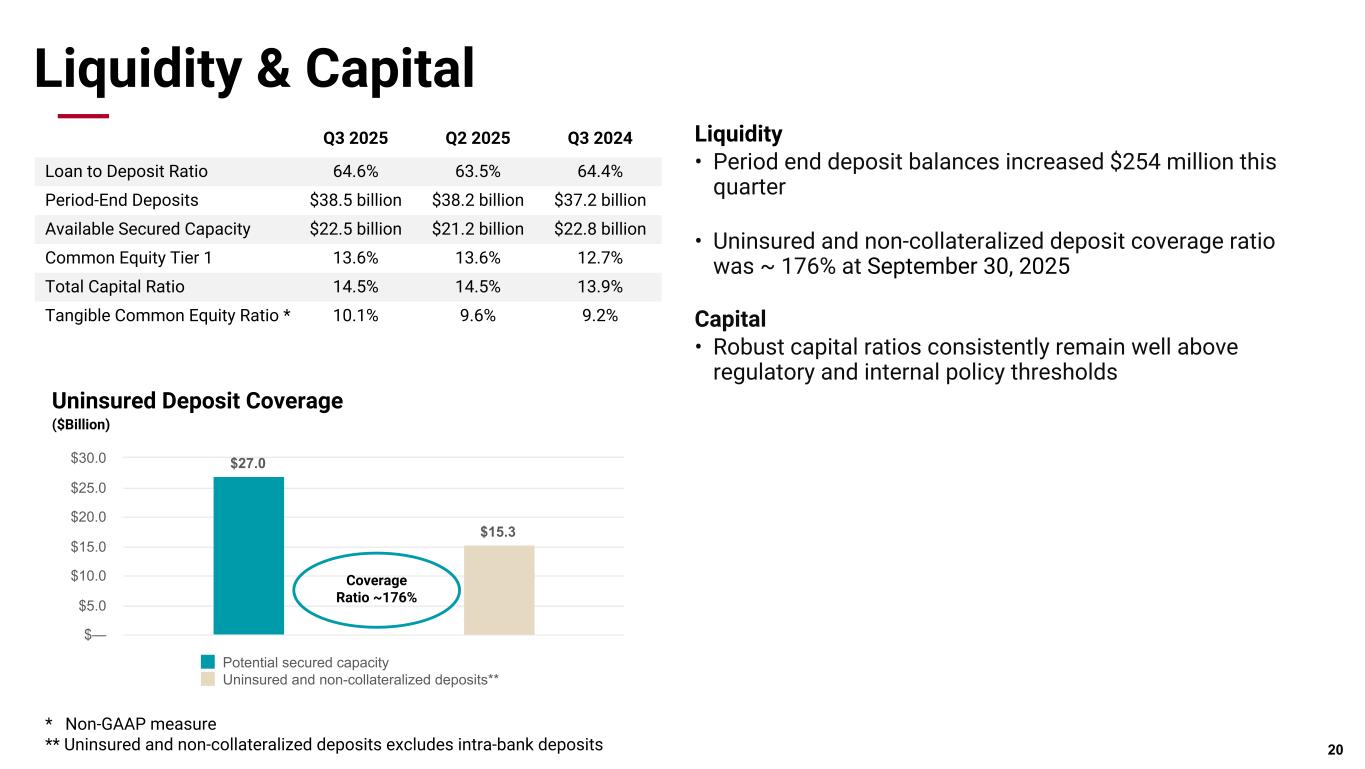
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Liquidity & Capital * Non-GAAP measure ** Uninsured and non-collateralized deposits excludes intra-bank deposits Liquidity • Period end deposit balances increased $254 million this quarter • Uninsured and non-collateralized deposit coverage ratio was ~ 176% at September 30, 2025 Capital • Robust capital ratios consistently remain well above regulatory and internal policy thresholds 20 Q3 2025 Q2 2025 Q3 2024 Loan to Deposit Ratio 64.6% 63.5% 64.4% Period-End Deposits $38.5 billion $38.2 billion $37.2 billion Available Secured Capacity $22.5 billion $21.2 billion $22.8 billion Common Equity Tier 1 13.6% 13.6% 12.7% Total Capital Ratio 14.5% 14.5% 13.9% Tangible Common Equity Ratio * 10.1% 9.6% 9.2% $27.0 $15.3 Potential secured capacity Uninsured and non-collateralized deposits** $— $5.0 $10.0 $15.0 $20.0 $25.0 $30.0 Coverage Ratio ~176% Uninsured Deposit Coverage ($Billion)
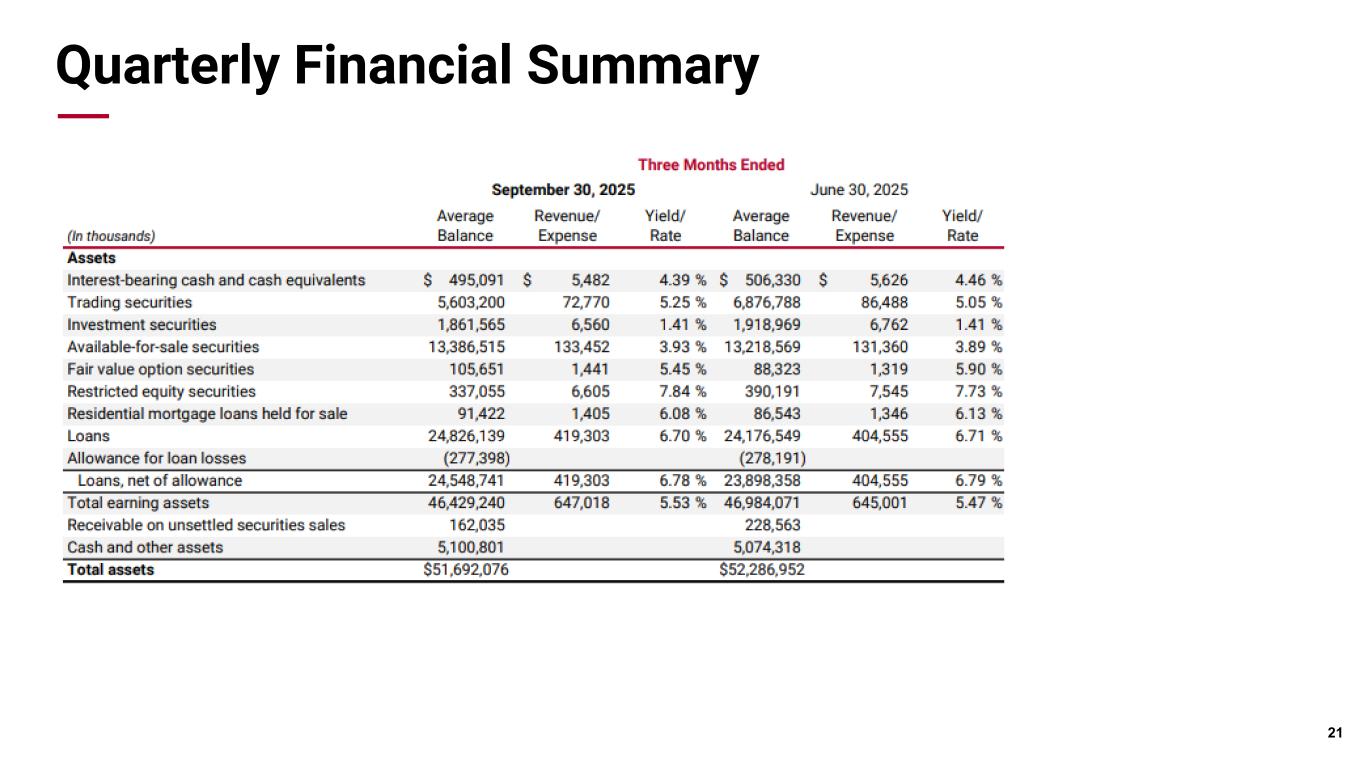
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Quarterly Financial Summary 21
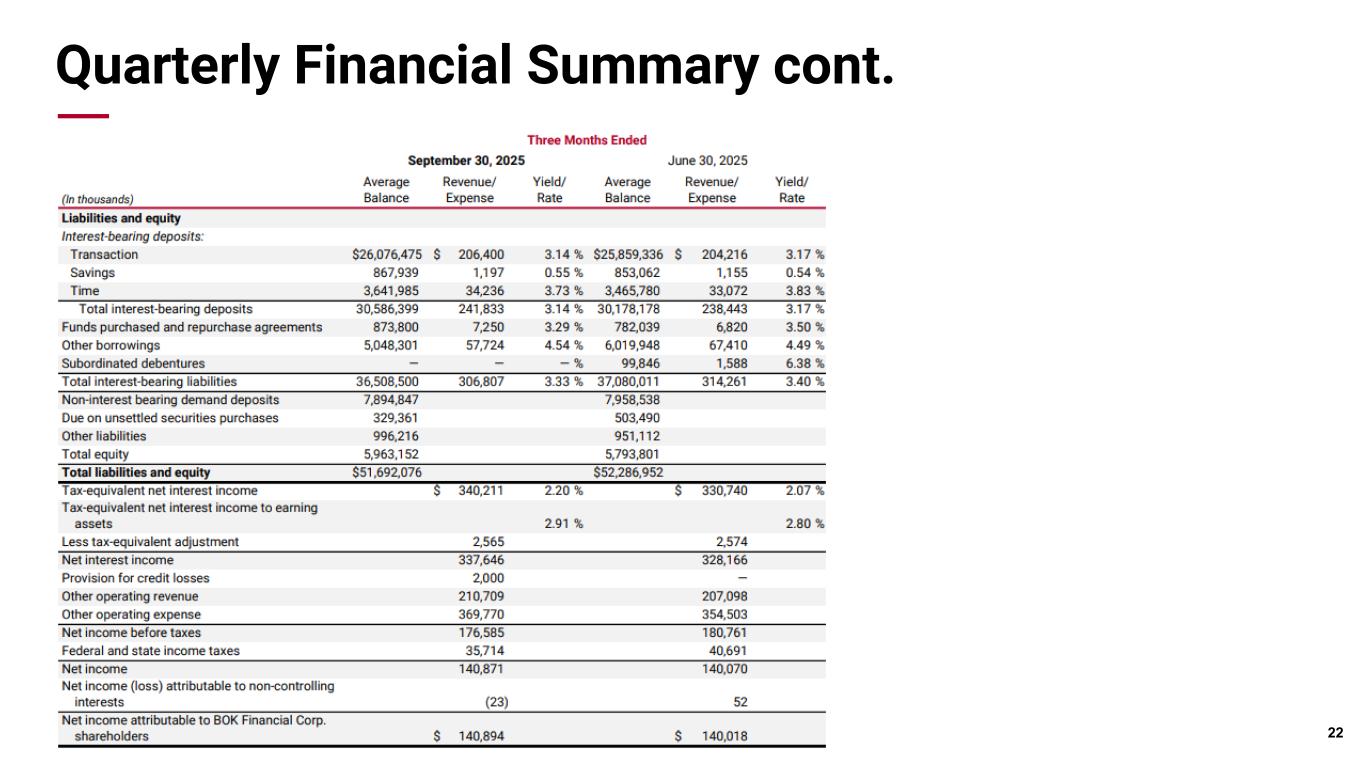
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic Quarterly Financial Summary cont. 22
Pri m ar y & se co nd ar y br an d co lor s Data viz colors Data viz monochromatic