CASY 8-K
Caseys General Stores Inc (CASY)
8-K
2026-06-24
For: 2026-06-24
View Original
Added on
June 24, 2026
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the
Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): June 24, 2026
(Exact name of registrant as specified in its charter)
|
(State or other jurisdiction of incorporation)
|
|
|
|
|
|
(Commission File Number)
|
(I.R.S. Employer Identification Number)
|
(Address of principal executive offices)
(Zip Code)
(Registrant's telephone number, including area code)
NONE
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
|
|
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425)
|
|
|
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12)
|
|
|
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))
|
|
|
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))
|
Securities registered pursuant to Section 12(b) of the Exchange Act:
|
Title of each class
|
Trading Symbol(s)
|
Name of each exchange on which registered
|
|
|
|
|
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (230.405 of this chapter) or Rule 12b-2 of
the Securities Exchange Act of 1934 (§240.12b-2 of this chapter). ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised
financial accounting standards provided pursuant to Section 13(a) of the Exchange Act ☐
| Item 7.01. |
Regulation FD Disclosure
|
As previously announced, on June 24, 2026, Casey's General Stores, Inc. will host its 2026 Investor Day in New York City. A copy of the presentation that will be utilized
during the event is attached as Exhibit 99.1 and is incorporated herein by reference.
The information contained in this Item, including the presentation attached as Exhibit 99.1, is being furnished and shall not be deemed “filed” for purposes of Section 18
of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities of that Section, and shall not be incorporated by reference into any registration statement or other document filed under the Securities Act of 1933, as
amended, or the Exchange Act, except as shall be expressly set forth by specific reference in such filing.
| Item 9.01. |
Financial Statements and Exhibits
|
| (d) |
Exhibits.
|
|
Exhibit No.
|
Description
|
|
2026 Investor Day Presentation dated June 24, 2026
|
|
|
104
|
Cover Page Interactive Data File (embedded within the Inline XBRL document)
|
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the
undersigned, hereunto duly authorized.
|
CASEY'S GENERAL STORES, INC.
|
||
|
Dated: June 24, 2026
|
By:
|
/s/ Stephen P. Bramlage, Jr.
|
|
Stephen P. Bramlage Jr.
|
||
|
Chief Financial Officer
|
||
Exhibit 99.1
INVESTOR DAY June 24 2026 Exhibit 99.1
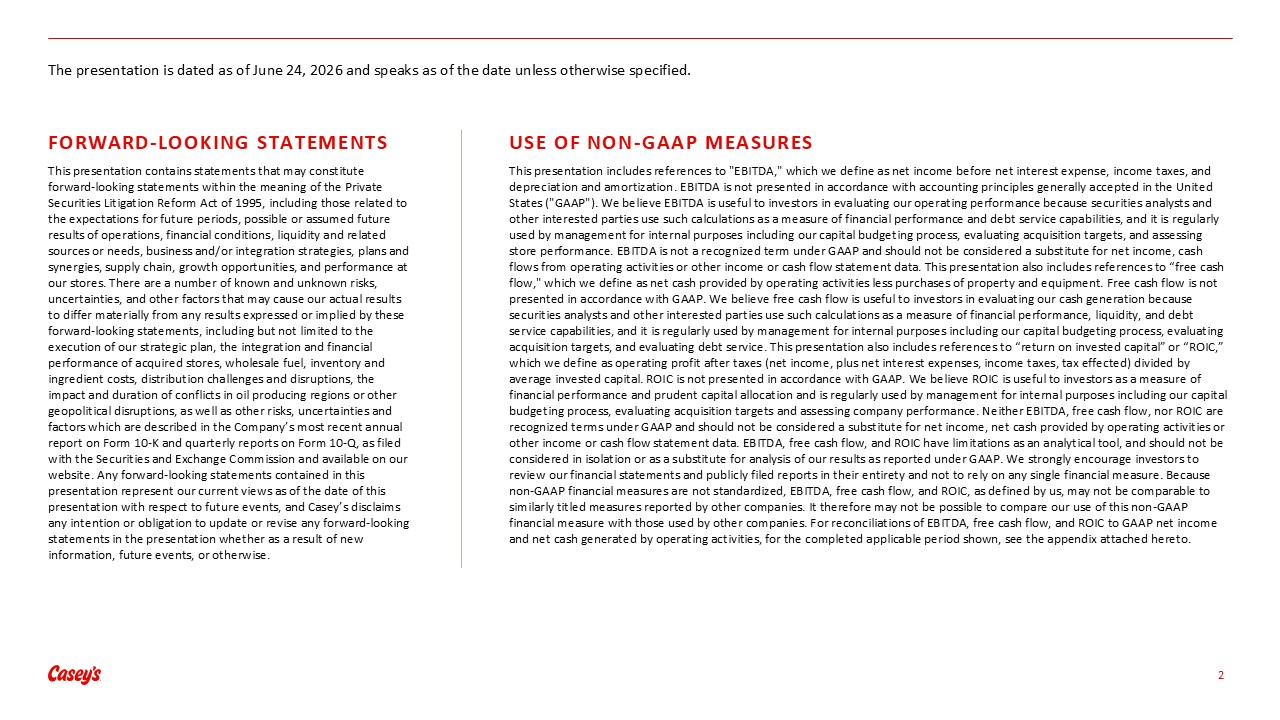
2 The presentation is dated as of June 24, 2026 and speaks as of the date unless
otherwise specified. FORWARD-LOOKING STATEMENTS This presentation contains statements that may constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995, including those related to the
expectations for future periods, possible or assumed future results of operations, financial conditions, liquidity and related sources or needs, business and/or integration strategies, plans and synergies, supply chain, growth opportunities, and
performance at our stores. There are a number of known and unknown risks, uncertainties, and other factors that may cause our actual results to differ materially from any results expressed or implied by these forward-looking statements, including
but not limited to the execution of our strategic plan, the integration and financial performance of acquired stores, wholesale fuel, inventory and ingredient costs, distribution challenges and disruptions, the impact and duration of conflicts in
oil producing regions or other geopolitical disruptions, as well as other risks, uncertainties and factors which are described in the Company’s most recent annual report on Form 10-K and quarterly reports on Form 10-Q, as filed with the
Securities and Exchange Commission and available on our website. Any forward-looking statements contained in this presentation represent our current views as of the date of this presentation with respect to future events, and Casey’s disclaims
any intention or obligation to update or revise any forward-looking statements in the presentation whether as a result of new information, future events, or otherwise. USE OF NON-GAAP MEASURES This presentation includes references to "EBITDA,"
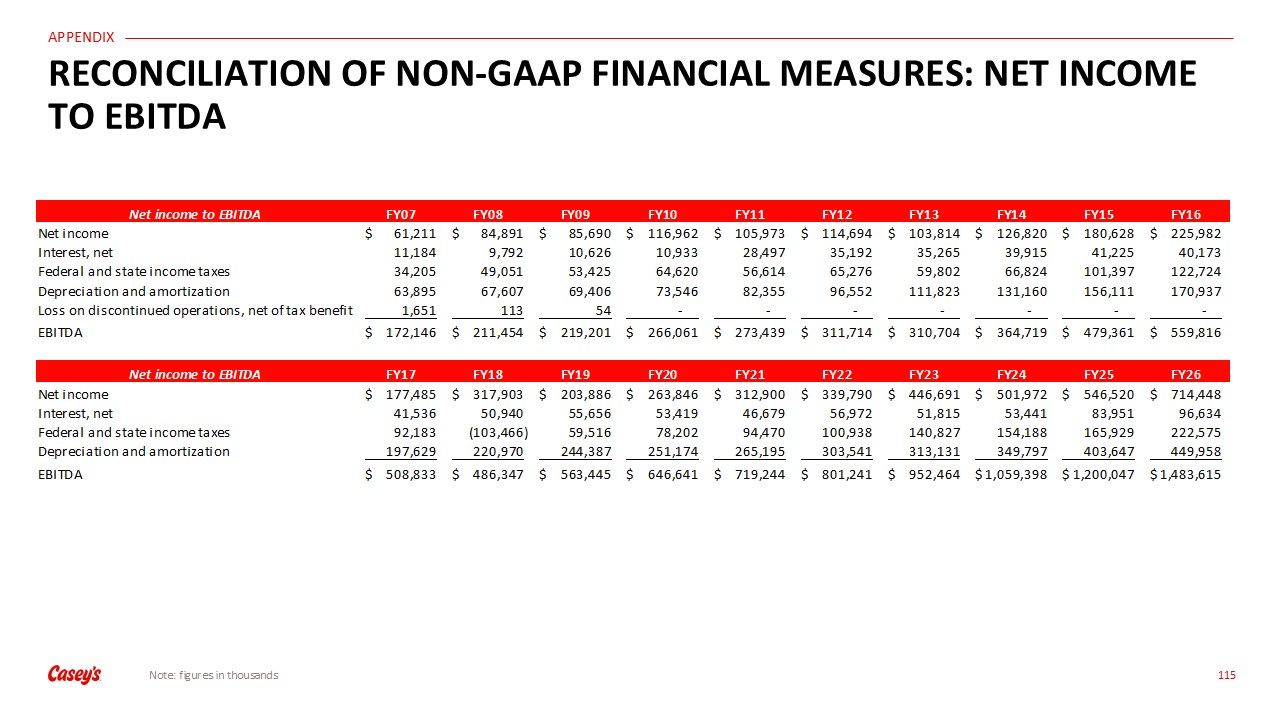
which we define as net income before net interest expense, income taxes, and depreciation and amortization. EBITDA is not presented in accordance with accounting principles generally accepted in the United States ("GAAP"). We believe EBITDA is
useful to investors in evaluating our operating performance because securities analysts and other interested parties use such calculations as a measure of financial performance and debt service capabilities, and it is regularly used by management
for internal purposes including our capital budgeting process, evaluating acquisition targets, and assessing store performance. EBITDA is not a recognized term under GAAP and should not be considered a substitute for net income, cash flows from
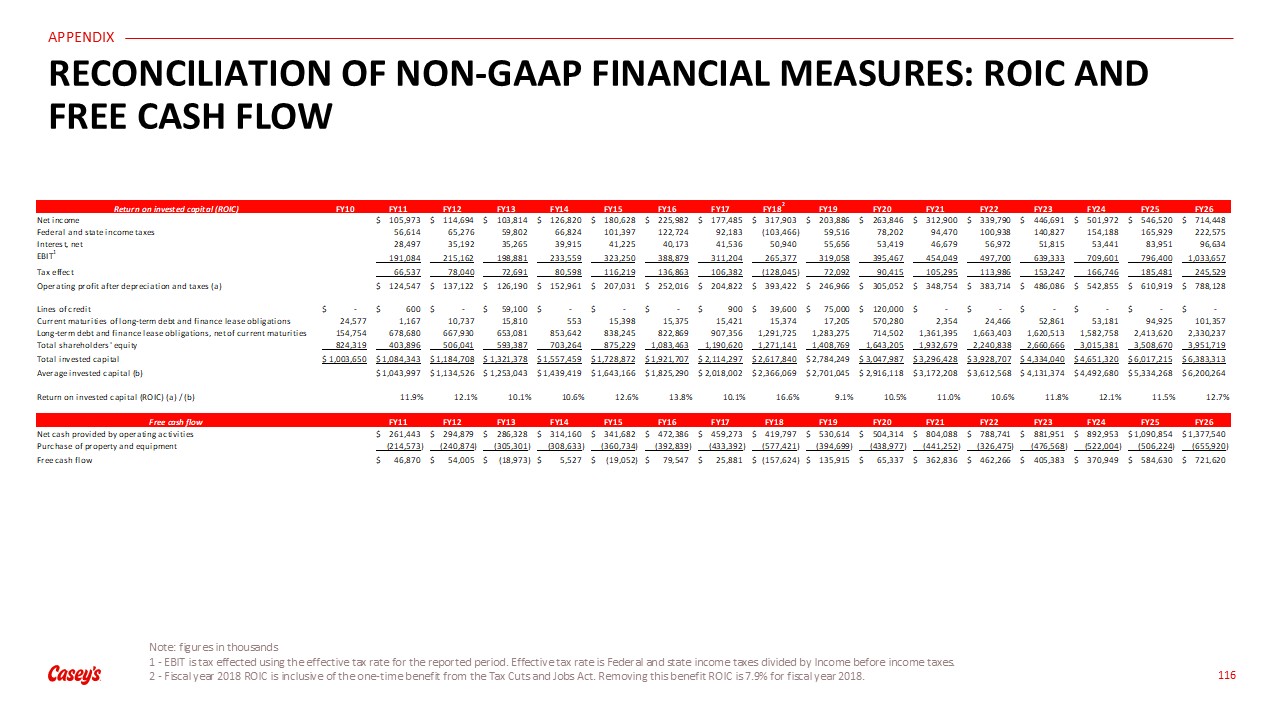
operating activities or other income or cash flow statement data. This presentation also includes references to “free cash flow," which we define as net cash provided by operating activities less purchases of property and equipment. Free cash
flow is not presented in accordance with GAAP. We believe free cash flow is useful to investors in evaluating our cash generation because securities analysts and other interested parties use such calculations as a measure of financial
performance, liquidity, and debt service capabilities, and it is regularly used by management for internal purposes including our capital budgeting process, evaluating acquisition targets, and evaluating debt service. This presentation also
includes references to “return on invested capital” or “ROIC,” which we define as operating profit after taxes (net income, plus net interest expenses, income taxes, tax effected) divided by average invested capital. ROIC is not presented in
accordance with GAAP. We believe ROIC is useful to investors as a measure of financial performance and prudent capital allocation and is regularly used by management for internal purposes including our capital budgeting process, evaluating
acquisition targets and assessing company performance. Neither EBITDA, free cash flow, nor ROIC are recognized terms under GAAP and should not be considered a substitute for net income, net cash provided by operating activities or other income or
cash flow statement data. EBITDA, free cash flow, and ROIC have limitations as an analytical tool, and should not be considered in isolation or as a substitute for analysis of our results as reported under GAAP. We strongly encourage investors to
review our financial statements and publicly filed reports in their entirety and not to rely on any single financial measure. Because non-GAAP financial measures are not standardized, EBITDA, free cash flow, and ROIC, as defined by us, may not be
comparable to similarly titled measures reported by other companies. It therefore may not be possible to compare our use of this non-GAAP financial measure with those used by other companies. For reconciliations of EBITDA, free cash flow, and
ROIC to GAAP net income and net cash generated by operating activities, for the completed applicable period shown, see the appendix attached hereto.

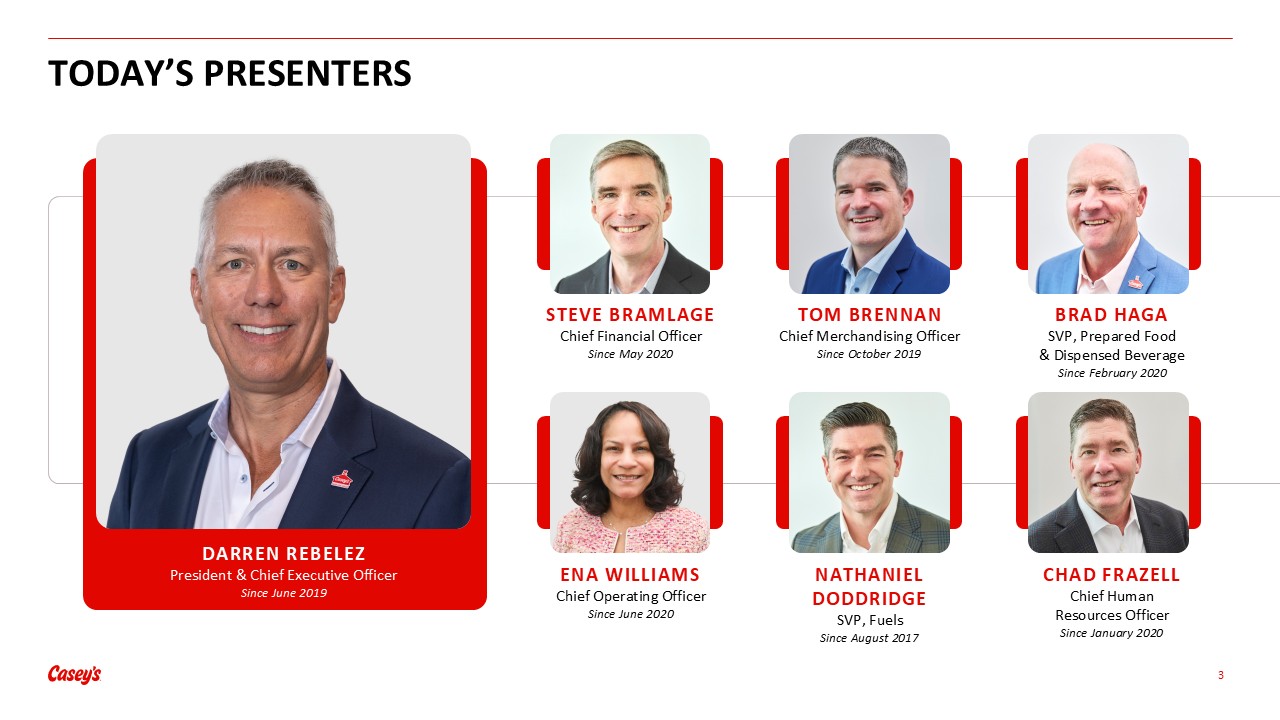
3 TODAY’S PRESENTERS DARREN REBELEZ President & Chief Executive
Officer Since June 2019 STEVE BRAMLAGE Chief Financial Officer Since May 2020 TOM BRENNAN Chief Merchandising Officer Since October 2019 ENA WILLIAMS Chief Operating Officer Since June 2020 BRAD HAGA SVP, Prepared Food & Dispensed
Beverage Since February 2020 CHAD FRAZELL Chief Human Resources Officer Since January 2020 NATHANIEL DODDRIDGE SVP, Fuels Since August 2017

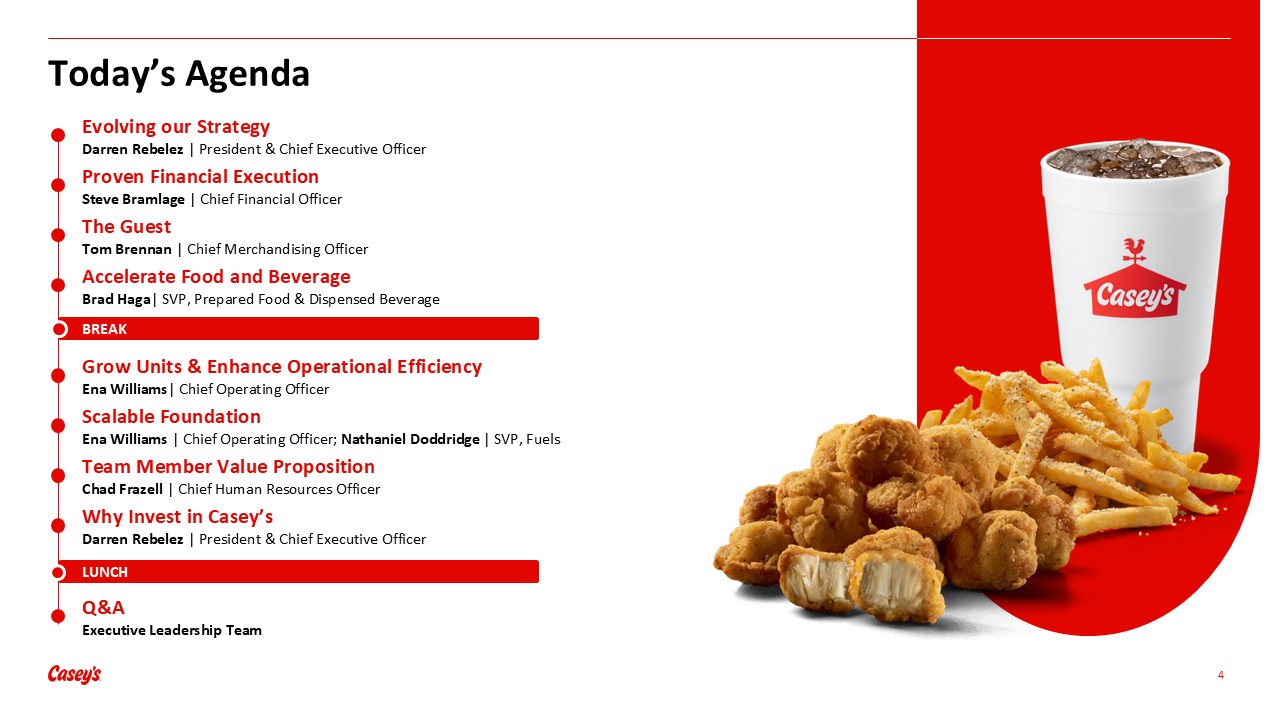
4 Today’s Agenda Evolving our Strategy Darren Rebelez | President & Chief
Executive Officer Q&A Executive Leadership Team Scalable Foundation Ena Williams | Chief Operating Officer; Nathaniel Doddridge | SVP, Fuels Accelerate Food and Beverage Brad Haga| SVP, Prepared Food & Dispensed Beverage Grow Units
& Enhance Operational Efficiency Ena Williams| Chief Operating Officer Proven Financial Execution Steve Bramlage | Chief Financial Officer Team Member Value Proposition Chad Frazell | Chief Human Resources Officer Why Invest in
Casey’s Darren Rebelez | President & Chief Executive Officer The Guest Tom Brennan | Chief Merchandising Officer BREAK LUNCH

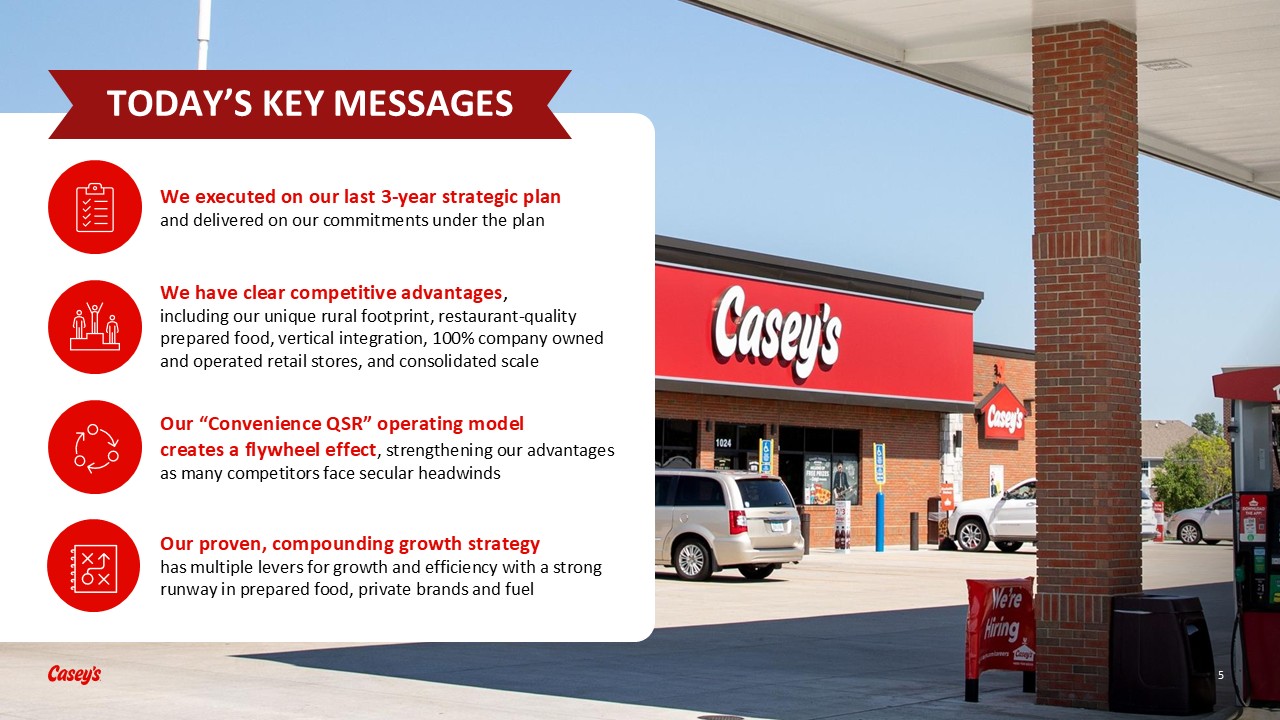
Our proven, compounding growth strategy has multiple levers for growth and
efficiency with a strong runway in prepared food, private brands and fuel Our “Convenience QSR” operating model creates a flywheel effect, strengthening our advantages as many competitors face secular headwinds We have clear competitive
advantages, including our unique rural footprint, restaurant-quality prepared food, vertical integration, 100% company owned and operated retail stores, and consolidated scale We executed on our last 3-year strategic plan and delivered on our
commitments under the plan TODAY’S KEY MESSAGES 5

6 EVOLVING OUR STRATEGY DARREN REBELEZ PRESIDENT & CHIEF EXECUTIVE OFFICER

AN INTRODUCTION TO CASEY’S 7

Note: Market data, number of locations, transactions, team members as of April 30,
2026. 1 - Inside is defined as the combination of grocery and general merchandise and prepared food and dispensed beverage. Same-store sales is defined as the total sales increase (or decrease) for stores open during the full time of the
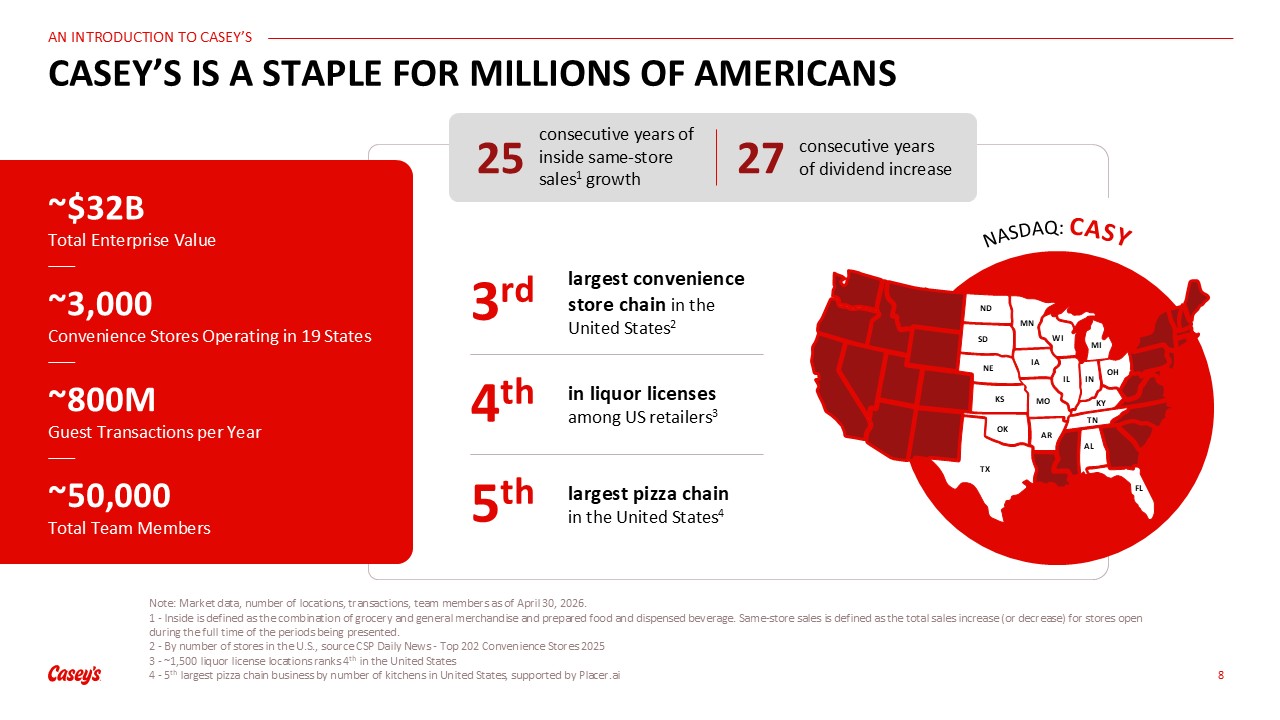
periods being presented. 2 - By number of stores in the U.S., source CSP Daily News - Top 202 Convenience Stores 2025 3 - ~1,500 liquor license locations ranks 4th in the United States 4 - 5th largest pizza chain business by number of kitchens
in United States, supported by Placer.ai 8 CASEY’S IS A STAPLE FOR MILLIONS OF AMERICANS 3rd largest convenience store chain in the United States2 4th in liquor licenses among US retailers3 5th largest pizza chain in the United
States4 NASDAQ: CASY ND SD WI MN IA NE IN OH IL KY KS MO OK TN TX AR AL FL MI ~$32B Total Enterprise Value ~3,000 Convenience Stores Operating in 19 States ~800M Guest Transactions per Year ~50,000 Total Team
Members 25 consecutive years of inside same-store sales1 growth 27 consecutive years of dividend increase

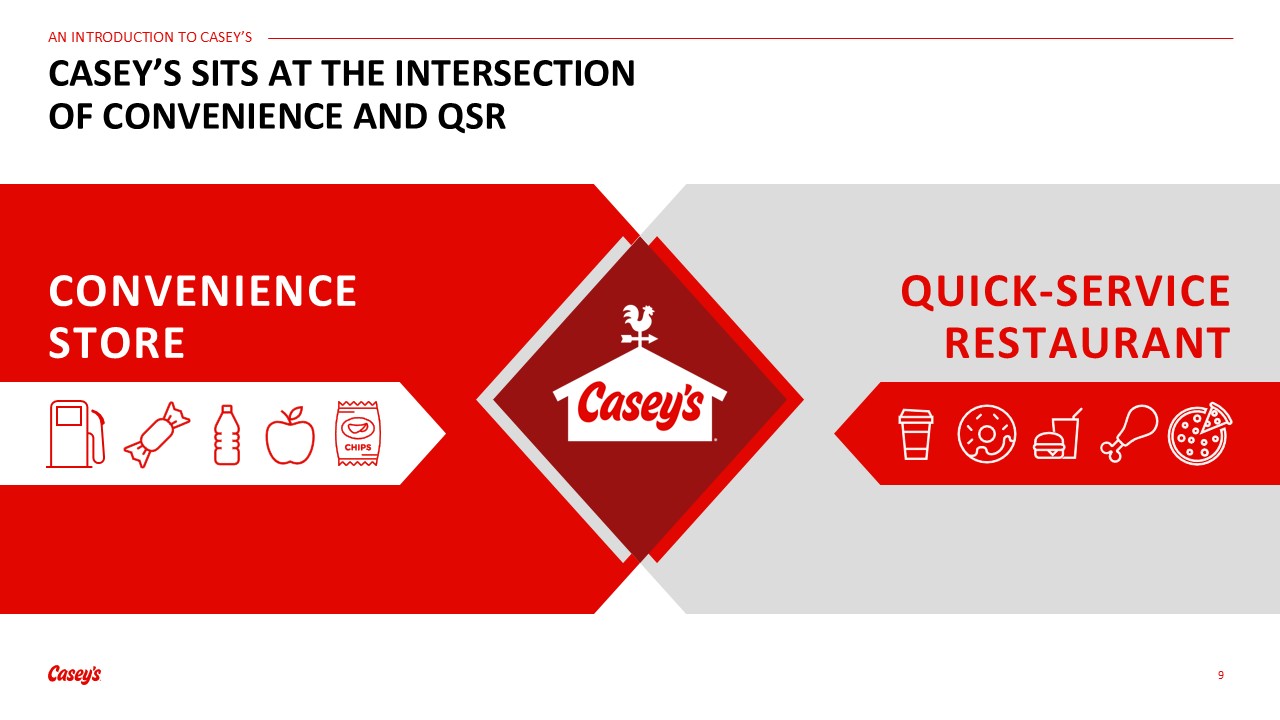
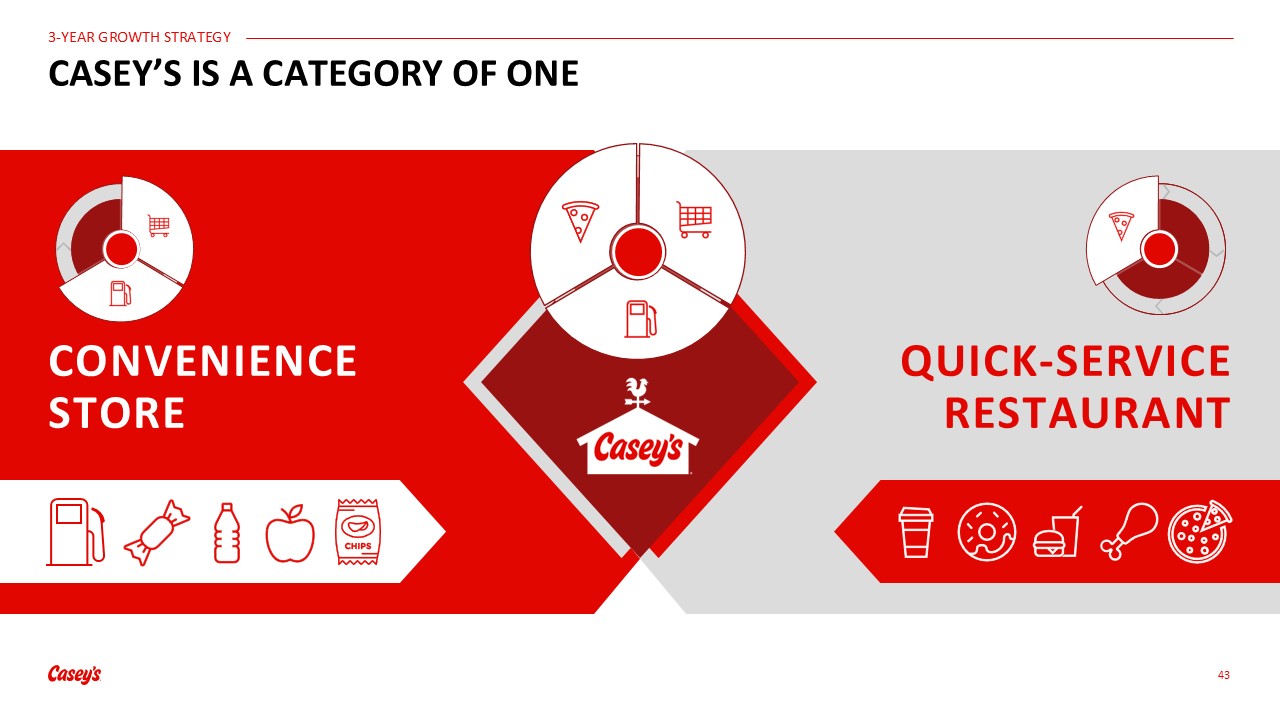
9 CASEY’S SITS AT THE INTERSECTION OF CONVENIENCE AND QSR CONVENIENCE
STORE QUICK-SERVICE RESTAURANT

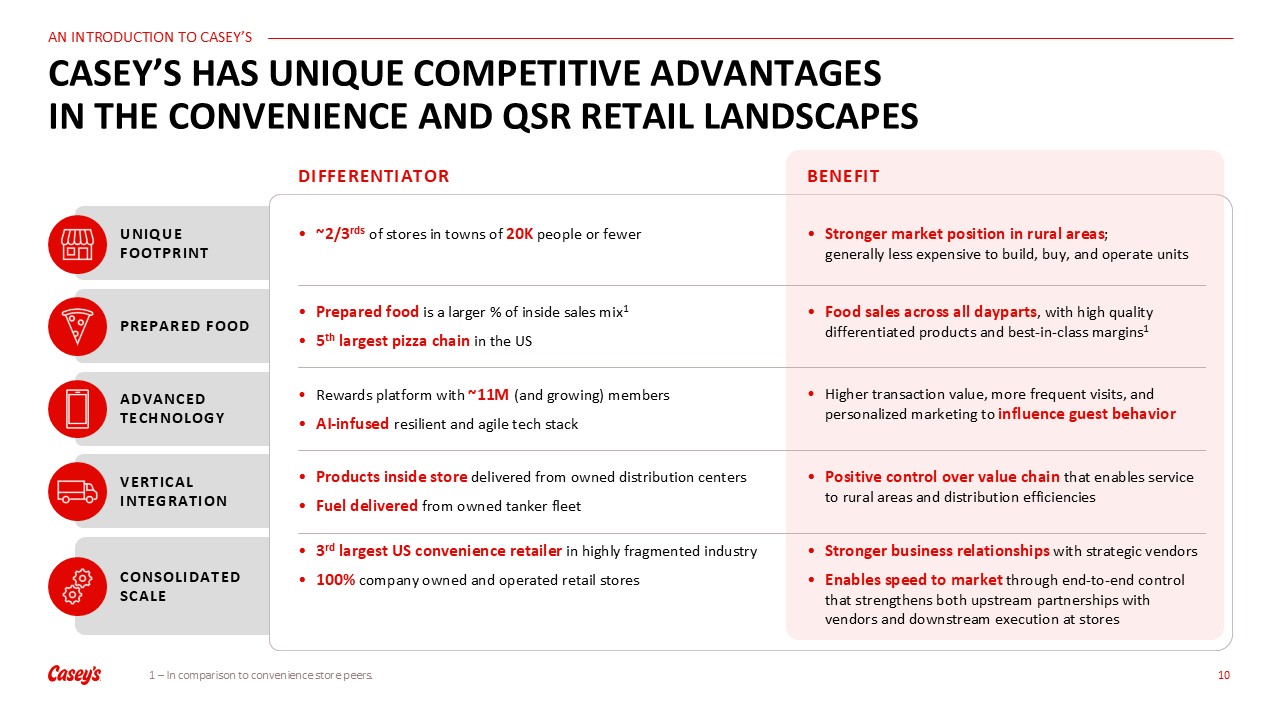
CASEY’S HAS UNIQUE COMPETITIVE ADVANTAGES IN THE CONVENIENCE AND QSR RETAIL
LANDSCAPES 10 DIFFERENTIATOR BENEFIT UNIQUE FOOTPRINT ~2/3rds of stores in towns of 20K people or fewer Stronger market position in rural areas; generally less expensive to build, buy, and operate units PREPARED FOOD Prepared food is a
larger % of inside sales mix1 5th largest pizza chain in the US Food sales across all dayparts, with high quality differentiated products and best-in-class margins1 ADVANCED TECHNOLOGY Rewards platform with ~11M (and growing)
members AI-infused resilient and agile tech stack Higher transaction value, more frequent visits, and personalized marketing to influence guest behavior VERTICAL INTEGRATION Products inside store delivered from owned distribution centers
Fuel delivered from owned tanker fleet Positive control over value chain that enables service to rural areas and distribution efficiencies CONSOLIDATED SCALE 3rd largest US convenience retailer in highly fragmented industry 100% company
owned and operated retail stores Stronger business relationships with strategic vendors Enables speed to market through end-to-end control that strengthens both upstream partnerships with vendors and downstream execution at stores 1 – In
comparison to convenience store peers.

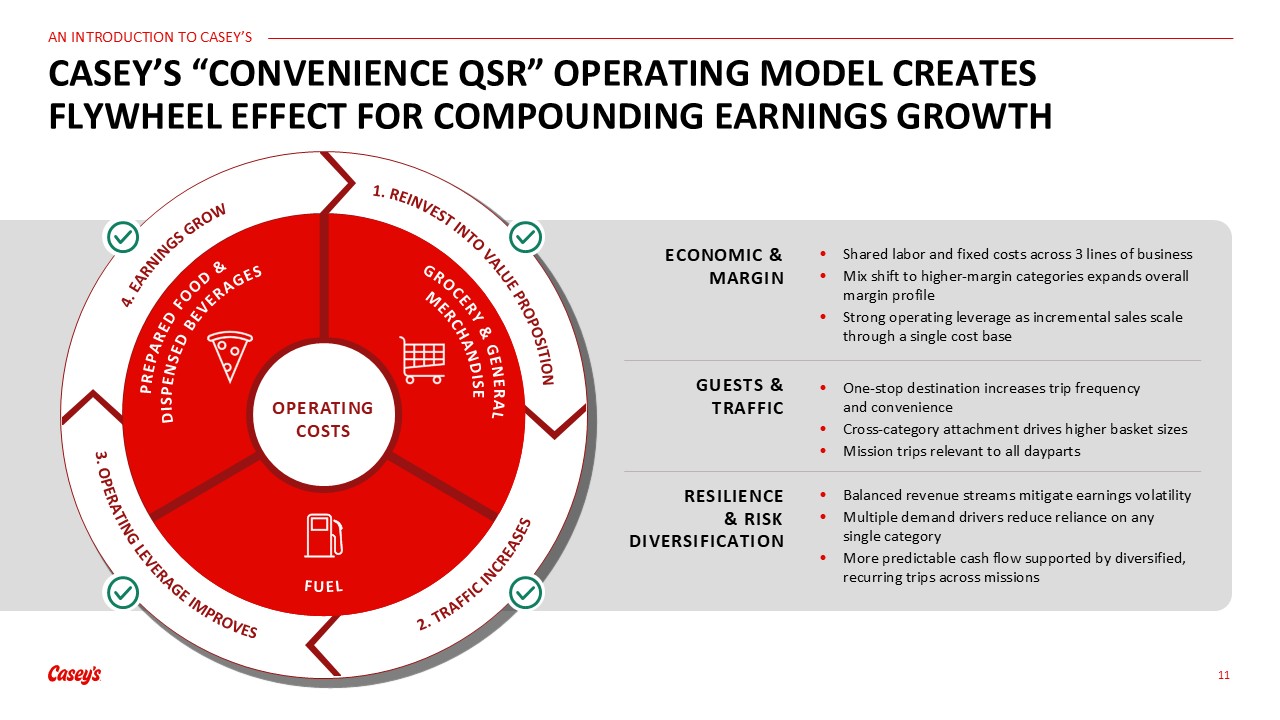
11 CASEY’S “CONVENIENCE QSR” OPERATING MODEL CREATES FLYWHEEL EFFECT FOR
COMPOUNDING EARNINGS GROWTH ECONOMIC & MARGIN Shared labor and fixed costs across 3 lines of business Mix shift to higher-margin categories expands overall margin profile Strong operating leverage as incremental sales scale through a
single cost base GUESTS & TRAFFIC One-stop destination increases trip frequency and convenience Cross-category attachment drives higher basket sizes Mission trips relevant to all dayparts RESILIENCE & RISK DIVERSIFICATION Balanced
revenue streams mitigate earnings volatility Multiple demand drivers reduce reliance on any single category More predictable cash flow supported by diversified, recurring trips across missions 3. OPERATING LEVERAGE IMPROVES 4. EARNINGS
GROW 1. REINVEST INTO VALUE PROPOSITION 2. TRAFFIC INCREASES PREPARED FOOD &DISPENSED BEVERAGES GROCERY & GENERAL MERCHANDISE FUEL OPERATINGCOSTS

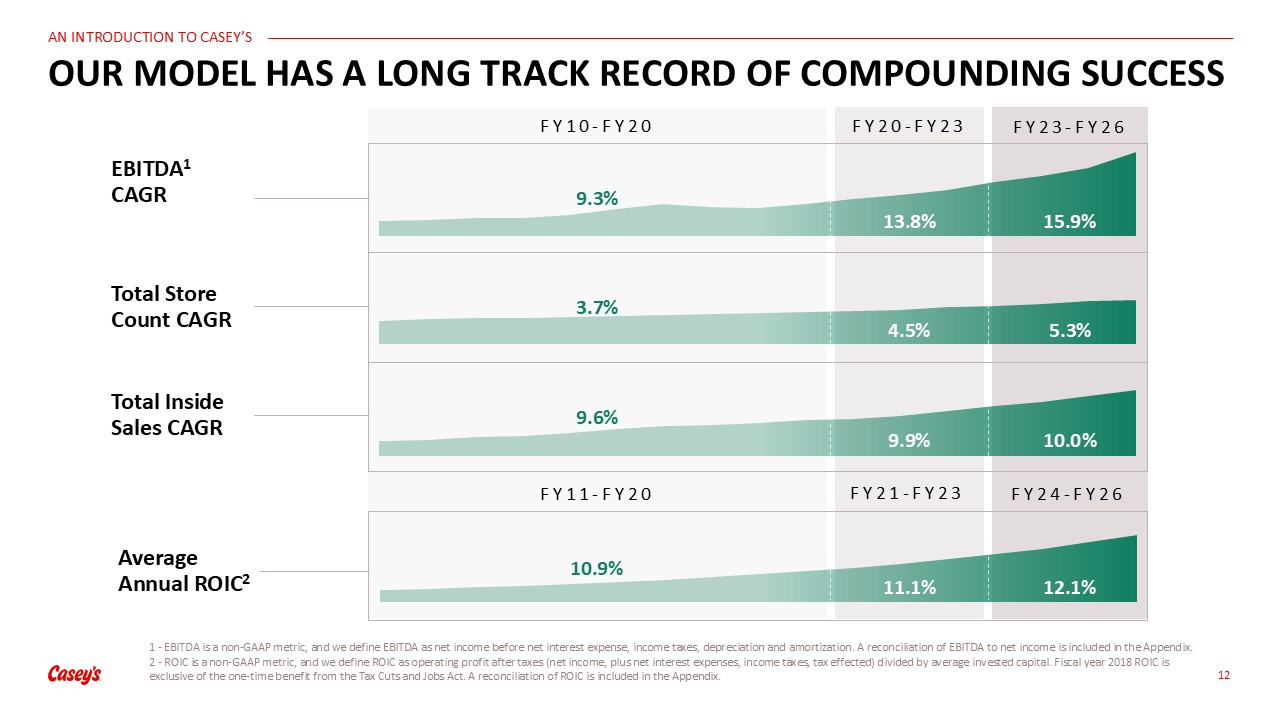
12 1 - EBITDA is a non-GAAP metric, and we define EBITDA as net income before net
interest expense, income taxes, depreciation and amortization. A reconciliation of EBITDA to net income is included in the Appendix. 2 - ROIC is a non-GAAP metric, and we define ROIC as operating profit after taxes (net income, plus net interest
expenses, income taxes, tax effected) divided by average invested capital. Fiscal year 2018 ROIC is exclusive of the one-time benefit from the Tax Cuts and Jobs Act. A reconciliation of ROIC is included in the Appendix. OUR MODEL HAS A LONG
TRACK RECORD OF COMPOUNDING SUCCESS EBITDA1 CAGR Total Store Count CAGR Total Inside Sales CAGR Average Annual
ROIC2 FY10-FY20 9.3% 3.7% 9.6% 10.9% FY20-FY23 13.8% 4.5% 9.9% 11.1% FY23-FY26 15.9% 5.3% 10.0% 12.1% FY11-FY20 FY21-FY23 FY24-FY26

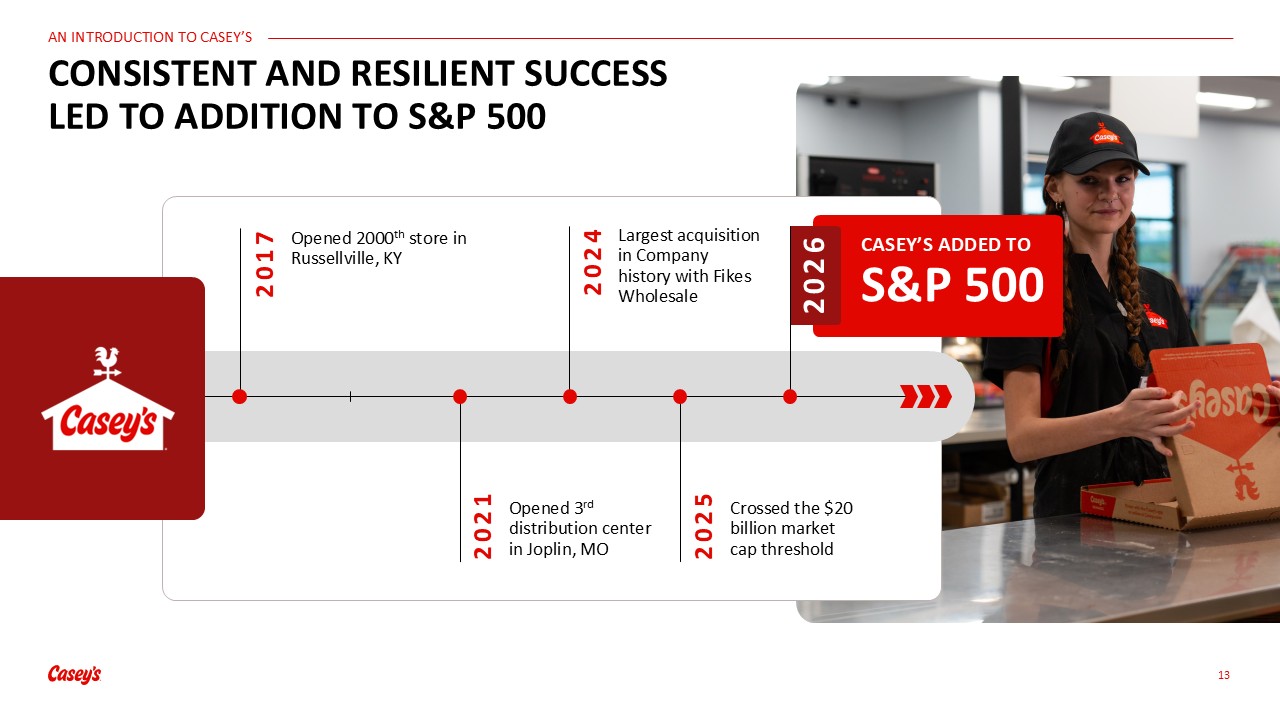
13 CONSISTENT AND RESILIENT SUCCESS LED TO ADDITION TO S&P 500 z 2017 Opened
2000th store in Russellville, KY 2024 Largest acquisition in Company history with Fikes Wholesale 2025 Crossed the $20 billion market cap threshold 2026 CASEY’S ADDED TO S&P 500 2021 Opened 3rd distribution center in Joplin, MO

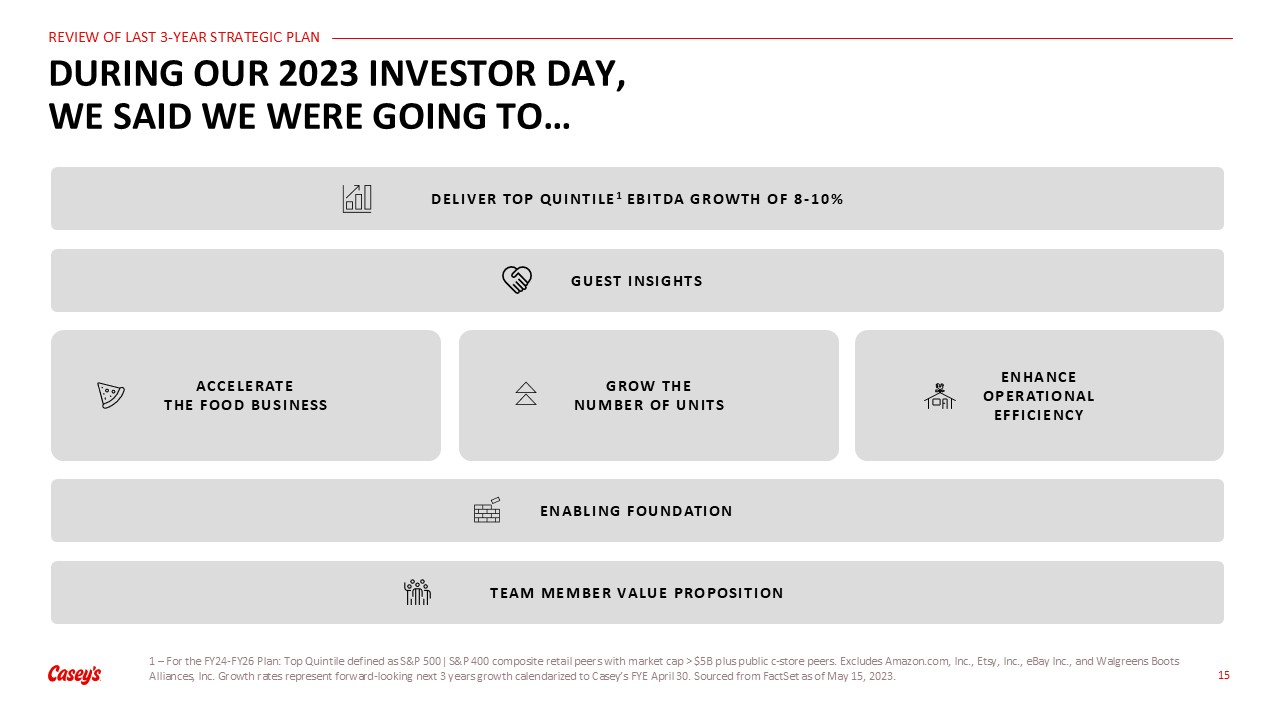
REVIEW OF LAST 3-YEAR STRATEGIC PLAN 14

guest insights Deliver top quintile1 EBITDA growth of 8-10% 1 – For the FY24-FY26
Plan: Top Quintile defined as S&P 500 ǀ S&P 400 composite retail peers with market cap > $5B plus public c-store peers. Excludes Amazon.com, Inc., Etsy, Inc., eBay Inc., and Walgreens Boots Alliances, Inc. Growth rates represent
forward-looking next 3 years growth calendarized to Casey’s FYE April 30. Sourced from FactSet as of May 15, 2023. 15 DURING OUR 2023 INVESTOR DAY, WE SAID WE WERE GOING TO… Team Member Value Proposition Enabling Foundation ENHANCE
OPERATIONALEFFICIENCY GROW THE NUMBER OF UNITS ACCELERATETHE FOOD BUSINESS

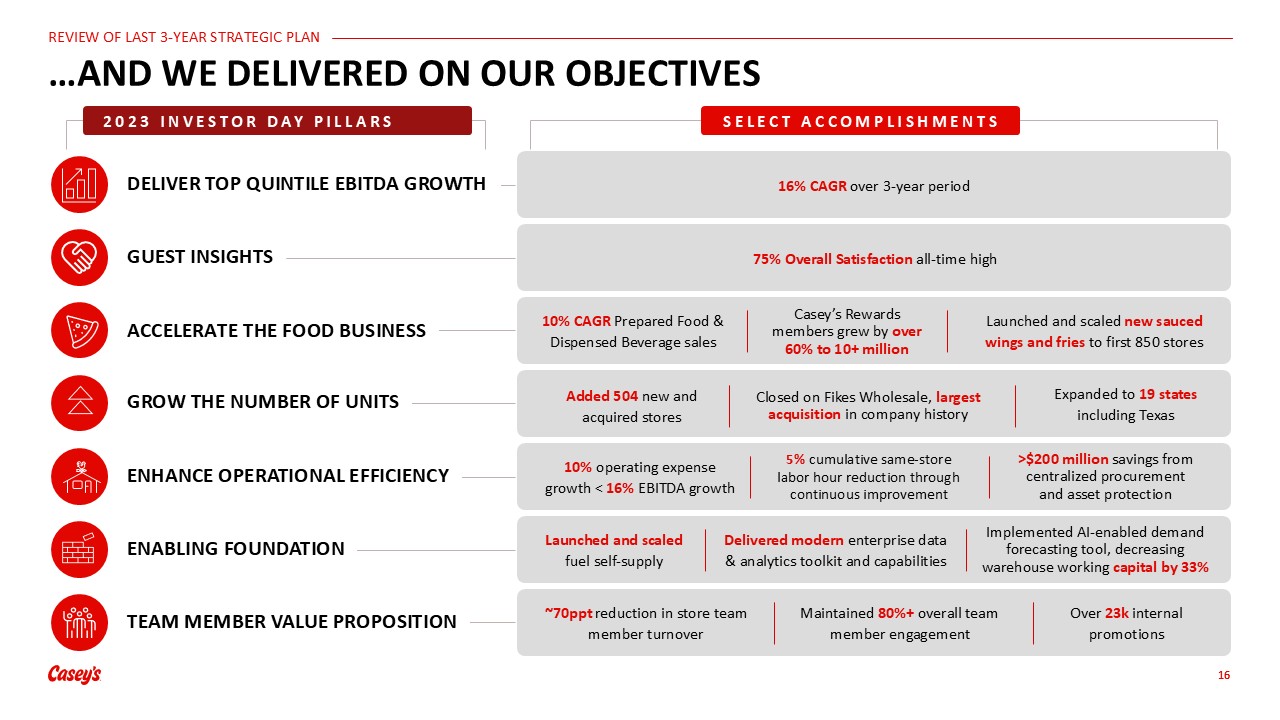
16 …AND WE DELIVERED ON OUR OBJECTIVES 16 ENABLING FOUNDATION Launched and
scaled fuel self-supply Delivered modern enterprise data & analytics toolkit and capabilities Implemented AI-enabled demand forecasting tool, decreasing warehouse working capital by 33% GROW THE NUMBER OF UNITS Added 504 new and acquired
stores Closed on Fikes Wholesale, largest acquisition in company history Expanded to 19 states including Texas DELIVER TOP QUINTILE EBITDA GROWTH 16% CAGR over 3-year period 2023 INVESTOR DAY PILLARS SELECT ACCOMPLISHMENTS ACCELERATE THE
FOOD BUSINESS 10% CAGR Prepared Food & Dispensed Beverage sales Casey’s Rewards members grew by over 60% to 10+ million Launched and scaled new sauced wings and fries to first 850 stores TEAM MEMBER VALUE PROPOSITION ~70ppt reduction in
store team member turnover Maintained 80%+ overall team member engagement Over 23k internal promotions ENHANCE OPERATIONAL EFFICIENCY 10% operating expense growth < 16% EBITDA growth 5% cumulative same-store labor hour reduction through
continuous improvement >$200 million savings from centralized procurement and asset protection GUEST INSIGHTS 75% Overall Satisfaction all-time high

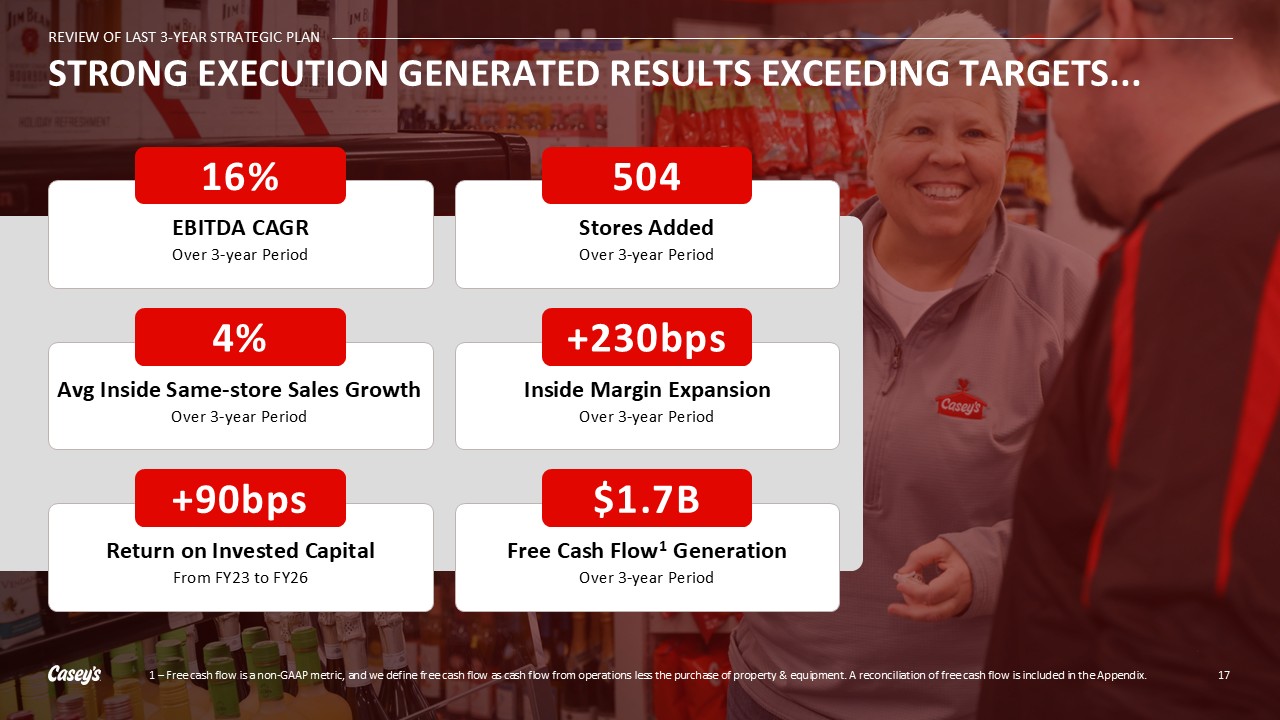
STRONG EXECUTION GENERATED RESULTS EXCEEDING TARGETS... REVIEW OF LAST 3-YEAR
STRATEGIC PLAN 1 – Free cash flow is a non-GAAP metric, and we define free cash flow as cash flow from operations less the purchase of property & equipment. A reconciliation of free cash flow is included in the Appendix. 17 504 Stores
AddedOver 3-year Period +230bps Inside Margin ExpansionOver 3-year Period 16% EBITDA CAGROver 3-year Period 4% Avg Inside Same-store Sales GrowthOver 3-year Period +90bps Return on Invested CapitalFrom FY23 to FY26 $1.7B Free Cash Flow1
Generation Over 3-year Period

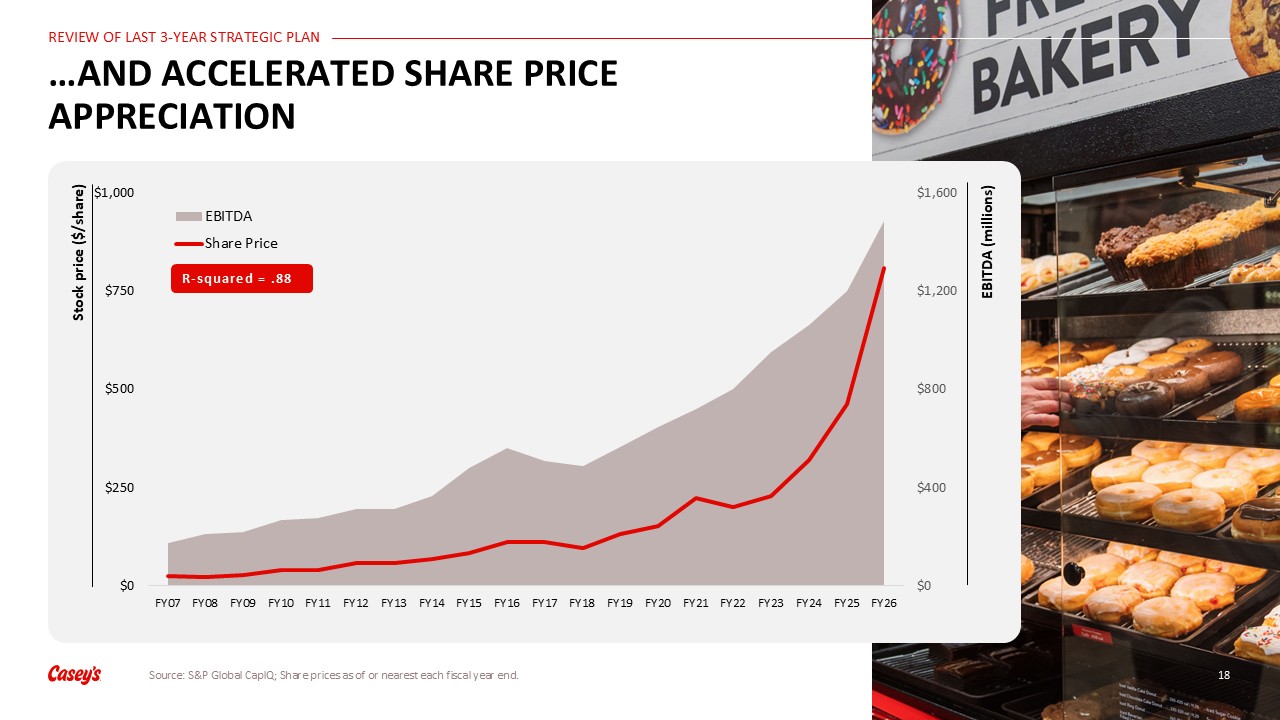
18 …AND ACCELERATED SHARE PRICE APPRECIATION R-squared = .88 Source: S&P
Global CapIQ; Share prices as of or nearest each fiscal year end.

19 INDUSTRY REVIEW 19

QSR INDUSTRY 20 PREPARED FOOD &DISPENSED BEVERAGES PREPARED FOOD
&DISPENSED BEVERAGES OPERATINGCOSTS

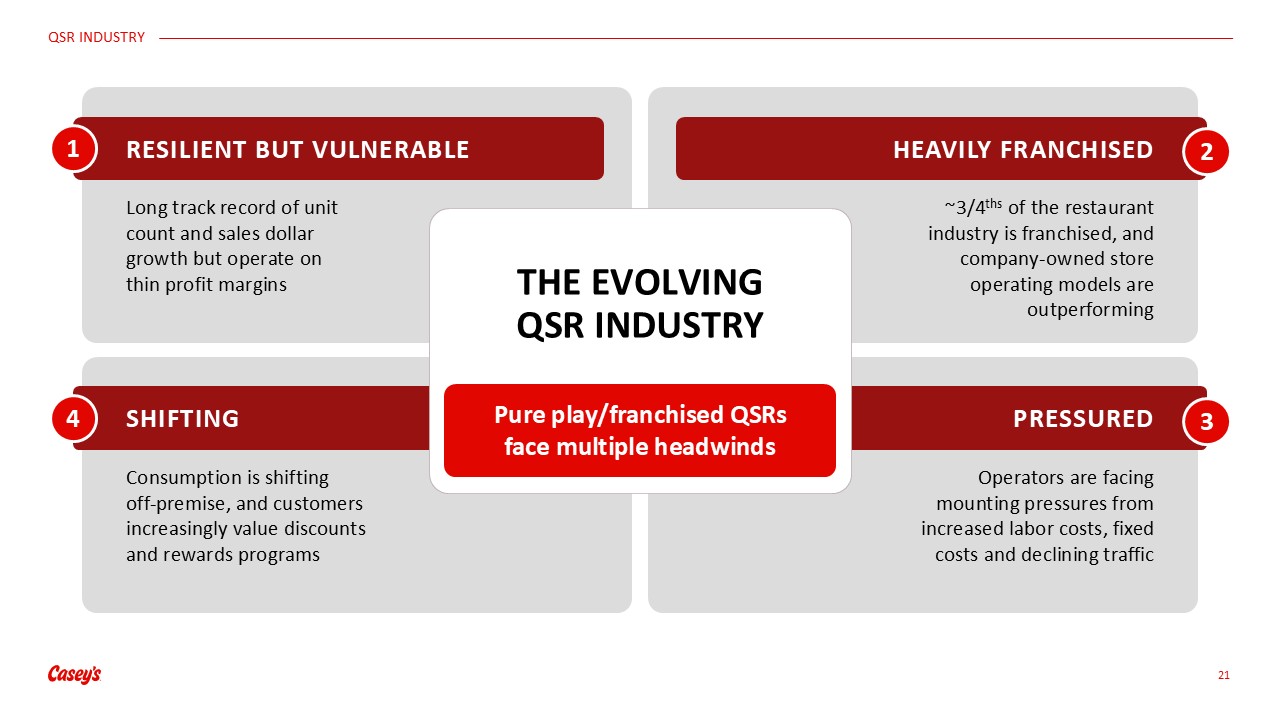
21 THE EVOLVING QSR INDUSTRY 1 RESILIENT BUT VULNERABLE Long track record of
unit count and sales dollar growth but operate on thin profit margins 2 HEAVILY FRANCHISED ~3/4ths of the restaurant industry is franchised, and company-owned store operating models are outperforming 4 SHIFTING Consumption is shifting
off-premise, and customers increasingly value discounts and rewards programs 3 PRESSURED Operators are facing mounting pressures from increased labor costs, fixed costs and declining traffic Pure play/franchised QSRs face multiple headwinds

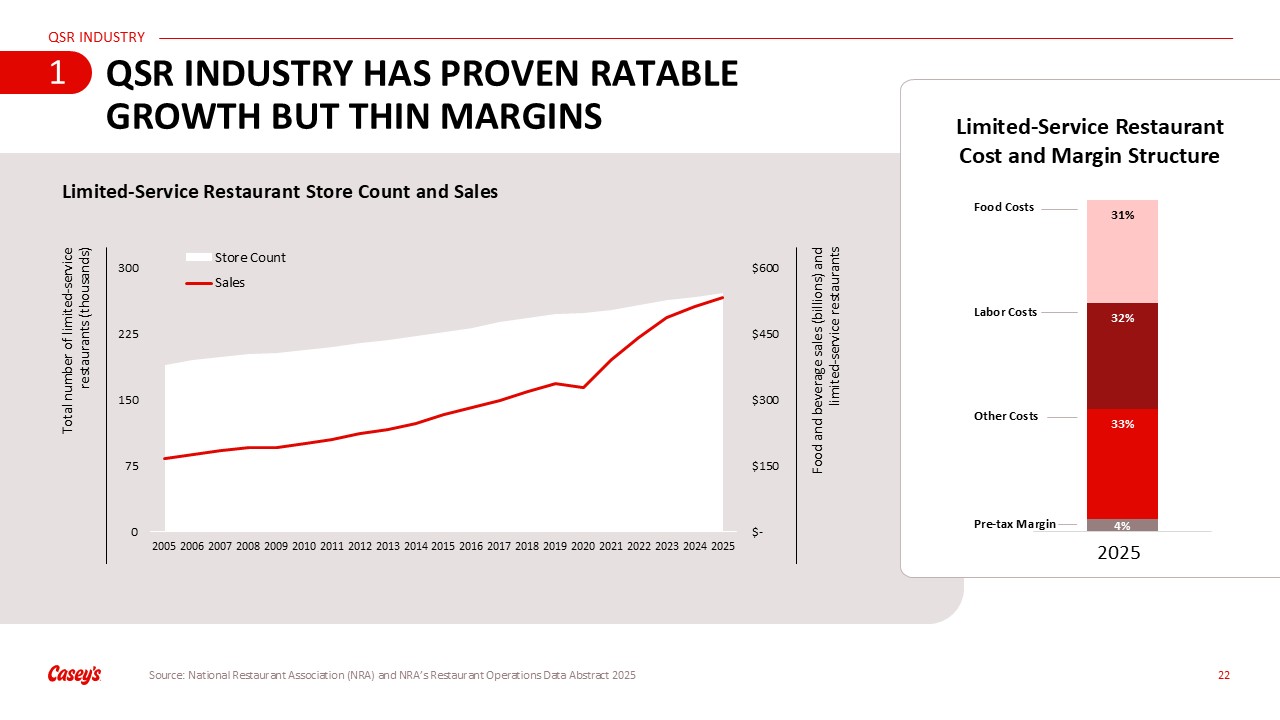
Source: National Restaurant Association (NRA) and NRA’s Restaurant Operations Data
Abstract 2025 22 QSR INDUSTRY HAS PROVEN RATABLE GROWTH BUT THIN MARGINS Limited-Service Restaurant Cost and Margin Structure Total number of limited-service restaurants (thousands) Food and beverage sales (billions) and limited-service
restaurants Food Costs Labor Costs Other Costs Pre-tax Margin 2025 1

Sources: Top 1,500 Chain Restaurants U.S. location share by ownership via Technomic
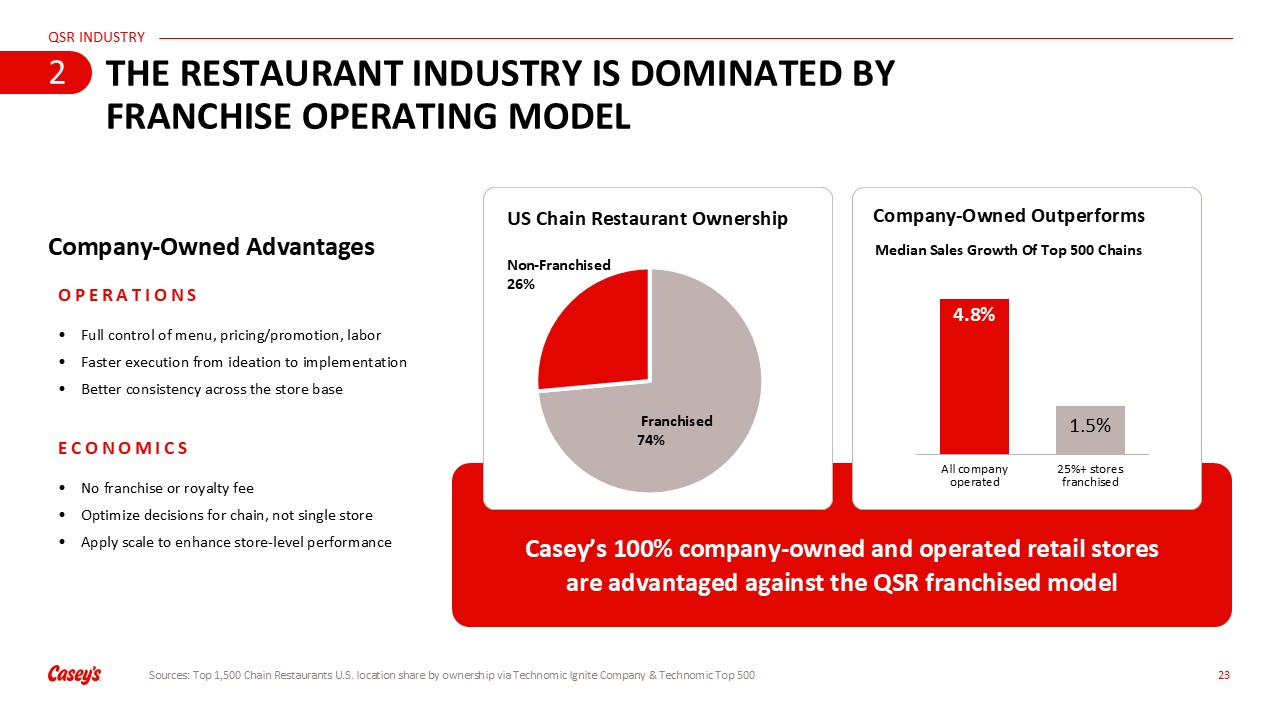
Ignite Company & Technomic Top 500 23 THE RESTAURANT INDUSTRY IS DOMINATED BY FRANCHISE OPERATING MODEL US Chain Restaurant Ownership Median Sales Growth Of Top 500 Chains Company-Owned Outperforms OPERATIONS Company-Owned
Advantages Full control of menu, pricing/promotion, labor Faster execution from ideation to implementation Better consistency across the store base Casey’s 100% company-owned and operated retail stores are advantaged against the QSR
franchised model ECONOMICS No franchise or royalty fee Optimize decisions for chain, not single store Apply scale to enhance store-level performance Non-Franchised 26% Franchised 74% 2

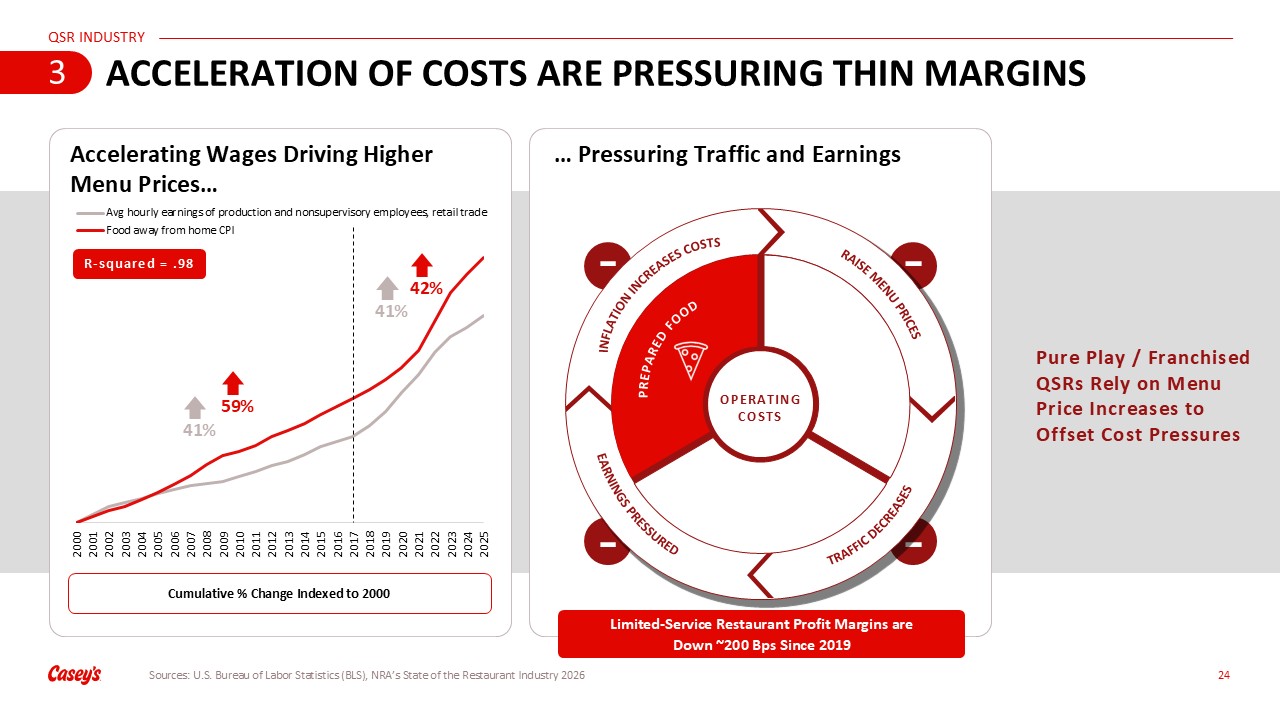
EARNINGS PRESSURED INFLATION INCREASES COSTS RAISE MENU PRICES TRAFFIC DECREASES
Accelerating Wages Driving Higher Menu Prices… R-squared = .98 Cumulative % Change Indexed to 2000 Sources: U.S. Bureau of Labor Statistics (BLS), NRA’s State of the Restaurant Industry 2026 24 ACCELERATION OF COSTS ARE PRESSURING THIN
MARGINS … Pressuring Traffic and Earnings PREPARED FOOD OPERATINGCOSTS Pure Play / Franchised QSRs Rely on Menu Price Increases to Offset Cost Pressures Limited-Service Restaurant Profit Margins are Down ~200 Bps Since
2019 41% 41% 59% 42% 3

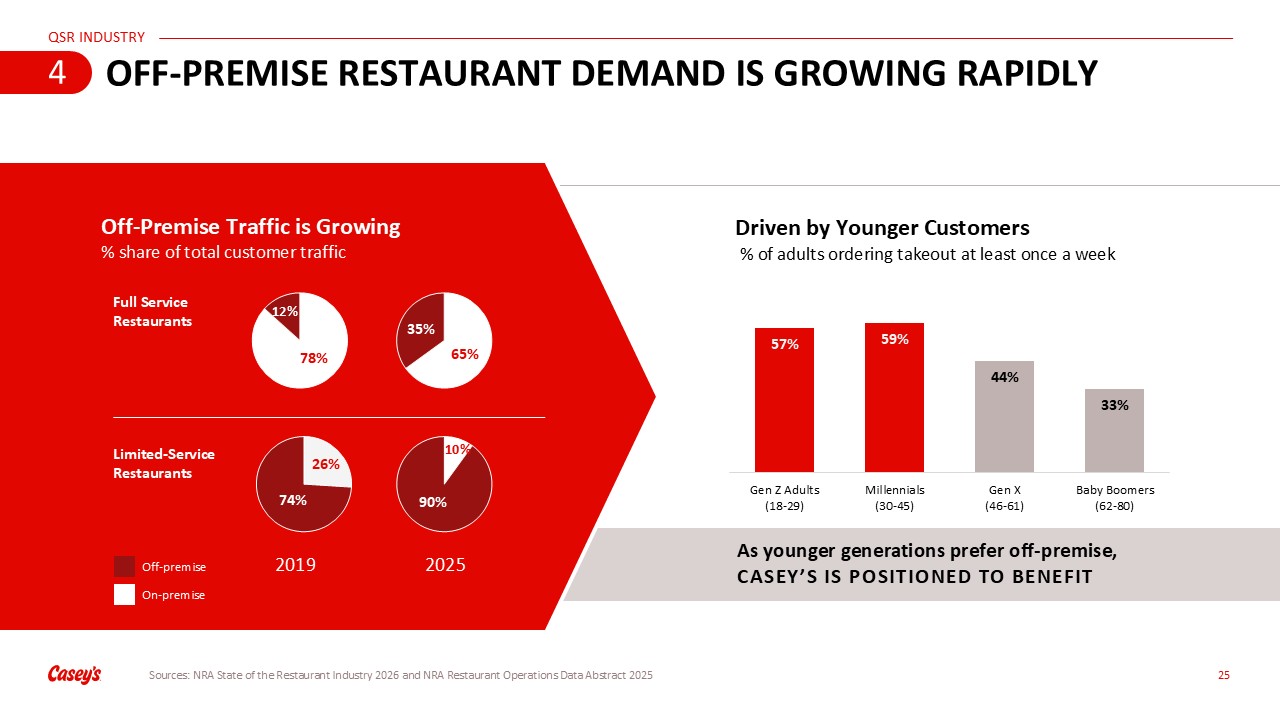
As younger generations prefer off-premise, CASEY’S IS POSITIONED TO BENEFIT
25 OFF-PREMISE RESTAURANT DEMAND IS GROWING RAPIDLY Off-Premise Traffic is Growing % share of total customer traffic 2019 2025 Full Service Restaurants Limited-Service Restaurants Off-premise On-premise Driven by Younger Customers
% of adults ordering takeout at least once a week 4 Sources: NRA State of the Restaurant Industry 2026 and NRA Restaurant Operations Data Abstract 2025

26 C-STORE INDUSTRY GROCERY & GENERAL MERCHANDISE OPERATINGCOSTS GROCERY
& GENERAL MERCHANDISE FUEL

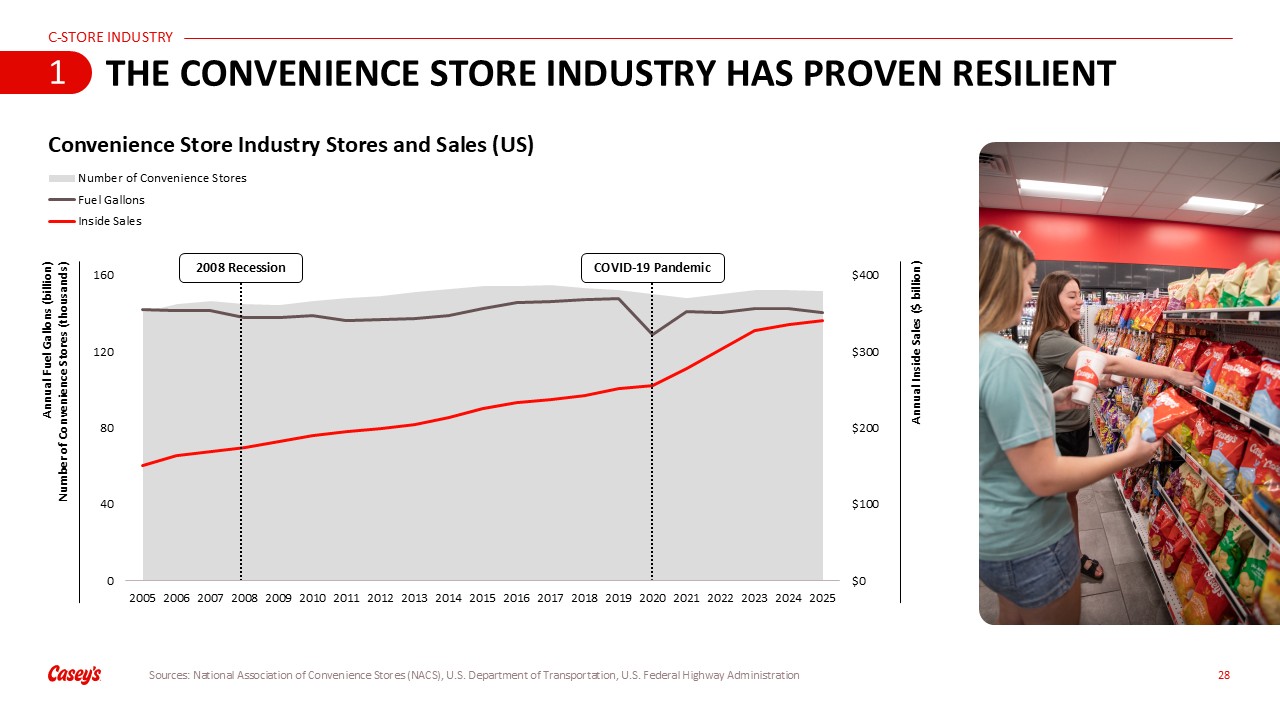
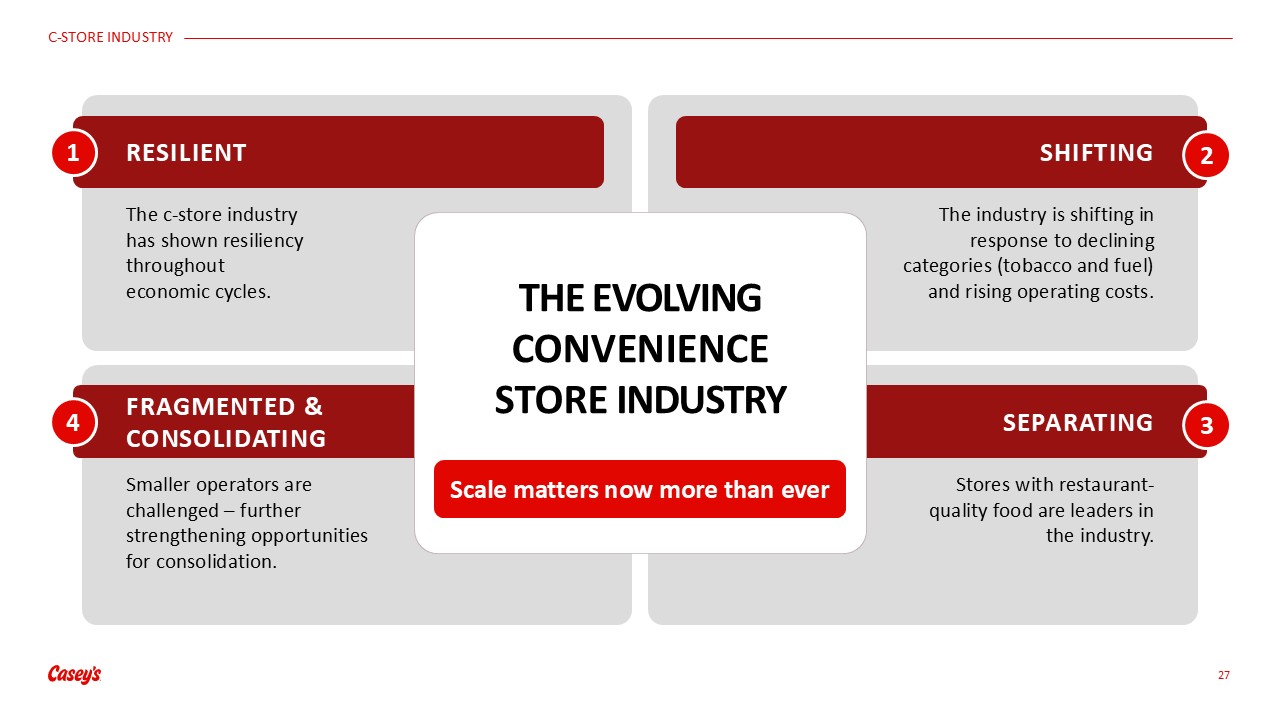
1 RESILIENT The c-store industry has shown resiliency throughout economic
cycles. 2 SHIFTING The industry is shifting in response to declining categories (tobacco and fuel) and rising operating costs. 4 FRAGMENTED & CONSOLIDATING Smaller operators are challenged – further strengthening opportunities for
consolidation. 3 SEPARATING Stores with restaurant-quality food are leaders in the industry. Scale matters now more than ever THE EVOLVING CONVENIENCE STORE INDUSTRY 27

Convenience Store Industry Stores and Sales (US) COVID-19 Pandemic 2008
Recession Annual Fuel Gallons (billion) Number of Convenience Stores (thousands) Annual Inside Sales ($ billion) 28 THE CONVENIENCE STORE INDUSTRY HAS PROVEN RESILIENT 1 Sources: National Association of Convenience Stores (NACS), U.S.
Department of Transportation, U.S. Federal Highway Administration

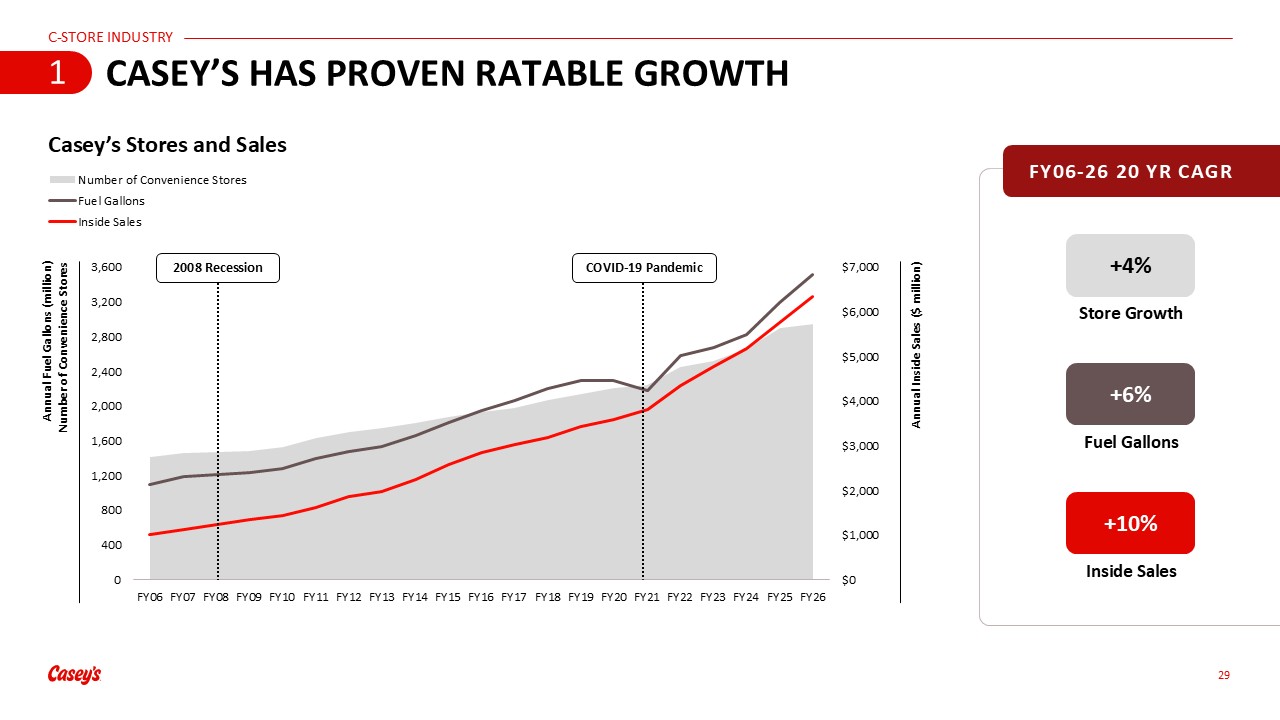
FY06-26 20 YR CAGR 29 CASEY’S HAS PROVEN RATABLE GROWTH Casey’s Stores and
Sales Annual Fuel Gallons (million) Number of Convenience Stores Annual Inside Sales ($ million) COVID-19 Pandemic 2008 Recession +10% Inside Sales +6% Fuel Gallons +4% Store Growth 1

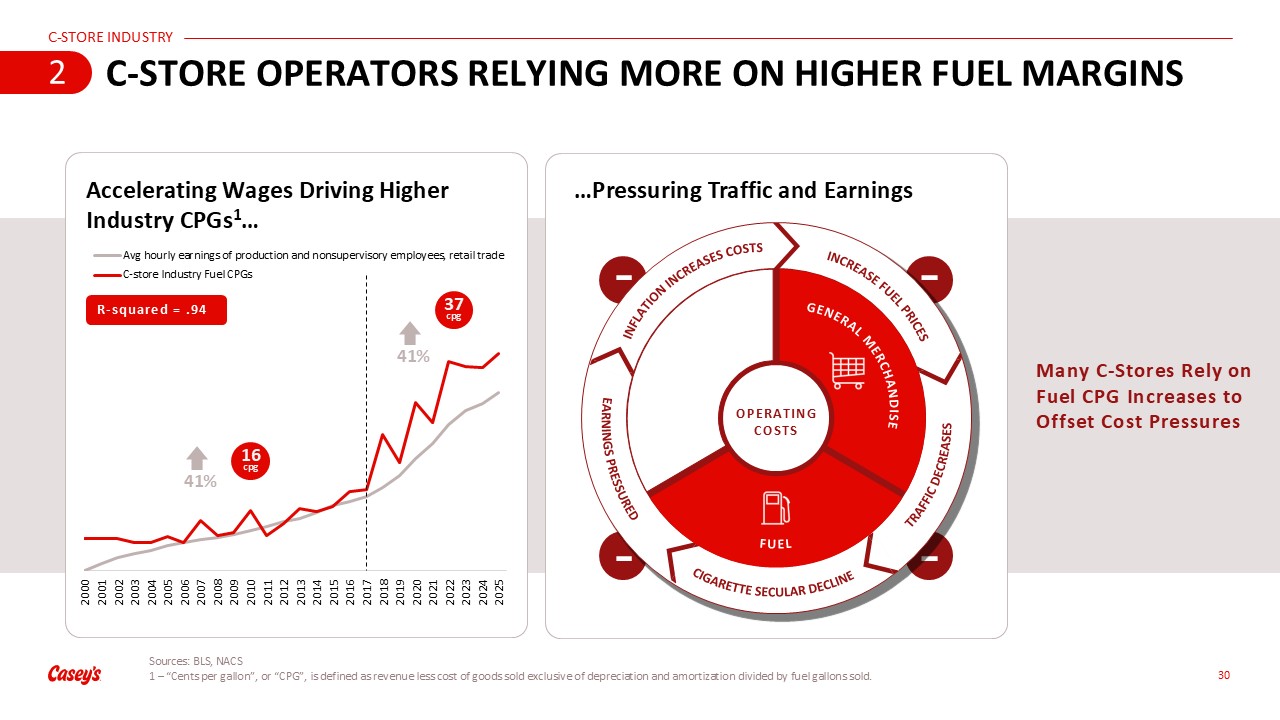
OPERATINGCOSTS PREPARED FOODS GENERAL MERCHANDISE FUEL Sources: BLS, NACS 1 –
“Cents per gallon”, or “CPG”, is defined as revenue less cost of goods sold exclusive of depreciation and amortization divided by fuel gallons sold. 30 C-STORE OPERATORS RELYING MORE ON HIGHER FUEL MARGINS 41% 16 cpg 41% R-squared =
.94 37 cpg 2 Many C-Stores Rely on Fuel CPG Increases to Offset Cost Pressures …Pressuring Traffic and Earnings Accelerating Wages Driving Higher Industry CPGs1… EARNINGS PRESSURED INFLATION INCREASES COSTS TRAFFIC DECREASES CIGARETTE
SECULAR DECLINE INCREASE FUEL PRICES

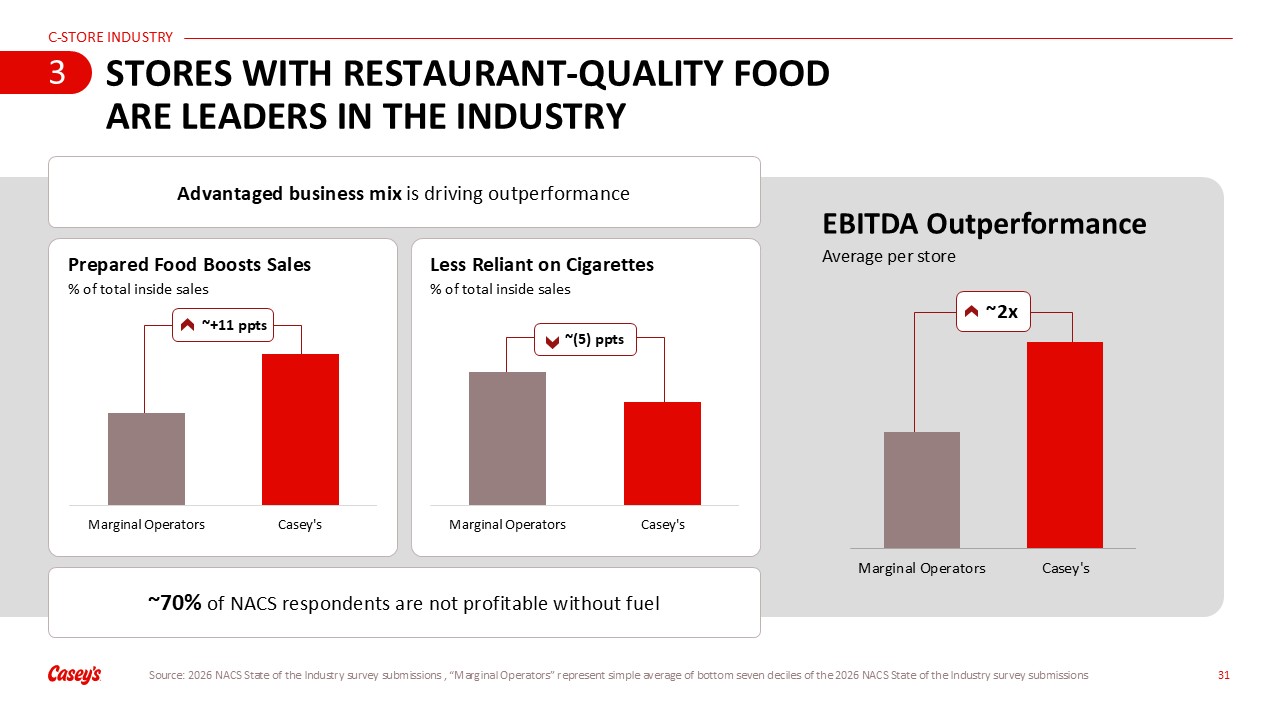
31 STORES WITH RESTAURANT-QUALITY FOOD ARE LEADERS IN THE INDUSTRY EBITDA
Outperformance Average per store ~2x Advantaged business mix is driving outperformance ~70% of NACS respondents are not profitable without fuel Less Reliant on Cigarettes Prepared Food Boosts Sales % of total inside sales % of total
inside sales ~+11 ppts ~(5) ppts 3 Source: 2026 NACS State of the Industry survey submissions , “Marginal Operators” represent simple average of bottom seven deciles of the 2026 NACS State of the Industry survey submissions

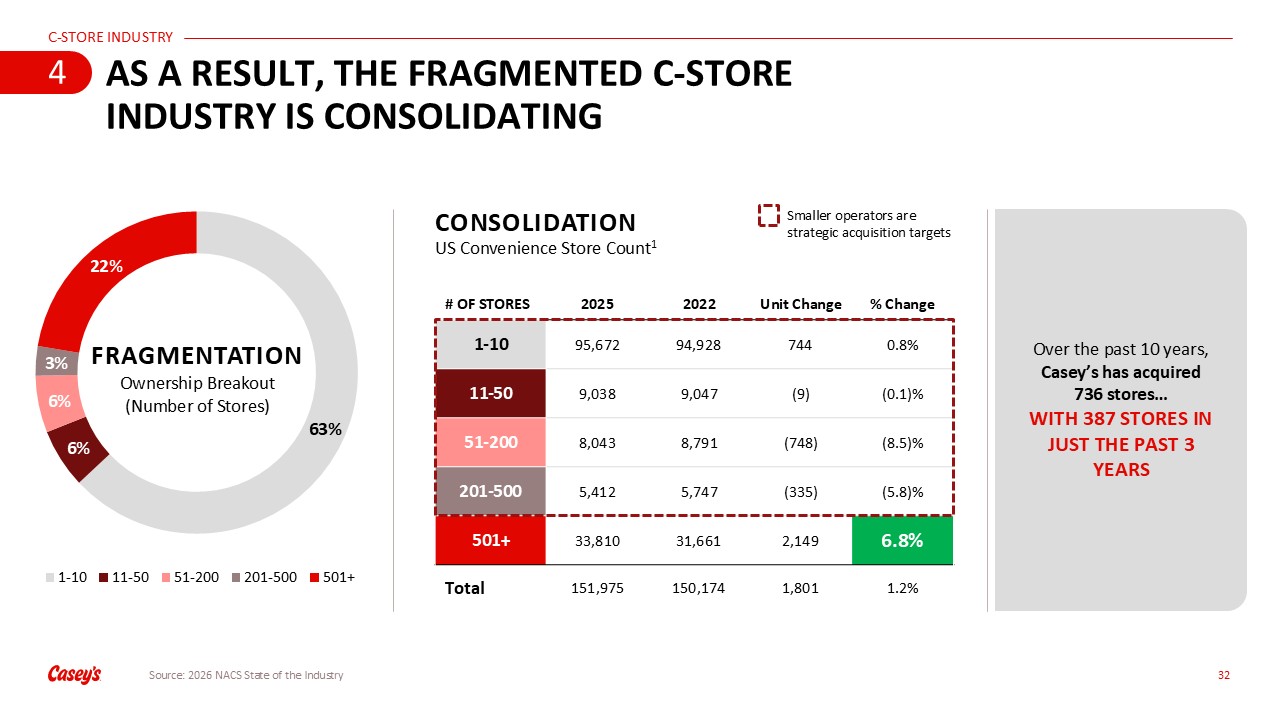
CONSOLIDATION FRAGMENTATION Ownership Breakout (Number of Stores) US Convenience
Store Count1 # OF STORES 2025 2022 Unit Change %
Change 1-10 95,672 94,928 744 0.8% 11-50 9,038 9,047 (9) (0.1)% 51-200 8,043 8,791 (748) (8.5)% 201-500 5,412 5,747 (335) (5.8)% 501+ 33,810 31,661 2,149 6.8% Total 151,975 150,174 1,801 1.2% Over the past 10 years,
Casey’s has acquired 736 stores… WITH 387 STORES IN JUST THE PAST 3 YEARS Source: 2026 NACS State of the Industry 32 AS A RESULT, THE FRAGMENTED C-STORE INDUSTRY IS CONSOLIDATING Smaller operators are strategic acquisition targets 4

33 CASEY’S ADVANTAGED POSITION OPERATINGCOSTS PREPARED FOOD &DISPENSED
BEVERAGES GROCERY & GENERAL MERCHANDISE FUEL

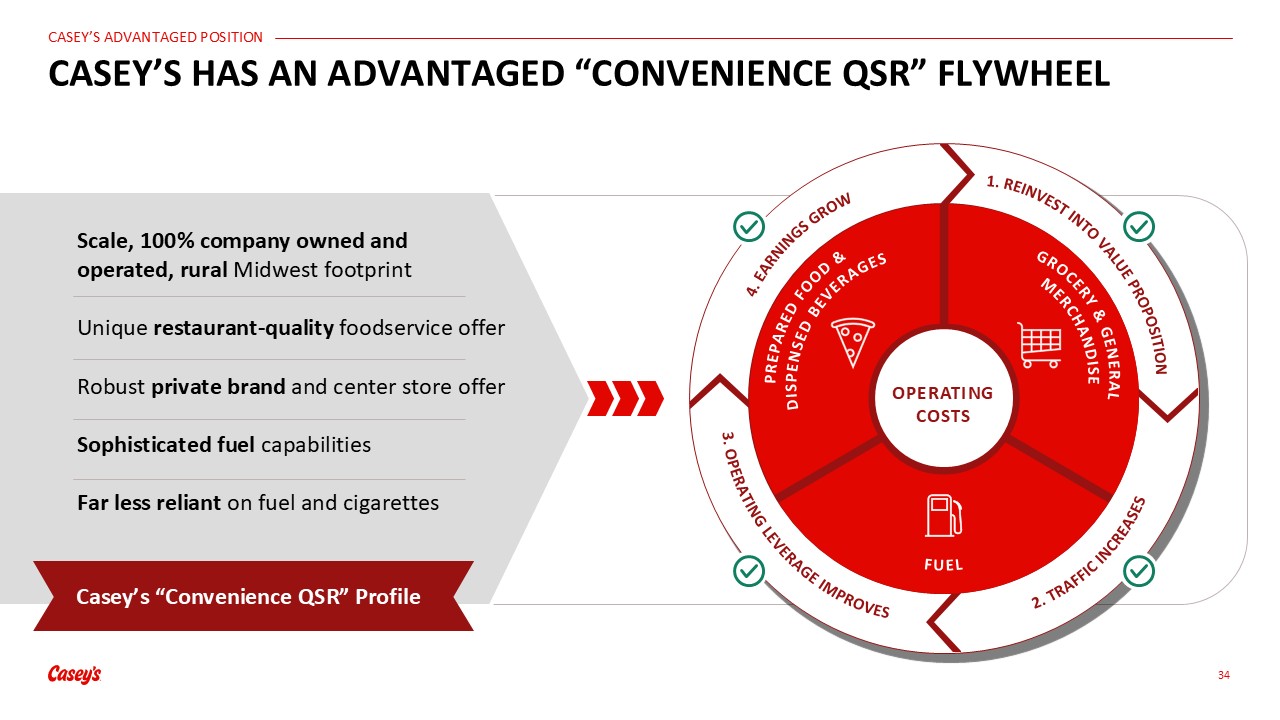
Scale, 100% company owned and operated, rural Midwest footprint Unique
restaurant-quality foodservice offer Robust private brand and center store offer Sophisticated fuel capabilities Far less reliant on fuel and cigarettes 34 CASEY’S HAS AN ADVANTAGED “CONVENIENCE QSR” FLYWHEEL Casey’s “Convenience QSR”
Profile 3. OPERATING LEVERAGE IMPROVES 4. EARNINGS GROW 1. REINVEST INTO VALUE PROPOSITION 2. TRAFFIC INCREASES PREPARED FOOD &DISPENSED BEVERAGES GROCERY & GENERAL MERCHANDISE FUEL OPERATINGCOSTS

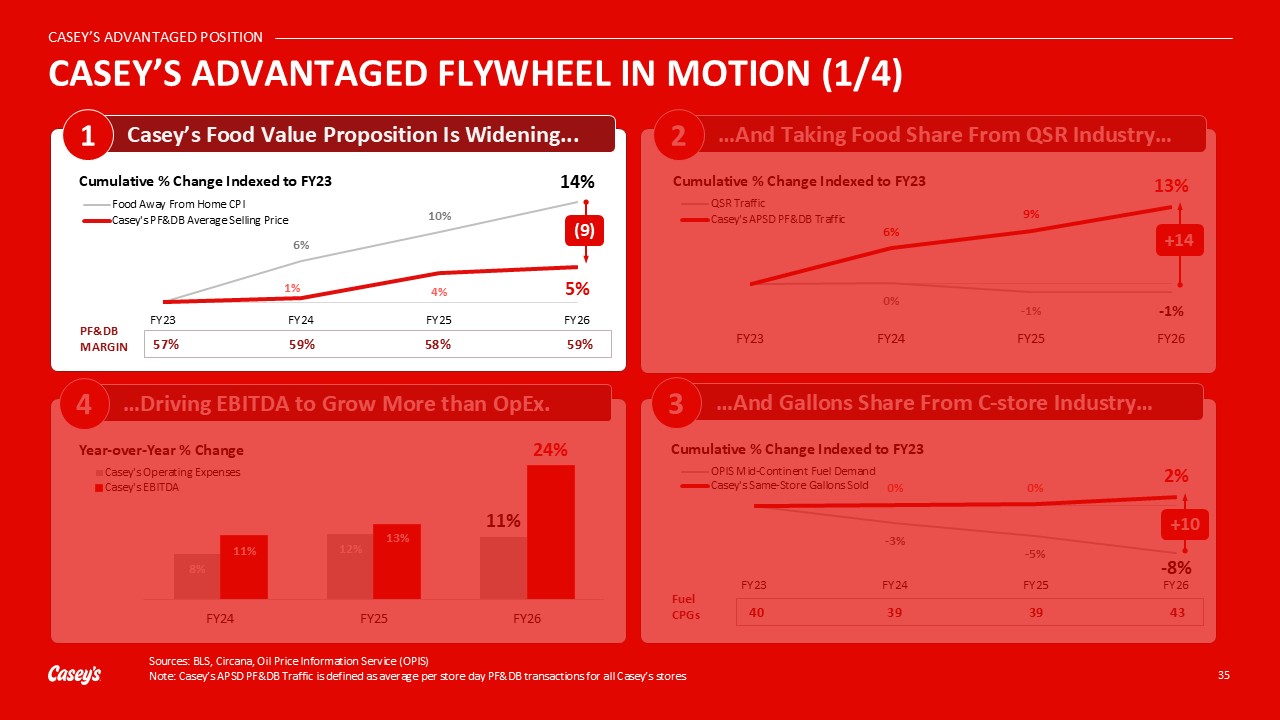
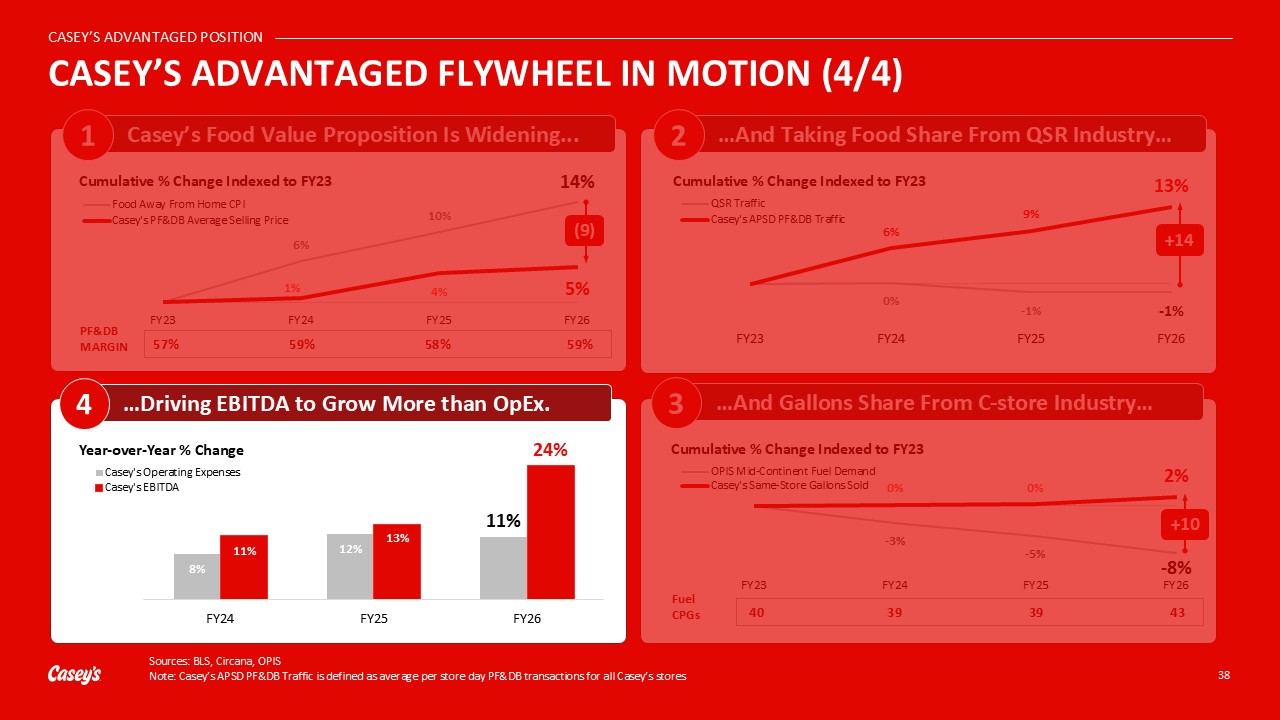
Fuel CPGs 40 39 39 43 3 …And Gallons Share From C-store
Industry… +10 CASEY’S ADVANTAGED FLYWHEEL IN MOTION (1/4) 35 4 …Driving EBITDA to Grow More than OpEx. 2 …And Taking Food Share From QSR Industry… +14 (9) PF&DB MARGIN 57% 59% 58% 59% 1 Casey’s Food Value Proposition Is
Widening... Sources: BLS, Circana, Oil Price Information Service (OPIS) Note: Casey’s APSD PF&DB Traffic is defined as average per store day PF&DB transactions for all Casey’s stores

Fuel CPGs 40 39 39 43 3 …And Gallons Share From C-store
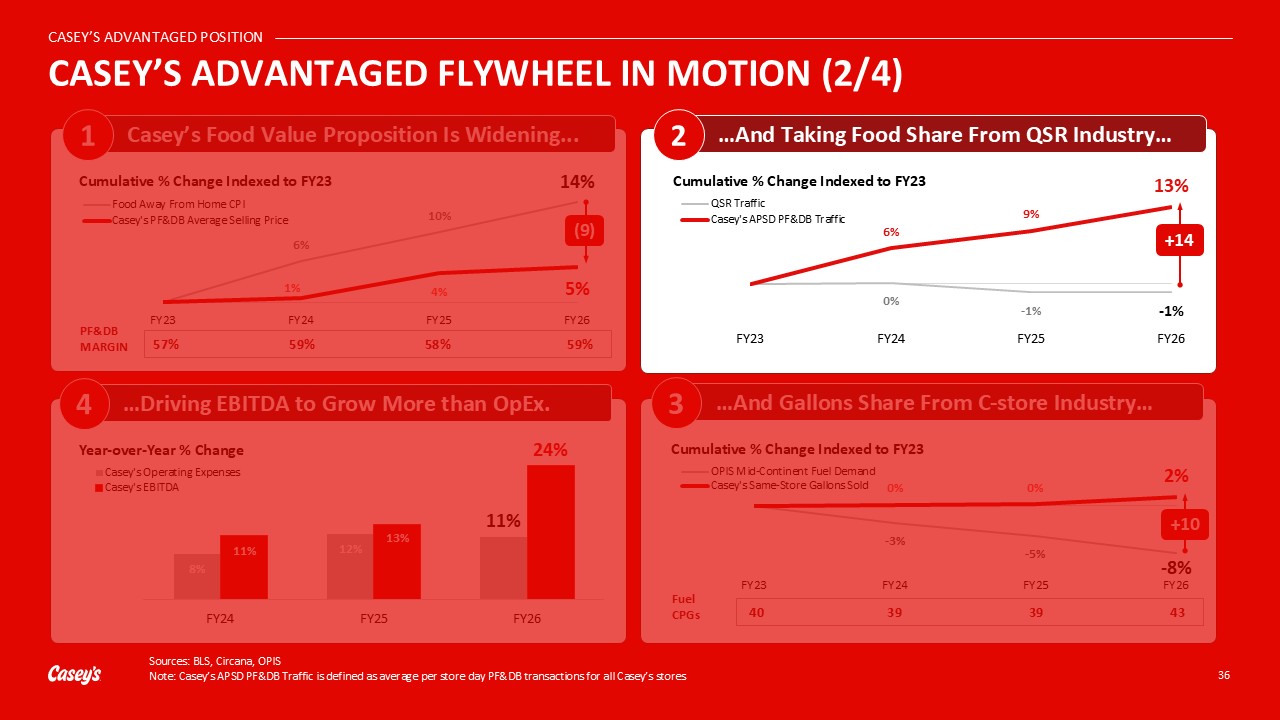
Industry… +10 CASEY’S ADVANTAGED FLYWHEEL IN MOTION (2/4) 36 4 …Driving EBITDA to Grow More than OpEx. (9) PF&DB MARGIN 57% 59% 58% 59% 1 Casey’s Food Value Proposition Is Widening... 2 …And Taking Food Share From QSR
Industry… +14 Sources: BLS, Circana, OPIS Note: Casey’s APSD PF&DB Traffic is defined as average per store day PF&DB transactions for all Casey’s stores

(9) PF&DB MARGIN 57% 59% 58% 59% 1 Casey’s Food Value Proposition Is
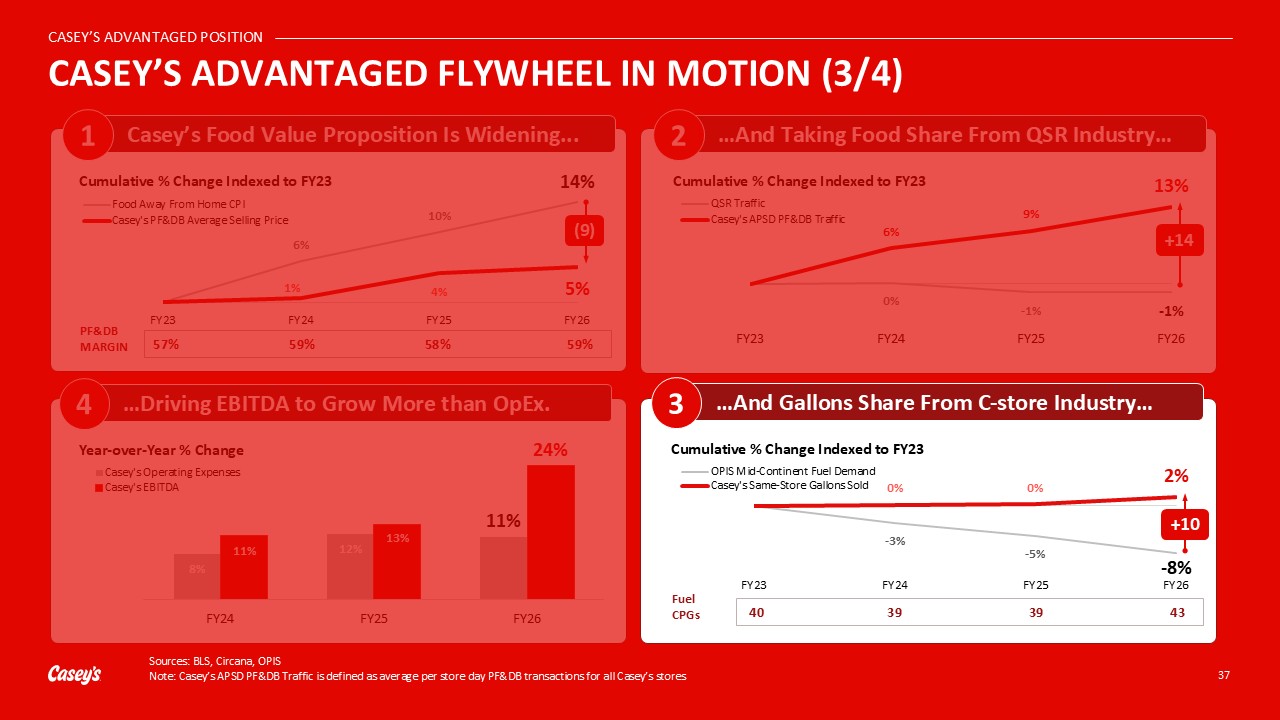
Widening... 2 …And Taking Food Share From QSR Industry… +14 4 …Driving EBITDA to Grow More than OpEx. Fuel CPGs 40 39 39 43 3 …And Gallons Share From C-store Industry… +10 CASEY’S ADVANTAGED FLYWHEEL IN MOTION (3/4) 37 Sources:
BLS, Circana, OPIS Note: Casey’s APSD PF&DB Traffic is defined as average per store day PF&DB transactions for all Casey’s stores

Fuel CPGs 40 39 39 43 3 …And Gallons Share From C-store
Industry… +10 CASEY’S ADVANTAGED FLYWHEEL IN MOTION (4/4) 38 (9) PF&DB MARGIN 57% 59% 58% 59% 1 Casey’s Food Value Proposition Is Widening... 2 …And Taking Food Share From QSR Industry… +14 4 …Driving EBITDA to Grow More than
OpEx. Sources: BLS, Circana, OPIS Note: Casey’s APSD PF&DB Traffic is defined as average per store day PF&DB transactions for all Casey’s stores

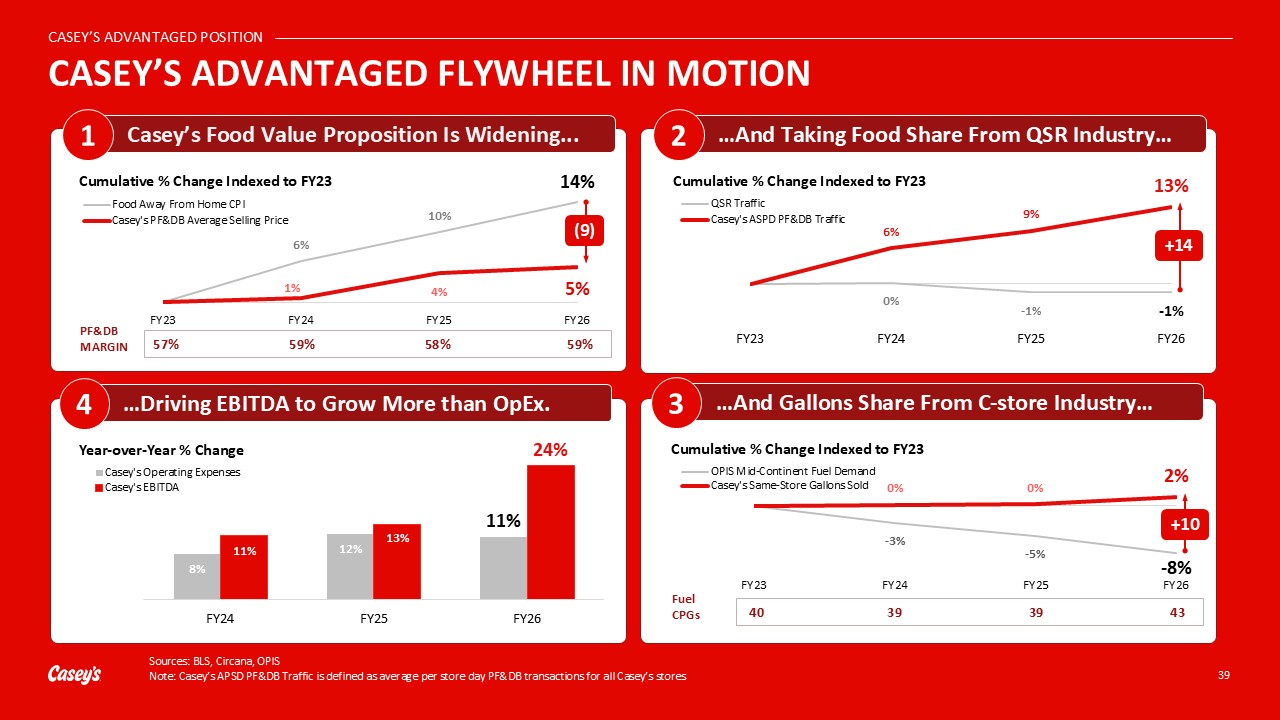
Fuel CPGs 40 39 39 43 3 …And Gallons Share From C-store
Industry… +10 CASEY’S ADVANTAGED FLYWHEEL IN MOTION 39 (9) PF&DB MARGIN 57% 59% 58% 59% 1 Casey’s Food Value Proposition Is Widening... 2 …And Taking Food Share From QSR Industry… +14 4 …Driving EBITDA to Grow More than
OpEx. Sources: BLS, Circana, OPIS Note: Casey’s APSD PF&DB Traffic is defined as average per store day PF&DB transactions for all Casey’s stores

ENTERING THE NEXT 3-YEAR GROWTH STRATEGY 40 From A Position Of Strength The
benefits of a ~3,000 (scale) store 100% company owned and operated retail chain with a self-distributed, rural footprint, “Convenience QSR” operating model have never been greater

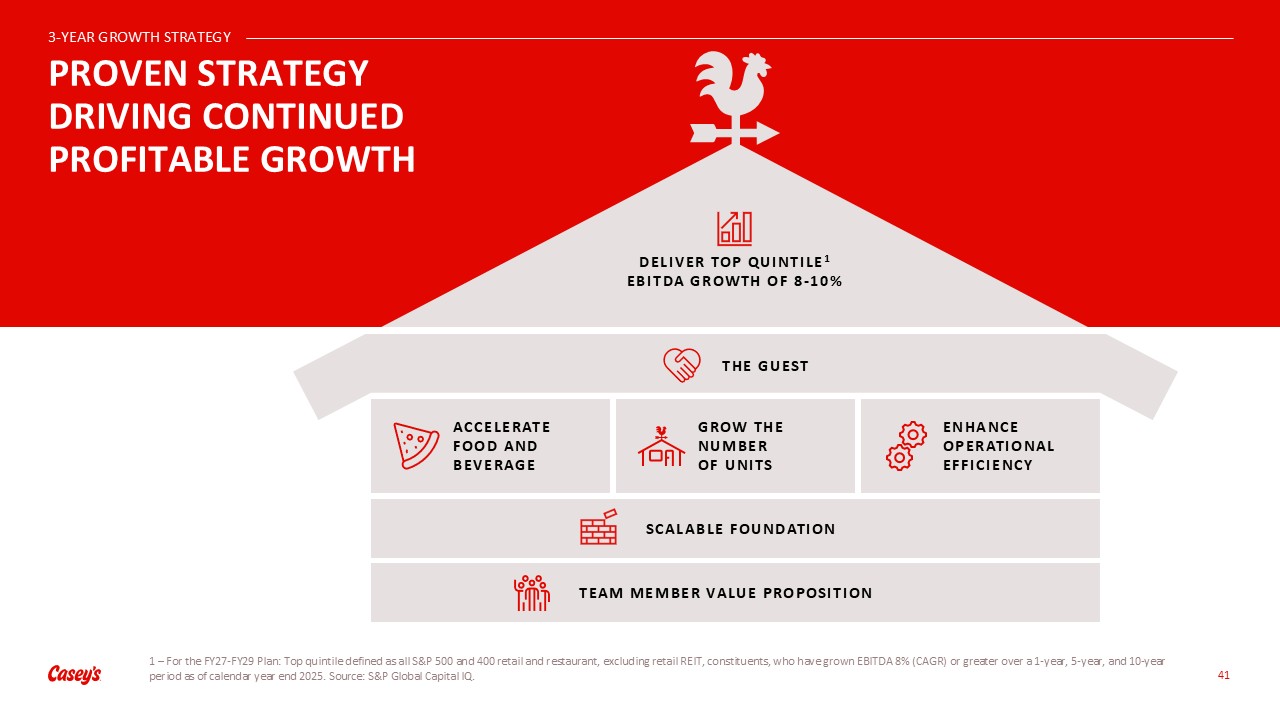
1 – For the FY27-FY29 Plan: Top quintile defined as all S&P 500 and 400 retail
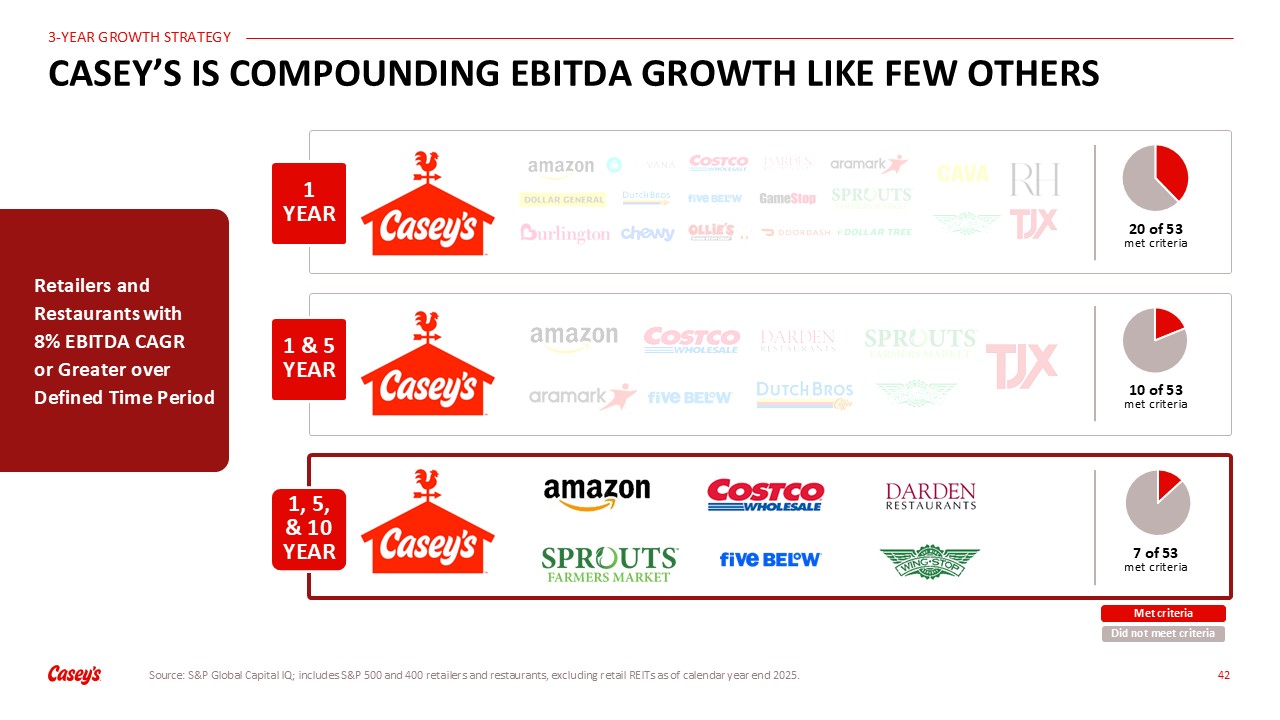
and restaurant, excluding retail REIT, constituents, who have grown EBITDA 8% (CAGR) or greater over a 1-year, 5-year, and 10-year period as of calendar year end 2025. Source: S&P Global Capital IQ. PROVEN STRATEGY DRIVING CONTINUED
PROFITABLE GROWTH 41 Deliver top quintile1 EBITDA growth of 8-10% ACCELERATEFOOD AND BEVERAGE SCALABLE Foundation Team Member Value Proposition GROW THE NUMBER OF UNITS ENHANCE OPERATIONALEFFICIENCY THE GUEST

20 of 53met criteria Met criteria Did not meet criteria 42 CASEY’S IS
COMPOUNDING EBITDA GROWTH LIKE FEW OTHERS 1 YEAR 1 & 5 YEAR 1, 5, & 10 YEAR Retailers and Restaurants with 8% EBITDA CAGR or Greater over Defined Time Period 10 of 53 met criteria 7 of 53 met criteria Source: S&P Global
Capital IQ; includes S&P 500 and 400 retailers and restaurants, excluding retail REITs as of calendar year end 2025.

43 CASEY’S IS A CATEGORY OF ONE QUICK-SERVICE RESTAURANT CONVENIENCE STORE

PROVEN FINANCIAL EXECUTION STEVE BRAMLAGE CHIEF FINANCIAL OFFICER Deliver top
quintile EBITDA growth of 8-10% ACCELERATEFOOD AND BEVERAGE SCALABLE Foundation Team Member Value Proposition THE GUEST GROW THE NUMBER OF UNITS ENHANCE OPERATIONALEFFICIENCY 44

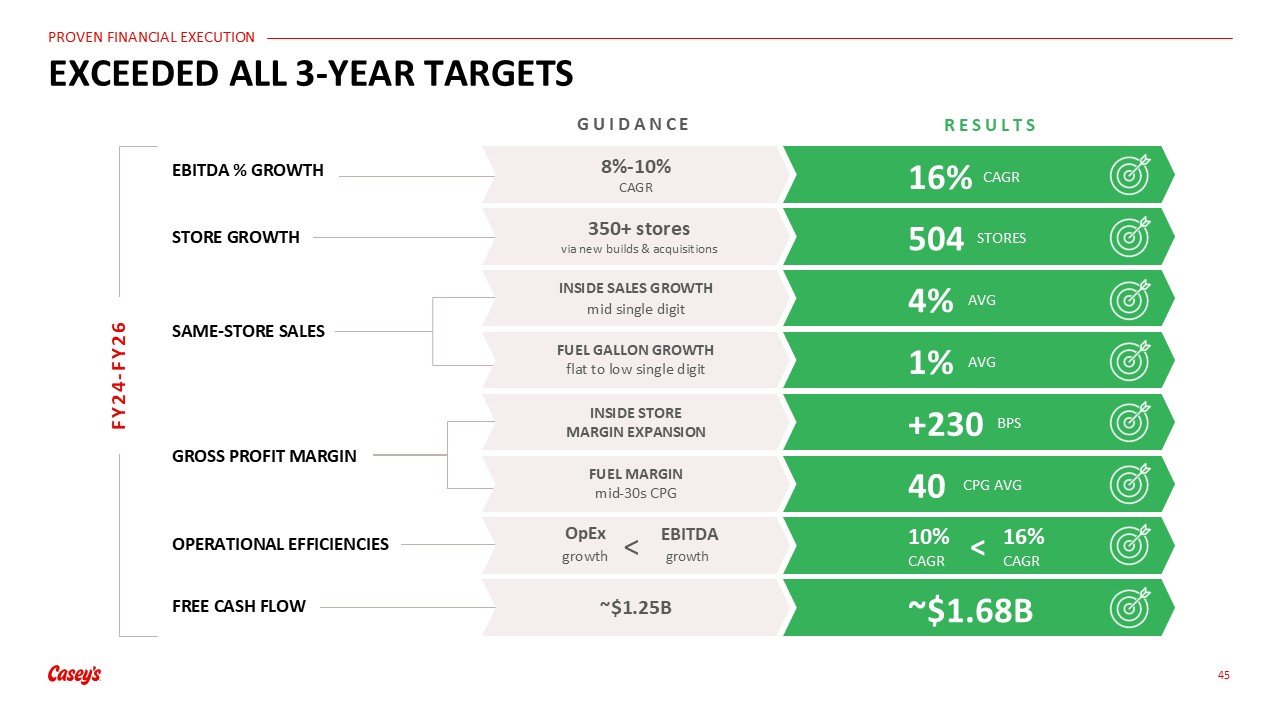
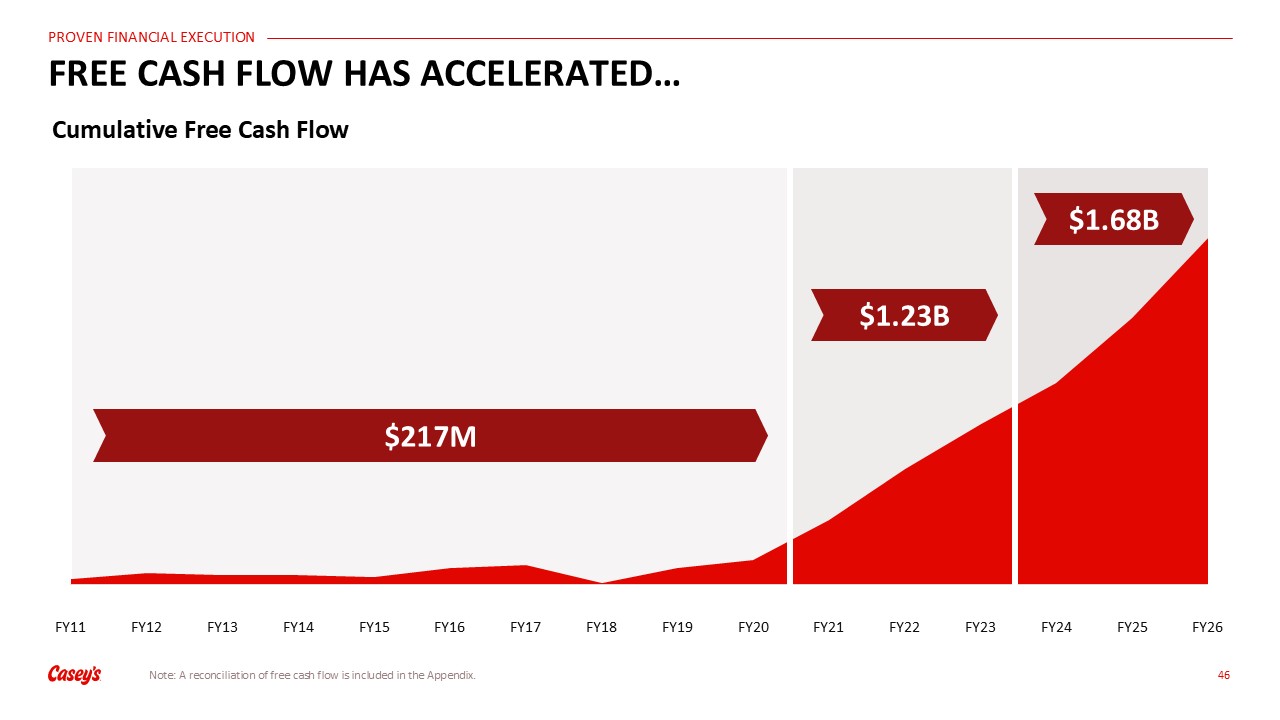
45 EXCEEDED ALL 3-YEAR TARGETS SAME-STORE SALES RESULTS GUIDANCE FREE CASH
FLOW FY24-FY26 EBITDA % GROWTH STORE GROWTH GROSS PROFIT MARGIN OPERATIONAL EFFICIENCIES 8%-10% CAGR 350+ stores via new builds & acquisitions ~$1.25B ~$1.68B INSIDE SALES GROWTH mid single digit FUEL GALLON GROWTH flat to low
single digit INSIDE STORE MARGIN EXPANSION FUEL MARGIN mid-30s CPG 10% CAGR < 16% CAGR EBITDA growth OpEx growth < 16% CAGR 504 STORES 4% AVG 1% AVG 40 CPG AVG +230 BPS

Note: A reconciliation of free cash flow is included in the Appendix. 46 FREE CASH
FLOW HAS ACCELERATED… $217M $1.23B $1.68B

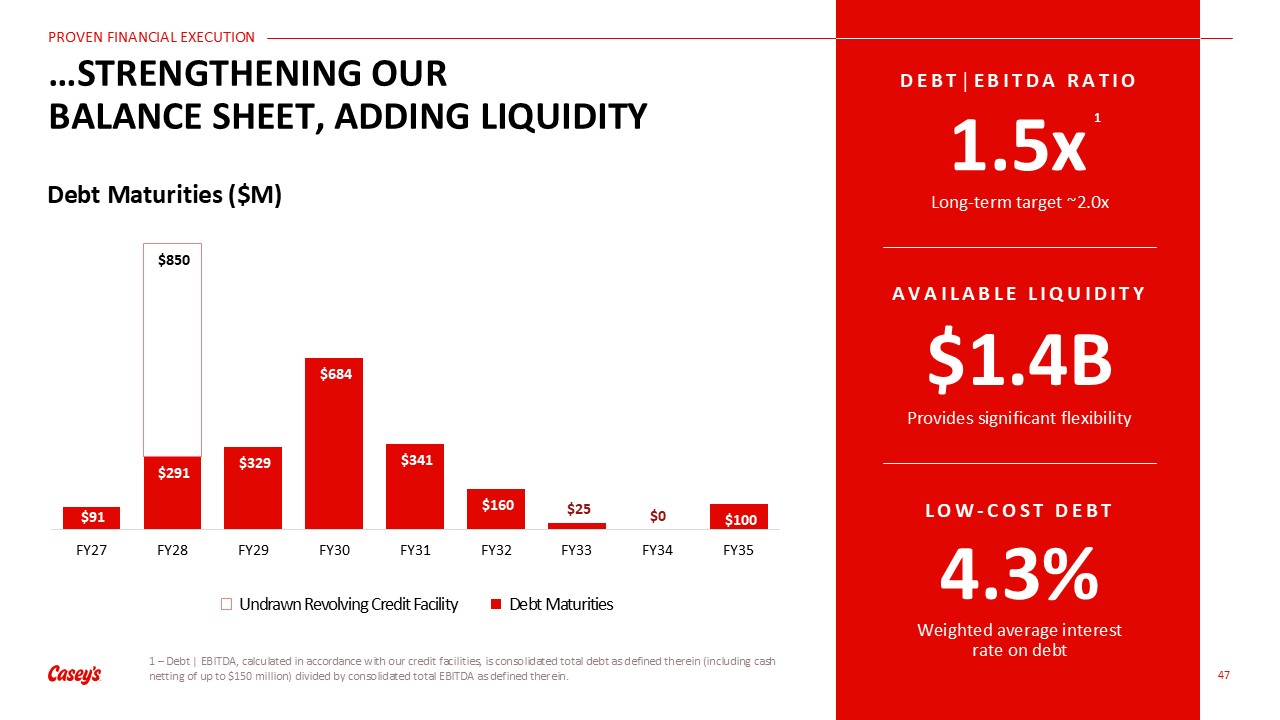
AVAILABLE LIQUIDITY $1.4B Provides significant flexibility LOW-COST
DEBT 4.3% Weighted average interest rate on debt 1 – Debt | EBITDA, calculated in accordance with our credit facilities, is consolidated total debt as defined therein (including cash netting of up to $150 million) divided by consolidated total
EBITDA as defined therein. 47 …STRENGTHENING OUR BALANCE SHEET, ADDING LIQUIDITY DEBT│EBITDA RATIO 1.5x Long-term target ~2.0x 1

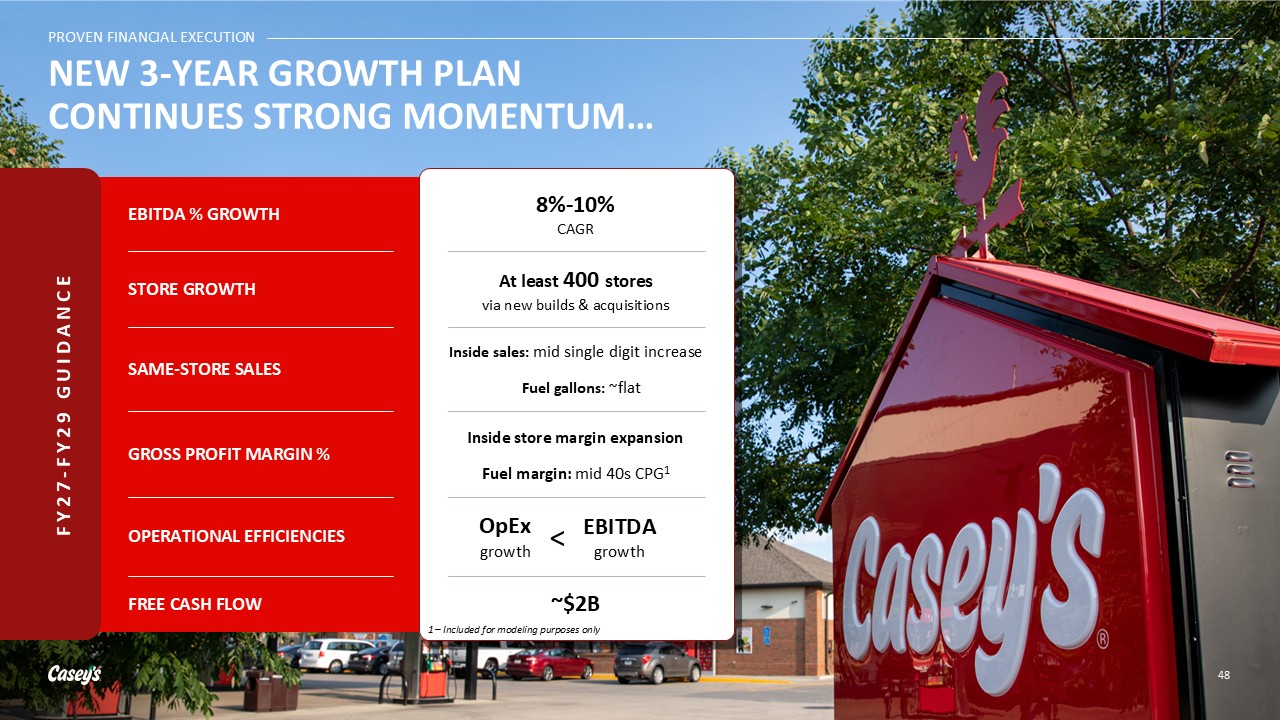
48 NEW 3-YEAR GROWTH PLAN CONTINUES STRONG MOMENTUM… EBITDA % GROWTH STORE
GROWTH SAME-STORE SALES GROSS PROFIT MARGIN % OPERATIONAL EFFICIENCIES FREE CASH FLOW 8%-10%CAGR At least 400 stores via new builds & acquisitions ~$2B Inside store margin expansion Fuel margin: mid 40s CPG1 FY27-FY29
GUIDANCE EBITDA growth OpEx growth < Inside sales: mid single digit increase Fuel gallons: ~flat PROVEN FINANCIAL EXECUTION 1 – Included for modeling purposes only

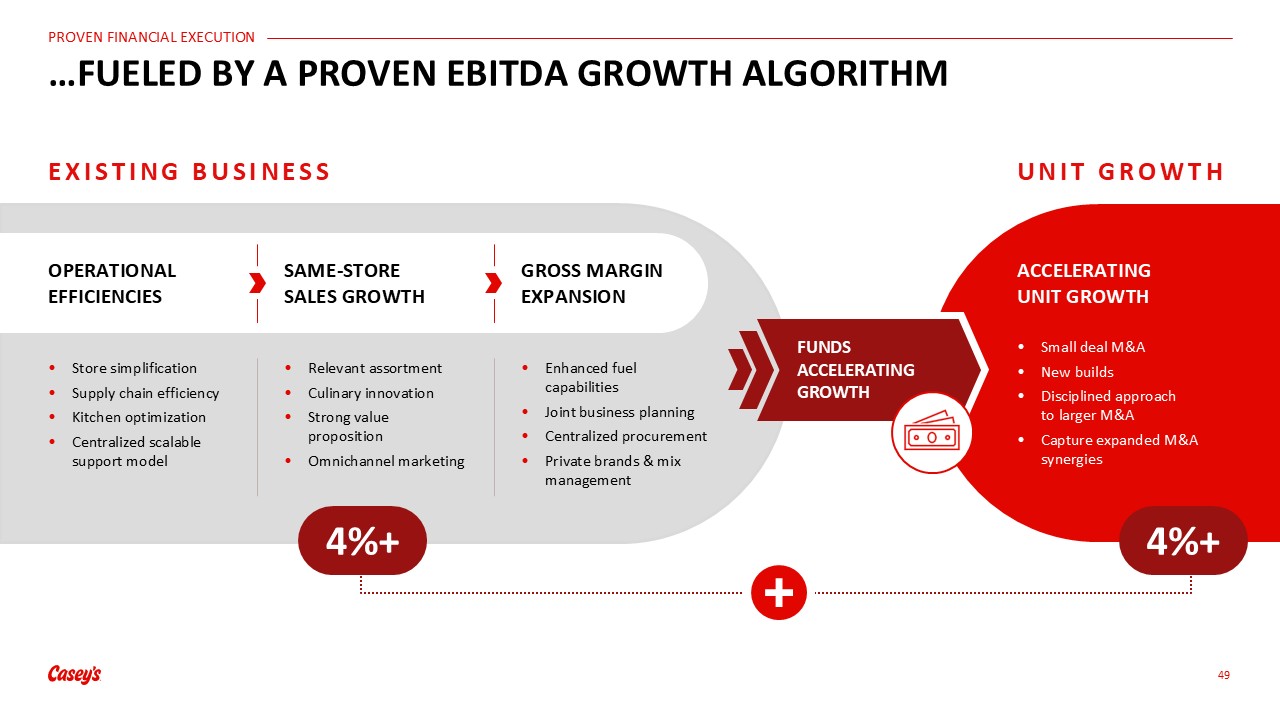
49 …FUELED BY A PROVEN EBITDA GROWTH ALGORITHM Small deal M&A New
builds Disciplined approach to larger M&A Capture expanded M&A synergies ACCELERATINGUNIT GROWTH OPERATIONAL EFFICIENCIES Store simplification Supply chain efficiency Kitchen optimization Centralized scalable support
model Enhanced fuel capabilities Joint business planning Centralized procurement Private brands & mix management GROSS MARGINEXPANSION Relevant assortment Culinary innovation Strong value proposition Omnichannel marketing SAME-STORE
SALES GROWTH FUNDS ACCELERATING GROWTH EXISTING BUSINESS UNIT GROWTH 4%+ 4%+

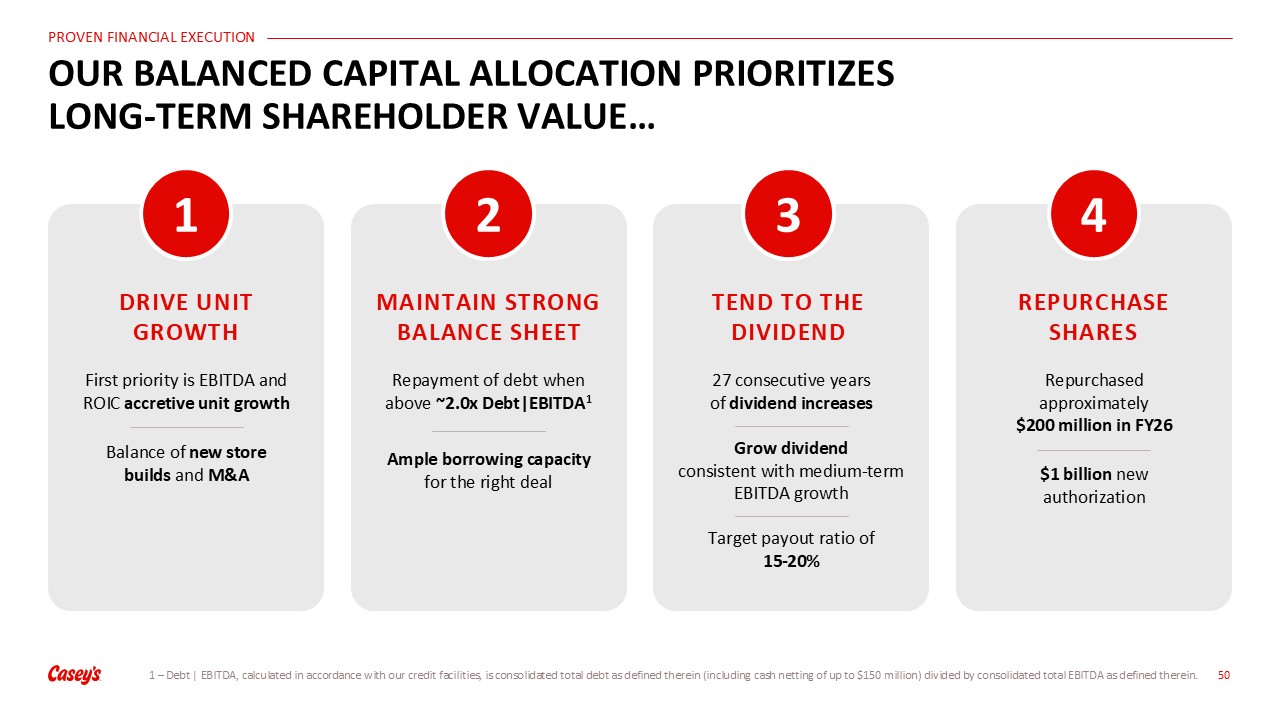
50 OUR BALANCED CAPITAL ALLOCATION PRIORITIZES LONG-TERM SHAREHOLDER
VALUE… 1 DRIVE UNIT GROWTH First priority is EBITDA and ROIC accretive unit growth Balance of new store builds and M&A 2 MAINTAIN STRONG BALANCE SHEET 3 TEND TO THE DIVIDEND 4 REPURCHASE SHARES Repayment of debt when above ~2.0x
Debt|EBITDA1 Ample borrowing capacity for the right deal 27 consecutive years of dividend increases Grow dividend consistent with medium-term EBITDA growth Target payout ratio of 15-20% Repurchased approximately $200 million in FY26 $1
billion new authorization 1 – Debt | EBITDA, calculated in accordance with our credit facilities, is consolidated total debt as defined therein (including cash netting of up to $150 million) divided by consolidated total EBITDA as defined
therein.

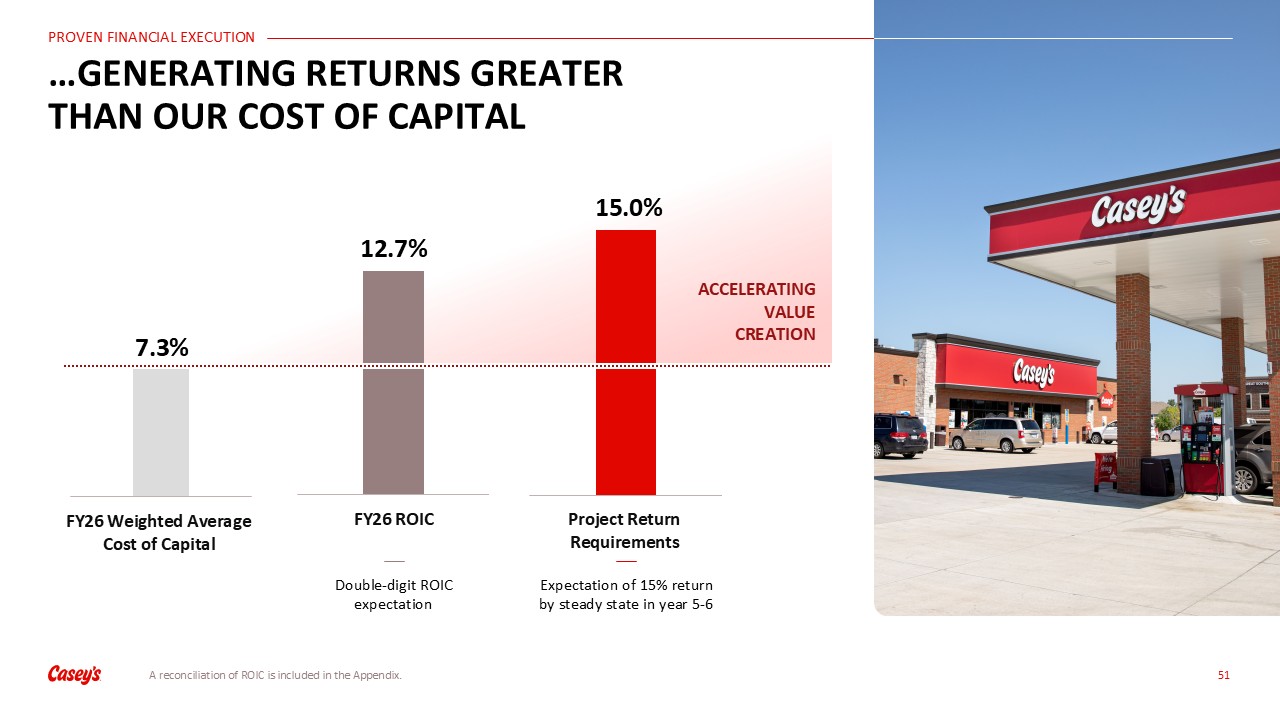
A reconciliation of ROIC is included in the Appendix. 51 …GENERATING RETURNS
GREATER THAN OUR COST OF CAPITAL Double-digit ROIC expectation Expectation of 15% return by steady state in year 5-6 ACCELERATING VALUE CREATION

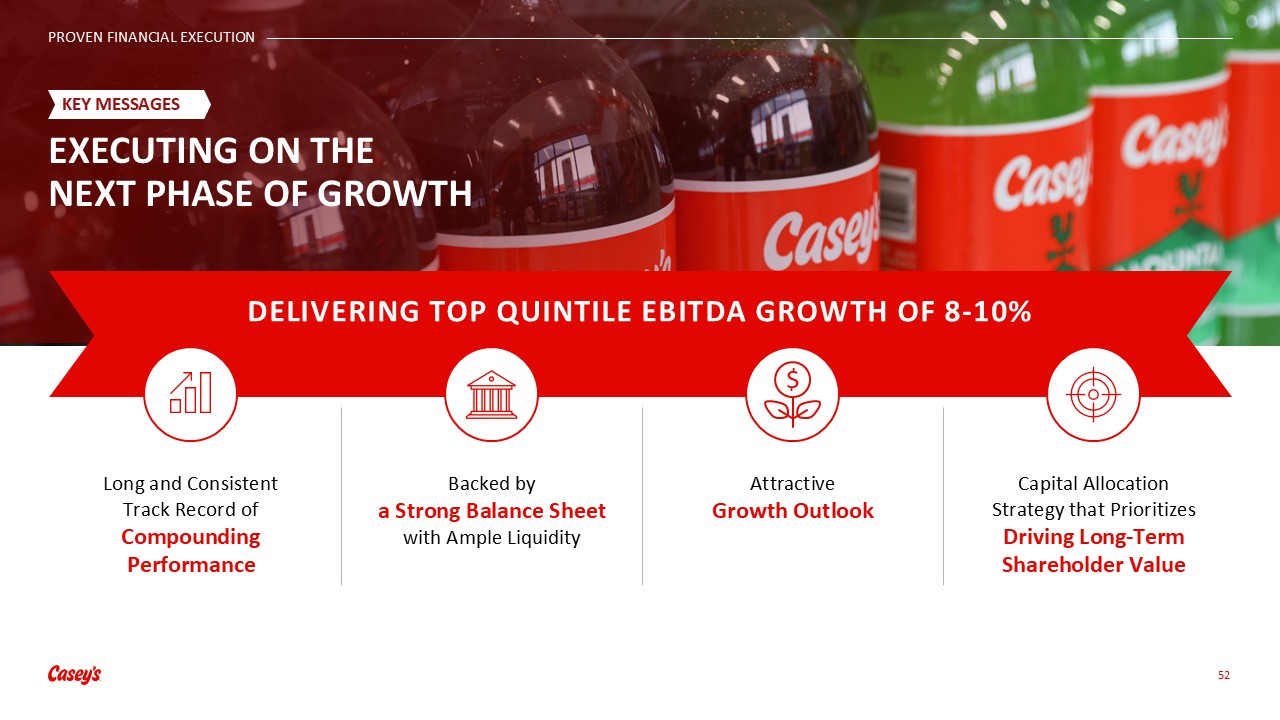
EXECUTING ON THE NEXT PHASE OF GROWTH 52 Long and Consistent Track Record of
Compounding Performance Backed by a Strong Balance Sheet with Ample Liquidity AttractiveGrowth Outlook Capital Allocation Strategy that Prioritizes Driving Long-Term Shareholder Value DELIVERING TOP QUINTILE EBITDA GROWTH OF 8-10% $ KEY
MESSAGES PROVEN FINANCIAL EXECUTION

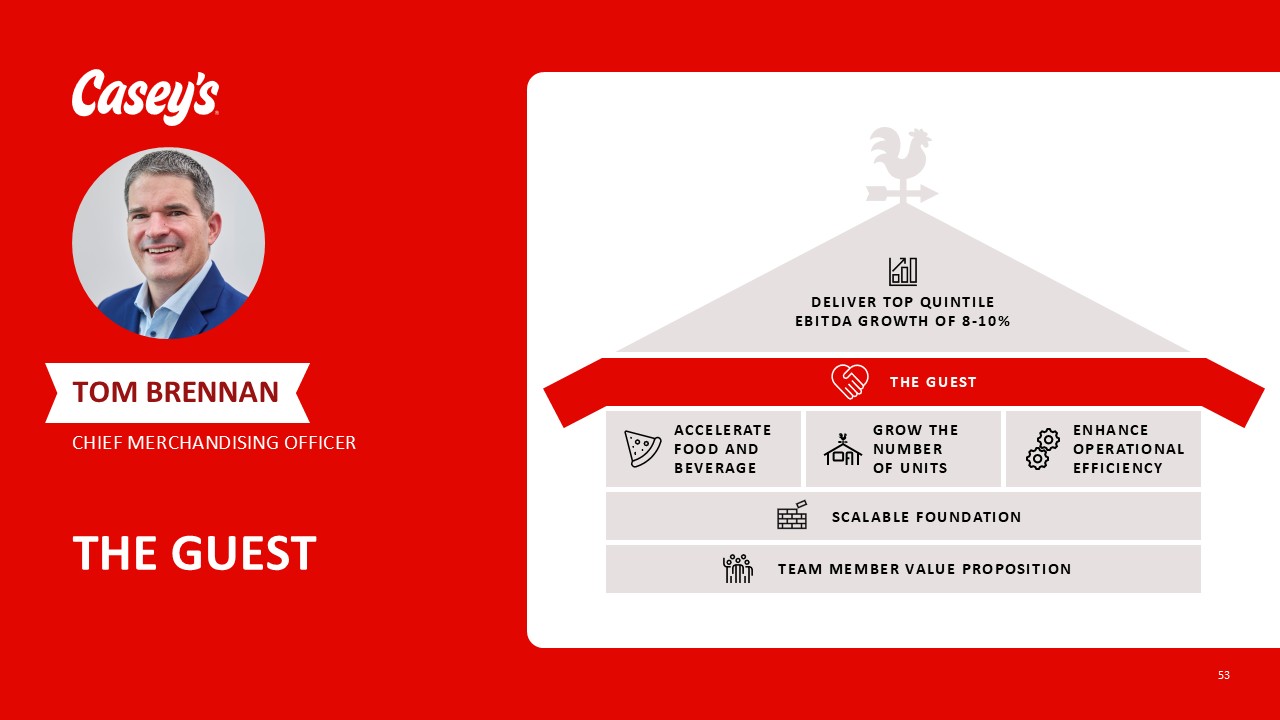
THE GUEST TOM BRENNAN CHIEF MERCHANDISING OFFICER Deliver top quintile EBITDA
growth of 8-10% SCALABLE Foundation Team Member Value Proposition THE GUEST ACCELERATEFOOD AND BEVERAGE GROW THE NUMBER OF UNITS ENHANCE OPERATIONALEFFICIENCY 53

54 Omni-Channel Marketing The Guest Category Management TODAY’S KEY
MESSAGES Our strong wallet share and favorable guest demographics support compounding growth. Our loyal guests are our focus, and our business model drives coverage across all dayparts. Vendor partnerships plus company owned and operated
stores and supply chain unlock exclusives and product launches that bring new guests. Loyalty and hyper-personalization is a structural advantage, increasing traffic and basket size. Nimble category management reallocates space and capital to
meet evolving guest needs.

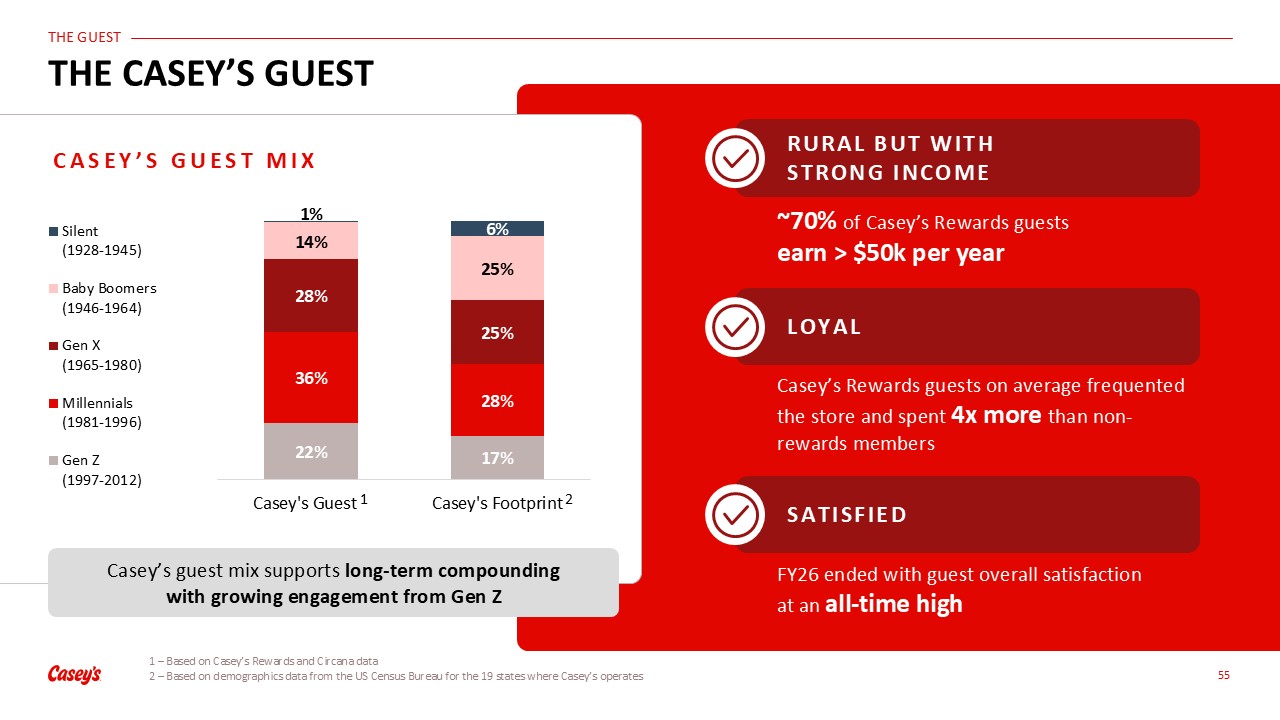
CASEY’S GUEST MIX 1 – Based on Casey’s Rewards and Circana data 2 – Based on
demographics data from the US Census Bureau for the 19 states where Casey’s operates 55 THE CASEY’S GUEST Casey’s guest mix supports long-term compounding with growing engagement from Gen Z RURAL BUT WITH STRONG INCOME ~70% of Casey’s
Rewards guests earn > $50k per year LOYAL Casey’s Rewards guests on average frequented the store and spent 4x more than non-rewards members SATISFIED FY26 ended with guest overall satisfaction at an all-time high 1 2

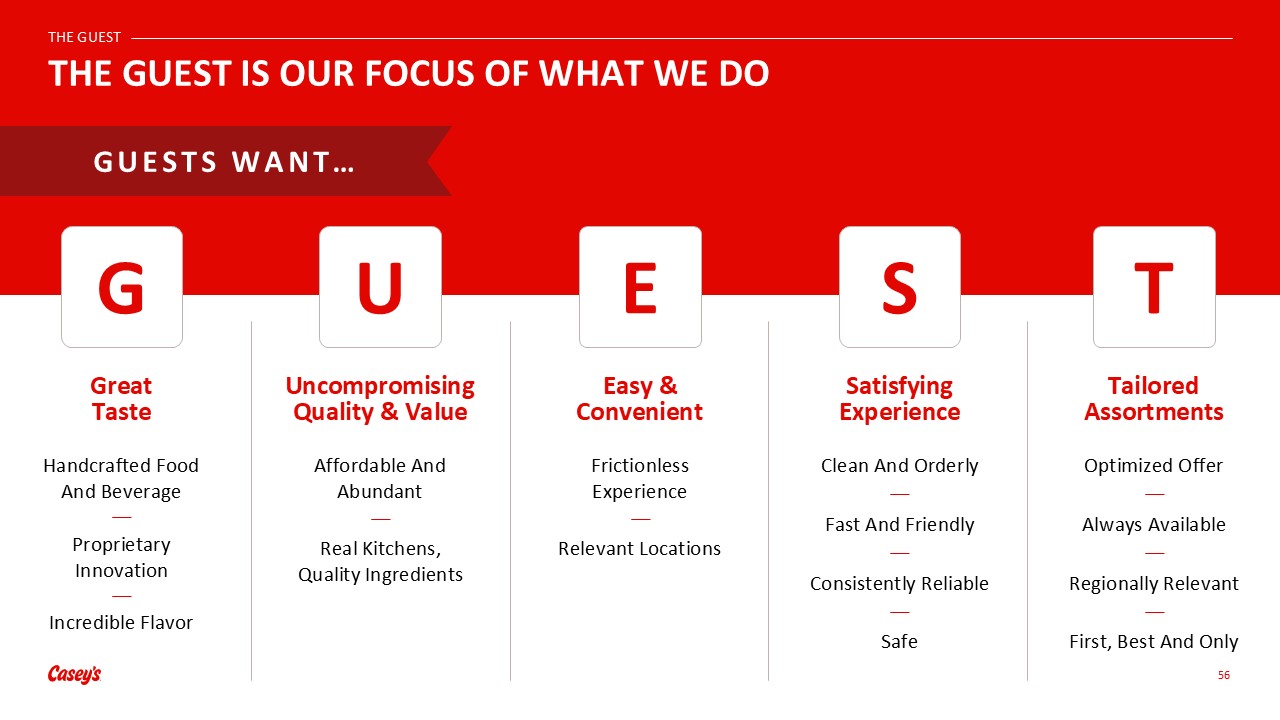
G 56 THE GUEST IS OUR FOCUS OF WHAT WE DO U E S T GUESTS WANT… Great
Taste Uncompromising Quality & Value Easy & Convenient Satisfying Experience Tailored Assortments Handcrafted Food And Beverage Proprietary Innovation Incredible Flavor Affordable And Abundant Real Kitchens, Quality
Ingredients Frictionless Experience Relevant Locations Clean And Orderly Fast And Friendly Consistently Reliable Safe Optimized Offer Always Available Regionally Relevant First, Best And Only

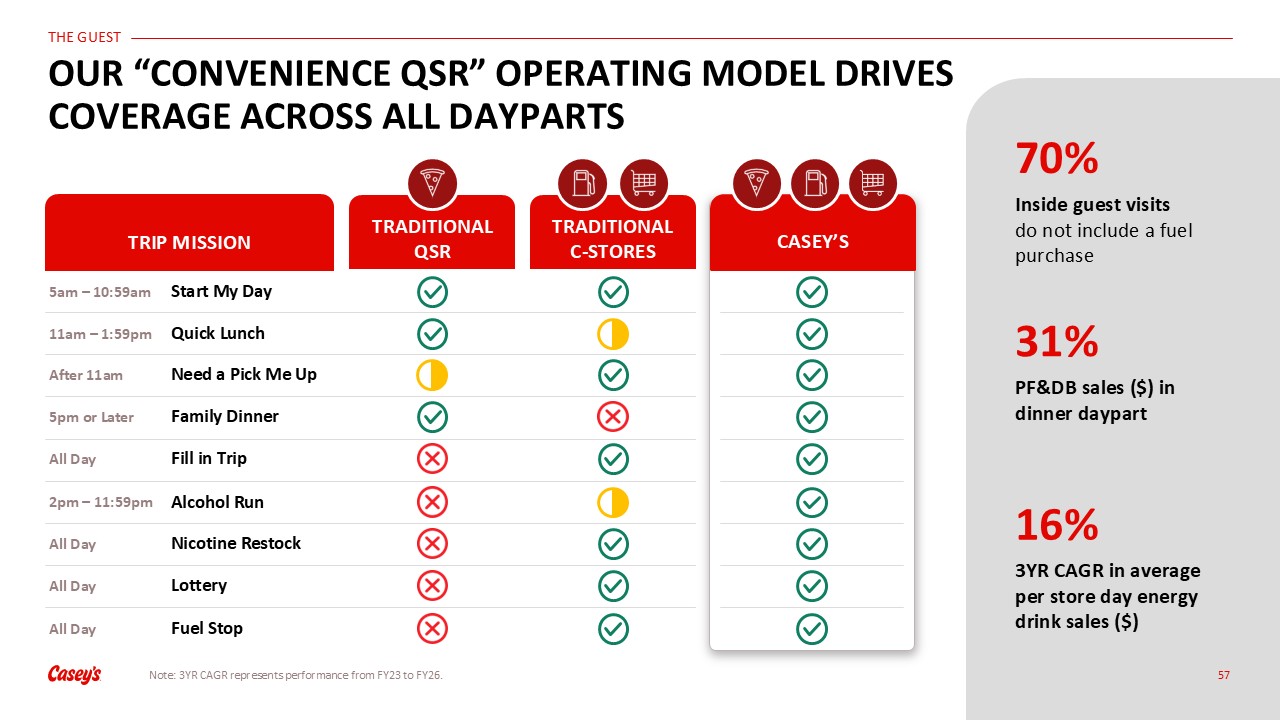
57 OUR “CONVENIENCE QSR” OPERATING MODEL DRIVESCOVERAGE ACROSS ALL DAYPARTS Start
My Day Quick Lunch Need a Pick Me Up Family Dinner Fill in Trip Alcohol Run Nicotine Restock Lottery Fuel Stop TRADITIONAL QSR TRADITIONAL C-STORES 5am – 10:59am 11am – 1:59pm After 11am 5pm or Later All Day 2pm – 11:59pm All
Day All Day All Day TRIP MISSION CASEY’S Inside guest visitsdo not include a fuel purchase 70% PF&DB sales ($) in dinner daypart 31% 3YR CAGR in average per store day energy drink sales ($) 16% Note: 3YR CAGR represents
performance from FY23 to FY26.

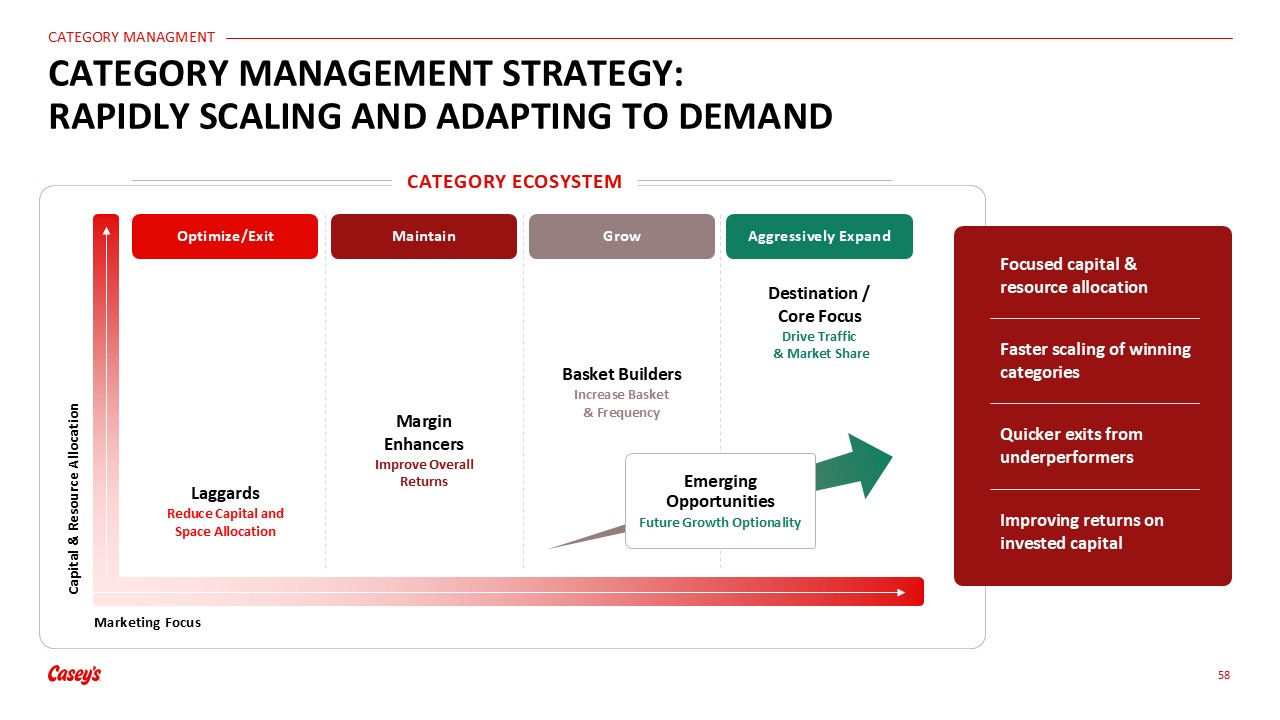
58 CATEGORY MANAGEMENT STRATEGY: RAPIDLY SCALING AND ADAPTING TO DEMAND Focused
capital & resource allocation Faster scaling of winning categories Quicker exits from underperformers Improving returns on invested capital Destination / Core Focus Drive Traffic & Market Share Basket Builders Increase Basket
& Frequency Margin Enhancers Improve Overall Returns Laggards Reduce Capital and Space Allocation Optimize/Exit Maintain Grow Aggressively Expand CATEGORY ECOSYSTEM Marketing Focus Capital & Resource Allocation Future
Growth Optionality Emerging Opportunities

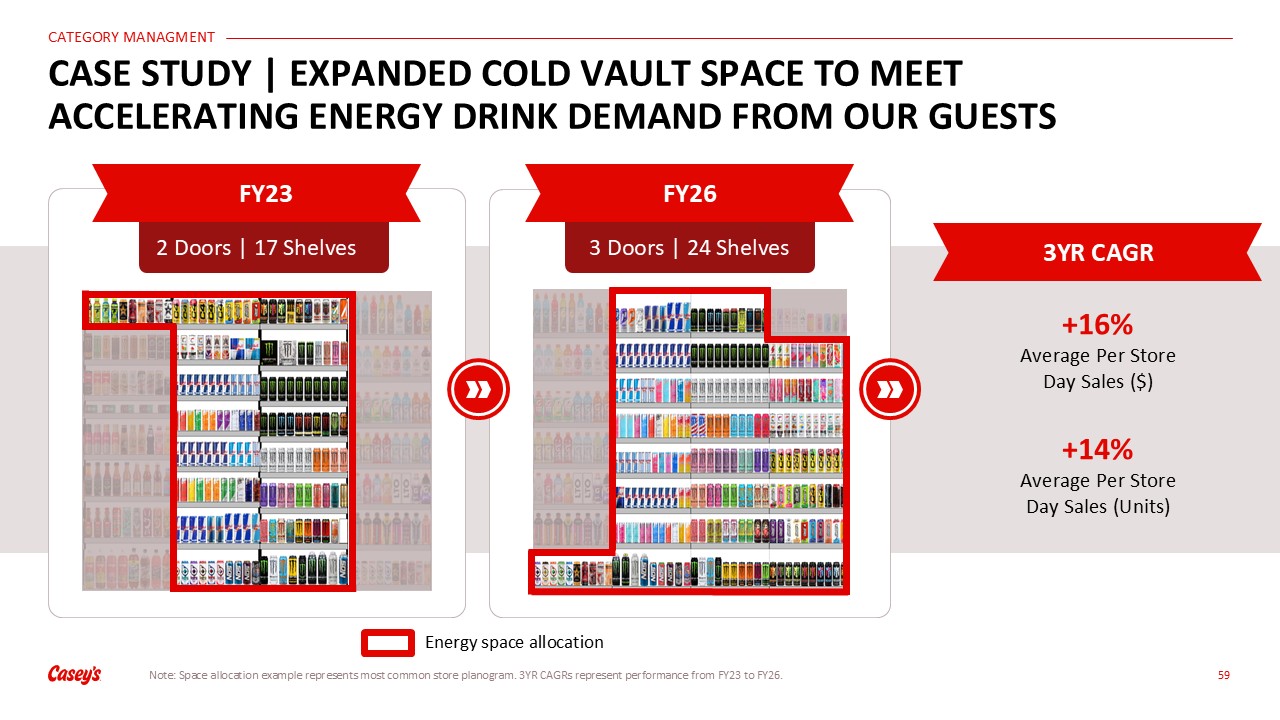
3 Doors | 24 Shelves Energy space allocation Note: Space allocation example
represents most common store planogram. 3YR CAGRs represent performance from FY23 to FY26. 59 CASE STUDY | EXPANDED COLD VAULT SPACE TO MEET ACCELERATING ENERGY DRINK DEMAND FROM OUR GUESTS FY23 FY26 2 Doors | 17 Shelves 2.1 Doors 17
Shelves +16% Average Per Store Day Sales ($) +14% Average Per Store Day Sales (Units) 3YR CAGR

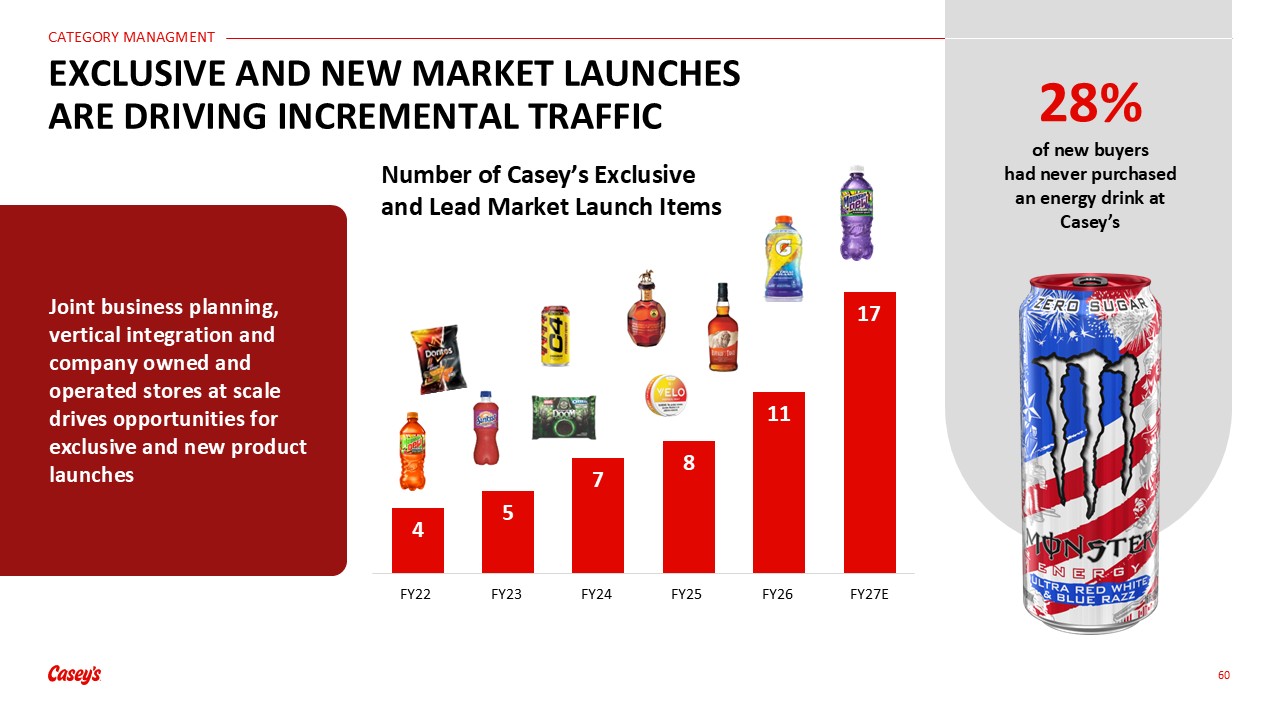
60 EXCLUSIVE AND NEW MARKET LAUNCHES ARE DRIVING INCREMENTAL TRAFFIC 28% of new
buyers had never purchased an energy drink at Casey’s Joint business planning, vertical integration and company owned and operated stores at scale drives opportunities for exclusive and new product launches Number of Casey’s Exclusive and Lead
Market Launch Items

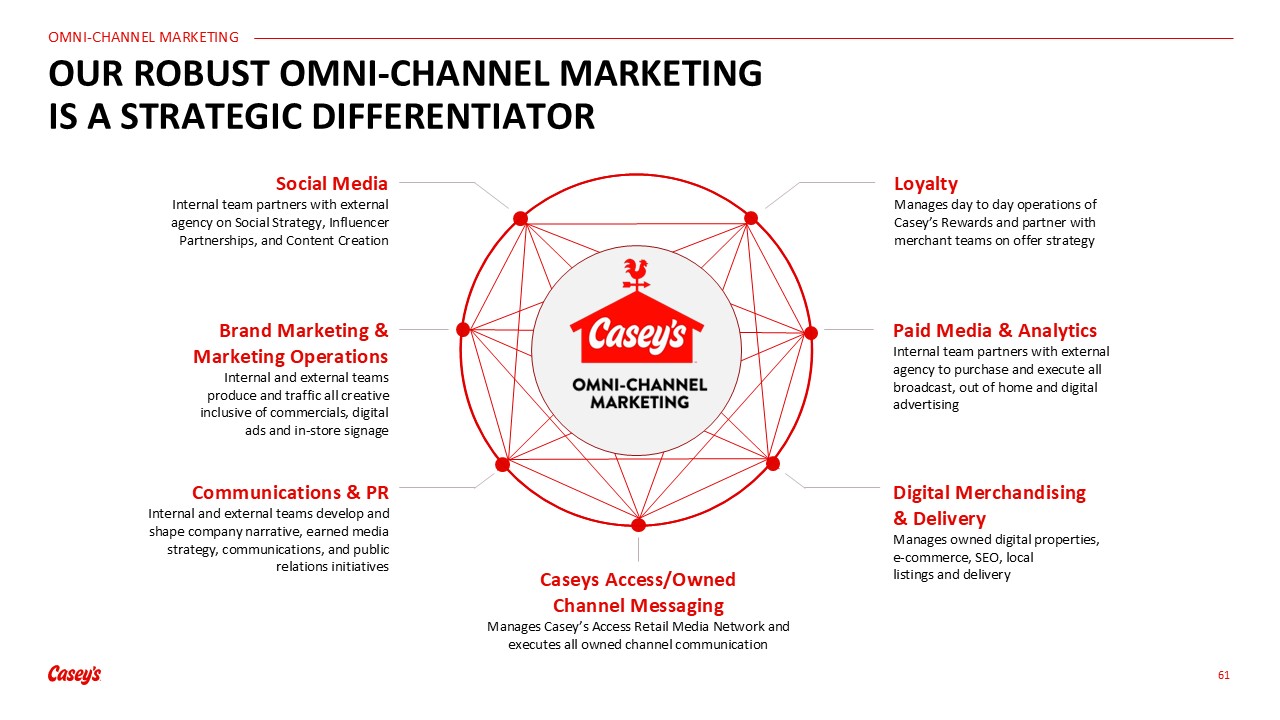
61 OUR ROBUST OMNI-CHANNEL MARKETING IS A STRATEGIC DIFFERENTIATOR Social Media
Internal team partners with external agency on Social Strategy, Influencer Partnerships, and Content Creation Loyalty Manages day to day operations of Casey’s Rewards and partner with merchant teams on offer strategy Paid Media &
Analytics Internal team partners with external agency to purchase and execute all broadcast, out of home and digital advertising Digital Merchandising & Delivery Manages owned digital properties, e-commerce, SEO, local listings and
delivery Caseys Access/Owned Channel Messaging Manages Casey’s Access Retail Media Network and executes all owned channel communication Communications & PR Internal and external teams develop and shape company narrative, earned media
strategy, communications, and public relations initiatives Brand Marketing & Marketing Operations Internal and external teams produce and traffic all creative inclusive of commercials, digital ads and in-store signage

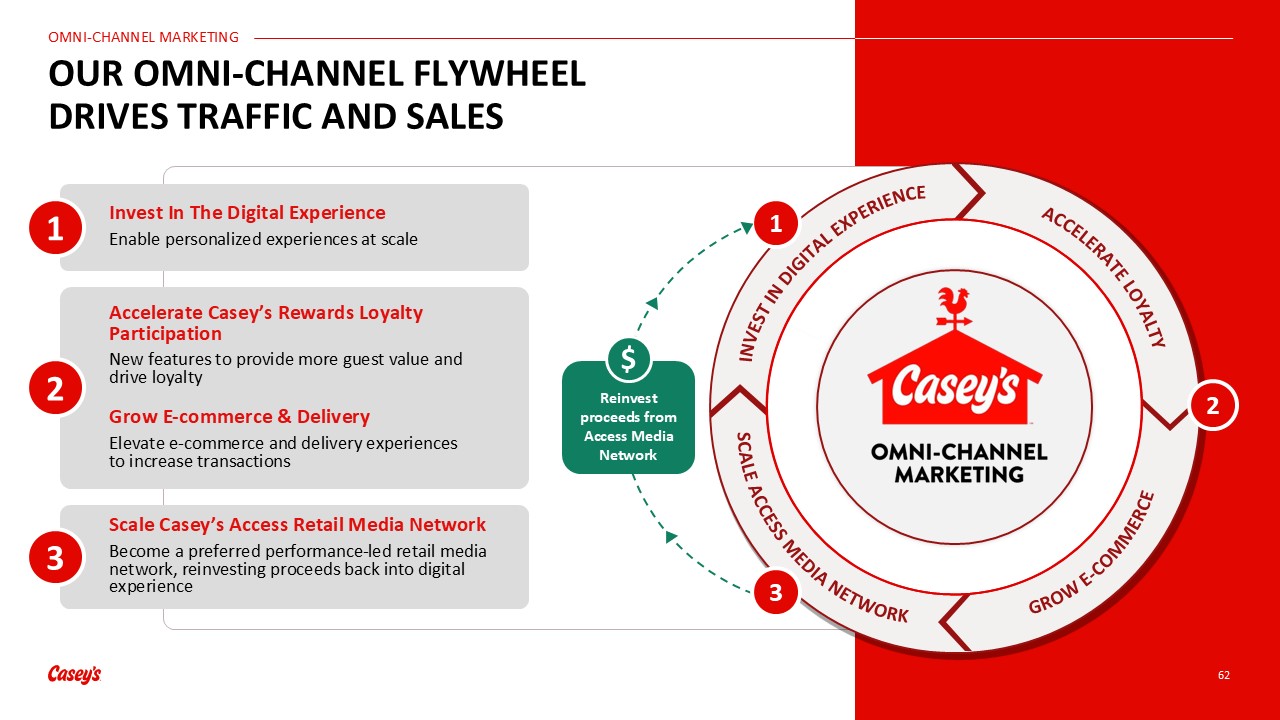
OUR OMNI-CHANNEL FLYWHEEL DRIVES TRAFFIC AND SALES 62 Invest In The Digital
Experience Enable personalized experiences at scale 1 2 Accelerate Casey’s Rewards Loyalty Participation New features to provide more guest value and drive loyalty Grow E-commerce & Delivery Elevate e-commerce and delivery experiences
to increase transactions Scale Casey’s Access Retail Media Network Become a preferred performance-led retail media network, reinvesting proceeds back into digital experience 3 SCALE ACCESS MEDIA NETWORK INVEST IN DIGITAL
EXPERIENCE ACCELERATE LOYALTY GROW E-COMMERCE 2 1 3 Reinvest proceeds from Access Media Network $

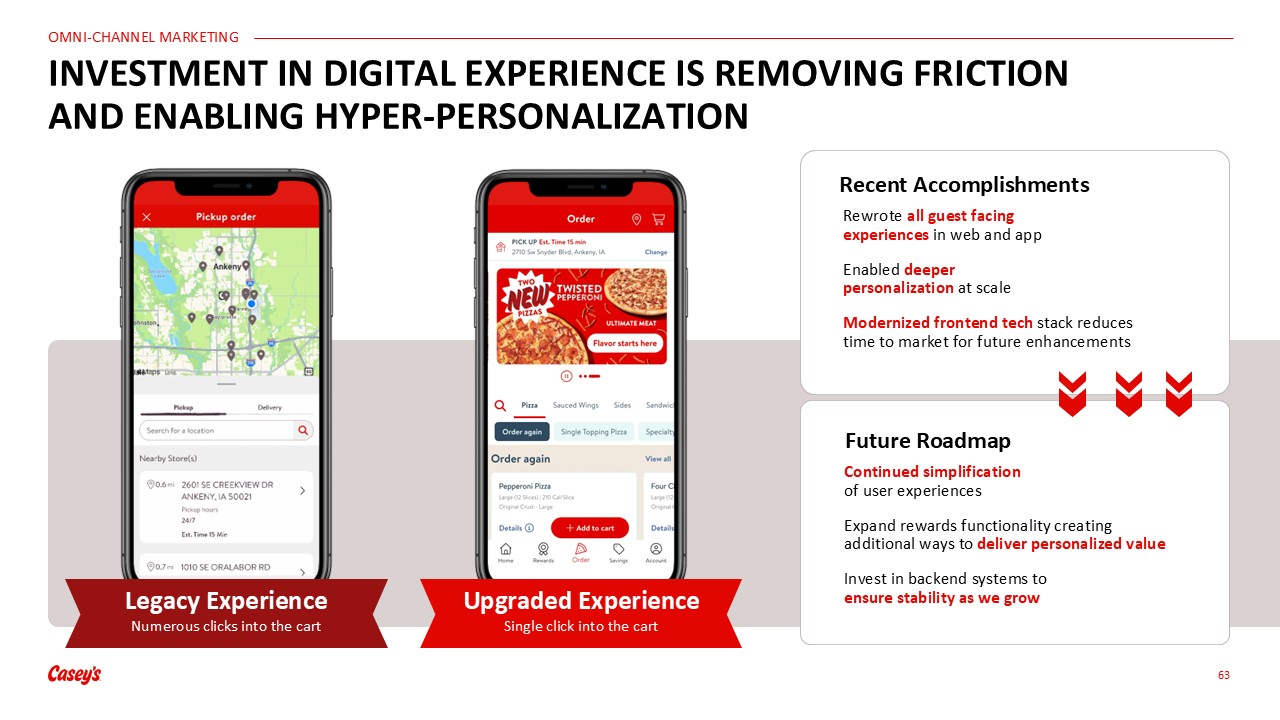
Rewrote all guest facing experiences in web and app Enabled deeper personalization
at scale Modernized frontend tech stack reduces time to market for future enhancements Continued simplification of user experiences Expand rewards functionality creating additional ways to deliver personalized value Invest in backend systems
to ensure stability as we grow 63 INVESTMENT IN DIGITAL EXPERIENCE IS REMOVING FRICTION AND ENABLING HYPER-PERSONALIZATION Recent Accomplishments Future Roadmap Upgraded Experience Single click into the cart Legacy Experience Numerous
clicks into the cart

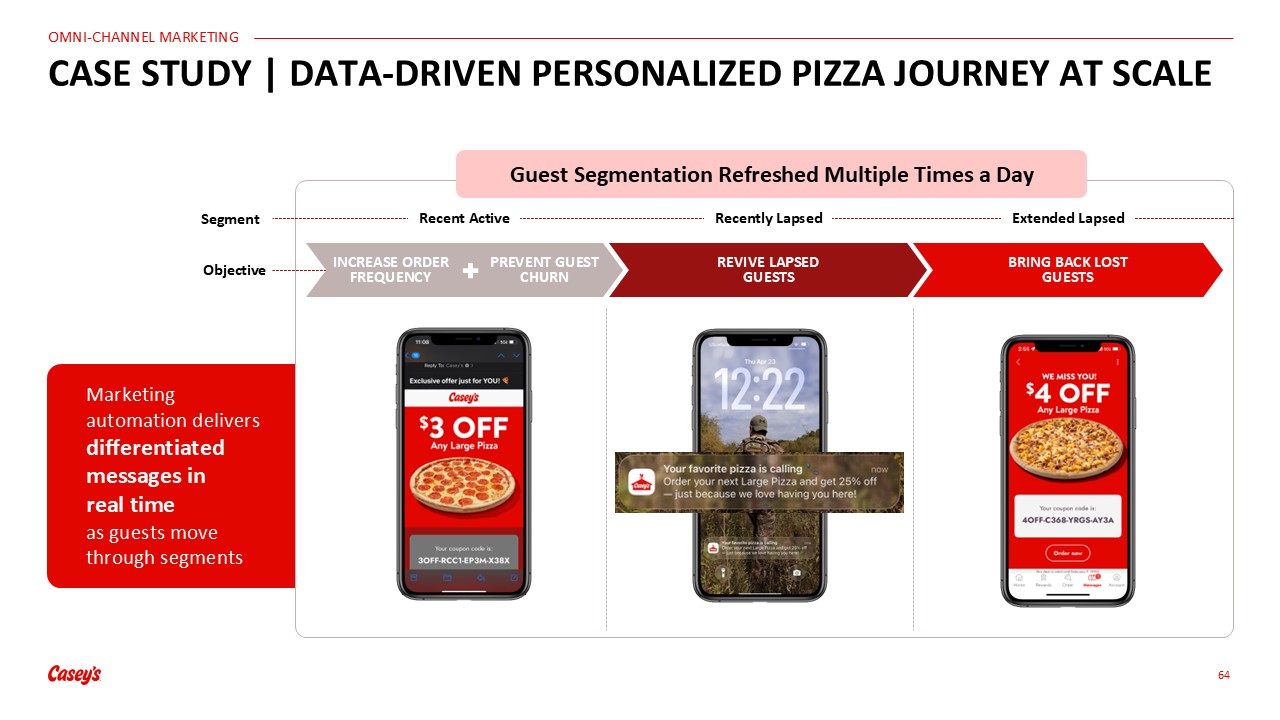
64 CASE STUDY | DATA-DRIVEN PERSONALIZED PIZZA JOURNEY AT SCALE Marketing
automation delivers differentiated messages in real time as guests move through segments Guest Segmentation Refreshed Multiple Times a Day Segment Recent Active Recently Lapsed Extended Lapsed Objective PREVENT GUEST CHURN REVIVE
LAPSED GUESTS BRING BACK LOST GUESTS INCREASE ORDER FREQUENCY

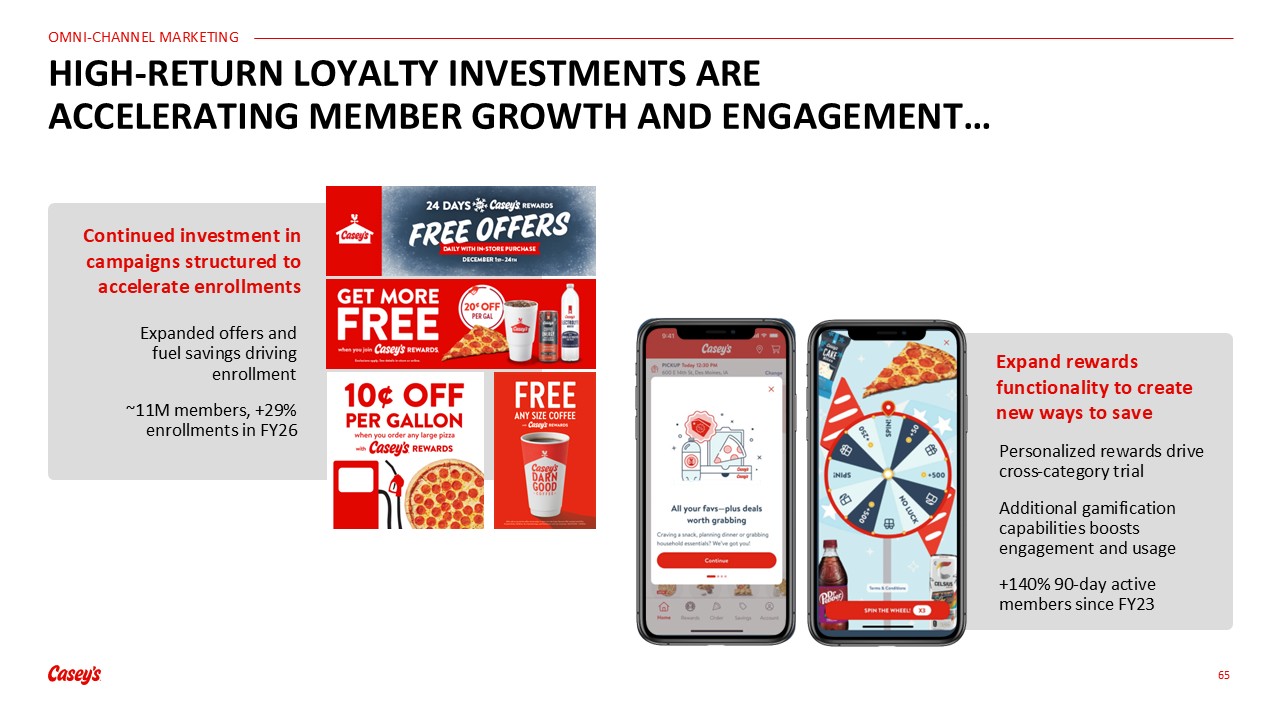
Continued investment in campaigns structured to accelerate enrollments Expanded
offers and fuel savings driving enrollment ~11M members, +29% enrollments in FY26 65 HIGH-RETURN LOYALTY INVESTMENTS ARE ACCELERATING MEMBER GROWTH AND ENGAGEMENT… Expand rewards functionality to create new ways to save Personalized rewards
drive cross-category trial Additional gamification capabilities boosts engagement and usage +140% 90-day active members since FY23

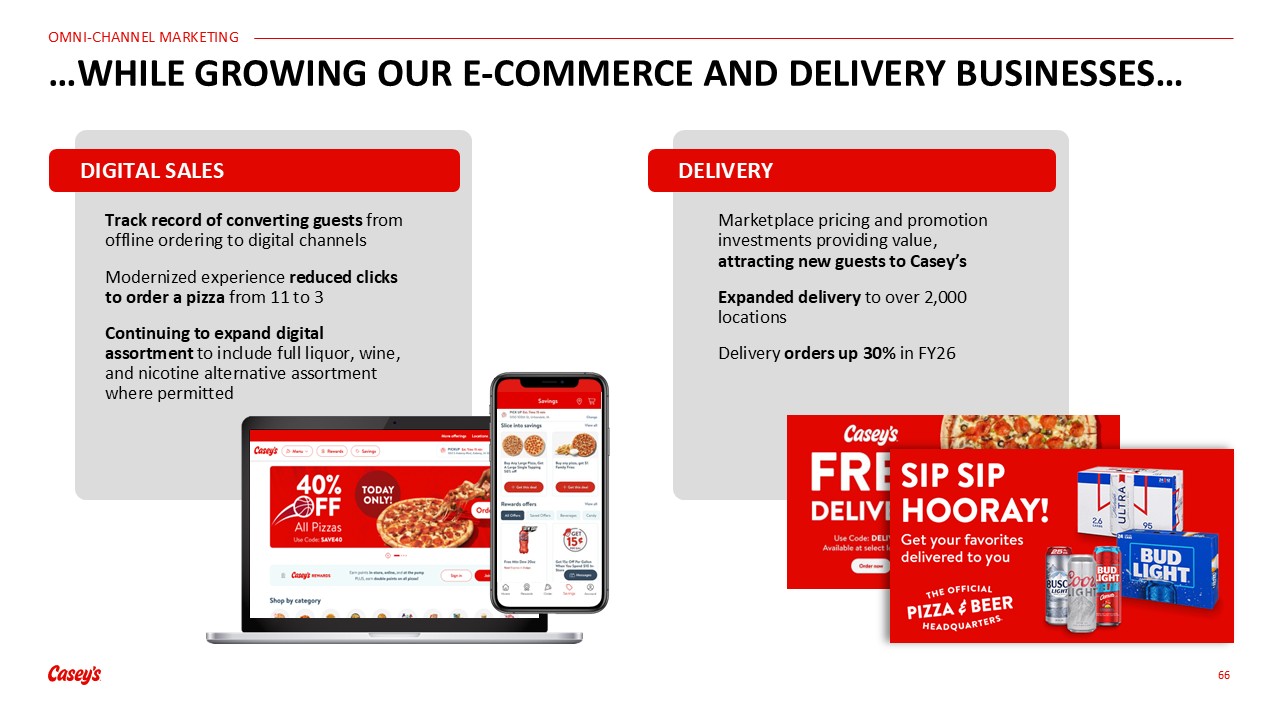
DIGITAL SALES DELIVERY Track record of converting guests from offline ordering to
digital channels Modernized experience reduced clicks to order a pizza from 11 to 3 Continuing to expand digital assortment to include full liquor, wine, and nicotine alternative assortment where permitted Marketplace pricing and promotion
investments providing value, attracting new guests to Casey’s Expanded delivery to over 2,000 locations Delivery orders up 30% in FY26 66 …WHILE GROWING OUR E-COMMERCE AND DELIVERY BUSINESSES…

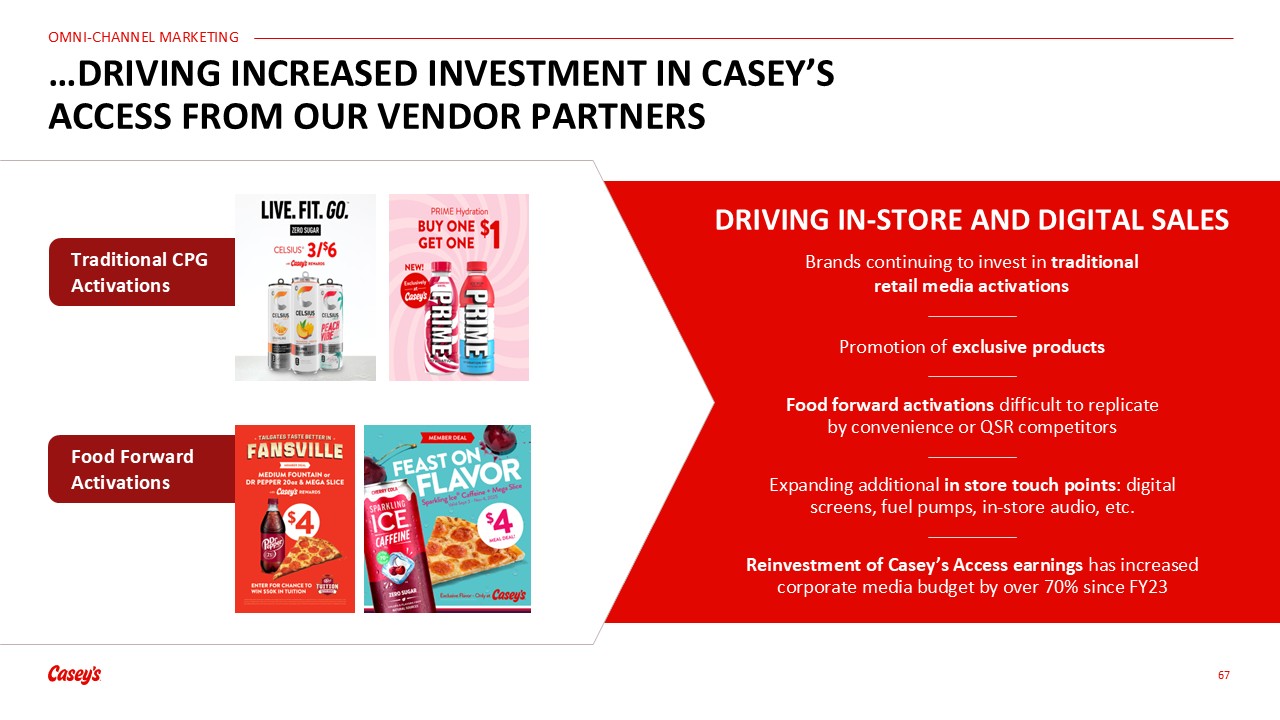
67 …DRIVING INCREASED INVESTMENT IN CASEY’S ACCESS FROM OUR VENDOR
PARTNERS Traditional CPG Activations Food Forward Activations DRIVING IN-STORE AND DIGITAL SALES Brands continuing to invest in traditional retail media activations Promotion of exclusive products Food forward activations difficult to
replicate by convenience or QSR competitors Expanding additional in store touch points: digital screens, fuel pumps, in-store audio, etc. Reinvestment of Casey’s Access earnings has increased corporate media budget by over 70% since FY23

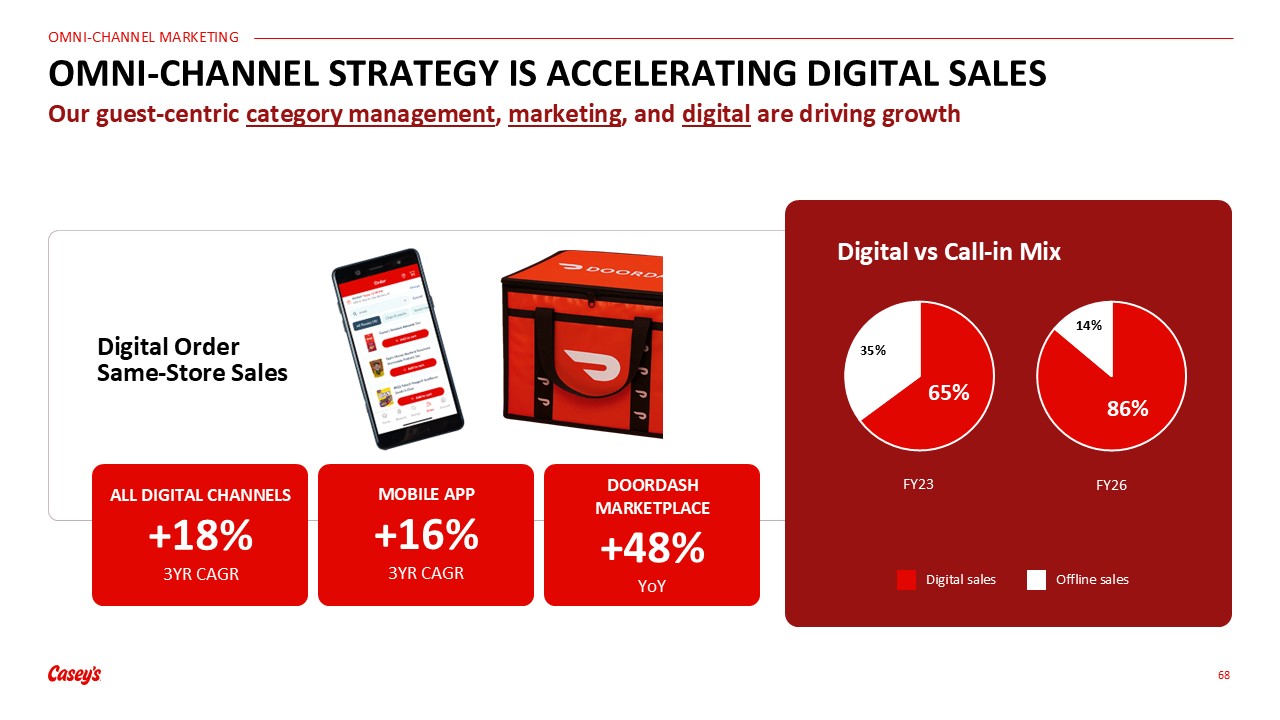
68 OMNI-CHANNEL STRATEGY IS ACCELERATING DIGITAL SALES Our guest-centric category
management, marketing, and digital are driving growth MOBILE APP +16% 3YR CAGR ALL DIGITAL CHANNELS+18% 3YR CAGR DOORDASH MARKETPLACE+48% YoY Digital Order Same-Store Sales Digital vs Call-in Mix FY23 FY26 Digital sales Offline sales

Deliver top quintile EBITDA growth of 8-10% SCALABLE Foundation Team Member Value
Proposition ACCELERATEFOOD AND BEVERAGE GROW THE NUMBER OF UNITS ENHANCE OPERATIONALEFFICIENCY 69 ACCELERATE FOOD AND BEVERAGE BRAD HAGA SVP, PREPARED FOOD & DISPENSED BEVERAGE THE GUEST

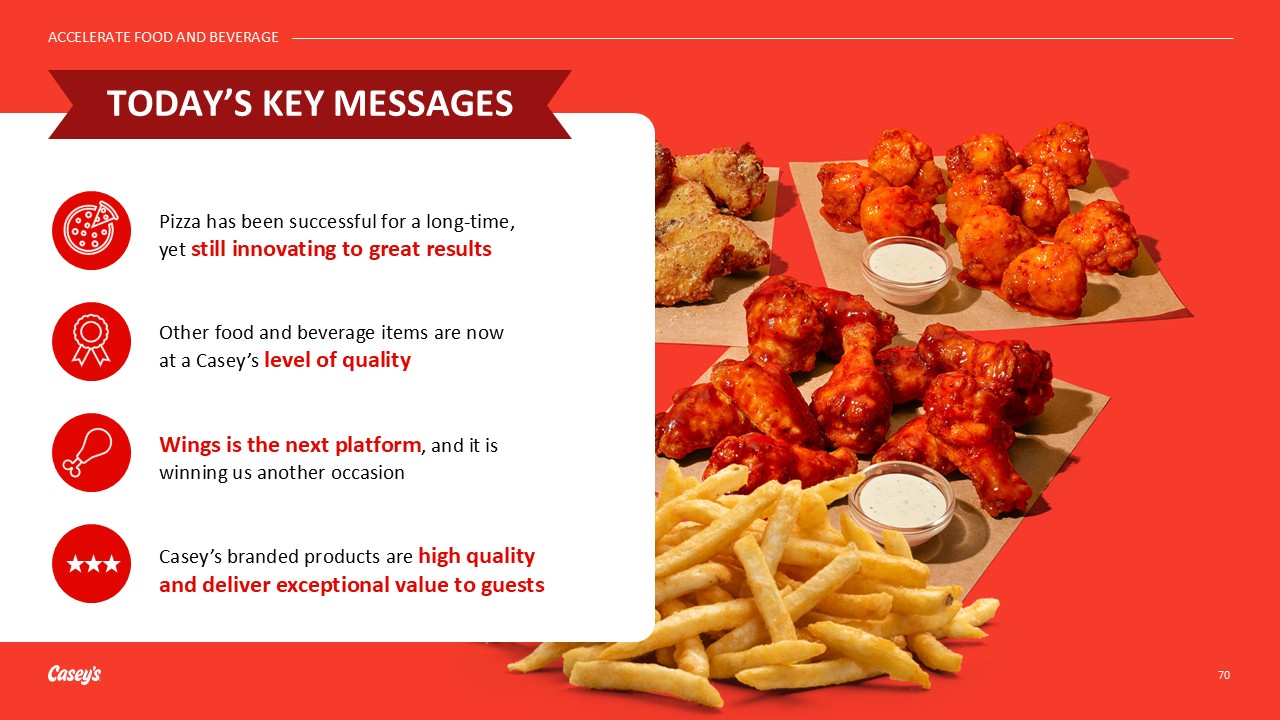
70 ACCELERATE FOOD AND BEVERAGE Wings is the next platform, and it is winning us
another occasion Other food and beverage items are now at a Casey’s level of quality Pizza has been successful for a long-time, yet still innovating to great results TODAY’S KEY MESSAGES Casey’s branded products are high quality and deliver
exceptional value to guests

OUR MENU HAS GROWN BEYOND PIZZA WINNING EVERY OCCASION 71 ACCELERATE FOOD AND
BEVERAGE

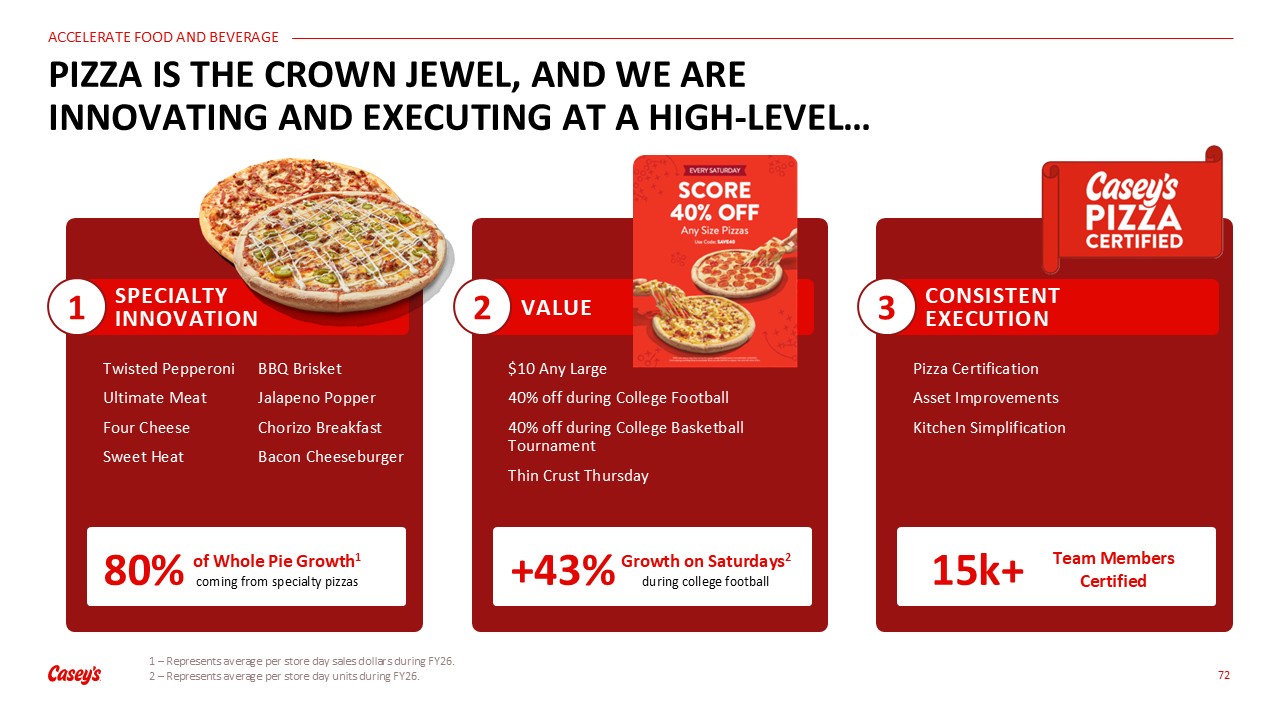
1 – Represents average per store day sales dollars during FY26. 2 – Represents
average per store day units during FY26. 72 PIZZA IS THE CROWN JEWEL, AND WE ARE INNOVATING AND EXECUTING AT A HIGH-LEVEL… Twisted Pepperoni Ultimate Meat Four Cheese Sweet Heat BBQ Brisket Jalapeno Popper Chorizo Breakfast Bacon
Cheeseburger 1 SPECIALTY INNOVATION of Whole Pie Growth1 coming from specialty pizzas 80% Pizza Certification Asset Improvements Kitchen Simplification 3 CONSISTENT EXECUTION $10 Any Large 40% off during College Football 40% off
during College Basketball Tournament Thin Crust Thursday 2 VALUE Growth on Saturdays2 during college football +43% Team Members Certified 15k+

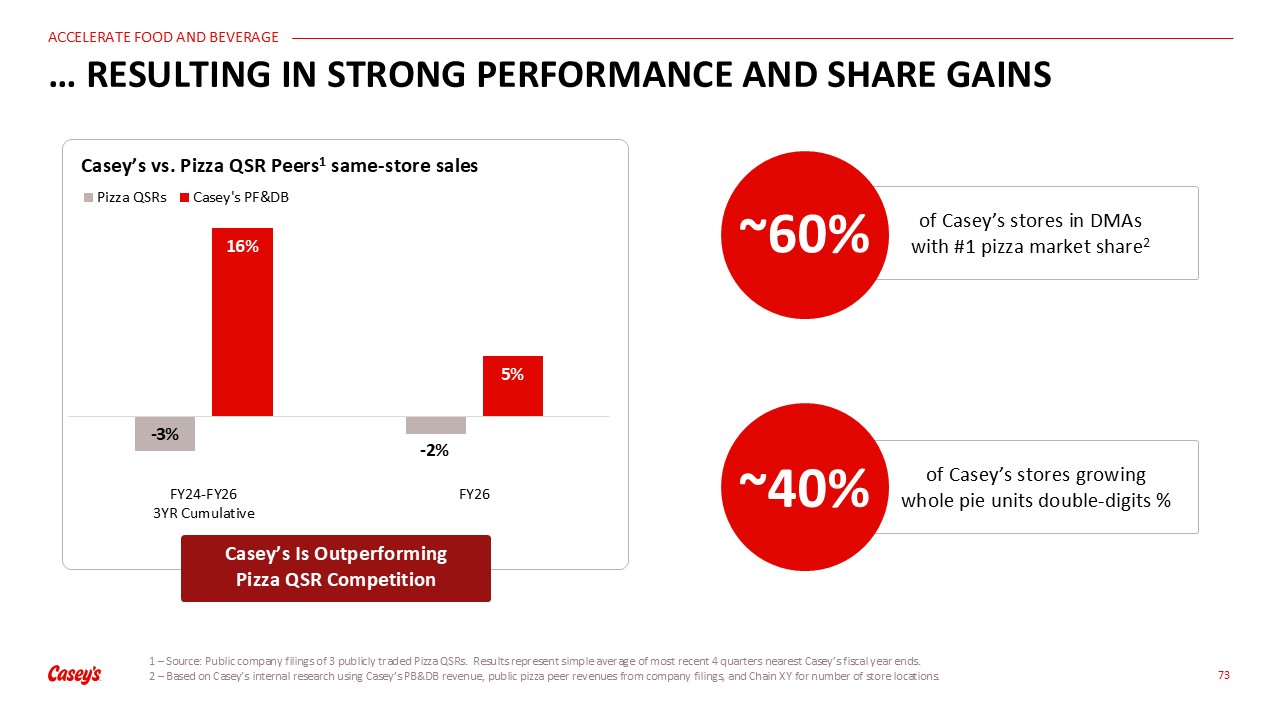
Casey’s Is Outperforming Pizza QSR Competition 1 – Source: Public company filings
of 3 publicly traded Pizza QSRs. Results represent simple average of most recent 4 quarters nearest Casey’s fiscal year ends. 2 – Based on Casey’s internal research using Casey’s PB&DB revenue, public pizza peer revenues from company
filings, and Chain XY for number of store locations. 73 … RESULTING IN STRONG PERFORMANCE AND SHARE GAINS Casey’s vs. Pizza QSR Peers1 same-store sales ~60% of Casey’s stores in DMAs with #1 pizza market share2 ~40% of Casey’s stores
growing whole pie units double-digits %

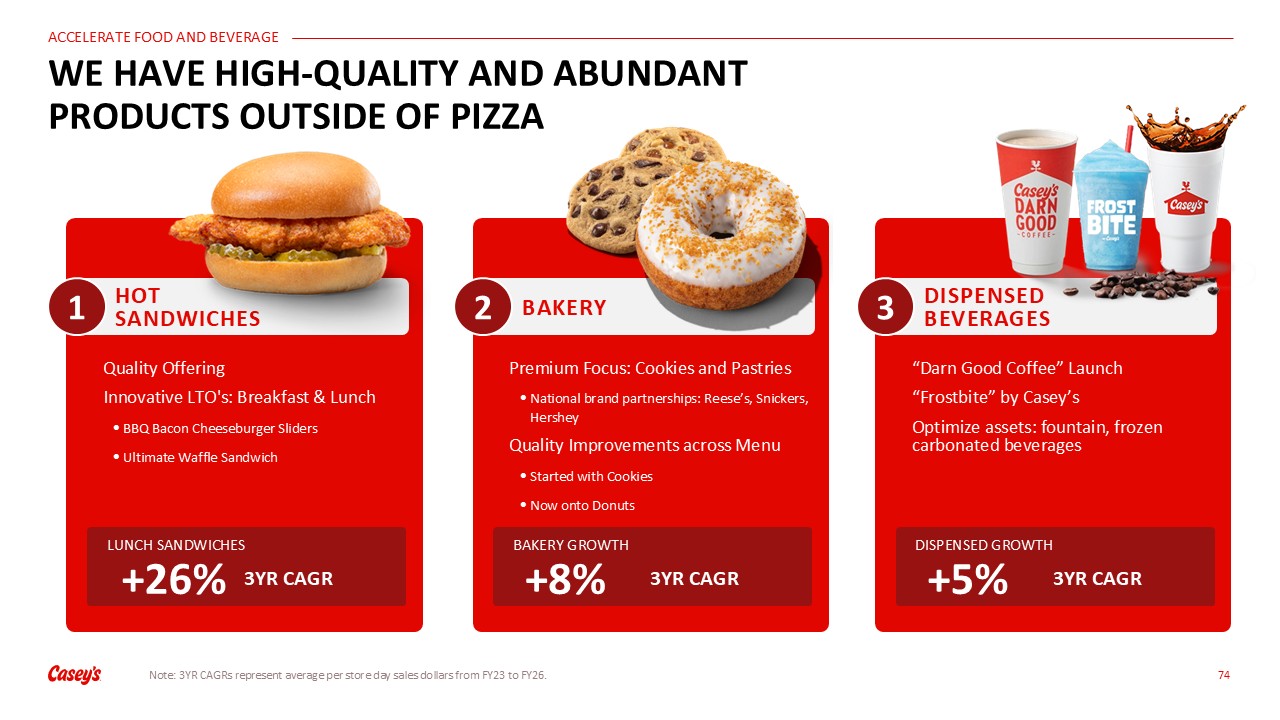
Note: 3YR CAGRs represent average per store day sales dollars from FY23 to
FY26. 74 WE HAVE HIGH-QUALITY AND ABUNDANT PRODUCTS OUTSIDE OF PIZZA Quality Offering Innovative LTO's: Breakfast & Lunch BBQ Bacon Cheeseburger Sliders Ultimate Waffle Sandwich 1 HOT SANDWICHES LUNCH SANDWICHES 3YR CAGR +26%
Premium Focus: Cookies and Pastries National brand partnerships: Reese’s, Snickers, Hershey Quality Improvements across Menu Started with Cookies Now onto Donuts 2 BAKERY BAKERY GROWTH 3YR CAGR +8% “Darn Good Coffee”
Launch “Frostbite” by Casey’s Optimize assets: fountain, frozen carbonated beverages 3 DISPENSED BEVERAGES DISPENSED GROWTH 3YR CAGR +5%

Video: Casey’s Innovation Process 75

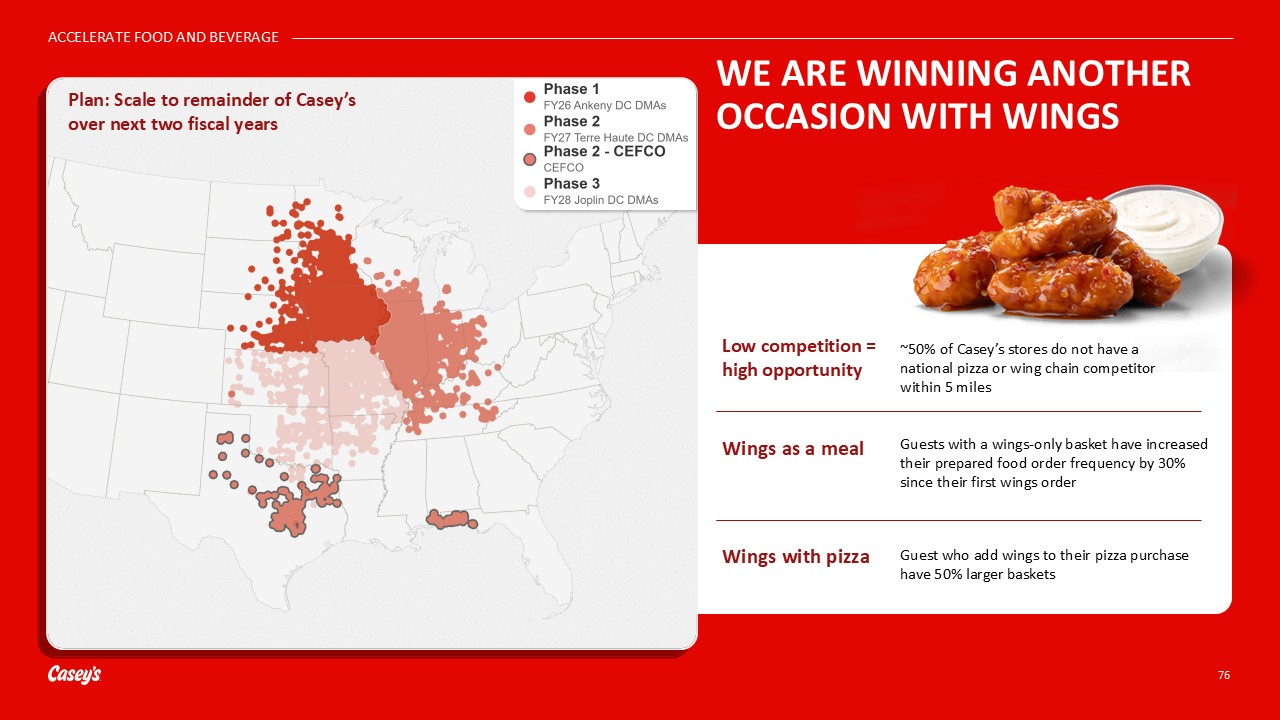
Scale to remainder of Casey’s stores over next 2 years 76 WE ARE WINNING ANOTHER
OCCASION WITH WINGS Low competition = high opportunity Wings as a meal Wings with pizza ~50% of Casey’s stores do not have a national pizza or wing chain competitor within 5 miles Guests with a wings-only basket have increased their prepared
food order frequency by 30% since their first wings order Guest who add wings to their pizza purchase have 50% larger baskets Plan: Scale to remainder of Casey’s over next two fiscal years

77 THE CASEY’S BRAND IS HIGH-QUALITY AT A GREAT VALUE FOR GUESTS Growing SKU
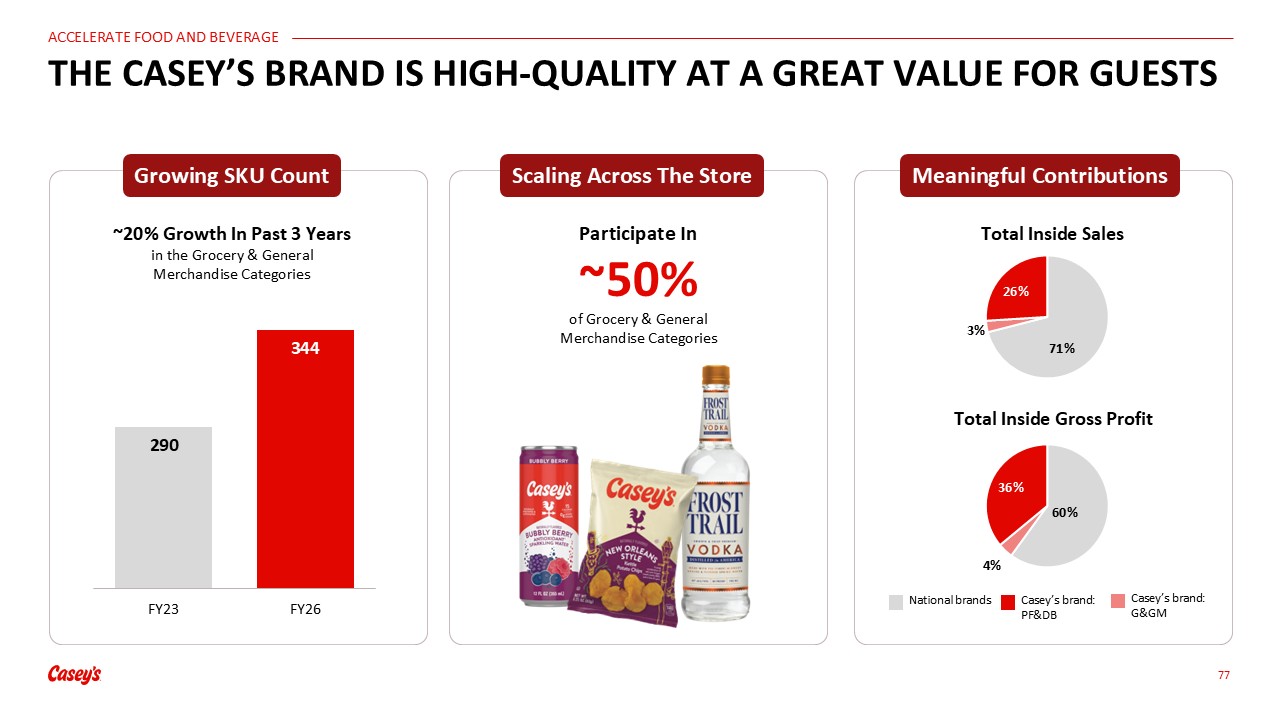
Count ~20% Growth In Past 3 Years in the Grocery & General Merchandise Categories Scaling Across The Store Participate In ~50% of Grocery & General Merchandise Categories Meaningful Contributions Total Inside Sales Total Inside
Gross Profit National brands Casey’s brand:PF&DB Casey’s brand:G&GM

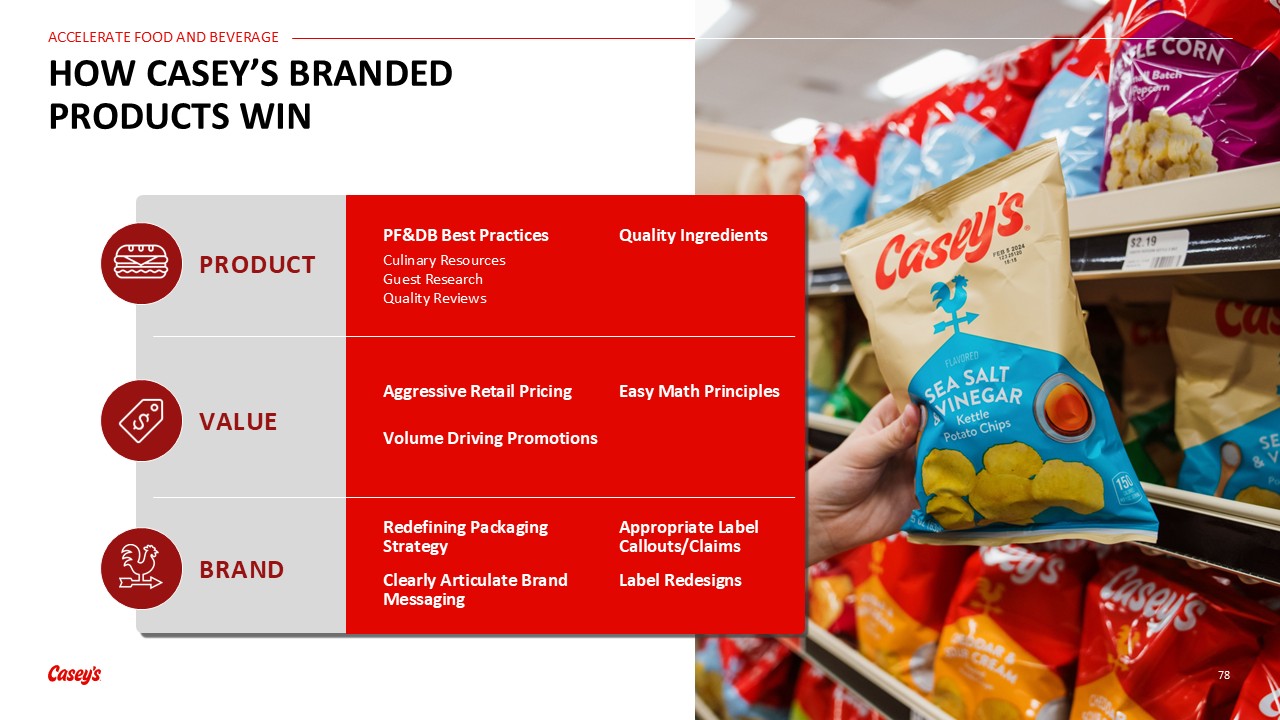
HOW CASEY’S BRANDED PRODUCTS WIN PF&DB Best Practices PRODUCT Culinary
Resources Guest Research Quality Reviews Quality Ingredients Redefining Packaging Strategy Clearly Articulate Brand Messaging BRAND Appropriate Label Callouts/Claims Label Redesigns Aggressive Retail Pricing VALUE Easy Math
Principles Volume Driving Promotions 78

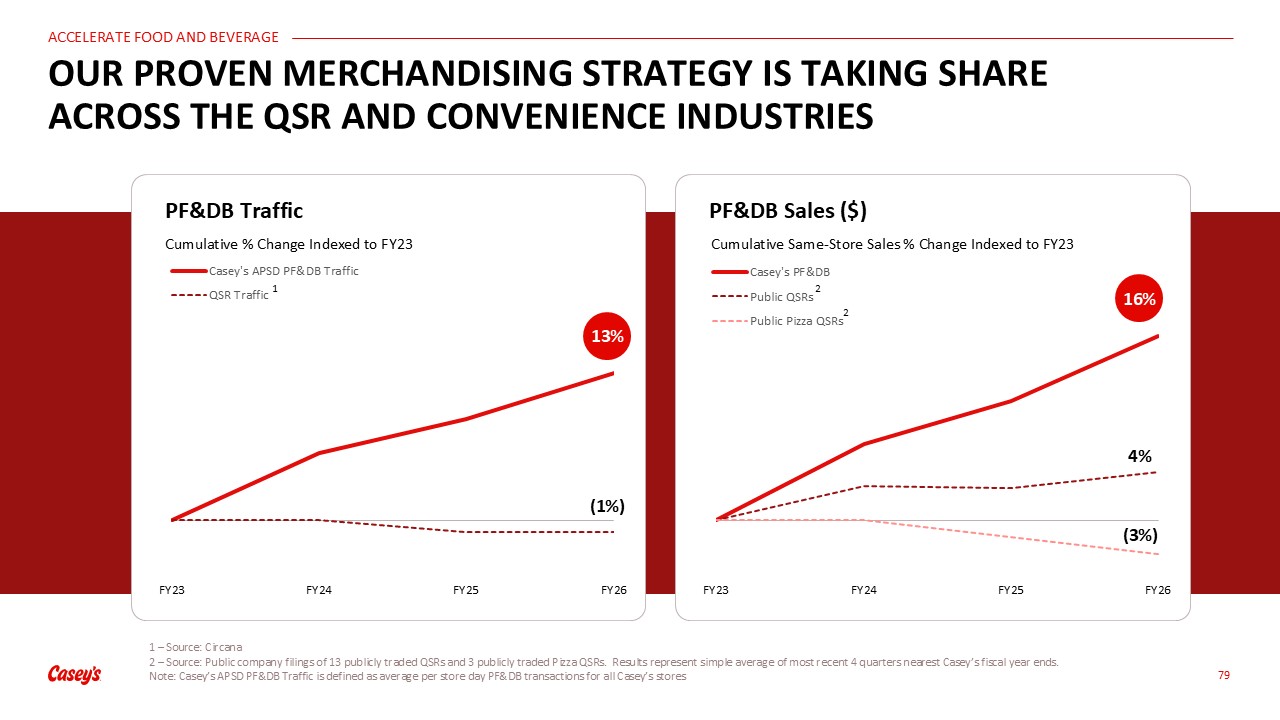
OUR PROVEN MERCHANDISING STRATEGY IS TAKING SHARE ACROSS THE QSR AND CONVENIENCE
INDUSTRIES 79 PF&DB Traffic (1%) 13% 1 – Source: Circana 2 – Source: Public company filings of 13 publicly traded QSRs and 3 publicly traded Pizza QSRs. Results represent simple average of most recent 4 quarters nearest Casey’s fiscal
year ends. Note: Casey’s APSD PF&DB Traffic is defined as average per store day PF&DB transactions for all Casey’s stores PF&DB Sales ($) 4% (3%) 16% 2 2 1

80 GROW THE NUMBER OF UNITS ENA WILLIAMS CHIEF OPERATING OFFICER Deliver top
quintile EBITDA growth of 8-10% SCALABLE Foundation Team Member Value Proposition THE GUEST ACCELERATEFOOD AND BEVERAGE GROW THE NUMBER OF UNITS ENHANCE OPERATIONALEFFICIENCY

Significant white space opportunity supports long runway of future
growth 3 Dual-engine approach delivers consistent unit growth at highly attractive economics 2 Long track record of ratable unit growth 1 KEY MESSAGES 81

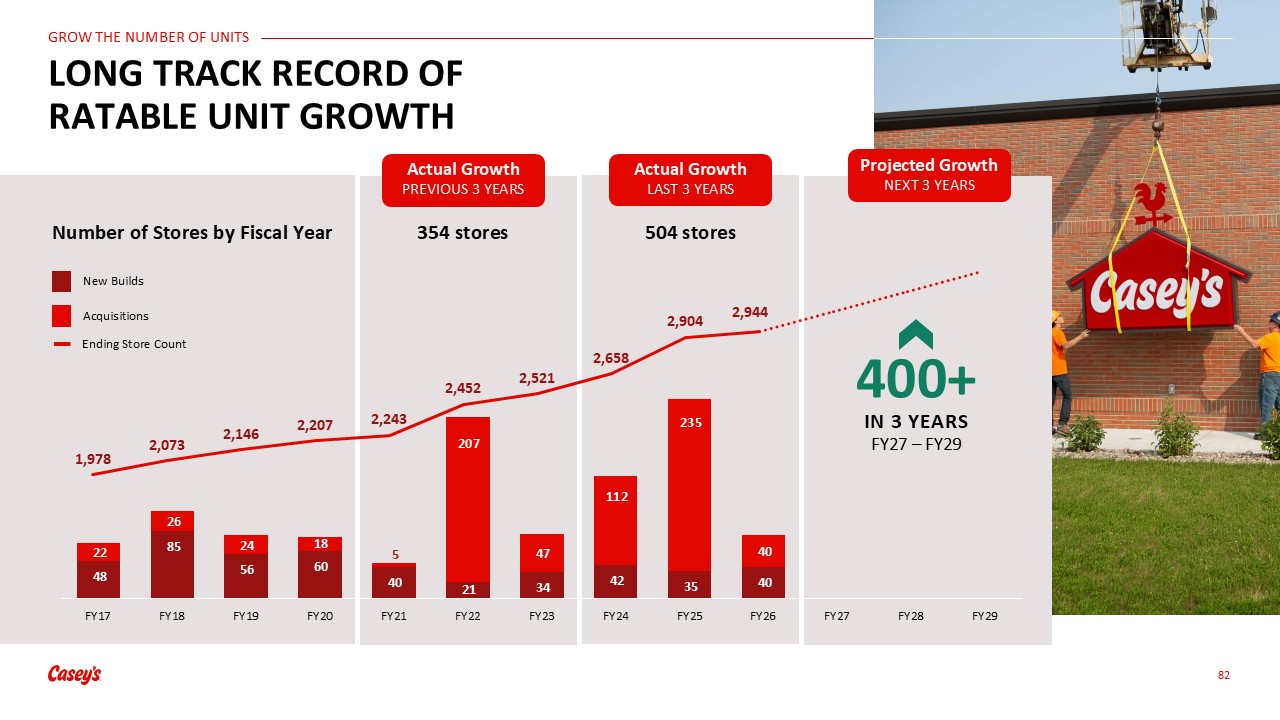
82 LONG TRACK RECORD OF RATABLE UNIT GROWTH Actual Growth LAST 3 YEARS Projected
Growth NEXT 3 YEARS Number of Stores by Fiscal Year Acquisitions New Builds Ending Store Count 400+ IN 3 YEARS FY27 – FY29 Actual Growth PREVIOUS 3 YEARS 504 stores 354 stores

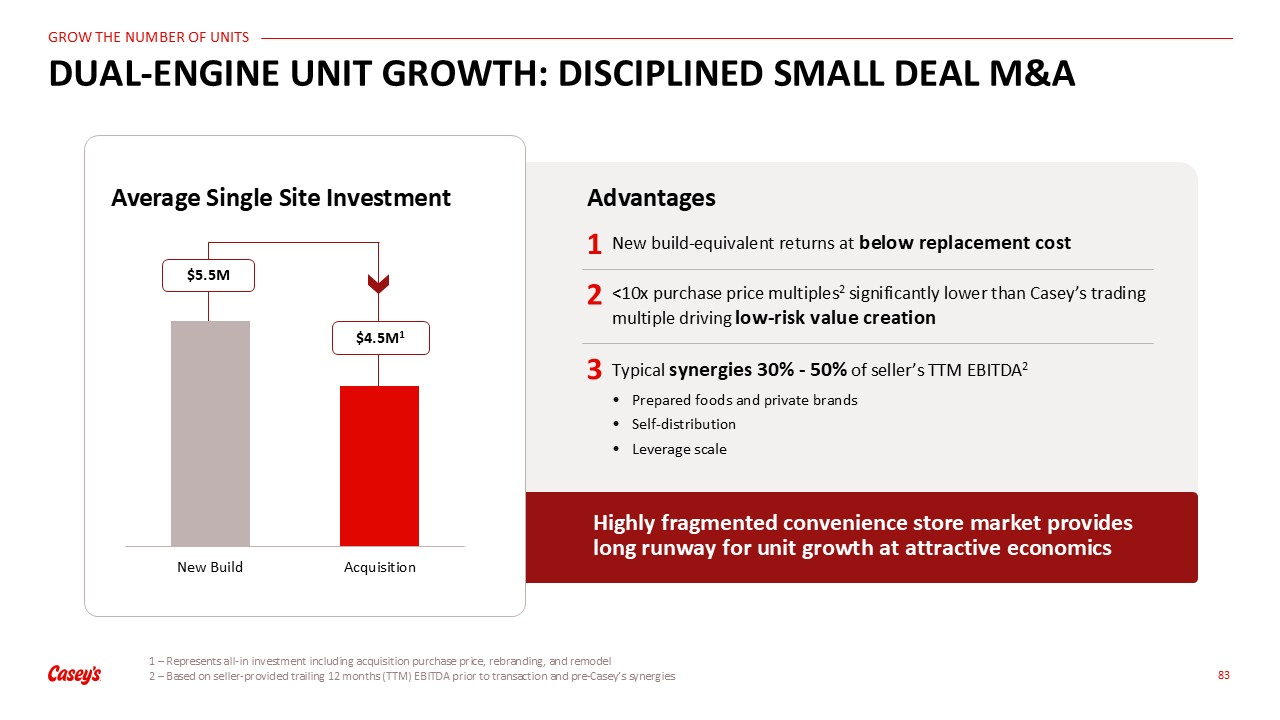
1 – Represents all-in investment including acquisition purchase price, rebranding,
and remodel 2 – Based on seller-provided trailing 12 months (TTM) EBITDA prior to transaction and pre-Casey’s synergies 83 DUAL-ENGINE UNIT GROWTH: DISCIPLINED SMALL DEAL M&A Average Single Site Investment $4.5M1 $5.5M New
build-equivalent returns at below replacement cost <10x purchase price multiples2 significantly lower than Casey’s trading multiple driving low-risk value creation Typical synergies 30% - 50% of seller’s TTM EBITDA2 Prepared foods and
private brands Self-distribution Leverage scale Advantages Highly fragmented convenience store market provides long runway for unit growth at attractive economics 1 2 3

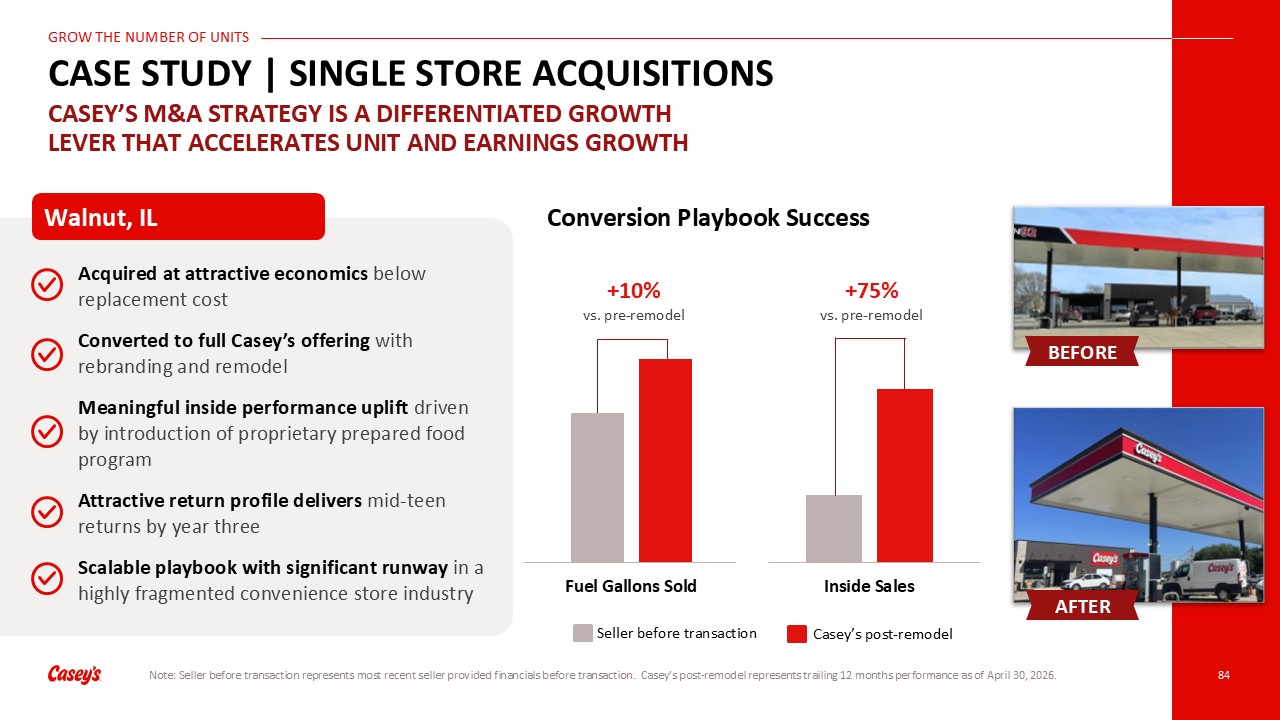
84 CASE STUDY | SINGLE STORE ACQUISITIONS CASEY’S M&A STRATEGY IS A
DIFFERENTIATED GROWTH LEVER THAT ACCELERATES UNIT AND EARNINGS GROWTH Seller before transaction Conversion Playbook Success Acquired at attractive economics below replacement cost Converted to full Casey’s offering with rebranding and
remodel Meaningful inside performance uplift driven by introduction of proprietary prepared food program Attractive return profile delivers mid-teen returns by year three Scalable playbook with significant runway in a highly fragmented
convenience store industry Casey’s post-remodel +10% vs. pre-remodel +75% vs. pre-remodel Walnut, IL BEFORE AFTER Note: Seller before transaction represents most recent seller provided financials before transaction. Casey’s post-remodel
represents trailing 12 months performance as of April 30, 2026.

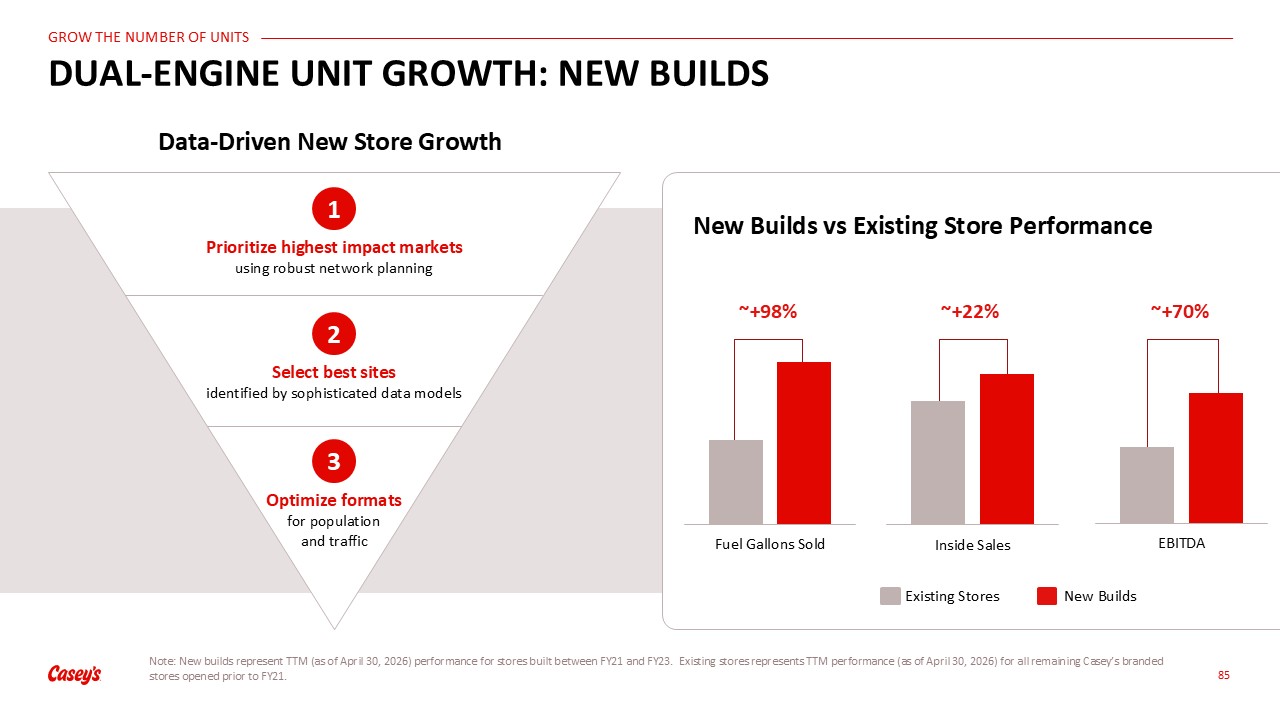
Data-Driven New Store Growth Note: New builds represent TTM (as of April 30, 2026)
performance for stores built between FY21 and FY23. Existing stores represents TTM performance (as of April 30, 2026) for all remaining Casey’s branded stores opened prior to FY21. 85 DUAL-ENGINE UNIT GROWTH: NEW BUILDS Existing Stores New
Builds vs Existing Store Performance New Builds 1 Prioritize highest impact marketsusing robust network planning 2 Select best sitesidentified by sophisticated data models 3 Optimize formatsfor populationand traffic ~+98% ~+70% ~+22%

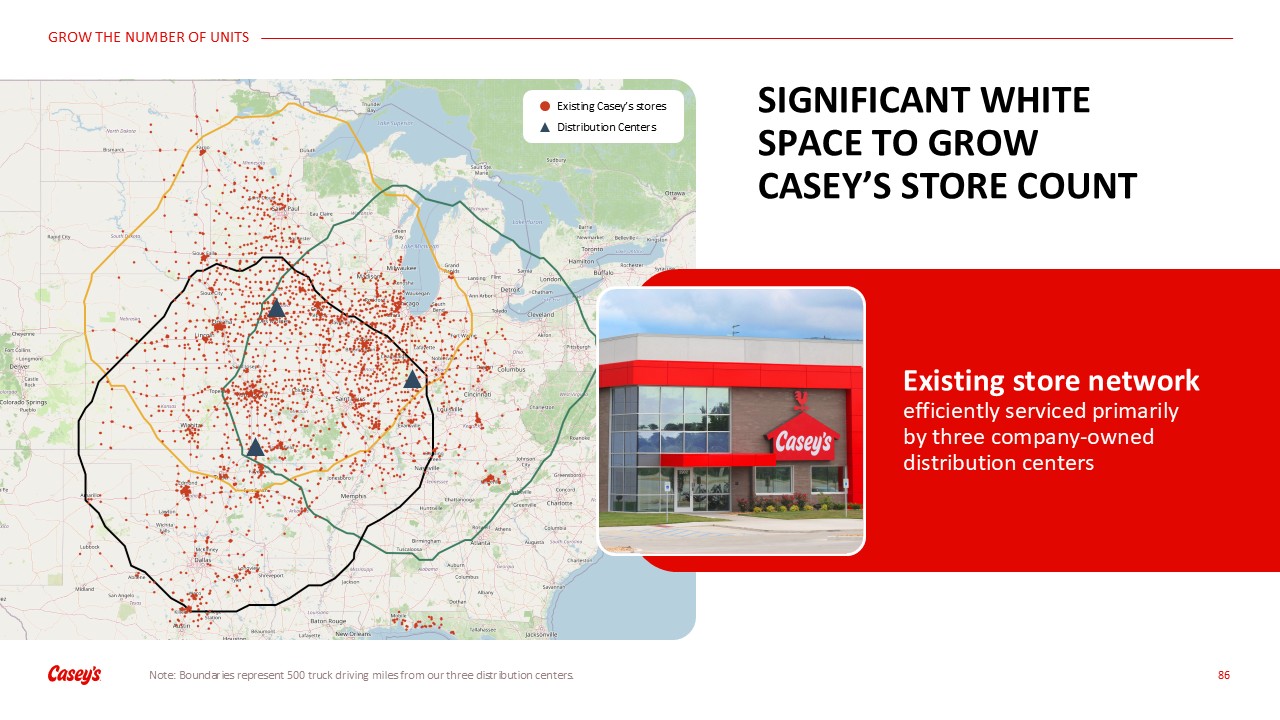
SIGNIFICANT WHITE SPACE TO GROW CASEY’S STORE COUNT 86 Note: Boundaries represent
500 truck driving miles from our three distribution centers. Existing store network efficiently serviced primarily by three company-owned distribution centers Existing Casey’s stores Distribution Centers

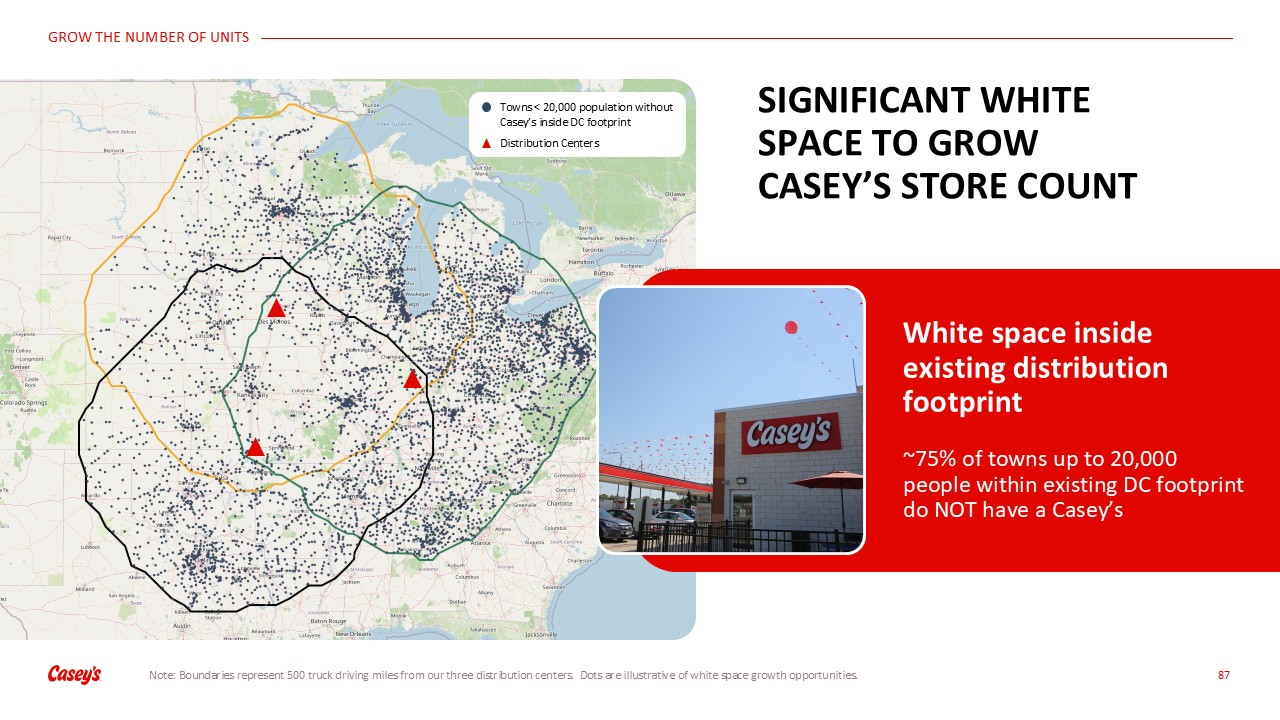
SIGNIFICANT WHITE SPACE TO GROW CASEY’S STORE COUNT 87 Note: Boundaries represent
500 truck driving miles from our three distribution centers. Dots are illustrative of white space growth opportunities. White space inside existing distribution footprint ~75% of towns up to 20,000 people within existing DC footprint do NOT
have a Casey’s Towns < 20,000 population without Casey’s inside DC footprint Distribution Centers

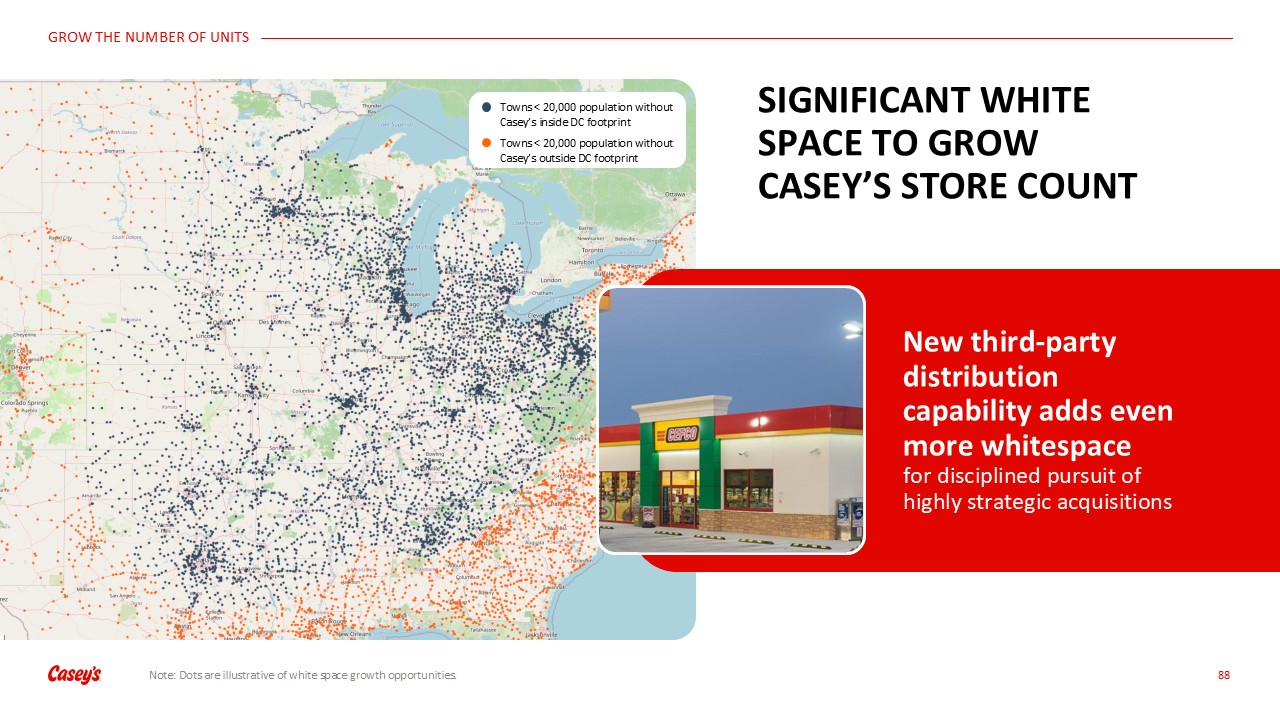
SIGNIFICANT WHITE SPACE TO GROW CASEY’S STORE COUNT 88 Note: Dots are
illustrative of white space growth opportunities. New third-party distribution capability adds even more whitespace for disciplined pursuit of highly strategic acquisitions Towns < 20,000 population without Casey’s inside DC footprint Towns
< 20,000 population without Casey’s outside DC footprint

Video: Built the Casey’s Way 89

90 ENHANCE OPERATIONAL EFFICIENCY ENA WILLIAMS CHIEF OPERATING OFFICER Deliver
top quintile EBITDA growth of 8-10% ACCELERATEFOOD AND BEVERAGE SCALABLE Foundation Team Member Value Proposition GROW THE NUMBER OF UNITS ENHANCE OPERATIONALEFFICIENCY THE GUEST

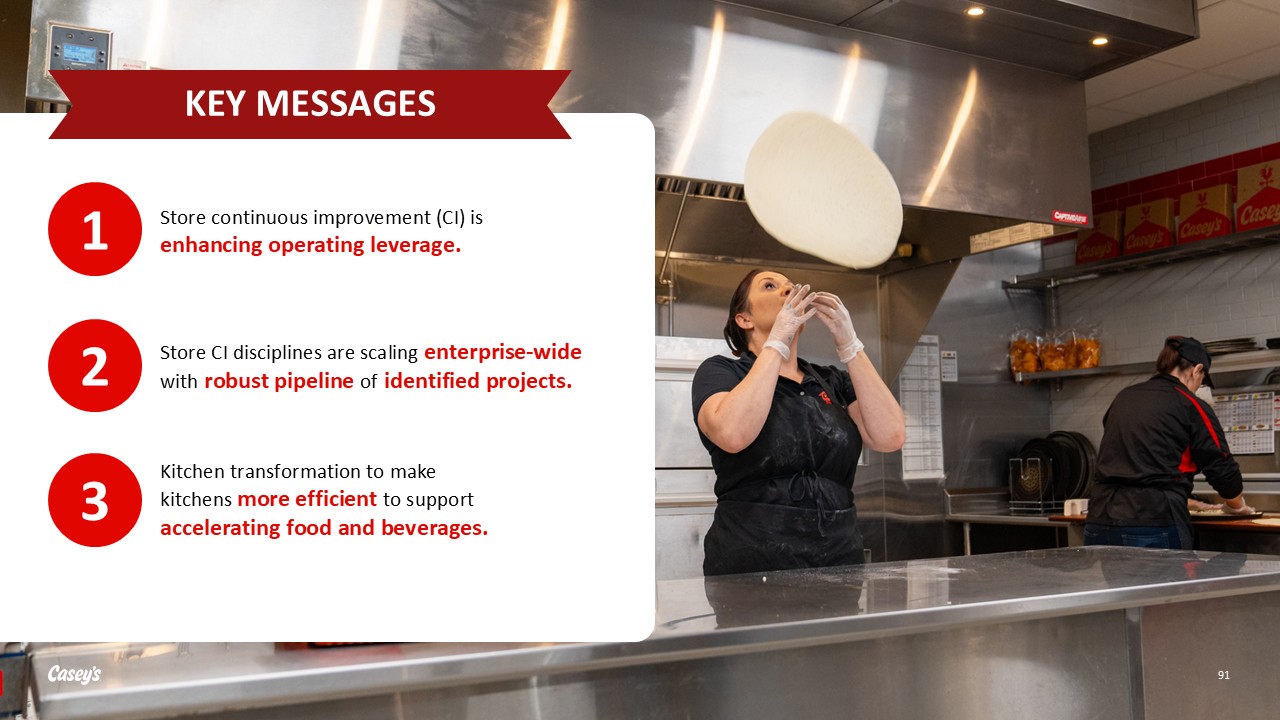
Kitchen transformation to make kitchens more efficient to support accelerating food
and beverages. 3 Store CI disciplines are scaling enterprise-wide with robust pipeline of identified projects. 2 Store continuous improvement (CI) is enhancing operating leverage. 1 KEY MESSAGES 91

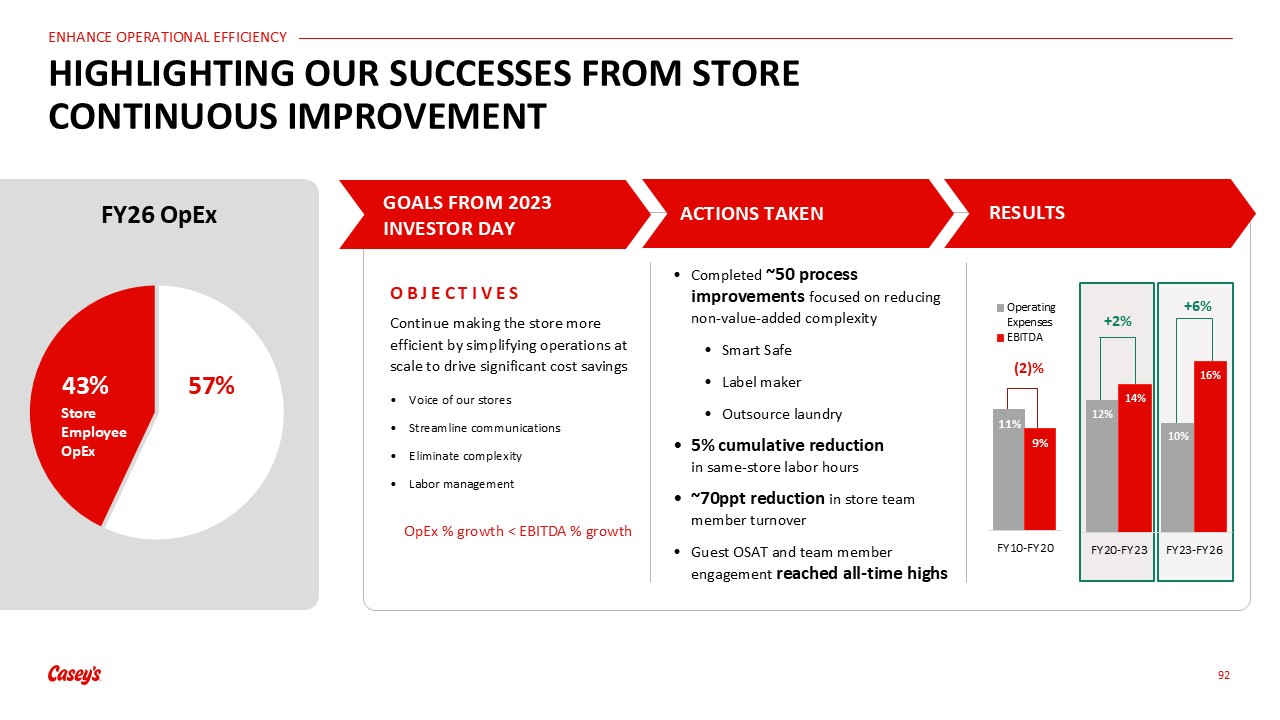
92 HIGHLIGHTING OUR SUCCESSES FROM STORE CONTINUOUS IMPROVEMENT GOALS FROM 2023
INVESTOR DAY OBJECTIVES Continue making the store more efficient by simplifying operations at scale to drive significant cost savings Voice of our stores Streamline communications Eliminate complexity Labor management OpEx % growth
< EBITDA % growth Completed ~50 process improvements focused on reducing non-value-added complexity Smart Safe Label maker Outsource laundry 5% cumulative reduction in same-store labor hours ~70ppt reduction in store team member
turnover Guest OSAT and team member engagement reached all-time highs ACTIONS TAKEN RESULTS FY26 OpEx Store Employee OpEx

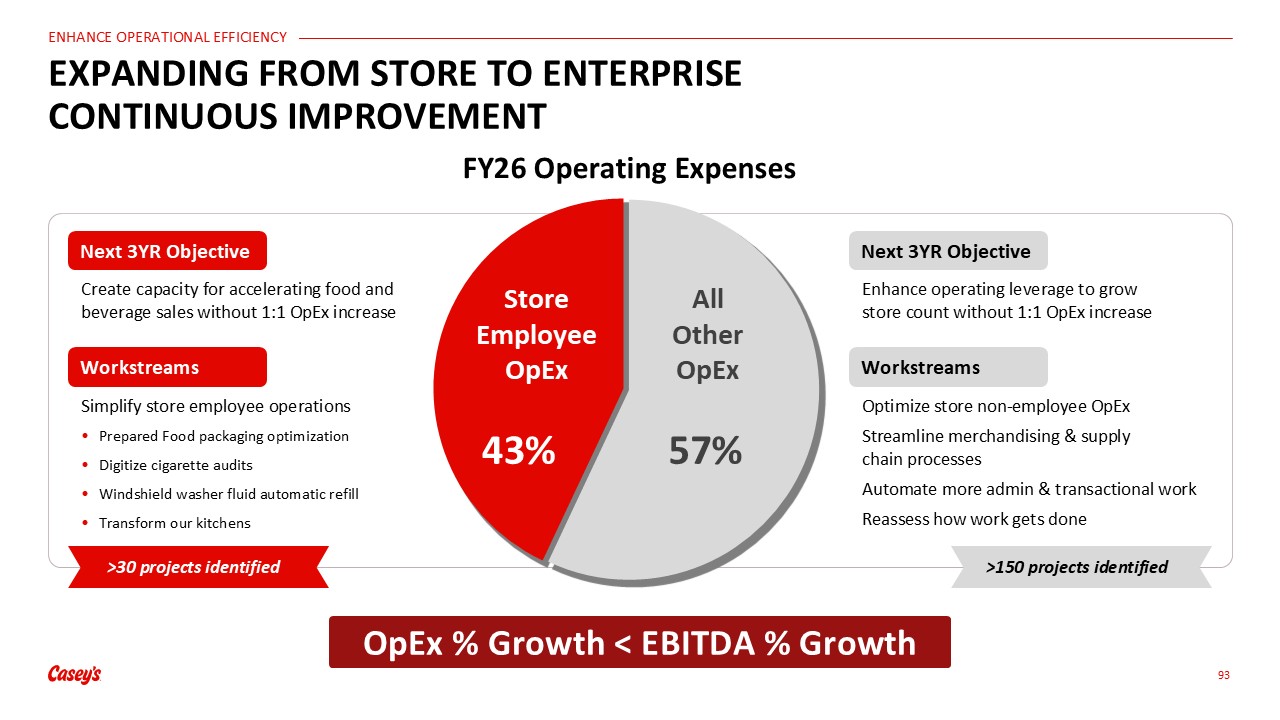
EXPANDING FROM STORE TO ENTERPRISE CONTINUOUS IMPROVEMENT FY26 Operating
Expenses Store Employee OpEx All Other OpEx 43% 57% Next 3YR Objective Create capacity for accelerating food and beverage sales without 1:1 OpEx increase Workstreams Simplify store employee operations Prepared Food packaging
optimization Digitize cigarette audits Windshield washer fluid automatic refill Transform our kitchens >30 projects identified Next 3YR Objective Enhance operating leverage to grow store count without 1:1 OpEx
increase Workstreams Optimize store non-employee OpEx >150 projects identified Streamline merchandising & supply chain processes Automate more admin & transactional work Reassess how work gets done OpEx % Growth < EBITDA %
Growth 93

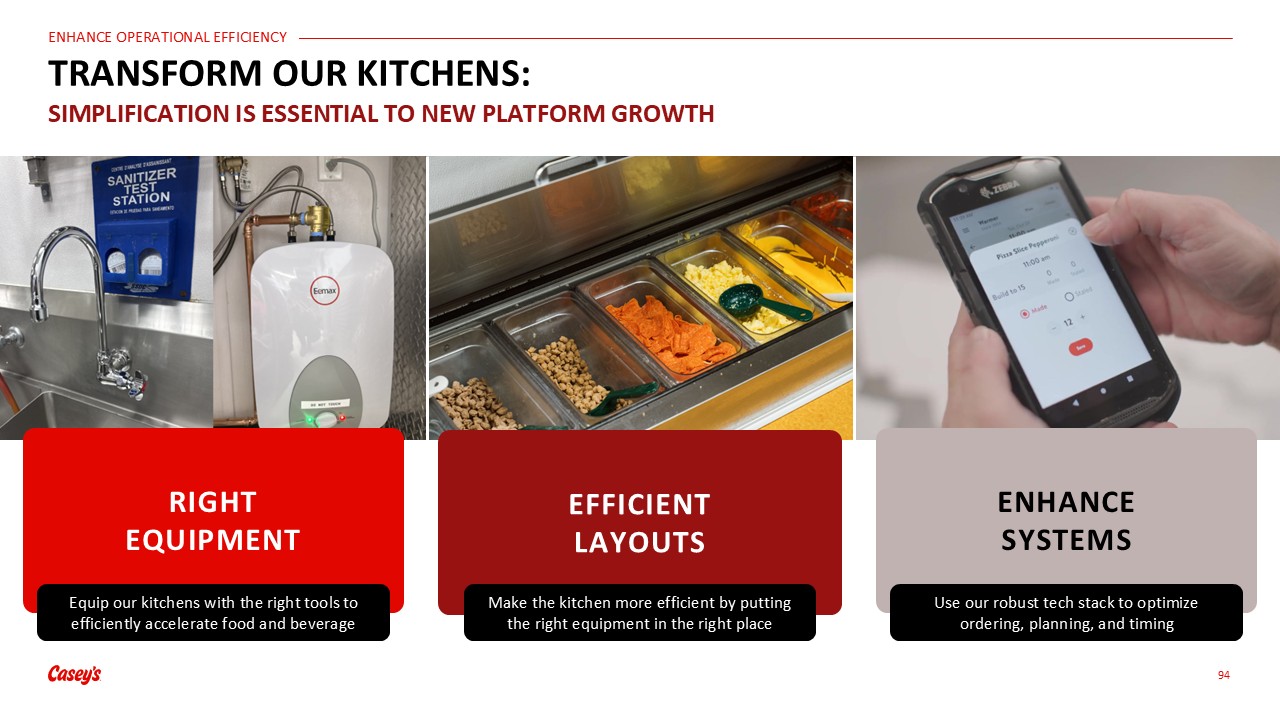
94 TRANSFORM OUR KITCHENS: SIMPLIFICATION IS ESSENTIAL TO NEW PLATFORM GROWTH
RIGHT EQUIPMENT EFFICIENTLAYOUTS ENHANCE SYSTEMS Equip our kitchens with the right tools to efficiently accelerate food and beverage Make the kitchen more efficient by putting the right equipment in the right place Use our robust tech
stack to optimize ordering, planning, and timing

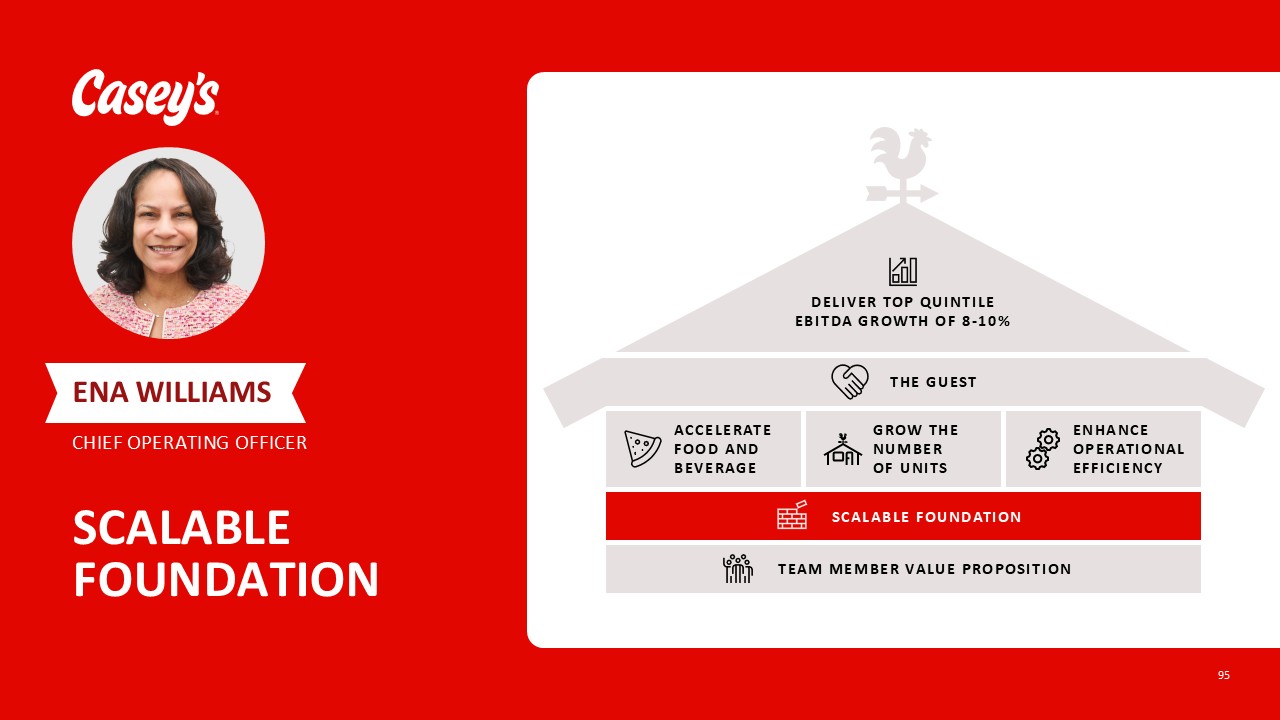
95 SCALABLE FOUNDATION ENA WILLIAMS CHIEF OPERATING OFFICER Deliver top
quintileEBITDA growth of 8-10% SCALABLE Foundation Team Member Value Proposition GROW THE NUMBER OF UNITS ENHANCE OPERATIONALEFFICIENCY ACCELERATEFOOD AND BEVERAGE THE GUEST

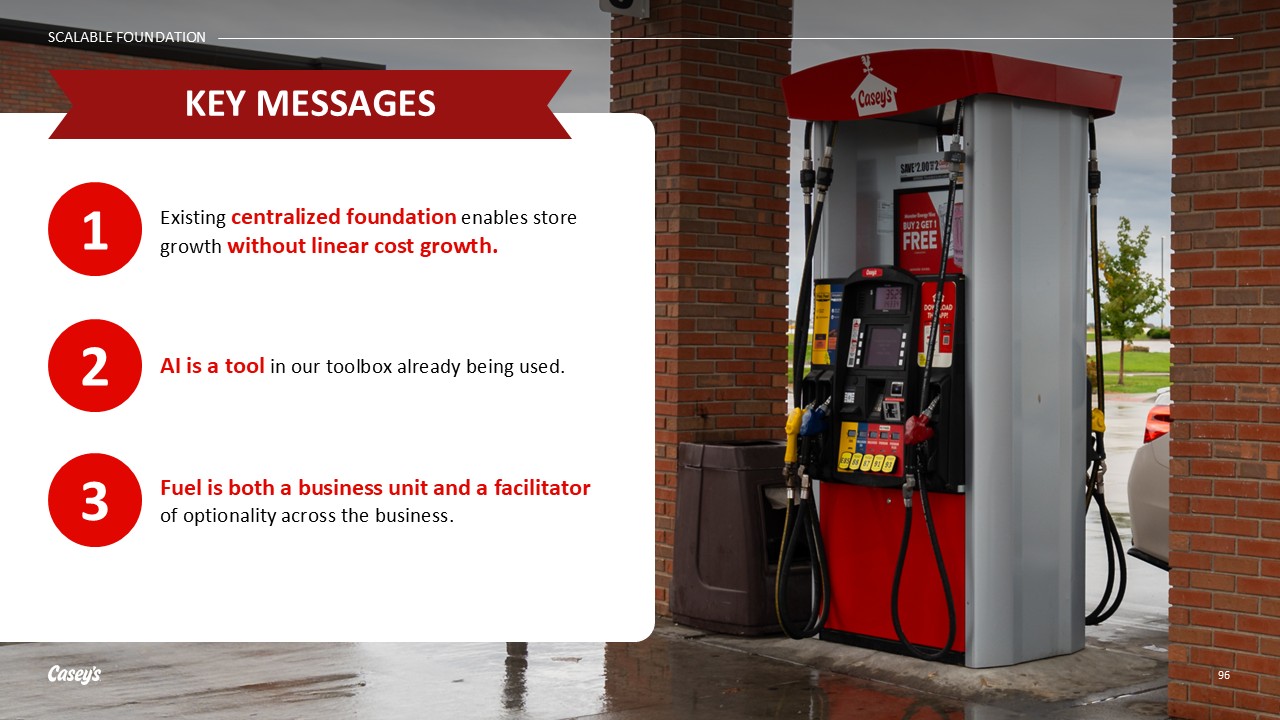
96 Fuel is both a business unit and a facilitator of optionality across the
business. 3 AI is a tool in our toolbox already being used. 2 Existing centralized foundation enables store growth without linear cost growth. 1 KEY MESSAGES SCALABLE FOUNDATION

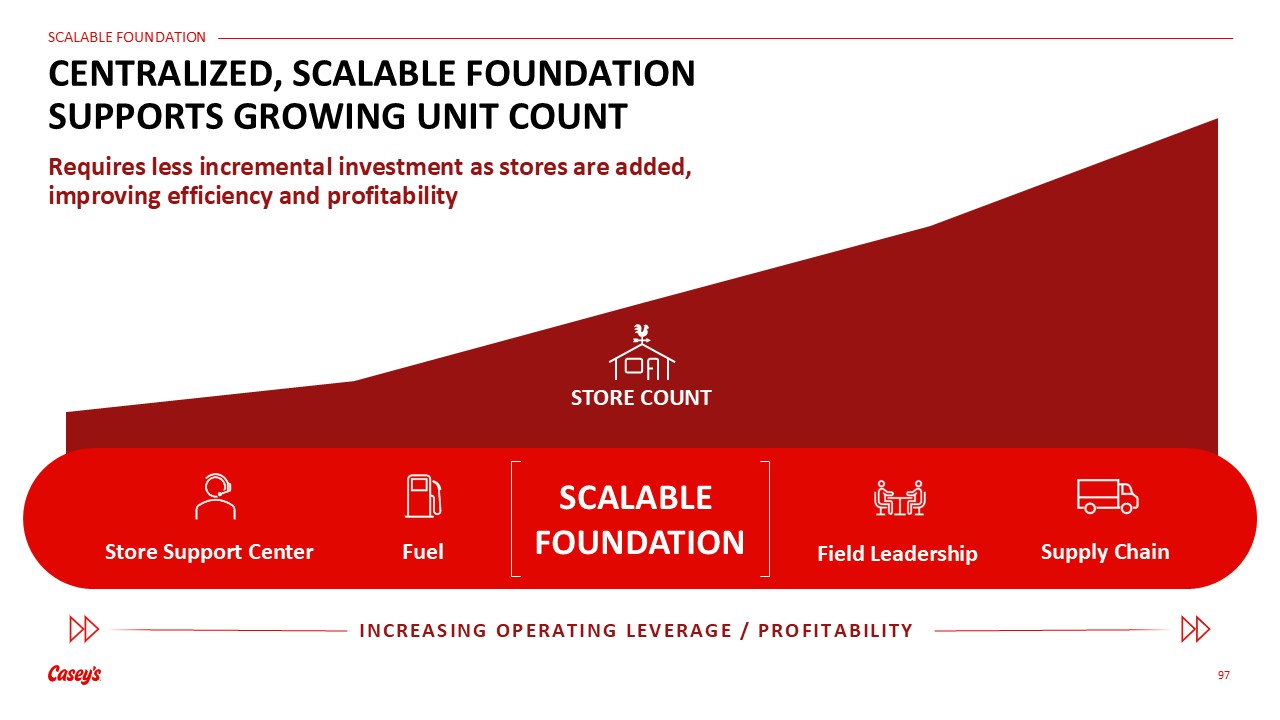
97 CENTRALIZED, SCALABLE FOUNDATION SUPPORTS GROWING UNIT COUNT INCREASING
OPERATING LEVERAGE / PROFITABILITY Fuel Field Leadership Supply Chain Store Support Center STORE COUNT SCALABLE Foundation Requires less incremental investment as stores are added, improving efficiency and profitability

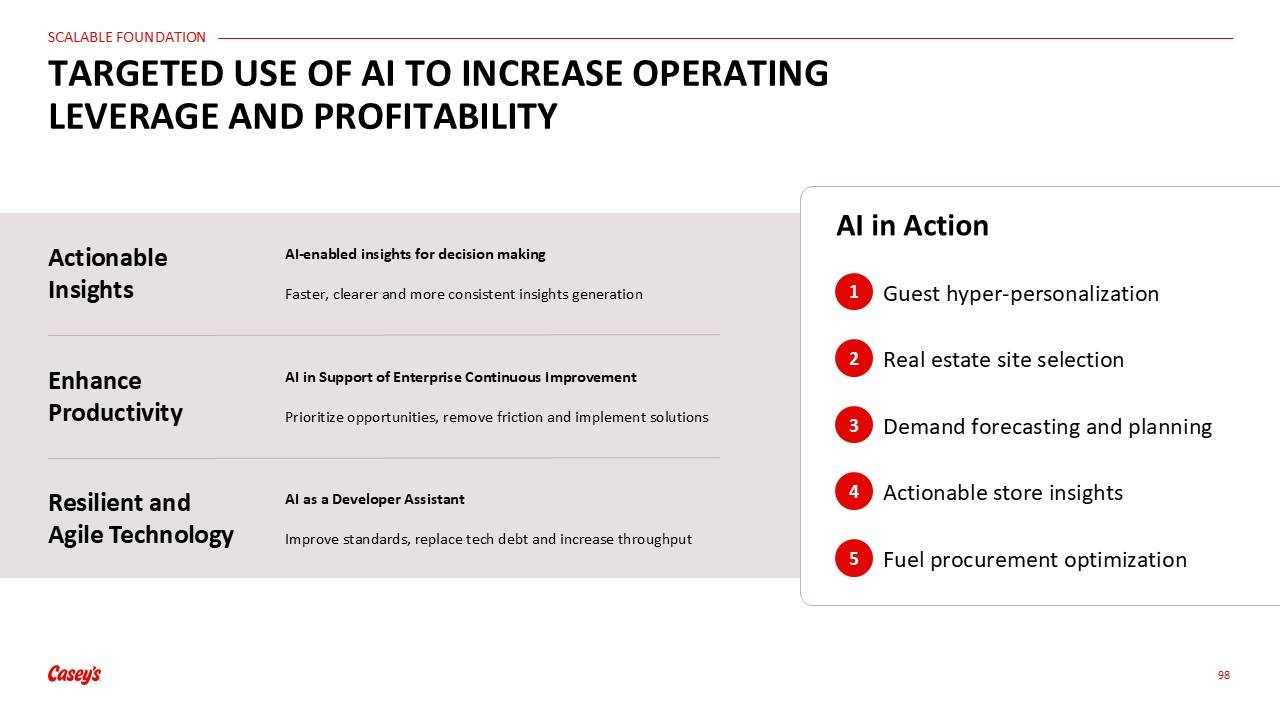
98 TARGETED USE OF AI TO INCREASE OPERATING LEVERAGE AND PROFITABILITY AI as a
Developer Assistant Improve standards, replace tech debt and increase throughput Resilient and Agile Technology AI in Support of Enterprise Continuous Improvement Prioritize opportunities, remove friction and implement solutions Enhance
Productivity AI-enabled insights for decision making Faster, clearer and more consistent insights generation Actionable Insights AI in Action Guest hyper-personalization 1 Real estate site selection 2 Demand forecasting and
planning 3 Actionable store insights 4 Fuel procurement optimization 5

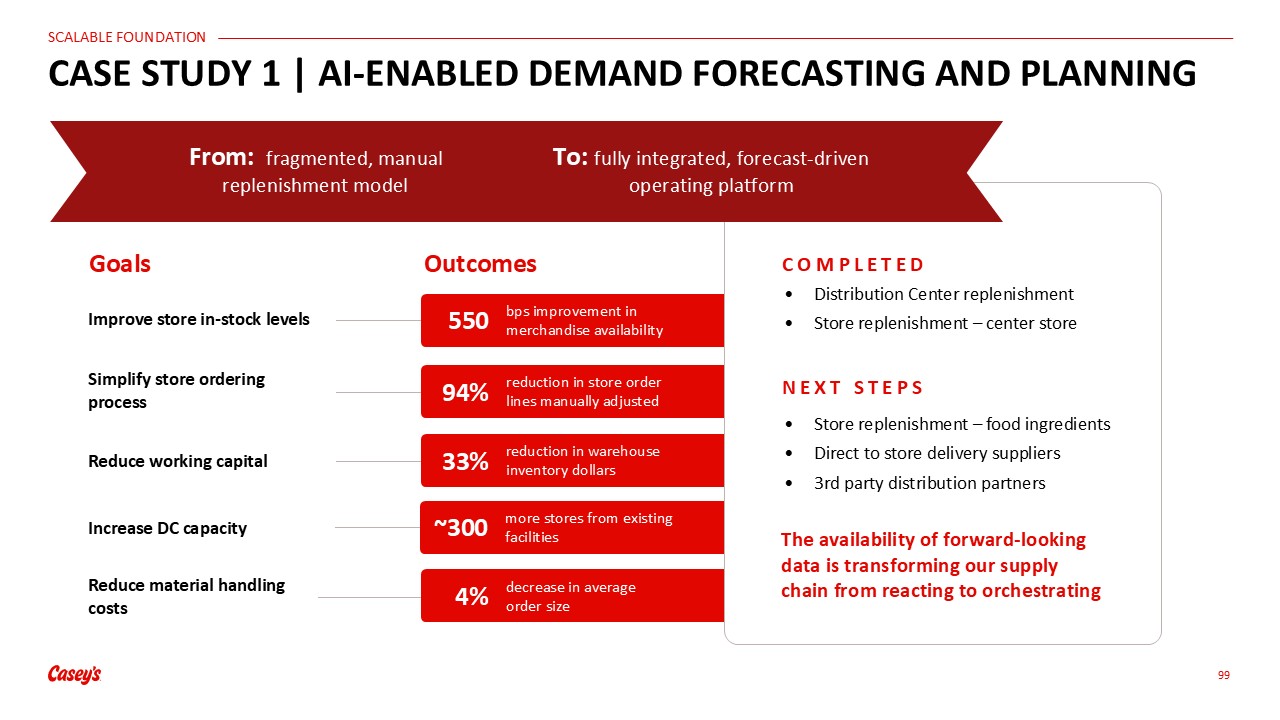
Improve store in-stock levels 99 CASE STUDY 1 | AI-ENABLED DEMAND FORECASTING AND
PLANNING Goals Distribution Center replenishment Store replenishment – center store COMPLETED NEXT STEPS From: fragmented, manual replenishment model To: fully integrated, forecast-driven operating platform Simplify store ordering
process Reduce working capital Reduce material handling costs Outcomes The availability of forward-looking data is transforming our supply chain from reacting to orchestrating 550 94% 33% 4% Store replenishment – food ingredients Direct
to store delivery suppliers 3rd party distribution partners bps improvement in merchandise availability reduction in store order lines manually adjusted reduction in warehouse inventory dollars decrease in average order size Increase DC
capacity ~300 more stores from existing facilities

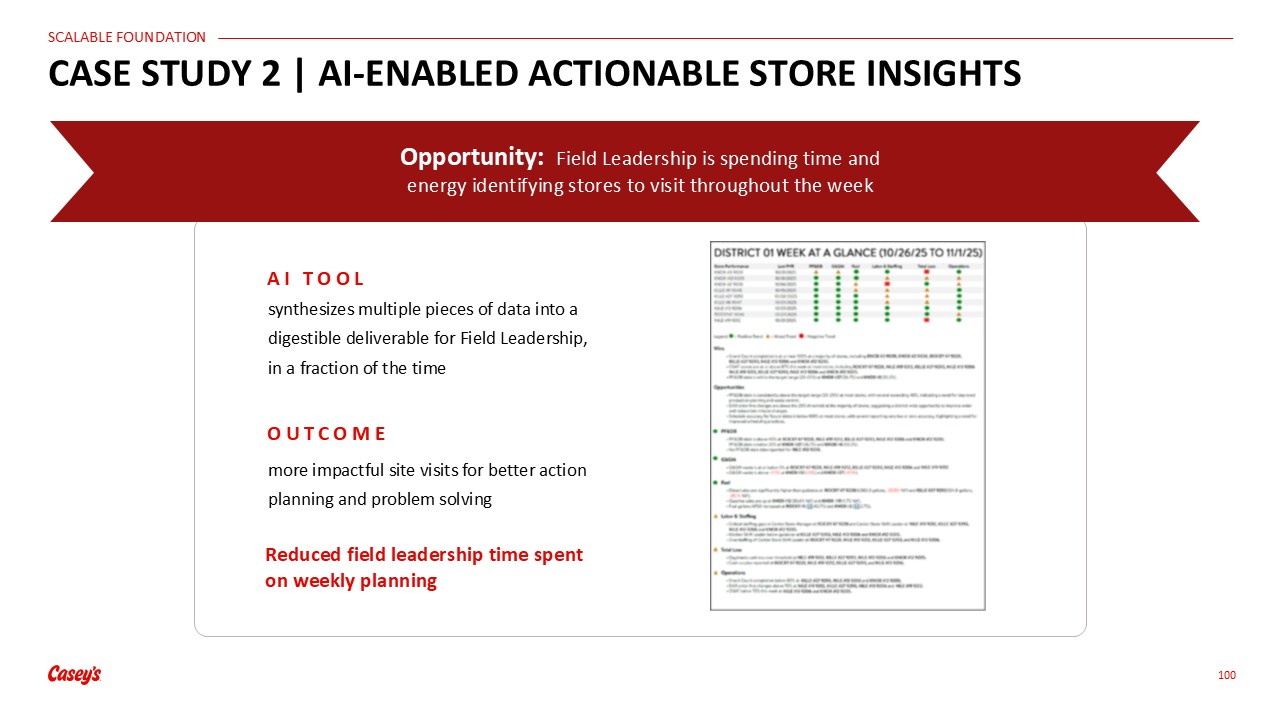
100 CASE STUDY 2 | AI-ENABLED ACTIONABLE STORE INSIGHTS Opportunity: Field
Leadership is spending time and energy identifying stores to visit throughout the week synthesizes multiple pieces of data into a digestible deliverable for Field Leadership, in a fraction of the time AI TOOL OUTCOME Reduced field leadership
time spent on weekly planning more impactful site visits for better action planning and problem solving

Fuel NATHANIEL DODDRIDGE SVP, FUELS SCALABLE FOUNDATION 101

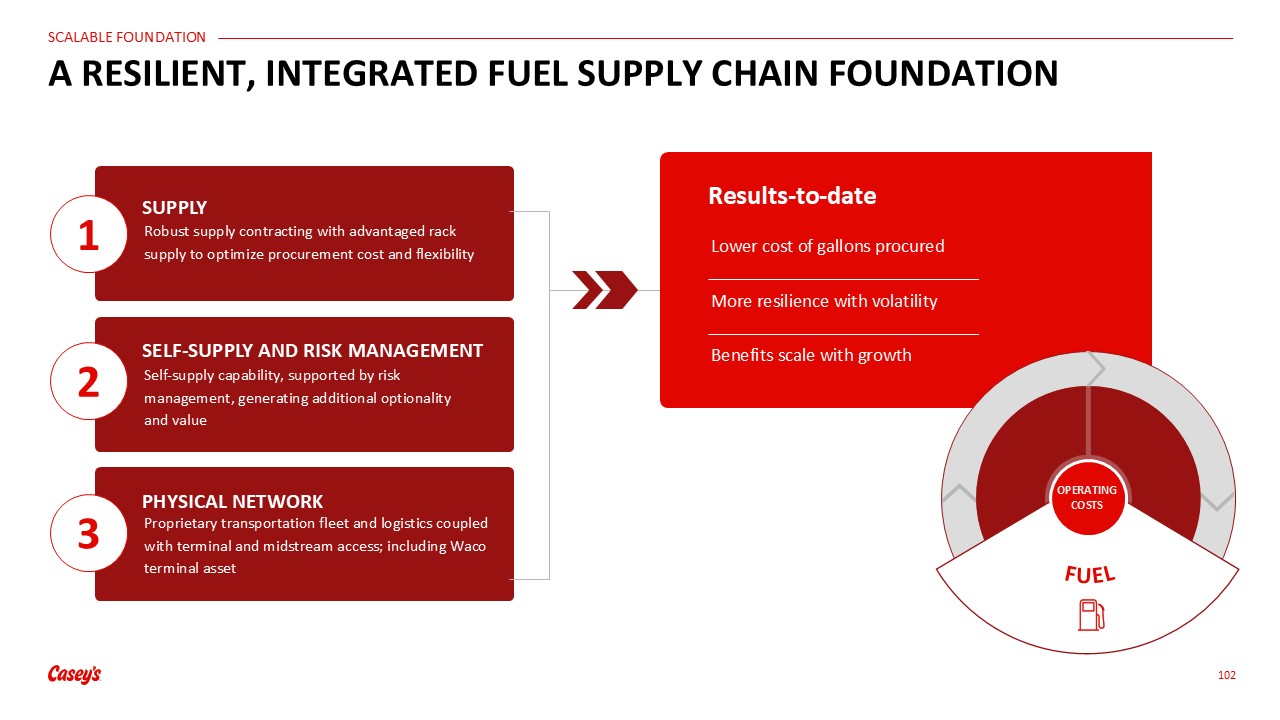
102 A RESILIENT, INTEGRATED FUEL SUPPLY CHAIN FOUNDATION 1 Robust supply
contracting with advantaged rack supply to optimize procurement cost and flexibility 2 Self-supply capability, supported by risk management, generating additional optionality and value 3 Proprietary transportation fleet and logistics coupled
with terminal and midstream access; including Waco terminal asset Lower cost of gallons procured More resilience with volatility Benefits scale with growth Results-to-date SUPPLY SELF-SUPPLY AND RISK MANAGEMENT PHYSICAL
NETWORK FUEL OPERATINGCOSTS

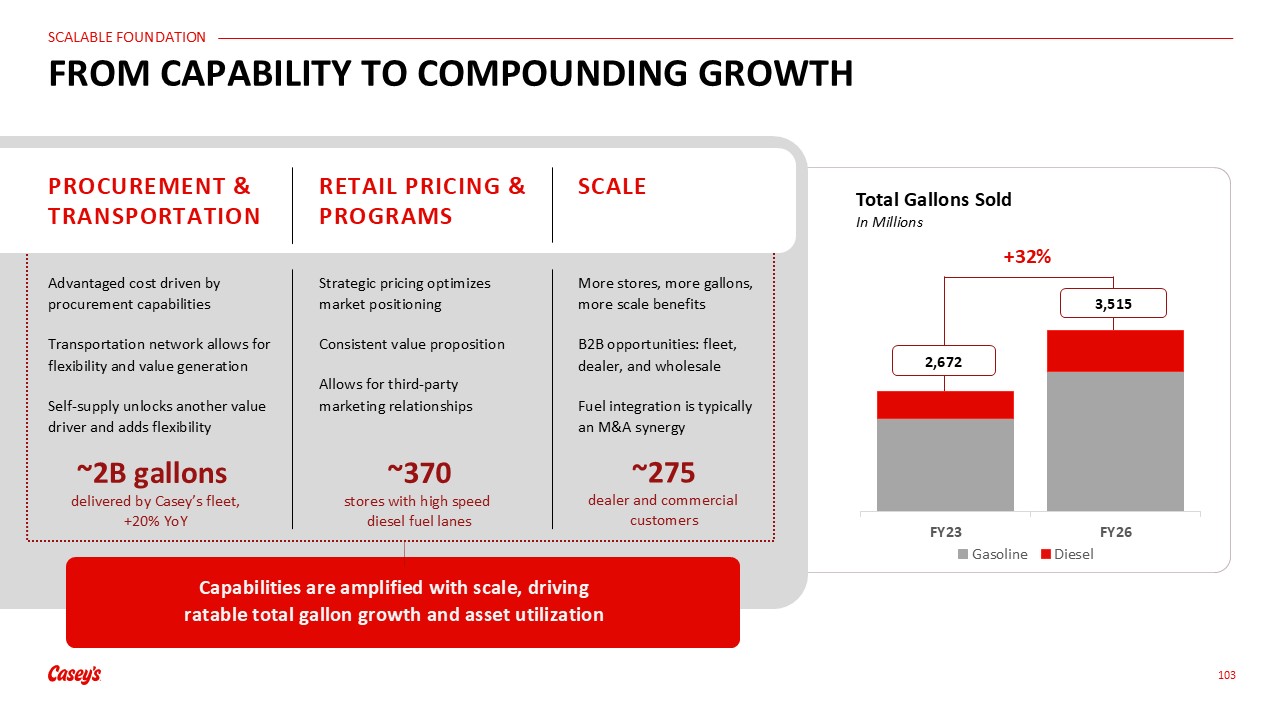
3,515 2,672 103 FROM CAPABILITY TO COMPOUNDING GROWTH Advantaged cost driven by
procurement capabilities Transportation network allows for flexibility and value generation Self-supply unlocks another value driver and adds flexibility PROCUREMENT & TRANSPORTATION Strategic pricing optimizes market
positioning Consistent value proposition Allows for third-party marketing relationships RETAIL PRICING & PROGRAMS More stores, more gallons, more scale benefits B2B opportunities: fleet, dealer, and wholesale Fuel integration is
typically an M&A synergy SCALE Capabilities are amplified with scale, driving ratable total gallon growth and asset utilization Total Gallons Sold In Millions +32% ~2B gallons delivered by Casey’s fleet, +20% YoY ~370 stores with
high speed diesel fuel lanes ~275 dealer and commercial customers

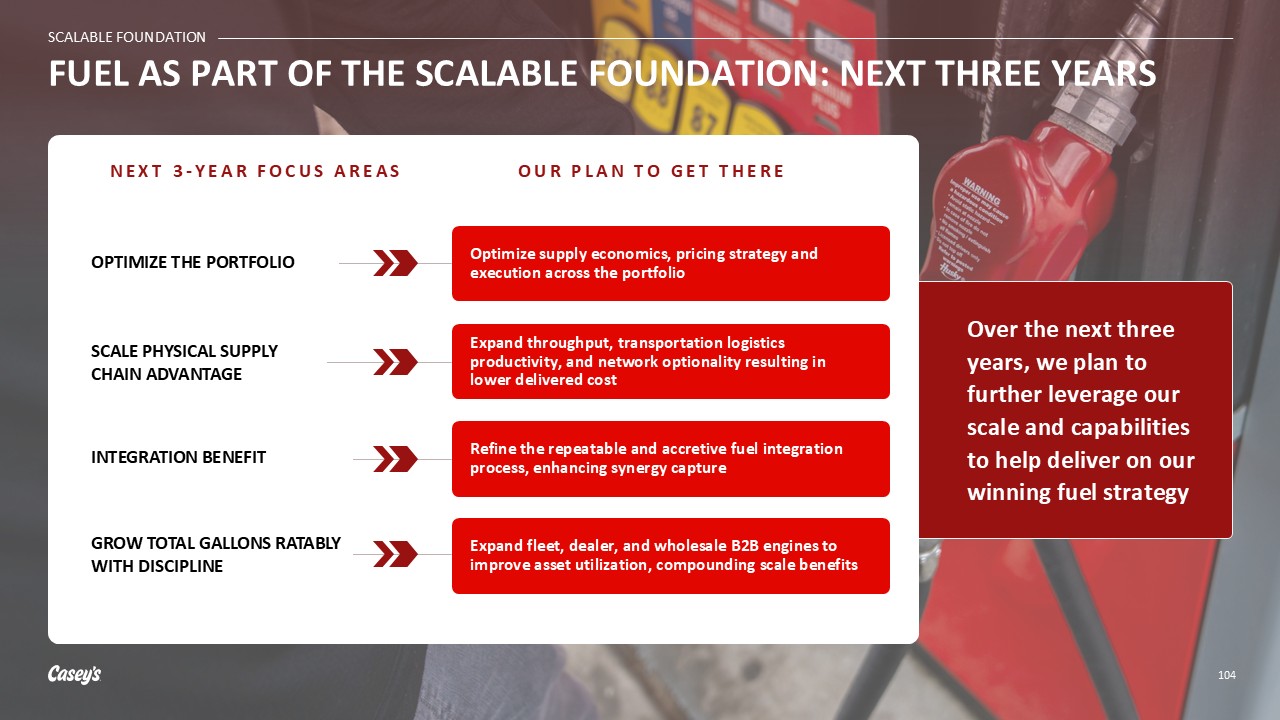
Over the next three years, we plan to further leverage our scale and capabilities to
help deliver on our winning fuel strategy FUEL AS PART OF THE SCALABLE FOUNDATION: NEXT THREE YEARS SCALABLE FOUNDATION NEXT 3-YEAR FOCUS AREAS OUR PLAN TO GET THERE Optimize supply economics, pricing strategy and execution across the
portfolio OPTIMIZE THE PORTFOLIO SCALE PHYSICAL SUPPLY CHAIN ADVANTAGE INTEGRATION BENEFIT GROW TOTAL GALLONS RATABLY WITH DISCIPLINE Expand throughput, transportation logistics productivity, and network optionality resulting in lower
delivered cost Refine the repeatable and accretive fuel integration process, enhancing synergy capture Expand fleet, dealer, and wholesale B2B engines to improve asset utilization, compounding scale benefits 104

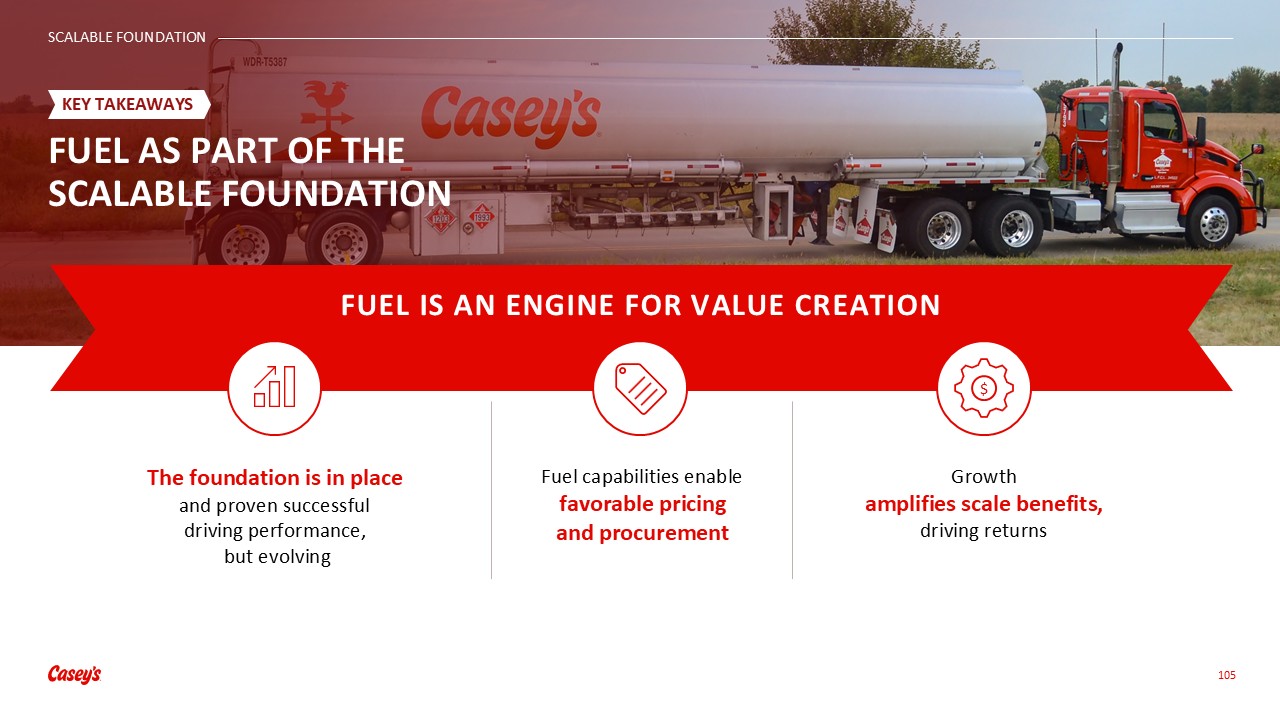
x FUEL AS PART OF THE SCALABLE FOUNDATION KEY TAKEAWAYS The foundation is in
place and proven successful driving performance, but evolving Fuel capabilities enable favorable pricing and procurement Growth amplifies scale benefits, driving returns FUEL IS AN ENGINE FOR VALUE CREATION SCALABLE FOUNDATION $ 105

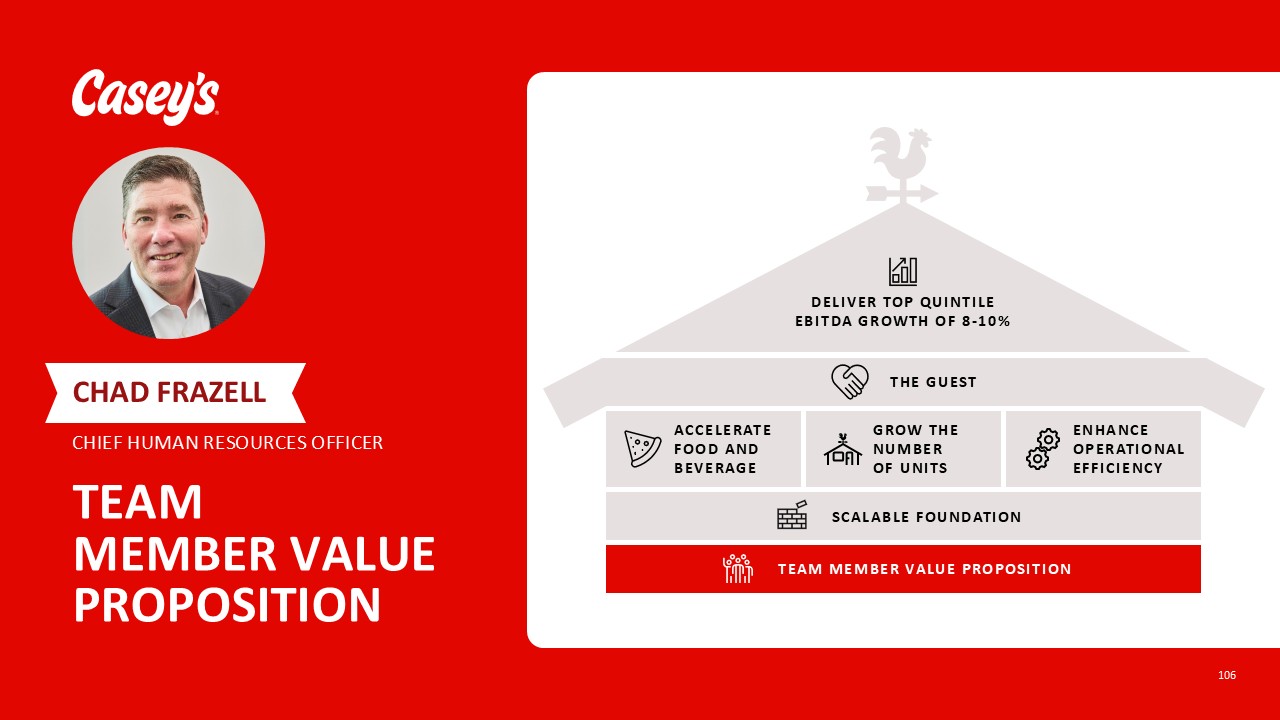
106 TEAM MEMBER VALUE PROPOSITION CHAD FRAZELL CHIEF HUMAN RESOURCES
OFFICER Deliver top quintile EBITDA growth of 8-10% ACCELERATEFOOD AND BEVERAGE SCALABLE Foundation Team Member Value Proposition THE GUEST GROW THE NUMBER OF UNITS ENHANCE OPERATIONALEFFICIENCY

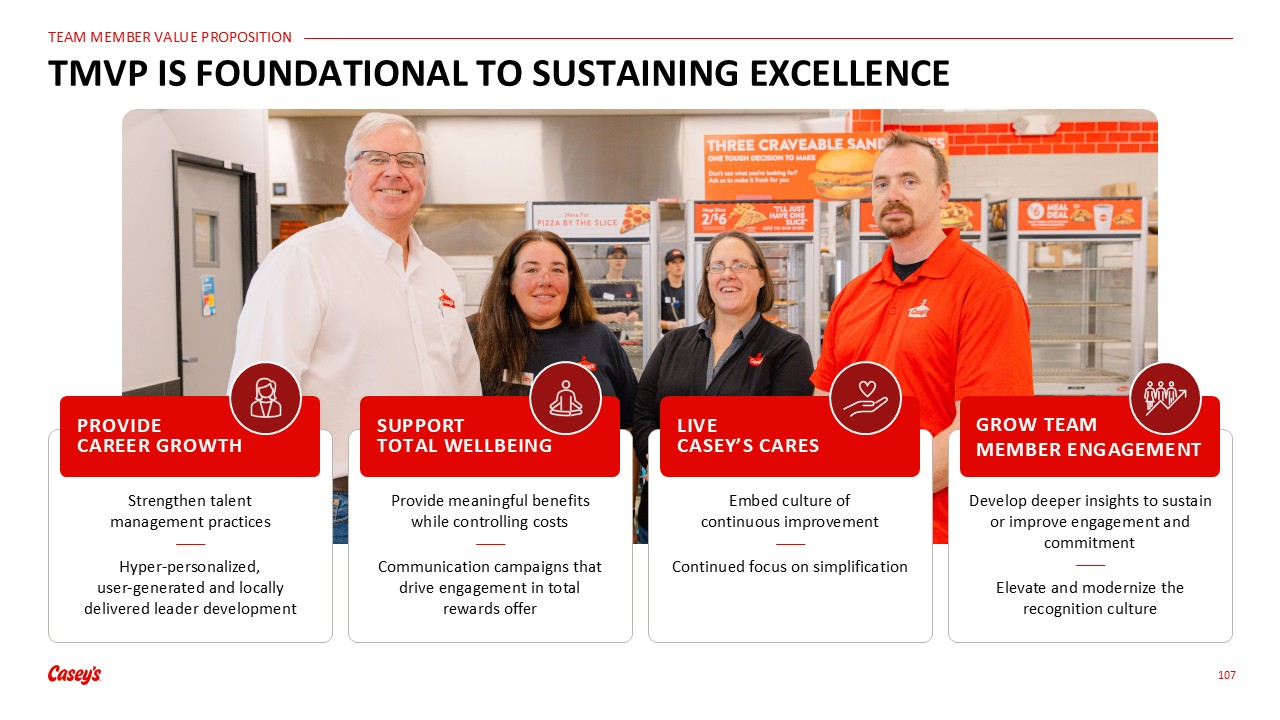
107 TMVP IS FOUNDATIONAL TO SUSTAINING EXCELLENCE GROW TEAM MEMBER
ENGAGEMENT Develop deeper insights to sustain or improve engagement and commitment Elevate and modernize the recognition culture LIVE CASEY’S CARES SUPPORT TOTAL WELLBEING PROVIDE CAREER GROWTH Embed culture of continuous
improvement Continued focus on simplification Provide meaningful benefits while controlling costs Communication campaigns that drive engagement in total rewards offer Strengthen talent management practices Hyper-personalized, user-generated
and locally delivered leader development

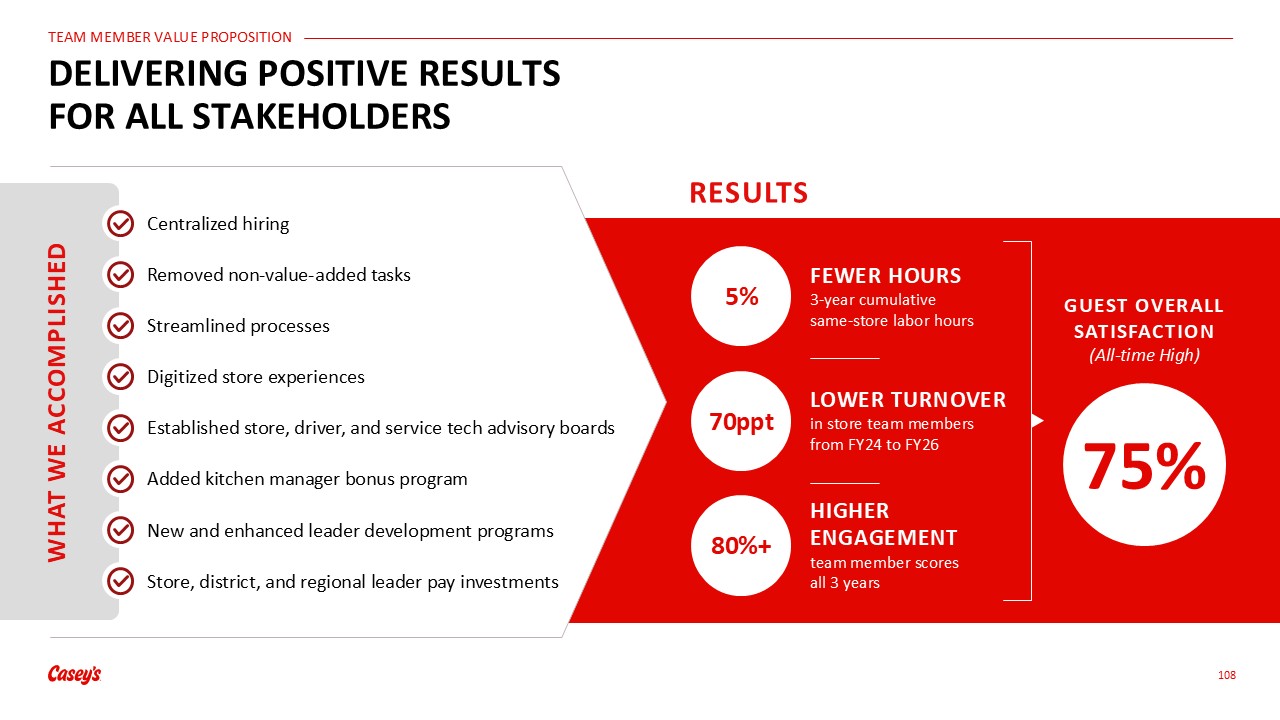
RESULTS 75% GUEST OVERALL SATISFACTION (All-time High) 5% FEWER HOURS 3-year
cumulative same-store labor hours 70ppt LOWER TURNOVER in store team members from FY24 to FY26 80%+ HIGHER ENGAGEMENT team member scores all 3 years 108 DELIVERING POSITIVE RESULTS FOR ALL STAKEHOLDERS WHAT WE
ACCOMPLISHED Centralized hiring Removed non-value-added tasks Streamlined processes Digitized store experiences Established store, driver, and service tech advisory boards Added kitchen manager bonus program New and enhanced leader
development programs Store, district, and regional leader pay investments

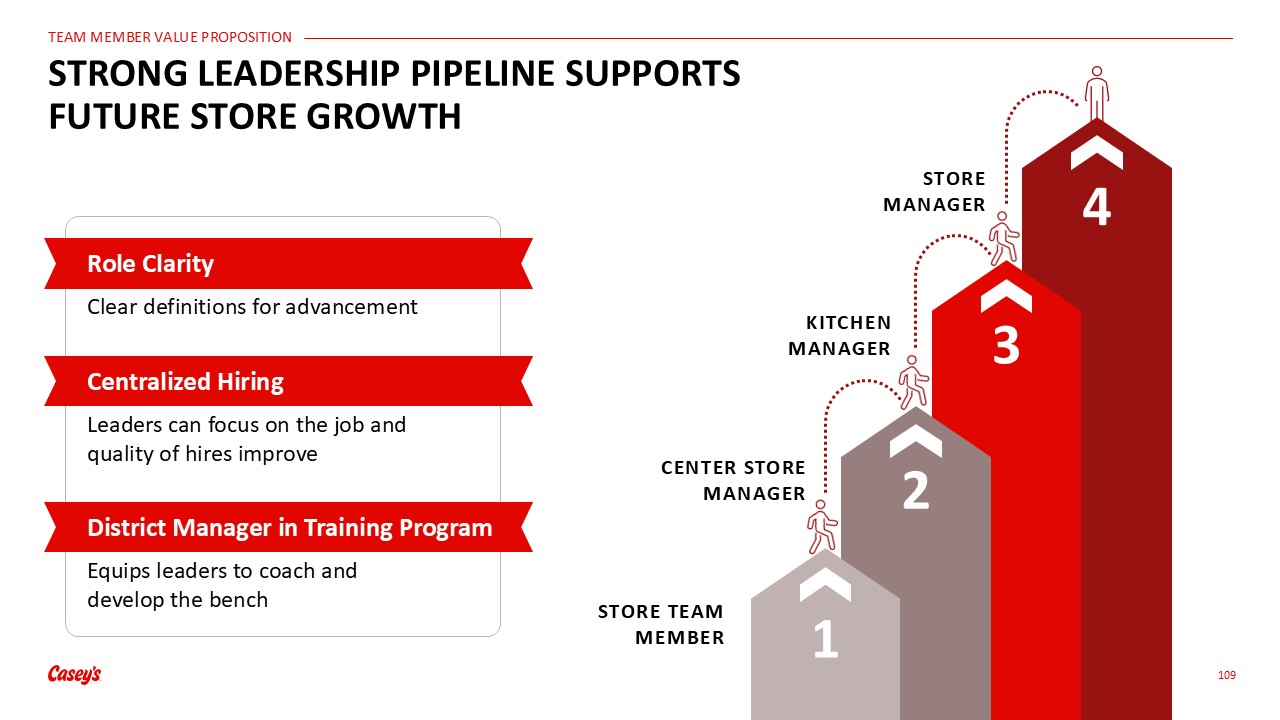
109 STRONG LEADERSHIP PIPELINE SUPPORTSFUTURE STORE GROWTH STORE MANAGER KITCHEN
MANAGER CENTER STORE MANAGER STORE TEAM MEMBER 4 3 2 1 Centralized Hiring Leaders can focus on the job and quality of hires improve District Manager in Training Program Equips leaders to coach and develop the bench Role Clarity
Clear definitions for advancement

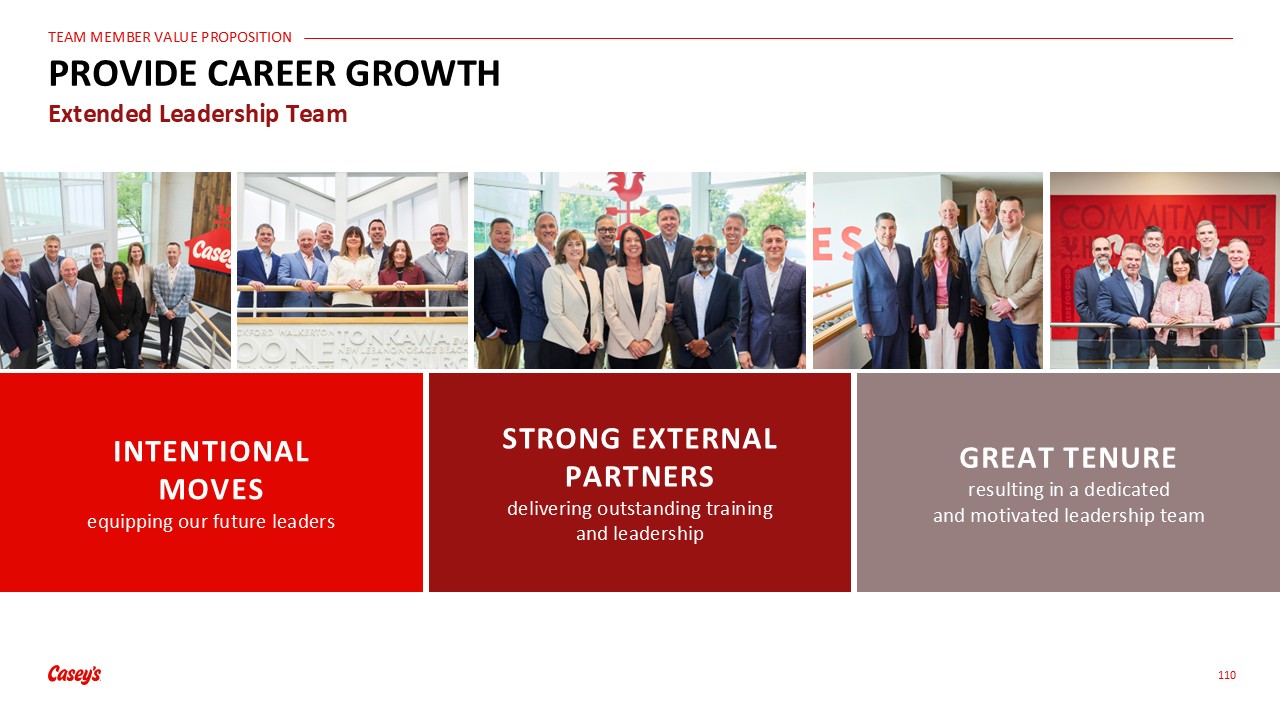
110 PROVIDE CAREER GROWTH Extended Leadership Team INTENTIONAL MOVES equipping
our future leaders STRONG EXTERNAL PARTNERS delivering outstanding training and leadership GREAT TENURE resulting in a dedicated and motivated leadership team

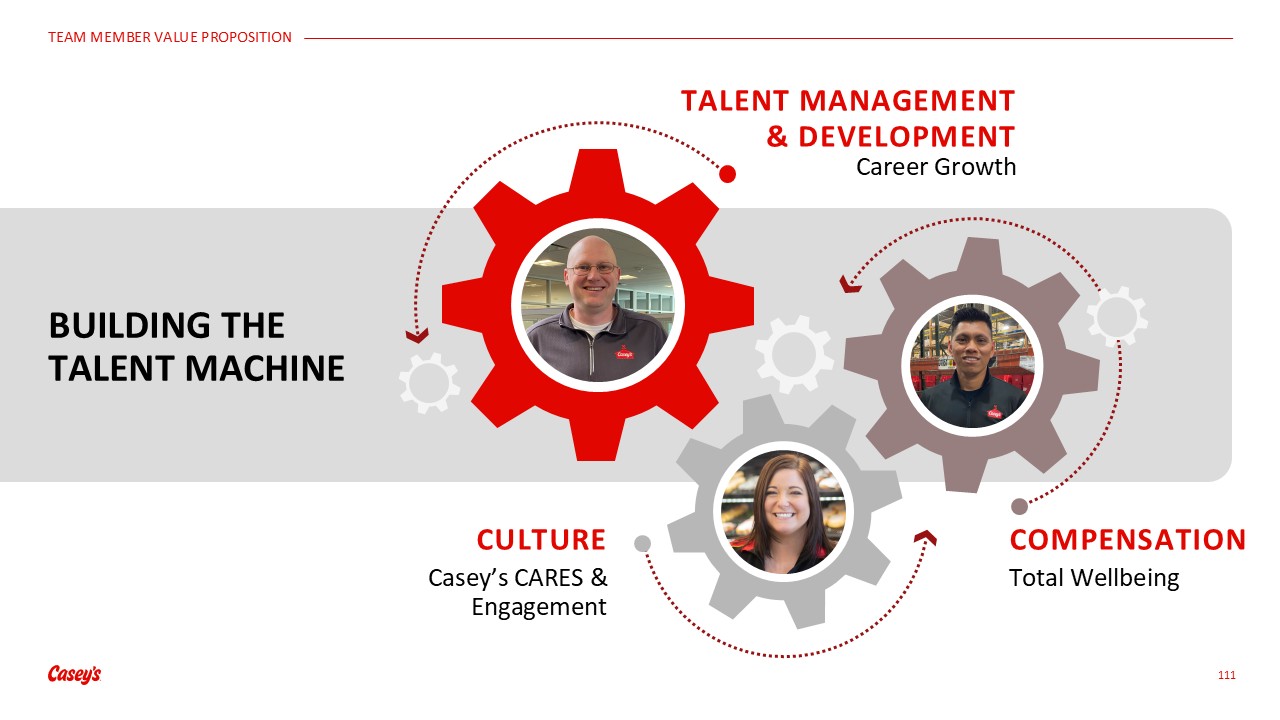
CULTURE COMPENSATION Casey’s CARES &Engagement TALENT MANAGEMENT &
DEVELOPMENT Career Growth Total Wellbeing 111 BUILDING THE TALENT MACHINE

112 Clear competitive advantages, including unique rural footprint,
restaurant-quality prepared food, vertical integration, 100% company owned and operated retail stores, and consolidated scale High quality products at a great value help grow loyal guest base, supported by ~11 million Casey’s Rewards
members Substantial whitespace opportunity with proven ability to grow units via our dual-engine approach of new store builds and acquisitions, with a track record of successful integration of larger deals The result has been durable, ratable
growth that has created long-term shareholder value Category-of-one at the intersection of convenience and QSR with a proven three-legged stool operating model that creates an unmatched flywheel for growth 1 WHY INVEST IN 3-YEAR GROWTH
STRATEGY Tenured leadership team with deep industry experience and a proven track record of delivering results

Q&A 113

Appendix 114

Note: figures in thousands RECONCILIATION OF NON-GAAP FINANCIAL MEASURES: NET
INCOME TO EBITDA 115

Note: figures in thousands 1 - EBIT is tax effected using the effective tax rate
for the reported period. Effective tax rate is Federal and state income taxes divided by Income before income taxes. 2 - Fiscal year 2018 ROIC is inclusive of the one-time benefit from the Tax Cuts and Jobs Act. Removing this benefit ROIC is
7.9% for fiscal year 2018. RECONCILIATION OF NON-GAAP FINANCIAL MEASURES: ROIC AND FREE CASH FLOW 116