CATY 8-K
Cathay General Bancorp (CATY)
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported):
(Exact name of registrant as specified in its charter)
|
|
|
|
|
|
|
(State or other jurisdiction of incorporation) |
|
(Commission File Number) |
|
(IRS Employer Identification No.) |
|
|
|
|
(Address of principal executive offices) |
(Zip Code) |
Registrant’s telephone number, including area code: (
Not Applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
|
Title of each class |
|
Trading Symbol(s) |
|
Name of each exchange on which registered |
|
|
|
|
|
|
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 or Rule 12b-2 of the Securities Exchange Act of 1934.
Emerging growth company
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02Results of Operations and Financial Condition.
On April 26, 2021, Cathay General Bancorp (the “Company”) announced, in a press release, its financial results for the quarter ended March 31, 2021. That press release is attached hereto as Exhibit 99.1.
Item 7.01. Regulation FD Disclosure
As announced in the press release attached hereto as Exhibit 99.1, the Company will host a conference call on Monday, April 26, 2021 at 3:00 p.m. Pacific Time to discuss its first quarter 2021 financial results. A presentation to accompany the conference call, which contains certain historical and forward-looking information relating to the Company (the “Presentation Materials”), has been made available on its website at www.cathaygeneralbancorp.com. A copy of the Presentation Materials is attached hereto as Exhibit 99.2.
The information included in this report pursuant to Item 2.02 and Item 7.01 of Form 8-K (including Exhibit 99.1 and Exhibit 99.2) shall not be deemed to be “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), or otherwise subject to the liabilities of that section, nor shall such information be deemed to be incorporated by reference in any filing under the Securities Act of 1933 or the Exchange Act.
Item 9.01Financial Statements and Exhibits.
(d)Exhibits
99.1Press Release of Cathay General Bancorp, dated April 26, 2021
99.2Presentation Materials, dated April 26, 2021
104 Cover Page Interactive Data File (embedded within the Inline XBRL document)
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned thereunto duly authorized.
Date: April 26, 2021
CATHAY GENERAL BANCORP
|
By: |
/s/ Heng W. Chen |
|
|
Heng W. Chen |
|
|
Executive Vice President and Chief Financial Officer |
Exhibit 99.1
Cathay General Bancorp Announces First Quarter 2021 Results
LOS ANGELES, April 26, 2021 /PRNewswire/ -- Cathay General Bancorp (the "Company", "we", "us", or "our") (Nasdaq: CATY), the holding company for Cathay Bank, today announced its unaudited financial results for the quarter ended March 31, 2021. The Company reported net income of $73.4 million, or $0.92 per share, for the first quarter of 2021.
FINANCIAL PERFORMANCE | |||||
|
| |||||
|
| Three months ended | ||||
(unaudited) | March 31, 2021 |
| December 31, 2020 |
| March 31, 2020 |
Net income | $73.4 million |
| $70.9 million |
| $46.9 million |
Basic earnings per common share | $0.92 |
| $0.89 |
| $0.59 |
Diluted earnings per common share | $0.92 |
| $0.89 |
| $0.59 |
Return on average assets | 1.57% |
| 1.50% |
| 1.05% |
Return on average total stockholders' equity | 12.23% |
| 11.75% |
| 8.12% |
Efficiency ratio | 47.03% |
| 49.61% |
| 44.60% |
|
|
|
|
|
|
|
FIRST QUARTER HIGHLIGHTS
- The net interest margin increased to 3.20% in the first quarter of 2021 from 3.12% in the fourth quarter of 2020.
- There was a reversal of provisions for credit losses of $13.6 million in the first quarter of 2021 compared to a reversal for loan losses of $5.0 million for the fourth quarter of 2020.
"For the first quarter of 2021, our net interest margin was 3.20%, increasing 8 basis points from the fourth quarter of 2020. Also, there was a reversal of provisions for credit losses of $13.6 million in the first quarter of 2021 primarily due to the improved macroeconomic conditions," commented Chang M. Liu, President and Chief Executive Officer of the Company.
FIRST QUARTER INCOME STATEMENT REVIEW
Net income for the quarter ended March 31, 2021, was $73.4 million, an increase of $26.5 million, or 56.5%, compared to net income of $46.9 million for the same quarter a year ago. Diluted earnings per share for the quarter ended March 31, 2021, was $0.92 per share compared to $0.59 per share for the same quarter a year ago.
Return on average stockholders' equity was 12.23% and return on average assets was 1.57% for the quarter ended March 31, 2021, compared to a return on average stockholders' equity of 8.12% and a return on average assets of 1.05% for the same quarter a year ago.
Net interest income before provision for credit losses
Net interest income before provision for credit losses increased $1.5 million, or 1.1%, to $141.8 million during the first quarter of 2021, compared to $140.3 million during the same quarter a year ago. The increase was due primarily to a decrease in interest expense from deposits, offset, in part, by a decrease in interest income from loans and securities.
The net interest margin was 3.20% for the first quarter of 2021 compared to 3.34% for the first quarter of 2020 and 3.12% for the fourth quarter of 2020.
For the first quarter of 2021, the yield on average interest-earning assets was 3.68%, the cost of funds on average interest-bearing liabilities was 0.67%, and the cost of interest-bearing deposits was 0.63%. In comparison, for the first quarter of 2020, the yield on average interest-earning assets was 4.44%, the cost of funds on average interest-bearing liabilities was 1.49%, and the cost of interest-bearing deposits was 1.44%. The decrease in the yield on average interest-earning assets resulted mainly from lower lending rates. The net interest spread, defined as the difference between the yield on average interest-earning assets and the cost of funds on average interest-bearing liabilities, was 3.01% for the quarter ended March 31, 2021, compared to 2.95% for the same quarter a year ago.
(Reversal)/provision for credit losses
As permitted under the Coronavirus, Aid, Relief and Economic Security Act (the "CARES Act") and as extended by the Consolidated Appropriations Act, 2021, the Company adopted the Current Expected Credit Losses ("CECL") methodology for estimated credit losses effective as of January 1, 2021. The adoption of CECL under a modified retrospective approach as of January 1, 2021 increased the allowance for loan losses by $13.9 million and allowance for unfunded credit commitments by $0.5 million and an after-tax decrease to opening retained earnings of $10.2 million. As of March 31, 2021, the allowance for loan losses decreased $19.9 million to $160.6 million, or 1.03% of gross loans, compared to $180.5 million, or 1.15% of gross loans, as of January 1, 2021. The change in the allowance for loan losses included a $12.1 million reversal for loan losses for the first quarter of 2021, as a result of the improving macroeconomic conditions and $7.8 million in net charge-offs. In the first quarter of 2020, a provision for loan losses of $25.0 million was recorded under the incurred loss method. The Company will continue to monitor the continuing impact of the COVID-19 pandemic on credit risks and losses, as well as on customer demand deposits and other liabilities and assets. The following table sets forth the charge-offs and recoveries for the periods indicated:
|
| Three months ended | ||||
|
| March 31, 2021 |
| December 31, 2020 |
| March 31, 2020 |
|
| (In thousands) (Unaudited) | ||||
Charge-offs: |
|
|
|
|
|
Commercial loans | $ 9,138 |
| $ 8,613 |
| $ 1,321 |
Total charge-offs | 9,138 |
| 8,613 |
| 1,321 |
Recoveries: |
|
|
|
|
|
Commercial loans | 1,269 |
| 912 |
| 1,208 |
Real estate loans(1) | 111 |
| 109 |
| 162 |
Total recoveries | 1,380 |
| 1,021 |
| 1,370 |
Net charge-offs/(recoveries) | $ 7,758 |
| $ 7,592 |
| $ (49) |
|
| |||||
(1) Real estate loans include commercial mortgage loans, residential mortgage loans, and equity lines. |
Allowance for credit losses
The following table presents a roll forward of the allowance for credit losses for the periods indicated:
|
| Three Months Ended March 31, 2021 |
| Three Months Ended December 31, 2020 |
| Three Months Ended March 31, 2020 | ||||||||||||
Allowance for Credit Losses Rollforward | Allowance
|
| Reserve for
|
| Total
|
| Allowance
|
| Reserve for
|
| Total
|
| Allowance
|
| Reserve for
|
| Total
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Beginning Balance | $ 166,538 |
| $ 5,880 |
| $ 172,418 |
| $ 179,131 |
| $ 5,663 |
| $ 184,794 |
| $ 123,224 |
| $ 3,855 |
| $ 127,079 |
Impact of ASU 2016-13 adoption | 13,913 |
| 539 |
| 14,452 |
| — |
| — |
| — |
| — |
| — |
| — |
Balance, at January 1, 2021 | 180,451 |
| 6,419 |
| 186,870 |
| 179,131 |
| 5,663 |
| 184,794 |
| 123,224 |
| 3,855 |
| 127,079 |
(Reversal)/provision for credit losses | (12,110) |
| (1,448) |
| (13,558) |
| (5,000) |
| 217 |
| (4,783) |
| 25,000 |
| (842) |
| 24,158 |
Charge-offs | (9,138) |
| — |
| (9,138) |
| (8,613) |
| — |
| (8,613) |
| (1,321) |
| — |
| (1,321) |
Recoveries | 1,380 |
| — |
| 1,380 |
| 1,020 |
| — |
| 1,020 |
| 1,370 |
| — |
| 1,370 |
Net (charge-offs)/recoveries | (7,758) |
| — |
| (7,758) |
| (7,593) |
| — |
| (7,593) |
| 49 |
| — |
| 49 |
Ending Balance | $ 160,583 |
| $ 4,971 |
| $ 165,554 |
| $ 166,538 |
| $ 5,880 |
| $ 172,418 |
| $ 148,273 |
| $ 3,013 |
| $ 151,286 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Non-interest income
Non-interest income, which includes revenues from depository service fees, letters of credit commissions, securities gains (losses), wire transfer fees, and other sources of fee income, was $10.0 million for the first quarter of 2021, an increase of $4.2 million, or 72.4%, compared to $5.8 million for the first quarter of 2020. The increase was primarily due to a $3.4 million decrease in net losses from equity securities and a $0.8 million increase in gain from sale of securities, when compared to the same quarter a year ago.
Non-interest expense
Non-interest expense increased $6.2 million, or 9.5%, to $71.4 million in the first quarter of 2021 compared to $65.2 million in the same quarter a year ago. The increase in non-interest expense in the first quarter of 2021 was primarily due to a decrease of $4.2 million in income from other real estate owned, an increase of $1.8 million in salaries and other employee benefits, an increase of $1.0 million in contributions to the Cathay Bank foundation, to combat anti-Asian American hate crimes, and an increase of $0.7 million in costs associated with debt redemption, offset, in part, by a decrease of $2.3 million in amortization expense of investments in low-income housing and alternative energy partnerships, when compared to the same quarter a year ago. The efficiency ratio was 47.0% in the first quarter of 2021 compared to 44.6% for the same quarter a year ago.
Income taxes
The effective tax rate for the first quarter of 2021 was 21.9% compared to 16.3% for the first quarter of 2020. The effective tax rate includes the impact of alternative energy investments and low-income housing tax credits.
BALANCE SHEET REVIEW
Gross loans were $15.7 billion as of March 31, 2021, an increase of $7.5 million, or 0.05%, from $15.6 billion as of December 31, 2020. The increase was primarily due to an increase of $93.5 million in Paycheck Protection Program Loans, offset, in part, by a decrease of $43.2 million, or 1.0%, in residential mortgage loans and $39.7 million, or 1.5%, in commercial loans not including Paycheck Protection Program Loans. During the first quarter of 2021, Cathay Bank funded 1,333 new PPP loans totaling $142.4 million. Loan fees recognized on PPP loans were $2.5 million in the first quarter of 2021 compared to $1.7 million in the fourth quarter of 2020.
The loan balances and composition as of March 31, 2021, compared to December 31, 2020 and March 31, 2020, are presented below:
|
|
|
|
|
|
|
|
| March 31, 2021 |
| December 31, 2020 |
| March 31, 2020 |
|
| (In thousands) (Unaudited) | ||||
Commercial loans | $ 2,556,247 |
| $ 2,595,926 |
| $ 2,973,078 |
Paycheck protection program loans | 334,446 |
| 240,907 |
| — |
Residential mortgage loans | 4,102,203 |
| 4,145,389 |
| 4,173,876 |
Commercial mortgage loans | 7,549,522 |
| 7,555,027 |
| 7,422,585 |
Equity lines | 428,318 |
| 424,555 |
| 385,317 |
Real estate construction loans | 677,816 |
| 679,492 |
| 577,240 |
Installment and other loans | 3,296 |
| 3,100 |
| 2,116 |
Gross loans | $ 15,651,848 |
| $ 15,644,396 |
| $ 15,534,212 |
|
|
|
|
|
|
|
Allowance for loan losses | (160,583) |
| (166,538) |
| (148,273) |
Unamortized deferred loan fees | (6,872) |
| (2,494) |
| (277) |
Total loans, net | $ 15,484,393 |
| $ 15,475,364 |
| $ 15,385,662 |
|
|
|
|
|
|
|
Total deposits were $16.4 billion as of March 31, 2021, an increase of $244.2 million, or 1.5%, from $16.1 billion as of December 31, 2020. The increases in noninterest-bearing demand deposits, money market deposits and savings deposits resulted from higher liquidity maintained by our depositors during these uncertain times and improved money market deposit generation. The decreases in time deposits resulted primarily from the runoff of wholesale time deposits and migration of some maturing time deposits to money market deposits. During the first quarter of 2021, our deposits excluding CD's increased by $695.5 million, or 29.5% annualized. The deposit balances and composition as of March 31, 2021, compared to December 31, 2020 and March 31, 2020, are presented below:
|
| March 31, 2021 |
| December 31, 2020 |
| March 31, 2020 |
|
| (In thousands) (Unaudited) | ||||
Non-interest-bearing demand deposits | $ 3,495,775 |
| $ 3,365,086 |
| $ 2,860,580 |
NOW deposits | 1,915,822 |
| 1,926,135 |
| 1,514,434 |
Money market deposits | 3,808,794 |
| 3,359,191 |
| 2,482,950 |
Savings deposits | 911,210 |
| 785,672 |
| 710,602 |
Time deposits | 6,222,032 |
| 6,673,317 |
| 7,521,584 |
Total deposits | $ 16,353,633 |
| $ 16,109,401 |
| $ 15,090,150 |
|
|
|
|
|
|
|
ASSET QUALITY REVIEW
As of March 31, 2021, total non-accrual loans were $94.4 million, an increase of $26.7 million, or 39.5%, from $67.7 million as of December 31, 2020, and an increase of $40.7 million, or 75.8%, from $53.7 million as of March 31, 2020. The increase from the fourth quarter was due primarily to an $18.8 million oil and gas commercial loan and a $10.1 million commercial mortgage loan placed on nonaccrual status during the first quarter of 2021.
The allowance for loan losses was $160.6 million and the allowance for off-balance sheet unfunded credit commitments was $5.0 million as of March 31, 2021. The allowances represent the amount estimated by management to be appropriate to absorb credit losses inherent in the loan portfolio, including unfunded credit commitments. The $160.6 million allowance for loan losses as of March 31, 2021, decreased $19.9 million, or 11.0%, from $180.5 million as of January 1, 2021. The allowance for loan losses represented 1.03% of period-end gross loans, and 166.26% of non-performing loans as of March 31, 2021. The comparable ratios were 1.06% of period-end gross loans, and 229.18% of non-performing loans as of December 31, 2020. The changes in non-performing assets and troubled debt restructurings as of March 31, 2021, compared to December 31, 2020 and March 31, 2020, are presented below:
(Dollars in thousands) (Unaudited) | March 31, 2021 |
| December 31, 2020 |
| % Change |
| March 31, 2020 |
| % Change |
Non-performing assets |
|
|
|
|
|
|
|
|
|
Accruing loans past due 90 days or more | $ 2,138 |
| $ 4,982 |
| (57) |
| $ 4,531 |
| (53) |
Non-accrual loans: |
|
|
|
|
|
|
|
|
|
Construction loans | 4,189 |
| 4,286 |
| (2) |
| 4,482 |
| (7) |
Commercial mortgage loans | 43,361 |
| 33,715 |
| 29 |
| 11,859 |
| 266 |
Commercial loans | 38,351 |
| 23,087 |
| 66 |
| 30,443 |
| 26 |
Residential mortgage loans | 8,545 |
| 6,596 |
| 30 |
| 6,949 |
| 23 |
Total non-accrual loans: | $ 94,446 |
| $ 67,684 |
| 40 |
| $ 53,733 |
| 76 |
Total non-performing loans | 96,584 |
| 72,666 |
| 33 |
| 58,264 |
| 66 |
Other real estate owned | 4,918 |
| 4,918 |
| - |
| 9,048 |
| (46) |
Total non-performing assets | $ 101,502 |
| $ 77,584 |
| 31 |
| $ 67,312 |
| 51 |
Accruing troubled debt restructurings (TDRs) | $ 27,864 |
| $ 27,721 |
| 1 |
| $ 34,364 |
| (19) |
|
|
|
|
|
|
|
|
|
|
|
Allowance for loan losses | $ 160,583 |
| $ 166,538 |
| (4) |
| $ 148,273 |
| 8 |
Total gross loans outstanding, at period-end | $ 15,651,848 |
| $ 15,644,396 |
| 0 |
| $ 15,534,212 |
| 1 |
|
|
|
|
|
|
|
|
|
|
|
Allowance for loan losses to non-performing loans, at period-end | 166.26% |
| 229.18% |
|
|
| 254.48% |
|
|
Allowance for loan losses to gross loans, at period-end | 1.03% |
| 1.06% |
|
|
| 0.95% |
|
|
The ratio of non-performing assets to total assets was 0.5% as of March 31, 2021, compared to 0.4% as of December 31, 2020. Total non-performing assets increased $23.9 million, or 30.8%, to $101.5 million as of March 31, 2021, compared to $77.6 million as of December 31, 2020, primarily due to an increase of $26.8 million, or 39.5%, in nonaccrual loans, offset, in part, by a decrease of $2.8 million, or 57.1%, in accruing loans past due 90 days or more.
CAPITAL ADEQUACY REVIEW
As of March 31, 2021, the Company's Tier 1 risk-based capital ratio of 13.94%, total risk-based capital ratio of 15.84%, and Tier 1 leverage capital ratio of 11.06%, calculated under the Basel III capital rules, continue to place the Company in the "well capitalized" category for regulatory purposes, which is defined as institutions with a Tier 1 risk-based capital ratio equal to or greater than 8%, a total risk-based capital ratio equal to or greater than 10%, and a Tier 1 leverage capital ratio equal to or greater than 5%. As of December 31, 2020, the Company's Tier 1 risk-based capital ratio was 13.53%, total risk-based capital ratio was 15.47%, and Tier 1 leverage capital ratio was 10.94%.
CONFERENCE CALL
Cathay General Bancorp will host a conference call to discuss its first quarter 2021 financial results this afternoon, Monday, April 26, 2021, at 3:00 p.m., Pacific Time. Analysts and investors may dial in and participate in the question-and-answer session. To access the call, please dial 1-855-761-3186 and enter Conference ID 5682513. A presentation to accompany the earnings call will be available at www.cathaygeneralbancorp.com. A listen-only live Webcast of the call will be available at www.cathaygeneralbancorp.com and a recorded version is scheduled to be available for replay for 12 months after the call.
ABOUT CATHAY GENERAL BANCORP
Cathay General Bancorp is the holding company for Cathay Bank, a California state-chartered bank. Founded in 1962, Cathay Bank offers a wide range of financial services. Cathay Bank currently operates 38 branches in California, 10 branches in New York State, four in Washington State, three in Illinois, two in Texas, one in Maryland, Massachusetts, Nevada, and New Jersey, one in Hong Kong, and a representative office in Taipei, Beijing, and Shanghai. Cathay Bank's website is at www.cathaybank.com. Cathay General Bancorp's website is at www.cathaygeneralbancorp.com. Information set forth on such websites is not incorporated into this press release.
FORWARD-LOOKING STATEMENTS
Statements made in this press release, other than statements of historical fact, are forward-looking statements within the meaning of the applicable provisions of the Private Securities Litigation Reform Act of 1995 regarding management's beliefs, projections, and assumptions concerning future results and events. These forward-looking statements may include, but are not limited to, such words as "aims," "anticipates," "believes," "can," "continue," "could," "estimates," "expects," "hopes," "intends," "may," "plans," "projects," "predicts," "potential," "possible," "optimistic," "seeks," "shall," "should," "will," and variations of these words and similar expressions. Forward-looking statements are based on estimates, beliefs, projections, and assumptions of management and are not guarantees of future performance. These forward-looking statements are subject to certain risks and uncertainties that could cause actual results to differ materially from our historical experience and our present expectations or projections. Such risks and uncertainties and other factors include, but are not limited to, adverse developments or conditions related to or arising from local, regional, national and international business, market and economic conditions and events (such as the COVID-19 pandemic) and the impact they may have on us, our customers and our operations, assets and liabilities; possible additional provisions for loan losses and charge-offs; credit risks of lending activities and deterioration in asset or credit quality; extensive laws and regulations and supervision that we are subject to including potential future supervisory action by bank supervisory authorities; increased costs of compliance and other risks associated with changes in regulation including the implementation of the Dodd-Frank Wall Street Reform and Consumer Protection Act; higher capital requirements from the implementation of the Basel III capital standards; compliance with the Bank Secrecy Act and other money laundering statutes and regulations; potential goodwill impairment; liquidity risk; fluctuations in interest rates; risks associated with acquisitions and the expansion of our business into new markets; inflation and deflation; real estate market conditions and the value of real estate collateral; our ability to generate anticipated returns on our investments and financings, including in tax-advantaged projects; environmental liabilities; our ability to compete with larger competitors; our ability to retain key personnel; successful management of reputational risk; natural disasters, public health crises (such as the COVID-19 pandemic) and geopolitical events; general economic or business conditions in Asia, and other regions where Cathay Bank has operations; failures, interruptions, or security breaches of our information systems; our ability to adapt our systems to technological changes; risk management processes and strategies; adverse results in legal proceedings; certain provisions in our charter and bylaws that may affect acquisition of the Company; changes in accounting standards or tax laws and regulations; market disruption and volatility; restrictions on dividends and other distributions by laws and regulations and by our regulators and our capital structure; issuance of preferred stock; successfully raising additional capital, if needed, and the resulting dilution of interests of holders of our common stock; the soundness of other financial institutions; and general competitive, economic political, and market conditions and fluctuations.
These and other factors are further described in Cathay General Bancorp's Annual Report on Form 10-K for the year ended December 31, 2020 (Item 1A in particular), other reports filed with the Securities and Exchange Commission ("SEC"), and other filings Cathay General Bancorp makes with the SEC from time to time. Actual results in any future period may also vary from the past results discussed in this press release. Given these risks and uncertainties, readers are cautioned not to place undue reliance on any forward-looking statements. Any forward-looking statement speaks only as of the date on which it is made, and, except as required by law, we undertake no obligation to update or review any forward-looking statement to reflect circumstances, developments or events occurring after the date on which the statement is made or to reflect the occurrence of unanticipated events.
CATHAY GENERAL BANCORP | ||||||
CONSOLIDATED FINANCIAL HIGHLIGHTS | ||||||
(Unaudited) | ||||||
|
| ||||||
|
|
| Three months ended | ||||
(Dollars in thousands, except per share data) |
| March 31, 2021 |
| December 31, 2020 |
| March 31, 2020 |
|
|
|
|
|
|
|
|
FINANCIAL PERFORMANCE |
|
|
|
|
|
|
Net interest income before (reversal)/provision for credit losses |
| $ 141,818 |
| $ 139,820 |
| $ 140,311 |
(Reversal)/provision for credit losses |
| (13,558) |
| (5,000) |
| 25,000 |
Net interest income after (reversal)/provision for credit losses |
| 155,376 |
| 144,820 |
| 115,311 |
Non-interest income |
| 10,000 |
| 11,451 |
| 5,786 |
Non-interest expense |
| 71,403 |
| 75,046 |
| 65,154 |
Income before income tax expense |
| 93,973 |
| 81,225 |
| 55,943 |
Income tax expense |
| 20,589 |
| 10,332 |
| 9,091 |
Net income |
| $ 73,384 |
| $ 70,893 |
| $ 46,852 |
|
|
|
|
|
|
|
|
Net income per common share |
|
|
|
|
|
|
Basic |
| $ 0.92 |
| $ 0.89 |
| $ 0.59 |
Diluted |
| $ 0.92 |
| $ 0.89 |
| $ 0.59 |
|
|
|
|
|
|
|
|
Cash dividends paid per common share |
| $ 0.31 |
| $ 0.31 |
| $ 0.31 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
SELECTED RATIOS |
|
|
|
|
|
|
Return on average assets |
| 1.57% |
| 1.50% |
| 1.05% |
Return on average total stockholders' equity |
| 12.23% |
| 11.75% |
| 8.12% |
Efficiency ratio |
| 47.03% |
| 49.61% |
| 44.60% |
Dividend payout ratio |
| 33.59% |
| 34.80% |
| 52.63% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
YIELD ANALYSIS (Fully taxable equivalent) |
|
|
|
|
|
|
Total interest-earning assets |
| 3.68% |
| 3.74% |
| 4.44% |
Total interest-bearing liabilities |
| 0.67% |
| 0.86% |
| 1.49% |
Net interest spread |
| 3.01% |
| 2.88% |
| 2.95% |
Net interest margin |
| 3.20% |
| 3.12% |
| 3.34% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
CAPITAL RATIOS |
| March 31, 2021 |
| December 31, 2020 |
| March 31, 2020 |
Tier 1 risk-based capital ratio |
| 13.94% |
| 13.53% |
| 12.38% |
Total risk-based capital ratio |
| 15.84% |
| 15.47% |
| 14.12% |
Tier 1 leverage capital ratio |
| 11.06% |
| 10.94% |
| 10.82% |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
CATHAY GENERAL BANCORP | ||||||
CONDENSED CONSOLIDATED BALANCE SHEETS | ||||||
(Unaudited) | ||||||
|
| ||||||
(In thousands, except share and per share data) |
| March 31, 2021 |
| December 31, 2020 |
| March 31, 2020 |
|
|
|
|
|
|
|
|
Assets |
|
|
|
|
|
|
Cash and due from banks |
| $ 141,885 |
| $ 138,616 |
| $ 136,350 |
Short-term investments and interest bearing deposits |
| 1,612,411 |
| 1,282,462 |
| 363,666 |
Securities available-for-sale (amortized cost of $898,463 at March 31, 2021, |
|
|
|
|
|
|
$1,019,230 at December 31, 2020 and $1,330,232 at March 31, 2020) |
| 908,844 |
| 1,036,550 |
| 1,355,173 |
Loans |
| 15,651,848 |
| 15,644,396 |
| 15,534,212 |
Less: Allowance for loan losses |
| (160,583) |
| (166,538) |
| (148,273) |
Unamortized deferred loan fees, net |
| (6,872) |
| (2,494) |
| (277) |
Loans, net |
| 15,484,393 |
| 15,475,364 |
| 15,385,662 |
Equity securities |
| 20,993 |
| 23,744 |
| 18,790 |
Federal Home Loan Bank stock |
| 17,250 |
| 17,250 |
| 17,250 |
Other real estate owned, net |
| 4,918 |
| 4,918 |
| 9,048 |
Affordable housing investments and alternative energy partnerships, net |
| 296,229 |
| 309,016 |
| 294,639 |
Premises and equipment, net |
| 101,864 |
| 102,998 |
| 103,481 |
Customers' liability on acceptances |
| 4,125 |
| 13,753 |
| 5,175 |
Accrued interest receivable |
| 58,216 |
| 59,032 |
| 53,110 |
Goodwill |
| 372,189 |
| 372,189 |
| 372,189 |
Other intangible assets, net |
| 5,249 |
| 5,434 |
| 6,187 |
Right-of-use assets- operating leases |
| 32,927 |
| 30,919 |
| 32,743 |
Other assets |
| 159,319 |
| 170,889 |
| 142,996 |
Total assets |
| $ 19,220,812 |
| $ 19,043,134 |
| $ 18,296,459 |
|
|
|
|
|
|
|
|
Liabilities and Stockholders' Equity |
|
|
|
|
|
|
Deposits |
|
|
|
|
|
|
Non-interest-bearing demand deposits |
| $ 3,495,775 |
| $ 3,365,086 |
| $ 2,860,580 |
Interest-bearing deposits: |
|
|
|
|
|
|
NOW deposits |
| 1,915,822 |
| 1,926,135 |
| 1,514,434 |
Money market deposits |
| 3,808,794 |
| 3,359,191 |
| 2,482,950 |
Savings deposits |
| 911,210 |
| 785,672 |
| 710,602 |
Time deposits |
| 6,222,032 |
| 6,673,317 |
| 7,521,584 |
Total deposits |
| 16,353,633 |
| 16,109,401 |
| 15,090,150 |
|
|
|
|
|
|
|
|
Short-term borrowings |
| — |
| — |
| 12,898 |
Advances from the Federal Home Loan Bank |
| 75,000 |
| 150,000 |
| 495,000 |
Other borrowings for affordable housing investments |
| 23,333 |
| 23,714 |
| 28,981 |
Long-term debt |
| 119,136 |
| 119,136 |
| 119,136 |
Deferred payments from acquisition |
| — |
| — |
| 7,716 |
Acceptances outstanding |
| 4,125 |
| 13,753 |
| 5,175 |
Lease liabilities - operating leases |
| 35,803 |
| 33,484 |
| 34,790 |
Other liabilities |
| 155,870 |
| 175,502 |
| 189,576 |
Total liabilities |
| 16,766,900 |
| 16,624,990 |
| 15,983,422 |
Stockholders' equity |
| 2,453,912 |
| 2,418,144 |
| 2,313,037 |
Total liabilities and equity |
| $ 19,220,812 |
| $ 19,043,134 |
| $ 18,296,459 |
|
|
|
|
|
|
|
|
Book value per common share |
| $ 30.83 |
| $ 30.41 |
| $ 29.12 |
Number of common shares outstanding |
| 79,595,025 |
| 79,508,265 |
| 79,420,267 |
|
|
|
|
|
|
|
|
CATHAY GENERAL BANCORP | ||||
CONDENSED CONSOLIDATED STATEMENTS OF OPERATIONS | ||||
(Unaudited) | ||||
|
| ||||
|
|
| Three months ended | ||
|
|
| March 31, 2021 | December 31, 2020 | March 31, 2020 |
|
|
| (In thousands, except share and per share data) | ||
INTEREST AND DIVIDEND INCOME |
|
|
|
|
Loan receivable, including loan fees |
| $ 159,721 | $ 163,618 | $ 177,870 |
Investment securities |
| 3,067 | 3,469 | 7,610 |
Federal Home Loan Bank stock |
| 217 | 217 | 305 |
Deposits with banks |
| 315 | 292 | 951 |
Total interest and dividend income |
| 163,320 | 167,596 | 186,736 |
|
|
|
|
|
|
INTEREST EXPENSE |
|
|
|
|
Time deposits |
| 14,009 | 19,416 | 35,155 |
Other deposits |
| 5,594 | 5,725 | 7,991 |
Advances from Federal Home Loan Bank |
| 475 | 1,180 | 1,552 |
Long-term debt |
| 1,424 | 1,455 | 1,440 |
Deferred payments from acquisition |
| — | — | 58 |
Short-term borrowings |
| — | — | 229 |
Total interest expense |
| 21,502 | 27,776 | 46,425 |
|
|
|
|
|
|
Net interest income before (reversal)/provision for credit losses |
| 141,818 | 139,820 | 140,311 |
(Reversal)/provision for credit losses |
| (13,558) | (5,000) | 25,000 |
Net interest income after (reversal)/provision for credit losses |
| 155,376 | 144,820 | 115,311 |
|
|
|
|
|
|
NON-INTEREST INCOME |
|
|
|
|
Net (losses)/gains from equity securities |
| (2,752) | 780 | (6,102) |
Securities gains, net |
| 853 | 542 | 6 |
Letters of credit commissions |
| 1,690 | 1,749 | 1,640 |
Depository service fees |
| 1,363 | 1,271 | 1,298 |
Other operating income |
| 8,846 | 7,109 | 8,944 |
Total non-interest income |
| 10,000 | 11,451 | 5,786 |
|
|
|
|
|
|
NON-INTEREST EXPENSE |
|
|
|
|
Salaries and employee benefits |
| 32,722 | 31,545 | 30,939 |
Occupancy expense |
| 5,046 | 5,199 | 5,177 |
Computer and equipment expense |
| 3,271 | 2,915 | 2,593 |
Professional services expense |
| 4,710 | 6,270 | 5,145 |
Data processing service expense |
| 3,655 | 3,893 | 3,666 |
FDIC and State assessments |
| 1,925 | 2,145 | 2,415 |
Marketing expense |
| 2,882 | 1,334 | 1,886 |
Other real estate owned expense/(income) |
| 94 | 138 | (4,104) |
Amortization of investments in low income housing and
|
| 11,570 | 15,228 | 13,890 |
Amortization of core deposit intangibles |
| 172 | 172 | 172 |
Cost associated with debt redemption |
| 732 | 693 | — |
Other operating expense |
| 4,624 | 5,514 | 3,375 |
Total non-interest expense |
| 71,403 | 75,046 | 65,154 |
|
|
|
|
|
|
Income before income tax expense |
| 93,973 | 81,225 | 55,943 |
Income tax expense |
| 20,589 | 10,332 | 9,091 |
Net income |
| $ 73,384 | $ 70,893 | $ 46,852 |
Net income per common share: |
|
|
|
|
Basic |
| $ 0.92 | $ 0.89 | $ 0.59 |
Diluted |
| $ 0.92 | $ 0.89 | $ 0.59 |
|
|
|
|
|
|
Cash dividends paid per common share |
| $ 0.31 | $ 0.31 | $ 0.31 |
Basic average common shares outstanding |
| 79,530,777 | 79,540,694 | 79,588,076 |
Diluted average common shares outstanding |
| 79,832,305 | 79,834,150 | 79,830,025 |
|
|
|
|
|
|
CATHAY GENERAL BANCORP | ||||||||
AVERAGE BALANCES – SELECTED CONSOLIDATED FINANCIAL INFORMATION | ||||||||
(Unaudited) | ||||||||
|
| ||||||||
|
| Three months ended |
| ||||||
(In thousands) | March 31, 2021 |
| December 31, 2020 |
| March 31, 2020 | |||
Interest-earning assets | Average
| Average
|
| Average
| Average
|
| Average
| Average
|
Loans (1) | $ 15,691,976 | 4.13% |
| $ 15,569,490 | 4.18% |
| $ 15,213,440 | 4.70% |
Taxable investment securities | 995,704 | 1.25% |
| 1,073,058 | 1.29% |
| 1,379,365 | 2.22% |
FHLB stock | 17,250 | 5.10% |
| 17,250 | 5.00% |
| 17,268 | 7.09% |
Deposits with banks | 1,283,375 | 0.10% |
| 1,156,764 | 0.10% |
| 311,024 | 1.23% |
Total interest-earning assets | $ 17,988,305 | 3.68% |
| $ 17,816,562 | 3.74% |
| $ 16,921,097 | 4.44% |
|
|
|
|
|
|
|
|
|
|
Interest-bearing liabilities |
|
|
|
|
|
|
|
|
Interest-bearing demand deposits | $ 1,890,390 | 0.14% |
| $ 1,694,831 | 0.15% |
| $ 1,388,597 | 0.21% |
Money market deposits | 3,552,217 | 0.54% |
| 3,295,103 | 0.59% |
| 2,437,997 | 1.15% |
Savings deposits | 845,543 | 0.10% |
| 797,438 | 0.11% |
| 733,372 | 0.18% |
Time deposits | 6,404,755 | 0.89% |
| 6,687,731 | 1.15% |
| 7,495,619 | 1.89% |
Total interest-bearing deposits | $ 12,692,905 | 0.63% |
| $ 12,475,103 | 0.80% |
| $ 12,055,585 | 1.44% |
Other borrowed funds | 123,424 | 1.56% |
| 237,467 | 1.98% |
| 392,029 | 1.89% |
Long-term debt | 119,136 | 4.85% |
| 119,136 | 4.86% |
| 119,136 | 4.86% |
Total interest-bearing liabilities | 12,935,465 | 0.67% |
| 12,831,706 | 0.86% |
| 12,566,750 | 1.49% |
|
|
|
|
|
|
|
|
|
|
Non-interest-bearing demand deposits | 3,406,460 |
|
| 3,365,075 |
|
| 2,863,889 |
|
|
|
|
|
|
|
|
|
|
|
Total deposits and other borrowed funds | $ 16,341,925 |
|
| $ 16,196,781 |
|
| $ 15,430,639 |
|
|
|
|
|
|
|
|
|
|
|
Total average assets | $ 19,002,097 |
|
| $ 18,843,635 |
|
| $ 18,003,041 |
|
Total average equity | $ 2,433,976 |
|
| $ 2,400,494 |
|
| $ 2,320,283 |
|
|
| ||||||||
(1) Yields and interest earned include net loan fees. Non-accrual loans are included in the average balance. |

CONTACT: Heng W. Chen, (626) 279-3652
Financial Earnings Results. First Quarter 2021 April 26, 2021 Exhibit 99.2
Forward Looking Statements This presentation contains forward-looking statements about Cathay General Bancorp and its subsidiaries (collectively referred to herein as the “Company,” “we,” “us,” or “our”) within the meaning of the applicable provisions of the Private Securities Litigation Reform Act of 1995. We intend such forward-looking statements to be covered by the safe harbor provision for forward-looking statements in these provisions. Statements that are not historical or current facts, including statements about beliefs, expectations and future economic performance, are “forward-looking statements” and are based on the information available to, and estimates, beliefs, projections, and assumptions made by, management as of the date on which such statements are first made. Forward-looking statements are not guarantees of future performance and are subject to inherent risks and uncertainties that could cause actual results to differ materially from those anticipated in the statements. These risks and uncertainties include, but are not limited to: local, regional, national and international business, market and economic conditions and events and the impact they may have on us, our customers and our operations, assets and liabilities; the impact on our business, operations, financial condition, liquidity, results of operations, prospects and trading prices of our shares arising out of the COVID-19 pandemic; possible additional provisions for loan losses and charge-offs; credit risks of lending activities and deterioration in asset or credit quality; extensive laws and regulations and supervision that we are subject to, including potential supervisory action by bank supervisory authorities; increased costs of compliance and other risks associated with changes in regulation; compliance with the Bank Secrecy Act and other money laundering statutes and regulations; potential goodwill impairment; liquidity risk; fluctuations in interest rates; risks associated with acquisitions and the expansion of our business into new markets; inflation and deflation; real estate market conditions and the value of real estate collateral; environmental liabilities; our ability to generate anticipated returns from our investments and/or financings in certain tax advantaged-projects; our ability to compete with larger competitors; our ability to retain key personnel; successful management of reputational risk; natural disasters, public health crises (including the occurrence of a contagious disease or illness, such as the COVID-19 pandemic) and geopolitical events; failures, interruptions, or security breaches of our information systems; our ability to adapt our systems to the expanding use of technology in banking; adverse results in legal proceedings; changes in accounting standards or tax laws and regulations; market disruption and volatility; restrictions on dividends and other distributions by laws and regulations and by our regulators and our capital structure; capital level requirements and successfully raising additional capital, if needed, and the resulting dilution of interests of holders of our common stock; and the soundness of other financial institutions. For a discussion of these and other risks that may cause actual results to differ from expectations, please see our Annual Report on Form 10-K (at Item 1A in particular) for the year ended December 31, 2020 and all subsequent reports and filings we make with the Securities and Exchange Commission under the applicable provisions of the Securities Exchange Act of 1934. Given these risks and uncertainties, readers are cautioned not to place undue reliance on any forward-looking statements. Any forward-looking statement speaks only as of the date on which it is first made and, except as required by law, we undertake no obligation to update or review any forward-looking statements to reflect circumstances, developments or events occurring after the date on which the statement is first made or to reflect the occurrence of unanticipated events. The information in this presentation may include financial information determined by methods other than in accordance with accounting principles generally accepted in the United States of America (“GAAP”). Our management uses these non-GAAP measures in its analysis of the Company’s performance. We believe that the presentation of certain non-GAAP measures provides useful supplemental information that is essential to a proper understanding of the operating results of our businesses. These non-GAAP disclosures should not be viewed as a substitute for operating results determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies.
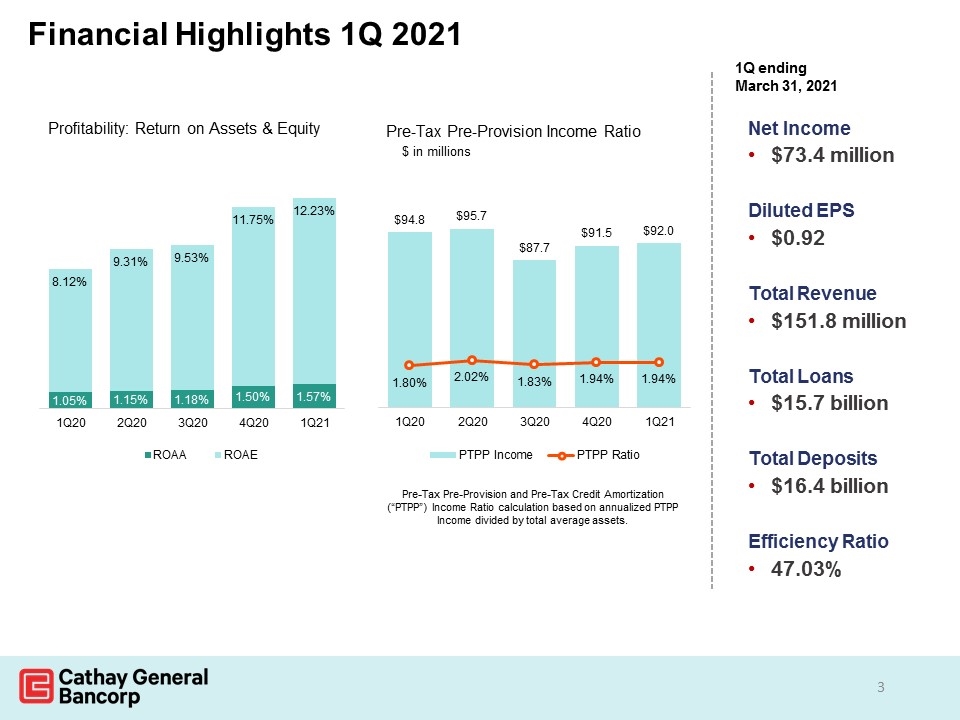
Financial Highlights 1Q 2021 1Q ending March 31, 2021 Net Income $73.4 million Diluted EPS $0.92 Total Revenue $151.8 million Total Loans $15.7 billion Total Deposits $16.4 billion Efficiency Ratio 47.03%
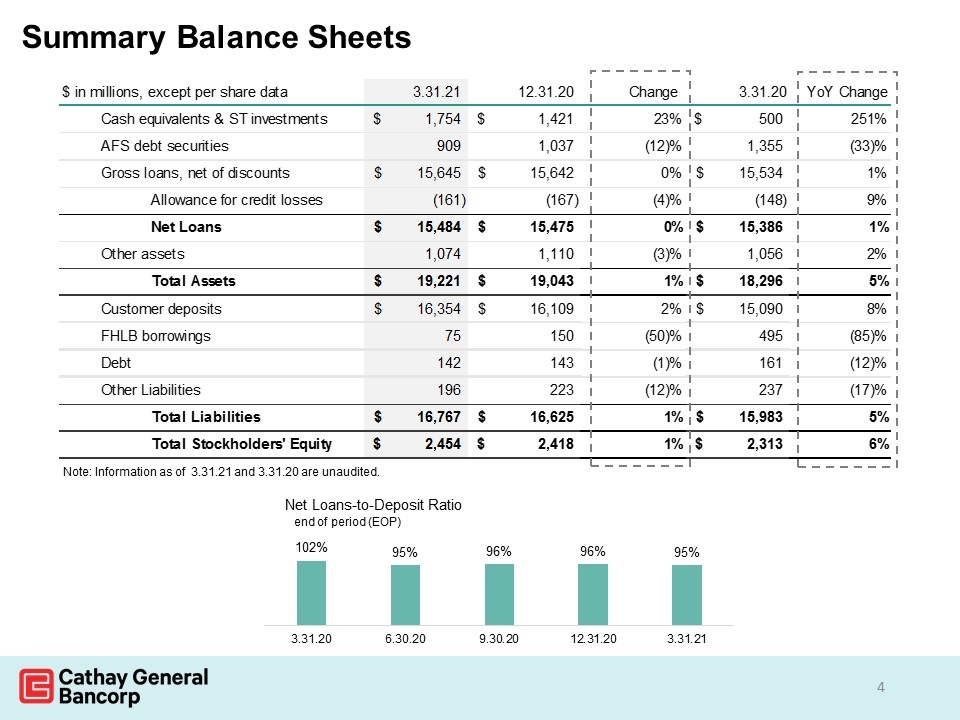
Summary Balance Sheets Note: Information as of 3.31.21 and 3.31.20 are unaudited. $ in millions, except per share data 3.31.21 12.31.20 Change 3.31.20 YoY Change Cash equivalents & ST investments $1,754 $1,421 0.23434201266713584 $500.01600000000002 2.5078877475920769 AFS debt securities 909 1037 -0.12343297974927681 1355.173 -0.32923693137333754 Gross loans, net of discounts $15,645 $15,642 1.917913310318653E-4 $15,533.934999999999 7.149830355283493E-3 Allowance for credit losses -161 -167 -3.59281437125748E-2 -148.273 8.5834912627383408E-2 Net Loans $15,484 $15,475 5.8158319870749153E-4 $15,385.662 6.3915351838614853E-3 Other assets 1074 1110 -3.2432432432432434E-2 1055.6079999999999 1.7423134345325275E-2 Total Assets $19,221 $19,043 9.3472667121776709E-3 $18,296.458999999999 5.0531143758472563E-2 Customer deposits $16,354 $16,109 1.5208889440685436E-2 $15,090 8.3764082173624965E-2 FHLB borrowings 75 150 -0.5 495 -0.84848484848484851 Debt 142 143 -6.9930069930069783E-3 161 -0.11801242236024845 Other Liabilities 196 223 -0.12107623318385652 237.25700000000001 -0.17389160277673577 Total Liabilities $16,767 $16,625 8.5413533834586275E-3 $15,983.257 4.9035249824237903E-2 Total Stockholders' Equity $2,454 $2,418 1.4888337468982549E-2 $2,313.369999999998 6.094282106166049E-2
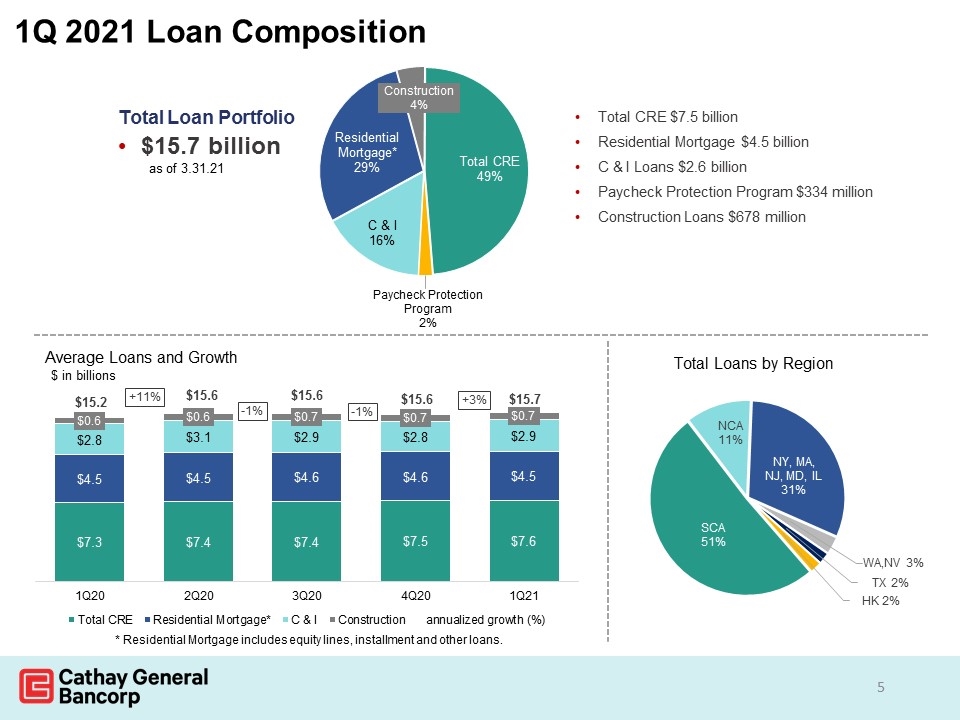
1Q 2021 Loan Composition Total Loan Portfolio $15.7 billion as of 3.31.21 * Residential Mortgage includes equity lines, installment and other loans. Total CRE $7.5 billion Residential Mortgage $4.5 billion C & I Loans $2.6 billion Paycheck Protection Program $334 million Construction Loans $678 million
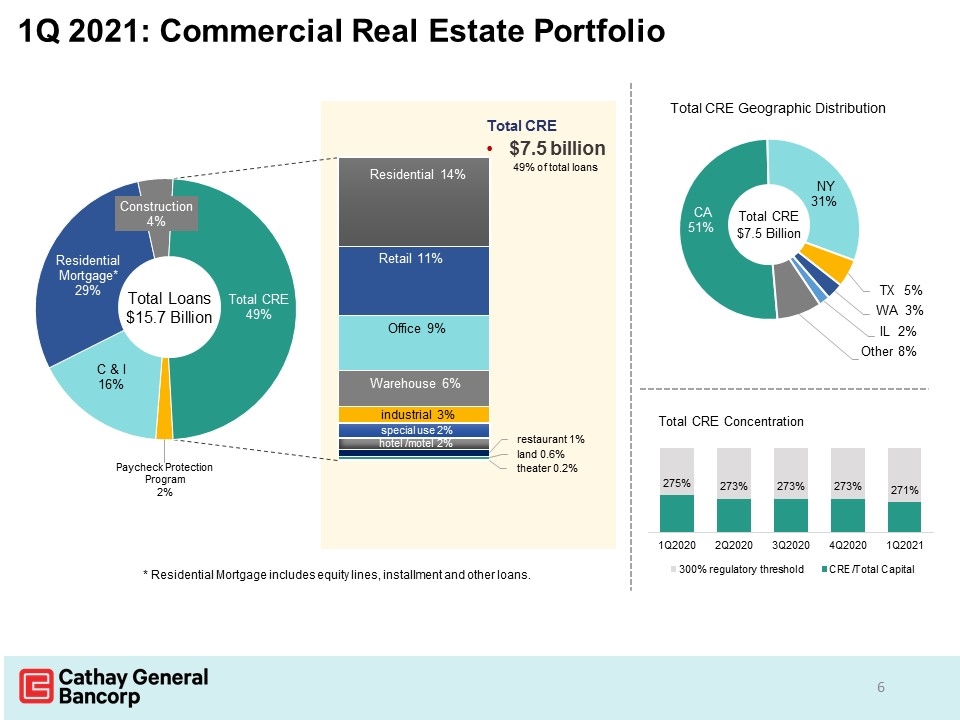
1Q 2021: Commercial Real Estate Portfolio Total CRE $7.5 billion 49% of total loans * Residential Mortgage includes equity lines, installment and other loans.
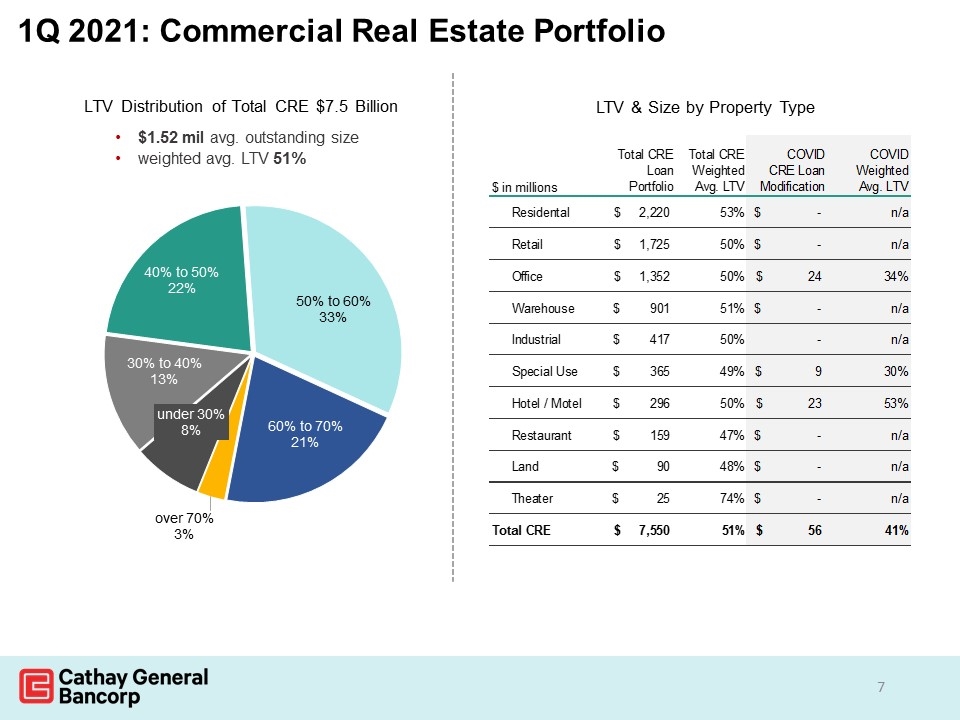
LTV & Size by Property Type 1Q 2021: Commercial Real Estate Portfolio $ in millions Total CRE Loan Portfolio Total CREWeighted Avg. LTV COVID CRE Loan Modification COVID Weighted Avg. LTV Residental $2,220 0.53300000000000003 $0 n/a Retail $1,725 0.496 $0 n/a Office $1,352 0.495 $24 0.33900000000000002 Warehouse $901 0.505 $0 n/a Industrial $417 0.502 - n/a Special Use $365 0.48599999999999999 $9 0.3 Hotel / Motel $296 0.495 $23 0.52900000000000003 Restaurant $159 0.47099999999999997 $0 n/a Land $90 0.48 $0 n/a Theater $25 0.73899999999999999 $0 n/a Total CRE $7,550 0.50700000000000001 $56 0.40899999999999997
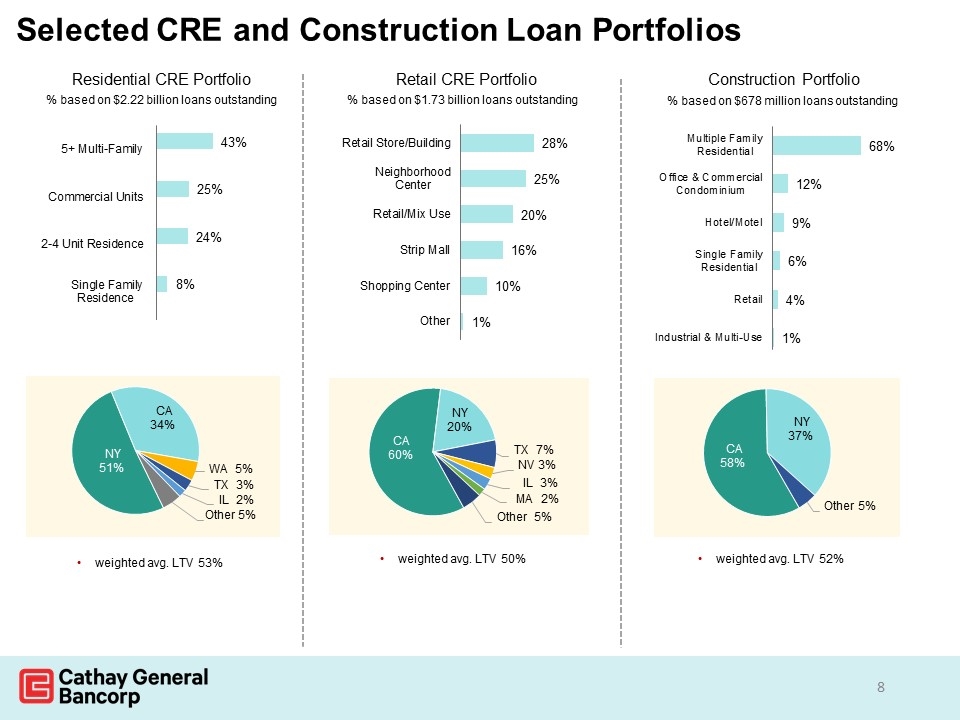
Selected CRE and Construction Loan Portfolios weighted avg. LTV 53% weighted avg. LTV 50% weighted avg. LTV 52%
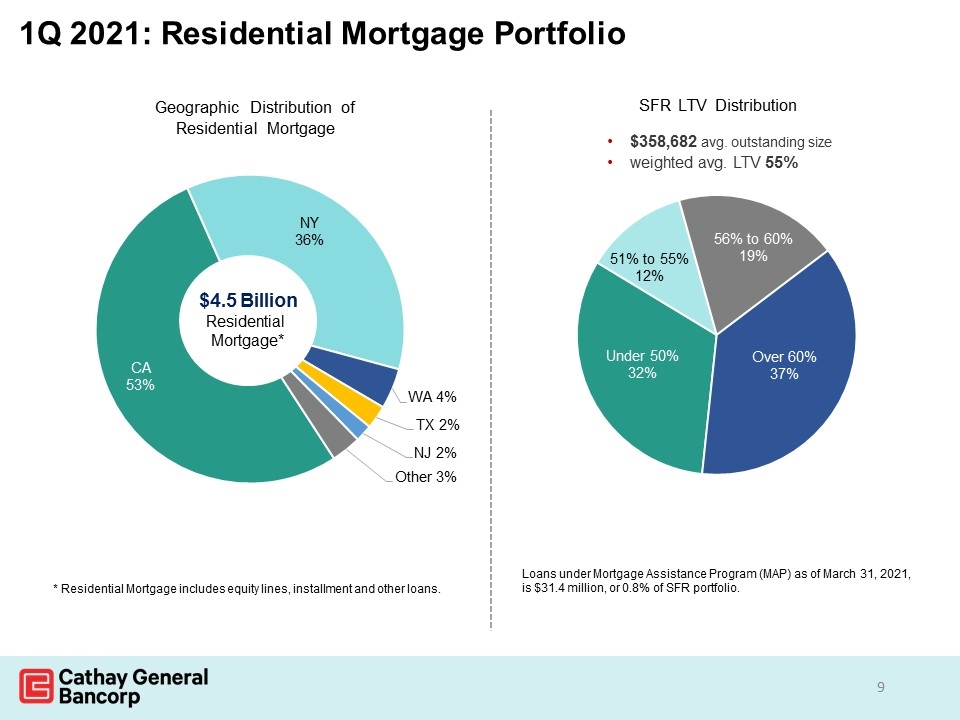
Geographic Distribution of Residential Mortgage 1Q 2021: Residential Mortgage Portfolio * Residential Mortgage includes equity lines, installment and other loans. Loans under Mortgage Assistance Program (MAP) as of March 31, 2021, is $31.4 million, or 0.8% of SFR portfolio.
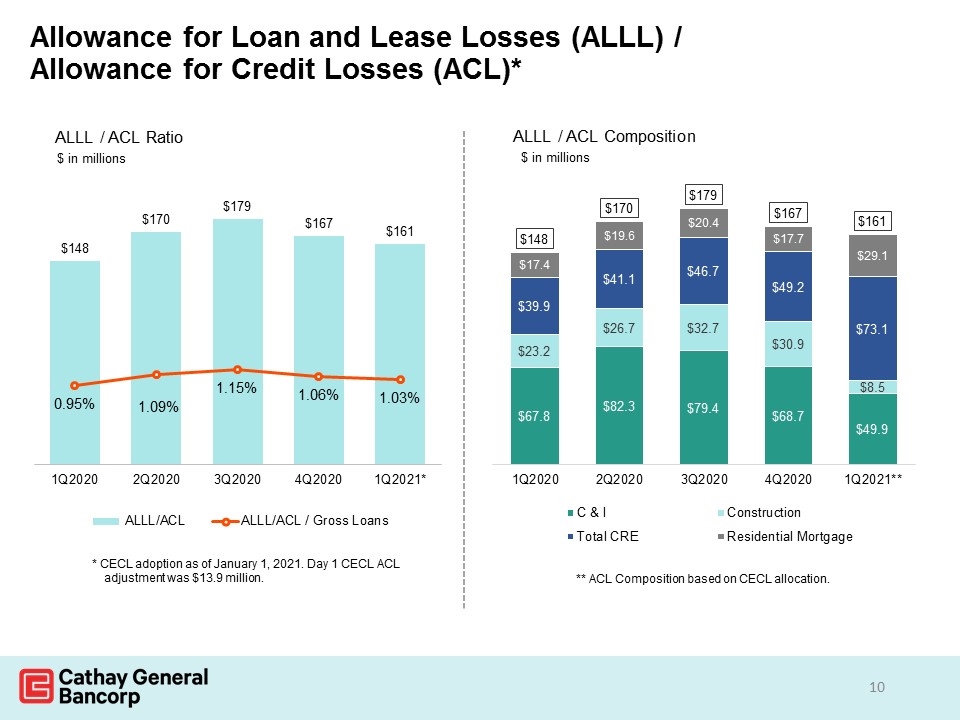
Allowance for Loan and Lease Losses (ALLL) / Allowance for Credit Losses (ACL)*
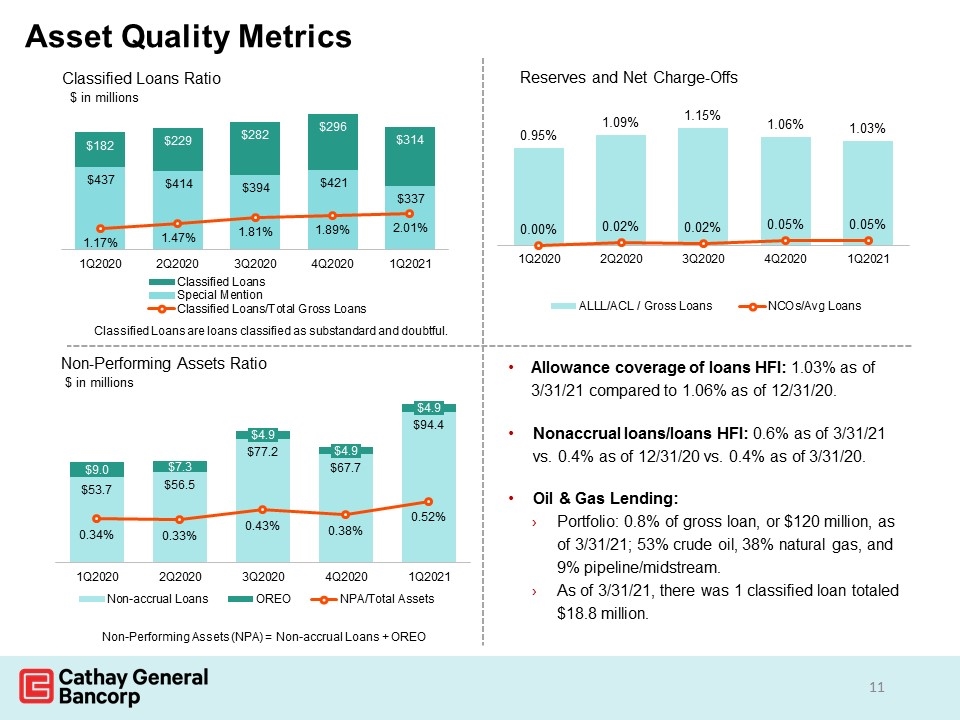
Asset Quality Metrics Allowance coverage of loans HFI: 1.03% as of 3/31/21 compared to 1.06% as of 12/31/20. Nonaccrual loans/loans HFI: 0.6% as of 3/31/21 vs. 0.4% as of 12/31/20 vs. 0.4% as of 3/31/20. Oil & Gas Lending: Portfolio: 0.8% of gross loan, or $120 million, as of 3/31/21; 53% crude oil, 38% natural gas, and 9% pipeline/midstream. As of 3/31/21, there was 1 classified loan totaled $18.8 million. Classified Loans are loans classified as substandard and doubtful. Non-Performing Assets (NPA) = Non-accrual Loans + OREO
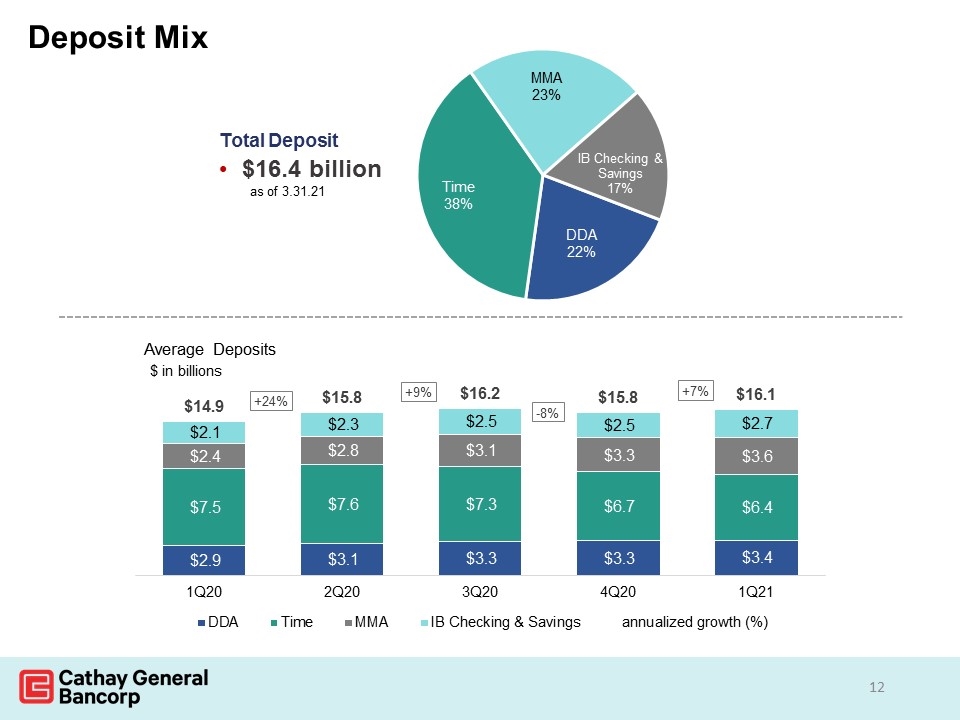
Deposit Mix Total Deposit $16.4 billion as of 3.31.21
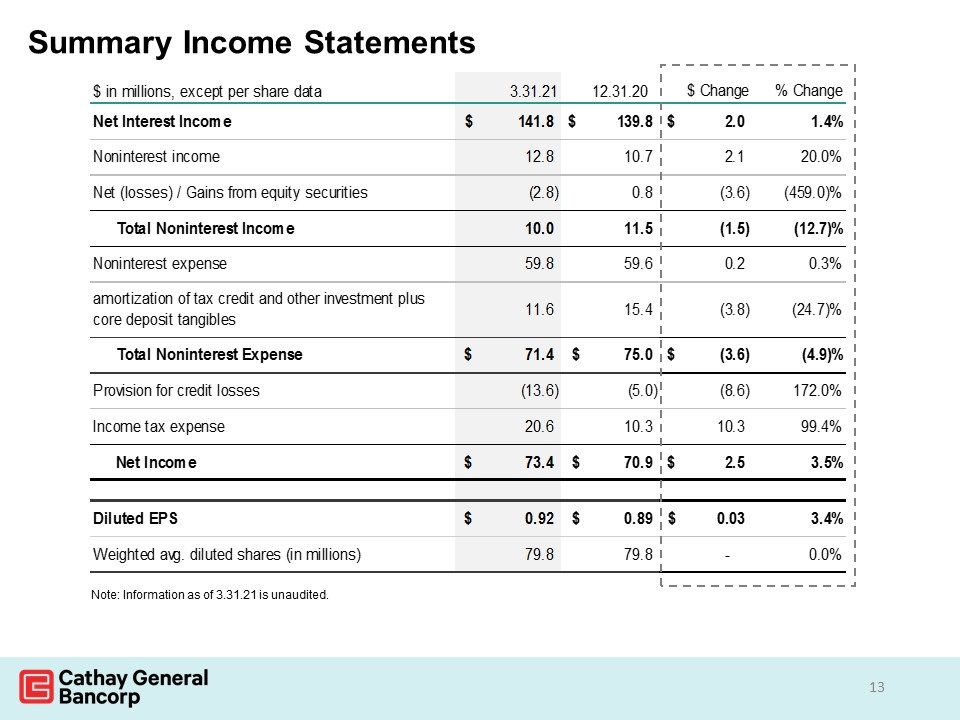
Summary Income Statements Note: Information as of 3.31.21 is unaudited. $ in millions, except per share data 3.31.21 12.31.20 $ Change % Change Net Interest Income $141.80000000000001 $139.82 $1.9800000000000182 1.4161064225% Noninterest income 12.8 10.67 2.1300000000000008 0.19962511715089043 Net (losses) / Gains from equity securities -2.8 0.78 -3.58 -4.5897435897435894 Total Noninterest Income 10 11.45 -1.4499999999999993 -0.12663755458515277 Noninterest expense 59.800000000000004 59.645000000000003 0.15500000000000114 .2598709028% amortization of tax credit and other investment plus core deposit tangibles 11.6 15.4 -3.8000000000000007 -0.24675324675324678 Total Noninterest Expense $71.400000000000006 $75.045000000000002 $-3.644999999999996 -4.8570857486% Provision for credit losses -13.6 -5 -8.6 1.72 Income tax expense 20.6 10.332000000000001 10.268000000000001 0.99380565234223772 Net Income $73.400000000000006 $70.892999999999972 $2.5070000000000334 3.5363152921% Diluted EPS $0.92 $0.89 $3.0000000000000027E-2 3.3707865169% Weighted avg. diluted shares (in millions) 79.834149999999994 79.834149999999994 0 0.0000000000%
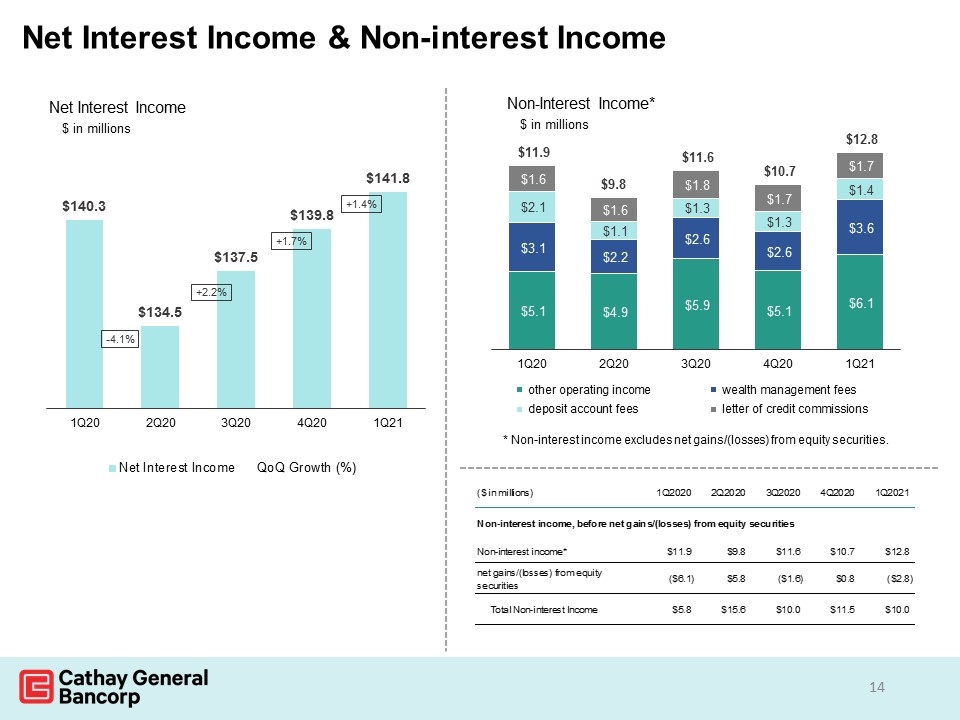
Net Interest Income & Non-interest Income $ in millions Non-Interest Income* * Non-interest income excludes net gains/(losses) from equity securities. Amortization Expense ($ in millions) 1Q2020 2Q2020 3Q2020 4Q2020 1Q2021 Non-interest income, before net gains/(losses) from equity securities Non-interest income* $11.888 $9.827 $11.6 $10.7 $12.8 net gains/(losses) from equity securities $-6.1020000000000003 $5.7789999999999999 $-1.6 $0.8 $-2.8 Total Non-interest Income $5.7859999999999996 $15.606 $10 $11.5 $10
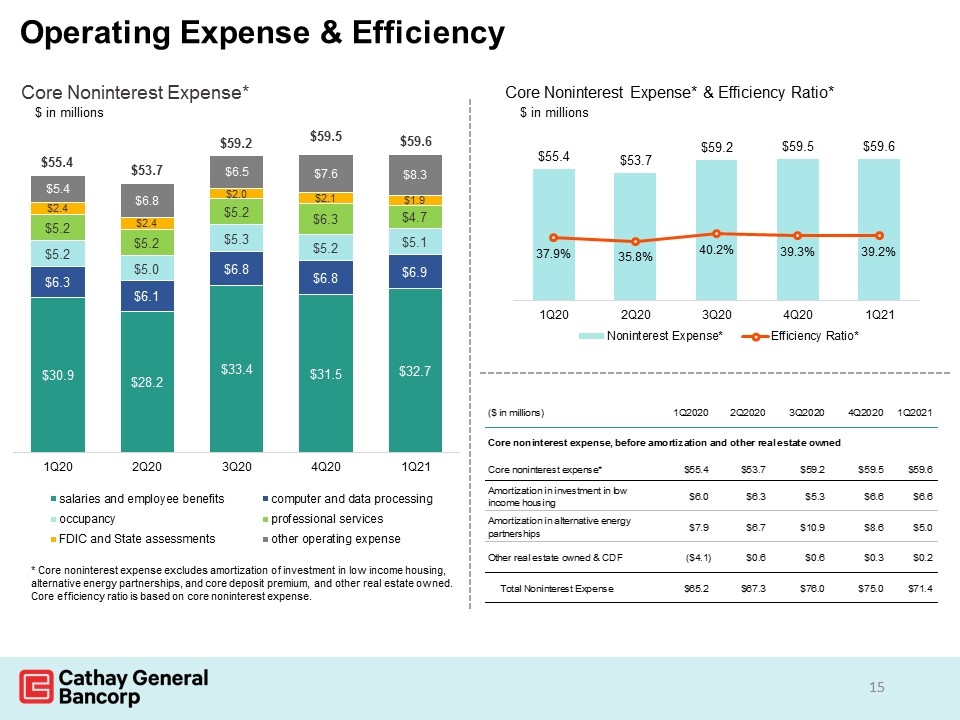
Operating Expense & Efficiency Amortization Expense ($ in millions) 1Q2020 2Q2020 3Q2020 4Q2020 1Q2021 Core noninterest expense, before amortization and other real estate owned Core noninterest expense* $55.4 $53.7 $59.2 $59.5 $59.6 Amortization in investment in low income housing $5.9805679999999999 $6.3 $5.3 $6.6 $6.6 Amortization in alternative energy partnerships $7.9090870000000004 $6.6656490000000002 $10.9 $8.6 $5 Other real estate owned & CDF $-4.0999999999999996 $0.623 $0.623 $0.3 $0.2 Total Noninterest Expense $65.189655000000002 $67.288649000000007 $76.02300000000001 $74.999999999999986 $71.400000000000006
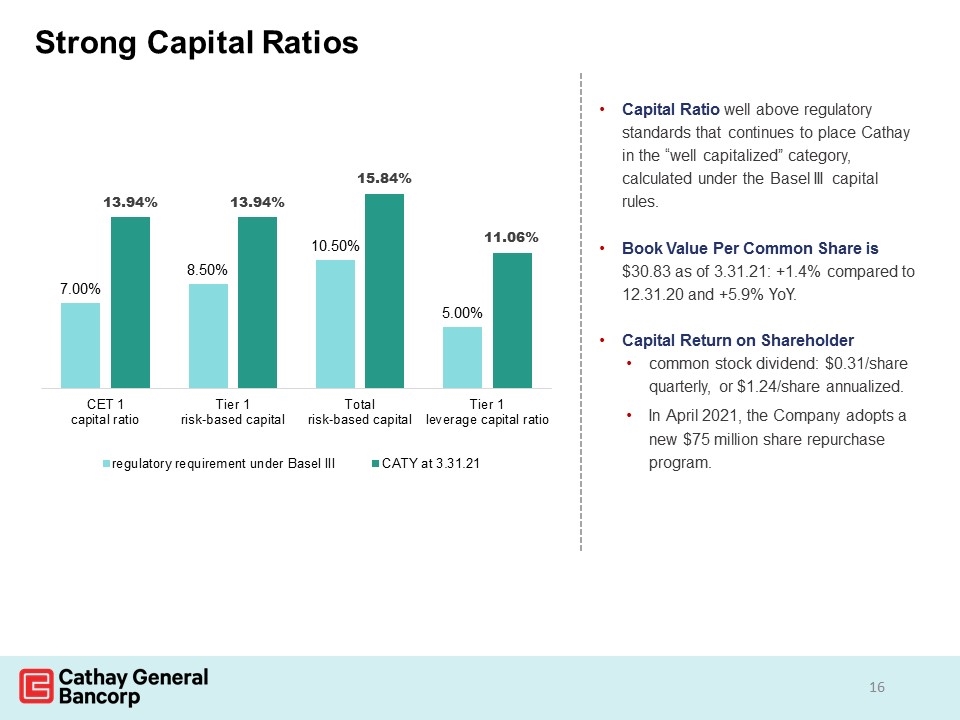
Strong Capital Ratios Capital Ratio well above regulatory standards that continues to place Cathay in the “well capitalized” category, calculated under the Basel III capital rules. Book Value Per Common Share is $30.83 as of 3.31.21: +1.4% compared to 12.31.20 and +5.9% YoY. Capital Return on Shareholder common stock dividend: $0.31/share quarterly, or $1.24/share annualized. In April 2021, the Company adopts a new $75 million share repurchase program.