
CBFV 8-K
CB Financial Services, Inc. (CBFV)
8-K
2025-04-23
For: 2025-04-23
View Original
Added on
April 10, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): April 23, 2025
| (Exact name of registrant as specified in its charter) | ||||||||
Commission file number: 001-36706
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | |||||||
| (Address of principal executive offices) | (Zip Code) | |||||||
( | ||||||||
| (Registrant’s telephone number, including area code) | ||||||||
| Not Applicable | ||||||||
| (Former name, former address and former fiscal year, if changed since last report) | ||||||||
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| (Title of each class) | (Trading symbol) | (Name of each exchange on which registered) | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter). ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition
period for complying with any new or revised financial accounting standard provided pursuant to Section 13(a) of the
Exchange Act. ☐
Item 2.02. Results of Operations and Financial Condition.
On April 23, 2025 , CB Financial Services, Inc. (the "Company") issued a press release announcing its financial results for the three months ended March 31, 2025, a copy of which is furnished herewith as Exhibit 99.1 and is incorporated herein by reference.
Item 7.01. Regulation FD Disclosure.
John H. Montgomery, President and Chief Executive Officer of the Company and Community Bank (the “Bank”), will meet with investors at the D.A. Davidson 27th Annual Financial Institutions Conference being held in Scottsdale, Arizona on May 5-7, 2025. A copy of the investor presentation to be used at the meeting is furnished herewith as Exhibit 99.2 and is incorporated herein by reference.
Item 8.01. Other Events.
On April 23, 2025 , the Company announced that its Board of Directors declared a cash dividend on the Company's outstanding shares of common stock. The dividend of $0.25 per share will be paid on or about May 30, 2025 to stockholders of record as of the close of business on May 16, 2025.
Item 9.01. Financial Statements and Exhibits.
(d)Exhibits
104. Cover Page Interactive Data File (embedded in Inline XBRL)
2
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| CB FINANCIAL SERVICES, INC. | ||||||||
Date: | By: | /s/ John H. Montgomery | ||||||
| John H. Montgomery | ||||||||
| President and Chief Executive Officer | ||||||||
3
EXHIBIT 99.1

CB Financial Services, Inc.
Announces First Quarter 2025 Financial Results and
Declares Quarterly Cash Dividend
WASHINGTON, PA., April 23, 2025 -- CB Financial Services, Inc. (“CB” or the “Company”) (NASDAQGM: CBFV), the holding company of Community Bank (the “Bank”), today announced its first quarter 2025 financial results.
| Three Months Ended | |||||||||||||||||
| 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | |||||||||||||
| (Dollars in thousands, except per share data) (Unaudited) | |||||||||||||||||
| Net Income (GAAP) | $ | 1,909 | $ | 2,529 | $ | 3,219 | $ | 2,650 | $ | 4,196 | |||||||
Net Income Adjustments | 808 | (562) | (293) | 24 | (1,000) | ||||||||||||
Adjusted Net Income (Non-GAAP) (1) | $ | 2,717 | $ | 1,967 | $ | 2,926 | $ | 2,674 | $ | 3,196 | |||||||
| Earnings per Common Share - Diluted (GAAP) | $ | 0.35 | $ | 0.46 | $ | 0.60 | $ | 0.51 | $ | 0.82 | |||||||
Adjusted Earnings per Common Share - Diluted (Non-GAAP) (1) | $ | 0.50 | $ | 0.35 | $ | 0.55 | $ | 0.52 | $ | 0.62 | |||||||
| Income Before Income Tax Expense (GAAP) | $ | 2,336 | $ | 3,051 | $ | 3,966 | $ | 3,210 | $ | 5,116 | |||||||
| Net (Recovery) Provision for Credit Losses | (40) | 683 | (41) | (36) | (37) | ||||||||||||
Pre-Provision Net Revenue (“PPNR”) | $ | 2,296 | $ | 3,734 | $ | 3,925 | $ | 3,174 | $ | 5,079 | |||||||
| Net Income Adjustments | $ | 1,023 | $ | (711) | $ | (383) | $ | 31 | $ | (1,023) | |||||||
Adjusted PPNR (Non-GAAP) (1) | $ | 3,319 | $ | 3,023 | $ | 3,542 | $ | 3,205 | $ | 4,056 | |||||||
(1) Refer to Explanation of Use of Non-GAAP Financial Measures and reconciliation of adjusted net income and adjusted earnings per common share - diluted as presented later in this Press Release.
2025 First Quarter Financial Highlights
•Total assets were $1.48 billion at March 31, 2025, an increase of $1.9 million from December 31, 2024 and $10.4 million from March 31, 2024. As growth remains tepid, the Bank has focused efforts on repositioning the balance sheet to maximize earnings while maintaining a steady risk profile. These strategic movements included:
◦Effectively managing cash and liquidity to reduce costly brokered time deposits.
◦Redeploying repayments of indirect automobile and residential mortgage loans into higher-yielding commercial loan products. Commercial loans totaled 56% of the Bank’s loan portfolio at March 31, 2025 compared to 52% at March 31, 2024.
◦Effecting changes in the Bank’s deposit mix by focusing on growth in lower cost core deposit relationships and reducing reliance on time deposits.
•Net interest margin (“NIM”) improved to 3.27% for the three months ended March 31, 2025 compared to 3.12% for the three months ended December 31, 2024. Main factors impacting the improved NIM included:
◦A reduction in the cost of funds to 2.03% from 2.29% resulting from the favorable change in the Bank’s deposit mix coupled with disciplined deposit pricing and the recent reduction in the federal funds rate.
◦A modest decrease in the yield on earning assets to 5.17% from 5.27% as the positive impact of the balance sheet repositioning strategies partially offset the effect of recent rate cuts on asset repricing.
•Noninterest expenses increased $349,000 to $9.8 million for the three months ended March 31, 2025 compared to $9.5 million for the three months ended December 31, 2024. During the quarter ended March 31, 2025, the Bank recognized $1.0 million in one-time expenses related to the previously announced reduction in force. This reduction in force coupled with other operational changes involving property management, recruitment and other activities are expected to result in annual, pre-tax cost savings of approximately $1.5 million. Excluding these one-time charges, noninterest expense decreased $654,000 as costs are being actively managed and controlled.
•Asset quality remains strong as nonperforming loans to total loans was 0.22% at March 31, 2025.
1
EXHIBIT 99.1
•Book value per share and tangible book value per share (Non-GAAP) was $29.08 and $27.17, respectively at March 31, 2025. The improvements since year-end resulted from increased equity due to current period net income and a decrease in accumulated other comprehensive losses, partially offset by treasury shares repurchased under the Company’s stock repurchase program and the payment of dividends.
•The Bank remains well-capitalized and is positioned for future growth.
Management Commentary
President and CEO John H. Montgomery commented, “Our first quarter operating results were a good start to the year, with an improvement in net interest margin along with solid first quarter loan production. The reduction in funding costs during the quarter more than offset the decline in asset yields, contributing to net interest margin growth for the first quarter compared to the prior quarter. In addition to softening deposit costs from the impact of the Federal Reserve rate cuts implemented during the second half of 2024, we reduced our concentration of time deposits during the quarter, which also helped lower our cost of funds. Impacting earnings for the quarter were $1.0 million in one-time non-recurring expenses associated with the previously announced reduction in staff earlier this year.
In a time of economic uncertainty and market volatility, we continue to focus our efforts on what we can control by managing a conservative balance sheet and mitigating risk, while focusing on core banking and our customers. The loan portfolio decreased $4.1 million on a quarter-over-quarter basis, due in part to the previously exited Indirect Lending Portfolio. Excluding this portfolio, total loans increased $4.2 million during the quarter, with commercial real estate and other loans posting the largest gains. In addition, our asset quality remained sound, with nonperforming loans at 0.22% of total loans at quarter-end.
Our focus on building core banking relationships while strategically reducing our reliance on time deposit only relationships is helping to favorably shift our deposit mix. Time and money market deposits decreased during the quarter, while interest-bearing demand, savings and noninterest-bearing demand deposits all increased. On a quarter-over-quarter basis, total deposits decreased by $2.4 million, with brokered time deposits remaining unchanged compared to the prior quarter end.
During the first quarter, we made forward progress in implementing our Specialty Treasury Payments & Services program as part of our long-term strategic initiative to drive revenue growth and enhance our core deposit base. Initial implementation of this strategy is expected near the end of 2025. While costs associated with this strategy will impact operating expenses over the next few quarters, we believe this investment in our franchise will benefit all stakeholders. With ample capital levels, an excellent deposit base, strong liquidity and sound credit quality, we are confident that we have the foundation to enter a period of growth and material revenue generation by the end of the year.”
Dividend Declaration
The Company’s Board of Directors declared a $0.25 quarterly cash dividend per outstanding share of common stock, payable on or about May 30, 2025, to stockholders of record as of the close of business on May 16, 2025.
2025 First Quarter Financial Review
Net Interest and Dividend Income
Net interest and dividend income decreased $280,000, or 2.4%, to $11.3 million for the three months ended March 31, 2025 compared to $11.6 million for the three months ended March 31, 2024.
•Net Interest Margin (NIM) (GAAP) decreased to 3.27% for the three months ended March 31, 2025 compared to 3.36% for the three months ended March 31, 2024. Fully tax equivalent (FTE) NIM (Non-GAAP) decreased 9 basis points (“bps”) to 3.28% for the three months ended March 31, 2025 compared to 3.37% for the three months ended March 31, 2024.
•Interest and dividend income decreased $139,000, or 0.8%, to $17.8 million for the three months ended March 31, 2025 compared to $18.0 million for the three months ended March 31, 2024.
◦Interest income on loans decreased $310,000, or 2.1%, to $14.5 million for the three months ended March 31, 2025 compared to $14.8 million for the three months ended March 31, 2024. The average balance of loans decreased $12.8 million to $1.08 billion from $1.09 billion, causing a $293,000 decrease in interest income on loans. The average yield on loans remained stable at 5.50% for both periods despite a 100bp reduction in the federal funds rate since September 2024. While this led to the downward repricing of variable and adjustable rate loans, the impact was negated by a reduction in lower yielding consumer loans due to the discontinuation of the indirect automobile loan product with the redeployment of those funds into higher yielding commercial loan products.
2
◦Interest income on taxable investment securities increased $474,000, or 20.6%, to $2.8 million for the three months ended March 31, 2025 compared to $2.3 million for the three months ended March 31, 2024 driven by a $42.6 million increase in average balances coupled with an 8 bp increase in average yield. The increase in volume was driven by a $56.2 million increase in the average balance of collateralized loan obligation (“CLO”) securities as the Bank executed a leverage strategy during 2024 to purchase these assets funded with cash reserves and brokered certificates of deposits.
◦Interest income on interest-earning deposits at other banks decreased $274,000 to $459,000 for the three months ended March 31, 2025 compared to $733,000 for the three months ended March 31, 2024 driven by a 91 bp decrease in the average yield and a $13.8 million decrease in average balances. The decreased in the yield was directly related to the Federal Reserve’s recent reductions in the federal funds rate.
•Interest expense increased $141,000, or 2.2%, to $6.5 million for the three months ended March 31, 2025 compared to $6.4 million for the three months ended March 31, 2024.
◦Interest expense on deposits increased $120,000, or 2.0%, to $6.1 million for the three months ended March 31, 2025 compared to $6.0 million for the three months ended March 31, 2024. Interest-bearing deposit balances increased $27.5 million, or 2.8%, to $1.0 billion as of March 31, 2025 compared to $978.3 million as of March 31, 2024, accounting for a $120,000 increase in interest expense.
◦While interest expense increased compared to the same quarter in the prior year, it decreased $1.4 million, or 17.3%, to $6.5 million for the three months ended March 31, 2025 compared to $7.9 million for the three months ended December 31, 2024. Interest-bearing deposits decreased $62.2 million as the Bank strategically reduced brokered deposits and time deposit only relationships. Additionally, the cost of interest-bearing deposits declined from 2.79% for the three months ended December 31, 2024 compared to 2.46% for the three months ended March 31, 2025 due to the change in the deposit mix and the recent Federal Reserve federal funds rate decreases.
Provision for Credit Losses
A recovery for credit losses was recorded for the three months ended March 31, 2025 of $40,000. The provision for credit losses - loans was $68,000 and was primarily due to qualitative adjustments on economic factors. The provision for credit losses - unfunded commitments was a $108,000 recovery and was due to a decrease in unfunded commitments and a decrease in funding rates. This compared to a net recovery of $37,000 recorded for the three months ended March 31, 2024 as the provision for credit losses - loans was a recovery of $143,000 and was primarily due to a decrease in loan balances while the provision for credit losses - unfunded commitments was $106,000 and was due to an increase in qualitative factors.
Noninterest Income
Noninterest income decreased $1.1 million, or 58.9%, to $787,000 for the three months ended March 31, 2025, compared to $1.9 million for the three months ended March 31, 2024. This decrease resulted primarily as prior period results included a $915,000 gain on bank owned life insurance resulting from one death claim and a $274,000 gain on the disposal of premises and equipment from the sale on one branch office building.
Noninterest Expense
Noninterest expense increased $1.4 million, or 16.3%, to $9.8 million for the three months ended March 31, 2025 compared to $8.4 million for the three months ended March 31, 2024. Salaries and benefits increased $1.5 million, or 31.9%, to $6.0 million primarily due to $1.0 million of one-time non-recurring expenses recognized for the three months ended March 31, 2025 associated with the previously announced reduction in force, merit increases, revenue producing staff additions and higher insurance benefit costs. Data processing expense increased $105,000 due to costs associated with the implementation of a new loan origination system and financial dashboard platform during mid-2024. Equipment expense increased $66,000 due to higher depreciation expense associated with interactive teller machines, security system upgrades and other equipment placed into service in 2024. Legal and professional fees increased $50,000 primarily due to timing differences related to external audit and tax services. Contracted services increased $29,000 due to costs associated with website administration and equity compensation management added during mid-2024 and treasury product consulting services started in the current year. These increases were partially offset as intangible amortization decreased $341,000 as the Bank’s core deposit intangibles were fully amortized in 2024.
Statement of Financial Condition Review
Assets
Total assets increased $1.9 million, or 0.1%, to $1.483 billion at March 31, 2025, compared to $1.482 billion at December 31, 2024.
3
•Cash and due from banks increased $11.7 million, or 23.6%, to $61.3 million at March 31, 2025, compared to $49.6 million at December 31, 2024.
•Securities decreased $3.5 million, or 1.3%, to $258.7 million at March 31, 2025, compared to $262.2 million at December 31, 2024. The securities balance was primarily impacted by principal repayments on amortizing securities and the sale of equity securities, partially offset by an increase in the market value of the portfolio.
Loans and Credit Quality
•Total loans decreased $4.1 million, or 0.4%, to $1.088 billion compared to $1.093 billion, and included decreases in consumer, commercial and industrial and residential real estate loans of $8.7 million, $4.6 million and $3.2 million, respectively, partially offset by increases in commercial real estate and other loans of $11.8 million and $701,000, respectively. The decrease in consumer loans resulted from a reduction in indirect automobile loan production due to the discontinuation of this product offering as of June 30, 2023. This portfolio is expected to continue to decline as resources are allocated and production efforts are focused on more profitable commercial products. Excluding the $8.3 million decrease in indirect automobile loans, total loans increased $4.2 million, or 0.4%. Loan production totaled $28.6 million while $15.6 million of loans were paid off since December 31, 2024.
•The allowance for credit losses (ACL) was $9.82 million at March 31, 2025 and $9.81 million at December 31, 2024. As a result, the ACL to total loans was 0.90% at March 31, 2025 and 0.90% at December 31, 2024. During the current year, the Company recorded a net recovery for credit losses of $40,000.
•Net charge-offs for the three months ended March 31, 2025 were $54,000, or 0.02% of average loans on an annualized basis. Net recoveries for the three months ended March 31, 2024 were $18,000, or 0.01% of average loans on an annualized basis.
•Nonperforming loans, which include nonaccrual loans and accruing loans past due 90 days or more, were $2.4 million at March 31, 2025 and $1.8 million at December 31, 2024. Nonperforming loans to total loans ratio was 0.22% at March 31, 2025 and 0.16% at December 31, 2024.
Total liabilities increased $1.0 million, or 0.1%, to $1.34 billion at March 31, 2025 compared to $1.33 billion at December 31, 2024.
Deposits
•Total deposits decreased $2.4 million to $1.281 billion as of March 31, 2025 compared to $1.284 billion at December 31, 2024. Time deposits decreased $29.1 million and money market deposits decreased $3.5 million while interest-bearing demand, savings and non interest-bearing demand deposits increased $24.4 million, $6.2 million and $504,000, respectively. This favorable change in the deposit mix was the result of an increased focus on building core banking relationships while strategically reducing time deposit only relationships. Brokered time deposits totaled $39.0 million as of March 31, 2025 and December 31, 2024, all of which mature within three months and were utilized to fund the purchase of floating rate CLO securities. At March 31, 2025, FDIC insured deposits totaled approximately 62.3% of total deposits while an additional 15.2% of total deposits were collateralized with investment securities.
Accrued Interest Payable and Other Liabilities
•Accrued interest payable and other liabilities increased $3.4 million, or 21.3%, to $19.3 million at March 31, 2025, compared to $16.0 million at December 31, 2024 primarily due to a $3.0 million syndicated national credit not yet settled.
Stockholders’ Equity
Stockholders’ equity increased $911,000, or 0.6%, to $148.3 million at March 31, 2025, compared to $147.4 million at December 31, 2024. The key factors positively impacting stockholders’ equity was $1.9 million of net income for the current year and a $1.9 million decrease in accumulated other comprehensive loss, partially offset by $2.4 million of treasury shares purchased under the stock repurchase program and the payment of $1.3 million in dividends since December 31, 2024.
Book value per share
Book value per common share was $29.08 at March 31, 2025 compared to $28.71 at December 31, 2024, an increase of $0.37.
Tangible book value per common share (Non-GAAP) was $27.17 at March 31, 2025, compared to $26.82 at December 31, 2024, an increase of $0.35.
Refer to “Explanation of Use of Non-GAAP Financial Measures” at the end of this Press Release.
4
About CB Financial Services, Inc.
CB Financial Services, Inc. is the bank holding company for Community Bank, a Pennsylvania-chartered commercial bank. Community Bank operates its branch network in southwestern Pennsylvania and West Virginia. Community Bank offers a broad array of retail and commercial lending and deposit services.
For more information about CB Financial Services, Inc. and Community Bank, visit our website at www.communitybank.tv.
Statement About Forward-Looking Statements
Statements contained in this press release that are not historical facts may constitute forward-looking statements as that term is defined in the Private Securities Litigation Reform Act of 1995 and such forward-looking statements are subject to significant risks and uncertainties. The Company intends such forward-looking statements to be covered by the safe harbor provisions contained in the Act. The Company’s ability to predict results or the actual effect of future plans or strategies is inherently uncertain. Factors which could have a material adverse effect on the operations and future prospects of the Company and its subsidiaries include, but are not limited to, general and local economic conditions, changes in market interest rates, deposit flows, demand for loans, real estate values and competition, competitive products and pricing, the ability of our customers to make scheduled loan payments, loan delinquency rates and trends, our ability to manage the risks involved in our business, our ability to control costs and expenses, inflation, market and monetary fluctuations, changes in federal and state legislation and regulation applicable to our business, actions by our competitors, and other factors that may be disclosed in the Company’s periodic reports as filed with the Securities and Exchange Commission. These risks and uncertainties should be considered in evaluating forward-looking statements and undue reliance should not be placed on such statements. The Company assumes no obligation to update any forward-looking statements except as may be required by applicable law or regulation.
Company Contact:
John H. Montgomery
President and Chief Executive Officer
Phone: (724) 223-8317
5
CB FINANCIAL SERVICES, INC. SELECTED CONSOLIDATED FINANCIAL INFORMATION | |||||||||||||||||||||||||||||
| (Dollars in thousands, except share and per share data) (Unaudited) | |||||||||||||||||||||||||||||
| Selected Financial Condition Data | 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | ||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||
| Cash and Due From Banks | $ | 61,274 | $ | 49,572 | $ | 147,325 | $ | 142,600 | $ | 73,691 | |||||||||||||||||||
| Securities | 258,699 | 262,153 | 270,881 | 268,769 | 232,276 | ||||||||||||||||||||||||
| Loans Held for Sale | 230 | 900 | 428 | 632 | 200 | ||||||||||||||||||||||||
| Loans | |||||||||||||||||||||||||||||
| Real Estate: | |||||||||||||||||||||||||||||
| Residential | 334,744 | 337,990 | 338,926 | 342,689 | 346,938 | ||||||||||||||||||||||||
| Commercial | 497,316 | 485,513 | 464,354 | 458,724 | 470,430 | ||||||||||||||||||||||||
| Construction | 54,597 | 54,705 | 43,515 | 44,038 | 44,323 | ||||||||||||||||||||||||
| Commercial and Industrial | 107,419 | 112,047 | 108,554 | 112,395 | 103,313 | ||||||||||||||||||||||||
| Consumer | 61,854 | 70,508 | 80,004 | 90,357 | 100,576 | ||||||||||||||||||||||||
| Other | 32,564 | 31,863 | 30,402 | 30,491 | 30,763 | ||||||||||||||||||||||||
| Total Loans | 1,088,494 | 1,092,626 | 1,065,755 | 1,078,694 | 1,096,343 | ||||||||||||||||||||||||
| Allowance for Credit Losses | (9,819) | (9,805) | (9,479) | (9,527) | (9,582) | ||||||||||||||||||||||||
| Loans, Net | 1,078,675 | 1,082,821 | 1,056,276 | 1,069,167 | 1,086,761 | ||||||||||||||||||||||||
| Premises and Equipment, Net | 20,392 | 20,708 | 20,838 | 20,326 | 19,548 | ||||||||||||||||||||||||
| Bank-Owned Life Insurance | 24,358 | 24,209 | 24,057 | 23,910 | 23,763 | ||||||||||||||||||||||||
| Goodwill | 9,732 | 9,732 | 9,732 | 9,732 | 9,732 | ||||||||||||||||||||||||
| Intangible Assets, Net | — | — | 88 | 353 | 617 | ||||||||||||||||||||||||
| Accrued Interest Receivable and Other Assets | 30,096 | 31,469 | 32,116 | 24,770 | 26,501 | ||||||||||||||||||||||||
| Total Assets | $ | 1,483,456 | $ | 1,481,564 | $ | 1,561,741 | $ | 1,560,259 | $ | 1,473,089 | |||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||
| Deposits | |||||||||||||||||||||||||||||
| Noninterest-Bearing Demand Accounts | $ | 267,392 | $ | 267,896 | $ | 267,022 | $ | 269,964 | $ | 275,182 | |||||||||||||||||||
| Interest-Bearing Demand Accounts | 341,212 | 316,764 | 326,505 | 324,688 | 323,134 | ||||||||||||||||||||||||
| Money Market Accounts | 228,005 | 231,458 | 220,789 | 229,998 | 208,375 | ||||||||||||||||||||||||
| Savings Accounts | 176,722 | 170,530 | 172,354 | 179,081 | 190,206 | ||||||||||||||||||||||||
| Time Deposits | 267,766 | 296,869 | 367,150 | 346,037 | 265,597 | ||||||||||||||||||||||||
| Total Deposits | 1,281,097 | 1,283,517 | 1,353,820 | 1,349,768 | 1,262,494 | ||||||||||||||||||||||||
| Other Borrowings | 34,728 | 34,718 | 34,708 | 34,698 | 34,688 | ||||||||||||||||||||||||
| Accrued Interest Payable and Other Liabilities | 19,342 | 15,951 | 24,073 | 32,911 | 34,317 | ||||||||||||||||||||||||
| Total Liabilities | 1,335,167 | 1,334,186 | 1,412,601 | 1,417,377 | 1,331,499 | ||||||||||||||||||||||||
| Stockholders’ Equity | 148,289 | 147,378 | 149,140 | 142,882 | 141,590 | ||||||||||||||||||||||||
| Total Liabilities and Stockholders’ Equity | $ | 1,483,456 | $ | 1,481,564 | $ | 1,561,741 | $ | 1,560,259 | $ | 1,473,089 | |||||||||||||||||||
6
| (Dollars in thousands, except share and per share data) (Unaudited) | |||||||||||||||||
| Three Months Ended | |||||||||||||||||
| Selected Operating Data | 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | ||||||||||||
| Interest and Dividend Income: | |||||||||||||||||
| Loans, Including Fees | $ | 14,528 | $ | 14,930 | $ | 14,945 | $ | 14,670 | $ | 14,838 | |||||||
| Securities: | |||||||||||||||||
| Taxable | 2,777 | 3,096 | 3,289 | 2,844 | 2,303 | ||||||||||||
| Dividends | 28 | 27 | 28 | 27 | 27 | ||||||||||||
| Other Interest and Dividend Income | 514 | 1,378 | 1,511 | 1,398 | 818 | ||||||||||||
| Total Interest and Dividend Income | 17,847 | 19,431 | 19,773 | 18,939 | 17,986 | ||||||||||||
| Interest Expense: | |||||||||||||||||
| Deposits | 6,111 | 7,492 | 7,892 | 7,065 | 5,991 | ||||||||||||
| Short-Term Borrowings | 23 | — | — | — | — | ||||||||||||
| Other Borrowings | 402 | 407 | 407 | 404 | 404 | ||||||||||||
| Total Interest Expense | 6,536 | 7,899 | 8,299 | 7,469 | 6,395 | ||||||||||||
| Net Interest and Dividend Income | 11,311 | 11,532 | 11,474 | 11,470 | 11,591 | ||||||||||||
| Provision (Recovery) for Credit Losses - Loans | 68 | 483 | 25 | 12 | (143) | ||||||||||||
| (Recovery) Provision for Credit Losses - Unfunded Commitments | (108) | 200 | (66) | (48) | 106 | ||||||||||||
| Net Interest and Dividend Income After Net (Recovery) Provision for Credit Losses | 11,351 | 10,849 | 11,515 | 11,506 | 11,628 | ||||||||||||
| Noninterest Income: | |||||||||||||||||
| Service Fees | 462 | 460 | 451 | 354 | 415 | ||||||||||||
| Insurance Commissions | 1 | 1 | 1 | 1 | 2 | ||||||||||||
| Other Commissions | 63 | 63 | 104 | 22 | 62 | ||||||||||||
| Net Gain on Sales of Loans | 22 | 3 | 18 | 9 | 22 | ||||||||||||
| Net (Loss) Gain on Securities | (69) | 3 | 245 | (31) | (166) | ||||||||||||
| Net Gain on Purchased Tax Credits | 4 | 12 | 12 | 12 | 12 | ||||||||||||
| Gain on Sale of Subsidiary | — | — | 138 | — | — | ||||||||||||
| Net Gain on Disposal of Premises and Equipment | — | — | — | — | 274 | ||||||||||||
| Income from Bank-Owned Life Insurance | 149 | 152 | 147 | 147 | 148 | ||||||||||||
| Net Gain on Bank-Owned Life Insurance Claims | — | — | — | — | 915 | ||||||||||||
| Other Income | 155 | 961 | 117 | 174 | 232 | ||||||||||||
| Total Noninterest Income | 787 | 1,655 | 1,233 | 688 | 1,916 | ||||||||||||
| Noninterest Expense: | |||||||||||||||||
| Salaries and Employee Benefits | 6,036 | 5,258 | 4,561 | 4,425 | 4,576 | ||||||||||||
| Occupancy | 750 | 652 | 755 | 940 | 749 | ||||||||||||
| Equipment | 330 | 313 | 280 | 298 | 264 | ||||||||||||
| Data Processing | 797 | 832 | 772 | 1,011 | 692 | ||||||||||||
| Federal Deposit Insurance Corporation Assessment | 176 | 172 | 177 | 161 | 129 | ||||||||||||
| Pennsylvania Shares Tax | 257 | 301 | 265 | 297 | 297 | ||||||||||||
| Contracted Services | 310 | 522 | 431 | 390 | 281 | ||||||||||||
| Legal and Professional Fees | 262 | 268 | 297 | 208 | 212 | ||||||||||||
| Advertising | 119 | 137 | 141 | 78 | 129 | ||||||||||||
| Other Real Estate Owned (Income) | — | 34 | 2 | 37 | (23) | ||||||||||||
| Amortization of Intangible Assets | — | 88 | 264 | 264 | 341 | ||||||||||||
| Other Expense | 765 | 876 | 837 | 875 | 781 | ||||||||||||
| Total Noninterest Expense | 9,802 | 9,453 | 8,782 | 8,984 | 8,428 | ||||||||||||
| Income Before Income Tax Expense | 2,336 | 3,051 | 3,966 | 3,210 | 5,116 | ||||||||||||
| Income Tax Expense | 427 | 522 | 747 | 560 | 920 | ||||||||||||
| Net Income | $ | 1,909 | $ | 2,529 | $ | 3,219 | $ | 2,650 | $ | 4,196 | |||||||
7
| Three Months Ended | |||||||||||||||||
| Per Common Share Data | 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | ||||||||||||
| Dividends Per Common Share | $ | 0.25 | $ | 0.25 | $ | 0.25 | $ | 0.25 | $ | 0.25 | |||||||
| Earnings Per Common Share - Basic | 0.37 | 0.49 | 0.63 | 0.52 | 0.82 | ||||||||||||
| Earnings Per Common Share - Diluted | 0.35 | 0.46 | 0.60 | 0.51 | 0.82 | ||||||||||||
| Weighted Average Common Shares Outstanding - Basic | 5,125,577 | 5,126,782 | 5,137,586 | 5,142,139 | 5,129,903 | ||||||||||||
| Weighted Average Common Shares Outstanding - Diluted | 5,471,006 | 5,544,829 | 5,346,750 | 5,152,657 | 5,142,286 | ||||||||||||
| 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | |||||||||||||
| Common Shares Outstanding | 5,099,069 | 5,132,654 | 5,129,921 | 5,141,911 | 5,142,901 | ||||||||||||
| Book Value Per Common Share | $ | 29.08 | $ | 28.71 | $ | 29.07 | $ | 27.79 | $ | 27.53 | |||||||
Tangible Book Value per Common Share (1) | 27.17 | 26.82 | 27.16 | 25.83 | 25.52 | ||||||||||||
| Stockholders’ Equity to Assets | 10.0 | % | 9.9 | % | 9.5 | % | 9.2 | % | 9.6 | % | |||||||
Tangible Common Equity to Tangible Assets (1) | 9.4 | 9.4 | 9.0 | 8.6 | 9.0 | ||||||||||||
| Three Months Ended | |||||||||||||||||
Selected Financial Ratios (2) | 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | ||||||||||||
| Return on Average Assets | 0.53 | % | 0.65 | % | 0.84 | % | 0.71 | % | 1.17 | % | |||||||
| Return on Average Equity | 5.24 | 6.80 | 8.80 | 7.58 | 12.03 | ||||||||||||
| Average Interest-Earning Assets to Average Interest-Bearing Liabilities | 134.70 | 133.33 | 133.26 | 135.69 | 137.07 | ||||||||||||
| Average Equity to Average Assets | 10.07 | 9.63 | 9.54 | 9.36 | 9.72 | ||||||||||||
| Net Interest Rate Spread | 2.61 | 2.41 | 2.36 | 2.44 | 2.67 | ||||||||||||
Net Interest Rate Spread (FTE) (1) | 2.63 | 2.42 | 2.38 | 2.46 | 2.68 | ||||||||||||
| Net Interest Margin | 3.27 | 3.12 | 3.11 | 3.18 | 3.36 | ||||||||||||
Net Interest Margin (FTE) (1) | 3.28 | 3.13 | 3.12 | 3.19 | 3.37 | ||||||||||||
Net Charge-Offs (Recoveries) to Average Loans | 0.02 | 0.06 | 0.03 | 0.02 | (0.01) | ||||||||||||
| Efficiency Ratio | 81.02 | 71.68 | 69.11 | 73.89 | 62.40 | ||||||||||||
| Asset Quality Ratios | 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | ||||||||||||
| Allowance for Credit Losses to Total Loans | 0.90 | % | 0.90 | % | 0.89 | % | 0.88 | % | 0.87 | % | |||||||
Allowance for Credit Losses to Nonperforming Loans (3) | 414.48 | 548.07 | 463.07 | 513.03 | 437.73 | ||||||||||||
Delinquent and Nonaccrual Loans to Total Loans (4) | 0.54 | 0.72 | 0.98 | 0.53 | 0.63 | ||||||||||||
Nonperforming Loans to Total Loans (3) | 0.22 | 0.16 | 0.19 | 0.17 | 0.20 | ||||||||||||
Nonperforming Assets to Total Assets (5) | 0.16 | 0.12 | 0.14 | 0.13 | 0.15 | ||||||||||||
Capital Ratios (6) | 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | ||||||||||||
| Common Equity Tier 1 Capital (to Risk Weighted Assets) | 14.94 | % | 14.78 | % | 14.79 | % | 14.62 | % | 14.50 | % | |||||||
| Tier 1 Capital (to Risk Weighted Assets) | 14.94 | 14.78 | 14.79 | 14.62 | 14.50 | ||||||||||||
| Total Capital (to Risk Weighted Assets) | 15.95 | 15.79 | 15.76 | 15.61 | 15.51 | ||||||||||||
| Tier 1 Leverage (to Adjusted Total Assets) | 10.36 | 9.98 | 9.96 | 9.98 | 10.28 | ||||||||||||
(1) Refer to Explanation of Use of Non-GAAP Financial Measures in this Press Release for the calculation of the measure and reconciliation to the most comparable GAAP measure.
(2) Interim period ratios are calculated on an annualized basis.
(3) Nonperforming loans consist of all nonaccrual loans and accruing loans that are 90 days or more past due.
(4) Delinquent loans consist of accruing loans that are 30 days or more past due.
(5) Nonperforming assets consist of nonperforming loans and other real estate owned.
(6) Capital ratios are for Community Bank only.
Certain items previously reported may have been reclassified to conform with the current reporting period’s format.
8
| AVERAGE BALANCES AND YIELDS | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| March 31, 2025 | December 31, 2024 | September 30, 2024 | June 30, 2024 | March 31, 2024 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average Balance | Interest and Dividends | Yield / Cost (1) | Average Balance | Interest and Dividends | Yield / Cost (1) | Average Balance | Interest and Dividends | Yield / Cost (1) | Average Balance | Interest and Dividends | Yield / Cost (1) | Average Balance | Interest and Dividends | Yield / Cost (1) | |||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) (Unaudited) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Assets: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-Earning Assets: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Loans, Net (2) | $ | 1,075,083 | $ | 14,584 | 5.50 | % | $ | 1,066,304 | $ | 14,975 | 5.59 | % | $ | 1,063,946 | $ | 14,987 | 5.60 | % | $ | 1,076,455 | $ | 14,711 | 5.50 | % | $ | 1,087,889 | $ | 14,877 | 5.50 | % | |||||||||||||||||||||||||||||
| Debt Securities | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Taxable | 278,362 | 2,777 | 3.99 | 284,002 | 3,096 | 4.36 | 288,208 | 3,289 | 4.56 | 266,021 | 2,844 | 4.28 | 235,800 | 2,303 | 3.91 | ||||||||||||||||||||||||||||||||||||||||||||
| Equity Securities | 2,674 | 28 | 4.19 | 2,693 | 27 | 4.01 | 2,693 | 28 | 4.16 | 2,693 | 27 | 4.01 | 2,693 | 27 | 4.01 | ||||||||||||||||||||||||||||||||||||||||||||
| Interest-Earning Deposits at Banks | 45,056 | 459 | 4.07 | 114,245 | 1,338 | 4.68 | 111,131 | 1,448 | 5.21 | 101,277 | 1,313 | 5.19 | 58,887 | 733 | 4.98 | ||||||||||||||||||||||||||||||||||||||||||||
| Other Interest-Earning Assets | 3,196 | 55 | 6.98 | 3,070 | 40 | 5.18 | 3,108 | 63 | 8.06 | 3,154 | 85 | 10.84 | 3,235 | 85 | 10.57 | ||||||||||||||||||||||||||||||||||||||||||||
| Total Interest-Earning Assets | 1,404,371 | 17,903 | 5.17 | 1,470,314 | 19,476 | 5.27 | 1,469,086 | 19,815 | 5.37 | 1,449,600 | 18,980 | 5.27 | 1,388,504 | 18,025 | 5.22 | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-Earning Assets | 63,324 | 65,786 | 57,602 | 53,564 | 54,910 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Assets | $ | 1,467,695 | $ | 1,536,100 | $ | 1,526,688 | $ | 1,503,164 | $ | 1,443,414 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities and Stockholders' Equity: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-Bearing Liabilities: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-Bearing Demand Accounts | $ | 317,799 | $ | 1,526 | 1.95 | % | $ | 328,129 | $ | 1,838 | 2.23 | % | $ | 316,301 | $ | 1,923 | 2.42 | % | $ | 325,069 | $ | 1,858 | 2.30 | % | $ | 334,880 | $ | 1,794 | 2.15 | % | |||||||||||||||||||||||||||||
| Money Market Accounts | 230,634 | 1,726 | 3.04 | 227,606 | 1,821 | 3.18 | 217,148 | 1,726 | 3.16 | 214,690 | 1,646 | 3.08 | 203,867 | 1,514 | 2.99 | ||||||||||||||||||||||||||||||||||||||||||||
| Savings Accounts | 172,322 | 41 | 0.10 | 170,612 | 45 | 0.10 | 175,753 | 46 | 0.10 | 184,944 | 52 | 0.11 | 191,444 | 59 | 0.12 | ||||||||||||||||||||||||||||||||||||||||||||
| Time Deposits | 285,093 | 2,818 | 4.01 | 341,686 | 3,788 | 4.41 | 358,498 | 4,197 | 4.66 | 308,956 | 3,509 | 4.57 | 248,118 | 2,624 | 4.25 | ||||||||||||||||||||||||||||||||||||||||||||
| Total Interest-Bearing Deposits | 1,005,848 | 6,111 | 2.46 | 1,068,033 | 7,492 | 2.79 | 1,067,700 | 7,892 | 2.94 | 1,033,659 | 7,065 | 2.75 | 978,309 | 5,991 | 2.46 | ||||||||||||||||||||||||||||||||||||||||||||
| Short-Term Borrowings | 1,985 | 23 | 4.70 | — | — | — | — | — | — | 2 | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||
| Other Borrowings | 34,723 | 402 | 4.70 | 34,713 | 407 | 4.66 | 34,702 | 407 | 4.67 | 34,692 | 404 | 4.68 | 34,682 | 404 | 4.69 | ||||||||||||||||||||||||||||||||||||||||||||
| Total Interest-Bearing Liabilities | 1,042,556 | 6,536 | 2.54 | 1,102,746 | 7,899 | 2.85 | 1,102,402 | 8,299 | 2.99 | 1,068,353 | 7,469 | 2.81 | 1,012,991 | 6,395 | 2.54 | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-Bearing Demand Deposits | 265,522 | 267,598 | 263,650 | 272,280 | 278,691 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
Total Funding and Cost of Funds | 1,308,078 | 2.03 | 1,370,344 | 2.29 | 1,366,052 | 2.42 | 1,340,633 | 2.24 | 1,291,682 | 1.99 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other Liabilities | 11,854 | 17,883 | 15,043 | 21,867 | 11,441 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Liabilities | 1,319,932 | 1,388,227 | 1,381,095 | 1,362,500 | 1,303,123 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Stockholders' Equity | 147,763 | 147,873 | 145,593 | 140,664 | 140,291 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Liabilities and Stockholders' Equity | $ | 1,467,695 | $ | 1,536,100 | $ | 1,526,688 | $ | 1,503,164 | $ | 1,443,414 | |||||||||||||||||||||||||||||||||||||||||||||||||
Net Interest Income (FTE) (Non-GAAP) (3) | $ | 11,367 | $ | 11,577 | $ | 11,516 | $ | 11,511 | $ | 11,630 | |||||||||||||||||||||||||||||||||||||||||||||||||
Net Interest-Earning Assets (4) | 361,815 | 367,568 | 366,684 | 381,247 | 375,513 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
Net Interest Rate Spread (FTE) (Non-GAAP) (3) (5) | 2.63 | % | 2.42 | % | 2.38 | % | 2.46 | % | 2.68 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
Net Interest Margin (FTE) (Non-GAAP) (3)(6) | 3.28 | 3.13 | 3.12 | 3.19 | 3.37 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
(1) Annualized based on three months ended results.
(2) Net of the allowance for credit losses and includes nonaccrual loans with a zero yield and Loans Held for Sale if applicable.
(3) Refer to Explanation and Use of Non-GAAP Financial Measures in this Press Release for the calculation of the measure and reconciliation to the most comparable GAAP measure.
(4) Net interest-earning assets represent total interest-earning assets less total interest-bearing liabilities.
(5) Net interest rate spread represents the difference between the weighted average yield on interest-earning assets and the weighted average cost of interest-bearing liabilities.
(6) Net interest margin represents annualized net interest income divided by average total interest-earning assets.
9
Explanation of Use of Non-GAAP Financial Measures
In addition to financial measures presented in accordance with generally accepted accounting principles (“GAAP”), we use, and this Press Release contains or references, certain Non-GAAP financial measures. We believe these Non-GAAP financial measures provide useful information in understanding our underlying results of operations or financial position and our business and performance trends as they facilitate comparisons with the performance of other companies in the financial services industry. Non-GAAP adjusted items impacting the Company's financial performance are identified to assist investors in providing a complete understanding of factors and trends affecting the Company’s business and in analyzing the Company’s operating results on the same basis as that applied by management. Although we believe that these Non-GAAP financial measures enhance the understanding of our business and performance, they should not be considered an alternative to GAAP or considered to be more important than financial results determined in accordance with GAAP, nor are they necessarily comparable with similar Non-GAAP measures which may be presented by other companies. Where Non-GAAP financial measures are used, the comparable GAAP financial measure, as well as the reconciliation to the comparable GAAP financial measure, can be found herein.
| 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | |||||||||||||
| (Dollars in thousands, except share and per share data) (Unaudited) | |||||||||||||||||
Total Assets (GAAP) | $ | 1,483,456 | $ | 1,481,564 | $ | 1,561,741 | $ | 1,560,259 | $ | 1,473,089 | |||||||
| Goodwill and Intangible Assets, Net | (9,732) | (9,732) | (9,820) | (10,085) | (10,349) | ||||||||||||
| Tangible Assets (Non-GAAP) (Numerator) | $ | 1,473,724 | $ | 1,471,832 | $ | 1,551,921 | $ | 1,550,174 | $ | 1,462,740 | |||||||
| Stockholders' Equity (GAAP) | $ | 148,289 | $ | 147,378 | $ | 149,140 | $ | 142,882 | $ | 141,590 | |||||||
| Goodwill and Intangible Assets, Net | (9,732) | (9,732) | (9,820) | (10,085) | (10,349) | ||||||||||||
| Tangible Common Equity or Tangible Book Value (Non-GAAP) (Denominator) | $ | 138,557 | $ | 137,646 | $ | 139,320 | $ | 132,797 | $ | 131,241 | |||||||
| Stockholders’ Equity to Assets (GAAP) | 10.0 | % | 9.9 | % | 9.5 | % | 9.2 | % | 9.6 | % | |||||||
| Tangible Common Equity to Tangible Assets (Non-GAAP) | 9.4 | % | 9.4 | % | 9.0 | % | 8.6 | % | 9.0 | % | |||||||
| Common Shares Outstanding (Denominator) | 5,099,069 | 5,132,654 | 5,129,921 | 5,141,911 | 5,142,901 | ||||||||||||
| Book Value per Common Share (GAAP) | $ | 29.08 | $ | 28.71 | $ | 29.07 | $ | 27.79 | $ | 27.53 | |||||||
| Tangible Book Value per Common Share (Non-GAAP) | $ | 27.17 | $ | 26.82 | $ | 27.16 | $ | 25.83 | $ | 25.52 | |||||||
| Three Months Ended | |||||||||||||||||
| 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | |||||||||||||
| (Dollars in thousands) (Unaudited) | |||||||||||||||||
| Net Income (GAAP) | $ | 1,909 | $ | 2,529 | $ | 3,219 | $ | 2,650 | $ | 4,196 | |||||||
| Amortization of Intangible Assets, Net | — | 88 | 264 | 264 | 341 | ||||||||||||
| Adjusted Net Income (Non-GAAP) (Numerator) | $ | 1,909 | $ | 2,617 | $ | 3,483 | $ | 2,914 | $ | 4,537 | |||||||
| Annualization Factor | 4.06 | 3.98 | 3.98 | 4.02 | 4.02 | ||||||||||||
| Average Stockholders' Equity (GAAP) | $ | 147,763 | $ | 147,873 | $ | 145,593 | $ | 140,664 | $ | 140,291 | |||||||
| Average Goodwill and Intangible Assets, Net | (9,732) | (9,758) | (9,987) | (10,242) | (10,553) | ||||||||||||
| Average Tangible Common Equity (Non-GAAP) (Denominator) | $ | 138,031 | $ | 138,115 | $ | 135,606 | $ | 130,422 | $ | 129,738 | |||||||
| Return on Average Equity (GAAP) | 5.24 | % | 6.80 | % | 8.80 | % | 7.58 | % | 12.03 | % | |||||||
| Return on Average Tangible Common Equity (Non-GAAP) | 5.61 | % | 7.54 | % | 10.22 | % | 8.99 | % | 14.07 | % | |||||||
10
| Three Months Ended | |||||||||||||||||
| 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | |||||||||||||
| (Dollars in thousands) (Unaudited) | |||||||||||||||||
| Interest Income (GAAP) | $ | 17,847 | $ | 19,431 | $ | 19,773 | $ | 18,939 | $ | 17,986 | |||||||
| Adjustment to FTE Basis | 56 | 45 | 42 | 41 | 39 | ||||||||||||
| Interest Income (FTE) (Non-GAAP) | 17,903 | 19,476 | 19,815 | 18,980 | 18,025 | ||||||||||||
| Interest Expense (GAAP) | 6,536 | 7,899 | 8,299 | 7,469 | 6,395 | ||||||||||||
| Net Interest Income (FTE) (Non-GAAP) | $ | 11,367 | $ | 11,577 | $ | 11,516 | $ | 11,511 | $ | 11,630 | |||||||
| Net Interest Rate Spread (GAAP) | 2.61 | % | 2.41 | % | 2.36 | % | 2.44 | % | 2.67 | % | |||||||
| Adjustment to FTE Basis | 0.02 | 0.01 | 0.02 | 0.02 | 0.01 | ||||||||||||
| Net Interest Rate Spread (FTE) (Non-GAAP) | 2.63 | % | 2.42 | % | 2.38 | % | 2.46 | % | 2.68 | % | |||||||
| Net Interest Margin (GAAP) | 3.27 | % | 3.12 | % | 3.11 | % | 3.18 | % | 3.36 | % | |||||||
| Adjustment to FTE Basis | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | ||||||||||||
| Net Interest Margin (FTE) (Non-GAAP) | 3.28 | % | 3.13 | % | 3.12 | % | 3.19 | % | 3.37 | % | |||||||
| Three Months Ended | |||||||||||||||||
| 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | |||||||||||||
| (Dollars in thousands) (Unaudited) | |||||||||||||||||
| Income Before Income Tax Expense (GAAP) | $ | 2,336 | $ | 3,051 | $ | 3,966 | $ | 3,210 | $ | 5,116 | |||||||
| Net (Recovery) Provision for Credit Losses | (40) | 683 | (41) | (36) | (37) | ||||||||||||
| PPNR | 2,296 | 3,734 | 3,925 | 3,174 | 5,079 | ||||||||||||
| Adjustments | |||||||||||||||||
| Net Loss (Gain) on Securities | 69 | (3) | (245) | 31 | 166 | ||||||||||||
| Gain on Sale of Subsidiary | — | — | (138) | — | — | ||||||||||||
| Net Gain on Disposal of Premises and Equipment | — | — | — | — | (274) | ||||||||||||
| Earn-out Payment Related to the Sale of EU | (49) | (708) | — | — | — | ||||||||||||
| Net Gain on Bank-Owned Life Insurance Claims | — | — | — | — | (915) | ||||||||||||
| Reduction in Force Expenses | 1,003 | — | — | — | — | ||||||||||||
| Adjusted PPNR (Non-GAAP) (Numerator) | $ | 3,319 | $ | 3,023 | $ | 3,542 | $ | 3,205 | $ | 4,056 | |||||||
| Annualization Factor | 4.06 | 3.98 | 3.98 | 4.02 | 4.02 | ||||||||||||
| Average Assets (Denominator) | $ | 1,467,695 | $ | 1,536,100 | $ | 1,526,688 | $ | 1,503,164 | $ | 1,443,414 | |||||||
| Adjusted PPNR Return on Average Assets (Non-GAAP) | 0.92 | % | 0.78 | % | 0.92 | % | 0.86 | % | 1.13 | % | |||||||
11
| Three Months Ended | |||||||||||||||||
| 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | |||||||||||||
| (Dollars in thousands, except share and per share data) (Unaudited) | |||||||||||||||||
| Net Income (GAAP) | $ | 1,909 | $ | 2,529 | $ | 3,219 | $ | 2,650 | $ | 4,196 | |||||||
| Adjustments | |||||||||||||||||
| Net Loss (Gain) on Securities | 69 | (3) | (245) | 31 | 166 | ||||||||||||
| Gain on Sale of Subsidiary | — | — | (138) | — | — | ||||||||||||
| Net Gain on Disposal of Premises and Equipment | — | — | — | — | (274) | ||||||||||||
| Earn-out Payment Related to the Sale of EU | (49) | (708) | — | — | — | ||||||||||||
| Net Gain on Bank-Owned Life Insurance Claims | — | — | — | — | (915) | ||||||||||||
| Reduction in Force Expenses | 1,003 | — | — | — | — | ||||||||||||
| Tax effect | (215) | 149 | 90 | (7) | 23 | ||||||||||||
| Adjusted Net Income (Non-GAAP) | $ | 2,717 | $ | 1,967 | $ | 2,926 | $ | 2,674 | $ | 3,196 | |||||||
| Weighted-Average Diluted Common Shares and Common Stock Equivalents Outstanding | 5,471,006 | 5,544,829 | 5,346,750 | 5,152,657 | 5,142,286 | ||||||||||||
| Earnings per Common Share - Diluted (GAAP) | $ | 0.35 | $ | 0.46 | $ | 0.60 | $ | 0.51 | $ | 0.82 | |||||||
| Adjusted Earnings per Common Share - Diluted (Non-GAAP) | $ | 0.50 | $ | 0.35 | $ | 0.55 | $ | 0.52 | $ | 0.62 | |||||||
| Net Income (GAAP) (Numerator) | $ | 1,909 | $ | 2,529 | $ | 3,219 | $ | 2,650 | $ | 4,196 | |||||||
| Annualization Factor | 4.06 | 3.98 | 3.98 | 4.02 | 4.02 | ||||||||||||
| Average Assets (Denominator) | 1,467,695 | 1,536,100 | 1,526,688 | 1,503,164 | 1,443,414 | ||||||||||||
| Return on Average Assets (GAAP) | 0.53 | % | 0.65 | % | 0.84 | % | 0.71 | % | 1.17 | % | |||||||
| Adjusted Net Income (Non-GAAP) (Numerator) | $ | 2,717 | $ | 1,967 | $ | 2,926 | $ | 2,674 | $ | 3,196 | |||||||
| Annualization Factor | 4.06 | 3.98 | 3.98 | 4.02 | 4.02 | ||||||||||||
| Average Assets (Denominator) | 1,467,695 | 1,536,100 | 1,526,688 | 1,503,164 | 1,443,414 | ||||||||||||
| Adjusted Return on Average Assets (Non-GAAP) | 0.75 | % | 0.51 | % | 0.76 | % | 0.72 | % | 0.89 | % | |||||||
| Three Months Ended | |||||||||||||||||
| 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | |||||||||||||
| (Dollars in thousands) (Unaudited) | |||||||||||||||||
| Net Income (GAAP) (Numerator) | $ | 1,909 | $ | 2,529 | $ | 3,219 | $ | 2,650 | $ | 4,196 | |||||||
| Annualization Factor | 4.06 | 3.98 | 3.98 | 4.02 | 4.02 | ||||||||||||
| Average Equity (GAAP) (Denominator) | 147,763 | 147,873 | 145,593 | 140,664 | 140,291 | ||||||||||||
| Return on Average Equity (GAAP) | 5.24 | % | 6.80 | % | 8.80 | % | 7.58 | % | 12.03 | % | |||||||
| Adjusted Net Income (Non-GAAP) (Numerator) | $ | 2,717 | $ | 1,967 | $ | 2,926 | $ | 2,674 | $ | 3,196 | |||||||
| Annualization Factor | 4.06 | 3.98 | 3.98 | 4.02 | 4.02 | ||||||||||||
| Average Equity (GAAP) (Denominator) | 147,763 | 147,873 | 145,593 | 140,664 | 140,291 | ||||||||||||
| Adjusted Return on Average Equity (Non-GAAP) | 7.46 | % | 5.29 | % | 8.00 | % | 7.65 | % | 9.16 | % | |||||||
12
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 2 Forward-Looking Statements and Non-GAAP Financial Measures Statements contained in this investor presentation that are not historical facts may constitute forward-looking statements as that term is defined in the Private Securities Litigation Reform Act of 1995 and such forward-looking statements are subject to significant risks and uncertainties. The Company intends such forward-looking statements to be covered by the safe harbor provisions contained in the Act. The Company’s ability to predict results or the actual effect of future plans or strategies is inherently uncertain. Factors which could have a material adverse effect on the operations and future prospects of the Company and its subsidiaries include, but are not limited to, general and local economic conditions, changes in market interest rates, deposit flows, demand for loans, real estate values and competition, competitive products and pricing, the ability of our clients to make scheduled loan payments, loan delinquency rates and trends, our ability to manage the risks involved in our business, our ability to control costs and expenses, inflation, market and monetary fluctuations, changes in federal and state legislation and regulation applicable to our business, actions by our competitors, and other factors that may be disclosed in the Company’s periodic reports as filed with the Securities and Exchange Commission. These risks and uncertainties should be considered in evaluating forward-looking statements and undue reliance should not be placed on such statements. The Company assumes no obligation to update any forward-looking statements except as may be required by applicable law or regulation. Explanation of Use of Non-GAAP Financial Measures In addition to financial measures presented in accordance with generally accepted accounting principles (“GAAP”), we use, and this investor presentation may contain or reference, certain non-GAAP financial measures. We believe these non-GAAP financial measures provide useful information in understanding our underlying results of operations or financial position and our business and performance trends as they facilitate comparisons with the performance of other companies in the financial services industry. Non-GAAP adjusted items impacting the Company's financial performance are identified to assist investors in providing a complete understanding of factors and trends affecting the Company’s business and in analyzing the Company’s operating results on the same basis as that applied by management. Although we believe that these non-GAAP financial measures enhance the understanding of our business and performance, they should not be considered an alternative to GAAP or considered to be more important than financial results determined in accordance with GAAP, nor are they necessarily comparable with similar non-GAAP measures which may be presented by other companies. Where non-GAAP financial measures are used, the comparable GAAP financial measure, as well as the reconciliation to the comparable GAAP financial measure, can be found within the referenced earnings release.
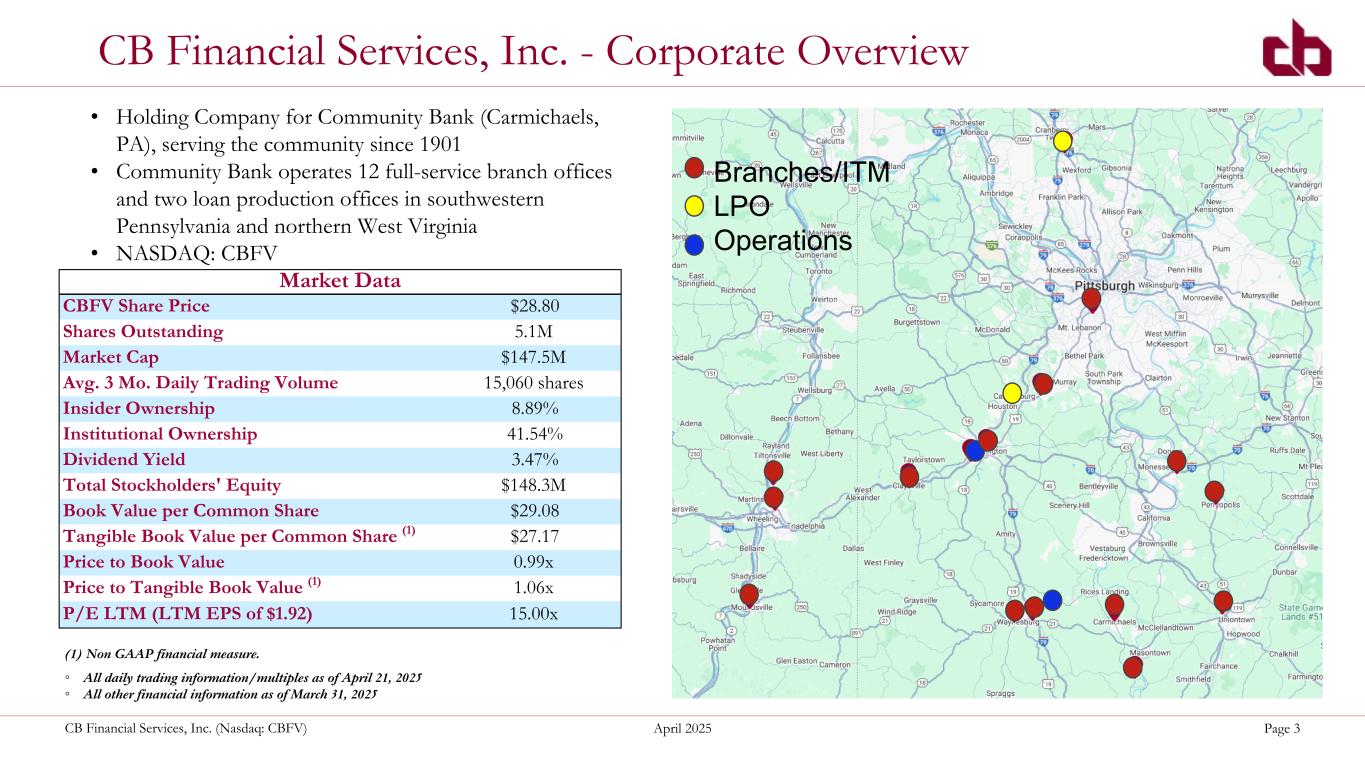
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 3 CB Financial Services, Inc. - Corporate Overview • Holding Company for Community Bank (Carmichaels, PA), serving the community since 1901 • Community Bank operates 12 full-service branch offices and two loan production offices in southwestern Pennsylvania and northern West Virginia • NASDAQ: CBFV Market Data CBFV Share Price $28.80 Shares Outstanding 5.1M Market Cap $147.5M Avg. 3 Mo. Daily Trading Volume 15,060 shares Insider Ownership 8.89% Institutional Ownership 41.54% Dividend Yield 3.47% Total Stockholders' Equity $148.3M Book Value per Common Share $29.08 Tangible Book Value per Common Share (1) $27.17 Price to Book Value 0.99x Price to Tangible Book Value (1) 1.06x P/E LTM (LTM EPS of $1.92) 15.00x ◦ All daily trading information/multiples as of April 21, 2025 ◦ All other financial information as of March 31, 2025 Washington Waynesburg Moundsville Canonsburg Uniontown Branches/ITM LPO Operations (1) Non GAAP financial measure.
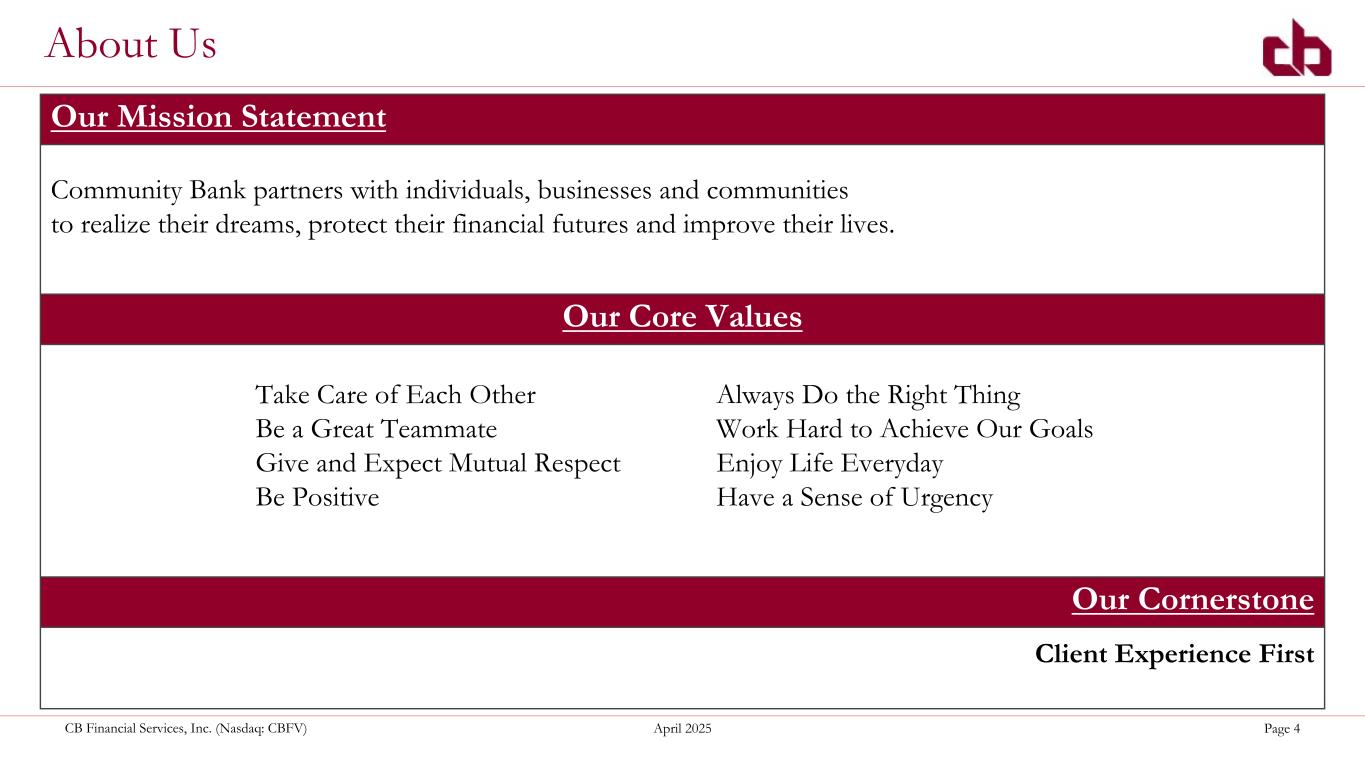
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 4 Community Bank partners with individuals, businesses and communities to realize their dreams, protect their financial futures and improve their lives. Take Care of Each Other Always Do the Right Thing Be a Great Teammate Work Hard to Achieve Our Goals Give and Expect Mutual Respect Enjoy Life Everyday Be Positive Have a Sense of Urgency Client Experience First Our Mission Statement Our Core Values Our Cornerstone About Us
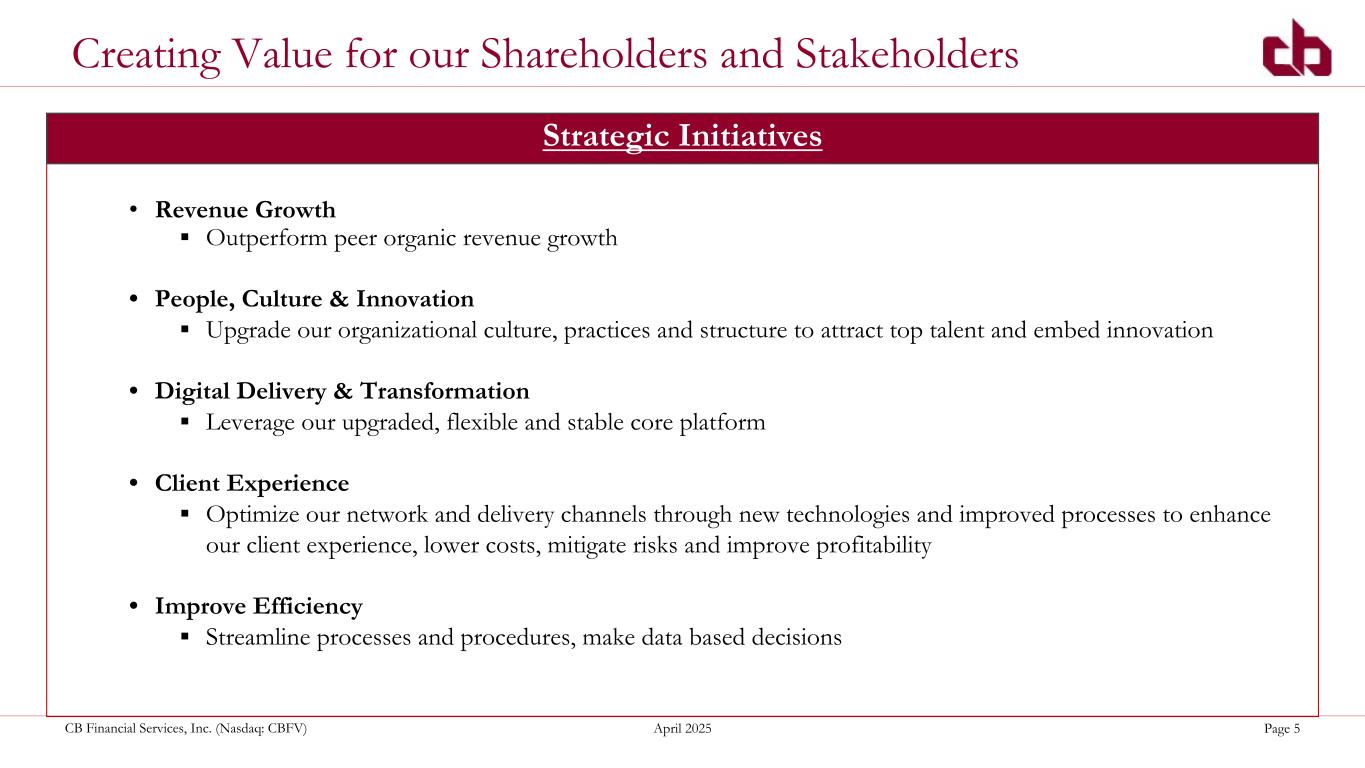
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 5 Creating Value for our Shareholders and Stakeholders • Revenue Growth ▪ Outperform peer organic revenue growth • People, Culture & Innovation ▪ Upgrade our organizational culture, practices and structure to attract top talent and embed innovation • Digital Delivery & Transformation ▪ Leverage our upgraded, flexible and stable core platform • Client Experience ▪ Optimize our network and delivery channels through new technologies and improved processes to enhance our client experience, lower costs, mitigate risks and improve profitability • Improve Efficiency ▪ Streamline processes and procedures, make data based decisions Strategic Initiatives
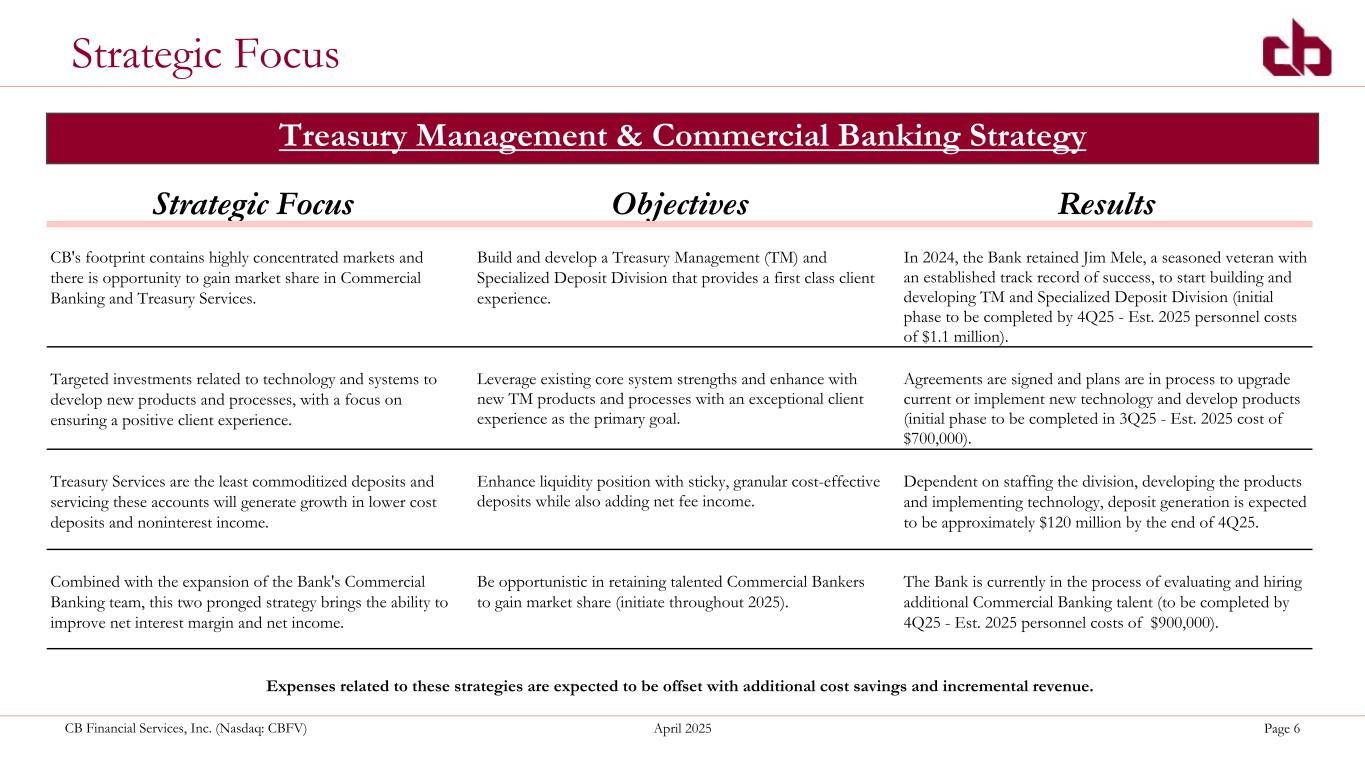
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 6 Strategic Focus Treasury Management & Commercial Banking Strategy Strategic Focus Objectives Results CB's footprint contains highly concentrated markets and there is opportunity to gain market share in Commercial Banking and Treasury Services. Build and develop a Treasury Management (TM) and Specialized Deposit Division that provides a first class client experience. In 2024, the Bank retained Jim Mele, a seasoned veteran with an established track record of success, to start building and developing TM and Specialized Deposit Division (initial phase to be completed by 4Q25 - Est. 2025 personnel costs of $1.1 million). Targeted investments related to technology and systems to develop new products and processes, with a focus on ensuring a positive client experience. Leverage existing core system strengths and enhance with new TM products and processes with an exceptional client experience as the primary goal. Agreements are signed and plans are in process to upgrade current or implement new technology and develop products (initial phase to be completed in 3Q25 - Est. 2025 cost of $700,000). Treasury Services are the least commoditized deposits and servicing these accounts will generate growth in lower cost deposits and noninterest income. Enhance liquidity position with sticky, granular cost-effective deposits while also adding net fee income. Dependent on staffing the division, developing the products and implementing technology, deposit generation is expected to be approximately $120 million by the end of 4Q25. Combined with the expansion of the Bank's Commercial Banking team, this two pronged strategy brings the ability to improve net interest margin and net income. Be opportunistic in retaining talented Commercial Bankers to gain market share (initiate throughout 2025). The Bank is currently in the process of evaluating and hiring additional Commercial Banking talent (to be completed by 4Q25 - Est. 2025 personnel costs of $900,000). Expenses related to these strategies are expected to be offset with additional cost savings and incremental revenue.
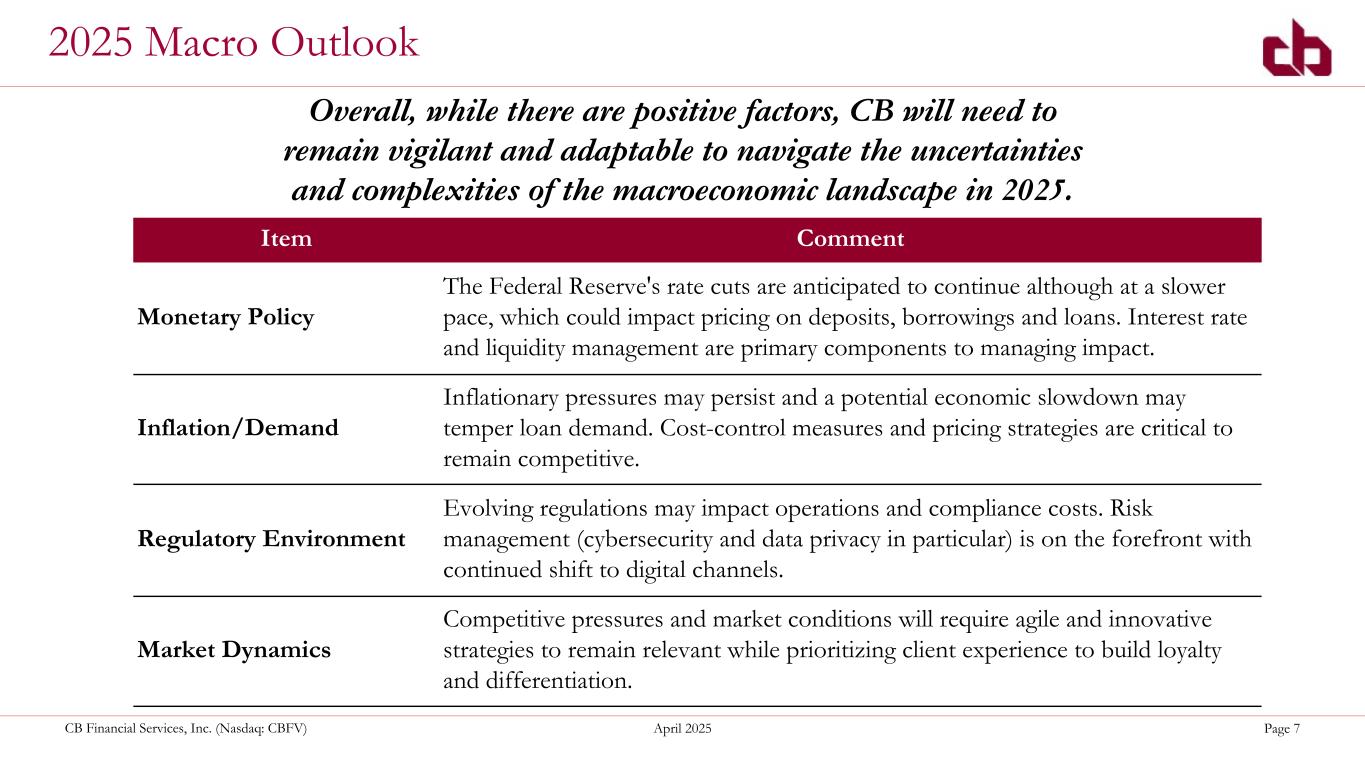
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 7 2025 Macro Outlook Item Comment Monetary Policy The Federal Reserve's rate cuts are anticipated to continue although at a slower pace, which could impact pricing on deposits, borrowings and loans. Interest rate and liquidity management are primary components to managing impact. Inflation/Demand Inflationary pressures may persist and a potential economic slowdown may temper loan demand. Cost-control measures and pricing strategies are critical to remain competitive. Regulatory Environment Evolving regulations may impact operations and compliance costs. Risk management (cybersecurity and data privacy in particular) is on the forefront with continued shift to digital channels. Market Dynamics Competitive pressures and market conditions will require agile and innovative strategies to remain relevant while prioritizing client experience to build loyalty and differentiation. Overall, while there are positive factors, CB will need to remain vigilant and adaptable to navigate the uncertainties and complexities of the macroeconomic landscape in 2025.
Q1 2025 Financial Highlights
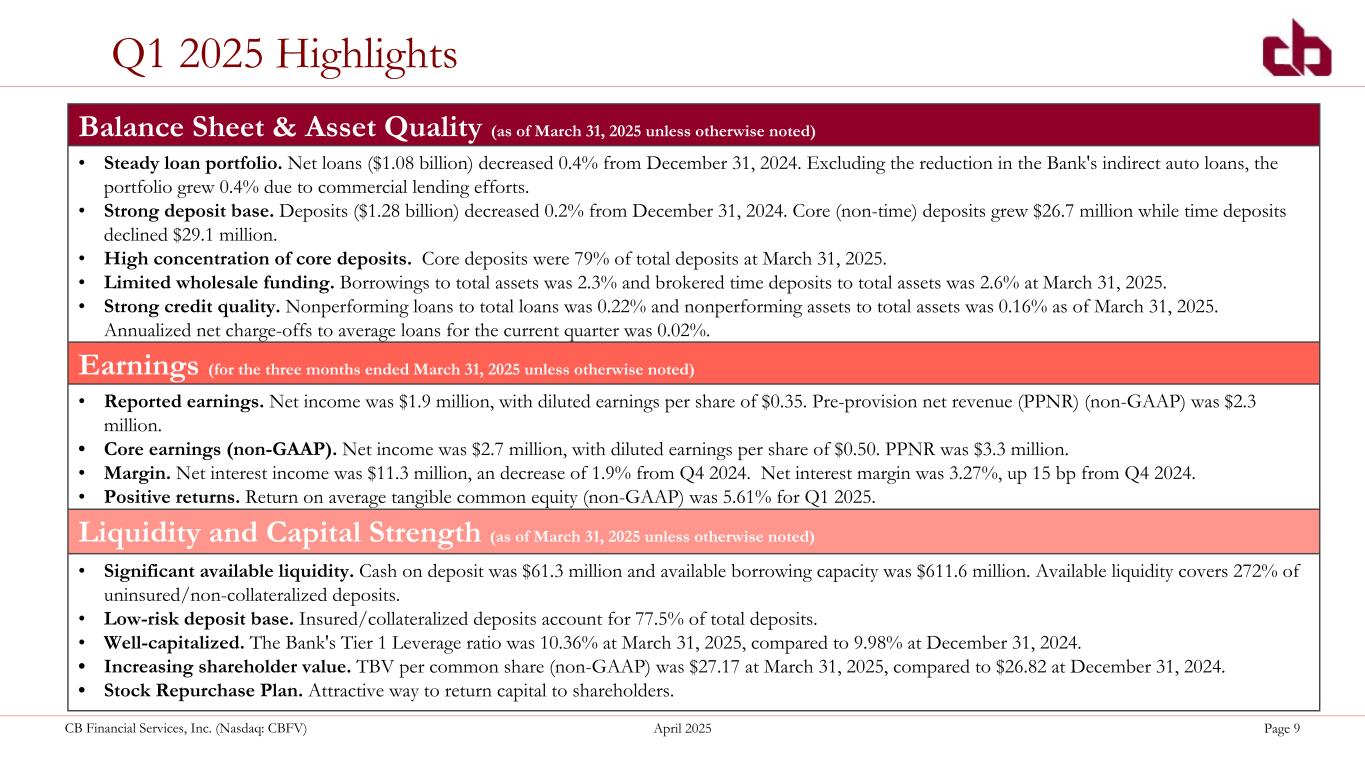
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 9 Q1 2025 Highlights Earnings (for the three months ended March 31, 2025 unless otherwise noted) • Reported earnings. Net income was $1.9 million, with diluted earnings per share of $0.35. Pre-provision net revenue (PPNR) (non-GAAP) was $2.3 million. • Core earnings (non-GAAP). Net income was $2.7 million, with diluted earnings per share of $0.50. PPNR was $3.3 million. • Margin. Net interest income was $11.3 million, an decrease of 1.9% from Q4 2024. Net interest margin was 3.27%, up 15 bp from Q4 2024. • Positive returns. Return on average tangible common equity (non-GAAP) was 5.61% for Q1 2025. Balance Sheet & Asset Quality (as of March 31, 2025 unless otherwise noted) • Steady loan portfolio. Net loans ($1.08 billion) decreased 0.4% from December 31, 2024. Excluding the reduction in the Bank's indirect auto loans, the portfolio grew 0.4% due to commercial lending efforts. • Strong deposit base. Deposits ($1.28 billion) decreased 0.2% from December 31, 2024. Core (non-time) deposits grew $26.7 million while time deposits declined $29.1 million. • High concentration of core deposits. Core deposits were 79% of total deposits at March 31, 2025. • Limited wholesale funding. Borrowings to total assets was 2.3% and brokered time deposits to total assets was 2.6% at March 31, 2025. • Strong credit quality. Nonperforming loans to total loans was 0.22% and nonperforming assets to total assets was 0.16% as of March 31, 2025. Annualized net charge-offs to average loans for the current quarter was 0.02%. Liquidity and Capital Strength (as of March 31, 2025 unless otherwise noted) • Significant available liquidity. Cash on deposit was $61.3 million and available borrowing capacity was $611.6 million. Available liquidity covers 272% of uninsured/non-collateralized deposits. • Low-risk deposit base. Insured/collateralized deposits account for 77.5% of total deposits. • Well-capitalized. The Bank's Tier 1 Leverage ratio was 10.36% at March 31, 2025, compared to 9.98% at December 31, 2024. • Increasing shareholder value. TBV per common share (non-GAAP) was $27.17 at March 31, 2025, compared to $26.82 at December 31, 2024. • Stock Repurchase Plan. Attractive way to return capital to shareholders.
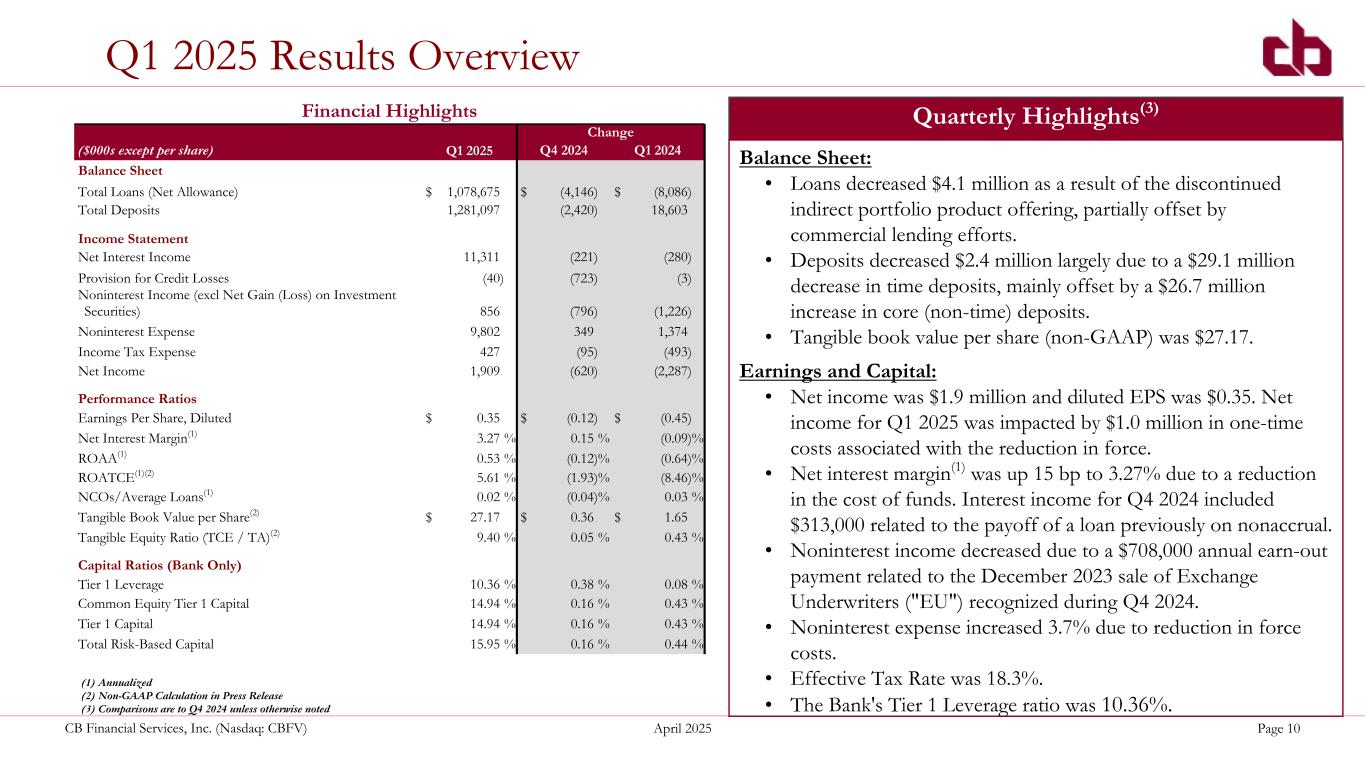
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 10 Financial Highlights Change ($000s except per share) Q1 2025 Q4 2024 Q1 2024 Balance Sheet Total Loans (Net Allowance) $ 1,078,675 $ (4,146) $ (8,086) Total Deposits 1,281,097 (2,420) 18,603 Income Statement Net Interest Income 11,311 (221) (280) Provision for Credit Losses (40) (723) (3) Noninterest Income (excl Net Gain (Loss) on Investment Securities) 856 (796) (1,226) Noninterest Expense 9,802 349 1,374 Income Tax Expense 427 (95) (493) Net Income 1,909 (620) (2,287) Performance Ratios Earnings Per Share, Diluted $ 0.35 $ (0.12) $ (0.45) Net Interest Margin(1) 3.27 % 0.15 % (0.09) % ROAA(1) 0.53 % (0.12) % (0.64) % ROATCE(1)(2) 5.61 % (1.93) % (8.46) % NCOs/Average Loans(1) 0.02 % (0.04) % 0.03 % Tangible Book Value per Share(2) $ 27.17 $ 0.36 $ 1.65 Tangible Equity Ratio (TCE / TA)(2) 9.40 % 0.05 % 0.43 % Capital Ratios (Bank Only) Tier 1 Leverage 10.36 % 0.38 % 0.08 % Common Equity Tier 1 Capital 14.94 % 0.16 % 0.43 % Tier 1 Capital 14.94 % 0.16 % 0.43 % Total Risk-Based Capital 15.95 % 0.16 % 0.44 % Q1 2025 Results Overview (1) Annualized (2) Non-GAAP Calculation in Press Release (3) Comparisons are to Q4 2024 unless otherwise noted Quarterly Highlights(3) Balance Sheet: • Loans decreased $4.1 million as a result of the discontinued indirect portfolio product offering, partially offset by commercial lending efforts. • Deposits decreased $2.4 million largely due to a $29.1 million decrease in time deposits, mainly offset by a $26.7 million increase in core (non-time) deposits. • Tangible book value per share (non-GAAP) was $27.17. Earnings and Capital: • Net income was $1.9 million and diluted EPS was $0.35. Net income for Q1 2025 was impacted by $1.0 million in one-time costs associated with the reduction in force. • Net interest margin(1) was up 15 bp to 3.27% due to a reduction in the cost of funds. Interest income for Q4 2024 included $313,000 related to the payoff of a loan previously on nonaccrual. • Noninterest income decreased due to a $708,000 annual earn-out payment related to the December 2023 sale of Exchange Underwriters ("EU") recognized during Q4 2024. • Noninterest expense increased 3.7% due to reduction in force costs. • Effective Tax Rate was 18.3%. • The Bank's Tier 1 Leverage ratio was 10.36%.
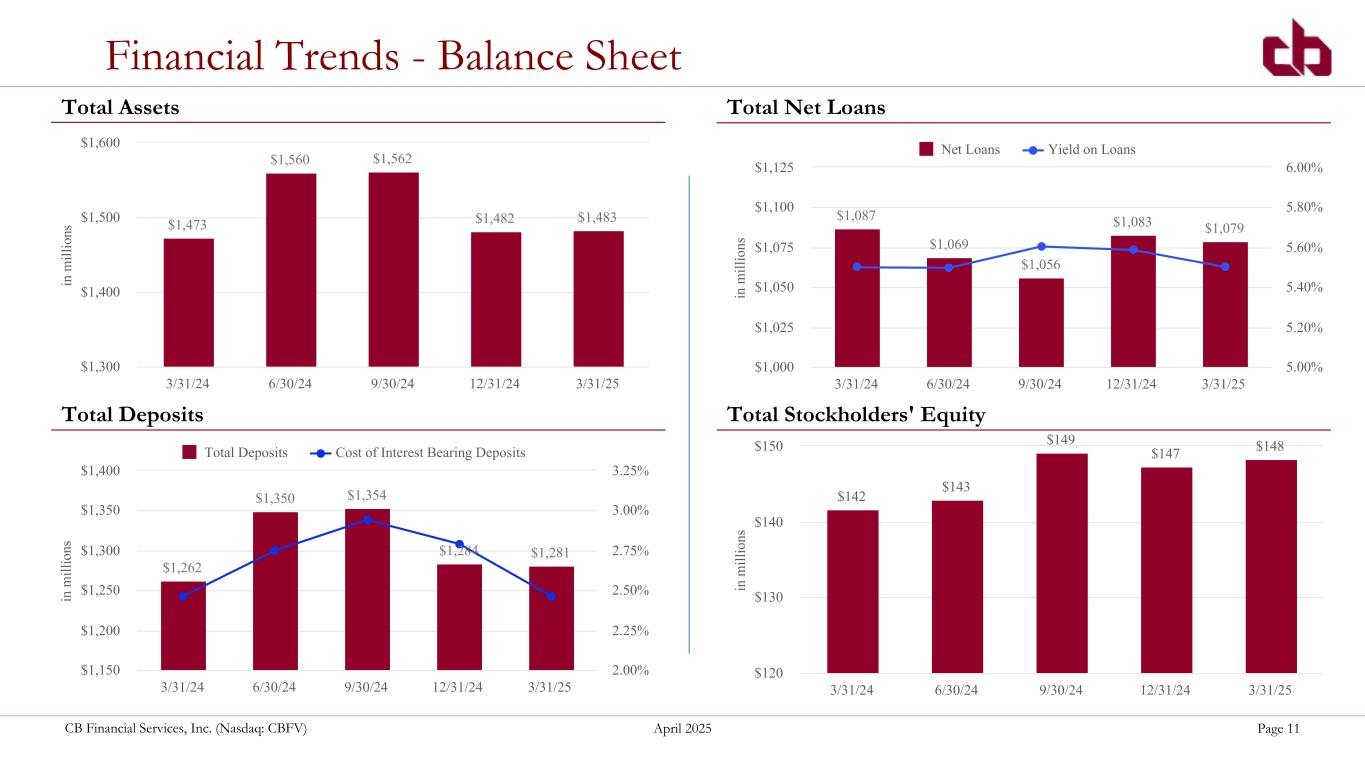
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 11 Financial Trends - Balance Sheet Total Net LoansTotal Assets Total Deposits Total Stockholders' Equity in m ill io ns $1,473 $1,560 $1,562 $1,482 $1,483 3/31/24 6/30/24 9/30/24 12/31/24 3/31/25 $1,300 $1,400 $1,500 $1,600 in m ill io ns $1,087 $1,069 $1,056 $1,083 $1,079 Net Loans Yield on Loans 3/31/24 6/30/24 9/30/24 12/31/24 3/31/25 $1,000 $1,025 $1,050 $1,075 $1,100 $1,125 5.00% 5.20% 5.40% 5.60% 5.80% 6.00% in m ill io ns $1,262 $1,350 $1,354 $1,284 $1,281 Total Deposits Cost of Interest Bearing Deposits 3/31/24 6/30/24 9/30/24 12/31/24 3/31/25 $1,150 $1,200 $1,250 $1,300 $1,350 $1,400 2.00% 2.25% 2.50% 2.75% 3.00% 3.25% in m ill io ns $142 $143 $149 $147 $148 3/31/24 6/30/24 9/30/24 12/31/24 3/31/25 $120 $130 $140 $150
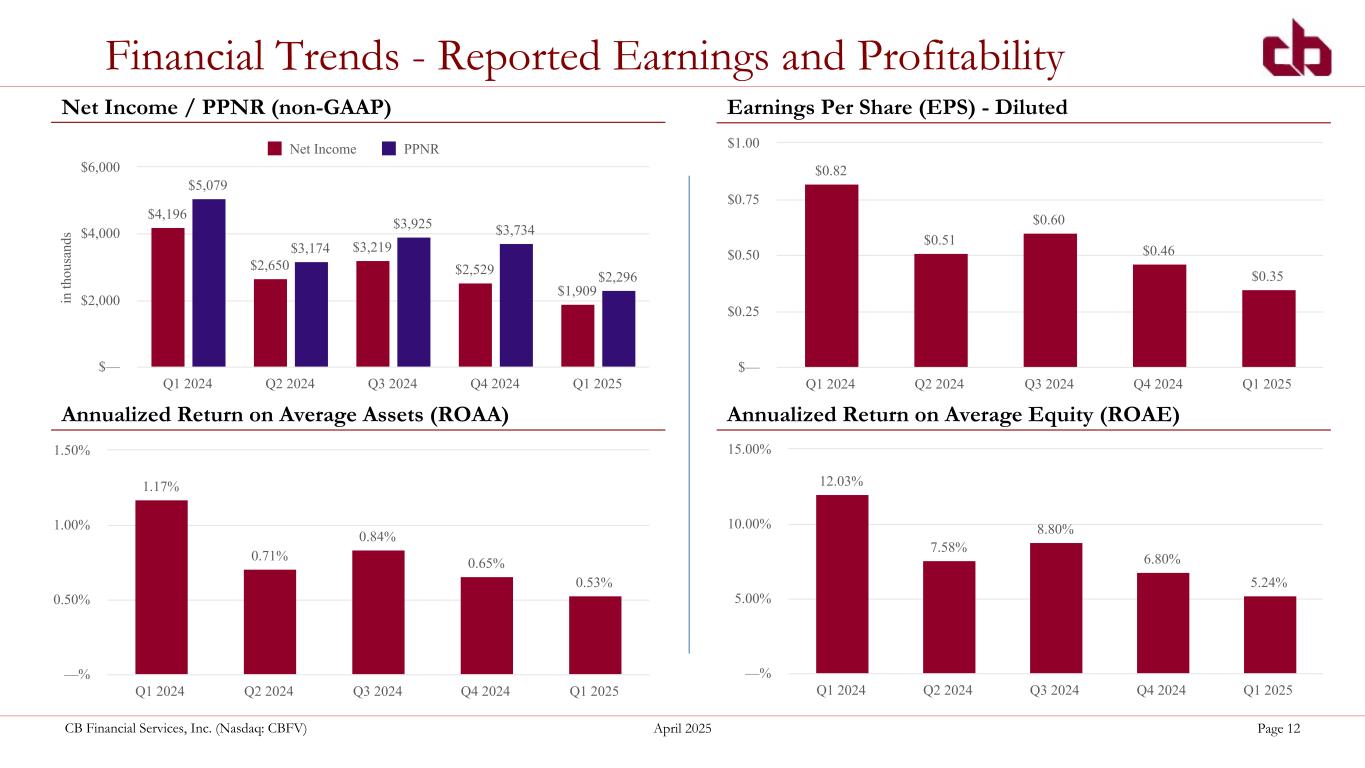
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 12 Financial Trends - Reported Earnings and Profitability Net Income / PPNR (non-GAAP) Earnings Per Share (EPS) - Diluted in th ou sa nd s $4,196 $2,650 $3,219 $2,529 $1,909 $5,079 $3,174 $3,925 $3,734 $2,296 Net Income PPNR Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 $— $2,000 $4,000 $6,000 $0.82 $0.51 $0.60 $0.46 $0.35 Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 $— $0.25 $0.50 $0.75 $1.00 Annualized Return on Average Equity (ROAE) 12.03% 7.58% 8.80% 6.80% 5.24% Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 —% 5.00% 10.00% 15.00% Annualized Return on Average Assets (ROAA) 1.17% 0.71% 0.84% 0.65% 0.53% Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 —% 0.50% 1.00% 1.50%
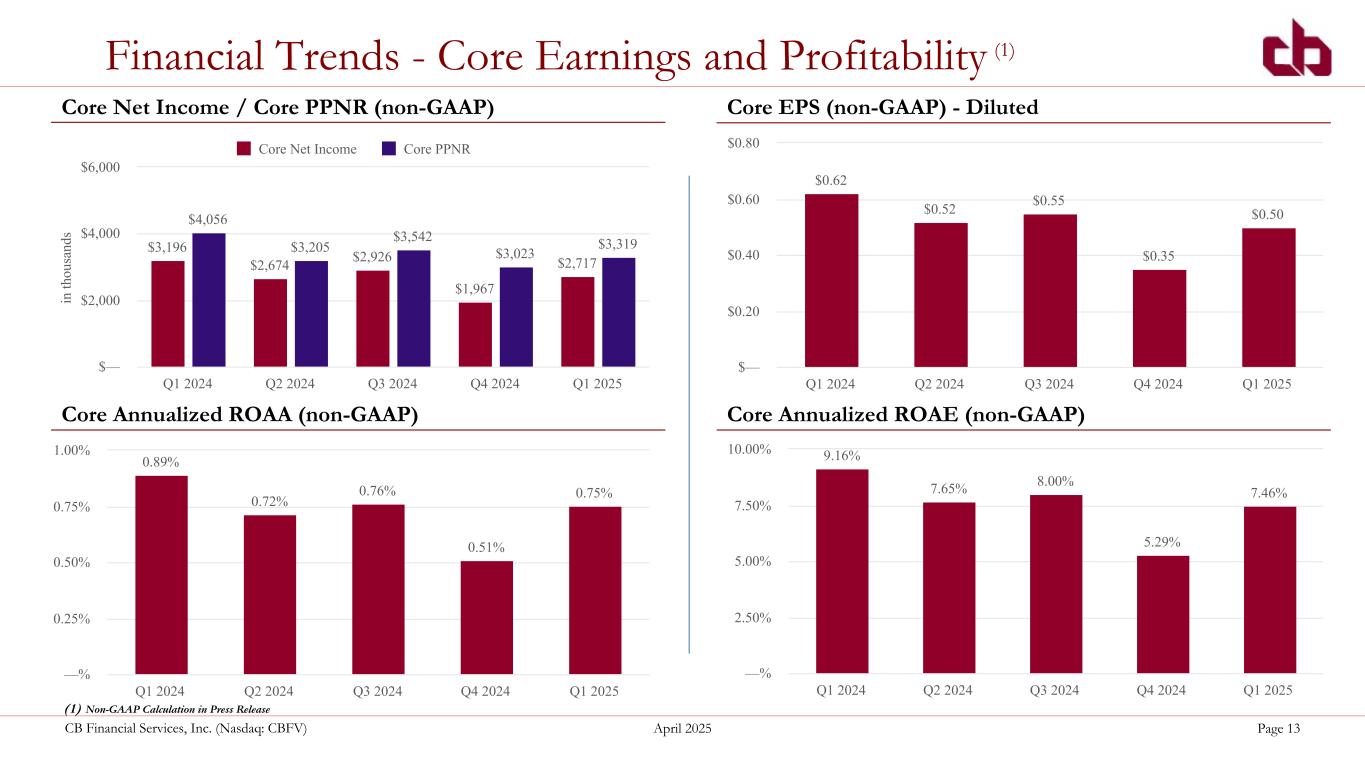
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 13 Financial Trends - Core Earnings and Profitability (1) Core Net Income / Core PPNR (non-GAAP) Core EPS (non-GAAP) - Diluted in th ou sa nd s $3,196 $2,674 $2,926 $1,967 $2,717 $4,056 $3,205 $3,542 $3,023 $3,319 Core Net Income Core PPNR Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 $— $2,000 $4,000 $6,000 $0.62 $0.52 $0.55 $0.35 $0.50 Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 $— $0.20 $0.40 $0.60 $0.80 Core Annualized ROAE (non-GAAP) 9.16% 7.65% 8.00% 5.29% 7.46% Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 —% 2.50% 5.00% 7.50% 10.00% Core Annualized ROAA (non-GAAP) 0.89% 0.72% 0.76% 0.51% 0.75% Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 —% 0.25% 0.50% 0.75% 1.00% (1) Non-GAAP Calculation in Press Release
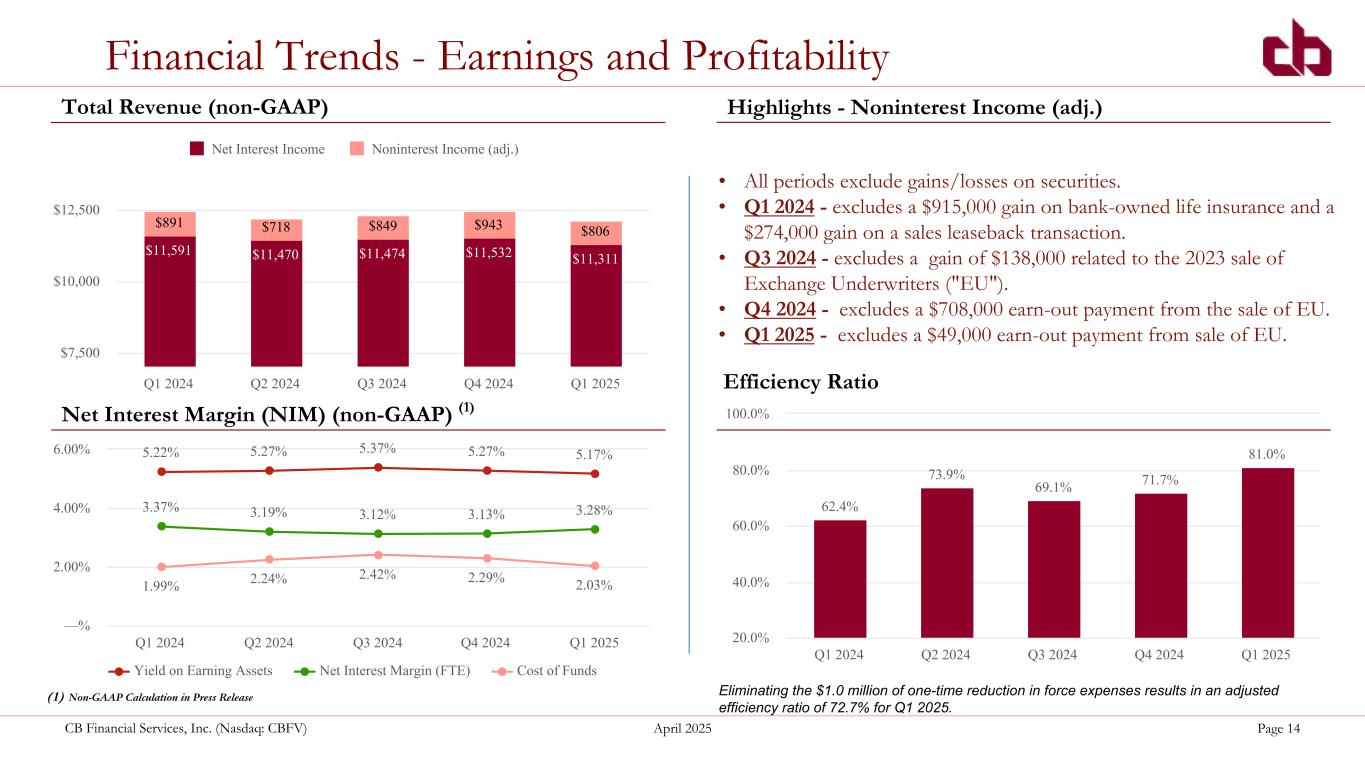
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 14 Financial Trends - Earnings and Profitability Total Revenue (non-GAAP) Highlights - Noninterest Income (adj.) Efficiency Ratio $11,591 $11,470 $11,474 $11,532 $11,311 $891 $718 $849 $943 $806 Net Interest Income Noninterest Income (adj.) Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 $7,500 $10,000 $12,500 62.4% 73.9% 69.1% 71.7% 81.0% Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 20.0% 40.0% 60.0% 80.0% 100.0%Net Interest Margin (NIM) (non-GAAP) (1) 5.22% 5.27% 5.37% 5.27% 5.17% 3.37% 3.19% 3.12% 3.13% 3.28% 1.99% 2.24% 2.42% 2.29% 2.03% Yield on Earning Assets Net Interest Margin (FTE) Cost of Funds Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 —% 2.00% 4.00% 6.00% • All periods exclude gains/losses on securities. • Q1 2024 - excludes a $915,000 gain on bank-owned life insurance and a $274,000 gain on a sales leaseback transaction. • Q3 2024 - excludes a gain of $138,000 related to the 2023 sale of Exchange Underwriters ("EU"). • Q4 2024 - excludes a $708,000 earn-out payment from the sale of EU. • Q1 2025 - excludes a $49,000 earn-out payment from sale of EU. (1) Non-GAAP Calculation in Press Release $11,591 $11,470 $11,474 $11,532 $11,311 $1,916 $688 $1,233 $1,655 $787 Net Interest Income Noninterest Income Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 $— $5,000 $10,000 $15,000 Eliminating the $1.0 million of one-time reduction in force expenses results in an adjusted efficiency ratio of 72.7% for Q1 2025.
Deposit Composition / Characteristics
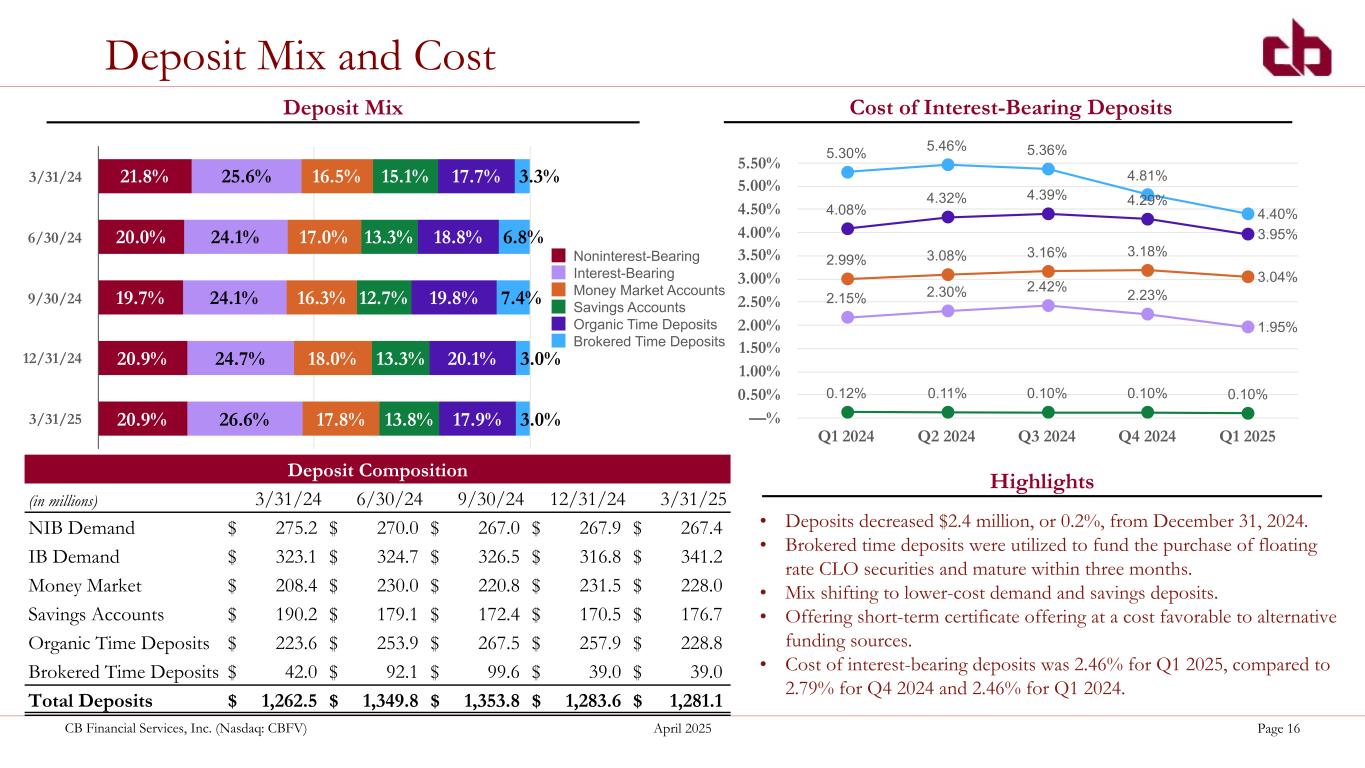
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 16 Deposit Mix and Cost 20.9% 26.6% 17.8% 13.8% 20.9% Non-Interest Bearing Demand Interest Bearing Demand Money Market Accounts Savings Accounts Time Deposits Deposit Mix Cost of Interest-Bearing Deposits 2.46% 2.75% 2.94% 2.79% 2.46% Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 —% 1.00% 2.00% 3.00% 4.00% Deposit Composition (in millions) 3/31/24 6/30/24 9/30/24 12/31/24 3/31/25 NIB Demand $ 275.2 $ 270.0 $ 267.0 $ 267.9 $ 267.4 IB Demand $ 323.1 $ 324.7 $ 326.5 $ 316.8 $ 341.2 Money Market $ 208.4 $ 230.0 $ 220.8 $ 231.5 $ 228.0 Savings Accounts $ 190.2 $ 179.1 $ 172.4 $ 170.5 $ 176.7 Organic Time Deposits $ 223.6 $ 253.9 $ 267.5 $ 257.9 $ 228.8 Brokered Time Deposits $ 42.0 $ 92.1 $ 99.6 $ 39.0 $ 39.0 Total Deposits $ 1,262.5 $ 1,349.8 $ 1,353.8 $ 1,283.6 $ 1,281.1 Highlights • Deposits decreased $2.4 million, or 0.2%, from December 31, 2024. • Brokered time deposits were utilized to fund the purchase of floating rate CLO securities and mature within three months. • Mix shifting to lower-cost demand and savings deposits. • Offering short-term certificate offering at a cost favorable to alternative funding sources. • Cost of interest-bearing deposits was 2.46% for Q1 2025, compared to 2.79% for Q4 2024 and 2.46% for Q1 2024. 2.15% 2.30% 2.42% 2.23% 1.95% 2.99% 3.08% 3.16% 3.18% 3.04% 0.12% 0.11% 0.10% 0.10% 0.10% 4.08% 4.32% 4.39% 4.29% 3.95% 5.30% 5.46% 5.36% 4.81% 4.40% Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 —% 0.50% 1.00% 1.50% 2.00% 2.50% 3.00% 3.50% 4.00% 4.50% 5.00% 5.50% Noninterest- Bearing Interest- Bearing Money Market Accounts Savings Accounts Time Deposits $— $100,000 $200,000 $300,000 $400,000 21.8% 20.0% 19.7% 20.9% 20.9% 25.6% 24.1% 24.1% 24.7% 26.6% 16.5% 17.0% 16.3% 18.0% 17.8% 15.1% 13.3% 12.7% 13.3% 13.8% 17.7% 18.8% 19.8% 20.1% 17.9% 3.3% 6.8% 7.4% 3.0% 3.0% Noninterest-Bearing Interest-Bearing Money Market Accounts Savings Accounts Organic Time Deposits Brokered Time Deposits 3/31/24 6/30/24 9/30/24 12/31/24 3/31/25
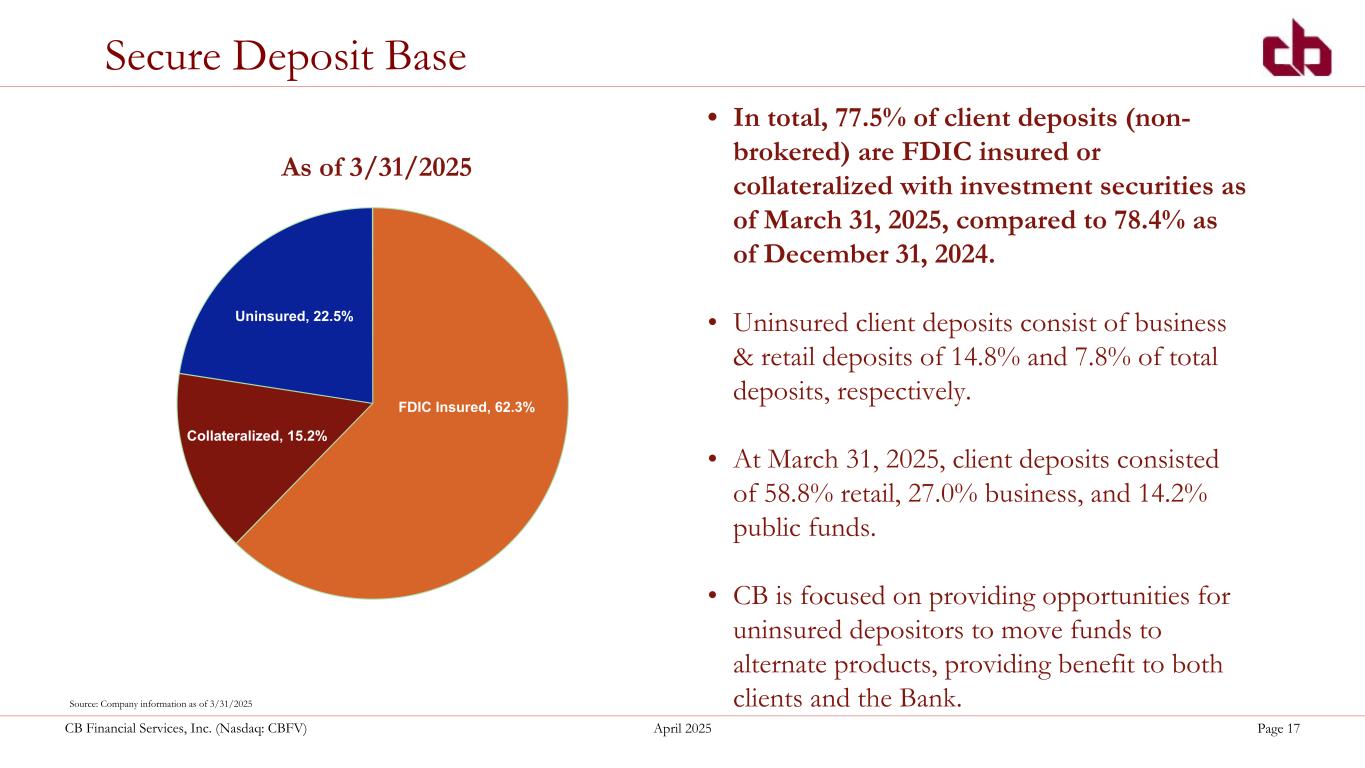
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 17 Secure Deposit Base • In total, 77.5% of client deposits (non- brokered) are FDIC insured or collateralized with investment securities as of March 31, 2025, compared to 78.4% as of December 31, 2024. • Uninsured client deposits consist of business & retail deposits of 14.8% and 7.8% of total deposits, respectively. • At March 31, 2025, client deposits consisted of 58.8% retail, 27.0% business, and 14.2% public funds. • CB is focused on providing opportunities for uninsured depositors to move funds to alternate products, providing benefit to both clients and the Bank. FDIC Insured, 62.3% Collateralized, 15.2% Uninsured, 22.5% Source: Company information as of 3/31/2025 As of 3/31/2025
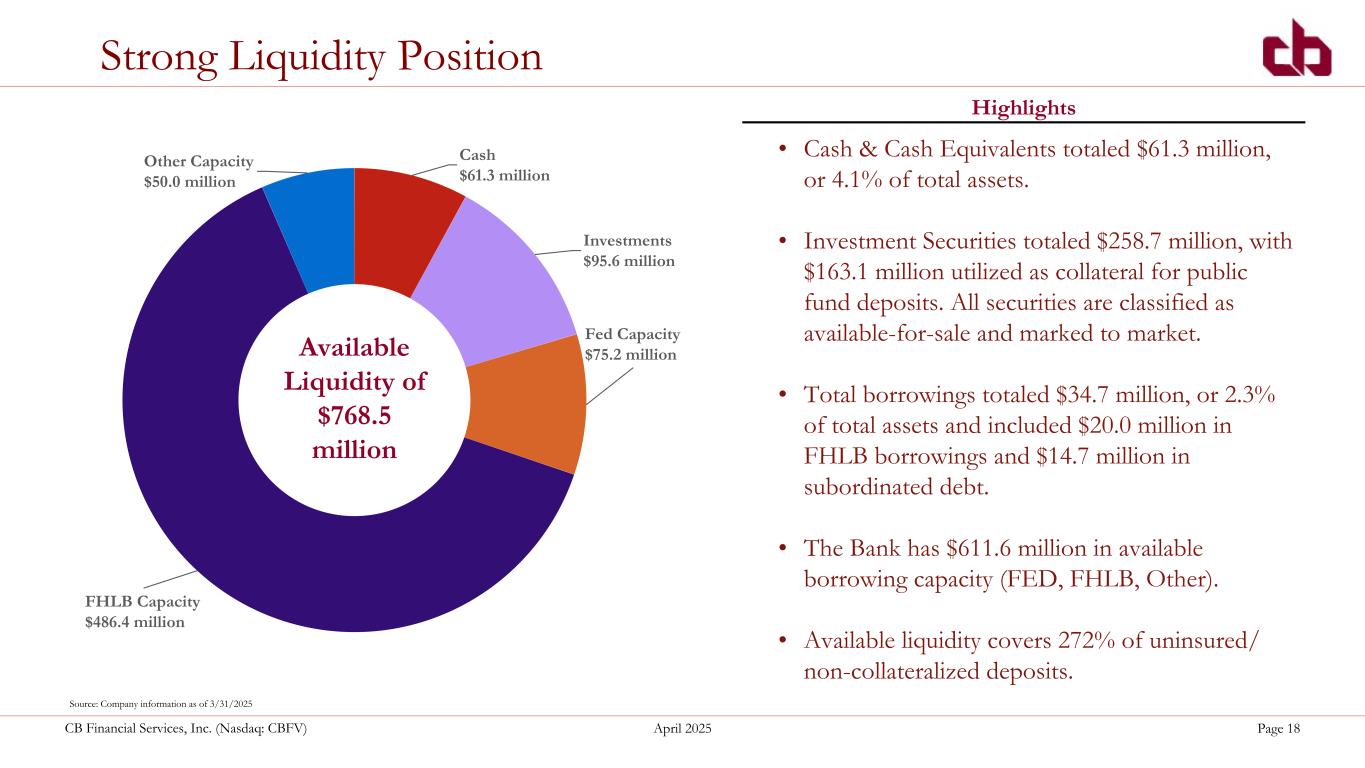
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 18 Strong Liquidity Position $4,118 2.6% $3,419 2.1% $50,220 31.2% $94,455 58.7% $7,945 4.9% $890 0.6% Government Agency Municipal MBS's CMO's Corporate Debt Marketable Equity Cash $61.3 million Investments $95.6 million Fed Capacity $75.2 million FHLB Capacity $486.4 million Other Capacity $50.0 million Available Liquidity of $768.5 million Highlights Source: Company information as of 3/31/2025 • Cash & Cash Equivalents totaled $61.3 million, or 4.1% of total assets. • Investment Securities totaled $258.7 million, with $163.1 million utilized as collateral for public fund deposits. All securities are classified as available-for-sale and marked to market. • Total borrowings totaled $34.7 million, or 2.3% of total assets and included $20.0 million in FHLB borrowings and $14.7 million in subordinated debt. • The Bank has $611.6 million in available borrowing capacity (FED, FHLB, Other). • Available liquidity covers 272% of uninsured/ non-collateralized deposits.
Loan Portfolio Composition
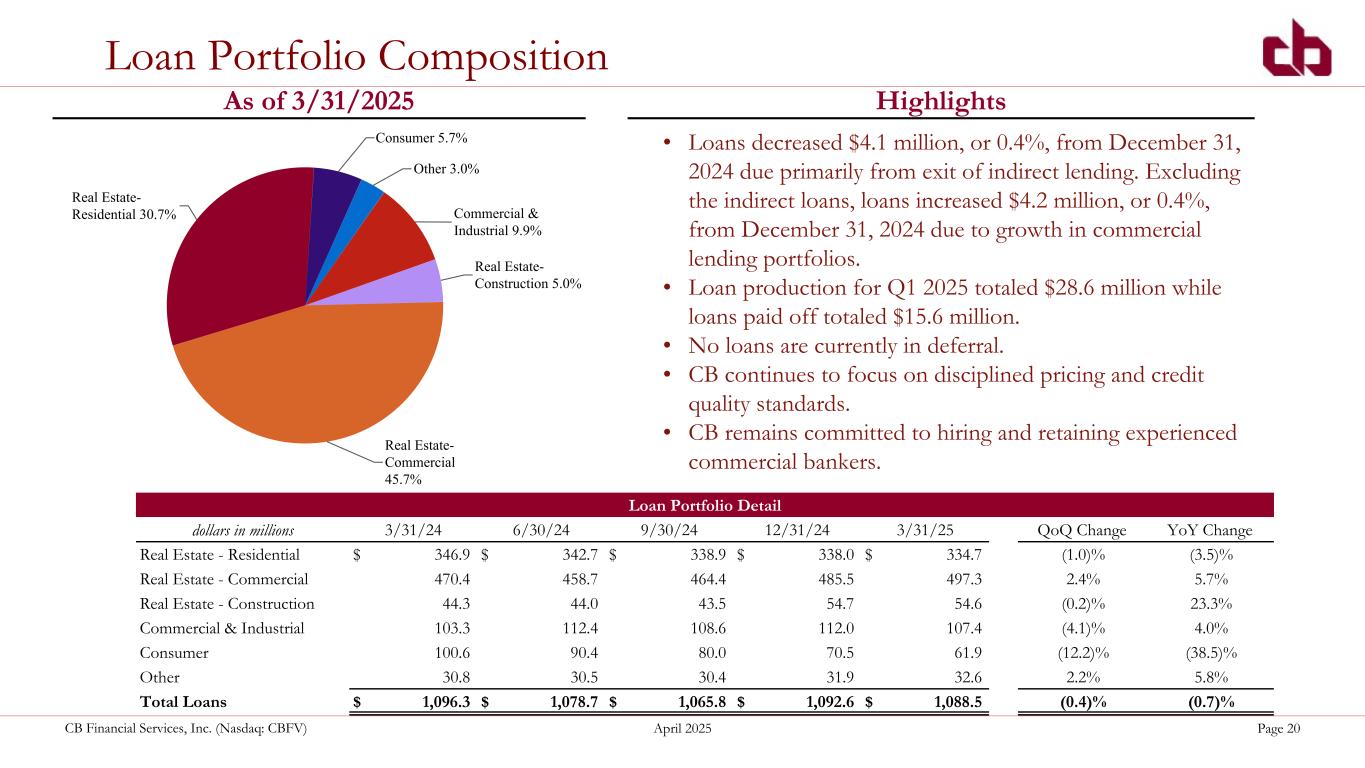
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 20 Loan Portfolio Composition Commercial & Industrial 9.9% Real Estate- Construction 5.0% Real Estate- Commercial 45.7% Real Estate- Residential 30.7% Consumer 5.7% Other 3.0% As of 3/31/2025 Loan Portfolio Detail dollars in millions 3/31/24 6/30/24 9/30/24 12/31/24 3/31/25 QoQ Change YoY Change Real Estate - Residential $ 346.9 $ 342.7 $ 338.9 $ 338.0 $ 334.7 (1.0)% (3.5)% Real Estate - Commercial 470.4 458.7 464.4 485.5 497.3 2.4% 5.7% Real Estate - Construction 44.3 44.0 43.5 54.7 54.6 (0.2)% 23.3% Commercial & Industrial 103.3 112.4 108.6 112.0 107.4 (4.1)% 4.0% Consumer 100.6 90.4 80.0 70.5 61.9 (12.2)% (38.5)% Other 30.8 30.5 30.4 31.9 32.6 2.2% 5.8% Total Loans $ 1,096.3 $ 1,078.7 $ 1,065.8 $ 1,092.6 $ 1,088.5 (0.4)% (0.7)% Highlights • Loans decreased $4.1 million, or 0.4%, from December 31, 2024 due primarily from exit of indirect lending. Excluding the indirect loans, loans increased $4.2 million, or 0.4%, from December 31, 2024 due to growth in commercial lending portfolios. • Loan production for Q1 2025 totaled $28.6 million while loans paid off totaled $15.6 million. • No loans are currently in deferral. • CB continues to focus on disciplined pricing and credit quality standards. • CB remains committed to hiring and retaining experienced commercial bankers.
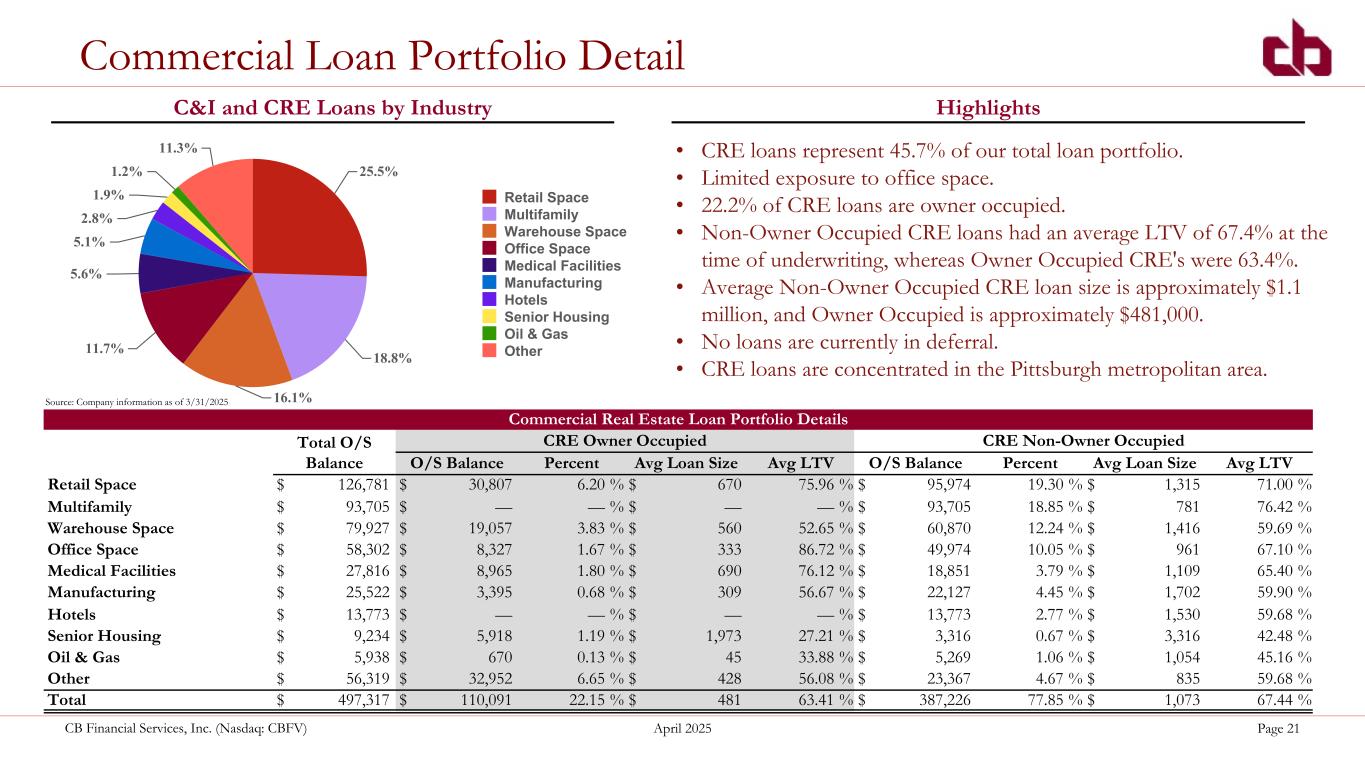
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 21 Commercial Loan Portfolio Detail 25.5% 18.8% 16.1% 11.7% 5.6% 5.1% 2.8% 1.9% 1.2% 11.3% Retail Space Multifamily Warehouse Space Office Space Medical Facilities Manufacturing Hotels Senior Housing Oil & Gas Other C&I and CRE Loans by Industry Highlights Commercial Real Estate Loan Portfolio Details Total O/S Balance CRE Owner Occupied CRE Non-Owner Occupied O/S Balance Percent Avg Loan Size Avg LTV O/S Balance Percent Avg Loan Size Avg LTV Retail Space $ 126,781 $ 30,807 6.20 % $ 670 75.96 % $ 95,974 19.30 % $ 1,315 71.00 % Multifamily $ 93,705 $ — — % $ — — % $ 93,705 18.85 % $ 781 76.42 % Warehouse Space $ 79,927 $ 19,057 3.83 % $ 560 52.65 % $ 60,870 12.24 % $ 1,416 59.69 % Office Space $ 58,302 $ 8,327 1.67 % $ 333 86.72 % $ 49,974 10.05 % $ 961 67.10 % Medical Facilities $ 27,816 $ 8,965 1.80 % $ 690 76.12 % $ 18,851 3.79 % $ 1,109 65.40 % Manufacturing $ 25,522 $ 3,395 0.68 % $ 309 56.67 % $ 22,127 4.45 % $ 1,702 59.90 % Hotels $ 13,773 $ — — % $ — — % $ 13,773 2.77 % $ 1,530 59.68 % Senior Housing $ 9,234 $ 5,918 1.19 % $ 1,973 27.21 % $ 3,316 0.67 % $ 3,316 42.48 % Oil & Gas $ 5,938 $ 670 0.13 % $ 45 33.88 % $ 5,269 1.06 % $ 1,054 45.16 % Other $ 56,319 $ 32,952 6.65 % $ 428 56.08 % $ 23,367 4.67 % $ 835 59.68 % Total $ 497,317 $ 110,091 22.15 % $ 481 63.41 % $ 387,226 77.85 % $ 1,073 67.44 % • CRE loans represent 45.7% of our total loan portfolio. • Limited exposure to office space. • 22.2% of CRE loans are owner occupied. • Non-Owner Occupied CRE loans had an average LTV of 67.4% at the time of underwriting, whereas Owner Occupied CRE's were 63.4%. • Average Non-Owner Occupied CRE loan size is approximately $1.1 million, and Owner Occupied is approximately $481,000. • No loans are currently in deferral. • CRE loans are concentrated in the Pittsburgh metropolitan area. Source: Company information as of 3/31/2025
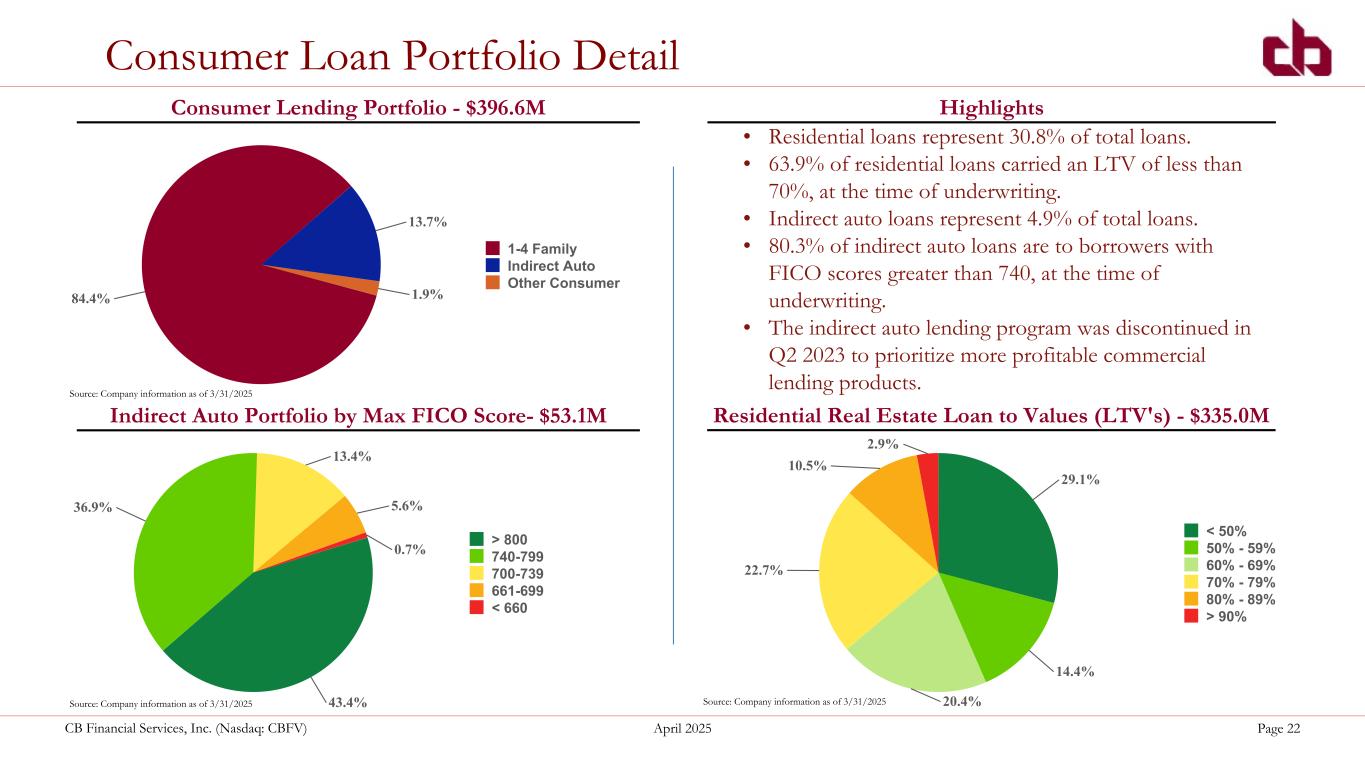
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 22 Consumer Loan Portfolio Detail 84.4% 13.7% 1.9% 1-4 Family Indirect Auto Other Consumer 29.1% 14.4% 20.4% 22.7% 10.5% 2.9% < 50% 50% - 59% 60% - 69% 70% - 79% 80% - 89% > 90% 43.4% 36.9% 13.4% 5.6% 0.7% > 800 740-799 700-739 661-699 < 660 Consumer Lending Portfolio - $396.6M Residential Real Estate Loan to Values (LTV's) - $335.0MIndirect Auto Portfolio by Max FICO Score- $53.1M Highlights • Residential loans represent 30.8% of total loans. • 63.9% of residential loans carried an LTV of less than 70%, at the time of underwriting. • Indirect auto loans represent 4.9% of total loans. • 80.3% of indirect auto loans are to borrowers with FICO scores greater than 740, at the time of underwriting. • The indirect auto lending program was discontinued in Q2 2023 to prioritize more profitable commercial lending products. Source: Company information as of 3/31/2025 Source: Company information as of 3/31/2025 Source: Company information as of 3/31/2025
Asset Quality, Capital Ratios and IRR
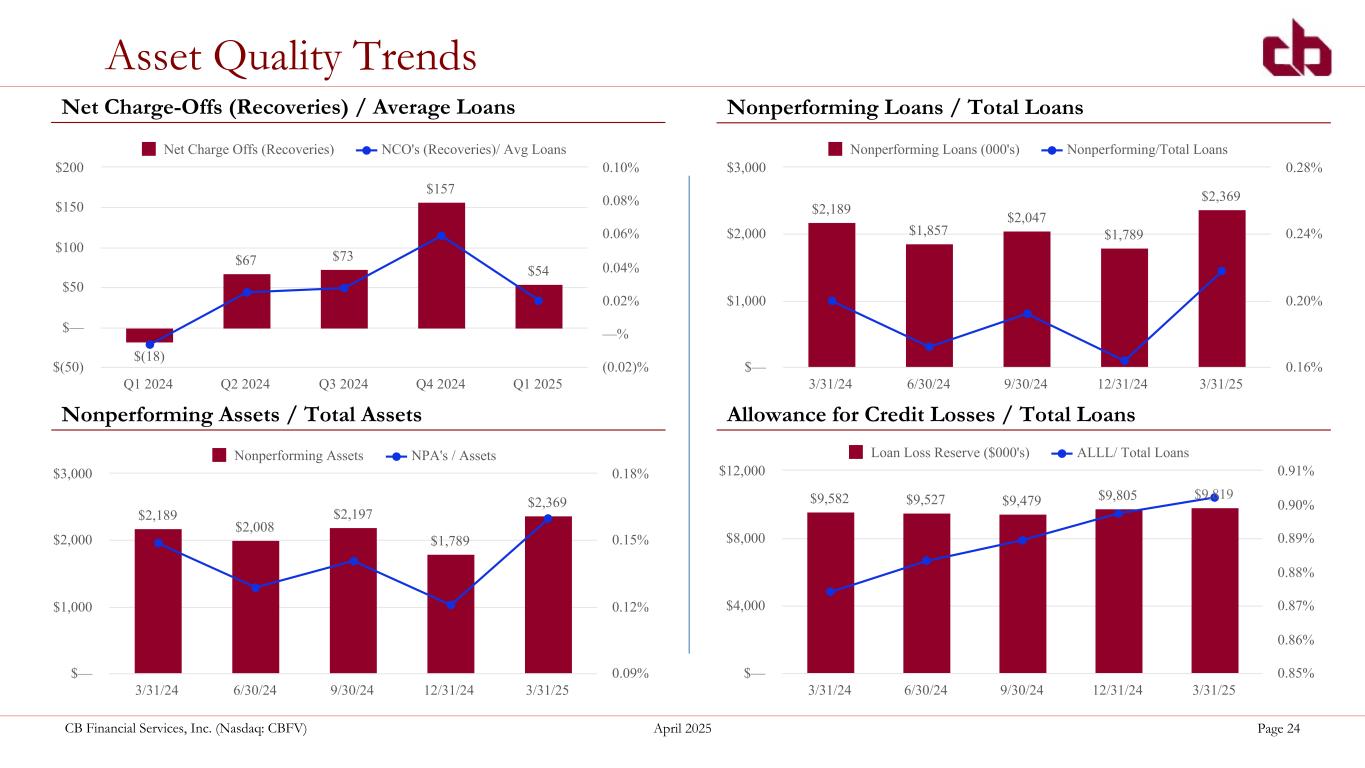
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 24 Asset Quality Trends Net Charge-Offs (Recoveries) / Average Loans Allowance for Credit Losses / Total LoansNonperforming Assets / Total Assets $2,189 $2,008 $2,197 $1,789 $2,369 Nonperforming Assets NPA's / Assets 3/31/24 6/30/24 9/30/24 12/31/24 3/31/25 $— $1,000 $2,000 $3,000 0.09% 0.12% 0.15% 0.18% Nonperforming Loans / Total Loans $2,189 $1,857 $2,047 $1,789 $2,369 Nonperforming Loans (000's) Nonperforming/Total Loans 3/31/24 6/30/24 9/30/24 12/31/24 3/31/25 $— $1,000 $2,000 $3,000 0.16% 0.20% 0.24% 0.28% $(18) $67 $73 $157 $54 Net Charge Offs (Recoveries) NCO's (Recoveries)/ Avg Loans Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 $(50) $— $50 $100 $150 $200 (0.02)% —% 0.02% 0.04% 0.06% 0.08% 0.10% $9,582 $9,527 $9,479 $9,805 $9,819 Loan Loss Reserve ($000's) ALLL/ Total Loans 3/31/24 6/30/24 9/30/24 12/31/24 3/31/25 $— $4,000 $8,000 $12,000 0.85% 0.86% 0.87% 0.88% 0.89% 0.90% 0.91%
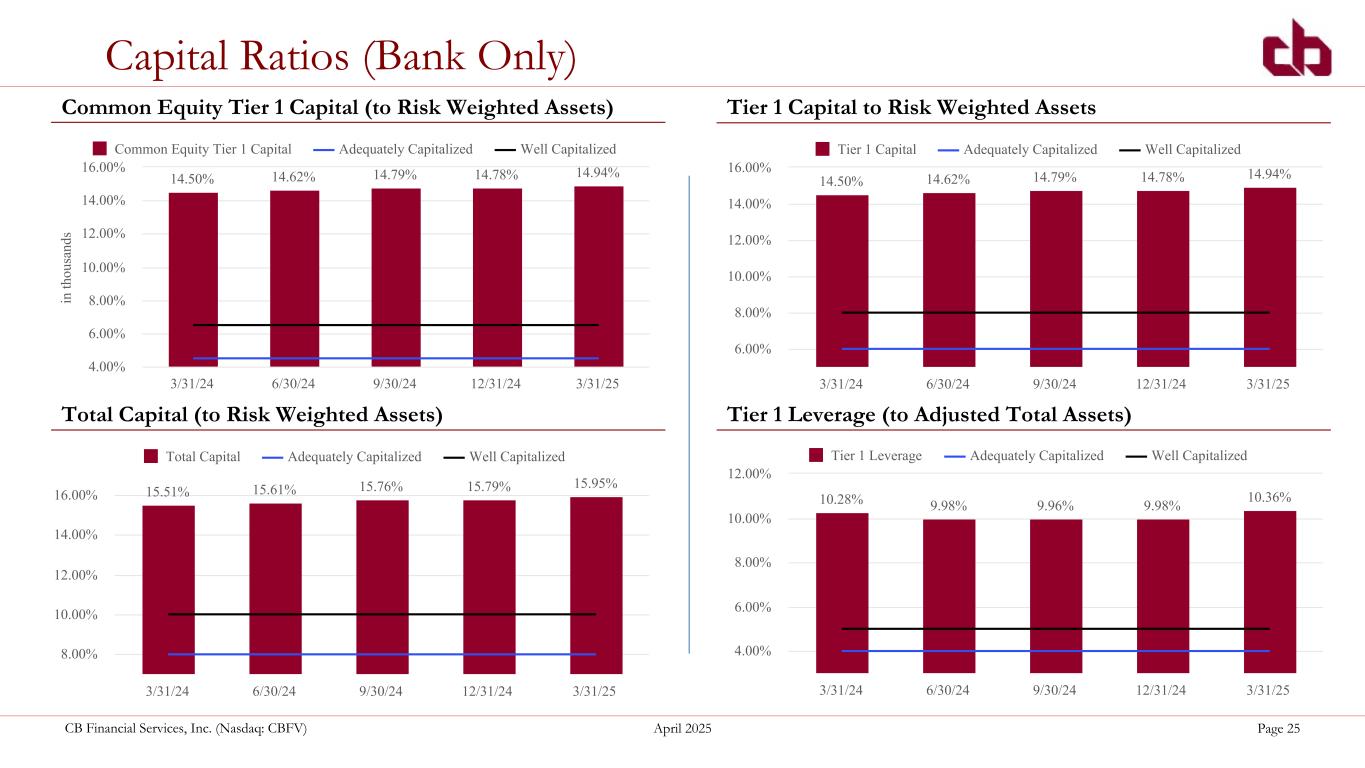
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 25 Capital Ratios (Bank Only) Common Equity Tier 1 Capital (to Risk Weighted Assets) Tier 1 Capital to Risk Weighted Assets in th ou sa nd s 14.50% 14.62% 14.79% 14.78% 14.94% Common Equity Tier 1 Capital Adequately Capitalized Well Capitalized 3/31/24 6/30/24 9/30/24 12/31/24 3/31/25 4.00% 6.00% 8.00% 10.00% 12.00% 14.00% 16.00% 14.50% 14.62% 14.79% 14.78% 14.94% Tier 1 Capital Adequately Capitalized Well Capitalized 3/31/24 6/30/24 9/30/24 12/31/24 3/31/25 6.00% 8.00% 10.00% 12.00% 14.00% 16.00% Tier 1 Leverage (to Adjusted Total Assets) 10.28% 9.98% 9.96% 9.98% 10.36% Tier 1 Leverage Adequately Capitalized Well Capitalized 3/31/24 6/30/24 9/30/24 12/31/24 3/31/25 4.00% 6.00% 8.00% 10.00% 12.00% Total Capital (to Risk Weighted Assets) 15.51% 15.61% 15.76% 15.79% 15.95% Total Capital Adequately Capitalized Well Capitalized 3/31/24 6/30/24 9/30/24 12/31/24 3/31/25 8.00% 10.00% 12.00% 14.00% 16.00%
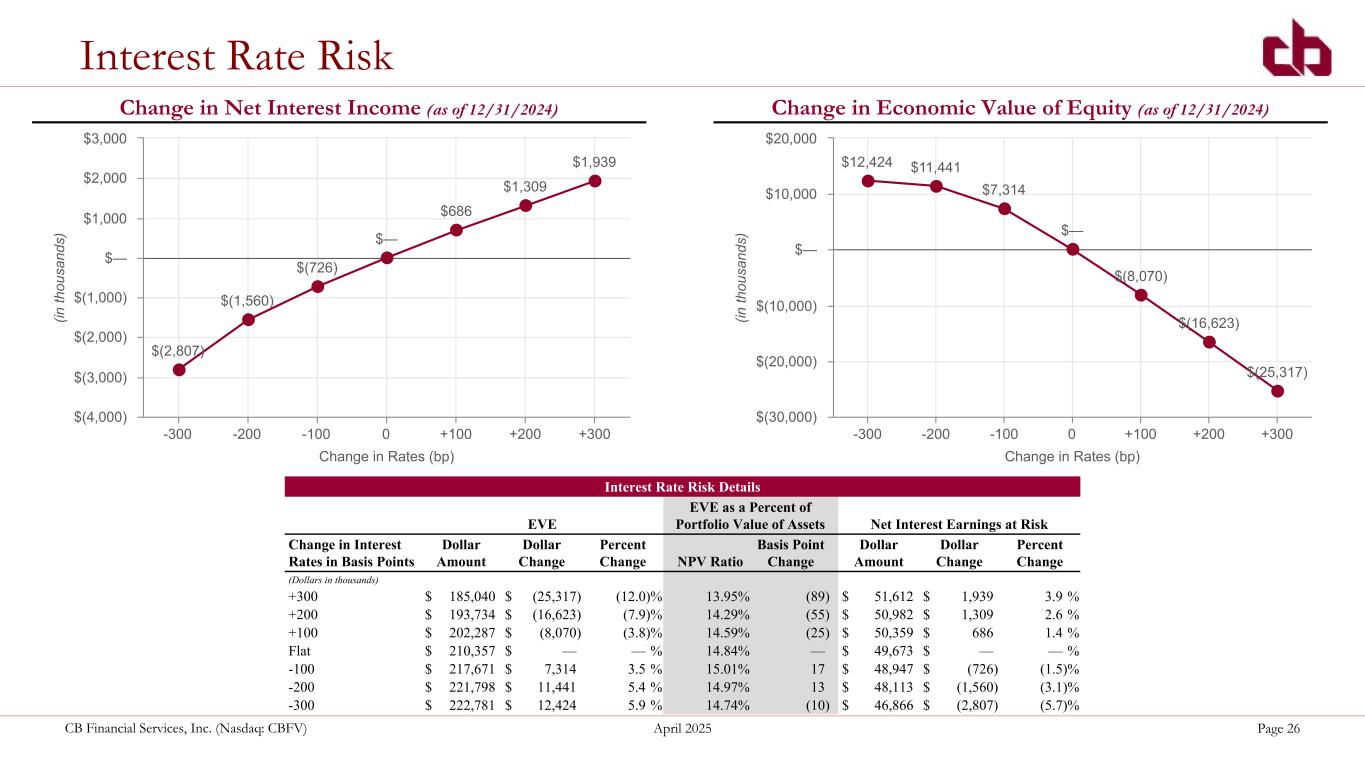
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 26 Change in Rates (bp) (in th ou sa nd s) $(2,807) $(1,560) $(726) $— $686 $1,309 $1,939 -300 -200 -100 0 +100 +200 +300 $(4,000) $(3,000) $(2,000) $(1,000) $— $1,000 $2,000 $3,000 Change in Rates (bp) (in th ou sa nd s) $12,424 $11,441 $7,314 $— $(8,070) $(16,623) $(25,317) -300 -200 -100 0 +100 +200 +300 $(30,000) $(20,000) $(10,000) $— $10,000 $20,000 Change in Net Interest Income (as of 12/31/2024) Change in Economic Value of Equity (as of 12/31/2024) Interest Rate Risk Interest Rate Risk Details EVE EVE as a Percent of Portfolio Value of Assets Net Interest Earnings at Risk Change in Interest Rates in Basis Points Dollar Amount Dollar Change Percent Change NPV Ratio Basis Point Change Dollar Amount Dollar Change Percent Change (Dollars in thousands) +300 $ 185,040 $ (25,317) (12.0) % 13.95 % (89) $ 51,612 $ 1,939 3.9 % +200 $ 193,734 $ (16,623) (7.9) % 14.29 % (55) $ 50,982 $ 1,309 2.6 % +100 $ 202,287 $ (8,070) (3.8) % 14.59 % (25) $ 50,359 $ 686 1.4 % Flat $ 210,357 $ — — % 14.84 % — $ 49,673 $ — — % -100 $ 217,671 $ 7,314 3.5 % 15.01 % 17 $ 48,947 $ (726) (1.5) % -200 $ 221,798 $ 11,441 5.4 % 14.97 % 13 $ 48,113 $ (1,560) (3.1) % -300 $ 222,781 $ 12,424 5.9 % 14.74 % (10) $ 46,866 $ (2,807) (5.7) %
Conclusions
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 28 Market Presence with Brand Recognition Seasoned Executive Leadership Deploying Technology to Enhance Client Experience Investment Summary Serving Stable Southwestern PA & Ohio River Valley markets Proven experience through all economic cycles Continuing to invest with a tech- forward and people-centric approach Investing for Growth Adding new talent, tech upgrades and investing in process improvement Rewarding Shareholders Stable quarterly dividend and active stock repurchase plan
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 29 Delivering Value to Shareholders Our goal is to continue operating as a high-performing, independent community bank, creating positive returns and adding significant value for our stakeholders. ◦ Committed to Improving Financial Performance ▪ Revenue Growth ▪ Consistent returns ◦ Dividend and Capital Reinvestment ▪ Regular and reliable dividend payouts ▪ Attractive dividend yield ▪ Capital reinvestment to produce higher returns ◦ Investing in Products and Strategies for Future Growth ▪ Specialty Treasury Payments & Services ▪ Commercial Banking ◦ Creating Franchise Value ◦ Supporting Local Communities (building value beyond financial returns)
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 30 ◦ Community bank model is highly-differentiated compared with large regional banks recently experiencing regulatory issues ◦ Intense focus on sales and service culture and quality product offerings which builds full relationships with our clients ◦ Utilize technology investments to enhance speed of process while improving client experience ◦ Enhance profitability and efficiency potential while continuing to invest for future growth ◦ Continue our track record of opportunistic growth in the robust Pittsburgh Metropolitan area and across our footprint ◦ Defend our relatively low-cost deposit base which enables the bank to protect net interest margin ◦ Leverage our credit culture and strong loan underwriting as a foundation to uphold our asset quality metrics Be the Community Bank of choice across our footprint Concluding Thoughts
CB Financial Services, Inc. (Nasdaq: CBFV) April 2025 Page 31 Company Contact John H. Montgomery President and Chief Executive Officer Phone: (724) 223-8317 Investor Relations The IR Group Diane Fitzgibbons, President Phone: (206) 388-5789 Email: [email protected] Bank Main Office: 100 N. Market Street Carmichaels, PA 15320 Corporate Center: 2111 North Franklin Drive, Suite 200 Washington, PA 15301 Contact Information