
CNO 8-K
CNO Financial Group, Inc. (CNO)
8-K
2026-02-05
For: 2026-02-05
View Original
Added on
April 11, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
Date of Report (Date of earliest event reported): February 5, 2026
(Exact Name of Registrant as Specified in Charter)
| (State or Other Jurisdiction of Incorporation) | (Commission File Number) | (I.R.S. Employer Identification No.) | ||||||
(Address of Principal Executive Offices) (Zip Code)
(317 ) 817-6100
(Registrant's telephone number, including area code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol | Name of each exchange on which registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
| Item 2.02. | Results of Operations and Financial Condition. | ||||
On February 5, 2026, CNO Financial Group, Inc. ("CNO" or the "Company") issued: (i) a press release announcing its financial results for the quarter ended December 31, 2025, a copy of which is attached hereto as Exhibit 99.1 and is incorporated herein by reference; (ii) the Quarterly Financial Supplement for December 31, 2025, a copy of which is attached hereto as Exhibit 99.2 and is incorporated herein by reference; and (iii) additional financial information related to its financial and operating results for the quarter ended December 31, 2025, a copy of which is attached hereto as Exhibit 99.3 and is incorporated herein by reference.
The information contained under Item 2.02 in this Current Report on Form 8-K (including Exhibits 99.1, 99.2 and 99.3) is being furnished and shall not be deemed "filed" for purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the "Exchange Act"), or otherwise subject to the liabilities of that Section. The information contained in this Current Report on Form 8-K shall not be incorporated by reference into any registration statement or other document pursuant to the Securities Act of 1933, as amended, or the Exchange Act, except as shall be expressly set forth by specific reference in any such filing.
| Item 9.01(d). | Financial Statements and Exhibits. | ||||
The following materials are furnished as exhibits to this Current Report on Form 8-K:
| 99.1 | |||||
| 99.2 | |||||
| 99.3 | |||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document). | ||||
2
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| CNO Financial Group, Inc. | |||||||||||
| Date: February 5, 2026 | |||||||||||
| By: | /s/ Joel T. Koehneman | ||||||||||
Joel T. Koehneman | |||||||||||
Senior Vice President and Chief Accounting Officer | |||||||||||
3
 News
For Immediate Release
CNO Financial Group Reports Fourth Quarter and Full Year 2025 Results
Carmel, Ind., February 5, 2026 - CNO Financial Group, Inc. (NYSE: CNO) today reported its fourth quarter and full year 2025 financial results:
•Achieved, and in most cases exceeded, all 2025 guidance metrics.
•Fourth quarter 2025 net income was $93 million, or $0.95 per diluted share, and net operating income(1) was $143 million, or $1.47 per diluted share.
•Full year 2025 net income was $229 million, or $2.30 per diluted share, and net operating income(1) was $439 million, or $4.40 per diluted share.
•Return on equity (ROE) of 8.9%; Operating ROE of 11.4%, excluding significant items(5).
•Book value per share of $27.92 and book value per diluted share, excluding accumulated other comprehensive loss,(2) of $38.81.
•Consistent sales momentum drove meaningful earnings growth as operating earnings per share grew 11%.
•Total new annualized premiums (NAP)(4) growth, up 15%, accelerated to a new full-year record for the company.
“CNO once again delivered an excellent quarter and full-year performance, demonstrating the consistent, repeatable results that continue to drive our momentum,” said Gary C. Bhojwani, chief executive officer. “We posted our 14th consecutive quarter of strong insurance sales, with total new annualized premiums up 15% for the year, and set multiple production records that underscore the strength of our business model.”
“Operating earnings per share grew 11%, supported by strong insurance product margin and investment results, growth in the business, and disciplined expense and capital management. For the year, we returned $386 million to shareholders, an 11% increase from 2024. This reflects the healthy free cash flow generation of the business, bolstered by our second reinsurance transaction with our Bermuda affiliate.”
“Our associates and agents continued to execute with focus and dedication, enabling us to grow the franchise while improving profitability and advancing our long-term strategic roadmap. We enter 2026 with a strong capital position and a path to achieving our 2027 ROE target.”
FINANCIAL SUMMARY
Quarter End
(Amounts in millions, except per share data)
(Unaudited)
Net income decreased in 4Q25 and increased in 4Q24 due to non-economic accounting impacts resulting from market volatility.
Net operating income, a non-GAAP(a) financial measure, excludes these non-economic accounting impacts as well as other non-operating items. Net operating income is used consistently by CNO’s management to evaluate the operating performance of the Company and is a measure commonly used in the life insurance industry. It differs from net income primarily because it excludes the non-operating items as defined in note (1). Management believes an analysis of net operating income is important in understanding the profitability and operating trends of the Company’s business. Net income is the most directly comparable GAAP measure.
In 4Q25, net income and net operating income(1) were unaffected by significant items, compared to unfavorable impacts in 4Q24 of $3.1 million, or $0.03 per diluted share. Significant items are detailed in note (6).
| Per diluted share | |||||||||||||||||||||||||||||||||||||||||
Quarter ended December 31, | Quarter ended December 31, | ||||||||||||||||||||||||||||||||||||||||
| 2025 | 2024 | % change | 2025 | 2024 | % change | ||||||||||||||||||||||||||||||||||||
Income from insurance products (b) | $ | 1.19 | $ | 1.01 | 18 | % | $ | 116.1 | $ | 107.0 | 9 | % | |||||||||||||||||||||||||||||
| Fee income | 0.19 | 0.20 | (5) | 19.1 | 20.6 | (7) | |||||||||||||||||||||||||||||||||||
Investment income not allocated to product lines (c) | 0.60 | 0.62 | (3) | 58.1 | 65.3 | (11) | |||||||||||||||||||||||||||||||||||
| Expenses not allocated to product lines | (0.20) | (0.18) | 11 | (19.8) | (19.0) | 4 | |||||||||||||||||||||||||||||||||||
| Operating earnings before taxes | 1.78 | 1.65 | 173.5 | 173.9 | |||||||||||||||||||||||||||||||||||||
| Income tax expense on operating income | (0.31) | (0.34) | (9) | (30.1) | (35.9) | (16) | |||||||||||||||||||||||||||||||||||
| Net operating income (1) | 1.47 | 1.31 | 12 | 143.4 | 138.0 | 4 | |||||||||||||||||||||||||||||||||||
Net realized investment losses from disposals, impairments and change in allowance for credit losses | (0.26) | (0.33) | (25.2) | (35.1) | |||||||||||||||||||||||||||||||||||||
| Net change in market value of investments recognized in earnings | (0.01) | (0.06) | (1.3) | (6.6) | |||||||||||||||||||||||||||||||||||||
| Changes in fair value of embedded derivative liabilities and market risk benefits | (0.02) | 0.88 | (1.5) | 92.6 | |||||||||||||||||||||||||||||||||||||
Expenses related to TechMod initiative | (0.10) | — | (9.9) | — | |||||||||||||||||||||||||||||||||||||
Goodwill and other asset impairment | (0.05) | — | (5.2) | — | |||||||||||||||||||||||||||||||||||||
| Net loss related to divested business | (0.18) | — | (17.3) | — | |||||||||||||||||||||||||||||||||||||
| Other | (0.02) | 0.07 | (1.7) | 7.3 | |||||||||||||||||||||||||||||||||||||
Non-operating income before taxes | (0.64) | 0.56 | (62.1) | 58.2 | |||||||||||||||||||||||||||||||||||||
Income tax expense on non-operating income | 0.12 | (0.13) | 11.6 | (13.3) | |||||||||||||||||||||||||||||||||||||
Net non-operating income | (0.52) | 0.43 | (50.5) | 44.9 | |||||||||||||||||||||||||||||||||||||
| Net income | $ | 0.95 | $ | 1.74 | $ | 92.9 | $ | 182.9 | |||||||||||||||||||||||||||||||||
| Weighted average diluted shares outstanding | 97.3 | 105.2 | |||||||||||||||||||||||||||||||||||||||
2
FINANCIAL SUMMARY
Year End
(Amounts in millions, except per share data)
(Unaudited)
Net income decreased in 2025 and increased in 2024 due to non-economic accounting impacts resulting from market volatility. Net income also decreased in 2025 due to a goodwill and intangible asset impairment.
Net operating income, a non-GAAP(a) financial measure, excludes these non-economic accounting impacts as well as other non-operating items including the goodwill and intangible asset impairment. Net operating income is used consistently by CNO’s management to evaluate the operating performance of the Company and is a measure commonly used in the life insurance industry. It differs from net income primarily because it excludes the non-operating items as defined in note (1). Management believes an analysis of net operating income is important in understanding the profitability and operating trends of the Company’s business. Net income is the most directly comparable GAAP measure.
Net income and net operating income(1) were favorably impacted by significant items of $37.5 million, or $0.38 per diluted share, in 2025 and $18.8 million, or $0.17 per diluted share, in 2024. Significant items are detailed in note (6).
| Per diluted share | |||||||||||||||||||||||||||||||||||||||||
Year ended December 31, | Year ended December 31, | ||||||||||||||||||||||||||||||||||||||||
| 2025 | 2024 | % change | 2025 | 2024 | % change | ||||||||||||||||||||||||||||||||||||
Income from insurance products (b) | $ | 4.57 | $ | 3.93 | 16 | % | $ | 456.3 | $ | 424.7 | 7 | % | |||||||||||||||||||||||||||||
| Fee income | 0.15 | 0.28 | (46) | 15.2 | 30.0 | (49) | |||||||||||||||||||||||||||||||||||
Investment income not allocated to product lines (c) | 1.70 | 1.55 | 10 | 169.4 | 167.9 | 1 | |||||||||||||||||||||||||||||||||||
| Expenses not allocated to product lines | (0.88) | (0.67) | 31 | (87.7) | (71.8) | 22 | |||||||||||||||||||||||||||||||||||
| Operating earnings before taxes | 5.54 | 5.09 | 553.2 | 550.8 | |||||||||||||||||||||||||||||||||||||
| Income tax expense on operating income | (1.14) | (1.12) | 2 | (114.0) | (121.5) | (6) | |||||||||||||||||||||||||||||||||||
| Net operating income (1) | 4.40 | 3.97 | 11 | 439.2 | 429.3 | 2 | |||||||||||||||||||||||||||||||||||
Net realized investment losses from disposals, impairments and change in allowance for credit losses | (0.69) | (0.67) | (69.0) | (72.7) | |||||||||||||||||||||||||||||||||||||
| Net change in market value of investments recognized in earnings | 0.14 | 0.21 | 14.3 | 22.8 | |||||||||||||||||||||||||||||||||||||
| Changes in fair value of embedded derivative liabilities and market risk benefits | (0.64) | 0.43 | (64.0) | 46.3 | |||||||||||||||||||||||||||||||||||||
Expenses related to TechMod initiative | (0.20) | — | (20.3) | — | |||||||||||||||||||||||||||||||||||||
Goodwill and other asset impairment | (1.02) | — | (101.9) | — | |||||||||||||||||||||||||||||||||||||
| Net loss related to divested business | (0.17) | — | (17.3) | — | |||||||||||||||||||||||||||||||||||||
| Other | (0.02) | (0.07) | (1.6) | (7.3) | |||||||||||||||||||||||||||||||||||||
Non-operating income before taxes | (2.60) | (0.10) | (259.8) | (10.9) | |||||||||||||||||||||||||||||||||||||
Income tax expense on non-operating income | 0.50 | 0.02 | 49.9 | 2.4 | |||||||||||||||||||||||||||||||||||||
Net non-operating income | (2.10) | (0.08) | (209.9) | (8.5) | |||||||||||||||||||||||||||||||||||||
| Net income | $ | 2.30 | $ | 3.89 | $ | 229.3 | $ | 420.8 | |||||||||||||||||||||||||||||||||
| Weighted average diluted shares outstanding | 99.8 | 108.1 | |||||||||||||||||||||||||||||||||||||||
____________________
(a) GAAP is defined as accounting principles generally accepted in the United States of America.
(b) Income from insurance products is the sum of the insurance product margins of the annuity, health and life product lines, less expenses allocated to the insurance product lines. It excludes the income from our fee income business, investment income not allocated to product lines, net expenses not allocated to product lines (primarily holding company expenses) and income taxes. Insurance product margin is management’s measure of the profitability of its annuity, health and life segments’ performance and consists of insurance policy income plus allocated investment income less insurance policy benefits, interest credited, commissions, advertising expense and amortization of acquisition costs.
(c) Investment income not allocated to product lines represents net investment income less: (i) equity returns credited to policyholder account balances; (ii) the investment income allocated to our product lines; (iii) interest expense on notes payable, investment borrowings and financing arrangements; (iv) expenses related to the funding agreement-backed notes ("FABN") program; and (v) certain expenses related to benefit plans that are offset by special-purpose investment income; plus (vi) the impact of annual option forfeitures related to fixed indexed annuity surrenders. Investment income not allocated to product lines includes investment income on investments in excess of amounts allocated to product lines, investments held by our holding companies, the spread we earn from our federal home loan bank ("FHLB") investment borrowing and FABN programs and variable components of investment income (including call and prepayment income, adjustments to returns on structured securities due to cash flow changes, income (loss) from company-owned life insurance ("COLI") and alternative investments income not allocated to product lines), net of interest expense on corporate debt and financing arrangements. The spread earned from our FHLB investment borrowing and FABN programs includes the investment income on the matched assets less: (i) interest on investment borrowings related to the FHLB investment borrowing program; (ii) interest credited on funding agreements; and (iii) amortization of deferred acquisition costs related to the FABN program.
3
FINANCIAL SUMMARY (continued)
Management vs. GAAP Measures
(Dollars in millions, except per share data)
(Unaudited)
Shareholders’ equity, excluding accumulated other comprehensive income (loss), and book value per share, excluding accumulated other comprehensive income (loss), are non-GAAP measures that are utilized by management to view the business without the effect of accumulated other comprehensive income (loss) which is primarily attributable to fluctuations in interest rates associated with fixed maturities, available for sale. Management views the business in this manner because the Company has the ability and generally, the intent, to hold investments to maturity and meaningful trends can be more easily identified without the fluctuations. In addition, shareholders' equity excludes net operating loss carryforwards in our non-GAAP return on equity measures as such assets are not discounted and, accordingly, will not provide a return to shareholders until after it is realized as a reduction to taxes that would otherwise be paid. Management believes that excluding this value from the equity component of this measure enhances the understanding of the effect these non-discounted assets have on operating returns.
___________________________________________________________________________________________________
| Year ended | |||||||||||
| December 31, | |||||||||||
| 2025 | 2024 | ||||||||||
Trailing four quarters: | |||||||||||
| Net Income | $ | 229.3 | $ | 420.8 | |||||||
| Net operating income (a non-GAAP financial measure) | 439.2 | 429.3 | |||||||||
| Net operating income, excluding significant items | 401.7 | 410.5 | |||||||||
Average of each of the trailing four quarters average: | |||||||||||
| Shareholders’ equity | $ | 2,566.4 | $ | 2,462.5 | |||||||
| Accumulated other comprehensive loss | 1,213.4 | 1,383.7 | |||||||||
| Shareholders’ equity, excluding accumulated other comprehensive loss | 3,779.8 | 3,846.2 | |||||||||
| Net operating loss carryforwards | (243.1) | (240.0) | |||||||||
| Shareholders' equity, excluding accumulated other comprehensive loss and net operating loss carryforwards | $ | 3,536.7 | $ | 3,606.2 | |||||||
Ratios: | |||||||||||
| Return on equity | 8.9 | % | 17.1 | % | |||||||
Operating return on equity (a non-GAAP financial measure) (5) | 12.4 | % | 11.9 | % | |||||||
Operating return on equity, excluding significant items (a non-GAAP financial measure) (5) | 11.4 | % | 11.4 | % | |||||||
| Shareholders’ equity | $ | 2,638.2 | $ | 2,515.2 | |||||||
| Accumulated other comprehensive loss | 1,115.0 | 1,371.4 | |||||||||
| Shareholders’ equity, excluding accumulated other comprehensive loss | 3,753.2 | 3,886.6 | |||||||||
| Basic shares outstanding | 94,484,339 | 101,618,957 | |||||||||
| Diluted shares outstanding | 96,714,213 | 104,052,793 | |||||||||
| Book value per share | $ | 27.92 | $ | 24.75 | |||||||
| Book value per diluted share | $ | 27.28 | $ | 24.17 | |||||||
Accumulated other comprehensive loss per diluted share | 11.53 | 13.18 | |||||||||
Book value per diluted share, excluding accumulated other comprehensive loss (a non-GAAP financial measure) (2) | $ | 38.81 | $ | 37.35 | |||||||
4
Non-Operating Items
Net investment losses in 4Q25 were $25.2 million, including the unfavorable change in the allowance for credit losses of $3.0 million. Net investment losses in 4Q24 were $35.1 million, including the unfavorable change in the allowance for credit losses of $7.8 million.
During 4Q25 and 4Q24, we recognized a decrease in earnings of $1.3 million and $6.6 million, respectively, due to the net change in market value of investments.
During 4Q25 and 4Q24, we recognized a decrease in earnings of $1.5 million and an increase of $92.6 million, respectively, resulting from changes in the estimated fair value of embedded derivative liabilities and market risk benefits related to our fixed indexed annuities. Such amounts include the impacts of changes in market interest rates and equity impacts used to determine the estimated fair values of the embedded derivatives and market risk benefits.
During 4Q25, we incurred $9.9 million of expense related to TechMod, our previously announced technology modernization initiative. This three-year project began in the second quarter of 2025 to modernize certain elements of our technology.
We recognized a $5.2 million non-operating charge for the impairment of other assets and a $17.3 million loss related to our exit from the fee services side of the Worksite business during 4Q25, as previously announced. Beginning in 4Q25, operating losses, including costs to exit this business, are reported in non-operating income. These operating losses were previously reported in operating income as a component of fee income.
Other non-operating items included a decrease in earnings of $1.7 million and an increase of $6.6 million for the mark-to-market change in the agent deferred compensation plan liability, which was impacted by changes in the underlying actuarial assumptions used to value the liability in 4Q25 and 4Q24, respectively. We recognize the mark-to-market change in the estimated value of this liability through earnings as assumptions change.
INVESTMENT PORTFOLIO
(Dollars in millions)
Fixed maturities, available for sale, at amortized cost by asset class as of December 31, 2025 are as follows:
| Investment grade | Below investment grade | Total | |||||||||||||||
| Corporate securities | $ | 13,876.5 | $ | 692.3 | $ | 14,568.8 | |||||||||||
| United States Treasury securities and obligations of the United States government and agencies | 207.2 | — | 207.2 | ||||||||||||||
| States and political subdivisions | 3,289.0 | 22.4 | 3,311.4 | ||||||||||||||
| Foreign governments | 130.9 | — | 130.9 | ||||||||||||||
| Asset-backed securities | 1,734.1 | 46.7 | 1,780.8 | ||||||||||||||
| Agency residential mortgage-backed securities | 838.3 | — | 838.3 | ||||||||||||||
| Non-agency residential mortgage-backed securities | 1,400.3 | 238.8 | (a) | 1,639.1 | |||||||||||||
| Collateralized loan obligations | 1,142.4 | — | 1,142.4 | ||||||||||||||
| Commercial mortgage-backed securities | 2,079.2 | 78.3 | 2,157.5 | ||||||||||||||
| Total | $ | 24,697.9 | $ | 1,078.5 | $ | 25,776.4 | |||||||||||
____________________
(a) Certain structured securities rated below investment grade by Nationally Recognized Statistical Rating Organizations may be assigned a NAIC 1 or NAIC 2 designation based on the cost basis of the security relative to estimated recoverable amounts as determined by the National Association of Insurance Commissioners ("NAIC").
As of December 31, 2025, the fair value of CNO’s available for sale fixed maturity portfolio was $23,886.8 million compared with an amortized cost of $25,776.4 million. Net unrealized losses were comprised of gross unrealized gains of $235.3 million and gross unrealized losses of $2,088.9 million as of December 31, 2025. The allowance for credit losses was $36.0 million at December 31, 2025.
Statutory (based on non-GAAP measures) and GAAP Capital Information
The consolidated statutory risk-based capital ratio of our U.S. based insurance subsidiaries was estimated at 380 percent at December 31, 2025, reflecting estimated 4Q25 statutory operating gain of $18.4 million. There were $273.8 million insurance company dividends, net of capital contributions, to the holding company during 4Q25.
During 4Q25, we repurchased $60.0 million of common stock under our securities repurchase program (including $0.9 million of repurchases settled in 1Q26). We repurchased 1.5 million common shares at an average cost of $40.74 per share. As of December 31, 2025, we had 94.5 million shares outstanding and had authority to repurchase up to an additional $420.4 million of our common stock. During 4Q25, dividends paid on common stock totaled $16.2 million.
5
Unrestricted cash and investments held by our holding company were $351.4 million at December 31, 2025 compared to $372.5 million at December 31, 2024.
Book value per common share was $27.92 at December 31, 2025 compared to $24.75 at December 31, 2024. Book value per diluted share, excluding accumulated other comprehensive income (loss) (2), was $38.81 at December 31, 2025 compared to $37.35 at December 31, 2024.
The debt-to-capital ratio was 33.6% and 42.2% at December 31, 2025 and 2024, respectively. Our debt-to-total capital ratio, excluding accumulated other comprehensive income (loss)(3), was 26.2% and 32.1% at December 31, 2025 and 2024, respectively. The reduction in the ratios from December 31, 2024 was primarily due to the repayment of the 2025 Notes in 2Q25.
Return on equity for the trailing four quarters ended December 31, 2025 and 2024 was 8.9% and 17.1%, respectively. Operating return on equity, excluding significant items(5), for the trailing four quarters ended December 31, 2025 and 2024 was 11.4%.
In this news release, CNO includes non-GAAP measures to enhance investors’ understanding of management’s view of the business. The non-GAAP measures are not a substitute for GAAP, but rather a supplement to increase transparency by providing a broader perspective. CNO’s definitions of non-GAAP measures may differ from other companies’ definitions. More detailed information including various GAAP and non-GAAP measurements are located at CNOinc.com in the Investors section under SEC Filings.
CAUTION REGARDING FORWARD-LOOKING STATEMENTS:
This press release may contain forward-looking statements within the meaning of federal securities laws. These prospective statements reflect management’s current expectations, but are not guarantees of future performance. Accordingly, please refer to CNO’s cautionary statement regarding forward-looking statements, and the business environment in which the Company operates, contained in the Company’s Form 10-K for the year ended December 31, 2024 and any subsequent Form 10-Q or Form 10-K on file with the Securities and Exchange Commission and on the Company’s website at CNOinc.com in the Investors section. CNO specifically disclaims any obligation to update or revise any forward-looking statement because of new information, future developments or otherwise.
EARNINGS RELEASE CONFERENCE CALL WEBCAST:
The Company will host a conference call to discuss results on February 6, 2026 at 11:00 a.m. Eastern Time. During the call, we will be referring to a presentation that will be available at the Investors section of the company's website.
To participate by dial-in, please register at https://events.q4inc.com/analyst/745932136?pwd=4a24Aol9. Upon registering, you will be provided with call details and a registrant ID used to track attendance on the conference call. Reminders will also be sent to registered participants via email.
For those investors who prefer to listen to the call online, we will be broadcasting the call live via webcast. The event can be accessed through the Investors section of the company's website: ir.CNOinc.com. Participants should go to the website at least 15 minutes before the event to register and download any necessary audio software.
ABOUT CNO FINANCIAL GROUP
CNO Financial Group, Inc. (NYSE: CNO) secures the future of middle-income America. CNO provides life and health insurance, annuities, and financial services through our family of brands, including Bankers Life, Colonial Penn, Optavise and Washington National. Our customers work hard to save for the future, and we help protect their health, income and retirement needs with 3.2 million policies and $38.8 billion in total assets. Our 3,300 associates, 5,000 exclusive agents and more than 7,000 independent partner agents guide individuals, families and businesses through a lifetime of financial decisions. For more information, visit CNOinc.com.
6
CNO FINANCIAL GROUP, INC. AND SUBSIDIARIES
CONSOLIDATED STATEMENT OF OPERATIONS
(Dollars in millions, except per share data)
(unaudited)
| Three months ended | Year ended | ||||||||||||||||||||||
| December 31, | December 31, | ||||||||||||||||||||||
| 2025 | 2024 | 2025 | 2024 | ||||||||||||||||||||
| Revenues: | |||||||||||||||||||||||
| Insurance policy income | $ | 662.2 | $ | 643.6 | $ | 2,622.6 | $ | 2,558.5 | |||||||||||||||
| Net investment income: | |||||||||||||||||||||||
| General account assets | 406.1 | 399.5 | 1,542.4 | 1,419.4 | |||||||||||||||||||
| Policyholder and other special-purpose portfolios | 22.4 | 17.1 | 181.0 | 329.4 | |||||||||||||||||||
| Investment gains (losses): | |||||||||||||||||||||||
| Realized investment losses | (21.6) | (26.2) | (59.6) | (75.6) | |||||||||||||||||||
| Other investment gains (losses) | (4.9) | (15.5) | 4.9 | 25.7 | |||||||||||||||||||
Total investment losses | (26.5) | (41.7) | (54.7) | (49.9) | |||||||||||||||||||
| Fee revenue and other income | 78.9 | 78.7 | 196.1 | 192.1 | |||||||||||||||||||
| Total revenues | 1,143.1 | 1,097.2 | 4,487.4 | 4,449.5 | |||||||||||||||||||
| Benefits and expenses: | |||||||||||||||||||||||
| Insurance policy benefits | 617.7 | 508.3 | 2,548.2 | 2,450.3 | |||||||||||||||||||
Liability for future policy benefits remeasurement loss | (14.9) | (12.0) | (70.7) | (41.1) | |||||||||||||||||||
| Change in fair value of market risk benefits | (4.4) | (14.9) | (12.4) | (60.5) | |||||||||||||||||||
| Interest expense | 53.2 | 62.0 | 230.9 | 254.4 | |||||||||||||||||||
| Amortization of deferred acquisition costs and present value of future profits | 72.1 | 65.3 | 278.0 | 251.2 | |||||||||||||||||||
Goodwill and other asset impairment | 5.2 | — | 101.9 | — | |||||||||||||||||||
Gain on extinguishment of borrowings related to variable interest entities | — | — | (1.5) | — | |||||||||||||||||||
| Other operating costs and expenses | 302.8 | 256.4 | 1,119.6 | 1,055.3 | |||||||||||||||||||
| Total benefits and expenses | 1,031.7 | 865.1 | 4,194.0 | 3,909.6 | |||||||||||||||||||
| Income before income taxes | 111.4 | 232.1 | 293.4 | 539.9 | |||||||||||||||||||
| Income tax expense | 18.5 | 49.2 | 64.1 | 119.1 | |||||||||||||||||||
| Net income | $ | 92.9 | $ | 182.9 | $ | 229.3 | $ | 420.8 | |||||||||||||||
| Earnings per common share: | |||||||||||||||||||||||
| Basic: | |||||||||||||||||||||||
| Weighted average shares outstanding | 95,136,000 | 102,778,000 | 97,763,000 | 106,144,000 | |||||||||||||||||||
| Net income | $ | 0.98 | $ | 1.78 | $ | 2.35 | $ | 3.96 | |||||||||||||||
| Diluted: | |||||||||||||||||||||||
| Weighted average shares outstanding | 97,278,000 | 105,230,000 | 99,822,000 | 108,116,000 | |||||||||||||||||||
| Net income | $ | 0.95 | $ | 1.74 | $ | 2.30 | $ | 3.89 | |||||||||||||||
NOTES
(1)Management believes that an analysis of net income applicable to common stock before: (i) net realized investment gains or losses from disposals, impairments and the change in allowance for credit losses, net of taxes; (ii) net change in market value of investments recognized in earnings, net of taxes; (iii) changes in fair value of embedded derivative liabilities and market risk benefits related to our fixed indexed annuities, net of taxes; (iv) fair value changes related to the agent deferred
compensation plan, net of taxes; (v) gains or losses related to material reinsurance transactions, net of taxes; (vi) loss on
extinguishment of debt, net of taxes; (vii) changes in the valuation allowance for deferred tax assets and other tax items; (viii) costs related to our three-year project to modernize certain elements of our technology ("TechMod") that are incremental to normal spend and will not recur following implementation, net of taxes; (ix) goodwill and other asset impairment expenses, net of taxes; (x) gains or losses related to divested business, net of taxes; and (xi) other non-operating items including earnings attributable to variable interest entities, net of taxes ("net operating income," a non-GAAP financial measure) is important to evaluate the financial performance of the company, and is a key measure commonly used in the life insurance industry. The income tax expense or benefit allocated to the items included in net non-operating income (loss) represents the current and deferred income tax expense or benefit allocated to the items included in non-operating earnings. Management believes this information helps provide a better understanding of the business and a more meaningful analysis of results of our insurance product lines. A reconciliation of net operating income to net income applicable to common stock is provided in the table on page 2 and page 3. Additional information concerning this non-
7
GAAP measure is included in our periodic filings with the Securities and Exchange Commission that are available on CNO's website, CNOinc.com, in the Investors section under SEC Filings.
(2)Book value per diluted share reflects the potential dilution that could occur if outstanding stock options were exercised and restricted stock and performance units were vested. The dilution from options, restricted shares and performance units is calculated using the treasury stock method. Under this method, we assume the proceeds from the exercise of the options (or the unrecognized compensation expense with respect to restricted stock and performance units) will be used to purchase shares of our common stock at the closing market price on the last day of the period. In addition, the calculation of this non-GAAP measure differs from the corresponding GAAP measure because accumulated other comprehensive income (loss) has been excluded from the value of capital used to determine this measure. Management believes this non-GAAP measure is useful because it removes the volatility that arises from changes in the unrealized appreciation (depreciation) of our investments.
(3)The calculation of this non-GAAP measure differs from the corresponding GAAP measure because accumulated other comprehensive income (loss) has been excluded from the value of capital used to determine this measure. Management believes this non-GAAP measure is useful because it removes the volatility that arises from changes in the unrealized appreciation (depreciation) of our investments.
(4)Measured by new annualized premiums for life and health products, which includes 10% of single premium whole life deposits and 100% of all other premiums (excluding annuities). Sales of third-party products are excluded.
(5)Operating return on equity and operating return on equity, excluding significant items are calculated as follows: (i) operating return on equity is equal to the trailing four quarters of net operating income(1) divided by average shareholders' equity, excluding accumulated other comprehensive income (loss) and net operating loss carryforwards, for the trailing four quarters; and (ii) operating return on equity, excluding significant items is equal to the trailing four quarters of net operating income(1), excluding significant items, divided by average shareholders' equity, excluding accumulated other comprehensive income (loss) and net operating loss carryforwards, for the trailing four quarters.
8
The following summarizes: (i) net operating income; (ii) significant items; (iii) net operating income, excluding significant items; and (iv) net income (loss) (dollars in millions):
| Net operating | ||||||||||||||||||||||||||||||||||||||
| Net operating | income, | |||||||||||||||||||||||||||||||||||||
| income, | excluding | Net | ||||||||||||||||||||||||||||||||||||
| excluding | significant | income - | ||||||||||||||||||||||||||||||||||||
| Net operating | Significant | significant | items - trailing | Net | trailing | |||||||||||||||||||||||||||||||||
| income | items | items (a) | four quarters | income (loss) | four quarters | |||||||||||||||||||||||||||||||||
| 1Q24 | $ | 57.5 | $ | — | $ | 57.5 | $ | 311.7 | $ | 112.3 | $ | 389.6 | ||||||||||||||||||||||||||
| 2Q24 | 114.6 | — | 114.6 | 364.0 | 116.3 | 432.2 | ||||||||||||||||||||||||||||||||
| 3Q24 | 119.2 | (21.9) | (b) | 97.3 | 376.9 | 9.3 | 274.2 | |||||||||||||||||||||||||||||||
| 4Q24 | 138.0 | 3.1 | (c) | 141.1 | 410.5 | 182.9 | 420.8 | |||||||||||||||||||||||||||||||
| 1Q25 | 81.1 | (5.3) | (d) | 75.8 | 428.8 | 21.5 | 330.0 | |||||||||||||||||||||||||||||||
| 2Q25 | 87.5 | — | 87.5 | 401.7 | 91.8 | 305.5 | ||||||||||||||||||||||||||||||||
| 3Q25 | 127.2 | (32.2) | (e) | 95.0 | 399.4 | 23.1 | 319.3 | |||||||||||||||||||||||||||||||
| 4Q25 | 143.4 | — | 143.4 | 401.7 | 92.9 | 229.3 | ||||||||||||||||||||||||||||||||
| (a) See note (6) for additional information. | ||||||||||||||||||||||||||||||||||||||
| (b) Comprised of $31.2 million of the net favorable impact arising from our comprehensive annual actuarial review and $2.9 million of the unfavorable impact related to a fixed asset impairment, net of tax expense of $6.4 million. | ||||||||||||||||||||||||||||||||||||||
| (c) Comprised of $3.9 million of the unfavorable impact arising from our comprehensive annual actuarial review, net of tax expense of $0.8 million. | ||||||||||||||||||||||||||||||||||||||
| (d) Comprised of $6.8 million of the favorable impact of an out-of-period adjustment which decreased reserves, net of tax expense of $1.5 million. | ||||||||||||||||||||||||||||||||||||||
| (e) Comprised of $41.3 million of the net favorable impact arising from our comprehensive annual actuarial review, net of tax expense of $9.1 million. | ||||||||||||||||||||||||||||||||||||||
A reconciliation of pre-tax operating earnings (a non-GAAP financial measure) to net income is as follows (dollars in millions):
| Year ended December 31, | |||||||||||||||||
| 4Q25 | 4Q24 | ||||||||||||||||
| Pre-tax operating earnings (a non-GAAP financial measure) | $ | 553.2 | $ | 550.8 | |||||||||||||
| Income tax expense | (114.0) | (121.5) | |||||||||||||||
| Net operating income | 439.2 | 429.3 | |||||||||||||||
| Non-operating items: | |||||||||||||||||
Net realized investment losses from disposals, impairments and change in allowance for credit losses | (69.0) | (72.7) | |||||||||||||||
| Net change in market value of investments recognized in earnings | 14.3 | 22.8 | |||||||||||||||
| Changes in fair value of embedded derivative liabilities and market risk benefits | (64.0) | 46.3 | |||||||||||||||
| Fair value changes related to the agent deferred compensation plan | (1.7) | 6.6 | |||||||||||||||
Expenses related to TechMod initiative | (20.3) | — | |||||||||||||||
Goodwill and other asset impairment | (101.9) | — | |||||||||||||||
| Net loss related to divested business | (17.3) | — | |||||||||||||||
| Other | 0.1 | (13.9) | |||||||||||||||
| Non-operating loss before taxes | (259.8) | (10.9) | |||||||||||||||
| Income tax benefit on non-operating loss | 49.9 | 2.4 | |||||||||||||||
| Net non-operating loss | (209.9) | (8.5) | |||||||||||||||
| Net income | $ | 229.3 | $ | 420.8 | |||||||||||||
9
A reconciliation of consolidated capital, excluding accumulated other comprehensive income (loss) and net operating loss carryforwards (a non-GAAP financial measure) to common shareholders’ equity, is as follows (dollars in millions):
| 1Q23 | 2Q23 | 3Q23 | 4Q23 | ||||||||||||||||||||||||||
| Consolidated capital, excluding accumulated other comprehensive | |||||||||||||||||||||||||||||
| income (loss) and net operating loss carryforwards | |||||||||||||||||||||||||||||
| (a non-GAAP financial measure) | $ | 3,543.8 | $ | 3,603.0 | $ | 3,744.2 | $ | 3,712.8 | |||||||||||||||||||||
| Net operating loss carryforwards | 152.4 | 126.3 | 102.6 | 79.6 | |||||||||||||||||||||||||
| Accumulated other comprehensive loss | (1,664.4) | (1,733.5) | (1,956.7) | (1,576.8) | |||||||||||||||||||||||||
| Common shareholders' equity | $ | 2,031.8 | $ | 1,995.8 | $ | 1,890.1 | $ | 2,215.6 | |||||||||||||||||||||
| 1Q24 | 2Q24 | 3Q24 | 4Q24 | ||||||||||||||||||||||||||
| Consolidated capital, excluding accumulated other comprehensive | |||||||||||||||||||||||||||||
| income (loss) and net operating loss carryforwards | |||||||||||||||||||||||||||||
| (a non-GAAP financial measure) | $ | 3,536.8 | $ | 3,596.7 | $ | 3,529.9 | $ | 3,810.0 | |||||||||||||||||||||
| Net operating loss carryforwards | 311.2 | 296.5 | 273.9 | 76.6 | |||||||||||||||||||||||||
| Accumulated other comprehensive loss | (1,480.3) | (1,464.3) | (1,116.0) | (1,371.4) | |||||||||||||||||||||||||
| Common shareholders' equity | $ | 2,367.7 | $ | 2,428.9 | $ | 2,687.8 | $ | 2,515.2 | |||||||||||||||||||||
| 1Q25 | 2Q25 | 3Q25 | 4Q25 | ||||||||||||||||||||||||||
| Consolidated capital, excluding accumulated other comprehensive | |||||||||||||||||||||||||||||
| income (loss) and net operating loss carryforwards | |||||||||||||||||||||||||||||
| (a non-GAAP financial measure) | $ | 3,498.9 | $ | 3,504.3 | $ | 3,483.6 | $ | 3,510.2 | |||||||||||||||||||||
| Net operating loss carryforwards | 295.3 | 271.1 | 246.3 | 243.0 | |||||||||||||||||||||||||
| Accumulated other comprehensive loss | (1,239.1) | (1,252.7) | (1,118.9) | (1,115.0) | |||||||||||||||||||||||||
| Common shareholders' equity | $ | 2,555.1 | $ | 2,522.7 | $ | 2,611.0 | $ | 2,638.2 | |||||||||||||||||||||
A reconciliation of consolidated capital, excluding accumulated other comprehensive loss and net operating loss carryforwards (a non-GAAP financial measure) to common shareholders’ equity, is as follows (dollars in millions):
| Trailing four quarter average | ||||||||||||||
| 4Q25 | 4Q24 | |||||||||||||
| Consolidated capital, excluding accumulated other comprehensive | ||||||||||||||
| income (loss) and net operating loss carryforwards | ||||||||||||||
| (a non-GAAP financial measure) | $ | 3,536.7 | $ | 3,606.2 | ||||||||||
| Net operating loss carryforwards | 243.1 | 240.0 | ||||||||||||
| Accumulated other comprehensive loss | (1,213.4) | (1,383.7) | ||||||||||||
| Common shareholders' equity | $ | 2,566.4 | $ | 2,462.5 | ||||||||||
10
(6) The tables below summarize the financial impact of significant items on our net operating income. Management believes that identifying the impact of these items enhances the understanding of our operating results (dollars in millions, except per share data).
| Year ended | ||||||||||||||||||||
| December 31, 2025 | ||||||||||||||||||||
| Actual results | Significant items | Excluding significant items | ||||||||||||||||||
Insurance product margin | ||||||||||||||||||||
| Annuity margin | $ | 238.6 | $ | (16.6) | (a) | $ | 222.0 | |||||||||||||
| Health margin | 556.6 | (21.1) | (a) | 535.5 | ||||||||||||||||
| Life margin | 272.4 | (10.4) | (a) | 262.0 | ||||||||||||||||
| Total insurance product margin | 1,067.6 | (48.1) | 1,019.5 | |||||||||||||||||
| Allocated expenses | (611.3) | — | (611.3) | |||||||||||||||||
Income from insurance products | 456.3 | (48.1) | 408.2 | |||||||||||||||||
| Fee income | 15.2 | — | 15.2 | |||||||||||||||||
Investment income not allocated to product lines | 169.4 | — | 169.4 | |||||||||||||||||
| Expenses not allocated to product lines | (87.7) | — | (87.7) | |||||||||||||||||
| Operating earnings before taxes | 553.2 | (48.1) | 505.1 | |||||||||||||||||
| Income tax (expense) benefit on operating income | (114.0) | 10.6 | (103.4) | |||||||||||||||||
Net operating income | $ | 439.2 | $ | (37.5) | $ | 401.7 | ||||||||||||||
| Net operating income per diluted share | $ | 4.40 | $ | (0.38) | $ | 4.02 | ||||||||||||||
___________
(a)Comprised of $41.3 million of the net favorable impact arising from our comprehensive annual actuarial review during 3Q25 and $6.8 million of the favorable impact of an out-of-period adjustment which decreased reserves, during 1Q25.
Three months ended | ||||||||||||||||||||
| September 30, 2025 | ||||||||||||||||||||
| Actual results | Significant items | Excluding significant items | ||||||||||||||||||
Insurance product margin | ||||||||||||||||||||
| Annuity margin | $ | 72.9 | $ | (16.6) | (a) | $ | 56.3 | |||||||||||||
| Health margin | 157.0 | (21.1) | (a) | 135.9 | ||||||||||||||||
| Life margin | 70.6 | (3.6) | (a) | 67.0 | ||||||||||||||||
| Total insurance product margin | 300.5 | (41.3) | 259.2 | |||||||||||||||||
| Allocated expenses | (151.0) | — | (151.0) | |||||||||||||||||
Income from insurance products | 149.5 | (41.3) | 108.2 | |||||||||||||||||
| Fee income | (3.9) | — | (3.9) | |||||||||||||||||
Investment income not allocated to product lines | 39.5 | — | 39.5 | |||||||||||||||||
| Expenses not allocated to product lines | (22.3) | — | (22.3) | |||||||||||||||||
| Operating earnings before taxes | 162.8 | (41.3) | 121.5 | |||||||||||||||||
| Income tax (expense) benefit on operating income | (35.6) | 9.1 | (26.5) | |||||||||||||||||
Net operating income | $ | 127.2 | $ | (32.2) | $ | 95.0 | ||||||||||||||
| Net operating income per diluted share | $ | 1.29 | $ | (0.33) | $ | 0.96 | ||||||||||||||
___________
(a)Comprised of $41.3 million of the net favorable impact arising from our comprehensive annual actuarial review.
11
Three months ended | ||||||||||||||||||||
| March 31, 2025 | ||||||||||||||||||||
| Actual results | Significant items | Excluding significant items | ||||||||||||||||||
Insurance product margin | ||||||||||||||||||||
| Annuity margin | $ | 54.5 | $ | — | $ | 54.5 | ||||||||||||||
| Health margin | 126.2 | — | 126.2 | |||||||||||||||||
| Life margin | 68.2 | (6.8) | (a) | 61.4 | ||||||||||||||||
| Total insurance product margin | 248.9 | (6.8) | 242.1 | |||||||||||||||||
| Allocated expenses | (161.2) | — | (161.2) | |||||||||||||||||
Income from insurance products | 87.7 | (6.8) | 80.9 | |||||||||||||||||
| Fee income | (0.8) | — | (0.8) | |||||||||||||||||
Investment income not allocated to product lines | 38.0 | — | 38.0 | |||||||||||||||||
| Expenses not allocated to product lines | (20.3) | — | (20.3) | |||||||||||||||||
| Operating earnings before taxes | 104.6 | (6.8) | 97.8 | |||||||||||||||||
| Income tax (expense) benefit on operating income | (23.5) | 1.5 | (22.0) | |||||||||||||||||
Net operating income | $ | 81.1 | $ | (5.3) | $ | 75.8 | ||||||||||||||
| Net operating income per diluted share | $ | 0.79 | $ | (0.05) | $ | 0.74 | ||||||||||||||
___________
(a)Comprised of $6.8 million of the favorable impact of an out-of-period adjustment, which decreased reserves.
Year ended | ||||||||||||||||||||
| December 31, 2024 | ||||||||||||||||||||
| Actual results | Significant items | Excluding significant items | ||||||||||||||||||
Insurance product margin | ||||||||||||||||||||
| Annuity margin | $ | 274.2 | $ | (36.2) | (a) | $ | 238.0 | |||||||||||||
| Health margin | 516.8 | 8.2 | (a) | 525.0 | ||||||||||||||||
| Life margin | 249.0 | 0.7 | (a) | 249.7 | ||||||||||||||||
| Total insurance product margin | 1,040.0 | (27.3) | 1,012.7 | |||||||||||||||||
| Allocated expenses | (615.3) | — | (615.3) | |||||||||||||||||
Income from insurance products | 424.7 | (27.3) | 397.4 | |||||||||||||||||
| Fee income | 30.0 | — | 30.0 | |||||||||||||||||
Investment income not allocated to product lines | 167.9 | — | 167.9 | |||||||||||||||||
| Expenses not allocated to product lines | (71.8) | 2.9 | (b) | (68.9) | ||||||||||||||||
| Operating earnings before taxes | 550.8 | (24.4) | 526.4 | |||||||||||||||||
| Income tax (expense) benefit on operating income | (121.5) | 5.6 | (115.9) | |||||||||||||||||
Net operating income | $ | 429.3 | $ | (18.8) | $ | 410.5 | ||||||||||||||
| Net operating income per diluted share | $ | 3.97 | $ | (0.17) | $ | 3.80 | ||||||||||||||
___________
(a)Comprised of $27.3 million of net favorable impact arising from our comprehensive annual actuarial review.
(b)Comprised of $2.9 million of the unfavorable impact related to a fixed asset impairment.
12
| Three months ended | ||||||||||||||||||||
| December 31, 2024 | ||||||||||||||||||||
| Actual results | Significant items | Excluding significant items | ||||||||||||||||||
| Insurance product margin | ||||||||||||||||||||
| Annuity margin | $ | 55.0 | $ | — | $ | 55.0 | ||||||||||||||
| Health margin | 130.1 | 3.9 | (a) | 134.0 | ||||||||||||||||
| Life margin | 68.0 | — | 68.0 | |||||||||||||||||
| Total insurance product margin | 253.1 | 3.9 | 257.0 | |||||||||||||||||
| Allocated expenses | (146.1) | — | (146.1) | |||||||||||||||||
| Income from insurance products | 107.0 | 3.9 | 110.9 | |||||||||||||||||
| Fee income | 20.6 | — | 20.6 | |||||||||||||||||
| Investment income not allocated to product lines | 65.3 | — | 65.3 | |||||||||||||||||
| Expenses not allocated to product lines | (19.0) | — | (19.0) | |||||||||||||||||
| Operating earnings before taxes | 173.9 | 3.9 | 177.8 | |||||||||||||||||
| Income tax (expense) benefit on operating income | (35.9) | (0.8) | (36.7) | |||||||||||||||||
| Net operating income | $ | 138.0 | $ | 3.1 | $ | 141.1 | ||||||||||||||
| Net operating income per diluted share | $ | 1.31 | $ | 0.03 | $ | 1.34 | ||||||||||||||
___________
(a)Comprised of $3.9 million of the unfavorable impact arising from our comprehensive annual actuarial review.
| Three months ended | ||||||||||||||||||||
| September 30, 2024 | ||||||||||||||||||||
| Actual results | Significant items (a) | Excluding significant items | ||||||||||||||||||
| Insurance product margin | ||||||||||||||||||||
| Annuity margin | $ | 91.1 | $ | (36.2) | (b) | $ | 54.9 | |||||||||||||
| Health margin | 127.8 | 4.3 | (b) | 132.1 | ||||||||||||||||
| Life margin | 63.3 | 0.7 | (b) | 64.0 | ||||||||||||||||
| Total insurance product margin | 282.2 | (31.2) | 251.0 | |||||||||||||||||
| Allocated expenses | (153.0) | — | (153.0) | |||||||||||||||||
| Income from insurance products | 129.2 | (31.2) | 98.0 | |||||||||||||||||
| Fee income | (2.7) | — | (2.7) | |||||||||||||||||
| Investment income not allocated to product lines | 45.5 | — | 45.5 | |||||||||||||||||
| Expenses not allocated to product lines | (18.5) | 2.9 | (c) | (15.6) | ||||||||||||||||
| Operating earnings before taxes | 153.5 | (28.3) | 125.2 | |||||||||||||||||
| Income tax (expense) benefit on operating income | (34.3) | 6.4 | (27.9) | |||||||||||||||||
| Net operating income | $ | 119.2 | $ | (21.9) | $ | 97.3 | ||||||||||||||
| Net operating income per diluted share | $ | 1.11 | $ | (0.19) | $ | 0.92 | ||||||||||||||
___________
(a)Significant items impacting the health margin were revised from $8.2 million reported in September 30, 2024 to $4.3 million.
(b)Comprised of $31.2 million of net favorable impact arising from our comprehensive annual actuarial review.
(c)Comprised of $2.9 million of the unfavorable impact related to a fixed asset impairment.
For further information:
CNO News Media
Valerie Dolenga
CNO Investor Relations
Adam Auvil
13

Quarterly Financial Supplement - 4Q25 | |||||||||||||||||
| February 5, 2026 | |||||||||||||||||
Page 1
| Table of Contents | Page | |||||||||||||
| Consolidated balance sheet | 3 | |||||||||||||
| Consolidated statement of operations | 4 | |||||||||||||
| Financial summary | 5 | |||||||||||||
| Insurance operations | 6 | |||||||||||||
| Margin from insurance products | 7-9 | |||||||||||||
| Collected premiums and insurance policy income | 10 | |||||||||||||
| Health and life new annualized premiums | 11 | |||||||||||||
| Computation of weighted average shares outstanding | 12 | |||||||||||||
| Annuities - account value rollforwards | 13 | |||||||||||||
| Consolidated statutory information of U.S. based insurance subsidiaries | 14 | |||||||||||||
| Investment income not allocated to product lines and investment income allocated to product lines | 15-16 | |||||||||||||
| Other investment data | 17 | |||||||||||||
| Significant items | 18-19 | |||||||||||||
| Notes | 20-21 | |||||||||||||
Page 2
CNO FINANCIAL GROUP, INC.
CONSOLIDATED BALANCE SHEET
(Dollars in millions)
(Unaudited)
| Mar-24 | Jun-24 | Sep-24 | Dec-24 | Mar-25 | Jun-25 | Sep-25 | Dec-25 | ||||||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||||||||
| Investments: | |||||||||||||||||||||||||||||||||||||||||||||||
| Fixed maturities, available for sale, at fair value | $ | 21,648.1 | $ | 22,617.9 | $ | 23,724.7 | $ | 22,730.1 | $ | 23,283.0 | $ | 23,047.0 | $ | 23,405.3 | $ | 23,886.8 | |||||||||||||||||||||||||||||||
Equity securities at fair value | 118.4 | 117.7 | 120.5 | 272.4 | 349.1 | 387.4 | 377.2 | 389.2 | |||||||||||||||||||||||||||||||||||||||
| Mortgage loans | 2,087.1 | 2,176.0 | 2,372.7 | 2,506.3 | 2,601.2 | 2,834.3 | 3,042.7 | 3,256.8 | |||||||||||||||||||||||||||||||||||||||
| Policy loans | 130.3 | 131.3 | 133.3 | 135.3 | 136.4 | 137.6 | 141.2 | 140.9 | |||||||||||||||||||||||||||||||||||||||
| Trading securities | 222.8 | 207.8 | 217.4 | 304.2 | 308.0 | 308.3 | 296.9 | 294.8 | |||||||||||||||||||||||||||||||||||||||
| Investments held by variable interest entities | 533.4 | 425.5 | 250.1 | 433.8 | 380.2 | 376.9 | 296.8 | 293.0 | |||||||||||||||||||||||||||||||||||||||
| Other invested assets | 1,471.3 | 1,554.0 | 1,595.5 | 1,491.5 | 1,386.7 | 1,500.5 | 1,617.0 | 1,737.0 | |||||||||||||||||||||||||||||||||||||||
Total investments | 26,211.4 | 27,230.2 | 28,414.2 | 27,873.6 | 28,444.6 | 28,592.0 | 29,177.1 | 29,998.5 | |||||||||||||||||||||||||||||||||||||||
| Cash and cash equivalents - unrestricted | 566.3 | 878.8 | 1,164.7 | 1,656.7 | 928.2 | 766.0 | 1,218.3 | 956.1 | |||||||||||||||||||||||||||||||||||||||
| Cash and cash equivalents held by variable interest entities | 83.5 | 113.3 | 80.6 | 341.0 | 96.6 | 50.0 | 23.3 | 27.4 | |||||||||||||||||||||||||||||||||||||||
| Accrued investment income | 252.0 | 262.5 | 276.2 | 286.4 | 289.6 | 279.4 | 282.0 | 286.0 | |||||||||||||||||||||||||||||||||||||||
| Present value of future profits | 175.5 | 170.4 | 165.7 | 161.0 | 156.5 | 152.1 | 147.8 | 143.6 | |||||||||||||||||||||||||||||||||||||||
| Deferred acquisition costs | 1,992.3 | 2,047.2 | 2,100.9 | 2,158.6 | 2,209.9 | 2,276.3 | 2,343.7 | 2,397.3 | |||||||||||||||||||||||||||||||||||||||
| Reinsurance receivables | 3,969.0 | 3,910.9 | 3,906.7 | 3,854.7 | 3,804.3 | 3,753.9 | 3,731.7 | 3,677.5 | |||||||||||||||||||||||||||||||||||||||
Income tax assets, net | 886.1 | 882.8 | 788.7 | 814.1 | 768.0 | 749.3 | 708.1 | 713.3 | |||||||||||||||||||||||||||||||||||||||
| Assets held in separate accounts | 3.3 | 3.2 | 3.3 | 3.3 | 3.1 | 2.9 | 2.7 | 2.8 | |||||||||||||||||||||||||||||||||||||||
| Other assets | 716.2 | 706.4 | 648.0 | 699.9 | 728.4 | 707.2 | 661.5 | 588.1 | |||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 34,855.6 | $ | 36,205.7 | $ | 37,549.0 | $ | 37,849.3 | $ | 37,429.2 | $ | 37,329.1 | $ | 38,296.2 | $ | 38,790.6 | |||||||||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities for insurance products: | |||||||||||||||||||||||||||||||||||||||||||||||
| Policyholder account balances | $ | 15,361.1 | $ | 16,247.9 | $ | 16,992.4 | $ | 17,594.2 | $ | 17,314.3 | $ | 17,609.0 | $ | 18,290.3 | $ | 18,912.6 | |||||||||||||||||||||||||||||||
| Future policy benefits | 11,932.2 | 11,695.1 | 12,258.2 | 11,705.5 | 11,773.0 | 11,787.7 | 11,975.5 | 11,898.0 | |||||||||||||||||||||||||||||||||||||||
| Market risk benefit liability | 99.6 | 93.0 | 74.1 | 60.0 | 73.6 | 63.8 | 52.6 | 48.1 | |||||||||||||||||||||||||||||||||||||||
| Liability for life insurance policy claims | 65.1 | 59.6 | 59.9 | 61.1 | 63.5 | 60.7 | 61.5 | 58.4 | |||||||||||||||||||||||||||||||||||||||
| Unearned and advanced premiums | 226.0 | 220.9 | 217.4 | 226.8 | 221.5 | 217.3 | 214.5 | 228.0 | |||||||||||||||||||||||||||||||||||||||
| Liabilities related to separate accounts | 3.3 | 3.2 | 3.3 | 3.3 | 3.1 | 2.9 | 2.7 | 2.8 | |||||||||||||||||||||||||||||||||||||||
| Other liabilities | 905.0 | 934.4 | 951.0 | 1,163.3 | 1,027.2 | 935.8 | 1,036.9 | 952.8 | |||||||||||||||||||||||||||||||||||||||
| Investment borrowings | 2,189.1 | 2,189.0 | 2,188.9 | 2,188.8 | 2,188.6 | 2,441.7 | 2,441.7 | 2,441.7 | |||||||||||||||||||||||||||||||||||||||
| Borrowings related to variable interest entities | 565.5 | 501.4 | 283.1 | 497.6 | 375.1 | 352.8 | 274.3 | 274.4 | |||||||||||||||||||||||||||||||||||||||
| Notes payable - direct corporate obligations | 1,141.0 | 1,832.3 | 1,832.9 | 1,833.5 | 1,834.2 | 1,334.7 | 1,335.2 | 1,335.6 | |||||||||||||||||||||||||||||||||||||||
| Total liabilities | 32,487.9 | 33,776.8 | 34,861.2 | 35,334.1 | 34,874.1 | 34,806.4 | 35,685.2 | 36,152.4 | |||||||||||||||||||||||||||||||||||||||
| Shareholders' equity | |||||||||||||||||||||||||||||||||||||||||||||||
| Common stock | 1.1 | 1.1 | 1.0 | 1.0 | 1.0 | 1.0 | 1.0 | 0.9 | |||||||||||||||||||||||||||||||||||||||
| Additional paid-in capital | 1,851.2 | 1,797.6 | 1,715.9 | 1,632.5 | 1,535.0 | 1,441.4 | 1,389.4 | 1,336.3 | |||||||||||||||||||||||||||||||||||||||
Retained earnings | 1,995.7 | 2,094.5 | 2,086.9 | 2,253.1 | 2,258.2 | 2,333.0 | 2,339.5 | 2,416.0 | |||||||||||||||||||||||||||||||||||||||
| Total shareholders' equity before accumulated other comprehensive loss | 3,848.0 | 3,893.2 | 3,803.8 | 3,886.6 | 3,794.2 | 3,775.4 | 3,729.9 | 3,753.2 | |||||||||||||||||||||||||||||||||||||||
| Accumulated other comprehensive loss | (1,480.3) | (1,464.3) | (1,116.0) | (1,371.4) | (1,239.1) | (1,252.7) | (1,118.9) | (1,115.0) | |||||||||||||||||||||||||||||||||||||||
| Total shareholders' equity | 2,367.7 | 2,428.9 | 2,687.8 | 2,515.2 | 2,555.1 | 2,522.7 | 2,611.0 | 2,638.2 | |||||||||||||||||||||||||||||||||||||||
| Total liabilities and shareholders' equity | $ | 34,855.6 | $ | 36,205.7 | $ | 37,549.0 | $ | 37,849.3 | $ | 37,429.2 | $ | 37,329.1 | $ | 38,296.2 | $ | 38,790.6 | |||||||||||||||||||||||||||||||
| Book value per common share | $ | 21.81 | $ | 22.80 | $ | 25.86 | $ | 24.75 | $ | 25.58 | $ | 25.92 | $ | 27.24 | $ | 27.92 | |||||||||||||||||||||||||||||||
| Book value per common share, excluding accumulated other comprehensive loss (1) (2) | $ | 35.44 | $ | 36.55 | $ | 36.60 | $ | 38.25 | $ | 37.98 | $ | 38.79 | $ | 38.92 | $ | 39.72 | |||||||||||||||||||||||||||||||
| Book value per diluted share, excluding accumulated other comprehensive loss (1) (3) | $ | 34.97 | $ | 36.00 | $ | 35.84 | $ | 37.35 | $ | 37.27 | $ | 38.05 | $ | 38.10 | $ | 38.81 | |||||||||||||||||||||||||||||||
Page 3
CNO FINANCIAL GROUP, INC.
CONSOLIDATED STATEMENT OF OPERATIONS
(Dollars in millions)
(Unaudited)
| 1Q | 2Q | 3Q | 4Q | YTD | 1Q | 2Q | 3Q | 4Q | YTD | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Revenues | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy income | $ | 628.4 | $ | 641.5 | $ | 645.0 | $ | 643.6 | $ | 2,558.5 | $ | 650.7 | $ | 651.3 | $ | 658.4 | $ | 662.2 | $ | 2,622.6 | |||||||||||||||||||||||||||||||||||||||
| Net investment income: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| General account assets | 301.9 | 351.7 | 366.3 | 399.5 | 1,419.4 | 375.1 | 378.3 | 382.9 | 406.1 | 1,542.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Policyholder and other special-purpose portfolios | 167.3 | 57.4 | 87.6 | 17.1 | 329.4 | (63.6) | 105.4 | 116.8 | 22.4 | 181.0 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Investment gains (losses): | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Realized investment losses | (10.0) | (26.3) | (13.1) | (26.2) | (75.6) | (3.8) | (21.3) | (12.9) | (21.6) | (59.6) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other investment gains (losses) | 17.8 | 9.1 | 14.3 | (15.5) | 25.7 | (3.0) | 2.9 | 9.9 | (4.9) | 4.9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total investment gains (losses) | 7.8 | (17.2) | 1.2 | (41.7) | (49.9) | (6.8) | (18.4) | (3.0) | (26.5) | (54.7) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Fee revenue and other income | 51.1 | 32.8 | 29.5 | 78.7 | 192.1 | 48.7 | 34.9 | 33.6 | 78.9 | 196.1 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total revenues | 1,156.5 | 1,066.2 | 1,129.6 | 1,097.2 | 4,449.5 | 1,004.1 | 1,151.5 | 1,188.7 | 1,143.1 | 4,487.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Benefits and expenses | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy benefits | 636.6 | 574.4 | 731.0 | 508.3 | 2,450.3 | 570.0 | 658.4 | 702.1 | 617.7 | 2,548.2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Liability for future policy benefits remeasurement (gain) loss | (6.4) | (30.0) | 7.3 | (12.0) | (41.1) | (12.2) | (12.8) | (30.8) | (14.9) | (70.7) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Change in fair value of market risk benefits | (18.9) | (5.8) | (20.9) | (14.9) | (60.5) | 15.3 | (10.9) | (12.4) | (4.4) | (12.4) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Interest expense | 60.2 | 64.2 | 68.0 | 62.0 | 254.4 | 62.0 | 59.1 | 56.6 | 53.2 | 230.9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of deferred acquisition costs and present value of future profits | 60.5 | 61.4 | 64.0 | 65.3 | 251.2 | 67.4 | 68.6 | 69.9 | 72.1 | 278.0 | |||||||||||||||||||||||||||||||||||||||||||||||||
Goodwill and other asset impairment | — | — | — | — | — | — | — | 96.7 | 5.2 | 101.9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Gain on extinguishment of borrowings related to variable interest entities | — | — | — | — | — | (1.5) | — | — | — | (1.5) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other operating costs and expenses | 278.3 | 251.4 | 269.2 | 256.4 | 1,055.3 | 275.3 | 271.1 | 270.4 | 302.8 | 1,119.6 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total benefits and expenses | 1,010.3 | 915.6 | 1,118.6 | 865.1 | 3,909.6 | 976.3 | 1,033.5 | 1,152.5 | 1,031.7 | 4,194.0 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Income before income taxes | 146.2 | 150.6 | 11.0 | 232.1 | 539.9 | 27.8 | 118.0 | 36.2 | 111.4 | 293.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Income tax expense | 33.9 | 34.3 | 1.7 | 49.2 | 119.1 | 6.3 | 26.2 | 13.1 | 18.5 | 64.1 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net income | $ | 112.3 | $ | 116.3 | $ | 9.3 | $ | 182.9 | $ | 420.8 | $ | 21.5 | $ | 91.8 | $ | 23.1 | $ | 92.9 | $ | 229.3 | |||||||||||||||||||||||||||||||||||||||
Page 4
CNO FINANCIAL GROUP, INC.
FINANCIAL SUMMARY
(Dollars in millions, except per share data)
(Unaudited)
| 1Q | 2Q | 3Q | 4Q | YTD | 1Q | 2Q | 3Q | 4Q | YTD | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance product margin (4) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Annuity margin | $ | 52.0 | $ | 76.1 | $ | 91.1 | $ | 55.0 | $ | 274.2 | $ | 54.5 | $ | 54.8 | $ | 72.9 | $ | 56.4 | $ | 238.6 | |||||||||||||||||||||||||||||||||||||||
| Health margin | 123.0 | 135.9 | 127.8 | 130.1 | 516.8 | 126.2 | 134.0 | 157.0 | 139.4 | 556.6 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Life margin | 54.6 | 63.1 | 63.3 | 68.0 | 249.0 | 68.2 | 63.6 | 70.6 | 70.0 | 272.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total insurance product margin | 229.6 | 275.1 | 282.2 | 253.1 | 1,040.0 | 248.9 | 252.4 | 300.5 | 265.8 | 1,067.6 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Allocated expenses | (161.6) | (154.6) | (153.0) | (146.1) | (615.3) | (161.2) | (149.4) | (151.0) | (149.7) | (611.3) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Income from insurance products (8) | 68.0 | 120.5 | 129.2 | 107.0 | 424.7 | 87.7 | 103.0 | 149.5 | 116.1 | 456.3 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Fee income | 11.3 | 0.8 | (2.7) | 20.6 | 30.0 | (0.8) | 0.8 | (3.9) | 19.1 | 15.2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Investment income not allocated to product lines (9) | 12.3 | 44.8 | 45.5 | 65.3 | 167.9 | 38.0 | 33.8 | 39.5 | 58.1 | 169.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Expenses not allocated to product lines | (16.8) | (17.5) | (18.5) | (19.0) | (71.8) | (20.3) | (25.3) | (22.3) | (19.8) | (87.7) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Operating earnings before taxes | 74.8 | 148.6 | 153.5 | 173.9 | 550.8 | 104.6 | 112.3 | 162.8 | 173.5 | 553.2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Income tax expense on operating income | (17.3) | (34.0) | (34.3) | (35.9) | (121.5) | (23.5) | (24.8) | (35.6) | (30.1) | (114.0) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net operating income (10) | 57.5 | 114.6 | 119.2 | 138.0 | 429.3 | 81.1 | 87.5 | 127.2 | 143.4 | 439.2 | |||||||||||||||||||||||||||||||||||||||||||||||||
Net realized investment losses from disposals, impairments and change in allowance for credit losses | (4.6) | (21.9) | (11.1) | (35.1) | (72.7) | (13.2) | (21.8) | (8.8) | (25.2) | (69.0) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net change in market value of investments recognized in earnings | 12.4 | 4.7 | 12.3 | (6.6) | 22.8 | 6.4 | 3.4 | 5.8 | (1.3) | 14.3 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Fair value changes related to agent deferred compensation plan | — | 3.5 | (3.5) | 6.6 | 6.6 | — | — | — | (1.7) | (1.7) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Changes in fair value of embedded derivative liabilities and market risk benefits | 64.0 | 16.8 | (127.1) | 92.6 | 46.3 | (69.6) | 25.2 | (18.1) | (1.5) | (64.0) | |||||||||||||||||||||||||||||||||||||||||||||||||
Expenses related to TechMod initiative | — | — | — | — | — | — | (3.2) | (7.2) | (9.9) | (20.3) | |||||||||||||||||||||||||||||||||||||||||||||||||
Goodwill and other asset impairment | — | — | — | — | — | — | — | (96.7) | (5.2) | (101.9) | |||||||||||||||||||||||||||||||||||||||||||||||||
Net loss related to divested business | — | — | — | — | — | — | — | — | (17.3) | (17.3) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other | (0.4) | (1.1) | (13.1) | 0.7 | (13.9) | (0.4) | 2.1 | (1.6) | — | 0.1 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net non-operating income (loss) before taxes | 71.4 | 2.0 | (142.5) | 58.2 | (10.9) | (76.8) | 5.7 | (126.6) | (62.1) | (259.8) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Income tax (expense) benefit on non-operating income (loss) | (16.6) | (0.3) | 32.6 | (13.3) | 2.4 | 17.2 | (1.4) | 22.5 | 11.6 | 49.9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net non-operating income (loss) | 54.8 | 1.7 | (109.9) | 44.9 | (8.5) | (59.6) | 4.3 | (104.1) | (50.5) | (209.9) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net income | $ | 112.3 | $ | 116.3 | $ | 9.3 | $ | 182.9 | $ | 420.8 | $ | 21.5 | $ | 91.8 | $ | 23.1 | $ | 92.9 | $ | 229.3 | |||||||||||||||||||||||||||||||||||||||
| Per diluted share | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net operating income | $ | 0.52 | $ | 1.05 | $ | 1.11 | $ | 1.31 | $ | 3.97 | $ | 0.79 | $ | 0.87 | $ | 1.29 | $ | 1.47 | $ | 4.40 | |||||||||||||||||||||||||||||||||||||||
| Net non-operating income (loss) | 0.49 | 0.01 | (1.02) | 0.43 | (0.08) | (0.58) | 0.04 | (1.05) | (0.52) | (2.10) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net income | $ | 1.01 | $ | 1.06 | $ | 0.09 | $ | 1.74 | $ | 3.89 | $ | 0.21 | $ | 0.91 | $ | 0.24 | $ | 0.95 | $ | 2.30 | |||||||||||||||||||||||||||||||||||||||
Page 5
CNO FINANCIAL GROUP, INC.
Insurance Operations
(Dollars in millions)
(Unaudited)
| 1Q | 2Q | 3Q | 4Q | YTD | 1Q | 2Q | 3Q | 4Q | YTD | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance product margin (4) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Annuity: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy income | $ | 7.3 | $ | 9.3 | $ | 11.2 | $ | 7.7 | $ | 35.5 | $ | 9.8 | $ | 8.4 | $ | 10.7 | $ | 10.4 | $ | 39.3 | |||||||||||||||||||||||||||||||||||||||
| Net investment income (5) (6) | 134.5 | 140.5 | 142.2 | 147.8 | 565.0 | 148.0 | 155.3 | 157.7 | 160.3 | 621.3 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy benefits | (11.3) | 8.4 | 25.9 | (7.8) | 15.2 | (10.3) | (10.0) | 6.2 | (10.9) | (25.0) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Interest credited (6) | (58.3) | (61.2) | (65.2) | (69.1) | (253.8) | (68.3) | (73.4) | (75.4) | (76.4) | (293.5) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization and non-deferred commissions | (20.2) | (20.9) | (23.0) | (23.6) | (87.7) | (24.7) | (25.5) | (26.3) | (27.0) | (103.5) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Annuity margin | 52.0 | 76.1 | 91.1 | 55.0 | 274.2 | 54.5 | 54.8 | 72.9 | 56.4 | 238.6 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Health: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy income | 398.4 | 403.6 | 406.9 | 409.4 | 1,618.3 | 412.0 | 412.5 | 416.0 | 420.9 | 1,661.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net investment income (5) | 74.3 | 75.1 | 75.0 | 75.2 | 299.6 | 75.1 | 75.9 | 75.4 | 75.5 | 301.9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy benefits | (308.5) | (302.3) | (314.1) | (314.7) | (1,239.6) | (320.3) | (313.3) | (293.3) | (314.9) | (1,241.8) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization and non-deferred commissions | (41.2) | (40.5) | (40.0) | (39.8) | (161.5) | (40.6) | (41.1) | (41.1) | (42.1) | (164.9) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Health margin | 123.0 | 135.9 | 127.8 | 130.1 | 516.8 | 126.2 | 134.0 | 157.0 | 139.4 | 556.6 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Life: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy income | 222.7 | 228.6 | 226.9 | 226.5 | 904.7 | 228.9 | 230.4 | 231.7 | 230.9 | 921.9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net investment income (5) (7) | 36.5 | 36.7 | 36.8 | 37.1 | 147.1 | 37.6 | 37.8 | 37.8 | 37.9 | 151.1 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy benefits | (144.0) | (144.6) | (143.5) | (143.9) | (576.0) | (138.1) | (144.5) | (142.6) | (143.0) | (568.2) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Interest credited (7) | (12.5) | (12.4) | (13.3) | (13.3) | (51.5) | (13.0) | (13.8) | (13.2) | (13.7) | (53.7) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization and non-deferred commissions | (23.5) | (24.3) | (25.1) | (25.1) | (98.0) | (26.0) | (27.6) | (28.3) | (29.1) | (111.0) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Advertising expense | (24.6) | (20.9) | (18.5) | (13.3) | (77.3) | (21.2) | (18.7) | (14.8) | (13.0) | (67.7) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Life margin | 54.6 | 63.1 | 63.3 | 68.0 | 249.0 | 68.2 | 63.6 | 70.6 | 70.0 | 272.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total insurance product margin | 229.6 | 275.1 | 282.2 | 253.1 | 1,040.0 | 248.9 | 252.4 | 300.5 | 265.8 | 1,067.6 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Allocated expenses: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Branch office expenses | (19.8) | (16.2) | (16.7) | (13.0) | (65.7) | (20.7) | (15.9) | (17.7) | (13.8) | (68.1) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other allocated expenses | (141.8) | (138.4) | (136.3) | (133.1) | (549.6) | (140.5) | (133.5) | (133.3) | (135.9) | (543.2) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Income from insurance products (8) | 68.0 | 120.5 | 129.2 | 107.0 | 424.7 | 87.7 | 103.0 | 149.5 | 116.1 | 456.3 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Fee income | 11.3 | 0.8 | (2.7) | 20.6 | 30.0 | (0.8) | 0.8 | (3.9) | 19.1 | 15.2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Investment income not allocated to product lines (9) | 12.3 | 44.8 | 45.5 | 65.3 | 167.9 | 38.0 | 33.8 | 39.5 | 58.1 | 169.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Expenses not allocated to product lines | (16.8) | (17.5) | (18.5) | (19.0) | (71.8) | (20.3) | (25.3) | (22.3) | (19.8) | (87.7) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Operating earnings before taxes | 74.8 | 148.6 | 153.5 | 173.9 | 550.8 | 104.6 | 112.3 | 162.8 | 173.5 | 553.2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Income tax expense on operating income | (17.3) | (34.0) | (34.3) | (35.9) | (121.5) | (23.5) | (24.8) | (35.6) | (30.1) | (114.0) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net operating income (10) | $ | 57.5 | $ | 114.6 | $ | 119.2 | $ | 138.0 | $ | 429.3 | $ | 81.1 | $ | 87.5 | $ | 127.2 | $ | 143.4 | $ | 439.2 | |||||||||||||||||||||||||||||||||||||||
Page 6
CNO FINANCIAL GROUP, INC.
Margin from Annuity Products
(Dollars in millions)
(Unaudited)
| 1Q | 2Q | 3Q | 4Q | YTD | 1Q | 2Q | 3Q | 4Q | YTD | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Annuity margin (4): | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fixed indexed annuities | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy income | $ | 6.0 | $ | 7.2 | $ | 8.7 | $ | 6.1 | $ | 28.0 | $ | 7.2 | $ | 6.7 | $ | 6.8 | $ | 6.9 | $ | 27.6 | |||||||||||||||||||||||||||||||||||||||
| Net investment income (5) (6) | 108.4 | 113.8 | 115.9 | 120.6 | 458.7 | 120.9 | 127.8 | 130.4 | 133.1 | 512.2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy benefits | (5.8) | (2.6) | 28.7 | (6.1) | 14.2 | (5.5) | (5.0) | 8.8 | (5.2) | (6.9) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Interest credited (6) | (46.7) | (49.4) | (53.3) | (55.7) | (205.1) | (55.7) | (60.8) | (62.1) | (63.7) | (242.3) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization and non-deferred commissions | (18.5) | (19.1) | (21.0) | (21.4) | (80.0) | (22.4) | (23.3) | (24.2) | (24.7) | (94.6) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Margin from fixed indexed annuities | $ | 43.4 | $ | 49.9 | $ | 79.0 | $ | 43.5 | $ | 215.8 | $ | 44.5 | $ | 45.4 | $ | 59.7 | $ | 46.4 | $ | 196.0 | |||||||||||||||||||||||||||||||||||||||
| Average net insurance liabilities (11) | $ | 9,636.3 | $ | 9,758.1 | $ | 9,899.4 | $ | 10,101.6 | $ | 9,848.9 | $ | 10,085.7 | $ | 10,543.4 | $ | 10,759.3 | $ | 10,941.4 | $ | 10,582.5 | |||||||||||||||||||||||||||||||||||||||
| Margin/average net insurance liabilities (12) | 1.80 | % | 2.05 | % | 3.19 | % | 1.72 | % | 2.19 | % | 1.76 | % | 1.72 | % | 2.22 | % | 1.70 | % | 1.85 | % | |||||||||||||||||||||||||||||||||||||||
| Fixed interest annuities | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy income | $ | 0.1 | $ | 0.4 | $ | 0.1 | $ | 0.6 | $ | 1.2 | $ | 0.5 | $ | 0.2 | $ | 0.8 | $ | 0.6 | $ | 2.1 | |||||||||||||||||||||||||||||||||||||||
| Net investment income (5) | 20.6 | 21.1 | 20.8 | 21.6 | 84.1 | 21.6 | 21.8 | 21.8 | 21.7 | 86.9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy benefits | (0.4) | 0.1 | (0.4) | 0.8 | 0.1 | 0.2 | (0.1) | 0.5 | 0.1 | 0.7 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Interest credited | (11.1) | (11.3) | (11.3) | (12.9) | (46.6) | (12.1) | (11.8) | (12.5) | (12.1) | (48.5) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization and non-deferred commissions | (1.6) | (1.6) | (1.9) | (2.1) | (7.2) | (2.1) | (2.1) | (2.1) | (2.1) | (8.4) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Margin from fixed interest annuities | $ | 7.6 | $ | 8.7 | $ | 7.3 | $ | 8.0 | $ | 31.6 | $ | 8.1 | $ | 8.0 | $ | 8.5 | $ | 8.2 | $ | 32.8 | |||||||||||||||||||||||||||||||||||||||
| Average net insurance liabilities (11) | $ | 1,588.0 | $ | 1,569.4 | $ | 1,568.2 | $ | 1,587.7 | $ | 1,578.3 | $ | 1,599.5 | $ | 1,591.7 | $ | 1,587.4 | $ | 1,587.2 | $ | 1,591.4 | |||||||||||||||||||||||||||||||||||||||
| Margin/average net insurance liabilities (12) | 1.91 | % | 2.22 | % | 1.86 | % | 2.02 | % | 2.00 | % | 2.03 | % | 2.01 | % | 2.14 | % | 2.07 | % | 2.06 | % | |||||||||||||||||||||||||||||||||||||||
| Other annuities | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy income | $ | 1.2 | $ | 1.7 | $ | 2.4 | $ | 1.0 | $ | 6.3 | $ | 2.1 | $ | 1.6 | $ | 3.0 | $ | 2.9 | $ | 9.6 | |||||||||||||||||||||||||||||||||||||||
| Net investment income (5) | 5.5 | 5.6 | 5.5 | 5.6 | 22.2 | 5.5 | 5.6 | 5.6 | 5.5 | 22.2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy benefits | (5.1) | 10.9 | (2.4) | (2.5) | 0.9 | (5.0) | (5.0) | (3.0) | (5.8) | (18.8) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Interest credited | (0.5) | (0.5) | (0.6) | (0.5) | (2.1) | (0.5) | (0.7) | (0.9) | (0.6) | (2.7) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization and non-deferred commissions | (0.1) | (0.2) | (0.1) | (0.1) | (0.5) | (0.2) | (0.1) | — | (0.2) | (0.5) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Margin from other annuities | $ | 1.0 | $ | 17.5 | $ | 4.8 | $ | 3.5 | $ | 26.8 | $ | 1.9 | $ | 1.4 | $ | 4.7 | $ | 1.8 | $ | 9.8 | |||||||||||||||||||||||||||||||||||||||
| Average net insurance liabilities (11) | $ | 439.9 | $ | 426.4 | $ | 414.4 | $ | 408.6 | $ | 422.3 | $ | 402.2 | $ | 398.5 | $ | 395.2 | $ | 392.1 | $ | 397.0 | |||||||||||||||||||||||||||||||||||||||
| Margin/average net insurance liabilities (12) | 0.91 | % | 16.42 | % | 4.63 | % | 3.43 | % | 6.35 | % | 1.89 | % | 1.41 | % | 4.76 | % | 1.84 | % | 2.47 | % | |||||||||||||||||||||||||||||||||||||||
| Total annuity margin | $ | 52.0 | $ | 76.1 | $ | 91.1 | $ | 55.0 | $ | 274.2 | $ | 54.5 | $ | 54.8 | $ | 72.9 | $ | 56.4 | $ | 238.6 | |||||||||||||||||||||||||||||||||||||||
| Average net insurance liabilities (11) | $ | 11,664.2 | $ | 11,753.9 | $ | 11,882.0 | $ | 12,097.9 | $ | 11,849.5 | $ | 12,087.4 | $ | 12,533.6 | $ | 12,741.9 | $ | 12,920.7 | $ | 12,570.9 | |||||||||||||||||||||||||||||||||||||||
| Margin/average net insurance liabilities (12) | 1.78 | % | 2.59 | % | 3.07 | % | 1.82 | % | 2.31 | % | 1.80 | % | 1.75 | % | 2.29 | % | 1.75 | % | 1.90 | % | |||||||||||||||||||||||||||||||||||||||
Page 7
CNO FINANCIAL GROUP, INC.
Margin from Health Products
(Dollars in millions)
(Unaudited)
| 1Q | 2Q | 3Q | 4Q | YTD | 1Q | 2Q | 3Q | 4Q | YTD | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Health margin (4): | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Supplemental health | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy income | $ | 179.7 | $ | 180.1 | $ | 182.0 | $ | 183.3 | $ | 725.1 | $ | 185.1 | $ | 185.0 | $ | 186.5 | $ | 188.2 | $ | 744.8 | |||||||||||||||||||||||||||||||||||||||
| Net investment income (5) | 39.0 | 39.4 | 39.6 | 39.7 | 157.7 | 39.8 | 40.5 | 40.2 | 40.6 | 161.1 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy benefits | (125.8) | (127.4) | (125.8) | (125.2) | (504.2) | (131.6) | (128.7) | (101.6) | (126.0) | (487.9) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization and non-deferred commissions | (27.5) | (27.0) | (27.2) | (27.1) | (108.8) | (27.7) | (28.2) | (28.0) | (28.7) | (112.6) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Margin from supplemental health | $ | 65.4 | $ | 65.1 | $ | 68.6 | $ | 70.7 | $ | 269.8 | $ | 65.6 | $ | 68.6 | $ | 97.1 | $ | 74.1 | $ | 305.4 | |||||||||||||||||||||||||||||||||||||||
| Margin/insurance policy income | 36 | % | 36 | % | 38 | % | 39 | % | 37 | % | 35 | % | 37 | % | 52 | % | 39 | % | 41 | % | |||||||||||||||||||||||||||||||||||||||
| Medicare supplement | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy income | $ | 151.7 | $ | 155.8 | $ | 156.3 | $ | 156.7 | $ | 620.5 | $ | 156.3 | $ | 155.9 | $ | 156.5 | $ | 158.3 | $ | 627.0 | |||||||||||||||||||||||||||||||||||||||
| Net investment income (5) | 1.4 | 1.3 | 1.3 | 1.3 | 5.3 | 1.2 | 1.2 | 1.2 | 1.2 | 4.8 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy benefits | (116.4) | (111.5) | (121.6) | (122.9) | (472.4) | (120.0) | (119.5) | (127.2) | (121.5) | (488.2) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization and non-deferred commissions | (10.2) | (10.1) | (9.7) | (9.5) | (39.5) | (9.4) | (9.4) | (9.3) | (9.4) | (37.5) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Margin from Medicare supplement | $ | 26.5 | $ | 35.5 | $ | 26.3 | $ | 25.6 | $ | 113.9 | $ | 28.1 | $ | 28.2 | $ | 21.2 | $ | 28.6 | $ | 106.1 | |||||||||||||||||||||||||||||||||||||||
| Margin/insurance policy income | 17 | % | 23 | % | 17 | % | 16 | % | 18 | % | 18 | % | 18 | % | 14 | % | 18 | % | 17 | % | |||||||||||||||||||||||||||||||||||||||
| Long-term care | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy income | $ | 67.0 | $ | 67.7 | $ | 68.6 | $ | 69.4 | $ | 272.7 | $ | 70.6 | $ | 71.6 | $ | 73.0 | $ | 74.4 | $ | 289.6 | |||||||||||||||||||||||||||||||||||||||
| Net investment income (5) | 33.9 | 34.4 | 34.1 | 34.2 | 136.6 | 34.1 | 34.2 | 34.0 | 33.7 | 136.0 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy benefits | (66.3) | (63.4) | (66.7) | (66.6) | (263.0) | (68.7) | (65.1) | (64.5) | (67.4) | (265.7) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization and non-deferred commissions | (3.5) | (3.4) | (3.1) | (3.2) | (13.2) | (3.5) | (3.5) | (3.8) | (4.0) | (14.8) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Margin from long-term care | $ | 31.1 | $ | 35.3 | $ | 32.9 | $ | 33.8 | $ | 133.1 | $ | 32.5 | $ | 37.2 | $ | 38.7 | $ | 36.7 | $ | 145.1 | |||||||||||||||||||||||||||||||||||||||
| Margin/insurance policy income | 46 | % | 52 | % | 48 | % | 49 | % | 49 | % | 46 | % | 52 | % | 53 | % | 49 | % | 50 | % | |||||||||||||||||||||||||||||||||||||||
| Total health margin | $ | 123.0 | $ | 135.9 | $ | 127.8 | $ | 130.1 | $ | 516.8 | $ | 126.2 | $ | 134.0 | $ | 157.0 | $ | 139.4 | $ | 556.6 | |||||||||||||||||||||||||||||||||||||||
| Margin/insurance policy income | 31 | % | 34 | % | 31 | % | 32 | % | 32 | % | 31 | % | 32 | % | 38 | % | 33 | % | 34 | % | |||||||||||||||||||||||||||||||||||||||
Page 8
CNO FINANCIAL GROUP, INC.
Margin from Life Products
(Dollars in millions)
(Unaudited)
| 1Q | 2Q | 3Q | 4Q | YTD | 1Q | 2Q | 3Q | 4Q | YTD | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Life margin (4): | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest sensitive life | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy income | $ | 46.6 | $ | 46.9 | $ | 47.0 | $ | 47.4 | $ | 187.9 | $ | 48.1 | $ | 48.0 | $ | 48.4 | $ | 48.9 | $ | 193.4 | |||||||||||||||||||||||||||||||||||||||
| Net investment income (5) (7) | 13.2 | 13.2 | 13.3 | 13.5 | 53.2 | 13.9 | 13.9 | 14.0 | 14.1 | 55.9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy benefits | (19.9) | (18.6) | (13.6) | (19.7) | (71.8) | (19.9) | (20.7) | (20.2) | (18.9) | (79.7) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Interest credited (7) | (12.3) | (12.3) | (13.2) | (13.1) | (50.9) | (12.9) | (13.7) | (13.1) | (13.5) | (53.2) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization and non-deferred commissions | (5.1) | (5.3) | (5.3) | (4.8) | (20.5) | (5.1) | (5.6) | (5.6) | (5.8) | (22.1) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Margin from interest sensitive life | $ | 22.5 | $ | 23.9 | $ | 28.2 | $ | 23.3 | $ | 97.9 | $ | 24.1 | $ | 21.9 | $ | 23.5 | $ | 24.8 | $ | 94.3 | |||||||||||||||||||||||||||||||||||||||
| Average net insurance liabilities (11) | $ | 1,056.1 | $ | 1,063.0 | $ | 1,070.8 | $ | 1,078.7 | $ | 1,067.2 | $ | 1,096.1 | $ | 1,106.9 | $ | 1,126.7 | $ | 1,124.0 | $ | 1,113.4 | |||||||||||||||||||||||||||||||||||||||
| Interest margin | $ | 0.9 | $ | 0.9 | $ | 0.1 | $ | 0.4 | $ | 2.3 | $ | 1.0 | $ | 0.2 | $ | 0.9 | $ | 0.6 | $ | 2.7 | |||||||||||||||||||||||||||||||||||||||
| Interest margin/average net insurance liabilities (12) | 0.34 | % | 0.34 | % | 0.04 | % | 0.15 | % | 0.22 | % | 0.36 | % | 0.07 | % | 0.32 | % | 0.21 | % | 0.24 | % | |||||||||||||||||||||||||||||||||||||||
| Underwriting margin | $ | 21.6 | $ | 23.0 | $ | 28.1 | $ | 22.9 | $ | 95.6 | $ | 23.1 | $ | 21.7 | $ | 22.6 | $ | 24.2 | $ | 91.6 | |||||||||||||||||||||||||||||||||||||||
| Underwriting margin/insurance policy income | 46 | % | 49 | % | 60 | % | 48 | % | 51 | % | 48 | % | 45 | % | 47 | % | 49 | % | 47 | % | |||||||||||||||||||||||||||||||||||||||
| Traditional life | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy income | $ | 176.1 | $ | 181.7 | $ | 179.9 | $ | 179.1 | $ | 716.8 | $ | 180.8 | $ | 182.4 | $ | 183.3 | $ | 182.0 | $ | 728.5 | |||||||||||||||||||||||||||||||||||||||
| Net investment income (5) | 23.3 | 23.5 | 23.5 | 23.6 | 93.9 | 23.7 | 23.9 | 23.8 | 23.8 | 95.2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance policy benefits | (124.1) | (126.0) | (129.9) | (124.2) | (504.2) | (118.2) | (123.8) | (122.4) | (124.1) | (488.5) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Interest credited | (0.2) | (0.1) | (0.1) | (0.2) | (0.6) | (0.1) | (0.1) | (0.1) | (0.2) | (0.5) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization and non-deferred commissions | (18.4) | (19.0) | (19.8) | (20.3) | (77.5) | (20.9) | (22.0) | (22.7) | (23.3) | (88.9) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Advertising expense | (24.6) | (20.9) | (18.5) | (13.3) | (77.3) | (21.2) | (18.7) | (14.8) | (13.0) | (67.7) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Margin from traditional life | $ | 32.1 | $ | 39.2 | $ | 35.1 | $ | 44.7 | $ | 151.1 | $ | 44.1 | $ | 41.7 | $ | 47.1 | $ | 45.2 | $ | 178.1 | |||||||||||||||||||||||||||||||||||||||
| Margin/insurance policy income | 18 | % | 22 | % | 20 | % | 25 | % | 21 | % | 24 | % | 23 | % | 26 | % | 25 | % | 24 | % | |||||||||||||||||||||||||||||||||||||||
| Margin excluding advertising expense/insurance policy income | 32 | % | 33 | % | 30 | % | 32 | % | 32 | % | 36 | % | 33 | % | 34 | % | 32 | % | 34 | % | |||||||||||||||||||||||||||||||||||||||
| Total life margin | $ | 54.6 | $ | 63.1 | $ | 63.3 | $ | 68.0 | $ | 249.0 | $ | 68.2 | $ | 63.6 | $ | 70.6 | $ | 70.0 | $ | 272.4 | |||||||||||||||||||||||||||||||||||||||
Page 9
CNO FINANCIAL GROUP, INC.
Collected Premiums and Insurance Policy Income
(Dollars in millions)
(Unaudited)
| 1Q | 2Q | 3Q | 4Q | YTD | 1Q | 2Q | 3Q | 4Q | YTD | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Collected premiums: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Annuity products | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fixed indexed annuities | $ | 345.5 | $ | 388.5 | $ | 398.8 | $ | 409.9 | $ | 1,542.7 | $ | 388.0 | $ | 470.2 | $ | 425.3 | $ | 456.4 | $ | 1,739.9 | |||||||||||||||||||||||||||||||||||||||
| Fixed interest annuities | 45.9 | 49.1 | 62.9 | 81.2 | 239.1 | 51.7 | 47.8 | 44.7 | 50.1 | 194.3 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other annuities | 1.9 | 1.5 | 3.4 | 2.0 | 8.8 | 2.3 | 2.5 | 2.5 | 1.8 | 9.1 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total annuity collected premiums | 393.3 | 439.1 | 465.1 | 493.1 | 1,790.6 | 442.0 | 520.5 | 472.5 | 508.3 | 1,943.3 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Health products | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Supplemental health | 181.4 | 179.8 | 181.3 | 183.2 | 725.7 | 184.8 | 184.6 | 184.8 | 190.3 | 744.5 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Medicare supplement | 155.7 | 152.4 | 153.1 | 164.5 | 625.7 | 151.1 | 153.0 | 154.4 | 168.3 | 626.8 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Long-term care | 67.7 | 67.9 | 68.7 | 71.9 | 276.2 | 69.8 | 71.9 | 73.4 | 77.1 | 292.2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total health collected premiums | 404.8 | 400.1 | 403.1 | 419.6 | 1,627.6 | 405.7 | 409.5 | 412.6 | 435.7 | 1,663.5 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Life products | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-sensitive life | 60.5 | 61.3 | 61.0 | 61.3 | 244.1 | 62.9 | 63.6 | 64.4 | 64.9 | 255.8 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Traditional life | 176.8 | 181.1 | 180.0 | 178.5 | 716.4 | 181.5 | 181.9 | 182.6 | 182.7 | 728.7 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total life collected premiums | 237.3 | 242.4 | 241.0 | 239.8 | 960.5 | 244.4 | 245.5 | 247.0 | 247.6 | 984.5 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total collected premiums | $ | 1,035.4 | $ | 1,081.6 | $ | 1,109.2 | $ | 1,152.5 | $ | 4,378.7 | $ | 1,092.1 | $ | 1,175.5 | $ | 1,132.1 | $ | 1,191.6 | $ | 4,591.3 | |||||||||||||||||||||||||||||||||||||||
| Insurance policy income: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Annuity products | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fixed indexed annuities | $ | 6.0 | $ | 7.2 | $ | 8.7 | $ | 6.1 | $ | 28.0 | $ | 7.2 | $ | 6.7 | $ | 6.8 | $ | 6.9 | $ | 27.6 | |||||||||||||||||||||||||||||||||||||||
| Fixed interest annuities | 0.1 | 0.4 | 0.1 | 0.6 | 1.2 | 0.5 | 0.2 | 0.8 | 0.6 | 2.1 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other annuities | 1.2 | 1.7 | 2.4 | 1.0 | 6.3 | 2.1 | 1.6 | 3.0 | 2.9 | 9.6 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total annuity insurance policy income | 7.3 | 9.3 | 11.2 | 7.7 | 35.5 | 9.8 | 8.5 | 10.6 | 10.4 | 39.3 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Health products | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Supplemental health | 179.7 | 180.1 | 182.0 | 183.3 | 725.1 | 185.1 | 185.0 | 186.5 | 188.2 | 744.8 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Medicare supplement | 151.7 | 155.8 | 156.3 | 156.7 | 620.5 | 156.3 | 155.9 | 156.5 | 158.3 | 627.0 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Long-term care | 67.0 | 67.7 | 68.6 | 69.4 | 272.7 | 70.6 | 71.6 | 73.0 | 74.4 | 289.6 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total health insurance policy income | 398.4 | 403.6 | 406.9 | 409.4 | 1,618.3 | 412.0 | 412.5 | 416.0 | 420.9 | 1,661.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Life products | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-sensitive life | 46.6 | 46.9 | 47.0 | 47.4 | 187.9 | 48.1 | 48.0 | 48.4 | 48.9 | 193.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Traditional life | 176.1 | 181.7 | 179.9 | 179.1 | 716.8 | 180.8 | 182.4 | 183.3 | 182.0 | 728.5 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total life insurance policy income | 222.7 | 228.6 | 226.9 | 226.5 | 904.7 | 228.9 | 230.4 | 231.7 | 230.9 | 921.9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total insurance policy income | $ | 628.4 | $ | 641.5 | $ | 645.0 | $ | 643.6 | $ | 2,558.5 | $ | 650.7 | $ | 651.4 | $ | 658.3 | $ | 662.2 | $ | 2,622.6 | |||||||||||||||||||||||||||||||||||||||
Page 10
CNO FINANCIAL GROUP, INC.
Health and Life
New Annualized Premiums ("NAP")
(Dollars in millions)
(Unaudited)
| 1Q | 2Q | 3Q | 4Q | YTD | 1Q | 2Q | 3Q | 4Q | YTD | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Consumer Division | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Health products: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Supplemental health | $ | 18.0 | $ | 18.2 | $ | 19.1 | $ | 23.7 | $ | 79.0 | $ | 19.5 | $ | 22.0 | $ | 23.5 | $ | 26.0 | $ | 91.0 | |||||||||||||||||||||||||||||||||||||||
| Medicare supplement | 9.7 | 10.3 | 10.0 | 16.6 | 46.6 | 12.0 | 12.2 | 13.3 | 31.8 | 69.3 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Long-term care | 10.6 | 10.7 | 11.6 | 10.2 | 43.1 | 10.2 | 10.1 | 12.4 | 12.1 | 44.8 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total Consumer Division health NAP | 38.3 | 39.2 | 40.7 | 50.5 | 168.7 | 41.7 | 44.3 | 49.2 | 69.9 | 205.1 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Life products: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest sensitive life | 4.4 | 5.0 | 4.2 | 4.0 | 17.6 | 3.6 | 5.6 | 4.5 | 4.2 | 17.9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Traditional life | 48.8 | 43.2 | 38.6 | 36.5 | 167.1 | 46.0 | 52.0 | 52.4 | 34.6 | 185.0 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total Consumer Division life NAP | 53.2 | 48.2 | 42.8 | 40.5 | 184.7 | 49.6 | 57.6 | 56.9 | 38.8 | 202.9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total Consumer Division health and life NAP | $ | 91.5 | $ | 87.4 | $ | 83.5 | $ | 91.0 | $ | 353.4 | $ | 91.3 | $ | 101.9 | $ | 106.1 | $ | 108.7 | $ | 408.0 | |||||||||||||||||||||||||||||||||||||||
| Worksite Division | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Health products: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Supplemental health | $ | 9.5 | $ | 11.4 | $ | 11.4 | $ | 13.0 | $ | 45.3 | $ | 10.3 | $ | 11.7 | $ | 13.4 | $ | 13.1 | $ | 48.5 | |||||||||||||||||||||||||||||||||||||||
| Life products: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest sensitive life | 3.5 | 4.1 | 4.5 | 4.6 | 16.7 | 4.1 | 6.3 | 5.6 | 6.7 | 22.7 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total Worksite Division health and life NAP | $ | 13.0 | $ | 15.5 | $ | 15.9 | $ | 17.6 | $ | 62.0 | $ | 14.4 | $ | 18.0 | $ | 19.0 | $ | 19.8 | $ | 71.2 | |||||||||||||||||||||||||||||||||||||||
| Total NAP (both divisions) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Health products: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Supplemental health | $ | 27.5 | $ | 29.6 | $ | 30.5 | $ | 36.7 | $ | 124.3 | $ | 29.8 | $ | 33.7 | $ | 36.9 | $ | 39.1 | $ | 139.5 | |||||||||||||||||||||||||||||||||||||||
| Medicare supplement | 9.7 | 10.3 | 10.0 | 16.6 | 46.6 | 12.0 | 12.2 | 13.3 | 31.8 | 69.3 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Long-term care | 10.6 | 10.7 | 11.6 | 10.2 | 43.1 | 10.2 | 10.1 | 12.4 | 12.1 | 44.8 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total health NAP | 47.8 | 50.6 | 52.1 | 63.5 | 214.0 | 52.0 | 56.0 | 62.6 | 83.0 | 253.6 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Life products: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest sensitive life | 7.9 | 9.1 | 8.7 | 8.6 | 34.3 | 7.7 | 11.9 | 10.1 | 10.9 | 40.6 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Traditional life | 48.8 | 43.2 | 38.6 | 36.5 | 167.1 | 46.0 | 52.0 | 52.4 | 34.6 | 185.0 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total life NAP | 56.7 | 52.3 | 47.3 | 45.1 | 201.4 | 53.7 | 63.9 | 62.5 | 45.5 | 225.6 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total NAP | $ | 104.5 | $ | 102.9 | $ | 99.4 | $ | 108.6 | $ | 415.4 | $ | 105.7 | $ | 119.9 | $ | 125.1 | $ | 128.5 | $ | 479.2 | |||||||||||||||||||||||||||||||||||||||
Page 11
CNO FINANCIAL GROUP, INC.
Computation of Weighted Average Shares Outstanding
(Shares in thousands)
| 1Q | 2Q | 3Q | 4Q | YTD | 1Q | 2Q | 3Q | 4Q | YTD | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Basic | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Shares outstanding, beginning of period | 109,357.5 | 108,568.6 | 106,513.6 | 103,923.0 | 109,357.5 | 101,619.0 | 99,893.9 | 97,319.0 | 95,841.0 | 101,619.0 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Weighted average share activity during the period: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Shares repurchased | (618.6) | (893.0) | (1,483.9) | (1,233.7) | (3,958.1) | (1,106.8) | (1,347.6) | (731.7) | (767.7) | (4,554.0) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Amounts related to employee benefit plans | 344.5 | 57.0 | 76.7 | 90.4 | 1,028.3 | 307.9 | 26.7 | 16.4 | 64.3 | 914.5 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Shares withheld for the payment of the exercise price and taxes related to employee benefit plans | (119.5) | (1.9) | (4.9) | (1.5) | (284.1) | (77.3) | (0.8) | (0.9) | (1.6) | (216.1) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Weighted average basic shares outstanding during the period | 108,963.9 | 107,730.7 | 105,101.5 | 102,778.2 | 106,143.6 | 100,742.8 | 98,572.2 | 96,602.8 | 95,136.0 | 97,763.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Basic shares outstanding, end of period | 108,568.6 | 106,513.6 | 103,923.0 | 101,619.0 | 101,619.0 | 99,893.9 | 97,319.0 | 95,841.0 | 94,484.3 | 94,484.3 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Diluted | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Weighted average basic shares outstanding | 108,963.9 | 107,730.7 | 105,101.5 | 102,778.2 | 106,143.6 | 100,742.8 | 98,572.2 | 96,602.8 | 95,136.0 | 97,763.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Common stock equivalent shares related to: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Employee benefit plans | 1,881.0 | 1,527.5 | 2,029.5 | 2,452.1 | 1,972.6 | 2,327.1 | 1,814.0 | 1,950.6 | 2,141.6 | 2,058.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Weighted average diluted shares outstanding during the period | 110,844.9 | 109,258.2 | 107,131.0 | 105,230.3 | 108,116.2 | 103,069.9 | 100,386.2 | 98,553.4 | 97,277.6 | 99,821.8 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Diluted shares outstanding, end of period | 110,036.5 | 108,140.0 | 106,141.8 | 104,052.8 | 104,052.8 | 101,796.1 | 99,221.4 | 97,902.8 | 96,714.2 | 96,714.2 | |||||||||||||||||||||||||||||||||||||||||||||||||
Page 12
CNO FINANCIAL GROUP, INC.
Annuities - Account Value Rollforwards
(Dollars in millions)
| 1Q | 2Q | 3Q | 4Q | YTD | 1Q | 2Q | 3Q | 4Q | YTD | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Fixed indexed annuities | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Policyholder account balances, beginning of period excluding contracts 100% ceded | $ | 9,999.2 | $ | 10,112.7 | $ | 10,279.1 | $ | 10,468.0 | $ | 9,999.2 | $ | 10,766.3 | $ | 10,952.1 | $ | 11,221.3 | $ | 11,433.0 | $ | 10,766.3 | |||||||||||||||||||||||||||||||||||||||
| Issuances (funds collected from new business) | 345.4 | 388.5 | 398.7 | 409.0 | 1,541.6 | 383.7 | 463.0 | 418.7 | 445.3 | 1,710.7 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Premiums received (premiums collected from inforce business) | 0.5 | 0.7 | 0.1 | 1.3 | 2.6 | 4.0 | 7.4 | 6.6 | 10.9 | 28.9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Policy charges | (6.5) | (7.9) | (8.8) | (6.5) | (29.7) | (6.8) | (6.9) | (6.9) | (6.7) | (27.3) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Surrenders and withdrawals | (232.2) | (235.2) | (239.1) | (221.1) | (927.6) | (233.3) | (221.6) | (215.6) | (249.3) | (919.8) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Benefit payments | (74.4) | (77.6) | (67.5) | (54.9) | (274.4) | (72.7) | (74.6) | (72.6) | (70.4) | (290.3) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Interest credited | 68.9 | 84.0 | 91.2 | 155.7 | 399.8 | 96.4 | 85.0 | 66.9 | 53.1 | 301.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other | 11.8 | 13.9 | 14.3 | 14.8 | 54.8 | 14.5 | 16.9 | 14.6 | 17.1 | 63.1 | |||||||||||||||||||||||||||||||||||||||||||||||||
Policyholder account balances, end of period excluding contracts 100% ceded | $ | 10,112.7 | $ | 10,279.1 | $ | 10,468.0 | $ | 10,766.3 | $ | 10,766.3 | $ | 10,952.1 | $ | 11,221.3 | $ | 11,433.0 | $ | 11,633.0 | $ | 11,633.0 | |||||||||||||||||||||||||||||||||||||||
| Fixed interest annuities | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Policyholder account balances, beginning of period excluding contracts 100% ceded | $ | 1,636.4 | $ | 1,610.6 | $ | 1,602.6 | $ | 1,612.7 | $ | 1,636.4 | $ | 1,646.6 | $ | 1,640.7 | $ | 1,634.7 | $ | 1,635.1 | $ | 1,646.6 | |||||||||||||||||||||||||||||||||||||||
| Issuances (funds collected from new business) | 45.1 | 48.5 | 62.3 | 80.5 | 236.4 | 50.9 | 47.1 | 44.2 | 49.5 | 191.7 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Premiums received (premiums collected from inforce business) | 1.0 | 0.5 | 1.0 | 0.4 | 2.9 | 0.7 | 1.0 | 0.2 | 0.3 | 2.2 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Policy charges | (0.3) | (0.3) | (0.4) | (0.4) | (1.4) | (0.4) | (0.5) | (0.5) | (0.4) | (1.8) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Surrenders and withdrawals | (52.8) | (42.4) | (39.2) | (37.1) | (171.5) | (41.4) | (40.9) | (35.4) | (37.6) | (155.3) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Benefit payments | (30.2) | (25.8) | (25.0) | (22.8) | (103.8) | (28.4) | (25.2) | (21.3) | (22.0) | (96.9) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Interest credited | 11.4 | 11.6 | 11.7 | 13.3 | 48.0 | 12.7 | 12.5 | 13.1 | 12.6 | 50.9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other | — | (0.1) | (0.3) | — | (0.4) | — | — | 0.1 | — | 0.1 | |||||||||||||||||||||||||||||||||||||||||||||||||
Policyholder account balances, end of period excluding contracts 100% ceded | $ | 1,610.6 | $ | 1,602.6 | $ | 1,612.7 | $ | 1,646.6 | $ | 1,646.6 | $ | 1,640.7 | $ | 1,634.7 | $ | 1,635.1 | $ | 1,637.5 | $ | 1,637.5 | |||||||||||||||||||||||||||||||||||||||
| Total annuities | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Policyholder account balances, beginning of period excluding contracts 100% ceded | $ | 11,635.6 | $ | 11,723.3 | $ | 11,881.7 | $ | 12,080.7 | $ | 11,635.6 | $ | 12,412.9 | $ | 12,592.8 | $ | 12,856.0 | $ | 13,068.1 | $ | 12,412.9 | |||||||||||||||||||||||||||||||||||||||
| Issuances (funds collected from new business) | 390.5 | 437.0 | 461.0 | 489.5 | 1,778.0 | 434.6 | 510.1 | 462.9 | 494.8 | 1,902.4 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Premiums received (premiums collected from inforce business) | 1.5 | 1.2 | 1.1 | 1.7 | 5.5 | 4.7 | 8.4 | 6.8 | 11.2 | 31.1 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Policy charges | (6.8) | (8.2) | (9.2) | (6.9) | (31.1) | (7.2) | (7.4) | (7.4) | (7.1) | (29.1) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Surrenders and withdrawals | (285.0) | (277.6) | (278.3) | (258.2) | (1,099.1) | (274.7) | (262.5) | (251.0) | (286.9) | (1,075.1) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Benefit payments | (104.6) | (103.4) | (92.5) | (77.7) | (378.2) | (101.1) | (99.8) | (93.9) | (92.4) | (387.2) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Interest credited | 80.3 | 95.6 | 102.9 | 169.0 | 447.8 | 109.1 | 97.5 | 80.0 | 65.7 | 352.3 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other | 11.8 | 13.8 | 14.0 | 14.8 | 54.4 | 14.5 | 16.9 | 14.7 | 17.1 | 63.2 | |||||||||||||||||||||||||||||||||||||||||||||||||
Policyholder account balances, end of period excluding contracts 100% ceded | $ | 11,723.3 | $ | 11,881.7 | $ | 12,080.7 | $ | 12,412.9 | $ | 12,412.9 | $ | 12,592.8 | $ | 12,856.0 | $ | 13,068.1 | $ | 13,270.5 | $ | 13,270.5 | |||||||||||||||||||||||||||||||||||||||
Page 13
CNO FINANCIAL GROUP, INC.
Consolidated Statutory Information of U.S. Based Insurance Subsidiaries (13)
(Dollars in millions)
(Unaudited)
| 1Q | 2Q | 3Q | 4Q | YTD | 1Q | 2Q | 3Q | 4Q | YTD | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 (a) | 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net gain from operations before interest expense and federal income taxes | $ | 40.3 | $ | 63.3 | $ | 58.9 | $ | 161.1 | $ | 323.6 | $ | 29.0 | $ | 37.7 | $ | 45.2 | $ | 95.3 | $ | 207.2 | |||||||||||||||||||||||||||||||||||||||
| Interest expense on surplus debentures held by parent company | 17.6 | 17.5 | 32.9 | 16.4 | 84.4 | 15.5 | 15.7 | 29.4 | 15.3 | 75.9 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net gain from operations before federal income taxes | 22.7 | 45.8 | 26.0 | 144.7 | 239.2 | 13.5 | 22.0 | 15.8 | 80.0 | 131.3 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Federal income tax expense (benefit) | 26.7 | 17.7 | 17.6 | (19.7) | 42.3 | — | — | 20.9 | 61.6 | 82.5 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net gain (loss) from operations before net realized capital gains (losses) | (4.0) | 28.1 | 8.4 | 164.4 | 196.9 | 13.5 | 22.0 | (5.1) | 18.4 | 48.8 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net realized capital gains (losses) | (4.2) | 7.4 | (0.5) | (23.0) | (20.3) | (1.2) | (2.6) | (11.1) | (48.5) | (63.4) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net income (loss) | $ | (8.2) | $ | 35.5 | $ | 7.9 | $ | 141.4 | $ | 176.6 | $ | 12.3 | $ | 19.4 | $ | (16.2) | $ | (30.1) | $ | (14.6) | |||||||||||||||||||||||||||||||||||||||
| Capital and surplus | $ | 1,487.3 | $ | 1,489.5 | $ | 1,446.6 | $ | 1,458.1 | $ | 1,458.1 | $ | 1,422.3 | $ | 1,417.8 | $ | 1,403.1 | $ | 1,405.3 | $ | 1,405.3 | |||||||||||||||||||||||||||||||||||||||
| Asset valuation reserve (AVR) | 351.8 | 369.8 | 393.2 | 407.1 | 407.1 | 428.5 | 459.3 | 485.0 | 508.7 | 508.7 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Capital, surplus and AVR | 1,839.1 | 1,859.3 | 1,839.8 | 1,865.2 | 1,865.2 | 1,850.8 | 1,877.1 | 1,888.1 | 1,914.0 | 1,914.0 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Interest maintenance reserve (IMR) | 362.1 | 344.0 | 338.1 | 334.2 | 334.2 | 331.5 | 315.8 | 298.3 | 252.6 | 252.6 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total statutory capital, surplus, AVR & IMR | $ | 2,201.2 | $ | 2,203.3 | $ | 2,177.9 | $ | 2,199.4 | $ | 2,199.4 | $ | 2,182.3 | $ | 2,192.9 | $ | 2,186.4 | $ | 2,166.6 | $ | 2,166.6 | |||||||||||||||||||||||||||||||||||||||
| Risk-based capital ratio | 391 | % | 394 | % | 388 | % | 383 | % | 383 | % | 379 | % | 378 | % | 380 | % | 380 | % | 380 | % | |||||||||||||||||||||||||||||||||||||||
___________
(a) Such amounts are preliminary as the statutory basis financial statements of our U.S. based insurance subsidiaries for 4Q25 will be filed with the respective insurance regulators on or about February 28, 2026. The 3Q2025 statutory capital and surplus, IMR and risk-based capital ratio were adjusted to reflect equal and offsetting timing impacts associated with the reinsurance transaction executed with our Bermuda reinsurance company in October 2025.
Page 14
CNO FINANCIAL GROUP, INC.
Investment Income Not Allocated to Product Lines (9)
(Dollars in millions)
(Unaudited)
| 1Q | 2Q | 3Q | 4Q | YTD | 1Q | 2Q | 3Q | 4Q | YTD | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Investment income not allocated: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Excluding variable components: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| From general account assets | $ | 27.6 | $ | 25.0 | $ | 28.8 | $ | 47.8 | $ | 129.2 | $ | 28.0 | $ | 24.1 | $ | 20.6 | $ | 32.3 | $ | 105.0 | ||||||||||||||||||||||||||||||||||||||||||
| Other investment income | 3.1 | 6.8 | 12.9 | 13.8 | 36.6 | 10.9 | 6.6 | 1.8 | 3.2 | 22.5 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Spread income: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| FHLB program: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Investment income | 41.7 | 42.4 | 41.0 | 36.1 | 161.2 | 35.4 | 36.6 | 40.6 | 37.8 | 150.4 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
Interest expense (a) | (31.4) | (31.4) | (31.8) | (28.6) | (123.2) | (26.0) | (27.7) | (29.7) | (27.8) | (111.2) | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net spread income on FHLB program | 10.3 | 11.0 | 9.2 | 7.5 | 38.0 | 9.4 | 8.9 | 10.9 | 10.0 | 39.2 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| FABN program: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Investment income | 14.9 | 19.6 | 28.6 | 33.6 | 96.7 | 34.3 | 36.9 | 37.6 | 42.9 | 151.7 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
Expenses (a)(b) | (7.6) | (10.9) | (20.6) | (24.9) | (64.0) | (27.9) | (27.7) | (29.1) | (32.9) | (117.6) | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net spread income on FABN program | 7.3 | 8.7 | 8.0 | 8.7 | 32.7 | 6.4 | 9.2 | 8.5 | 10.0 | 34.1 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
Interest expense on corporate debt (a) | (15.7) | (21.8) | (27.2) | (27.1) | (91.8) | (27.2) | (24.6) | (20.3) | (20.4) | (92.5) | ||||||||||||||||||||||||||||||||||||||||||||||||||||
Interest expense on financing arrangements (a) | (1.2) | (1.2) | (1.1) | (1.2) | (4.7) | (1.0) | (1.0) | (0.8) | (0.9) | (3.7) | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total excluding variable components | 31.4 | 28.5 | 30.6 | 49.5 | 140.0 | 26.5 | 23.2 | 20.7 | 34.2 | 104.6 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Variable components: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Net income from assets supporting deferred compensation plans: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Investment income | 11.1 | 5.5 | 10.1 | 1.2 | 27.9 | (2.1) | 15.0 | 11.3 | 4.6 | 28.8 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
Expenses (a) | (9.6) | (4.2) | (8.2) | (2.3) | (24.3) | 2.8 | (14.9) | (10.4) | (4.2) | (26.7) | ||||||||||||||||||||||||||||||||||||||||||||||||||||
Net income from assets supporting deferred compensation plans | 1.5 | 1.3 | 1.9 | (1.1) | 3.6 | 0.7 | 0.1 | 0.9 | 0.4 | 2.1 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alternative investment income (loss): | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Total alternative income | (24.3) | 11.9 | 8.9 | 17.1 | 13.6 | 12.9 | 11.7 | 15.8 | 24.1 | 64.5 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Allocated to product lines | (7.1) | (6.4) | (6.5) | (8.2) | (28.2) | (6.0) | (6.0) | (5.9) | (5.0) | (22.9) | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Allocated to FABN program | — | (0.4) | 0.6 | (0.9) | (0.7) | — | (0.7) | 0.1 | (0.1) | (0.7) | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Excess alternative investment income (loss) | (31.4) | 5.1 | 3.0 | 8.0 | (15.3) | 6.9 | 5.0 | 10.0 | 19.0 | 40.9 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
Trading account income | 2.1 | 1.0 | 1.3 | 0.5 | 4.9 | 1.6 | 2.0 | 1.2 | 0.9 | 5.7 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
Hedge variance related to fixed indexed products (a) | 0.5 | — | (0.4) | 2.1 | 2.2 | (0.5) | 1.5 | — | (0.2) | 0.8 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
Impact of annual option forfeitures related to fixed indexed annuity surrenders (a) | 6.2 | 6.0 | 7.4 | 6.4 | 26.0 | 3.5 | 1.5 | 3.8 | 5.6 | 14.4 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
Impacts of change in projected cash flows, prepayment and call income and other | 2.0 | 2.9 | 1.7 | (0.1) | 6.5 | (0.7) | 0.5 | 2.9 | (1.8) | 0.9 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total variable components | (19.1) | 16.3 | 14.9 | 15.8 | 27.9 | 11.5 | 10.6 | 18.8 | 23.9 | 64.8 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total investment income not allocated to product lines | $ | 12.3 | $ | 44.8 | $ | 45.5 | $ | 65.3 | $ | 167.9 | $ | 38.0 | $ | 33.8 | $ | 39.5 | $ | 58.1 | $ | 169.4 | ||||||||||||||||||||||||||||||||||||||||||
| Reconciliation to net investment income: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total investment income not allocated to product lines | $ | 12.3 | $ | 44.8 | $ | 45.5 | $ | 65.3 | $ | 167.9 | $ | 38.0 | $ | 33.8 | $ | 39.5 | $ | 58.1 | $ | 169.4 | ||||||||||||||||||||||||||||||||||||||||||
Investment income on variable interest entities reported as non-operating income | 12.6 | 9.6 | 5.3 | 6.0 | 33.5 | 7.2 | 7.0 | 4.5 | 4.6 | 23.3 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Add back amounts reported as benefits and expenses | 58.8 | 63.5 | 81.9 | 75.6 | 279.8 | 76.3 | 92.9 | 86.5 | 80.8 | 336.5 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Change in market values of the underlying options supporting fixed indexed products | 140.2 | 38.9 | 67.2 | 9.6 | 255.9 | (70.7) | 81.1 | 98.2 | 11.3 | 119.9 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Amounts allocated to products | 245.3 | 252.3 | 254.0 | 260.1 | 1,011.7 | 260.7 | 268.9 | 271.0 | 273.7 | 1,074.3 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net investment income | $ | 469.2 | $ | 409.1 | $ | 453.9 | $ | 416.6 | $ | 1,748.8 | $ | 311.5 | $ | 483.7 | $ | 499.7 | $ | 428.5 | $ | 1,723.4 | ||||||||||||||||||||||||||||||||||||||||||
___________
(a) Amounts reported as benefits and expenses
(b) Comprised of interest credited and amortization of deferred acquisition costs
Page 15
CNO FINANCIAL GROUP, INC.
Investment Income Allocated to Product Lines (5)
(Dollars in millions)
(Unaudited)
| 1Q | 2Q | 3Q | 4Q | YTD | 1Q | 2Q | 3Q | 4Q | YTD | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Average net insurance liabilities (11) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Annuity: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fixed indexed annuities | $ | 9,636.3 | $ | 9,758.1 | $ | 9,899.4 | $ | 10,101.6 | $ | 9,848.9 | $ | 10,085.7 | $ | 10,543.4 | $ | 10,759.3 | $ | 10,941.4 | $ | 10,582.5 | ||||||||||||||||||||||||||||||||||||||||||
| Fixed interest annuities | 1,588.0 | 1,569.4 | 1,568.2 | 1,587.7 | 1,578.3 | 1,599.5 | 1,591.7 | 1,587.4 | 1,587.2 | 1,591.4 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other annuities | 439.9 | 426.4 | 414.4 | 408.6 | 422.3 | 402.2 | 398.5 | 395.2 | 392.1 | 397.0 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total annuity average net insurance liabilities (11) | 11,664.2 | 11,753.9 | 11,882.0 | 12,097.9 | 11,849.5 | 12,087.4 | 12,533.6 | 12,741.9 | 12,920.7 | 12,570.9 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Health: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Supplemental health | 3,346.3 | 3,351.1 | 3,361.1 | 3,372.5 | 3,357.8 | 3,387.4 | 3,405.3 | 3,405.2 | 3,407.0 | 3,401.2 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Medicare supplement | 114.8 | 111.6 | 105.8 | 111.9 | 111.0 | 113.1 | 102.0 | 95.7 | 95.6 | 101.6 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Long-term care | 2,698.7 | 2,696.1 | 2,693.4 | 2,694.3 | 2,695.6 | 2,695.7 | 2,694.5 | 2,691.0 | 2,689.1 | 2,692.6 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total health average net insurance liabilities (11) | 6,159.8 | 6,158.8 | 6,160.3 | 6,178.7 | 6,164.4 | 6,196.2 | 6,201.8 | 6,191.9 | 6,191.7 | 6,195.4 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Life: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest sensitive | 1,056.1 | 1,063.0 | 1,070.8 | 1,078.7 | 1,067.2 | 1,096.1 | 1,106.9 | 1,126.7 | 1,124.0 | 1,113.4 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Traditional | 1,994.1 | 1,997.3 | 2,007.6 | 2,019.9 | 2,004.7 | 2,020.3 | 2,011.9 | 2,002.5 | 2,006.7 | 2,010.4 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total life average net insurance liabilities (11) | 3,050.2 | 3,060.3 | 3,078.4 | 3,098.6 | 3,071.9 | 3,116.4 | 3,118.8 | 3,129.2 | 3,130.7 | 3,123.8 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total average net insurance liabilities (11) | $ | 20,874.2 | $ | 20,973.0 | $ | 21,120.7 | $ | 21,375.2 | $ | 21,085.8 | $ | 21,400.0 | $ | 21,854.2 | $ | 22,063.0 | $ | 22,243.1 | $ | 21,890.1 | ||||||||||||||||||||||||||||||||||||||||||
| Average yield on allocated investments | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Annuity: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fixed indexed annuities | 4.50 | % | 4.66 | % | 4.68 | % | 4.78 | % | 4.66 | % | 4.79 | % | 4.85 | % | 4.85 | % | 4.87 | % | 4.84 | % | ||||||||||||||||||||||||||||||||||||||||||
| Fixed interest annuities | 5.19 | % | 5.38 | % | 5.31 | % | 5.44 | % | 5.33 | % | 5.40 | % | 5.48 | % | 5.49 | % | 5.47 | % | 5.46 | % | ||||||||||||||||||||||||||||||||||||||||||
| Other annuities | 5.00 | % | 5.25 | % | 5.31 | % | 5.48 | % | 5.26 | % | 5.47 | % | 5.62 | % | 5.67 | % | 5.61 | % | 5.59 | % | ||||||||||||||||||||||||||||||||||||||||||
| Average yield on investments allocated to annuities | 4.61 | % | 4.78 | % | 4.79 | % | 4.89 | % | 4.77 | % | 4.90 | % | 4.95 | % | 4.95 | % | 4.96 | % | 4.94 | % | ||||||||||||||||||||||||||||||||||||||||||
| Health: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Supplemental health | 4.66 | % | 4.70 | % | 4.71 | % | 4.71 | % | 4.70 | % | 4.70 | % | 4.76 | % | 4.72 | % | 4.77 | % | 4.74 | % | ||||||||||||||||||||||||||||||||||||||||||
| Medicare supplement | 4.73 | % | 4.89 | % | 4.91 | % | 4.65 | % | 4.77 | % | 4.24 | % | 4.71 | % | 5.02 | % | 5.02 | % | 4.72 | % | ||||||||||||||||||||||||||||||||||||||||||
| Long-term care | 5.02 | % | 5.10 | % | 5.06 | % | 5.08 | % | 5.07 | % | 5.06 | % | 5.08 | % | 5.05 | % | 5.01 | % | 5.05 | % | ||||||||||||||||||||||||||||||||||||||||||
| Average yield on investments allocated to health products | 4.82 | % | 4.88 | % | 4.87 | % | 4.87 | % | 4.86 | % | 4.85 | % | 4.90 | % | 4.87 | % | 4.88 | % | 4.87 | % | ||||||||||||||||||||||||||||||||||||||||||
| Life: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest sensitive | 5.00 | % | 4.97 | % | 4.97 | % | 5.01 | % | 4.99 | % | 5.07 | % | 5.02 | % | 4.97 | % | 5.02 | % | 5.02 | % | ||||||||||||||||||||||||||||||||||||||||||
| Traditional | 4.67 | % | 4.71 | % | 4.68 | % | 4.67 | % | 4.68 | % | 4.69 | % | 4.75 | % | 4.75 | % | 4.74 | % | 4.74 | % | ||||||||||||||||||||||||||||||||||||||||||
| Average yield on investments allocated to life products | 4.79 | % | 4.80 | % | 4.78 | % | 4.79 | % | 4.79 | % | 4.83 | % | 4.85 | % | 4.83 | % | 4.84 | % | 4.84 | % | ||||||||||||||||||||||||||||||||||||||||||
| Total average yield | 4.70 | % | 4.81 | % | 4.81 | % | 4.87 | % | 4.80 | % | 4.87 | % | 4.92 | % | 4.91 | % | 4.92 | % | 4.91 | % | ||||||||||||||||||||||||||||||||||||||||||
| Allocated investment income | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Annuity: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fixed indexed annuities | $ | 108.4 | $ | 113.8 | $ | 115.9 | $ | 120.6 | $ | 458.7 | $ | 120.9 | $ | 127.8 | $ | 130.4 | $ | 133.1 | $ | 512.2 | ||||||||||||||||||||||||||||||||||||||||||
| Fixed interest annuities | 20.6 | 21.1 | 20.8 | 21.6 | 84.1 | 21.6 | 21.8 | 21.8 | 21.7 | 86.9 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other annuities | 5.5 | 5.6 | 5.5 | 5.6 | 22.2 | 5.5 | 5.6 | 5.6 | 5.5 | 22.2 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total investment income allocated to annuities | 134.5 | 140.5 | 142.2 | 147.8 | 565.0 | 148.0 | 155.2 | 157.8 | 160.3 | 621.3 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Health: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Supplemental health | 39.0 | 39.4 | 39.6 | 39.7 | 157.7 | 39.8 | 40.5 | 40.2 | 40.6 | 161.1 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Medicare supplement | 1.4 | 1.3 | 1.3 | 1.3 | 5.3 | 1.2 | 1.2 | 1.2 | 1.2 | 4.8 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Long-term care | 33.9 | 34.4 | 34.1 | 34.2 | 136.6 | 34.1 | 34.2 | 34.0 | 33.7 | 136.0 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total investment income allocated to health products | 74.3 | 75.1 | 75.0 | 75.2 | 299.6 | 75.1 | 75.9 | 75.4 | 75.5 | 301.9 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Life: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest sensitive | 13.2 | 13.2 | 13.3 | 13.5 | 53.2 | 13.9 | 13.9 | 14.0 | 14.1 | 55.9 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Traditional | 23.3 | 23.5 | 23.5 | 23.6 | 93.9 | 23.7 | 23.9 | 23.8 | 23.8 | 95.2 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total investment income allocated to life products | 36.5 | 36.7 | 36.8 | 37.1 | 147.1 | 37.6 | 37.8 | 37.8 | 37.9 | 151.1 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total allocated investment income | $ | 245.3 | $ | 252.3 | $ | 254.0 | $ | 260.1 | $ | 1,011.7 | $ | 260.7 | $ | 268.9 | $ | 271.0 | $ | 273.7 | $ | 1,074.3 | ||||||||||||||||||||||||||||||||||||||||||
Page 16
CNO FINANCIAL GROUP, INC.
Other Investment Data
(Dollars in millions)
(Unaudited)
| 1Q | 2Q | 3Q | 4Q | 1Q | 2Q | 3Q | 4Q | |||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2025 | 2025 | 2025 | 2025 | |||||||||||||||||||||||||||||||||||||||||||
| Average book value of invested assets and cash | $ | 27,897.0 | $ | 28,577.4 | $ | 29,716.2 | $ | 30,398.9 | $ | 30,755.7 | $ | 30,732.5 | $ | 30,878.3 | $ | 31,461.7 | ||||||||||||||||||||||||||||||||||
| New money rate (14) | 6.17 | % | 6.41 | % | 6.50 | % | 6.72 | % | 6.43 | % | 6.42 | % | 6.20 | % | 6.11 | % | ||||||||||||||||||||||||||||||||||
| Book yield (15) | 4.64 | % | 4.73 | % | 4.78 | % | 4.78 | % | 4.81 | % | 4.83 | % | 4.83 | % | 4.84 | % | ||||||||||||||||||||||||||||||||||
| Earned yield (16) | 4.06 | % | 4.71 | % | 4.71 | % | 5.16 | % | 4.71 | % | 4.73 | % | 4.77 | % | 5.04 | % | ||||||||||||||||||||||||||||||||||
Fair value of invested assets and cash | $ | 26,088.0 | $ | 27,528.0 | $ | 29,233.7 | $ | 28,964.4 | $ | 28,900.6 | $ | 28,899.5 | $ | 29,998.9 | $ | 30,601.7 | ||||||||||||||||||||||||||||||||||
Equity returns credited to policyholders | 139.7 | 38.9 | 67.6 | 7.5 | (70.2) | 79.5 | 98.2 | 11.5 | ||||||||||||||||||||||||||||||||||||||||||
Page 17
CNO FINANCIAL GROUP, INC.
2025 Significant Items
(Dollars in millions, except per share amounts)
(Unaudited)
The table below summarizes the financial impact of significant items on our 2025 net operating income. Management believes that identifying the impact of these items enhances the understanding of our operating results.
Year ended | ||||||||||||||||||||
| December 31, 2025 | ||||||||||||||||||||
| Actual results | Significant items | Excluding significant items | ||||||||||||||||||
| Insurance product margin (4) | ||||||||||||||||||||
| Annuity margin | $ | 238.6 | $ | (16.6) | (a) | $ | 222.0 | |||||||||||||
| Health margin | 556.6 | (21.1) | (a) | 535.5 | ||||||||||||||||
| Life margin | 272.4 | (10.4) | (a) | 262.0 | ||||||||||||||||
| Total insurance product margin | 1,067.6 | (48.1) | 1,019.5 | |||||||||||||||||
| Allocated expenses | (611.3) | — | (611.3) | |||||||||||||||||
| Income from insurance products (5) | 456.3 | (48.1) | 408.2 | |||||||||||||||||
| Fee income | 15.2 | — | 15.2 | |||||||||||||||||
| Investment income not allocated to product lines (9) | 169.4 | — | 169.4 | |||||||||||||||||
| Expenses not allocated to product lines | (87.7) | — | (87.7) | |||||||||||||||||
| Operating earnings before taxes | 553.2 | (48.1) | 505.1 | |||||||||||||||||
| Income tax (expense) benefit on operating income | (114.0) | 10.6 | (103.4) | |||||||||||||||||
| Net operating income (10) | $ | 439.2 | $ | (37.5) | $ | 401.7 | ||||||||||||||
| Net operating income per diluted share | $ | 4.40 | $ | (0.38) | $ | 4.02 | ||||||||||||||
___________
(a)Comprised of $41.3 million of the net favorable impact arising from our comprehensive annual actuarial review and $6.8 million of the favorable impact of an out-of-period adjustment which decreased reserves..
3Q25 Significant Items
(Dollars in millions, except per share amounts)
(Unaudited)
The table below summarizes the financial impact of significant items on our net operating income for the three months ended September 30, 2025. Management believes that identifying the impact of these items enhances the understanding of our operating results.
Three months ended | ||||||||||||||||||||
| September 30, 2025 | ||||||||||||||||||||
| Actual results | Significant items | Excluding significant items | ||||||||||||||||||
| Insurance product margin (4) | ||||||||||||||||||||
| Annuity margin | $ | 72.9 | $ | (16.6) | (a) | $ | 56.3 | |||||||||||||
| Health margin | 157.0 | (21.1) | (a) | 135.9 | ||||||||||||||||
| Life margin | 70.6 | (3.6) | (a) | 67.0 | ||||||||||||||||
| Total insurance product margin | 300.5 | (41.3) | 259.2 | |||||||||||||||||
| Allocated expenses | (151.0) | — | (151.0) | |||||||||||||||||
| Income from insurance products (5) | 149.5 | (41.3) | 108.2 | |||||||||||||||||
| Fee income | (3.9) | — | (3.9) | |||||||||||||||||
| Investment income not allocated to product lines (9) | 39.5 | — | 39.5 | |||||||||||||||||
| Expenses not allocated to product lines | (22.3) | — | (22.3) | |||||||||||||||||
| Operating earnings before taxes | 162.8 | (41.3) | 121.5 | |||||||||||||||||
| Income tax (expense) benefit on operating income | (35.6) | 9.1 | (26.5) | |||||||||||||||||
| Net operating income (10) | $ | 127.2 | $ | (32.2) | $ | 95.0 | ||||||||||||||
| Net operating income per diluted share | $ | 1.29 | $ | (0.33) | $ | 0.96 | ||||||||||||||
___________
(a)Comprised of $41.3 million of the net favorable impact arising from our comprehensive annual actuarial review.
Page 18
1Q25 Significant Items
(Dollars in millions, except per share amounts)
(Unaudited)
The table below summarizes the financial impact of significant items on our net operating income for the three months ended March 31, 2025. Management believes that identifying the impact of these items enhances the understanding of our operating results.
Three months ended | ||||||||||||||||||||
| March 31, 2025 | ||||||||||||||||||||
| Actual results | Significant items | Excluding significant items | ||||||||||||||||||
| Insurance product margin (4) | ||||||||||||||||||||
| Annuity margin | $ | 54.5 | $ | — | $ | 54.5 | ||||||||||||||
| Health margin | 126.2 | — | 126.2 | |||||||||||||||||
| Life margin | 68.2 | (6.8) | (a) | 61.4 | ||||||||||||||||
| Total insurance product margin | 248.9 | (6.8) | 242.1 | |||||||||||||||||
| Allocated expenses | (161.2) | — | (161.2) | |||||||||||||||||
| Income from insurance products (5) | 87.7 | (6.8) | 80.9 | |||||||||||||||||
| Fee income | (0.8) | — | (0.8) | |||||||||||||||||
| Investment income not allocated to product lines (9) | 38.0 | — | 38.0 | |||||||||||||||||
| Expenses not allocated to product lines | (20.3) | — | (20.3) | |||||||||||||||||
| Operating earnings before taxes | 104.6 | (6.8) | 97.8 | |||||||||||||||||
| Income tax (expense) benefit on operating income | (23.5) | 1.5 | (22.0) | |||||||||||||||||
| Net operating income (10) | $ | 81.1 | $ | (5.3) | $ | 75.8 | ||||||||||||||
| Net operating income per diluted share | $ | 0.79 | $ | (0.05) | $ | 0.74 | ||||||||||||||
___________
(a)Comprised of $6.8 million of the favorable impact of an out-of-period adjustment which decreased reserves.
2024 Significant Items
(Dollars in millions, except per share amounts)
(Unaudited)
The table below summarizes the financial impact of significant items on our 2024 net operating income. Management believes that identifying the impact of these items enhances the understanding of our operating results.
Year ended | ||||||||||||||||||||
| December 31, 2024 | ||||||||||||||||||||
| Actual results | Significant items | Excluding significant items | ||||||||||||||||||
| Insurance product margin (4) | ||||||||||||||||||||
| Annuity margin | $ | 274.2 | $ | (36.2) | (a) | $ | 238.0 | |||||||||||||
| Health margin | 516.8 | 8.2 | (a) | 525.0 | ||||||||||||||||
| Life margin | 249.0 | 0.7 | (a) | 249.7 | ||||||||||||||||
| Total insurance product margin | 1,040.0 | (27.3) | 1,012.7 | |||||||||||||||||
| Allocated expenses | (615.3) | — | (615.3) | |||||||||||||||||
| Income from insurance products (5) | 424.7 | (27.3) | 397.4 | |||||||||||||||||
| Fee income | 30.0 | — | 30.0 | |||||||||||||||||
| Investment income not allocated to product lines (9) | 167.9 | — | 167.9 | |||||||||||||||||
| Expenses not allocated to product lines | (71.8) | 2.9 | (b) | (68.9) | ||||||||||||||||
| Operating earnings before taxes | 550.8 | (24.4) | 526.4 | |||||||||||||||||
| Income tax (expense) benefit on operating income | (121.5) | 5.6 | (115.9) | |||||||||||||||||
| Net operating income (10) | $ | 429.3 | $ | (18.8) | $ | 410.5 | ||||||||||||||
| Net operating income per diluted share | $ | 3.97 | $ | (0.17) | $ | 3.80 | ||||||||||||||
___________
(a)Comprised of $27.3 million of net favorable impact arising from our comprehensive annual actuarial review.
(b)Comprised of $2.9 million of the unfavorable impact related to a fixed asset impairment.
Page 19
4Q24 Significant Items
(Dollars in millions, except per share amounts)
(Unaudited)
The table below summarizes the financial impact of significant items on our net operating income for the three months ended December 31, 2024. Management believes that identifying the impact of these items enhances the understanding of our operating results.
| Three months ended | ||||||||||||||||||||
| December 31, 2024 | ||||||||||||||||||||
| Actual results | Significant items | Excluding significant items | ||||||||||||||||||
| Insurance product margin (4) | ||||||||||||||||||||
| Annuity margin | $ | 55.0 | $ | — | $ | 55.0 | ||||||||||||||
| Health margin | 130.1 | 3.9 | (a) | 134.0 | ||||||||||||||||
| Life margin | 68.0 | — | 68.0 | |||||||||||||||||
| Total insurance product margin | 253.1 | 3.9 | 257.0 | |||||||||||||||||
| Allocated expenses | (146.1) | — | (146.1) | |||||||||||||||||
| Income from insurance products (5) | 107.0 | 3.9 | 110.9 | |||||||||||||||||
| Fee income | 20.6 | — | 20.6 | |||||||||||||||||
| Investment income not allocated to product lines (9) | 65.3 | — | 65.3 | |||||||||||||||||
| Expenses not allocated to product lines | (19.0) | — | (19.0) | |||||||||||||||||
| Operating earnings before taxes | 173.9 | 3.9 | 177.8 | |||||||||||||||||
| Income tax (expense) benefit on operating income | (35.9) | (0.8) | (36.7) | |||||||||||||||||
| Net operating income (10) | $ | 138.0 | $ | 3.1 | $ | 141.1 | ||||||||||||||
| Net operating income per diluted share | $ | 1.31 | $ | 0.03 | $ | 1.34 | ||||||||||||||
___________
(a)Comprised of $3.9 million of the unfavorable impact arising from our comprehensive annual actuarial review.
3Q24 Significant Items
(Dollars in millions, except per share amounts)
(Unaudited)
The table below summarizes the financial impact of significant items on our net operating income for the three months ended September 30, 2024. Management believes that identifying the impact of these items enhances the understanding of our operating results.
| Three months ended | ||||||||||||||||||||
| September 30, 2024 | ||||||||||||||||||||
| Actual results | Significant items (a) | Excluding significant items | ||||||||||||||||||
| Insurance product margin (4) | ||||||||||||||||||||
| Annuity margin | $ | 91.1 | $ | (36.2) | (b) | $ | 54.9 | |||||||||||||
| Health margin | 127.8 | 4.3 | (b) | 132.1 | ||||||||||||||||
| Life margin | 63.3 | 0.7 | (b) | 64.0 | ||||||||||||||||
| Total insurance product margin | 282.2 | (31.2) | 251.0 | |||||||||||||||||
| Allocated expenses | (153.0) | — | (153.0) | |||||||||||||||||
| Income from insurance products (5) | 129.2 | (31.2) | 98.0 | |||||||||||||||||
| Fee income | (2.7) | — | (2.7) | |||||||||||||||||
| Investment income not allocated to product lines (9) | 45.5 | — | 45.5 | |||||||||||||||||
| Expenses not allocated to product lines | (18.5) | 2.9 | (c) | (15.6) | ||||||||||||||||
| Operating earnings before taxes | 153.5 | (28.3) | 125.2 | |||||||||||||||||
| Income tax (expense) benefit on operating income | (34.3) | 6.4 | (27.9) | |||||||||||||||||
| Net operating income (10) | $ | 119.2 | $ | (21.9) | $ | 97.3 | ||||||||||||||
| Net operating income per diluted share | $ | 1.11 | $ | (0.19) | $ | 0.92 | ||||||||||||||
___________
(a)Significant items impacting the health margin were revised from $8.2 million reported in September 30, 2024 to $4.3 million.
(b)Comprised of $31.2 million of net favorable impact arising from our comprehensive annual actuarial review.
(c)Comprised of $2.9 million of the unfavorable impact related to a fixed asset impairment.
Page 20
Notes
(1)Excludes accumulated other comprehensive income (loss). Management believes this non-GAAP measure is useful because it removes the volatility that arises from changes in the unrealized appreciation (depreciation) of our investments.
(2)Shareholders' equity divided by common shares outstanding.
(3)Book value per diluted share reflects the potential dilution that could occur if outstanding stock options were exercised and restricted stock and performance units were vested. The dilution from options, restricted shares and performance units is calculated using the treasury stock method. Under this method, we assume the proceeds from the exercise of the options (or the unrecognized compensation expense with respect to restricted stock and performance units) will be used to purchase shares of our common stock at the closing market price on the last day of the period.
(4)Insurance product margin is management’s measure of profitability of its annuity, health and life product lines’ performance and consists of insurance policy income plus allocated investment income less insurance policy benefits, interest credited, commissions, advertising expense and amortization of acquisition costs. See note (8) for definition of income from insurance products.
(5)Investment income is allocated to the product lines using the book yield of investments backing the block of business, which is applied to the average net insurance liabilities for the block in each period. See note (11) for definition of net insurance liabilities.
(6)Excludes the change in market values of the underlying options supporting the fixed indexed annuity products and corresponding amount credited to policyholder account balances. Such amounts were $128.6 million, $34.9 million, $62.1 million, $6.2 million, $(63.5) million, $70.4 million, $89.4 million, and $10.2 million in 1Q24, 2Q24, 3Q24, 4Q24, 1Q25, 2Q25, 3Q25 and 4Q25, respectively.
(7)Excludes the change in market values of the underlying options supporting the fixed indexed life products and corresponding amount credited to policyholder account balances. Such amounts were $11.1 million, $4.0 million, $5.5 million, $1.3 million, $(6.7) million, $9.1 million, $8.8 million, and $1.3 million in 1Q24, 2Q24, 3Q24, 4Q24, 1Q25, 2Q25, 3Q25 and 4Q25, respectively.
(8)Income from insurance products is the sum of the insurance product margins of the annuity, health and life product lines, less expenses allocated to the insurance product lines. It excludes the income from our fee income business, investment income not allocated to product lines, net expenses not allocated to product lines (primarily holding company expenses) and income taxes. Management believes this information helps provide an additional understanding of the business and a more meaningful analysis of results of our insurance product lines. Income from insurance products, a non-GAAP measure, is a component of net operating income, which is reconciled to net income on page 5 of this Quarterly Financial Supplement.
(9)Investment income not allocated to product lines represents net investment income less: (i) equity returns credited to policyholder account balances; (ii) the investment income allocated to our product lines; (iii) interest expense on notes payable, investment borrowings and financing arrangements; (iv) expenses related to the FABN program; and (v) certain expenses related to benefit plans that are offset by special-purpose investment income; plus (vi) the impact of annual option forfeitures related to fixed indexed annuity surrenders. Investment income not allocated to product lines includes investment income on investments in excess of amounts allocated to product lines, investments held by our holding companies, the spread we earn from our FHLB investment borrowing and FABN programs and variable components of investment income (including call and prepayment income, adjustments to returns on structured securities due to cash flow changes, income (loss) from company-owned life insurance ("COLI") and alternative investment income not allocated to product lines), net of interest expense on corporate debt and financing arrangements. The spread earned from our FHLB investment borrowing and FABN programs includes the investment income on the matched assets less: (i) interest on investment borrowings related to the FHLB investment borrowing program; (ii) interest credited on funding agreements; and (iii) amortization of deferred acquisition costs related to the FABN program.
(10)Management believes that an analysis of net income applicable to common stock before: (i) net realized investment gains or losses from disposals, impairments and the change in allowance for credit losses, net of taxes; (ii) net change in market value of investments recognized in earnings, net of taxes; (iii) changes in fair value of embedded derivative liabilities and market risk benefits ("MRBs") related to our fixed indexed annuities, net of taxes; (iv) fair value changes related to the agent deferred compensation plan, net of taxes; (v) gains or losses related to material reinsurance transactions, net of taxes; (vi) loss on extinguishment of debt, net of taxes; (vii) changes in the valuation allowance for deferred tax assets and other tax items; and (viii) costs related to our three-year project to modernize certain elements of our technology ("TechMod") that are incremental to normal spend and will not recur following implementation, net of taxes; (ix) goodwill and other asset impairment expenses, net of taxes; (x) gains or losses related to divested business, net of taxes; and (xi) other non-operating items including earnings attributable to variable interest entities, net of taxes ("net operating income," a non-GAAP financial measure) is important to evaluate the financial performance of the company, and is a key measure commonly used in the life insurance industry. The income tax expense or benefit allocated to the items included in net non-operating income (loss) represents the current and deferred income tax expense or benefit allocated to the items included in non-operating earnings. Management believes this information helps provide a better understanding of the business and a more meaningful analysis of results of our insurance product lines. The table above reconciles the non-GAAP measure to the corresponding GAAP measure.
(11)Net insurance liabilities for the purpose of allocating investment income to product lines are equal to: (i) policyholder account values for interest sensitive products; (ii) total reserves before the fair value adjustments reflected in accumulated other comprehensive income (loss), if applicable, for all other products; less (iii) amounts related to reinsured business; (iv) deferred acquisition costs; (v) the present value of future profits; and (vi) the value of unexpired options credited to insurance liabilities.
(12)Margin/average net insurance liabilities for quarterly periods is calculated by annualizing the quarters' margin divided by the average net insurance liabilities.
(13)Based on statutory accounting practices prescribed or permitted by regulatory authorities for CNO Financial's U.S. based insurance subsidiaries after appropriate elimination of intercompany accounts among such subsidiaries. Such accounting practices differ from accounting principles generally accepted in the United States of America.
Page 21
(14)The new money rate is for the investments purchased during the period to support our insurance products and capital. It excludes the new money rate on investments purchased with investment borrowings under our FHLB and FABN programs and investments purchased by the variable interest entities.
(15)Book yield on fixed maturity investments, excluding investments held in the: (i) FHLB and FABN programs; and (ii) the investments held by the variable interest entities.
(16)Earned yield is the investment income earned during the period divided by the average book value of the investment portfolio, excluding: (i) investments held in the FHLB and FABN programs; and (ii) the investments held by the variable interest entities.
Page 22
1 Unless otherwise specified, comparisons in this presentation are between 4Q24 and 4Q25. Fourth Quarter 2025 Financial and operating results for the period ended December 31, 2025 February 5, 2026
2 Certain statements made in this presentation should be considered forward-looking statements as defined in the Private Securities Litigation Reform Act of 1995. These include statements about future results of operations and capital plans. We caution investors that these forward-looking statements are not guarantees of future performance, and actual results may differ materially. Investors should consider the important risks and uncertainties that may cause actual results to differ, including those included in our press release issued on February 5, 2026, our Quarterly Reports on Form 10-Q, our Annual Report on Form 10-K and other filings we make with the Securities and Exchange Commission. We assume no obligation to update this presentation, which speaks as of today’s date. Forward-Looking Statements This presentation contains financial measures that differ from the comparable measures under Generally Accepted Accounting Principles (GAAP). Reconciliations between those non-GAAP measures and the comparable GAAP measures are included in the Appendix, or on the page such measure is presented. While management believes the measures are useful to enhance understanding and comparability of our financial results, these non-GAAP measures should not be considered substitutes for the most directly comparable GAAP measures. Additional information concerning non-GAAP measures is included in our periodic filings with the Securities and Exchange Commission that are available in the “Investors – Financials – SEC Filings” section of CNO’s website, CNOinc.com. Non-GAAP Measures IMPORTANT LEGAL INFORMATION
3 OUR PURPOSE We secure the future of middle-income America. OUR MISSION We secure the future of middle-income America by providing insurance and financial services that help protect their health, income and retirement needs, while building enduring value for all our stakeholders.
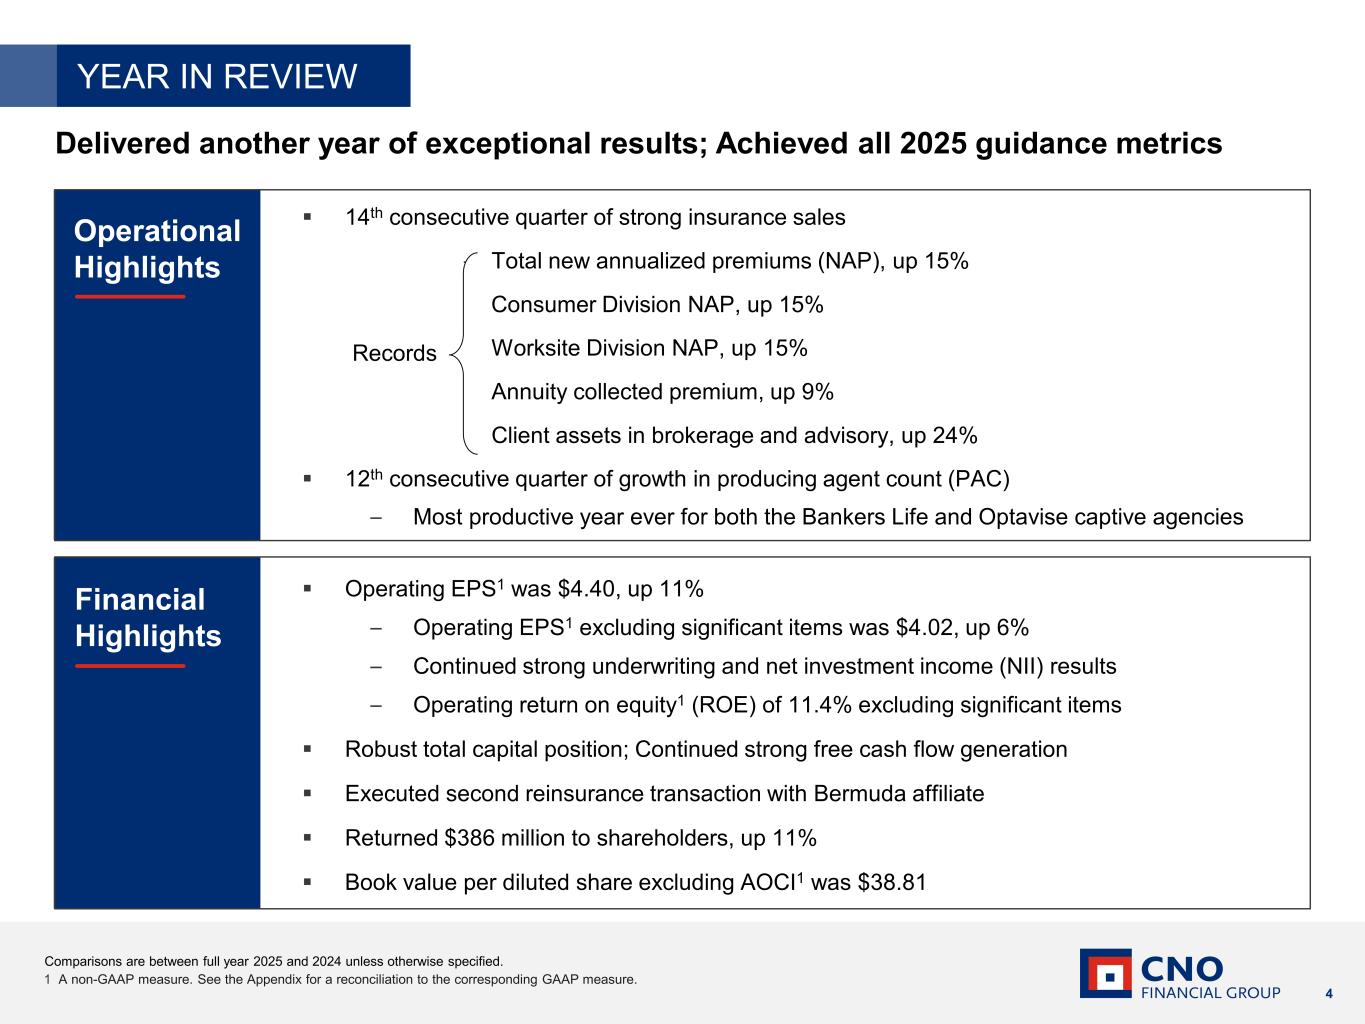
4 1 A non-GAAP measure. See the Appendix for a reconciliation to the corresponding GAAP measure. Operational Highlights Financial Highlights YEAR IN REVIEW Delivered another year of exceptional results; Achieved all 2025 guidance metrics Operating EPS1 was $4.40, up 11% – Operating EPS1 excluding significant items was $4.02, up 6% – Continued strong underwriting and net investment income (NII) results – Operating return on equity1 (ROE) of 11.4% excluding significant items Robust total capital position; Continued strong free cash flow generation Executed second reinsurance transaction with Bermuda affiliate Returned $386 million to shareholders, up 11% Book value per diluted share excluding AOCI1 was $38.81 14th consecutive quarter of strong insurance sales – Total new annualized premiums (NAP), up 15% – Consumer Division NAP, up 15% – Worksite Division NAP, up 15% – Annuity collected premium, up 9% – Client assets in brokerage and advisory, up 24% 12th consecutive quarter of growth in producing agent count (PAC) – Most productive year ever for both the Bankers Life and Optavise captive agencies Records Comparisons are between full year 2025 and 2024 unless otherwise specified.
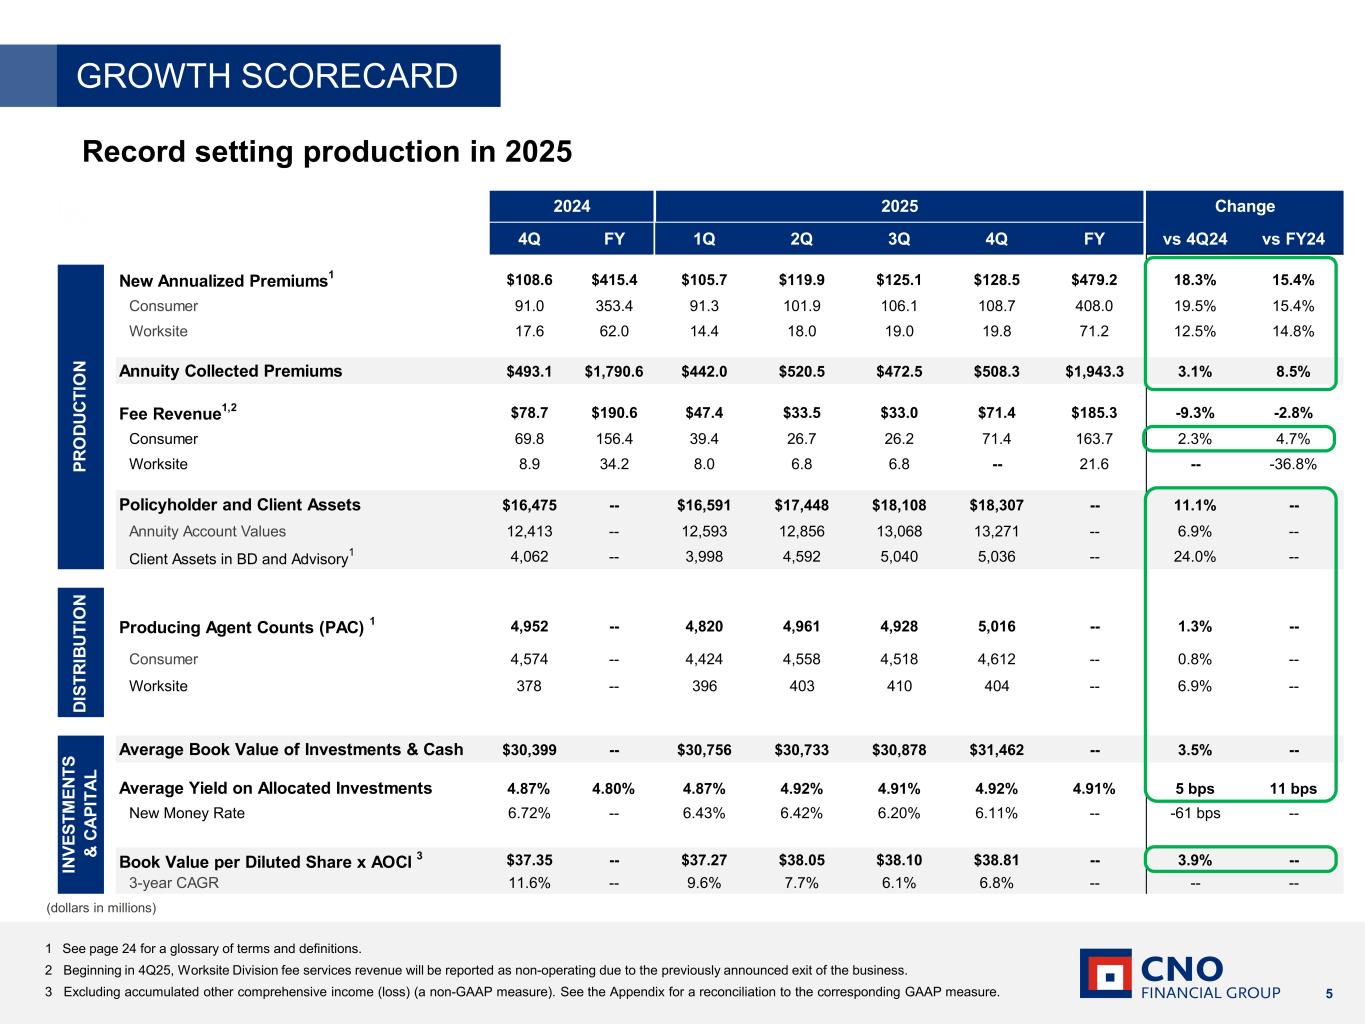
5 4Q FY 1Q 2Q 3Q 4Q FY vs 4Q24 vs FY24 New Annualized Premiums1 $108.6 $415.4 $105.7 $119.9 $125.1 $128.5 $479.2 18.3% 15.4% Consumer 91.0 353.4 91.3 101.9 106.1 108.7 408.0 19.5% 15.4% Worksite 17.6 62.0 14.4 18.0 19.0 19.8 71.2 12.5% 14.8% Annuity Collected Premiums $493.1 $1,790.6 $442.0 $520.5 $472.5 $508.3 $1,943.3 3.1% 8.5% Fee Revenue1,2 $78.7 $190.6 $47.4 $33.5 $33.0 $71.4 $185.3 -9.3% -2.8% Consumer 69.8 156.4 39.4 26.7 26.2 71.4 163.7 2.3% 4.7% Worksite 8.9 34.2 8.0 6.8 6.8 -- 21.6 -- -36.8% Policyholder and Client Assets $16,475 -- $16,591 $17,448 $18,108 $18,307 -- 11.1% -- Annuity Account Values 12,413 -- 12,593 12,856 13,068 13,271 -- 6.9% -- Client Assets in BD and Advisory1 4,062 -- 3,998 4,592 5,040 5,036 -- 24.0% -- Producing Agent Counts (PAC) 1 4,952 -- 4,820 4,961 4,928 5,016 -- 1.3% -- Consumer 4,574 -- 4,424 4,558 4,518 4,612 -- 0.8% -- Worksite 378 -- 396 403 410 404 -- 6.9% -- Average Book Value of Investments & Cash $30,399 -- $30,756 $30,733 $30,878 $31,462 -- 3.5% -- Average Yield on Allocated Investments 4.87% 4.80% 4.87% 4.92% 4.91% 4.92% 4.91% 5 bps 11 bps New Money Rate 6.72% -- 6.43% 6.42% 6.20% 6.11% -- -61 bps -- Book Value per Diluted Share x AOCI 3 $37.35 -- $37.27 $38.05 $38.10 $38.81 -- 3.9% -- 3-year CAGR 11.6% -- 9.6% 7.7% 6.1% 6.8% -- -- -- Change20252024 IN VE ST M EN TS & CA PI TA L PR O DU CT IO N DI ST RI BU TI O N GROWTH SCORECARD Record setting production in 2025 (dollars in millions) 1 See page 24 for a glossary of terms and definitions. 2 Beginning in 4Q25, Worksite Division fee services revenue will be reported as non-operating due to the previously announced exit of the business. 3 Excluding accumulated other comprehensive income (loss) (a non-GAAP measure). See the Appendix for a reconciliation to the corresponding GAAP measure.
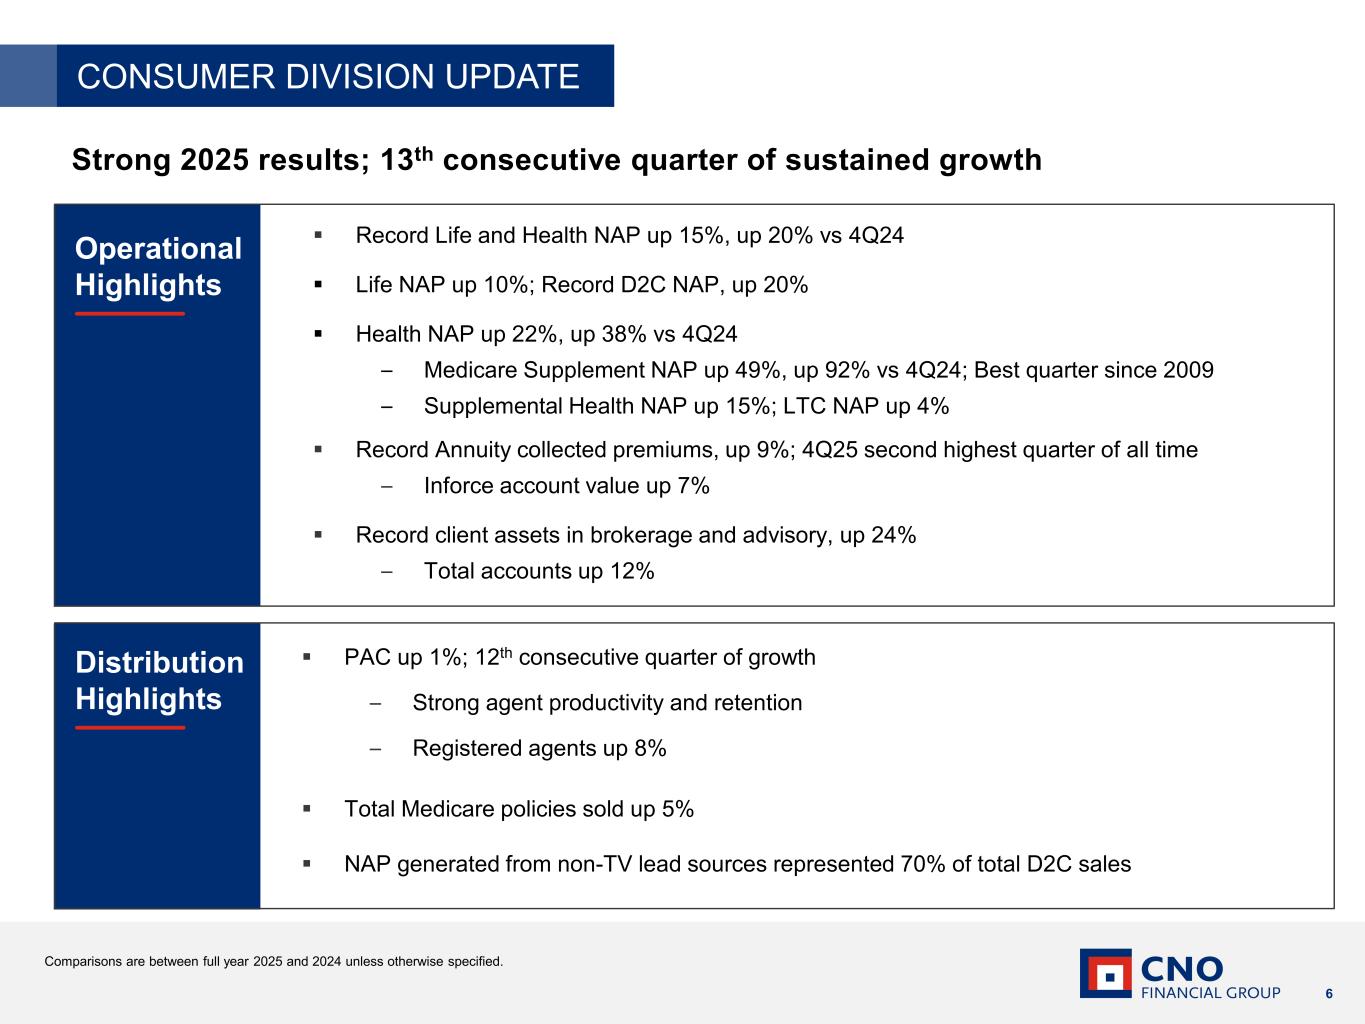
6 CONSUMER DIVISION UPDATE Strong 2025 results; 13th consecutive quarter of sustained growth PAC up 1%; 12th consecutive quarter of growth – Strong agent productivity and retention – Registered agents up 8% Total Medicare policies sold up 5% NAP generated from non-TV lead sources represented 70% of total D2C sales Record Life and Health NAP up 15%, up 20% vs 4Q24 Life NAP up 10%; Record D2C NAP, up 20% Health NAP up 22%, up 38% vs 4Q24 – Medicare Supplement NAP up 49%, up 92% vs 4Q24; Best quarter since 2009 – Supplemental Health NAP up 15%; LTC NAP up 4% Record Annuity collected premiums, up 9%; 4Q25 second highest quarter of all time – Inforce account value up 7% Record client assets in brokerage and advisory, up 24% – Total accounts up 12% Operational Highlights Distribution Highlights Comparisons are between full year 2025 and 2024 unless otherwise specified.
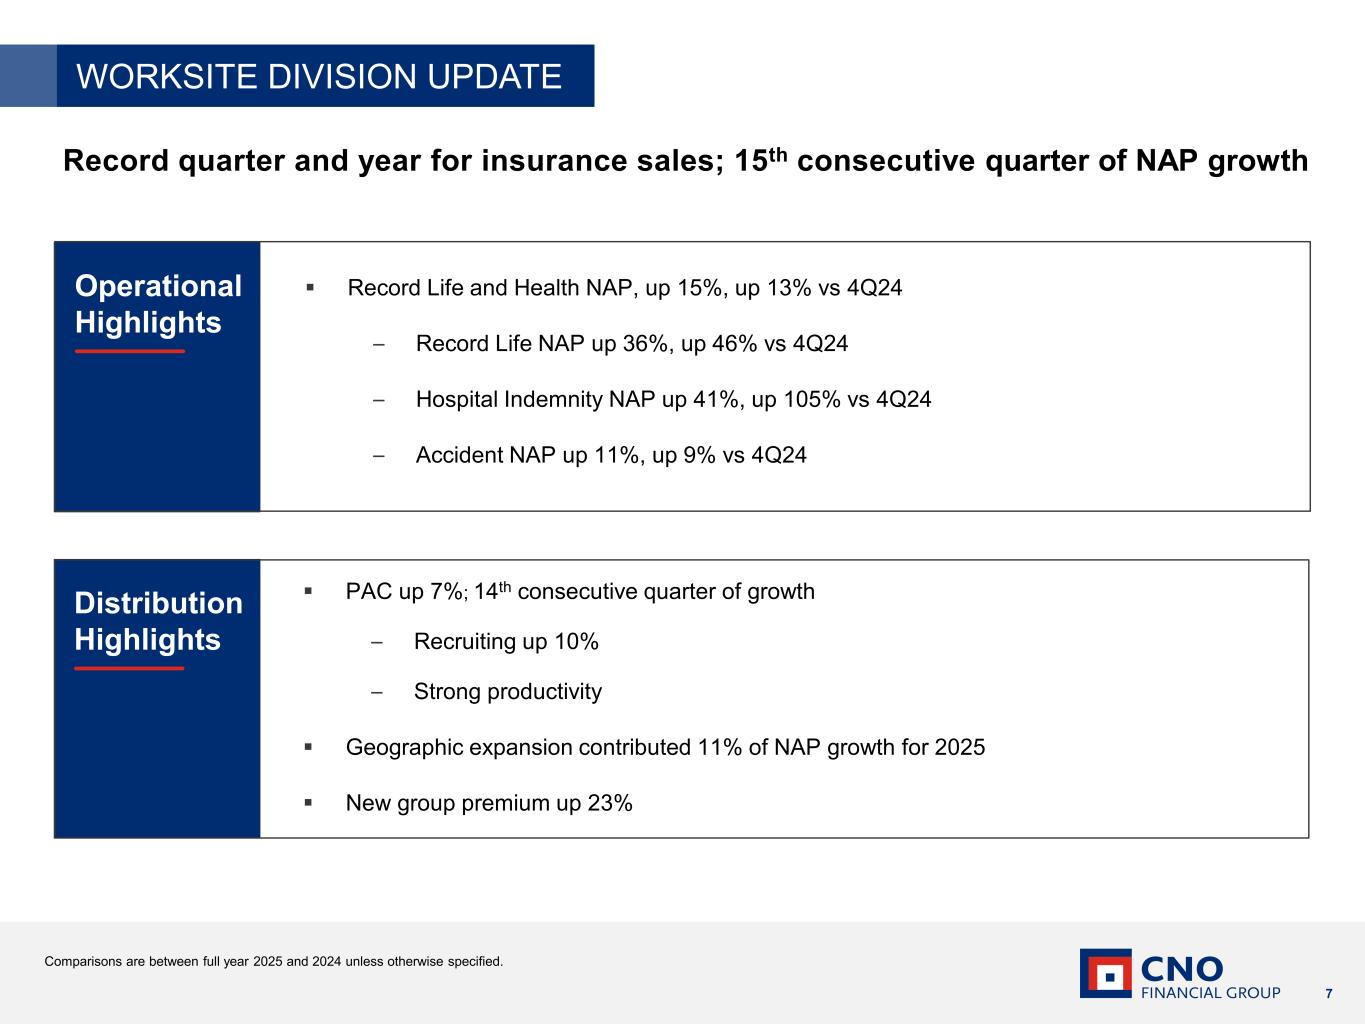
7 WORKSITE DIVISION UPDATE Record quarter and year for insurance sales; 15th consecutive quarter of NAP growth Record Life and Health NAP, up 15%, up 13% vs 4Q24 – Record Life NAP up 36%, up 46% vs 4Q24 – Hospital Indemnity NAP up 41%, up 105% vs 4Q24 – Accident NAP up 11%, up 9% vs 4Q24 PAC up 7%; 14th consecutive quarter of growth – Recruiting up 10% – Strong productivity Geographic expansion contributed 11% of NAP growth for 2025 New group premium up 23% Operational Highlights Distribution Highlights Comparisons are between full year 2025 and 2024 unless otherwise specified.
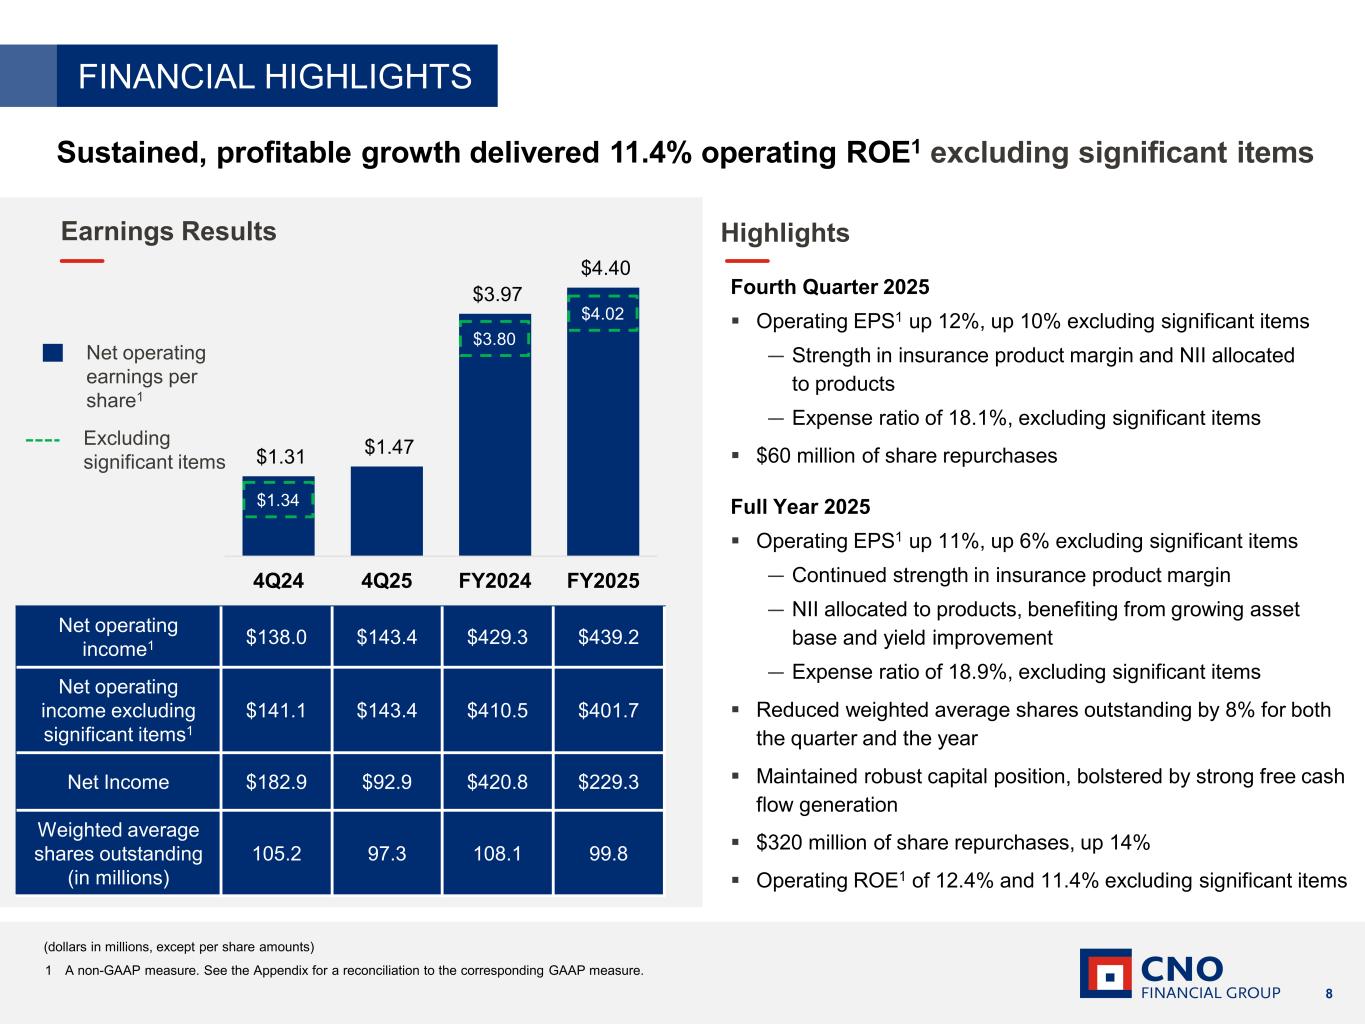
8 1 A non-GAAP measure. See the Appendix for a reconciliation to the corresponding GAAP measure. Net operating earnings per share1 (dollars in millions, except per share amounts) Earnings Results FINANCIAL HIGHLIGHTS Excluding significant items Sustained, profitable growth delivered 11.4% operating ROE1 excluding significant items Highlights Net operating income1 $138.0 $143.4 $429.3 $439.2 Net operating income excluding significant items1 $141.1 $143.4 $410.5 $401.7 Net Income $182.9 $92.9 $420.8 $229.3 Weighted average shares outstanding (in millions) 105.2 97.3 108.1 99.8 $1.31 $1.47 $3.97 $4.40 4Q24 4Q25 FY2024 FY2025 $1.34 $3.80 Fourth Quarter 2025 Operating EPS1 up 12%, up 10% excluding significant items — Strength in insurance product margin and NII allocated to products — Expense ratio of 18.1%, excluding significant items $60 million of share repurchases Full Year 2025 Operating EPS1 up 11%, up 6% excluding significant items — Continued strength in insurance product margin — NII allocated to products, benefiting from growing asset base and yield improvement — Expense ratio of 18.9%, excluding significant items Reduced weighted average shares outstanding by 8% for both the quarter and the year Maintained robust capital position, bolstered by strong free cash flow generation $320 million of share repurchases, up 14% Operating ROE1 of 12.4% and 11.4% excluding significant items $4.02
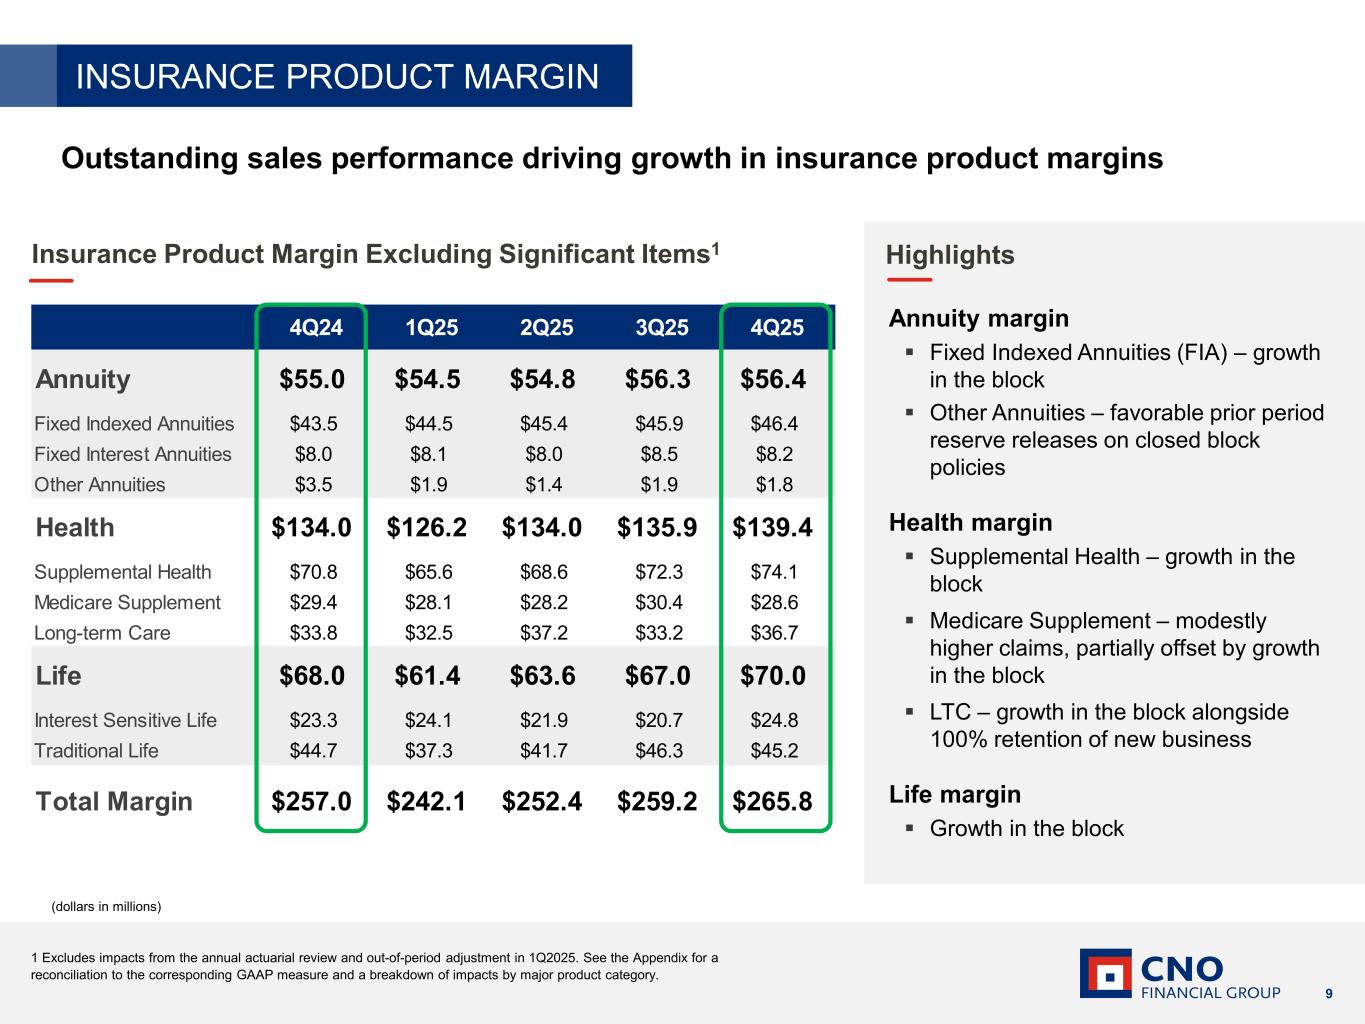
9 (dollars in millions) Insurance Product Margin Excluding Significant Items1 1 Excludes impacts from the annual actuarial review and out-of-period adjustment in 1Q2025. See the Appendix for a reconciliation to the corresponding GAAP measure and a breakdown of impacts by major product category. Annuity margin Fixed Indexed Annuities (FIA) – growth in the block Other Annuities – favorable prior period reserve releases on closed block policies Health margin Supplemental Health – growth in the block Medicare Supplement – modestly higher claims, partially offset by growth in the block LTC – growth in the block alongside 100% retention of new business Life margin Growth in the block Highlights INSURANCE PRODUCT MARGIN Outstanding sales performance driving growth in insurance product margins 4Q24 1Q25 2Q25 3Q25 4Q25 Annuity $55.0 $54.5 $54.8 $56.3 $56.4 Fixed Indexed Annuities $43.5 $44.5 $45.4 $45.9 $46.4 Fixed Interest Annuities $8.0 $8.1 $8.0 $8.5 $8.2 Other Annuities $3.5 $1.9 $1.4 $1.9 $1.8 Health $134.0 $126.2 $134.0 $135.9 $139.4 Supplemental Health $70.8 $65.6 $68.6 $72.3 $74.1 Medicare Supplement $29.4 $28.1 $28.2 $30.4 $28.6 Long-term Care $33.8 $32.5 $37.2 $33.2 $36.7 Life $68.0 $61.4 $63.6 $67.0 $70.0 Interest Sensitive Life $23.3 $24.1 $21.9 $20.7 $24.8 Traditional Life $44.7 $37.3 $41.7 $46.3 $45.2 Total Margin $257.0 $242.1 $252.4 $259.2 $265.8
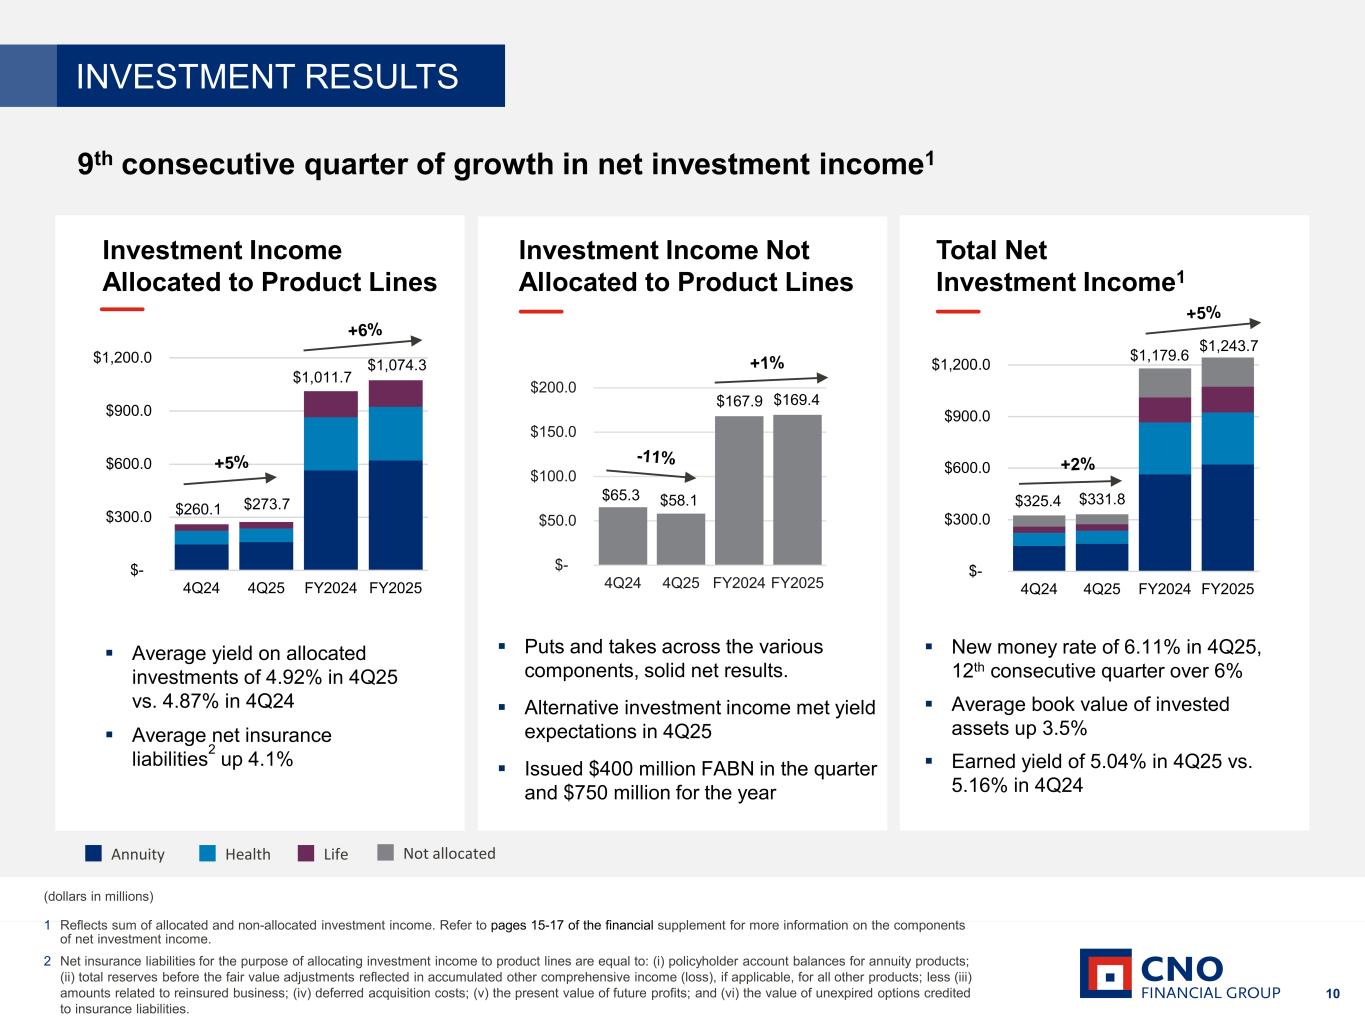
10 1 Reflects sum of allocated and non-allocated investment income. Refer to pages 15-17 of the financial supplement for more information on the components of net investment income. 2 Net insurance liabilities for the purpose of allocating investment income to product lines are equal to: (i) policyholder account balances for annuity products; (ii) total reserves before the fair value adjustments reflected in accumulated other comprehensive income (loss), if applicable, for all other products; less (iii) amounts related to reinsured business; (iv) deferred acquisition costs; (v) the present value of future profits; and (vi) the value of unexpired options credited to insurance liabilities. Average yield on allocated investments of 4.92% in 4Q25 vs. 4.87% in 4Q24 Average net insurance liabilities2 up 4.1% Puts and takes across the various components, solid net results. Alternative investment income met yield expectations in 4Q25 Issued $400 million FABN in the quarter and $750 million for the year Investment Income Allocated to Product Lines Investment Income Not Allocated to Product Lines Annuity Health Life Not allocated $- $300.0 $600.0 $900.0 $1,200.0 4Q24 4Q25 FY2024 FY2025 $- $50.0 $100.0 $150.0 $200.0 4Q24 4Q25 FY2024 FY2025 $- $300.0 $600.0 $900.0 $1,200.0 4Q24 4Q25 FY2024 FY2025 INVESTMENT RESULTS (dollars in millions) New money rate of 6.11% in 4Q25, 12th consecutive quarter over 6% Average book value of invested assets up 3.5% Earned yield of 5.04% in 4Q25 vs. 5.16% in 4Q24 $260.1 $273.7 $1,011.7 $1,074.3 $65.3 $58.1 $167.9 $169.4 $1,243.7$1,179.6 $331.8$325.4 9th consecutive quarter of growth in net investment income1 Total Net Investment Income1
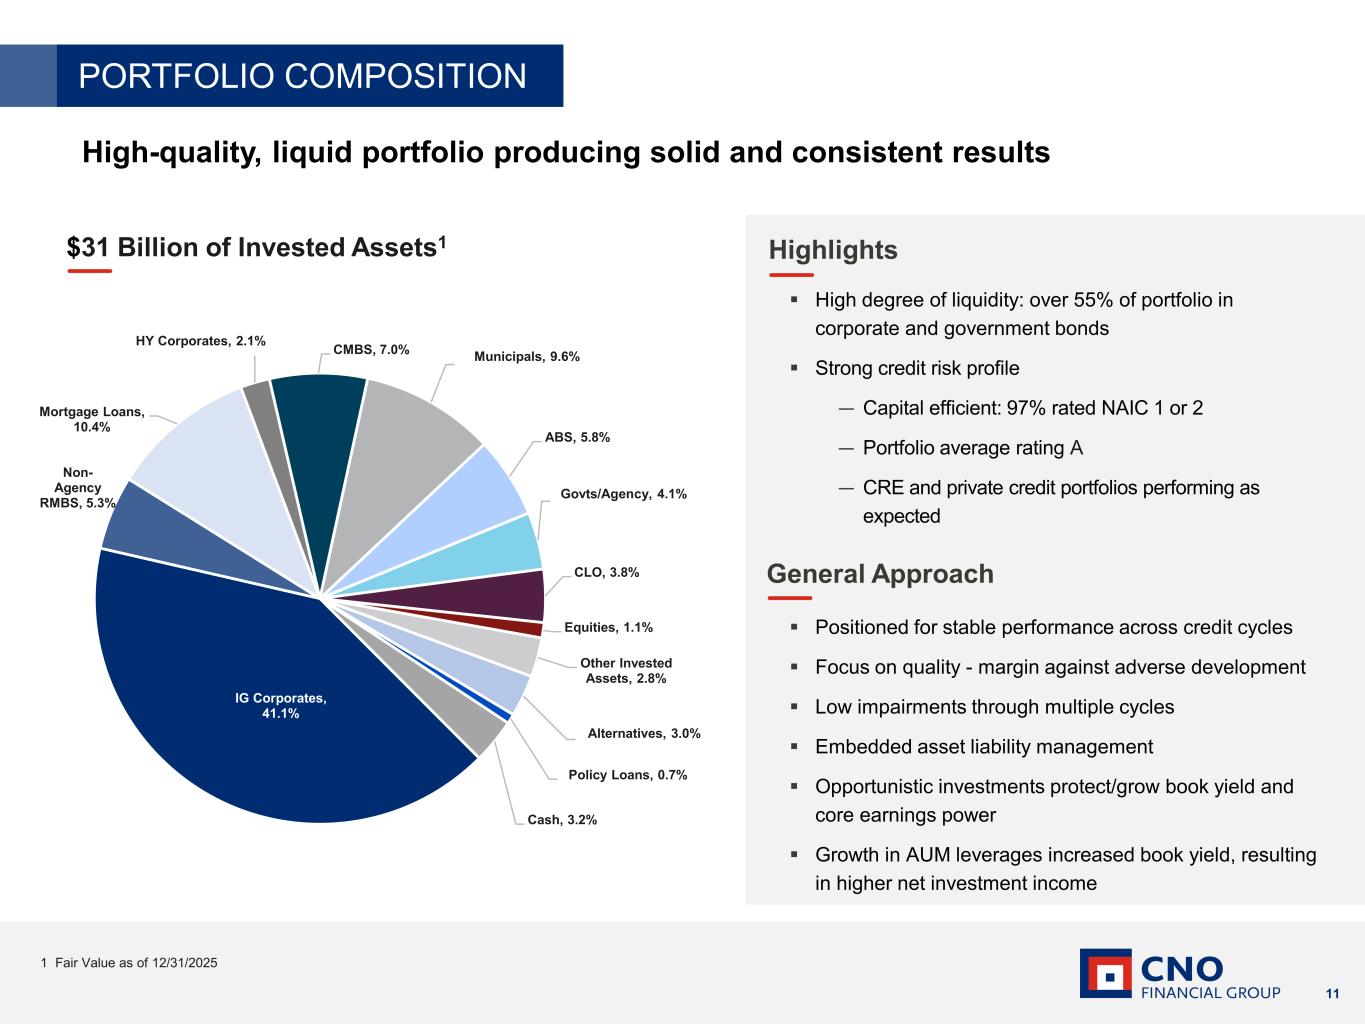
11 1 Fair Value as of 12/31/2025 PORTFOLIO COMPOSITION High-quality, liquid portfolio producing solid and consistent results Highlights General Approach $31 Billion of Invested Assets1 High degree of liquidity: over 55% of portfolio in corporate and government bonds Strong credit risk profile — Capital efficient: 97% rated NAIC 1 or 2 — Portfolio average rating A — CRE and private credit portfolios performing as expected Positioned for stable performance across credit cycles Focus on quality - margin against adverse development Low impairments through multiple cycles Embedded asset liability management Opportunistic investments protect/grow book yield and core earnings power Growth in AUM leverages increased book yield, resulting in higher net investment income IG Corporates, 41.1% Non- Agency RMBS, 5.3% Mortgage Loans, 10.4% HY Corporates, 2.1% CMBS, 7.0% Municipals, 9.6% ABS, 5.8% Govts/Agency, 4.1% CLO, 3.8% Equities, 1.1% Other Invested Assets, 2.8% Alternatives, 3.0% Policy Loans, 0.7% Cash, 3.2%
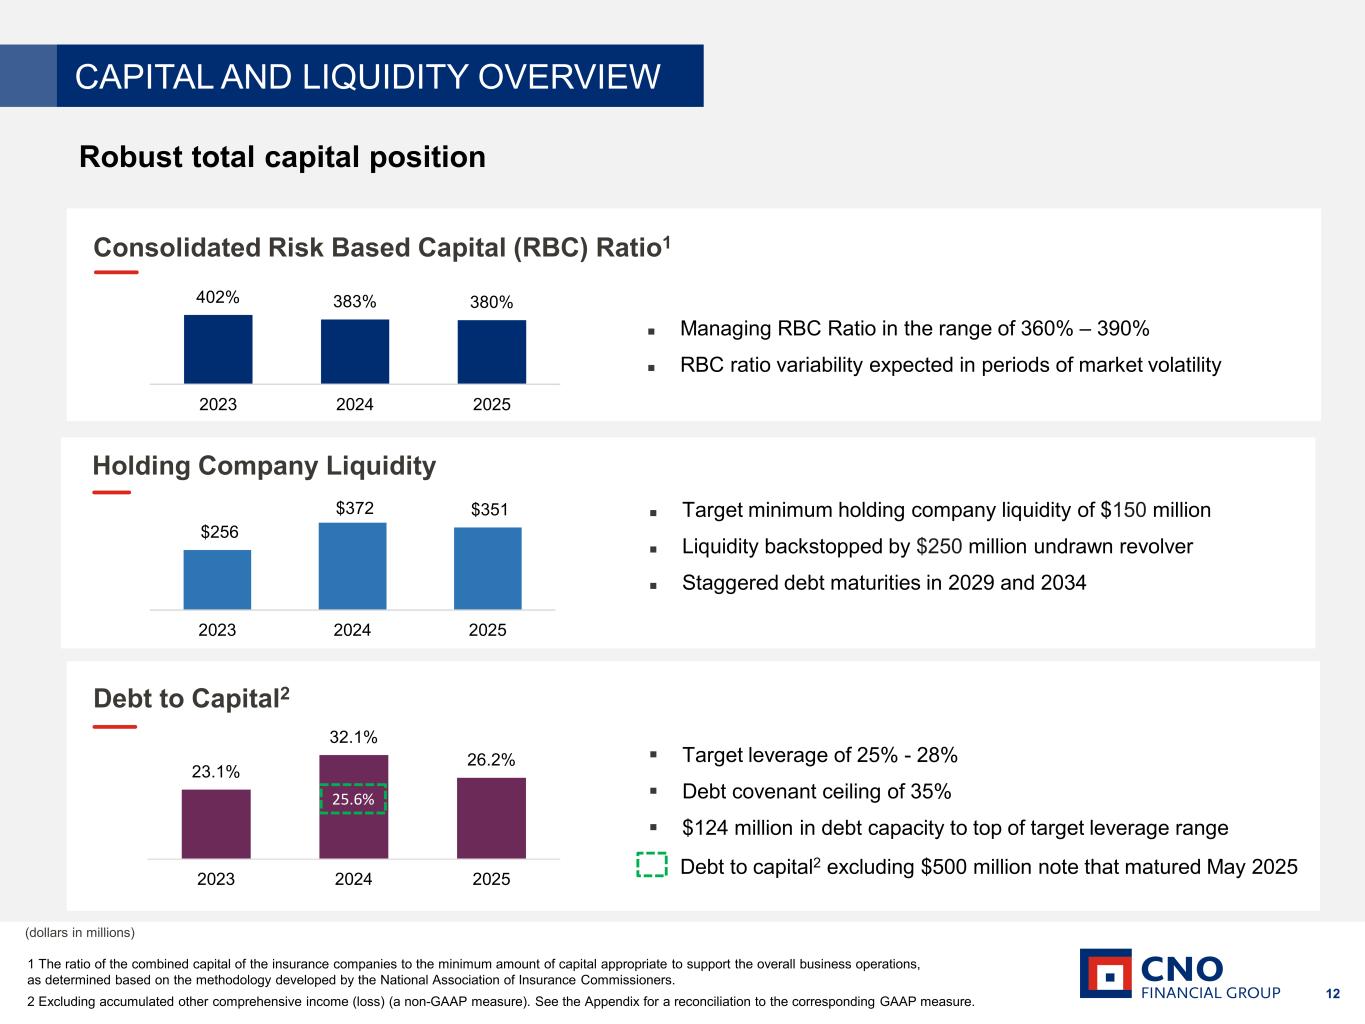
12 Debt to Capital2 Consolidated Risk Based Capital (RBC) Ratio1 Holding Company Liquidity 1 The ratio of the combined capital of the insurance companies to the minimum amount of capital appropriate to support the overall business operations, as determined based on the methodology developed by the National Association of Insurance Commissioners. 2 Excluding accumulated other comprehensive income (loss) (a non-GAAP measure). See the Appendix for a reconciliation to the corresponding GAAP measure. (dollars in millions) Managing RBC Ratio in the range of 360% – 390% RBC ratio variability expected in periods of market volatility Target leverage of 25% - 28% Debt covenant ceiling of 35% $124 million in debt capacity to top of target leverage range Target minimum holding company liquidity of $150 million Liquidity backstopped by $250 million undrawn revolver Staggered debt maturities in 2029 and 2034 CAPITAL AND LIQUIDITY OVERVIEW Robust total capital position Debt to capital2 excluding $500 million note that matured May 2025 402% 383% 380% 2023 2024 2025 $256 $372 $351 2023 2024 2025 23.1% 32.1% 26.2% 2023 2024 2025 25.6%
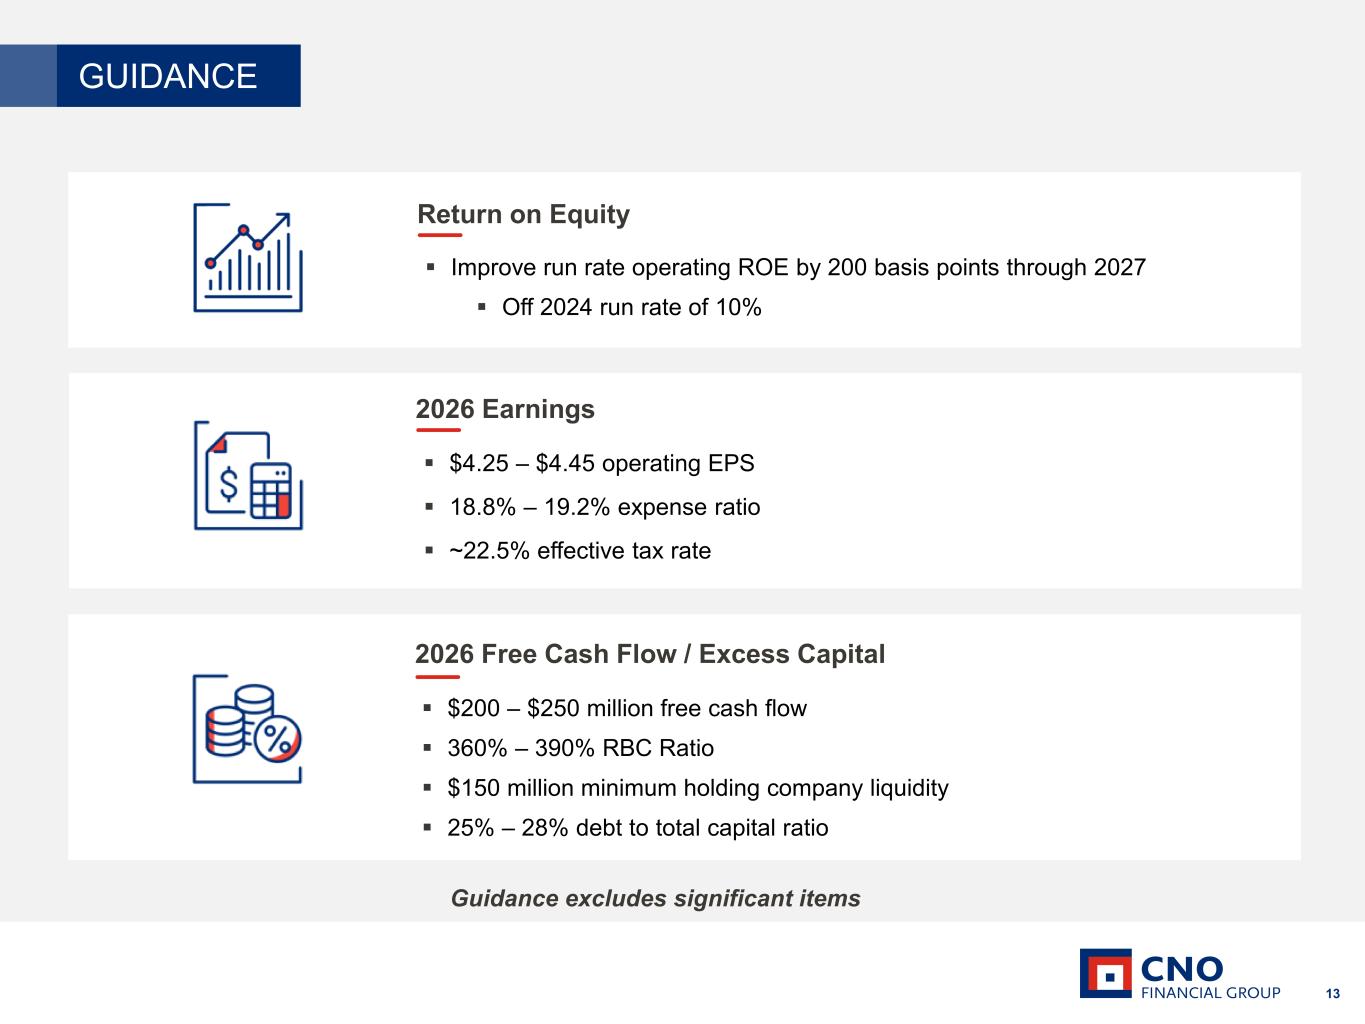
13 2026 Earnings 2026 Free Cash Flow / Excess Capital GUIDANCE Guidance excludes significant items $4.25 – $4.45 operating EPS 18.8% – 19.2% expense ratio ~22.5% effective tax rate $200 – $250 million free cash flow 360% – 390% RBC Ratio $150 million minimum holding company liquidity 25% – 28% debt to total capital ratio Return on Equity Improve run rate operating ROE by 200 basis points through 2027 Off 2024 run rate of 10%
14 4 5 3 2 1 Exclusive middle-market focus and “last-mile” captive distribution create a durable competitive moat Significant demographic tailwinds Proven investment results built on a foundation of strong asset quality and disciplined management Strong balance sheet and robust free cash flow resilient against market events WHY INVEST IN CNO 6 Track record of execution and delivering on our promises Delivering growth while improving ROE and modernizing the business
15 Questions and Answers
16 Cash Flow Profile Slide 17 Broker-Dealer/Registered Investment Advisor Slide 18 Expense Ratio Slide 19 Levers To Drive Operating ROE Slide 20 Financial Results Seasonality Slide 21 New Money Summary Slide 22 Private Credit Slide 23 Long-Term Care Insurance Slide 24 Glossary of Terms and Definitions Slide 25 Tax Asset Summary Slide 26 Appendix 1: Quarter in Review
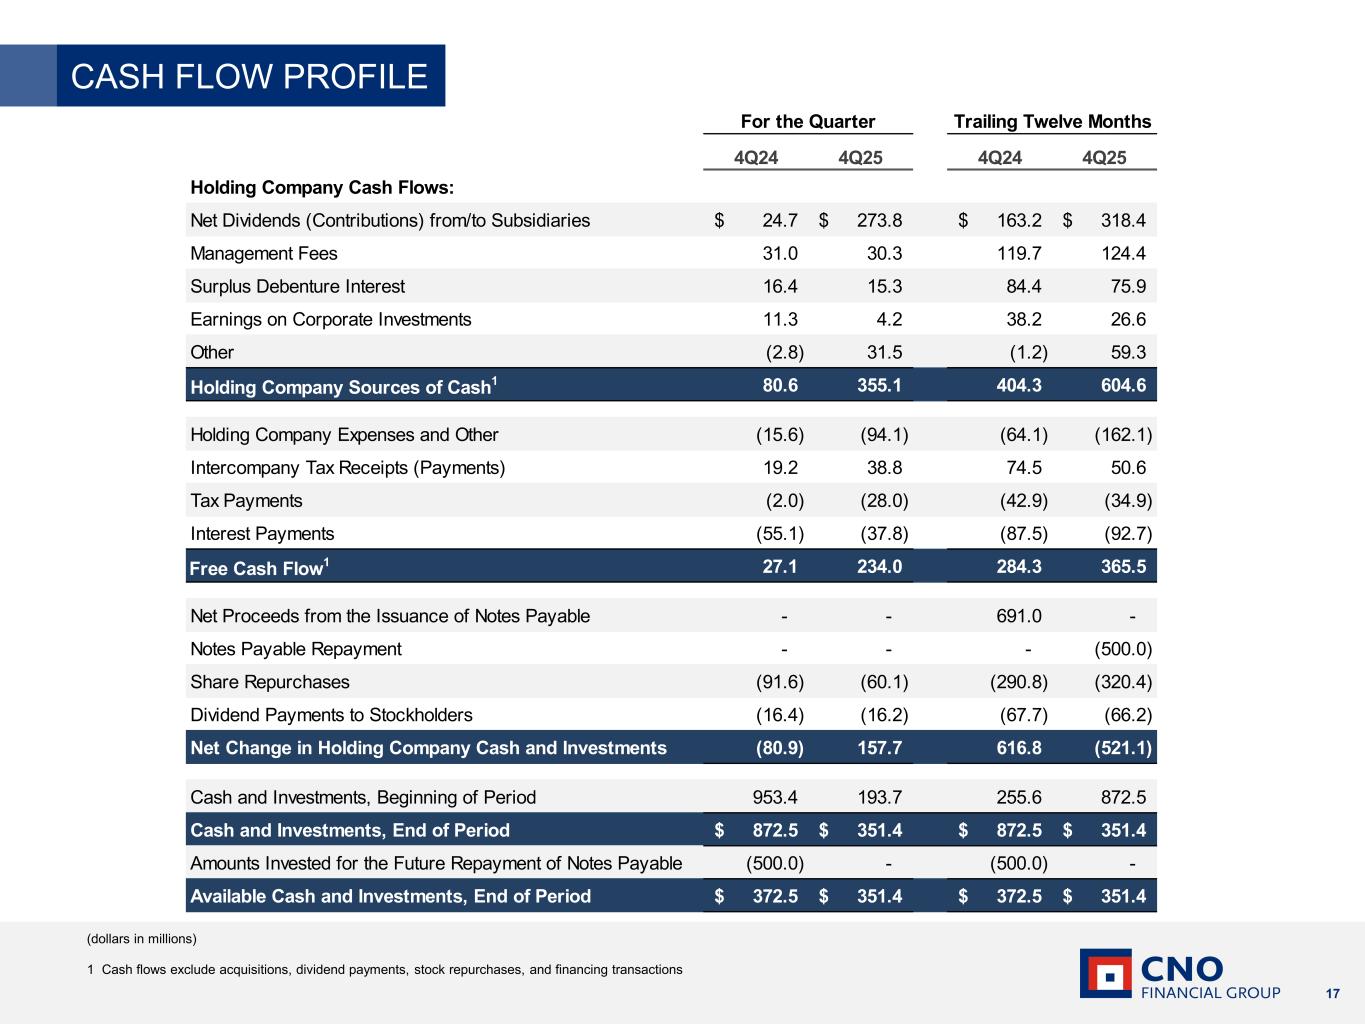
17 1 Cash flows exclude acquisitions, dividend payments, stock repurchases, and financing transactions (dollars in millions) CASH FLOW PROFILE 4Q24 4Q25 4Q24 4Q25 Holding Company Cash Flows: Net Dividends (Contributions) from/to Subsidiaries 24.7$ 273.8$ 163.2$ 318.4$ Management Fees 31.0 30.3 119.7 124.4 Surplus Debenture Interest 16.4 15.3 84.4 75.9 Earnings on Corporate Investments 11.3 4.2 38.2 26.6 Other (2.8) 31.5 (1.2) 59.3 Holding Company Sources of Cash1 80.6 355.1 404.3 604.6 Holding Company Expenses and Other (15.6) (94.1) (64.1) (162.1) Intercompany Tax Receipts (Payments) 19.2 38.8 74.5 50.6 Tax Payments (2.0) (28.0) (42.9) (34.9) Interest Payments (55.1) (37.8) (87.5) (92.7) Free Cash Flow1 27.1 234.0 284.3 365.5 Net Proceeds from the Issuance of Notes Payable - - 691.0 - Notes Payable Repayment - - - (500.0) Share Repurchases (91.6) (60.1) (290.8) (320.4) Dividend Payments to Stockholders (16.4) (16.2) (67.7) (66.2) Net Change in Holding Company Cash and Investments (80.9) 157.7 616.8 (521.1) Cash and Investments, Beginning of Period 953.4 193.7 255.6 872.5 Cash and Investments, End of Period 872.5$ 351.4$ 872.5$ 351.4$ Amounts Invested for the Future Repayment of Notes Payable (500.0) - (500.0) - Available Cash and Investments, End of Period 372.5$ 351.4$ 372.5$ 351.4$ Trailing Twelve MonthsFor the Quarter
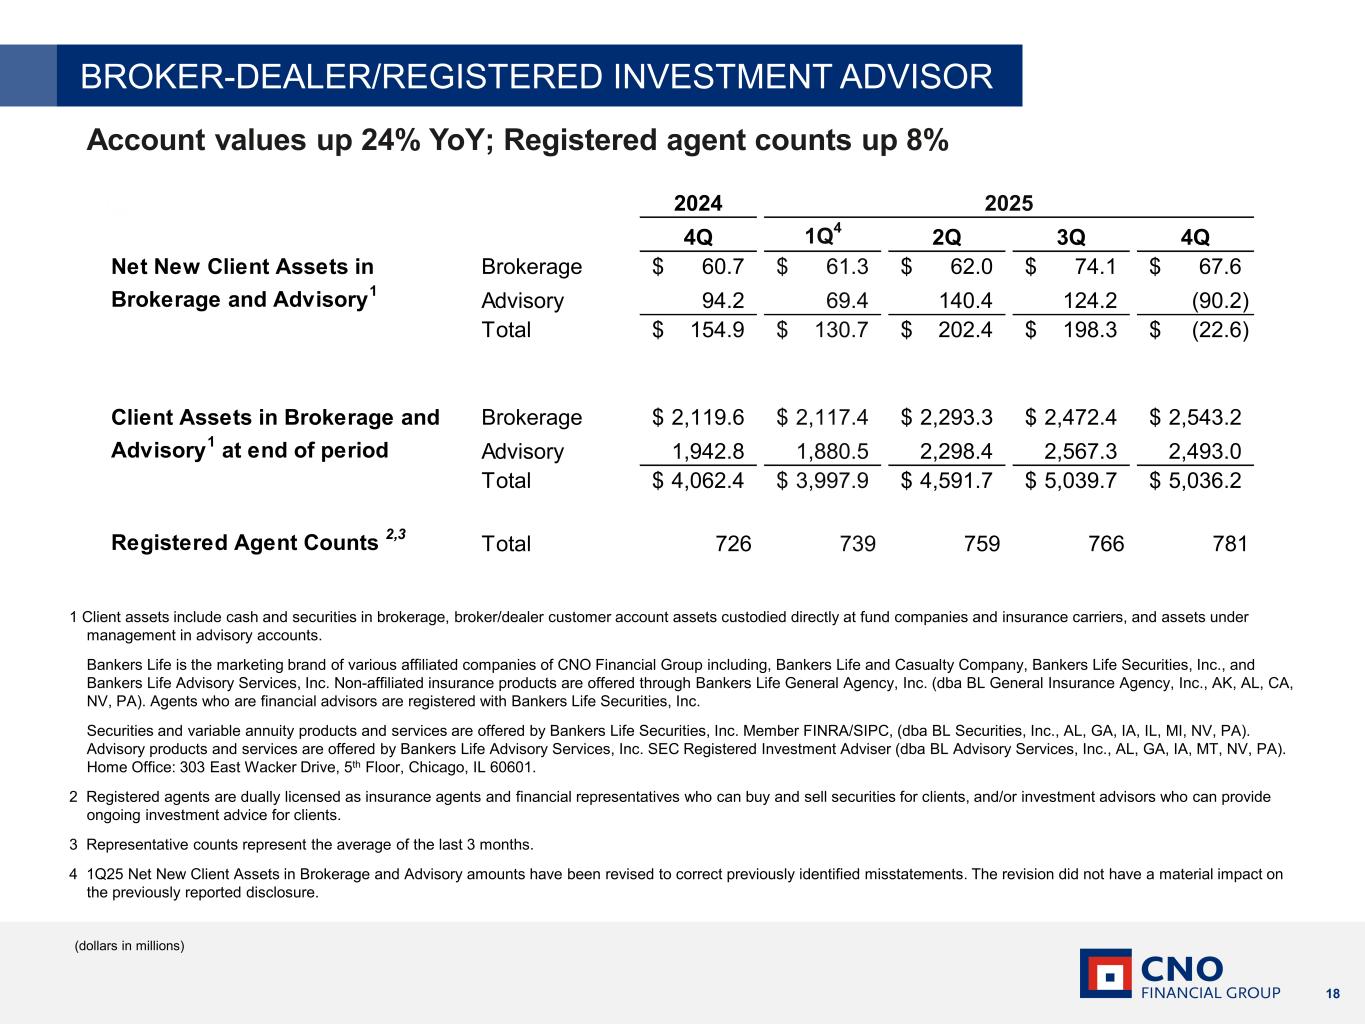
18 Account values up 24% YoY; Registered agent counts up 8% 1 Client assets include cash and securities in brokerage, broker/dealer customer account assets custodied directly at fund companies and insurance carriers, and assets under management in advisory accounts. Bankers Life is the marketing brand of various affiliated companies of CNO Financial Group including, Bankers Life and Casualty Company, Bankers Life Securities, Inc., and Bankers Life Advisory Services, Inc. Non-affiliated insurance products are offered through Bankers Life General Agency, Inc. (dba BL General Insurance Agency, Inc., AK, AL, CA, NV, PA). Agents who are financial advisors are registered with Bankers Life Securities, Inc. Securities and variable annuity products and services are offered by Bankers Life Securities, Inc. Member FINRA/SIPC, (dba BL Securities, Inc., AL, GA, IA, IL, MI, NV, PA). Advisory products and services are offered by Bankers Life Advisory Services, Inc. SEC Registered Investment Adviser (dba BL Advisory Services, Inc., AL, GA, IA, MT, NV, PA). Home Office: 303 East Wacker Drive, 5th Floor, Chicago, IL 60601. 2 Registered agents are dually licensed as insurance agents and financial representatives who can buy and sell securities for clients, and/or investment advisors who can provide ongoing investment advice for clients. 3 Representative counts represent the average of the last 3 months. 4 1Q25 Net New Client Assets in Brokerage and Advisory amounts have been revised to correct previously identified misstatements. The revision did not have a material impact on the previously reported disclosure. (dollars in millions) BROKER-DEALER/REGISTERED INVESTMENT ADVISOR 4Q 1Q4 2Q 3Q 4Q Net New Client Assets in Brokerage 60.7$ 61.3$ 62.0$ 74.1$ 67.6$ Brokerage and Advisory1 Advisory 94.2 69.4 140.4 124.2 (90.2) Total 154.9$ 130.7$ 202.4$ 198.3$ (22.6)$ Client Assets in Brokerage and Brokerage 2,119.6$ 2,117.4$ 2,293.3$ 2,472.4$ 2,543.2$ Advisory1 at end of period Advisory 1,942.8 1,880.5 2,298.4 2,567.3 2,493.0 Total 4,062.4$ 3,997.9$ 4,591.7$ 5,039.7$ 5,036.2$ Registered Agent Counts 2,3 Total 726 739 759 766 781 2024 2025
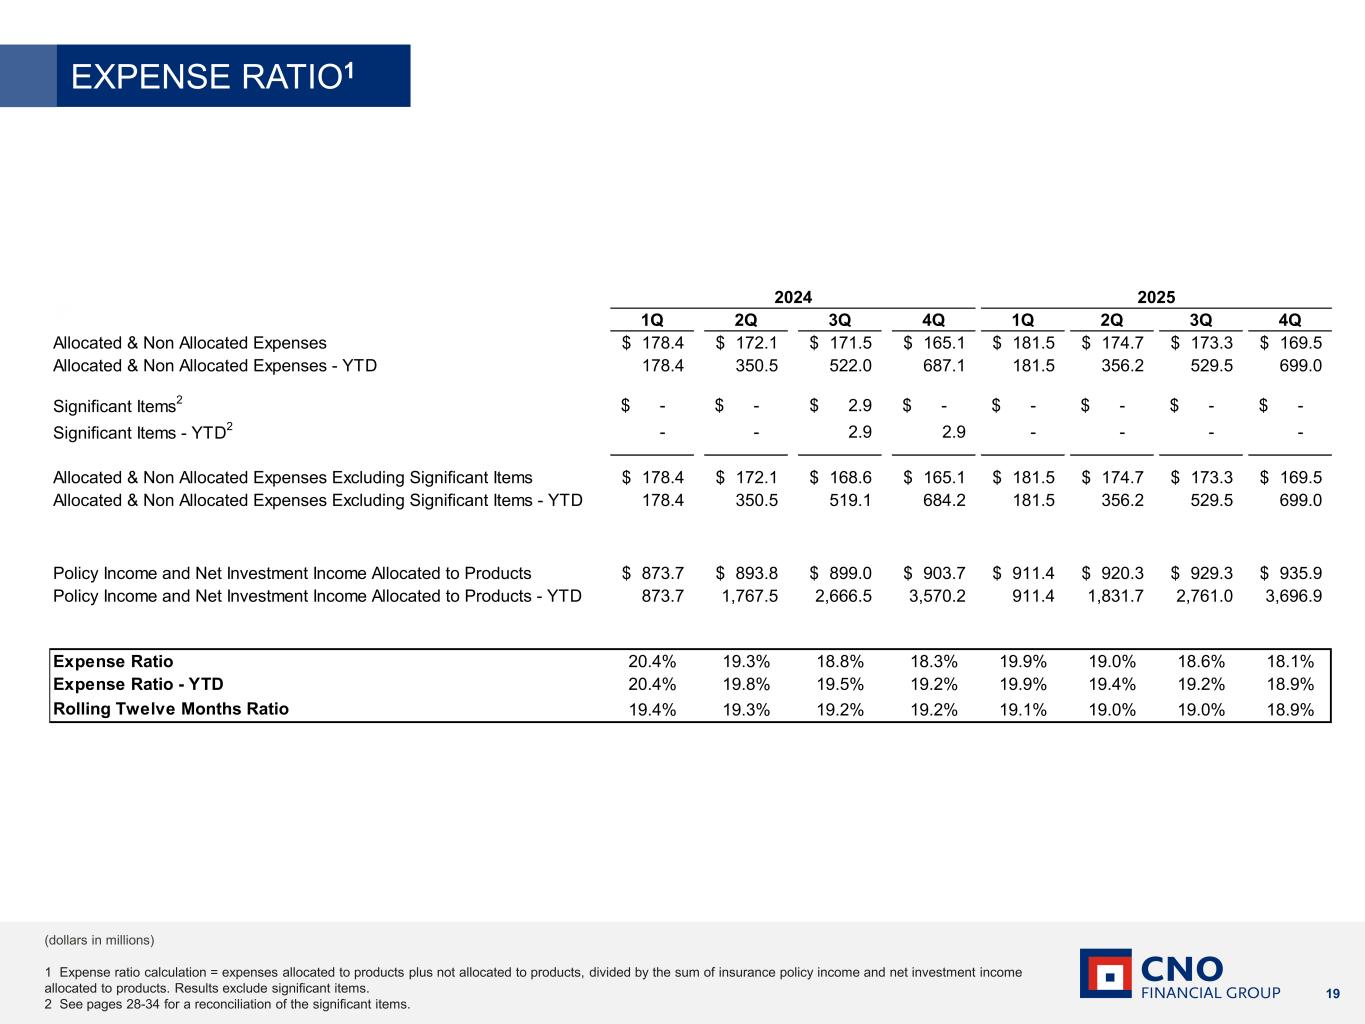
19 1 Expense ratio calculation = expenses allocated to products plus not allocated to products, divided by the sum of insurance policy income and net investment income allocated to products. Results exclude significant items. 2 See pages 28-34 for a reconciliation of the significant items. EXPENSE RATIO1 (dollars in millions) 1Q 2Q 3Q 4Q 1Q 2Q 3Q 4Q Allocated & Non Allocated Expenses 178.4$ 172.1$ 171.5$ 165.1$ 181.5$ 174.7$ 173.3$ 169.5$ Allocated & Non Allocated Expenses - YTD 178.4 350.5 522.0 687.1 181.5 356.2 529.5 699.0 Significant Items2 -$ -$ 2.9$ -$ -$ -$ -$ -$ Significant Items - YTD2 - - 2.9 2.9 - - - - Allocated & Non Allocated Expenses Excluding Significant Items 178.4$ 172.1$ 168.6$ 165.1$ 181.5$ 174.7$ 173.3$ 169.5$ Allocated & Non Allocated Expenses Excluding Significant Items - YTD 178.4 350.5 519.1 684.2 181.5 356.2 529.5 699.0 Policy Income and Net Investment Income Allocated to Products 873.7$ 893.8$ 899.0$ 903.7$ 911.4$ 920.3$ 929.3$ 935.9$ Policy Income and Net Investment Income Allocated to Products - YTD 873.7 1,767.5 2,666.5 3,570.2 911.4 1,831.7 2,761.0 3,696.9 Expense Ratio 20.4% 19.3% 18.8% 18.3% 19.9% 19.0% 18.6% 18.1% Expense Ratio - YTD 20.4% 19.8% 19.5% 19.2% 19.9% 19.4% 19.2% 18.9% Rolling Twelve Months Ratio 19.4% 19.3% 19.2% 19.2% 19.1% 19.0% 19.0% 18.9% 2024 2025
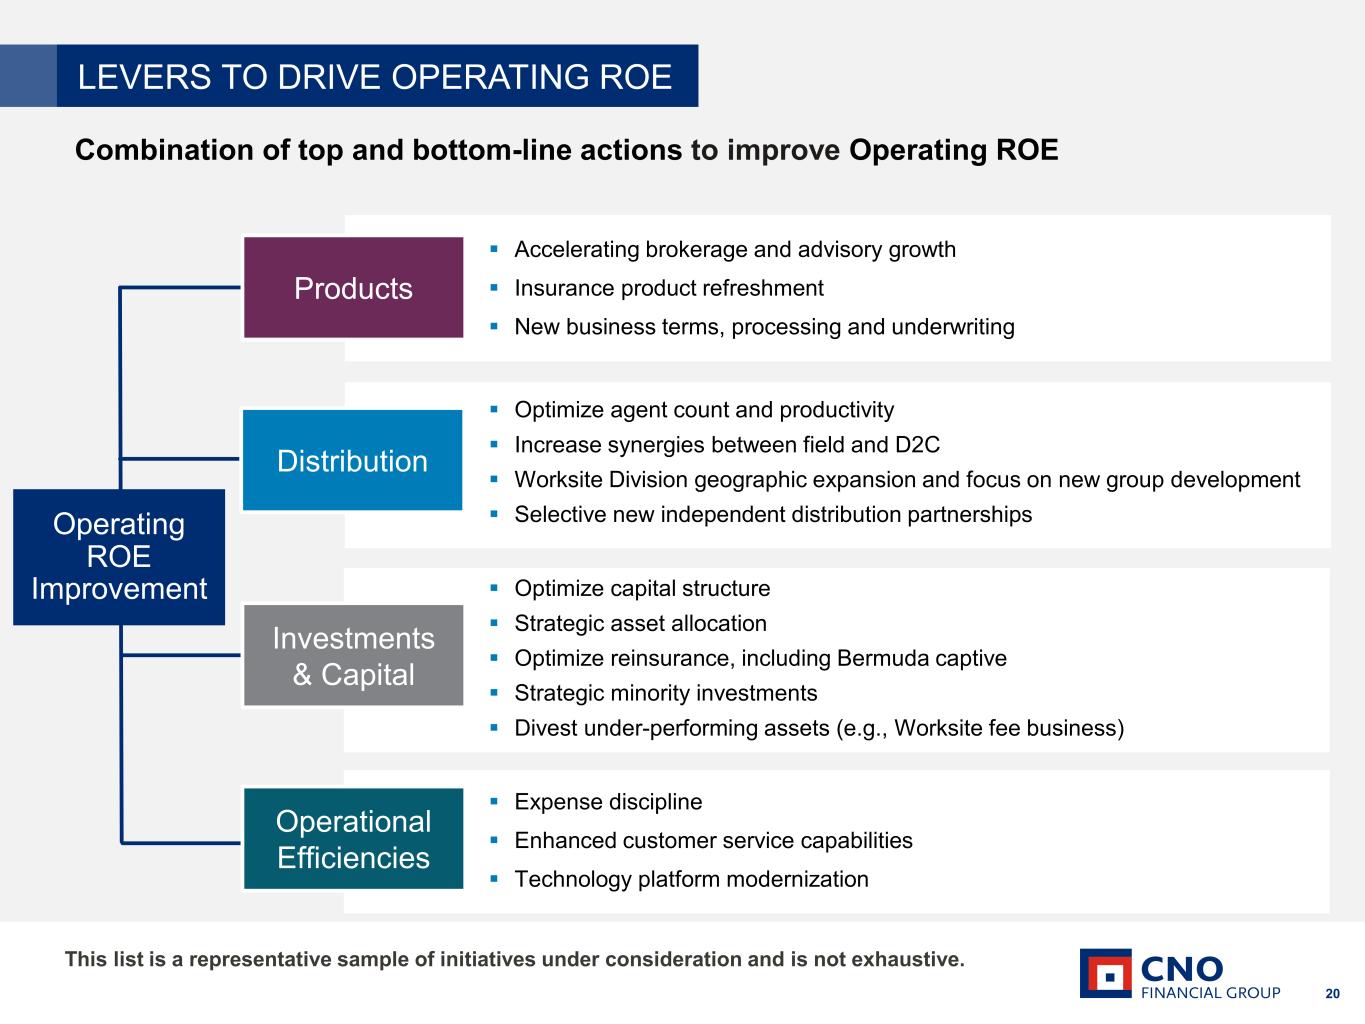
20 LEVERS TO DRIVE OPERATING ROE Combination of top and bottom-line actions to improve Operating ROE Accelerating brokerage and advisory growth Insurance product refreshment New business terms, processing and underwriting Optimize agent count and productivity Increase synergies between field and D2C Worksite Division geographic expansion and focus on new group development Selective new independent distribution partnerships Optimize capital structure Strategic asset allocation Optimize reinsurance, including Bermuda captive Strategic minority investments Divest under-performing assets (e.g., Worksite fee business) Expense discipline Enhanced customer service capabilities Technology platform modernization Products Distribution Investments & Capital Operational Efficiencies Operating ROE Improvement This list is a representative sample of initiatives under consideration and is not exhaustive.
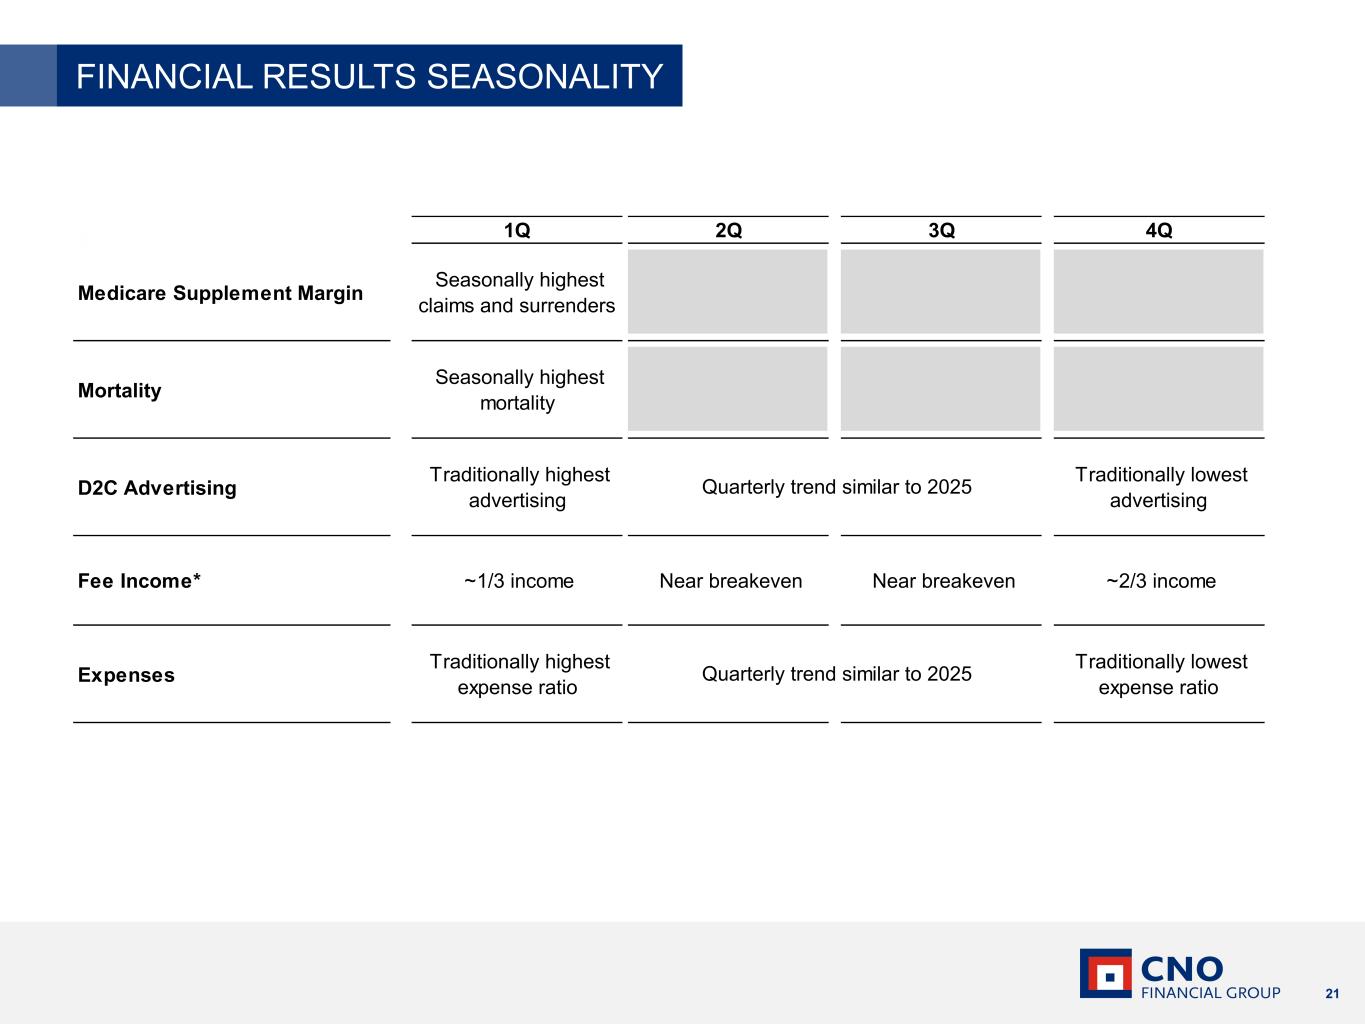
21 FINANCIAL RESULTS SEASONALITY 1Q 2Q 3Q 4Q Medicare Supplement Margin Seasonally highest claims and surrenders Mortality Seasonally highest mortality D2C Advertising Traditionally highest advertising Traditionally lowest advertising Fee Income* ~1/3 income Near breakeven Near breakeven ~2/3 income Expenses Traditionally highest expense ratio Traditionally lowest expense ratio Quarterly trend similar to 2025 Quarterly trend similar to 2025
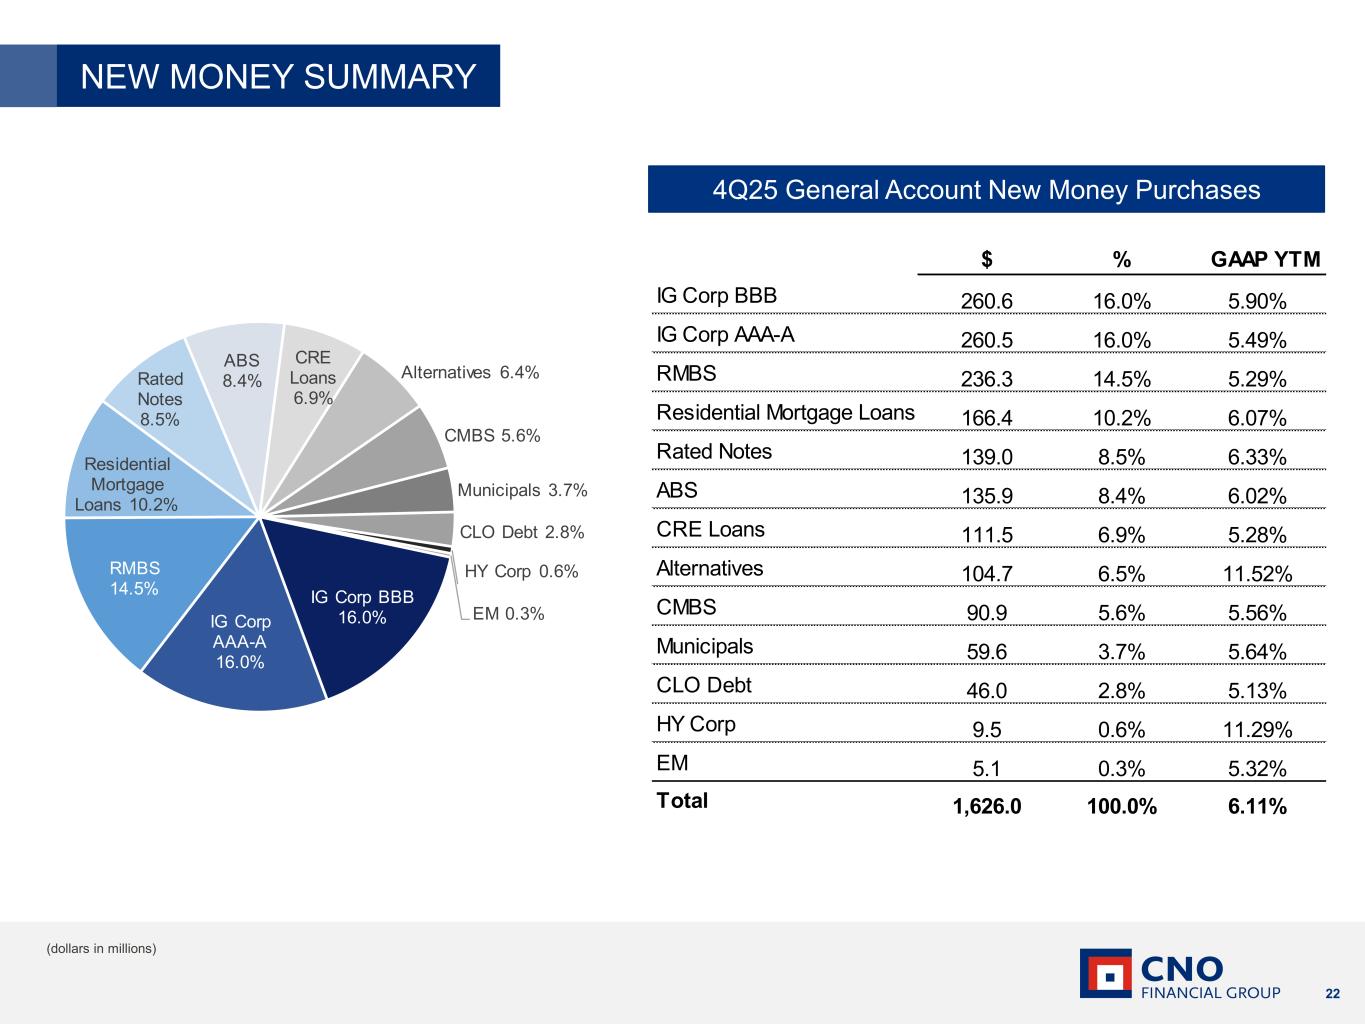
22 4Q25 General Account New Money Purchases NEW MONEY SUMMARY (dollars in millions) IG Corp BBB 16.0%IG Corp AAA-A 16.0% RMBS 14.5% Residential Mortgage Loans 10.2% Rated Notes 8.5% ABS 8.4% CRE Loans 6.9% Alternatives 6.4% CMBS 5.6% Municipals 3.7% CLO Debt 2.8% HY Corp 0.6% EM 0.3% $ % GAAP YTM IG Corp BBB 260.6 16.0% 5.90% IG Corp AAA-A 260.5 16.0% 5.49% RMBS 236.3 14.5% 5.29% Residential Mortgage Loans 166.4 10.2% 6.07% Rated Notes 139.0 8.5% 6.33% ABS 135.9 8.4% 6.02% CRE Loans 111.5 6.9% 5.28% Alternatives 104.7 6.5% 11.52% CMBS 90.9 5.6% 5.56% Municipals 59.6 3.7% 5.64% CLO Debt 46.0 2.8% 5.13% HY Corp 9.5 0.6% 11.29% EM 5.1 0.3% 5.32% Total 1,626.0 100.0% 6.11%
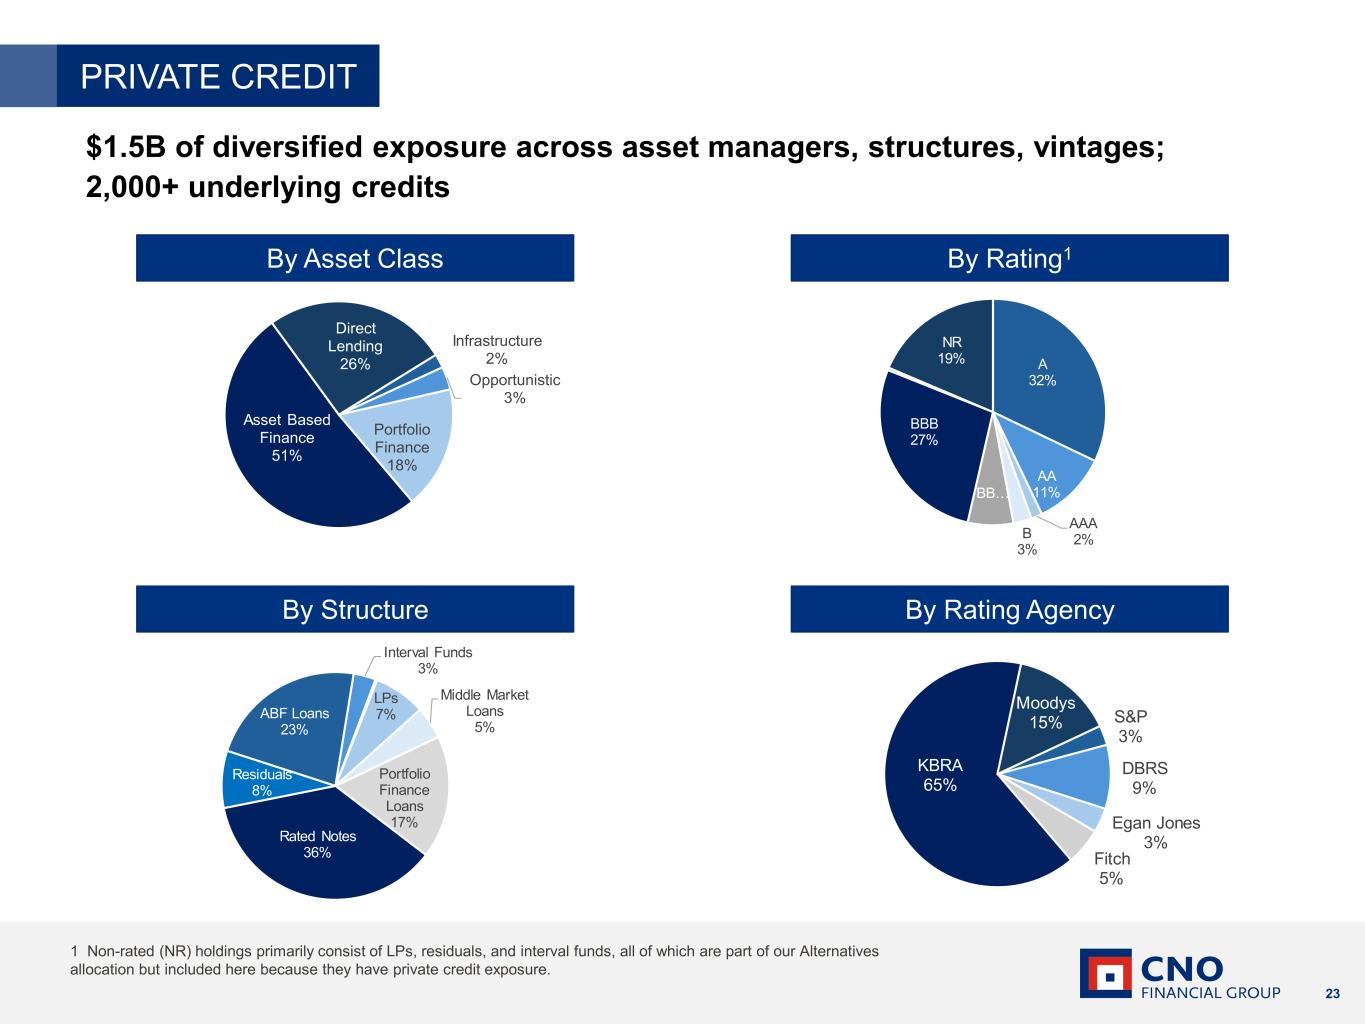
23 PRIVATE CREDIT $1.5B of diversified exposure across asset managers, structures, vintages; 2,000+ underlying credits 1 Non-rated (NR) holdings primarily consist of LPs, residuals, and interval funds, all of which are part of our Alternatives allocation but included here because they have private credit exposure. By Asset Class By Rating1 By Structure By Rating Agency Asset Based Finance 51% Direct Lending 26% Infrastructure 2% Opportunistic 3% Portfolio Finance 18% A 32% AA 11% AAA 2%B 3% BB… BBB 27% NR 19% ABF Loans 23% Interval Funds 3% LPs 7% Middle Market Loans 5% Portfolio Finance Loans 17% Rated Notes 36% Residuals 8% DBRS 9% Egan Jones 3% Fitch 5% KBRA 65% Moodys 15% S&P 3%
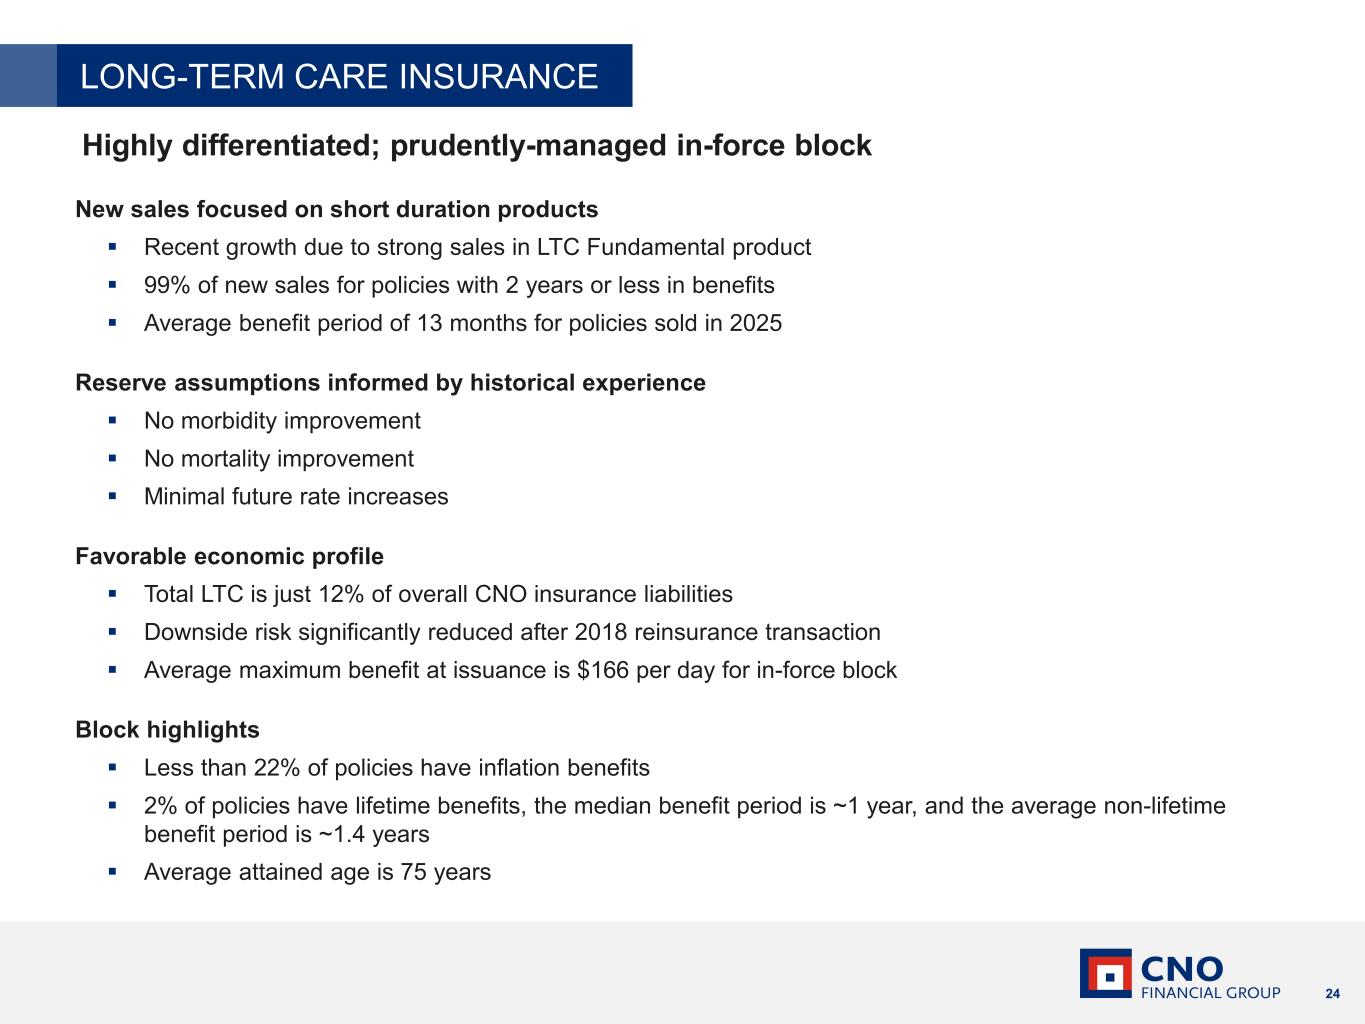
24 New sales focused on short duration products Recent growth due to strong sales in LTC Fundamental product 99% of new sales for policies with 2 years or less in benefits Average benefit period of 13 months for policies sold in 2025 Reserve assumptions informed by historical experience No morbidity improvement No mortality improvement Minimal future rate increases Favorable economic profile Total LTC is just 12% of overall CNO insurance liabilities Downside risk significantly reduced after 2018 reinsurance transaction Average maximum benefit at issuance is $166 per day for in-force block Block highlights Less than 22% of policies have inflation benefits 2% of policies have lifetime benefits, the median benefit period is ~1 year, and the average non-lifetime benefit period is ~1.4 years Average attained age is 75 years Highly differentiated; prudently-managed in-force block LONG-TERM CARE INSURANCE
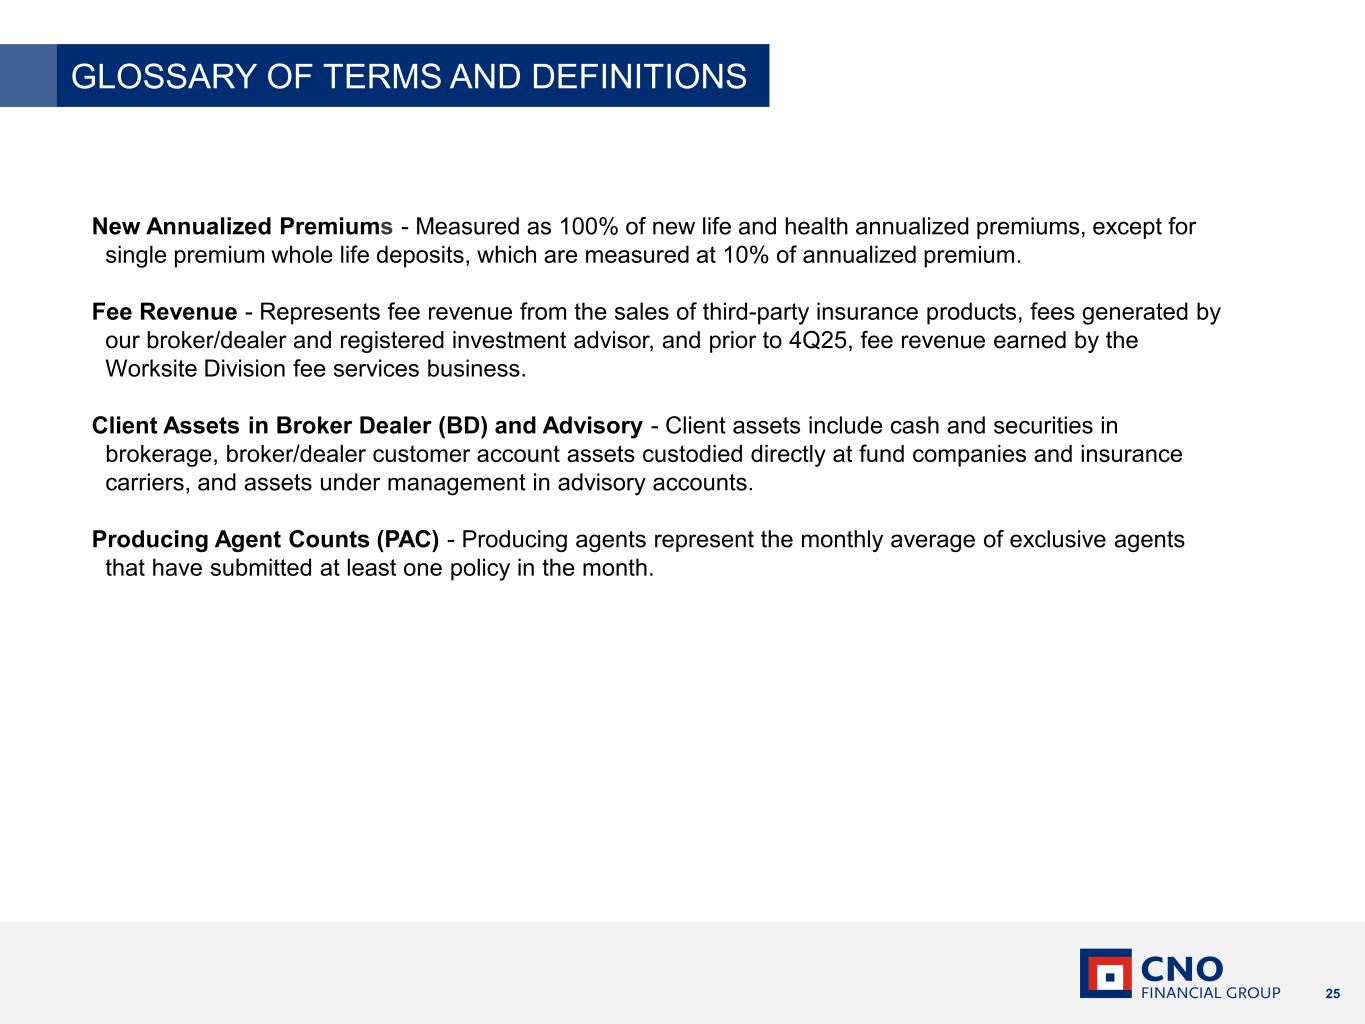
25 GLOSSARY OF TERMS AND DEFINITIONS New Annualized Premiums - Measured as 100% of new life and health annualized premiums, except for single premium whole life deposits, which are measured at 10% of annualized premium. Fee Revenue - Represents fee revenue from the sales of third-party insurance products, fees generated by our broker/dealer and registered investment advisor, and prior to 4Q25, fee revenue earned by the Worksite Division fee services business. Client Assets in Broker Dealer (BD) and Advisory - Client assets include cash and securities in brokerage, broker/dealer customer account assets custodied directly at fund companies and insurance carriers, and assets under management in advisory accounts. Producing Agent Counts (PAC) - Producing agents represent the monthly average of exclusive agents that have submitted at least one policy in the month.
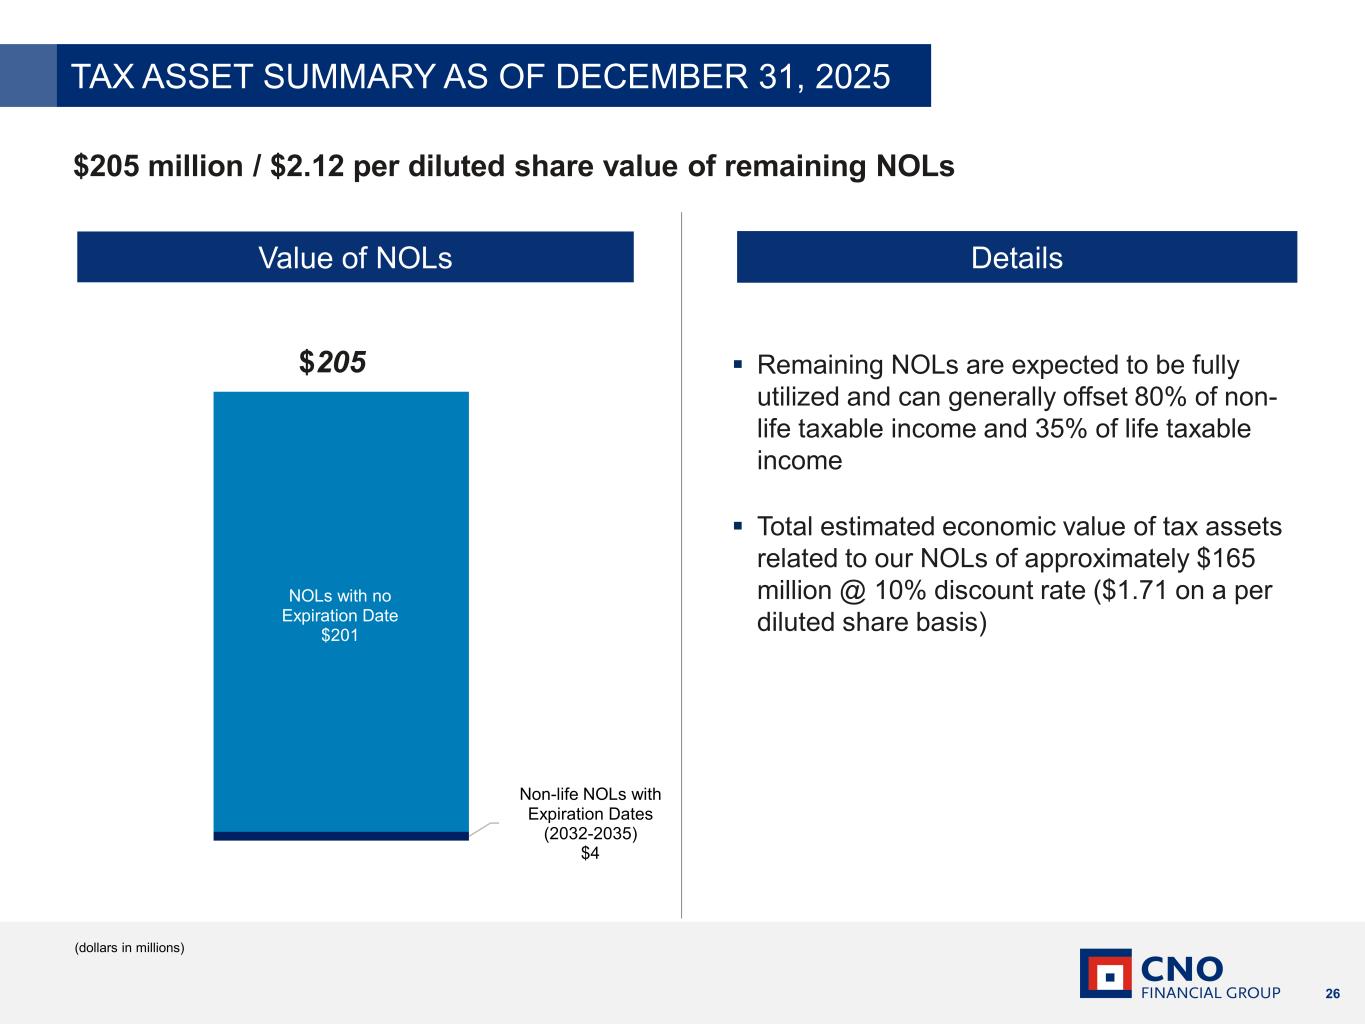
26 Value of NOLs Details Remaining NOLs are expected to be fully utilized and can generally offset 80% of non- life taxable income and 35% of life taxable income Total estimated economic value of tax assets related to our NOLs of approximately $165 million @ 10% discount rate ($1.71 on a per diluted share basis) $205 (dollars in millions) $205 million / $2.12 per diluted share value of remaining NOLs TAX ASSET SUMMARY AS OF DECEMBER 31, 2025 Non-life NOLs with Expiration Dates (2032-2035) $4 NOLs with no Expiration Date $201
27 Appendix 2: Financial Exhibits Non-GAAP Financial Measures Slides 28 - 45
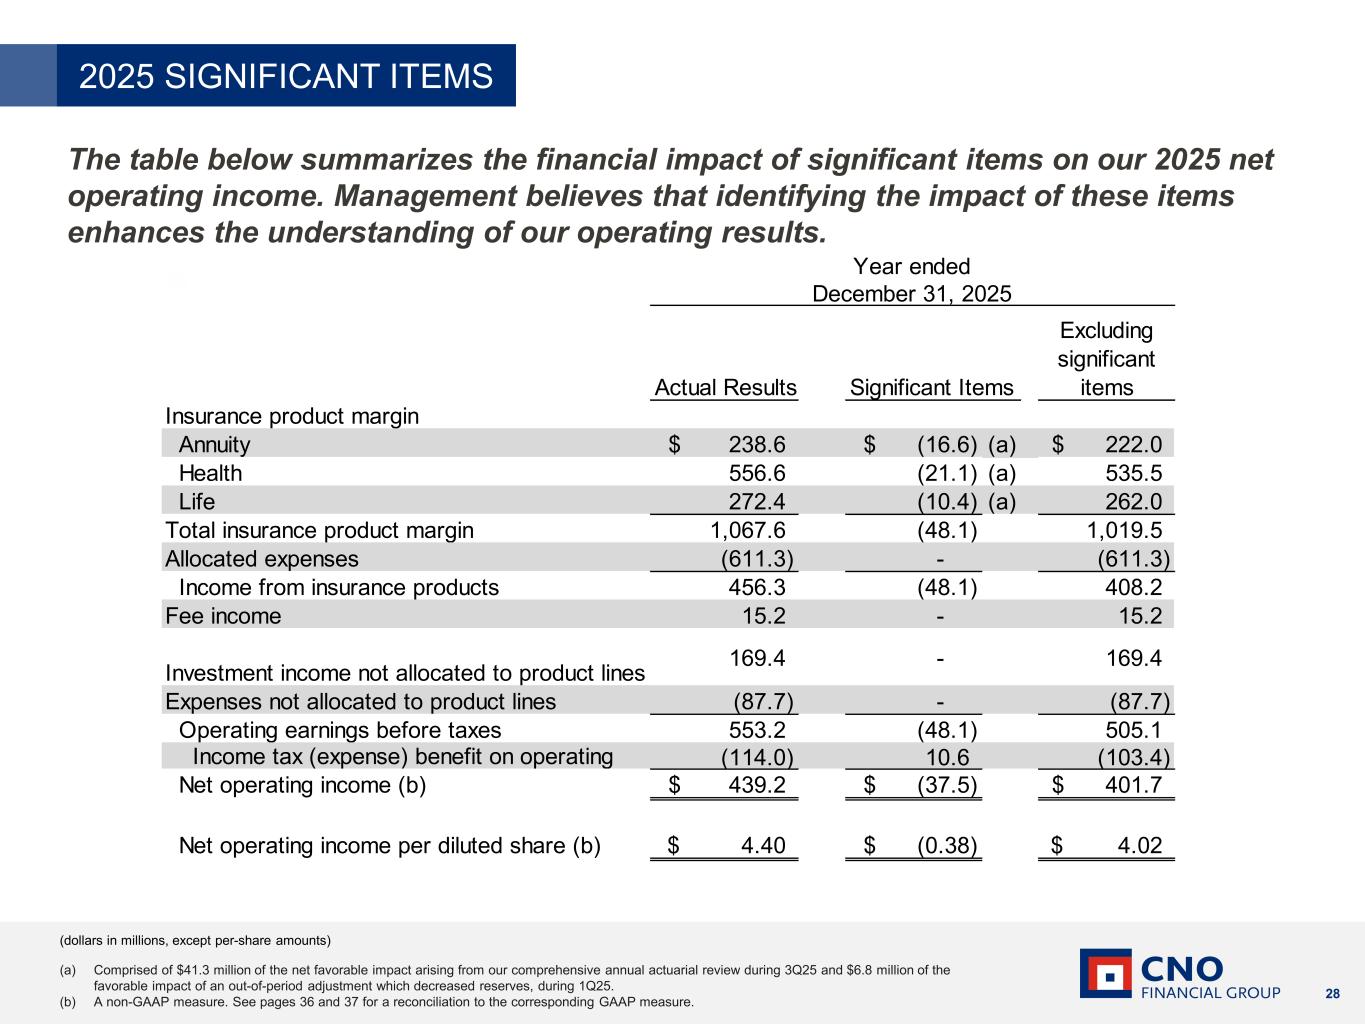
28 2025 SIGNIFICANT ITEMS The table below summarizes the financial impact of significant items on our 2025 net operating income. Management believes that identifying the impact of these items enhances the understanding of our operating results. (dollars in millions, except per-share amounts) Actual Results Significant Items Excluding significant items Insurance product margin Annuity 238.6$ (16.6)$ (a) 222.0$ Health 556.6 (21.1) (a) 535.5 Life 272.4 (10.4) (a) 262.0 Total insurance product margin 1,067.6 (48.1) 1,019.5 Allocated expenses (611.3) - (611.3) Income from insurance products 456.3 (48.1) 408.2 Fee income 15.2 - 15.2 Investment income not allocated to product lines 169.4 - 169.4 Expenses not allocated to product lines (87.7) - (87.7) Operating earnings before taxes 553.2 (48.1) 505.1 Income tax (expense) benefit on operating (114.0) 10.6 (103.4) Net operating income (b) 439.2$ (37.5)$ 401.7$ Net operating income per diluted share (b) 4.40$ (0.38)$ 4.02$ December 31, 2025 Year ended (a) Comprised of $41.3 million of the net favorable impact arising from our comprehensive annual actuarial review during 3Q25 and $6.8 million of the favorable impact of an out-of-period adjustment which decreased reserves, during 1Q25. (b) A non-GAAP measure. See pages 36 and 37 for a reconciliation to the corresponding GAAP measure.
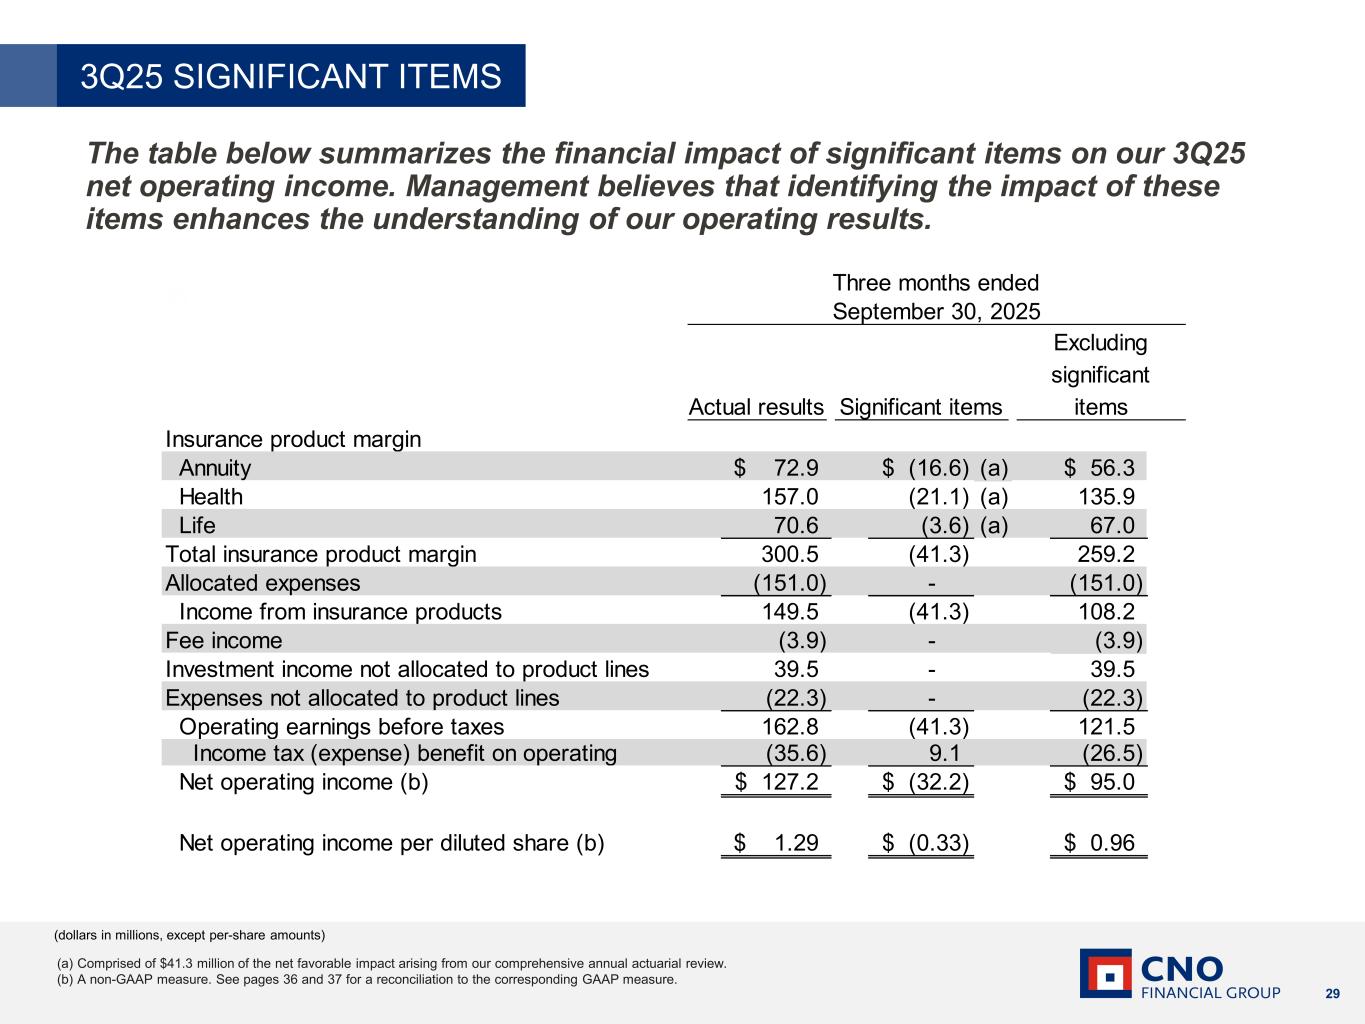
29 (dollars in millions, except per-share amounts) The table below summarizes the financial impact of significant items on our 3Q25 net operating income. Management believes that identifying the impact of these items enhances the understanding of our operating results. 3Q25 SIGNIFICANT ITEMS (a) Comprised of $41.3 million of the net favorable impact arising from our comprehensive annual actuarial review. (b) A non-GAAP measure. See pages 36 and 37 for a reconciliation to the corresponding GAAP measure. Insurance product margin Annuity 72.9$ (16.6)$ (a) 56.3$ Health 157.0 (21.1) (a) 135.9 Life 70.6 (3.6) (a) 67.0 Total insurance product margin 300.5 (41.3) 259.2 Allocated expenses (151.0) - (151.0) Income from insurance products 149.5 (41.3) 108.2 Fee income (3.9) - (3.9) Investment income not allocated to product lines 39.5 - 39.5 Expenses not allocated to product lines (22.3) - (22.3) Operating earnings before taxes 162.8 (41.3) 121.5 Income tax (expense) benefit on operating (35.6) 9.1 (26.5) Net operating income (b) 127.2$ (32.2)$ 95.0$ Net operating income per diluted share (b) 1.29$ (0.33)$ 0.96$ Three months ended September 30, 2025 Actual results Significant items Excluding significant items
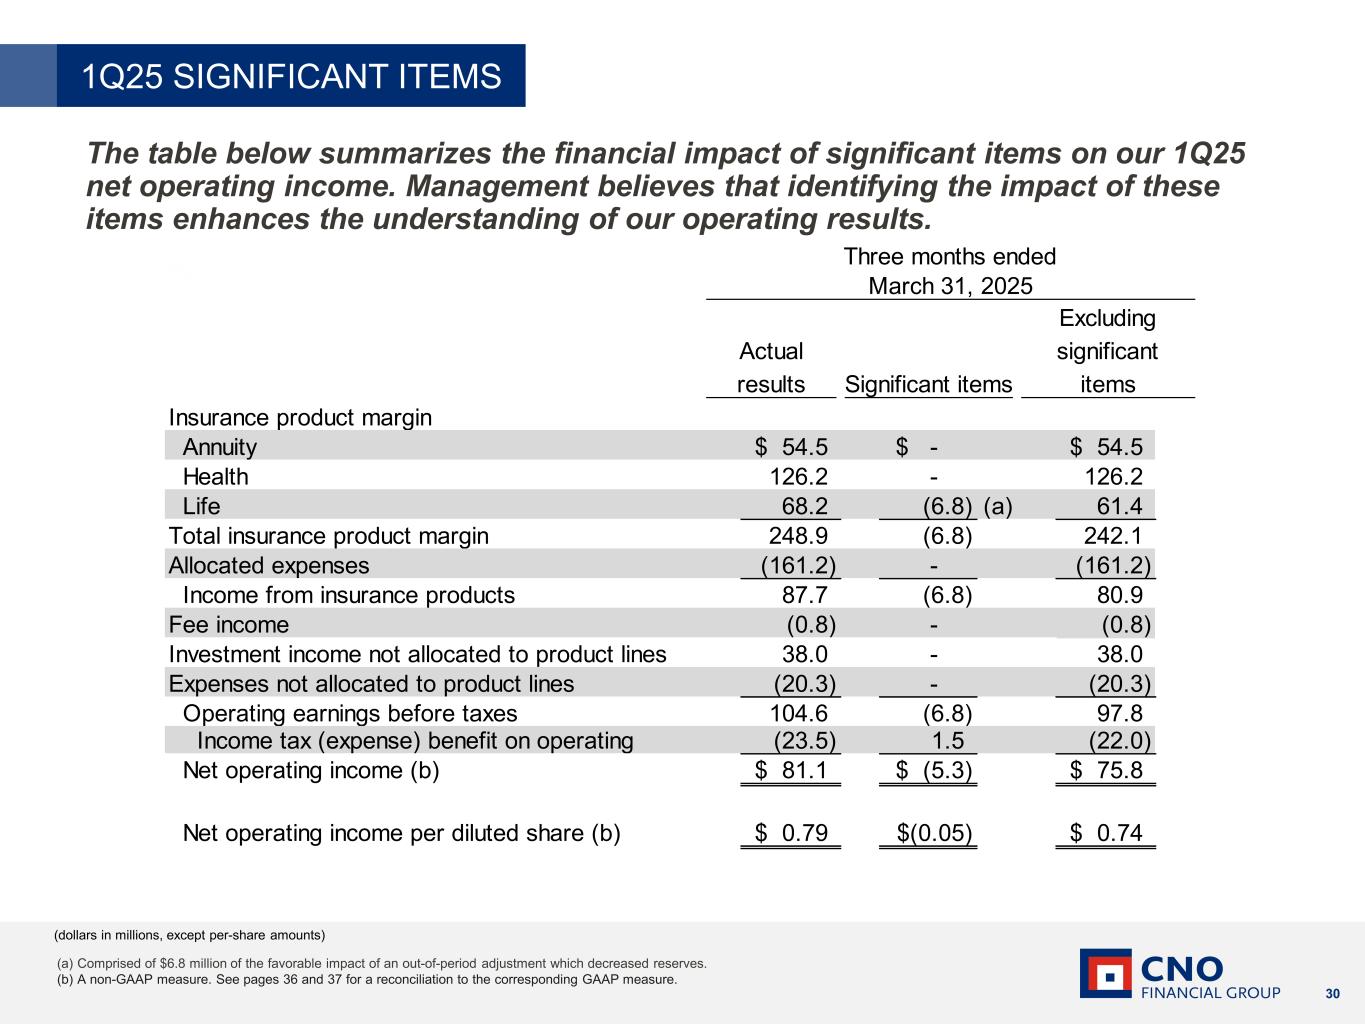
30 (dollars in millions, except per-share amounts) The table below summarizes the financial impact of significant items on our 1Q25 net operating income. Management believes that identifying the impact of these items enhances the understanding of our operating results. 1Q25 SIGNIFICANT ITEMS (a) Comprised of $6.8 million of the favorable impact of an out-of-period adjustment which decreased reserves. (b) A non-GAAP measure. See pages 36 and 37 for a reconciliation to the corresponding GAAP measure. Insurance product margin Annuity 54.5$ -$ 54.5$ Health 126.2 - 126.2 Life 68.2 (6.8) (a) 61.4 Total insurance product margin 248.9 (6.8) 242.1 Allocated expenses (161.2) - (161.2) Income from insurance products 87.7 (6.8) 80.9 Fee income (0.8) - (0.8) Investment income not allocated to product lines 38.0 - 38.0 Expenses not allocated to product lines (20.3) - (20.3) Operating earnings before taxes 104.6 (6.8) 97.8 Income tax (expense) benefit on operating (23.5) 1.5 (22.0) Net operating income (b) 81.1$ (5.3)$ 75.8$ Net operating income per diluted share (b) 0.79$ (0.05)$ 0.74$ Three months ended March 31, 2025 Actual results Significant items Excluding significant items
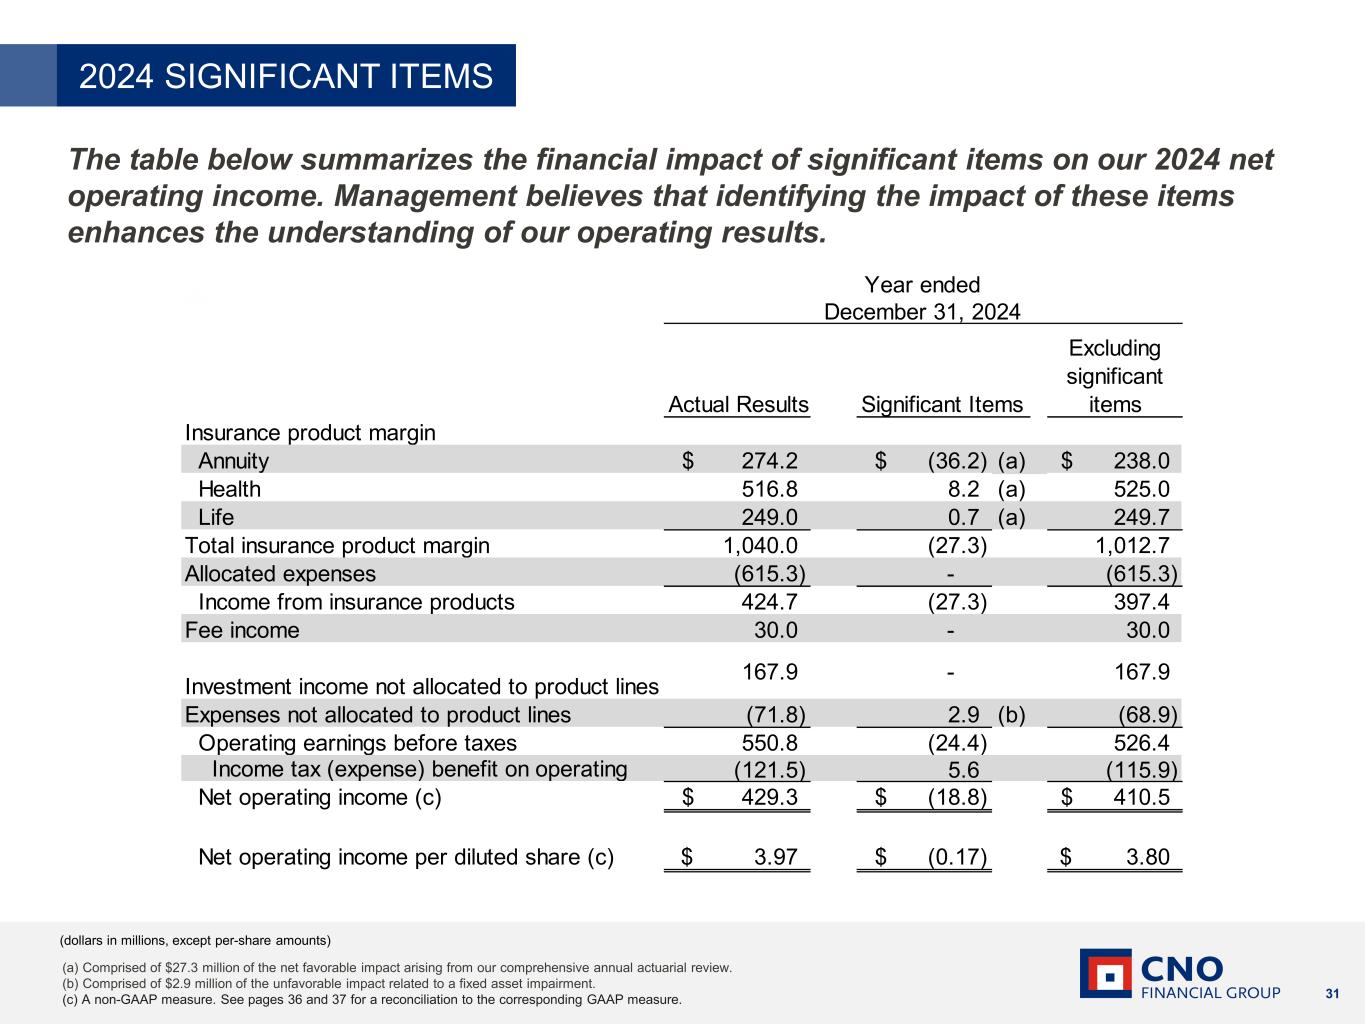
31 2024 SIGNIFICANT ITEMS The table below summarizes the financial impact of significant items on our 2024 net operating income. Management believes that identifying the impact of these items enhances the understanding of our operating results. (dollars in millions, except per-share amounts) (a) Comprised of $27.3 million of the net favorable impact arising from our comprehensive annual actuarial review. (b) Comprised of $2.9 million of the unfavorable impact related to a fixed asset impairment. (c) A non-GAAP measure. See pages 36 and 37 for a reconciliation to the corresponding GAAP measure. Actual Results Significant Items Excluding significant items Insurance product margin Annuity 274.2$ (36.2)$ (a) 238.0$ Health 516.8 8.2 (a) 525.0 Life 249.0 0.7 (a) 249.7 Total insurance product margin 1,040.0 (27.3) 1,012.7 Allocated expenses (615.3) - (615.3) Income from insurance products 424.7 (27.3) 397.4 Fee income 30.0 - 30.0 Investment income not allocated to product lines 167.9 - 167.9 Expenses not allocated to product lines (71.8) 2.9 (b) (68.9) Operating earnings before taxes 550.8 (24.4) 526.4 Income tax (expense) benefit on operating (121.5) 5.6 (115.9) Net operating income (c) 429.3$ (18.8)$ 410.5$ Net operating income per diluted share (c) 3.97$ (0.17)$ 3.80$ December 31, 2024 Year ended
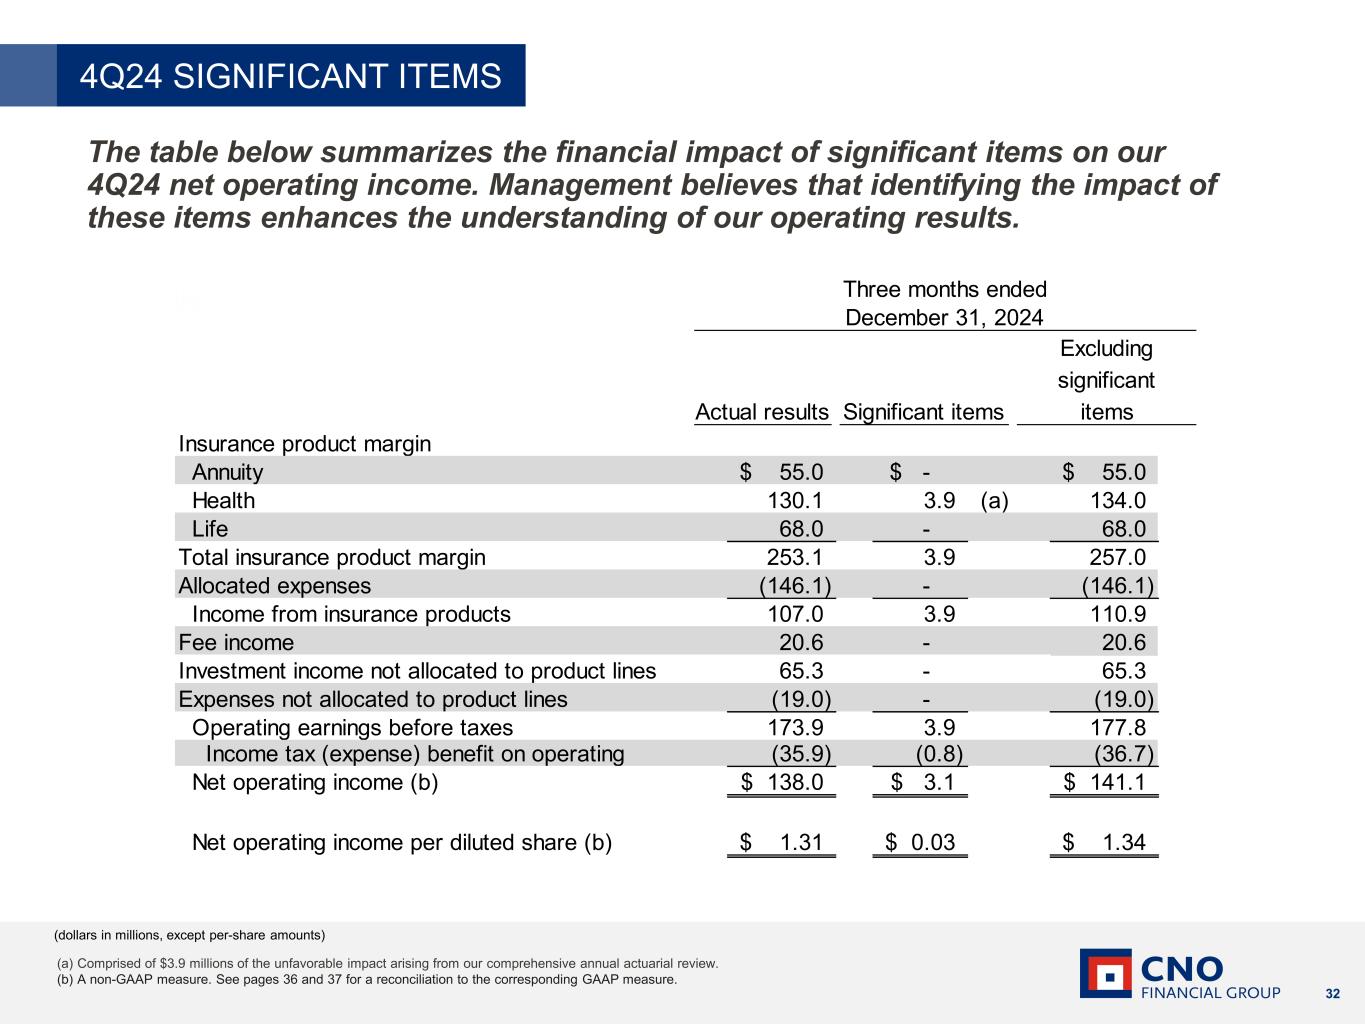
32 (dollars in millions, except per-share amounts) The table below summarizes the financial impact of significant items on our 4Q24 net operating income. Management believes that identifying the impact of these items enhances the understanding of our operating results. 4Q24 SIGNIFICANT ITEMS (a) Comprised of $3.9 millions of the unfavorable impact arising from our comprehensive annual actuarial review. (b) A non-GAAP measure. See pages 36 and 37 for a reconciliation to the corresponding GAAP measure. Insurance product margin Annuity 55.0$ -$ 55.0$ Health 130.1 3.9 (a) 134.0 Life 68.0 - 68.0 Total insurance product margin 253.1 3.9 257.0 Allocated expenses (146.1) - (146.1) Income from insurance products 107.0 3.9 110.9 Fee income 20.6 - 20.6 Investment income not allocated to product lines 65.3 - 65.3 Expenses not allocated to product lines (19.0) - (19.0) Operating earnings before taxes 173.9 3.9 177.8 Income tax (expense) benefit on operating (35.9) (0.8) (36.7) Net operating income (b) 138.0$ 3.1$ 141.1$ Net operating income per diluted share (b) 1.31$ 0.03$ 1.34$ Three months ended December 31, 2024 Actual results Significant items Excluding significant items
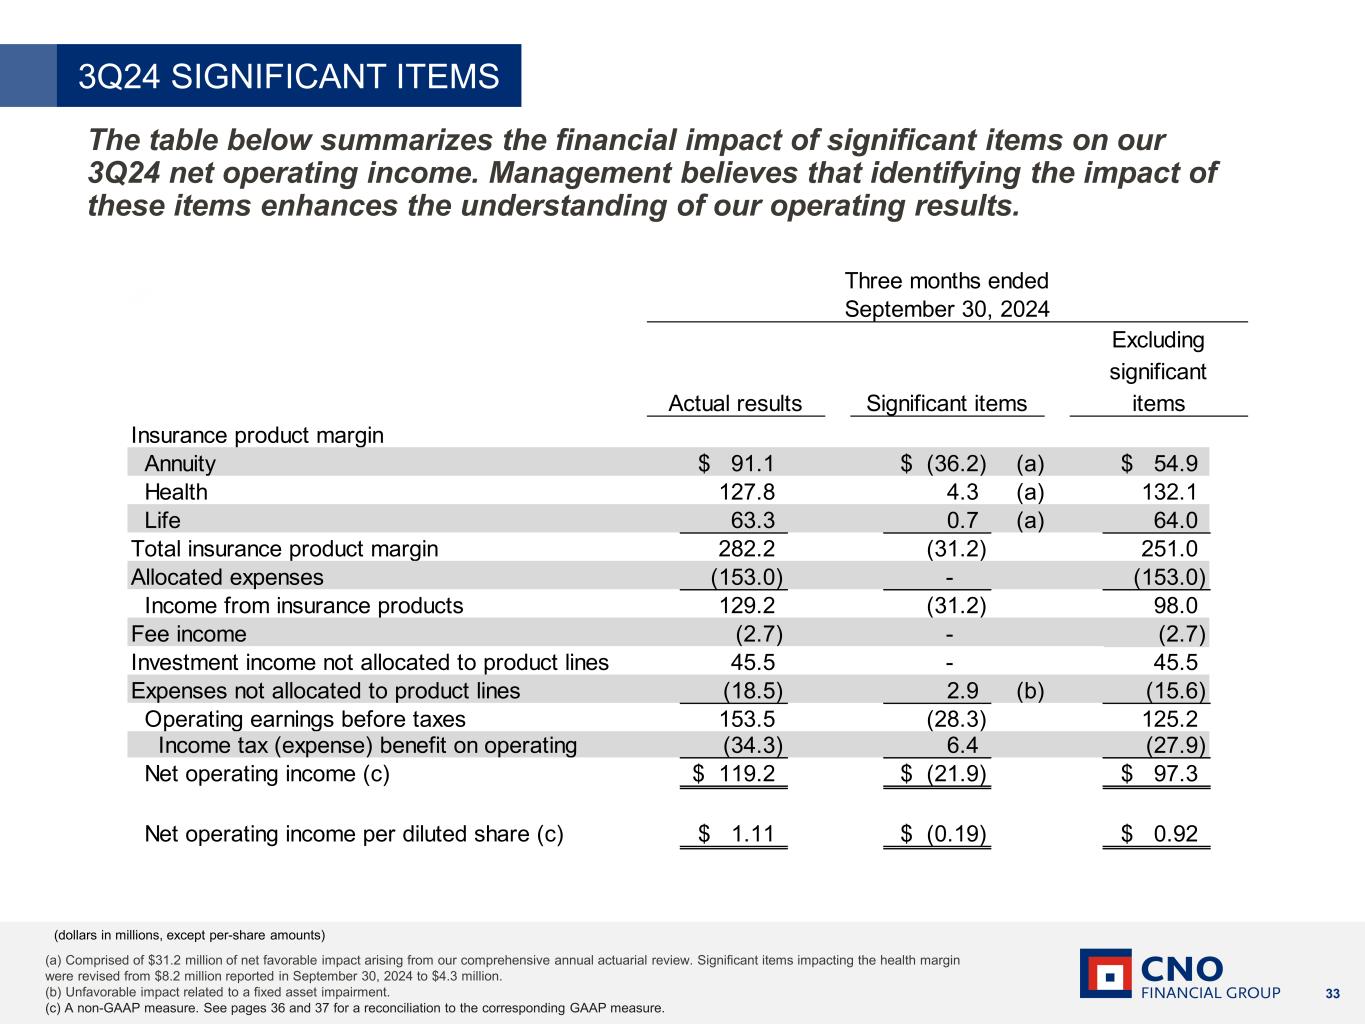
33 (dollars in millions, except per-share amounts) (a) Comprised of $31.2 million of net favorable impact arising from our comprehensive annual actuarial review. Significant items impacting the health margin were revised from $8.2 million reported in September 30, 2024 to $4.3 million. (b) Unfavorable impact related to a fixed asset impairment. (c) A non-GAAP measure. See pages 36 and 37 for a reconciliation to the corresponding GAAP measure. The table below summarizes the financial impact of significant items on our 3Q24 net operating income. Management believes that identifying the impact of these items enhances the understanding of our operating results. 3Q24 SIGNIFICANT ITEMS Insurance product margin Annuity 91.1$ (36.2)$ (a) 54.9$ Health 127.8 4.3 (a) 132.1 Life 63.3 0.7 (a) 64.0 Total insurance product margin 282.2 (31.2) 251.0 Allocated expenses (153.0) - (153.0) Income from insurance products 129.2 (31.2) 98.0 Fee income (2.7) - (2.7) Investment income not allocated to product lines 45.5 - 45.5 Expenses not allocated to product lines (18.5) 2.9 (b) (15.6) Operating earnings before taxes 153.5 (28.3) 125.2 Income tax (expense) benefit on operating (34.3) 6.4 (27.9) Net operating income (c) 119.2$ (21.9)$ 97.3$ Net operating income per diluted share (c) 1.11$ (0.19)$ 0.92$ Three months ended September 30, 2024 Actual results Significant items Excluding significant items
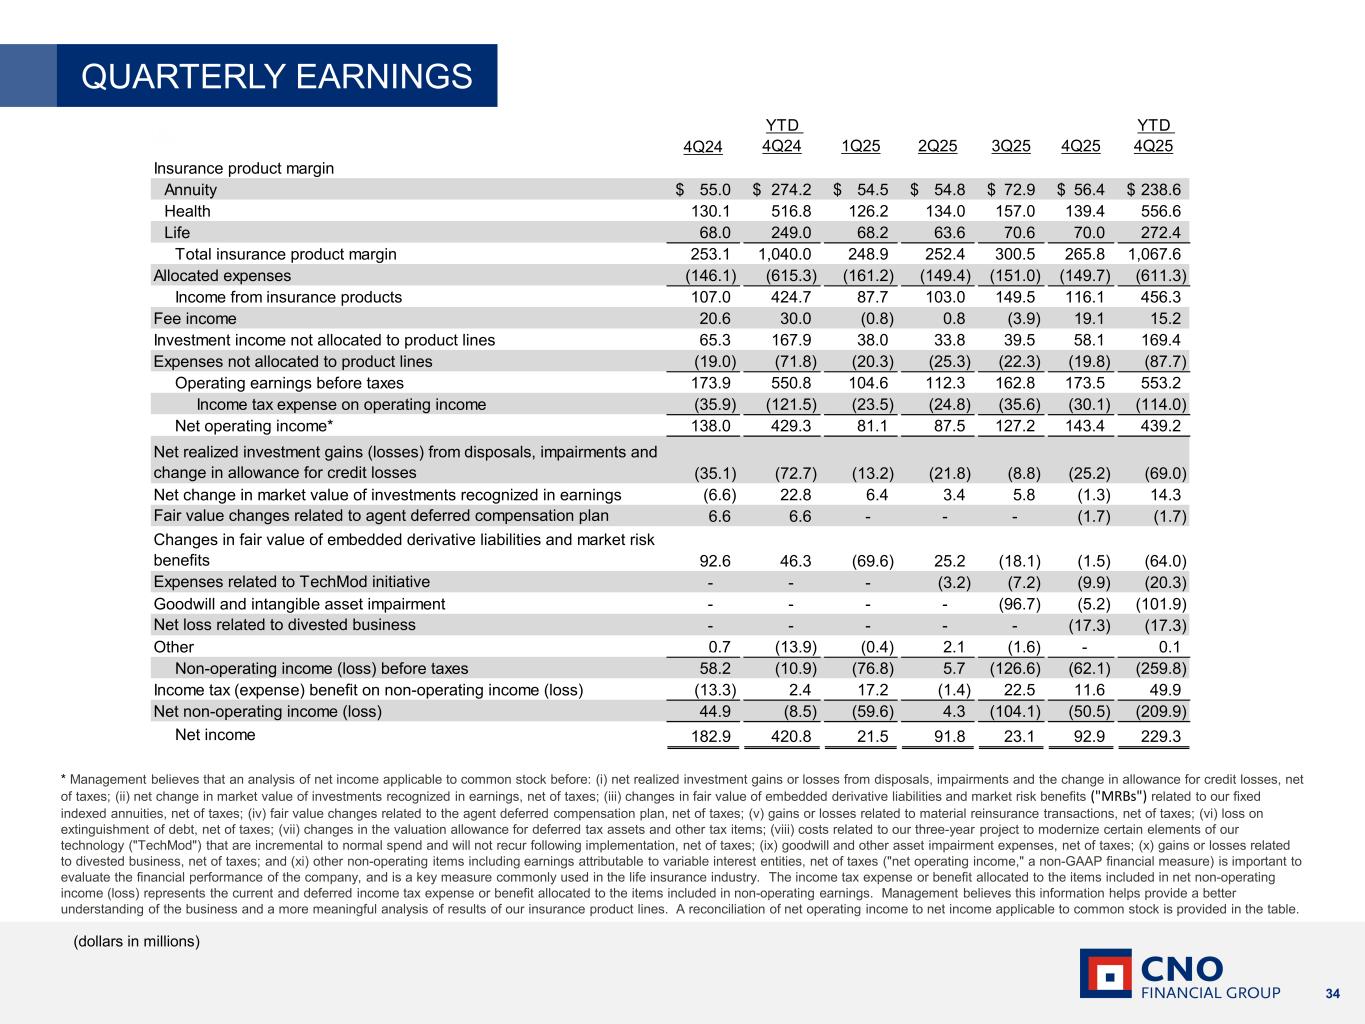
34 (dollars in millions) * Management believes that an analysis of net income applicable to common stock before: (i) net realized investment gains or losses from disposals, impairments and the change in allowance for credit losses, net of taxes; (ii) net change in market value of investments recognized in earnings, net of taxes; (iii) changes in fair value of embedded derivative liabilities and market risk benefits ("MRBs") related to our fixed indexed annuities, net of taxes; (iv) fair value changes related to the agent deferred compensation plan, net of taxes; (v) gains or losses related to material reinsurance transactions, net of taxes; (vi) loss on extinguishment of debt, net of taxes; (vii) changes in the valuation allowance for deferred tax assets and other tax items; (viii) costs related to our three-year project to modernize certain elements of our technology ("TechMod") that are incremental to normal spend and will not recur following implementation, net of taxes; (ix) goodwill and other asset impairment expenses, net of taxes; (x) gains or losses related to divested business, net of taxes; and (xi) other non-operating items including earnings attributable to variable interest entities, net of taxes ("net operating income," a non-GAAP financial measure) is important to evaluate the financial performance of the company, and is a key measure commonly used in the life insurance industry. The income tax expense or benefit allocated to the items included in net non-operating income (loss) represents the current and deferred income tax expense or benefit allocated to the items included in non-operating earnings. Management believes this information helps provide a better understanding of the business and a more meaningful analysis of results of our insurance product lines. A reconciliation of net operating income to net income applicable to common stock is provided in the table. QUARTERLY EARNINGS 4Q24 YTD 4Q24 1Q25 2Q25 3Q25 4Q25 YTD 4Q25 Insurance product margin Annuity 55.0$ 274.2$ 54.5$ 54.8$ 72.9$ 56.4$ 238.6$ Health 130.1 516.8 126.2 134.0 157.0 139.4 556.6 Life 68.0 249.0 68.2 63.6 70.6 70.0 272.4 Total insurance product margin 253.1 1,040.0 248.9 252.4 300.5 265.8 1,067.6 Allocated expenses (146.1) (615.3) (161.2) (149.4) (151.0) (149.7) (611.3) Income from insurance products 107.0 424.7 87.7 103.0 149.5 116.1 456.3 Fee income 20.6 30.0 (0.8) 0.8 (3.9) 19.1 15.2 Investment income not allocated to product lines 65.3 167.9 38.0 33.8 39.5 58.1 169.4 Expenses not allocated to product lines (19.0) (71.8) (20.3) (25.3) (22.3) (19.8) (87.7) Operating earnings before taxes 173.9 550.8 104.6 112.3 162.8 173.5 553.2 Income tax expense on operating income (35.9) (121.5) (23.5) (24.8) (35.6) (30.1) (114.0) Net operating income* 138.0 429.3 81.1 87.5 127.2 143.4 439.2 Net realized investment gains (losses) from disposals, impairments and change in allowance for credit losses (35.1) (72.7) (13.2) (21.8) (8.8) (25.2) (69.0) Net change in market value of investments recognized in earnings (6.6) 22.8 6.4 3.4 5.8 (1.3) 14.3 Fair value changes related to agent deferred compensation plan 6.6 6.6 - - - (1.7) (1.7) Changes in fair value of embedded derivative liabilities and market risk benefits 92.6 46.3 (69.6) 25.2 (18.1) (1.5) (64.0) Expenses related to TechMod initiative - - - (3.2) (7.2) (9.9) (20.3) Goodwill and intangible asset impairment - - - - (96.7) (5.2) (101.9) Net loss related to divested business - - - - - (17.3) (17.3) Other 0.7 (13.9) (0.4) 2.1 (1.6) - 0.1 Non-operating income (loss) before taxes 58.2 (10.9) (76.8) 5.7 (126.6) (62.1) (259.8) Income tax (expense) benefit on non-operating income (loss) (13.3) 2.4 17.2 (1.4) 22.5 11.6 49.9 Net non-operating income (loss) 44.9 (8.5) (59.6) 4.3 (104.1) (50.5) (209.9) Net income 182.9 420.8 21.5 91.8 23.1 92.9 229.3
35 The following provides additional information regarding certain non-GAAP measures used in this presentation. A non-GAAP measure is a numerical measure of a company’s performance, financial position, or cash flows that excludes or includes amounts that are normally excluded or included in the most directly comparable measure calculated and presented in accordance with GAAP. While management believes these measures are useful to enhance understanding and comparability of our financial results, these non-GAAP measures should not be considered as substitutes for the most directly comparable GAAP measures. Additional information concerning non-GAAP measures is included in our periodic filings with the Securities and Exchange Commission that are available in the “Investors – SEC Filings” section of CNO’s website, www.CNOinc.com. Operating earnings measures Management believes that an analysis of net income applicable to common stock before: (i) net realized investment gains or losses from disposals, impairments and the change in allowance for credit losses, net of taxes; (ii) net change in market value of investments recognized in earnings, net of taxes; (iii) changes in fair value of embedded derivative liabilities and MRBs related to our fixed indexed annuities, net of taxes; (iv) fair value changes related to the agent deferred compensation plan, net of taxes; (v) gains or losses related to material reinsurance transactions, net of taxes; (vi) loss on extinguishment of debt, net of taxes; (vii) changes in the valuation allowance for deferred tax assets and other tax items; and (viii) costs related to TechMod that are incremental to normal spend and will not recur following implementation, net of taxes; (ix) goodwill and other asset impairment expenses, net of taxes; (x) gains or losses related to divested business, net of taxes; and (xi) other non-operating items including earnings attributable to variable interest entities, net of taxes ("net operating income," a non-GAAP financial measure) is important to evaluate the financial performance of the company, and is a key measure commonly used in the life insurance industry. The income tax expense or benefit allocated to the items included in net non-operating income (loss) represents the current and deferred income tax expense or benefit allocated to the items included in non-operating earnings. Management believes this information helps provide a better understanding of the business and a more meaningful analysis of results of our insurance product lines. INFORMATION RELATED TO CERTAIN NON-GAAP FINANCIAL MEASURES
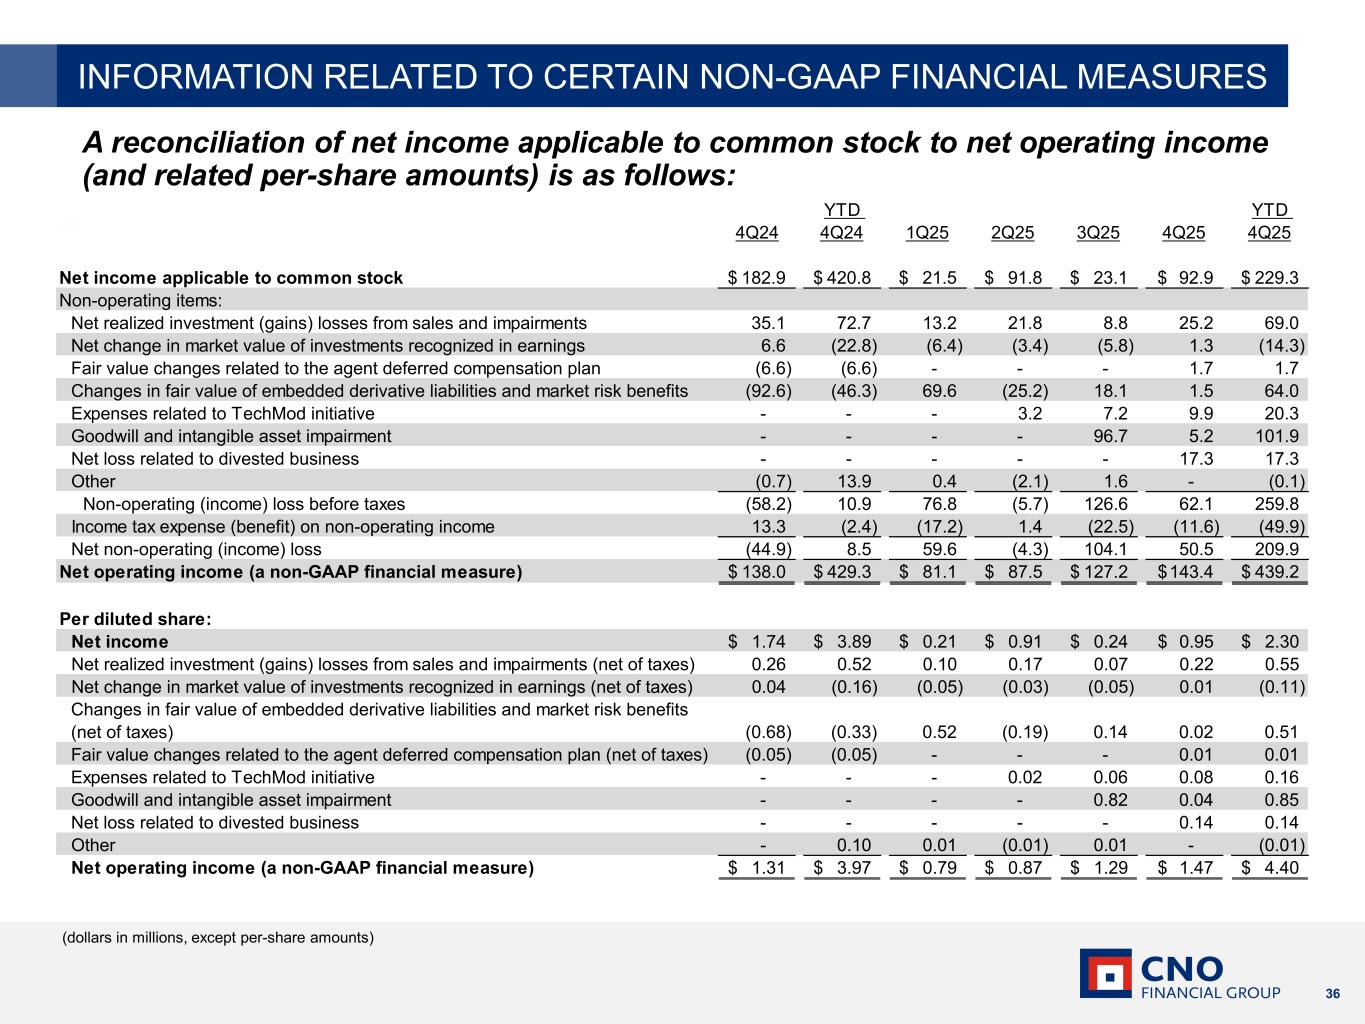
36 A reconciliation of net income applicable to common stock to net operating income (and related per-share amounts) is as follows: (dollars in millions, except per-share amounts) INFORMATION RELATED TO CERTAIN NON-GAAP FINANCIAL MEASURES 4Q24 YTD 4Q24 1Q25 2Q25 3Q25 4Q25 YTD 4Q25 Net income applicable to common stock 182.9$ 420.8$ 21.5$ 91.8$ 23.1$ 92.9$ 229.3$ Non-operating items: Net realized investment (gains) losses from sales and impairments 35.1 72.7 13.2 21.8 8.8 25.2 69.0 Net change in market value of investments recognized in earnings 6.6 (22.8) (6.4) (3.4) (5.8) 1.3 (14.3) Fair value changes related to the agent deferred compensation plan (6.6) (6.6) - - - 1.7 1.7 Changes in fair value of embedded derivative liabilities and market risk benefits (92.6) (46.3) 69.6 (25.2) 18.1 1.5 64.0 Expenses related to TechMod initiative - - - 3.2 7.2 9.9 20.3 Goodwill and intangible asset impairment - - - - 96.7 5.2 101.9 Net loss related to divested business - - - - - 17.3 17.3 Other (0.7) 13.9 0.4 (2.1) 1.6 - (0.1) Non-operating (income) loss before taxes (58.2) 10.9 76.8 (5.7) 126.6 62.1 259.8 Income tax expense (benefit) on non-operating income 13.3 (2.4) (17.2) 1.4 (22.5) (11.6) (49.9) Net non-operating (income) loss (44.9) 8.5 59.6 (4.3) 104.1 50.5 209.9 Net operating income (a non-GAAP financial measure) 138.0$ 429.3$ 81.1$ 87.5$ 127.2$ 143.4$ 439.2$ Per diluted share: Net income 1.74$ 3.89$ 0.21$ 0.91$ 0.24$ 0.95$ 2.30$ Net realized investment (gains) losses from sales and impairments (net of taxes) 0.26 0.52 0.10 0.17 0.07 0.22 0.55 Net change in market value of investments recognized in earnings (net of taxes) 0.04 (0.16) (0.05) (0.03) (0.05) 0.01 (0.11) Changes in fair value of embedded derivative liabilities and market risk benefits (net of taxes) (0.68) (0.33) 0.52 (0.19) 0.14 0.02 0.51 Fair value changes related to the agent deferred compensation plan (net of taxes) (0.05) (0.05) - - - 0.01 0.01 Expenses related to TechMod initiative - - - 0.02 0.06 0.08 0.16 Goodwill and intangible asset impairment - - - - 0.82 0.04 0.85 Net loss related to divested business - - - - - 0.14 0.14 Other - 0.10 0.01 (0.01) 0.01 - (0.01) Net operating income (a non-GAAP financial measure) 1.31$ 3.97$ 0.79$ 0.87$ 1.29$ 1.47$ 4.40$
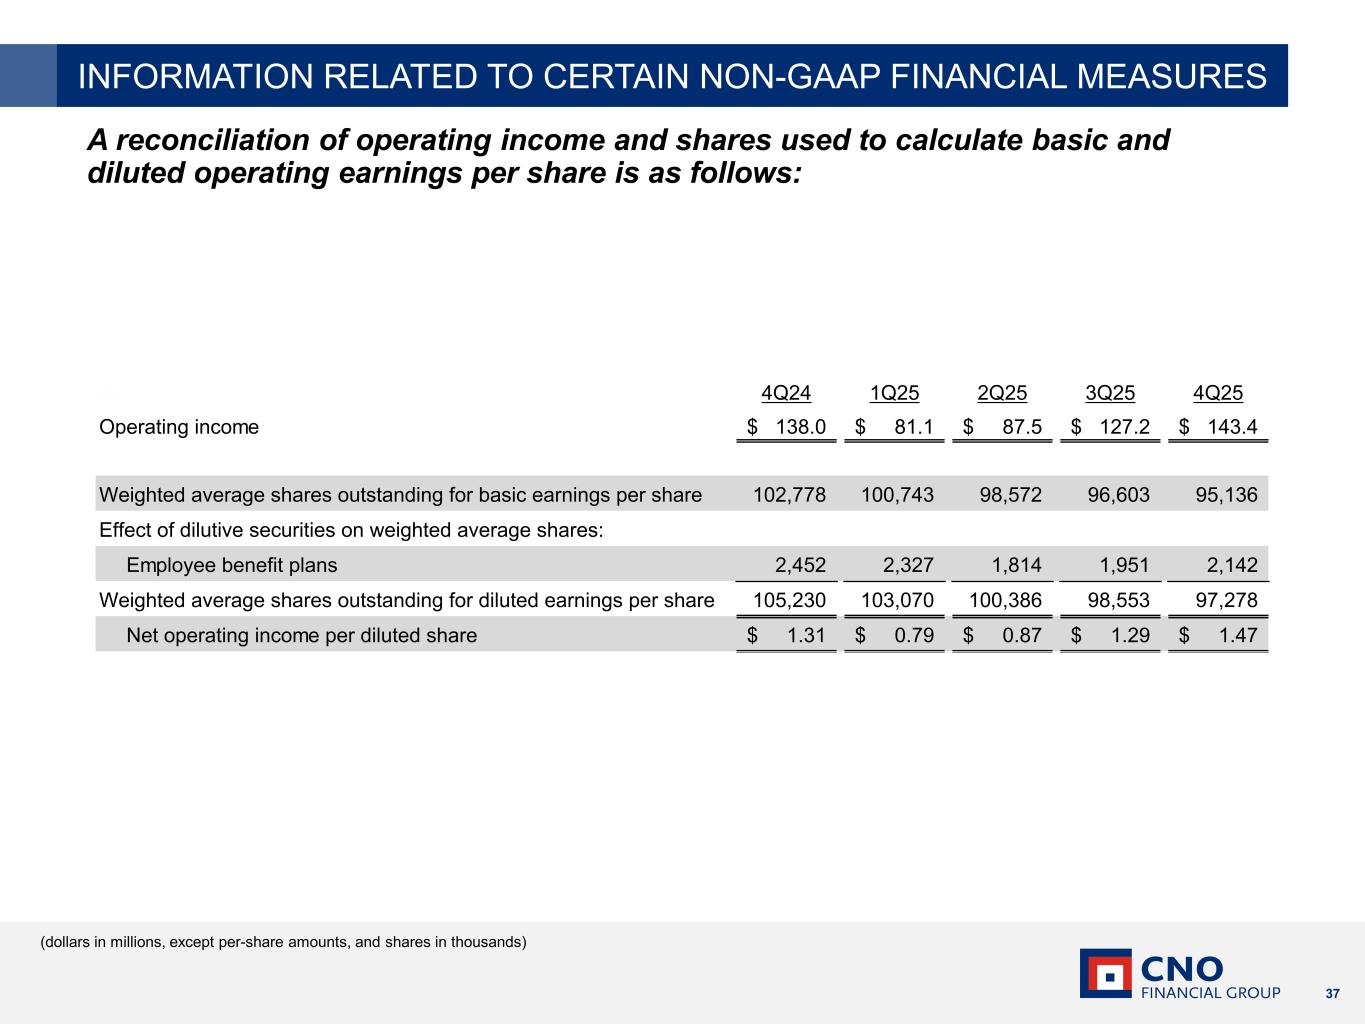
37 A reconciliation of operating income and shares used to calculate basic and diluted operating earnings per share is as follows: (dollars in millions, except per-share amounts, and shares in thousands) INFORMATION RELATED TO CERTAIN NON-GAAP FINANCIAL MEASURES 4Q24 1Q25 2Q25 3Q25 4Q25 Operating income 138.0$ 81.1$ 87.5$ 127.2$ 143.4$ Weighted average shares outstanding for basic earnings per share 102,778 100,743 98,572 96,603 95,136 Effect of dilutive securities on weighted average shares: Employee benefit plans 2,452 2,327 1,814 1,951 2,142 Weighted average shares outstanding for diluted earnings per share 105,230 103,070 100,386 98,553 97,278 Net operating income per diluted share 1.31$ 0.79$ 0.87$ 1.29$ 1.47$
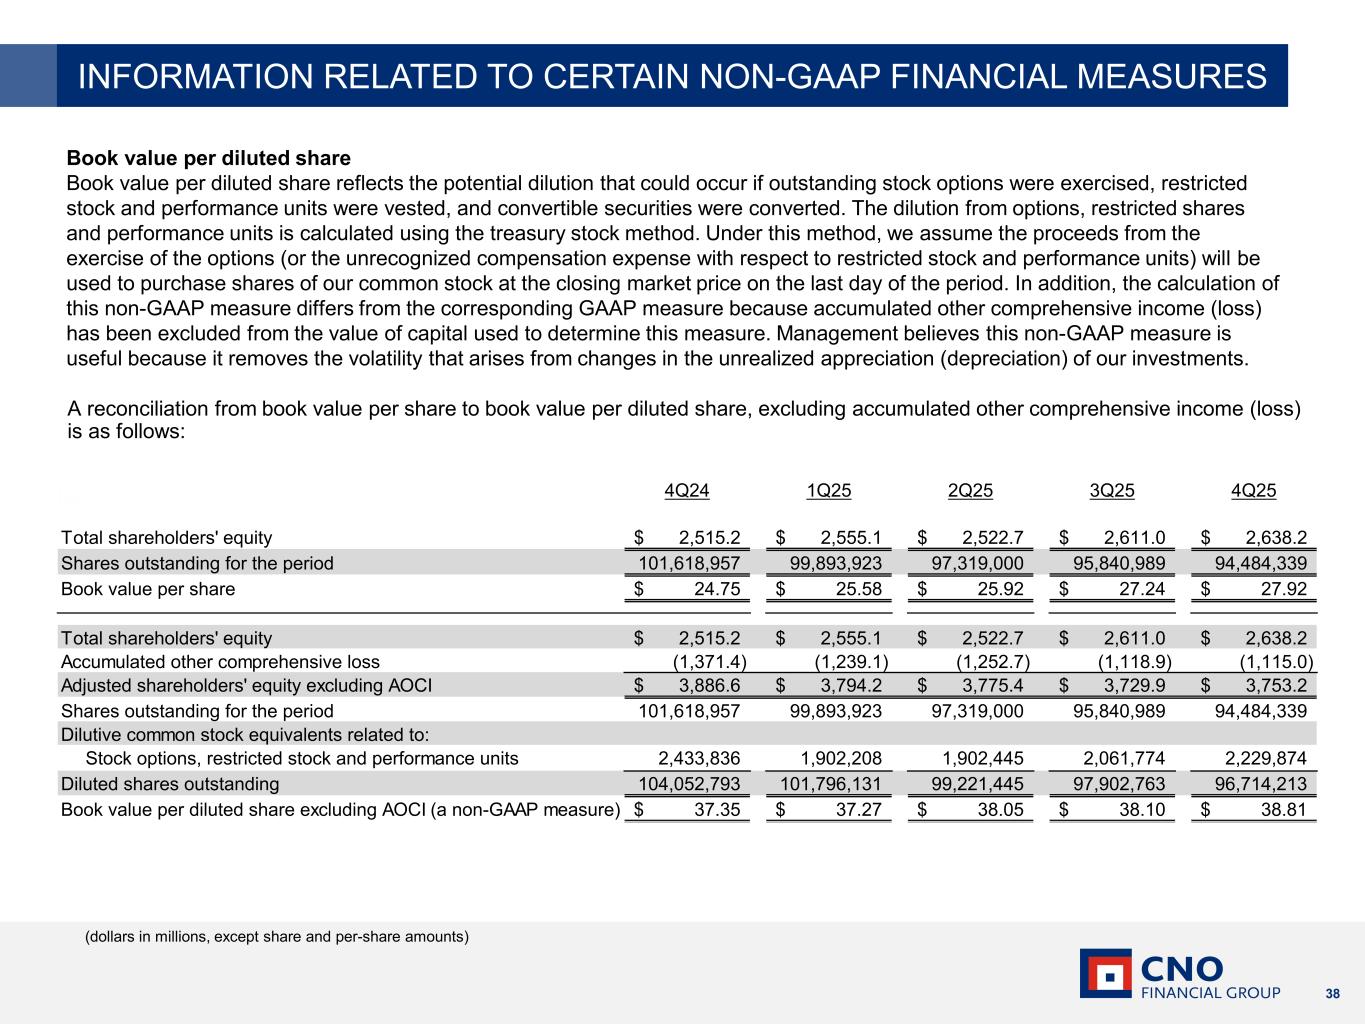
38 Book value per diluted share Book value per diluted share reflects the potential dilution that could occur if outstanding stock options were exercised, restricted stock and performance units were vested, and convertible securities were converted. The dilution from options, restricted shares and performance units is calculated using the treasury stock method. Under this method, we assume the proceeds from the exercise of the options (or the unrecognized compensation expense with respect to restricted stock and performance units) will be used to purchase shares of our common stock at the closing market price on the last day of the period. In addition, the calculation of this non-GAAP measure differs from the corresponding GAAP measure because accumulated other comprehensive income (loss) has been excluded from the value of capital used to determine this measure. Management believes this non-GAAP measure is useful because it removes the volatility that arises from changes in the unrealized appreciation (depreciation) of our investments. A reconciliation from book value per share to book value per diluted share, excluding accumulated other comprehensive income (loss) is as follows: (dollars in millions, except share and per-share amounts) INFORMATION RELATED TO CERTAIN NON-GAAP FINANCIAL MEASURES 4Q24 1Q25 2Q25 3Q25 4Q25 Total shareholders' equity 2,515.2$ 2,555.1$ 2,522.7$ 2,611.0$ 2,638.2$ Shares outstanding for the period 101,618,957 99,893,923 97,319,000 95,840,989 94,484,339 Book value per share 24.75$ 25.58$ 25.92$ 27.24$ 27.92$ Total shareholders' equity 2,515.2$ 2,555.1$ 2,522.7$ 2,611.0$ 2,638.2$ Accumulated other comprehensive loss (1,371.4) (1,239.1) (1,252.7) (1,118.9) (1,115.0) Adjusted shareholders' equity excluding AOCI 3,886.6$ 3,794.2$ 3,775.4$ 3,729.9$ 3,753.2$ Shares outstanding for the period 101,618,957 99,893,923 97,319,000 95,840,989 94,484,339 Dilutive common stock equivalents related to: Stock options, restricted stock and performance units 2,433,836 1,902,208 1,902,445 2,061,774 2,229,874 Diluted shares outstanding 104,052,793 101,796,131 99,221,445 97,902,763 96,714,213 Book value per diluted share excluding AOCI (a non-GAAP measure) 37.35$ 37.27$ 38.05$ 38.10$ 38.81$
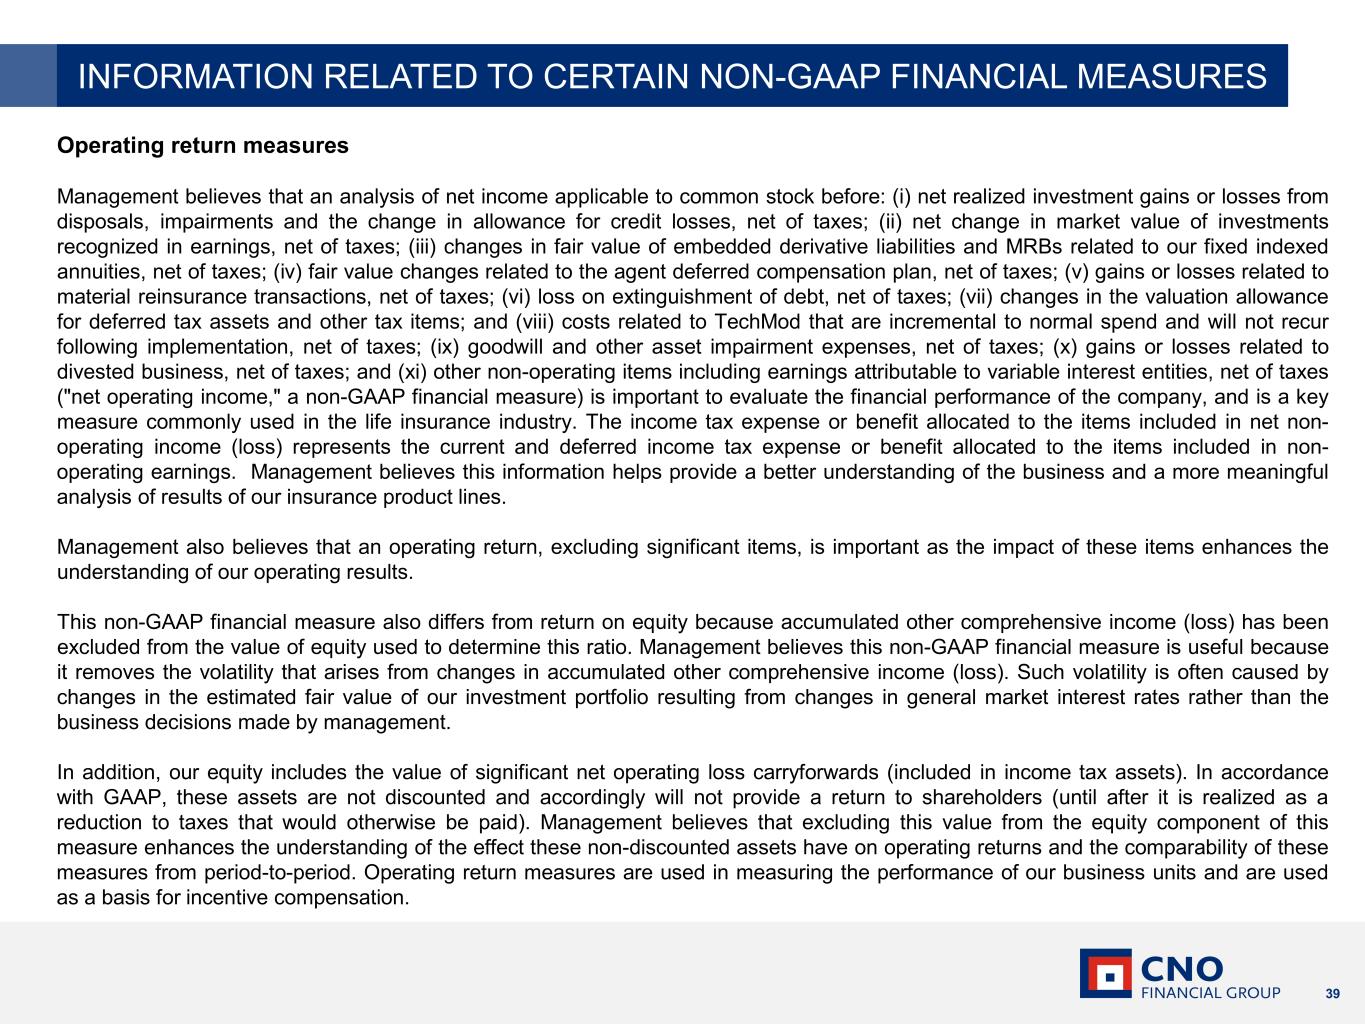
39 Operating return measures Management believes that an analysis of net income applicable to common stock before: (i) net realized investment gains or losses from disposals, impairments and the change in allowance for credit losses, net of taxes; (ii) net change in market value of investments recognized in earnings, net of taxes; (iii) changes in fair value of embedded derivative liabilities and MRBs related to our fixed indexed annuities, net of taxes; (iv) fair value changes related to the agent deferred compensation plan, net of taxes; (v) gains or losses related to material reinsurance transactions, net of taxes; (vi) loss on extinguishment of debt, net of taxes; (vii) changes in the valuation allowance for deferred tax assets and other tax items; and (viii) costs related to TechMod that are incremental to normal spend and will not recur following implementation, net of taxes; (ix) goodwill and other asset impairment expenses, net of taxes; (x) gains or losses related to divested business, net of taxes; and (xi) other non-operating items including earnings attributable to variable interest entities, net of taxes ("net operating income," a non-GAAP financial measure) is important to evaluate the financial performance of the company, and is a key measure commonly used in the life insurance industry. The income tax expense or benefit allocated to the items included in net non- operating income (loss) represents the current and deferred income tax expense or benefit allocated to the items included in non- operating earnings. Management believes this information helps provide a better understanding of the business and a more meaningful analysis of results of our insurance product lines. Management also believes that an operating return, excluding significant items, is important as the impact of these items enhances the understanding of our operating results. This non-GAAP financial measure also differs from return on equity because accumulated other comprehensive income (loss) has been excluded from the value of equity used to determine this ratio. Management believes this non-GAAP financial measure is useful because it removes the volatility that arises from changes in accumulated other comprehensive income (loss). Such volatility is often caused by changes in the estimated fair value of our investment portfolio resulting from changes in general market interest rates rather than the business decisions made by management. In addition, our equity includes the value of significant net operating loss carryforwards (included in income tax assets). In accordance with GAAP, these assets are not discounted and accordingly will not provide a return to shareholders (until after it is realized as a reduction to taxes that would otherwise be paid). Management believes that excluding this value from the equity component of this measure enhances the understanding of the effect these non-discounted assets have on operating returns and the comparability of these measures from period-to-period. Operating return measures are used in measuring the performance of our business units and are used as a basis for incentive compensation. INFORMATION RELATED TO CERTAIN NON-GAAP FINANCIAL MEASURES
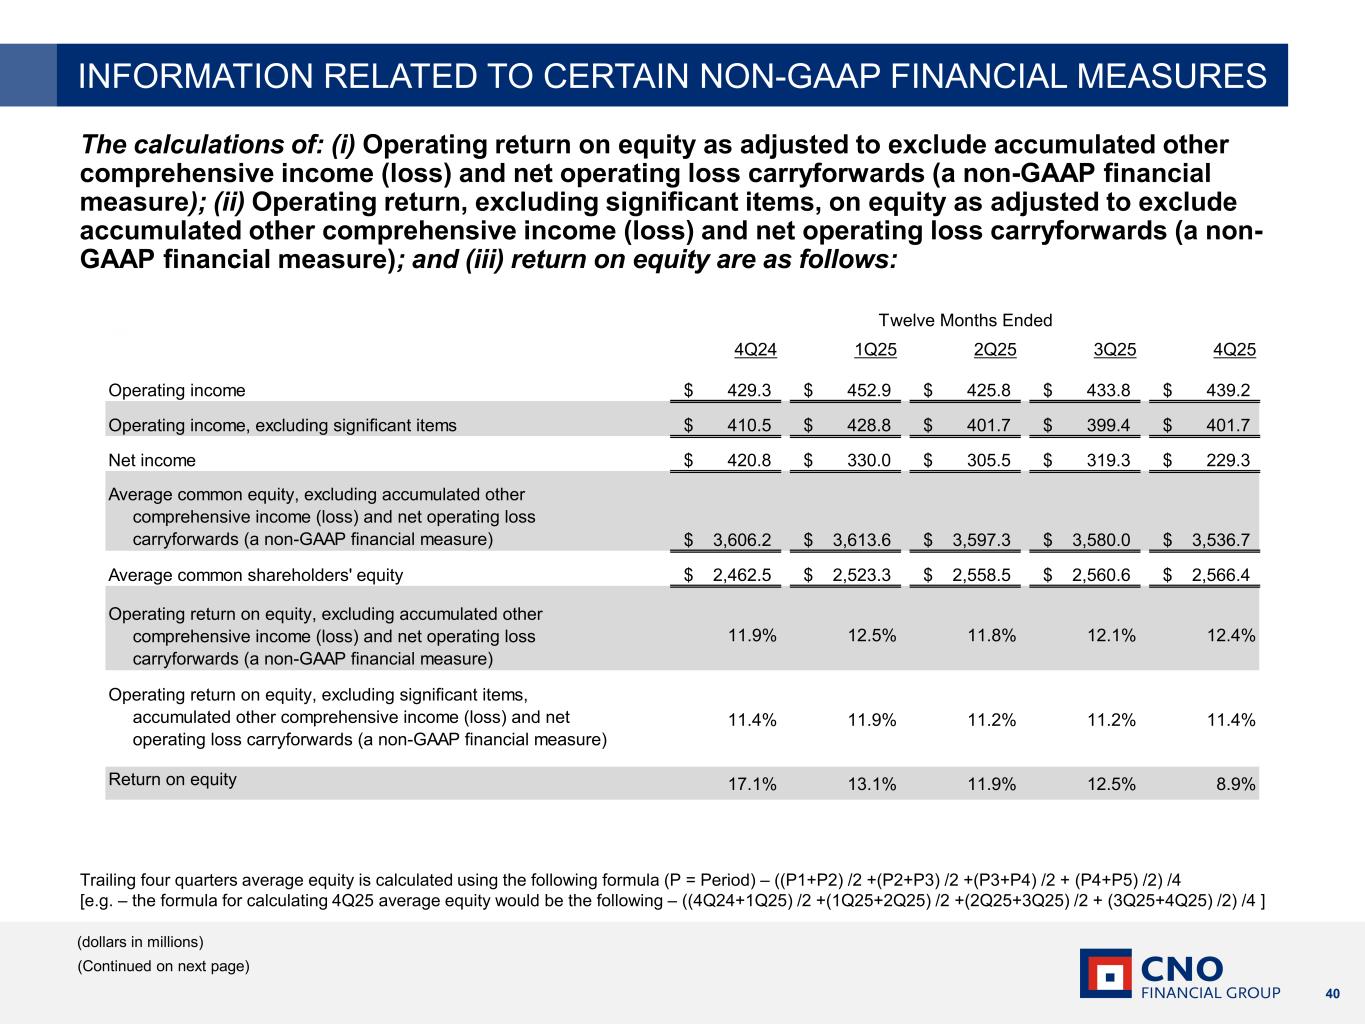
40 The calculations of: (i) Operating return on equity as adjusted to exclude accumulated other comprehensive income (loss) and net operating loss carryforwards (a non-GAAP financial measure); (ii) Operating return, excluding significant items, on equity as adjusted to exclude accumulated other comprehensive income (loss) and net operating loss carryforwards (a non- GAAP financial measure); and (iii) return on equity are as follows: (dollars in millions) (Continued on next page) Trailing four quarters average equity is calculated using the following formula (P = Period) – ((P1+P2) /2 +(P2+P3) /2 +(P3+P4) /2 + (P4+P5) /2) /4 [e.g. – the formula for calculating 4Q25 average equity would be the following – ((4Q24+1Q25) /2 +(1Q25+2Q25) /2 +(2Q25+3Q25) /2 + (3Q25+4Q25) /2) /4 ] INFORMATION RELATED TO CERTAIN NON-GAAP FINANCIAL MEASURES 4Q24 1Q25 2Q25 3Q25 4Q25 Operating income 429.3$ 452.9$ 425.8$ 433.8$ 439.2$ Operating income, excluding significant items 410.5$ 428.8$ 401.7$ 399.4$ 401.7$ Net income 420.8$ 330.0$ 305.5$ 319.3$ 229.3$ Average common equity, excluding accumulated other comprehensive income (loss) and net operating loss carryforwards (a non-GAAP financial measure) 3,606.2$ 3,613.6$ 3,597.3$ 3,580.0$ 3,536.7$ Average common shareholders' equity 2,462.5$ 2,523.3$ 2,558.5$ 2,560.6$ 2,566.4$ Operating return on equity, excluding accumulated other comprehensive income (loss) and net operating loss carryforwards (a non-GAAP financial measure) 11.9% 12.5% 11.8% 12.1% 12.4% Operating return on equity, excluding significant items, accumulated other comprehensive income (loss) and net operating loss carryforwards (a non-GAAP financial measure) 11.4% 11.9% 11.2% 11.2% 11.4% Return on equity 17.1% 13.1% 11.9% 12.5% 8.9% Twelve Months Ended
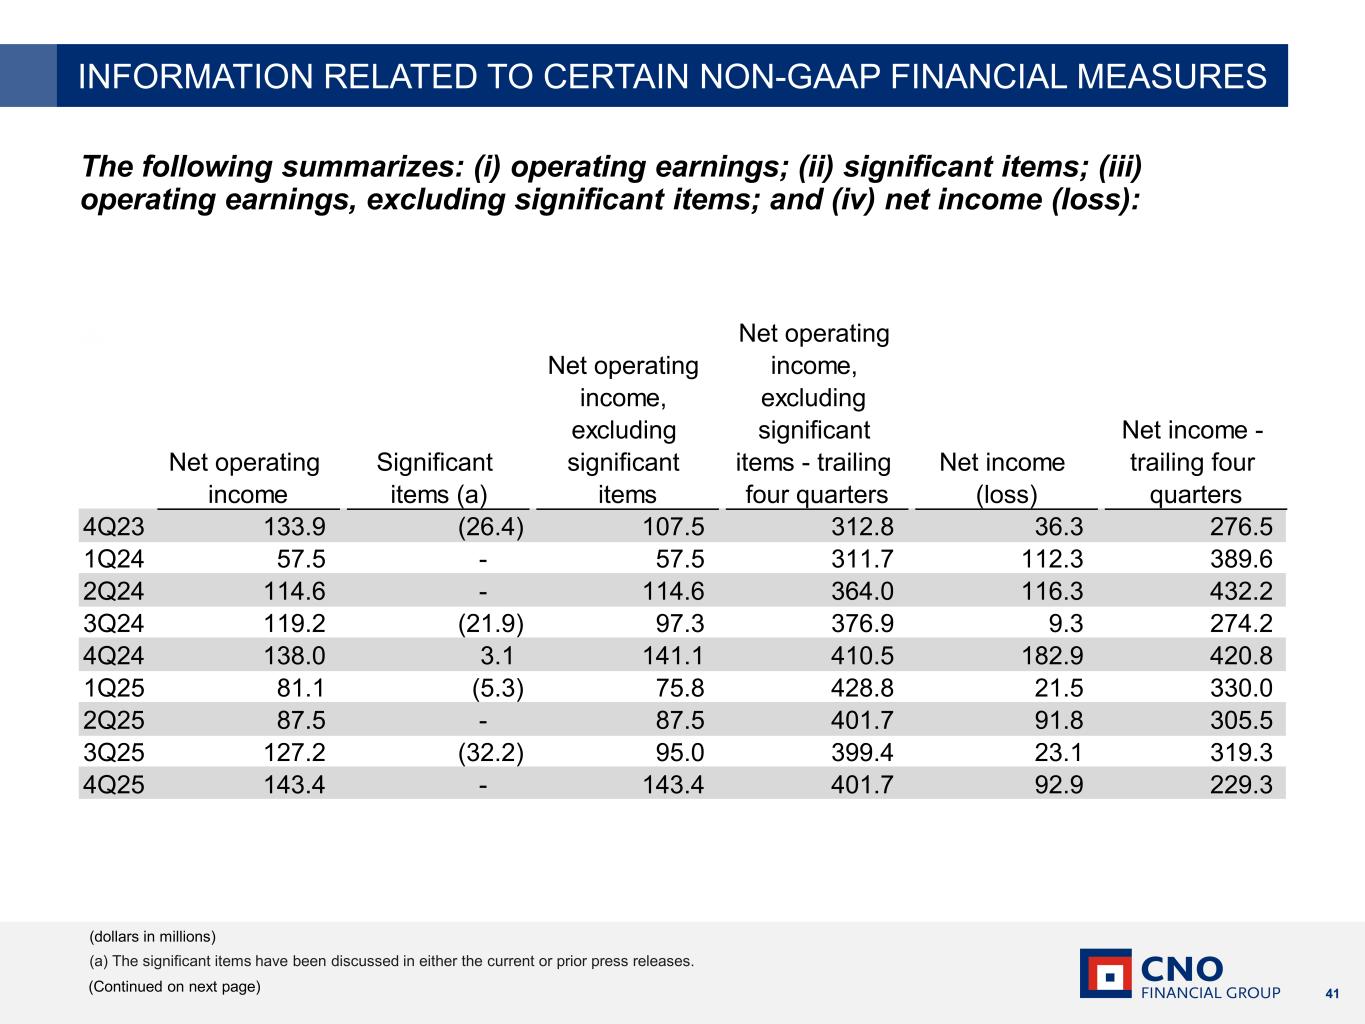
41 The following summarizes: (i) operating earnings; (ii) significant items; (iii) operating earnings, excluding significant items; and (iv) net income (loss): (dollars in millions) (a) The significant items have been discussed in either the current or prior press releases. (Continued on next page) INFORMATION RELATED TO CERTAIN NON-GAAP FINANCIAL MEASURES Net operating income Significant items (a) Net operating income, excluding significant items Net operating income, excluding significant items - trailing four quarters Net income (loss) Net income - trailing four quarters 4Q23 133.9 (26.4) 107.5 312.8 36.3 276.5 1Q24 57.5 - 57.5 311.7 112.3 389.6 2Q24 114.6 - 114.6 364.0 116.3 432.2 3Q24 119.2 (21.9) 97.3 376.9 9.3 274.2 4Q24 138.0 3.1 141.1 410.5 182.9 420.8 1Q25 81.1 (5.3) 75.8 428.8 21.5 330.0 2Q25 87.5 - 87.5 401.7 91.8 305.5 3Q25 127.2 (32.2) 95.0 399.4 23.1 319.3 4Q25 143.4 - 143.4 401.7 92.9 229.3
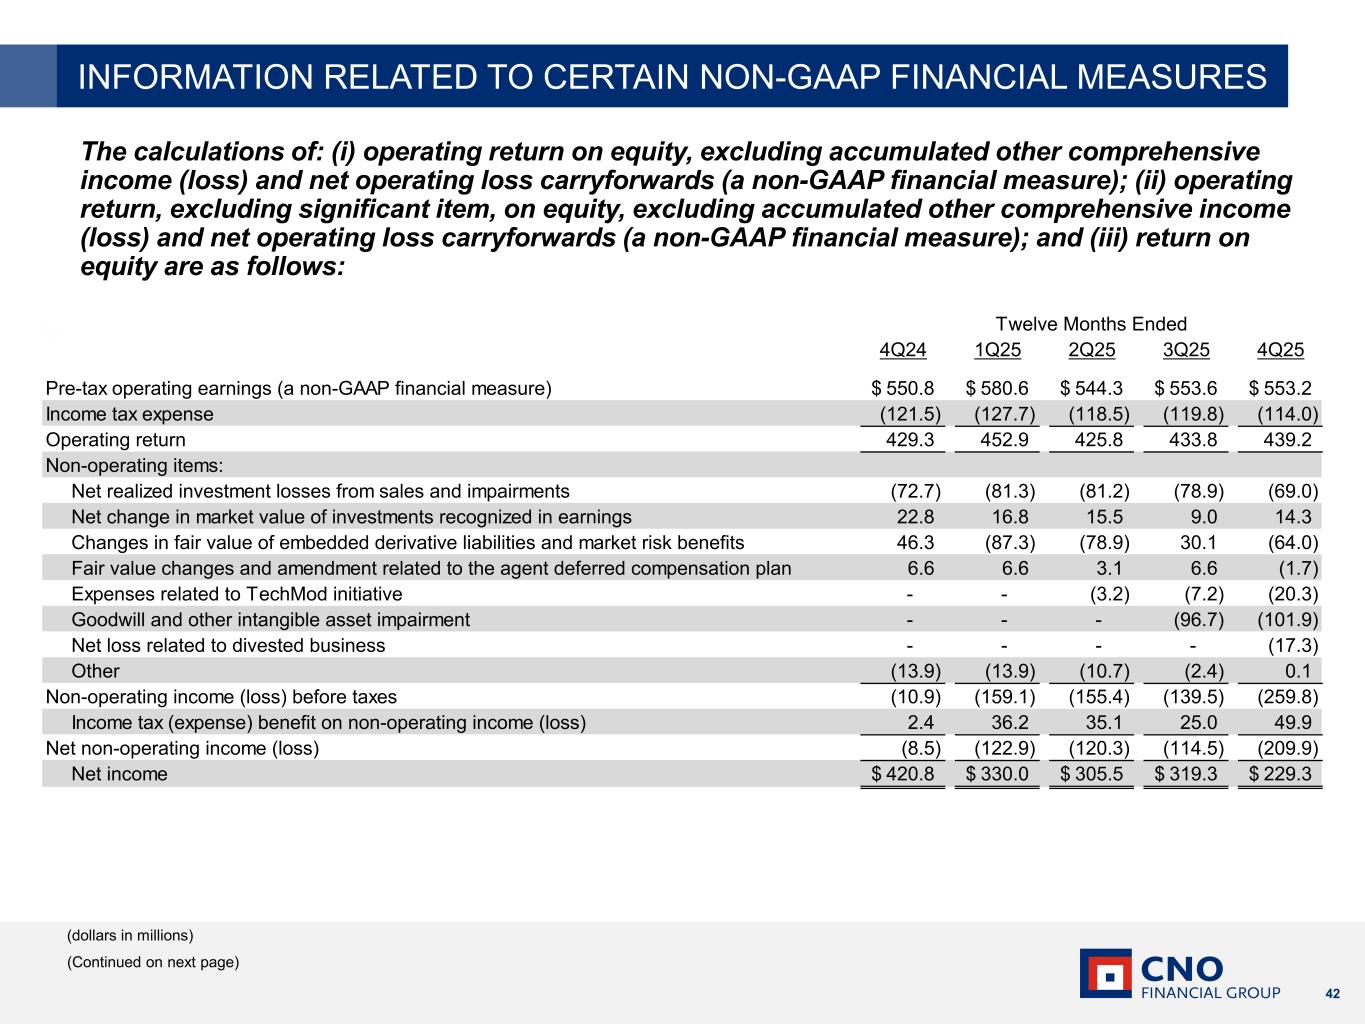
42 The calculations of: (i) operating return on equity, excluding accumulated other comprehensive income (loss) and net operating loss carryforwards (a non-GAAP financial measure); (ii) operating return, excluding significant item, on equity, excluding accumulated other comprehensive income (loss) and net operating loss carryforwards (a non-GAAP financial measure); and (iii) return on equity are as follows: (dollars in millions) (Continued on next page) INFORMATION RELATED TO CERTAIN NON-GAAP FINANCIAL MEASURES 4Q24 1Q25 2Q25 3Q25 4Q25 Pre-tax operating earnings (a non-GAAP financial measure) 550.8$ 580.6$ 544.3$ 553.6$ 553.2$ Income tax expense (121.5) (127.7) (118.5) (119.8) (114.0) Operating return 429.3 452.9 425.8 433.8 439.2 Non-operating items: Net realized investment losses from sales and impairments (72.7) (81.3) (81.2) (78.9) (69.0) Net change in market value of investments recognized in earnings 22.8 16.8 15.5 9.0 14.3 Changes in fair value of embedded derivative liabilities and market risk benefits 46.3 (87.3) (78.9) 30.1 (64.0) Fair value changes and amendment related to the agent deferred compensation plan 6.6 6.6 3.1 6.6 (1.7) Expenses related to TechMod initiative - - (3.2) (7.2) (20.3) Goodwill and other intangible asset impairment - - - (96.7) (101.9) Net loss related to divested business - - - - (17.3) Other (13.9) (13.9) (10.7) (2.4) 0.1 Non-operating income (loss) before taxes (10.9) (159.1) (155.4) (139.5) (259.8) Income tax (expense) benefit on non-operating income (loss) 2.4 36.2 35.1 25.0 49.9 Net non-operating income (loss) (8.5) (122.9) (120.3) (114.5) (209.9) Net income 420.8$ 330.0$ 305.5$ 319.3$ 229.3$ Twelve Months Ended
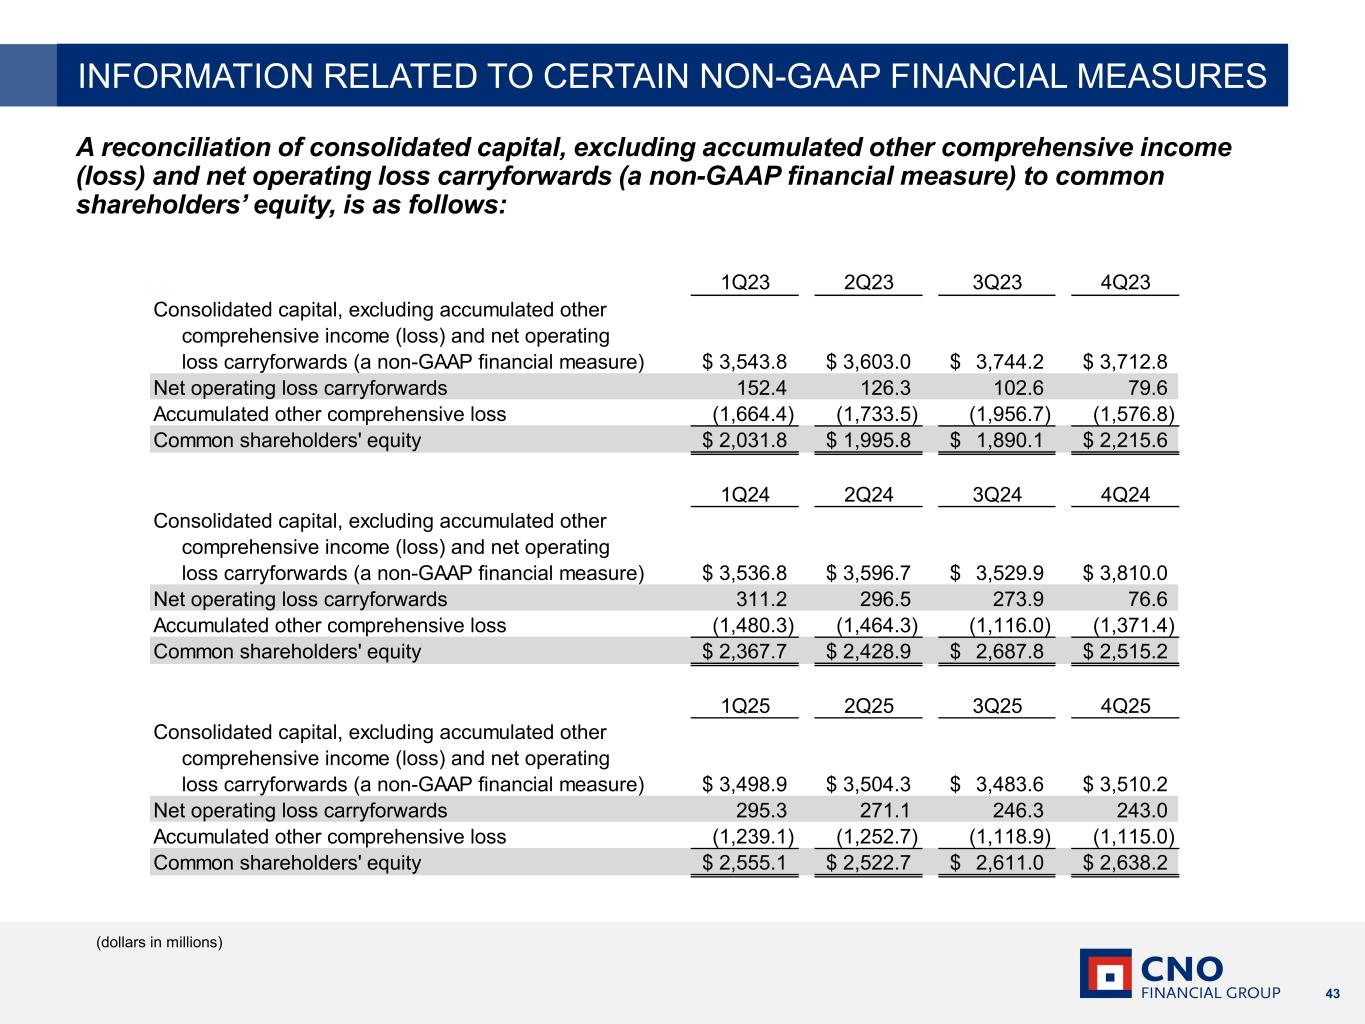
43 A reconciliation of consolidated capital, excluding accumulated other comprehensive income (loss) and net operating loss carryforwards (a non-GAAP financial measure) to common shareholders’ equity, is as follows: (dollars in millions) 1Q23 2Q23 3Q23 4Q23 Consolidated capital, excluding accumulated other comprehensive income (loss) and net operating loss carryforwards (a non-GAAP financial measure) 3,543.8$ 3,603.0$ 3,744.2$ 3,712.8$ Net operating loss carryforwards 152.4 126.3 102.6 79.6 Accumulated other comprehensive loss (1,664.4) (1,733.5) (1,956.7) (1,576.8) Common shareholders' equity 2,031.8$ 1,995.8$ 1,890.1$ 2,215.6$ 1Q24 2Q24 3Q24 4Q24 Consolidated capital, excluding accumulated other comprehensive income (loss) and net operating loss carryforwards (a non-GAAP financial measure) 3,536.8$ 3,596.7$ 3,529.9$ 3,810.0$ Net operating loss carryforwards 311.2 296.5 273.9 76.6 Accumulated other comprehensive loss (1,480.3) (1,464.3) (1,116.0) (1,371.4) Common shareholders' equity 2,367.7$ 2,428.9$ 2,687.8$ 2,515.2$ 1Q25 2Q25 3Q25 4Q25 Consolidated capital, excluding accumulated other comprehensive income (loss) and net operating loss carryforwards (a non-GAAP financial measure) 3,498.9$ 3,504.3$ 3,483.6$ 3,510.2$ Net operating loss carryforwards 295.3 271.1 246.3 243.0 Accumulated other comprehensive loss (1,239.1) (1,252.7) (1,118.9) (1,115.0) Common shareholders' equity 2,555.1$ 2,522.7$ 2,611.0$ 2,638.2$ INFORMATION RELATED TO CERTAIN NON-GAAP FINANCIAL MEASURES
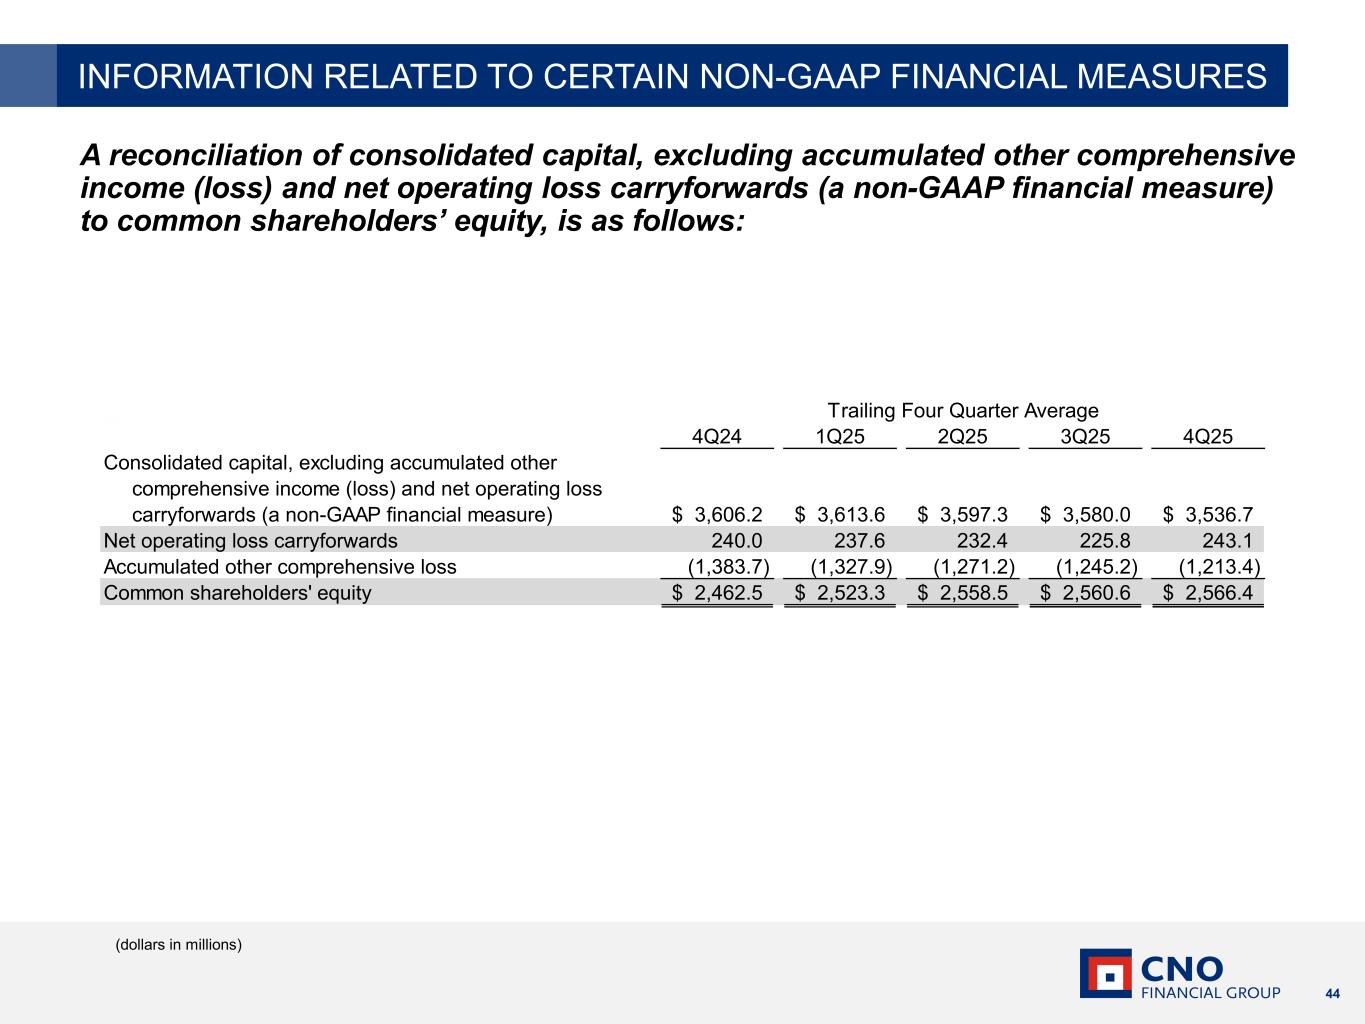
44 A reconciliation of consolidated capital, excluding accumulated other comprehensive income (loss) and net operating loss carryforwards (a non-GAAP financial measure) to common shareholders’ equity, is as follows: (dollars in millions) INFORMATION RELATED TO CERTAIN NON-GAAP FINANCIAL MEASURES 4Q24 1Q25 2Q25 3Q25 4Q25 Consolidated capital, excluding accumulated other comprehensive income (loss) and net operating loss carryforwards (a non-GAAP financial measure) 3,606.2$ 3,613.6$ 3,597.3$ 3,580.0$ 3,536.7$ Net operating loss carryforwards 240.0 237.6 232.4 225.8 243.1 Accumulated other comprehensive loss (1,383.7) (1,327.9) (1,271.2) (1,245.2) (1,213.4) Common shareholders' equity 2,462.5$ 2,523.3$ 2,558.5$ 2,560.6$ 2,566.4$ Trailing Four Quarter Average
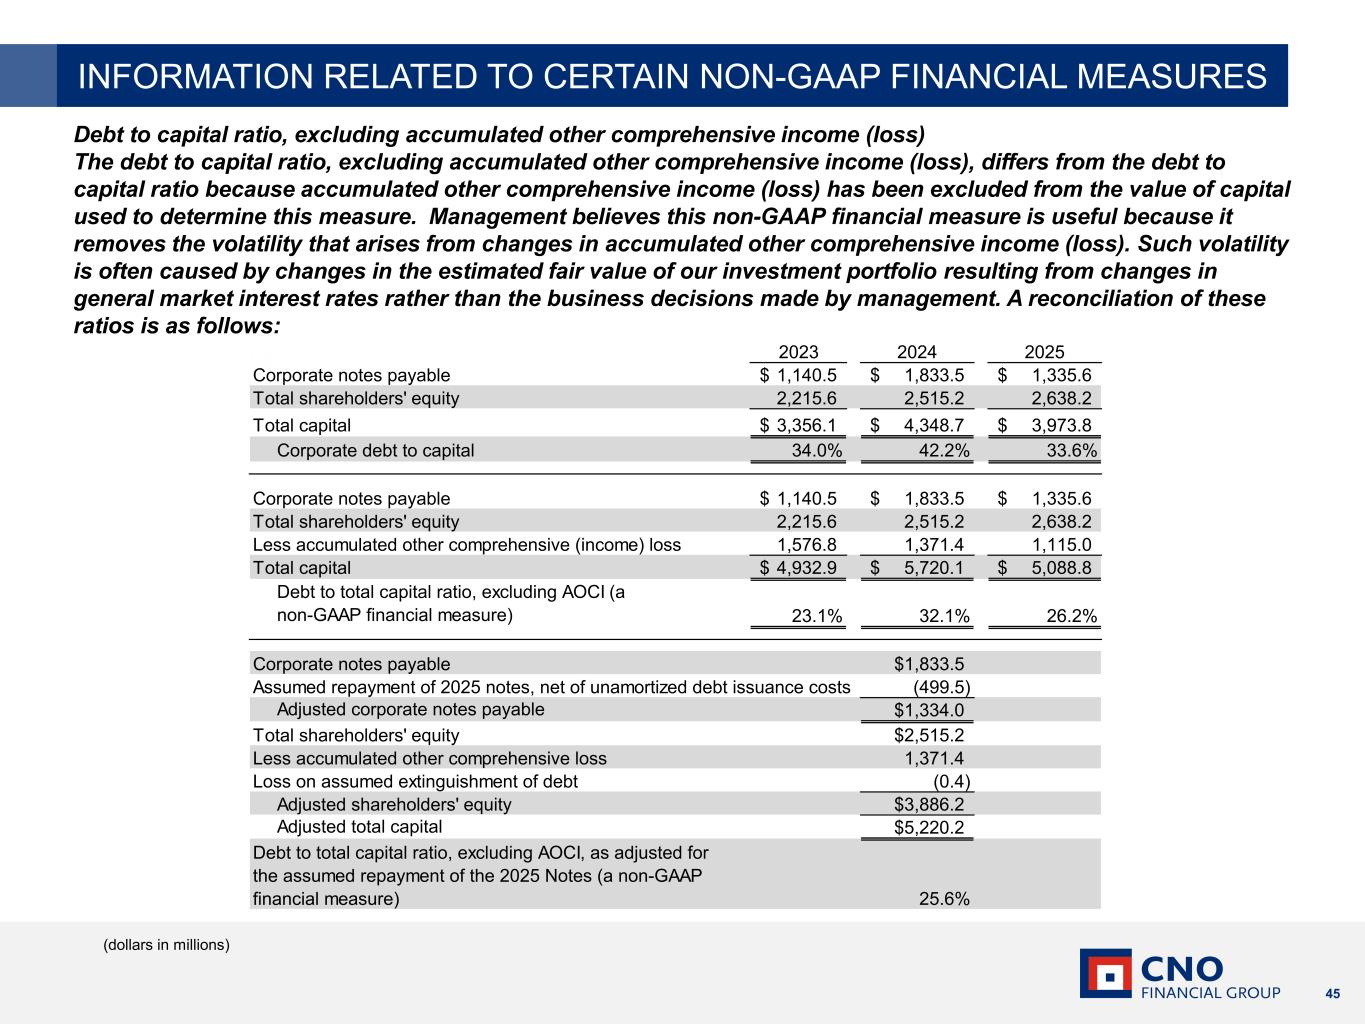
45 Debt to capital ratio, excluding accumulated other comprehensive income (loss) The debt to capital ratio, excluding accumulated other comprehensive income (loss), differs from the debt to capital ratio because accumulated other comprehensive income (loss) has been excluded from the value of capital used to determine this measure. Management believes this non-GAAP financial measure is useful because it removes the volatility that arises from changes in accumulated other comprehensive income (loss). Such volatility is often caused by changes in the estimated fair value of our investment portfolio resulting from changes in general market interest rates rather than the business decisions made by management. A reconciliation of these ratios is as follows: (dollars in millions) INFORMATION RELATED TO CERTAIN NON-GAAP FINANCIAL MEASURES 2023 2024 2025 Corporate notes payable 1,140.5$ 1,833.5$ 1,335.6$ Total shareholders' equity 2,215.6 2,515.2 2,638.2 Total capital 3,356.1$ 4,348.7$ 3,973.8$ Corporate debt to capital 34.0% 42.2% 33.6% Corporate notes payable 1,140.5$ 1,833.5$ 1,335.6$ Total shareholders' equity 2,215.6 2,515.2 2,638.2 Less accumulated other comprehensive (income) loss 1,576.8 1,371.4 1,115.0 Total capital 4,932.9$ 5,720.1$ 5,088.8$ Debt to total capital ratio, excluding AOCI (a non-GAAP financial measure) 23.1% 32.1% 26.2% Corporate notes payable $1,833.5 (499.5) Adjusted corporate notes payable $1,334.0 Total shareholders' equity $2,515.2 Less accumulated other comprehensive loss 1,371.4 Loss on assumed extinguishment of debt (0.4) Adjusted shareholders' equity $3,886.2 Adjusted total capital $5,220.2 Debt to total capital ratio, excluding AOCI, as adjusted for the assumed repayment of the 2025 Notes (a non-GAAP financial measure) 25.6% Assumed repayment of 2025 notes, net of unamortized debt issuance costs