
COLB 8-K
Columbia Banking System, Inc. (COLB)
8-K
2024-01-24
For: 2024-01-24
View Original
Added on
April 10, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities and Exchange Act of 1934
Date of Report: January 24, 2024
(Date of earliest event reported)
(Exact Name of Registrant as Specified in Its Charter)
(State or Other Jurisdiction of Incorporation or Organization) | (Commission File Number) | (I.R.S. Employer Identification Number) | ||||||
(address of Principal Executive Offices)(Zip Code)
(253 ) 305-1900
(Registrant's Telephone Number, Including Area Code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
[ ☐ ] Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425)
[ ☐ ] Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12)
[ ☐ ] Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))
[ ☐ ] Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))
Securities registered pursuant to Section 12(b) of the Act:
| TITLE OF EACH CLASS | TRADING SYMBOL | NAME OF EXCHANGE | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company [ ☐ ]
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. [ ]
| Item 2.02 | Results of Operations and Financial Condition. | ||||
On January 24, 2024, Columbia Banking System, Inc. issued a press release announcing fourth quarter and full year 2023 financial results. The release is attached hereto as Exhibit 99.1. The information included in the press release is considered to be "furnished" under the Securities Exchange Act of 1934, as amended (the "Exchange Act"). Columbia Banking System, Inc. will include final financial statements and additional analyses for the year ended December 31, 2023 as part of its annual report on Form 10-K covering that period.
| Item 7.01 | Regulation FD Disclosure. | ||||
Columbia Banking System, Inc. is filing an investor slide presentation that it intends to review in conjunction with its earnings release conference call on January 24, 2024. The slides are included as Exhibit 99.2 to this report and shall not be deemed to be "filed" for the purposes of Section 18 of the Exchange Act, or otherwise subject to the liability of that section, and shall not be incorporated by reference into any registration statement or other document filed under the Securities Act of 1933, as amended, or the Exchange Act, except as shall be expressly set forth by specific reference in such filing.
| Item 9.01 | Financial Statements and Exhibits. | ||||
| (d) | EXHIBITS | ||||
| 104 Cover Page Interactive Data File (embedded within the Inline XBRL document) | |||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
Columbia Banking System, Inc. (Registrant) | |||||
Dated: January 24, 2024 | By: /s/ Ronald L. Farnsworth Ronald L. Farnsworth Executive Vice President/Chief Financial Officer | ||||
EXHIBIT 99.1
 | Fourth Quarter 2023 Results •Net income of $94 million, or $0.45 per diluted common share •Operating net income of $91 million, or $0.44 per diluted common share1 •Consolidated asset balances of $52 billion at quarter end •Loan balances of $37 billion and deposit balances of $42 billion at quarter end •Estimated CET1 and total capital ratios of 9.6% and 11.8% at quarter end | ||||
00
COLUMBIA BANKING SYSTEM, INC. REPORTS FOURTH QUARTER 2023 RESULTS | ||||||||||||||||||||
| $0.45 | $0.44 | $23.95 | $16.12 | |||||||||||||||||
| Earnings per diluted common share | Operating earnings per diluted common share 1 | Book value per common share | Tangible book value per common share 1 | |||||||||||||||||
0
| CEO Commentary | ||
"It was a historic year for Columbia Banking System and Umpqua Bank,” said Clint Stein, President and CEO. “We closed and integrated the transformational combination of the Northwest's premier banking organizations, expanding our footprint to encompass eight Western states as we achieved our cost-savings targets ahead of schedule and above our original projections. With the integration behind us, we are now turning our focus to optimizing performance and driving shareholder value. The fourth quarter was noisy with the FDIC special assessment and some one-time expense items. Our cost of funds is not immune to the higher-rate environment, as we had some 2022 vintage CDs reprice and saw a material increase in public deposits impact our margin. However, we believe neither of these items dilutes the quality of our core deposit base. Our scale, products, and services empower our talented base of associates to win business, which we believe long-term will drive consistent, repeatable performance.” | ||
–Clint Stein, President and CEO of Columbia Banking System, Inc. | ||
4Q23 HIGHLIGHTS (COMPARED TO 3Q23) | ||||||||
| Net Interest Income and NIM | •Net interest income decreased to $454 million from $481 million in 3Q23 due primarily to higher deposit costs that more than offset a decline in the cost of wholesale borrowings. | |||||||
•Net interest margin was 3.78%, down 13 basis points from the prior quarter. Higher earning asset yields and a more profitable mix of earning assets were offset by higher deposit costs. Higher balances in public deposits and CD repricing contributed to the quarter's net interest margin contraction. | ||||||||
| Non-Interest Income and Expense | •Non-interest income increased by $22 million due primarily to a $28 million favorable change in cumulative non-merger fair value accounting and hedges. Lower mortgage banking revenue reflects an anticipated decline in servicing revenue following the MSR asset sale that closed on September 30, 2023. | |||||||
•Non-interest expense increased by $33 million due to a $33 million FDIC special assessment recorded during the quarter and other elevated expense items, which offset lower merger-related expense. | ||||||||
| Credit Quality | •Net charge-offs were 0.31% of average loans and leases (annualized) compared to 0.25% in the prior quarter. Charge-off activity remains primarily centered in the FinPac portfolio. | |||||||
•Provision expense of $55 million reflects changes in the economic forecasts used in credit models and portfolio migration trends. | ||||||||
•Non-performing assets to total assets was 0.22% compared to 0.20% at September 30, 2023. | ||||||||
| Capital | •Estimated total risk-based capital ratio of 11.8% and estimated common equity tier 1 risk-based capital ratio of 9.6%. | |||||||
•Declared a quarterly cash dividend of $0.36 per common share on November 13, 2023, which was paid December 11, 2023. | ||||||||
| Notable items | •Consolidated five branches in January 2024. | |||||||
•Incurred $7 million in merger-related expense. | ||||||||
4Q23 KEY FINANCIAL DATA | |||||||||||||||||
| PERFORMANCE METRICS | 4Q23 | 3Q23 | 4Q22 | ||||||||||||||
| Return on average assets | 0.72% | 1.02% | 1.04% | ||||||||||||||
| Return on average common equity | 7.90% | 11.07% | 13.50% | ||||||||||||||
Return on average tangible common equity 1 | 12.19% | 16.93% | 13.53% | ||||||||||||||
Operating return on average assets 1 | 0.70% | 1.23% | 1.24% | ||||||||||||||
Operating return on average common equity 1 | 7.73% | 13.40% | 16.14% | ||||||||||||||
Operating return on average tangible common equity 1 | 11.92% | 20.48% | 16.18% | ||||||||||||||
| Net interest margin | 3.78% | 3.91% | 4.01% | ||||||||||||||
| Efficiency ratio | 64.81% | 57.82% | 57.24% | ||||||||||||||
INCOME STATEMENT ($ in 000s, excl. per share data) | 4Q23 | 3Q23 | 4Q22 | ||||||||||||||
| Net interest income | $453,623 | $480,875 | $305,479 | ||||||||||||||
| Provision for credit losses | $54,909 | $36,737 | $32,948 | ||||||||||||||
| Non-interest income | $65,533 | $43,981 | $34,879 | ||||||||||||||
| Non-interest expense | $337,176 | $304,147 | $194,982 | ||||||||||||||
Pre-provision net revenue 1 | $181,980 | $220,709 | $145,376 | ||||||||||||||
Operating pre-provision net revenue1 | $179,213 | $258,687 | $167,094 | ||||||||||||||
Earnings per common share - diluted 2 | $0.45 | $0.65 | $0.64 | ||||||||||||||
Operating earnings per common share - diluted 1,2 | $0.44 | $0.79 | $0.76 | ||||||||||||||
Dividends paid per share 2 | $0.36 | $0.36 | $0.35 | ||||||||||||||
| BALANCE SHEET | 4Q23 | 3Q23 | 4Q22 | ||||||||||||||
| Total assets | $52.2 | B | $52.0 | B | $31.8 | B | |||||||||||
| Loans and leases | $37.4 | B | $37.2 | B | $26.2 | B | |||||||||||
| Total deposits | $41.6 | B | $41.6 | B | $27.1 | B | |||||||||||
Book value per common share 2 | $23.95 | $22.21 | $19.18 | ||||||||||||||
| Tangible book value per share1,2 | $16.12 | $14.22 | $19.14 | ||||||||||||||
Investor Contact
Jacquelynne "Jacque" Bohlen, SVP/Investor Relations Director, 503-727-4117, [email protected]
1 "Non-GAAP" financial measure. See GAAP to Non-GAAP Reconciliation for the comparable GAAP measurement.
2 Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958.
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 2
Organizational Update
Columbia Banking System, Inc. ("Columbia", "we", or "our") realized $143 million in annualized net merger-related cost-savings as of December 31, 2023, outpacing the $135 million target communicated when the combination was announced. As the integration process is now largely complete, we do not intend to provide future updates on cost savings realizations. However, Columbia has a history of prudent expense management, and the company will continue to evaluate opportunities for improved efficiency as part of the normal course of business to offset franchise development investments. As previously disclosed, Umpqua Bank, the primary subsidiary of Columbia, consolidated five branches during January 2024.
On February 28, 2023, Columbia completed its merger with Umpqua Holdings Corporation ("UHC"), combining the two premier banks in the Northwest to create one of the largest banks headquartered in the West (the "merger"). Columbia's financial results for any periods ended prior to February 28, 2023 reflect UHC results only on a standalone basis. In addition, Columbia's reported financial results for the first quarter of 2023 reflect UHC financial results only until the closing of the merger after the close of business on February 28, 2023. As a result of these two factors, Columbia's financial results for each of the quarters of 2023 and the year ended December 31, 2023 may not be directly comparable to prior reported periods. The number of shares issued and outstanding, earnings per share, additional paid-in capital, and all references to share quantities or metrics of Columbia have been retrospectively restated to reflect the equivalent number of shares issued in the merger as the merger was treated as a reverse merger. Under the reverse acquisition method of accounting, the assets and liabilities of Columbia as of February 28, 2023 ("historical Columbia") were recorded at their respective fair values.
Net Interest Income
Net interest income was $454 million for the fourth quarter of 2023, down $27 million from the prior quarter. The decline reflects higher deposit costs that more than offset a decline in the cost of wholesale borrowings.
Columbia's net interest margin was 3.78% for the fourth quarter of 2023, down 13 basis points from 3.91% for the third quarter of 2023. The cost of interest-bearing deposits increased 53 basis points on a linked-quarter basis to 2.54% for the fourth quarter of 2023, which compares to 2.71% for the month of December and 2.75% at December 31, 2023. Deposit costs were impacted by the full quarter's run rate of brokered deposits added during the third quarter to replace maturing FHLB advances. Further, higher public deposit balances, which reflect seasonal tax-related trends and a focused effort to attract relationship-based public funds in local communities as we work to reduce wholesale funding, also had an impact. Public balances tend to carry a higher interest rate than most other non-maturity deposit balances. Time deposits also contributed to the quarter's increased cost of deposits as many maturing balances repriced over 200 basis points higher at the expiration of their 12- and 13-month terms. Columbia's cost of interest-bearing liabilities increased 30 basis points on a linked-quarter basis to 3.02% for the fourth quarter of 2023, which compares to 3.15% for the month of December and 3.19% at December 31, 2023. A reduction in the balance of average wholesale borrowings resulted in a smaller increase in the cost of interest-bearing liabilities compared to interest-bearing deposits. Please refer to the Q4 2023 Earnings Presentation for additional net interest margin change details and interest rate sensitivity information as well as to our non-GAAP disclosures in this press release for the impact of purchase accounting accretion and amortization on individual line items.
Non-interest Income
Non-interest income was $66 million for the fourth quarter of 2023, up $22 million from the prior quarter. A $28 million favorable change in fair value adjustments and mortgage servicing rights ("MSR") hedging activity reflects a net fair value gain of $13 million in the fourth quarter, compared to a net fair value loss of $15 million in the third quarter, as detailed in our non-GAAP disclosures. This benefit was partially offset by lower mortgage servicing income following the September 30, 2023 sale of approximately one-third of Columbia's MSR assets, which reduced the serviced loan portfolio by an equivalent amount.
Non-interest Expense
Non-interest expense was $337 million for the fourth quarter of 2023, up $33 million from the prior quarter. The increase was driven by a recorded $33 million expense for the special assessment from the FDIC to replenish the Deposit Insurance Fund following bank closures earlier in 2023. The fourth quarter was also impacted by other elevated expense items that offset a $12 million decline in merger-related expense, which was $7 million in the fourth quarter. Please refer to the Q4 2023 Earnings Presentation for additional expense details, including an update on realized merger-related cost-savings through December 31, 2023.
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 3
Balance Sheet
Total consolidated assets were $52.2 billion as of December 31, 2023, essentially unchanged from September 30, 2023. Cash and cash equivalents was $2.2 billion as of December 31, 2023, a decrease of $241 million relative to September 30, 2023. Including secured off-balance sheet lines of credit, total available liquidity was $18.7 billion as of December 31, 2023, representing 36% of total assets, 45% of total deposits, and 138% of uninsured deposits. Available for sale ("AFS") securities, which are held on balance sheet at fair value, were $8.8 billion as of December 31, 2023, an increase of $326 million relative to September 30, 2023, as an increase in the fair value of the portfolio and accretion of the discount on historical Columbia securities more than offset paydowns. Columbia did not purchase any securities during the fourth quarter. Please refer to the Q4 2023 Earnings Presentation for additional details related to our securities portfolio and liquidity position.
Gross loans and leases were $37.4 billion as of December 31, 2023, an increase of $271 million relative to September 30, 2023. "Higher outstanding commercial term and line balances and other relationship-driven expansion contributed to 3% annualized loan growth in the fourth quarter," stated Chris Merrywell, President of Umpqua Bank. "Our bankers remain laser-focused on generating business founded through relationships that drive balanced growth." Please refer to the Q4 2023 Earnings Presentation for additional details related to our loan portfolio, which include underwriting characteristics, the composition of our commercial portfolios, and disclosure related to our office portfolio.
Total deposits were $41.6 billion as of December 31, 2023, essentially unchanged from September 30, 2023. "While total deposit balances were stable between September and December, the mix reflects a shift into interest-bearing demand accounts," commented Mr. Merrywell. "Non-interest bearing balance changes continue to reflect customers' use of cash, which includes tax payments and lower escrow balances during the fourth quarter. Our targeted efforts to expand our network of public deposits throughout our communities helped offset seasonal customer declines without the use of wholesale funding." Please refer to the Q4 2023 Earnings Presentation for additional details related to deposit characteristics and flows.
Credit Quality
The allowance for credit losses was $464 million, or 1.24% of loans and leases, as of December 31, 2023, compared to $438 million, or 1.18% of loans and leases, as of September 30, 2023. The provision for credit losses was $55 million for the fourth quarter of 2023, and it reflects changes in the economic forecasts used in credit models and portfolio migration trends. Please refer to the Q4 2023 Earnings Presentation for additional details related to the allowance for credit losses and other credit trends.
Net charge-offs were 0.31% of average loans and leases (annualized) for the fourth quarter of 2023, compared to 0.25% for the third quarter of 2023. Net charge-off activity continued to be centered in the FinPac portfolio as bank charge-off activity was low at 0.06% of average bank loans. As of December 31, 2023, non-performing assets were $114 million, or 0.22% of total assets, compared to $106 million, or 0.20% of total assets, as of September 30, 2023.
Capital
As of December 31, 2023, Columbia's book value per common share increased to $23.95, compared to $22.21 at September 30, 2023. The linked-quarter change in book value primarily reflects a change in accumulated other comprehensive (loss) income ("AOCI") to $(340) million at December 31, 2023, compared to $(680) million at the prior quarter-end. The change in AOCI is due primarily to a decrease in the tax-effected net unrealized loss on AFS securities to $322 million as of December 31, 2023, compared to $650 million as of September 30, 2023. As of December 31, 2023, 54% of the AFS securities portfolio was in an unrealized gain position. Tangible book value per common share1 correspondingly increased to $16.12, compared to $14.22 at September 30, 2023.
Columbia's estimated total risk-based capital ratio was 11.8% and its estimated common equity tier 1 risk-based capital ratio was 9.6% as of December 31, 2023, compared to 11.6% and 9.5%, respectively, as of September 30, 2023. Columbia remains above current “well-capitalized” regulatory minimums. "Our regulatory capital ratios continued to expand in the fourth quarter," stated Ron Farnsworth, Chief Financial Officer of Columbia. "We expect our capital position to continue to build over time, supporting our franchise expansion and increasing flexibility for capital return." The regulatory capital ratios as of December 31, 2023 are estimates, pending completion and filing of Columbia's regulatory reports.
1 "Non-GAAP" financial measure. See GAAP to Non-GAAP Reconciliation for the comparable GAAP measurement.
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 4
Earnings Presentation and Conference Call Information
Columbia's Q4 2023 Earnings Presentation provides additional disclosure. A copy will be available on our investor relations page: www.columbiabankingsystem.com.
Columbia will host its fourth quarter 2023 earnings conference call on January 24, 2024, at 2:00 p.m. PT (5:00 p.m. ET). During the call, Columbia's management will provide an update on recent activities and discuss its fourth quarter 2023 financial results. Participants may register for the call using the below link to receive dial-in details and their own unique PINs or join the audiocast. It is recommended you join 10 minutes prior to the start time.
Register for the call: https://register.vevent.com/register/BI2ed0e3ce03e94a7a968c1bbb26fa939c
Join the audiocast: https://edge.media-server.com/mmc/p/eo4z866c/
Access the replay through Columbia's investor relations page: www.columbiabankingsystem.com
About Columbia Banking System, Inc.
Columbia (Nasdaq: COLB) is headquartered in Tacoma, Washington and is the parent company of Umpqua Bank, an award-winning western U.S. regional bank based in Lake Oswego, Oregon. In March of 2023, Columbia and Umpqua combined two of the Pacific Northwest's premier financial institutions under the Umpqua Bank brand to create one of the largest banks headquartered in the West and a top-30 U.S. bank. With over $50 billion of assets, Umpqua Bank combines the resources, sophistication and expertise of a national bank with a commitment to deliver personalized service at scale. The bank operates in Arizona, California, Colorado, Idaho, Nevada, Oregon, Utah, and Washington and supports consumers and businesses through a full suite of services, including retail and commercial banking; Small Business Administration lending; institutional and corporate banking; and equipment leasing. Umpqua Bank customers also have access to comprehensive investment and wealth management expertise as well as healthcare and private banking through Columbia Wealth Management and Columbia Trust Company, a subsidiary of Columbia. Learn more at www.columbiabankingsystem.com.
Forward-Looking Statements
This press release includes forward-looking statements within the meaning of the "Safe-Harbor" provisions of the Private Securities Litigation Reform Act of 1995, which management believes are a benefit to shareholders. These statements are necessarily subject to risk and uncertainty and actual results could differ materially due to various risk factors, including those set forth from time to time in our filings with the Securities and Exchange Commission (the "SEC"). You should not place undue reliance on forward-looking statements, and we undertake no obligation to update any such statements. Forward-looking statements can be identified by words such as "anticipates," "intends," "plans," "seeks," "believes," "estimates," "expects," "target," "projects," "outlook," "forecast," "will," "may," "could," "should," "can" and similar references to future periods. In this press release we make forward-looking statements about strategic and growth initiatives and the result of such activity. Risks that could cause results to differ from forward-looking statements we make include, without limitation: current and future economic and market conditions, including the effects of declines in housing and commercial real estate prices, high unemployment rates, continued inflation and any recession or slowdown in economic growth particularly in the western United States; economic forecast variables that are either materially worse or better than end of quarter projections and deterioration in the economy that could result in increased loan and lease losses, especially those risks associated with concentrations in real estate related loans; our ability to effectively manage problem credits; the impact of bank failures or adverse developments at or news developments concerning other banks on general investor sentiment regarding the liquidity and stability of banks; changes in interest rates that could significantly reduce net interest income and negatively affect asset yields and valuations and funding sources; changes in the scope and cost of FDIC insurance and other coverage; our ability to successfully implement efficiency and operational excellence initiatives; our ability to successfully develop and market new products and technology; changes in laws or regulations; any failure to realize the anticipated benefits of the merger when expected or at all; potential adverse reactions or changes to business or employee relationships, including those resulting from the completion of the merger and integration of the companies; the effect of geopolitical instability, including wars, conflicts and terrorist attacks; and natural disasters and other similar unexpected events outside of our control. We also caution that the amount and timing of any future common stock dividends or repurchases will depend on the earnings, cash requirements and financial condition of Columbia, market conditions, capital requirements, applicable law and regulations (including federal securities laws and federal banking regulations), and other factors deemed relevant by Columbia's Board of Directors, and may be subject to regulatory approval or conditions.
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 5
| TABLE INDEX | |||||
| Page | |||||
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 6
| Columbia Banking System, Inc. | |||||||||||||||||||||||||||||||||||||||||
| Consolidated Statements of Operations | |||||||||||||||||||||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | % Change (2) | ||||||||||||||||||||||||||||||||||||||||
| ($ in thousands, except per share data) | Dec 31, 2023 | Sep 30, 2023 | Jun 30, 2023 | Mar 31, 2023 | Dec 31, 2022 | Seq. Quarter | Year over Year | ||||||||||||||||||||||||||||||||||
| Interest income: | |||||||||||||||||||||||||||||||||||||||||
| Loans and leases | $ | 577,741 | $ | 569,670 | $ | 552,679 | $ | 413,525 | $ | 322,350 | 1 | % | 79 | % | |||||||||||||||||||||||||||
| Interest and dividends on investments: | |||||||||||||||||||||||||||||||||||||||||
| Taxable | 78,010 | 80,066 | 79,036 | 39,729 | 18,108 | (3) | % | 331 | % | ||||||||||||||||||||||||||||||||
| Exempt from federal income tax | 6,966 | 6,929 | 6,817 | 3,397 | 1,288 | 1 | % | 441 | % | ||||||||||||||||||||||||||||||||
| Dividends | 4,862 | 4,941 | 2,581 | 719 | 182 | (2) | % | nm | |||||||||||||||||||||||||||||||||
| Temporary investments and interest bearing deposits | 24,055 | 34,407 | 34,616 | 18,581 | 10,319 | (30) | % | 133 | % | ||||||||||||||||||||||||||||||||
| Total interest income | 691,634 | 696,013 | 675,729 | 475,951 | 352,247 | (1) | % | 96 | % | ||||||||||||||||||||||||||||||||
| Interest expense: | |||||||||||||||||||||||||||||||||||||||||
| Deposits | 170,659 | 126,974 | 100,408 | 63,613 | 31,174 | 34 | % | 447 | % | ||||||||||||||||||||||||||||||||
| Securities sold under agreement to repurchase and federal funds purchased | 1,226 | 1,220 | 1,071 | 406 | 323 | 0 | % | 280 | % | ||||||||||||||||||||||||||||||||
| Borrowings | 56,066 | 77,080 | 81,004 | 28,764 | 8,023 | (27) | % | nm | |||||||||||||||||||||||||||||||||
| Junior and other subordinated debentures | 10,060 | 9,864 | 9,271 | 8,470 | 7,248 | 2 | % | 39 | % | ||||||||||||||||||||||||||||||||
| Total interest expense | 238,011 | 215,138 | 191,754 | 101,253 | 46,768 | 11 | % | 409 | % | ||||||||||||||||||||||||||||||||
| Net interest income | 453,623 | 480,875 | 483,975 | 374,698 | 305,479 | (6) | % | 48 | % | ||||||||||||||||||||||||||||||||
| Provision for credit losses | 54,909 | 36,737 | 16,014 | 105,539 | 32,948 | 49 | % | 67 | % | ||||||||||||||||||||||||||||||||
| Non-interest income: | |||||||||||||||||||||||||||||||||||||||||
| Service charges on deposits | 17,349 | 17,410 | 16,454 | 14,312 | 12,139 | 0 | % | 43 | % | ||||||||||||||||||||||||||||||||
| Card-based fees | 14,593 | 15,674 | 13,435 | 11,561 | 9,017 | (7) | % | 62 | % | ||||||||||||||||||||||||||||||||
| Financial services and trust revenue | 3,011 | 4,651 | 4,512 | 1,297 | 25 | (35) | % | nm | |||||||||||||||||||||||||||||||||
| Residential mortgage banking revenue (loss), net | 4,212 | 7,103 | (2,342) | 7,816 | (1,812) | (41) | % | nm | |||||||||||||||||||||||||||||||||
| Gain on sale of debt securities, net | 9 | 4 | — | — | — | 125 | % | nm | |||||||||||||||||||||||||||||||||
| Gain (loss) on equity securities, net | 2,636 | (2,055) | (697) | 2,416 | 284 | nm | nm | ||||||||||||||||||||||||||||||||||
| Gain on loan and lease sales, net | 1,161 | 1,871 | 442 | 940 | 1,531 | (38) | % | (24) | % | ||||||||||||||||||||||||||||||||
| BOLI income | 4,331 | 4,440 | 4,063 | 2,790 | 2,033 | (2) | % | 113 | % | ||||||||||||||||||||||||||||||||
| Other income (loss) | 18,231 | (5,117) | 3,811 | 13,603 | 11,662 | nm | 56 | % | |||||||||||||||||||||||||||||||||
| Total non-interest income | 65,533 | 43,981 | 39,678 | 54,735 | 34,879 | 49 | % | 88 | % | ||||||||||||||||||||||||||||||||
| Non-interest expense: | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 157,572 | 159,041 | 163,398 | 136,092 | 107,982 | (1) | % | 46 | % | ||||||||||||||||||||||||||||||||
| Occupancy and equipment, net | 48,160 | 43,070 | 50,550 | 41,700 | 34,021 | 12 | % | 42 | % | ||||||||||||||||||||||||||||||||
| Intangible amortization | 33,204 | 29,879 | 35,553 | 12,660 | 1,019 | 11 | % | nm | |||||||||||||||||||||||||||||||||
| FDIC assessments | 42,510 | 11,200 | 11,579 | 6,113 | 3,487 | 280 | % | nm | |||||||||||||||||||||||||||||||||
| Merger-related expense | 7,174 | 18,938 | 29,649 | 115,898 | 11,637 | (62) | % | (38) | % | ||||||||||||||||||||||||||||||||
| Other expenses | 48,556 | 42,019 | 37,830 | 30,355 | 36,836 | 16 | % | 32 | % | ||||||||||||||||||||||||||||||||
| Total non-interest expense | 337,176 | 304,147 | 328,559 | 342,818 | 194,982 | 11 | % | 73 | % | ||||||||||||||||||||||||||||||||
| Income (loss) before provision (benefit) for income taxes | 127,071 | 183,972 | 179,080 | (18,924) | 112,428 | (31) | % | 13 | % | ||||||||||||||||||||||||||||||||
| Provision (benefit) for income taxes | 33,540 | 48,127 | 45,703 | (4,886) | 29,464 | (30) | % | 14 | % | ||||||||||||||||||||||||||||||||
| Net income (loss) | $ | 93,531 | $ | 135,845 | $ | 133,377 | $ | (14,038) | $ | 82,964 | (31) | % | 13 | % | |||||||||||||||||||||||||||
Weighted average basic shares outstanding (1) | 208,083 | 208,070 | 207,977 | 156,383 | 129,321 | 0 | % | 61 | % | ||||||||||||||||||||||||||||||||
Weighted average diluted shares outstanding (1) | 208,739 | 208,645 | 208,545 | 156,383 | 129,801 | 0 | % | 61 | % | ||||||||||||||||||||||||||||||||
Earnings (loss) per common share – basic (1) | $ | 0.45 | $ | 0.65 | $ | 0.64 | $ | (0.09) | $ | 0.64 | (31) | % | (30) | % | |||||||||||||||||||||||||||
Earnings (loss) per common share – diluted (1) | $ | 0.45 | $ | 0.65 | $ | 0.64 | $ | (0.09) | $ | 0.64 | (31) | % | (30) | % | |||||||||||||||||||||||||||
(1) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958.
(2) Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm."
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 7
| Columbia Banking System, Inc. | ||||||||||||||||||||
| Consolidated Statements of Operations | ||||||||||||||||||||
| (Unaudited) | ||||||||||||||||||||
| Twelve months ended | % Change (2) | |||||||||||||||||||
| ($ in thousands, except per share data) | Dec 31, 2023 | Dec 31, 2022 | Year over Year | |||||||||||||||||
| Interest income: | ||||||||||||||||||||
| Loans and leases | $ | 2,113,615 | $ | 1,050,258 | 101 | % | ||||||||||||||
| Interest and dividends on investments: | ||||||||||||||||||||
| Taxable | 276,841 | 72,264 | 283 | % | ||||||||||||||||
| Exempt from federal income tax | 24,109 | 5,351 | 351 | % | ||||||||||||||||
| Dividends | 13,103 | 438 | nm | |||||||||||||||||
| Temporary investments and interest bearing deposits | 111,659 | 19,706 | 467 | % | ||||||||||||||||
| Total interest income | 2,539,327 | 1,148,017 | 121 | % | ||||||||||||||||
| Interest expense: | ||||||||||||||||||||
| Deposits | 461,654 | 48,195 | nm | |||||||||||||||||
| Securities sold under agreement to repurchase and federal funds purchased | 3,923 | 997 | 293 | % | ||||||||||||||||
| Borrowings | 242,914 | 8,920 | nm | |||||||||||||||||
| Junior and other subordinated debentures | 37,665 | 19,889 | 89 | % | ||||||||||||||||
| Total interest expense | 746,156 | 78,001 | nm | |||||||||||||||||
| Net interest income | 1,793,171 | 1,070,016 | 68 | % | ||||||||||||||||
| Provision for credit losses | 213,199 | 84,016 | 154 | % | ||||||||||||||||
| Non-interest income: | ||||||||||||||||||||
| Service charges on deposits | 65,525 | 48,365 | 35 | % | ||||||||||||||||
| Card-based fees | 55,263 | 37,370 | 48 | % | ||||||||||||||||
| Brokerage revenue | 13,471 | 90 | nm | |||||||||||||||||
| Residential mortgage banking revenue, net | 16,789 | 106,859 | (84) | % | ||||||||||||||||
| Gain on sale of debt securities, net | 13 | 2 | nm | |||||||||||||||||
| Gain (loss) on equity securities, net | 2,300 | (7,099) | nm | |||||||||||||||||
| Gain on loan and lease sales, net | 4,414 | 6,696 | (34) | % | ||||||||||||||||
| BOLI income | 15,624 | 8,253 | 89 | % | ||||||||||||||||
| Other income (loss) | 30,528 | (1,008) | nm | |||||||||||||||||
| Total non-interest income | 203,927 | 199,528 | 2 | % | ||||||||||||||||
| Non-interest expense: | ||||||||||||||||||||
| Salaries and employee benefits | 616,103 | 441,226 | 40 | % | ||||||||||||||||
| Occupancy and equipment, net | 183,480 | 138,451 | 33 | % | ||||||||||||||||
| Intangible amortization | 111,296 | 4,095 | nm | |||||||||||||||||
| FDIC assessments | 71,402 | 13,964 | 411 | % | ||||||||||||||||
| Merger-related expense | 171,659 | 17,356 | nm | |||||||||||||||||
| Other expenses | 158,760 | 119,858 | 32 | % | ||||||||||||||||
| Total non-interest expense | 1,312,700 | 734,950 | 79 | % | ||||||||||||||||
| Income before provision for income taxes | 471,199 | 450,578 | 5 | % | ||||||||||||||||
| Provision for income taxes | 122,484 | 113,826 | 8 | % | ||||||||||||||||
| Net income | $ | 348,715 | $ | 336,752 | 4 | % | ||||||||||||||
Weighted average basic shares outstanding (1) | 195,304 | 129,277 | 51 | % | ||||||||||||||||
Weighted average diluted shares outstanding (1) | 195,871 | 129,732 | 51 | % | ||||||||||||||||
Earnings per common share – basic (1) | $ | 1.79 | $ | 2.60 | (31) | % | ||||||||||||||
Earnings per common share – diluted (1) | $ | 1.78 | $ | 2.60 | (32) | % | ||||||||||||||
(1) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958.
(2) Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm."
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 8
| Columbia Banking System, Inc. Consolidated Balance Sheets | |||||||||||||||||||||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||||||||||||||||||||
% Change (2) | |||||||||||||||||||||||||||||||||||||||||
| ($ in thousands, except per share data) | Dec 31, 2023 | Sep 30, 2023 | Jun 30, 2023 | Mar 31, 2023 | Dec 31, 2022 | Seq. Quarter | Year over Year | ||||||||||||||||||||||||||||||||||
| Assets: | |||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | $ | 498,496 | $ | 492,474 | $ | 538,653 | $ | 555,919 | $ | 327,313 | 1 | % | 52 | % | |||||||||||||||||||||||||||
| Interest bearing cash and temporary investments | 1,664,038 | 1,911,221 | 2,868,563 | 3,079,266 | 967,330 | (13) | % | 72 | % | ||||||||||||||||||||||||||||||||
| Investment securities: | |||||||||||||||||||||||||||||||||||||||||
| Equity and other, at fair value | 76,995 | 73,638 | 76,361 | 76,532 | 72,959 | 5 | % | 6 | % | ||||||||||||||||||||||||||||||||
| Available for sale, at fair value | 8,829,870 | 8,503,986 | 8,998,428 | 9,249,600 | 3,196,166 | 4 | % | 176 | % | ||||||||||||||||||||||||||||||||
| Held to maturity, at amortized cost | 2,300 | 2,344 | 2,388 | 2,432 | 2,476 | (2) | % | (7) | % | ||||||||||||||||||||||||||||||||
| Loans held for sale | 30,715 | 60,313 | 183,633 | 49,338 | 71,647 | (49) | % | (57) | % | ||||||||||||||||||||||||||||||||
| Loans and leases | 37,441,951 | 37,170,598 | 37,049,299 | 37,091,280 | 26,155,981 | 1 | % | 43 | % | ||||||||||||||||||||||||||||||||
| Allowance for credit losses on loans and leases | (440,871) | (416,560) | (404,603) | (417,464) | (301,135) | 6 | % | 46 | % | ||||||||||||||||||||||||||||||||
| Net loans and leases | 37,001,080 | 36,754,038 | 36,644,696 | 36,673,816 | 25,854,846 | 1 | % | 43 | % | ||||||||||||||||||||||||||||||||
| Restricted equity securities | 179,274 | 168,524 | 258,524 | 246,525 | 47,144 | 6 | % | 280 | % | ||||||||||||||||||||||||||||||||
| Premises and equipment, net | 338,970 | 337,855 | 368,698 | 375,190 | 176,016 | 0 | % | 93 | % | ||||||||||||||||||||||||||||||||
| Operating lease right-of-use assets | 115,811 | 114,220 | 119,255 | 127,296 | 78,598 | 1 | % | 47 | % | ||||||||||||||||||||||||||||||||
| Goodwill | 1,029,234 | 1,029,234 | 1,029,234 | 1,030,142 | — | 0 | % | nm | |||||||||||||||||||||||||||||||||
| Other intangible assets, net | 603,679 | 636,883 | 666,762 | 702,315 | 4,745 | (5) | % | nm | |||||||||||||||||||||||||||||||||
| Residential mortgage servicing rights, at fair value | 109,243 | 117,640 | 172,929 | 178,800 | 185,017 | (7) | % | (41) | % | ||||||||||||||||||||||||||||||||
| Bank owned life insurance | 680,948 | 648,232 | 643,727 | 641,922 | 331,759 | 5 | % | 105 | % | ||||||||||||||||||||||||||||||||
| Deferred tax asset, net | 347,203 | 469,841 | 362,880 | 351,229 | 132,823 | (26) | % | 161 | % | ||||||||||||||||||||||||||||||||
| Other assets | 665,740 | 673,372 | 657,365 | 653,904 | 399,800 | (1) | % | 67 | % | ||||||||||||||||||||||||||||||||
| Total assets | $ | 52,173,596 | $ | 51,993,815 | $ | 53,592,096 | $ | 53,994,226 | $ | 31,848,639 | 0 | % | 64 | % | |||||||||||||||||||||||||||
| Liabilities: | |||||||||||||||||||||||||||||||||||||||||
| Deposits | |||||||||||||||||||||||||||||||||||||||||
| Non-interest bearing | $ | 14,256,452 | $ | 15,532,948 | $ | 16,019,408 | $ | 17,215,781 | $ | 10,288,849 | (8) | % | 39 | % | |||||||||||||||||||||||||||
| Interest bearing | 27,350,568 | 26,091,420 | 24,815,509 | 24,370,566 | 16,776,763 | 5 | % | 63 | % | ||||||||||||||||||||||||||||||||
| Total deposits | 41,607,020 | 41,624,368 | 40,834,917 | 41,586,347 | 27,065,612 | 0 | % | 54 | % | ||||||||||||||||||||||||||||||||
| Securities sold under agreements to repurchase | 252,119 | 258,383 | 294,914 | 271,047 | 308,769 | (2) | % | (18) | % | ||||||||||||||||||||||||||||||||
| Borrowings | 3,950,000 | 3,985,000 | 6,250,000 | 5,950,000 | 906,175 | (1) | % | 336 | % | ||||||||||||||||||||||||||||||||
| Junior subordinated debentures, at fair value | 316,440 | 331,545 | 312,872 | 297,721 | 323,639 | (5) | % | (2) | % | ||||||||||||||||||||||||||||||||
| Junior and other subordinated debentures, at amortized cost | 107,895 | 107,952 | 108,009 | 108,066 | 87,813 | 0 | % | 23 | % | ||||||||||||||||||||||||||||||||
| Operating lease liabilities | 130,576 | 129,845 | 132,099 | 140,648 | 91,694 | 1 | % | 42 | % | ||||||||||||||||||||||||||||||||
| Other liabilities | 814,512 | 924,560 | 831,097 | 755,674 | 585,111 | (12) | % | 39 | % | ||||||||||||||||||||||||||||||||
| Total liabilities | 47,178,562 | 47,361,653 | 48,763,908 | 49,109,503 | 29,368,813 | 0 | % | 61 | % | ||||||||||||||||||||||||||||||||
| Shareholders' equity: | |||||||||||||||||||||||||||||||||||||||||
| Common stock | 5,802,747 | 5,798,167 | 5,792,792 | 5,788,553 | 3,450,493 | 0 | % | 68 | % | ||||||||||||||||||||||||||||||||
| Accumulated deficit | (467,571) | (485,576) | (545,842) | (603,696) | (543,803) | (4) | % | (14) | % | ||||||||||||||||||||||||||||||||
| Accumulated other comprehensive loss | (340,142) | (680,429) | (418,762) | (300,134) | (426,864) | (50) | % | (20) | % | ||||||||||||||||||||||||||||||||
| Total shareholders' equity | 4,995,034 | 4,632,162 | 4,828,188 | 4,884,723 | 2,479,826 | 8 | % | 101 | % | ||||||||||||||||||||||||||||||||
| Total liabilities and shareholders' equity | $ | 52,173,596 | $ | 51,993,815 | $ | 53,592,096 | $ | 53,994,226 | $ | 31,848,639 | 0 | % | 64 | % | |||||||||||||||||||||||||||
Common shares outstanding at period end (1) | 208,585 | 208,575 | 208,514 | 208,429 | 129,321 | 0 | % | 61 | % | ||||||||||||||||||||||||||||||||
(1) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958.
(2) Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm."
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 9
| Columbia Banking System, Inc. | ||||||||||||||||||||||||||||||||||||||||||||
| Financial Highlights | ||||||||||||||||||||||||||||||||||||||||||||
| (Unaudited) | ||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | % Change | |||||||||||||||||||||||||||||||||||||||||||
| Dec 31, 2023 | Sep 30, 2023 | Jun 30, 2023 | Mar 31, 2023 | Dec 31, 2022 | Seq. Quarter | Year over Year | ||||||||||||||||||||||||||||||||||||||
Per Common Share Data: (5) | ||||||||||||||||||||||||||||||||||||||||||||
Dividends (5) | $ | 0.36 | $ | 0.36 | $ | 0.36 | $ | 0.35 | $ | 0.35 | 0 | % | 3 | % | ||||||||||||||||||||||||||||||
Book value (5) | $ | 23.95 | $ | 22.21 | $ | 23.16 | $ | 23.44 | $ | 19.18 | 8 | % | 25 | % | ||||||||||||||||||||||||||||||
Tangible book value (1),(5) | $ | 16.12 | $ | 14.22 | $ | 15.02 | $ | 15.12 | $ | 19.14 | 13 | % | (16) | % | ||||||||||||||||||||||||||||||
| Performance Ratios: | ||||||||||||||||||||||||||||||||||||||||||||
Efficiency ratio (2) | 64.81 | % | 57.82 | % | 62.60 | % | 79.71 | % | 57.24 | % | 6.99 | 7.57 | ||||||||||||||||||||||||||||||||
| Return on average assets ("ROAA") | 0.72 | % | 1.02 | % | 1.00 | % | (0.14) | % | 1.04 | % | (0.30) | (0.32) | ||||||||||||||||||||||||||||||||
Pre-provision net revenue ("PPNR") ROAA (1) | 1.39 | % | 1.65 | % | 1.46 | % | 0.89 | % | 1.82 | % | (0.26) | (0.43) | ||||||||||||||||||||||||||||||||
| Return on average common equity | 7.90 | % | 11.07 | % | 10.84 | % | (1.70) | % | 13.50 | % | (3.17) | (5.60) | ||||||||||||||||||||||||||||||||
Return on average tangible common equity (1) | 12.19 | % | 16.93 | % | 16.63 | % | (2.09) | % | 13.53 | % | (4.74) | (1.34) | ||||||||||||||||||||||||||||||||
Performance Ratios - Operating: (1) | ||||||||||||||||||||||||||||||||||||||||||||
Operating efficiency ratio (1), (2) | 64.47 | % | 51.97 | % | 54.85 | % | 53.46 | % | 52.01 | % | 12.50 | 12.46 | ||||||||||||||||||||||||||||||||
Operating ROAA (1) | 0.70 | % | 1.23 | % | 1.27 | % | 0.74 | % | 1.24 | % | (0.53) | (0.54) | ||||||||||||||||||||||||||||||||
Operating PPNR ROAA (1) | 1.37 | % | 1.94 | % | 1.82 | % | 2.01 | % | 2.10 | % | (0.57) | (0.73) | ||||||||||||||||||||||||||||||||
Operating return on average common equity (1) | 7.73 | % | 13.40 | % | 13.77 | % | 8.66 | % | 16.14 | % | (5.67) | (8.41) | ||||||||||||||||||||||||||||||||
Operating return on average tangible common equity (1) | 11.92 | % | 20.48 | % | 21.13 | % | 10.64 | % | 16.18 | % | (8.56) | (4.26) | ||||||||||||||||||||||||||||||||
| Average Balance Sheet Yields, Rates, & Ratios: | ||||||||||||||||||||||||||||||||||||||||||||
| Yield on loans and leases | 6.13 | % | 6.08 | % | 5.95 | % | 5.55 | % | 4.92 | % | 0.05 | 1.21 | ||||||||||||||||||||||||||||||||
Yield on earning assets (2) | 5.75 | % | 5.65 | % | 5.48 | % | 5.19 | % | 4.62 | % | 0.10 | 1.13 | ||||||||||||||||||||||||||||||||
| Cost of interest bearing deposits | 2.54 | % | 2.01 | % | 1.64 | % | 1.32 | % | 0.77 | % | 0.53 | 1.77 | ||||||||||||||||||||||||||||||||
| Cost of interest bearing liabilities | 3.02 | % | 2.72 | % | 2.45 | % | 1.82 | % | 1.05 | % | 0.30 | 1.97 | ||||||||||||||||||||||||||||||||
| Cost of total deposits | 1.63 | % | 1.23 | % | 0.99 | % | 0.80 | % | 0.46 | % | 0.40 | 1.17 | ||||||||||||||||||||||||||||||||
Cost of total funding (3) | 2.05 | % | 1.81 | % | 1.61 | % | 1.16 | % | 0.65 | % | 0.24 | 1.40 | ||||||||||||||||||||||||||||||||
Net interest margin (2) | 3.78 | % | 3.91 | % | 3.93 | % | 4.08 | % | 4.01 | % | (0.13) | (0.23) | ||||||||||||||||||||||||||||||||
| Average interest bearing cash / Average interest earning assets | 3.64 | % | 5.17 | % | 5.47 | % | 4.33 | % | 3.62 | % | (1.53) | 0.02 | ||||||||||||||||||||||||||||||||
| Average loans and leases / Average interest earning assets | 78.04 | % | 75.64 | % | 75.18 | % | 80.96 | % | 85.32 | % | 2.40 | (7.28) | ||||||||||||||||||||||||||||||||
| Average loans and leases / Average total deposits | 89.91 | % | 90.63 | % | 90.98 | % | 93.01 | % | 95.85 | % | (0.72) | (5.94) | ||||||||||||||||||||||||||||||||
| Average non-interest bearing deposits / Average total deposits | 35.88 | % | 38.55 | % | 40.05 | % | 39.55 | % | 40.30 | % | (2.67) | (4.42) | ||||||||||||||||||||||||||||||||
Average total deposits / Average total funding (3) | 90.02 | % | 86.66 | % | 85.59 | % | 91.36 | % | 94.52 | % | 3.36 | (4.50) | ||||||||||||||||||||||||||||||||
| Select Credit & Capital Ratios: | ||||||||||||||||||||||||||||||||||||||||||||
Non-performing loans and leases to total loans and leases | 0.30 | % | 0.28 | % | 0.22 | % | 0.20 | % | 0.22 | % | 0.02 | 0.08 | ||||||||||||||||||||||||||||||||
Non-performing assets to total assets | 0.22 | % | 0.20 | % | 0.15 | % | 0.14 | % | 0.18 | % | 0.02 | 0.04 | ||||||||||||||||||||||||||||||||
| Allowance for credit losses to loans and leases | 1.24 | % | 1.18 | % | 1.15 | % | 1.18 | % | 1.21 | % | 0.06 | 0.03 | ||||||||||||||||||||||||||||||||
Total risk-based capital ratio (4) | 11.8 | % | 11.6 | % | 11.3 | % | 10.9 | % | 13.7 | % | 0.20 | (1.90) | ||||||||||||||||||||||||||||||||
Common equity tier 1 risk-based capital ratio (4) | 9.6 | % | 9.5 | % | 9.2 | % | 8.9 | % | 11.0 | % | 0.10 | (1.40) | ||||||||||||||||||||||||||||||||
(1) See GAAP to Non-GAAP Reconciliation.
(2) Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate.
(3) Total funding = Total deposits + Total borrowings.
(4) Estimated holding company ratios.
(5) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958.
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 10
| Columbia Banking System, Inc. | ||||||||||||||||||||
| Financial Highlights | ||||||||||||||||||||
| (Unaudited) | ||||||||||||||||||||
| Twelve months ended | % Change | |||||||||||||||||||
| Dec 31, 2023 | Dec 31, 2022 | Year over Year | ||||||||||||||||||
Per Common Share Data: (4) | ||||||||||||||||||||
Dividends (4) | $ | 1.43 | $ | 1.40 | 2.14 | % | ||||||||||||||
| Performance Ratios: | ||||||||||||||||||||
Efficiency ratio (2) | 65.59 | % | 57.83 | % | 7.76 | |||||||||||||||
| ROAA | 0.70 | % | 1.09 | % | (0.39) | |||||||||||||||
PPNR ROAA (1) | 1.38 | % | 1.73 | % | (0.35) | |||||||||||||||
| Return on average common equity | 7.81 | % | 13.07 | % | (5.26) | |||||||||||||||
Return on average tangible common equity (1) | 11.46 | % | 13.11 | % | (1.65) | |||||||||||||||
Performance Ratios - Operating: (1) | ||||||||||||||||||||
Operating efficiency ratio (1), (2) | 56.21 | % | 55.66 | % | 0.55 | |||||||||||||||
Operating ROAA (1) | 1.00 | % | 1.17 | % | (0.17) | |||||||||||||||
Operating PPNR ROAA (1) | 1.77 | % | 1.83 | % | (0.06) | |||||||||||||||
Operating return on average common equity (1) | 11.12 | % | 13.97 | % | (2.85) | |||||||||||||||
Operating return on average tangible common equity (1) | 16.32 | % | 14.00 | % | 2.32 | |||||||||||||||
| Average Balance Sheet Yields, Rates, & Ratios: | ||||||||||||||||||||
| Yield on loans and leases | 5.95 | % | 4.29 | % | 1.66 | |||||||||||||||
Yield on earning assets (2) | 5.54 | % | 3.88 | % | 1.66 | |||||||||||||||
| Cost of interest bearing deposits | 1.93 | % | 0.31 | % | 1.62 | |||||||||||||||
| Cost of interest bearing liabilities | 2.56 | % | 0.47 | % | 2.09 | |||||||||||||||
| Cost of total deposits | 1.19 | % | 0.18 | % | 1.01 | |||||||||||||||
Cost of total funding (3) | 1.69 | % | 0.28 | % | 1.41 | |||||||||||||||
Net interest margin (2) | 3.91 | % | 3.62 | % | 0.29 | |||||||||||||||
| Average interest bearing cash / Average interest earning assets | 4.68 | % | 5.28 | % | (0.60) | |||||||||||||||
| Average loans and leases / Average interest earning assets | 77.21 | % | 81.96 | % | (4.75) | |||||||||||||||
| Average loans and leases / Average total deposits | 91.01 | % | 90.91 | % | 0.10 | |||||||||||||||
| Average non-interest bearing deposits / Average total deposits | 38.37 | % | 41.48 | % | (3.11) | |||||||||||||||
Average total deposits / Average total funding (3) | 88.18 | % | 96.06 | % | (7.88) | |||||||||||||||
(1) See GAAP to Non-GAAP Reconciliation.
(2) Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate.
(3) Total funding = Total deposits + Total borrowings.
(4) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958.
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 11
| Columbia Banking System, Inc. | |||||||||||||||||||||||||||||||||||||||||
| Loan & Lease Portfolio Balances and Mix | |||||||||||||||||||||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||||||||||||||||||||
| Dec 31, 2023 | Sep 30, 2023 | Jun 30, 2023 | Mar 31, 2023 | Dec 31, 2022 | % Change | ||||||||||||||||||||||||||||||||||||
| ($ in thousands) | Amount | Amount | Amount | Amount | Amount | Seq. Quarter | Year over Year | ||||||||||||||||||||||||||||||||||
| Loans and leases: | |||||||||||||||||||||||||||||||||||||||||
| Commercial real estate: | |||||||||||||||||||||||||||||||||||||||||
| Non-owner occupied term, net | $ | 6,482,940 | $ | 6,490,638 | $ | 6,434,673 | $ | 6,353,550 | $ | 3,894,840 | 0 | % | 66 | % | |||||||||||||||||||||||||||
| Owner occupied term, net | 5,195,605 | 5,235,227 | 5,254,401 | 5,156,848 | 2,567,761 | (1) | % | 102 | % | ||||||||||||||||||||||||||||||||
| Multifamily, net | 5,704,734 | 5,684,495 | 5,622,875 | 5,590,587 | 5,285,791 | 0 | % | 8 | % | ||||||||||||||||||||||||||||||||
| Construction & development, net | 1,747,302 | 1,669,918 | 1,528,924 | 1,467,561 | 1,077,346 | 5 | % | 62 | % | ||||||||||||||||||||||||||||||||
| Residential development, net | 323,899 | 354,922 | 388,641 | 440,667 | 200,838 | (9) | % | 61 | % | ||||||||||||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||||||||||||||
| Term, net | 5,536,765 | 5,437,915 | 5,449,787 | 5,906,774 | 3,029,547 | 2 | % | 83 | % | ||||||||||||||||||||||||||||||||
| Lines of credit & other, net | 2,430,127 | 2,353,548 | 2,268,790 | 2,184,762 | 960,054 | 3 | % | 153 | % | ||||||||||||||||||||||||||||||||
| Leases & equipment finance, net | 1,729,512 | 1,728,991 | 1,740,037 | 1,746,267 | 1,706,172 | 0 | % | 1 | % | ||||||||||||||||||||||||||||||||
| Residential: | |||||||||||||||||||||||||||||||||||||||||
| Mortgage, net | 6,157,166 | 6,121,838 | 6,272,898 | 6,187,964 | 5,647,035 | 1 | % | 9 | % | ||||||||||||||||||||||||||||||||
| Home equity loans & lines, net | 1,938,166 | 1,899,948 | 1,898,958 | 1,870,002 | 1,631,965 | 2 | % | 19 | % | ||||||||||||||||||||||||||||||||
| Consumer & other, net | 195,735 | 193,158 | 189,315 | 186,298 | 154,632 | 1 | % | 27 | % | ||||||||||||||||||||||||||||||||
| Total loans and leases, net of deferred fees and costs | $ | 37,441,951 | $ | 37,170,598 | $ | 37,049,299 | $ | 37,091,280 | $ | 26,155,981 | 1 | % | 43 | % | |||||||||||||||||||||||||||
| Loans and leases mix: | |||||||||||||||||||||||||||||||||||||||||
| Commercial real estate: | |||||||||||||||||||||||||||||||||||||||||
| Non-owner occupied term, net | 17 | % | 17 | % | 17 | % | 16 | % | 15 | % | |||||||||||||||||||||||||||||||
| Owner occupied term, net | 14 | % | 14 | % | 14 | % | 14 | % | 10 | % | |||||||||||||||||||||||||||||||
| Multifamily, net | 15 | % | 15 | % | 15 | % | 15 | % | 20 | % | |||||||||||||||||||||||||||||||
| Construction & development, net | 5 | % | 4 | % | 4 | % | 4 | % | 4 | % | |||||||||||||||||||||||||||||||
| Residential development, net | 1 | % | 1 | % | 1 | % | 1 | % | 1 | % | |||||||||||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||||||||||||||
| Term, net | 15 | % | 15 | % | 15 | % | 16 | % | 12 | % | |||||||||||||||||||||||||||||||
| Lines of credit & other, net | 6 | % | 6 | % | 6 | % | 6 | % | 4 | % | |||||||||||||||||||||||||||||||
| Leases & equipment finance, net | 5 | % | 5 | % | 5 | % | 5 | % | 6 | % | |||||||||||||||||||||||||||||||
| Residential: | |||||||||||||||||||||||||||||||||||||||||
| Mortgage, net | 16 | % | 17 | % | 17 | % | 17 | % | 21 | % | |||||||||||||||||||||||||||||||
| Home equity loans & lines, net | 5 | % | 5 | % | 5 | % | 5 | % | 6 | % | |||||||||||||||||||||||||||||||
| Consumer & other, net | 1 | % | 1 | % | 1 | % | 1 | % | 1 | % | |||||||||||||||||||||||||||||||
| Total | 100 | % | 100 | % | 100 | % | 100 | % | 100 | % | |||||||||||||||||||||||||||||||
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 12
| Columbia Banking System, Inc. | |||||||||||||||||||||||||||||||||||||||||
| Deposit Portfolio Balances and Mix | |||||||||||||||||||||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||||||||||||||||||||
| Dec 31, 2023 | Sep 30, 2023 | Jun 30, 2023 | Mar 31, 2023 | Dec 31, 2022 | % Change | ||||||||||||||||||||||||||||||||||||
| ($ in thousands) | Amount | Amount | Amount | Amount | Amount | Seq. Quarter | Year over Year | ||||||||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||||||||||||||
| Demand, non-interest bearing | $ | 14,256,452 | $ | 15,532,948 | $ | 16,019,408 | $ | 17,215,781 | $ | 10,288,849 | (8) | % | 39 | % | |||||||||||||||||||||||||||
| Demand, interest bearing | 8,044,432 | 6,898,831 | 6,300,082 | 5,900,462 | 4,080,469 | 17 | % | 97 | % | ||||||||||||||||||||||||||||||||
| Money market | 10,324,454 | 10,349,217 | 10,115,908 | 10,681,422 | 7,721,011 | 0 | % | 34 | % | ||||||||||||||||||||||||||||||||
| Savings | 2,754,113 | 3,018,706 | 3,171,714 | 3,469,112 | 2,265,052 | (9) | % | 22 | % | ||||||||||||||||||||||||||||||||
| Time | 6,227,569 | 5,824,666 | 5,227,805 | 4,319,570 | 2,710,231 | 7 | % | 130 | % | ||||||||||||||||||||||||||||||||
| Total | $ | 41,607,020 | $ | 41,624,368 | $ | 40,834,917 | $ | 41,586,347 | $ | 27,065,612 | 0 | % | 54 | % | |||||||||||||||||||||||||||
Total core deposits (1) | $ | 37,423,402 | $ | 37,597,830 | $ | 37,639,368 | $ | 39,155,298 | $ | 25,616,010 | 0 | % | 46 | % | |||||||||||||||||||||||||||
| Deposit mix: | |||||||||||||||||||||||||||||||||||||||||
| Demand, non-interest bearing | 34 | % | 37 | % | 39 | % | 41 | % | 38 | % | |||||||||||||||||||||||||||||||
| Demand, interest bearing | 19 | % | 17 | % | 15 | % | 14 | % | 15 | % | |||||||||||||||||||||||||||||||
| Money market | 25 | % | 25 | % | 25 | % | 26 | % | 29 | % | |||||||||||||||||||||||||||||||
| Savings | 7 | % | 7 | % | 8 | % | 9 | % | 8 | % | |||||||||||||||||||||||||||||||
| Time | 15 | % | 14 | % | 13 | % | 10 | % | 10 | % | |||||||||||||||||||||||||||||||
| Total | 100 | % | 100 | % | 100 | % | 100 | % | 100 | % | |||||||||||||||||||||||||||||||
(1) Core deposits are defined as total deposits less time deposits greater than $250,000 and all brokered deposits.
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 13
| Columbia Banking System, Inc. | ||||||||||||||||||||||||||||||||||||||||||||
| Credit Quality – Non-performing Assets | ||||||||||||||||||||||||||||||||||||||||||||
| (Unaudited) | ||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | % Change (2) | |||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | Dec 31, 2023 | Sep 30, 2023 | Jun 30, 2023 | Mar 31, 2023 | Dec 31, 2022 | Seq. Quarter | Year over Year | |||||||||||||||||||||||||||||||||||||
| Non-performing assets: | ||||||||||||||||||||||||||||||||||||||||||||
| Loans and leases on non-accrual status: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate, net | $ | 28,689 | $ | 26,053 | $ | 10,994 | $ | 15,612 | $ | 5,011 | 10 | % | 473 | % | ||||||||||||||||||||||||||||||
| Commercial, net | 45,682 | 44,341 | 39,316 | 42,301 | 25,691 | 3 | % | 78 | % | |||||||||||||||||||||||||||||||||||
| Total loans and leases on non-accrual status | 74,371 | 70,394 | 50,310 | 57,913 | 30,702 | 6 | % | 142 | % | |||||||||||||||||||||||||||||||||||
Loans and leases past due 90+ days and accruing (1): | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate, net | 870 | 71 | 184 | 1 | 1 | nm | nm | |||||||||||||||||||||||||||||||||||||
| Commercial, net | 8,232 | 8,606 | 7,720 | 151 | 7,909 | (4) | % | 4 | % | |||||||||||||||||||||||||||||||||||
Residential, net (1) | 29,102 | 25,180 | 21,370 | 17,423 | 19,894 | 16 | % | 46 | % | |||||||||||||||||||||||||||||||||||
| Consumer & other, net | 326 | 240 | 399 | 140 | 134 | 36 | % | 143 | % | |||||||||||||||||||||||||||||||||||
Total loans and leases past due 90+ days and accruing (1) | 38,530 | 34,097 | 29,673 | 17,715 | 27,938 | 13 | % | 38 | % | |||||||||||||||||||||||||||||||||||
| Total non-performing loans and leases | 112,901 | 104,491 | 79,983 | 75,628 | 58,640 | 8 | % | 93 | % | |||||||||||||||||||||||||||||||||||
| Other real estate owned | 1,036 | 1,170 | 278 | 409 | 203 | (11) | % | 410 | % | |||||||||||||||||||||||||||||||||||
| Total non-performing assets | $ | 113,937 | $ | 105,661 | $ | 80,261 | $ | 76,037 | $ | 58,843 | 8 | % | 94 | % | ||||||||||||||||||||||||||||||
| Loans and leases past due 31-89 days | $ | 85,235 | $ | 82,918 | $ | 73,376 | $ | 78,641 | $ | 64,893 | 3 | % | 31 | % | ||||||||||||||||||||||||||||||
| Loans and leases past due 31-89 days to total loans and leases | 0.23 | % | 0.22 | % | 0.20 | % | 0.21 | % | 0.25 | % | 0.01 | (0.02) | ||||||||||||||||||||||||||||||||
Non-performing loans and leases to total loans and leases (1) | 0.30 | % | 0.28 | % | 0.22 | % | 0.20 | % | 0.22 | % | 0.02 | 0.08 | ||||||||||||||||||||||||||||||||
Non-performing assets to total assets (1) | 0.22 | % | 0.20 | % | 0.15 | % | 0.14 | % | 0.18 | % | 0.02 | 0.04 | ||||||||||||||||||||||||||||||||
(1) Excludes certain mortgage loans guaranteed by Ginnie Mae, which Columbia has the unilateral right to repurchase but has not done so, totaling $1.0 million, $700,000, $1.6 million, $5.4 million, and $6.6 million at December 31, 2023, September 30, 2023, June 30, 2023, March 31, 2023, and December 31, 2022, respectively.
(2) Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm."
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 14
| Columbia Banking System, Inc. | ||||||||||||||||||||||||||||||||||||||||||||
| Credit Quality – Allowance for Credit Losses | ||||||||||||||||||||||||||||||||||||||||||||
| (Unaudited) | ||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | % Change (2) | |||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | Dec 31, 2023 | Sep 30, 2023 | Jun 30, 2023 | Mar 31, 2023 | Dec 31, 2022 | Seq. Quarter | Year over Year | |||||||||||||||||||||||||||||||||||||
| Allowance for credit losses on loans and leases (ACLLL) | ||||||||||||||||||||||||||||||||||||||||||||
| Balance, beginning of period | $ | 416,560 | $ | 404,603 | $ | 417,464 | $ | 301,135 | $ | 283,065 | 3 | % | 47 | % | ||||||||||||||||||||||||||||||
| Initial ACL recorded for PCD loans acquired during the period | — | — | — | 26,492 | — | nm | nm | |||||||||||||||||||||||||||||||||||||
Provision for credit losses on loans and leases (1) | 53,183 | 35,082 | 15,216 | 106,498 | 30,580 | 52 | % | 74 | % | |||||||||||||||||||||||||||||||||||
| Charge-offs | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate, net | (629) | — | (174) | — | (128) | nm | 391 | % | ||||||||||||||||||||||||||||||||||||
| Commercial, net | (31,949) | (26,629) | (32,036) | (19,248) | (14,721) | 20 | % | 117 | % | |||||||||||||||||||||||||||||||||||
| Residential, net | (89) | (206) | (4) | (248) | (53) | (57) | % | 68 | % | |||||||||||||||||||||||||||||||||||
| Consumer & other, net | (1,841) | (1,884) | (1,264) | (773) | (906) | (2) | % | 103 | % | |||||||||||||||||||||||||||||||||||
| Total charge-offs | (34,508) | (28,719) | (33,478) | (20,269) | (15,808) | 20 | % | 118 | % | |||||||||||||||||||||||||||||||||||
| Recoveries | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate, net | 35 | 31 | 209 | 58 | 163 | 13 | % | (79) | % | |||||||||||||||||||||||||||||||||||
| Commercial, net | 4,414 | 4,901 | 4,511 | 3,058 | 2,708 | (10) | % | 63 | % | |||||||||||||||||||||||||||||||||||
| Residential, net | 781 | 156 | 63 | 123 | 24 | 401 | % | nm | ||||||||||||||||||||||||||||||||||||
| Consumer & other, net | 406 | 506 | 618 | 369 | 403 | (20) | % | 1 | % | |||||||||||||||||||||||||||||||||||
| Total recoveries | 5,636 | 5,594 | 5,401 | 3,608 | 3,298 | 1 | % | 71 | % | |||||||||||||||||||||||||||||||||||
| Net (charge-offs) recoveries | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate, net | (594) | 31 | 35 | 58 | 35 | nm | nm | |||||||||||||||||||||||||||||||||||||
| Commercial, net | (27,535) | (21,728) | (27,525) | (16,190) | (12,013) | 27 | % | 129 | % | |||||||||||||||||||||||||||||||||||
| Residential, net | 692 | (50) | 59 | (125) | (29) | nm | nm | |||||||||||||||||||||||||||||||||||||
| Consumer & other, net | (1,435) | (1,378) | (646) | (404) | (503) | 4 | % | 185 | % | |||||||||||||||||||||||||||||||||||
| Total net charge-offs | (28,872) | (23,125) | (28,077) | (16,661) | (12,510) | 25 | % | 131 | % | |||||||||||||||||||||||||||||||||||
| Balance, end of period | $ | 440,871 | $ | 416,560 | $ | 404,603 | $ | 417,464 | $ | 301,135 | 6 | % | 46 | % | ||||||||||||||||||||||||||||||
| Reserve for unfunded commitments | ||||||||||||||||||||||||||||||||||||||||||||
| Balance, beginning of period | $ | 21,482 | $ | 19,827 | $ | 19,029 | $ | 14,221 | $ | 11,853 | 8 | % | 81 | % | ||||||||||||||||||||||||||||||
| Initial ACL recorded for unfunded commitments acquired during the period | — | — | — | 5,767 | — | nm | nm | |||||||||||||||||||||||||||||||||||||
| Provision (recapture) for credit losses on unfunded commitments | 1,726 | 1,655 | 798 | (959) | 2,368 | 4 | % | (27) | % | |||||||||||||||||||||||||||||||||||
| Balance, end of period | 23,208 | 21,482 | 19,827 | 19,029 | 14,221 | 8 | % | 63 | % | |||||||||||||||||||||||||||||||||||
| Total Allowance for credit losses (ACL) | $ | 464,079 | $ | 438,042 | $ | 424,430 | $ | 436,493 | $ | 315,356 | 6 | % | 47 | % | ||||||||||||||||||||||||||||||
| Net charge-offs to average loans and leases (annualized) | 0.31 | % | 0.25 | % | 0.30 | % | 0.23 | % | 0.19 | % | 0.06 | 0.12 | ||||||||||||||||||||||||||||||||
| Recoveries to gross charge-offs | 16.33 | % | 19.48 | % | 16.13 | % | 17.80 | % | 20.86 | % | (3.15) | (4.53) | ||||||||||||||||||||||||||||||||
| ACLLL to loans and leases | 1.18 | % | 1.12 | % | 1.09 | % | 1.13 | % | 1.15 | % | 0.06 | 0.03 | ||||||||||||||||||||||||||||||||
| ACL to loans and leases | 1.24 | % | 1.18 | % | 1.15 | % | 1.18 | % | 1.21 | % | 0.06 | 0.03 | ||||||||||||||||||||||||||||||||
(1) For the quarter ended March 31, 2023, the provision for credit losses on loans and leases includes $88.4 million initial provision related to non-PCD loans acquired during the period.
(2) Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm."
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 15
| Columbia Banking System, Inc. | |||||||||||||||||||||||
| Credit Quality – Allowance for Credit Losses | |||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||
| Twelve Months Ended | % Change (2) | ||||||||||||||||||||||
| ($ in thousands) | Dec 31, 2023 | Dec 31, 2022 | Year over Year | ||||||||||||||||||||
| Allowance for credit losses on loans and leases (ACLLL) | |||||||||||||||||||||||
| Balance, beginning of period | $ | 301,135 | $ | 248,412 | 21 | % | |||||||||||||||||
| Initial ACL recorded for PCD loans acquired during the period | 26,492 | — | nm | ||||||||||||||||||||
Provision for credit losses on loans and leases (1) | 209,979 | 83,605 | 151 | % | |||||||||||||||||||
| Charge-offs | |||||||||||||||||||||||
| Commercial real estate, net | (803) | (136) | 490 | % | |||||||||||||||||||
| Commercial, net | (109,862) | (41,073) | 167 | % | |||||||||||||||||||
| Residential, net | (547) | (224) | 144 | % | |||||||||||||||||||
| Consumer & other, net | (5,762) | (3,556) | 62 | % | |||||||||||||||||||
| Total charge-offs | (116,974) | (44,989) | 160 | % | |||||||||||||||||||
| Recoveries | |||||||||||||||||||||||
| Commercial real estate, net | 333 | 384 | (13) | % | |||||||||||||||||||
| Commercial, net | 16,884 | 11,029 | 53 | % | |||||||||||||||||||
| Residential, net | 1,123 | 662 | 70 | % | |||||||||||||||||||
| Consumer & other, net | 1,899 | 2,032 | (7) | % | |||||||||||||||||||
| Total recoveries | 20,239 | 14,107 | 43 | % | |||||||||||||||||||
| Net (charge-offs) recoveries | |||||||||||||||||||||||
| Commercial real estate, net | (470) | 248 | (290) | % | |||||||||||||||||||
| Commercial, net | (92,978) | (30,044) | 209 | % | |||||||||||||||||||
| Residential, net | 576 | 438 | 32 | % | |||||||||||||||||||
| Consumer & other, net | (3,863) | (1,524) | 153 | % | |||||||||||||||||||
| Total net charge-offs | (96,735) | (30,882) | 213 | % | |||||||||||||||||||
| Balance, end of period | $ | 440,871 | $ | 301,135 | 46 | % | |||||||||||||||||
| Reserve for unfunded commitments | |||||||||||||||||||||||
| Balance, beginning of period | $ | 14,221 | $ | 12,767 | 11 | % | |||||||||||||||||
| Initial ACL recorded for unfunded commitments acquired during the period | 5,767 | — | nm | ||||||||||||||||||||
| Provision for credit losses on unfunded commitments | 3,220 | 1,454 | 121 | % | |||||||||||||||||||
| Balance, end of period | 23,208 | 14,221 | 63 | % | |||||||||||||||||||
| Total Allowance for credit losses (ACL) | $ | 464,079 | $ | 315,356 | 47 | % | |||||||||||||||||
| Net charge-offs to average loans and leases (annualized) | 0.27 | % | 0.13 | % | 0.14 | ||||||||||||||||||
| Recoveries to gross charge-offs | 17.30 | % | 31.36 | % | (14.06) | ||||||||||||||||||
(1) For the twelve months ended December 31, 2023, the provision for credit losses on loans and leases includes $88.4 million initial provision related to non-PCD loans acquired during the period.
(2) Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm."
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 16
| Columbia Banking System, Inc. | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Consolidated Average Balance Sheets, Net Interest Income, and Yields/Rates | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| December 31, 2023 | September 30, 2023 | December 31, 2022 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | Average Balance | Interest Income or Expense | Average Yields or Rates | Average Balance | Interest Income or Expense | Average Yields or Rates | Average Balance | Interest Income or Expense | Average Yields or Rates | ||||||||||||||||||||||||||||||||||||||||||||
| INTEREST-EARNING ASSETS: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans held for sale | $ | 48,868 | $ | 649 | 5.31 | % | $ | 199,855 | $ | 1,741 | 3.49 | % | $ | 110,850 | $ | 1,603 | 5.79 | % | |||||||||||||||||||||||||||||||||||
Loans and leases (1) | 37,333,310 | 577,092 | 6.13 | % | 37,050,518 | 567,929 | 6.08 | % | 25,855,556 | 320,747 | 4.92 | % | |||||||||||||||||||||||||||||||||||||||||
| Taxable securities | 7,903,053 | 82,872 | 4.19 | % | 8,356,165 | 85,007 | 4.07 | % | 3,042,044 | 18,290 | 2.40 | % | |||||||||||||||||||||||||||||||||||||||||
Non-taxable securities (2) | 809,551 | 8,073 | 3.99 | % | 844,417 | 8,085 | 3.83 | % | 200,825 | 1,571 | 3.13 | % | |||||||||||||||||||||||||||||||||||||||||
| Temporary investments and interest-bearing cash | 1,743,447 | 24,055 | 5.47 | % | 2,530,150 | 34,407 | 5.40 | % | 1,095,854 | 10,319 | 3.74 | % | |||||||||||||||||||||||||||||||||||||||||
| Total interest-earning assets | 47,838,229 | $ | 692,741 | 5.75 | % | 48,981,105 | $ | 697,169 | 5.65 | % | 30,305,129 | $ | 352,530 | 4.62 | % | ||||||||||||||||||||||||||||||||||||||
| Goodwill and other intangible assets | 1,652,282 | 1,684,093 | 5,298 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Other assets | 2,341,845 | 2,346,163 | 1,327,063 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 51,832,356 | $ | 53,011,361 | $ | 31,637,490 | |||||||||||||||||||||||||||||||||||||||||||||||
| INTEREST-BEARING LIABILITIES: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing demand deposits | $ | 7,617,427 | $ | 44,861 | 2.34 | % | $ | 6,578,849 | $ | 25,209 | 1.52 | % | $ | 4,005,643 | $ | 5,372 | 0.53 | % | |||||||||||||||||||||||||||||||||||
| Money market deposits | 10,276,894 | 61,055 | 2.36 | % | 10,249,028 | 50,039 | 1.94 | % | 7,651,974 | 17,473 | 0.91 | % | |||||||||||||||||||||||||||||||||||||||||
| Savings deposits | 2,880,622 | 698 | 0.10 | % | 3,109,779 | 1,253 | 0.16 | % | 2,345,564 | 226 | 0.04 | % | |||||||||||||||||||||||||||||||||||||||||
| Time deposits | 5,847,400 | 64,045 | 4.35 | % | 5,184,089 | 50,473 | 3.86 | % | 2,100,803 | 8,103 | 1.53 | % | |||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 26,622,343 | 170,659 | 2.54 | % | 25,121,745 | 126,974 | 2.01 | % | 16,103,984 | 31,174 | 0.77 | % | |||||||||||||||||||||||||||||||||||||||||
| Repurchase agreements and federal funds purchased | 245,989 | 1,226 | 1.98 | % | 268,444 | 1,220 | 1.80 | % | 354,624 | 323 | 0.36 | % | |||||||||||||||||||||||||||||||||||||||||
| Borrowings | 3,918,261 | 56,066 | 5.68 | % | 5,603,207 | 77,080 | 5.46 | % | 796,414 | 8,023 | 4.00 | % | |||||||||||||||||||||||||||||||||||||||||
| Junior and other subordinated debentures | 440,007 | 10,060 | 9.07 | % | 420,582 | 9,864 | 9.30 | % | 413,708 | 7,248 | 6.95 | % | |||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 31,226,600 | $ | 238,011 | 3.02 | % | 31,413,978 | $ | 215,138 | 2.72 | % | 17,668,730 | $ | 46,768 | 1.05 | % | ||||||||||||||||||||||||||||||||||||||
| Non-interest-bearing deposits | 14,899,001 | 15,759,720 | 10,870,842 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Other liabilities | 1,011,019 | 970,688 | 659,279 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities | 47,136,620 | 48,144,386 | 29,198,851 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Common equity | 4,695,736 | 4,866,975 | 2,438,639 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and shareholders' equity | $ | 51,832,356 | $ | 53,011,361 | $ | 31,637,490 | |||||||||||||||||||||||||||||||||||||||||||||||
NET INTEREST INCOME (2) | $ | 454,730 | $ | 482,031 | $ | 305,762 | |||||||||||||||||||||||||||||||||||||||||||||||
| NET INTEREST SPREAD | 2.73 | % | 2.93 | % | 3.57 | % | |||||||||||||||||||||||||||||||||||||||||||||||
NET INTEREST INCOME TO EARNING ASSETS OR NET INTEREST MARGIN (1), (2) | 3.78 | % | 3.91 | % | 4.01 | % | |||||||||||||||||||||||||||||||||||||||||||||||
(1)Non-accrual loans and leases are included in the average balance.
(2)Tax-exempt income has been adjusted to a tax equivalent basis at a 21% tax rate. The amount of such adjustment was an addition to recorded income of approximately $1.1 million for the three months ended December 31, 2023, as compared to $1.2 million for the three months ended September 30, 2023 and $283,000 for the three months ended December 31, 2022.
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 17
| Columbia Banking System, Inc. | |||||||||||||||||||||||||||||||||||
| Consolidated Average Balance Sheets, Net Interest Income, and Yields/Rates | |||||||||||||||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||||||||||||||
| Twelve months ended | |||||||||||||||||||||||||||||||||||
| December 31, 2023 | December 31, 2022 | ||||||||||||||||||||||||||||||||||
| ($ in thousands) | Average Balance | Interest Income or Expense | Average Yields or Rates | Average Balance | Interest Income or Expense | Average Yields or Rates | |||||||||||||||||||||||||||||
| INTEREST-EARNING ASSETS: | |||||||||||||||||||||||||||||||||||
| Loans held for sale | $ | 87,675 | $ | 3,871 | 4.42 | % | $ | 208,141 | $ | 8,812 | 4.23 | % | |||||||||||||||||||||||
Loans and leases (1) | 35,412,594 | 2,109,744 | 5.95 | % | 24,225,518 | 1,041,446 | 4.29 | % | |||||||||||||||||||||||||||
| Taxable securities | 7,479,573 | 289,944 | 3.88 | % | 3,343,721 | 72,702 | 2.17 | % | |||||||||||||||||||||||||||
Non-taxable securities (2) | 740,376 | 28,236 | 3.81 | % | 216,943 | 6,669 | 3.07 | % | |||||||||||||||||||||||||||
| Temporary investments and interest-bearing cash | 2,147,348 | 111,659 | 5.20 | % | 1,561,808 | 19,706 | 1.26 | % | |||||||||||||||||||||||||||
| Total interest-earning assets | 45,867,566 | $ | 2,543,454 | 5.54 | % | 29,556,131 | $ | 1,149,335 | 3.88 | % | |||||||||||||||||||||||||
| Goodwill and other intangible assets | 1,423,075 | 6,847 | |||||||||||||||||||||||||||||||||
| Other assets | 2,205,678 | 1,254,418 | |||||||||||||||||||||||||||||||||
| Total assets | $ | 49,496,319 | $ | 30,817,396 | |||||||||||||||||||||||||||||||
| INTEREST-BEARING LIABILITIES: | |||||||||||||||||||||||||||||||||||
| Interest-bearing demand deposits | $ | 6,280,333 | $ | 97,162 | 1.55 | % | $ | 3,886,390 | $ | 8,185 | 0.21 | % | |||||||||||||||||||||||
| Money market deposits | 9,962,837 | 185,035 | 1.86 | % | 7,552,666 | 26,415 | 0.35 | % | |||||||||||||||||||||||||||
| Savings deposits | 2,994,333 | 3,384 | 0.11 | % | 2,411,448 | 880 | 0.04 | % | |||||||||||||||||||||||||||
| Time deposits | 4,743,615 | 176,073 | 3.71 | % | 1,743,988 | 12,715 | 0.73 | % | |||||||||||||||||||||||||||
| Total interest-bearing deposits | 23,981,118 | 461,654 | 1.93 | % | 15,594,492 | 48,195 | 0.31 | % | |||||||||||||||||||||||||||
| Repurchase agreements and federal funds purchased | 269,853 | 3,923 | 1.45 | % | 465,600 | 997 | 0.21 | % | |||||||||||||||||||||||||||
| Borrowings | 4,522,656 | 242,914 | 5.37 | % | 226,665 | 8,920 | 3.94 | % | |||||||||||||||||||||||||||
| Junior and other subordinated debentures | 421,195 | 37,665 | 8.94 | % | 399,568 | 19,889 | 4.98 | % | |||||||||||||||||||||||||||
| Total interest-bearing liabilities | 29,194,822 | $ | 746,156 | 2.56 | % | 16,686,325 | $ | 78,001 | 0.47 | % | |||||||||||||||||||||||||
| Non-interest-bearing deposits | 14,927,443 | 11,053,921 | |||||||||||||||||||||||||||||||||
| Other liabilities | 907,329 | 501,573 | |||||||||||||||||||||||||||||||||
| Total liabilities | 45,029,594 | 28,241,819 | |||||||||||||||||||||||||||||||||
| Common equity | 4,466,725 | 2,575,577 | |||||||||||||||||||||||||||||||||
| Total liabilities and shareholders' equity | $ | 49,496,319 | $ | 30,817,396 | |||||||||||||||||||||||||||||||
NET INTEREST INCOME (2) | $ | 1,797,298 | $ | 1,071,334 | |||||||||||||||||||||||||||||||
| NET INTEREST SPREAD | 2.98 | % | 3.41 | % | |||||||||||||||||||||||||||||||
NET INTEREST INCOME TO EARNING ASSETS OR NET INTEREST MARGIN (1), (2) | 3.91 | % | 3.62 | % | |||||||||||||||||||||||||||||||
(1)Non-accrual loans and leases are included in the average balance.
(2)Tax-exempt income has been adjusted to a tax equivalent basis at a 21% tax rate. The amount of such adjustment was an addition to recorded income of approximately $4.1 million for the twelve months ended December 31, 2023, as compared to $1.3 million for the same period in 2022.
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 18
| Columbia Banking System, Inc. | |||||||||||||||||||||||||||||||||||||||||
| Residential Mortgage Banking Activity | |||||||||||||||||||||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | % Change (1) | ||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | Dec 31, 2023 | Sep 30, 2023 | Jun 30, 2023 | Mar 31, 2023 | Dec 31, 2022 | Seq. Quarter | Year over Year | ||||||||||||||||||||||||||||||||||
| Residential mortgage banking revenue: | |||||||||||||||||||||||||||||||||||||||||
| Origination and sale | $ | 2,686 | $ | 2,442 | $ | 3,166 | $ | 3,587 | $ | 4,252 | 10 | % | (37) | % | |||||||||||||||||||||||||||
| Servicing | 5,966 | 8,887 | 9,167 | 9,397 | 9,184 | (33) | % | (35) | % | ||||||||||||||||||||||||||||||||
| Change in fair value of MSR asset: | |||||||||||||||||||||||||||||||||||||||||
| Changes due to collection/realization of expected cash flows over time | (3,215) | (4,801) | (4,797) | (4,881) | (4,986) | (33) | % | (36) | % | ||||||||||||||||||||||||||||||||
| Changes due to valuation inputs or assumptions | (6,251) | 5,308 | (2,242) | (2,937) | (9,914) | (218) | % | (37) | % | ||||||||||||||||||||||||||||||||
| MSR hedge gain (loss) | 5,026 | (4,733) | (7,636) | 2,650 | (348) | nm | nm | ||||||||||||||||||||||||||||||||||
| Total | $ | 4,212 | $ | 7,103 | $ | (2,342) | $ | 7,816 | $ | (1,812) | (41) | % | nm | ||||||||||||||||||||||||||||
| Closed loan volume for-sale | $ | 87,033 | $ | 103,333 | $ | 119,476 | $ | 131,726 | $ | 216,833 | (16) | % | (60) | % | |||||||||||||||||||||||||||
| Gain on sale margin | 3.09 | % | 2.36 | % | 2.65 | % | 2.72 | % | 1.96 | % | 0.73 | 1.13 | |||||||||||||||||||||||||||||
| Residential mortgage servicing rights: | |||||||||||||||||||||||||||||||||||||||||
| Balance, beginning of period | $ | 117,640 | $ | 172,929 | $ | 178,800 | $ | 185,017 | $ | 196,177 | (32) | % | (40) | % | |||||||||||||||||||||||||||
| Additions for new MSR capitalized | 920 | 1,658 | 1,168 | 1,601 | 3,740 | (45) | % | (75) | % | ||||||||||||||||||||||||||||||||
| Sale of MSR assets | 149 | (57,454) | — | — | — | nm | nm | ||||||||||||||||||||||||||||||||||
| Change in fair value of MSR asset: | |||||||||||||||||||||||||||||||||||||||||
| Changes due to collection/realization of expected cash flows over time | (3,215) | (4,801) | (4,797) | (4,881) | (4,986) | (33) | % | (36) | % | ||||||||||||||||||||||||||||||||
| Changes due to valuation inputs or assumptions | (6,251) | 5,308 | (2,242) | (2,937) | (9,914) | (218) | % | (37) | % | ||||||||||||||||||||||||||||||||
| Balance, end of period | $ | 109,243 | $ | 117,640 | $ | 172,929 | $ | 178,800 | $ | 185,017 | (7) | % | (41) | % | |||||||||||||||||||||||||||
| Residential mortgage loans serviced for others | $ | 8,175,664 | $ | 8,240,950 | $ | 12,726,615 | $ | 12,914,046 | $ | 13,020,189 | (1) | % | (37) | % | |||||||||||||||||||||||||||
| MSR as % of serviced portfolio | 1.34 | % | 1.43 | % | 1.36 | % | 1.38 | % | 1.42 | % | (0.09) | (0.08) | |||||||||||||||||||||||||||||
(1) Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm."
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 19
| Columbia Banking System, Inc. | |||||||||||||||||
| Residential Mortgage Banking Activity | |||||||||||||||||
| (Unaudited) | |||||||||||||||||
| Twelve Months Ended | % Change (1) | ||||||||||||||||
| ($ in thousands) | Dec 31, 2023 | Dec 31, 2022 | Year over Year | ||||||||||||||
| Residential mortgage banking revenue: | |||||||||||||||||
| Origination and sale | $ | 11,881 | $ | 46,712 | (75) | % | |||||||||||
| Servicing | 33,417 | 37,358 | (11) | % | |||||||||||||
| Change in fair value of MSR asset: | |||||||||||||||||
| Changes due to collection/realization of expected cash flows over time | (17,694) | (20,272) | (13) | % | |||||||||||||
| Changes due to valuation inputs or assumptions | (6,122) | 57,537 | (111) | % | |||||||||||||
| MSR hedge loss | (4,693) | (14,476) | (68) | % | |||||||||||||
| Total | $ | 16,789 | $ | 106,859 | (84) | % | |||||||||||
| Closed loan volume for-sale | $ | 441,568 | $ | 1,839,466 | (76) | % | |||||||||||
| Gain on sale margin | 2.69 | % | 2.54 | % | 0.15 | ||||||||||||
| Residential mortgage servicing rights: | |||||||||||||||||
| Balance, beginning of period | $ | 185,017 | $ | 123,615 | 50 | % | |||||||||||
| Additions for new MSR capitalized | 5,347 | 24,137 | (78) | % | |||||||||||||
| Sale of MSR assets | (57,305) | — | nm | ||||||||||||||
| Change in fair value of MSR asset: | |||||||||||||||||
| Changes due to collection/realization of expected cash flows over time | (17,694) | (20,272) | (13) | % | |||||||||||||
| Changes due to valuation inputs or assumptions | (6,122) | 57,537 | (111) | % | |||||||||||||
| Balance, end of period | $ | 109,243 | $ | 185,017 | (41) | % | |||||||||||
(1) Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm."
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 20
Non-GAAP Financial Measures
In addition to results presented in accordance with generally accepted accounting principles in the United States of America ("GAAP"), this press release contains certain non-GAAP financial measures. The company believes presenting certain non-GAAP financial measures provides investors with information useful in understanding our financial performance, our performance trends, and our financial position. We utilize these measures for internal planning and forecasting purposes. We, as well as securities analysts, investors, and other interested parties, also use these measures to compare peer company operating performance. We believe that our presentation and discussion, together with the accompanying reconciliations, provides a complete understanding of factors and trends affecting our business and allows investors to view performance in a manner similar to management. These non-GAAP measures should not be considered a substitution for GAAP basis measures and results, and we strongly encourage investors to review our consolidated financial statements in their entirety and not to rely on any single financial measure. Because non-GAAP financial measures are not standardized, it may not be possible to compare these financial measures with other companies’ non-GAAP financial measures having the same or similar names.
| Columbia Banking System, Inc. | |||||||||||||||||||||||||||||||||||||||||||||||
| GAAP to Non-GAAP Reconciliation | |||||||||||||||||||||||||||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | % Change (2) | ||||||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands, except per share data) | Dec 31, 2023 | Sep 30, 2023 | Jun 30, 2023 | Mar 31, 2023 | Dec 31, 2022 | Seq. Quarter | Year over Year | ||||||||||||||||||||||||||||||||||||||||
| Total shareholders' equity | a | $ | 4,995,034 | $ | 4,632,162 | $ | 4,828,188 | $ | 4,884,723 | $ | 2,479,826 | 8 | % | 101 | % | ||||||||||||||||||||||||||||||||
| Less: Goodwill | 1,029,234 | 1,029,234 | 1,029,234 | 1,030,142 | — | 0 | % | nm | |||||||||||||||||||||||||||||||||||||||
| Less: Other intangible assets, net | 603,679 | 636,883 | 666,762 | 702,315 | 4,745 | (5) | % | nm | |||||||||||||||||||||||||||||||||||||||
| Tangible common shareholders' equity | b | $ | 3,362,121 | $ | 2,966,045 | $ | 3,132,192 | $ | 3,152,266 | $ | 2,475,081 | 13 | % | 36 | % | ||||||||||||||||||||||||||||||||
| Total assets | c | $ | 52,173,596 | $ | 51,993,815 | $ | 53,592,096 | $ | 53,994,226 | $ | 31,848,639 | 0 | % | 64 | % | ||||||||||||||||||||||||||||||||
| Less: Goodwill | 1,029,234 | 1,029,234 | 1,029,234 | 1,030,142 | — | 0 | % | nm | |||||||||||||||||||||||||||||||||||||||
| Less: Other intangible assets, net | 603,679 | 636,883 | 666,762 | 702,315 | 4,745 | (5) | % | nm | |||||||||||||||||||||||||||||||||||||||
| Tangible assets | d | $ | 50,540,683 | $ | 50,327,698 | $ | 51,896,100 | $ | 52,261,769 | $ | 31,843,894 | 0 | % | 59 | % | ||||||||||||||||||||||||||||||||
Common shares outstanding at period end (1) | e | 208,585 | 208,575 | 208,514 | 208,429 | 129,321 | 0 | % | 61 | % | |||||||||||||||||||||||||||||||||||||
| Total shareholders' equity to total assets ratio | a / c | 9.57 | % | 8.91 | % | 9.01 | % | 9.05 | % | 7.79 | % | 0.66 | 1.78 | ||||||||||||||||||||||||||||||||||
| Tangible common equity ratio | b / d | 6.65 | % | 5.89 | % | 6.04 | % | 6.03 | % | 7.77 | % | 0.76 | (1.12) | ||||||||||||||||||||||||||||||||||
Book value per common share (1) | a / e | $ | 23.95 | $ | 22.21 | $ | 23.16 | $ | 23.44 | $ | 19.18 | 8 | % | 25 | % | ||||||||||||||||||||||||||||||||
Tangible book value per common share (1) | b / e | $ | 16.12 | $ | 14.22 | $ | 15.02 | $ | 15.12 | $ | 19.14 | 13 | % | (16) | % | ||||||||||||||||||||||||||||||||
(1) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958.
(2) Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm."
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 21
| Columbia Banking System, Inc. | |||||||||||||||||||||||||||||||||||||||||||||||
| GAAP to Non-GAAP Reconciliation - Continued | |||||||||||||||||||||||||||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | % Change (1) | ||||||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | Dec 31, 2023 | Sep 30, 2023 | Jun 30, 2023 | Mar 31, 2023 | Dec 31, 2022 | Seq. Quarter | Year over Year | ||||||||||||||||||||||||||||||||||||||||
| Non-Interest Income Adjustments | |||||||||||||||||||||||||||||||||||||||||||||||
| Gain on sale of debt securities, net | $ | 9 | $ | 4 | $ | — | $ | — | $ | — | 125 | % | nm | ||||||||||||||||||||||||||||||||||
| (Loss) gain on equity securities, net | 2,636 | (2,055) | (697) | 2,416 | 284 | nm | nm | ||||||||||||||||||||||||||||||||||||||||
| Gain (loss) on swap derivatives | (8,042) | 5,700 | 1,288 | (3,543) | (2,329) | (241) | % | 245 | % | ||||||||||||||||||||||||||||||||||||||
| Change in fair value of certain loans held for investment | 19,354 | (19,247) | (6,965) | 9,488 | 4,192 | nm | 362 | % | |||||||||||||||||||||||||||||||||||||||
| Change in fair value of MSR due to valuation inputs or assumptions | (6,251) | 5,308 | (2,242) | (2,937) | (9,914) | (218) | % | (37) | % | ||||||||||||||||||||||||||||||||||||||
| MSR hedge (loss) gain | 5,026 | (4,733) | (7,636) | 2,650 | (348) | nm | nm | ||||||||||||||||||||||||||||||||||||||||
| Total non-interest income adjustments | a | $ | 12,732 | $ | (15,023) | $ | (16,252) | $ | 8,074 | $ | (8,115) | nm | nm | ||||||||||||||||||||||||||||||||||
| Non-Interest Expense Adjustments | |||||||||||||||||||||||||||||||||||||||||||||||
| Merger-related expense | $ | 7,174 | $ | 18,938 | $ | 29,649 | $ | 115,898 | $ | 11,637 | (62) | % | (38) | % | |||||||||||||||||||||||||||||||||
| Exit and disposal costs | 2,791 | 4,017 | 2,119 | 1,291 | 1,966 | (31) | % | 42 | % | ||||||||||||||||||||||||||||||||||||||
| Total non-interest expense adjustments | b | $ | 9,965 | $ | 22,955 | $ | 31,768 | $ | 117,189 | $ | 13,603 | (57) | % | (27) | % | ||||||||||||||||||||||||||||||||
| Net interest income | c | $ | 453,623 | $ | 480,875 | $ | 483,975 | $ | 374,698 | $ | 305,479 | (6) | % | 48 | % | ||||||||||||||||||||||||||||||||
| Non-interest income (GAAP) | d | $ | 65,533 | $ | 43,981 | $ | 39,678 | $ | 54,735 | $ | 34,879 | 49 | % | 88 | % | ||||||||||||||||||||||||||||||||
| Less: Non-interest income adjustments | a | (12,732) | 15,023 | 16,252 | (8,074) | 8,115 | (185) | % | (257) | % | |||||||||||||||||||||||||||||||||||||
| Operating non-interest income (non-GAAP) | e | $ | 52,801 | $ | 59,004 | $ | 55,930 | $ | 46,661 | $ | 42,994 | (11) | % | 23 | % | ||||||||||||||||||||||||||||||||
| Revenue (GAAP) | f=c+d | $ | 519,156 | $ | 524,856 | $ | 523,653 | $ | 429,433 | $ | 340,358 | (1) | % | 53 | % | ||||||||||||||||||||||||||||||||
| Operating revenue (non-GAAP) | g=c+e | $ | 506,424 | $ | 539,879 | $ | 539,905 | $ | 421,359 | $ | 348,473 | (6) | % | 45 | % | ||||||||||||||||||||||||||||||||
| Non-interest expense (GAAP) | h | $ | 337,176 | $ | 304,147 | $ | 328,559 | $ | 342,818 | $ | 194,982 | 11 | % | 73 | % | ||||||||||||||||||||||||||||||||
| Less: Non-interest expense adjustments | b | (9,965) | (22,955) | (31,768) | (117,189) | (13,603) | (57) | % | (27) | % | |||||||||||||||||||||||||||||||||||||
| Operating non-interest expense (non-GAAP) | i | $ | 327,211 | $ | 281,192 | $ | 296,791 | $ | 225,629 | $ | 181,379 | 16 | % | 80 | % | ||||||||||||||||||||||||||||||||
| Net income (loss) (GAAP) | j | $ | 93,531 | $ | 135,845 | $ | 133,377 | $ | (14,038) | $ | 82,964 | (31) | % | 13 | % | ||||||||||||||||||||||||||||||||
| Provision (benefit) for income taxes | 33,540 | 48,127 | 45,703 | (4,886) | 29,464 | (30) | % | 14 | % | ||||||||||||||||||||||||||||||||||||||
| Income (loss) before provision for income taxes | 127,071 | 183,972 | 179,080 | (18,924) | 112,428 | (31) | % | 13 | % | ||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 54,909 | 36,737 | 16,014 | 105,539 | 32,948 | 49 | % | 67 | % | ||||||||||||||||||||||||||||||||||||||
| Pre-provision net revenue (PPNR) (non-GAAP) | k | 181,980 | 220,709 | 195,094 | 86,615 | 145,376 | (18) | % | 25 | % | |||||||||||||||||||||||||||||||||||||
| Less: Non-interest income adjustments | a | (12,732) | 15,023 | 16,252 | (8,074) | 8,115 | (185) | % | (257) | % | |||||||||||||||||||||||||||||||||||||
| Add: Non-interest expense adjustments | b | 9,965 | 22,955 | 31,768 | 117,189 | 13,603 | (57) | % | (27) | % | |||||||||||||||||||||||||||||||||||||
| Operating PPNR (non-GAAP) | l | $ | 179,213 | $ | 258,687 | $ | 243,114 | $ | 195,730 | $ | 167,094 | (31) | % | 7 | % | ||||||||||||||||||||||||||||||||
| Net income (loss) (GAAP) | j | $ | 93,531 | $ | 135,845 | $ | 133,377 | $ | (14,038) | $ | 82,964 | (31) | % | 13 | % | ||||||||||||||||||||||||||||||||
| Less: Non-interest income adjustments | a | (12,732) | 15,023 | 16,252 | (8,074) | 8,115 | (185) | % | (257) | % | |||||||||||||||||||||||||||||||||||||
| Add: Non-interest expense adjustments | b | 9,965 | 22,955 | 31,768 | 117,189 | 13,603 | (57) | % | (27) | % | |||||||||||||||||||||||||||||||||||||
| Tax effect of adjustments | 691 | (9,482) | (11,981) | (23,565) | (5,459) | nm | nm | ||||||||||||||||||||||||||||||||||||||||
| Operating net income (non-GAAP) | m | $ | 91,455 | $ | 164,341 | $ | 169,416 | $ | 71,512 | $ | 99,223 | (44) | % | (8) | % | ||||||||||||||||||||||||||||||||
(1) Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm."
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 22
| Columbia Banking System, Inc. | |||||||||||||||||||||||||||||||||||||||||||||||
| GAAP to Non-GAAP Reconciliation - Continued | |||||||||||||||||||||||||||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | % Change (3) | ||||||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands, except per share data) | Dec 31, 2023 | Sep 30, 2023 | Jun 30, 2023 | Mar 31, 2023 | Dec 31, 2022 | Seq. Quarter | Year over Year | ||||||||||||||||||||||||||||||||||||||||
| Average assets | n | $ | 51,832,356 | $ | 53,011,361 | $ | 53,540,574 | $ | 39,425,975 | $ | 31,637,490 | (2) | % | 64 | % | ||||||||||||||||||||||||||||||||
| Less: Average goodwill and other intangible assets, net | 1,652,282 | 1,684,093 | 1,718,705 | 623,042 | 5,298 | (2) | % | nm | |||||||||||||||||||||||||||||||||||||||
| Average tangible assets | o | $ | 50,180,074 | $ | 51,327,268 | $ | 51,821,869 | $ | 38,802,933 | $ | 31,632,192 | (2) | % | 59 | % | ||||||||||||||||||||||||||||||||
| Average common shareholders' equity | p | $ | 4,695,736 | $ | 4,866,975 | $ | 4,935,239 | $ | 3,349,761 | $ | 2,438,639 | (4) | % | 93 | % | ||||||||||||||||||||||||||||||||
| Less: Average goodwill and other intangible assets, net | 1,652,282 | 1,684,093 | 1,718,705 | 623,042 | 5,298 | (2) | % | nm | |||||||||||||||||||||||||||||||||||||||
| Average tangible common equity | q | $ | 3,043,454 | $ | 3,182,882 | $ | 3,216,534 | $ | 2,726,719 | $ | 2,433,341 | (4) | % | 25 | % | ||||||||||||||||||||||||||||||||
Weighted average basic shares outstanding (1) | r | 208,083 | 208,070 | 207,977 | 156,383 | 129,321 | 0 | % | 61 | % | |||||||||||||||||||||||||||||||||||||
Weighted average diluted shares outstanding (1) | s | 208,739 | 208,645 | 208,545 | 156,383 | 129,801 | 0 | % | 61 | % | |||||||||||||||||||||||||||||||||||||
| Select Per-Share & Performance Metrics | |||||||||||||||||||||||||||||||||||||||||||||||
Earnings-per-share - basic (1) | j / r | $ | 0.45 | $ | 0.65 | $ | 0.64 | $ | (0.09) | $ | 0.64 | (31) | % | (30) | % | ||||||||||||||||||||||||||||||||
Earnings-per-share - diluted (1) | j / s | $ | 0.45 | $ | 0.65 | $ | 0.64 | $ | (0.09) | $ | 0.64 | (31) | % | (30) | % | ||||||||||||||||||||||||||||||||
Efficiency ratio (2) | h / f | 64.81 | % | 57.82 | % | 62.60 | % | 79.71 | % | 57.24 | % | 6.99 | 7.57 | ||||||||||||||||||||||||||||||||||
| ROAA | j / n | 0.72 | % | 1.02 | % | 1.00 | % | (0.14) | % | 1.04 | % | (0.30) | (0.32) | ||||||||||||||||||||||||||||||||||
| Return on average tangible assets | j / o | 0.74 | % | 1.05 | % | 1.03 | % | (0.15) | % | 1.04 | % | (0.31) | (0.30) | ||||||||||||||||||||||||||||||||||
| PPNR ROAA | k / n | 1.39 | % | 1.65 | % | 1.46 | % | 0.89 | % | 1.82 | % | (0.26) | (0.43) | ||||||||||||||||||||||||||||||||||
| Return on average common equity | j / p | 7.90 | % | 11.07 | % | 10.84 | % | (1.70) | % | 13.50 | % | (3.17) | (5.60) | ||||||||||||||||||||||||||||||||||
| Return on average tangible common equity | j / q | 12.19 | % | 16.93 | % | 16.63 | % | (2.09) | % | 13.53 | % | (4.74) | (1.34) | ||||||||||||||||||||||||||||||||||
| Operating Per-Share & Performance Metrics | |||||||||||||||||||||||||||||||||||||||||||||||
Operating earnings-per-share - basic (1) | m / r | $ | 0.44 | $ | 0.79 | $ | 0.81 | $ | 0.46 | $ | 0.77 | (44) | % | (43) | % | ||||||||||||||||||||||||||||||||
Operating earnings-per-share - diluted (1) | m / s | $ | 0.44 | $ | 0.79 | $ | 0.81 | $ | 0.46 | $ | 0.76 | (44) | % | (42) | % | ||||||||||||||||||||||||||||||||
Operating efficiency ratio (2) | i / g | 64.47 | % | 51.97 | % | 54.85 | % | 53.46 | % | 52.01 | % | 12.50 | 12.46 | ||||||||||||||||||||||||||||||||||
| Operating ROAA | m / n | 0.70 | % | 1.23 | % | 1.27 | % | 0.74 | % | 1.24 | % | (0.53) | (0.54) | ||||||||||||||||||||||||||||||||||
| Operating return on average tangible assets | m / o | 0.72 | % | 1.27 | % | 1.31 | % | 0.75 | % | 1.24 | % | (0.55) | (0.52) | ||||||||||||||||||||||||||||||||||
| Operating PPNR ROAA | l / n | 1.37 | % | 1.94 | % | 1.82 | % | 2.01 | % | 2.10 | % | (0.57) | (0.73) | ||||||||||||||||||||||||||||||||||
| Operating return on average common equity | m / p | 7.73 | % | 13.40 | % | 13.77 | % | 8.66 | % | 16.14 | % | (5.67) | (8.41) | ||||||||||||||||||||||||||||||||||
| Operating return on average tangible common equity | m / q | 11.92 | % | 20.48 | % | 21.13 | % | 10.64 | % | 16.18 | % | (8.56) | (4.26) | ||||||||||||||||||||||||||||||||||
(1) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958.
(2) Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate and added to stated revenue for this calculation.
(3) Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm."
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 23
| Columbia Banking System, Inc. | |||||||||||||||||||||||
| GAAP to Non-GAAP Reconciliation - Continued | |||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||
| Twelve Months Ended | % Change (1) | ||||||||||||||||||||||
| ($ in thousands) | Dec 31, 2023 | Dec 31, 2022 | Year over Year | ||||||||||||||||||||
| Non-Interest Income Adjustments | |||||||||||||||||||||||
| Gain on sale of debt securities, net | $ | 13 | $ | 2 | nm | ||||||||||||||||||
| Gain (loss) on equity securities, net | 2,300 | (7,099) | (132) | % | |||||||||||||||||||
| (Loss) gain on swap derivatives | (4,597) | 16,249 | (128) | % | |||||||||||||||||||
| Change in fair value of certain loans held for investment | 2,630 | (58,464) | (104) | % | |||||||||||||||||||
| Change in fair value of MSR due to valuation inputs or assumptions | (6,122) | 57,537 | (111) | % | |||||||||||||||||||
| MSR hedge loss | (4,693) | (14,476) | (68) | % | |||||||||||||||||||
| Total non-interest income adjustments | a | $ | (10,469) | $ | (6,251) | 67 | % | ||||||||||||||||
| Non-Interest Expense Adjustments | |||||||||||||||||||||||
| Merger-related expense | $ | 171,659 | $ | 17,356 | nm | ||||||||||||||||||
| Exit and disposal costs | 10,218 | 6,805 | 50 | % | |||||||||||||||||||
| Total non-interest expense adjustments | b | $ | 181,877 | $ | 24,161 | nm | |||||||||||||||||
| Net interest income | c | $ | 1,793,171 | $ | 1,070,016 | 68 | % | ||||||||||||||||
| Non-interest income (GAAP) | d | $ | 203,927 | $ | 199,528 | 2 | % | ||||||||||||||||
| Less: Non-interest income adjustments | a | 10,469 | 6,251 | 67 | % | ||||||||||||||||||
| Operating non-interest income (non-GAAP) | e | $ | 214,396 | $ | 205,779 | 4 | % | ||||||||||||||||
| Revenue (GAAP) | f=c+d | $ | 1,997,098 | $ | 1,269,544 | 57 | % | ||||||||||||||||
| Operating revenue (non-GAAP) | g=c+e | $ | 2,007,567 | $ | 1,275,795 | 57 | % | ||||||||||||||||
| Non-interest expense (GAAP) | h | $ | 1,312,700 | $ | 734,950 | 79 | % | ||||||||||||||||
| Less: Non-interest expense adjustments | b | (181,877) | (24,161) | nm | |||||||||||||||||||
| Operating non-interest expense (non-GAAP) | i | $ | 1,130,823 | $ | 710,789 | 59 | % | ||||||||||||||||
| Net income (GAAP) | j | $ | 348,715 | $ | 336,752 | 4 | % | ||||||||||||||||
| Provision for income taxes | 122,484 | 113,826 | 8 | % | |||||||||||||||||||
| Income before provision for income taxes | 471,199 | 450,578 | 5 | % | |||||||||||||||||||
| Provision for credit losses | 213,199 | 84,016 | 154 | % | |||||||||||||||||||
| Pre-provision net revenue (PPNR) (non-GAAP) | k | 684,398 | 534,594 | 28 | % | ||||||||||||||||||
| Less: Non-interest income adjustments | a | 10,469 | 6,251 | 67 | % | ||||||||||||||||||
| Add: Non-interest expense adjustments | b | 181,877 | 24,161 | nm | |||||||||||||||||||
| Operating PPNR (non-GAAP) | l | $ | 876,744 | $ | 565,006 | 55 | % | ||||||||||||||||
| Net income (GAAP) | j | $ | 348,715 | $ | 336,752 | 4 | % | ||||||||||||||||
| Less: Non-interest income adjustments | a | 10,469 | 6,251 | 67 | % | ||||||||||||||||||
| Add: Non-interest expense adjustments | b | 181,877 | 24,161 | nm | |||||||||||||||||||
| Tax effect of adjustments | (44,337) | (7,479) | 493 | % | |||||||||||||||||||
| Operating net income (non-GAAP) | m | $ | 496,724 | $ | 359,685 | 38 | % | ||||||||||||||||
(1) Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm." | |||||||||||||||||||||||
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 24
| Columbia Banking System, Inc. | |||||||||||||||||||||||
| GAAP to Non-GAAP Reconciliation - Continued | |||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||
| Twelve Months Ended | % Change (1) | ||||||||||||||||||||||
| ($ in thousands) | Dec 31, 2023 | Dec 31, 2022 | Year over Year | ||||||||||||||||||||
| Average assets | n | $ | 49,496,319 | $ | 30,817,396 | 61 | % | ||||||||||||||||
| Less: Average goodwill and other intangible assets, net | 1,423,075 | 6,847 | nm | ||||||||||||||||||||
| Average tangible assets | o | $ | 48,073,244 | $ | 30,810,549 | 56 | % | ||||||||||||||||
| Average common shareholders' equity | p | $ | 4,466,725 | $ | 2,575,577 | 73 | % | ||||||||||||||||
| Less: Average goodwill and other intangible assets, net | 1,423,075 | 6,847 | nm | ||||||||||||||||||||
| Average tangible common equity | q | $ | 3,043,650 | $ | 2,568,730 | 18 | % | ||||||||||||||||
Weighted average basic shares outstanding (1) | r | 195,304 | 129,277 | 51 | % | ||||||||||||||||||
Weighted average diluted shares outstanding (1) | s | 195,871 | 129,732 | 51 | % | ||||||||||||||||||
| Select Per-Share & Performance Metrics | |||||||||||||||||||||||
Earnings-per-share - basic (1) | j / r | $ | 1.79 | $ | 2.60 | (31) | % | ||||||||||||||||
Earnings-per-share - diluted (1) | j / s | $ | 1.78 | $ | 2.60 | (32) | % | ||||||||||||||||
Efficiency ratio (2) | h / f | 65.59 | % | 57.83 | % | 7.76 | |||||||||||||||||
| ROAA | j / n | 0.70 | % | 1.09 | % | (0.39) | |||||||||||||||||
| Return on average tangible assets | j / o | 0.73 | % | 1.09 | % | (0.36) | |||||||||||||||||
| PPNR ROAA | k/n | 1.38 | % | 1.73 | % | (0.35) | |||||||||||||||||
| Return on average common equity | j / p | 7.81 | % | 13.07 | % | (5.26) | |||||||||||||||||
| Return on average tangible common equity | j / q | 11.46 | % | 13.11 | % | (1.65) | |||||||||||||||||
| Operating Per-Share & Performance Metrics | |||||||||||||||||||||||
Operating earnings-per-share - basic (1) | m / r | $ | 2.54 | $ | 2.78 | (9) | % | ||||||||||||||||
Operating earnings-per-share - diluted (1) | m / s | $ | 2.54 | $ | 2.77 | (8) | % | ||||||||||||||||
Operating efficiency ratio (2) | i / g | 56.21 | % | 55.66 | % | 0.55 | |||||||||||||||||
| Operating ROAA | m / n | 1.00 | % | 1.17 | % | (0.17) | |||||||||||||||||
| Operating return on average tangible assets | m / o | 1.03 | % | 1.17 | % | (0.14) | |||||||||||||||||
| Operating PPNR ROAA | l / n | 1.77 | % | 1.83 | % | (0.06) | |||||||||||||||||
| Operating return on average common equity | m / p | 11.12 | % | 13.97 | % | (2.85) | |||||||||||||||||
| Operating return on average tangible common equity | m / q | 16.32 | % | 14.00 | % | 2.32 | |||||||||||||||||
(1) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958.
(2) Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate and added to stated revenue for this calculation.
(3) Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm."
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 25
| Columbia Banking System, Inc. | |||||||||||||||||||||||||||||||||||||||||||||||
| GAAP to Non-GAAP Reconciliation - Continued | |||||||||||||||||||||||||||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | % Change (4) | ||||||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | Dec 31, 2023 | Sep 30, 2023 | Jun 30, 2023 | Mar 31, 2023 | Dec 31, 2022 | Seq. Quarter | Year over Year | ||||||||||||||||||||||||||||||||||||||||
| Loans and leases interest income | a | $ | 577,092 | $ | 567,929 | $ | 551,997 | $ | 412,726 | $ | 320,747 | 2 | % | 80 | % | ||||||||||||||||||||||||||||||||
Less: Acquired loan accretion - rate related (2), (3) | b | 26,914 | 28,963 | 30,548 | 11,832 | 387 | (7) | % | nm | ||||||||||||||||||||||||||||||||||||||
Less: Acquired loan accretion - credit related (3) | c | 5,430 | 6,370 | 7,100 | 3,806 | — | (15) | % | nm | ||||||||||||||||||||||||||||||||||||||
| Adjusted loans and leases interest income | d=a-b-c | $ | 544,748 | $ | 532,596 | $ | 514,349 | $ | 397,088 | $ | 320,360 | 2 | % | 70 | % | ||||||||||||||||||||||||||||||||
| Taxable securities interest income | e | $ | 82,872 | $ | 85,007 | $ | 81,617 | $ | 40,448 | $ | 18,290 | (3) | % | 353 | % | ||||||||||||||||||||||||||||||||
| Less: Acquired taxable securities accretion - rate related | f | 34,290 | 39,219 | 34,801 | 15,356 | — | (13) | % | nm | ||||||||||||||||||||||||||||||||||||||
| Adjusted Taxable securities interest income | g=e-f | $ | 48,582 | $ | 45,788 | $ | 46,816 | $ | 25,092 | $ | 18,290 | 6 | % | 166 | % | ||||||||||||||||||||||||||||||||
Non-taxable securities interest income (1) | h | $ | 8,073 | $ | 8,085 | $ | 8,010 | $ | 4,068 | $ | 1,571 | 0 | % | 414 | % | ||||||||||||||||||||||||||||||||
| Less: Acquired non-taxable securities accretion - rate related | i | 2,309 | 2,288 | 2,274 | 901 | — | 1 | % | nm | ||||||||||||||||||||||||||||||||||||||
Adjusted Taxable securities interest income (1) | j=h-i | $ | 5,764 | $ | 5,797 | $ | 5,736 | $ | 3,167 | $ | 1,571 | (1) | % | 267 | % | ||||||||||||||||||||||||||||||||
Interest income (1) | k | $ | 692,741 | $ | 697,169 | $ | 676,922 | $ | 476,622 | $ | 352,530 | (1) | % | 97 | % | ||||||||||||||||||||||||||||||||
| Less: Acquired loan and securities accretion - rate related | l=b+f+i | 63,513 | 70,470 | 67,623 | 28,089 | 387 | (10) | % | nm | ||||||||||||||||||||||||||||||||||||||
| Less: Acquired loan accretion - credit related | c | 5,430 | 6,370 | 7,100 | 3,806 | — | (15) | % | nm | ||||||||||||||||||||||||||||||||||||||
Adjusted interest income (1) | m=k-l-c | $ | 623,798 | $ | 620,329 | $ | 602,199 | $ | 444,727 | $ | 352,143 | 1 | % | 77 | % | ||||||||||||||||||||||||||||||||
| Interest-bearing deposits interest expense | n | $ | 170,659 | $ | 126,974 | $ | 100,408 | $ | 63,613 | $ | 31,174 | 34 | % | 447 | % | ||||||||||||||||||||||||||||||||
| Less: Acquired deposit accretion | o | (187) | (373) | (280) | (93) | — | (50) | % | nm | ||||||||||||||||||||||||||||||||||||||
| Adjusted interest-bearing deposits interest expense | p=n-o | $ | 170,846 | $ | 127,347 | $ | 100,688 | $ | 63,706 | $ | 31,174 | 34 | % | 448 | % | ||||||||||||||||||||||||||||||||
| Interest expense | q | $ | 238,011 | $ | 215,138 | $ | 191,754 | $ | 101,253 | $ | 46,768 | 11 | % | 409 | % | ||||||||||||||||||||||||||||||||
Less: Acquired interest-bearing liabilities accretion (2) | r | (244) | (430) | (337) | (150) | (57) | (43) | % | 328 | % | |||||||||||||||||||||||||||||||||||||
| Adjusted interest expense | s=q-r | $ | 238,255 | $ | 215,568 | $ | 192,091 | $ | 101,403 | $ | 46,825 | 11 | % | 409 | % | ||||||||||||||||||||||||||||||||
Net Interest Income (1) | t | $ | 454,730 | $ | 482,031 | $ | 485,168 | $ | 375,369 | $ | 305,762 | (6) | % | 49 | % | ||||||||||||||||||||||||||||||||
Less: Acquired loan, securities, and interest-bearing liabilities accretion - rate related (3) | u=l-r | 63,757 | 70,900 | 67,960 | 28,239 | 444 | (10) | % | nm | ||||||||||||||||||||||||||||||||||||||
Less: Acquired loan accretion - credit related (3) | c | 5,430 | 6,370 | 7,100 | 3,806 | — | (15) | % | nm | ||||||||||||||||||||||||||||||||||||||
Adjusted net interest income (1) | v=t-u-c | $ | 385,543 | $ | 404,761 | $ | 410,108 | $ | 343,324 | $ | 305,318 | (5) | % | 26 | % | ||||||||||||||||||||||||||||||||
| Average loans and leases | aa | 37,333,310 | 37,050,518 | 37,169,315 | 29,998,630 | 25,855,556 | 1 | % | 44 | % | |||||||||||||||||||||||||||||||||||||
| Average taxable securities | ab | 7,903,053 | 8,356,165 | 8,656,147 | 4,960,966 | 3,042,044 | (5) | % | 160 | % | |||||||||||||||||||||||||||||||||||||
| Average non-taxable securities | ac | 809,551 | 844,417 | 865,278 | 437,020 | 200,825 | (4) | % | 303 | % | |||||||||||||||||||||||||||||||||||||
| Average interest-earning assets | ad | 47,838,229 | 48,981,105 | 49,442,518 | 37,055,705 | 30,305,129 | (2) | % | 58 | % | |||||||||||||||||||||||||||||||||||||
| Average interest-bearing deposits | ae | 26,622,343 | 25,121,745 | 24,494,717 | 19,496,551 | 16,103,984 | 6 | % | 65 | % | |||||||||||||||||||||||||||||||||||||
| Average interest-bearing liabilities | af | 31,226,600 | 31,413,978 | 31,372,416 | 22,548,264 | 17,668,730 | (1) | % | 77 | % | |||||||||||||||||||||||||||||||||||||
(1)Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate.
(2)Includes discount accretion related to UHC's 2014 acquisition of Sterling Financial Corporation.
(3)The cumulative fair value discount on historical Columbia loans was established as of February 28, 2023, and the allocation between the credit-related discount and the rate-related discount was established at that time. Our disclosure of credit-related and rate-related discount accretion is an estimate based on the relative allocation of these two items to the discount at the closing of the merger.
(4)Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm."
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 26
| Columbia Banking System, Inc. | |||||||||||||||||||||||||||||||||||||||||||||||
| GAAP to Non-GAAP Reconciliation - Continued | |||||||||||||||||||||||||||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | % Change | ||||||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | Dec 31, 2023 | Sep 30, 2023 | Jun 30, 2023 | Mar 31, 2023 | Dec 31, 2022 | Seq. Quarter | Year over Year | ||||||||||||||||||||||||||||||||||||||||
| Average yield on loans and leases | a / aa | 6.13 | % | 6.08 | % | 5.95 | % | 5.55 | % | 4.92 | % | 0.05 | 1.21 | ||||||||||||||||||||||||||||||||||
Less: Acquired loan accretion - rate related (2),(3) | b / aa | 0.29 | % | 0.31 | % | 0.33 | % | 0.16 | % | 0.01 | % | (0.02) | 0.28 | ||||||||||||||||||||||||||||||||||
Less: Acquired loan accretion - credit related (3) | c / aa | 0.06 | % | 0.07 | % | 0.08 | % | 0.05 | % | — | % | (0.01) | 0.06 | ||||||||||||||||||||||||||||||||||
| Adjusted average yield on loans and leases | d / aa | 5.78 | % | 5.70 | % | 5.54 | % | 5.34 | % | 4.91 | % | 0.08 | 0.87 | ||||||||||||||||||||||||||||||||||
| Average yield on taxable securities | e / ab | 4.19 | % | 4.07 | % | 3.77 | % | 3.26 | % | 2.40 | % | 0.12 | 1.79 | ||||||||||||||||||||||||||||||||||
| Less: Acquired taxable securities accretion - rate related | f / ab | 1.72 | % | 1.86 | % | 1.61 | % | 1.26 | % | — | % | (0.14) | 1.72 | ||||||||||||||||||||||||||||||||||
| Adjusted average yield on taxable securities | g / ab | 2.47 | % | 2.21 | % | 2.16 | % | 2.00 | % | 2.40 | % | 0.26 | 0.07 | ||||||||||||||||||||||||||||||||||
Average yield on non-taxable securities (1) | h / ac | 3.99 | % | 3.83 | % | 3.70 | % | 3.72 | % | 3.13 | % | 0.16 | 0.86 | ||||||||||||||||||||||||||||||||||
| Less: Acquired non-taxable securities accretion - rate related | i / ac | 1.13 | % | 1.07 | % | 1.05 | % | 0.84 | % | — | % | 0.06 | 1.13 | ||||||||||||||||||||||||||||||||||
Adjusted yield on non-taxable securities (1) | j / ac | 2.86 | % | 2.76 | % | 2.65 | % | 2.88 | % | 3.13 | % | 0.10 | (0.27) | ||||||||||||||||||||||||||||||||||
Average yield on interest-earning assets (1) | k / ad | 5.75 | % | 5.65 | % | 5.48 | % | 5.19 | % | 4.62 | % | 0.10 | 1.13 | ||||||||||||||||||||||||||||||||||
| Less: Acquired loan and securities accretion - rate related | l / ad | 0.53 | % | 0.57 | % | 0.55 | % | 0.31 | % | 0.01 | % | (0.04) | 0.52 | ||||||||||||||||||||||||||||||||||
| Less: Acquired loan accretion - credit related | c / ad | 0.05 | % | 0.05 | % | 0.06 | % | 0.04 | % | — | % | — | 0.05 | ||||||||||||||||||||||||||||||||||
Adjusted average yield on interest-earning assets (1) | m / ad | 5.17 | % | 5.03 | % | 4.87 | % | 4.84 | % | 4.61 | % | 0.14 | 0.56 | ||||||||||||||||||||||||||||||||||
| Average rate on interest-bearing deposits | n / ae | 2.54 | % | 2.01 | % | 1.64 | % | 1.32 | % | 0.77 | % | 0.53 | 1.77 | ||||||||||||||||||||||||||||||||||
| Less: Acquired deposit accretion | o / ae | — | % | (0.01) | % | — | % | — | % | — | % | 0.01 | — | ||||||||||||||||||||||||||||||||||
| Adjusted average rate on interest-bearing deposits | p / ae | 2.54 | % | 2.02 | % | 1.64 | % | 1.32 | % | 0.77 | % | 0.52 | 1.77 | ||||||||||||||||||||||||||||||||||
| Average rate on interest-bearing liabilities | q / af | 3.02 | % | 2.72 | % | 2.45 | % | 1.82 | % | 1.05 | % | 0.30 | 1.97 | ||||||||||||||||||||||||||||||||||
Less: Acquired interest-bearing liabilities accretion (2) | r / af | — | % | (0.01) | % | — | % | — | % | — | % | 0.01 | — | ||||||||||||||||||||||||||||||||||
| Adjusted average rate on interest-bearing liabilities | s / af | 3.02 | % | 2.73 | % | 2.45 | % | 1.82 | % | 1.05 | % | 0.29 | 1.97 | ||||||||||||||||||||||||||||||||||
Net interest margin (1) | t / ad | 3.78 | % | 3.91 | % | 3.93 | % | 4.08 | % | 4.01 | % | (0.13) | (0.23) | ||||||||||||||||||||||||||||||||||
Less: Acquired loan, securities, and interest-bearing liabilities accretion - rate related (3) | u / ad | 0.53 | % | 0.58 | % | 0.55 | % | 0.31 | % | — | % | (0.05) | 0.53 | ||||||||||||||||||||||||||||||||||
Less: Acquired loan accretion - credit related (3) | c / ad | 0.05 | % | 0.05 | % | 0.06 | % | 0.04 | % | — | % | — | 0.05 | ||||||||||||||||||||||||||||||||||
Adjusted net interest margin (1) | v / ad | 3.20 | % | 3.28 | % | 3.32 | % | 3.73 | % | 4.01 | % | (0.08) | (0.81) | ||||||||||||||||||||||||||||||||||
(1)Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate.
(2) Includes discount accretion related to UHC's 2014 acquisition of Sterling Financial Corporation.
(3)The cumulative fair value discount on historical Columbia loans was established as of February 28, 2023, and the allocation between the credit-related discount and the rate-related discount was established at that time. Our disclosure of credit-related and rate-related discount accretion is an estimate based on the relative allocation of these two items to the discount at the closing of the merger.
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 27
| Columbia Banking System, Inc. | |||||||||||||||||||||||
| GAAP to Non-GAAP Reconciliation - Continued | |||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||
| Twelve Months Ended | |||||||||||||||||||||||
| ($ in thousands) | Dec 31, 2023 | Dec 31, 2022 | Year over Year (4) | ||||||||||||||||||||
| Loans and leases interest income | a | $ | 2,109,744 | $ | 1,041,446 | 103 | % | ||||||||||||||||
Less: Acquired loan accretion - rate related (2), (3) | b | 98,257 | 3,677 | nm | |||||||||||||||||||
Less: Acquired loan accretion - credit related (3) | c | 22,706 | — | nm | |||||||||||||||||||
| Adjusted loans and leases interest income | d=a-b-c | $ | 1,988,781 | $ | 1,037,769 | 92 | % | ||||||||||||||||
| Taxable securities interest income | e | $ | 289,944 | $ | 72,702 | 299 | % | ||||||||||||||||
| Less: Acquired taxable securities accretion - rate related | f | 123,666 | — | nm | |||||||||||||||||||
| Adjusted Taxable securities interest income | g=e-f | $ | 166,278 | $ | 72,702 | 129 | % | ||||||||||||||||
Non-taxable securities interest income (1) | h | $ | 28,236 | $ | 6,669 | 323 | % | ||||||||||||||||
| Less: Acquired non-taxable securities accretion - rate related | i | 7,772 | — | nm | |||||||||||||||||||
Adjusted Taxable securities interest income (1) | j=h-i | $ | 20,464 | $ | 6,669 | 207 | % | ||||||||||||||||
Interest income (1) | k | $ | 2,543,454 | $ | 1,149,335 | 121 | % | ||||||||||||||||
| Less: Acquired loan and securities accretion - rate related | l=b+f+i | 229,695 | 3,677 | nm | |||||||||||||||||||
| Less: Acquired loan accretion - credit related | c | 22,706 | — | nm | |||||||||||||||||||
Adjusted interest income (1) | m=k-l-c | $ | 2,291,053 | $ | 1,145,658 | 100 | % | ||||||||||||||||
| Interest-bearing deposits interest expense | n | $ | 461,654 | $ | 48,195 | nm | |||||||||||||||||
| Less: Acquired deposit accretion | o | (933) | — | nm | |||||||||||||||||||
| Adjusted interest-bearing deposits interest expense | p=n-o | $ | 462,587 | $ | 48,195 | nm | |||||||||||||||||
| Interest expense | q | $ | 746,156 | $ | 78,001 | nm | |||||||||||||||||
Less: Acquired interest-bearing liabilities accretion (2) | r | (1,161) | (228) | 409 | % | ||||||||||||||||||
| Adjusted interest expense | s=q-r | $ | 747,317 | $ | 78,229 | nm | |||||||||||||||||
Net Interest Income (1) | t | $ | 1,797,298 | $ | 1,071,334 | 68 | % | ||||||||||||||||
Less: Acquired loan, securities, and interest-bearing liabilities accretion - rate related (3) | u=l-r | 230,856 | 3,905 | nm | |||||||||||||||||||
Less: Acquired loan accretion - credit related (3) | c | 22,706 | — | nm | |||||||||||||||||||
Adjusted net interest income (1) | v=t-u-c | $ | 1,543,736 | $ | 1,067,429 | 45 | % | ||||||||||||||||
| Average loans and leases | aa | 35,412,594 | 24,225,518 | 46 | % | ||||||||||||||||||
| Average taxable securities | ab | 7,479,573 | 3,343,721 | 124 | % | ||||||||||||||||||
| Average non-taxable securities | ac | 740,376 | 216,943 | 241 | % | ||||||||||||||||||
| Average interest-earning assets | ad | 45,867,566 | 29,556,131 | 55 | % | ||||||||||||||||||
| Average interest-bearing deposits | ae | 23,981,118 | 15,594,492 | 54 | % | ||||||||||||||||||
| Average interest-bearing liabilities | af | 29,194,822 | 16,686,325 | 75 | % | ||||||||||||||||||
(1)Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate.
(2)Includes discount accretion related to UHC's 2014 acquisition of Sterling Financial Corporation.
(3)The cumulative fair value discount on historical Columbia loans was established as of February 28, 2023, and the allocation between the credit-related discount and the rate-related discount was established at that time. Our disclosure of credit-related and rate-related discount accretion is an estimate based on the relative allocation of these two items to the discount at the closing of the merger.
(4)Percentage changes greater than +/-500% are considered not meaningful and are presented as "nm."
Columbia Banking System, Inc. Reports Fourth Quarter 2023 Results
January 24, 2024
Page 28
| Columbia Banking System, Inc. | |||||||||||||||||||||||
| GAAP to Non-GAAP Reconciliation - Continued | |||||||||||||||||||||||
| (Unaudited) | |||||||||||||||||||||||
| Twelve Months Ended | |||||||||||||||||||||||
| ($ in thousands) | Dec 31, 2023 | Dec 31, 2022 | Year over Year | ||||||||||||||||||||
| Average yield on loans and leases | a / aa | 5.95 | % | 4.29 | % | 1.66 | |||||||||||||||||
Less: Acquired loan accretion - rate related (2),(3) | b / aa | 0.28 | % | 0.02 | % | 0.26 | |||||||||||||||||
Less: Acquired loan accretion - credit related (3) | c / aa | 0.06 | % | — | % | 0.06 | |||||||||||||||||
| Adjusted average yield on loans and leases | d / aa | 5.61 | % | 4.27 | % | 1.34 | |||||||||||||||||
| Average yield on taxable securities | e / ab | 3.88 | % | 2.17 | % | 1.71 | |||||||||||||||||
| Less: Acquired taxable securities accretion - rate related | f / ab | 1.65 | % | — | % | 1.65 | |||||||||||||||||
| Adjusted average yield on taxable securities | g / ab | 2.23 | % | 2.17 | % | 0.06 | |||||||||||||||||
Average yield on non-taxable securities (1) | h / ac | 3.81 | % | 3.07 | % | 0.74 | |||||||||||||||||
| Less: Acquired non-taxable securities accretion - rate related | i / ac | 1.05 | % | — | % | 1.05 | |||||||||||||||||
Adjusted yield on non-taxable securities (1) | j / ac | 2.76 | % | 3.07 | % | (0.31) | |||||||||||||||||
Average yield on interest-earning assets (1) | k / ad | 5.54 | % | 3.88 | % | 1.66 | |||||||||||||||||
| Less: Acquired loan and securities accretion - rate related | l / ad | 0.50 | % | 0.01 | % | 0.49 | |||||||||||||||||
| Less: Acquired loan accretion - credit related | c / ad | 0.05 | % | — | % | 0.05 | |||||||||||||||||
Adjusted average yield on interest-earning assets (1) | m / ad | 4.99 | % | 3.87 | % | 1.12 | |||||||||||||||||
| Average rate on interest-bearing deposits | n / ae | 1.93 | % | 0.31 | % | 1.62 | |||||||||||||||||
| Less: Acquired deposit accretion | o / ae | — | % | — | % | — | |||||||||||||||||
| Adjusted average rate on interest-bearing deposits | p / ae | 1.93 | % | 0.31 | % | 1.62 | |||||||||||||||||
| Average rate on interest-bearing liabilities | q / af | 2.56 | % | 0.47 | % | 2.09 | |||||||||||||||||
Less: Acquired interest-bearing liabilities accretion (2) | r / af | — | % | — | % | — | |||||||||||||||||
| Adjusted average rate on interest-bearing liabilities | s / af | 2.56 | % | 0.47 | % | 2.09 | |||||||||||||||||
Net interest margin (1) | t / ad | 3.91 | % | 3.62 | % | 0.29 | |||||||||||||||||
Less: Acquired loan, securities, and interest-bearing liabilities accretion - rate related (3) | u / ad | 0.50 | % | 0.01 | % | 0.49 | |||||||||||||||||
Less: Acquired loan accretion - credit related (3) | c / ad | 0.05 | % | — | % | 0.05 | |||||||||||||||||
Adjusted net interest margin (1) | v / ad | 3.36 | % | 3.61 | % | (0.25) | |||||||||||||||||
(1)Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate.
(2) Includes discount accretion related to UHC's 2014 acquisition of Sterling Financial Corporation.
(3)The cumulative fair value discount on historical Columbia loans was established as of February 28, 2023, and the allocation between the credit-related discount and the rate-related discount was established at that time. Our disclosure of credit-related and rate-related discount accretion is an estimate based on the relative allocation of these two items to the discount at the closing of the merger.
4th Quarter 2023 Earnings Presentation January 24, 2024
Disclaimer FORWARD-LOOKING STATEMENTS This presentation includes forward-looking statements within the meaning of the "Safe-Harbor" provisions of the Private Securities Litigation Reform Act of 1995, which management believes are a benefit to shareholders. These statements are necessarily subject to risk and uncertainty and actual results could differ materially due to various risk factors, including those set forth from time to time in our filings with the Securities and Exchange Commission (the "SEC"). You should not place undue reliance on forward-looking statements, and we undertake no obligation to update any such statements. Forward-looking statements can be identified by words such as "anticipates," "intends," "plans," "seeks," "believes," "estimates," "expects," "target," "projects," "outlook," "forecast," "will," "may," "could," "should," "can" and similar references to future periods. In this press release we make forward-looking statements about strategic and growth initiatives and the result of such activity. Risks that could cause results to differ from forward-looking statements we make include, without limitation: current and future economic and market conditions, including the effects of declines in housing and commercial real estate prices, high unemployment rates, continued inflation and any recession or slowdown in economic growth particularly in the western United States; economic forecast variables that are either materially worse or better than end of quarter projections and deterioration in the economy that could result in increased loan and lease losses, especially those risks associated with concentrations in real estate related loans; our ability to effectively manage problem credits; the impact of bank failures or adverse developments at or news developments concerning other banks on general investor sentiment regarding the liquidity and stability of banks; changes in interest rates that could significantly reduce net interest income and negatively affect asset yields and valuations and funding sources; changes in the scope and cost of FDIC insurance and other coverage; our ability to successfully implement efficiency and operational excellence initiatives; our ability to successfully develop and market new products and technology; changes in laws or regulations; any failure to realize the anticipated benefits of the merger when expected or at all; potential adverse reactions or changes to business or employee relationships, including those resulting from the completion of the merger and integration of the companies; the effect of geopolitical instability, including wars, conflicts and terrorist attacks; and natural disasters and other similar unexpected events outside of our control. We also caution that the amount and timing of any future common stock dividends or repurchases will depend on the earnings, cash requirements and financial condition of Columbia, market conditions, capital requirements, applicable law and regulations (including federal securities laws and federal banking regulations), and other factors deemed relevant by Columbia's Board of Directors, and may be subject to regulatory approval or conditions. NON-GAAP FINANCIAL MEASURES In addition to results in accordance with GAAP, this presentation contains certain non-GAAP financial measures. A reconciliation of GAAP to non-GAAP measures is included in the Appendix. We believe presenting certain non-GAAP financial measures provides investors with information useful in understanding our financial performance, our performance trends, and our financial position. We utilize these measures for internal planning and forecasting purposes. We, as well as securities analysts, investors, and other interested parties, also use these measures to compare peer company operating performance. We believe that our presentation and discussion, together with the accompanying reconciliations, provide a complete understanding of factors and trends affecting our business and allows investors to view performance in a manner similar to management. These non-GAAP measures should not be considered a substitution for GAAP basis measures and results, and we strongly encourage investors to review our consolidated financial statements in their entirety and not to rely on any single financial measure. Because non-GAAP financial measures are not standardized, it may not be possible to compare these financial measures with other companies’ non-GAAP financial measures having the same or similar names. REVERSE ACQUISITION METHOD OF ACCOUNTING On February 28, 2023, Columbia Banking System, Inc. ("Columbia", "we" or "our") completed its merger with Umpqua Holdings Corporation ("UHC"), combining the two premier banks in the Northwest to create one of the largest banks headquartered in the West (the "merger"). Columbia's financial results for any periods ended prior to February 28, 2023 reflect UHC results only on a standalone basis. In addition, Columbia's reported financial results for the first quarter of 2023 reflect UHC financial results only until the closing of the merger after the close of business on February 28, 2023. As a result of these two factors, Columbia's financial results for each of the quarters of 2023 and the year ended December 31, 2023 may not be directly comparable to prior reported periods. The number of shares issued and outstanding, earnings per share, additional paid-in capital, and all references to share quantities or metrics of Columbia have been retrospectively restated to reflect the equivalent number of shares issued in the merger as the merger was treated as a reverse merger. Under the reverse acquisition method of accounting, the assets and liabilities of Columbia as of February 28, 2023 ("historical Columbia") were recorded at their respective fair values. 2
FINANCIAL HIGHLIGHTS AND SUMMARY FINANCIAL STATEMENTS Q4 2023
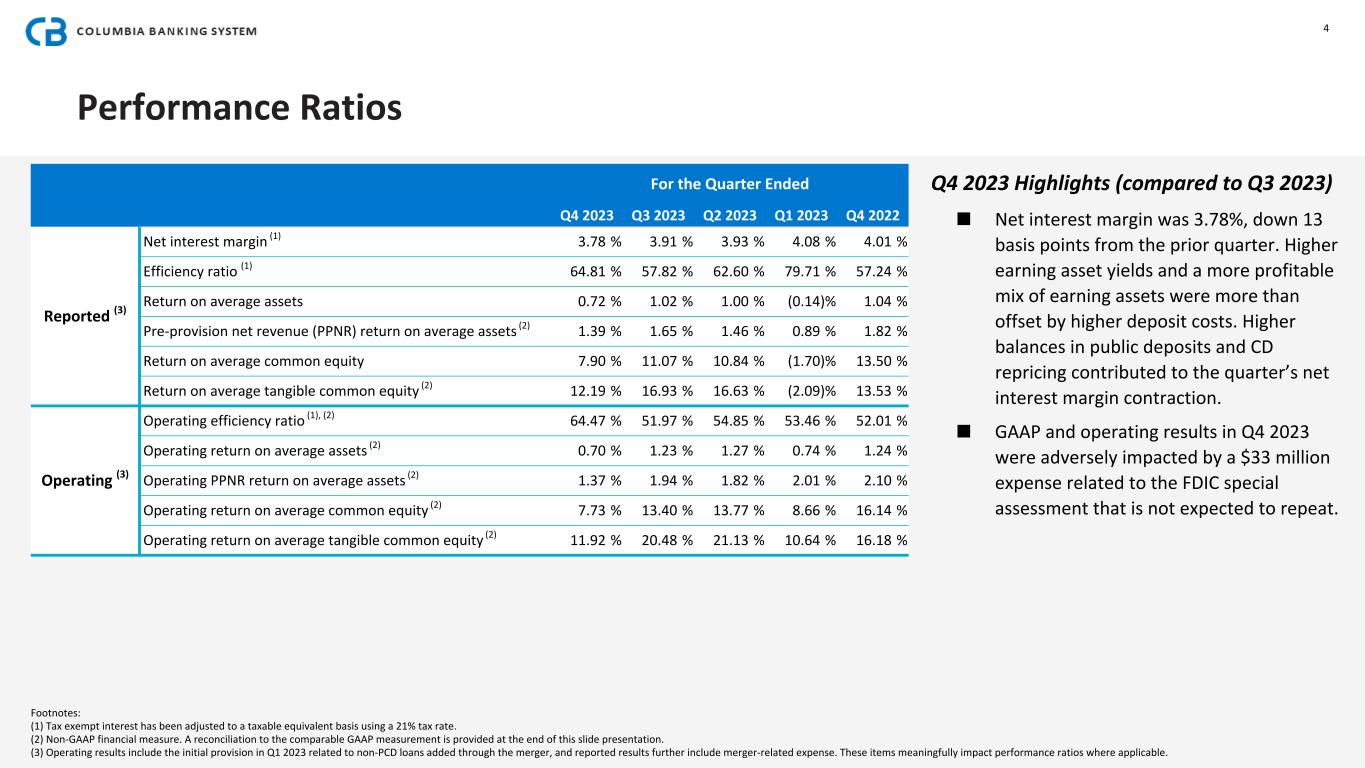
Performance Ratios Footnotes: (1) Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate. (2) Non-GAAP financial measure. A reconciliation to the comparable GAAP measurement is provided at the end of this slide presentation. (3) Operating results include the initial provision in Q1 2023 related to non-PCD loans added through the merger, and reported results further include merger-related expense. These items meaningfully impact performance ratios where applicable. For the Quarter Ended Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 Reported (3) Net interest margin (1) 3.78 % 3.91 % 3.93 % 4.08 % 4.01 % Efficiency ratio (1) 64.81 % 57.82 % 62.60 % 79.71 % 57.24 % Return on average assets 0.72 % 1.02 % 1.00 % (0.14) % 1.04 % Pre-provision net revenue (PPNR) return on average assets (2) 1.39 % 1.65 % 1.46 % 0.89 % 1.82 % Return on average common equity 7.90 % 11.07 % 10.84 % (1.70) % 13.50 % Return on average tangible common equity (2) 12.19 % 16.93 % 16.63 % (2.09) % 13.53 % Operating (3) Operating efficiency ratio (1), (2) 64.47 % 51.97 % 54.85 % 53.46 % 52.01 % Operating return on average assets (2) 0.70 % 1.23 % 1.27 % 0.74 % 1.24 % Operating PPNR return on average assets (2) 1.37 % 1.94 % 1.82 % 2.01 % 2.10 % Operating return on average common equity (2) 7.73 % 13.40 % 13.77 % 8.66 % 16.14 % Operating return on average tangible common equity (2) 11.92 % 20.48 % 21.13 % 10.64 % 16.18 % Q4 2023 Highlights (compared to Q3 2023) ■ Net interest margin was 3.78%, down 13 basis points from the prior quarter. Higher earning asset yields and a more profitable mix of earning assets were more than offset by higher deposit costs. Higher balances in public deposits and CD repricing contributed to the quarter’s net interest margin contraction. ■ GAAP and operating results in Q4 2023 were adversely impacted by a $33 million expense related to the FDIC special assessment that is not expected to repeat. 4
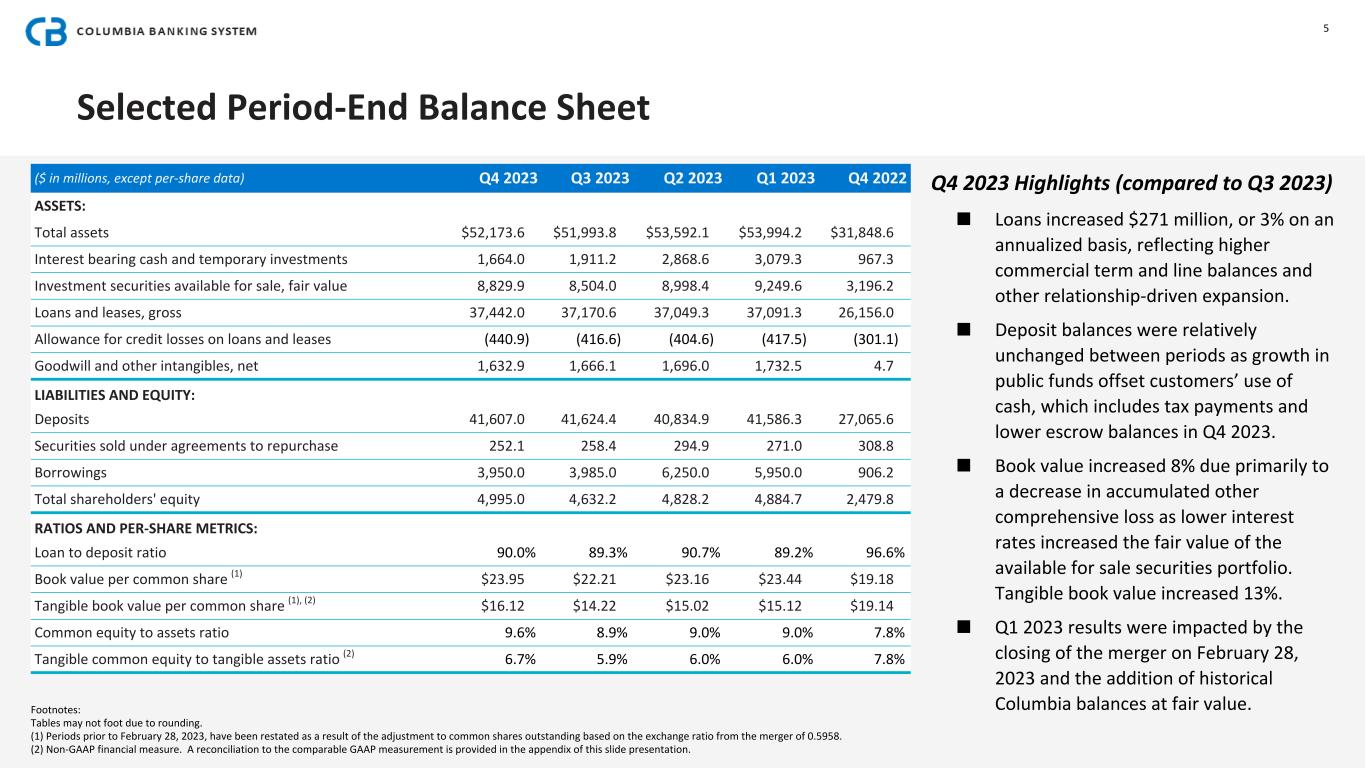
Selected Period-End Balance Sheet Footnotes: Tables may not foot due to rounding. (1) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958. (2) Non-GAAP financial measure. A reconciliation to the comparable GAAP measurement is provided in the appendix of this slide presentation. ($ in millions, except per-share data) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 ASSETS: Total assets $52,173.6 $51,993.8 $53,592.1 $53,994.2 $31,848.6 Interest bearing cash and temporary investments 1,664.0 1,911.2 2,868.6 3,079.3 967.3 Investment securities available for sale, fair value 8,829.9 8,504.0 8,998.4 9,249.6 3,196.2 Loans and leases, gross 37,442.0 37,170.6 37,049.3 37,091.3 26,156.0 Allowance for credit losses on loans and leases (440.9) (416.6) (404.6) (417.5) (301.1) Goodwill and other intangibles, net 1,632.9 1,666.1 1,696.0 1,732.5 4.7 LIABILITIES AND EQUITY: Deposits 41,607.0 41,624.4 40,834.9 41,586.3 27,065.6 Securities sold under agreements to repurchase 252.1 258.4 294.9 271.0 308.8 Borrowings 3,950.0 3,985.0 6,250.0 5,950.0 906.2 Total shareholders' equity 4,995.0 4,632.2 4,828.2 4,884.7 2,479.8 RATIOS AND PER-SHARE METRICS: Loan to deposit ratio 90.0% 89.3% 90.7% 89.2% 96.6% Book value per common share (1) $23.95 $22.21 $23.16 $23.44 $19.18 Tangible book value per common share (1), (2) $16.12 $14.22 $15.02 $15.12 $19.14 Common equity to assets ratio 9.6% 8.9% 9.0% 9.0% 7.8% Tangible common equity to tangible assets ratio (2) 6.7% 5.9% 6.0% 6.0% 7.8% 5 Q4 2023 Highlights (compared to Q3 2023) ■ Loans increased $271 million, or 3% on an annualized basis, reflecting higher commercial term and line balances and other relationship-driven expansion. ■ Deposit balances were relatively unchanged between periods as growth in public funds offset customers’ use of cash, which includes tax payments and lower escrow balances in Q4 2023. ■ Book value increased 8% due primarily to a decrease in accumulated other comprehensive loss as lower interest rates increased the fair value of the available for sale securities portfolio. Tangible book value increased 13%. ■ Q1 2023 results were impacted by the closing of the merger on February 28, 2023 and the addition of historical Columbia balances at fair value.
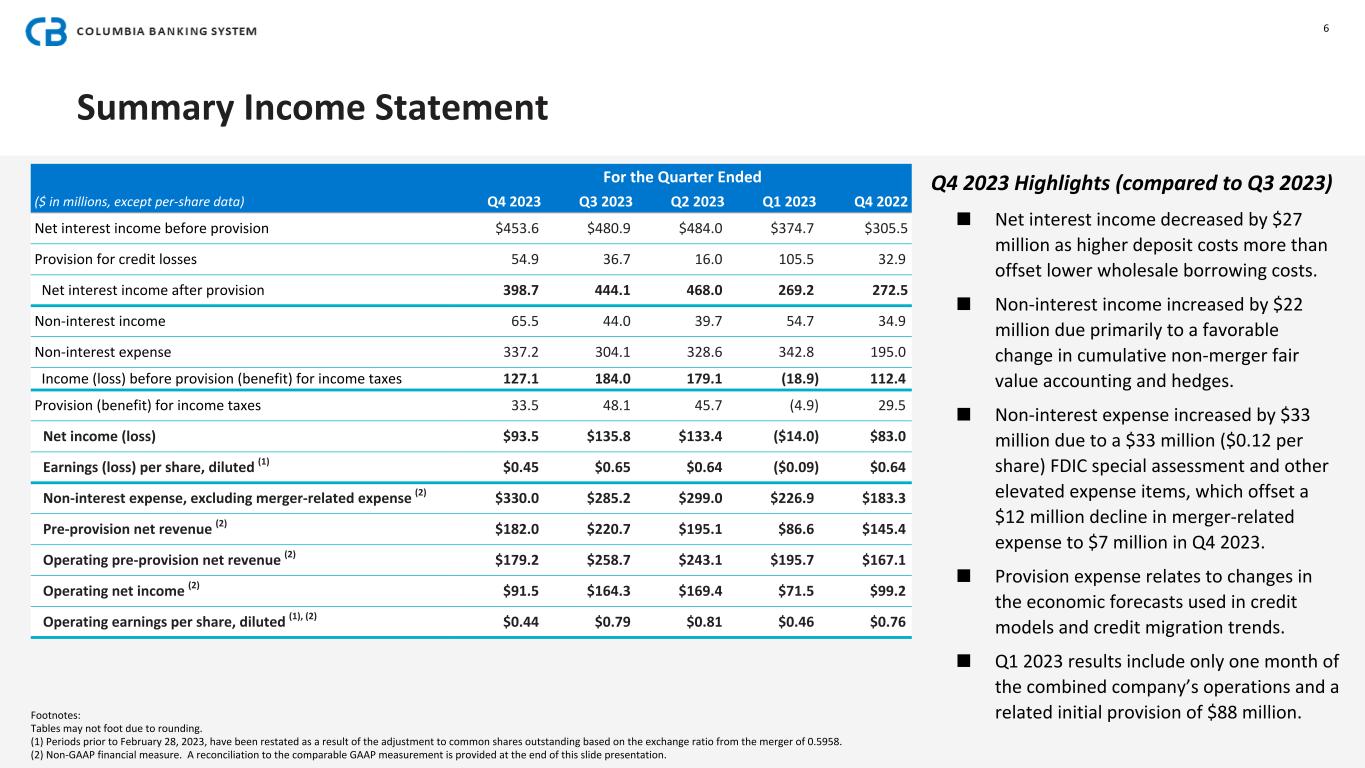
Summary Income Statement Footnotes: Tables may not foot due to rounding. (1) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958. (2) Non-GAAP financial measure. A reconciliation to the comparable GAAP measurement is provided at the end of this slide presentation. For the Quarter Ended ($ in millions, except per-share data) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 Net interest income before provision $453.6 $480.9 $484.0 $374.7 $305.5 Provision for credit losses 54.9 36.7 16.0 105.5 32.9 Net interest income after provision 398.7 444.1 468.0 269.2 272.5 Non-interest income 65.5 44.0 39.7 54.7 34.9 Non-interest expense 337.2 304.1 328.6 342.8 195.0 Income (loss) before provision (benefit) for income taxes 127.1 184.0 179.1 (18.9) 112.4 Provision (benefit) for income taxes 33.5 48.1 45.7 (4.9) 29.5 Net income (loss) $93.5 $135.8 $133.4 ($14.0) $83.0 Earnings (loss) per share, diluted (1) $0.45 $0.65 $0.64 ($0.09) $0.64 Non-interest expense, excluding merger-related expense (2) $330.0 $285.2 $299.0 $226.9 $183.3 Pre-provision net revenue (2) $182.0 $220.7 $195.1 $86.6 $145.4 Operating pre-provision net revenue (2) $179.2 $258.7 $243.1 $195.7 $167.1 Operating net income (2) $91.5 $164.3 $169.4 $71.5 $99.2 Operating earnings per share, diluted (1), (2) $0.44 $0.79 $0.81 $0.46 $0.76 6 Q4 2023 Highlights (compared to Q3 2023) ■ Net interest income decreased by $27 million as higher deposit costs more than offset lower wholesale borrowing costs. ■ Non-interest income increased by $22 million due primarily to a favorable change in cumulative non-merger fair value accounting and hedges. ■ Non-interest expense increased by $33 million due to a $33 million ($0.12 per share) FDIC special assessment and other elevated expense items, which offset a $12 million decline in merger-related expense to $7 million in Q4 2023. ■ Provision expense relates to changes in the economic forecasts used in credit models and credit migration trends. ■ Q1 2023 results include only one month of the combined company’s operations and a related initial provision of $88 million.
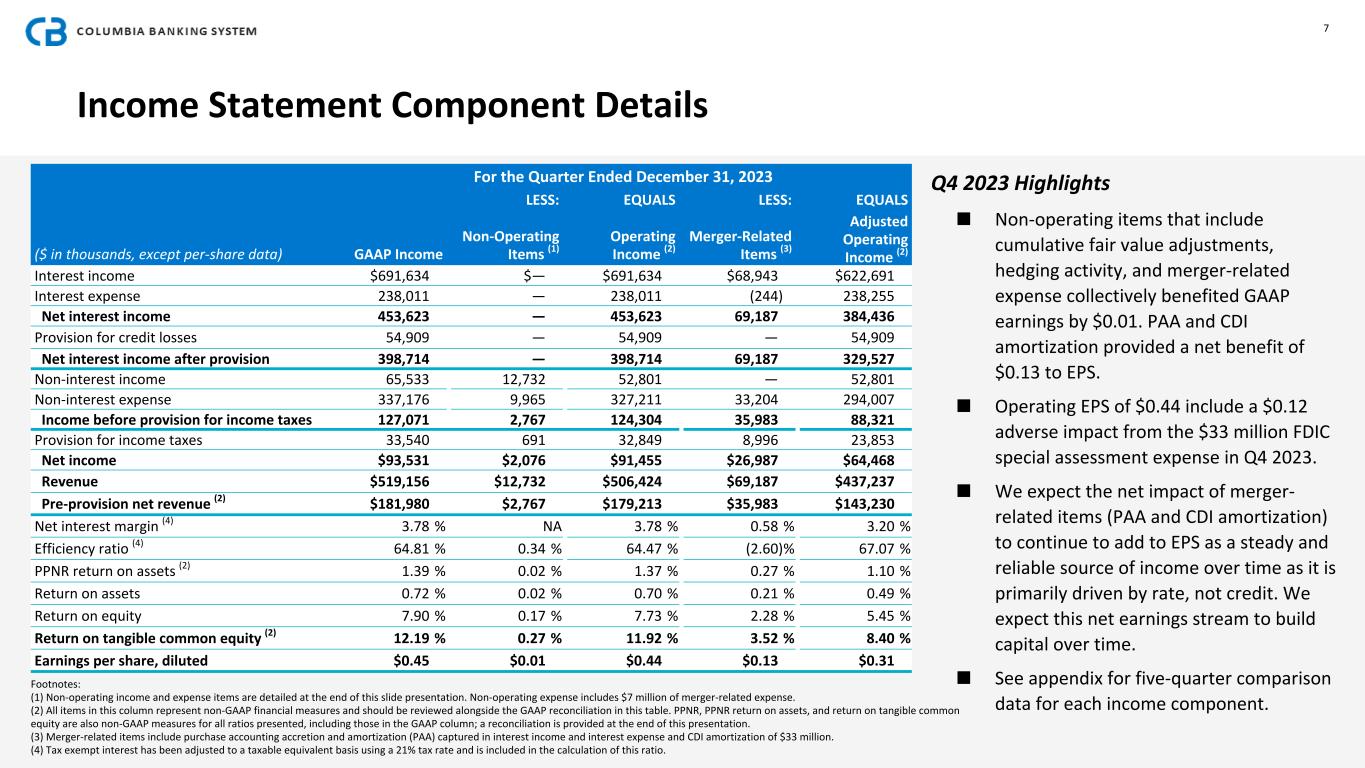
Income Statement Component Details For the Quarter Ended December 31, 2023 LESS: EQUALS LESS: EQUALS ($ in thousands, except per-share data) GAAP Income Non-Operating Items (1) Operating Income (2) Merger-Related Items (3) Adjusted Operating Income (2) Interest income $691,634 $— $691,634 $68,943 $622,691 Interest expense 238,011 — 238,011 (244) 238,255 Net interest income 453,623 — 453,623 69,187 384,436 Provision for credit losses 54,909 — 54,909 — 54,909 Net interest income after provision 398,714 — 398,714 69,187 329,527 Non-interest income 65,533 12,732 52,801 — 52,801 Non-interest expense 337,176 9,965 327,211 33,204 294,007 Income before provision for income taxes 127,071 2,767 124,304 35,983 88,321 Provision for income taxes 33,540 691 32,849 8,996 23,853 Net income $93,531 $2,076 $91,455 $26,987 $64,468 Revenue $519,156 $12,732 $506,424 $69,187 $437,237 Pre-provision net revenue (2) $181,980 $2,767 $179,213 $35,983 $143,230 Net interest margin (4) 3.78 % NA 3.78 % 0.58 % 3.20 % Efficiency ratio (4) 64.81 % 0.34 % 64.47 % (2.60) % 67.07 % PPNR return on assets (2) 1.39 % 0.02 % 1.37 % 0.27 % 1.10 % Return on assets 0.72 % 0.02 % 0.70 % 0.21 % 0.49 % Return on equity 7.90 % 0.17 % 7.73 % 2.28 % 5.45 % Return on tangible common equity (2) 12.19 % 0.27 % 11.92 % 3.52 % 8.40 % Earnings per share, diluted $0.45 $0.01 $0.44 $0.13 $0.31 7 Q4 2023 Highlights ■ Non-operating items that include cumulative fair value adjustments, hedging activity, and merger-related expense collectively benefited GAAP earnings by $0.01. PAA and CDI amortization provided a net benefit of $0.13 to EPS. ■ Operating EPS of $0.44 include a $0.12 adverse impact from the $33 million FDIC special assessment expense in Q4 2023. ■ We expect the net impact of merger- related items (PAA and CDI amortization) to continue to add to EPS as a steady and reliable source of income over time as it is primarily driven by rate, not credit. We expect this net earnings stream to build capital over time. ■ See appendix for five-quarter comparison data for each income component. Footnotes: (1) Non-operating income and expense items are detailed at the end of this slide presentation. Non-operating expense includes $7 million of merger-related expense. (2) All items in this column represent non-GAAP financial measures and should be reviewed alongside the GAAP reconciliation in this table. PPNR, PPNR return on assets, and return on tangible common equity are also non-GAAP measures for all ratios presented, including those in the GAAP column; a reconciliation is provided at the end of this presentation. (3) Merger-related items include purchase accounting accretion and amortization (PAA) captured in interest income and interest expense and CDI amortization of $33 million. (4) Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate and is included in the calculation of this ratio.
INCOME STATEMENT HIGHLIGHTS Q4 2023
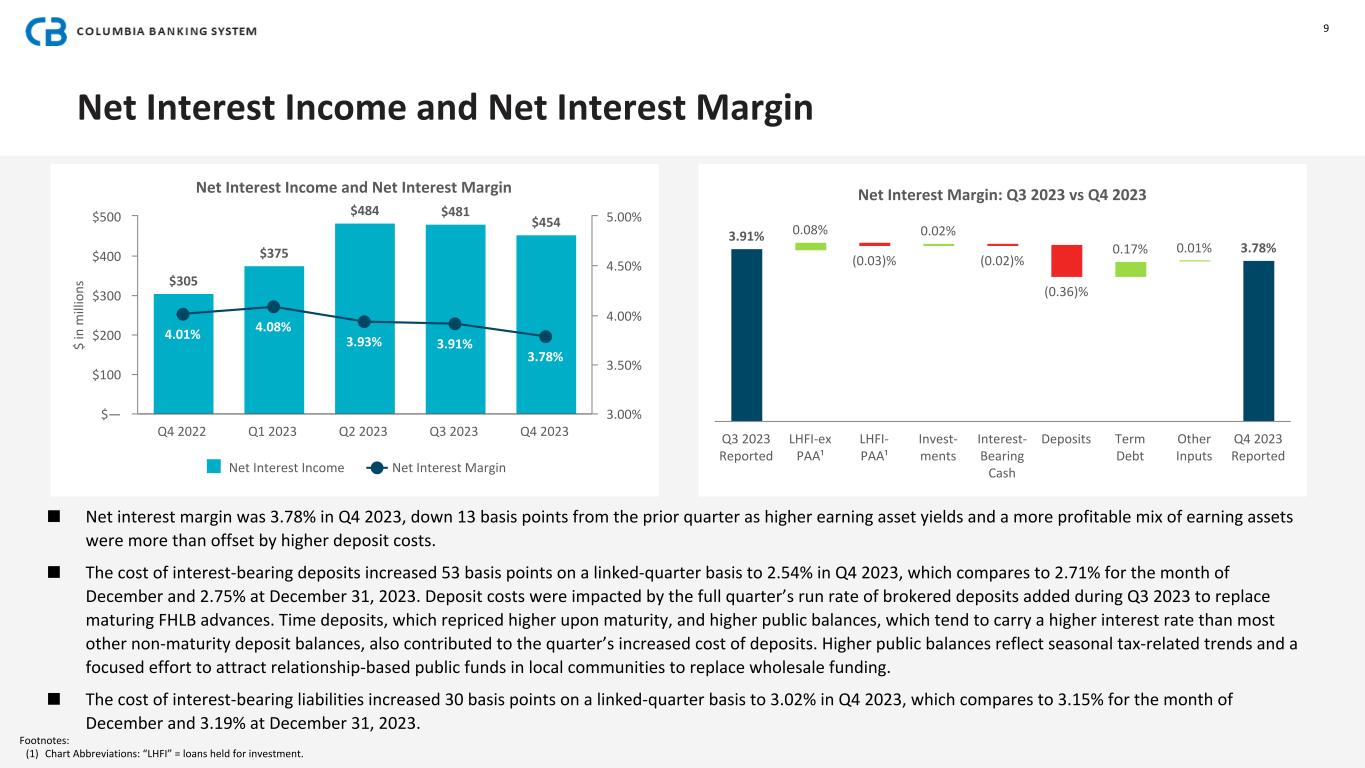
Net Interest Income and Net Interest Margin Footnotes: (1) Chart Abbreviations: “LHFI” = loans held for investment. $ in m ill io ns Net Interest Income and Net Interest Margin $305 $375 $484 $481 $454 4.01% 4.08% 3.93% 3.91% 3.78% Net Interest Income Net Interest Margin Q4 2022 Q1 2023 Q2 2023 Q3 2023 Q4 2023 $— $100 $200 $300 $400 $500 3.00% 3.50% 4.00% 4.50% 5.00% Net Interest Margin: Q3 2023 vs Q4 2023 3.91% 0.08% (0.03)% 0.02% (0.02)% (0.36)% 0.17% 0.01% 3.78% Q3 2023 Reported LHFI-ex PAA¹ LHFI- PAA¹ Invest- ments Interest- Bearing Cash Deposits Term Debt Other Inputs Q4 2023 Reported 9 ■ Net interest margin was 3.78% in Q4 2023, down 13 basis points from the prior quarter as higher earning asset yields and a more profitable mix of earning assets were more than offset by higher deposit costs. ■ The cost of interest-bearing deposits increased 53 basis points on a linked-quarter basis to 2.54% in Q4 2023, which compares to 2.71% for the month of December and 2.75% at December 31, 2023. Deposit costs were impacted by the full quarter’s run rate of brokered deposits added during Q3 2023 to replace maturing FHLB advances. Time deposits, which repriced higher upon maturity, and higher public balances, which tend to carry a higher interest rate than most other non-maturity deposit balances, also contributed to the quarter’s increased cost of deposits. Higher public balances reflect seasonal tax-related trends and a focused effort to attract relationship-based public funds in local communities to replace wholesale funding. ■ The cost of interest-bearing liabilities increased 30 basis points on a linked-quarter basis to 3.02% in Q4 2023, which compares to 3.15% for the month of December and 3.19% at December 31, 2023.
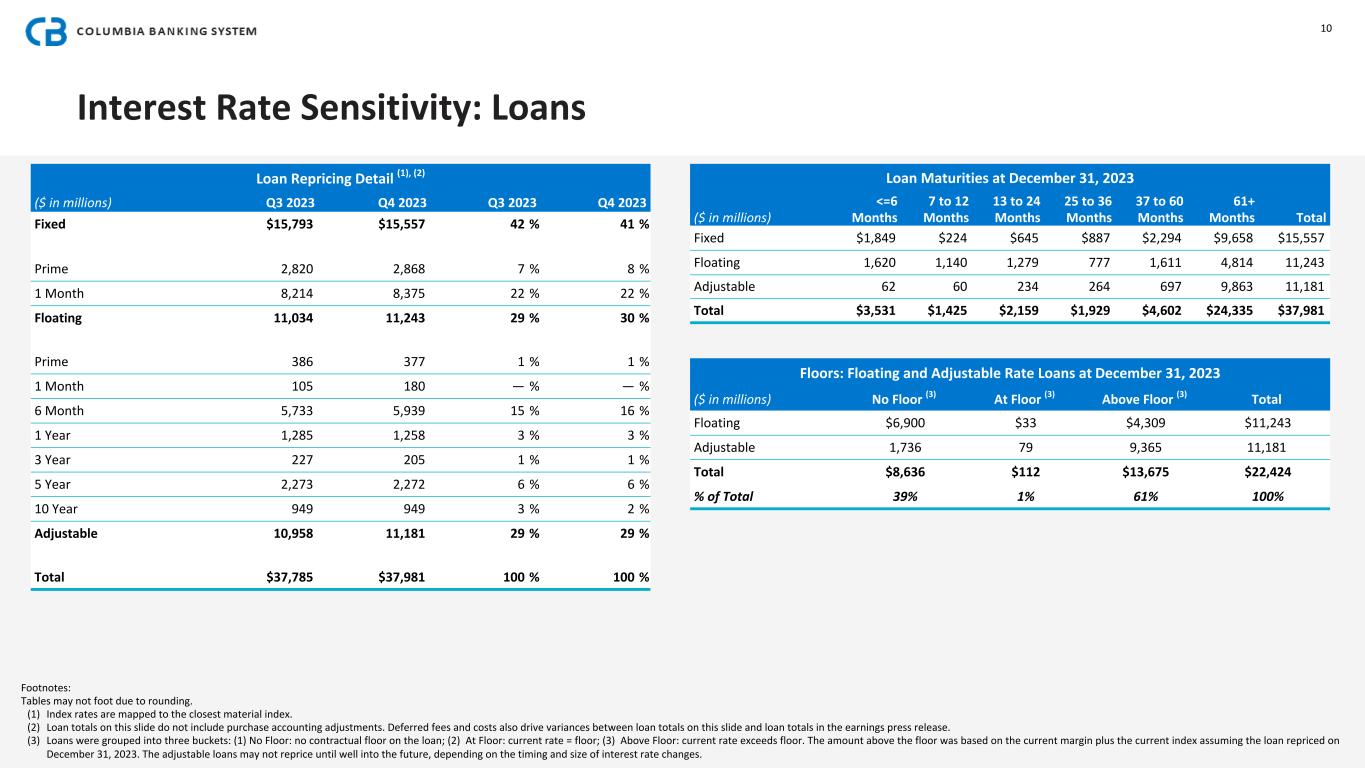
Loan Repricing Detail (1), (2) ($ in millions) Q3 2023 Q4 2023 Q3 2023 Q4 2023 Fixed $15,793 $15,557 42 % 41 % Prime 2,820 2,868 7 % 8 % 1 Month 8,214 8,375 22 % 22 % Floating 11,034 11,243 29 % 30 % Prime 386 377 1 % 1 % 1 Month 105 180 — % — % 6 Month 5,733 5,939 15 % 16 % 1 Year 1,285 1,258 3 % 3 % 3 Year 227 205 1 % 1 % 5 Year 2,273 2,272 6 % 6 % 10 Year 949 949 3 % 2 % Adjustable 10,958 11,181 29 % 29 % Total $37,785 $37,981 100 % 100 % Loan Maturities at December 31, 2023 <=6 7 to 12 13 to 24 25 to 36 37 to 60 61+ ($ in millions) Months Months Months Months Months Months Total Fixed $1,849 $224 $645 $887 $2,294 $9,658 $15,557 Floating 1,620 1,140 1,279 777 1,611 4,814 11,243 Adjustable 62 60 234 264 697 9,863 11,181 Total $3,531 $1,425 $2,159 $1,929 $4,602 $24,335 $37,981 Interest Rate Sensitivity: Loans Floors: Floating and Adjustable Rate Loans at December 31, 2023 ($ in millions) No Floor (3) At Floor (3) Above Floor (3) Total Floating $6,900 $33 $4,309 $11,243 Adjustable 1,736 79 9,365 11,181 Total $8,636 $112 $13,675 $22,424 % of Total 39% 1% 61% 100% 10 Footnotes: Tables may not foot due to rounding. (1) Index rates are mapped to the closest material index. (2) Loan totals on this slide do not include purchase accounting adjustments. Deferred fees and costs also drive variances between loan totals on this slide and loan totals in the earnings press release. (3) Loans were grouped into three buckets: (1) No Floor: no contractual floor on the loan; (2) At Floor: current rate = floor; (3) Above Floor: current rate exceeds floor. The amount above the floor was based on the current margin plus the current index assuming the loan repriced on December 31, 2023. The adjustable loans may not reprice until well into the future, depending on the timing and size of interest rate changes.
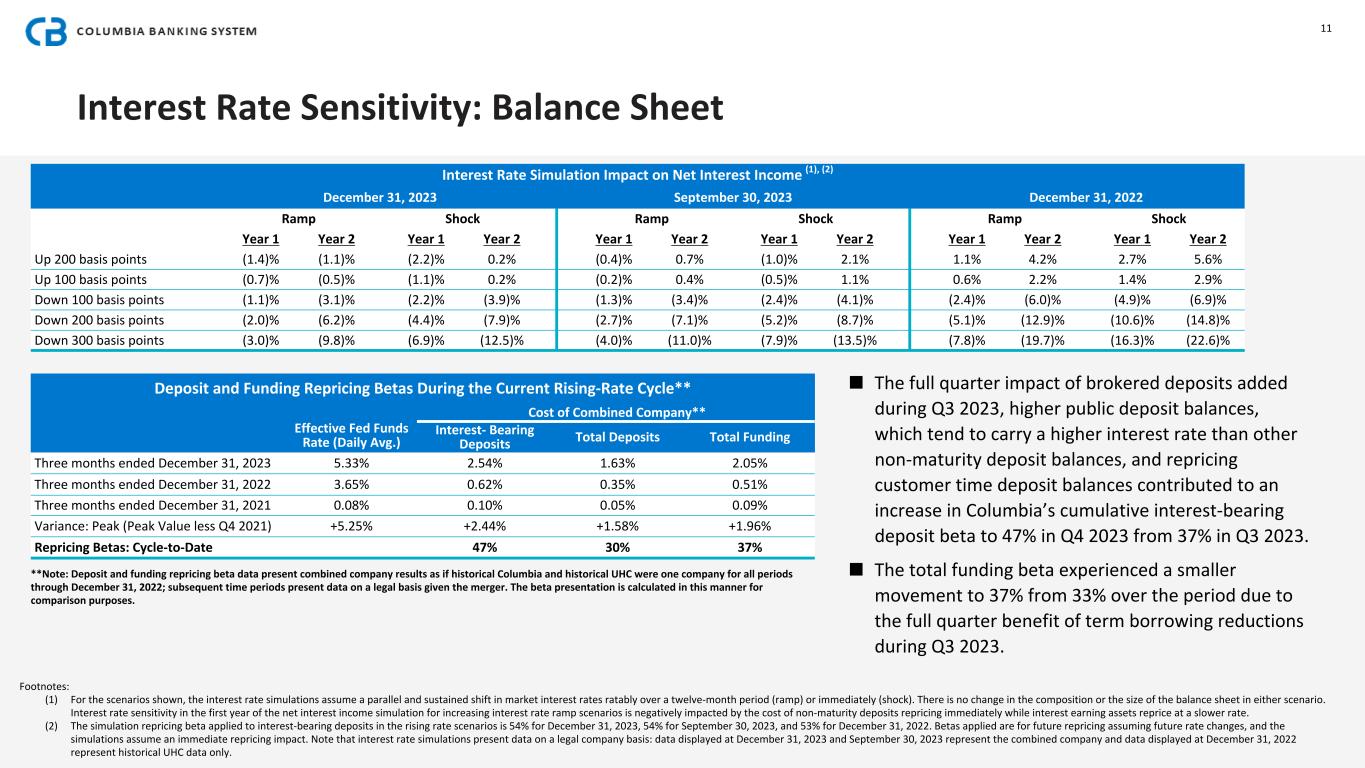
Interest Rate Sensitivity: Balance Sheet Interest Rate Simulation Impact on Net Interest Income (1), (2) December 31, 2023 September 30, 2023 December 31, 2022 Ramp Shock Ramp Shock Ramp Shock Year 1 Year 2 Year 1 Year 2 Year 1 Year 2 Year 1 Year 2 Year 1 Year 2 Year 1 Year 2 Up 200 basis points (1.4)% (1.1)% (2.2)% 0.2% (0.4)% 0.7% (1.0)% 2.1% 1.1% 4.2% 2.7% 5.6% Up 100 basis points (0.7)% (0.5)% (1.1)% 0.2% (0.2)% 0.4% (0.5)% 1.1% 0.6% 2.2% 1.4% 2.9% Down 100 basis points (1.1)% (3.1)% (2.2)% (3.9)% (1.3)% (3.4)% (2.4)% (4.1)% (2.4)% (6.0)% (4.9)% (6.9)% Down 200 basis points (2.0)% (6.2)% (4.4)% (7.9)% (2.7)% (7.1)% (5.2)% (8.7)% (5.1)% (12.9)% (10.6)% (14.8)% Down 300 basis points (3.0)% (9.8)% (6.9)% (12.5)% (4.0)% (11.0)% (7.9)% (13.5)% (7.8)% (19.7)% (16.3)% (22.6)% Footnotes: (1) For the scenarios shown, the interest rate simulations assume a parallel and sustained shift in market interest rates ratably over a twelve-month period (ramp) or immediately (shock). There is no change in the composition or the size of the balance sheet in either scenario. Interest rate sensitivity in the first year of the net interest income simulation for increasing interest rate ramp scenarios is negatively impacted by the cost of non-maturity deposits repricing immediately while interest earning assets reprice at a slower rate. (2) The simulation repricing beta applied to interest-bearing deposits in the rising rate scenarios is 54% for December 31, 2023, 54% for September 30, 2023, and 53% for December 31, 2022. Betas applied are for future repricing assuming future rate changes, and the simulations assume an immediate repricing impact. Note that interest rate simulations present data on a legal company basis: data displayed at December 31, 2023 and September 30, 2023 represent the combined company and data displayed at December 31, 2022 represent historical UHC data only. ■ The full quarter impact of brokered deposits added during Q3 2023, higher public deposit balances, which tend to carry a higher interest rate than other non-maturity deposit balances, and repricing customer time deposit balances contributed to an increase in Columbia’s cumulative interest-bearing deposit beta to 47% in Q4 2023 from 37% in Q3 2023. ■ The total funding beta experienced a smaller movement to 37% from 33% over the period due to the full quarter benefit of term borrowing reductions during Q3 2023. 11 Deposit and Funding Repricing Betas During the Current Rising-Rate Cycle** Effective Fed Funds Rate (Daily Avg.) Cost of Combined Company** Interest- Bearing Deposits Total Deposits Total Funding Three months ended December 31, 2023 5.33% 2.54% 1.63% 2.05% Three months ended December 31, 2022 3.65% 0.62% 0.35% 0.51% Three months ended December 31, 2021 0.08% 0.10% 0.05% 0.09% Variance: Peak (Peak Value less Q4 2021) +5.25% +2.44% +1.58% +1.96% Repricing Betas: Cycle-to-Date 47% 30% 37% **Note: Deposit and funding repricing beta data present combined company results as if historical Columbia and historical UHC were one company for all periods through December 31, 2022; subsequent time periods present data on a legal basis given the merger. The beta presentation is calculated in this manner for comparison purposes.
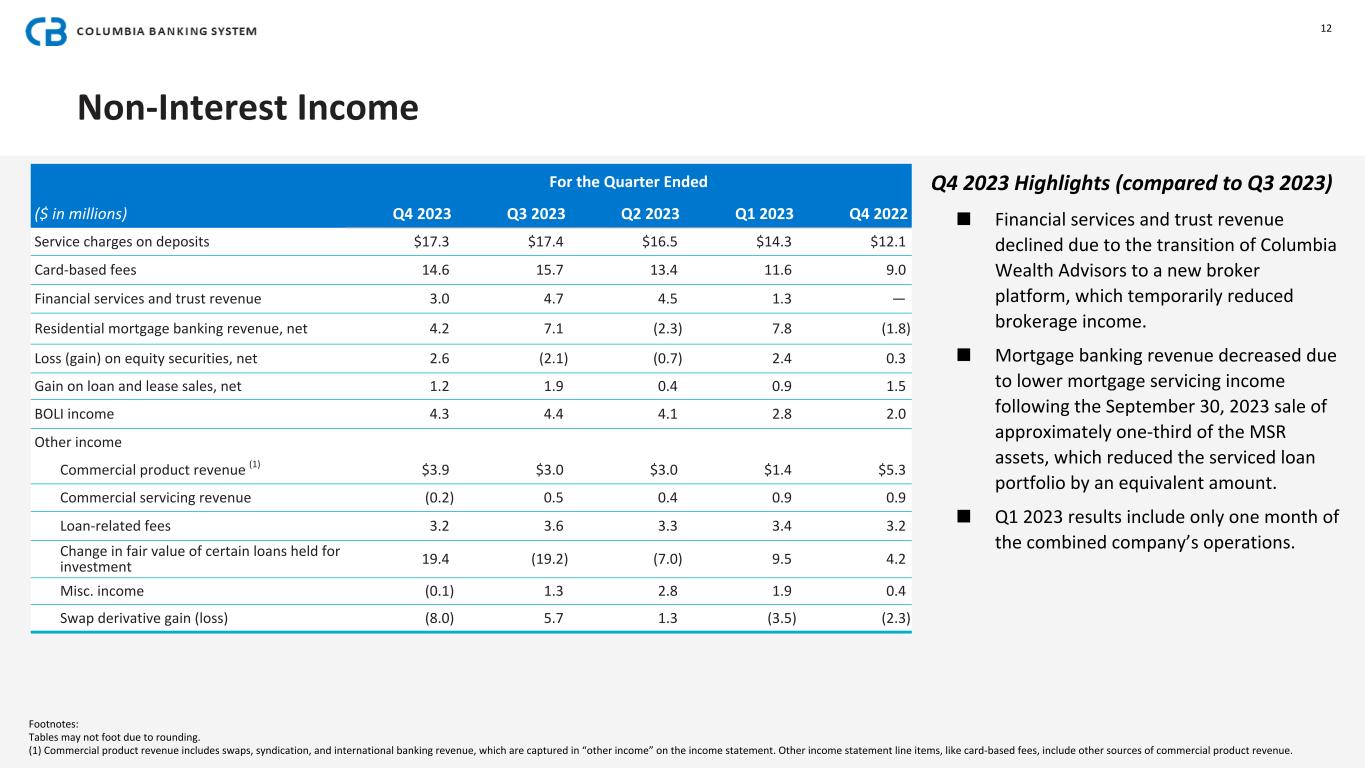
Non-Interest Income Footnotes: Tables may not foot due to rounding. (1) Commercial product revenue includes swaps, syndication, and international banking revenue, which are captured in “other income” on the income statement. Other income statement line items, like card-based fees, include other sources of commercial product revenue. For the Quarter Ended ($ in millions) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 Service charges on deposits $17.3 $17.4 $16.5 $14.3 $12.1 Card-based fees 14.6 15.7 13.4 11.6 9.0 Financial services and trust revenue 3.0 4.7 4.5 1.3 — Residential mortgage banking revenue, net 4.2 7.1 (2.3) 7.8 (1.8) Loss (gain) on equity securities, net 2.6 (2.1) (0.7) 2.4 0.3 Gain on loan and lease sales, net 1.2 1.9 0.4 0.9 1.5 BOLI income 4.3 4.4 4.1 2.8 2.0 Other income Commercial product revenue (1) $3.9 $3.0 $3.0 $1.4 $5.3 Commercial servicing revenue (0.2) 0.5 0.4 0.9 0.9 Loan-related fees 3.2 3.6 3.3 3.4 3.2 Change in fair value of certain loans held for investment 19.4 (19.2) (7.0) 9.5 4.2 Misc. income (0.1) 1.3 2.8 1.9 0.4 Swap derivative gain (loss) (8.0) 5.7 1.3 (3.5) (2.3) 12 Q4 2023 Highlights (compared to Q3 2023) ■ Financial services and trust revenue declined due to the transition of Columbia Wealth Advisors to a new broker platform, which temporarily reduced brokerage income. ■ Mortgage banking revenue decreased due to lower mortgage servicing income following the September 30, 2023 sale of approximately one-third of the MSR assets, which reduced the serviced loan portfolio by an equivalent amount. ■ Q1 2023 results include only one month of the combined company’s operations.
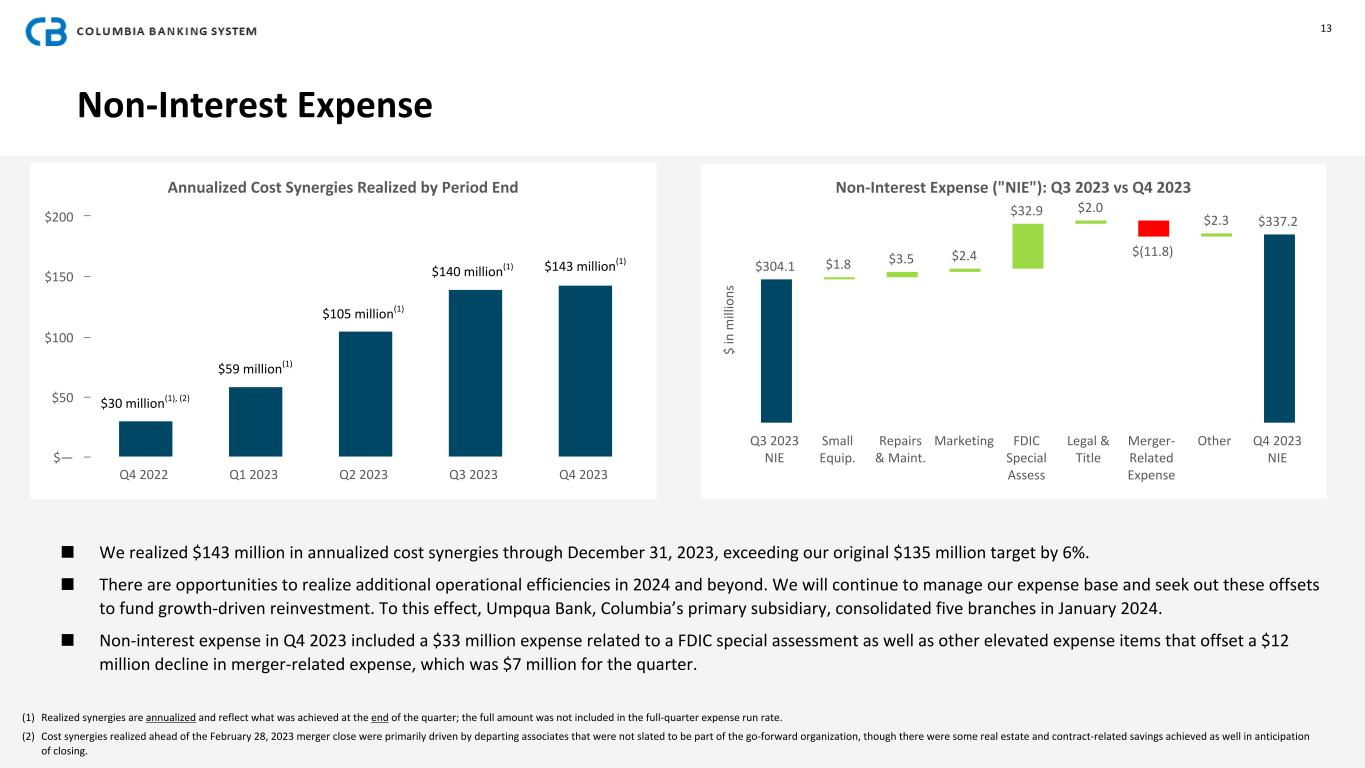
Non-Interest Expense 13 Annualized Cost Synergies Realized by Period End Q4 2022 Q1 2023 Q2 2023 Q3 2023 Q4 2023 $— $50 $100 $150 $200 $30 million(1), (2) $59 million(1) $105 million(1) $140 million(1) ■ We realized $143 million in annualized cost synergies through December 31, 2023, exceeding our original $135 million target by 6%. ■ There are opportunities to realize additional operational efficiencies in 2024 and beyond. We will continue to manage our expense base and seek out these offsets to fund growth-driven reinvestment. To this effect, Umpqua Bank, Columbia’s primary subsidiary, consolidated five branches in January 2024. ■ Non-interest expense in Q4 2023 included a $33 million expense related to a FDIC special assessment as well as other elevated expense items that offset a $12 million decline in merger-related expense, which was $7 million for the quarter. (1) Realized synergies are annualized and reflect what was achieved at the end of the quarter; the full amount was not included in the full-quarter expense run rate. (2) Cost synergies realized ahead of the February 28, 2023 merger close were primarily driven by departing associates that were not slated to be part of the go-forward organization, though there were some real estate and contract-related savings achieved as well in anticipation of closing. $143 million(1) $ in m ill io ns Non-Interest Expense ("NIE"): Q3 2023 vs Q4 2023 $304.1 $1.8 $3.5 $2.4 $32.9 $2.0 $(11.8) $2.3 $337.2 Q3 2023 NIE Small Equip. Repairs & Maint. Marketing FDIC Special Assess Legal & Title Merger- Related Expense Other Q4 2023 NIE
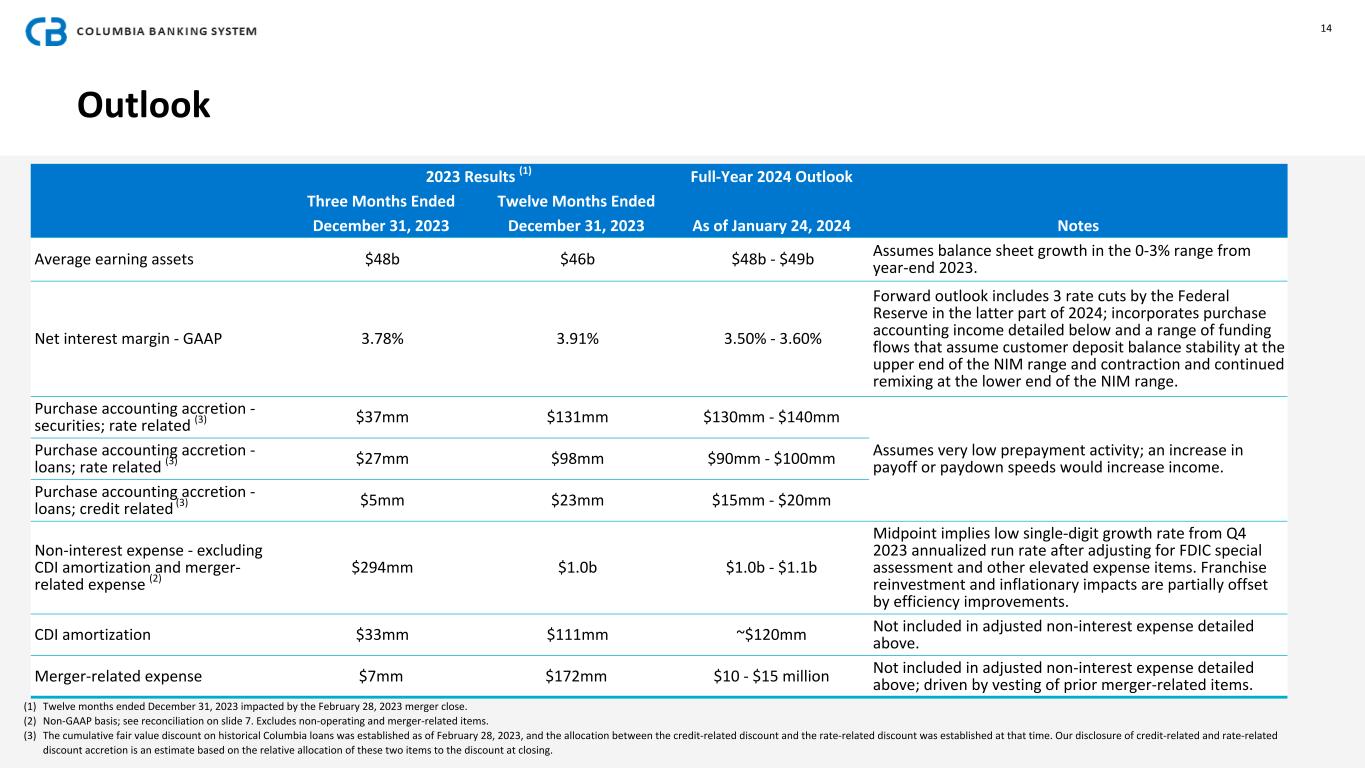
Outlook (1) Twelve months ended December 31, 2023 impacted by the February 28, 2023 merger close. (2) Non-GAAP basis; see reconciliation on slide 7. Excludes non-operating and merger-related items. (3) The cumulative fair value discount on historical Columbia loans was established as of February 28, 2023, and the allocation between the credit-related discount and the rate-related discount was established at that time. Our disclosure of credit-related and rate-related discount accretion is an estimate based on the relative allocation of these two items to the discount at closing. 2023 Results (1) Full-Year 2024 Outlook Three Months Ended Twelve Months Ended December 31, 2023 December 31, 2023 As of January 24, 2024 Notes Average earning assets $48b $46b $48b - $49b Assumes balance sheet growth in the 0-3% range from year-end 2023. Net interest margin - GAAP 3.78% 3.91% 3.50% - 3.60% Forward outlook includes 3 rate cuts by the Federal Reserve in the latter part of 2024; incorporates purchase accounting income detailed below and a range of funding flows that assume customer deposit balance stability at the upper end of the NIM range and contraction and continued remixing at the lower end of the NIM range. Purchase accounting accretion - securities; rate related (3) $37mm $131mm $130mm - $140mm Assumes very low prepayment activity; an increase in payoff or paydown speeds would increase income. Purchase accounting accretion - loans; rate related (3) $27mm $98mm $90mm - $100mm Purchase accounting accretion - loans; credit related (3) $5mm $23mm $15mm - $20mm Non-interest expense - excluding CDI amortization and merger- related expense (2) $294mm $1.0b $1.0b - $1.1b Midpoint implies low single-digit growth rate from Q4 2023 annualized run rate after adjusting for FDIC special assessment and other elevated expense items. Franchise reinvestment and inflationary impacts are partially offset by efficiency improvements. CDI amortization $33mm $111mm ~$120mm Not included in adjusted non-interest expense detailed above. Merger-related expense $7mm $172mm $10 - $15 million Not included in adjusted non-interest expense detailed above; driven by vesting of prior merger-related items. 14
BALANCE SHEET HIGHLIGHTS Q4 2023
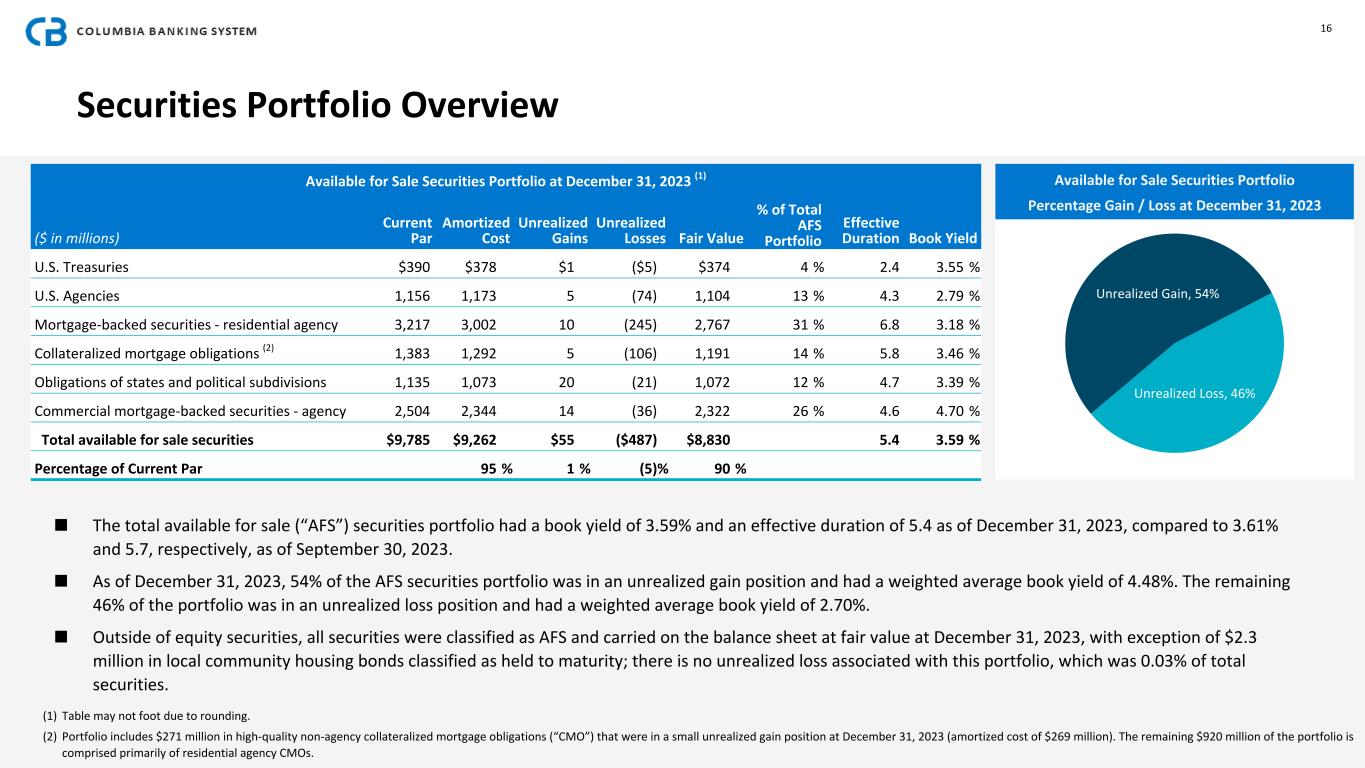
Available for Sale Securities Portfolio at December 31, 2023 (1) ($ in millions) Current Par Amortized Cost Unrealized Gains Unrealized Losses Fair Value % of Total AFS Portfolio Effective Duration Book Yield U.S. Treasuries $390 $378 $1 ($5) $374 4 % 2.4 3.55 % U.S. Agencies 1,156 1,173 5 (74) 1,104 13 % 4.3 2.79 % Mortgage-backed securities - residential agency 3,217 3,002 10 (245) 2,767 31 % 6.8 3.18 % Collateralized mortgage obligations (2) 1,383 1,292 5 (106) 1,191 14 % 5.8 3.46 % Obligations of states and political subdivisions 1,135 1,073 20 (21) 1,072 12 % 4.7 3.39 % Commercial mortgage-backed securities - agency 2,504 2,344 14 (36) 2,322 26 % 4.6 4.70 % Total available for sale securities $9,785 $9,262 $55 ($487) $8,830 5.4 3.59 % Percentage of Current Par 95 % 1 % (5) % 90 % 16 Securities Portfolio Overview (1) Table may not foot due to rounding. (2) Portfolio includes $271 million in high-quality non-agency collateralized mortgage obligations (“CMO”) that were in a small unrealized gain position at December 31, 2023 (amortized cost of $269 million). The remaining $920 million of the portfolio is comprised primarily of residential agency CMOs. ■ The total available for sale (“AFS”) securities portfolio had a book yield of 3.59% and an effective duration of 5.4 as of December 31, 2023, compared to 3.61% and 5.7, respectively, as of September 30, 2023. ■ As of December 31, 2023, 54% of the AFS securities portfolio was in an unrealized gain position and had a weighted average book yield of 4.48%. The remaining 46% of the portfolio was in an unrealized loss position and had a weighted average book yield of 2.70%. ■ Outside of equity securities, all securities were classified as AFS and carried on the balance sheet at fair value at December 31, 2023, with exception of $2.3 million in local community housing bonds classified as held to maturity; there is no unrealized loss associated with this portfolio, which was 0.03% of total securities. Unrealized Gain, 54% Unrealized Loss, 46% Available for Sale Securities Portfolio Percentage Gain / Loss at December 31, 2023
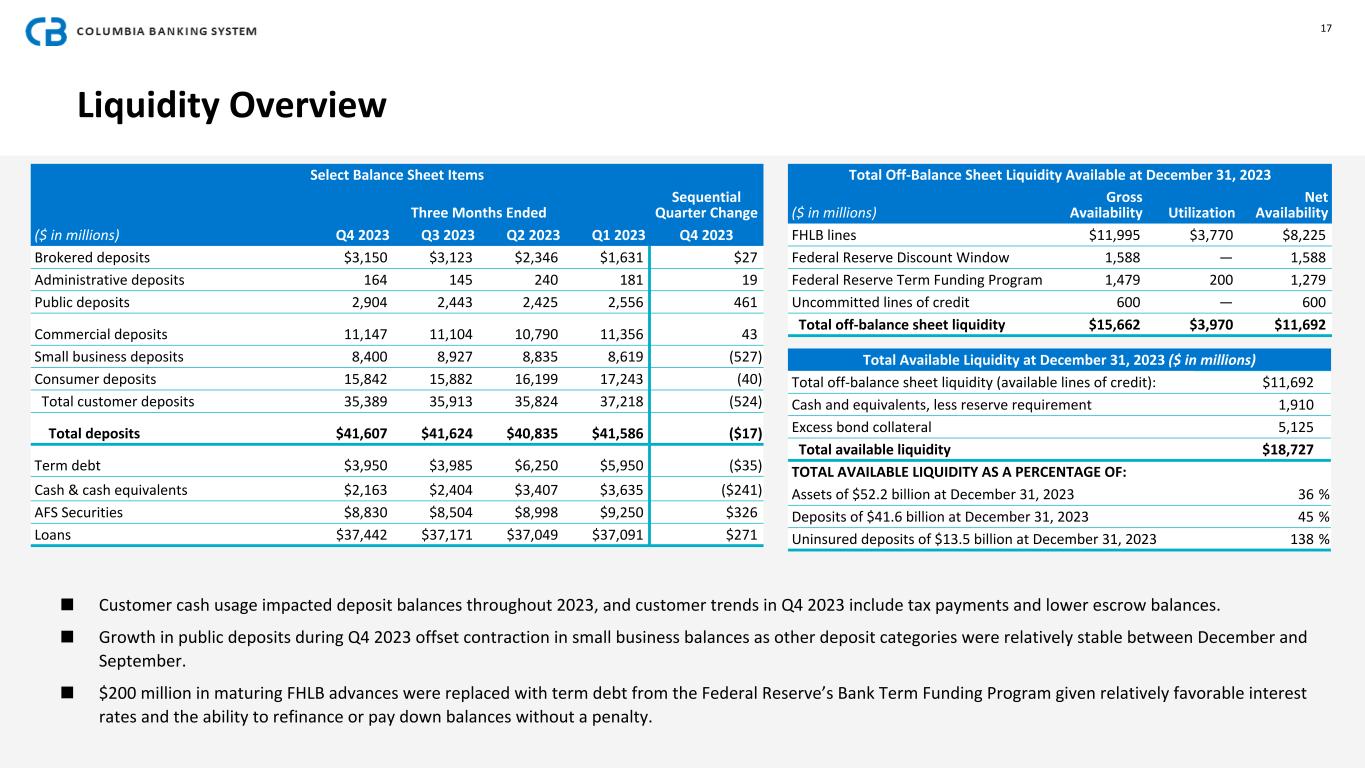
Liquidity Overview Total Available Liquidity at December 31, 2023 ($ in millions) Total off-balance sheet liquidity (available lines of credit): $11,692 Cash and equivalents, less reserve requirement 1,910 Excess bond collateral 5,125 Total available liquidity $18,727 TOTAL AVAILABLE LIQUIDITY AS A PERCENTAGE OF: Assets of $52.2 billion at December 31, 2023 36 % Deposits of $41.6 billion at December 31, 2023 45 % Uninsured deposits of $13.5 billion at December 31, 2023 138 % Total Off-Balance Sheet Liquidity Available at December 31, 2023 ($ in millions) Gross Availability Utilization Net Availability FHLB lines $11,995 $3,770 $8,225 Federal Reserve Discount Window 1,588 — 1,588 Federal Reserve Term Funding Program 1,479 200 1,279 Uncommitted lines of credit 600 — 600 Total off-balance sheet liquidity $15,662 $3,970 $11,692 17 ■ Customer cash usage impacted deposit balances throughout 2023, and customer trends in Q4 2023 include tax payments and lower escrow balances. ■ Growth in public deposits during Q4 2023 offset contraction in small business balances as other deposit categories were relatively stable between December and September. ■ $200 million in maturing FHLB advances were replaced with term debt from the Federal Reserve’s Bank Term Funding Program given relatively favorable interest rates and the ability to refinance or pay down balances without a penalty. Select Balance Sheet Items Three Months Ended Sequential Quarter Change ($ in millions) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2023 Brokered deposits $3,150 $3,123 $2,346 $1,631 $27 Administrative deposits 164 145 240 181 19 Public deposits 2,904 2,443 2,425 2,556 461 Commercial deposits 11,147 11,104 10,790 11,356 43 Small business deposits 8,400 8,927 8,835 8,619 (527) Consumer deposits 15,842 15,882 16,199 17,243 (40) Total customer deposits 35,389 35,913 35,824 37,218 (524) Total deposits $41,607 $41,624 $40,835 $41,586 ($17) Term debt $3,950 $3,985 $6,250 $5,950 ($35) Cash & cash equivalents $2,163 $2,404 $3,407 $3,635 ($241) AFS Securities $8,830 $8,504 $8,998 $9,250 $326 Loans $37,442 $37,171 $37,049 $37,091 $271
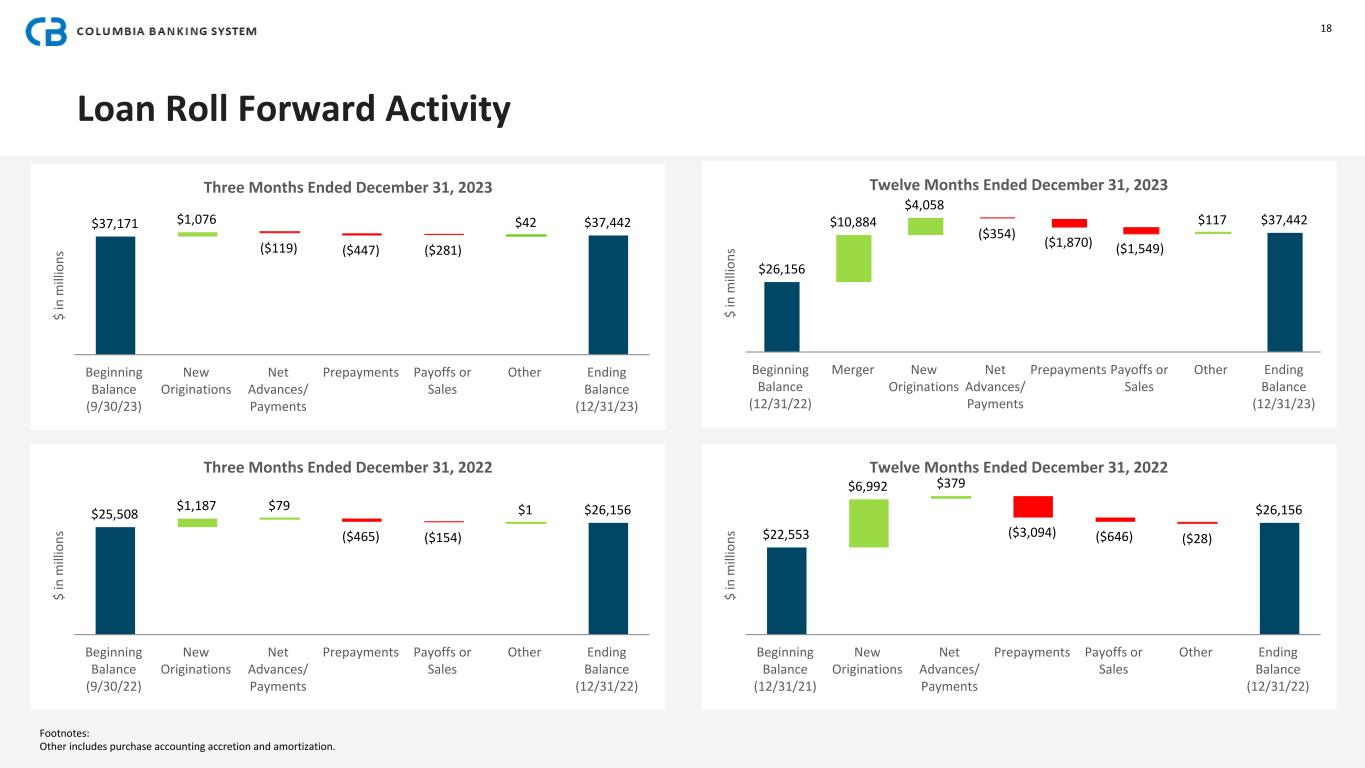
Loan Roll Forward Activity $ in m ill io ns Three Months Ended December 31, 2023 $37,171 $1,076 ($119) ($447) ($281) $42 $37,442 Beginning Balance (9/30/23) New Originations Net Advances/ Payments Prepayments Payoffs or Sales Other Ending Balance (12/31/23) 18 Footnotes: Other includes purchase accounting accretion and amortization. $ in m ill io ns Twelve Months Ended December 31, 2023 $26,156 $10,884 $4,058 ($354) ($1,870) ($1,549) $117 $37,442 Beginning Balance (12/31/22) Merger New Originations Net Advances/ Payments Prepayments Payoffs or Sales Other Ending Balance (12/31/23) $ in m ill io ns Three Months Ended December 31, 2022 $25,508 $1,187 $79 ($465) ($154) $1 $26,156 Beginning Balance (9/30/22) New Originations Net Advances/ Payments Prepayments Payoffs or Sales Other Ending Balance (12/31/22) $ in m ill io ns Twelve Months Ended December 31, 2022 $22,553 $6,992 $379 ($3,094) ($646) ($28) $26,156 Beginning Balance (12/31/21) New Originations Net Advances/ Payments Prepayments Payoffs or Sales Other Ending Balance (12/31/22)
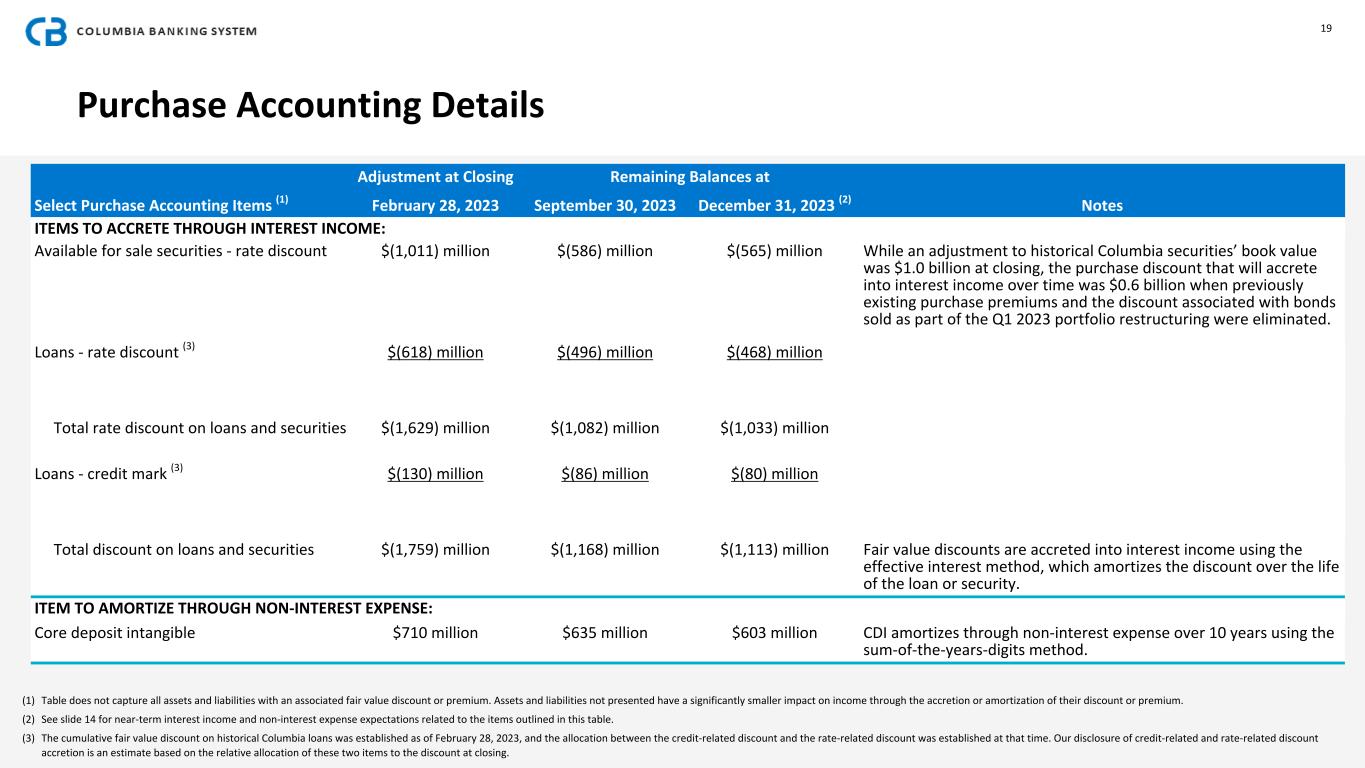
Purchase Accounting Details (1) Table does not capture all assets and liabilities with an associated fair value discount or premium. Assets and liabilities not presented have a significantly smaller impact on income through the accretion or amortization of their discount or premium. (2) See slide 14 for near-term interest income and non-interest expense expectations related to the items outlined in this table. (3) The cumulative fair value discount on historical Columbia loans was established as of February 28, 2023, and the allocation between the credit-related discount and the rate-related discount was established at that time. Our disclosure of credit-related and rate-related discount accretion is an estimate based on the relative allocation of these two items to the discount at closing. Adjustment at Closing Remaining Balances at Select Purchase Accounting Items (1) February 28, 2023 September 30, 2023 December 31, 2023 (2) Notes ITEMS TO ACCRETE THROUGH INTEREST INCOME: Available for sale securities - rate discount $(1,011) million $(586) million $(565) million While an adjustment to historical Columbia securities’ book value was $1.0 billion at closing, the purchase discount that will accrete into interest income over time was $0.6 billion when previously existing purchase premiums and the discount associated with bonds sold as part of the Q1 2023 portfolio restructuring were eliminated. Loans - rate discount (3) $(618) million $(496) million $(468) million Total rate discount on loans and securities $(1,629) million $(1,082) million $(1,033) million Loans - credit mark (3) $(130) million $(86) million $(80) million Total discount on loans and securities $(1,759) million $(1,168) million $(1,113) million Fair value discounts are accreted into interest income using the effective interest method, which amortizes the discount over the life of the loan or security. ITEM TO AMORTIZE THROUGH NON-INTEREST EXPENSE: Core deposit intangible $710 million $635 million $603 million CDI amortizes through non-interest expense over 10 years using the sum-of-the-years-digits method. 19
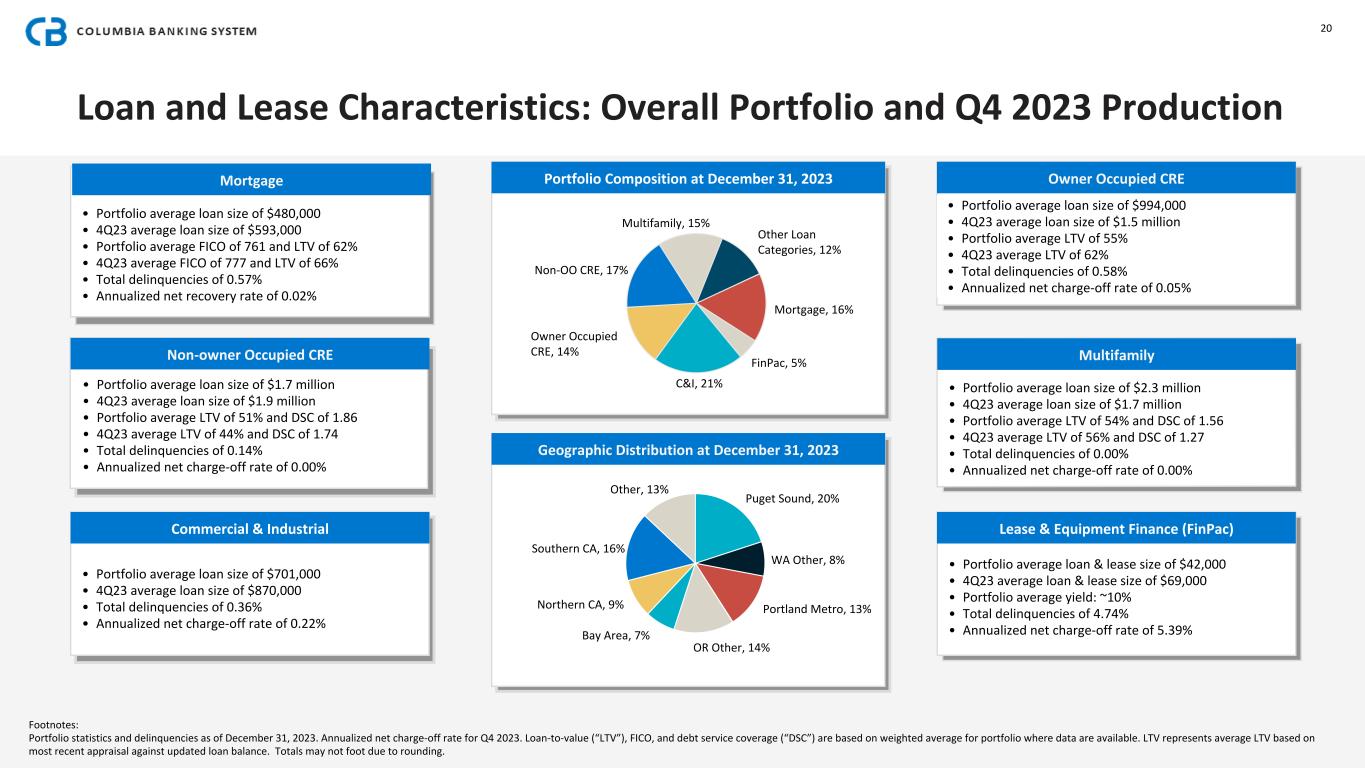
Loan and Lease Characteristics: Overall Portfolio and Q4 2023 Production Footnotes: Portfolio statistics and delinquencies as of December 31, 2023. Annualized net charge-off rate for Q4 2023. Loan-to-value (“LTV”), FICO, and debt service coverage (“DSC”) are based on weighted average for portfolio where data are available. LTV represents average LTV based on most recent appraisal against updated loan balance. Totals may not foot due to rounding. • Portfolio average loan size of $480,000 • 4Q23 average loan size of $593,000 • Portfolio average FICO of 761 and LTV of 62% • 4Q23 average FICO of 777 and LTV of 66% • Total delinquencies of 0.57% • Annualized net recovery rate of 0.02% Non-owner Occupied CRE • Portfolio average loan size of $1.7 million • 4Q23 average loan size of $1.9 million • Portfolio average LTV of 51% and DSC of 1.86 • 4Q23 average LTV of 44% and DSC of 1.74 • Total delinquencies of 0.14% • Annualized net charge-off rate of 0.00% Commercial & Industrial • Portfolio average loan size of $701,000 • 4Q23 average loan size of $870,000 • Total delinquencies of 0.36% • Annualized net charge-off rate of 0.22% Multifamily • Portfolio average loan size of $2.3 million • 4Q23 average loan size of $1.7 million • Portfolio average LTV of 54% and DSC of 1.56 • 4Q23 average LTV of 56% and DSC of 1.27 • Total delinquencies of 0.00% • Annualized net charge-off rate of 0.00% Owner Occupied CRE • Portfolio average loan size of $994,000 • 4Q23 average loan size of $1.5 million • Portfolio average LTV of 55% • 4Q23 average LTV of 62% • Total delinquencies of 0.58% • Annualized net charge-off rate of 0.05% Lease & Equipment Finance (FinPac) • Portfolio average loan & lease size of $42,000 • 4Q23 average loan & lease size of $69,000 • Portfolio average yield: ~10% • Total delinquencies of 4.74% • Annualized net charge-off rate of 5.39% Puget Sound, 20% WA Other, 8% Portland Metro, 13% OR Other, 14% Bay Area, 7% Northern CA, 9% Southern CA, 16% Other, 13% Mortgage, 16% FinPac, 5% C&I, 21% Owner Occupied CRE, 14% Non-OO CRE, 17% Multifamily, 15% Other Loan Categories, 12% Portfolio Composition at December 31, 2023 Geographic Distribution at December 31, 2023 Mortgage 20
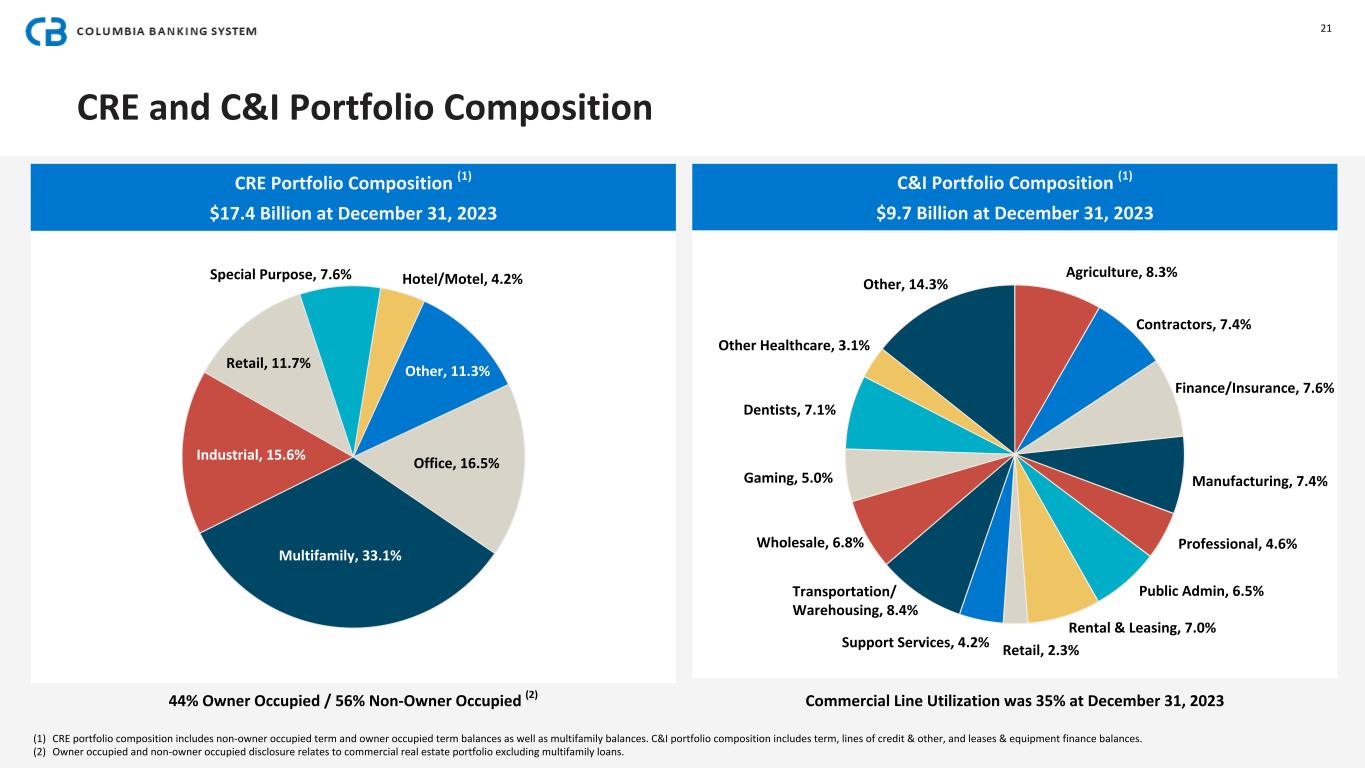
CRE and C&I Portfolio Composition Agriculture, 8.3% Contractors, 7.4% Finance/Insurance, 7.6% Manufacturing, 7.4% Professional, 4.6% Public Admin, 6.5% Rental & Leasing, 7.0% Retail, 2.3%Support Services, 4.2% Transportation/ Warehousing, 8.4% Wholesale, 6.8% Gaming, 5.0% Dentists, 7.1% Other Healthcare, 3.1% Other, 14.3% Office, 16.5% Multifamily, 33.1% Industrial, 15.6% Retail, 11.7% Special Purpose, 7.6% Hotel/Motel, 4.2% Other, 11.3% CRE Portfolio Composition (1) $17.4 Billion at December 31, 2023 C&I Portfolio Composition (1) $9.7 Billion at December 31, 2023 (1) CRE portfolio composition includes non-owner occupied term and owner occupied term balances as well as multifamily balances. C&I portfolio composition includes term, lines of credit & other, and leases & equipment finance balances. (2) Owner occupied and non-owner occupied disclosure relates to commercial real estate portfolio excluding multifamily loans. 44% Owner Occupied / 56% Non-Owner Occupied (2) Commercial Line Utilization was 35% at December 31, 2023 21
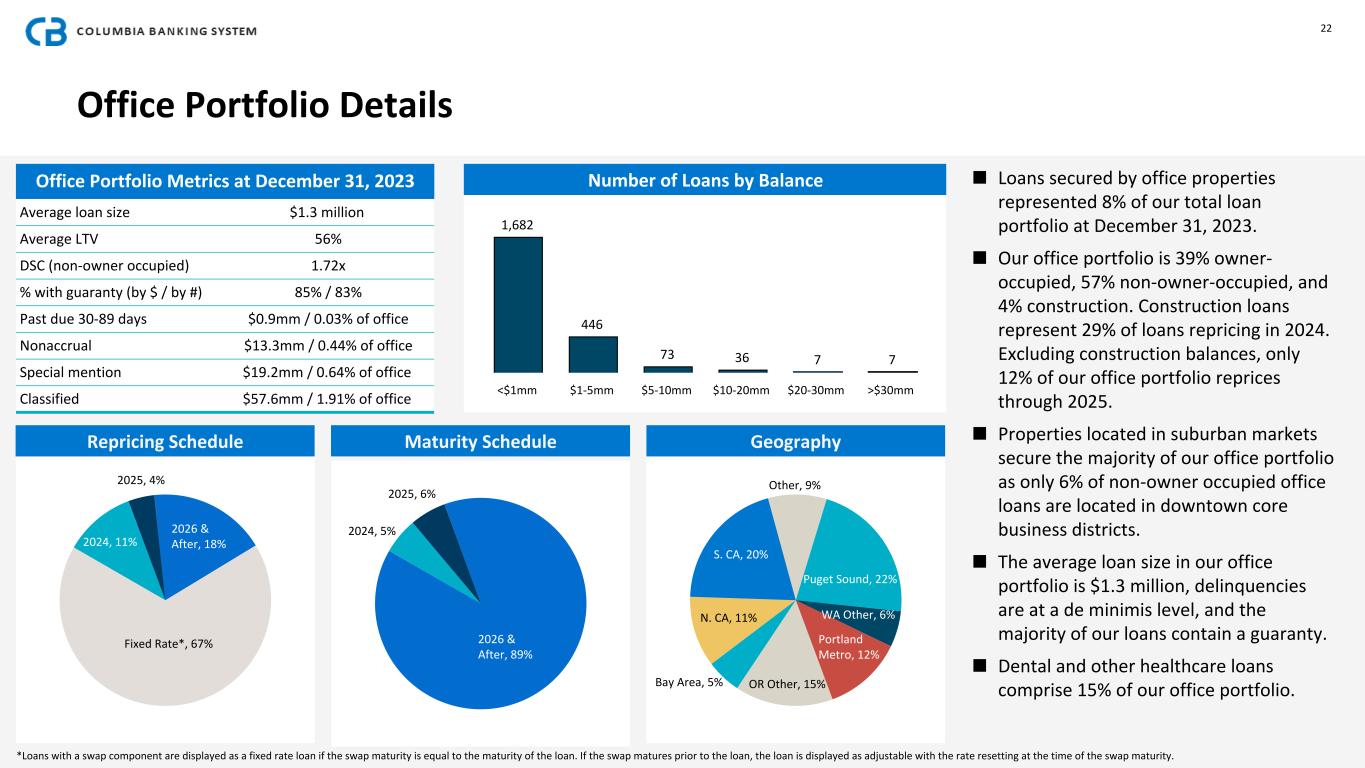
Office Portfolio Details Puget Sound, 22% WA Other, 6% Portland Metro, 12% OR Other, 15%Bay Area, 5% N. CA, 11% S. CA, 20% Other, 9% Office Portfolio Metrics at December 31, 2023 Average loan size $1.3 million Average LTV 56% DSC (non-owner occupied) 1.72x % with guaranty (by $ / by #) 85% / 83% Past due 30-89 days $0.9mm / 0.03% of office Nonaccrual $13.3mm / 0.44% of office Special mention $19.2mm / 0.64% of office Classified $57.6mm / 1.91% of office Number of Loans by Balance Geography 22 ■ Loans secured by office properties represented 8% of our total loan portfolio at December 31, 2023. ■ Our office portfolio is 39% owner- occupied, 57% non-owner-occupied, and 4% construction. Construction loans represent 29% of loans repricing in 2024. Excluding construction balances, only 12% of our office portfolio reprices through 2025. ■ Properties located in suburban markets secure the majority of our office portfolio as only 6% of non-owner occupied office loans are located in downtown core business districts. ■ The average loan size in our office portfolio is $1.3 million, delinquencies are at a de minimis level, and the majority of our loans contain a guaranty. ■ Dental and other healthcare loans comprise 15% of our office portfolio. 1,746 441 71 38 7 6 <$1mm $1-5mm $5-10mm $10-20mm $20-30mm >$30mm 2024, 11% 2025, 4% 2026 & After, 18% Fixed Rate*, 67% Repricing Schedule *Loans with a swap component are displayed as a fixed rate loan if the swap maturity is equal to the maturity of the loan. If the swap matures prior to the loan, the loan is displayed as adjustable with the rate resetting at the time of the swap maturity. 2024, 5% 2025, 6% 2026 & After, 89% Maturity Schedule , 19 8 9 6 7 1,682 6 3 6
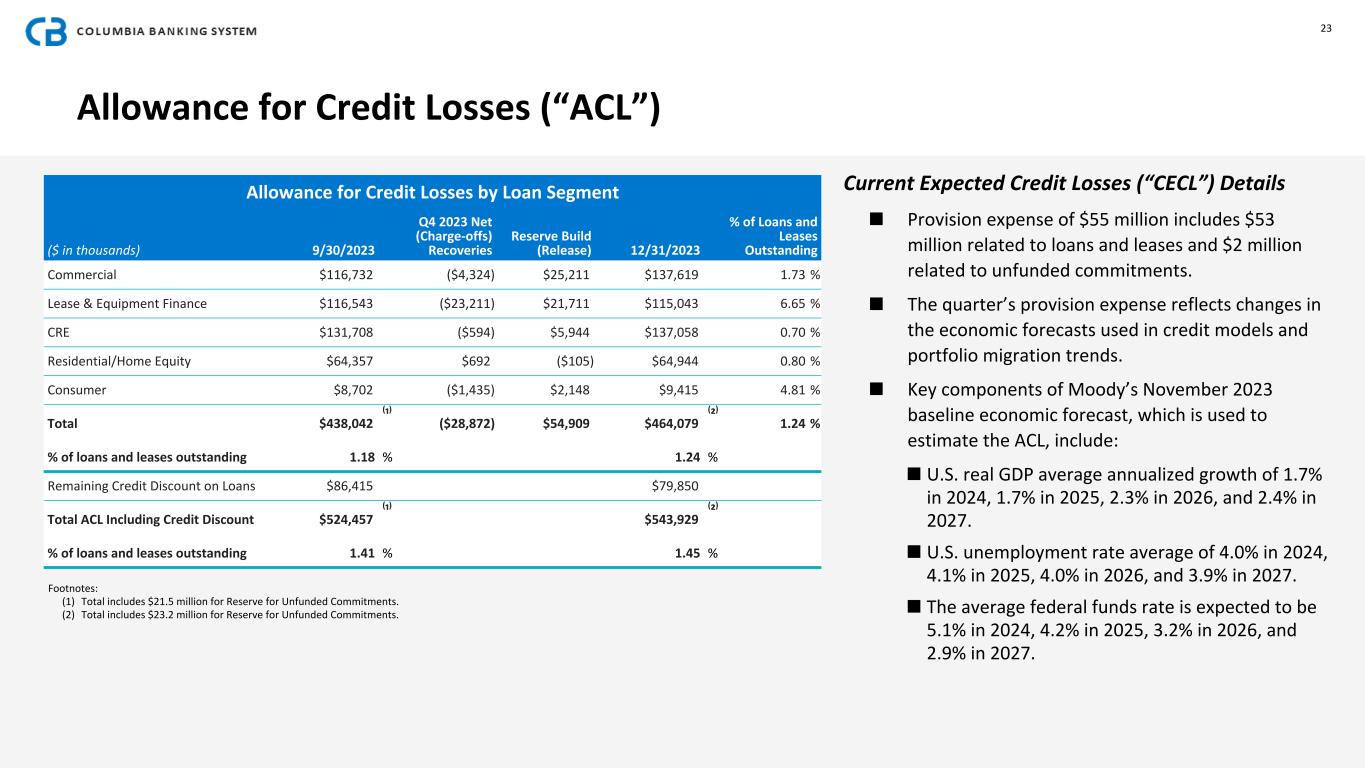
Allowance for Credit Losses (“ACL”) Footnotes: (1) Total includes $21.5 million for Reserve for Unfunded Commitments. (2) Total includes $23.2 million for Reserve for Unfunded Commitments. Allowance for Credit Losses by Loan Segment ($ in thousands) 9/30/2023 Q4 2023 Net (Charge-offs) Recoveries Reserve Build (Release) 12/31/2023 % of Loans and Leases Outstanding Commercial $116,732 ($4,324) $25,211 $137,619 1.73 % Lease & Equipment Finance $116,543 ($23,211) $21,711 $115,043 6.65 % CRE $131,708 ($594) $5,944 $137,058 0.70 % Residential/Home Equity $64,357 $692 ($105) $64,944 0.80 % Consumer $8,702 ($1,435) $2,148 $9,415 4.81 % Total $438,042 (¹) ($28,872) $54,909 $464,079 (²) 1.24 % % of loans and leases outstanding 1.18 % 1.24 % Remaining Credit Discount on Loans $86,415 $79,850 Total ACL Including Credit Discount $524,457 (¹) $543,929 (²) % of loans and leases outstanding 1.41 % 1.45 % 23 Current Expected Credit Losses (“CECL”) Details ■ Provision expense of $55 million includes $53 million related to loans and leases and $2 million related to unfunded commitments. ■ The quarter’s provision expense reflects changes in the economic forecasts used in credit models and portfolio migration trends. ■ Key components of Moody’s November 2023 baseline economic forecast, which is used to estimate the ACL, include: ■ U.S. real GDP average annualized growth of 1.7% in 2024, 1.7% in 2025, 2.3% in 2026, and 2.4% in 2027. ■ U.S. unemployment rate average of 4.0% in 2024, 4.1% in 2025, 4.0% in 2026, and 3.9% in 2027. ■ The average federal funds rate is expected to be 5.1% in 2024, 4.2% in 2025, 3.2% in 2026, and 2.9% in 2027.
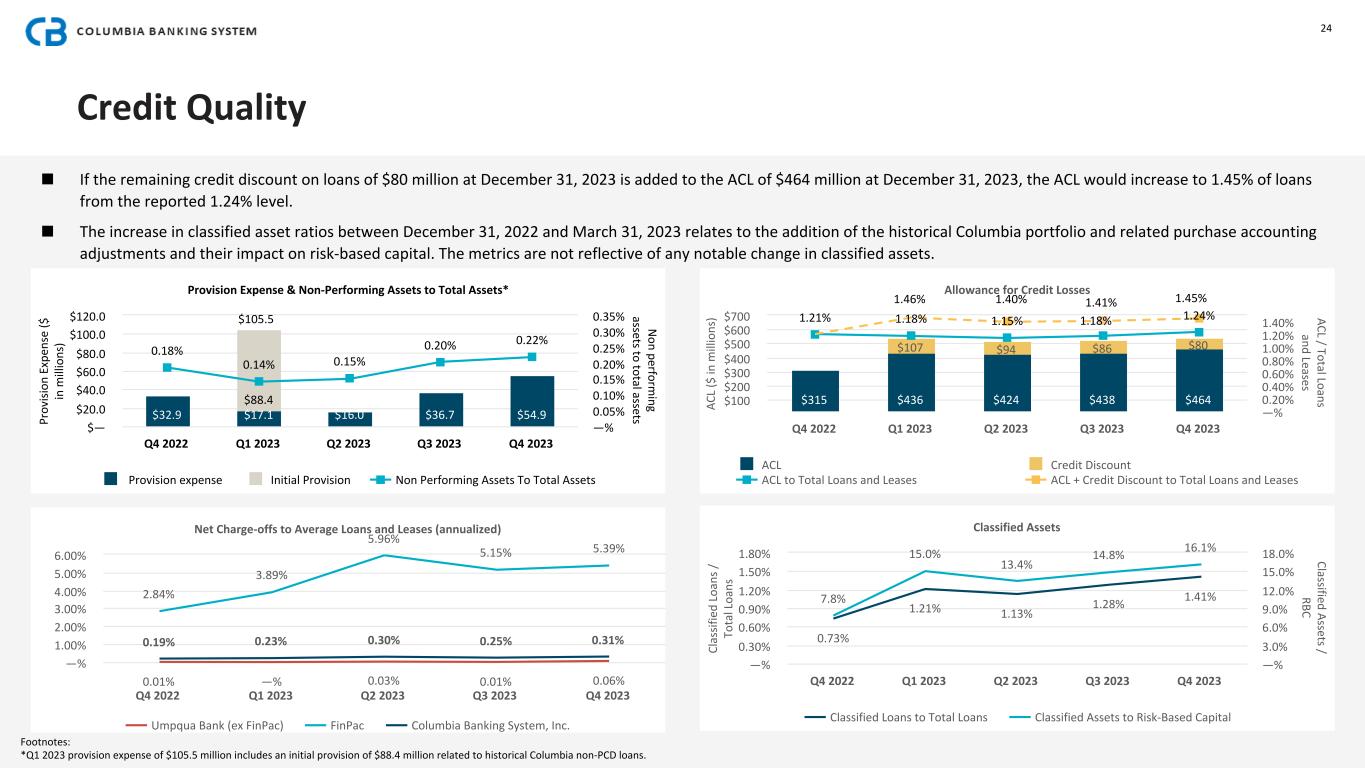
Credit Quality Pr ov is io n Ex pe ns e ($ in m ill io ns ) N on perform ing assets to total assets Provision Expense & Non-Performing Assets to Total Assets* $32.9 $17.1 $16.0 $36.7 $54.9 $88.4 0.18% 0.14% 0.15% 0.20% 0.22% Provision expense Initial Provision Non Performing Assets To Total Assets Q4 2022 Q1 2023 Q2 2023 Q3 2023 Q4 2023 $— $20.0 $40.0 $60.0 $80.0 $100.0 $120.0 —% 0.05% 0.10% 0.15% 0.20% 0.25% 0.30% 0.35% Cl as si fie d Lo an s / To ta l L oa ns Classified A ssets / RBC Classified Assets 0.73% 1.21% 1.13% 1.28% 1.41%7.8% 15.0% 13.4% 14.8% 16.1% Classified Loans to Total Loans Classified Assets to Risk-Based Capital Q4 2022 Q1 2023 Q2 2023 Q3 2023 Q4 2023 —% 0.30% 0.60% 0.90% 1.20% 1.50% 1.80% —% 3.0% 6.0% 9.0% 12.0% 15.0% 18.0% A xi s Ti tle Net Charge-offs to Average Loans and Leases (annualized) 0.01% —% 0.03% 0.01% 0.06% 2.84% 3.89% 5.96% 5.15% 5.39% 0.19% 0.23% 0.30% 0.25% 0.31% Umpqua Bank (ex FinPac) FinPac Columbia Banking System, Inc. Q4 2022 Q1 2023 Q2 2023 Q3 2023 Q4 2023 —% 1.00% 2.00% 3.00% 4.00% 5.00% 6.00% 24 ■ If the remaining credit discount on loans of $80 million at December 31, 2023 is added to the ACL of $464 million at December 31, 2023, the ACL would increase to 1.45% of loans from the reported 1.24% level. ■ The increase in classified asset ratios between December 31, 2022 and March 31, 2023 relates to the addition of the historical Columbia portfolio and related purchase accounting adjustments and their impact on risk-based capital. The metrics are not reflective of any notable change in classified assets. A CL ($ in m ill io ns ) A CL / Total Loans and Leases Allowance for Credit Losses $315 $436 $424 $438 $464 $107 $94 $86 $80 1.21% 1.18% 1.15% 1.24% ACL Credit Discount ACL to Total Loans and Leases ACL + Credit Discount to Total Loans and Leases Q4 2022 Q1 2023 Q2 2023 Q3 2023 Q4 2023 $100 $200 $300 $400 $500 $600 $700 —% 0.20% 0.40% 0.60% 0.80% 1.00% 1.20% 1.40%$105.5 Footnotes: *Q1 2023 provision expense of $105.5 million includes an initial provision of $88.4 million related to historical Columbia non-PCD loans. 1.41% 1.18% 1.45%1.40%1.46%
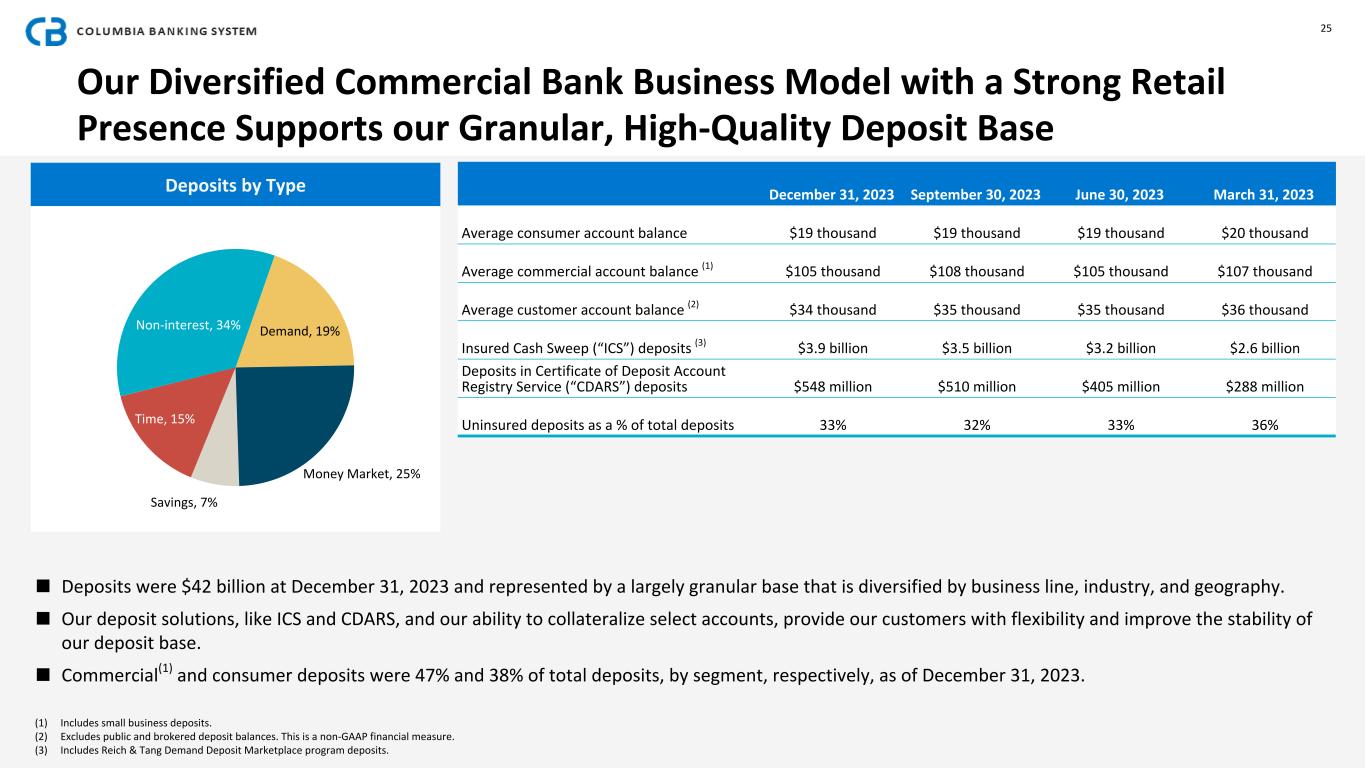
Our Diversified Commercial Bank Business Model with a Strong Retail Presence Supports our Granular, High-Quality Deposit Base (1) Includes small business deposits. (2) Excludes public and brokered deposit balances. This is a non-GAAP financial measure. (3) Includes Reich & Tang Demand Deposit Marketplace program deposits. December 31, 2023 September 30, 2023 June 30, 2023 March 31, 2023 Average consumer account balance $19 thousand $19 thousand $19 thousand $20 thousand Average commercial account balance (1) $105 thousand $108 thousand $105 thousand $107 thousand Average customer account balance (2) $34 thousand $35 thousand $35 thousand $36 thousand Insured Cash Sweep (“ICS”) deposits (3) $3.9 billion $3.5 billion $3.2 billion $2.6 billion Deposits in Certificate of Deposit Account Registry Service (“CDARS”) deposits $548 million $510 million $405 million $288 million Uninsured deposits as a % of total deposits 33% 32% 33% 36% Non-interest, 34% Demand, 19% Money Market, 25% Savings, 7% Time, 15% Deposits by Type 25 ■ Deposits were $42 billion at December 31, 2023 and represented by a largely granular base that is diversified by business line, industry, and geography. ■ Our deposit solutions, like ICS and CDARS, and our ability to collateralize select accounts, provide our customers with flexibility and improve the stability of our deposit base. ■ Commercial(1) and consumer deposits were 47% and 38% of total deposits, by segment, respectively, as of December 31, 2023.
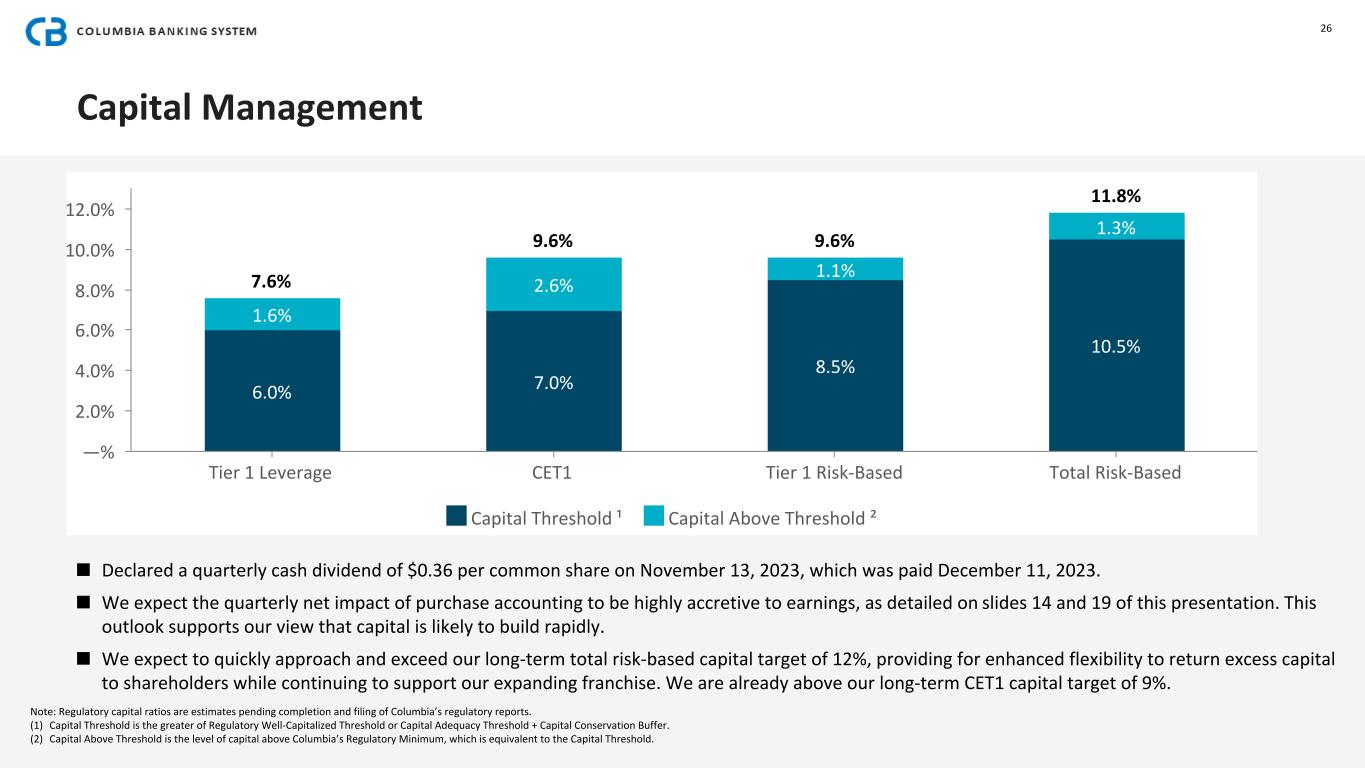
Capital Management 26 7.6% 9.6% 9.6% 11.8% 6.0% 7.0% 8.5% 10.5% 1.6% 2.6% 1.1% 1.3% Capital Threshold ¹ Capital Above Threshold ² Tier 1 Leverage CET1 Tier 1 Risk-Based Total Risk-Based —% 2.0% 4.0% 6.0% 8.0% 10.0% 12.0% ■ Declared a quarterly cash dividend of $0.36 per common share on November 13, 2023, which was paid December 11, 2023. ■ We expect the quarterly net impact of purchase accounting to be highly accretive to earnings, as detailed on slides 14 and 19 of this presentation. This outlook supports our view that capital is likely to build rapidly. ■ We expect to quickly approach and exceed our long-term total risk-based capital target of 12%, providing for enhanced flexibility to return excess capital to shareholders while continuing to support our expanding franchise. We are already above our long-term CET1 capital target of 9%. Note: Regulatory capital ratios are estimates pending completion and filing of Columbia’s regulatory reports. (1) Capital Threshold is the greater of Regulatory Well-Capitalized Threshold or Capital Adequacy Threshold + Capital Conservation Buffer. (2) Capital Above Threshold is the level of capital above Columbia’s Regulatory Minimum, which is equivalent to the Capital Threshold.
APPENDIX Income Statement Component Details Comparisons and Other Non-GAAP Reconciliation
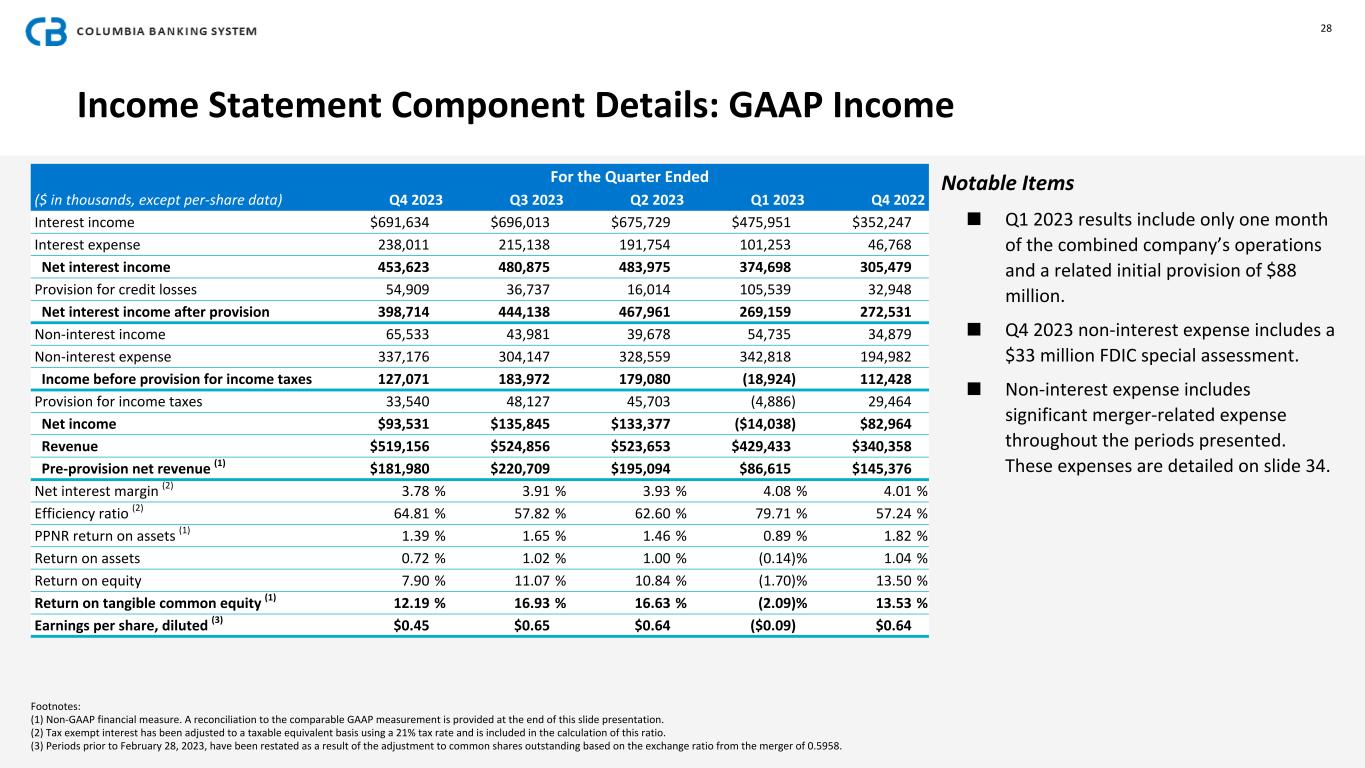
Income Statement Component Details: GAAP Income For the Quarter Ended ($ in thousands, except per-share data) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 Interest income $691,634 $696,013 $675,729 $475,951 $352,247 Interest expense 238,011 215,138 191,754 101,253 46,768 Net interest income 453,623 480,875 483,975 374,698 305,479 Provision for credit losses 54,909 36,737 16,014 105,539 32,948 Net interest income after provision 398,714 — 444,138 — 467,961 — 269,159 — 272,531 Non-interest income 65,533 43,981 39,678 54,735 34,879 Non-interest expense 337,176 304,147 328,559 342,818 194,982 Income before provision for income taxes 127,071 183,972 179,080 (18,924) 112,428 Provision for income taxes 33,540 48,127 45,703 (4,886) 29,464 Net income $93,531 $135,845 $133,377 ($14,038) $82,964 Revenue $519,156 $— $524,856 $— $523,653 $— $429,433 $— $340,358 Pre-provision net revenue (1) $181,980 $220,709 $195,094 $86,615 $145,376 Net interest margin (2) 3.78 % 3.91 % 3.93 % 4.08 % 4.01 % Efficiency ratio (2) 64.81 % 57.82 % 62.60 % 79.71 % 57.24 % PPNR return on assets (1) 1.39 % 1.65 % 1.46 % 0.89 % 1.82 % Return on assets 0.72 % 1.02 % 1.00 % (0.14) % 1.04 % Return on equity 7.90 % 11.07 % 10.84 % (1.70) % 13.50 % Return on tangible common equity (1) 12.19 % 16.93 % 16.63 % (2.09) % 13.53 % Earnings per share, diluted (3) $0.45 $0.65 $0.64 ($0.09) $0.64 28 Footnotes: (1) Non-GAAP financial measure. A reconciliation to the comparable GAAP measurement is provided at the end of this slide presentation. (2) Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate and is included in the calculation of this ratio. (3) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958. Notable Items ■ Q1 2023 results include only one month of the combined company’s operations and a related initial provision of $88 million. ■ Q4 2023 non-interest expense includes a $33 million FDIC special assessment. ■ Non-interest expense includes significant merger-related expense throughout the periods presented. These expenses are detailed on slide 34.
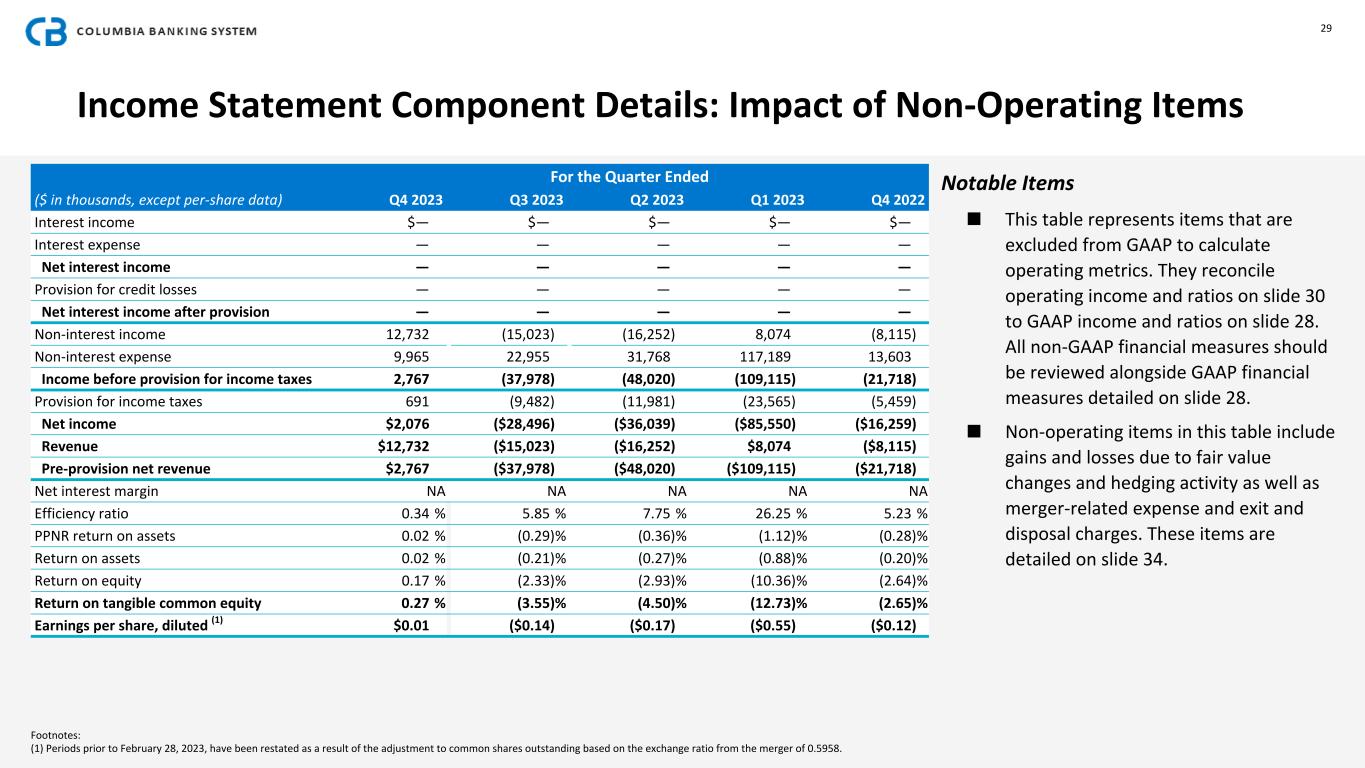
Income Statement Component Details: Impact of Non-Operating Items For the Quarter Ended ($ in thousands, except per-share data) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 Interest income $— $— $— $— $— Interest expense — — — — — Net interest income — — — — — Provision for credit losses — — — — — Net interest income after provision — — — — — Non-interest income 12,732 (15,023) (16,252) 8,074 (8,115) Non-interest expense 9,965 22,955 31,768 117,189 13,603 Income before provision for income taxes 2,767 (37,978) (48,020) (109,115) (21,718) Provision for income taxes 691 (9,482) (11,981) (23,565) (5,459) Net income $2,076 ($28,496) ($36,039) ($85,550) ($16,259) Revenue $12,732 ($15,023) ($16,252) $8,074 ($8,115) Pre-provision net revenue $2,767 ($37,978) ($48,020) ($109,115) ($21,718) Net interest margin NA NA NA NA NA Efficiency ratio 0.34 % 5.85 % 7.75 % 26.25 % 5.23 % PPNR return on assets 0.02 % (0.29) % (0.36) % (1.12) % (0.28) % Return on assets 0.02 % (0.21) % (0.27) % (0.88) % (0.20) % Return on equity 0.17 % (2.33) % (2.93) % (10.36) % (2.64) % Return on tangible common equity 0.27 % (3.55) % (4.50) % (12.73) % (2.65) % Earnings per share, diluted (1) $0.01 ($0.14) ($0.17) ($0.55) ($0.12) 29 Notable Items ■ This table represents items that are excluded from GAAP to calculate operating metrics. They reconcile operating income and ratios on slide 30 to GAAP income and ratios on slide 28. All non-GAAP financial measures should be reviewed alongside GAAP financial measures detailed on slide 28. ■ Non-operating items in this table include gains and losses due to fair value changes and hedging activity as well as merger-related expense and exit and disposal charges. These items are detailed on slide 34. Footnotes: (1) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958.
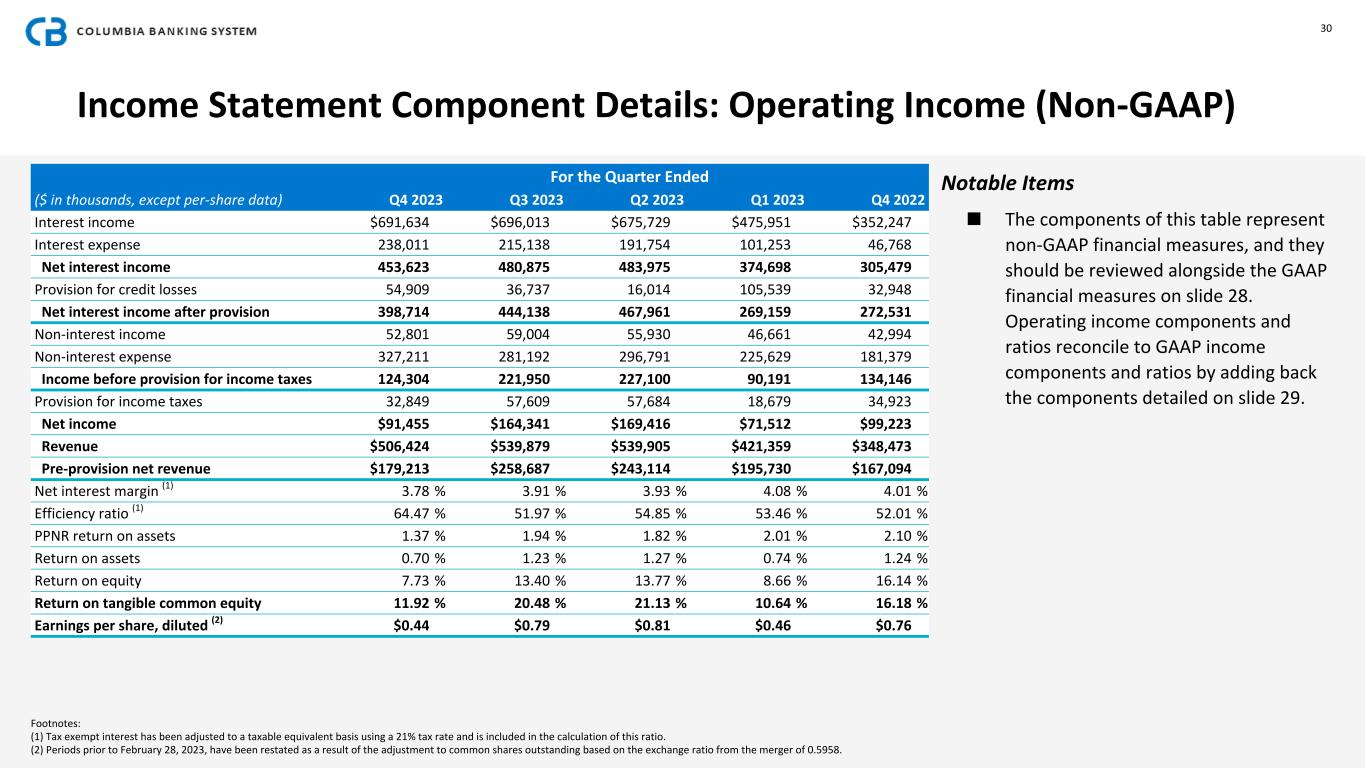
Income Statement Component Details: Operating Income (Non-GAAP) For the Quarter Ended ($ in thousands, except per-share data) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 Interest income $691,634 $696,013 $675,729 $475,951 $352,247 Interest expense 238,011 215,138 191,754 101,253 46,768 Net interest income 453,623 480,875 483,975 374,698 305,479 Provision for credit losses 54,909 36,737 16,014 105,539 32,948 Net interest income after provision 398,714 444,138 467,961 269,159 272,531 Non-interest income 52,801 59,004 55,930 46,661 42,994 Non-interest expense 327,211 281,192 296,791 225,629 181,379 Income before provision for income taxes 124,304 221,950 227,100 90,191 134,146 Provision for income taxes 32,849 57,609 57,684 18,679 34,923 Net income $91,455 $164,341 $169,416 $71,512 $99,223 Revenue $506,424 $539,879 $539,905 $421,359 $348,473 Pre-provision net revenue $179,213 $258,687 $243,114 $195,730 $167,094 Net interest margin (1) 3.78 % 3.91 % 3.93 % 4.08 % 4.01 % Efficiency ratio (1) 64.47 % 51.97 % 54.85 % 53.46 % 52.01 % PPNR return on assets 1.37 % 1.94 % 1.82 % 2.01 % 2.10 % Return on assets 0.70 % 1.23 % 1.27 % 0.74 % 1.24 % Return on equity 7.73 % 13.40 % 13.77 % 8.66 % 16.14 % Return on tangible common equity 11.92 % 20.48 % 21.13 % 10.64 % 16.18 % Earnings per share, diluted (2) $0.44 $0.79 $0.81 $0.46 $0.76 30 Footnotes: (1) Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate and is included in the calculation of this ratio. (2) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958. Notable Items ■ The components of this table represent non-GAAP financial measures, and they should be reviewed alongside the GAAP financial measures on slide 28. Operating income components and ratios reconcile to GAAP income components and ratios by adding back the components detailed on slide 29.
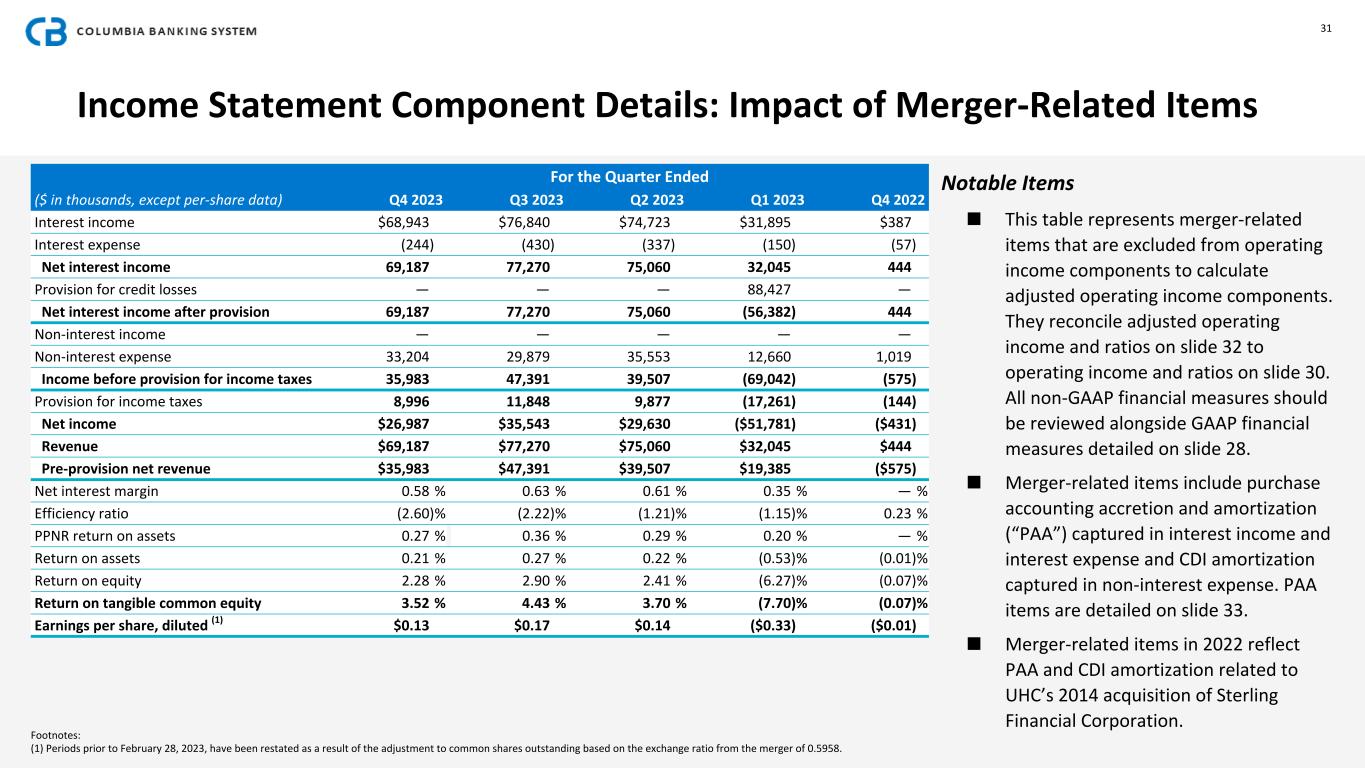
Income Statement Component Details: Impact of Merger-Related Items For the Quarter Ended ($ in thousands, except per-share data) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 Interest income $68,943 $76,840 $74,723 $31,895 $387 Interest expense (244) (430) (337) (150) (57) Net interest income 69,187 77,270 75,060 32,045 444 Provision for credit losses — — — 88,427 — Net interest income after provision 69,187 77,270 75,060 (56,382) 444 Non-interest income — — — — — Non-interest expense 33,204 29,879 35,553 12,660 1,019 Income before provision for income taxes 35,983 47,391 39,507 (69,042) (575) Provision for income taxes 8,996 11,848 9,877 (17,261) (144) Net income $26,987 $35,543 $29,630 ($51,781) ($431) Revenue $69,187 $77,270 $75,060 $32,045 $444 Pre-provision net revenue $35,983 $47,391 $39,507 $19,385 ($575) Net interest margin 0.58 % 0.63 % 0.61 % 0.35 % — % Efficiency ratio (2.60) % (2.22) % (1.21) % (1.15) % 0.23 % PPNR return on assets 0.27 % 0.36 % 0.29 % 0.20 % — % Return on assets 0.21 % 0.27 % 0.22 % (0.53) % (0.01) % Return on equity 2.28 % 2.90 % 2.41 % (6.27) % (0.07) % Return on tangible common equity 3.52 % 4.43 % 3.70 % (7.70) % (0.07) % Earnings per share, diluted (1) $0.13 $0.17 $0.14 ($0.33) ($0.01) 31 Notable Items ■ This table represents merger-related items that are excluded from operating income components to calculate adjusted operating income components. They reconcile adjusted operating income and ratios on slide 32 to operating income and ratios on slide 30. All non-GAAP financial measures should be reviewed alongside GAAP financial measures detailed on slide 28. ■ Merger-related items include purchase accounting accretion and amortization (“PAA”) captured in interest income and interest expense and CDI amortization captured in non-interest expense. PAA items are detailed on slide 33. ■ Merger-related items in 2022 reflect PAA and CDI amortization related to UHC’s 2014 acquisition of Sterling Financial Corporation. Footnotes: (1) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958.
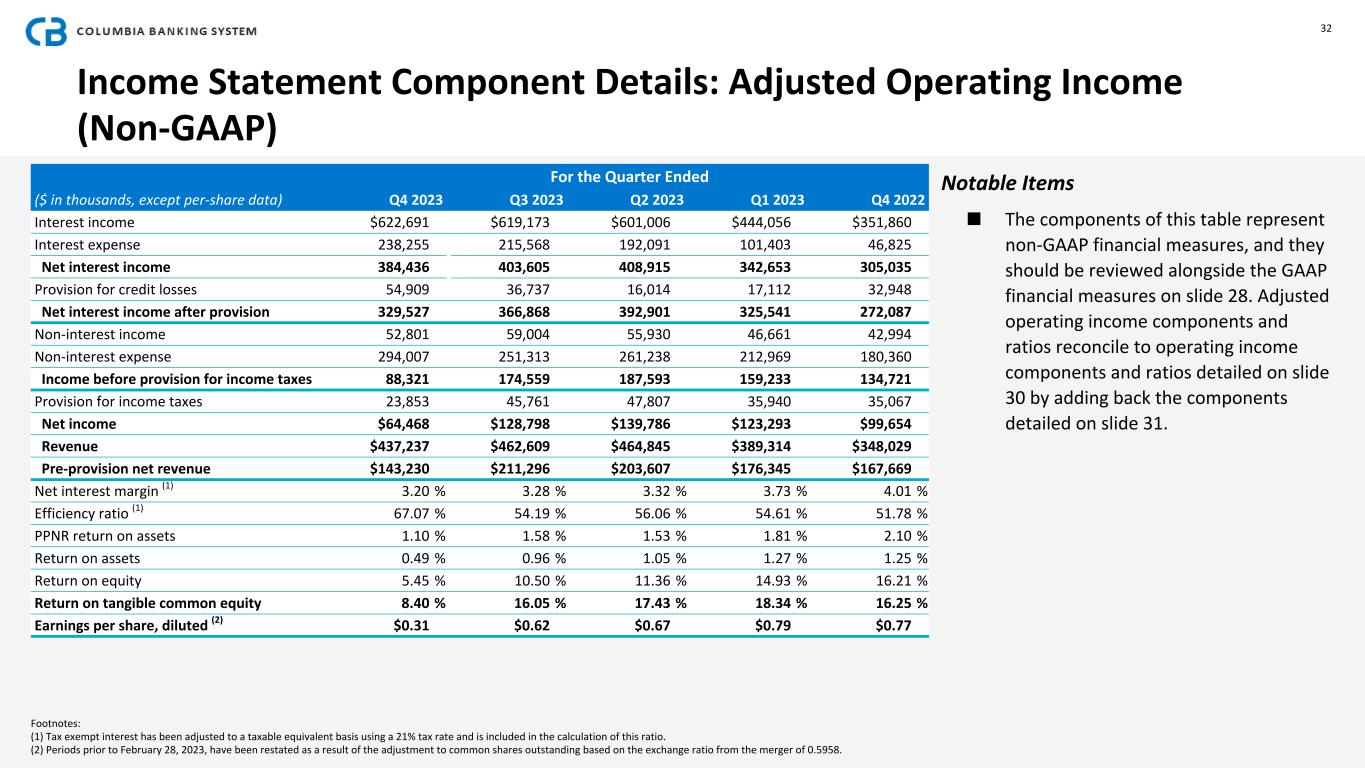
Income Statement Component Details: Adjusted Operating Income (Non-GAAP) For the Quarter Ended ($ in thousands, except per-share data) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 Interest income $622,691 $619,173 $601,006 $444,056 $351,860 Interest expense 238,255 215,568 192,091 101,403 46,825 Net interest income 384,436 403,605 408,915 342,653 305,035 Provision for credit losses 54,909 36,737 16,014 17,112 32,948 Net interest income after provision 329,527 366,868 392,901 325,541 272,087 Non-interest income 52,801 59,004 55,930 46,661 42,994 Non-interest expense 294,007 251,313 261,238 212,969 180,360 Income before provision for income taxes 88,321 174,559 187,593 159,233 134,721 Provision for income taxes 23,853 45,761 47,807 35,940 35,067 Net income $64,468 $128,798 $139,786 $123,293 $99,654 Revenue $437,237 $462,609 $464,845 $389,314 $348,029 Pre-provision net revenue $143,230 $211,296 $203,607 $176,345 $167,669 Net interest margin (1) 3.20 % 3.28 % 3.32 % 3.73 % 4.01 % Efficiency ratio (1) 67.07 % 54.19 % 56.06 % 54.61 % 51.78 % PPNR return on assets 1.10 % 1.58 % 1.53 % 1.81 % 2.10 % Return on assets 0.49 % 0.96 % 1.05 % 1.27 % 1.25 % Return on equity 5.45 % 10.50 % 11.36 % 14.93 % 16.21 % Return on tangible common equity 8.40 % 16.05 % 17.43 % 18.34 % 16.25 % Earnings per share, diluted (2) $0.31 $0.62 $0.67 $0.79 $0.77 32 Notable Items ■ The components of this table represent non-GAAP financial measures, and they should be reviewed alongside the GAAP financial measures on slide 28. Adjusted operating income components and ratios reconcile to operating income components and ratios detailed on slide 30 by adding back the components detailed on slide 31. Footnotes: (1) Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate and is included in the calculation of this ratio. (2) Periods prior to February 28, 2023, have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958.
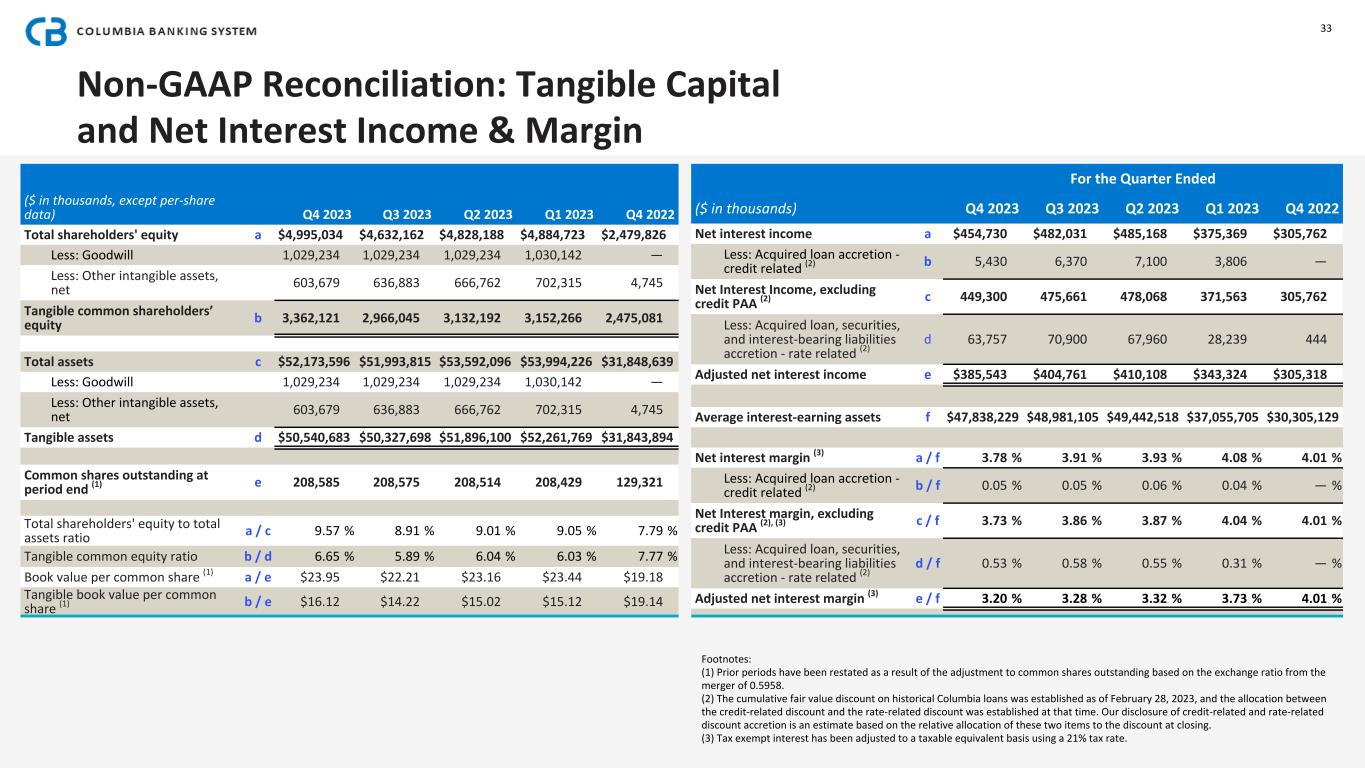
Non-GAAP Reconciliation: Tangible Capital and Net Interest Income & Margin ($ in thousands, except per-share data) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 Total shareholders' equity a $4,995,034 $4,632,162 $4,828,188 $4,884,723 $2,479,826 Less: Goodwill 1,029,234 1,029,234 1,029,234 1,030,142 — Less: Other intangible assets, net 603,679 636,883 666,762 702,315 4,745 Tangible common shareholders’ equity b 3,362,121 2,966,045 3,132,192 3,152,266 2,475,081 Total assets c $52,173,596 $51,993,815 $53,592,096 $53,994,226 $31,848,639 Less: Goodwill 1,029,234 1,029,234 1,029,234 1,030,142 — Less: Other intangible assets, net 603,679 636,883 666,762 702,315 4,745 Tangible assets d $50,540,683 $50,327,698 $51,896,100 $52,261,769 $31,843,894 Common shares outstanding at period end (1) e 208,585 208,575 208,514 208,429 129,321 Total shareholders' equity to total assets ratio a / c 9.57 % 8.91 % 9.01 % 9.05 % 7.79 % Tangible common equity ratio b / d 6.65 % 5.89 % 6.04 % 6.03 % 7.77 % Book value per common share (1) a / e $23.95 $22.21 $23.16 $23.44 $19.18 Tangible book value per common share (1) b / e $16.12 $14.22 $15.02 $15.12 $19.14 Footnotes: (1) Prior periods have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958. (2) The cumulative fair value discount on historical Columbia loans was established as of February 28, 2023, and the allocation between the credit-related discount and the rate-related discount was established at that time. Our disclosure of credit-related and rate-related discount accretion is an estimate based on the relative allocation of these two items to the discount at closing. (3) Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate. 33 For the Quarter Ended ($ in thousands) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 Net interest income a $454,730 $482,031 $485,168 $375,369 $305,762 Less: Acquired loan accretion - credit related (2) b 5,430 6,370 7,100 3,806 — Net Interest Income, excluding credit PAA (2) c 449,300 475,661 478,068 371,563 305,762 Less: Acquired loan, securities, and interest-bearing liabilities accretion - rate related (2) d 63,757 70,900 67,960 28,239 444 Adjusted net interest income e $385,543 $404,761 $410,108 $343,324 $305,318 Average interest-earning assets f $47,838,229 $48,981,105 $49,442,518 $37,055,705 $30,305,129 Net interest margin (3) a / f 3.78 % 3.91 % 3.93 % 4.08 % 4.01 % Less: Acquired loan accretion - credit related (2) b / f 0.05 % 0.05 % 0.06 % 0.04 % — % Net Interest margin, excluding credit PAA (2), (3) c / f 3.73 % 3.86 % 3.87 % 4.04 % 4.01 % Less: Acquired loan, securities, and interest-bearing liabilities accretion - rate related (2) d / f 0.53 % 0.58 % 0.55 % 0.31 % — % Adjusted net interest margin (3) e / f 3.20 % 3.28 % 3.32 % 3.73 % 4.01 %
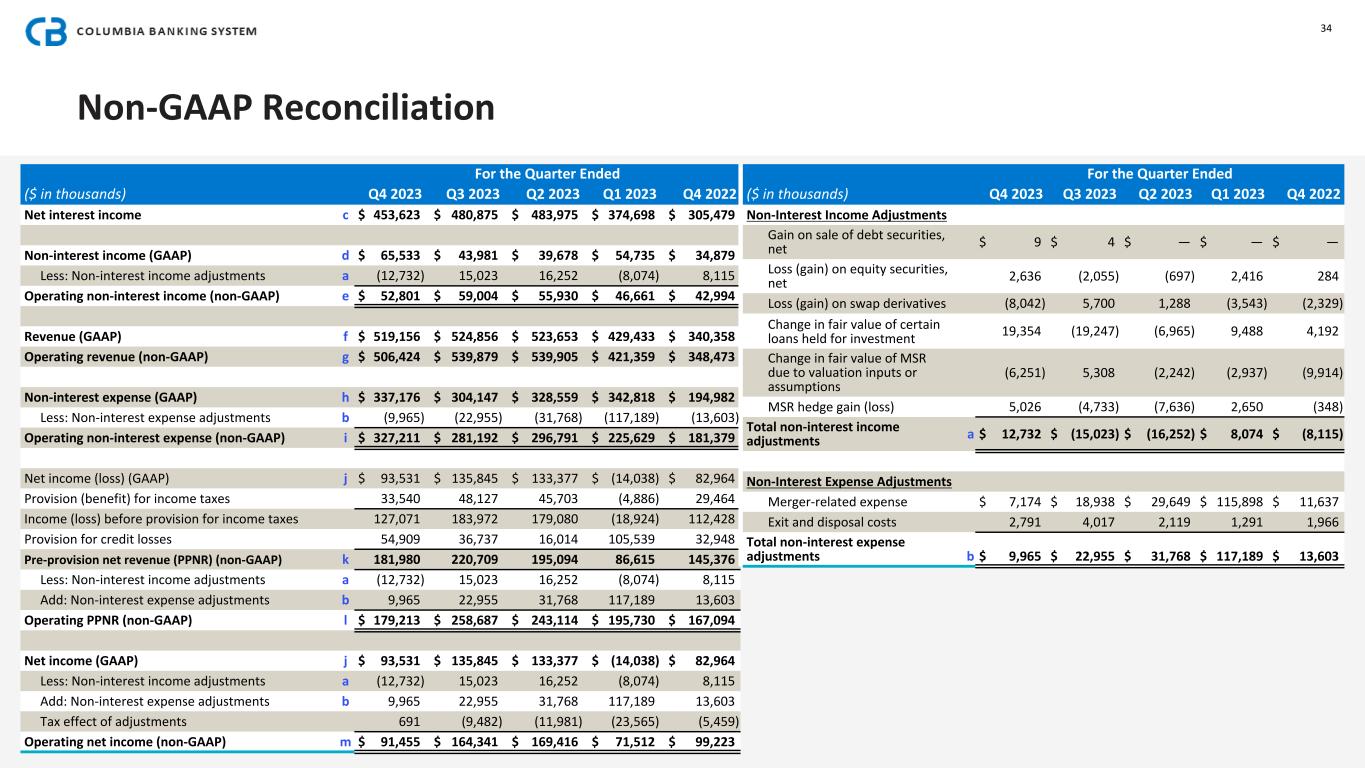
Non-GAAP Reconciliation For the Quarter Ended ($ in thousands) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 Net interest income c $ 453,623 $ 480,875 $ 483,975 $ 374,698 $ 305,479 Non-interest income (GAAP) d $ 65,533 $ 43,981 $ 39,678 $ 54,735 $ 34,879 Less: Non-interest income adjustments a (12,732) 15,023 16,252 (8,074) 8,115 Operating non-interest income (non-GAAP) e $ 52,801 $ 59,004 $ 55,930 $ 46,661 $ 42,994 Revenue (GAAP) f $ 519,156 $ 524,856 $ 523,653 $ 429,433 $ 340,358 Operating revenue (non-GAAP) g $ 506,424 $ 539,879 $ 539,905 $ 421,359 $ 348,473 Non-interest expense (GAAP) h $ 337,176 $ 304,147 $ 328,559 $ 342,818 $ 194,982 Less: Non-interest expense adjustments b (9,965) (22,955) (31,768) (117,189) (13,603) Operating non-interest expense (non-GAAP) i $ 327,211 $ 281,192 $ 296,791 $ 225,629 $ 181,379 Net income (loss) (GAAP) j $ 93,531 $ 135,845 $ 133,377 $ (14,038) $ 82,964 Provision (benefit) for income taxes 33,540 48,127 45,703 (4,886) 29,464 Income (loss) before provision for income taxes 127,071 183,972 179,080 (18,924) 112,428 Provision for credit losses 54,909 36,737 16,014 105,539 32,948 Pre-provision net revenue (PPNR) (non-GAAP) k 181,980 220,709 195,094 86,615 145,376 Less: Non-interest income adjustments a (12,732) 15,023 16,252 (8,074) 8,115 Add: Non-interest expense adjustments b 9,965 22,955 31,768 117,189 13,603 Operating PPNR (non-GAAP) l $ 179,213 $ 258,687 $ 243,114 $ 195,730 $ 167,094 Net income (GAAP) j $ 93,531 $ 135,845 $ 133,377 $ (14,038) $ 82,964 Less: Non-interest income adjustments a (12,732) 15,023 16,252 (8,074) 8,115 Add: Non-interest expense adjustments b 9,965 22,955 31,768 117,189 13,603 Tax effect of adjustments 691 (9,482) (11,981) (23,565) (5,459) Operating net income (non-GAAP) m $ 91,455 $ 164,341 $ 169,416 $ 71,512 $ 99,223 For the Quarter Ended ($ in thousands) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 Non-Interest Income Adjustments Gain on sale of debt securities, net $ 9 $ 4 $ — $ — $ — Loss (gain) on equity securities, net 2,636 (2,055) (697) 2,416 284 Loss (gain) on swap derivatives (8,042) 5,700 1,288 (3,543) (2,329) Change in fair value of certain loans held for investment 19,354 (19,247) (6,965) 9,488 4,192 Change in fair value of MSR due to valuation inputs or assumptions (6,251) 5,308 (2,242) (2,937) (9,914) MSR hedge gain (loss) 5,026 (4,733) (7,636) 2,650 (348) Total non-interest income adjustments a $ 12,732 $ (15,023) $ (16,252) $ 8,074 $ (8,115) Non-Interest Expense Adjustments Merger-related expense $ 7,174 $ 18,938 $ 29,649 $ 115,898 $ 11,637 Exit and disposal costs 2,791 4,017 2,119 1,291 1,966 Total non-interest expense adjustments b $ 9,965 $ 22,955 $ 31,768 $ 117,189 $ 13,603 34
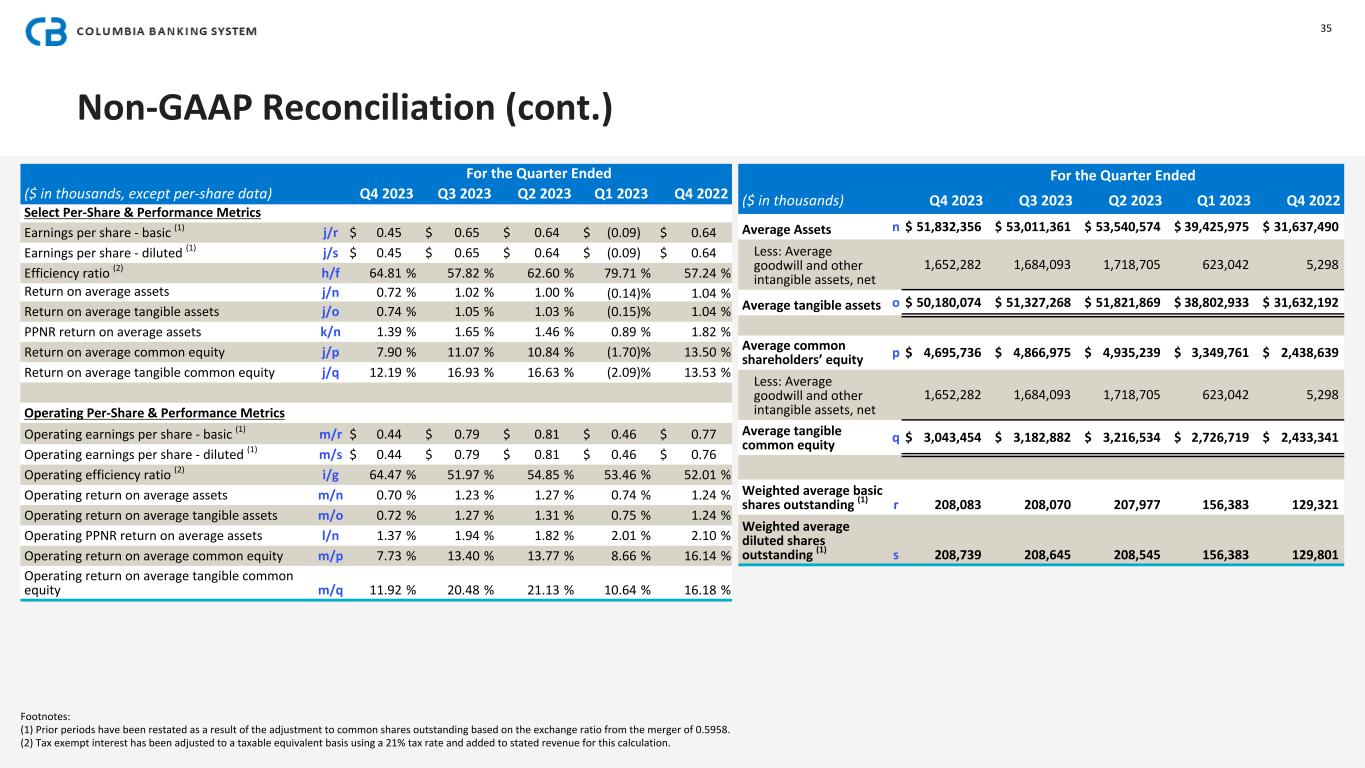
Non-GAAP Reconciliation (cont.) For the Quarter Ended ($ in thousands, except per-share data) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 Select Per-Share & Performance Metrics Earnings per share - basic (1) j/r $ 0.45 $ 0.65 $ 0.64 $ (0.09) $ 0.64 Earnings per share - diluted (1) j/s $ 0.45 $ 0.65 $ 0.64 $ (0.09) $ 0.64 Efficiency ratio (2) h/f 64.81 % 57.82 % 62.60 % 79.71 % 57.24 % Return on average assets j/n 0.72 % 1.02 % 1.00 % (0.14) % 1.04 % Return on average tangible assets j/o 0.74 % 1.05 % 1.03 % (0.15) % 1.04 % PPNR return on average assets k/n 1.39 % 1.65 % 1.46 % 0.89 % 1.82 % Return on average common equity j/p 7.90 % 11.07 % 10.84 % (1.70) % 13.50 % Return on average tangible common equity j/q 12.19 % 16.93 % 16.63 % (2.09) % 13.53 % Operating Per-Share & Performance Metrics Operating earnings per share - basic (1) m/r $ 0.44 $ 0.79 $ 0.81 $ 0.46 $ 0.77 Operating earnings per share - diluted (1) m/s $ 0.44 $ 0.79 $ 0.81 $ 0.46 $ 0.76 Operating efficiency ratio (2) i/g 64.47 % 51.97 % 54.85 % 53.46 % 52.01 % Operating return on average assets m/n 0.70 % 1.23 % 1.27 % 0.74 % 1.24 % Operating return on average tangible assets m/o 0.72 % 1.27 % 1.31 % 0.75 % 1.24 % Operating PPNR return on average assets l/n 1.37 % 1.94 % 1.82 % 2.01 % 2.10 % Operating return on average common equity m/p 7.73 % 13.40 % 13.77 % 8.66 % 16.14 % Operating return on average tangible common equity m/q 11.92 % 20.48 % 21.13 % 10.64 % 16.18 % For the Quarter Ended ($ in thousands) Q4 2023 Q3 2023 Q2 2023 Q1 2023 Q4 2022 Average Assets n $ 51,832,356 $ 53,011,361 $ 53,540,574 $ 39,425,975 $ 31,637,490 Less: Average goodwill and other intangible assets, net 1,652,282 1,684,093 1,718,705 623,042 5,298 Average tangible assets o $ 50,180,074 $ 51,327,268 $ 51,821,869 $ 38,802,933 $ 31,632,192 Average common shareholders’ equity p $ 4,695,736 $ 4,866,975 $ 4,935,239 $ 3,349,761 $ 2,438,639 Less: Average goodwill and other intangible assets, net 1,652,282 1,684,093 1,718,705 623,042 5,298 Average tangible common equity q $ 3,043,454 $ 3,182,882 $ 3,216,534 $ 2,726,719 $ 2,433,341 Weighted average basic shares outstanding (1) r 208,083 208,070 207,977 156,383 129,321 Weighted average diluted shares outstanding (1) s 208,739 208,645 208,545 156,383 129,801 Footnotes: (1) Prior periods have been restated as a result of the adjustment to common shares outstanding based on the exchange ratio from the merger of 0.5958. (2) Tax exempt interest has been adjusted to a taxable equivalent basis using a 21% tax rate and added to stated revenue for this calculation. 35