
CUBI 8-K
Customers Bancorp, Inc. (CUBI)
8-K
2021-07-28
For: 2021-07-28
View Original
Added on
April 09, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d)
of the
Securities Exchange Act of 1934
Date of Report (date of earliest event reported): July 28, 2021
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation or organization) | (Commission File number) | (IRS Employer Identification No.) | ||||||
(Address of principal executive offices, including zip code)
(610 ) 933-2000
(Registrant’s telephone number, including area code)
N/A
(Former name, former address and former fiscal year, if changed since last report)
Check the appropriate box below if the form 8-K filing is intended to simultaneously satisfy the filing obligations of the registrant under any of the following provisions (see General Instructions A.2. below):
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(g) of the Act:
| Title of Each Class | Trading Symbols | Name of Each Exchange on which Registered | ||||||||||||
Preferred Stock, Series C, par value $1.00 per share | ||||||||||||||
Preferred Stock, Series D, par value $1.00 per share | ||||||||||||||
Preferred Stock, Series E, par value $1.00 per share | ||||||||||||||
Preferred Stock, Series F, par value $1.00 per share | ||||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (17 CFR §230.405) or Rule 12b-2 of the Securities Exchange Act of 1934 (17 CFR §240.12b-2). Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02. Results of Operations and Financial Condition
On July 28, 2021 , Customers Bancorp, Inc. (the "Company") issued a press release announcing unaudited financial information for the quarter ended June 30, 2021, a copy of which is included as Exhibit 99.1 to this Current Report on Form 8-K and incorporated by reference herein.
Item 7.01 Regulation FD Disclosure
The Company has posted to its website a slide presentation which is attached hereto as Exhibit 99.2 to this Current Report on Form 8-K and incorporated into this Item 7.01 by reference.
The information in this Current Report on Form 8-K, including Exhibits 99.1 and 99.2 attached hereto and incorporated by reference into Item 2.02 and Item 7.01, respectively, shall not be deemed "filed" for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities under that Section. Furthermore, such information, including the exhibits attached hereto, shall not be deemed incorporated by reference into any of the Company's reports or filings with the SEC, whether made before or after the date hereof, except as expressly set forth by specific reference in such report or filing. The information in this Current Report on Form 8-K, including the exhibits attached hereto, shall not be deemed an admission as to the materiality of any information in this Current Report on Form 8-K that is required to be disclosed solely to satisfy the requirements of Regulation FD.
Item 9.01. Financial Statements and Exhibits
(d) Exhibits.
| Exhibit | Description | |||||||
| Press Release dated July 28, 2021 | ||||||||
| Slide presentation dated July 2021 | ||||||||
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, hereunto duly authorized.
| CUSTOMERS BANCORP, INC. | |||||
By: /s/ Carla A. Leibold | |||||
| Name: Carla A. Leibold | |||||
| Title: Executive Vice President - Chief Financial Officer | |||||
Date: July 28, 2021
EXHIBIT INDEX
Exhibit 99.1
Customers Bancorp, Inc.
701 Reading Avenue
West Reading, PA 19611
Contacts:
Jay Sidhu, Chairman & CEO 610-935-8693
Sam Sidhu, President 484-744-8985
Carla Leibold, CFO 484-923-8802
Jay Sidhu, Chairman & CEO 610-935-8693
Sam Sidhu, President 484-744-8985
Carla Leibold, CFO 484-923-8802
Customers Bancorp Reports Second Quarter 2021 Results
Record Net Income of $58.0 million, or $1.72 Per Diluted Share,
ROAA of 1.27% and ROCE of 23.22%
Top 5 Bank PPP Lender in U.S. by Loan Count
~325,000 Loans Funded Totaling $9.5 billion
~$335 million of Deferred Origination Fees Earned
Tangible Book Value Increased 29% over Q2 2020
•Q2 2021 net income available to common shareholders was $58.0 million, or $1.72 per diluted share, up 182% over Q2 2020.
•Q2 2021 core earnings (a non-GAAP measure) were $59.3 million, or $1.76 per diluted share, up 177% over Q2 2020.
•Q2 2021 ROAA was 1.27% and Core ROAA (a non-GAAP measure) was 1.30%. Q2 2020 ROAA was 0.62% and Core ROAA (a non-GAAP measure) was 0.68%.
•Q2 2021 ROCE was 23.22% and Core ROCE (a non-GAAP measure) was 23.72%. Q2 2020 ROCE was 9.97% and Core ROCE (a non-GAAP measure) was 11.16%.
•Adjusted pre-tax pre-provision net income (a non-GAAP measure) for Q2 2021 was $86.5 million, an increase of 60% over Q2 2020. Q2 2021 adjusted pre-tax pre-provision return on average assets (a non-GAAP measure) was 1.80% compared to 1.48% for Q2 2020.
•Q2 2021 results include a provision for credit losses on loans and leases of $3.3 million, compared to a benefit of $2.9 million in Q1 2021. At June 30, 2021, the coverage of credit loss reserves for loans and leases held for investment, excluding Paycheck Protection Program ("PPP") loans (a non-GAAP measure), was 1.61% compared to 1.71% at March 31, 2021.
•Non-performing assets were 0.24% of total assets at June 30, 2021 compared to 0.26% at March 31, 2021. Allowance for credit losses equaled 270% of non-performing loans at June 30, 2021, up from 264% at March 31, 2021.
•Net interest income for Q2 2021 grew $6.0 million, or 4.5%, over Q1 2021 and $46.8 million, or 50.9%, over Q2 2020.
•Q2 2021 net interest margin (a non-GAAP measure) remained stable at 2.98%. Q2 2021 net interest margin, excluding the impact of PPP loans (a non-GAAP measure), increased by 31 basis points to 3.30% from Q1 2021.
•Total loans and leases increased $1.7 billion, or 11.0% year-over-year. Total loans and leases, excluding PPP loans (a non-GAAP measure), increased $132.2 million, or 1.3% year-over-year, as growth in the core commercial and industrial (C&I), consumer and loans to mortgage companies portfolios was offset in part by runoff in the multi-family loan portfolio.
1
•Total deposits increased $2.9 billion, or 26.5% year-over-year, which included a $2.4 billion or 51.9% increase in demand deposits. The total cost of deposits dropped 44 basis points from 0.91% in the year-ago quarter.
•Total deferments declined to $98.2 million, or 0.9% of total loans and leases excluding PPP loans (a non-GAAP measure) at June 30, 2021, down from $189.1 million, or 1.7% of total loans and leases excluding PPP loans (a non-GAAP measure) at March 31, 2021.
•Q2 2021 efficiency ratio was 46.59% compared to 50.73% for Q2 2020. Q2 2021 core efficiency ratio was 44.33% compared to 47.84% in Q2 2020 (non-GAAP measures).
•Fully divested foreign equity holdings in Q2 2021 reducing overall taxable capital gains resulting from BankMobile divestiture in Q1 2021.
•On track to soft launch a private real-time, blockchain-based B2B payments platform with integration of digital and legacy payment rails within the next 60 days. The platform will deliver enhanced payments functionality for our business clients and is expected to generate additional deposit growth in targeted niches, such as real estate, monetary and currency exchanges and institutional investments.
•Preferred stock redemption planned prior to year-end.
West Reading, PA, July 28, 2021 - Customers Bancorp, Inc. (NYSE: CUBI), the parent company of Customers Bank (collectively "Customers" or "CUBI"), today reported second quarter 2021 ("Q2 2021") net income to common shareholders of $58.0 million, or $1.72 per diluted share, up from first quarter 2021 ("Q1 2021") net income to common shareholders of $33.2 million, or $1.01 per diluted share. Q1 2021 results included a net loss from discontinued operations of $38.0 million, which reduced GAAP earnings by $1.16 per diluted share, resulting from the divestiture of BankMobile Technologies, Inc. on January 4, 2021. Core earnings for Q2 2021 totaled $59.3 million, or $1.76 per diluted share compared to Q1 2021 core earnings of $70.3 million, or $2.14 per diluted share (non-GAAP measures). Adjusted pre-tax pre-provision net income was $86.5 million for Q2 2021 compared to $86.8 million for Q1 2021 (non-GAAP measures). Net interest margin, tax equivalent ("NIM") remained stable at 3% for Q2 2021 and Q1 2021. Excluding PPP loans, NIM expanded 31 basis points in Q2 2021 as compared to Q1 2021, largely benefiting from the balance sheet restructuring that occurred in Q1 2021, further reductions in deposit costs and disciplined pricing strategy (non-GAAP measures).
“As the Paycheck Protection Program ("PPP") comes to a close, we couldn't be happier with our overall execution and results in this program,” remarked Customers Bancorp Chairman and CEO, Jay Sidhu. “Not only have we supported hundreds of thousands of small businesses, not-for-profits, and the communities we serve, we leveraged our technology expertise to build valuable fintech partnerships, established hundreds of thousands of new customer accounts ripe for in-house analytics and cross-selling and significantly improved our capital position and tangible book value at the same time. All of this was achieved while decreasing the risk profile of Customers Bank. At June 30, 2021, we have strong capital and reserves, exceptional asset quality and expect to report the highest full year earnings in our company's history. This leaves us very well positioned to support future growth and to redeem a portion of our preferred stock later this year, an EPS enhancing action, which was approved by our Board earlier today. We remain optimistic about our future.” Mr. Sidhu concluded.
2
Key Balance Sheet Trends
Total loans and leases increased $1.7 billion, or 11.0%, to $17.0 billion at June 30, 2021 compared to the year-ago period. PPP loans were $6.3 billion at June 30, 2021, an increase of $1.5 billion compared to the year-ago period, driven by $4.1 billion and $0.2 billion in originations from the new round and earlier rounds of PPP loans, respectively. This increase in PPP loans was offset by $2.8 billion in forgiveness from the earlier rounds of PPP loans. Additionally, the loan mix improved year-over-year as commercial and industrial loans and leases increased $233.2 million to $2.3 billion, commercial real estate owner occupied loans increased $108.9 million to $653.6 million, commercial loans to mortgage companies increased $90.1 million to $2.9 billion, and consumer installment loans increased $319.8 million to $1.6 billion. These increases in loans and leases were partially offset by decreases in multi-family loans of $526.1 million to $1.5 billion, commercial real estate non-owner occupied loans of $55.7 million to $1.2 billion and residential mortgages of $79.4 million to $273.5 million. “Looking ahead, we see continued growth in core C&I and consumer loans offsetting some of the expected decreases in loans to mortgage companies in the second half of this year," stated Sidhu.
Total deposits increased $2.9 billion, or 26.5%, to $13.9 billion at June 30, 2021 compared to the year-ago period. Total demand deposits increased $2.4 billion, or 51.9%, to $6.9 billion, money market deposits increased $1.5 billion, or 44.2%, to $4.9 billion, and savings deposits increased $287.0 million, or 25.1%, to $1.4 billion. These increases were offset, in part, by a decrease in time deposits of $1.2 billion, or 66.5%, to $627.2 million. The total cost of deposits declined by 44 basis points to 0.47% in Q2 2021 from 0.91% in the year-ago quarter. At July 15, 2021, the spot cost of deposits was 0.44%. "We expect our deposit costs to be at or below 40 basis points by September 30, 2021," stated Sidhu.
Very Strong Growth in Tangible Common Equity and Tangible Book Value Per Share
Customers experienced significant improvements in regulatory capital ratios in Q2 2021 as compared to a year ago. Customers Bancorp's tangible common equity (a non-GAAP measure) increased by $253.6 million to $1.0 billion at June 30, 2021 from $775.8 million at June 30, 2020, and the tangible book value per common share (a non-GAAP measure) increased to $31.82 at June 30, 2021 from $24.62 at June 30, 2020, an increase of 29.2%. Customers remains well capitalized by all regulatory measures, leaving us well positioned to redeem a portion of the preferred stock prior to year-end subject to routine and customary regulatory approval. At the Customers Bancorp level, the total risk based capital ratio (estimate) and tangible common equity to tangible assets ratio ("TCE ratio"), excluding PPP loans (a non-GAAP measure), were 13.2% and 7.7%, respectively, at June 30, 2021. At March 31, 2021, Customers Bancorp's total risk based capital ratio and TCE ratio, excluding PPP loans (a non-GAAP measure), were 12.4% and 7.1%, respectively. "As a consequence of PPP related income and a potential cyclical decline in mortgage warehouse loans, we expect our capital levels to increase sharply in the second half of 2021 with the TCE ratio excluding PPP loans to be close to 9% by December 31, 2021," commented Customers Bancorp CFO, Carla Leibold.
Loan Portfolio Management During the COVID-19 Crisis
Over the last decade, Customers has developed a suite of commercial and retail loan products with one particularly important common denominator: relatively low credit risk assumption. The Bank’s C&I, mortgage warehouse, specialty finance lines of business, and multi-family loans for example, are characterized by conservative underwriting standards and low loss rates. Because of this emphasis, the Bank’s credit quality to-date has been healthy despite a highly adverse economic environment. Maintaining strong asset quality also requires a highly active portfolio monitoring process. In addition to frequent client outreach and monitoring at the individual loan level, Customers employs a bottom-up data driven approach to analyze its commercial portfolio.
Strong commercial loan portfolio with very low concentration in COVID-19 impacted industries and CRE
•Total commercial deferments declined to $89.8 million, or 0.8% of total loans and leases, excluding PPP loans (a non-GAAP measure), at June 30, 2021, down from $176.1 million, or 1.6% of total loans and leases, excluding PPP loans, at March 31, 2021. Customers' commercial deferments peaked at about $1.2 billion in July 2020.
•Exposure to industry segments significantly impacted by COVID-19 is not substantial. At June 30, 2021, Customers had $82.8 million in energy and utilities exposure (with no deferments); $62.0 million in colleges
3
and universities (with no deferments); $62.2 million in CRE retail sales exposure (mostly auto sales; with no deferments); $29.9 million in franchise restaurants and dining (with no deferments); and $26.1 million in entertainment only businesses (with no deferments).
•At June 30, 2021, the hospitality portfolio was $399.3 million, or 3.8% of total loans and leases, excluding PPP loans, with $59.2 million in deferment. Approximately 79.5% ($317.4 million) represents “flagged” facilities, with the majority of the non-flagged being high-end destination hotels in Cape May (NJ), Avalon (NJ), and Long Island (NY). We believe the majority of the hotels have sufficient cash resources to get through the COVID-19 crisis.
•At June 30, 2021, the healthcare portfolio was approximately $460 million, comprised predominantly of skilled nursing, which has been deemed an essential business and through a number of federal and state actions has been provided immunity from liability for COVID-19 related deaths. No deferments have been requested and there are no delinquencies.
•The multi-family portfolio is highly seasoned, with a weighted average loan to value of 61.7% as of quarter-end. 55.77% of the portfolio was in New York City, of which 70.53% was in rent controlled/regulated properties. As of June 30, 2021, no deferments have been requested.
•At June 30, 2021, investment CRE had a weighted average loan to value of 63.2%, with approximately 52% of the portfolio housed in New York, Philadelphia and surrounding markets. As of June 30, 2021, $4.4 million of the portfolio was on deferment, with minimal exposure to the office market.
Consumer installment, mortgage and home equity loan portfolios continue to perform well
•Total consumer-related deferments declined to $8.4 million, or 0.1% of total loans and leases, excluding PPP loans (a non-GAAP measure), at June 30, 2021, down from $13.0 million at March 31, 2021.
•The $1.6 billion consumer installment loan portfolio outperformed industry peers with deferments dropping to 0.31% and 30+ day delinquency at only 0.66%. Strong credit quality (avg. FICO at origination: 740), low concentration in at-risk job segments, and outstanding performance of CB Direct originations have resulted in solid results through the end of Q2 2021.
•The consumer installment portfolio has been managed to moderate growth and strengthening credit quality, by replacing run-off with CB Direct originations with higher FICO scores.
Key Profitability Trends
Net Interest Income
Net interest income totaled $138.8 million in Q2 2021, an increase of $6.0 million from Q1 2021, primarily due to a $755.1 million net increase in average interest-earning assets and a decrease in the cost of interest-bearing liabilities. Interest-earning asset growth was driven by increases in consumer loans and the latest round of PPP loans, offset in part by PPP loan forgiveness from the first two rounds, which accelerated the recognition of net deferred loan origination fees, and decreases in commercial loans to mortgage companies and multi-family loans. Compared to Q1 2021, total loan yields decreased 28 basis points to 3.74%. The decrease is attributable to lower yields on commercial and industrial loans and leases, increased originations of PPP loans in the latest round and lower forgiveness of PPP loans from the first two rounds, offset in part by higher yields on consumer loans. Total borrowing costs decreased by 23 basis points to 0.77% primarily due to the balance sheet restructuring completed in Q1 2021 and lower utilization of the FRB PPP Liquidity Facility, costing 0.35%, due to the PPP loan forgiveness from the first two rounds and excess cash available to fund additional PPP round 3 originations. FHLB advances and federal funds purchased were also paid off during Q2 2021 due to sufficient liquidity. "It is difficult to predict net interest income in future periods because the timing of PPP forgiveness results in the accelerated recognition of net deferred fees and also affects the amount of net interest income expected to be earned while the PPP loans are held on our balance sheet," commented Mr. Sidhu.
Provision for Credit Losses
The provision for credit losses on loans and leases in Q2 2021 was $3.3 million, compared to a $2.9 million benefit (release) in Q1 2021. The provision in Q2 2021 primarily resulted from an increase in provision for consumer installment loans from continued growth, offset in part by the benefit (release) to the provision for commercial loans resulting from continuing improvement in forecasts of macroeconomic conditions since Q4 2020. The allowance for credit losses on loans and leases represented 1.6% of total loans and leases receivable, excluding PPP loans (a non-GAAP measure) at June 30, 2021, compared to 1.7% at March 31, 2021,and 2.2% at June 30, 2020. Customers' non-
4
performing loans at June 30, 2021 were only 0.27% of total loans and leases, a significant improvement from 0.56% at June 30, 2020.
Non-Interest Income
Non-interest income totaled $16.8 million for Q2 2021, a decrease of $1.6 million compared to Q1 2021. The decrease in non-interest income primarily resulted from decreases of $21.8 million in gain on sale of investment securities and $3.0 million in unrealized gain on derivatives, offset in part by a $24.5 million decrease in loss on cash flow hedge derivative terminations recorded in Q1 2021. In Q2 2021, the change in the fair value of foreign equity securities and the sale of the foreign subsidiaries that held those securities resulted in a net loss of $1.1 million.
Non-Interest Expense
Non-interest expense totaled $70.8 million for Q2 2021, an increase of $8.9 million compared to Q1 2021. The increase was primarily due to approximately $2.5 million of compensation expense associated with an executive's retirement and other one-time benefits, $2.4 million of increased PPP-related costs primarily due to outside professional services used to support the PPP forgiveness process and our participation in the latest round of PPP, increased consumer installment servicing expense of $1.0 million, increased stock-based compensation of $0.9 million related to new awards, and a benefit (release) to credit losses for unfunded commitments of $1.3 million recorded in Q1 2021. "Looking ahead, we expect non-interest expenses to be lower in Q3 2021," stated Ms. Leibold.
Taxes
Income tax expense from continuing operations increased by $2.5 million to $20.1 million in Q2 2021 from $17.6 million in Q1 2021 primarily due to an increase in compensation expense associated with an executive's retirement that exceeded the limit for tax deduction purposes, along with an increase in projected pre-tax income from continuing operations. Customers expects the full-year 2021 effective tax rate from continuing operations to be approximately 23% to 25%, which is comparable to previous years.
Net Loss From Discontinued Operations
The divestiture of BankMobile Technologies, Inc. was completed on January 4, 2021, and its historical financial results are presented as discontinued operations.
Outlook
“Looking ahead, we are very optimistic about the prospects of our company. The best in class tech agility of Customers Bancorp has allowed us to be a major participant in the third round of PPP and to incubate new lines of businesses that leverage our fintech relationships. We expect to launch a private real-time, blockchain-based B2B payments platform with integration of digital and legacy payment rails. The platform will deliver enhanced payments functionality for our business clients and is expected to generate additional deposit growth in targeted niches, such as real estate, monetary and currency exchanges and institutional investments. We also expect our tangible common equity and regulatory capital levels to achieve targeted levels within the next 12 months and our credit quality to remain in line with or better than peers. The financial benefits of PPP aside, we project our recurring earnings power to expand to at least the $4.00 level during 2021 and 2022 and expect to achieve $6.00 in core EPS in 2025 rather than 2026,” concluded Mr. Sidhu.
Our updated financial guidance is as follows:
•Loan growth, excluding PPP and mortgage warehouse balances, is expected to average in the mid-to-high single digits over the next several quarters.
•The balance of commercial loans to mortgage companies is expected to decline to $1.6 billion - $2.4 billion at December 31, 2021.
•The Total Capital Ratio is expected to be about 14.0% by year-end 2021. The TCE ratio excluding PPP loans is expected to be close to 9.0% by year-end 2021.
•We project the NIM, excluding PPP loans, to remain within the 3.25% - 3.50% range for the second half of 2021.
•We project an effective tax rate from continuing operations for 2021 of 23.0% - 25.0%.
•We now expect to earn at least $6.00 in core EPS in 2021 and 2022. Our core EPS guidance includes the net interest income expected to be earned on the PPP loans.
5
•Excluding PPP loans, we expect to earn at least $4 in core EPS in 2021 and 2022 and expect to achieve $6 in core EPS by 2025 rather than 2026.
2021 NIM expansion is expected to be achieved by:
•Remixing the loan portfolio away from commercial loans to mortgage companies toward other C&I categories and consumer installment loans.
•Restructuring of the asset and liability side of the balance sheet that was completed in Q1 2021.
•Bringing our total cost of deposits down to around 35 basis points by year-end 2021.
6
Webcast
Date: Thursday, July 29, 2021
Time: 9:00 AM EDT
The live audio webcast, presentation slides, and earnings press release will be made available at https://www.customersbank.com/investor-relations/ and at the Customers Bancorp 2nd Quarter Earnings Webcast.
You may submit questions in advance of the live webcast by emailing Customers' Communications & Marketing Director, David Patti at [email protected]; questions may also be asked during the webcast through the webcast application.
The webcast will be archived for viewing on the Customers Bancorp Investor Relations page and available beginning approximately two hours after the conclusion of the live event.
Institutional Background
Customers Bancorp, Inc. (NYSE:CUBI) is a bank holding company located in West Reading, Pennsylvania engaged in banking and related businesses through its bank subsidiary, Customers Bank, a full-service bank with $19.6 billion in assets at June 30, 2021. A member of the Federal Reserve System with deposits insured by the Federal Deposit Insurance Corporation, Customers Bank is an equal opportunity lender that provides a range of banking and lending services to small and medium-sized businesses, professionals, individuals and families. Services and products are available wherever permitted by law through mobile-first apps, online portals, and a network of offices and branches.
“Safe Harbor” Statement
In addition to historical information, this press release may contain “forward-looking statements” within the meaning of the “safe harbor” provisions of the Private Securities Litigation Reform Act of 1995. These forward-looking statements include statements with respect to Customers Bancorp, Inc.’s strategies, goals, beliefs, expectations, estimates, intentions, capital raising efforts, financial condition and results of operations, future performance and business. Statements preceded by, followed by, or that include the words “may,” “could,” “should,” “pro forma,” “looking forward,” “would,” “believe,” “expect,” “anticipate,” “estimate,” “intend,” “plan,” or similar expressions generally indicate a forward-looking statement. These forward-looking statements involve risks and uncertainties that are subject to change based on various important factors (some of which, in whole or in part, are beyond Customers Bancorp, Inc.’s control). Numerous competitive, economic, regulatory, legal and technological events and factors, among others, could cause Customers Bancorp, Inc.’s financial performance to differ materially from the goals, plans, objectives, intentions and expectations expressed in such forward-looking statements, including: the adverse impact on the U.S. economy, including the markets in which we operate, of the coronavirus outbreak, and the impact of a slowing U.S. economy and increased unemployment on the performance of our loan and lease portfolio, the market value of our investment securities, the demand for our products and services and the availability of sources of funding; the effects of actions by the federal government, including the Board of Governors of the Federal Reserve System and other government agencies, that affect market interest rates and the money supply; actions that we and our customers take in response to these developments and the effects such actions have on our operations, products, services and customer relationships; and the effects of any changes in accounting standards or policies. Customers Bancorp, Inc. cautions that the foregoing factors are not exclusive, and neither such factors nor any such forward-looking statement takes into account the impact of any future events. All forward-looking statements and information set forth herein are based on management’s current beliefs and assumptions as of the date hereof and speak only as of the date they are made. For a more complete discussion of the assumptions, risks and uncertainties related to our business, you are encouraged to review Customers Bancorp, Inc.’s filings with the Securities and Exchange Commission, including its most recent annual report on Form 10-K for the year ended December 31, 2020, subsequently filed quarterly reports on Form 10-Q and current reports on Form 8-K, including any amendments thereto, that update or provide information in addition to the information included in the Form 10-K and Form 10-Q filings, if any. Customers Bancorp, Inc. does not undertake to update any forward-looking statement whether written or oral, that may be made from time to time by Customers Bancorp, Inc. or by or on behalf of Customers Bank, except as may be required under applicable law.
7
Q2 2021 Overview
The following table presents a summary of key earnings and performance metrics for the quarter ended June 30, 2021 and the preceding four quarters:
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| EARNINGS SUMMARY - UNAUDITED | |||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data and stock price data) | Q2 | Q1 | Q4 | Q3 | Q2 | Six Months Ended June 30, | |||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | 2021 | 2020 | |||||||||||||||||||||||
| GAAP Profitability Metrics: | |||||||||||||||||||||||||||||
| Net income available to common shareholders (from continuing and discontinued operations) | $ | 58,042 | $ | 33,204 | $ | 52,831 | $ | 47,085 | $ | 19,137 | $ | 91,246 | $ | 18,621 | |||||||||||||||
| Per share amounts: | |||||||||||||||||||||||||||||
| Earnings per share - basic | $ | 1.80 | $ | 1.04 | $ | 1.67 | $ | 1.49 | $ | 0.61 | $ | 2.84 | $ | 0.59 | |||||||||||||||
| Earnings per share - diluted | $ | 1.72 | $ | 1.01 | $ | 1.65 | $ | 1.48 | $ | 0.61 | $ | 2.74 | $ | 0.59 | |||||||||||||||
Book value per common share (1) | $ | 31.94 | $ | 30.13 | $ | 28.37 | $ | 26.43 | $ | 25.08 | $ | 31.94 | $ | 25.08 | |||||||||||||||
CUBI stock price (1) | $ | 38.99 | $ | 31.82 | $ | 18.18 | $ | 11.20 | $ | 12.02 | $ | 38.99 | $ | 12.02 | |||||||||||||||
CUBI stock price as % of book value (1) | 122 | % | 106 | % | 64 | % | 42 | % | 48 | % | 122 | % | 48 | % | |||||||||||||||
| Average shares outstanding - basic | 32,279,625 | 31,883,946 | 31,638,447 | 31,517,504 | 31,477,591 | 32,082,878 | 31,434,371 | ||||||||||||||||||||||
| Average shares outstanding - diluted | 33,741,468 | 32,841,711 | 31,959,100 | 31,736,311 | 31,625,771 | 33,294,075 | 31,625,669 | ||||||||||||||||||||||
Shares outstanding (1) | 32,353,256 | 32,238,762 | 31,705,088 | 31,555,124 | 31,510,287 | 32,353,256 | 31,510,287 | ||||||||||||||||||||||
| Return on average assets ("ROAA") | 1.27 | % | 0.80 | % | 1.23 | % | 1.12 | % | 0.62 | % | 1.04 | % | 0.40 | % | |||||||||||||||
| Return on average common equity ("ROCE") | 23.22 | % | 14.66 | % | 24.26 | % | 23.05 | % | 9.97 | % | 19.15 | % | 4.74 | % | |||||||||||||||
| Efficiency ratio | 46.59 | % | 48.89 | % | 43.56 | % | 46.76 | % | 50.73 | % | 47.64 | % | 52.52 | % | |||||||||||||||
Non-GAAP Profitability Metrics (2): | |||||||||||||||||||||||||||||
| Core earnings | $ | 59,303 | $ | 70,308 | $ | 54,588 | $ | 38,439 | $ | 21,413 | $ | 129,611 | $ | 26,499 | |||||||||||||||
| Adjusted pre-tax pre-provision net income | $ | 86,467 | $ | 86,769 | $ | 77,896 | $ | 64,146 | $ | 53,931 | $ | 173,236 | $ | 98,154 | |||||||||||||||
| Per share amounts: | |||||||||||||||||||||||||||||
| Core earnings per share - diluted | $ | 1.76 | $ | 2.14 | $ | 1.71 | $ | 1.21 | $ | 0.68 | $ | 3.89 | $ | 0.84 | |||||||||||||||
Tangible book value per common share (1) | $ | 31.82 | $ | 30.01 | $ | 27.92 | $ | 25.97 | $ | 24.62 | $ | 31.82 | $ | 24.62 | |||||||||||||||
CUBI stock price as % of tangible book value (1) | 123 | % | 106 | % | 65 | % | 43 | % | 49 | % | 123 | % | 49 | % | |||||||||||||||
| Core ROAA | 1.30 | % | 1.61 | % | 1.26 | % | 0.93 | % | 0.68 | % | 1.45 | % | 0.52 | % | |||||||||||||||
| Core ROCE | 23.72 | % | 31.03 | % | 25.06 | % | 18.82 | % | 11.16 | % | 27.20 | % | 6.75 | % | |||||||||||||||
| Adjusted ROAA - pre-tax and pre-provision | 1.80 | % | 1.90 | % | 1.70 | % | 1.43 | % | 1.48 | % | 1.85 | % | 1.50 | % | |||||||||||||||
| Adjusted ROCE - pre-tax and pre-provision | 33.27 | % | 36.80 | % | 34.20 | % | 29.73 | % | 26.24 | % | 34.95 | % | 23.16 | % | |||||||||||||||
| Net interest margin, tax equivalent | 2.98 | % | 3.00 | % | 2.78 | % | 2.50 | % | 2.65 | % | 2.99 | % | 2.80 | % | |||||||||||||||
| Net interest margin, tax equivalent, excluding PPP loans | 3.30 | % | 2.99 | % | 3.04 | % | 2.86 | % | 2.97 | % | 3.14 | % | 2.98 | % | |||||||||||||||
| Core efficiency ratio | 44.33 | % | 41.13 | % | 42.89 | % | 46.10 | % | 47.84 | % | 42.76 | % | 50.25 | % | |||||||||||||||
| Asset Quality: | |||||||||||||||||||||||||||||
| Net charge-offs | $ | 6,591 | $ | 12,521 | $ | 8,472 | $ | 17,299 | $ | 10,325 | $ | 19,112 | $ | 29,035 | |||||||||||||||
| Annualized net charge-offs to average total loans and leases | 0.16 | % | 0.33 | % | 0.21 | % | 0.45 | % | 0.32 | % | 0.24 | % | 0.52 | % | |||||||||||||||
Non-performing loans ("NPLs") to total loans and leases (1) | 0.27 | % | 0.30 | % | 0.45 | % | 0.38 | % | 0.56 | % | 0.27 | % | 0.56 | % | |||||||||||||||
Reserves to NPLs (1) | 269.96 | % | 264.21 | % | 204.48 | % | 244.70 | % | 185.36 | % | 269.96 | % | 185.36 | % | |||||||||||||||
| Non-performing assets ("NPAs") to total assets | 0.24 | % | 0.26 | % | 0.39 | % | 0.34 | % | 0.48 | % | 0.24 | % | 0.48 | % | |||||||||||||||
Customers Bank Capital Ratios (3): | |||||||||||||||||||||||||||||
| Common equity Tier 1 capital to risk-weighted assets | 12.35 | % | 11.75 | % | 10.62 | % | 10.12 | % | 10.64 | % | 12.35 | % | 10.64 | % | |||||||||||||||
| Tier 1 capital to risk-weighted assets | 12.35 | % | 11.75 | % | 10.62 | % | 10.12 | % | 10.64 | % | 12.35 | % | 10.64 | % | |||||||||||||||
| Total capital to risk-weighted assets | 13.72 | % | 13.11 | % | 12.06 | % | 11.62 | % | 12.30 | % | 13.72 | % | 12.30 | % | |||||||||||||||
| Tier 1 capital to average assets (leverage ratio) | 9.07 | % | 9.35 | % | 9.21 | % | 9.29 | % | 9.59 | % | 9.07 | % | 9.59 | % | |||||||||||||||
| (1) Metric is a spot balance for the last day of each quarter presented. | |||||||||||||||||||||||||||||
| (2) Non-GAAP measures exclude net loss from discontinued operations, loss on sale of foreign subsidiaries, unrealized gains (losses) on loans held for sale, investment securities gains and losses, loss on cash flow hedge derivative terminations, severance expense, merger and acquisition-related expenses, losses realized from the sale of non-QM residential mortgage loans, loss upon acquisition of interest-only GNMA securities, legal reserves, credit valuation adjustments on derivatives, risk participation agreement mark-to-market adjustments, goodwill and intangible assets, and PPP loans. These notable items are not included in Customers' disclosures of core earnings and other core profitability metrics. Please note that not each of the aforementioned adjustments affected the reported amount in each of the periods presented. Customers' reasons for the use of these non-GAAP measures and a detailed reconciliation between the non-GAAP measures and the comparable GAAP amounts are included at the end of this document. | |||||||||||||||||||||||||||||
| (3) Regulatory capital ratios are estimated for Q2 2021 and actual for the remaining periods. In accordance with regulatory capital rules, Customers elected an option to delay the estimated impact of CECL on its regulatory capital over a five-year transition period ending January 1, 2025. As a result, capital ratios and amounts as of Q2 2021 exclude the impact of the increased allowance for credit losses on loans and leases and unfunded loan commitments attributed to the adoption of CECL and 25% of the quarterly provision for credit losses for subsequent quarters through Q4 2021. | |||||||||||||||||||||||||||||
8
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| CONSOLIDATED STATEMENTS OF OPERATIONS - UNAUDITED | |||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Q2 | Q1 | Q4 | Q3 | Q2 | June 30, | ||||||||||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | 2021 | 2020 | |||||||||||||||||||||||||||||||||||
| Interest income: | |||||||||||||||||||||||||||||||||||||||||
| Loans and leases | $ | 153,608 | $ | 152,117 | $ | 145,414 | $ | 132,107 | $ | 118,447 | $ | 305,725 | $ | 234,527 | |||||||||||||||||||||||||||
| Investment securities | 8,327 | 7,979 | 6,777 | 6,297 | 6,155 | 16,306 | 11,132 | ||||||||||||||||||||||||||||||||||
| Other | 946 | 1,019 | 902 | 1,246 | 616 | 1,965 | 4,902 | ||||||||||||||||||||||||||||||||||
| Total interest income | 162,881 | 161,115 | 153,093 | 139,650 | 125,218 | 323,996 | 250,561 | ||||||||||||||||||||||||||||||||||
| Interest expense: | |||||||||||||||||||||||||||||||||||||||||
| Deposits | 15,653 | 15,658 | 16,107 | 18,347 | 23,238 | 31,311 | 57,591 | ||||||||||||||||||||||||||||||||||
| FHLB advances | 963 | 5,192 | 5,749 | 5,762 | 4,736 | 6,155 | 10,127 | ||||||||||||||||||||||||||||||||||
| Subordinated debt | 2,689 | 2,689 | 2,688 | 2,689 | 2,689 | 5,378 | 5,378 | ||||||||||||||||||||||||||||||||||
| FRB PPP liquidity facility, federal funds purchased and other borrowings | 4,819 | 4,845 | 5,603 | 5,413 | 2,573 | 9,664 | 4,163 | ||||||||||||||||||||||||||||||||||
| Total interest expense | 24,124 | 28,384 | 30,147 | 32,211 | 33,236 | 52,508 | 77,259 | ||||||||||||||||||||||||||||||||||
| Net interest income | 138,757 | 132,731 | 122,946 | 107,439 | 91,982 | 271,488 | 173,302 | ||||||||||||||||||||||||||||||||||
| Provision (benefit) for credit losses on loans and leases | 3,291 | (2,919) | (2,913) | 12,955 | 20,946 | 372 | 52,732 | ||||||||||||||||||||||||||||||||||
| Net interest income after provision (benefit) for credit losses on loans and leases | 135,466 | 135,650 | 125,859 | 94,484 | 71,036 | 271,116 | 120,570 | ||||||||||||||||||||||||||||||||||
| Non-interest income: | |||||||||||||||||||||||||||||||||||||||||
| Interchange and card revenue | 84 | 85 | 91 | 92 | 193 | 169 | 463 | ||||||||||||||||||||||||||||||||||
| Deposit fees | 891 | 863 | 823 | 650 | 502 | 1,754 | 1,054 | ||||||||||||||||||||||||||||||||||
| Commercial lease income | 5,311 | 5,205 | 4,853 | 4,510 | 4,508 | 10,516 | 8,776 | ||||||||||||||||||||||||||||||||||
| Bank-owned life insurance | 2,765 | 1,679 | 1,744 | 1,746 | 1,757 | 4,444 | 3,519 | ||||||||||||||||||||||||||||||||||
| Mortgage warehouse transactional fees | 3,265 | 4,247 | 3,681 | 3,320 | 2,582 | 7,512 | 4,533 | ||||||||||||||||||||||||||||||||||
| Gain (loss) on sale of SBA and other loans | 1,900 | 1,575 | 1,689 | 286 | 23 | 3,475 | 34 | ||||||||||||||||||||||||||||||||||
| Mortgage banking income (loss) | 386 | 463 | 346 | 1,013 | 38 | 849 | 334 | ||||||||||||||||||||||||||||||||||
| Gain (loss) on sale of investment securities | 1,812 | 23,566 | 44 | 11,707 | 4,353 | 25,378 | 8,328 | ||||||||||||||||||||||||||||||||||
| Unrealized gain (loss) on investment securities | 1,746 | 974 | 1,387 | 238 | 1,200 | 2,720 | (178) | ||||||||||||||||||||||||||||||||||
| Loss on sale of foreign subsidiaries | (2,840) | — | — | — | — | (2,840) | — | ||||||||||||||||||||||||||||||||||
| Unrealized gain (loss) on derivatives | (439) | 2,537 | 804 | 549 | (4,158) | 2,098 | (5,304) | ||||||||||||||||||||||||||||||||||
| Loss on cash flow hedge derivative terminations | — | (24,467) | — | — | — | (24,467) | — | ||||||||||||||||||||||||||||||||||
| Other | 1,941 | 1,741 | 621 | 753 | 713 | 3,682 | 1,312 | ||||||||||||||||||||||||||||||||||
| Total non-interest income | 16,822 | 18,468 | 16,083 | 24,864 | 11,711 | 35,290 | 22,871 | ||||||||||||||||||||||||||||||||||
| Non-interest expense: | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 28,023 | 23,971 | 25,600 | 24,752 | 23,192 | 51,994 | 43,716 | ||||||||||||||||||||||||||||||||||
| Technology, communication and bank operations | 19,618 | 19,988 | 16,021 | 13,005 | 11,103 | 39,606 | 21,642 | ||||||||||||||||||||||||||||||||||
| Professional services | 8,234 | 6,289 | 5,449 | 4,421 | 2,974 | 14,523 | 6,519 | ||||||||||||||||||||||||||||||||||
| Occupancy | 2,482 | 2,621 | 2,742 | 3,368 | 2,639 | 5,103 | 5,252 | ||||||||||||||||||||||||||||||||||
| Commercial lease depreciation | 4,415 | 4,291 | 3,982 | 3,663 | 3,643 | 8,706 | 7,070 | ||||||||||||||||||||||||||||||||||
| FDIC assessments, non-income taxes and regulatory fees | 2,602 | 2,719 | 2,642 | 3,784 | 2,368 | 5,321 | 5,235 | ||||||||||||||||||||||||||||||||||
| Merger and acquisition related expenses | — | 418 | 709 | 658 | — | 418 | — | ||||||||||||||||||||||||||||||||||
| Loan workout | 102 | (261) | 123 | 846 | 1,808 | (159) | 2,175 | ||||||||||||||||||||||||||||||||||
| Advertising and promotion | 313 | 561 | — | — | 372 | 874 | 1,795 | ||||||||||||||||||||||||||||||||||
| Other | 5,034 | 1,330 | 2,665 | 1,788 | 1,692 | 6,364 | 5,354 | ||||||||||||||||||||||||||||||||||
| Total non-interest expense | 70,823 | 61,927 | 59,933 | 56,285 | 49,791 | 132,750 | 98,758 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense | 81,465 | 92,191 | 82,009 | 63,063 | 32,956 | 173,656 | 44,683 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 20,124 | 17,560 | 23,447 | 12,016 | 7,980 | 37,684 | 11,254 | ||||||||||||||||||||||||||||||||||
| Net income from continuing operations | 61,341 | 74,631 | 58,562 | 51,047 | 24,976 | 135,972 | 33,429 | ||||||||||||||||||||||||||||||||||
| Loss from discontinued operations before income taxes | — | (20,354) | (3,539) | (347) | (3,190) | (20,354) | (9,911) | ||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) from discontinued operations | — | 17,682 | (1,222) | 185 | (932) | 17,682 | (2,299) | ||||||||||||||||||||||||||||||||||
| Net loss from discontinued operations | — | (38,036) | (2,317) | (532) | (2,258) | (38,036) | (7,612) | ||||||||||||||||||||||||||||||||||
| Net income | 61,341 | 36,595 | 56,245 | 50,515 | 22,718 | 97,936 | 25,817 | ||||||||||||||||||||||||||||||||||
| Preferred stock dividends | 3,299 | 3,391 | 3,414 | 3,430 | 3,581 | 6,690 | 7,196 | ||||||||||||||||||||||||||||||||||
| Net income available to common shareholders | $ | 58,042 | $ | 33,204 | $ | 52,831 | $ | 47,085 | $ | 19,137 | $ | 91,246 | $ | 18,621 | |||||||||||||||||||||||||||
| Basic earnings per common share from continuing operations | $ | 1.80 | $ | 2.23 | $ | 1.74 | $ | 1.51 | $ | 0.68 | $ | 4.03 | $ | 0.83 | |||||||||||||||||||||||||||
| Basic earnings per common share | $ | 1.80 | $ | 1.04 | $ | 1.67 | $ | 1.49 | $ | 0.61 | $ | 2.84 | $ | 0.59 | |||||||||||||||||||||||||||
| Diluted earnings per common share from continuing operations | $ | 1.72 | $ | 2.17 | $ | 1.73 | $ | 1.50 | $ | 0.68 | $ | 3.88 | $ | 0.83 | |||||||||||||||||||||||||||
| Diluted earnings per common share | $ | 1.72 | $ | 1.01 | $ | 1.65 | $ | 1.48 | $ | 0.61 | $ | 2.74 | $ | 0.59 | |||||||||||||||||||||||||||
9
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| CONSOLIDATED BALANCE SHEET - UNAUDITED | |||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | |||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | |||||||||||||||||||||||||
| ASSETS | |||||||||||||||||||||||||||||
| Cash and due from banks | $ | 36,837 | $ | 3,123 | $ | 78,090 | $ | 5,822 | $ | 44,577 | |||||||||||||||||||
| Interest earning deposits | 393,663 | 512,241 | 615,264 | 325,594 | 1,022,753 | ||||||||||||||||||||||||
| Cash and cash equivalents | 430,500 | 515,364 | 693,354 | 331,416 | 1,067,330 | ||||||||||||||||||||||||
| Investment securities, at fair value | 1,526,792 | 1,441,904 | 1,210,285 | 1,133,831 | 681,382 | ||||||||||||||||||||||||
| Loans held for sale | 34,540 | 46,106 | 79,086 | 26,689 | 464,164 | ||||||||||||||||||||||||
| Loans receivable, mortgage warehouse, at fair value | 2,855,284 | 3,407,622 | 3,616,432 | 3,913,593 | 2,793,164 | ||||||||||||||||||||||||
| Loans receivable, PPP | 6,305,056 | 5,178,089 | 4,561,365 | 4,964,105 | 4,760,427 | ||||||||||||||||||||||||
| Loans and leases receivable | 7,772,142 | 7,536,489 | 7,575,368 | 7,700,892 | 7,272,447 | ||||||||||||||||||||||||
| Allowance for credit losses on loans and leases | (125,436) | (128,736) | (144,176) | (155,561) | (159,905) | ||||||||||||||||||||||||
| Total loans and leases receivable, net of allowance for credit losses on loans and leases | 16,807,046 | 15,993,464 | 15,608,989 | 16,423,029 | 14,666,133 | ||||||||||||||||||||||||
| FHLB, Federal Reserve Bank, and other restricted stock | 39,895 | 69,420 | 71,368 | 70,387 | 91,023 | ||||||||||||||||||||||||
| Accrued interest receivable | 90,009 | 83,186 | 80,412 | 65,668 | 49,911 | ||||||||||||||||||||||||
| Bank premises and equipment, net | 10,391 | 10,943 | 11,225 | 11,308 | 7,879 | ||||||||||||||||||||||||
| Bank-owned life insurance | 329,421 | 281,923 | 280,067 | 277,826 | 275,842 | ||||||||||||||||||||||||
| Goodwill and other intangibles | 3,853 | 3,911 | 3,969 | 4,028 | 4,086 | ||||||||||||||||||||||||
| Other assets | 362,661 | 371,439 | 338,438 | 354,010 | 512,209 | ||||||||||||||||||||||||
| Assets of discontinued operations | — | — | 62,055 | 80,535 | 83,159 | ||||||||||||||||||||||||
| Total assets | $ | 19,635,108 | $ | 18,817,660 | $ | 18,439,248 | $ | 18,778,727 | $ | 17,903,118 | |||||||||||||||||||
| LIABILITIES AND SHAREHOLDERS' EQUITY | |||||||||||||||||||||||||||||
| Demand, non-interest bearing deposits | $ | 2,699,869 | $ | 2,687,628 | $ | 2,356,998 | $ | 2,327,017 | $ | 1,879,789 | |||||||||||||||||||
| Interest bearing deposits | 11,174,070 | 9,784,812 | 8,952,931 | 8,512,060 | 9,086,086 | ||||||||||||||||||||||||
| Total deposits | 13,873,939 | 12,472,440 | 11,309,929 | 10,839,077 | 10,965,875 | ||||||||||||||||||||||||
| Federal funds purchased | — | 365,000 | 250,000 | 680,000 | — | ||||||||||||||||||||||||
| FHLB advances | — | 850,000 | 850,000 | 850,000 | 850,000 | ||||||||||||||||||||||||
| Other borrowings | 124,240 | 124,138 | 124,037 | 123,935 | 123,833 | ||||||||||||||||||||||||
| Subordinated debt | 181,534 | 181,464 | 181,394 | 181,324 | 181,255 | ||||||||||||||||||||||||
| FRB PPP liquidity facility | 3,865,865 | 3,284,156 | 4,415,016 | 4,811,009 | 4,419,967 | ||||||||||||||||||||||||
| Accrued interest payable and other liabilities | 338,801 | 351,741 | 152,082 | 185,927 | 296,192 | ||||||||||||||||||||||||
| Liabilities of discontinued operations | — | — | 39,704 | 55,964 | 58,149 | ||||||||||||||||||||||||
| Total liabilities | 18,384,379 | 17,628,939 | 17,322,162 | 17,727,236 | 16,895,271 | ||||||||||||||||||||||||
| Preferred stock | 217,471 | 217,471 | 217,471 | 217,471 | 217,471 | ||||||||||||||||||||||||
| Common stock | 33,634 | 33,519 | 32,986 | 32,836 | 32,791 | ||||||||||||||||||||||||
| Additional paid in capital | 519,294 | 515,318 | 455,592 | 452,965 | 450,665 | ||||||||||||||||||||||||
| Retained earnings | 496,844 | 438,802 | 438,581 | 385,750 | 338,665 | ||||||||||||||||||||||||
| Accumulated other comprehensive income (loss) | 5,266 | 5,391 | (5,764) | (15,751) | (9,965) | ||||||||||||||||||||||||
| Treasury stock, at cost | (21,780) | (21,780) | (21,780) | (21,780) | (21,780) | ||||||||||||||||||||||||
| Total shareholders' equity | 1,250,729 | 1,188,721 | 1,117,086 | 1,051,491 | 1,007,847 | ||||||||||||||||||||||||
| Total liabilities & shareholders' equity | $ | 19,635,108 | $ | 18,817,660 | $ | 18,439,248 | $ | 18,778,727 | $ | 17,903,118 | |||||||||||||||||||
10
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | ||||||||||||||||||||||||||
| AVERAGE BALANCE SHEET / NET INTEREST MARGIN - UNAUDITED | ||||||||||||||||||||||||||
| (Dollars in thousands) | ||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||
| June 30, 2021 | March 31, 2021 | June 30, 2020 | ||||||||||||||||||||||||
| Average Balance | Average Yield or Cost (%) | Average Balance | Average Yield or Cost (%) | Average Balance | Average Yield or Cost (%) | |||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||
| Interest earning deposits | $ | 646,342 | 0.12% | $ | 1,177,315 | 0.10% | $ | 384,622 | 0.12% | |||||||||||||||||
Investment securities (1) | 1,512,644 | 2.20% | 1,357,558 | 2.35% | 705,389 | 3.49% | ||||||||||||||||||||
| Loans and leases: | ||||||||||||||||||||||||||
| Commercial loans to mortgage companies | 2,737,629 | 3.09% | 3,122,098 | 3.09% | 2,456,067 | 2.91% | ||||||||||||||||||||
| Multi-family loans | 1,551,370 | 3.88% | 1,689,174 | 3.80% | 2,009,847 | 3.87% | ||||||||||||||||||||
Commercial and industrial loans and leases (2) | 2,878,045 | 3.59% | 2,848,328 | 3.97% | 2,460,060 | 4.05% | ||||||||||||||||||||
| Loans receivable, PPP | 6,133,184 | 2.69% | 4,623,213 | 3.41% | 2,754,920 | 1.71% | ||||||||||||||||||||
| Non-owner occupied commercial real estate loans | 1,368,695 | 3.86% | 1,348,938 | 3.85% | 1,392,131 | 3.81% | ||||||||||||||||||||
| Residential mortgages | 346,284 | 3.62% | 373,497 | 3.78% | 429,609 | 3.53% | ||||||||||||||||||||
| Installment loans | 1,467,595 | 9.37% | 1,323,863 | 9.04% | 1,288,999 | 8.72% | ||||||||||||||||||||
Total loans and leases (3) | 16,482,802 | 3.74% | 15,329,111 | 4.02% | 12,791,633 | 3.72% | ||||||||||||||||||||
| Other interest-earning assets | 57,208 | 5.32% | 79,960 | 3.64% | 98,377 | 2.06% | ||||||||||||||||||||
| Total interest-earning assets | 18,698,996 | 3.49% | 17,943,944 | 3.64% | 13,980,021 | 3.60% | ||||||||||||||||||||
| Non-interest-earning assets | 607,952 | 581,777 | 616,683 | |||||||||||||||||||||||
| Assets of discontinued operations | — | — | 78,880 | |||||||||||||||||||||||
| Total assets | $ | 19,306,948 | $ | 18,525,721 | $ | 14,675,584 | ||||||||||||||||||||
| Liabilities | ||||||||||||||||||||||||||
| Interest checking accounts | $ | 3,503,242 | 0.76% | $ | 2,691,723 | 0.84% | $ | 2,482,222 | 0.75% | |||||||||||||||||
| Money market deposit accounts | 4,859,614 | 0.47% | 4,435,930 | 0.55% | 3,034,457 | 0.85% | ||||||||||||||||||||
| Other savings accounts | 1,456,777 | 0.57% | 1,414,350 | 0.69% | 1,177,554 | 1.94% | ||||||||||||||||||||
| Certificates of deposit | 658,698 | 0.78% | 666,239 | 0.97% | 1,734,062 | 1.51% | ||||||||||||||||||||
Total interest-bearing deposits (4) | 10,478,331 | 0.60% | 9,208,242 | 0.69% | 8,428,295 | 1.11% | ||||||||||||||||||||
| FRB PPP liquidity facility | 3,858,733 | 0.35% | 3,941,718 | 0.35% | 942,258 | 0.35% | ||||||||||||||||||||
| Borrowings | 531,757 | 3.85% | 1,171,826 | 3.23% | 2,282,761 | 1.62% | ||||||||||||||||||||
| Total interest-bearing liabilities | 14,868,821 | 0.65% | 14,321,786 | 0.80% | 11,653,314 | 1.15% | ||||||||||||||||||||
Non-interest-bearing deposits (4) | 2,889,781 | 2,819,871 | 1,890,955 | |||||||||||||||||||||||
| Total deposits and borrowings | 17,758,602 | 0.54% | 17,141,657 | 0.67% | 13,544,269 | 0.99% | ||||||||||||||||||||
| Other non-interest-bearing liabilities | 328,251 | 247,798 | 88,913 | |||||||||||||||||||||||
| Liabilities of discontinued operations | — | — | 53,268 | |||||||||||||||||||||||
| Total liabilities | 18,086,853 | 17,389,455 | 13,686,450 | |||||||||||||||||||||||
| Shareholders' equity | 1,220,095 | 1,136,266 | 989,134 | |||||||||||||||||||||||
| Total liabilities and shareholders' equity | $ | 19,306,948 | $ | 18,525,721 | $ | 14,675,584 | ||||||||||||||||||||
| Interest spread | 2.95% | 2.97% | 2.61% | |||||||||||||||||||||||
| Net interest margin | 2.98% | 3.00% | 2.65% | |||||||||||||||||||||||
Net interest margin tax equivalent (5) | 2.98% | 3.00% | 2.65% | |||||||||||||||||||||||
Net interest margin tax equivalent excl. PPP (6) | 3.30% | 2.99% | 2.97% | |||||||||||||||||||||||
| (1) For presentation in this table, average balances and the corresponding average yields for investment securities are based upon historical cost, adjusted for amortization of premiums and accretion of discounts. | ||||||||||||||||||||||||||
| (2) Includes owner occupied commercial real estate loans. | ||||||||||||||||||||||||||
| (3) Includes non-accrual loans, the effect of which is to reduce the yield earned on loans and leases, and deferred loan fees. | ||||||||||||||||||||||||||
(4) Total costs of deposits (including interest bearing and non-interest bearing) were 0.47%, 0.53% and 0.91% for the three months ended June 30, 2021, March 31, 2021 and June 30, 2020, respectively. | ||||||||||||||||||||||||||
| (5) Non-GAAP tax-equivalent basis, using an estimated marginal tax rate of 26% for the three months ended June 30, 2021, March 31, 2021 and June 30, 2020, presented to approximate interest income as a taxable asset. Management uses non-GAAP measures to present historical periods comparable to the current period presentation. In addition, management believes the use of these non-GAAP measures provides additional clarity when assessing Customers’ financial results. These disclosures should not be viewed as substitutes for results determined to be in accordance with U.S. GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other entities. | ||||||||||||||||||||||||||
| (6) Non-GAAP tax-equivalent basis, as described in note (5) for the three months ended June 30, 2021, March 31, 2021 and June 30, 2020, excluding net interest income from PPP loans and related borrowings, along with the related PPP loan balances and PPP fees receivable from interest-earning assets. Management uses non-GAAP measures to present historical periods comparable to the current period presentation. In addition, management believes the use of these non-GAAP measures provides additional clarity when assessing Customers’ financial results. These disclosures should not be viewed as substitutes for results determined to be in accordance with U.S. GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other entities. | ||||||||||||||||||||||||||
11
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||
| AVERAGE BALANCE SHEET / NET INTEREST MARGIN - UNAUDITED | |||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||
| Six Months Ended | |||||||||||||||||
| June 30, 2021 | June 30, 2020 | ||||||||||||||||
| Average Balance | Average Yield or Cost (%) | Average Balance | Average Yield or Cost (%) | ||||||||||||||
| Assets | |||||||||||||||||
| Interest earning deposits | $ | 910,362 | 0.11% | $ | 578,435 | 1.03% | |||||||||||
Investment securities (1) | 1,435,529 | 2.27% | 635,838 | 3.50% | |||||||||||||
| Loans and leases: | |||||||||||||||||
| Commercial loans to mortgage companies | 2,928,802 | 3.09% | 2,148,863 | 3.30% | |||||||||||||
| Multi-family loans | 1,619,891 | 3.84% | 2,111,853 | 3.97% | |||||||||||||
Commercial and industrial loans and leases (2) | 2,863,268 | 3.78% | 2,460,435 | 4.37% | |||||||||||||
| Loans receivable, PPP | 5,382,370 | 3.00% | 1,377,460 | 1.71% | |||||||||||||
| Non-owner occupied commercial real estate loans | 1,358,871 | 3.86% | 1,363,795 | 4.07% | |||||||||||||
| Residential mortgages | 359,815 | 3.71% | 437,782 | 3.75% | |||||||||||||
| Installment loans | 1,396,126 | 9.22% | 1,274,024 | 8.93% | |||||||||||||
Total loans and leases (3) | 15,909,143 | 3.88% | 11,174,212 | 4.22% | |||||||||||||
| Other interest-earning assets | 68,521 | 4.34% | 89,890 | 4.31% | |||||||||||||
| Total interest-earning assets | 18,323,555 | 3.56% | 12,478,375 | 4.04% | |||||||||||||
| Non-interest-earning assets | 594,936 | 565,304 | |||||||||||||||
| Assets of discontinued operations | — | 80,816 | |||||||||||||||
| Total assets | $ | 18,918,491 | $ | 13,124,495 | |||||||||||||
| Liabilities | |||||||||||||||||
| Interest checking accounts | $ | 3,099,725 | 0.80% | $ | 1,888,160 | 0.98% | |||||||||||
| Money market deposit accounts | 4,648,942 | 0.51% | 3,335,006 | 1.37% | |||||||||||||
| Other savings accounts | 1,435,681 | 0.63% | 1,159,479 | 1.99% | |||||||||||||
| Certificates of deposit | 662,447 | 0.87% | 1,629,416 | 1.76% | |||||||||||||
Total interest-bearing deposits (4) | 9,846,795 | 0.64% | 8,012,061 | 1.45% | |||||||||||||
| FRB PPP liquidity facility | 3,899,996 | 0.35% | 471,129 | 0.35% | |||||||||||||
| Borrowings | 850,024 | 3.42% | 1,756,080 | 2.16% | |||||||||||||
| Total interest-bearing liabilities | 14,596,815 | 0.72% | 10,239,270 | 1.52% | |||||||||||||
Non-interest-bearing deposits (4) | 2,855,019 | 1,732,163 | |||||||||||||||
| Total deposits and borrowings | 17,451,834 | 0.61% | 11,971,433 | 1.30% | |||||||||||||
| Other non-interest-bearing liabilities | 288,246 | 92,218 | |||||||||||||||
| Liabilities of discontinued operations | — | 53,600 | |||||||||||||||
| Total liabilities | 17,740,080 | 12,117,251 | |||||||||||||||
| Shareholders' equity | 1,178,411 | 1,007,244 | |||||||||||||||
| Total liabilities and shareholders' equity | $ | 18,918,491 | $ | 13,124,495 | |||||||||||||
| Interest spread | 2.96% | 2.74% | |||||||||||||||
| Net interest margin | 2.99% | 2.79% | |||||||||||||||
Net interest margin tax equivalent (5) | 2.99% | 2.80% | |||||||||||||||
Net interest margin tax equivalent excl. PPP (6) | 3.14% | 2.98% | |||||||||||||||
| (1) For presentation in this table, average balances and the corresponding average yields for investment securities are based upon historical cost, adjusted for amortization of premiums and accretion of discounts. | |||||||||||||||||
| (2) Includes owner occupied commercial real estate loans. | |||||||||||||||||
| (3) Includes non-accrual loans, the effect of which is to reduce the yield earned on loans and leases, and deferred loan fees. | |||||||||||||||||
(4) Total costs of deposits (including interest bearing and non-interest bearing) were 0.50% and 1.19% for the six months ended June 30, 2021 and 2020, respectively. | |||||||||||||||||
| (5) Non-GAAP tax-equivalent basis, using an estimated marginal tax rate of 26% for the six months ended June 30, 2021 and 2020, presented to approximate interest income as a taxable asset. Management uses non-GAAP measures to present historical periods comparable to the current period presentation. In addition, management believes the use of these non-GAAP measures provides additional clarity when assessing Customers’ financial results. These disclosures should not be viewed as substitutes for results determined to be in accordance with U.S. GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other entities. | |||||||||||||||||
| (6) Non-GAAP tax-equivalent basis as described in note (5), for the six months ended June 30, 2021 and 2020, excluding net interest income from PPP loans and related borrowings, along with the related PPP loan balances and PPP fees receivable from interest-earning assets. Management uses non-GAAP measures to present historical periods comparable to the current period presentation. In addition, management believes the use of these non-GAAP measures provides additional clarity when assessing Customers’ financial results. These disclosures should not be viewed as substitutes for results determined to be in accordance with U.S. GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other entities. | |||||||||||||||||
12
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| PERIOD END LOAN AND LEASE COMPOSITION - UNAUDITED | |||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | |||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | |||||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||
| Multi-family | $ | 1,497,485 | $ | 1,659,529 | $ | 1,761,301 | $ | 1,950,300 | $ | 2,023,571 | |||||||||||||||||||
| Loans to mortgage companies | 2,922,217 | 3,463,490 | 3,657,350 | 3,947,828 | 2,832,112 | ||||||||||||||||||||||||
| Commercial & industrial | 2,293,723 | 2,164,784 | 2,304,206 | 2,186,480 | 2,060,494 | ||||||||||||||||||||||||
| Commercial real estate owner occupied | 653,649 | 590,093 | 572,338 | 557,595 | 544,772 | ||||||||||||||||||||||||
| Loans receivable, PPP | 6,305,056 | 5,178,089 | 4,561,365 | 4,964,105 | 4,760,427 | ||||||||||||||||||||||||
| Commercial real estate non-owner occupied | 1,206,646 | 1,194,832 | 1,213,815 | 1,233,882 | 1,262,373 | ||||||||||||||||||||||||
| Construction | 179,198 | 156,837 | 140,905 | 122,963 | 128,834 | ||||||||||||||||||||||||
| Total commercial loans and leases | 15,057,974 | 14,407,654 | 14,211,280 | 14,963,153 | 13,612,583 | ||||||||||||||||||||||||
| Consumer: | |||||||||||||||||||||||||||||
| Residential | 273,493 | 295,654 | 323,322 | 343,775 | 352,941 | ||||||||||||||||||||||||
| Manufactured housing | 57,904 | 59,977 | 62,243 | 64,638 | 66,865 | ||||||||||||||||||||||||
| Installment | 1,577,651 | 1,405,021 | 1,235,406 | 1,233,713 | 1,257,813 | ||||||||||||||||||||||||
| Total consumer loans | 1,909,048 | 1,760,652 | 1,620,971 | 1,642,126 | 1,677,619 | ||||||||||||||||||||||||
| Total loans and leases | $ | 16,967,022 | $ | 16,168,306 | $ | 15,832,251 | $ | 16,605,279 | $ | 15,290,202 | |||||||||||||||||||
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| PERIOD END DEPOSIT COMPOSITION - UNAUDITED | |||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | |||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | |||||||||||||||||||||||||
| Demand, non-interest bearing | $ | 2,699,869 | $ | 2,687,628 | $ | 2,356,998 | $ | 2,327,017 | $ | 1,879,789 | |||||||||||||||||||
| Demand, interest bearing | 4,206,355 | 3,228,941 | 2,384,691 | 2,308,627 | 2,666,209 | ||||||||||||||||||||||||
| Total demand deposits | 6,906,224 | 5,916,569 | 4,741,689 | 4,635,644 | 4,545,998 | ||||||||||||||||||||||||
| Savings | 1,431,756 | 1,483,482 | 1,314,817 | 1,173,641 | 1,144,788 | ||||||||||||||||||||||||
| Money market | 4,908,809 | 4,406,508 | 4,601,492 | 4,057,366 | 3,404,709 | ||||||||||||||||||||||||
| Time deposits | 627,150 | 665,881 | 651,931 | 972,426 | 1,870,380 | ||||||||||||||||||||||||
| Total deposits | $ | 13,873,939 | $ | 12,472,440 | $ | 11,309,929 | $ | 10,839,077 | $ | 10,965,875 | |||||||||||||||||||
13
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||||||||
| ASSET QUALITY - UNAUDITED | |||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | As of June 30, 2021 | As of March 31, 2021 | As of June 30, 2020 | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans | Non accrual /NPLs | Allowance for credit losses | Total NPLs to total loans | Total reserves to total NPLs | Total loans | Non accrual /NPLs | Allowance for credit losses | Total NPLs to total loans | Total reserves to total NPLs | Total loans | Non accrual /NPLs | Allowance for credit losses | Total NPLs to total loans | Total reserves to total NPLs | |||||||||||||||||||||||||||||||||
| Loan type | |||||||||||||||||||||||||||||||||||||||||||||||
| Multi-family | $ | 1,497,485 | $ | 21,595 | $ | 5,028 | 1.44 | % | 23.28 | % | $ | 1,640,278 | $ | 20,530 | $ | 8,026 | 1.25 | % | 39.09 | % | $ | 1,581,839 | $ | 7,013 | $ | 14,697 | 0.44 | % | 209.57 | % | |||||||||||||||||
Commercial & industrial(1) | 2,360,656 | 6,717 | 8,127 | 0.28 | % | 120.99 | % | 2,220,652 | 7,544 | 7,503 | 0.34 | % | 99.46 | % | 2,099,442 | 9,974 | 12,302 | 0.48 | % | 123.34 | % | ||||||||||||||||||||||||||
| Commercial real estate owner occupied | 653,649 | 2,688 | 4,464 | 0.41 | % | 166.07 | % | 590,093 | 3,242 | 5,935 | 0.55 | % | 183.07 | % | 544,772 | 4,022 | 11,405 | 0.74 | % | 283.57 | % | ||||||||||||||||||||||||||
| Commercial real estate non-owner occupied | 1,206,646 | — | 7,374 | — | % | — | % | 1,194,832 | 2,356 | 11,621 | 0.20 | % | 493.25 | % | 1,244,773 | 30,257 | 26,493 | 2.43 | % | 87.56 | % | ||||||||||||||||||||||||||
| Construction | 179,198 | — | 2,643 | — | % | — | % | 156,837 | — | 4,103 | — | % | — | % | 128,834 | — | 5,297 | — | % | — | % | ||||||||||||||||||||||||||
| Total commercial loans and leases receivable | 5,897,634 | 31,000 | 27,636 | 0.53 | % | 89.15 | % | 5,802,692 | 33,672 | 37,188 | 0.58 | % | 110.44 | % | 5,599,660 | 51,266 | 70,194 | 0.92 | % | 136.92 | % | ||||||||||||||||||||||||||
| Residential | 266,911 | 8,991 | 2,299 | 3.37 | % | 25.57 | % | 293,805 | 9,353 | 3,209 | 3.18 | % | 34.31 | % | 348,109 | 7,857 | 4,550 | 2.26 | % | 57.91 | % | ||||||||||||||||||||||||||
| Manufactured housing | 57,904 | 3,239 | 4,372 | 5.59 | % | 134.98 | % | 59,977 | 2,871 | 4,799 | 4.79 | % | 167.15 | % | 66,865 | 3,331 | 6,014 | 4.98 | % | 180.55 | % | ||||||||||||||||||||||||||
| Installment | 1,549,693 | 2,728 | 91,129 | 0.18 | % | 3340.51 | % | 1,380,015 | 2,185 | 83,540 | 0.16 | % | 3823.34 | % | 1,257,813 | 4,887 | 79,147 | 0.39 | % | 1619.54 | % | ||||||||||||||||||||||||||
| Total consumer loans receivable | 1,874,508 | 14,958 | 97,800 | 0.80 | % | 653.83 | % | 1,733,797 | 14,409 | 91,548 | 0.83 | % | 635.35 | % | 1,672,787 | 16,075 | 89,711 | 0.96 | % | 558.08 | % | ||||||||||||||||||||||||||
Loans and leases receivable(1) | 7,772,142 | 45,958 | 125,436 | 0.59 | % | 272.94 | % | 7,536,489 | 48,081 | 128,736 | 0.64 | % | 267.75 | % | 7,272,447 | 67,341 | 159,905 | 0.93 | % | 237.46 | % | ||||||||||||||||||||||||||
| Loans receivable, PPP | 6,305,056 | — | — | — | % | — | % | 5,178,089 | — | — | — | % | — | % | 4,760,427 | — | — | — | % | — | % | ||||||||||||||||||||||||||
| Loans receivable, mortgage warehouse, at fair value | 2,855,284 | — | — | — | % | — | % | 3,407,622 | — | — | — | % | — | % | 2,793,164 | — | — | — | % | — | % | ||||||||||||||||||||||||||
| Total loans held for sale | 34,540 | 507 | — | 1.47 | % | — | % | 46,106 | 643 | — | 1.39 | % | — | % | 464,164 | 18,925 | — | 4.08 | % | — | % | ||||||||||||||||||||||||||
| Total portfolio | $ | 16,967,022 | $ | 46,465 | $ | 125,436 | 0.27 | % | 269.96 | % | $ | 16,168,306 | $ | 48,724 | $ | 128,736 | 0.30 | % | 264.21 | % | $ | 15,290,202 | $ | 86,266 | $ | 159,905 | 0.56 | % | 185.36 | % | |||||||||||||||||
(1) Excluding loans receivable, PPP from total loans and leases receivable is a non-GAAP measure. Management believes the use of these non-GAAP measures provides additional clarity when assessing Customers' financial results. These disclosures should not be viewed as substitutes for results determined to be in accordance with U.S. GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other entities. Please refer to the reconciliation schedules that follow this table.
14
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| NET CHARGE-OFFS/(RECOVERIES) - UNAUDITED | |||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||
| Q2 | Q1 | Q4 | Q3 | Q2 | Six Months Ended June 30, | ||||||||||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | 2021 | 2020 | |||||||||||||||||||||||||||||||||||
| Loan type | |||||||||||||||||||||||||||||||||||||||||
| Multi-family | $ | — | $ | 1,132 | $ | — | $ | — | $ | — | $ | 1,132 | $ | — | |||||||||||||||||||||||||||
| Commercial & industrial | (283) | 375 | 155 | (55) | (4) | 92 | 39 | ||||||||||||||||||||||||||||||||||
| Commercial real estate owner occupied | (1) | 134 | 12 | 44 | (2) | 133 | (5) | ||||||||||||||||||||||||||||||||||
| Commercial real estate non-owner occupied | (59) | (10) | (35) | 8,923 | 2,801 | (69) | 15,598 | ||||||||||||||||||||||||||||||||||
| Construction | (114) | (5) | (6) | (6) | (113) | (119) | (116) | ||||||||||||||||||||||||||||||||||
| Residential | (12) | 40 | 46 | (17) | (26) | 28 | (55) | ||||||||||||||||||||||||||||||||||
| Installment | 7,060 | 10,855 | 8,300 | 8,410 | 7,669 | 17,915 | 13,575 | ||||||||||||||||||||||||||||||||||
| Total net charge-offs (recoveries) from loans held for investment | $ | 6,591 | $ | 12,521 | $ | 8,472 | $ | 17,299 | $ | 10,325 | $ | 19,112 | $ | 29,036 | |||||||||||||||||||||||||||
15
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED | |||||||||||||||||||||||||||||
Customers believes that the non-GAAP measurements disclosed within this document are useful for investors, regulators, management and others to evaluate our core results of operations and financial condition relative to other financial institutions. These non-GAAP financial measures are frequently used by securities analysts, investors, and other interested parties in the evaluation of companies in Customers' industry. These non-GAAP financial measures exclude from corresponding GAAP measures the impact of certain elements that we do not believe are representative of our ongoing financial results, which we believe enhance an overall understanding of our performance and increases comparability of our period to period results. Investors should consider our performance and financial condition as reported under GAAP and all other relevant information when assessing our performance or financial condition. The non-GAAP measures presented are not necessarily comparable to non-GAAP measures that may be presented by other financial institutions. Although non-GAAP financial measures are frequently used in the evaluation of a company, they have limitations as analytical tools and should not be considered in isolation or as a substitute for analysis of our results of operations or financial condition as reported under GAAP.
The following tables present reconciliations of GAAP to non-GAAP measures disclosed within this document.
| Core Earnings - Customers Bancorp | Six Months Ended June 30, | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Q2 2021 | Q1 2021 | Q4 2020 | Q3 2020 | Q2 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | ||||||||||||||||||||||||||||||||||||||||||||||||
| GAAP net income to common shareholders | $ | 58,042 | $ | 1.72 | $ | 33,204 | $ | 1.01 | $ | 52,831 | $ | 1.65 | $ | 47,085 | $ | 1.48 | $ | 19,137 | $ | 0.61 | $ | 91,246 | $ | 2.74 | $ | 18,621 | $ | 0.59 | ||||||||||||||||||||||||||||||||||
| Reconciling items (after tax): | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net loss from discontinued operations | — | — | 38,036 | 1.16 | 2,317 | 0.07 | 532 | 0.02 | 2,258 | 0.07 | 38,036 | 1.14 | 7,612 | 0.24 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Severance expense | 1,517 | 0.04 | — | — | — | — | — | — | — | — | 1,517 | 0.05 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| Merger and acquisition related expenses | — | — | 320 | 0.01 | 508 | 0.02 | 530 | 0.02 | — | — | 320 | 0.01 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| Legal reserves | — | — | — | — | — | — | 258 | 0.01 | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (2,694) | (0.08) | (18,773) | (0.57) | (1,419) | (0.04) | (9,662) | (0.30) | (4,543) | (0.14) | (21,467) | (0.64) | (6,331) | (0.20) | ||||||||||||||||||||||||||||||||||||||||||||||||
| Loss on sale of foreign subsidiaries | 2,150 | 0.06 | — | — | — | — | — | — | — | — | 2,150 | 0.06 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| Loss on cash flow hedge derivative terminations | — | — | 18,716 | 0.57 | — | — | — | — | — | — | 18,716 | 0.56 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| Derivative credit valuation adjustment | 288 | 0.01 | (1,195) | (0.04) | (448) | (0.01) | (304) | (0.01) | 4,527 | 0.14 | (907) | (0.03) | 6,563 | 0.21 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Risk participation agreement mark-to-market adjustment | — | — | — | — | — | — | — | — | (1,080) | (0.03) | — | — | (1,080) | (0.03) | ||||||||||||||||||||||||||||||||||||||||||||||||
| Unrealized losses on loans held for sale | — | — | — | — | 799 | 0.03 | — | — | 1,114 | 0.04 | — | — | 1,114 | 0.04 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Core earnings | $ | 59,303 | $ | 1.76 | $ | 70,308 | $ | 2.14 | $ | 54,588 | $ | 1.71 | $ | 38,439 | $ | 1.21 | $ | 21,413 | $ | 0.68 | $ | 129,611 | $ | 3.89 | $ | 26,499 | $ | 0.84 | ||||||||||||||||||||||||||||||||||
16
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | |||||||||||||||||||||||||||||
| Core Return on Average Assets - Customers Bancorp | Six Months Ended June 30, | ||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q2 2021 | Q1 2021 | Q4 2020 | Q3 2020 | Q2 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||
| GAAP net income | $ | 61,341 | $ | 36,595 | $ | 56,245 | $ | 50,515 | $ | 22,718 | $ | 97,936 | $ | 25,817 | |||||||||||||||||||||||||||
| Reconciling items (after tax): | |||||||||||||||||||||||||||||||||||||||||
| Net loss from discontinued operations | — | 38,036 | 2,317 | 532 | 2,258 | 38,036 | 7,612 | ||||||||||||||||||||||||||||||||||
| Severance expense | 1,517 | — | — | — | — | 1,517 | — | ||||||||||||||||||||||||||||||||||
Merger and acquisition related expenses | — | 320 | 508 | 530 | — | 320 | — | ||||||||||||||||||||||||||||||||||
| Legal reserves | — | — | — | 258 | — | — | — | ||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (2,694) | (18,773) | (1,419) | (9,662) | (4,543) | (21,467) | (6,331) | ||||||||||||||||||||||||||||||||||
| Loss on sale of foreign subsidiaries | 2,150 | — | — | — | — | 2,150 | — | ||||||||||||||||||||||||||||||||||
| Loss on cash flow hedge derivative terminations | — | 18,716 | — | — | — | 18,716 | — | ||||||||||||||||||||||||||||||||||
| Derivative credit valuation adjustment | 288 | (1,195) | (448) | (304) | 4,527 | (907) | 6,563 | ||||||||||||||||||||||||||||||||||
| Risk participation agreement mark-to-market adjustment | — | — | — | — | (1,080) | — | (1,080) | ||||||||||||||||||||||||||||||||||
| Unrealized losses on loans held for sale | — | — | 799 | — | 1,114 | — | 1,114 | ||||||||||||||||||||||||||||||||||
Core net income | $ | 62,602 | $ | 73,699 | $ | 58,002 | $ | 41,869 | $ | 24,994 | $ | 136,301 | $ | 33,695 | |||||||||||||||||||||||||||
Average total assets | $ | 19,306,948 | $ | 18,525,721 | $ | 18,250,719 | $ | 17,865,574 | $ | 14,675,584 | $ | 18,918,491 | $ | 13,124,495 | |||||||||||||||||||||||||||
| Core return on average assets | 1.30 | % | 1.61 | % | 1.26 | % | 0.93 | % | 0.68 | % | 1.45 | % | 0.52 | % | |||||||||||||||||||||||||||
| Adjusted Net Income and Adjusted ROAA - Pre-Tax Pre-Provision - Customers Bancorp | Six Months Ended June 30, | ||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q2 2021 | Q1 2021 | Q4 2020 | Q3 2020 | Q2 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||
| GAAP net income | $ | 61,341 | $ | 36,595 | $ | 56,245 | $ | 50,515 | $ | 22,718 | $ | 97,936 | $ | 25,817 | |||||||||||||||||||||||||||
| Reconciling items: | |||||||||||||||||||||||||||||||||||||||||
Income tax expense | 20,124 | 17,560 | 23,447 | 12,016 | 7,980 | 37,684 | 11,254 | ||||||||||||||||||||||||||||||||||
Provision (benefit) for credit losses on loans and leases | 3,291 | (2,919) | (2,913) | 12,955 | 20,946 | 372 | 52,732 | ||||||||||||||||||||||||||||||||||
| Provision (benefit) for credit losses on unfunded commitments | 45 | (1,286) | (968) | (527) | (356) | (1,241) | 395 | ||||||||||||||||||||||||||||||||||
| Severance expense | 2,004 | — | — | — | — | 2,004 | — | ||||||||||||||||||||||||||||||||||
| Net loss from discontinued operations | — | 38,036 | 2,317 | 532 | 2,258 | 38,036 | 7,612 | ||||||||||||||||||||||||||||||||||
Merger and acquisition related expenses | — | 418 | 709 | 658 | — | 418 | — | ||||||||||||||||||||||||||||||||||
| Legal reserves | — | — | — | 320 | — | — | — | ||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (3,558) | (24,540) | (1,431) | (11,945) | (5,553) | (28,098) | (8,150) | ||||||||||||||||||||||||||||||||||
| Loss on sale of foreign subsidiaries | 2,840 | — | — | — | — | 2,840 | — | ||||||||||||||||||||||||||||||||||
| Loss on cash flow hedge derivative terminations | — | 24,467 | — | — | — | 24,467 | — | ||||||||||||||||||||||||||||||||||
| Derivative credit valuation adjustment | 380 | (1,562) | (625) | (378) | 5,895 | (1,182) | 8,451 | ||||||||||||||||||||||||||||||||||
| Risk participation agreement mark-to-market adjustment | — | — | — | — | (1,407) | — | (1,407) | ||||||||||||||||||||||||||||||||||
| Unrealized losses on loans held for sale | — | — | 1,115 | — | 1,450 | — | 1,450 | ||||||||||||||||||||||||||||||||||
Adjusted net income - pre-tax pre-provision | $ | 86,467 | $ | 86,769 | $ | 77,896 | $ | 64,146 | $ | 53,931 | $ | 173,236 | $ | 98,154 | |||||||||||||||||||||||||||
Average total assets | $ | 19,306,948 | $ | 18,525,721 | $ | 18,250,719 | $ | 17,865,574 | $ | 14,675,584 | $ | 18,918,491 | $ | 13,124,495 | |||||||||||||||||||||||||||
| Adjusted ROAA - pre-tax pre-provision | 1.80 | % | 1.90 | % | 1.70 | % | 1.43 | % | 1.48 | % | 1.85 | % | 1.50 | % | |||||||||||||||||||||||||||
17
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | |||||||||||||||||||||||||||||
| Core Return on Average Common Equity - Customers Bancorp | Six Months Ended June 30, | ||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q2 2021 | Q1 2021 | Q4 2020 | Q3 2020 | Q2 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||
| GAAP net income to common shareholders | $ | 58,042 | $ | 33,204 | $ | 52,831 | $ | 47,085 | $ | 19,137 | $ | 91,246 | $ | 18,621 | |||||||||||||||||||||||||||
| Reconciling items (after tax): | |||||||||||||||||||||||||||||||||||||||||
| Net loss from discontinued operations | — | 38,036 | 2,317 | 532 | 2,258 | 38,036 | 7,612 | ||||||||||||||||||||||||||||||||||
| Severance expense | 1,517 | — | — | — | — | 1,517 | — | ||||||||||||||||||||||||||||||||||
Merger and acquisition related expenses | — | 320 | 508 | 530 | — | 320 | — | ||||||||||||||||||||||||||||||||||
| Legal reserves | — | — | — | 258 | — | — | — | ||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (2,694) | (18,773) | (1,419) | (9,662) | (4,543) | (21,467) | (6,331) | ||||||||||||||||||||||||||||||||||
| Loss on sale of foreign subsidiaries | 2,150 | — | — | — | — | 2,150 | — | ||||||||||||||||||||||||||||||||||
| Loss on cash flow hedge derivative terminations | — | 18,716 | — | — | — | 18,716 | — | ||||||||||||||||||||||||||||||||||
| Derivative credit valuation adjustment | 288 | (1,195) | (448) | (304) | 4,527 | (907) | 6,563 | ||||||||||||||||||||||||||||||||||
| Risk participation agreement mark-to-market adjustment | — | — | — | — | (1,080) | — | (1,080) | ||||||||||||||||||||||||||||||||||
| Unrealized losses on loans held for sale | — | — | 799 | — | 1,114 | — | 1,114 | ||||||||||||||||||||||||||||||||||
Core earnings | $ | 59,303 | $ | 70,308 | $ | 54,588 | $ | 38,439 | $ | 21,413 | $ | 129,611 | $ | 26,499 | |||||||||||||||||||||||||||
| Average total common shareholders' equity | $ | 1,002,624 | $ | 918,795 | $ | 866,411 | $ | 812,577 | $ | 771,663 | $ | 960,940 | $ | 789,774 | |||||||||||||||||||||||||||
| Core return on average common equity | 23.72 | % | 31.03 | % | 25.06 | % | 18.82 | % | 11.16 | % | 27.20 | % | 6.75 | % | |||||||||||||||||||||||||||
| Adjusted ROCE - Pre-Tax Pre-Provision - Customers Bancorp | Six Months Ended June 30, | ||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q2 2021 | Q1 2021 | Q4 2020 | Q3 2020 | Q2 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||
| GAAP net income to common shareholders | $ | 58,042 | $ | 33,204 | $ | 52,831 | $ | 47,085 | $ | 19,137 | $ | 91,246 | $ | 18,621 | |||||||||||||||||||||||||||
| Reconciling items: | |||||||||||||||||||||||||||||||||||||||||
Income tax expense | 20,124 | 17,560 | 23,447 | 12,016 | 7,980 | 37,684 | 11,254 | ||||||||||||||||||||||||||||||||||
Provision (benefit) for credit losses on loan and leases | 3,291 | (2,919) | (2,913) | 12,955 | 20,946 | 372 | 52,732 | ||||||||||||||||||||||||||||||||||
| Provision (benefit) for credit losses on unfunded commitments | 45 | (1,286) | (968) | (527) | (356) | (1,241) | 395 | ||||||||||||||||||||||||||||||||||
| Net loss from discontinued operations | — | 38,036 | 2,317 | 532 | 2,258 | 38,036 | 7,612 | ||||||||||||||||||||||||||||||||||
| Severance expense | 2,004 | — | — | — | — | 2,004 | — | ||||||||||||||||||||||||||||||||||
Merger and acquisition related expenses | — | 418 | 709 | 658 | — | 418 | — | ||||||||||||||||||||||||||||||||||
| Legal reserves | — | — | — | 320 | — | — | — | ||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (3,558) | (24,540) | (1,431) | (11,945) | (5,553) | (28,098) | (8,150) | ||||||||||||||||||||||||||||||||||
| Loss on sale of foreign subsidiaries | 2,840 | — | — | — | — | 2,840 | — | ||||||||||||||||||||||||||||||||||
| Loss on cash flow hedge derivative terminations | — | 24,467 | — | — | — | 24,467 | — | ||||||||||||||||||||||||||||||||||
| Derivative credit valuation adjustment | 380 | (1,562) | (625) | (378) | 5,895 | (1,182) | 8,451 | ||||||||||||||||||||||||||||||||||
| Risk participation agreement mark-to-market adjustment | — | — | — | — | (1,407) | — | (1,407) | ||||||||||||||||||||||||||||||||||
| Unrealized losses on loans held for sale | — | — | 1,115 | — | 1,450 | — | 1,450 | ||||||||||||||||||||||||||||||||||
Pre-tax pre-provision adjusted net income available to common shareholders | $ | 83,168 | $ | 83,378 | $ | 74,482 | $ | 60,716 | $ | 50,350 | $ | 166,546 | $ | 90,958 | |||||||||||||||||||||||||||
Average total common shareholders' equity | $ | 1,002,624 | $ | 918,795 | $ | 866,411 | $ | 812,577 | $ | 771,663 | $ | 960,940 | $ | 789,774 | |||||||||||||||||||||||||||
| Adjusted ROCE - pre-tax pre-provision | 33.27 | % | 36.80 | % | 34.20 | % | 29.73 | % | 26.24 | % | 34.95 | % | 23.16 | % | |||||||||||||||||||||||||||
18
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | |||||||||||||||||||||||||||||
| Net Interest Margin, Tax Equivalent - Customers Bancorp | Six Months Ended June 30, | ||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q2 2021 | Q1 2021 | Q4 2020 | Q3 2020 | Q2 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||
| GAAP net interest income | $ | 138,757 | $ | 132,731 | $ | 122,946 | $ | 107,439 | $ | 91,982 | $ | 271,488 | $ | 173,302 | |||||||||||||||||||||||||||
| Tax-equivalent adjustment | 289 | 292 | 219 | 225 | 225 | 581 | 430 | ||||||||||||||||||||||||||||||||||
| Net interest income tax equivalent | $ | 139,046 | $ | 133,023 | $ | 123,165 | $ | 107,664 | $ | 92,207 | $ | 272,069 | $ | 173,732 | |||||||||||||||||||||||||||
| Average total interest earning assets | $ | 18,698,996 | $ | 17,943,944 | $ | 17,601,999 | $ | 17,121,145 | $ | 13,980,021 | $ | 18,323,555 | $ | 12,478,375 | |||||||||||||||||||||||||||
| Net interest margin, tax equivalent | 2.98 | % | 3.00 | % | 2.78 | % | 2.50 | % | 2.65 | % | 2.99 | % | 2.80 | % | |||||||||||||||||||||||||||
| Net Interest Margin, Tax Equivalent, Excluding PPP - Customers Bancorp | Six Months Ended June 30, | ||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q2 2021 | Q1 2021 | Q4 2020 | Q3 2020 | Q2 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||
| GAAP net interest income | $ | 138,757 | $ | 132,731 | $ | 122,946 | $ | 107,439 | $ | 91,982 | $ | 271,488 | $ | 173,302 | |||||||||||||||||||||||||||
| PPP net interest income | (35,785) | (34,842) | (25,257) | (20,018) | (9,308) | (70,627) | (9,308) | ||||||||||||||||||||||||||||||||||
| Tax-equivalent adjustment | 289 | 292 | 219 | 225 | 225 | 581 | 430 | ||||||||||||||||||||||||||||||||||
| Net interest income, tax equivalent, excluding PPP | $ | 103,261 | $ | 98,181 | $ | 97,908 | $ | 87,646 | $ | 82,899 | $ | 201,442 | $ | 164,424 | |||||||||||||||||||||||||||
| GAAP average total interest earning assets | $ | 18,698,996 | $ | 17,943,944 | $ | 17,601,999 | $ | 17,121,145 | $ | 13,980,021 | $ | 18,323,555 | $ | 12,478,375 | |||||||||||||||||||||||||||
| Average PPP loans | (6,133,184) | (4,623,213) | (4,782,606) | (4,909,197) | (2,754,920) | (5,382,370) | (1,377,460) | ||||||||||||||||||||||||||||||||||
| Adjusted average total interest earning assets | $ | 12,565,812 | $ | 13,320,731 | $ | 12,819,393 | $ | 12,211,948 | $ | 11,225,101 | $ | 12,941,185 | $ | 11,100,915 | |||||||||||||||||||||||||||
| Net interest margin, tax equivalent, excluding PPP | 3.30 | % | 2.99 | % | 3.04 | % | 2.86 | % | 2.97 | % | 3.14 | % | 2.98 | % | |||||||||||||||||||||||||||
| Core Efficiency Ratio - Customers Bancorp | Six Months Ended June 30, | ||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q2 2021 | Q1 2021 | Q4 2020 | Q3 2020 | Q2 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||
| GAAP net interest income | $ | 138,757 | $ | 132,731 | $ | 122,946 | $ | 107,439 | $ | 91,982 | $ | 271,488 | $ | 173,302 | |||||||||||||||||||||||||||
| GAAP non-interest income | $ | 16,822 | $ | 18,468 | $ | 16,083 | $ | 24,864 | $ | 11,711 | $ | 35,290 | $ | 22,871 | |||||||||||||||||||||||||||
| (Gains) losses on investment securities | (3,558) | (24,540) | (1,431) | (11,945) | (5,553) | (28,098) | (8,150) | ||||||||||||||||||||||||||||||||||
| Derivative credit valuation adjustment | 380 | (1,562) | (625) | (378) | 5,895 | (1,182) | 8,451 | ||||||||||||||||||||||||||||||||||
| Risk participation agreement mark-to-market adjustment | — | — | — | — | (1,407) | — | (1,407) | ||||||||||||||||||||||||||||||||||
| Unrealized losses on loans held for sale | — | — | 1,115 | — | 1,450 | — | 1,450 | ||||||||||||||||||||||||||||||||||
| Loss on cash flow hedge derivative terminations | — | 24,467 | — | — | — | 24,467 | — | ||||||||||||||||||||||||||||||||||
| Loss on sale of foreign subsidiaries | 2,840 | — | — | — | — | 2,840 | — | ||||||||||||||||||||||||||||||||||
| Core non-interest income | 16,484 | 16,833 | 15,142 | 12,541 | 12,096 | 33,317 | 23,215 | ||||||||||||||||||||||||||||||||||
| Core revenue | $ | 155,241 | $ | 149,564 | $ | 138,088 | $ | 119,980 | $ | 104,078 | $ | 304,805 | $ | 196,517 | |||||||||||||||||||||||||||
| GAAP non-interest expense | $ | 70,823 | $ | 61,927 | $ | 59,933 | $ | 56,285 | $ | 49,791 | $ | 132,750 | $ | 98,758 | |||||||||||||||||||||||||||
| Severance expense | (2,004) | — | — | — | — | (2,004) | — | ||||||||||||||||||||||||||||||||||
| Legal reserves | — | — | — | (320) | — | — | — | ||||||||||||||||||||||||||||||||||
| Merger and acquisition related expenses | — | (418) | (709) | (658) | — | (418) | — | ||||||||||||||||||||||||||||||||||
| Core non-interest expense | $ | 68,819 | $ | 61,509 | $ | 59,224 | $ | 55,307 | $ | 49,791 | $ | 130,328 | $ | 98,758 | |||||||||||||||||||||||||||
Core efficiency ratio (1) | 44.33 | % | 41.13 | % | 42.89 | % | 46.10 | % | 47.84 | % | 42.76 | % | 50.25 | % | |||||||||||||||||||||||||||
(1) Core efficiency ratio calculated as core non-interest expense divided by core revenue.
19
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | |||||||||||||||||||||||||||||
| Tangible Common Equity to Tangible Assets - Customers Bancorp | |||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q2 2021 | Q1 2021 | Q4 2020 | Q3 2020 | Q2 2020 | ||||||||||||||||||||||||
| GAAP total shareholders' equity | $ | 1,250,729 | $ | 1,188,721 | $ | 1,117,086 | $ | 1,051,491 | $ | 1,007,847 | |||||||||||||||||||
| Reconciling items: | |||||||||||||||||||||||||||||
| Preferred stock | (217,471) | (217,471) | (217,471) | (217,471) | (217,471) | ||||||||||||||||||||||||
Goodwill and other intangibles (1) | (3,853) | (3,911) | (14,298) | (14,437) | (14,575) | ||||||||||||||||||||||||
| Tangible common equity | $ | 1,029,405 | $ | 967,339 | $ | 885,317 | $ | 819,583 | $ | 775,801 | |||||||||||||||||||
| GAAP total assets | $ | 19,635,108 | $ | 18,817,660 | $ | 18,439,248 | $ | 18,778,727 | $ | 17,903,118 | |||||||||||||||||||
| Reconciling items: | |||||||||||||||||||||||||||||
Goodwill and other intangibles (1) | (3,853) | (3,911) | (14,298) | (14,437) | (14,575) | ||||||||||||||||||||||||
| Tangible assets | $ | 19,631,255 | $ | 18,813,749 | $ | 18,424,950 | $ | 18,764,290 | $ | 17,888,543 | |||||||||||||||||||
| Tangible common equity to tangible assets | 5.24 | % | 5.14 | % | 4.80 | % | 4.37 | % | 4.34 | % | |||||||||||||||||||
(1) Includes goodwill and other intangibles reported in assets of discontinued operations.
| Tangible Book Value per Common Share - Customers Bancorp | |||||||||||||||||||||||||||||
| (dollars in thousands except share and per share data) | Q2 2021 | Q1 2021 | Q4 2020 | Q3 2020 | Q2 2020 | ||||||||||||||||||||||||
| GAAP total shareholders' equity | $ | 1,250,729 | $ | 1,188,721 | $ | 1,117,086 | $ | 1,051,491 | $ | 1,007,847 | |||||||||||||||||||
| Reconciling Items: | |||||||||||||||||||||||||||||
| Preferred stock | (217,471) | (217,471) | (217,471) | (217,471) | (217,471) | ||||||||||||||||||||||||
Goodwill and other intangibles (1) | (3,853) | (3,911) | (14,298) | (14,437) | (14,575) | ||||||||||||||||||||||||
| Tangible common equity | $ | 1,029,405 | $ | 967,339 | $ | 885,317 | $ | 819,583 | $ | 775,801 | |||||||||||||||||||
| Common shares outstanding | 32,353,256 | 32,238,762 | 31,705,088 | 31,555,124 | 31,510,287 | ||||||||||||||||||||||||
| Tangible book value per common share | $ | 31.82 | $ | 30.01 | $ | 27.92 | $ | 25.97 | $ | 24.62 | |||||||||||||||||||
(1) Includes goodwill and other intangibles reported in assets of discontinued operations.
| Total Loans and Leases, excluding PPP | |||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q2 2021 | Q1 2021 | Q4 2020 | Q3 2020 | Q2 2020 | ||||||||||||||||||||||||
| Total loans and leases | $ | 16,967,022 | $ | 16,168,306 | $ | 15,832,251 | $ | 16,605,279 | $ | 15,290,202 | |||||||||||||||||||
| Loans receivable, PPP | (6,305,056) | (5,178,089) | (4,561,365) | (4,964,105) | (4,760,427) | ||||||||||||||||||||||||
| Loans and leases, excluding PPP | $ | 10,661,966 | $ | 10,990,217 | $ | 11,270,886 | $ | 11,641,174 | $ | 10,529,775 | |||||||||||||||||||
| Total Assets, excluding PPP | |||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q2 2021 | Q1 2021 | Q4 2020 | Q3 2020 | Q2 2020 | ||||||||||||||||||||||||
| Total assets | $ | 19,635,108 | $ | 18,817,660 | $ | 18,439,248 | $ | 18,778,727 | $ | 17,903,118 | |||||||||||||||||||
| Loans receivable, PPP | (6,305,056) | (5,178,089) | (4,561,365) | (4,964,105) | (4,760,427) | ||||||||||||||||||||||||
| Total assets, excluding PPP | $ | 13,330,052 | $ | 13,639,571 | $ | 13,877,883 | $ | 13,814,622 | $ | 13,142,691 | |||||||||||||||||||
20
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | |||||||||||||||||||||||||||||
| Coverage of credit loss reserves for loans and leases held for investment, excluding PPP | |||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q2 2021 | Q1 2021 | Q4 2020 | Q3 2020 | Q2 2020 | ||||||||||||||||||||||||
| Loans and leases receivable | $ | 14,077,198 | $ | 12,714,578 | $ | 12,136,733 | $ | 12,664,997 | $ | 12,032,874 | |||||||||||||||||||
| Loans receivable, PPP | (6,305,056) | (5,178,089) | (4,561,365) | (4,964,105) | (4,760,427) | ||||||||||||||||||||||||
| Loans and leases held for investment, excluding PPP | $ | 7,772,142 | $ | 7,536,489 | $ | 7,575,368 | $ | 7,700,892 | $ | 7,272,447 | |||||||||||||||||||
| Allowance for credit losses on loans and leases | $ | 125,436 | $ | 128,736 | $ | 144,176 | $ | 155,561 | $ | 159,905 | |||||||||||||||||||
| Coverage of credit loss reserves for loans and leases held for investment, excluding PPP | 1.61 | % | 1.71 | % | 1.90 | % | 2.02 | % | 2.20 | % | |||||||||||||||||||
| Tangible Common Equity to Tangible Assets, excluding PPP - Customers Bancorp | |||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q2 2021 | Q1 2021 | Q4 2020 | Q3 2020 | Q2 2020 | ||||||||||||||||||||||||
| GAAP total shareholders' equity | $ | 1,250,729 | $ | 1,188,721 | $ | 1,117,086 | $ | 1,051,491 | $ | 1,007,847 | |||||||||||||||||||
| Reconciling items: | |||||||||||||||||||||||||||||
| Preferred stock | (217,471) | (217,471) | (217,471) | (217,471) | (217,471) | ||||||||||||||||||||||||
Goodwill and other intangibles (1) | (3,853) | (3,911) | (14,298) | (14,437) | (14,575) | ||||||||||||||||||||||||
| Tangible common equity | $ | 1,029,405 | $ | 967,339 | $ | 885,317 | $ | 819,583 | $ | 775,801 | |||||||||||||||||||
| GAAP total assets | $ | 19,635,108 | $ | 18,817,660 | $ | 18,439,248 | $ | 18,778,727 | $ | 17,903,118 | |||||||||||||||||||
| Loans receivable, PPP | (6,305,056) | (5,178,089) | (4,561,365) | (4,964,105) | (4,760,427) | ||||||||||||||||||||||||
| Total assets, excluding PPP | $ | 13,330,052 | $ | 13,639,571 | $ | 13,877,883 | $ | 13,814,622 | $ | 13,142,691 | |||||||||||||||||||
| Reconciling items: | |||||||||||||||||||||||||||||
Goodwill and other intangibles (1) | (3,853) | (3,911) | (14,298) | (14,437) | (14,575) | ||||||||||||||||||||||||
| Tangible assets | $ | 13,326,199 | $ | 13,635,660 | $ | 13,863,585 | $ | 13,800,185 | $ | 13,128,116 | |||||||||||||||||||
| Tangible common equity to tangible assets | 7.72 | % | 7.09 | % | 6.39 | % | 5.94 | % | 5.91 | % | |||||||||||||||||||
(1) Includes goodwill and other intangibles reported in assets of discontinued operations.
| Deferments to total loans and leases, excluding PPP | |||||||||||||||||
| (dollars in thousands except per share data) | Q2 2021 | Q1 2021 | Q4 2020 | ||||||||||||||
| Total loans and leases | $ | 16,967,022 | $ | 16,168,306 | $ | 15,832,251 | |||||||||||
| Loans receivable, PPP | (6,305,056) | (5,178,089) | (4,561,365) | ||||||||||||||
| Total loans and leases, excluding PPP | $ | 10,661,966 | $ | 10,990,217 | $ | 11,270,886 | |||||||||||
| Commercial deferments | $ | 89,800 | $ | 176,100 | $ | 202,100 | |||||||||||
| Consumer deferments | 8,400 | 13,000 | 16,400 | ||||||||||||||
| Total deferments | $ | 98,200 | $ | 189,100 | $ | 218,500 | |||||||||||
| Commercial deferments to total loans and leases, excluding PPP | 0.8 | % | 1.6 | % | 1.8 | % | |||||||||||
| Consumer deferments to total loans and leases, excluding PPP | 0.1 | 0.1 | 0.1 | ||||||||||||||
| Total deferments to total loans and leases, excluding PPP | 0.9 | % | 1.7 | % | 1.9 | % | |||||||||||
21
Second Quarter 2021 | Earnings Conference Call July 29, 2021 NYSE: CUBI “High Tech Forward-Thinking Bank Supported by High Touch” Customers Bancorp, Inc.
2 In addition to historical information, this presentation may contain “forward-looking statements” within the meaning of the “safe harbor” provisions of the Private Securities Litigation Reform Act of 1995. These forward-looking statements include statements with respect to Customers Bancorp, Inc.’s strategies, goals, beliefs, expectations, estimates, intentions, capital raising efforts, financial condition and results of operations, future performance and business. Statements preceded by, followed by, or that include the words “may,” “could,” “should,” “pro forma,” “looking forward,” “would,” “believe,” “expect,” “anticipate,” “estimate,” “intend,” “plan,” or similar expressions generally indicate a forward-looking statement. These forward-looking statements involve risks and uncertainties that are subject to change based on various important factors (some of which, in whole or in part, are beyond Customers Bancorp, Inc.’s control). Numerous competitive, economic, regulatory, legal and technological events and factors, among others, could cause Customers Bancorp, Inc.’s financial performance to differ materially from the goals, plans, objectives, intentions and expectations expressed in such forward-looking statements, including: the adverse impact on the U.S. economy, including the markets in which we operate, of the coronavirus outbreak, and the impact of a slowing U.S. economy and increased unemployment on the performance of our loan and lease portfolio, the market value of our investment securities, the demand for our products and services and the availability of sources of funding; the effects of actions by the federal government, including the Board of Governors of the Federal Reserve System and other government agencies, that affect market interest rates and the money supply; the actions that we and our customers take in response to these developments and the effects such actions have on our operations, products, services and customer relationships; and the effects of any changes in accounting standards or policies. Customers Bancorp, Inc. cautions that the foregoing factors are not exclusive, and neither such factors nor any such forward-looking statement takes into account the impact of any future events. All forward-looking statements and information set forth herein are based on management’s current beliefs and assumptions as of the date hereof and speak only as of the date they are made. For a more complete discussion of the assumptions, risks and uncertainties related to our business, you are encouraged to review Customers Bancorp, Inc.’s filings with the Securities and Exchange Commission, including its most recent annual report on Form 10-K for the year ended December 31, 2020, subsequently filed quarterly reports on Form 10-Q and current reports on Form 8-K, including any amendments thereto, that update or provide information in addition to the information included in the Form 10-K and Form 10-Q filings, if any. Customers Bancorp, Inc. does not undertake to update any forward- looking statement whether written or oral, that may be made from time to time by Customers Bancorp, Inc. or by or on behalf of Customers Bank, except as may be required under applicable law. This does not constitute an offer to sell, or a solicitation of an offer to buy, any security in any state or jurisdiction in which such offer, solicitation or sale would be unlawful. Forward-Looking Statements
I. Overview
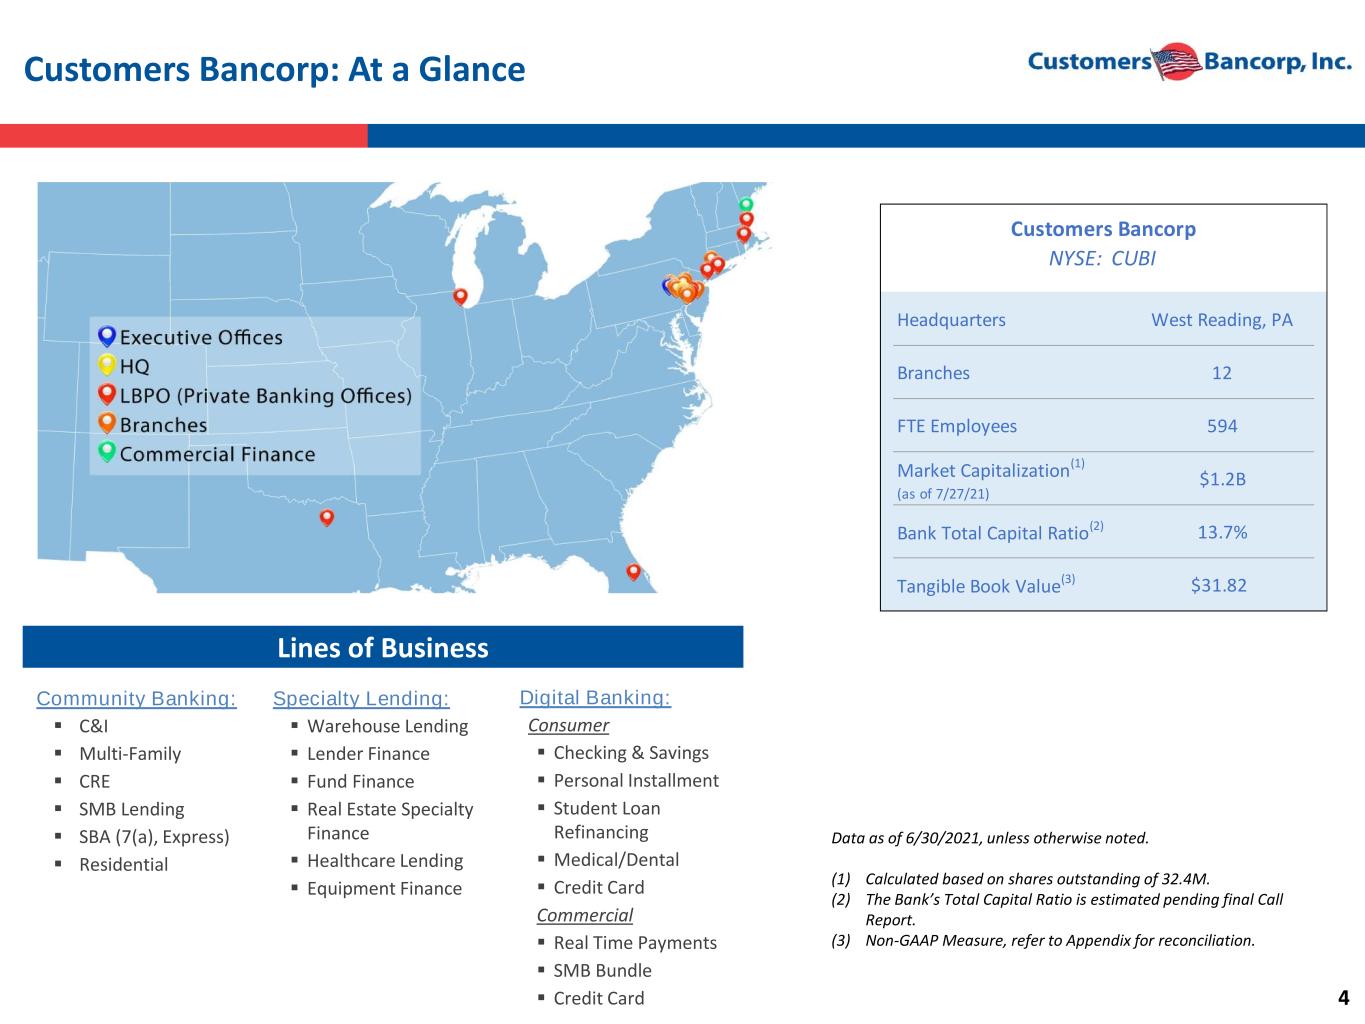
4 Customers Bancorp: At a Glance Data as of 6/30/2021, unless otherwise noted. (1) Calculated based on shares outstanding of 32.4M. (2) The Bank’s Total Capital Ratio is estimated pending final Call Report. (3) Non-GAAP Measure, refer to Appendix for reconciliation. Lines of Business Community Banking: ▪ C&I ▪ Multi-Family ▪ CRE ▪ SMB Lending ▪ SBA (7(a), Express) ▪ Residential Specialty Lending: ▪ Warehouse Lending ▪ Lender Finance ▪ Fund Finance ▪ Real Estate Specialty Finance ▪ Healthcare Lending ▪ Equipment Finance Digital Banking: Consumer ▪ Checking & Savings ▪ Personal Installment ▪ Student Loan Refinancing ▪ Medical/Dental ▪ Credit Card Commercial ▪ Real Time Payments ▪ SMB Bundle ▪ Credit Card Headquarters West Reading, PA Branches 12 FTE Employees 594 Market Capitalization(1) (as of 7/27/21) $1.2B Bank Total Capital Ratio(2) 13.7% Tangible Book Value(3) $31.82 Customers Bancorp NYSE: CUBI
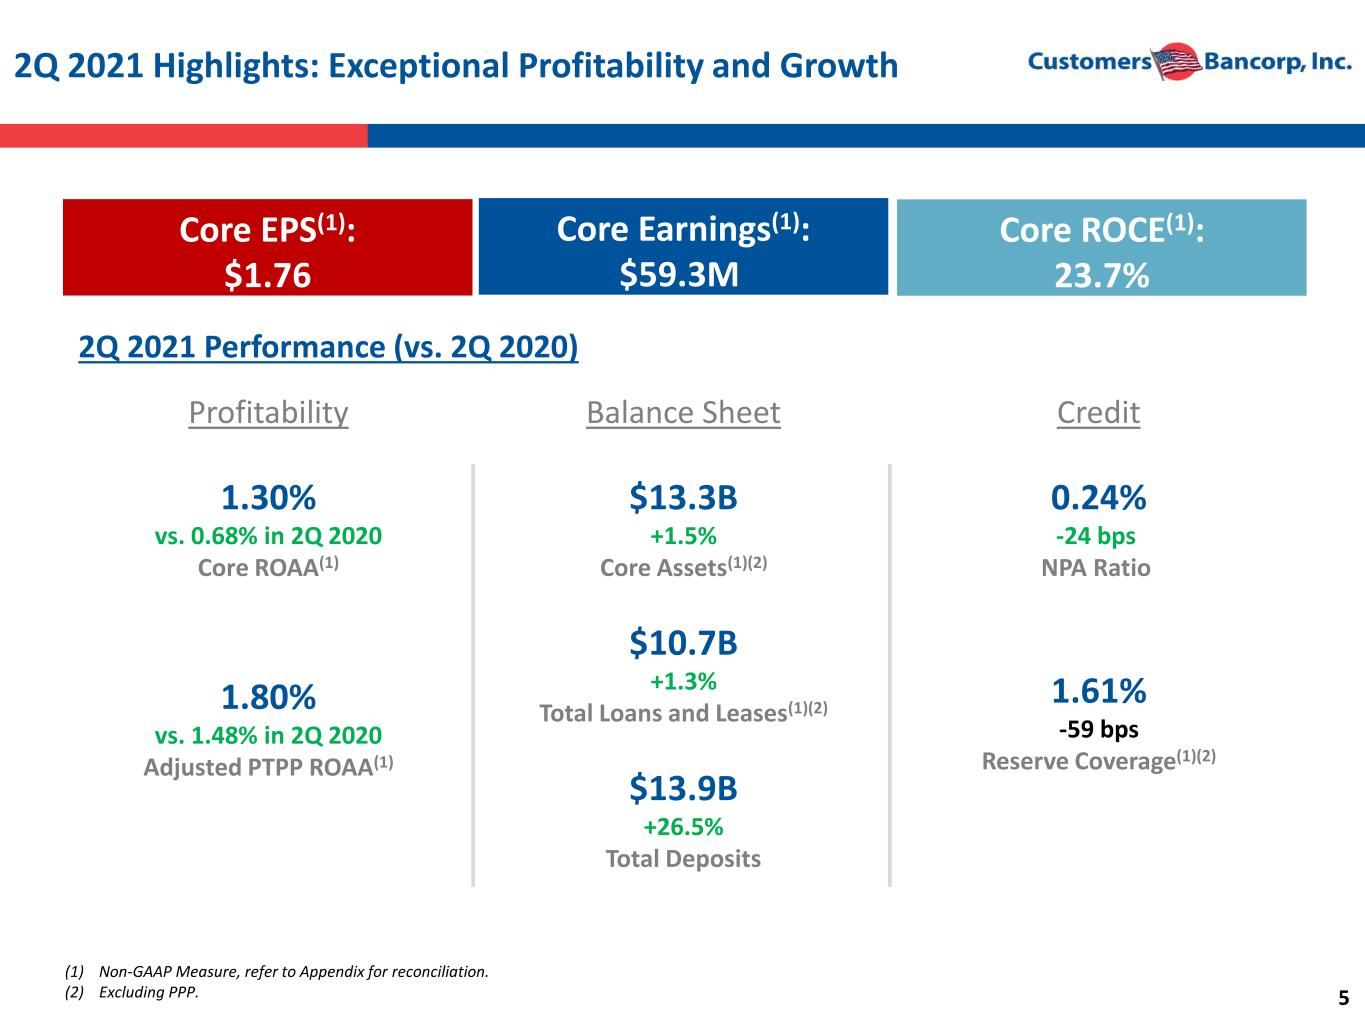
5 2Q 2021 Highlights: Exceptional Profitability and Growth 2Q 2021 Performance (vs. 2Q 2020) 1.30% vs. 0.68% in 2Q 2020 Core ROAA(1) $13.3B +1.5% Core Assets(1)(2) 0.24% -24 bps NPA Ratio 1.80% vs. 1.48% in 2Q 2020 Adjusted PTPP ROAA(1) $10.7B +1.3% Total Loans and Leases(1)(2) 1.61% -59 bps Reserve Coverage(1)(2) $13.9B +26.5% Total Deposits Profitability Balance Sheet Credit (1) Non-GAAP Measure, refer to Appendix for reconciliation. (2) Excluding PPP. Core EPS(1): $1.76 Core Earnings(1): $59.3M Core ROCE(1): 23.7%
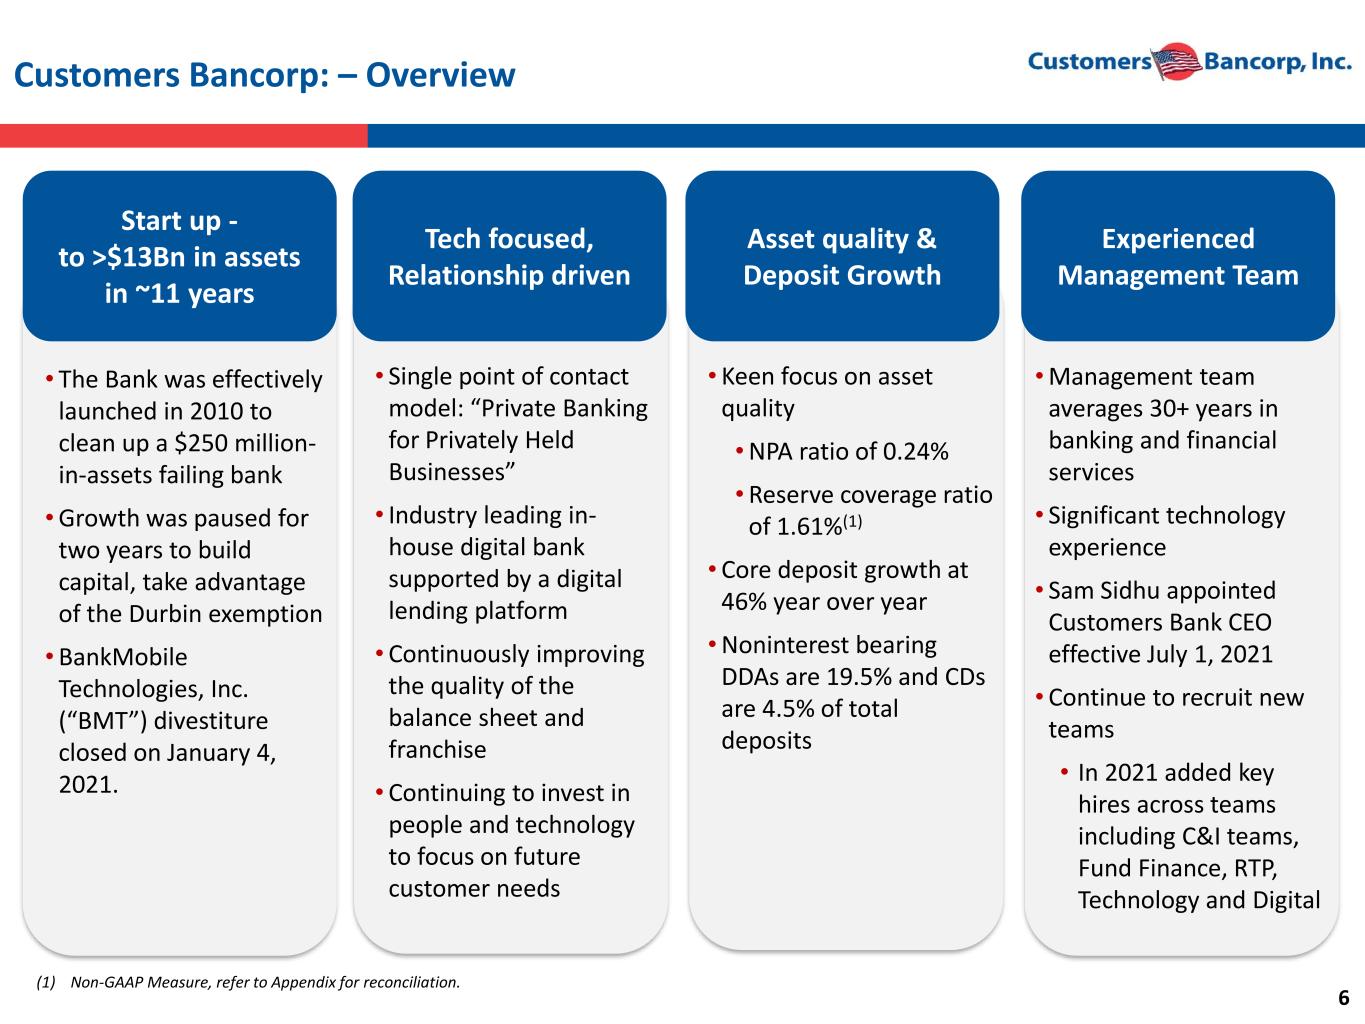
6 (1) Non-GAAP Measure, refer to Appendix for reconciliation. Start up - to >$13Bn in assets in ~11 years Tech focused, Relationship driven Asset quality & Deposit Growth Experienced Management Team • The Bank was effectively launched in 2010 to clean up a $250 million- in-assets failing bank •Growth was paused for two years to build capital, take advantage of the Durbin exemption •BankMobile Technologies, Inc. (“BMT”) divestiture closed on January 4, 2021. • Single point of contact model: “Private Banking for Privately Held Businesses” • Industry leading in- house digital bank supported by a digital lending platform • Continuously improving the quality of the balance sheet and franchise • Continuing to invest in people and technology to focus on future customer needs • Keen focus on asset quality •NPA ratio of 0.24% •Reserve coverage ratio of 1.61%(1) • Core deposit growth at 46% year over year •Noninterest bearing DDAs are 19.5% and CDs are 4.5% of total deposits •Management team averages 30+ years in banking and financial services • Significant technology experience • Sam Sidhu appointed Customers Bank CEO effective July 1, 2021 • Continue to recruit new teams • In 2021 added key hires across teams including C&I teams, Fund Finance, RTP, Technology and Digital Customers Bancorp: – Overview
II. Business Highlights
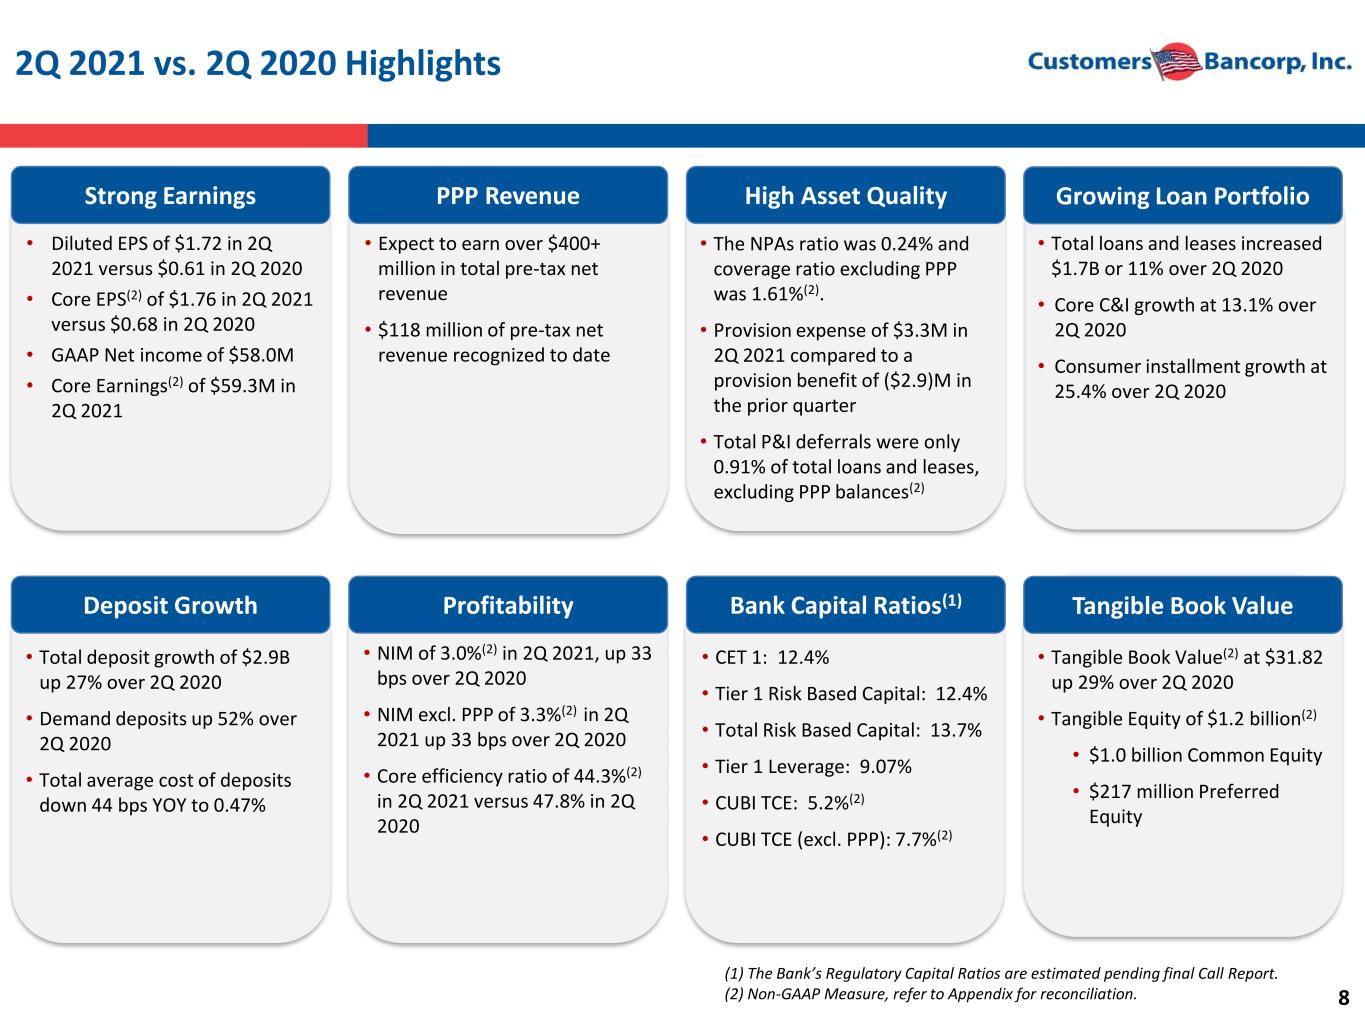
8 2Q 2021 vs. 2Q 2020 Highlights Strong Earnings PPP Revenue High Asset Quality Growing Loan Portfolio Deposit Growth Profitability Bank Capital Ratios(1) Tangible Book Value • Diluted EPS of $1.72 in 2Q 2021 versus $0.61 in 2Q 2020 • Core EPS(2) of $1.76 in 2Q 2021 versus $0.68 in 2Q 2020 • GAAP Net income of $58.0M • Core Earnings(2) of $59.3M in 2Q 2021 • Expect to earn over $400+ million in total pre-tax net revenue • $118 million of pre-tax net revenue recognized to date • The NPAs ratio was 0.24% and coverage ratio excluding PPP was 1.61%(2). • Provision expense of $3.3M in 2Q 2021 compared to a provision benefit of ($2.9)M in the prior quarter • Total P&I deferrals were only 0.91% of total loans and leases, excluding PPP balances(2) • Total loans and leases increased $1.7B or 11% over 2Q 2020 • Core C&I growth at 13.1% over 2Q 2020 • Consumer installment growth at 25.4% over 2Q 2020 • Total deposit growth of $2.9B up 27% over 2Q 2020 • Demand deposits up 52% over 2Q 2020 • Total average cost of deposits down 44 bps YOY to 0.47% • NIM of 3.0%(2) in 2Q 2021, up 33 bps over 2Q 2020 • NIM excl. PPP of 3.3%(2) in 2Q 2021 up 33 bps over 2Q 2020 • Core efficiency ratio of 44.3%(2) in 2Q 2021 versus 47.8% in 2Q 2020 • CET 1: 12.4% • Tier 1 Risk Based Capital: 12.4% • Total Risk Based Capital: 13.7% • Tier 1 Leverage: 9.07% • CUBI TCE: 5.2%(2) • CUBI TCE (excl. PPP): 7.7%(2) • Tangible Book Value(2) at $31.82 up 29% over 2Q 2020 • Tangible Equity of $1.2 billion(2) • $1.0 billion Common Equity • $217 million Preferred Equity (1) The Bank’s Regulatory Capital Ratios are estimated pending final Call Report. (2) Non-GAAP Measure, refer to Appendix for reconciliation.
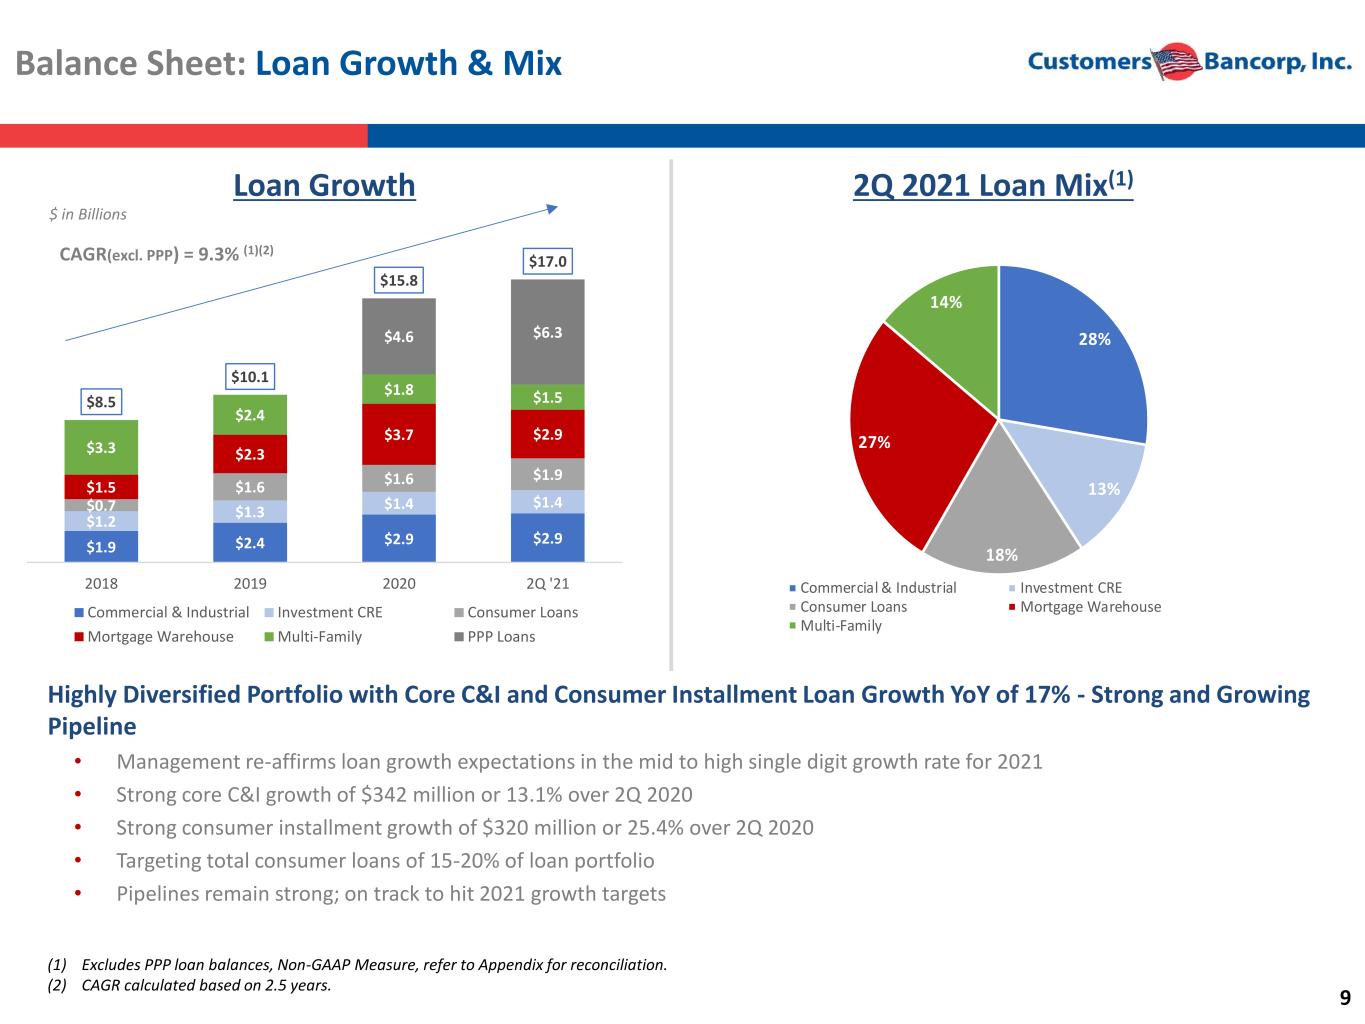
9 Balance Sheet: Loan Growth & Mix (1) Excludes PPP loan balances, Non-GAAP Measure, refer to Appendix for reconciliation. (2) CAGR calculated based on 2.5 years. Highly Diversified Portfolio with Core C&I and Consumer Installment Loan Growth YoY of 17% - Strong and Growing Pipeline • Management re-affirms loan growth expectations in the mid to high single digit growth rate for 2021 • Strong core C&I growth of $342 million or 13.1% over 2Q 2020 • Strong consumer installment growth of $320 million or 25.4% over 2Q 2020 • Targeting total consumer loans of 15-20% of loan portfolio • Pipelines remain strong; on track to hit 2021 growth targets Loan Growth 2Q 2021 Loan Mix(1) $ in Billions 28% 13% 18% 27% 14% Commercial & Industrial Investment CRE Consumer Loans Mortgage Warehouse Multi-Family $1.9 $2.4 $2.9 $2.9 $1.2 $1.3 $1.4 $1.4$0.7 $1.6 $1.6 $1.9 $1.5 $2.3 $3.7 $2.9 $3.3 $2.4 $1.8 $1.5 $4.6 $6.3 $8.5 $10.1 $15.8 $17.0 2018 2019 2020 2Q '21 Commercial & Industrial Investment CRE Consumer Loans Mortgage Warehouse Multi-Family PPP Loans CAGR(excl. PPP) = 9.3% (1)(2)
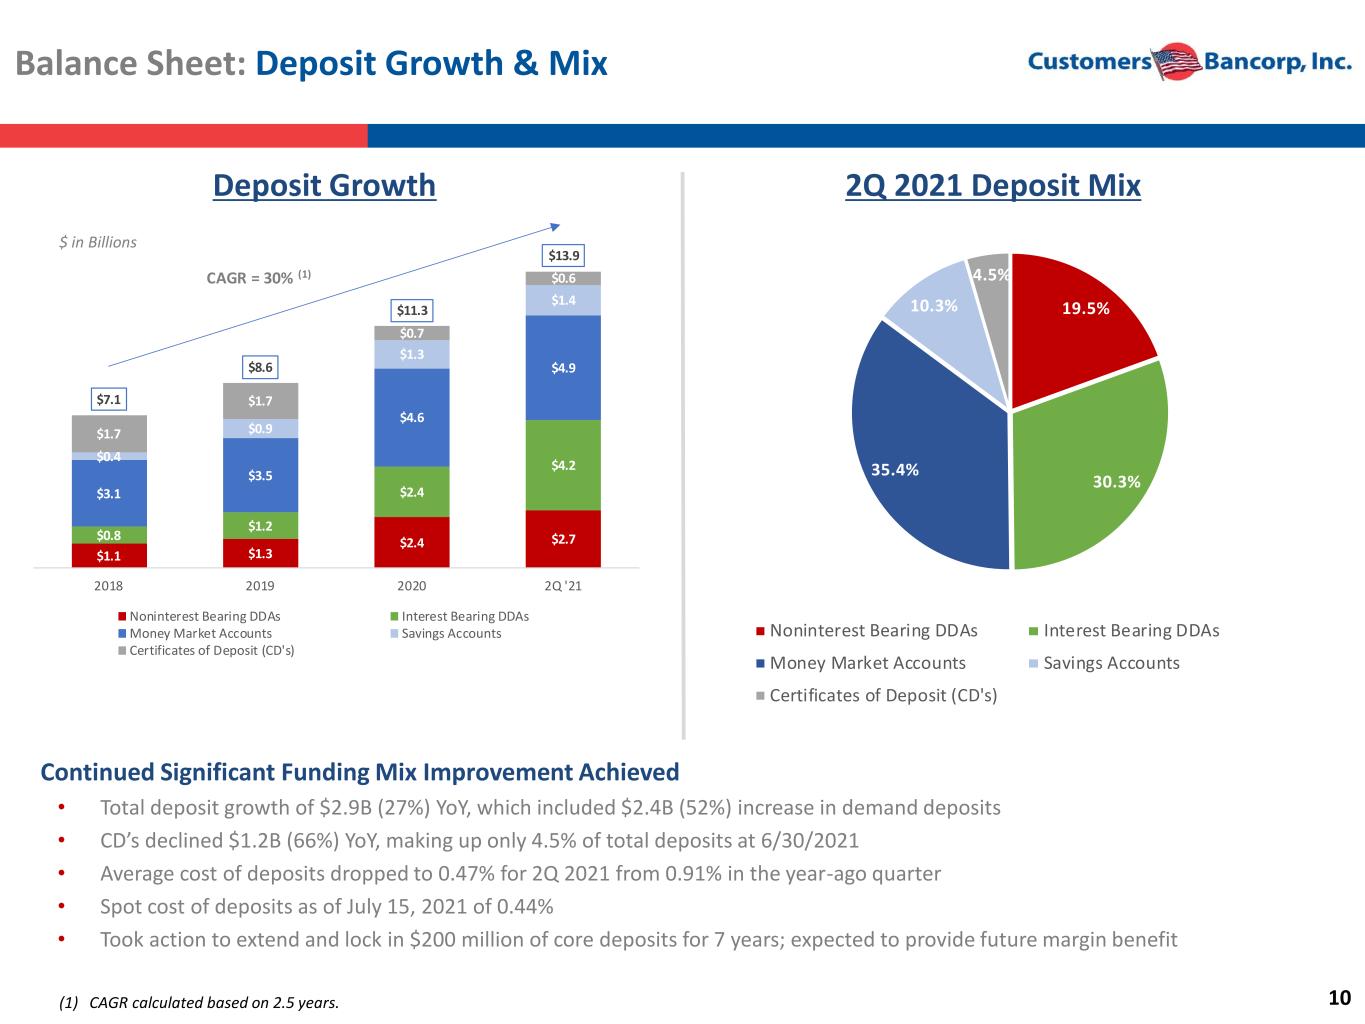
10 Balance Sheet: Deposit Growth & Mix Continued Significant Funding Mix Improvement Achieved • Total deposit growth of $2.9B (27%) YoY, which included $2.4B (52%) increase in demand deposits • CD’s declined $1.2B (66%) YoY, making up only 4.5% of total deposits at 6/30/2021 • Average cost of deposits dropped to 0.47% for 2Q 2021 from 0.91% in the year-ago quarter • Spot cost of deposits as of July 15, 2021 of 0.44% • Took action to extend and lock in $200 million of core deposits for 7 years; expected to provide future margin benefit Deposit Growth 2Q 2021 Deposit Mix $ in Billions (1) CAGR calculated based on 2.5 years. 19.5% 30.3% 35.4% 10.3% 4.5% Noninterest Bearing DDAs Interest Bearing DDAs Money Market Accounts Savings Accounts Certificates of Deposit (CD's) $1.1 $1.3 $2.4 $2.7$0.8 $1.2 $2.4 $4.2 $3.1 $3.5 $4.6 $4.9 $0.4 $0.9 $1.3 $1.4 $1.7 $1.7 $0.7 $0.6 $7.1 $8.6 $11.3 $13.9 2018 2019 2020 2Q '21 Noninterest Bearing DDAs Interest Bearing DDAs Money Market Accounts Savings Accounts Certificates of Deposit (CD's) CAGR = 30% (1)
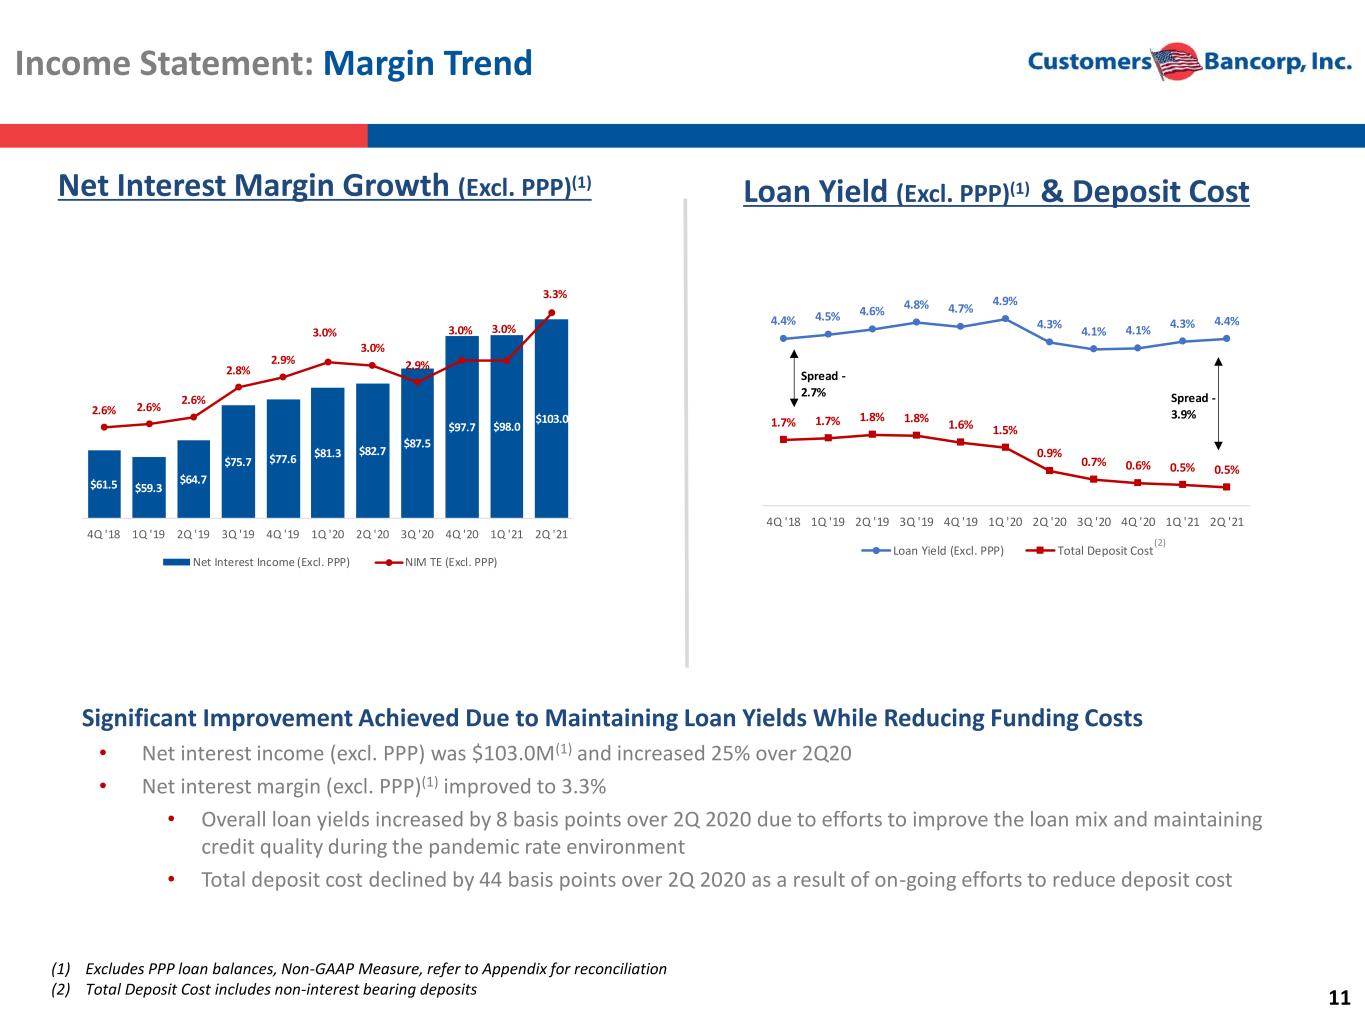
11 Income Statement: Margin Trend Significant Improvement Achieved Due to Maintaining Loan Yields While Reducing Funding Costs • Net interest income (excl. PPP) was $103.0M(1) and increased 25% over 2Q20 • Net interest margin (excl. PPP)(1) improved to 3.3% • Overall loan yields increased by 8 basis points over 2Q 2020 due to efforts to improve the loan mix and maintaining credit quality during the pandemic rate environment • Total deposit cost declined by 44 basis points over 2Q 2020 as a result of on-going efforts to reduce deposit cost Net Interest Margin Growth (Excl. PPP)(1) Loan Yield (Excl. PPP)(1) & Deposit Cost (1) Excludes PPP loan balances, Non-GAAP Measure, refer to Appendix for reconciliation (2) Total Deposit Cost includes non-interest bearing deposits $61.5 $59.3 $64.7 $75.7 $77.6 $81.3 $82.7 $87.5 $97.7 $98.0 $103.0 2.6% 2.6% 2.6% 2.8% 2.9% 3.0% 3.0% 2.9% 3.0% 3.0% 3.3% 4Q '18 1Q '19 2Q '19 3Q '19 4Q '19 1Q '20 2Q '20 3Q '20 4Q '20 1Q '21 2Q '21 Net Interest Income (Excl. PPP) NIM TE (Excl. PPP) 4.4% 4.5% 4.6% 4.8% 4.7% 4.9% 4.3% 4.1% 4.1% 4.3% 4.4% 1.7% 1.7% 1.8% 1.8% 1.6% 1.5% 0.9% 0.7% 0.6% 0.5% 0.5% 4Q '18 1Q '19 2Q '19 3Q '19 4Q '19 1Q '20 2Q '20 3Q '20 4Q '20 1Q '21 2Q '21 Loan Yield (Excl. PPP) Total Deposit Cost Spread - 2.7% Spread - 3.9% (2)
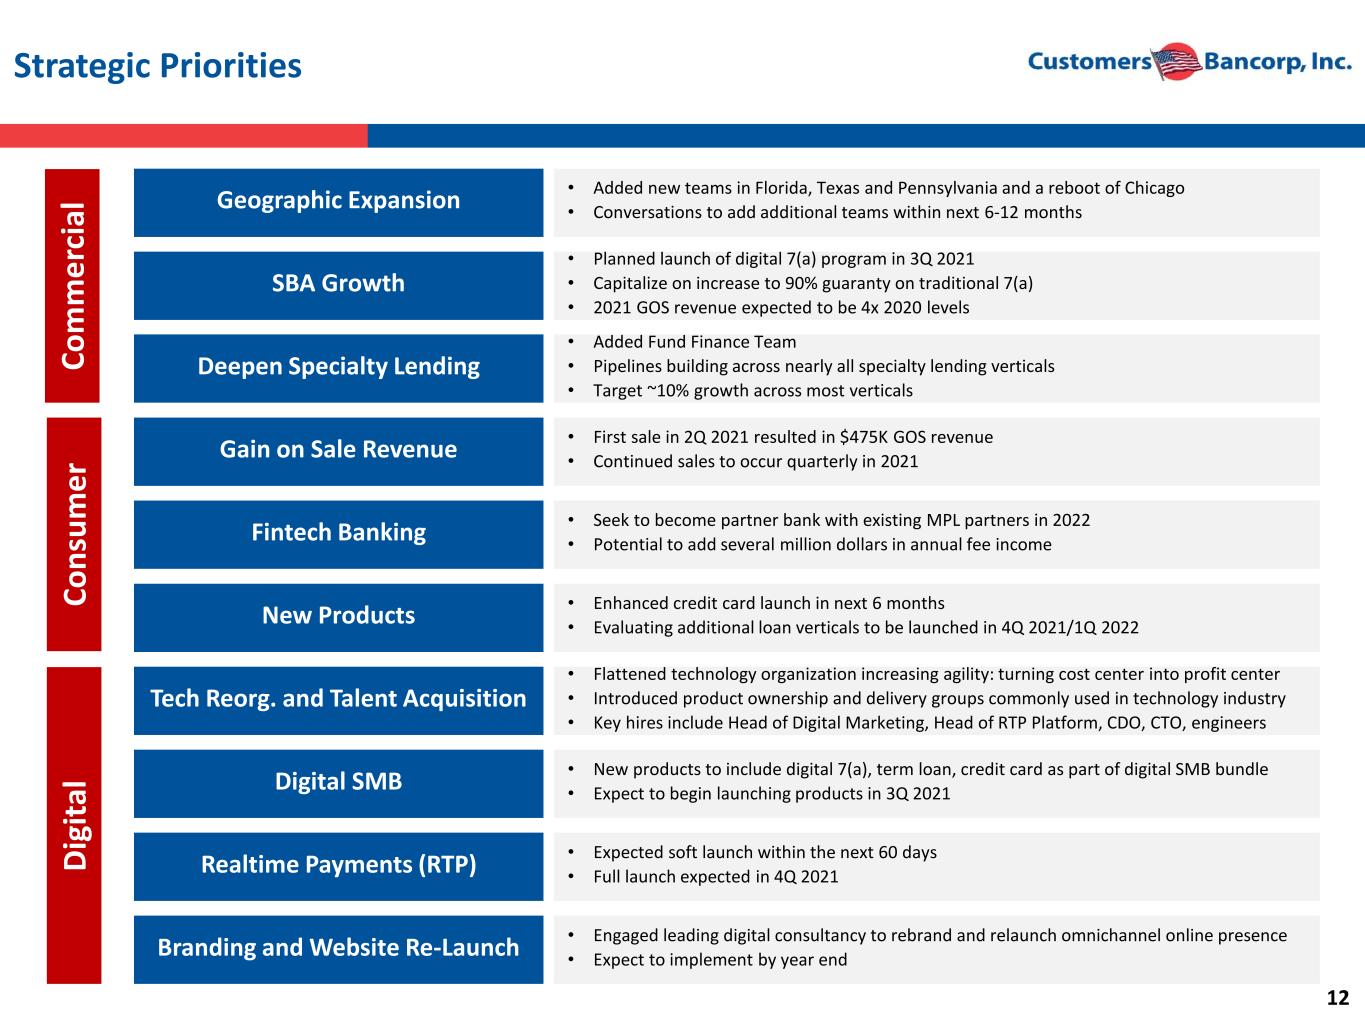
12 Strategic Priorities Geographic Expansion • Added new teams in Florida, Texas and Pennsylvania and a reboot of Chicago • Conversations to add additional teams within next 6-12 months SBA Growth • Planned launch of digital 7(a) program in 3Q 2021 • Capitalize on increase to 90% guaranty on traditional 7(a) • 2021 GOS revenue expected to be 4x 2020 levels Deepen Specialty Lending • Added Fund Finance Team • Pipelines building across nearly all specialty lending verticals • Target ~10% growth across most verticals Gain on Sale Revenue • First sale in 2Q 2021 resulted in $475K GOS revenue • Continued sales to occur quarterly in 2021 Fintech Banking • Seek to become partner bank with existing MPL partners in 2022 • Potential to add several million dollars in annual fee income New Products • Enhanced credit card launch in next 6 months • Evaluating additional loan verticals to be launched in 4Q 2021/1Q 2022 Tech Reorg. and Talent Acquisition • Flattened technology organization increasing agility: turning cost center into profit center • Introduced product ownership and delivery groups commonly used in technology industry • Key hires include Head of Digital Marketing, Head of RTP Platform, CDO, CTO, engineers Digital SMB • New products to include digital 7(a), term loan, credit card as part of digital SMB bundle • Expect to begin launching products in 3Q 2021 Realtime Payments (RTP) • Expected soft launch within the next 60 days • Full launch expected in 4Q 2021 Branding and Website Re-Launch • Engaged leading digital consultancy to rebrand and relaunch omnichannel online presence • Expect to implement by year end C o m m e rc ia l C o n su m e r D ig it al
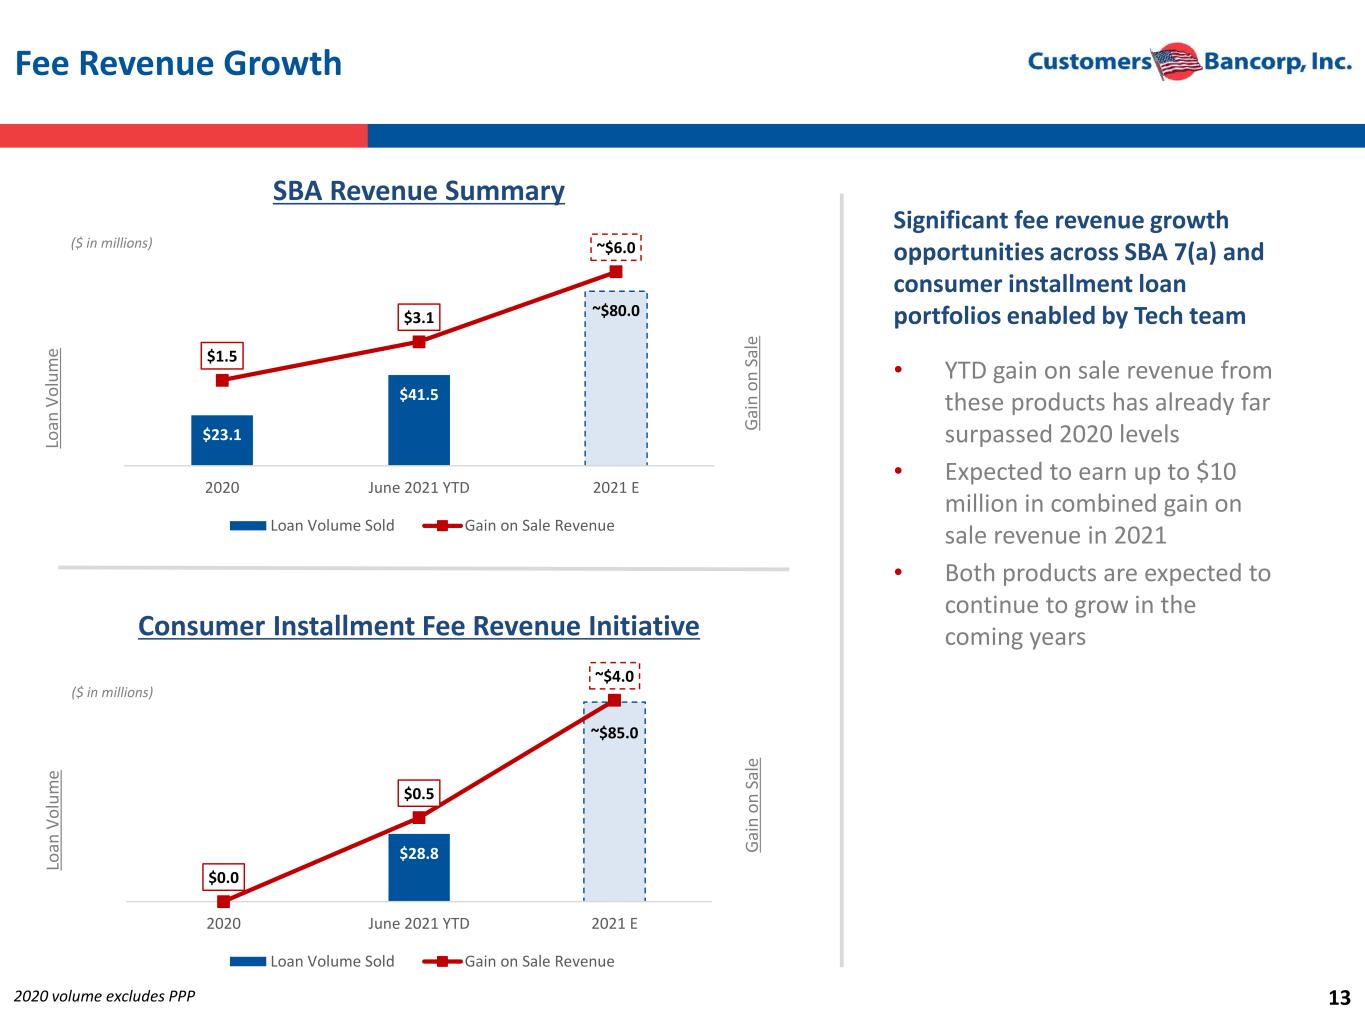
13 Fee Revenue Growth SBA Revenue Summary ($ in millions) Lo an V o lu m e G ai n o n S al e 2020 volume excludes PPP Consumer Installment Fee Revenue Initiative Significant fee revenue growth opportunities across SBA 7(a) and consumer installment loan portfolios enabled by Tech team • YTD gain on sale revenue from these products has already far surpassed 2020 levels • Expected to earn up to $10 million in combined gain on sale revenue in 2021 • Both products are expected to continue to grow in the coming years ($ in millions) Lo an V o lu m e G ai n o n S al e $23.1 $41.5 ~$80.0 $1.5 $3.1 ~$6.0 2020 June 2021 YTD 2021 E Loan Volume Sold Gain on Sale Revenue $0.0 $28.8 ~$85.0 $0.0 $0.5 ~$4.0 2020 June 2021 YTD 2021 E Loan Volume Sold Gain on Sale Revenue
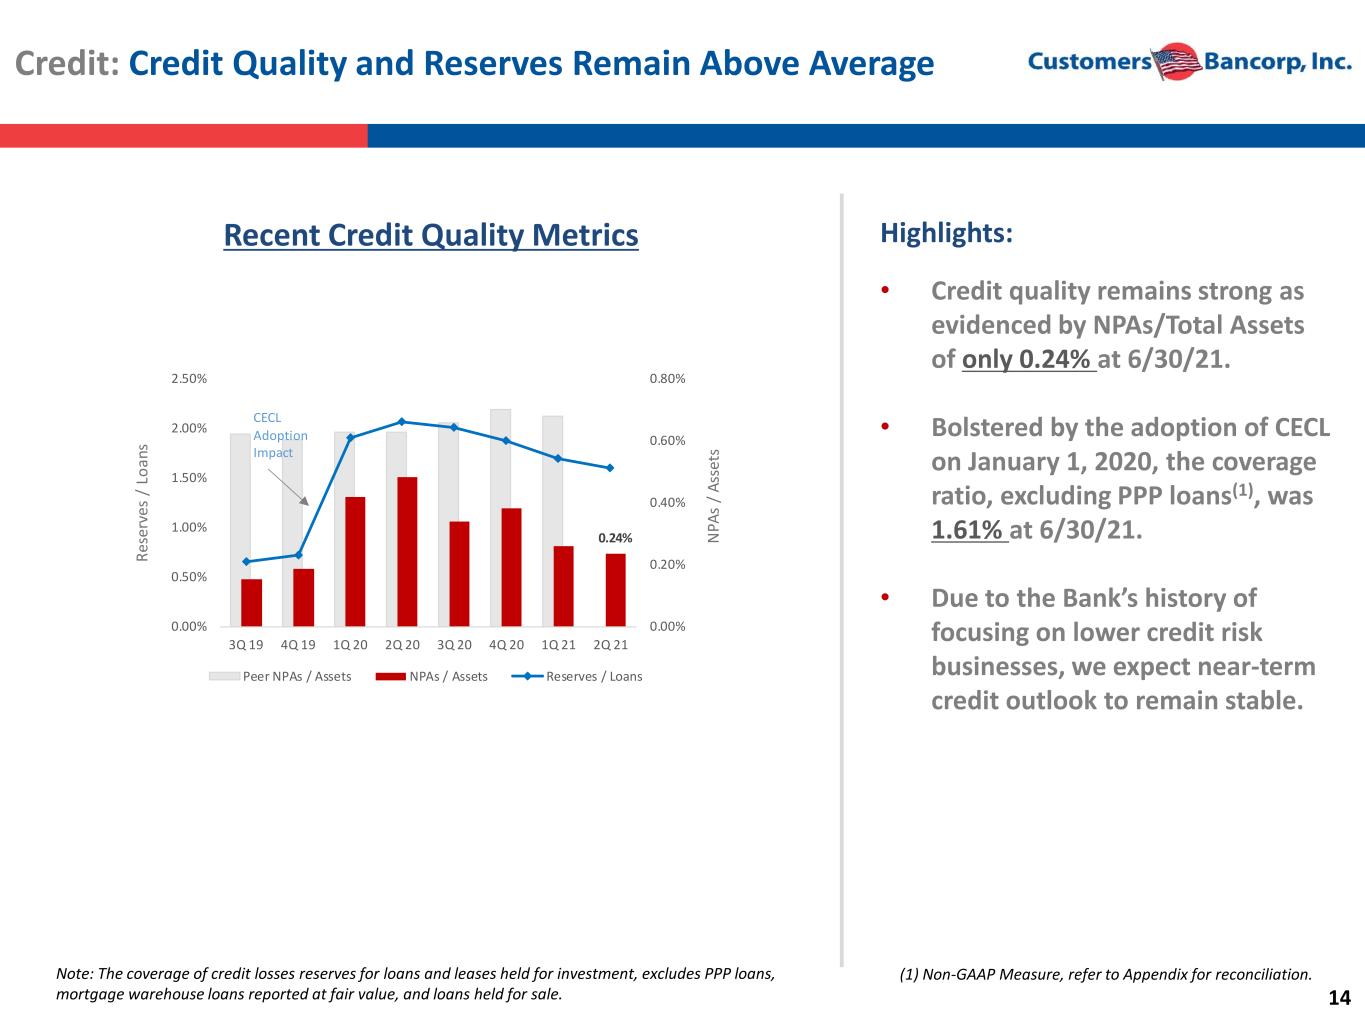
14 Credit: Credit Quality and Reserves Remain Above Average Recent Credit Quality Metrics Highlights: • Credit quality remains strong as evidenced by NPAs/Total Assets of only 0.24% at 6/30/21. • Bolstered by the adoption of CECL on January 1, 2020, the coverage ratio, excluding PPP loans(1), was 1.61% at 6/30/21. • Due to the Bank’s history of focusing on lower credit risk businesses, we expect near-term credit outlook to remain stable. Note: The coverage of credit losses reserves for loans and leases held for investment, excludes PPP loans, mortgage warehouse loans reported at fair value, and loans held for sale. (1) Non-GAAP Measure, refer to Appendix for reconciliation. 0.24% 0.00% 0.20% 0.40% 0.60% 0.80% 0.00% 0.50% 1.00% 1.50% 2.00% 2.50% 3Q 19 4Q 19 1Q 20 2Q 20 3Q 20 4Q 20 1Q 21 2Q 21 Peer NPAs / Assets NPAs / Assets Reserves / Loans R es er ve s / Lo an s N PA s / A ss et s CECL Adoption Impact
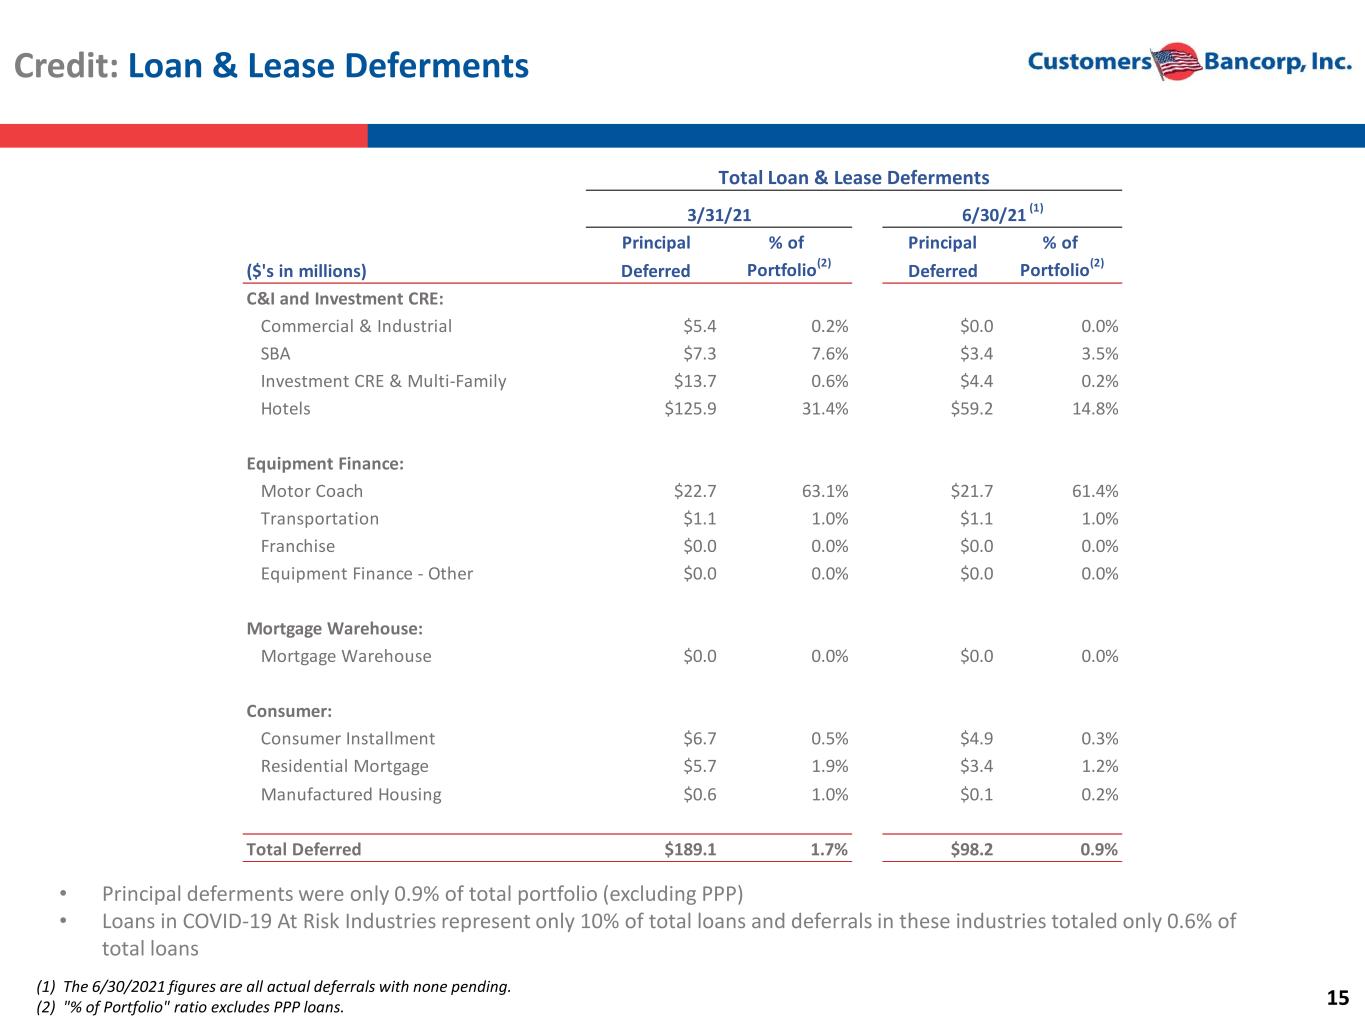
15 Credit: Loan & Lease Deferments (1) The 6/30/2021 figures are all actual deferrals with none pending. (2) "% of Portfolio" ratio excludes PPP loans. • Principal deferments were only 0.9% of total portfolio (excluding PPP) • Loans in COVID-19 At Risk Industries represent only 10% of total loans and deferrals in these industries totaled only 0.6% of total loans Principal % of Principal % of ($'s in millions) Deferred Portfolio(2) Deferred Portfolio(2) C&I and Investment CRE: Commercial & Industrial $5.4 0.2% $0.0 0.0% SBA $7.3 7.6% $3.4 3.5% Investment CRE & Multi-Family $13.7 0.6% $4.4 0.2% Hotels $125.9 31.4% $59.2 14.8% Equipment Finance: Motor Coach $22.7 63.1% $21.7 61.4% Transportation $1.1 1.0% $1.1 1.0% Franchise $0.0 0.0% $0.0 0.0% Equipment Finance - Other $0.0 0.0% $0.0 0.0% Mortgage Warehouse: Mortgage Warehouse $0.0 0.0% $0.0 0.0% Consumer: Consumer Installment $6.7 0.5% $4.9 0.3% Residential Mortgage $5.7 1.9% $3.4 1.2% Manufactured Housing $0.6 1.0% $0.1 0.2% Total Deferred $189.1 1.7% $98.2 0.9% 3/31/21 6/30/21 (1) Total Loan & Lease Deferments
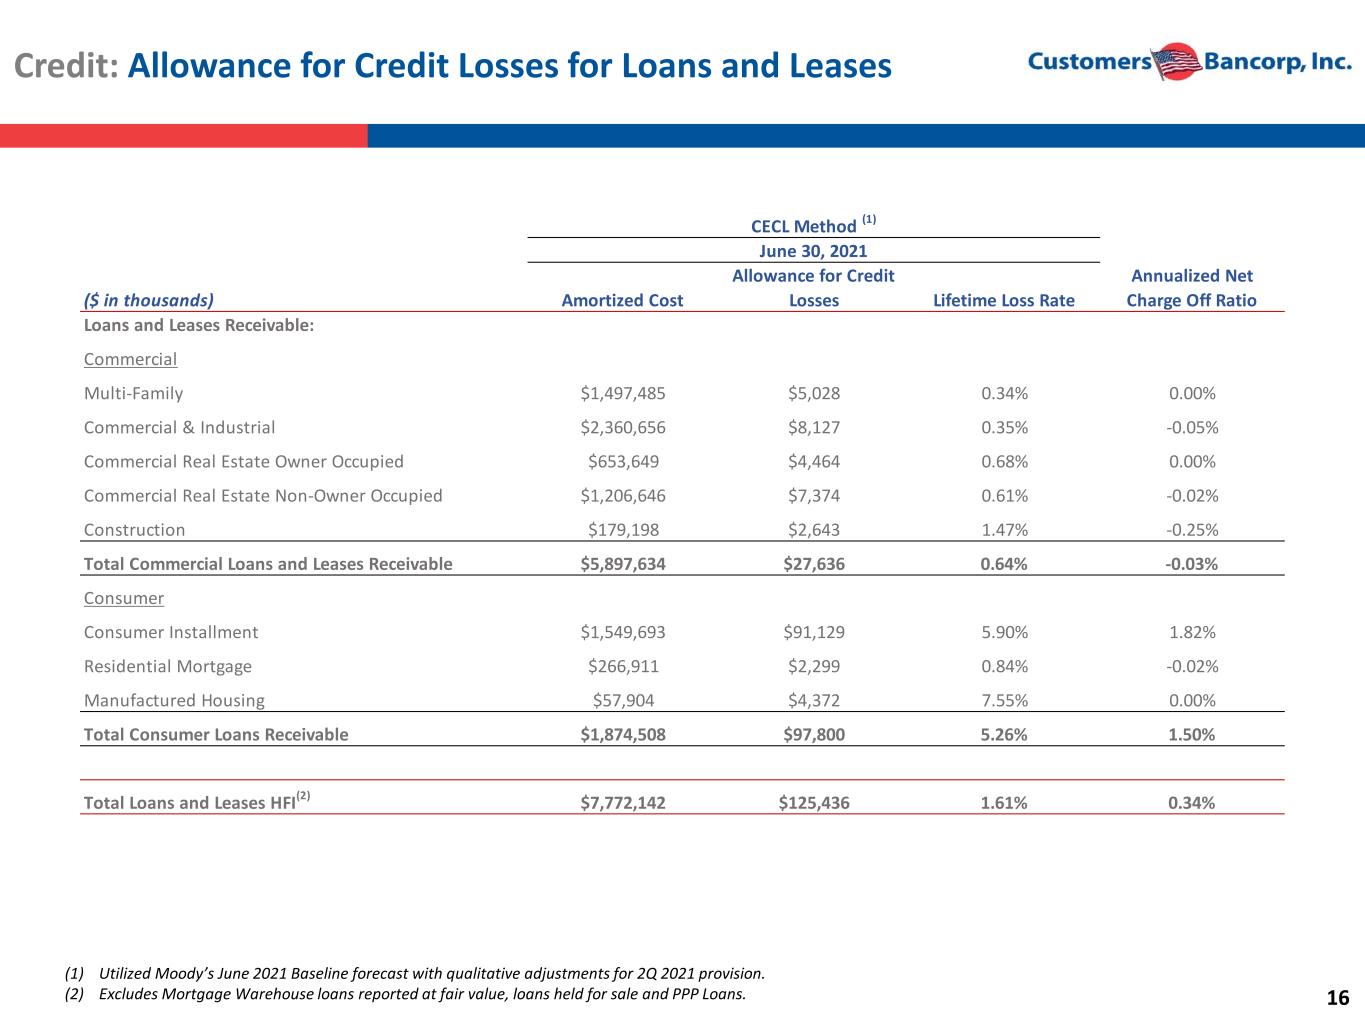
16 Credit: Allowance for Credit Losses for Loans and Leases (1) Utilized Moody’s June 2021 Baseline forecast with qualitative adjustments for 2Q 2021 provision. (2) Excludes Mortgage Warehouse loans reported at fair value, loans held for sale and PPP Loans. ($ in thousands) Amortized Cost Allowance for Credit Losses Lifetime Loss Rate Annualized Net Charge Off Ratio Loans and Leases Receivable: Commercial Multi-Family $1,497,485 $5,028 0.34% 0.00% Commercial & Industrial $2,360,656 $8,127 0.35% -0.05% Commercial Real Estate Owner Occupied $653,649 $4,464 0.68% 0.00% Commercial Real Estate Non-Owner Occupied $1,206,646 $7,374 0.61% -0.02% Construction $179,198 $2,643 1.47% -0.25% Total Commercial Loans and Leases Receivable $5,897,634 $27,636 0.64% -0.03% Consumer Consumer Installment $1,549,693 $91,129 5.90% 1.82% Residential Mortgage $266,911 $2,299 0.84% -0.02% Manufactured Housing $57,904 $4,372 7.55% 0.00% Total Consumer Loans Receivable $1,874,508 $97,800 5.26% 1.50% Total Loans and Leases HFI (2) $7,772,142 $125,436 1.61% 0.34% CECL Method (1) June 30, 2021
IV. Technology Driven Business Model
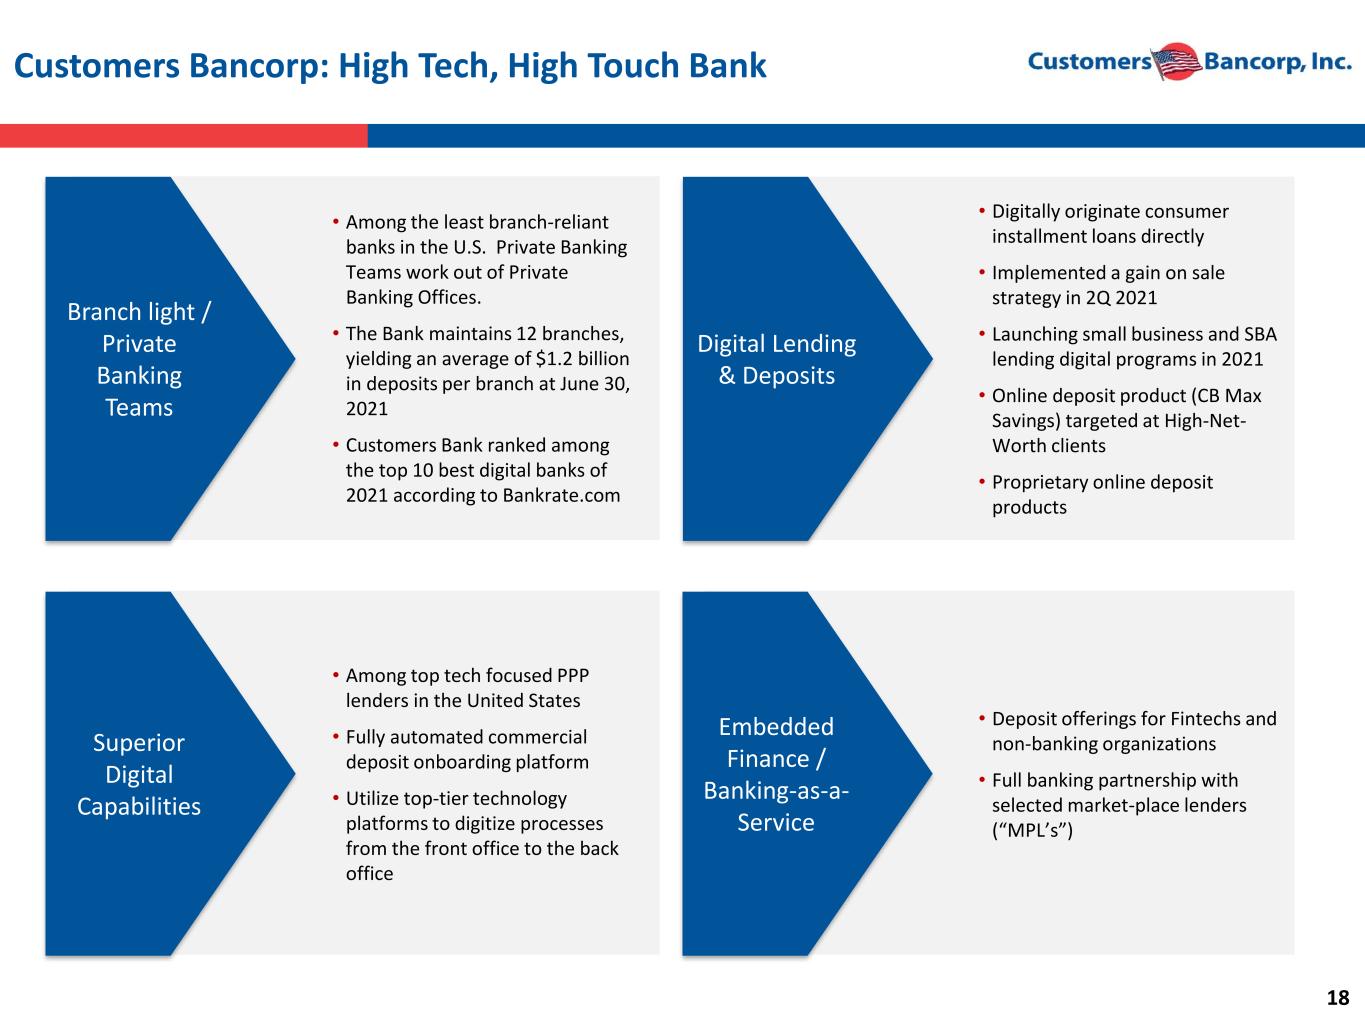
18 Customers Bancorp: High Tech, High Touch Bank Branch light / Private Banking Teams Superior Digital Capabilities Digital Lending & Deposits Embedded Finance / Banking-as-a- Service • Among the least branch-reliant banks in the U.S. Private Banking Teams work out of Private Banking Offices. • The Bank maintains 12 branches, yielding an average of $1.2 billion in deposits per branch at June 30, 2021 • Customers Bank ranked among the top 10 best digital banks of 2021 according to Bankrate.com • Among top tech focused PPP lenders in the United States • Fully automated commercial deposit onboarding platform • Utilize top-tier technology platforms to digitize processes from the front office to the back office • Digitally originate consumer installment loans directly • Implemented a gain on sale strategy in 2Q 2021 • Launching small business and SBA lending digital programs in 2021 • Online deposit product (CB Max Savings) targeted at High-Net- Worth clients • Proprietary online deposit products • Deposit offerings for Fintechs and non-banking organizations • Full banking partnership with selected market-place lenders (“MPL’s”)
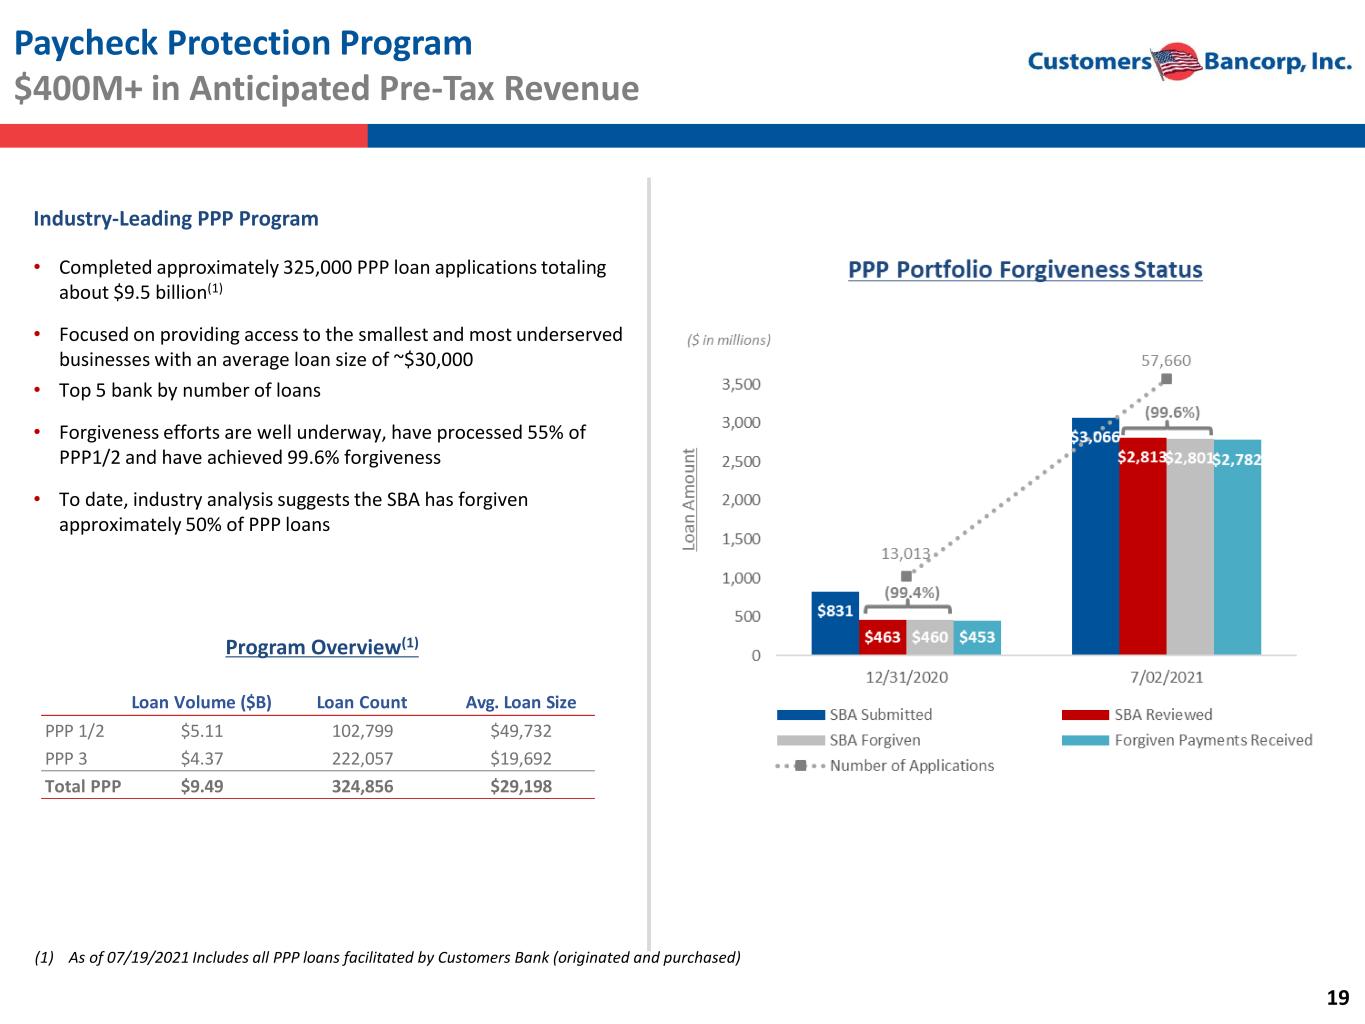
19 Loan Volume ($B) Loan Count Avg. Loan Size PPP 1/2 $5.11 102,799 $49,732 PPP 3 $4.37 222,057 $19,692 Total PPP $9.49 324,856 $29,198 Paycheck Protection Program $400M+ in Anticipated Pre-Tax Revenue Industry-Leading PPP Program • Completed approximately 325,000 PPP loan applications totaling about $9.5 billion(1) • Focused on providing access to the smallest and most underserved businesses with an average loan size of ~$30,000 • Top 5 bank by number of loans • Forgiveness efforts are well underway, have processed 55% of PPP1/2 and have achieved 99.6% forgiveness • To date, industry analysis suggests the SBA has forgiven approximately 50% of PPP loans (1) As of 07/19/2021 Includes all PPP loans facilitated by Customers Bank (originated and purchased) Program Overview(1)
V. Outlook
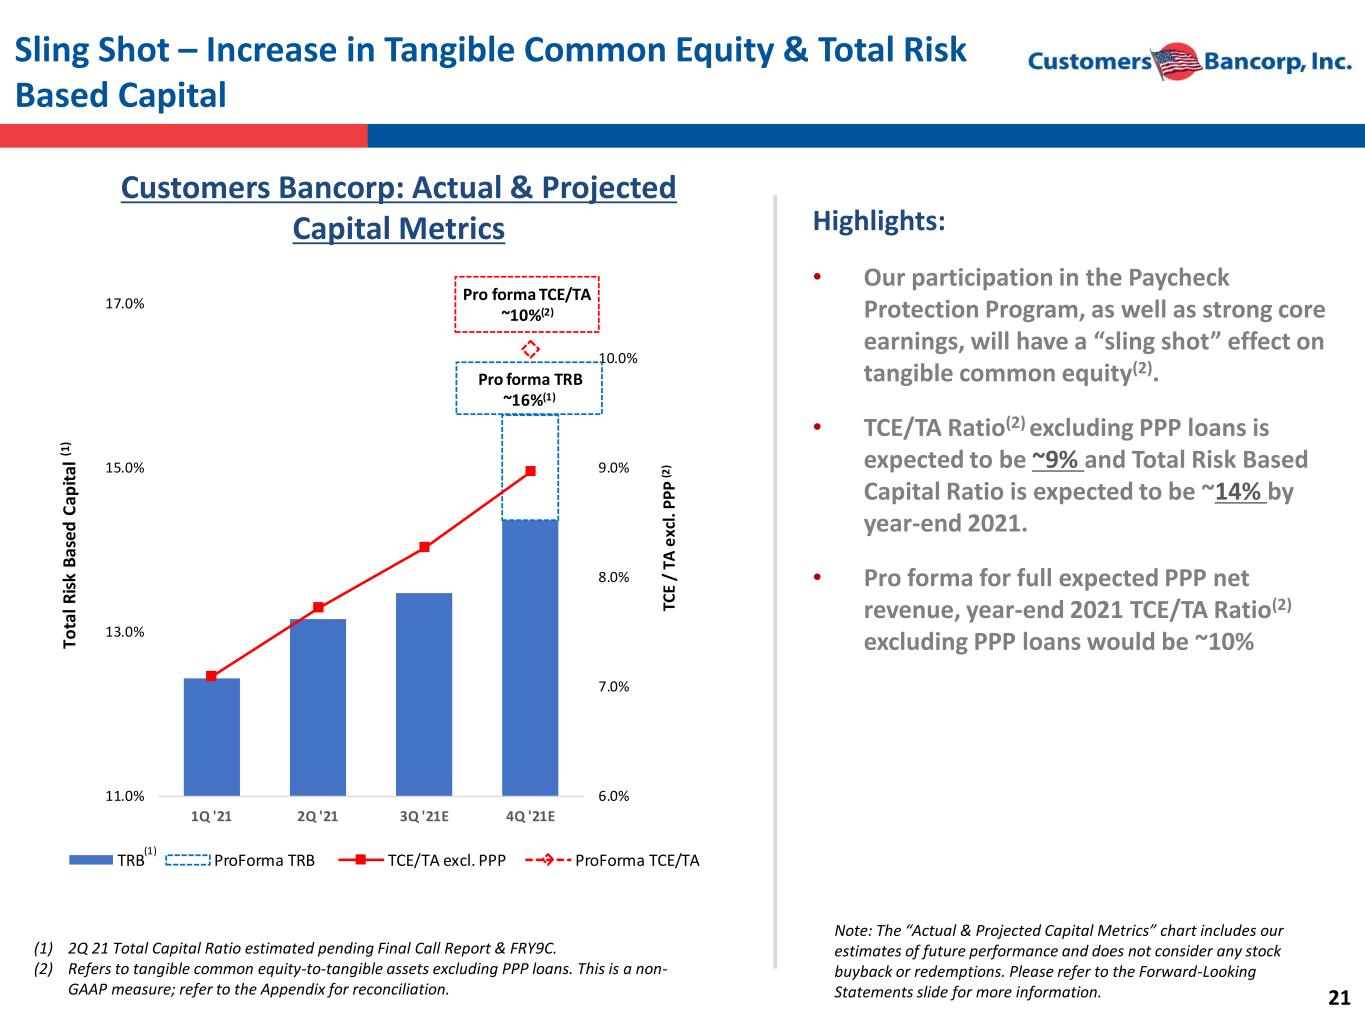
21 Sling Shot – Increase in Tangible Common Equity & Total Risk Based Capital Customers Bancorp: Actual & Projected Capital Metrics (1) 2Q 21 Total Capital Ratio estimated pending Final Call Report & FRY9C. (2) Refers to tangible common equity-to-tangible assets excluding PPP loans. This is a non- GAAP measure; refer to the Appendix for reconciliation. Note: The “Actual & Projected Capital Metrics” chart includes our estimates of future performance and does not consider any stock buyback or redemptions. Please refer to the Forward-Looking Statements slide for more information. Highlights: • Our participation in the Paycheck Protection Program, as well as strong core earnings, will have a “sling shot” effect on tangible common equity(2). • TCE/TA Ratio(2) excluding PPP loans is expected to be ~9% and Total Risk Based Capital Ratio is expected to be ~14% by year-end 2021. • Pro forma for full expected PPP net revenue, year-end 2021 TCE/TA Ratio(2) excluding PPP loans would be ~10% 6.0% 7.0% 8.0% 9.0% 10.0% 11.0% 13.0% 15.0% 17.0% 1Q '21 2Q '21 3Q '21E 4Q '21E TC E / TA e xc l. P P P (2 ) TRB ProForma TRB TCE/TA excl. PPP ProForma TCE/TA Pro forma TCE/TA ~10%(2) Pro forma TRB ~16%(1) To ta l R is k B as ed C ap it al (1 ) (1)
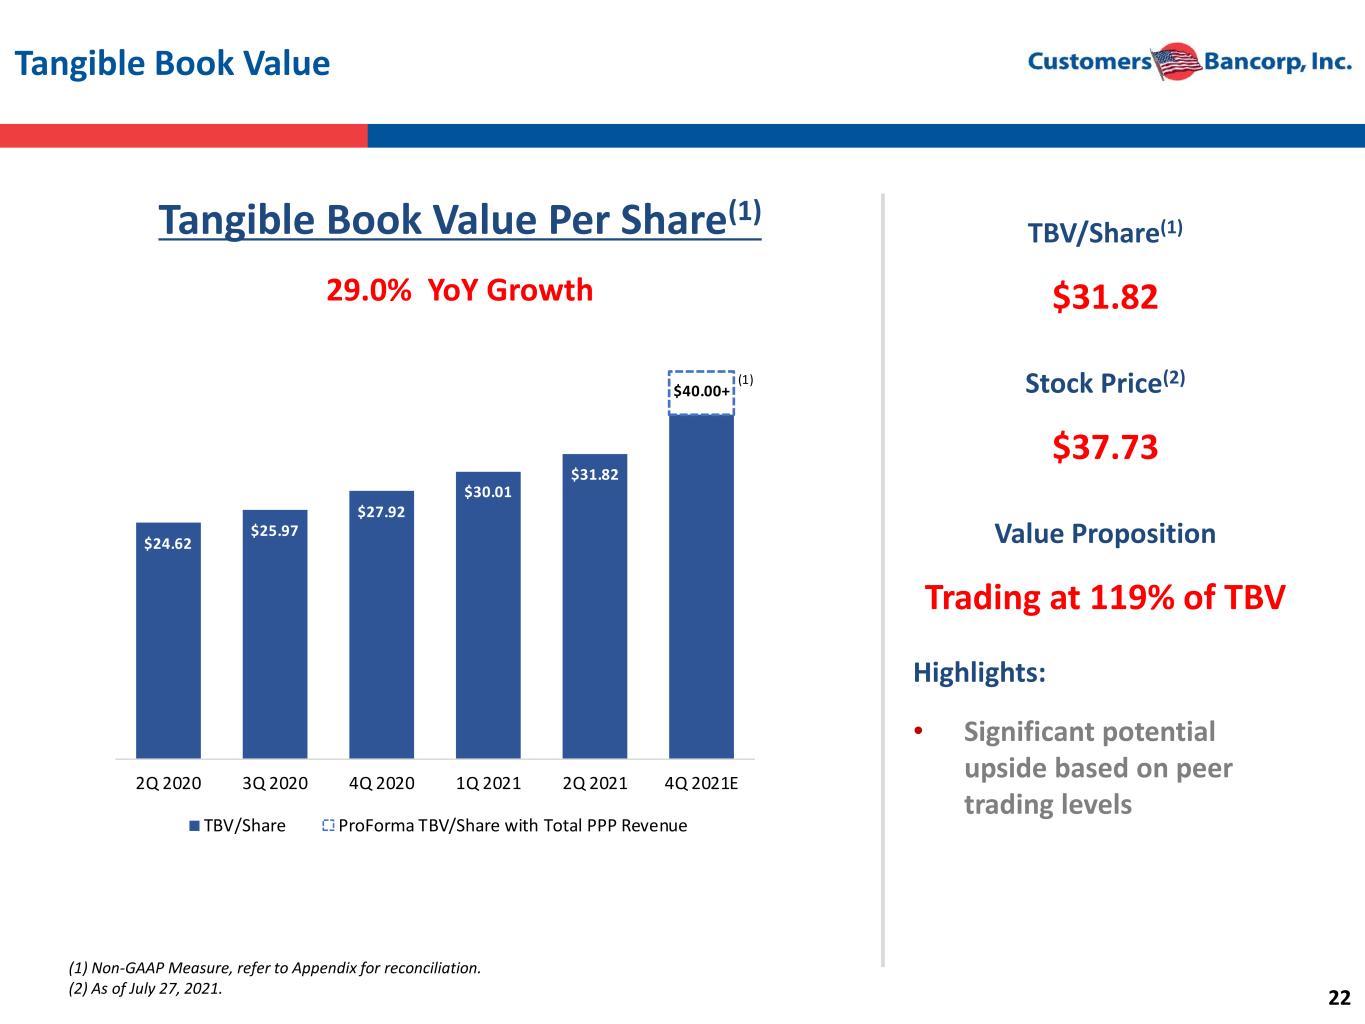
22 Tangible Book Value Tangible Book Value Per Share(1) 29.0% YoY Growth TBV/Share(1) $31.82 Stock Price(2) $37.73 Value Proposition Trading at 119% of TBV Highlights: • Significant potential upside based on peer trading levels (1) Non-GAAP Measure, refer to Appendix for reconciliation. (2) As of July 27, 2021. $24.62 $25.97 $27.92 $30.01 $31.82 2Q 2020 3Q 2020 4Q 2020 1Q 2021 2Q 2021 4Q 2021E TBV/Share ProForma TBV/Share with Total PPP Revenue (1) $40.00+
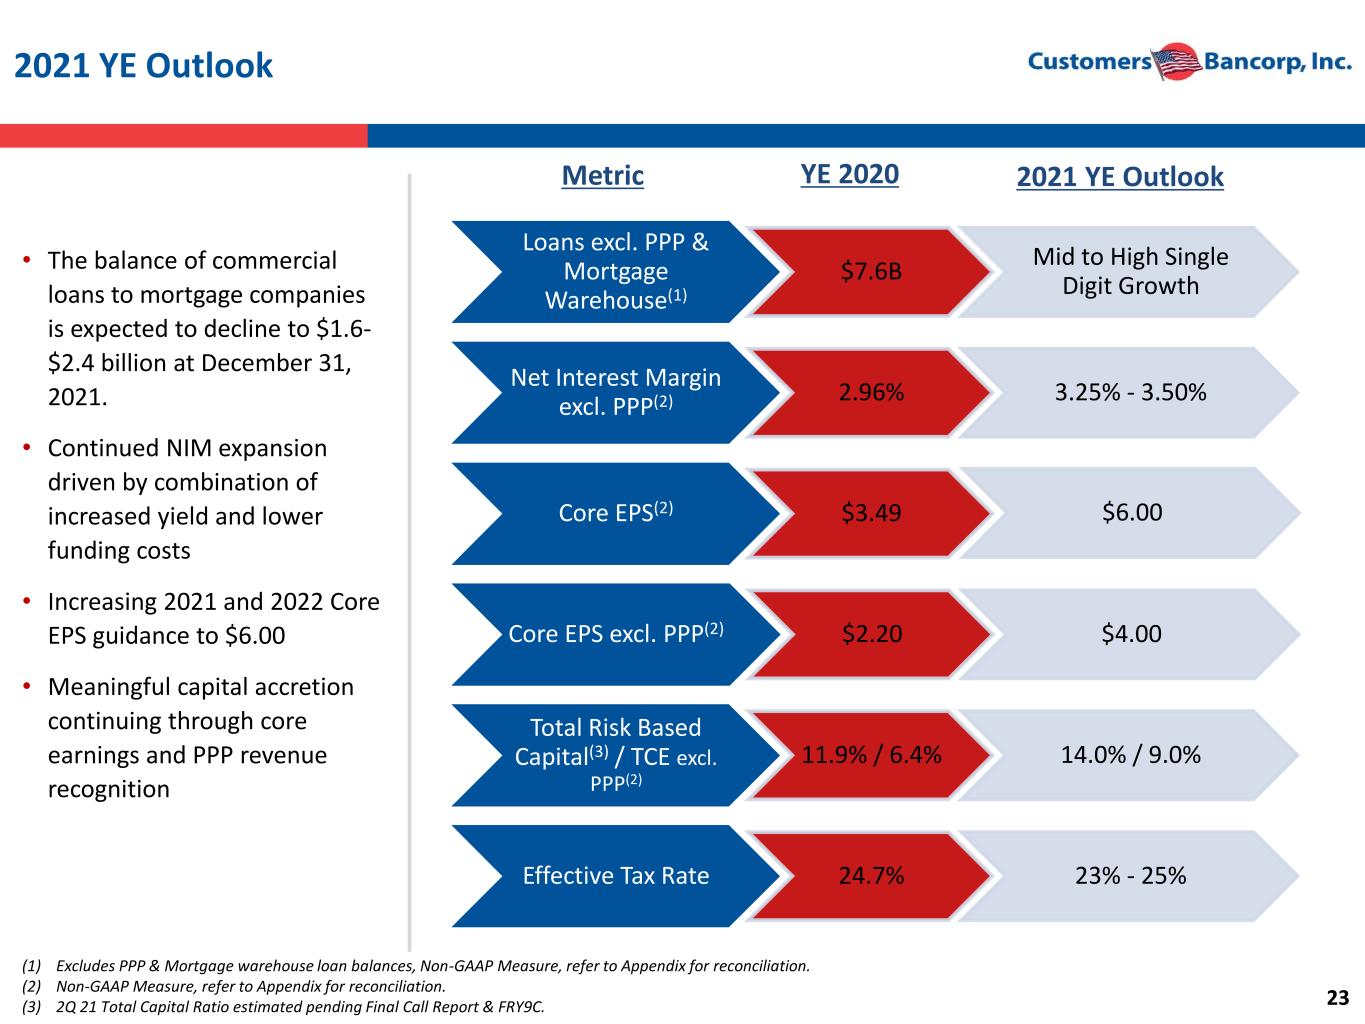
23 2021 YE Outlook • The balance of commercial loans to mortgage companies is expected to decline to $1.6- $2.4 billion at December 31, 2021. • Continued NIM expansion driven by combination of increased yield and lower funding costs • Increasing 2021 and 2022 Core EPS guidance to $6.00 • Meaningful capital accretion continuing through core earnings and PPP revenue recognition Loans excl. PPP & Mortgage Warehouse(1) $7.6B Mid to High Single Digit Growth Net Interest Margin excl. PPP(2) 2.96% 3.25% - 3.50% Core EPS(2) $3.49 $6.00 Core EPS excl. PPP(2) $2.20 $4.00 Total Risk Based Capital(3) / TCE excl. PPP(2) 11.9% / 6.4% 14.0% / 9.0% Effective Tax Rate 24.7% 23% - 25% Metric YE 2020 2021 YE Outlook (1) Excludes PPP & Mortgage warehouse loan balances, Non-GAAP Measure, refer to Appendix for reconciliation. (2) Non-GAAP Measure, refer to Appendix for reconciliation. (3) 2Q 21 Total Capital Ratio estimated pending Final Call Report & FRY9C.
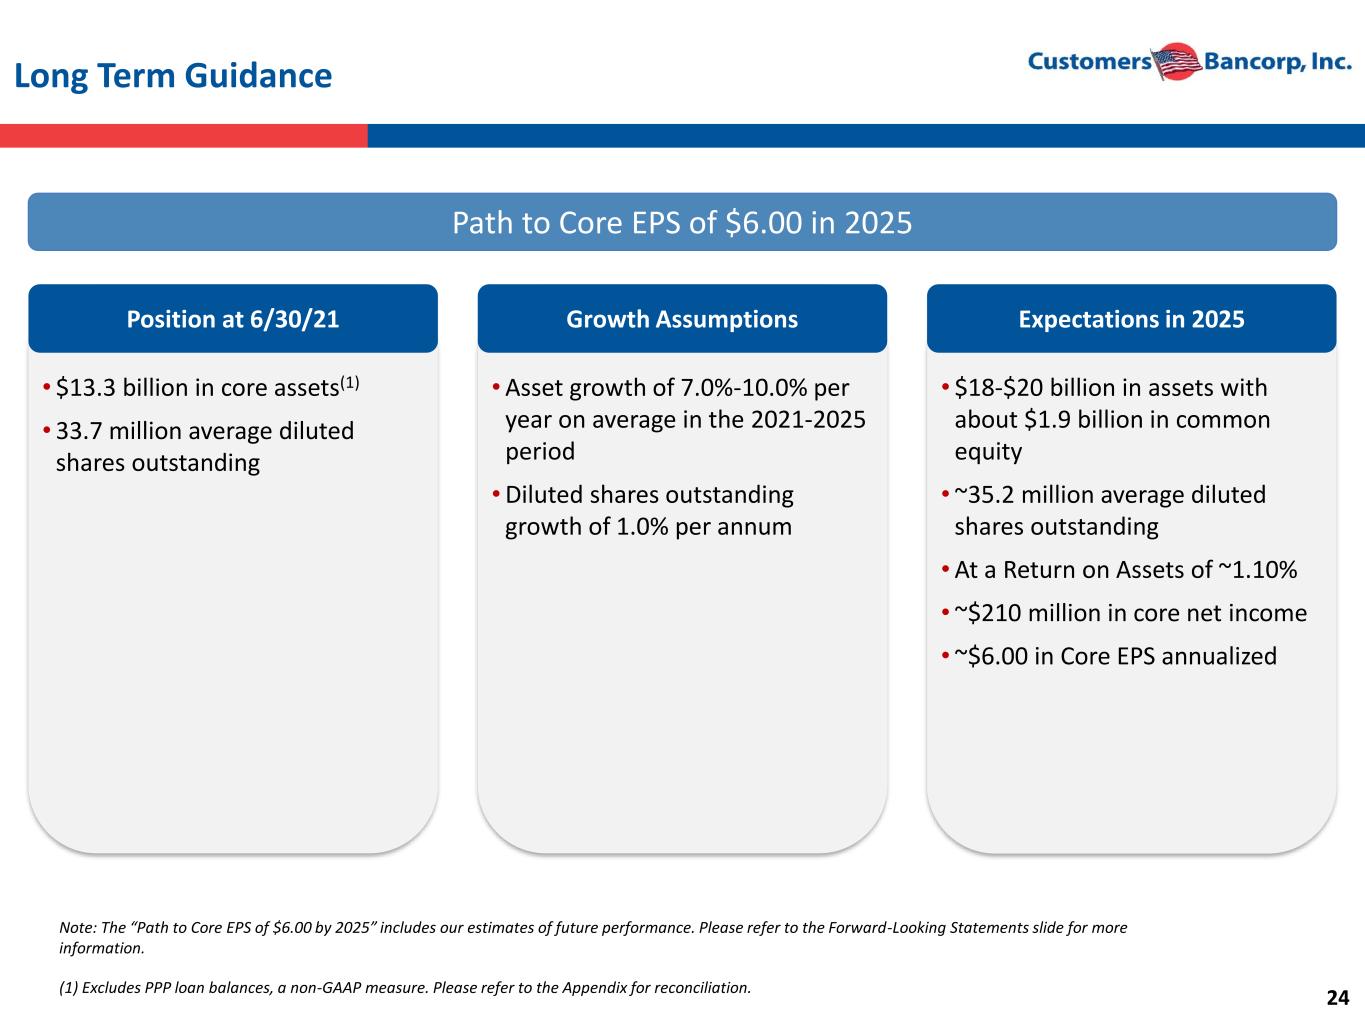
24 Long Term Guidance Note: The “Path to Core EPS of $6.00 by 2025” includes our estimates of future performance. Please refer to the Forward-Looking Statements slide for more information. (1) Excludes PPP loan balances, a non-GAAP measure. Please refer to the Appendix for reconciliation. Path to Core EPS of $6.00 in 2025 Position at 6/30/21 Growth Assumptions Expectations in 2025 • $13.3 billion in core assets(1) • 33.7 million average diluted shares outstanding •Asset growth of 7.0%-10.0% per year on average in the 2021-2025 period •Diluted shares outstanding growth of 1.0% per annum • $18-$20 billion in assets with about $1.9 billion in common equity • ~35.2 million average diluted shares outstanding •At a Return on Assets of ~1.10% • ~$210 million in core net income • ~$6.00 in Core EPS annualized
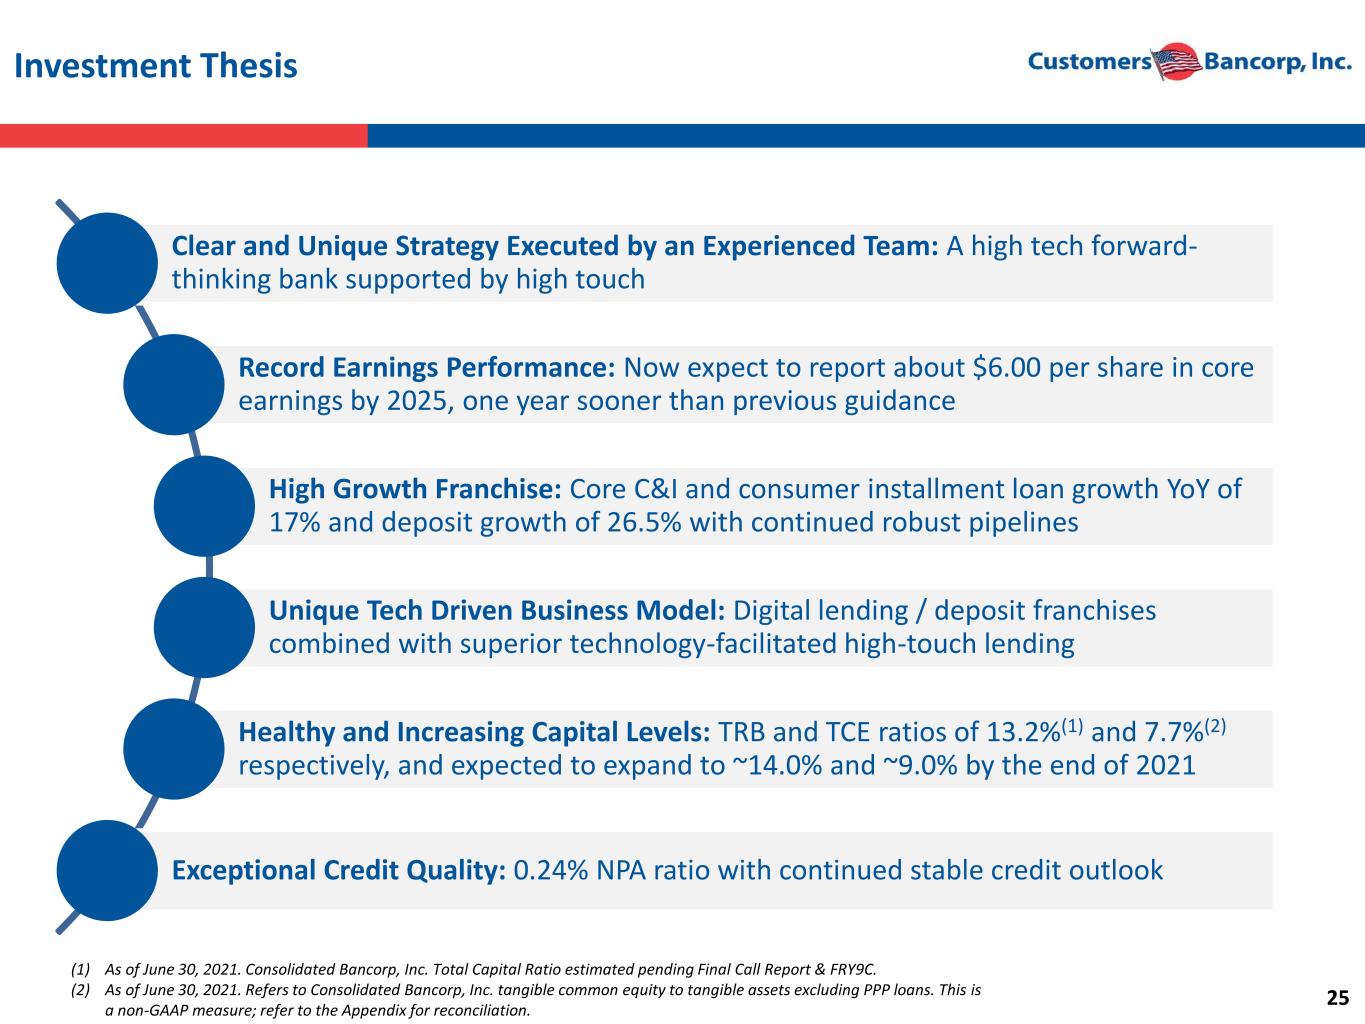
25 Investment Thesis (1) As of June 30, 2021. Consolidated Bancorp, Inc. Total Capital Ratio estimated pending Final Call Report & FRY9C. (2) As of June 30, 2021. Refers to Consolidated Bancorp, Inc. tangible common equity to tangible assets excluding PPP loans. This is a non-GAAP measure; refer to the Appendix for reconciliation. Clear and Unique Strategy Executed by an Experienced Team: A high tech forward- thinking bank supported by high touch Record Earnings Performance: Now expect to report about $6.00 per share in core earnings by 2025, one year sooner than previous guidance High Growth Franchise: Core C&I and consumer installment loan growth YoY of 17% and deposit growth of 26.5% with continued robust pipelines Unique Tech Driven Business Model: Digital lending / deposit franchises combined with superior technology-facilitated high-touch lending Healthy and Increasing Capital Levels: TRB and TCE ratios of 13.2%(1) and 7.7%(2) respectively, and expected to expand to ~14.0% and ~9.0% by the end of 2021 Exceptional Credit Quality: 0.24% NPA ratio with continued stable credit outlook
VI. Appendix
27 Environmental, social and governance (ESG) considerations are integrated across our business units and incorporated into the policies and principles that govern how our company operates. We continuously seek to address some of the practical challenges in balancing short- and long-term business trade-offs in order to ensure that our stakeholders and shareholders prosper together. Customers Bank’s approach to ESG management includes promoting sound corporate governance, risk management and controls, investing in our Team Members and cultivating a diverse and inclusive work environment, strengthening the communities in which our Team Members live and work, and operating our business in a way that demonstrates Customers’ dedication to environmental sustainability. Environmental, Social & Governance Report Our Communities Use of investment and philanthropic capital to expand access to economic opportunity in the communities where we do business has been core to Customers since its founding more than 10 years ago. Our Team Members Customers Bank is committed to developing high performing Team Members and fostering a richly diverse and inclusive workplace culture. Our Environment Customers Bank provides financing solutions that generate positive environmental and social impacts and actively manages the environmental impacts of the company’s branches and office locations. Our Risk Culture Customers Bank’s tone at the top and risk culture underpins our ability to function with integrity and accountability and to systematically and independently review risks and opportunities while building sustainable value for the company. Our Corporate Governance & Ethics Supported by unwavering management commitment and an engaged Board, Customers Bank is continually focused on enhancing the structures, processes and controls in place that support and promote accountability, transparency and ethical behavior.
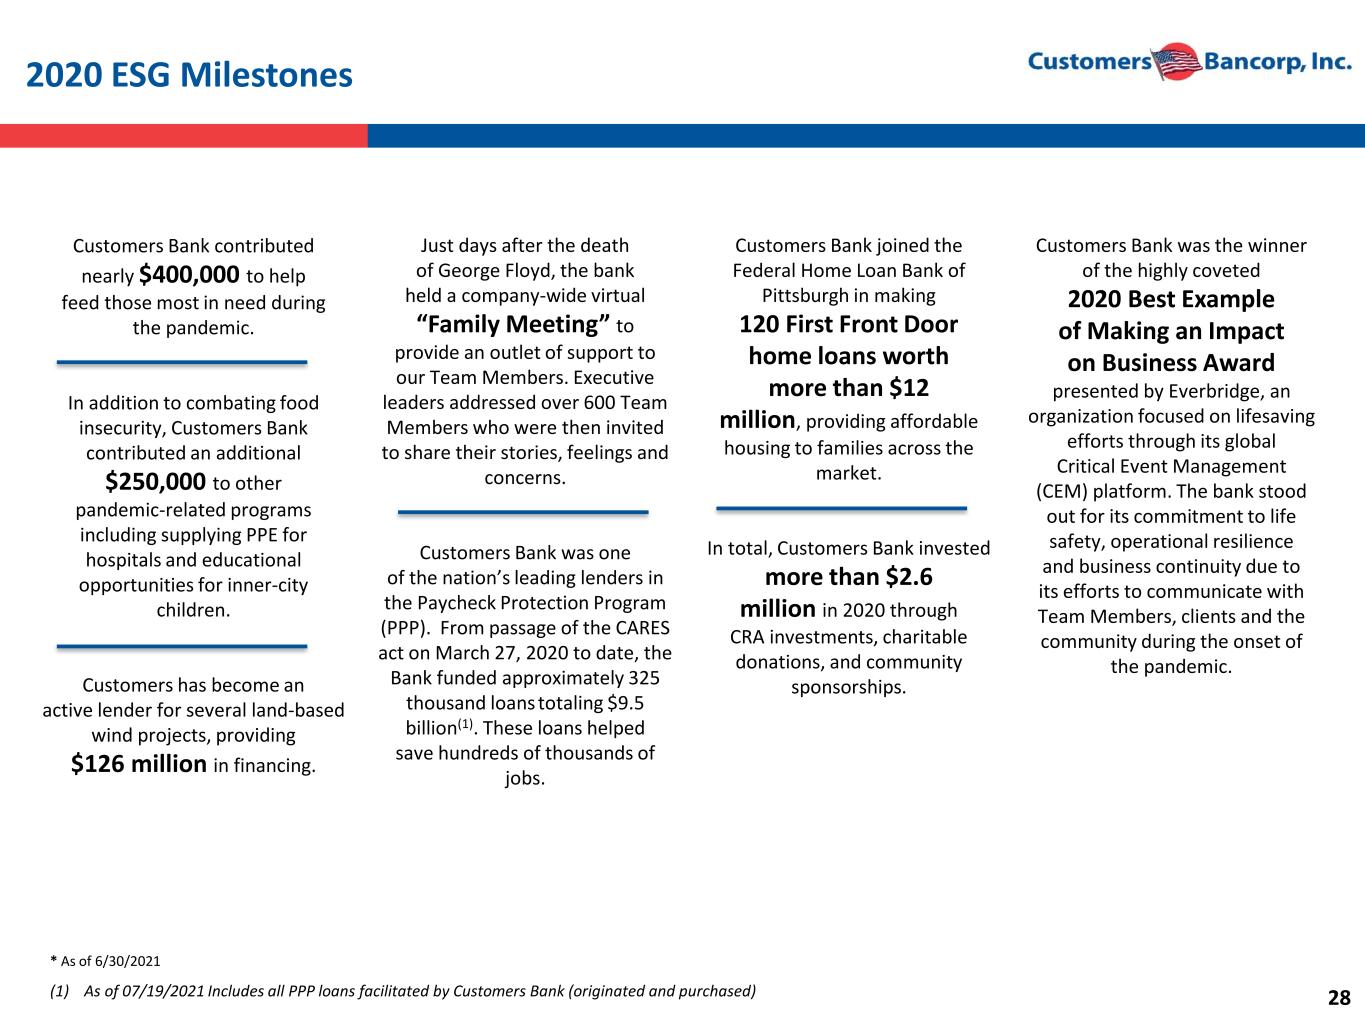
28 2020 ESG Milestones Just days after the death of George Floyd, the bank held a company-wide virtual “Family Meeting” to provide an outlet of support to our Team Members. Executive leaders addressed over 600 Team Members who were then invited to share their stories, feelings and concerns. Customers Bank was one of the nation’s leading lenders in the Paycheck Protection Program (PPP). From passage of the CARES act on March 27, 2020 to date, the Bank funded approximately 325 thousand loans totaling $9.5 billion(1). These loans helped save hundreds of thousands of jobs. Customers Bank joined the Federal Home Loan Bank of Pittsburgh in making 120 First Front Door home loans worth more than $12 million, providing affordable housing to families across the market. In total, Customers Bank invested more than $2.6 million in 2020 through CRA investments, charitable donations, and community sponsorships. Customers Bank was the winner of the highly coveted 2020 Best Example of Making an Impact on Business Award presented by Everbridge, an organization focused on lifesaving efforts through its global Critical Event Management (CEM) platform. The bank stood out for its commitment to life safety, operational resilience and business continuity due to its efforts to communicate with Team Members, clients and the community during the onset of the pandemic. Customers Bank contributed nearly $400,000 to help feed those most in need during the pandemic. In addition to combating food insecurity, Customers Bank contributed an additional $250,000 to other pandemic-related programs including supplying PPE for hospitals and educational opportunities for inner-city children. Customers has become an active lender for several land-based wind projects, providing $126 million in financing. * As of 6/30/2021 (1) As of 07/19/2021 Includes all PPP loans facilitated by Customers Bank (originated and purchased)
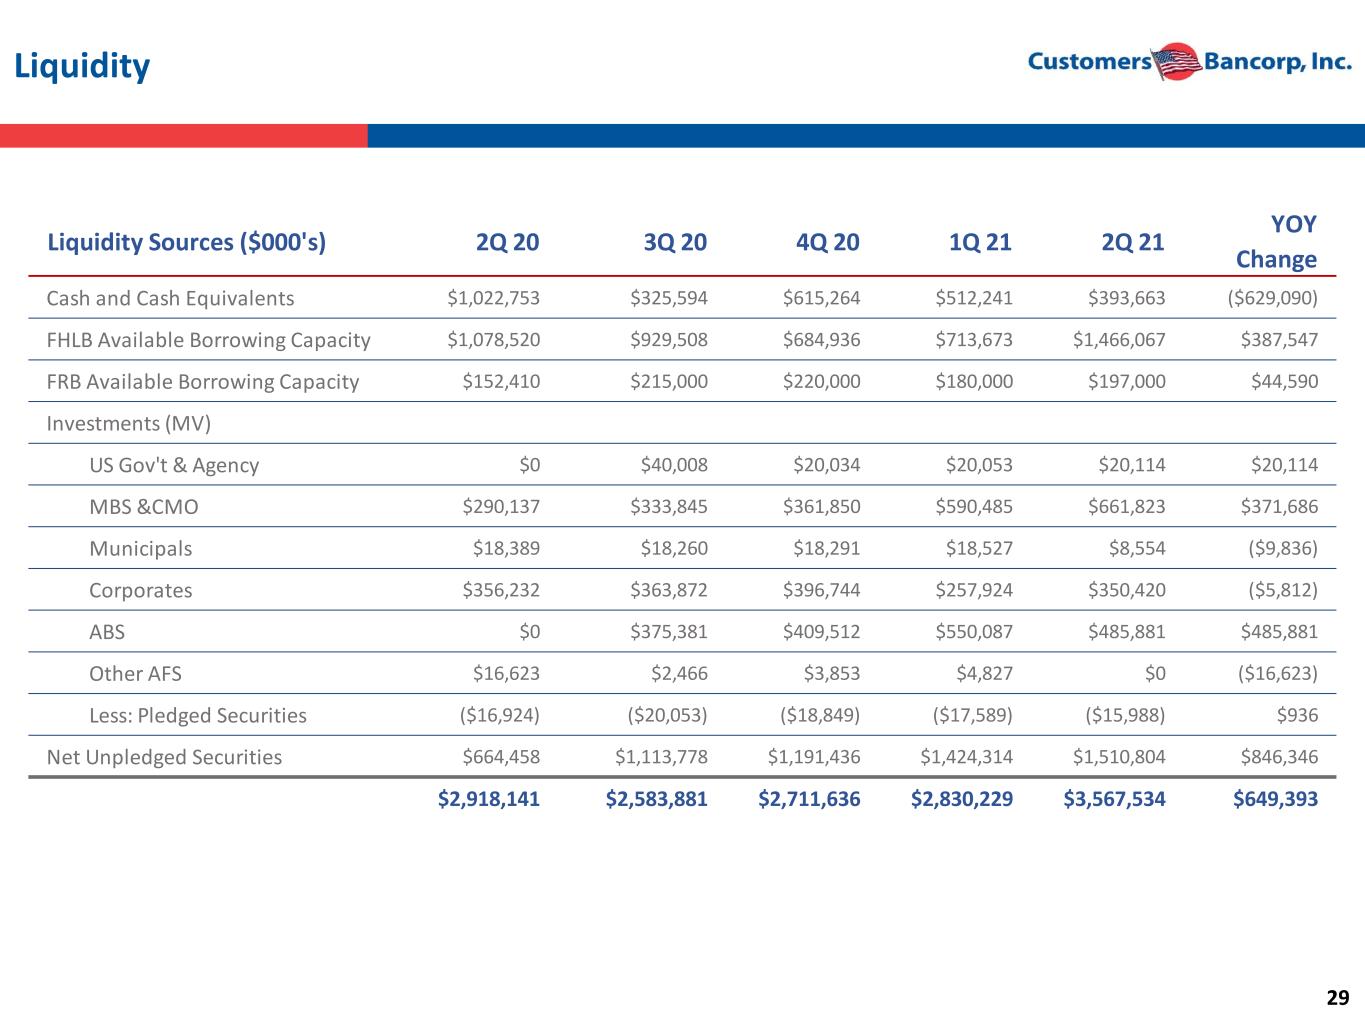
29 Liquidity Liquidity Sources ($000's) 2Q 20 3Q 20 4Q 20 1Q 21 2Q 21 YOY Change Cash and Cash Equivalents $1,022,753 $325,594 $615,264 $512,241 $393,663 ($629,090) FHLB Available Borrowing Capacity $1,078,520 $929,508 $684,936 $713,673 $1,466,067 $387,547 FRB Available Borrowing Capacity $152,410 $215,000 $220,000 $180,000 $197,000 $44,590 Investments (MV) US Gov't & Agency $0 $40,008 $20,034 $20,053 $20,114 $20,114 MBS &CMO $290,137 $333,845 $361,850 $590,485 $661,823 $371,686 Municipals $18,389 $18,260 $18,291 $18,527 $8,554 ($9,836) Corporates $356,232 $363,872 $396,744 $257,924 $350,420 ($5,812) ABS $0 $375,381 $409,512 $550,087 $485,881 $485,881 Other AFS $16,623 $2,466 $3,853 $4,827 $0 ($16,623) Less: Pledged Securities ($16,924) ($20,053) ($18,849) ($17,589) ($15,988) $936 Net Unpledged Securities $664,458 $1,113,778 $1,191,436 $1,424,314 $1,510,804 $846,346 $2,918,141 $2,583,881 $2,711,636 $2,830,229 $3,567,534 $649,393
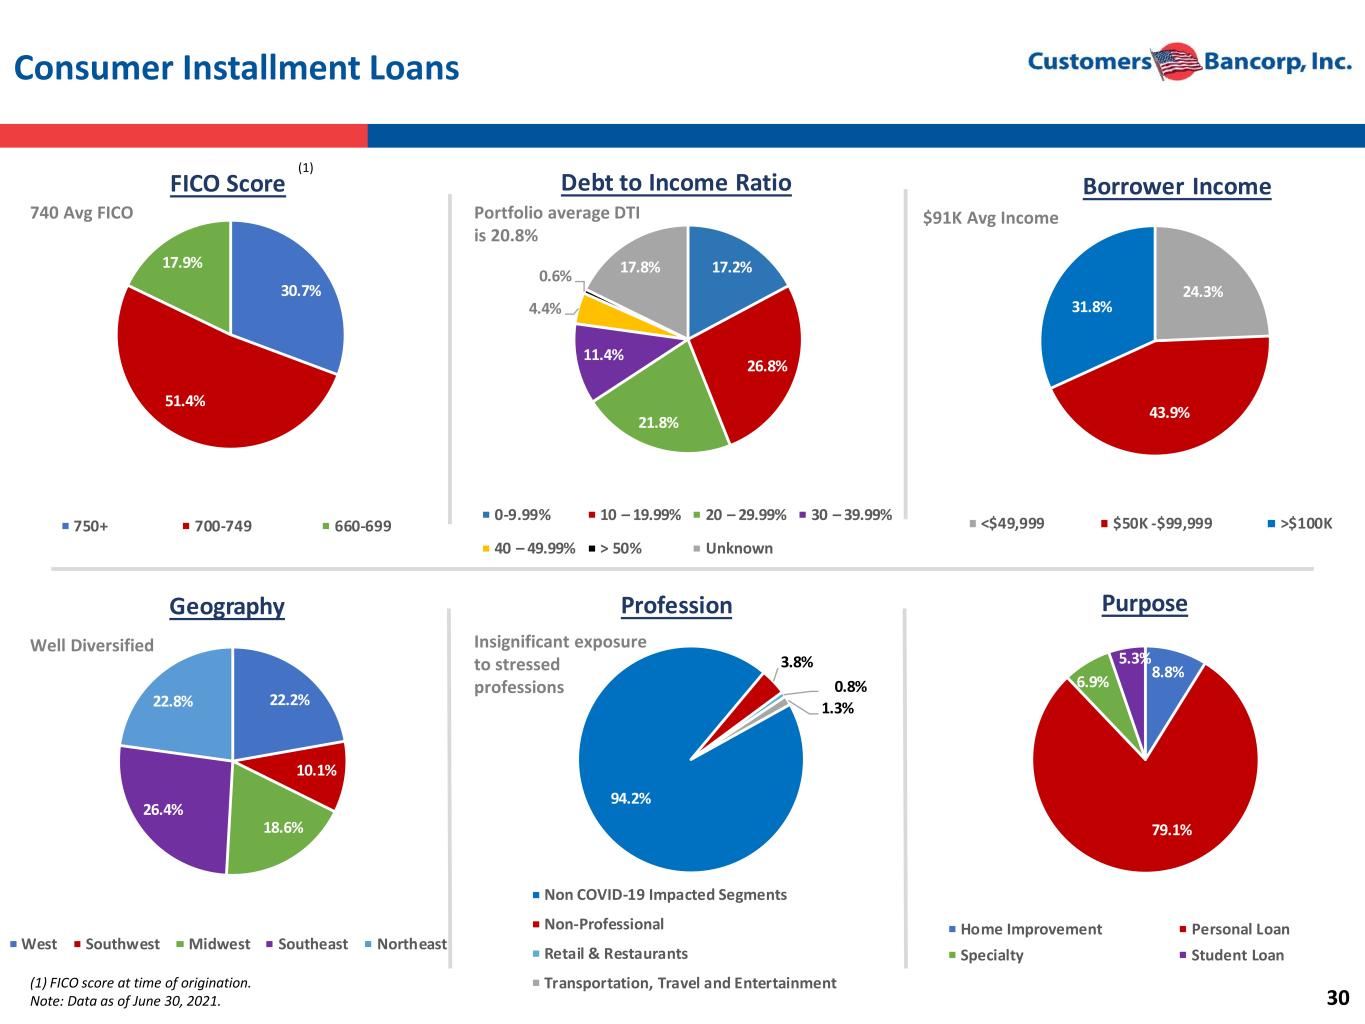
30 Consumer Installment Loans Well Diversified Insignificant exposure to stressed professions $91K Avg Income740 Avg FICO Portfolio average DTI is 20.8% (1) FICO score at time of origination. Note: Data as of June 30, 2021. (1) 17.2% 26.8% 21.8% 11.4% 4.4% 0.6% 17.8% Debt to Income Ratio 0-9.99% 10 – 19.99% 20 – 29.99% 30 – 39.99% 40 – 49.99% > 50% Unknown 30.7% 51.4% 17.9% FICO Score 750+ 700-749 660-699 24.3% 43.9% 31.8% Borrower Income <$49,999 $50K -$99,999 >$100K 22.2% 10.1% 18.6% 26.4% 22.8% Geography West Southwest Midwest Southeast Northeast 94.2% 3.8% 0.8% 1.3% Profession Non COVID-19 Impacted Segments Non-Professional Retail & Restaurants Transportation, Travel and Entertainment 8.8% 79.1% 6.9% 5.3% Purpose Home Improvement Personal Loan Specialty Student Loan
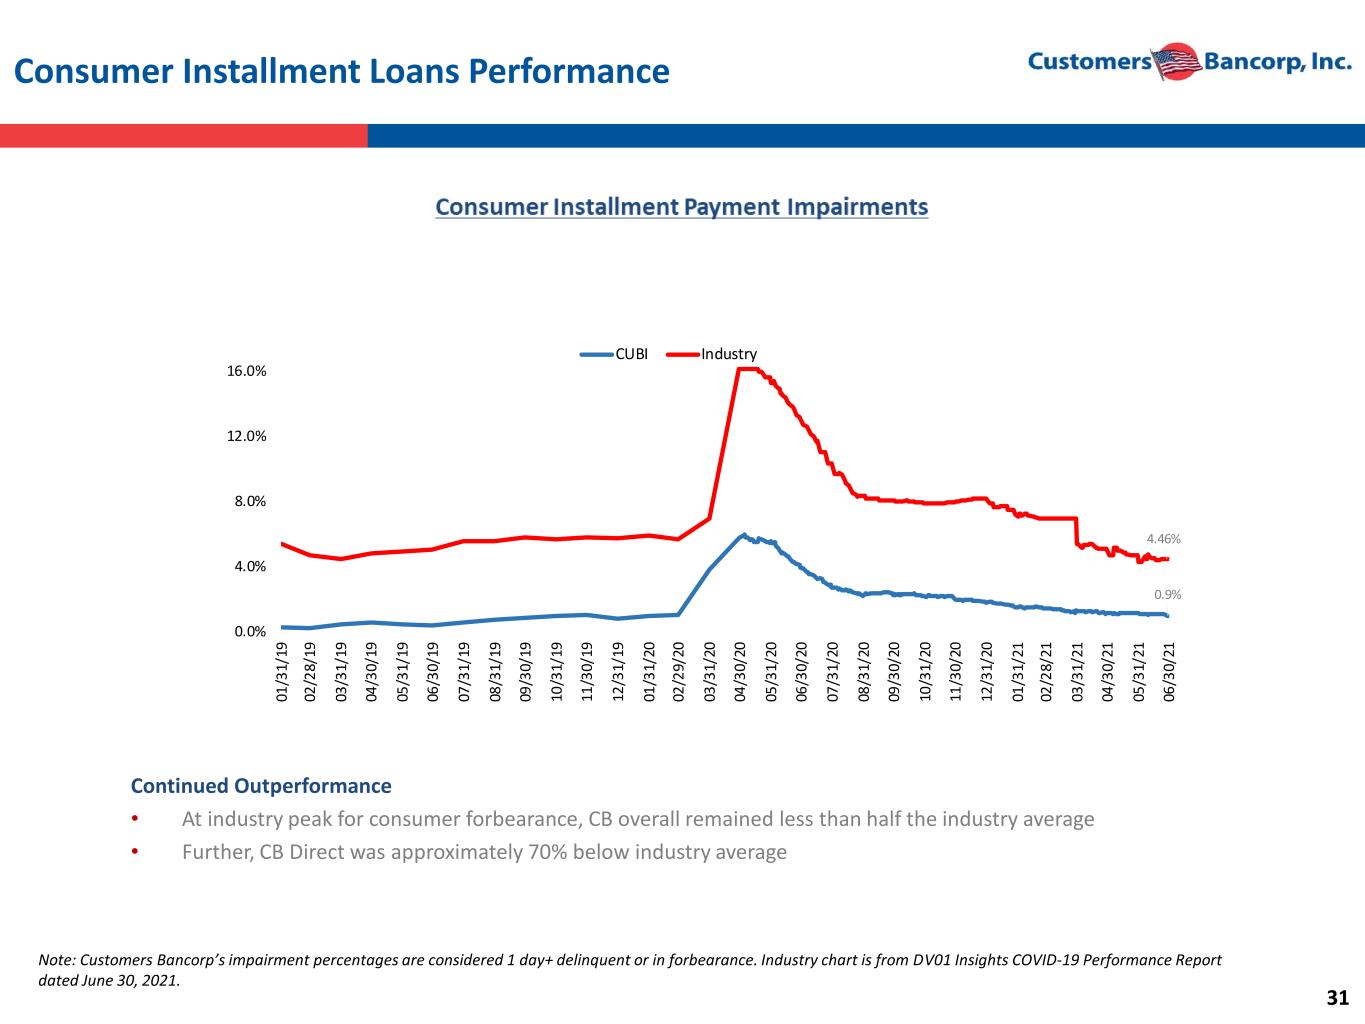
31 Consumer Installment Loans Performance Note: Customers Bancorp’s impairment percentages are considered 1 day+ delinquent or in forbearance. Industry chart is from DV01 Insights COVID-19 Performance Report dated June 30, 2021. Continued Outperformance • At industry peak for consumer forbearance, CB overall remained less than half the industry average • Further, CB Direct was approximately 70% below industry average 4.46% 0.9% 0.0% 4.0% 8.0% 12.0% 16.0% 01 /3 1/ 19 02 /2 8/ 19 03 /3 1/ 19 04 /3 0/ 19 05 /3 1/ 19 06 /3 0/ 19 07 /3 1/ 19 08 /3 1/ 19 09 /3 0/ 19 10 /3 1/ 19 11 /3 0/ 19 12 /3 1/ 19 01 /3 1/ 20 02 /2 9/ 20 03 /3 1/ 20 04 /3 0/ 20 05 /3 1/ 20 06 /3 0/ 20 07 /3 1/ 20 08 /3 1/ 20 09 /3 0/ 20 10 /3 1/ 20 11 /3 0/ 20 12 /3 1/ 20 01 /3 1/ 21 02 /2 8/ 21 03 /3 1/ 21 04 /3 0/ 21 05 /3 1/ 21 06 /3 0/ 21 CUBI Industry
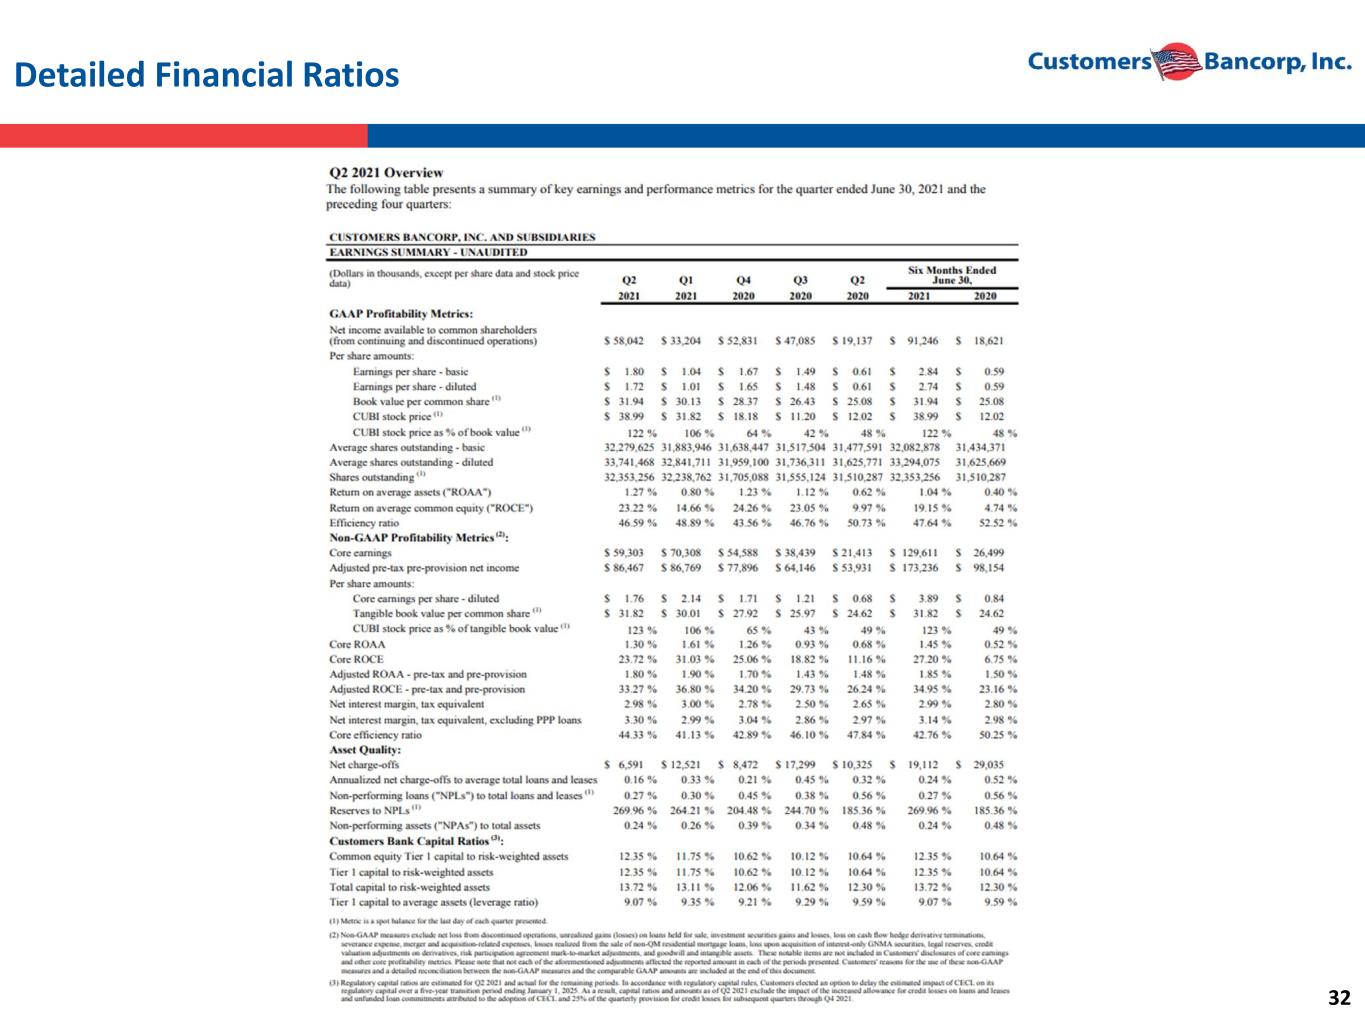
32 Detailed Financial Ratios
33 Customers believes that the non-GAAP measurements disclosed within this document are useful for investors, regulators, management and others to evaluate our core results of operations and financial condition relative to other financial institutions. These non-GAAP financial measures are frequently used by securities analysts, investors, and other interested parties in the evaluation of companies in Customers' industry. These non-GAAP financial measures exclude from corresponding GAAP measures the impact of certain elements that we do not believe are representative of our ongoing financial results, which we believe enhance an overall understanding of our performance and increases comparability of our period to period results. Investors should consider our performance and financial condition as reported under GAAP and all other relevant information when assessing our performance or financial condition. The non-GAAP measures presented are not necessarily comparable to non-GAAP measures that may be presented by other financial institutions. Although non-GAAP financial measures are frequently used in the evaluation of a company, they have limitations as analytical tools and should not be considered in isolation or as a substitute for analysis of our results of operations or financial condition as reported under GAAP. The following tables present reconciliations of GAAP to non-GAAP measures disclosed within this document. Reconciliation of Non-GAAP Measures - Unaudited
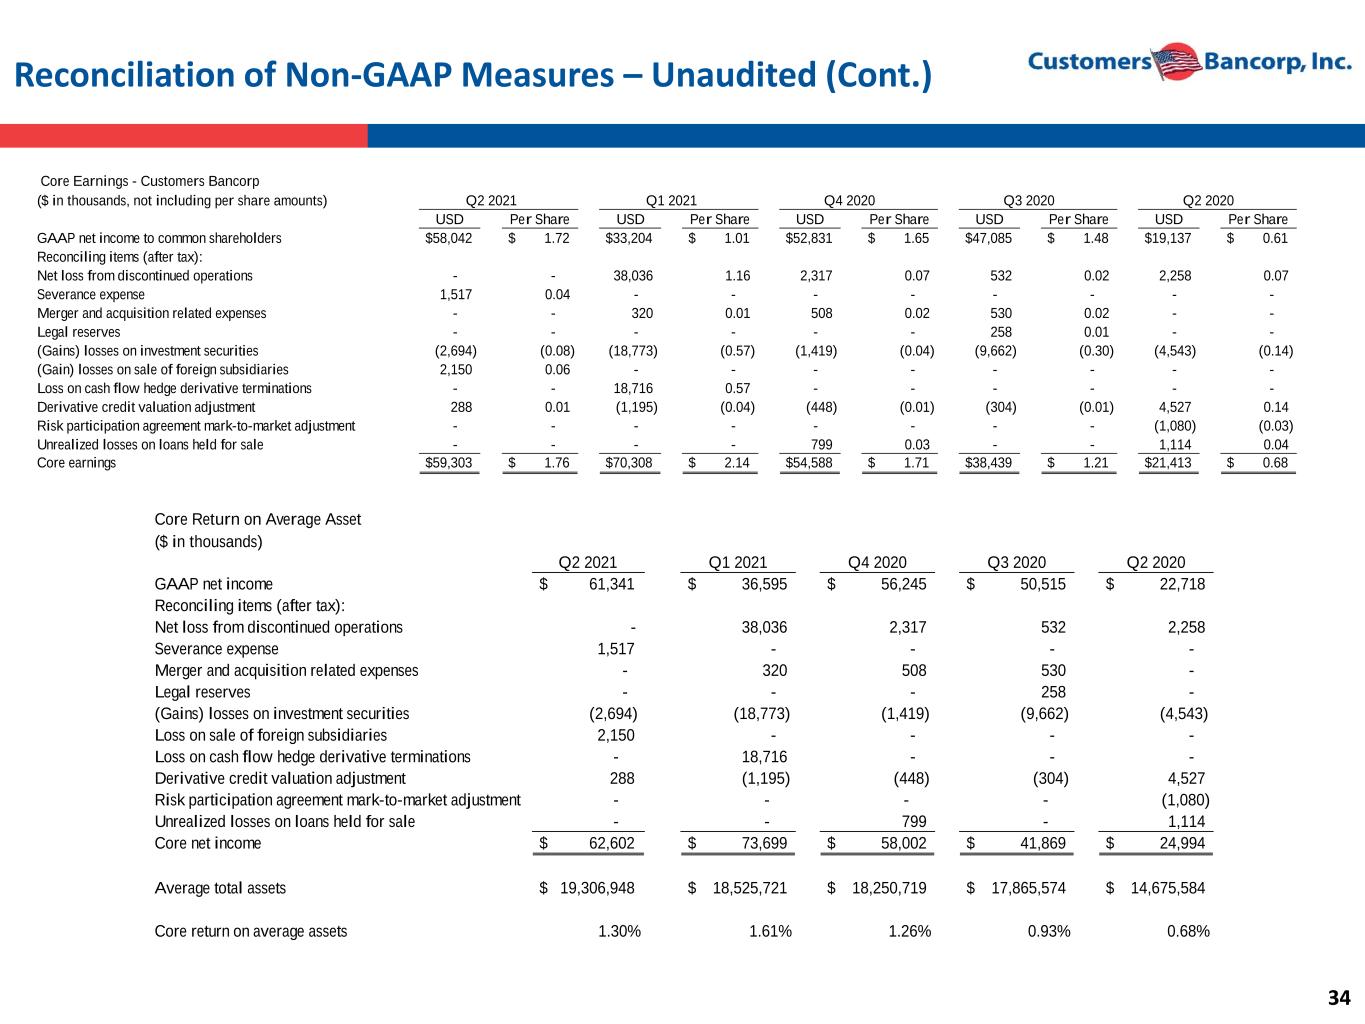
34 Reconciliation of Non-GAAP Measures – Unaudited (Cont.) ($ in thousands, not including per share amounts) Q2 2021 Q1 2021 Q4 2020 Q3 2020 Q2 2020 USD Per Share USD Per Share USD Per Share USD Per Share USD Per Share GAAP net income to common shareholders $58,042 $ 1.72 $33,204 $ 1.01 $52,831 $ 1.65 $47,085 $ 1.48 $19,137 $ 0.61 Reconciling items (after tax): Net loss from discontinued operations - - 38,036 1.16 2,317 0.07 532 0.02 2,258 0.07 Severance expense 1,517 0.04 - - - - - - - - Merger and acquisition related expenses - - 320 0.01 508 0.02 530 0.02 - - Legal reserves - - - - - - 258 0.01 - - (Gains) losses on investment securities (2,694) (0.08) (18,773) (0.57) (1,419) (0.04) (9,662) (0.30) (4,543) (0.14) (Gain) losses on sale of foreign subsidiaries 2,150 0.06 - - - - - - - - Loss on cash flow hedge derivative terminations - - 18,716 0.57 - - - - - - Derivative credit valuation adjustment 288 0.01 (1,195) (0.04) (448) (0.01) (304) (0.01) 4,527 0.14 Risk participation agreement mark-to-market adjustment - - - - - - - - (1,080) (0.03) Unrealized losses on loans held for sale - - - - 799 0.03 - - 1,114 0.04 Core earnings $59,303 $ 1.76 $70,308 $ 2.14 $54,588 $ 1.71 $38,439 $ 1.21 $21,413 $ 0.68 Core Earnings - Customers Bancorp Core Return on Average Asset ($ in thousands) Q2 2021 Q1 2021 Q4 2020 Q3 2020 Q2 2020 GAAP net income $ 61,341 $ 36,595 $ 56,245 $ 50,515 $ 22,718 Reconciling items (after tax): Net loss from discontinued operations - 38,036 2,317 532 2,258 Severance expense 1,517 - - - - Merger and acquisition related expenses - 320 508 530 - Legal reserves - - - 258 - (Gains) losses on investment securities (2,694) (18,773) (1,419) (9,662) (4,543) Loss on sale of foreign subsidiaries 2,150 - - - - Loss on cash flow hedge derivative terminations - 18,716 - - - Derivative credit valuation adjustment 288 (1,195) (448) (304) 4,527 Risk participation agreement mark-to-market adjustment - - - - (1,080) Unrealized losses on loans held for sale - - 799 - 1,114 Core net income $ 62,602 $ 73,699 $ 58,002 $ 41,869 $ 24,994 Average total assets $ 19,306,948 $ 18,525,721 $ 18,250,719 $ 17,865,574 $ 14,675,584 Core return on average assets 1.30% 1.61% 1.26% 0.93% 0.68%
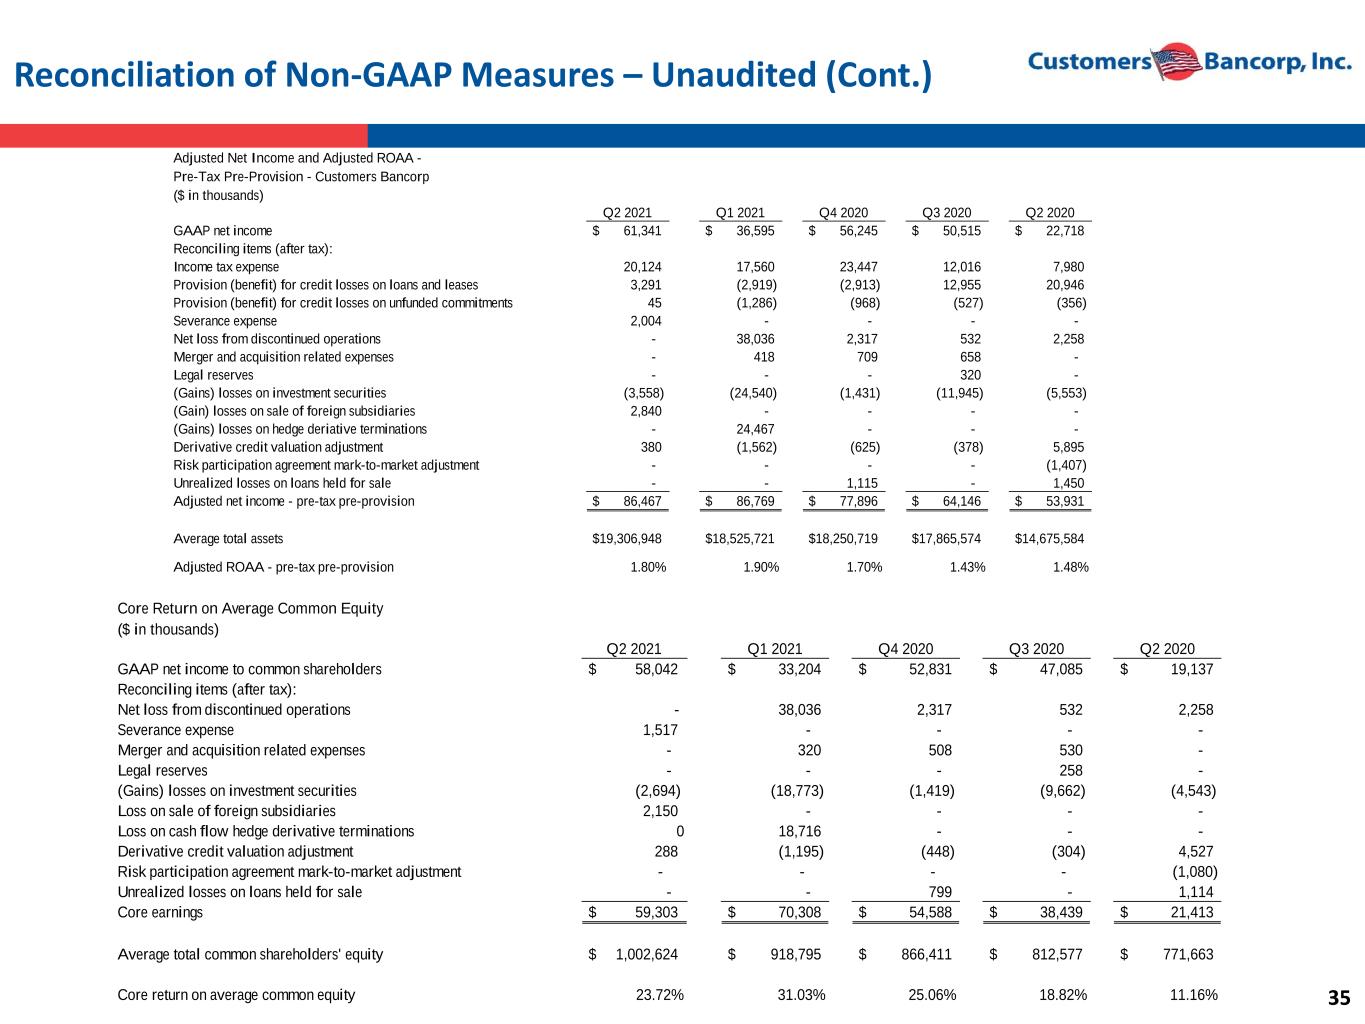
35 Reconciliation of Non-GAAP Measures – Unaudited (Cont.) Adjusted Net Income and Adjusted ROAA - Pre-Tax Pre-Provision - Customers Bancorp ($ in thousands) Q2 2021 Q1 2021 Q4 2020 Q3 2020 Q2 2020 GAAP net income $ 61,341 $ 36,595 $ 56,245 $ 50,515 $ 22,718 Reconciling items (after tax): Income tax expense 20,124 17,560 23,447 12,016 7,980 Provision (benefit) for credit losses on loans and leases 3,291 (2,919) (2,913) 12,955 20,946 Provision (benefit) for credit losses on unfunded commitments 45 (1,286) (968) (527) (356) Severance expense 2,004 - - - - Net loss from discontinued operations - 38,036 2,317 532 2,258 Merger and acquisition related expenses - 418 709 658 - Legal reserves - - - 320 - (Gains) losses on investment securities (3,558) (24,540) (1,431) (11,945) (5,553) (Gain) losses on sale of foreign subsidiaries 2,840 - - - - (Gains) losses on hedge deriative terminations - 24,467 - - - Derivative credit valuation adjustment 380 (1,562) (625) (378) 5,895 Risk participation agreement mark-to-market adjustment - - - - (1,407) Unrealized losses on loans held for sale - - 1,115 - 1,450 Adjusted net income - pre-tax pre-provision $ 86,467 $ 86,769 $ 77,896 $ 64,146 $ 53,931 Average total assets $19,306,948 $18,525,721 $18,250,719 $17,865,574 $14,675,584 Adjusted ROAA - pre-tax pre-provision 1.80% 1.90% 1.70% 1.43% 1.48% Core Return on Average Common Equity ($ in thousands) Q2 2021 Q1 2021 Q4 2020 Q3 2020 Q2 2020 GAAP net income to common shareholders $ 58,042 $ 33,204 $ 52,831 $ 47,085 $ 19,137 Reconciling items (after tax): Net loss from discontinued operations - 38,036 2,317 532 2,258 Severance expense 1,517 - - - - Merger and acquisition related expenses - 320 508 530 - Legal reserves - - - 258 - (Gains) losses on investment securities (2,694) (18,773) (1,419) (9,662) (4,543) Loss on sale of foreign subsidiaries 2,150 - - - - Loss on cash flow hedge derivative terminations 0 18,716 - - - Derivative credit valuation adjustment 288 (1,195) (448) (304) 4,527 Risk participation agreement mark-to-market adjustment - - - - (1,080) Unrealized losses on loans held for sale - - 799 - 1,114 Core earnings $ 59,303 $ 70,308 $ 54,588 $ 38,439 $ 21,413 Average total common shareholders' equity $ 1,002,624 $ 918,795 $ 866,411 $ 812,577 $ 771,663 Core return on average common equity 23.72% 31.03% 25.06% 18.82% 11.16%
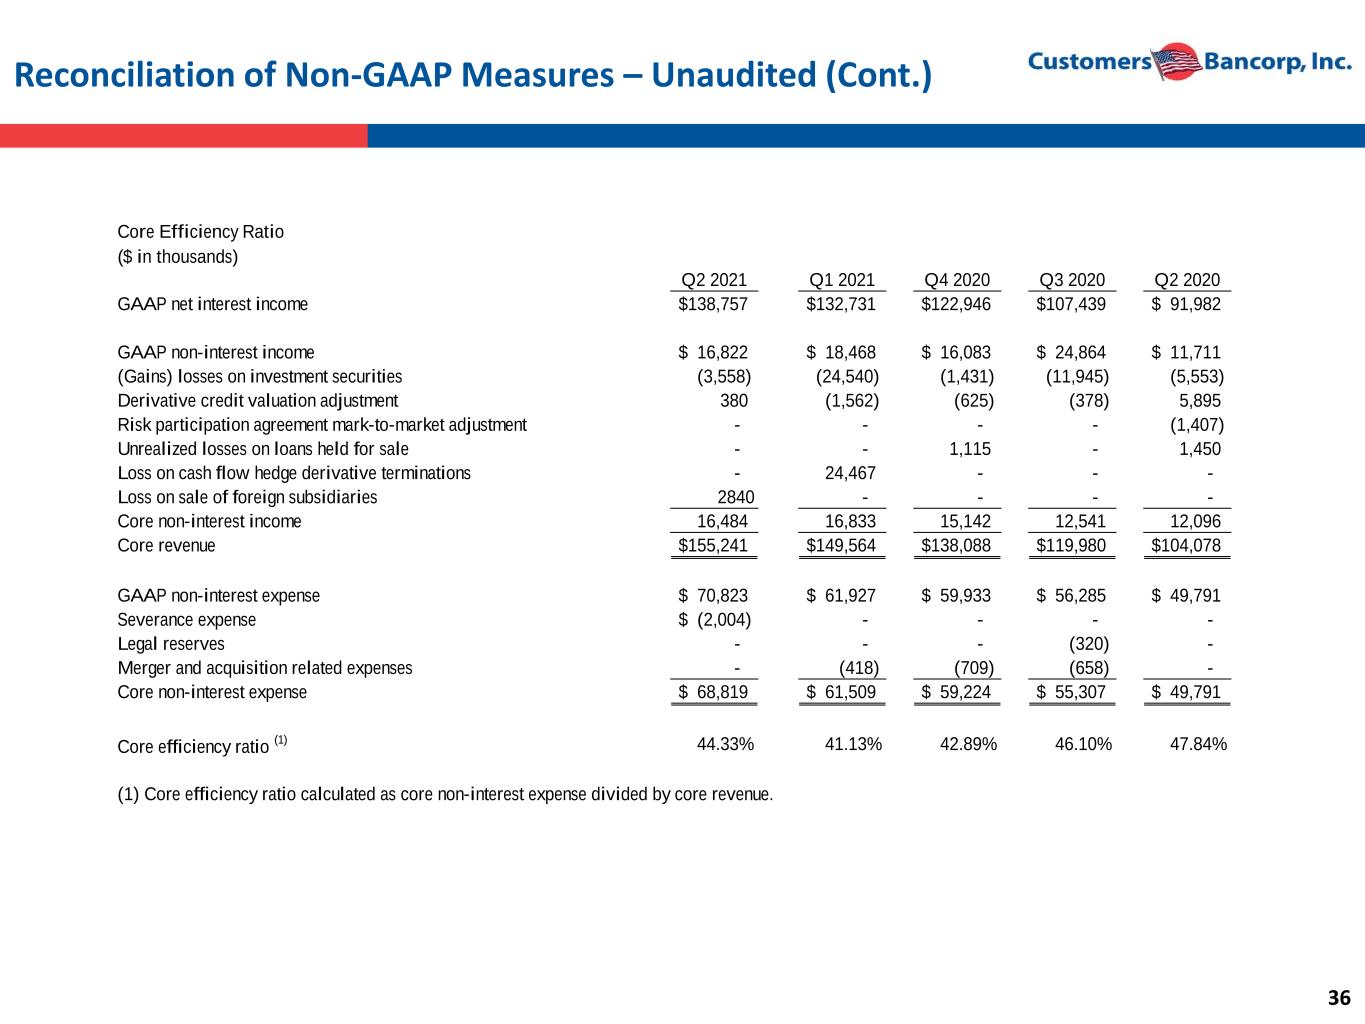
36 Reconciliation of Non-GAAP Measures – Unaudited (Cont.) Core Efficiency Ratio ($ in thousands) Q2 2021 Q1 2021 Q4 2020 Q3 2020 Q2 2020 GAAP net interest income $138,757 $132,731 $122,946 $107,439 $ 91,982 GAAP non-interest income $ 16,822 $ 18,468 $ 16,083 $ 24,864 $ 11,711 (Gains) losses on investment securities (3,558) (24,540) (1,431) (11,945) (5,553) Derivative credit valuation adjustment 380 (1,562) (625) (378) 5,895 Risk participation agreement mark-to-market adjustment - - - - (1,407) Unrealized losses on loans held for sale - - 1,115 - 1,450 Loss on cash flow hedge derivative terminations - 24,467 - - - Loss on sale of foreign subsidiaries 2840 - - - - Core non-interest income 16,484 16,833 15,142 12,541 12,096 Core revenue $155,241 $149,564 $138,088 $119,980 $104,078 GAAP non-interest expense $ 70,823 $ 61,927 $ 59,933 $ 56,285 $ 49,791 Severance expense $ (2,004) - - - - Legal reserves - - - (320) - Merger and acquisition related expenses - (418) (709) (658) - Core non-interest expense $ 68,819 $ 61,509 $ 59,224 $ 55,307 $ 49,791 Core efficiency ratio (1) 44.33% 41.13% 42.89% 46.10% 47.84% (1) Core efficiency ratio calculated as core non-interest expense divided by core revenue.
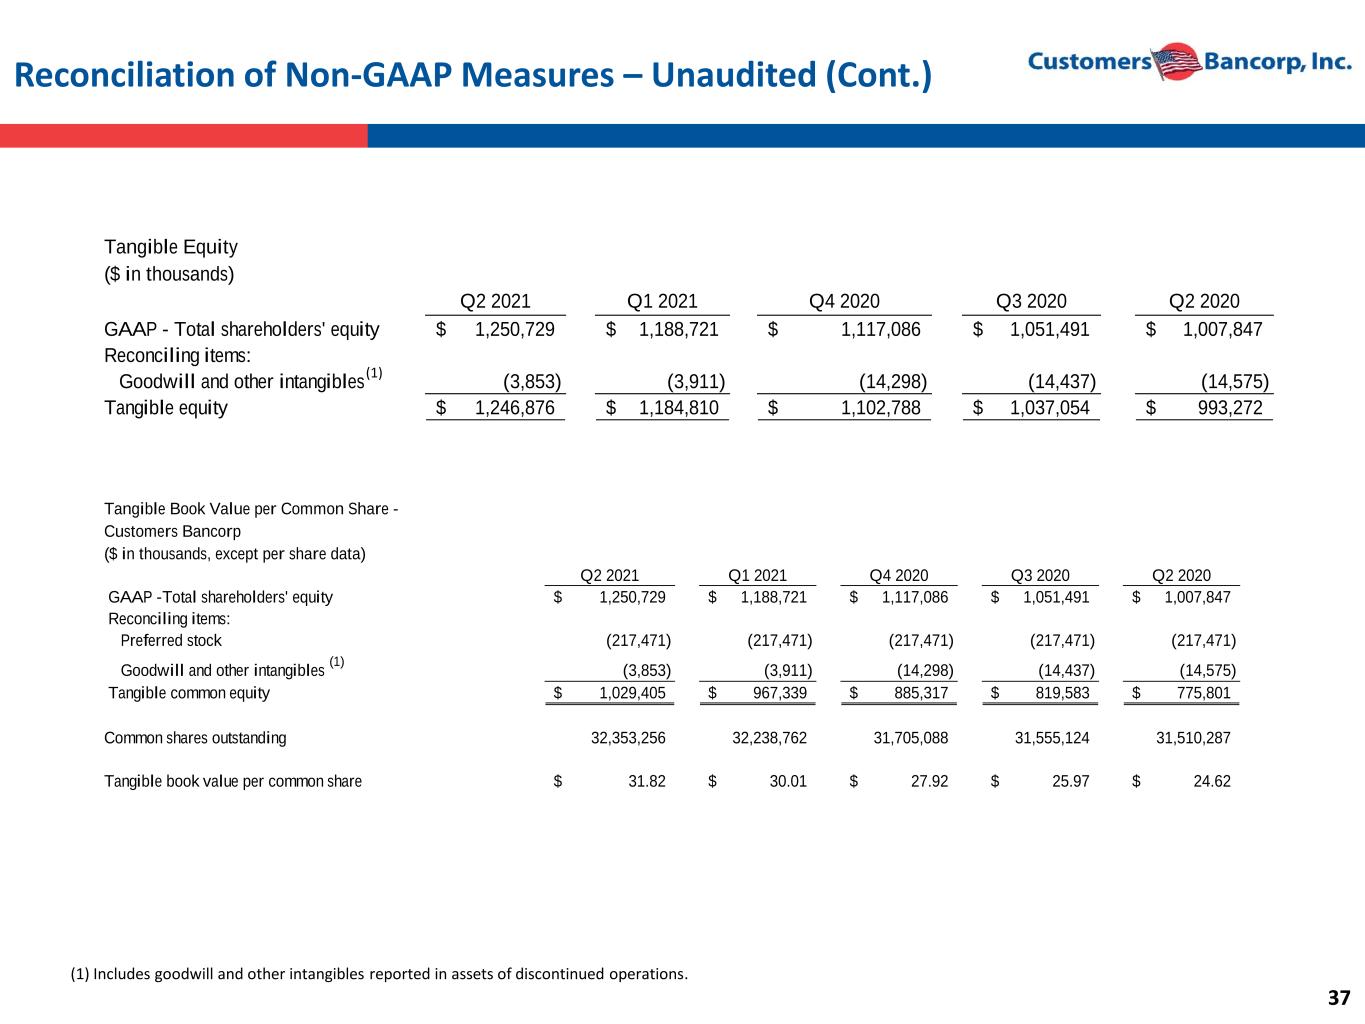
37 Reconciliation of Non-GAAP Measures – Unaudited (Cont.) Tangible Equity ($ in thousands) Q2 2021 Q1 2021 Q4 2020 Q3 2020 Q2 2020 GAAP - Total shareholders' equity 1,250,729$ 1,188,721$ 1,117,086$ 1,051,491$ 1,007,847$ Reconciling items: Goodwill and other intangibles (3,853) (3,911) (14,298) (14,437) (14,575) Tangible equity 1,246,876$ 1,184,810$ 1,102,788$ 1,037,054$ 993,272$ Tangible Book Value per Common Share - Customers Bancorp ($ in thousands, except per share data) Q2 2021 Q1 2021 Q4 2020 Q3 2020 Q2 2020 GAAP -Total shareholders' equity 1,250,729$ 1,188,721$ 1,117,086$ 1,051,491$ 1,007,847$ Reconciling items: Preferred stock (217,471) (217,471) (217,471) (217,471) (217,471) Goodwill and other intangibles (1) (3,853) (3,911) (14,298) (14,437) (14,575) Tangible common equity 1,029,405$ 967,339$ 885,317$ 819,583$ 775,801$ Common shares outstanding 32,353,256 32,238,762 31,705,088 31,555,124 31,510,287 Tangible book value per common share 31.82$ 30.01$ 27.92$ 25.97$ 24.62$ (1) Includes goodwill and other intangibles reported in assets of discontinued operations. (1)
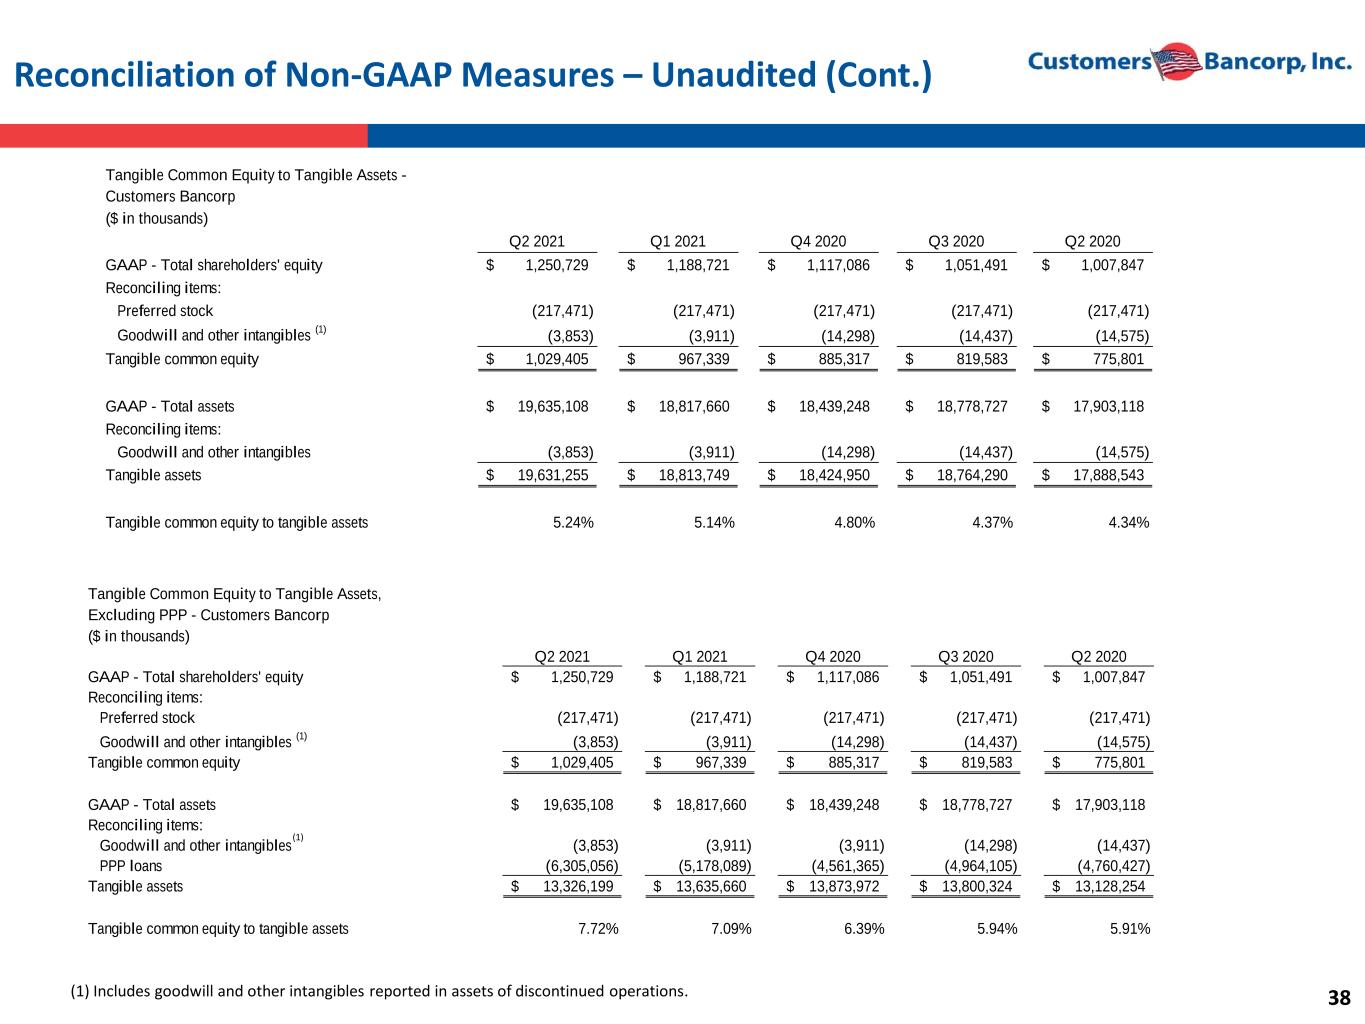
38 Reconciliation of Non-GAAP Measures – Unaudited (Cont.) Tangible Common Equity to Tangible Assets - Customers Bancorp ($ in thousands) Q2 2021 Q1 2021 Q4 2020 Q3 2020 Q2 2020 GAAP - Total shareholders' equity 1,250,729$ 1,188,721$ 1,117,086$ 1,051,491$ 1,007,847$ Reconciling items: Preferred stock (217,471) (217,471) (217,471) (217,471) (217,471) Goodwill and other intangibles (1) (3,853) (3,911) (14,298) (14,437) (14,575) Tangible common equity 1,029,405$ 967,339$ 885,317$ 819,583$ 775,801$ GAAP - Total assets 19,635,108$ 18,817,660$ 18,439,248$ 18,778,727$ 17,903,118$ Reconciling items: Goodwill and other intangibles (3,853) (3,911) (14,298) (14,437) (14,575) Tangible assets 19,631,255$ 18,813,749$ 18,424,950$ 18,764,290$ 17,888,543$ Tangible common equity to tangible assets 5.24% 5.14% 4.80% 4.37% 4.34% Tangible Common Equity to Tangible Assets, Excluding PPP - Customers Bancorp ($ in thousands) Q2 2021 Q1 2021 Q4 2020 Q3 2020 Q2 2020 GAAP - Total shareholders' equity 1,250,729$ 1,188,721$ 1,117,086$ 1,051,491$ 1,007,847$ Reconciling items: Preferred stock (217,471) (217,471) (217,471) (217,471) (217,471) Goodwill and other intangibles (1) (3,853) (3,911) (14,298) (14,437) (14,575) Tangible common equity 1,029,405$ 967,339$ 885,317$ 819,583$ 775,801$ GAAP - Total assets 19,635,108$ 18,817,660$ 18,439,248$ 18,778,727$ 17,903,118$ Reconciling items: Goodwill and other intangibles (3,853) (3,911) (3,911) (14,298) (14,437) PPP loans (6,305,056) (5,178,089) (4,561,365) (4,964,105) (4,760,427) Tangible assets 13,326,199$ 13,635,660$ 13,873,972$ 13,800,324$ 13,128,254$ Tangible common equity to tangible assets 7.72% 7.09% 6.39% 5.94% 5.91% (1) (1) Includes goodwill and other intangibles reported in assets of discontinued operations.
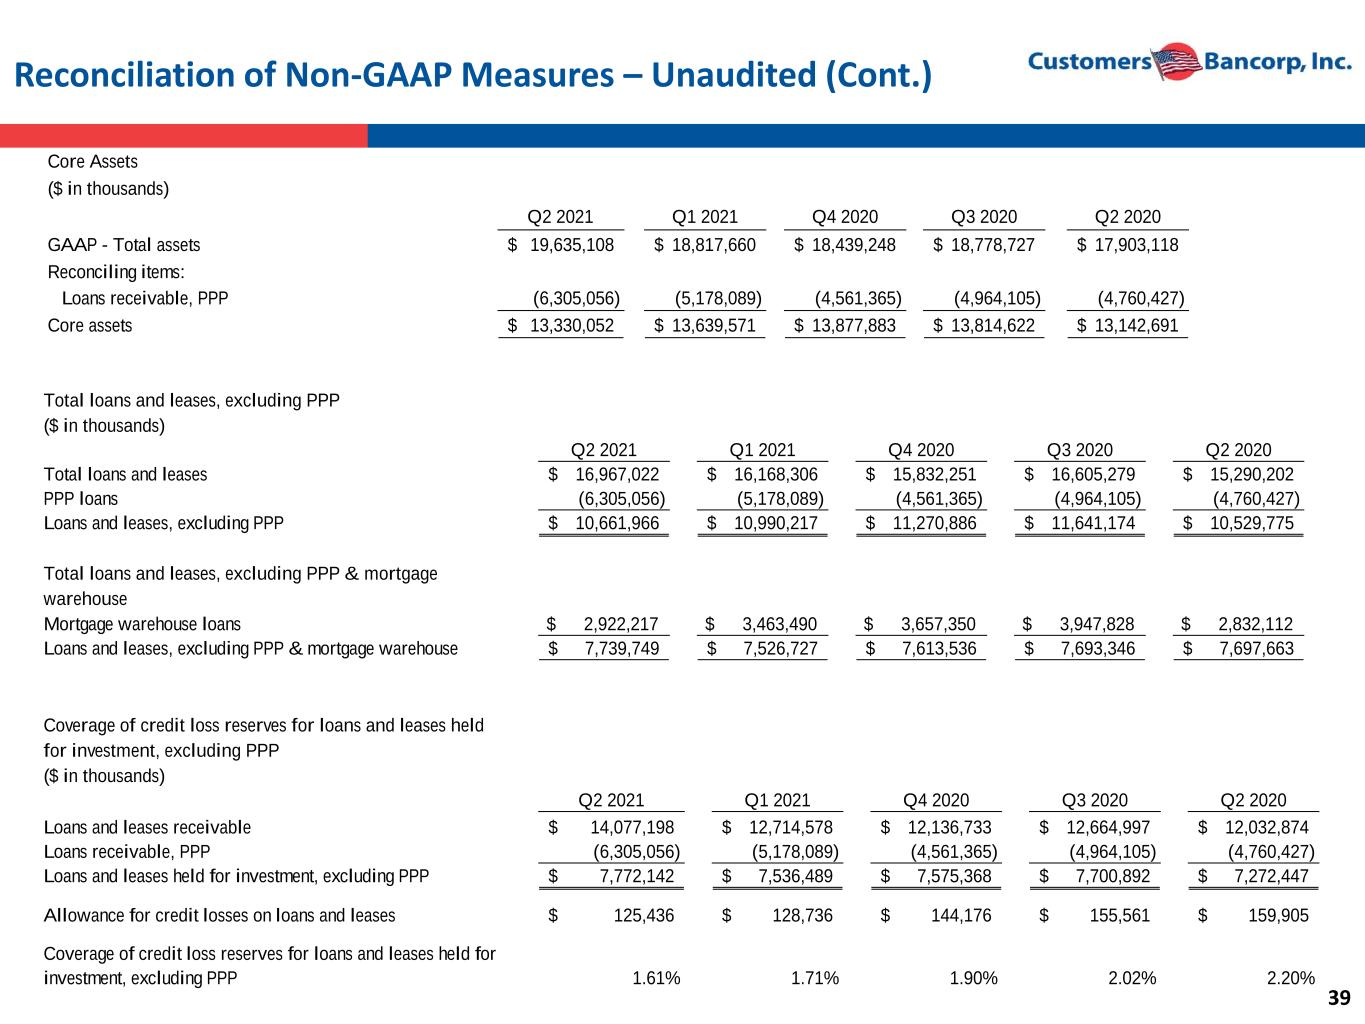
39 Reconciliation of Non-GAAP Measures – Unaudited (Cont.) Core Assets ($ in thousands) Q2 2021 Q1 2021 Q4 2020 Q3 2020 Q2 2020 GAAP - Total assets 19,635,108$ 18,817,660$ 18,439,248$ 18,778,727$ 17,903,118$ Reconciling items: Loans receivable, PPP (6,305,056) (5,178,089) (4,561,365) (4,964,105) (4,760,427) Core assets 13,330,052$ 13,639,571$ 13,877,883$ 13,814,622$ 13,142,691$ Total loans and leases, excluding PPP ($ in thousands) Q2 2021 Q1 2021 Q4 2020 Q3 2020 Q2 2020 Total loans and leases 16,967,022$ 16,168,306$ 15,832,251$ 16,605,279$ 15,290,202$ PPP loans (6,305,056) (5,178,089) (4,561,365) (4,964,105) (4,760,427) Loans and leases, excluding PPP 10,661,966$ 10,990,217$ 11,270,886$ 11,641,174$ 10,529,775$ Total loans and leases, excluding PPP & mortgage warehouse Mortgage warehouse loans $ 2,922,217 $ 3,463,490 $ 3,657,350 $ 3,947,828 $ 2,832,112 Loans and leases, excluding PPP & mortgage warehouse 7,739,749$ 7,526,727$ 7,613,536$ 7,693,346$ 7,697,663$ Coverage of credit loss reserves for loans and leases held for investment, excluding PPP ($ in thousands) Q2 2021 Q1 2021 Q4 2020 Q3 2020 Q2 2020 Loans and leases receivable 14,077,198$ 12,714,578$ 12,136,733$ 12,664,997$ 12,032,874$ Loans receivable, PPP (6,305,056) (5,178,089) (4,561,365) (4,964,105) (4,760,427) Loans and leases held for investment, excluding PPP 7,772,142$ 7,536,489$ 7,575,368$ 7,700,892$ 7,272,447$ Allowance for credit losses on loans and leases 125,436$ 128,736$ 144,176$ 155,561$ 159,905$ Coverage of credit loss reserves for loans and leases held for investment, excluding PPP 1.61% 1.71% 1.90% 2.02% 2.20%
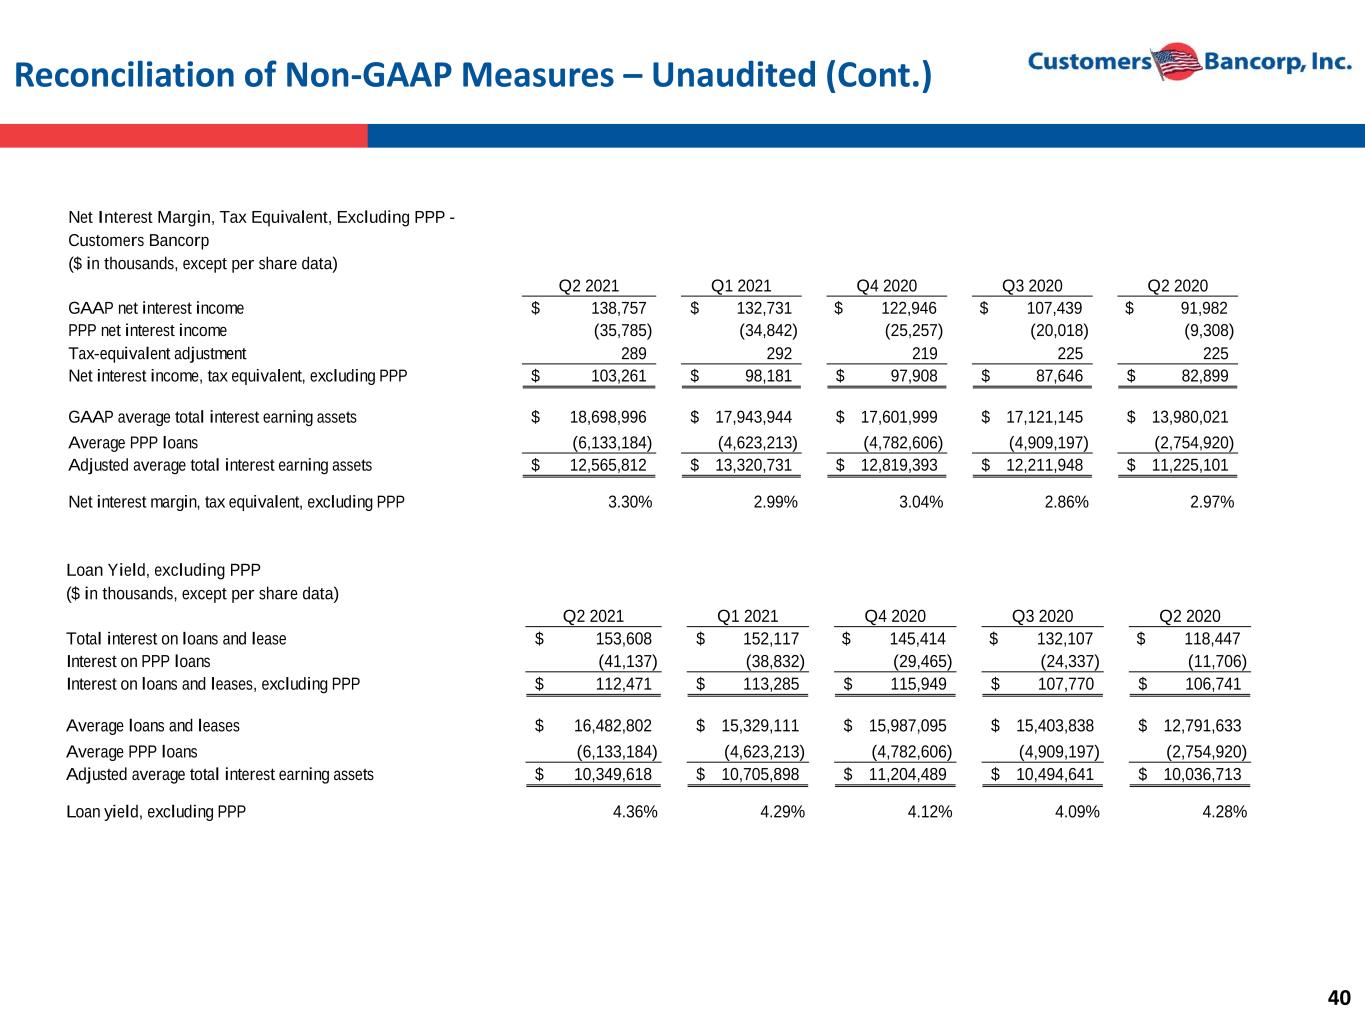
40 Reconciliation of Non-GAAP Measures – Unaudited (Cont.) Net Interest Margin, Tax Equivalent, Excluding PPP - Customers Bancorp ($ in thousands, except per share data) Q2 2021 Q1 2021 Q4 2020 Q3 2020 Q2 2020 GAAP net interest income 138,757$ 132,731$ $ 122,946 $ 107,439 $ 91,982 PPP net interest income (35,785) (34,842) (25,257) (20,018) (9,308) Tax-equivalent adjustment 289 292 219 225 225 Net interest income, tax equivalent, excluding PPP 103,261$ 98,181$ 97,908$ 87,646$ 82,899$ GAAP average total interest earning assets 18,698,996$ 17,943,944$ 17,601,999$ 17,121,145$ 13,980,021$ Average PPP loans (6,133,184) (4,623,213) (4,782,606) (4,909,197) (2,754,920) Adjusted average total interest earning assets 12,565,812$ 13,320,731$ 12,819,393$ 12,211,948$ 11,225,101$ Net interest margin, tax equivalent, excluding PPP 3.30% 2.99% 3.04% 2.86% 2.97% Loan Yield, excluding PPP ($ in thousands, except per share data) Q2 2021 Q1 2021 Q4 2020 Q3 2020 Q2 2020 Total interest on loans and lease 153,608$ 152,117$ $ 145,414 $ 132,107 $ 118,447 Interest on PPP loans (41,137) (38,832) (29,465) (24,337) (11,706) Interest on loans and leases, excluding PPP 112,471$ 113,285$ 115,949$ 107,770$ 106,741$ Average loans and leases 16,482,802$ 15,329,111$ 15,987,095$ 15,403,838$ 12,791,633$ Average PPP loans (6,133,184) (4,623,213) (4,782,606) (4,909,197) (2,754,920) Adjusted average total interest earning assets 10,349,618$ 10,705,898$ 11,204,489$ 10,494,641$ 10,036,713$ Loan yield, excluding PPP 4.36% 4.29% 4.12% 4.09% 4.28%
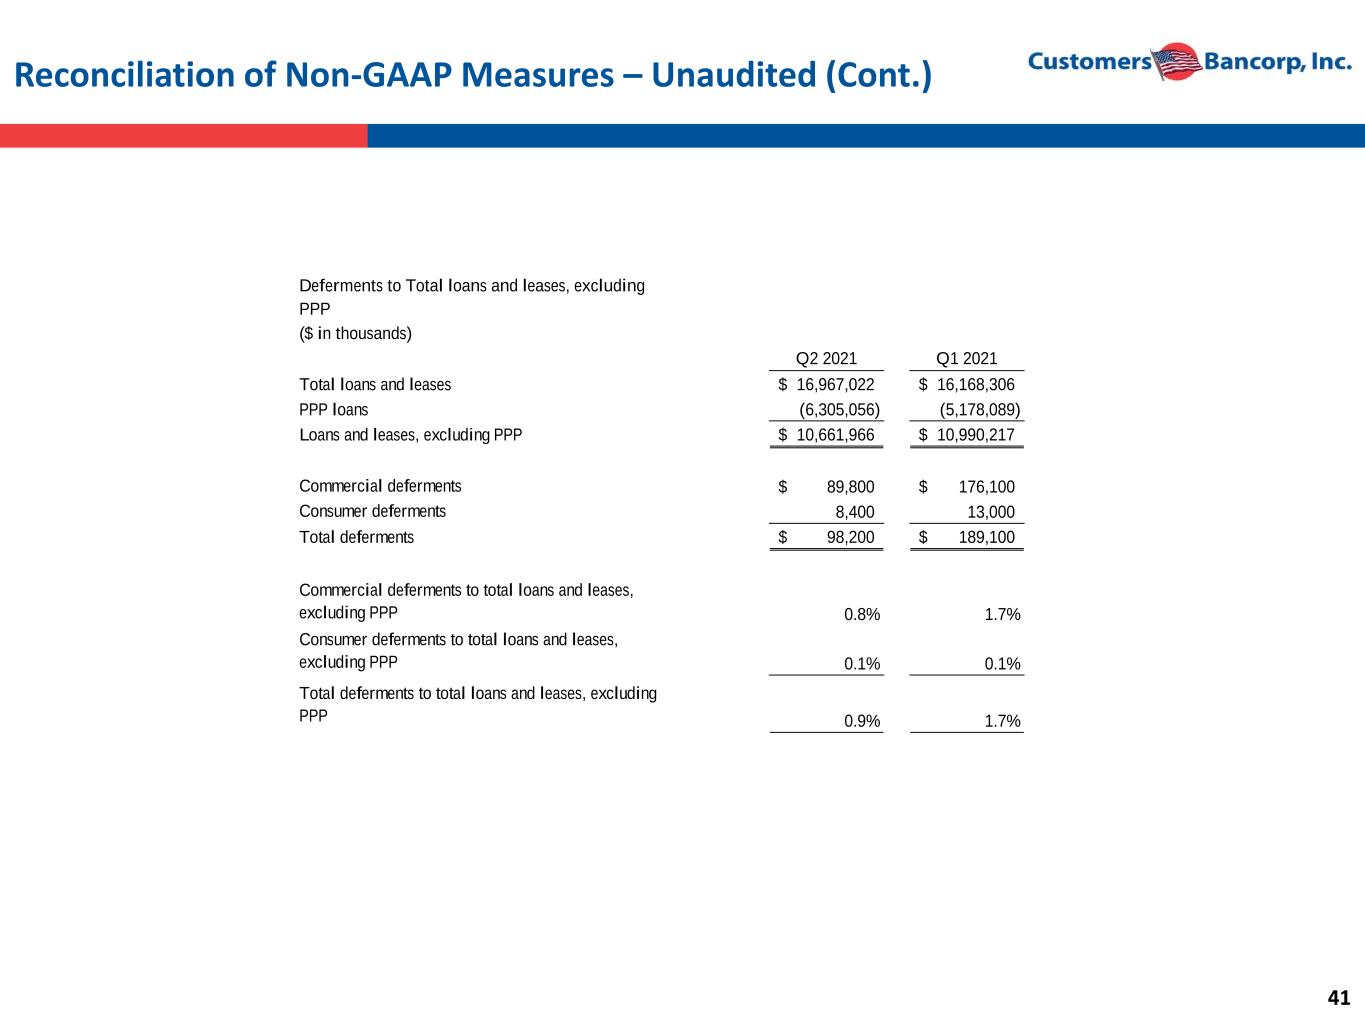
41 Reconciliation of Non-GAAP Measures – Unaudited (Cont.) Deferments to Total loans and leases, excluding PPP ($ in thousands) Q2 2021 Q1 2021 Total loans and leases 16,967,022$ 16,168,306$ PPP loans (6,305,056) (5,178,089) Loans and leases, excluding PPP 10,661,966$ 10,990,217$ Commercial deferments 89,800$ 176,100$ Consumer deferments 8,400 13,000 Total deferments 98,200$ 189,100$ Commercial deferments to total loans and leases, excluding PPP 0.8% 1.7% Consumer deferments to total loans and leases, excluding PPP 0.1% 0.1% Total deferments to total loans and leases, excluding PPP 0.9% 1.7%
42 Contacts Leadership: Carla Leibold CFO of Customers Bancorp, Inc and Customers Bank Jay Sidhu Chairman & CEO of Customers Bancorp, Inc and Executive Chairman of Customers Bank Sam Sidhu President of Customers Bancorp, Inc and President & CEO of Customers Bank Andrew Bowman EVP & Chief Credit Officer Analysts: B. Riley Financial Steve Moss D.A. Davidson Company Russell Gunther Hovde Group Will Curtiss Jefferies LLC Casey Haire Keefe, Bruyette & Woods Michael Perito Maxim Group Michael Diana Piper Sandler Companies Frank Schiraldi Wedbush Peter Winter