
CUBI 8-K
Customers Bancorp, Inc. (CUBI)
8-K
2025-10-23
For: 2025-10-23
View Original
Added on
April 09, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d)
of the
Securities Exchange Act of 1934
Date of Report (date of earliest event reported): October 23, 2025
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation or organization) | (Commission File number) | (IRS Employer Identification No.) | ||||||
(Address of principal executive offices, including zip code)
(610 ) 933-2000
(Registrant’s telephone number, including area code)
N/A
(Former name, former address and former fiscal year, if changed since last report)
Check the appropriate box below if the form 8-K filing is intended to simultaneously satisfy the filing obligations of the registrant under any of the following provisions (see General Instructions A.2. below):
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class | Trading Symbols | Name of Each Exchange on which Registered | ||||||||||||
Preferred Stock, Series F, par value $1.00 per share | ||||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (17 CFR §230.405) or Rule 12b-2 of the Securities Exchange Act of 1934 (17 CFR §240.12b-2). Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02. Results of Operations and Financial Condition
On October 23, 2025 , Customers Bancorp, Inc. (the "Company") issued a press release announcing unaudited financial information for the quarter ended September 30, 2025, a copy of which is included as Exhibit 99.1 to this Current Report on Form 8-K and incorporated by reference herein.
Item 7.01 Regulation FD Disclosure
The Company has posted to its website a slide presentation which is attached hereto as Exhibit 99.2 to this Current Report on Form 8-K and incorporated into this Item 7.01 by reference.
The information in this Current Report on Form 8-K, including Exhibits 99.1 and 99.2 attached hereto and incorporated by reference into Item 2.02 and Item 7.01, respectively, shall not be deemed "filed" for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities under that Section. Furthermore, such information, including the exhibits attached hereto, shall not be deemed incorporated by reference into any of the Company's reports or filings with the SEC, whether made before or after the date hereof, except as expressly set forth by specific reference in such report or filing. The information in this Current Report on Form 8-K, including the exhibits attached hereto, shall not be deemed an admission as to the materiality of any information in this Current Report on Form 8-K that is required to be disclosed solely to satisfy the requirements of Regulation FD.
Item 9.01. Financial Statements and Exhibits
(d) Exhibits.
| Exhibit | Description | |||||||
| Press Release dated October 23, 2025 | ||||||||
| Slide presentation dated October 2025 | ||||||||
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, hereunto duly authorized.
| CUSTOMERS BANCORP, INC. | |||||
By: /s/ Mark R. McCollom | |||||
| Name: Mark R. McCollom | |||||
| Title: Executive Vice President - Chief Financial Officer | |||||
Date: October 23, 2025
EXHIBIT INDEX
| Exhibit No. | Description | |||||||
| Press Release dated October 23, 2025 | ||||||||
| Slide presentation dated October 2025 | ||||||||
Exhibit 99.1
Customers Bancorp, Inc. (NYSE:CUBI)
701 Reading Avenue
West Reading, PA 19611
Contacts:
Jordan Baucum, Head of Corporate Communications 951-608-8314
Jordan Baucum, Head of Corporate Communications 951-608-8314
Customers Bancorp Reports Results for Third Quarter 2025
Third Quarter 2025 Highlights
•Q3 2025 net income available to common shareholders was $73.7 million, or $2.20 per diluted share; ROAA was 1.26% and ROCE was 15.57%.
•Q3 2025 core earnings*1 were $73.5 million, or $2.20 per diluted share; Core ROAA* was 1.25% and Core ROCE* was 15.52%.
•Q3 2025 net interest margin, tax equivalent (“NIM”) was 3.46%, compared to Q2 2025 NIM of 3.27%, an increase of 19 basis points, primarily due to higher interest income from loan and leases and higher average non-interest bearing deposit balances.
•CET 1 ratio of 13.0%2 at September 30, 2025, compared to 12.1% at June 30, 2025 primarily driven by the successful common equity raise.
•Q3 2025 book value per share and tangible book value per share* both grew by approximately $3.48, or 6.2% over Q2 2025, or 24.8% annualized, with a tangible book value per share* of $59.72 at September 30, 2025.
CEO Commentary
West Reading, Pa, October 23, 2025 - “We are pleased with our third quarter results that show the company’s continued execution of its strategic priorities and underscore our success in growing franchise value,” said Customers Bancorp Chairman and CEO Jay Sidhu.
“During the quarter, we successfully raised $163 million of common equity (net of issuance costs) which further strengthened our already solid capital position and gives us flexibility to potentially redeem the remaining tranche of preferred stock in our capital structure in the fourth quarter of 2025. The success of this offering reflects a clear vote of confidence in our strategy, our team, and the disciplined execution of our business model. We appreciate the trust our new shareholders have placed in us, and we are fully committed to execute to continue to deliver top tier returns.
Our Q3 2025 GAAP earnings were $73.7 million, or $2.20 per diluted share, and core earnings* were $73.5 million, or $2.20 per diluted share. Asset quality remains strong with our NPA ratio at just 0.25% of total assets and reserve levels are robust at 534% of total non-performing loans at the end of Q3 2025. Our TCE / TA ratio* increased by 50 basis points to 8.4% while our balance sheet grew by 7.6%. We believe that our unique strategy, the investments we have continued to make, and the exceptional talent across our organization position us strongly for continued success,” Jay Sidhu continued.
*Non-GAAP measure. Customers’ reasons for the use of the non-GAAP measure and a detailed reconciliation between the non-GAAP measure and the comparable GAAP amount are included at the end of this document. | ||||||||
1 Excludes pre-tax gains on investment securities of $0.3 million. | ||||||||
2 Regulatory capital ratios as of September 30, 2025 are estimates. | ||||||||
1
Key Balance Sheet Trends
Loans and Leases Held for Investment
Loans and leases held for investment were $16.3 billion at September 30, 2025, up $893 million, or 5.8%, from June 30, 2025. Specialized lending increased by $629 million, or 9.7% quarter-over-quarter, to $7.1 billion. Multifamily loans increased by $109 million, or 4.9% to $2.4 billion. Consumer installment loans increased by $89 million, or 11.1% to $891 million. Non-owner occupied commercial real estate loans increased by $85 million, or 5.7% to $1.6 billion. Construction loans increased by $25 million, or 25.0% to $123 million and other commercial & industrial loans increased by $18 million, or 1.8% to $1.1 billion. These increases were partially offset by decreases in mortgage finance loans of $49 million, or 3.0% to $1.6 billion, and owner-occupied commercial real estate loans of $6 million, or 0.6% to $1.1 billion.
Loans and leases held for investment of $16.3 billion at September 30, 2025 were up $2.5 billion, or 18.1%, year-over-year. Specialized lending increased by $1.6 billion, or 29.5%, year-over-year. Non-owner occupied commercial real estate loans increased by $256 million, or 19.3%. Multifamily loans increased by $241 million, or 11.4%. Mortgage finance loans increased by $209 million, or 15.3%. Consumer installment loans increased $171 million, or 23.8%, inclusive of the transfer from loans held for sale in Q1 2025. Owner-occupied commercial real estate loans increased by $77 million, or 7.8%. These increases were partially offset by decreases in construction loans of $51 million, or 29.4%, and other commercial and industrial loans of $31 million, or 2.9%.
Investment Securities
At September 30, 2025, total investment securities were $2.8 billion, an increase of $82 million compared to June 30, 2025 and a decrease of $664 million compared to a year ago.
At September 30, 2025, the AFS debt securities portfolio had a spot yield of 5.81%, an effective duration of approximately 2.1 years, and approximately 29% are variable rate. Additionally, 67% of the AFS securities portfolio was AAA rated at September 30, 2025.
At September 30, 2025, the HTM debt securities portfolio represented only 3.3% of total assets, had a spot yield of 3.68% and an effective duration of approximately 3.7 years. Additionally, at September 30, 2025, approximately 58% of the HTM securities were AAA rated and $0.3 billion were credit enhanced asset backed securities with no current expectation of credit losses.
Deposits
Total deposits increased $1.4 billion to $20.4 billion at September 30, 2025 as compared to the prior quarter. The total average cost of deposits decreased by 8 basis points to 2.77% in Q3 2025 from 2.85% in the prior quarter. Total estimated uninsured deposits were $6.8 billion1, or 33% of total deposits (inclusive of accrued interest) at September 30, 2025 with immediately available liquidity covering approximately 146% of these deposits.
Total deposits increased $2.3 billion, or 13%, to $20.4 billion at September 30, 2025 as compared to a year ago. The total average cost of deposits decreased by 69 basis points to 2.77% in Q3 2025 from 3.46% in the prior year.
Borrowings
Total borrowings increased slightly to $1.5 billion at September 30, 2025 as compared to the prior quarter. Total borrowings increased $79 million, or 6%, to $1.5 billion at September 30, 2025 as compared to a year ago. This increase primarily resulted from net draws of $85 million in FHLB advances.
1 Uninsured deposits (estimate) of $8.7 billion to be reported on the Bank’s call report, less deposits of $1.7 billion collateralized by standby letters of credit from the FHLB and from our affiliates of $227 million.
2
Capital
Customers Bancorp’s common equity increased $263 million to $2.0 billion, and tangible common equity* increased $263 million to $2.0 billion, at September 30, 2025 compared to the prior quarter, respectively, primarily from earnings of $74 million and the issuance of 2,518,248 shares at $68.50 (before issuance costs) on September 5, 2025. Customers Bancorp’s common equity increased $380 million to $2.0 billion, and tangible common equity* increased $380 million to $2.0 billion, at September 30, 2025 compared to a year ago, respectively, primarily from earnings of $162 million, the issuance of 2,518,248 shares and a decrease in AOCI of $55 million (net of taxes) mostly from decreased unrealized losses on investment securities, offset in part by $7 million of common share repurchases. Book value per common share increased to $59.83 from $56.36 and $53.07, and tangible book value per common share* increased to $59.72 from $56.24 and $52.96, at September 30, 2025, June 30, 2025 and September 30, 2024, respectively.
Credit Quality
The provision for credit losses in Q3 2025 was $27 million, compared to $21 million in Q2 2025 and $17 million in Q3 2024.
Net charge-offs were $15 million in Q3 2025, compared to $13 million in Q2 2025, and $17 million in Q3 2024.
The allowance for credit losses on loans and leases was $152 million at September 30, 2025, compared to $147 million at June 30, 2025 and $133 million at September 30, 2024.
Non-performing loans at September 30, 2025 decreased to 0.17% of total loans and leases, compared to 0.18% at June 30, 2025 and 0.34% at September 30, 2024.
Key Profitability Trends
Net Interest Income
Net interest income totaled $201.9 million in Q3 2025, an increase of $25.2 million from Q2 2025. This increase was driven by an increase in interest income of $33.5 million primarily due to higher average loan balances, higher average interesting earning deposits, and higher discount accretion.
“Net interest margin continued to expand in the quarter as we realized the benefits of deposit led loan growth, growth in non-interest bearing and lower-cost deposits, and well managed funding costs,” stated Customers Bancorp President Sam Sidhu. “We continue to have positive drivers to net interest income on both sides of the balance sheet. We have a strong loan pipeline and our primarily deposit focused commercial banking team recruitment strategy continued to gain momentum with an additional 4 teams joining in the third quarter. This represents 7 new teams in 2025 and our recruitment pipeline remains strong,” stated Sam Sidhu.
Net interest income totaled $201.9 million in Q3 2025, an increase of $43.4 million from Q3 2024. This increase was primarily due to lower interest expense from a favorable shift in deposit mix and lower market interest rates, and higher interest income primarily due to higher average loan balances, higher average interesting earning deposits, and higher discount accretion.
Non-Interest Income
Reported non-interest income totaled $30.2 million for Q3 2025, an increase of $0.6 million compared to $29.6 million for Q2 2025. The increase was primarily due to an increase in loan fees primarily resulting from the settlement of certain stock warrants and a decrease in net loss on sale of investment securities, partially offset by a decrease in other non-interest income of $4.3 million primarily from a decrease of $1.5 million in gain on sale of leased assets and $1.8 million of fees in Q2 2025 associated with the sunsetting of a loan origination program with a fintech company, which was acquired by a bank.
3
Non-interest income totaled $30.2 million for Q3 2025, an increase of $21.6 million compared to Q3 2024. The increase was primarily due to $14.3 million of loss on leases of commercial clean vehicles that were accounted for as sales-type leases and included within net gain (loss) on sale of loans and leases in Q3 2024 and increases in loan fees of $3.4 million primarily resulting from the settlement of certain stock warrants and deposit account fees of $1.8 million. The commercial clean vehicle leases generated the same amount of investment tax credits that were included as a benefit to income tax expense in Q3 2024.
Non-Interest Expense
Non-interest expenses totaled $105.2 million in Q3 2025, a decrease of $1.4 million compared to Q2 2025. The decrease was primarily attributable to decreases of $3.4 million in FDIC assessments and $1.6 million in professional fees, partially offset by an increase of $2.9 million in salaries and employee benefits primarily due to higher headcount and incentives.
“As previously communicated, we continued to reinvest a portion of the benefit of our operational excellence initiatives to further strengthen our human capital, risk management and technology infrastructure to support the next phase of growth. Even with these investments our efficiency ratio declined for the fourth consecutive quarter as we drove positive operating leverage,” stated Sam Sidhu.
Non-interest expenses totaled $105.2 million in Q3 2025, an increase of $1.2 million compared to Q3 2024. The increase was primarily attributable to increases of $3.2 million in professional fees including the investment in our risk management infrastructure, $1.7 million in commercial lease depreciation, $1.4 million in occupancy and $1.0 million in salaries and employee benefits associated with the Bank’s growth. These increases were partially offset by decreases of $3.2 million in technology, communication and bank operations primarily due to lower deposit servicing fees, provision for credit losses on unfunded lending commitments and fees paid to a fintech company related to a consumer installment loan origination program.
Taxes
Income tax expense increased by $6.6 million to a provision of $24.6 million in Q3 2025 from $18.0 million in Q2 2025 primarily due to higher pre-tax income, and increased by $25.3 million from a benefit of $0.7 million in Q3 2024 primarily due to higher pre-tax income and lower estimated income tax credits for 2025. The effective tax rate was 24.5% for Q3 2025.
Outlook
“We were very pleased with our third quarter results and remain focused on executing in those areas which differentiate us from our peers. We believe that truly exceptional service, sophisticated product offerings, recruitment of top talent, and a single-point-of-contact service model will deliver sustainable long-term growth. Importantly, our cubiX platform is proving to be a mission-critical real-time payments solution for our commercial clients and our team recruitment strategy is continuing to gain momentum, which we feel will continue to differentiate our company and drive long-term franchise value. We believe we are incredibly well positioned to continue to take market share winning new client relationships and that we have the right strategy, the right team, and a client-centric culture to achieve our goals in 2025 and beyond,” concluded Sam Sidhu.
4
Webcast
Date: Friday, October 24, 2025
Time: 9:00 AM EDT
The live audio webcast, presentation slides, and earnings press release will be made available at https://www.customersbank.com and at the Customers Bancorp 3rd Quarter Earnings Webcast.
You may submit questions in advance of the live webcast by emailing our Head of Corporate Communications, Jordan Baucum at [email protected].
The webcast will be archived for viewing on the Customers Bank Investor Relations page and available beginning approximately two hours after the conclusion of the live event.
Institutional Background
Customers Bancorp, Inc. (NYSE:CUBI) is one of the nation’s top-performing banking companies with over $24 billion in assets making it one of the 80 largest bank holding companies in the U.S. Customers Bank’s commercial and consumer clients benefit from a full suite of technology-enabled tailored product experiences delivered by best-in-class customer service distinguished by a Single Point of Contact approach. In addition to traditional lines such as C&I lending, commercial real estate lending and multifamily lending, Customers Bank also provides a number of national corporate banking services to specialized lending clients. Major accolades include:
•Named a Top 10 Performing Bank by American Banker for five consecutive years (2021-2025), including the #1 spot in 2024 among midsize banks ($10B to $50B in assets)
•No. 72 out of the 100 largest publicly traded banks in 2025 Forbes Best Banks list
•2024 Inc. Magazine Best in Business List in Financial Services Category
•Net Promoter Score of 73 compared to industry average of 41
A member of the Federal Reserve System with deposits insured by the Federal Deposit Insurance Corporation, Customers Bank is an equal opportunity lender. Learn more: www.customersbank.com.
“Safe Harbor” Statement
In addition to historical information, this press release may contain “forward-looking statements” within the meaning of the “safe harbor” provisions of the Private Securities Litigation Reform Act of 1995. These forward-looking statements include statements with respect to Customers Bancorp, Inc.’s strategies, goals, beliefs, expectations, estimates, intentions, capital raising efforts, financial condition and results of operations, future performance and business. Statements preceded by, followed by, or that include the words “may,” “could,” “should,” “pro forma,” “looking forward,” “would,” “believe,” “expect,” “anticipate,” “estimate,” “intend,” “plan,” “project,” or similar expressions generally indicate a forward-looking statement. These forward-looking statements involve risks and uncertainties that are subject to change based on various important factors (some of which, in whole or in part, are beyond Customers Bancorp, Inc.’s control). Numerous competitive, economic, regulatory, legal and technological events and factors, among others, could cause Customers Bancorp, Inc.’s financial performance to differ materially from the goals, plans, objectives, intentions and expectations expressed in such forward-looking statements, including: a continuation of the recent turmoil in the banking industry, responsive measures taken by us and regulatory authorities to mitigate and manage related risks, regulatory actions taken that address related issues and the costs and obligations associated therewith, such as the FDIC special assessments; the potential for negative consequences resulting from regulatory violations, investigations and examinations, including potential supervisory actions, the assessment of fines and penalties, the imposition of sanctions, the need to undertake remedial actions and possible damage to our reputation; effects of competition on deposit rates and growth, loan rates and growth and net interest margin; failure to identify and adequately and promptly address cybersecurity risks, including data breaches and cyberattacks; public health crises and pandemics and their effects on the economic and business environments in which we operate; geopolitical conditions,
5
including acts or threats of terrorism, actions taken by the United States or other governments in response to acts or threats of terrorism and military conflicts, including the war between Russia and Ukraine and ongoing conflict in the Middle East, which could impact economic conditions in the United States; the impact that changes in the economy have on the performance of our loan and lease portfolio, the market value of our investment securities, the demand for our products and services and the availability of sources of funding; the effects of actions by the federal government, including the Board of Governors of the Federal Reserve System and other government agencies, that affect market interest rates and the money supply; actions that we and our customers take in response to these developments and the effects such actions have on our operations, products, services and customer relationships; higher inflation and its impacts; the effects of changes in U.S. trade policies, including the imposition of tariffs and retaliatory tariffs on its trading partners; and the effects of any changes in accounting standards or policies. Customers Bancorp, Inc. cautions that the foregoing factors are not exclusive, and neither such factors nor any such forward-looking statement takes into account the impact of any future events. All forward-looking statements and information set forth herein are based on management’s current beliefs and assumptions as of the date hereof and speak only as of the date they are made. For a more complete discussion of the assumptions, risks and uncertainties related to our business, you are encouraged to review Customers Bancorp, Inc.’s filings with the Securities and Exchange Commission, including its most recent annual report on Form 10-K for the year ended December 31, 2024, subsequently filed quarterly reports on Form 10-Q and current reports on Form 8-K, including any amendments thereto, that update or provide information in addition to the information included in the Form 10-K and Form 10-Q filings, if any. Customers Bancorp, Inc. does not undertake to update any forward-looking statement whether written or oral, that may be made from time to time by Customers Bancorp, Inc. or by or on behalf of Customers Bank, except as may be required under applicable law.
6
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||||||||
FINANCIAL HIGHLIGHTS - UNAUDITED | |||||||||||||||||||||||||||||||||||||||||||||||
(Dollars in thousands, except per share data and stock price data) | Q3 | Q2 | Q1 | Q4 | Q3 | Nine Months Ended September 30, | |||||||||||||||||||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2024 | 2024 | 2025 | 2024 | |||||||||||||||||||||||||||||||||||||||||
| GAAP Profitability Metrics: | |||||||||||||||||||||||||||||||||||||||||||||||
| Net income available to common shareholders | $ | 73,726 | $ | 55,846 | $ | 9,523 | $ | 23,266 | $ | 42,937 | $ | 139,095 | $ | 143,163 | |||||||||||||||||||||||||||||||||
Per share amounts: | |||||||||||||||||||||||||||||||||||||||||||||||
| Earnings per share - diluted | $ | 2.20 | $ | 1.73 | $ | 0.29 | $ | 0.71 | $ | 1.31 | $ | 4.24 | $ | 4.37 | |||||||||||||||||||||||||||||||||
Book value per common share | $ | 59.83 | $ | 56.36 | $ | 54.85 | $ | 54.20 | $ | 53.07 | $ | 59.83 | $ | 53.07 | |||||||||||||||||||||||||||||||||
Return on average assets (“ROAA”) | 1.26 | % | 1.09 | % | 0.23 | % | 0.48 | % | 0.88 | % | 0.87 | % | 0.97 | % | |||||||||||||||||||||||||||||||||
Return on average common equity (“ROCE”) | 15.57 | % | 12.79 | % | 2.23 | % | 5.50 | % | 10.44 | % | 10.41 | % | 12.10 | % | |||||||||||||||||||||||||||||||||
| Net interest margin, tax equivalent | 3.46 | % | 3.27 | % | 3.13 | % | 3.11 | % | 3.06 | % | 3.30 | % | 3.16 | % | |||||||||||||||||||||||||||||||||
| Efficiency ratio | 45.39 | % | 51.23 | % | 52.94 | % | 56.86 | % | 62.40 | % | 49.62 | % | 55.97 | % | |||||||||||||||||||||||||||||||||
Non-GAAP Profitability Metrics (1): | |||||||||||||||||||||||||||||||||||||||||||||||
| Core earnings | $ | 73,473 | $ | 58,147 | $ | 50,002 | $ | 44,168 | $ | 43,838 | $ | 181,622 | $ | 138,937 | |||||||||||||||||||||||||||||||||
| Per share amounts: | |||||||||||||||||||||||||||||||||||||||||||||||
| Core earnings per share - diluted | $ | 2.20 | $ | 1.80 | $ | 1.54 | $ | 1.36 | $ | 1.34 | $ | 5.54 | $ | 4.24 | |||||||||||||||||||||||||||||||||
Tangible book value per common share | $ | 59.72 | $ | 56.24 | $ | 54.74 | $ | 54.08 | $ | 52.96 | $ | 59.72 | $ | 52.96 | |||||||||||||||||||||||||||||||||
| Core ROAA | 1.25 | % | 1.10 | % | 0.97 | % | 0.86 | % | 0.89 | % | 1.11 | % | 0.95 | % | |||||||||||||||||||||||||||||||||
| Core ROCE | 15.52 | % | 13.32 | % | 11.72 | % | 10.44 | % | 10.66 | % | 13.59 | % | 11.74 | % | |||||||||||||||||||||||||||||||||
| Core efficiency ratio | 45.40 | % | 51.56 | % | 52.69 | % | 56.12 | % | 61.69 | % | 49.65 | % | 56.29 | % | |||||||||||||||||||||||||||||||||
Balance Sheet Trends: | |||||||||||||||||||||||||||||||||||||||||||||||
Total assets | $ | 24,260,163 | $ | 22,550,800 | $ | 22,423,044 | $ | 22,308,241 | $ | 21,456,082 | $ | 24,260,163 | $ | 21,456,082 | |||||||||||||||||||||||||||||||||
Total cash and investment securities | $ | 6,997,783 | $ | 6,234,043 | $ | 6,424,406 | $ | 6,797,562 | $ | 6,564,528 | $ | 6,997,783 | $ | 6,564,528 | |||||||||||||||||||||||||||||||||
Total loans and leases | $ | 16,303,147 | $ | 15,412,400 | $ | 15,097,968 | $ | 14,653,556 | $ | 14,053,116 | $ | 16,303,147 | $ | 14,053,116 | |||||||||||||||||||||||||||||||||
Non-interest bearing demand deposits | $ | 6,380,879 | $ | 5,481,065 | $ | 5,552,605 | $ | 5,608,288 | $ | 4,670,809 | $ | 6,380,879 | $ | 4,670,809 | |||||||||||||||||||||||||||||||||
Total deposits | $ | 20,405,023 | $ | 18,976,018 | $ | 18,932,925 | $ | 18,846,461 | $ | 18,069,389 | $ | 20,405,023 | $ | 18,069,389 | |||||||||||||||||||||||||||||||||
| Asset Quality: | |||||||||||||||||||||||||||||||||||||||||||||||
| Net charge-offs | $ | 15,371 | $ | 13,115 | $ | 17,144 | $ | 14,612 | $ | 17,044 | $ | 45,630 | $ | 53,723 | |||||||||||||||||||||||||||||||||
| Annualized net charge-offs to average total loans and leases | 0.39 | % | 0.35 | % | 0.48 | % | 0.41 | % | 0.50 | % | 0.40 | % | 0.54 | % | |||||||||||||||||||||||||||||||||
Nonaccrual / non-performing loans (“NPLs”) | $ | 28,421 | $ | 28,443 | $ | 43,513 | $ | 43,275 | $ | 47,326 | $ | 28,421 | $ | 47,326 | |||||||||||||||||||||||||||||||||
NPLs to total loans and leases | 0.17 | % | 0.18 | % | 0.29 | % | 0.30 | % | 0.34 | % | 0.17 | % | 0.34 | % | |||||||||||||||||||||||||||||||||
Reserves to NPLs | 534.14 | % | 518.29 | % | 324.22 | % | 316.06 | % | 281.36 | % | 534.14 | % | 281.36 | % | |||||||||||||||||||||||||||||||||
Non-performing assets (“NPAs”) | $ | 61,057 | $ | 60,778 | $ | 57,960 | $ | 55,807 | $ | 47,326 | $ | 61,057 | $ | 47,326 | |||||||||||||||||||||||||||||||||
NPAs to total assets | 0.25 | % | 0.27 | % | 0.26 | % | 0.25 | % | 0.22 | % | 0.25 | % | 0.22 | % | |||||||||||||||||||||||||||||||||
7
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||||||||
FINANCIAL HIGHLIGHTS - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||||||||||||||||||||
(Dollars in thousands, except per share data and stock price data) | Q3 | Q2 | Q1 | Q4 | Q3 | Nine Months Ended September 30, | |||||||||||||||||||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2024 | 2024 | 2025 | 2024 | |||||||||||||||||||||||||||||||||||||||||
Capital Metrics: | |||||||||||||||||||||||||||||||||||||||||||||||
Common equity to total assets | 8.4 | % | 7.9 | % | 7.7 | % | 7.6 | % | 7.8 | % | 8.4 | % | 7.8 | % | |||||||||||||||||||||||||||||||||
Tangible common equity to tangible assets (1) | 8.4 | % | 7.9 | % | 7.7 | % | 7.6 | % | 7.7 | % | 8.4 | % | 7.7 | % | |||||||||||||||||||||||||||||||||
Common equity Tier 1 capital ratio (2) | 13.0 | % | 12.05 | % | 11.72 | % | 12.09 | % | 12.46 | % | 13.0 | % | 12.46 | % | |||||||||||||||||||||||||||||||||
Total risk based capital ratio (2) | 15.4 | % | 14.49 | % | 14.61 | % | 14.88 | % | 15.36 | % | 15.4 | % | 15.36 | % | |||||||||||||||||||||||||||||||||
Customers Bank Capital Ratios (2): | |||||||||||||||||||||||||||||||||||||||||||||||
| Common equity Tier 1 capital to risk-weighted assets | 13.3 | % | 13.00 | % | 12.40 | % | 12.96 | % | 13.64 | % | 13.3 | % | 13.64 | % | |||||||||||||||||||||||||||||||||
| Total capital to risk-weighted assets | 14.6 | % | 14.43 | % | 13.92 | % | 14.34 | % | 15.06 | % | 14.6 | % | 15.06 | % | |||||||||||||||||||||||||||||||||
| Tier 1 capital to average assets (leverage ratio) | 8.8 | % | 8.86 | % | 8.43 | % | 8.65 | % | 9.08 | % | 8.8 | % | 9.08 | % | |||||||||||||||||||||||||||||||||
Share amounts: | |||||||||||||||||||||||||||||||||||||||||||||||
| Average shares outstanding - basic | 32,340,813 | 31,585,390 | 31,447,623 | 31,346,920 | 31,567,797 | 31,794,547 | 31,563,660 | ||||||||||||||||||||||||||||||||||||||||
| Average shares outstanding - diluted | 33,460,055 | 32,374,061 | 32,490,572 | 32,557,621 | 32,766,488 | 32,778,447 | 32,773,365 | ||||||||||||||||||||||||||||||||||||||||
Shares outstanding | 34,163,506 | 31,606,934 | 31,479,132 | 31,346,507 | 31,342,107 | 34,163,506 | 31,342,107 | ||||||||||||||||||||||||||||||||||||||||
(1) Customers’ reasons for the use of these non-GAAP measures and a detailed reconciliation between the non-GAAP measures and the comparable GAAP amounts are included at the end of this document. | |||||||||||||||||||||||||||||||||||||||||||||||
(2) Regulatory capital ratios are estimated for Q3 2025 and actual for the remaining periods. In accordance with regulatory capital rules, Customers elected to apply the CECL capital transition provisions which delayed the effects of CECL on regulatory capital for two years until January 1, 2022, followed by a three-year transition period. The cumulative CECL capital transition impact as of December 31, 2021 which amounted to $61.6 million was phased in at 25% per year beginning on January 1, 2022 through December 31, 2024. As of September 30, 2025, our regulatory capital ratios reflected the full effect of CECL on regulatory capital. | |||||||||||||||||||||||||||||||||||||||||||||||
8
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
CONSOLIDATED STATEMENTS OF OPERATIONS - UNAUDITED | |||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | Nine Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Q3 | Q2 | Q1 | Q4 | Q3 | September 30, | ||||||||||||||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2024 | 2024 | 2025 | 2024 | |||||||||||||||||||||||||||||||||||
| Interest income: | |||||||||||||||||||||||||||||||||||||||||
| Loans and leases | $ | 272,131 | $ | 246,869 | $ | 231,008 | $ | 230,534 | $ | 228,659 | $ | 750,008 | $ | 670,923 | |||||||||||||||||||||||||||
| Investment securities | 36,091 | 37,381 | 34,339 | 39,638 | 46,265 | 107,811 | 140,653 | ||||||||||||||||||||||||||||||||||
| Interest earning deposits | 49,639 | 39,972 | 42,914 | 48,147 | 44,372 | 132,525 | 142,695 | ||||||||||||||||||||||||||||||||||
| Loans held for sale | 1,589 | 1,806 | 4,761 | 9,447 | 10,907 | 8,156 | 36,626 | ||||||||||||||||||||||||||||||||||
| Other | 2,029 | 1,973 | 1,887 | 2,140 | 1,910 | 5,889 | 7,031 | ||||||||||||||||||||||||||||||||||
| Total interest income | 361,479 | 328,001 | 314,909 | 329,906 | 332,113 | 1,004,389 | 997,928 | ||||||||||||||||||||||||||||||||||
| Interest expense: | |||||||||||||||||||||||||||||||||||||||||
| Deposits | 141,983 | 134,045 | 131,308 | 144,974 | 155,829 | 407,336 | 458,338 | ||||||||||||||||||||||||||||||||||
| FHLB advances | 12,945 | 12,717 | 11,801 | 12,595 | 12,590 | 37,463 | 39,512 | ||||||||||||||||||||||||||||||||||
| Subordinated debt | 3,251 | 3,229 | 3,212 | 3,349 | 3,537 | 9,692 | 8,960 | ||||||||||||||||||||||||||||||||||
| Other borrowings | 1,388 | 1,307 | 1,142 | 1,167 | 1,612 | 3,837 | 4,535 | ||||||||||||||||||||||||||||||||||
| Total interest expense | 159,567 | 151,298 | 147,463 | 162,085 | 173,568 | 458,328 | 511,345 | ||||||||||||||||||||||||||||||||||
| Net interest income | 201,912 | 176,703 | 167,446 | 167,821 | 158,545 | 546,061 | 486,583 | ||||||||||||||||||||||||||||||||||
| Provision for credit losses | 26,543 | 20,781 | 28,297 | 21,194 | 17,066 | 75,621 | 52,257 | ||||||||||||||||||||||||||||||||||
| Net interest income after provision for credit losses | 175,369 | 155,922 | 139,149 | 146,627 | 141,479 | 470,440 | 434,326 | ||||||||||||||||||||||||||||||||||
| Non-interest income: | |||||||||||||||||||||||||||||||||||||||||
| Commercial lease income | 11,536 | 11,056 | 10,668 | 10,604 | 10,093 | 33,260 | 30,058 | ||||||||||||||||||||||||||||||||||
| Loan fees | 11,443 | 9,106 | 7,235 | 8,639 | 8,011 | 27,784 | 18,524 | ||||||||||||||||||||||||||||||||||
| Bank-owned life insurance | 2,165 | 2,249 | 4,660 | 2,125 | 2,049 | 9,074 | 7,317 | ||||||||||||||||||||||||||||||||||
| Mortgage finance transactional fees | 1,298 | 1,175 | 933 | 1,010 | 1,087 | 3,406 | 3,091 | ||||||||||||||||||||||||||||||||||
| Net gain (loss) on sale of loans and leases | — | — | 2 | (852) | (14,548) | 2 | (14,776) | ||||||||||||||||||||||||||||||||||
| Net gain (loss) on sale of investment securities | 186 | (1,797) | — | (26,260) | — | (1,611) | (749) | ||||||||||||||||||||||||||||||||||
| Impairment loss on debt securities | — | — | (51,319) | — | — | (51,319) | — | ||||||||||||||||||||||||||||||||||
| Unrealized gain on equity method investments | — | — | — | 389 | — | — | 11,041 | ||||||||||||||||||||||||||||||||||
| Other | 3,563 | 7,817 | 3,331 | 3,954 | 1,865 | 14,711 | 6,319 | ||||||||||||||||||||||||||||||||||
| Total non-interest income (loss) | 30,191 | 29,606 | (24,490) | (391) | 8,557 | 35,307 | 60,825 | ||||||||||||||||||||||||||||||||||
| Non-interest expense: | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 48,723 | 45,848 | 42,674 | 47,147 | 47,717 | 137,245 | 128,689 | ||||||||||||||||||||||||||||||||||
| Technology, communication and bank operations | 10,415 | 10,382 | 11,312 | 13,435 | 13,588 | 32,109 | 51,719 | ||||||||||||||||||||||||||||||||||
| Commercial lease depreciation | 9,463 | 8,743 | 8,463 | 8,933 | 7,811 | 26,669 | 23,610 | ||||||||||||||||||||||||||||||||||
| Professional services | 12,281 | 13,850 | 11,857 | 13,473 | 9,048 | 37,988 | 21,505 | ||||||||||||||||||||||||||||||||||
| Loan servicing | 4,167 | 4,053 | 4,630 | 4,584 | 3,778 | 12,850 | 11,325 | ||||||||||||||||||||||||||||||||||
| Occupancy | 4,370 | 3,551 | 3,412 | 3,335 | 2,987 | 11,333 | 8,454 | ||||||||||||||||||||||||||||||||||
| FDIC assessments, non-income taxes and regulatory fees | 8,505 | 11,906 | 11,750 | 10,077 | 7,902 | 32,161 | 31,607 | ||||||||||||||||||||||||||||||||||
| Advertising and promotion | 636 | 461 | 528 | 1,645 | 908 | 1,625 | 2,844 | ||||||||||||||||||||||||||||||||||
| Other | 6,657 | 7,832 | 8,145 | 7,746 | 10,279 | 22,634 | 26,886 | ||||||||||||||||||||||||||||||||||
| Total non-interest expense | 105,217 | 106,626 | 102,771 | 110,375 | 104,018 | 314,614 | 306,639 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense (benefit) | 100,343 | 78,902 | 11,888 | 35,861 | 46,018 | 191,133 | 188,512 | ||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) | 24,598 | 17,963 | (1,024) | 8,946 | (725) | 41,537 | 33,958 | ||||||||||||||||||||||||||||||||||
| Net income | 75,745 | 60,939 | 12,912 | 26,915 | 46,743 | 149,596 | 154,554 | ||||||||||||||||||||||||||||||||||
| Preferred stock dividends | 2,019 | 3,185 | 3,389 | 3,649 | 3,806 | 8,593 | 11,391 | ||||||||||||||||||||||||||||||||||
| Loss on redemption of preferred stock | — | 1,908 | — | — | — | 1,908 | — | ||||||||||||||||||||||||||||||||||
| Net income available to common shareholders | $ | 73,726 | $ | 55,846 | $ | 9,523 | $ | 23,266 | $ | 42,937 | $ | 139,095 | $ | 143,163 | |||||||||||||||||||||||||||
| Basic earnings per common share | $ | 2.28 | $ | 1.77 | $ | 0.30 | $ | 0.74 | $ | 1.36 | $ | 4.37 | $ | 4.54 | |||||||||||||||||||||||||||
| Diluted earnings per common share | 2.20 | 1.73 | 0.29 | 0.71 | 1.31 | 4.24 | 4.37 | ||||||||||||||||||||||||||||||||||
9
CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
CONSOLIDATED BALANCE SHEET - UNAUDITED | |||||||||||||||||||||||||||||
(Dollars in thousands) | |||||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | |||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2024 | 2024 | |||||||||||||||||||||||||
ASSETS | |||||||||||||||||||||||||||||
| Cash and due from banks | $ | 57,951 | $ | 72,986 | $ | 62,146 | $ | 56,787 | $ | 39,429 | |||||||||||||||||||
| Interest earning deposits | 4,127,688 | 3,430,525 | 3,366,544 | 3,729,144 | 3,048,593 | ||||||||||||||||||||||||
| Cash and cash equivalents | 4,185,639 | 3,503,511 | 3,428,690 | 3,785,931 | 3,088,022 | ||||||||||||||||||||||||
| Investment securities, at fair value | 2,010,820 | 1,877,406 | 2,057,555 | 2,019,694 | 2,412,069 | ||||||||||||||||||||||||
| Investment securities held to maturity | 801,324 | 853,126 | 938,161 | 991,937 | 1,064,437 | ||||||||||||||||||||||||
| Loans held for sale | 30,897 | 32,963 | 37,529 | 204,794 | 275,420 | ||||||||||||||||||||||||
| Loans and leases receivable | 14,673,636 | 13,719,829 | 13,555,820 | 13,127,634 | 12,527,283 | ||||||||||||||||||||||||
| Loans receivable, mortgage finance, at fair value | 1,486,978 | 1,536,254 | 1,366,460 | 1,321,128 | 1,250,413 | ||||||||||||||||||||||||
| Loans receivable, installment, at fair value | 111,636 | 123,354 | 138,159 | — | — | ||||||||||||||||||||||||
| Allowance for credit losses on loans and leases | (151,809) | (147,418) | (141,076) | (136,775) | (133,158) | ||||||||||||||||||||||||
| Total loans and leases receivable, net of allowance for credit losses on loans and leases | 16,120,441 | 15,232,019 | 14,919,363 | 14,311,987 | 13,644,538 | ||||||||||||||||||||||||
| FHLB, Federal Reserve Bank, and other restricted stock | 103,290 | 100,590 | 96,758 | 96,214 | 95,035 | ||||||||||||||||||||||||
| Accrued interest receivable | 106,379 | 101,481 | 105,800 | 108,351 | 115,588 | ||||||||||||||||||||||||
| Bank premises and equipment, net | 15,340 | 5,978 | 6,653 | 6,668 | 6,730 | ||||||||||||||||||||||||
| Bank-owned life insurance | 303,212 | 300,747 | 298,551 | 297,641 | 295,531 | ||||||||||||||||||||||||
| Other real estate owned | 12,432 | 12,306 | — | — | — | ||||||||||||||||||||||||
| Goodwill and other intangibles | 3,629 | 3,629 | 3,629 | 3,629 | 3,629 | ||||||||||||||||||||||||
| Other assets | 566,760 | 527,044 | 530,355 | 481,395 | 455,083 | ||||||||||||||||||||||||
| Total assets | $ | 24,260,163 | $ | 22,550,800 | $ | 22,423,044 | $ | 22,308,241 | $ | 21,456,082 | |||||||||||||||||||
| LIABILITIES AND SHAREHOLDERS’ EQUITY | |||||||||||||||||||||||||||||
| Demand, non-interest bearing deposits | $ | 6,380,879 | $ | 5,481,065 | $ | 5,552,605 | $ | 5,608,288 | $ | 4,670,809 | |||||||||||||||||||
| Interest bearing deposits | 14,024,144 | 13,494,953 | 13,380,320 | 13,238,173 | 13,398,580 | ||||||||||||||||||||||||
| Total deposits | 20,405,023 | 18,976,018 | 18,932,925 | 18,846,461 | 18,069,389 | ||||||||||||||||||||||||
| FHLB advances | 1,195,437 | 1,195,377 | 1,133,456 | 1,128,352 | 1,117,229 | ||||||||||||||||||||||||
| Other borrowings | 99,173 | 99,138 | 99,103 | 99,068 | 99,033 | ||||||||||||||||||||||||
| Subordinated debt | 182,718 | 182,649 | 182,579 | 182,509 | 182,439 | ||||||||||||||||||||||||
| Accrued interest payable and other liabilities | 251,753 | 234,060 | 210,421 | 215,168 | 186,812 | ||||||||||||||||||||||||
| Total liabilities | 22,134,104 | 20,687,242 | 20,558,484 | 20,471,558 | 19,654,902 | ||||||||||||||||||||||||
| Preferred stock | 82,201 | 82,201 | 137,794 | 137,794 | 137,794 | ||||||||||||||||||||||||
| Common stock | 36,161 | 36,123 | 35,995 | 35,758 | 35,734 | ||||||||||||||||||||||||
| Additional paid in capital | 662,252 | 572,473 | 570,172 | 575,333 | 571,609 | ||||||||||||||||||||||||
| Retained earnings | 1,465,106 | 1,391,380 | 1,335,534 | 1,326,011 | 1,302,745 | ||||||||||||||||||||||||
| Accumulated other comprehensive income (loss), net | (51,089) | (71,325) | (67,641) | (96,560) | (106,082) | ||||||||||||||||||||||||
| Treasury stock, at cost | (68,572) | (147,294) | (147,294) | (141,653) | (140,620) | ||||||||||||||||||||||||
| Total shareholders’ equity | 2,126,059 | 1,863,558 | 1,864,560 | 1,836,683 | 1,801,180 | ||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 24,260,163 | $ | 22,550,800 | $ | 22,423,044 | $ | 22,308,241 | $ | 21,456,082 | |||||||||||||||||||
10
CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| AVERAGE BALANCE SHEET / NET INTEREST MARGIN - UNAUDITED | |||||||||||||||||||||||||||||||||||||||||||||||||||||
(Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| September 30, 2025 | June 30, 2025 | September 30, 2024 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Average Balance | Interest Income or Expense | Average Yield or Cost (%) | Average Balance | Interest Income or Expense | Average Yield or Cost (%) | Average Balance | Interest Income or Expense | Average Yield or Cost (%) | |||||||||||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest earning deposits | $ | 4,409,220 | $ | 49,639 | 4.47% | $ | 3,565,168 | $ | 39,972 | 4.50% | $ | 3,224,940 | $ | 44,372 | 5.47% | ||||||||||||||||||||||||||||||||||||||
Investment securities (1) | 2,931,351 | 36,091 | 4.88% | 2,890,878 | 37,381 | 5.19% | 3,706,974 | 46,265 | 4.97% | ||||||||||||||||||||||||||||||||||||||||||||
| Loans and leases: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial & industrial: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Specialized lending loans and leases (2) | 7,317,299 | 136,652 | 7.41% | 6,785,684 | 126,854 | 7.50% | 5,805,389 | 124,667 | 8.54% | ||||||||||||||||||||||||||||||||||||||||||||
Other commercial & industrial loans (2) | 1,492,155 | 35,475 | 9.43% | 1,484,528 | 25,862 | 6.99% | 1,533,057 | 24,654 | 6.40% | ||||||||||||||||||||||||||||||||||||||||||||
| Mortgage finance loans | 1,478,871 | 18,454 | 4.95% | 1,501,484 | 18,349 | 4.90% | 1,267,656 | 17,723 | 5.56% | ||||||||||||||||||||||||||||||||||||||||||||
| Multifamily loans | 2,306,373 | 25,931 | 4.46% | 2,317,381 | 25,281 | 4.38% | 2,071,340 | 21,147 | 4.06% | ||||||||||||||||||||||||||||||||||||||||||||
| Non-owner occupied commercial real estate loans | 1,635,937 | 24,148 | 5.86% | 1,581,087 | 23,003 | 5.84% | 1,411,533 | 21,065 | 5.94% | ||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgages | 551,436 | 6,647 | 4.78% | 537,008 | 6,344 | 4.74% | 525,285 | 6,082 | 4.61% | ||||||||||||||||||||||||||||||||||||||||||||
| Installment loans | 938,890 | 26,413 | 11.16% | 879,972 | 22,982 | 10.48% | 1,029,812 | 24,228 | 9.36% | ||||||||||||||||||||||||||||||||||||||||||||
Total loans and leases (3) | 15,720,961 | 273,720 | 6.91% | 15,087,144 | 248,675 | 6.61% | 13,644,072 | 239,566 | 6.99% | ||||||||||||||||||||||||||||||||||||||||||||
| Other interest-earning assets | 140,011 | 2,029 | 5.75% | 133,824 | 1,973 | 5.91% | 118,914 | 1,910 | 6.39% | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest-earning assets | 23,201,543 | 361,479 | 6.19% | 21,677,014 | 328,001 | 6.07% | 20,694,900 | 332,113 | 6.39% | ||||||||||||||||||||||||||||||||||||||||||||
| Non-interest-earning assets | 729,180 | 685,975 | 535,504 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 23,930,723 | $ | 22,362,989 | $ | 21,230,404 | |||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest checking accounts | $ | 4,983,168 | $ | 48,105 | 3.83% | $ | 4,935,587 | $ | 47,245 | 3.84% | $ | 5,787,026 | $ | 65,554 | 4.51% | ||||||||||||||||||||||||||||||||||||||
| Money market deposit accounts | 4,360,446 | 42,980 | 3.91% | 4,137,035 | 40,397 | 3.92% | 3,676,994 | 42,128 | 4.56% | ||||||||||||||||||||||||||||||||||||||||||||
| Other savings accounts | 1,485,652 | 14,724 | 3.93% | 1,325,639 | 12,767 | 3.86% | 1,563,970 | 18,426 | 4.69% | ||||||||||||||||||||||||||||||||||||||||||||
| Certificates of deposit | 3,108,831 | 36,174 | 4.62% | 2,852,645 | 33,636 | 4.73% | 2,339,937 | 29,721 | 5.05% | ||||||||||||||||||||||||||||||||||||||||||||
Total interest-bearing deposits (4) | 13,938,097 | 141,983 | 4.04% | 13,250,906 | 134,045 | 4.06% | 13,367,927 | 155,829 | 4.64% | ||||||||||||||||||||||||||||||||||||||||||||
| Borrowings | 1,429,981 | 17,584 | 4.88% | 1,417,370 | 17,253 | 4.88% | 1,334,905 | 17,739 | 5.29% | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 15,368,078 | 159,567 | 4.12% | 14,668,276 | 151,298 | 4.14% | 14,702,832 | 173,568 | 4.70% | ||||||||||||||||||||||||||||||||||||||||||||
Non-interest-bearing deposits (4) | 6,362,360 | 5,593,581 | 4,557,815 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total deposits and borrowings | 21,730,438 | 2.91% | 20,261,857 | 2.99% | 19,260,647 | 3.59% | |||||||||||||||||||||||||||||||||||||||||||||||
| Other non-interest-bearing liabilities | 239,969 | 221,465 | 195,722 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities | 21,970,407 | 20,483,322 | 19,456,369 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | 1,960,316 | 1,879,667 | 1,774,035 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 23,930,723 | $ | 22,362,989 | $ | 21,230,404 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | 201,912 | 176,703 | 158,545 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Tax-equivalent adjustment | 360 | 366 | 392 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest earnings | $ | 202,272 | $ | 177,069 | $ | 158,937 | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest spread | 3.27% | 3.07% | 2.80% | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest margin | 3.46% | 3.27% | 3.05% | ||||||||||||||||||||||||||||||||||||||||||||||||||
Net interest margin tax equivalent (5) | 3.46% | 3.27% | 3.06% | ||||||||||||||||||||||||||||||||||||||||||||||||||
(1) For presentation in this table, average balances and the corresponding average yields for investment securities are based upon historical cost, adjusted for amortization of premiums and accretion of discounts. | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| (2) Includes owner occupied commercial real estate loans. | |||||||||||||||||||||||||||||||||||||||||||||||||||||
(3) Includes non-accrual loans, the effect of which is to reduce the yield earned on loans and leases, and deferred loan fees. | |||||||||||||||||||||||||||||||||||||||||||||||||||||
(4) Total costs of deposits (including interest bearing and non-interest bearing) were 2.77%, 2.85% and 3.46% for the three months ended September 30, 2025, June 30, 2025 and September 30, 2024, respectively. | |||||||||||||||||||||||||||||||||||||||||||||||||||||
(5) Tax-equivalent basis, using an estimated marginal tax rate of 26% for the three months ended September 30, 2025, June 30, 2025 and September 30, 2024, presented to approximate interest income as a taxable asset. | |||||||||||||||||||||||||||||||||||||||||||||||||||||
11
CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||
| AVERAGE BALANCE SHEET / NET INTEREST MARGIN - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||||||||
(Dollars in thousands) | |||||||||||||||||||||||||||||||||||
| Nine Months Ended | |||||||||||||||||||||||||||||||||||
| September 30, 2025 | September 30, 2024 | ||||||||||||||||||||||||||||||||||
Average Balance | Interest Income or Expense | Average Yield or Cost (%) | Average Balance | Interest Income or Expense | Average Yield or Cost (%) | ||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||
| Interest earning deposits | $ | 3,946,022 | $ | 132,525 | 4.49% | $ | 3,471,011 | $ | 142,695 | 5.49% | |||||||||||||||||||||||||
Investment securities (1) | 2,973,600 | 107,811 | 4.85% | 3,736,770 | 140,653 | 5.03% | |||||||||||||||||||||||||||||
| Loans and leases: | |||||||||||||||||||||||||||||||||||
| Commercial & industrial: | |||||||||||||||||||||||||||||||||||
Specialized lending loans and leases (2) | 6,862,095 | 384,457 | 7.49% | 5,507,963 | 361,234 | 8.76% | |||||||||||||||||||||||||||||
Other commercial & industrial loans (2) | 1,506,324 | 85,270 | 7.57% | 1,575,815 | 76,487 | 6.48% | |||||||||||||||||||||||||||||
| Mortgage finance loans | 1,411,814 | 51,555 | 4.88% | 1,151,173 | 45,640 | 5.30% | |||||||||||||||||||||||||||||
| Multifamily loans | 2,299,335 | 74,876 | 4.35% | 2,100,501 | 63,863 | 4.06% | |||||||||||||||||||||||||||||
| Non-owner occupied commercial real estate loans | 1,589,446 | 68,715 | 5.78% | 1,385,685 | 61,714 | 5.95% | |||||||||||||||||||||||||||||
| Residential mortgages | 539,762 | 19,219 | 4.76% | 522,876 | 17,745 | 4.53% | |||||||||||||||||||||||||||||
| Installment loans | 919,021 | 74,072 | 10.78% | 1,131,633 | 80,866 | 9.55% | |||||||||||||||||||||||||||||
Total loans and leases (3) | 15,127,797 | 758,164 | 6.70% | 13,375,646 | 707,549 | 7.07% | |||||||||||||||||||||||||||||
| Other interest-earning assets | 133,921 | 5,889 | 5.88% | 112,365 | 7,031 | 8.36% | |||||||||||||||||||||||||||||
| Total interest-earning assets | 22,181,340 | 1,004,389 | 6.05% | 20,695,792 | 997,928 | 6.44% | |||||||||||||||||||||||||||||
| Non-interest-earning assets | 694,136 | 487,991 | |||||||||||||||||||||||||||||||||
| Total assets | $ | 22,875,476 | $ | 21,183,783 | |||||||||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||||||||
| Interest checking accounts | $ | 5,090,947 | $ | 145,253 | 3.81% | $ | 5,682,240 | $ | 191,132 | 4.49% | |||||||||||||||||||||||||
| Money market deposit accounts | 4,128,528 | 121,144 | 3.92% | 3,419,880 | 117,106 | 4.57% | |||||||||||||||||||||||||||||
| Other savings accounts | 1,322,135 | 38,182 | 3.86% | 1,708,625 | 61,008 | 4.77% | |||||||||||||||||||||||||||||
| Certificates of deposit | 2,905,047 | 102,757 | 4.73% | 2,374,982 | 89,092 | 5.01% | |||||||||||||||||||||||||||||
Total interest-bearing deposits (4) | 13,446,657 | 407,336 | 4.05% | 13,185,727 | 458,338 | 4.64% | |||||||||||||||||||||||||||||
| Borrowings | 1,398,401 | 50,992 | 4.88% | 1,431,520 | 53,007 | 4.95% | |||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 14,845,058 | 458,328 | 4.13% | 14,617,247 | 511,345 | 4.67% | |||||||||||||||||||||||||||||
Non-interest-bearing deposits (4) | 5,891,249 | 4,626,580 | |||||||||||||||||||||||||||||||||
| Total deposits and borrowings | 20,736,307 | 2.95% | 19,243,827 | 3.55% | |||||||||||||||||||||||||||||||
| Other non-interest-bearing liabilities | 235,938 | 221,278 | |||||||||||||||||||||||||||||||||
| Total liabilities | 20,972,245 | 19,465,105 | |||||||||||||||||||||||||||||||||
| Shareholders’ equity | 1,903,231 | 1,718,678 | |||||||||||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 22,875,476 | $ | 21,183,783 | |||||||||||||||||||||||||||||||
| Net interest income | 546,061 | 486,583 | |||||||||||||||||||||||||||||||||
| Tax-equivalent adjustment | 1,089 | 1,179 | |||||||||||||||||||||||||||||||||
| Net interest earnings | $ | 547,150 | $ | 487,762 | |||||||||||||||||||||||||||||||
| Interest spread | 3.10% | 2.89% | |||||||||||||||||||||||||||||||||
| Net interest margin | 3.29% | 3.15% | |||||||||||||||||||||||||||||||||
Net interest margin tax equivalent (5) | 3.30% | 3.16% | |||||||||||||||||||||||||||||||||
(1) For presentation in this table, average balances and the corresponding average yields for investment securities are based upon historical cost, adjusted for amortization of premiums and accretion of discounts. | |||||||||||||||||||||||||||||||||||
| (2) Includes owner occupied commercial real estate loans. | |||||||||||||||||||||||||||||||||||
(3) Includes non-accrual loans, the effect of which is to reduce the yield earned on loans and leases, and deferred loan fees. | |||||||||||||||||||||||||||||||||||
(4) Total costs of deposits (including interest bearing and non-interest bearing) were 2.82% and 3.44% for the nine months ended September 30, 2025 and 2024, respectively. | |||||||||||||||||||||||||||||||||||
(5) Tax-equivalent basis, using an estimated marginal tax rate of 26% for the nine months ended September 30, 2025 and 2024, presented to approximate interest income as a taxable asset. | |||||||||||||||||||||||||||||||||||
12
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| PERIOD END LOAN AND LEASE COMPOSITION - UNAUDITED | |||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | |||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2024 | 2024 | |||||||||||||||||||||||||
| Loans and leases held for investment | |||||||||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||
| Commercial & industrial: | |||||||||||||||||||||||||||||
| Specialized lending | $ | 7,083,620 | $ | 6,454,661 | $ | 6,070,093 | $ | 5,842,420 | $ | 5,468,507 | |||||||||||||||||||
Other commercial & industrial | 1,056,173 | 1,037,684 | 1,062,933 | 1,062,631 | 1,087,222 | ||||||||||||||||||||||||
Mortgage finance | 1,577,038 | 1,625,764 | 1,477,896 | 1,440,847 | 1,367,617 | ||||||||||||||||||||||||
| Multifamily | 2,356,590 | 2,247,282 | 2,322,123 | 2,252,246 | 2,115,978 | ||||||||||||||||||||||||
| Commercial real estate owner occupied | 1,058,741 | 1,065,006 | 1,139,126 | 1,100,944 | 981,904 | ||||||||||||||||||||||||
| Commercial real estate non-owner occupied | 1,582,332 | 1,497,385 | 1,438,906 | 1,359,130 | 1,326,591 | ||||||||||||||||||||||||
| Construction | 123,290 | 98,626 | 154,647 | 147,209 | 174,509 | ||||||||||||||||||||||||
| Total commercial loans and leases | 14,837,784 | 14,026,408 | 13,665,724 | 13,205,427 | 12,522,328 | ||||||||||||||||||||||||
| Consumer: | |||||||||||||||||||||||||||||
| Residential | 514,544 | 520,570 | 496,772 | 496,559 | 500,786 | ||||||||||||||||||||||||
| Manufactured housing | 28,749 | 30,287 | 31,775 | 33,123 | 34,481 | ||||||||||||||||||||||||
| Installment: | |||||||||||||||||||||||||||||
| Personal | 570,768 | 457,728 | 493,276 | 463,854 | 453,739 | ||||||||||||||||||||||||
| Other | 320,405 | 344,444 | 372,892 | 249,799 | 266,362 | ||||||||||||||||||||||||
| Total installment loans | 891,173 | 802,172 | 866,168 | 713,653 | 720,101 | ||||||||||||||||||||||||
| Total consumer loans | 1,434,466 | 1,353,029 | 1,394,715 | 1,243,335 | 1,255,368 | ||||||||||||||||||||||||
| Total loans and leases held for investment | $ | 16,272,250 | $ | 15,379,437 | $ | 15,060,439 | $ | 14,448,762 | $ | 13,777,696 | |||||||||||||||||||
| Loans held for sale | |||||||||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||
| Commercial real estate non-owner occupied | $ | 4,700 | $ | — | $ | — | $ | — | $ | — | |||||||||||||||||||
| Total commercial loans and leases | 4,700 | — | — | — | — | ||||||||||||||||||||||||
| Consumer: | |||||||||||||||||||||||||||||
| Residential | 2,229 | 5,180 | 1,465 | 1,836 | 2,523 | ||||||||||||||||||||||||
| Installment: | |||||||||||||||||||||||||||||
| Personal | 23,728 | 27,682 | 36,000 | 40,903 | 55,799 | ||||||||||||||||||||||||
| Other | 240 | 101 | 64 | 162,055 | 217,098 | ||||||||||||||||||||||||
| Total installment loans | 23,968 | 27,783 | 36,064 | 202,958 | 272,897 | ||||||||||||||||||||||||
| Total consumer loans | 26,197 | 32,963 | 37,529 | 204,794 | 275,420 | ||||||||||||||||||||||||
| Total loans held for sale | $ | 30,897 | $ | 32,963 | $ | 37,529 | $ | 204,794 | $ | 275,420 | |||||||||||||||||||
| Total loans and leases portfolio | $ | 16,303,147 | $ | 15,412,400 | $ | 15,097,968 | $ | 14,653,556 | $ | 14,053,116 | |||||||||||||||||||
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| PERIOD END DEPOSIT COMPOSITION - UNAUDITED | |||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | |||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2024 | 2024 | |||||||||||||||||||||||||
| Demand, non-interest bearing | $ | 6,380,879 | $ | 5,481,065 | $ | 5,552,605 | $ | 5,608,288 | $ | 4,670,809 | |||||||||||||||||||
| Demand, interest bearing | 5,050,437 | 4,912,839 | 5,137,961 | 5,553,698 | 5,606,500 | ||||||||||||||||||||||||
| Total demand deposits | 11,431,316 | 10,393,904 | 10,690,566 | 11,161,986 | 10,277,309 | ||||||||||||||||||||||||
| Savings | 1,554,533 | 1,375,072 | 1,327,854 | 1,131,819 | 1,399,968 | ||||||||||||||||||||||||
| Money market | 4,339,371 | 4,206,516 | 4,057,458 | 3,844,451 | 3,961,028 | ||||||||||||||||||||||||
| Time deposits | 3,079,803 | 3,000,526 | 2,857,047 | 2,708,205 | 2,431,084 | ||||||||||||||||||||||||
| Total deposits | $ | 20,405,023 | $ | 18,976,018 | $ | 18,932,925 | $ | 18,846,461 | $ | 18,069,389 | |||||||||||||||||||
13
CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||||||||||||||
ASSET QUALITY - UNAUDITED | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| As of September 30, 2025 | As of June 30, 2025 | As of September 30, 2024 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Loan type | Total loans | Allowance for credit losses | Total reserves to total loans | Total loans | Allowance for credit losses | Total reserves to total loans | Total loans | Allowance for credit losses | Total reserves to total loans | ||||||||||||||||||||||||||||||||||||||||||||
Commercial: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Commercial & industrial, including specialized lending | $ | 8,229,853 | $ | 34,395 | 0.42 | % | $ | 7,581,855 | $ | 36,262 | 0.48 | % | $ | 6,672,933 | $ | 25,191 | 0.38 | % | |||||||||||||||||||||||||||||||||||
| Multifamily | 2,356,590 | 19,973 | 0.85 | % | 2,247,282 | 20,864 | 0.93 | % | 2,115,978 | 18,090 | 0.85 | % | |||||||||||||||||||||||||||||||||||||||||
| Commercial real estate owner occupied | 1,058,741 | 10,991 | 1.04 | % | 1,065,006 | 12,514 | 1.18 | % | 981,904 | 10,913 | 1.11 | % | |||||||||||||||||||||||||||||||||||||||||
| Commercial real estate non-owner occupied | 1,582,332 | 19,784 | 1.25 | % | 1,497,385 | 20,679 | 1.38 | % | 1,326,591 | 17,303 | 1.30 | % | |||||||||||||||||||||||||||||||||||||||||
| Construction | 123,290 | 1,978 | 1.60 | % | 98,626 | 2,160 | 2.19 | % | 174,509 | 1,606 | 0.92 | % | |||||||||||||||||||||||||||||||||||||||||
| Total commercial loans and leases receivable | 13,350,806 | 87,121 | 0.65 | % | 12,490,154 | 92,479 | 0.74 | % | 11,271,915 | 73,103 | 0.65 | % | |||||||||||||||||||||||||||||||||||||||||
Consumer: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Residential | 514,544 | 6,345 | 1.23 | % | 520,570 | 6,331 | 1.22 | % | 500,786 | 5,838 | 1.17 | % | |||||||||||||||||||||||||||||||||||||||||
| Manufactured housing | 28,749 | 3,508 | 12.20 | % | 30,287 | 3,721 | 12.29 | % | 34,481 | 4,080 | 11.83 | % | |||||||||||||||||||||||||||||||||||||||||
| Installment | 779,537 | 54,835 | 7.03 | % | 678,818 | 44,887 | 6.61 | % | 720,101 | 50,137 | 6.96 | % | |||||||||||||||||||||||||||||||||||||||||
| Total consumer loans receivable | 1,322,830 | 64,688 | 4.89 | % | 1,229,675 | 54,939 | 4.47 | % | 1,255,368 | 60,055 | 4.78 | % | |||||||||||||||||||||||||||||||||||||||||
Loans and leases receivable held for investment | 14,673,636 | 151,809 | 1.03 | % | 13,719,829 | 147,418 | 1.07 | % | 12,527,283 | 133,158 | 1.06 | % | |||||||||||||||||||||||||||||||||||||||||
| Loans receivable, mortgage finance, at fair value | 1,486,978 | — | — | % | 1,536,254 | — | — | % | 1,250,413 | — | — | % | |||||||||||||||||||||||||||||||||||||||||
| Loans receivable, installment, at fair value | 111,636 | — | — | % | 123,354 | — | — | % | — | — | — | % | |||||||||||||||||||||||||||||||||||||||||
| Loans held for sale | 30,897 | — | — | % | 32,963 | — | — | % | 275,420 | — | — | % | |||||||||||||||||||||||||||||||||||||||||
| Total loans and leases portfolio | $ | 16,303,147 | $ | 151,809 | 0.93 | % | $ | 15,412,400 | $ | 147,418 | 0.96 | % | $ | 14,053,116 | $ | 133,158 | 0.95 | % | |||||||||||||||||||||||||||||||||||
14
CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||||||||||||||
ASSET QUALITY - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| As of September 30, 2025 | As of June 30, 2025 | As of September 30, 2024 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Loan type | Non accrual /NPLs | Total NPLs to total loans | Total reserves to total NPLs | Non accrual /NPLs | Total NPLs to total loans | Total reserves to total NPLs | Non accrual /NPLs | Total NPLs to total loans | Total reserves to total NPLs | ||||||||||||||||||||||||||||||||||||||||||||
Commercial: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Commercial & industrial, including specialized lending | $ | 4,430 | 0.05 | % | 776.41 | % | $ | 4,218 | 0.06 | % | 859.70 | % | $ | 4,615 | 0.07 | % | 545.85 | % | |||||||||||||||||||||||||||||||||||
| Multifamily | — | — | % | — | % | — | — | % | — | % | 11,834 | 0.56 | % | 152.86 | % | ||||||||||||||||||||||||||||||||||||||
| Commercial real estate owner occupied | 3,932 | 0.37 | % | 279.53 | % | 7,005 | 0.66 | % | 178.64 | % | 8,613 | 0.88 | % | 126.70 | % | ||||||||||||||||||||||||||||||||||||||
| Commercial real estate non-owner occupied | — | — | % | — | % | 62 | 0.00 | % | 33353.23 | % | 763 | 0.06 | % | 2267.76 | % | ||||||||||||||||||||||||||||||||||||||
| Construction | — | — | % | — | % | — | — | % | — | % | — | — | % | — | % | ||||||||||||||||||||||||||||||||||||||
| Total commercial loans and leases receivable | 8,362 | 0.06 | % | 1041.87 | % | 11,285 | 0.09 | % | 819.49 | % | 25,825 | 0.23 | % | 283.07 | % | ||||||||||||||||||||||||||||||||||||||
Consumer: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Residential | 7,631 | 1.48 | % | 83.15 | % | 8,234 | 1.58 | % | 76.89 | % | 7,997 | 1.60 | % | 73.00 | % | ||||||||||||||||||||||||||||||||||||||
| Manufactured housing | 1,315 | 4.57 | % | 266.77 | % | 1,608 | 5.31 | % | 231.41 | % | 1,869 | 5.42 | % | 218.30 | % | ||||||||||||||||||||||||||||||||||||||
| Installment | 4,225 | 0.54 | % | 1297.87 | % | 4,944 | 0.73 | % | 907.91 | % | 6,328 | 0.88 | % | 792.30 | % | ||||||||||||||||||||||||||||||||||||||
| Total consumer loans receivable | 13,171 | 1.00 | % | 491.14 | % | 14,786 | 1.20 | % | 371.56 | % | 16,194 | 1.29 | % | 370.85 | % | ||||||||||||||||||||||||||||||||||||||
| Loans and leases receivable | 21,533 | 0.15 | % | 705.01 | % | 26,071 | 0.19 | % | 565.45 | % | 42,019 | 0.34 | % | 316.90 | % | ||||||||||||||||||||||||||||||||||||||
| Loans receivable, mortgage finance, at fair value | — | — | % | — | % | — | — | % | — | % | — | — | % | — | % | ||||||||||||||||||||||||||||||||||||||
| Loans receivable, installment, at fair value | 1,872 | 1.68 | % | — | % | 1,961 | 1.59 | % | — | % | — | — | % | — | % | ||||||||||||||||||||||||||||||||||||||
| Loans held for sale | 5,016 | 16.23 | % | — | % | 411 | 1.25 | % | — | % | 5,307 | 1.93 | % | — | % | ||||||||||||||||||||||||||||||||||||||
| Total loans and leases portfolio | $ | 28,421 | 0.17 | % | 534.14 | % | $ | 28,443 | 0.18 | % | 518.29 | % | $ | 47,326 | 0.34 | % | 281.36 | % | |||||||||||||||||||||||||||||||||||
15
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| NET CHARGE-OFFS/(RECOVERIES) - UNAUDITED | |||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||
| Q3 | Q2 | Q1 | Q4 | Q3 | Nine Months Ended September 30, | ||||||||||||||||||||||||||||||||||||
2025 | 2025 | 2025 | 2024 | 2024 | 2025 | 2024 | |||||||||||||||||||||||||||||||||||
Loan type | |||||||||||||||||||||||||||||||||||||||||
| Commercial & industrial, including specialized lending | $ | 2,180 | $ | 3,871 | $ | 3,231 | $ | 3,653 | $ | 5,056 | $ | 9,282 | $ | 14,393 | |||||||||||||||||||||||||||
| Multifamily | — | — | 3,834 | — | 2,167 | 3,834 | 4,073 | ||||||||||||||||||||||||||||||||||
| Commercial real estate owner occupied | 335 | 411 | 16 | 339 | 4 | 762 | 26 | ||||||||||||||||||||||||||||||||||
| Commercial real estate non-owner occupied | 3,073 | — | — | 145 | — | 3,073 | — | ||||||||||||||||||||||||||||||||||
| Construction | — | (3) | (3) | — | (3) | (6) | (10) | ||||||||||||||||||||||||||||||||||
| Residential | 25 | (4) | — | (18) | (21) | 21 | (23) | ||||||||||||||||||||||||||||||||||
| Installment | 9,758 | 8,840 | 10,066 | 10,493 | 9,841 | 28,664 | 35,264 | ||||||||||||||||||||||||||||||||||
| Total net charge-offs (recoveries) from loans held for investment | $ | 15,371 | $ | 13,115 | $ | 17,144 | $ | 14,612 | $ | 17,044 | $ | 45,630 | $ | 53,723 | |||||||||||||||||||||||||||
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
LOANS AND LEASES RISK RATINGS - UNAUDITED | |||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | |||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2024 | 2024 | |||||||||||||||||||||||||
Loans and leases (1) risk ratings: | |||||||||||||||||||||||||||||
Commercial loans and leases | |||||||||||||||||||||||||||||
| Pass | $ | 12,927,467 | $ | 12,047,656 | $ | 11,815,403 | $ | 11,403,930 | $ | 10,844,500 | |||||||||||||||||||
Special Mention | 187,794 | 174,587 | 189,155 | 175,055 | 178,026 | ||||||||||||||||||||||||
Substandard | 230,079 | 256,849 | 276,018 | 282,563 | 218,921 | ||||||||||||||||||||||||
| Total commercial loans and leases | 13,345,340 | 12,479,092 | 12,280,576 | 11,861,548 | 11,241,447 | ||||||||||||||||||||||||
| Consumer loans | |||||||||||||||||||||||||||||
| Performing | 1,308,987 | 1,209,377 | 1,242,753 | 1,227,359 | 1,240,581 | ||||||||||||||||||||||||
| Non-performing | 13,843 | 20,298 | 13,803 | 15,976 | 14,787 | ||||||||||||||||||||||||
| Total consumer loans | 1,322,830 | 1,229,675 | 1,256,556 | 1,243,335 | 1,255,368 | ||||||||||||||||||||||||
Loans and leases receivable (1) | $ | 14,668,170 | $ | 13,708,767 | $ | 13,537,132 | $ | 13,104,883 | $ | 12,496,815 | |||||||||||||||||||
(1) Risk ratings are assigned to loans and leases held for investment, and excludes loans held for sale, loans receivable, mortgage finance, at fair value, loans receivable, installment, at fair value and eligible PPP loans that are fully guaranteed by the Small Business Administration.
16
CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED | |||||||||||||||||||||||||||||
We believe that the non-GAAP measurements disclosed within this document are useful for investors, regulators, management and others to evaluate our core results of operations and financial condition relative to other financial institutions. These non-GAAP financial measures are frequently used by securities analysts, investors, and other interested parties in the evaluation of companies in our industry. These non-GAAP financial measures exclude from corresponding GAAP measures the impact of certain elements that we do not believe are representative of our ongoing financial results, which we believe enhance an overall understanding of our performance and increases comparability of our period to period results. Investors should consider our performance and financial condition as reported under GAAP and all other relevant information when assessing our performance or financial condition. The non-GAAP measures presented are not necessarily comparable to non-GAAP measures that may be presented by other financial institutions. Although non-GAAP financial measures are frequently used in the evaluation of a company, they have limitations as analytical tools and should not be considered in isolation or as a substitute for analysis of our results of operations or financial condition as reported under GAAP. Starting in Q3 2025, certain adjustments to GAAP measures were no longer included as our intention going forward is to limit these adjustments to those items of greatest significance.
The following tables present reconciliations of GAAP to non-GAAP measures disclosed within this document.
Core Earnings and Adjusted Core Earnings - Customers Bancorp | Nine Months Ended September 30, | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | ||||||||||||||||||||||||||||||||||||||||||||||||
| GAAP net income to common shareholders | $ | 73,726 | $ | 2.20 | $ | 55,846 | $ | 1.73 | $ | 9,523 | $ | 0.29 | $ | 23,266 | $ | 0.71 | $ | 42,937 | $ | 1.31 | $ | 139,095 | $ | 4.24 | $ | 143,163 | $ | 4.37 | ||||||||||||||||||||||||||||||||||
| Reconciling items (after tax): | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Severance expense | — | — | — | — | — | — | 1,198 | 0.04 | 540 | 0.02 | — | — | 2,468 | 0.08 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Impairment loss on debt securities | — | — | — | — | 39,875 | 1.23 | — | — | — | — | 39,875 | 1.22 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| Legal settlement | — | — | — | — | — | — | 157 | 0.00 | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (253) | (0.01) | 1,388 | 0.04 | (124) | 0.00 | 20,035 | 0.62 | (322) | (0.01) | 1,011 | 0.03 | 296 | 0.01 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Derivative credit valuation adjustment | — | — | — | — | 210 | 0.01 | (306) | (0.01) | 185 | 0.01 | 210 | 0.01 | 310 | 0.01 | ||||||||||||||||||||||||||||||||||||||||||||||||
| FDIC special assessment | — | — | — | — | — | — | — | — | — | — | — | — | 518 | 0.02 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Unrealized (gain) on equity method investments | — | — | — | — | — | — | (292) | (0.01) | — | — | — | — | (8,316) | (0.25) | ||||||||||||||||||||||||||||||||||||||||||||||||
| Loss on redemption of preferred stock | — | — | 1,908 | 0.06 | — | — | — | — | — | — | 1,908 | 0.06 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| Unrealized (gain) loss on loans held for sale | — | — | (223) | (0.01) | 518 | 0.02 | 110 | 0.00 | 498 | 0.02 | 295 | 0.01 | 498 | 0.02 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Loan program termination fees | — | — | (772) | (0.02) | — | — | — | — | — | — | (772) | (0.02) | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| Core earnings | $ | 73,473 | $ | 2.20 | $ | 58,147 | $ | 1.80 | $ | 50,002 | $ | 1.54 | $ | 44,168 | $ | 1.36 | $ | 43,838 | $ | 1.34 | $ | 181,622 | $ | 5.54 | $ | 138,937 | $ | 4.24 | ||||||||||||||||||||||||||||||||||
17
CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||
(Dollars in thousands, except per share data) | |||||||||||||||||||||||||||||
Core Return on Average Assets and Adjusted Core Return on Average Assets - Customers Bancorp | Nine Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| GAAP net income | $ | 75,745 | $ | 60,939 | $ | 12,912 | $ | 26,915 | $ | 46,743 | $ | 149,596 | $ | 154,554 | |||||||||||||||||||||||||||
| Reconciling items (after tax): | |||||||||||||||||||||||||||||||||||||||||
| Severance expense | — | — | — | 1,198 | 540 | — | 2,468 | ||||||||||||||||||||||||||||||||||
| Impairment loss on debt securities | — | — | 39,875 | — | — | 39,875 | — | ||||||||||||||||||||||||||||||||||
| Legal settlement | — | — | — | 157 | — | — | — | ||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (253) | 1,388 | (124) | 20,035 | (322) | 1,011 | 296 | ||||||||||||||||||||||||||||||||||
| Derivative credit valuation adjustment | — | — | 210 | (306) | 185 | 210 | 310 | ||||||||||||||||||||||||||||||||||
| FDIC special assessment | — | — | — | — | — | — | 518 | ||||||||||||||||||||||||||||||||||
| Unrealized (gain) on equity method investments | — | — | — | (292) | — | — | (8,316) | ||||||||||||||||||||||||||||||||||
| Unrealized (gain) loss on loans held for sale | — | (223) | 518 | 110 | 498 | 295 | 498 | ||||||||||||||||||||||||||||||||||
| Loan program termination fees | — | (772) | — | — | — | (772) | — | ||||||||||||||||||||||||||||||||||
Core net income | $ | 75,492 | $ | 61,332 | $ | 53,391 | $ | 47,817 | $ | 47,644 | $ | 190,215 | $ | 150,328 | |||||||||||||||||||||||||||
Average total assets | $ | 23,930,723 | $ | 22,362,989 | $ | 22,314,963 | $ | 22,179,970 | $ | 21,230,404 | $ | 22,875,476 | $ | 21,183,783 | |||||||||||||||||||||||||||
| Core return on average assets | 1.25 | % | 1.10 | % | 0.97 | % | 0.86 | % | 0.89 | % | 1.11 | % | 0.95 | % | |||||||||||||||||||||||||||
Core Return on Average Common Equity and Adjusted Core Return on Average Common Equity - Customers Bancorp | Nine Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| GAAP net income to common shareholders | $ | 73,726 | $ | 55,846 | $ | 9,523 | $ | 23,266 | $ | 42,937 | $ | 139,095 | $ | 143,163 | |||||||||||||||||||||||||||
| Reconciling items (after tax): | |||||||||||||||||||||||||||||||||||||||||
| Severance expense | — | — | — | 1,198 | 540 | — | 2,468 | ||||||||||||||||||||||||||||||||||
| Impairment loss on debt securities | — | — | 39,875 | — | — | 39,875 | — | ||||||||||||||||||||||||||||||||||
| Legal settlement | — | — | — | 157 | — | — | — | ||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (253) | 1,388 | (124) | 20,035 | (322) | 1,011 | 296 | ||||||||||||||||||||||||||||||||||
| Derivative credit valuation adjustment | — | — | 210 | (306) | 185 | 210 | 310 | ||||||||||||||||||||||||||||||||||
| FDIC special assessment | — | — | — | — | — | — | 518 | ||||||||||||||||||||||||||||||||||
| Unrealized (gain) on equity method investments | — | — | — | (292) | — | — | (8,316) | ||||||||||||||||||||||||||||||||||
| Loss on redemption of preferred stock | — | 1,908 | — | — | — | 1,908 | — | ||||||||||||||||||||||||||||||||||
| Unrealized (gain) loss on loans held for sale | — | (223) | 518 | 110 | 498 | 295 | 498 | ||||||||||||||||||||||||||||||||||
| Loan program termination fees | — | (772) | — | — | — | (772) | — | ||||||||||||||||||||||||||||||||||
| Core earnings | $ | 73,473 | $ | 58,147 | $ | 50,002 | $ | 44,168 | $ | 43,838 | $ | 181,622 | $ | 138,937 | |||||||||||||||||||||||||||
Average total common shareholders’ equity | $ | 1,878,115 | $ | 1,751,037 | $ | 1,730,910 | $ | 1,683,838 | $ | 1,636,242 | $ | 1,787,227 | $ | 1,580,885 | |||||||||||||||||||||||||||
| Core return on average common equity | 15.52 | % | 13.32 | % | 11.72 | % | 10.44 | % | 10.66 | % | 13.59 | % | 11.74 | % | |||||||||||||||||||||||||||
18
CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||
(Dollars in thousands, except per share data) | |||||||||||||||||||||||||||||
Core Efficiency Ratio and Adjusted Core Efficiency Ratio - Customers Bancorp | Nine Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| GAAP net interest income | $ | 201,912 | $ | 176,703 | $ | 167,446 | $ | 167,821 | $ | 158,545 | $ | 546,061 | $ | 486,583 | |||||||||||||||||||||||||||
GAAP non-interest income (loss) | $ | 30,191 | $ | 29,606 | $ | (24,490) | $ | (391) | $ | 8,557 | $ | 35,307 | $ | 60,825 | |||||||||||||||||||||||||||
| (Gains) losses on investment securities | (334) | 1,797 | (160) | 26,678 | (394) | 1,303 | 425 | ||||||||||||||||||||||||||||||||||
| Derivative credit valuation adjustment | — | — | 270 | (407) | 226 | 270 | 390 | ||||||||||||||||||||||||||||||||||
| Unrealized (gain) on equity method investments | — | — | — | (389) | — | — | (11,041) | ||||||||||||||||||||||||||||||||||
| Unrealized (gain) loss on loans held for sale | — | (289) | 667 | 147 | 607 | 378 | 607 | ||||||||||||||||||||||||||||||||||
| Impairment loss on debt securities | — | — | 51,319 | — | — | 51,319 | — | ||||||||||||||||||||||||||||||||||
| Loan program termination fees | — | (1,000) | — | — | — | (1,000) | — | ||||||||||||||||||||||||||||||||||
| Core non-interest income | 29,857 | 30,114 | 27,606 | 25,638 | 8,996 | 87,577 | 51,206 | ||||||||||||||||||||||||||||||||||
| Core revenue | $ | 231,769 | $ | 206,817 | $ | 195,052 | $ | 193,459 | $ | 167,541 | $ | 633,638 | $ | 537,789 | |||||||||||||||||||||||||||
| GAAP non-interest expense | $ | 105,217 | $ | 106,626 | $ | 102,771 | $ | 110,375 | $ | 104,018 | $ | 314,614 | $ | 306,639 | |||||||||||||||||||||||||||
| Severance expense | — | — | — | (1,595) | (659) | — | (3,219) | ||||||||||||||||||||||||||||||||||
| FDIC special assessment | — | — | — | — | — | — | (683) | ||||||||||||||||||||||||||||||||||
| Legal settlement | — | — | — | (209) | — | — | — | ||||||||||||||||||||||||||||||||||
| Core non-interest expense | $ | 105,217 | $ | 106,626 | $ | 102,771 | $ | 108,571 | $ | 103,359 | $ | 314,614 | $ | 302,737 | |||||||||||||||||||||||||||
Core efficiency ratio (1) | 45.40 | % | 51.56 | % | 52.69 | % | 56.12 | % | 61.69 | % | 49.65 | % | 56.29 | % | |||||||||||||||||||||||||||
(1) Core efficiency ratio calculated as core non-interest expense divided by core revenue.
| Tangible Common Equity to Tangible Assets - Customers Bancorp | |||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | ||||||||||||||||||||||||
GAAP total shareholders’ equity | $ | 2,126,059 | $ | 1,863,558 | $ | 1,864,560 | $ | 1,836,683 | $ | 1,801,180 | |||||||||||||||||||
| Reconciling items: | |||||||||||||||||||||||||||||
| Preferred stock | (82,201) | (82,201) | (137,794) | (137,794) | (137,794) | ||||||||||||||||||||||||
| Goodwill and other intangibles | (3,629) | (3,629) | (3,629) | (3,629) | (3,629) | ||||||||||||||||||||||||
| Tangible common equity | $ | 2,040,229 | $ | 1,777,728 | $ | 1,723,137 | $ | 1,695,260 | $ | 1,659,757 | |||||||||||||||||||
| GAAP total assets | $ | 24,260,163 | $ | 22,550,800 | $ | 22,423,044 | $ | 22,308,241 | $ | 21,456,082 | |||||||||||||||||||
| Reconciling items: | |||||||||||||||||||||||||||||
| Goodwill and other intangibles | (3,629) | (3,629) | (3,629) | (3,629) | (3,629) | ||||||||||||||||||||||||
| Tangible assets | $ | 24,256,534 | $ | 22,547,171 | $ | 22,419,415 | $ | 22,304,612 | $ | 21,452,453 | |||||||||||||||||||
| Tangible common equity to tangible assets | 8.4 | % | 7.9 | % | 7.7 | % | 7.6 | % | 7.7 | % | |||||||||||||||||||
19
CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||
(Dollars in thousands, except per share data) | |||||||||||||||||||||||||||||
| Tangible Book Value per Common Share - Customers Bancorp | |||||||||||||||||||||||||||||
| (Dollars in thousands, except share and per share data) | Q3 2025 | Q2 2025 | Q1 2025 | Q4 2024 | Q3 2024 | ||||||||||||||||||||||||
GAAP total shareholders’ equity | $ | 2,126,059 | $ | 1,863,558 | $ | 1,864,560 | $ | 1,836,683 | $ | 1,801,180 | |||||||||||||||||||
| Reconciling Items: | |||||||||||||||||||||||||||||
| Preferred stock | (82,201) | (82,201) | (137,794) | (137,794) | (137,794) | ||||||||||||||||||||||||
| Goodwill and other intangibles | (3,629) | (3,629) | (3,629) | (3,629) | (3,629) | ||||||||||||||||||||||||
| Tangible common equity | $ | 2,040,229 | $ | 1,777,728 | $ | 1,723,137 | $ | 1,695,260 | $ | 1,659,757 | |||||||||||||||||||
| Common shares outstanding | 34,163,506 | 31,606,934 | 31,479,132 | 31,346,507 | 31,342,107 | ||||||||||||||||||||||||
| Tangible book value per common share | $ | 59.72 | $ | 56.24 | $ | 54.74 | $ | 54.08 | $ | 52.96 | |||||||||||||||||||
20
Let’s take on tomorrow. Investor Presentation: Q3’25 October 2025
Let’s take on tomorrow. 2 © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED In addition to historical information, this presentation may contain “forward-looking statements” within the meaning of the “safe harbor” provisions of the Private Securities Litigation Reform Act of 1995. These forward-looking statements include statements with respect to Customers Bancorp, Inc.’s strategies, goals, beliefs, expectations, estimates, intentions, capital raising efforts, financial condition and results of operations, future performance and business. Statements preceded by, followed by, or that include the words “may,” “could,” “should,” “pro forma,” “looking forward,” “would,” “believe,” “expect,” “anticipate,” “estimate,” “intend,” “plan,” “project,” or similar expressions generally indicate a forward-looking statement. These forward-looking statements involve risks and uncertainties that are subject to change based on various important factors (some of which, in whole or in part, are beyond Customers Bancorp, Inc.’s control). Numerous competitive, economic, regulatory, legal and technological events and factors, among others, could cause Customers Bancorp, Inc.’s financial performance to differ materially from the goals, plans, objectives, intentions and expectations expressed in such forward-looking statements, including: a continuation of the recent turmoil in the banking industry, responsive measures taken by us and regulatory authorities to mitigate and manage related risks, regulatory actions taken that address related issues and the costs and obligations associated therewith, such as the FDIC special assessments; the potential for negative consequences resulting from regulatory violations, investigations and examinations, including potential supervisory actions, the assessment of fines and penalties, the imposition of sanctions, the need to undertake remedial actions and possible damage to our reputation; effects of competition on deposit rates and growth, loan rates and growth and net interest margin; failure to identify and adequately and promptly address cybersecurity risks, including data breaches and cyberattacks; public health crises and pandemics and their effects on the economic and business environments in which we operate; geopolitical conditions, including acts or threats of terrorism, actions taken by the United States or other governments in response to acts or threats of terrorism and military conflicts, including the war between Russia and Ukraine and ongoing conflict in the Middle East, which could impact economic conditions in the United States; the impact that changes in the economy have on the performance of our loan and lease portfolio, the market value of our investment securities, the demand for our products and services and the availability of sources of funding; the effects of actions by the federal government, including the Board of Governors of the Federal Reserve System and other government agencies, that affect market interest rates and the money supply; actions that we and our customers take in response to these developments and the effects such actions have on our operations, products, services and customer relationships; higher inflation and its impacts; the effects of changes in U.S. trade policies, including the imposition of tariffs and retaliatory tariffs on its trading partners; and the effects of any changes in accounting standards or policies. Customers Bancorp, Inc. cautions that the foregoing factors are not exclusive, and neither such factors nor any such forward-looking statement takes into account the impact of any future events. All forward-looking statements and information set forth herein are based on management’s current beliefs and assumptions as of the date hereof and speak only as of the date they are made. For a more complete discussion of the assumptions, risks and uncertainties related to our business, you are encouraged to review Customers Bancorp, Inc.’s filings with the Securities and Exchange Commission, including its most recent annual report on Form 10-K for the year ended December 31, 2024, subsequently filed quarterly reports on Form 10-Q and current reports on Form 8-K, including any amendments thereto, that update or provide information in addition to the information included in the Form 10-K and Form 10-Q filings, if any. Customers Bancorp, Inc. does not undertake to update any forward-looking statement whether written or oral, that may be made from time to time by Customers Bancorp, Inc. or by or on behalf of Customers Bank, except as may be required under applicable law. Forward-Looking Statements
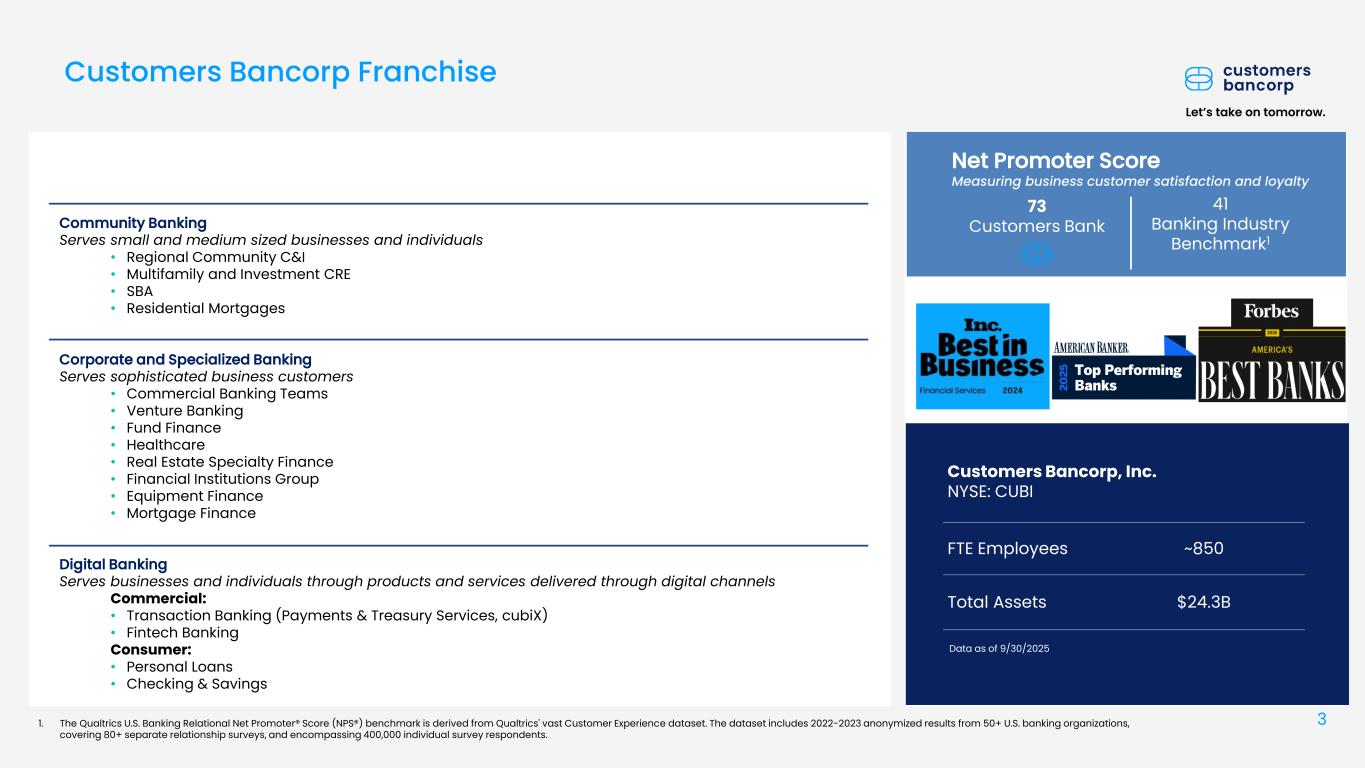
Let’s take on tomorrow. 3 © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Customers Bancorp Franchise Customers Bancorp, Inc. NYSE: CUBI FTE Employees ~850 Total Assets $24.3B Data as of 9/30/2025 41 Banking Industry Benchmark1 73 Customers Bank Net Promoter Score Measuring business customer satisfaction and loyalty Community Banking Serves small and medium sized businesses and individuals • Regional Community C&I • Multifamily and Investment CRE • SBA • Residential Mortgages Corporate and Specialized Banking Serves sophisticated business customers • Commercial Banking Teams • Venture Banking • Fund Finance • Healthcare • Real Estate Specialty Finance • Financial Institutions Group • Equipment Finance • Mortgage Finance Digital Banking Serves businesses and individuals through products and services delivered through digital channels Commercial: • Transaction Banking (Payments & Treasury Services, cubiX) • Fintech Banking Consumer: • Personal Loans • Checking & Savings 1. The Qualtrics U.S. Banking Relational Net Promoter® Score (NPS®) benchmark is derived from Qualtrics' vast Customer Experience dataset. The dataset includes 2022-2023 anonymized results from 50+ U.S. banking organizations, covering 80+ separate relationship surveys, and encompassing 400,000 individual survey respondents.
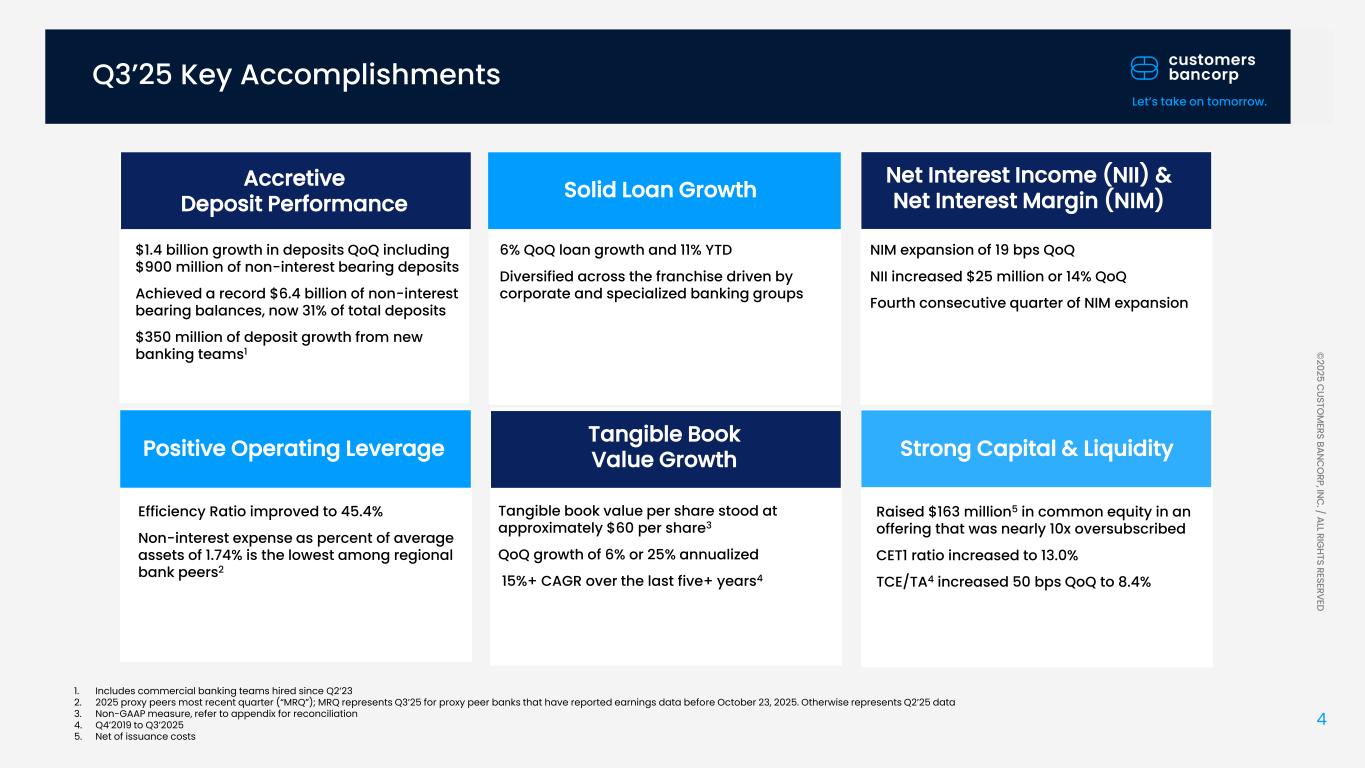
Let’s take on tomorrow. 4 © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Q3’25 Key Accomplishments 1. Includes commercial banking teams hired since Q2’23 2. 2025 proxy peers most recent quarter (“MRQ”); MRQ represents Q3’25 for proxy peer banks that have reported earnings data before October 23, 2025. Otherwise represents Q2’25 data 3. Non-GAAP measure, refer to appendix for reconciliation 4. Q4’2019 to Q3’2025 5. Net of issuance costs Let’s take on tomorrow. 6% QoQ loan growth and 11% YTD Diversified across the franchise driven by corporate and specialized banking groups $1.4 billion growth in deposits QoQ including $900 million of non-interest bearing deposits Achieved a record $6.4 billion of non-interest bearing balances, now 31% of total deposits $350 million of deposit growth from new banking teams1 Solid Loan GrowthAccretive Deposit Performance NIM expansion of 19 bps QoQ NII increased $25 million or 14% QoQ Fourth consecutive quarter of NIM expansion Net Interest Income (NII) & Net Interest Margin (NIM) Raised $163 million5 in common equity in an offering that was nearly 10x oversubscribed CET1 ratio increased to 13.0% TCE/TA4 increased 50 bps QoQ to 8.4% Tangible book value per share stood at approximately $60 per share3 QoQ growth of 6% or 25% annualized 15%+ CAGR over the last five+ years4 Strong Capital & LiquidityTangible Book Value Growth Efficiency Ratio improved to 45.4% Non-interest expense as percent of average assets of 1.74% is the lowest among regional bank peers2 Positive Operating Leverage
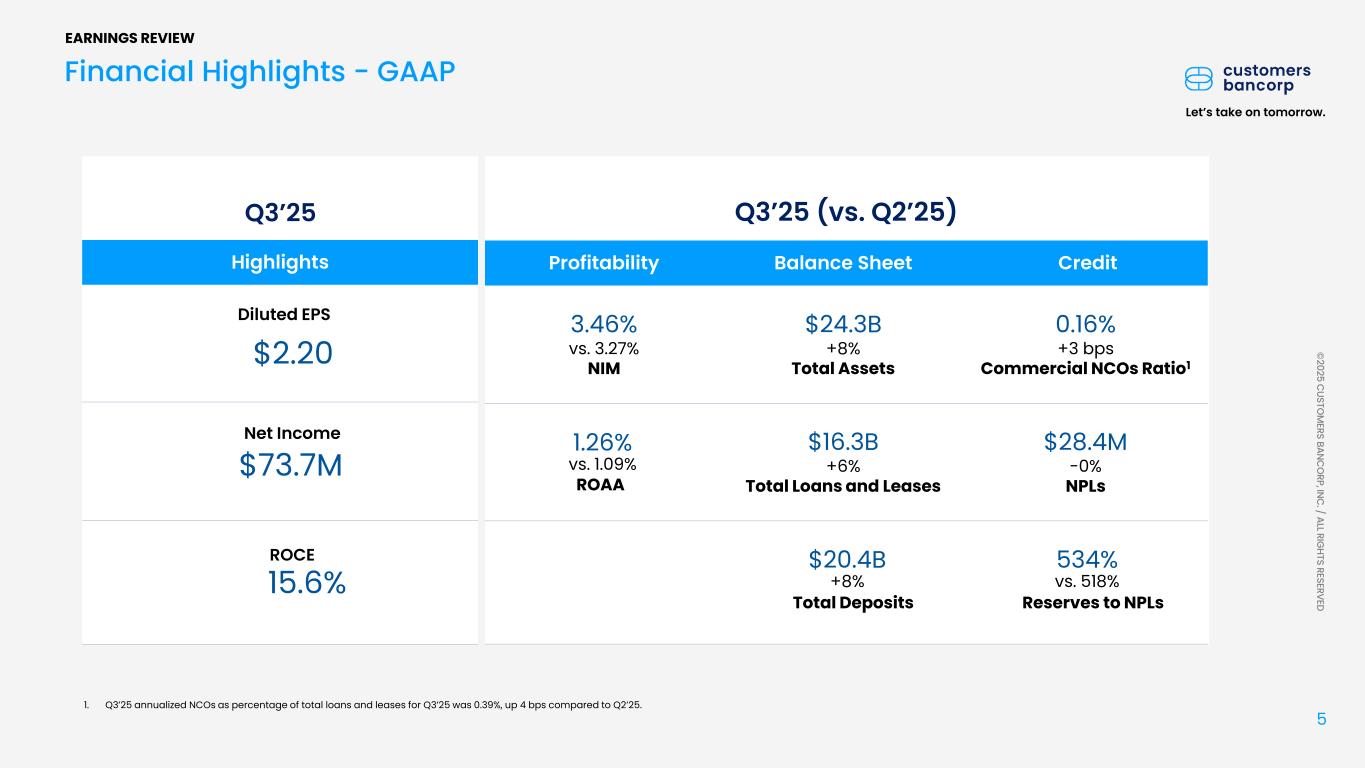
5 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Q3’25 (vs. Q2’25) Profitability Balance Sheet Credit 3.46% vs. 3.27% NIM $24.3B +8% Total Assets 0.16% +3 bps Commercial NCOs Ratio1 $16.3B +6% Total Loans and Leases $28.4M -0% NPLs Financial Highlights - GAAP Highlights Q3’25 EARNINGS REVIEW Total Deposits $20.4B +8% Reserves to NPLs 534% vs. 518% $2.20 Diluted EPS $73.7M Net Income ROCE 15.6% ROAA 1.26% vs. 1.09% 1. Q3’25 annualized NCOs as percentage of total loans and leases for Q3’25 was 0.39%, up 4 bps compared to Q2’25.
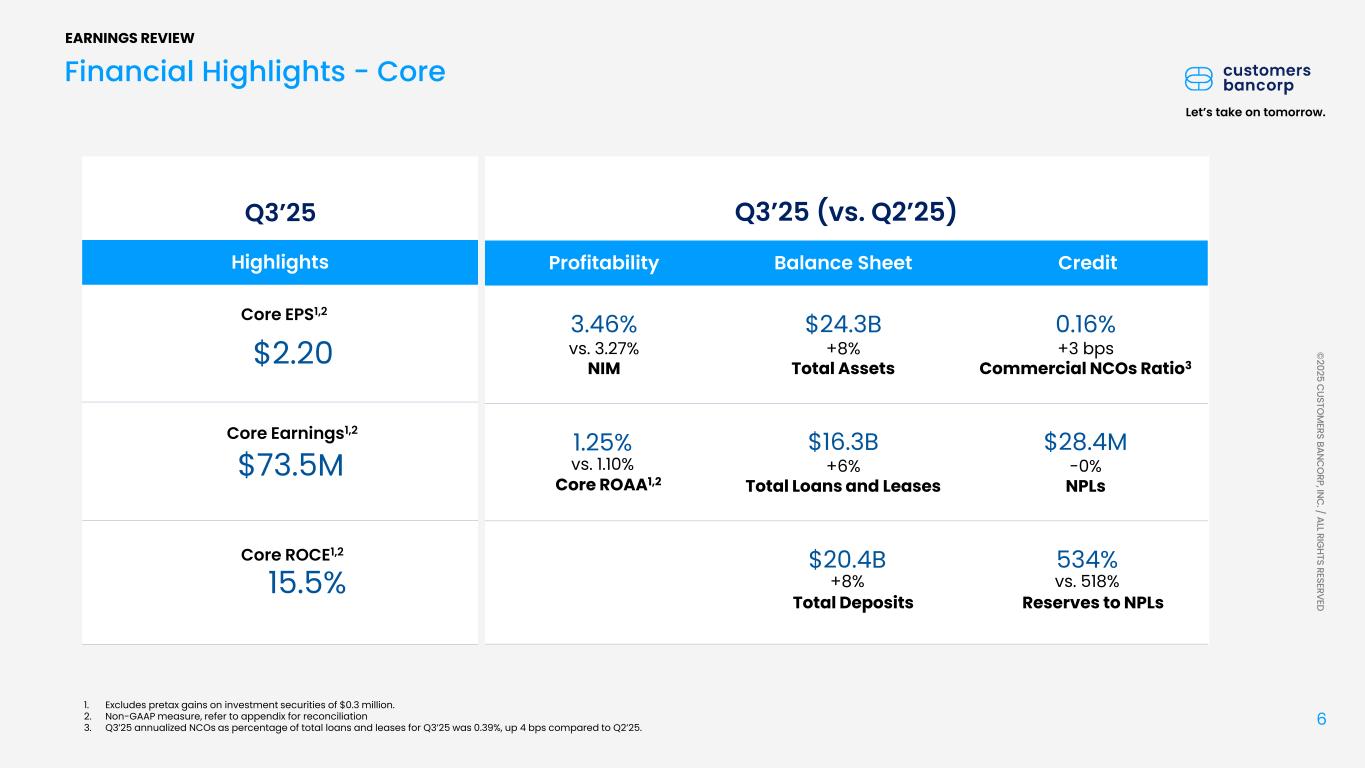
6 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Q3’25 (vs. Q2’25) Profitability Balance Sheet Credit 3.46% vs. 3.27% NIM $24.3B +8% Total Assets 0.16% +3 bps Commercial NCOs Ratio3 $16.3B +6% Total Loans and Leases $28.4M -0% NPLs Financial Highlights - Core Highlights Q3’25 EARNINGS REVIEW Total Deposits $20.4B +8% Reserves to NPLs 534% vs. 518% $2.20 Core EPS1,2 $73.5M Core Earnings1,2 Core ROCE1,2 15.5% Core ROAA1,2 1.25% vs. 1.10% 1. Excludes pretax gains on investment securities of $0.3 million. 2. Non-GAAP measure, refer to appendix for reconciliation 3. Q3’25 annualized NCOs as percentage of total loans and leases for Q3’25 was 0.39%, up 4 bps compared to Q2’25.
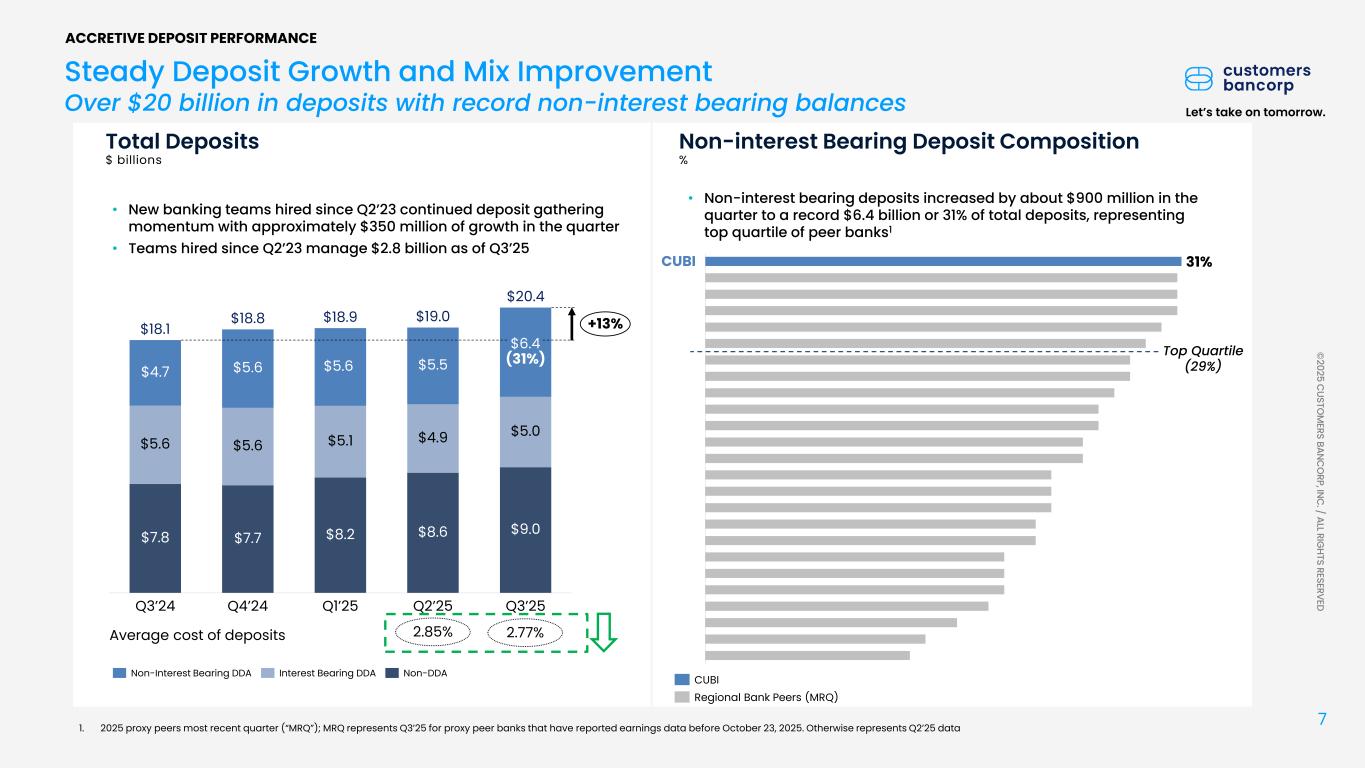
7 © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Let’s take on tomorrow. Total Deposits $ billions Steady Deposit Growth and Mix Improvement Over $20 billion in deposits with record non-interest bearing balances Average cost of deposits 2.85% ACCRETIVE DEPOSIT PERFORMANCE $4.7 $5.6 $7.8 Q3’24 $5.6 $5.6 $7.7 Q4’24 $5.6 $5.1 $8.2 Q1’25 $5.5 $4.9 $8.6 Q2’25 $6.4 (31%) $5.0 $9.0 Q3’25 $18.1 $18.8 $18.9 $19.0 $20.4 +13% Non-Interest Bearing DDA Interest Bearing DDA Non-DDA Non-interest Bearing Deposit Composition % 1. 2025 proxy peers most recent quarter (“MRQ”); MRQ represents Q3’25 for proxy peer banks that have reported earnings data before October 23, 2025. Otherwise represents Q2’25 data • New banking teams hired since Q2’23 continued deposit gathering momentum with approximately $350 million of growth in the quarter • Teams hired since Q2’23 manage $2.8 billion as of Q3’25 Top Quartile (29%) • Non-interest bearing deposits increased by about $900 million in the quarter to a record $6.4 billion or 31% of total deposits, representing top quartile of peer banks1 31%CUBI 2.77% Regional Bank Peers (MRQ) CUBI
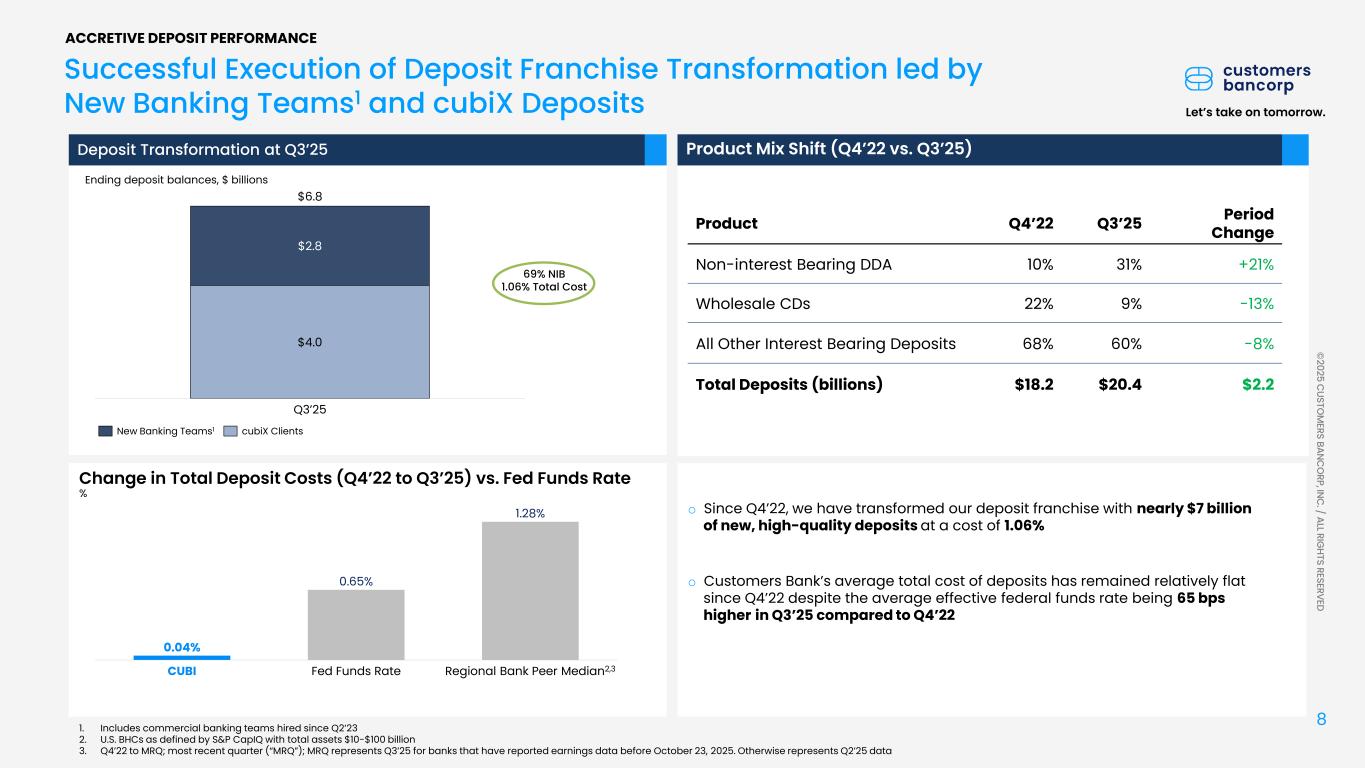
8 © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Let’s take on tomorrow. Kk s 1. Includes commercial banking teams hired since Q2’23 2. U.S. BHCs as defined by S&P CapIQ with total assets $10-$100 billion 3. Q4’22 to MRQ; most recent quarter (“MRQ”); MRQ represents Q3’25 for banks that have reported earnings data before October 23, 2025. Otherwise represents Q2’25 data Deposit Transformation at Q3’25 Successful Execution of Deposit Franchise Transformation led by New Banking Teams1 and cubiX Deposits 69% NIB 1.06% Total Cost ACCRETIVE DEPOSIT PERFORMANCE $4.0 $2.8 Q3’25 $6.8 New Banking Teams1 cubiX Clients o Since Q4’22, we have transformed our deposit franchise with nearly $7 billion of new, high-quality deposits at a cost of 1.06% o Customers Bank’s average total cost of deposits has remained relatively flat since Q4’22 despite the average effective federal funds rate being 65 bps higher in Q3’25 compared to Q4’22 Change in Total Deposit Costs (Q4’22 to Q3’25) vs. Fed Funds Rate % 0.04% 0.65% 1.28% CUBI Fed Funds Rate Regional Bank Peer Median2,3 Product Mix Shift (Q4’22 vs. Q3’25) Ending deposit balances, $ billions Product Q4’22 Q3’25 Period Change Non-interest Bearing DDA 10% 31% +21% Wholesale CDs 22% 9% -13% All Other Interest Bearing Deposits 68% 60% -8% Total Deposits (billions) $18.2 $20.4 $2.2
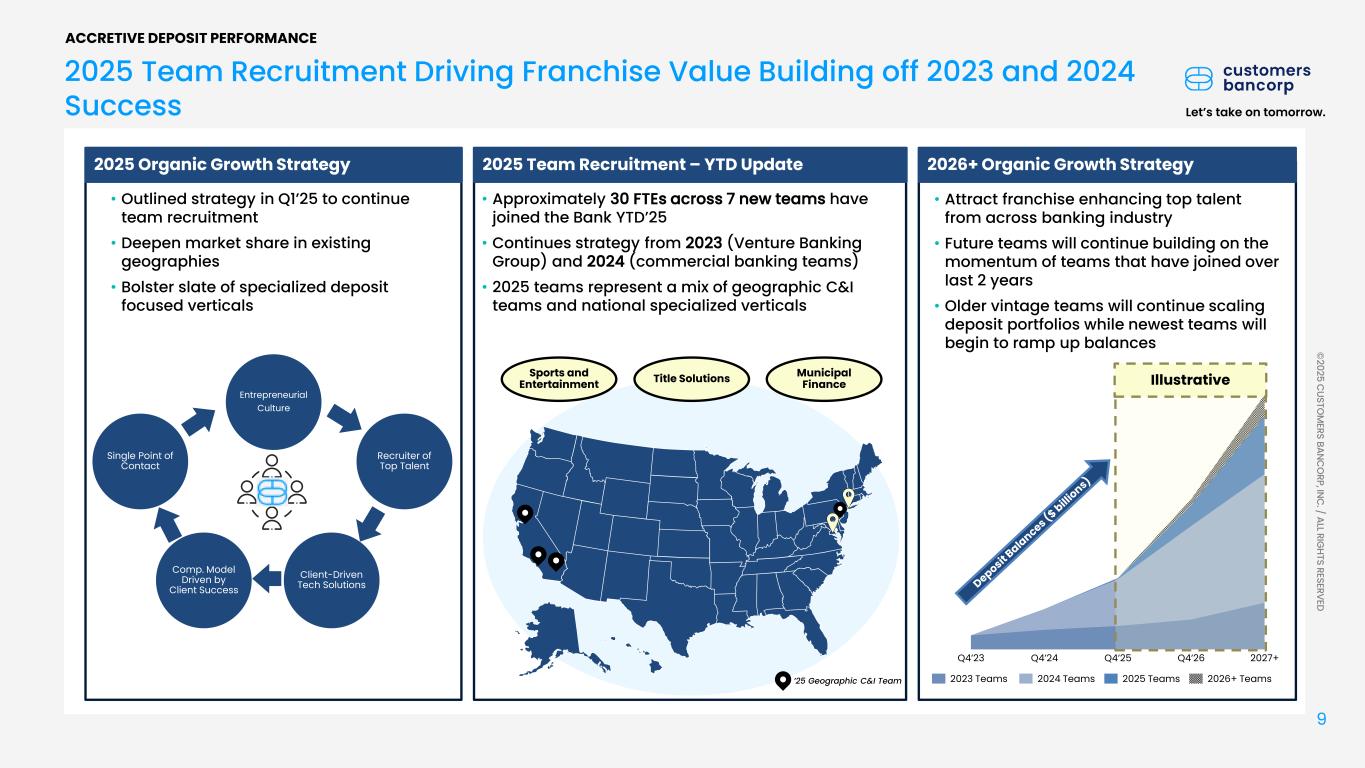
9 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED 2025 Team Recruitment Driving Franchise Value Building off 2023 and 2024 Success ACCRETIVE DEPOSIT PERFORMANCE Title Solutions • Outlined strategy in Q1’25 to continue team recruitment • Deepen market share in existing geographies • Bolster slate of specialized deposit focused verticals 2025 Organic Growth Strategy Entrepreneurial Culture Recruiter of Top Talent Comp. Model Driven by Client Success Single Point of Contact Client-Driven Tech Solutions • Approximately 30 FTEs across 7 new teams have joined the Bank YTD’25 • Continues strategy from 2023 (Venture Banking Group) and 2024 (commercial banking teams) • 2025 teams represent a mix of geographic C&I teams and national specialized verticals 2025 Team Recruitment – YTD Update • Attract franchise enhancing top talent from across banking industry • Future teams will continue building on the momentum of teams that have joined over last 2 years • Older vintage teams will continue scaling deposit portfolios while newest teams will begin to ramp up balances 2026+ Organic Growth Strategy Q4’23 Q4’24 Q4’25 Q4’26 2027+ 2023 Teams 2024 Teams 2025 Teams 2026+ Teams IllustrativeSports and Entertainment Municipal Finance ’25 Geographic C&I Team
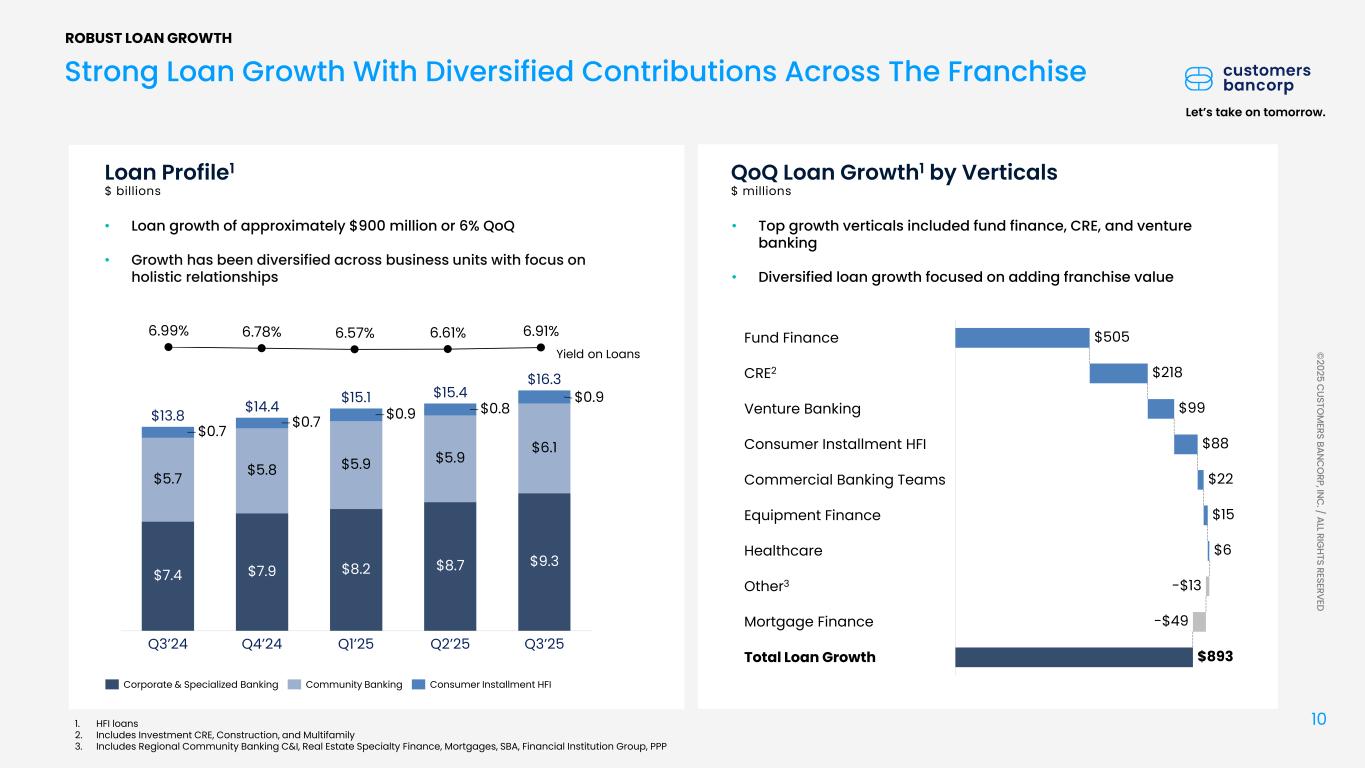
10 © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Let’s take on tomorrow. Strong Loan Growth With Diversified Contributions Across The Franchise Loan Profile1 $ billions $0.7 $5.7 $7.4 Q3’24 $0.7 $5.8 $7.9 Q4’24 $0.9 $5.9 $8.2 Q1’25 $0.8 $5.9 $8.7 Q2’25 $0.9 $6.1 $9.3 Q3’25 $13.8 $14.4 $15.1 $15.4 $16.3 6.99% 6.78% 6.57% 6.61% 6.91% Yield on Loans • Loan growth of approximately $900 million or 6% QoQ • Growth has been diversified across business units with focus on holistic relationships ROBUST LOAN GROWTH Corporate & Specialized Banking Community Banking Consumer Installment HFI 1. HFI loans 2. Includes Investment CRE, Construction, and Multifamily 3. Includes Regional Community Banking C&I, Real Estate Specialty Finance, Mortgages, SBA, Financial Institution Group, PPP QoQ Loan Growth1 by Verticals $ millions Fund Finance CRE2 Venture Banking Consumer Installment HFI Commercial Banking Teams Equipment Finance Healthcare Other3 Mortgage Finance Total Loan Growth $505 $218 $99 $88 $22 $15 $6 -$13 -$49 $893 • Top growth verticals included fund finance, CRE, and venture banking • Diversified loan growth focused on adding franchise value
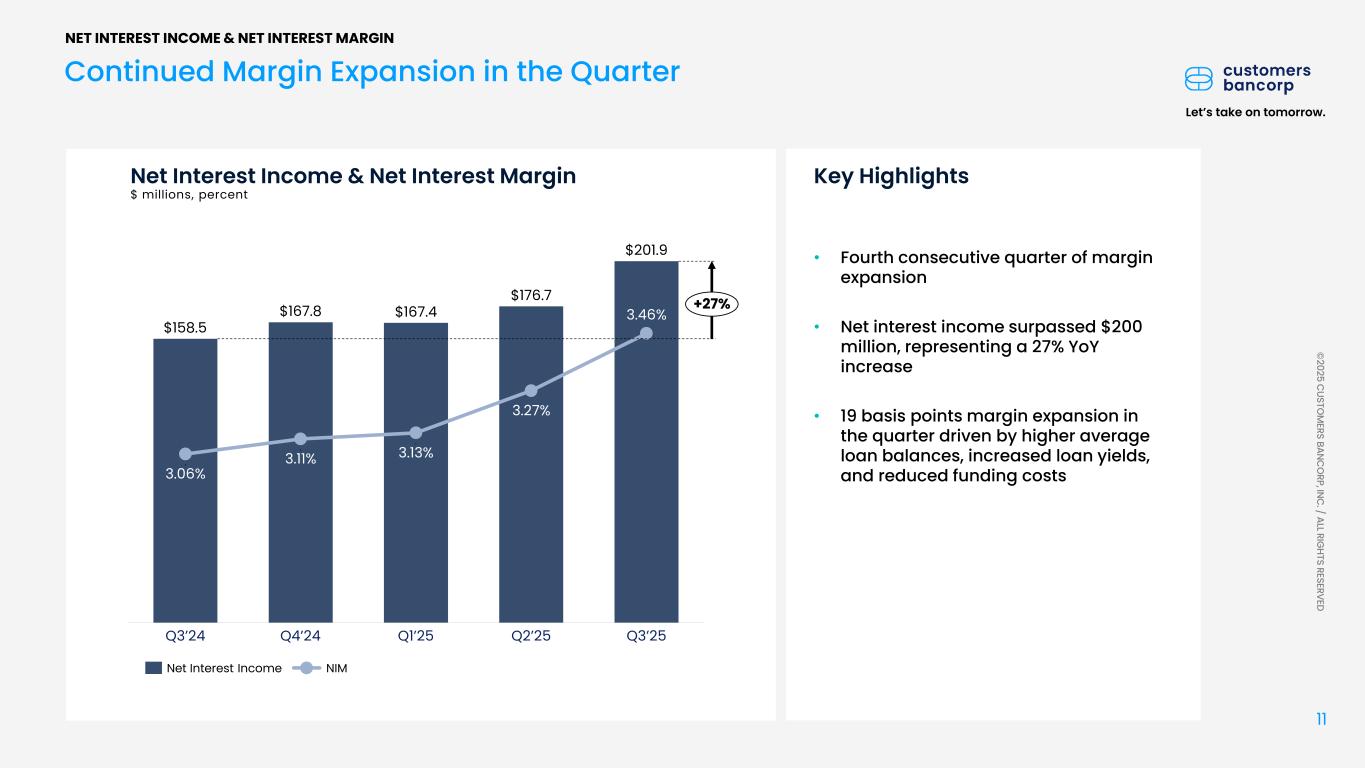
11 © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Let’s take on tomorrow. Continued Margin Expansion in the Quarter Net Interest Income & Net Interest Margin $ millions, percent 3.06% 3.11% 3.13% 3.27% 3.46% Q3’24 Q4’24 Q1’25 Q2’25 Q3’25 $158.5 $167.8 $167.4 $176.7 $201.9 +27% NET INTEREST INCOME & NET INTEREST MARGIN • Fourth consecutive quarter of margin expansion • Net interest income surpassed $200 million, representing a 27% YoY increase • 19 basis points margin expansion in the quarter driven by higher average loan balances, increased loan yields, and reduced funding costs Key Highlights Net Interest Income NIM
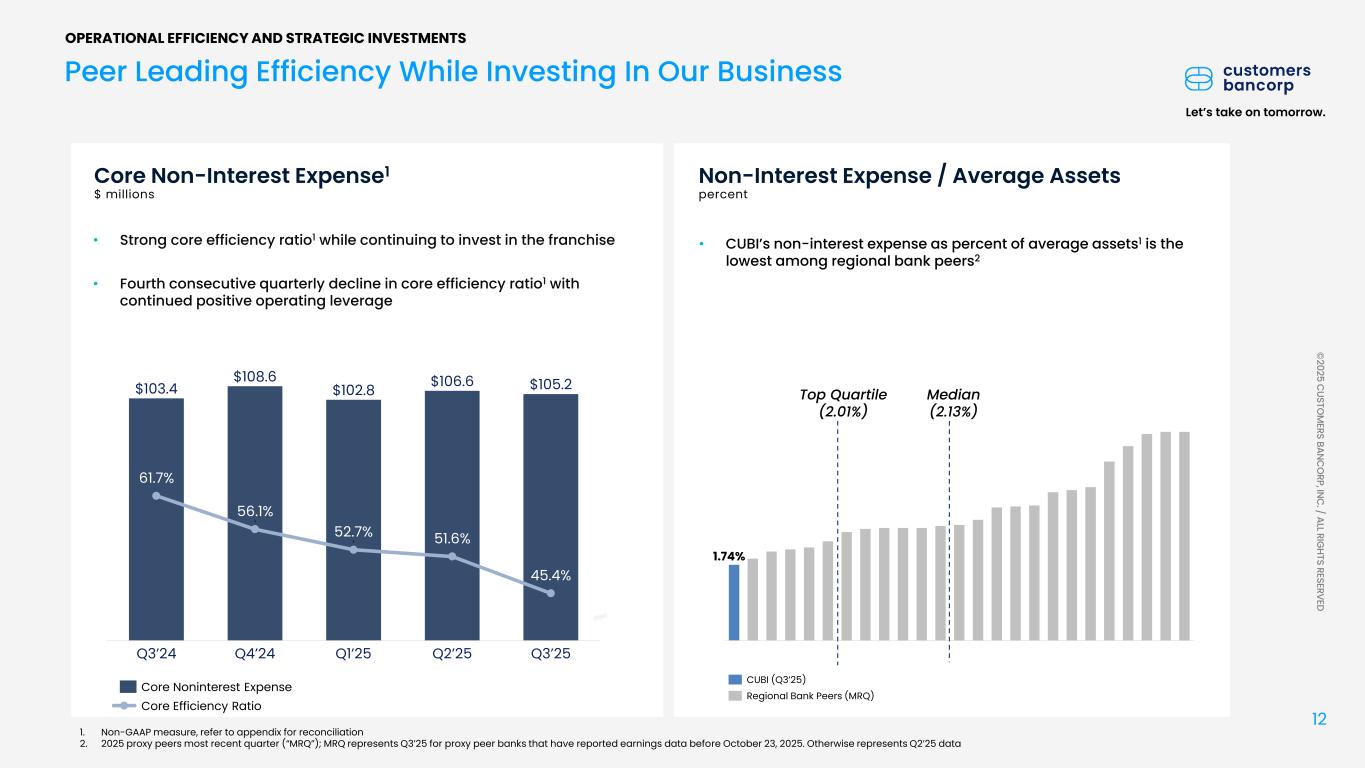
12 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Peer Leading Efficiency While Investing In Our Business $103.4 $108.6 $102.8 $106.6 $105.2 61.7% Q3’24 56.1% Q4’24 52.7% Q1’25 51.6% Q2’25 45.4% Q3’25 Core Non-Interest Expense1 $ millions • Strong core efficiency ratio1 while continuing to invest in the franchise • Fourth consecutive quarterly decline in core efficiency ratio1 with continued positive operating leverage Non-Interest Expense / Average Assets percent • CUBI’s non-interest expense as percent of average assets1 is the lowest among regional bank peers2 1.74% CUBI (Q3’25) Regional Bank Peers (MRQ) 1. Non-GAAP measure, refer to appendix for reconciliation 2. 2025 proxy peers most recent quarter (“MRQ”); MRQ represents Q3’25 for proxy peer banks that have reported earnings data before October 23, 2025. Otherwise represents Q2’25 data Top Quartile (2.01%) Median (2.13%) OPERATIONAL EFFICIENCY AND STRATEGIC INVESTMENTS Core Noninterest Expense Core Efficiency Ratio
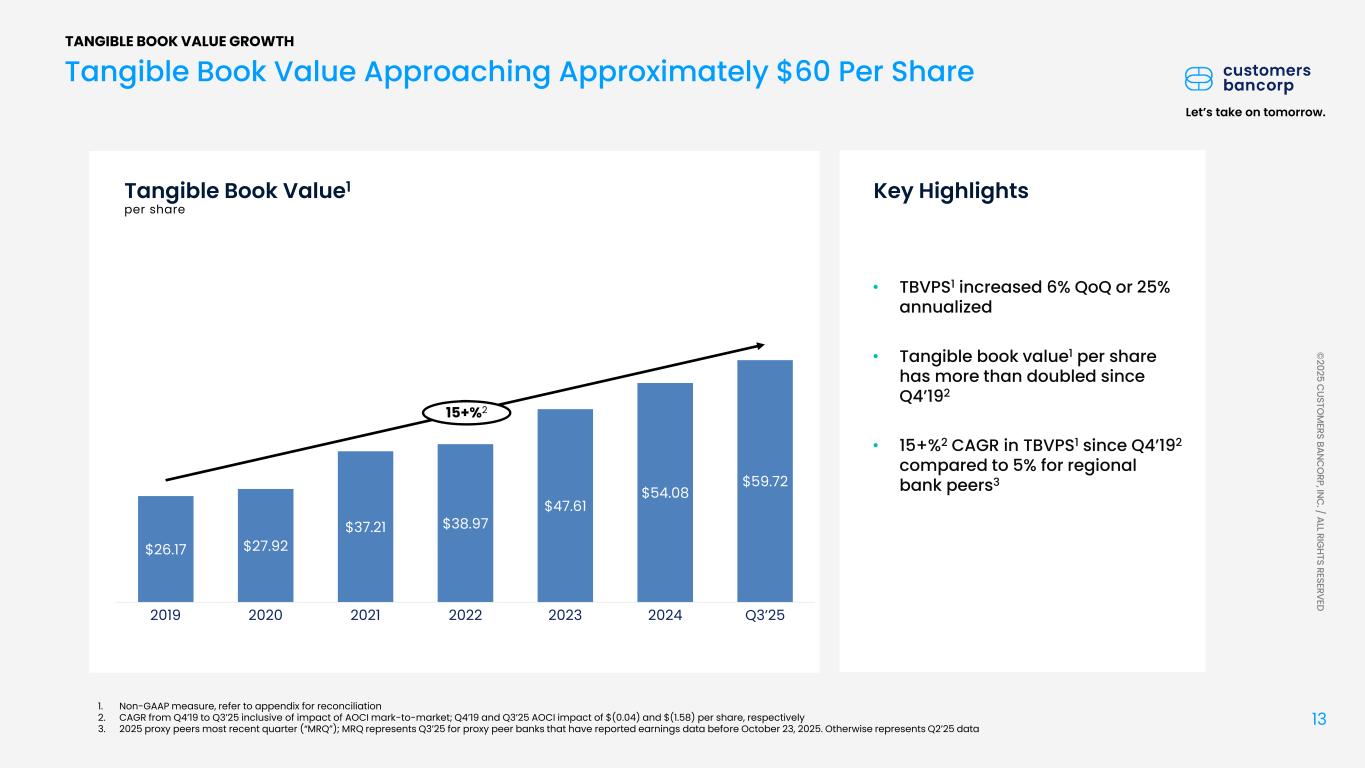
13 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Tangible Book Value1 per share Tangible Book Value Approaching Approximately $60 Per Share 1. Non-GAAP measure, refer to appendix for reconciliation 2. CAGR from Q4’19 to Q3’25 inclusive of impact of AOCI mark-to-market; Q4’19 and Q3’25 AOCI impact of $(0.04) and $(1.58) per share, respectively 3. 2025 proxy peers most recent quarter (“MRQ”); MRQ represents Q3’25 for proxy peer banks that have reported earnings data before October 23, 2025. Otherwise represents Q2’25 data $26.17 $27.92 $37.21 $38.97 $47.61 $54.08 $59.72 2019 2020 2021 2022 2023 2024 Q3’25 +15% TANGIBLE BOOK VALUE GROWTH • TBVPS1 increased 6% QoQ or 25% annualized • Tangible book value1 per share has more than doubled since Q4’192 • 15+%2 CAGR in TBVPS1 since Q4’192 compared to 5% for regional bank peers3 Key Highlights 15+ 2
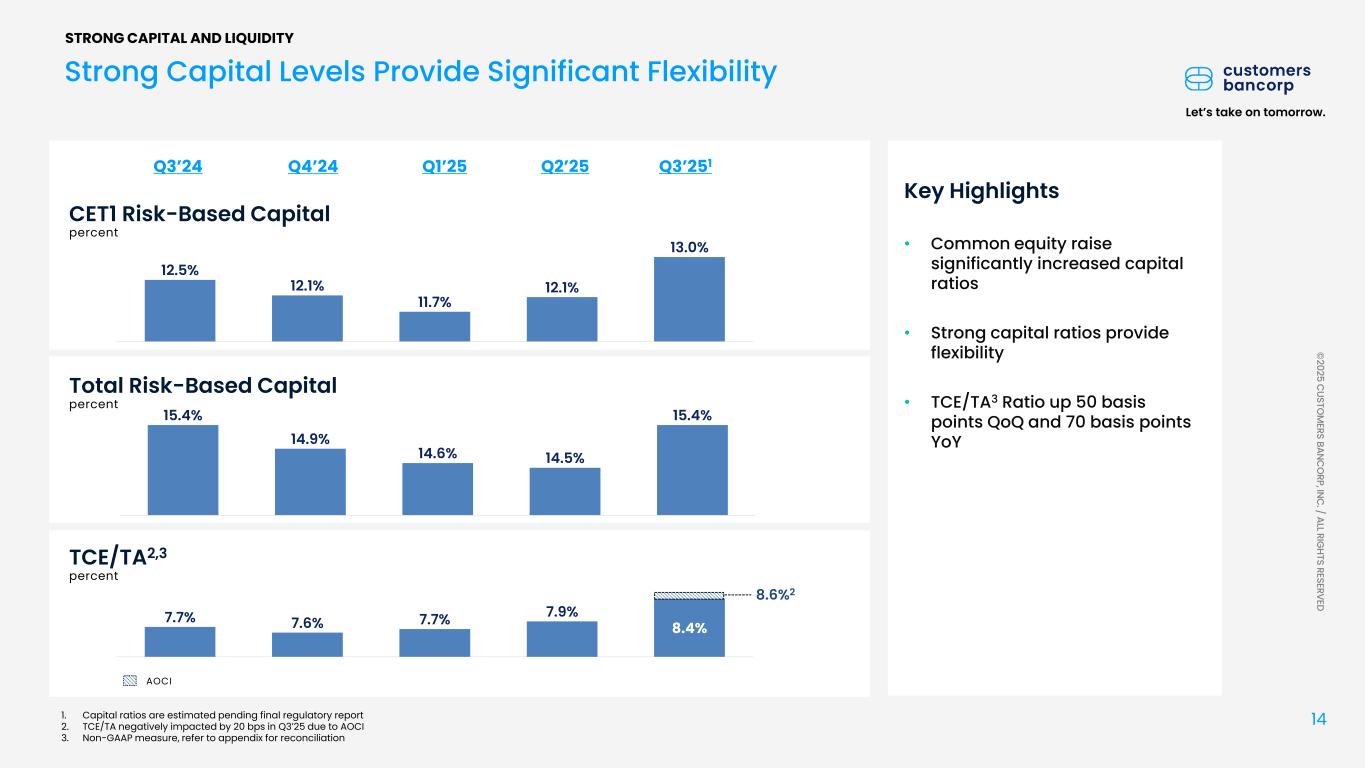
14 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED ` ` 15.4% 14.9% 14.6% 14.5% 15.4% Total Risk-Based Capital percent 7.7% 7.6% 7.7% 7.9% 8.4% TCE/TA2,3 percent 1. Capital ratios are estimated pending final regulatory report 2. TCE/TA negatively impacted by 20 bps in Q3’25 due to AOCI 3. Non-GAAP measure, refer to appendix for reconciliation Strong Capital Levels Provide Significant Flexibility 12.5% 12.1% 11.7% 12.1% 13.0% CET1 Risk-Based Capital percent STRONG CAPITAL AND LIQUIDITY • Common equity raise significantly increased capital ratios • Strong capital ratios provide flexibility • TCE/TA3 Ratio up 50 basis points QoQ and 70 basis points YoY Q3’24 Q4’24 Q1’25 8.6%2 Key Highlights AOCI Q2’25 Q3’251
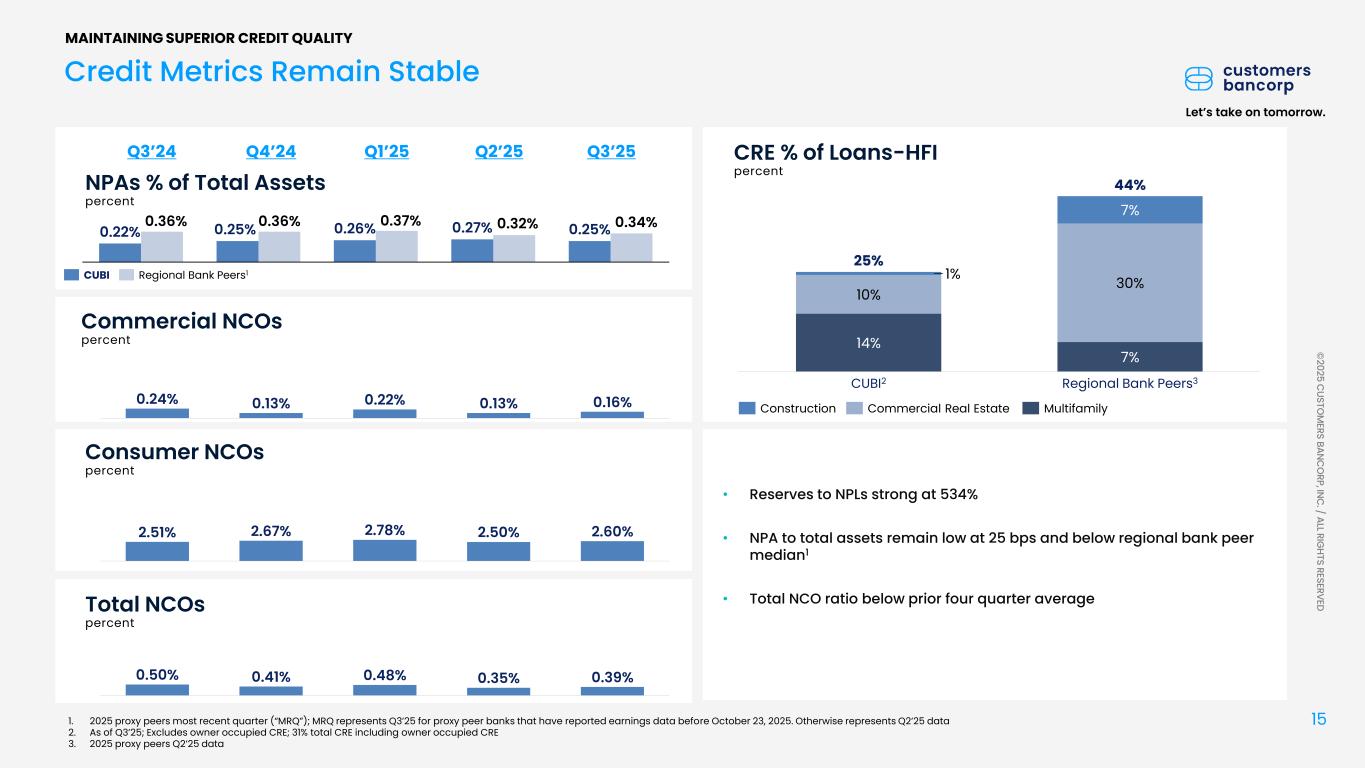
15 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Commercial NCOs percent NPAs % of Total Assets percent Credit Metrics Remain Stable 0.24% 0.13% 0.22% 0.13% 0.16% 2.51% 2.67% 2.78% 2.50% 2.60% 0.50% 0.41% 0.48% 0.35% 0.39% Consumer NCOs percent Total NCOs percent MAINTAINING SUPERIOR CREDIT QUALITY v 1. 2025 proxy peers most recent quarter (“MRQ”); MRQ represents Q3’25 for proxy peer banks that have reported earnings data before October 23, 2025. Otherwise represents Q2’25 data 2. As of Q3’25; Excludes owner occupied CRE; 31% total CRE including owner occupied CRE 3. 2025 proxy peers Q2’25 data 14% 7% 10% 30%1% 7% CUBI2 Regional Bank Peers3 25% 44% Construction Commercial Real Estate Multifamily CRE % of Loans-HFI percent V • Reserves to NPLs strong at 534% • NPA to total assets remain low at 25 bps and below regional bank peer median1 • Total NCO ratio below prior four quarter average Q3’24 Q4’24 Q1’25 Q2’25 Q3’25 0.22% 0.25% 0.26% 0.27% 0.25%0.36% 0.36% 0.37% 0.32% 0.34% CUBI Regional Bank Peers1
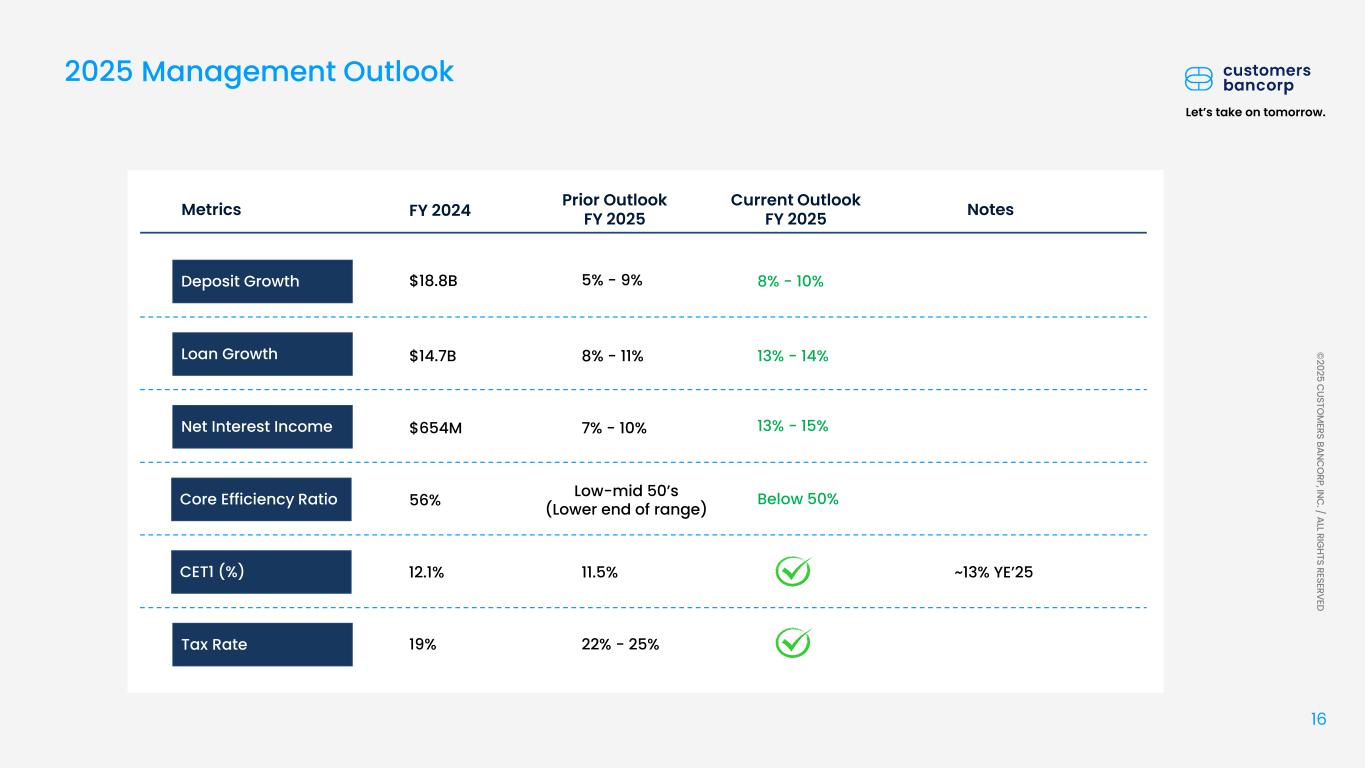
16 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED 2025 Management Outlook Metrics Prior Outlook FY 2025 Core Efficiency Ratio Low-mid 50’s (Lower end of range) 5% - 9%Deposit Growth Loan Growth Net Interest Income 8% - 11% 7% - 10% Tax Rate 22% - 25% CET1 (%) 11.5% FY 2024 56% $18.8B $14.7B $654M 19% 12.1% NotesCurrent Outlook FY 2025 13% - 14% 13% - 15% 8% - 10% Below 50% ~13% YE’25
ANALYST COVERAGE D.A. Davidson Companies Peter Winter Hovde Group David Bishop Keefe, Bruyette & Woods Inc. Kelly Motta Maxim Group LLC Michael Diana Stephens Inc. Matt Breese Raymond James Steve Moss B. Riley Securities, Inc. Hal Goetsch TD Cowen Janet Lee 2025 New Analyst
APPENDIX
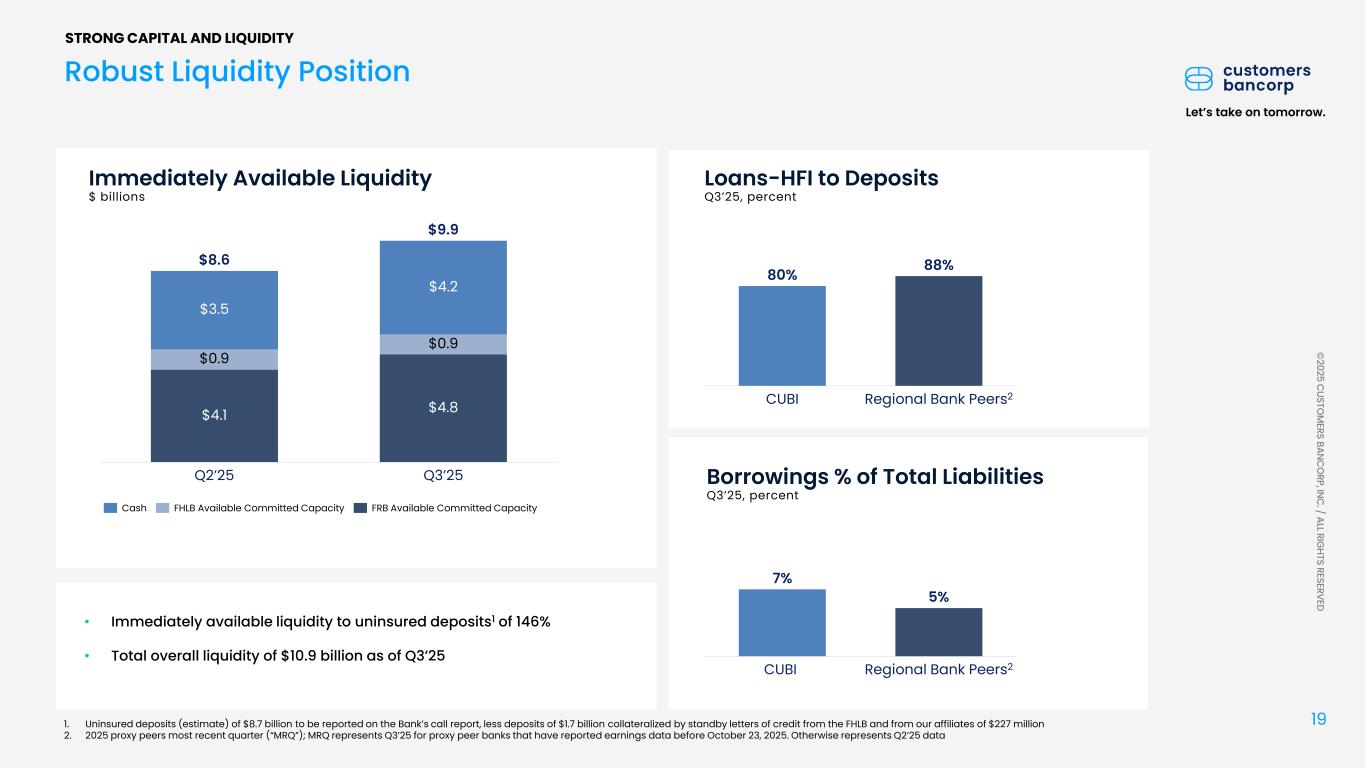
19 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Robust Liquidity Position Immediately Available Liquidity $ billions $3.5 $0.9 $4.1 Q2’25 $4.2 $0.9 $4.8 Q3’25 $8.6 $9.9 Cash FHLB Available Committed Capacity FRB Available Committed Capacity 1. Uninsured deposits (estimate) of $8.7 billion to be reported on the Bank’s call report, less deposits of $1.7 billion collateralized by standby letters of credit from the FHLB and from our affiliates of $227 million 2. 2025 proxy peers most recent quarter (“MRQ”); MRQ represents Q3’25 for proxy peer banks that have reported earnings data before October 23, 2025. Otherwise represents Q2’25 data STRONG CAPITAL AND LIQUIDITY • Immediately available liquidity to uninsured deposits1 of 146% • Total overall liquidity of $10.9 billion as of Q3’25 Loans-HFI to Deposits Q3’25, percent CUBI Regional Bank Peers2 80% 88% Borrowings % of Total Liabilities Q3’25, percent CUBI Regional Bank Peers2 7% 5%
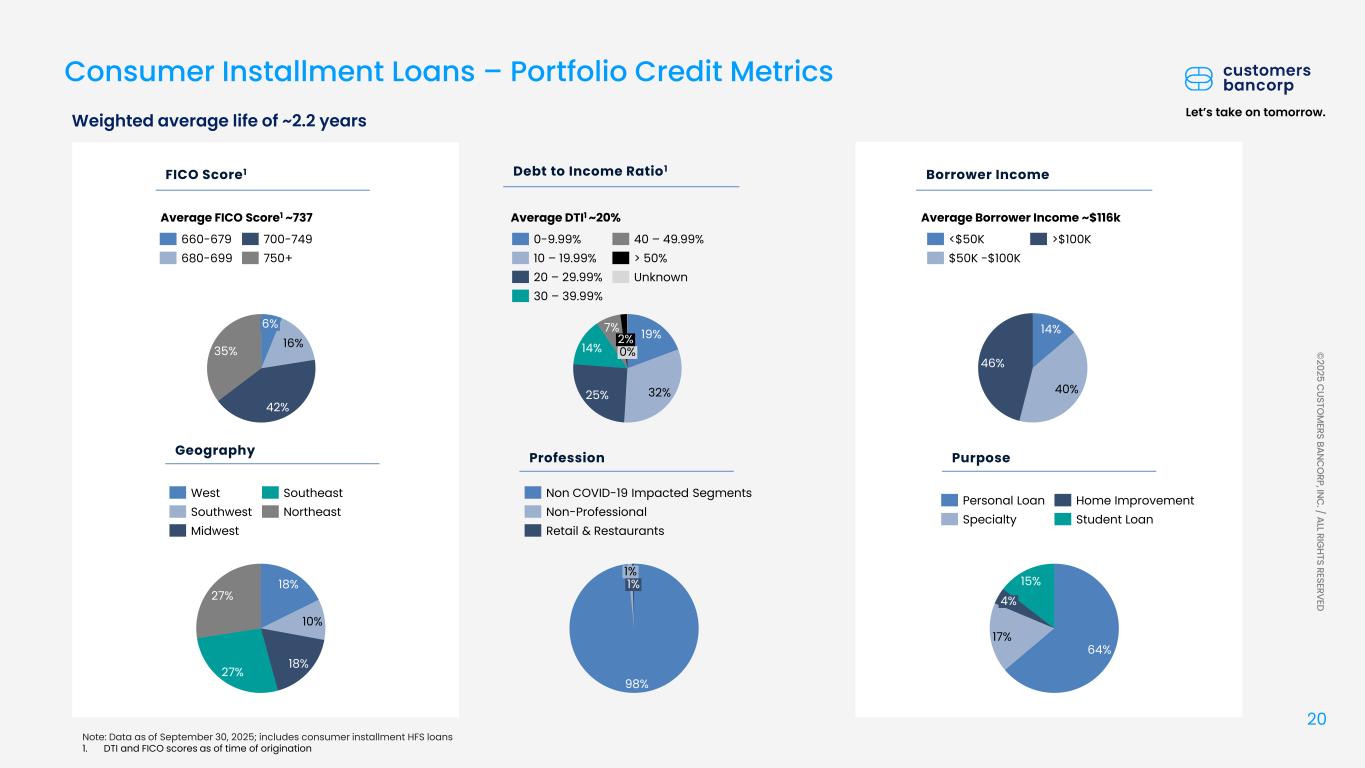
20 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED 16% 42% 35% 6% FICO Score1 660-679 680-699 700-749 750+ 19% 32%25% 14% 7% 2% 0% 0-9.99% 10 – 19.99% 20 – 29.99% 30 – 39.99% 40 – 49.99% > 50% Unknown Geography Profession Debt to Income Ratio1 Borrower Income 14% 40% 46% <$50K $50K -$100K >$100K 18% 10% 18% 27% 27% West Southwest Midwest Southeast Northeast Consumer Installment Loans – Portfolio Credit Metrics Purpose 64% 17% 15% 4% Personal Loan Specialty Home Improvement Student Loan 98% 1% 1% Non COVID-19 Impacted Segments Non-Professional Retail & Restaurants Average FICO Score1 ~737 Average DTI1 ~20% Average Borrower Income ~$116k Weighted average life of ~2.2 years Note: Data as of September 30, 2025; includes consumer installment HFS loans 1. DTI and FICO scores as of time of origination
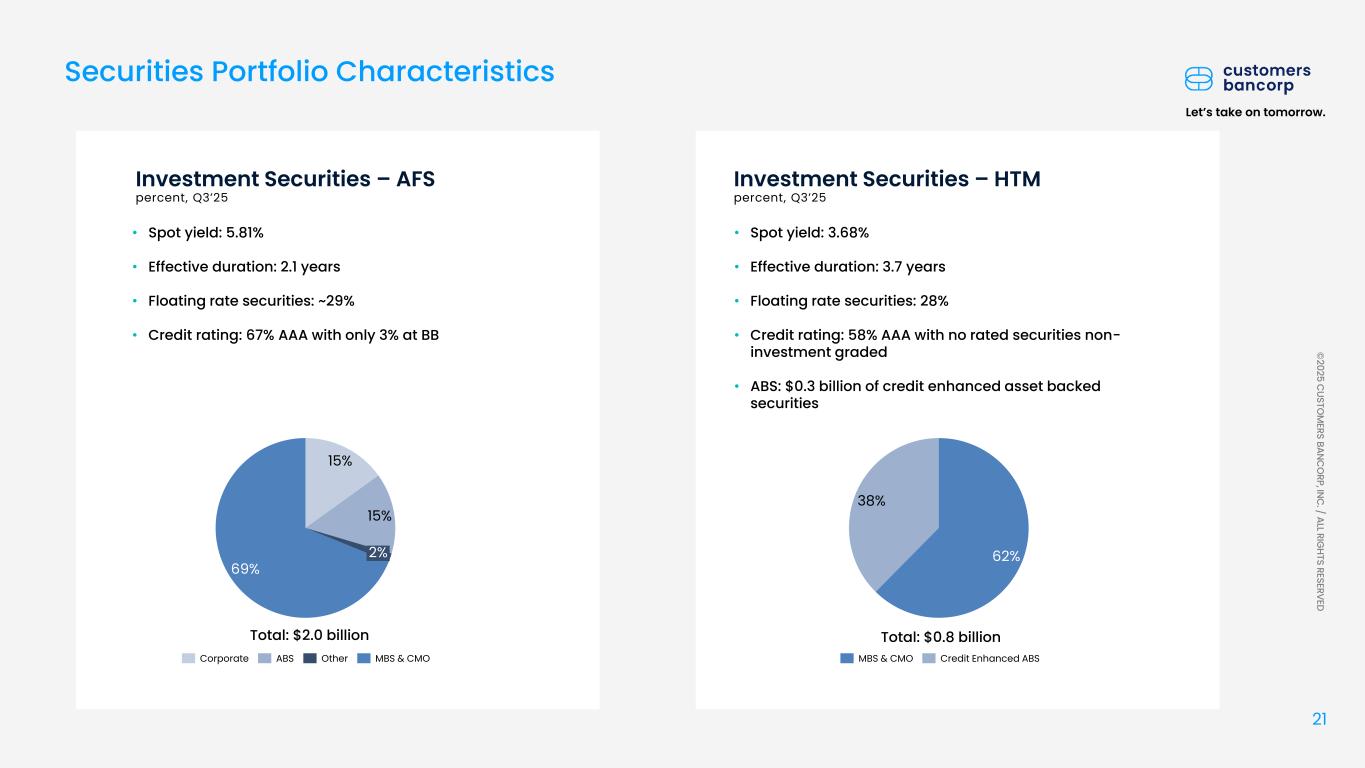
21 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Investment Securities – AFS percent, Q3’25 Securities Portfolio Characteristics • Spot yield: 5.81% • Effective duration: 2.1 years • Floating rate securities: ~29% • Credit rating: 67% AAA with only 3% at BB Investment Securities – HTM percent, Q3’25 • Spot yield: 3.68% • Effective duration: 3.7 years • Floating rate securities: 28% • Credit rating: 58% AAA with no rated securities non- investment graded • ABS: $0.3 billion of credit enhanced asset backed securities 62% 38% MBS & CMO Credit Enhanced ABS Total: $0.8 billion Corporate ABS Other MBS & CMO Total: $2.0 billion 15% 15% 69% 2%
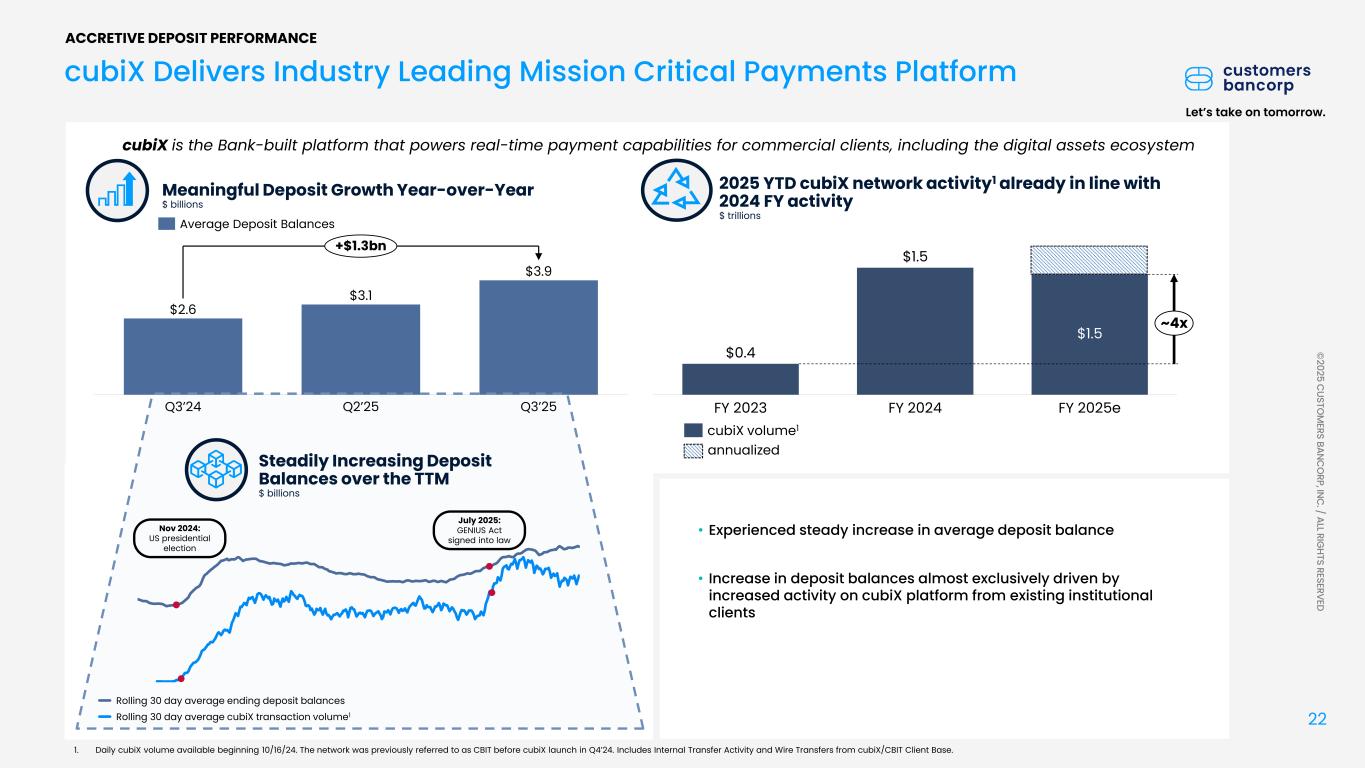
22 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVEDh h h cubiX Delivers Industry Leading Mission Critical Payments Platform ACCRETIVE DEPOSIT PERFORMANCE cubiX is the Bank-built platform that powers real-time payment capabilities for commercial clients, including the digital assets ecosystem $2.6 $3.1 $3.9 Q3’24 Q2’25 Q3’25 +$1.3bn Meaningful Deposit Growth Year-over-Year $ billions Average Deposit Balances • Experienced steady increase in average deposit balance • Increase in deposit balances almost exclusively driven by increased activity on cubiX platform from existing institutional clients Steadily Increasing Deposit Balances over the TTM $ billions FY 2023 FY 2024 $1.5 FY 2025e $0.4 $1.5 ~4x cubiX volume1 2025 YTD cubiX network activity1 already in line with 2024 FY activity $ trillions Rolling 30 day average ending deposit balances Rolling 30 day average cubiX transaction volume1 Nov 2024: US presidential election 1. Daily cubiX volume available beginning 10/16/24. The network was previously referred to as CBIT before cubiX launch in Q4’24. Includes Internal Transfer Activity and Wire Transfers from cubiX/CBIT Client Base. July 2025: GENIUS Act signed into law annualized
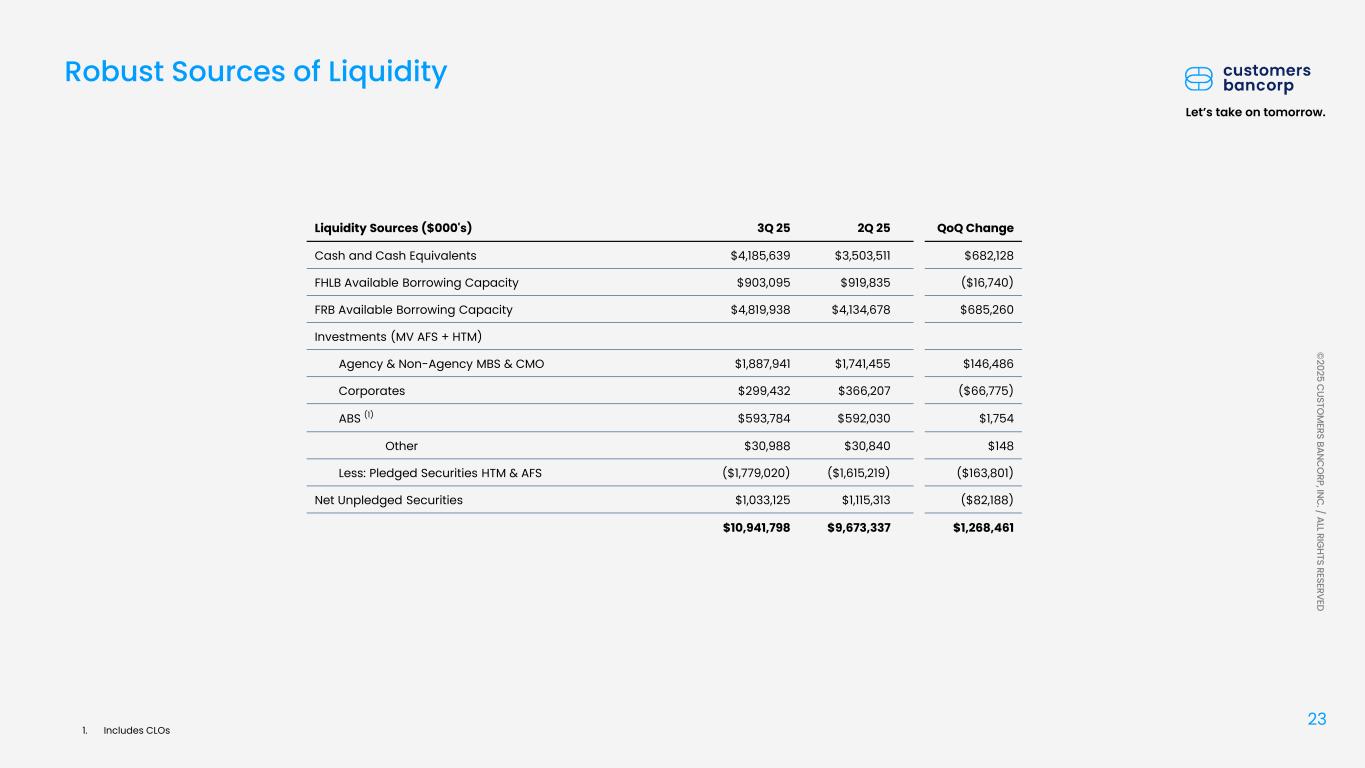
23 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Robust Sources of Liquidity 1. Includes CLOs Liquidity Sources ($000's) 3Q 25 2Q 25 QoQ Change Cash and Cash Equivalents $4,185,639 $3,503,511 $682,128 FHLB Available Borrowing Capacity $903,095 $919,835 ($16,740) FRB Available Borrowing Capacity $4,819,938 $4,134,678 $685,260 Investments (MV AFS + HTM) Agency & Non-Agency MBS & CMO $1,887,941 $1,741,455 $146,486 Corporates $299,432 $366,207 ($66,775) ABS (1) $593,784 $592,030 $1,754 Other $30,988 $30,840 $148 Less: Pledged Securities HTM & AFS ($1,779,020) ($1,615,219) ($163,801) Net Unpledged Securities $1,033,125 $1,115,313 ($82,188) $10,941,798 $9,673,337 $1,268,461
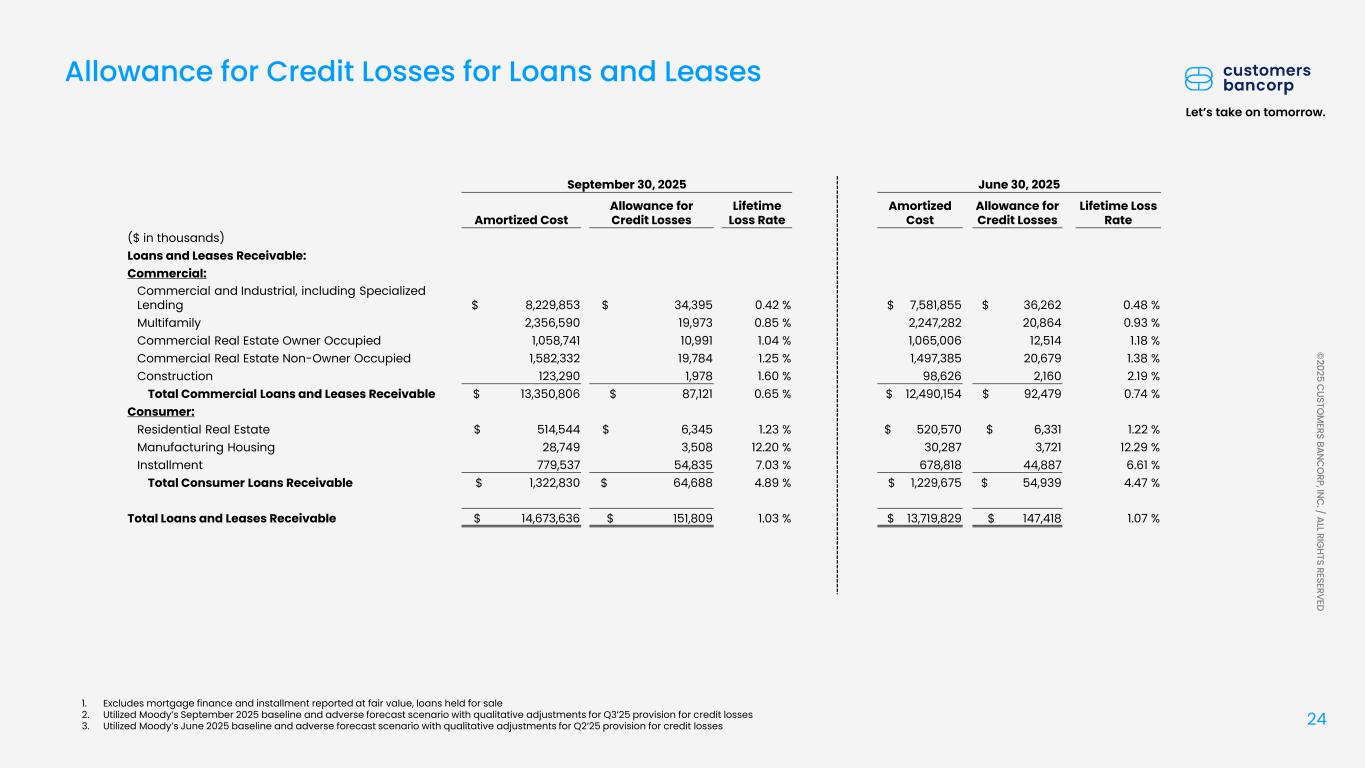
24 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED 1. Excludes mortgage finance and installment reported at fair value, loans held for sale 2. Utilized Moody’s September 2025 baseline and adverse forecast scenario with qualitative adjustments for Q3’25 provision for credit losses 3. Utilized Moody’s June 2025 baseline and adverse forecast scenario with qualitative adjustments for Q2’25 provision for credit losses Allowance for Credit Losses for Loans and Leases September 30, 2025 June 30, 2025 Amortized Cost Allowance for Credit Losses Lifetime Loss Rate Amortized Cost Allowance for Credit Losses Lifetime Loss Rate ($ in thousands) Loans and Leases Receivable: Commercial: Commercial and Industrial, including Specialized Lending $ 8,229,853 $ 34,395 0.42 % $ 7,581,855 $ 36,262 0.48 % Multifamily 2,356,590 19,973 0.85 % 2,247,282 20,864 0.93 % Commercial Real Estate Owner Occupied 1,058,741 10,991 1.04 % 1,065,006 12,514 1.18 % Commercial Real Estate Non-Owner Occupied 1,582,332 19,784 1.25 % 1,497,385 20,679 1.38 % Construction 123,290 1,978 1.60 % 98,626 2,160 2.19 % Total Commercial Loans and Leases Receivable $ 13,350,806 $ 87,121 0.65 % $ 12,490,154 $ 92,479 0.74 % Consumer: Residential Real Estate $ 514,544 $ 6,345 1.23 % $ 520,570 $ 6,331 1.22 % Manufacturing Housing 28,749 3,508 12.20 % 30,287 3,721 12.29 % Installment 779,537 54,835 7.03 % 678,818 44,887 6.61 % Total Consumer Loans Receivable $ 1,322,830 $ 64,688 4.89 % $ 1,229,675 $ 54,939 4.47 % Total Loans and Leases Receivable $ 14,673,636 $ 151,809 1.03 % $ 13,719,829 $ 147,418 1.07 %
25 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Customers believes that the non-GAAP measurements disclosed within this document are useful for investors, regulators, management and others to evaluate our core results of operations and financial condition relative to other financial institutions. These non-GAAP financial measures are frequently used by securities analysts, investors, and other interested parties in the evaluation of companies in Customers' industry. These non-GAAP financial measures exclude from corresponding GAAP measures the impact of certain elements that we do not believe are representative of our ongoing financial results, which we believe enhance an overall understanding of our performance and increases comparability of our period to period results. Investors should consider our performance and financial condition as reported under GAAP and all other relevant information when assessing our performance or financial condition. The non-GAAP measures presented are not necessarily comparable to non-GAAP measures that may be presented by other financial institutions. Although non-GAAP financial measures are frequently used in the evaluation of a company, they have limitations as analytical tools and should not be considered in isolation or as a substitute for analysis of our results of operations or financial condition as reported under GAAP. Starting in Q3 2025, certain adjustments to GAAP measures were no longer included as our intention going forward is to limit these adjustments to those items of greatest significance. The following tables present reconciliations of GAAP to non-GAAP measures disclosed within this document. Reconciliation of Non-GAAP Measures - Unaudited
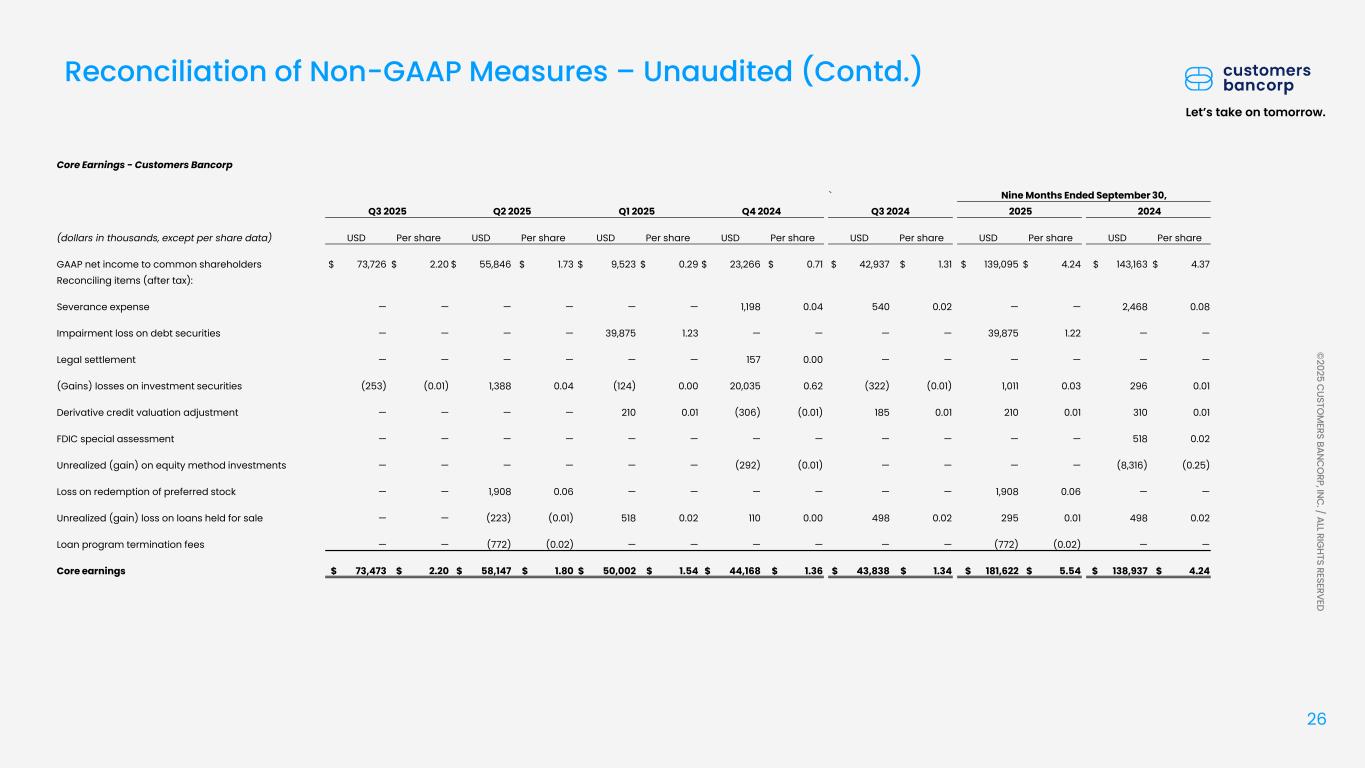
26 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Reconciliation of Non-GAAP Measures – Unaudited (Contd.) Core Earnings - Customers Bancorp ` Nine Months Ended September 30, Q3 2025 Q2 2025 Q1 2025 Q4 2024 Q3 2024 2025 2024 (dollars in thousands, except per share data) USD Per share USD Per share USD Per share USD Per share USD Per share USD Per share USD Per share GAAP net income to common shareholders $ 73,726 $ 2.20 $ 55,846 $ 1.73 $ 9,523 $ 0.29 $ 23,266 $ 0.71 $ 42,937 $ 1.31 $ 139,095 $ 4.24 $ 143,163 $ 4.37 Reconciling items (after tax): Severance expense — — — — — — 1,198 0.04 540 0.02 — — 2,468 0.08 Impairment loss on debt securities — — — — 39,875 1.23 — — — — 39,875 1.22 — — Legal settlement — — — — — — 157 0.00 — — — — — — (Gains) losses on investment securities (253) (0.01) 1,388 0.04 (124) 0.00 20,035 0.62 (322) (0.01) 1,011 0.03 296 0.01 Derivative credit valuation adjustment — — — — 210 0.01 (306) (0.01) 185 0.01 210 0.01 310 0.01 FDIC special assessment — — — — — — — — — — — — 518 0.02 Unrealized (gain) on equity method investments — — — — — — (292) (0.01) — — — — (8,316) (0.25) Loss on redemption of preferred stock — — 1,908 0.06 — — — — — — 1,908 0.06 — — Unrealized (gain) loss on loans held for sale — — (223) (0.01) 518 0.02 110 0.00 498 0.02 295 0.01 498 0.02 Loan program termination fees — — (772) (0.02) — — — — — — (772) (0.02) — — Core earnings $ 73,473 $ 2.20 $ 58,147 $ 1.80 $ 50,002 $ 1.54 $ 44,168 $ 1.36 $ 43,838 $ 1.34 $ 181,622 $ 5.54 $ 138,937 $ 4.24
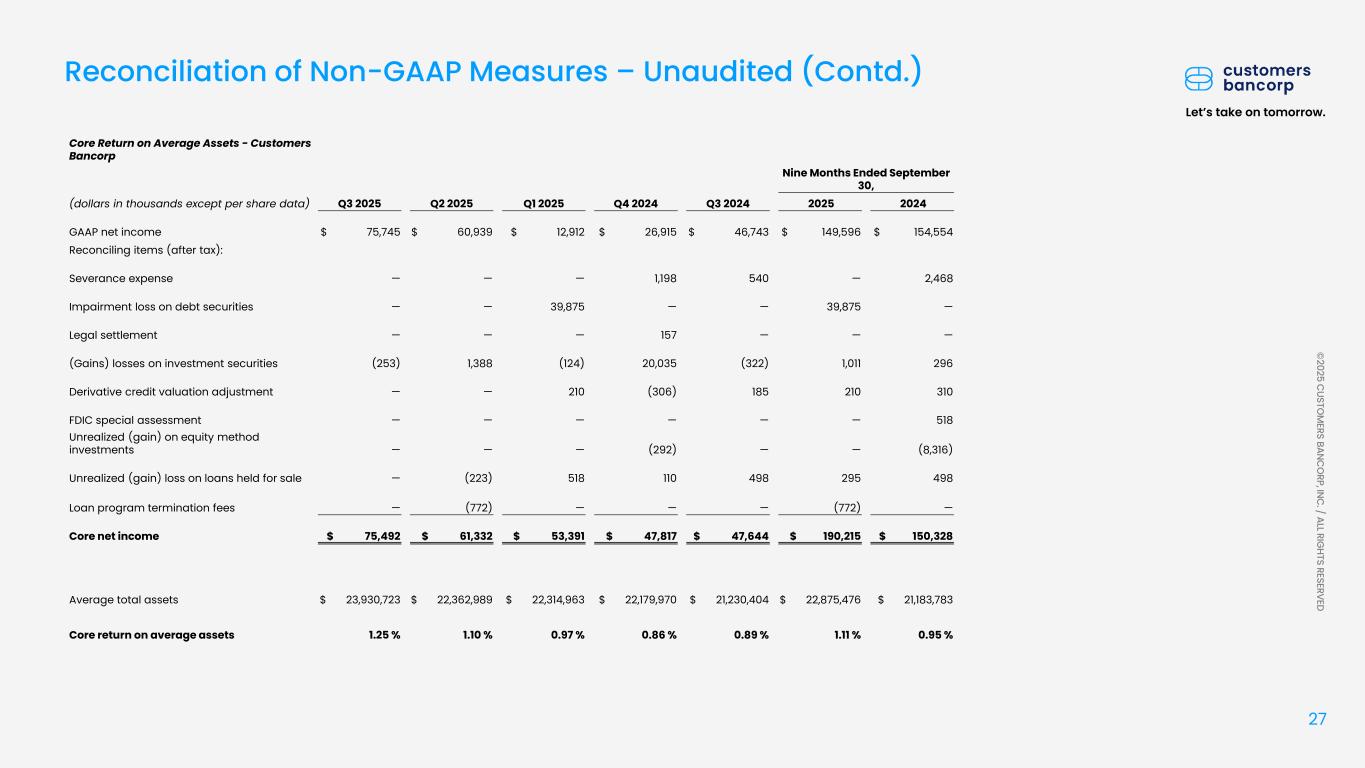
27 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Reconciliation of Non-GAAP Measures – Unaudited (Contd.) Core Return on Average Assets - Customers Bancorp Nine Months Ended September 30, (dollars in thousands except per share data) Q3 2025 Q2 2025 Q1 2025 Q4 2024 Q3 2024 2025 2024 GAAP net income $ 75,745 $ 60,939 $ 12,912 $ 26,915 $ 46,743 $ 149,596 $ 154,554 Reconciling items (after tax): Severance expense — — — 1,198 540 — 2,468 Impairment loss on debt securities — — 39,875 — — 39,875 — Legal settlement — — — 157 — — — (Gains) losses on investment securities (253) 1,388 (124) 20,035 (322) 1,011 296 Derivative credit valuation adjustment — — 210 (306) 185 210 310 FDIC special assessment — — — — — — 518 Unrealized (gain) on equity method investments — — — (292) — — (8,316) Unrealized (gain) loss on loans held for sale — (223) 518 110 498 295 498 Loan program termination fees — (772) — — — (772) — Core net income $ 75,492 $ 61,332 $ 53,391 $ 47,817 $ 47,644 $ 190,215 $ 150,328 Average total assets $ 23,930,723 $ 22,362,989 $ 22,314,963 $ 22,179,970 $ 21,230,404 $ 22,875,476 $ 21,183,783 Core return on average assets 1.25 % 1.10 % 0.97 % 0.86 % 0.89 % 1.11 % 0.95 %
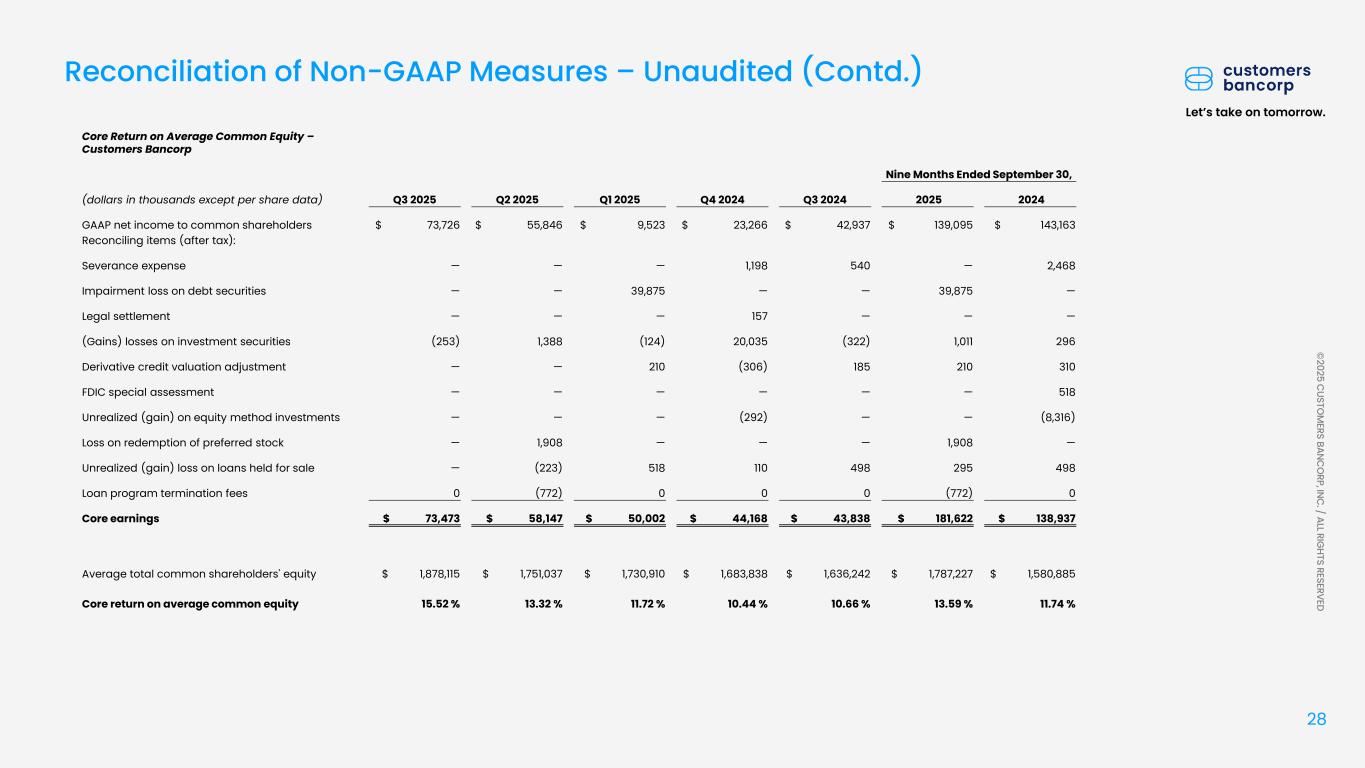
28 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Reconciliation of Non-GAAP Measures – Unaudited (Contd.) Core Return on Average Common Equity – Customers Bancorp Nine Months Ended September 30, (dollars in thousands except per share data) Q3 2025 Q2 2025 Q1 2025 Q4 2024 Q3 2024 2025 2024 GAAP net income to common shareholders $ 73,726 $ 55,846 $ 9,523 $ 23,266 $ 42,937 $ 139,095 $ 143,163 Reconciling items (after tax): Severance expense — — — 1,198 540 — 2,468 Impairment loss on debt securities — — 39,875 — — 39,875 — Legal settlement — — — 157 — — — (Gains) losses on investment securities (253) 1,388 (124) 20,035 (322) 1,011 296 Derivative credit valuation adjustment — — 210 (306) 185 210 310 FDIC special assessment — — — — — — 518 Unrealized (gain) on equity method investments — — — (292) — — (8,316) Loss on redemption of preferred stock — 1,908 — — — 1,908 — Unrealized (gain) loss on loans held for sale — (223) 518 110 498 295 498 Loan program termination fees 0 (772) 0 0 0 (772) 0 Core earnings $ 73,473 $ 58,147 $ 50,002 $ 44,168 $ 43,838 $ 181,622 $ 138,937 Average total common shareholders' equity $ 1,878,115 $ 1,751,037 $ 1,730,910 $ 1,683,838 $ 1,636,242 $ 1,787,227 $ 1,580,885 Core return on average common equity 15.52 % 13.32 % 11.72 % 10.44 % 10.66 % 13.59 % 11.74 %
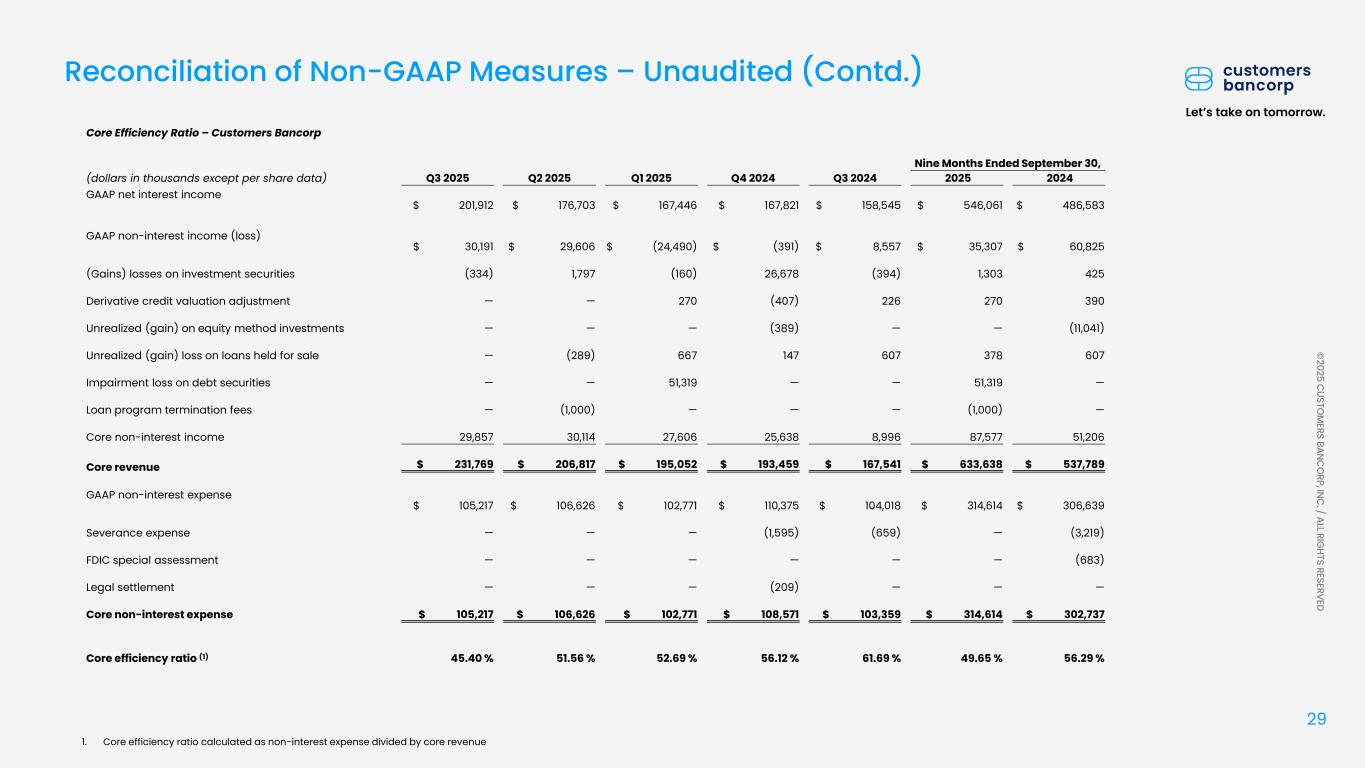
29 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Reconciliation of Non-GAAP Measures – Unaudited (Contd.) 1. Core efficiency ratio calculated as non-interest expense divided by core revenue Core Efficiency Ratio – Customers Bancorp Nine Months Ended September 30, (dollars in thousands except per share data) Q3 2025 Q2 2025 Q1 2025 Q4 2024 Q3 2024 2025 2024 GAAP net interest income $ 201,912 $ 176,703 $ 167,446 $ 167,821 $ 158,545 $ 546,061 $ 486,583 GAAP non-interest income (loss) $ 30,191 $ 29,606 $ (24,490) $ (391) $ 8,557 $ 35,307 $ 60,825 (Gains) losses on investment securities (334) 1,797 (160) 26,678 (394) 1,303 425 Derivative credit valuation adjustment — — 270 (407) 226 270 390 Unrealized (gain) on equity method investments — — — (389) — — (11,041) Unrealized (gain) loss on loans held for sale — (289) 667 147 607 378 607 Impairment loss on debt securities — — 51,319 — — 51,319 — Loan program termination fees — (1,000) — — — (1,000) — Core non-interest income 29,857 30,114 27,606 25,638 8,996 87,577 51,206 Core revenue $ 231,769 $ 206,817 $ 195,052 $ 193,459 $ 167,541 $ 633,638 $ 537,789 GAAP non-interest expense $ 105,217 $ 106,626 $ 102,771 $ 110,375 $ 104,018 $ 314,614 $ 306,639 Severance expense — — — (1,595) (659) — (3,219) FDIC special assessment — — — — — — (683) Legal settlement — — — (209) — — — Core non-interest expense $ 105,217 $ 106,626 $ 102,771 $ 108,571 $ 103,359 $ 314,614 $ 302,737 Core efficiency ratio (1) 45.40 % 51.56 % 52.69 % 56.12 % 61.69 % 49.65 % 56.29 %
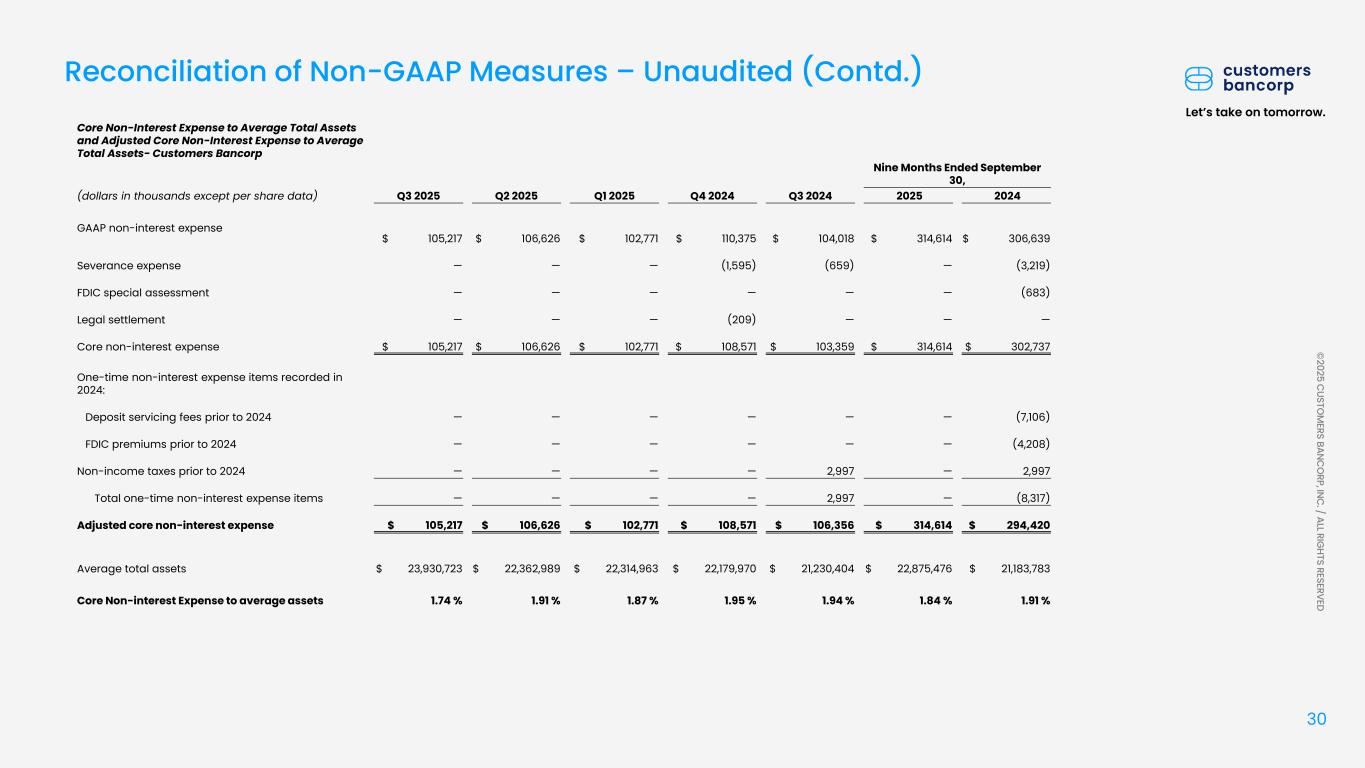
30 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Reconciliation of Non-GAAP Measures – Unaudited (Contd.) Core Non-Interest Expense to Average Total Assets and Adjusted Core Non-Interest Expense to Average Total Assets- Customers Bancorp Nine Months Ended September 30, (dollars in thousands except per share data) Q3 2025 Q2 2025 Q1 2025 Q4 2024 Q3 2024 2025 2024 GAAP non-interest expense $ 105,217 $ 106,626 $ 102,771 $ 110,375 $ 104,018 $ 314,614 $ 306,639 Severance expense — — — (1,595) (659) — (3,219) FDIC special assessment — — — — — — (683) Legal settlement — — — (209) — — — Core non-interest expense $ 105,217 $ 106,626 $ 102,771 $ 108,571 $ 103,359 $ 314,614 $ 302,737 One-time non-interest expense items recorded in 2024: Deposit servicing fees prior to 2024 — — — — — — (7,106) FDIC premiums prior to 2024 — — — — — — (4,208) Non-income taxes prior to 2024 — — — — 2,997 — 2,997 Total one-time non-interest expense items — — — — 2,997 — (8,317) Adjusted core non-interest expense $ 105,217 $ 106,626 $ 102,771 $ 108,571 $ 106,356 $ 314,614 $ 294,420 Average total assets $ 23,930,723 $ 22,362,989 $ 22,314,963 $ 22,179,970 $ 21,230,404 $ 22,875,476 $ 21,183,783 Core Non-interest Expense to average assets 1.74 % 1.91 % 1.87 % 1.95 % 1.94 % 1.84 % 1.91 %
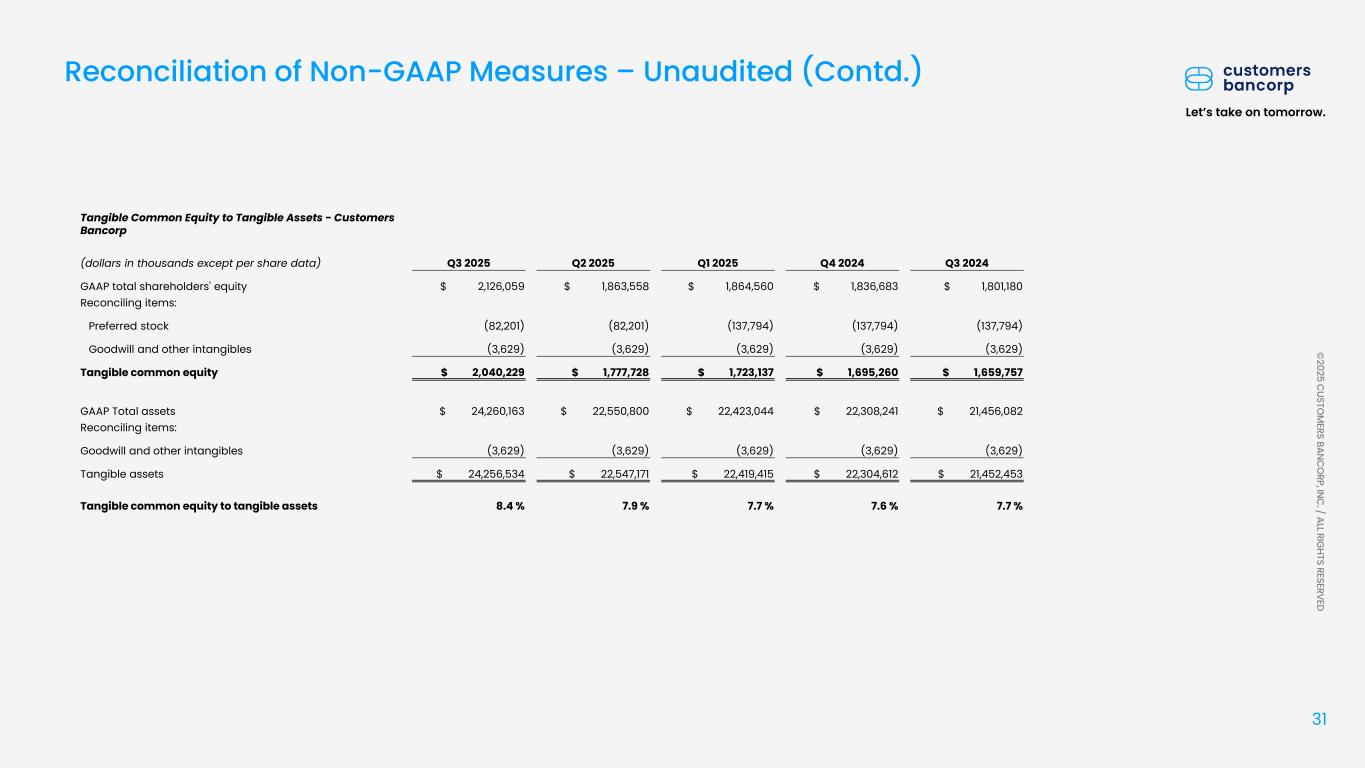
31 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Reconciliation of Non-GAAP Measures – Unaudited (Contd.) Tangible Common Equity to Tangible Assets - Customers Bancorp (dollars in thousands except per share data) Q3 2025 Q2 2025 Q1 2025 Q4 2024 Q3 2024 GAAP total shareholders' equity $ 2,126,059 $ 1,863,558 $ 1,864,560 $ 1,836,683 $ 1,801,180 Reconciling items: Preferred stock (82,201) (82,201) (137,794) (137,794) (137,794) Goodwill and other intangibles (3,629) (3,629) (3,629) (3,629) (3,629) Tangible common equity $ 2,040,229 $ 1,777,728 $ 1,723,137 $ 1,695,260 $ 1,659,757 GAAP Total assets $ 24,260,163 $ 22,550,800 $ 22,423,044 $ 22,308,241 $ 21,456,082 Reconciling items: Goodwill and other intangibles (3,629) (3,629) (3,629) (3,629) (3,629) Tangible assets $ 24,256,534 $ 22,547,171 $ 22,419,415 $ 22,304,612 $ 21,452,453 Tangible common equity to tangible assets 8.4 % 7.9 % 7.7 % 7.6 % 7.7 %
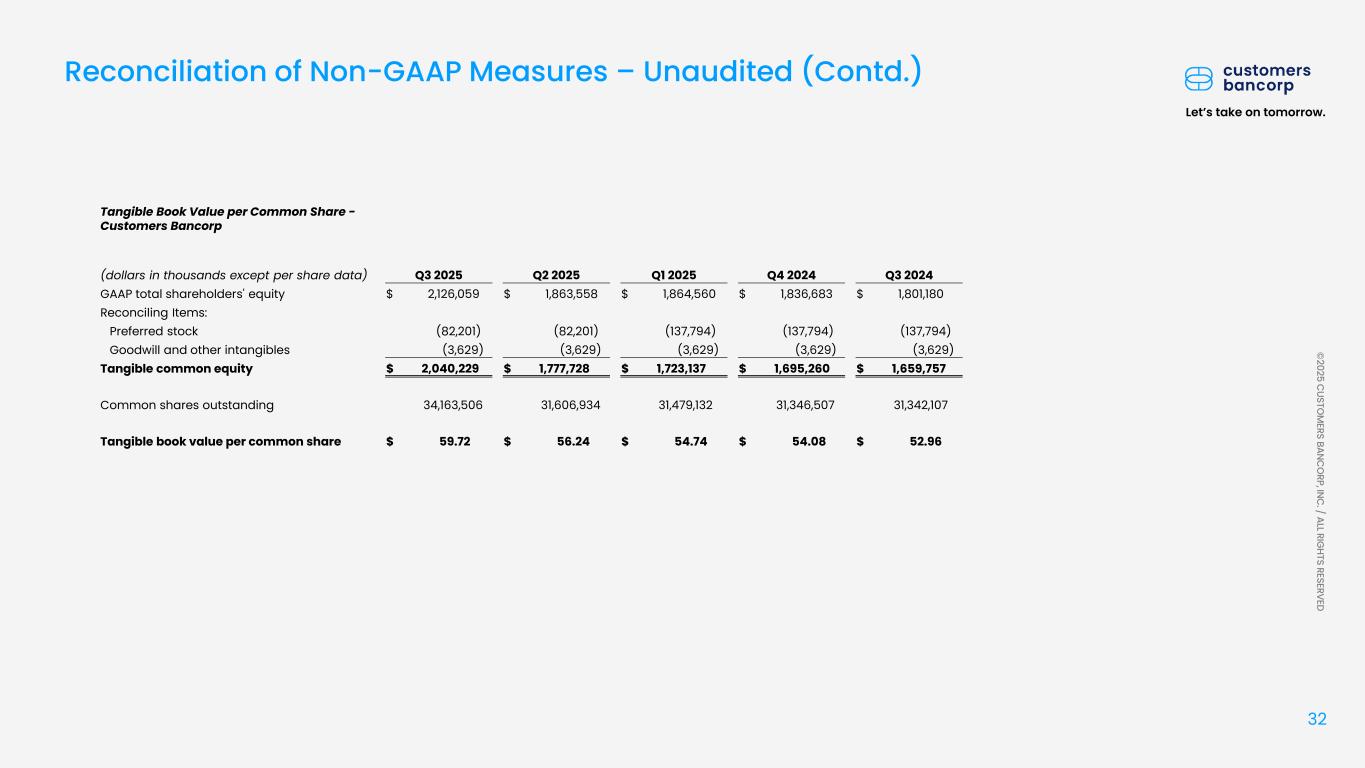
32 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Reconciliation of Non-GAAP Measures – Unaudited (Contd.) Tangible Book Value per Common Share - Customers Bancorp (dollars in thousands except per share data) Q3 2025 Q2 2025 Q1 2025 Q4 2024 Q3 2024 GAAP total shareholders' equity $ 2,126,059 $ 1,863,558 $ 1,864,560 $ 1,836,683 $ 1,801,180 Reconciling Items: Preferred stock (82,201) (82,201) (137,794) (137,794) (137,794) Goodwill and other intangibles (3,629) (3,629) (3,629) (3,629) (3,629) Tangible common equity $ 2,040,229 $ 1,777,728 $ 1,723,137 $ 1,695,260 $ 1,659,757 Common shares outstanding 34,163,506 31,606,934 31,479,132 31,346,507 31,342,107 Tangible book value per common share $ 59.72 $ 56.24 $ 54.74 $ 54.08 $ 52.96
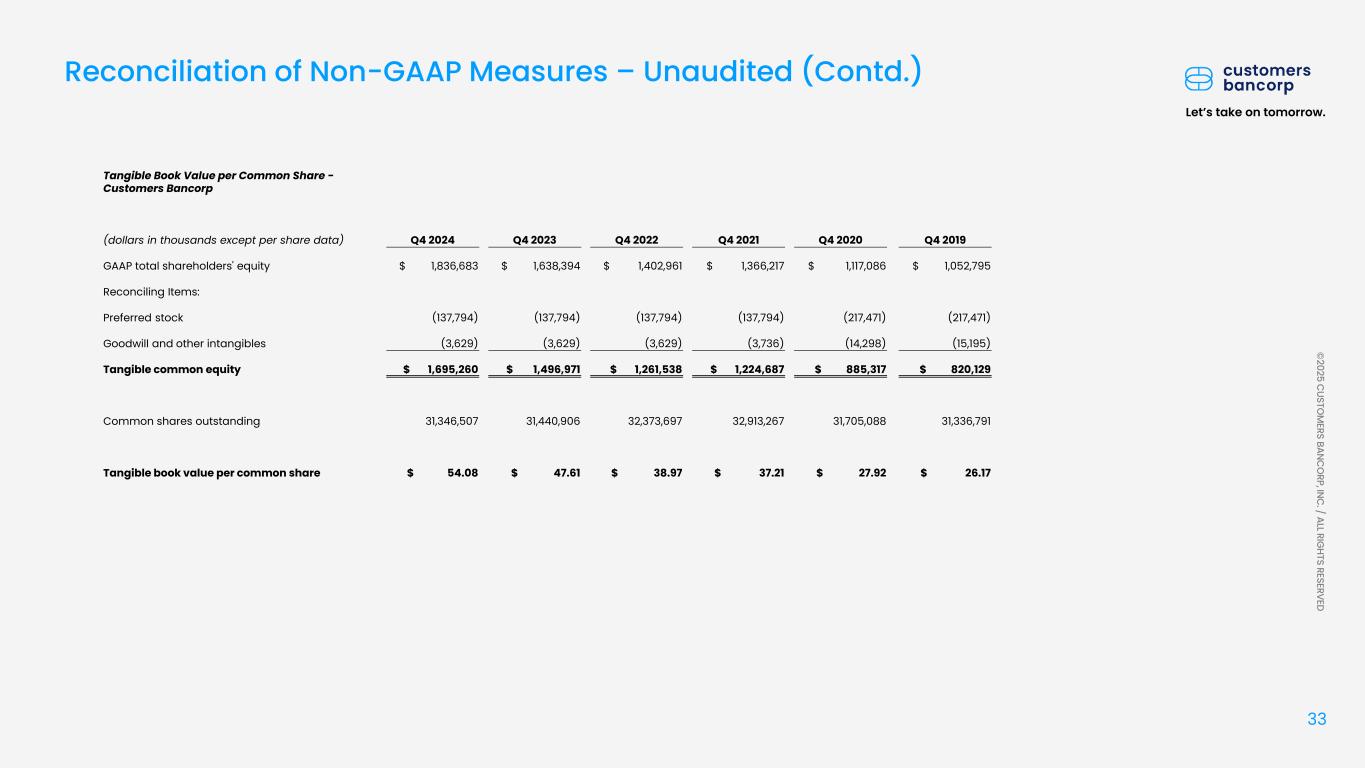
33 Let’s take on tomorrow. © 2025 C USTO M ERS BANC O RP, INC . / ALL RIG HTS RESERVED Reconciliation of Non-GAAP Measures – Unaudited (Contd.) Tangible Book Value per Common Share - Customers Bancorp (dollars in thousands except per share data) Q4 2024 Q4 2023 Q4 2022 Q4 2021 Q4 2020 Q4 2019 GAAP total shareholders' equity $ 1,836,683 $ 1,638,394 $ 1,402,961 $ 1,366,217 $ 1,117,086 $ 1,052,795 Reconciling Items: Preferred stock (137,794) (137,794) (137,794) (137,794) (217,471) (217,471) Goodwill and other intangibles (3,629) (3,629) (3,629) (3,736) (14,298) (15,195) Tangible common equity $ 1,695,260 $ 1,496,971 $ 1,261,538 $ 1,224,687 $ 885,317 $ 820,129 Common shares outstanding 31,346,507 31,440,906 32,373,697 32,913,267 31,705,088 31,336,791 Tangible book value per common share $ 54.08 $ 47.61 $ 38.97 $ 37.21 $ 27.92 $ 26.17