
CUBI 8-K
Customers Bancorp, Inc. (CUBI)
8-K
2020-01-22
For: 2020-01-22
View Original
Added on
April 09, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d)
of the
Securities Exchange Act of 1934
Date of Report (date of earliest event reported): January 22, 2020
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation or organization) | (Commission File number) | (IRS Employer Identification No.) | ||||||
(Address of principal executive offices, including zip code)
(610 ) 933-2000
(Registrant’s telephone number, including area code)
N/A
(Former name, former address and former fiscal year, if changed since last report)
Check the appropriate box below if the form 8-K filing is intended to simultaneously satisfy the filing obligations of the registrant under any of the following provisions (see General Instructions A.2. below):
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (17 CFR §230.405) or Rule 12b-2 of the Securities Exchange Act of 1934 (17 CFR §240.12b-2). Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
| Title of Each Class | Trading Symbols | Name of Each Exchange on which Registered | ||||||||||||
Preferred Stock, Series C, par value $1.00 per share | ||||||||||||||
Preferred Stock, Series D, par value $1.00 per share | ||||||||||||||
Preferred Stock, Series E, par value $1.00 per share | ||||||||||||||
Preferred Stock, Series F, par value $1.00 per share | ||||||||||||||
Securities registered pursuant to Section 12(g) of the Act: None
Item 2.02. Results of Operations and Financial Condition
On January 22, 2020 , Customers Bancorp, Inc. (the "Company") issued a press release announcing unaudited financial information for the quarter and year ended December 31, 2019, a copy of which is included as Exhibit 99.1 to this Current Report on Form 8-K and incorporated by reference herein.
Item 7.01 Regulation FD Disclosure
The Company has posted to its website a slide presentation which is attached hereto as Exhibit 99.2 to this Current Report on Form 8-K and incorporated into this Item 7.01 by reference.
The information in this Current Report on Form 8-K, including Exhibits 99.1 and 99.2 attached hereto and incorporated by reference into Item 2.02 and Item 7.01, respectively, shall not be deemed "filed" for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities under that Section. Furthermore, such information, including the exhibits attached hereto, shall not be deemed incorporated by reference into any of the Company's reports or filings with the SEC, whether made before or after the date hereof, except as expressly set forth by specific reference in such report or filing. The information in this Current Report on Form 8-K, including the exhibits attached hereto, shall not be deemed an admission as to the materiality of any information in this Current Report on Form 8-K that is required to be disclosed solely to satisfy the requirements of Regulation FD.
Item 9.01. Financial Statements and Exhibits
(d) Exhibits.
| Exhibit | Description | |||||||
| Press Release dated January 22, 2020 | ||||||||
| Slide presentation dated January 2020 | ||||||||
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, hereunto duly authorized.
| CUSTOMERS BANCORP, INC. | |||||
By: /s/ Carla A. Leibold | |||||
| Name: Carla A. Leibold | |||||
| Title: Executive Vice President - Chief Financial Officer and Treasurer | |||||
Date: January 22, 2020
EXHIBIT INDEX
| Exhibit No. | Description | |||||||
| Press Release dated January 22, 2020 | ||||||||
| Slide presentation dated January 2020 | ||||||||
Exhibit 99.1
Customers Bancorp, Inc.
1015 Penn Avenue
Wyomissing, PA 19610
Contacts:
Jay Sidhu, Chairman & CEO 610-935-8693
Richard Ehst, President & COO 610-917-3263
Carla Leibold, CFO 484-923-8802
Sam Sidhu, Head of Corporate Development 212-843-2485
Customers Bancorp Reports Full Year 2019 Net Income up 13% Over Full Year 2018 and Fourth Quarter 2019 Net Income up 68% Over Fourth Quarter 2018
Record Q4 2019 GAAP Earnings up $10 million Over Q4 2018, and Core Earnings up $7 million
Year-end Assets Exceed $10 billion as CUBI Resumes Growth Strategy and
Reaffirms Target of $3 Core EPS for 2020 and Sets Goal of $6 Core EPS for 2025
•Q4 2019 GAAP Earnings Per Diluted Share of $0.75 and Q4 2019 Core Earnings Per Diluted Share of $0.76
•Q4 2019 Return on Average Assets of 0.97% up 37% Over Q4 2018 and Q4 2019 Pre-Tax and Pre-Provision Adjusted Return on Average Assets of 1.59% up 42% Over Q4 2018
•Q4 2019 Net Interest Margin Expands 6 Basis Points From Q3 2019 to 2.89%
•Customers Bank Business Banking Segment Q4 2019 Net Income Increases 27% Over Q4 2018. BankMobile Segment Moves From a Loss of $3.3 Million in Q4 2018 to a Profit of $1.7 Million in Q4 2019
•CUBI Stock Price up 31% in 2019, Trading at only 89% of Book Value and 91% of Tangible Book Value, and 8.4x the 2020 Consensus EPS Estimate of $2.84, at Year-end 2019
Wyomissing, PA, January 22, 2020 - Customers Bancorp, Inc. (NYSE: CUBI) the parent company of Customers Bank and its operating division BankMobile (collectively “Customers” or "CUBI"), today reported record fourth quarter 2019 ("Q4 2019") net income to common shareholders of $23.9 million, or $0.75 per diluted share, up from $23.5 million in third quarter 2019 ("Q3 2019") and $14.2 million in fourth quarter 2018 ("Q4 2018"). Core earnings for Q4 2019 totaled $24.3 million, or $0.76 per diluted share, up from $23.0 million in Q3 2019 and $17.0 million in Q4 2018 (non-GAAP measures). Q4 2019 core earnings per diluted share was up 43% over Q4 2018 core earnings per diluted share (non-GAAP measures). Net interest margin, tax equivalent ("NIM") (a non-GAAP measure), expanded 6 basis points during Q4 2019 to 2.89%. Full year 2019 ("FY 2019") net income to common shareholders was $64.9 million, or $2.05 per diluted share, up from full year 2018 ("FY 2018") net income to common shareholders of $57.2 million, or $1.78 per diluted share. Core earnings for FY 2019 totaled $71.2 million, or $2.25 per diluted share, compared to core earnings of $78.5 million, or $2.43 per diluted share,
1
for FY 2018 (non-GAAP measures). FY 2019 NIM expanded 17 basis points to 2.75% from FY 2018 NIM of 2.58% (non-GAAP measures).
| (Dollars in thousands, except earnings per share amounts) | |||||||||||||||||||||||||||||||||||||||||||||||
| Net Income to Common Shareholders (GAAP) | |||||||||||||||||||||||||||||||||||||||||||||||
| Q4 2019 | EPS | Q4 2018 | EPS | FY 2019 | EPS | FY 2018 | EPS | ||||||||||||||||||||||||||||||||||||||||
| Customers Bank Business Banking | $ | 22,218 | $ | 0.70 | $ | 17,521 | $ | 0.55 | $ | 69,751 | $ | 2.20 | $ | 70,698 | $ | 2.19 | |||||||||||||||||||||||||||||||
| BankMobile | 1,693 | 0.05 | (3,274) | (0.10) | (4,883) | (0.15) | (13,462) | (0.42) | |||||||||||||||||||||||||||||||||||||||
| Consolidated | $ | 23,911 | $ | 0.75 | $ | 14,247 | $ | 0.44 | $ | 64,868 | $ | 2.05 | $ | 57,236 | $ | 1.78 | |||||||||||||||||||||||||||||||
| Core Earnings (Non-GAAP Measure) | |||||||||||||||||||||||||||||||||||||||||||||||
| Q4 2019 | EPS | Q4 2018 | EPS | FY 2019 | EPS | FY 2018 | EPS | ||||||||||||||||||||||||||||||||||||||||
| Customers Bank Business Banking | $ | 22,503 | $ | 0.71 | $ | 19,911 | $ | 0.62 | $ | 75,235 | $ | 2.38 | $ | 88,633 | $ | 2.75 | |||||||||||||||||||||||||||||||
| BankMobile | 1,769 | 0.06 | (2,919) | (0.09) | (4,034) | (0.13) | (10,150) | (0.31) | |||||||||||||||||||||||||||||||||||||||
| Consolidated | $ | 24,272 | $ | 0.76 | $ | 16,992 | $ | 0.53 | $ | 71,202 | $ | 2.25 | $ | 78,483 | $ | 2.43 | |||||||||||||||||||||||||||||||
•Total assets were $11.5 billion at December 31, 2019, compared to $11.7 billion at September 30, 2019 and $9.8 billion at December 31, 2018. Total assets at December 31, 2019 reflected a change in management's strategy to expand beyond $10 billion in assets during the quarter.
•Loan mix improved year-over-year, as commercial and industrial ("C&I") loans and leases, excluding commercial loans to mortgage companies, increased $487 million, or 26%. Commercial loans to mortgage companies increased $844 million, or 58%, year-over-year as the continued low interest rate environment resulted in a higher 2019 year-end balance than historically experienced. Other consumer loans increased $1.1 billion year-over-year. Multi-family loans decreased $893 million, or 27%, year-over-year, consistent with management's strategy to reduce its overall exposure in this loan portfolio.
•Total deposits increased $1.5 billion, or 21%, year-over-year, which included a $653 million, or 34%, increase in demand deposits.
•The BankMobile segment reported Q4 2019 GAAP earnings per diluted share of $0.05, an increase of $0.15 from a loss per diluted share of $(0.10) in Q4 2018 and the second consecutive quarter of segment profitability.
•NIM (a non-GAAP measure) expanded 6 basis points from Q3 2019 to 2.89% in Q4 2019 and up 32 basis points over Q4 2018; this marks our fifth consecutive quarter of NIM expansion from the trough of 2.47% reported in Q3 2018.
•Core earnings in Q4 2019 was impacted by a $0.8 million ($0.02 per diluted share) loss realized from the sale of non-qualifying ("non-QM") residential mortgage loans and a $0.3 million ($0.01 per diluted share) gain on investment securities.
•Core earnings in FY 2019 was impacted by a loss upon acquisition of interest-only GNMA securities of $7.5 million ($0.18 per diluted share), $2.3 million ($0.06 per diluted share) of gains on investment securities, $2 million ($0.05 per diluted share) of legal reserve accruals, a $0.8 million ($0.02 per diluted share) loss realized from the sale of non-QM residential mortgage loans and $0.5 million ($0.01 per diluted share) of severance expense.
•The return on average assets ("ROAA") was 0.97% in Q4 2019, up from 0.95% in Q3 2019 and 0.71% in Q4 2018. Core ROAA (a non-GAAP measure) was 0.98% in Q4 2019, up from 0.94% in Q3 2019 and 0.82% in Q4 2018.
•The pre-tax and pre-provision adjusted ROAA (a non-GAAP measure) for Q4 2019 was 1.59%, up from 1.38% in Q3 2019 and 1.12% in Q4 2018.
2
•The return on average common equity ("ROCE") was 11.58 % in Q4 2019 compared to 11.81% in Q3 2019 and up from 7.58% in Q4 2018. Core ROCE (a non-GAAP measure) was 11.76% in Q4 2019, up from 11.59% in Q3 2019 and 9.05% in Q4 2018.
•Asset quality remains strong. Non-performing loans were only 0.21% of total loans and leases at December 31, 2019 and reserves equaled 265% of non-performing loans. Net charge-offs were only $4.4 million, or 18 basis points of average total loans and leases on an annualized basis, during Q4 2019.
•Reflecting changes in loan mix, the provision for loan losses was $9.7 million in Q4 2019, compared to $4.4 million in Q3 2019 and $1.4 million in Q4 2018.
•Q4 2019 book value per common share was $26.66 and tangible book value per common share (a non-GAAP measure) was $26.17. Tangible book value per common share has increased at a compound annual growth rate of about 10% over the past five years.
•On December 9, 2019, Customers Bancorp completed a public offering of $74.8 million of its 15-year fixed rate 5.375% Subordinated Notes due 2034, which qualifies as Tier 2 capital. $50 million of the net proceeds from that offering were contributed to Customers Bank as qualifying Tier 1 capital.
•Based on the January 17, 2020 closing price of $22.56, Customers Bancorp common equity is trading at 0.86x tangible book value of $26.17 (a non-GAAP measure) and 7.9x the 2020 consensus EPS estimate of $2.84.
Jay Sidhu, CEO and Chairman of Customers Bancorp, Inc. stated, "We are pleased to report that we ended Q4 2019 with record earnings, superior asset quality, strong control in expenses, and our fifth consecutive quarter of net interest margin expansion, a reflection of improved loan mix, core deposit growth, disciplined pricing strategy and absolute focus on efficiency improvement and risk management. We are also excited that BankMobile attained profitability for the second consecutive quarter and its White Label banking strategy has already generated over $80 million of very low-cost deposits to Customers, a number that is expected to grow over time."
3
Status Report on Strategic Priorities Articulated at Analyst Day in October 2018
Improve Profitability: Target a 2.75% NIM by Q4 2019 and a 1.25% Core ROAA in 2-3 years
As stated during our 2018 Analysts Day in October 2018, Customers expects to remain focused on growing its core businesses, while improving margins, capital and profitability. Through favorable mix shifts in both assets and liabilities, while maintaining its superior credit quality culture and extreme focus on productivity improvement, Customers improved the overall quality of its balance sheet and deposit franchise, expanded its net interest margin, enhanced liquidity and remains relatively neutral to interest rate changes. The strategies articulated at the 2018 Analysts Day in October 2018 and subsequent 2019 progress are summarized below:
• | Target ROAA in top quartile of peer group, which we expect will equate to a ROAA of 1.25% or higher over the next 2-3 years. ROAA was 0.97% in Q4 2019, up significantly from Q4 2018 ROAA of 0.71%. The pre-tax and pre-provision adjusted ROAA (a non-GAAP measure) was 1.59% for Q4 2019, up from 1.12% in Q4 2018. | ||||
• | Achieve NIM expansion to 2.75% or greater by Q4 2019, with a full year 2019 NIM above 2.70%, through an expected shift in asset and funding mix. Actual results are materially better. NIM was 2.89% in Q4 2019, up from 2.83% in Q3 2019 and 2.57% in Q4 2018. FY 2019 NIM was 2.75%, up from FY 2018 NIM of 2.58%. Since Q3 2018, Customers effectively restructured its balance sheet resulting in NIM expansion of 42 basis points (non-GAAP measures). | ||||
• | BankMobile growth and maturity was expected with profitability achieved by year end 2019. BankMobile reached profitability in Q3 2019 and maintained profitability in Q4 2019. BankMobile is expected to remain profitable in 2020. | ||||
• | Expense control. Customers' efficiency ratio was 56.98% in Q4 2019, down from 61.58% in Q3 2019 and 69.99% in Q4 2018. Customers' efficiency ratio for FY 2019 was 65.15%, down from 65.35% for FY 2018. | ||||
• | Growth in core deposits and good quality higher-yielding loans. Demand Deposit Accounts ("DDAs") grew 34% year-over-year. Lower yielding multi-family loans decreased by $893 million, or 27%, year-over-year and were replaced by higher yielding C&I loans and leases and other consumer loans, which had net growth of $487 million and $1.1 billion year-over-year, respectively. | ||||
• | Maintain strong credit quality and superior risk management. Non-Performing Loans ("NPLs") were only 0.21% of total loans and leases at December 31, 2019. Reserves to NPLs at December 31, 2019 were 265%, an improvement from 147% at December 31, 2018. The Bank is relatively neutral to interest rate changes at December 31, 2019. We remain very focused on a strong Risk Management culture throughout the company. | ||||
• | Evaluate opportunities to redeem our preferred stock as it becomes callable. Redeeming all of the preferred stock as it becomes callable would result in an increase to our diluted earnings per share by approximately $0.46 annually. Customers will continue to analyze the best ways to execute this strategy over the next two years, subject to liquidity and capital needs. | ||||
Focus on Capital Allocation
The tangible common equity to tangible assets ratio (a non-GAAP measure) was 7.13% and the estimated common equity Tier 1 capital to risk-weighted assets ratio was 8.00% at December 31, 2019, while the leverage ratio was 9.26%. Capital ratios increased from Q3 2019. Customers Bancorp, Inc. also raised $74.8 million in 15-year fixed rate subordinated notes during Q4 2019, $50.0 million of which was contributed to Customers Bank as qualifying Tier 1 capital with the remaining net proceeds retained by Customers Bancorp increasing its liquidity position. Mr. Sidhu stated, "As capital builds, we will evaluate the best uses for our excess capital, which may include calling our preferred equity as it becomes callable, starting in 2020."
4
BankMobile Segment Update
BankMobile, a division of Customers Bank, operates a branchless digital bank offering low cost banking services to over two million Americans, with approximately 1.1 million active deposit customers. Customers reported in Q4 2018 that it expects to retain BankMobile for up to a 2-3 year period, but will regularly evaluate the best options for BankMobile.
BankMobile deposits averaged $543 million in Q4 2019, with an average cost of just 0.21%, and Q4 2019 revenues were $22.3 million and FY 2019 revenues were $86.4 million. The Q4 2019 segment earnings increased to $1.7 million, or $0.05 per diluted share, compared to a net loss of $3.3 million, or $(0.10) per diluted share in Q4 2018, principally due to an increase in net interest income, partially offset by an increase in provision for loan losses. BankMobile had its second consecutive quarter of profitability and is expected to remain profitable in 2020. "We remain in the investment mode for our white label and other unique Banking as a Service ("BaaS") strategic opportunities for BankMobile," stated Luvleen Sidhu, President and Chief Executive Officer of BankMobile. "The profitability improvement has come from increasing revenues from our student banking business while watching our expenses. We are very optimistic about our longer term opportunities to supplement this profitability and growth with continued expansion of our BaaS business," Luvleen Sidhu concluded. "Since Customers Bancorp, Inc. decided to cross the $10 billion asset mark at December 31, 2019, Customers will explore all strategic options for BankMobile in 2020," concluded Jay Sidhu, Customers Bancorp, Inc. CEO and Chairman.
5
Q4 2019 Overview
The following table presents a summary of key earnings and performance metrics for the quarter ended December 31, 2019, the preceding four quarters, and the twelve months ended December 31, 2019 and 2018, respectively:
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | ||||||||||||||||||||||||||
| EARNINGS SUMMARY - UNAUDITED | ||||||||||||||||||||||||||
| (Dollars in thousands, except per share data and stock price data) | Q4 | Q3 | Q2 | Q1 | Q4 | Twelve Months Ended December 31, | ||||||||||||||||||||
| 2019 | 2019 | 2019 | 2019 | 2018 | 2019 | 2018 | ||||||||||||||||||||
| GAAP Profitability Metrics: | ||||||||||||||||||||||||||
| Net income available to common shareholders | $ | 23,911 | $ | 23,451 | $ | 5,681 | $ | 11,825 | $ | 14,247 | $ | 64,868 | $ | 57,236 | ||||||||||||
| Per share amounts: | ||||||||||||||||||||||||||
| Earnings per share - basic | $ | 0.76 | $ | 0.75 | $ | 0.18 | $ | 0.38 | $ | 0.45 | $ | 2.08 | $ | 1.81 | ||||||||||||
| Earnings per share - diluted | $ | 0.75 | $ | 0.74 | $ | 0.18 | $ | 0.38 | $ | 0.44 | $ | 2.05 | $ | 1.78 | ||||||||||||
Book value per common share (1) | $ | 26.66 | $ | 25.66 | $ | 24.80 | $ | 24.44 | $ | 23.85 | $ | 26.66 | $ | 23.85 | ||||||||||||
CUBI stock price (1) | $ | 23.81 | $ | 20.74 | $ | 21.00 | $ | 18.31 | $ | 18.20 | $ | 23.81 | $ | 18.20 | ||||||||||||
CUBI stock price as % of book value (1) | 89 | % | 81 | % | 85 | % | 75 | % | 76 | % | 89 | % | 76 | % | ||||||||||||
| Average shares outstanding - basic | 31,306,813 | 31,223,777 | 31,154,292 | 31,047,191 | 31,616,740 | 31,183,841 | 31,570,118 | |||||||||||||||||||
| Average shares outstanding - diluted | 31,876,341 | 31,644,728 | 31,625,741 | 31,482,867 | 32,051,030 | 31,646,216 | 32,233,098 | |||||||||||||||||||
Shares outstanding (1) | 31,336,791 | 31,245,776 | 31,202,023 | 31,131,247 | 31,003,028 | 31,336,791 | 31,003,028 | |||||||||||||||||||
| Return on average assets ("ROAA") | 0.97 | % | 0.95 | % | 0.36 | % | 0.64 | % | 0.71 | % | 0.74 | % | 0.69 | % | ||||||||||||
| Return on average common equity ("ROCE") | 11.58 % | 11.81 | % | 2.96 | % | 6.38 | % | 7.58 | % | 8.30 | % | 7.90 | % | |||||||||||||
| Efficiency ratio | 56.98 % | 61.58 | % | 77.32 | % | 68.32 | % | 69.99 | % | 65.15 | % | 65.35 | % | |||||||||||||
Non-GAAP Profitability Metrics (2): | ||||||||||||||||||||||||||
| Core earnings | $ | 24,272 | $ | 23,024 | $ | 12,083 | $ | 11,823 | $ | 16,992 | $ | 71,202 | $ | 78,483 | ||||||||||||
| Per share amounts: | ||||||||||||||||||||||||||
| Core earnings per share - diluted | $ | 0.76 | $ | 0.73 | $ | 0.38 | $ | 0.38 | $ | 0.53 | $ | 2.25 | $ | 2.43 | ||||||||||||
Tangible book value per common share (1) | $ | 26.17 | $ | 25.16 | $ | 24.30 | $ | 23.92 | $ | 23.32 | $ | 26.17 | $ | 23.32 | ||||||||||||
CUBI stock price as % of tangible book value (1) | 91 | % | 82 | % | 86 | % | 77 | % | 78 | % | 91 | % | 78 | % | ||||||||||||
| Net interest margin, tax equivalent | 2.89 | % | 2.83 | % | 2.64 | % | 2.59 | % | 2.57 | % | 2.75 | % | 2.58 | % | ||||||||||||
Tangible common equity to tangible assets (1) | 7.13 | % | 6.71 | % | 6.79 | % | 7.35 | % | 7.36 | % | 7.13 | % | 7.36 | % | ||||||||||||
| Core ROAA | 0.98 | % | 0.94 | % | 0.61 | % | 0.64 | % | 0.82 | % | 0.80 | % | 0.89 | % | ||||||||||||
| Core ROCE | 11.76 | % | 11.59 | % | 6.31 | % | 6.38 | % | 9.05 | % | 9.11 | % | 10.83 | % | ||||||||||||
| Adjusted pre-tax pre-provision net income | $ | 45,238 | $ | 39,178 | $ | 25,446 | $ | 25,036 | $ | 27,957 | $ | 134,895 | $ | 124,410 | ||||||||||||
| Adjusted ROAA - pre-tax and pre-provision | 1.59 | % | 1.38 | % | 0.98 | % | 1.04 | % | 1.12 | % | 1.26 | % | 1.19 | % | ||||||||||||
| Adjusted ROCE - pre-tax and pre-provision | 20.16 | % | 17.91 | % | 11.39 | % | 11.57 | % | 12.96 | % | 15.40 | % | 15.18 | % | ||||||||||||
| Core efficiency ratio | 56.45 | % | 59.51 | % | 69.90 | % | 68.32 | % | 66.18 | % | 62.96 | % | 63.23 | % | ||||||||||||
| Asset Quality: | ||||||||||||||||||||||||||
| Net charge-offs | $ | 4,362 | $ | 1,761 | $ | 637 | $ | 1,060 | $ | 2,154 | $ | 7,821 | $ | 3,685 | ||||||||||||
| Annualized net charge-offs to average total loans and leases | 0.18 | % | 0.07 | % | 0.03 | % | 0.05 | % | 0.10 | % | 0.08 | % | 0.04 | % | ||||||||||||
Non-performing loans ("NPLs") to total loans and leases (1) | 0.21 | % | 0.17 | % | 0.15 | % | 0.26 | % | 0.32 | % | 0.21 | % | 0.32 | % | ||||||||||||
Reserves to NPLs (1) | 264.67 | % | 290.38 | % | 330.36 | % | 194.15 | % | 147.16 | % | 264.67 | % | 147.16 | % | ||||||||||||
Regulatory Ratios (3): | ||||||||||||||||||||||||||
| Common equity Tier 1 capital to risk-weighted assets | 8.00 | % | 7.81 | % | 8.04 | % | 8.91 | % | 8.96 | % | 8.00 | % | 8.96 | % | ||||||||||||
| Tier 1 capital to risk-weighted assets | 10.11 | % | 9.95 | % | 10.32 | % | 11.47 | % | 11.58 | % | 10.11 | % | 11.58 | % | ||||||||||||
| Total capital to risk-weighted assets | 12.21 | % | 11.36 | % | 11.76 | % | 12.92 | % | 13.00 | % | 12.21 | % | 13.00 | % | ||||||||||||
| Tier 1 capital to average assets (leverage ratio) | 9.26 | % | 9.01 | % | 9.51 | % | 10.01 | % | 9.66 | % | 9.26 | % | 9.66 | % | ||||||||||||
| (1) Metric is a spot balance for the last day of each quarter presented. | ||||||||||||||||||||||||||
| (2) Non-GAAP measures exclude investment securities gains and losses, severance expense, merger and acquisition-related expenses, losses realized from the sale of lower-yielding multi-family loans, losses realized from the sale of non-QM residential mortgage loans, loss upon acquisition of interest-only GNMA securities, legal reserves and goodwill and intangible assets. These notable items are not included in Customers' disclosures of core earnings and other core profitability metrics. Please note that not each of the aforementioned adjustments affected the reported amount in each of the periods presented. Customers' reasons for the use of these non-GAAP measures and a detailed reconciliation between the non-GAAP measures and the comparable GAAP amounts are included at the end of this document. | ||||||||||||||||||||||||||
(3) Regulatory capital ratios are estimated for Q4 2019. | ||||||||||||||||||||||||||
6
Net Interest Income
FY 2019 net interest income was $277.3 million, up almost $20 million from $257.9 million for FY 2018. Net interest income totaled $77.6 million in Q4 2019, an increase of $1.9 million from Q3 2019, primarily due to an increase in the average balance of non-interest bearing deposits of about $150 million and a 16 basis point decline in the cost of interest-bearing liabilities. Compared to Q3 2019, total loan yields decreased 11 basis points to 4.68%. The cost of interest-bearing deposits in Q4 2019 decreased by 18 basis points due to two Federal Reserve interest rate cuts in September 2019 and October 2019. Borrowing costs increased 5 basis points to 2.91% due to the issuance of $25 million in five-year 4.5% senior notes in September 2019 and $74.8 million in 15-year 5.375% subordinated notes in December 2019, partially offset by two Federal Reserve interest rate cuts in September 2019 and October 2019.
Q4 2019 net interest income increased $16.1 million from Q4 2018, primarily due to 32 basis points of NIM (a non-GAAP measure) expansion and a $1.2 billion increase in average interest-earning assets. Compared to Q4 2018, total loan yields increased 31 basis points to 4.68%. Given Federal Reserve interest rate hikes in 2018 and interest rate cuts in the second half of 2019, the cost of interest-bearing liabilities remained flat at 2.17%.
Total loans and leases increased $1.5 billion, or 17.6%, to $10.1 billion at December 31, 2019 compared to the year-ago period. Mortgage warehouse loans increased $844 million to $2.3 billion, C&I loans and leases increased $487 million to $2.4 billion, commercial real estate non-owner occupied loans increased $98 million to $1.2 billion and other consumer loans increased $1.1 billion to $1.2 billion. These increases were offset in part by planned decreases in multi-family loans of $893 million to $2.4 billion and residential mortgages of $190 million to $378 million.
Total deposits increased $1.5 billion, or 21.1%, to $8.6 billion at December 31, 2019 compared to the year-ago period. Total demand deposits increased $653 million, or 33.9%, to $2.6 billion, savings deposits increased $535 million, or 139.0%, to $919 million, and money market deposits increased $385 million, or 12.4%, to $3.5 billion. These increases were offset in part by a decrease in time deposits of $66 million, or 3.8%, to $1.7 billion. In July 2018, Customers launched a new digital, on-line savings banking product with a goal of gathering retail deposits. At December 31, 2019, this new product generated $863 million in retail deposits, an increase of $330 million since September 30, 2019.
Provision, Credit Quality and Risk Management
The provision for loan and lease losses totaled $24.2 million for FY 2019, up from $5.6 million in FY 2018, while NPLs to total loans and leases improved to 0.21% at December 31, 2019 from 0.32% at December 31, 2018. The provision for loan and lease losses totaled $9.7 million in Q4 2019, compared to $4.4 million in Q3 2019 and $1.4 million in Q4 2018. The Q4 2019 provision expense included $5.0 million for quarter-over-quarter changes in the mix of the loan portfolio and $0.5 million for specifically identified loans. Net charge-offs for Q4 2019 were $4.4 million, or 18 basis points of average loans and leases on an annualized basis, compared to net charge-offs of $1.8 million, or 7 basis points in Q3 2019, and $2.2 million, or 10 basis points in Q4 2018.
Risk management is a critical component of how Customers creates long-term shareholder value, and Customers believes that asset quality is one of the most important risks in banking to be understood and managed. Customers believes that asset quality risks must be diligently addressed during good economic times with prudent underwriting standards so that when the economy deteriorates the bank's capital is sufficient to absorb all losses without threatening its ability to operate and serve its community and other constituents. "Customers' non-performing loans at December 31, 2019 were only 0.21% of total loans and leases, compared to our peer group non-performing loans of approximately 0.74% in the most recent period available, and industry average non-performing loans of 1.03% in the most recent period available. Our expectation is superior asset quality performance in good times and in difficult years," said Mr. Sidhu.
7
Non-Interest Income
Non-interest income totaled $80.9 million for FY 2019, an increase of $21.9 million compared to FY 2018. Non-interest income totaled $25.8 million in Q4 2019, an increase of $2.4 million compared to Q3 2019. The increase in non-interest income primarily resulted from increases of $2.8 million in gains on sales of SBA loans, $2.4 million in other non-interest income and $0.8 million in commercial lease income, partially offset by decreases of $1.0 million in gains on sales of investment securities, $1.0 million in unrealized gains on investment securities, $0.9 million in mortgage banking income and $0.4 million in interchange and card revenue. The increase in gains on sales of SBA loans resulted from a strategic shift to no longer retain all SBA loans on our balance sheet in Q4 2019. The increase in other non-interest income primarily resulted from derivative transactions and the increase in commercial lease income resulted from the continued growth of our Equipment Finance Group. The decrease in gain on sales of investment securities resulted from the gain realized from the sale of $95 million of corporate bonds during Q3 2019. The decrease in unrealized gains on investment securities primarily resulted from a smaller improvement in the fair values of the interest-only GNMA securities and equity securities issued by a foreign entity during Q4 2019. The decrease in mortgage banking income primarily resulted from a $0.8 million loss realized from the sale of $230 million of non-QM residential mortgage loans in Q4 2019. The decrease in interchange and card revenue primarily resulted from a seasonal decrease in activity at BankMobile, coinciding with the end of the academic semester.
Non-Interest Expense
Non-interest expense totaled $231.9 million for FY 2019, an increase of $11.7 million compared to FY 2018. Non-interest expense totaled $58.7 million in Q4 2019, a decrease of $0.9 million compared to Q3 2019. The decrease in non-interest expense in Q4 2019 primarily resulted from decreases of $2.6 million in provision for operating losses, $1.9 million in professional services and $1.9 million in other non-interest expense, partially offset by increases of $3.3 million in FDIC assessments, $1.6 million in technology and $0.5 million in salaries and employee benefits. The decrease in the provision for operating losses primarily resulted from an internet-based organized crime ring which targeted BankMobile checking accounts in Q3 2019. The decrease in professional services primarily resulted from successful concentrated cost savings initiatives in Q4 2019. The decrease in other non-interest expense primarily resulted from legal reserve accruals totaling $2.0 million recognized in Q3 2019 for previously disclosed legal matters. The increase in FDIC assessments primarily resulted from a $2.6 million small bank assessment credit provided by the FDIC in Q3 2019 related to Customers' contribution to the growth of the FDIC's deposit insurance fund since July 2016. The increase in technology primarily resulted from continued investment in Customers' digital transformation initiatives. The increase in salaries and employee benefits primarily resulted from an increase in full-time equivalents.
Taxes
Customers' effective tax rate was 21.3% for Q4 2019, compared to 22.9% for Q3 2019 and 22.2% for Q4 2018. The decrease in the effective tax rate from Q3 2019 and Q4 2018 was primarily driven by strategic initiatives to lower Customers' effective tax rate through effective use of available tax credits and changes in the apportionment of revenues to states with lower tax costs. Customers expects the full-year 2020 effective tax rate to be approximately 22% to 24%.
Significantly Lowering Commercial Real Estate Concentration
Customers' total commercial real estate ("CRE") loan exposures subject to regulatory concentration guidelines of $3.7 billion as of December 31, 2019 included construction loans of $0.1 billion, multi-family loans of $2.4 billion, and non-owner occupied commercial real estate loans of $1.1 billion, which represent 294% of total risk-based capital on a combined basis, a reduction from a 361% commercial real estate concentration as of December 31, 2018. Customers' loans subject to regulatory CRE concentration guidelines had a 3 year cumulative reduction of 16.0% as of the end of Q4 2019, a deceleration from cumulative growth of 10.6% a year ago.
8
Customers' loans collateralized by multi-family properties were approximately 23.8% of Customers' total loan portfolio and approximately 191% of total risk-based capital at December 31, 2019, down from approximately 38.4% and 270%, respectively, at December 31, 2018. Following are some key characteristics of Customers' multi-family loan portfolio:
•Mostly concentrated in New York City with an emphasis on properties subject to some type of rent control; and principally to high net worth families;
•Current average loan size is approximately $6.9 million;
•Current weighted average annual debt service coverage ratio is 1.51x;
•Current weighted average loan-to-value for the portfolio is 60.1%;
•All loans are individually stressed with an increase of 1% and 2% to the cap rate and an increase of 1.5% and 3% in loan interest rates;
•All properties are inspected prior to a loan being granted and inspected thereafter on an annual basis by dedicated portfolio managers or outside inspectors; and
•Credit approval process is independent of customer sales and portfolio management process.
Recap of 2019 and Looking Ahead to 2020 and Beyond
Mr. Sidhu stated, "Customers' core earnings per share was $2.25 for 2019, in line with our internal expectations and higher than targets we had made public. After diligent consideration and analysis, we decided to end 2019 with total assets above $10 billion. This decision reflects our desire and optimism to continue to grow the Customers Bank Business Banking segment while giving careful consideration to the future strategic options for our BankMobile segment."
Looking ahead to 2020, Mr. Sidhu continued "Customers is projecting core earnings per share of $3.00 for 2020 with continued improvement in all profitability metrics." Mr. Sidhu continued, "In addition, management and our Board of Directors have been actively engaged in developing a vision and strategy for 2025 and are pleased to make public our confidence in achieving $6 per share in annual core earnings by the end of 2025."
Conference Call
Date: Thursday, January 23, 2020
Time: 9:00 AM EST
US Dial-in: +1 (800) 368-1029
International Dial-in: +1 (334) 777-6981
Participant Code: 094854
Please dial in at least 10 minutes before the start of the call to ensure timely participation. Slides accompanying the presentation will be available on Customers' website at https://www.customersbank.com/investor-relations/ prior to the call.
Please submit any questions you have regarding the earnings in advance to [email protected] and the executives will address them on the call. Customers will also open the lines to questions following management's presentation of the fourth quarter results. A playback of the call will be available beginning January 23, 2020 at 12:00 PM EST until 12:00 PM EST on February 22, 2020. To listen, call within the United States +1 (888) 203-1112, or +1 (719) 457-0820 when calling internationally. Please use the replay passcode 3422011.
9
Institutional Background
Customers Bancorp, Inc. is a bank holding company located in Wyomissing, Pennsylvania engaged in banking and related businesses through its bank subsidiary, Customers Bank. Customers Bank is a community-based, full-service bank with assets of approximately $11.5 billion at December 31, 2019. A member of the Federal Reserve System with deposits insured by the Federal Deposit Insurance Corporation, Customers Bank is an equal opportunity lender that provides a range of banking services to small and medium-sized businesses, professionals, individuals and families through offices in Pennsylvania, Illinois, New York, Rhode Island, Massachusetts, New Hampshire and New Jersey. Committed to fostering customer loyalty, Customers Bank uses a High Tech/High Touch strategy that includes use of industry-leading technology to provide customers better access to their money, as well as Concierge Banking® by appointment at customers’ homes or offices 12 hours a day, seven days a week. Customers Bank offers a continually expanding portfolio of loans to small businesses, multi-family projects, mortgage companies and consumers.
Customers Bancorp, Inc.'s voting common shares are listed on the New York Stock Exchange under the symbol CUBI. Additional information about Customers Bancorp, Inc. can be found on the Company’s website, www.customersbank.com.
“Safe Harbor” Statement
In addition to historical information, this press release may contain ''forward-looking statements'' within the meaning of the ''safe harbor'' provisions of the Private Securities Litigation Reform Act of 1995. These forward-looking statements include statements with respect to Customers Bancorp, Inc.'s strategies, goals, beliefs, expectations, estimates, intentions, capital raising efforts, financial condition and results of operations, future performance and business. Statements preceded by, followed by, or that include the words ''may,'' ''could,'' ''should,'' ''pro forma,'' ''looking forward,'' ''would,'' ''believe,'' ''expect,'' ''anticipate,'' ''estimate,'' ''intend,'' ''plan,'' or similar expressions generally indicate a forward-looking statement. These forward-looking statements involve risks and uncertainties that are subject to change based on various important factors (some of which, in whole or in part, are beyond Customers Bancorp, Inc.'s control). Numerous competitive, economic, regulatory, legal and technological factors, among others, could cause Customers Bancorp, Inc.'s financial performance to differ materially from the goals, plans, objectives, intentions and expectations expressed in such forward-looking statements. In addition, important factors relating to the acquisition of the Disbursements business, the combination of Customers' BankMobile business with the acquired Disbursements business, the implementation of Customers Bancorp, Inc.'s strategy to retain BankMobile for 2-3 years, the possibility that the expected benefits of retaining BankMobile for 2-3 years may not be achieved, or the possible effects on Customers' results of operations if BankMobile is never divested could cause Customers Bancorp's actual results to differ from those in the forward-looking statements. Customers Bancorp, Inc. cautions that the foregoing factors are not exclusive, and neither such factors nor any such forward-looking statement takes into account the impact of any future events. All forward-looking statements and information set forth herein are based on management's current beliefs and assumptions as of the date hereof and speak only as of the date they are made. For a more complete discussion of the assumptions, risks and uncertainties related to our business, you are encouraged to review Customers Bancorp, Inc.'s filings with the Securities and Exchange Commission, including its most recent annual report on Form 10-K for the year ended December 31, 2018, subsequently filed quarterly reports on Form 10-Q and current reports on Form 8-K, including any amendments thereto, that update or provide information in addition to the information included in the Form 10-K and Form 10-Q filings, if any. Customers Bancorp, Inc. does not undertake to update any forward-looking statement whether written or oral, that may be made from time to time by Customers Bancorp, Inc. or by or on behalf of Customers Bank.
10
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| CONSOLIDATED STATEMENTS OF OPERATIONS - UNAUDITED | |||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | Twelve Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Q4 | Q3 | Q2 | Q1 | Q4 | December 31, | ||||||||||||||||||||||||||||||||||||
| 2019 | 2019 | 2019 | 2019 | 2018 | 2019 | 2018 | |||||||||||||||||||||||||||||||||||
| Interest income: | |||||||||||||||||||||||||||||||||||||||||
| Loans and leases | $ | 116,365 | $ | 118,444 | $ | 103,567 | $ | 93,116 | $ | 94,248 | $ | 431,491 | $ | 373,234 | |||||||||||||||||||||||||||
| Investment securities | 5,125 | 5,867 | 6,481 | 6,241 | 6,277 | 23,713 | 33,209 | ||||||||||||||||||||||||||||||||||
| Other | 2,505 | 2,407 | 1,902 | 1,718 | 2,778 | 8,535 | 11,508 | ||||||||||||||||||||||||||||||||||
| Total interest income | 123,995 | 126,718 | 111,950 | 101,075 | 103,303 | 463,739 | 417,951 | ||||||||||||||||||||||||||||||||||
| Interest expense: | |||||||||||||||||||||||||||||||||||||||||
| Deposits | 35,992 | 38,267 | 35,980 | 31,225 | 34,029 | 141,464 | 110,808 | ||||||||||||||||||||||||||||||||||
| FHLB advances | 6,056 | 7,563 | 7,607 | 5,293 | 3,662 | 26,519 | 31,043 | ||||||||||||||||||||||||||||||||||
| Subordinated debt | 1,930 | 1,684 | 1,684 | 1,684 | 1,684 | 6,983 | 6,737 | ||||||||||||||||||||||||||||||||||
| Other borrowings | 2,424 | 3,469 | 2,000 | 3,569 | 2,404 | 11,463 | 11,486 | ||||||||||||||||||||||||||||||||||
| Total interest expense | 46,402 | 50,983 | 47,271 | 41,771 | 41,779 | 186,429 | 160,074 | ||||||||||||||||||||||||||||||||||
| Net interest income | 77,593 | 75,735 | 64,679 | 59,304 | 61,524 | 277,310 | 257,877 | ||||||||||||||||||||||||||||||||||
| Provision for loan and lease losses | 9,689 | 4,426 | 5,346 | 4,767 | 1,385 | 24,227 | 5,642 | ||||||||||||||||||||||||||||||||||
| Net interest income after provision for loan and lease losses | 67,904 | 71,309 | 59,333 | 54,537 | 60,139 | 253,083 | 252,235 | ||||||||||||||||||||||||||||||||||
| Non-interest income: | |||||||||||||||||||||||||||||||||||||||||
| Interchange and card revenue | 6,506 | 6,869 | 6,760 | 8,806 | 7,568 | 28,941 | 30,695 | ||||||||||||||||||||||||||||||||||
| Deposit fees | 3,616 | 3,642 | 3,348 | 2,209 | 2,099 | 12,815 | 7,824 | ||||||||||||||||||||||||||||||||||
| Commercial lease income | 3,839 | 3,080 | 2,730 | 2,401 | 1,982 | 12,051 | 5,354 | ||||||||||||||||||||||||||||||||||
| Bank-owned life insurance | 1,795 | 1,824 | 1,836 | 1,816 | 1,852 | 7,272 | 7,620 | ||||||||||||||||||||||||||||||||||
| Mortgage warehouse transactional fees | 1,983 | 2,150 | 1,681 | 1,314 | 1,495 | 7,128 | 7,158 | ||||||||||||||||||||||||||||||||||
| Gain (loss) on sale of SBA and other loans | 2,770 | — | — | — | (110) | 2,770 | 3,294 | ||||||||||||||||||||||||||||||||||
| Mortgage banking income (loss) | (635) | 283 | 250 | 167 | 73 | 66 | 606 | ||||||||||||||||||||||||||||||||||
| Loss upon acquisition of interest-only GNMA securities | — | — | (7,476) | — | — | (7,476) | — | ||||||||||||||||||||||||||||||||||
| Gain (loss) on sale of investment securities | — | 1,001 | — | — | — | 1,001 | (18,659) | ||||||||||||||||||||||||||||||||||
| Unrealized gain (loss) on investment securities | 310 | 1,333 | (347) | 2 | (101) | 1,299 | (1,634) | ||||||||||||||||||||||||||||||||||
| Other | 5,629 | 3,187 | 3,254 | 3,003 | 5,019 | 15,071 | 16,740 | ||||||||||||||||||||||||||||||||||
| Total non-interest income | 25,813 | 23,369 | 12,036 | 19,718 | 19,877 | 80,938 | 58,998 | ||||||||||||||||||||||||||||||||||
| Non-interest expense: | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 27,697 | 27,193 | 26,920 | 25,823 | 26,706 | 107,632 | 104,841 | ||||||||||||||||||||||||||||||||||
| Technology, communication and bank operations | 10,370 | 8,755 | 12,402 | 11,953 | 11,531 | 43,481 | 44,454 | ||||||||||||||||||||||||||||||||||
| Professional services | 6,470 | 8,348 | 5,718 | 4,573 | 5,674 | 25,109 | 20,237 | ||||||||||||||||||||||||||||||||||
| Occupancy | 3,470 | 3,661 | 3,064 | 2,903 | 2,933 | 13,098 | 11,809 | ||||||||||||||||||||||||||||||||||
| Commercial lease depreciation | 2,840 | 2,459 | 2,252 | 1,923 | 1,550 | 9,473 | 4,388 | ||||||||||||||||||||||||||||||||||
| FDIC assessments, non-income taxes, and regulatory fees | 2,492 | (777) | 2,157 | 1,988 | 1,892 | 5,861 | 8,642 | ||||||||||||||||||||||||||||||||||
| Provision for operating losses | 1,415 | 3,998 | 2,446 | 1,779 | 1,685 | 9,638 | 5,616 | ||||||||||||||||||||||||||||||||||
| Advertising and promotion | 899 | 976 | 1,360 | 809 | 917 | 4,044 | 2,446 | ||||||||||||||||||||||||||||||||||
| Merger and acquisition related expenses | 100 | — | — | — | 470 | 100 | 4,391 | ||||||||||||||||||||||||||||||||||
| Loan workout | 230 | 495 | 643 | 320 | 360 | 1,687 | 2,183 | ||||||||||||||||||||||||||||||||||
| Other real estate owned (income) expenses | 247 | 108 | (14) | 57 | 285 | 398 | 449 | ||||||||||||||||||||||||||||||||||
| Other | 2,510 | 4,376 | 2,634 | 1,856 | 3,042 | 11,380 | 10,723 | ||||||||||||||||||||||||||||||||||
| Total non-interest expense | 58,740 | 59,592 | 59,582 | 53,984 | 57,045 | 231,901 | 220,179 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense | 34,977 | 35,086 | 11,787 | 20,271 | 22,971 | 102,120 | 91,054 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 7,451 | 8,020 | 2,491 | 4,831 | 5,109 | 22,793 | 19,359 | ||||||||||||||||||||||||||||||||||
| Net income | 27,526 | 27,066 | 9,296 | 15,440 | 17,862 | 79,327 | 71,695 | ||||||||||||||||||||||||||||||||||
| Preferred stock dividends | 3,615 | 3,615 | 3,615 | 3,615 | 3,615 | 14,459 | 14,459 | ||||||||||||||||||||||||||||||||||
| Net income available to common shareholders | $ | 23,911 | $ | 23,451 | $ | 5,681 | $ | 11,825 | $ | 14,247 | $ | 64,868 | $ | 57,236 | |||||||||||||||||||||||||||
| Basic earnings per common share | $ | 0.76 | $ | 0.75 | $ | 0.18 | $ | 0.38 | $ | 0.45 | $ | 2.08 | $ | 1.81 | |||||||||||||||||||||||||||
| Diluted earnings per common share | $ | 0.75 | $ | 0.74 | $ | 0.18 | $ | 0.38 | $ | 0.44 | $ | 2.05 | $ | 1.78 | |||||||||||||||||||||||||||
11
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| CONSOLIDATED BALANCE SHEET - UNAUDITED | |||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||
| December 31, | September 30, | June 30, | March 31, | December 31, | |||||||||||||||||||||||||
| 2019 | 2019 | 2019 | 2019 | 2018 | |||||||||||||||||||||||||
| ASSETS | |||||||||||||||||||||||||||||
| Cash and due from banks | $ | 33,095 | $ | 12,555 | $ | 24,757 | $ | 41,723 | $ | 17,696 | |||||||||||||||||||
| Interest-earning deposits | 179,410 | 169,663 | 71,038 | 75,939 | 44,439 | ||||||||||||||||||||||||
| Cash and cash equivalents | 212,505 | 182,218 | 95,795 | 117,662 | 62,135 | ||||||||||||||||||||||||
| Investment securities, at fair value | 595,876 | 608,714 | 708,359 | 678,142 | 665,012 | ||||||||||||||||||||||||
| Loans held for sale | 486,328 | 502,854 | 5,697 | 1,602 | 1,507 | ||||||||||||||||||||||||
| Loans receivable, mortgage warehouse, at fair value | 2,245,758 | 2,438,530 | 2,001,540 | 1,480,195 | 1,405,420 | ||||||||||||||||||||||||
| Loans and leases receivable | 7,318,988 | 7,336,237 | 7,714,106 | 7,264,049 | 7,138,074 | ||||||||||||||||||||||||
| Allowance for loan and lease losses | (56,379) | (51,053) | (48,388) | (43,679) | (39,972) | ||||||||||||||||||||||||
| Total loans and leases receivable, net of allowance for loan and lease losses | 9,508,367 | 9,723,714 | 9,667,258 | 8,700,565 | 8,503,522 | ||||||||||||||||||||||||
| FHLB, Federal Reserve Bank, and other restricted stock | 84,214 | 81,853 | 101,947 | 80,416 | 89,685 | ||||||||||||||||||||||||
| Accrued interest receivable | 38,072 | 38,412 | 38,506 | 35,716 | 32,955 | ||||||||||||||||||||||||
| Bank premises and equipment, net | 9,389 | 14,075 | 10,095 | 10,542 | 11,063 | ||||||||||||||||||||||||
| Bank-owned life insurance | 272,546 | 270,526 | 268,682 | 266,740 | 264,559 | ||||||||||||||||||||||||
| Other real estate owned | 173 | 204 | 1,076 | 976 | 816 | ||||||||||||||||||||||||
| Goodwill and other intangibles | 15,195 | 15,521 | 15,847 | 16,173 | 16,499 | ||||||||||||||||||||||||
| Other assets | 298,052 | 285,699 | 269,165 | 235,360 | 185,672 | ||||||||||||||||||||||||
| Total assets | $ | 11,520,717 | $ | 11,723,790 | $ | 11,182,427 | $ | 10,143,894 | $ | 9,833,425 | |||||||||||||||||||
| LIABILITIES AND SHAREHOLDERS' EQUITY | |||||||||||||||||||||||||||||
| Demand, non-interest bearing deposits | $ | 1,343,391 | $ | 1,569,918 | $ | 1,380,698 | $ | 1,372,358 | $ | 1,122,171 | |||||||||||||||||||
| Interest-bearing deposits | 7,305,545 | 7,355,767 | 6,805,079 | 6,052,960 | 6,020,065 | ||||||||||||||||||||||||
| Total deposits | 8,648,936 | 8,925,685 | 8,185,777 | 7,425,318 | 7,142,236 | ||||||||||||||||||||||||
| Federal funds purchased | 538,000 | 373,000 | 406,000 | 388,000 | 187,000 | ||||||||||||||||||||||||
| FHLB advances | 850,000 | 1,040,800 | 1,262,100 | 1,025,832 | 1,248,070 | ||||||||||||||||||||||||
| Other borrowings | 123,630 | 123,528 | 99,055 | 123,963 | 123,871 | ||||||||||||||||||||||||
| Subordinated debt | 181,115 | 109,050 | 109,026 | 109,002 | 108,977 | ||||||||||||||||||||||||
| Accrued interest payable and other liabilities | 126,241 | 132,577 | 129,064 | 93,406 | 66,455 | ||||||||||||||||||||||||
| Total liabilities | 10,467,922 | 10,704,640 | 10,191,022 | 9,165,521 | 8,876,609 | ||||||||||||||||||||||||
| Preferred stock | 217,471 | 217,471 | 217,471 | 217,471 | 217,471 | ||||||||||||||||||||||||
| Common stock | 32,617 | 32,526 | 32,483 | 32,412 | 32,252 | ||||||||||||||||||||||||
| Additional paid in capital | 444,218 | 441,499 | 439,067 | 436,713 | 434,314 | ||||||||||||||||||||||||
| Retained earnings | 381,519 | 357,608 | 334,157 | 328,476 | 316,651 | ||||||||||||||||||||||||
| Accumulated other comprehensive loss | (1,250) | (8,174) | (9,993) | (14,919) | (22,663) | ||||||||||||||||||||||||
| Treasury stock, at cost | (21,780) | (21,780) | (21,780) | (21,780) | (21,209) | ||||||||||||||||||||||||
| Total shareholders' equity | 1,052,795 | 1,019,150 | 991,405 | 978,373 | 956,816 | ||||||||||||||||||||||||
| Total liabilities & shareholders' equity | $ | 11,520,717 | $ | 11,723,790 | $ | 11,182,427 | $ | 10,143,894 | $ | 9,833,425 | |||||||||||||||||||
12
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | ||||||||||||||||||||||||||
| AVERAGE BALANCE SHEET / NET INTEREST MARGIN - UNAUDITED | ||||||||||||||||||||||||||
| (Dollars in thousands) | ||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||
| December 31, 2019 | September 30, 2019 | December 31, 2018 | ||||||||||||||||||||||||
| Average Balance | Average Yield or Cost (%) | Average Balance | Average Yield or Cost (%) | Average Balance | Average Yield or Cost (%) | |||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||
| Interest earning deposits | $ | 150,382 | 2.21% | $ | 100,343 | 3.26% | $ | 185,145 | 2.24% | |||||||||||||||||
Investment securities (1) | 584,955 | 3.50% | 652,142 | 3.60% | 697,474 | 3.60% | ||||||||||||||||||||
| Loans and leases: | ||||||||||||||||||||||||||
| Commercial loans to mortgage companies | 2,158,626 | 4.16% | 2,103,612 | 4.58% | 1,409,197 | 5.03% | ||||||||||||||||||||
| Multi-family loans | 2,654,919 | 3.96% | 2,929,650 | 3.91% | 3,445,267 | 3.76% | ||||||||||||||||||||
Commercial and industrial loans and leases (2) | 2,318,313 | 4.79% | 2,159,067 | 5.24% | 1,823,189 | 4.93% | ||||||||||||||||||||
| Non-owner occupied commercial real estate loans | 1,325,630 | 4.55% | 1,294,246 | 4.57% | 1,224,750 | 4.40% | ||||||||||||||||||||
| Residential mortgages | 631,370 | 4.05% | 729,603 | 4.11% | 599,797 | 4.02% | ||||||||||||||||||||
| Other consumer loans | 765,765 | 9.11% | 600,256 | 9.47% | 60,210 | 9.26% | ||||||||||||||||||||
Total loans and leases (3) | 9,854,623 | 4.68% | 9,816,434 | 4.79% | 8,562,410 | 4.37% | ||||||||||||||||||||
| Other interest-earning assets | 86,770 | 7.63% | 98,279 | 6.39% | 73,091 | 9.41% | ||||||||||||||||||||
| Total interest-earning assets | 10,676,730 | 4.61% | 10,667,198 | 4.72% | 9,518,120 | 4.31% | ||||||||||||||||||||
| Non-interest-earning assets | 580,477 | 591,946 | 429,247 | |||||||||||||||||||||||
| Total assets | $ | 11,257,207 | $ | 11,259,144 | $ | 9,947,367 | ||||||||||||||||||||
| Liabilities | ||||||||||||||||||||||||||
| Interest checking accounts | $ | 1,152,349 | 1.65% | $ | 1,014,590 | 1.83% | $ | 767,154 | 1.60% | |||||||||||||||||
| Money market deposit accounts | 3,190,543 | 2.01% | 3,100,975 | 2.22% | 3,391,542 | 2.08% | ||||||||||||||||||||
| Other savings accounts | 722,487 | 2.09% | 561,790 | 2.19% | 350,304 | 1.99% | ||||||||||||||||||||
| Certificates of deposit | 2,012,497 | 2.21% | 2,227,817 | 2.34% | 2,141,598 | 2.11% | ||||||||||||||||||||
Total interest-bearing deposits (4) | 7,077,876 | 2.02% | 6,905,172 | 2.20% | 6,650,598 | 2.03% | ||||||||||||||||||||
| Borrowings | 1,424,550 | 2.91% | 1,770,459 | 2.86% | 983,540 | 3.13% | ||||||||||||||||||||
| Total interest-bearing liabilities | 8,502,426 | 2.17% | 8,675,631 | 2.33% | 7,634,138 | 2.17% | ||||||||||||||||||||
Non-interest-bearing deposits (4) | 1,580,050 | 1,431,810 | 1,261,330 | |||||||||||||||||||||||
| Total deposits and borrowings | 10,082,476 | 1.83% | 10,107,441 | 2.00% | 8,895,468 | 1.86% | ||||||||||||||||||||
| Other non-interest-bearing liabilities | 138,242 | 146,347 | 89,202 | |||||||||||||||||||||||
| Total liabilities | 10,220,718 | 10,253,788 | 8,984,670 | |||||||||||||||||||||||
| Shareholders' equity | 1,036,489 | 1,005,356 | 962,697 | |||||||||||||||||||||||
| Total liabilities and shareholders' equity | $ | 11,257,207 | $ | 11,259,144 | $ | 9,947,367 | ||||||||||||||||||||
| Interest spread | 2.78% | 2.71% | 2.45% | |||||||||||||||||||||||
| Net interest margin | 2.89% | 2.82% | 2.57% | |||||||||||||||||||||||
Net interest margin tax equivalent (5) | 2.89% | 2.83% | 2.57% | |||||||||||||||||||||||
| (1) For presentation in this table, average balances and the corresponding average yields for investment securities are based upon historical cost, adjusted for amortization of premiums and accretion of discounts. | ||||||||||||||||||||||||||
| (2) Includes owner occupied commercial real estate loans. | ||||||||||||||||||||||||||
| (3) Includes non-accrual loans, the effect of which is to reduce the yield earned on loans and leases, and deferred loan fees. | ||||||||||||||||||||||||||
| (4) Total costs of deposits (including interest bearing and non-interest bearing) were 1.65%, 1.82% and 1.71% for the three months ended December 31, 2019, September 30, 2019 and December 31, 2018, respectively. | ||||||||||||||||||||||||||
| (5) Non-GAAP tax-equivalent basis, using an estimated marginal tax rate of 26% for the three months ended December 31, 2019, September 30, 2019 and December 31, 2018, presented to approximate interest income as a taxable asset. Management uses non-GAAP measures to present historical periods comparable to the current period presentation. In addition, management believes the use of these non-GAAP measures provides additional clarity when assessing Customers’ financial results. These disclosures should not be viewed as substitutes for results determined to be in accordance with U.S. GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other entities. | ||||||||||||||||||||||||||
13
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||
| AVERAGE BALANCE SHEET / NET INTEREST MARGIN - UNAUDITED | |||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||
| Twelve Months Ended | |||||||||||||||||
| December 31, 2019 | December 31, 2018 | ||||||||||||||||
| Average Balance | Average Yield or Cost (%) | Average Balance | Average Yield or Cost (%) | ||||||||||||||
| Assets | |||||||||||||||||
| Interest earning deposits | $ | 103,833 | 2.68% | $ | 217,168 | 1.90% | |||||||||||
Investment securities (1) | 653,694 | 3.63% | 1,005,688 | 3.30% | |||||||||||||
| Loans and leases: | |||||||||||||||||
| Commercial loans to mortgage companies | 1,799,489 | 4.58% | 1,610,168 | 4.92% | |||||||||||||
| Multi-family loans | 2,982,185 | 3.87% | 3,549,511 | 3.82% | |||||||||||||
Commercial and industrial loans and leases (2) | 2,111,181 | 5.08% | 1,743,696 | 4.72% | |||||||||||||
| Non-owner occupied commercial real estate loans | 1,243,236 | 4.53% | 1,257,545 | 4.32% | |||||||||||||
| Residential mortgages | 694,889 | 4.15% | 497,772 | 4.05% | |||||||||||||
| Other consumer loans | 445,166 | 9.28% | 20,028 | 8.78% | |||||||||||||
Total loans and leases (3) | 9,276,146 | 4.65% | 8,678,720 | 4.30% | |||||||||||||
| Other interest-earning assets | 90,035 | 6.39% | 110,223 | 6.71% | |||||||||||||
| Total interest-earning assets | 10,123,708 | 4.58% | 10,011,799 | 4.17% | |||||||||||||
| Non-interest-earning assets | 543,962 | 406,303 | |||||||||||||||
| Total assets | $ | 10,667,670 | $ | 10,418,102 | |||||||||||||
| Liabilities | |||||||||||||||||
| Interest checking accounts | $ | 955,630 | 1.82% | $ | 630,335 | 1.49% | |||||||||||
| Money market deposit accounts | 3,151,328 | 2.18% | 3,417,779 | 1.77% | |||||||||||||
| Other savings accounts | 538,375 | 2.12% | 135,994 | 1.67% | |||||||||||||
| Certificates of deposit | 1,943,361 | 2.26% | 2,066,896 | 1.87% | |||||||||||||
Total interest-bearing deposits (4) | 6,588,694 | 2.15% | 6,251,004 | 1.77% | |||||||||||||
| Borrowings | 1,523,171 | 2.95% | 1,951,921 | 2.52% | |||||||||||||
| Total interest-bearing liabilities | 8,111,865 | 2.30% | 8,202,925 | 1.95% | |||||||||||||
Non-interest-bearing deposits (4) | 1,430,149 | 1,189,638 | |||||||||||||||
| Total deposits and borrowings | 9,542,014 | 1.95% | 9,392,563 | 1.70% | |||||||||||||
| Other non-interest-bearing liabilities | 126,325 | 83,563 | |||||||||||||||
| Total liabilities | 9,668,339 | 9,476,126 | |||||||||||||||
| Shareholders' equity | 999,331 | 941,976 | |||||||||||||||
| Total liabilities and shareholders' equity | $ | 10,667,670 | $ | 10,418,102 | |||||||||||||
| Interest spread | 2.63% | 2.47% | |||||||||||||||
| Net interest margin | 2.74% | 2.58% | |||||||||||||||
Net interest margin tax equivalent (5) | 2.75% | 2.58% | |||||||||||||||
| (1) For presentation in this table, average balances and the corresponding average yields for investment securities are based upon historical cost, adjusted for amortization of premiums and accretion of discounts. | |||||||||||||||||
| (2) Includes owner occupied commercial real estate loans. | |||||||||||||||||
| (3) Includes non-accrual loans, the effect of which is to reduce the yield earned on loans and leases, and deferred loan fees. | |||||||||||||||||
| (4) Total costs of deposits (including interest bearing and non-interest bearing) were 1.76% and 1.49% for the twelve months ended December 31, 2019 and December 31, 2018, respectively. | |||||||||||||||||
| (5) Non-GAAP tax-equivalent basis, using an estimated marginal tax rate of 26% for both the year ended December 31, 2019 and 2018, presented to approximate interest income as a taxable asset. Management uses non-GAAP measures to present historical periods comparable to the current period presentation. In addition, management believes the use of these non-GAAP measures provides additional clarity when assessing Customers’ financial results. These disclosures should not be viewed as substitutes for results determined to be in accordance with U.S. GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other entities. | |||||||||||||||||
14
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| SEGMENT REPORTING - UNAUDITED | |||||||||||||||||||||||||||||
(Dollars in thousands, except per share amounts) | |||||||||||||||||||||||||||||
The following tables present Customers' business segment results for the three and twelve months ended December 31, 2019 and 2018:
| Three Months Ended December 31, 2019 | Three Months Ended December 31, 2018 | ||||||||||||||||||||||||||||||||||
| Customers Bank Business Banking | BankMobile | Consolidated | Customers Bank Business Banking | BankMobile | Consolidated | ||||||||||||||||||||||||||||||
Interest income (1) | $ | 112,212 | $ | 11,783 | $ | 123,995 | $ | 98,129 | $ | 5,174 | $ | 103,303 | |||||||||||||||||||||||
| Interest expense | 46,111 | 291 | 46,402 | 41,592 | 187 | 41,779 | |||||||||||||||||||||||||||||
| Net interest income | 66,101 | 11,492 | 77,593 | 56,537 | 4,987 | 61,524 | |||||||||||||||||||||||||||||
| Provision for loan and lease losses | 6,846 | 2,843 | 9,689 | (200) | 1,585 | 1,385 | |||||||||||||||||||||||||||||
| Non-interest income | 14,964 | 10,849 | 25,813 | 9,352 | 10,525 | 19,877 | |||||||||||||||||||||||||||||
| Non-interest expense | 41,494 | 17,246 | 58,740 | 38,778 | 18,267 | 57,045 | |||||||||||||||||||||||||||||
| Income (loss) before income tax expense (benefit) | 32,725 | 2,252 | 34,977 | 27,311 | (4,340) | 22,971 | |||||||||||||||||||||||||||||
| Income tax expense (benefit) | 6,892 | 559 | 7,451 | 6,175 | (1,066) | 5,109 | |||||||||||||||||||||||||||||
| Net income (loss) | 25,833 | 1,693 | 27,526 | 21,136 | (3,274) | 17,862 | |||||||||||||||||||||||||||||
| Preferred stock dividends | 3,615 | — | 3,615 | 3,615 | — | 3,615 | |||||||||||||||||||||||||||||
| Net income (loss) available to common shareholders | $ | 22,218 | $ | 1,693 | $ | 23,911 | $ | 17,521 | $ | (3,274) | $ | 14,247 | |||||||||||||||||||||||
| Basic earnings (loss) per common share | $ | 0.71 | $ | 0.05 | $ | 0.76 | $ | 0.55 | $ | (0.10) | $ | 0.45 | |||||||||||||||||||||||
| Diluted earnings (loss) per common share | $ | 0.70 | $ | 0.05 | $ | 0.75 | $ | 0.55 | $ | (0.10) | $ | 0.44 | |||||||||||||||||||||||
(1) Amounts reported include funds transfer pricing of $0.7 million and $3.8 million for the three months ended December 31, 2019 and 2018, respectively, credited to BankMobile for the value provided to the Customers Bank Business Banking segment for the use of excess low/no cost deposits.
15
| Twelve Months Ended December 31, 2019 | Twelve Months Ended December 31, 2018 | ||||||||||||||||||||||||||||||||||
| Customers Bank Business Banking | BankMobile | Consolidated | Customers Bank Business Banking | BankMobile | Consolidated | ||||||||||||||||||||||||||||||
Interest income (2) | $ | 422,094 | $ | 41,645 | $ | 463,739 | $ | 400,948 | $ | 17,003 | $ | 417,951 | |||||||||||||||||||||||
| Interest expense | 185,513 | 916 | 186,429 | 159,674 | 400 | 160,074 | |||||||||||||||||||||||||||||
| Net interest income | 236,581 | 40,729 | 277,310 | 241,274 | 16,603 | 257,877 | |||||||||||||||||||||||||||||
| Provision for loan and lease losses | 10,091 | 14,136 | 24,227 | 2,928 | 2,714 | 5,642 | |||||||||||||||||||||||||||||
| Non-interest income | 35,268 | 45,670 | 80,938 | 17,499 | 41,499 | 58,998 | |||||||||||||||||||||||||||||
| Non-interest expense | 153,333 | 78,568 | 231,901 | 146,946 | 73,233 | 220,179 | |||||||||||||||||||||||||||||
| Income (loss) before income tax expense (benefit) | 108,425 | (6,305) | 102,120 | 108,899 | (17,845) | 91,054 | |||||||||||||||||||||||||||||
| Income tax expense (benefit) | 24,215 | (1,422) | 22,793 | 23,742 | (4,383) | 19,359 | |||||||||||||||||||||||||||||
| Net income (loss) | 84,210 | (4,883) | 79,327 | 85,157 | (13,462) | 71,695 | |||||||||||||||||||||||||||||
| Preferred stock dividends | 14,459 | — | 14,459 | 14,459 | — | 14,459 | |||||||||||||||||||||||||||||
| Net income (loss) available to common shareholders | $ | 69,751 | $ | (4,883) | $ | 64,868 | $ | 70,698 | $ | (13,462) | $ | 57,236 | |||||||||||||||||||||||
| Basic earnings (loss) per common share | $ | 2.24 | $ | (0.16) | $ | 2.08 | $ | 2.24 | $ | (0.43) | $ | 1.81 | |||||||||||||||||||||||
| Diluted earnings (loss) per common share | $ | 2.20 | $ | (0.15) | $ | 2.05 | $ | 2.19 | $ | (0.42) | $ | 1.78 | |||||||||||||||||||||||
As of December 31, 2019 and 2018 | |||||||||||||||||||||||||||||||||||
| Goodwill and other intangibles | $ | 3,629 | $ | 11,566 | $ | 15,195 | $ | 3,629 | $ | 12,870 | $ | 16,499 | |||||||||||||||||||||||
Total assets (3) | $ | 10,990,550 | $ | 530,167 | $ | 11,520,717 | $ | 9,688,146 | $ | 145,279 | $ | 9,833,425 | |||||||||||||||||||||||
| Total deposits | $ | 8,247,836 | $ | 401,100 | $ | 8,648,936 | $ | 6,766,378 | $ | 375,858 | $ | 7,142,236 | |||||||||||||||||||||||
Total non-deposit liabilities (3) | $ | 1,789,329 | $ | 29,657 | $ | 1,818,986 | $ | 1,719,225 | $ | 15,148 | $ | 1,734,373 | |||||||||||||||||||||||
(2) Amounts reported include funds transfer pricing of $8.8 million and $15.7 million for the twelve months ended December 31, 2019 and 2018, respectively, credited to BankMobile for the value provided to the Customers Bank Business Banking segment for the use of excess low/no cost deposits.
(3) Amounts reported exclude inter-segment receivables.
16
The following tables present Customers' business segment results for the quarter ended December 31, 2019, the preceding four quarters, and the twelve months ended December 31, 2019 and 2018, respectively:
| Customers Bank Business Banking: | Twelve Months Ended December 31, | |||||||||||||||||||||||||||||||||||||||||||
| Q4 2019 | Q3 2019 | Q2 2019 | Q1 2019 | Q4 2018 | 2019 | 2018 | ||||||||||||||||||||||||||||||||||||||
Interest income (1) | $ | 112,212 | $ | 113,995 | $ | 103,014 | $ | 92,871 | $ | 98,129 | $ | 422,094 | $ | 400,948 | ||||||||||||||||||||||||||||||
| Interest expense | 46,111 | 50,734 | 47,061 | 41,605 | 41,592 | 185,513 | 159,674 | |||||||||||||||||||||||||||||||||||||
| Net interest income | 66,101 | 63,261 | 55,953 | 51,266 | 56,537 | 236,581 | 241,274 | |||||||||||||||||||||||||||||||||||||
| Provision for loan and lease losses | 6,846 | 2,475 | (2,206) | 2,976 | (200) | 10,091 | 2,928 | |||||||||||||||||||||||||||||||||||||
| Non-interest income (loss) | 14,964 | 11,757 | 970 | 7,577 | 9,352 | 35,268 | 17,499 | |||||||||||||||||||||||||||||||||||||
| Non-interest expense | 41,494 | 38,347 | 38,107 | 35,384 | 38,778 | 153,333 | 146,946 | |||||||||||||||||||||||||||||||||||||
| Income before income tax expense | 32,725 | 34,196 | 21,022 | 20,483 | 27,311 | 108,425 | 108,899 | |||||||||||||||||||||||||||||||||||||
| Income tax expense | 6,892 | 7,814 | 4,629 | 4,880 | 6,175 | 24,215 | 23,742 | |||||||||||||||||||||||||||||||||||||
| Net income | 25,833 | 26,382 | 16,393 | 15,603 | 21,136 | 84,210 | 85,157 | |||||||||||||||||||||||||||||||||||||
| Preferred stock dividends | 3,615 | 3,615 | 3,615 | 3,615 | 3,615 | 14,459 | 14,459 | |||||||||||||||||||||||||||||||||||||
| Net income available to common shareholders | $ | 22,218 | $ | 22,767 | $ | 12,778 | $ | 11,988 | $ | 17,521 | $ | 69,751 | $ | 70,698 | ||||||||||||||||||||||||||||||
| Basic earnings per common share | $ | 0.71 | $ | 0.73 | $ | 0.41 | $ | 0.39 | $ | 0.55 | $ | 2.24 | $ | 2.24 | ||||||||||||||||||||||||||||||
| Diluted earnings per common share | $ | 0.70 | $ | 0.72 | $ | 0.40 | $ | 0.38 | $ | 0.55 | $ | 2.20 | $ | 2.19 | ||||||||||||||||||||||||||||||
(1) Amounts reported include funds transfer pricing of $0.7 million, $0.3 million, $2.2 million, $5.6 million and $3.8 million for the three months ended December 31, 2019, September 30, 2019, June 30, 2019, March 31, 2019, and December 31, 2018, respectively. Amounts reported also include funds transfer pricing of $8.8 million and $15.7 million for the twelve months ended December 31, 2019 and 2018, respectively. These amounts are credited to BankMobile for the value provided to the Customers Bank Business Banking segment for the use of excess low/no cost deposits.
| BankMobile: | Twelve Months Ended December 31, | |||||||||||||||||||||||||||||||||||||||||||
| Q4 2019 | Q3 2019 | Q2 2019 | Q1 2019 | Q4 2018 | 2019 | 2018 | ||||||||||||||||||||||||||||||||||||||
Interest income (2) | $ | 11,783 | $ | 12,723 | $ | 8,936 | $ | 8,204 | $ | 5,174 | $ | 41,645 | $ | 17,003 | ||||||||||||||||||||||||||||||
| Interest expense | 291 | 249 | 210 | 166 | 187 | 916 | 400 | |||||||||||||||||||||||||||||||||||||
| Net interest income | 11,492 | 12,474 | 8,726 | 8,038 | 4,987 | 40,729 | 16,603 | |||||||||||||||||||||||||||||||||||||
| Provision for loan and lease losses | 2,843 | 1,951 | 7,552 | 1,791 | 1,585 | 14,136 | 2,714 | |||||||||||||||||||||||||||||||||||||
| Non-interest income | 10,849 | 11,612 | 11,066 | 12,141 | 10,525 | 45,670 | 41,499 | |||||||||||||||||||||||||||||||||||||
| Non-interest expense | 17,246 | 21,245 | 21,475 | 18,600 | 18,267 | 78,568 | 73,233 | |||||||||||||||||||||||||||||||||||||
| Loss before income tax expense or benefit | 2,252 | 890 | (9,235) | (212) | (4,340) | (6,305) | (17,845) | |||||||||||||||||||||||||||||||||||||
| Income tax benefit | 559 | 206 | (2,138) | (49) | (1,066) | (1,422) | (4,383) | |||||||||||||||||||||||||||||||||||||
| Net loss available to common shareholders | $ | 1,693 | $ | 684 | $ | (7,097) | $ | (163) | $ | (3,274) | $ | (4,883) | $ | (13,462) | ||||||||||||||||||||||||||||||
| Basic loss per common share | $ | 0.05 | $ | 0.02 | $ | (0.23) | $ | (0.01) | $ | (0.10) | $ | (0.16) | $ | (0.43) | ||||||||||||||||||||||||||||||
| Diluted loss per common share | $ | 0.05 | $ | 0.02 | $ | (0.22) | $ | (0.01) | $ | (0.10) | $ | (0.15) | $ | (0.42) | ||||||||||||||||||||||||||||||
Deposit balances (3) | ||||||||||||||||||||||||||||||||||||||||||||
| Disbursements business deposits | $ | 319,263 | $ | 598,064 | $ | 409,683 | $ | 615,710 | $ | 370,690 | ||||||||||||||||||||||||||||||||||
| White label deposits | 81,837 | 67,541 | 46,514 | 11,046 | 5,168 | |||||||||||||||||||||||||||||||||||||||
| Total deposits | $ | 401,100 | $ | 665,605 | $ | 456,197 | $ | 626,756 | $ | 375,858 | ||||||||||||||||||||||||||||||||||
(2) Amounts reported include funds transfer pricing of $0.7 million, $0.3 million, $2.2 million, $5.6 million and $3.8 million for the three months ended December 31, 2019, September 30, 2019, June 30, 2019, March 31, 2019, and December 31, 2018, respectively. Amounts reported also include funds transfer pricing of $8.8 million and $15.7 million for the twelve months ended December 31, 2019 and 2018, respectively. These amounts are credited to BankMobile for the value provided to the Customers Bank Business Banking segment for the use of excess low/no cost deposits.
(3) As of December 31, 2019, September 30, 2019, June 30, 2019, March 31, 2019, and December 31, 2018.
17
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| PERIOD END LOAN AND LEASE COMPOSITION - UNAUDITED | |||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||
| December 31, | September 30, | June 30, | March 31, | December 31, | |||||||||||||||||||||||||
| 2019 | 2019 | 2019 | 2019 | 2018 | |||||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||
| Multi-family | $ | 2,392,146 | $ | 2,800,018 | $ | 3,017,531 | $ | 3,212,312 | $ | 3,285,297 | |||||||||||||||||||
| Mortgage warehouse | 2,305,953 | 2,549,286 | 2,054,307 | 1,535,343 | 1,461,810 | ||||||||||||||||||||||||
| Commercial & industrial | 2,381,792 | 2,252,843 | 2,131,790 | 1,983,081 | 1,894,887 | ||||||||||||||||||||||||
| Commercial real estate non-owner occupied | 1,223,529 | 1,268,557 | 1,176,575 | 1,107,336 | 1,125,106 | ||||||||||||||||||||||||
| Construction | 118,418 | 61,200 | 59,811 | 53,372 | 56,491 | ||||||||||||||||||||||||
| Total commercial loans and leases | 8,421,838 | 8,931,904 | 8,440,014 | 7,891,444 | 7,823,591 | ||||||||||||||||||||||||
| Consumer: | |||||||||||||||||||||||||||||
| Residential | 378,470 | 631,866 | 654,556 | 626,668 | 568,068 | ||||||||||||||||||||||||
| Manufactured housing | 70,398 | 72,616 | 75,597 | 77,778 | 79,731 | ||||||||||||||||||||||||
| Other consumer | 1,178,283 | 643,553 | 552,839 | 153,153 | 74,035 | ||||||||||||||||||||||||
| Total consumer loans | 1,627,151 | 1,348,035 | 1,282,992 | 857,599 | 721,834 | ||||||||||||||||||||||||
| Deferred (fees)/costs and unamortized (discounts)/premiums, net | 2,085 | (2,318) | (1,663) | (3,197) | (424) | ||||||||||||||||||||||||
| Total loans and leases | $ | 10,051,074 | $ | 10,277,621 | $ | 9,721,343 | $ | 8,745,846 | $ | 8,545,001 | |||||||||||||||||||
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| PERIOD END DEPOSIT COMPOSITION - UNAUDITED | |||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||
| December 31, | September 30, | June 30, | March 31, | December 31, | |||||||||||||||||||||||||
| 2019 | 2019 | 2019 | 2019 | 2018 | |||||||||||||||||||||||||
| Demand, non-interest bearing | $ | 1,343,391 | $ | 1,569,918 | $ | 1,380,698 | $ | 1,372,358 | $ | 1,122,171 | |||||||||||||||||||
| Demand, interest bearing | 1,235,292 | 1,139,675 | 925,180 | 811,490 | 803,948 | ||||||||||||||||||||||||
| Savings | 919,214 | 591,336 | 529,532 | 417,346 | 384,545 | ||||||||||||||||||||||||
| Money market | 3,482,505 | 3,201,883 | 2,912,266 | 3,265,823 | 3,097,391 | ||||||||||||||||||||||||
| Time deposits | 1,668,534 | 2,422,873 | 2,438,101 | 1,558,301 | 1,734,181 | ||||||||||||||||||||||||
| Total deposits | $ | 8,648,936 | $ | 8,925,685 | $ | 8,185,777 | $ | 7,425,318 | $ | 7,142,236 | |||||||||||||||||||
18
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||||||||
| ASSET QUALITY - UNAUDITED | |||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | As of December 31, 2019 | As of September 30, 2019 | As of December 31, 2018 | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans | Non accrual /NPLs | Total credit reserves | Total NPLs to total loans | Total reserves to total NPLs | Total loans | Non accrual /NPLs | Total credit reserves | Total NPLs to total loans | Total reserves to total NPLs | Total loans | Non accrual /NPLs | Total credit reserves | Total NPLs to total loans | Total reserves to total NPLs | |||||||||||||||||||||||||||||||||
| Loan type | |||||||||||||||||||||||||||||||||||||||||||||||
| Multi-family | $ | 1,909,274 | $ | 4,117 | $ | 6,157 | 0.22 | % | 149.55 | % | $ | 2,300,244 | $ | — | $ | 7,498 | — | % | — | % | $ | 3,285,297 | $ | 1,155 | $ | 11,462 | 0.04 | % | 992.38 | % | |||||||||||||||||
Commercial & industrial (1) | 2,441,987 | 6,494 | 17,791 | 0.27 | % | 273.96 | % | 2,363,599 | 7,382 | 18,765 | 0.31 | % | 254.20 | % | 1,951,277 | 18,801 | 15,465 | 0.96 | % | 82.26 | % | ||||||||||||||||||||||||||
| Commercial real estate non-owner occupied | 1,223,529 | 76 | 6,243 | 0.01 | % | 8214.47 | % | 1,268,557 | 83 | 6,440 | 0.01 | % | 7759.04 | % | 1,125,106 | 129 | 6,093 | 0.01 | % | 4723.26 | % | ||||||||||||||||||||||||||
| Construction | 118,418 | — | 1,262 | — | % | — | % | 61,200 | — | 658 | — | % | — | % | 56,491 | — | 624 | — | % | — | % | ||||||||||||||||||||||||||
| Total commercial loans and leases receivable | 5,693,208 | 10,687 | 31,453 | 0.19 | % | 294.31 | % | 5,993,600 | 7,465 | 33,361 | 0.12 | % | 446.90 | % | 6,418,171 | 20,085 | 33,644 | 0.31 | % | 167.51 | % | ||||||||||||||||||||||||||
| Residential | 375,014 | 6,128 | 3,218 | 1.63 | % | 52.51 | % | 628,786 | 6,093 | 4,083 | 0.97 | % | 67.01 | % | 566,561 | 5,605 | 3,654 | 0.99 | % | 65.19 | % | ||||||||||||||||||||||||||
| Manufactured housing | 70,398 | 1,655 | 1,178 | 2.35 | % | 71.18 | % | 72,616 | 1,567 | 1,051 | 2.16 | % | 67.07 | % | 79,731 | 1,693 | 633 | 2.12 | % | 37.39 | % | ||||||||||||||||||||||||||
| Other consumer | 1,178,283 | 1,551 | 20,648 | 0.13 | % | 1331.27 | % | 643,553 | 1,140 | 12,582 | 0.18 | % | 1103.68 | % | 74,035 | 111 | 2,529 | 0.15 | % | 2278.38 | % | ||||||||||||||||||||||||||
| Total consumer loans receivable | 1,623,695 | 9,334 | 25,044 | 0.57 | % | 268.31 | % | 1,344,955 | 8,800 | 17,716 | 0.65 | % | 201.32 | % | 720,327 | 7,409 | 6,816 | 1.03 | % | 92.00 | % | ||||||||||||||||||||||||||
| Deferred (fees) costs and unamortized (discounts) premiums, net | 2,085 | — | — | — | % | — | % | (2,318) | — | — | — | % | — | % | (424) | — | — | — | % | — | % | ||||||||||||||||||||||||||
| Loans and leases receivable | 7,318,988 | 20,021 | 56,497 | 0.27 | % | 282.19 | % | 7,336,237 | 16,265 | 51,077 | 0.22 | % | 314.03 | % | 7,138,074 | 27,494 | 40,460 | 0.39 | % | 147.16 | % | ||||||||||||||||||||||||||
| Loans receivable, mortgage warehouse, at fair value | 2,245,758 | — | — | — | % | — | % | 2,438,530 | — | — | — | % | — | % | 1,405,420 | — | — | — | % | — | % | ||||||||||||||||||||||||||
| Total loans held for sale | 486,328 | 1,325 | — | 0.27 | % | — | % | 502,854 | 1,325 | — | 0.26 | % | — | % | 1,507 | — | — | — | % | — | % | ||||||||||||||||||||||||||
| Total portfolio | $ | 10,051,074 | $ | 21,346 | $ | 56,497 | 0.21 | % | 264.67 | % | $ | 10,277,621 | $ | 17,590 | $ | 51,077 | 0.17 | % | 290.38 | % | $ | 8,545,001 | $ | 27,494 | $ | 40,460 | 0.32 | % | 147.16 | % | |||||||||||||||||
| (1) Commercial & industrial loans, including owner occupied commercial real estate loans. | |||||||||||||||||||||||||||||||||||||||||||||||
19
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| NET CHARGE-OFFS/(RECOVERIES) - UNAUDITED | |||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | Twelve Months Ended December 31, | ||||||||||||||||||||||||||||||||||||||||
| Q4 | Q3 | Q2 | Q1 | Q4 | |||||||||||||||||||||||||||||||||||||
| 2019 | 2019 | 2019 | 2019 | 2018 | 2019 | 2018 | |||||||||||||||||||||||||||||||||||
| Loan type | |||||||||||||||||||||||||||||||||||||||||
| Multi-family | $ | — | $ | — | $ | (7) | $ | 541 | $ | — | $ | 534 | $ | — | |||||||||||||||||||||||||||
Commercial & industrial (1) | (225) | 15 | (186) | (239) | 1,457 | (635) | 1,740 | ||||||||||||||||||||||||||||||||||
| Commercial real estate non-owner occupied | (8) | (8) | (114) | (6) | (10) | (136) | (246) | ||||||||||||||||||||||||||||||||||
| Residential | 181 | (5) | 61 | 33 | 52 | 270 | 390 | ||||||||||||||||||||||||||||||||||
| Other consumer | 4,414 | 1,759 | 883 | 731 | 655 | 7,787 | 1,801 | ||||||||||||||||||||||||||||||||||
| Total net charge-offs (recoveries) from loans held for investment | $ | 4,362 | $ | 1,761 | $ | 637 | $ | 1,060 | $ | 2,154 | $ | 7,820 | $ | 3,685 | |||||||||||||||||||||||||||
| (1) Commercial & industrial loans, including owner occupied commercial real estate. | |||||||||||||||||||||||||||||||||||||||||
20
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED | |||||||||||||||||||||||||||||
Customers believes that the non-GAAP measurements disclosed within this document are useful for investors, regulators, management and others to evaluate our core results of operations and financial condition relative to other financial institutions. These non-GAAP financial measures are frequently used by securities analysts, investors, and other interested parties in the evaluation of companies in Customers' industry. These non-GAAP financial measures exclude from corresponding GAAP measures the impact of certain elements that we do not believe are representative of our ongoing financial results, which we believe enhance an overall understanding of our performance and increases comparability of our period to period results. Investors should consider our performance and financial condition as reported under GAAP and all other relevant information when assessing our performance or financial condition. Although non-GAAP financial measures are frequently used in the evaluation of a company, they have limitations as analytical tools and should not be considered in isolation or as a substitute for analysis of our results of operations or financial condition as reported under GAAP.
The following tables present reconciliations of GAAP to non-GAAP measures disclosed within this document.
| Core Earnings - Customers Bancorp | Twelve Months Ended December 31, | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Q4 2019 | Q3 2019 | Q2 2019 | Q1 2019 | Q4 2018 | 2019 | 2018 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | ||||||||||||||||||||||||||||||||||||||||||||||||
| GAAP net income to common shareholders | $ | 23,911 | $ | 0.75 | $ | 23,451 | $ | 0.74 | $ | 5,681 | $ | 0.18 | $ | 11,825 | $ | 0.38 | $ | 14,247 | $ | 0.44 | $ | 64,868 | $ | 2.05 | $ | 57,236 | $ | 1.78 | ||||||||||||||||||||||||||||||||||
| Reconciling items (after tax): | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Severance expense | — | — | — | — | 373 | 0.01 | — | — | 1,421 | 0.04 | 373 | 0.01 | 1,421 | 0.04 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Loss upon acquisition of interest-only GNMA securities | — | — | — | — | 5,682 | 0.18 | — | — | — | — | 5,682 | 0.18 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| Merger and acquisition related expenses | 76 | — | — | — | — | — | — | — | 355 | 0.01 | 76 | — | 3,312 | 0.10 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Losses on sale of multi-family loans | — | — | — | — | — | — | — | — | 868 | 0.03 | — | — | 868 | 0.03 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Legal reserves | — | — | 1,520 | 0.05 | — | — | — | — | — | — | 1,520 | 0.05 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (310) | (0.01) | (1,947) | (0.06) | 347 | 0.01 | (2) | — | 101 | — | (1,912) | (0.06) | 15,646 | 0.49 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Losses on sale of non-QM residential mortgage loans | 595 | 0.02 | — | — | — | — | — | — | — | — | 595 | 0.02 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| Core earnings | $ | 24,272 | $ | 0.76 | $ | 23,024 | $ | 0.73 | $ | 12,083 | $ | 0.38 | $ | 11,823 | $ | 0.38 | $ | 16,992 | $ | 0.53 | $ | 71,202 | $ | 2.25 | $ | 78,483 | $ | 2.43 | ||||||||||||||||||||||||||||||||||
21
| Core Return on Average Assets - Customers Bancorp | Twelve Months Ended December 31, | ||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q4 2019 | Q3 2019 | Q2 2019 | Q1 2019 | Q4 2018 | 2019 | 2018 | ||||||||||||||||||||||||||||||||||
| GAAP net income | $ | 27,526 | $ | 27,066 | $ | 9,296 | $ | 15,440 | $ | 17,862 | $ | 79,327 | $ | 71,695 | |||||||||||||||||||||||||||
| Reconciling items (after tax): | |||||||||||||||||||||||||||||||||||||||||
| Severance expense | — | — | 373 | — | 1,421 | 373 | 1,421 | ||||||||||||||||||||||||||||||||||
| Loss upon acquisition of interest-only GNMA securities | — | — | 5,682 | — | — | 5,682 | — | ||||||||||||||||||||||||||||||||||
Merger and acquisition related expenses | 76 | — | — | — | 355 | 76 | 3,312 | ||||||||||||||||||||||||||||||||||
| Losses on sale of multi-family loans | — | — | — | — | 868 | — | 868 | ||||||||||||||||||||||||||||||||||
| Legal reserves | — | 1,520 | — | — | — | 1,520 | — | ||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (310) | (1,947) | 347 | (2) | 101 | (1,912) | 15,646 | ||||||||||||||||||||||||||||||||||
| Losses on sale of non-QM residential mortgage loans | 595 | — | — | — | — | 595 | — | ||||||||||||||||||||||||||||||||||
Core net income | $ | 27,887 | $ | 26,639 | $ | 15,698 | $ | 15,438 | $ | 20,607 | $ | 85,661 | $ | 92,942 | |||||||||||||||||||||||||||
Average total assets | $ | 11,257,207 | $ | 11,259,144 | $ | 10,371,842 | $ | 9,759,529 | $ | 9,947,367 | $ | 10,667,670 | $ | 10,418,102 | |||||||||||||||||||||||||||
| Core return on average assets | 0.98 | % | 0.94 | % | 0.61 | % | 0.64 | % | 0.82 | % | 0.80 | % | 0.89 | % | |||||||||||||||||||||||||||
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||
(Dollars in thousands, except per share data)
| Adjusted Net Income and Adjusted ROAA - Pre-Tax Pre-Provision - Customers Bancorp | Twelve Months Ended December 31, | ||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q4 2019 | Q3 2019 | Q2 2019 | Q1 2019 | Q4 2018 | 2019 | 2018 | ||||||||||||||||||||||||||||||||||
| GAAP net income | $ | 27,526 | $ | 27,066 | $ | 9,296 | $ | 15,440 | $ | 17,862 | $ | 79,327 | $ | 71,695 | |||||||||||||||||||||||||||
| Reconciling items: | |||||||||||||||||||||||||||||||||||||||||
Income tax expense | 7,451 | 8,020 | 2,491 | 4,831 | 5,109 | 22,793 | 19,359 | ||||||||||||||||||||||||||||||||||
Provision for loan and lease losses | 9,689 | 4,426 | 5,346 | 4,767 | 1,385 | 24,227 | 5,642 | ||||||||||||||||||||||||||||||||||
| Severance expense | — | — | 490 | — | 1,869 | 490 | 1,869 | ||||||||||||||||||||||||||||||||||
| Loss upon acquisition of interest-only GNMA securities | — | — | 7,476 | — | — | 7,476 | — | ||||||||||||||||||||||||||||||||||
Merger and acquisition related expenses | 100 | — | — | — | 470 | 100 | 4,391 | ||||||||||||||||||||||||||||||||||
| Losses on sale of multi-family loans | — | — | — | — | 1,161 | — | 1,161 | ||||||||||||||||||||||||||||||||||
| Legal reserves | — | 2,000 | — | — | — | 2,000 | — | ||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (310) | (2,334) | 347 | (2) | 101 | (2,300) | 20,293 | ||||||||||||||||||||||||||||||||||
| Losses on sale of non-QM residential mortgage loans | 782 | — | — | — | — | 782 | — | ||||||||||||||||||||||||||||||||||
Adjusted net income - pre-tax pre-provision | $ | 45,238 | $ | 39,178 | $ | 25,446 | $ | 25,036 | $ | 27,957 | $ | 134,895 | $ | 124,410 | |||||||||||||||||||||||||||
Average total assets | $ | 11,257,207 | $ | 11,259,144 | $ | 10,371,842 | $ | 9,759,529 | $ | 9,947,367 | $ | 10,667,670 | $ | 10,418,102 | |||||||||||||||||||||||||||
| Adjusted ROAA - pre-tax pre-provision | 1.59 | % | 1.38 | % | 0.98 | % | 1.04 | % | 1.12 | % | 1.26 | % | 1.19 | % | |||||||||||||||||||||||||||
22
| Core Return on Average Common Equity - Customers Bancorp | Twelve Months Ended December 31, | ||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q4 2019 | Q3 2019 | Q2 2019 | Q1 2019 | Q4 2018 | 2019 | 2018 | ||||||||||||||||||||||||||||||||||
| GAAP net income to common shareholders | $ | 23,911 | $ | 23,451 | $ | 5,681 | $ | 11,825 | $ | 14,247 | $ | 64,868 | $ | 57,236 | |||||||||||||||||||||||||||
| Reconciling items (after tax): | |||||||||||||||||||||||||||||||||||||||||
| Severance expense | — | — | 373 | — | 1,421 | 373 | 1,421 | ||||||||||||||||||||||||||||||||||
| Loss upon acquisition of interest-only GNMA securities | — | — | 5,682 | — | — | 5,682 | — | ||||||||||||||||||||||||||||||||||
Merger and acquisition related expenses | 76 | — | — | — | 355 | 76 | 3,312 | ||||||||||||||||||||||||||||||||||
| Losses on sale of multi-family loans | — | — | — | — | 868 | — | 868 | ||||||||||||||||||||||||||||||||||
| Legal reserves | — | 1,520 | — | — | — | 1,520 | — | ||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (310) | (1,947) | 347 | (2) | 101 | (1,912) | 15,646 | ||||||||||||||||||||||||||||||||||
| Losses on sale of non-QM residential mortgage loans | 595 | — | — | — | — | 595 | — | ||||||||||||||||||||||||||||||||||
Core earnings | $ | 24,272 | $ | 23,024 | $ | 12,083 | $ | 11,823 | $ | 16,992 | $ | 71,202 | $ | 78,483 | |||||||||||||||||||||||||||
| Average total common shareholders' equity | $ | 819,018 | $ | 787,885 | $ | 768,592 | $ | 751,133 | $ | 745,226 | $ | 781,860 | $ | 724,505 | |||||||||||||||||||||||||||
| Core return on average common equity | 11.76 | % | 11.59 | % | 6.31 | % | 6.38 | % | 9.05 | % | 9.11 | % | 10.83 | % | |||||||||||||||||||||||||||
23
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||
(Dollars in thousands, except per share data)
| Adjusted ROCE - Pre-Tax Pre-Provision - Customers Bancorp | Twelve Months Ended December 31, | ||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q4 2019 | Q3 2019 | Q2 2019 | Q1 2019 | Q4 2018 | 2019 | 2018 | ||||||||||||||||||||||||||||||||||
| GAAP net income to common shareholders | $ | 23,911 | $ | 23,451 | $ | 5,681 | $ | 11,825 | $ | 14,247 | $ | 64,868 | $ | 57,236 | |||||||||||||||||||||||||||
| Reconciling items: | |||||||||||||||||||||||||||||||||||||||||
Income tax expense | 7,451 | 8,020 | 2,491 | 4,831 | 5,109 | 22,793 | 19,359 | ||||||||||||||||||||||||||||||||||
Provision for loan and lease losses | 9,689 | 4,426 | 5,346 | 4,767 | 1,385 | 24,227 | 5,642 | ||||||||||||||||||||||||||||||||||
| Severance expense | — | — | 490 | — | 1,869 | 490 | 1,869 | ||||||||||||||||||||||||||||||||||
| Loss upon acquisition of interest-only GNMA securities | — | — | 7,476 | — | — | 7,476 | — | ||||||||||||||||||||||||||||||||||
Merger and acquisition related expenses | 100 | — | — | — | 470 | 100 | 4,391 | ||||||||||||||||||||||||||||||||||
| Losses on sale of multi-family loans | — | — | — | — | 1,161 | — | 1,161 | ||||||||||||||||||||||||||||||||||
| Legal reserves | — | 2,000 | — | — | — | 2,000 | — | ||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (310) | (2,334) | 347 | (2) | 101 | (2,300) | 20,293 | ||||||||||||||||||||||||||||||||||
| Losses on sale of non-QM residential mortgage loans | 782 | — | — | — | — | 782 | — | ||||||||||||||||||||||||||||||||||
Pre-tax pre-provision adjusted net income available to common shareholders | $ | 41,623 | $ | 35,563 | $ | 21,831 | $ | 21,421 | $ | 24,342 | $ | 120,436 | $ | 109,951 | |||||||||||||||||||||||||||
Average total common shareholders' equity | $ | 819,018 | $ | 787,885 | $ | 768,592 | $ | 751,133 | $ | 745,226 | $ | 781,860 | $ | 724,505 | |||||||||||||||||||||||||||
| Adjusted ROCE - pre-tax pre-provision | 20.16 | % | 17.91 | % | 11.39 | % | 11.57 | % | 12.96 | % | 15.40 | % | 15.18 | % | |||||||||||||||||||||||||||
| Net Interest Margin, Tax Equivalent - Customers Bancorp | Twelve Months Ended December 31, | ||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q4 2019 | Q3 2019 | Q2 2019 | Q1 2019 | Q4 2018 | 2019 | 2018 | ||||||||||||||||||||||||||||||||||
| GAAP net interest income | $ | 77,593 | $ | 75,735 | $ | 64,679 | $ | 59,304 | $ | 61,524 | $ | 277,310 | $ | 257,877 | |||||||||||||||||||||||||||
| Tax-equivalent adjustment | 187 | 184 | 183 | 181 | 171 | 735 | 685 | ||||||||||||||||||||||||||||||||||
| Net interest income tax equivalent | $ | 77,780 | $ | 75,919 | $ | 64,862 | $ | 59,485 | $ | 61,695 | $ | 278,045 | $ | 258,562 | |||||||||||||||||||||||||||
| Average total interest earning assets | $ | 10,676,730 | $ | 10,667,198 | $ | 9,851,150 | $ | 9,278,413 | $ | 9,518,120 | $ | 10,123,708 | $ | 10,011,799 | |||||||||||||||||||||||||||
| Net interest margin, tax equivalent | 2.89 | % | 2.83 | % | 2.64 | % | 2.59 | % | 2.57 | % | 2.75 | % | 2.58 | % | |||||||||||||||||||||||||||
24
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||
(Dollars in thousands, except per share data)
| Core Efficiency Ratio - Customers Bancorp | Twelve Months Ended December 31, | ||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q4 2019 | Q3 2019 | Q2 2019 | Q1 2019 | Q4 2018 | 2019 | 2018 | ||||||||||||||||||||||||||||||||||
| GAAP net interest income | $ | 77,593 | $ | 75,735 | $ | 64,679 | $ | 59,304 | $ | 61,524 | $ | 277,310 | $ | 257,877 | |||||||||||||||||||||||||||
| GAAP non-interest income | $ | 25,813 | $ | 23,369 | $ | 12,036 | $ | 19,718 | $ | 19,877 | $ | 80,938 | $ | 58,998 | |||||||||||||||||||||||||||
| Loss upon acquisition of interest-only GNMA securities | — | — | 7,476 | — | — | 7,476 | — | ||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (310) | (2,334) | 347 | (2) | 101 | (2,300) | 20,293 | ||||||||||||||||||||||||||||||||||
| Losses on sale of multi-family loans | — | — | — | — | 1,161 | — | 1,161 | ||||||||||||||||||||||||||||||||||
| Losses on sale of non-QM residential mortgage loans | 782 | — | — | — | — | 782 | — | ||||||||||||||||||||||||||||||||||
| Core non-interest income | 26,285 | 21,035 | 19,859 | 19,716 | 21,139 | 86,896 | 80,452 | ||||||||||||||||||||||||||||||||||
| Core revenue | $ | 103,878 | $ | 96,770 | $ | 84,538 | $ | 79,020 | $ | 82,663 | $ | 364,206 | $ | 338,329 | |||||||||||||||||||||||||||
| GAAP non-interest expense | $ | 58,740 | $ | 59,592 | $ | 59,582 | $ | 53,984 | $ | 57,045 | $ | 231,901 | $ | 220,179 | |||||||||||||||||||||||||||
| Severance expense | — | — | (490) | — | (1,869) | (490) | (1,869) | ||||||||||||||||||||||||||||||||||
| Legal reserves | — | (2,000) | — | — | — | (2,000) | — | ||||||||||||||||||||||||||||||||||
| Merger and acquisition related expenses | (100) | — | — | — | (470) | (100) | (4,391) | ||||||||||||||||||||||||||||||||||
| Core non-interest expense | $ | 58,640 | $ | 57,592 | $ | 59,092 | $ | 53,984 | $ | 54,706 | $ | 229,311 | $ | 213,919 | |||||||||||||||||||||||||||
Core efficiency ratio (1) | 56.45 | % | 59.51 | % | 69.90 | % | 68.32 | % | 66.18 | % | 62.96 | % | 63.23 | % | |||||||||||||||||||||||||||
(1) Core efficiency ratio calculated as core non-interest expense divided by core revenue.
| Tangible Common Equity to Tangible Assets - Customers Bancorp | |||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | Q4 2019 | Q3 2019 | Q2 2019 | Q1 2019 | Q4 2018 | ||||||||||||||||||||||||
| GAAP - Total shareholders' equity | $ | 1,052,795 | $ | 1,019,150 | $ | 991,405 | $ | 978,373 | $ | 956,816 | |||||||||||||||||||
| Reconciling items: | |||||||||||||||||||||||||||||
| Preferred stock | (217,471) | (217,471) | (217,471) | (217,471) | (217,471) | ||||||||||||||||||||||||
| Goodwill and other intangibles | (15,195) | (15,521) | (15,847) | (16,173) | (16,499) | ||||||||||||||||||||||||
| Tangible common equity | $ | 820,129 | $ | 786,158 | $ | 758,087 | $ | 744,729 | $ | 722,846 | |||||||||||||||||||
| Total assets | $ | 11,520,717 | $ | 11,723,790 | $ | 11,182,427 | $ | 10,143,894 | $ | 9,833,425 | |||||||||||||||||||
| Reconciling items: | |||||||||||||||||||||||||||||
| Goodwill and other intangibles | (15,195) | (15,521) | (15,847) | (16,173) | (16,499) | ||||||||||||||||||||||||
| Tangible assets | $ | 11,505,522 | $ | 11,708,269 | $ | 11,166,580 | $ | 10,127,721 | $ | 9,816,926 | |||||||||||||||||||
| Tangible common equity to tangible assets | 7.13 | % | 6.71 | % | 6.79 | % | 7.35 | % | 7.36 | % | |||||||||||||||||||
25
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||
(Dollars in thousands, except per share data)
| Tangible Book Value per Common Share - Customers Bancorp | |||||||||||||||||||||||||||||
| (dollars in thousands except share and per share data) | Q4 2019 | Q3 2019 | Q2 2019 | Q1 2019 | Q4 2018 | ||||||||||||||||||||||||
| GAAP - Total shareholders' equity | $ | 1,052,795 | $ | 1,019,150 | $ | 991,405 | $ | 978,373 | $ | 956,816 | |||||||||||||||||||
| Reconciling Items: | |||||||||||||||||||||||||||||
| Preferred stock | (217,471) | (217,471) | (217,471) | (217,471) | (217,471) | ||||||||||||||||||||||||
| Goodwill and other intangibles | (15,195) | (15,521) | (15,847) | (16,173) | (16,499) | ||||||||||||||||||||||||
| Tangible common equity | $ | 820,129 | $ | 786,158 | $ | 758,087 | $ | 744,729 | $ | 722,846 | |||||||||||||||||||
| Common shares outstanding | 31,336,791 | 31,245,776 | 31,202,023 | 31,131,247 | 31,003,028 | ||||||||||||||||||||||||
| Tangible book value per common share | $ | 26.17 | $ | 25.16 | $ | 24.30 | $ | 23.92 | $ | 23.32 | |||||||||||||||||||
| Tangible Book Value per Common Share - CAGR - Customers Bancorp | |||||||||||||||||||||||||||||||||||
| (dollars in thousands except share and per share data) | Q4 2019 | Q4 2018 | Q4 2017 | Q4 2016 | Q4 2015 | Q4 2014 | |||||||||||||||||||||||||||||
| GAAP - Total shareholders' equity | $ | 1,052,795 | $ | 956,816 | $ | 920,964 | $ | 855,872 | $ | 553,902 | $ | 443,145 | |||||||||||||||||||||||
| Reconciling Items: | |||||||||||||||||||||||||||||||||||
| Preferred stock | (217,471) | (217,471) | (217,471) | (217,471) | (55,569) | — | |||||||||||||||||||||||||||||
| Goodwill and other intangibles | (15,195) | (16,499) | (16,295) | (17,621) | (3,651) | (3,664) | |||||||||||||||||||||||||||||
| Tangible common equity | $ | 820,129 | $ | 722,846 | $ | 687,198 | $ | 620,780 | $ | 494,682 | $ | 439,481 | |||||||||||||||||||||||
| Common shares outstanding | 31,336,791 | 31,003,028 | 31,382,503 | 30,289,917 | 26,901,801 | 26,745,529 | |||||||||||||||||||||||||||||
| Tangible book value per common share | $ | 26.17 | $ | 23.32 | $ | 21.90 | $ | 20.49 | $ | 18.39 | $ | 16.43 | |||||||||||||||||||||||
| CAGR | 9.76 | % | |||||||||||||||||||||||||||||||||
26
| CUSTOMERS BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| RECONCILIATION OF GAAP TO NON-GAAP MEASURES - UNAUDITED (CONTINUED) | |||||||||||||||||||||||||||||
(Dollars in thousands, except per share data)
| Core Earnings - Customers Bank Business Banking Segment | Twelve Months Ended December 31, | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Q4 2019 | Q3 2019 | Q2 2019 | Q1 2019 | Q4 2018 | 2019 | 2018 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | ||||||||||||||||||||||||||||||||||||||||||||||||
| GAAP net income to common shareholders | $ | 22,218 | $ | 0.70 | $ | 22,767 | $ | 0.72 | $ | 12,778 | $ | 0.40 | $ | 11,988 | $ | 0.38 | $ | 17,521 | $ | 0.55 | $ | 69,751 | $ | 2.20 | $ | 70,698 | $ | 2.19 | ||||||||||||||||||||||||||||||||||
| Reconciling items (after tax): | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Severance expense | — | — | — | — | 359 | 0.01 | — | — | 1,421 | 0.04 | 359 | 0.01 | 1,421 | 0.04 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Loss upon acquisition of interest-only GNMA securities | — | — | — | — | 5,682 | 0.18 | — | — | — | — | 5,682 | 0.18 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| Losses on sale of multi-family loans | — | — | — | — | — | — | — | — | 868 | 0.03 | — | — | 868 | 0.03 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Legal reserves | — | — | 760 | 0.02 | — | — | — | — | — | — | 760 | 0.02 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| (Gains) losses on investment securities | (310) | (0.01) | (1,947) | (0.06) | 347 | 0.01 | (2) | — | 101 | — | (1,912) | (0.06) | 15,646 | 0.49 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Losses on sale of non-QM residential mortgage loans | 595 | 0.02 | — | — | — | — | — | — | — | — | 595 | 0.02 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| Core earnings | $ | 22,503 | $ | 0.71 | $ | 21,580 | $ | 0.68 | $ | 19,166 | $ | 0.61 | $ | 11,986 | $ | 0.38 | $ | 19,911 | $ | 0.62 | $ | 75,235 | $ | 2.38 | $ | 88,633 | $ | 2.75 | ||||||||||||||||||||||||||||||||||
| Core Earnings (Loss) - BankMobile Segment | Twelve Months Ended December 31, | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Q4 2019 | Q3 2019 | Q2 2019 | Q1 2019 | Q4 2018 | 2019 | 2018 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | USD | Per share | ||||||||||||||||||||||||||||||||||||||||||||||||
| GAAP net loss to common shareholders | $ | 1,693 | $ | 0.05 | $ | 684 | $ | 0.02 | $ | (7,097) | $ | (0.22) | $ | (163) | $ | (0.01) | $ | (3,274) | $ | (0.10) | $ | (4,883) | $ | (0.15) | $ | (13,462) | $ | (0.42) | ||||||||||||||||||||||||||||||||||
| Reconciling items (after tax): | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Severance expense | — | — | — | — | 13 | — | — | — | — | — | 13 | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| Legal reserves | — | — | 760 | 0.02 | — | — | — | — | — | — | 760 | 0.02 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||||
| Merger and acquisition related expenses | 76 | — | — | — | — | — | — | — | 355 | 0.01 | 76 | — | 3,312 | 0.10 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Core loss | $ | 1,769 | $ | 0.06 | $ | 1,444 | $ | 0.05 | $ | (7,084) | $ | (0.22) | $ | (163) | $ | (0.01) | $ | (2,919) | $ | (0.09) | $ | (4,034) | $ | (0.13) | $ | (10,150) | $ | (0.31) | ||||||||||||||||||||||||||||||||||
27
Q4 2019 Earnings Call Presentation January 23, 2020 NYSE: CUBI Member FDIC
Forward-Looking Statements This presentation, as well as other written or oral communications made from time to time by us, contains forward‐looking information within the meaning of the safe harbor provisions of the U.S. Private Securities Litigation Reform Act of 1995. These statements relate to future events or future predictions, including events or predictions relating to future financial performance, and are generally identifiable by the use of forward‐looking terminology such as “believe,” “expect,” “may,” “will,” “should,” “plan,” “intend,” or “anticipate” or the negative thereof or comparable terminology. Forward‐ looking statements in this presentation include, among other matters, guidance for our financial performance, and our financial performance targets. Forward‐looking statements reflect numerous assumptions, estimates and forecasts as to future events. No assurance can be given that the assumptions, estimates and forecasts underlying such forward‐looking statements will accurately reflect future conditions, or that any guidance, goals, targets or projected results will be realized. The assumptions, estimates and forecasts underlying such forward‐looking statements involve judgments with respect to, among other things, future economic, competitive, regulatory and financial market conditions and future business decisions, which may not be realized and which are inherently subject to significant business, economic, competitive and regulatory uncertainties and known and unknown risks, including the risks described under “Risk Factors” in our Annual Report on Form 10‐K for the year ended December 31, 2018 and subsequent Quarterly Reports on Form 10‐Qand current reports on Form 8‐K, including any amendments thereto, as such factors may be updated from time to time in our filings with the SEC. Our actual results may differ materially from those reflected in the forward‐looking statements. In addition to the risks described under “Risk Factors” in our filings with the SEC, important factors to consider and evaluate with respect to our forward‐looking statements include: • changes in external competitive market factors that might impact our results of operations; • changes in laws and regulations, including without limitation, changes in capital requirements under Basel III; • the potential effects of heightened regulatory requirements applicable to banks with assets in excess of $10 billion; • changes in our business strategy or an inability to execute our strategy due to the occurrence of unanticipated events; • our ability to identify potential candidates for, and consummate, acquisition or investment transactions; • the timing of acquisition, investment or disposition transactions; • constraints on our ability to consummate an attractive acquisition or investment transaction because of significant competition for these opportunities; • local, regional and national economic conditions and events and the impact they may have on us and our customers; • costs and effects of regulatory and legal developments, including the results of regulatory examinations and the outcome of regulatory or other governmental inquiries and proceedings, such as fines or restrictions on our business activities; • our ability to attract deposits and other sources of liquidity; • changes in the financial performance and/or condition of our borrowers; • changes in the level of non‐performing and classified assets and charge‐offs; • changes in estimates of future loan loss reserve requirements based upon the periodic review thereof under relevant regulatory and accounting requirements, including the adoption of the Current Expected Credit Losses standard; • inflation, interest rate, securities market and monetary fluctuations, including the discontinuance of LIBOR; • timely development and acceptance of new banking products and services and perceived overall value of these products and services by users, including the products and services being developed and introduced to the market by the BankMobile division of Customers Bank; • changes in consumer spending, borrowing and saving habits; • technological changes; • our ability to increase market share and control expenses; • continued volatility in the credit and equity markets and its effect on the general economy; • effects of changes in accounting policies and practices, as may be adopted by the regulatory agencies, the Financial Accounting Standards Board and other accounting standard setters; • the businesses of Customers Bank and any acquisition targets or merger partners and subsidiaries not integrating successfully or such integration being more difficult, time‐consuming or costly than expected; 2
Forward-Looking Statements (Cont.) • material differences in the actual financial results of merger and acquisition activities compared with our expectations, such as with respect to the full realization of anticipated cost savings and revenue enhancements within the expected time frame; • our ability to successfully implement our growth strategy, control expenses and maintain liquidity; • Customers Bank's ability to pay dividends to Customers Bancorp; • risks relating to BankMobile, including: • the implementation of Customers Bancorp, Inc.'s strategy to retain BankMobile for 2‐3 years, the possibility that the expected benefits of retaining BankMobile for 2‐3 years may not be achieved, or the possible effects on Customers' results of operations if BankMobile is never divested causing Customers Bancorp's actual results to differ from those in the forward‐ looking statements; • our ability to successfully complete a divestiture of BankMobile and the timing of completion; • the ability of Customers and an acquirer of BankMobile to meet all of the conditions to completion of the proposed divestiture; • our ability to execute on our White Label strategy to grow demand deposits through strategic partnerships; • material variances in the adoption rate of BankMobile's services by new students • the usage rate of BankMobile's services by current student customers compared to our expectations; • the levels of usage of other BankMobile student customers following graduation of additional product and service offerings of BankMobile or Customers Bank, including mortgages and consumer loans, and the mix of products and services used; • our ability to implement changes to BankMobile's product and service offerings under current and future regulations and governmental policies; • our ability to effectively manage revenue and expense fluctuations that may occur with respect to BankMobile's student‐oriented business activities, which result from seasonal factors related to the higher‐education academic year; and • BankMobile's ability to successfully implement its growth strategy and control expenses. • risks related to planned changes in our balance sheet, including: • our ability to reduce the size of our multi‐family loan portfolio; • our ability to execute our digital distribution strategy; • our ability to manage the risk of change in our loan mix to include a greater proportion of consumer loans; and • our ability to earn increased net interest income to recover reduced interchange income due to the loss of the small issuer exemption to the Durbin Amendment. You are cautioned not to place undue reliance on any forward‐looking statements we make, which speak only as of the date they are made. We do not undertake any obligation to release publicly or otherwise provide any revisions to any forward‐looking statements we may make, including any forward‐looking financial information, to reflect events or circumstances occurring after the date hereof or to reflect the occurrence of unanticipated events, except as may be required under applicable law. This presentation shall not constitute an offer to sell or the solicitation of an offer to sell or the solicitation of an offer to buy any securities, nor shall there be any sale of securities in any jurisdiction in which such offer, solicitation or sale would be unlawful prior to registration or qualification under the securities laws of any such jurisdiction. 3
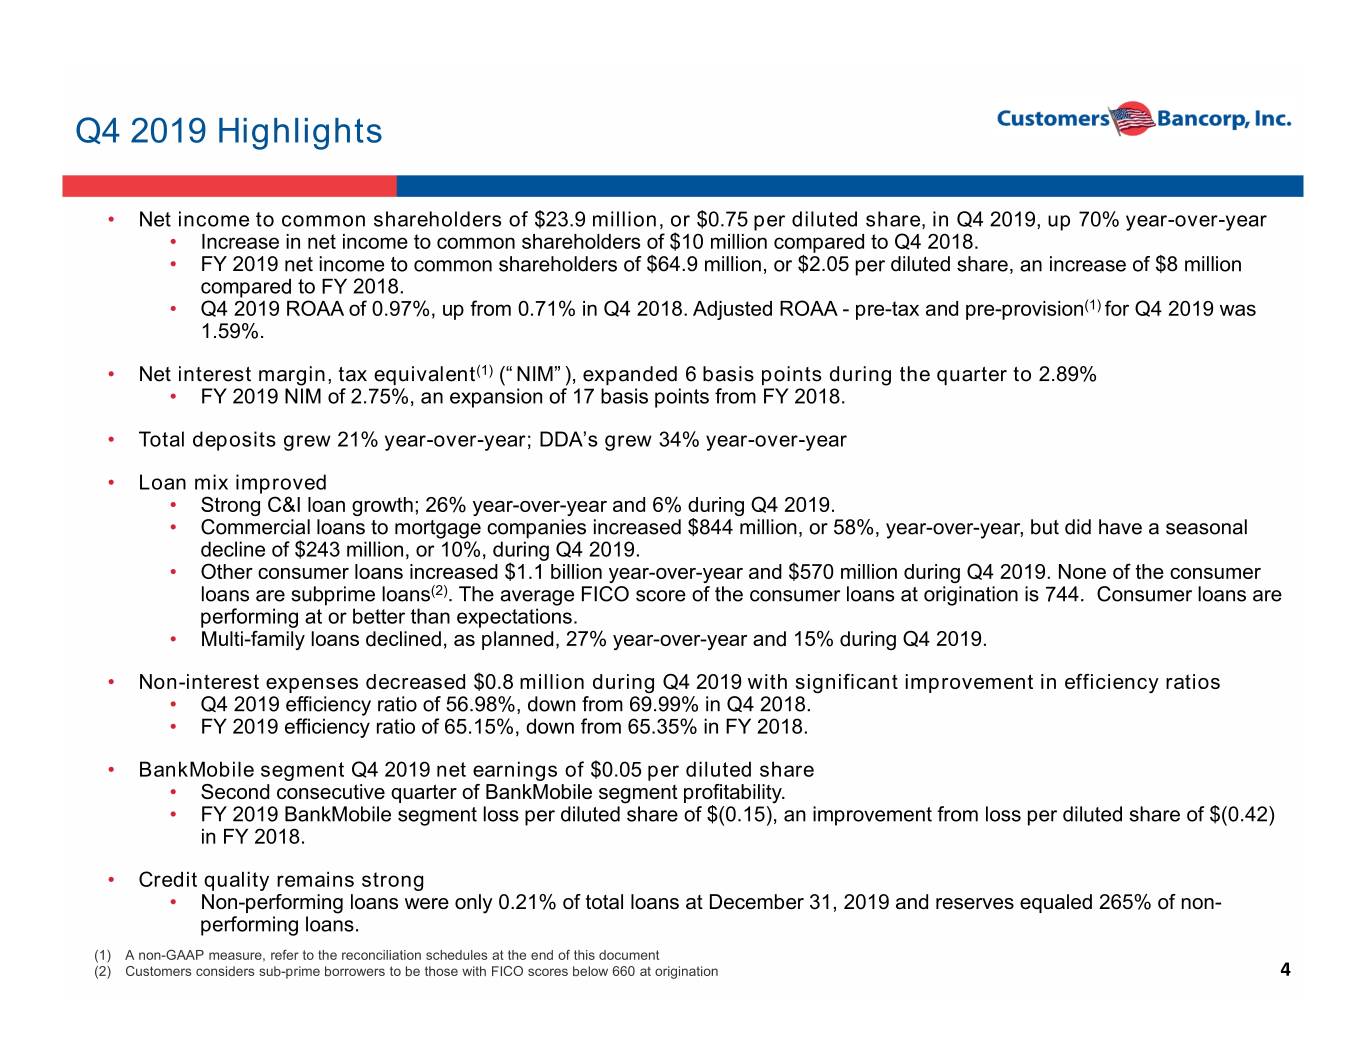
Q4 2019 Highlights • Net income to common shareholders of $23.9 million, or $0.75 per diluted share, in Q4 2019, up 70% year-over-year • Increase in net income to common shareholders of $10 million compared to Q4 2018. • FY 2019 net income to common shareholders of $64.9 million, or $2.05 per diluted share, an increase of $8 million compared to FY 2018. • Q4 2019 ROAA of 0.97%, up from 0.71% in Q4 2018. Adjusted ROAA - pre-tax and pre-provision(1) for Q4 2019 was 1.59%. • Net interest margin, tax equivalent(1) (“NIM”), expanded 6 basis points during the quarter to 2.89% • FY 2019 NIM of 2.75%, an expansion of 17 basis points from FY 2018. • Total deposits grew 21% year-over-year; DDA’s grew 34% year-over-year • Loan mix improved • Strong C&I loan growth; 26% year-over-year and 6% during Q4 2019. • Commercial loans to mortgage companies increased $844 million, or 58%, year-over-year, but did have a seasonal decline of $243 million, or 10%, during Q4 2019. • Other consumer loans increased $1.1 billion year-over-year and $570 million during Q4 2019. None of the consumer loans are subprime loans(2). The average FICO score of the consumer loans at origination is 744. Consumer loans are performing at or better than expectations. • Multi-family loans declined, as planned, 27% year-over-year and 15% during Q4 2019. • Non-interest expenses decreased $0.8 million during Q4 2019 with significant improvement in efficiency ratios • Q4 2019 efficiency ratio of 56.98%, down from 69.99% in Q4 2018. • FY 2019 efficiency ratio of 65.15%, down from 65.35% in FY 2018. • BankMobile segment Q4 2019 net earnings of $0.05 per diluted share • Second consecutive quarter of BankMobile segment profitability. • FY 2019 BankMobile segment loss per diluted share of $(0.15), an improvement from loss per diluted share of $(0.42) in FY 2018. • Credit quality remains strong • Non-performing loans were only 0.21% of total loans at December 31, 2019 and reserves equaled 265% of non- performing loans. (1) A non-GAAP measure, refer to the reconciliation schedules at the end of this document (2) Customers considers sub-prime borrowers to be those with FICO scores below 660 at origination 4
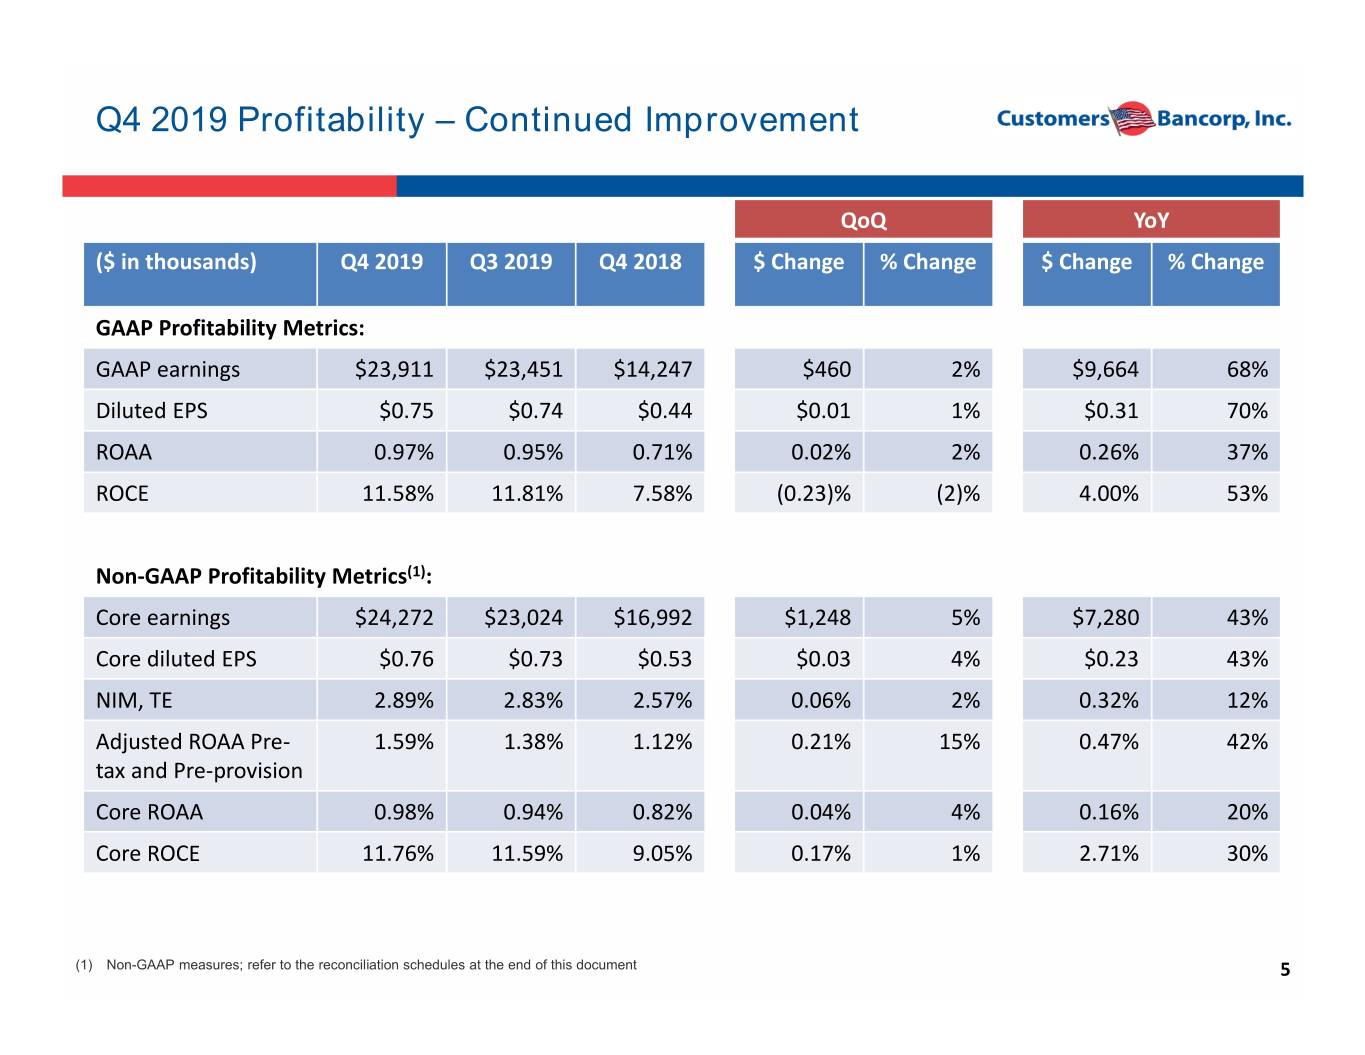
Q4 2019 Profitability – Continued Improvement QoQ YoY ($ in thousands) Q4 2019 Q3 2019 Q4 2018 $ Change % Change $ Change % Change GAAP Profitability Metrics: GAAP earnings $23,911 $23,451 $14,247 $460 2% $9,664 68% Diluted EPS $0.75 $0.74 $0.44 $0.01 1% $0.31 70% ROAA 0.97% 0.95% 0.71% 0.02% 2% 0.26% 37% ROCE 11.58% 11.81% 7.58% (0.23)% (2)% 4.00% 53% Non‐GAAP Profitability Metrics(1): Core earnings $24,272 $23,024 $16,992 $1,248 5% $7,280 43% Core diluted EPS $0.76 $0.73 $0.53 $0.03 4% $0.23 43% NIM, TE 2.89% 2.83% 2.57% 0.06% 2% 0.32% 12% Adjusted ROAA Pre‐ 1.59% 1.38% 1.12% 0.21% 15% 0.47% 42% tax and Pre‐provision Core ROAA 0.98% 0.94% 0.82% 0.04% 4% 0.16% 20% Core ROCE 11.76% 11.59% 9.05% 0.17% 1% 2.71% 30% (1) Non-GAAP measures; refer to the reconciliation schedules at the end of this document 5
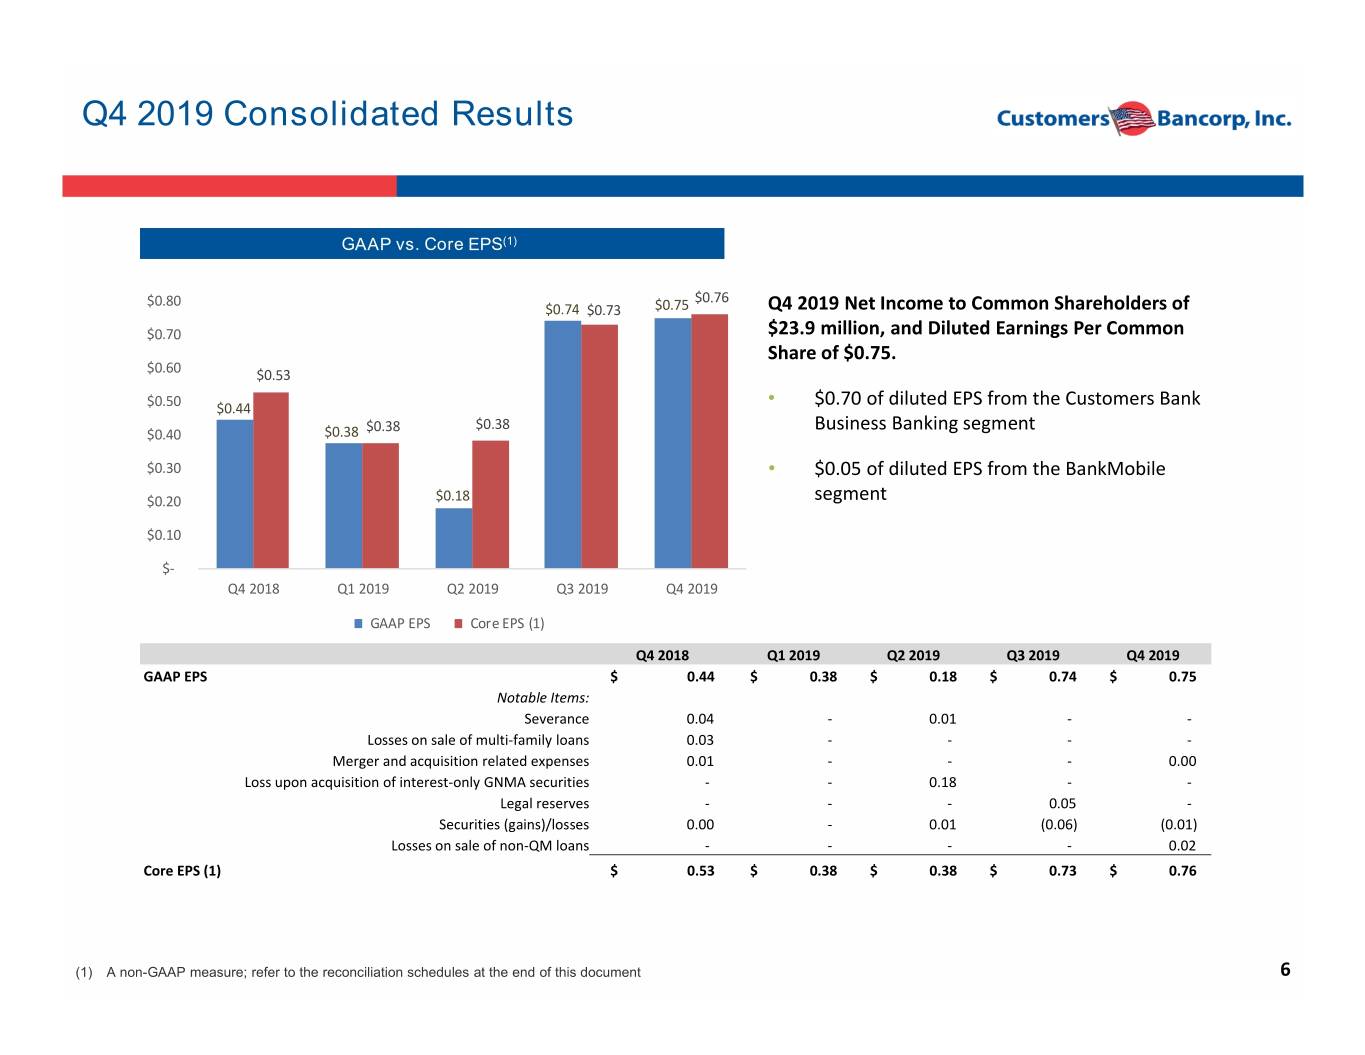
Q4 2019 Consolidated Results GAAP vs. Core EPS(1) $0.80 $0.76 $0.74 $0.73 $0.75 Q4 2019 Net Income to Common Shareholders of $0.70 $23.9 million, and Diluted Earnings Per Common Share of $0.75. $0.60 $0.53 • $0.50 $0.44 $0.70 of diluted EPS from the Customers Bank $0.38 $0.38 Business Banking segment $0.40 $0.38 $0.30 • $0.05 of diluted EPS from the BankMobile $0.20 $0.18 segment $0.10 $‐ Q4 2018 Q1 2019 Q2 2019 Q3 2019 Q4 2019 GAAP EPS Core EPS (1) Q4 2018 Q1 2019 Q2 2019 Q3 2019 Q4 2019 GAAP EPS $ 0.44 $ 0.38 $ 0.18 $ 0.74 $ 0.75 Notable Items: Severance 0.04 ‐0.01 ‐ ‐ Losses on sale of multi‐family loans 0.03 ‐ ‐ ‐ ‐ Merger and acquisition related expenses 0.01 ‐ ‐ ‐0.00 Loss upon acquisition of interest‐only GNMA securities ‐ ‐0.18 ‐ ‐ Legal reserves ‐ ‐ ‐0.05 ‐ Securities (gains)/losses 0.00 ‐0.01 (0.06) (0.01) Losses on sale of non‐QM loans ‐ ‐ ‐ ‐0.02 Core EPS (1) $ 0.53 $ 0.38 $ 0.38 $ 0.73 $ 0.76 (1) A non-GAAP measure; refer to the reconciliation schedules at the end of this document 6
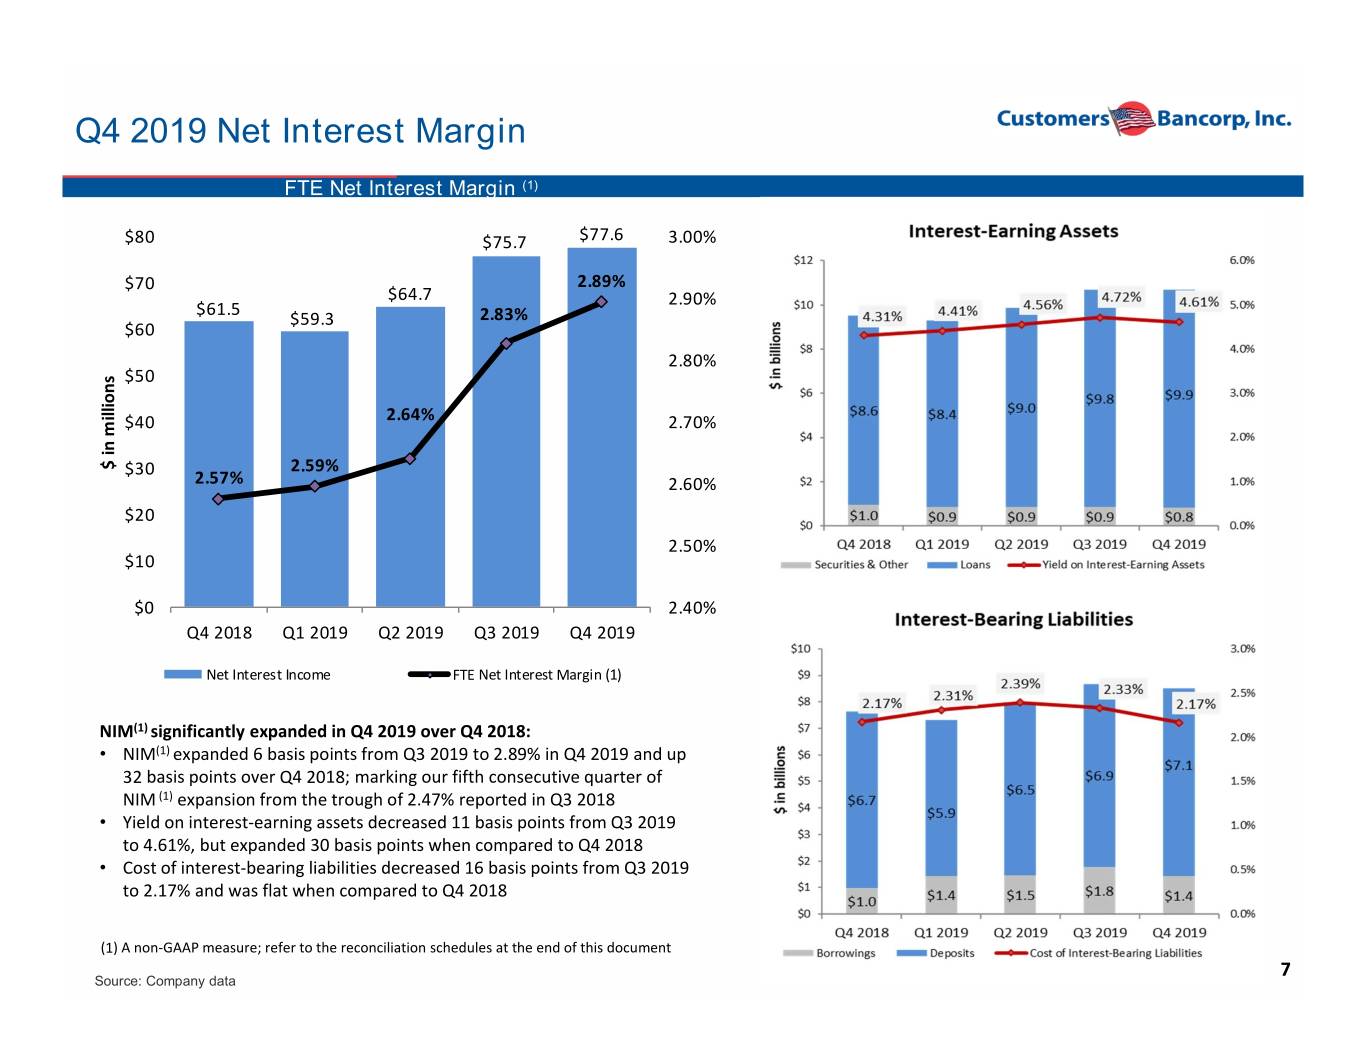
Q4 2019 Net Interest Margin FTE Net Interest Margin (1) $80 $75.7 $77.6 3.00% $70 2.89% $64.7 2.90% $61.5 $59.3 2.83% $60 2.80% $50 $40 2.64% 2.70% millions in $ $30 2.59% 2.57% 2.60% $20 2.50% $10 $0 2.40% Q4 2018 Q1 2019 Q2 2019 Q3 2019 Q4 2019 Net Interest Income FTE Net Interest Margin (1) NIM(1) significantly expanded in Q4 2019 over Q4 2018: • NIM(1) expanded 6 basis points from Q3 2019 to 2.89% in Q4 2019 and up 32 basis points over Q4 2018; marking our fifth consecutive quarter of NIM (1) expansion from the trough of 2.47% reported in Q3 2018 • Yield on interest‐earning assets decreased 11 basis points from Q3 2019 to 4.61%, but expanded 30 basis points when compared to Q4 2018 • Cost of interest‐bearing liabilities decreased 16 basis points from Q3 2019 to 2.17% and was flat when compared to Q4 2018 (1) A non‐GAAP measure; refer to the reconciliation schedules at the end of this document 7 Source: Company data
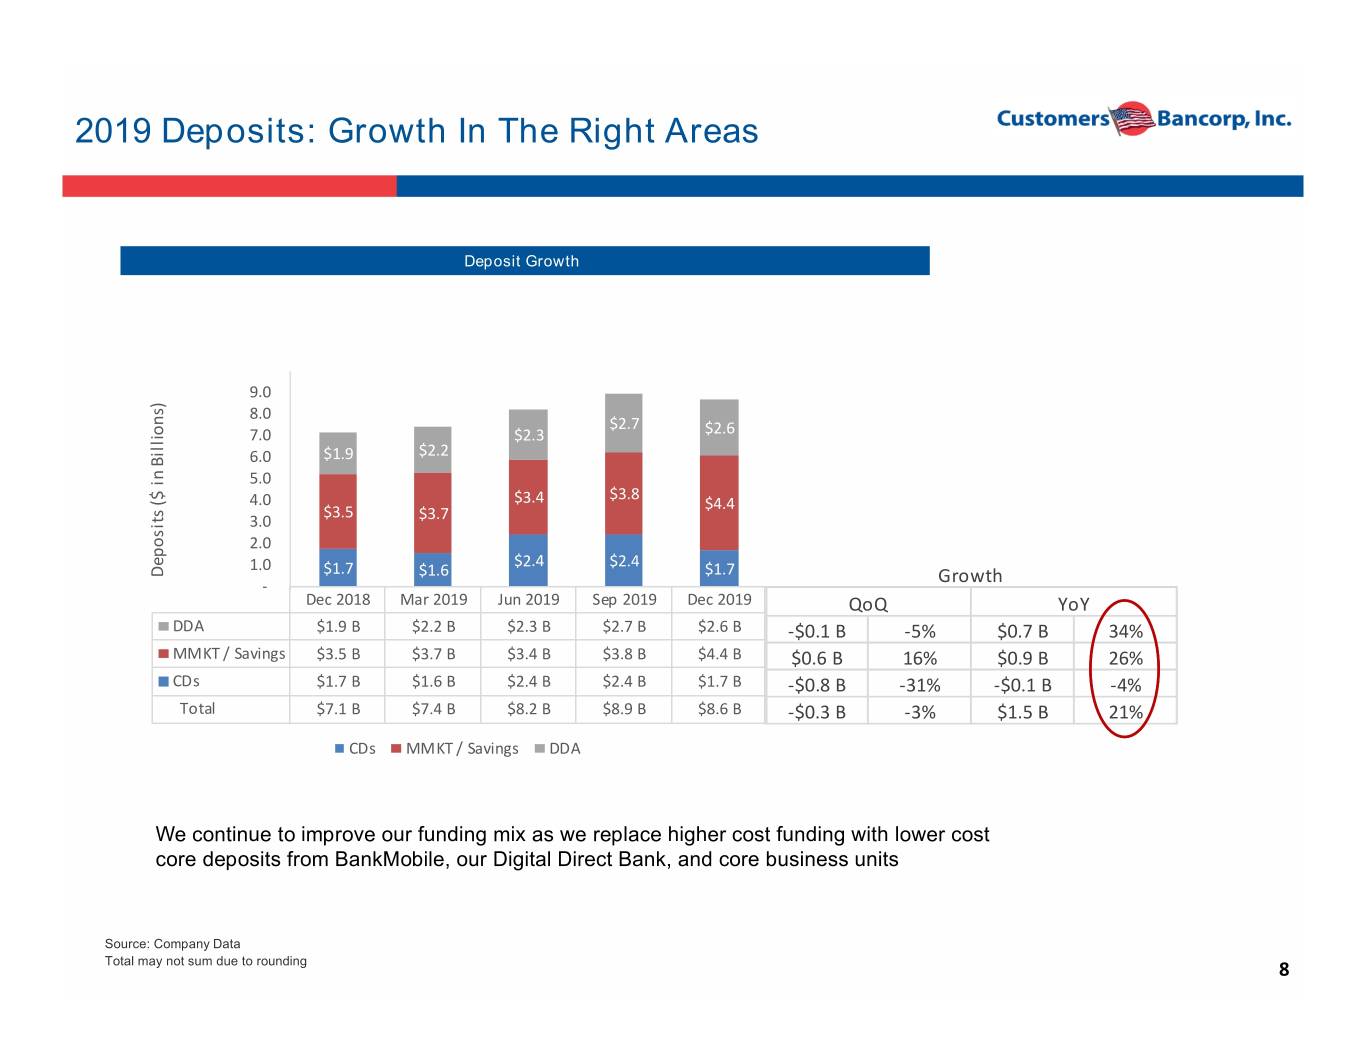
2019 Deposits: Growth In The Right Areas Deposit Growth 9.0 8.0 $2.7 7.0 $2.3 $2.6 6.0 $1.9 $2.2 Billions) in 5.0 $3.8 ($ $3.4 4.0 $3.5 $4.4 3.0 $3.7 2.0 1.0 $2.4 $2.4 Deposits $1.7 $1.6 $1.7 Growth ‐ Dec 2018 Mar 2019 Jun 2019 Sep 2019 Dec 2019 QoQ YoY DDA $1.9 B$2.2 B$2.3 B$2.7 B$2.6 B ‐$0.1 B ‐5% $0.7 B 34% MMKT / Savings $3.5 B$3.7 B$3.4 B$3.8 B$4.4 B $0.6 B 16% $0.9 B 26% CDs $1.7 B$1.6 B$2.4 B$2.4 B$1.7 B ‐$0.8 B ‐31% ‐$0.1 B ‐4% Total $7.1 B$7.4 B$8.2 B$8.9 B$8.6 B ‐$0.3 B ‐3% $1.5 B 21% CDs MMKT / Savings DDA We continue to improve our funding mix as we replace higher cost funding with lower cost core deposits from BankMobile, our Digital Direct Bank, and core business units Source: Company Data Total may not sum due to rounding 8
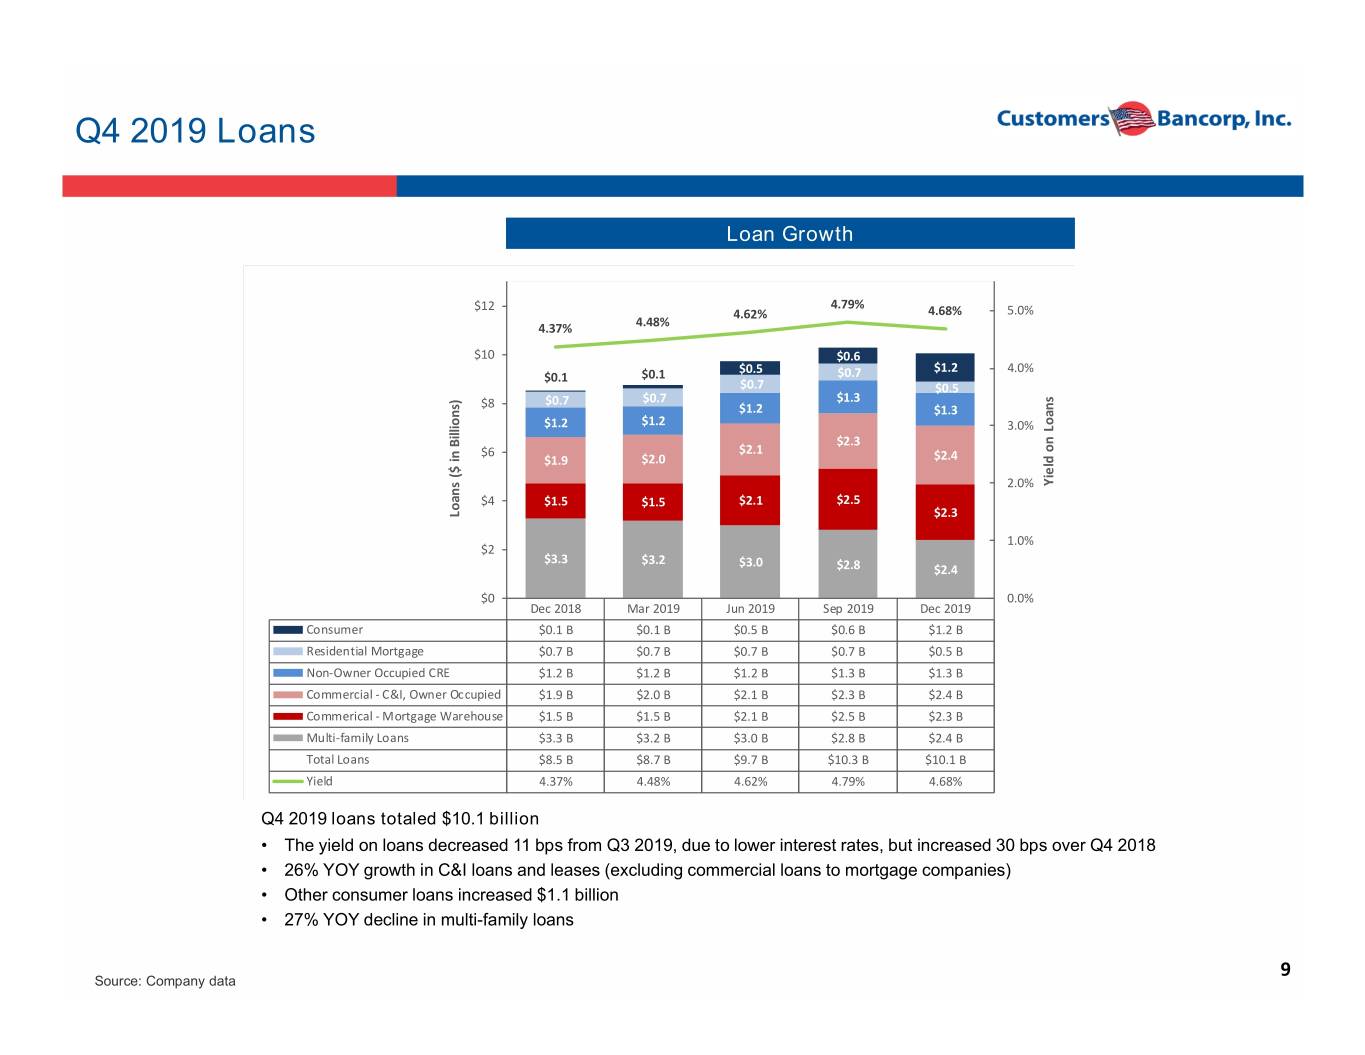
Q4 2019 Loans Loan Growth $12 4.79% 4.62% 4.68% 5.0% 4.37% 4.48% $10 $0.6 $0.5 $1.2 4.0% $0.1 $0.1 $0.7 $0.7 $0.5 $8 $0.7 $0.7 $1.3 $1.2 $1.3 $1.2 $1.2 3.0% Loans Billions) $2.3 on $6 $2.1 in $2.4 $1.9 $2.0 ($ 2.0% Yield $4 $1.5 $1.5 $2.1 $2.5 Loans $2.3 1.0% $2 $3.3 $3.2 $3.0 $2.8 $2.4 $0 0.0% Dec 2018 Mar 2019 Jun 2019 Sep 2019 Dec 2019 Consumer $0.1 B$0.1 B$0.5 B$0.6 B$1.2 B Residential Mortgage $0.7 B$0.7 B$0.7 B$0.7 B$0.5 B Non‐Owner Occupied CRE $1.2 B$1.2 B$1.2 B$1.3 B$1.3 B Commercial ‐ C&I, Owner Occupied $1.9 B$2.0 B$2.1 B$2.3 B$2.4 B Commerical ‐ Mortgage Warehouse $1.5 B$1.5 B$2.1 B$2.5 B$2.3 B Multi‐family Loans $3.3 B$3.2 B$3.0 B$2.8 B$2.4 B Total Loans $8.5 B$8.7 B$9.7 B $10.3 B$10.1 B Yield 4.37% 4.48% 4.62% 4.79% 4.68% Q4 2019 loans totaled $10.1 billion • The yield on loans decreased 11 bps from Q3 2019, due to lower interest rates, but increased 30 bps over Q4 2018 • 26% YOY growth in C&I loans and leases (excluding commercial loans to mortgage companies) • Other consumer loans increased $1.1 billion • 27% YOY decline in multi-family loans 9 Source: Company data
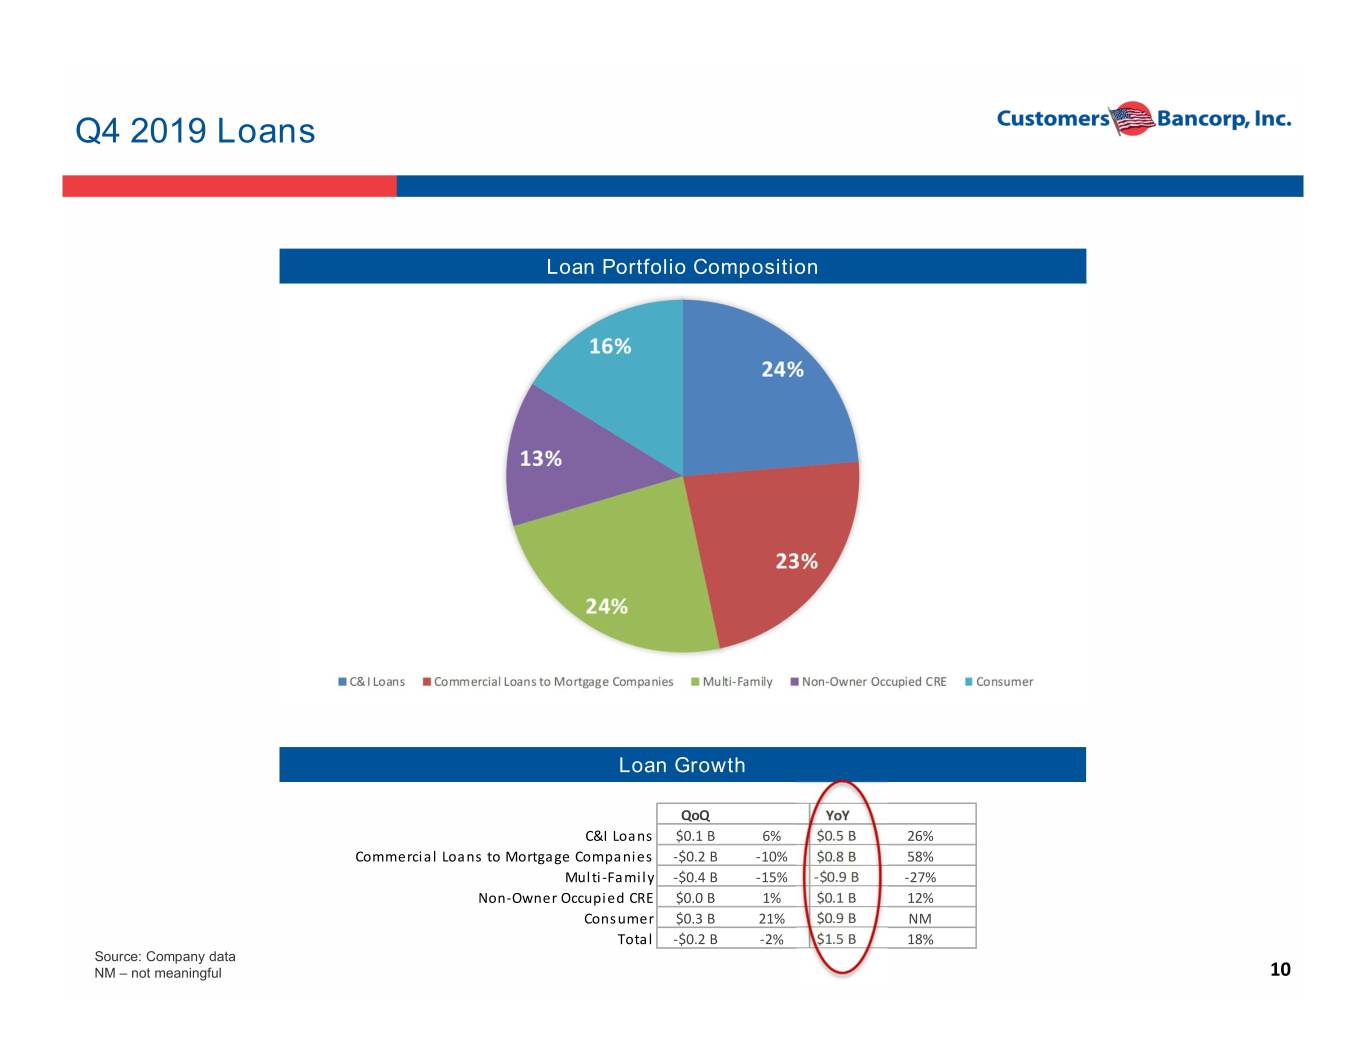
Q4 2019 Loans Loan Portfolio Composition Loan Growth QoQ YoY C&I Loans $0.1 B 6% $0.5 B 26% Commercial Loans to Mortgage Compa ni es ‐$0.2 B ‐10% $0.8 B 58% Multi‐Family ‐$0.4 B ‐15% ‐$0.9 B ‐27% Non‐Owner Occupied CRE $0.0 B 1% $0.1 B 12% Cons umer $0.3 B 21% $0.9 BNM Total ‐$0.2 B ‐2% $1.5 B 18% Source: Company data NM – not meaningful 10
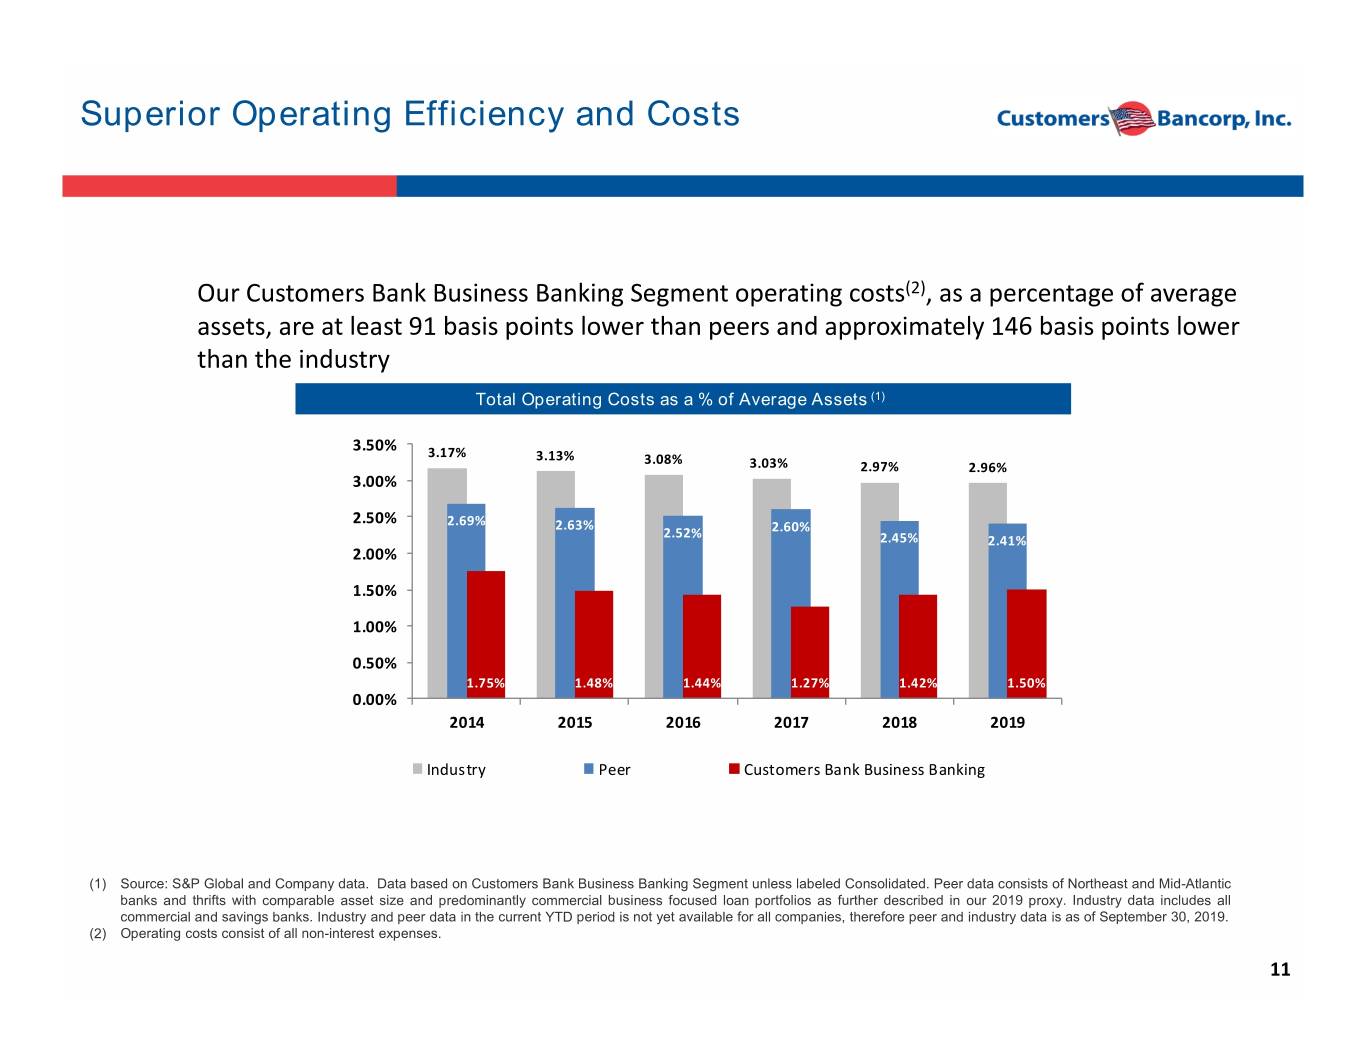
Superior Operating Efficiency and Costs Our Customers Bank Business Banking Segment operating costs(2), as a percentage of average assets, are at least 91 basis points lower than peers and approximately 146 basis points lower than the industry Total Operating Costs as a % of Average Assets (1) 3.50% 3.17% 3.13% 3.08% 3.03% 2.97% 2.96% 3.00% 2.50% 2.69% 2.63% 2.52% 2.60% 2.45% 2.41% 2.00% 1.50% 1.00% 0.50% 1.75% 1.48% 1.44% 1.27% 1.42% 1.50% 0.00% 2014 2015 2016 2017 2018 2019 Industry Peer Customers Bank Business Banking (1) Source: S&P Global and Company data. Data based on Customers Bank Business Banking Segment unless labeled Consolidated. Peer data consists of Northeast and Mid-Atlantic banks and thrifts with comparable asset size and predominantly commercial business focused loan portfolios as further described in our 2019 proxy. Industry data includes all commercial and savings banks. Industry and peer data in the current YTD period is not yet available for all companies, therefore peer and industry data is as of September 30, 2019. (2) Operating costs consist of all non-interest expenses. 11
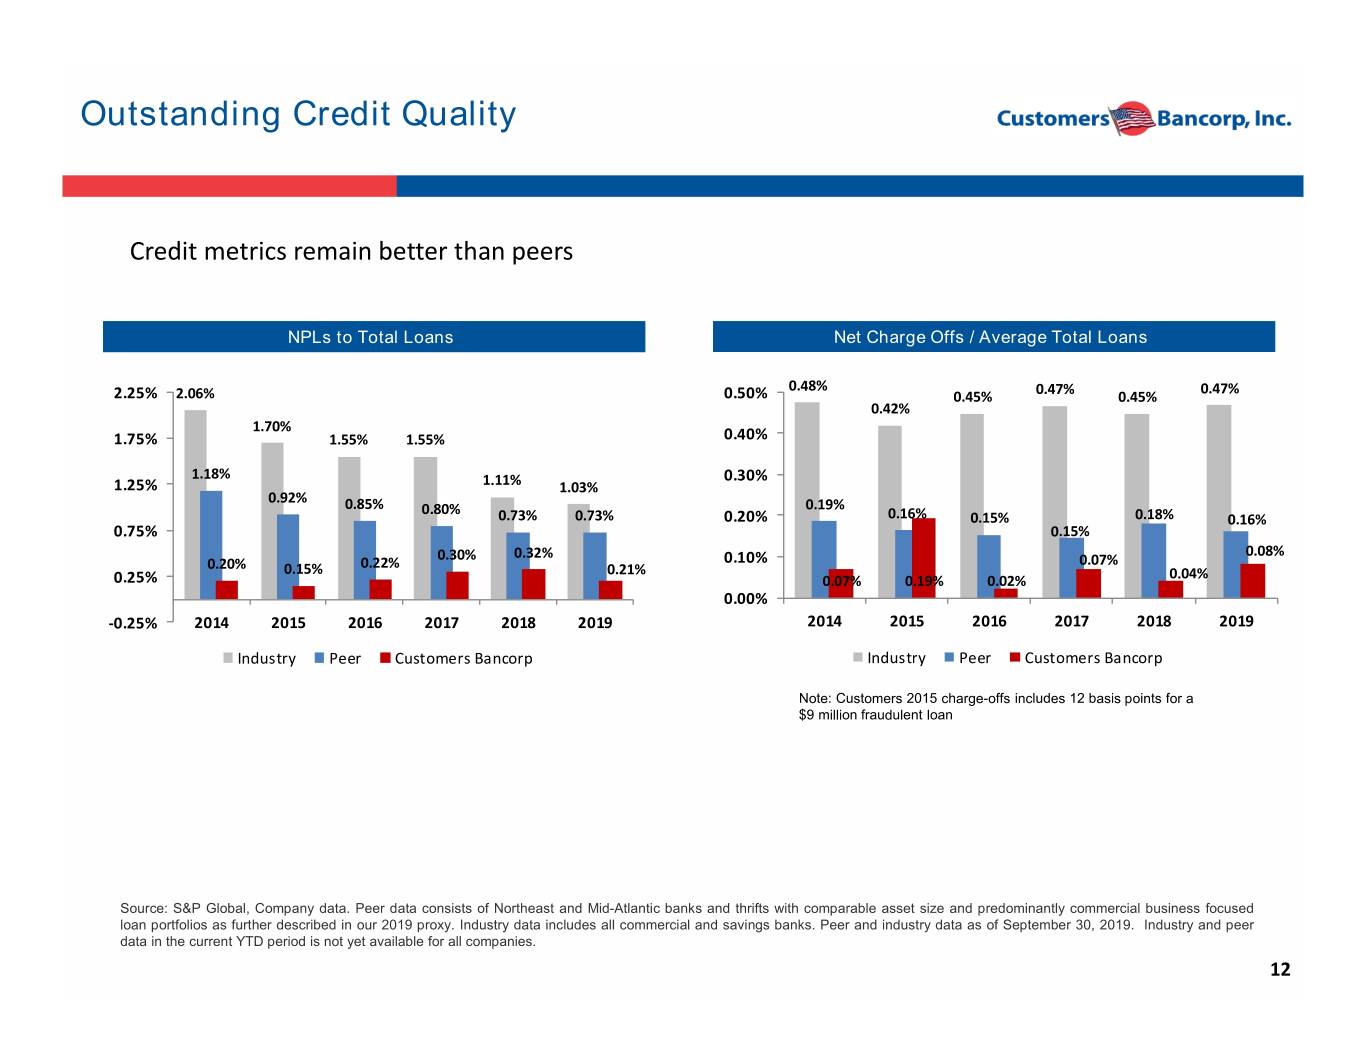
Outstanding Credit Quality Credit metrics remain better than peers NPLs to Total Loans Net Charge Offs / Average Total Loans 0.48% 0.47% 0.47% 2.25% 2.06% 0.50% 0.45% 0.45% 0.42% 1.70% 1.75% 1.55% 1.55% 0.40% 1.18% 0.30% 1.25% 1.11% 1.03% 0.92% 0.85% 0.80% 0.19% 0.73% 0.73% 0.20% 0.16% 0.15% 0.18% 0.16% 0.75% 0.15% 0.08% 0.30% 0.32% 0.10% 0.07% 0.20% 0.15% 0.22% 0.21% 0.25% 0.07% 0.19% 0.02% 0.04% 0.00% ‐0.25% 2014 2015 2016 2017 2018 2019 2014 2015 2016 2017 2018 2019 Industry Peer Customers Bancorp Industry Peer Customers Bancorp Note: Customers 2015 charge-offs includes 12 basis points for a $9 million fraudulent loan Source: S&P Global, Company data. Peer data consists of Northeast and Mid-Atlantic banks and thrifts with comparable asset size and predominantly commercial business focused loan portfolios as further described in our 2019 proxy. Industry data includes all commercial and savings banks. Peer and industry data as of September 30, 2019. Industry and peer data in the current YTD period is not yet available for all companies. 12
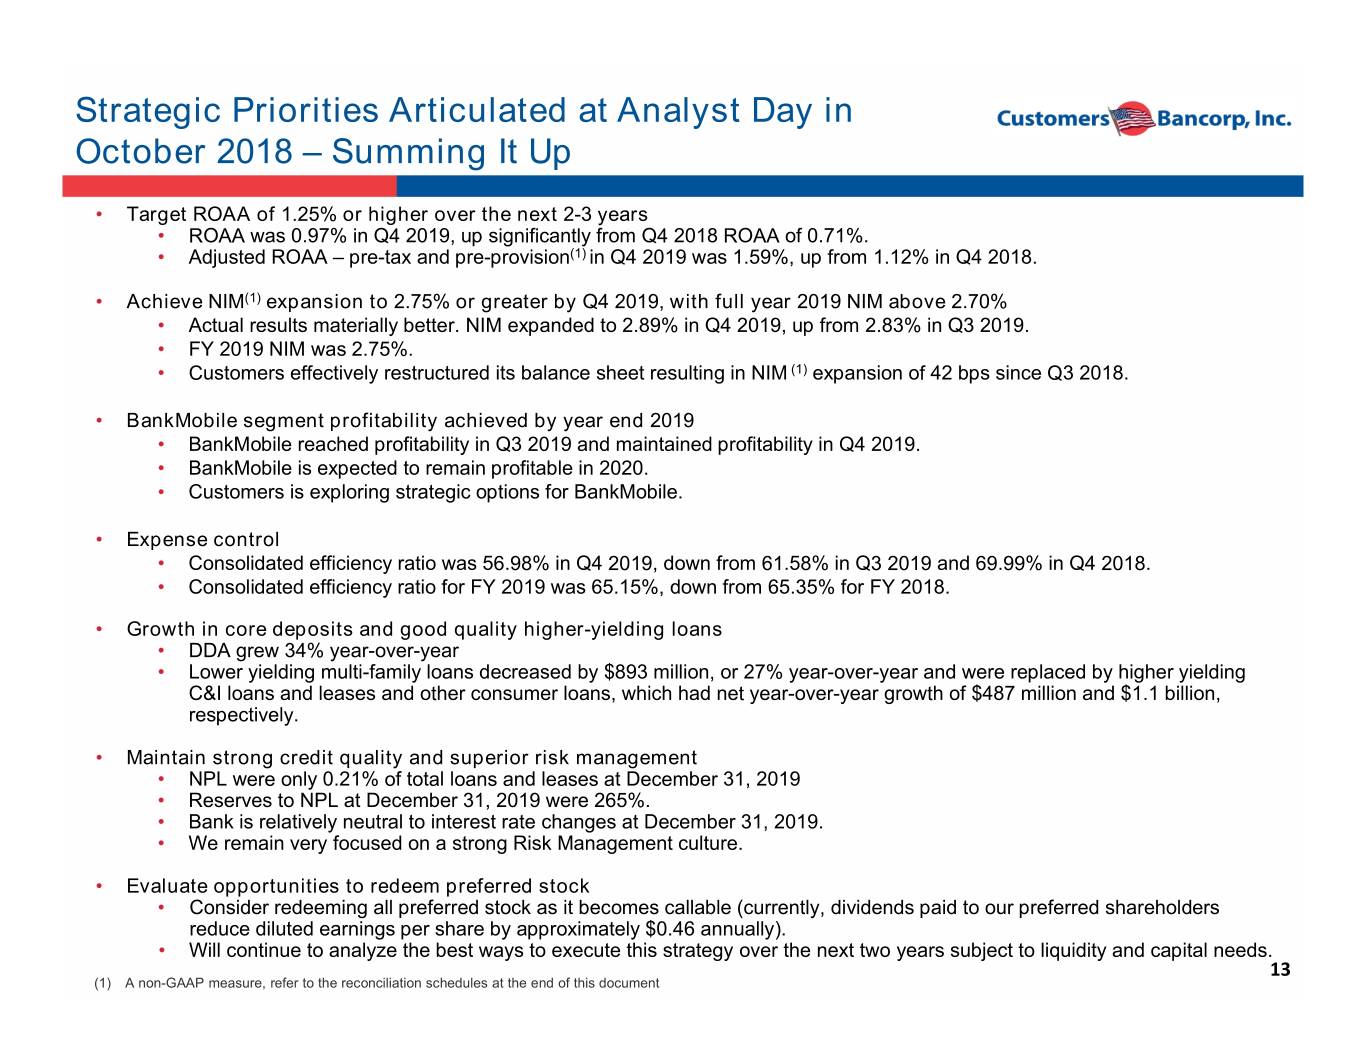
Strategic Priorities Articulated at Analyst Day in October 2018 – Summing It Up • Target ROAA of 1.25% or higher over the next 2-3 years • ROAA was 0.97% in Q4 2019, up significantly from Q4 2018 ROAA of 0.71%. • Adjusted ROAA – pre-tax and pre-provision(1) in Q4 2019 was 1.59%, up from 1.12% in Q4 2018. • Achieve NIM(1) expansion to 2.75% or greater by Q4 2019, with full year 2019 NIM above 2.70% • Actual results materially better. NIM expanded to 2.89% in Q4 2019, up from 2.83% in Q3 2019. • FY 2019 NIM was 2.75%. • Customers effectively restructured its balance sheet resulting in NIM (1) expansion of 42 bps since Q3 2018. • BankMobile segment profitability achieved by year end 2019 • BankMobile reached profitability in Q3 2019 and maintained profitability in Q4 2019. • BankMobile is expected to remain profitable in 2020. • Customers is exploring strategic options for BankMobile. • Expense control • Consolidated efficiency ratio was 56.98% in Q4 2019, down from 61.58% in Q3 2019 and 69.99% in Q4 2018. • Consolidated efficiency ratio for FY 2019 was 65.15%, down from 65.35% for FY 2018. • Growth in core deposits and good quality higher-yielding loans • DDA grew 34% year-over-year • Lower yielding multi-family loans decreased by $893 million, or 27% year-over-year and were replaced by higher yielding C&I loans and leases and other consumer loans, which had net year-over-year growth of $487 million and $1.1 billion, respectively. • Maintain strong credit quality and superior risk management • NPL were only 0.21% of total loans and leases at December 31, 2019 • Reserves to NPL at December 31, 2019 were 265%. • Bank is relatively neutral to interest rate changes at December 31, 2019. • We remain very focused on a strong Risk Management culture. • Evaluate opportunities to redeem preferred stock • Consider redeeming all preferred stock as it becomes callable (currently, dividends paid to our preferred shareholders reduce diluted earnings per share by approximately $0.46 annually). • Will continue to analyze the best ways to execute this strategy over the next two years subject to liquidity and capital needs. 13 (1) A non-GAAP measure, refer to the reconciliation schedules at the end of this document
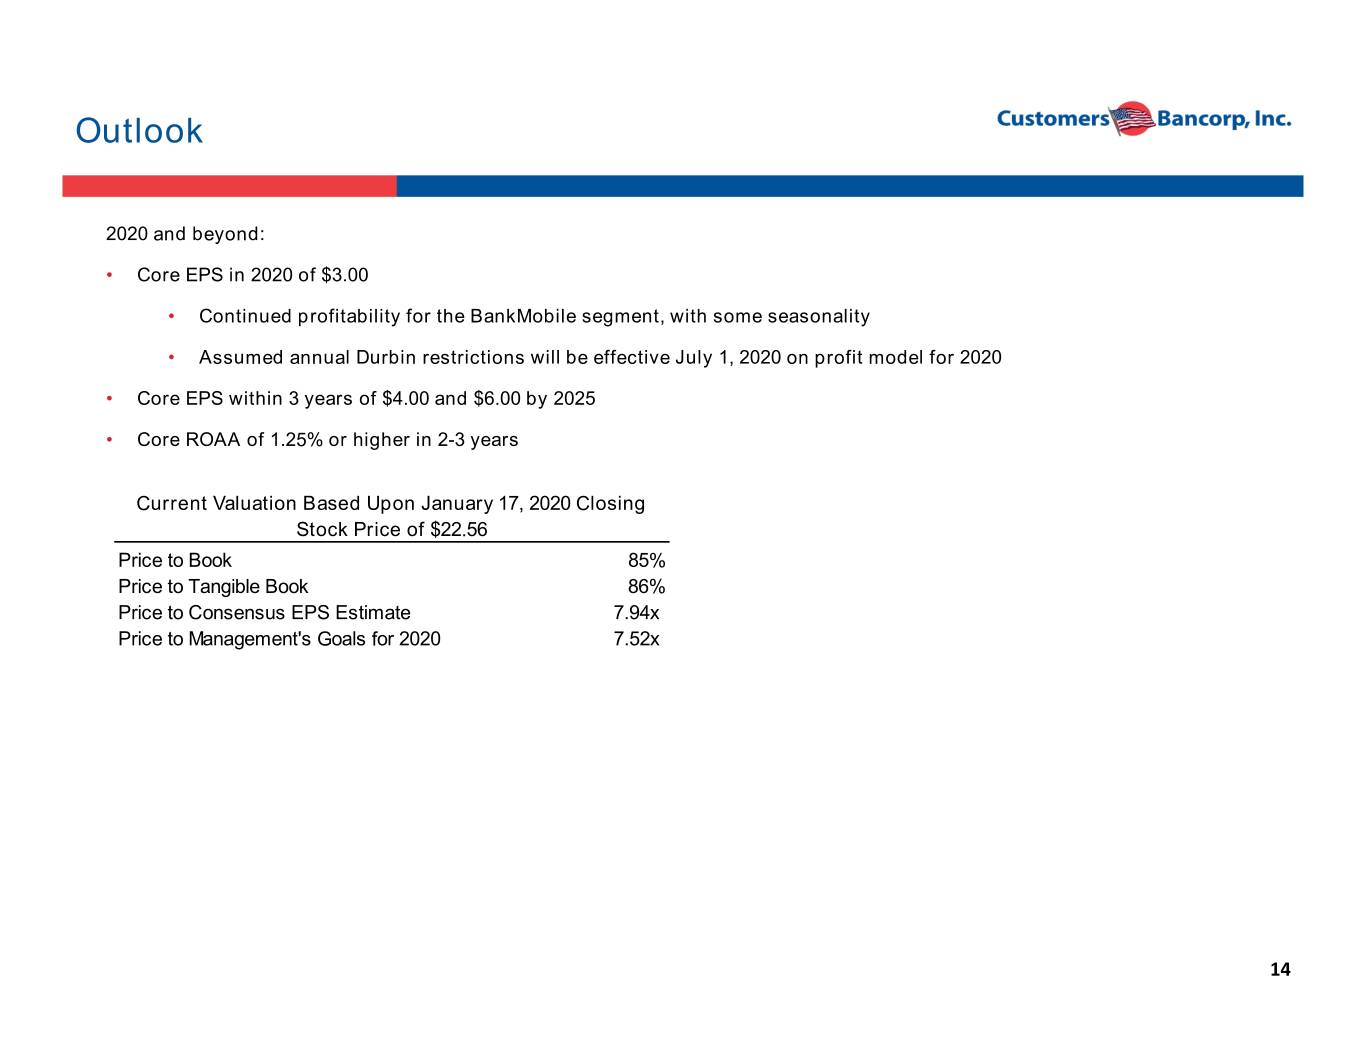
Outlook 2020 and beyond: • Core EPS in 2020 of $3.00 • Continued profitability for the BankMobile segment, with some seasonality • Assumed annual Durbin restrictions will be effective July 1, 2020 on profit model for 2020 • Core EPS within 3 years of $4.00 and $6.00 by 2025 • Core ROAA of 1.25% or higher in 2-3 years Current Valuation Based Upon January 17, 2020 Closing Stock Price of $22.56 Price to Book 85% Price to Tangible Book 86% Price to Consensus EPS Estimate 7.94x Price to Management's Goals for 2020 7.52x 14
Contacts Company: Carla Leibold, CFO of Customers Bancorp, Inc and Customers Bank Tel: 484‐923‐8802 [email protected] Jay Sidhu Chairman & CEO of Customers Bancorp, Inc. and Executive Chairman of Customers Bank Tel: 610‐935‐8693 [email protected] Richard Ehst President & COO of Customers Bancorp, Inc. and CEO of Customers Bank Tel: 610‐917‐3263 [email protected] Sam Sidhu COO of Customers Bank & Head of Corporate Development of Customers Bancorp Tel: 212‐843‐2485 [email protected] 15
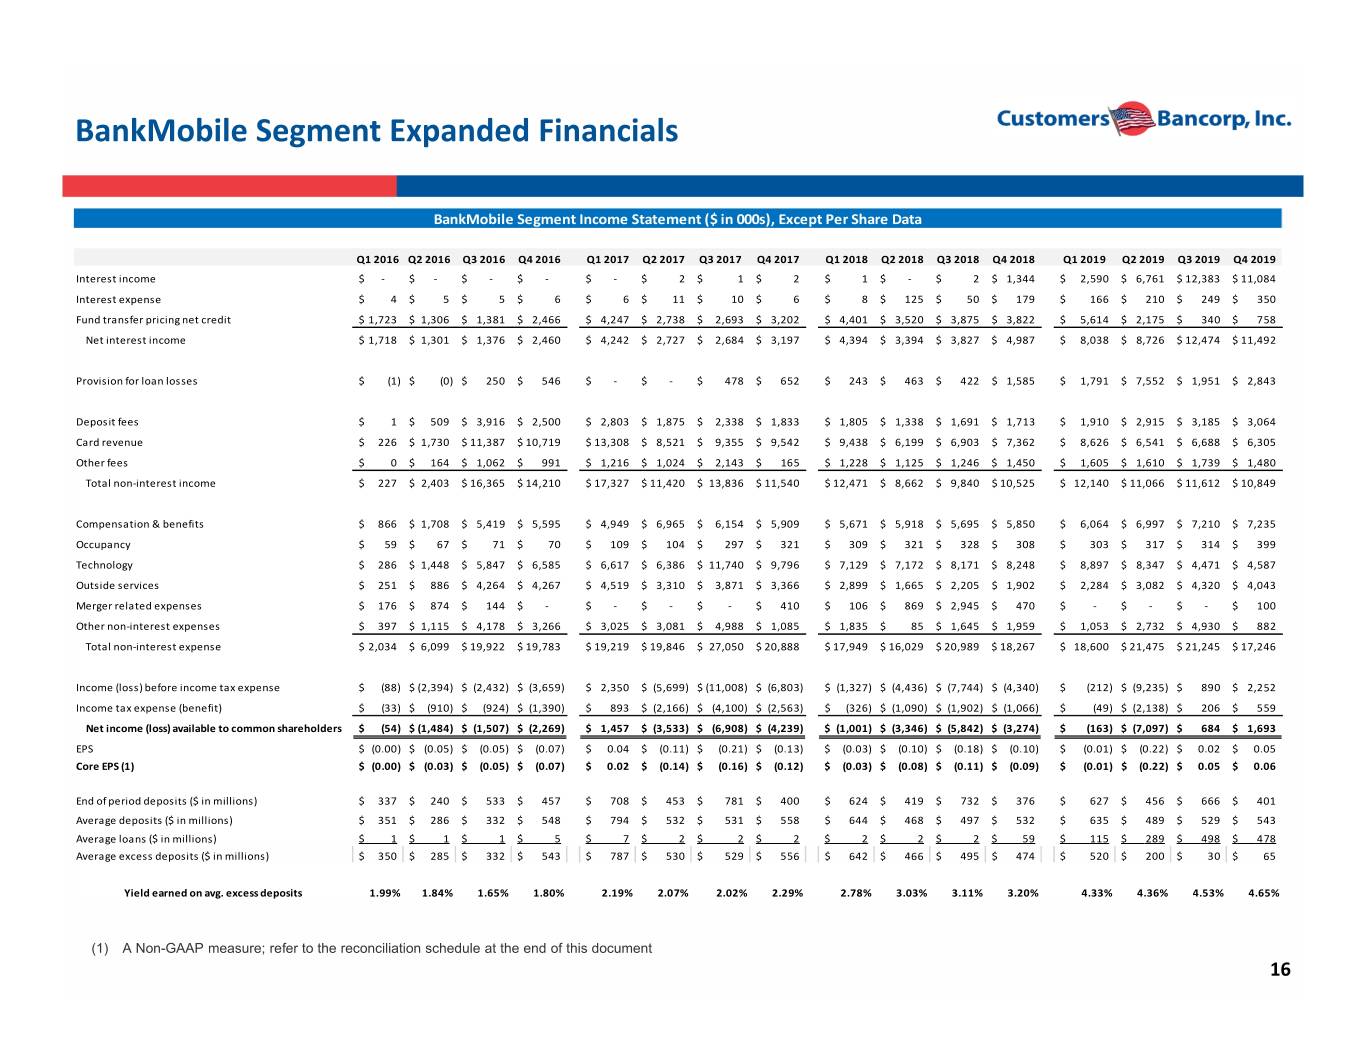
BankMobile Segment Expanded Financials BankMobile Segment Income Statement ($ in 000s), Except Per Share Data Q1 2016 Q2 2016 Q3 2016 Q4 2016 Q1 2017 Q2 2017 Q3 2017 Q4 2017 Q1 2018 Q2 2018 Q3 2018 Q4 2018 Q1 2019 Q2 2019 Q3 2019 Q4 2019 Interest income ‐$ $ ‐ $ ‐ $ ‐ $ ‐ $ 2 $ 1 $ 2 $ 1 $ ‐ $ 2 $ 1,344 $ 2,590 $ 6,761 $ 12,383 $ 11,084 Interest expense$ 4 $ 5 $ 5 $ 6 $ 6 $ 11 $ 10 $ 6 $ 8 $ 125 $ 50 $ 179 $ 166 $ 210 $ 249 $ 350 Fund transfer pricing net credit$ 1,723 $ 1,306 $ 1,381 $ 2,466 $ 4,247 $ 2,738 $ 2,693 $ 3,202 $ 4,401 $ 3,520 $ 3,875 $ 3,822 $ 5,614 $ 2,175 $ 340 $ 758 Net interest income$ 1,718 $ 1,301 $ 1,376 $ 2,460 $ 4,242 $ 2,727 $ 2,684 $ 3,197 $ 4,394 $ 3,394 $ 3,827 $ 4,987 $ 8,038 $ 8,726 $ 12,474 $ 11,492 Provision for loan losses$ (1) $ (0) $ 250 $ 546 $ ‐ $ ‐ $ 478 $ 652 $ 243 $ 463 $ 422 $ 1,585 $ 1,791 $ 7,552 $ 1,951 $ 2,843 Deposit fees$ 1 $ 509 $ 3,916 $ 2,500 $ 2,803 $ 1,875 $ 2,338 $ 1,833 $ 1,805 $ 1,338 $ 1,691 $ 1,713 $ 1,910 $ 2,915 $ 3,185 $ 3,064 Card revenue$ 226 $ 1,730 $ 11,387 $ 10,719 $ 13,308 $ 8,521 $ 9,355 $ 9,542 $ 9,438 $ 6,199 $ 6,903 $ 7,362 $ 8,626 $ 6,541 $ 6,688 $ 6,305 Other fees$ 0 $ 164 $ 1,062 $ 991 $ 1,216 $ 1,024 $ 2,143 $ 165 $ 1,228 $ 1,125 $ 1,246 $ 1,450 $ 1,605 $ 1,610 $ 1,739 $ 1,480 Total non‐interest income$ 227 $ 2,403 $ 16,365 $ 14,210 $ 17,327 $ 11,420 $ 13,836 $ 11,540 $ 12,471 $ 8,662 $ 9,840 $ 10,525 $ 12,140 $ 11,066 $ 11,612 $ 10,849 Compensation & benefits$ 866 $ 1,708 $ 5,419 $ 5,595 $ 4,949 $ 6,965 $ 6,154 $ 5,909 $ 5,671 $ 5,918 $ 5,695 $ 5,850 $ 6,064 $ 6,997 $ 7,210 $ 7,235 Occupancy$ 59 $ 67 $ 71 $ 70 $ 109 $ 104 $ 297 $ 321 $ 309 $ 321 $ 328 $ 308 $ 303 $ 317 $ 314 $ 399 Technology$ 286 $ 1,448 $ 5,847 $ 6,585 $ 6,617 $ 6,386 $ 11,740 $ 9,796 $ 7,129 $ 7,172 $ 8,171 $ 8,248 $ 8,897 $ 8,347 $ 4,471 $ 4,587 Outside services$ 251 $ 886 $ 4,264 $ 4,267 $ 4,519 $ 3,310 $ 3,871 $ 3,366 $ 2,899 $ 1,665 $ 2,205 $ 1,902 $ 2,284 $ 3,082 $ 4,320 $ 4,043 Merger related expenses$ 176 $ 874 $ 144 $ ‐ $ ‐ $ ‐ $ ‐ $ 410 $ 106 $ 869 $ 2,945 $ 470 $ ‐ $ ‐ $ ‐ $ 100 Other non‐interest expenses$ 397 $ 1,115 $ 4,178 $ 3,266 $ 3,025 $ 3,081 $ 4,988 $ 1,085 $ 1,835 $ 85 $ 1,645 $ 1,959 $ 1,053 $ 2,732 $ 4,930 $ 882 Total non‐interest expense$ 2,034 $ 6,099 $ 19,922 $ 19,783 $ 19,219 $ 19,846 $ 27,050 $ 20,888 $ 17,949 $ 16,029 $ 20,989 $ 18,267 $ 18,600 $ 21,475 $ 21,245 $ 17,246 Income (loss) before income tax expense$ (88) $ (2,394) $ (2,432) $ (3,659) $ 2,350 $ (5,699) $ (11,008) $ (6,803) $ (1,327) $ (4,436) $ (7,744) $ (4,340) $ (212) $ (9,235) $ 890 $ 2,252 Income tax expense (benefit)$ (33)$ (910) $ (924) $ (1,390) $ 893 $ (2,166) $ (4,100) $ (2,563) $ (326) $ (1,090) $ (1,902) $ (1,066) $ (49) $ (2,138) $ 206 $ 559 Net income (loss) available to common shareholders$ (54) $ (1,484) $ (1,507) $ (2,269) $ 1,457 $ (3,533) $ (6,908) $ (4,239) $ (1,001) $ (3,346) $ (5,842) $ (3,274) $ (163) $ (7,097) $ 684 $ 1,693 EPS$ (0.00) $ (0.05) $ (0.05) $ (0.07) $ 0.04 $ (0.11) $ (0.21) $ (0.13) $ (0.03) $ (0.10) $ (0.18) $ (0.10) $ (0.01) $ (0.22) $ 0.02 $ 0.05 Core EPS (1)$ (0.00) $ (0.03) $ (0.05) $ (0.07) $ 0.02 $ (0.14) $ (0.16) $ (0.12) $ (0.03) $ (0.08) $ (0.11) $ (0.09) $ (0.01) $ (0.22) $ 0.05 $ 0.06 End of period deposits ($ in millions)$ 337 $ 240 $ 533 $ 457 $ 708 $ 453 $ 781 $ 400 $ 624 $ 419 $ 732 $ 376 $ 627 $ 456 $ 666 $ 401 Average deposits ($ in millions)$ 351 $ 286 $ 332 $ 548 $ 794 $ 532 $ 531 $ 558 $ 644$ 468$ 497 $ 532 $ 635 $ 489 $ 529 $ 543 Average loans ($ in millions)$ $ 1 1 $ 1 $ 5 $ 7 $ 2 $ 2 $ 2 $ 2 $ 2 $ 2 $ 59 $ 115 $ 289 $ 498 $ 478 Average excess deposits ($ in millions)$ 350 $ 285 $ 332 $ 543 $ 787 $ 530 $ 529 $ 556 $ 642 $ 466 $ 495 $ 474 $ 520 $ 200 $ 30 $ 65 Yield earned on avg. excess deposits 1.99% 1.84% 1.65% 1.80% 2.19% 2.07% 2.02% 2.29% 2.78% 3.03% 3.11% 3.20% 4.33% 4.36% 4.53% 4.65% (1) A Non-GAAP measure; refer to the reconciliation schedule at the end of this document 16
Reconciliation of Non‐GAAP Measures ‐ Unaudited Customers believes that the non-GAAP measurements disclosed within this document are useful for investors, regulators, management and others to evaluate our core results of operations and financial condition relative to other financial institutions. These non-GAAP financial measures are frequently used by securities analysts, investors, and other interested parties in the evaluation of companies in Customers' industry. These non-GAAP financial measures exclude from corresponding GAAP measures the impact of certain elements that we do not believe are representative of our ongoing financial results, which we believe enhance an overall understanding of our performance and increases comparability of our period to period results. Investors should consider our performance and financial condition as reported under GAAP and all other relevant information when assessing our performance or financial condition. Although non-GAAP financial measures are frequently used in the evaluation of a company, they have limitations as analytical tools and should not be considered in isolation or as a substitute for analysis of our results of operations or financial condition as reported under GAAP. The following tables present reconciliations of GAAP to non-GAAP measures disclosed within this document. 17
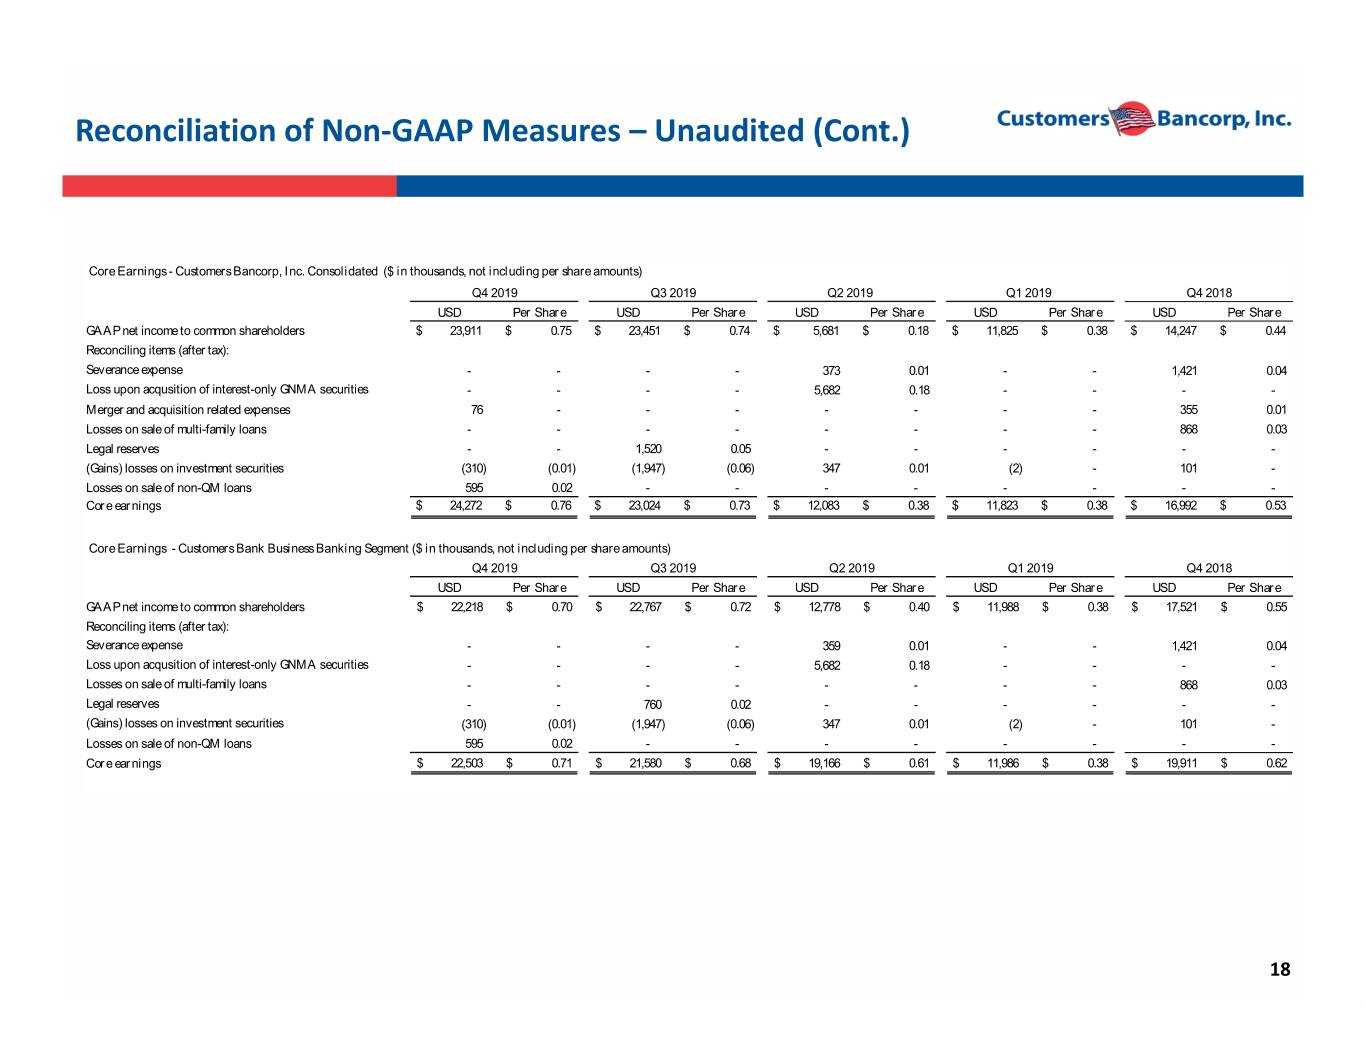
Reconciliation of Non‐GAAP Measures – Unaudited (Cont.) Core Earnings - Customers Bancorp, Inc. Consolidated ($ in thousands, not including per share amounts) Q4 2019 Q3 2019 Q2 2019 Q1 2019 Q4 2018 USD Per Share USD Per Share USD Per Share USD Per Share USD Per Share GAAP net income to common shareholders $ 23,911 $ 0.75 $ 23,451 $ 0.74 $ 5,681 $ 0.18 $ 11,825 $ 0.38 $ 14,247 $ 0.44 Reconciling items (after tax): Severance expense - - - - 373 0.01 - - 1,421 0.04 Loss upon acqusition of interest-only GNMA securities - - - - 5,682 0.18 - - - - Merger and acquisition related expenses 76 - - - - - - - 355 0.01 Loss es on sale of multi-family loans - - - - - - - - 868 0.03 Legal res erves - - 1,520 0.05 - - - - - - (Gains) losses on investment securities (310) (0.01) (1,947) (0.06) 347 0.01 (2) - 101 - Losses on sale of non-QM loans 595 0.02 - - - - - - - - Core earnings $ 24,272 $ 0.76 $ 23,024 $ 0.73 $ 12,083 $ 0.38 $ 11,823 $ 0.38 $ 16,992 $ 0.53 Core Earnings - Customers Bank Business Banking Segment ($ in thousands, not including per share amounts) Q4 2019 Q3 2019 Q2 2019 Q1 2019 Q4 2018 USD Per Share USD Per Share USD Per Share USD Per Share USD Per Share GAAP net income to common shareholders$ 22,218 $ 0.70 $ 22,767 $ 0.72 $ 12,778 $ 0.40 $ 11,988 $ 0.38 $ 17,521 $ 0.55 Reconciling items (after tax): Severance expense - - - - 359 0.01 - - 1,421 0.04 Loss upon acqusition of interest-only GNMA securities - - - - 5,682 0.18 - - - - Loss es on sale of multi-family loans - - - - - - - - 868 0.03 Legal res erves - - 760 0.02 - - - - - - (Gains) losses on investment securities (310) (0.01) (1,947) (0.06) 347 0.01 (2) - 101 - Losses on sale of non-QM loans 595 0.02 - - - - - - - - Core earnings $ 22,503 $ 0.71 $ 21,580 $ 0.68 $ 19,166 $ 0.61 $ 11,986 $ 0.38 $ 19,911 $ 0.62 18
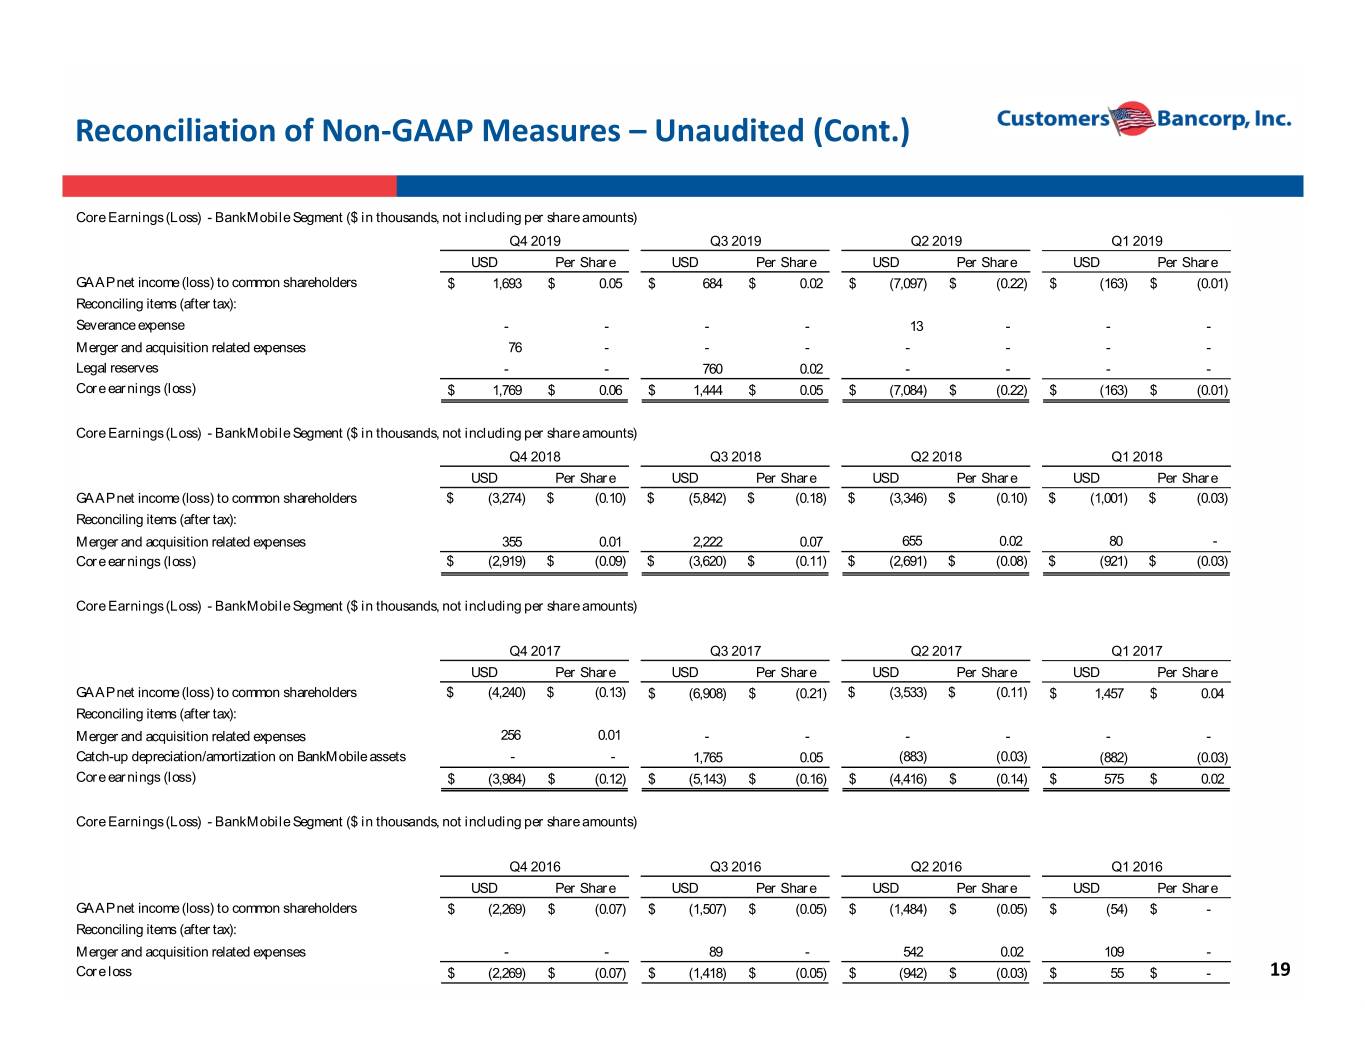
Reconciliation of Non‐GAAP Measures – Unaudited (Cont.) Core Earnings (Loss) - BankMobile Segment ($ in thousands, not including per share amounts) Q4 2019 Q3 2019 Q2 2019 Q1 2019 USD Per Share USD Per Share USD Per Share USD Per Share GAAP net income (loss) to common shareholders $ 1,693 $ 0.05 $ 684 $ 0.02 $ (7,097) $ (0.22) $ (163) $ (0.01) Reconciling items (after tax): Severance expense - - - - 13 - - - Merger and acquisition related expenses 76 - - - - - - - Legal reserves - - 760 0.02 - - - - Core earnings (loss) $ 1,769 $ 0.06 $ 1,444 $ 0.05 $ (7,084) $ (0.22) $ (163) $ (0.01) Core Earnings (Loss) - BankMobile Segment ($ in thousands, not including per share amounts) Q4 2018 Q3 2018 Q2 2018 Q1 2018 USD Per Share USD Per Share USD Per Share USD Per Share GAAP net income (loss) to common shareholders $ (3,274) $ (0.10) $ (5,842) $ (0.18) $ (3,346) $ (0.10) $ (1,001) $ (0.03) Reconciling items (after tax): Merger and acquisition related expenses 355 0.01 2,222 0.07 655 0.02 80 - Core earnings (loss) $ (2,919) $ (0.09) $ (3,620) $ (0.11) $ (2,691) $ (0.08) $ (921) $ (0.03) Core Earnings (Loss) - BankMobile Segment ($ in thousands, not including per share amounts) Q4 2017 Q3 2017 Q2 2017 Q1 2017 USD Per Share USD Per Share USD Per Share USD Per Share GAAP net income (loss) to common shareholders $ (4,240) $ (0.13) $ (6,908) $ (0.21) $ (3,533) $ (0.11) $ 1,457 $ 0.04 Reconciling items (after tax): Merger and acquisition related expenses 256 0.01 - - - - - - Catch-up depreciation/amortization on BankMobile assets - - 1,765 0.05 (883) (0.03) (882) (0.03) Core earnings (loss) $ (3,984) $ (0.12) $ (5,143) $ (0.16) $ (4,416) $ (0.14) $ 575 $ 0.02 Core Earnings (Loss) - BankMobile Segment ($ in thousands, not including per share amounts) Q4 2016 Q3 2016 Q2 2016 Q1 2016 USD Per Share USD Per Share USD Per Share USD Per Share GAAP net income (loss) to common shareholders $ (2,269) $ (0.07) $ (1,507) $ (0.05) $ (1,484) $ (0.05) $ (54) $ - Reconciling items (after tax): Merger and acquisition related expenses - - 89 - 542 0.02 109 - Core loss $ (2,269) $ (0.07) $ (1,418) $ (0.05) $ (942) $ (0.03) $ 55 $ - 19
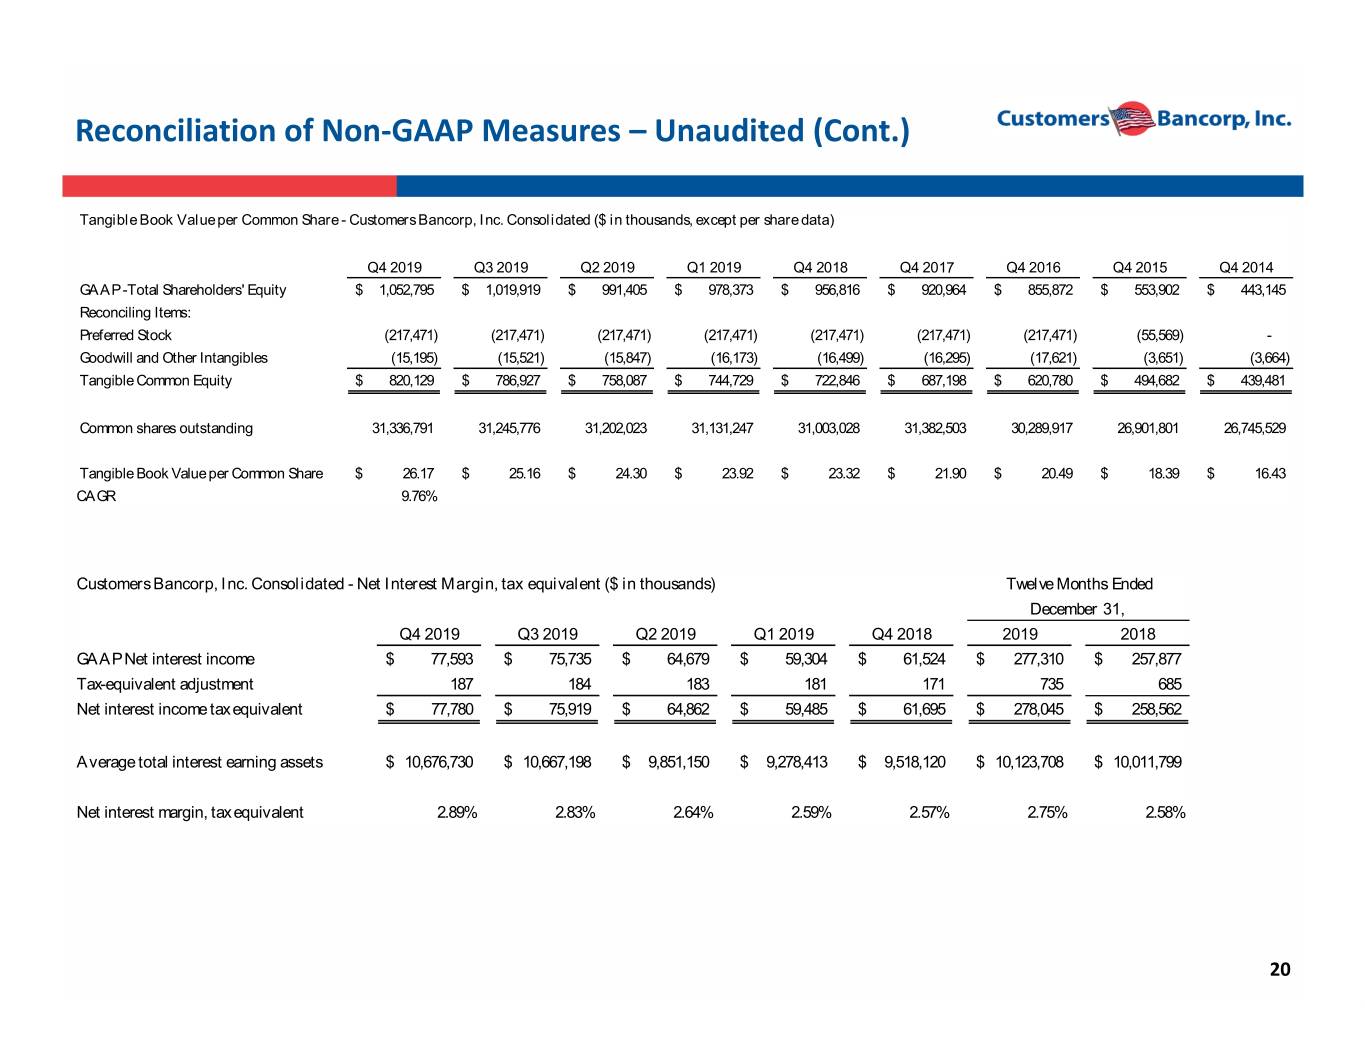
Reconciliation of Non‐GAAP Measures – Unaudited (Cont.) Tangible Book Value per Common Share - Customers Bancorp, Inc. Consolidated ($ in thousands, except per share data) Q4 2019 Q3 2019 Q2 2019 Q1 2019 Q4 2018 Q4 2017 Q4 2016 Q4 2015 Q4 2014 GAAP -Total Shareholders' Equity $ 1,052,795 $ 1,019,919 $ 991,405 $ 978,373 $ 956,816 $ 920,964 $ 855,872 $ 553,902 $ 443,145 Reconciling Items: Preferred Stock (217,471) (217,471) (217,471) (217,471) (217,471) (217,471) (217,471) (55,569) - Goodwill and Other Intangibles (15,195) (15,521) (15,847) (16,173) (16,499) (16,295) (17,621) (3,651) (3,664) Tangible Common Equity $ 820,129 $ 786,927 $ 758,087 $ 744,729 $ 722,846 $ 687,198 $ 620,780 $ 494,682 $ 439,481 Common shares outstanding 31,336,791 31,245,776 31,202,023 31,131,247 31,003,028 31,382,503 30,289,917 26,901,801 26,745,529 Tangible Book Value per Common Share $ 26.17 $ 25.16 $ 24.30 $ 23.92 $ 23.32 $ 21.90 $ 20.49 $ 18.39 $ 16.43 CAGR 9.76% Customers Bancorp, Inc. Consolidated - Net Interest Margin, tax equivalent ($ in thousands) Twelve Months Ended December 31, Q4 2019 Q3 2019 Q2 2019 Q1 2019 Q4 2018 2019 2018 GAAP Net interest income$ 77,593 $ 75,735 $ 64,679 $ 59,304 $ 61,524 $ 277,310 $ 257,877 Tax-equivalent adjustment 187 184 183 181 171 735 685 Net interest income tax equivalent$ 77,780 $ 75,919 $ 64,862 $ 59,485 $ 61,695 $ 278,045 $ 258,562 Average total interest earning assets$ 10,676,730 $ 10,667,198 $ 9,851,150 $ 9,278,413 $ 9,518,120 $ 10,123,708 $ 10,011,799 Net interest margin, tax equivalent 2.89% 2.83% 2.64% 2.59% 2.57% 2.75% 2.58% 20
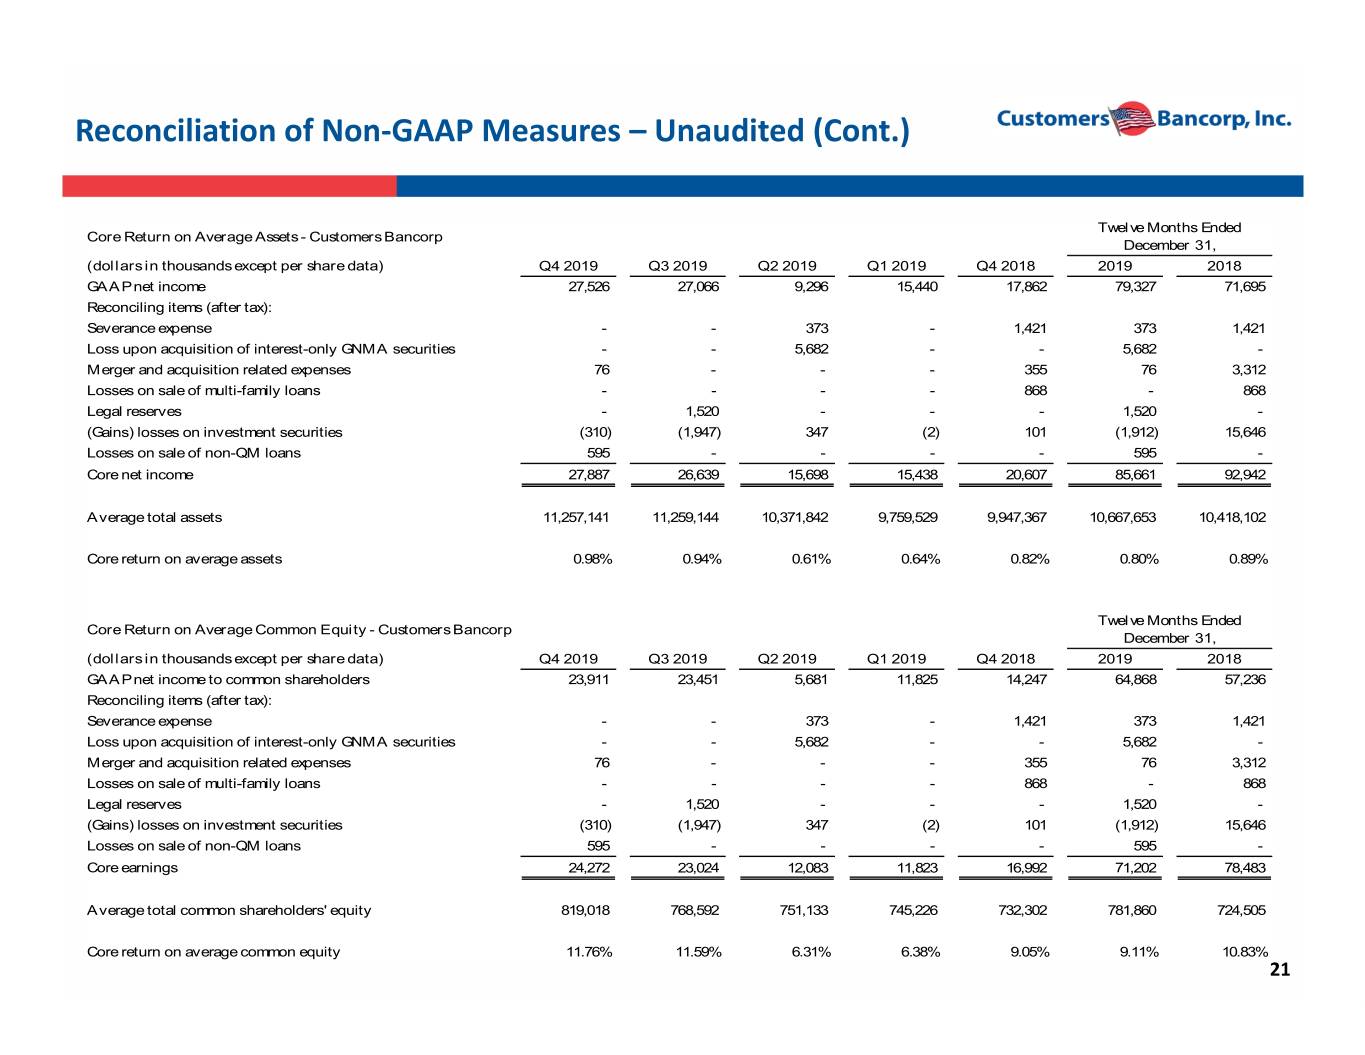
Reconciliation of Non‐GAAP Measures – Unaudited (Cont.) Twelve Months Ended Core Return on Average Assets - Customers Bancorp December 31, (dollars in thousands except per share data) Q4 2019 Q3 2019 Q2 2019 Q1 2019 Q4 2018 2019 2018 GAAP net income 27,526 27,066 9,296 15,440 17,862 79,327 71,695 Reconciling items (after tax): Severance expense - - 373 - 1,421 373 1,421 Loss upon acquisition of interest-only GNMA securities - - 5,682 - - 5,682 - Merger and acquisition related expenses 76 - - - 355 76 3,312 Losses on sale of multi-family loans - - - - 868 - 868 Legal reserves - 1,520 - - - 1,520 - (Gains) losses on investment securities (310) (1,947) 347 (2) 101 (1,912) 15,646 Losses on sale of non-QM loans 595 - - - - 595 - Core net income 27,887 26,639 15,698 15,438 20,607 85,661 92,942 Average total assets 11,257,141 11,259,144 10,371,842 9,759,529 9,947,367 10,667,653 10,418,102 Core return on average assets 0.98% 0.94% 0.61% 0.64% 0.82% 0.80% 0.89% Twelve Months Ended Core Return on Average Common Equity - Customers Bancorp December 31, (dollars in thousands except per share data) Q4 2019 Q3 2019 Q2 2019 Q1 2019 Q4 2018 2019 2018 GAAP net income to common shareholders 23,911 23,451 5,681 11,825 14,247 64,868 57,236 Reconciling items (after tax): Severance expense - - 373 - 1,421 373 1,421 Loss upon acquisition of interest-only GNMA securities - - 5,682 - - 5,682 - Merger and acquisition related expenses 76 - - - 355 76 3,312 Losses on sale of multi-family loans - - - - 868 - 868 Legal reserves - 1,520 - - - 1,520 - (Gains) losses on investment securities (310) (1,947) 347 (2) 101 (1,912) 15,646 Losses on sale of non-QM loans 595 - - - - 595 - 21 Core earnings 24,272 23,024 12,083 11,823 16,992 71,202 78,483 Average total common shareholders' equity 819,018 768,592 751,133 745,226 732,302 781,860 724,505 Core return on average common equity 11.76% 11.59% 6.31% 6.38% 9.05% 9.11% 10.83%
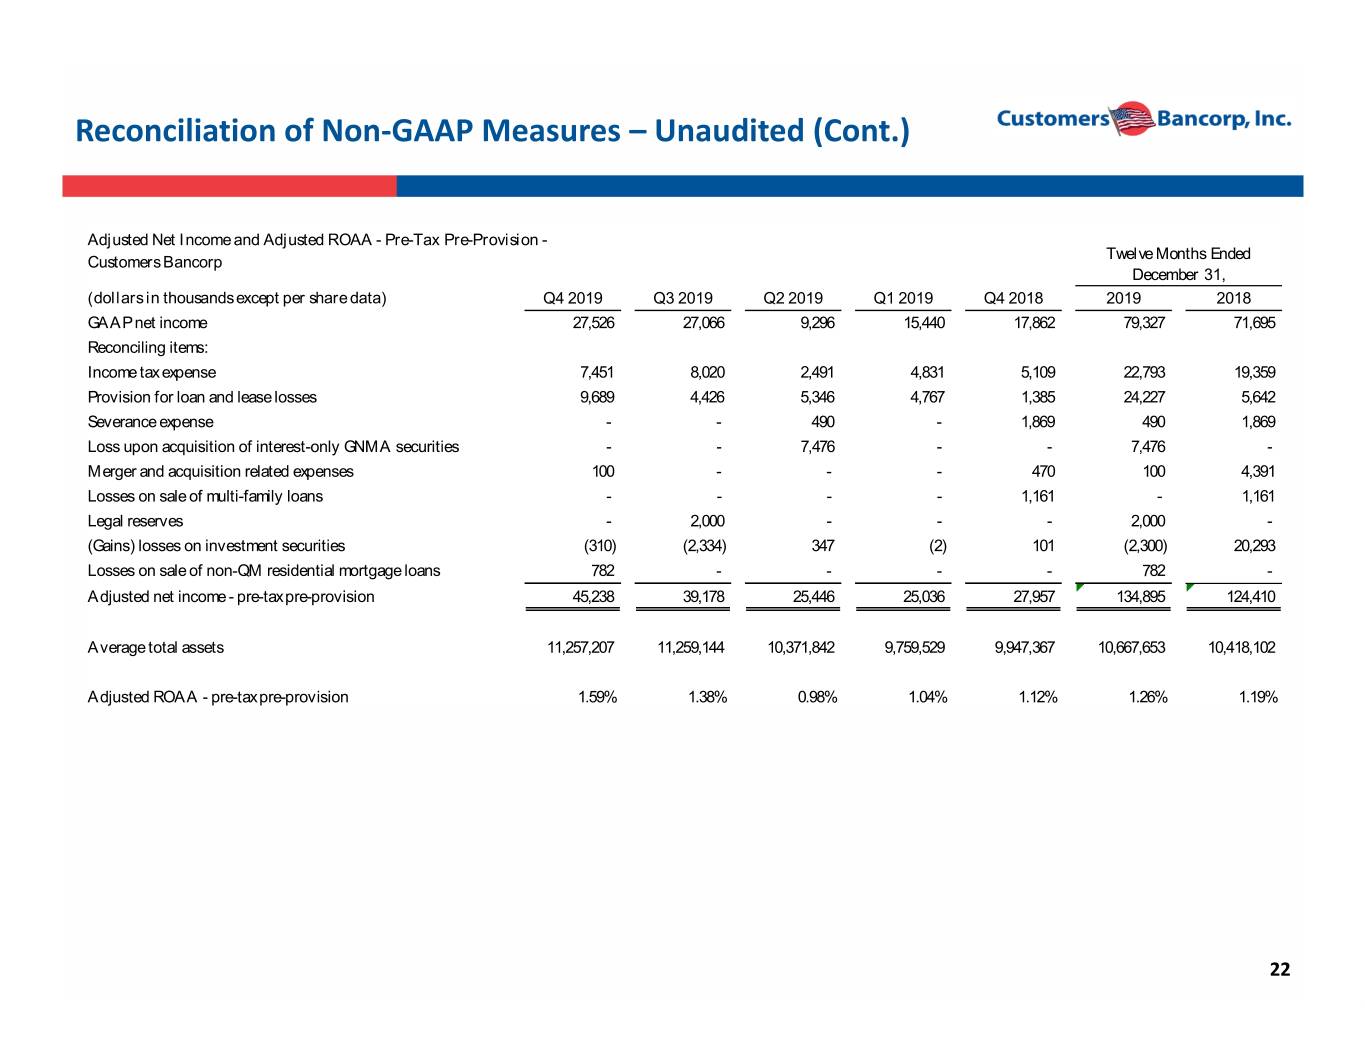
Reconciliation of Non‐GAAP Measures – Unaudited (Cont.) Adjusted Net Income and Adjusted ROAA - Pre-Tax Pre-Provision - Twelve Months Ended Customers Bancorp December 31, (dollars in thousands except per share data) Q4 2019 Q3 2019 Q2 2019 Q1 2019 Q4 2018 2019 2018 GAAP net income 27,526 27,066 9,296 15,440 17,862 79,327 71,695 Reconciling items: Income tax expense 7,451 8,020 2,491 4,831 5,109 22,793 19,359 Provision for loan and lease losses 9,689 4,426 5,346 4,767 1,385 24,227 5,642 Severance expense - - 490 - 1,869 490 1,869 Loss upon acquisition of interest-only GNMA securities - - 7,476 - - 7,476 - Merger and acquisition related expenses 100 - - - 470 100 4,391 Losses on sale of multi-family loans - - - - 1,161 - 1,161 Legal reserves - 2,000 - - - 2,000 - (Gains) losses on investment securities (310) (2,334) 347 (2) 101 (2,300) 20,293 Losses on sale of non-QM residential mortgage loans 782 - - - - 782 - Adjusted net income - pre-tax pre-provision 45,238 39,178 25,446 25,036 27,957 134,895 124,410 Average total assets 11,257,207 11,259,144 10,371,842 9,759,529 9,947,367 10,667,653 10,418,102 Adjusted ROAA - pre-tax pre-provision 1.59% 1.38% 0.98% 1.04% 1.12% 1.26% 1.19% 22