
ESS 8-K
Essex Property Trust, Inc. (ESS)
8-K
2026-07-29
For: 2026-07-29
View Original
Added on
July 29, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
Current Report Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of Report (Date of Earliest Event Reported): July 29, 2026
(Exact Name of Registrant as Specified in Its Charter)
(Commission File Number)
|
|
|
|
|
|
|
|
|
(State or Other Jurisdiction of Incorporation)
|
(I.R.S. Employer Identification No.)
|
(Address of principal executive offices, including zip code)
(650 ) 655-7800
(Registrant’s telephone number, including area code)
Not Applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the
following provisions:
|
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425)
|
|
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12)
|
|
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))
|
|
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))
|
Securities registered pursuant to Section 12(b) of the Act:
|
Title of each class
|
Trading
Symbol(s)
|
Name of each exchange on which registered
|
||
|
|
|
|
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405
of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter):
|
Essex Property Trust, Inc.
|
Emerging growth company
|
|
|
Essex Portfolio, L.P.
|
Emerging growth company
|
|
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for
complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
| Item 2.02. |
Results of Operations and Financial Condition.
|
On July 29, 2026, Essex Property Trust, Inc. (the “Company”) issued a press release and supplemental information announcing the Company’s financial results
for the three and six months ended June 30, 2026. The Company has posted a copy of the press release and supplemental information on the Company’s website at www.essex.com. A copy of the press release and supplemental information is
attached hereto as Exhibit 99.1 and incorporated by reference herein.
The information in this report (including Exhibit 99.1) is being furnished pursuant to Item 2.02 and shall not be deemed to be “filed” for purposes of
Section 18 of the Securities Exchange Act of 1934 (the “Exchange Act”), or otherwise subject to the liabilities of that section, nor shall it be deemed to be incorporated by reference in any filing under the Securities Act of 1933 or the Exchange
Act.
| Item 9.01. |
Financial Statements and Exhibits.
|
(d) Exhibits.
|
Exhibit No.
|
Description
|
|
|
Press Release and Supplemental Information for the three and six months ended June 30, 2026.
|
||
|
104
|
Cover Page Interactive Data File - the cover page XBRL tags are embedded within the Inline XBRL document.
|
|
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, the registrants have duly caused
this report to be signed on their behalf by the undersigned, hereunto duly authorized.
|
Date: July 29,
2026
|
ESSEX PROPERTY TRUST, INC.
|
|
|
/s/ Barbara Pak
|
||
|
Name:
|
Barbara Pak
|
|
|
Title:
|
Executive Vice President and Chief Financial Officer
|
|
|
ESSEX PORTFOLIO, L.P.
|
||
|
By:
|
Essex Property Trust, Inc.
|
|
|
Its:
|
General Partner
|
|
|
/s/ Barbara Pak
|
||
|
Name:
|
Barbara Pak
|
|
|
Title:
|
Executive Vice President and Chief Financial Officer
|
|
Exhibit 99.1
Second Quarter 2026
Earnings Release and Supplemental Data
|
Pages 1 - 9
|
|
|
S-1 & S-2
|
|
|
S-3
|
|
|
S-4
|
|
|
S-5
|
|
|
S-6
|
|
|
S-7
|
|
|
S-8
|
|
|
S-9
|
|
|
S-9.1
|
|
|
S-10
|
|
|
S-11
|
|
|
S-12
|
|
|
S-13
|
|
|
S-14
|
|
|
S-15
|
|
|
S-15.1
|
|
|
S-16
|
|
|
S-16.1
|
|
|
S-17.1 – S-17.4
|
1100 Park Place Suite 200 San Mateo California 94403 telephone 650 655 7800 facsimile 650 655 7810
www.essex.com
Essex Announces Second Quarter 2026 Results
and Raises Full-Year 2026 Guidance
San Mateo, California—July 29, 2026—Essex Property Trust, Inc. (NYSE: ESS) (the “Company”)
announced today its second quarter 2026 earnings results and related business activities.
Net Income, Funds from Operations (“FFO”), and Core FFO per diluted share for the three and six-month periods ended June 30, 2026 are detailed below.
|
Three Months Ended
June 30,
|
%
|
Six Months Ended
June 30,
|
%
|
|||||||||||||||
|
2026
|
2025
|
Change
|
2026
|
2025
|
Change
|
|||||||||||||
|
Per Diluted Share
|
||||||||||||||||||
|
Net Income
|
$0.97
|
$3.44
|
-71.8%
|
|
$2.62
|
$6.59
|
-60.2%
|
|
||||||||||
|
Total FFO (1)
|
$3.32
|
$4.03
|
-17.6%
|
|
$7.49
|
$8.00
|
-6.4%
|
|
||||||||||
|
Core FFO
|
$4.08
|
$4.03
|
1.2%
|
|
$8.15
|
$8.00
|
1.9%
|
|
||||||||||
| (1) |
The decrease is primarily attributable to legal settlements. See page S-3 of the supplemental financial information for details.
|
Second Quarter 2026 Highlights:
| • |
Reported Net Income per diluted share for the second quarter of 2026 of $0.97, compared to $3.44 in the second quarter of 2025. The decrease is primarily attributable to a gain on
sale of real estate and land recognized in the second quarter of 2025.
|
| • |
Grew Core FFO per diluted share by 1.2% compared to the second quarter of 2025, exceeding the midpoint of the Company’s guidance range by $0.10 per diluted share. The outperformance was primarily
attributable to higher same-property and non-same-property net operating income (“NOI”).
|
| • |
Achieved same-property revenue and NOI growth of 2.7% and 2.6%, respectively, compared to the second quarter of 2025. On a sequential basis, same-property revenue and NOI improved 0.8% and 1.2%,
respectively.
|
| • |
Disposed of a co-investment apartment community at a total contract price of $105.3 million ($52.6 million at pro rata share).
|
| • |
Received $87.8 million from the full redemption of three structured finance investments.
|
| • |
Revised full-year 2026 guidance range as detailed in the table below:
|
|
Full-Year 2026 Revised Guidance
|
Revised
Range
|
Revised
Midpoint
|
Change at
Midpoint
|
||||||
|
Net Income per diluted share
|
$5.47 - $5.69
|
$5.58
|
($0.29)
|
|
|||||
|
Core FFO per diluted share
|
$16.03 - $16.25
|
$16.14
|
+$0.20
|
||||||
|
Same-Property Revenues
|
2.5% to 3.1%
|
2.8%
|
|
+0.40%
|
|
||||
|
Same-Property Operating Expenses
|
2.5% to 3.0%
|
2.8%
|
|
(0.25%)
|
|
||||
|
Same-Property NOI
|
2.3% to 3.3%
|
2.8%
|
|
+0.70%
|
|
1100 Park Place Suite 200 San Mateo California 94403 telephone 650 655 7800 facsimile 650 655 7810
www.essex.com
Same-Property Operations
Same-property operating results exclude any properties that are not comparable for the periods presented. The table below illustrates the percentage change in
same-property revenue on a year-over-year basis for the three and six-month periods ended June 30, 2026 and on a sequential basis for the three-month period ended June 30, 2026:
|
Revenue Change
|
||||||||||||
|
Q2 2026
vs. Q2 2025
|
YTD 2026
vs. YTD 2025
|
Q2 2026
vs. Q1 2026
|
% of Total Q2
2026 Revenues
|
|||||||||
|
Southern California
|
||||||||||||
|
Los Angeles County
|
1.0%
|
|
1.3%
|
-0.7%
|
16.8%
|
|||||||
|
Orange County
|
2.7%
|
2.8%
|
0.5%
|
10.1%
|
||||||||
|
San Diego County
|
1.1%
|
1.8%
|
0.1%
|
9.8%
|
||||||||
|
Ventura County
|
1.7%
|
1.8%
|
-0.1%
|
4.7%
|
||||||||
|
Total Southern California
|
1.5%
|
1.9%
|
-0.2%
|
41.4%
|
||||||||
|
Northern California
|
||||||||||||
|
Santa Clara County
|
4.5%
|
4.6%
|
1.7%
|
21.0%
|
||||||||
|
Alameda County
|
3.6%
|
3.3%
|
1.8%
|
7.0%
|
||||||||
|
San Mateo County
|
5.4%
|
5.2%
|
2.3%
|
4.6%
|
||||||||
|
Contra Costa County
|
2.3%
|
1.9%
|
0.8%
|
5.1%
|
||||||||
|
San Francisco
|
7.0%
|
5.7%
|
3.2%
|
3.0%
|
||||||||
|
Total Northern California
|
4.4%
|
4.1%
|
1.8%
|
40.7%
|
||||||||
|
Seattle Metro
|
1.7%
|
2.0%
|
0.8%
|
17.9%
|
||||||||
|
Same-Property Portfolio
|
2.7%
|
2.8%
|
0.8%
|
100%
|
||||||||
The table below illustrates the components that drove the change in same-property revenue on a year-over-year basis for the three and six-month periods ended June 30, 2026
and on a sequential basis for the three-month period ended June 30, 2026:
|
Same-Property Revenue Components
|
Q2 2026
vs. Q2 2025
|
YTD 2026
vs. YTD 2025
|
Q2 2026
vs. Q1 2026
|
||||||
|
Scheduled Rents
|
2.2%
|
2.2%
|
0.9%
|
||||||
|
Delinquency
|
-0.1%
|
0.0%
|
-0.1%
|
||||||
|
Cash Concessions
|
0.0%
|
-0.1%
|
0.0%
|
||||||
|
Vacancy
|
0.0%
|
0.1%
|
-0.2%
|
||||||
|
Other Income
|
0.6%
|
0.6%
|
0.2%
|
||||||
|
Q2 2026 Same-Property Revenue Growth
|
2.7%
|
2.8%
|
0.8%
|
|
Year-Over-Year Change
|
Year-Over-Year Change
|
|||||||||||||||||
|
Q2 2026 compared to Q2 2025
|
YTD 2026 compared to YTD 2025
|
|||||||||||||||||
|
Revenues
|
Operating
Expenses
|
NOI
|
Revenues
|
Operating
Expenses
|
NOI
|
|||||||||||||
|
Southern California
|
1.5%
|
|
2.5%
|
1.1%
|
1.9%
|
2.2%
|
1.7%
|
|||||||||||
|
Northern California
|
4.4%
|
-1.2%
|
6.8%
|
4.1%
|
-0.5%
|
6.2%
|
||||||||||||
|
Seattle Metro
|
1.7%
|
14.2%
|
-2.7%
|
2.0%
|
4.7%
|
1.0%
|
||||||||||||
|
Same-Property Portfolio
|
2.7%
|
2.8%
|
2.6%
|
2.8%
|
1.5%
|
3.3%
|
||||||||||||
|
Sequential Change
|
|||||||||
|
Q2 2026 compared to Q1 2026
|
|||||||||
|
Revenues
|
Operating
Expenses
|
NOI
|
|||||||
|
Southern California
|
-0.2%
|
|
1.0%
|
-0.6%
|
|||||
|
Northern California
|
1.8%
|
-2.1%
|
3.4%
|
||||||
|
Seattle Metro
|
0.8%
|
1.2%
|
0.6%
|
||||||
|
Same-Property Portfolio
|
0.8%
|
-0.2%
|
1.2%
|
||||||
|
Financial Occupancies
|
|||||||||
|
Quarter Ended
|
|||||||||
|
6/30/2026
|
3/31/2026
|
6/30/2025
|
|||||||
|
Southern California
|
95.7%
|
96.1%
|
95.6%
|
||||||
|
Northern California
|
96.8%
|
96.9%
|
96.6%
|
||||||
|
Seattle Metro
|
96.4%
|
96.6%
|
96.4%
|
||||||
|
Same-Property Portfolio
|
96.3%
|
96.5%
|
96.2%
|
||||||
Investment Activity
Dispositions
In June 2026, Wesco V, LLC (“Wesco V”), a joint venture in which the Company owns a 50% interest, sold a 218-unit apartment home community located in San Jose, CA for a
total contract price of $105.3 million ($52.6 million at pro rata share). The Company recorded a gain on sale of co-investment communities of $9.2 million at pro rata share in the second quarter, which has been excluded from Total and Core FFO.
Other Investments
In the second quarter of 2026, the Company received cash proceeds of $87.8 million from the full redemption of three structured finance investments
yielding a weighted average return of 11.6%. The Company recorded $0.2 million of income from prepayment penalties as the result of an early redemption, which has been excluded from Core FFO.
Subsequent to quarter end, Wesco VII, LLC (“Wesco VII”), a joint venture in which the Company owns a 50% interest, originated two preferred equity
investments in stabilized apartment communities totaling $36.2 million ($18.1 million at pro rata share). Both investments were fully funded at closing and yield an initial preferred return of 11.5%.
Balance Sheet and Liquidity
Common Stock and Liquidity
In the second quarter of 2026, the Company repurchased 48,261 shares of its common stock through the Company’s stock repurchase plan, totaling $11.7 million, including commissions, at an average
price per share of $242.47. Year-to-date, the Company has repurchased 254,001 shares of its common stock totaling $61.9 million, including commissions, at an average price per share of $243.76. In May 2026, the Board of Directors approved the
replacement of the Company’s prior repurchase program with a new, $500.0 million stock repurchase plan. As of June 30, 2026, the Company had $500.0 million of purchase authority remaining under its stock repurchase plan.
As of June 30, 2026, the Company had approximately $1.4 billion in liquidity via available capacity on its unsecured credit facilities, cash and cash
equivalents, and marketable securities.
Guidance
For the second quarter of 2026, the Company exceeded
the midpoint of the guidance range provided in its first quarter 2026 earnings release for Core FFO by $0.10 per diluted share.
The following table provides a reconciliation of second quarter 2026 Core FFO per diluted share to the midpoint of the guidance provided in the Company’s first quarter
2026 earnings release.
|
Per Diluted
Share
|
||||
|
Guidance midpoint of Core FFO per diluted share for Q2 2026
|
$
|
3.98
|
||
|
Same-Property NOI (1)
|
0.05
|
|||
|
Non-Same-Property NOI
|
0.03
|
|||
|
Interest Income and Other
|
0.02
|
|||
|
Core FFO per diluted share for Q2 2026 reported
|
$
|
4.08
|
||
| (1) |
Includes $0.03 of lower property taxes due to refunds which are one-time in nature.
|
2026 Full-Year and Third Quarter Guidance
|
Per Diluted Share
|
Previous
Range
|
Revised
Range
|
Revised
Midpoint
|
Change at
Midpoint
|
||||||||
|
Net Income
|
$5.62 - $6.12
|
$5.47 - $5.69
|
$5.58
|
($0.29)
|
||||||||
|
Total FFO
|
$15.71 - $16.21
|
$15.37 - $15.59
|
$15.48
|
($0.48)
|
||||||||
|
Core FFO
|
$15.69 - $16.19
|
$16.03 - $16.25
|
$16.14
|
+$0.20
|
||||||||
|
Q3 2026 Core FFO
|
N/A
|
$3.93 - $4.05
|
$3.99
|
N/A
|
||||||||
|
Same-Property Portfolio Growth (1)
|
||||||||||||
|
Revenues
|
1.7% to 3.1%
|
2.5% to 3.1%
|
2.8%
|
|
+0.40%
|
|
||||||
|
Operating Expenses
|
2.5% to 3.5%
|
2.5% to 3.0%
|
2.8%
|
|
(0.25%)
|
|
||||||
|
Net Operating Income
|
0.8% to 3.4%
|
2.3% to 3.3%
|
2.8%
|
|
+0.70%
|
|
| (1) |
Reflects guidance on a cash basis based on 52,135 apartment homes. On a GAAP basis, the midpoints of the Company’s same-property revenue and NOI guidance are 2.9% and 2.9%,
respectively.
|
Sequential Components to 2026 Third Quarter Core FFO Guidance Midpoint
|
Per Diluted
Share
|
||||
|
Core FFO per diluted share for Q2 2026 reported
|
$
|
4.08
|
||
|
Consolidated Revenues
|
0.06
|
|||
|
Consolidated Operating Expenses (1)
|
(0.12)
|
|||
|
FFO from Co-Investments
|
(0.03)
|
|
||
|
Guidance midpoint of Core FFO per diluted share for Q3 2026
|
$
|
3.99
|
||
| (1) |
The sequential decline from consolidated operating expenses is primarily driven by higher utilities costs (consistent with typical seasonality), higher taxes due to one-time
property tax refunds that were recorded in the second quarter of 2026, and timing of controllable spend.
|
For additional details regarding the Company’s 2026 FFO guidance range, see page S-15 and S-16.1 of the supplemental financial information.
Conference Call with Management
The Company will host an earnings conference call with management to discuss its quarterly results on Thursday, July 30, 2026 at 11 a.m. PST (2 p.m. EST), which will be
broadcast live via the Internet at www.essex.com, and accessible via phone by dialing toll-free, (877) 407-0784, or toll/international, (201) 689-8560. No passcode is necessary.
A rebroadcast of the live call will be available online for 30 days and digitally for 7
days. To access the replay online, go to www.essex.com and select the second quarter 2026 earnings link. To access the replay, dial (844) 512-2921 using the replay pin number 13761419. If you are unable to access the information via the Company’s website, please contact the Investor Relations Department at [email protected] or calling (650) 655-7800.
Corporate Profile
Essex Property Trust, Inc., an S&P 500 company, is a fully integrated real estate investment trust (REIT) that acquires, develops,
redevelops, and manages multifamily residential properties in selected West Coast markets. Essex currently has ownership interests in 258 apartment communities comprising over 62,000 apartment homes with an additional property in active development.
Additional information about the Company can be found on the Company’s website at www.essex.com.
This press release and accompanying supplemental financial information has been furnished to the Securities and Exchange Commission electronically on Form 8-K and can be
accessed from the Company’s website at www.essex.com. If you are unable to obtain the information via the Web, please contact the Investor Relations Department at (650) 655-7800.
FFO Reconciliation
FFO, as defined by the National Association of Real Estate Investment Trusts (“Nareit”), is generally considered
by industry analysts as an appropriate measure of performance of an equity REIT. Generally, FFO adjusts the net income of equity REITs for non-cash charges such as depreciation and amortization of rental properties, impairment charges, gains on sales
of real estate and extraordinary items. Management considers FFO and FFO which excludes non-core items, which is referred to as “Core FFO,” to be useful supplemental operating performance measures of an equity REIT because, together with net income and
cash flows, FFO and Core FFO provide investors with additional bases to evaluate the operating performance and ability of a REIT to incur and service debt and to fund acquisitions and other capital expenditures and to pay dividends. By excluding gains
or losses related to sales of depreciated operating properties and land and excluding real estate depreciation (which can vary among owners of identical assets in similar condition based on historical cost accounting and useful life estimates), FFO can
help investors compare the operating performance of a real estate company between periods or as compared to different companies. By further adjusting for items that are not considered part of the Company’s core business operations, Core FFO allows
investors to compare the core operating performance of the Company to its performance in prior reporting periods and to the operating performance of other real estate companies without the effect of items that by their nature are not comparable from
period to period and tend to obscure the Company’s actual operating results. FFO and Core FFO do not represent net income or cash flows from operations as defined by U.S. generally accepted accounting principles (“GAAP”) and are not intended to
indicate whether cash flows will be sufficient to fund cash needs. These measures should not be considered as alternatives to net income as an indicator of the REIT’s operating performance or to cash flows as a measure of liquidity. FFO and Core FFO do
not measure whether cash flow is sufficient to fund all cash needs including principal amortization, capital improvements and distributions to stockholders. FFO and Core FFO also do not represent cash flows generated from operating, investing or
financing activities as defined under GAAP. Management has consistently applied the Nareit definition of FFO to all periods presented. However, there is judgment involved and other REITs’ calculation of FFO may vary from the Nareit definition for this
measure, and thus their disclosures of FFO may not be comparable to the Company’s calculation.
The following table sets forth the Company’s calculation of FFO and Core FFO per diluted share for the three and six-month periods ended June 30, 2026 and 2025 (dollars in
thousands, except for share and per share amounts):
|
Three Months Ended
June 30,
|
Six Months Ended
June 30,
|
|||||||||||||||
|
2026
|
2025
|
2026
|
2025
|
|||||||||||||
|
Net income available to common stockholders
|
$
|
62,462
|
$
|
221,362
|
$
|
168,648
|
$
|
424,472
|
||||||||
|
Adjustments:
|
||||||||||||||||
|
Depreciation and amortization
|
154,073
|
151,501
|
308,968
|
302,788
|
||||||||||||
|
Gains not included in FFO
|
(11,231
|
)
|
(126,174
|
)
|
(11,231
|
)
|
(237,534
|
)
|
||||||||
|
Depreciation and amortization from unconsolidated co-investments
|
13,167
|
14,406
|
26,483
|
28,784
|
||||||||||||
|
Noncontrolling interest related to Operating Partnership units
|
2,123
|
7,781
|
5,792
|
15,060
|
||||||||||||
|
Depreciation attributable to third party ownership and other
|
(38
|
)
|
(38
|
)
|
(77
|
)
|
(84
|
)
|
||||||||
|
FFO attributable to common stockholders and unitholders
|
$
|
220,556
|
$
|
268,838
|
$
|
498,583
|
$
|
533,486
|
||||||||
|
FFO per share – diluted
|
$
|
3.32
|
$
|
4.03
|
$
|
7.49
|
$
|
8.00
|
||||||||
|
Tax (benefit) expense on unconsolidated technology co-investments
|
$
|
(363
|
)
|
$
|
(232
|
)
|
$
|
3,251
|
$
|
(395
|
)
|
|||||
|
Realized and unrealized gains on marketable securities, net
|
(5,716
|
)
|
(2,492
|
)
|
(3,990
|
)
|
(2,401
|
)
|
||||||||
|
Provision for credit losses
|
(256
|
)
|
14
|
(222
|
)
|
11
|
||||||||||
|
Equity loss (income) from unconsolidated technology co-investments
|
849
|
104
|
(16,187
|
)
|
(1,612
|
)
|
||||||||||
|
Loss on early retirement of debt
|
-
|
-
|
-
|
762
|
||||||||||||
|
Income from early redemption of preferred equity investments and notes receivable
|
(179
|
)
|
-
|
(179
|
)
|
-
|
||||||||||
|
General and administrative and other, net (1)
|
56,785
|
2,661
|
61,330
|
3,937
|
||||||||||||
|
Insurance reimbursements and other, net
|
(247
|
)
|
(339
|
)
|
(298
|
)
|
(700
|
)
|
||||||||
|
Core FFO attributable to common stockholders and unitholders
|
$
|
271,429
|
$
|
268,554
|
$
|
542,288
|
$
|
533,088
|
||||||||
|
Core FFO per share – diluted
|
$
|
4.08
|
$
|
4.03
|
$
|
8.15
|
$
|
8.00
|
||||||||
|
Weighted average number of shares outstanding diluted (2)
|
66,462,974
|
66,670,784
|
66,575,154
|
66,663,894
|
||||||||||||
| (1) |
Includes political advocacy costs of $0.1 million and $1.7 million for the three and six months ended June 30, 2026, respectively, and $0.3 million and $0.4
million for the three and six months ended June 30, 2025, respectively. During the three months ended June 30, 2026, the Company reached a settlement to fully resolve its case related to RealPage, Inc. totaling $36.5 million and another
litigation matter totaling $19.3 million.
|
| (2) |
Assumes conversion of all outstanding limited partnership units in Essex Portfolio, L.P. (the “Operating Partnership”) into shares of the Company’s common
stock and excludes DownREIT limited partnership units.
|
Net Operating Income (“NOI”) and Same-Property NOI Reconciliations
NOI and Same-Property NOI are considered by management to be important supplemental performance measures to earnings from operations included in the Company’s consolidated
statements of income. The presentation of same-property NOI assists with the presentation of the Company’s operations prior to the allocation of depreciation and any corporate-level or financing-related costs. NOI reflects the operating performance of
a community and allows for an easy comparison of the operating performance of individual communities or groups of communities. In addition, because prospective buyers of real estate have different financing and overhead structures, with varying
marginal impacts to overhead by acquiring real estate, NOI is considered by many in the real estate industry to be a useful measure for determining the value of a real estate asset or group of assets. The Company defines same-property NOI as
same-property revenues less same-property operating expenses, including property taxes. Please see the reconciliation of earnings from operations to NOI and same-property NOI, which in the table below is the NOI for stabilized properties consolidated
by the Company for the periods presented (dollars in thousands):
|
Three Months Ended
June 30,
|
Six Months Ended
June 30,
|
|||||||||||||||
|
2026
|
2025
|
2026
|
2025
|
|||||||||||||
|
Earnings from operations
|
$
|
109,373
|
$
|
279,700
|
$
|
264,566
|
$
|
536,781
|
||||||||
|
Adjustments:
|
||||||||||||||||
|
Corporate-level property management expenses
|
13,432
|
12,220
|
26,830
|
24,552
|
||||||||||||
|
Depreciation and amortization
|
154,073
|
151,501
|
308,968
|
302,788
|
||||||||||||
|
Management and other fees from affiliates
|
(2,318
|
)
|
(2,223
|
)
|
(4,631
|
)
|
(4,717
|
)
|
||||||||
|
General and administrative
|
73,149
|
17,157
|
93,163
|
33,449
|
||||||||||||
|
Gain on sale of real estate and land
|
(2,000
|
)
|
(126,174
|
)
|
(2,000
|
)
|
(237,204
|
)
|
||||||||
|
NOI
|
345,709
|
332,181
|
686,896
|
655,649
|
||||||||||||
|
Less: Non-same property NOI
|
(28,878
|
)
|
(23,457
|
)
|
(56,996
|
)
|
(46,157
|
)
|
||||||||
|
Same-Property NOI
|
$
|
316,831
|
$
|
308,724
|
$
|
629,900
|
$
|
609,492
|
||||||||
Safe Harbor Statement Under The Private Litigation Reform Act of 1995:
This press release includes “forward-looking statements” within the meaning of Section 27A of the Securities Act of
1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements are statements which are not historical facts, including statements regarding the Company’s expectations, estimates, assumptions, hopes,
intentions, beliefs and strategies regarding the future. Words such as “expects,” “assumes,” “anticipates,” “may,” “will,” “intends,” “plans,” “projects,” “believes,” “seeks,” “future,” “estimates,” and variations of such words and similar expressions
are intended to identify such forward-looking statements. Such forward-looking statements include, among other things, statements regarding the Company’s third quarter and full-year
2026 guidance (including net income, Total FFO and Core FFO, same-property growth and related assumptions) and anticipated yield on certain investments. While the Company’s management believes the assumptions underlying its forward-looking statements
are reasonable, such forward-looking statements involve known and unknown risks, uncertainties and other factors, many of which are beyond the Company’s control, which could cause the actual results, performance or achievements of the Company to be
materially different from any future results, performance or achievements expressed or implied by such forward-looking statements. The Company cannot assure the future results or outcome of the matters described in these statements; rather, these
statements merely reflect the Company’s current expectations of the approximate outcomes of the matters discussed.
Factors that might cause the Company’s actual results, performance or achievements to differ materially from those expressed or implied by these forward-looking statements include, but are not limited to, the following: assumptions related to our third quarter and full-year 2026 guidance; occupancy rates and rental demand may be adversely affected by competition and local economic and market conditions; there may be increased interest
rates, inflation, escalated operating costs and possible recessionary impacts; tariffs, geopolitical tensions and regional conflicts, and the related impacts on macroeconomic conditions, including, among other things, interest rates and inflation;
the terms of any refinancing may not be as favorable as the terms of existing indebtedness; the Company’s inability to maintain its investment grade credit rating with the rating agencies; the Company may be unsuccessful in the management of its
relationships with its co-investment partners; the Company may fail to achieve its business objectives; time of actual completion and/or stabilization of development and redevelopment projects; estimates of future income from an acquired property may
prove to be inaccurate; future cash flows may be inadequate to meet operating requirements and/or may be insufficient to provide for dividend payments in accordance with REIT requirements; changes in laws or regulations and the anticipated or actual
impact of future changes in laws or regulations; unexpected difficulties in leasing of future development projects; volatility in financial and securities markets; the Company’s failure to successfully operate acquired properties; unforeseen consequences from cyber-intrusion; government approvals, actions and initiatives, including the need for compliance with environmental requirements; and those further risks, special
considerations, and other factors referred to in the Company’s annual report on Form 10-K for the year ended December 31, 2025, quarterly reports on Form 10-Q, and those risk factors and special considerations set forth in the Company’s other
filings with the SEC which may cause the actual results, performance or achievements of the Company to be materially different from any future results, performance or achievements expressed or implied by such forward-looking statements. All
forward-looking statements are made as of the date hereof, the Company assumes no obligation to update or supplement this information for any reason, and therefore, they may not represent the Company’s estimates and assumptions after the date of this
press release.
Definitions and Reconciliations
Non-GAAP financial measures and certain other capitalized terms, as used in this earnings release and supplemental financial information, are defined and further explained
on pages S-17.1 through S-17.4, “Reconciliations of Non-GAAP Financial Measures and Other Terms,” of the accompanying supplemental financial information. The supplemental financial information is available on the Company’s website at www.essex.com.
Contact Information
Loren Rainey
Sr. Director, Investor Relations
(650) 655-7800
ESSEX PROPERTY TRUST, INC.
Consolidated Operating Results
(Dollars in thousands, except share and per share amounts)
|
|
Three Months Ended
|
Six Months Ended
|
||||||||||||||
|
|
June 30,
|
June 30,
|
||||||||||||||
|
|
2026
|
2025
|
2026
|
2025
|
||||||||||||
|
|
||||||||||||||||
|
Revenues:
|
||||||||||||||||
|
Rental and other property
|
$
|
486,731
|
$
|
467,610
|
$
|
969,174
|
$
|
929,699
|
||||||||
|
Management and other fees from affiliates
|
2,318
|
2,223
|
4,631
|
4,717
|
||||||||||||
|
|
489,049
|
469,833
|
973,805
|
934,416
|
||||||||||||
|
|
||||||||||||||||
|
Expenses:
|
||||||||||||||||
|
Property operating
|
141,022
|
135,429
|
282,278
|
274,050
|
||||||||||||
|
Corporate-level property management expenses
|
13,432
|
12,220
|
26,830
|
24,552
|
||||||||||||
|
Depreciation and amortization
|
154,073
|
151,501
|
308,968
|
302,788
|
||||||||||||
|
General and administrative
|
73,149
|
17,157
|
93,163
|
33,449
|
||||||||||||
|
|
381,676
|
316,307
|
711,239
|
634,839
|
||||||||||||
|
Gain on sale of real estate and land
|
2,000
|
126,174
|
2,000
|
237,204
|
||||||||||||
|
Earnings from operations
|
109,373
|
279,700
|
264,566
|
536,781
|
||||||||||||
|
Interest expense, net (1)
|
(65,609
|
)
|
(64,191
|
)
|
(129,631
|
)
|
(125,723
|
)
|
||||||||
|
Interest and other income
|
9,087
|
6,808
|
10,123
|
11,097
|
||||||||||||
|
Equity income from co-investments
|
13,715
|
8,977
|
37,330
|
22,186
|
||||||||||||
|
Tax benefit (expense) on unconsolidated technology co-investments
|
363
|
232
|
(3,251
|
)
|
395
|
|||||||||||
|
Loss on early retirement of debt
|
-
|
-
|
-
|
(762
|
)
|
|||||||||||
|
Gain on remeasurement of co-investment
|
-
|
-
|
-
|
330
|
||||||||||||
|
Net income
|
66,929
|
231,526
|
179,137
|
444,304
|
||||||||||||
|
Net income attributable to noncontrolling interest
|
(4,467
|
)
|
(10,164
|
)
|
(10,489
|
)
|
(19,832
|
)
|
||||||||
|
Net income available to common stockholders
|
$
|
62,462
|
$
|
221,362
|
$
|
168,648
|
$
|
424,472
|
||||||||
|
|
||||||||||||||||
|
Net income per share - basic
|
$
|
0.97
|
$
|
3.44
|
$
|
2.62
|
$
|
6.60
|
||||||||
|
|
||||||||||||||||
|
Shares used in income per share - basic
|
64,265,835
|
64,385,988
|
64,359,851
|
64,350,640
|
||||||||||||
|
|
||||||||||||||||
|
Net income per share - diluted
|
$
|
0.97
|
$
|
3.44
|
$
|
2.62
|
$
|
6.59
|
||||||||
|
|
||||||||||||||||
|
Shares used in income per share - diluted
|
64,279,012
|
64,407,613
|
64,369,794
|
64,378,953
|
||||||||||||
| (1) |
Refer to page S-17.2, the section titled “Interest Expense, Net” for additional information.
|
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
Consolidated Operating Results - Selected Line Item Detail
(Dollars in thousands)
|
Three Months Ended
|
Six Months Ended
|
|||||||||||||||
|
June 30,
|
June 30,
|
|||||||||||||||
|
2026
|
2025
|
2026
|
2025
|
|||||||||||||
|
Rental and other property
|
||||||||||||||||
|
Rental income
|
$
|
479,418
|
$
|
460,686
|
$
|
955,230
|
$
|
916,546
|
||||||||
|
Other property
|
7,313
|
6,924
|
13,944
|
13,153
|
||||||||||||
|
Rental and other property
|
$
|
486,731
|
$
|
467,610
|
$
|
969,174
|
$
|
929,699
|
||||||||
|
Property operating expenses
|
||||||||||||||||
|
Real estate taxes
|
$
|
51,414
|
$
|
49,035
|
$
|
103,539
|
$
|
101,629
|
||||||||
|
Utilities
|
31,065
|
28,588
|
63,727
|
58,362
|
||||||||||||
|
Personnel costs
|
26,966
|
26,744
|
53,488
|
52,995
|
||||||||||||
|
Maintenance and repairs
|
16,559
|
16,130
|
30,741
|
30,872
|
||||||||||||
|
Administrative
|
8,348
|
8,024
|
16,894
|
16,349
|
||||||||||||
|
Insurance and other
|
6,670
|
6,908
|
13,889
|
13,843
|
||||||||||||
|
Property operating expenses
|
$
|
141,022
|
$
|
135,429
|
$
|
282,278
|
$
|
274,050
|
||||||||
|
Interest and other income
|
||||||||||||||||
|
Marketable securities and other income
|
$
|
2,890
|
$
|
3,976
|
$
|
5,635
|
$
|
7,992
|
||||||||
|
Realized and unrealized gains on marketable securities, net
|
5,716
|
2,492
|
3,990
|
2,401
|
||||||||||||
|
Provision for credit losses
|
256
|
(14
|
)
|
222
|
(11
|
)
|
||||||||||
|
Insurance reimbursements and other, net
|
225
|
354
|
276
|
715
|
||||||||||||
|
Interest and other income
|
$
|
9,087
|
$
|
6,808
|
$
|
10,123
|
$
|
11,097
|
||||||||
|
Equity income from co-investments
|
||||||||||||||||
|
Equity income (loss) from co-investments
|
$
|
1,890
|
$
|
(221
|
)
|
$
|
2,880
|
$
|
(523
|
)
|
||||||
|
Income from preferred equity investments
|
3,242
|
9,317
|
8,831
|
21,112
|
||||||||||||
|
Equity (loss) income from unconsolidated technology co-investments
|
(849
|
)
|
(104
|
)
|
16,187
|
1,612
|
||||||||||
|
Insurance reimbursements and other, net
|
22
|
(15
|
)
|
22
|
(15
|
)
|
||||||||||
|
Gain on sale of co-investment communities
|
9,231
|
-
|
9,231
|
-
|
||||||||||||
|
Income from early redemption of preferred equity investments
|
179
|
-
|
179
|
-
|
||||||||||||
|
Equity income from co-investments
|
$
|
13,715
|
$
|
8,977
|
$
|
37,330
|
$
|
22,186
|
||||||||
|
Noncontrolling interest
|
||||||||||||||||
|
Limited partners of Essex Portfolio, L.P.
|
$
|
2,123
|
$
|
7,781
|
$
|
5,792
|
$
|
15,060
|
||||||||
|
DownREIT limited partners’ distributions
|
2,296
|
2,339
|
4,608
|
4,678
|
||||||||||||
|
Third-party ownership interest
|
48
|
44
|
89
|
94
|
||||||||||||
|
Noncontrolling interest
|
$
|
4,467
|
$
|
10,164
|
$
|
10,489
|
$
|
19,832
|
||||||||
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
(Dollars in thousands, except share and per share amounts and in footnotes)
|
|
Three Months Ended
|
Six Months Ended
|
||||||||||||||||||||
|
|
June 30,
|
June 30,
|
||||||||||||||||||||
|
|
2026
|
2025
|
% Change
|
2026
|
2025
|
% Change
|
||||||||||||||||
|
|
||||||||||||||||||||||
|
Funds from operations attributable to common stockholders and
unitholders (FFO) |
||||||||||||||||||||||
|
Net income available to common stockholders
|
$
|
62,462
|
$
|
221,362
|
$
|
168,648
|
$
|
424,472
|
||||||||||||||
|
Adjustments:
|
||||||||||||||||||||||
|
Depreciation and amortization
|
154,073
|
151,501
|
308,968
|
302,788
|
||||||||||||||||||
|
Gains not included in FFO
|
(11,231
|
)
|
(126,174
|
)
|
(11,231
|
)
|
(237,534
|
)
|
||||||||||||||
|
Depreciation and amortization from unconsolidated co-investments
|
13,167
|
14,406
|
26,483
|
28,784
|
||||||||||||||||||
|
Noncontrolling interest related to Operating Partnership units
|
2,123
|
7,781
|
5,792
|
15,060
|
||||||||||||||||||
|
Depreciation attributable to third party ownership and other
|
(38
|
)
|
(38
|
)
|
(77
|
)
|
(84
|
)
|
||||||||||||||
|
Funds from operations attributable to common stockholders and unitholders
|
$
|
220,556
|
$
|
268,838
|
$
|
498,583
|
$
|
533,486
|
||||||||||||||
|
FFO per share - diluted
|
$
|
3.32
|
$
|
4.03
|
-17.6%
|
|
$
|
7.49
|
$
|
8.00
|
-6.4%
|
|
||||||||||
|
|
||||||||||||||||||||||
|
Components of the change in FFO
|
||||||||||||||||||||||
|
Non-core items:
|
||||||||||||||||||||||
|
Tax (benefit) expense on unconsolidated technology co-investments
|
$
|
(363
|
)
|
$
|
(232
|
)
|
$
|
3,251
|
$
|
(395
|
)
|
|||||||||||
|
Realized and unrealized gains on marketable securities, net
|
(5,716
|
)
|
(2,492
|
)
|
(3,990
|
)
|
(2,401
|
)
|
||||||||||||||
|
Provision for credit losses
|
(256
|
)
|
14
|
(222
|
)
|
11
|
||||||||||||||||
|
Equity loss (income) from unconsolidated technology co-investments
|
849
|
104
|
(16,187
|
)
|
(1,612
|
)
|
||||||||||||||||
|
Loss on early retirement of debt
|
-
|
-
|
-
|
762
|
||||||||||||||||||
|
Income from early redemption of preferred equity investments and notes receivable
|
(179
|
)
|
-
|
(179
|
)
|
-
|
||||||||||||||||
|
General and administrative and other, net (2)
|
56,785
|
2,661
|
61,330
|
3,937
|
||||||||||||||||||
|
Insurance reimbursements and other, net
|
(247
|
)
|
(339
|
)
|
(298
|
)
|
(700
|
)
|
||||||||||||||
|
Core funds from operations attributable to common stockholders and unitholders
|
$
|
271,429
|
$
|
268,554
|
$
|
542,288
|
$
|
533,088
|
||||||||||||||
|
Core FFO per share - diluted
|
$
|
4.08
|
$
|
4.03
|
1.2%
|
|
$
|
8.15
|
$
|
8.00
|
1.9%
|
|
||||||||||
|
|
||||||||||||||||||||||
|
Weighted average number of shares outstanding - diluted (3)
|
66,462,974
|
66,670,784
|
66,575,154
|
66,663,894
|
||||||||||||||||||
|
(1)
|
Refer to page S-17.2, the section titled “Funds from Operations (“FFO”) and Core FFO” for additional information on the Company’s definition and use of FFO and Core FFO.
|
|
(2)
|
Includes political advocacy costs of $0.1 million and $1.7 million for the three and six months ended June 30, 2026, respectively, and $0.3 million and $0.4 million for the three and six months
ended June 30, 2025, respectively. During the three months ended June 30, 2026, the Company reached a settlement to fully resolve its case related to RealPage, Inc. totaling $36.5 million and another litigation matter totaling
$19.3 million.
|
|
(3)
|
Assumes conversion of all outstanding limited partnership units in the Operating Partnership into shares of the Company’s common stock and excludes DownREIT limited partnership units.
|
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
(Dollars in thousands)
|
|
June 30, 2026
|
December 31, 2025
|
||||||
|
Real estate investments:
|
||||||||
|
Land and land improvements
|
$
|
3,363,169
|
$
|
3,363,169
|
||||
|
Buildings and improvements
|
15,171,737
|
15,073,416
|
||||||
|
|
18,534,906
|
18,436,585
|
||||||
|
Less: accumulated depreciation
|
(6,837,403
|
)
|
(6,532,003
|
)
|
||||
|
|
11,697,503
|
11,904,582
|
||||||
|
Real estate under development
|
184,130
|
157,122
|
||||||
|
Co-investments
|
612,512
|
630,550
|
||||||
|
|
12,494,145
|
12,692,254
|
||||||
|
Cash and cash equivalents, including restricted cash
|
66,344
|
85,586
|
||||||
|
Marketable securities
|
92,165
|
98,070
|
||||||
|
Notes and other receivables
|
96,334
|
141,591
|
||||||
|
Operating lease right-of-use assets
|
49,077
|
50,833
|
||||||
|
Prepaid expenses and other assets
|
100,237
|
90,675
|
||||||
|
Total assets
|
$
|
12,898,302
|
$
|
13,159,009
|
||||
|
|
||||||||
|
Unsecured debt, net
|
$
|
5,569,283
|
$
|
6,015,921
|
||||
|
Mortgage notes payable, net
|
784,217
|
784,348
|
||||||
|
Lines of credit and commercial paper
|
345,000
|
-
|
||||||
|
Distributions in excess of investments in co-investments
|
107,874
|
98,837
|
||||||
|
Operating lease liabilities
|
49,753
|
51,487
|
||||||
|
Other liabilities
|
529,286
|
471,521
|
||||||
|
Total liabilities
|
7,385,413
|
7,422,114
|
||||||
|
Redeemable noncontrolling interest
|
27,373
|
28,263
|
||||||
|
Equity:
|
||||||||
|
Common stock
|
6
|
6
|
||||||
|
Additional paid-in capital
|
6,626,545
|
6,683,514
|
||||||
|
Distributions in excess of accumulated earnings
|
(1,312,602
|
)
|
(1,148,195
|
)
|
||||
|
Accumulated other comprehensive income, net
|
9,124
|
6,047
|
||||||
|
Total stockholders’ equity
|
5,323,073
|
5,541,372
|
||||||
|
Noncontrolling interest
|
162,443
|
167,260
|
||||||
|
Total equity
|
5,485,516
|
5,708,632
|
||||||
|
Total liabilities and equity
|
$
|
12,898,302
|
$
|
13,159,009
|
||||
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
(Dollars in thousands, except in footnotes)
|
Scheduled principal payments, unamortized premiums (discounts) and (debt issuance costs) are as follows - excludes lines of credit and commercial paper:
|
|||||||||||||||||||||||||||||||||||
|
Weighted Average
|
Unsecured
|
Secured
|
Total
|
Weighted
Average
Interest
Rate
|
Percentage
of Total
Debt
|
||||||||||||||||||||||||||||||
|
Balance
Outstanding
|
Interest
Rate
|
Maturity
in Years
|
|||||||||||||||||||||||||||||||||
|
Unsecured Debt, net
|
|||||||||||||||||||||||||||||||||||
|
Bonds public - fixed rate
|
$
|
5,000,000
|
3.7
|
%
|
7.2
|
2026
|
$
|
-
|
$
|
98,860
|
$
|
98,860
|
3.5
|
%
|
1.5
|
%
|
|||||||||||||||||||
|
Term loan
|
600,000
|
4.1
|
%
|
4.2
|
2027
|
350,000
|
84,397
|
434,397
|
3.7
|
%
|
6.8
|
%
|
|||||||||||||||||||||||
|
Unamortized discounts and debt
|
2028
|
450,000
|
68,332
|
518,332
|
2.2
|
%
|
8.1
|
%
|
|||||||||||||||||||||||||||
|
issuance costs, net
|
(30,717
|
)
|
-
|
-
|
2029
|
500,000
|
1,456
|
501,456
|
4.1
|
%
|
7.9
|
%
|
|||||||||||||||||||||||
|
Total unsecured debt, net
|
5,569,283
|
3.7
|
%
|
6.9
|
2030
|
850,000
|
66,592
|
916,592
|
3.6
|
%
|
14.4
|
%
|
|||||||||||||||||||||||
|
Mortgage Notes Payable, net
|
2031
|
900,000
|
1,740
|
901,740
|
2.9
|
%
|
14.1
|
%
|
|||||||||||||||||||||||||||
|
Fixed rate - secured
|
528,291
|
4.7
|
%
|
4.9
|
2032
|
650,000
|
1,903
|
651,903
|
2.6
|
%
|
10.2
|
%
|
|||||||||||||||||||||||
|
Variable rate - secured (1)
|
258,235
|
3.4
|
%
|
12.8
|
2033
|
-
|
330,126
|
330,126
|
4.9
|
%
|
5.2
|
%
|
|||||||||||||||||||||||
|
Unamortized premiums and debt
|
2034
|
550,000
|
2,275
|
552,275
|
5.5
|
%
|
8.6
|
%
|
|||||||||||||||||||||||||||
|
issuance costs, net
|
(2,309
|
)
|
-
|
-
|
2035
|
400,000
|
2,487
|
402,487
|
5.5
|
%
|
6.3
|
%
|
|||||||||||||||||||||||
|
Total mortgage notes payable, net
|
784,217
|
4.3
|
%
|
7.5
|
2036
|
350,000
|
2,719
|
352,719
|
5.0
|
%
|
5.5
|
%
|
|||||||||||||||||||||||
|
Unsecured Lines of Credit and Commercial Paper
|
Thereafter
|
600,000
|
125,639
|
725,639
|
3.6
|
%
|
11.4
|
%
|
|||||||||||||||||||||||||||
|
Line of credit (2)
|
-
|
4.5
|
%
|
N/A
|
Subtotal
|
5,600,000
|
786,526
|
6,386,526
|
3.8
|
%
|
100.0
|
%
|
|||||||||||||||||||||||
|
Line of credit (3)
|
-
|
4.5
|
%
|
N/A
|
Debt Issuance Costs
|
(27,659
|
)
|
(2,257
|
)
|
(29,916
|
)
|
-
|
-
|
||||||||||||||||||||||
|
Commercial paper (4)
|
345,000
|
4.0
|
%
|
N/A
|
(Discounts)/Premiums
|
(3,058
|
)
|
(52
|
)
|
(3,110
|
)
|
-
|
-
|
||||||||||||||||||||||
|
Total lines of credit and commercial paper
|
345,000
|
4.0
|
%
|
N/A
|
Total
|
$
|
5,569,283
|
$
|
784,217
|
$
|
6,353,500
|
3.8
|
%
|
100.0
|
%
|
||||||||||||||||||||
|
Total debt, net
|
$
|
6,698,500
|
3.8
|
%
|
6.7
|
||||||||||||||||||||||||||||||
Capitalized interest for the three and six months ended June 30, 2026 was approximately $1.5 million and $2.8 million, respectively.
| (1) |
$258.2 million of variable rate debt is tax exempt to the note holders.
|
| (2) |
This unsecured line of credit facility has a capacity of $1.5 billion, a scheduled maturity date in January 2030 and two 6-month extension options, exercisable at the Company’s option. The underlying
interest rate on this line is SOFR plus 0.775%, which is based on a tiered rate structure tied to the Company’s long-term unsecured credit ratings.
|
| (3) |
This unsecured line of credit facility has a capacity of $75.0 million, a scheduled maturity date in July 2028. The underlying interest rate on this line is SOFR plus 0.775%, which is based on a tiered
rate structure tied to the Company’s long-term unsecured credit ratings.
|
| (4) |
The Company has a commercial paper program under which it can issue unsecured short-term notes, up to $750 million, which are backstopped by and reduce the borrowing capacity of the Company’s $1.5
billion unsecured line of credit facility.
|
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
Capitalization Data, Public Bond Covenants, Credit Ratings and Selected Credit Ratios - June 30, 2026
(Dollars and shares in thousands, except per share amounts)
|
Capitalization Data
|
Public Bond Covenants (1)
|
Actual
|
Requirement
|
|||||||||
|
Total debt, net
|
$
|
6,698,500
|
||||||||||
|
Common stock and potentially dilutive securities
|
Debt to Total Assets:
|
34%
|
|
< 65%
|
||||||||
|
Common stock outstanding
|
64,268
|
|||||||||||
|
Limited partnership units (1)
|
2,184
|
Secured Debt to Total Assets:
|
4%
|
< 40%
|
||||||||
|
Options-treasury method
|
21
|
|||||||||||
|
Total shares of common stock and potentially dilutive securities
|
66,473
|
Interest Coverage:
|
508%
|
> 150%
|
||||||||
|
Common stock price per share as of June 30, 2026
|
$
|
291.59
|
Unsecured Debt Ratio (2):
|
297%
|
> 150%
|
|||||||
|
Total equity capitalization
|
$
|
19,382,862
|
Selected Credit Ratios (3)
|
Actual
|
||||||||
|
Total market capitalization
|
$
|
26,081,362
|
Net Indebtedness Divided by Adjusted EBITDAre, normalized and annualized:
|
5.4
|
||||||||
|
|
||||||||||||
|
Ratio of debt to total market capitalization
|
25.7
|
%
|
Unencumbered NOI to Adjusted Total NOI:
|
93%
|
||||||||
|
|
|
|||||||||||
|
Credit Ratings
|
|
|
||||||||||
|
Rating Agency
|
Rating
|
Outlook
|
||||||||||
|
Moody’s
|
Baa1
|
Stable
|
(1) Refer to page S-17.4 for additional information on the Company’s Public Bond Covenants.
|
|||||||||
|
Standard & Poor’s
|
BBB+
|
Stable
|
(2) Unsecured Debt Ratio is unsecured assets (excluding investments in co-investments) divided by
unsecured indebtedness.
|
|||||||||
|
(1) Assumes conversion of all outstanding limited partnership units in the Operating Partnership
into shares of the Company’s common stock.
|
(3) Refer to pages S-17.1 to S-17.4, the section titled “Reconciliations of Non-GAAP Financial
Measures and Other Terms” for additional information on the Company’s Selected Credit Ratios.
|
|||||||||||
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
|
Apartment Homes
|
Average Monthly Rental Rate (1)
|
Percent of NOI (2)
|
||||||||||||||||||||||||||||||||||||||
|
Region - County
|
Consolidated
|
Unconsolidated
Co-investments |
Apartment
Homes in
Development (3)
|
Total
|
Consolidated
|
Unconsolidated
Co-investments (4) |
Total (4)
|
Consolidated
|
Unconsolidated
Co-investments (4) |
Total (4)
|
||||||||||||||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||||||||||
|
Southern California
|
||||||||||||||||||||||||||||||||||||||||
|
Los Angeles County
|
9,666
|
1,586
|
-
|
11,252
|
$
|
2,739
|
$
|
2,582
|
$
|
2,725
|
15.0
|
%
|
19.2
|
%
|
15.3
|
%
|
||||||||||||||||||||||||
|
Orange County
|
5,741
|
265
|
-
|
6,006
|
2,754
|
2,531
|
2,749
|
10.7
|
%
|
3.3
|
%
|
10.2
|
%
|
|||||||||||||||||||||||||||
|
San Diego County
|
5,449
|
443
|
-
|
5,892
|
2,715
|
3,096
|
2,730
|
9.9
|
%
|
7.6
|
%
|
9.7
|
%
|
|||||||||||||||||||||||||||
|
Ventura County and Other
|
2,760
|
373
|
-
|
3,133
|
2,548
|
3,291
|
2,602
|
4.9
|
%
|
6.8
|
%
|
5.0
|
%
|
|||||||||||||||||||||||||||
|
Total Southern California
|
23,616
|
2,667
|
-
|
26,283
|
2,715
|
2,758
|
2,717
|
40.5
|
%
|
36.9
|
%
|
40.2
|
%
|
|||||||||||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||||||||||
|
Northern California
|
||||||||||||||||||||||||||||||||||||||||
|
Santa Clara County (5)
|
10,673
|
779
|
-
|
11,452
|
3,248
|
3,233
|
3,247
|
23.2
|
%
|
12.9
|
%
|
22.5
|
%
|
|||||||||||||||||||||||||||
|
Alameda County
|
3,970
|
1,328
|
-
|
5,298
|
2,676
|
2,667
|
2,675
|
6.6
|
%
|
17.4
|
%
|
7.3
|
%
|
|||||||||||||||||||||||||||
|
San Mateo County
|
2,483
|
195
|
543
|
3,221
|
3,515
|
3,965
|
3,532
|
6.1
|
%
|
4.2
|
%
|
6.0
|
%
|
|||||||||||||||||||||||||||
|
Contra Costa County
|
2,619
|
-
|
-
|
2,619
|
2,809
|
-
|
2,809
|
4.7
|
%
|
0.0
|
%
|
4.4
|
%
|
|||||||||||||||||||||||||||
|
San Francisco
|
1,356
|
537
|
-
|
1,893
|
3,121
|
3,709
|
3,218
|
2.3
|
%
|
8.9
|
%
|
2.8
|
%
|
|||||||||||||||||||||||||||
|
Total Northern California
|
21,101
|
2,839
|
543
|
24,483
|
3,109
|
3,084
|
3,107
|
42.9
|
%
|
43.4
|
%
|
43.0
|
%
|
|||||||||||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||||||||||
|
Seattle Metro
|
10,899
|
1,759
|
-
|
12,658
|
2,284
|
2,171
|
2,275
|
16.6
|
%
|
19.7
|
%
|
16.8
|
%
|
|||||||||||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||||||||||
|
Total
|
55,616
|
7,265
|
543
|
63,424
|
$
|
2,780
|
$
|
2,745
|
$
|
2,778
|
100.0
|
%
|
100.0
|
%
|
100.0
|
%
|
||||||||||||||||||||||||
| (1) |
Average monthly rental rate is defined as the total scheduled monthly rental income (actual rent for occupied apartment homes plus market rent for vacant apartment homes) for the quarter ended June 30,
2026, divided by the number of apartment homes as of June 30, 2026.
|
| (2) |
Represents the percentage of actual NOI for the quarter ended June 30, 2026. See “Net Operating Income (“NOI”) and Same-Property NOI Reconciliations” on page S-17.3.
|
| (3) |
Includes development communities with no rental income.
|
| (4) |
At Company’s pro rata share.
|
| (5) |
Includes one community in Santa Cruz County.
|
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
(Dollars in thousands)
|
Apartment
Homes
|
Q2 ‘26
|
Q1 ‘26
|
Q4 ‘25
|
Q3 ‘25
|
Q2 ‘25
|
|||||||||||||||||||
|
Rental and other property revenues:
|
||||||||||||||||||||||||
|
Same-property
|
52,135
|
$
|
446,035
|
$
|
442,572
|
$
|
439,591
|
$
|
437,290
|
$
|
434,370
|
|||||||||||||
|
Acquisitions (2)
|
2,140
|
21,495
|
20,761
|
17,712
|
13,398
|
11,099
|
||||||||||||||||||
|
Non-residential/other, net (3)
|
1,341
|
19,404
|
19,225
|
19,093
|
19,939
|
21,974
|
||||||||||||||||||
|
Straight-line rent concessions (4)
|
-
|
(203
|
)
|
(115
|
)
|
927
|
315
|
167
|
||||||||||||||||
|
Total rental and other property revenues
|
55,616
|
486,731
|
482,443
|
477,323
|
470,942
|
467,610
|
||||||||||||||||||
|
Property operating expenses:
|
||||||||||||||||||||||||
|
Same-property
|
129,204
|
129,503
|
130,636
|
133,237
|
125,646
|
|||||||||||||||||||
|
Acquisitions (2)
|
7,544
|
8,273
|
6,873
|
5,019
|
4,177
|
|||||||||||||||||||
|
Non-residential/other, net (3) (5)
|
4,274
|
3,480
|
3,991
|
5,180
|
5,606
|
|||||||||||||||||||
|
Total property operating expenses
|
141,022
|
141,256
|
141,500
|
143,436
|
135,429
|
|||||||||||||||||||
|
Net operating income (NOI):
|
||||||||||||||||||||||||
|
Same-property
|
316,831
|
313,069
|
308,955
|
304,053
|
308,724
|
|||||||||||||||||||
|
Acquisitions (2)
|
13,951
|
12,488
|
10,839
|
8,379
|
6,922
|
|||||||||||||||||||
|
Non-residential/other, net (3) (5)
|
15,130
|
15,745
|
15,102
|
14,759
|
16,368
|
|||||||||||||||||||
|
Straight-line rent concessions (4)
|
(203
|
)
|
(115
|
)
|
927
|
315
|
167
|
|||||||||||||||||
|
Total NOI
|
$
|
345,709
|
$
|
341,187
|
$
|
335,823
|
$
|
327,506
|
$
|
332,181
|
||||||||||||||
|
Same-property metrics
|
||||||||||||||||||||||||
|
Operating margin
|
71
|
%
|
71
|
%
|
70
|
%
|
70
|
%
|
71
|
%
|
||||||||||||||
|
Annualized turnover
|
40
|
%
|
33
|
%
|
36
|
%
|
44
|
%
|
39
|
%
|
||||||||||||||
|
Financial occupancy
|
96.3
|
%
|
96.5
|
%
|
96.4
|
%
|
96.0
|
%
|
96.2
|
%
|
||||||||||||||
|
Delinquency as a % of scheduled rent
|
0.5
|
%
|
0.4
|
%
|
0.5
|
%
|
0.5
|
%
|
0.4
|
%
|
||||||||||||||
|
Same-property net effective rate growth (6)
|
||||||||||||||||||||||||
|
New lease
|
1.0
|
%
|
-2.4
|
%
|
-4.3
|
%
|
-0.6
|
%
|
3.3
|
%
|
||||||||||||||
|
Renewal
|
4.8
|
%
|
3.9
|
%
|
4.7
|
%
|
4.3
|
%
|
4.1
|
%
|
||||||||||||||
|
Blended
|
3.6
|
%
|
1.4
|
%
|
1.0
|
%
|
2.5
|
%
|
3.8
|
%
|
||||||||||||||
| (1) |
Includes consolidated communities only.
|
| (2) |
Acquisitions include properties acquired which did not have comparable stabilized results as of January 1, 2025.
|
| (3) |
Non-residential/other, net consists of revenues generated from retail space, commercial properties, held for sale properties, disposition properties, properties undergoing significant construction
activities that do not meet our redevelopment criteria, properties subject to upcoming ground lease expirations, two communities located in the California counties of Santa Barbara and Santa Cruz, which the Company does not consider its
core markets, and properties without comparable operating results in the reported periods.
|
| (4) |
Represents straight-line concessions for residential operating communities. Same-property revenues reflect concessions on a cash basis. Total rental and other property revenues reflect concessions on a
straight-line basis in accordance with U.S. GAAP.
|
| (5) |
Includes other expenses and intercompany eliminations pertaining to self-insurance.
|
| (6) |
Represents the percentage change in all lease tradeouts, including the impact of leasing incentives.
|
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
Same-Property Revenue Results by County - Second Quarter 2026 vs. Second Quarter 2025 and First Quarter 2026
(Dollars in thousands, except average monthly rental rates)
|
Q2 ‘26
% of Actual
NOI
|
Average Monthly Rental Rate
|
Financial Occupancy
|
Gross Revenues
|
Sequential Gross
Revenues
|
||||||||||||||||||||||||||||||||||||||||||||||||
|
Region - County
|
Apartment
Homes
|
Q2 ‘26
|
Q2 ‘25
|
%
Change
|
Q2 ‘26
|
Q2 ‘25
|
%
Change
|
Q2 ‘26
|
Q2 ‘25
|
%
Change
|
Q1 ‘26
|
%
Change
|
||||||||||||||||||||||||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||||||||||||||||||||||
|
Southern California
|
||||||||||||||||||||||||||||||||||||||||||||||||||||
|
Los Angeles County
|
9,189
|
15.5
|
%
|
$
|
2,680
|
$
|
2,663
|
0.6
|
%
|
95.4
|
%
|
95.0
|
%
|
0.4
|
%
|
$
|
75,119
|
$
|
74,373
|
1.0
|
%
|
$
|
75,672
|
-0.7
|
%
|
|||||||||||||||||||||||||||
|
Orange County
|
5,341
|
10.7
|
%
|
2,732
|
2,667
|
2.4
|
%
|
96.0
|
%
|
96.2
|
%
|
-0.2
|
%
|
44,902
|
43,737
|
2.7
|
%
|
44,672
|
0.5
|
%
|
||||||||||||||||||||||||||||||||
|
San Diego County
|
5,207
|
10.2
|
%
|
2,722
|
2,692
|
1.1
|
%
|
96.1
|
%
|
96.1
|
%
|
0.0
|
%
|
43,748
|
43,271
|
1.1
|
%
|
43,690
|
0.1
|
%
|
||||||||||||||||||||||||||||||||
|
Ventura County
|
2,652
|
5.1
|
%
|
2,542
|
2,500
|
1.7
|
%
|
95.8
|
%
|
95.8
|
%
|
0.0
|
%
|
20,984
|
20,624
|
1.7
|
%
|
21,003
|
-0.1
|
%
|
||||||||||||||||||||||||||||||||
|
Total Southern California
|
22,389
|
41.5
|
%
|
2,686
|
2,651
|
1.3
|
%
|
95.7
|
%
|
95.6
|
%
|
0.1
|
%
|
184,753
|
182,005
|
1.5
|
%
|
185,037
|
-0.2
|
%
|
||||||||||||||||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||||||||||||||||||||||
|
Northern California
|
||||||||||||||||||||||||||||||||||||||||||||||||||||
|
Santa Clara County
|
9,279
|
21.5
|
%
|
3,235
|
3,112
|
4.0
|
%
|
97.1
|
%
|
96.7
|
%
|
0.4
|
%
|
93,446
|
89,406
|
4.5
|
%
|
91,907
|
1.7
|
%
|
||||||||||||||||||||||||||||||||
|
Alameda County
|
3,729
|
6.8
|
%
|
2,663
|
2,597
|
2.5
|
%
|
96.4
|
%
|
96.4
|
%
|
0.0
|
%
|
31,427
|
30,335
|
3.6
|
%
|
30,878
|
1.8
|
%
|
||||||||||||||||||||||||||||||||
|
San Mateo County
|
1,864
|
4.9
|
%
|
3,459
|
3,293
|
5.0
|
%
|
97.3
|
%
|
96.8
|
%
|
0.5
|
%
|
20,332
|
19,283
|
5.4
|
%
|
19,876
|
2.3
|
%
|
||||||||||||||||||||||||||||||||
|
Contra Costa County
|
2,619
|
5.0
|
%
|
2,809
|
2,758
|
1.8
|
%
|
96.3
|
%
|
96.2
|
%
|
0.1
|
%
|
22,920
|
22,398
|
2.3
|
%
|
22,746
|
0.8
|
%
|
||||||||||||||||||||||||||||||||
|
San Francisco
|
1,356
|
2.5
|
%
|
3,121
|
2,927
|
6.6
|
%
|
96.1
|
%
|
96.8
|
%
|
-0.7
|
%
|
13,525
|
12,646
|
7.0
|
%
|
13,107
|
3.2
|
%
|
||||||||||||||||||||||||||||||||
|
Total Northern California
|
18,847
|
40.7
|
%
|
3,077
|
2,966
|
3.7
|
%
|
96.8
|
%
|
96.6
|
%
|
0.2
|
%
|
181,650
|
174,068
|
4.4
|
%
|
178,514
|
1.8
|
%
|
||||||||||||||||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||||||||||||||||||||||
|
Seattle Metro
|
10,899
|
17.8
|
%
|
2,284
|
2,258
|
1.2
|
%
|
96.4
|
%
|
96.4
|
%
|
0.0
|
%
|
79,632
|
78,297
|
1.7
|
%
|
79,021
|
0.8
|
%
|
||||||||||||||||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||||||||||||||||||||||
|
Total Same-Property
|
52,135
|
100.0
|
%
|
$
|
2,743
|
$
|
2,683
|
2.2
|
%
|
96.3
|
%
|
96.2
|
%
|
0.1
|
%
|
$
|
446,035
|
$
|
434,370
|
2.7
|
%
|
$
|
442,572
|
0.8
|
%
|
|||||||||||||||||||||||||||
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
Same-Property Revenue Results by County - Six months ended June 30, 2026 vs. Six months ended June 30, 2025
(Dollars in thousands, except average monthly rental rates)
|
|
YTD 2026
% of
Actual NOI
|
Average Monthly Rental Rate
|
Financial Occupancy
|
Gross Revenues
|
||||||||||||||||||||||||||||||||||||||||
|
Region - County
|
Apartment
Homes
|
YTD 2026
|
YTD 2025
|
%
Change
|
YTD 2026
|
YTD 2025
|
%
Change
|
YTD 2026
|
YTD 2025
|
%
Change
|
||||||||||||||||||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||||||||||||||
|
Southern California
|
||||||||||||||||||||||||||||||||||||||||||||
|
Los Angeles County
|
9,189
|
15.8
|
%
|
$
|
2,679
|
$
|
2,657
|
0.8
|
%
|
95.5
|
%
|
95.2
|
%
|
0.3
|
%
|
$
|
150,791
|
$
|
148,790
|
1.3
|
%
|
|||||||||||||||||||||||
|
Orange County
|
5,341
|
10.7
|
%
|
2,722
|
2,660
|
2.3
|
%
|
96.1
|
%
|
96.2
|
%
|
-0.1
|
%
|
89,574
|
87,139
|
2.8
|
%
|
|||||||||||||||||||||||||||
|
San Diego County
|
5,207
|
10.3
|
%
|
2,716
|
2,682
|
1.3
|
%
|
96.4
|
%
|
96.0
|
%
|
0.4
|
%
|
87,438
|
85,873
|
1.8
|
%
|
|||||||||||||||||||||||||||
|
Ventura County
|
2,652
|
5.1
|
%
|
2,534
|
2,488
|
1.8
|
%
|
96.2
|
%
|
96.3
|
%
|
-0.1
|
%
|
41,987
|
41,237
|
1.8
|
%
|
|||||||||||||||||||||||||||
|
Total Southern California
|
22,389
|
41.9
|
%
|
2,681
|
2,644
|
1.4
|
%
|
95.9
|
%
|
95.7
|
%
|
0.2
|
%
|
369,790
|
363,039
|
1.9
|
%
|
|||||||||||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||||||||||||||
|
Northern California
|
||||||||||||||||||||||||||||||||||||||||||||
|
Santa Clara County
|
9,279
|
21.4
|
%
|
3,210
|
3,092
|
3.8
|
%
|
97.0
|
%
|
96.7
|
%
|
0.3
|
%
|
185,353
|
177,281
|
4.6
|
%
|
|||||||||||||||||||||||||||
|
Alameda County
|
3,729
|
6.7
|
%
|
2,646
|
2,587
|
2.3
|
%
|
96.6
|
%
|
96.5
|
%
|
0.1
|
%
|
62,305
|
60,305
|
3.3
|
%
|
|||||||||||||||||||||||||||
|
San Mateo County
|
1,864
|
4.7
|
%
|
3,429
|
3,264
|
5.1
|
%
|
97.3
|
%
|
97.1
|
%
|
0.2
|
%
|
40,208
|
38,230
|
5.2
|
%
|
|||||||||||||||||||||||||||
|
Contra Costa County
|
2,619
|
5.0
|
%
|
2,793
|
2,751
|
1.5
|
%
|
96.5
|
%
|
96.5
|
%
|
0.0
|
%
|
45,666
|
44,806
|
1.9
|
%
|
|||||||||||||||||||||||||||
|
San Francisco
|
1,356
|
2.5
|
%
|
3,089
|
2,916
|
5.9
|
%
|
96.4
|
%
|
96.9
|
%
|
-0.5
|
%
|
26,632
|
25,207
|
5.7
|
%
|
|||||||||||||||||||||||||||
|
Total Northern California
|
18,847
|
40.3
|
%
|
3,054
|
2,949
|
3.6
|
%
|
96.9
|
%
|
96.7
|
%
|
0.2
|
%
|
360,164
|
345,829
|
4.1
|
%
|
|||||||||||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||||||||||||||
|
Seattle Metro
|
10,899
|
17.8
|
%
|
2,277
|
2,245
|
1.4
|
%
|
96.5
|
%
|
96.3
|
%
|
0.2
|
%
|
158,653
|
155,511
|
2.0
|
%
|
|||||||||||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||||||||||||||
|
Total Same-Property
|
52,135
|
100.0
|
%
|
$
|
2,731
|
$
|
2,671
|
2.2
|
%
|
96.4
|
%
|
96.2
|
%
|
0.2
|
%
|
$
|
888,607
|
$
|
864,379
|
2.8
|
%
|
|||||||||||||||||||||||
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
(Dollars in thousands)
|
Based on 52,135 apartment homes
|
||||||||||||||||
|
Q2 ‘26
|
Q2 ‘25
|
% Change
|
% of
Operating
Expense
|
|||||||||||||
|
Same-property operating expenses:
|
||||||||||||||||
|
Real estate taxes
|
$
|
46,040
|
$
|
44,572
|
3.3
|
%
|
35.6
|
%
|
||||||||
|
Utilities
|
28,404
|
26,224
|
8.3
|
%
|
22.0
|
%
|
||||||||||
|
Personnel costs
|
24,861
|
24,855
|
0.0
|
%
|
19.2
|
%
|
||||||||||
|
Maintenance and repairs
|
15,185
|
15,122
|
0.4
|
%
|
11.8
|
%
|
||||||||||
|
Administrative
|
6,361
|
6,363
|
0.0
|
%
|
4.9
|
%
|
||||||||||
|
Insurance and other
|
8,353
|
8,510
|
-1.8
|
%
|
6.5
|
%
|
||||||||||
|
Total same-property operating expenses
|
$
|
129,204
|
$
|
125,646
|
2.8
|
%
|
100.0
|
%
|
||||||||
|
YTD 2026
|
YTD 2025
|
% Change
|
% of
Operating
Expense
|
|||||||||||||
|
Same-property operating expenses:
|
||||||||||||||||
|
Real estate taxes
|
$
|
93,269
|
$
|
93,113
|
0.2
|
%
|
36.1
|
%
|
||||||||
|
Utilities
|
58,062
|
53,754
|
8.0
|
%
|
22.4
|
%
|
||||||||||
|
Personnel costs
|
49,179
|
49,201
|
0.0
|
%
|
19.0
|
%
|
||||||||||
|
Maintenance and repairs
|
28,161
|
28,698
|
-1.9
|
%
|
10.9
|
%
|
||||||||||
|
Administrative
|
12,967
|
12,920
|
0.4
|
%
|
5.0
|
%
|
||||||||||
|
Insurance and other
|
17,069
|
17,201
|
-0.8
|
%
|
6.6
|
%
|
||||||||||
|
Total same-property operating expenses
|
$
|
258,707
|
$
|
254,887
|
1.5
|
%
|
100.0
|
%
|
||||||||
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
(Dollars in millions, except per apartment home amounts in thousands)
|
Project Name – Location
|
Ownership
%
|
Estimated
Apartment
Homes
|
Estimated
Commercial
sq. feet
|
Incurred to
Date (1)
|
Remaining
Costs
|
Estimated
Total Cost
|
Cost per
Apartment
Home (2)
|
Construction
Start
|
Initial
Occupancy
|
Stabilized
Operations
|
||||||||||||||||||||||||||||||
|
Development Projects - Consolidated
|
||||||||||||||||||||||||||||||||||||||||
|
7 South Linden - South San Francisco, CA
|
100%
|
|
543
|
-
|
$
|
150
|
$
|
161
|
$
|
311
|
$
|
573
|
Q1 2025
|
Q1 2028
|
Q1 2030
|
|||||||||||||||||||||||||
|
Total Development Projects - Consolidated
|
543
|
-
|
150
|
161
|
311
|
$
|
573
|
|||||||||||||||||||||||||||||||||
|
Land Held for Future Development - Consolidated
|
||||||||||||||||||||||||||||||||||||||||
|
Other Projects - Various
|
100%
|
|
-
|
-
|
34
|
-
|
34
|
|||||||||||||||||||||||||||||||||
|
Total Development Pipeline - Consolidated
|
543
|
-
|
$
|
184
|
$
|
161
|
$
|
345
|
||||||||||||||||||||||||||||||||
| (1) |
For the second quarter of 2026, the Company’s cost includes $1.5 million of capitalized interest and $0.6 million of capitalized overhead.
|
| (2) |
Net of the estimated allocation to the retail component of the project, as applicable.
|
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
(Dollars in thousands, except in footnotes and per apartment home amounts)
|
Revenue Generating Capital Expenditures (2)
|
Q2 ‘26
|
Trailing 4
Quarters
|
||||||
|
Same-property portfolio
|
$
|
12,915
|
$
|
66,852
|
||||
|
Non-same property portfolio
|
2,641
|
6,130
|
||||||
|
Total revenue generating capital expenditures
|
$
|
15,556
|
$
|
72,982
|
||||
|
Number of same-property interior renovations
|
948
|
2,392
|
||||||
|
Number of total consolidated interior renovations
|
978
|
2,533
|
||||||
|
Non-Revenue Generating Capital Expenditures (3)
|
Q2 ‘26
|
Trailing 4
Quarters
|
||||||
|
Non-revenue generating capital expenditures
|
$
|
31,166
|
$
|
111,904
|
||||
|
Average apartment homes in quarter
|
55,616
|
55,390
|
||||||
|
Capital expenditures per apartment home
|
$
|
560
|
$
|
2,020
|
||||
|
(1)
|
The Company incurred less than $0.1 million of capitalized interest, $4.7 million of capitalized overhead and less than $0.1 million of co-investment fees related to redevelopment in Q2 2026.
|
|
(2)
|
Represents revenue generating expenditures, such as full-scale redevelopments, interior unit turn renovations, enhanced amenities, certain sustainability initiatives that generate higher revenues or
expense savings and accessory dwelling units.
|
|
(3)
|
Represents roof replacements, paving, building and mechanical systems, exterior painting, siding, etc. Non-revenue generating capital expenditures does not include costs related to retail, furniture
and fixtures, expenditures in which the Company has been reimbursed or expects to be reimbursed, and expenditures incurred due to changes in governmental regulation that the Company would not have incurred otherwise.
|
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
Co-investments and Preferred Equity Investments - June 30, 2026
(Dollars in thousands, except in footnotes)
|
Weighted
Average
Essex
Ownership
Percentage
|
Apartment
Homes |
Total
Undepreciated
Book Value
|
Debt
Amount
|
Essex
Book Value
|
Weighted
Average
Borrowing
Rate (1)
|
Remaining
Term of Debt
(in Years) |
Three Months
Ended
June 30,
2026
|
Six Months
Ended
June 30,
2026
|
||||||||||||||||||||||||
|
Operating and Other Unconsolidated Joint Ventures
|
NOI
|
|||||||||||||||||||||||||||||||
|
Wesco I, III, IV, V, VI (2) (3)
|
55%
|
|
5,547
|
$
|
1,988,872
|
$
|
1,270,964
|
$
|
68,998
|
3.2
|
%
|
2.5
|
$
|
30,699
|
$
|
60,504
|
||||||||||||||||
|
BEX IV, 500 Folsom
|
50%
|
732
|
617,883
|
176,400
|
133,022
|
3.5
|
%
|
20.0
|
5,877
|
11,196
|
||||||||||||||||||||||
|
Other (4)
|
53%
|
986
|
387,133
|
291,476
|
109,746
|
3.6
|
%
|
11.0
|
6,270
|
11,943
|
||||||||||||||||||||||
|
Total Operating and Other Unconsolidated Joint Ventures
|
7,265
|
$
|
2,993,888
|
$
|
1,738,840
|
$
|
311,766
|
3.3
|
%
|
5.7
|
$
|
42,846
|
$
|
83,643
|
||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||
|
|
Essex Portion of NOI and
Expenses
|
|||||||||||||||||||||||||||||||
|
NOI
|
$
|
23,403
|
$
|
45,766
|
||||||||||||||||||||||||||||
|
Depreciation
|
(13,167
|
)
|
(26,483
|
)
|
||||||||||||||||||||||||||||
|
Interest expense and other, net
|
(8,346
|
)
|
(16,403
|
)
|
||||||||||||||||||||||||||||
|
Equity (loss) income from unconsolidated technology co-investments
|
(849
|
)
|
16,187
|
|||||||||||||||||||||||||||||
|
Insurance reimbursements and other, net
|
22
|
22
|
||||||||||||||||||||||||||||||
|
Gain on sale of co-investment communities
|
9,231
|
9,231
|
||||||||||||||||||||||||||||||
|
Net income from operating and other co-investments
|
$
|
10,294
|
$
|
28,320
|
||||||||||||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||
|
|
Weighted
Average
Preferred
Return
|
Weighted
Average
Expected
Term
|
Income from Preferred Equity
Investments
|
|||||||||||||||||||||||||||||
|
Income from preferred equity investments
|
$
|
3,242
|
$
|
8,831
|
||||||||||||||||||||||||||||
|
Income from early redemption of preferred equity investments
|
179
|
179
|
||||||||||||||||||||||||||||||
|
Preferred Equity Investments (5)
|
$
|
192,872
|
10.2
|
%
|
2.1
|
$
|
3,421
|
$
|
9,010
|
|||||||||||||||||||||||
|
|
||||||||||||||||||||||||||||||||
|
Total Co-investments
|
$
|
504,638
|
$
|
13,715
|
$
|
37,330
|
||||||||||||||||||||||||||
| (1) |
Represents the year-to-date annual weighted average borrowing rate.
|
| (2) |
As of June 30, 2026, the Company’s investments in Wesco I, Wesco III, and Wesco IV were classified as a liability of $104.2 million due to distributions received in excess of the
Company’s investment.
|
| (3) |
Wesco III, IV and VI have in-place interest rate swaps totaling a notional amount of $624.3 million at an average all-in fixed rate of 2.7% which expire in December 2026 and
March 2027. During the second quarter of 2026, these Wesco entities entered into replacement swaps which take effect at the existing swap maturities totaling a notional amount of $340.3 million of new interest rate swaps at an average all-in
fixed rate of 5.2% which expire in June 2029.
|
| (4) |
As of June 30, 2026, the Company’s investments in Expo and Silver were classified as a liability of $3.7 million due to distributions received in excess of the Company’s
investment. The weighted average Essex ownership percentage excludes our investments in unconsolidated technology co-investments.
|
| (5) |
As of June 30, 2026, the Company is invested in 8 preferred equity investments, including one preferred equity investment held by Wesco VII, LLC.
|
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
Summary of Apartment Community Acquisitions and Dispositions Activity - Year to date as of June 30, 2026
(Dollars in thousands, except for average monthly rent)
| Acquisitions | ||||||||||||||||||||
| Property Name |
Location
|
Apartment
Homes
|
Year Built
|
Essex
Ownership
Percentage
|
Entity |
Date
|
Total Contract
Price at
Pro Rata Share
|
Price per
Apartment Home
|
Average
Monthly Rent
|
|||||||||||
|
Neither Essex nor its unconsolidated joint ventures acquired any apartment communities during the year to date as of June 30, 2026.
|
||||||||||||||||||||
|
Dispositions
|
||||||||||||||||||||
|
Property Name
|
Location
|
Apartment
Homes
|
Year Built
|
Essex
Ownership
Percentage
|
Entity
|
Date
|
Total Contract
Price at
Pro Rata Share
|
Price per
Apartment Home (1)
|
||||||||||||
|
Meridian at Midtown
|
San Jose, CA
|
218
|
2015
|
50%
|
|
JV
|
Jun-26
|
$ |
52,625
|
$ |
460
|
|||||||||
|
Q2 2026
|
218
|
$
|
52,625
|
$
|
460
|
|||||||||||||||
|
2026 Total
|
218
|
$
|
52,625
|
$
|
460
|
|||||||||||||||
| (1) |
Price per apartment home excludes value allocated to the retail component, as applicable.
|
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
Assumptions for 2026 FFO Guidance Range
(Dollars in thousands, except per share data)
The guidance projections below are based on current expectations and are forward-looking. The guidance on this page is given for Net Operating Income (“NOI”) and Total
and Core FFO. See pages S-17.1 to S-17.4 for the definitions of non-GAAP financial measures and other terms.
|
Six Months Ended
|
2026 Full-Year Guidance Range
|
||||||||||||
|
June 30, 2026 (1)
|
Low End
|
High End
|
Comments about 2026 Full-Year Guidance
|
||||||||||
|
Total NOI from Consolidated Communities
|
$
|
686,896
|
$
|
1,365,500
|
$
|
1,377,500
|
Includes same-property NOI growth range of
2.3% to 3.3%
|
||||||
|
|
|||||||||||||
|
Management Fees
|
|
4,631
|
8,900
|
9,500
|
|||||||||
|
|
|||||||||||||
|
Interest Expense
|
|||||||||||||
|
Interest expense, before capitalized interest
|
(132,479
|
)
|
(266,200
|
)
|
(264,600
|
)
|
|||||||
|
Interest capitalized
|
2,848
|
6,400
|
7,000
|
||||||||||
|
Net interest expense
|
(129,631
|
)
|
(259,800
|
)
|
(257,600
|
)
|
|||||||
|
Recurring Income and Expenses
|
|||||||||||||
|
Interest and other income
|
5,635
|
7,900
|
8,900
|
Updated to reflect the early redemption of a subordinated loan that occurred in the second quarter
|
|||||||||
|
FFO from co-investments
|
38,194
|
68,500
|
70,100
|
Updated to reflect year-to-date investment and redemption activity
|
|||||||||
|
General and administrative
|
(31,833
|
)
|
(62,000
|
)
|
(64,000
|
)
|
|||||||
|
Corporate-level property management expenses
|
(26,830
|
)
|
(53,000
|
)
|
(54,000
|
)
|
|||||||
|
Non-controlling interest
|
(4,774
|
)
|
(9,900
|
)
|
(9,300
|
)
|
|||||||
|
Total recurring income and expenses
|
(19,608
|
)
|
(48,500
|
)
|
(48,300
|
)
|
|||||||
|
Non-Core Income and Expenses
|
|||||||||||||
|
Tax expense on unconsolidated co-investments
|
(3,251
|
)
|
(3,251
|
)
|
(3,251
|
)
|
|||||||
|
Realized and unrealized gains on marketable securities, net
|
3,990
|
3,990
|
3,990
|
||||||||||
|
Provision for credit losses
|
222
|
222
|
222
|
||||||||||
|
Equity income from unconsolidated technology co-investments
|
16,187
|
16,187
|
16,187
|
||||||||||
|
Income from early redemption of preferred equity investments
|
179
|
179
|
179
|
||||||||||
|
General and administrative and other, net
|
(61,330
|
)
|
(61,330
|
)
|
(61,330
|
)
|
Updated to reflect legal settlements
|
||||||
|
Insurance reimbursements and other, net
|
298
|
298
|
298
|
||||||||||
|
Total non-core income and expenses
|
(43,705
|
)
|
(43,705
|
)
|
(43,705
|
)
|
|||||||
|
Funds from Operations (2)
|
$
|
498,583
|
$
|
1,022,395
|
$
|
1,037,395
|
|||||||
|
|
|||||||||||||
|
Funds from Operations per diluted Share
|
$
|
7.49
|
$
|
15.37
|
$
|
15.59
|
|||||||
|
|
|||||||||||||
|
% Change - Funds from Operations
|
-6.4
|
%
|
-3.8
|
%
|
-2.4
|
%
|
|||||||
|
|
|||||||||||||
|
Core Funds from Operations (excludes non-core items)
|
$
|
542,288
|
$
|
1,066,100
|
$
|
1,081,100
|
|||||||
|
|
|||||||||||||
|
Core Funds from Operations per diluted Share
|
$
|
8.15
|
$
|
16.03
|
$
|
16.25
|
|||||||
|
|
|||||||||||||
|
% Change - Core Funds from Operations
|
1.9
|
%
|
0.6
|
%
|
1.9
|
%
|
|||||||
|
|
|||||||||||||
|
EPS - Diluted
|
$
|
2.62
|
$
|
5.47
|
$
|
5.69
|
|||||||
|
|
|||||||||||||
|
Weighted average shares outstanding - FFO calculation
|
66,575
|
66,525
|
66,525
|
Reflects YTD share repurchases
|
|||||||||
| (1) |
All non-core items are excluded from the 2026 actuals and included in the non-core income and expense section of the FFO reconciliation.
|
| (2) |
2026 guidance excludes inestimable projected gain/(loss) on sale of real estate and land, gain/(loss) on sale of marketable securities, gain/(loss) on early retirement of debt,
and promote income until they are realized within the reporting period presented in the report.
|
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
Reconciliation of Projected EPS, FFO and Core FFO per diluted share
With respect to the Company’s guidance regarding its projected FFO and Core FFO, which guidance is set forth in the earnings release and on page
S-15 of this supplement, a reconciliation of projected net income per share to projected FFO per share and projected Core FFO per share, as set forth in such guidance, is presented in the table below.
|
2026 Guidance Range (1)
|
||||||||||||||||||||
|
Six Months
|
||||||||||||||||||||
|
Ended June 30,
|
3rd Quarter 2026
|
Full-Year 2026
|
||||||||||||||||||
|
2026
|
Low
|
High
|
Low
|
High
|
||||||||||||||||
|
EPS - diluted
|
$
|
2.62
|
$
|
1.41
|
$
|
1.53
|
$
|
5.47
|
$
|
5.69
|
||||||||||
|
Conversion from GAAP share count
|
(0.09
|
)
|
(0.05
|
)
|
(0.05
|
)
|
(0.18
|
)
|
(0.18
|
)
|
||||||||||
|
Depreciation and amortization
|
5.04
|
2.52
|
2.52
|
10.07
|
10.07
|
|||||||||||||||
|
Noncontrolling interest related to Operating Partnership units
|
0.09
|
0.05
|
0.05
|
0.18
|
0.18
|
|||||||||||||||
|
Gain on sale of real estate and land
|
(0.17
|
)
|
-
|
-
|
(0.17
|
)
|
(0.17
|
)
|
||||||||||||
|
FFO per share - diluted
|
$
|
7.49
|
$
|
3.93
|
$
|
4.05
|
$
|
15.37
|
$
|
15.59
|
||||||||||
|
Tax expense on unconsolidated co-investments
|
0.05
|
-
|
-
|
0.05
|
0.05
|
|||||||||||||||
|
Realized and unrealized gains on marketable securities, net
|
(0.06
|
)
|
-
|
-
|
(0.06
|
)
|
(0.06
|
)
|
||||||||||||
|
Provision for credit losses
|
-
|
-
|
-
|
-
|
-
|
|||||||||||||||
|
Equity income from unconsolidated technology co-investments
|
(0.24
|
)
|
-
|
-
|
(0.24
|
)
|
(0.24
|
)
|
||||||||||||
|
Loss on early retirement of debt, net
|
-
|
-
|
-
|
-
|
-
|
|||||||||||||||
|
Co-investment promote income
|
-
|
-
|
-
|
-
|
-
|
|||||||||||||||
|
General and administrative and other, net
|
0.91
|
-
|
-
|
0.91
|
0.91
|
|||||||||||||||
|
Insurance reimbursements and other, net
|
-
|
-
|
-
|
-
|
-
|
|||||||||||||||
|
Core FFO per share - diluted
|
$
|
8.15
|
$
|
3.93
|
$
|
4.05
|
$
|
16.03
|
$
|
16.25
|
||||||||||
| (1) |
2026 guidance excludes inestimable projected gain/(loss) on sale of real estate and land, gain/(loss) on sale of marketable securities, gain/(loss) on early retirement of debt,
and promote income until they are realized within the reporting period presented in the report.
|
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
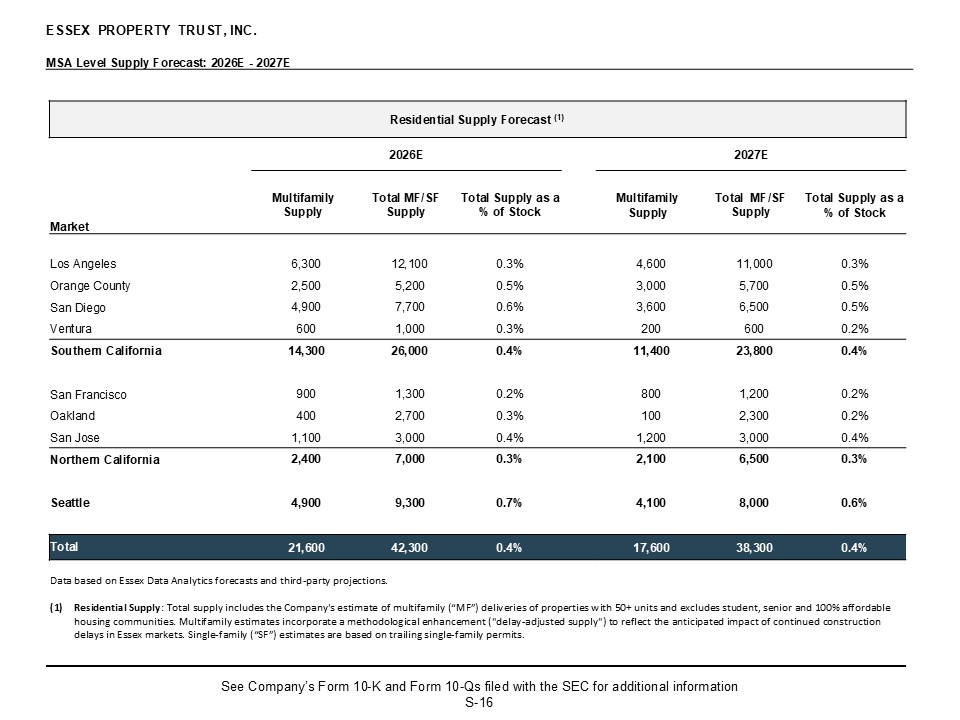
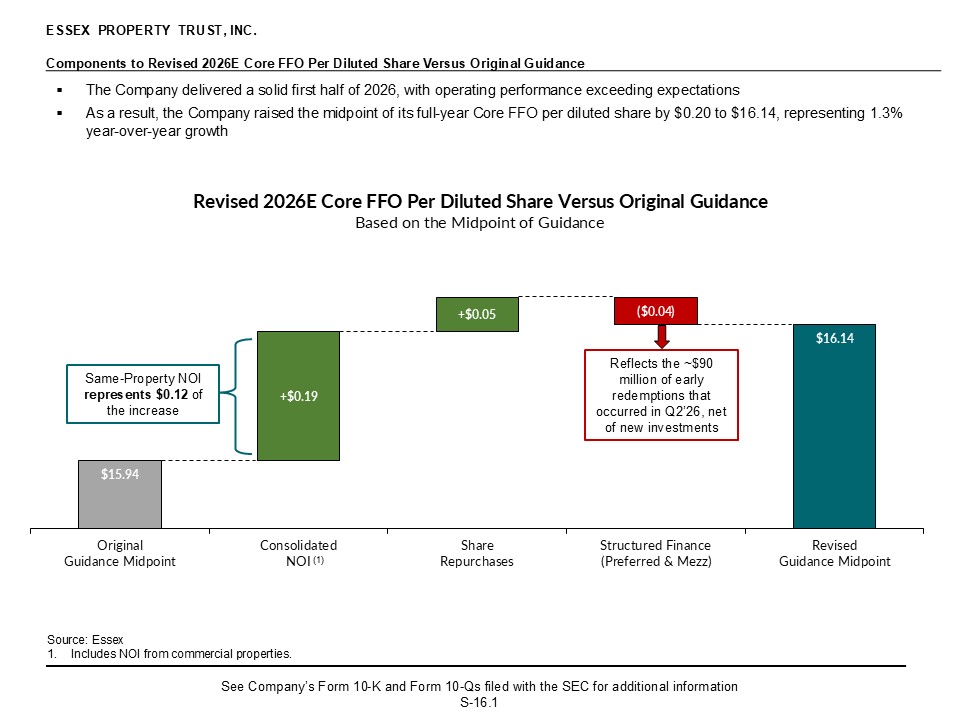
ESSEX PROPERTY TRUST, INC.
Reconciliations of Non-GAAP Financial Measures and Other Terms
Adjusted EBITDAre Reconciliation
The National Association of Real Estate Investment Trusts (“Nareit”) defines earnings before interest, taxes, depreciation and amortization for real estate (“EBITDAre”)
(September 2017 White Paper) as net income (computed in accordance with U.S. generally accepted accounting principles (“U.S. GAAP”)) before interest expense, income taxes, depreciation and amortization expense, and further adjusted for gains and
losses from sales of depreciated operating properties, impairment write-downs of depreciated operating properties, impairment write-downs of investments in unconsolidated entities caused by a decrease in value of depreciated operating properties
within the joint venture and adjustments to reflect the Company’s share of EBITDAre of investments in unconsolidated entities.
The Company believes that EBITDAre is useful to investors, creditors and rating agencies as a supplemental measure of the Company’s ability to incur and service debt
because it is a recognized measure of performance by the real estate industry, and by excluding gains or losses related to sales or impairment of depreciated operating properties, EBITDAre can help compare the Company’s credit strength between
periods or as compared to different companies.
Adjusted EBITDAre represents EBITDAre further adjusted for non-comparable items and is a component of the credit ratio, “Net Indebtedness Divided by Adjusted EBITDAre,
normalized and annualized,” presented on page S-6, in the section titled “Selected Credit Ratios,” and it is not intended to be a measure of free cash flow for management’s discretionary use, as it does not consider certain cash requirements such as
income tax payments, debt service requirements, capital expenditures and other fixed charges.
Adjusted EBITDAre is an important metric in evaluating the credit strength of the Company and its ability to service its debt obligations. The Company believes that
Adjusted EBITDAre is useful to investors, creditors and rating agencies because it allows investors to compare the Company’s credit strength to prior reporting periods and to other companies without the effect of items that by their nature are not
comparable from period to period and tend to obscure the Company’s actual credit quality.
EBITDAre and Adjusted EBITDAre are not recognized measurements under U.S. GAAP. Because not all companies use identical calculations, the Company’s presentation of
EBITDAre and Adjusted EBITDAre may not be comparable to similarly titled measures of other companies.
The reconciliations of Net Income available to common stockholders to EBITDAre and Adjusted EBITDAre are presented in the table below:
|
(Dollars in thousands)
|
Three
Months Ended
June 30,
2026
|
|||
|
|
||||
|
Net income available to common stockholders
|
$
|
62,462
|
||
|
Adjustments:
|
||||
|
Net income attributable to noncontrolling interest
|
4,467
|
|||
|
Interest expense, net (1)
|
65,609
|
|||
|
Depreciation and amortization
|
154,073
|
|||
|
Income tax provision
|
108
|
|||
|
Gain on sale of real estate and land
|
(2,000
|
)
|
||
|
Gain on sale of co-investment communities
|
(9,231
|
)
|
||
|
Co-investment EBITDAre adjustments
|
21,305
|
|||
|
EBITDAre
|
296,793
|
|||
|
|
||||
|
Realized and unrealized gains on marketable securities, net
|
(5,716
|
)
|
||
|
Provision for credit losses
|
(256
|
)
|
||
|
Equity loss from unconsolidated technology co-investments
|
849
|
|||
|
Tax benefit on unconsolidated technology co-investments
|
(363
|
)
|
||
|
General and administrative and other, net
|
56,785
|
|||
|
Insurance reimbursements and other, net
|
(247
|
)
|
||
|
Income from early redemption of preferred equity investments
|
(179
|
)
|
||
|
Adjusted EBITDAre
|
$
|
347,666
|
||
| (1) |
Interest expense, net includes items such as gains on derivatives and the amortization of deferred charges.
|
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
Reconciliations of Non-GAAP Financial Measures and Other Terms
Annualized Turnover
Annualized turnover is defined as the number of apartment homes turned over during the quarter, annualized, divided by the total number of apartment homes.
Financial Occupancy
Financial occupancy is defined as the percentage resulting from dividing actual rental income by total scheduled rental income. Actual rental income represents
contractual rental income pursuant to leases without considering delinquency and concessions. Total scheduled rental income represents the value of all apartment homes, with occupied apartment homes valued at contractual rental rates pursuant to
leases and vacant apartment homes valued at estimated market rents.
New Lease Net Effective Rate Growth and Renewal Net Effective Rate Growth
New lease net effective rate growth and renewal net effective rate growth represent the percentage change in all lease tradeouts, including the impact of leasing
incentives. Prior to 2026, the rate growth was based on the change in similar term lease tradeouts, including the impact of leasing incentives, and all periods presented have been updated to conform with the current methodology.
Disposition Yield
Net operating income that the Company anticipates giving up in the next 12 months less an estimate of property management costs allocated to the project divided by the
gross sales price of the asset.
Acquisition Yield
Net operating income that the Company expects to achieve in the next 12 months less an estimate of property management costs allocated to the project and less an
estimate for capital expenditures per unit divided by the gross sales price of the asset.
Encumbered
Encumbered means any mortgage, deed of trust, lien, charge, pledge, security interest, security agreement or other encumbrance of any kind.
Funds From Operations (“FFO”) and Core FFO
FFO, as defined by Nareit, is generally considered by industry analysts as an appropriate measure of performance of an equity REIT. Generally, FFO adjusts the net
income of equity REITs for non-cash charges such as depreciation and amortization of rental properties, impairment charges, gains on sales of real estate and extraordinary items. Management considers FFO and FFO which excludes non-core items, which
is referred to as “Core FFO,” to be useful supplemental operating performance measures of an equity REIT because, together with net income and cash flows, FFO and Core FFO provide investors with additional bases to evaluate the operating
performance and ability of a REIT to incur and service debt and to fund acquisitions and other capital expenditures and to pay dividends. By excluding gains or losses related to sales of depreciated operating properties and land and excluding real
estate depreciation (which can vary among owners of identical assets in similar condition based on historical cost accounting and useful life estimates), FFO can help investors compare the operating performance of a real estate company between
periods or as compared to different companies. By further adjusting for items that are not considered part of the Company’s core business operations, Core FFO allows investors to compare the core operating performance of the Company to its
performance in prior reporting periods and to the operating performance of other real estate companies without the effect of items that by their nature are not comparable from period to period and tend to obscure the Company’s actual operating
results.
FFO and Core FFO do not represent net income or cash flows from operations as defined by U.S. GAAP and are not intended to indicate whether cash flows will be
sufficient to fund cash needs. These measures should not be considered as alternatives to net income as an indicator of the REIT’s operating performance or to cash flows as a measure of liquidity. FFO and Core FFO do not measure whether cash flow
is sufficient to fund all cash needs including principal amortization, capital improvements and distributions to stockholders. FFO and Core FFO also do not represent cash flows generated from operating, investing or financing activities as defined
under GAAP. Management has consistently applied the Nareit definition of FFO to all periods presented. However, there is judgment involved and other REITs’ calculation of FFO may vary from the Nareit definition for this measure, and thus their
disclosures of FFO may not be comparable to the Company’s calculation.
The reconciliations of FFO and Core FFO per diluted share are detailed on page S-3 in the section titled “Consolidated Funds From Operations”.
Interest Expense, Net
Interest expense, net is presented on page S-1 in the section titled “Consolidated Operating Results”. Interest expense, net includes items such as gains on
derivatives and the amortization of deferred charges and is presented in the table below:
|
|
Three Months Ended
|
Six Months Ended
|
||||||||||||||
|
|
June 30,
|
June 30,
|
June 30,
|
June 30,
|
||||||||||||
|
(Dollars in thousands)
|
2026
|
2025
|
2026
|
2025
|
||||||||||||
|
|
||||||||||||||||
|
Interest expense
|
$
|
66,835
|
$
|
65,262
|
$
|
132,399
|
$
|
127,994
|
||||||||
|
Adjustments:
|
||||||||||||||||
|
Total return swap income
|
(1,226
|
)
|
(1,071
|
)
|
(2,768
|
)
|
(2,271
|
)
|
||||||||
|
Interest expense, net
|
$
|
65,609
|
$
|
64,191
|
$
|
129,631
|
$
|
125,723
|
||||||||
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
Reconciliations of Non-GAAP Financial Measures and Other Terms
Net Indebtedness Divided by Adjusted EBITDAre
This credit ratio is presented on page S-6 in the section titled “Selected Credit Ratios.” This credit ratio is calculated by dividing net indebtedness by Adjusted
EBITDAre, as annualized based on the most recent quarter, and adjusted for estimated net operating income from properties acquired or disposed of during the quarter. This ratio is presented by the Company because it provides rating agencies and
investors an additional means of comparing the Company’s ability to service debt obligations to that of other companies. Net indebtedness is total debt, net less unamortized premiums, discounts, debt issuance costs, unrestricted cash and cash
equivalents, and marketable securities. The reconciliation of Adjusted EBITDAre is set forth in “Adjusted EBITDAre Reconciliation” on page S-17.1 The calculation of this credit ratio and a reconciliation of net indebtedness to total debt at pro
rata share for co-investments, net is presented in the table below:
|
(Dollars in thousands)
|
June 30,
2026
|
|||
|
Total consolidated debt, net
|
$
|
6,698,500
|
||
|
Total debt from co-investments at pro rata share
|
953,985
|
|||
|
Adjustments:
|
||||
|
Consolidated unamortized premiums, discounts, and debt issuance costs
|
33,026
|
|||
|
Pro rata co-investments unamortized premiums, discounts, and debt issuance costs
|
4,206
|
|||
|
Consolidated cash and cash equivalents-unrestricted
|
(58,327
|
)
|
||
|
Pro rata co-investment cash and cash equivalents-unrestricted
|
(33,961
|
)
|
||
|
Marketable securities
|
(92,165
|
)
|
||
|
Net Indebtedness
|
$
|
7,505,264
|
||
|
Adjusted EBITDAre, annualized (1)
|
$
|
1,390,664
|
||
|
Other EBITDAre normalization adjustments, net, annualized (2)
|
(7,712
|
)
|
||
|
Adjusted EBITDAre, normalized and annualized
|
$
|
1,382,952
|
||
|
Net Indebtedness Divided by Adjusted EBITDAre, normalized and annualized
|
5.4
|
|||
| (1) |
Based on the amount for the most recent quarter, multiplied by four.
|
| (2) |
Adjustments made for properties in lease-up, acquired, or disposed during the most recent quarter and other partial quarter activity, multiplied by four.
|
Net Operating Income (“NOI”) and Same-Property NOI Reconciliations
NOI and same-property NOI are considered by management to be important supplemental performance measures to earnings from operations included in the Company’s
consolidated statements of income. The presentation of same-property NOI assists with the presentation of the Company’s operations prior to the allocation of depreciation and any corporate-level or financing-related costs. NOI reflects the
operating performance of a community and allows for an easy comparison of the operating performance of individual communities or groups of communities.
In addition, because prospective buyers of real estate have different financing and overhead structures, with varying marginal impacts to overhead by acquiring real
estate, NOI is considered by many in the real estate industry to be a useful measure for determining the value of a real estate asset or group of assets. The Company defines same-property NOI as same-property revenues less same-property operating
expenses, including property taxes. Please see the reconciliation of earnings from operations to NOI and same-property NOI, which in the table below is the NOI for stabilized properties consolidated by the Company for the periods presented:
|
|
Three Months Ended
|
Six Months Ended
|
||||||||||||||
|
(Dollars in thousands)
|
June 30,
2026
|
June 30,
2025
|
June 30,
2026
|
June 30,
2025
|
||||||||||||
|
|
||||||||||||||||
|
Earnings from operations
|
$
|
109,373
|
$
|
279,700
|
$
|
264,566
|
$
|
536,781
|
||||||||
|
Adjustments:
|
||||||||||||||||
|
Corporate-level property management expenses
|
13,432
|
12,220
|
26,830
|
24,552
|
||||||||||||
|
Depreciation and amortization
|
154,073
|
151,501
|
308,968
|
302,788
|
||||||||||||
|
Management and other fees from affiliates
|
(2,318
|
)
|
(2,223
|
)
|
(4,631
|
)
|
(4,717
|
)
|
||||||||
|
General and administrative
|
73,149
|
17,157
|
93,163
|
33,449
|
||||||||||||
|
Gain on sale of real estate and land
|
(2,000
|
)
|
(126,174
|
)
|
(2,000
|
)
|
(237,204
|
)
|
||||||||
|
NOI
|
345,709
|
332,181
|
686,896
|
655,649
|
||||||||||||
|
Less: Non-same property NOI
|
(28,878
|
)
|
(23,457
|
)
|
(56,996
|
)
|
(46,157
|
)
|
||||||||
|
Same-Property NOI
|
$
|
316,831
|
$
|
308,724
|
$
|
629,900
|
$
|
609,492
|
||||||||
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information
ESSEX PROPERTY TRUST, INC.
Reconciliations of Non-GAAP Financial Measures and Other Terms
Public Bond Covenants
Public Bond Covenants refer to certain covenants set forth in instruments governing the Company’s unsecured indebtedness. These instruments require the Company to meet
specified financial covenants, including covenants relating to net worth, fixed charge coverage, debt service coverage, the amounts of total indebtedness and secured indebtedness, leverage and certain investment limitations. These covenants may
restrict the Company’s ability to expand or fully pursue its business strategies. The Company’s ability to comply with these covenants may be affected by changes in the Company’s operating and financial performance, changes in general business and
economic conditions, adverse regulatory developments or other events adversely impacting it. The breach of any of these covenants could result in a default under the Company’s indebtedness, which could cause those and other obligations to become
due and payable. If any of the Company’s indebtedness is accelerated, the Company may not be able to repay it. For risks related to failure to comply with these covenants, see “Item 1A: Risk Factors - Risks Related to Our Indebtedness and
Financings” in the Company’s annual report on Form 10-K and other reports filed by the Company with the Securities and Exchange Commission (“SEC”).
The ratios set forth on page S-6 in the section titled “Public Bond Covenants” are provided only to show the Company’s compliance with certain specified covenants that
are contained in indentures related to the Company’s issuance of Senior Notes, which indentures are filed by the Company with the SEC. See, for example, the indenture and supplemental indenture dated December 12, 2025, filed by the Company as
Exhibit 4.1 and Exhibit 4.2 to the Company’s Form 8-K, filed on December 12, 2025. These ratios should not be used for any other purpose, including without limitation to evaluate the Company’s financial condition or results of operations, nor do
they indicate the Company’s covenant compliance as of any other date or for any other period. The capitalized terms in the disclosure are defined in the indentures filed by the Company with the SEC and may differ materially from similar terms used
by other companies that present information about their covenant compliance.
Same-Property Revenue Growth with Concessions on a GAAP basis
|
Three Months Ended
|
Six Months Ended
|
|||||||||||||||
|
(Dollars in millions)
|
June 30,
2026
|
June 30,
2025
|
June 30,
2026
|
June 30,
2025
|
||||||||||||
|
Reported rental revenue (1)
|
$
|
446.1
|
$
|
434.4
|
$
|
888.6
|
$
|
864.4
|
||||||||
|
Straight-line rent impact to rental revenue
|
(0.3
|
)
|
0.3
|
(0.5
|
)
|
(0.1
|
)
|
|||||||||
|
GAAP rental revenue
|
$
|
445.8
|
$
|
434.7
|
$
|
888.1
|
$
|
864.3
|
||||||||
|
% change - reported rental revenue
|
2.7
|
%
|
2.8
|
%
|
||||||||||||
|
% change - GAAP rental revenue
|
2.6
|
%
|
2.8
|
%
|
||||||||||||
| (1) |
Same-property rental revenue reflects concessions on a cash basis.
|
Secured Debt
Secured Debt means debt of the Company or any of its subsidiaries which is secured by an encumbrance on any property or assets of the Company or any of its
subsidiaries. The Company’s total amount of Secured Debt is set forth on page S-5.
Unencumbered NOI to Adjusted Total NOI
This ratio is presented on page S-6 in the section titled “Selected Credit Ratios”. Unencumbered NOI means the sum of NOI for those real estate assets which are not
subject to an encumbrance securing debt. The ratio of Unencumbered NOI to Adjusted Total NOI for the three months ended June 30, 2026, annualized, is calculated by dividing Unencumbered NOI, annualized for the three months ended June 30, 2026 and
as further adjusted for pro forma NOI for properties acquired or sold during the recent quarter, by Adjusted Total NOI as annualized. The calculation and reconciliation of NOI is set forth in “Net Operating Income (“NOI”) and Same-Property NOI
Reconciliations” above. This ratio is presented by the Company because it provides rating agencies and investors an additional means of comparing the Company’s ability to service debt obligations to that of other companies.
The calculation of this ratio is presented in the table below:
|
(Dollars in thousands)
|
Annualized
Q2 ‘26 (1)
|
|||
|
NOI
|
$
|
1,382,836
|
||
|
Adjustments:
|
||||
|
Pro forma NOI from real estate assets sold and/or acquired
|
-
|
|||
|
Other, net (2)
|
(2,724
|
)
|
||
|
Adjusted Total NOI
|
1,380,112
|
|||
|
Less: Encumbered NOI
|
(94,099
|
)
|
||
|
Unencumbered NOI
|
$
|
1,286,013
|
||
|
Encumbered NOI
|
$
|
94,099
|
||
|
Unencumbered NOI
|
1,286,013
|
|||
|
Adjusted Total NOI
|
$
|
1,380,112
|
||
|
Unencumbered NOI to Adjusted Total NOI
|
93
|
%
|
||
|
(1)
|
This table is based on the amounts for the most recent quarter, multiplied by four.
|
| (2) |
Includes intercompany eliminations pertaining to self-insurance and other expenses.
|
See Company’s Form 10-K and Form 10-Qs filed with the SEC for additional information