
EWBC 8-K
East West Bancorp Inc (EWBC)
8-K
2021-10-21
For: 2021-10-21
View Original
Added on
April 12, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 OR 15(d) of
The Securities Exchange Act of 1934
Date of Report (Date of earliest event reported)
(Exact name of registrant as specified in its charter)
(State or other jurisdiction of incorporation)
(Commission File Number)
(IRS Employer Identification No.)
(Address of principal executive offices) (Zip code)
(626 ) 768-6000
(Registrant’s telephone number, including area code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02. Results of Operations and Financial Condition
On October 21, 2021, East West Bancorp, Inc. (the “Company”) announced its financial results for the quarter ended September 30, 2021. A copy of the Company’s press release (the “Press Release”) is attached as Exhibit 99.1 to this Current Report on Form 8-K and is incorporated by reference in this Item 2.02. The Press Release is “furnished” pursuant to General Instruction B.2 of Form 8-K and the information provided in Item 2.02 of this report, including Exhibit 99.1, shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934 (the “Exchange Act”), or otherwise subject to the liabilities under that Section. The information provided in Item 2.02 of this report, including Exhibit 99.1, shall not be deemed incorporated by reference into any filings the Company has made or may make under the Securities Act of 1933 (the “Securities Act”) or the Exchange Act, except as otherwise expressly stated in such filing.
Item 7.01. Regulation FD Disclosure
On October 21, 2021, the Company will hold a conference call to discuss its financial results for the quarter ended September 30, 2021 and other matters relating to the Company. The Company has also made available on its website, www.eastwestbank.com, presentation materials containing certain historical and forward-looking information relating to the Company (the “Presentation Materials”). The Presentation Materials are furnished as Exhibit 99.2 and are incorporated by reference in this Item 7.01. All information in Exhibit 99.2 is presented as of the particular date or dates referenced therein, and the Company does not undertake any obligation to, and disclaims any duty to, update any of the information provided. The information provided in Item 7.01 of this report, including Exhibit 99.2, shall not be deemed “filed” for purposes of Section 18 of the Exchange Act, or otherwise subject to the liabilities under that Section, nor shall such information be deemed incorporated by reference into any filings the Company has made or may make under the Securities Act or the Exchange Act, except as otherwise expressly stated in such filing.
Item 9.01. Financial Statements and Exhibits
(d) Exhibits
| Press Release, dated October 21, 2021. | |||||
| Presentation Materials, dated October 21, 2021. | |||||
| 104 | Cover Page Interactive Data (formatted in Inline XBRL). | ||||
2
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| EAST WEST BANCORP, INC. | |||||||||||
| Date: October 21, 2021 | By: | /s/ Irene H. Oh | |||||||||
| Irene H. Oh | |||||||||||
| Executive Vice President and Chief Financial Officer | |||||||||||
3
| Exhibit 99.1 | |||||
 | East West Bancorp, Inc. | ||||
| 135 N. Los Robles Ave., 7th Fl. | |||||
| Pasadena, CA 91101 | |||||
| Tel. 626.768.6000 | |||||
NEWS RELEASE | |||||||||||
| FOR INVESTOR INQUIRIES, CONTACT: | |||||
Irene Oh | Julianna Balicka | ||||
Chief Financial Officer | Director of Investor Relations and Corporate Finance | ||||
T: (626) 768-6360 | T: (626) 768-6985 | ||||
| E: [email protected] | E: [email protected] | ||||
EAST WEST BANCORP REPORTS NET INCOME FOR THIRD QUARTER 2021
OF $225 MILLION AND DILUTED EARNINGS PER SHARE OF $1.57
Pasadena, California – October 21, 2021 – East West Bancorp, Inc. (“East West” or the “Company”) (Nasdaq: EWBC), parent company of East West Bank, today reported its financial results for the third quarter of 2021. Third quarter 2021 net income was $225.4 million, or $1.57 per diluted share; return on average assets was 1.46%, and return on average equity was 15.75%.
“This was another quarter of outstanding results. Our total loans reached a record $40.5 billion as of September 30, 2021. Loans grew by 11% annualized from June 30, 2021, and by 11% from September 30, 2020, excluding the impact of the Paycheck Protection Program. This growth has come from all of our major loan portfolios of commercial, residential mortgage and commercial real estate,” stated Dominic Ng, Chairman and Chief Executive Officer of East West.
“Total deposits reached a record $53.4 billion as of September 30, 2021, driven by excellent growth in demand deposits. This has transformed our deposit mix. Noninterest-bearing demand deposits now make up 43% of total balances, compared with 36% a year ago.”
“Our robust organic balance sheet growth drove a 21% annualized increase in revenue quarter-over-quarter, even as interest rates remained low. This revenue expansion was achieved while maintaining solid expense discipline, resulting in adjusted pre-tax, pre-provision income1 growth of 26% annualized from the second quarter,” continued Ng. “Overall, we earned an attractive return on average tangible equity2 of 17.25% in the third quarter of 2021.”
“We are looking forward to finishing the year on a high note, and extending the momentum and excellent performance from 2021 into continued growth and success in 2022,” concluded Ng.
FINANCIAL HIGHLIGHTS
| Three Months Ended | Qtr-o-Qtr Change | Yr-o-Yr Change | |||||||||||||||||||||||||||||||||
| ($ in millions) | September 30, 2021 | $ | % Ann. | $ | % | ||||||||||||||||||||||||||||||
| Total Loans (incl. PPP) | $40,482 | $408 | 4% | $3,040 | 8% | ||||||||||||||||||||||||||||||
| Total Loans (excl. PPP) | 39,674 | 1,034 | 11 | 4,005 | 11 | ||||||||||||||||||||||||||||||
| Total Deposits | 53,356 | 774 | 6 | 11,676 | 28 | ||||||||||||||||||||||||||||||
| Total Revenue | $469 | $24 | 21% | $90 | 24% | ||||||||||||||||||||||||||||||
Adj. Pre-tax Pre-provision Income1 | 302 | 19 | 26 | 78 | 35 | ||||||||||||||||||||||||||||||
| Net Income | 225 | 1 | 1 | 66 | 41 | ||||||||||||||||||||||||||||||
1 See reconciliation of GAAP to non-GAAP financial measures in Table 12. | |||||||||||
2 See reconciliation of GAAP to non-GAAP financial measures in Table 13. | |||||||||||
1
BALANCE SHEET
•Record Assets – Total assets reached $61.0 billion as of September 30, 2021, up by $1.1 billion, or 7% annualized, from $59.9 billion as of June 30, 2021. Year-over-year, total assets grew 21% from $50.4 billion as of September 30, 2020.
Third quarter 2021 average interest-earning assets of $58.2 billion grew by $3.3 billion, or 24% linked quarter annualized. The growth in average interest-earning assets mainly consisted of a $2.0 billion increase in average interest-bearing cash and deposits with banks, a $785.7 million increase in average available-for-sale (“AFS”) debt securities, and a $337.9 million increase in average loans. Excluding Paycheck Protection Program (“PPP”) loans, average loans grew by $1.1 billion.
•Record Loans – Total loans reached $40.5 billion as of September 30, 2021, up by $408.4 million, or 4% annualized, from $40.1 billion as of June 30, 2021. Excluding PPP loans, total loans grew by $1.0 billion, or 11% linked quarter annualized. During the third quarter of 2021, $645.0 million of PPP loans outstanding were forgiven by the Small Business Administration (“SBA”). PPP loans totaled $807.3 million as of September 30, 2021. Year-over-year, total loans, excluding PPP, grew 11% from $35.7 billion as of September 30, 2020.
Third quarter 2021 average loans of $40.0 billion grew by $337.9 million, or 3% linked quarter annualized. Excluding PPP loans, average loans grew by $1.1 billion, or 12% annualized, from the second quarter of 2021. The strongest growth was from average C&I loans excluding PPP, which increased 16% linked quarter annualized, followed by residential mortgage loans, which also increased 16% linked quarter annualized. Average total CRE loans grew by 5% linked quarter annualized.
•Record Deposits – Total deposits reached $53.4 billion as of September 30, 2021, up by $773.6 million, or 6% annualized, from $52.6 billion as of June 30, 2021, and up 28% year-over-year from $41.7 billion as of September 30, 2020. Noninterest-bearing demand deposits reached a record $23.2 billion as of September 30, 2021, up by $1.4 billion, or 25% annualized, from $21.8 billion as of June 30, 2021, and up 55% year-over-year from $14.9 billion as of September 30, 2020. Noninterest-bearing demand deposits made up 43% of total deposits as of September 30, 2021, up from 41% as of June 30, 2021 and 36% as of September 30, 2020.
Third quarter 2021 average deposits of $53.5 billion grew by $3.3 billion, or 26% linked quarter annualized. Growth in the third quarter was led by noninterest-bearing demand deposits, which increased by $3.5 billion or 69% linked quarter annualized. Time deposits decreased quarter-over-quarter, reflecting run-off of higher rate certificates of deposit.
•Strong Capital Levels – As of September 30, 2021, stockholders’ equity was $5.7 billion, or $40.10 per common share, and tangible equity3 per common share was $36.75. Tangible equity per common share increased by 3% quarter-over-quarter and increased by 12% year-over-year. As of September 30, 2021, the tangible equity to tangible assets ratio3 was 8.62%, the common equity tier 1 (“CET1”) capital ratio was 12.8%, and the total risk-based capital ratio was 14.2%.
3 See reconciliation of GAAP to non-GAAP financial measures in Table 13. | |||||||||||
2
OPERATING RESULTS
Third Quarter Earnings – Third quarter 2021 net income was $225.4 million, or $1.57 per diluted share, compared with $224.7 million, or $1.57 per diluted share, for the second quarter of 2021.
Third Quarter 2021 Compared to Second Quarter 2021
Net Interest Income and Net Interest Margin
Net interest income (“NII”) totaled $395.7 million, an increase of 20% annualized from $376.5 million. Net interest margin (“NIM”) of 2.70% decreased by five basis points from 2.75%.
•Excluding the impact of PPP loans, adjusted NII4 totaled $380.5 million, an increase of 21% annualized from $361.1 million. PPP loans contributed $15.2 million to NII in the third quarter, compared with $15.4 million in the second quarter.
•NII growth reflected growth in average balances of loans, securities and other earning assets, as well as the benefit of a lower cost of funds, partially offset by lower yields on earning assets.
•Adjusted NIM4 of 2.64% declined by nine basis points from 2.73%. The quarter-over-quarter adjusted NIM compression was largely due to the $2.0 billion growth in average interest-bearing cash and deposits with banks, which earned an average yield of 0.25% in the third quarter. Strong deposit growth in excess of loan growth drove the increase in these assets.
•The third quarter adjusted average loan yield4 of 3.56% was two basis points lower than 3.58% for the second quarter.
•The average cost of funds of 0.14% decreased by four basis points from 0.18%. This reflected growth in noninterest-bearing demand deposits, the payoff of higher-cost FHLB advances that matured during the second quarter, and a continued decline in the cost of interest-bearing deposits.
Noninterest Income
Noninterest income totaled $73.1 million in the third quarter, up $4.7 million, or 7%, from $68.4 million in the second quarter.
•Quarter-over-quarter, deposit account fees grew, due to growth in treasury management services, and gains on sale of SBA loans increased, due to a higher volume of SBA 7A loans sold. This was offset by decreases in lending fees and wealth management fees.
•Interest rate contracts (“IRC”) and other derivative income was $7.2 million in the third quarter, compared to a loss of $3.2 million in the second quarter. The quarter-over-quarter increase was due to a favorable change in credit valuation adjustment, which reflected an increase in long-term benchmark interest rates, as well as higher customer-driven IRC revenue.
4 See reconciliation of GAAP to non-GAAP financial measures in Table 14. | |||||||||||
3
Noninterest Expense
Noninterest expense totaled $205.4 million. Third quarter noninterest expense consisted of $166.7 million of adjusted noninterest expense5, $38.0 million in amortization of tax credit and other investments, and $0.7 million in amortization of core deposit intangibles.
•Adjusted noninterest expense of $166.7 million increased by 3% from $161.5 million in the second quarter. The largest quarter-over-quarter change was in other operating expense, which increased to $21.0 million, compared with $17.9 million in the second quarter, due to higher loan-related expenses and charitable contributions.
•Amortization of tax credit and other investments totaled $38.0 million, compared with $27.3 million in the second quarter. The quarter-over-quarter change in the amortization of tax credits and other investments partially reflects the impact of investments that closed in the third quarter. For the fourth quarter, the Company expects the amortization of tax credit and other investments to be approximately $30 million.
•The adjusted efficiency ratio5 was 35.6% in the third quarter, compared with 36.3% in the second quarter.
TAX RELATED ITEMS
Third quarter 2021 income tax expense was $48.0 million and the effective tax rate was 17.5%. Year-to-date through the third quarter of 2021, the effective tax rate was 16%. For the full year, the Company expects the effective tax rate to be approximately 17%.
ASSET QUALITY
Quarter-over-quarter, nonperforming assets decreased by 24%, to 0.28% of total assets, and criticized loans were down 2%, to 2.50% of loans held-for-investment (“HFI”). The allowance for loan losses (“ALLL”) totaled $560.4 million, or 1.38% of loans HFI, as of September 30, 2021, compared with $585.7 million, or 1.46% of loans HFI, as of June 30, 2021.
1
•Quarter-over-quarter, the ALLL decreased by $25.3 million, and the ALLL coverage ratio of loans HFI decreased by eight basis points. The change in the ALLL largely reflects an improved macroeconomic forecast as of September 30, 2021, compared with June 30, 2021. Consequently, the Company recorded a negative $10.0 million provision for credit losses during the third quarter of 2021.
•Third quarter 2021 net charge-offs were $13.5 million, or annualized 0.13% of average loans HFI, essentially unchanged from $13.3 million, or annualized 0.13% of average loans HFI, for the second quarter of 2021.
•Quarter-over-quarter, nonperforming assets decreased by $53.1 million, or 24%, and the nonperforming asset ratio improved by 10 basis points. As of September 30, 2021, nonperforming assets were $172.6 million, or 0.28% of total assets, compared with $225.7 million, or 0.38% of total assets, as of June 30, 2021.
•Quarter-over-quarter, criticized loans decreased by $21.7 million, or 2%, and the criticized loans ratio improved by eight basis points. As of September 30, 2021, criticized loans totaled $1,010 million, or 2.50% of loans HFI, compared with $1,032 million, or 2.58% of loans HFI, as of June 30, 2021.
5 See reconciliation of GAAP to non-GAAP financial measures in Table 12. | |||||||||||
4
CAPITAL STRENGTH
Capital levels for East West are strong. The following table presents the regulatory capital ratios as of September 30, 2021, June 30, 2021, and September 30, 2020.
| EWBC Risk-Based Capital Ratios | ||||||||||||||||||||||||||
| ($ in millions) | September 30, 2021 (a) | June 30, 2021 (a) | September 30, 2020 (a) | |||||||||||||||||||||||
| CET1 capital ratio | 12.8% | 12.8% | 12.8% | |||||||||||||||||||||||
| Tier 1 capital ratio | 12.8% | 12.8% | 12.8% | |||||||||||||||||||||||
| Total capital ratio | 14.2% | 14.3% | 14.5% | |||||||||||||||||||||||
| Leverage ratio | 8.8% | 9.1% | 9.8% | |||||||||||||||||||||||
Risk-Weighted Assets (“RWA”) (b) | $42,128 | $40,609 | $36,922 | |||||||||||||||||||||||
(a)The Company has elected to use the 2020 CECL transition provision in the calculation of its September 30, 2021, June 30, 2021 and September 30, 2020 regulatory capital ratios. The Company’s September 30, 2021 regulatory capital ratios and RWA are preliminary.
(b)Under regulatory guidelines, on-balance sheet assets and credit equivalent amounts of derivatives and off-balance sheet items are assigned to one of several broad risk categories based on the nature of the obligor, or, if relevant, the guarantor or the nature of any collateral. The aggregate dollar value in each risk category is then multiplied by the risk weight associated with that category. The resulting weighted values from each of the risk categories are aggregated for determining total RWA.
DIVIDEND PAYOUT AND CAPITAL ACTIONS
East West’s Board of Directors has declared fourth quarter 2021 dividends for the Company’s common stock. The common stock cash dividend of $0.33 per share is payable on November 15, 2021, to stockholders of record on November 1, 2021.
On March 3, 2020, East West’s Board of Directors authorized the repurchase of up to $500 million of East West’s common stock. East West did not repurchase any shares during the third quarter of 2021, and has not repurchased any shares since the first quarter of 2020, under this authorization.
Conference Call
East West will host a conference call to discuss third quarter 2021 earnings with the public on Thursday, October 21, 2021 at 8:30 a.m. PT/11:30 a.m. ET. The public and investment community are invited to listen as management discusses third quarter 2021 results and operating developments.
•The following dial-in information is provided for participation in the conference call: calls within the U.S. – (877) 506-6399; calls within Canada – (855) 669-9657; international calls – (412) 902-6699.
•A presentation to accompany the earnings call will be available on the Investor Relations page of the Company’s website at www.eastwestbank.com/investors.
•A listen-only live broadcast of the call will also be available on the Investor Relations page of the Company’s website at www.eastwestbank.com/investors.
•A replay of the conference call will be available on October 21, 2021 at 11:30 a.m. PT through November 21, 2021. The replay numbers are: within the U.S. – (877) 344-7529; within Canada – (855) 669-9658; international calls – (412) 317-0088; and the replay access code is: 10160606.
5
About East West
East West Bancorp, Inc. is a public company with total assets of $61.0 billion and is traded on the Nasdaq Global Select Market under the symbol “EWBC”. The Company’s wholly owned subsidiary, East West Bank, is one of the largest independent banks headquartered in California, operating over 120 locations in the United States and in China. The Company’s markets in the United States include California, Georgia, Massachusetts, Nevada, New York, Texas and Washington. In China, East West’s presence includes full service branches in Hong Kong, Shanghai, Shantou and Shenzhen, and representative offices in Beijing, Chongqing, Guangzhou, and Xiamen. For more information on East West, visit the Company’s website at www.eastwestbank.com.
Forward-Looking Statements
Certain matters set forth herein (including any exhibits hereto) contain forward-looking statements that are intended to be covered by the safe harbor for such statements provided by the Private Securities Litigation Reform Act of 1995. In addition, the Company may make forward-looking statements in other documents that it files with, or furnishes to, the U.S. Securities and Exchange Commission (the “SEC”) and management may make forward-looking statements to analysts, investors, media members and others. Forward-looking statements are statements that are not historical facts, and are based on current expectations, estimates and projections about the Company’s industry, management’s beliefs and certain assumptions made by management, many of which, by their nature, are inherently uncertain and beyond the Company’s control, such as the future impacts of the COVID-19 pandemic. These statements relate to the Company’s financial condition, results of operations, plans, objectives, future performance and/or business. They usually can be identified by the use of forward-looking language, such as “likely result in,” “expects,” “anticipates,” “estimates,” “forecasts,” “projects,” “intends to,” “assumes,” “believes,” “plans,” “trend,” “objective,” “continues,” “remains,” “will,” “would,” “should,” “could,” “may,” “might,” “can,” or similar expressions, and the negative thereof. You should not place undue reliance on these statements, as they are subject to risks and uncertainties, including, but not limited to, those described in the documents incorporated by reference. When considering these forward-looking statements, you should keep in mind these risks and uncertainties, as well as any cautionary statements the Company may make. Moreover, you should treat these statements as speaking only as of the date they are made and based only on information then actually known to the Company.
There are a number of important factors that could cause future results to differ materially from historical performance and these forward-looking statements. Factors that might cause such differences, some of which are beyond the Company’s control, include, but are not limited to: changes in the U.S. economy, including an economic slowdown, inflation, deflation, housing prices, employment levels, rate of growth and general business conditions; changes in local, regional and global business, economic and political conditions and geopolitical events; the economic, financial, reputational and other impacts of the ongoing COVID-19 global pandemic and variants thereof and any other pandemic, epidemic or health-related crisis, as well as a deterioration of asset quality and an increase in credit losses due to the COVID-19 global pandemic; changes in laws or the regulatory environment including regulatory reform initiatives and policies of the U.S. Department of Treasury, the Federal Reserve, the Federal Deposit Insurance Corporation, the Office of the Comptroller of the Currency, the SEC, the Consumer Financial Protection Bureau, and the DFPI; the changes and effects thereof in trade, monetary and fiscal policies and laws, including the ongoing trade dispute between the U.S. and the People’s Republic of China; changes in the commercial and consumer real estate markets; changes in consumer or commercial spending, and savings and borrowing habits, patterns and behaviors; fluctuations in the Company’s stock price; changes in income tax laws and regulations; the Company’s ability to compete effectively against financial institutions in its banking markets and other entities, including as a result of emerging technologies; the soundness of other financial institutions; success and timing of the Company’s business strategies; the Company’s ability to retain key officers and employees; impact on the Company’s funding costs, net interest income and net interest margin from changes in key variable market interest rates, competition, regulatory requirements and the Company’s product mix; changes in the Company’s costs of operation, compliance and expansion; the Company’s ability to adopt and successfully integrate new technologies into its business in a strategic manner; impact of the benchmark interest rate reform in the U.S. including the transition away from USD LIBOR to alternative reference rates; impact of a communications or technology disruption, failure in, or breach of, the Company’s operational or security systems or infrastructure, or those of third parties with whom the Company does business, including as a result of cyber-attacks, and other similar matters which could result in, among other things, confidential and/or proprietary information being disclosed or misused and materially impact the Company’s ability to provide services to its clients; adequacy of the Company’s risk management framework, disclosure controls and procedures and internal control over financial reporting; future credit quality and performance, including the Company’s expectations regarding future credit losses and allowance levels; impact of adverse changes to the Company’s credit ratings from major credit rating agencies; impact of adverse judgments or settlements in litigation; impact on the Company’s operations due to political developments, disease pandemics, wars, civil unrest, terrorism or other hostilities that may disrupt or increase volatility in securities or otherwise affect business and economic conditions; heightened regulatory and governmental oversight and scrutiny of the Company’s business practices, including dealings with consumers; impact of reputational risk from negative publicity, fines and penalties and other negative consequences from regulatory violations, legal actions and the Company’s interactions with business partners, counterparties, service providers and other third parties; impact of regulatory enforcement actions; changes in accounting standards as may be required by the Financial Accounting Standards Board or other regulatory agencies and their impact on critical accounting policies and assumptions; impact of other potential federal tax changes and spending cuts; the Company’s capital requirements and its ability to generate capital internally or raise capital on favorable terms; impact on the Company’s liquidity due to changes in the Company’s ability to pay dividends and repurchase common stock and to receive dividends from its subsidiaries; any future strategic acquisitions or divestitures; changes in the equity and debt securities markets; fluctuations in foreign currency exchange rates; impact of increased focus on social, environmental and sustainability matters, which may affect the Company’s operations as well as those of its customers and the economy more broadly; significant turbulence or disruption in the capital or financial markets, which could result in, among other things, a reduction in the availability of funding or increases in funding costs, declines in asset values and/or recognition of allowance for credit losses on securities held in the Company’s AFS debt securities portfolio; and impact of climate change, natural or man-made disasters or calamities, such as wildfires, droughts and earthquakes, all of which are particularly common in California, or other events that may directly or indirectly result in a negative impact on the Company’s financial performance.
For a more detailed discussion of some of the factors that might cause such differences, see the Company’s 2020 Form 10-K under the heading Item 1A. Risk Factors and the information set forth under Item 1A. Risk Factors in the Company’s Quarterly Reports on Form 10-Q. The Company does not undertake, and specifically disclaims any obligation to update or revise any forward-looking statements to reflect the occurrence of events or circumstances after the date of such statements except as required by law.
6
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | ||||||||||||||||||||||||||||||||||||||
| CONDENSED CONSOLIDATED BALANCE SHEET | ||||||||||||||||||||||||||||||||||||||
| ($ and shares in thousands, except per share data) | ||||||||||||||||||||||||||||||||||||||
| (unaudited) | ||||||||||||||||||||||||||||||||||||||
| Table 1 | ||||||||||||||||||||||||||||||||||||||
| September 30, 2021 % or Basis Point Change | ||||||||||||||||||||||||||||||||||||||
| September 30, 2021 | June 30, 2021 | September 30, 2020 | Qtr-o-Qtr | Yr-o-Yr | ||||||||||||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | $ | 594,631 | $ | 626,716 | $ | 503,376 | (5.1) | % | 18.1 | % | ||||||||||||||||||||||||||||
| Interest-bearing cash with banks | 4,258,270 | 5,371,089 | 4,003,565 | (20.7) | 6.4 | |||||||||||||||||||||||||||||||||
| Cash and cash equivalents | 4,852,901 | 5,997,805 | 4,506,941 | (19.1) | 7.7 | |||||||||||||||||||||||||||||||||
| Interest-bearing deposits with banks | 855,162 | 830,279 | 699,465 | 3.0 | 22.3 | |||||||||||||||||||||||||||||||||
| Assets purchased under resale agreements (“resale agreements”) | 2,596,142 | 2,299,184 | 1,210,000 | 12.9 | 114.6 | |||||||||||||||||||||||||||||||||
| Available-for-sale (“AFS”) debt securities (amortized cost of $9,783,180, $8,411,142 and $4,471,694) | 9,713,006 | 8,399,460 | 4,539,160 | 15.6 | 114.0 | |||||||||||||||||||||||||||||||||
Federal Home Loan Bank (“FHLB”) and Federal Reserve Bank (“FRB”) stock | 77,200 | 76,931 | 79,172 | 0.3 | (2.5) | |||||||||||||||||||||||||||||||||
| Loans held-for-sale (“HFS”) | — | 1,819 | 4,148 | (100.0) | (100.0) | |||||||||||||||||||||||||||||||||
| Loans held-for-investment (''HFI'') (net of allowance for loan losses of $560,404, $585,724 and $618,252) | 39,921,301 | 39,485,775 | 36,818,877 | 1.1 | 8.4 | |||||||||||||||||||||||||||||||||
Investments in qualified affordable housing partnerships, net | 297,367 | 287,432 | 192,913 | 3.5 | 54.1 | |||||||||||||||||||||||||||||||||
Investments in tax credit and other investments, net | 367,428 | 364,187 | 254,512 | 0.9 | 44.4 | |||||||||||||||||||||||||||||||||
| Goodwill | 465,697 | 465,697 | 465,697 | — | — | |||||||||||||||||||||||||||||||||
| Operating lease right-of-use assets | 99,785 | 102,609 | 96,092 | (2.8) | 3.8 | |||||||||||||||||||||||||||||||||
| Other assets | 1,713,121 | 1,543,698 | 1,504,500 | 11.0 | 13.9 | |||||||||||||||||||||||||||||||||
| Total assets | $ | 60,959,110 | $ | 59,854,876 | $ | 50,371,477 | 1.8 | % | 21.0 | % | ||||||||||||||||||||||||||||
| Liabilities and Stockholders’ Equity | ||||||||||||||||||||||||||||||||||||||
| Deposits | $ | 53,356,190 | $ | 52,582,575 | $ | 41,680,555 | 1.5 | % | 28.0 | % | ||||||||||||||||||||||||||||
| Short-term borrowings | — | — | 59,613 | — | (100.0) | |||||||||||||||||||||||||||||||||
| FHLB advances | 248,898 | 248,464 | 657,185 | 0.2 | (62.1) | |||||||||||||||||||||||||||||||||
| Assets sold under repurchase agreements (“repurchase agreements”) | 300,000 | 300,000 | 348,063 | — | (13.8) | |||||||||||||||||||||||||||||||||
| Long-term debt and finance lease liabilities | 151,795 | 151,997 | 1,579,317 | (1) | (0.1) | (90.4) | ||||||||||||||||||||||||||||||||
| Operating lease liabilities | 107,107 | 110,105 | 103,673 | (2.7) | 3.3 | |||||||||||||||||||||||||||||||||
| Accrued expenses and other liabilities | 1,104,919 | 914,187 | 816,965 | 20.9 | 35.2 | |||||||||||||||||||||||||||||||||
| Total liabilities | 55,268,909 | 54,307,328 | 45,245,371 | 1.8 | 22.2 | |||||||||||||||||||||||||||||||||
| Stockholders’ equity | 5,690,201 | 5,547,548 | 5,126,106 | 2.6 | 11.0 | |||||||||||||||||||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 60,959,110 | $ | 59,854,876 | $ | 50,371,477 | 1.8 | % | 21.0 | % | ||||||||||||||||||||||||||||
| Book value per common share | $ | 40.10 | $ | 39.10 | $ | 36.22 | 2.6 | % | 10.7 | % | ||||||||||||||||||||||||||||
Tangible equity (2) per common share | $ | 36.75 | $ | 35.75 | $ | 32.85 | 2.8 | 11.9 | ||||||||||||||||||||||||||||||
| Number of common shares at period-end | 141,884 | 141,878 | 141,507 | 0.0 | 0.3 | |||||||||||||||||||||||||||||||||
Tangible equity to tangible assets ratio (2) | 8.62 | % | 8.54 | % | 9.32 | % | 8 | bps | (70) | bps | ||||||||||||||||||||||||||||
(1)Includes $1.43 billion of advances from the Federal Reserve Paycheck Protection Program Liquidity Facility (“PPPLF”) as of September 30, 2020.
(2)See reconciliation of GAAP to non-GAAP financial measures in Table 13.
7
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||
| TOTAL LOANS AND DEPOSITS DETAIL | |||||||||||||||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||
| Table 2 | |||||||||||||||||||||||||||||||||||
| September 30, 2021 % Change | |||||||||||||||||||||||||||||||||||
| September 30, 2021 | June 30, 2021 | September 30, 2020 | Qtr-o-Qtr | Yr-o-Yr | |||||||||||||||||||||||||||||||
| Loans: | |||||||||||||||||||||||||||||||||||
Commercial: | |||||||||||||||||||||||||||||||||||
Commercial and industrial (“C&I”) (1) | $ | 13,831,649 | $ | 13,790,461 | $ | 13,305,024 | 0.3 | % | 4.0 | % | |||||||||||||||||||||||||
Commercial real estate (“CRE”): | |||||||||||||||||||||||||||||||||||
CRE | 11,818,065 | 11,711,369 | 11,037,987 | 0.9 | 7.1 | ||||||||||||||||||||||||||||||
Multifamily residential | 3,340,378 | 3,219,796 | 3,057,274 | 3.7 | 9.3 | ||||||||||||||||||||||||||||||
Construction and land | 376,921 | 460,678 | 578,407 | (18.2) | (34.8) | ||||||||||||||||||||||||||||||
Total CRE | 15,535,364 | 15,391,843 | 14,673,668 | 0.9 | 5.9 | ||||||||||||||||||||||||||||||
Consumer: | |||||||||||||||||||||||||||||||||||
Residential mortgage: | |||||||||||||||||||||||||||||||||||
Single-family residential | 9,021,801 | 8,869,370 | 7,785,759 | 1.7 | 15.9 | ||||||||||||||||||||||||||||||
| Home equity lines of credit (“HELOCs”) | 1,963,622 | 1,872,166 | 1,514,388 | 4.9 | 29.7 | ||||||||||||||||||||||||||||||
Total residential mortgage | 10,985,423 | 10,741,536 | 9,300,147 | 2.3 | 18.1 | ||||||||||||||||||||||||||||||
Other consumer | 129,269 | 147,659 | 158,290 | (12.5) | (18.3) | ||||||||||||||||||||||||||||||
Total loans HFI (2) | 40,481,705 | 40,071,499 | 37,437,129 | 1.0 | 8.1 | ||||||||||||||||||||||||||||||
Loans HFS | — | 1,819 | 4,148 | (100.0) | (100.0) | ||||||||||||||||||||||||||||||
Total loans (2) | 40,481,705 | 40,073,318 | 37,441,277 | 1.0 | 8.1 | ||||||||||||||||||||||||||||||
| Allowance for loan losses | (560,404) | (585,724) | (618,252) | (4.3) | (9.4) | ||||||||||||||||||||||||||||||
Net loans (2) | $ | 39,921,301 | $ | 39,487,594 | $ | 36,823,025 | 1.1 | 8.4 | |||||||||||||||||||||||||||
Deposits: | |||||||||||||||||||||||||||||||||||
Noninterest-bearing demand | $ | 23,175,471 | $ | 21,816,721 | $ | 14,924,917 | 6.2 | % | 55.3 | % | |||||||||||||||||||||||||
Interest-bearing checking | 6,530,601 | 6,762,178 | 5,731,573 | (3.4) | 13.9 | ||||||||||||||||||||||||||||||
Money market | 12,555,879 | 12,853,812 | 9,553,574 | (2.3) | 31.4 | ||||||||||||||||||||||||||||||
Savings | 2,855,597 | 2,719,106 | 2,401,318 | 5.0 | 18.9 | ||||||||||||||||||||||||||||||
Time deposits | 8,238,642 | 8,430,758 | 9,069,173 | (2.3) | (9.2) | ||||||||||||||||||||||||||||||
Total deposits | $ | 53,356,190 | $ | 52,582,575 | $ | 41,680,555 | 1.5 | % | 28.0 | % | |||||||||||||||||||||||||
(1)Includes $807.3 million, $1.43 billion and $1.77 billion of Paycheck Protection Program (“PPP”) loans as of September 30, 2021, June 30, 2021 and September 30, 2020, respectively.
(2)Includes net deferred loan fees, unearned fees, unamortized premiums and unaccreted discounts of $(54.3) million, $(67.0) million and $(67.0) million as of September 30, 2021, June 30, 2021 and September 30, 2020, respectively. Net origination fees related to PPP loans were $(13.5) million, $(25.9) million and $(22.6) million as of September 30, 2021, June 30, 2021 and September 30, 2020, respectively.
8
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||
| CONDENSED CONSOLIDATED STATEMENT OF INCOME | |||||||||||||||||||||||||||||||||||
| ($ and shares in thousands, except per share data) | |||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||
| Table 3 | |||||||||||||||||||||||||||||||||||
| Three Months Ended | September 30, 2021 % Change | ||||||||||||||||||||||||||||||||||
| September 30, 2021 | June 30, 2021 | September 30, 2020 | Qtr-o-Qtr | Yr-o-Yr | |||||||||||||||||||||||||||||||
Interest and dividend income (1) | $ | 415,307 | $ | 399,333 | $ | 365,728 | 4.0 | % | 13.6 | % | |||||||||||||||||||||||||
Interest expense | 19,601 | 22,860 | 41,598 | (14.3) | (52.9) | ||||||||||||||||||||||||||||||
Net interest income before provision for credit losses | 395,706 | 376,473 | 324,130 | 5.1 | 22.1 | ||||||||||||||||||||||||||||||
| (Reversal of) provision for credit losses | (10,000) | (15,000) | 10,000 | (33.3) | NM | ||||||||||||||||||||||||||||||
Net interest income after provision for credit losses | 405,706 | 391,473 | 314,130 | 3.6 | 29.2 | ||||||||||||||||||||||||||||||
| Noninterest income | 73,109 | 68,431 | 54,503 | (2) | 6.8 | 34.1 | |||||||||||||||||||||||||||||
| Noninterest expense | 205,384 | 189,523 | 172,573 | (2) | 8.4 | 19.0 | |||||||||||||||||||||||||||||
Income before income taxes | 273,431 | 270,381 | 196,060 | 1.1 | 39.5 | ||||||||||||||||||||||||||||||
Income tax expense | 47,982 | 45,639 | 36,523 | 5.1 | 31.4 | ||||||||||||||||||||||||||||||
Net income | $ | 225,449 | $ | 224,742 | $ | 159,537 | 0.3 | % | 41.3 | % | |||||||||||||||||||||||||
Earnings per share (“EPS”) | |||||||||||||||||||||||||||||||||||
- Basic | $ | 1.59 | $ | 1.58 | $ | 1.13 | 0.3 | % | 40.9 | % | |||||||||||||||||||||||||
- Diluted | $ | 1.57 | $ | 1.57 | $ | 1.12 | 0.2 | 40.2 | |||||||||||||||||||||||||||
Weighted-average number of shares outstanding | |||||||||||||||||||||||||||||||||||
- Basic | 141,880 | 141,868 | 141,498 | 0.0 | % | 0.3 | % | ||||||||||||||||||||||||||||
- Diluted | 143,143 | 143,040 | 142,043 | 0.1 | 0.8 | ||||||||||||||||||||||||||||||
| Three Months Ended | September 30, 2021 % Change | ||||||||||||||||||||||||||||||||||
| September 30, 2021 | June 30, 2021 | September 30, 2020 | Qtr-o-Qtr | Yr-o-Yr | |||||||||||||||||||||||||||||||
Noninterest income: | |||||||||||||||||||||||||||||||||||
Lending fees | $ | 17,516 | $ | 21,092 | $ | 18,736 | (17.0) | % | (6.5) | % | |||||||||||||||||||||||||
| Deposit account fees | 18,508 | 17,342 | 12,573 | 6.7 | 47.2 | ||||||||||||||||||||||||||||||
| Interest rate contracts and other derivative income (loss) | 7,156 | (3,172) | 5,538 | (325.6) | 29.2 | ||||||||||||||||||||||||||||||
Foreign exchange income | 13,101 | 13,007 | 3,310 | 0.7 | 295.8 | ||||||||||||||||||||||||||||||
Wealth management fees | 5,598 | 7,951 | 4,553 | (29.6) | 23.0 | ||||||||||||||||||||||||||||||
Net gains on sales of loans | 3,329 | 1,491 | 361 | 123.3 | 822.2 | ||||||||||||||||||||||||||||||
Gains on sales of AFS debt securities | 354 | 632 | 698 | (44.0) | (49.3) | ||||||||||||||||||||||||||||||
| Other investment income | 5,349 | 7,596 | 5,239 | (2) | (29.6) | 2.1 | |||||||||||||||||||||||||||||
Other income | 2,198 | 2,492 | 3,495 | (11.8) | (37.1) | ||||||||||||||||||||||||||||||
| Total noninterest income | $ | 73,109 | $ | 68,431 | $ | 54,503 | (2) | 6.8 | % | 34.1 | % | ||||||||||||||||||||||||
Noninterest expense: | |||||||||||||||||||||||||||||||||||
Compensation and employee benefits | $ | 105,751 | $ | 105,426 | $ | 99,756 | 0.3 | % | 6.0 | % | |||||||||||||||||||||||||
Occupancy and equipment expense | 15,851 | 15,377 | 16,648 | 3.1 | (4.8) | ||||||||||||||||||||||||||||||
Deposit insurance premiums and regulatory assessments | 4,641 | 4,274 | 4,006 | 8.6 | 15.9 | ||||||||||||||||||||||||||||||
| Deposit account expense | 4,136 | 3,817 | 3,113 | 8.4 | 32.9 | ||||||||||||||||||||||||||||||
| Data processing | 3,575 | 4,035 | 3,590 | (11.4) | (0.4) | ||||||||||||||||||||||||||||||
| Computer software expense | 8,426 | 7,521 | 8,539 | 12.0 | (1.3) | ||||||||||||||||||||||||||||||
| Consulting expense | 1,635 | 1,868 | 1,224 | (12.5) | 33.6 | ||||||||||||||||||||||||||||||
Legal expense | 2,363 | 1,975 | 1,366 | 19.6 | 73.0 | ||||||||||||||||||||||||||||||
Other operating expense | 20,998 | 17,939 | 17,122 | 17.1 | 22.6 | ||||||||||||||||||||||||||||||
| Amortization of tax credit and other investments | 38,008 | 27,291 | 17,209 | (2) | 39.3 | 120.9 | |||||||||||||||||||||||||||||
| Total noninterest expense | $ | 205,384 | $ | 189,523 | $ | 172,573 | (2) | 8.4 | % | 19.0 | % | ||||||||||||||||||||||||
NM - Not meaningful.
(1)Includes $15.2 million, $15.4 million and $7.8 million of interest income related to PPP loans for the three months ended September 30, 2021, June 30, 2021 and September 30, 2020, respectively.
(2)Starting fourth quarter of 2020, the Company reclassified certain income/losses from equity method investments from Amortization of tax credit and other investments to Other investment income, with no effect on net income. September 30, 2020 comparative amounts have been revised to conform with the current presentation.
9
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||
| CONDENSED CONSOLIDATED STATEMENT OF INCOME | |||||||||||||||||||||||
| ($ and shares in thousands, except per share data) | |||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||
| Table 4 | |||||||||||||||||||||||
| Nine Months Ended | September 30, 2021 % Change | ||||||||||||||||||||||
| September 30, 2021 | September 30, 2020 | Yr-o-Yr | |||||||||||||||||||||
Interest and dividend income (1) | $ | 1,196,026 | $ | 1,213,694 | (1.5)% | ||||||||||||||||||
Interest expense | 70,152 | 183,082 | (61.7) | ||||||||||||||||||||
Net interest income before provision for credit losses | 1,125,874 | 1,030,612 | 9.2 | ||||||||||||||||||||
| (Reversal of ) provision for credit losses | (25,000) | 186,313 | (113.4) | ||||||||||||||||||||
Net interest income after provision for credit losses | 1,150,874 | 844,299 | 36.3 | ||||||||||||||||||||
| Noninterest income | 214,406 | 165,715 | (2) | 29.4 | |||||||||||||||||||
| Noninterest expense | 585,984 | 537,671 | (2) | 9.0 | |||||||||||||||||||
Income before income taxes | 779,296 | 472,343 | 65.0 | ||||||||||||||||||||
Income tax expense | 124,111 | 68,630 | 80.8 | ||||||||||||||||||||
Net income | $ | 655,185 | $ | 403,713 | 62.3% | ||||||||||||||||||
EPS | |||||||||||||||||||||||
- Basic | $ | 4.62 | $ | 2.83 | 63.2% | ||||||||||||||||||
- Diluted | $ | 4.58 | $ | 2.82 | 62.3 | ||||||||||||||||||
Weighted-average number of shares outstanding | |||||||||||||||||||||||
- Basic | 141,799 | 142,595 | (0.6)% | ||||||||||||||||||||
- Diluted | 143,051 | 143,082 | (0.0) | ||||||||||||||||||||
| Nine Months Ended | September 30, 2021 % Change | ||||||||||||||||||||||
| September 30, 2021 | September 30, 2020 | Yr-o-Yr | |||||||||||||||||||||
Noninterest income: | |||||||||||||||||||||||
Lending fees | $ | 56,965 | $ | 56,455 | 0.9% | ||||||||||||||||||
Deposit account fees | 51,233 | 33,892 | 51.2 | ||||||||||||||||||||
| Interest rate contracts and other derivative income | 20,981 | 18,718 | 12.1 | ||||||||||||||||||||
Foreign exchange income | 35,634 | 15,691 | 127.1 | ||||||||||||||||||||
Wealth management fees | 20,460 | 12,997 | 57.4 | ||||||||||||||||||||
Net gains on sales of loans | 6,601 | 1,443 | 357.4 | ||||||||||||||||||||
| Gains on sales of AFS debt securities | 1,178 | 11,867 | (90.1) | ||||||||||||||||||||
| Other investment income | 13,870 | 6,652 | (2) | 108.5 | |||||||||||||||||||
Other income | 7,484 | 8,000 | (6.5) | ||||||||||||||||||||
| Total noninterest income | $ | 214,406 | $ | 165,715 | (2) | 29.4% | |||||||||||||||||
Noninterest expense: | |||||||||||||||||||||||
Compensation and employee benefits | $ | 318,985 | $ | 298,671 | 6.8% | ||||||||||||||||||
Occupancy and equipment expense | 47,150 | 49,941 | (5.6) | ||||||||||||||||||||
Deposit insurance premiums and regulatory assessments | 12,791 | 11,133 | 14.9 | ||||||||||||||||||||
| Deposit account expense | 11,845 | 10,029 | 18.1 | ||||||||||||||||||||
Data processing | 12,088 | 11,896 | 1.6 | ||||||||||||||||||||
Computer software expense | 23,106 | 22,006 | 5.0 | ||||||||||||||||||||
Consulting expense | 4,978 | 3,854 | 29.2 | ||||||||||||||||||||
Legal expense | 5,840 | 6,093 | (4.2) | ||||||||||||||||||||
Other operating expense | 58,544 | 57,489 | 1.8 | ||||||||||||||||||||
| Amortization of tax credit and other investments | 90,657 | 57,819 | (2) | 56.8 | |||||||||||||||||||
| Repurchase agreements’ extinguishment cost | — | 8,740 | (100.0) | ||||||||||||||||||||
| Total noninterest expense | $ | 585,984 | $ | 537,671 | (2) | 9.0% | |||||||||||||||||
(1)Includes $45.6 million and $29.1 million of interest income related to PPP loans for the nine months ended September 30, 2021 and 2020, respectively.
(2)Starting fourth quarter of 2020, the Company reclassified certain income/losses from equity method investments from Amortization of tax credit and other investments to Other investment income, with no effect on net income. September 30, 2020 comparative amounts have been revised to conform with the current presentation.
10
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| SELECTED AVERAGE BALANCES | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Table 5 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | September 30, 2021 % Change | Nine Months Ended | September 30, 2021 % Change | ||||||||||||||||||||||||||||||||||||||||||||||||||
| September 30, 2021 | June 30, 2021 | September 30, 2020 | Qtr-o-Qtr | Yr-o-Yr | September 30, 2021 | September 30, 2020 | Yr-o-Yr | ||||||||||||||||||||||||||||||||||||||||||||||
Loans: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Commercial: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
C&I (1) | $ | 13,531,338 | $ | 13,811,966 | $ | 13,235,845 | (2.0)% | 2.2% | $ | 13,678,462 | $ | 12,988,486 | 5.3% | ||||||||||||||||||||||||||||||||||||||||
| CRE: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
CRE | 11,747,607 | 11,616,916 | 10,942,780 | 1.1 | 7.4 | 11,564,946 | 10,747,669 | 7.6 | |||||||||||||||||||||||||||||||||||||||||||||
Multifamily residential | 3,248,281 | 3,125,001 | 3,107,294 | 3.9 | 4.5 | 3,139,209 | 2,995,227 | 4.8 | |||||||||||||||||||||||||||||||||||||||||||||
Construction and land | 415,812 | 477,860 | 564,219 | (13.0) | (26.3) | 480,514 | 599,957 | (19.9) | |||||||||||||||||||||||||||||||||||||||||||||
Total CRE | 15,411,700 | 15,219,777 | 14,614,293 | 1.3 | 5.5 | 15,184,669 | 14,342,853 | 5.9 | |||||||||||||||||||||||||||||||||||||||||||||
Consumer: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Residential mortgage: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Single-family residential | 8,962,533 | 8,650,706 | 7,695,838 | 3.6 | 16.5 | 8,645,135 | 7,487,347 | 15.5 | |||||||||||||||||||||||||||||||||||||||||||||
HELOCs | 1,912,629 | 1,800,213 | 1,475,098 | 6.2 | 29.7 | 1,793,928 | 1,454,237 | 23.4 | |||||||||||||||||||||||||||||||||||||||||||||
Total residential mortgage | 10,875,162 | 10,450,919 | 9,170,936 | 4.1 | 18.6 | 10,439,063 | 8,941,584 | 16.7 | |||||||||||||||||||||||||||||||||||||||||||||
Other consumer | 141,951 | 139,608 | 139,371 | 1.7 | 1.9 | 139,557 | 214,936 | (35.1) | |||||||||||||||||||||||||||||||||||||||||||||
Total loans (2) | $ | 39,960,151 | $ | 39,622,270 | $ | 37,160,445 | 0.9% | 7.5% | $ | 39,441,751 | $ | 36,487,859 | 8.1% | ||||||||||||||||||||||||||||||||||||||||
Interest-earning assets | $ | 58,239,480 | $ | 54,901,209 | $ | 47,428,586 | 6.1% | 22.8% | $ | 55,350,645 | $ | 45,076,734 | 22.8% | ||||||||||||||||||||||||||||||||||||||||
Total assets | $ | 61,359,533 | $ | 57,771,837 | $ | 50,247,259 | 6.2% | 22.1% | $ | 58,263,002 | $ | 47,753,030 | 22.0% | ||||||||||||||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Noninterest-bearing demand | $ | 23,169,323 | $ | 19,717,315 | $ | 14,296,475 | 17.5% | 62.1% | $ | 20,345,370 | $ | 12,987,813 | 56.6% | ||||||||||||||||||||||||||||||||||||||||
Interest-bearing checking | 6,646,515 | 6,671,358 | 5,663,873 | (0.4) | 17.3 | 6,571,231 | 5,119,568 | 28.4 | |||||||||||||||||||||||||||||||||||||||||||||
Money market | 12,604,827 | 12,596,515 | 9,981,704 | 0.1 | 26.3 | 12,262,173 | 9,630,918 | 27.3 | |||||||||||||||||||||||||||||||||||||||||||||
Savings | 2,792,702 | 2,676,865 | 2,259,788 | 4.3 | 23.6 | 2,715,114 | 2,162,365 | 25.6 | |||||||||||||||||||||||||||||||||||||||||||||
Time deposits | 8,283,265 | 8,518,936 | 9,008,907 | (2.8) | (8.1) | 8,635,249 | 9,633,582 | (10.4) | |||||||||||||||||||||||||||||||||||||||||||||
Total deposits | $ | 53,496,632 | $ | 50,180,989 | $ | 41,210,747 | 6.6% | 29.8% | $ | 50,529,137 | $ | 39,534,246 | 27.8% | ||||||||||||||||||||||||||||||||||||||||
Interest-bearing liabilities | $ | 31,039,410 | $ | 31,394,114 | $ | 29,552,756 | (1.1)% | 5.0% | $ | 31,099,675 | $ | 28,506,736 | 9.1% | ||||||||||||||||||||||||||||||||||||||||
Stockholders’ equity | $ | 5,680,306 | $ | 5,425,952 | $ | 5,079,351 | 4.7% | 11.8% | $ | 5,482,705 | $ | 5,028,122 | 9.0% | ||||||||||||||||||||||||||||||||||||||||
(1)Includes average balances of PPP loans of $1.11 billion, $1.87 billion and $1.76 billion for the three months ended September 30, 2021, June 30, 2021 and September 30, 2020, respectively, and $1.63 billion and $1.08 billion for the nine months ended September 30, 2021 and 2020, respectively.
(2)Includes loans HFS.
11
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| QUARTER-TO-DATE AVERAGE BALANCES, YIELDS AND RATES | |||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||||||||
| Table 6 | |||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||||||||||||||
| September 30, 2021 | June 30, 2021 | ||||||||||||||||||||||||||||||||||||||||
| Average | Average | Average | Average | ||||||||||||||||||||||||||||||||||||||
| Balance | Interest | Yield/Rate (1) | Balance | Interest | Yield/Rate (1) | ||||||||||||||||||||||||||||||||||||
Assets | |||||||||||||||||||||||||||||||||||||||||
Interest-earning assets: | |||||||||||||||||||||||||||||||||||||||||
Interest-bearing cash and deposits with banks | $ | 7,036,823 | $ | 4,521 | 0.25 | % | $ | 5,072,225 | $ | 3,628 | 0.29 | % | |||||||||||||||||||||||||||||
| Resale agreements | 2,382,741 | 8,957 | 1.49 | % | 2,129,567 | 8,021 | 1.51 | % | |||||||||||||||||||||||||||||||||
AFS debt securities | 8,782,682 | 37,826 | 1.71 | % | 7,997,005 | 34,690 | 1.74 | % | |||||||||||||||||||||||||||||||||
Loans (2) | 39,960,151 | 363,503 | 3.61 | % | 39,622,270 | 352,453 | 3.57 | % | |||||||||||||||||||||||||||||||||
FHLB and FRB stock | 77,083 | 500 | 2.57 | % | 80,142 | 541 | 2.71 | % | |||||||||||||||||||||||||||||||||
Total interest-earning assets | 58,239,480 | 415,307 | 2.83 | % | 54,901,209 | 399,333 | 2.92 | % | |||||||||||||||||||||||||||||||||
Noninterest-earning assets: | |||||||||||||||||||||||||||||||||||||||||
Cash and due from banks | 627,640 | 600,053 | |||||||||||||||||||||||||||||||||||||||
| Allowance for loan losses | (584,827) | (607,523) | |||||||||||||||||||||||||||||||||||||||
Other assets | 3,077,240 | 2,878,098 | |||||||||||||||||||||||||||||||||||||||
Total assets | $ | 61,359,533 | $ | 57,771,837 | |||||||||||||||||||||||||||||||||||||
Liabilities and Stockholders’ Equity | |||||||||||||||||||||||||||||||||||||||||
Interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||||||||
Checking deposits | $ | 6,646,515 | $ | 3,186 | 0.19 | % | $ | 6,671,358 | $ | 3,777 | 0.23 | % | |||||||||||||||||||||||||||||
Money market deposits | 12,604,827 | 3,446 | 0.11 | % | 12,596,515 | 3,712 | 0.12 | % | |||||||||||||||||||||||||||||||||
Savings deposits | 2,792,702 | 1,943 | 0.28 | % | 2,676,865 | 2,078 | 0.31 | % | |||||||||||||||||||||||||||||||||
Time deposits | 8,283,265 | 7,395 | 0.35 | % | 8,518,936 | 8,431 | 0.40 | % | |||||||||||||||||||||||||||||||||
Federal funds purchased and other short-term borrowings | 620 | — | — | % | 336 | — | — | % | |||||||||||||||||||||||||||||||||
FHLB advances | 248,614 | 857 | 1.37 | % | 474,887 | 2,099 | 1.77 | % | |||||||||||||||||||||||||||||||||
| Repurchase agreements | 310,997 | 2,012 | 2.57 | % | 303,118 | 1,991 | 2.63 | % | |||||||||||||||||||||||||||||||||
Long-term debt and finance lease liabilities | 151,870 | 762 | 1.99 | % | 152,099 | 772 | 2.04 | % | |||||||||||||||||||||||||||||||||
Total interest-bearing liabilities | 31,039,410 | 19,601 | 0.25 | % | 31,394,114 | 22,860 | 0.29 | % | |||||||||||||||||||||||||||||||||
Noninterest-bearing liabilities and stockholders’ equity: | |||||||||||||||||||||||||||||||||||||||||
Demand deposits | 23,169,323 | 19,717,315 | |||||||||||||||||||||||||||||||||||||||
Accrued expenses and other liabilities | 1,470,494 | 1,234,456 | |||||||||||||||||||||||||||||||||||||||
Stockholders’ equity | 5,680,306 | 5,425,952 | |||||||||||||||||||||||||||||||||||||||
Total liabilities and stockholders’ equity | $ | 61,359,533 | $ | 57,771,837 | |||||||||||||||||||||||||||||||||||||
Interest rate spread | 2.58 | % | 2.63 | % | |||||||||||||||||||||||||||||||||||||
Net interest income and net interest margin | $ | 395,706 | 2.70 | % | $ | 376,473 | 2.75 | % | |||||||||||||||||||||||||||||||||
Adjusted net interest income and adjusted net interest margin (3) | $ | 380,494 | 2.64 | % | $ | 361,096 | 2.73 | % | |||||||||||||||||||||||||||||||||
(1)Annualized.
(2)Includes loans HFS.
(3)Net interest income and net interest margin for the three months ended September 30, 2021 and June 30, 2021 have been adjusted for the impact of PPP loans. See reconciliation of GAAP to non-GAAP financial measures in Table 14.
12
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| QUARTER-TO-DATE AVERAGE BALANCES, YIELDS AND RATES | |||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||||||||
| Table 7 | |||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||||||||||||||
| September 30, 2021 | September 30, 2020 | ||||||||||||||||||||||||||||||||||||||||
| Average | Average | Average | Average | ||||||||||||||||||||||||||||||||||||||
| Balance | Interest | Yield/Rate (1) | Balance | Interest | Yield/Rate (1) | ||||||||||||||||||||||||||||||||||||
Assets | |||||||||||||||||||||||||||||||||||||||||
Interest-earning assets: | |||||||||||||||||||||||||||||||||||||||||
Interest-bearing cash and deposits with banks | $ | 7,036,823 | $ | 4,521 | 0.25 | % | $ | 4,904,394 | $ | 5,045 | 0.41 | % | |||||||||||||||||||||||||||||
| Resale agreements | 2,382,741 | 8,957 | 1.49 | % | 1,225,217 | 5,295 | 1.72 | % | |||||||||||||||||||||||||||||||||
AFS debt securities | 8,782,682 | 37,826 | 1.71 | % | 4,059,456 | 18,493 | 1.81 | % | |||||||||||||||||||||||||||||||||
Loans (2) | 39,960,151 | 363,503 | 3.61 | % | 37,160,445 | 336,542 | 3.60 | % | |||||||||||||||||||||||||||||||||
FHLB and FRB stock | 77,083 | 500 | 2.57 | % | 79,074 | 353 | 1.78 | % | |||||||||||||||||||||||||||||||||
Total interest-earning assets | 58,239,480 | 415,307 | 2.83 | % | 47,428,586 | 365,728 | 3.07 | % | |||||||||||||||||||||||||||||||||
Noninterest-earning assets: | |||||||||||||||||||||||||||||||||||||||||
Cash and due from banks | 627,640 | 522,699 | |||||||||||||||||||||||||||||||||||||||
| Allowance for loan losses | (584,827) | (632,216) | |||||||||||||||||||||||||||||||||||||||
Other assets | 3,077,240 | 2,928,190 | |||||||||||||||||||||||||||||||||||||||
Total assets | $ | 61,359,533 | $ | 50,247,259 | |||||||||||||||||||||||||||||||||||||
Liabilities and Stockholders’ Equity | |||||||||||||||||||||||||||||||||||||||||
Interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||||||||
Checking deposits | $ | 6,646,515 | $ | 3,186 | 0.19 | % | $ | 5,663,873 | $ | 4,345 | 0.31 | % | |||||||||||||||||||||||||||||
Money market deposits | 12,604,827 | 3,446 | 0.11 | % | 9,981,704 | 6,837 | 0.27 | % | |||||||||||||||||||||||||||||||||
Savings deposits | 2,792,702 | 1,943 | 0.28 | % | 2,259,788 | 1,481 | 0.26 | % | |||||||||||||||||||||||||||||||||
Time deposits | 8,283,265 | 7,395 | 0.35 | % | 9,008,907 | 21,135 | 0.93 | % | |||||||||||||||||||||||||||||||||
Federal funds purchased and other short-term borrowings | 620 | — | — | % | 84,858 | 407 | 1.91 | % | |||||||||||||||||||||||||||||||||
FHLB advances | 248,614 | 857 | 1.37 | % | 656,906 | 3,146 | 1.91 | % | |||||||||||||||||||||||||||||||||
| Repurchase agreements | 310,997 | 2,012 | 2.57 | % | 317,097 | 2,155 | 2.70 | % | |||||||||||||||||||||||||||||||||
Long-term debt and finance lease liabilities | 151,870 | 762 | 1.99 | % | 1,579,623 | (3) | 2,092 | 0.53 | % | ||||||||||||||||||||||||||||||||
Total interest-bearing liabilities | 31,039,410 | 19,601 | 0.25 | % | 29,552,756 | 41,598 | 0.56 | % | |||||||||||||||||||||||||||||||||
Noninterest-bearing liabilities and stockholders’ equity: | |||||||||||||||||||||||||||||||||||||||||
Demand deposits | 23,169,323 | 14,296,475 | |||||||||||||||||||||||||||||||||||||||
Accrued expenses and other liabilities | 1,470,494 | 1,318,677 | |||||||||||||||||||||||||||||||||||||||
Stockholders’ equity | 5,680,306 | 5,079,351 | |||||||||||||||||||||||||||||||||||||||
Total liabilities and stockholders’ equity | $ | 61,359,533 | $ | 50,247,259 | |||||||||||||||||||||||||||||||||||||
Interest rate spread | 2.58 | % | 2.51 | % | |||||||||||||||||||||||||||||||||||||
Net interest income and net interest margin | $ | 395,706 | 2.70 | % | $ | 324,130 | 2.72 | % | |||||||||||||||||||||||||||||||||
Adjusted net interest income and adjusted net interest margin (4) | $ | 380,494 | 2.64 | % | $ | 317,611 | 2.77 | % | |||||||||||||||||||||||||||||||||
(1)Annualized.
(2)Includes loans HFS.
(3)Primarily includes average balances of PPPLF, which was repaid in full during the fourth quarter of 2020.
(4)Net interest income and net interest margin for the three months ended September 30, 2021 and September 30, 2020 have been adjusted for the impact of PPP loans. Net interest margin for the three months ended September 30, 2020 has been adjusted for advances from the PPPLF. See reconciliation of GAAP to non-GAAP financial measures in Table 14.
13
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| YEAR-TO-DATE AVERAGE BALANCES, YIELDS AND RATES | |||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||||||||
| Table 8 | |||||||||||||||||||||||||||||||||||||||||
| Nine Months Ended | |||||||||||||||||||||||||||||||||||||||||
| September 30, 2021 | September 30, 2020 | ||||||||||||||||||||||||||||||||||||||||
| Average | Average | Average | Average | ||||||||||||||||||||||||||||||||||||||
| Balance | Interest | Yield/Rate (1) | Balance | Interest | Yield/Rate (1) | ||||||||||||||||||||||||||||||||||||
Assets | |||||||||||||||||||||||||||||||||||||||||
Interest-earning assets: | |||||||||||||||||||||||||||||||||||||||||
Interest-bearing cash and deposits with banks | $ | 6,078,982 | $ | 11,781 | 0.26 | % | $ | 3,775,242 | $ | 20,717 | 0.73 | % | |||||||||||||||||||||||||||||
Resale agreements (2) | 1,994,776 | 23,077 | 1.55 | % | 1,048,923 | 16,434 | 2.09 | % | |||||||||||||||||||||||||||||||||
| AFS debt securities | 7,755,029 | 101,616 | 1.75 | % | 3,685,837 | 59,639 | 2.16 | % | |||||||||||||||||||||||||||||||||
Loans (3) | 39,441,751 | 1,057,964 | 3.59 | % | 36,487,859 | 1,115,804 | 4.08 | % | |||||||||||||||||||||||||||||||||
FHLB and FRB stock | 80,107 | 1,588 | 2.65 | % | 78,873 | 1,100 | 1.86 | % | |||||||||||||||||||||||||||||||||
Total interest-earning assets | 55,350,645 | 1,196,026 | 2.89 | % | 45,076,734 | 1,213,694 | 3.60 | % | |||||||||||||||||||||||||||||||||
Noninterest-earning assets: | |||||||||||||||||||||||||||||||||||||||||
Cash and due from banks | 602,830 | 510,750 | |||||||||||||||||||||||||||||||||||||||
Allowance for loan losses | (603,523) | (563,912) | |||||||||||||||||||||||||||||||||||||||
Other assets | 2,913,050 | 2,729,458 | |||||||||||||||||||||||||||||||||||||||
Total assets | $ | 58,263,002 | $ | 47,753,030 | |||||||||||||||||||||||||||||||||||||
Liabilities and Stockholders’ Equity | |||||||||||||||||||||||||||||||||||||||||
Interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||||||||
Checking deposits | $ | 6,571,231 | $ | 11,177 | 0.23 | % | $ | 5,119,568 | $ | 19,995 | 0.52 | % | |||||||||||||||||||||||||||||
Money market deposits | 12,262,173 | 11,869 | 0.13 | % | 9,630,918 | 37,178 | 0.52 | % | |||||||||||||||||||||||||||||||||
Savings deposits | 2,715,114 | 5,762 | 0.28 | % | 2,162,365 | 4,743 | 0.29 | % | |||||||||||||||||||||||||||||||||
Time deposits | 8,635,250 | 26,982 | 0.42 | % | 9,633,582 | 94,684 | 1.31 | % | |||||||||||||||||||||||||||||||||
Federal funds purchased and other short-term borrowings | 1,871 | 42 | 3.00 | % | 128,846 | 1,228 | 1.27 | % | |||||||||||||||||||||||||||||||||
FHLB advances | 457,273 | 6,025 | 1.76 | % | 667,935 | 10,655 | 2.13 | % | |||||||||||||||||||||||||||||||||
Repurchase agreements (2) | 304,745 | 5,981 | 2.62 | % | 355,923 | 9,686 | 3.64 | % | |||||||||||||||||||||||||||||||||
Long-term debt and finance lease liabilities | 152,018 | 2,314 | 2.04 | % | 807,599 | (4) | 4,913 | 0.81 | % | ||||||||||||||||||||||||||||||||
Total interest-bearing liabilities | 31,099,675 | 70,152 | 0.30 | % | 28,506,736 | 183,082 | 0.86 | % | |||||||||||||||||||||||||||||||||
Noninterest-bearing liabilities and stockholders’ equity: | |||||||||||||||||||||||||||||||||||||||||
Demand deposits | 20,345,370 | 12,987,813 | |||||||||||||||||||||||||||||||||||||||
Accrued expenses and other liabilities | 1,335,252 | 1,230,359 | |||||||||||||||||||||||||||||||||||||||
Stockholders’ equity | 5,482,705 | 5,028,122 | |||||||||||||||||||||||||||||||||||||||
Total liabilities and stockholders’ equity | $ | 58,263,002 | $ | 47,753,030 | |||||||||||||||||||||||||||||||||||||
Interest rate spread | 2.59 | % | 2.74 | % | |||||||||||||||||||||||||||||||||||||
Net interest income and net interest margin | $ | 1,125,874 | 2.72 | % | $ | 1,030,612 | 3.05 | % | |||||||||||||||||||||||||||||||||
Adjusted net interest income and adjusted net interest margin (5) | $ | 1,080,268 | 2.69 | % | $ | 1,003,267 | 3.05 | % | |||||||||||||||||||||||||||||||||
(1)Annualized.
(2)Average balances of resale and repurchase agreements for the nine months ended September 30, 2020 have been reported net, pursuant to ASC 210-20-45-11, Balance Sheet Offsetting: Repurchase and Reverse Repurchase Agreements. The weighted-average yields of gross resale and gross repurchase agreements for the nine months ended September 30, 2020 were 2.09% and 3.48%, respectively.
(3)Includes loans HFS.
(4)Primarily includes average balances of PPPLF, which was repaid in full during the fourth quarter of 2020.
(5)Net interest income and net interest margin for the nine months ended September 30, 2021 and September 30, 2020 have been adjusted for the impact of PPP loans. Net interest margin for the nine months ended September 30, 2020 has been adjusted for advances from the PPPLF. See reconciliation of GAAP to non-GAAP financial measures in Table 14.
14
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | ||||||||||||||||||||||||||||||||||||||
| SELECTED RATIOS | ||||||||||||||||||||||||||||||||||||||
| (unaudited) | ||||||||||||||||||||||||||||||||||||||
| Table 9 | ||||||||||||||||||||||||||||||||||||||
Three Months Ended (1) | September 30, 2021 Basis Point Change | |||||||||||||||||||||||||||||||||||||
| September 30, 2021 | June 30, 2021 | September 30, 2020 | Qtr-o-Qtr | Yr-o-Yr | ||||||||||||||||||||||||||||||||||
Return on average assets | 1.46 | % | 1.56 | % | 1.26 | % | (10) | bps | 20 | bps | ||||||||||||||||||||||||||||
Return on average equity | 15.75 | % | 16.61 | % | 12.50 | % | (86) | 325 | ||||||||||||||||||||||||||||||
Return on average tangible equity (2) | 17.25 | % | 18.28 | % | 13.88 | % | (103) | 337 | ||||||||||||||||||||||||||||||
Interest rate spread | 2.58 | % | 2.63 | % | 2.51 | % | (5) | 7 | ||||||||||||||||||||||||||||||
Net interest margin | 2.70 | % | 2.75 | % | 2.72 | % | (5) | (2) | ||||||||||||||||||||||||||||||
Adjusted net interest margin (2) | 2.64 | % | 2.73 | % | 2.77 | % | (9) | (13) | ||||||||||||||||||||||||||||||
Average loan yield | 3.61 | % | 3.57 | % | 3.60 | % | 4 | 1 | ||||||||||||||||||||||||||||||
Adjusted average loan yield (2) | 3.56 | % | 3.58 | % | 3.70 | % | (2) | (14) | ||||||||||||||||||||||||||||||
Yield on average interest-earning assets | 2.83 | % | 2.92 | % | 3.07 | % | (9) | (24) | ||||||||||||||||||||||||||||||
Average cost of interest-bearing deposits | 0.21 | % | 0.24 | % | 0.50 | % | (3) | (29) | ||||||||||||||||||||||||||||||
Average cost of deposits | 0.12 | % | 0.14 | % | 0.33 | % | (2) | (21) | ||||||||||||||||||||||||||||||
Average cost of funds | 0.14 | % | 0.18 | % | 0.38 | % | (4) | (24) | ||||||||||||||||||||||||||||||
Adjusted pre-tax, pre-provision profitability ratio (2) | 1.95 | % | 1.97 | % | 1.78 | % | (2) | 17 | ||||||||||||||||||||||||||||||
Adjusted noninterest expense/average assets (2) | 1.08 | % | 1.12 | % | 1.22 | % | (4) | (14) | ||||||||||||||||||||||||||||||
Efficiency ratio | 43.81 | % | 42.60 | % | 45.58 | % | 121 | (177) | ||||||||||||||||||||||||||||||
Adjusted efficiency ratio (2) | 35.55 | % | 36.30 | % | 40.79 | % | (75) | bps | (524) | bps | ||||||||||||||||||||||||||||
Nine Months Ended (1) | September 30, 2021 Basis Point Change | |||||||||||||||||||||||||||||||||||||
| September 30, 2021 | September 30, 2020 | Yr-o-Yr | ||||||||||||||||||||||||||||||||||||
Return on average assets | 1.50 | % | 1.13 | % | 37 | bps | ||||||||||||||||||||||||||||||||
Return on average equity | 15.98 | % | 10.73 | % | 525 | |||||||||||||||||||||||||||||||||
Return on average tangible equity (2) | 17.56 | % | 11.95 | % | 561 | |||||||||||||||||||||||||||||||||
Interest rate spread | 2.59 | % | 2.74 | % | (15) | |||||||||||||||||||||||||||||||||
Net interest margin | 2.72 | % | 3.05 | % | (33) | |||||||||||||||||||||||||||||||||
Adjusted net interest margin (2) | 2.69 | % | 3.05 | % | (36) | |||||||||||||||||||||||||||||||||
Average loan yield | 3.59 | % | 4.08 | % | (49) | |||||||||||||||||||||||||||||||||
Adjusted average loan yield (2) | 3.58 | % | 4.10 | % | (52) | |||||||||||||||||||||||||||||||||
Yield on average interest-earning assets | 2.89 | % | 3.60 | % | (71) | |||||||||||||||||||||||||||||||||
Average cost of interest-bearing deposits | 0.25 | % | 0.79 | % | (54) | |||||||||||||||||||||||||||||||||
Average cost of deposits | 0.15 | % | 0.53 | % | (38) | |||||||||||||||||||||||||||||||||
Average cost of funds | 0.18 | % | 0.59 | % | (41) | |||||||||||||||||||||||||||||||||
Adjusted pre-tax, pre-provision profitability ratio (2) | 1.94 | % | 2.04 | % | (10) | |||||||||||||||||||||||||||||||||
Adjusted noninterest expense/average assets (2) | 1.13 | % | 1.31 | % | (18) | |||||||||||||||||||||||||||||||||
Efficiency ratio | 43.72 | % | 44.94 | % | (122) | |||||||||||||||||||||||||||||||||
Adjusted efficiency ratio (2) | 36.80 | % | 39.14 | % | (234) | bps | ||||||||||||||||||||||||||||||||
(1)Annualized except for efficiency ratio.
(2)See reconciliation of GAAP to non-GAAP financial measures in Tables 12, 13 and 14.
15
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||
| ALLOWANCE FOR LOAN LOSSES & OFF-BALANCE-SHEET CREDIT EXPOSURES | |||||||||||||||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||
| Table 10 | |||||||||||||||||||||||||||||||||||
| Three Months Ended September 30, 2021 | |||||||||||||||||||||||||||||||||||
| Commercial | Consumer | ||||||||||||||||||||||||||||||||||
| C&I | Total CRE | Total Residential Mortgage | Other Consumer | Total | |||||||||||||||||||||||||||||||
| Allowance for loan losses, June 30, 2021 | $ | 362,528 | $ | 199,530 | $ | 19,468 | $ | 4,198 | $ | 585,724 | |||||||||||||||||||||||||
| (Reversal of) provision for credit losses on loans | (a) | (23,365) | 8,527 | 2,972 | 130 | (11,736) | |||||||||||||||||||||||||||||
| Gross charge-offs | (1,154) | (16,903) | (912) | (10) | (18,979) | ||||||||||||||||||||||||||||||
| Gross recoveries | 4,203 | 1,106 | 156 | — | 5,465 | ||||||||||||||||||||||||||||||
| Total net recoveries (charge-offs) | 3,049 | (15,797) | (756) | (10) | (13,514) | ||||||||||||||||||||||||||||||
| Foreign currency translation adjustment | (70) | — | — | — | (70) | ||||||||||||||||||||||||||||||
| Allowance for loan losses, September 30, 2021 | $ | 342,142 | $ | 192,260 | $ | 21,684 | $ | 4,318 | $ | 560,404 | |||||||||||||||||||||||||
| Three Months Ended June 30, 2021 | |||||||||||||||||||||||||||||||||||
| Commercial | Consumer | ||||||||||||||||||||||||||||||||||
| C&I | Total CRE | Total Residential Mortgage | Other Consumer | Total | |||||||||||||||||||||||||||||||
| Allowance for loan losses, March 31, 2021 | $ | 394,084 | $ | 192,895 | $ | 18,509 | $ | 2,018 | $ | 607,506 | |||||||||||||||||||||||||
| (Reversal of) provision for credit losses on loans | (a) | (22,586) | 10,747 | 859 | 2,209 | (8,771) | |||||||||||||||||||||||||||||
| Gross charge-offs | (10,572) | (4,456) | — | (32) | (15,060) | ||||||||||||||||||||||||||||||
| Gross recoveries | 1,338 | 344 | 100 | 3 | 1,785 | ||||||||||||||||||||||||||||||
| Total net (charge-offs) recoveries | (9,234) | (4,112) | 100 | (29) | (13,275) | ||||||||||||||||||||||||||||||
| Foreign currency translation adjustment | 264 | — | — | — | 264 | ||||||||||||||||||||||||||||||
| Allowance for loan losses, June 30, 2021 | $ | 362,528 | $ | 199,530 | $ | 19,468 | $ | 4,198 | $ | 585,724 | |||||||||||||||||||||||||
| Three Months Ended September 30, 2020 | |||||||||||||||||||||||||||||||||||
| Commercial | Consumer | ||||||||||||||||||||||||||||||||||
| C&I | Total CRE | Total Residential Mortgage | Other Consumer | Total | |||||||||||||||||||||||||||||||
| Allowance for loan losses, June 30, 2020 | $ | 380,723 | $ | 219,649 | $ | 29,181 | $ | 2,518 | $ | 632,071 | |||||||||||||||||||||||||
| Provision for (reversal of) credit losses on loans | (a) | 31,691 | (18,397) | (3,329) | (76) | 9,889 | |||||||||||||||||||||||||||||
| Gross charge-offs | (25,111) | (1,414) | — | (124) | (26,649) | ||||||||||||||||||||||||||||||
| Gross recoveries | 1,218 | 1,180 | 43 | — | 2,441 | ||||||||||||||||||||||||||||||
| Total net (charge-offs) recoveries | (23,893) | (234) | 43 | (124) | (24,208) | ||||||||||||||||||||||||||||||
| Foreign currency translation adjustment | 500 | — | — | — | 500 | ||||||||||||||||||||||||||||||
| Allowance for loan losses, September 30, 2020 | $ | 389,021 | $ | 201,018 | $ | 25,895 | $ | 2,318 | $ | 618,252 | |||||||||||||||||||||||||
16
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||
| ALLOWANCE FOR LOAN LOSSES & OFF-BALANCE-SHEET CREDIT EXPOSURES | |||||||||||||||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||
| Table 10 (continued) | |||||||||||||||||||||||||||||||||||
| Nine Months Ended September 30, 2021 | |||||||||||||||||||||||||||||||||||
| Commercial | Consumer | ||||||||||||||||||||||||||||||||||
| C&I | Total CRE | Total Residential Mortgage | Other Consumer | Total | |||||||||||||||||||||||||||||||
| Allowance for loan losses, December 31, 2020 | $ | 398,040 | $ | 201,603 | $ | 18,210 | $ | 2,130 | $ | 619,983 | |||||||||||||||||||||||||
| (Reversal of) provision for credit losses on loans | (a) | (42,112) | 16,198 | 4,229 | 2,226 | (19,459) | |||||||||||||||||||||||||||||
| Gross charge-offs | (20,162) | (28,642) | (1,091) | (43) | (49,938) | ||||||||||||||||||||||||||||||
| Gross recoveries | 6,301 | 3,101 | 336 | 5 | 9,743 | ||||||||||||||||||||||||||||||
| Total net charge-offs | (13,861) | (25,541) | (755) | (38) | (40,195) | ||||||||||||||||||||||||||||||
| Foreign currency translation adjustment | 75 | — | — | — | 75 | ||||||||||||||||||||||||||||||
| Allowance for loan losses, September 30, 2021 | $ | 342,142 | $ | 192,260 | $ | 21,684 | $ | 4,318 | $ | 560,404 | |||||||||||||||||||||||||
| Nine Months Ended September 30, 2020 | |||||||||||||||||||||||||||||||||||
| Commercial | Consumer | ||||||||||||||||||||||||||||||||||
| C&I | Total CRE | Total Residential Mortgage | Other Consumer | Total | |||||||||||||||||||||||||||||||
| Allowance for loan losses, December 31, 2019 | $ | 238,376 | $ | 82,739 | $ | 33,792 | $ | 3,380 | $ | 358,287 | |||||||||||||||||||||||||
| Impact of ASU 2016-13 adoption | 74,237 | 54,168 | (5,468) | 2,221 | 125,158 | ||||||||||||||||||||||||||||||
| Allowance for loan losses, January 1, 2020 | $ | 312,613 | $ | 136,907 | $ | 28,324 | $ | 5,601 | $ | 483,445 | |||||||||||||||||||||||||
| Provision for (reversal of) credit losses on loans | (a) | 130,171 | 54,550 | (2,679) | (3,197) | 178,845 | |||||||||||||||||||||||||||||
| Gross charge-offs | (57,466) | (2,688) | (221) | (180) | (60,555) | ||||||||||||||||||||||||||||||
| Gross recoveries | 3,395 | 12,249 | 471 | 94 | 16,209 | ||||||||||||||||||||||||||||||
| Total net (charge-offs) recoveries | (54,071) | 9,561 | 250 | (86) | (44,346) | ||||||||||||||||||||||||||||||
| Foreign currency translation adjustment | 308 | — | — | — | 308 | ||||||||||||||||||||||||||||||
| Allowance for loan losses, September 30, 2020 | $ | 389,021 | $ | 201,018 | $ | 25,895 | $ | 2,318 | $ | 618,252 | |||||||||||||||||||||||||
| Three Months Ended | Nine Months Ended | ||||||||||||||||||||||||||||||||||
| September 30, 2021 | June 30, 2021 | September 30, 2020 | September 30, 2021 | September 30, 2020 | |||||||||||||||||||||||||||||||
| Unfunded Credit Facilities | |||||||||||||||||||||||||||||||||||
Allowance for unfunded credit commitments, beginning of period (1) | $ | 26,300 | $ | 32,529 | $ | 28,972 | $ | 33,577 | $ | 11,158 | |||||||||||||||||||||||||
| Impact of ASU 2016-13 adoption | — | — | — | — | 10,457 | ||||||||||||||||||||||||||||||
| Provision for (reversal of) credit losses on unfunded credit commitments | (b) | 1,736 | (6,229) | 111 | (5,541) | 7,468 | |||||||||||||||||||||||||||||
Allowance for unfunded credit commitments, end of period (1) | $ | 28,036 | $ | 26,300 | $ | 29,083 | $ | 28,036 | $ | 29,083 | |||||||||||||||||||||||||
| (Reversal of) provision for credit losses | (a)+(b) | $ | (10,000) | $ | (15,000) | $ | 10,000 | $ | (25,000) | $ | 186,313 | ||||||||||||||||||||||||
(1)Included in Accrued expense and other liabilities on the Consolidated Balance Sheet.
17
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||
| CRITICIZED LOANS, NONPERFORMING ASSETS AND CREDIT QUALITY RATIOS | |||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||
| Table 11 | |||||||||||||||||||||||
| Criticized Loans | September 30, 2021 | June 30, 2021 | September 30, 2020 | ||||||||||||||||||||
| Special mention loans | $ | 448,497 | $ | 386,807 | $ | 722,920 | |||||||||||||||||
| Classified loans | 561,787 | 645,180 | 758,496 | ||||||||||||||||||||
| Total criticized loans | $ | 1,010,284 | $ | 1,031,987 | $ | 1,481,416 | |||||||||||||||||
Nonperforming Assets | September 30, 2021 | June 30, 2021 | September 30, 2020 | ||||||||||||||||||||
| Nonaccrual loans: | |||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||
| C&I | $ | 97,157 | $ | 83,225 | $ | 145,986 | |||||||||||||||||
| Total CRE | 15,359 | 81,573 | 59,724 | ||||||||||||||||||||
| Consumer: | |||||||||||||||||||||||
| Total residential mortgage | 18,153 | 30,489 | 28,289 | ||||||||||||||||||||
| Other consumer | 2,491 | 2,503 | 2,495 | ||||||||||||||||||||
| Total nonaccrual loans | 133,160 | 197,790 | 236,494 | ||||||||||||||||||||
| Other real estate owned, net | 28,800 | 14,914 | 19,504 | ||||||||||||||||||||
| Other nonperforming assets | 10,681 | 13,025 | 3,890 | ||||||||||||||||||||
| Total nonperforming assets | $ | 172,641 | $ | 225,729 | $ | 259,888 | |||||||||||||||||
| Credit Quality Ratios | September 30, 2021 | June 30, 2021 | September 30, 2020 | ||||||||||||||||||||
Annualized quarterly net charge-offs to average loans HFI | 0.13 | % | 0.13 | % | 0.26 | % | |||||||||||||||||
| Special mention loans to loans HFI | 1.11 | % | 0.97 | % | 1.93 | % | |||||||||||||||||
| Classified loans to loans HFI | 1.39 | % | 1.61 | % | 2.03 | % | |||||||||||||||||
| Criticized loans to loans HFI | 2.50 | % | 2.58 | % | 3.96 | % | |||||||||||||||||
| Nonperforming assets to total assets | 0.28 | % | 0.38 | % | 0.52 | % | |||||||||||||||||
| Nonaccrual loans to loans HFI | 0.33 | % | 0.49 | % | 0.63 | % | |||||||||||||||||
| Allowance for loan losses to loans HFI | 1.38 | % | 1.46 | % | 1.65 | % | |||||||||||||||||
18
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | ||||||||||||||||||||||||||
| GAAP TO NON-GAAP RECONCILIATION | ||||||||||||||||||||||||||
| ($ in thousands) | ||||||||||||||||||||||||||
| (unaudited) | ||||||||||||||||||||||||||
| Table 12 | ||||||||||||||||||||||||||
| Adjusted efficiency ratio represents adjusted noninterest expense divided by revenue. Adjusted pre-tax, pre-provision profitability ratio represents revenue less adjusted noninterest expense, divided by average total assets. Adjusted noninterest expense excludes the amortization of tax credit and other investments, the amortization of core deposit intangibles and the extinguishment cost on repurchase agreements. Management believes that the measures and ratios presented below provide clarity to financial statement users regarding the ongoing performance of the Company and allow comparability to prior periods. | ||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||
| September 30, 2021 | June 30, 2021 | September 30, 2020 | ||||||||||||||||||||||||
| Net interest income before provision for credit losses | (a) | $ | 395,706 | $ | 376,473 | $ | 324,130 | |||||||||||||||||||
Total noninterest income (1) | 73,109 | 68,431 | 54,503 | |||||||||||||||||||||||
| Total revenue | (b) | $ | 468,815 | $ | 444,904 | $ | 378,633 | |||||||||||||||||||
Total noninterest expense (1) | (c) | $ | 205,384 | $ | 189,523 | $ | 172,573 | |||||||||||||||||||
Less: Amortization of tax credit and other investments (1) | (38,008) | (27,291) | (17,209) | |||||||||||||||||||||||
| Amortization of core deposit intangibles | (705) | (710) | (927) | |||||||||||||||||||||||
| Adjusted noninterest expense | (d) | $ | 166,671 | $ | 161,522 | $ | 154,437 | |||||||||||||||||||
| Efficiency ratio | (c)/(b) | 43.81 | % | 42.60 | % | 45.58 | % | |||||||||||||||||||
| Adjusted efficiency ratio | (d)/(b) | 35.55 | % | 36.30 | % | 40.79 | % | |||||||||||||||||||
| Adjusted pre-tax, pre-provision income | (b)-(d) = (e) | $ | 302,144 | $ | 283,382 | $ | 224,196 | |||||||||||||||||||
| Average total assets | (f) | $ | 61,359,533 | $ | 57,771,837 | $ | 50,247,259 | |||||||||||||||||||
Adjusted pre-tax, pre-provision profitability ratio (2) | (e)/(f) | 1.95 | % | 1.97 | % | 1.78 | % | |||||||||||||||||||
Adjusted noninterest expense/average assets (2) | (d)/(f) | 1.08 | % | 1.12 | % | 1.22 | % | |||||||||||||||||||
| Nine Months Ended | ||||||||||||||||||||||||||
| September 30, 2021 | September 30, 2020 | |||||||||||||||||||||||||
| Net interest income before provision for credit losses | (g) | $ | 1,125,874 | $ | 1,030,612 | |||||||||||||||||||||
Total noninterest income (1) | 214,406 | 165,715 | ||||||||||||||||||||||||
| Total revenue | (h) | $ | 1,340,280 | $ | 1,196,327 | |||||||||||||||||||||
Total noninterest expense (1) | (i) | $ | 585,984 | $ | 537,671 | |||||||||||||||||||||
Less: Amortization of tax credit and other investments (1) | (90,657) | (57,819) | ||||||||||||||||||||||||
| Amortization of core deposit intangibles | (2,147) | (2,811) | ||||||||||||||||||||||||
| Repurchase agreements’ extinguishment cost | — | (8,740) | ||||||||||||||||||||||||
| Adjusted noninterest expense | (j) | $ | 493,180 | $ | 468,301 | |||||||||||||||||||||
| Efficiency ratio | (i)/(h) | 43.72 | % | 44.94 | % | |||||||||||||||||||||
| Adjusted efficiency ratio | (j)/(h) | 36.80 | % | 39.14 | % | |||||||||||||||||||||
| Adjusted pre-tax, pre-provision income | (h)-(j) = (k) | $ | 847,100 | $ | 728,026 | |||||||||||||||||||||
| Average total assets | (l) | $ | 58,263,002 | $ | 47,753,030 | |||||||||||||||||||||
Adjusted pre-tax, pre-provision profitability ratio (2) | (k)/(l) | 1.94 | % | 2.04 | % | |||||||||||||||||||||
Adjusted noninterest expense/average assets (2) | (j)/(l) | 1.13 | % | 1.31 | % | |||||||||||||||||||||
(1)Starting fourth quarter of 2020, the Company reclassified certain income/losses from equity-method investments from Amortization of tax credit and other investments to Other investment income, with no effect on net income. Prior-period amounts have been revised to conform with the current presentation.
(2)Annualized.
19
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | ||||||||||||||||||||||||||
| GAAP TO NON-GAAP RECONCILIATION | ||||||||||||||||||||||||||
| ($ in thousands) | ||||||||||||||||||||||||||
| (unaudited) | ||||||||||||||||||||||||||
| Table 13 | ||||||||||||||||||||||||||
The Company uses certain non-GAAP financial measures to provide supplemental information regarding the Company’s performance. Tangible equity and tangible equity to tangible assets ratio are non-GAAP financial measures. Tangible equity and tangible assets represent stockholders’ equity and total assets, respectively, which have been reduced by goodwill and other intangible assets. Given that the use of such measures and ratios is more prevalent in the banking industry, and such measures and ratios are used by banking regulators and analysts, the Company has included them below for discussion. | ||||||||||||||||||||||||||
| September 30, 2021 | June 30, 2021 | September 30, 2020 | ||||||||||||||||||||||||
| Stockholders’ equity | (a) | $ | 5,690,201 | $ | 5,547,548 | $ | 5,126,106 | |||||||||||||||||||
| Less: Goodwill | (465,697) | (465,697) | (465,697) | |||||||||||||||||||||||
Other intangible assets (1) | (9,849) | (10,309) | (12,369) | |||||||||||||||||||||||
| Tangible equity | (b) | $ | 5,214,655 | $ | 5,071,542 | $ | 4,648,040 | |||||||||||||||||||
| Total assets | (c) | $ | 60,959,110 | $ | 59,854,876 | $ | 50,371,477 | |||||||||||||||||||
| Less: Goodwill | (465,697) | (465,697) | (465,697) | |||||||||||||||||||||||
Other intangible assets (1) | (9,849) | (10,309) | (12,369) | |||||||||||||||||||||||
| Tangible assets | (d) | $ | 60,483,564 | $ | 59,378,870 | $ | 49,893,411 | |||||||||||||||||||
| Total stockholders’ equity to total assets ratio | (a)/(c) | 9.33 | % | 9.27 | % | 10.18 | % | |||||||||||||||||||
| Tangible equity to tangible assets ratio | (b)/(d) | 8.62 | % | 8.54 | % | 9.32 | % | |||||||||||||||||||
| Return on average tangible equity represents tangible net income divided by average tangible equity. Tangible net income excludes the after-tax impacts of the amortization of core deposit intangibles and mortgage servicing assets. Given that the use of such measures and ratios is more prevalent in the banking industry, and such measures and ratios are used by banking regulators and analysts, the Company has included them below for discussion. | ||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Nine Months Ended | |||||||||||||||||||||||||||||||||||||
| September 30, 2021 | June 30, 2021 | September 30, 2020 | September 30, 2021 | September 30, 2020 | ||||||||||||||||||||||||||||||||||
| Net Income | $ | 225,449 | $ | 224,742 | $ | 159,537 | $ | 655,185 | $ | 403,713 | ||||||||||||||||||||||||||||
Add: Amortization of core deposit intangibles | 705 | 710 | 927 | 2,147 | 2,811 | |||||||||||||||||||||||||||||||||
Amortization of mortgage servicing assets | 430 | 420 | 450 | 1,264 | 1,492 | |||||||||||||||||||||||||||||||||
Tax effect of amortization adjustments (2) | (322) | (321) | (390) | (968) | (1,220) | |||||||||||||||||||||||||||||||||
| Tangible net income | (e) | $ | 226,262 | $ | 225,551 | $ | 160,524 | $ | 657,628 | $ | 406,796 | |||||||||||||||||||||||||||
| Average stockholders’ equity | $ | 5,680,306 | $ | 5,425,952 | $ | 5,079,351 | $ | 5,482,705 | $ | 5,028,122 | ||||||||||||||||||||||||||||
| Less: Average goodwill | (465,697) | (465,697) | (465,697) | (465,697) | (465,697) | |||||||||||||||||||||||||||||||||
Average other intangible assets (1) | (10,135) | (10,827) | (13,083) | (10,847) | (14,302) | |||||||||||||||||||||||||||||||||
| Average tangible equity | (f) | $ | 5,204,474 | $ | 4,949,428 | $ | 4,600,571 | $ | 5,006,161 | $ | 4,548,123 | |||||||||||||||||||||||||||
Return on average tangible equity (3) | (e)/(f) | 17.25 | % | 18.28 | % | 13.88 | % | 17.56 | % | 11.95 | % | |||||||||||||||||||||||||||
(1)Includes core deposit intangibles and mortgage servicing assets.
(2)Applied statutory tax rate of 28.37% for the three and nine months ended September 30, 2021, and the three months ended June 30, 2021. Applied statutory tax rate of 28.35% for the three and nine months ended September 30, 2020.
(3)Annualized.
20
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | ||||||||||||||||||||||||||||||||||||||
| GAAP TO NON-GAAP RECONCILIATION | ||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | ||||||||||||||||||||||||||||||||||||||
| (unaudited) | ||||||||||||||||||||||||||||||||||||||
| Table 14 | ||||||||||||||||||||||||||||||||||||||
In April 2020, the Company started accepting applications under the PPP administered by the Small Business Administration (“SBA”) under the Coronavirus Aid, Relief, and Economic Security Act and began to originate loans to qualified small businesses. In January 2021, the Company began processing applications under the second round of the SBA’s PPP in response to the Consolidated Appropriations Act, 2021 signed by the President on December 27, 2020. The PPP ended on May 31, 2021. These loans are included in the Company’s C&I portfolio, have an interest rate of one percent and are 100% guaranteed by the SBA. Loan processing fees paid to the Company from the SBA are accounted for as loan origination fees, where net deferred fees are recognized on a straight line basis over the estimated life of the loan as a yield adjustment on the loans. If a loan is paid off or forgiven by the SBA prior to its projected estimated life, the remaining unamortized deferred fees will be recognized as interest income in that period. The Company drew down $1.44 billion from the PPPLF during the second quarter of 2020. The remaining balance of $1.43 billion as of September 2020 was repaid in full during the fourth quarter of 2020. Adjusted loan yield and adjusted net interest margin for the three and nine months ended September 30, 2021 and 2020, and three months ended June 30, 2020 exclude the impact of PPP loans. Net interest margin for the three and nine months ended September 30, 2020 has also been adjusted for advances from the PPPLF. Management believes that presenting the adjusted average loan yield and adjusted net interest margin provide comparability to prior periods and these non-GAAP financial measures provide supplemental information regarding the Company’s performance. | ||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Nine Months Ended | |||||||||||||||||||||||||||||||||||||
| Yield on Average Loans | September 30, 2021 | June 30, 2021 | September 30, 2020 | September 30, 2021 | September 30, 2020 | |||||||||||||||||||||||||||||||||
| Interest income on loans | (a) | $ | 363,503 | $ | 352,453 | $ | 336,542 | $ | 1,057,964 | $ | 1,115,804 | |||||||||||||||||||||||||||
Less: Interest income on PPP loans | (15,212) | (15,377) | (7,778) | (45,606) | (29,067) | |||||||||||||||||||||||||||||||||
| Adjusted interest income on loans | (b) | $ | 348,291 | $ | 337,076 | $ | 328,764 | $ | 1,012,358 | $ | 1,086,737 | |||||||||||||||||||||||||||
| Average loans | (c) | $ | 39,960,151 | $ | 39,622,270 | $ | 37,160,445 | $ | 39,441,751 | $ | 36,487,859 | |||||||||||||||||||||||||||
| Less: Average PPP loans | (1,111,404) | (1,870,385) | (1,764,411) | (1,634,617) | (1,078,985) | |||||||||||||||||||||||||||||||||
| Adjusted average loans | (d) | $ | 38,848,747 | $ | 37,751,885 | $ | 35,396,034 | $ | 37,807,134 | $ | 35,408,874 | |||||||||||||||||||||||||||
Average loan yield (1) | (a)/(c) | 3.61 | % | 3.57 | % | 3.60 | % | 3.59 | % | 4.08 | % | |||||||||||||||||||||||||||
Adjusted average loan yield (1) | (b)/(d) | 3.56 | % | 3.58 | % | 3.70 | % | 3.58 | % | 4.10 | % | |||||||||||||||||||||||||||
| Net Interest Margin | ||||||||||||||||||||||||||||||||||||||
| Net interest income before provision for credit losses | (e) | $ | 395,706 | $ | 376,473 | $ | 324,130 | $ | 1,125,874 | $ | 1,030,612 | |||||||||||||||||||||||||||
Less: Interest income on PPP loans | (15,212) | (15,377) | (7,778) | (45,606) | (29,067) | |||||||||||||||||||||||||||||||||
| Add: Interest expense on advances from the PPPLF | — | — | 1,259 | — | 1,722 | |||||||||||||||||||||||||||||||||
| Adjusted net interest income | (f) | $ | 380,494 | $ | 361,096 | $ | 317,611 | $ | 1,080,268 | $ | 1,003,267 | |||||||||||||||||||||||||||
| Average interest-earning assets | (g) | $ | 58,239,480 | $ | 54,901,209 | $ | 47,428,586 | $ | 55,350,645 | $ | 45,076,734 | |||||||||||||||||||||||||||
| Less: Average PPP loans | (1,111,404) | (1,870,385) | (1,764,411) | (1,634,617) | (1,078,985) | |||||||||||||||||||||||||||||||||
Adjusted average interest-earning assets | (h) | $ | 57,128,076 | $ | 53,030,824 | $ | 45,664,175 | $ | 53,716,028 | $ | 43,997,749 | |||||||||||||||||||||||||||
Net interest margin (1) | (e)/(g) | 2.70 | % | 2.75 | % | 2.72 | % | 2.72 | % | 3.05 | % | |||||||||||||||||||||||||||
Adjusted net interest margin (1) | (f)/(h) | 2.64 | % | 2.73 | % | 2.77 | % | 2.69 | % | 3.05 | % | |||||||||||||||||||||||||||
(1)Annualized.
21
EWBC Earnings Results Third Quarter 2021 October 21, 2021

Forward-Looking Statements 2 Forward-Looking Statements This presentation contains forward-looking statements that are intended to be covered by the safe harbor for such statements provided by the Private Securities Litigation Reform Act of 1995. These statements are based on the current beliefs and expectations of the management of East West Bancorp, Inc. (the “Company”) and are subject to significant risks and uncertainties. You should not place undue reliance on these statements. Factors that could cause the Company’s actual results to differ materially from those described in the forward-looking statements include, among others, changes in the U.S. economy or local, regional and global business, economic and political conditions and geopolitical events; the impacts of the ongoing COVID-19 pandemic; changes in laws or the regulatory environment, including trade, monetary and fiscal policies and laws; and changes in the commercial and consumer real estate markets and in consumer spending and savings habits. These factors also consist of those contained in the Company’s filings with the Securities and Exchange Commission, including the “Risk Factors” section of the Company’s Annual Report on Form 10-K for the year ended December 31, 2020. When considering these forward-looking statements, you should keep in mind these risks and uncertainties, as well as any cautionary statements the Company may make. These statements speak only as of the date they are made and are based only on information then actually known to the Company. The Company does not undertake to update any forward-looking statements except as required by law. Non-GAAP Financial Measures Certain financial information in this presentation has not been prepared in accordance with U.S. generally accepted accounting principles (“GAAP”) and is presented on a non-GAAP basis. Investors should refer to the reconciliations included in this presentation and should consider the Company’s non-GAAP measures in addition to, not as a substitute for or superior to, measures prepared in accordance with GAAP. These measures may not be comparable to similarly titled measures used by other companies.
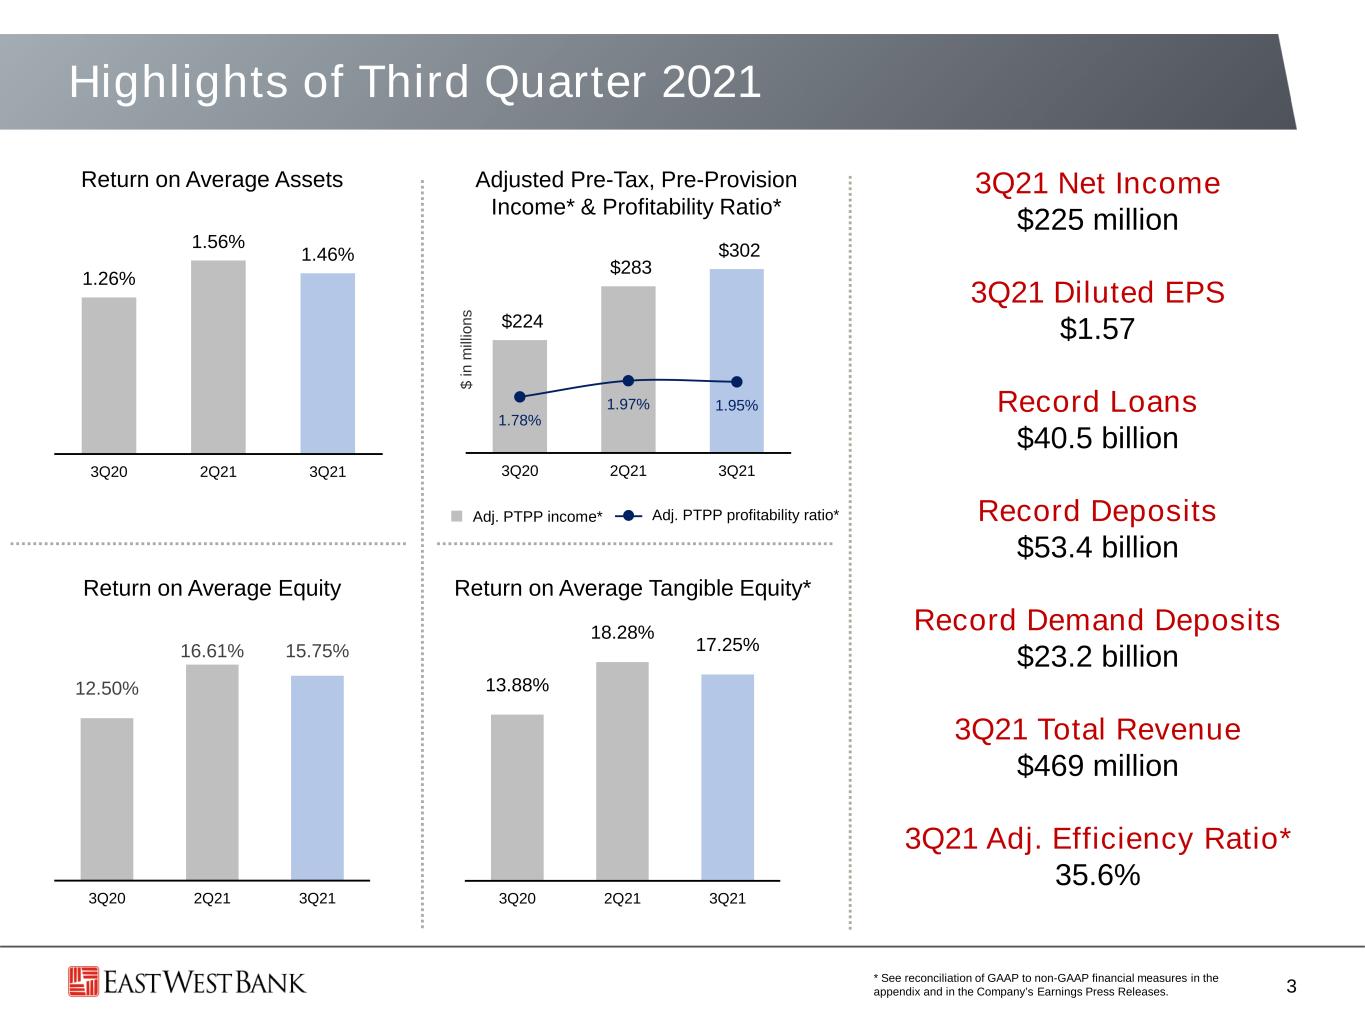
Highlights of Third Quarter 2021 3 3Q21 Net Income $225 million 3Q21 Diluted EPS $1.57 Record Loans $40.5 billion Record Deposits $53.4 billion Record Demand Deposits $23.2 billion 3Q21 Total Revenue $469 million 3Q21 Adj. Efficiency Ratio* 35.6% Return on Average Assets Adjusted Pre-Tax, Pre-Provision Income* & Profitability Ratio* Return on Average Tangible Equity*Return on Average Equity Adj. PTPP income* Adj. PTPP profitability ratio* $ in m ill io ns * See reconciliation of GAAP to non-GAAP financial measures in the appendix and in the Company’s Earnings Press Releases. 1.26% 1.56% 1.46% 3Q20 2Q21 3Q21 $224 $283 $302 1.78% 1.97% 1.95% $100 $180 $260 3Q20 2Q21 3Q21 12.50% 16.61% 15.75% 3Q20 2Q21 3Q21 13.88% 18.28% 17.25% 3Q20 2Q21 3Q21
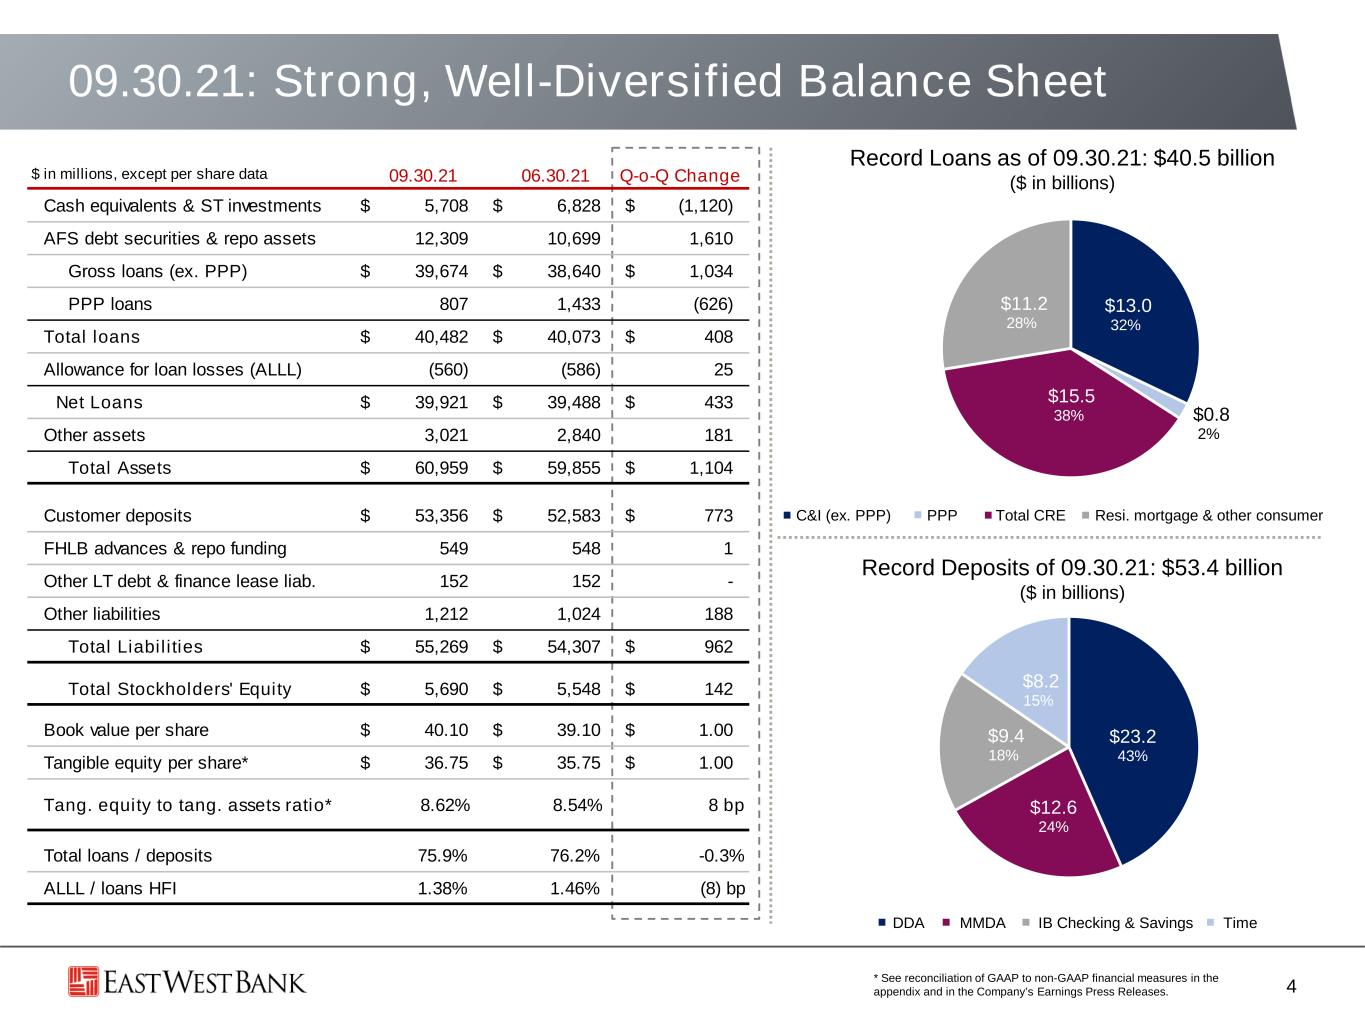
4 09.30.21: Strong, Well-Diversified Balance Sheet Record Loans as of 09.30.21: $40.5 billion ($ in billions) C&I (ex. PPP) Resi. mortgage & other consumerTotal CREPPP IB Checking & SavingsMMDADDA Time Record Deposits of 09.30.21: $53.4 billion ($ in billions) * See reconciliation of GAAP to non-GAAP financial measures in the appendix and in the Company’s Earnings Press Releases. $13.0 32% $0.8 2% $15.5 38% $11.2 28% $23.2 43% $12.6 24% $9.4 18% $8.2 15% $ in millions, except per share data 09.30.21 06.30.21 Cash equivalents & ST investments $ 5,708 $ 6,828 $ (1,120) AFS debt securities & repo assets 12,309 10,699 1,610 Gross loans (ex. PPP) $ 39,674 $ 38,640 $ 1,034 PPP loans 807 1,433 (626) Total loans $ 40,482 $ 40,073 $ 408 Allowance for loan losses (ALLL) (560) (586) 25 Net Loans $ 39,921 $ 39,488 $ 433 Other assets 3,021 2,840 181 Total Assets $ 60,959 $ 59,855 $ 1,104 Customer deposits $ 53,356 $ 52,583 $ 773 FHLB advances & repo funding 549 548 1 Other LT debt & finance lease liab. 152 152 - Other liabilities 1,212 1,024 188 Total Liabilities $ 55,269 $ 54,307 $ 962 Total Stockholders' Equity $ 5,690 $ 5,548 $ 142 Book value per share $ 40.10 $ 39.10 $ 1.00 Tangible equity per share* $ 36.75 $ 35.75 $ 1.00 Tang. equity to tang. assets ratio* 8.62% 8.54% 8 bp Total loans / deposits 75.9% 76.2% -0.3% ALLL / loans HFI 1.38% 1.46% (8) bp Q-o-Q Change
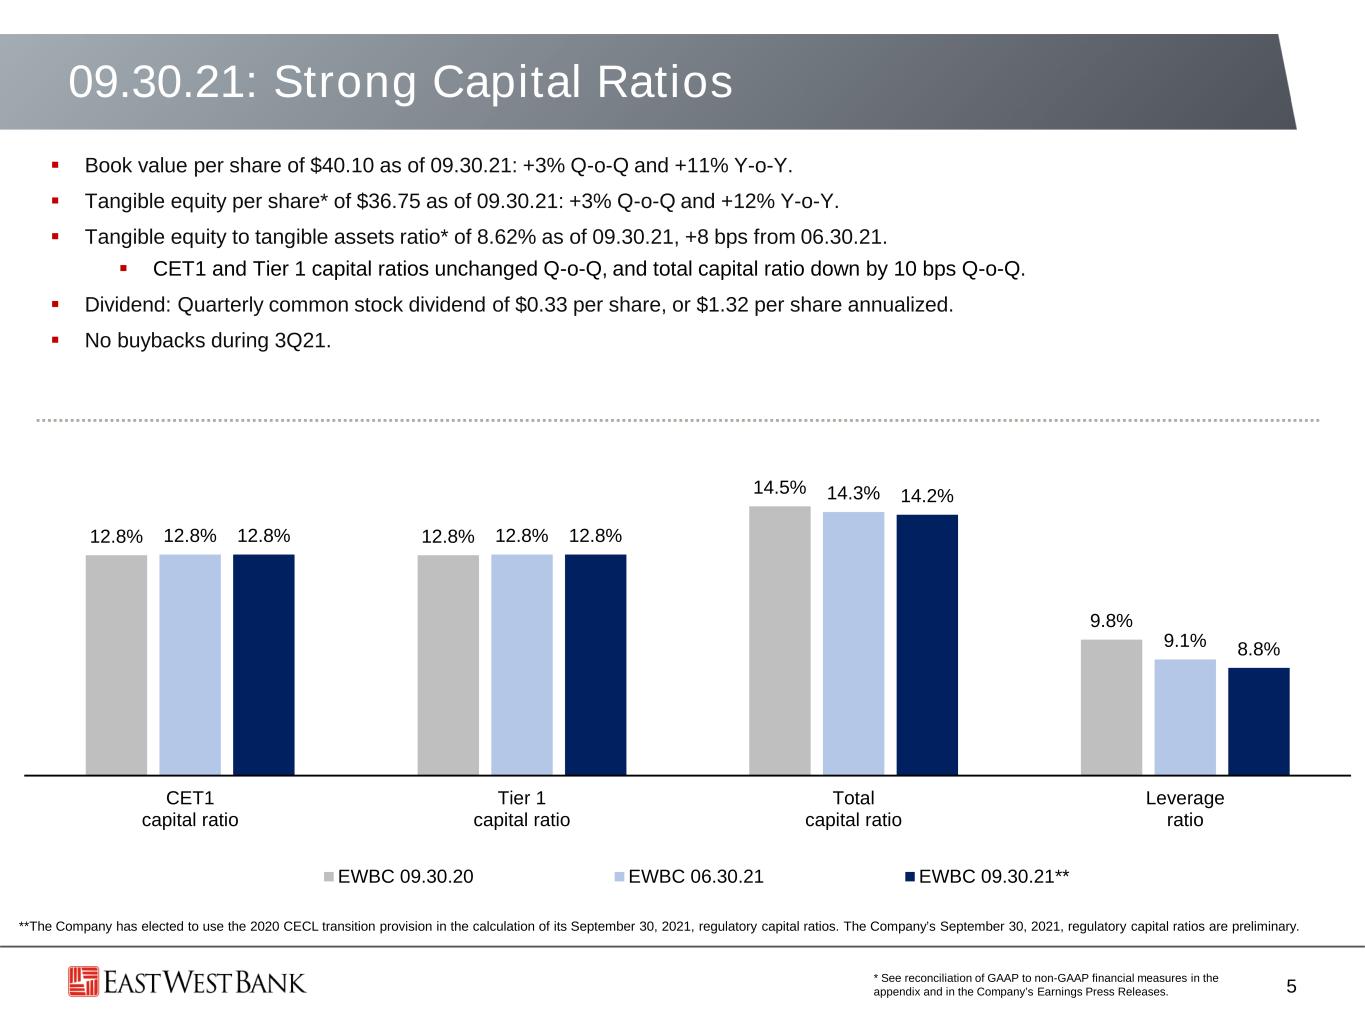
09.30.21: Strong Capital Ratios Book value per share of $40.10 as of 09.30.21: +3% Q-o-Q and +11% Y-o-Y. Tangible equity per share* of $36.75 as of 09.30.21: +3% Q-o-Q and +12% Y-o-Y. Tangible equity to tangible assets ratio* of 8.62% as of 09.30.21, +8 bps from 06.30.21. CET1 and Tier 1 capital ratios unchanged Q-o-Q, and total capital ratio down by 10 bps Q-o-Q. Dividend: Quarterly common stock dividend of $0.33 per share, or $1.32 per share annualized. No buybacks during 3Q21. 5 **The Company has elected to use the 2020 CECL transition provision in the calculation of its September 30, 2021, regulatory capital ratios. The Company’s September 30, 2021, regulatory capital ratios are preliminary. * See reconciliation of GAAP to non-GAAP financial measures in the appendix and in the Company’s Earnings Press Releases. 12.8% 12.8% 14.5% 9.8% 12.8% 12.8% 14.3% 9.1% 12.8% 12.8% 14.2% 8.8% CET1 capital ratio Tier 1 capital ratio Total capital ratio Leverage ratio EWBC 09.30.20 EWBC 06.30.21 EWBC 09.30.21**
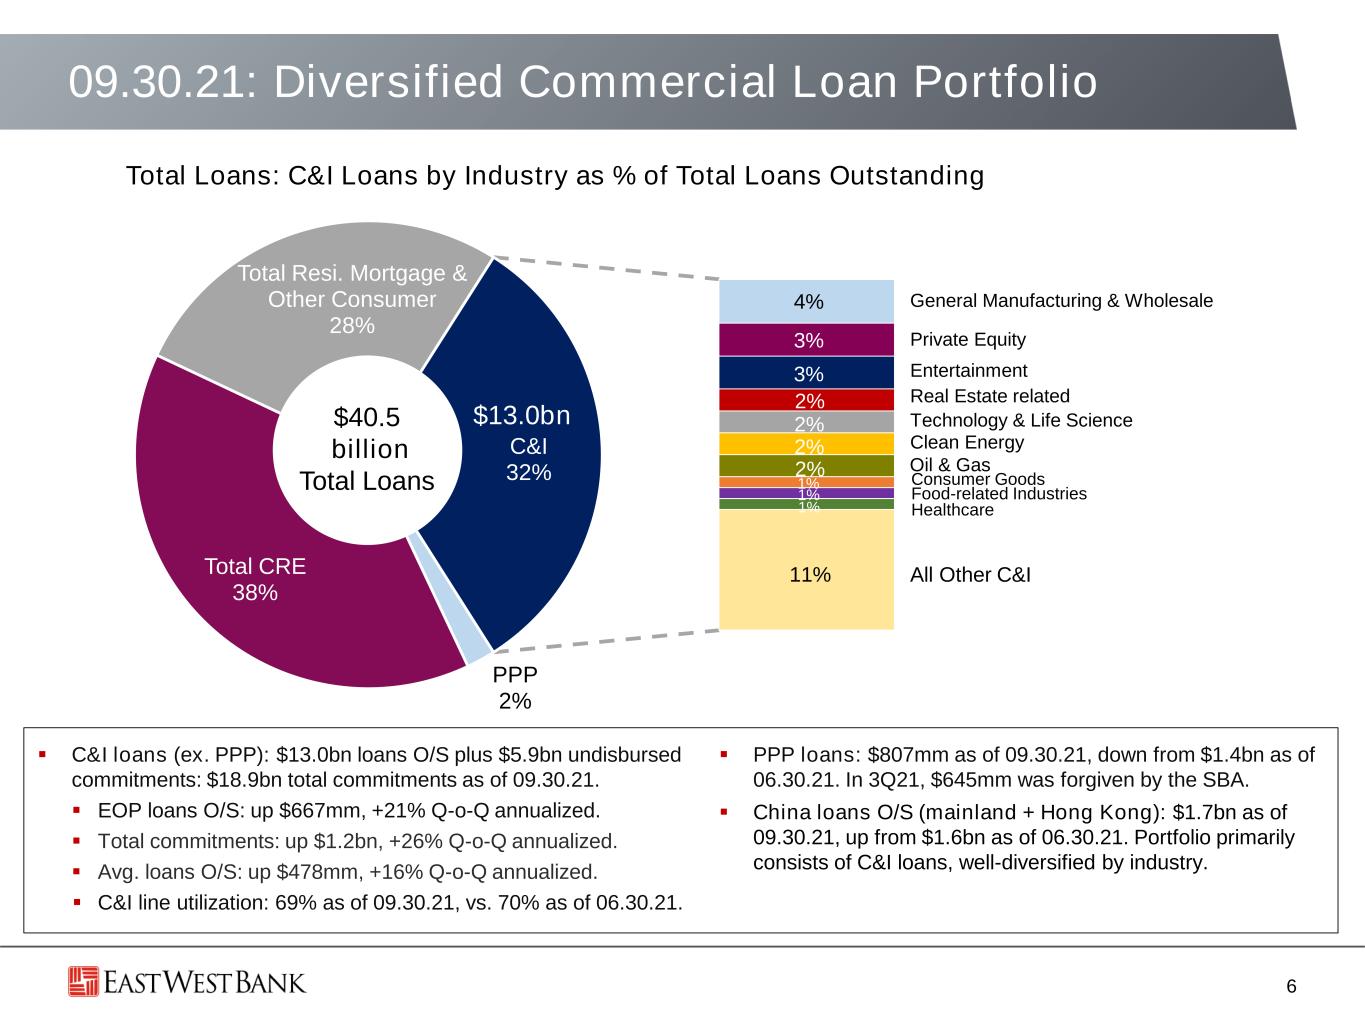
PPP 2% Total CRE 38% Total Resi. Mortgage & Other Consumer 28% C&I 32% 6 Total Loans: C&I Loans by Industry as % of Total Loans Outstanding 09.30.21: Diversified Commercial Loan Portfolio C&I loans (ex. PPP): $13.0bn loans O/S plus $5.9bn undisbursed commitments: $18.9bn total commitments as of 09.30.21. EOP loans O/S: up $667mm, +21% Q-o-Q annualized. Total commitments: up $1.2bn, +26% Q-o-Q annualized. Avg. loans O/S: up $478mm, +16% Q-o-Q annualized. C&I line utilization: 69% as of 09.30.21, vs. 70% as of 06.30.21. PPP loans: $807mm as of 09.30.21, down from $1.4bn as of 06.30.21. In 3Q21, $645mm was forgiven by the SBA. China loans O/S (mainland + Hong Kong): $1.7bn as of 09.30.21, up from $1.6bn as of 06.30.21. Portfolio primarily consists of C&I loans, well-diversified by industry. $13.0bn 4% 3% 3% 2% 2% 2% 2% 11% General Manufacturing & Wholesale Private Equity Entertainment Oil & Gas Real Estate related Clean Energy Technology & Life Science Food-related Industries Consumer Goods Healthcare All Other C&I 1% 1% 1% $40.5 billion Total Loans
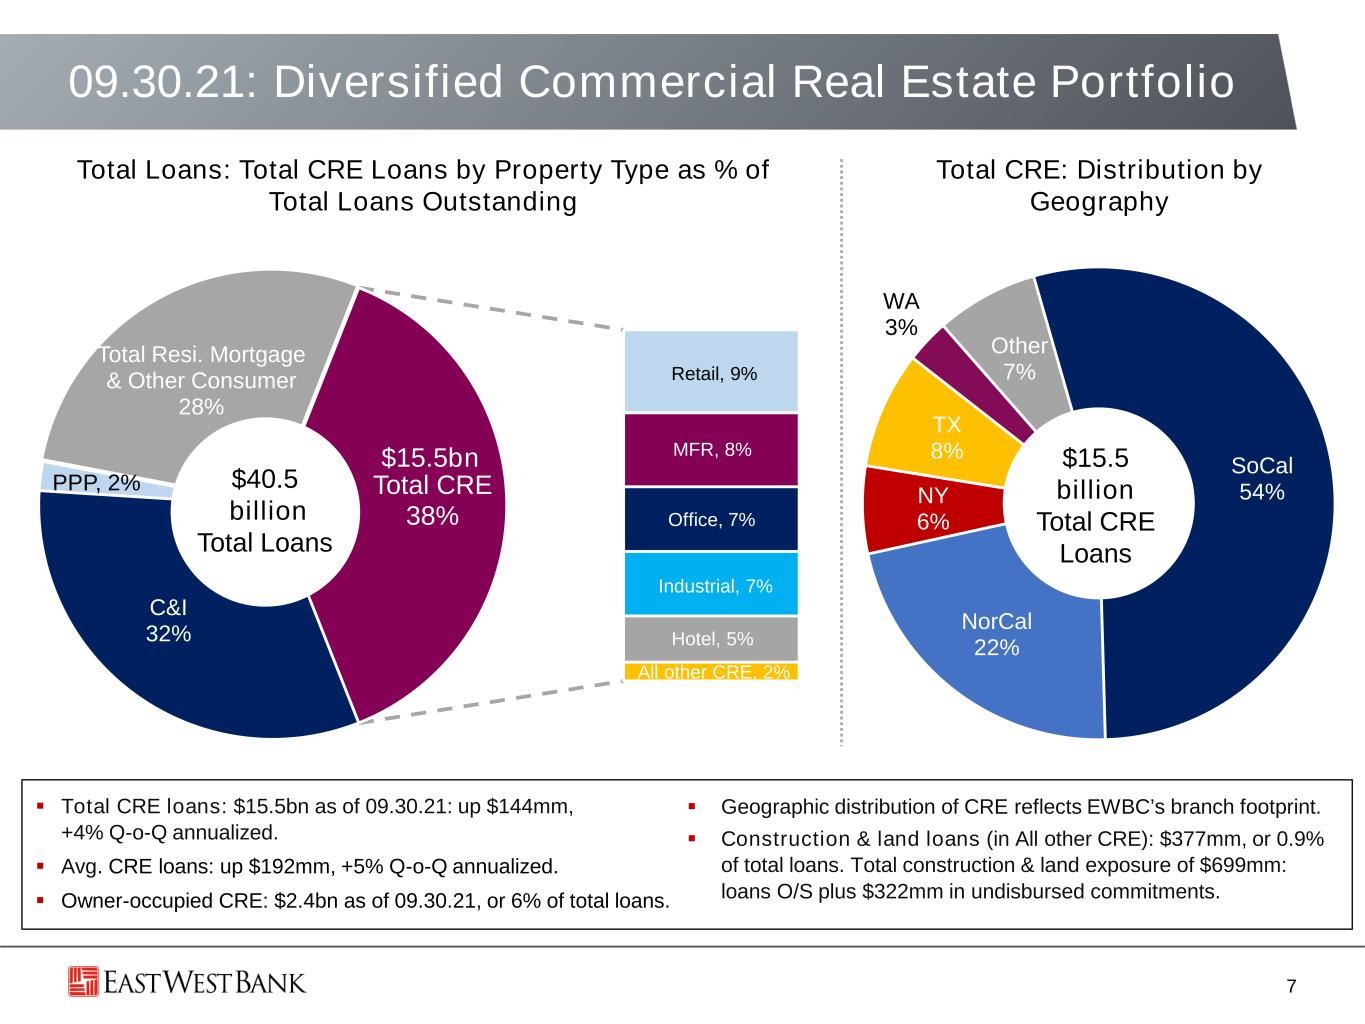
C&I 32% PPP, 2% Retail, 9% MFR, 8% Office, 7% Industrial, 7% Hotel, 5% All other CRE, 2% Total Resi. Mortgage & Other Consumer 28% Total CRE 38% SoCal 54% NorCal 22% NY 6% TX 8% WA 3% Other 7% 09.30.21: Diversified Commercial Real Estate Portfolio 7 Total Loans: Total CRE Loans by Property Type as % of Total Loans Outstanding Total CRE loans: $15.5bn as of 09.30.21: up $144mm, +4% Q-o-Q annualized. Avg. CRE loans: up $192mm, +5% Q-o-Q annualized. Owner-occupied CRE: $2.4bn as of 09.30.21, or 6% of total loans. Geographic distribution of CRE reflects EWBC’s branch footprint. Construction & land loans (in All other CRE): $377mm, or 0.9% of total loans. Total construction & land exposure of $699mm: loans O/S plus $322mm in undisbursed commitments. $15.5 billion Total CRE Loans Total CRE: Distribution by Geography $15.5bn $40.5 billion Total Loans
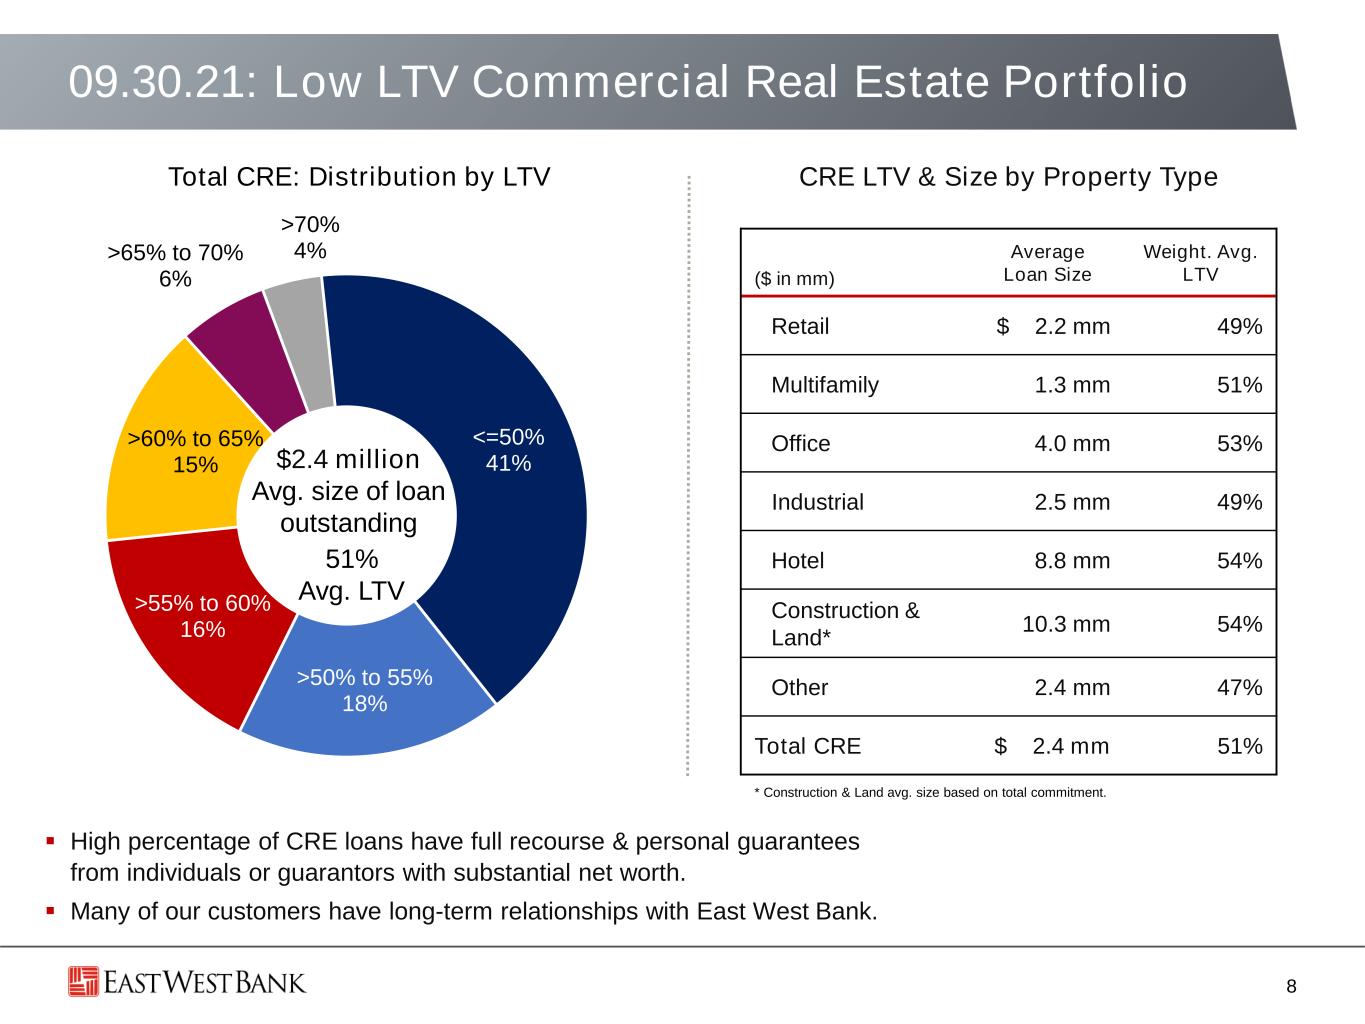
Total CRE: Distribution by LTV 8 09.30.21: Low LTV Commercial Real Estate Portfolio ($ in mm) Average Loan Size Weight. Avg. LTV Retail $ 2.2 mm 49% Multifamily 1.3 mm 51% Office 4.0 mm 53% Industrial 2.5 mm 49% Hotel 8.8 mm 54% Construction & Land* 10.3 mm 54% Other 2.4 mm 47% Total CRE $ 2.4 mm 51% CRE LTV & Size by Property Type * Construction & Land avg. size based on total commitment. High percentage of CRE loans have full recourse & personal guarantees from individuals or guarantors with substantial net worth. Many of our customers have long-term relationships with East West Bank. $2.4 million Avg. size of loan outstanding 51% Avg. LTV <=50% 41% >50% to 55% 18% >55% to 60% 16% >60% to 65% 15% >65% to 70% 6% >70% 4%
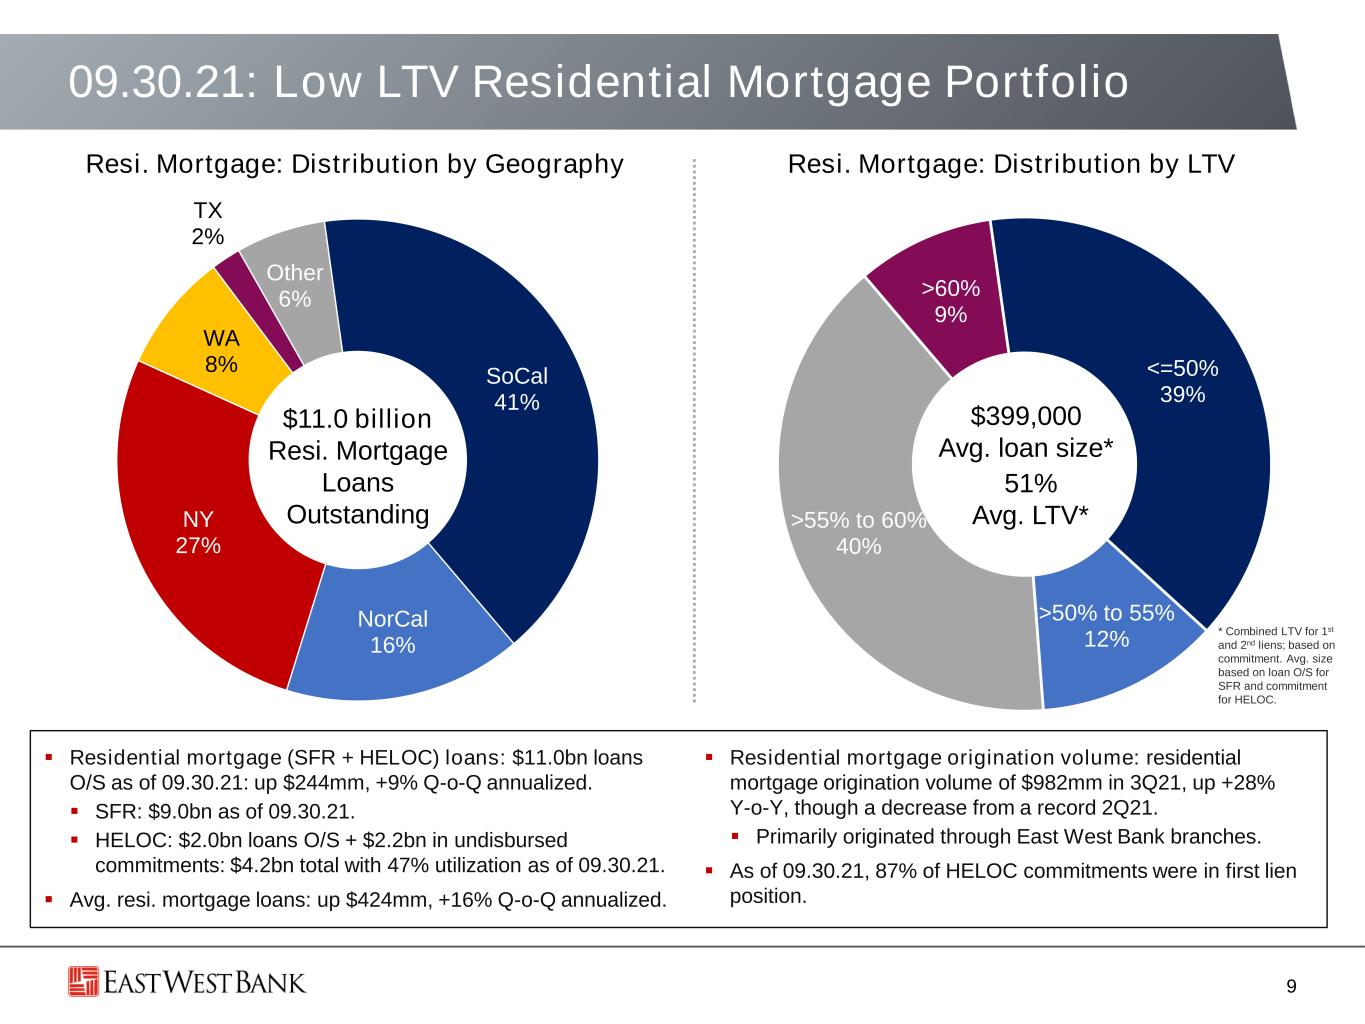
<=50% 39% >50% to 55% 12% >55% to 60% 40% >60% 9% SoCal 41% NorCal 16% NY 27% WA 8% TX 2% Other 6% 09.30.21: Low LTV Residential Mortgage Portfolio 9 Resi. Mortgage: Distribution by Geography Resi. Mortgage: Distribution by LTV $11.0 billion Resi. Mortgage Loans Outstanding $399,000 Avg. loan size* 51% Avg. LTV* Residential mortgage (SFR + HELOC) loans: $11.0bn loans O/S as of 09.30.21: up $244mm, +9% Q-o-Q annualized. SFR: $9.0bn as of 09.30.21. HELOC: $2.0bn loans O/S + $2.2bn in undisbursed commitments: $4.2bn total with 47% utilization as of 09.30.21. Avg. resi. mortgage loans: up $424mm, +16% Q-o-Q annualized. Residential mortgage origination volume: residential mortgage origination volume of $982mm in 3Q21, up +28% Y-o-Y, though a decrease from a record 2Q21. Primarily originated through East West Bank branches. As of 09.30.21, 87% of HELOC commitments were in first lien position. * Combined LTV for 1st and 2nd liens; based on commitment. Avg. size based on loan O/S for SFR and commitment for HELOC.
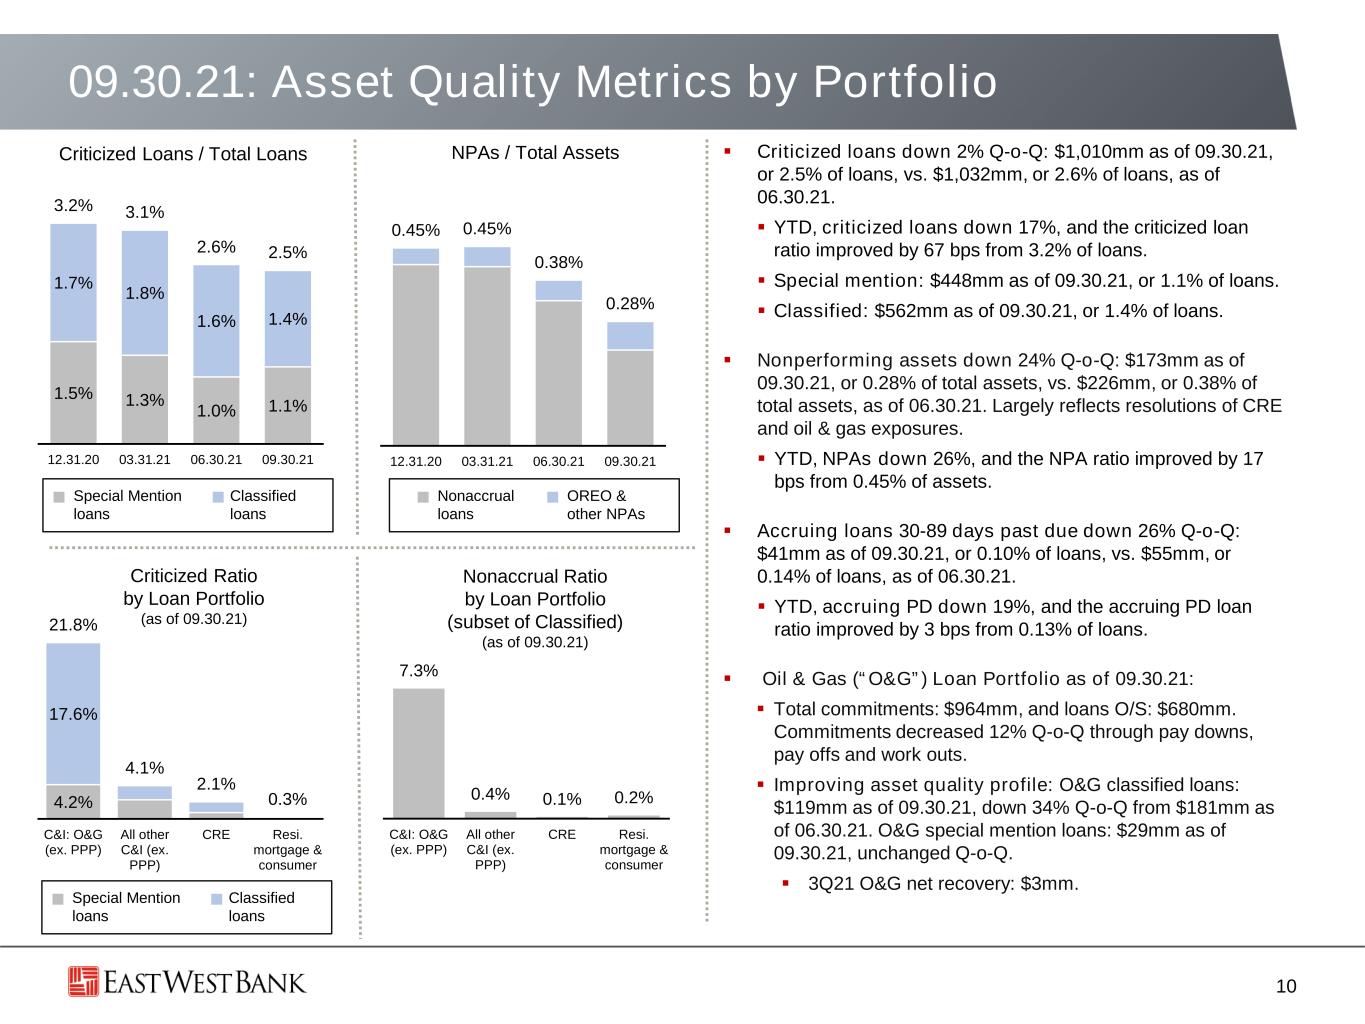
7.3% 0.4% 0.1% 0.2% C&I: O&G (ex. PPP) All other C&I (ex. PPP) CRE Resi. mortgage & consumer 4.2% 17.6% 21.8% 4.1% 2.1% 0.3% C&I: O&G (ex. PPP) All other C&I (ex. PPP) CRE Resi. mortgage & consumer Nonaccrual Ratio by Loan Portfolio (subset of Classified) (as of 09.30.21) 09.30.21: Asset Quality Metrics by Portfolio 10 Criticized Loans / Total Loans Criticized Ratio by Loan Portfolio (as of 09.30.21) NPAs / Total Assets Nonaccrual loans OREO & other NPAs Criticized loans down 2% Q-o-Q: $1,010mm as of 09.30.21, or 2.5% of loans, vs. $1,032mm, or 2.6% of loans, as of 06.30.21. YTD, criticized loans down 17%, and the criticized loan ratio improved by 67 bps from 3.2% of loans. Special mention: $448mm as of 09.30.21, or 1.1% of loans. Classified: $562mm as of 09.30.21, or 1.4% of loans. Nonperforming assets down 24% Q-o-Q: $173mm as of 09.30.21, or 0.28% of total assets, vs. $226mm, or 0.38% of total assets, as of 06.30.21. Largely reflects resolutions of CRE and oil & gas exposures. YTD, NPAs down 26%, and the NPA ratio improved by 17 bps from 0.45% of assets. Accruing loans 30-89 days past due down 26% Q-o-Q: $41mm as of 09.30.21, or 0.10% of loans, vs. $55mm, or 0.14% of loans, as of 06.30.21. YTD, accruing PD down 19%, and the accruing PD loan ratio improved by 3 bps from 0.13% of loans. Oil & Gas (“O&G”) Loan Portfolio as of 09.30.21: Total commitments: $964mm, and loans O/S: $680mm. Commitments decreased 12% Q-o-Q through pay downs, pay offs and work outs. Improving asset quality profile: O&G classified loans: $119mm as of 09.30.21, down 34% Q-o-Q from $181mm as of 06.30.21. O&G special mention loans: $29mm as of 09.30.21, unchanged Q-o-Q. 3Q21 O&G net recovery: $3mm. Special Mention loans Classified loans Special Mention loans Classified loans 1.5% 1.3% 1.0% 1.1% 1.7% 1.8% 1.6% 1.4% 3.2% 3.1% 2.6% 2.5% 12.31.20 03.31.21 06.30.21 09.30.21 0.45% 0.45% 0.38% 0.28% 12.31.20 03.31.21 06.30.21 09.30.21
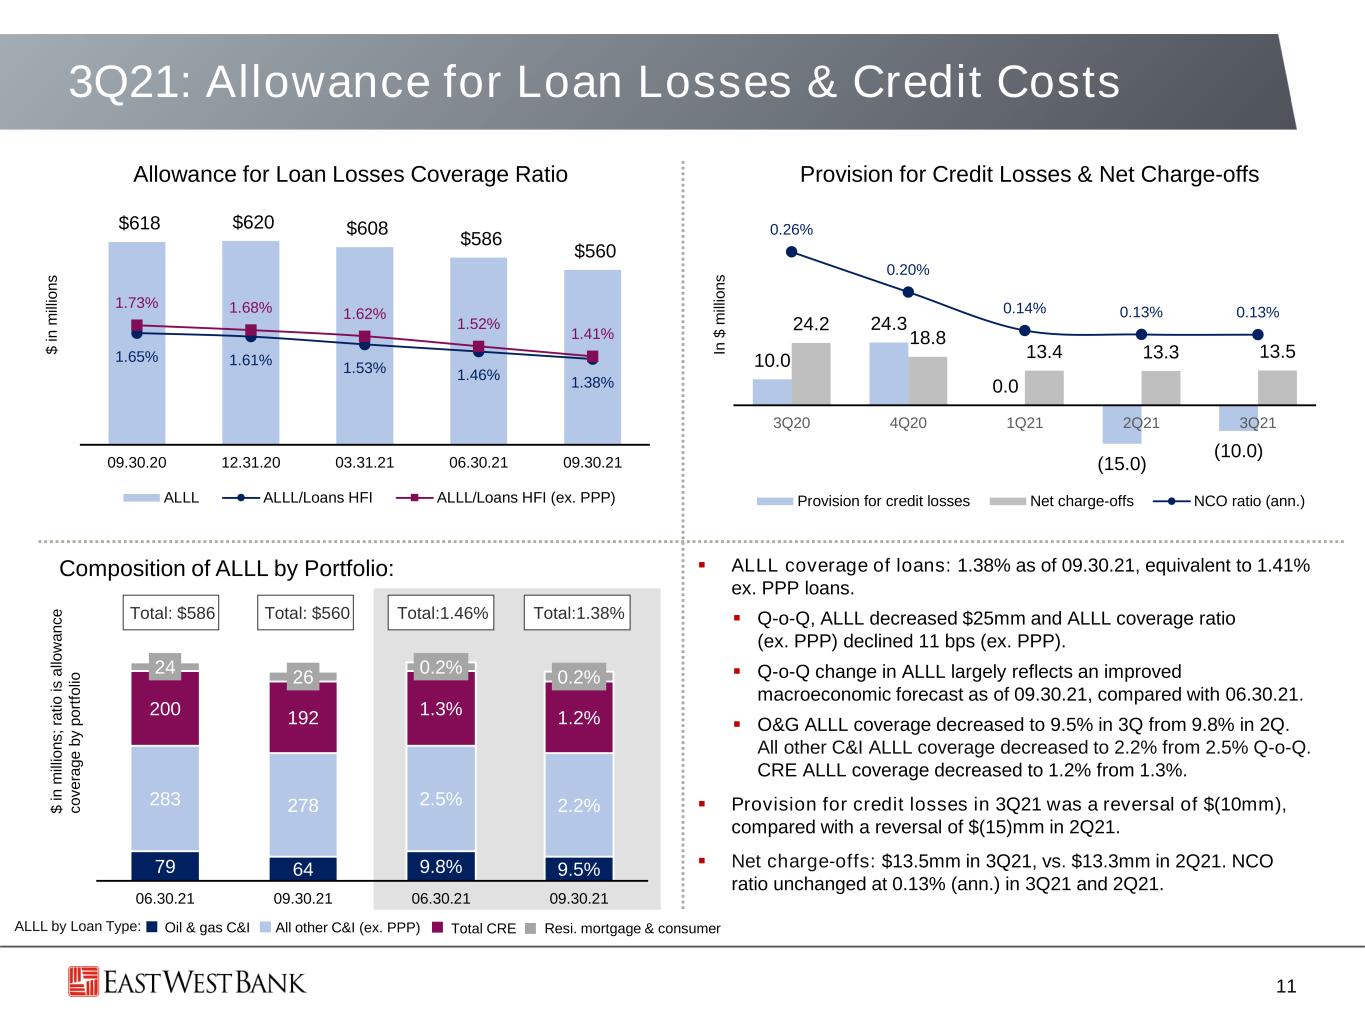
$618 $620 $608 $586 $560 1.65% 1.61% 1.53% 1.46% 1.38% 1.73% 1.68% 1.62% 1.52% 1.41% $200 $700 09.30.20 12.31.20 03.31.21 06.30.21 09.30.21 ALLL ALLL/Loans HFI ALLL/Loans HFI (ex. PPP) 10.0 24.3 0.0 (15.0) (10.0) 24.2 18.8 13.4 13.3 13.5 0.26% 0.20% 0.14% 0.13% 0.13% -0.05%-20.0 3Q20 4Q20 1Q21 2Q21 3Q21 Provision for credit losses Net charge-offs NCO ratio (ann.) ALLL by Loan Type: ALLL coverage of loans: 1.38% as of 09.30.21, equivalent to 1.41% ex. PPP loans. Q-o-Q, ALLL decreased $25mm and ALLL coverage ratio (ex. PPP) declined 11 bps (ex. PPP). Q-o-Q change in ALLL largely reflects an improved macroeconomic forecast as of 09.30.21, compared with 06.30.21. O&G ALLL coverage decreased to 9.5% in 3Q from 9.8% in 2Q. All other C&I ALLL coverage decreased to 2.2% from 2.5% Q-o-Q. CRE ALLL coverage decreased to 1.2% from 1.3%. Provision for credit losses in 3Q21 was a reversal of $(10mm), compared with a reversal of $(15)mm in 2Q21. Net charge-offs: $13.5mm in 3Q21, vs. $13.3mm in 2Q21. NCO ratio unchanged at 0.13% (ann.) in 3Q21 and 2Q21. 3Q21: Allowance for Loan Losses & Credit Costs 11 Composition of ALLL by Portfolio: Allowance for Loan Losses Coverage Ratio $ in m ill io ns Provision for Credit Losses & Net Charge-offs In $ m ill io ns Total: $586 $ in m ill io ns ; r at io is a llo w an ce co ve ra ge b y po rtf ol io Total:1.46%Total: $560 Total:1.38% Oil & gas C&I Total CREAll other C&I (ex. PPP) Resi. mortgage & consumer 79 64 9.8% 9.5% 283 278 2.5% 2.2% 200 192 1.3% 1.2% 24 26 0.2% 0.2% 06.30.21 09.30.21 06.30.21 09.30.21
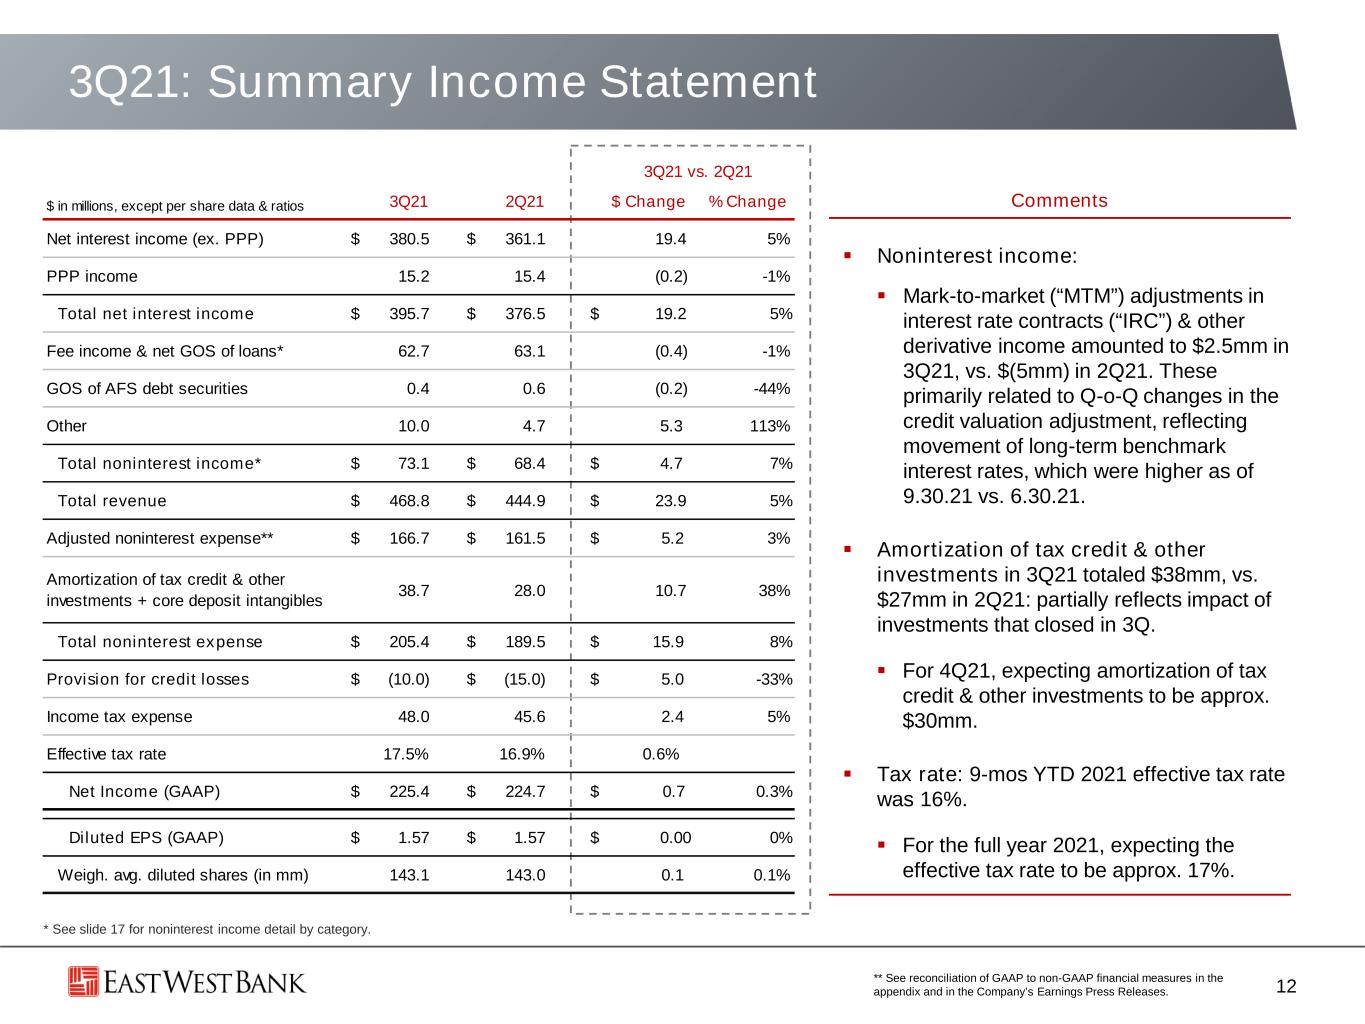
3Q21: Summary Income Statement 12 * See slide 17 for noninterest income detail by category. Comments Noninterest income: Mark-to-market (“MTM”) adjustments in interest rate contracts (“IRC”) & other derivative income amounted to $2.5mm in 3Q21, vs. $(5mm) in 2Q21. These primarily related to Q-o-Q changes in the credit valuation adjustment, reflecting movement of long-term benchmark interest rates, which were higher as of 9.30.21 vs. 6.30.21. Amortization of tax credit & other investments in 3Q21 totaled $38mm, vs. $27mm in 2Q21: partially reflects impact of investments that closed in 3Q. For 4Q21, expecting amortization of tax credit & other investments to be approx. $30mm. Tax rate: 9-mos YTD 2021 effective tax rate was 16%. For the full year 2021, expecting the effective tax rate to be approx. 17%. ** See reconciliation of GAAP to non-GAAP financial measures in the appendix and in the Company’s Earnings Press Releases. 3Q21 vs. 2Q21 $ in millions, except per share data & ratios 3Q21 2Q21 $ Change % Change Net interest income (ex. PPP) $ 380.5 $ 361.1 19.4 5% PPP income 15.2 15.4 (0.2) -1% Total net interest income $ 395.7 $ 376.5 $ 19.2 5% Fee income & net GOS of loans* 62.7 63.1 (0.4) -1% GOS of AFS debt securities 0.4 0.6 (0.2) -44% Other 10.0 4.7 5.3 113% Total noninterest income* $ 73.1 $ 68.4 $ 4.7 7% Total revenue $ 468.8 $ 444.9 $ 23.9 5% Adjusted noninterest expense** $ 166.7 $ 161.5 $ 5.2 3% Amortization of tax credit & other investments + core deposit intangibles 38.7 28.0 10.7 38% Total noninterest expense $ 205.4 $ 189.5 $ 15.9 8% Provision for credit losses $ (10.0) $ (15.0) $ 5.0 -33% Income tax expense 48.0 45.6 2.4 5% Effective tax rate 17.5% 16.9% 0.6% Net Income (GAAP) $ 225.4 $ 224.7 $ 0.7 0.3% Diluted EPS (GAAP) $ 1.57 $ 1.57 $ 0.00 0% Weigh. avg. diluted shares (in mm) 143.1 143.0 0.1 0.1%
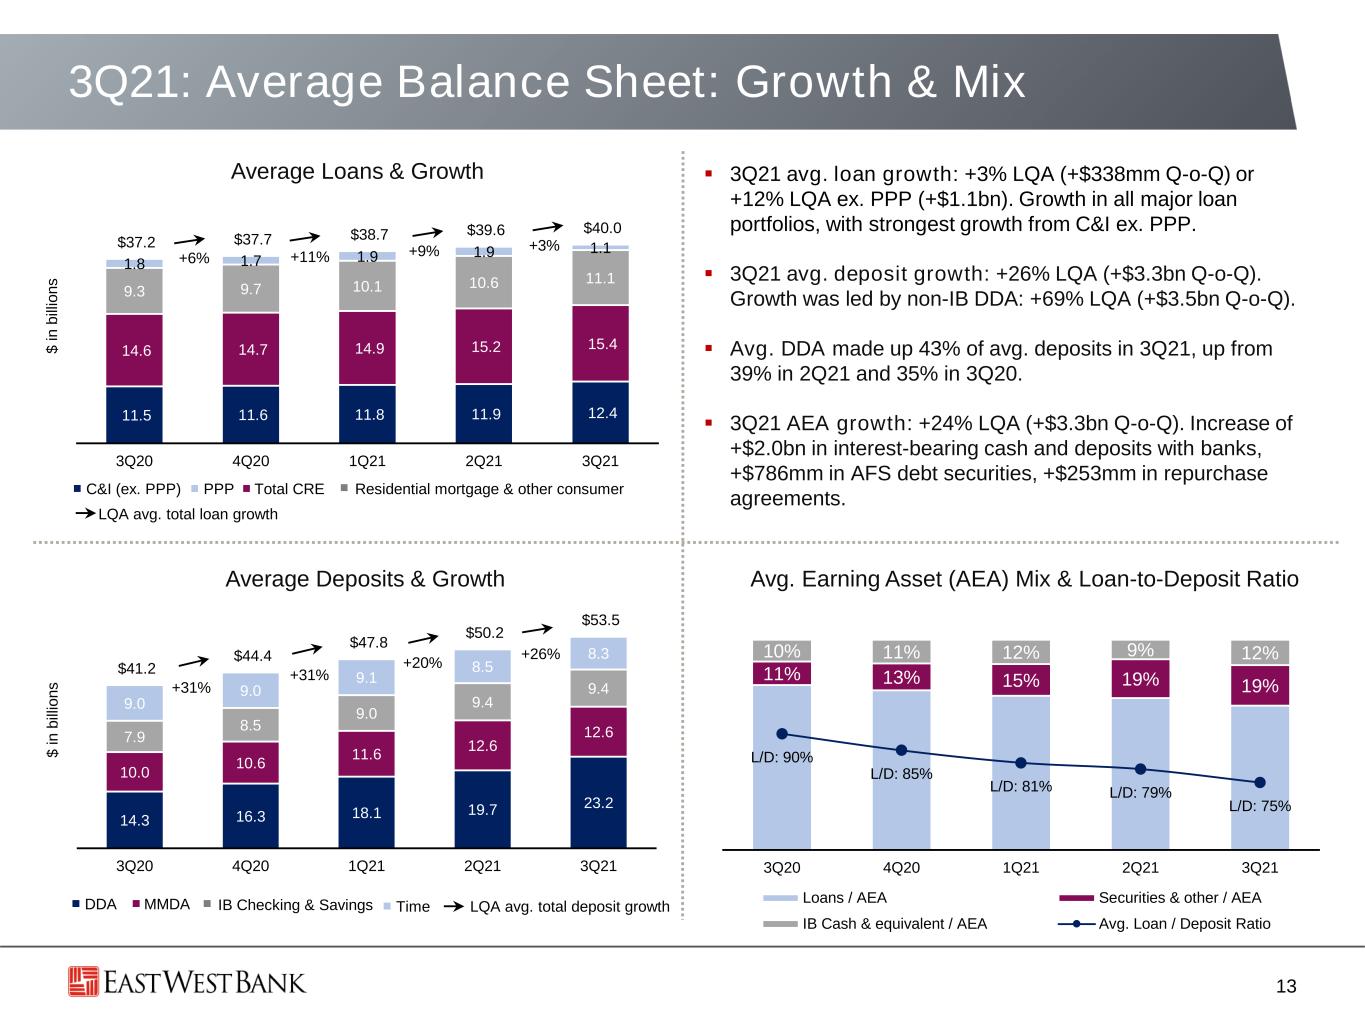
14.3 16.3 18.1 19.7 23.2 10.0 10.6 11.6 12.6 12.67.9 8.5 9.0 9.4 9.4 9.0 9.0 9.1 8.5 8.3 $41.2 $44.4 $47.8 $50.2 $53.5 3Q20 4Q20 1Q21 2Q21 3Q21 11% 13% 15% 19% 19% 10% 11% 12% 9% 12% L/D: 90% L/D: 85% L/D: 81% L/D: 79% L/D: 75% 40%-20% 100% 3Q20 4Q20 1Q21 2Q21 3Q21 Loans / AEA Securities & other / AEA IB Cash & equivalent / AEA Avg. Loan / Deposit Ratio 11.5 11.6 11.8 11.9 12.4 14.6 14.7 14.9 15.2 15.4 9.3 9.7 10.1 10.6 11.1 1.8 1.7 1.9 1.9 1.1$37.2 $37.7 $38.7 $39.6 $40.0 3Q20 4Q20 1Q21 2Q21 3Q21 3Q21: Average Balance Sheet: Growth & Mix 13 3Q21 avg. loan growth: +3% LQA (+$338mm Q-o-Q) or +12% LQA ex. PPP (+$1.1bn). Growth in all major loan portfolios, with strongest growth from C&I ex. PPP. 3Q21 avg. deposit growth: +26% LQA (+$3.3bn Q-o-Q). Growth was led by non-IB DDA: +69% LQA (+$3.5bn Q-o-Q). Avg. DDA made up 43% of avg. deposits in 3Q21, up from 39% in 2Q21 and 35% in 3Q20. 3Q21 AEA growth: +24% LQA (+$3.3bn Q-o-Q). Increase of +$2.0bn in interest-bearing cash and deposits with banks, +$786mm in AFS debt securities, +$253mm in repurchase agreements. $ in b ill io ns Average Loans & Growth +11% +9%+6% LQA avg. total loan growth C&I (ex. PPP) Total CRE Residential mortgage & other consumerPPP Average Deposits & Growth Avg. Earning Asset (AEA) Mix & Loan-to-Deposit Ratio LQA avg. total deposit growthDDA MMDA IB Checking & Savings Time $ in b ill io ns +26% +31% +20% +31% +3%
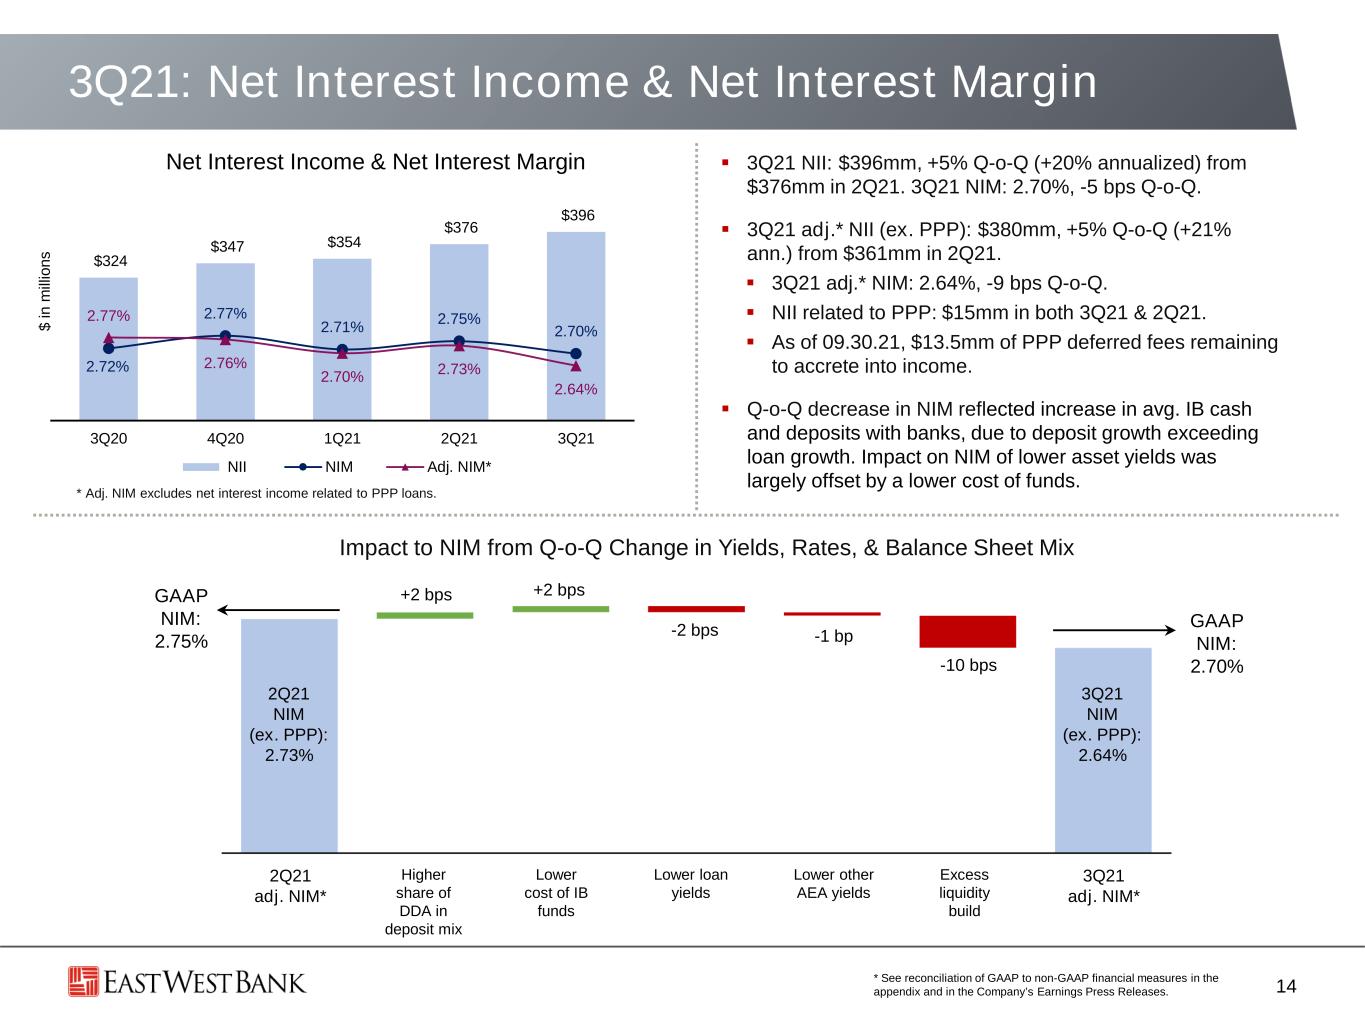
$324 $347 $354 $376 $396 2.72% 2.77% 2.71% 2.75% 2.70% 2.77% 2.76% 2.70% 2.73% 2.64% 3Q20 4Q20 1Q21 2Q21 3Q21 NII NIM Adj. NIM* 3Q21: Net Interest Income & Net Interest Margin 14 3Q21 NII: $396mm, +5% Q-o-Q (+20% annualized) from $376mm in 2Q21. 3Q21 NIM: 2.70%, -5 bps Q-o-Q. 3Q21 adj.* NII (ex. PPP): $380mm, +5% Q-o-Q (+21% ann.) from $361mm in 2Q21. 3Q21 adj.* NIM: 2.64%, -9 bps Q-o-Q. NII related to PPP: $15mm in both 3Q21 & 2Q21. As of 09.30.21, $13.5mm of PPP deferred fees remaining to accrete into income. Q-o-Q decrease in NIM reflected increase in avg. IB cash and deposits with banks, due to deposit growth exceeding loan growth. Impact on NIM of lower asset yields was largely offset by a lower cost of funds. Impact to NIM from Q-o-Q Change in Yields, Rates, & Balance Sheet Mix $ in m ill io ns 2Q21 adj. NIM* 3Q21 adj. NIM* Higher share of DDA in deposit mix GAAP NIM: 2.75% +2 bps +2 bps -2 bps -1 bp 2Q21 NIM (ex. PPP): 2.73% GAAP NIM: 2.70% Excess liquidity build Lower other AEA yields Lower loan yields * See reconciliation of GAAP to non-GAAP financial measures in the appendix and in the Company’s Earnings Press Releases. Net Interest Income & Net Interest Margin * Adj. NIM excludes net interest income related to PPP loans. Lower cost of IB funds 3Q21 NIM (ex. PPP): 2.64% -10 bps
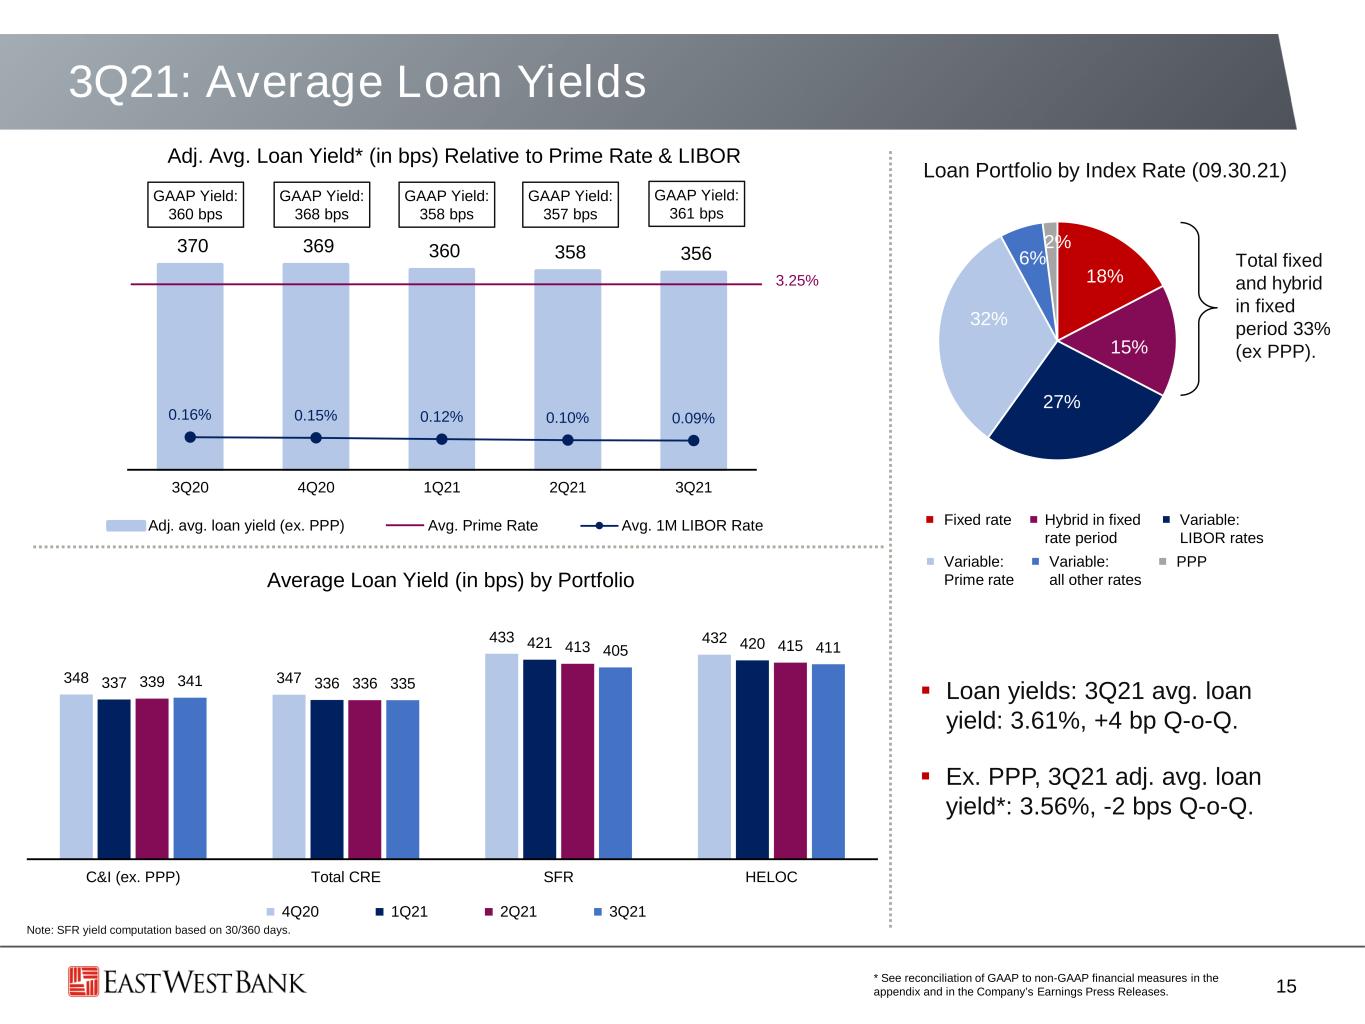
18% 15% 27% 32% 6% 2%370 369 360 358 356 0.16% 0.15% 0.12% 0.10% 0.09% 0 400 -1% 4% 3Q20 4Q20 1Q21 2Q21 3Q21 Adj. avg. loan yield (ex. PPP) Avg. Prime Rate Avg. 1M LIBOR Rate 3Q21: Average Loan Yields 15 Adj. Avg. Loan Yield* (in bps) Relative to Prime Rate & LIBOR Average Loan Yield (in bps) by Portfolio GAAP Yield: 361 bps GAAP Yield: 368 bps GAAP Yield: 358 bps * See reconciliation of GAAP to non-GAAP financial measures in the appendix and in the Company’s Earnings Press Releases. GAAP Yield: 357 bps Total fixed and hybrid in fixed period 33% (ex PPP). Variable: LIBOR rates Hybrid in fixed rate period Fixed rate Variable: Prime rate Variable: all other rates PPP Loan Portfolio by Index Rate (09.30.21) Loan yields: 3Q21 avg. loan yield: 3.61%, +4 bp Q-o-Q. Ex. PPP, 3Q21 adj. avg. loan yield*: 3.56%, -2 bps Q-o-Q. Note: SFR yield computation based on 30/360 days. 3.25% GAAP Yield: 360 bps 348 347 433 432 337 336 421 420 339 336 413 415 341 335 405 411 C&I (ex. PPP) Total CRE SFR HELOC 4Q20 1Q21 2Q21 3Q21
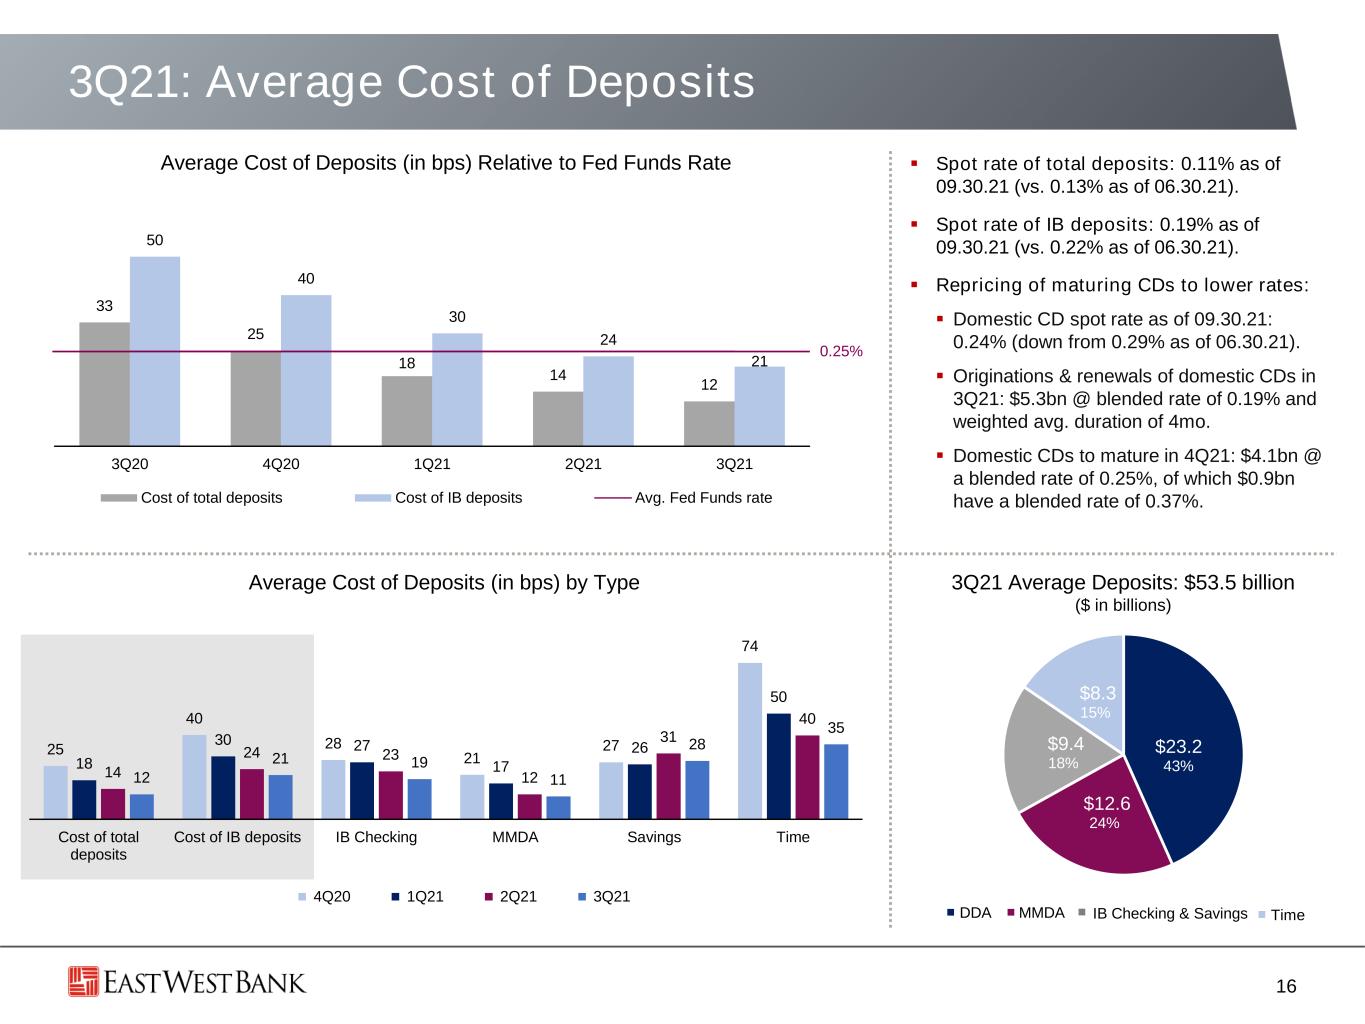
33 25 18 14 12 50 40 30 24 21 0.00 3Q20 4Q20 1Q21 2Q21 3Q21 Cost of total deposits Cost of IB deposits Avg. Fed Funds rate 3Q21: Average Cost of Deposits 16 Average Cost of Deposits (in bps) Relative to Fed Funds Rate Spot rate of total deposits: 0.11% as of 09.30.21 (vs. 0.13% as of 06.30.21). Spot rate of IB deposits: 0.19% as of 09.30.21 (vs. 0.22% as of 06.30.21). Repricing of maturing CDs to lower rates: Domestic CD spot rate as of 09.30.21: 0.24% (down from 0.29% as of 06.30.21). Originations & renewals of domestic CDs in 3Q21: $5.3bn @ blended rate of 0.19% and weighted avg. duration of 4mo. Domestic CDs to mature in 4Q21: $4.1bn @ a blended rate of 0.25%, of which $0.9bn have a blended rate of 0.37%. Average Cost of Deposits (in bps) by Type DDA MMDA IB Checking & Savings Time 3Q21 Average Deposits: $53.5 billion ($ in billions) 0.25% $23.2 43% $12.6 24% $9.4 18% $8.3 15% 25 40 28 21 27 74 18 30 27 17 26 50 14 24 23 12 31 40 12 21 19 11 28 35 Cost of total deposits Cost of IB deposits IB Checking MMDA Savings Time 4Q20 1Q21 2Q21 3Q21
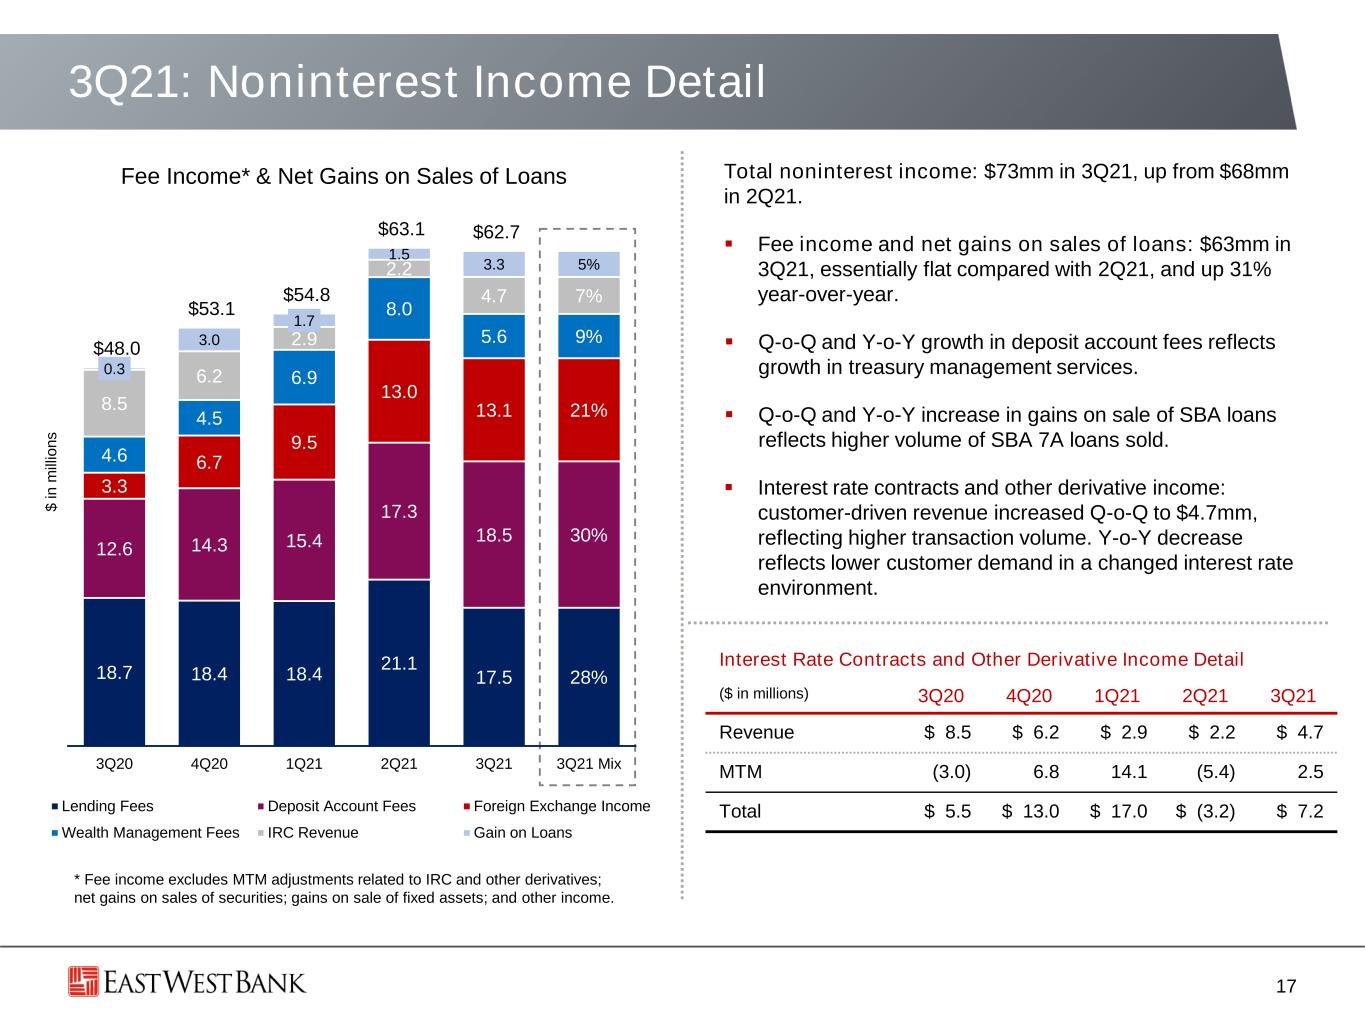
3Q21: Noninterest Income Detail Total noninterest income: $73mm in 3Q21, up from $68mm in 2Q21. Fee income and net gains on sales of loans: $63mm in 3Q21, essentially flat compared with 2Q21, and up 31% year-over-year. Q-o-Q and Y-o-Y growth in deposit account fees reflects growth in treasury management services. Q-o-Q and Y-o-Y increase in gains on sale of SBA loans reflects higher volume of SBA 7A loans sold. Interest rate contracts and other derivative income: customer-driven revenue increased Q-o-Q to $4.7mm, reflecting higher transaction volume. Y-o-Y decrease reflects lower customer demand in a changed interest rate environment. 17 Interest Rate Contracts and Other Derivative Income Detail ($ in millions) 3Q20 4Q20 1Q21 2Q21 3Q21 Revenue $ 8.5 $ 6.2 $ 2.9 $ 2.2 $ 4.7 MTM (3.0) 6.8 14.1 (5.4) 2.5 Total $ 5.5 $ 13.0 $ 17.0 $ (3.2) $ 7.2 * Fee income excludes MTM adjustments related to IRC and other derivatives; net gains on sales of securities; gains on sale of fixed assets; and other income. Fee Income* & Net Gains on Sales of Loans $ in m ill io ns 18.7 18.4 18.4 21.1 17.5 28% 12.6 14.3 15.4 17.3 18.5 30% 3.3 6.7 9.5 13.0 13.1 21% 4.6 4.5 6.9 8.0 5.6 9% 8.5 6.2 2.9 2.2 4.7 7% 0.3 3.0 1.7 1.5 3.3 5% $48.0 $53.1 $54.8 $63.1 $62.7 0.0 50.0 3Q20 4Q20 1Q21 2Q21 3Q21 3Q21 Mix Lending Fees Deposit Account Fees Foreign Exchange Income Wealth Management Fees IRC Revenue Gain on Loans
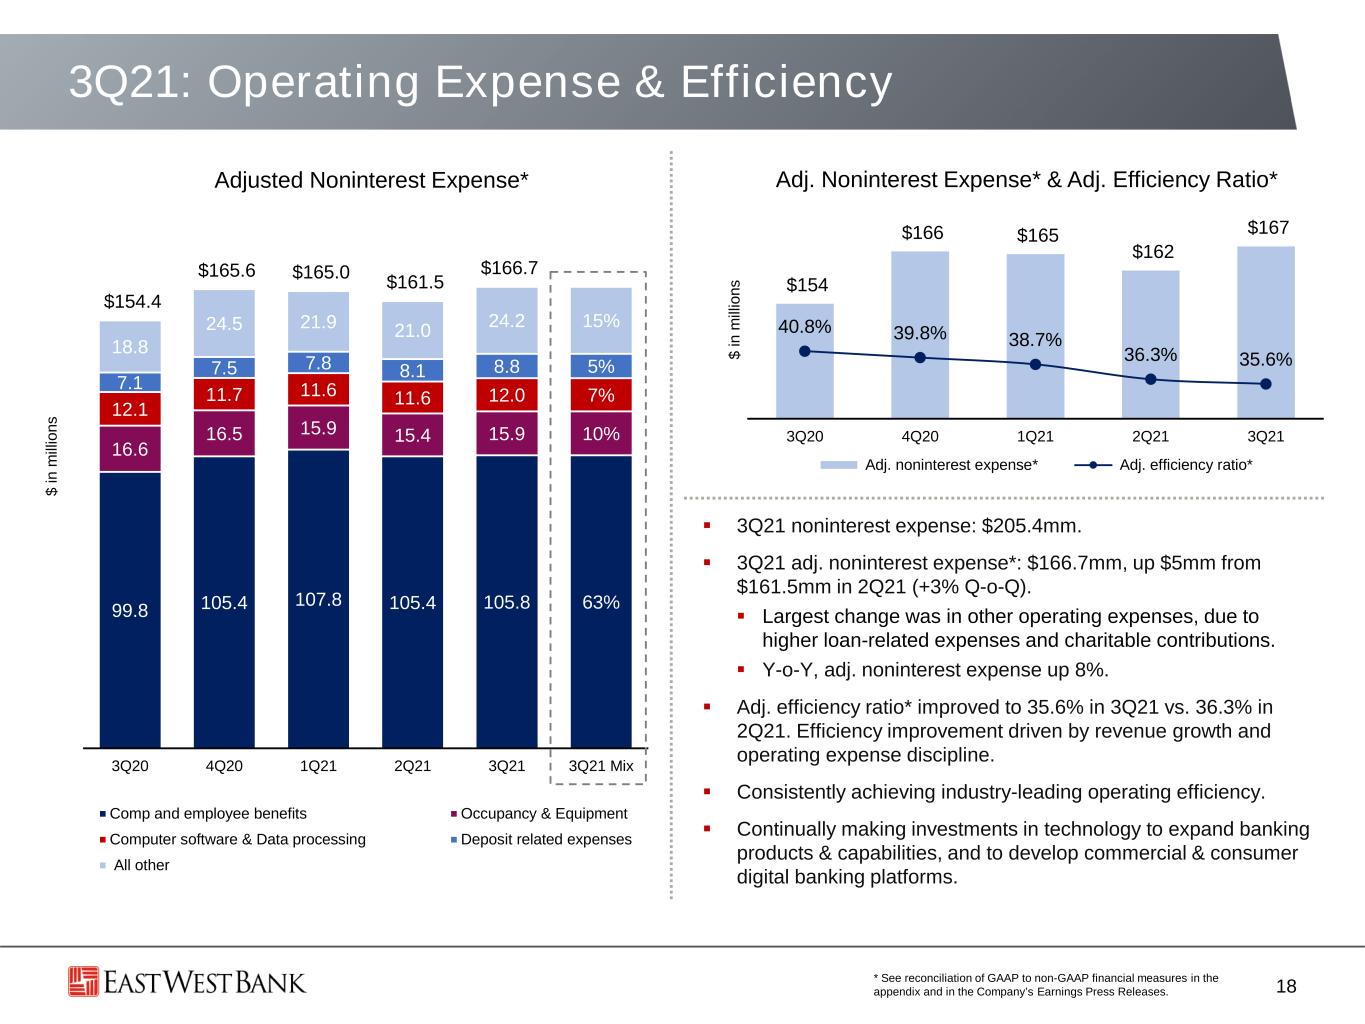
99.8 105.4 107.8 105.4 105.8 63% 16.6 16.5 15.9 15.4 15.9 10% 12.1 11.7 11.6 11.6 12.0 7%7.1 7.5 7.8 8.1 8.8 5% 18.8 24.5 21.9 21.0 24.2 15% $154.4 $165.6 $165.0 $161.5 $166.7 3Q20 4Q20 1Q21 2Q21 3Q21 3Q21 Mix Comp and employee benefits Occupancy & Equipment Computer software & Data processing Deposit related expenses All other 3Q21: Operating Expense & Efficiency 18 Adjusted Noninterest Expense* $ in m ill io ns Adj. Noninterest Expense* & Adj. Efficiency Ratio* 3Q21 noninterest expense: $205.4mm. 3Q21 adj. noninterest expense*: $166.7mm, up $5mm from $161.5mm in 2Q21 (+3% Q-o-Q). Largest change was in other operating expenses, due to higher loan-related expenses and charitable contributions. Y-o-Y, adj. noninterest expense up 8%. Adj. efficiency ratio* improved to 35.6% in 3Q21 vs. 36.3% in 2Q21. Efficiency improvement driven by revenue growth and operating expense discipline. Consistently achieving industry-leading operating efficiency. Continually making investments in technology to expand banking products & capabilities, and to develop commercial & consumer digital banking platforms. $ in m ill io ns * See reconciliation of GAAP to non-GAAP financial measures in the appendix and in the Company’s Earnings Press Releases. $154 $166 $165 $162 $167 40.8% 39.8% 38.7% 36.3% 35.6% 30.0% 60.0% $130 3Q20 4Q20 1Q21 2Q21 3Q21 Adj. noninterest expense* Adj. efficiency ratio*
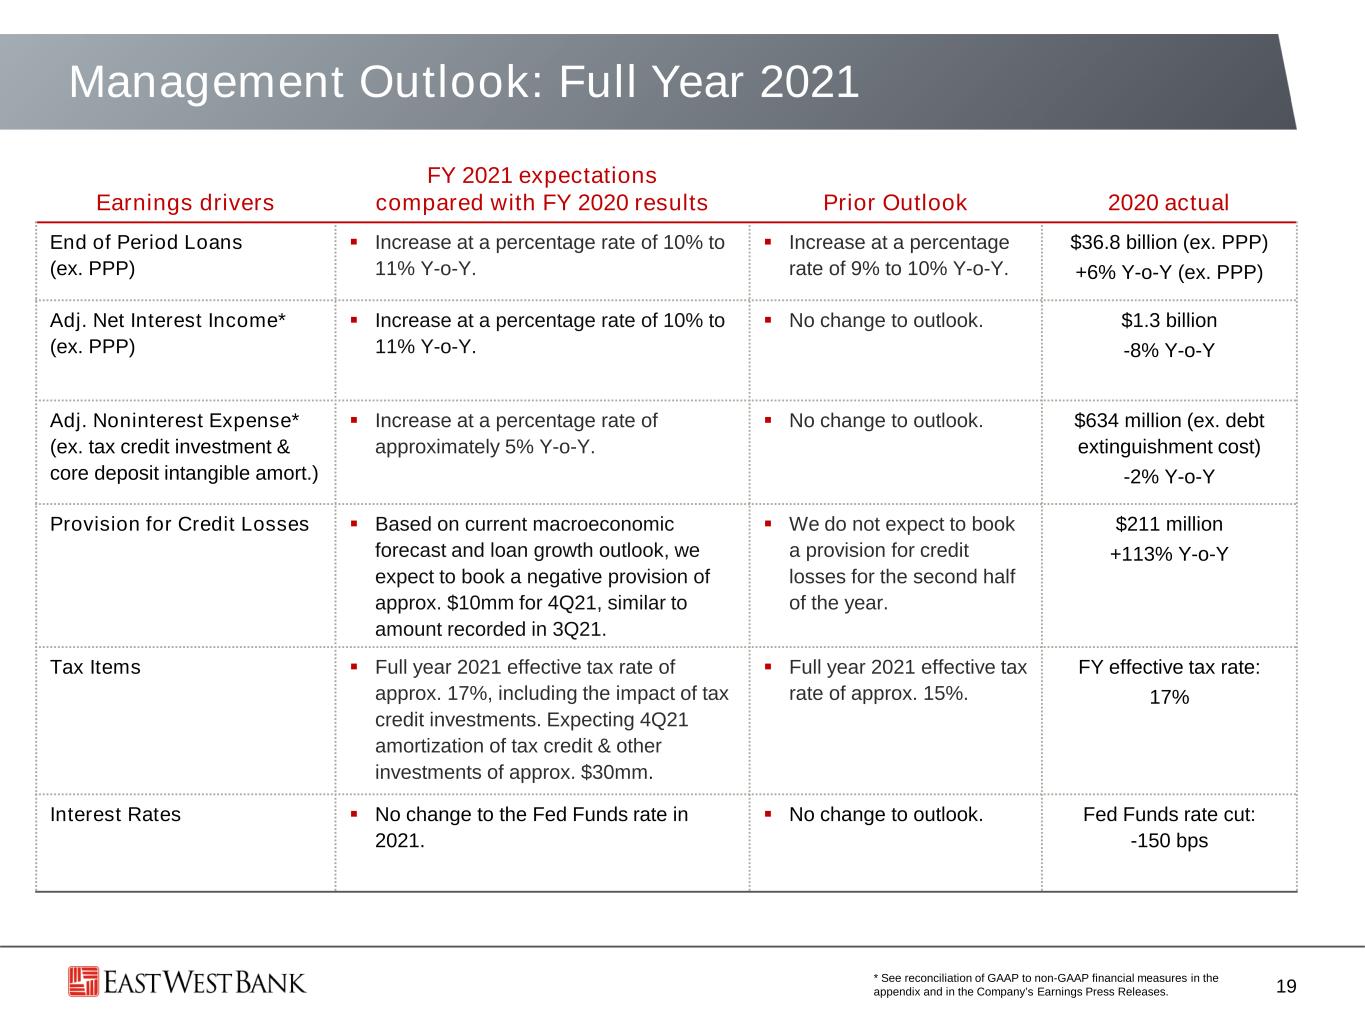
Management Outlook: Full Year 2021 19 Earnings drivers FY 2021 expectations compared with FY 2020 results Prior Outlook 2020 actual End of Period Loans (ex. PPP) Increase at a percentage rate of 10% to 11% Y-o-Y. Increase at a percentage rate of 9% to 10% Y-o-Y. $36.8 billion (ex. PPP) +6% Y-o-Y (ex. PPP) Adj. Net Interest Income* (ex. PPP) Increase at a percentage rate of 10% to 11% Y-o-Y. No change to outlook. $1.3 billion -8% Y-o-Y Adj. Noninterest Expense* (ex. tax credit investment & core deposit intangible amort.) Increase at a percentage rate of approximately 5% Y-o-Y. No change to outlook. $634 million (ex. debt extinguishment cost) -2% Y-o-Y Provision for Credit Losses Based on current macroeconomic forecast and loan growth outlook, we expect to book a negative provision of approx. $10mm for 4Q21, similar to amount recorded in 3Q21. We do not expect to book a provision for credit losses for the second half of the year. $211 million +113% Y-o-Y Tax Items Full year 2021 effective tax rate of approx. 17%, including the impact of tax credit investments. Expecting 4Q21 amortization of tax credit & other investments of approx. $30mm. Full year 2021 effective tax rate of approx. 15%. FY effective tax rate: 17% Interest Rates No change to the Fed Funds rate in 2021. No change to outlook. Fed Funds rate cut: -150 bps * See reconciliation of GAAP to non-GAAP financial measures in the appendix and in the Company’s Earnings Press Releases.
APPENDIX
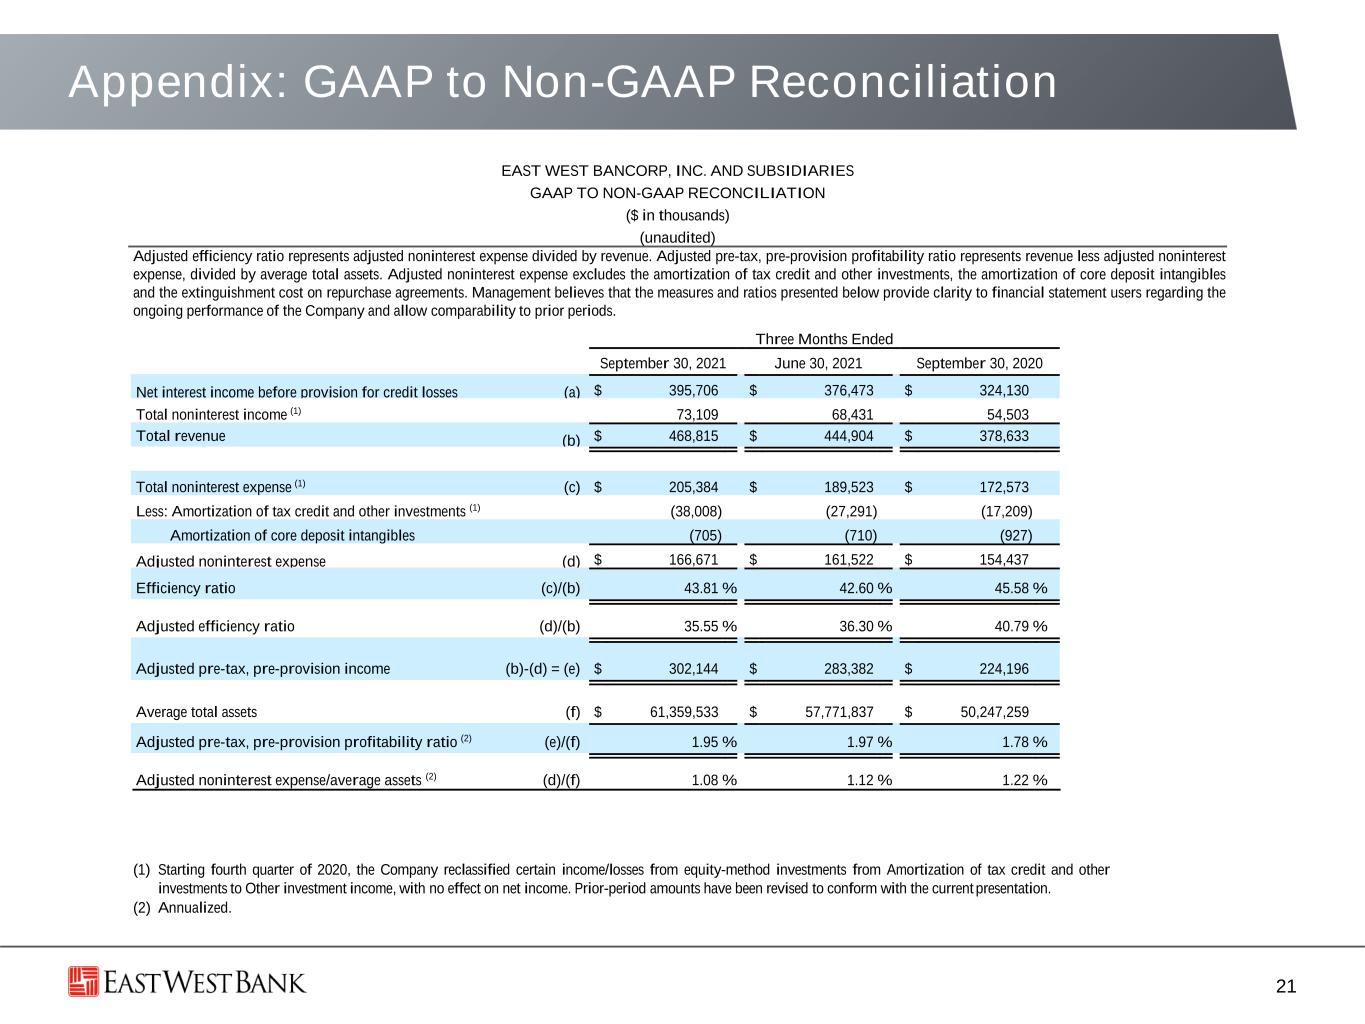
Three Months Ended September 30, 2021 June 30, 2021 September 30, 2020 Net interest income before provision for credit losses (a) $ 395,706 $ 376,473 $ 324,130 Total noninterest income (1) 73,109 68,431 54,503 Total revenue (b) $ 468,815 $ 444,904 $ 378,633 Total noninterest expense (1) (c) $ 205,384 $ 189,523 $ 172,573 Less: Amortization of tax credit and other investments (1) (38,008) (27,291) (17,209) Amortization of core deposit intangibles (705) (710) (927) Adjusted noninterest expense (d) $ 166,671 $ 161,522 $ 154,437 Efficiency ratio (c)/(b) 43.81 % 42.60 % 45.58 % Adjusted efficiency ratio (d)/(b) 35.55 % 36.30 % 40.79 % Adjusted pre-tax, pre-provision income (b)-(d) = (e) $ 302,144 $ 283,382 $ 224,196 Average total assets (f) $ 61,359,533 $ 57,771,837 $ 50,247,259 Adjusted pre-tax, pre-provision profitability ratio (2) (e)/(f) 1.95 % 1.97 % 1.78 % Adjusted noninterest expense/average assets (2) (d)/(f) 1.08 % 1.12 % 1.22 % Appendix: GAAP to Non-GAAP Reconciliation 21 EAST WEST BANCORP, INC. AND SUBSIDIARIES GAAP TO NON-GAAP RECONCILIATION ($ in thousands) (unaudited) Adjusted efficiency ratio represents adjusted noninterest expense divided by revenue. Adjusted pre-tax, pre-provision profitability ratio represents revenue less adjusted noninterest expense, divided by average total assets. Adjusted noninterest expense excludes the amortization of tax credit and other investments, the amortization of core deposit intangibles and the extinguishment cost on repurchase agreements. Management believes that the measures and ratios presented below provide clarity to financial statement users regarding the ongoing performance of the Company and allow comparability to prior periods. (1) Starting fourth quarter of 2020, the Company reclassified certain income/losses from equity-method investments from Amortization of tax credit and other investments to Other investment income, with no effect on net income. Prior-period amounts have been revised to conform with the current presentation. (2) Annualized.
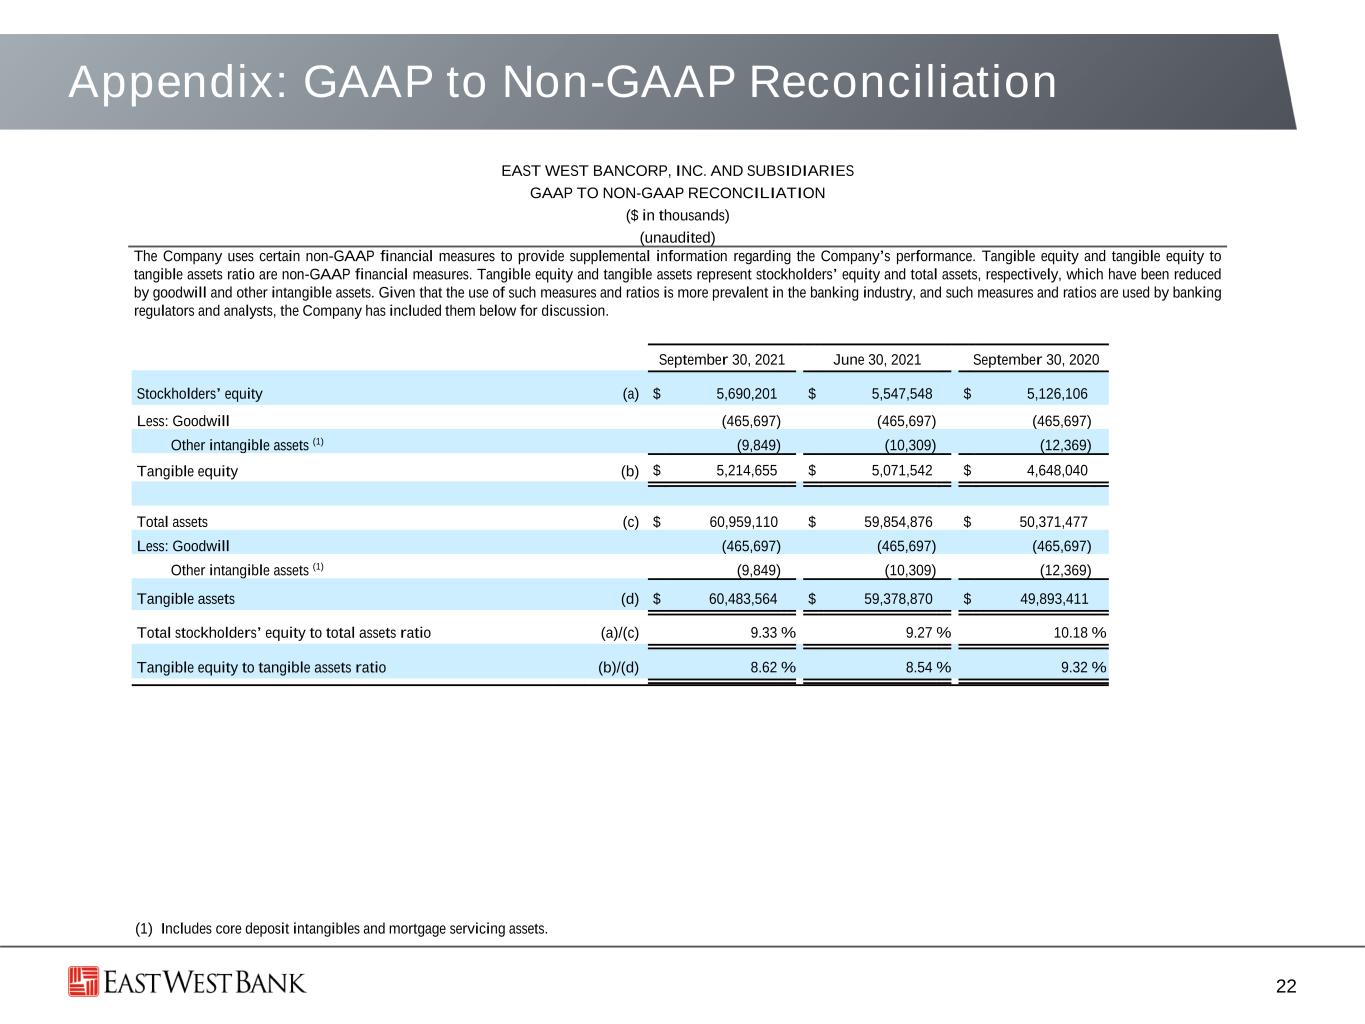
Appendix: GAAP to Non-GAAP Reconciliation 22 EAST WEST BANCORP, INC. AND SUBSIDIARIES GAAP TO NON-GAAP RECONCILIATION ($ in thousands) (unaudited) The Company uses certain non-GAAP financial measures to provide supplemental information regarding the Company’s performance. Tangible equity and tangible equity to tangible assets ratio are non-GAAP financial measures. Tangible equity and tangible assets represent stockholders’ equity and total assets, respectively, which have been reduced by goodwill and other intangible assets. Given that the use of such measures and ratios is more prevalent in the banking industry, and such measures and ratios are used by banking regulators and analysts, the Company has included them below for discussion. (1) Includes core deposit intangibles and mortgage servicing assets. September 30, 2021 June 30, 2021 September 30, 2020 Stockholders’ equity (a) $ 5,690,201 $ 5,547,548 $ 5,126,106 Less: Goodwill (465,697) (465,697) (465,697) Other intangible assets (1) (9,849) (10,309) (12,369) Tangible equity (b) $ 5,214,655 $ 5,071,542 $ 4,648,040 Total assets (c) $ 60,959,110 $ 59,854,876 $ 50,371,477 Less: Goodwill (465,697) (465,697) (465,697) Other intangible assets (1) (9,849) (10,309) (12,369) Tangible assets (d) $ 60,483,564 $ 59,378,870 $ 49,893,411 Total stockholders’ equity to total assets ratio (a)/(c) 9.33 % 9.27 % 10.18 % Tangible equity to tangible assets ratio (b)/(d) 8.62 % 8.54 % 9.32 %
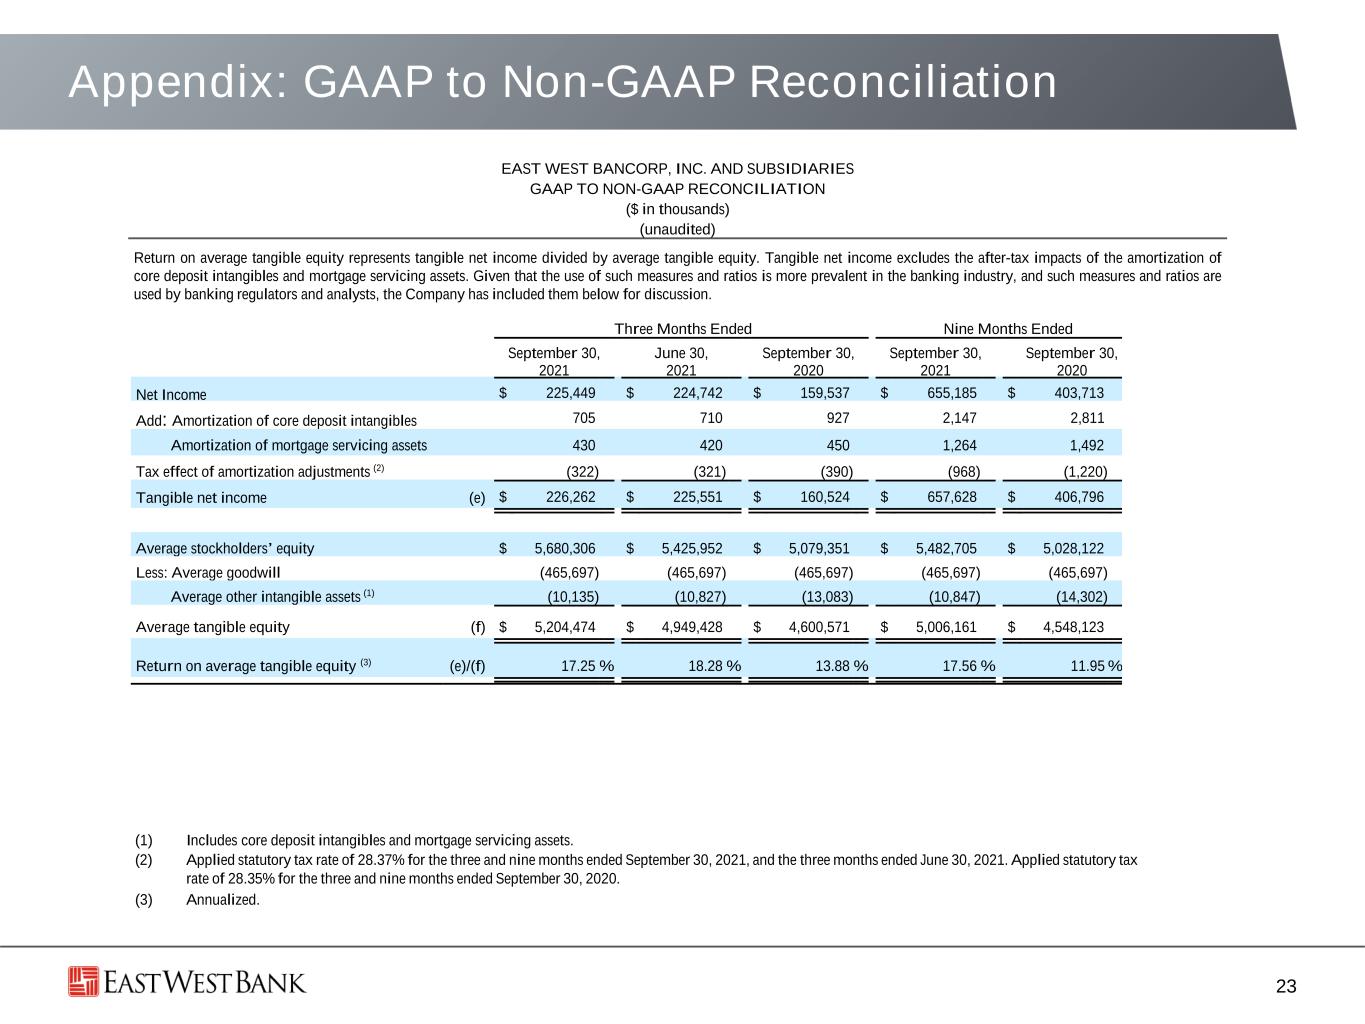
Appendix: GAAP to Non-GAAP Reconciliation 23 EAST WEST BANCORP, INC. AND SUBSIDIARIES GAAP TO NON-GAAP RECONCILIATION ($ in thousands) (unaudited) Return on average tangible equity represents tangible net income divided by average tangible equity. Tangible net income excludes the after-tax impacts of the amortization of core deposit intangibles and mortgage servicing assets. Given that the use of such measures and ratios is more prevalent in the banking industry, and such measures and ratios are used by banking regulators and analysts, the Company has included them below for discussion. (1) Includes core deposit intangibles and mortgage servicing assets. (2) Applied statutory tax rate of 28.37% for the three and nine months ended September 30, 2021, and the three months ended June 30, 2021. Applied statutory tax rate of 28.35% for the three and nine months ended September 30, 2020. (3) Annualized. Three Months Ended Nine Months Ended September 30, 2021 June 30, 2021 September 30, 2020 September 30, 2021 September 30, 2020 Net Income $ 225,449 $ 224,742 $ 159,537 $ 655,185 $ 403,713 Add: Amortization of core deposit intangibles 705 710 927 2,147 2,811 Amortization of mortgage servicing assets 430 420 450 1,264 1,492 Tax effect of amortization adjustments (2) (322) (321) (390) (968) (1,220) Tangible net income (e) $ 226,262 $ 225,551 $ 160,524 $ 657,628 $ 406,796 Average stockholders’ equity $ 5,680,306 $ 5,425,952 $ 5,079,351 $ 5,482,705 $ 5,028,122 Less: Average goodwill (465,697) (465,697) (465,697) (465,697) (465,697) Average other intangible assets (1) (10,135) (10,827) (13,083) (10,847) (14,302) Average tangible equity (f) $ 5,204,474 $ 4,949,428 $ 4,600,571 $ 5,006,161 $ 4,548,123 Return on average tangible equity (3) (e)/(f) 17.25 % 18.28 % 13.88 % 17.56 % 11.95 %
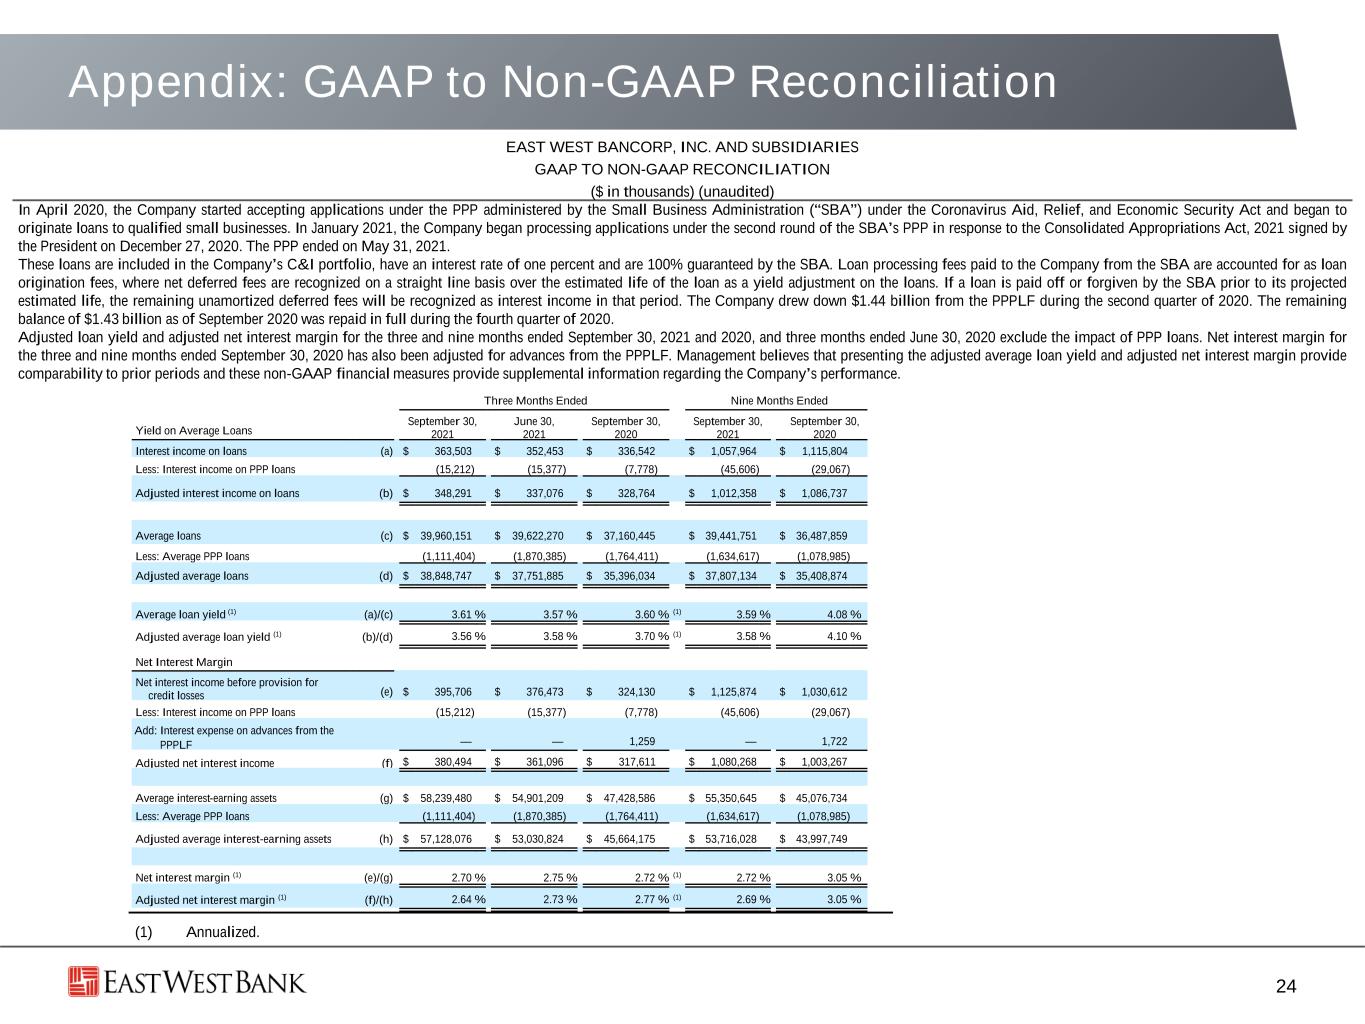
24 Appendix: GAAP to Non-GAAP Reconciliation EAST WEST BANCORP, INC. AND SUBSIDIARIES GAAP TO NON-GAAP RECONCILIATION ($ in thousands) (unaudited) In April 2020, the Company started accepting applications under the PPP administered by the Small Business Administration (“SBA”) under the Coronavirus Aid, Relief, and Economic Security Act and began to originate loans to qualified small businesses. In January 2021, the Company began processing applications under the second round of the SBA’s PPP in response to the Consolidated Appropriations Act, 2021 signed by the President on December 27, 2020. The PPP ended on May 31, 2021. These loans are included in the Company’s C&I portfolio, have an interest rate of one percent and are 100% guaranteed by the SBA. Loan processing fees paid to the Company from the SBA are accounted for as loan origination fees, where net deferred fees are recognized on a straight line basis over the estimated life of the loan as a yield adjustment on the loans. If a loan is paid off or forgiven by the SBA prior to its projected estimated life, the remaining unamortized deferred fees will be recognized as interest income in that period. The Company drew down $1.44 billion from the PPPLF during the second quarter of 2020. The remaining balance of $1.43 billion as of September 2020 was repaid in full during the fourth quarter of 2020. Adjusted loan yield and adjusted net interest margin for the three and nine months ended September 30, 2021 and 2020, and three months ended June 30, 2020 exclude the impact of PPP loans. Net interest margin for the three and nine months ended September 30, 2020 has also been adjusted for advances from the PPPLF. Management believes that presenting the adjusted average loan yield and adjusted net interest margin provide comparability to prior periods and these non-GAAP financial measures provide supplemental information regarding the Company’s performance. (1) Annualized. Three Months Ended Nine Months Ended Yield on Average Loans September 30, 2021 June 30, 2021 September 30, 2020 September 30, 2021 September 30, 2020 Interest income on loans (a) $ 363,503 $ 352,453 $ 336,542 $ 1,057,964 $ 1,115,804 Less: Interest income on PPP loans (15,212) (15,377) (7,778) (45,606) (29,067) Adjusted interest income on loans (b) $ 348,291 $ 337,076 $ 328,764 $ 1,012,358 $ 1,086,737 Average loans (c) $ 39,960,151 $ 39,622,270 $ 37,160,445 $ 39,441,751 $ 36,487,859 Less: Average PPP loans (1,111,404) (1,870,385) (1,764,411) (1,634,617) (1,078,985) Adjusted average loans (d) $ 38,848,747 $ 37,751,885 $ 35,396,034 $ 37,807,134 $ 35,408,874 Average loan yield (1) (a)/(c) 3.61 % 3.57 % 3.60 % (1) 3.59 % 4.08 % Adjusted average loan yield (1) (b)/(d) 3.56 % 3.58 % 3.70 % (1) 3.58 % 4.10 % Net Interest Margin Net interest income before provision for credit losses (e) $ 395,706 $ 376,473 $ 324,130 $ 1,125,874 $ 1,030,612 Less: Interest income on PPP loans (15,212) (15,377) (7,778) (45,606) (29,067) Add: Interest expense on advances from the PPPLF — — 1,259 — 1,722 Adjusted net interest income (f) $ 380,494 $ 361,096 $ 317,611 $ 1,080,268 $ 1,003,267 Average interest-earning assets (g) $ 58,239,480 $ 54,901,209 $ 47,428,586 $ 55,350,645 $ 45,076,734 Less: Average PPP loans (1,111,404) (1,870,385) (1,764,411) (1,634,617) (1,078,985) Adjusted average interest-earning assets (h) $ 57,128,076 $ 53,030,824 $ 45,664,175 $ 53,716,028 $ 43,997,749 Net interest margin (1) (e)/(g) 2.70 % 2.75 % 2.72 % (1) 2.72 % 3.05 % Adjusted net interest margin (1) (f)/(h) 2.64 % 2.73 % 2.77 % (1) 2.69 % 3.05 %