
EWBC 8-K
East West Bancorp Inc (EWBC)
8-K
2023-01-26
For: 2023-01-26
View Original
Added on
April 12, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 OR 15(d) of
The Securities Exchange Act of 1934
Date of Report (Date of earliest event reported)
(Exact name of registrant as specified in its charter)
(State or other jurisdiction of incorporation)
(Commission File Number)
(IRS Employer Identification No.)
(Address of principal executive offices) (Zip code)
(626 ) 768-6000
(Registrant’s telephone number, including area code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02. Results of Operations and Financial Condition
On January 26, 2023, East West Bancorp, Inc. (the “Company”) announced its financial results for the quarter and full year ended December 31, 2022. A copy of the Company’s press release (the “Press Release”) is attached as Exhibit 99.1 to this Current Report on Form 8-K and is incorporated by reference in this Item 2.02. The Press Release is “furnished” pursuant to General Instruction B.2 of Form 8-K and the information provided in Item 2.02 of this report, including Exhibit 99.1, shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934 (the “Exchange Act”), or otherwise subject to the liabilities of such Section. The information provided in Item 2.02 of this report, including Exhibit 99.1, shall not be deemed incorporated by reference into any filings the Company has made or may make under the Securities Act of 1933 (the “Securities Act”) or the Exchange Act, except as otherwise expressly stated in such filing.
Item 7.01. Regulation FD Disclosure
On January 26, 2023, the Company will hold a conference call to discuss its financial results for the quarter and full year ended December 31, 2022 and other matters relating to the Company. The Company has also made available on its website, www.eastwestbank.com, presentation materials containing certain historical and forward-looking information relating to the Company (the “Presentation Materials”). The Presentation Materials are furnished as Exhibit 99.2 and are incorporated by reference in this Item 7.01. All information in Exhibit 99.2 is presented as of the particular date or dates referenced therein, and the Company does not undertake any obligation to, and disclaims any duty to, update any of the information provided. The information provided in Item 7.01 of this report, including Exhibit 99.2, shall not be deemed “filed” for purposes of Section 18 of the Exchange Act, or otherwise subject to the liabilities of such Section, nor shall such information be deemed incorporated by reference into any filings the Company has made or may make under the Securities Act or the Exchange Act, except as otherwise expressly stated in such filing.
Item 9.01. Financial Statements and Exhibits
(d) Exhibits
| Press Release, dated January 26, 2023. | |||||
| Presentation Materials, dated January 26, 2023. | |||||
| 104 | Cover Page Interactive Data (formatted in Inline XBRL). | ||||
2
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| EAST WEST BANCORP, INC. | |||||||||||
| Date: January 26, 2023 | By: | /s/ Irene H. Oh | |||||||||
| Irene H. Oh | |||||||||||
| Executive Vice President and Chief Financial Officer | |||||||||||
3
| Exhibit 99.1 | |||||
 | East West Bancorp, Inc. | ||||
| 135 N. Los Robles Ave., 7th Fl. | |||||
| Pasadena, CA 91101 | |||||
| Tel. 626.768.6000 | |||||
NEWS RELEASE | |||||||||||
| FOR INVESTOR INQUIRIES, CONTACT: | |||||
Irene Oh | Julianna Balicka | ||||
Chief Financial Officer | Director of Investor Relations and Corporate Finance | ||||
T: (626) 768-6360 | T: (626) 768-6985 | ||||
| E: [email protected] | E: [email protected] | ||||
EAST WEST BANCORP REPORTS RECORD NET INCOME FOR FULL YEAR 2022
OF $1.1 BILLION AND RECORD DILUTED EARNINGS PER SHARE OF $7.92;
INCREASES DIVIDEND BY 20%
Pasadena, California – January 26, 2023 – East West Bancorp, Inc. (“East West” or the “Company”) (Nasdaq: EWBC), parent company of East West Bank, reported its financial results for the full year and fourth quarter of 2022. Full year 2022 net income was a record $1.1 billion, or $7.92 per diluted share, which grew 30% year-over-year. Fourth quarter 2022 net income was $336.8 million, or $2.37 per diluted share, which grew 56% year-over-year. Total loans reached a record $48.2 billion as of December 31, 2022, up 16% year-over-year, and total deposits grew to a record $56.0 billion, up 5% from a year ago.
“2023 marks the 50th anniversary of East West. I am very proud of the milestones and growth that East West has achieved throughout its history. We have distinguished ourselves with a long, well-established track record of strong financial performance,” stated Dominic Ng, Chairman and Chief Executive Officer of East West. “For the fourth quarter of 2022, we earned an industry-leading 2.1% return on average assets and 25.0% return on average tangible equity1.”
“East West Federal Savings Bank was founded in 1973 with a mission to serve the financial needs of Asian immigrants in Los Angeles, who were overlooked by mainstream banks. As our customers grew and prospered, achieving their personal and business ambitions, so did East West. With over $60 billion in total assets and annual earnings over $1 billion, East West has grown to be the largest independent bank headquartered in Southern California. Our customer base and geographic footprint expanded, along with the breadth and technological sophistication of our lending, deposit, and fee-based products and services. Today, we provide a seamless banking experience for clients on both sides of the Pacific, executing on our vision to be the bridge between the East and the West,” continued Ng.
“In celebrating our 50th anniversary, we are honored to be the bank of choice for our customers, and thankful and proud of all our associates for their dedication to our clients and East West. We are positive about 2023 and expect to continue our track record of outstanding profitability, achieved through solid revenue growth and disciplined expense management, while maintaining healthy capital levels. As we start the year, we are pleased to announce a 20% increase in our common stock dividend,” concluded Ng.
1 Return on average tangible equity is a non-GAAP financial measure. See reconciliation of GAAP to non-GAAP measures in Table 13. | |||||||||||
1
FINANCIAL HIGHLIGHTS
| Twelve Months Ended | Year-over-Year Change | ||||||||||||||||||||||
| ($ in millions, except per share data) | December 31, 2022 | $ | % | ||||||||||||||||||||
| Total Loans | $48,228 | $6,534 | 16% | ||||||||||||||||||||
| Total Deposits | 55,968 | 2,617 | 5 | ||||||||||||||||||||
| Total Revenue | $2,345 | $527 | 29% | ||||||||||||||||||||
Adj. Pre-tax, Pre-provision Income2 | 1,600 | 454 | 40 | ||||||||||||||||||||
| Net Income | 1,128 | 255 | 29 | ||||||||||||||||||||
| Diluted Earnings per Share | $7.92 | $1.82 | 30% | ||||||||||||||||||||
BALANCE SHEET
•Record Assets – Total assets reached $64.1 billion as of December 31, 2022, an increase of $1.5 billion or 2.5% from $62.6 billion as of September 30, 2022. Year-over-year, total assets grew $3.2 billion or 5.3% from $60.9 billion as of December 31, 2021.
Fourth quarter 2022 average interest-earning assets of $60.4 billion were up $897.5 million, or 1.5% (6.0% annualized), from $59.5 billion in the third quarter of 2022. Quarter-over-quarter, average loan growth of $752.6 million and growth in interest-bearing cash and deposits with banks of $696.7 million was partially offset by decreases in debt securities and assets purchased under resale agreements.
•Record Loans – Total loans reached $48.2 billion as of December 31, 2022, an increase of $771.3 million, or 1.6% (6.4% annualized), from $47.5 billion as of September 30, 2022. Year-over-year, total loans grew $6.5 billion, or 15.7%, from $41.7 billion as of December 31, 2021.
Fourth quarter 2022 average loans of $47.6 billion grew $752.6 million, or 1.6% (6.4% annualized), from the third quarter. Average loan growth was well-balanced across all our major loan categories of commercial real estate, commercial & industrial, and residential mortgage.
•Record Deposits – Total deposits were $56.0 billion as of December 31, 2022, an increase of $2.1 billion, or 3.9% (15.5% annualized), from $53.9 billion as of September 30, 2022. Year-over-year, deposits grew $2.6 billion, or 4.9%, from $53.4 billion as of December 31, 2021.
Fourth quarter 2022 average deposits of $55.0 billion increased $932.2 million, or 1.7% (6.8% annualized) from the third quarter, driven by growth in time deposits, partially offset by declines in other deposit categories. Growth in time deposits in the fourth quarter reflected a successful branch-based CD campaign. Average noninterest-bearing deposits made up 39% of average total deposits in the fourth quarter of 2022, compared with 41% in the third quarter of 2022 and 44% in the fourth quarter of 2021.
•Strong Capital Levels – As of December 31, 2022, stockholders’ equity was $6.0 billion, or $42.46 per common share, up 5.7% quarter-over-quarter, and tangible equity3 per common share was $39.10, up 6.2% from September 30, 2022. As of December 31, 2022, the stockholders’ equity to assets ratio was 9.33%, an increase of 28 basis points quarter-over-quarter, and the tangible equity to tangible assets ratio3 was 8.66%, an increase of 31 basis points quarter-over-quarter. The common equity tier 1 (“CET1”) capital ratio was 12.7%, and the total risk-based capital ratio was 14.0% as of December 31, 2022; all regulatory capital ratios expanded quarter-over-quarter.
•Dividend Increase – The first quarter 2023 common stock dividend was increased by 20%, or eight cents per share. The new quarterly dividend is $0.48 per share, up from $0.40 per share. The new annual dividend is $1.92 per share, compared with $1.60 per share previously.
2 Adjusted pre-tax, pre-provision income is a non-GAAP financial measure. See reconciliation of GAAP to non-GAAP measures in Table 12. | |||||||||||
3 Tangible equity and the tangible equity to tangible assets ratio are non-GAAP financial measures. See reconciliation of GAAP to non-GAAP measures in Table 13. | |||||||||||
2
OPERATING RESULTS
Full Year Earnings – Full year 2022 net income was $1.1 billion, an increase of 29.2% from $873.0 million for the full year 2021. Full year 2022 diluted earnings per share were $7.92, an increase of 29.8% from $6.10 per diluted share for the full year 2021.
Fourth Quarter Earnings – Fourth quarter 2022 net income was $336.8 million, an increase of 14.0% (55.6% annualized) from $295.3 million for the third quarter of 2022, and an increase of 54.6% from $217.8 million for the fourth quarter of 2021. Fourth quarter 2022 diluted earnings per share were $2.37, an increase of 13.9% (55.2% annualized) from $2.08 per diluted share for the third quarter 2022, and an increase of 55.9% from $1.52 per diluted share for the year-ago quarter.
Fourth Quarter 2022 Compared to Third Quarter 2022
Net Interest Income and Net Interest Margin
Record net interest income (“NII”) totaled $605.5 million, an increase of 9.7% (38.6% annualized) from $551.8 million. Net interest margin (“NIM”) of 3.98% expanded 30 basis points from 3.68%.
•NII growth and NIM expansion were driven by higher earning asset yields, partially offset by higher cost of funds.
•The average loan yield was 5.59%, up 84 basis points from the third quarter. The average interest-earning asset yield was 5.00%, up 81 basis points from the third quarter. Average loans made up 79% of average interest-earning assets in the fourth quarter of 2022, essentially unchanged from the third quarter of 2022.
•The average cost of funds was 1.11%, up 56 basis points from the third quarter. The average cost of deposits was 1.06%, up 55 basis points, and the average cost of interest-bearing deposits was 1.74%, up 88 basis points from the third quarter.
•The changes in yields and rates reflected rising benchmark interest rates.
Noninterest Income
Noninterest income totaled $64.9 million in the fourth quarter, a decrease of $10.6 million, or 14.1%, from $75.6 million in the third quarter.
•Fee income and net gains on sales of loans were $66.0 million, a decrease of $3.1 million, or 4.5% (17.7% annualized), from $69.0 million in the third quarter.
•Interest rate contracts (“IRC”) and other derivative income was a loss of $0.6 million in the fourth quarter, compared with income of $8.8 million in the third quarter. The quarter-over-quarter decrease of $9.4 million was due to an unfavorable change in the credit valuation adjustment. The mark-to-market on IRC and other derivatives was $(4.6) million in the fourth quarter, compared with $4.8 million in the third quarter. Customer-driven IRC revenue of $4.0 million in the fourth quarter was essentially unchanged from the third quarter.
Noninterest Expense
Noninterest expense totaled $257.1 million in the fourth quarter, compared with $216.0 million in the third quarter. Fourth quarter noninterest expense consisted of $192.1 million of adjusted noninterest expense4, $64.6 million in amortization of tax credit and other investments, and $0.4 million in amortization of core deposit intangibles.
•Adjusted noninterest expense of $192.1 million decreased $3.5 million, or 1.8% (7.1% annualized), from $195.6 million in the third quarter, largely driven by lower compensation and employee benefits expense.
•Amortization of tax credit and other investments totaled $64.6 million in the fourth quarter, compared with $19.9 million in the third quarter. Quarter-over-quarter variability in the amortization of tax credits and other investments partially reflects the impact of investments that close in a given period.
•The adjusted efficiency ratio4 was 28.7% in the fourth quarter, compared with 31.2% in the third quarter.
TAX RELATED ITEMS
Full year 2022 income tax expense was $283.6 million, and the effective tax rate was 20.1%, compared with income tax expense of $183.4 million and an effective tax rate of 17.4% for the full year 2021. Fourth quarter 2022 income tax expense was $51.6 million, and the effective tax rate was 13.3%, compared with income tax expense of $89.0 million and an effective tax rate of 23.2% for the third quarter of 2022.
4 Adjusted noninterest expense and the adjusted efficiency ratio are non-GAAP financial measures. See reconciliation of GAAP to non-GAAP measures in Table 12. | |||||||||||
3
ASSET QUALITY
The asset quality of our loan portfolio continued to be solid and stable, with decreases in both classified and special mention loans, as well as very low nonperforming asset and net charge-off ratios. Provision for credit losses was $25.0 million for the fourth quarter of 2022, compared with $27.0 million for the third quarter of 2022.
•Criticized loans decreased $9.2 million, or 1.0%, quarter-over-quarter to $896.0 million as of December 31, 2022, down from $905.2 million as of September 30, 2022. Classified loans decreased 1.6% quarter-over-quarter to $427.5 million, and special mention loans decreased 0.5% to $468.5 million.
•The criticized loans ratio decreased five basis points quarter-over-quarter to 1.86% of loans held-for-investment (“HFI”) as of December 31, 2022, down from 1.91% as of September 30, 2022. The classified loans ratio decreased three basis points quarter-over-quarter to 0.89%, and the special mention loans ratio decreased two basis points to 0.97%.
•As of December 31, 2022, nonperforming assets were $99.8 million, or 0.16% of total assets, compared with $97.0 million, or 0.16% of total assets, as of September 30, 2022.
•Fourth quarter 2022 net charge-offs were $10.1 million, or annualized 0.08% of average loans HFI, compared with net charge-offs of $6.6 million, or annualized 0.06% of average loans HFI, for the third quarter of 2022.
•The allowance for loan losses totaled $595.6 million, or 1.24% of loans HFI, as of December 31, 2022, compared with $582.5 million, or 1.23% of loans HFI, as of September 30, 2022.
CAPITAL STRENGTH
Capital levels for East West are strong. The following table presents the regulatory capital metrics as of December 31, 2022, September 30, 2022 and December 31, 2021.
| EWBC Risk-Based Capital Ratios | |||||||||||||||||||||||||||||
| ($ in millions) | December 31, 2022 (a) | September 30, 2022 (a) | December 31, 2021 (a) | ||||||||||||||||||||||||||
| CET1 capital ratio | 12.7% | 12.3% | 12.8% | ||||||||||||||||||||||||||
| Tier 1 capital ratio | 12.7% | 12.3% | 12.8% | ||||||||||||||||||||||||||
| Total capital ratio | 14.0% | 13.6% | 14.1% | ||||||||||||||||||||||||||
| Leverage ratio | 9.8% | 9.6% | 9.0% | ||||||||||||||||||||||||||
Risk-Weighted Assets (“RWA”) (b) | $50,087 | $49,266 | $43,585 | ||||||||||||||||||||||||||
(a)The Company has elected to use the 2020 CECL transition provision in the calculation of its December 31, 2022, September 30, 2022 and December 31, 2021 regulatory capital ratios. The Company’s December 31, 2022 regulatory capital ratios and RWA are preliminary.
(b)Under regulatory guidelines, on-balance sheet assets and credit equivalent amounts of derivatives and off-balance sheet items are assigned to one of several broad risk categories based on the nature of the obligor, or, if relevant, the guarantor or the nature of any collateral. The aggregate dollar value in each risk category is then multiplied by the risk weight associated with that category. The resulting weighted values from each of the risk categories are aggregated for determining total RWA.
DIVIDEND PAYOUT AND CAPITAL ACTIONS
East West’s Board of Directors has declared first quarter 2023 dividends for the Company’s common stock. The common stock cash dividend of $0.48 per share is payable on February 21, 2023, to stockholders of record on February 6, 2023. This represents a 20% increase, or eight cents per share, to the quarterly common stock dividend, up from $0.40 per share previously. The new annual dividend is $1.92 per share, compared with $1.60 per share previously.
On March 3, 2020, East West’s Board of Directors authorized the repurchase of up to $500 million of East West’s common stock, of which $254 million remains available. East West did not repurchase any shares during the fourth quarter of 2022.
4
Conference Call
East West will host a conference call to discuss fourth quarter and full year 2022 earnings with the public on Thursday, January 26, 2023, at 8:30 a.m. PT/11:30 a.m. ET. The public and investment community are invited to listen as management discusses fourth quarter and full year 2022 results and operating developments.
•The following dial-in information is provided for participation in the conference call: calls within the U.S. – (877) 506-6399; calls within Canada – (855) 669-9657; international calls – (412) 902-6699.
•A presentation to accompany the earnings call will be available on the Investor Relations page of the Company’s website at www.eastwestbank.com/investors.
•A listen-only live broadcast of the call will also be available on the Investor Relations page of the Company’s website at www.eastwestbank.com/investors.
•A replay of the conference call will be available on January 26, 2023, at 11:30 a.m. PT/2:30 p.m. ET through February 26, 2023. The replay numbers are: within the U.S. – (877) 344-7529; within Canada – (855) 669-9658; international calls – (412) 317-0088; and the replay access code is: 4372128.
5
About East West
East West Bancorp, Inc. is a public company with total assets of $64.1 billion and is traded on the Nasdaq Global Select Market under the symbol “EWBC”. The Company’s wholly-owned subsidiary, East West Bank, is the largest independent bank headquartered in Southern California, operating over 120 locations in the United States and in Asia. The Company’s markets in the United States include California, Georgia, Illinois, Massachusetts, Nevada, New York, Texas and Washington. In China, East West’s presence includes full-service branches in Hong Kong, Shanghai, Shantou and Shenzhen, and representative offices in Beijing, Chongqing, Guangzhou, and Xiamen. East West also has a representative office in Singapore. For more information on East West, visit the Company’s website at www.eastwestbank.com.
Forward-Looking Statements
Certain matters set forth herein (including any exhibits hereto) contain forward-looking statements that are intended to be covered by the safe harbor for such statements provided by the Private Securities Litigation Reform Act of 1995. In addition, the Company may make forward-looking statements in other documents that it files with, or furnishes to, the U.S. Securities and Exchange Commission (“SEC”) and management may make forward-looking statements to analysts, investors, media members and others. Forward-looking statements are those that do not relate to historical facts and that are based on current expectations, beliefs, estimates, assumptions and projections, many of which, by their nature, are inherently uncertain and beyond the Company’s control. Forward-looking statements may relate to various matters, including the Company’s financial condition, results of operations, plans, objectives, future performance, business or industry, and usually can be identified by the use of forward-looking words, such as “anticipates,” “assumes,” “believes,” “can,” “continues,” “could,” “estimates,” “expects,” “forecasts,” “goal,” “intends,” “likely,” “may,” “might,” “objective,” “plans,” “potential,” “projects,” “remains,” “should,” “target,” “trend,” “will,” “would,” or similar expressions or variations thereof, and the negative thereof, but these terms are not the exclusive means of identifying such statements. You should not place undue reliance on forward-looking statements, as they are subject to risks and uncertainties, including, but not limited to, those described below. When considering these forward-looking statements, you should keep in mind these risks and uncertainties, as well as any cautionary statements the Company may make.
There are various important factors that could cause future results to differ materially from historical performance and any forward-looking statements. Factors that might cause such differences, include, but are not limited to: changes in the global economy, including an economic slowdown, capital or financial market disruption, supply chain disruption, level of inflation, interest rate environment, housing prices, employment levels, rate of growth and general business conditions, which could result in, among other things, reduced demand for loans, reduced availability of funding or increases in funding costs, declines in asset values and /or recognition of allowance for credit losses on securities held in the Company’s portfolio; changes in local, regional and global business, economic and political conditions and geopolitical events, such as the military conflict between Russia and Ukraine; the economic, financial, reputational and other impacts of the ongoing Coronavirus Disease 2019 (“COVID-19”) pandemic, including variants thereof, and any other pandemic, epidemic or health-related crisis; changes in laws or the regulatory environment, including regulatory reform initiatives and policies of the U.S. Department of the Treasury, the Board of Governors of the Federal Reserve System (“Federal Reserve”), the Federal Deposit Insurance Corporation, the Office of the Comptroller of the Currency, the SEC, the Consumer Financial Protection Bureau and the California Department of Financial Protection and Innovation - Division of Financial Institutions; changes and effects thereof in trade, monetary and fiscal policies and laws, including the ongoing trade, economic and political disputes between the U.S. and the People’s Republic of China and the monetary policies of the Federal Reserve; changes in the commercial and consumer real estate markets; changes in consumer or commercial spending, savings and borrowing habits, and patterns and behaviors; the impact from potential changes to income tax laws and regulations, federal spending and economic stimulus programs; the impact of any future federal government shutdown and uncertainty regarding the federal government’s debt limit; the Company’s ability to compete effectively against financial institutions and other entities, including as a result of emerging technologies; the soundness of other financial institutions; the success and timing of the Company’s business strategies; the Company’s ability to retain key officers and employees; impact on the Company’s funding costs, net interest income and net interest margin from changes in key variable market interest rates, competition, regulatory requirements and the Company’s product mix; changes in the Company’s costs of operation, compliance and expansion; the Company’s ability to adopt and successfully integrate new technologies into its business in a strategic manner; the impact of the benchmark interest rate reform in the U.S. including the transition away from the U.S. dollar (“USD”) London Interbank Offered Rate (“LIBOR”) to alternative reference rates; the impact of communications or technology disruption, failure in, or breach of, the Company’s operational or security systems or infrastructure, or those of third party vendors with which the Company does business, including as a result of cyber-attacks; and other similar matters which could result in, among other things, confidential and/or proprietary information being disclosed or misused, and materially impact the Company’s ability to provide services to its clients; the adequacy of the Company’s risk management framework, disclosure controls and procedures and internal control over financial reporting; future credit quality and performance, including the Company’s expectations regarding future credit losses and allowance levels; the impact of adverse changes to the Company’s credit ratings from major credit rating agencies; the impact of adverse judgments or settlements in litigation; the impact on the Company’s operations due to political developments, pandemics, wars, civil unrest, terrorism or other hostilities that may disrupt or increase volatility in securities or otherwise affect business and economic conditions; heightened regulatory and governmental oversight and scrutiny of the Company’s business practices, including dealings with consumers; the impact of reputational risk from negative publicity, fines, penalties and other negative consequences from regulatory violations, legal actions and the Company’s interactions with business partners, counterparties, service providers and other third parties; the impact of regulatory investigations and enforcement actions; changes in accounting standards as may be required by the Financial Accounting Standards Board or other regulatory agencies and their impact on critical accounting policies and assumptions; the Company’s capital requirements and its ability to generate capital internally or raise capital on favorable terms; the impact on the Company’s liquidity due to changes in the Company’s ability to receive dividends from its subsidiaries; any strategic acquisitions or divestitures; changes in the equity and debt securities markets; fluctuations in the Company’s stock price; fluctuations in foreign currency exchange rates; the impact of increased focus on social, environmental and sustainability matters, which may affect the Company’s operations as well as those of its customers and the economy more broadly; and the impact of climate change, natural or man-made disasters or calamities, such as wildfires, droughts and earthquakes, all of which are particularly common in California, or other events that may directly or indirectly result in a negative impact on the Company’s financial performance.
For a more detailed discussion of some of the factors that might cause such differences, see the Company’s Annual Report on Form 10-K for the year ended December 31, 2021 under the heading Item 1A. Risk Factors and the information set forth under Item 1A. Risk Factors in the Company’s Quarterly Reports on Form 10-Q. You should treat forward-looking statements as speaking only as of the date they are made and then actually known to the Company. The Company does not undertake, and specifically disclaims any obligation to update or revise any forward-looking statements to reflect the occurrence of events or circumstances after the date of such statements except as required by law.
6
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| CONDENSED CONSOLIDATED BALANCE SHEET | |||||||||||||||||||||||||||||||||||||||||
| ($ and shares in thousands, except per share data) | |||||||||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||||||||
| Table 1 | |||||||||||||||||||||||||||||||||||||||||
December 31, 2022 % or Basis Point Change | |||||||||||||||||||||||||||||||||||||||||
| December 31, 2022 | September 30, 2022 | December 31, 2021 | Qtr-o-Qtr | Yr-o-Yr | |||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | $ | 534,980 | $ | 554,260 | $ | 527,317 | (3.5) | % | 1.5 | % | |||||||||||||||||||||||||||||||
| Interest-bearing cash with banks | 2,946,804 | 1,609,093 | 3,385,618 | 83.1 | (13.0) | ||||||||||||||||||||||||||||||||||||
| Cash and cash equivalents | 3,481,784 | 2,163,353 | 3,912,935 | 60.9 | (11.0) | ||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits with banks | 139,021 | 630,543 | 736,492 | (78.0) | (81.1) | ||||||||||||||||||||||||||||||||||||
| Assets purchased under resale agreements (“resale agreements”) | 792,192 | 892,986 | 2,353,503 | (11.3) | (66.3) | ||||||||||||||||||||||||||||||||||||
Available-for-sale (“AFS”) debt securities (amortized cost of $6,879,225, $6,771,354 and $10,087,179) | 6,034,993 | 5,906,090 | 9,965,353 | 2.2 | (39.4) | ||||||||||||||||||||||||||||||||||||
Held-to-maturity (“HTM”) debt securities, at amortized cost (fair value of $2,455,171 and $2,459,135 in 2022) | 3,001,868 | 3,012,667 | — | (0.4) | 100.0 | ||||||||||||||||||||||||||||||||||||
| Loans held-for-sale (“HFS”) | 25,644 | 14,500 | 635 | 76.9 | NM | ||||||||||||||||||||||||||||||||||||
Loans held-for-investment (''HFI'') (net of allowance for loan losses of $595,645, $582,517 and $541,579) | 47,606,785 | 46,859,738 | 41,152,202 | 1.6 | 15.7 | ||||||||||||||||||||||||||||||||||||
| Investments in qualified affordable housing partnerships, tax credit and other investments, net | 763,256 | 725,254 | 628,263 | 5.2 | 21.5 | ||||||||||||||||||||||||||||||||||||
| Goodwill | 465,697 | 465,697 | 465,697 | — | — | ||||||||||||||||||||||||||||||||||||
| Operating lease right-of-use assets | 103,681 | 105,411 | 98,632 | (1.6) | 5.1 | ||||||||||||||||||||||||||||||||||||
| Other assets | 1,697,229 | 1,799,822 | 1,556,989 | (5.7) | 9.0 | ||||||||||||||||||||||||||||||||||||
| Total assets | $ | 64,112,150 | $ | 62,576,061 | $ | 60,870,701 | 2.5 | % | 5.3 | % | |||||||||||||||||||||||||||||||
| Liabilities and Stockholders’ Equity | |||||||||||||||||||||||||||||||||||||||||
| Deposits | $ | 55,967,849 | $ | 53,857,362 | $ | 53,350,532 | 3.9 | % | 4.9 | % | |||||||||||||||||||||||||||||||
| Federal funds purchased | — | 200,000 | — | (100.0) | — | ||||||||||||||||||||||||||||||||||||
| FHLB advances | — | 324,920 | 249,331 | (100.0) | (100.0) | ||||||||||||||||||||||||||||||||||||
| Assets sold under repurchase agreements (“repurchase agreements”) | 300,000 | 611,785 | 300,000 | (51.0) | — | ||||||||||||||||||||||||||||||||||||
| Long-term debt and finance lease liabilities | 152,400 | 152,610 | 151,997 | (0.1) | 0.3 | ||||||||||||||||||||||||||||||||||||
| Operating lease liabilities | 111,931 | 113,477 | 105,534 | (1.4) | 6.1 | ||||||||||||||||||||||||||||||||||||
| Accrued expenses and other liabilities | 1,595,358 | 1,655,239 | 876,089 | (3.6) | 82.1 | ||||||||||||||||||||||||||||||||||||
| Total liabilities | 58,127,538 | 56,915,393 | 55,033,483 | 2.1 | 5.6 | ||||||||||||||||||||||||||||||||||||
| Stockholders’ equity | 5,984,612 | 5,660,668 | 5,837,218 | 5.7 | 2.5 | ||||||||||||||||||||||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 64,112,150 | $ | 62,576,061 | $ | 60,870,701 | 2.5 | % | 5.3 | % | |||||||||||||||||||||||||||||||
| Book value per common share | $ | 42.46 | $ | 40.17 | $ | 41.13 | 5.7 | % | 3.2 | % | |||||||||||||||||||||||||||||||
Tangible equity (1) per common share | $ | 39.10 | $ | 36.80 | $ | 37.79 | 6.2 | 3.5 | |||||||||||||||||||||||||||||||||
| Number of common shares at period-end | 140,948 | 140,918 | 141,908 | 0.0 | (0.7) | ||||||||||||||||||||||||||||||||||||
| Total stockholders’ equity to total assets ratio | 9.33 | % | 9.05 | % | 9.59 | % | 28 | bps | (26) | bps | |||||||||||||||||||||||||||||||
Tangible equity to tangible assets ratio (1) | 8.66 | % | 8.35 | % | 8.88 | % | 31 | bps | (22) | bps | |||||||||||||||||||||||||||||||
NM - Not meaningful.
(1)Tangible equity and the tangible equity to tangible assets ratio are non-GAAP financial measures. See reconciliation of GAAP to non-GAAP measures in Table 13.
7
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||
| TOTAL LOANS AND DEPOSITS DETAIL | |||||||||||||||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||
| Table 2 | |||||||||||||||||||||||||||||||||||
December 31, 2022 % Change | |||||||||||||||||||||||||||||||||||
| December 31, 2022 | September 30, 2022 | December 31, 2021 | Qtr-o-Qtr | Yr-o-Yr | |||||||||||||||||||||||||||||||
| Loans: | |||||||||||||||||||||||||||||||||||
Commercial: | |||||||||||||||||||||||||||||||||||
Commercial and industrial (“C&I”) (1) | $ | 15,711,095 | $ | 15,625,072 | $ | 14,150,608 | 0.6 | % | 11.0 | % | |||||||||||||||||||||||||
Commercial real estate (“CRE”): | |||||||||||||||||||||||||||||||||||
CRE | 13,857,870 | 13,573,157 | 12,155,047 | 2.1 | 14.0 | ||||||||||||||||||||||||||||||
Multifamily residential | 4,573,068 | 4,559,302 | 3,675,605 | 0.3 | 24.4 | ||||||||||||||||||||||||||||||
Construction and land | 638,420 | 556,894 | 346,486 | 14.6 | 84.3 | ||||||||||||||||||||||||||||||
Total CRE | 19,069,358 | 18,689,353 | 16,177,138 | 2.0 | 17.9 | ||||||||||||||||||||||||||||||
Consumer: | |||||||||||||||||||||||||||||||||||
Residential mortgage: | |||||||||||||||||||||||||||||||||||
Single-family residential | 11,223,027 | 10,855,345 | 9,093,702 | 3.4 | 23.4 | ||||||||||||||||||||||||||||||
| Home equity lines of credit (“HELOCs”) | 2,122,655 | 2,184,924 | 2,144,821 | (2.8) | (1.0) | ||||||||||||||||||||||||||||||
Total residential mortgage | 13,345,682 | 13,040,269 | 11,238,523 | 2.3 | 18.7 | ||||||||||||||||||||||||||||||
Other consumer | 76,295 | 87,561 | 127,512 | (12.9) | (40.2) | ||||||||||||||||||||||||||||||
Total loans HFI (2) | 48,202,430 | 47,442,255 | 41,693,781 | 1.6 | 15.6 | ||||||||||||||||||||||||||||||
Loans HFS | 25,644 | 14,500 | 635 | 76.9 | NM | ||||||||||||||||||||||||||||||
Total loans (2) | 48,228,074 | 47,456,755 | 41,694,416 | 1.6 | 15.7 | ||||||||||||||||||||||||||||||
| Allowance for loan losses | (595,645) | (582,517) | (541,579) | 2.3 | 10.0 | ||||||||||||||||||||||||||||||
Net loans (2) | $ | 47,632,429 | $ | 46,874,238 | $ | 41,152,837 | 1.6 | 15.7 | |||||||||||||||||||||||||||
Deposits: | |||||||||||||||||||||||||||||||||||
Noninterest-bearing demand | $ | 21,051,090 | $ | 21,645,394 | $ | 22,845,464 | (2.7) | % | (7.9) | % | |||||||||||||||||||||||||
Interest-bearing checking | 6,672,165 | 6,822,343 | 6,524,721 | (2.2) | 2.3 | ||||||||||||||||||||||||||||||
Money market | 12,265,024 | 12,113,292 | 13,130,300 | 1.3 | (6.6) | ||||||||||||||||||||||||||||||
Savings | 2,649,037 | 2,917,770 | 2,888,065 | (9.2) | (8.3) | ||||||||||||||||||||||||||||||
Time deposits | 13,330,533 | 10,358,563 | 7,961,982 | 28.7 | 67.4 | ||||||||||||||||||||||||||||||
Total deposits | $ | 55,967,849 | $ | 53,857,362 | $ | 53,350,532 | 3.9 | % | 4.9 | % | |||||||||||||||||||||||||
NM - Not meaningful.
(1)Includes $99.0 million, $110.9 million and $534.2 million of Paycheck Protection Program (“PPP”) loans as of December 31, 2022, September 30, 2022 and December 31, 2021, respectively. Excluding PPP loans, total loans were $48.13 billion, $47.35 billion and $41.16 billion as of December 31, 2022, September 30, 2022 and December 31, 2021, respectively.
(2)Includes $(70.4) million, $(60.3) million and $(50.7) million of net deferred loan fees and net unamortized premiums as of December 31, 2022, September 30, 2022 and December 31, 2021, respectively.
8
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||
| CONDENSED CONSOLIDATED STATEMENT OF INCOME | |||||||||||||||||||||||||||||||||||
| ($ and shares in thousands, except per share data) | |||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||
| Table 3 | |||||||||||||||||||||||||||||||||||
| Three Months Ended | December 31, 2022 % Change | ||||||||||||||||||||||||||||||||||
| December 31, 2022 | September 30, 2022 | December 31, 2021 | Qtr-o-Qtr | Yr-o-Yr | |||||||||||||||||||||||||||||||
Interest and dividend income (1) | $ | 761,212 | $ | 628,236 | $ | 422,708 | 21.2 | % | 80.1 | % | |||||||||||||||||||||||||
Interest expense | 155,705 | 76,427 | 17,011 | 103.7 | 815.3 | ||||||||||||||||||||||||||||||
| Net interest income before provision for (reversal of) credit losses | 605,507 | 551,809 | 405,697 | 9.7 | 49.3 | ||||||||||||||||||||||||||||||
| Provision for (reversal of) credit losses | 25,000 | 27,000 | (10,000) | (7.4) | NM | ||||||||||||||||||||||||||||||
| Net interest income after provision for (reversal of) credit losses | 580,507 | 524,809 | 415,697 | 10.6 | 39.6 | ||||||||||||||||||||||||||||||
| Noninterest income | 64,927 | 75,552 | 71,489 | (14.1) | (9.2) | ||||||||||||||||||||||||||||||
| Noninterest expense | 257,110 | 215,973 | 210,105 | 19.0 | 22.4 | ||||||||||||||||||||||||||||||
Income before income taxes | 388,324 | 384,388 | 277,081 | 1.0 | 40.1 | ||||||||||||||||||||||||||||||
Income tax expense | 51,561 | 89,049 | 59,285 | (42.1) | (13.0) | ||||||||||||||||||||||||||||||
Net income | $ | 336,763 | $ | 295,339 | $ | 217,796 | 14.0 | % | 54.6 | % | |||||||||||||||||||||||||
Earnings per share (“EPS”) | |||||||||||||||||||||||||||||||||||
- Basic | $ | 2.39 | $ | 2.10 | $ | 1.53 | 14.0 | % | 55.7 | % | |||||||||||||||||||||||||
- Diluted | $ | 2.37 | $ | 2.08 | $ | 1.52 | 13.9 | 55.9 | |||||||||||||||||||||||||||
Weighted-average number of shares outstanding | |||||||||||||||||||||||||||||||||||
- Basic | 140,947 | 140,917 | 141,907 | 0.0 | % | (0.7) | % | ||||||||||||||||||||||||||||
- Diluted | 142,138 | 142,011 | 143,323 | 0.1 | (0.8) | ||||||||||||||||||||||||||||||
| Three Months Ended | December 31, 2022 % Change | ||||||||||||||||||||||||||||||||||
| December 31, 2022 | September 30, 2022 | December 31, 2021 | Qtr-o-Qtr | Yr-o-Yr | |||||||||||||||||||||||||||||||
Noninterest income: | |||||||||||||||||||||||||||||||||||
Lending fees | $ | 19,339 | $ | 20,289 | $ | 20,739 | (4.7) | % | (6.8) | % | |||||||||||||||||||||||||
| Deposit account fees | 22,112 | 23,636 | 20,028 | (6.4) | 10.4 | ||||||||||||||||||||||||||||||
| Interest rate contracts and other derivative (loss) income | (638) | 8,761 | 1,932 | NM | NM | ||||||||||||||||||||||||||||||
Foreign exchange income | 14,015 | 10,083 | 13,343 | 39.0 | 5.0 | ||||||||||||||||||||||||||||||
Wealth management fees | 6,071 | 8,903 | 5,291 | (31.8) | 14.7 | ||||||||||||||||||||||||||||||
Net gains on sales of loans | 443 | 2,129 | 2,308 | (79.2) | (80.8) | ||||||||||||||||||||||||||||||
Gains on sales of AFS debt securities | — | — | 390 | — | (100.0) | ||||||||||||||||||||||||||||||
| Other investment income (loss) | 1,127 | (580) | 2,982 | NM | (62.2) | ||||||||||||||||||||||||||||||
Other income | 2,458 | 2,331 | 4,476 | 5.4 | (45.1) | ||||||||||||||||||||||||||||||
| Total noninterest income | $ | 64,927 | $ | 75,552 | $ | 71,489 | (14.1) | % | (9.2) | % | |||||||||||||||||||||||||
Noninterest expense: | |||||||||||||||||||||||||||||||||||
Compensation and employee benefits | $ | 120,422 | $ | 127,580 | $ | 114,743 | (5.6) | % | 4.9 | % | |||||||||||||||||||||||||
Occupancy and equipment expense | 15,648 | 15,920 | 15,846 | (1.7) | (1.2) | ||||||||||||||||||||||||||||||
Deposit insurance premiums and regulatory assessments | 4,930 | 4,875 | 4,772 | 1.1 | 3.3 | ||||||||||||||||||||||||||||||
| Deposit account expense | 8,437 | 6,707 | 4,307 | 25.8 | 95.9 | ||||||||||||||||||||||||||||||
| Data processing | 3,641 | 3,725 | 4,175 | (2.3) | (12.8) | ||||||||||||||||||||||||||||||
| Computer software expense | 7,504 | 6,889 | 7,494 | 8.9 | 0.1 | ||||||||||||||||||||||||||||||
Other operating expense | 31,923 | 30,403 | 26,968 | 5.0 | 18.4 | ||||||||||||||||||||||||||||||
| Amortization of tax credit and other investments | 64,605 | 19,874 | 31,800 | 225.1 | 103.2 | ||||||||||||||||||||||||||||||
| Total noninterest expense | $ | 257,110 | $ | 215,973 | $ | 210,105 | 19.0 | % | 22.4 | % | |||||||||||||||||||||||||
NM - Not meaningful.
(1)Includes $293 thousand, $524 thousand and $9.6 million of interest income related to PPP loans for the three months ended December 31, 2022, September 30, 2022 and December 31, 2021, respectively.
9
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||
| CONDENSED CONSOLIDATED STATEMENT OF INCOME | |||||||||||||||||||||||
| ($ and shares in thousands, except per share data) | |||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||
| Table 4 | |||||||||||||||||||||||
| Year Ended | December 31, 2022 % Change | ||||||||||||||||||||||
| December 31, 2022 | December 31, 2021 | Yr-o-Yr | |||||||||||||||||||||
Interest and dividend income (1) | $ | 2,321,231 | $ | 1,618,734 | 43.4% | ||||||||||||||||||
Interest expense | 275,350 | 87,163 | 215.9 | ||||||||||||||||||||
| Net interest income before provision for (reversal of) credit losses | 2,045,881 | 1,531,571 | 33.6 | ||||||||||||||||||||
| Provision for (reversal of) credit losses | 73,500 | (35,000) | NM | ||||||||||||||||||||
| Net interest income after provision for (reversal of) credit losses | 1,972,381 | 1,566,571 | 25.9 | ||||||||||||||||||||
| Noninterest income | 298,666 | 285,895 | 4.5 | ||||||||||||||||||||
| Noninterest expense | 859,393 | 796,089 | 8.0 | ||||||||||||||||||||
Income before income taxes | 1,411,654 | 1,056,377 | 33.6 | ||||||||||||||||||||
Income tax expense | 283,571 | 183,396 | 54.6 | ||||||||||||||||||||
Net income | $ | 1,128,083 | $ | 872,981 | 29.2% | ||||||||||||||||||
EPS | |||||||||||||||||||||||
- Basic | $ | 7.98 | $ | 6.16 | 29.7% | ||||||||||||||||||
- Diluted | $ | 7.92 | $ | 6.10 | 29.8 | ||||||||||||||||||
Weighted-average number of shares outstanding | |||||||||||||||||||||||
- Basic | 141,326 | 141,826 | (0.4)% | ||||||||||||||||||||
- Diluted | 142,492 | 143,140 | (0.5) | ||||||||||||||||||||
| Year Ended | December 31, 2022 % Change | ||||||||||||||||||||||
| December 31, 2022 | December 31, 2021 | Yr-o-Yr | |||||||||||||||||||||
Noninterest income: | |||||||||||||||||||||||
Lending fees | $ | 79,208 | $ | 77,704 | 1.9% | ||||||||||||||||||
Deposit account fees | 88,435 | 71,261 | 24.1 | ||||||||||||||||||||
| Interest rate contracts and other derivative income | 29,057 | 22,913 | 26.8 | ||||||||||||||||||||
Foreign exchange income | 48,158 | 48,977 | (1.7) | ||||||||||||||||||||
Wealth management fees | 27,565 | 25,751 | 7.0 | ||||||||||||||||||||
Net gains on sales of loans | 6,411 | 8,909 | (28.0) | ||||||||||||||||||||
| Gains on sales of AFS debt securities | 1,306 | 1,568 | (16.7) | ||||||||||||||||||||
| Other investment income | 7,037 | 16,852 | (58.2) | ||||||||||||||||||||
Other income | 11,489 | 11,960 | (3.9) | ||||||||||||||||||||
| Total noninterest income | $ | 298,666 | $ | 285,895 | 4.5% | ||||||||||||||||||
Noninterest expense: | |||||||||||||||||||||||
Compensation and employee benefits | $ | 477,635 | $ | 433,728 | 10.1% | ||||||||||||||||||
Occupancy and equipment expense | 62,501 | 62,996 | (0.8) | ||||||||||||||||||||
Deposit insurance premiums and regulatory assessments | 19,449 | 17,563 | 10.7 | ||||||||||||||||||||
| Deposit account expense | 25,508 | 16,152 | 57.9 | ||||||||||||||||||||
Data processing | 14,517 | 16,263 | (10.7) | ||||||||||||||||||||
Computer software expense | 28,259 | 30,600 | (7.7) | ||||||||||||||||||||
Other operating expense | 118,166 | 96,330 | 22.7 | ||||||||||||||||||||
| Amortization of tax credit and other investments | 113,358 | 122,457 | (7.4) | ||||||||||||||||||||
| Total noninterest expense | $ | 859,393 | $ | 796,089 | 8.0% | ||||||||||||||||||
NM - Not meaningful.
(1)Includes $7.3 million and $55.2 million of interest income related to PPP loans for the years ended December 31, 2022 and 2021, respectively.
10
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| SELECTED AVERAGE BALANCES | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Table 5 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | December 31, 2022 % Change | Year Ended | December 31, 2022 % Change | ||||||||||||||||||||||||||||||||||||||||||||||||||
| December 31, 2022 | September 30, 2022 | December 31, 2021 | Qtr-o-Qtr | Yr-o-Yr | December 31, 2022 | December 31, 2021 | Yr-o-Yr | ||||||||||||||||||||||||||||||||||||||||||||||
Loans: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Commercial: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
C&I (1) | $ | 15,496,386 | $ | 15,282,661 | $ | 13,592,203 | 1.4% | 14.0% | $ | 15,013,560 | $ | 13,656,720 | 9.9% | ||||||||||||||||||||||||||||||||||||||||
| CRE: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
CRE | 13,699,042 | 13,533,482 | 11,954,535 | 1.2 | 14.6 | 13,145,204 | 11,663,144 | 12.7 | |||||||||||||||||||||||||||||||||||||||||||||
| Multifamily residential | 4,604,628 | 4,531,351 | 3,434,274 | 1.6 | 34.1 | 4,252,605 | 3,213,582 | 32.3 | |||||||||||||||||||||||||||||||||||||||||||||
| Construction and land | 591,962 | 532,800 | 340,940 | 11.1 | 73.6 | 499,044 | 445,333 | 12.1 | |||||||||||||||||||||||||||||||||||||||||||||
Total CRE | 18,895,632 | 18,597,633 | 15,729,749 | 1.6 | 20.1 | 17,896,853 | 15,322,059 | 16.8 | |||||||||||||||||||||||||||||||||||||||||||||
Consumer: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Residential mortgage: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Single-family residential | 10,988,102 | 10,676,022 | 9,031,677 | 2.9 | 21.7 | 10,106,609 | 8,742,565 | 15.6 | |||||||||||||||||||||||||||||||||||||||||||||
HELOCs | 2,145,416 | 2,216,355 | 2,052,383 | (3.2) | 4.5 | 2,208,725 | 1,859,073 | 18.8 | |||||||||||||||||||||||||||||||||||||||||||||
| Total residential mortgage | 13,133,518 | 12,892,377 | 11,084,060 | 1.9 | 18.5 | 12,315,334 | 10,601,638 | 16.2 | |||||||||||||||||||||||||||||||||||||||||||||
Other consumer | 81,596 | 81,870 | 126,557 | (0.3) | (35.5) | 93,711 | 136,280 | (31.2) | |||||||||||||||||||||||||||||||||||||||||||||
Total loans (2) | $ | 47,607,132 | $ | 46,854,541 | $ | 40,532,569 | 1.6% | 17.5% | $ | 45,319,458 | $ | 39,716,697 | 14.1% | ||||||||||||||||||||||||||||||||||||||||
Interest-earning assets | $ | 60,376,151 | $ | 59,478,689 | $ | 58,944,082 | 1.5% | 2.4% | $ | 59,309,062 | $ | 56,256,388 | 5.4% | ||||||||||||||||||||||||||||||||||||||||
Total assets | $ | 64,252,730 | $ | 63,079,444 | $ | 62,183,137 | 1.9% | 3.3% | $ | 62,838,282 | $ | 59,251,091 | 6.1% | ||||||||||||||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Noninterest-bearing demand | $ | 21,419,290 | $ | 22,423,633 | $ | 24,019,333 | (4.5)% | (10.8)% | $ | 22,784,258 | $ | 21,271,410 | 7.1% | ||||||||||||||||||||||||||||||||||||||||
Interest-bearing checking | 6,543,349 | 6,879,632 | 6,462,471 | (4.9) | 1.3 | 6,696,200 | 6,543,817 | 2.3 | |||||||||||||||||||||||||||||||||||||||||||||
Money market | 12,197,782 | 12,351,571 | 12,920,174 | (1.2) | (5.6) | 12,443,437 | 12,428,025 | 0.1 | |||||||||||||||||||||||||||||||||||||||||||||
Savings | 2,747,166 | 2,961,634 | 2,841,352 | (7.2) | (3.3) | 2,901,940 | 2,746,933 | 5.6 | |||||||||||||||||||||||||||||||||||||||||||||
Time deposits | 12,076,193 | 9,435,063 | 8,072,917 | 28.0 | 49.6 | 9,473,744 | 8,493,511 | 11.5 | |||||||||||||||||||||||||||||||||||||||||||||
Total deposits | $ | 54,983,780 | $ | 54,051,533 | $ | 54,316,247 | 1.7% | 1.2% | $ | 54,299,579 | $ | 51,483,696 | 5.5% | ||||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities | $ | 34,372,853 | $ | 32,703,323 | $ | 31,011,536 | 5.1% | 10.8% | $ | 32,322,744 | $ | 31,077,459 | 4.0% | ||||||||||||||||||||||||||||||||||||||||
Stockholders’ equity | $ | 5,834,623 | $ | 5,772,638 | $ | 5,786,237 | 1.1% | 0.8% | $ | 5,783,025 | $ | 5,559,212 | 4.0% | ||||||||||||||||||||||||||||||||||||||||
(1)Average balances of PPP loans were $104.6 million, $127.6 million and $677.2 million for the three months ended December 31, 2022, September 30, 2022 and December 31, 2021, respectively, and $215.4 million and $1.39 billion for the years ended December 31, 2022 and 2021, respectively.
(2)Includes loans HFS.
11
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| QUARTER-TO-DATE AVERAGE BALANCES, YIELDS AND RATES | |||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||||||||
| Table 6 | |||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||||||||||||||
| December 31, 2022 | September 30, 2022 | ||||||||||||||||||||||||||||||||||||||||
| Average | Average | Average | Average | ||||||||||||||||||||||||||||||||||||||
| Balance | Interest | Yield/Rate (1) | Balance | Interest | Yield/Rate (1) | ||||||||||||||||||||||||||||||||||||
Assets | |||||||||||||||||||||||||||||||||||||||||
Interest-earning assets: | |||||||||||||||||||||||||||||||||||||||||
Interest-bearing cash and deposits with banks | $ | 2,983,726 | $ | 23,986 | 3.19 | % | $ | 2,287,010 | $ | 9,080 | 1.58 | % | |||||||||||||||||||||||||||||
| Resale agreements | 833,170 | 6,062 | 2.89 | % | 1,037,292 | 6,769 | 2.59 | % | |||||||||||||||||||||||||||||||||
| AFS debt securities | 5,869,336 | 46,224 | 3.12 | % | 6,204,729 | 38,383 | 2.45 | % | |||||||||||||||||||||||||||||||||
| HTM debt securities | 3,004,412 | 12,747 | 1.68 | % | 3,017,063 | 12,709 | 1.67 | % | |||||||||||||||||||||||||||||||||
Loans (2) | 47,607,132 | 671,323 | 5.59 | % | 46,854,541 | 560,452 | 4.75 | % | |||||||||||||||||||||||||||||||||
FHLB and FRB stock | 78,375 | 870 | 4.40 | % | 78,054 | 843 | 4.28 | % | |||||||||||||||||||||||||||||||||
Total interest-earning assets | 60,376,151 | 761,212 | 5.00 | % | 59,478,689 | 628,236 | 4.19 | % | |||||||||||||||||||||||||||||||||
Noninterest-earning assets: | |||||||||||||||||||||||||||||||||||||||||
Cash and due from banks | 640,509 | 615,836 | |||||||||||||||||||||||||||||||||||||||
| Allowance for loan losses | (583,271) | (566,369) | |||||||||||||||||||||||||||||||||||||||
Other assets | 3,819,341 | 3,551,288 | |||||||||||||||||||||||||||||||||||||||
Total assets | $ | 64,252,730 | $ | 63,079,444 | |||||||||||||||||||||||||||||||||||||
| Liabilities and Stockholders’ Equity | |||||||||||||||||||||||||||||||||||||||||
Interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||||||||
Checking deposits | $ | 6,543,349 | $ | 16,735 | 1.01 | % | $ | 6,879,632 | $ | 8,493 | 0.49 | % | |||||||||||||||||||||||||||||
Money market deposits | 12,197,782 | 62,246 | 2.02 | % | 12,351,571 | 33,101 | 1.06 | % | |||||||||||||||||||||||||||||||||
Savings deposits | 2,747,166 | 2,714 | 0.39 | % | 2,961,634 | 2,268 | 0.30 | % | |||||||||||||||||||||||||||||||||
Time deposits | 12,076,193 | 65,772 | 2.16 | % | 9,435,063 | 25,032 | 1.05 | % | |||||||||||||||||||||||||||||||||
Federal funds purchased and other short-term borrowings | 47,142 | 374 | 3.15 | % | 211,794 | 1,177 | 2.20 | % | |||||||||||||||||||||||||||||||||
FHLB advances | 40,178 | 225 | 2.22 | % | 86,243 | 392 | 1.80 | % | |||||||||||||||||||||||||||||||||
| Repurchase agreements | 568,520 | 5,507 | 3.84 | % | 624,821 | 4,421 | 2.81 | % | |||||||||||||||||||||||||||||||||
Long-term debt and finance lease liabilities | 152,523 | 2,132 | 5.55 | % | 152,565 | 1,543 | 4.01 | % | |||||||||||||||||||||||||||||||||
Total interest-bearing liabilities | 34,372,853 | 155,705 | 1.80 | % | 32,703,323 | 76,427 | 0.93 | % | |||||||||||||||||||||||||||||||||
Noninterest-bearing liabilities and stockholders’ equity: | |||||||||||||||||||||||||||||||||||||||||
Demand deposits | 21,419,290 | 22,423,633 | |||||||||||||||||||||||||||||||||||||||
Accrued expenses and other liabilities | 2,625,964 | 2,179,850 | |||||||||||||||||||||||||||||||||||||||
Stockholders’ equity | 5,834,623 | 5,772,638 | |||||||||||||||||||||||||||||||||||||||
Total liabilities and stockholders’ equity | $ | 64,252,730 | $ | 63,079,444 | |||||||||||||||||||||||||||||||||||||
Interest rate spread | 3.20 | % | 3.26 | % | |||||||||||||||||||||||||||||||||||||
| Net interest income and net interest margin | $ | 605,507 | 3.98 | % | $ | 551,809 | 3.68 | % | |||||||||||||||||||||||||||||||||
(1)Annualized.
(2)Includes loans HFS. Average balances of PPP loans were $104.6 million and $127.6 million for the three months ended December 31, 2022 and September 30, 2022, respectively.
12
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| QUARTER-TO-DATE AVERAGE BALANCES, YIELDS AND RATES | |||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||||||||
| Table 7 | |||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||||||||||||||
| December 31, 2022 | December 31, 2021 | ||||||||||||||||||||||||||||||||||||||||
| Average | Average | Average | Average | ||||||||||||||||||||||||||||||||||||||
| Balance | Interest | Yield/Rate (1) | Balance | Interest | Yield/Rate (1) | ||||||||||||||||||||||||||||||||||||
Assets | |||||||||||||||||||||||||||||||||||||||||
Interest-earning assets: | |||||||||||||||||||||||||||||||||||||||||
Interest-bearing cash and deposits with banks | $ | 2,983,726 | $ | 23,986 | 3.19 | % | $ | 6,050,870 | $ | 3,750 | 0.25 | % | |||||||||||||||||||||||||||||
| Resale agreements | 833,170 | 6,062 | 2.89 | % | 2,440,636 | 9,162 | 1.49 | % | |||||||||||||||||||||||||||||||||
| AFS debt securities | 5,869,336 | 46,224 | 3.12 | % | 9,842,691 | 42,367 | 1.71 | % | |||||||||||||||||||||||||||||||||
| HTM debt securities | 3,004,412 | 12,747 | 1.68 | % | — | — | — | % | |||||||||||||||||||||||||||||||||
Loans (2) | 47,607,132 | 671,323 | 5.59 | % | 40,532,569 | 366,936 | 3.59 | % | |||||||||||||||||||||||||||||||||
FHLB and FRB stock | 78,375 | 870 | 4.40 | % | 77,316 | 493 | 2.53 | % | |||||||||||||||||||||||||||||||||
Total interest-earning assets | 60,376,151 | 761,212 | 5.00 | % | 58,944,082 | 422,708 | 2.85 | % | |||||||||||||||||||||||||||||||||
Noninterest-earning assets: | |||||||||||||||||||||||||||||||||||||||||
Cash and due from banks | 640,509 | 652,126 | |||||||||||||||||||||||||||||||||||||||
| Allowance for loan losses | (583,271) | (558,645) | |||||||||||||||||||||||||||||||||||||||
Other assets | 3,819,341 | 3,145,574 | |||||||||||||||||||||||||||||||||||||||
Total assets | $ | 64,252,730 | $ | 62,183,137 | |||||||||||||||||||||||||||||||||||||
Liabilities and Stockholders’ Equity | |||||||||||||||||||||||||||||||||||||||||
Interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||||||||
Checking deposits | $ | 6,543,349 | $ | 16,735 | 1.01 | % | $ | 6,462,471 | $ | 1,846 | 0.11 | % | |||||||||||||||||||||||||||||
Money market deposits | 12,197,782 | 62,246 | 2.02 | % | 12,920,174 | 3,172 | 0.10 | % | |||||||||||||||||||||||||||||||||
Savings deposits | 2,747,166 | 2,714 | 0.39 | % | 2,841,352 | 1,734 | 0.24 | % | |||||||||||||||||||||||||||||||||
Time deposits | 12,076,193 | 65,772 | 2.16 | % | 8,072,917 | 6,617 | 0.33 | % | |||||||||||||||||||||||||||||||||
Federal funds purchased and other short-term borrowings | 47,142 | 374 | 3.15 | % | 730 | — | — | % | |||||||||||||||||||||||||||||||||
FHLB advances | 40,178 | 225 | 2.22 | % | 249,048 | 856 | 1.36 | % | |||||||||||||||||||||||||||||||||
| Repurchase agreements | 568,520 | 5,507 | 3.84 | % | 313,075 | 2,018 | 2.56 | % | |||||||||||||||||||||||||||||||||
Long-term debt and finance lease liabilities | 152,523 | 2,132 | 5.55 | % | 151,769 | 768 | 2.01 | % | |||||||||||||||||||||||||||||||||
Total interest-bearing liabilities | 34,372,853 | 155,705 | 1.80 | % | 31,011,536 | 17,011 | 0.22 | % | |||||||||||||||||||||||||||||||||
Noninterest-bearing liabilities and stockholders’ equity: | |||||||||||||||||||||||||||||||||||||||||
Demand deposits | 21,419,290 | 24,019,333 | |||||||||||||||||||||||||||||||||||||||
Accrued expenses and other liabilities | 2,625,964 | 1,366,031 | |||||||||||||||||||||||||||||||||||||||
Stockholders’ equity | 5,834,623 | 5,786,237 | |||||||||||||||||||||||||||||||||||||||
Total liabilities and stockholders’ equity | $ | 64,252,730 | $ | 62,183,137 | |||||||||||||||||||||||||||||||||||||
Interest rate spread | 3.20 | % | 2.63 | % | |||||||||||||||||||||||||||||||||||||
Net interest income and net interest margin | $ | 605,507 | 3.98 | % | $ | 405,697 | 2.73 | % | |||||||||||||||||||||||||||||||||
(1)Annualized.
(2)Includes loans HFS. Average balances of PPP loans were $104.6 million and $677.2 million for the three months ended December 31, 2022 and December 31, 2021, respectively.
13
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| YEAR-TO-DATE AVERAGE BALANCES, YIELDS AND RATES | |||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||||||||
| Table 8 | |||||||||||||||||||||||||||||||||||||||||
| Year Ended | |||||||||||||||||||||||||||||||||||||||||
| December 31, 2022 | December 31, 2021 | ||||||||||||||||||||||||||||||||||||||||
| Average | Average | Average | Average | ||||||||||||||||||||||||||||||||||||||
| Balance | Interest | Yield/Rate | Balance | Interest | Yield/Rate | ||||||||||||||||||||||||||||||||||||
Assets | |||||||||||||||||||||||||||||||||||||||||
Interest-earning assets: | |||||||||||||||||||||||||||||||||||||||||
Interest-bearing cash and deposits with banks | $ | 3,127,234 | $ | 41,113 | 1.31 | % | $ | 6,071,896 | $ | 15,531 | 0.26 | % | |||||||||||||||||||||||||||||
| Resale agreements | 1,398,080 | 29,767 | 2.13 | % | 2,107,157 | 32,239 | 1.53 | % | |||||||||||||||||||||||||||||||||
| AFS debt securities | 6,629,945 | 152,514 | 2.30 | % | 8,281,234 | 143,983 | 1.74 | % | |||||||||||||||||||||||||||||||||
| HTM debt securities | 2,756,382 | 46,392 | 1.68 | % | — | — | — | % | |||||||||||||||||||||||||||||||||
Loans (1) | 45,319,458 | 2,048,301 | 4.52 | % | 39,716,697 | 1,424,900 | 3.59 | % | |||||||||||||||||||||||||||||||||
FHLB and FRB stock | 77,963 | 3,144 | 4.03 | % | 79,404 | 2,081 | 2.62 | % | |||||||||||||||||||||||||||||||||
Total interest-earning assets | 59,309,062 | 2,321,231 | 3.91 | % | 56,256,388 | 1,618,734 | 2.88 | % | |||||||||||||||||||||||||||||||||
Noninterest-earning assets: | |||||||||||||||||||||||||||||||||||||||||
Cash and due from banks | 652,673 | 615,255 | |||||||||||||||||||||||||||||||||||||||
Allowance for loan losses | (559,746) | (592,211) | |||||||||||||||||||||||||||||||||||||||
Other assets | 3,436,293 | 2,971,659 | |||||||||||||||||||||||||||||||||||||||
Total assets | $ | 62,838,282 | $ | 59,251,091 | |||||||||||||||||||||||||||||||||||||
Liabilities and Stockholders’ Equity | |||||||||||||||||||||||||||||||||||||||||
Interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||||||||
Checking deposits | $ | 6,696,200 | $ | 29,808 | 0.45 | % | $ | 6,543,817 | $ | 13,023 | 0.20 | % | |||||||||||||||||||||||||||||
Money market deposits | 12,443,437 | 107,442 | 0.86 | % | 12,428,025 | 15,041 | 0.12 | % | |||||||||||||||||||||||||||||||||
Savings deposits | 2,901,940 | 8,550 | 0.29 | % | 2,746,933 | 7,496 | 0.27 | % | |||||||||||||||||||||||||||||||||
Time deposits | 9,473,744 | 106,038 | 1.12 | % | 8,493,511 | 33,599 | 0.40 | % | |||||||||||||||||||||||||||||||||
Federal funds purchased and other short-term borrowings | 81,719 | 1,801 | 2.20 | % | 1,584 | 42 | 2.65 | % | |||||||||||||||||||||||||||||||||
FHLB advances | 105,966 | 1,754 | 1.66 | % | 404,789 | 6,881 | 1.70 | % | |||||||||||||||||||||||||||||||||
| Repurchase agreements | 467,413 | 14,362 | 3.07 | % | 306,845 | 7,999 | 2.61 | % | |||||||||||||||||||||||||||||||||
Long-term debt and finance lease liabilities | 152,325 | 5,595 | 3.67 | % | 151,955 | 3,082 | 2.03 | % | |||||||||||||||||||||||||||||||||
Total interest-bearing liabilities | 32,322,744 | 275,350 | 0.85 | % | 31,077,459 | 87,163 | 0.28 | % | |||||||||||||||||||||||||||||||||
Noninterest-bearing liabilities and stockholders’ equity: | |||||||||||||||||||||||||||||||||||||||||
Demand deposits | 22,784,258 | 21,271,410 | |||||||||||||||||||||||||||||||||||||||
Accrued expenses and other liabilities | 1,948,255 | 1,343,010 | |||||||||||||||||||||||||||||||||||||||
Stockholders’ equity | 5,783,025 | 5,559,212 | |||||||||||||||||||||||||||||||||||||||
Total liabilities and stockholders’ equity | $ | 62,838,282 | $ | 59,251,091 | |||||||||||||||||||||||||||||||||||||
Interest rate spread | 3.06 | % | 2.60 | % | |||||||||||||||||||||||||||||||||||||
Net interest income and net interest margin | $ | 2,045,881 | 3.45 | % | $ | 1,531,571 | 2.72 | % | |||||||||||||||||||||||||||||||||
(1)Includes loans HFS. Average balances of PPP loans were $215.4 million and $1.39 billion for the years ended December 31, 2022 and 2021, respectively.
14
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | ||||||||||||||||||||||||||||||||||||||
| SELECTED RATIOS | ||||||||||||||||||||||||||||||||||||||
| (unaudited) | ||||||||||||||||||||||||||||||||||||||
| Table 9 | ||||||||||||||||||||||||||||||||||||||
Three Months Ended (1) | December 31, 2022 Basis Point Change | |||||||||||||||||||||||||||||||||||||
| December 31, 2022 | September 30, 2022 | December 31, 2021 | Qtr-o-Qtr | Yr-o-Yr | ||||||||||||||||||||||||||||||||||
Return on average assets | 2.08 | % | 1.86 | % | 1.39 | % | 22 | bps | 69 | bps | ||||||||||||||||||||||||||||
Return on average equity | 22.90 | % | 20.30 | % | 14.93 | % | 260 | 797 | ||||||||||||||||||||||||||||||
Tangible return on average tangible equity (2) | 24.96 | % | 22.16 | % | 16.32 | % | 280 | 864 | ||||||||||||||||||||||||||||||
Interest rate spread | 3.20 | % | 3.26 | % | 2.63 | % | (6) | 57 | ||||||||||||||||||||||||||||||
Net interest margin | 3.98 | % | 3.68 | % | 2.73 | % | 30 | 125 | ||||||||||||||||||||||||||||||
Average loan yield | 5.59 | % | 4.75 | % | 3.59 | % | 84 | 200 | ||||||||||||||||||||||||||||||
Yield on average interest-earning assets | 5.00 | % | 4.19 | % | 2.85 | % | 81 | 215 | ||||||||||||||||||||||||||||||
Average cost of interest-bearing deposits | 1.74 | % | 0.86 | % | 0.18 | % | 88 | 156 | ||||||||||||||||||||||||||||||
Average cost of deposits | 1.06 | % | 0.51 | % | 0.10 | % | 55 | 96 | ||||||||||||||||||||||||||||||
Average cost of funds | 1.11 | % | 0.55 | % | 0.12 | % | 56 | 99 | ||||||||||||||||||||||||||||||
Adjusted pre-tax, pre-provision profitability ratio (3) | 2.95 | % | 2.72 | % | 1.91 | % | 23 | 104 | ||||||||||||||||||||||||||||||
Adjusted noninterest expense/average assets (3) | 1.19 | % | 1.23 | % | 1.13 | % | (4) | 6 | ||||||||||||||||||||||||||||||
Efficiency ratio | 38.35 | % | 34.43 | % | 44.03 | % | 392 | (568) | ||||||||||||||||||||||||||||||
Adjusted efficiency ratio (3) | 28.66 | % | 31.18 | % | 37.24 | % | (252) | bps | (858) | bps | ||||||||||||||||||||||||||||
| Year Ended | December 31, 2022 Basis Point Change | |||||||||||||||||||||||||||||||||||||
| December 31, 2022 | December 31, 2021 | Yr-o-Yr | ||||||||||||||||||||||||||||||||||||
Return on average assets | 1.80 | % | 1.47 | % | 33 | bps | ||||||||||||||||||||||||||||||||
Return on average equity | 19.51 | % | 15.70 | % | 381 | |||||||||||||||||||||||||||||||||
Tangible return on average tangible equity (2) | 21.29 | % | 17.24 | % | 405 | |||||||||||||||||||||||||||||||||
Interest rate spread | 3.06 | % | 2.60 | % | 46 | |||||||||||||||||||||||||||||||||
Net interest margin | 3.45 | % | 2.72 | % | 73 | |||||||||||||||||||||||||||||||||
Average loan yield | 4.52 | % | 3.59 | % | 93 | |||||||||||||||||||||||||||||||||
Yield on average interest-earning assets | 3.91 | % | 2.88 | % | 103 | |||||||||||||||||||||||||||||||||
Average cost of interest-bearing deposits | 0.80 | % | 0.23 | % | 57 | |||||||||||||||||||||||||||||||||
Average cost of deposits | 0.46 | % | 0.13 | % | 33 | |||||||||||||||||||||||||||||||||
Average cost of funds | 0.50 | % | 0.17 | % | 33 | |||||||||||||||||||||||||||||||||
Adjusted pre-tax, pre-provision profitability ratio (3) | 2.55 | % | 1.94 | % | 61 | |||||||||||||||||||||||||||||||||
Adjusted noninterest expense/average assets (3) | 1.18 | % | 1.13 | % | 5 | |||||||||||||||||||||||||||||||||
Efficiency ratio | 36.65 | % | 43.80 | % | (715) | |||||||||||||||||||||||||||||||||
Adjusted efficiency ratio (3) | 31.74 | % | 36.91 | % | (517) | bps | ||||||||||||||||||||||||||||||||
(1)Annualized except for efficiency ratio.
(2)Tangible return on average tangible equity is a non-GAAP financial measure. See reconciliation of GAAP to non-GAAP measures in Table 13.
(3)Adjusted pre-tax, pre-provision profitability ratio, adjusted noninterest expense/average assets and the adjusted efficiency ratio are non-GAAP financial measures. See reconciliation of GAAP to non-GAAP measures in Table 12.
15
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||
| ALLOWANCE FOR LOAN LOSSES & OFF-BALANCE SHEET CREDIT EXPOSURES | |||||||||||||||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||
| Table 10 | |||||||||||||||||||||||||||||||||||
| Three Months Ended December 31, 2022 | |||||||||||||||||||||||||||||||||||
| Commercial | Consumer | ||||||||||||||||||||||||||||||||||
| C&I | Total CRE | Total Residential Mortgage | Other Consumer | Total | |||||||||||||||||||||||||||||||
Allowance for loan losses, September 30, 2022 | $ | 371,749 | $ | 178,487 | $ | 30,587 | $ | 1,694 | $ | 582,517 | |||||||||||||||||||||||||
| (Reversal of) provision for credit losses on loans | (a) | (263) | 13,790 | 9,363 | (118) | 22,772 | |||||||||||||||||||||||||||||
| Gross charge-offs | (416) | (10,804) | — | (16) | (11,236) | ||||||||||||||||||||||||||||||
| Gross recoveries | 136 | 873 | 89 | — | 1,098 | ||||||||||||||||||||||||||||||
| Total net (charge-offs) recoveries | (280) | (9,931) | 89 | (16) | (10,138) | ||||||||||||||||||||||||||||||
| Foreign currency translation adjustment | 494 | — | — | — | 494 | ||||||||||||||||||||||||||||||
Allowance for loan losses, December 31, 2022 | $ | 371,700 | $ | 182,346 | $ | 40,039 | $ | 1,560 | $ | 595,645 | |||||||||||||||||||||||||
| Three Months Ended September 30, 2022 | |||||||||||||||||||||||||||||||||||
| Commercial | Consumer | ||||||||||||||||||||||||||||||||||
| C&I | Total CRE | Total Residential Mortgage | Other Consumer | Total | |||||||||||||||||||||||||||||||
| Allowance for loan losses, June 30, 2022 | $ | 363,282 | $ | 173,479 | $ | 25,060 | $ | 1,449 | $ | 563,270 | |||||||||||||||||||||||||
| Provision for credit losses on loans | (a) | 9,575 | 11,163 | 6,281 | 255 | 27,274 | |||||||||||||||||||||||||||||
| Gross charge-offs | (6,894) | (6,226) | (775) | (10) | (13,905) | ||||||||||||||||||||||||||||||
| Gross recoveries | 7,172 | 71 | 21 | — | 7,264 | ||||||||||||||||||||||||||||||
| Total net recoveries (charge-offs) | 278 | (6,155) | (754) | (10) | (6,641) | ||||||||||||||||||||||||||||||
| Foreign currency translation adjustment | (1,386) | — | — | — | (1,386) | ||||||||||||||||||||||||||||||
Allowance for loan losses, September 30, 2022 | $ | 371,749 | $ | 178,487 | $ | 30,587 | $ | 1,694 | $ | 582,517 | |||||||||||||||||||||||||
| Three Months Ended December 31, 2021 | |||||||||||||||||||||||||||||||||||
| Commercial | Consumer | ||||||||||||||||||||||||||||||||||
| C&I | Total CRE | Total Residential Mortgage | Other Consumer | Total | |||||||||||||||||||||||||||||||
Allowance for loan losses, September 30, 2021 | $ | 342,142 | $ | 192,260 | $ | 21,684 | $ | 4,318 | $ | 560,404 | |||||||||||||||||||||||||
| Provision for (reversal of) credit losses on loans | (a) | 2,395 | (9,416) | (1,519) | (940) | (9,480) | |||||||||||||||||||||||||||||
| Gross charge-offs | (12,328) | (2,872) | — | (1,454) | (16,654) | ||||||||||||||||||||||||||||||
| Gross recoveries | 5,605 | 836 | 430 | — | 6,871 | ||||||||||||||||||||||||||||||
| Total net (charge-offs) recoveries | (6,723) | (2,036) | 430 | (1,454) | (9,783) | ||||||||||||||||||||||||||||||
| Foreign currency translation adjustment | 438 | — | — | — | 438 | ||||||||||||||||||||||||||||||
Allowance for loan losses, December 31, 2021 | $ | 338,252 | $ | 180,808 | $ | 20,595 | $ | 1,924 | $ | 541,579 | |||||||||||||||||||||||||
16
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||
| ALLOWANCE FOR LOAN LOSSES & OFF-BALANCE-SHEET CREDIT EXPOSURES | |||||||||||||||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||||||||||||||
| Table 10 (continued) | |||||||||||||||||||||||||||||||||||
| Year Ended December 31, 2022 | |||||||||||||||||||||||||||||||||||
| Commercial | Consumer | ||||||||||||||||||||||||||||||||||
| C&I | Total CRE | Total Residential Mortgage | Other Consumer | Total | |||||||||||||||||||||||||||||||
Allowance for loan losses, December 31, 2021 | $ | 338,252 | $ | 180,808 | $ | 20,595 | $ | 1,924 | $ | 541,579 | |||||||||||||||||||||||||
| Provision for (reversal of) credit losses on loans | (a) | 37,604 | 17,430 | 19,991 | (258) | 74,767 | |||||||||||||||||||||||||||||
| Gross charge-offs | (18,738) | (18,108) | (968) | (106) | (37,920) | ||||||||||||||||||||||||||||||
| Gross recoveries | 16,824 | 2,216 | 421 | — | 19,461 | ||||||||||||||||||||||||||||||
| Total net charge-offs | (1,914) | (15,892) | (547) | (106) | (18,459) | ||||||||||||||||||||||||||||||
| Foreign currency translation adjustment | (2,242) | — | — | — | (2,242) | ||||||||||||||||||||||||||||||
Allowance for loan losses, December 31, 2022 | $ | 371,700 | $ | 182,346 | $ | 40,039 | $ | 1,560 | $ | 595,645 | |||||||||||||||||||||||||
| Year Ended December 31, 2021 | |||||||||||||||||||||||||||||||||||
| Commercial | Consumer | ||||||||||||||||||||||||||||||||||
| C&I | Total CRE | Total Residential Mortgage | Other Consumer | Total | |||||||||||||||||||||||||||||||
Allowance for loan losses, December 31, 2020 | $ | 398,040 | $ | 201,603 | $ | 18,210 | $ | 2,130 | $ | 619,983 | |||||||||||||||||||||||||
| (Reversal of) provision for credit losses on loans | (a) | (39,732) | 6,782 | 2,710 | 1,286 | (28,954) | |||||||||||||||||||||||||||||
| Gross charge-offs | (32,490) | (31,514) | (1,091) | (1,497) | (66,592) | ||||||||||||||||||||||||||||||
| Gross recoveries | 11,906 | 3,937 | 766 | 5 | 16,614 | ||||||||||||||||||||||||||||||
| Total net charge-offs | (20,584) | (27,577) | (325) | (1,492) | (49,978) | ||||||||||||||||||||||||||||||
| Foreign currency translation adjustment | 528 | — | — | — | 528 | ||||||||||||||||||||||||||||||
Allowance for loan losses, December 31, 2021 | $ | 338,252 | $ | 180,808 | $ | 20,595 | $ | 1,924 | $ | 541,579 | |||||||||||||||||||||||||
| Three Months Ended | Year Ended | ||||||||||||||||||||||||||||||||||
| December 31, 2022 | September 30, 2022 | December 31, 2021 | December 31, 2022 | December 31, 2021 | |||||||||||||||||||||||||||||||
| Unfunded Credit Facilities | |||||||||||||||||||||||||||||||||||
Allowance for unfunded credit commitments, beginning of period (1) | $ | 24,041 | $ | 24,304 | $ | 28,036 | $ | 27,514 | $ | 33,577 | |||||||||||||||||||||||||
| Provision for (reversal of) credit losses on unfunded credit commitments | (b) | 2,228 | (274) | (520) | (1,267) | (6,046) | |||||||||||||||||||||||||||||
| Foreign currency translation adjustment | (5) | 11 | (2) | 17 | (17) | ||||||||||||||||||||||||||||||
Allowance for unfunded credit commitments, end of period (1) | $ | 26,264 | $ | 24,041 | $ | 27,514 | $ | 26,264 | $ | 27,514 | |||||||||||||||||||||||||
| Provision for (reversal of) credit losses | (a)+(b) | $ | 25,000 | $ | 27,000 | $ | (10,000) | $ | 73,500 | $ | (35,000) | ||||||||||||||||||||||||
(1)Included in Accrued expenses and other liabilities on the Condensed Consolidated Balance Sheet.
17
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | |||||||||||||||||||||||
| CRITICIZED LOANS, NONPERFORMING ASSETS AND CREDIT QUALITY RATIOS | |||||||||||||||||||||||
| ($ in thousands) | |||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||
| Table 11 | |||||||||||||||||||||||
| Criticized Loans | December 31, 2022 | September 30, 2022 | December 31, 2021 | ||||||||||||||||||||
| Special mention loans | $ | 468,471 | $ | 470,964 | $ | 384,694 | |||||||||||||||||
| Classified loans | 427,509 | 434,242 | 448,362 | ||||||||||||||||||||
Total criticized loans (1) | $ | 895,980 | $ | 905,206 | $ | 833,056 | |||||||||||||||||
Nonperforming Assets | December 31, 2022 | September 30, 2022 | December 31, 2021 | ||||||||||||||||||||
| Nonaccrual loans: | |||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||
| C&I | $ | 50,428 | $ | 47,988 | $ | 59,023 | |||||||||||||||||
| Total CRE | 23,413 | 11,209 | 9,942 | ||||||||||||||||||||
| Consumer: | |||||||||||||||||||||||
| Total residential mortgage | 25,586 | 23,309 | 24,164 | ||||||||||||||||||||
| Other consumer | 99 | 37 | 52 | ||||||||||||||||||||
| Total nonaccrual loans | 99,526 | 82,543 | 93,181 | ||||||||||||||||||||
| Other real estate owned, net | 270 | — | 363 | ||||||||||||||||||||
| Other nonperforming assets | — | — | 9,938 | ||||||||||||||||||||
| Nonperforming loans HFS | — | 14,500 | — | ||||||||||||||||||||
| Total nonperforming assets | $ | 99,796 | $ | 97,043 | $ | 103,482 | |||||||||||||||||
| Credit Quality Ratios | December 31, 2022 | September 30, 2022 | December 31, 2021 | ||||||||||||||||||||
| Annualized quarterly net charge-offs to average loans HFI | 0.08 | % | 0.06 | % | 0.10 | % | |||||||||||||||||
| Annual net charge-offs to average loans HFI | 0.04 | % | N/A | 0.13 | % | ||||||||||||||||||
| Special mention loans to loans HFI | 0.97 | % | 0.99 | % | 0.92 | % | |||||||||||||||||
| Classified loans to loans HFI | 0.89 | % | 0.92 | % | 1.08 | % | |||||||||||||||||
| Criticized loans to loans HFI | 1.86 | % | 1.91 | % | 2.00 | % | |||||||||||||||||
| Nonperforming assets to total assets | 0.16 | % | 0.16 | % | 0.17 | % | |||||||||||||||||
| Nonaccrual loans to loans HFI | 0.21 | % | 0.17 | % | 0.22 | % | |||||||||||||||||
| Allowance for loan losses to loans HFI | 1.24 | % | 1.23 | % | 1.30 | % | |||||||||||||||||
(1)Excludes loans HFS.
18
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | ||||||||||||||||||||||||||
| GAAP TO NON-GAAP RECONCILIATION | ||||||||||||||||||||||||||
| ($ in thousands) | ||||||||||||||||||||||||||
| (unaudited) | ||||||||||||||||||||||||||
| Table 12 | ||||||||||||||||||||||||||
| The Company uses certain non-GAAP financial measures to provide supplemental information regarding the Company’s performance. Adjusted efficiency ratio represents adjusted noninterest expense divided by revenue. Adjusted pre-tax, pre-provision profitability ratio represents total revenue less adjusted noninterest expense, divided by average total assets. Adjusted noninterest expense excludes the amortization of tax credit and other investments and the amortization of core deposit intangibles. Management believes that the measures and ratios presented below provide clarity to financial statement users regarding the ongoing performance of the Company and allow comparability to prior periods. | ||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||
| December 31, 2022 | September 30, 2022 | December 31, 2021 | ||||||||||||||||||||||||
| Net interest income before provision for (reversal of) credit losses | $ | 605,507 | $ | 551,809 | $ | 405,697 | ||||||||||||||||||||
| Total noninterest income | 64,927 | 75,552 | 71,489 | |||||||||||||||||||||||
| Total revenue | (a) | $ | 670,434 | $ | 627,361 | $ | 477,186 | |||||||||||||||||||
| Total noninterest expense | (b) | $ | 257,110 | $ | 215,973 | $ | 210,105 | |||||||||||||||||||
| Less: Amortization of tax credit and other investments | (64,605) | (19,874) | (31,800) | |||||||||||||||||||||||
| Amortization of core deposit intangibles | (381) | (485) | (602) | |||||||||||||||||||||||
| Adjusted noninterest expense | (c) | $ | 192,124 | $ | 195,614 | $ | 177,703 | |||||||||||||||||||
| Efficiency ratio | (b)/(a) | 38.35 | % | 34.43 | % | 44.03 | % | |||||||||||||||||||
| Adjusted efficiency ratio | (c)/(a) | 28.66 | % | 31.18 | % | 37.24 | % | |||||||||||||||||||
| Adjusted pre-tax, pre-provision income | (a)-(c) = (d) | $ | 478,310 | $ | 431,747 | $ | 299,483 | |||||||||||||||||||
| Average total assets | (e) | $ | 64,252,730 | $ | 63,079,444 | $ | 62,183,137 | |||||||||||||||||||
Adjusted pre-tax, pre-provision profitability ratio (1) | (d)/(e) | 2.95 | % | 2.72 | % | 1.91 | % | |||||||||||||||||||
Adjusted noninterest expense/average assets (1) | (c)/(e) | 1.19 | % | 1.23 | % | 1.13 | % | |||||||||||||||||||
| Year Ended | ||||||||||||||||||||||||||
| December 31, 2022 | December 31, 2021 | |||||||||||||||||||||||||
| Net interest income before provision for (reversal of) credit losses | $ | 2,045,881 | $ | 1,531,571 | ||||||||||||||||||||||
| Total noninterest income | 298,666 | 285,895 | ||||||||||||||||||||||||
| Total revenue | (f) | $ | 2,344,547 | $ | 1,817,466 | |||||||||||||||||||||
| Total noninterest expense | (g) | $ | 859,393 | $ | 796,089 | |||||||||||||||||||||
| Less: Amortization of tax credit and other investments | (113,358) | (122,457) | ||||||||||||||||||||||||
| Amortization of core deposit intangibles | (1,865) | (2,749) | ||||||||||||||||||||||||
| Adjusted noninterest expense | (h) | $ | 744,170 | $ | 670,883 | |||||||||||||||||||||
| Efficiency ratio | (g)/(f) | 36.65 | % | 43.80 | % | |||||||||||||||||||||
| Adjusted efficiency ratio | (h)/(f) | 31.74 | % | 36.91 | % | |||||||||||||||||||||
| Adjusted pre-tax, pre-provision income | (f)-(h) = (i) | $ | 1,600,377 | $ | 1,146,583 | |||||||||||||||||||||
| Average total assets | (j) | $ | 62,838,282 | $ | 59,251,091 | |||||||||||||||||||||
| Adjusted pre-tax, pre-provision profitability ratio | (i)/(j) | 2.55 | % | 1.94 | % | |||||||||||||||||||||
| Adjusted noninterest expense/average assets | (h)/(j) | 1.18 | % | 1.13 | % | |||||||||||||||||||||
(1)Annualized.
19
| EAST WEST BANCORP, INC. AND SUBSIDIARIES | ||||||||||||||||||||||||||
| GAAP TO NON-GAAP RECONCILIATION | ||||||||||||||||||||||||||
| ($ in thousands) | ||||||||||||||||||||||||||
| (unaudited) | ||||||||||||||||||||||||||
| Table 13 | ||||||||||||||||||||||||||
The Company uses certain non-GAAP financial measures to provide supplemental information regarding the Company’s performance. Tangible equity and tangible equity to tangible assets ratio are non-GAAP financial measures. Tangible equity and tangible assets represent stockholders’ equity and total assets, respectively, which have been reduced by goodwill and other intangible assets. Given that the use of such measures and ratios is more prevalent in the banking industry, and such measures and ratios are used by banking regulators and analysts, the Company has included them below for discussion. | ||||||||||||||||||||||||||
| December 31, 2022 | September 30, 2022 | December 31, 2021 | ||||||||||||||||||||||||
| Stockholders’ equity | (a) | $ | 5,984,612 | $ | 5,660,668 | $ | 5,837,218 | |||||||||||||||||||
| Less: Goodwill | (465,697) | (465,697) | (465,697) | |||||||||||||||||||||||
Other intangible assets (1) | (7,998) | (8,667) | (9,334) | |||||||||||||||||||||||
| Tangible equity | (b) | $ | 5,510,917 | $ | 5,186,304 | $ | 5,362,187 | |||||||||||||||||||
| Total assets | (c) | $ | 64,112,150 | $ | 62,576,061 | $ | 60,870,701 | |||||||||||||||||||
| Less: Goodwill | (465,697) | (465,697) | (465,697) | |||||||||||||||||||||||
Other intangible assets (1) | (7,998) | (8,667) | (9,334) | |||||||||||||||||||||||
| Tangible assets | (d) | $ | 63,638,455 | $ | 62,101,697 | $ | 60,395,670 | |||||||||||||||||||
| Total stockholders’ equity to total assets ratio | (a)/(c) | 9.33 | % | 9.05 | % | 9.59 | % | |||||||||||||||||||
| Tangible equity to tangible assets ratio | (b)/(d) | 8.66 | % | 8.35 | % | 8.88 | % | |||||||||||||||||||
| Tangible return on average tangible equity represents tangible net income divided by average tangible equity. Tangible net income excludes the after-tax impacts of the amortization of core deposit intangibles and mortgage servicing assets. Given that the use of such measures and ratios is more prevalent in the banking industry, and such measures and ratios are used by banking regulators and analysts, the Company has included them below for discussion. | ||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Year Ended | |||||||||||||||||||||||||||||||||||||
| December 31, 2022 | September 30, 2022 | December 31, 2021 | December 31, 2022 | December 31, 2021 | ||||||||||||||||||||||||||||||||||
| Net income | (e) | $ | 336,763 | $ | 295,339 | $ | 217,796 | $ | 1,128,083 | $ | 872,981 | |||||||||||||||||||||||||||
Add: Amortization of core deposit intangibles | 381 | 485 | 602 | 1,865 | 2,749 | |||||||||||||||||||||||||||||||||
Amortization of mortgage servicing assets | 329 | 340 | 415 | 1,425 | 1,679 | |||||||||||||||||||||||||||||||||
Tax effect of amortization adjustments (2) | (209) | (237) | (293) | (966) | (1,274) | |||||||||||||||||||||||||||||||||
| Tangible net income | (f) | $ | 337,264 | $ | 295,927 | $ | 218,520 | $ | 1,130,407 | $ | 876,135 | |||||||||||||||||||||||||||
| Average stockholders’ equity | (g) | $ | 5,834,623 | $ | 5,772,638 | $ | 5,786,237 | $ | 5,783,025 | $ | 5,559,212 | |||||||||||||||||||||||||||
| Less: Average goodwill | (465,697) | (465,697) | (465,697) | (465,697) | (465,697) | |||||||||||||||||||||||||||||||||
Average other intangible assets (1) | (8,378) | (8,379) | (9,611) | (8,695) | (10,535) | |||||||||||||||||||||||||||||||||
| Average tangible equity | (h) | $ | 5,360,548 | $ | 5,298,562 | $ | 5,310,929 | $ | 5,308,633 | $ | 5,082,980 | |||||||||||||||||||||||||||
| Return on average equity | (e)/(g) | 22.90 | % | (3) | 20.30 | % | (3) | 14.93 | % | (3) | 19.51 | % | 15.70 | % | ||||||||||||||||||||||||
| Tangible return on average tangible equity | (f)/(h) | 24.96 | % | (3) | 22.16 | % | (3) | 16.32 | % | (3) | 21.29 | % | 17.24 | % | ||||||||||||||||||||||||
(1)Includes core deposit intangibles and mortgage servicing assets.
(2)Applied statutory tax rate of 29.37% for the three and twelve months ended December 31, 2022. Applied statutory tax rate of 28.77% for the three months ended September 30, 2022, and for the three and twelve months ended December 31, 2021.
(3)Annualized.
20

EWBC Earnings Results Fourth Quarter and Full Year 2022 January 26, 2023
Forward-Looking Statements 2 Forward-Looking Statements This presentation contains forward-looking statements that are intended to be covered by the safe harbor for such statements provided by the Private Securities Litigation Reform Act of 1995. These statements are based on the current beliefs and expectations of the management of East West Bancorp, Inc. (the “Company”) and are subject to significant risks and uncertainties. You should not place undue reliance on these statements. Factors that could cause the Company’s actual results to differ materially from those described in the forward-looking statements include, among others, changes in the U.S. economy or local, regional and global business, economic and political conditions and geopolitical events; the impacts of the ongoing COVID-19 pandemic; changes in laws or the regulatory environment, including trade, monetary and fiscal policies and laws; and changes in the commercial and consumer real estate markets and in consumer spending and savings habits. These factors also consist of those contained in the Company’s filings with the Securities and Exchange Commission, including the “Risk Factors” section of the Company’s Annual Report on Form 10-K for the year ended December 31, 2021. When considering these forward-looking statements, you should keep in mind these risks and uncertainties, as well as any cautionary statements the Company may make. These statements speak only as of the date they are made and are based only on information then actually known to the Company. The Company does not undertake to update any forward-looking statements except as required by law. Non-GAAP Financial Measures Certain financial information in this presentation has not been prepared in accordance with U.S. generally accepted accounting principles (“GAAP”) and is presented on a non-GAAP basis. Investors should refer to the reconciliations included in this presentation and should consider the Company’s non-GAAP measures in addition to, not as a substitute for or superior to, measures prepared in accordance with GAAP. These measures may not be comparable to similarly titled measures used by other companies.

17.2% 21.3% FY 2021 FY 2022 15.7% 19.5% FY 2021 FY 2022 Highlights of Fourth Quarter and Full Year 2022 3 Return on Average Assets Adjusted Pre-Tax, Pre-Provision Income* & Profitability Ratio* Tangible Return on Average Tangible Equity* Return on Average Equity Adj. PTPP income* Adj. PTPP profitability ratio* $ i n m ill io n s 4Q22 Net income $337 million 2022 Net income $1.1 billion 4Q22 Diluted EPS $2.37 2022 Diluted EPS $7.92 4Q22 Revenue $670 million 2022 Revenue $2.3 billion Record loans $48.2 billion Record deposits $56.0 billion Tangible equity*/share $39.10 1.39% 1.86% 2.08% 4Q21 3Q22 4Q22 1.47% 1.80% FY 2021 FY 2022 14.9% 20.3% 22.9% 4Q21 3Q22 4Q22 16.3% 22.2% 25.0% 4Q21 3Q22 4Q22 $299 $432 $478 1.91% 2.72% 2.95% $200 $280 $360 $440 4Q21 3Q22 4Q22 $1,147 $1,600 1.94% 2.55% FY 2021 FY 2022 * See reconciliation of GAAP to non-GAAP financial measures in the appendix and in the Company’s Earnings Press Releases.

4 12.31.22: Strong, Well-Diversified Balance Sheet Record Loans as of 12.31.22: $48.2 billion ($ in billions) C&I Resi. mortgage & other consumerTotal CRE IB Checking & SavingsMMDADDA Time Total Deposits as of 12.31.22: $56.0 billion ($ in billions) * See reconciliation of GAAP to non-GAAP financial measures in the appendix and in the Company’s Earnings Press Releases. $21.1 38% $12.3 22% $9.3 16% $13.3 24% $15.7 33% $19.1 39% $13.4 28% $ in millions, except per share data 12.31.22 09.30.22 Cash equivalents & ST investments $ 3,621 $ 2,794 $ 827 Repo assets 792 893 (101) AFS debt securities 6,035 5,906 129 HTM debt securities 3,002 3,013 (11) Total Loans 48,228 47,457 771 Allowance for loan losses (ALLL) (596) (583) (13) Net Loans $ 47,632 $ 46,874 $ 758 Other assets 3,030 3,096 (66) Total Assets $ 64,112 $ 62,576 $ 1,536 Customer deposits $ 55,968 $ 53,857 $ 2,111 Fed Funds, FHLB advances & repo funding 300 1,137 (837) Long-term debt & finance lease liab. 152 153 (1) Other liabilities 1,708 1,768 (60) Total Liabilities $ 58,128 $ 56,915 $ 1,213 Total Stockholders' Equity $ 5,985 $ 5,661 $ 324 Book value per share $ 42.46 $ 40.17 $ 2.29 Tangible equity* per share $ 39.10 $ 36.80 $ 2.30 Tang. equity to tang. assets ratio* 8.66% 8.35% 31 bps Loans to deposits ratio 86.2% 88.1% (194) bps Q-o-Q Change
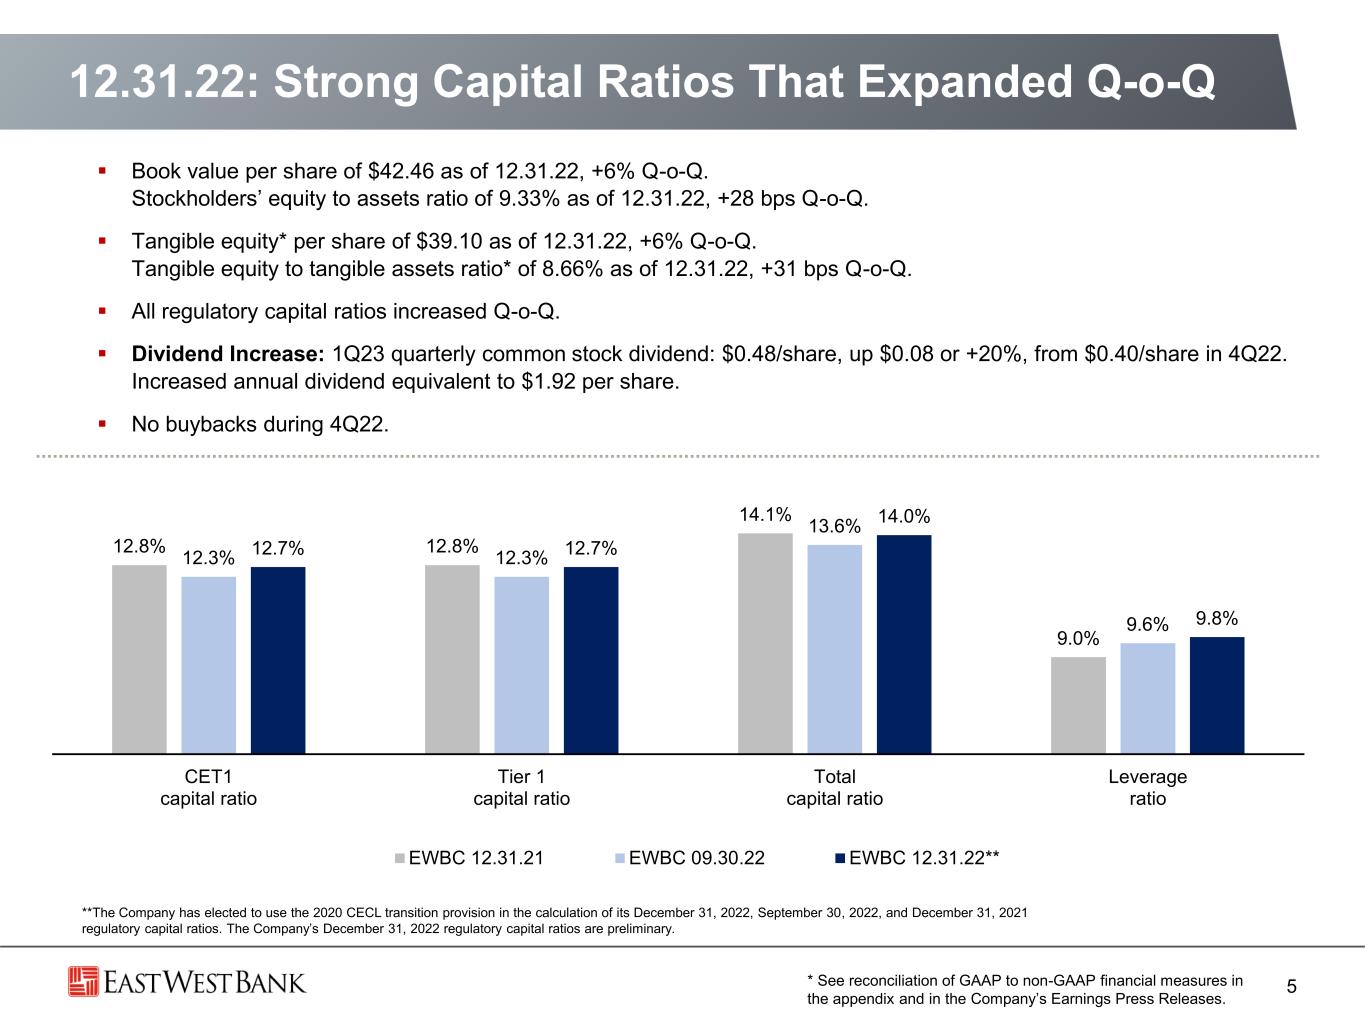
12.31.22: Strong Capital Ratios That Expanded Q-o-Q ▪ Book value per share of $42.46 as of 12.31.22, +6% Q-o-Q. Stockholders’ equity to assets ratio of 9.33% as of 12.31.22, +28 bps Q-o-Q. ▪ Tangible equity* per share of $39.10 as of 12.31.22, +6% Q-o-Q. Tangible equity to tangible assets ratio* of 8.66% as of 12.31.22, +31 bps Q-o-Q. ▪ All regulatory capital ratios increased Q-o-Q. ▪ Dividend Increase: 1Q23 quarterly common stock dividend: $0.48/share, up $0.08 or +20%, from $0.40/share in 4Q22. Increased annual dividend equivalent to $1.92 per share. ▪ No buybacks during 4Q22. 5 **The Company has elected to use the 2020 CECL transition provision in the calculation of its December 31, 2022, September 30, 2022, and December 31, 2021 regulatory capital ratios. The Company’s December 31, 2022 regulatory capital ratios are preliminary. * See reconciliation of GAAP to non-GAAP financial measures in the appendix and in the Company’s Earnings Press Releases. 12.8% 12.8% 14.1% 9.0% 12.3% 12.3% 13.6% 9.6% 12.7% 12.7% 14.0% 9.8% CET1 capital ratio Tier 1 capital ratio Total capital ratio Leverage ratio EWBC 12.31.21 EWBC 09.30.22 EWBC 12.31.22**

Total CRE 39% Total Resi. Mortgage & Other Consumer 28% C&I 33% 6 12.31.22: Diversified Commercial Loan Portfolio ▪ C&I loans: $15.7bn loans O/S plus $7.1bn undisbursed commitments: $22.8bn total commitments as of 12.31.22. ▪ Portfolio well-diversified by industry. ▪ Utilization: 69% as of 12.31.22, vs. 70% as of 09.30.22. ▪ Growth: total commitments: +3% (+10% ann.) Q-o-Q & EOP loans O/S: +1% (+2% ann.) Q-o-Q. ▪ China loans O/S (mainland + Hong Kong): $2.14bn as of 12.31.22, up +2% (+7% ann.) from $2.10bn as of 09.30.22. Portfolio primarily consists of C&I loans, well-diversified by industry. Total Loans: C&I Loans by Industry as % of Total Loans Outstanding $15.7bn$48.2 billion Total Loans 5% 11% Private Equity & Fund Finance Tech & Telecom: 1%; Hospitality & Leisure:1% Oil & Gas: 1%; Consumer Nondurable Goods: 1% All Other C&I } 4% 3% 2% 2% 2% Media & Entertainment Infrastructure & Clean Energy General Manufacturing & Wholesale Real Estate Investment & Management Agriculture & Food-related Industries
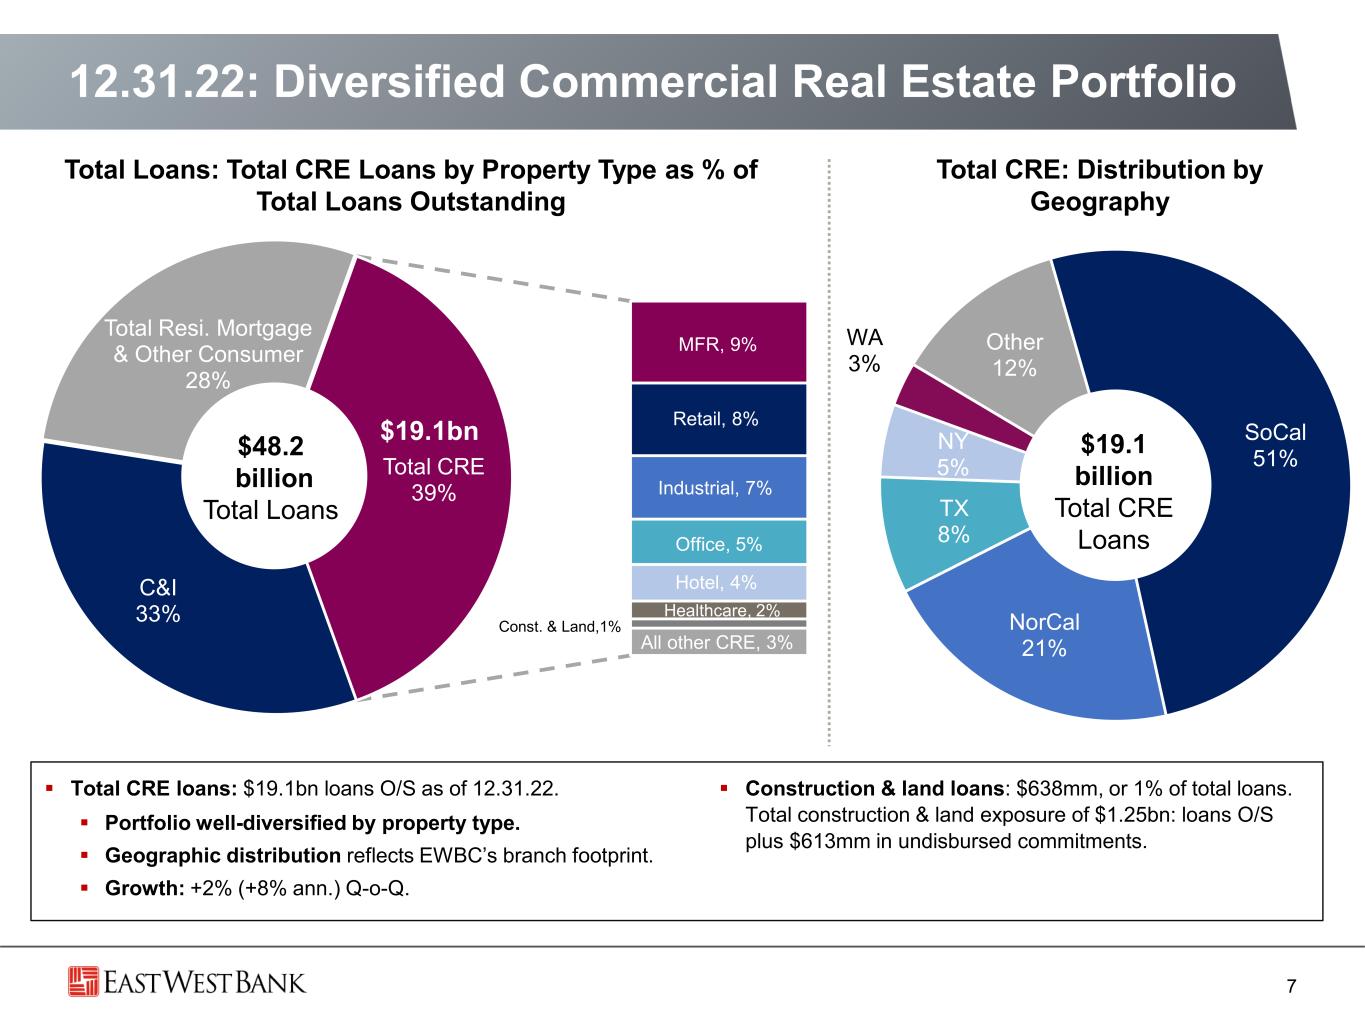
C&I 33% MFR, 9% Retail, 8% Industrial, 7% Office, 5% Hotel, 4% Healthcare, 2% All other CRE, 3% Total Resi. Mortgage & Other Consumer 28% Total CRE 39% SoCal 51% NorCal 21% TX 8% NY 5% WA 3% Other 12% 12.31.22: Diversified Commercial Real Estate Portfolio 7 Total Loans: Total CRE Loans by Property Type as % of Total Loans Outstanding ▪ Total CRE loans: $19.1bn loans O/S as of 12.31.22. ▪ Portfolio well-diversified by property type. ▪ Geographic distribution reflects EWBC’s branch footprint. ▪ Growth: +2% (+8% ann.) Q-o-Q. ▪ Construction & land loans: $638mm, or 1% of total loans. Total construction & land exposure of $1.25bn: loans O/S plus $613mm in undisbursed commitments. $19.1 billion Total CRE Loans Total CRE: Distribution by Geography $19.1bn$48.2 billion Total Loans Const. & Land,1%

<=50% 41% >50% to 55% 16% >55% to 60% 16% >60% to 65% 17% >65% to 70% 6% >70% 4% Total CRE: Distribution by LTV 8 12.31.22: Low LTV Commercial Real Estate Portfolio CRE Size & LTV by Property Type 1 Weighted avg. LTV based on commitment. * Construction & Land avg. size based on total commitment. ▪ High percentage of CRE loans have full recourse & personal guarantees from individuals or guarantors with substantial net worth. ▪ Many of our customers have long-term relationships with East West Bank. $2.8 million Avg. size of loan outstanding 51% Avg. LTV ($ in millions) Total Portfolio Size Weighted Avg. LTV1 Average Loan Size Multifamily 4,573$ 52% 1.6$ Retail 4,076$ 49% 2.4$ Industrial 3,617$ 48% 3.0$ Office 2,523$ 53% 4.2$ Hotel 2,086$ 53% 9.1$ Healthcare 797$ 57% 4.2$ Construction & Land* 638$ 57% 13.7$ Other 759$ 49% 2.8$ Total CRE 19,069$ 51% 2.8$
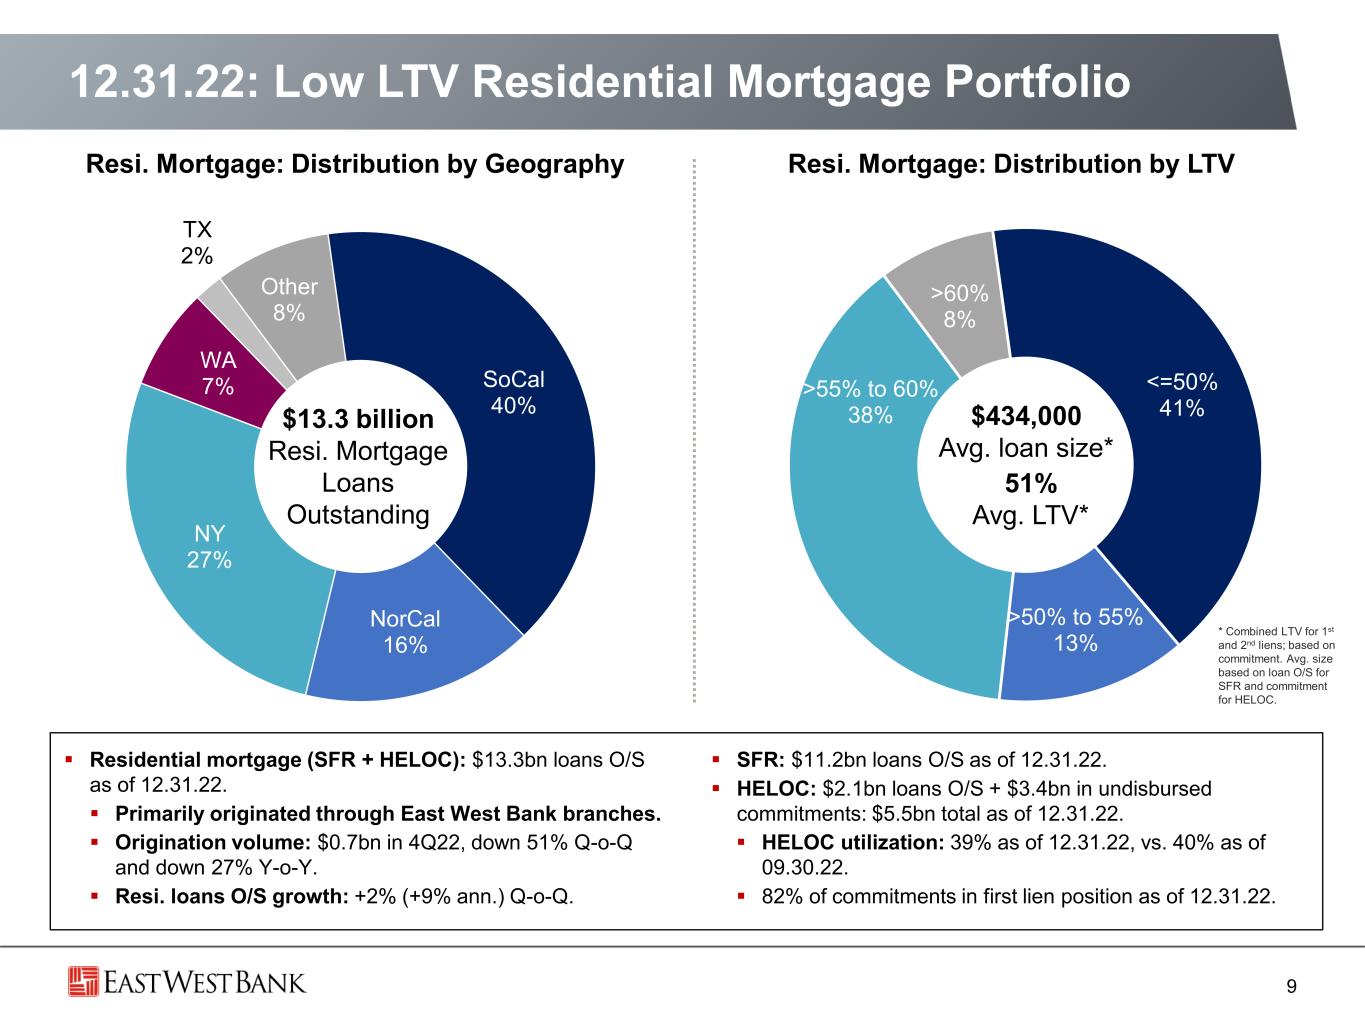
SoCal 40% NorCal 16% NY 27% WA 7% TX 2% Other 8% 12.31.22: Low LTV Residential Mortgage Portfolio 9 Resi. Mortgage: Distribution by Geography Resi. Mortgage: Distribution by LTV $13.3 billion Resi. Mortgage Loans Outstanding $434,000 Avg. loan size* 51% Avg. LTV* ▪ Residential mortgage (SFR + HELOC): $13.3bn loans O/S as of 12.31.22. ▪ Primarily originated through East West Bank branches. ▪ Origination volume: $0.7bn in 4Q22, down 51% Q-o-Q and down 27% Y-o-Y. ▪ Resi. loans O/S growth: +2% (+9% ann.) Q-o-Q. ▪ SFR: $11.2bn loans O/S as of 12.31.22. ▪ HELOC: $2.1bn loans O/S + $3.4bn in undisbursed commitments: $5.5bn total as of 12.31.22. ▪ HELOC utilization: 39% as of 12.31.22, vs. 40% as of 09.30.22. ▪ 82% of commitments in first lien position as of 12.31.22. * Combined LTV for 1st and 2nd liens; based on commitment. Avg. size based on loan O/S for SFR and commitment for HELOC. <=50% 41% >50% to 55% 13% >55% to 60% 38% >60% 8%
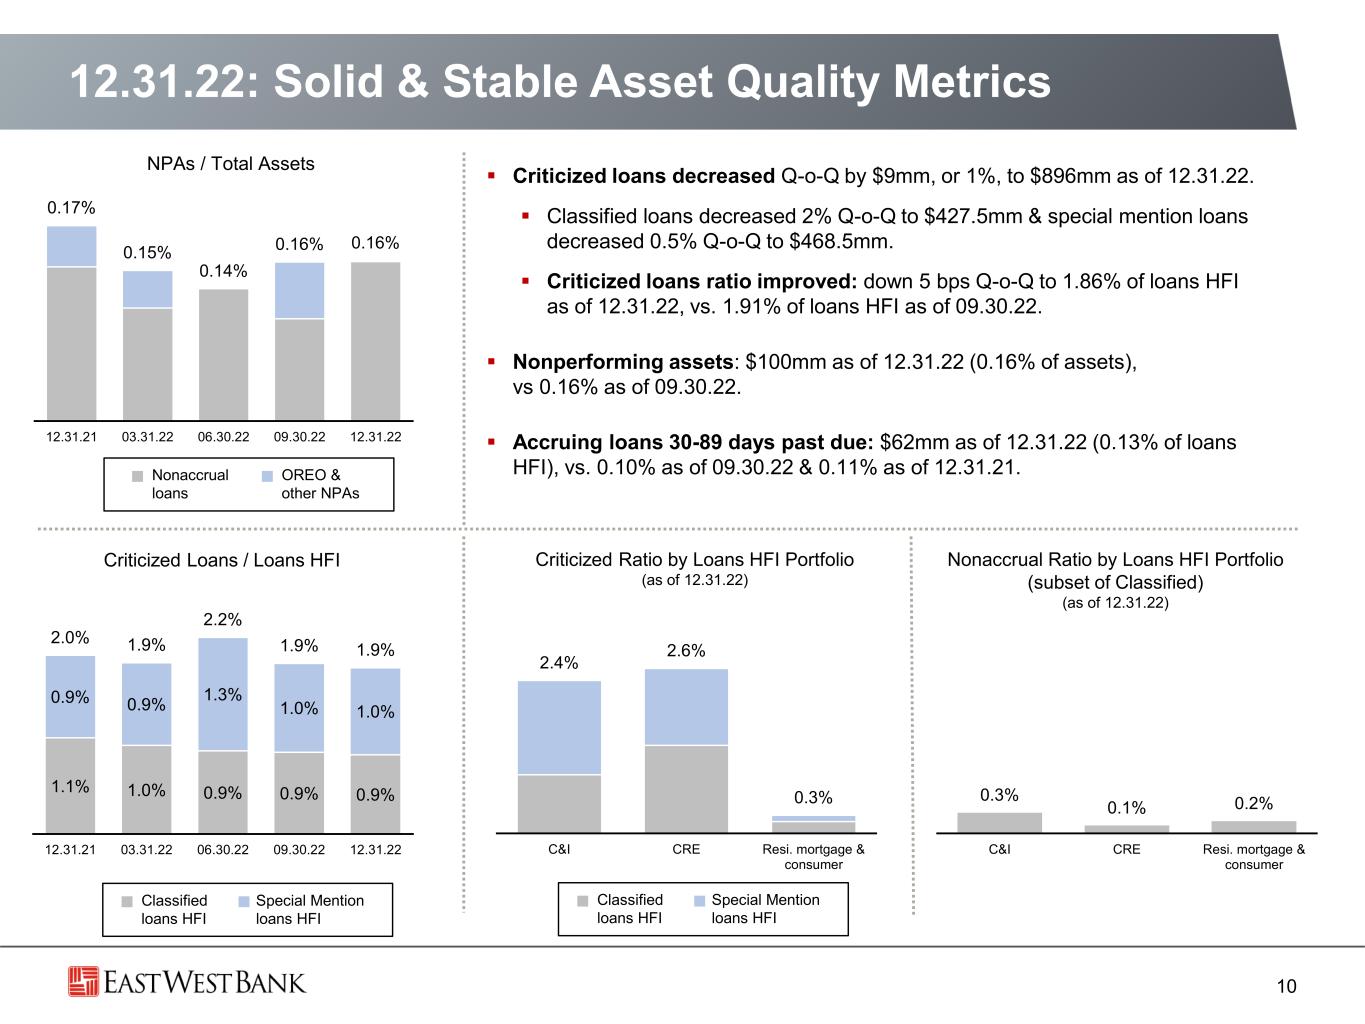
1.1% 1.0% 0.9% 0.9% 0.9% 0.9% 0.9% 1.3% 1.0% 1.0% 2.0% 1.9% 2.2% 1.9% 1.9% 12.31.21 03.31.22 06.30.22 09.30.22 12.31.22 2.4% 2.6% 0.3% C&I CRE Resi. mortgage & consumer 0.3% 0.1% 0.2% C&I CRE Resi. mortgage & consumer 12.31.22: Solid & Stable Asset Quality Metrics 10 Nonaccrual loans OREO & other NPAs Classified loans HFI Special Mention loans HFI Classified loans HFI Special Mention loans HFI Nonaccrual Ratio by Loans HFI Portfolio (subset of Classified) (as of 12.31.22) NPAs / Total Assets Criticized Ratio by Loans HFI Portfolio (as of 12.31.22) Criticized Loans / Loans HFI ▪ Criticized loans decreased Q-o-Q by $9mm, or 1%, to $896mm as of 12.31.22. ▪ Classified loans decreased 2% Q-o-Q to $427.5mm & special mention loans decreased 0.5% Q-o-Q to $468.5mm. ▪ Criticized loans ratio improved: down 5 bps Q-o-Q to 1.86% of loans HFI as of 12.31.22, vs. 1.91% of loans HFI as of 09.30.22. ▪ Nonperforming assets: $100mm as of 12.31.22 (0.16% of assets), vs 0.16% as of 09.30.22. ▪ Accruing loans 30-89 days past due: $62mm as of 12.31.22 (0.13% of loans HFI), vs. 0.10% as of 09.30.22 & 0.11% as of 12.31.21. 0.17% 0.15% 0.14% 0.16% 0.16% 12.31.21 03.31.22 06.30.22 09.30.22 12.31.22

4Q22: Allowance for Loan Losses & Credit Costs 11 Allowance for Loan Losses Coverage Ratio $ i n m ill io n s Provision for Credit Losses & Net Charge-offs $ i n m ill io n s HFI represents Held for Investment. $(10) $8 $13.5 $27 $25 $10 $8 $(7) $7 $10 0.10% 0.08% -0.06% 0.06% 0.08% -0.09% $(25) 4Q21 1Q22 2Q22 3Q22 4Q22 Provision for credit losses Net charge-offs NCO ratio (ann.) Composition of ALLL by Portfolio: $ i n m ill io n s ; ra ti o i s a llo w a n c e c o v e ra g e b y p o rt fo lio ALLL by Loan Portfolio: C&I (ex. PPP) Total CRE Resi. mortgage & consumer Total: $583 Total:1.23%Total: $596 Total:1.24% 372 372 2.40% 2.38% 178 182 0.95% 0.96% 33 42 0.25% 0.31% 09.30.22 12.31.22 09.30.22 12.31.22 ▪ ALLL coverage of loans: 1.24% as of 12.31.22, vs. 1.23% as of 09.30.22. ▪ Build in ALLL coverage largely reflects current macroeconomic outlook and credit model drivers. ▪ Build in residential mortgage & consumer loan ALLL coverage largely due to changes in the Consumer Price Index (CPI) and the Housing Price Index (HPI). ▪ Net charge-offs in 4Q22 of $10mm, or annualized 0.08% of avg. loans, vs. 0.06% annualized in 3Q22. ▪ Provision for credit losses in 4Q22: $25mm, vs. $27mm in 3Q22. $542 $546 $563 $583 $596 1.30% 1.25% 1.21% 1.23% 1.24% 1.00% $400 12.31.21 03.31.22 06.30.22 09.30.22 12.31.22 ALLL ALLL/Loans HFI

4Q22: Summary Income Statement 12 * See slide 17 for noninterest income detail by category. Comments ▪ Record net interest income: $605.5mm, up 10% Q-o-Q (+39% LQA). ▪ Customer-driven fee income and GOS of SBA loans: $66mm, down 4.5% Q-o-Q. ▪ Interest rate contracts (“IRC”) and other derivative income was a loss of $0.6mm in 4Q22, compared with income of $8.8mm 3Q22. The Q-o-Q decrease of $9.4mm was due to an unfavorable change in the credit valuation adjustment. Customer-driven IRC revenue in 4Q22 quarter was essentially unchanged from 3Q22 at $4mm. ▪ Amortization of tax credit & other investments: $65mm in 4Q22, vs. $20mm in 3Q22: Q-o-Q variability reflects the impact of investments that close in a given period. ▪ Tax expense: The full-year 2022 effective tax rate was 20%, compared with 17% in 2021. The lower effective tax rate in 4Q22 of 13% reflected impact of tax credit investments that closed in 4Q22. ** See reconciliation of GAAP to non-GAAP financial measures in the appendix and in the Company’s Earnings Press Releases. 4Q22 vs. 3Q22 $ in millions, except per share data & ratios 4Q22 3Q22 $ Change % Change Total net interest income $ 605.5 $ 551.8 $ 53.7 10% Fee income & net GOS of loans* 66.0 69.0 (3.0) -4.5% Other (1.1) 6.6 (7.7) -117% Total noninterest income $ 64.9 $ 75.6 $ (10.7) -14% Total revenue $ 670.4 $ 627.4 $ 43.0 7% Adjusted noninterest expense** $ 192.1 $ 195.6 $ (3.5) -2% Amortization of tax credit & other investments + core deposit intangibles 65.0 20.4 44.6 219% Total noninterest expense $ 257.1 $ 216.0 $ 41.1 19% Provision for credit losses $ 25.0 $ 27.0 $ (2.0) -7% Income tax expense 51.6 89.0 (37.4) -42% Effective tax rate 13% 23% -10% Net Income (GAAP) $ 336.8 $ 295.3 $ 41.5 14% Diluted EPS $ 2.37 $ 2.08 $ 0.29 14% Weigh. avg. diluted shares (in mm) 142.1 142.0 0.1 0.1%
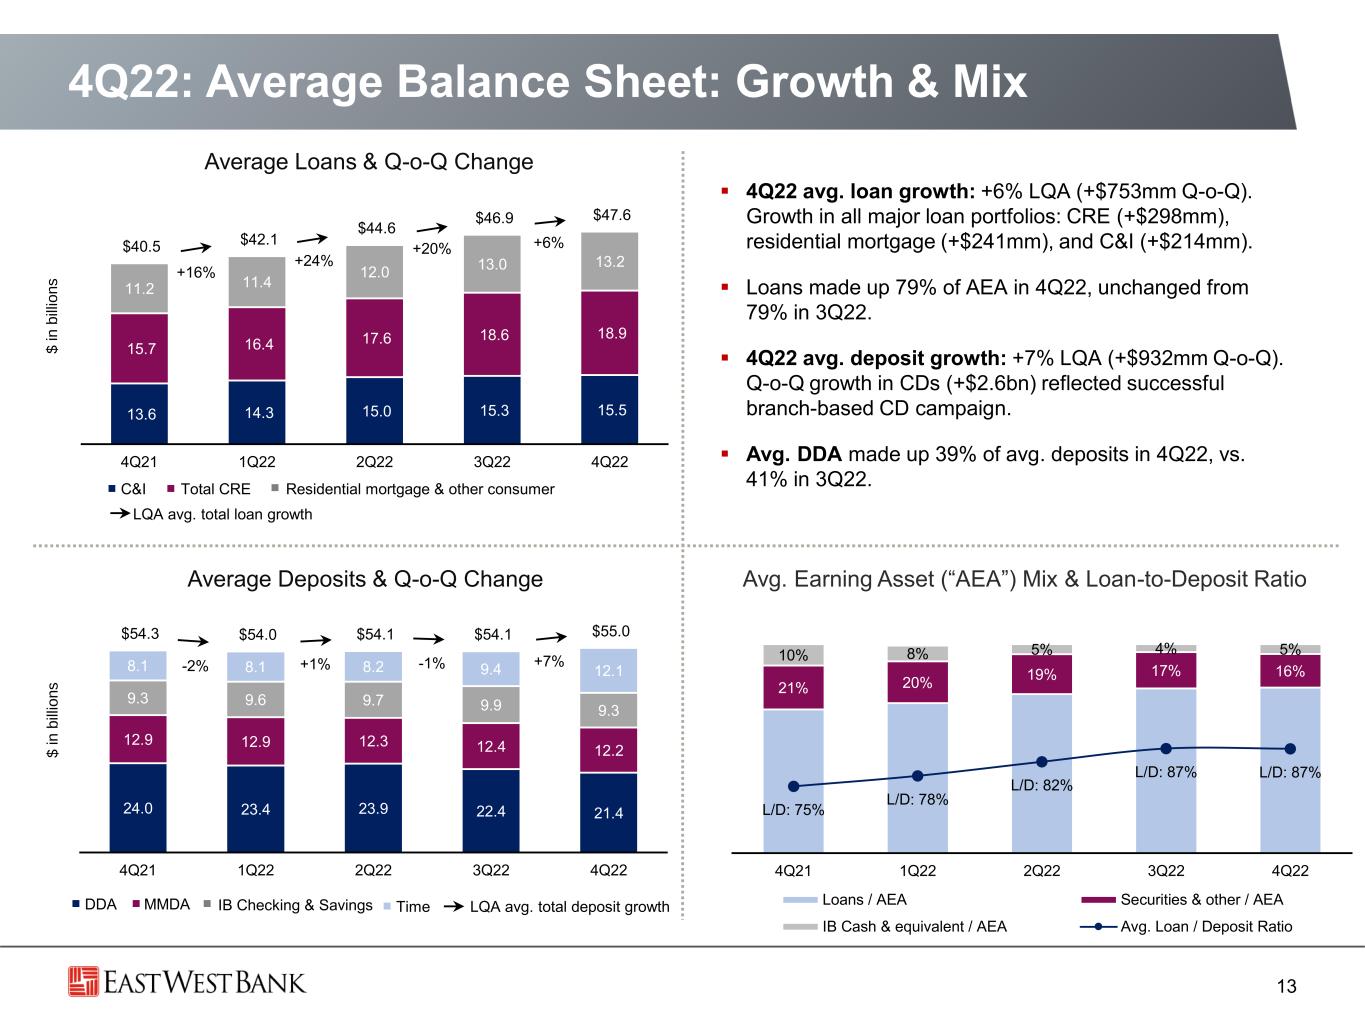
24.0 23.4 23.9 22.4 21.4 12.9 12.9 12.3 12.4 12.2 9.3 9.6 9.7 9.9 9.3 8.1 8.1 8.2 9.4 12.1 $54.3 $54.0 $54.1 $54.1 $55.0 4Q21 1Q22 2Q22 3Q22 4Q22 13.6 14.3 15.0 15.3 15.5 15.7 16.4 17.6 18.6 18.9 11.2 11.4 12.0 13.0 13.2 $40.5 $42.1 $44.6 $46.9 $47.6 4Q21 1Q22 2Q22 3Q22 4Q22 4Q22: Average Balance Sheet: Growth & Mix 13 ▪ 4Q22 avg. loan growth: +6% LQA (+$753mm Q-o-Q). Growth in all major loan portfolios: CRE (+$298mm), residential mortgage (+$241mm), and C&I (+$214mm). ▪ Loans made up 79% of AEA in 4Q22, unchanged from 79% in 3Q22. ▪ 4Q22 avg. deposit growth: +7% LQA (+$932mm Q-o-Q). Q-o-Q growth in CDs (+$2.6bn) reflected successful branch-based CD campaign. ▪ Avg. DDA made up 39% of avg. deposits in 4Q22, vs. 41% in 3Q22. $ i n b ill io n s Average Loans & Q-o-Q Change +16% +24% +6% LQA avg. total loan growth C&I Total CRE Residential mortgage & other consumer Average Deposits & Q-o-Q Change Avg. Earning Asset (“AEA”) Mix & Loan-to-Deposit Ratio LQA avg. total deposit growthDDA MMDA IB Checking & Savings Time $ i n b ill io n s -1%-2% +1% +7% +20% 21% 20% 19% 17% 16% 10% 8% 5% 4% 5% L/D: 75% L/D: 78% L/D: 82% L/D: 87% L/D: 87% 4Q21 1Q22 2Q22 3Q22 4Q22 Loans / AEA Securities & other / AEA IB Cash & equivalent / AEA Avg. Loan / Deposit Ratio
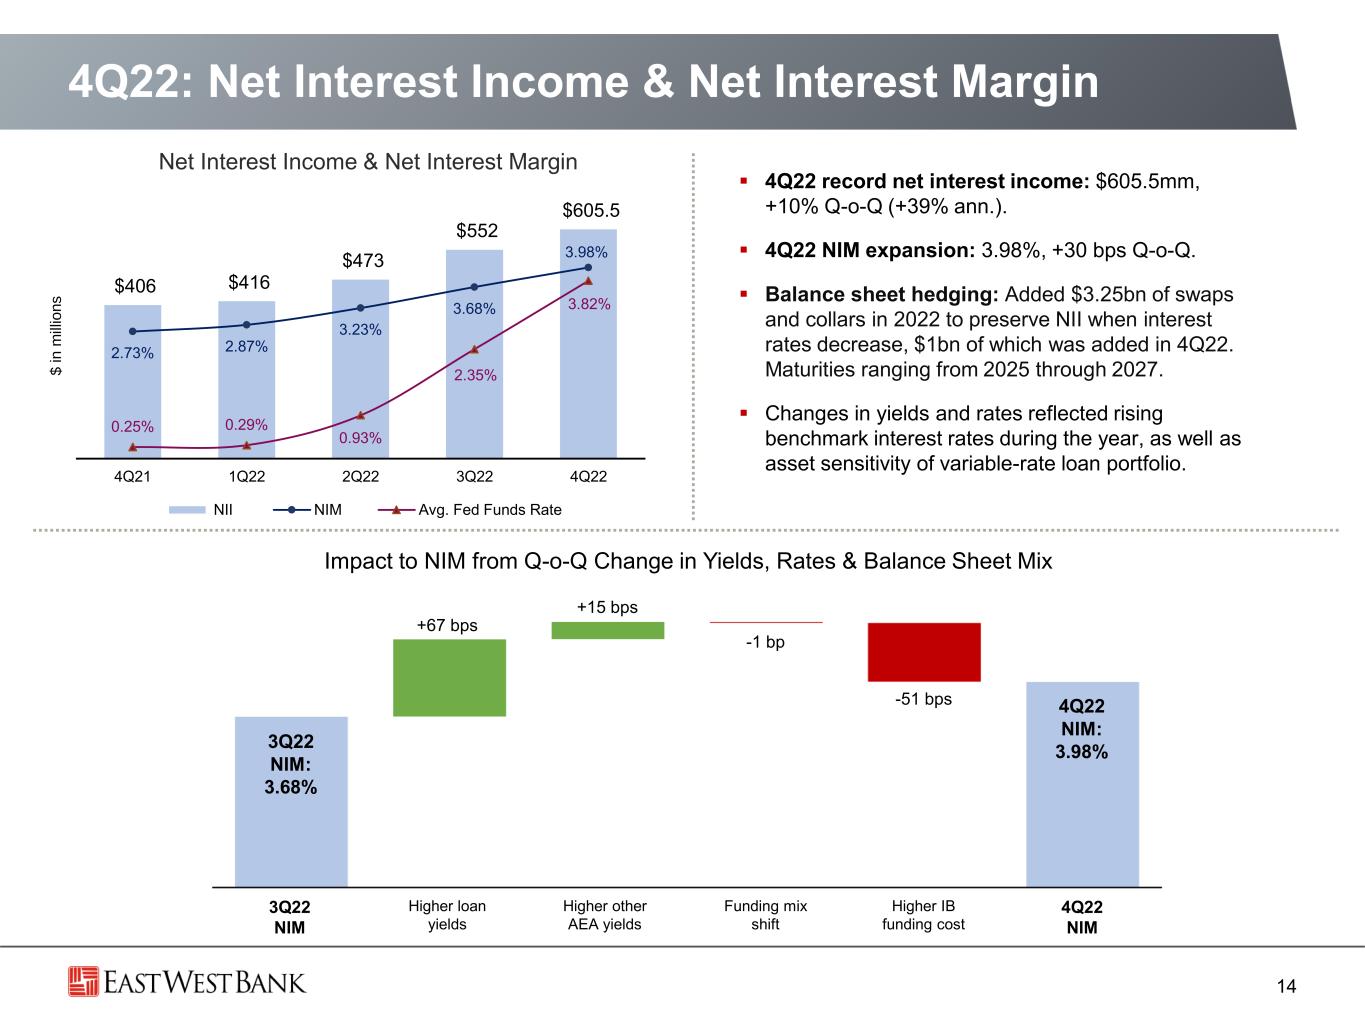
4Q22: Net Interest Income & Net Interest Margin 14 ▪ 4Q22 record net interest income: $605.5mm, +10% Q-o-Q (+39% ann.). ▪ 4Q22 NIM expansion: 3.98%, +30 bps Q-o-Q. ▪ Balance sheet hedging: Added $3.25bn of swaps and collars in 2022 to preserve NII when interest rates decrease, $1bn of which was added in 4Q22. Maturities ranging from 2025 through 2027. ▪ Changes in yields and rates reflected rising benchmark interest rates during the year, as well as asset sensitivity of variable-rate loan portfolio. Impact to NIM from Q-o-Q Change in Yields, Rates & Balance Sheet Mix $ i n m ill io n s 3Q22 NIM 4Q22 NIM +67 bps +15 bps 3Q22 NIM: 3.68% Net Interest Income & Net Interest Margin Higher loan yields 4Q22 NIM: 3.98% Higher other AEA yields -51 bps Higher IB funding cost -1 bp Funding mix shift $406 $416 $473 $552 $605.5 2.73% 2.87% 3.23% 3.68% 3.98% 0.25% 0.29% 0.93% 2.35% 3.82% 4Q21 1Q22 2Q22 3Q22 4Q22 NII NIM Avg. Fed Funds Rate

411 422 520 668 818 HELOC 407 403 404 416 431 SFR 327 342 411 507 593 Total CRE 322 336 427 559 676 C&I* 359 363 395 475 559 0.09% 0.22% 0.98% 2.46% 3.90% 4Q21 1Q22 2Q22 3Q22 4Q22 Avg. loan yield (in bps) Avg. 1M LIBOR 4Q22: Loan Yields: Average & Spot 15 Loan Coupon Spot Rate (in bps) by Portfolio * C&I spot rate excludes PPP, credit cards, deposit overdraft & micro-finance. Avg. Loan Yield (in bps) Relative to LIBOR 12.31.21 03.31.22 Total fixed rate and hybrid in fixed period: 39%. Variable: LIBOR or SOFR rates Hybrid in fixed rate period Fixed rate Variable: Prime rate Variable: all other rates Loan Portfolio by Index Rate (12.31.22) 06.30.22 C&I: 87% variable rate. Total CRE: 64% variable rate, of which 42%** had customer-level interest rate derivative contracts in place. Customers’ debt service is protected and EWBC retains benefits of variable rate loans on its balance sheet. SFR: 44% hybrid in fixed-rate period & 40% fixed rate. HELOC: Prime- based, variable rate portfolio. Avg. Loan Yield: Avg. yield in 4Q22: 5.59%, comprising 5.53% in avg. coupon rate plus 0.06% in other yield adjustments. Coupon spot rate was 5.92% as of 12.31.22. 09.30.22 ** Derivative contract coverage by portfolio: 47% of variable-rate CRE & 34% of variable-rate MFR. 12.31.22 21% 18% 27% 30% 4%
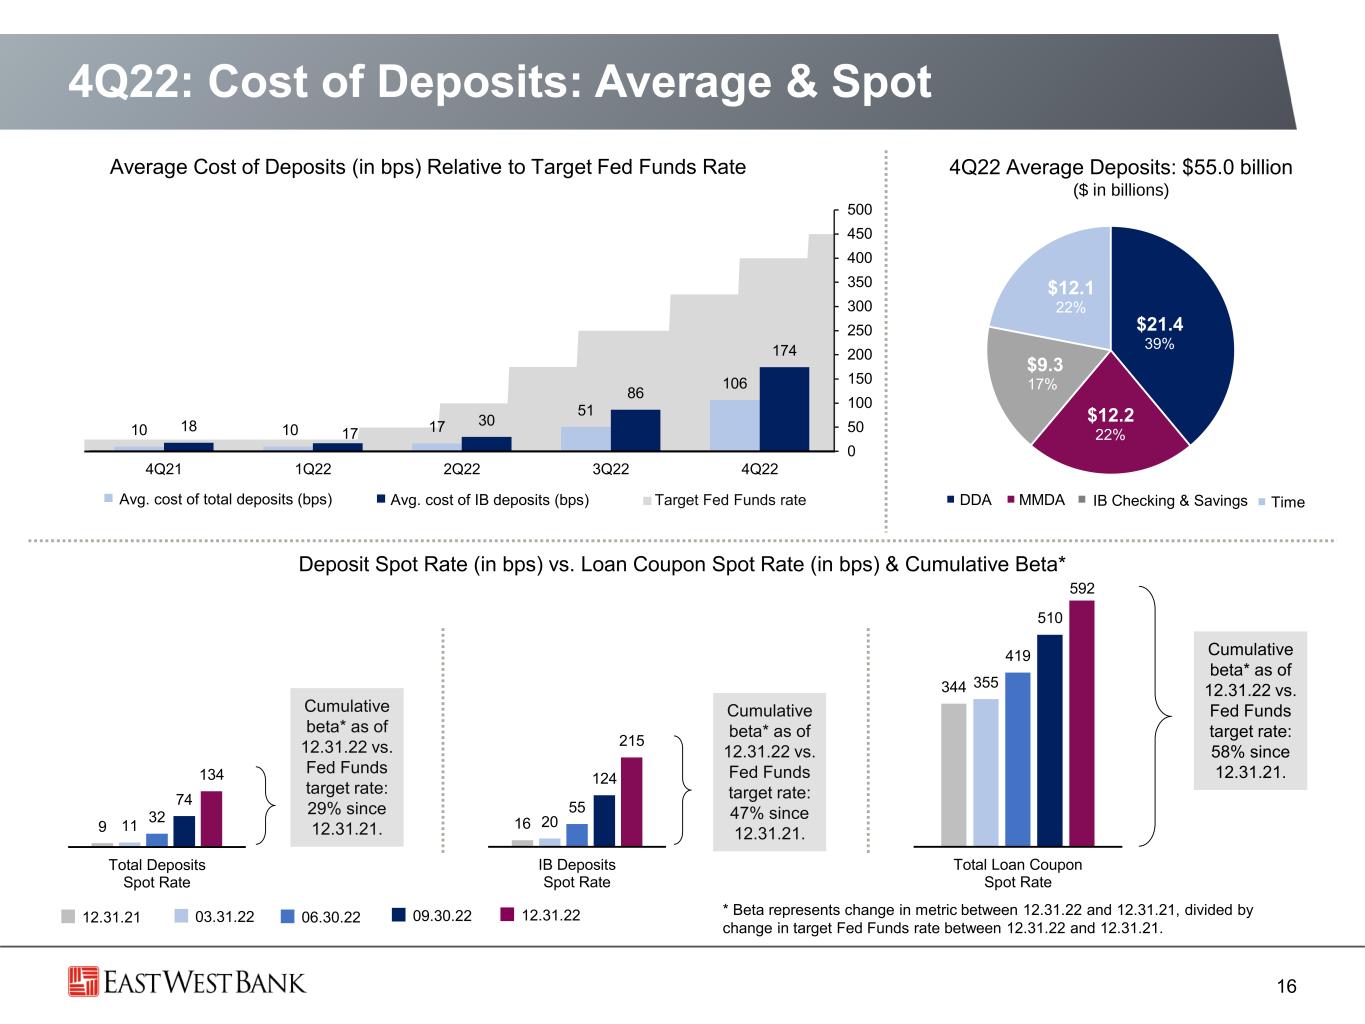
16 20 55 124 215 IB Deposits Spot Rate 9 11 32 74 134 Total Deposits Spot Rate Target Fed Funds rate 4Q22: Cost of Deposits: Average & Spot 16 Average Cost of Deposits (in bps) Relative to Target Fed Funds Rate Deposit Spot Rate (in bps) vs. Loan Coupon Spot Rate (in bps) & Cumulative Beta* DDA MMDA IB Checking & Savings Time Cumulative beta* as of 12.31.22 vs. Fed Funds target rate: 29% since 12.31.21. Cumulative beta* as of 12.31.22 vs. Fed Funds target rate: 47% since 12.31.21. Cumulative beta* as of 12.31.22 vs. Fed Funds target rate: 58% since 12.31.21. * Beta represents change in metric between 12.31.22 and 12.31.21, divided by change in target Fed Funds rate between 12.31.22 and 12.31.21. 12.31.21 03.31.22 06.30.22 09.30.22 Avg. cost of total deposits (bps) Avg. cost of IB deposits (bps) $21.4 39% $12.2 22% $9.3 17% $12.1 22% 4Q22 Average Deposits: $55.0 billion ($ in billions) 344 355 419 510 592 Total Loan Coupon Spot Rate 12.31.22 10/1/2021 1/1/2022 4/1/2022 7/1/2022 10/1/2022 10 10 17 51 106 18 17 30 86 174 0 50 100 150 200 250 300 350 400 450 500 4Q21 1Q22 2Q22 3Q22 4Q22

4Q22: Noninterest Income Detail ▪ Total noninterest income: $65mm in 4Q22, compared with $76mm in 3Q22. ▪ Fee income and net gains on sales of loans: $66mm in 4Q22: down 4.5% Q-o-Q (-18% ann.) and up 4% Y-o-Y. ▪ Q-o-Q increase in foreign exchange income. ▪ Y-o-Y increase in deposit account fees, wealth management fees, foreign exchange income, and IRC revenue. 17 Interest Rate Contracts (“IRC”) and Other Derivative Income Detail ($ in millions) 4Q21 3Q22 4Q22 Revenue $ 1.6 $ 4.0 $ 4.0 MTM 0.3 4.8 (4.6) Total $ 1.9 $ 8.8 $ (0.6) * Fee income excludes MTM adjustments related to IRC and other derivatives; net gains on sales of securities; other investment income and other income. Fee Income* & Net Gains on Sales of Loans $ i n m ill io n s 20 24 22 21 20 19 13 10 14 5 9 6 2 4 4 2 2 1$63 $69 $66 4Q21 3Q22 4Q22 Gains on Sales of Loans IRC Revenue Wealth Mgmt. Fees FX Income Lending Fees Deposit Acct. Fees
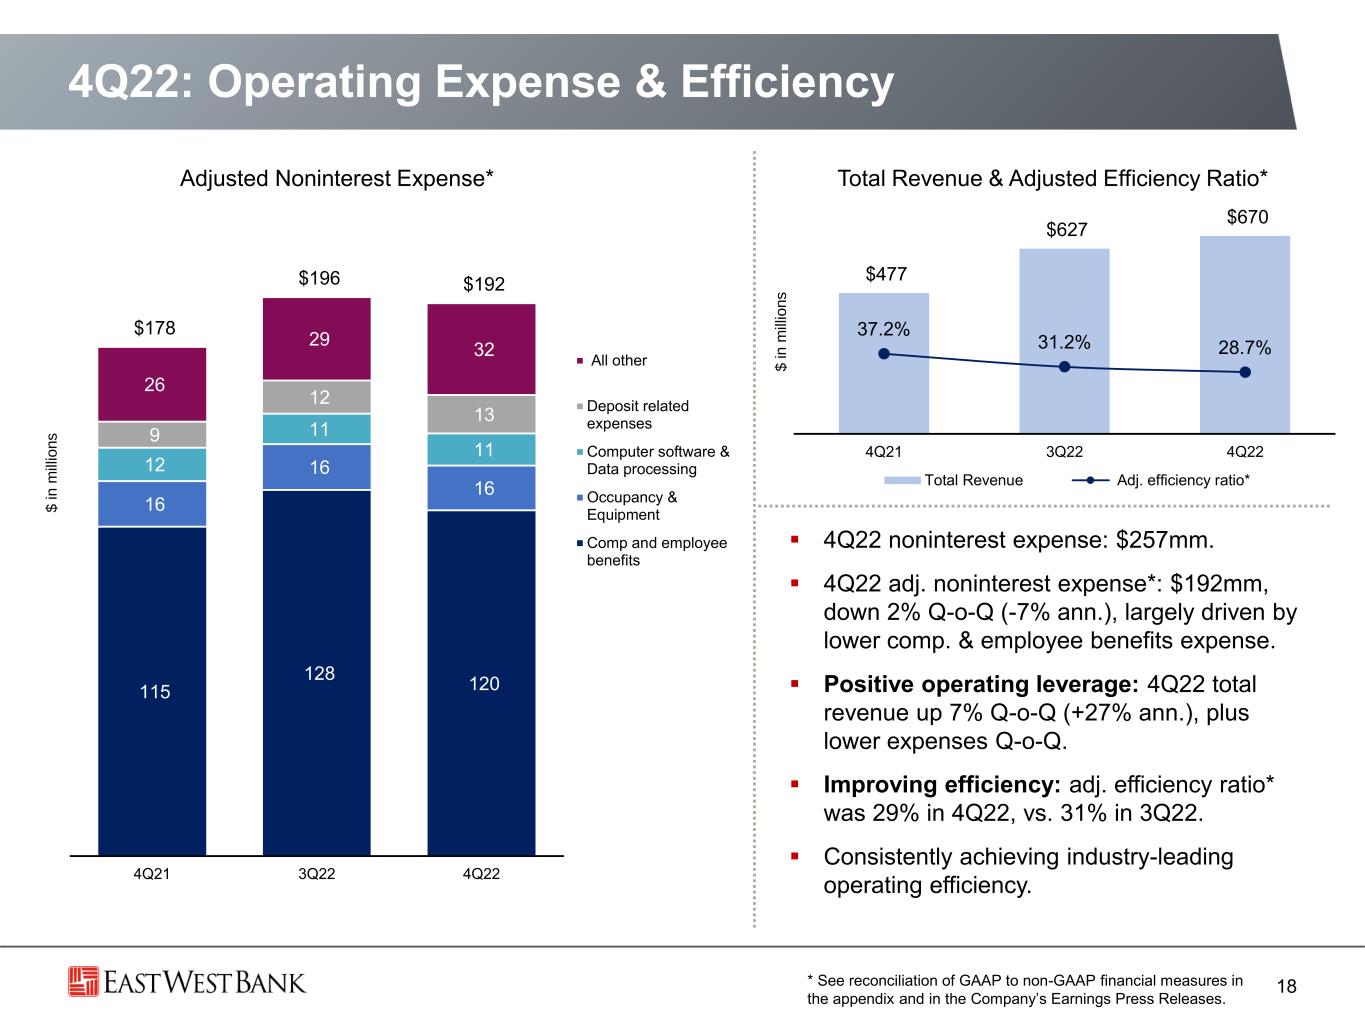
4Q22: Operating Expense & Efficiency 18 Adjusted Noninterest Expense* $ i n m ill io n s Total Revenue & Adjusted Efficiency Ratio* ▪ 4Q22 noninterest expense: $257mm. ▪ 4Q22 adj. noninterest expense*: $192mm, down 2% Q-o-Q (-7% ann.), largely driven by lower comp. & employee benefits expense. ▪ Positive operating leverage: 4Q22 total revenue up 7% Q-o-Q (+27% ann.), plus lower expenses Q-o-Q. ▪ Improving efficiency: adj. efficiency ratio* was 29% in 4Q22, vs. 31% in 3Q22. ▪ Consistently achieving industry-leading operating efficiency. * See reconciliation of GAAP to non-GAAP financial measures in the appendix and in the Company’s Earnings Press Releases. $477 $627 $670 37.2% 31.2% 28.7% 4Q21 3Q22 4Q22 Total Revenue Adj. efficiency ratio* 115 128 120 16 16 16 12 11 11 9 12 13 26 29 32 $178 $196 $192 4Q21 3Q22 4Q22 All other Deposit related expenses Computer software & Data processing Occupancy & Equipment Comp and employee benefits $ i n m ill io n s
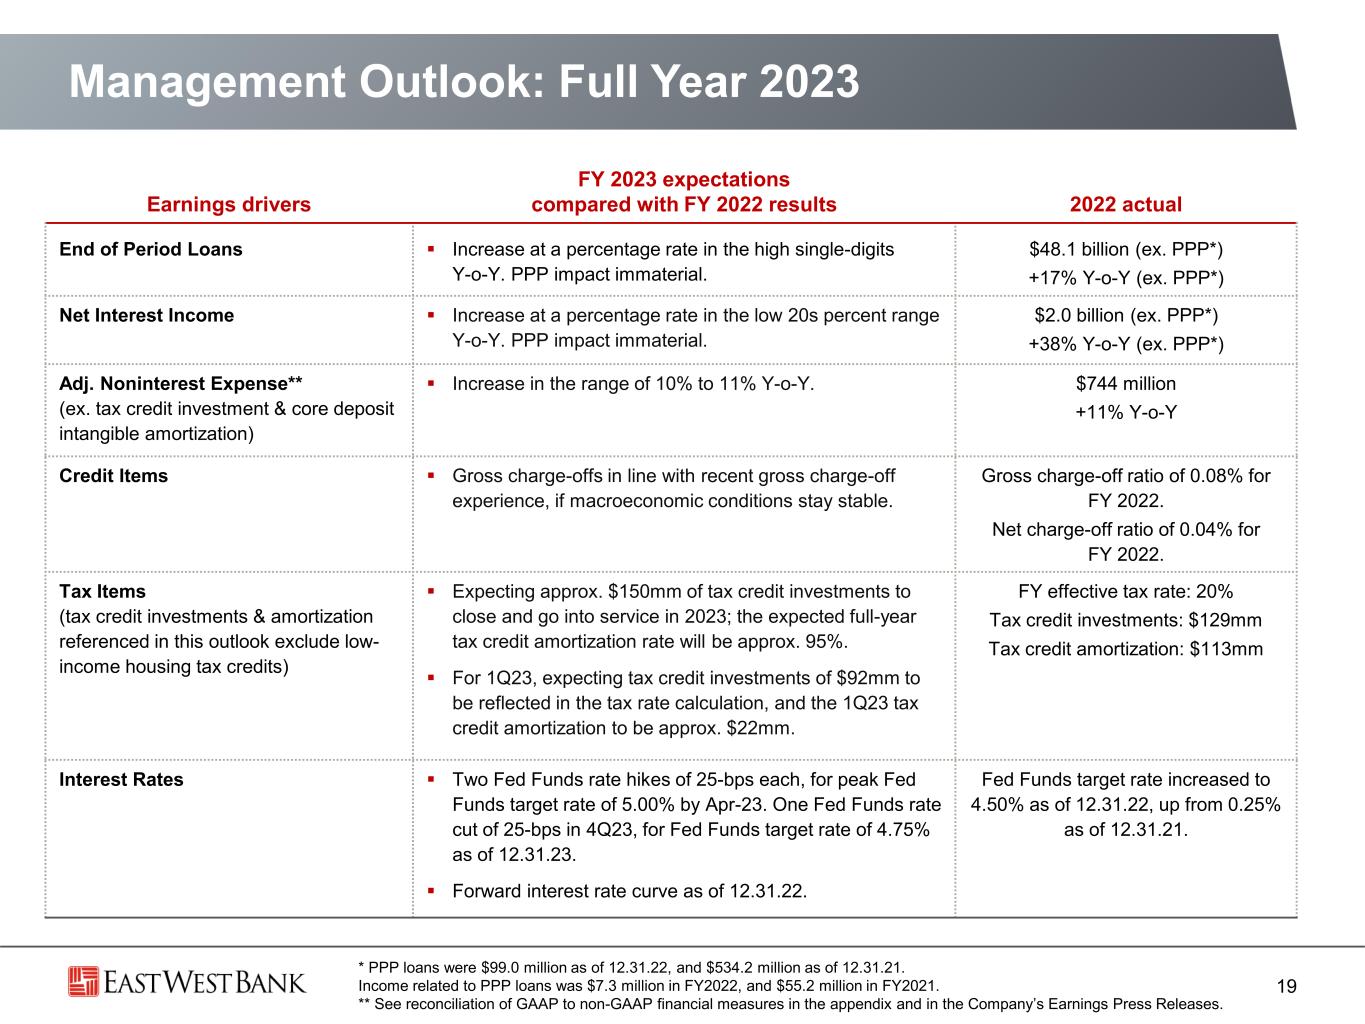
Management Outlook: Full Year 2023 19 * PPP loans were $99.0 million as of 12.31.22, and $534.2 million as of 12.31.21. Income related to PPP loans was $7.3 million in FY2022, and $55.2 million in FY2021. ** See reconciliation of GAAP to non-GAAP financial measures in the appendix and in the Company’s Earnings Press Releases. Earnings drivers FY 2023 expectations compared with FY 2022 results 2022 actual End of Period Loans ▪ Increase at a percentage rate in the high single-digits Y-o-Y. PPP impact immaterial. $48.1 billion (ex. PPP*) +17% Y-o-Y (ex. PPP*) Net Interest Income ▪ Increase at a percentage rate in the low 20s percent range Y-o-Y. PPP impact immaterial. $2.0 billion (ex. PPP*) +38% Y-o-Y (ex. PPP*) Adj. Noninterest Expense** (ex. tax credit investment & core deposit intangible amortization) ▪ Increase in the range of 10% to 11% Y-o-Y. $744 million +11% Y-o-Y Credit Items ▪ Gross charge-offs in line with recent gross charge-off experience, if macroeconomic conditions stay stable. Gross charge-off ratio of 0.08% for FY 2022. Net charge-off ratio of 0.04% for FY 2022. Tax Items (tax credit investments & amortization referenced in this outlook exclude low- income housing tax credits) ▪ Expecting approx. $150mm of tax credit investments to close and go into service in 2023; the expected full-year tax credit amortization rate will be approx. 95%. ▪ For 1Q23, expecting tax credit investments of $92mm to be reflected in the tax rate calculation, and the 1Q23 tax credit amortization to be approx. $22mm. FY effective tax rate: 20% Tax credit investments: $129mm Tax credit amortization: $113mm Interest Rates ▪ Two Fed Funds rate hikes of 25-bps each, for peak Fed Funds target rate of 5.00% by Apr-23. One Fed Funds rate cut of 25-bps in 4Q23, for Fed Funds target rate of 4.75% as of 12.31.23. ▪ Forward interest rate curve as of 12.31.22. Fed Funds target rate increased to 4.50% as of 12.31.22, up from 0.25% as of 12.31.21.

APPENDIX
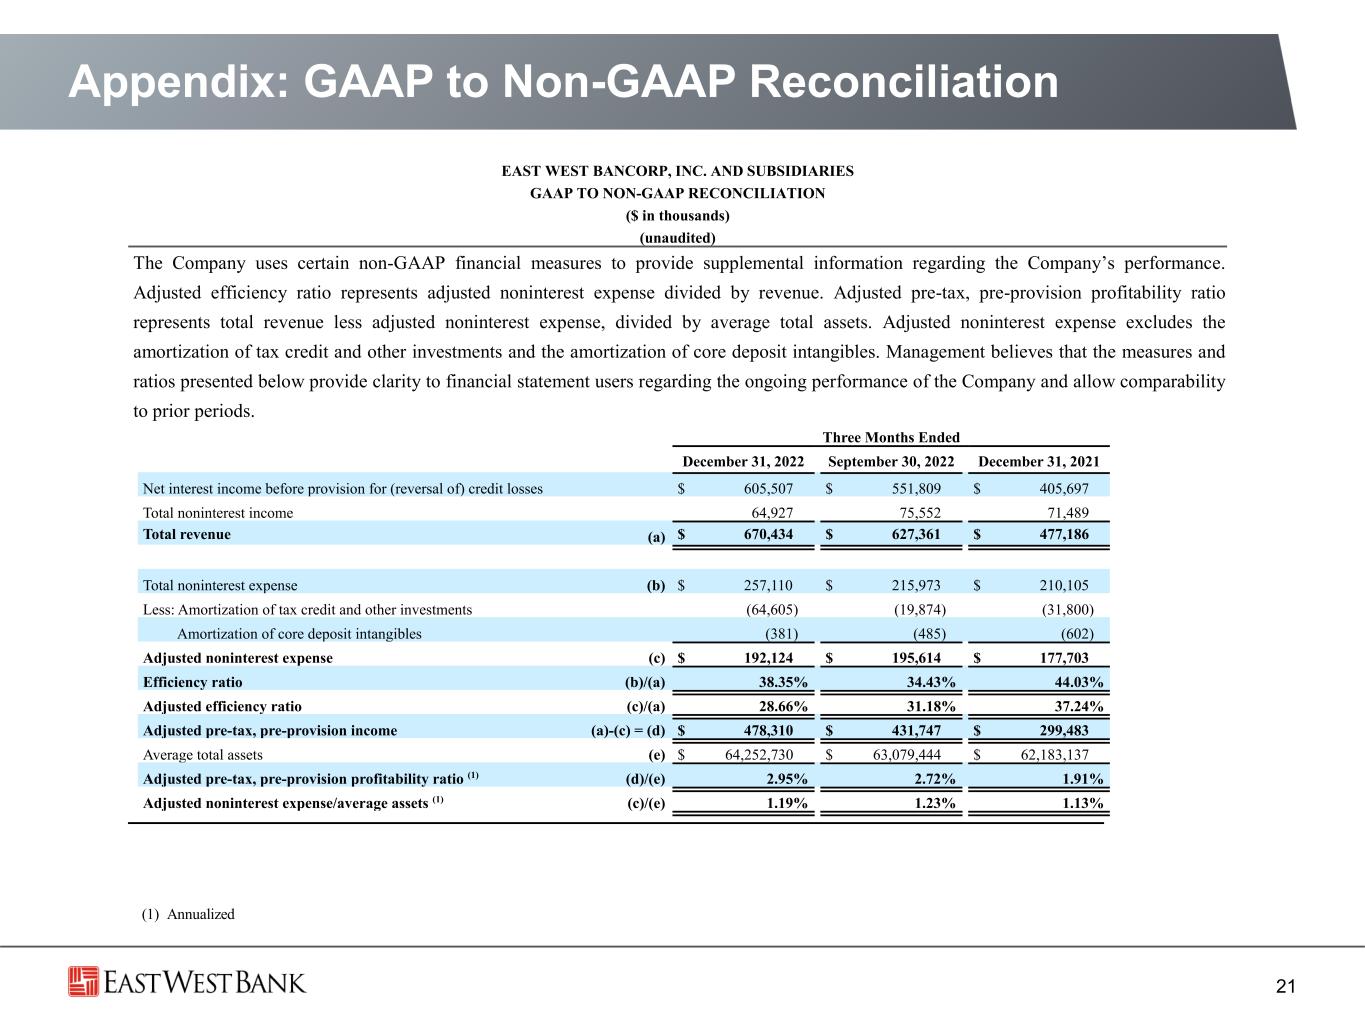
Appendix: GAAP to Non-GAAP Reconciliation 21 EAST WEST BANCORP, INC. AND SUBSIDIARIES GAAP TO NON-GAAP RECONCILIATION ($ in thousands) (unaudited) The Company uses certain non-GAAP financial measures to provide supplemental information regarding the Company’s performance. Adjusted efficiency ratio represents adjusted noninterest expense divided by revenue. Adjusted pre-tax, pre-provision profitability ratio represents total revenue less adjusted noninterest expense, divided by average total assets. Adjusted noninterest expense excludes the amortization of tax credit and other investments and the amortization of core deposit intangibles. Management believes that the measures and ratios presented below provide clarity to financial statement users regarding the ongoing performance of the Company and allow comparability to prior periods. (1) Annualized Three Months Ended December 31, 2022 September 30, 2022 December 31, 2021 Net interest income before provision for (reversal of) credit losses $ 605,507 $ 551,809 $ 405,697 Total noninterest income 64,927 75,552 71,489 Total revenue (a) $ 670,434 $ 627,361 $ 477,186 Total noninterest expense (b) $ 257,110 $ 215,973 $ 210,105 Less: Amortization of tax credit and other investments (64,605) (19,874) (31,800) Amortization of core deposit intangibles (381) (485) (602) Adjusted noninterest expense (c) $ 192,124 $ 195,614 $ 177,703 Efficiency ratio (b)/(a) 38.35% 34.43% 44.03% Adjusted efficiency ratio (c)/(a) 28.66% 31.18% 37.24% Adjusted pre-tax, pre-provision income (a)-(c) = (d) $ 478,310 $ 431,747 $ 299,483 Average total assets (e) $ 64,252,730 $ 63,079,444 $ 62,183,137 Adjusted pre-tax, pre-provision profitability ratio (1) (d)/(e) 2.95% 2.72% 1.91% Adjusted noninterest expense/average assets (1) (c)/(e) 1.19% 1.23% 1.13%

Appendix: GAAP to Non-GAAP Reconciliation 22 EAST WEST BANCORP, INC. AND SUBSIDIARIES GAAP TO NON-GAAP RECONCILIATION ($ in thousands) (unaudited) The Company uses certain non-GAAP financial measures to provide supplemental information regarding the Company’s performance. Tangible equity and tangible equity to tangible assets ratio are non-GAAP financial measures. Tangible equity and tangible assets represent stockholders’ equity and total assets, respectively, which have been reduced by goodwill and other intangible assets. Given that the use of such measures and ratios is more prevalent in the banking industry, and such measures and ratios are used by banking regulators and analysts, the Company has included them below for discussion. (1) Includes core deposit intangibles and mortgage servicing assets. December 31, 2022 September 30, 2022 December 31, 2021 Stockholders’ equity (a) $ 5,984,612 $ 5,660,668 $ 5,837,218 Less: Goodwill (465,697) (465,697) (465,697) Other intangible assets (1) (7,998) (8,667) (9,334) Tangible equity (b) $ 5,510,917 $ 5,186,304 $ 5,362,187 Total assets (c) $ 64,112,150 $ 62,576,061 $ 60,870,701 Less: Goodwill (465,697) (465,697) (465,697) Other intangible assets (1) (7,998) (8,667) (9,334) Tangible assets (d) $ 63,638,455 $ 62,101,697 $ 60,395,670 Total stockholders’ equity to total assets ratio (a)/(c) 9.33% 9.05% 9.59% Tangible equity to tangible assets ratio (b)/(d) 8.66% 8.35% 8.88%

Appendix: GAAP to Non-GAAP Reconciliation 23 EAST WEST BANCORP, INC. AND SUBSIDIARIES GAAP TO NON-GAAP RECONCILIATION ($ in thousands) (unaudited) Tangible return on average tangible equity represents tangible net income divided by average tangible equity. Tangible net income excludes the after-tax impacts of the amortization of core deposit intangibles and mortgage servicing assets. Given that the use of such measures and ratios is more prevalent in the banking industry, and such measures and ratios are used by banking regulators and analysts, the Company has included them below for discussion. (1) Includes core deposit intangibles and mortgage servicing assets. (2) Applied statutory tax rate of 29.37% for the three and twelve months ended December 31, 2022. Applied statutory tax rate of 28.77% for the three months ended September 30, 2022, and for the three and twelve months ended December 31, 2021. (3) Annualized. Three Months Ended Year Ended December 31, 2022 September 30, 2022 December 31, 2021 December 31, 2022 December 31, 2021 Net income (e) $ 336,763 $ 295,339 $ 217,796 $ 1,128,083 $ 872,981 Add: Amortization of core deposit intangibles 381 485 602 1,865 2,749 Amortization of mortgage servicing assets 329 340 415 1,425 1,679 Tax effect of amortization adjustments (2) (209) (237) (293) (966) (1,274) Tangible net income (f) $ 337,264 $ 295,927 $ 218,520 $ 1,130,407 $ 876,135 Average stockholders’ equity (g) $ 5,834,623 $ 5,772,638 $ 5,786,237 $ 5,783,025 $ 5,559,212 Less: Average goodwill (465,697) (465,697) (465,697) (465,697) (465,697) Average other intangible assets (1) (8,378) (8,379) (9,611) (8,695) (10,535) Average tangible equity (h) $ 5,360,548 $ 5,298,562 $ 5,310,929 $ 5,308,633 $ 5,082,980 Return on average equity (e)/(g) 22.90% (3) 20.30% (3) 14.93% (3) 19.51% 15.70% Tangible return on average tangible equity (f)/(h) 24.96% (3) 22.16% (3) 16.32% (3) 21.29% 17.24%