
FULT 8-K
Fulton Financial Corp (FULT)
8-K
2020-10-20
For: 2020-10-20
View Original
Added on
April 12, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of Report (date of earliest event reported)
(Exact name of registrant as specified in its charter)
(State or other jurisdiction of incorporation) | (Commission File Number) | (I.R.S. Employer Identification No.) | ||||||||||||
(Address of Principal Executive Offices) | (Zip Code) | |||||||||||||
(717 ) 291-2411
(Registrant's telephone number, including area code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.
o
Item 2.02 Results of Operations and Financial Condition.
On October 20, 2020 , Fulton Financial Corporation (the "Corporation") issued a press release (the "Press Release") announcing its results of operations for the third quarter ended September 30, 2020. A copy of the Press Release and supplementary financial information which accompanied the Press Release, are attached as Exhibit 99.1 to this Current Report and are incorporated herein by reference. The Corporation also posted on its Investor Relations website, www.fult.com, presentation materials the Corporation intends to use during a conference call and webcast to discuss those results on Wednesday, October 21, 2020 at 10:00 a.m. Eastern Time. A copy of the presentation materials is attached as Exhibit 99.2 to this Current Report and is incorporated herein by reference.
The information in the preceding paragraph, as well as Exhibit 99.2 referenced therein, shall not be deemed "filed" for purposes of the Securities Exchange Act of 1934, as amended (the "Exchange Act"), nor shall it be incorporated by reference in any filing under the Securities Act of 1933, as amended (the "Securities Act"). The information included in Exhibit 99.1 shall be considered "filed" for purposes of the Exchange Act and therefore may be incorporated by reference in filings under the Securities Act.
Item 8.01 Other Events
On October 1, 2020, the Corporation reported in its Current Report on Form 8-K that its wholly-owned banking subsidiary, Fulton Bank, National Association (the "Bank"), as part of the Bank's ongoing strategic optimization of its network of financial centers to adapt to the evolving needs and expectations of its customers, would be closing 21 financial center offices and consolidating the operations of those offices into nearby financial centers operated by the Bank. In connection with the financial center closures, the Corporation reported that it expects to incur pre-tax costs of approximately $11.5 million, consisting of $6.5 million of write-offs of premises and equipment, $4 million of lease termination charges and $1 million of future cash expenditures in connection with employee severance, and that these costs are expected to be recognized in the third and fourth quarters of 2020, and the first quarter of 2021. The Corporation also reported that it expects that the closure of these financial centers will reduce annual pre-tax operating expense by approximately $7 million, beginning in the first quarter of 2021.
The financial center optimization effort is part of a much larger company-wide strategic operating expense review that was prompted by the prolonged and continuing effects of COVID-19, and the expectation that interest rates will remain very low for the next several years. It is also a recognition of the need to accelerate the timetable for certain technology and digital investments that were in progress.
The strategic operating expense review involves a number of changes that are expected to result in annual expense savings of $25 million in operating cost, inclusive of the previously reported financial center consolidation savings. The expense review involves the elimination of positions and expense reductions in a number of other areas across the enterprise. Of the expected $25 million in annual expense savings, the Corporation
expects to reinvest a portion to accelerate digital transformation initiatives.
It is expected that the savings will not be fully realized until mid-2021. In addition, it is expected that a pre-tax charge within the range of $17 to $19 million will be realized for this initiative for employee severance, fixed asset write-offs and lease termination charges, among others. Of this charge, $16 to $17 million is expected to be incurred in the fourth quarter of 2020, with the remaining charges of up to approximately $1 million pre-tax being recognized in the first quarter of 2021.
The information in this Item 8.01 is deemed "filed" for purposes of Section 18 of the Exchange Act and, therefore, may be incorporated by reference in filings under the Securities Act.
Forward-Looking Statements
This Current Report on Form 8-K, including the Exhibits hereto, may contain forward-looking statements with respect to the Corporation’s financial condition, results of operations and business. Do not unduly rely on forward-looking statements. Forward-looking statements can be identified by the use of words such as "may," "should," "will," "could," "estimates," "predicts," "potential," "continue," "anticipates," "believes," "plans," "expects," "future," "intends," "projects," the negative of these terms and other comparable terminology. Statements relating to the expectations regarding the Bank's financial center optimization and strategic operating expense review contained
in Item 8.01 of this Current Report on Form 8-K and the "outlook" or "Q4 2020 Outlook" contained in Exhibit 99.2 to this Current Report are forward-looking statements. These forward-looking statements may include projections of, or guidance on, the Corporation’s future financial performance, expected levels of future expenses, including future credit losses, anticipated growth strategies, descriptions of new business initiatives and anticipated trends in the Corporation’s business or financial results.
Forward-looking statements are neither historical facts, nor assurance of future performance. Instead, they are based on current beliefs, expectations and assumptions regarding the future of the Corporation’s business, future plans and strategies, projections, anticipated events and trends, the economy and other future conditions. Because forward-looking statements relate to the future, they are subject to inherent uncertainties, risks and changes in circumstances that are difficult to predict and many of which are outside of the Corporation’s control, and actual results and financial condition may differ materially from those indicated in the forward-looking statements. Therefore, you should not unduly rely on any of these forward-looking statements. Any forward-looking statement is based only on information currently available and speaks only as of the date when made. The Corporation undertakes no obligation, other than as required by law, to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise.
A discussion of certain risks and uncertainties affecting the Corporation, and some of the factors that could cause the Corporation's actual results to differ materially from those described in the forward-looking statements, can be found in the sections entitled "Risk Factors" and "Management's Discussion and Analysis of Financial Condition and Results of Operations" in the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2019, Quarterly Reports on Form 10-Q for the quarters ended March 31, 2020 and June 30, 2020 and other current and periodic reports, which have been or will be filed with the Securities and Exchange Commission and are or will be available in the Investor Relations section of the Corporation's website (www.fult.com) and on the Securities and Exchange Commission's website (www.sec.gov).
Item 9.01 Financial Statements and Exhibits.
(d) Exhibits.
| Exhibit No. | Description | ||||
Press release dated | |||||
Presentation materials to be discussed during the conference call and webcast on October 21, 2020, deemed "furnished" under the Securities Exchange Act of 1934. | |||||
| 104 | Cover page Interactive Data File (the cover page XBRL tags are embedded within the Inline XBRL document) | ||||
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
Date: | FULTON FINANCIAL CORPORATION | ||||
By: /s/ Mark R. McCollom | |||||
| Mark R. McCollom | |||||
| Senior Executive Vice President and | |||||
| Chief Financial Officer | |||||
Exhibit 99.1
FULTON FINANCIAL
CORPORATION
FOR IMMEDIATE RELEASE
Media Contact: Laura Wakeley (717) 291-2616
Investor Contact: Mark McCollom (717) 327-2567
Fulton Financial Announces Third Quarter Earnings
(October 20, 2020) – Lancaster, PA – Fulton Financial Corporation (NASDAQ:FULT) (“Fulton” or the “Corporation”) reported net income of $62 million, or $0.38 per diluted share, for the third quarter of 2020.
“While it is still too early to fully assess the impact of COVID-19 on our regional economy, we were pleased that our third quarter produced stronger results than we had initially predicted in both our commercial and consumer lines of business,” said E. Philip Wenger, Chairman and CEO. “In particular, our mortgage business achieved record growth in the third quarter, coming on the heels of a record second quarter. Loan growth, fee income and credit quality also exceeded our expectations. And after a strategic, company-wide review, we are taking steps to significantly reduce our annual operating expenses for the future, with the goal of prudently managing the company for the longer term.”
Net Interest Income and Balance Sheet
Net interest income for the third quarter of 2020 was $154 million, consistent with the second quarter of 2020. Net interest margin for the third quarter of 2020 decreased 11 basis points, to 2.70%, from 2.81% in the second quarter of 2020.
Total average assets for the third quarter of 2020 were $25.2 billion, an increase of $1.0 billion from the second quarter of 2020. Average loans, net of unearned income, of $18.9 billion increased $0.5 billion from the second quarter of 2020. The increase was principally due to loans originated under the Paycheck Protection Program ("PPP") during the second quarter, which had an outstanding balance of $2.0 billion as of September 30, 2020.
Average loans and yields, by type, for the third quarter of 2020 in comparison to the second quarter of 2020 are summarized in the following table:
| Three months ended | |||||||||||||||||||||||||||||||||||
| September 30, 2020 | June 30, 2020 | Growth | |||||||||||||||||||||||||||||||||
| Balance | Yield (1) | Balance | Yield (1) | $ | % | ||||||||||||||||||||||||||||||
| (dollars in thousands) | |||||||||||||||||||||||||||||||||||
| Average Loans, net of unearned income, by type: | |||||||||||||||||||||||||||||||||||
| Real estate - commercial mortgage | $ | 6,986,528 | 3.27 | % | $ | 6,875,872 | 3.47 | % | $ | 110,656 | 1.6 | % | |||||||||||||||||||||||
| Commercial and industrial(2) | 5,983,872 | 2.53 | % | 5,710,145 | 2.83 | % | 273,727 | 4.8 | % | ||||||||||||||||||||||||||
| Real estate - residential mortgage | 2,975,516 | 3.73 | % | 2,769,682 | 3.88 | % | 205,834 | 7.4 | % | ||||||||||||||||||||||||||
| Real estate - home equity | 1,237,602 | 3.87 | % | 1,271,190 | 3.91 | % | (33,588) | (2.6) | % | ||||||||||||||||||||||||||
| Real estate - construction | 981,589 | 3.84 | % | 941,079 | 3.53 | % | 40,510 | 4.3 | % | ||||||||||||||||||||||||||
| Consumer | 464,851 | 4.07 | % | 465,728 | 4.17 | % | (877) | (0.2) | % | ||||||||||||||||||||||||||
| Equipment lease financing | 279,217 | 3.96 | % | 284,658 | 3.44 | % | (5,441) | (1.9) | % | ||||||||||||||||||||||||||
| Other(3) | (28,656) | N/A | 13,443 | N/A | (42,099) | N/M | |||||||||||||||||||||||||||||
| Total Average Loans, net of unearned income | $ | 18,880,519 | 3.38 | % | $ | 18,331,797 | 3.52 | % | $ | 548,722 | 3.0 | % | |||||||||||||||||||||||
| (1) Presented on a fully-taxable equivalent basis using a 21% Federal tax rate and statutory interest expense disallowances. | |||||||||||||||||||||||||||||||||||
| (2) Includes average PPP loans of $2.0 billion and $1.3 billion for the three months ended September 30, 2020 and June 30, 2020, respectively. | |||||||||||||||||||||||||||||||||||
| (3) Consists of overdrafts and net origination fees and costs. | |||||||||||||||||||||||||||||||||||
Total average liabilities increased $1.0 billion, from the second quarter of 2020 driven by increases in demand and savings deposits. Average deposits and interest rates, by type, for the third quarter of 2020 in comparison to the second quarter of 2020 are summarized in the following table:
| Three months ended | |||||||||||||||||||||||||||||||||||
| September 30, 2020 | June 30, 2020 | Growth | |||||||||||||||||||||||||||||||||
| Balance | Rate | Balance | Rate | $ | % | ||||||||||||||||||||||||||||||
| (dollars in thousands) | |||||||||||||||||||||||||||||||||||
| Average Deposits, by type: | |||||||||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 6,270,683 | — | $ | 5,789,788 | — | $ | 480,895 | 8.3 | % | |||||||||||||||||||||||||
| Interest-bearing demand | 5,591,548 | 0.14 | % | 5,103,419 | 0.17 | % | 488,129 | 9.6 | % | ||||||||||||||||||||||||||
| Savings | 5,716,050 | 0.16 | % | 5,446,368 | 0.25 | % | 269,682 | 5.0 | % | ||||||||||||||||||||||||||
| Total average demand and savings | 17,578,281 | 0.10 | % | 16,339,575 | 0.14 | % | 1,238,706 | 7.6 | % | ||||||||||||||||||||||||||
| Brokered | 314,721 | 0.56 | % | 312,121 | 0.54 | % | 2,600 | 0.8 | % | ||||||||||||||||||||||||||
| Time | 2,495,445 | 1.58 | % | 2,624,962 | 1.71 | % | (129,517) | (4.9) | % | ||||||||||||||||||||||||||
| Total Average Deposits | $ | 20,388,447 | 0.29 | % | $ | 19,276,658 | 0.36 | % | $ | 1,111,789 | 5.8 | % | |||||||||||||||||||||||
Asset Quality
The provision for credit losses for the third quarter of 2020 was $7 million, which reflects current expected credit losses based on forecasted economic and other assumptions, including the estimated impacts of COVID-19, over the remaining expected lives of financial assets and off-balance-sheet credit exposures.
Non-performing assets were $147 million, or 0.57% of total assets, at September 30, 2020, representing a decrease, when expressed as a percentage of total assets from June 30, 2020.
Annualized net recoveries for the quarter ended September 30, 2020 were 0.05% of total average loans, compared to annualized net charge-offs of 0.09% and 0.15% for the quarters ended June 30, 2020 and September 30, 2019, respectively. The third quarter of 2020 annualized net recoveries were primarily due to $5 million in real estate construction recoveries.
Non-interest Income
Non-interest income in the third quarter of 2020, excluding investment securities gains, was $63 million, an increase of $10 million, or 20%, from the second quarter of 2020, primarily driven by an increase of $7 million in mortgage banking income, although increases in nearly all non-interest income categories were experienced in the third quarter of 2020 in comparison to the second quarter of 2020.
In the third quarter of 2020, a $1.5 million impairment of mortgage servicing assets was recognized, as compared to a $6.6 million impairment in the second quarter of 2020. This impairment charge is recorded as a reduction to mortgage banking income.
Compared to the third quarter of 2019, non-interest income, excluding investment securities gains, increased $8 million, or 14%, in the third quarter of 2020 due mainly to increases in mortgage banking income. There was no mortgage servicing asset impairment charge in the third quarter of 2019.
Net investment securities gains declined by $3 million in the third quarter of 2020 in comparison to the second quarter of 2020. The second quarter of 2020 included net securities gains of $3 million related to a limited balance sheet restructuring that also involved the redemption of FHLB advances that resulted in $3 million of prepayment penalties recorded in non-interest expense in the same period.
Non-interest Expense
Non-interest expense was $139 million in the third quarter of 2020, a decrease of $4 million compared to the second quarter of 2020. The second quarter of 2020 included a $3 million prepayment penalty on redemption of FHLB advances.
Compared to the third quarter of 2019, non-interest expense decreased $8 million, or 5%, due primarily to decreases in other outside services, FHLB prepayment penalties, marketing and intangible amortization, partially offset by increases in salaries and employee benefits and FDIC insurance. FDIC insurance expense was reduced in the third quarter of 2019 as a result of the receipt of $3 million of assessment credits.
As a result of a recent strategic operating expense review, the Corporation is making a number of changes that are expected to result in annual expense savings of $25 million, inclusive of the previously
reported financial center closure savings. Of the expected $25 million in annual expense savings, the Corporation expects to reinvest a portion to accelerate digital transformation initiatives.
It is expected that the savings will not be fully realized until mid-2021. In addition, it is expected that a pre-tax charge within the range of $17 to $19 million will be realized for this initiative for employee severance, fixed asset write-offs and lease termination charges, among others. Of this charge, $16 to $17 million is expected to be incurred in the fourth quarter of 2020, with the remaining charges of up to approximately $1 million pre-tax being recognized in the first quarter of 2021.
Income Tax Expense
The effective income tax rate for the third quarter of 2020 was 13%, as compared to 14% for both the second quarter of 2020 and third quarter of 2019.
Additional information on Fulton is available on the Internet at www.fult.com.
Safe Harbor Statement
This news release may contain forward-looking statements with respect to the
Corporation’s financial condition, results of operations and business. Do not unduly rely on forward-looking statements. Forward-looking statements can be identified by the use of words such as "may," "should," "will," "could," "estimates," "predicts," "potential," "continue," "anticipates," "believes," "plans," "expects," "future," "intends," “projects,” the negative of these terms and other comparable terminology. These forward-looking statements may include projections of, or guidance on, the Corporation’s future financial performance, expected levels of future expenses. including future credit losses, anticipated growth strategies, descriptions of new business initiatives and anticipated trends in the Corporation’s business or financial results.
Forward-looking statements are neither historical facts, nor assurance of future performance. Instead, they are based on current beliefs, expectations and assumptions regarding the future of the Corporation’s business, future plans and strategies, projections, anticipated events and trends, the economy and other future conditions. Because forward-looking statements relate to the future, they are subject to inherent uncertainties, risks and changes in circumstances that are difficult to predict and many of which are outside of the Corporation’s control, and actual results and financial condition may differ materially from those indicated in the forward-looking statements. Therefore, you should not unduly rely on any of these forward-looking statements. Any forward-looking statement is based only on information currently available and speaks only as of the date when made. The Corporation undertakes no obligation, other than as required by law, to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise.
A discussion of certain risks and uncertainties affecting the Corporation, and some of the factors that could cause the Corporation's actual results to differ materially from those described in the forward-looking statements, can be found in the sections entitled "Risk Factors" and "Management's Discussion and Analysis of Financial Condition and Results of Operations" in the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2019, Quarterly Reports on Form 10-Q for the quarters ended March 31, 2020 and June 30, 2020 and other current and periodic reports, which have been or will
be filed with the Securities and Exchange Commission and are or will be available in the Investor Relations section of the Corporation's website (www.fult.com) and on the Securities and Exchange Commission's website (www.sec.gov).
Non-GAAP Financial Measures
The Corporation uses certain non-GAAP financial measures in this earnings release. These non-GAAP financial measures are reconciled to the most comparable GAAP measures in tables at the end of this release.
| FULTON FINANCIAL CORPORATION | ||||||||||||||||||||||||||||||||
| SUMMARY CONSOLIDATED FINANCIAL INFORMATION (UNAUDITED) | ||||||||||||||||||||||||||||||||
| in thousands, except per-share data and percentages | ||||||||||||||||||||||||||||||||
| Three months ended | ||||||||||||||||||||||||||||||||
| Sep 30 | Jun 30 | Mar 31 | Dec 31 | Sep 30 | ||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2019 | 2019 | ||||||||||||||||||||||||||||
| Ending Balances | ||||||||||||||||||||||||||||||||
| Investments | $ | 3,097,721 | $ | 2,974,813 | $ | 3,141,440 | $ | 2,867,378 | $ | 2,705,610 | ||||||||||||||||||||||
| Loans, net of unearned income | 19,028,621 | 18,704,722 | 17,077,403 | 16,837,526 | 16,686,866 | |||||||||||||||||||||||||||
| Total assets | 25,543,281 | 24,617,863 | 22,929,859 | 21,886,040 | 21,703,618 | |||||||||||||||||||||||||||
| Deposits | 20,730,051 | 19,884,208 | 17,365,026 | 17,393,913 | 17,342,717 | |||||||||||||||||||||||||||
| Shareholders' equity | 2,390,261 | 2,340,501 | 2,285,748 | 2,342,176 | 2,324,016 | |||||||||||||||||||||||||||
| Average Balances | ||||||||||||||||||||||||||||||||
| Investments | $ | 2,977,672 | $ | 3,096,632 | $ | 3,071,828 | $ | 2,830,999 | $ | 2,829,672 | ||||||||||||||||||||||
| Loans, net of unearned income | 18,880,519 | 18,331,797 | 16,860,067 | 16,768,057 | 16,436,507 | |||||||||||||||||||||||||||
| Total assets | 25,169,508 | 24,139,116 | 22,252,099 | 21,812,438 | 21,457,800 | |||||||||||||||||||||||||||
| Deposits | 20,388,447 | 19,276,658 | 17,121,428 | 17,449,565 | 16,950,667 | |||||||||||||||||||||||||||
| Shareholders' equity | 2,374,091 | 2,309,133 | 2,337,016 | 2,341,397 | 2,315,585 | |||||||||||||||||||||||||||
| Income Statement | ||||||||||||||||||||||||||||||||
| Net interest income | $ | 154,116 | $ | 152,754 | $ | 160,746 | $ | 159,270 | $ | 161,260 | ||||||||||||||||||||||
| Provision for credit losses | 7,080 | 19,570 | 44,030 | 20,530 | 2,170 | |||||||||||||||||||||||||||
| Non-interest income | 63,248 | 55,922 | 54,644 | 55,281 | 59,813 | |||||||||||||||||||||||||||
| Non-interest expense | 139,147 | 143,006 | 142,552 | 138,974 | 146,770 | |||||||||||||||||||||||||||
| Income before taxes | 71,137 | 46,101 | 28,808 | 55,047 | 72,133 | |||||||||||||||||||||||||||
| Net income | 61,607 | 39,559 | 26,047 | 47,789 | 62,108 | |||||||||||||||||||||||||||
| Per Share | ||||||||||||||||||||||||||||||||
| Net income (basic) | $ | 0.38 | $ | 0.24 | $ | 0.16 | $ | 0.29 | $ | 0.38 | ||||||||||||||||||||||
| Net income (diluted) | $ | 0.38 | $ | 0.24 | $ | 0.16 | $ | 0.29 | $ | 0.37 | ||||||||||||||||||||||
| Cash dividends | $ | 0.13 | $ | 0.13 | $ | 0.13 | $ | 0.17 | $ | 0.13 | ||||||||||||||||||||||
| Shareholders' equity (tangible)(1) | $ | 11.44 | $ | 11.15 | $ | 10.84 | $ | 11.00 | $ | 10.91 | ||||||||||||||||||||||
| Weighted average shares (basic) | 162,061 | 161,715 | 163,475 | 164,135 | 165,324 | |||||||||||||||||||||||||||
| Weighted average shares (diluted) | 162,579 | 162,267 | 164,417 | 165,039 | 166,126 | |||||||||||||||||||||||||||
| (1) Non-GAAP financial measure. Refer to the calculation on the page titled “Reconciliation of Non-GAAP Measures” at the end of this document. | ||||||||||||||||||||||||||||||||
| Three months ended | ||||||||||||||||||||||||||||||||
| Sep 30 | Jun 30 | Mar 31 | Dec 31 | Sep 30 | ||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2019 | 2019 | ||||||||||||||||||||||||||||
| Asset Quality(2) | ||||||||||||||||||||||||||||||||
| Net (recoveries) charge-offs to average loans (annualized) | (0.05) | % | 0.09 | % | 0.26 | % | 0.65 | % | 0.15 | % | ||||||||||||||||||||||
| Non-performing loans to total loans | 0.75 | % | 0.75 | % | 0.82 | % | 0.84 | % | 0.81 | % | ||||||||||||||||||||||
| Non-performing assets to total assets | 0.57 | % | 0.59 | % | 0.64 | % | 0.68 | % | 0.66 | % | ||||||||||||||||||||||
| ACL - loans(3) to total loans | 1.40 | % | 1.37 | % | 1.40 | % | 0.97 | % | 1.00 | % | ||||||||||||||||||||||
| ACL - loans(3) to non-performing loans | 188 | % | 183 | % | 170 | % | 116 | % | 122 | % | ||||||||||||||||||||||
| Non-performing assets to shareholders' equity (tangible) and ACL - loans (1)(3) | 6.91 | % | 7.04 | % | 7.37 | % | 7.51 | % | 7.35 | % | ||||||||||||||||||||||
| Asset Quality, excluding PPP(1)(4) | ||||||||||||||||||||||||||||||||
| Net (recoveries) charge-offs to average adjusted loans (annualized) | (0.06) | % | 0.10 | % | — | % | — | % | — | % | ||||||||||||||||||||||
| Non-performing loans to total adjusted loans | 0.83 | % | 0.83 | % | — | % | — | % | — | % | ||||||||||||||||||||||
| ACL - loans(3) to total adjusted loans | 1.56 | % | 1.53 | % | — | % | — | % | — | % | ||||||||||||||||||||||
| Profitability | ||||||||||||||||||||||||||||||||
| Return on average assets | 0.97 | % | 0.66 | % | 0.47 | % | 0.87 | % | 1.15 | % | ||||||||||||||||||||||
| Return on average shareholders' equity | 10.32 | % | 6.89 | % | 4.48 | % | 8.10 | % | 10.64 | % | ||||||||||||||||||||||
| Return on average shareholders' equity (tangible)(1) | 13.50 | % | 8.99 | % | 5.84 | % | 10.52 | % | 14.03 | % | ||||||||||||||||||||||
| Net interest margin | 2.70 | % | 2.81 | % | 3.21 | % | 3.22 | % | 3.31 | % | ||||||||||||||||||||||
| Efficiency ratio(1) | 62.3 | % | 66.4 | % | 64.5 | % | 63.1 | % | 63.6 | % | ||||||||||||||||||||||
| Capital Ratios | ||||||||||||||||||||||||||||||||
| Tangible common equity ratio(1) | 7.4 | % | 7.5 | % | 7.8 | % | 8.5 | % | 8.5 | % | ||||||||||||||||||||||
| Tier 1 leverage ratio(5) | 7.4 | % | 7.6 | % | 7.9 | % | 8.4 | % | 8.5 | % | ||||||||||||||||||||||
| Common equity Tier 1 capital ratio(5) | 9.5 | % | 9.5 | % | 9.4 | % | 9.7 | % | 9.6 | % | ||||||||||||||||||||||
| Tier 1 capital ratio(5) | 9.5 | % | 9.5 | % | 9.4 | % | 9.7 | % | 9.6 | % | ||||||||||||||||||||||
| Total risk-based capital ratio(5) | 13.9 | % | 13.8 | % | 13.8 | % | 11.8 | % | 12.0 | % | ||||||||||||||||||||||
| (1) Non-GAAP financial measure. Refer to the calculation on the page titled “Reconciliation of Non-GAAP Measures” at the end of this document. | ||||||||||||||||||||||||||||||||
| (2) Effective January 1, 2020, Fulton adopted Accounting Standards Update 2016-13, “Financial Instruments—Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments,” referred to as the current expected credit loss model (“CECL”). This accounting standard requires that credit losses for financial assets and off-balance-sheet ("OBS") credit exposures be measured based on expected credit losses, rather than on incurred credit losses as in prior periods. | ||||||||||||||||||||||||||||||||
| (3) "ACL - loans" relates to the allowance for credit losses ("ACL") specifically on "Loans, net of unearned income" and does not include the ACL related to OBS credit exposures. | ||||||||||||||||||||||||||||||||
| (4) Asset quality information excluding Paycheck Protection Program (PPP) loans. Refer to the calculation on the page titled "Reconciliation of Non-GAAP Measures" at the end of this document. | ||||||||||||||||||||||||||||||||
(5) Regulatory capital ratios as of September 30, 2020 are preliminary and prior periods are actual. | ||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | ||||||||||||||||||||||||||||||||||||||||||||
| CONDENSED CONSOLIDATED ENDING BALANCE SHEETS (UNAUDITED) | ||||||||||||||||||||||||||||||||||||||||||||
| dollars in thousands | ||||||||||||||||||||||||||||||||||||||||||||
| % Change from | ||||||||||||||||||||||||||||||||||||||||||||
| Sep 30 | Jun 30 | Mar 31 | Dec 31 | Sep 30 | Jun 30 | Sep 30 | ||||||||||||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2019 | 2019 | 2020 | 2019 | ||||||||||||||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | $ | 139,304 | $ | 141,702 | $ | 181,777 | $ | 132,283 | $ | 120,671 | (1.7) | % | 15.4 | % | ||||||||||||||||||||||||||||||
| Other interest-earning assets | 1,489,550 | 1,007,939 | 793,572 | 482,930 | 572,499 | 47.8 | % | 160.2 | % | |||||||||||||||||||||||||||||||||||
| Loans held for sale | 93,621 | 77,415 | 40,645 | 37,828 | 33,945 | 20.9 | % | 175.8 | % | |||||||||||||||||||||||||||||||||||
| Investment securities | 3,097,721 | 2,974,813 | 3,141,440 | 2,867,378 | 2,705,610 | 4.1 | % | 14.5 | % | |||||||||||||||||||||||||||||||||||
| Loans, net of unearned income | 19,028,621 | 18,704,722 | 17,077,403 | 16,837,526 | 16,686,866 | 1.7 | % | 14.0 | % | |||||||||||||||||||||||||||||||||||
| Less: ACL - loans(1) | (266,825) | (256,537) | (238,508) | (163,622) | (166,135) | 4.0 | % | 60.6 | % | |||||||||||||||||||||||||||||||||||
| Net loans | 18,761,796 | 18,448,185 | 16,838,895 | 16,673,904 | 16,520,731 | 1.7 | % | 13.6 | % | |||||||||||||||||||||||||||||||||||
| Premises and equipment | 236,943 | 239,596 | 236,908 | 240,046 | 237,344 | (1.1) | % | (0.2) | % | |||||||||||||||||||||||||||||||||||
| Accrued interest receivable | 70,766 | 73,720 | 59,365 | 60,898 | 60,447 | (4.0) | % | 17.1 | % | |||||||||||||||||||||||||||||||||||
| Goodwill and intangible assets | 534,907 | 535,039 | 535,171 | 535,303 | 534,178 | — | % | 0.1 | % | |||||||||||||||||||||||||||||||||||
| Other assets | 1,118,673 | 1,119,454 | 1,102,086 | 855,470 | 918,193 | (0.1) | % | 21.8 | % | |||||||||||||||||||||||||||||||||||
| Total Assets | $ | 25,543,281 | $ | 24,617,863 | $ | 22,929,859 | $ | 21,886,040 | $ | 21,703,618 | 3.8 | % | 17.7 | % | ||||||||||||||||||||||||||||||
| LIABILITIES AND SHAREHOLDERS' EQUITY | ||||||||||||||||||||||||||||||||||||||||||||
| Deposits | $ | 20,730,051 | $ | 19,884,208 | $ | 17,365,026 | $ | 17,393,913 | $ | 17,342,717 | 4.3 | % | 19.5 | % | ||||||||||||||||||||||||||||||
| Short-term borrowings | 611,727 | 572,551 | 1,386,808 | 883,241 | 832,860 | 6.8 | % | (26.6) | % | |||||||||||||||||||||||||||||||||||
| Other liabilities | 515,230 | 525,407 | 513,811 | 384,941 | 477,311 | (1.9) | % | 7.9 | % | |||||||||||||||||||||||||||||||||||
| FHLB advances and long-term debt | 1,296,012 | 1,295,196 | 1,378,466 | 881,769 | 726,714 | 0.1 | % | 78.3 | % | |||||||||||||||||||||||||||||||||||
| Total Liabilities | 23,153,020 | 22,277,362 | 20,644,111 | 19,543,864 | 19,379,602 | 3.9 | % | 19.5 | % | |||||||||||||||||||||||||||||||||||
| Shareholders' equity | 2,390,261 | 2,340,501 | 2,285,748 | 2,342,176 | 2,324,016 | 2.1 | % | 2.9 | % | |||||||||||||||||||||||||||||||||||
| Total Liabilities and Shareholders' Equity | $ | 25,543,281 | $ | 24,617,863 | $ | 22,929,859 | $ | 21,886,040 | $ | 21,703,618 | 3.8 | % | 17.7 | % | ||||||||||||||||||||||||||||||
| LOANS, DEPOSITS AND SHORT-TERM BORROWINGS DETAIL: | ||||||||||||||||||||||||||||||||||||||||||||
| Loans, by type: | ||||||||||||||||||||||||||||||||||||||||||||
| Real estate - commercial mortgage | $ | 7,046,330 | $ | 6,934,936 | $ | 6,895,069 | $ | 6,700,776 | $ | 6,604,634 | 1.6 | % | 6.7 | % | ||||||||||||||||||||||||||||||
| Commercial and industrial | 4,007,278 | 4,033,439 | 4,450,557 | 4,445,634 | 4,493,379 | (0.6) | % | (10.8) | % | |||||||||||||||||||||||||||||||||||
| Real estate - residential mortgage | 3,061,835 | 2,862,226 | 2,718,290 | 2,641,465 | 2,570,793 | 7.0 | % | 19.1 | % | |||||||||||||||||||||||||||||||||||
| Real estate - home equity | 1,222,709 | 1,251,455 | 1,292,677 | 1,314,944 | 1,346,115 | (2.3) | % | (9.2) | % | |||||||||||||||||||||||||||||||||||
| Real estate - construction | 1,007,534 | 972,909 | 947,768 | 971,079 | 913,644 | 3.6 | % | 10.3 | % | |||||||||||||||||||||||||||||||||||
| Consumer | 469,551 | 465,610 | 468,172 | 463,164 | 464,213 | 0.8 | % | 1.1 | % | |||||||||||||||||||||||||||||||||||
| Equipment lease financing | 280,286 | 281,897 | 289,726 | 284,537 | 280,649 | (0.6) | % | (0.1) | % | |||||||||||||||||||||||||||||||||||
| PPP | 1,960,165 | 1,937,034 | — | — | — | 1.2 | % | N/M | ||||||||||||||||||||||||||||||||||||
| Other(2) | (27,067) | (34,784) | 15,144 | 15,927 | 13,439 | (22.2) | % | N/M | ||||||||||||||||||||||||||||||||||||
| Total Loans, net of unearned income | $ | 19,028,621 | $ | 18,704,722 | $ | 17,077,403 | $ | 16,837,526 | $ | 16,686,866 | 1.7 | % | 14.0 | % | ||||||||||||||||||||||||||||||
| Deposits, by type: | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 6,378,077 | $ | 6,239,055 | $ | 4,531,872 | $ | 4,453,324 | $ | 4,240,478 | 2.2 | % | 50.4 | % | ||||||||||||||||||||||||||||||
| Interest-bearing demand | 5,813,935 | 5,099,405 | 4,724,520 | 4,720,188 | 4,771,109 | 14.0 | % | 21.9 | % | |||||||||||||||||||||||||||||||||||
| Savings | 5,805,431 | 5,667,893 | 5,092,865 | 5,153,941 | 5,094,387 | 2.4 | % | 14.0 | % | |||||||||||||||||||||||||||||||||||
| Total demand and savings | 17,997,443 | 17,006,353 | 14,349,257 | 14,327,453 | 14,105,974 | 5.8 | % | 27.6 | % | |||||||||||||||||||||||||||||||||||
| Brokered | 317,588 | 310,689 | 313,337 | 264,531 | 256,870 | 2.2 | % | 23.6 | % | |||||||||||||||||||||||||||||||||||
| Time | 2,415,020 | 2,567,166 | 2,702,432 | 2,801,929 | 2,979,873 | (5.9) | % | (19.0) | % | |||||||||||||||||||||||||||||||||||
| Total Deposits | $ | 20,730,051 | $ | 19,884,208 | $ | 17,365,026 | $ | 17,393,913 | $ | 17,342,717 | 4.3 | % | 19.5 | % | ||||||||||||||||||||||||||||||
| Short-term borrowings, by type: | ||||||||||||||||||||||||||||||||||||||||||||
| Customer funding | $ | 611,727 | $ | 572,551 | $ | 461,808 | $ | 383,241 | $ | 337,860 | 6.8 | % | 81.1 | % | ||||||||||||||||||||||||||||||
| Federal funds purchased | — | — | 200,000 | — | 20,000 | N/M | N/M | |||||||||||||||||||||||||||||||||||||
| Short-term FHLB advances | — | — | 725,000 | 500,000 | 475,000 | N/M | N/M | |||||||||||||||||||||||||||||||||||||
| Total Short-term Borrowings | $ | 611,727 | $ | 572,551 | $ | 1,386,808 | $ | 883,241 | $ | 832,860 | 6.8 | % | (26.6) | % | ||||||||||||||||||||||||||||||
| N/M - Not meaningful | ||||||||||||||||||||||||||||||||||||||||||||
| (1) "ACL - loans" relates to the ACL specifically on "Loans, net of unearned income" and does not include the ACL related to OBS credit exposures. | ||||||||||||||||||||||||||||||||||||||||||||
| (2) Consists of overdrafts and net origination fees and costs. | ||||||||||||||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| CONDENSED CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| dollars in thousands | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | % Change from | Nine months ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Sep 30 | Jun 30 | Mar 31 | Dec 31 | Sep 30 | Jun 30 | Sep 30 | Sep 30 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2019 | 2019 | 2020 | 2019 | 2020 | 2019 | % Change | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest Income: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest income | $ | 179,159 | $ | 180,696 | $ | 199,378 | $ | 202,159 | $ | 208,413 | (0.9) | % | (14.0) | % | $ | 559,233 | $ | 623,147 | (10.3) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest expense | 25,043 | 27,942 | 38,632 | 42,889 | 47,153 | (10.4) | % | (46.9) | % | 91,617 | 134,028 | (31.6) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net Interest Income | 154,116 | 152,754 | 160,746 | 159,270 | 161,260 | 0.9 | % | (4.4) | % | 467,616 | 489,119 | (4.4) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 7,080 | 19,570 | 44,030 | 20,530 | 2,170 | (63.8) | % | N/M | 70,680 | 12,295 | N/M | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net Interest Income after Provision | 147,036 | 133,184 | 116,716 | 138,740 | 159,090 | 10.4 | % | (7.6) | % | 396,936 | 476,824 | (16.8) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-Interest Income: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Wealth management | 14,943 | 13,407 | 15,055 | 14,419 | 13,867 | 11.5 | % | 7.8 | % | 43,405 | 41,259 | 5.2 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mortgage banking | 16,801 | 9,964 | 6,234 | 5,076 | 6,658 | 68.6 | % | 152.3 | % | 32,998 | 18,023 | 83.1 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Consumer banking: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Card | 5,002 | 4,966 | 4,685 | 4,991 | 5,791 | 0.7 | % | (13.6) | % | 14,653 | 15,524 | (5.6) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Overdraft | 3,015 | 2,107 | 4,058 | 4,750 | 4,682 | 43.1 | % | (35.6) | % | 9,180 | 13,199 | (30.4) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other consumer banking | 2,406 | 2,065 | 2,496 | 2,688 | 2,860 | 16.5 | % | (15.9) | % | 6,967 | 8,354 | (16.6) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total consumer banking | 10,423 | 9,138 | 11,239 | 12,429 | 13,333 | 14.1 | % | (21.8) | % | 30,800 | 37,077 | (16.9) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial banking: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Merchant and card | 6,237 | 5,326 | 5,624 | 5,841 | 6,166 | 17.1 | % | 1.2 | % | 17,187 | 18,236 | (5.8) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cash management | 4,742 | 4,503 | 4,742 | 4,697 | 4,696 | 5.3 | % | 1.0 | % | 13,987 | 13,695 | 2.1 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Capital markets | 4,696 | 5,004 | 5,075 | 5,939 | 4,448 | (6.2) | % | 5.6 | % | 14,775 | 11,015 | 34.1 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other commercial banking | 2,636 | 1,914 | 2,978 | 3,664 | 3,478 | 37.7 | % | (24.2) | % | 7,528 | 10,109 | (25.5) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial banking | 18,311 | 16,748 | 18,419 | 20,141 | 18,788 | 9.3 | % | (2.5) | % | 53,477 | 53,055 | 0.8 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other | 2,769 | 3,660 | 3,651 | 3,216 | 2,675 | (24.3) | % | 3.5 | % | 10,080 | 6,733 | 49.7 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-interest income before investment securities gains | 63,246 | 52,917 | 54,598 | 55,281 | 55,321 | 19.5 | % | 14.3 | % | 170,761 | 156,147 | 9.4 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Investment securities gains, net | 2 | 3,005 | 46 | — | 4,492 | N/M | N/M | 3,053 | 4,733 | (35.5) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Non-Interest Income | 63,248 | 55,922 | 54,644 | 55,281 | 59,813 | 13.1 | % | 5.7 | % | 173,814 | 160,880 | 8.0 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-Interest Expense: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 79,227 | 81,012 | 80,228 | 76,975 | 78,211 | (2.2) | % | 1.3 | % | 240,467 | 234,959 | 2.3 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net occupancy | 13,221 | 13,144 | 13,486 | 13,080 | 12,368 | 0.6 | % | 6.9 | % | 39,851 | 39,746 | 0.3 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Data processing and software | 12,285 | 12,193 | 11,645 | 11,468 | 11,590 | 0.8 | % | 6.0 | % | 36,123 | 33,211 | 8.8 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other outside services | 7,617 | 7,600 | 7,881 | 8,215 | 12,163 | 0.2 | % | (37.4) | % | 23,098 | 31,774 | (27.3) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equipment | 3,711 | 3,193 | 3,418 | 3,475 | 3,459 | 16.2 | % | 7.3 | % | 10,322 | 10,100 | 2.2 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Professional fees | 2,879 | 3,331 | 4,202 | 2,873 | 3,331 | (13.6) | % | (13.6) | % | 10,412 | 10,261 | 1.5 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Marketing | 1,147 | 1,303 | 1,579 | 1,503 | 3,322 | (12.0) | % | (65.5) | % | 4,029 | 8,345 | (51.7) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of tax credit investments | 1,694 | 1,450 | 1,450 | 1,505 | 1,533 | 16.8 | % | 10.5 | % | 4,594 | 4,516 | 1.7 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| FDIC insurance | 1,578 | 2,133 | 2,808 | 2,177 | 239 | (26.0) | % | N/M | 6,519 | 5,603 | 16.3 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Intangible amortization | 132 | 132 | 132 | 142 | 1,071 | — | % | (87.7) | % | 397 | 1,285 | (69.1) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Prepayment penalty on FHLB advances | — | 2,878 | — | — | 4,326 | N/M | N/M | 2,878 | 4,326 | (33.5) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other | 15,654 | 14,637 | 15,723 | 17,561 | 15,157 | 6.9 | % | 3.3 | % | 46,014 | 44,636 | 3.1 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Non-Interest Expense | 139,147 | 143,006 | 142,552 | 138,974 | 146,770 | (2.7) | % | (5.2) | % | 424,705 | 428,762 | (0.9) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Income Before Income Taxes | 71,137 | 46,100 | 28,808 | 55,047 | 72,133 | 54.3 | % | (1.4) | % | 146,045 | 208,942 | (30.1) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Income tax expense | 9,529 | 6,542 | 2,761 | 7,258 | 10,025 | 45.7 | % | (4.9) | % | 18,832 | 30,391 | (38.0) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net Income | $ | 61,607 | $ | 39,559 | $ | 26,047 | $ | 47,789 | $ | 62,108 | 55.7 | % | (0.8) | % | $ | 127,213 | $ | 178,551 | (28.8) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| PER SHARE: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net income: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Basic | $ | 0.38 | $ | 0.24 | $ | 0.16 | $ | 0.29 | $ | 0.38 | 58.3 | % | — | % | $ | 0.78 | $ | 1.06 | (26.4) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Diluted | 0.38 | 0.24 | 0.16 | 0.29 | 0.37 | 58.3 | % | 2.7 | % | 0.78 | 1.06 | (26.4) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cash dividends | 0.13 | 0.13 | 0.13 | 0.17 | 0.13 | — | % | — | % | $ | 0.39 | $ | 0.39 | — | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Weighted average shares (basic) | 162,061 | 161,715 | 163,475 | 164,135 | 165,324 | 0.2 | % | (2.0) | % | 162,416 | 167,834 | (3.2) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Weighted average shares (diluted) | 162,579 | 162,267 | 164,417 | 165,039 | 166,126 | 0.2 | % | (2.1) | % | 163,083 | 168,722 | (3.3) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| CONDENSED CONSOLIDATED AVERAGE BALANCE SHEET ANALYSIS (UNAUDITED) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| dollars in thousands | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three months ended | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| September 30, 2020 | June 30, 2020 | September 30, 2019 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average | Interest | Yield/ | Average | Interest | Yield/ | Average | Interest | Yield/ | ||||||||||||||||||||||||||||||||||||||||||||||||
| Balance | (1) | Rate | Balance | (1) | Rate | Balance | (1) | Rate | ||||||||||||||||||||||||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning assets: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans, net of unearned income | $ | 18,880,519 | $ | 160,344 | 3.38 | % | $ | 18,331,797 | $ | 160,613 | 3.52 | % | $ | 16,436,507 | $ | 188,280 | 4.55 | % | ||||||||||||||||||||||||||||||||||||||
| Taxable investment securities | 2,011,893 | 13,150 | 2.61 | % | 2,200,870 | 15,171 | 2.76 | % | 2,282,292 | 15,565 | 2.73 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Tax-exempt investment securities | 861,764 | 6,899 | 3.19 | % | 830,836 | 6,737 | 3.23 | % | 516,907 | 4,650 | 3.57 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Total Investment Securities | 2,873,657 | 20,049 | 2.79 | % | 3,031,706 | 21,908 | 2.89 | % | 2,799,199 | 20,215 | 2.88 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Loans held for sale | 79,999 | 728 | 3.64 | % | 55,608 | 509 | 3.66 | % | 31,898 | 466 | 5.83 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Other interest-earning assets | 1,387,327 | 1,028 | 0.30 | % | 815,910 | 766 | 0.38 | % | 509,579 | 2,709 | 2.12 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Total Interest-earning Assets | 23,221,502 | 182,149 | 3.13 | % | 22,235,021 | 183,796 | 3.32 | % | 19,777,183 | 211,670 | 4.25 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-earning assets: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 138,567 | 153,728 | 120,967 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Premises and equipment | 239,183 | 240,417 | 240,383 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other assets | 1,835,190 | 1,761,038 | 1,491,115 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Less: ACL - loans(2) | (264,934) | (251,088) | (171,848) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Assets | $ | 25,169,508 | $ | 24,139,116 | $ | 21,457,800 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| LIABILITIES AND SHAREHOLDERS' EQUITY | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Demand deposits | $ | 5,591,548 | $ | 1,913 | 0.14 | % | $ | 5,103,419 | $ | 2,219 | 0.17 | % | $ | 4,448,112 | $ | 9,163 | 0.82 | % | ||||||||||||||||||||||||||||||||||||||
| Savings deposits | 5,716,050 | 2,347 | 0.16 | % | 5,446,368 | 3,331 | 0.25 | % | 5,026,316 | 11,059 | 0.87 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Brokered deposits | 314,721 | 440 | 0.56 | % | 312,121 | 422 | 0.54 | % | 253,426 | 1,536 | 2.40 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Time deposits | 2,495,445 | 9,931 | 1.58 | % | 2,624,962 | 11,145 | 1.71 | % | 2,974,993 | 13,979 | 1.86 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Total Interest-bearing Deposits | 14,117,764 | 14,631 | 0.41 | % | 13,486,870 | 17,118 | 0.51 | % | 12,702,847 | 35,737 | 1.12 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Short-term borrowings | 613,127 | 370 | 0.24 | % | 707,771 | 517 | 0.29 | % | 919,697 | 4,156 | 1.78 | % | ||||||||||||||||||||||||||||||||||||||||||||
| FHLB advances and long-term debt | 1,295,515 | 10,042 | 3.10 | % | 1,361,421 | 10,307 | 3.03 | % | 842,706 | 7,260 | 3.44 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Total Interest-bearing Liabilities | 16,026,406 | 25,043 | 0.62 | % | 15,556,062 | 27,942 | 0.72 | % | 14,465,250 | 47,153 | 1.29 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Demand deposits | 6,270,683 | 5,789,788 | 4,247,820 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Deposits/Cost of Deposits | 20,388,447 | 0.29 | % | 19,276,658 | 0.36 | % | 16,950,667 | 0.84 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Other | 498,328 | 484,133 | 429,145 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Liabilities | 22,795,417 | $ | 21,829,983 | 19,142,215 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Interest-bearing liabilities and non-interest bearing deposits ("Cost of Funds") | 22,297,089 | 0.45 | % | 21,345,850 | 0.53 | % | 18,713,070 | 1.00 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders' equity | 2,374,091 | 2,309,133 | 2,315,585 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Liabilities and Shareholders' Equity | $ | 25,169,508 | $ | 24,139,116 | $ | 21,457,800 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income/net interest margin (fully taxable equivalent) | 157,106 | 2.70 | % | 155,854 | 2.81 | % | 164,517 | 3.31 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Tax equivalent adjustment | (2,990) | (3,100) | (3,257) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 154,116 | $ | 152,754 | $ | 161,260 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| (1) Presented on a fully taxable-equivalent basis using a 21% federal tax rate and statutory interest expense disallowances. | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (2) "ACL - loans" relates to the ACL specifically on "Loans, net of unearned income" and does not include the ACL related to OBS credit exposures. | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| AVERAGE LOANS, DEPOSITS AND SHORT-TERM BORROWINGS DETAIL (UNAUDITED): | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| dollars in thousands | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three months ended | % Change from | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Sep 30 | Jun 30 | Mar 31 | Dec 31 | Sep 30 | Jun 30 | Sep 30 | |||||||||||||||||||||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2019 | 2019 | 2020 | 2019 | |||||||||||||||||||||||||||||||||||||||||||||||
| Loans, by type: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Real estate - commercial mortgage | $ | 6,986,528 | $ | 6,875,872 | $ | 6,746,766 | $ | 6,561,029 | $ | 6,489,456 | 1.6 | % | 7.7 | % | |||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 4,030,750 | 4,451,228 | 4,446,750 | 4,574,047 | 4,414,992 | (9.4) | % | (8.7) | % | ||||||||||||||||||||||||||||||||||||||||||||
| Real estate - residential mortgage | 2,975,516 | 2,769,682 | 2,670,019 | 2,606,136 | 2,512,899 | 7.4 | % | 18.4 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Real estate - home equity | 1,237,602 | 1,271,190 | 1,300,132 | 1,331,088 | 1,364,161 | (2.6) | % | (9.3) | % | ||||||||||||||||||||||||||||||||||||||||||||
| Real estate - construction | 981,589 | 941,079 | 929,529 | 934,556 | 905,060 | 4.3 | % | 8.5 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Consumer | 464,851 | 465,728 | 466,415 | 464,606 | 457,524 | (0.2) | % | 1.6 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Equipment lease financing | 279,217 | 284,658 | 284,566 | 281,451 | 277,555 | (1.9) | % | 0.6 | % | ||||||||||||||||||||||||||||||||||||||||||||
| PPP | 1,953,122 | 1,258,917 | — | — | — | 55.1 | % | N/M | |||||||||||||||||||||||||||||||||||||||||||||
| Other(1) | (28,656) | 13,443 | 15,890 | 14,058 | 14,860 | N/M | N/M | ||||||||||||||||||||||||||||||||||||||||||||||
| Total Loans, net of unearned income | $ | 18,880,519 | $ | 18,331,797 | $ | 16,860,067 | $ | 16,766,971 | $ | 16,436,507 | 3.0 | % | 14.9 | % | |||||||||||||||||||||||||||||||||||||||
| Deposits, by type: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 6,270,683 | $ | 5,789,788 | $ | 4,307,027 | $ | 4,324,568 | $ | 4,247,820 | 8.3 | % | 47.6 | % | |||||||||||||||||||||||||||||||||||||||
| Interest-bearing demand | 5,591,548 | 5,103,419 | 4,649,905 | 4,699,040 | 4,448,112 | 9.6 | % | 25.7 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Savings | 5,716,050 | 5,446,368 | 5,127,662 | 5,205,260 | 5,026,316 | 5.0 | % | 13.7 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Total demand and savings | 17,578,281 | 16,339,575 | 14,084,594 | 14,228,868 | 13,722,248 | 7.6 | % | 28.1 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Brokered | 314,721 | 312,121 | 275,359 | 261,689 | 253,426 | 0.8 | % | 24.2 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Time | 2,495,445 | 2,624,962 | 2,761,474 | 2,959,008 | 2,974,993 | (4.9) | % | (16.1) | % | ||||||||||||||||||||||||||||||||||||||||||||
| Total Deposits | $ | 20,388,447 | $ | 19,276,658 | $ | 17,121,427 | $ | 17,449,565 | $ | 16,950,667 | 5.8 | % | 20.3 | % | |||||||||||||||||||||||||||||||||||||||
| Short-term borrowings, by type: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Customer funding | $ | 613,127 | $ | 546,716 | $ | 428,240 | $ | 377,529 | $ | 332,893 | 12.1 | % | 84.2 | % | |||||||||||||||||||||||||||||||||||||||
| Federal funds purchased | — | 74,231 | 186,868 | 91,467 | 101,022 | N/M | N/M | ||||||||||||||||||||||||||||||||||||||||||||||
| Short-term FHLB advances and other borrowings | — | 86,824 | 687,937 | 248,815 | 485,782 | N/M | N/M | ||||||||||||||||||||||||||||||||||||||||||||||
| Total Short-term borrowings | $ | 613,127 | $ | 707,771 | $ | 1,303,045 | $ | 717,811 | $ | 919,697 | (13.4) | % | (33.3) | % | |||||||||||||||||||||||||||||||||||||||
| (1) Consists of overdrafts and net origination fees and costs. | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | ||||||||||||||||||||||||||||||||||||||||||||
| CONDENSED CONSOLIDATED AVERAGE BALANCE SHEET ANALYSIS (UNAUDITED) | ||||||||||||||||||||||||||||||||||||||||||||
| dollars in thousands | ||||||||||||||||||||||||||||||||||||||||||||
| Nine months ended September 30 | ||||||||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | |||||||||||||||||||||||||||||||||||||||||||
| Average | Interest | Yield/ | Average | Interest | Yield/ | |||||||||||||||||||||||||||||||||||||||
| Balance | (1) | Rate | Balance | (1) | Rate | |||||||||||||||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning assets: | ||||||||||||||||||||||||||||||||||||||||||||
| Loans, net of unearned income | $ | 18,027,253 | $ | 498,455 | 3.69 | % | $ | 16,316,540 | $ | 565,095 | 4.63 | % | ||||||||||||||||||||||||||||||||
| Taxable investment securities | 2,165,180 | 44,615 | 2.75 | % | 2,305,472 | 46,935 | 2.71 | % | ||||||||||||||||||||||||||||||||||||
| Tax-exempt investment securities | 804,484 | 19,596 | 3.24 | % | 468,689 | 12,940 | 3.66 | % | ||||||||||||||||||||||||||||||||||||
| Total Investment Securities | 2,969,664 | 64,211 | 2.88 | % | 2,774,161 | 59,875 | 2.87 | % | ||||||||||||||||||||||||||||||||||||
| Loans held for sale | 54,355 | 1,557 | 3.82 | % | 24,357 | 1,056 | 5.78 | % | ||||||||||||||||||||||||||||||||||||
| Other interest-earning assets | 936,819 | 4,325 | 0.62 | % | 428,982 | 6,879 | 2.14 | % | ||||||||||||||||||||||||||||||||||||
| Total Interest-earning Assets | 21,988,091 | 568,548 | 3.45 | % | 19,544,040 | 632,905 | 4.33 | % | ||||||||||||||||||||||||||||||||||||
| Noninterest-earning assets: | ||||||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 143,496 | 116,019 | ||||||||||||||||||||||||||||||||||||||||||
| Premises and equipment | 239,739 | 239,402 | ||||||||||||||||||||||||||||||||||||||||||
| Other assets | 1,729,351 | 1,337,482 | ||||||||||||||||||||||||||||||||||||||||||
| Less: ACL - loans(2) | (242,300) | (165,733) | ||||||||||||||||||||||||||||||||||||||||||
| Total Assets | $ | 23,858,377 | $ | 21,071,210 | ||||||||||||||||||||||||||||||||||||||||
| LIABILITIES AND SHAREHOLDERS' EQUITY | ||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||||||||
| Demand deposits | $ | 5,116,696 | $ | 9,933 | 0.26 | % | $ | 4,263,869 | $ | 24,854 | 0.78 | % | ||||||||||||||||||||||||||||||||
| Savings deposits | 5,431,071 | 12,788 | 0.31 | % | 4,955,403 | 31,570 | 0.85 | % | ||||||||||||||||||||||||||||||||||||
| Brokered deposits | 300,795 | 1,935 | 0.86 | % | 240,045 | 4,500 | 2.51 | % | ||||||||||||||||||||||||||||||||||||
| Time deposits | 2,626,802 | 33,533 | 1.71 | % | 2,853,147 | 37,050 | 1.74 | % | ||||||||||||||||||||||||||||||||||||
| Total Interest-bearing Deposits | 13,475,364 | 58,189 | 0.58 | % | 12,312,464 | 97,974 | 1.06 | % | ||||||||||||||||||||||||||||||||||||
| Short-term borrowings | 873,694 | 4,960 | 0.76 | % | 894,116 | 12,200 | 1.81 | % | ||||||||||||||||||||||||||||||||||||
| FHLB advances and long-term debt | 1,240,253 | 28,468 | 3.06 | % | 965,111 | 23,854 | 3.30 | % | ||||||||||||||||||||||||||||||||||||
| Total Interest-bearing Liabilities | 15,589,311 | 91,617 | 0.78 | % | 14,171,691 | 134,028 | 1.26 | % | ||||||||||||||||||||||||||||||||||||
| Noninterest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||||||||
| Demand deposits | 5,458,807 | 4,223,927 | ||||||||||||||||||||||||||||||||||||||||||
| Total Deposits/Cost of Deposits | 18,934,171 | 0.41 | % | 16,536,391 | 0.79 | % | ||||||||||||||||||||||||||||||||||||||
| Other | 470,055 | 381,427 | ||||||||||||||||||||||||||||||||||||||||||
| Total Liabilities | 21,518,173 | 18,777,045 | ||||||||||||||||||||||||||||||||||||||||||
| Total Interest-bearing liabilities and non-interest bearing deposits ("Cost of Funds") | 21,048,118 | 0.58 | % | 18,395,618 | 0.97 | % | ||||||||||||||||||||||||||||||||||||||
| Shareholders' equity | 2,340,204 | 2,294,165 | ||||||||||||||||||||||||||||||||||||||||||
| Total Liabilities and Shareholders' Equity | $ | 23,858,377 | $ | 21,071,210 | ||||||||||||||||||||||||||||||||||||||||
| Net interest income/net interest margin (fully taxable equivalent) | 476,931 | 2.90 | % | 498,877 | 3.41 | % | ||||||||||||||||||||||||||||||||||||||
| Tax equivalent adjustment | (9,315) | (9,758) | ||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 467,616 | $ | 489,119 | ||||||||||||||||||||||||||||||||||||||||
| (1) Presented on a fully taxable-equivalent basis using a 21% federal tax rate and statutory interest expense disallowances. | ||||||||||||||||||||||||||||||||||||||||||||
| (2) "ACL - loans" relates to the ACL specifically on "Loans, net of unearned income" and does not include the ACL related to OBS credit exposures. | ||||||||||||||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| AVERAGE LOANS, DEPOSITS AND SHORT-TERM BORROWINGS DETAIL (UNAUDITED): | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| dollars in thousands | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Nine months ended September 30 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | % Change | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans, by type: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Real estate - commercial mortgage | $ | 6,870,148 | $ | 6,431,012 | 6.8 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 4,308,559 | 4,438,894 | (2.9) | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Real estate - residential mortgage | 2,805,694 | 2,386,264 | 17.6 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Real estate - home equity | 1,269,525 | 1,400,371 | (9.3) | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Real estate - construction | 950,845 | 926,036 | 2.7 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Consumer | 465,661 | 442,678 | 5.2 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Equipment lease financing | 282,800 | 278,463 | 1.6 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| PPP | 1,073,900 | — | N/M | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Other(1) | 121 | 12,822 | (99.1) | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total Loans, net of unearned income | $ | 18,027,253 | $ | 16,316,540 | 10.5 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Deposits, by type: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 5,458,807 | $ | 4,223,927 | 29.2 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing demand | 5,116,696 | 4,263,869 | 20.0 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Savings | 5,431,071 | 4,955,403 | 9.6 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total demand and savings | 16,006,574 | 13,443,199 | 19.1 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Brokered | 300,795 | 240,045 | 25.3 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Time | 2,626,802 | 2,853,147 | (7.9) | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total Deposits | $ | 18,934,171 | $ | 16,536,391 | 14.5 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Short-term borrowings, by type: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Customer funding | $ | 529,667 | $ | 348,721 | 51.9 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Federal funds purchased | 86,715 | 146,432 | (40.8) | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Short-term FHLB advances and other borrowings | 257,312 | 398,963 | (35.5) | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total Short-term Borrowings | $ | 873,694 | $ | 894,116 | (2.3) | % | |||||||||||||||||||||||||||||||||||||||||||||||
| (1) Consists of overdrafts and net origination fees and costs. | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | ||||||||||||||||||||||||||||||||||||||
| ASSET QUALITY INFORMATION (UNAUDITED) | ||||||||||||||||||||||||||||||||||||||
| dollars in thousands | ||||||||||||||||||||||||||||||||||||||
| Three months ended | ||||||||||||||||||||||||||||||||||||||
| Sep 30 | Jun 30 | Mar 31 | Dec 31 | Sep 30 | ||||||||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2019 | 2019 | ||||||||||||||||||||||||||||||||||
| Allowance for credit losses related to Loans, net of unearned income: | ||||||||||||||||||||||||||||||||||||||
| Balance at beginning of period | $ | 256,537 | $ | 238,508 | $ | 163,620 | $ | 166,135 | $ | 170,233 | ||||||||||||||||||||||||||||
| Impact of adopting CECL | — | — | 45,724 | — | — | |||||||||||||||||||||||||||||||||
| Loans charged off: | ||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | (2,969) | (3,480) | (10,899) | (30,547) | (7,181) | |||||||||||||||||||||||||||||||||
| Real estate - commercial mortgage | (746) | (2,324) | (855) | (68) | (394) | |||||||||||||||||||||||||||||||||
| Consumer and home equity | (1,093) | (1,303) | (1,529) | (1,416) | (1,375) | |||||||||||||||||||||||||||||||||
| Real estate - residential mortgage | (198) | (235) | (187) | (223) | (533) | |||||||||||||||||||||||||||||||||
| Real estate - construction | — | (17) | — | — | (45) | |||||||||||||||||||||||||||||||||
| Equipment lease financing and other | (483) | (688) | (533) | (727) | (600) | |||||||||||||||||||||||||||||||||
| Total loans charged off | (5,489) | (8,047) | (14,003) | (32,981) | (10,128) | |||||||||||||||||||||||||||||||||
| Recoveries of loans previously charged off: | ||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 2,103 | 2,978 | 1,734 | 2,487 | 2,311 | |||||||||||||||||||||||||||||||||
| Real estate - commercial mortgage | 100 | 95 | 244 | 1,453 | 444 | |||||||||||||||||||||||||||||||||
| Consumer and home equity | 491 | 649 | 646 | 437 | 348 | |||||||||||||||||||||||||||||||||
| Real estate - residential mortgage | 95 | 112 | 85 | 206 | 440 | |||||||||||||||||||||||||||||||||
| Real estate - construction | 4,873 | — | 70 | 1,098 | 164 | |||||||||||||||||||||||||||||||||
| Equipment lease financing and other | 185 | 92 | 108 | 182 | 107 | |||||||||||||||||||||||||||||||||
| Recoveries of loans previously charged off | 7,847 | 3,926 | 2,887 | 5,863 | 3,814 | |||||||||||||||||||||||||||||||||
| Net loans recovered (charged off) | 2,358 | (4,121) | (11,116) | (27,118) | (6,314) | |||||||||||||||||||||||||||||||||
| Provision for credit losses | 7,930 | 22,150 | 40,280 | 24,603 | 2,216 | |||||||||||||||||||||||||||||||||
| Balance at end of period | $ | 266,825 | $ | 256,537 | $ | 238,508 | $ | 163,620 | $ | 166,135 | ||||||||||||||||||||||||||||
| Net (recoveries) charge-offs to average loans (annualized) | (0.05) | % | 0.09 | % | 0.26 | % | 0.65 | % | 0.15 | % | ||||||||||||||||||||||||||||
Allowance credit losses related to OBS Credit Exposures(1) | ||||||||||||||||||||||||||||||||||||||
| Balance at beginning of period | $ | 16,383 | $ | 18,963 | $ | 2,588 | $ | 6,662 | $ | 6,708 | ||||||||||||||||||||||||||||
| Impact of adopting CECL | — | — | 12,625 | — | — | |||||||||||||||||||||||||||||||||
| Provision for credit losses | (850) | (2,580) | 3,750 | (4,074) | (46) | |||||||||||||||||||||||||||||||||
| Balance at end of period | $ | 15,533 | $ | 16,383 | $ | 18,963 | $ | 2,588 | $ | 6,662 | ||||||||||||||||||||||||||||
| NON-PERFORMING ASSETS: | ||||||||||||||||||||||||||||||||||||||
| Non-accrual loans | $ | 128,321 | $ | 125,037 | $ | 120,345 | $ | 125,098 | $ | 124,287 | ||||||||||||||||||||||||||||
| Loans 90 days past due and accruing | 13,761 | 14,767 | 19,593 | 16,057 | 11,689 | |||||||||||||||||||||||||||||||||
| Total non-performing loans | 142,082 | 139,804 | 139,938 | 141,155 | 135,976 | |||||||||||||||||||||||||||||||||
| Other real estate owned | 4,565 | 5,418 | 6,593 | 6,831 | 7,706 | |||||||||||||||||||||||||||||||||
| Total non-performing assets | $ | 146,647 | $ | 145,222 | $ | 146,531 | $ | 147,986 | $ | 143,682 | ||||||||||||||||||||||||||||
| NON-PERFORMING LOANS, BY TYPE: | ||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 37,224 | $ | 39,730 | $ | 41,318 | $ | 49,491 | $ | 37,126 | ||||||||||||||||||||||||||||
| Real estate - commercial mortgage | 43,426 | 42,374 | 36,538 | 37,279 | 45,710 | |||||||||||||||||||||||||||||||||
| Real estate - residential mortgage | 28,287 | 22,887 | 25,832 | 22,411 | 20,150 | |||||||||||||||||||||||||||||||||
| Consumer and home equity | 12,292 | 11,911 | 11,226 | 11,026 | 11,012 | |||||||||||||||||||||||||||||||||
| Real estate - construction | 4,051 | 4,525 | 4,379 | 4,306 | 4,312 | |||||||||||||||||||||||||||||||||
| Equipment lease financing and other | 16,802 | 18,377 | 20,645 | 16,642 | 17,666 | |||||||||||||||||||||||||||||||||
| Total non-performing loans | $ | 142,082 | $ | 139,804 | $ | 139,938 | $ | 141,155 | $ | 135,976 | ||||||||||||||||||||||||||||
| (1) The allowance for credit losses related to OBS Credit Exposures is presented in "other liabilities" on the consolidated balance sheets. | ||||||||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | ||||||||||||||||||||||||||||||||||||||||||||||||||
| RECONCILIATION OF NON-GAAP MEASURES (UNAUDITED) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| in thousands, except per share data and percentages | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Explanatory note: | This press release contains supplemental financial information, as detailed below, which has been derived by methods other than Generally Accepted Accounting Principles ("GAAP"). The Corporation has presented these non-GAAP financial measures because it believes that these measures provide useful and comparative information to assess trends in the Corporation's results of operations. Presentation of these non-GAAP financial measures is consistent with how the Corporation evaluates its performance internally and these non-GAAP financial measures are frequently used by securities analysts, investors and other interested parties in the evaluation of companies in the Corporation's industry. Management believes that these non-GAAP financial measures, in addition to GAAP measures, are also useful to investors to evaluate the Corporation's results. Investors should recognize that the Corporation's presentation of these non-GAAP financial measures might not be comparable to similarly-titled measures of other companies. These non-GAAP financial measures should not be considered a substitute for GAAP basis measures, and the Corporation strongly encourages a review of its condensed consolidated financial statements in their entirety. Reconciliations of these non-GAAP financial measures to the most directly comparable GAAP measure follow: | |||||||||||||||||||||||||||||||||||||||||||||||||
| Three months ended | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Sep 30 | Jun 30 | Mar 31 | Dec 31 | Sep 30 | ||||||||||||||||||||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2019 | 2019 | ||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders' equity (tangible), per share | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders' equity | $ | 2,390,261 | $ | 2,340,501 | $ | 2,285,748 | $ | 2,342,176 | $ | 2,324,016 | ||||||||||||||||||||||||||||||||||||||||
| Less: Goodwill and intangible assets | (534,907) | (535,039) | (535,171) | (535,303) | (534,178) | |||||||||||||||||||||||||||||||||||||||||||||
| Tangible shareholders' equity (numerator) | $ | 1,855,354 | $ | 1,805,462 | $ | 1,750,577 | $ | 1,806,873 | $ | 1,789,838 | ||||||||||||||||||||||||||||||||||||||||
| Shares outstanding, end of period (denominator) | 162,134 | 161,958 | 161,435 | 164,218 | 164,036 | |||||||||||||||||||||||||||||||||||||||||||||
| Shareholders' equity (tangible), per share | $ | 11.44 | $ | 11.15 | $ | 10.84 | $ | 11.00 | $ | 10.91 | ||||||||||||||||||||||||||||||||||||||||
| Return on average shareholders' equity (tangible) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net income | $ | 61,607 | $ | 39,559 | $ | 26,047 | $ | 47,789 | $ | 62,108 | ||||||||||||||||||||||||||||||||||||||||
| Plus: Intangible amortization, net of tax | 103 | 104 | 104 | 112 | 846 | |||||||||||||||||||||||||||||||||||||||||||||
| (Numerator) | $ | 61,711 | $ | 39,663 | $ | 26,151 | $ | 47,901 | $ | 62,954 | ||||||||||||||||||||||||||||||||||||||||
| Average shareholders' equity | $ | 2,374,091 | $ | 2,309,133 | $ | 2,337,016 | $ | 2,341,397 | $ | 2,315,585 | ||||||||||||||||||||||||||||||||||||||||
| Less: Average goodwill and intangible assets | (534,971) | (535,103) | (535,235) | (534,190) | (535,184) | |||||||||||||||||||||||||||||||||||||||||||||
| Average tangible shareholders' equity (denominator) | $ | 1,839,120 | $ | 1,774,030 | $ | 1,801,781 | $ | 1,807,207 | $ | 1,780,401 | ||||||||||||||||||||||||||||||||||||||||
| Return on average shareholders' equity (tangible), annualized | 13.50 | % | 8.99 | % | 5.84 | % | 10.52 | % | 14.03 | % | ||||||||||||||||||||||||||||||||||||||||
| Tangible Common Equity to Tangible Assets (TCE Ratio) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders' equity | $ | 2,390,261 | $ | 2,340,501 | $ | 2,285,748 | $ | 2,342,176 | $ | 2,324,016 | ||||||||||||||||||||||||||||||||||||||||
| Less: Goodwill and intangible assets | (534,907) | (535,039) | (535,171) | (535,303) | (534,178) | |||||||||||||||||||||||||||||||||||||||||||||
| Tangible shareholders' equity (numerator) | $ | 1,855,354 | $ | 1,805,462 | $ | 1,750,577 | $ | 1,806,873 | $ | 1,789,838 | ||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 25,543,281 | $ | 24,617,863 | $ | 22,929,859 | $ | 21,886,040 | $ | 21,703,618 | ||||||||||||||||||||||||||||||||||||||||
| Less: Goodwill and intangible assets | (534,907) | (535,039) | (535,171) | (535,303) | (534,178) | |||||||||||||||||||||||||||||||||||||||||||||
| Total tangible assets (denominator) | $ | 25,008,374 | $ | 24,082,824 | $ | 22,394,688 | $ | 21,350,737 | $ | 21,169,440 | ||||||||||||||||||||||||||||||||||||||||
| Tangible Common Equity to Tangible Assets | 7.42 | % | 7.50 | % | 7.82 | % | 8.46 | % | 8.45 | % | ||||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-interest expense | $ | 139,147 | $ | 143,006 | $ | 142,552 | $ | 138,974 | $ | 146,770 | ||||||||||||||||||||||||||||||||||||||||
| Less: Intangible amortization | (132) | (132) | (132) | (142) | (1,071) | |||||||||||||||||||||||||||||||||||||||||||||
| Less: Amortization of tax credit investments | (1,694) | (1,450) | (1,450) | (1,505) | (1,533) | |||||||||||||||||||||||||||||||||||||||||||||
| Less: Prepayment penalty of FHLB advances | — | (2,878) | — | — | (4,326) | |||||||||||||||||||||||||||||||||||||||||||||
| Non-interest expense (numerator) | $ | 137,321 | $ | 138,546 | $ | 140,970 | $ | 137,327 | $ | 139,840 | ||||||||||||||||||||||||||||||||||||||||
| Net interest income (fully taxable equivalent) | $ | 157,106 | $ | 155,854 | $ | 163,970 | $ | 162,479 | $ | 164,517 | ||||||||||||||||||||||||||||||||||||||||
| Plus: Total Non-interest income | 63,248 | 55,922 | 54,644 | 55,281 | 59,813 | |||||||||||||||||||||||||||||||||||||||||||||
| Less: Investment securities gains, net | (2) | (3,005) | (46) | — | (4,492) | |||||||||||||||||||||||||||||||||||||||||||||
| Total revenue (denominator) | $ | 220,353 | $ | 208,771 | $ | 218,568 | $ | 217,760 | $ | 219,838 | ||||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | 62.3 | % | 66.4 | % | 64.5 | % | 63.1 | % | 63.6 | % | ||||||||||||||||||||||||||||||||||||||||
| Non-performing assets to shareholders' equity (tangible) and ACL - loans(1) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-performing assets (numerator) | $ | 146,647 | $ | 145,222 | $ | 146,531 | $ | 147,986 | $ | 143,682 | ||||||||||||||||||||||||||||||||||||||||
| Tangible shareholders' equity | $ | 1,855,354 | $ | 1,805,462 | 1,750,577 | 1,806,873 | $ | 1,789,838 | ||||||||||||||||||||||||||||||||||||||||||
| Plus: ACL - loans | 266,825 | 256,537 | 238,508 | 163,622 | 166,135 | |||||||||||||||||||||||||||||||||||||||||||||
| Tangible shareholders' equity and ACL - loans (denominator) | $ | 2,122,179 | $ | 2,061,999 | $ | 1,989,085 | $ | 1,970,495 | $ | 1,955,973 | ||||||||||||||||||||||||||||||||||||||||
| Non-performing assets to tangible shareholders' equity and ACL - loans | 6.91 | % | 7.04 | % | 7.37 | % | 7.51 | % | 7.35 | % | ||||||||||||||||||||||||||||||||||||||||
| Three months ended | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Sep 30 | Jun 30 | Mar 31 | Dec 31 | Sep 30 | ||||||||||||||||||||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2019 | 2019 | ||||||||||||||||||||||||||||||||||||||||||||||
| Asset Quality, excluding PPP | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net loans recovered (charged-off) (numerator) | $ | 2,358 | $ | (4,121) | $ | (11,116) | $ | (27,118) | $ | (6,314) | ||||||||||||||||||||||||||||||||||||||||
| Average loans, net of unearned income | $ | 18,880,519 | $ | 18,331,797 | $ | 16,860,067 | $ | 16,766,971 | $ | 16,436,507 | ||||||||||||||||||||||||||||||||||||||||
| Less: Average PPP loans | (1,953,122) | (1,258,917) | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Total adjusted average loans (denominator) | $ | 16,927,397 | $ | 17,072,880 | $ | 16,860,067 | $ | 16,766,971 | $ | 16,436,507 | ||||||||||||||||||||||||||||||||||||||||
| Net (recoveries) charge-offs to adjusted average loans (annualized) | (0.06) | % | 0.10 | % | 0.26 | % | 0.65 | % | 0.15 | % | ||||||||||||||||||||||||||||||||||||||||
| Non-performing loans (numerator) | $ | 142,082 | $ | 139,804 | $ | 139,938 | $ | 141,155 | $ | 135,976 | ||||||||||||||||||||||||||||||||||||||||
| Loans, net of unearned income | $ | 19,028,621 | $ | 18,704,722 | $ | 17,077,403 | $ | 16,837,526 | $ | 16,686,866 | ||||||||||||||||||||||||||||||||||||||||
| Less: PPP loans | (1,960,165) | (1,937,034) | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Total adjusted loans (denominator) | $ | 17,068,456 | $ | 16,767,688 | $ | 17,077,403 | $ | 16,837,526 | $ | 16,686,866 | ||||||||||||||||||||||||||||||||||||||||
| Non-performing loans to adjusted total loans | 0.83 | % | 0.83 | % | 0.82 | % | 0.84 | % | 0.81 | % | ||||||||||||||||||||||||||||||||||||||||
| ACL - loans (numerator) | $ | 266,825 | $ | 256,537 | 238,508 | 163,622 | $ | 166,135 | ||||||||||||||||||||||||||||||||||||||||||
| Loans, net of unearned income | $ | 19,028,621 | $ | 18,704,722 | $ | 17,077,403 | $ | 16,837,526 | $ | 16,686,866 | ||||||||||||||||||||||||||||||||||||||||
| Less: PPP loans | (1,960,165) | (1,937,034) | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Total adjusted loans (denominator) | $ | 17,068,456 | $ | 16,767,688 | $ | 17,077,403 | $ | 16,837,526 | $ | 16,686,866 | ||||||||||||||||||||||||||||||||||||||||
| ACL - loans to adjusted total loans | 1.56 | % | 1.53 | % | 1.40 | % | 0.97 | % | 1.00 | % | ||||||||||||||||||||||||||||||||||||||||
| Note: numbers may not sum due to rounding. | ||||||||||||||||||||||||||||||||||||||||||||||||||
| (1) "ACL - loans" relates to the ACL specifically on "Loans, net of unearned income" and does not include the ACL related to OBS credit exposures. | ||||||||||||||||||||||||||||||||||||||||||||||||||
2020 THIRD QUARTER RESULTS NASDAQ: FULT Data as of September 30, 2020 unless otherwise noted
FORWARD-LOOKING STATEMENTS This presentation may contain forward-looking statements with respect to the Corporation’s financial condition, results of operations and business. Do not unduly rely on forward-looking statements. Forward-looking statements can be identified by the use of words such as "may," "should," "will," "could," "estimates," "predicts," "potential," "continue," "anticipates," "believes," "plans," "expects," "future," "intends," “projects,” the negative of these terms and other comparable terminology. These forward-looking statements may include projections of, or guidance on, the Corporation’s future financial performance, expected levels of future expenses, including future credit losses, anticipated growth strategies, descriptions of new business initiatives and anticipated trends in the Corporation’s business or financial results. Management’s Q4 2020 Outlook contained herein is comprised of forward-looking statements. Forward-looking statements are neither historical facts, nor assurance of future performance. Instead, they are based on current beliefs, expectations and assumptions regarding the future of the Corporation’s business, future plans and strategies, projections, anticipated events and trends, the economy and other future conditions. Because forward-looking statements relate to the future, they are subject to inherent uncertainties, risks and changes in circumstances that are difficult to predict and many of which are outside of the Corporation’s control, and actual results and financial condition may differ materially from those indicated in the forward-looking statements. Therefore, you should not unduly rely on any of these forward-looking statements. Any forward-looking statement is based only on information currently available and speaks only as of the date when made. The Corporation undertakes no obligation, other than as required by law, to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise. A discussion of certain risks and uncertainties affecting the Corporation, and some of the factors that could cause the Corporation’s actual results to differ materially from those described in the forward-looking statements, can be found in the sections entitled “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2019, Quarterly Reports on Form 10-Q for the quarters end March 31, 2020 and June 30, 2020 and other current and periodic reports, which have been, or will be, filed with the Securities and Exchange Commission and are or will be available in the Investor Relations section of the Corporation’s website (www.fult.com) and on the Securities and Exchange Commission’s website (www.sec.gov). The Corporation uses certain non-GAAP financial measures in this presentation. These non-GAAP financial measures are reconciled to the most comparable GAAP measures at the end of this presentation. 2
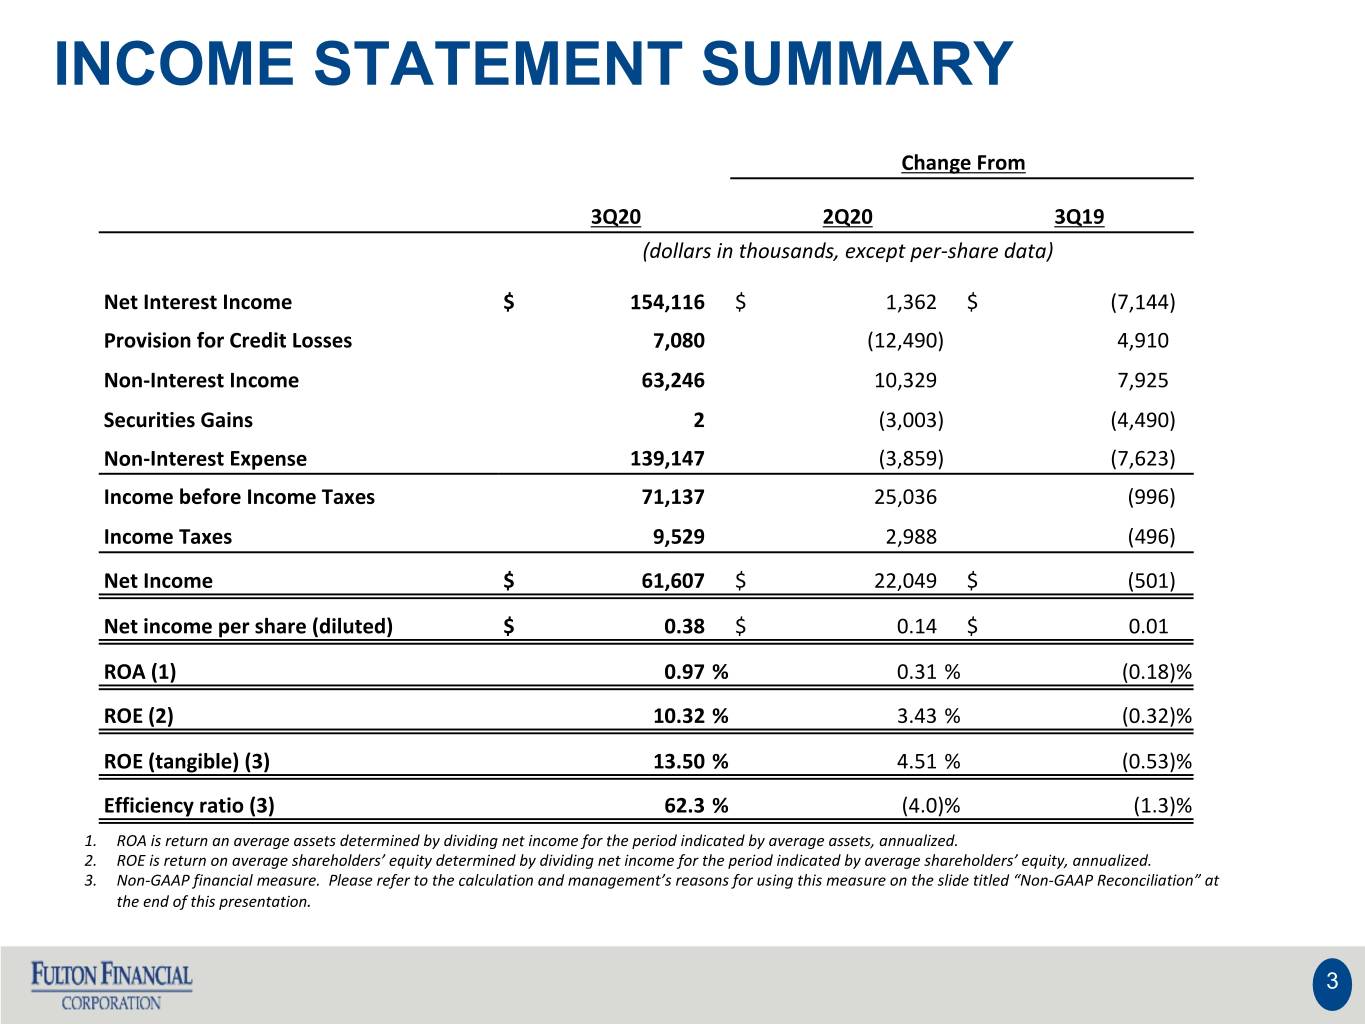
INCOME STATEMENT SUMMARY Change From 3Q20 2Q20 3Q19 (dollars in thousands, except per-share data) Net Interest Income $ 154,116 $ 1,362 $ (7,144) Provision for Credit Losses 7,080 (12,490) 4,910 Non-Interest Income 63,246 10,329 7,925 Securities Gains 2 (3,003) (4,490) Non-Interest Expense 139,147 (3,859) (7,623) Income before Income Taxes 71,137 25,036 (996) Income Taxes 9,529 2,988 (496) Net Income $ 61,607 $ 22,049 $ (501) Net income per share (diluted) $ 0.38 $ 0.14 $ 0.01 ROA (1) 0.97 % 0.31 % (0.18) % ROE (2) 10.32 % 3.43 % (0.32) % ROE (tangible) (3) 13.50 % 4.51 % (0.53) % Efficiency ratio (3) 62.3 % (4.0) % (1.3) % 1. ROA is return an average assets determined by dividing net income for the period indicated by average assets, annualized. 2. ROE is return on average shareholders’ equity determined by dividing net income for the period indicated by average shareholders’ equity, annualized. 3. Non-GAAP financial measure. Please refer to the calculation and management’s reasons for using this measure on the slide titled “Non-GAAP Reconciliation” at the end of this presentation. 3
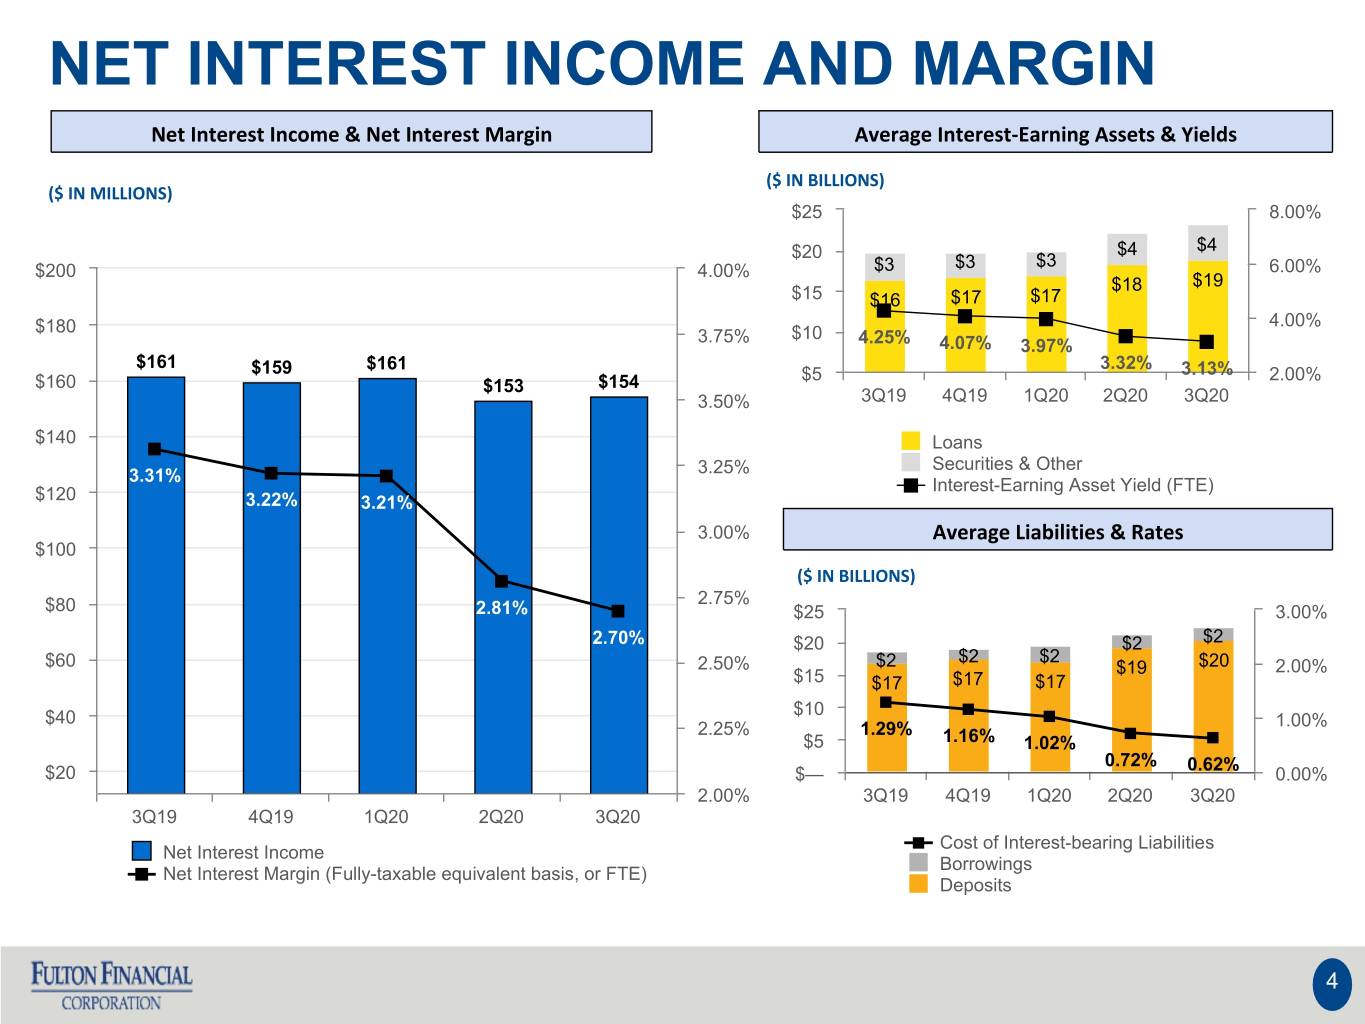
NET INTEREST INCOME AND MARGIN Net Interest Income & Net Interest Margin Average Interest-Earning Assets & Yields ($ IN BILLIONS) ($ IN MILLIONS) $25 8.00% $4 $20 $4 $3 $200 4.00% $3 $3 6.00% $18 $19 $15 $16 $17 $17 $180 4.00% 3.75% $10 4.25% 4.07% 3.97% $161 $159 $161 3.32% 3.13% $5 2.00% $160 $153 $154 3.50% 3Q19 4Q19 1Q20 2Q20 3Q20 $140 Loans Securities & Other 3.31% 3.25% Interest-Earning Asset Yield (FTE) $120 3.22% 3.21% 3.00% Average Liabilities & Rates $100 ($ IN BILLIONS) 2.75% $80 2.81% $25 3.00% 2.70% $2 $20 $2 $2 $2 $60 2.50% $2 $19 $20 2.00% $15 $17 $17 $17 $10 $40 1.00% 2.25% 1.29% 1.16% $5 1.02% 0.72% 0.62% $20 $— 0.00% 2.00% 3Q19 4Q19 1Q20 2Q20 3Q20 3Q19 4Q19 1Q20 2Q20 3Q20 Cost of Interest-bearing Liabilities Net Interest Income Borrowings Net Interest Margin (Fully-taxable equivalent basis, or FTE) Deposits 4
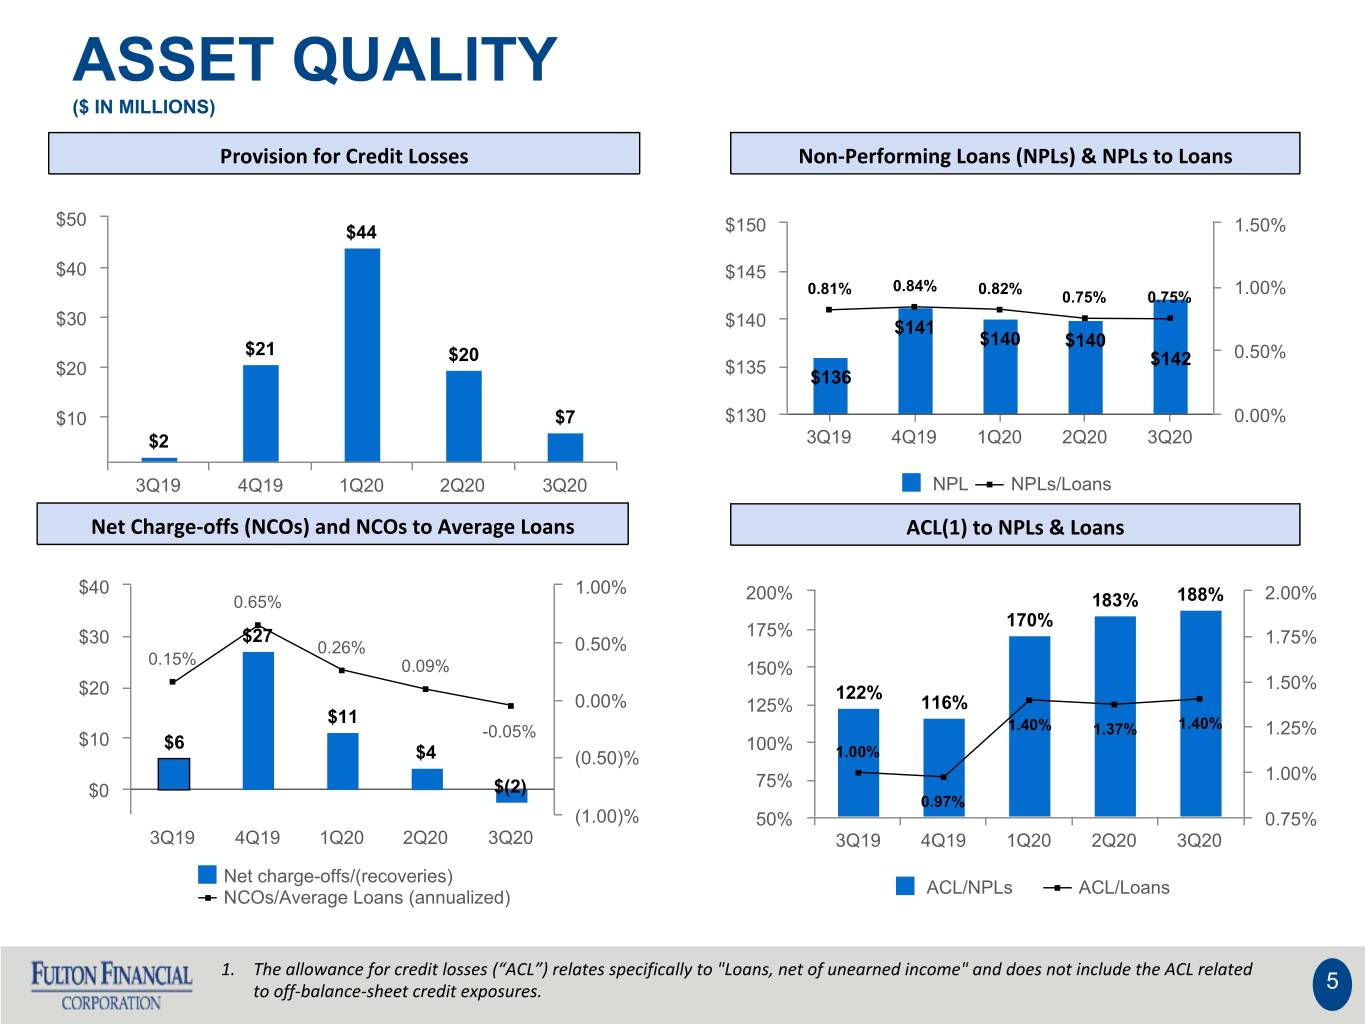
ASSET QUALITY ($ IN MILLIONS) Provision for Credit Losses Non-Performing Loans (NPLs) & NPLs to Loans $50 $44 $150 1.50% $40 $145 0.81% 0.84% 0.82% 1.00% 0.75% 0.75% $30 $140 $141 $140 $140 $21 $20 0.50% $135 $142 $20 $136 $10 $7 $130 0.00% 3Q19 4Q19 1Q20 2Q20 3Q20 $2 3Q19 4Q19 1Q20 2Q20 3Q20 NPL NPLs/Loans Net Charge-offs (NCOs) and NCOs to Average Loans ACL(1) to NPLs & Loans $40 1.00% 0.65% 200% 183% 188% 2.00% 170% $30 $27 175% 1.75% 0.26% 0.50% 0.15% 0.09% 150% 1.50% $20 122% 0.00% 125% 116% $11 -0.05% 1.40% 1.37% 1.40% 1.25% $10 $6 100% $4 (0.50)% 1.00% 1.00% $(2) 75% $0 0.97% (1.00)% 50% 0.75% 3Q19 4Q19 1Q20 2Q20 3Q20 3Q19 4Q19 1Q20 2Q20 3Q20 Net charge-offs/(recoveries) ACL/NPLs ACL/Loans NCOs/Average Loans (annualized) 1. The allowance for credit losses (“ACL”) relates specifically to "Loans, net of unearned income" and does not include the ACL related to off-balance-sheet credit exposures. 5
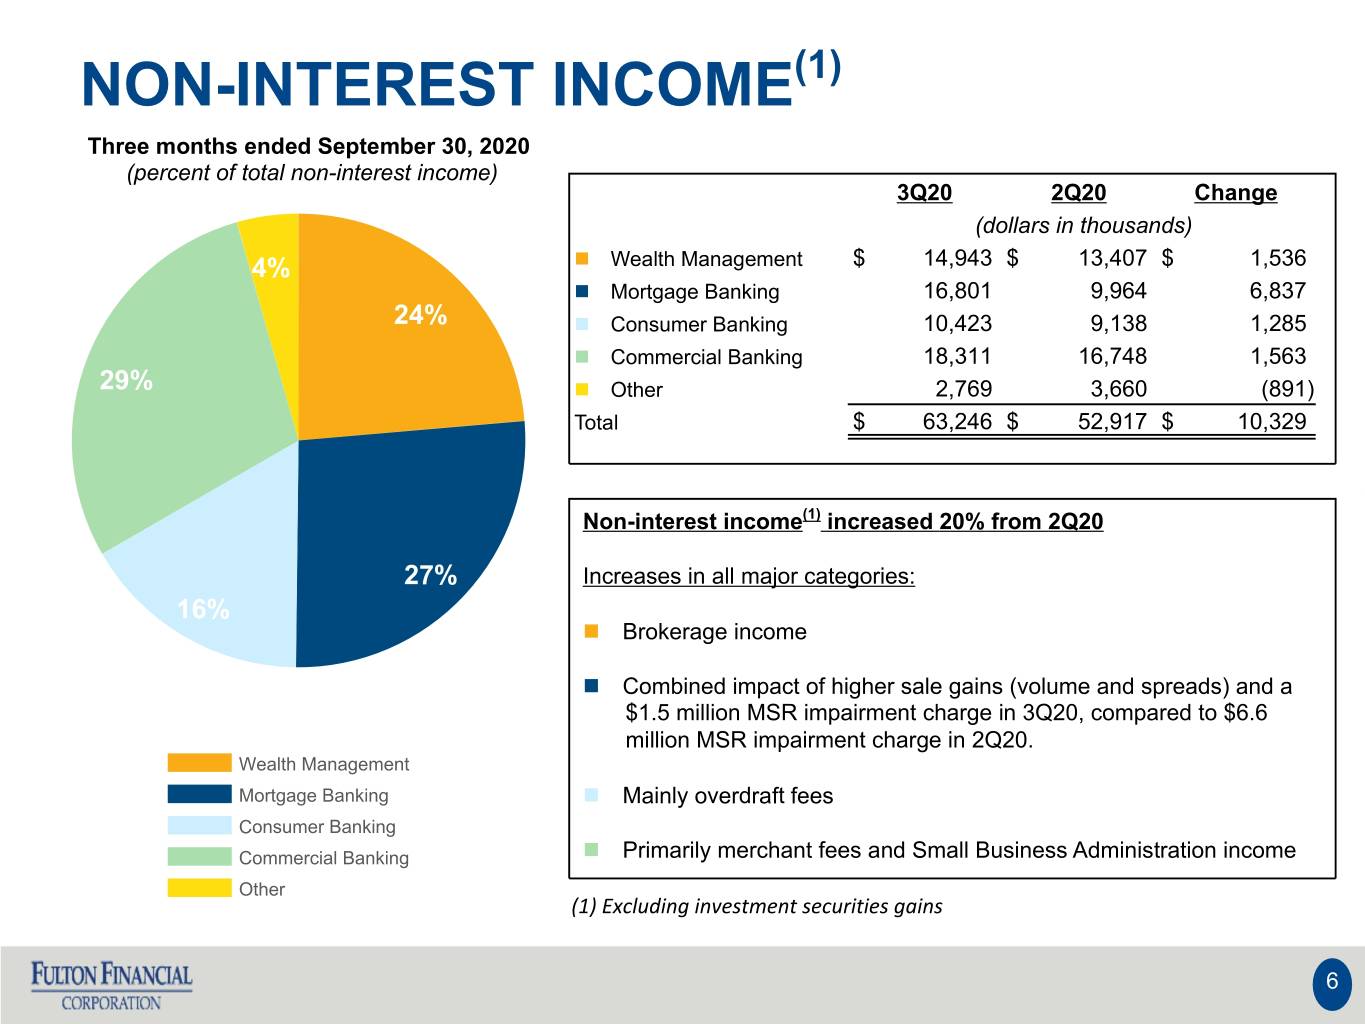
NON-INTEREST INCOME(1) Three months ended September 30, 2020 (percent of total non-interest income) 3Q20 2Q20 Change (dollars in thousands) n Wealth Management $ 14,943 $ 13,407 $ 1,536 4% n Mortgage Banking 16,801 9,964 6,837 24% n Consumer Banking 10,423 9,138 1,285 n Commercial Banking 18,311 16,748 1,563 29% n Other 2,769 3,660 (891) Total $ 63,246 $ 52,917 $ 10,329 Non-interest income(1) increased 20% from 2Q20 27% Increases in all major categories: 16% n Brokerage income n Combined impact of higher sale gains (volume and spreads) and a $1.5 million MSR impairment charge in 3Q20, compared to $6.6 million MSR impairment charge in 2Q20. Wealth Management Mortgage Banking n Mainly overdraft fees Consumer Banking Commercial Banking n Primarily merchant fees and Small Business Administration income Other (1) Excluding investment securities gains 6
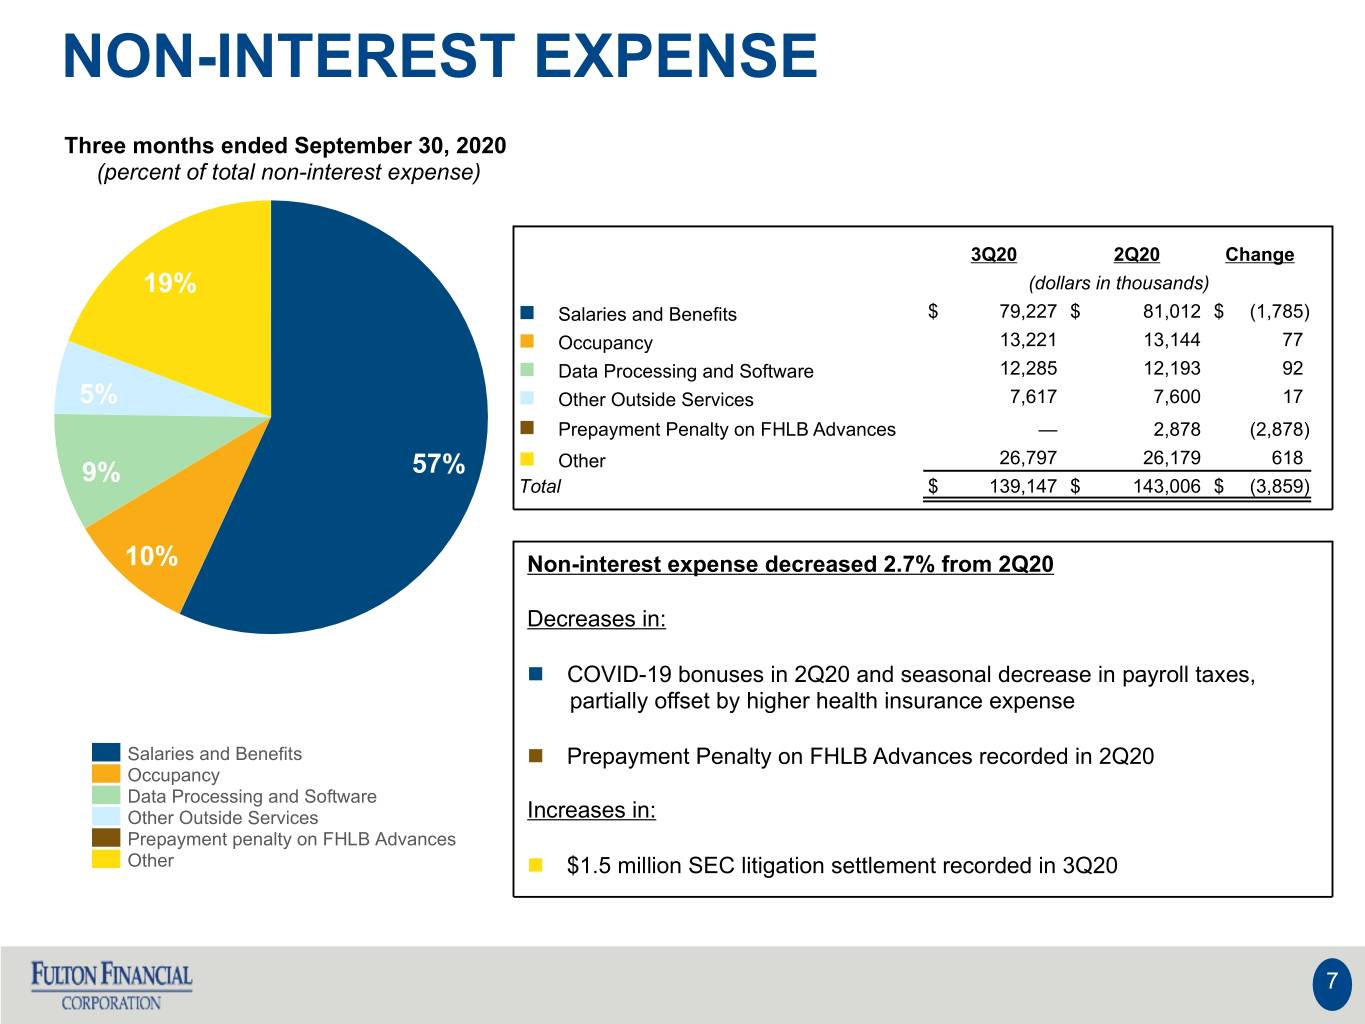
NON-INTEREST EXPENSE Three months ended September 30, 2020 (percent of total non-interest expense) 3Q20 2Q20 Change 19% (dollars in thousands) n Salaries and Benefits $ 79,227 $ 81,012 $ (1,785) n Occupancy 13,221 13,144 77 n Data Processing and Software 12,285 12,193 92 5% n Other Outside Services 7,617 7,600 17 n Prepayment Penalty on FHLB Advances — 2,878 (2,878) 57% n Other 26,797 26,179 618 9% Total $ 139,147 $ 143,006 $ (3,859) 10% Non-interest expense decreased 2.7% from 2Q20 Decreases in: n COVID-19 bonuses in 2Q20 and seasonal decrease in payroll taxes, partially offset by higher health insurance expense Salaries and Benefits n Prepayment Penalty on FHLB Advances recorded in 2Q20 Occupancy Data Processing and Software Other Outside Services Increases in: Prepayment penalty on FHLB Advances Other n $1.5 million SEC litigation settlement recorded in 3Q20 7

COST SAVING INITIATIVES Comprehensive review of expenses undertaken over the past 4 months resulting in the following cost savings initiatives: Anticipated Pre-Tax Charges $20.0 • Previously disclosed 21 financial centers expected Projected to be closed and consolidated in January 2021 $16-$17 • Further cost savings initiatives planned related to $15.0 delivery systems, reallocation of management responsibilities and flattening of reporting structures, vendor contracts and streamlining of other functions $10.0 • Including the 21 financial center closures and consolidation announced on October 1, 2020, initiatives expected to result in annualized pre-tax $5.0 Projected savings of $25 million to be fully-realized in 2Q21 Actual $0-$1 $0.8 • A portion of the savings to be reinvested to accelerate digital transformation $— 3Q20 4Q20 1Q21 dollars in millions • Anticipate aggregate pre-tax charges of $17 to $19 million to be recorded, which are expected to be recovered through non-interest expense reductions within approximately 8 months 8
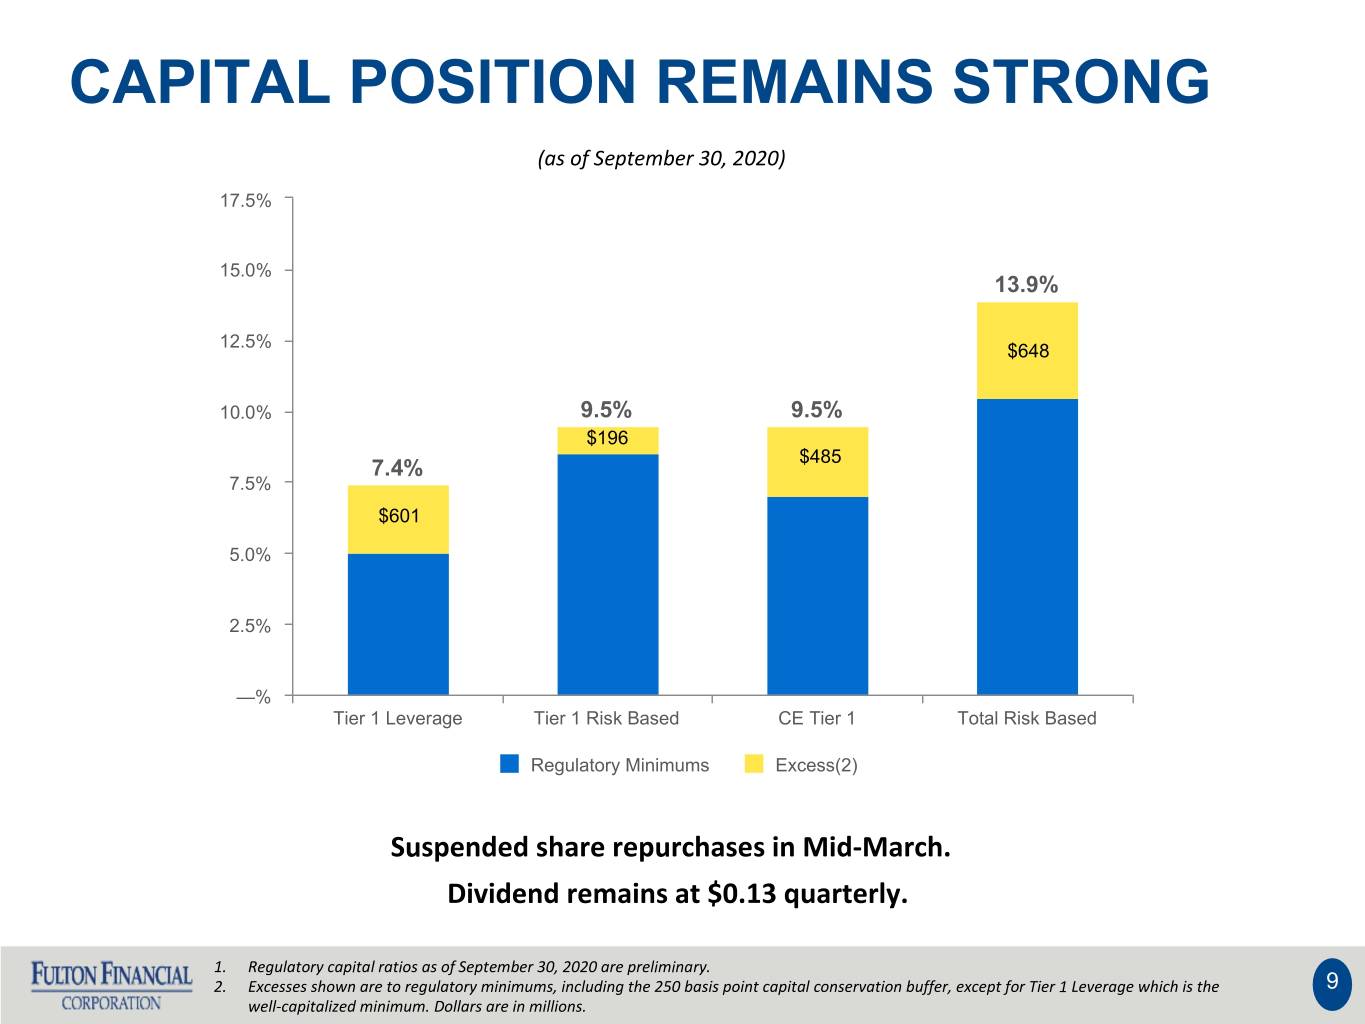
CAPITAL POSITION REMAINS STRONG (as of September 30, 2020) 17.5% 15.0% 13.9% 12.5% $648 10.0% 9.5% 9.5% $196 $485 7.4% 7.5% $601 5.0% 2.5% —% Tier 1 Leverage Tier 1 Risk Based CE Tier 1 Total Risk Based Regulatory Minimums Excess(2) Suspended share repurchases in Mid-March. Dividend remains at $0.13 quarterly. 1. Regulatory capital ratios as of September 30, 2020 are preliminary. 2. Excesses shown are to regulatory minimums, including the 250 basis point capital conservation buffer, except for Tier 1 Leverage which is the 9 well-capitalized minimum. Dollars are in millions.
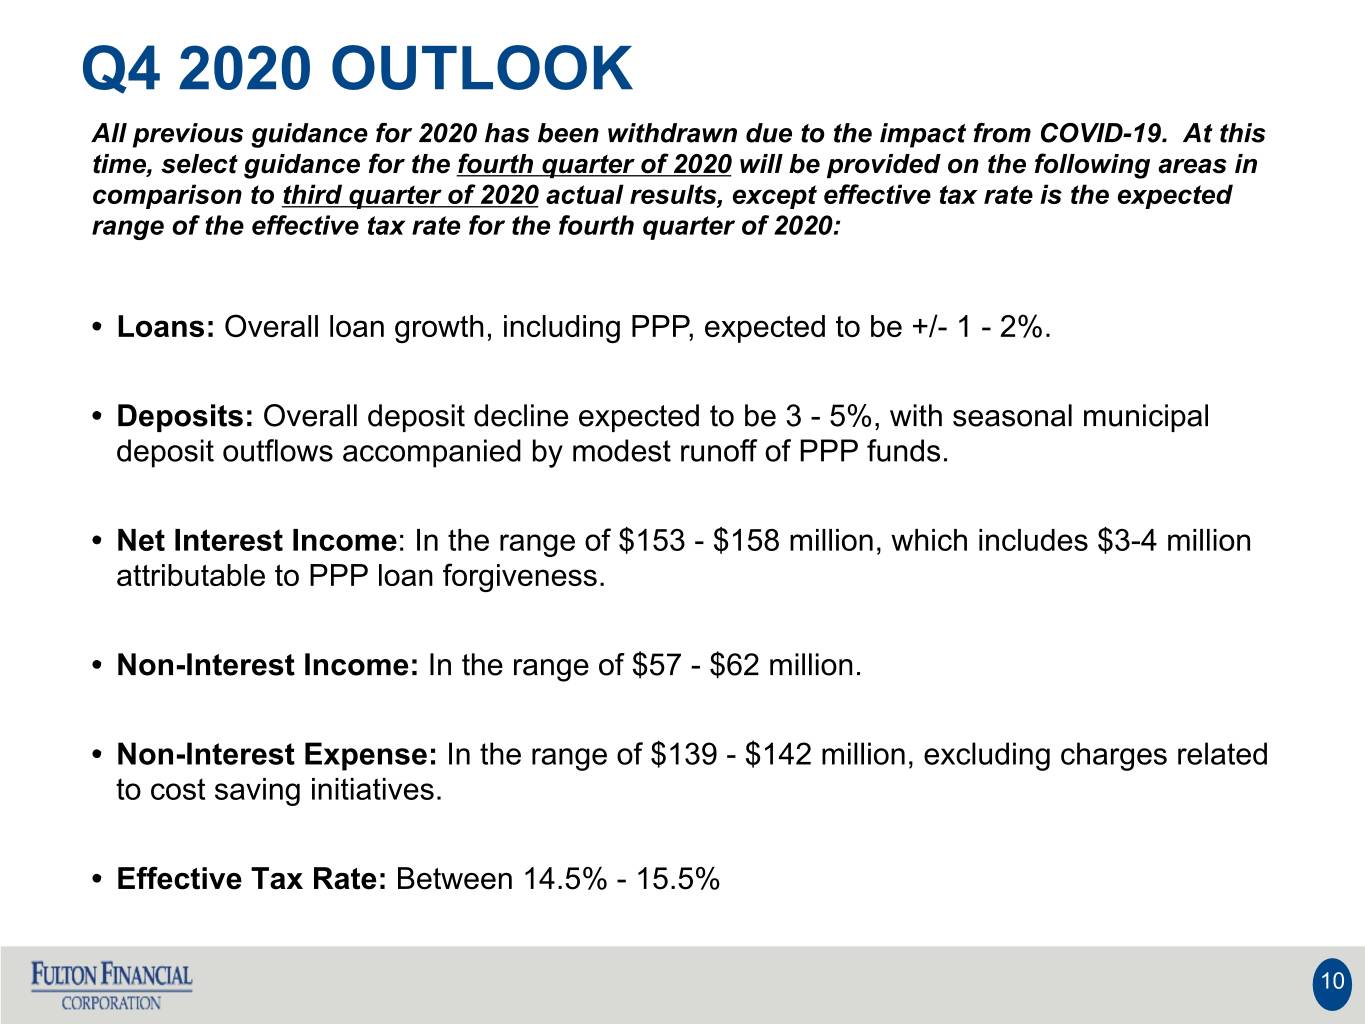
Q4 2020 OUTLOOK All previous guidance for 2020 has been withdrawn due to the impact from COVID-19. At this time, select guidance for the fourth quarter of 2020 will be provided on the following areas in comparison to third quarter of 2020 actual results, except effective tax rate is the expected range of the effective tax rate for the fourth quarter of 2020: • Loans: Overall loan growth, including PPP, expected to be +/- 1 - 2%. • Deposits: Overall deposit decline expected to be 3 - 5%, with seasonal municipal deposit outflows accompanied by modest runoff of PPP funds. • Net Interest Income: In the range of $153 - $158 million, which includes $3-4 million attributable to PPP loan forgiveness. • Non-Interest Income: In the range of $57 - $62 million. • Non-Interest Expense: In the range of $139 - $142 million, excluding charges related to cost saving initiatives. • Effective Tax Rate: Between 14.5% - 15.5% 10
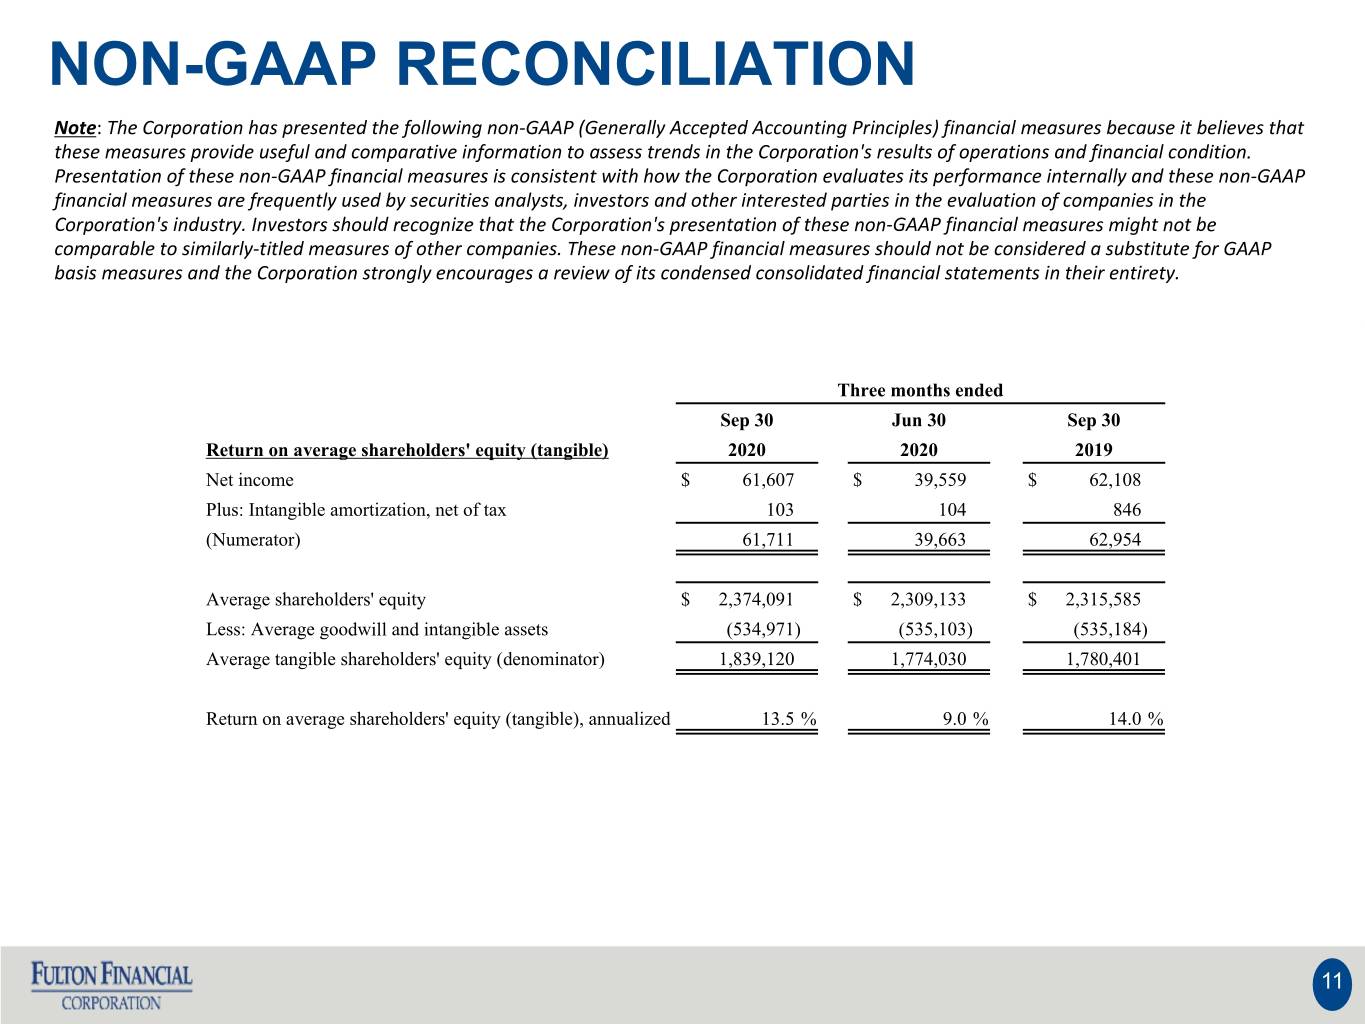
NON-GAAP RECONCILIATION Note: The Corporation has presented the following non-GAAP (Generally Accepted Accounting Principles) financial measures because it believes that these measures provide useful and comparative information to assess trends in the Corporation's results of operations and financial condition. Presentation of these non-GAAP financial measures is consistent with how the Corporation evaluates its performance internally and these non-GAAP financial measures are frequently used by securities analysts, investors and other interested parties in the evaluation of companies in the Corporation's industry. Investors should recognize that the Corporation's presentation of these non-GAAP financial measures might not be comparable to similarly-titled measures of other companies. These non-GAAP financial measures should not be considered a substitute for GAAP basis measures and the Corporation strongly encourages a review of its condensed consolidated financial statements in their entirety. Three months ended Sep 30 Jun 30 Sep 30 Return on average shareholders' equity (tangible) 2020 2020 2019 Net income $ 61,607 $ 39,559 $ 62,108 Plus: Intangible amortization, net of tax 103 104 846 (Numerator) 61,711 39,663 62,954 Average shareholders' equity $ 2,374,091 $ 2,309,133 $ 2,315,585 Less: Average goodwill and intangible assets (534,971) (535,103) (535,184) Average tangible shareholders' equity (denominator) 1,839,120 1,774,030 1,780,401 Return on average shareholders' equity (tangible), annualized 13.5 % 9.0 % 14.0 % 11
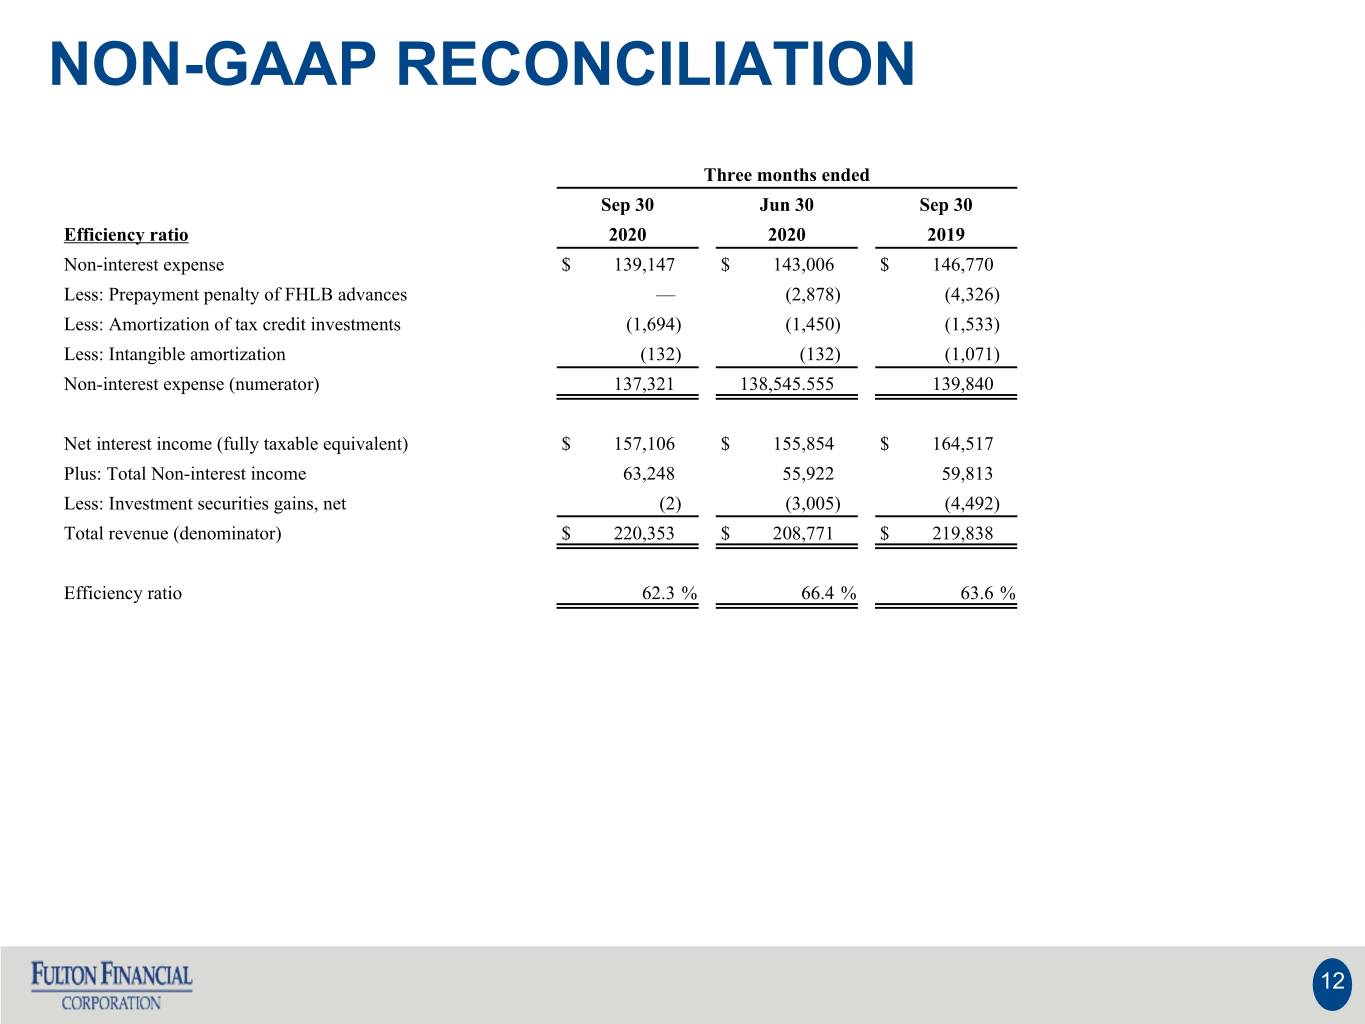
NON-GAAP RECONCILIATION Three months ended Sep 30 Jun 30 Sep 30 Efficiency ratio 2020 2020 2019 Non-interest expense $ 139,147 $ 143,006 $ 146,770 Less: Prepayment penalty of FHLB advances — (2,878) (4,326) Less: Amortization of tax credit investments (1,694) (1,450) (1,533) Less: Intangible amortization (132) (132) (1,071) Non-interest expense (numerator) 137,321 138,545.555 139,840 Net interest income (fully taxable equivalent) $ 157,106 $ 155,854 $ 164,517 Plus: Total Non-interest income 63,248 55,922 59,813 Less: Investment securities gains, net (2) (3,005) (4,492) Total revenue (denominator) $ 220,353 $ 208,771 $ 219,838 Efficiency ratio 62.3 % 66.4 % 63.6 % 12
APPENDIX - CREDIT DISCLOSURES Additional detail on deferrals and select industries (data as of September 30, 2020; all industry classifications based on NAICS codes) 13
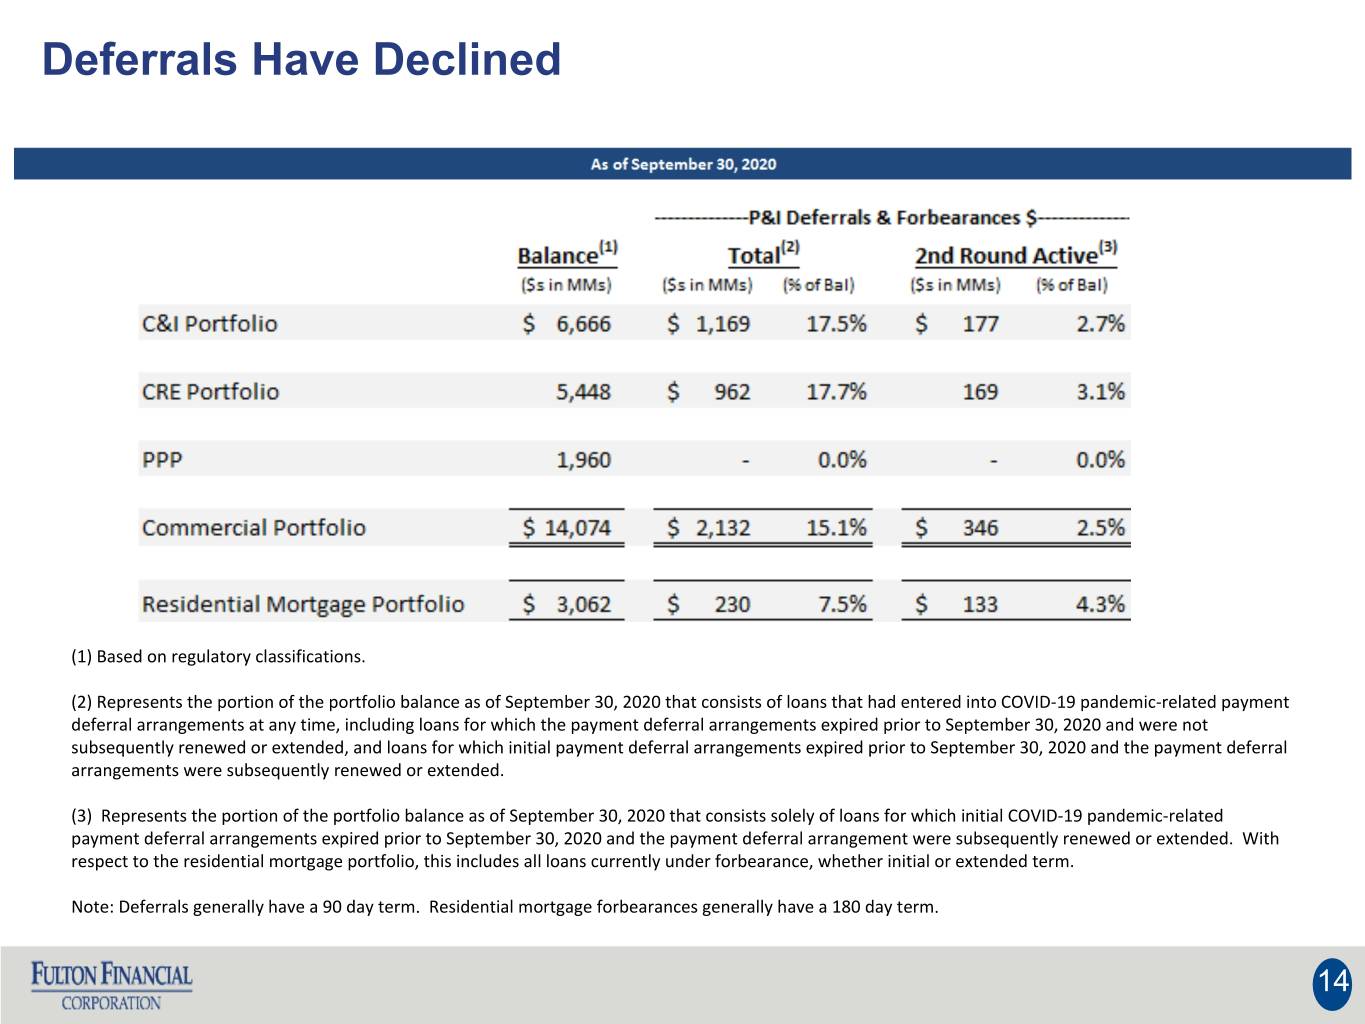
Deferrals Have Declined (1) Based on regulatory classifications. (2) Represents the portion of the portfolio balance as of September 30, 2020 that consists of loans that had entered into COVID-19 pandemic-related payment deferral arrangements at any time, including loans for which the payment deferral arrangements expired prior to September 30, 2020 and were not subsequently renewed or extended, and loans for which initial payment deferral arrangements expired prior to September 30, 2020 and the payment deferral arrangements were subsequently renewed or extended. (3) Represents the portion of the portfolio balance as of September 30, 2020 that consists solely of loans for which initial COVID-19 pandemic-related payment deferral arrangements expired prior to September 30, 2020 and the payment deferral arrangement were subsequently renewed or extended. With respect to the residential mortgage portfolio, this includes all loans currently under forbearance, whether initial or extended term. Note: Deferrals generally have a 90 day term. Residential mortgage forbearances generally have a 180 day term. 14
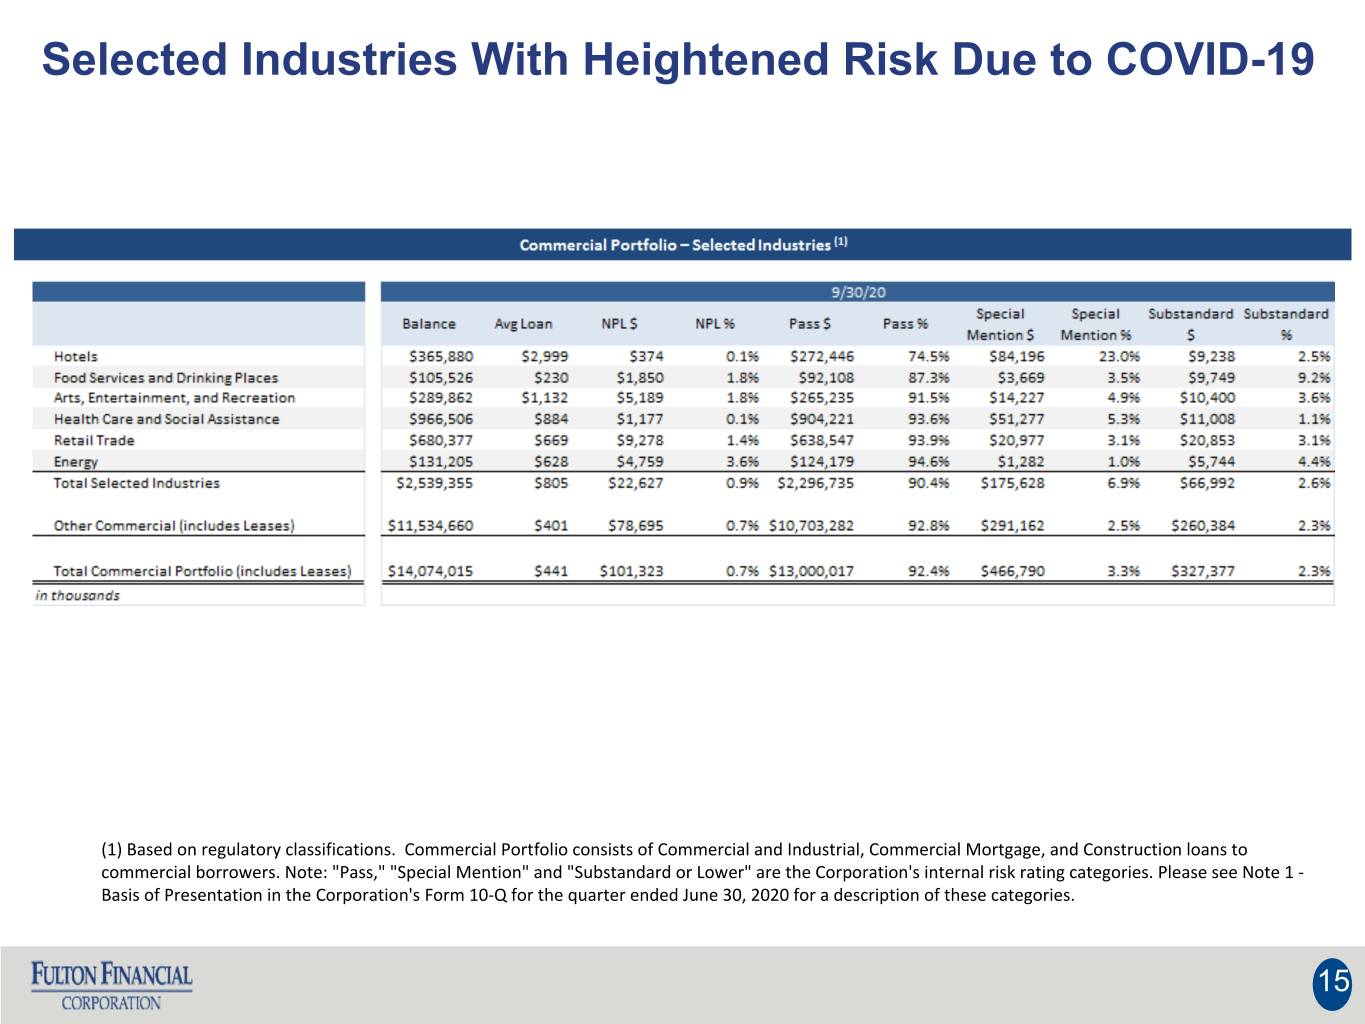
Selected Industries With Heightened Risk Due to COVID-19 (1) Based on regulatory classifications. Commercial Portfolio consists of Commercial and Industrial, Commercial Mortgage, and Construction loans to commercial borrowers. Note: "Pass," "Special Mention" and "Substandard or Lower" are the Corporation's internal risk rating categories. Please see Note 1 - Basis of Presentation in the Corporation's Form 10-Q for the quarter ended June 30, 2020 for a description of these categories. 15
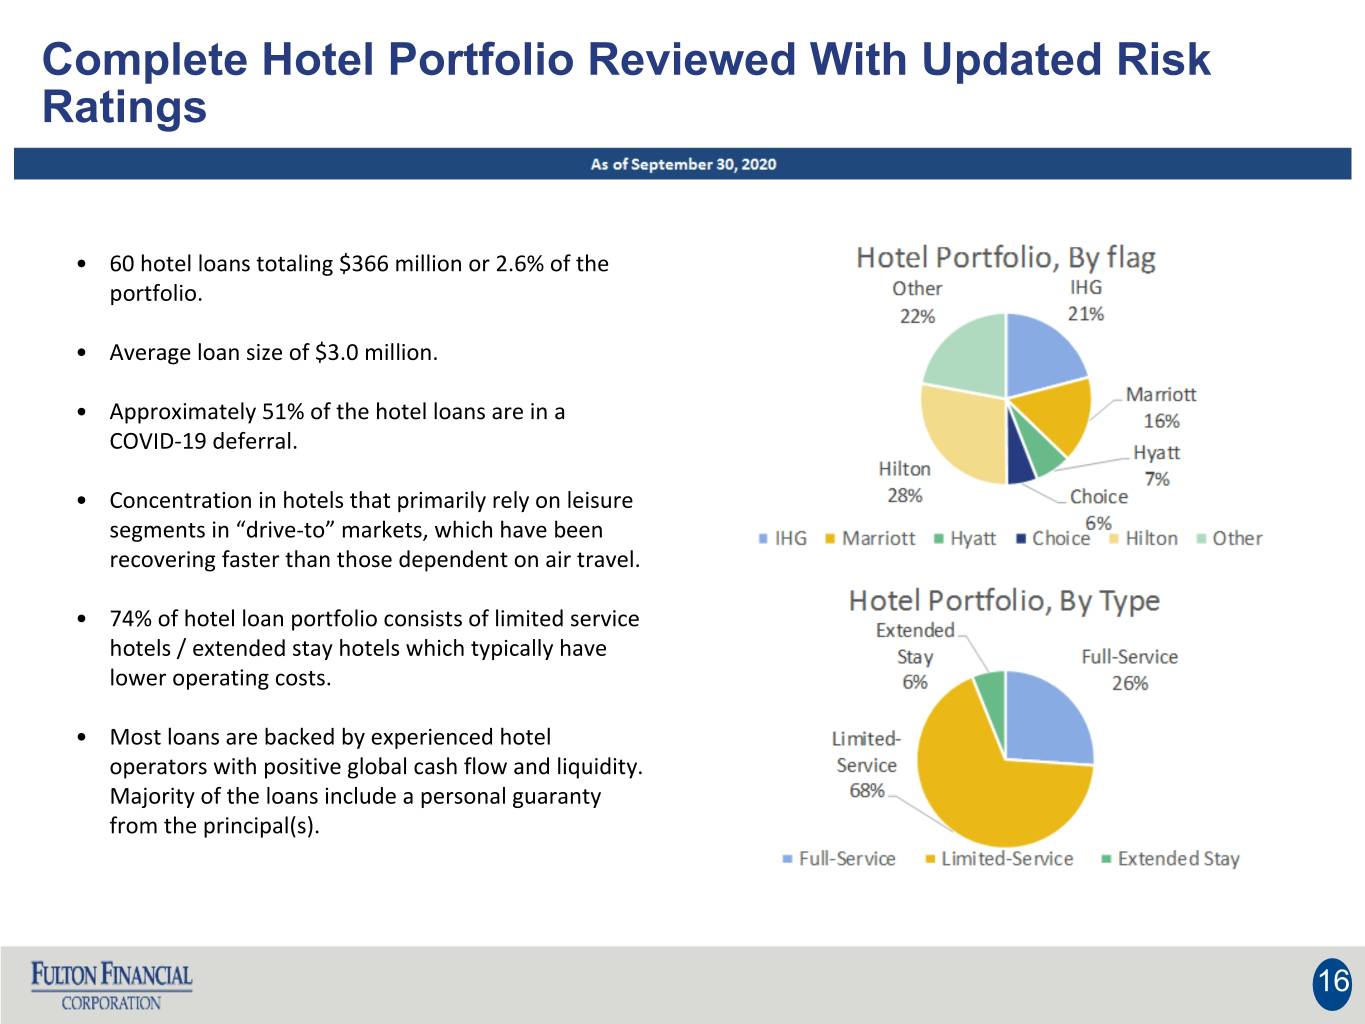
Complete Hotel Portfolio Reviewed With Updated Risk Ratings • 60 hotel loans totaling $366 million or 2.6% of the portfolio. • Average loan size of $3.0 million. • Approximately 51% of the hotel loans are in a COVID-19 deferral. • Concentration in hotels that primarily rely on leisure segments in “drive-to” markets, which have been recovering faster than those dependent on air travel. • 74% of hotel loan portfolio consists of limited service hotels / extended stay hotels which typically have lower operating costs. • Most loans are backed by experienced hotel operators with positive global cash flow and liquidity. Majority of the loans include a personal guaranty from the principal(s). 16
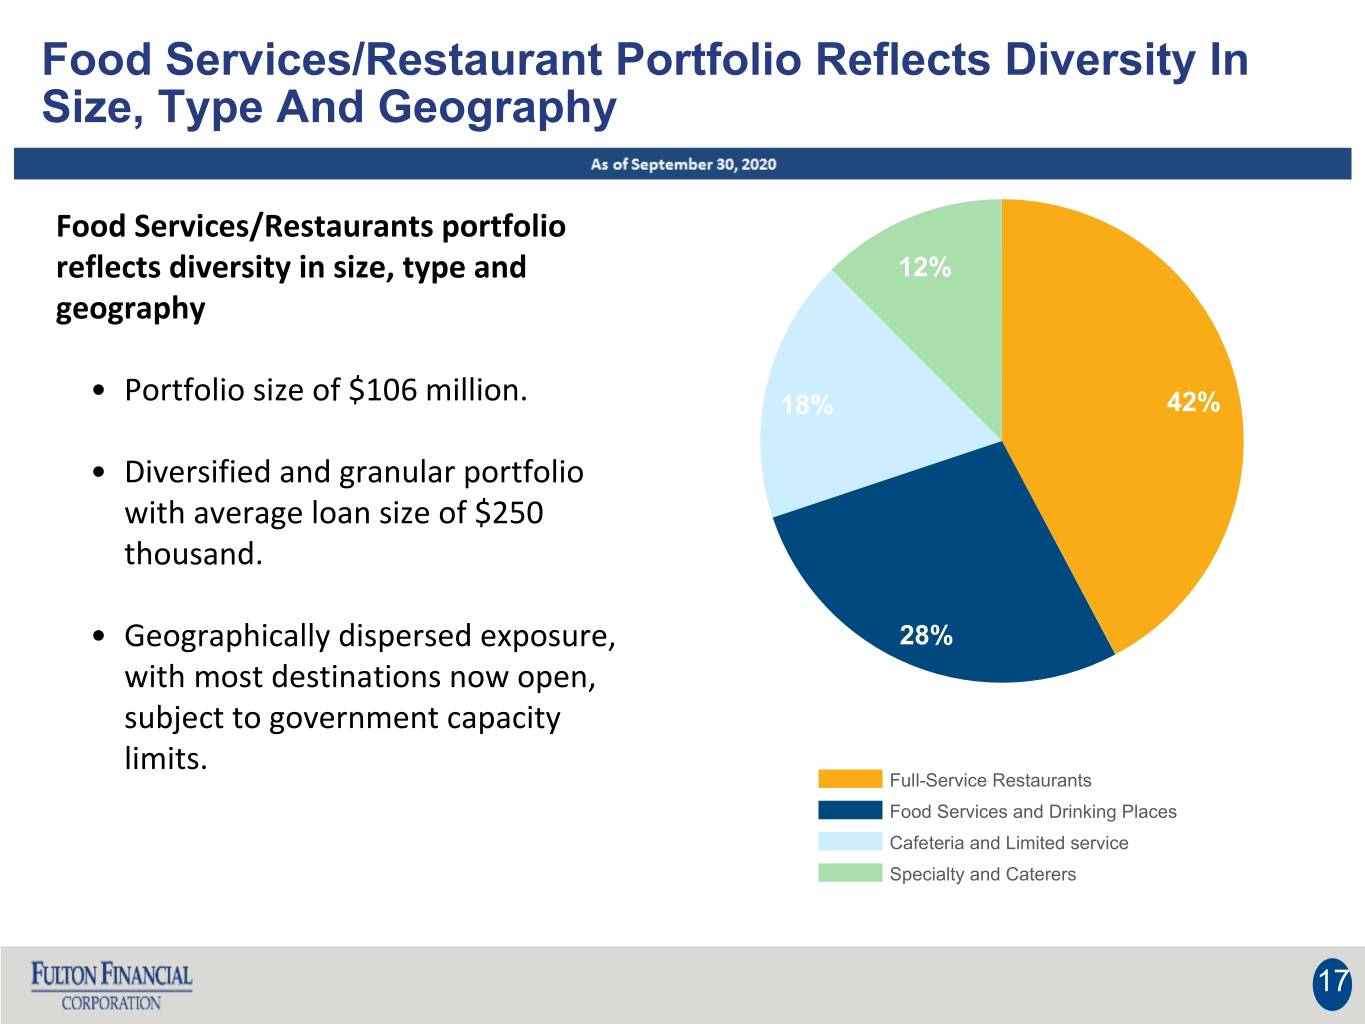
Food Services/Restaurant Portfolio Reflects Diversity In Size, Type And Geography Food Services/Restaurants portfolio reflects diversity in size, type and 12% geography • Portfolio size of $106 million. 18% 42% • Diversified and granular portfolio with average loan size of $250 thousand. • Geographically dispersed exposure, 28% with most destinations now open, subject to government capacity limits. Full-Service Restaurants Food Services and Drinking Places Cafeteria and Limited service Specialty and Caterers 17
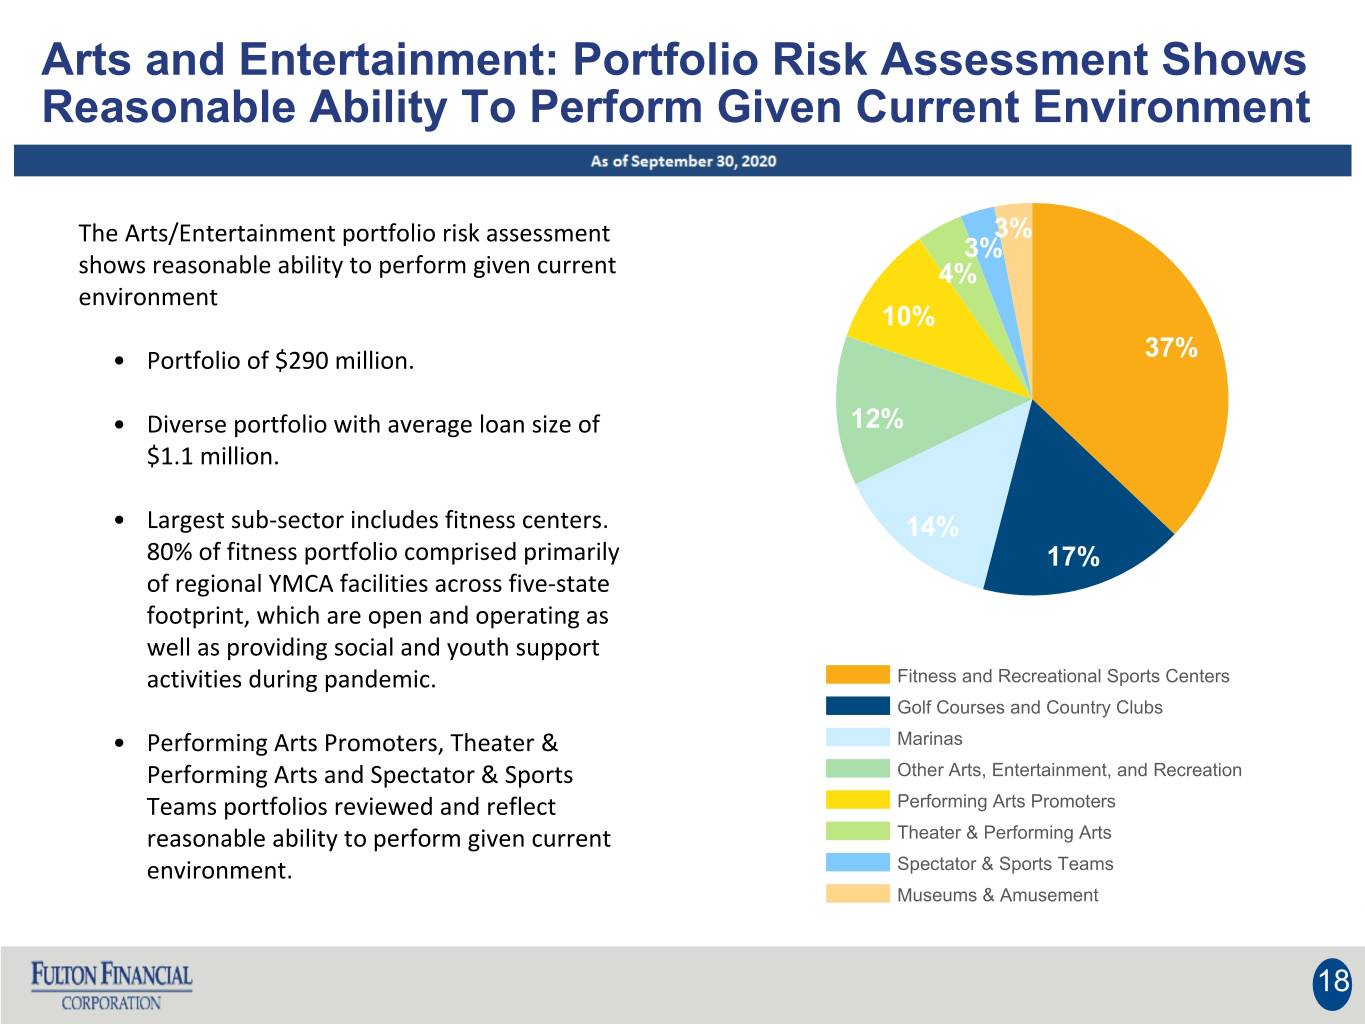
Arts and Entertainment: Portfolio Risk Assessment Shows Reasonable Ability To Perform Given Current Environment The Arts/Entertainment portfolio risk assessment 3% 3% shows reasonable ability to perform given current 4% environment 10% 37% • Portfolio of $290 million. • Diverse portfolio with average loan size of 12% $1.1 million. • Largest sub-sector includes fitness centers. 14% 80% of fitness portfolio comprised primarily 17% of regional YMCA facilities across five-state footprint, which are open and operating as well as providing social and youth support activities during pandemic. Fitness and Recreational Sports Centers Golf Courses and Country Clubs • Performing Arts Promoters, Theater & Marinas Performing Arts and Spectator & Sports Other Arts, Entertainment, and Recreation Teams portfolios reviewed and reflect Performing Arts Promoters reasonable ability to perform given current Theater & Performing Arts environment. Spectator & Sports Teams Museums & Amusement 18
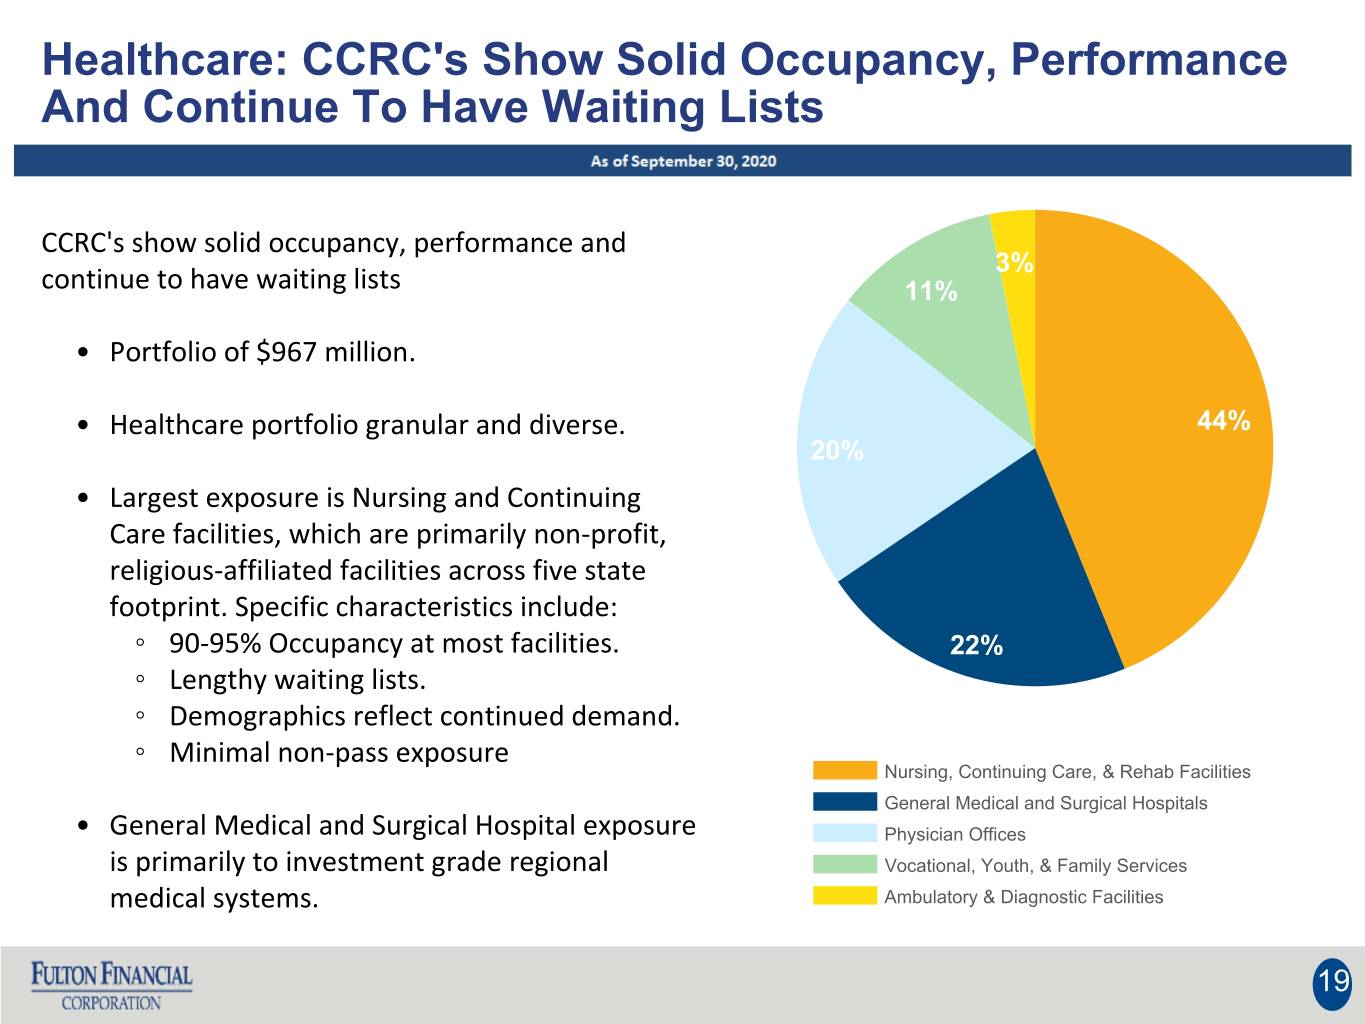
Healthcare: CCRC's Show Solid Occupancy, Performance And Continue To Have Waiting Lists CCRC's show solid occupancy, performance and 3% continue to have waiting lists 11% • Portfolio of $967 million. • Healthcare portfolio granular and diverse. 44% 20% • Largest exposure is Nursing and Continuing Care facilities, which are primarily non-profit, religious-affiliated facilities across five state footprint. Specific characteristics include: ◦ 90-95% Occupancy at most facilities. 22% ◦ Lengthy waiting lists. ◦ Demographics reflect continued demand. Minimal non-pass exposure ◦ Nursing, Continuing Care, & Rehab Facilities General Medical and Surgical Hospitals • General Medical and Surgical Hospital exposure Physician Offices is primarily to investment grade regional Vocational, Youth, & Family Services medical systems. Ambulatory & Diagnostic Facilities 19
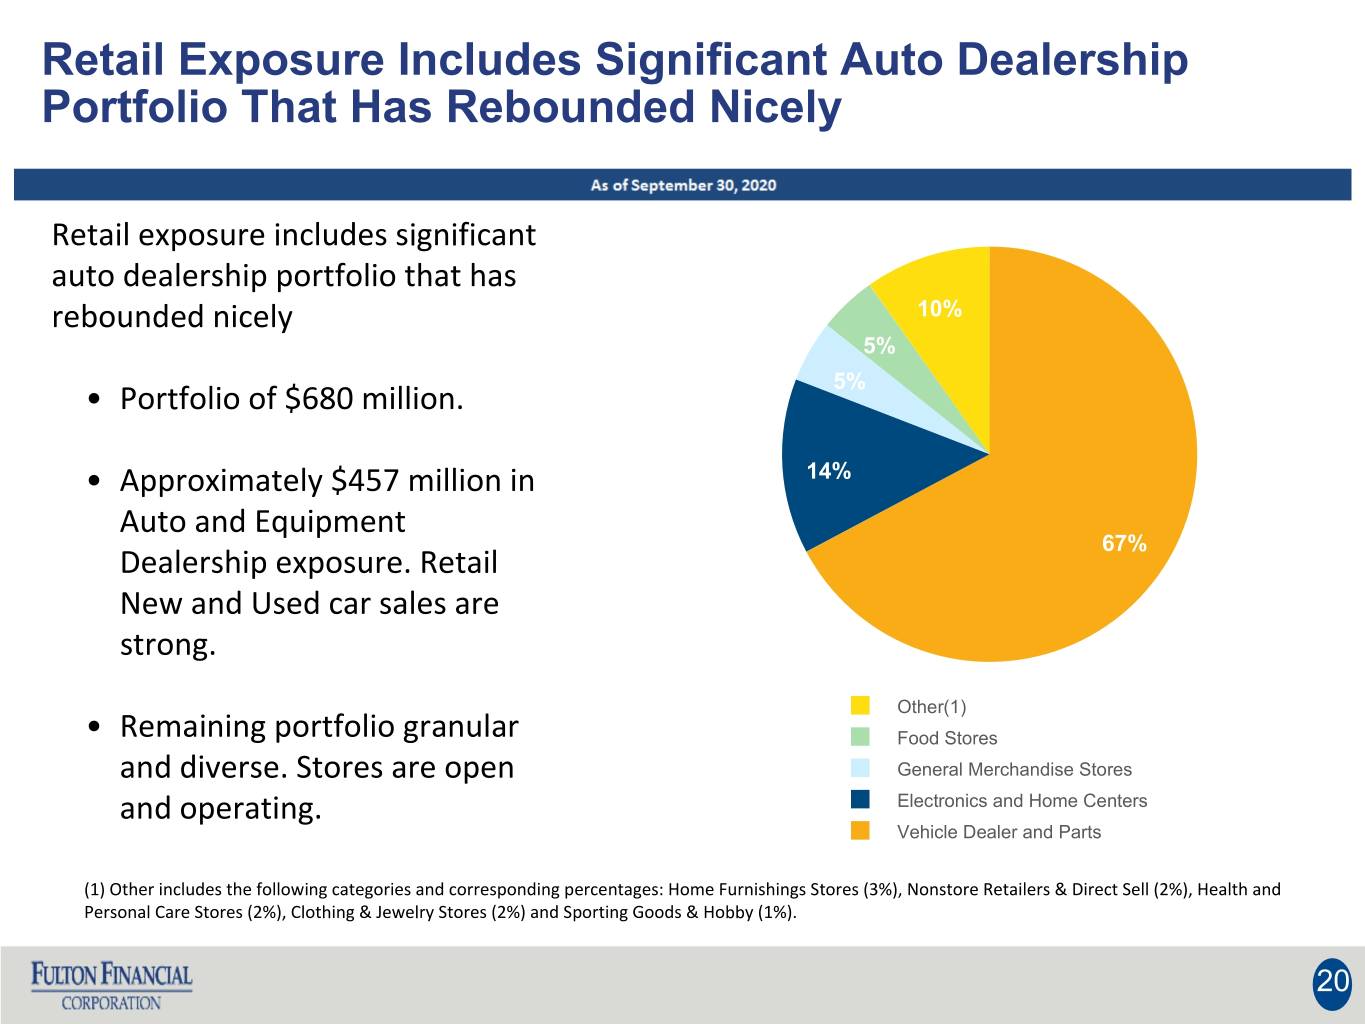
Retail Exposure Includes Significant Auto Dealership Portfolio That Has Rebounded Nicely Retail exposure includes significant auto dealership portfolio that has rebounded nicely 10% 5% 5% • Portfolio of $680 million. • Approximately $457 million in 14% Auto and Equipment 67% Dealership exposure. Retail New and Used car sales are strong. Other(1) • Remaining portfolio granular Food Stores and diverse. Stores are open General Merchandise Stores and operating. Electronics and Home Centers Vehicle Dealer and Parts (1) Other includes the following categories and corresponding percentages: Home Furnishings Stores (3%), Nonstore Retailers & Direct Sell (2%), Health and Personal Care Stores (2%), Clothing & Jewelry Stores (2%) and Sporting Goods & Hobby (1%). 20
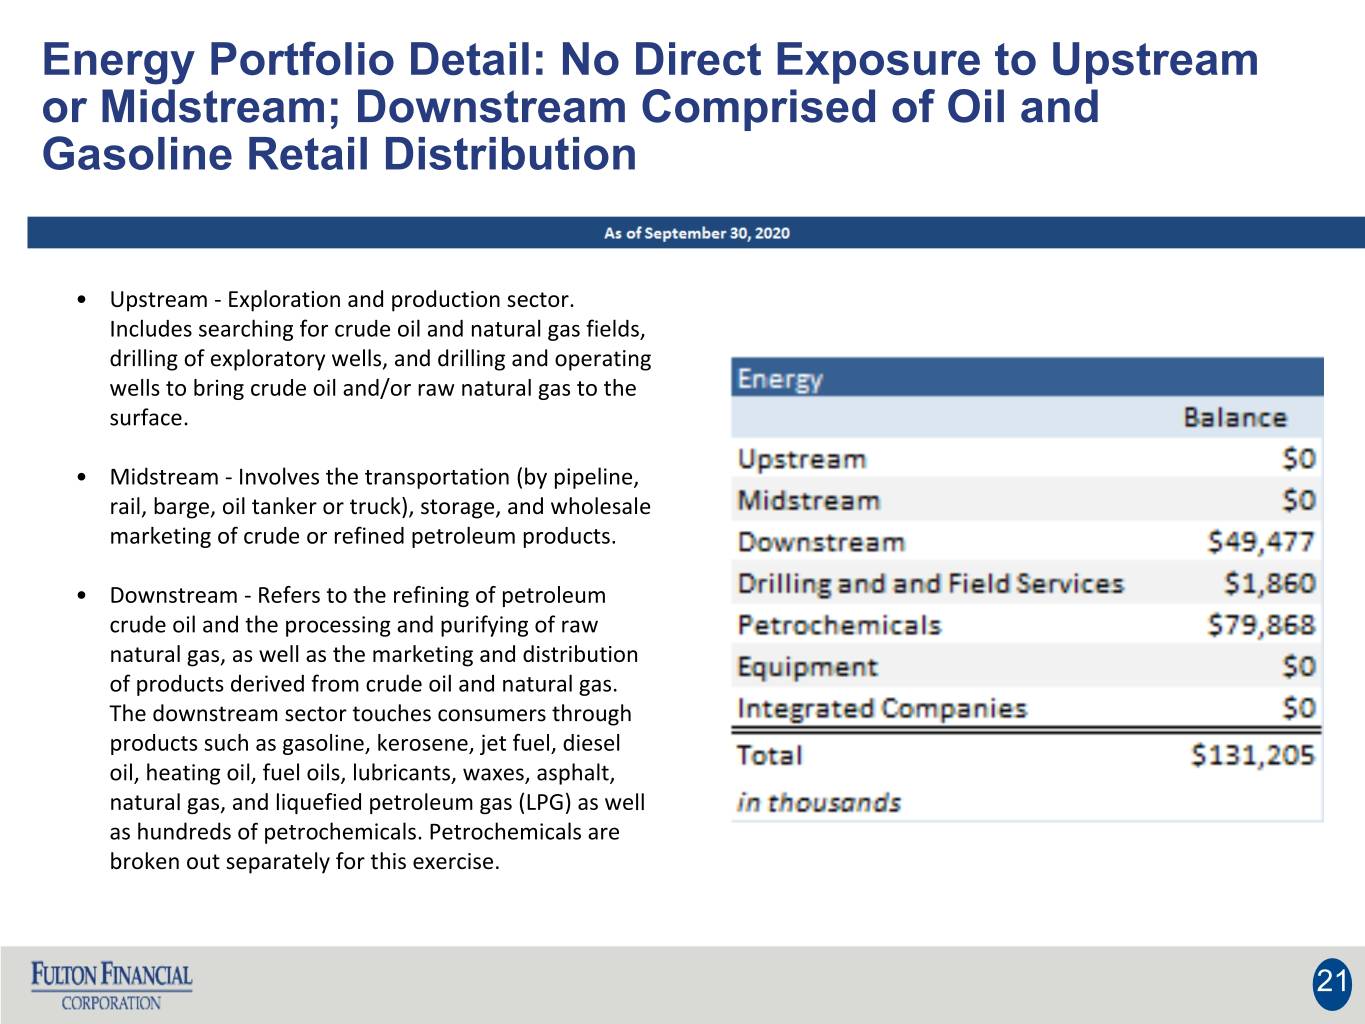
Energy Portfolio Detail: No Direct Exposure to Upstream or Midstream; Downstream Comprised of Oil and Gasoline Retail Distribution • Upstream - Exploration and production sector. Includes searching for crude oil and natural gas fields, drilling of exploratory wells, and drilling and operating wells to bring crude oil and/or raw natural gas to the surface. • Midstream - Involves the transportation (by pipeline, rail, barge, oil tanker or truck), storage, and wholesale marketing of crude or refined petroleum products. • Downstream - Refers to the refining of petroleum crude oil and the processing and purifying of raw natural gas, as well as the marketing and distribution of products derived from crude oil and natural gas. The downstream sector touches consumers through products such as gasoline, kerosene, jet fuel, diesel oil, heating oil, fuel oils, lubricants, waxes, asphalt, natural gas, and liquefied petroleum gas (LPG) as well as hundreds of petrochemicals. Petrochemicals are broken out separately for this exercise. 21