
FULT 8-K
Fulton Financial Corp (FULT)
8-K
2021-01-19
For: 2021-01-19
View Original
Added on
April 12, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of Report (date of earliest event reported)
(Exact name of registrant as specified in its charter)
(State or other jurisdiction of incorporation) | (Commission File Number) | (I.R.S. Employer Identification No.) | ||||||||||||
(Address of Principal Executive Offices) | (Zip Code) | |||||||||||||
(717 ) 291-2411
(Registrant's telephone number, including area code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
Depositary Shares, Each Representing 1/40th Interest in a Share of Fixed Rate Non-Cumulative Perpetual Preferred Stock, Series A | FULTP | The Nasdaq Stock Market, LLC | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.
o
Item 2.02 Results of Operations and Financial Condition.
On January 19, 2021 , Fulton Financial Corporation (the "Corporation") issued a press release (the "Press Release") announcing its results of operations for the fourth quarter and year ended December 31, 2020. A copy of the Press Release and supplementary financial information which accompanied the Press Release, are attached as Exhibit 99.1 to this Current Report and are incorporated herein by reference. The Corporation also posted on its Investor Relations website, www.fult.com, presentation materials the Corporation intends to use during a conference call and webcast to discuss those results on Wednesday, January 20, 2021 at 10:00 a.m. Eastern Time. A copy of the presentation materials is attached as Exhibit 99.2 to this Current Report and is incorporated herein by reference.
The information in the preceding paragraph, as well as Exhibit 99.2 referenced therein, shall not be deemed "filed" for purposes of the Securities Exchange Act of 1934, as amended (the "Exchange Act"), nor shall it be incorporated by reference in any filing under the Securities Act of 1933, as amended (the "Securities Act"). The information included in Exhibit 99.1 shall be considered "filed" for purposes of the Exchange Act and therefore may be incorporated by reference in filings under the Securities Act.
Forward-Looking Statements
This Current Report on Form 8-K, including the Exhibits hereto, may contain forward-looking statements with respect to the Corporation’s financial condition, results of operations and business. Do not unduly rely on forward-looking statements. Forward-looking statements can be identified by the use of words such as "may," "should," "will," "could," "estimates," "predicts," "potential," "continue," "anticipates," "believes," "plans," "expects," "future," "intends," "projects," the negative of these terms and other comparable terminology. These forward-looking statements may include projections of, or guidance on, the Corporation’s future financial performance, expected levels of future expenses, including future credit losses, anticipated growth strategies, descriptions of new business initiatives and anticipated trends in the Corporation’s business or financial results. Management’s "2021 Outlook" contained in Exhibit 99.2 to this Current Report is comprised of forward-looking statements.
Forward-looking statements are neither historical facts, nor assurance of future performance. Instead, they are based on current beliefs, expectations and assumptions regarding the future of the Corporation’s business, future plans and strategies, projections, anticipated events and trends, the economy and other future conditions. Because forward-looking statements relate to the future, they are subject to inherent uncertainties, risks and changes in circumstances that are difficult to predict and many of which are outside of the Corporation’s control, and actual results and financial condition may differ materially from those indicated in the forward-looking statements. Therefore, you should not unduly rely on any of these forward-looking statements. Any forward-looking statement is based only on information currently available and speaks only as of the date when made. The Corporation undertakes no obligation, other than as required by law, to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise.
A discussion of certain risks and uncertainties affecting the Corporation, and some of the factors that could cause the Corporation's actual results to differ materially from those described in the forward-looking statements, can be found in the sections entitled "Risk Factors" and "Management's Discussion and Analysis of Financial Condition and Results of Operations" in the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2019, Quarterly Reports on Form 10-Q for the quarters ended March 31, 2020, June 30, 2020 and September 30, 2020 and other current and periodic reports, which have been or will be filed with the Securities and Exchange Commission and are or will be available in the Investor Relations section of the Corporation's website (www.fult.com) and on the Securities and Exchange Commission's website (www.sec.gov).
Item 9.01 Financial Statements and Exhibits.
(d) Exhibits.
| Exhibit No. | Description | ||||
Press release dated | |||||
Presentation materials to be discussed during the conference call and webcast on January 20, 2021, deemed "furnished" under the Securities Exchange Act of 1934. | |||||
| 104 | Cover page Interactive Data File (the cover page XBRL tags are embedded within the Inline XBRL document) | ||||
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
Date: | FULTON FINANCIAL CORPORATION | ||||
| By: /s/ Mark R. McCollom | |||||
| Mark R. McCollom | |||||
| Senior Executive Vice President and | |||||
| Chief Financial Officer | |||||
Exhibit 99.1
FULTON FINANCIAL
CORPORATION
FOR IMMEDIATE RELEASE
Media Contact: Laura Wakeley (717) 291-2616
Investor Contact: Matt Jozwiak (717) 327-2657
Fulton Financial Announces Fourth Quarter and 2020 Results
2020 Key Accomplishments
•Successful implementation of COVID-19 safety response protocols to protect customers and team members
•Rapid implementation of remote work program
•PPP/Main Street Lending programs in place to aid customers
•Residential mortgage business at historic highs
•Implementation of strategic operating expense reduction initiatives
•Successful access to the capital markets with subordinated debt and preferred stock offerings
(January 19, 2021) – Lancaster, PA – Fulton Financial Corporation (NASDAQ:FULT) (“Fulton” or the “Corporation”) reported net income available to common shareholders of $49 million, or $0.30 per diluted share, for the fourth quarter of 2020 and $176 million, or $1.08 per diluted share, for the year ended December 31, 2020.
“We were pleased with our company’s achievements for the 4th quarter and for the year as a whole, given the challenges presented by the lingering presence of COVID-19,” said E. Philip Wenger, Chairman and CEO of Fulton Financial Corporation. “The low interest rate environment continued to put pressure on our margin, but even in this challenging environment, we had stable asset quality, were able to provide Paycheck Protection Program and Main Street loans to our customers, helped our mortgage business grow to historic highs, and saw wealth management business performance that was beyond our expectations.”
Net Interest Income and Balance Sheet
Net interest income for the fourth quarter of 2020 was $162 million, $7.5 million higher than the third quarter of 2020. Net interest margin for the fourth quarter of 2020 increased 5 basis points, to 2.75%, from 2.70% in the third quarter of 2020. The increases in net interest income and net interest margin were primarily due to the forgiveness of Paycheck Protection Program ("PPP") loans and the acceleration of the recognition of related fee income as well as growth in average loans and investments securities during the quarter. For the year ended December 31, 2020, net interest income was $629 million, a decrease of $19 million in comparison to the year ended December 31, 2019, as the 90 basis
point decline in yields on average interest-earning assets outpaced the 42 basis point decline in the cost of funds. The net interest margin in 2020 was 2.86% compared 3.36% in 2019.
Total average assets for the fourth quarter of 2020 were $25.7 billion, an increase of $580 million from the third quarter of 2020. Average loans, net of unearned income, were $19.0 billion, relatively unchanged compared to the third quarter of 2020. Beginning in the second quarter of 2020, average loans included loans originated under PPP. PPP loans had an average balance of $1.8 billion for the fourth quarter of 2020, compared to $2.0 billion for the third quarter of 2020.
Average loans and yields, by type, for the fourth quarter of 2020 in comparison to the third quarter of 2020 are summarized in the following table:
| Three months ended | |||||||||||||||||||||||||||||||||||
| December 31, 2020 | September 30, 2020 | Growth | |||||||||||||||||||||||||||||||||
| Balance | Yield (1) | Balance | Yield (1) | $ | % | ||||||||||||||||||||||||||||||
| (dollars in thousands) | |||||||||||||||||||||||||||||||||||
| Average Loans, net of unearned income, by type: | |||||||||||||||||||||||||||||||||||
| Real estate - commercial mortgage | $ | 7,101,363 | 3.21 | % | $ | 6,986,528 | 3.27 | % | $ | 114,835 | 1.6 | % | |||||||||||||||||||||||
| Commercial and industrial(2) | 5,855,305 | 2.57 | % | 5,983,872 | 2.53 | % | (128,567) | (2.1) | % | ||||||||||||||||||||||||||
| Real estate - residential mortgage | 3,087,529 | 3.65 | % | 2,975,516 | 3.73 | % | 112,013 | 3.8 | % | ||||||||||||||||||||||||||
| Real estate - home equity | 1,212,113 | 3.91 | % | 1,237,602 | 3.87 | % | (25,489) | (2.1) | % | ||||||||||||||||||||||||||
| Real estate - construction | 1,009,284 | 3.11 | % | 981,589 | 3.84 | % | 27,695 | 2.8 | % | ||||||||||||||||||||||||||
| Consumer | 468,678 | 4.07 | % | 464,851 | 4.07 | % | 3,827 | 0.8 | % | ||||||||||||||||||||||||||
| Equipment lease financing | 279,059 | 3.98 | % | 279,217 | 3.96 | % | (158) | (0.1) | % | ||||||||||||||||||||||||||
| Other(3) | (18,817) | N/A | (28,656) | N/A | 9,839 | (34.3) | % | ||||||||||||||||||||||||||||
| Total Average Loans, net of unearned income | $ | 18,994,514 | 3.45 | % | $ | 18,880,519 | 3.38 | % | $ | 113,995 | 0.6 | % | |||||||||||||||||||||||
| (1) Presented on a fully-taxable equivalent basis using a 21% Federal tax rate and statutory interest expense disallowances. | |||||||||||||||||||||||||||||||||||
| (2) Includes average PPP loans of $1.8 billion and $2.0 billion for the three months ended December 31, 2020 and September 30, 2020, respectively. | |||||||||||||||||||||||||||||||||||
| (3) Consists of overdrafts and net origination fees and costs. | |||||||||||||||||||||||||||||||||||
Total average assets for the year ended December 31, 2020 were $24.3 billion, an increase of $3.1 billion from 2019. Average loans, net of unearned income, were $18.3 billion, an increase of $1.8 billion from 2019. Included in average loans are loans originated under the PPP, which had an average balance of $1.3 billion for the year ended December 31, 2020. The remaining increase was mainly in residential mortgage loans.
Total average liabilities increased $409 million from the third quarter of 2020 driven by increases in demand and savings deposits. Average deposits and interest rates, by type, for the fourth quarter of 2020 in comparison to the third quarter of 2020 are summarized in the following table:
| Three months ended | |||||||||||||||||||||||||||||||||||
| December 31, 2020 | September 30, 2020 | Growth | |||||||||||||||||||||||||||||||||
| Balance | Rate | Balance | Rate | $ | % | ||||||||||||||||||||||||||||||
| (dollars in thousands) | |||||||||||||||||||||||||||||||||||
| Average Deposits, by type: | |||||||||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 6,477,228 | — | $ | 6,270,683 | — | $ | 206,545 | 3.3 | % | |||||||||||||||||||||||||
| Interest-bearing demand | 5,762,150 | 0.10 | % | 5,591,548 | 0.14 | % | 170,602 | 3.1 | % | ||||||||||||||||||||||||||
| Savings | 5,905,137 | 0.13 | % | 5,716,050 | 0.16 | % | 189,087 | 3.3 | % | ||||||||||||||||||||||||||
| Total average demand and savings | 18,144,515 | 0.07 | % | 17,578,281 | 0.10 | % | 566,234 | 3.2 | % | ||||||||||||||||||||||||||
| Brokered | 340,451 | 0.53 | % | 314,721 | 0.56 | % | 25,730 | 8.2 | % | ||||||||||||||||||||||||||
| Time | 2,306,556 | 1.39 | % | 2,495,445 | 1.58 | % | (188,889) | (7.6) | % | ||||||||||||||||||||||||||
| Total Average Deposits | $ | 20,791,522 | 0.23 | % | $ | 20,388,447 | 0.29 | % | $ | 403,075 | 2.0 | % | |||||||||||||||||||||||
Total average liabilities for the year ended December 31, 2020 increased $3 billion from 2019 driven by increases in demand and savings deposits.
Asset Quality
The provision for credit losses was $6 million, $7 million and $21 million for the fourth quarter of 2020, third quarter of 2020 and fourth quarter of 2019, respectively. For the year ended December 31, 2020, the provision for credit losses was $77 million compared to $33 million in 2019. Effective January 1, 2020 Fulton adopted ASU 2016-13, referred to as the current expected credit loss model. As such, the provision for credit losses in 2020 reflects current expected credit losses based on forecasted economic and other assumptions, including the estimated impacts of COVID-19, over the remaining expected lives of financial assets and off-balance-sheet credit exposures, whereas the 2019 methodology applied an incurred loss model.
Non-performing assets were $151 million, or 0.58% of total assets, at December 31, 2020, compared to $147 million, or 0.57% of total assets, at September 30, 2020.
Annualized net recoveries for the quarter ended December 31, 2020 were 0.07% of total average loans, compared to annualized net recoveries of 0.05% and annualized net charge-offs of 0.65% for the quarters ended September 30, 2020 and December 31, 2019, respectively. Net charge-offs for 2020 were 0.05% of total average loans compared to 0.22% in 2019.
Non-interest Income
Non-interest income in the fourth quarter of 2020, excluding investment securities gains, was $56 million, a decrease of $8 million, or 12%, from the third quarter of 2020, primarily driven by decreases $7 million in mortgage banking income and $1 million in capital markets revenue. The decrease in mortgage banking income was mainly due to seasonal decreases in the volume of loans sold.
Compared to the fourth quarter of 2019, non-interest income, excluding investment securities gains, in the fourth quarter of 2020 was relatively unchanged as increases in mortgage banking and wealth management income offset decreases in a number of other categories.
For the year ended December 31, 2020, non-interest income, excluding investment securities gains, was $226 million, an increase of $15 million, or 7%, from 2019. The increase was driven by a $19 million increase in mortgage banking income, with mortgage sale gains increasing $36 million due to higher volumes and spreads, partially offset by a $10.5 million of mortgage servicing rights asset impairment charges for the year and higher mortgage servicing rights asset amortization, due to higher refinance activity. In addition, wealth management and capital markets revenue each increased by $3 million. Partially offsetting these increases were decreases of $5 million in overdraft fees in consumer banking and $4 million in other service charges on deposits in other commercial banking.
During both 2020 and 2019, Fulton completed balance sheet restructurings involving sales of investment securities and corresponding prepayments of FHLB advances. As a result of these transactions, $3 million and $5 million of investment securities gains were realized during 2020 and 2019, respectively, and prepayment penalties of $3 million and $4 million were incurred during 2020 and 2019, respectively.
Non-interest Expense
Non-interest expense was $155 million in the fourth quarter of 2020, an increase of $16 million, or 11%, compared to the third quarter of 2020, with $15 million and $1 million attributable to charges related to cost savings initiatives recognized in the fourth quarter of 2020 and the third quarter of 2020, respectively. Those charges in the fourth quarter of 2020 included $4.6 million of employee severance for impacted employees (salaries and benefits) and $4.8 million of write-offs of fixed assets and $5.8 million of lease termination charges (other expense) resulting from 21 financial center closures.
Compared to the fourth quarter of 2019, non-interest expense increased $16 million, or 11%, due primarily to the previously discussed charges associated with the cost savings initiatives.
The cost savings anticipated from the implementation of the cost savings initiatives are not expected to be fully realized until mid-2021. Of the anticipated $25 million in annual expense savings, the Corporation expects to reinvest a portion of the savings to accelerate digital transformation initiatives.
For the year end December 31, 2020, non-interest expense was $579 million, an increase of $12 million, or 2%, from 2019. This increase was primarily due to expenses related to the cost savings initiatives, which totaled $16 million for the year, as well as increases of $3 million in data processing and software and $1 million in FDIC insurance. These increases were partially offset by decreases of $9 million in other outside services and $5 million in marketing.
Income Tax Expense
The effective income tax rate (ETR) for the fourth quarter of 2020 was 10%, as compared to 13% for both the third quarter of 2020 and fourth quarter of 2019. For the year ended December 31, 2020, the ETR was 12% compared 14% in 2019. The decreases resulted from lower income before income taxes.
Shareholders' Equity
In the fourth quarter of 2020, the Corporation issued $200 million of Fixed Rate Non-Cumulative Perpetual Preferred Stock ("Preferred Stock") at a rate of 5.125%. The Corporation received net
proceeds from the offering of $192.9 million after issuance costs. Dividends on the Preferred Stock were $2.1 million in the fourth quarter, or approximately $0.01 per diluted share.
Additional information on Fulton is available on the Internet at www.fult.com.
Safe Harbor Statement
This news release may contain forward-looking statements with respect to the
Corporation’s financial condition, results of operations and business. Do not unduly rely on forward-looking statements. Forward-looking statements can be identified by the use of words such as "may," "should," "will," "could," "estimates," "predicts," "potential," "continue," "anticipates," "believes," "plans," "expects," "future," "intends," “projects,” the negative of these terms and other comparable terminology. These forward-looking statements may include projections of, or guidance on, the Corporation’s future financial performance, expected levels of future expenses, including future credit losses, anticipated growth strategies, descriptions of new business initiatives and anticipated trends in the Corporation’s business or financial results.
Forward-looking statements are neither historical facts, nor assurance of future performance. Instead, they are based on current beliefs, expectations and assumptions regarding the future of the Corporation’s business, future plans and strategies, projections, anticipated events and trends, the economy and other future conditions. Because forward-looking statements relate to the future, they are subject to inherent uncertainties, risks and changes in circumstances that are difficult to predict and many of which are outside of the Corporation’s control, and actual results and financial condition may differ materially from those indicated in the forward-looking statements. Therefore, you should not unduly rely on any of these forward-looking statements. Any forward-looking statement is based only on information currently available and speaks only as of the date when made. The Corporation undertakes no obligation, other than as required by law, to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise.
A discussion of certain risks and uncertainties affecting the Corporation, and some of the factors that could cause the Corporation's actual results to differ materially from those described in the forward-looking statements, can be found in the sections entitled "Risk Factors" and "Management's Discussion and Analysis of Financial Condition and Results of Operations" in the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2019, Quarterly Reports on Form 10-Q for the quarters ended March 31, 2020, June 30, 2020 and September 30, 2020 and other current and periodic reports, which have been or will be filed with the Securities and Exchange Commission and are or will be available in the Investor Relations section of the Corporation's website (www.fult.com) and on the Securities and Exchange Commission's website (www.sec.gov).
Non-GAAP Financial Measures
The Corporation uses certain non-GAAP financial measures in this earnings release. These non-GAAP financial measures are reconciled to the most comparable GAAP measures in tables at the end of this release.
| FULTON FINANCIAL CORPORATION | ||||||||||||||||||||||||||||||||
| SUMMARY CONSOLIDATED FINANCIAL INFORMATION (UNAUDITED) | ||||||||||||||||||||||||||||||||
| in thousands, except per-share data and percentages | ||||||||||||||||||||||||||||||||
| Three months ended | ||||||||||||||||||||||||||||||||
| Dec 31 | Sep 30 | Jun 30 | Mar 31 | Dec 31 | ||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2020 | 2019 | ||||||||||||||||||||||||||||
| Ending Balances | ||||||||||||||||||||||||||||||||
| Investments | $ | 3,340,424 | $ | 3,097,721 | $ | 2,974,813 | $ | 3,141,440 | $ | 2,867,378 | ||||||||||||||||||||||
| Loans, net of unearned income | 18,900,820 | 19,028,621 | 18,704,722 | 17,077,403 | 16,837,526 | |||||||||||||||||||||||||||
| Total assets | 25,906,733 | 25,543,281 | 24,617,863 | 22,929,859 | 21,886,040 | |||||||||||||||||||||||||||
| Deposits | 20,839,207 | 20,730,051 | 19,884,208 | 17,365,026 | 17,393,913 | |||||||||||||||||||||||||||
| Shareholders' equity | 2,616,828 | 2,390,261 | 2,340,501 | 2,285,748 | 2,342,176 | |||||||||||||||||||||||||||
| Average Balances | ||||||||||||||||||||||||||||||||
| Investments | $ | 3,221,289 | $ | 2,977,672 | $ | 3,096,632 | $ | 3,071,828 | $ | 2,830,999 | ||||||||||||||||||||||
| Loans, net of unearned income | 18,994,514 | 18,880,519 | 18,331,797 | 16,860,067 | 16,768,057 | |||||||||||||||||||||||||||
| Total assets | 25,749,405 | 25,169,508 | 24,139,116 | 22,252,099 | 21,812,438 | |||||||||||||||||||||||||||
| Deposits | 20,791,522 | 20,388,447 | 19,276,658 | 17,121,428 | 17,449,565 | |||||||||||||||||||||||||||
| Shareholders' equity | 2,544,866 | 2,374,091 | 2,309,133 | 2,337,016 | 2,341,397 | |||||||||||||||||||||||||||
| Income Statement | ||||||||||||||||||||||||||||||||
| Net interest income | $ | 161,591 | $ | 154,116 | $ | 152,754 | $ | 160,746 | $ | 159,270 | ||||||||||||||||||||||
| Provision for credit losses | 6,240 | 7,080 | 19,570 | 44,030 | 20,530 | |||||||||||||||||||||||||||
| Non-interest income | 55,574 | 63,248 | 55,922 | 54,644 | 55,281 | |||||||||||||||||||||||||||
| Non-interest expense | 154,737 | 139,147 | 143,006 | 142,552 | 138,974 | |||||||||||||||||||||||||||
| Income before taxes | 56,187 | 71,137 | 46,101 | 28,808 | 55,047 | |||||||||||||||||||||||||||
| Net income available to common shareholders | 48,690 | 61,607 | 39,559 | 26,047 | 47,789 | |||||||||||||||||||||||||||
| Per Share | ||||||||||||||||||||||||||||||||
| Net income available to common shareholders (basic) | $ | 0.30 | $ | 0.38 | $ | 0.24 | $ | 0.16 | $ | 0.29 | ||||||||||||||||||||||
| Net income available to common shareholders (diluted) | $ | 0.30 | $ | 0.38 | $ | 0.24 | $ | 0.16 | $ | 0.29 | ||||||||||||||||||||||
| Cash dividends | $ | 0.17 | $ | 0.13 | $ | 0.13 | $ | 0.13 | $ | 0.17 | ||||||||||||||||||||||
| Common shareholders' equity | $ | 14.93 | $ | 14.74 | $ | 14.45 | $ | 14.16 | $ | 14.26 | ||||||||||||||||||||||
| Common shareholders' equity (tangible)(1) | $ | 11.62 | $ | 11.44 | $ | 11.15 | $ | 10.84 | $ | 11.00 | ||||||||||||||||||||||
| Weighted average shares (basic) | 162,242 | 162,061 | 161,715 | 163,475 | 164,135 | |||||||||||||||||||||||||||
| Weighted average shares (diluted) | 163,071 | 162,579 | 162,267 | 164,417 | 165,039 | |||||||||||||||||||||||||||
| (1) Non-GAAP financial measure. Refer to the calculation on the page titled “Reconciliation of Non-GAAP Measures” at the end of this document. | ||||||||||||||||||||||||||||||||
| Three months ended | ||||||||||||||||||||||||||||||||
| Dec 31 | Sep 30 | Jun 30 | Mar 31 | Dec 31 | ||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2020 | 2019 | ||||||||||||||||||||||||||||
| Asset Quality(2) | ||||||||||||||||||||||||||||||||
| Net (recoveries) charge-offs to average loans (annualized) | (0.07) | % | (0.05) | % | 0.09 | % | 0.26 | % | 0.65 | % | ||||||||||||||||||||||
| Non-performing loans to total loans | 0.78 | % | 0.75 | % | 0.75 | % | 0.82 | % | 0.84 | % | ||||||||||||||||||||||
| Non-performing assets to total assets | 0.58 | % | 0.57 | % | 0.59 | % | 0.64 | % | 0.68 | % | ||||||||||||||||||||||
| ACL - loans(3) to total loans | 1.47 | % | 1.40 | % | 1.37 | % | 1.40 | % | 0.97 | % | ||||||||||||||||||||||
| ACL - loans(3) to non-performing loans | 189 | % | 188 | % | 183 | % | 170 | % | 116 | % | ||||||||||||||||||||||
| Non-performing assets to common shareholders' equity (tangible) and ACL - loans (1)(3) | 6.42 | % | 6.91 | % | 7.04 | % | 7.37 | % | 7.51 | % | ||||||||||||||||||||||
| Asset Quality, excluding PPP(1)(4) | ||||||||||||||||||||||||||||||||
| Net (recoveries) charge-offs to average adjusted loans (annualized) | (0.08) | % | (0.06) | % | 0.10 | % | — | % | — | % | ||||||||||||||||||||||
| Non-performing loans to total adjusted loans | 0.85 | % | 0.83 | % | 0.83 | % | — | % | — | % | ||||||||||||||||||||||
| ACL - loans(3) to total adjusted loans | 1.60 | % | 1.56 | % | 1.53 | % | — | % | — | % | ||||||||||||||||||||||
| Profitability | ||||||||||||||||||||||||||||||||
| Return on average assets | 0.79 | % | 0.97 | % | 0.66 | % | 0.47 | % | 0.87 | % | ||||||||||||||||||||||
| Return on average shareholders' equity | 7.95 | % | 10.32 | % | 6.89 | % | 4.48 | % | 8.10 | % | ||||||||||||||||||||||
| Return on average common shareholders' equity (tangible)(1) | 10.32 | % | 13.50 | % | 8.99 | % | 5.84 | % | 10.52 | % | ||||||||||||||||||||||
| Net interest margin | 2.75 | % | 2.70 | % | 2.81 | % | 3.21 | % | 3.22 | % | ||||||||||||||||||||||
| Efficiency ratio(1) | 69.5 | % | 62.3 | % | 66.4 | % | 64.5 | % | 63.1 | % | ||||||||||||||||||||||
| Efficiency ratio, net 2020 cost savings initiatives(1) | 62.5 | % | 62.0 | % | 66.4 | % | 64.5 | % | 63.1 | % | ||||||||||||||||||||||
| Capital Ratios | ||||||||||||||||||||||||||||||||
| Tangible common equity ratio(1) | 7.4 | % | 7.4 | % | 7.5 | % | 7.8 | % | 8.5 | % | ||||||||||||||||||||||
| Tier 1 leverage ratio(5) | 8.1 | % | 7.4 | % | 7.6 | % | 7.9 | % | 8.4 | % | ||||||||||||||||||||||
| Common equity Tier 1 capital ratio(5) | 9.4 | % | 9.5 | % | 9.5 | % | 9.4 | % | 9.7 | % | ||||||||||||||||||||||
| Tier 1 capital ratio(5) | 10.3 | % | 9.5 | % | 9.5 | % | 9.4 | % | 9.7 | % | ||||||||||||||||||||||
| Total risk-based capital ratio(5) | 14.5 | % | 13.9 | % | 13.8 | % | 13.8 | % | 11.8 | % | ||||||||||||||||||||||
| (1) Non-GAAP financial measure. Refer to the calculation on the page titled "Reconciliation of Non-GAAP Measures" at the end of this document. | ||||||||||||||||||||||||||||||||
| (2) Effective January 1, 2020, Fulton adopted Accounting Standards Update 2016-13, "Financial Instruments—Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments," referred to as the current expected credit loss model ("CECL"). This accounting standard requires that credit losses for financial assets and off-balance-sheet ("OBS") credit exposures be measured based on expected credit losses, rather than on incurred credit losses as in prior periods. | ||||||||||||||||||||||||||||||||
| (3) "ACL - loans" relates to the allowance for credit losses ("ACL") specifically on "Loans, net of unearned income" and does not include the ACL related to OBS credit exposures. | ||||||||||||||||||||||||||||||||
| (4) Asset quality information excluding Paycheck Protection Program ("PPP") loans. Refer to the calculation on the page titled "Reconciliation of Non-GAAP Measures" at the end of this document. | ||||||||||||||||||||||||||||||||
(5) Regulatory capital ratios as of December 31, 2020 are preliminary and prior periods are actual. | ||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | ||||||||||||||||||||||||||||||||||||||||||||
| CONDENSED CONSOLIDATED ENDING BALANCE SHEETS (UNAUDITED) | ||||||||||||||||||||||||||||||||||||||||||||
| dollars in thousands | ||||||||||||||||||||||||||||||||||||||||||||
| % Change from | ||||||||||||||||||||||||||||||||||||||||||||
| Dec 31 | Sep 30 | Jun 30 | Mar 31 | Dec 31 | Sep 30 | Dec 31 | ||||||||||||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2020 | 2019 | 2020 | 2019 | ||||||||||||||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | $ | 120,462 | $ | 139,304 | $ | 141,702 | $ | 181,777 | $ | 132,283 | (13.5) | % | (8.9) | % | ||||||||||||||||||||||||||||||
| Other interest-earning assets | 1,819,499 | 1,489,550 | 1,007,939 | 793,572 | 482,930 | 22.2 | % | N/M | ||||||||||||||||||||||||||||||||||||
| Loans held for sale | 83,886 | 93,621 | 77,415 | 40,645 | 37,828 | (10.4) | % | N/M | ||||||||||||||||||||||||||||||||||||
| Investment securities | 3,340,424 | 3,097,721 | 2,974,813 | 3,141,440 | 2,867,378 | 7.8 | % | 16.5 | % | |||||||||||||||||||||||||||||||||||
| Loans, net of unearned income | 18,900,820 | 19,028,621 | 18,704,722 | 17,077,403 | 16,837,526 | (0.7) | % | 12.3 | % | |||||||||||||||||||||||||||||||||||
| Less: ACL - loans(1) | (277,567) | (266,825) | (256,537) | (238,508) | (163,622) | 4.0 | % | 69.6 | % | |||||||||||||||||||||||||||||||||||
| Net loans | 18,623,253 | 18,761,796 | 18,448,185 | 16,838,895 | 16,673,904 | (0.7) | % | 11.7 | % | |||||||||||||||||||||||||||||||||||
| Premises and equipment | 231,480 | 236,943 | 239,596 | 236,908 | 240,046 | (2.3) | % | (3.6) | % | |||||||||||||||||||||||||||||||||||
| Accrued interest receivable | 72,942 | 70,766 | 73,720 | 59,365 | 60,898 | 3.1 | % | 19.8 | % | |||||||||||||||||||||||||||||||||||
| Goodwill and intangible assets | 536,659 | 534,907 | 535,039 | 535,171 | 535,303 | 0.3 | % | 0.3 | % | |||||||||||||||||||||||||||||||||||
| Other assets | 1,078,128 | 1,118,673 | 1,119,454 | 1,102,086 | 855,470 | (3.6) | % | 26.0 | % | |||||||||||||||||||||||||||||||||||
| Total Assets | $ | 25,906,733 | $ | 25,543,281 | $ | 24,617,863 | $ | 22,929,859 | $ | 21,886,040 | 1.4 | % | 18.4 | % | ||||||||||||||||||||||||||||||
| LIABILITIES AND SHAREHOLDERS' EQUITY | ||||||||||||||||||||||||||||||||||||||||||||
| Deposits | $ | 20,839,207 | $ | 20,730,051 | $ | 19,884,208 | $ | 17,365,026 | $ | 17,393,913 | 0.5 | % | 19.8 | % | ||||||||||||||||||||||||||||||
| Short-term borrowings | 630,066 | 611,727 | 572,551 | 1,386,808 | 883,241 | 3.0 | % | (28.7) | % | |||||||||||||||||||||||||||||||||||
| Other liabilities | 524,369 | 515,230 | 525,407 | 513,811 | 384,941 | 1.8 | % | 36.2 | % | |||||||||||||||||||||||||||||||||||
| FHLB advances and long-term debt | 1,296,263 | 1,296,012 | 1,295,196 | 1,378,466 | 881,769 | — | % | 47.0 | % | |||||||||||||||||||||||||||||||||||
| Total Liabilities | 23,289,905 | 23,153,020 | 22,277,362 | 20,644,111 | 19,543,864 | 0.6 | % | 19.2 | % | |||||||||||||||||||||||||||||||||||
| Shareholders' equity | 2,616,828 | 2,390,261 | 2,340,501 | 2,285,748 | 2,342,176 | 9.5 | % | 11.7 | % | |||||||||||||||||||||||||||||||||||
| Total Liabilities and Shareholders' Equity | $ | 25,906,733 | $ | 25,543,281 | $ | 24,617,863 | $ | 22,929,859 | $ | 21,886,040 | 1.4 | % | 18.4 | % | ||||||||||||||||||||||||||||||
| LOANS, DEPOSITS AND SHORT-TERM BORROWINGS DETAIL: | ||||||||||||||||||||||||||||||||||||||||||||
| Loans, by type: | ||||||||||||||||||||||||||||||||||||||||||||
| Real estate - commercial mortgage | $ | 7,105,092 | $ | 7,046,330 | $ | 6,934,936 | $ | 6,895,069 | $ | 6,700,776 | 0.8 | % | 6.0 | % | ||||||||||||||||||||||||||||||
| Commercial and industrial | 4,088,561 | 4,007,278 | 4,033,439 | 4,450,557 | 4,445,634 | 2.0 | % | (8.0) | % | |||||||||||||||||||||||||||||||||||
| Real estate - residential mortgage | 3,141,915 | 3,061,835 | 2,862,226 | 2,718,290 | 2,641,465 | 2.6 | % | 18.9 | % | |||||||||||||||||||||||||||||||||||
| Real estate - home equity | 1,202,913 | 1,222,709 | 1,251,455 | 1,292,677 | 1,314,944 | (1.6) | % | (8.5) | % | |||||||||||||||||||||||||||||||||||
| Real estate - construction | 1,047,218 | 1,007,534 | 972,909 | 947,768 | 971,079 | 3.9 | % | 7.8 | % | |||||||||||||||||||||||||||||||||||
| Consumer | 466,772 | 469,551 | 465,610 | 468,172 | 463,164 | (0.6) | % | 0.8 | % | |||||||||||||||||||||||||||||||||||
| Equipment lease financing | 279,118 | 280,286 | 281,897 | 289,726 | 284,537 | (0.4) | % | (1.9) | % | |||||||||||||||||||||||||||||||||||
| Other(2) | (12,481) | (27,067) | (34,784) | 15,144 | 15,927 | (53.9) | % | N/M | ||||||||||||||||||||||||||||||||||||
| Loans, net of unearned income before PPP | 17,319,108 | 17,068,456 | 16,767,688 | 17,077,403 | 16,837,526 | 1.5 | % | 2.9 | % | |||||||||||||||||||||||||||||||||||
| PPP | 1,581,712 | 1,960,165 | 1,937,034 | — | — | (19.3) | % | N/M | ||||||||||||||||||||||||||||||||||||
| Total Loans, net of unearned income | $ | 18,900,820 | $ | 19,028,621 | $ | 18,704,722 | $ | 17,077,403 | $ | 16,837,526 | (0.7) | % | 12.3 | % | ||||||||||||||||||||||||||||||
| Deposits, by type: | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 6,531,002 | $ | 6,378,077 | $ | 6,239,055 | $ | 4,531,872 | $ | 4,453,324 | 2.4 | % | 46.7 | % | ||||||||||||||||||||||||||||||
| Interest-bearing demand | 5,818,564 | 5,813,935 | 5,099,405 | 4,724,520 | 4,720,188 | 0.1 | % | 23.3 | % | |||||||||||||||||||||||||||||||||||
| Savings | 5,929,792 | 5,805,431 | 5,667,893 | 5,092,865 | 5,153,941 | 2.1 | % | 15.1 | % | |||||||||||||||||||||||||||||||||||
| Total demand and savings | 18,279,358 | 17,997,443 | 17,006,353 | 14,349,257 | 14,327,453 | 1.6 | % | 27.6 | % | |||||||||||||||||||||||||||||||||||
| Brokered | 335,185 | 317,588 | 310,689 | 313,337 | 264,531 | 5.5 | % | 26.7 | % | |||||||||||||||||||||||||||||||||||
| Time | 2,224,664 | 2,415,020 | 2,567,166 | 2,702,432 | 2,801,929 | (7.9) | % | (20.6) | % | |||||||||||||||||||||||||||||||||||
| Total Deposits | $ | 20,839,207 | $ | 20,730,051 | $ | 19,884,208 | $ | 17,365,026 | $ | 17,393,913 | 0.5 | % | 19.8 | % | ||||||||||||||||||||||||||||||
| Short-term borrowings, by type: | ||||||||||||||||||||||||||||||||||||||||||||
| Customer funding | $ | 630,066 | $ | 611,727 | $ | 572,551 | $ | 461,808 | $ | 383,241 | 3.0 | % | 64.4 | % | ||||||||||||||||||||||||||||||
| Federal funds purchased | — | — | — | 200,000 | — | N/M | N/M | |||||||||||||||||||||||||||||||||||||
| Short-term FHLB advances | — | — | — | 725,000 | 500,000 | N/M | (100.0) | % | ||||||||||||||||||||||||||||||||||||
| Total Short-term Borrowings | $ | 630,066 | $ | 611,727 | $ | 572,551 | $ | 1,386,808 | $ | 883,241 | 3.0 | % | (28.7) | % | ||||||||||||||||||||||||||||||
| N/M - Not meaningful | ||||||||||||||||||||||||||||||||||||||||||||
| (1) "ACL - loans" relates to the ACL specifically on "Loans, net of unearned income" and does not include the ACL related to OBS credit exposures. | ||||||||||||||||||||||||||||||||||||||||||||
| (2) Consists of overdrafts and net origination fees and costs. | ||||||||||||||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| CONDENSED CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| dollars in thousands | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | % Change from | Years ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Dec 31 | Sep 30 | Jun 30 | Mar 31 | Dec 31 | Sep 30 | Dec 31 | Dec 31 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2020 | 2019 | 2020 | 2019 | 2020 | 2019 | % Change | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest Income: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest income | $ | 183,645 | $ | 179,159 | $ | 180,696 | $ | 199,378 | $ | 202,159 | 2.5 | % | (9.2) | % | $ | 742,878 | $ | 825,306 | (10.0) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest expense | 22,054 | 25,043 | 27,942 | 38,632 | 42,889 | (11.9) | % | (48.6) | % | 113,671 | 176,917 | (35.7) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net Interest Income | 161,591 | 154,116 | 152,754 | 160,746 | 159,270 | 4.9 | % | 1.5 | % | 629,207 | 648,389 | (3.0) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 6,240 | 7,080 | 19,570 | 44,030 | 20,530 | (11.9) | % | (69.6) | % | 76,920 | 32,825 | N/M | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net Interest Income after Provision | 155,351 | 147,036 | 133,184 | 116,716 | 138,740 | 5.7 | % | 12.0 | % | 552,287 | 615,564 | (10.3) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-Interest Income: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Wealth management | 15,653 | 14,943 | 13,407 | 15,055 | 14,419 | 4.7 | % | 8.6 | % | 59,058 | 55,678 | 6.1 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mortgage banking | 9,311 | 16,801 | 9,964 | 6,234 | 5,076 | (44.6) | % | 83.4 | % | 42,309 | 23,099 | 83.2 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Consumer banking: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Card | 5,123 | 5,002 | 4,966 | 4,685 | 4,991 | 2.4 | % | 2.7 | % | 19,777 | 20,515 | (3.6) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Overdraft | 3,376 | 3,015 | 2,107 | 4,058 | 4,750 | 12.0 | % | (28.9) | % | 12,556 | 17,949 | (30.0) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other consumer banking | 2,298 | 2,406 | 2,065 | 2,496 | 2,688 | (4.5) | % | (14.5) | % | 9,266 | 11,039 | (16.1) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total consumer banking | 10,798 | 10,423 | 9,138 | 11,239 | 12,429 | 3.6 | % | (13.1) | % | 41,598 | 49,503 | (16.0) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial banking: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Merchant and card | 5,953 | 6,237 | 5,326 | 5,624 | 5,841 | (4.6) | % | 1.9 | % | 23,139 | 24,077 | (3.9) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cash management | 4,737 | 4,742 | 4,503 | 4,742 | 4,697 | (0.1) | % | 0.9 | % | 18,725 | 18,392 | 1.8 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Capital markets | 3,513 | 4,696 | 5,004 | 5,075 | 5,939 | (25.2) | % | (40.8) | % | 18,288 | 14,875 | 22.9 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other commercial banking | 2,606 | 2,636 | 1,914 | 2,978 | 3,664 | (1.2) | % | (28.9) | % | 10,134 | 13,773 | (26.4) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial banking | 16,809 | 18,311 | 16,748 | 18,419 | 20,141 | (8.2) | % | (16.5) | % | 70,286 | 71,117 | (1.2) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other | 3,004 | 2,769 | 3,660 | 3,651 | 3,216 | 8.5 | % | (6.6) | % | 13,084 | 12,030 | 8.8 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-interest income before investment securities gains | 55,574 | 63,246 | 52,917 | 54,598 | 55,281 | (12.1) | % | 0.5 | % | 226,335 | 211,427 | 7.1 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Investment securities gains, net | — | 2 | 3,005 | 46 | — | (100.0) | % | N/M | 3,053 | 4,733 | (35.5) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Non-Interest Income | 55,574 | 63,248 | 55,922 | 54,644 | 55,281 | (12.1) | % | 0.5 | % | 229,388 | 216,160 | 6.1 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-Interest Expense: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 83,929 | 79,227 | 81,012 | 80,228 | 76,975 | 5.9 | % | 9.0 | % | 324,395 | 311,934 | 4.0 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net occupancy | 13,161 | 13,221 | 13,144 | 13,486 | 13,080 | (0.5) | % | 0.6 | % | 53,013 | 52,826 | 0.4 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Data processing and software | 11,951 | 12,285 | 12,193 | 11,645 | 11,468 | (2.7) | % | 4.2 | % | 48,073 | 44,679 | 7.6 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other outside services | 8,334 | 7,617 | 7,600 | 7,881 | 8,215 | 9.4 | % | 1.4 | % | 31,432 | 39,989 | (21.4) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equipment | 3,563 | 3,711 | 3,193 | 3,418 | 3,475 | (4.0) | % | 2.5 | % | 13,885 | 13,575 | 2.3 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Professional fees | 2,424 | 2,879 | 3,331 | 4,202 | 2,873 | (15.8) | % | (15.6) | % | 12,835 | 13,134 | (2.3) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Marketing | 1,098 | 1,147 | 1,303 | 1,579 | 1,503 | (4.3) | % | (27.0) | % | 5,127 | 9,848 | (47.9) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of tax credit investments | 1,532 | 1,694 | 1,450 | 1,450 | 1,505 | (9.6) | % | 1.8 | % | 6,126 | 6,021 | 1.7 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| FDIC insurance | 2,346 | 1,578 | 2,133 | 2,808 | 2,177 | 48.7 | % | 7.8 | % | 8,865 | 7,780 | 13.9 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Intangible amortization | 132 | 132 | 132 | 132 | 142 | 0.2 | % | (6.8) | % | 529 | 1,427 | (63.0) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Prepayment penalty on FHLB advances | — | — | 2,878 | — | — | N/M | N/M | 2,878 | 4,326 | (33.5) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other | 26,268 | 15,654 | 14,637 | 15,723 | 17,561 | 67.8 | % | 49.6 | % | 72,282 | 62,197 | 16.2 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Non-Interest Expense | 154,737 | 139,145 | 143,006 | 142,552 | 138,974 | 11.2 | % | 11.3 | % | 579,440 | 567,736 | 2.1 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Income Before Income Taxes | 56,187 | 71,139 | 46,100 | 28,808 | 55,047 | (21.0) | % | 2.1 | % | 202,235 | 263,988 | (23.4) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Income tax expense | 5,362 | 9,529 | 6,542 | 2,761 | 7,258 | (43.7) | % | (26.1) | % | 24,194 | 37,649 | (35.7) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net Income | 50,825 | 61,610 | 39,558 | 26,047 | 47,789 | (17.5) | % | 6.4 | % | 178,040 | 226,339 | (21.3) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Preferred stock dividends | (2,135) | — | — | — | — | N/M | N/M | (2,135) | — | N/M | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net Income Available to Common Shareholders | $ | 48,690 | $ | 61,610 | $ | 39,558 | $ | 26,047 | $ | 47,789 | (21.0) | % | 1.9 | % | $ | 175,905 | $ | 226,339 | (22.3) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| PER SHARE: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net income: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Basic | $ | 0.30 | $ | 0.38 | $ | 0.24 | $ | 0.16 | $ | 0.29 | (21.1) | % | 3.4 | % | $ | 1.08 | $ | 1.36 | (20.6) | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Diluted | 0.30 | 0.38 | 0.24 | 0.16 | 0.29 | (21.1) | % | 3.4 | % | 1.08 | 1.35 | (20.0) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cash dividends | 0.17 | 0.13 | 0.13 | 0.13 | 0.17 | 30.8 | % | — | % | 0.56 | 0.56 | — | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Weighted average shares (basic) | 162,242 | 162,061 | 161,715 | 163,475 | 164,135 | 0.1 | % | (1.2) | % | 162,372 | 166,902 | (2.7) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Weighted average shares (diluted) | 163,071 | 162,579 | 162,267 | 164,417 | 165,039 | 0.3 | % | (1.2) | % | 163,090 | 167,792 | (2.8) | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| CONDENSED CONSOLIDATED AVERAGE BALANCE SHEET ANALYSIS (UNAUDITED) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| dollars in thousands | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three months ended | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| December 31, 2020 | September 30, 2020 | December 31, 2019 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average | Interest | Yield/ | Average | Interest | Yield/ | Average | Interest | Yield/ | ||||||||||||||||||||||||||||||||||||||||||||||||
| Balance | (1) | Rate | Balance | (1) | Rate | Balance | (1) | Rate | ||||||||||||||||||||||||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning assets: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans, net of unearned income | $ | 18,994,514 | $ | 164,329 | 3.45 | % | $ | 18,880,519 | $ | 160,344 | 3.38 | % | $ | 16,768,057 | $ | 182,024 | 4.31 | % | ||||||||||||||||||||||||||||||||||||||
| Taxable investment securities | 2,233,730 | 13,559 | 2.43 | % | 2,011,893 | 13,150 | 2.61 | % | 2,198,252 | 15,621 | 2.84 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Tax-exempt investment securities | 886,329 | 7,044 | 3.17 | % | 861,764 | 6,899 | 3.19 | % | 594,487 | 5,058 | 3.38 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Total Investment Securities | 3,120,059 | 20,603 | 2.64 | % | 2,873,657 | 20,048 | 2.79 | % | 2,792,739 | 20,679 | 2.96 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Loans held for sale | 76,871 | 521 | 2.71 | % | 79,999 | 728 | 3.64 | % | 30,062 | 295 | 3.93 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Other interest-earning assets | 1,668,454 | 1,179 | 0.28 | % | 1,387,327 | 1,028 | 0.30 | % | 492,560 | 2,370 | 1.92 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Total Interest-earning Assets | 23,859,898 | 186,632 | 3.12 | % | 23,221,502 | 182,149 | 3.13 | % | 20,083,418 | 205,368 | 4.07 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-earning assets: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 126,190 | 138,567 | 128,417 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Premises and equipment | 236,265 | 239,183 | 239,294 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other assets | 1,799,381 | 1,835,190 | 1,528,758 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Less: ACL - loans(2) | (272,329) | (264,934) | (167,449) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Assets | $ | 25,749,405 | $ | 25,169,508 | $ | 21,812,438 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| LIABILITIES AND SHAREHOLDERS' EQUITY | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Demand deposits | $ | 5,762,150 | $ | 1,457 | 0.10 | % | $ | 5,591,548 | $ | 1,913 | 0.14 | % | $ | 4,699,040 | $ | 8,494 | 0.72 | % | ||||||||||||||||||||||||||||||||||||||
| Savings deposits | 5,905,137 | 1,866 | 0.13 | % | 5,716,050 | 2,347 | 0.16 | % | 5,205,260 | 10,253 | 0.78 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Brokered deposits | 340,451 | 451 | 0.53 | % | 314,721 | 440 | 0.56 | % | 261,689 | 1,279 | 1.94 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Time deposits | 2,306,556 | 8,082 | 1.39 | % | 2,495,445 | 9,931 | 1.58 | % | 2,959,008 | 13,775 | 1.86 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Total Interest-bearing Deposits | 14,314,294 | 11,856 | 0.33 | % | 14,117,764 | 14,631 | 0.41 | % | 13,124,997 | 33,801 | 1.02 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Short-term borrowings | 622,623 | 268 | 0.17 | % | 613,127 | 370 | 0.24 | % | 717,811 | 2,343 | 1.29 | % | ||||||||||||||||||||||||||||||||||||||||||||
| FHLB advances and long-term debt | 1,296,139 | 9,930 | 3.06 | % | 1,295,515 | 10,042 | 3.10 | % | 875,802 | 6,745 | 3.07 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Total Interest-bearing Liabilities | 16,233,056 | 22,054 | 0.54 | % | 16,026,406 | 25,043 | 0.62 | % | 14,718,610 | 42,889 | 1.16 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Demand deposits | 6,477,228 | 6,270,683 | 4,324,568 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Deposits/Cost of Deposits | 20,791,522 | 0.23 | % | 20,388,447 | 0.29 | % | 17,449,565 | 0.77 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Other | 494,255 | 498,328 | 427,863 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Liabilities | 23,204,539 | $ | 22,795,417 | 19,471,041 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Interest-bearing liabilities and non-interest bearing deposits ("Cost of Funds") | 22,710,284 | 0.39 | % | 22,297,089 | 0.45 | % | 19,043,178 | 0.89 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders' equity | 2,544,866 | 2,374,091 | 2,341,397 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Liabilities and Shareholders' Equity | $ | 25,749,405 | $ | 25,169,508 | $ | 21,812,438 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income/net interest margin (fully taxable equivalent) | 164,578 | 2.75 | % | 157,106 | 2.70 | % | $ | 162,479 | 3.22 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Tax equivalent adjustment | (2,987) | (2,990) | $ | (3,209) | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 161,591 | $ | 154,116 | $ | 159,270 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| (1) Presented on a fully taxable-equivalent basis using a 21% federal tax rate and statutory interest expense disallowances. | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (2) "ACL - loans" relates to the ACL specifically on "Loans, net of unearned income" and does not include the ACL related to OBS credit exposures. | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | ||||||||||||||||||||||||||||||||||||||||||||
| AVERAGE LOANS, DEPOSITS AND SHORT-TERM BORROWINGS DETAIL (UNAUDITED): | ||||||||||||||||||||||||||||||||||||||||||||
| dollars in thousands | ||||||||||||||||||||||||||||||||||||||||||||
| Three months ended | % Change from | |||||||||||||||||||||||||||||||||||||||||||
| Dec 31 | Sep 30 | Jun 30 | Mar 31 | Dec 31 | Sep 30 | Dec 31 | ||||||||||||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2020 | 2019 | 2020 | 2019 | ||||||||||||||||||||||||||||||||||||||
| Loans, by type: | ||||||||||||||||||||||||||||||||||||||||||||
| Real estate - commercial mortgage | $ | 7,101,363 | $ | 6,986,528 | $ | 6,875,872 | $ | 6,746,766 | $ | 6,561,029 | 1.6 | % | 8.2 | % | ||||||||||||||||||||||||||||||
| Commercial and industrial | 4,024,879 | 4,030,750 | 4,451,228 | 4,446,750 | 4,574,047 | (0.1) | % | (12.0) | % | |||||||||||||||||||||||||||||||||||
| Real estate - residential mortgage | 3,087,529 | 2,975,516 | 2,769,682 | 2,670,019 | 2,606,136 | 3.8 | % | 18.5 | % | |||||||||||||||||||||||||||||||||||
| Real estate - home equity | 1,212,113 | 1,237,602 | 1,271,190 | 1,300,132 | 1,331,088 | (2.1) | % | (8.9) | % | |||||||||||||||||||||||||||||||||||
| Real estate - construction | 1,009,284 | 981,589 | 941,079 | 929,529 | 934,556 | 2.8 | % | 8.0 | % | |||||||||||||||||||||||||||||||||||
| Consumer | 468,678 | 464,851 | 465,728 | 466,415 | 464,606 | 0.8 | % | 0.9 | % | |||||||||||||||||||||||||||||||||||
| Equipment lease financing | 279,059 | 279,217 | 284,658 | 284,566 | 281,451 | (0.1) | % | (0.8) | % | |||||||||||||||||||||||||||||||||||
| Other(1) | (18,817) | (28,656) | 13,443 | 15,890 | 14,058 | (34.3) | % | N/M | ||||||||||||||||||||||||||||||||||||
| Loans, net of unearned income before PPP | 17,164,088 | 16,927,397 | 17,072,880 | 16,860,067 | 16,766,971 | 1.4 | % | 2.4 | % | |||||||||||||||||||||||||||||||||||
| PPP | 1,830,426 | 1,953,122 | 1,258,917 | — | — | (6.3) | % | N/M | ||||||||||||||||||||||||||||||||||||
| Total Loans, net of unearned income | $ | 18,994,514 | $ | 18,880,519 | $ | 18,331,797 | $ | 16,860,067 | $ | 16,766,971 | 0.6 | % | 13.3 | % | ||||||||||||||||||||||||||||||
| Deposits, by type: | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 6,477,228 | $ | 6,270,683 | $ | 5,789,788 | $ | 4,307,027 | $ | 4,324,568 | 3.3 | % | 49.8 | % | ||||||||||||||||||||||||||||||
| Interest-bearing demand | 5,762,150 | 5,591,548 | 5,103,419 | 4,649,905 | 4,699,040 | 3.1 | % | 22.6 | % | |||||||||||||||||||||||||||||||||||
| Savings | 5,905,137 | 5,716,050 | 5,446,368 | 5,127,662 | 5,205,260 | 3.3 | % | 13.4 | % | |||||||||||||||||||||||||||||||||||
| Total demand and savings | 18,144,515 | 17,578,281 | 16,339,575 | 14,084,594 | 14,228,868 | 3.2 | % | 27.5 | % | |||||||||||||||||||||||||||||||||||
| Brokered | 340,451 | 314,721 | 312,121 | 275,359 | 261,689 | 8.2 | % | 30.1 | % | |||||||||||||||||||||||||||||||||||
| Time | 2,306,556 | 2,495,445 | 2,624,962 | 2,761,474 | 2,959,008 | (7.6) | % | (22.0) | % | |||||||||||||||||||||||||||||||||||
| Total Deposits | $ | 20,791,522 | $ | 20,388,447 | $ | 19,276,658 | $ | 17,121,427 | $ | 17,449,565 | 2.0 | % | 19.2 | % | ||||||||||||||||||||||||||||||
| Short-term borrowings, by type: | ||||||||||||||||||||||||||||||||||||||||||||
| Customer funding | $ | 622,623 | $ | 613,127 | $ | 546,716 | $ | 428,240 | $ | 377,529 | 1.5 | % | 64.9 | % | ||||||||||||||||||||||||||||||
| Federal funds purchased | — | — | 74,231 | 186,868 | 91,467 | N/M | (100.0) | % | ||||||||||||||||||||||||||||||||||||
| Short-term FHLB advances and other borrowings | — | — | 86,824 | 687,937 | 248,815 | N/M | (100.0) | % | ||||||||||||||||||||||||||||||||||||
| Total Short-term borrowings | $ | 622,623 | $ | 613,127 | $ | 707,771 | $ | 1,303,045 | $ | 717,811 | 1.5 | % | (13.3) | % | ||||||||||||||||||||||||||||||
| (1) Consists of overdrafts and net origination fees and costs. | ||||||||||||||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | ||||||||||||||||||||||||||||||||||||||||||||
| CONDENSED CONSOLIDATED AVERAGE BALANCE SHEET ANALYSIS (UNAUDITED) | ||||||||||||||||||||||||||||||||||||||||||||
| dollars in thousands | ||||||||||||||||||||||||||||||||||||||||||||
| Year ended December 31 | ||||||||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | |||||||||||||||||||||||||||||||||||||||||||
| Average | Interest | Yield/ | Average | Interest | Yield/ | |||||||||||||||||||||||||||||||||||||||
| Balance | (1) | Rate | Balance | (1) | Rate | |||||||||||||||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning assets: | ||||||||||||||||||||||||||||||||||||||||||||
| Loans, net of unearned income | $ | 18,270,390 | $ | 662,785 | 3.63 | % | $ | 16,430,347 | $ | 747,119 | 4.55 | % | ||||||||||||||||||||||||||||||||
| Taxable investment securities | 2,182,410 | 58,173 | 2.66 | % | 2,278,448 | 62,556 | 2.74 | % | ||||||||||||||||||||||||||||||||||||
| Tax-exempt investment securities | 825,057 | 26,641 | 3.22 | % | 500,398 | 17,998 | 3.57 | % | ||||||||||||||||||||||||||||||||||||
| Total Investment Securities | 3,007,467 | 84,814 | 2.82 | % | 2,778,846 | 80,554 | 2.89 | % | ||||||||||||||||||||||||||||||||||||
| Loans held for sale | 60,015 | 2,077 | 3.46 | % | 25,795 | 1,351 | 5.24 | % | ||||||||||||||||||||||||||||||||||||
| Other interest-earning assets | 1,120,727 | 5,504 | 0.49 | % | 445,008 | 9,249 | 2.08 | % | ||||||||||||||||||||||||||||||||||||
| Total Interest-earning Assets | 22,458,599 | 755,181 | 3.36 | % | 19,679,996 | 838,273 | 4.26 | % | ||||||||||||||||||||||||||||||||||||
| Noninterest-earning assets: | ||||||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 139,146 | 119,144 | ||||||||||||||||||||||||||||||||||||||||||
| Premises and equipment | 238,864 | 239,376 | ||||||||||||||||||||||||||||||||||||||||||
| Other assets | 1,746,956 | 1,385,689 | ||||||||||||||||||||||||||||||||||||||||||
| Less: ACL - loans(2) | (249,848) | (166,165) | ||||||||||||||||||||||||||||||||||||||||||
| Total Assets | $ | 24,333,717 | $ | 21,258,040 | ||||||||||||||||||||||||||||||||||||||||
| LIABILITIES AND SHAREHOLDERS' EQUITY | ||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||||||||
| Demand deposits | $ | 5,278,941 | $ | 11,390 | 0.22 | % | $ | 4,384,059 | $ | 33,348 | 0.76 | % | ||||||||||||||||||||||||||||||||
| Savings deposits | 5,550,234 | 14,654 | 0.26 | % | 5,018,381 | 41,823 | 0.83 | % | ||||||||||||||||||||||||||||||||||||
| Brokered deposits | 310,763 | 2,387 | 0.77 | % | 245,501 | 5,779 | 2.35 | % | ||||||||||||||||||||||||||||||||||||
| Time deposits | 2,546,305 | 41,615 | 1.63 | % | 2,869,326 | 50,825 | 1.77 | % | ||||||||||||||||||||||||||||||||||||
| Total Interest-bearing Deposits | 13,686,243 | 70,045 | 0.51 | % | 12,517,267 | 131,775 | 1.05 | % | ||||||||||||||||||||||||||||||||||||
| Short-term borrowings | 810,583 | 5,227 | 0.64 | % | 849,679 | 14,543 | 1.70 | % | ||||||||||||||||||||||||||||||||||||
| FHLB advances and long-term debt | 1,254,300 | 38,398 | 3.06 | % | 942,600 | 30,599 | 3.25 | % | ||||||||||||||||||||||||||||||||||||
| Total Interest-bearing Liabilities | 15,751,126 | 113,671 | 0.72 | % | 14,309,546 | 176,917 | 1.24 | % | ||||||||||||||||||||||||||||||||||||
| Noninterest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||||||||
| Demand deposits | 5,714,803 | 4,249,294 | ||||||||||||||||||||||||||||||||||||||||||
| Total Deposits/Cost of Deposits | 19,401,046 | 0.36 | % | 16,766,561 | 0.79 | % | ||||||||||||||||||||||||||||||||||||||
| Other | 476,139 | 393,130 | ||||||||||||||||||||||||||||||||||||||||||
| Total Liabilities | 21,942,068 | 18,951,970 | ||||||||||||||||||||||||||||||||||||||||||
| Total Interest-bearing liabilities and non-interest bearing deposits ("Cost of Funds") | 21,465,929 | 0.53 | % | 18,558,840 | 0.95 | % | ||||||||||||||||||||||||||||||||||||||
| Shareholders' equity | 2,391,649 | 2,306,070 | ||||||||||||||||||||||||||||||||||||||||||
| Total Liabilities and Shareholders' Equity | $ | 24,333,717 | $ | 21,258,040 | ||||||||||||||||||||||||||||||||||||||||
| Net interest income/net interest margin (fully taxable equivalent) | 641,510 | 2.86 | % | 661,356 | 3.36 | % | ||||||||||||||||||||||||||||||||||||||
| Tax equivalent adjustment | (12,303) | (12,967) | ||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 629,207 | $ | 648,389 | ||||||||||||||||||||||||||||||||||||||||
| (1) Presented on a fully taxable-equivalent basis using a 21% federal tax rate and statutory interest expense disallowances. | ||||||||||||||||||||||||||||||||||||||||||||
| (2) "ACL - loans" relates to the ACL specifically on "Loans, net of unearned income" and does not include the ACL related to OBS credit exposures. | ||||||||||||||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | |||||||||||||||||||||||
| AVERAGE LOANS, DEPOSITS AND SHORT-TERM BORROWINGS DETAIL (UNAUDITED): | |||||||||||||||||||||||
| dollars in thousands | |||||||||||||||||||||||
| Year ended December 31 | |||||||||||||||||||||||
| 2020 | 2019 | % Change | |||||||||||||||||||||
| Loans, by type: | |||||||||||||||||||||||
| Real estate - commercial mortgage | $ | 6,928,269 | $ | 6,463,783 | 7.2 | % | |||||||||||||||||
| Commercial and industrial | 4,237,252 | 4,473,549 | (5.3) | % | |||||||||||||||||||
| Real estate - residential mortgage | 2,876,538 | 2,441,684 | 17.8 | % | |||||||||||||||||||
| Real estate - home equity | 1,255,094 | 1,382,908 | (9.2) | % | |||||||||||||||||||
| Real estate - construction | 965,534 | 928,183 | 4.0 | % | |||||||||||||||||||
| Consumer | 466,419 | 448,205 | 4.1 | % | |||||||||||||||||||
| Equipment lease financing | 281,859 | 279,489 | 0.8 | % | |||||||||||||||||||
| Other(1) | (4,640) | 12,546 | N/M | ||||||||||||||||||||
| Loans, net of unearned income before PPP | 17,006,325 | 16,430,347 | 3.5 | % | |||||||||||||||||||
| PPP | 1,264,065 | — | N/M | ||||||||||||||||||||
| Total Loans, net of unearned income | $ | 18,270,390 | $ | 16,430,347 | 11.2 | % | |||||||||||||||||
| Deposits, by type: | |||||||||||||||||||||||
| Noninterest-bearing demand | $ | 5,714,803 | $ | 4,249,294 | 34.5 | % | |||||||||||||||||
| Interest-bearing demand | 5,278,941 | 4,384,059 | 20.4 | % | |||||||||||||||||||
| Savings | 5,550,234 | 5,018,381 | 10.6 | % | |||||||||||||||||||
| Total demand and savings | 16,543,978 | 13,651,734 | 21.2 | % | |||||||||||||||||||
| Brokered | 310,763 | 245,501 | 26.6 | % | |||||||||||||||||||
| Time | 2,546,305 | 2,869,326 | (11.3) | % | |||||||||||||||||||
| Total Deposits | $ | 19,401,046 | $ | 16,766,561 | 15.7 | % | |||||||||||||||||
| Short-term borrowings, by type: | |||||||||||||||||||||||
| Customer funding | $ | 553,033 | $ | 355,983 | 55.4 | % | |||||||||||||||||
| Federal funds purchased | 64,918 | 132,578 | (51.0) | % | |||||||||||||||||||
| Short-term FHLB advances and other borrowings | 192,632 | 361,118 | (46.7) | % | |||||||||||||||||||
| Total Short-term Borrowings | $ | 810,583 | $ | 849,679 | (4.6) | % | |||||||||||||||||
| (1) Consists of overdrafts and net origination fees and costs. | |||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | |||||||||||||||||||||||||||||||||||||||||||||||
| ASSET QUALITY INFORMATION (UNAUDITED) | |||||||||||||||||||||||||||||||||||||||||||||||
| dollars in thousands | |||||||||||||||||||||||||||||||||||||||||||||||
| Three months ended | Year ended | ||||||||||||||||||||||||||||||||||||||||||||||
| Dec 31 | Sep 30 | Jun 30 | Mar 31 | Dec 31 | Dec 31 | Dec 31 | |||||||||||||||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2020 | 2019 | 2020 | 2019 | |||||||||||||||||||||||||||||||||||||||||
| Allowance for credit losses related to Loans, net of unearned income: | |||||||||||||||||||||||||||||||||||||||||||||||
| Balance at beginning of period | $ | 266,825 | $ | 256,537 | $ | 238,508 | $ | 163,620 | $ | 166,135 | $ | 163,622 | $ | 160,537 | |||||||||||||||||||||||||||||||||
| Impact of adopting CECL | — | — | — | 45,724 | — | 45,724 | — | ||||||||||||||||||||||||||||||||||||||||
| Loans charged off: | |||||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | (1,567) | (2,969) | (3,480) | (10,899) | (30,547) | (18,915) | (42,410) | ||||||||||||||||||||||||||||||||||||||||
| Real estate - commercial mortgage | (300) | (746) | (2,324) | (855) | (68) | (4,225) | (1,837) | ||||||||||||||||||||||||||||||||||||||||
| Consumer and home equity | (668) | (1,093) | (1,303) | (1,529) | (1,416) | (4,593) | (4,694) | ||||||||||||||||||||||||||||||||||||||||
| Real estate - residential mortgage | — | (198) | (235) | (187) | (223) | (620) | (1,545) | ||||||||||||||||||||||||||||||||||||||||
| Real estate - construction | — | — | (17) | — | — | (17) | (143) | ||||||||||||||||||||||||||||||||||||||||
| Equipment lease financing and other | (483) | (483) | (688) | (533) | (727) | (2,187) | (2,560) | ||||||||||||||||||||||||||||||||||||||||
| Total loans charged off | (3,018) | (5,489) | (8,047) | (14,003) | (32,981) | (30,557) | (53,189) | ||||||||||||||||||||||||||||||||||||||||
| Recoveries of loans previously charged off: | |||||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 4,581 | 2,103 | 2,978 | 1,734 | 2,487 | 11,396 | 8,721 | ||||||||||||||||||||||||||||||||||||||||
| Real estate - commercial mortgage | 588 | 100 | 95 | 244 | 1,453 | 1,027 | 2,202 | ||||||||||||||||||||||||||||||||||||||||
| Consumer and home equity | 594 | 491 | 649 | 646 | 437 | 2,380 | 1,994 | ||||||||||||||||||||||||||||||||||||||||
| Real estate - residential mortgage | 199 | 95 | 112 | 85 | 206 | 491 | 989 | ||||||||||||||||||||||||||||||||||||||||
| Real estate - construction | 179 | 4,873 | — | 70 | 1,098 | 5,122 | 2,591 | ||||||||||||||||||||||||||||||||||||||||
| Equipment lease financing and other | 219 | 185 | 92 | 108 | 182 | 604 | 666 | ||||||||||||||||||||||||||||||||||||||||
| Recoveries of loans previously charged off | 6,360 | 7,847 | 3,926 | 2,887 | 5,863 | 21,020 | 17,163 | ||||||||||||||||||||||||||||||||||||||||
| Net loans recovered (charged off) | 3,342 | 2,358 | (4,121) | (11,116) | (27,118) | (9,537) | (36,026) | ||||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 7,400 | 7,930 | 22,150 | 40,280 | 24,603 | 77,760 | 39,111 | ||||||||||||||||||||||||||||||||||||||||
| Balance at end of period | $ | 277,567 | $ | 266,825 | $ | 256,537 | $ | 238,508 | $ | 163,620 | $ | 277,569 | $ | 163,622 | |||||||||||||||||||||||||||||||||
| Net (recoveries) charge-offs to average loans (annualized) | (0.07) | % | (0.05) | % | 0.09 | % | 0.26 | % | 0.65 | % | 0.05 | % | 0.22 | % | |||||||||||||||||||||||||||||||||
Allowance credit losses related to OBS Credit Exposures(1) | |||||||||||||||||||||||||||||||||||||||||||||||
| Balance at beginning of period | $ | 15,533 | $ | 16,383 | $ | 18,963 | $ | 2,588 | $ | 6,662 | |||||||||||||||||||||||||||||||||||||
| Impact of adopting CECL | — | — | — | 12,625 | — | ||||||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | (1,160) | (850) | (2,580) | 3,750 | (4,074) | ||||||||||||||||||||||||||||||||||||||||||
| Balance at end of period | $ | 14,373 | $ | 15,533 | $ | 16,383 | $ | 18,963 | $ | 2,588 | |||||||||||||||||||||||||||||||||||||
| NON-PERFORMING ASSETS: | |||||||||||||||||||||||||||||||||||||||||||||||
| Non-accrual loans | $ | 137,198 | $ | 128,321 | $ | 125,037 | $ | 120,345 | $ | 125,098 | |||||||||||||||||||||||||||||||||||||
| Loans 90 days past due and accruing | 9,929 | 13,761 | 14,767 | 19,593 | 16,057 | ||||||||||||||||||||||||||||||||||||||||||
| Total non-performing loans | 147,127 | 142,082 | 139,804 | 139,938 | 141,155 | ||||||||||||||||||||||||||||||||||||||||||
| Other real estate owned | 4,178 | 4,565 | 5,418 | 6,593 | 6,831 | ||||||||||||||||||||||||||||||||||||||||||
| Total non-performing assets | $ | 151,305 | $ | 146,647 | $ | 145,222 | $ | 146,531 | $ | 147,986 | |||||||||||||||||||||||||||||||||||||
| NON-PERFORMING LOANS, BY TYPE: | |||||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 32,610 | $ | 37,224 | $ | 39,730 | $ | 41,318 | $ | 49,491 | |||||||||||||||||||||||||||||||||||||
| Real estate - commercial mortgage | 52,647 | 43,426 | 42,374 | 36,538 | 37,279 | ||||||||||||||||||||||||||||||||||||||||||
| Real estate - residential mortgage | 30,793 | 28,287 | 22,887 | 25,832 | 22,411 | ||||||||||||||||||||||||||||||||||||||||||
| Consumer and home equity | 13,090 | 12,292 | 11,911 | 11,226 | 11,026 | ||||||||||||||||||||||||||||||||||||||||||
| Real estate - construction | 1,550 | 4,051 | 4,525 | 4,379 | 4,306 | ||||||||||||||||||||||||||||||||||||||||||
| Equipment lease financing and other | 16,437 | 16,802 | 18,377 | 20,645 | 16,642 | ||||||||||||||||||||||||||||||||||||||||||
| Total non-performing loans | $ | 147,127 | $ | 142,082 | $ | 139,804 | $ | 139,938 | $ | 141,155 | |||||||||||||||||||||||||||||||||||||
| (1) The allowance for credit losses related to OBS Credit Exposures is presented in "other liabilities" on the consolidated balance sheets. | |||||||||||||||||||||||||||||||||||||||||||||||
| FULTON FINANCIAL CORPORATION | ||||||||||||||||||||||||||||||||||||||||||||||||||
| RECONCILIATION OF NON-GAAP MEASURES (UNAUDITED) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| in thousands, except per share data and percentages | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Explanatory note: | This press release contains supplemental financial information, as detailed below, which has been derived by methods other than Generally Accepted Accounting Principles ("GAAP"). The Corporation has presented these non-GAAP financial measures because it believes that these measures provide useful and comparative information to assess trends in the Corporation's results of operations. Presentation of these non-GAAP financial measures is consistent with how the Corporation evaluates its performance internally and these non-GAAP financial measures are frequently used by securities analysts, investors and other interested parties in the evaluation of companies in the Corporation's industry. Management believes that these non-GAAP financial measures, in addition to GAAP measures, are also useful to investors to evaluate the Corporation's results. Investors should recognize that the Corporation's presentation of these non-GAAP financial measures might not be comparable to similarly-titled measures of other companies. These non-GAAP financial measures should not be considered a substitute for GAAP basis measures, and the Corporation strongly encourages a review of its condensed consolidated financial statements in their entirety. Reconciliations of these non-GAAP financial measures to the most directly comparable GAAP measure follow: | |||||||||||||||||||||||||||||||||||||||||||||||||
| Three months ended | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Dec 31 | Sep 30 | Jun 30 | Mar 31 | Dec 31 | ||||||||||||||||||||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2020 | 2019 | ||||||||||||||||||||||||||||||||||||||||||||||
| Common shareholders' equity (tangible), per share | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders' equity | $ | 2,616,828 | $ | 2,390,261 | $ | 2,340,501 | $ | 2,285,748 | $ | 2,342,176 | ||||||||||||||||||||||||||||||||||||||||
| Less: Preferred stock | (192,878) | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Less: Goodwill and intangible assets | (536,659) | (534,907) | (535,039) | (535,171) | (535,303) | |||||||||||||||||||||||||||||||||||||||||||||
| Tangible common shareholders' equity (numerator) | $ | 1,887,291 | $ | 1,855,354 | $ | 1,805,462 | $ | 1,750,577 | $ | 1,806,873 | ||||||||||||||||||||||||||||||||||||||||
| Shares outstanding, end of period (denominator) | 162,350 | 162,134 | 161,958 | 161,435 | 164,218 | |||||||||||||||||||||||||||||||||||||||||||||
| Common shareholders' equity (tangible), per share | $ | 11.62 | $ | 11.44 | $ | 11.15 | $ | 10.84 | $ | 11.00 | ||||||||||||||||||||||||||||||||||||||||
| Return on average common shareholders' equity (tangible) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net income available to common shareholders | $ | 48,690 | $ | 61,610 | $ | 39,558 | $ | 26,047 | $ | 47,789 | ||||||||||||||||||||||||||||||||||||||||
| Plus: Intangible amortization, net of tax | 104 | 103 | 104 | 104 | 112 | |||||||||||||||||||||||||||||||||||||||||||||
| (Numerator) | $ | 48,794 | $ | 61,713 | $ | 39,662 | $ | 26,151 | $ | 47,901 | ||||||||||||||||||||||||||||||||||||||||
| Average shareholders' equity | $ | 2,544,866 | $ | 2,374,091 | $ | 2,309,133 | $ | 2,337,016 | $ | 2,341,397 | ||||||||||||||||||||||||||||||||||||||||
| Less: Average preferred stock | (127,639) | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Less: Average goodwill and intangible assets | (535,474) | (534,971) | (535,103) | (535,235) | (534,190) | |||||||||||||||||||||||||||||||||||||||||||||
| Average tangible common shareholders' equity (denominator) | $ | 1,881,753 | $ | 1,839,120 | $ | 1,774,030 | $ | 1,801,781 | $ | 1,807,207 | ||||||||||||||||||||||||||||||||||||||||
| Return on average common shareholders' equity (tangible), annualized | 10.32 | % | 13.50 | % | 8.99 | % | 5.84 | % | 10.52 | % | ||||||||||||||||||||||||||||||||||||||||
| Tangible common equity to tangible assets (TCE Ratio) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders' equity | $ | 2,616,828 | $ | 2,390,261 | $ | 2,340,501 | $ | 2,285,748 | $ | 2,342,176 | ||||||||||||||||||||||||||||||||||||||||
| Less: Preferred stock | (192,878) | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Less: Goodwill and intangible assets | (536,659) | (534,907) | (535,039) | (535,171) | (535,303) | |||||||||||||||||||||||||||||||||||||||||||||
| Tangible common shareholders' equity (numerator) | $ | 1,887,291 | $ | 1,855,354 | $ | 1,805,462 | $ | 1,750,577 | $ | 1,806,873 | ||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 25,906,733 | $ | 25,543,281 | $ | 24,617,863 | $ | 22,929,859 | $ | 21,886,040 | ||||||||||||||||||||||||||||||||||||||||
| Less: Goodwill and intangible assets | (536,659) | (534,907) | (535,039) | (535,171) | (535,303) | |||||||||||||||||||||||||||||||||||||||||||||
| Total tangible assets (denominator) | $ | 25,370,074 | $ | 25,008,374 | $ | 24,082,824 | $ | 22,394,688 | $ | 21,350,737 | ||||||||||||||||||||||||||||||||||||||||
| Tangible common equity to tangible assets | 7.44 | % | 7.42 | % | 7.50 | % | 7.82 | % | 8.46 | % | ||||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-interest expense | $ | 154,737 | $ | 139,145 | $ | 143,006 | $ | 142,552 | $ | 138,974 | ||||||||||||||||||||||||||||||||||||||||
| Less: Amortization of tax credit investments | (1,532) | (1,694) | (1,450) | (1,450) | (1,505) | |||||||||||||||||||||||||||||||||||||||||||||
| Less: Intangible amortization | (132) | (132) | (132) | (132) | (142) | |||||||||||||||||||||||||||||||||||||||||||||
| Less: Prepayment penalty on FHLB advances | — | — | (2,878) | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Non-interest expense (numerator) | $ | 153,073 | $ | 137,319 | $ | 138,546 | $ | 140,970 | $ | 137,327 | ||||||||||||||||||||||||||||||||||||||||
| Net interest income (fully taxable equivalent) | $ | 164,578 | $ | 157,106 | $ | 155,854 | $ | 163,970 | $ | 162,479 | ||||||||||||||||||||||||||||||||||||||||
| Plus: Total Non-interest income | 55,574 | 63,248 | 55,922 | 54,644 | 55,281 | |||||||||||||||||||||||||||||||||||||||||||||
| Less: Investment securities gains, net | — | (2) | (3,005) | (46) | — | |||||||||||||||||||||||||||||||||||||||||||||
| Total revenue (denominator) | $ | 220,151 | $ | 220,353 | $ | 208,771 | $ | 218,568 | $ | 217,760 | ||||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | 69.5 | % | 62.3 | % | 66.4 | % | 64.5 | % | 63.1 | % | ||||||||||||||||||||||||||||||||||||||||
| Three months ended | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Dec 31 | Sep 30 | Jun 30 | Mar 31 | Dec 31 | ||||||||||||||||||||||||||||||||||||||||||||||
| 2020 | 2020 | 2020 | 2020 | 2019 | ||||||||||||||||||||||||||||||||||||||||||||||
| Efficiency ratio, net 2020 cost savings initiatives | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-interest expense | $ | 154,737 | $ | 139,145 | $ | 143,006 | $ | 142,552 | $ | 138,974 | ||||||||||||||||||||||||||||||||||||||||
| Less: Amortization of tax credit investments | (1,532) | (1,694) | (1,450) | (1,450) | (1,505) | |||||||||||||||||||||||||||||||||||||||||||||
| Less: Intangible amortization | (132) | (132) | (132) | (132) | (142) | |||||||||||||||||||||||||||||||||||||||||||||
| Less: 2020 cost savings initiatives | (15,400) | (800) | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Less: Prepayment penalty on FHLB advances | — | — | (2,878) | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Non-interest expense (numerator) | $ | 137,673 | $ | 136,519 | $ | 138,546 | $ | 140,970 | $ | 137,327 | ||||||||||||||||||||||||||||||||||||||||
| Net interest income (fully taxable equivalent) | $ | 164,578 | $ | 157,106 | $ | 155,854 | $ | 163,970 | $ | 162,479 | ||||||||||||||||||||||||||||||||||||||||
| Plus: Total Non-interest income | 55,574 | 63,248 | 55,922 | 54,644 | 55,281 | |||||||||||||||||||||||||||||||||||||||||||||
| Less: Investment securities gains, net | — | (2) | (3,005) | (46) | — | |||||||||||||||||||||||||||||||||||||||||||||
| Total revenue (denominator) | $ | 220,151 | $ | 220,353 | $ | 208,771 | $ | 218,568 | $ | 217,760 | ||||||||||||||||||||||||||||||||||||||||
| Efficiency ratio, net 2020 cost savings initiatives | 62.5 | % | 62.0 | % | 66.4 | % | 64.5 | % | 63.1 | % | ||||||||||||||||||||||||||||||||||||||||
| Non-performing assets to common shareholders' equity (tangible) and ACL - loans(1) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-performing assets (numerator) | $ | 151,305 | $ | 146,647 | $ | 145,222 | $ | 146,531 | $ | 147,986 | ||||||||||||||||||||||||||||||||||||||||
| Tangible common shareholders' equity | $ | 1,887,291 | $ | 1,855,354 | $ | 1,805,462 | $ | 1,750,577 | $ | 1,806,873 | ||||||||||||||||||||||||||||||||||||||||
| Plus: ACL - loans | 277,567 | 266,825 | 256,537 | 238,508 | 163,622 | |||||||||||||||||||||||||||||||||||||||||||||
| Tangible common shareholders' equity and ACL - loans (denominator) | $ | 2,164,858 | $ | 2,122,179 | $ | 2,061,999 | $ | 1,989,085 | $ | 1,970,495 | ||||||||||||||||||||||||||||||||||||||||
| Non-performing assets to tangible common shareholders' equity and ACL - loans | 6.99 | % | 6.91 | % | 7.04 | % | 7.37 | % | 7.51 | % | ||||||||||||||||||||||||||||||||||||||||
| Asset Quality, excluding PPP | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net loans recovered (charged-off) (numerator) | $ | 3,342 | $ | 2,358 | $ | (4,121) | $ | (11,116) | $ | (27,118) | ||||||||||||||||||||||||||||||||||||||||
| Average loans, net of unearned income | $ | 18,994,514 | $ | 18,880,519 | $ | 18,331,797 | $ | 16,860,067 | $ | 16,766,971 | ||||||||||||||||||||||||||||||||||||||||
| Less: Average PPP loans | (1,830,426) | (1,953,122) | (1,258,917) | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Total adjusted average loans (denominator) | $ | 17,164,088 | $ | 16,927,397 | $ | 17,072,880 | $ | 16,860,067 | $ | 16,766,971 | ||||||||||||||||||||||||||||||||||||||||
| Net (recoveries) charge-offs to adjusted average loans (annualized) | (0.08) | % | (0.06) | % | 0.10 | % | 0.26 | % | 0.65 | % | ||||||||||||||||||||||||||||||||||||||||
| Non-performing loans (numerator) | $ | 147,127 | $ | 142,082 | $ | 139,804 | $ | 139,938 | $ | 141,155 | ||||||||||||||||||||||||||||||||||||||||
| Loans, net of unearned income | $ | 18,900,820 | $ | 19,028,621 | $ | 18,704,722 | $ | 17,077,403 | $ | 16,837,526 | ||||||||||||||||||||||||||||||||||||||||
| Less: PPP loans | (1,581,712) | (1,960,165) | (1,937,034) | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Total adjusted loans (denominator) | $ | 17,319,108 | $ | 17,068,456 | $ | 16,767,688 | $ | 17,077,403 | $ | 16,837,526 | ||||||||||||||||||||||||||||||||||||||||
| Non-performing loans to adjusted total loans | 0.85 | % | 0.83 | % | 0.83 | % | 0.82 | % | 0.84 | % | ||||||||||||||||||||||||||||||||||||||||
| ACL - loans (numerator) | $ | 277,567 | $ | 266,825 | 256,537 | 238,508 | $ | 163,622 | ||||||||||||||||||||||||||||||||||||||||||
| Loans, net of unearned income | $ | 18,900,820 | $ | 19,028,621 | $ | 18,704,722 | $ | 17,077,403 | $ | 16,837,526 | ||||||||||||||||||||||||||||||||||||||||
| Less: PPP loans | (1,581,712) | (1,960,165) | (1,937,034) | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Total adjusted loans (denominator) | $ | 17,319,108 | $ | 17,068,456 | $ | 16,767,688 | $ | 17,077,403 | $ | 16,837,526 | ||||||||||||||||||||||||||||||||||||||||
| ACL - loans to adjusted total loans | 1.60 | % | 1.56 | % | 1.53 | % | 1.40 | % | 0.97 | % | ||||||||||||||||||||||||||||||||||||||||
| Note: numbers may not sum due to rounding. | ||||||||||||||||||||||||||||||||||||||||||||||||||
| (1) "ACL - loans" relates to the ACL specifically on "Loans, net of unearned income" and does not include the ACL related to OBS credit exposures. | ||||||||||||||||||||||||||||||||||||||||||||||||||
2020 AND FOURTH QUARTER RESULTS NASDAQ: FULT Data as of December 31, 2020 unless otherwise noted
This presentation may contain forward-looking statements with respect to the Corporation’s financial condition, results of operations and business. Do not unduly rely on forward-looking statements. Forward-looking statements can be identified by the use of words such as "may," "should," "will," "could," "estimates," "predicts," "potential," "continue," "anticipates," "believes," "plans," "expects," "future," "intends," “projects,” the negative of these terms and other comparable terminology. These forward-looking statements may include projections of, or guidance on, the Corporation’s future financial performance, expected levels of future expenses, including future credit losses, anticipated growth strategies, descriptions of new business initiatives and anticipated trends in the Corporation’s business or financial results. Management’s 2021 Outlook contained herein is comprised of forward-looking statements. Forward-looking statements are neither historical facts, nor assurance of future performance. Instead, they are based on current beliefs, expectations and assumptions regarding the future of the Corporation’s business, future plans and strategies, projections, anticipated events and trends, the economy and other future conditions. Because forward-looking statements relate to the future, they are subject to inherent uncertainties, risks and changes in circumstances that are difficult to predict and many of which are outside of the Corporation’s control, and actual results and financial condition may differ materially from those indicated in the forward-looking statements. Therefore, you should not unduly rely on any of these forward-looking statements. Any forward-looking statement is based only on information currently available and speaks only as of the date when made. The Corporation undertakes no obligation, other than as required by law, to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise. A discussion of certain risks and uncertainties affecting the Corporation, and some of the factors that could cause the Corporation’s actual results to differ materially from those described in the forward-looking statements, can be found in the sections entitled “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2019, Quarterly Reports on Form 10-Q for the quarters end March 31, 2020, June 30, 2020 and September 30, 2020 and other current and periodic reports, which have been, or will be, filed with the Securities and Exchange Commission and are or will be available in the Investor Relations section of the Corporation’s website (www.fult.com) and on the Securities and Exchange Commission’s website (www.sec.gov). The Corporation uses certain non-GAAP financial measures in this presentation. These non-GAAP financial measures are reconciled to the most comparable GAAP measures at the end of this presentation. FORWARD-LOOKING STATEMENTS 2
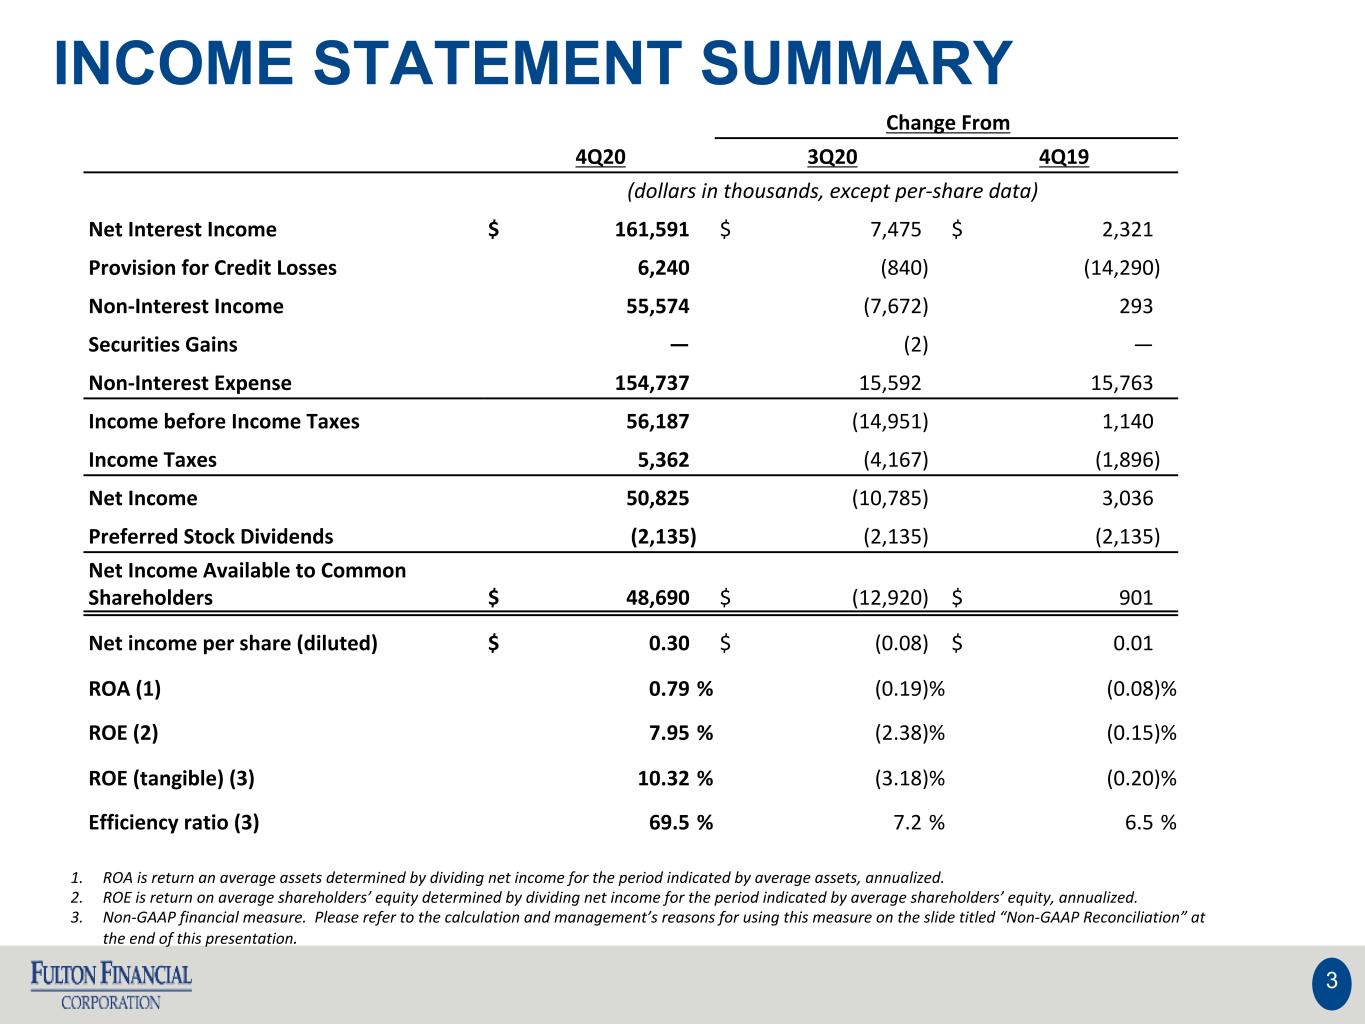
1. ROA is return an average assets determined by dividing net income for the period indicated by average assets, annualized. 2. ROE is return on average shareholders’ equity determined by dividing net income for the period indicated by average shareholders’ equity, annualized. 3. Non-GAAP financial measure. Please refer to the calculation and management’s reasons for using this measure on the slide titled “Non-GAAP Reconciliation” at the end of this presentation. INCOME STATEMENT SUMMARY 3 Change From 4Q20 3Q20 4Q19 (dollars in thousands, except per-share data) Net Interest Income $ 161,591 $ 7,475 $ 2,321 Provision for Credit Losses 6,240 (840) (14,290) Non-Interest Income 55,574 (7,672) 293 Securities Gains — (2) — Non-Interest Expense 154,737 15,592 15,763 Income before Income Taxes 56,187 (14,951) 1,140 Income Taxes 5,362 (4,167) (1,896) Net Income 50,825 (10,785) 3,036 Preferred Stock Dividends (2,135) (2,135) (2,135) Net Income Available to Common Shareholders $ 48,690 $ (12,920) $ 901 Net income per share (diluted) $ 0.30 $ (0.08) $ 0.01 ROA (1) 0.79 % (0.19) % (0.08) % ROE (2) 7.95 % (2.38) % (0.15) % ROE (tangible) (3) 10.32 % (3.18) % (0.20) % Efficiency ratio (3) 69.5 % 7.2 % 6.5 %
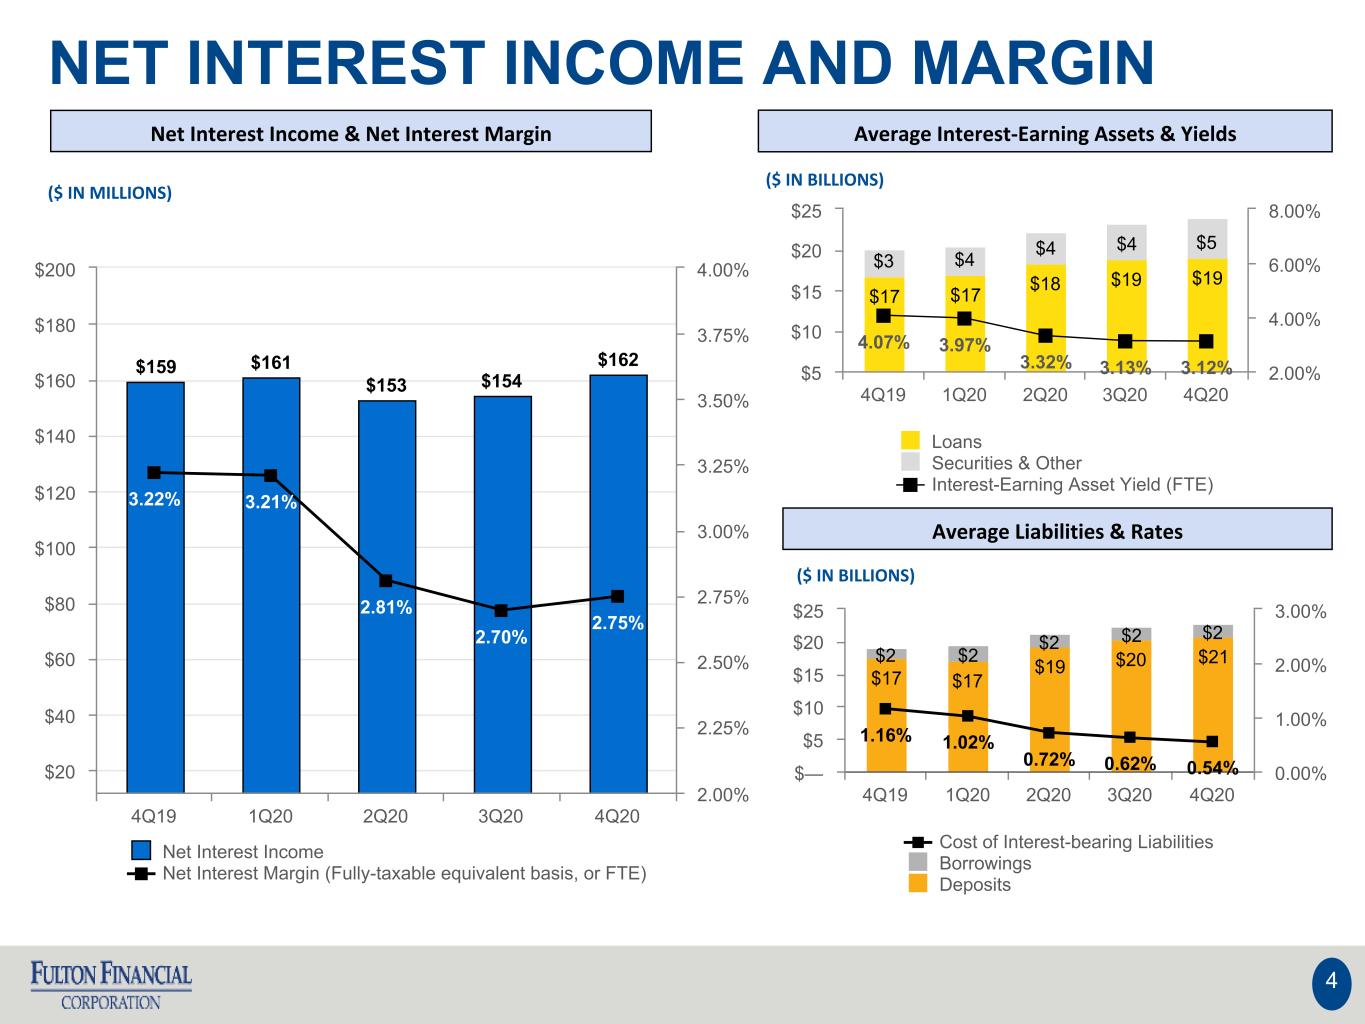
NET INTEREST INCOME AND MARGIN Net Interest Income & Net Interest Margin Average Interest-Earning Assets & Yields Average Liabilities & Rates ($ IN MILLIONS) ($ IN BILLIONS) ($ IN BILLIONS) 4 $17 $17 $19 $20 $21 $2 $2 $2 $2 $2 1.16% 1.02% 0.72% 0.62% 0.54% Cost of Interest-bearing Liabilities Borrowings Deposits 4Q19 1Q20 2Q20 3Q20 4Q20 $— $5 $10 $15 $20 $25 0.00% 1.00% 2.00% 3.00% $159 $161 $153 $154 $162 3.22% 3.21% 2.81% 2.70% 2.75% Net Interest Income Net Interest Margin (Fully-taxable equivalent basis, or FTE) 4Q19 1Q20 2Q20 3Q20 4Q20 $20 $40 $60 $80 $100 $120 $140 $160 $180 $200 2.00% 2.25% 2.50% 2.75% 3.00% 3.25% 3.50% 3.75% 4.00% $17 $17 $18 $19 $19 $3 $4 $4 $4 $5 4.07% 3.97% 3.32% 3.13% 3.12% Loans Securities & Other Interest-Earning Asset Yield (FTE) 4Q19 1Q20 2Q20 3Q20 4Q20 $5 $10 $15 $20 $25 2.00% 4.00% 6.00% 8.00%
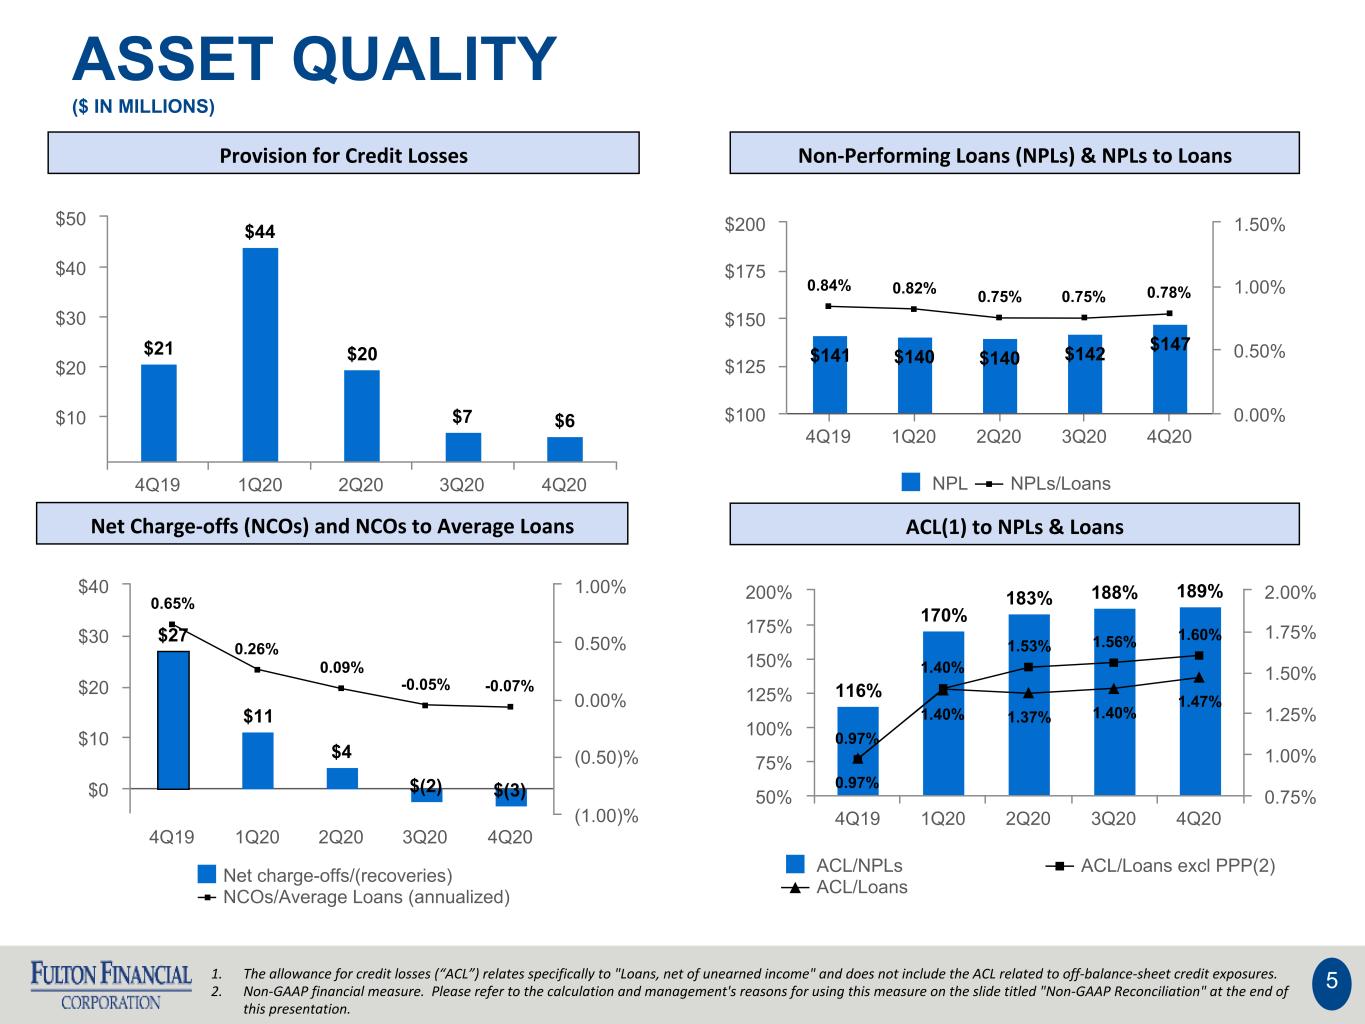
ASSET QUALITY ($ IN MILLIONS) Provision for Credit Losses Non-Performing Loans (NPLs) & NPLs to Loans Net Charge-offs (NCOs) and NCOs to Average Loans ACL(1) to NPLs & Loans 51. The allowance for credit losses (“ACL”) relates specifically to "Loans, net of unearned income" and does not include the ACL related to off-balance-sheet credit exposures. 2. Non-GAAP financial measure. Please refer to the calculation and management's reasons for using this measure on the slide titled "Non-GAAP Reconciliation" at the end of this presentation. $21 $44 $20 $7 $6 4Q19 1Q20 2Q20 3Q20 4Q20 $10 $20 $30 $40 $50 $141 $140 $140 $142 $147 0.84% 0.82% 0.75% 0.75% 0.78% NPL NPLs/Loans 4Q19 1Q20 2Q20 3Q20 4Q20 $100 $125 $150 $175 $200 0.00% 0.50% 1.00% 1.50% $27 $11 $4 $(2) $(3) 0.65% 0.26% 0.09% -0.05% -0.07% Net charge-offs/(recoveries) NCOs/Average Loans (annualized) 4Q19 1Q20 2Q20 3Q20 4Q20 $0 $10 $20 $30 $40 (1.00)% (0.50)% 0.00% 0.50% 1.00% 116% 170% 183% 188% 189% 0.97% 1.40% 1.53% 1.56% 1.60% 0.97% 1.40% 1.37% 1.40% 1.47% ACL/NPLs ACL/Loans excl PPP(2) ACL/Loans 4Q19 1Q20 2Q20 3Q20 4Q20 50% 75% 100% 125% 150% 175% 200% 0.75% 1.00% 1.25% 1.50% 1.75% 2.00%
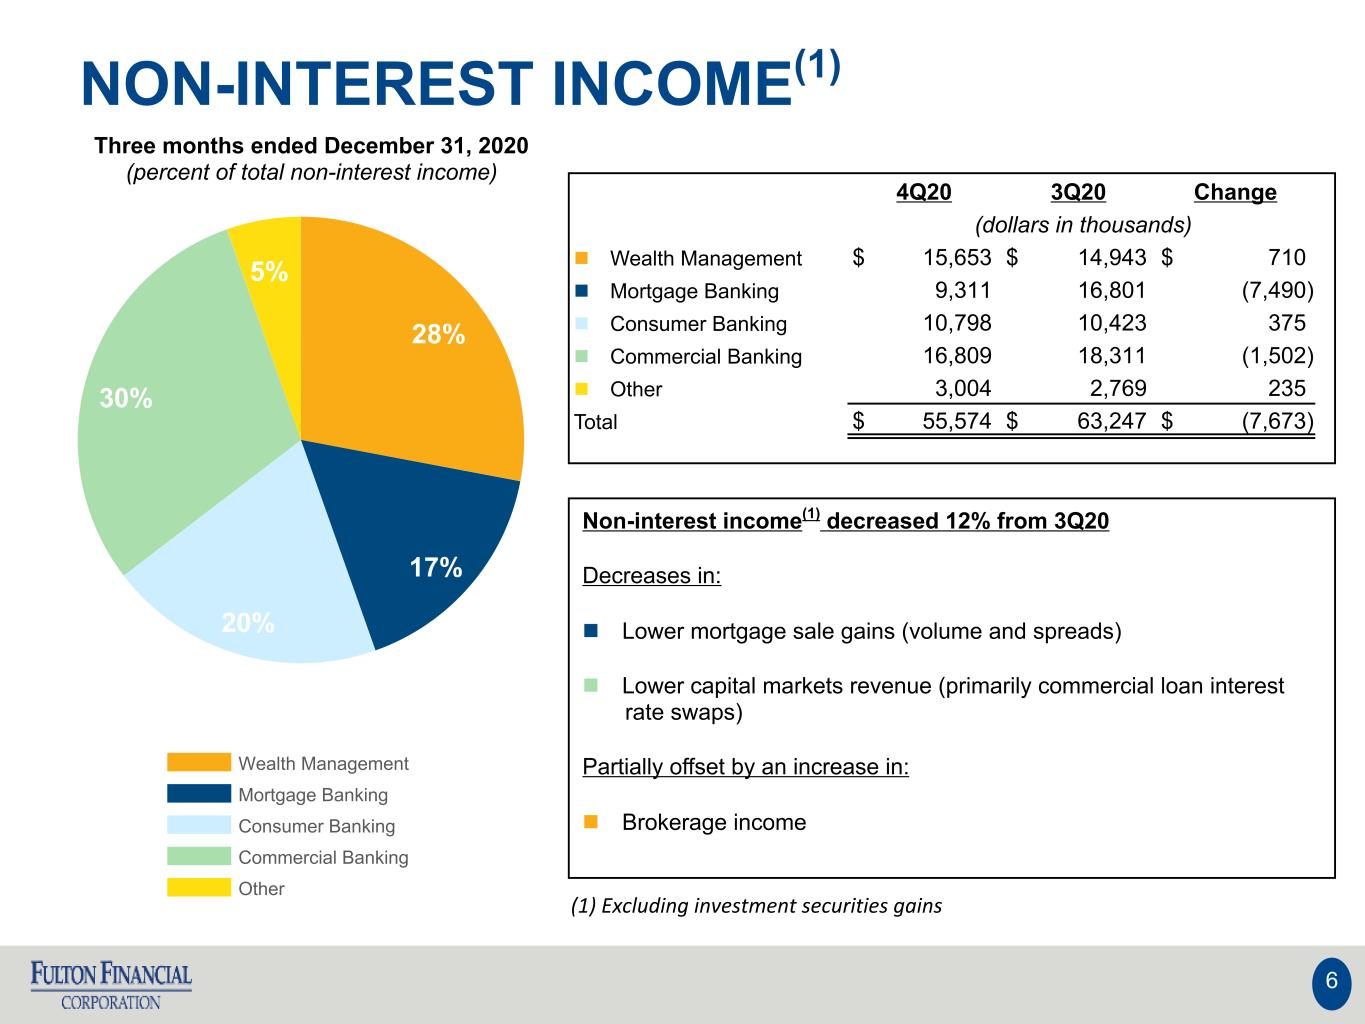
NON-INTEREST INCOME(1) (1) Excluding investment securities gains Three months ended December 31, 2020 (percent of total non-interest income) 6 Non-interest income(1) decreased 12% from 3Q20 Decreases in: n Lower mortgage sale gains (volume and spreads) n Lower capital markets revenue (primarily commercial loan interest rate swaps) Partially offset by an increase in: n Brokerage income 28% 17% 20% 30% 5% Wealth Management Mortgage Banking Consumer Banking Commercial Banking Other 4Q20 3Q20 Change (dollars in thousands) n Wealth Management $ 15,653 $ 14,943 $ 710 n Mortgage Banking 9,311 16,801 (7,490) n Consumer Banking 10,798 10,423 375 n Commercial Banking 16,809 18,311 (1,502) n Other 3,004 2,769 235 Total $ 55,574 $ 63,247 $ (7,673)
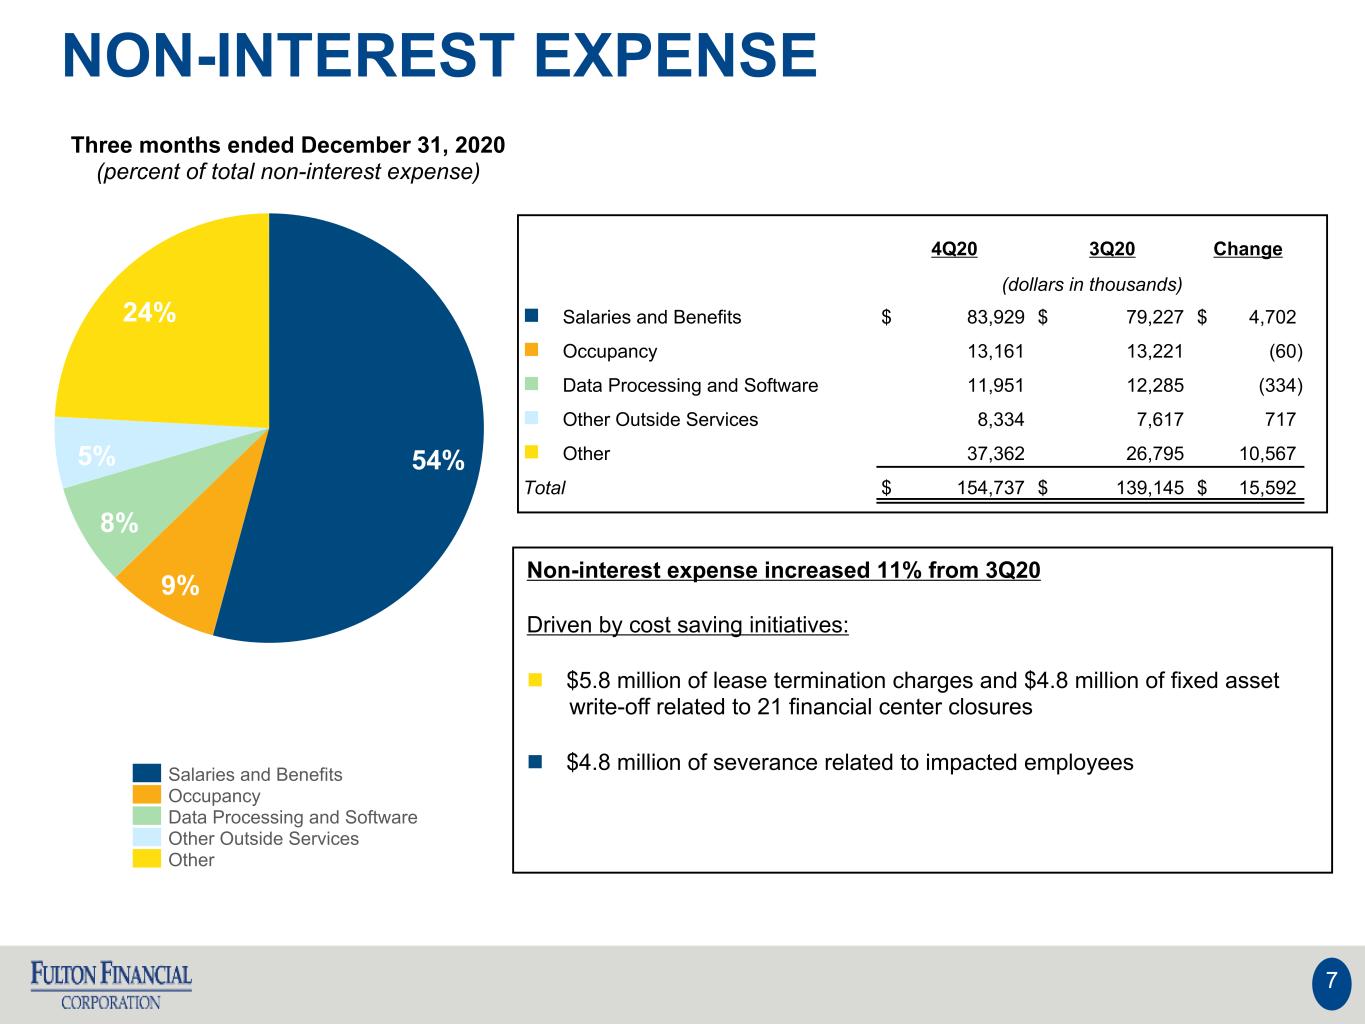
NON-INTEREST EXPENSE Three months ended December 31, 2020 (percent of total non-interest expense) 7 54% 9% 8% 5% 24% Salaries and Benefits Occupancy Data Processing and Software Other Outside Services Other 4Q20 3Q20 Change (dollars in thousands) n Salaries and Benefits $ 83,929 $ 79,227 $ 4,702 n Occupancy 13,161 13,221 (60) n Data Processing and Software 11,951 12,285 (334) n Other Outside Services 8,334 7,617 717 n Other 37,362 26,795 10,567 Total $ 154,737 $ 139,145 $ 15,592 Non-interest expense increased 11% from 3Q20 Driven by cost saving initiatives: n $5.8 million of lease termination charges and $4.8 million of fixed asset write-off related to 21 financial center closures n $4.8 million of severance related to impacted employees
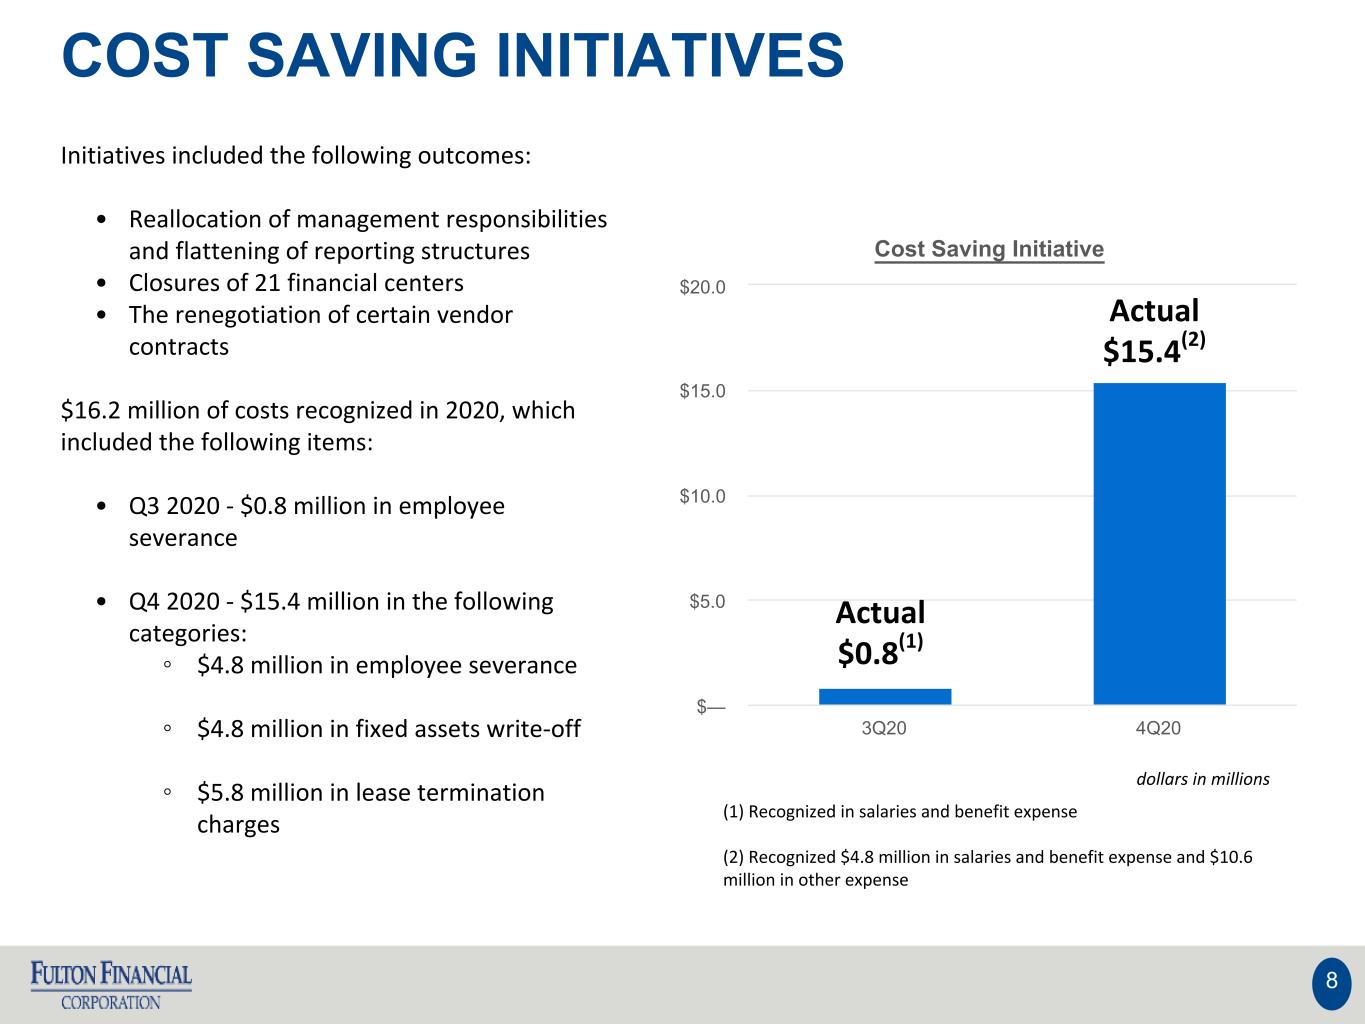
COST SAVING INITIATIVES 8 Initiatives included the following outcomes: • Reallocation of management responsibilities and flattening of reporting structures • Closures of 21 financial centers • The renegotiation of certain vendor contracts $16.2 million of costs recognized in 2020, which included the following items: • Q3 2020 - $0.8 million in employee severance • Q4 2020 - $15.4 million in the following categories: ◦ $4.8 million in employee severance ◦ $4.8 million in fixed assets write-off ◦ $5.8 million in lease termination charges Cost Saving Initiative 3Q20 4Q20 $— $5.0 $10.0 $15.0 $20.0 dollars in millions Actual $0.8(1) Actual $15.4(2) (1) Recognized in salaries and benefit expense (2) Recognized $4.8 million in salaries and benefit expense and $10.6 million in other expense
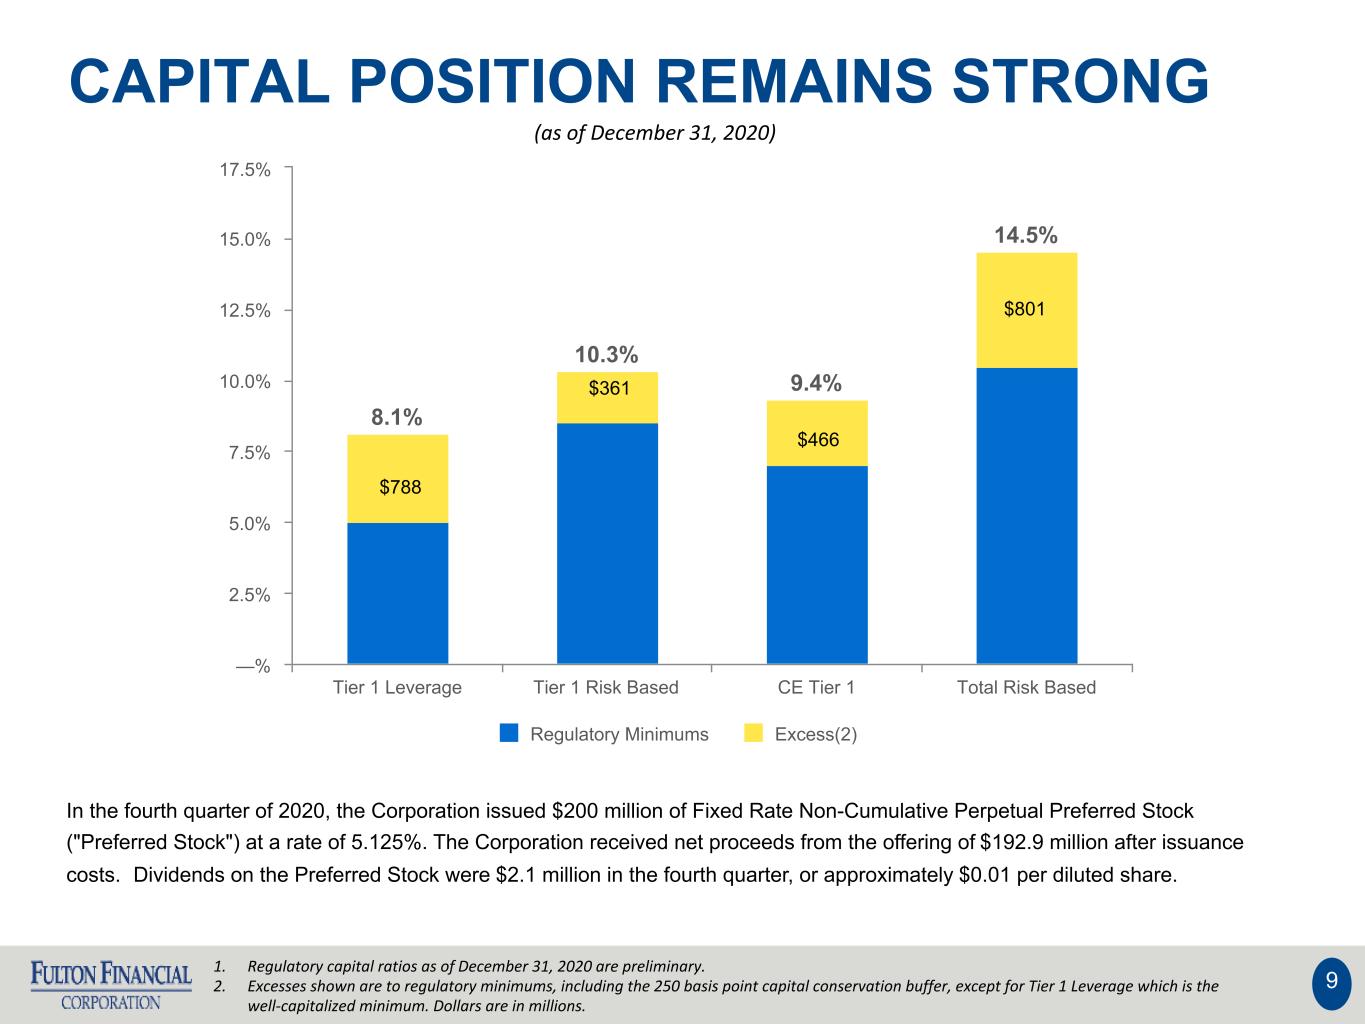
CAPITAL POSITION REMAINS STRONG 9 In the fourth quarter of 2020, the Corporation issued $200 million of Fixed Rate Non-Cumulative Perpetual Preferred Stock ("Preferred Stock") at a rate of 5.125%. The Corporation received net proceeds from the offering of $192.9 million after issuance costs. Dividends on the Preferred Stock were $2.1 million in the fourth quarter, or approximately $0.01 per diluted share. 1. Regulatory capital ratios as of December 31, 2020 are preliminary. 2. Excesses shown are to regulatory minimums, including the 250 basis point capital conservation buffer, except for Tier 1 Leverage which is the well-capitalized minimum. Dollars are in millions. 8.1% 10.3% 9.4% 14.5% Regulatory Minimums Excess(2) Tier 1 Leverage Tier 1 Risk Based CE Tier 1 Total Risk Based —% 2.5% 5.0% 7.5% 10.0% 12.5% 15.0% 17.5% $788 $361 $466 $801 (as of December 31, 2020)
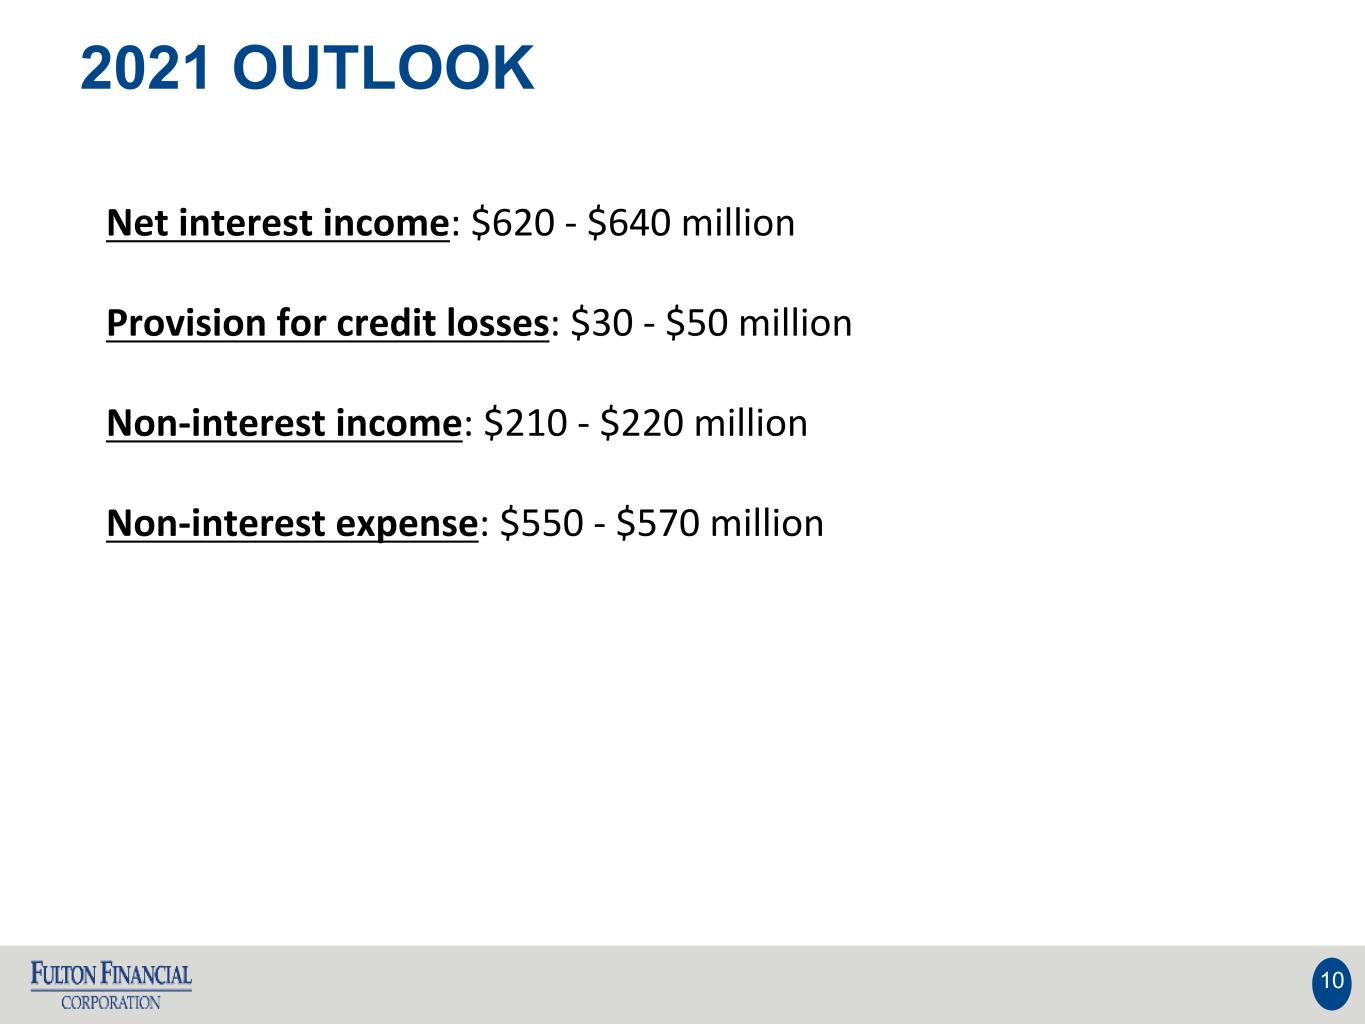
2021 OUTLOOK 10 Net interest income: $620 - $640 million Provision for credit losses: $30 - $50 million Non-interest income: $210 - $220 million Non-interest expense: $550 - $570 million
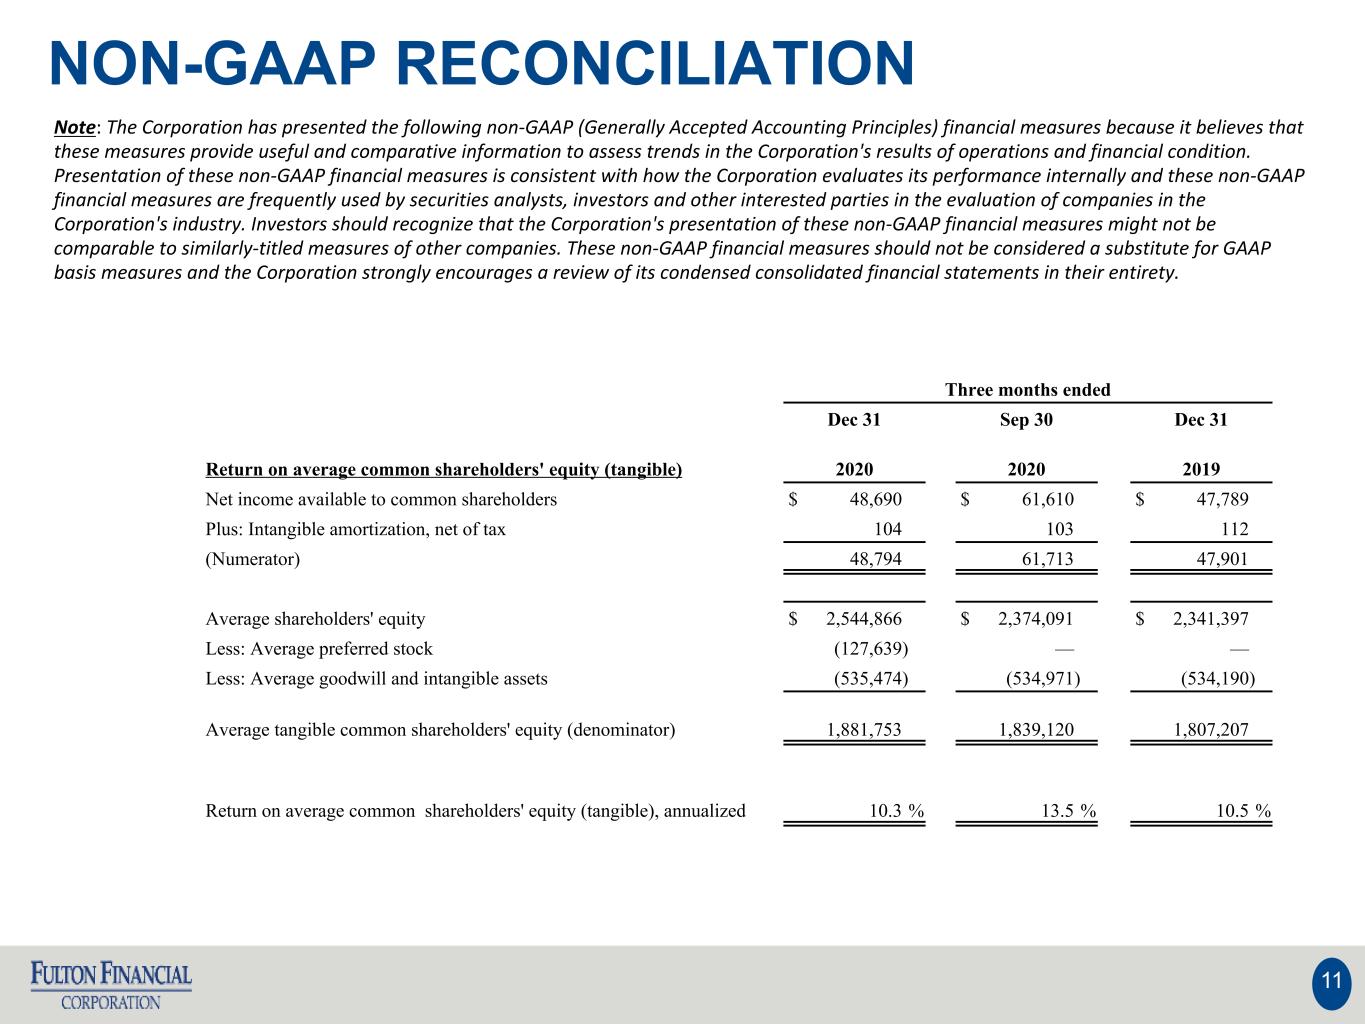
NON-GAAP RECONCILIATION Note: The Corporation has presented the following non-GAAP (Generally Accepted Accounting Principles) financial measures because it believes that these measures provide useful and comparative information to assess trends in the Corporation's results of operations and financial condition. Presentation of these non-GAAP financial measures is consistent with how the Corporation evaluates its performance internally and these non-GAAP financial measures are frequently used by securities analysts, investors and other interested parties in the evaluation of companies in the Corporation's industry. Investors should recognize that the Corporation's presentation of these non-GAAP financial measures might not be comparable to similarly-titled measures of other companies. These non-GAAP financial measures should not be considered a substitute for GAAP basis measures and the Corporation strongly encourages a review of its condensed consolidated financial statements in their entirety. 11 Three months ended Dec 31 Sep 30 Dec 31 Return on average common shareholders' equity (tangible) 2020 2020 2019 Net income available to common shareholders $ 48,690 $ 61,610 $ 47,789 Plus: Intangible amortization, net of tax 104 103 112 (Numerator) 48,794 61,713 47,901 Average shareholders' equity $ 2,544,866 $ 2,374,091 $ 2,341,397 Less: Average preferred stock (127,639) — — Less: Average goodwill and intangible assets (535,474) (534,971) (534,190) Average tangible common shareholders' equity (denominator) 1,881,753 1,839,120 1,807,207 Return on average common shareholders' equity (tangible), annualized 10.3 % 13.5 % 10.5 %
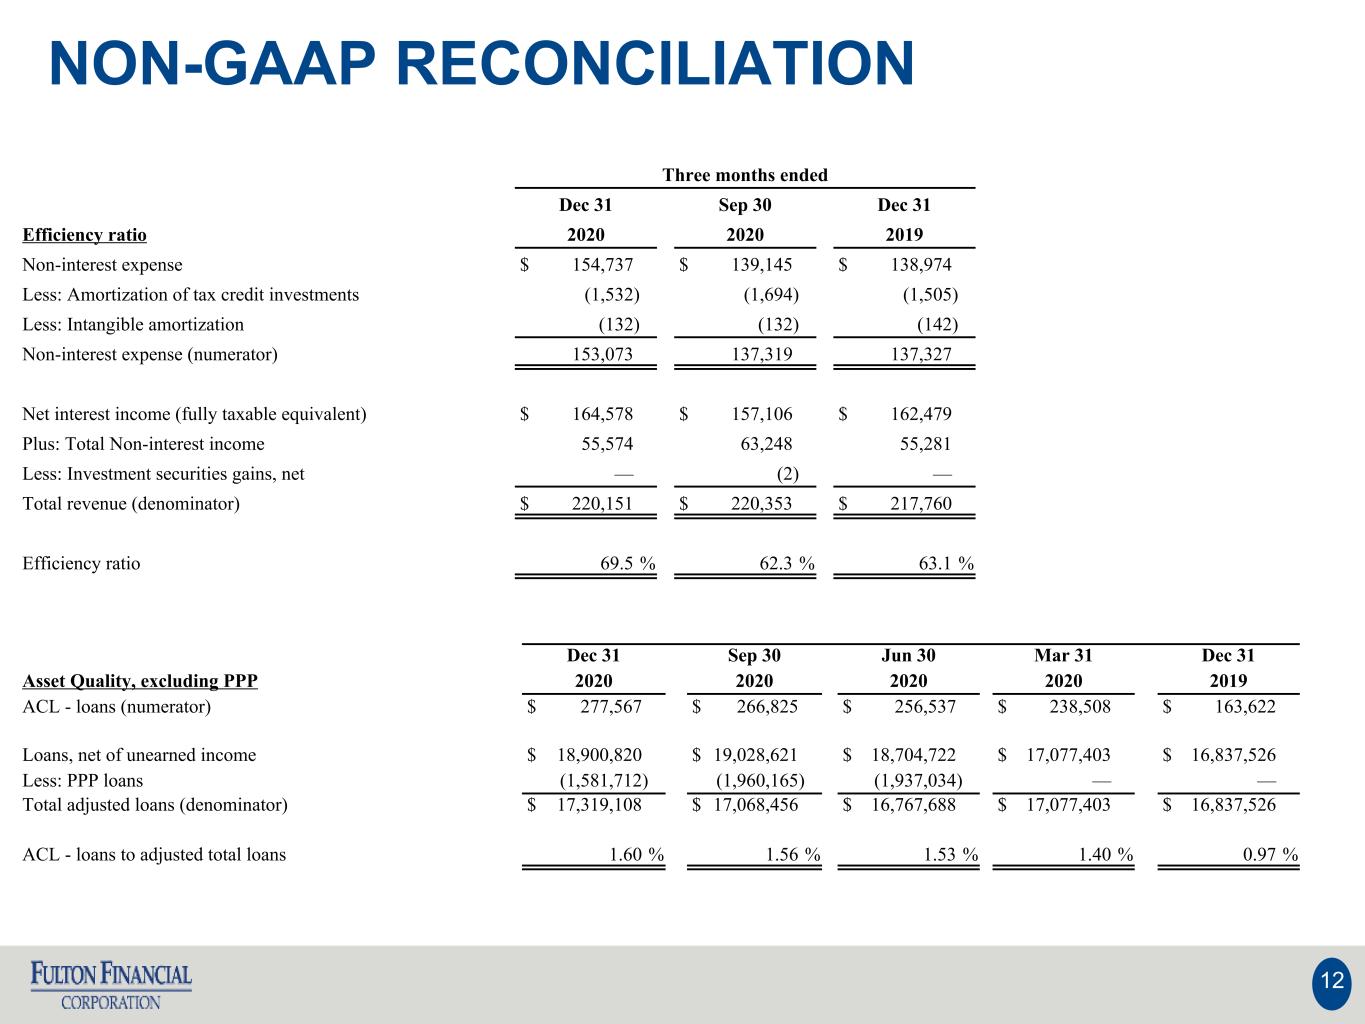
NON-GAAP RECONCILIATION 12 Three months ended Dec 31 Sep 30 Dec 31 Efficiency ratio 2020 2020 2019 Non-interest expense $ 154,737 $ 139,145 $ 138,974 Less: Amortization of tax credit investments (1,532) (1,694) (1,505) Less: Intangible amortization (132) (132) (142) Non-interest expense (numerator) 153,073 137,319 137,327 Net interest income (fully taxable equivalent) $ 164,578 $ 157,106 $ 162,479 Plus: Total Non-interest income 55,574 63,248 55,281 Less: Investment securities gains, net — (2) — Total revenue (denominator) $ 220,151 $ 220,353 $ 217,760 Efficiency ratio 69.5 % 62.3 % 63.1 % Dec 31 Sep 30 Jun 30 Mar 31 Dec 31 Asset Quality, excluding PPP 2020 2020 2020 2020 2019 ACL - loans (numerator) $ 277,567 $ 266,825 $ 256,537 $ 238,508 $ 163,622 Loans, net of unearned income $ 18,900,820 $ 19,028,621 $ 18,704,722 $ 17,077,403 $ 16,837,526 Less: PPP loans (1,581,712) (1,960,165) (1,937,034) — — Total adjusted loans (denominator) $ 17,319,108 $ 17,068,456 $ 16,767,688 $ 17,077,403 $ 16,837,526 ACL - loans to adjusted total loans 1.60 % 1.56 % 1.53 % 1.40 % 0.97 %
APPENDIX - CREDIT DISCLOSURES 13 Additional detail on deferrals and select industries (data as of December 31, 2020; all industry classifications based on NAICS codes)
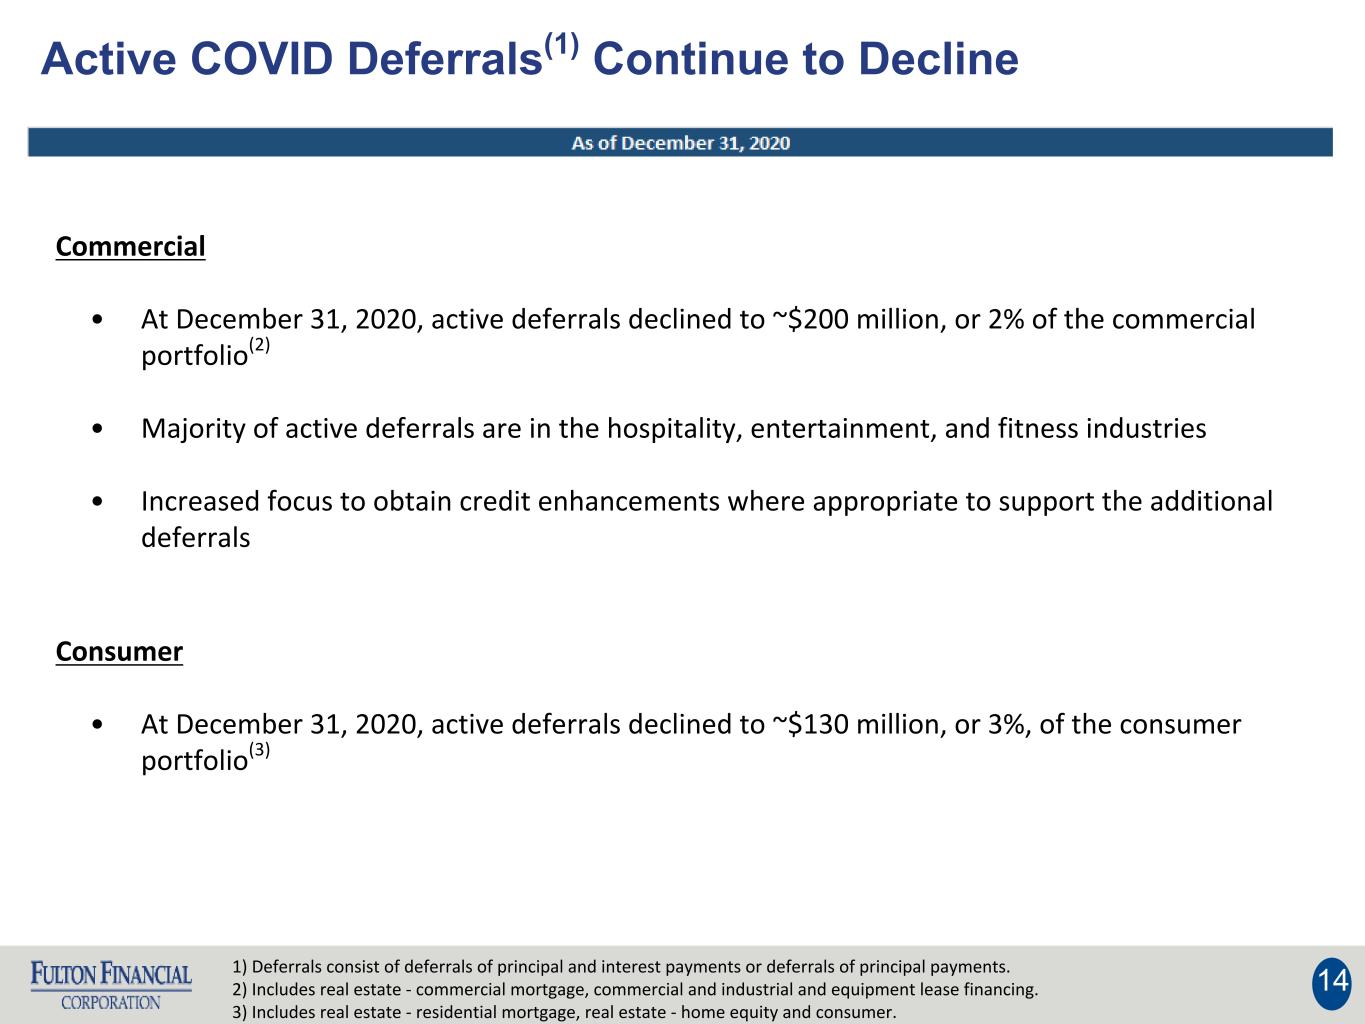
Active COVID Deferrals(1) Continue to Decline 14 Commercial • At December 31, 2020, active deferrals declined to ~$200 million, or 2% of the commercial portfolio(2) • Majority of active deferrals are in the hospitality, entertainment, and fitness industries • Increased focus to obtain credit enhancements where appropriate to support the additional deferrals Consumer • At December 31, 2020, active deferrals declined to ~$130 million, or 3%, of the consumer portfolio(3) 1) Deferrals consist of deferrals of principal and interest payments or deferrals of principal payments. 2) Includes real estate - commercial mortgage, commercial and industrial and equipment lease financing. 3) Includes real estate - residential mortgage, real estate - home equity and consumer.
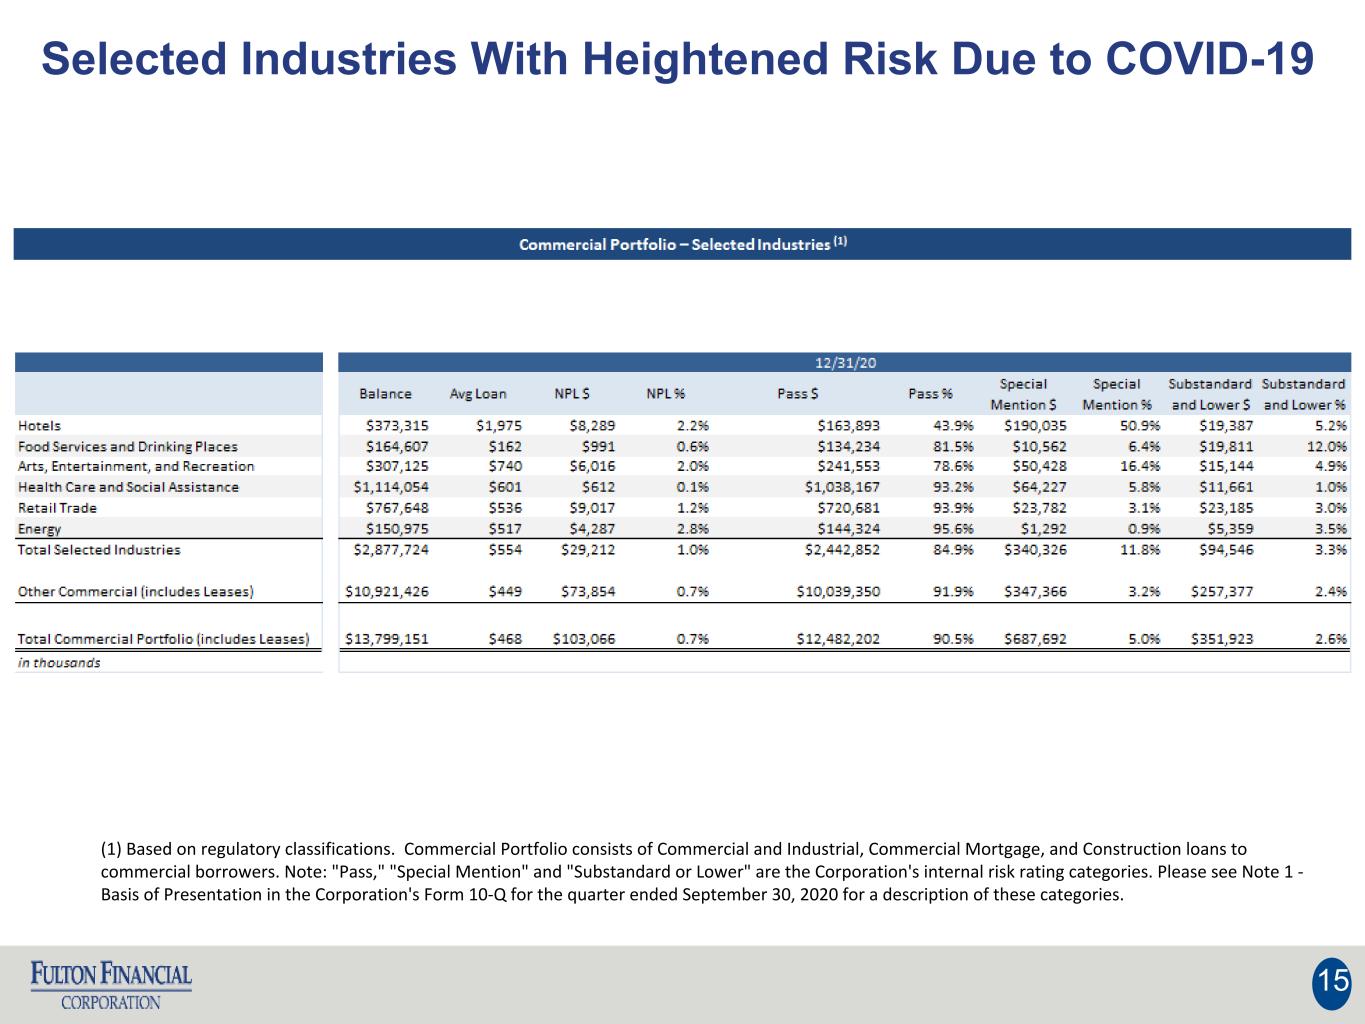
Selected Industries With Heightened Risk Due to COVID-19 15 (1) Based on regulatory classifications. Commercial Portfolio consists of Commercial and Industrial, Commercial Mortgage, and Construction loans to commercial borrowers. Note: "Pass," "Special Mention" and "Substandard or Lower" are the Corporation's internal risk rating categories. Please see Note 1 - Basis of Presentation in the Corporation's Form 10-Q for the quarter ended September 30, 2020 for a description of these categories.
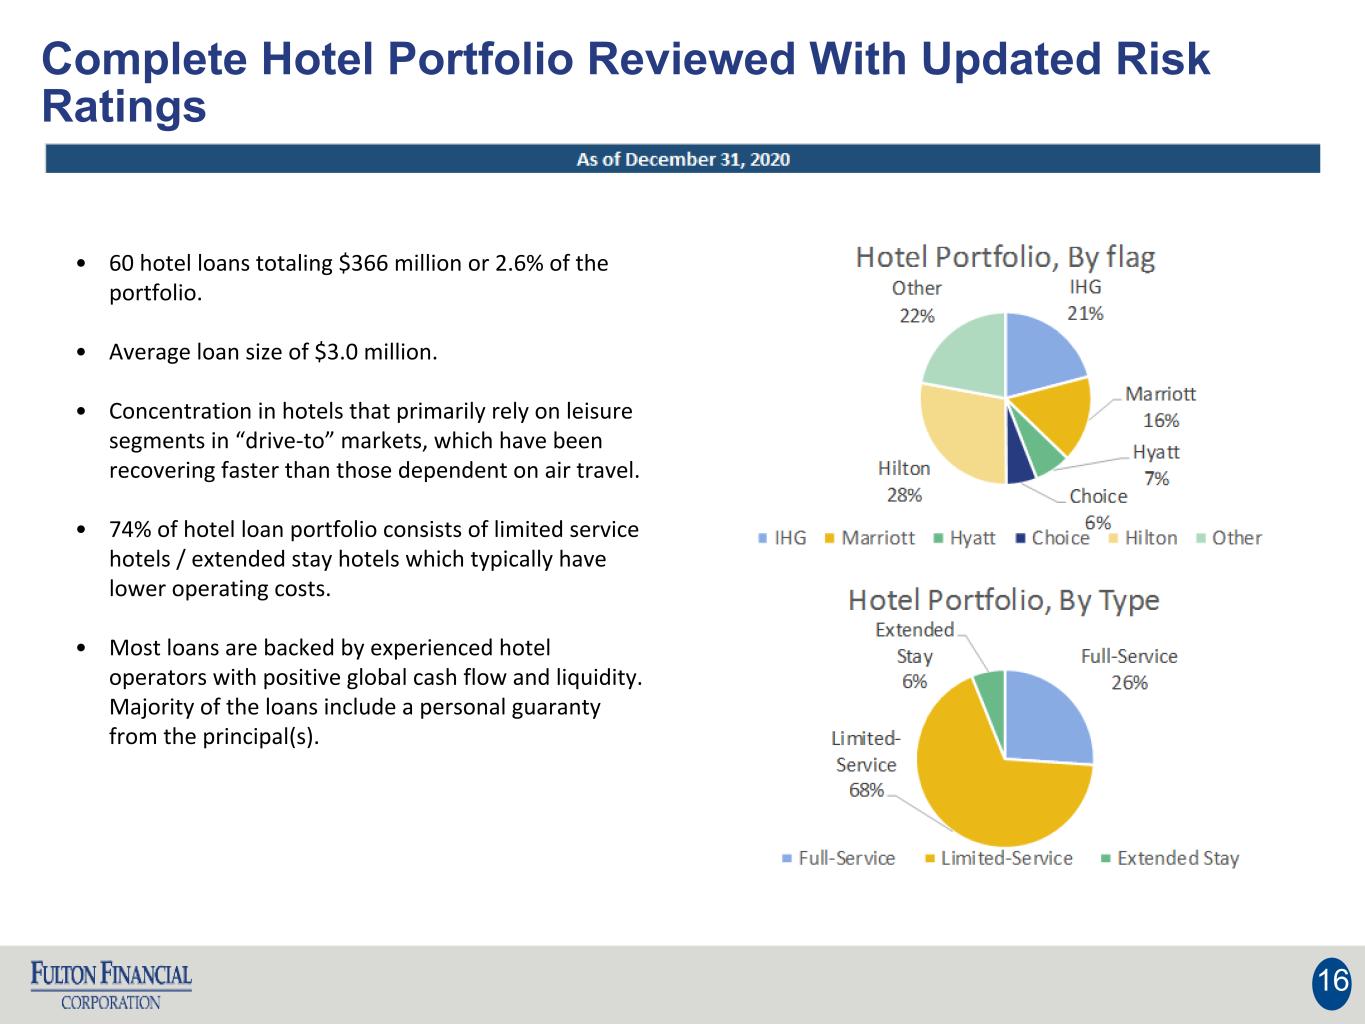
Complete Hotel Portfolio Reviewed With Updated Risk Ratings 16 • 60 hotel loans totaling $366 million or 2.6% of the portfolio. • Average loan size of $3.0 million. • Concentration in hotels that primarily rely on leisure segments in “drive-to” markets, which have been recovering faster than those dependent on air travel. • 74% of hotel loan portfolio consists of limited service hotels / extended stay hotels which typically have lower operating costs. • Most loans are backed by experienced hotel operators with positive global cash flow and liquidity. Majority of the loans include a personal guaranty from the principal(s).
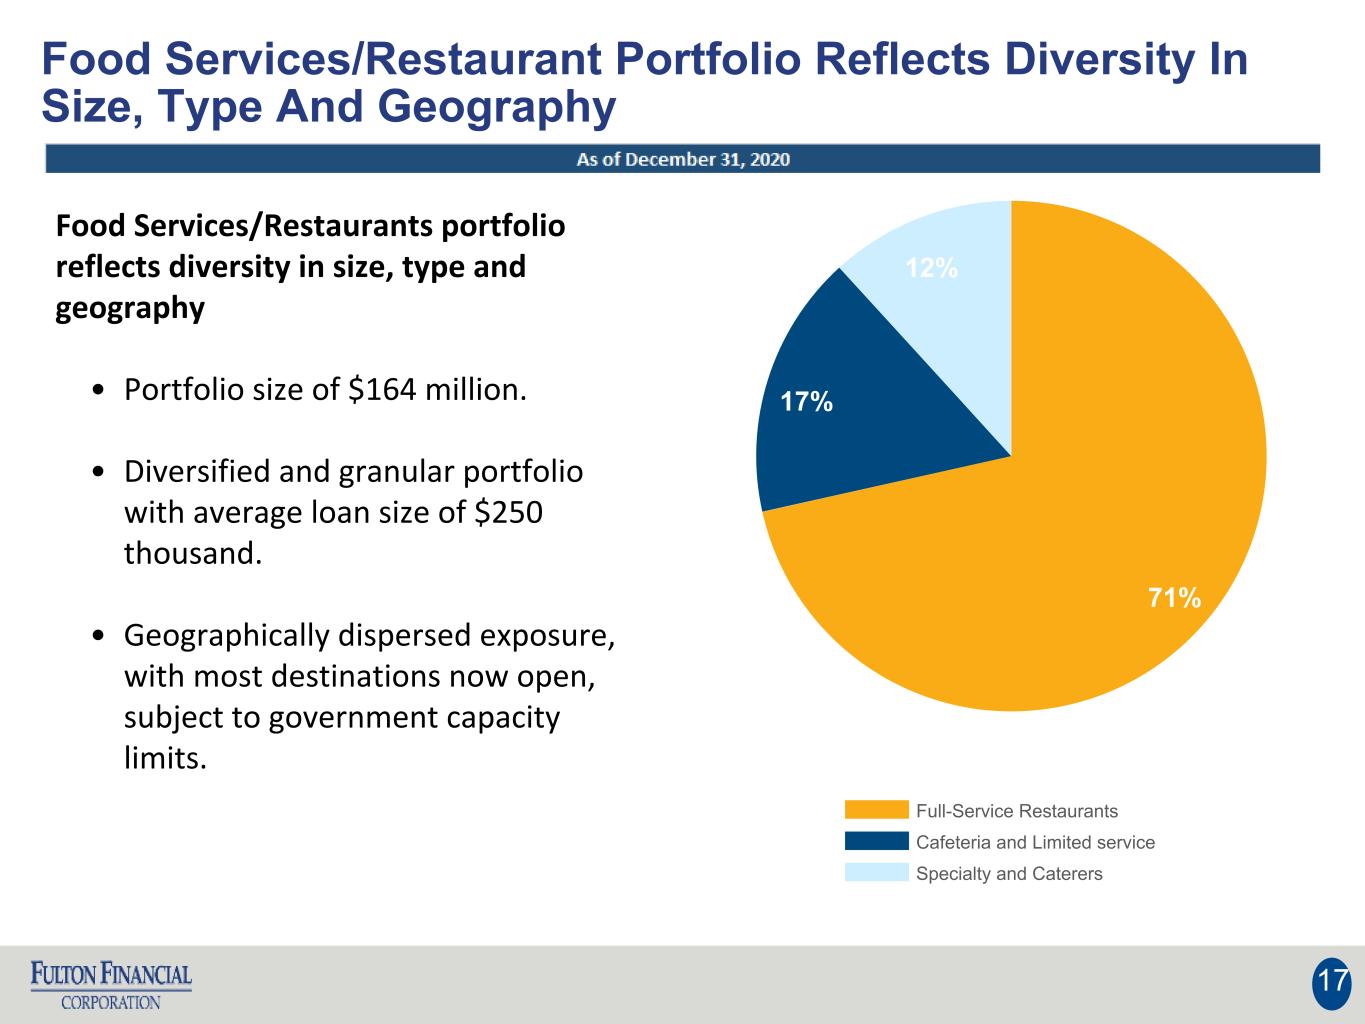
Food Services/Restaurant Portfolio Reflects Diversity In Size, Type And Geography 17 Food Services/Restaurants portfolio reflects diversity in size, type and geography • Portfolio size of $164 million. • Diversified and granular portfolio with average loan size of $250 thousand. • Geographically dispersed exposure, with most destinations now open, subject to government capacity limits. 71% 17% 12% Full-Service Restaurants Cafeteria and Limited service Specialty and Caterers
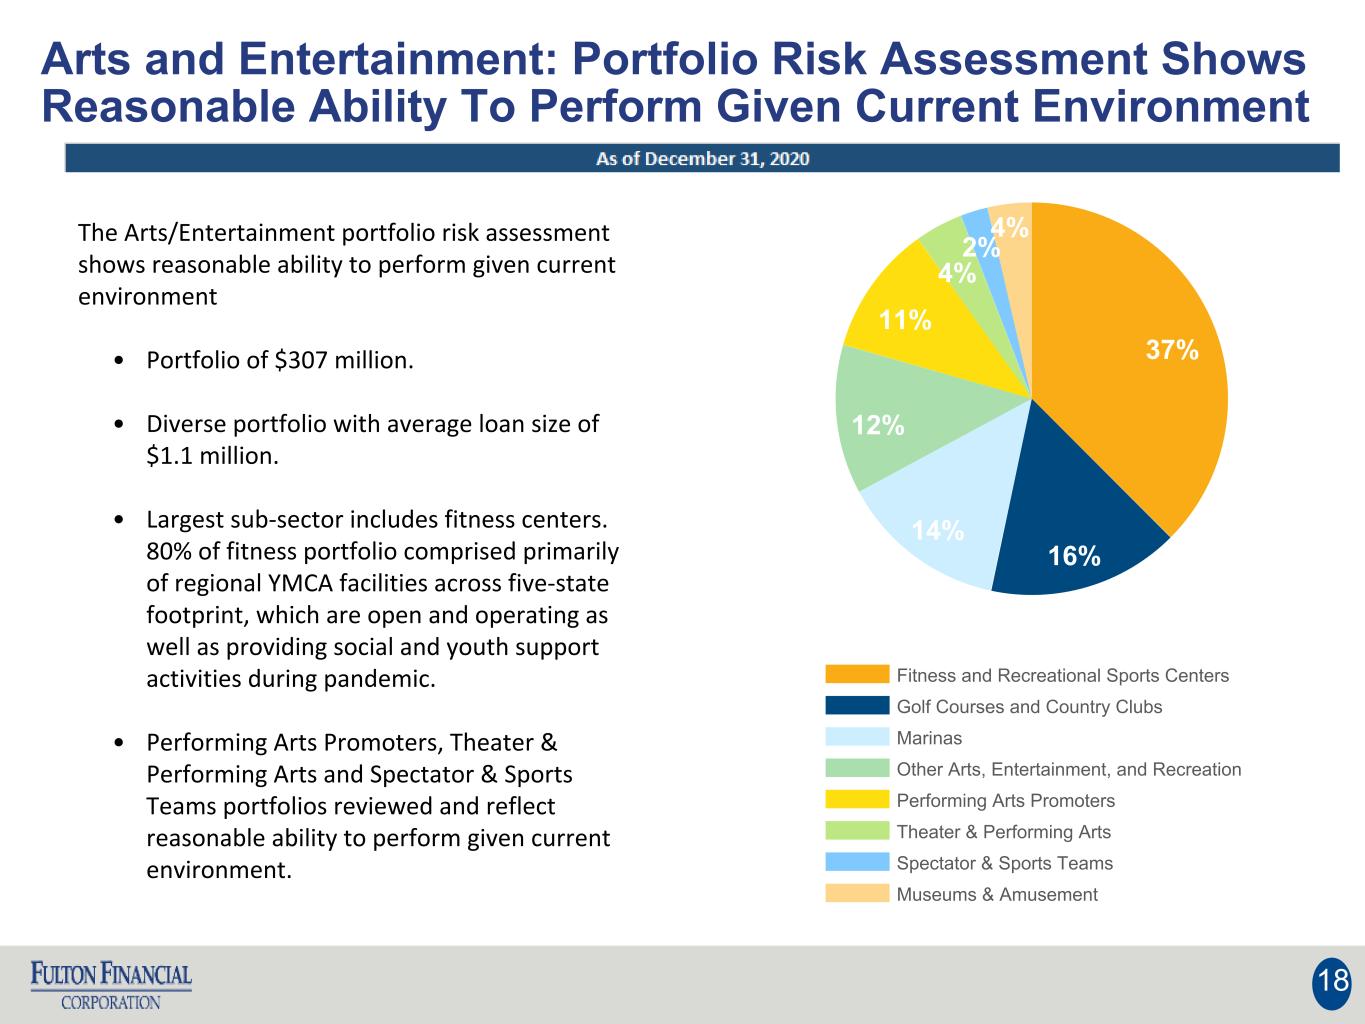
Arts and Entertainment: Portfolio Risk Assessment Shows Reasonable Ability To Perform Given Current Environment 18 The Arts/Entertainment portfolio risk assessment shows reasonable ability to perform given current environment • Portfolio of $307 million. • Diverse portfolio with average loan size of $1.1 million. • Largest sub-sector includes fitness centers. 80% of fitness portfolio comprised primarily of regional YMCA facilities across five-state footprint, which are open and operating as well as providing social and youth support activities during pandemic. • Performing Arts Promoters, Theater & Performing Arts and Spectator & Sports Teams portfolios reviewed and reflect reasonable ability to perform given current environment. 37% 16% 14% 12% 11% 4% 2% 4% Fitness and Recreational Sports Centers Golf Courses and Country Clubs Marinas Other Arts, Entertainment, and Recreation Performing Arts Promoters Theater & Performing Arts Spectator & Sports Teams Museums & Amusement
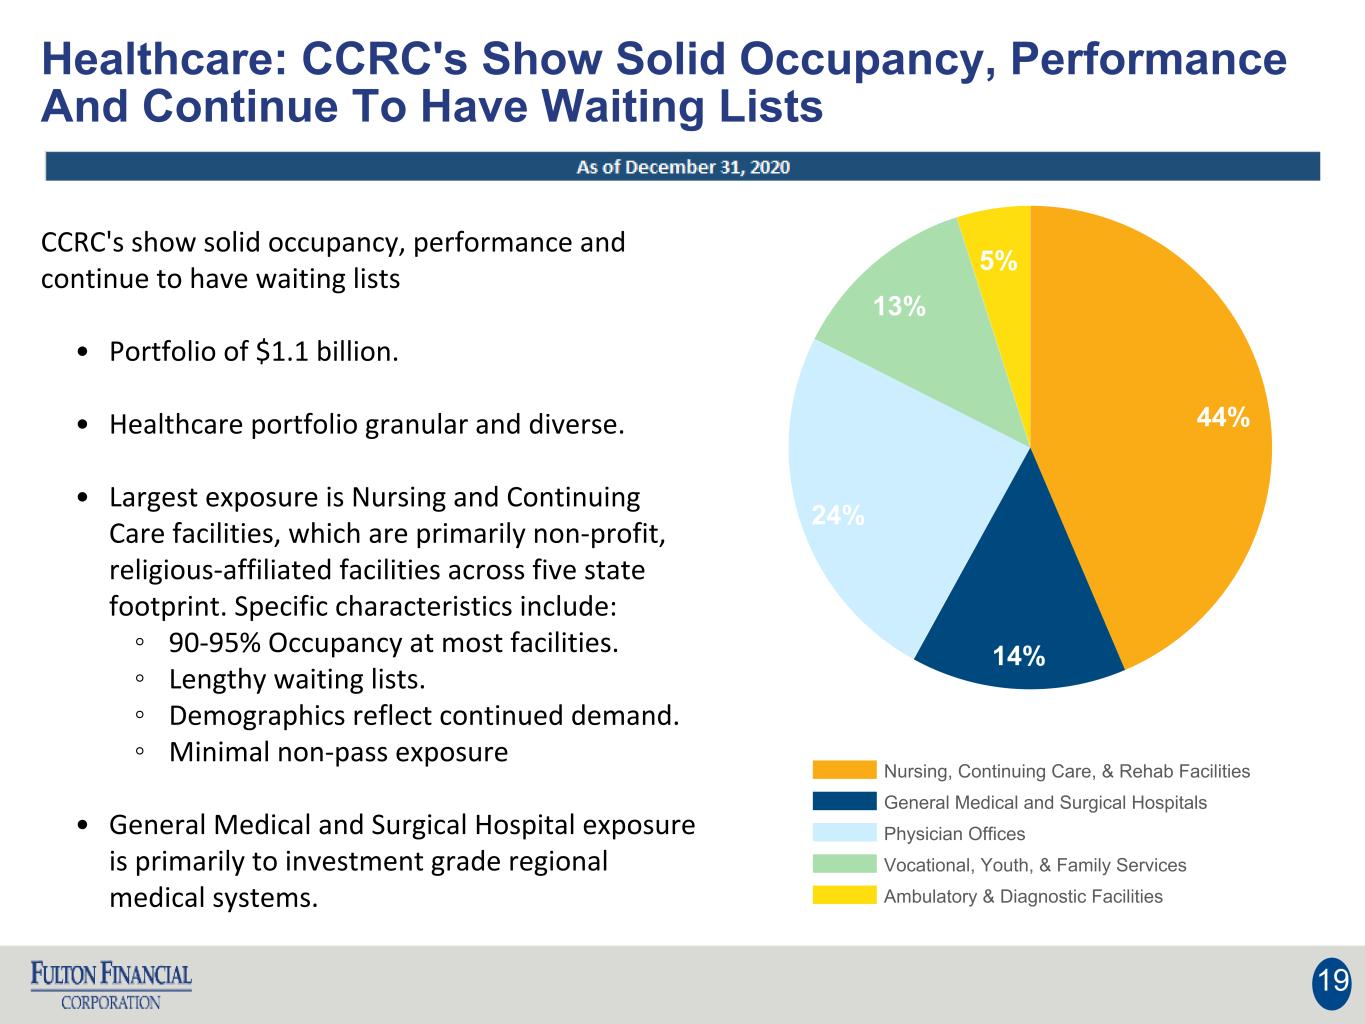
Healthcare: CCRC's Show Solid Occupancy, Performance And Continue To Have Waiting Lists 19 CCRC's show solid occupancy, performance and continue to have waiting lists • Portfolio of $1.1 billion. • Healthcare portfolio granular and diverse. • Largest exposure is Nursing and Continuing Care facilities, which are primarily non-profit, religious-affiliated facilities across five state footprint. Specific characteristics include: ◦ 90-95% Occupancy at most facilities. ◦ Lengthy waiting lists. ◦ Demographics reflect continued demand. ◦ Minimal non-pass exposure • General Medical and Surgical Hospital exposure is primarily to investment grade regional medical systems. 44% 14% 24% 13% 5% Nursing, Continuing Care, & Rehab Facilities General Medical and Surgical Hospitals Physician Offices Vocational, Youth, & Family Services Ambulatory & Diagnostic Facilities
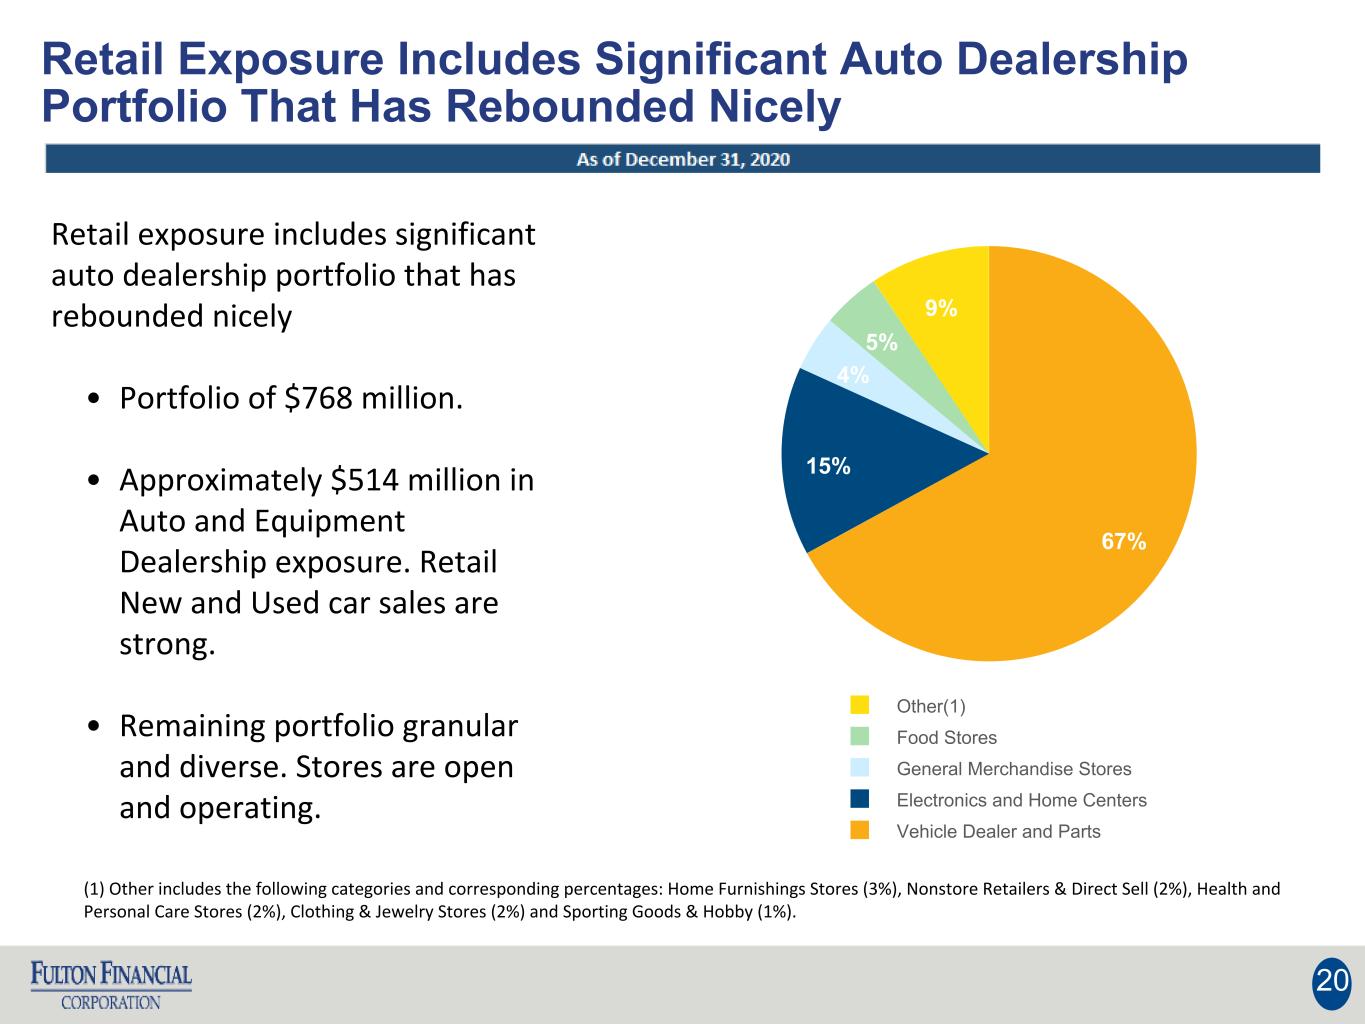
Retail Exposure Includes Significant Auto Dealership Portfolio That Has Rebounded Nicely 20 Retail exposure includes significant auto dealership portfolio that has rebounded nicely • Portfolio of $768 million. • Approximately $514 million in Auto and Equipment Dealership exposure. Retail New and Used car sales are strong. • Remaining portfolio granular and diverse. Stores are open and operating. 67% 15% 4% 5% 9% Other(1) Food Stores General Merchandise Stores Electronics and Home Centers Vehicle Dealer and Parts (1) Other includes the following categories and corresponding percentages: Home Furnishings Stores (3%), Nonstore Retailers & Direct Sell (2%), Health and Personal Care Stores (2%), Clothing & Jewelry Stores (2%) and Sporting Goods & Hobby (1%).
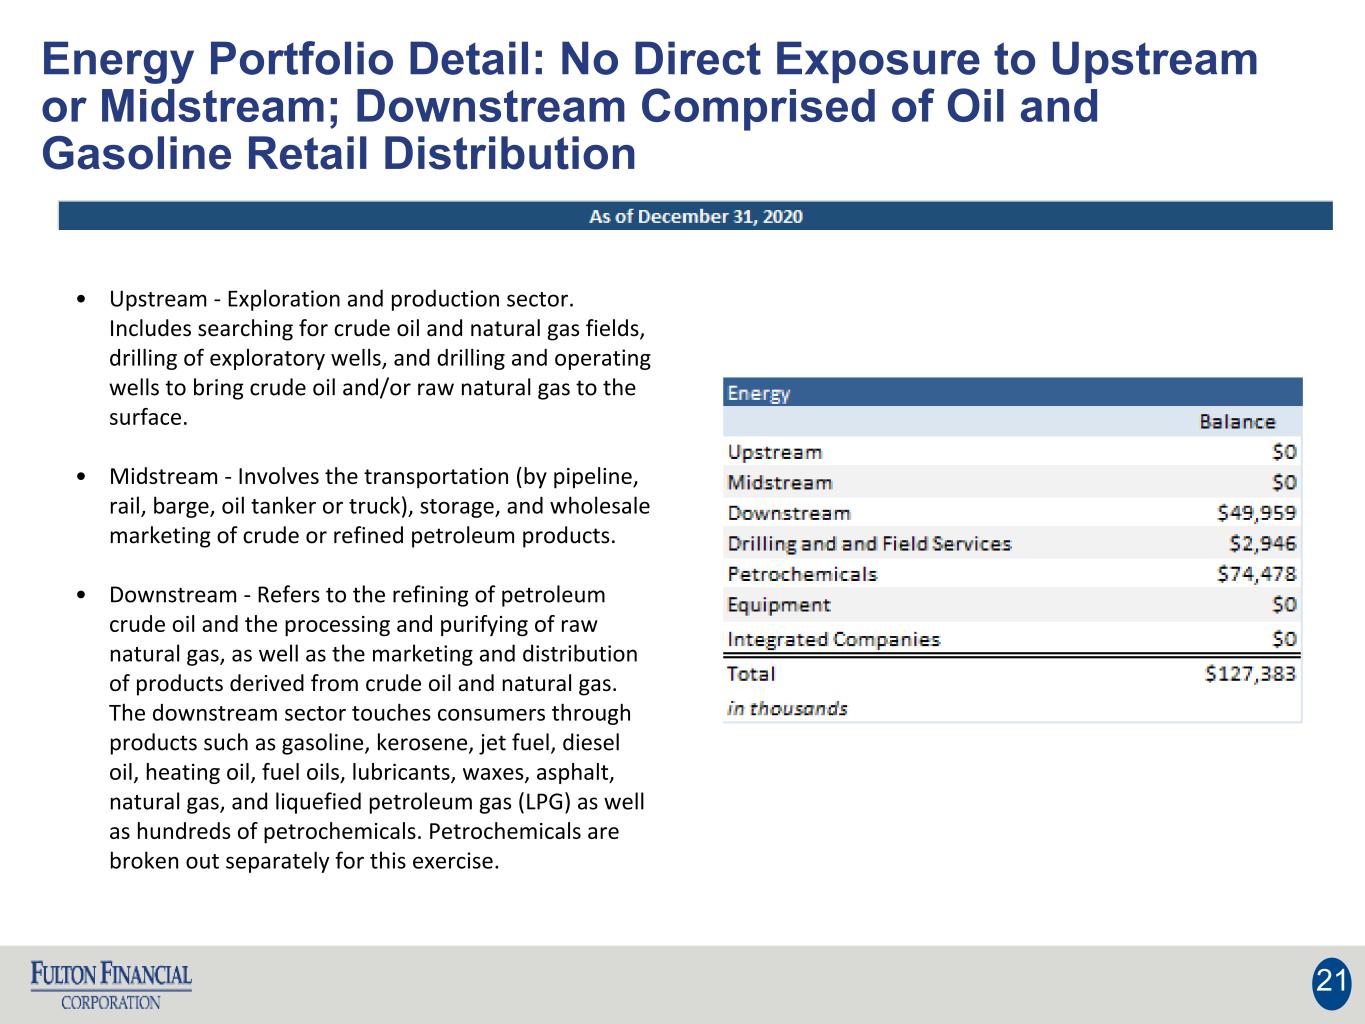
Energy Portfolio Detail: No Direct Exposure to Upstream or Midstream; Downstream Comprised of Oil and Gasoline Retail Distribution 21 • Upstream - Exploration and production sector. Includes searching for crude oil and natural gas fields, drilling of exploratory wells, and drilling and operating wells to bring crude oil and/or raw natural gas to the surface. • Midstream - Involves the transportation (by pipeline, rail, barge, oil tanker or truck), storage, and wholesale marketing of crude or refined petroleum products. • Downstream - Refers to the refining of petroleum crude oil and the processing and purifying of raw natural gas, as well as the marketing and distribution of products derived from crude oil and natural gas. The downstream sector touches consumers through products such as gasoline, kerosene, jet fuel, diesel oil, heating oil, fuel oils, lubricants, waxes, asphalt, natural gas, and liquefied petroleum gas (LPG) as well as hundreds of petrochemicals. Petrochemicals are broken out separately for this exercise.