
FWRD 8-K
Forward Air Corp (FWRD)
8-K
2026-08-05
For: 2026-08-05
View Original
Added on
August 05, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
________________________
FORM 8-K
______________
CURRENT REPORT
Pursuant to Section 13 or 15(d) of
the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): August 5, 2026
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (I.R.S. Employer Identification No.) | ||||||||||||||||
| (Address of principal executive offices) | (Zip Code) | ||||||||||||||||
| (Commission File Number) | ||
Registrant’s telephone number, including area code: (817 ) 552-5270
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02. Results of Operations and Financial Condition.
On August 5, 2026, Forward Air Corporation (the “Company”) issued a press release announcing its financial results for the three months ended June 30, 2026. On August 5, 2026, the Company also posted an earnings presentation on the Company’s Investor Relations website at ir.forwardaircorp.com.
The information furnished under this Item 2.02, including Exhibit 99.1 and Exhibit 99.2, is being furnished and shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), nor shall it be deemed incorporated by reference in any filing under the Securities Act of 1933, as amended, or the Exchange Act, except as shall be expressly set forth by specific reference in such filing.
Item 9.01. Financial Statements and Exhibits.
(d) Exhibits.
| No. | Exhibit | |||||||
| 99.1 | ||||||||
| 99.2 | ||||||||
| 104 | Cover Page Interactive File (the cover page tags are embedded within the Inline XBRL document) | |||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| FORWARD AIR CORPORATION | |||||||||||
Date: August 5, 2026 | By: | /s/ Shawn Stewart | |||||||||
| Name: | Shawn Stewart | ||||||||||
| Title: | President and Chief Executive Officer | ||||||||||
NEWS RELEASE
FORWARD AIR CORPORATION REPORTS SECOND QUARTER 2026 RESULTS
Reports Highest Quarterly Operating Revenue in Company History
Expedited Freight Segment Leads Strong Results with Best Operating Revenue, Operating Income, Reported EBITDA and Margin in Last Two and a Half Years
Liquidity Remains Robust at $401 Million
DALLAS – (BUSINESS WIRE) – August 5, 2026 – Forward Air Corporation (NASDAQ:FWRD) (the “Company,” “Forward,” “we,” “our,” or “us”) today reported financial results for the three months ended June 30, 2026, as presented in the tables below.
“We are pleased to deliver another solid quarter and we are seeing momentum from our transformational efforts, combined with an improving freight market,” said Shawn Stewart, President and Chief Executive Officer. “This contributed to reporting $673 million in consolidated operating revenue, which is the best in Forward Air Corporation’s history. Consolidated EBITDA for the quarter was $93 million, an improvement of $14 million, compared to $79 million a year ago.
“On a segment basis, the Expedited Freight segment made significant strides and reported its best operating revenue, operating income, Reported EBITDA and margin in the last two and a half years. The Omni Logistics segment saw an increase in demand for its contract logistics and air and ocean services and, excluding the impact of goodwill impairment, achieved its best Reported EBITDA and margin since the transaction in early 2024. Finally, the Intermodal segment had its best Reported EBITDA result in five quarters and best margin in six quarters. We believe the Intermodal segment is beginning to see the benefits of a strong pipeline and recently enacted strategic rate increases to several accounts.
“Our overall performance demonstrates the strength of our strategy, our portfolio of logistics offerings across a spectrum of services and the commitment and resilience of our team. As market conditions continue to improve, we remain focused on executing our plan and delivering sustainable, long-term value for our stakeholders,” concluded Stewart.
Jamie Pierson, Chief Financial Officer, added, “We reported consolidated operating revenue of $673 million in the second quarter compared to $619 million a year ago. In the second quarter, we reported an operating loss of $201 million that included a non-cash goodwill impairment charge of $244 million related to the Omni Logistics segment. Operating income, excluding the goodwill impairment charge, was $43 million, which is more than double the $20 million in operating income we reported in the second quarter last year.
“On a last twelve months basis Consolidated EBITDA, a non-GAAP measure calculated pursuant to our Term Loan Credit Agreement, was $319 million.
“Liquidity remained very strong at $401 million at the end of the second quarter comprised of $139 million in cash and $261 million of availability under our credit facility. This is in line with where we ended the first quarter 2026 and an improvement of $33 million compared to $368 million in total liquidity at the end of the second quarter 2025,” concluded Pierson.
| Three Months Ended June 30, | |||||||||||||||||||||||
| (in thousands, except per share data) | 2026 | 2025 | $ Change | % Change | |||||||||||||||||||
| Operating revenues | $ | 673,036 | $ | 618,844 | $ | 54,192 | 8.8 | % | |||||||||||||||
| Operating (loss) income | $ | (201,312) | $ | 19,522 | $ | (220,834) | nm | ||||||||||||||||
| Operating margin | (29.9) | % | 3.2 | % | (3,310) bps | ||||||||||||||||||
| Loss from continuing operations | $ | (243,856) | $ | (20,364) | $ | (223,492) | nm | ||||||||||||||||
| Net loss from continuing per diluted share | $ | (6.33) | $ | (0.41) | $ | (5.92) | nm | ||||||||||||||||
| Net cash (used in) provided by operating activities | $ | (4,883) | $ | (13,217) | $ | 8,334 | 63.1 | % | |||||||||||||||
Non-GAAP Financial Measures: (1) | |||||||||||||||||||||||
| Consolidated EBITDA | $ | 92,985 | $ | 79,081 | $ | 13,904 | 17.6 | % | |||||||||||||||
| Adjusted operating income | $ | 42,694 | $ | 19,522 | $ | 23,172 | 118.7 | % | |||||||||||||||
| Free cash flow | $ | (6,971) | $ | (17,157) | $ | 10,186 | 59.4 | % | |||||||||||||||
nm = not meaningful
Review of Financial Results
Forward Air will hold a conference call to discuss second quarter 2026 results on Wednesday, August 5 at 4:30 p.m. ET. The Company’s conference call will be available online on the Investor Relations portion of the Company’s website at ir.forwardaircorp.com, or by dialing (800) 579-2543, Access Code: FWRDQ226.
A replay of the conference call will be available on the Investor Relations portion of the Company’s website at ir.forwardaircorp.com, which we use as a primary mechanism to communicate with our investors. Investors are urged to monitor the Investor Relations portion of the Company’s website to easily find or navigate to current and pertinent information about us.
About Forward Air Corporation
Forward is a leading asset-light provider of transportation services across the United States, Canada and Latin America. We provide expedited less-than-truckload services, including local pick-up and delivery, shipment consolidation/deconsolidation, warehousing, and customs brokerage by utilizing a comprehensive national network of terminals. In addition, we offer truckload brokerage services, including dedicated fleet services, and intermodal, first- and last-mile, high-value drayage services, both to and from seaports and railheads, dedicated contract and Container Freight Station warehouse and handling services. Forward also operates a full portfolio of multimodal solutions, both domestically and internationally, via Omni Logistics. Omni Logistics is a global provider of air, ocean and ground services for mission-critical freight. We are more than a transportation company. Forward is a single resource for your shipping needs. For more information, visit our website at www.forwardair.com.
2
Forward Air Corporation
Condensed Consolidated Statements of Operations
(unaudited and in thousands, except per share amounts)
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||
| June 30, | June 30, | ||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | ||||||||||||||||||||
| Operating revenues: | |||||||||||||||||||||||
| Expedited Freight | $ | 319,062 | $ | 257,696 | $ | 591,769 | $ | 507,077 | |||||||||||||||
| Omni Logistics | 338,547 | 328,316 | 640,965 | 651,786 | |||||||||||||||||||
| Intermodal | 59,724 | 59,146 | 112,816 | 121,638 | |||||||||||||||||||
| Corporate and Eliminations | (44,297) | (26,314) | (90,468) | (48,376) | |||||||||||||||||||
| Operating revenues | 673,036 | 618,844 | 1,255,082 | 1,232,125 | |||||||||||||||||||
| Operating expenses: | |||||||||||||||||||||||
| Purchased transportation | 335,892 | 303,300 | 619,669 | 607,562 | |||||||||||||||||||
| Salaries, wages and employee benefits | 130,040 | 145,490 | 245,616 | 287,405 | |||||||||||||||||||
| Operating leases | 50,252 | 49,505 | 99,965 | 98,298 | |||||||||||||||||||
| Depreciation and amortization | 38,262 | 36,806 | 76,783 | 74,166 | |||||||||||||||||||
| Insurance and claims | 13,678 | 15,536 | 27,176 | 30,542 | |||||||||||||||||||
| Fuel expense | 6,644 | 5,278 | 11,571 | 10,927 | |||||||||||||||||||
| Other operating expenses | 55,574 | 43,407 | 111,167 | 98,940 | |||||||||||||||||||
| Impairment of goodwill | 244,006 | — | 244,006 | — | |||||||||||||||||||
| Total operating expenses | 874,348 | 599,322 | 1,435,953 | 1,207,840 | |||||||||||||||||||
| Operating (loss) income: | |||||||||||||||||||||||
| Expedited Freight | 34,893 | 19,495 | 54,939 | 35,129 | |||||||||||||||||||
| Omni Logistics | (230,010) | 7,186 | (229,280) | 10,561 | |||||||||||||||||||
| Intermodal | 6,101 | 4,415 | 7,325 | 9,957 | |||||||||||||||||||
| Corporate and Eliminations | (12,296) | (11,574) | (13,855) | (31,362) | |||||||||||||||||||
| Operating (loss) income | (201,312) | 19,522 | (180,871) | 24,285 | |||||||||||||||||||
| Other income and expenses: | |||||||||||||||||||||||
| Interest expense, net | (43,721) | (45,326) | (87,308) | (90,873) | |||||||||||||||||||
| Foreign exchange (loss) gain | (566) | (4,653) | 1,132 | (5,575) | |||||||||||||||||||
| Other income (expense), net | 1,569 | (6,656) | (15,388) | (6,552) | |||||||||||||||||||
| Total other expense | (42,718) | (56,635) | (101,564) | (103,000) | |||||||||||||||||||
| Loss from continuing operations before income taxes | (244,030) | (37,113) | (282,435) | (78,715) | |||||||||||||||||||
| Income tax (benefit) expense | (174) | (16,749) | 1,619 | 2,840 | |||||||||||||||||||
| Loss from continuing operations | (243,856) | (20,364) | (284,054) | (81,555) | |||||||||||||||||||
| Loss from discontinued operations, net of tax | (2,075) | — | (2,075) | — | |||||||||||||||||||
| Net loss | (245,931) | (20,364) | (286,129) | (81,555) | |||||||||||||||||||
| Net loss attributable to noncontrolling interest | (38,631) | (7,781) | (44,510) | (18,335) | |||||||||||||||||||
| Net loss attributable to Forward Air | $ | (207,300) | $ | (12,583) | $ | (241,619) | $ | (63,220) | |||||||||||||||
| Basic and diluted net loss per share attributable to Forward Air: | |||||||||||||||||||||||
| Continuing operations | $ | (6.33) | $ | (0.41) | $ | (7.49) | $ | (2.09) | |||||||||||||||
| Discontinued operations | (0.05) | — | (0.05) | — | |||||||||||||||||||
| Net loss per basic and diluted share | $ | (6.38) | $ | (0.41) | $ | (7.54) | $ | (2.09) | |||||||||||||||
3
Expedited Freight Segment Information and Operating Statistics
(unaudited and in thousands, except per shipment and per hundredweight)
| Three Months Ended June 30, | |||||||||||||||||||||||||||||||||||
| 2026 | % of Revenue | 2025 | % of Revenue | $ Change | % Change | ||||||||||||||||||||||||||||||
| Operating revenues: | |||||||||||||||||||||||||||||||||||
Network (1) | $ | 225,971 | 70.8 | % | $ | 193,829 | 75.2 | % | $ | 32,142 | 16.6 | % | |||||||||||||||||||||||
| Truckload | 69,237 | 21.7 | % | 42,636 | 16.5 | % | 26,601 | 62.4 | % | ||||||||||||||||||||||||||
| Other | 23,854 | 7.5 | % | 21,231 | 8.3 | % | 2,623 | 12.4 | % | ||||||||||||||||||||||||||
| Total operating revenues | 319,062 | 100.0 | % | 257,696 | 100.0 | % | 61,366 | 23.8 | % | ||||||||||||||||||||||||||
| Operating expenses: | |||||||||||||||||||||||||||||||||||
| Purchased transportation | 167,936 | 52.6 | % | 124,448 | 48.3 | % | 43,488 | 34.9 | % | ||||||||||||||||||||||||||
| Salaries, wages and employee benefits | 57,568 | 18.0 | % | 53,938 | 20.9 | % | 3,630 | 6.7 | % | ||||||||||||||||||||||||||
| Operating leases | 16,416 | 5.1 | % | 17,355 | 6.7 | % | (939) | (5.4) | % | ||||||||||||||||||||||||||
| Depreciation and amortization | 8,495 | 2.7 | % | 10,357 | 4.0 | % | (1,862) | (18.0) | % | ||||||||||||||||||||||||||
| Insurance and claims | 10,018 | 3.1 | % | 10,693 | 4.1 | % | (675) | (6.3) | % | ||||||||||||||||||||||||||
| Fuel expense | 3,668 | 1.1 | % | 2,518 | 1.0 | % | 1,150 | 45.7 | % | ||||||||||||||||||||||||||
| Other operating expenses | 20,068 | 6.5 | % | 18,892 | 7.4 | % | 1,176 | 6.2 | % | ||||||||||||||||||||||||||
| Total operating expenses | 284,169 | 89.1 | % | 238,201 | 92.4 | % | 45,968 | 19.3 | % | ||||||||||||||||||||||||||
| Operating income | $ | 34,893 | 10.9 | % | $ | 19,495 | 7.6 | % | $ | 15,398 | 79.0 | % | |||||||||||||||||||||||
(1)Network revenue is comprised of all revenue, including linehaul, pickup and/or delivery, and fuel surcharge revenue, excluding accessorial and Truckload revenue.
| Three Months Ended | |||||||||||||||||
| June 30, | |||||||||||||||||
| 2026 | 2025 | % Change | |||||||||||||||
| Business days | 64 | 64 | — | % | |||||||||||||
Tonnage (1) | |||||||||||||||||
| Total pounds | 665,073 | 623,394 | 6.7 | % | |||||||||||||
| Pounds per day | 10,392 | 9,741 | 6.7 | % | |||||||||||||
Shipments (1) | |||||||||||||||||
| Total shipments | 749 | 739 | 1.4 | % | |||||||||||||
| Shipments per day | 11.7 | 11.5 | 1.7 | % | |||||||||||||
| Weight per shipment | 888 | 843 | 5.3 | % | |||||||||||||
Revenue per hundredweight (2) | $ | 33.98 | $ | 31.09 | 9.3 | % | |||||||||||
Revenue per hundredweight, ex fuel (2) | $ | 24.26 | $ | 24.82 | (2.3) | % | |||||||||||
Revenue per shipment (2) | $ | 301.75 | $ | 261.82 | 15.3 | % | |||||||||||
Revenue per shipment, ex fuel (2) | $ | 215.41 | $ | 209.24 | 2.9 | % | |||||||||||
(1)Excludes accessorial and Truckload products.
(2)Includes intercompany revenue between the Network and Truckload revenue streams.
4
Omni Logistics Segment Information
(unaudited and in thousands)
| Three Months Ended June 30, | |||||||||||||||||||||||||||||||||||
| 2026 | % of Revenue | 2025 | % of Revenue | $ Change | % Change | ||||||||||||||||||||||||||||||
| Operating revenues: | |||||||||||||||||||||||||||||||||||
| Ground | $ | 132,854 | 39.2 | % | $ | 155,430 | 47.3 | % | $ | (22,576) | (14.5) | % | |||||||||||||||||||||||
| Contract Logistics | 112,332 | 33.2 | % | 97,469 | 29.7 | % | 14,863 | 15.2 | % | ||||||||||||||||||||||||||
| Air and Ocean | 93,361 | 27.6 | % | 75,417 | 23.0 | % | 17,944 | 23.8 | % | ||||||||||||||||||||||||||
| Total operating revenues | 338,547 | 100.0 | % | 328,316 | 100.0 | % | 10,231 | 3.1 | % | ||||||||||||||||||||||||||
| Operating expenses: | |||||||||||||||||||||||||||||||||||
| Purchased transportation | 190,166 | 56.2 | % | 185,040 | 56.4 | % | 5,126 | 2.8 | % | ||||||||||||||||||||||||||
| Salaries, wages and employee benefits | 62,226 | 18.4 | % | 61,584 | 18.8 | % | 642 | 1.0 | % | ||||||||||||||||||||||||||
| Operating leases | 27,466 | 8.1 | % | 25,686 | 7.8 | % | 1,780 | 6.9 | % | ||||||||||||||||||||||||||
| Depreciation and amortization | 23,878 | 7.1 | % | 22,419 | 6.8 | % | 1,459 | 6.5 | % | ||||||||||||||||||||||||||
| Insurance and claims | 276 | 0.1 | % | 1,248 | 0.4 | % | (972) | (77.9) | % | ||||||||||||||||||||||||||
| Fuel expense | 457 | 0.1 | % | 888 | 0.3 | % | (431) | (48.5) | % | ||||||||||||||||||||||||||
| Other operating expenses | 20,082 | 5.9 | % | 24,265 | 7.4 | % | (4,183) | (17.2) | % | ||||||||||||||||||||||||||
| Impairment of goodwill | 244,006 | 72.1 | % | — | — | % | 244,006 | nm | |||||||||||||||||||||||||||
| Total operating expenses | 568,557 | 167.9 | % | 321,130 | 97.8 | % | 247,427 | 77.0 | % | ||||||||||||||||||||||||||
| Operating (loss) income | $ | (230,010) | (67.9) | % | $ | 7,186 | 2.2 | % | $ | (237,196) | nm | ||||||||||||||||||||||||
nm = not meaningful
Intermodal Segment Information
(unaudited and in thousands)
| Three Months Ended June 30, | |||||||||||||||||||||||||||||||||||
| 2026 | % of Revenue | 2025 | % of Revenue | $ Change | % Change | ||||||||||||||||||||||||||||||
| Operating revenues | $ | 59,724 | 100.0 | % | $ | 59,146 | 100.0 | % | $ | 578 | 1.0 | % | |||||||||||||||||||||||
| Operating expenses: | |||||||||||||||||||||||||||||||||||
| Purchased transportation | 22,087 | 37.0 | % | 20,049 | 33.9 | % | 2,038 | 10.2 | % | ||||||||||||||||||||||||||
| Salaries, wages and employee benefits | 13,783 | 23.1 | % | 15,385 | 26.0 | % | (1,602) | (10.4) | % | ||||||||||||||||||||||||||
| Operating leases | 6,100 | 10.2 | % | 5,336 | 9.0 | % | 764 | 14.3 | % | ||||||||||||||||||||||||||
| Depreciation and amortization | 3,882 | 6.5 | % | 4,502 | 7.6 | % | (620) | (13.8) | % | ||||||||||||||||||||||||||
| Insurance and claims | 1,799 | 3.0 | % | 3,147 | 5.3 | % | (1,348) | (42.8) | % | ||||||||||||||||||||||||||
| Fuel expense | 2,541 | 4.3 | % | 1,857 | 3.1 | % | 684 | 36.8 | % | ||||||||||||||||||||||||||
| Other operating expenses | 3,431 | 5.7 | % | 4,455 | 7.6 | % | (1,024) | (23.0) | % | ||||||||||||||||||||||||||
| Total operating expenses | 53,623 | 89.8 | % | 54,731 | 92.5 | % | (1,108) | (2.0) | % | ||||||||||||||||||||||||||
| Operating income | $ | 6,101 | 10.2 | % | $ | 4,415 | 7.5 | % | $ | 1,686 | 38.2 | % | |||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||
| June 30, | |||||||||||||||||
| 2026 | 2025 | % Change | |||||||||||||||
| Drayage shipments | 61,909 | 62,313 | (0.6) | % | |||||||||||||
| Drayage revenue per shipment | $ | 942 | $ | 862 | 9.3 | % | |||||||||||
5
Forward Air Corporation
Condensed Consolidated Balance Sheets
(unaudited and in thousands)
| June 30, 2026 | December 31, 2025 | ||||||||||
| ASSETS | |||||||||||
| Current assets: | |||||||||||
| Cash and cash equivalents | $ | 139,448 | $ | 105,996 | |||||||
| Accounts receivable, net | 369,469 | 343,559 | |||||||||
| Other receivables | 6,104 | 6,147 | |||||||||
| Prepaid expenses | 26,465 | 28,045 | |||||||||
| Other current assets | 41,630 | 37,254 | |||||||||
| Total current assets | 583,116 | 521,001 | |||||||||
| Property and equipment, net | 274,670 | 297,882 | |||||||||
| Operating lease right-of-use assets | 361,426 | 412,535 | |||||||||
| Goodwill | 278,706 | 522,712 | |||||||||
| Other intangible assets, net | 860,915 | 906,791 | |||||||||
| Other long-term assets | 52,012 | 58,023 | |||||||||
| Total assets | $ | 2,410,845 | $ | 2,718,944 | |||||||
| LIABILITIES AND SHAREHOLDERS' (DEFICIT) EQUITY | |||||||||||
| Current liabilities: | |||||||||||
| Accounts payable | $ | 118,651 | $ | 121,752 | |||||||
| Accrued expenses | 118,551 | 114,422 | |||||||||
| Other current liabilities | 81,911 | 69,130 | |||||||||
| Current portion of finance lease obligations | 14,961 | 15,995 | |||||||||
| Current portion of operating lease liabilities | 107,497 | 107,026 | |||||||||
| Total current liabilities | 441,571 | 428,325 | |||||||||
| Long-term debt | 1,693,340 | 1,687,248 | |||||||||
| Liabilities under Tax Receivable Agreement | 26,794 | 11,548 | |||||||||
| Finance lease obligations, less current portion | 16,804 | 22,387 | |||||||||
| Operating lease liabilities, less current portion | 277,379 | 327,011 | |||||||||
| Deferred income taxes | 24,358 | 27,221 | |||||||||
| Other long-term liabilities | 53,265 | 53,540 | |||||||||
| Total liabilities | 2,533,511 | 2,557,280 | |||||||||
| Shareholders' (deficit) equity: | |||||||||||
| Preferred stock | — | — | |||||||||
| Common stock | 337 | 313 | |||||||||
| Additional paid-in capital | 575,818 | 559,551 | |||||||||
| Accumulated deficit | (690,324) | (447,100) | |||||||||
| Accumulated other comprehensive income | (1,261) | 580 | |||||||||
| Total Forward Air shareholders' (deficit) equity | (115,430) | 113,344 | |||||||||
| Noncontrolling interest | (7,236) | 48,320 | |||||||||
| Total shareholders' (deficit) equity | (122,666) | 161,664 | |||||||||
| Total liabilities and shareholders' (deficit) equity | $ | 2,410,845 | $ | 2,718,944 | |||||||
6
Forward Air Corporation
Condensed Consolidated Statements of Cash Flows
(unaudited and in thousands)
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||
| June 30, | June 30, | ||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | ||||||||||||||||||||
| OPERATING ACTIVITIES: | |||||||||||||||||||||||
| Net loss | $ | (245,931) | $ | (20,364) | $ | (286,129) | $ | (81,555) | |||||||||||||||
| Adjustments to reconcile net loss to net cash (used in) provided by operating activities: | |||||||||||||||||||||||
| Depreciation and amortization | 38,262 | 36,806 | 76,783 | 74,166 | |||||||||||||||||||
| Impairment of goodwill | 244,006 | — | 244,006 | — | |||||||||||||||||||
| Share-based compensation expense | 491 | 4,711 | 4,032 | 7,669 | |||||||||||||||||||
| Change in Tax Receivable Agreement liability | (1,219) | 6,864 | 15,488 | 6,864 | |||||||||||||||||||
| Deferred income tax benefit | (604) | (1,933) | (2,774) | (4,725) | |||||||||||||||||||
| Non-cash interest expense | 3,654 | 3,473 | 7,227 | 6,846 | |||||||||||||||||||
| Gain on sale of business | (3,649) | — | (3,649) | — | |||||||||||||||||||
| Other | 1,774 | 1,326 | 4,191 | 2,399 | |||||||||||||||||||
| Changes in operating assets and liabilities: | |||||||||||||||||||||||
| Accounts receivable | (46,494) | 4,200 | (36,020) | (16,945) | |||||||||||||||||||
| Other receivables | (2,551) | 743 | (499) | 309 | |||||||||||||||||||
| Other current and noncurrent assets | 4,029 | 8,952 | 932 | 9,719 | |||||||||||||||||||
| Accounts payable, accrued expenses and other current liabilities | 3,349 | (57,995) | 17,267 | 9,651 | |||||||||||||||||||
| Net cash (used in) provided by operating activities | (4,883) | (13,217) | 40,855 | 14,398 | |||||||||||||||||||
| INVESTING ACTIVITIES: | |||||||||||||||||||||||
| Proceeds from sale of property and equipment | 1,125 | 804 | 2,553 | 1,495 | |||||||||||||||||||
| Purchases of property and equipment | (3,213) | (4,744) | (10,159) | (16,650) | |||||||||||||||||||
| Proceeds from sale of business, net | 8,739 | — | 8,739 | — | |||||||||||||||||||
| Other | — | 55 | — | 31 | |||||||||||||||||||
| Net cash provided by (used in) investing activities | 6,651 | (3,885) | 1,133 | (15,124) | |||||||||||||||||||
| FINANCING ACTIVITIES: | |||||||||||||||||||||||
| Repayments of finance lease obligations | (4,149) | (4,945) | (8,374) | (9,376) | |||||||||||||||||||
| Proceeds from borrowings under credit facility | — | 60,000 | — | 85,000 | |||||||||||||||||||
| Repayments of borrowings under credit facility | — | (60,000) | — | (85,000) | |||||||||||||||||||
| Proceeds from common stock issued under employee stock purchase plan | 734 | 434 | 734 | 434 | |||||||||||||||||||
| Payment of minimum tax withholdings on share-based awards and other | (120) | (107) | (805) | (1,001) | |||||||||||||||||||
| Net cash used in financing activities | (3,535) | (4,618) | (8,445) | (9,943) | |||||||||||||||||||
| Effect of exchange rate changes on cash | 193 | 353 | (91) | 710 | |||||||||||||||||||
| NET CHANGE IN CASH, CASH EQUIVALENTS, RESTRICTED CASH AND RESTRICTED CASH EQUIVALENTS | (1,574) | (21,367) | 33,452 | (9,959) | |||||||||||||||||||
| Cash, cash equivalents, restricted cash and restricted cash equivalents at beginning of period | 141,022 | 116,674 | 105,996 | 105,266 | |||||||||||||||||||
| Cash, cash equivalents, restricted cash and restricted cash equivalents at end of period | $ | 139,448 | $ | 95,307 | $ | 139,448 | $ | 95,307 | |||||||||||||||
7
Forward Air Corporation Reconciliation of Non-GAAP Financial Measures
In this press release, the Company includes financial measures that are derived on the basis of methodologies other than in accordance with United States generally accepted accounting principles (“GAAP”). The Company believes that meaningful analysis of its financial performance requires an understanding of the factors underlying that performance, including an understanding of items that are non-operational. Management uses these non-GAAP financial measures in making financial, operating, compensation and planning decisions as well as evaluating the Company’s performance.
For the three and six months ended June 30, 2026 and 2025, this press release contains the following non-GAAP financial measures: earnings before interest, taxes, depreciation and amortization for each segment (“Reported EBITDA”), Consolidated EBITDA, Adjusted Operating Income and free cash flow.
All non-GAAP financial measures are presented on a continuing operations basis.
The Company believes that Reported EBITDA improves comparability from period to period by removing the impact of its capital structure (interest and financing expenses), asset base (depreciation and amortization) and tax impacts. The Company believes that free cash flow is an important measure of its ability to repay maturing debt or fund other uses of capital that it believes will enhance shareholder value.
The Company is also providing Consolidated EBITDA calculated in accordance with our credit agreement as we believe it provides investors with important information regarding our financial condition and compliance with our obligations under our credit agreement.
Non-GAAP financial measures should be viewed in addition to, and not as an alternative to or substitute for, the Company’s financial results prepared in accordance with GAAP. The Company has included, for the periods indicated, a reconciliation of the non-GAAP financial measure to the most directly comparable GAAP financial measure. Investors and other readers are encouraged to review the related GAAP financial measures and the reconciliations of the non-GAAP measures to their most directly comparable GAAP measures set forth below.
8
The following is a reconciliation of net loss to Consolidated EBITDA:
| Three Months Ended | Six Months Ended | Last Twelve Months | |||||||||||||||||||||||||||
| June 30, | June 30, | ||||||||||||||||||||||||||||
| (in thousands) | 2026 | 2025 | 2026 | 2025 | June 30, 2026 | ||||||||||||||||||||||||
| Net loss | $ | (245,931) | $ | (20,364) | $ | (286,129) | $ | (81,555) | $ | (346,299) | |||||||||||||||||||
| Interest expense, net | 43,721 | 45,326 | 87,308 | 90,873 | 177,182 | ||||||||||||||||||||||||
| Income tax (benefit) expense | (174) | (16,749) | 1,619 | 2,840 | (6,693) | ||||||||||||||||||||||||
| Depreciation and amortization | 38,262 | 36,806 | 76,783 | 74,166 | 155,255 | ||||||||||||||||||||||||
| Reported EBITDA | (164,122) | 45,019 | (120,419) | 86,324 | (20,555) | ||||||||||||||||||||||||
| Impairment of goodwill | 244,006 | — | 244,006 | — | 244,006 | ||||||||||||||||||||||||
| Loss from discontinued operations, net of tax | 2,075 | — | 2,075 | — | 2,075 | ||||||||||||||||||||||||
| Transaction and integration costs | 4,709 | 5,949 | 7,523 | 19,875 | 19,097 | ||||||||||||||||||||||||
| Severance costs | 1,114 | 830 | 1,654 | 2,404 | 4,993 | ||||||||||||||||||||||||
| Change in Tax Receivable Agreement liability | (1,219) | 6,864 | 15,488 | 6,864 | 6,878 | ||||||||||||||||||||||||
| Optimization project costs | 152 | 691 | 152 | 1,722 | 20,840 | ||||||||||||||||||||||||
| Gain on disposition of business, net | (2,874) | — | (2,874) | — | (2,874) | ||||||||||||||||||||||||
| Proforma savings | — | 4,352 | — | 8,704 | 5,413 | ||||||||||||||||||||||||
| Proforma dispositions | 1,078 | 953 | 1,498 | 864 | 612 | ||||||||||||||||||||||||
| Other | 8,066 | 14,423 | 14,680 | 25,546 | 38,079 | ||||||||||||||||||||||||
| Consolidated EBITDA | $ | 92,985 | $ | 79,081 | $ | 163,783 | $ | 152,303 | $ | 318,564 | |||||||||||||||||||
The following is a reconciliation of operating (loss) income to operating income, excluding the goodwill impairment charge, or adjusted operating income:
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||
| June 30, | June 30, | ||||||||||||||||||||||
| (in thousands) | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||
| Operating (loss) income | $ | (201,312) | $ | 19,522 | $ | (180,871) | $ | 24,285 | |||||||||||||||
| Impairment of goodwill | 244,006 | — | 244,006 | — | |||||||||||||||||||
| Adjusted operating income | $ | 42,694 | $ | 19,522 | $ | 63,135 | $ | 24,285 | |||||||||||||||
The following is a reconciliation of net cash (used in) provided by operating activities to free cash flow:
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||
| June 30, | June 30, | ||||||||||||||||||||||
(in thousands) | 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||
| Net cash (used in) provided by operating activities | $ | (4,883) | $ | (13,217) | $ | 40,855 | $ | 14,398 | |||||||||||||||
| Proceeds from sale of property and equipment | 1,125 | 804 | 2,553 | 1,495 | |||||||||||||||||||
| Purchases of property and equipment | (3,213) | (4,744) | (10,159) | (16,650) | |||||||||||||||||||
| Free cash flow | $ | (6,971) | $ | (17,157) | $ | 33,249 | $ | (757) | |||||||||||||||
9
Note Regarding Forward-Looking Statements
This press release contains “forward-looking statements” within the meaning of the safe harbor provisions of the U.S. Private Securities Litigation Reform Act of 1995. Forward-looking statements can be identified by words such as: “anticipate,” “intend,” “plan,” “goal,” “seek,” “believe,” “project,” “estimate,” “expect,” “strategy,” “future,” “likely,” “may,” “should,” “will” and similar references to future periods. Forward-looking statements included in this press release relate to management’s expectations regarding: the Company’s beliefs regarding the Intermodal segment and changing market conditions.
Forward-looking statements are neither historical facts nor assurances of future performance. Instead, they are based only on our current beliefs, expectations and assumptions regarding the future of our business, future plans and strategies, projections, anticipated events and trends, the economy and other future conditions. Because forward-looking statements relate to the future, they are subject to inherent uncertainties, risks and changes in circumstances that are difficult to predict and many of which are outside of our control. Our actual results and financial condition may differ materially from those indicated in the forward-looking statements. The following is a list of factors, among others, that could cause actual results to differ materially from those contemplated by the forward-looking statements: economic factors such as tariffs, recessions, inflation, higher interest rates and downturns in customer business cycles, the risk of customer loss, the risk of management and employee loss, the creditworthiness of our customers and their ability to pay for services rendered, our inability to maintain our historical growth rate because of a decreased volume of freight or decreased average revenue per pound of freight moving through our network, market acceptance of our service offerings, increasing competition and pricing pressure, our dependence on our senior management team and the potential effects of changes in employee status, seasonal trends, the occurrence of certain weather events, restrictions in our charter and bylaws, and the risks described in our Annual Report on Form 10-K for the year ended December 31, 2025, and as may be identified in our subsequent Quarterly Reports on Form 10-Q and Current Reports on Form 8-K.
We caution readers that any forward-looking statement made by us in this press release is based only on information currently available to us and they should not place undue reliance on any forward-looking statement, which reflect management's opinion as of the date on which it is made. We undertake no obligation to publicly update any forward-looking statement, whether written or oral, that may be made from time to time, whether as a result of new information, future developments or otherwise unless required by law.
Contact:
Investors:
Tony Carreño
Media:
Hannah Weeg
10
Forward Air Corporation Earnings Presentation 2Q26 August 5, 2026
E a r n i n g s P r e s e n t a t i o n Statements & Disclaimers 2 Forward Looking Statements This presentation contains “forward-looking statements” within the meaning of the safe harbor provisions of the U.S. Private Securities Litigation Reform Act of 1995. Forward-looking statements can be identified by words such as: “anticipate,” “intend,” “plan,” “goal,” “seek,” “believe,” “project,” “estimate,” “expect,” “strategy,” “future,” “likely,” “may,” “should,” “will” and similar references to future periods. Forward-looking statements included in this presentation relate to: expectations regarding customer demand for services of Forward Air Corporation (“Forward,” “we,” “us” or “our”); our outlook on the freight market, including expectations regarding freight market conditions, capacity and the pace and extent of any freight market recovery; our expectations regarding operational and administrative transformations after the Omni acquisition; our projections with respect to revenue growth following the realization of such synergies; our goals to achieve sustainable growth and long-term profitability; our expectations regarding the proposed transition of a portion of business of one of our customers, including our expectations regarding the non-binding memorandum of understanding with the customer, the amount of revenue and services expected to be retained, the term of any retained services and the anticipated timing of any transition; our plans and expectations regarding the disposition of non-core assets, including the anticipated timing and completion of the sale of our Intermodal business and the expected use of proceeds therefrom; our deleveraging goals; and our future debt service requirements. Forward-looking statements are neither historical facts nor assurances of future performance. Instead, they are based only on our current beliefs, expectations and assumptions regarding the future of our business, future plans and strategies, projections, anticipated events and trends, the economy and other future conditions. Because forward-looking statements relate to the future, they are subject to inherent uncertainties, risks and changes in circumstances that are difficult to predict and many of which are outside of our control. Our actual results and financial condition may differ materially from those indicated in the forward-looking statements. The following is a list of factors, among others, that could cause actual results to differ materially from those contemplated by the forward-looking statements: economic factors such as recessions, inflation, higher interest rates and downturns in customer business cycles; the outcome of our review of strategic alternatives; our ability to execute on a strategic sale of non-core assets, including our Intermodal business, on the anticipated timing and terms, or at all; the risk that we do not enter into a definitive agreement with the customer with which we have entered into a non-binding memorandum of understanding, or that the customer transitions a greater portion of its business than currently anticipated or the transition otherwise occurs on terms less favorable than expected; our ability to achieve ongoing strategic, financial and other benefits as we continue to transform our business after the acquisition of Omni Logistics, including the realization of expected synergies and the achievement of deleveraging targets within the expected timeframes or at all; the risk of customer loss; the risk of management and employee loss; the creditworthiness of our customers and their ability to pay for services rendered; our inability to maintain our historical growth rate because of a decreased volume of freight or decreased average revenue per pound of freight moving through our network; the availability and compensation of qualified Leased Capacity Providers and freight handlers as well as contracted, third-party carriers needed to serve our customers’ transportation needs; our inability to manage our information systems and the occurrence of cybersecurity risks and events; market acceptance of our service offerings; claims for property damage, personal injuries or workers’ compensation; enforcement of and changes in governmental regulations; environmental, tax, insurance and accounting matters; the handling of hazardous materials; changes in fuel prices; loss of a major customer; increasing competition and pricing pressure; evolving macroeconomic factors, including the imposition of additional tariffs, potential escalation from trading partners, the uncertainty surrounding trade policy, including the extent to which increased tariffs will affect our operations and strategic plan, and our limited visibility into the impact of tariffs on third-party shipments; our dependence on our senior management team and the potential effects of changes in employee status; seasonal trends; the occurrence of certain weather events; restrictions in our charter and bylaws; and the risks described in our Annual Report on Form 10-K for the year ended December 31, 2025, and as may be identified in our subsequent Quarterly Reports on Form 10-Q and Current Reports on Form 8-K. We caution readers that any forward-looking statement made by us in this presentation is based only on information currently available to us, and readers should not place undue reliance on any forward-looking statement, which reflects management’s opinion only as of the date on which it is made. We undertake no obligation to publicly update any forward-looking statement, whether written or oral, that may be made from time to time, whether as a result of new information, future developments or otherwise unless required by law. Non-GAAP Measures To supplement the financial measures prepared in accordance with generally accepted accounting principles in the United States (“GAAP”), we have included Adjusted EBITDA, Adjusted EBITDA Margin %, Consolidated EBITDA, Consolidated EBITDA Margin %, Adjusted Operating Income, Net Leverage Ratio, Net Debt, Reported EBITDA, Reported EBITDA Margin %, LTM Reported EBITDA, LTM Reported EBITDA Margin %, Unlevered Free Cash Flow and Adjusted Operating Cash Flow, each of which is a non-GAAP financial measure (each, a “Non- GAAP Measure”), in this presentation. The reconciliation of each Non-GAAP Measure to the most directly comparable financial measure calculated and presented in accordance with GAAP can be found in the Appendix to this presentation. Because each Non-GAAP Measure excludes certain items as described herein, it may not be indicative of the results that Forward expects to recognize for future periods. As a result, each Non-GAAP Measure should be considered in addition to, and not a substitute for, financial information prepared in accordance with GAAP. The Company is also providing Consolidated EBITDA, Liquidity, and Net Leverage Ratio calculated in accordance with Forward’s credit agreement as we believe these measures provide investors with important information regarding our liquidity, financial condition and compliance with our obligations under our credit agreement.
01 Combined Overview 02 2Q26 Results 03 Liquidity, Leverage and Cash Flow 04 Investment Rationale 05 Closing Summary 06 Appendix E a r n i n g s P r e s e n t a t i o n Agenda 3
E a r n i n g s P r e s e n t a t i o n Combined Overview 4
C o m b i n e d O v e r v i e w Who We Are: A Story of Transformation and Excellence Our Heritage Forward Air's revolutionary expedited ground freight network, established in 1981, and Omni’s innovative logistics solutions, founded in 2000, represent decades of excellence in logistics innovation. Our Combined Strength Together, we have created a logistics powerhouse that combines Forward Air's robust North American LTL network with Omni's global logistics solutions, delivering unprecedented value and capabilities to our customers. Our Future This strategic union positions us as a leading force in global logistics, offering comprehensive solutions that span continents and streamline supply chains. 5
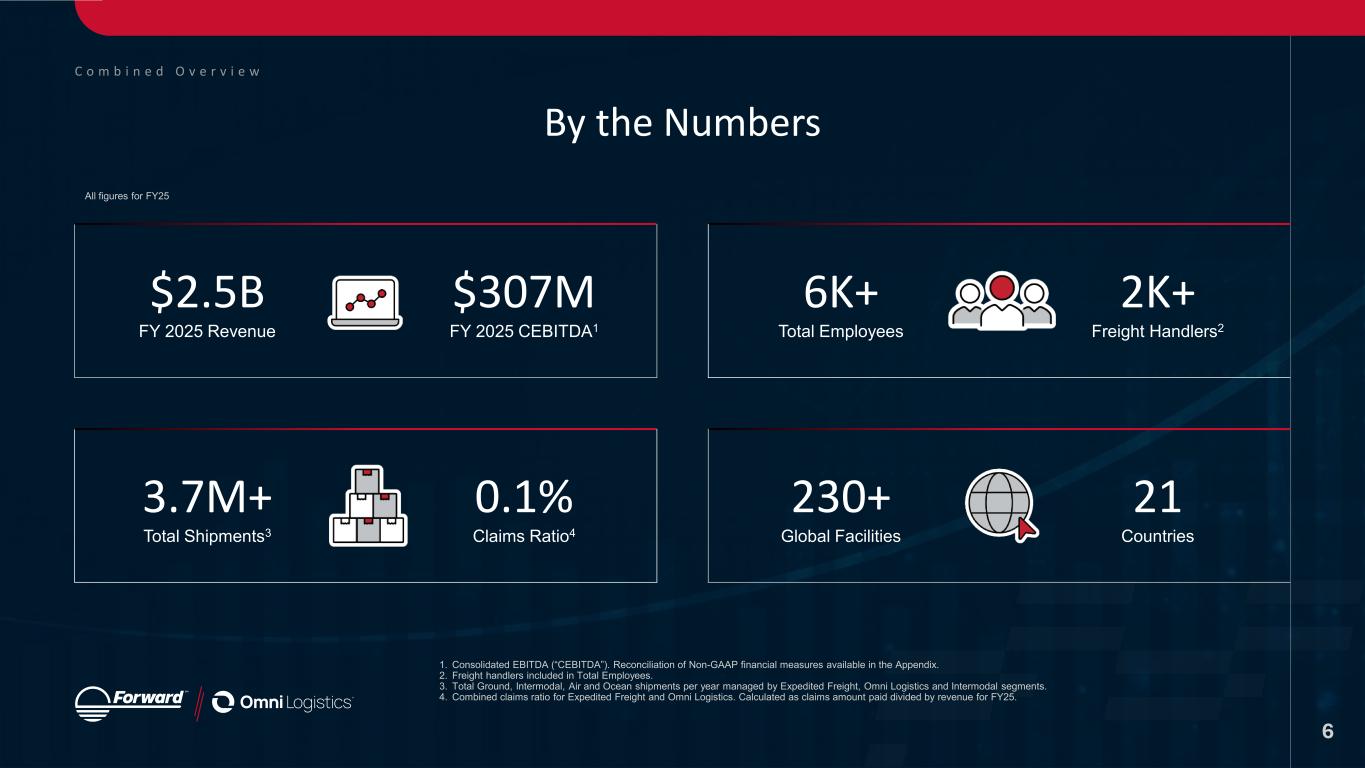
C o m b i n e d O v e r v i e w By the Numbers $2.5B FY 2025 Revenue $307M FY 2025 CEBITDA1 6K+ Total Employees 2K+ Freight Handlers2 3.7M+ Total Shipments3 0.1% Claims Ratio4 230+ Global Facilities 21 Countries 6 1. Consolidated EBITDA (“CEBITDA”). Reconciliation of Non-GAAP financial measures available in the Appendix. 2. Freight handlers included in Total Employees. 3. Total Ground, Intermodal, Air and Ocean shipments per year managed by Expedited Freight, Omni Logistics and Intermodal segments. 4. Combined claims ratio for Expedited Freight and Omni Logistics. Calculated as claims amount paid divided by revenue for FY25. All figures for FY25
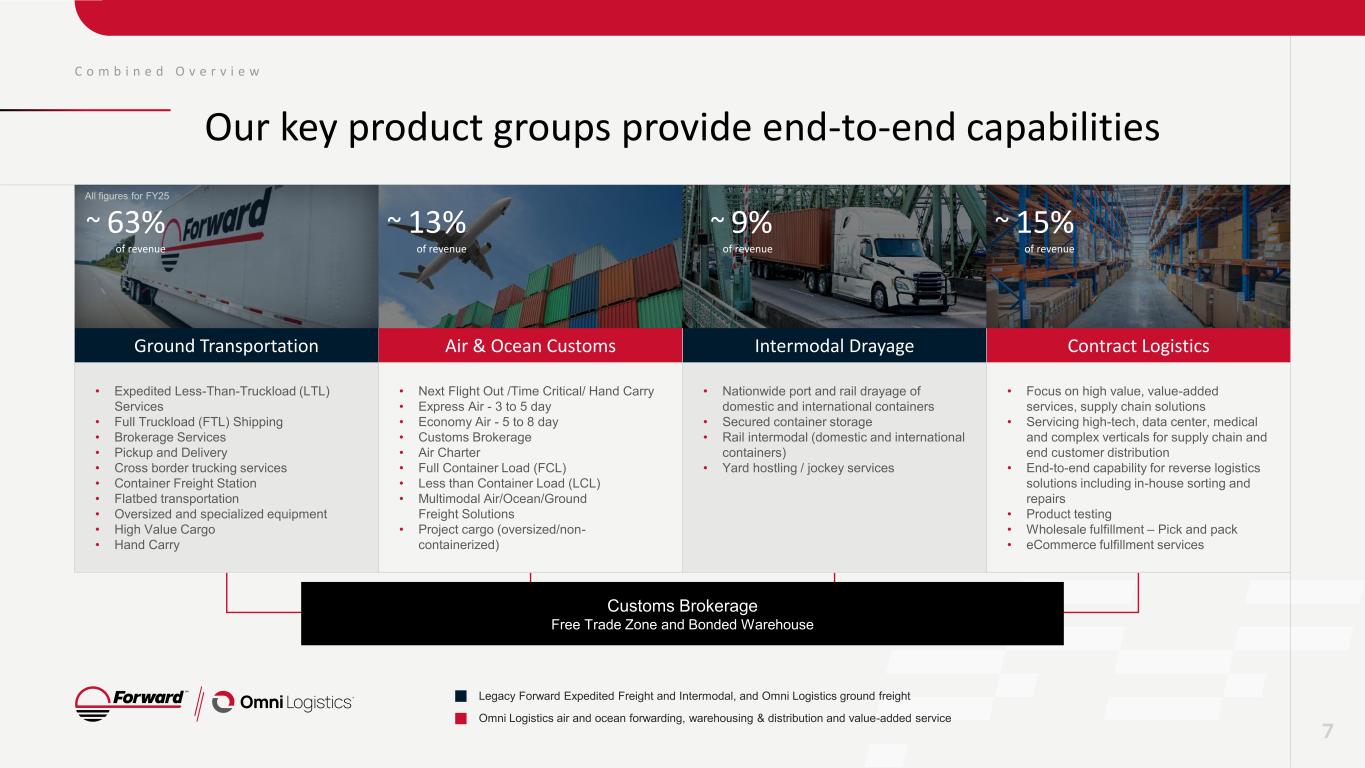
Ground Transportation Air & Ocean Customs Intermodal Drayage Contract Logistics • Expedited Less-Than-Truckload (LTL) Services • Full Truckload (FTL) Shipping • Brokerage Services • Pickup and Delivery • Cross border trucking services • Container Freight Station • Flatbed transportation • Oversized and specialized equipment • High Value Cargo • Hand Carry • Next Flight Out /Time Critical/ Hand Carry • Express Air - 3 to 5 day • Economy Air - 5 to 8 day • Customs Brokerage • Air Charter • Full Container Load (FCL) • Less than Container Load (LCL) • Multimodal Air/Ocean/Ground Freight Solutions • Project cargo (oversized/non- containerized) • Nationwide port and rail drayage of domestic and international containers • Secured container storage • Rail intermodal (domestic and international containers) • Yard hostling / jockey services • Focus on high value, value-added services, supply chain solutions • Servicing high-tech, data center, medical and complex verticals for supply chain and end customer distribution • End-to-end capability for reverse logistics solutions including in-house sorting and repairs • Product testing • Wholesale fulfillment – Pick and pack • eCommerce fulfillment services Customs Brokerage Free Trade Zone and Bonded Warehouse C o m b i n e d O v e r v i e w Our key product groups provide end-to-end capabilities 7 ~ 63% of revenue Legacy Forward Expedited Freight and Intermodal, and Omni Logistics ground freight Omni Logistics air and ocean forwarding, warehousing & distribution and value-added service All figures for FY25 ~ 13% of revenue ~ 9% of revenue ~ 15% of revenue
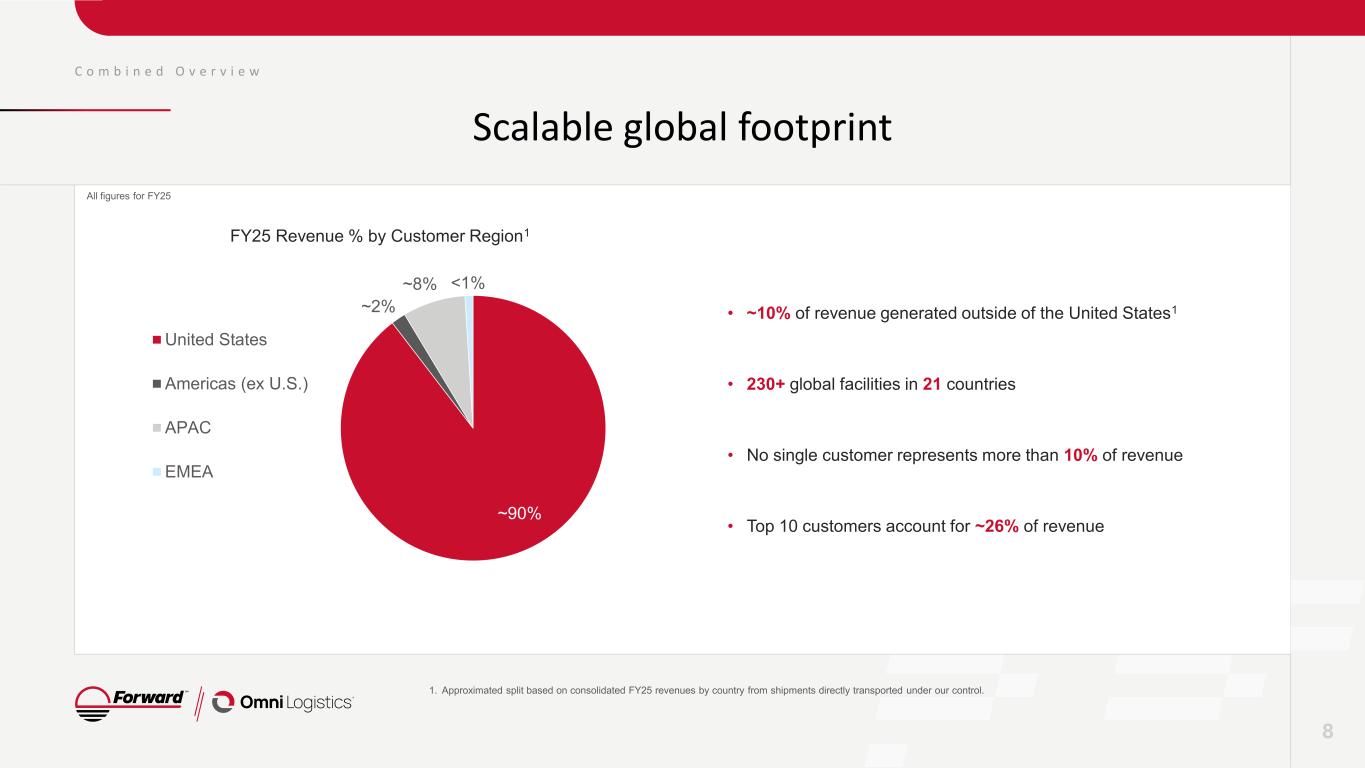
C o m b i n e d O v e r v i e w Scalable global footprint 1. Approximated split based on consolidated FY25 revenues by country from shipments directly transported under our control. 8 ~90% ~2% ~8% <1% United States Americas (ex U.S.) APAC EMEA • ~10% of revenue generated outside of the United States1 • 230+ global facilities in 21 countries • No single customer represents more than 10% of revenue • Top 10 customers account for ~26% of revenue FY25 Revenue % by Customer Region1 All figures for FY25
E a r n i n g s P r e s e n t a t i o n 2Q26 Results 9
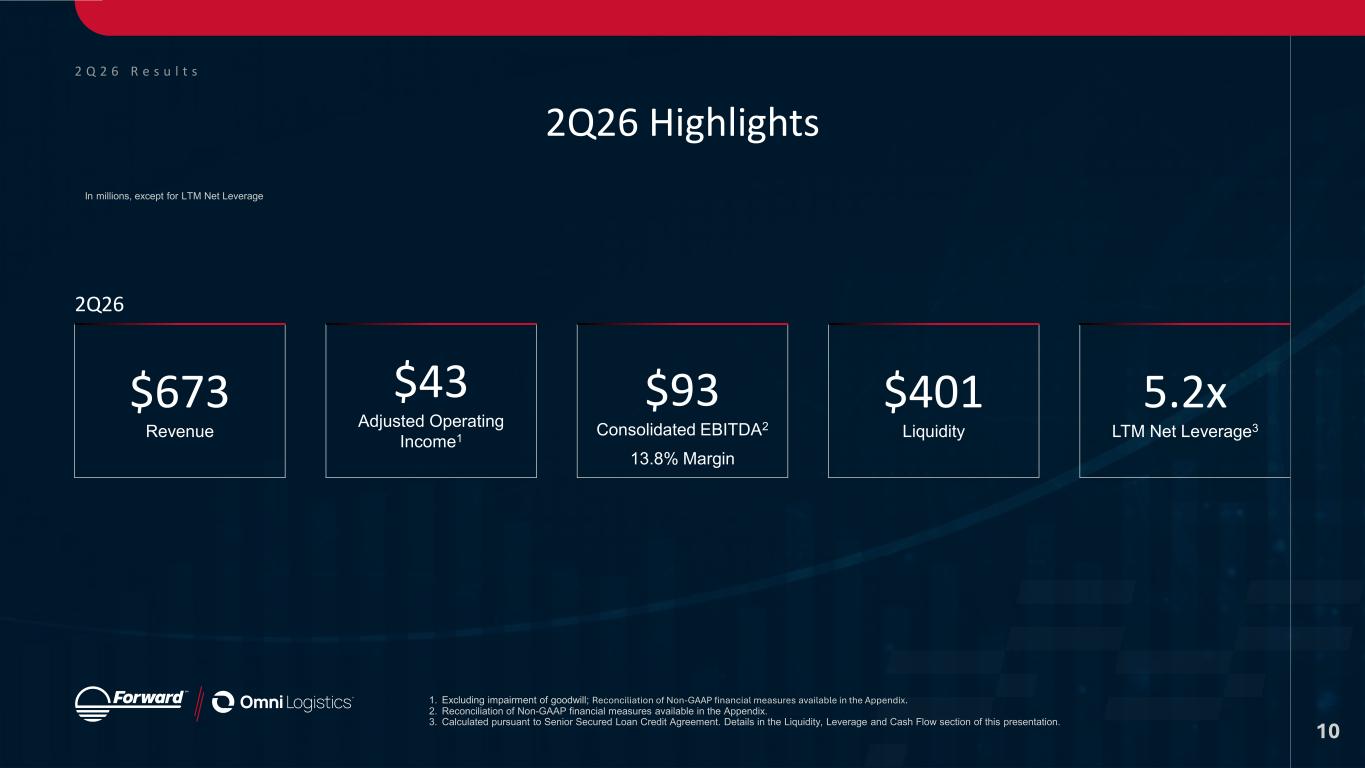
2 Q 2 6 R e s u l t s 2Q26 Highlights 2Q26 $673 Revenue $43 Adjusted Operating Income1 $93 Consolidated EBITDA2 13.8% Margin $401 Liquidity 5.2x LTM Net Leverage3 10 1. Excluding impairment of goodwill; Reconciliation of Non-GAAP financial measures available in the Appendix. 2. Reconciliation of Non-GAAP financial measures available in the Appendix. 3. Calculated pursuant to Senior Secured Loan Credit Agreement. Details in the Liquidity, Leverage and Cash Flow section of this presentation. In millions, except for LTM Net Leverage
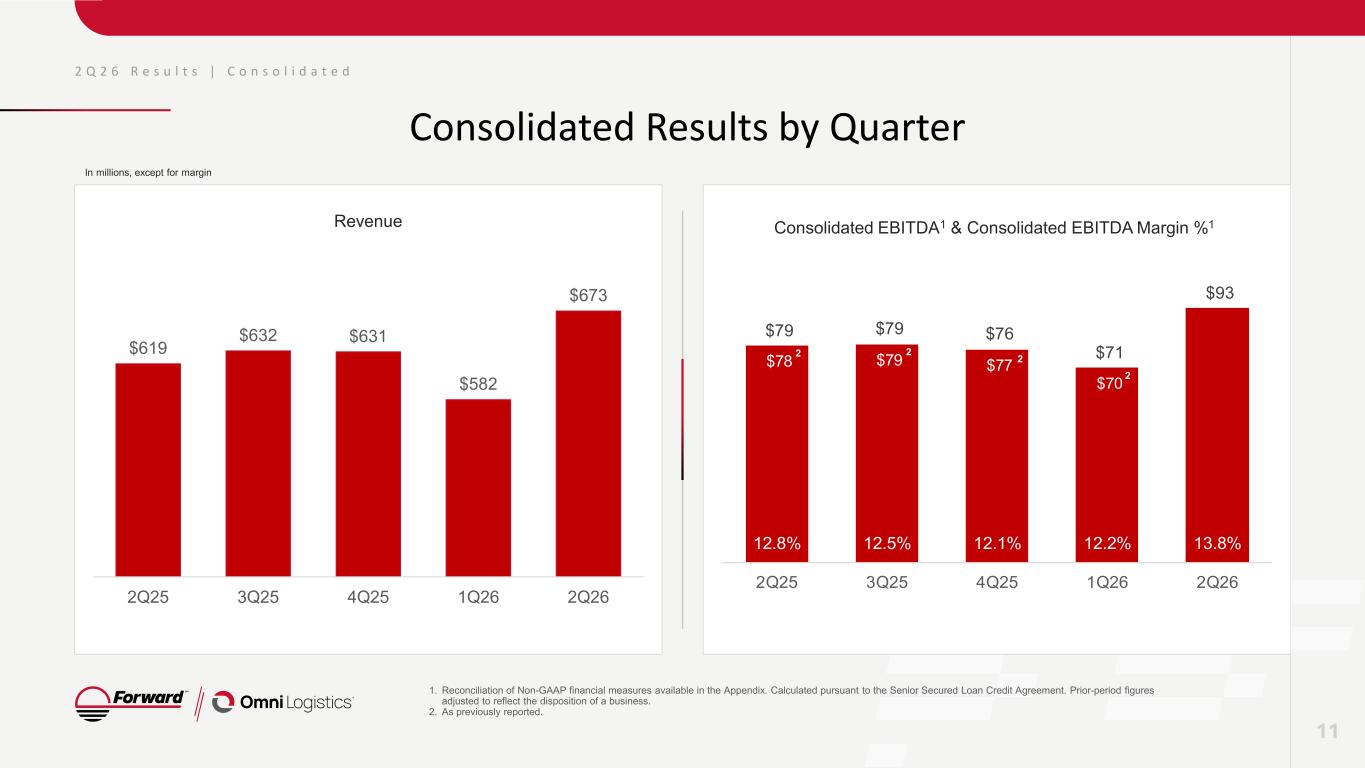
$619 $632 $631 $582 $673 2Q25 3Q25 4Q25 1Q26 2Q26 2 Q 2 6 R e s u l t s | C o n s o l i d a t e d Consolidated Results by Quarter 1. Reconciliation of Non-GAAP financial measures available in the Appendix. Calculated pursuant to the Senior Secured Loan Credit Agreement. Prior-period figures adjusted to reflect the disposition of a business. 2. As previously reported. Revenue Consolidated EBITDA1 & Consolidated EBITDA Margin %1 11 In millions, except for margin 2 22 2 2 2 2 2 0 2. 2. 2. 2.2 . 2 2 2 2 2 2 2 2 22
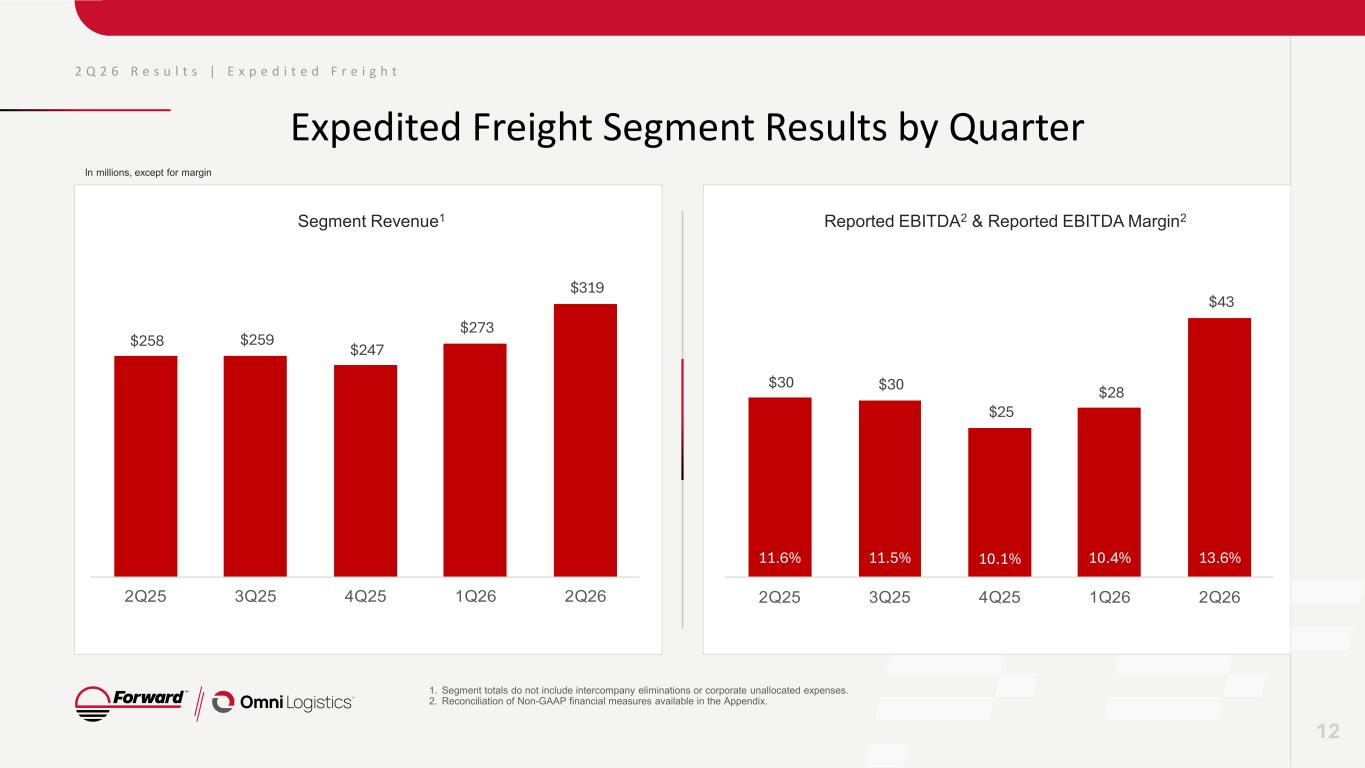
2 Q 2 6 R e s u l t s | E x p e d i t e d F r e i g h t Expedited Freight Segment Results by Quarter 1. Segment totals do not include intercompany eliminations or corporate unallocated expenses. 2. Reconciliation of Non-GAAP financial measures available in the Appendix. Segment Revenue1 Reported EBITDA2 & Reported EBITDA Margin2 12 In millions, except for margin 2 2 2 2 2 2 2 2 2 2 2 2 2 2
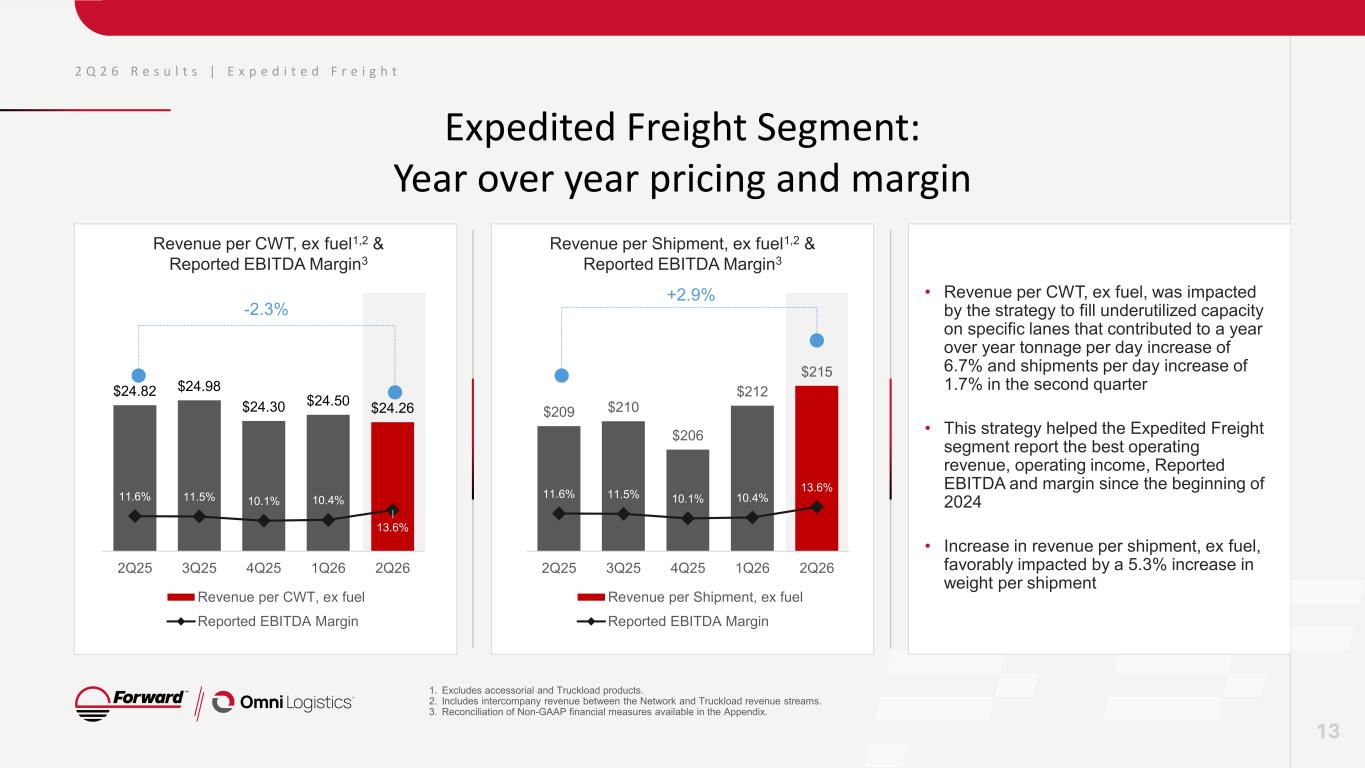
2 Q 2 6 R e s u l t s | E x p e d i t e d F r e i g h t Expedited Freight Segment: Year over year pricing and margin 13 Revenue per CWT, ex fuel1,2 & Reported EBITDA Margin3 Revenue per Shipment, ex fuel1,2 & Reported EBITDA Margin3 $24.82 $24.98 $24.30 $24.50 $24.26 11.6% 11.5% 10.1% 10.4% 13.6% 2Q25 3Q25 4Q25 1Q26 2Q26 Revenue per CWT, ex fuel Reported EBITDA Margin -2.3% $209 $210 $206 $212 $215 11.6% 11.5% 10.1% 10.4% 13.6% 2Q25 3Q25 4Q25 1Q26 2Q26 Revenue per Shipment, ex fuel Reported EBITDA Margin +2.9% 1. Excludes accessorial and Truckload products. 2. Includes intercompany revenue between the Network and Truckload revenue streams. 3. Reconciliation of Non-GAAP financial measures available in the Appendix. • Revenue per CWT, ex fuel, was impacted by the strategy to fill underutilized capacity on specific lanes that contributed to a year over year tonnage per day increase of 6.7% and shipments per day increase of 1.7% in the second quarter • This strategy helped the Expedited Freight segment report the best operating revenue, operating income, Reported EBITDA and margin since the beginning of 2024 • Increase in revenue per shipment, ex fuel, favorably impacted by a 5.3% increase in weight per shipment
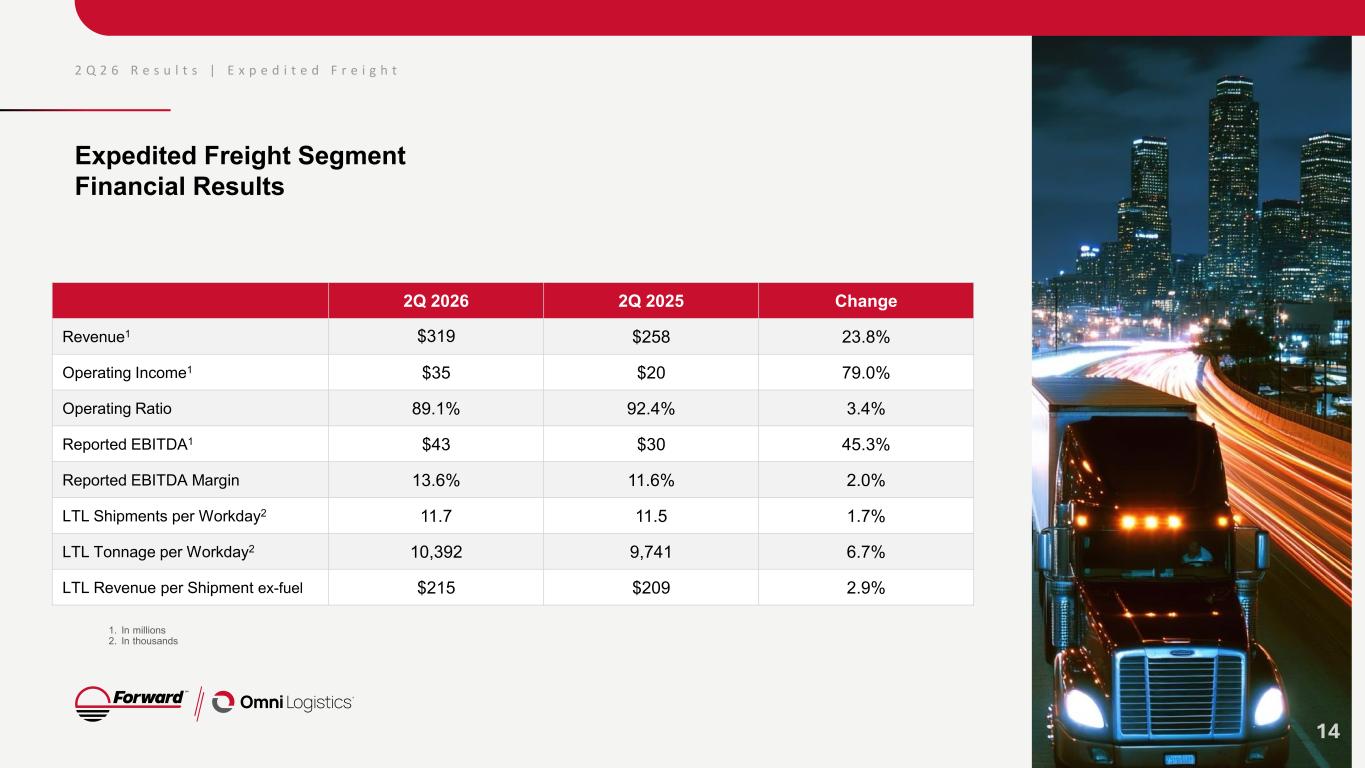
2 Q 2 6 R e s u l t s | E x p e d i t e d F r e i g h t Expedited Freight Segment Financial Results 2Q 2026 2Q 2025 Change Revenue1 $319 $258 23.8% Operating Income1 $35 $20 79.0% Operating Ratio 89.1% 92.4% 3.4% Reported EBITDA1 $43 $30 45.3% Reported EBITDA Margin 13.6% 11.6% 2.0% LTL Shipments per Workday2 11.7 11.5 1.7% LTL Tonnage per Workday2 10,392 9,741 6.7% LTL Revenue per Shipment ex-fuel $215 $209 2.9% 14 1. In millions 2. In thousands
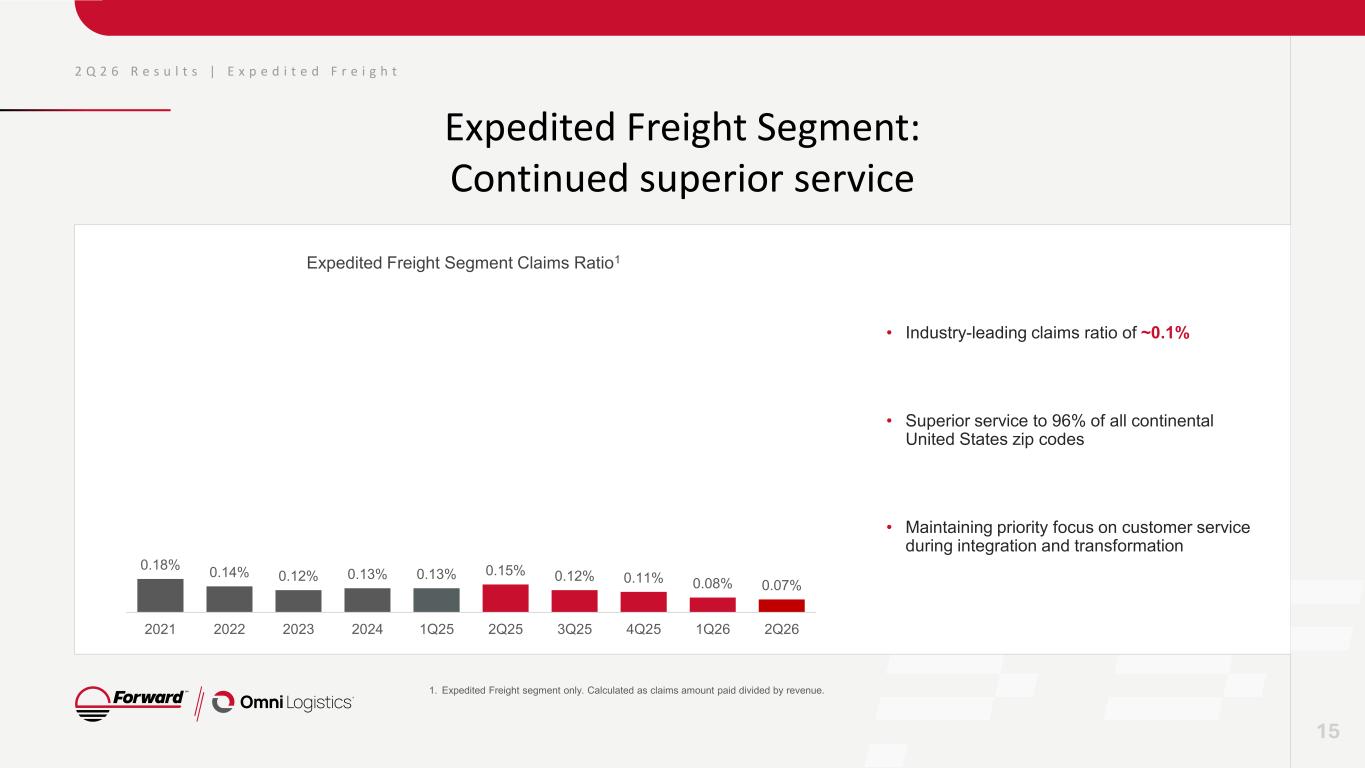
0.18% 0.14% 0.12% 0.13% 0.13% 0.15% 0.12% 0.11% 0.08% 0.07% 2021 2022 2023 2024 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 2 Q 2 6 R e s u l t s | E x p e d i t e d F r e i g h t Expedited Freight Segment: Continued superior service 15 Expedited Freight Segment Claims Ratio1 • Industry-leading claims ratio of ~0.1% • Superior service to 96% of all continental United States zip codes • Maintaining priority focus on customer service during integration and transformation 1. Expedited Freight segment only. Calculated as claims amount paid divided by revenue.
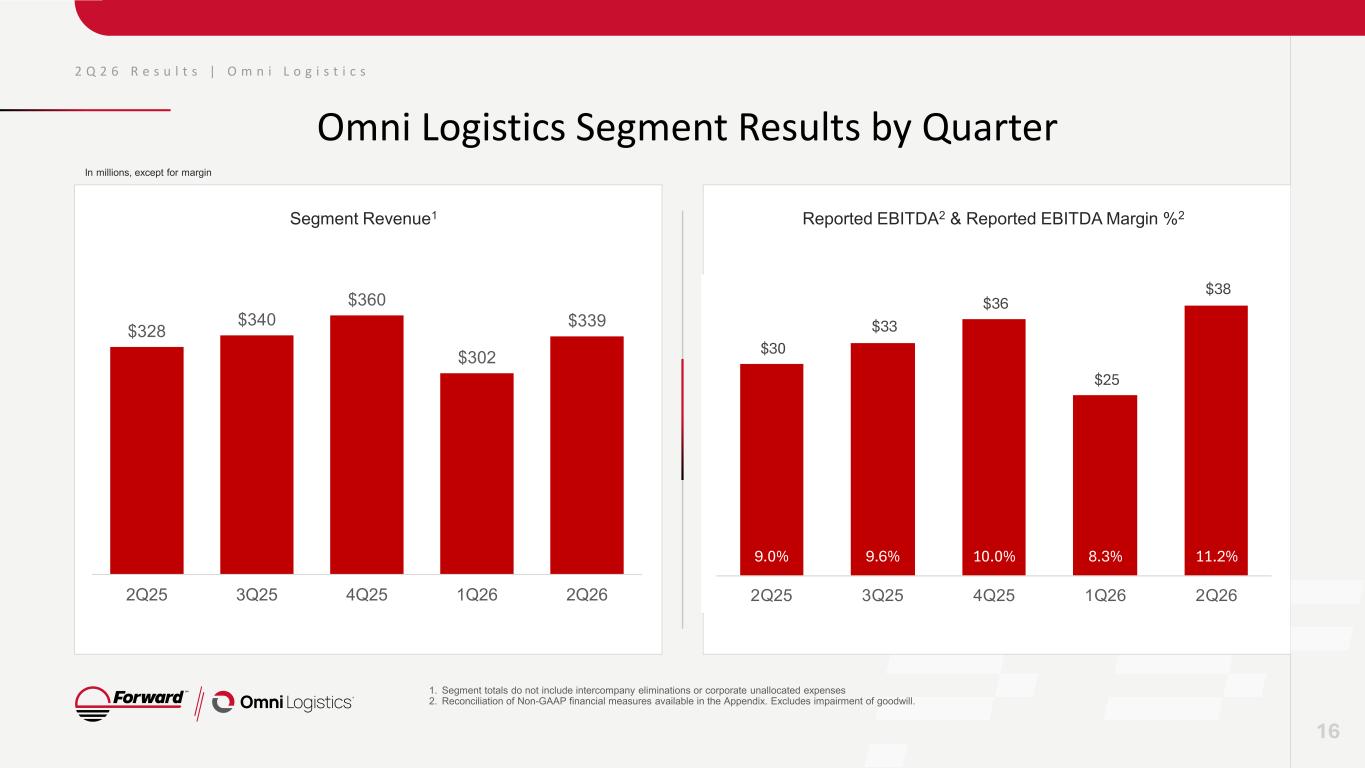
2 Q 2 6 R e s u l t s | O m n i L o g i s t i c s Omni Logistics Segment Results by Quarter Reported EBITDA2 & Reported EBITDA Margin %2Segment Revenue1 16 1. Segment totals do not include intercompany eliminations or corporate unallocated expenses 2. Reconciliation of Non-GAAP financial measures available in the Appendix. Excludes impairment of goodwill. $328 $340 $360 $302 $339 2Q25 3Q25 4Q25 1Q26 2Q26 In millions, except for margin 2 2 2 2 2 2 2
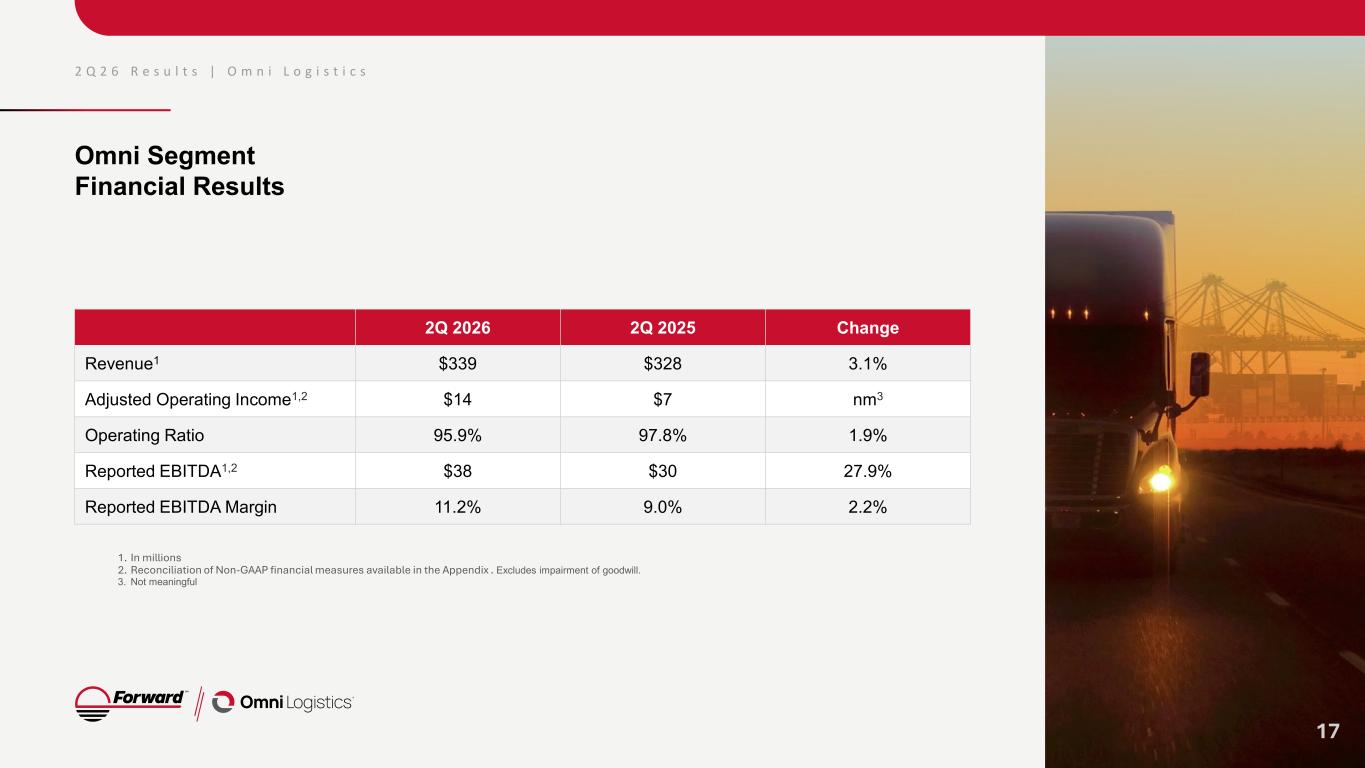
Omni Segment Financial Results 2Q 2026 2Q 2025 Change Revenue1 $339 $328 3.1% Adjusted Operating Income1,2 $14 $7 nm3 Operating Ratio 95.9% 97.8% 1.9% Reported EBITDA1,2 $38 $30 27.9% Reported EBITDA Margin 11.2% 9.0% 2.2% 2 Q 2 6 R e s u l t s | O m n i L o g i s t i c s 17 1. In millions 2. Reconciliation of Non-GAAP financial measures available in the Appendix . Excludes impairment of goodwill. 3. Not meaningful
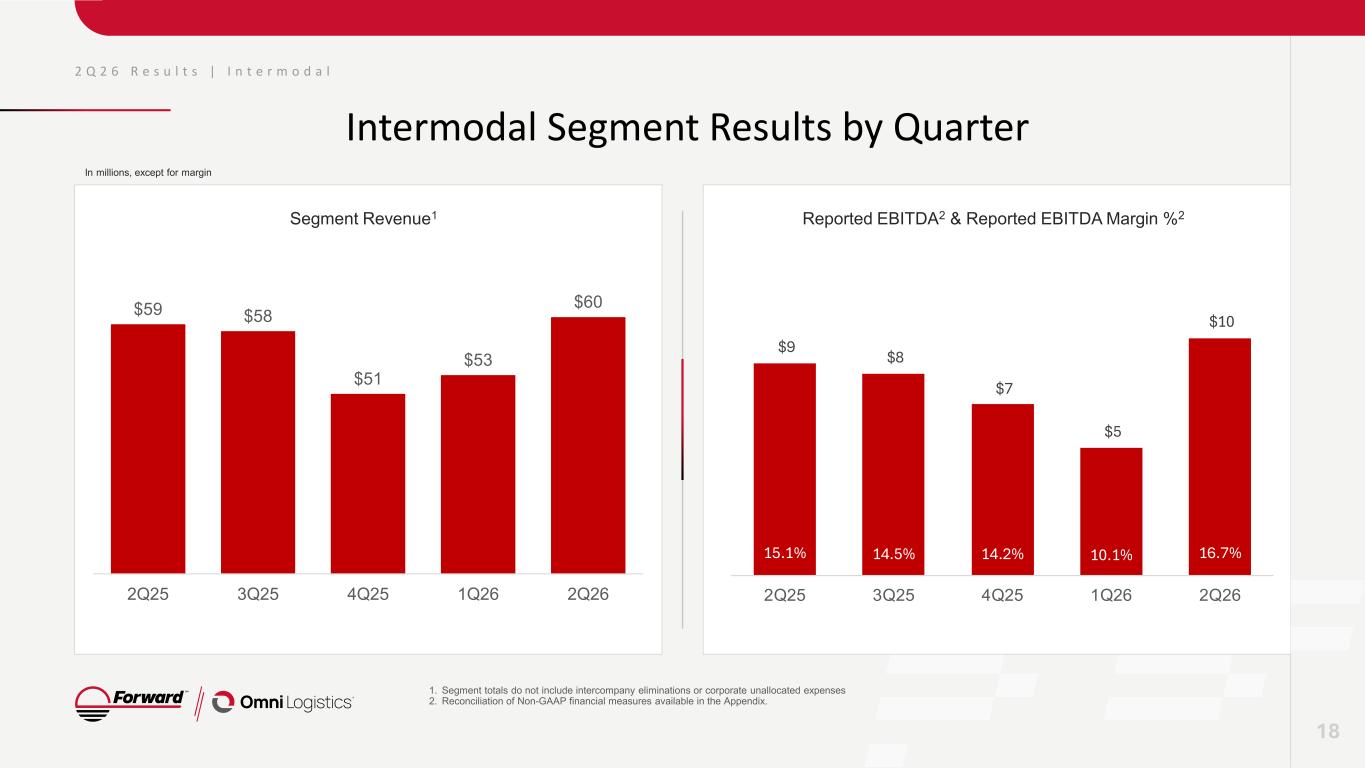
2 Q 2 6 R e s u l t s | I n t e r m o d a l Intermodal Segment Results by Quarter 1. Segment totals do not include intercompany eliminations or corporate unallocated expenses 2. Reconciliation of Non-GAAP financial measures available in the Appendix. Reported EBITDA2 & Reported EBITDA Margin %2Segment Revenue1 $59 $58 $51 $53 $60 2Q25 3Q25 4Q25 1Q26 2Q26 In millions, except for margin 18 2 2 2 2 2 2 2
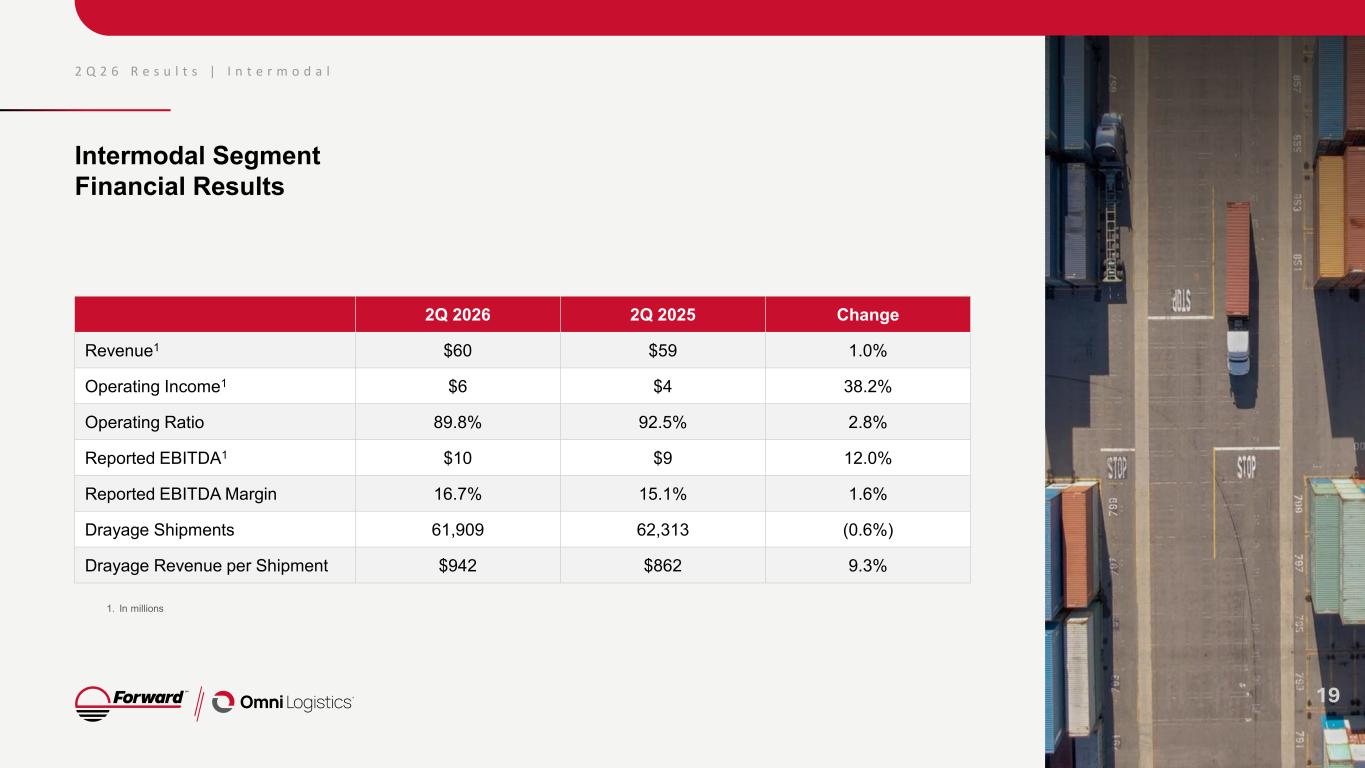
Intermodal Segment Financial Results 2Q 2026 2Q 2025 Change Revenue1 $60 $59 1.0% Operating Income1 $6 $4 38.2% Operating Ratio 89.8% 92.5% 2.8% Reported EBITDA1 $10 $9 12.0% Reported EBITDA Margin 16.7% 15.1% 1.6% Drayage Shipments 61,909 62,313 (0.6%) Drayage Revenue per Shipment $942 $862 9.3% 2 Q 2 6 R e s u l t s | I n t e r m o d a l 19 1. In millions
E a r n i n g s P r e s e n t a t i o n Liquidity, Leverage and Cash Flow 20
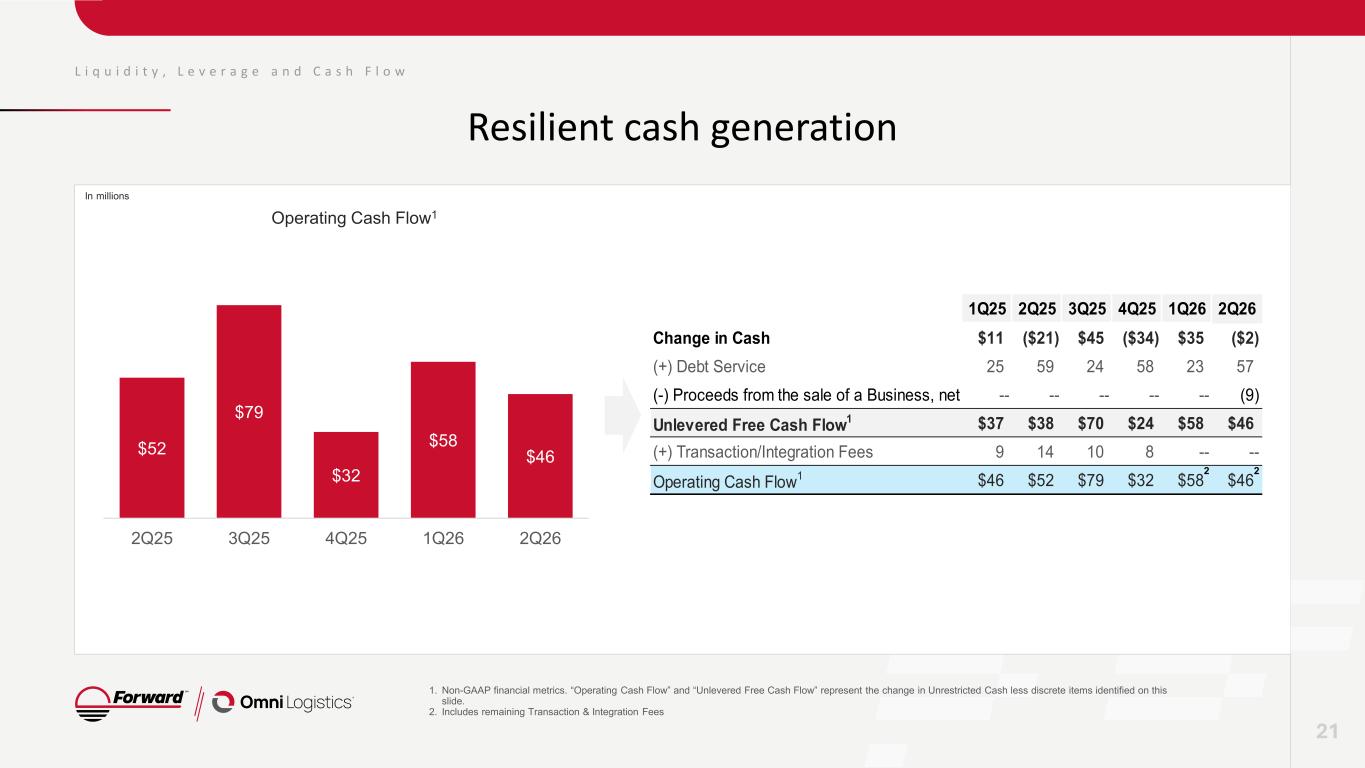
L i q u i d i t y , L e v e r a g e a n d C a s h F l o w Resilient cash generation 1. Non-GAAP financial metrics. “Operating Cash Flow” and “Unlevered Free Cash Flow” represent the change in Unrestricted Cash less discrete items identified on this slide. 2. Includes remaining Transaction & Integration Fees 21 Operating Cash Flow1 In millions $52 $79 $32 $58 $46 2Q25 3Q25 4Q25 1Q26 2Q26 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 Change in Cash $11 ($21) $45 ($34) $35 ($2) (+) Debt Service 25 59 24 58 23 57 (-) Proceeds from the sale of a Business, net -- -- -- -- -- (9) Unlevered Free Cash Flow 1 $37 $38 $70 $24 $58 $46 (+) Transaction/Integration Fees 9 14 10 8 -- -- Operating Cash Flow 1 $46 $52 $79 $32 $58 $46 2 2
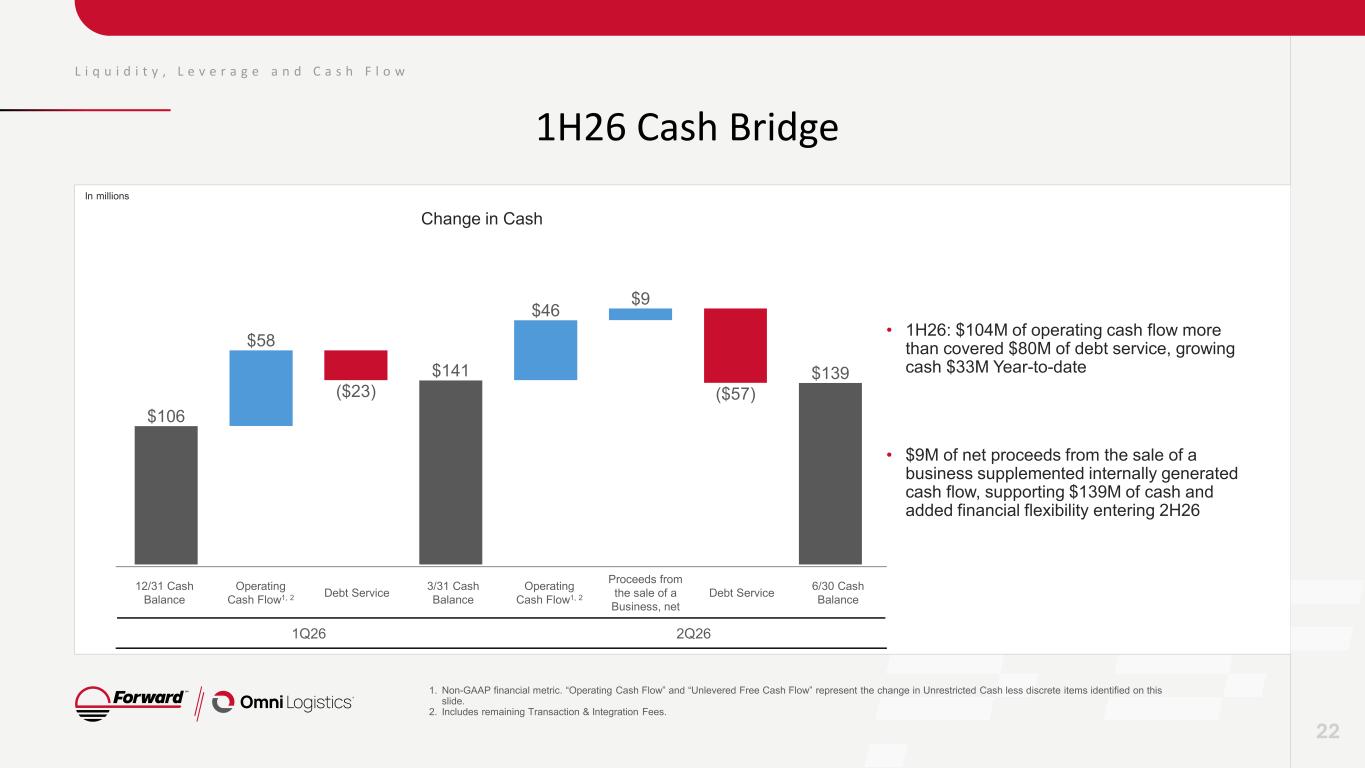
L i q u i d i t y , L e v e r a g e a n d C a s h F l o w 1H26 Cash Bridge 22 Change in Cash 1. Non-GAAP financial metric. “Operating Cash Flow” and “Unlevered Free Cash Flow” represent the change in Unrestricted Cash less discrete items identified on this slide. 2. Includes remaining Transaction & Integration Fees. • 1H26: $104M of operating cash flow more than covered $80M of debt service, growing cash $33M Year-to-date • $9M of net proceeds from the sale of a business supplemented internally generated cash flow, supporting $139M of cash and added financial flexibility entering 2H26 In millions $106 $58 ($23) $141 $46 $9 ($57) $139 12/31 Cash Balance Operating Cash Flow1, 2 Debt Service 3/31 Cash Balance Operating Cash Flow1, 2 Proceeds from the sale of a Business, net Debt Service 6/30 Cash Balance 1Q26 2Q26
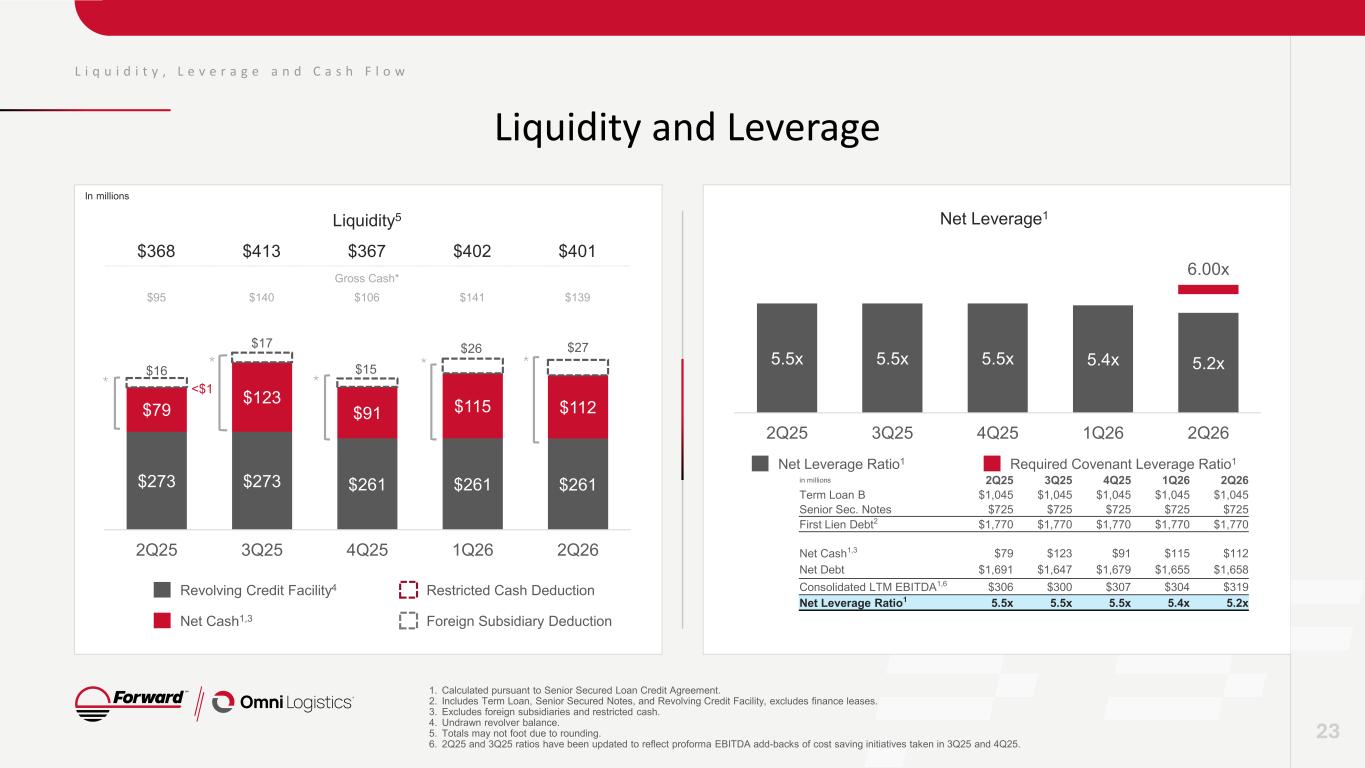
$273 $273 $261 $261 $261 $79 $123 $91 $115 $112 <$1 $16 $17 $15 $26 $27 2Q25 3Q25 4Q25 1Q26 2Q26 L i q u i d i t y , L e v e r a g e a n d C a s h F l o w Liquidity and Leverage Net Leverage1 Net Leverage Ratio1 Required Covenant Leverage Ratio1 Net Cash1,3 Revolving Credit Facility4 Restricted Cash Deduction Foreign Subsidiary Deduction * 23 * * * * 1. Calculated pursuant to Senior Secured Loan Credit Agreement. 2. Includes Term Loan, Senior Secured Notes, and Revolving Credit Facility, excludes finance leases. 3. Excludes foreign subsidiaries and restricted cash. 4. Undrawn revolver balance. 5. Totals may not foot due to rounding. 6. 2Q25 and 3Q25 ratios have been updated to reflect proforma EBITDA add-backs of cost saving initiatives taken in 3Q25 and 4Q25. In millions 5.5x 5.5x 5.5x 5.4x 5.2x 6.00x 2Q25 3Q25 4Q25 1Q26 2Q26 Liquidity5 $368 $413 $367 $402 $401 Gross Cash* $95 $140 $106 $141 $139 in millions 2Q25 3Q25 4Q25 1Q26 2Q26 Term Loan B $1,045 $1,045 $1,045 $1,045 $1,045 Senior Sec. Notes $725 $725 $725 $725 $725 First Lien Debt2 $1,770 $1,770 $1,770 $1,770 $1,770 Net Cash1,3 $79 $123 $91 $115 $112 Net Debt $1,691 $1,647 $1,679 $1,655 $1,658 Consolidated LTM EBITDA1,6 $306 $300 $307 $304 $319 Net Leverage Ratio1 5.5x 5.5x 5.5x 5.4x 5.2x
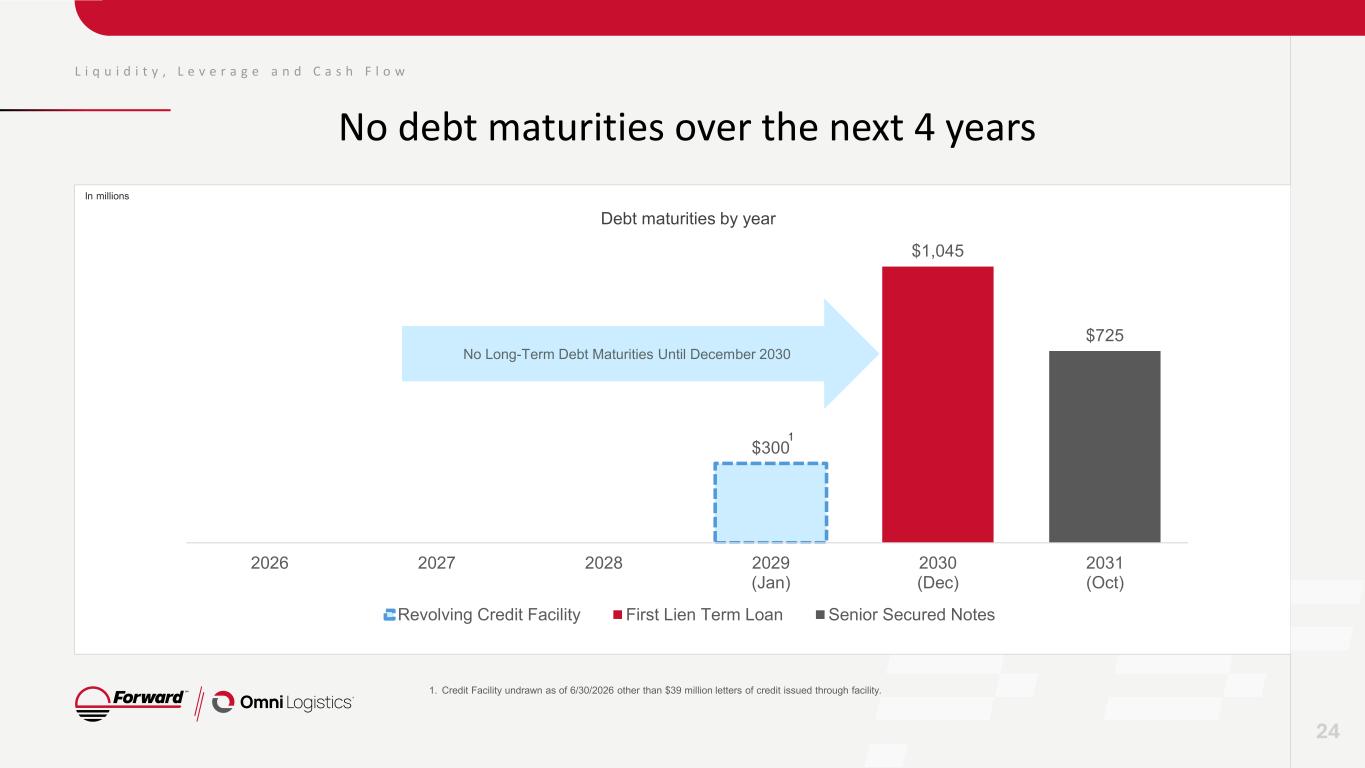
L i q u i d i t y , L e v e r a g e a n d C a s h F l o w No debt maturities over the next 4 years 1. Credit Facility undrawn as of 6/30/2026 other than $39 million letters of credit issued through facility. 24 $300 $1,045 $725 2026 2027 2028 2029 (Jan) 2030 (Dec) 2031 (Oct) Revolving Credit Facility First Lien Term Loan Senior Secured Notes No Long-Term Debt Maturities Until December 2030 Debt maturities by year In millions
E a r n i n g s P r e s e n t a t i o n Investment Rationale 25
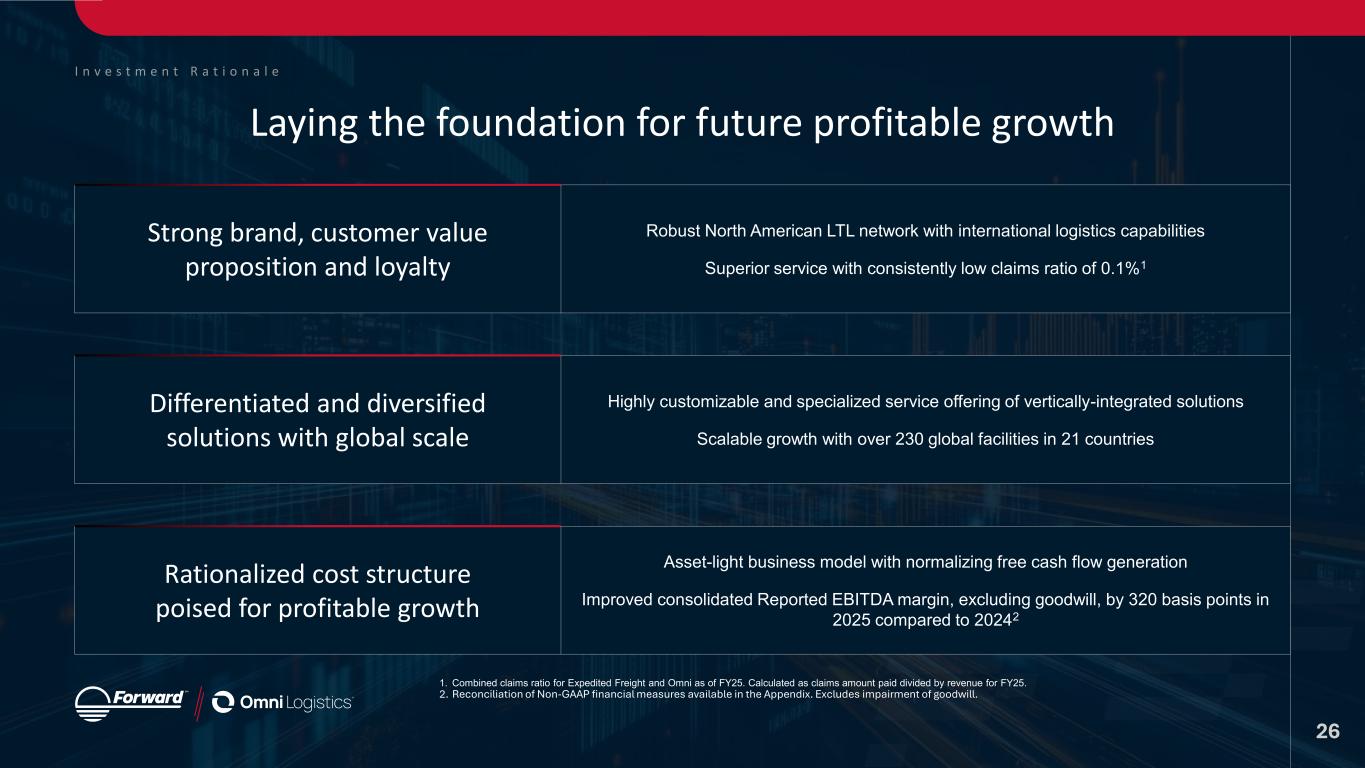
I n v e s t m e n t R a t i o n a l e Laying the foundation for future profitable growth Strong brand, customer value proposition and loyalty Robust North American LTL network with international logistics capabilities Superior service with consistently low claims ratio of 0.1%1 Differentiated and diversified solutions with global scale Highly customizable and specialized service offering of vertically-integrated solutions Scalable growth with over 230 global facilities in 21 countries Rationalized cost structure poised for profitable growth Asset-light business model with normalizing free cash flow generation Improved consolidated Reported EBITDA margin, excluding goodwill, by 320 basis points in 2025 compared to 20242 26 1. Combined claims ratio for Expedited Freight and Omni as of FY25. Calculated as claims amount paid divided by revenue for FY25. 2. Reconciliation of Non-GAAP financial measures available in the Appendix. Excludes impairment of goodwill.
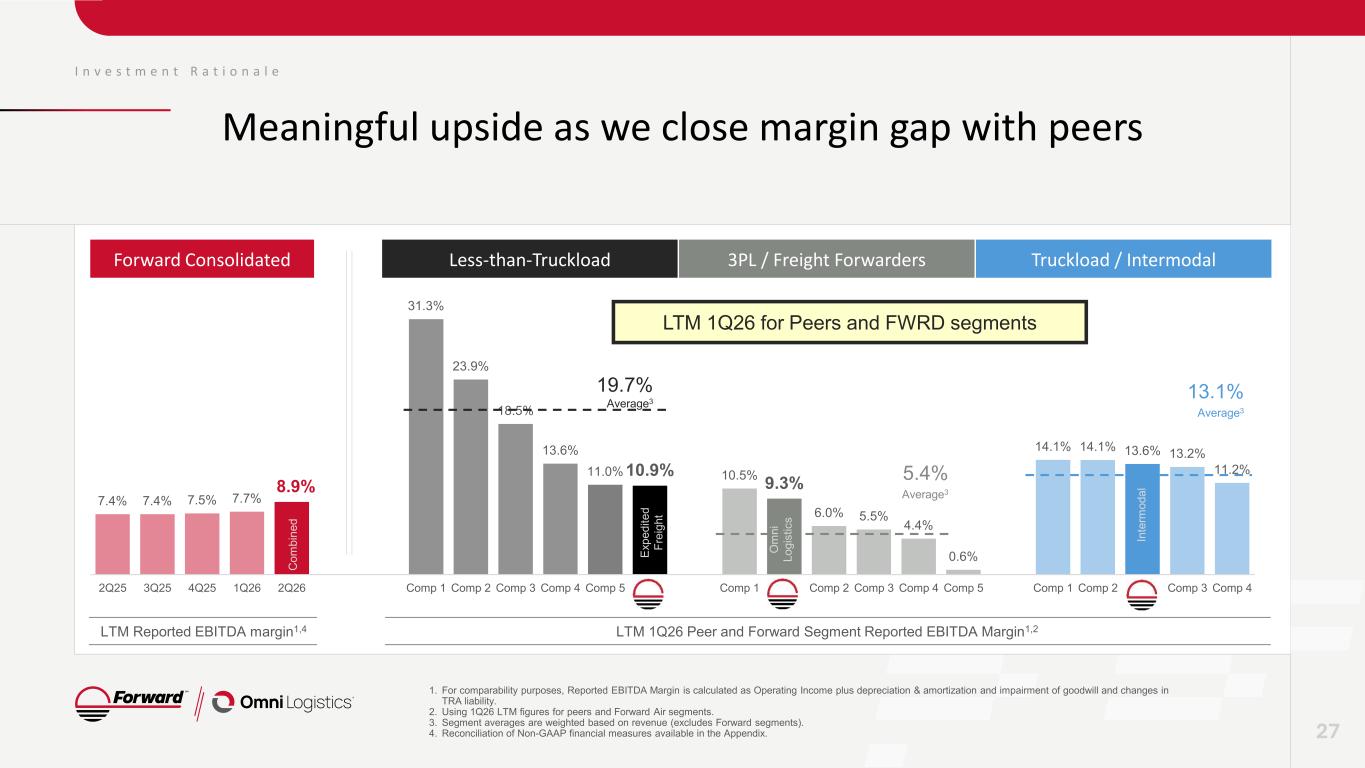
7.4% 7.4% 7.5% 7.7% 8.9% 31.3% 23.9% 18.5% 13.6% 11.0% 10.9% 10.5% 9.3% 6.0% 5.5% 4.4% 0.6% 14.1% 14.1% 13.6% 13.2% 11.2% 2Q25 3Q25 4Q25 1Q26 2Q26 Comp 1 Comp 2 Comp 3 Comp 4 Comp 5 Comp 1 Comp 2 Comp 3 Comp 4 Comp 5 Comp 1 Comp 2 Comp 3 Comp 4 I n v e s t m e n t R a t i o n a l e Meaningful upside as we close margin gap with peers 1. For comparability purposes, Reported EBITDA Margin is calculated as Operating Income plus depreciation & amortization and impairment of goodwill and changes in TRA liability. 2. Using 1Q26 LTM figures for peers and Forward Air segments. 3. Segment averages are weighted based on revenue (excludes Forward segments). 4. Reconciliation of Non-GAAP financial measures available in the Appendix. 19.7% Average3 5.4% Average3 13.1% Average3 27 Forward Consolidated Less-than-Truckload 3PL / Freight Forwarders Truckload / Intermodal LTM Reported EBITDA margin1,4 LTM 1Q26 Peer and Forward Segment Reported EBITDA Margin1,2 E x p e d it e d F re ig h t O m n i L o g is ti c s In te rm o d a l C o m b in e d LTM 1Q26 for Peers and FWRD segments
E a r n i n g s P r e s e n t a t i o n Closing Summary 01 Reports highest quarterly operating revenue in company history 02 Expedited Freight segment leads strong quarter and reports best results since the beginning of 2024 03 Intermodal segment reports best Reported EBITDA in five quarters and best margin in six quarters 04 Liquidity remains robust at $401 million 05 Seeing the benefits of diversified product portfolio 28
E a r n i n g s P r e s e n t a t i o n Appendix 29
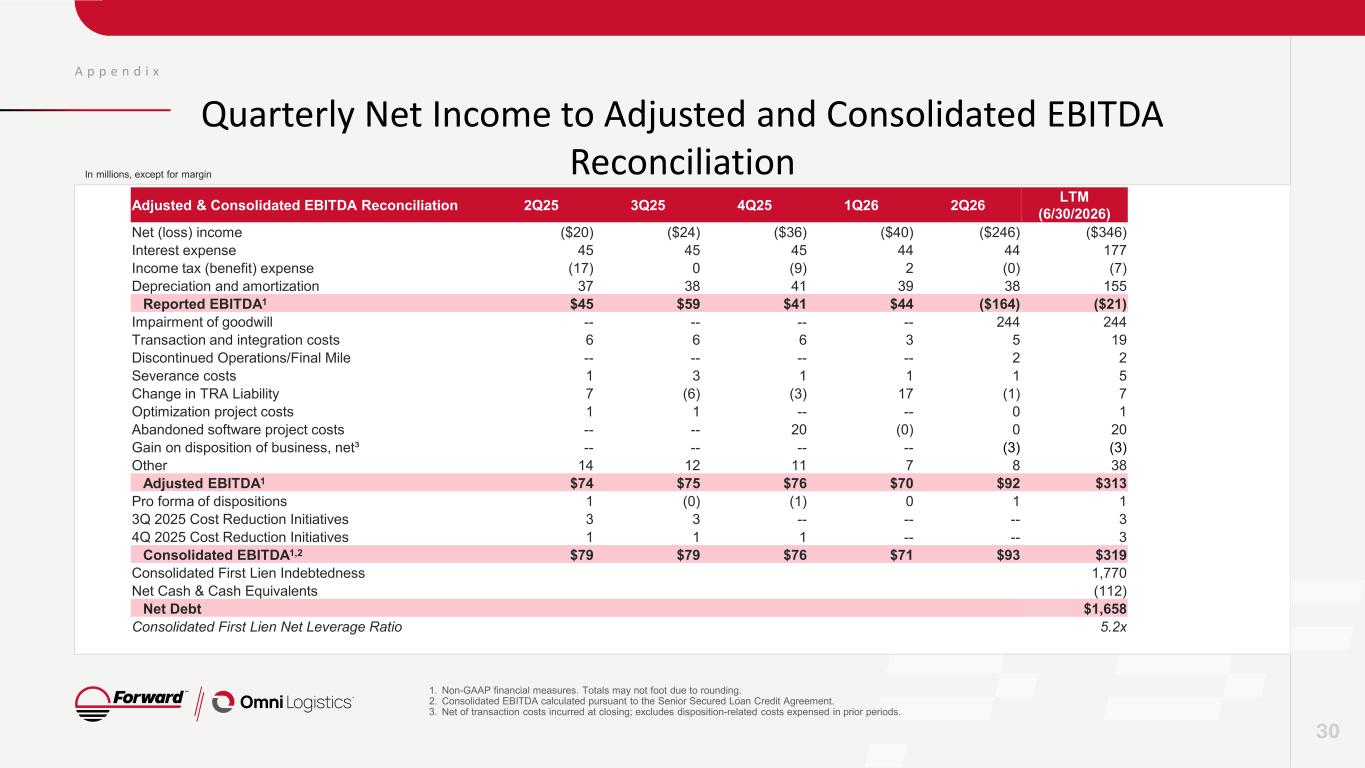
A p p e n d i x 30 1. Non-GAAP financial measures. Totals may not foot due to rounding. 2. Consolidated EBITDA calculated pursuant to the Senior Secured Loan Credit Agreement. 3. Net of transaction costs incurred at closing; excludes disposition-related costs expensed in prior periods. In millions, except for margin Quarterly Net Income to Adjusted and Consolidated EBITDA Reconciliation Adjusted & Consolidated EBITDA Reconciliation 2Q25 3Q25 4Q25 1Q26 2Q26 LTM (6/30/2026) Net (loss) income ($20) ($24) ($36) ($40) ($246) ($346) Interest expense 45 45 45 44 44 177 Income tax (benefit) expense (17) 0 (9) 2 (0) (7) Depreciation and amortization 37 38 41 39 38 155 Reported EBITDA1 $45 $59 $41 $44 ($164) ($21) Impairment of goodwill -- -- -- -- 244 244 Transaction and integration costs 6 6 6 3 5 19 Discontinued Operations/Final Mile -- -- -- -- 2 2 Severance costs 1 3 1 1 1 5 Change in TRA Liability 7 (6) (3) 17 (1) 7 Optimization project costs 1 1 -- -- 0 1 Abandoned software project costs -- -- 20 (0) 0 20 Gain on disposition of business, net³ -- -- -- -- (3) (3) Other 14 12 11 7 8 38 Adjusted EBITDA1 $74 $75 $76 $70 $92 $313 Pro forma of dispositions 1 (0) (1) 0 1 1 3Q 2025 Cost Reduction Initiatives 3 3 -- -- -- 3 4Q 2025 Cost Reduction Initiatives 1 1 1 -- -- 3 Consolidated EBITDA1,2 $79 $79 $76 $71 $93 $319 Consolidated First Lien Indebtedness 1,770 Net Cash & Cash Equivalents (112) Net Debt $1,658 Consolidated First Lien Net Leverage Ratio 5.2x
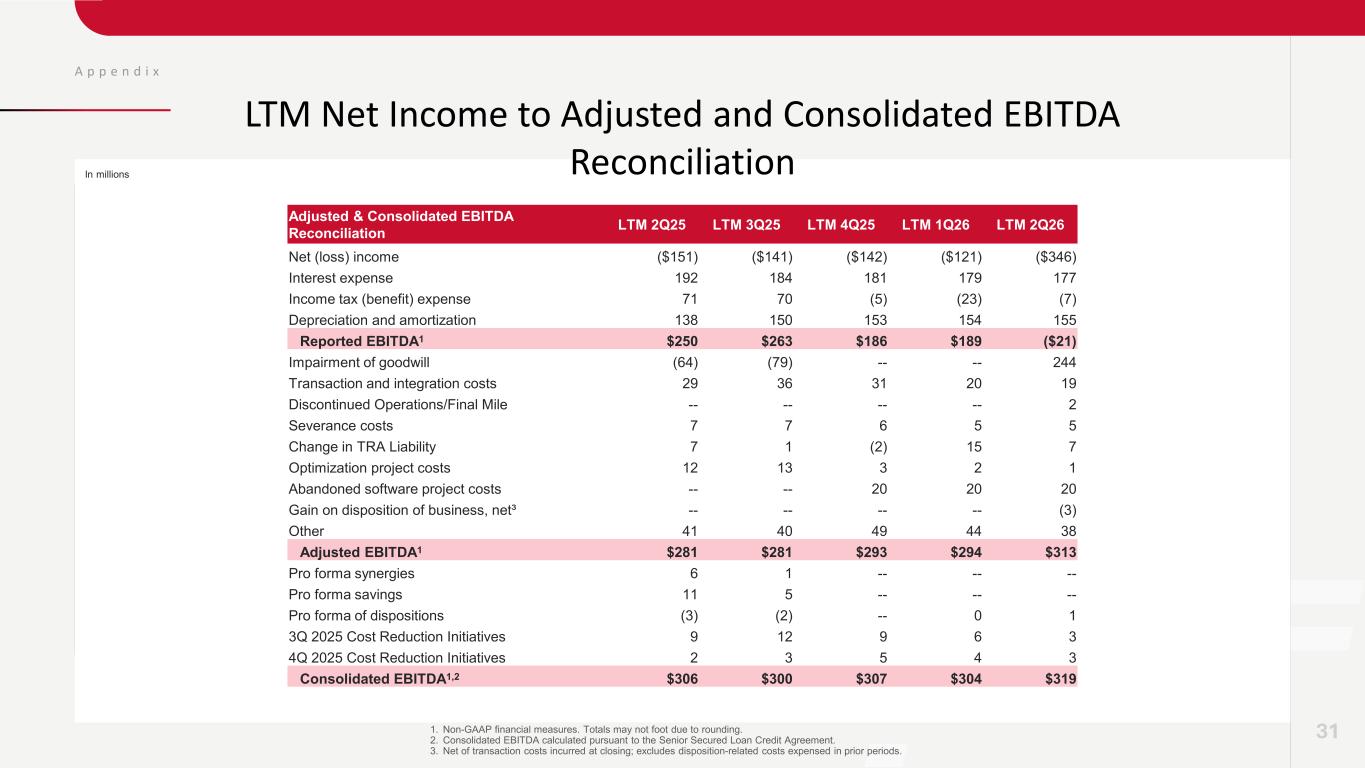
A p p e n d i x 311. Non-GAAP financial measures. Totals may not foot due to rounding. 2. Consolidated EBITDA calculated pursuant to the Senior Secured Loan Credit Agreement. 3. Net of transaction costs incurred at closing; excludes disposition-related costs expensed in prior periods. In millions LTM Net Income to Adjusted and Consolidated EBITDA Reconciliation Adjusted & Consolidated EBITDA Reconciliation LTM 2Q25 LTM 3Q25 LTM 4Q25 LTM 1Q26 LTM 2Q26 Net (loss) income ($151) ($141) ($142) ($121) ($346) Interest expense 192 184 181 179 177 Income tax (benefit) expense 71 70 (5) (23) (7) Depreciation and amortization 138 150 153 154 155 Reported EBITDA1 $250 $263 $186 $189 ($21) Impairment of goodwill (64) (79) -- -- 244 Transaction and integration costs 29 36 31 20 19 Discontinued Operations/Final Mile -- -- -- -- 2 Severance costs 7 7 6 5 5 Change in TRA Liability 7 1 (2) 15 7 Optimization project costs 12 13 3 2 1 Abandoned software project costs -- -- 20 20 20 Gain on disposition of business, net³ -- -- -- -- (3) Other 41 40 49 44 38 Adjusted EBITDA1 $281 $281 $293 $294 $313 Pro forma synergies 6 1 -- -- -- Pro forma savings 11 5 -- -- -- Pro forma of dispositions (3) (2) -- 0 1 3Q 2025 Cost Reduction Initiatives 9 12 9 6 3 4Q 2025 Cost Reduction Initiatives 2 3 5 4 3 Consolidated EBITDA1,2 $306 $300 $307 $304 $319
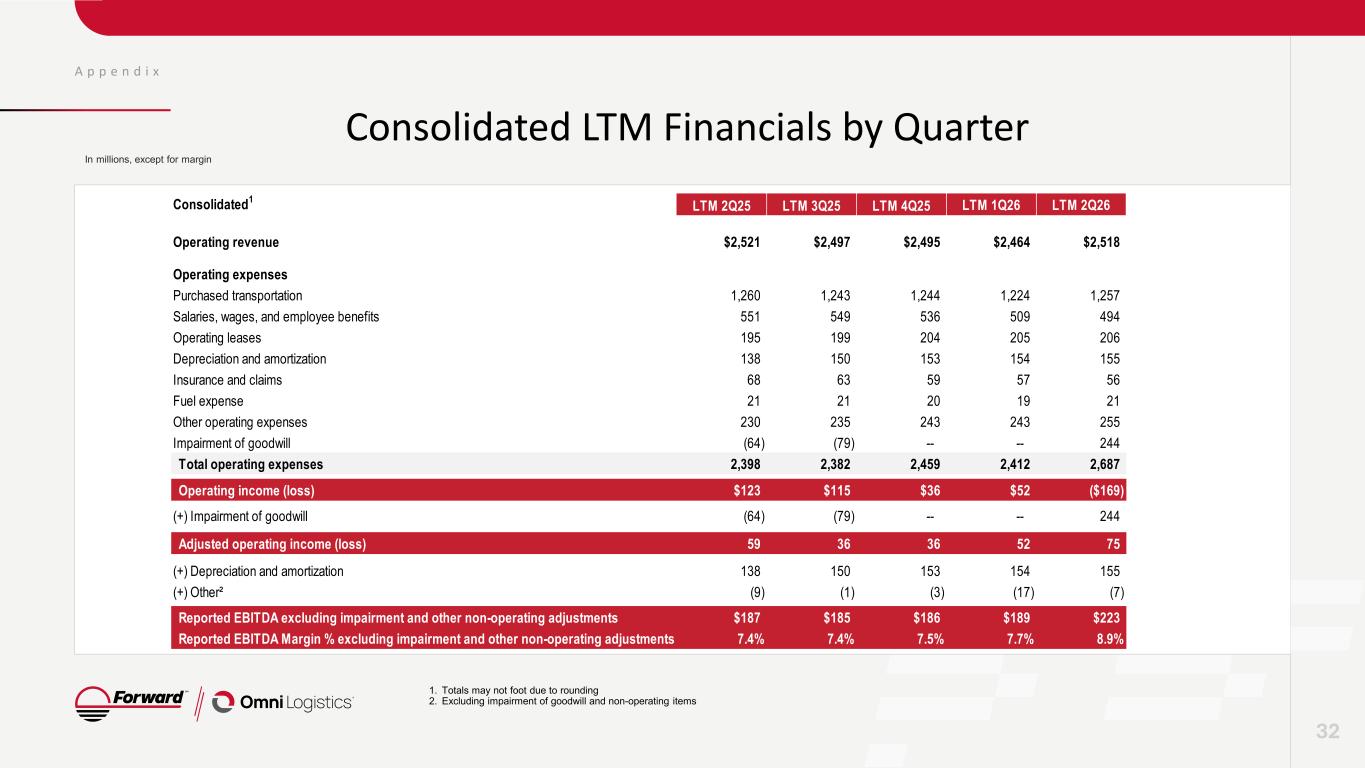
A p p e n d i x Consolidated LTM Financials by Quarter 32 1. Totals may not foot due to rounding 2. Excluding impairment of goodwill and non-operating items In millions, except for margin Consolidated 1 LTM 2Q25 LTM 3Q25 LTM 4Q25 LTM 1Q26 LTM 2Q26 Operating revenue $2,521 $2,497 $2,495 $2,464 $2,518 Operating expenses Purchased transportation 1,260 1,243 1,244 1,224 1,257 Salaries, wages, and employee benefits 551 549 536 509 494 Operating leases 195 199 204 205 206 Depreciation and amortization 138 150 153 154 155 Insurance and claims 68 63 59 57 56 Fuel expense 21 21 20 19 21 Other operating expenses 230 235 243 243 255 Impairment of goodwill (64) (79) -- -- 244 Total operating expenses 2,398 2,382 2,459 2,412 2,687 Operating income (loss) $123 $115 $36 $52 ($169) (+) Impairment of goodwill (64) (79) -- -- 244 Adjusted operating income (loss) 59 36 36 52 75 (+) Depreciation and amortization 138 150 153 154 155 (+) Other² (9) (1) (3) (17) (7) Reported EBITDA excluding impairment and other non-operating adjustments $187 $185 $186 $189 $223 Reported EBITDA Margin % excluding impairment and other non-operating adjustments 7.4% 7.4% 7.5% 7.7% 8.9% 2
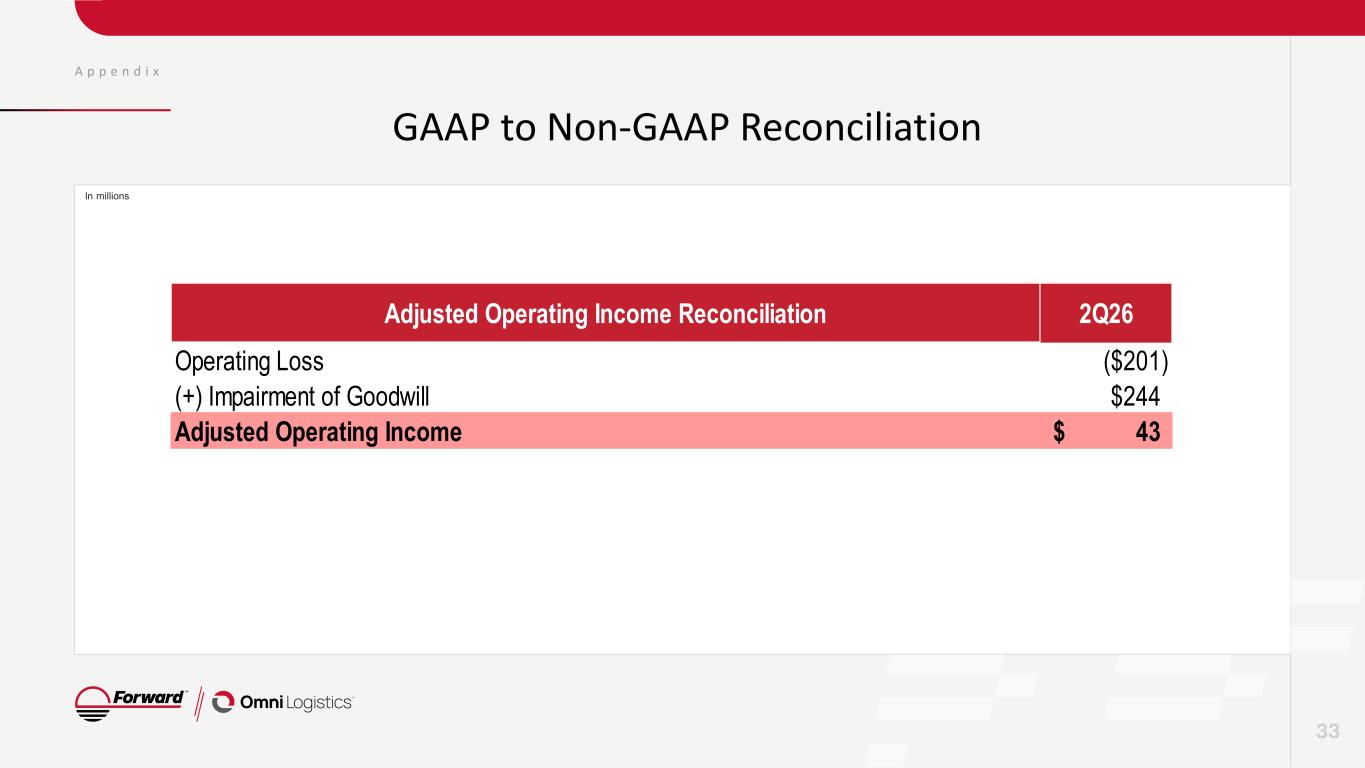
A p p e n d i x GAAP to Non-GAAP Reconciliation 33 In millions Adjusted Operating Income Reconciliation 2Q26 Operating Loss ($201) (+) Impairment of Goodwill $244 Adjusted Operating Income 43$
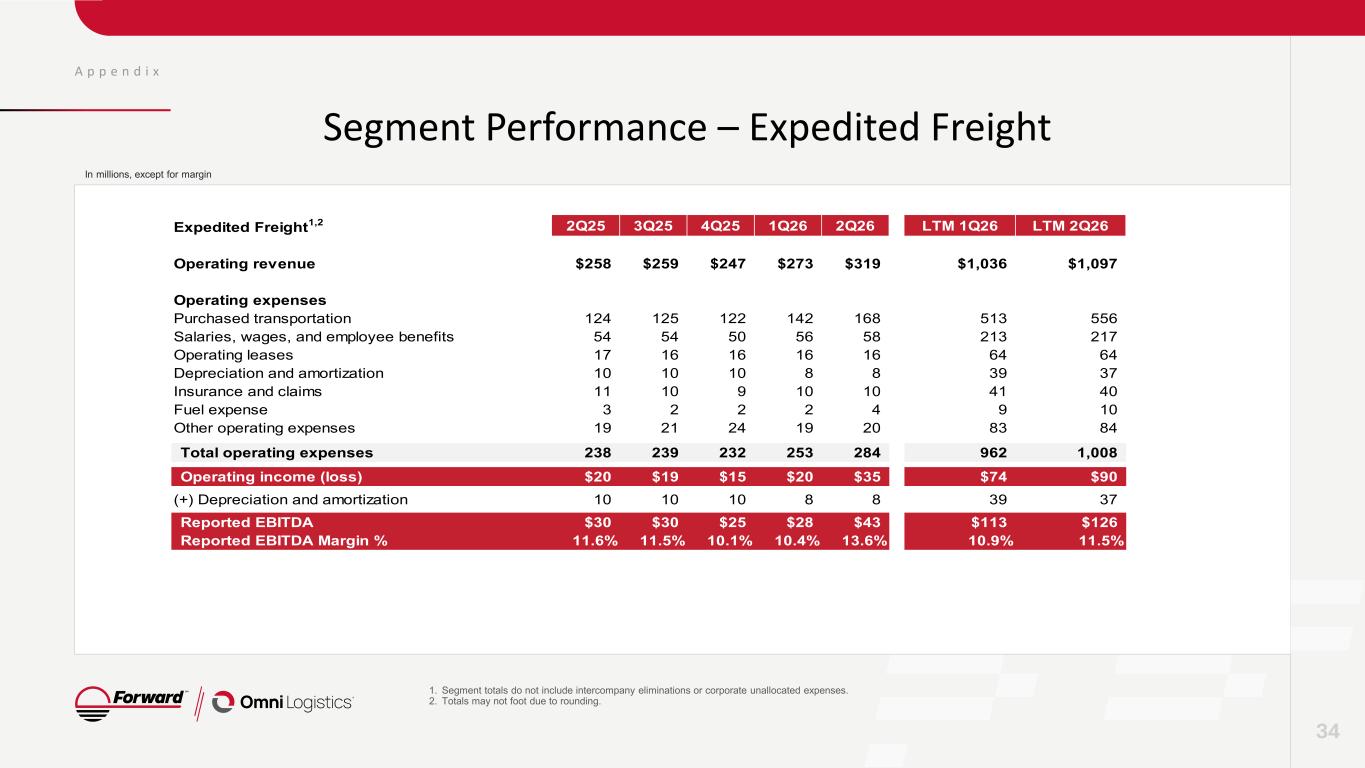
A p p e n d i x Segment Performance – Expedited Freight 34 1. Segment totals do not include intercompany eliminations or corporate unallocated expenses. 2. Totals may not foot due to rounding. In millions, except for margin Expedited Freight 1,2 2Q25 3Q25 4Q25 1Q26 2Q26 LTM 1Q26 LTM 2Q26 Operating revenue $258 $259 $247 $273 $319 $1,036 $1,097 Operating expenses Purchased transportation 124 125 122 142 168 513 556 Salaries, wages, and employee benefits 54 54 50 56 58 213 217 Operating leases 17 16 16 16 16 64 64 Depreciation and amortization 10 10 10 8 8 39 37 Insurance and claims 11 10 9 10 10 41 40 Fuel expense 3 2 2 2 4 9 10 Other operating expenses 19 21 24 19 20 83 84 -- -- Total operating expenses 238 239 232 253 284 962 1,008 Operating income (loss) $20 $19 $15 $20 $35 $74 $90 (+) Depreciation and amortization 10 10 10 8 8 39 37 Reported EBITDA $30 $30 $25 $28 $43 $113 $126 Reported EBITDA Margin % 11.6% 11.5% 10.1% 10.4% 13.6% 10.9% 11.5%
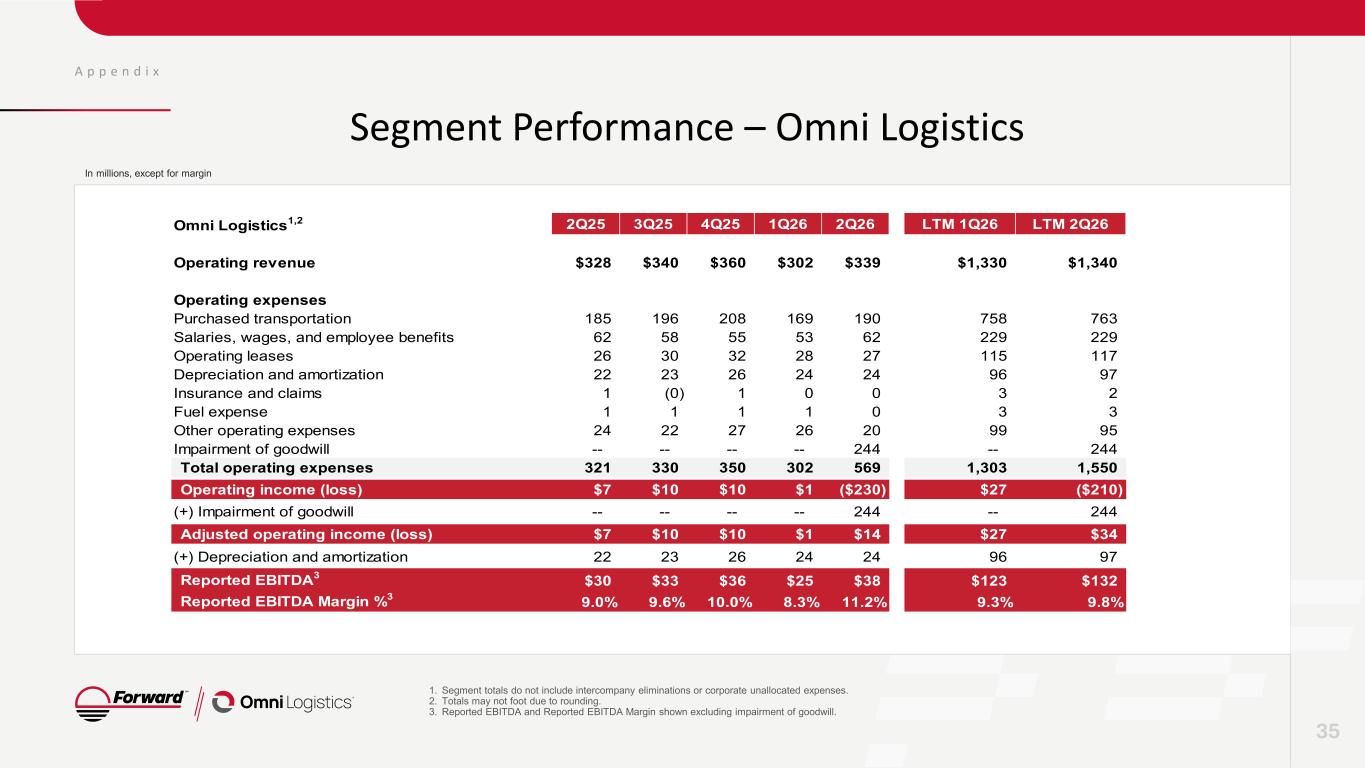
A p p e n d i x Segment Performance – Omni Logistics 35 1. Segment totals do not include intercompany eliminations or corporate unallocated expenses. 2. Totals may not foot due to rounding. 3. Reported EBITDA and Reported EBITDA Margin shown excluding impairment of goodwill. In millions, except for margin Omni Logistics 1,2 2Q25 3Q25 4Q25 1Q26 2Q26 LTM 1Q26 LTM 2Q26 Operating revenue $328 $340 $360 $302 $339 $1,330 $1,340 Operating expenses Purchased transportation 185 196 208 169 190 758 763 Salaries, wages, and employee benefits 62 58 55 53 62 229 229 Operating leases 26 30 32 28 27 115 117 Depreciation and amortization 22 23 26 24 24 96 97 Insurance and claims 1 (0) 1 0 0 3 2 Fuel expense 1 1 1 1 0 3 3 Other operating expenses 24 22 27 26 20 99 95 Impairment of goodwill -- -- -- -- 244 -- 244 Total operating expenses 321 330 350 302 569 1,303 1,550 Operating income (loss) $7 $10 $10 $1 ($230) $27 ($210) (+) Impairment of goodwill -- -- -- -- 244 -- 244 Adjusted operating income (loss) $7 $10 $10 $1 $14 $27 $342.1% 2.6% (+) Depreciation and amortization 22 23 26 24 24 96 97 Reported EBITDA 3 $30 $33 $36 $25 $38 $123 $132 Reported EBITDA Margin % 3 9.0% 9.6% 10.0% 8.3% 11.2% 9.3% 9.8%
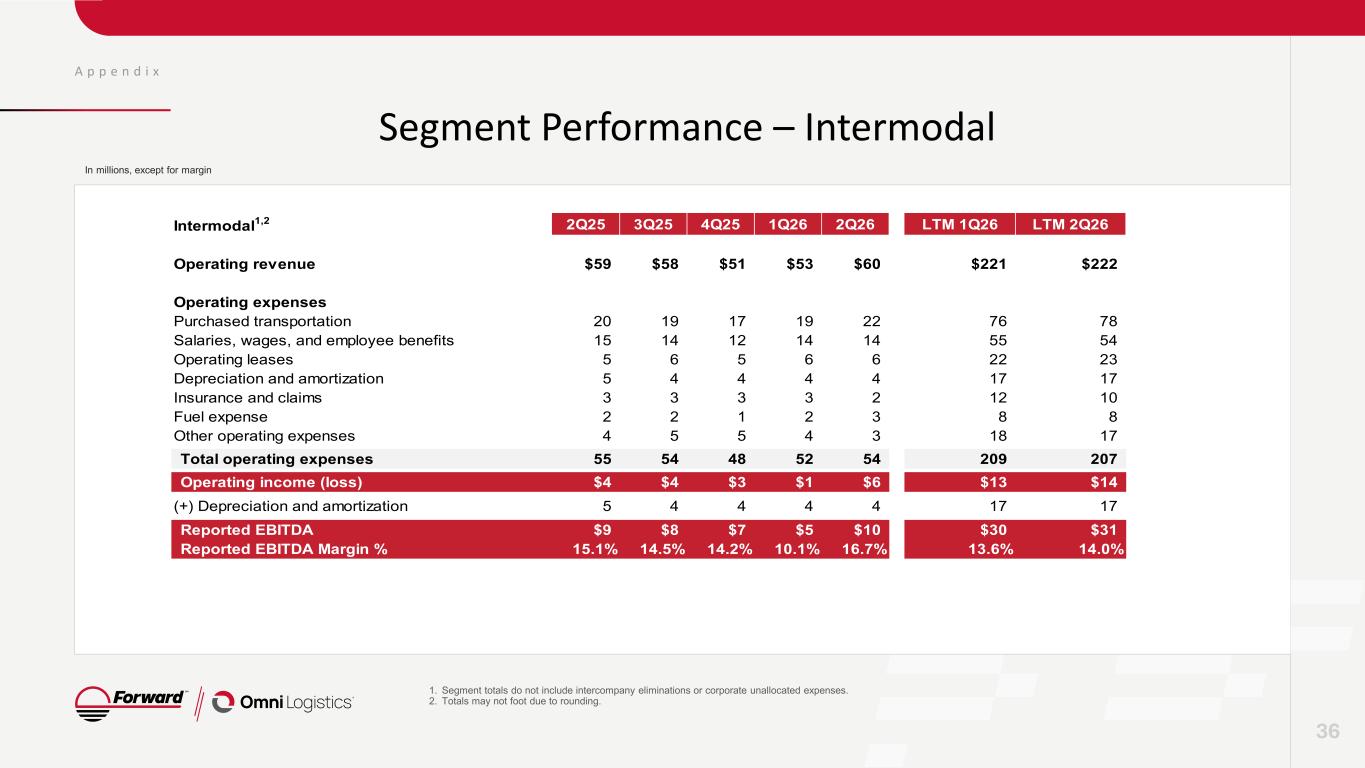
A p p e n d i x Segment Performance – Intermodal 36 1. Segment totals do not include intercompany eliminations or corporate unallocated expenses. 2. Totals may not foot due to rounding. In millions, except for margin Intermodal 1,2 2Q25 3Q25 4Q25 1Q26 2Q26 LTM 1Q26 LTM 2Q26 Operating revenue $59 $58 $51 $53 $60 $221 $222 Operating expenses Purchased transportation 20 19 17 19 22 76 78 Salaries, wages, and employee benefits 15 14 12 14 14 55 54 Operating leases 5 6 5 6 6 22 23 Depreciation and amortization 5 4 4 4 4 17 17 Insurance and claims 3 3 3 3 2 12 10 Fuel expense 2 2 1 2 3 8 8 Other operating expenses 4 5 5 4 3 18 17 -- -- Total operating expenses 55 54 48 52 54 209 207 Operating income (loss) $4 $4 $3 $1 $6 $13 $14 (+) Depreciation and amortization 5 4 4 4 4 17 17 Reported EBITDA $9 $8 $7 $5 $10 $30 $31 Reported EBITDA Margin % 15.1% 14.5% 14.2% 10.1% 16.7% 13.6% 14.0%
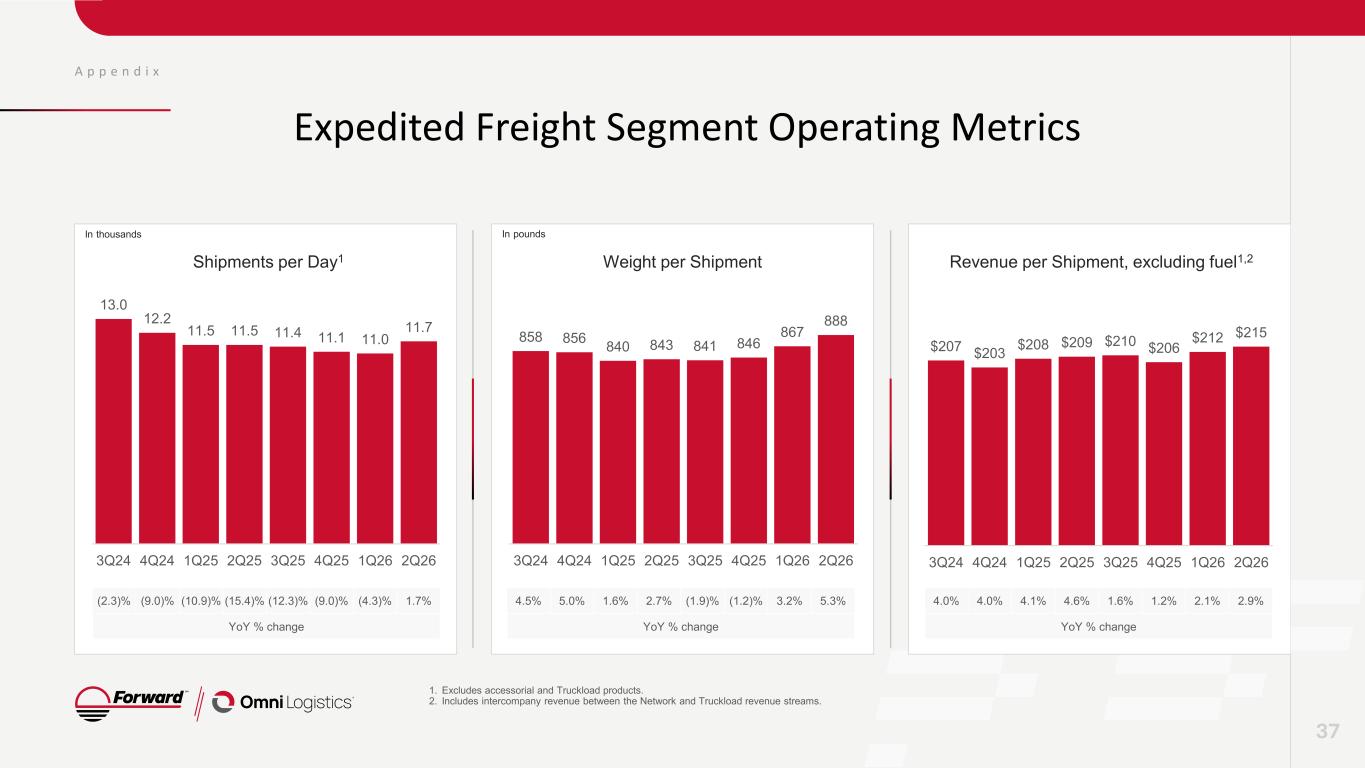
A p p e n d i x Expedited Freight Segment Operating Metrics 37 Shipments per Day1 Weight per Shipment Revenue per Shipment, excluding fuel1,2 In thousands In pounds (2.3)% (9.0)% (10.9)% (15.4)% (12.3)% (9.0)% (4.3)% 1.7% YoY % change 4.5% 5.0% 1.6% 2.7% (1.9)% (1.2)% 3.2% 5.3% YoY % change 4.0% 4.0% 4.1% 4.6% 1.6% 1.2% 2.1% 2.9% YoY % change 1. Excludes accessorial and Truckload products. 2. Includes intercompany revenue between the Network and Truckload revenue streams. 13.0 12.2 11.5 11.5 11.4 11.1 11.0 11.7 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 858 856 840 843 841 846 867 888 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 $207 $203 $208 $209 $210 $206 $212 $215 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26
Forward Air Corporation (NASDAQ: FWRD) IR Contact | Tony Carreño [email protected] https://ir.forwardaircorp.com