
HBNC 8-K
Horizon Bancorp Inc /In/ (HBNC)
8-K
2026-01-21
For: 2026-01-21
View Original
Added on
April 11, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, DC 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 OR 15(d) of The Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): January 21, 2026
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||
(Address of principal executive offices, including zip code)
(219 ) 879-0211
(Registrant's telephone number, including area code)
Not Applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
1
Item 2.02 Results of Operations and Financial Condition
On January 21, 2026, Horizon Bancorp, Inc. (the “Company”) issued a press release announcing earnings and other financial results for the three–months ended December 31, 2025. A copy of the press release is furnished as Exhibit 99.1 to this report and incorporated here by reference.
Item 7.01 Regulation FD Disclosure
Investor Presentation
The Company has prepared presentation materials (the “Investor Presentation”) that management intends to use during its previously announced Earnings Conference Call on Thursday, January 22, 2026 at 7:30 a.m. Central Time, and from time to time thereafter in presentations about the Company’s operations and performance. The Company may use the Investor Presentation, possibly with modifications, in presentations to current and potential investors, analysts, lenders, business partners, acquisition candidates, customers, employees and others with an interest in the Company and its business.
A copy of the Investor Presentation is furnished as Exhibit 99.2 to this report and incorporated here by reference. The Investor Presentation is also available on the Company’s investor website at www.horizonbank.com. Materials on the Company’s investor website are not part of or incorporated by reference into this report.
In accordance with General Instruction B.2 of Form 8–K, the information in this Current Report on Form 8–K, including Exhibits 99.1 and 99.2, shall not be deemed to be “filed” for purposes of Section 18 of the Securities and Exchange Act of 1934, as amended (the “Exchange Act”), or otherwise subject to the liability of that section, and shall not be incorporated by reference into any registration statement or other document filed under the Securities Act of 1933, as amended, or the Exchange Act, except as shall be expressly set forth by specific reference in such filing.
Item 9.01 Financial Statements and Exhibits
| (d) Exhibits | |||||||||||
| EXHIBIT INDEX | |||||||||||
| Exhibit No. | Description | Location | |||||||||
| 99.1 | Attached | ||||||||||
| 99.2 | Attached | ||||||||||
| 104 | Cover Page Interactive Data File (Embedded within the Inline XBRL document) | Within the Inline XBRL document | |||||||||
2
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| Date: | January 21, 2026 | HORIZON BANCORP, INC. | |||||||||
| By: | /s/ John R. Stewart, CFA | ||||||||||
| John R. Stewart, CFA | |||||||||||
| Executive Vice President & Chief Financial Officer | |||||||||||
3
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
| Contact: | John R. Stewart, CFA | ||||
| EVP, Chief Financial Officer | |||||
| Phone: | (219) 814–5833 | ||||
| Fax: | (219) 874–9280 | ||||
| Date: | January 21, 2026 | ||||
FOR IMMEDIATE RELEASE
Horizon Bancorp, Inc. Reports Positive Fourth Quarter 2025 Results, Entering 2026 with Peer Leading Performance Metrics
Michigan City, Indiana, January 21, 2026 (GLOBE NEWSWIRE) – (NASDAQ GS: HBNC) – Horizon Bancorp, Inc. (“Horizon” or the “Company”), the parent company of Horizon Bank (the “Bank”), announced its unaudited financial results for the three months ended December 31, 2025.
“Horizon’s fourth quarter results demonstrate excellent execution of the balance sheet repositioning and the core strength of our community banking model. We have delivered on our commitment to shareholders to create a top performing community bank with durable, peer-leading performance metrics and shareholder returns. The fourth quarter exceeded our prior performance estimates, with annualized return on average assets exceeding 1.60%, returns on average equity approaching 16%, and a net interest margin of 4.29%. We are pleased with the results for our shareholders and the transparency the quarter provided to highlight the strength of Horizon’s community banking model, which remains the cornerstone of our value proposition", President and CEO, Thomas Prame stated. "More importantly, the Company is kicking off the new year from a position of strength, with the franchise well positioned to deliver durable earnings and continued top-tier profitability metrics in 2026. The commercial loan engine continues to produce disciplined and high-quality growth, which we expect to fund through our client-focused branch distribution network and our relationship-based community bankers. Credit quality remains excellent, and expenses continue to be well managed. As we look ahead, we will remain focused on creating sustainable long-term value for our shareholders through our disciplined operating model, consistent profitable growth and peer leading capital generation".
Net income for the three months ended December 31, 2025 was $26.9 million, or $0.53 per diluted share, compared to a net loss of $222.0 million, or $(4.69), for the third quarter of 2025 and a net loss of $10.9 million, or $(0.25) per diluted share, for the fourth quarter of 2024.
Net loss for the twelve months ended December 31, 2025 was $150.5 million, or $(3.24) per diluted share, compared to net income of $35.4 million, or $0.80, for the twelve months ended December 31, 2024.
1
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
Fourth Quarter 2025 Highlights
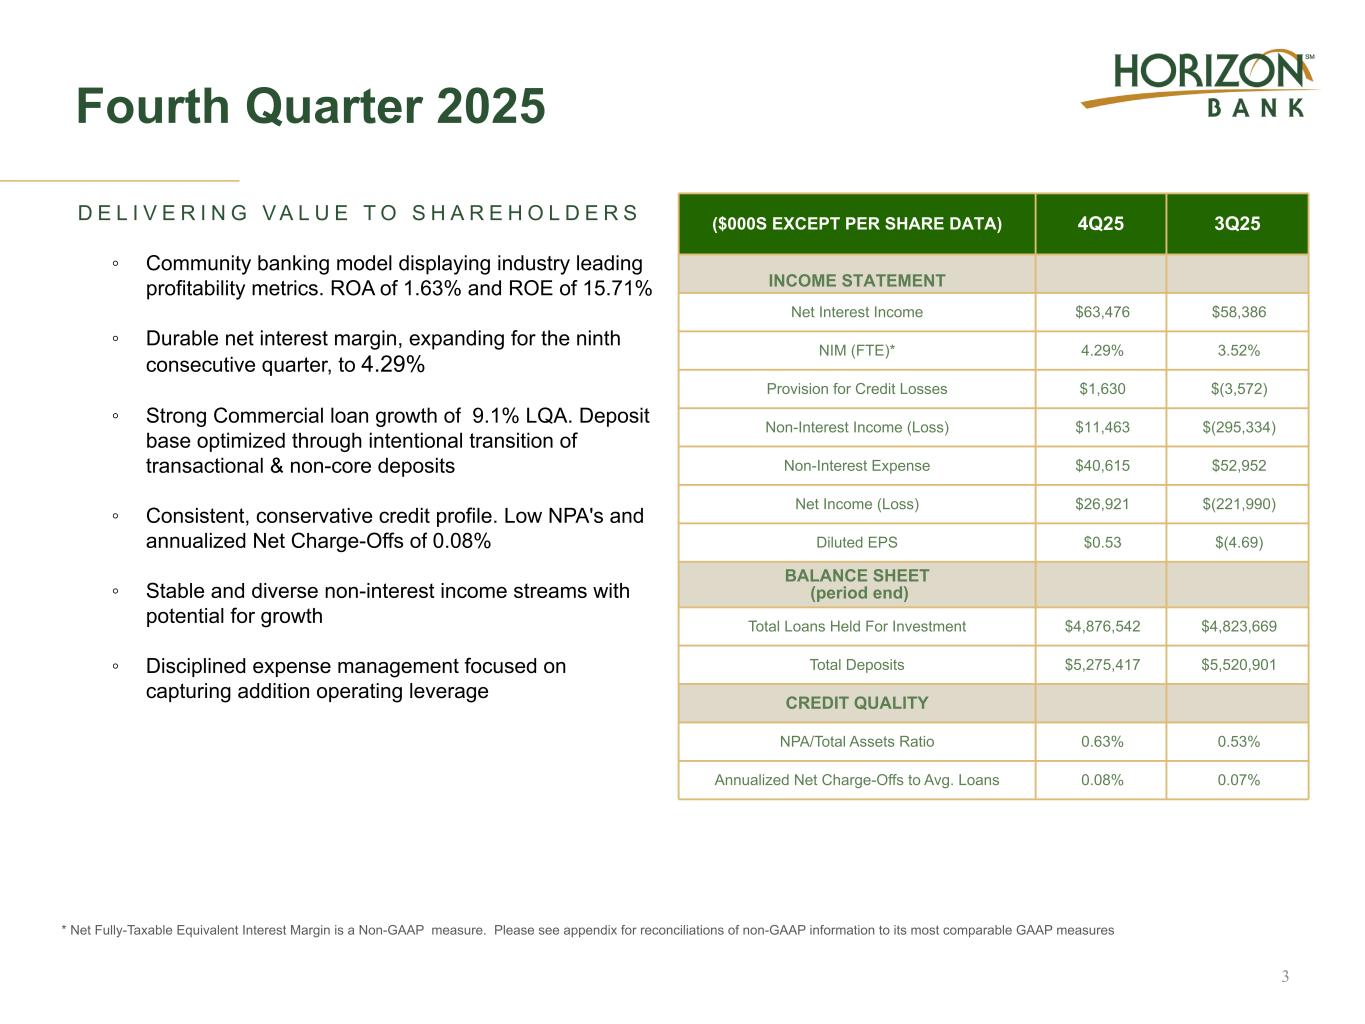
•Strong performance of the core community banking model, combined with the successful completion of the balance sheet repositioning efforts, resulted in significant performance improvement for the quarter. The Company's return on average assets and return on average equity improved to 1.63% and 15.71%, respectively. The franchise is well positioned to continue to achieve top performance metrics moving forward.
•Net interest income of $63.5 million increased 8.7% compared with $58.4 million for the three months ended September 30, 2025, and 19.5% compared with $53.1 million in the year ago period. The net interest margin, on a fully taxable equivalent ("FTE") basis1, expanded for the ninth consecutive quarter, to 4.29%, compared with 3.52% for the three months ended September 30, 2025 and 2.97% for the three months ended December 31, 2024.
•Total loans held for investment ("HFI") increased 4.4% compared to the linked quarter annualized, with strong organic commercial loan growth of $75.8 million, or 9.1% annualized. Loan pipelines continue to be consistent, reflective of Horizon’s attractive markets and embedded community banking model.
•Funding remains durable with costs trending favorably. Non-interest bearing deposits remained relatively flat, while declines in interest-bearing balances largely reflected the communicated planned exit of high-cost, transactional deposits. Total interest-bearing liability cost performed well, decreasing by another 34 bps during the quarter.
•Credit quality remained strong, with annualized net charge offs of 0.08% of average loans during the fourth quarter. Non-performing assets remain well within expected ranges, with non-performing assets to total assets of 63 bps for the fourth quarter.
•Expenses continued to be well managed, and were comparable to the third quarter when considering a select few items related to the balance sheet activities, displaying management's continued commitment to generate positive operating leverage through a more efficient expense base.
1 Non-GAAP financial metric. See non-GAAP reconciliation included herein for the most directly comparable GAAP measure.
2
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
| Financial Highlights | |||||||||||||||||||||||||||||
| (Dollars in Thousands Except Share and Per Share Data and Ratios) | |||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||
| December 31, | September 30, | June 30, | March 31, | December 31, | |||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2025 | 2024 | |||||||||||||||||||||||||
| Income statement: | |||||||||||||||||||||||||||||
| Net interest income | $ | 63,476 | $ | 58,386 | $ | 55,355 | $ | 52,267 | $ | 53,127 | |||||||||||||||||||
| Provision for credit losses | 1,630 | (3,572) | 2,462 | 1,376 | 1,171 | ||||||||||||||||||||||||
| Non-interest income (loss) | 11,463 | (295,334) | 10,920 | 16,499 | (28,954) | ||||||||||||||||||||||||
| Non-interest expense | 40,615 | 52,952 | 39,417 | 39,306 | 44,935 | ||||||||||||||||||||||||
| Income tax expense (benefit) | 5,773 | (64,338) | 3,752 | 4,141 | (11,051) | ||||||||||||||||||||||||
| Net Income (Loss) | $ | 26,921 | $ | (221,990) | $ | 20,644 | $ | 23,943 | $ | (10,882) | |||||||||||||||||||
| Per share data: | |||||||||||||||||||||||||||||
| Basic earnings (loss) per share | $ | 0.53 | $ | (4.69) | $ | 0.47 | $ | 0.55 | $ | (0.25) | |||||||||||||||||||
| Diluted earnings (loss) per share | 0.53 | (4.69) | 0.47 | 0.54 | (0.25) | ||||||||||||||||||||||||
| Cash dividends declared per common share | 0.16 | 0.16 | 0.16 | 0.16 | 0.16 | ||||||||||||||||||||||||
| Book value per common share | 13.50 | 12.96 | 18.06 | 17.72 | 17.46 | ||||||||||||||||||||||||
| Market value - high | 18.47 | 16.88 | 15.88 | 17.76 | 18.76 | ||||||||||||||||||||||||
| Market value - low | 15.04 | 15.01 | 12.92 | 15.00 | 14.57 | ||||||||||||||||||||||||
| Weighted average shares outstanding - Basic | 50,975,693 | 47,311,642 | 43,794,490 | 43,777,109 | 43,721,211 | ||||||||||||||||||||||||
| Weighted average shares outstanding - Diluted | 51,277,134 | 47,311,642 | 44,034,663 | 43,954,164 | 43,721,211 | ||||||||||||||||||||||||
| Common shares outstanding (end of period) | 50,978,030 | 50,970,530 | 43,801,507 | 43,785,932 | 43,722,086 | ||||||||||||||||||||||||
| Key ratios: | |||||||||||||||||||||||||||||
| Return on average assets | 1.63 | % | (12.07) | % | 1.09 | % | 1.25 | % | (0.56) | % | |||||||||||||||||||
| Return on average stockholders' equity | 15.71 | (120.37) | 10.49 | 12.44 | (5.73) | ||||||||||||||||||||||||
| Total equity to total assets | 10.69 | 9.84 | 10.34 | 10.18 | 9.79 | ||||||||||||||||||||||||
| Total loans to deposit ratio | 92.62 | 87.41 | 87.52 | 85.21 | 87.75 | ||||||||||||||||||||||||
| Allowance for credit losses to HFI loans | 1.05 | 1.04 | 1.09 | 1.07 | 1.07 | ||||||||||||||||||||||||
Annualized net charge-offs of average total loans (1) | 0.08 | 0.07 | 0.02 | 0.07 | 0.05 | ||||||||||||||||||||||||
| Efficiency ratio | 54.20 | (22.35) | 59.47 | 57.16 | 185.89 | ||||||||||||||||||||||||
Key metrics (Non-GAAP) (2) | |||||||||||||||||||||||||||||
| Net FTE interest margin | 4.29 | % | 3.52 | % | 3.23 | % | 3.04 | % | 2.97 | % | |||||||||||||||||||
| Return on average tangible common equity | 20.66 | (155.03) | 13.24 | 15.79 | (7.35) | ||||||||||||||||||||||||
| Tangible common equity to tangible assets | 8.38 | 7.60 | 8.37 | 8.19 | 7.83 | ||||||||||||||||||||||||
| Tangible book value per common share | $ | 10.32 | $ | 9.76 | $ | 14.32 | $ | 13.96 | $ | 13.68 | |||||||||||||||||||
(1) Average total loans includes loans held for investment and held for sale. | |||||||||||||||||||||||||||||
(2) Non-GAAP financial metrics. See non-GAAP reconciliation included herein for the most directly comparable GAAP measures. | |||||||||||||||||||||||||||||
3
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
Income Statement Highlights
Net Interest Income
Net interest income was $63.5 million in the fourth quarter of 2025, compared to $58.4 million in the third quarter of 2025, driven by the continued expansion of the Company's net FTE interest margin1, which increased to 4.29% for the fourth quarter of 2025, compared to 3.52% for the third quarter of 2025. The margin saw continued expansion as a by product of the balance sheet repositioning, stronger realized deposit betas relative to recent reductions in short-term interest rates and relatively stable overall earning asset yields since affecting the balance sheet actions in late August.
Provision for Credit Losses
During the fourth quarter of 2025, the Company recorded a provision for credit losses of $1.6 million. This compares to a recorded benefit for credit losses of $3.6 million during the third quarter of 2025, and a provision for credit losses expense of $1.2 million during the fourth quarter of 2024. The increase in the provision for credit losses during the fourth quarter of 2025 when compared with the third quarter of 2025 was primarily attributable to the release of approximately $3.1 million in total Allowance against the sold portion of the Indirect Auto portfolio and the release of the $0.2 million reserve against the previous Held-To-Maturity investment portfolio in the third quarter, which did not recur in the fourth quarter. Additionally, the Provision increased primarily due to changes in the baseline economic outlook.
For the fourth quarter of 2025, Net Charge-Offs were $1.0 million, or an annualized 0.08% of average loans outstanding, compared to Net Charge-Offs of $0.8 million, or an annualized 0.07% of average loans outstanding for the third quarter of 2025, and Net Charge-Offs of $0.6 million, or an annualized 0.05% of average loans outstanding, in the fourth quarter of 2024.
The Company’s Allowance for Credit Losses as a percentage of period-end loans HFI was 1.05% at December 31, 2025, compared to 1.04% at September 30, 2025 and 1.07% at December 31, 2024.
Non-Interest Income
| For the Quarter Ended | December 31, | September 30, | June 30, | March 31, | December 31, | ||||||||||||||||||||||||
| (Dollars in Thousands) | 2025 | 2025 | 2025 | 2025 | 2024 | ||||||||||||||||||||||||
| Non-interest (Loss) Income | |||||||||||||||||||||||||||||
| Service charges on deposit accounts | $ | 3,341 | $ | 3,474 | $ | 3,208 | $ | 3,208 | $ | 3,276 | |||||||||||||||||||
| Wire transfer fees | 66 | 71 | 69 | 71 | 124 | ||||||||||||||||||||||||
| Interchange fees | 3,445 | 3,510 | 3,403 | 3,241 | 3,353 | ||||||||||||||||||||||||
| Fiduciary activities | 1,560 | 1,363 | 1,251 | 1,326 | 1,313 | ||||||||||||||||||||||||
| Gain (loss) on sale of investment securities | 1 | (299,132) | — | (407) | (39,140) | ||||||||||||||||||||||||
| Gain on sale of mortgage loans | 1,296 | 1,208 | 1,219 | 1,076 | 1,071 | ||||||||||||||||||||||||
| Mortgage servicing income net of impairment | 352 | 351 | 375 | 385 | 376 | ||||||||||||||||||||||||
| Increase in cash value of bank owned life insurance | 360 | 379 | 346 | 335 | 335 | ||||||||||||||||||||||||
| Other income (loss) | 1,042 | (6,558) | 1,049 | 7,264 | 338 | ||||||||||||||||||||||||
| Total non-interest (loss) income | $ | 11,463 | $ | (295,334) | $ | 10,920 | $ | 16,499 | $ | (28,954) | |||||||||||||||||||
Total Non-Interest Income was $11.5 million in the fourth quarter of 2025, compared to Non-Interest (Loss) of $295.3 million in the third quarter of 2025. The increase in Non-Interest Income of $306.8 million is due to the $299.1 million loss on the sale investment securities and the pre-tax loss of $7.7 million on the sale of the Company's Indirect Auto portfolio, both of which were related to the balance sheet repositioning efforts during the third quarter, which did not recur. Other categories remained relatively unchanged when compared with the prior period.
1 Non-GAAP financial metric. See non-GAAP reconciliation included herein for the most directly comparable GAAP measure.
4
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
Non-Interest Expense
| For the Quarter Ended | December 31, | September 30, | June 30, | March 31, | December 31, | ||||||||||||||||||||||||
| (Dollars in Thousands) | 2025 | 2025 | 2025 | 2025 | 2024 | ||||||||||||||||||||||||
| Non-interest Expense | |||||||||||||||||||||||||||||
| Salaries and employee benefits | $ | 21,895 | $ | 22,698 | $ | 22,731 | $ | 22,414 | $ | 25,564 | |||||||||||||||||||
| Net occupancy expenses | 3,718 | 3,321 | 3,127 | 3,702 | 3,431 | ||||||||||||||||||||||||
| Data processing | 3,128 | 2,933 | 2,951 | 2,872 | 2,841 | ||||||||||||||||||||||||
| Professional fees | 1,083 | 808 | 735 | 826 | 736 | ||||||||||||||||||||||||
| Outside services and consultants | 3,035 | 3,844 | 3,278 | 3,265 | 4,470 | ||||||||||||||||||||||||
| Loan expense | 1,183 | 1,237 | 1,231 | 689 | 1,285 | ||||||||||||||||||||||||
| FDIC insurance expense | 1,251 | 1,345 | 1,216 | 1,288 | 1,193 | ||||||||||||||||||||||||
| Core deposit intangible amortization | 706 | 706 | 816 | 816 | 843 | ||||||||||||||||||||||||
| Merger related expenses | — | — | — | 305 | — | ||||||||||||||||||||||||
| Prepayment penalties | — | 12,680 | — | — | — | ||||||||||||||||||||||||
| Other losses | 732 | 131 | 245 | 228 | 371 | ||||||||||||||||||||||||
| Other expense | 3,884 | 3,249 | 3,087 | 2,901 | 4,201 | ||||||||||||||||||||||||
| Total non-interest expense | $ | 40,615 | $ | 52,952 | $ | 39,417 | $ | 39,306 | $ | 44,935 | |||||||||||||||||||
Total Non-Interest Expense was $40.6 million in the fourth quarter of 2025, compared with $53.0 million in the third quarter of 2025. The decrease in Non-Interest Expense during the fourth quarter of 2025 when compared with the prior period was primarily driven by a $12.7 million prepayment penalty related to the payoff of $700 million in FHLB advances during the third quarter, which did not recur. The increase in Other Losses was the result of the write off of unamortized issuance costs of $0.7 million related to the early redemption of the Company's subordinated notes due 2030. Apart from this specific item, expenses were relatively unchanged from the prior quarter, with declines in personnel expense offset by higher seasonal occupancy expenses, marketing expense and higher professional expense from legal fees to settle certain legacy items.
Income Taxes
Horizon recorded a net tax expense of $5.8 million for the fourth quarter of 2025, resulting in an effective tax rate of 17.7%, which is consistent with the Company's estimated annual effective tax rate.
Balance Sheet Highlights
Total assets decreased by $275.9 million, or 4.1%, to $6.4 billion as of December 31, 2025, from $6.7 billion as of September 30, 2025. The decrease in total assets is primarily due to the decrease in interest earning deposits of $309.2 million, a decrease in other assets of $10.8 million, a decrease in cash of $9.6 million, and a decrease in total investment securities of $4.5 million. Total loans were $4.9 billion at December 31, 2025, an increase of $60.7 million from September 30, 2025 balances, primarily driven by organic commercial loan growth.
Total deposits decreased by $245.5 million, or 4.4%, to $5.3 billion as of December 31, 2025 when compared to balances as of September 30, 2025, which is largely attributable to the intentional runoff of another $195 million in higher-cost transactional deposit balances. The decrease also was driven by a decrease in time deposits of $97.2 million, a decrease of interest bearing deposits of $75.6 million, and a decrease in savings and money market deposits of $28.5 million. Non-interest bearing deposit balances decreased $44.2 million in the current period, which is largely attributable to seasonal trends, but increased from the year ago period. Subordinated notes balances decreased by $55.8 million during the quarter related to the early redemption of the Company's subordinated notes due 2030, as previously planned.
5
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
Capital
The following table presents the Consolidated Regulatory Capital Ratios of the Company for the previous three quarters, and the Company’s preliminary estimate of its consolidated regulatory capital ratios for the quarter ended December 31, 2025:
| For the Quarter Ended | December 31, | September 30, | June 30, | March 31, | ||||||||||||||||||||||
| 2025* | 2025 | 2025 | 2025 | |||||||||||||||||||||||
| Consolidated Capital Ratios | ||||||||||||||||||||||||||
| Total capital (to risk-weighted assets) | 14.37 | % | 15.00 | % | 14.44 | % | 14.26 | % | ||||||||||||||||||
| Tier 1 capital (to risk-weighted assets) | 11.52 | 11.27 | 12.48 | 12.33 | ||||||||||||||||||||||
| Common equity tier 1 capital (to risk-weighted assets) | 10.43 | 10.17 | 11.48 | 11.32 | ||||||||||||||||||||||
| Tier 1 capital (to average assets) | 9.57 | 8.22 | 9.59 | 9.25 | ||||||||||||||||||||||
| *Preliminary estimate - may be subject to change | ||||||||||||||||||||||||||
As of December 31, 2025, the ratio of total stockholders’ equity to total assets is 10.69%. Book value per common share was $13.50, increasing $0.54 during the fourth quarter of 2025.
Tangible common equity1 totaled $525.9 million at December 31, 2025, and the ratio of tangible common equity to tangible assets1 was 8.38% at December 31, 2025, up from 7.60% at September 30, 2025. Tangible book value, which excludes intangible assets from total equity, per common share1 was $10.32, increasing $0.56 during the fourth quarter of 2025.
Credit Quality
As of December 31, 2025, total non-accrual loans increased by $3.1 million from September 30, 2025, to 0.67% of total loans HFI. Total non-performing assets increased $4.9 million, to $40.6 million, compared to $35.7 million as of September 30, 2025. The ratio of non-performing assets to total assets was 0.63%, compared to 0.53% as of September 30, 2025.
For the quarter ended December 31, 2025, net charge-offs were $1.0 million, compared to $0.8 million as of September 30, 2025, or 0.08% annualized of average loans.
1 Non-GAAP financial metric. See non-GAAP reconciliation included herein for the most directly comparable GAAP measure.
6
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
Earnings Conference Call
As previously announced, Horizon will host a conference call to review its fourth quarter financial results and operating performance.
Participants may access the live conference call on January 22, 2026 at 7:30 a.m. CT (8:30 a.m. ET) by dialing 833-974-2379 from the United States, 866-450-4696 from Canada or 1-412-317-5772 from international locations and requesting the “Horizon Bancorp, Inc. Call.” Participants are asked to dial in approximately 10 minutes prior to the call.
A telephone replay of the call will be available approximately one hour after the end of the conference through January 30, 2026. The replay may be accessed by dialing 855-669-9658 from the United States and Canada, or 1–412–317-0088 from other international locations, and entering the access code 1841881.
About Horizon Bancorp, Inc.
Horizon Bancorp, Inc. (NASDAQ GS: HBNC) is the $6.4 billion-asset commercial bank holding company for Horizon Bank, which serves customers across diverse and economically attractive Midwestern markets through convenient digital and virtual tools, as well as its Indiana and Michigan branches. Horizon's retail offerings include prime residential and other secured consumer lending to in-market customers, as well as a range of personal banking and wealth management solutions. Horizon also provides a comprehensive array of in-market business banking and treasury management services, as well as equipment financing solutions for customers regionally and nationally, with commercial lending representing over half of total loans. More information on Horizon, headquartered in Northwest Indiana's Michigan City, is available at horizonbank.com and investor.horizonbank.com.
Use of Non-GAAP Financial Measures
Certain information set forth in this press release refers to financial measures determined by methods other than in accordance with GAAP. Specifically, we have included non-GAAP financial measures relating to net income, diluted earnings per share, pre-tax, pre-provision net income, net interest margin, tangible stockholders’ equity and tangible book value per share, efficiency ratio, the return on average assets, the return on average common equity, and return on average tangible equity. In each case, we have identified special circumstances that we consider to be non-recurring and have excluded them. Horizon believes these non-GAAP financial measures are helpful to investors and provide a greater understanding of our business and financial results without giving effect to one-time costs and non–recurring items. These measures are not necessarily comparable to similar measures that may be presented by other companies and should not be considered in isolation or as a substitute for the related GAAP measure. See the tables and other information below and contained elsewhere in this press release for reconciliations of the non-GAAP information identified herein and its most comparable GAAP measures.
7
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
Forward Looking Statements
This press release may contain forward–looking statements regarding the financial performance, business prospects, growth and operating strategies of Horizon Bancorp, Inc. and its affiliates (collectively, “Horizon”). For these statements, Horizon claims the protection of the safe harbor for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. Statements in this press release should be considered in conjunction with the other information available about Horizon, including the information in the filings we make with the Securities and Exchange Commission (the “SEC”). Forward-looking statements provide current expectations or forecasts of future events and are not guarantees of future performance. The forward-looking statements are based on management’s expectations and are subject to a number of risks and uncertainties. We have tried, wherever possible, to identify such statements by using words such as “anticipate,” “estimate,” “project,” “intend,” “plan,” “believe,” “will” and similar expressions in connection with any discussion of future operating or financial performance.
Although management believes that the expectations reflected in such forward-looking statements are reasonable, actual results may differ materially from those expressed or implied in such statements. Risks and uncertainties that could cause actual results to differ materially include: changes in U.S. trade policies, including the imposition of tariffs and retaliatory tariffs, changes within the domestic and international macroeconomic environment, including trade policy, monetary and fiscal policy, inflation levels, and conditions in the investment, credit, interest rate, and derivatives markets, and their impact on Horizon and its customers; current financial conditions within the banking industry; changes in the level and volatility of interest rates, changes in spreads on earning assets and changes in interest bearing liabilities; increased interest rate sensitivity; loss of key Horizon personnel; increases in disintermediation; potential loss of fee income, including interchange fees, as new and emerging alternative payment platforms take a greater market share of the payment systems; estimates of fair value of certain of Horizon’s assets and liabilities; changes in prepayment speeds, loan originations, credit losses, market values, collateral securing loans and other assets; changes in sources of liquidity; legislative and regulatory actions and reforms; changes in accounting policies or procedures as may be adopted and required by regulatory agencies; litigation, regulatory enforcement, and legal compliance risk and costs; rapid technological developments and changes; cyber terrorism and data security breaches; the rising costs of cybersecurity; the ability of the U.S. federal government to manage federal debt limits; climate change and social justice initiatives; the inability to realize cost savings or revenues or to effectively implement integration plans and other consequences associated with mergers, acquisitions, and divestitures; acts of terrorism, war and global conflicts, and the effects of foreign and military policies of the U.S. government; and supply chain disruptions and delays. These and additional factors that could cause actual results to differ materially from those expressed in the forward-looking statements are discussed in Horizon’s reports (such as the Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, and Current Reports on Form 8-K) filed with the SEC and available at the SEC’s website (www.sec.gov). Undue reliance should not be placed on the forward–looking statements, which speak only as of the date hereof. Horizon does not undertake, and specifically disclaims any obligation, to publicly release the result of any revisions that may be made to update any forward-looking statement to reflect the events or circumstances after the date on which the forward–looking statement is made, or reflect the occurrence of unanticipated events, except to the extent required by law.
8
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
| Condensed Consolidated Statements of Income | |||||||||||||||||||||||||||||
| (Dollars in Thousands Except Per Share Data, Unaudited) | |||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||
| December 31, | September 30, | June 30, | March 31, | December 31, | |||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2025 | 2024 | |||||||||||||||||||||||||
| Interest Income | |||||||||||||||||||||||||||||
| Loans receivable | $ | 77,238 | $ | 79,561 | $ | 78,618 | $ | 74,457 | $ | 76,747 | |||||||||||||||||||
| Investment securities - taxable | 7,688 | 6,631 | 5,941 | 6,039 | 6,814 | ||||||||||||||||||||||||
| Investment securities - tax-exempt | 2,498 | 4,581 | 6,088 | 6,192 | 6,301 | ||||||||||||||||||||||||
| Other | 1,864 | 2,063 | 830 | 2,487 | 3,488 | ||||||||||||||||||||||||
| Total interest income | 89,288 | 92,836 | 91,477 | 89,175 | 93,350 | ||||||||||||||||||||||||
| Interest Expense | |||||||||||||||||||||||||||||
| Deposits | 21,228 | 25,726 | 26,052 | 25,601 | 27,818 | ||||||||||||||||||||||||
| Borrowed funds | 1,749 | 5,924 | 8,171 | 9,188 | 10,656 | ||||||||||||||||||||||||
| Subordinated notes | 1,811 | 1,731 | 829 | 829 | 829 | ||||||||||||||||||||||||
| Junior subordinated debentures issued to capital trusts | 1,024 | 1,069 | 1,070 | 1,290 | 920 | ||||||||||||||||||||||||
| Total interest expense | 25,812 | 34,450 | 36,122 | 36,908 | 40,223 | ||||||||||||||||||||||||
| Net Interest Income | 63,476 | 58,386 | 55,355 | 52,267 | 53,127 | ||||||||||||||||||||||||
| Provision for credit losses | 1,630 | (3,572) | 2,462 | 1,376 | 1,171 | ||||||||||||||||||||||||
| Net Interest Income after Provision for Credit Losses | 61,846 | 61,958 | 52,893 | 50,891 | 51,956 | ||||||||||||||||||||||||
| Non-interest Income | |||||||||||||||||||||||||||||
| Service charges on deposit accounts | 3,341 | 3,474 | 3,208 | 3,208 | 3,276 | ||||||||||||||||||||||||
| Wire transfer fees | 66 | 71 | 69 | 71 | 124 | ||||||||||||||||||||||||
| Interchange fees | 3,445 | 3,510 | 3,403 | 3,241 | 3,353 | ||||||||||||||||||||||||
| Fiduciary activities | 1,560 | 1,363 | 1,251 | 1,326 | 1,313 | ||||||||||||||||||||||||
| Gain (loss) on sale of investment securities | 1 | (299,132) | — | (407) | (39,140) | ||||||||||||||||||||||||
| Gain on sale of mortgage loans | 1,296 | 1,208 | 1,219 | 1,076 | 1,071 | ||||||||||||||||||||||||
| Mortgage servicing income net of impairment | 352 | 351 | 375 | 385 | 376 | ||||||||||||||||||||||||
| Increase in cash value of bank owned life insurance | 360 | 379 | 346 | 335 | 335 | ||||||||||||||||||||||||
| Other income (loss) | 1,042 | (6,558) | 1,049 | 7,264 | 338 | ||||||||||||||||||||||||
| Total non-interest income (loss) | 11,463 | (295,334) | 10,920 | 16,499 | (28,954) | ||||||||||||||||||||||||
| Non-interest Expense | |||||||||||||||||||||||||||||
| Salaries and employee benefits | 21,895 | 22,698 | 22,731 | 22,414 | 25,564 | ||||||||||||||||||||||||
| Net occupancy expenses | 3,718 | 3,321 | 3,127 | 3,702 | 3,431 | ||||||||||||||||||||||||
| Data processing | 3,128 | 2,933 | 2,951 | 2,872 | 2,841 | ||||||||||||||||||||||||
| Professional fees | 1,083 | 808 | 735 | 826 | 736 | ||||||||||||||||||||||||
| Outside services and consultants | 3,035 | 3,844 | 3,278 | 3,265 | 4,470 | ||||||||||||||||||||||||
| Loan expense | 1,183 | 1,237 | 1,231 | 689 | 1,285 | ||||||||||||||||||||||||
| FDIC insurance expense | 1,251 | 1,345 | 1,216 | 1,288 | 1,193 | ||||||||||||||||||||||||
| Core deposit intangible amortization | 706 | 706 | 816 | 816 | 843 | ||||||||||||||||||||||||
| Merger related expenses | — | — | — | 305 | — | ||||||||||||||||||||||||
| Prepayment penalties | — | 12,680 | — | — | — | ||||||||||||||||||||||||
| Other losses | 732 | 131 | 245 | 228 | 371 | ||||||||||||||||||||||||
| Other expense | 3,884 | 3,249 | 3,087 | 2,901 | 4,201 | ||||||||||||||||||||||||
| Total non-interest expense | 40,615 | 52,953 | 39,417 | 39,306 | 44,935 | ||||||||||||||||||||||||
| Income (Loss) Before Income Taxes | 32,694 | (286,328) | 24,396 | 28,084 | (21,933) | ||||||||||||||||||||||||
| Income tax expense (benefit) | 5,773 | (64,338) | 3,752 | 4,141 | (11,051) | ||||||||||||||||||||||||
| Net Income (Loss) | $ | 26,921 | $ | (221,990) | $ | 20,644 | $ | 23,943 | $ | (10,882) | |||||||||||||||||||
| Basic Earnings (Loss) Per Share | $ | 0.53 | $ | (4.69) | $ | 0.47 | $ | 0.55 | $ | (0.25) | |||||||||||||||||||
| Diluted Earnings (Loss) Per Share | 0.53 | (4.69) | 0.47 | 0.54 | (0.25) | ||||||||||||||||||||||||
9
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
| Condensed Consolidated Balance Sheet | |||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | |||||||||||||||||||||||||||||
| Three Months Ended for the Period | |||||||||||||||||||||||||||||
| December 31, | September 30, | June 30, | March 31, | December 31, | |||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2025 | 2024 | |||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||
| Interest earning assets | |||||||||||||||||||||||||||||
| Federal funds sold | $ | — | $ | — | $ | 2,024 | $ | — | $ | — | |||||||||||||||||||
| Interest earning deposits | 72,646 | 381,860 | 34,174 | 80,023 | 201,131 | ||||||||||||||||||||||||
| Interest earning time deposits | — | — | — | — | 735 | ||||||||||||||||||||||||
| Federal Home Loan Bank stock | 45,713 | 45,713 | 45,412 | 45,412 | 53,826 | ||||||||||||||||||||||||
| Investment securities, held for trading | 3,883 | 598 | — | — | — | ||||||||||||||||||||||||
| Investment securities, available for sale | 875,414 | 883,242 | 231,999 | 231,431 | 233,677 | ||||||||||||||||||||||||
| Investment securities, held to maturity | — | — | 1,819,087 | 1,843,851 | 1,867,690 | ||||||||||||||||||||||||
| Loans held for sale | 9,778 | 1,921 | 2,994 | 3,253 | 67,597 | ||||||||||||||||||||||||
| Gross loans held for investment (HFI) | 4,876,542 | 4,823,669 | 4,985,582 | 4,909,815 | 4,847,040 | ||||||||||||||||||||||||
| Total Interest earning assets | 5,883,976 | 6,137,003 | 7,121,272 | 7,113,784 | 7,271,696 | ||||||||||||||||||||||||
| Non-interest earning assets | |||||||||||||||||||||||||||||
| Allowance for credit losses | (51,299) | (50,178) | (54,399) | (52,654) | (51,980) | ||||||||||||||||||||||||
| Cash | 66,813 | 76,395 | 101,719 | 89,643 | 92,300 | ||||||||||||||||||||||||
| Cash value of life insurance | 36,732 | 37,762 | 37,755 | 37,409 | 37,450 | ||||||||||||||||||||||||
| Other assets | 215,460 | 226,247 | 148,773 | 143,675 | 152,635 | ||||||||||||||||||||||||
| Goodwill | 155,211 | 155,211 | 155,211 | 155,211 | 155,211 | ||||||||||||||||||||||||
| Other intangible assets | 7,180 | 7,886 | 8,592 | 9,407 | 10,223 | ||||||||||||||||||||||||
| Premises and equipment, net | 92,805 | 93,413 | 93,398 | 93,499 | 93,864 | ||||||||||||||||||||||||
| Interest receivable | 29,733 | 28,758 | 39,730 | 38,663 | 39,747 | ||||||||||||||||||||||||
| Total non-interest earning assets | 552,635 | 575,494 | 530,779 | 514,855 | 529,450 | ||||||||||||||||||||||||
| Total assets | $ | 6,436,611 | $ | 6,712,497 | $ | 7,652,051 | $ | 7,628,639 | $ | 7,801,146 | |||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||
| Savings and money market deposits | $ | 3,094,231 | $ | 3,198,332 | $ | 3,385,413 | $ | 3,393,371 | $ | 3,446,681 | |||||||||||||||||||
| Time deposits | 1,102,478 | 1,199,681 | 1,193,180 | 1,245,088 | 1,089,153 | ||||||||||||||||||||||||
| Borrowings | 160,118 | 160,206 | 880,336 | 812,218 | 1,142,340 | ||||||||||||||||||||||||
| Repurchase agreements | 88,468 | 86,966 | 95,089 | 87,851 | 89,912 | ||||||||||||||||||||||||
| Subordinated notes | 98,215 | 154,011 | 55,807 | 55,772 | 55,738 | ||||||||||||||||||||||||
| Junior subordinated debentures issued to capital trusts | 57,688 | 57,636 | 57,583 | 57,531 | 57,477 | ||||||||||||||||||||||||
| Total interest earning liabilities | 4,601,198 | 4,856,832 | 5,667,408 | 5,651,832 | 5,881,301 | ||||||||||||||||||||||||
| Non-interest bearing deposits | 1,078,708 | 1,122,888 | 1,121,163 | 1,127,324 | 1,064,818 | ||||||||||||||||||||||||
| Interest payable | 12,892 | 12,395 | 14,007 | 11,441 | 11,137 | ||||||||||||||||||||||||
| Other liabilities | 55,562 | 59,611 | 58,621 | 61,981 | 80,308 | ||||||||||||||||||||||||
| Total liabilities | 5,748,360 | 6,051,726 | 6,861,199 | 6,852,578 | 7,037,564 | ||||||||||||||||||||||||
| Stockholders’ Equity | |||||||||||||||||||||||||||||
| Preferred stock | — | — | — | — | — | ||||||||||||||||||||||||
| Common stock | — | — | — | — | — | ||||||||||||||||||||||||
| Additional paid-in capital | 459,243 | 458,734 | 360,758 | 360,522 | 363,761 | ||||||||||||||||||||||||
| Retained earnings | 255,004 | 236,312 | 466,497 | 452,945 | 436,122 | ||||||||||||||||||||||||
| Accumulated other comprehensive (loss) | (25,996) | (34,275) | (36,403) | (37,406) | (36,301) | ||||||||||||||||||||||||
| Total stockholders’ equity | 688,251 | 660,771 | 790,852 | 776,061 | 763,582 | ||||||||||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 6,436,611 | $ | 6,712,497 | $ | 7,652,051 | $ | 7,628,639 | $ | 7,801,146 | |||||||||||||||||||
10
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
| Loans and Deposits | |||||||||||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | |||||||||||||||||||||||||||||||||||||||||
| December 31, | September 30, | June 30, | March 31, | December 31, | % Change | ||||||||||||||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2025 | 2024 | Q4'25 vs Q3'25 | Q4'25 vs Q4'24 | |||||||||||||||||||||||||||||||||||
| Loans: | |||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | $ | 2,421,863 | $ | 2,366,956 | $ | 2,321,951 | $ | 2,262,910 | $ | 2,202,858 | 2 | % | 10 | % | |||||||||||||||||||||||||||
| Commercial & Industrial | 1,010,545 | 989,609 | 976,740 | 918,541 | 875,297 | 2 | % | 15 | % | ||||||||||||||||||||||||||||||||
| Total commercial | 3,432,408 | 3,356,565 | 3,298,691 | 3,181,451 | 3,078,155 | 2 | % | 12 | % | ||||||||||||||||||||||||||||||||
| Residential Real estate | 772,427 | 783,850 | 786,026 | 801,726 | 802,909 | (1) | % | (4) | % | ||||||||||||||||||||||||||||||||
| Mortgage warehouse | — | — | — | — | — | — | % | — | % | ||||||||||||||||||||||||||||||||
| Consumer | 671,707 | 683,254 | 900,865 | 926,638 | 965,976 | (2) | % | (30) | % | ||||||||||||||||||||||||||||||||
| Total loans held for investment | 4,876,542 | 4,823,669 | 4,985,582 | 4,909,815 | 4,847,040 | 1 | % | 1 | % | ||||||||||||||||||||||||||||||||
| Loans held for sale | 9,778 | 1,921 | 2,994 | 3,253 | 67,597 | 409 | % | (86) | % | ||||||||||||||||||||||||||||||||
| Total loans | $ | 4,886,320 | $ | 4,825,590 | $ | 4,988,576 | $ | 4,913,068 | $ | 4,914,637 | 1 | % | (1) | % | |||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||||||||||||||
| Interest bearing deposits | $ | 1,639,857 | $ | 1,715,471 | $ | 1,713,058 | $ | 1,713,991 | $ | 1,767,983 | (4) | % | (7) | % | |||||||||||||||||||||||||||
| Savings and money market deposits | 1,454,374 | 1,482,861 | 1,672,355 | 1,679,380 | 1,678,697 | (2) | % | (13) | % | ||||||||||||||||||||||||||||||||
| Time deposits | 1,102,478 | 1,199,681 | 1,193,180 | 1,245,088 | 1,089,153 | (8) | % | 1 | % | ||||||||||||||||||||||||||||||||
| Total Interest bearing deposits | 4,196,709 | 4,398,013 | 4,578,593 | 4,638,459 | 4,535,833 | (5) | % | (7) | % | ||||||||||||||||||||||||||||||||
| Non-interest bearing deposits | |||||||||||||||||||||||||||||||||||||||||
| Non-interest bearing deposits | 1,078,708 | 1,122,888 | 1,121,164 | 1,127,324 | 1,064,819 | (4) | % | 1 | % | ||||||||||||||||||||||||||||||||
| Total deposits | $ | 5,275,417 | $ | 5,520,901 | $ | 5,699,757 | $ | 5,765,784 | $ | 5,600,652 | (4) | % | (6) | % | |||||||||||||||||||||||||||
11
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
| Average Balance Sheet | |||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | |||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||
December 31, 2025 | September 30, 2025 | December 31, 2024 | |||||||||||||||||||||||||||
| Average Balance | Interest(4)(6) | Average Rate(4) | Average Balance | Interest(4)(6) | Average Rate(4) | Average Balance | Interest(4)(6) | Average Rate(4) | |||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||
| Interest earning assets | |||||||||||||||||||||||||||||
| Interest earning deposits (incl. Fed Funds Sold) | $ | 182,017 | $ | 1,866 | 4.07 | % | $ | 185,665 | $ | 2,062 | 4.41 | % | $ | 290,693 | $ | 3,488 | 4.77 | % | |||||||||||
| Federal Home Loan Bank stock | 45,713 | 616 | 5.35 | % | 45,549 | 862 | 7.51 | % | 53,826 | 1,516 | 11.20 | % | |||||||||||||||||
| Investment securities - taxable (1) | 570,786 | 7,687 | 5.34 | % | 792,829 | 5,769 | 2.89 | % | 1,079,377 | 5,298 | 1.95 | % | |||||||||||||||||
| Investment securities - non-taxable (1) | 312,988 | 2,546 | 3.23 | % | 763,488 | 5,799 | 3.01 | % | 1,129,622 | 7,976 | 2.81 | % | |||||||||||||||||
| Total investment securities | 883,774 | 10,233 | 4.59 | % | 1,556,317 | 11,568 | 2.95 | % | 2,208,999 | 13,274 | 2.39 | % | |||||||||||||||||
| Loans receivable (2) (3) | 4,855,824 | 77,628 | 6.34 | % | 4,979,211 | 79,941 | 6.37 | % | 4,842,660 | 77,142 | 6.34 | % | |||||||||||||||||
| Total interest earning assets | 5,967,328 | 90,343 | 6.01 | % | 6,766,742 | 94,433 | 5.54 | % | 7,396,178 | 95,420 | 5.13 | % | |||||||||||||||||
| Non-interest earning assets | |||||||||||||||||||||||||||||
| Cash and due from banks | 74,102 | 83,616 | 85,776 | ||||||||||||||||||||||||||
| Allowance for credit losses | (49,815) | (54,072) | (52,697) | ||||||||||||||||||||||||||
| Other assets | 545,520 | 501,590 | 409,332 | ||||||||||||||||||||||||||
| Total average assets | $ | 6,537,135 | $ | 7,297,876 | $ | 7,838,589 | |||||||||||||||||||||||
| Liabilities and Stockholders' Equity | |||||||||||||||||||||||||||||
| Interest bearing liabilities | |||||||||||||||||||||||||||||
| Interest bearing demand deposits | $ | 1,686,435 | $ | 5,572 | 1.31 | % | $ | 1,708,446 | $ | 6,687 | 1.55 | % | $ | 1,716,598 | $ | 6,861 | 1.59 | % | |||||||||||
| Saving and money market deposits | 1,445,144 | 5,587 | 1.53 | % | 1,636,428 | 8,204 | 1.99 | % | 1,701,012 | 9,336 | 2.18 | % | |||||||||||||||||
| Time deposits | 1,134,417 | 10,071 | 3.52 | % | 1,198,279 | 10,835 | 3.59 | % | 1,160,527 | 11,621 | 3.98 | % | |||||||||||||||||
| Total Deposits | 4,265,996 | 21,230 | 1.97 | % | 4,543,153 | 25,726 | 2.25 | % | 4,578,137 | 27,818 | 2.42 | % | |||||||||||||||||
| Borrowings | 150,304 | 1,452 | 3.83 | % | 601,889 | 5,535 | 3.65 | % | 1,130,301 | 10,138 | 3.57 | % | |||||||||||||||||
| Repurchase agreements | 87,160 | 295 | 1.34 | % | 88,721 | 389 | 1.74 | % | 91,960 | 518 | 2.24 | % | |||||||||||||||||
| Subordinated notes | 98,185 | 1,812 | 7.32 | % | 91,032 | 1,731 | 7.54 | % | 55,717 | 829 | 5.92 | % | |||||||||||||||||
| Junior subordinated debentures issued to capital trusts | 57,655 | 1,023 | 7.04 | % | 57,602 | 1,069 | 7.36 | % | 57,443 | 920 | 6.37 | % | |||||||||||||||||
| Total interest bearing liabilities | 4,659,300 | 25,812 | 2.20 | % | 5,382,397 | 34,450 | 2.54 | % | 5,913,558 | 40,223 | 2.71 | % | |||||||||||||||||
| Non-interest bearing liabilities | |||||||||||||||||||||||||||||
| Demand deposits | 1,137,639 | 1,120,719 | 1,099,574 | ||||||||||||||||||||||||||
| Accrued interest payable and other liabilities | 60,375 | 63,103 | 70,117 | ||||||||||||||||||||||||||
| Stockholders' equity | 679,821 | 731,657 | 755,340 | ||||||||||||||||||||||||||
| Total average liabilities and stockholders' equity | $ | 6,537,135 | $ | 7,297,876 | $ | 7,838,589 | |||||||||||||||||||||||
| Net FTE interest income (non-GAAP) (5) | $ | 64,531 | $ | 59,983 | $ | 55,197 | |||||||||||||||||||||||
| Less FTE adjustments (4) | 1,055 | 1,597 | 2,070 | ||||||||||||||||||||||||||
| Net Interest Income | $ | 63,476 | $ | 58,386 | $ | 53,127 | |||||||||||||||||||||||
| Net FTE interest margin (Non-GAAP) (4)(5) | 4.29 | % | 3.52 | % | 2.97 | % | |||||||||||||||||||||||
(1) Securities balances represent daily average balances for the fair value of securities. The average rate is calculated based on the daily average balance for the amortized cost of securities. | |||||||||||||||||||||||||||||
(2) Includes fees on loans held for sale and held for investment. The inclusion of loan fees does not have a material effect on the average interest rate. | |||||||||||||||||||||||||||||
(3) Non-accruing loans for the purpose of the computation above are included in the daily average loan amounts outstanding. Loan totals are shown net of unearned income and deferred loan fees. | |||||||||||||||||||||||||||||
(4) Management believes fully taxable equivalent, or FTE, interest income is useful to investors in evaluating the Company's performance as a comparison of the returns between a tax-free investment and a taxable alternative. The Company adjusts interest income and average rates for tax-exempt loans and securities to an FTE basis utilizing a 21% tax rate. | |||||||||||||||||||||||||||||
(5) Non-GAAP financial metric. See non-GAAP reconciliation included herein for the most directly comparable GAAP measure. | |||||||||||||||||||||||||||||
(6) Includes dividend income on Federal Home Loan Bank stock | |||||||||||||||||||||||||||||
12
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
| Credit Quality | |||||||||||||||||||||||||||||||||||||||||
| (Dollars in Thousands Except Ratios, Unaudited) | |||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | |||||||||||||||||||||||||||||||||||||||||
| December 31, | September 30, | June 30, | March 31, | December 31, | % Change | ||||||||||||||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2025 | 2024 | Q4'25 vs Q3'25 | Q4'25 vs Q4'24 | |||||||||||||||||||||||||||||||||||
| Non-accrual loans | |||||||||||||||||||||||||||||||||||||||||
| Commercial | $ | 14,549 | $ | 12,303 | $ | 7,547 | $ | 8,172 | $ | 5,658 | 18 | % | 157 | % | |||||||||||||||||||||||||||
| Residential Real estate | 10,087 | 9,256 | 9,525 | 12,763 | 11,215 | 9 | % | (10) | % | ||||||||||||||||||||||||||||||||
| Mortgage warehouse | — | — | — | — | — | — | % | — | % | ||||||||||||||||||||||||||||||||
| Consumer | 7,821 | 7,799 | 7,222 | 7,875 | 8,919 | — | % | (12) | % | ||||||||||||||||||||||||||||||||
| Total non-accrual loans | 32,457 | 29,358 | 24,294 | 28,810 | 25,792 | 11 | % | 26 | % | ||||||||||||||||||||||||||||||||
| 90 days and greater delinquent - accruing interest | 2,489 | 1,608 | 2,113 | 1,582 | 1,166 | 55 | % | 113 | % | ||||||||||||||||||||||||||||||||
| Total non-performing loans | $ | 34,946 | $ | 30,966 | $ | 26,407 | $ | 30,392 | $ | 26,958 | 13 | % | 30 | % | |||||||||||||||||||||||||||
| Other real estate owned | |||||||||||||||||||||||||||||||||||||||||
| Commercial | $ | 539 | $ | 272 | $ | 176 | $ | 360 | $ | 407 | 98 | % | 32 | % | |||||||||||||||||||||||||||
| Residential Real estate | 672 | 769 | 463 | 641 | — | (13) | % | — | % | ||||||||||||||||||||||||||||||||
| Mortgage warehouse | — | — | — | — | — | — | % | — | % | ||||||||||||||||||||||||||||||||
| Consumer | 480 | 480 | 480 | 34 | 17 | — | % | 2701 | % | ||||||||||||||||||||||||||||||||
| Total other real estate owned | 1,691 | 1,521 | 1,119 | 1,035 | 424 | 11 | % | 299 | % | ||||||||||||||||||||||||||||||||
Other non-performing assets (1) | $ | 3,991 | $ | 3,228 | $ | 2,937 | $ | — | $ | — | 24 | % | — | % | |||||||||||||||||||||||||||
| Total non-performing assets | $ | 40,628 | $ | 35,715 | $ | 30,463 | $ | 31,427 | $ | 27,382 | 14 | % | 48 | % | |||||||||||||||||||||||||||
| Loan data: | |||||||||||||||||||||||||||||||||||||||||
| Accruing 30 to 89 days past due loans | $ | 24,580 | $ | 24,784 | $ | 31,401 | $ | 19,034 | $ | 23,075 | (1) | % | 7 | % | |||||||||||||||||||||||||||
| Substandard loans | 59,365 | 63,236 | 64,100 | 66,714 | 64,535 | (6) | % | (8) | % | ||||||||||||||||||||||||||||||||
| Net charge-offs (recoveries) | |||||||||||||||||||||||||||||||||||||||||
| Commercial | $ | 436 | $ | 294 | $ | 84 | $ | (47) | $ | (32) | 48 | % | (1462) | % | |||||||||||||||||||||||||||
| Residential Real estate | (25) | 19 | 52 | (47) | (10) | (231) | % | 149 | % | ||||||||||||||||||||||||||||||||
| Mortgage warehouse | — | — | — | — | — | — | % | — | % | ||||||||||||||||||||||||||||||||
| Consumer | 559 | 518 | 118 | 963 | 668 | 8 | % | (16) | % | ||||||||||||||||||||||||||||||||
| Total net charge-offs | $ | 970 | $ | 831 | $ | 254 | $ | 869 | $ | 626 | 17 | % | 55 | % | |||||||||||||||||||||||||||
| Allowance for credit losses | |||||||||||||||||||||||||||||||||||||||||
| Commercial | $ | 35,473 | $ | 34,390 | $ | 34,413 | $ | 32,640 | $ | 30,953 | 3 | % | 15 | % | |||||||||||||||||||||||||||
| Residential Real estate | 3,183 | 3,082 | 3,229 | 3,167 | 2,715 | 3 | % | 17 | % | ||||||||||||||||||||||||||||||||
| Mortgage warehouse | — | — | — | — | — | — | % | — | % | ||||||||||||||||||||||||||||||||
| Consumer | 12,643 | 12,706 | 16,757 | 16,847 | 18,312 | — | % | (31) | % | ||||||||||||||||||||||||||||||||
| Total allowance for credit losses | $ | 51,299 | $ | 50,178 | $ | 54,399 | $ | 52,654 | $ | 51,980 | 2 | % | (1) | % | |||||||||||||||||||||||||||
| Credit quality ratios | |||||||||||||||||||||||||||||||||||||||||
| Non-accrual loans to HFI loans | 0.67 | % | 0.61 | % | 0.49 | % | 0.59 | % | 0.53 | % | |||||||||||||||||||||||||||||||
| Non-performing assets to total assets | 0.63 | % | 0.53 | % | 0.40 | % | 0.41 | % | 0.35 | % | |||||||||||||||||||||||||||||||
| Annualized net charge-offs of average total loans | 0.08 | % | 0.07 | % | 0.02 | % | 0.07 | % | 0.05 | % | |||||||||||||||||||||||||||||||
| Allowance for credit losses to HFI loans | 1.05 | % | 1.04 | % | 1.09 | % | 1.07 | % | 1.07 | % | |||||||||||||||||||||||||||||||
(1) Other non-performing assets consist of a single available for sale debt security placed on non-accrual status. | |||||||||||||||||||||||||||||||||||||||||
13
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
| Non–GAAP Reconciliation of Net Fully-Taxable Equivalent ("FTE") Interest Margin | ||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||||||||
| December 31, | September 30, | June 30, | March 31, | December 31, | ||||||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2025 | 2024 | ||||||||||||||||||||||||||||
| Interest income (GAAP) | (A) | $ | 89,288 | $ | 92,836 | $ | 91,477 | $ | 89,175 | $ | 93,350 | |||||||||||||||||||||
| Taxable-equivalent adjustment: | ||||||||||||||||||||||||||||||||
| Investment securities - tax exempt (1) | 665 | 1,218 | 1,619 | 1,646 | 1,675 | |||||||||||||||||||||||||||
| Loan receivable (2) | 390 | 379 | 382 | 383 | 395 | |||||||||||||||||||||||||||
| Interest income (non-GAAP) | (B) | 90,343 | 94,433 | 93,478 | 91,204 | 95,420 | ||||||||||||||||||||||||||
| Interest expense (GAAP) | (C) | 25,812 | 34,450 | 36,122 | 36,908 | 40,223 | ||||||||||||||||||||||||||
| Net interest income (GAAP) | (D) =(A) - (C) | $ | 63,476 | $ | 58,386 | $ | 55,355 | $ | 52,267 | $ | 53,127 | |||||||||||||||||||||
| Net FTE interest income (non-GAAP) | (E) = (B) - (C) | $ | 64,531 | $ | 59,983 | $ | 57,356 | $ | 54,296 | $ | 55,197 | |||||||||||||||||||||
| Average interest earning assets | (F) | 5,967,328 | 6,766,742 | 7,125,467 | 7,234,724 | 7,396,178 | ||||||||||||||||||||||||||
| Net FTE interest margin (non-GAAP) | (G) = (E*) / (F) | 4.29 | % | 3.52 | % | 3.23 | % | 3.04 | % | 2.97 | % | |||||||||||||||||||||
(1) The following represents municipal securities interest income for investment securities classified as available-for-sale and held-to-maturity | ||||||||||||||||||||||||||||||||
(2) The following represents municipal loan interest income for loan receivables classified as held for sale and held for investment | ||||||||||||||||||||||||||||||||
| *Annualized | ||||||||||||||||||||||||||||||||
| Non–GAAP Reconciliation of Return on Average Tangible Common Equity | ||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||||||||
| December 31, | September 30, | June 30, | March 31, | December 31, | ||||||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2025 | 2024 | ||||||||||||||||||||||||||||
| Net income (loss) (GAAP) | (A) | $ | 26,921 | $ | (221,990) | $ | 20,644 | $ | 23,941 | $ | (10,882) | |||||||||||||||||||||
| Average stockholders' equity | (B) | $ | 679,821 | $ | 731,657 | $ | 789,535 | $ | 780,269 | $ | 755,340 | |||||||||||||||||||||
| Average intangible assets | (C) | 162,838 | 163,552 | 164,320 | 165,138 | 165,973 | ||||||||||||||||||||||||||
| Average tangible equity (Non-GAAP) | (D) = (B) - (C) | $ | 516,983 | $ | 568,105 | $ | 625,215 | $ | 615,131 | $ | 589,367 | |||||||||||||||||||||
| Return on average tangible common equity ("ROACE") (non-GAAP) | (E) = (A*) / (D) | 20.66 | % | (155.03) | % | 13.24 | % | 15.48 | % | (7.35) | % | |||||||||||||||||||||
| *Annualized | ||||||||||||||||||||||||||||||||
| Non–GAAP Reconciliation of Tangible Common Equity to Tangible Assets | ||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||||||||
| December 31, | September 30, | June 30, | March 31, | December 31, | ||||||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2025 | 2024 | ||||||||||||||||||||||||||||
| Total stockholders' equity (GAAP) | (A) | $ | 688,251 | $ | 660,771 | $ | 790,852 | $ | 776,061 | $ | 763,582 | |||||||||||||||||||||
| Intangible assets (end of period) | (B) | 162,391 | 163,097 | 163,803 | 164,618 | 165,434 | ||||||||||||||||||||||||||
| Total tangible common equity (non-GAAP) | (C) = (A) - (B) | $ | 525,860 | $ | 497,674 | $ | 627,049 | $ | 611,443 | $ | 598,148 | |||||||||||||||||||||
| Total assets (GAAP) | (D) | $ | 6,436,611 | $ | 6,712,497 | $ | 7,652,051 | $ | 7,628,636 | $ | 7,801,146 | |||||||||||||||||||||
| Intangible assets (end of period) | (B) | 162,391 | 163,097 | 163,803 | 164,618 | 165,434 | ||||||||||||||||||||||||||
| Total tangible assets (non-GAAP) | (E) = (D) - (B) | $ | 6,274,220 | $ | 6,549,400 | $ | 7,488,248 | $ | 7,464,018 | $ | 7,635,712 | |||||||||||||||||||||
| Tangible common equity to tangible assets (Non-GAAP) | (G) = (C) / (E) | 8.38 | % | 7.60 | % | 8.37 | % | 8.19 | % | 7.83 | % | |||||||||||||||||||||
14
Horizon Bancorp, Inc. Reports Fourth Quarter 2025 Results
| Non–GAAP Reconciliation of Tangible Book Value Per Share | ||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||||||||
| December 31, | September 30, | June 30, | March 31, | December 31, | ||||||||||||||||||||||||||||
| 2025 | 2025 | 2025 | 2025 | 2024 | ||||||||||||||||||||||||||||
| Total stockholders' equity (GAAP) | (A) | $ | 688,251 | $ | 660,771 | $ | 790,852 | $ | 776,061 | $ | 763,582 | |||||||||||||||||||||
| Intangible assets (end of period) | (B) | 162,391 | 163,097 | 163,803 | 164,618 | 165,434 | ||||||||||||||||||||||||||
| Total tangible common equity (non-GAAP) | (C) = (A) - (B) | $ | 525,860 | $ | 497,674 | $ | 627,049 | $ | 611,443 | $ | 598,148 | |||||||||||||||||||||
| Common shares outstanding | (D) | 50,978,030 | 50,971,000 | 43,801,507 | 43,786,000 | 43,722,086 | ||||||||||||||||||||||||||
| Tangible book value per common share (non-GAAP) | (E) = (C) / (D) | $ | 10.32 | $ | 9.76 | $ | 14.32 | $ | 13.96 | $ | 13.68 | |||||||||||||||||||||
15
Beyond ordinary banking Investor Presentation H o r i z o n B a n c o r p , I n c . ( N A S D A Q : H B N C ) Ye a r E n d e d D e c e m b e r 3 1 , 2 0 2 5 J a n u a r y 2 2 , 2 0 2 6
Important Information Forward-Looking Statements This press release may contain forward–looking statements regarding the financial performance, business prospects, growth and operating strategies of Horizon Bancorp, Inc. and its affiliates (collectively, “Horizon”). For these statements, Horizon claims the protection of the safe harbor for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. Statements in this press release should be considered in conjunction with the other information available about Horizon, including the information in the filings we make with the Securities and Exchange Commission (the “SEC”). Forward-looking statements provide current expectations or forecasts of future events and are not guarantees of future performance. The forward-looking statements are based on management’s expectations and are subject to a number of risks and uncertainties. We have tried, wherever possible, to identify such statements by using words such as “anticipate,” “estimate,” “project,” “intend,” “plan,” “believe,” “will” and similar expressions in connection with any discussion of future operating or financial performance. Although management believes that the expectations reflected in such forward-looking statements are reasonable, actual results may differ materially from those expressed or implied in such statements. Risks and uncertainties that could cause actual results to differ materially include: changes in U.S. trade policies, including the imposition of tariffs and retaliatory tariffs, changes within the domestic and international macroeconomic environment, including trade policy, monetary and fiscal policy, inflation levels, and conditions in the investment, credit, interest rate, and derivatives markets, and their impact on Horizon and its customers; current financial conditions within the banking industry; changes in the level and volatility of interest rates, changes in spreads on earning assets and changes in interest bearing liabilities; increased interest rate sensitivity; loss of key Horizon personnel; increases in disintermediation; potential loss of fee income, including interchange fees, as new and emerging alternative payment platforms take a greater market share of the payment systems; estimates of fair value of certain of Horizon’s assets and liabilities; changes in prepayment speeds, loan originations, credit losses, market values, collateral securing loans and other assets; changes in sources of liquidity; legislative and regulatory actions and reforms; changes in accounting policies or procedures as may be adopted and required by regulatory agencies; litigation, regulatory enforcement, and legal compliance risk and costs; rapid technological developments and changes; cyber terrorism and data security breaches; the rising costs of cybersecurity; the ability of the U.S. federal government to manage federal debt limits; climate change and social justice initiatives; the inability to realize cost savings or revenues or to effectively implement integration plans and other consequences associated with mergers, acquisitions, and divestitures; acts of terrorism, war and global conflicts, and the effects of foreign and military policies of the U.S. government; and supply chain disruptions and delays. These and additional factors that could cause actual results to differ materially from those expressed in the forward-looking statements are discussed in Horizon’s reports (such as the Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, and Current Reports on Form 8-K) filed with the SEC and available at the SEC’s website (www.sec.gov). Undue reliance should not be placed on the forward–looking statements, which speak only as of the date hereof. Horizon does not undertake, and specifically disclaims any obligation, to publicly release the result of any revisions that may be made to update any forward-looking statement to reflect the events or circumstances after the date on which the forward–looking statement is made, or reflect the occurrence of unanticipated events, except to the extent required by law. 2
Fourth Quarter 2025 * Net Fully-Taxable Equivalent Interest Margin is a Non-GAAP measure. Please see appendix for reconciliations of non-GAAP information to its most comparable GAAP measures 3 D E L I V E R I N G V A L U E T O S H A R E H O L D E R S ◦ Community banking model displaying industry leading profitability metrics. ROA of 1.63% and ROE of 15.71% ◦ Durable net interest margin, expanding for the ninth consecutive quarter, to 4.29% ◦ Strong Commercial loan growth of 9.1% LQA. Deposit base optimized through intentional transition of transactional & non-core deposits ◦ Consistent, conservative credit profile. Low NPA's and annualized Net Charge-Offs of 0.08% ◦ Stable and diverse non-interest income streams with potential for growth ◦ Disciplined expense management focused on capturing addition operating leverage ($000S EXCEPT PER SHARE DATA) 4Q25 3Q25 INCOME STATEMENT Net Interest Income $63,476 $58,386 NIM (FTE)* 4.29% 3.52% Provision for Credit Losses $1,630 $(3,572) Non-Interest Income (Loss) $11,463 $(295,334) Non-Interest Expense $40,615 $52,952 Net Income (Loss) $26,921 $(221,990) Diluted EPS $0.53 $(4.69) BALANCE SHEET (period end) Total Loans Held For Investment $4,876,542 $4,823,669 Total Deposits $5,275,417 $5,520,901 CREDIT QUALITY NPA/Total Assets Ratio 0.63% 0.53% Annualized Net Charge-Offs to Avg. Loans 0.08% 0.07%
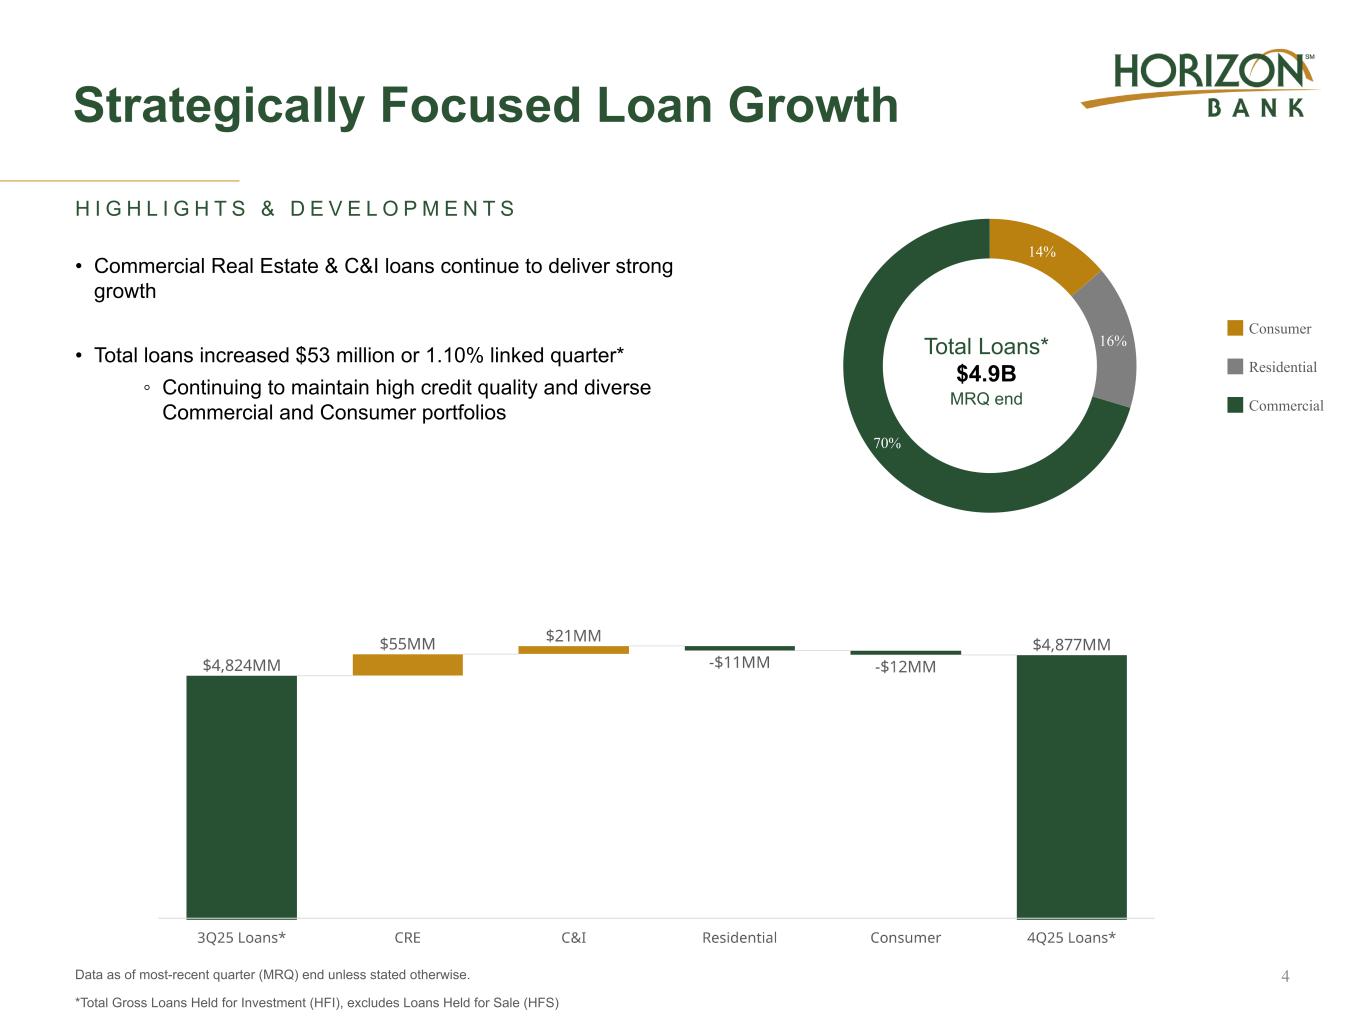
Strategically Focused Loan Growth Data as of most-recent quarter (MRQ) end unless stated otherwise. *Total Gross Loans Held for Investment (HFI), excludes Loans Held for Sale (HFS) 4 14% 16% 70% Consumer Residential Commercial H I G H L I G H T S & D E V E L O P M E N T S • Commercial Real Estate & C&I loans continue to deliver strong growth • Total loans increased $53 million or 1.10% linked quarter* ◦ Continuing to maintain high credit quality and diverse Commercial and Consumer portfolios Total Loans* $4.9B MRQ end
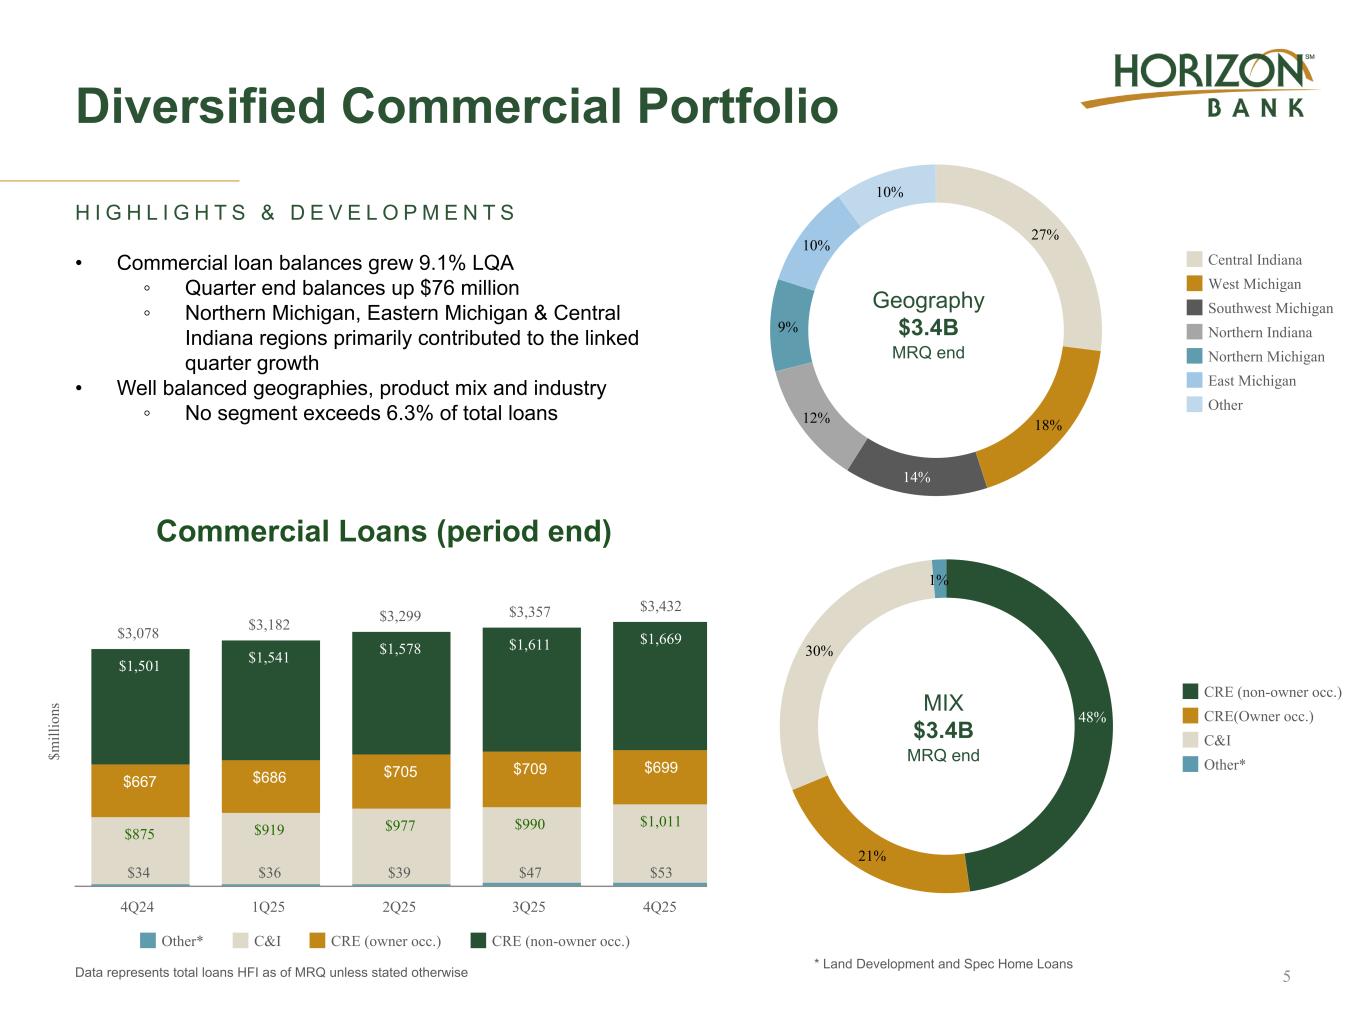
Diversified Commercial Portfolio * Land Development and Spec Home Loans H I G H L I G H T S & D E V E L O P M E N T S • Commercial loan balances grew 9.1% LQA ◦ Quarter end balances up $76 million ◦ Northern Michigan, Eastern Michigan & Central Indiana regions primarily contributed to the linked quarter growth • Well balanced geographies, product mix and industry ◦ No segment exceeds 6.3% of total loans Data represents total loans HFI as of MRQ unless stated otherwise 5 27% 18% 14% 12% 9% 10% 10% Central Indiana West Michigan Southwest Michigan Northern Indiana Northern Michigan East Michigan Other $m ill io ns Commercial Loans (period end) $3,078 $3,182 $3,299 $3,357 $3,432 $34 $36 $39 $47 $53 $875 $919 $977 $990 $1,011 $667 $686 $705 $709 $699 $1,501 $1,541 $1,578 $1,611 $1,669 Other* C&I CRE (owner occ.) CRE (non-owner occ.) 4Q24 1Q25 2Q25 3Q25 4Q25 Geography $3.4B MRQ end 48% 21% 30% 1% CRE (non-owner occ.) CRE(Owner occ.) C&I Other* MIX $3.4B MRQ end
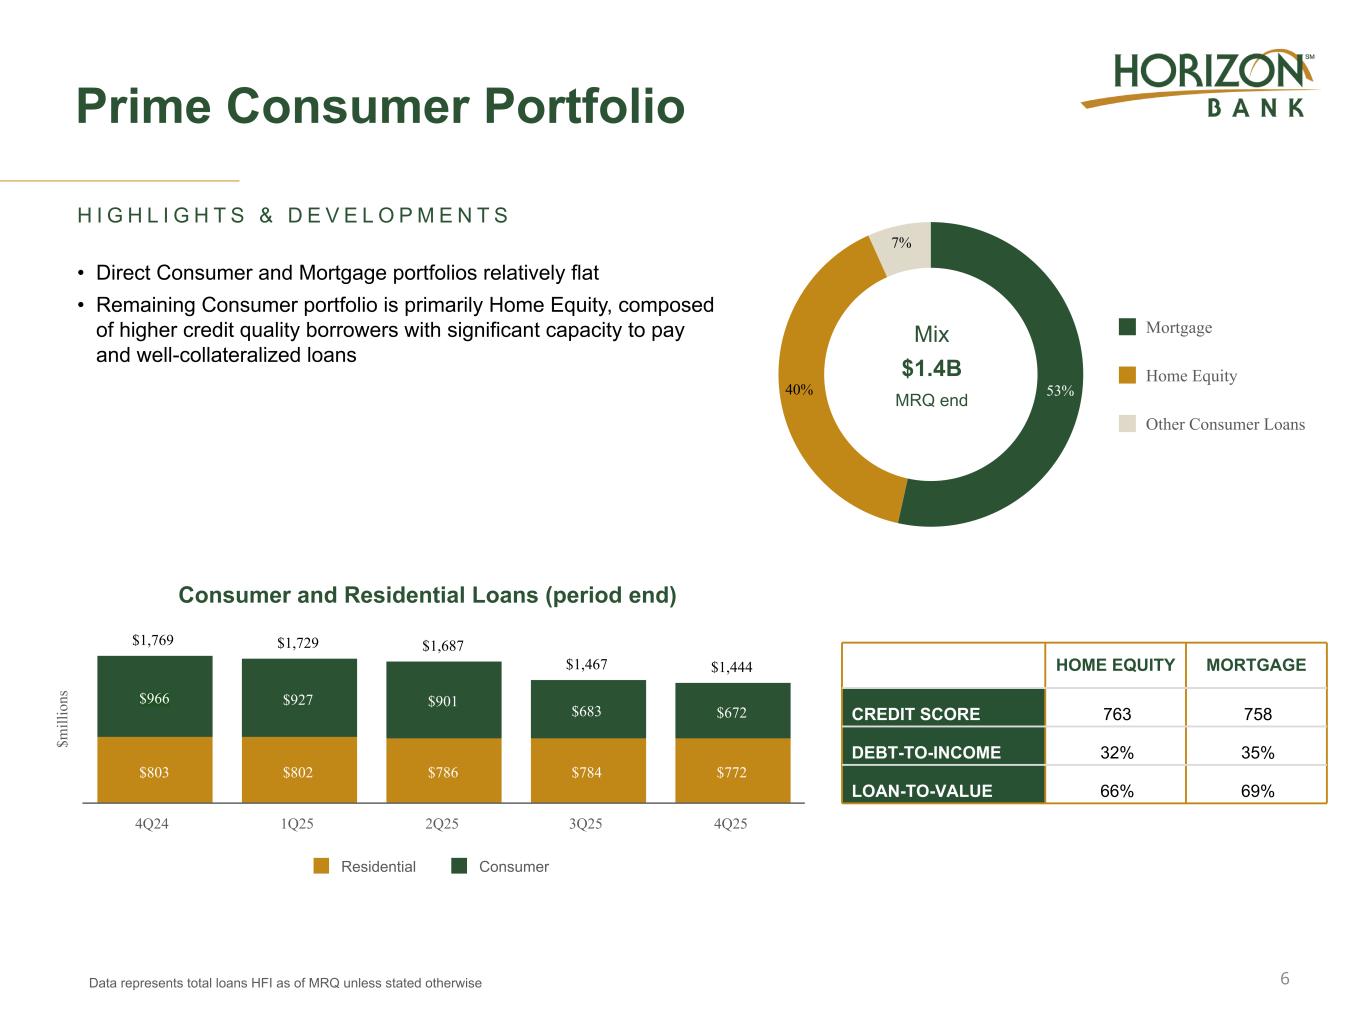
Prime Consumer Portfolio H I G H L I G H T S & D E V E L O P M E N T S • Direct Consumer and Mortgage portfolios relatively flat • Remaining Consumer portfolio is primarily Home Equity, composed of higher credit quality borrowers with significant capacity to pay and well-collateralized loans 6Data represents total loans HFI as of MRQ unless stated otherwise HOME EQUITY MORTGAGE CREDIT SCORE 763 758 DEBT-TO-INCOME 32% 35% LOAN-TO-VALUE 66% 69% 53%40% 7% Mortgage Home Equity Other Consumer Loans Mix $1.4B MRQ end $m ill io ns Consumer and Residential Loans (period end) $1,769 $1,729 $1,687 $1,467 $1,444 $803 $802 $786 $784 $772 $966 $927 $901 $683 $672 Residential Consumer 4Q24 1Q25 2Q25 3Q25 4Q25
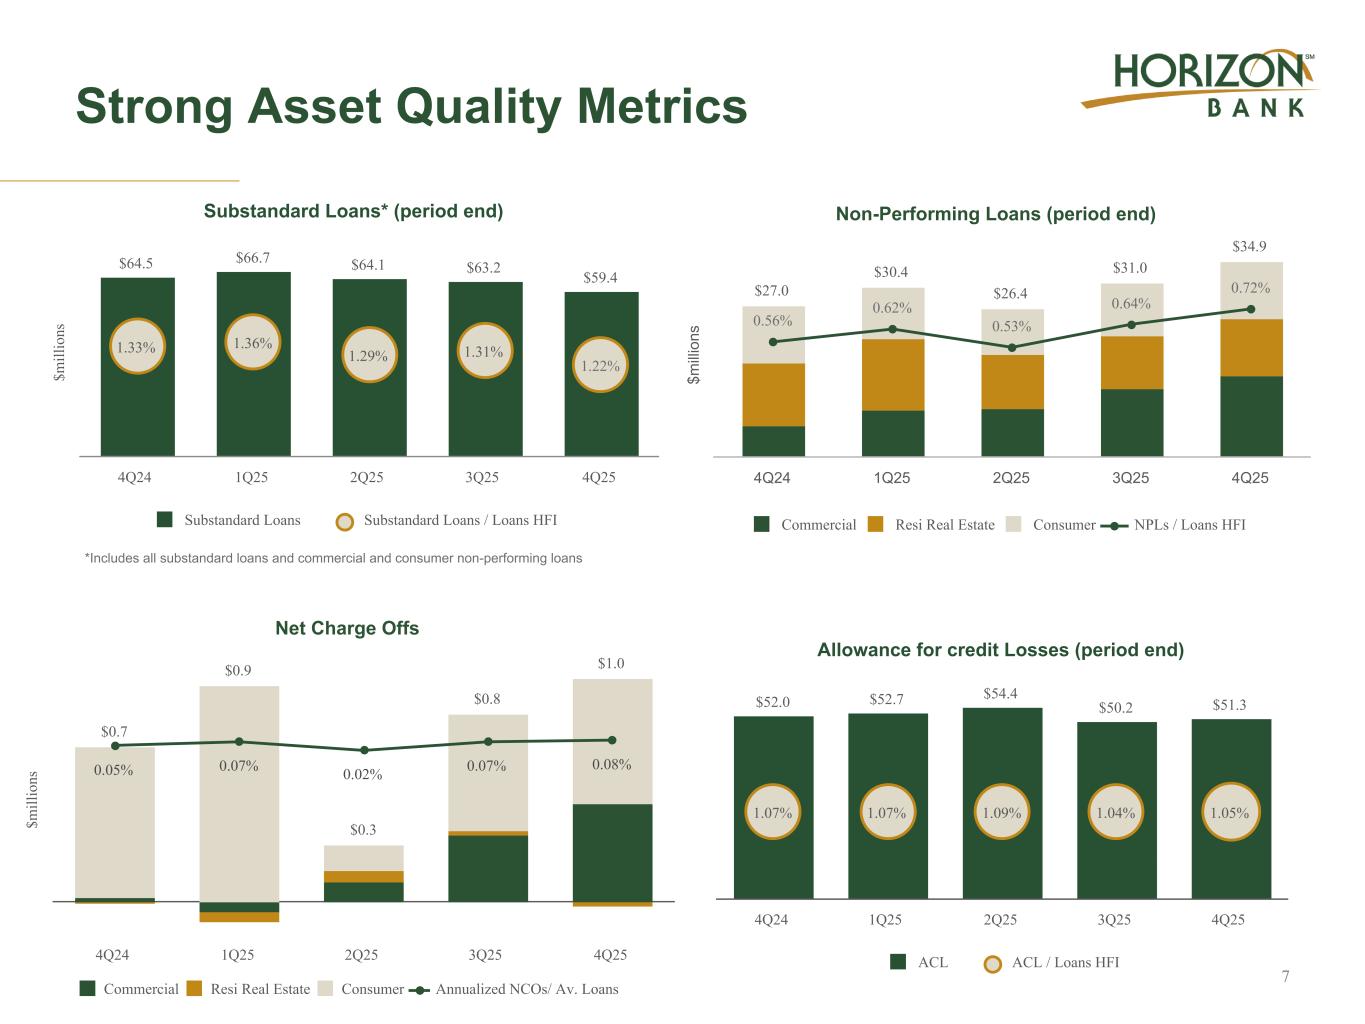
Strong Asset Quality Metrics 7 *Includes all substandard loans and commercial and consumer non-performing loans $m ill io ns Substandard Loans* (period end) $64.5 $66.7 $64.1 $63.2 $59.4 1.33% 1.36% 1.29% 1.31% 1.22% Substandard Loans Substandard Loans / Loans HFI 4Q24 1Q25 2Q25 3Q25 4Q25 $m ill io ns Non-Performing Loans (period end) $27.0 $30.4 $26.4 $31.0 $34.9 0.56% 0.62% 0.53% 0.64% 0.72% Commercial Resi Real Estate Consumer NPLs / Loans HFI 4Q24 1Q25 2Q25 3Q25 4Q25 $m ill io ns Net Charge Offs $0.7 $0.9 $0.3 $0.8 $1.0 0.05% 0.07% 0.02% 0.07% 0.08% Commercial Resi Real Estate Consumer Annualized NCOs/ Av. Loans 4Q24 1Q25 2Q25 3Q25 4Q25 Allowance for credit Losses (period end) $52.0 $52.7 $54.4 $50.2 $51.3 1.07% 1.07% 1.09% 1.04% 1.05% ACL ACL / Loans HFI 4Q24 1Q25 2Q25 3Q25 4Q25
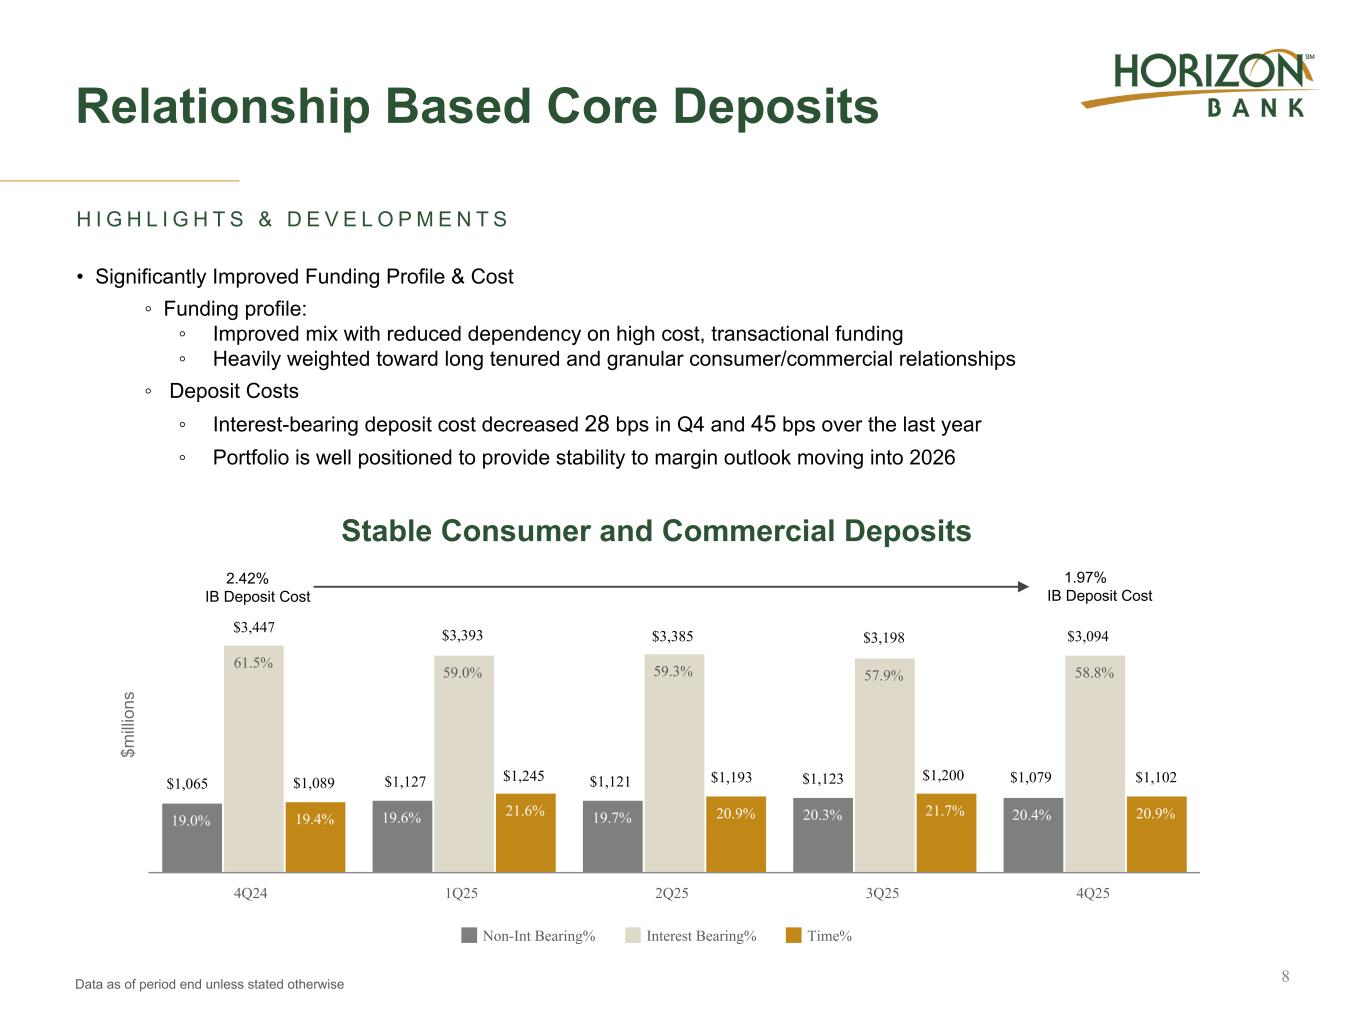
Data as of period end unless stated otherwise Relationship Based Core Deposits 8 H I G H L I G H T S & D E V E L O P M E N T S • Significantly Improved Funding Profile & Cost ◦ Funding profile: ◦ Improved mix with reduced dependency on high cost, transactional funding ◦ Heavily weighted toward long tenured and granular consumer/commercial relationships ◦ Deposit Costs ◦ Interest-bearing deposit cost decreased 28 bps in Q4 and 45 bps over the last year ◦ Portfolio is well positioned to provide stability to margin outlook moving into 2026 $m illi on s Stable Consumer and Commercial Deposits 19.0% 19.6% 19.7% 20.3% 20.4% 61.5% 59.0% 59.3% 57.9% 58.8% 19.4% 21.6% 20.9% 21.7% 20.9% Non-Int Bearing% Interest Bearing% Time% 4Q24 1Q25 2Q25 3Q25 4Q25 $1,065 $3,447 $1,089 $1,127 $3,393 $1,245 $1,193 $3,385 $1,121 $1,200 $3,198 $1,123 $1,102 $3,094 $1,079 2.42% IB Deposit Cost 1.97% IB Deposit Cost
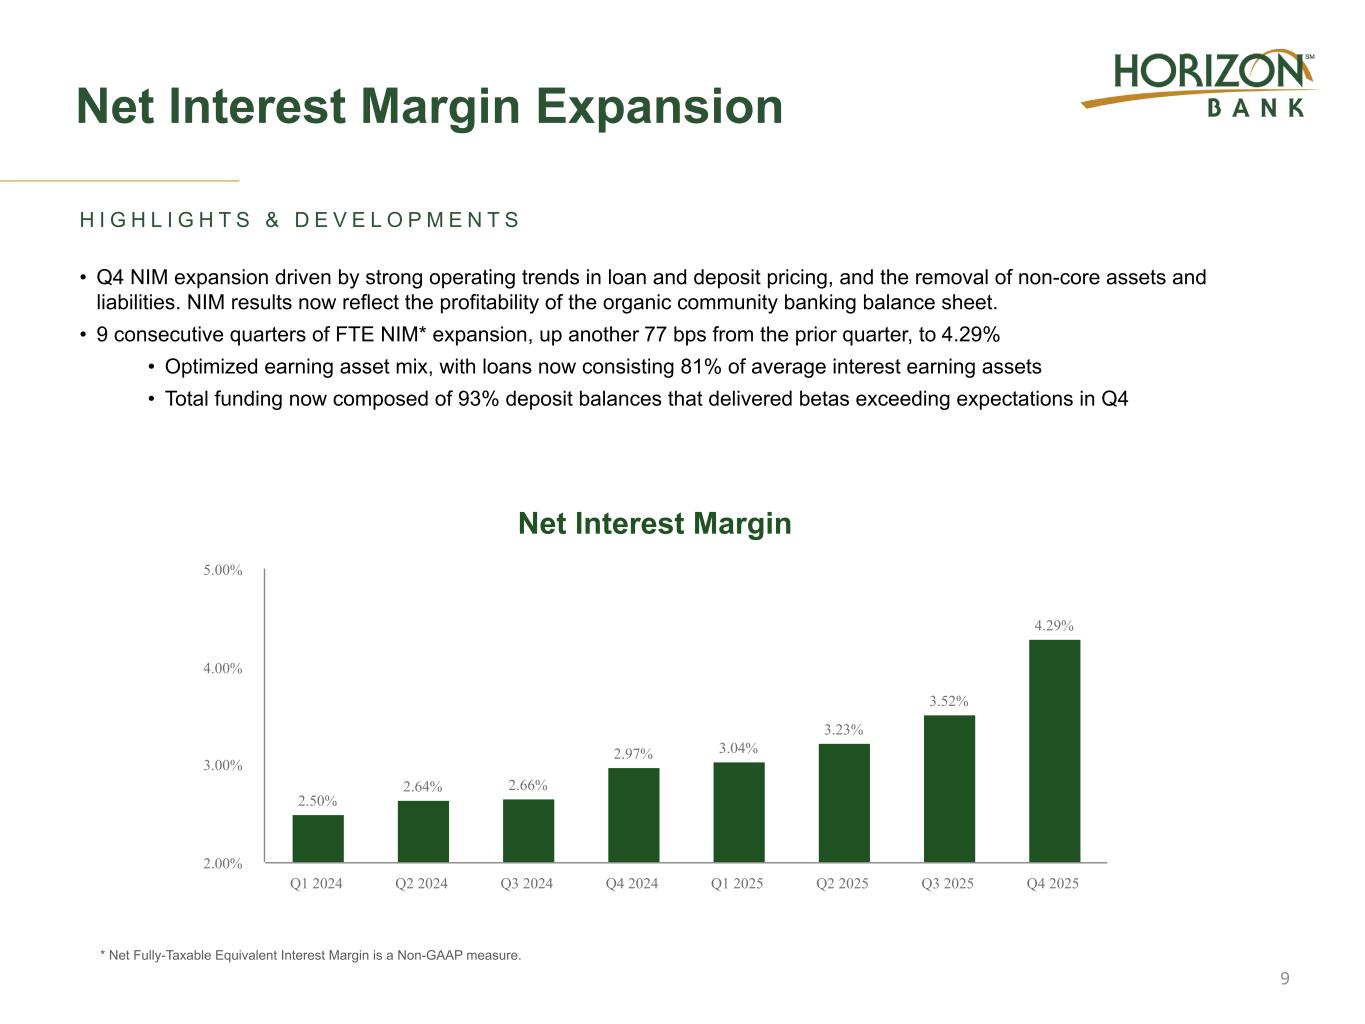
Net Interest Margin Expansion * Net Fully-Taxable Equivalent Interest Margin is a Non-GAAP measure. 9 Net Interest Margin 2.50% 2.64% 2.66% 2.97% 3.04% 3.23% 3.52% 4.29% Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 Q2 2025 Q3 2025 Q4 2025 2.00% 3.00% 4.00% 5.00% H I G H L I G H T S & D E V E L O P M E N T S • Q4 NIM expansion driven by strong operating trends in loan and deposit pricing, and the removal of non-core assets and liabilities. NIM results now reflect the profitability of the organic community banking balance sheet. • 9 consecutive quarters of FTE NIM* expansion, up another 77 bps from the prior quarter, to 4.29% • Optimized earning asset mix, with loans now consisting 81% of average interest earning assets • Total funding now composed of 93% deposit balances that delivered betas exceeding expectations in Q4
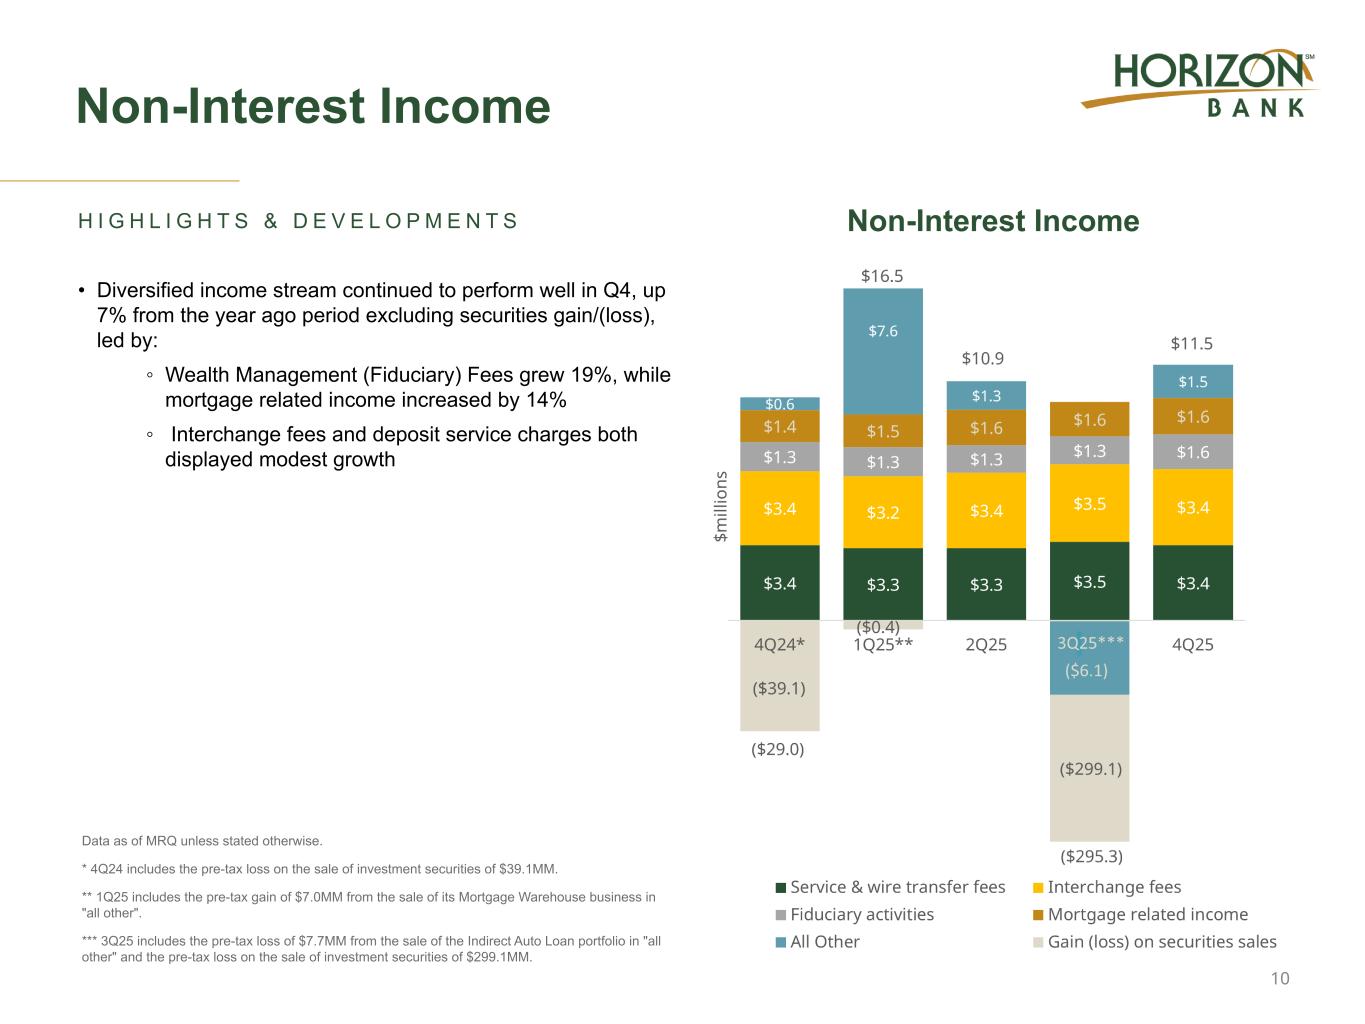
H I G H L I G H T S & D E V E L O P M E N T S • Diversified income stream continued to perform well in Q4, up 7% from the year ago period excluding securities gain/(loss), led by: ◦ Wealth Management (Fiduciary) Fees grew 19%, while mortgage related income increased by 14% ◦ Interchange fees and deposit service charges both displayed modest growth 10 Data as of MRQ unless stated otherwise. * 4Q24 includes the pre-tax loss on the sale of investment securities of $39.1MM. ** 1Q25 includes the pre-tax gain of $7.0MM from the sale of its Mortgage Warehouse business in "all other". *** 3Q25 includes the pre-tax loss of $7.7MM from the sale of the Indirect Auto Loan portfolio in "all other" and the pre-tax loss on the sale of investment securities of $299.1MM. Non-Interest Income Non-Interest Income
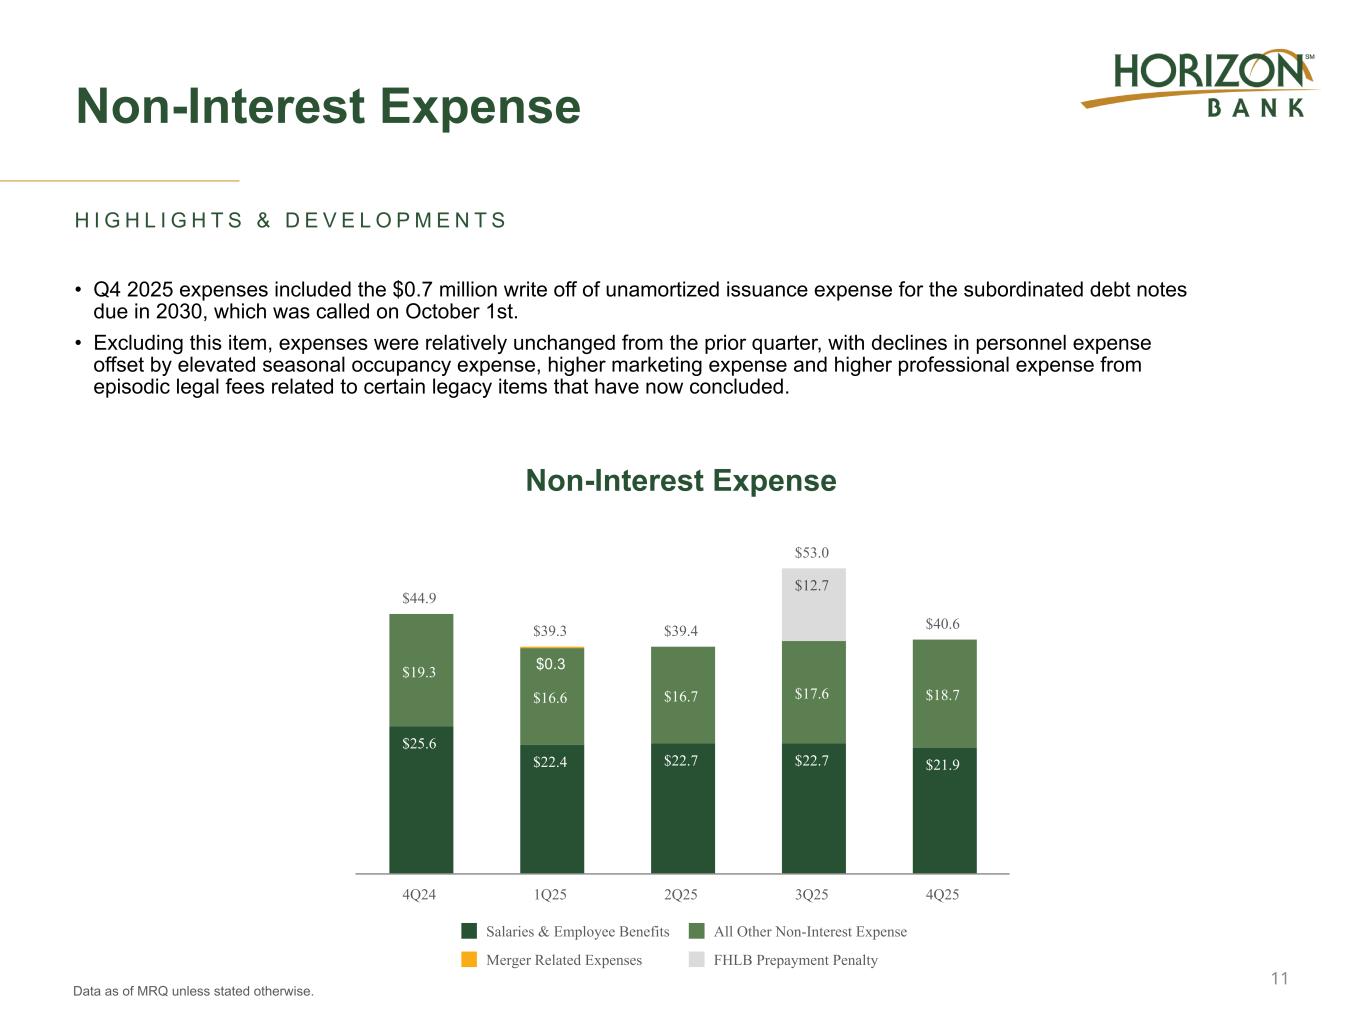
Non-Interest Expense 11 Data as of MRQ unless stated otherwise. H I G H L I G H T S & D E V E L O P M E N T S • Q4 2025 expenses included the $0.7 million write off of unamortized issuance expense for the subordinated debt notes due in 2030, which was called on October 1st. • Excluding this item, expenses were relatively unchanged from the prior quarter, with declines in personnel expense offset by elevated seasonal occupancy expense, higher marketing expense and higher professional expense from episodic legal fees related to certain legacy items that have now concluded. Non-Interest Expense $44.9 $39.3 $39.4 $53.0 $40.6 $25.6 $22.4 $22.7 $22.7 $21.9 $19.3 $16.6 $16.7 $17.6 $18.7 $0.3 $12.7 Salaries & Employee Benefits All Other Non-Interest Expense Merger Related Expenses FHLB Prepayment Penalty 4Q24 1Q25 2Q25 3Q25 4Q25
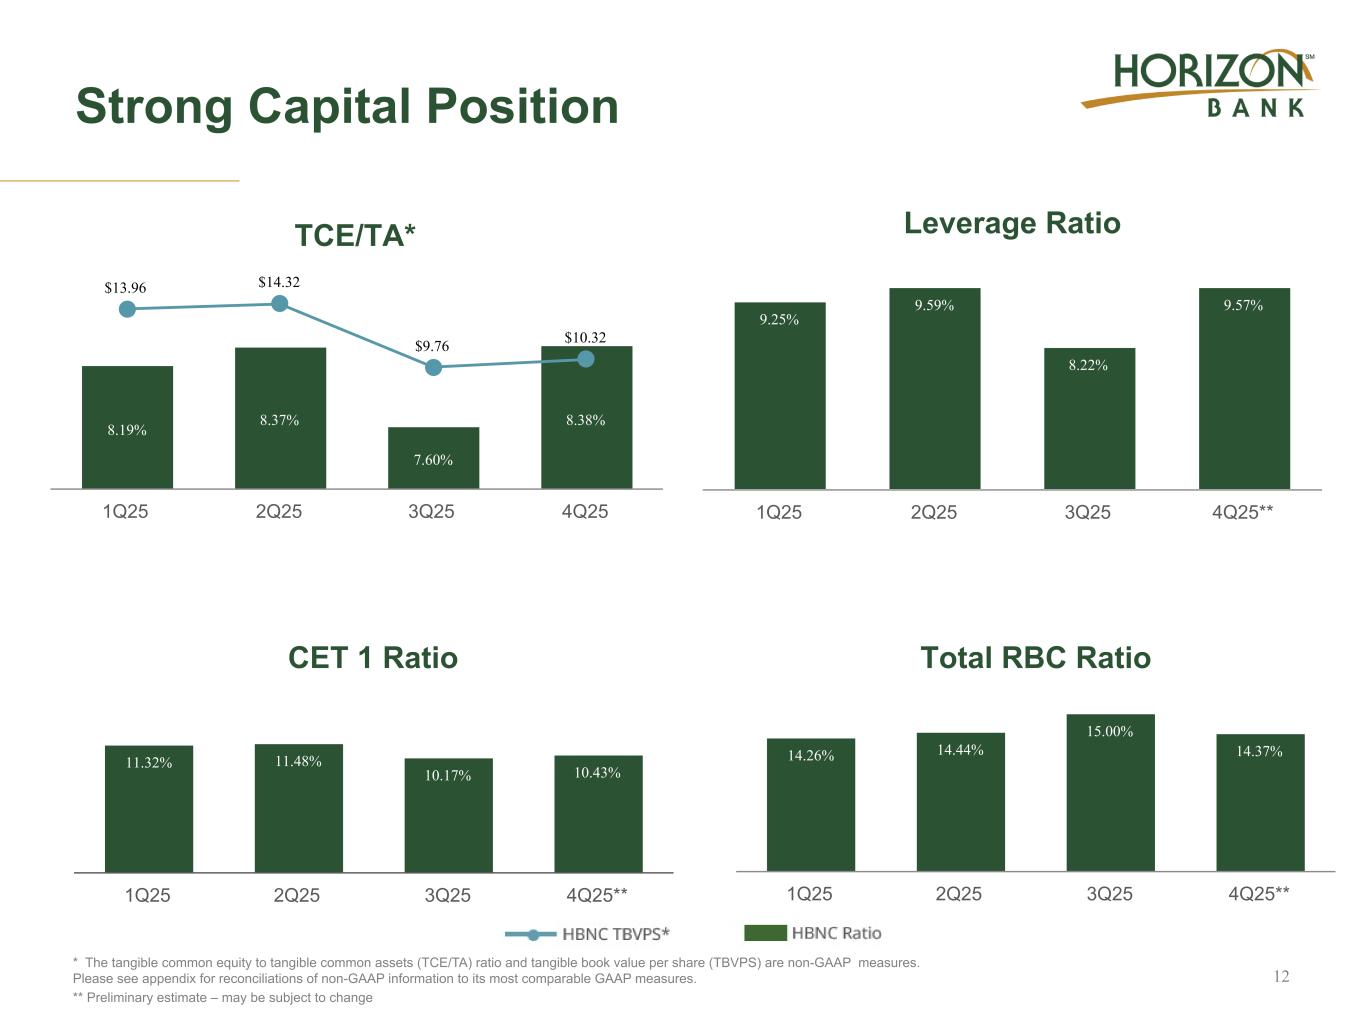
Strong Capital Position * The tangible common equity to tangible common assets (TCE/TA) ratio and tangible book value per share (TBVPS) are non-GAAP measures. Please see appendix for reconciliations of non-GAAP information to its most comparable GAAP measures. ** Preliminary estimate – may be subject to change 12 TCE/TA* 8.19% 8.37% 7.60% 8.38% $13.96 $14.32 $9.76 $10.32 1Q25 2Q25 3Q25 4Q25 Leverage Ratio 9.25% 9.59% 8.22% 9.57% 1Q25 2Q25 3Q25 4Q25** CET 1 Ratio 11.32% 11.48% 10.17% 10.43% 1Q25 2Q25 3Q25 4Q25** Total RBC Ratio 14.26% 14.44% 15.00% 14.37% 1Q25 2Q25 3Q25 4Q25**
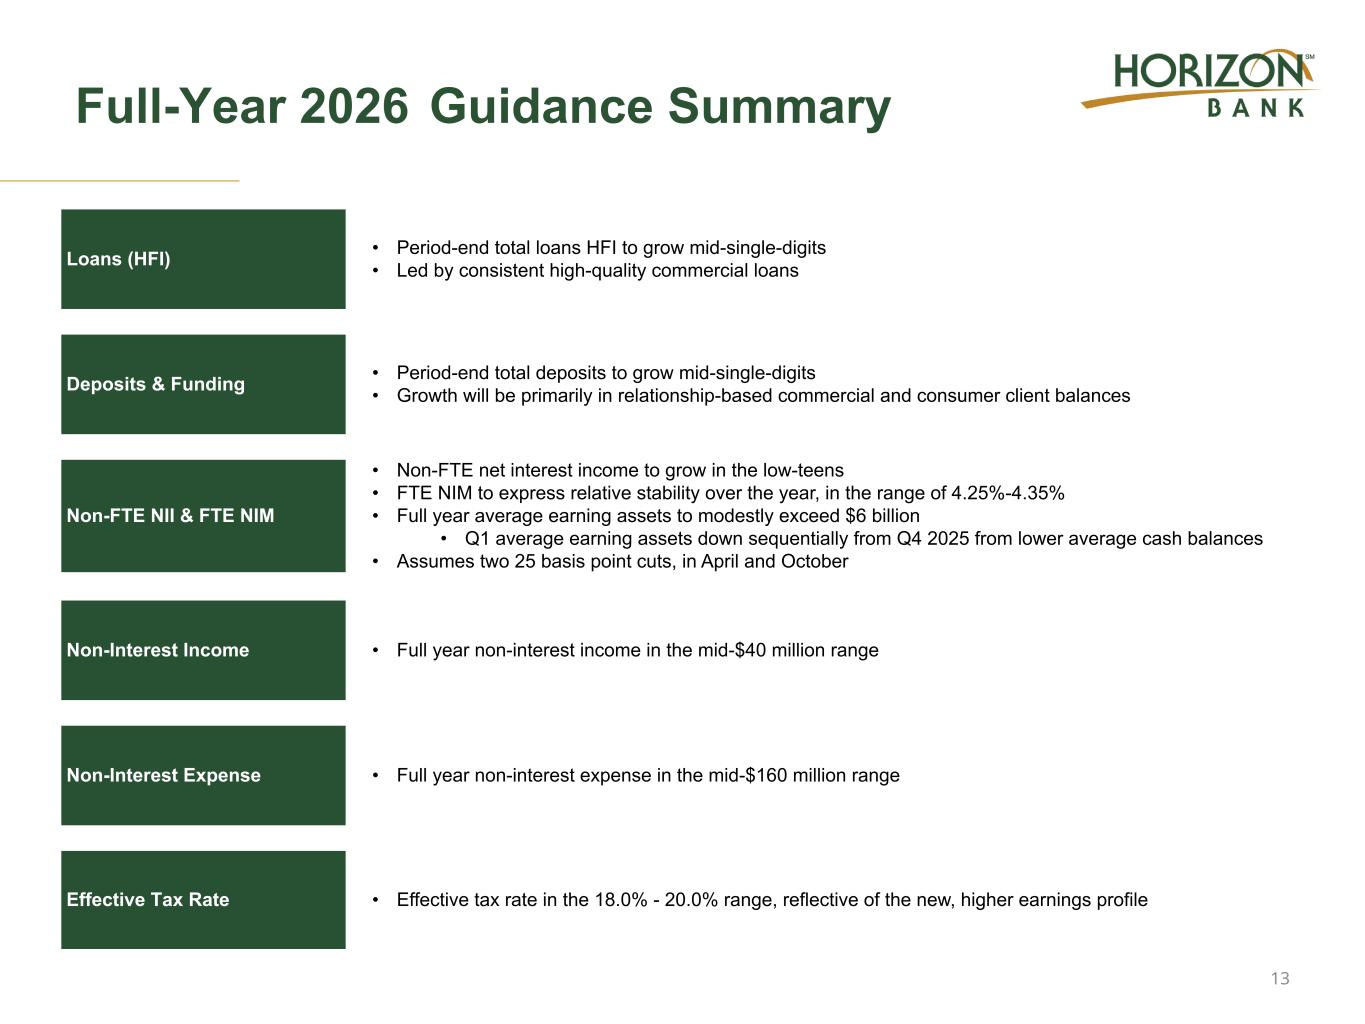
Full-Year 2026 Guidance Summary Loans (HFI) • Period-end total loans HFI to grow mid-single-digits • Led by consistent high-quality commercial loans Deposits & Funding • Period-end total deposits to grow mid-single-digits • Growth will be primarily in relationship-based commercial and consumer client balances Non-FTE NII & FTE NIM • Non-FTE net interest income to grow in the low-teens • FTE NIM to express relative stability over the year, in the range of 4.25%-4.35% • Full year average earning assets to modestly exceed $6 billion • Q1 average earning assets down sequentially from Q4 2025 from lower average cash balances • Assumes two 25 basis point cuts, in April and October Non-Interest Income • Full year non-interest income in the mid-$40 million range Non-Interest Expense • Full year non-interest expense in the mid-$160 million range Effective Tax Rate • Effective tax rate in the 18.0% - 20.0% range, reflective of the new, higher earnings profile 13
Appendix
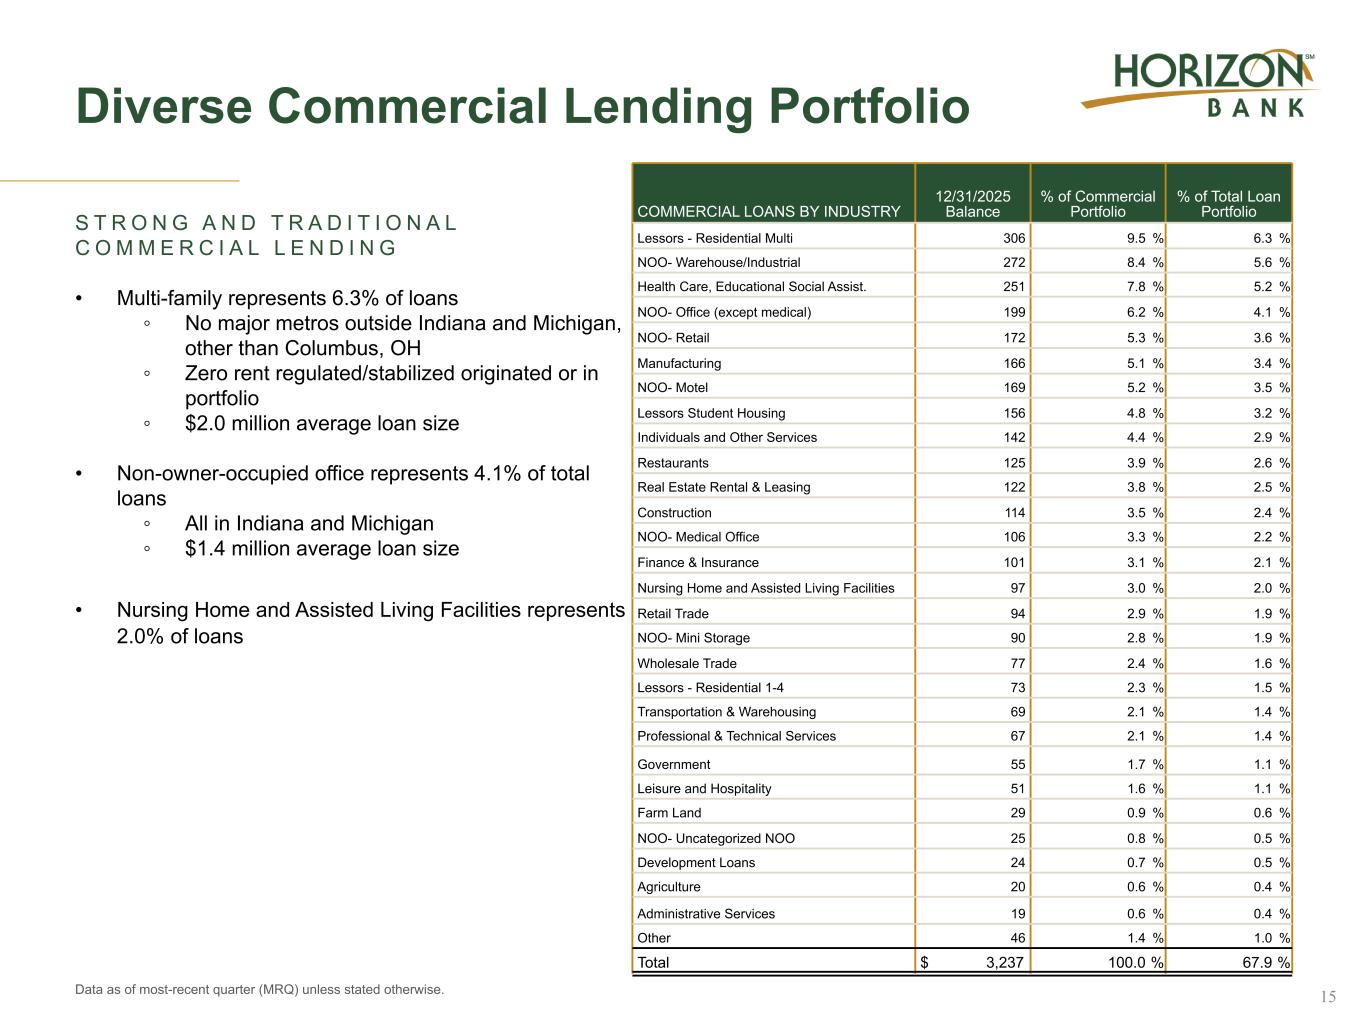
Diverse Commercial Lending Portfolio S T R O N G A N D T R A D I T I O N A L C O M M E R C I A L L E N D I N G • Multi-family represents 6.3% of loans ◦ No major metros outside Indiana and Michigan, other than Columbus, OH ◦ Zero rent regulated/stabilized originated or in portfolio ◦ $2.0 million average loan size • Non-owner-occupied office represents 4.1% of total loans ◦ All in Indiana and Michigan ◦ $1.4 million average loan size • Nursing Home and Assisted Living Facilities represents 2.0% of loans Data as of most-recent quarter (MRQ) unless stated otherwise. 15 COMMERCIAL LOANS BY INDUSTRY 12/31/2025 Balance % of Commercial Portfolio % of Total Loan Portfolio Lessors - Residential Multi 306 9.5 % 6.3 % NOO- Warehouse/Industrial 272 8.4 % 5.6 % Health Care, Educational Social Assist. 251 7.8 % 5.2 % NOO- Office (except medical) 199 6.2 % 4.1 % NOO- Retail 172 5.3 % 3.6 % Manufacturing 166 5.1 % 3.4 % NOO- Motel 169 5.2 % 3.5 % Lessors Student Housing 156 4.8 % 3.2 % Individuals and Other Services 142 4.4 % 2.9 % Restaurants 125 3.9 % 2.6 % Real Estate Rental & Leasing 122 3.8 % 2.5 % Construction 114 3.5 % 2.4 % NOO- Medical Office 106 3.3 % 2.2 % Finance & Insurance 101 3.1 % 2.1 % Nursing Home and Assisted Living Facilities 97 3.0 % 2.0 % Retail Trade 94 2.9 % 1.9 % NOO- Mini Storage 90 2.8 % 1.9 % Wholesale Trade 77 2.4 % 1.6 % Lessors - Residential 1-4 73 2.3 % 1.5 % Transportation & Warehousing 69 2.1 % 1.4 % Professional & Technical Services 67 2.1 % 1.4 % Government 55 1.7 % 1.1 % Leisure and Hospitality 51 1.6 % 1.1 % Farm Land 29 0.9 % 0.6 % NOO- Uncategorized NOO 25 0.8 % 0.5 % Development Loans 24 0.7 % 0.5 % Agriculture 20 0.6 % 0.4 % Administrative Services 19 0.6 % 0.4 % Other 46 1.4 % 1.0 % Total $ 3,237 100.0 % 67.9 %
Use of Non-GAAP Financial Measures Certain information set forth in this press release refers to financial measures determined by methods other than in accordance with GAAP. Specifically, we have included non-GAAP financial measures relating to net income, diluted earnings per share, pre-tax, pre- provision net income, net interest margin, tangible stockholders’ equity and tangible book value per share, efficiency ratio, the return on average assets, the return on average common equity, and return on average tangible equity. In each case, we have identified special circumstances that we consider to be non-recurring and have excluded them. Horizon believes these non-GAAP financial measures are helpful to investors and provide a greater understanding of our business and financial results without giving effect to one-time costs and non–recurring items. These measures are not necessarily comparable to similar measures that may be presented by other companies and should not be considered in isolation or as a substitute for the related GAAP measure. See the tables and other information below and contained elsewhere in this press release for reconciliations of the non-GAAP information identified herein and its most comparable GAAP measures. 16
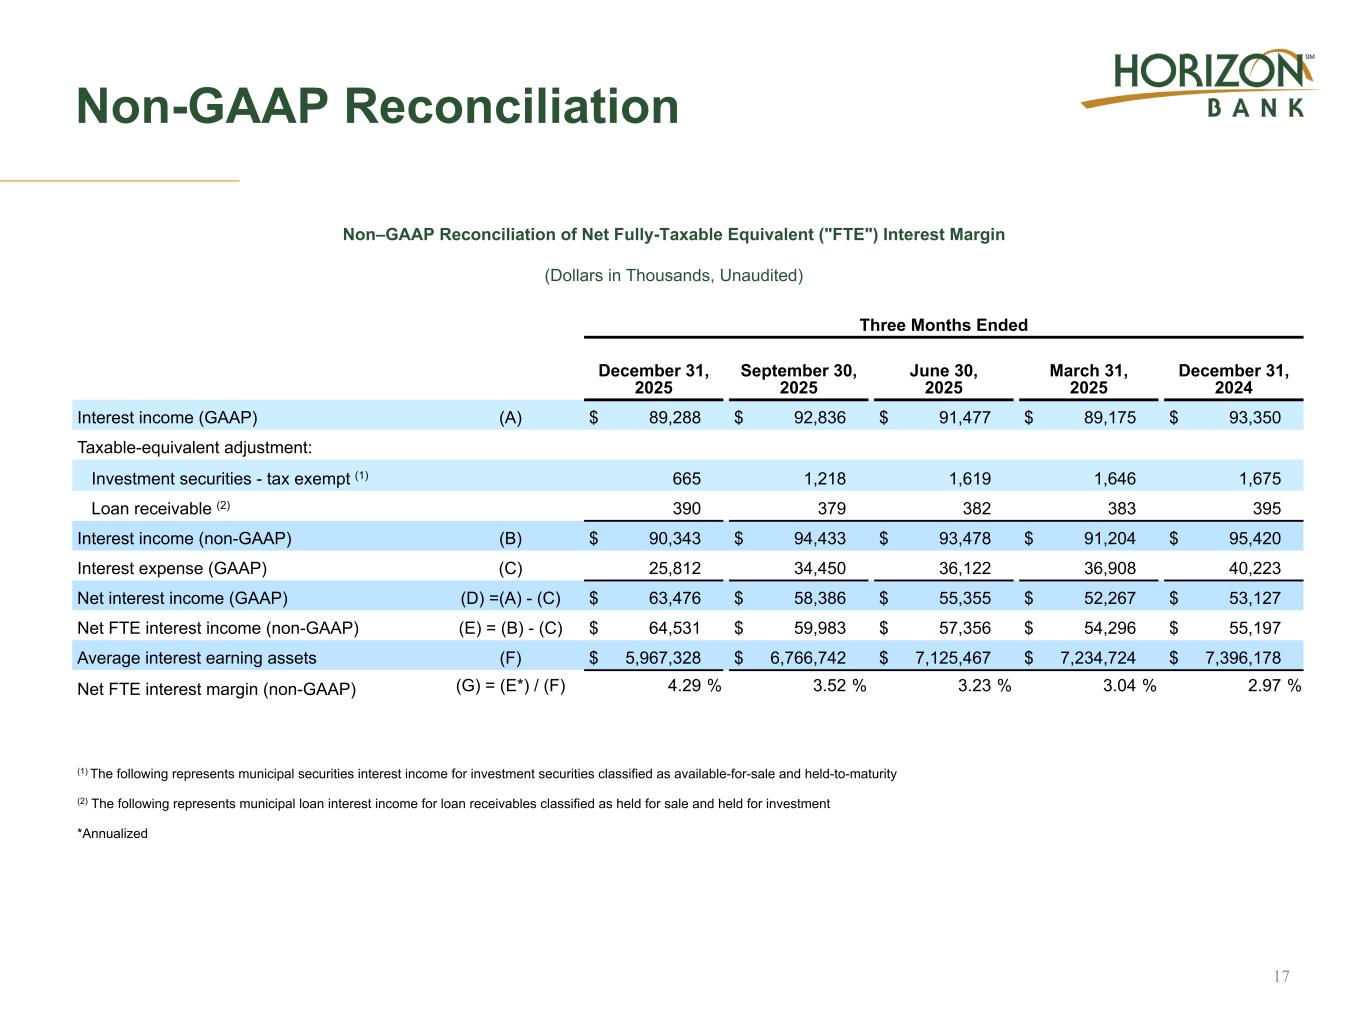
Non-GAAP Reconciliation 17 Three Months Ended December 31, 2025 September 30, 2025 June 30, 2025 March 31, 2025 December 31, 2024 Interest income (GAAP) (A) $ 89,288 $ 92,836 $ 91,477 $ 89,175 $ 93,350 Taxable-equivalent adjustment: Investment securities - tax exempt (1) 665 1,218 1,619 1,646 1,675 Loan receivable (2) 390 379 382 383 395 Interest income (non-GAAP) (B) $ 90,343 $ 94,433 $ 93,478 $ 91,204 $ 95,420 Interest expense (GAAP) (C) 25,812 34,450 36,122 36,908 40,223 Net interest income (GAAP) (D) =(A) - (C) $ 63,476 $ 58,386 $ 55,355 $ 52,267 $ 53,127 Net FTE interest income (non-GAAP) (E) = (B) - (C) $ 64,531 $ 59,983 $ 57,356 $ 54,296 $ 55,197 Average interest earning assets (F) $ 5,967,328 $ 6,766,742 $ 7,125,467 $ 7,234,724 $ 7,396,178 Net FTE interest margin (non-GAAP) (G) = (E*) / (F) 4.29 % 3.52 % 3.23 % 3.04 % 2.97 % (1) The following represents municipal securities interest income for investment securities classified as available-for-sale and held-to-maturity (2) The following represents municipal loan interest income for loan receivables classified as held for sale and held for investment *Annualized Non–GAAP Reconciliation of Net Fully-Taxable Equivalent ("FTE") Interest Margin (Dollars in Thousands, Unaudited)
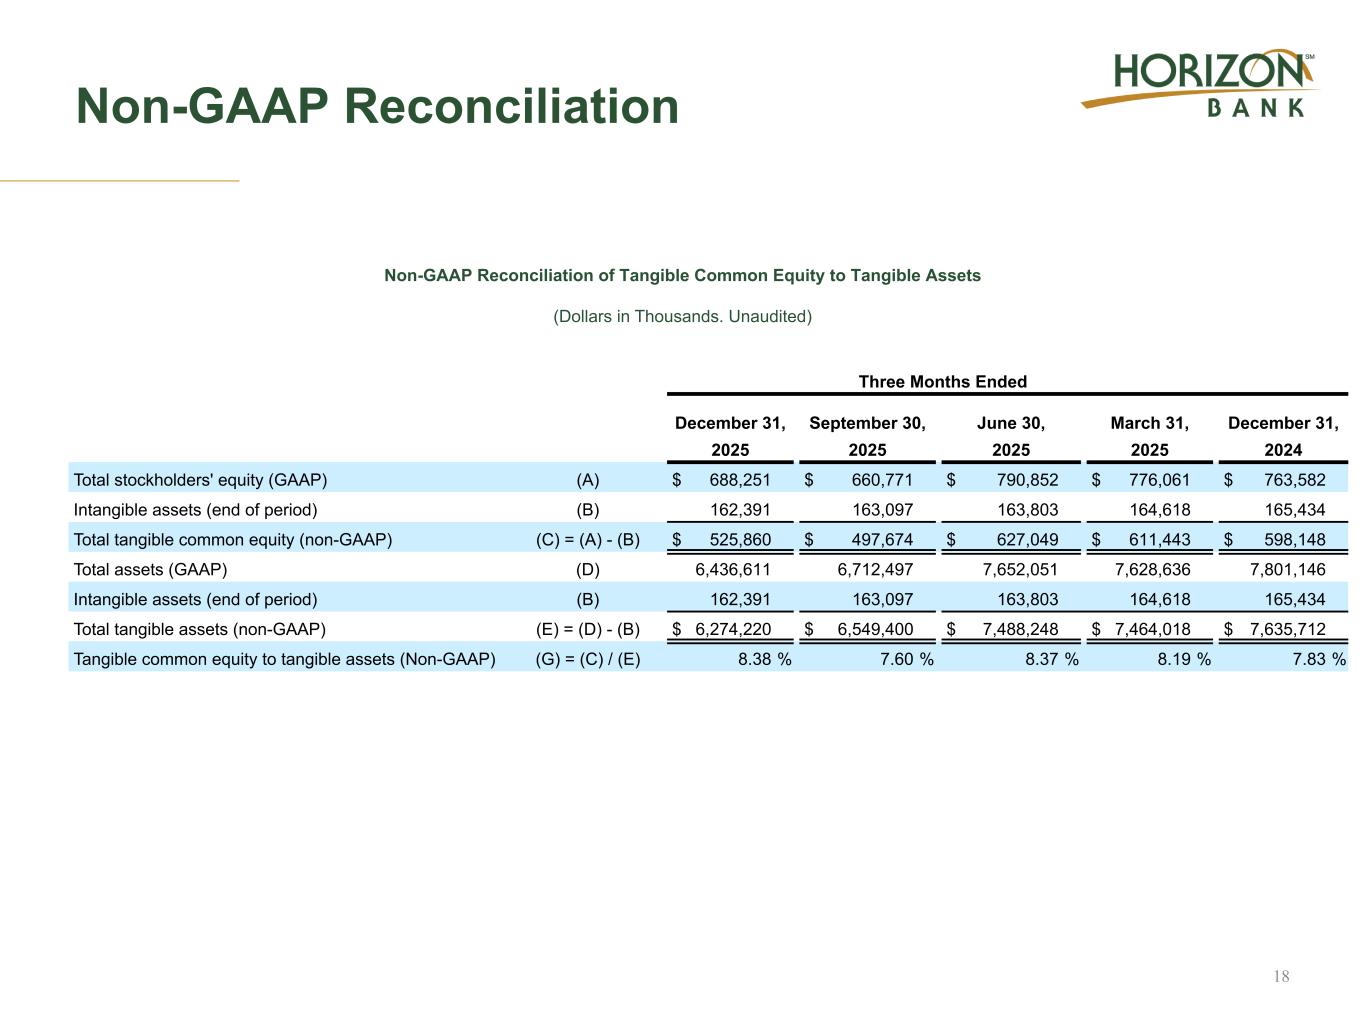
Non-GAAP Reconciliation 18 Three Months Ended December 31, September 30, June 30, March 31, December 31, 2025 2025 2025 2025 2024 Total stockholders' equity (GAAP) (A) $ 688,251 $ 660,771 $ 790,852 $ 776,061 $ 763,582 Intangible assets (end of period) (B) 162,391 163,097 163,803 164,618 165,434 Total tangible common equity (non-GAAP) (C) = (A) - (B) $ 525,860 $ 497,674 $ 627,049 $ 611,443 $ 598,148 Total assets (GAAP) (D) 6,436,611 6,712,497 7,652,051 7,628,636 7,801,146 Intangible assets (end of period) (B) 162,391 163,097 163,803 164,618 165,434 Total tangible assets (non-GAAP) (E) = (D) - (B) $ 6,274,220 $ 6,549,400 $ 7,488,248 $ 7,464,018 $ 7,635,712 Tangible common equity to tangible assets (Non-GAAP) (G) = (C) / (E) 8.38 % 7.60 % 8.37 % 8.19 % 7.83 % Non-GAAP Reconciliation of Tangible Common Equity to Tangible Assets (Dollars in Thousands. Unaudited)
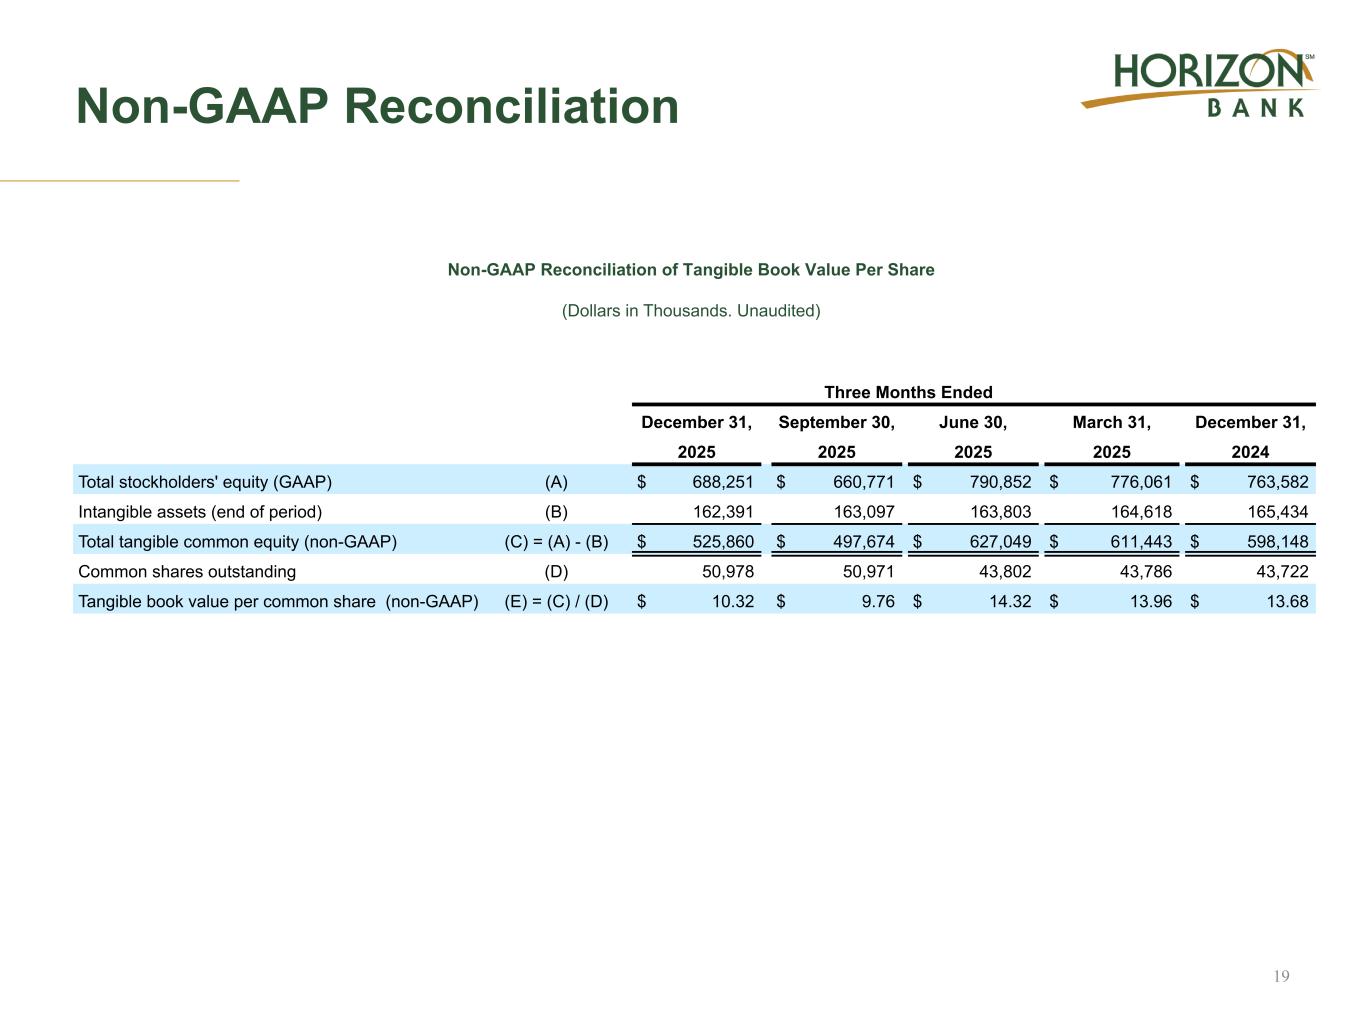
Non-GAAP Reconciliation 19 Three Months Ended December 31, September 30, June 30, March 31, December 31, 2025 2025 2025 2025 2024 Total stockholders' equity (GAAP) (A) $ 688,251 $ 660,771 $ 790,852 $ 776,061 $ 763,582 Intangible assets (end of period) (B) 162,391 163,097 163,803 164,618 165,434 Total tangible common equity (non-GAAP) (C) = (A) - (B) $ 525,860 $ 497,674 $ 627,049 $ 611,443 $ 598,148 Common shares outstanding (D) 50,978 50,971 43,802 43,786 43,722 Tangible book value per common share (non-GAAP) (E) = (C) / (D) $ 10.32 $ 9.76 $ 14.32 $ 13.96 $ 13.68 Non-GAAP Reconciliation of Tangible Book Value Per Share (Dollars in Thousands. Unaudited)
Thank you John R. Stewart, CFA® Executive Vice President & Chief Financial Officer 515 Franklin Street, Michigan City, IN 46360 219-814-5833 Investor.HorizonBank.com