
HBNC 8-K
Horizon Bancorp Inc /In/ (HBNC)
8-K
2021-07-27
For: 2021-07-27
View Original
Added on
April 11, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, DC 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 OR 15(d) of The Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): July 27, 2021
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||
(Address of principal executive offices, including zip code)
(219 ) 879-0211
(Registrant's telephone number, including area code)
Not Applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
1
Item 2.02 Results of Operations and Financial Condition
On July 27, 2021, Horizon Bancorp, Inc. (the “Company”) issued a press release announcing earnings and other financial results for the three month period ended June 30, 2021. A copy of the press release is furnished as Exhibit 99.1 to this report and incorporated here by reference.
Item 7.01 Regulation FD Disclosure
Investor Presentation
The Company has prepared presentation materials (the “Investor Presentation”) that management intends to use during its previously announced Earnings Conference Call on Wednesday, July 28, 2021 at 7:30 a.m. Central Time, and from time to time thereafter in presentations about the Company’s operations and performance. The Investor Presentation also contains information relating to the Company’s COVID–19 response and planning efforts to date. The Company may use the Investor Presentation, possibly with modifications, in presentations to current and potential investors, analysts, lenders, business partners, acquisition candidates, customers, employees and others with an interest in the Company and its business.
A copy of the Investor Presentation is furnished as Exhibit 99.2 to this report and incorporated here by reference. The Investor Presentation is also available on the Company’s investor website at www.horizonbank.com. Materials on the Company’s investor website are not part of or incorporated by reference into this report.
In accordance with General Instruction B.2 of Form 8–K, the information in this Current Report on Form 8–K, including Exhibits 99.1 and 99.2, shall not be deemed to be “filed” for purposes of Section 18 of the Securities and Exchange Act of 1934, as amended (the “Exchange Act”), or otherwise subject to the liability of that section, and shall not be incorporated by reference into any registration statement or other document filed under the Securities Act of 1933, as amended, or the Exchange Act, except as shall be expressly set forth by specific reference in such filing.
Item 9.01 Financial Statements and Exhibits
| (d) Exhibits | |||||||||||
| EXHIBIT INDEX | |||||||||||
| Exhibit No. | Description | Location | |||||||||
| 99.1 | Attached | ||||||||||
| 99.2 | |||||||||||
| 104 | Cover Page Interactive Data File (Embedded within the Inline XBRL document) | Within the Inline XBRL document | |||||||||
2
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| Date: | July 27, 2021 | HORIZON BANCORP, INC. | |||||||||
| By: | /s/ Mark E. Secor | ||||||||||
| Mark E. Secor, | |||||||||||
| Executive Vice President & Chief Financial Officer | |||||||||||
3
| Contract: | Mark E. Secor | ||||
| Chief Financial Officer | |||||
| Phone: | (219) 873-2611 | ||||
| Fax: | (219) 874-9280 | ||||
| Date: | July 27, 2021 | ||||
FOR IMMEDIATE RELEASE
Horizon Bancorp, Inc. Announces Strong Second Quarter 2021
Financial Results Including EPS of $0.50
Michigan City, Indiana, July 27, 2021 (GLOBE NEWSWIRE) — (NASDAQ GS: HBNC) — Horizon Bancorp, Inc. (“Horizon” or the “Company”) announced its unaudited financial results for the three and six months ending June 30, 2021.
“Horizon achieved strong earnings in the second quarter, along with increased non–interest income, stable net interest income, lower deposit costs and strong asset quality metrics,” Chairman and CEO Craig M. Dwight said. “With an improving commercial lending pipeline, and ample liquidity and capital, Horizon is very well positioned for loan growth more in line with historic levels in a recovering economy. We also continue to focus on disciplined management of our highly efficient operations and initiated plans to consolidate 10 locations this summer, reassigning employees to other open positions and investing savings into digital capabilities and opportunities in our growing Indiana and Michigan markets. We also announced the acquisition of 14 Michigan branches to extend our low–cost deposit franchise in a financially and strategically attractive transaction that is on schedule for completion during the third quarter.”
Second Quarter 2021 Highlights
•Net income grew to a record $22.2 million, up 8.6% from the linked quarter and 51.5% from the year–ago period. Diluted earnings per share (“EPS”) of $0.50 includes the $0.01 after–tax impact of expenses associated with Horizon’s agreement to acquire 14 TCF National Bank branches, approximately $976 million in deposits and approximately $278 million in loans in a financially and strategically attractive extension of Horizon’s low–cost deposit franchise in Michigan, announced in the quarter. EPS was $0.46 for the first quarter of 2021 and $0.33 for the second quarter of 2020.
•Pre–tax, pre–provision net income grew to a second–quarter record $24.5 million, up 0.9% from the linked quarter and 3.2% from the year–ago period. This non–GAAP financial measure is utilized by banks to provide a greater understanding of pre–tax profitability before giving effect to credit loss expense. (See the “Non–GAAP Reconciliation of Pre–Tax, Pre–Provision Income” table below.)
•Net interest income was $42.6 million for the quarter, compared to $42.5 million for the first quarter of 2021 and $43.0 million for the second quarter of 2020. Reported net interest margin (“NIM”) was 3.14% and adjusted NIM was 3.13%, with reported NIM declining by 15 basis points and adjusted NIM decreasing by four basis points from the first quarter of 2021. (See the “Non–GAAP Reconciliation of Net Interest Margin” table for the definition of this non–GAAP calculation of adjusted NIM.) An estimated seven basis points attributed to Federal Paycheck Protection Program (“PPP”) lending improved the margin, offset by an estimated 21 basis point compression attributed to excess liquidity held during the quarter, for both NIM and adjusted NIM.
•Horizon’s in–market consumer and commercial deposit relationships, combined with strategic pricing moves to manage deposit growth and runoff of higher–priced time deposits, contributed to continued improvement in the cost of interest bearing liabilities, which declined to 0.45% in the quarter, compared to 0.50% in the first quarter of 2021 and 0.74% in the second quarter of 2020.
1
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
•Non–interest expense was $33.4 million in the quarter, or 2.18% of average assets on an annualized basis, compared to $32.2 million, or 2.20%, in the first quarter of 2021 and $30.4 million, or 2.18%, in the second quarter of 2020.
•The efficiency ratio for the period was 57.73% compared to 57.03% for the first quarter of 2021 and 56.23% for the second quarter of 2020. The adjusted efficiency ratio was 57.45% compared to 57.97% for the first quarter of 2021 and 56.49% for the second quarter of 2020. (See the “Non-GAAP Calculation and Reconciliation of Efficiency Ratio and Adjusted Efficiency Ratio” table below.)
•Horizon experienced an increased return on average assets (“ROAA”) of 1.45% and return on average common equity (“ROACE”) of 12.59% in the quarter, as well as adjusted ROAA of 1.46% and adjusted ROACE of 12.61%, excluding the impact of acquisition expenses and prepayment penalties, net of tax, and death benefits on bank owned life insurance. (See the “Non–GAAP Reconciliation of Return on Average Assets” and the “Non–GAAP Reconciliation of Return on Average Common Equity” tables below.)
•Horizon recorded a provision release of $1.5 million and maintained solid asset quality metrics at period end, including non–performing loans declining 10.9% during the quarter to $22.3 million, or 0.63% of total loans, substandard loans declining 4.6% to $82.5 million, or 2.3% of total loans, net charge–offs declining 81.3% to $39,000, or 0.00% of average loans for the period, and COVID–19 deferrals declining 42.7% to $52.5 million, or 1.5% of total loans.
•Total non–interest income grew to $15.2 million, up 9.6% from the linked quarter and 36.7% from the year–ago period, due to favorable impact of mortgage production, bank owned life insurance, banking fees and fiduciary activities. Following record residential lending in 2020, mortgage–related non–interest income remained strong in the second three months of 2021, with gain on mortgage loan sales of $5.6 million and net mortgage servicing income of $1.5 million. The Horizon Bank (the “Bank”) originated $173.0 million in mortgage loans during the quarter, with 61% of volume from purchases, as Horizon continued to focus residential lending on prime borrowers in Indiana and Michigan markets.
•Loans, excluding PPP lending, totaled $3.36 billion on June 30, 2021, were lower reflecting cash reserves maintained by many current and prospective commercial borrowers and retail households through the quarter. Loans, excluding PPP lending, totaled $3.42 billion on March 31, 2021 and $3.69 billion on June 30, 2020.
•Horizon’s book value per share and tangible book value per share increased to all–time highs of $16.16 and $12.24, respectively. (See the “Non–GAAP Reconciliation of Tangible Stockholders’ Equity and Tangible Book Value per Share” table below.)
•As part of the Company's annual branch performance review and a third–party analysis of the Bank's retail network, Horizon's Board of Directors approved the permanent closure of nine Indiana branch locations and one in Michigan to occur on August 27, 2021.
•Horizon increased cash dividends paid in the quarter by 8.3% to $0.13 per share, as previously announced. As of June 30, 2021, in excess of $129 million in cash was maintained at the holding company, providing considerable future optionality to build shareholder value.
Summary
| For the Three Months Ended | ||||||||||||||||||||
| June 30, | March 31, | June 30, | ||||||||||||||||||
| Net Interest Income and Net Interest Margin | 2021 | 2021 | 2020 | |||||||||||||||||
| Net interest income | $ | 42,632 | $ | 42,538 | $ | 42,996 | ||||||||||||||
| Net interest margin | 3.14 | % | 3.29 | % | 3.47 | % | ||||||||||||||
| Adjusted net interest margin | 3.13 | % | 3.17 | % | 3.35 | % | ||||||||||||||
“Expected net interest margin compression in the second quarter continued to reflect pressure on total earning assets as we invested significant liquidity in lower–yielding assets. This was partially offset by a four basis point increase in average loan yields and a five basis point reduction in our already low average cost of interest bearing liabilities,” Mr. Dwight commented.
2
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
“We continue to believe that Horizon's ample liquidity and capital positions us well to quickly respond to both commercial and consumer credit needs that we expect to accelerate as stimulus dollars are spent down and a recovering economy enhances demand.”
| For the Three Months Ended | ||||||||||||||||||||
| June 30, | March 31, | June 30, | ||||||||||||||||||
| Asset Yields and Funding Costs | 2021 | 2021 | 2020 | |||||||||||||||||
| Interest earning assets | 3.48 | % | 3.66 | % | 4.05 | % | ||||||||||||||
| Interest bearing liabilities | 0.45 | % | 0.50 | % | 0.74 | % | ||||||||||||||
| For the Three Months Ended | ||||||||||||||||||||
| Non–interest Income and | June 30, | March 31, | June 30, | |||||||||||||||||
| Mortgage Banking Income | 2021 | 2021 | 2020 | |||||||||||||||||
| Total non–interest income | $ | 15,207 | $ | 13,873 | $ | 11,125 | ||||||||||||||
| Gain on sale of mortgage loans | 5,612 | 5,296 | 6,620 | |||||||||||||||||
| Mortgage servicing income net of impairment | 1,503 | 213 | (2,760) | |||||||||||||||||
| For the Three Months Ended | ||||||||||||||||||||
| June 30, | March 31, | June 30, | ||||||||||||||||||
| Non–interest Expense | 2021 | 2021 | 2020 | |||||||||||||||||
| Total non–interest expense | $ | 33,388 | $ | 32,172 | $ | 30,432 | ||||||||||||||
| Annualized non–interest expense to average assets | 2.18 | % | 2.20 | % | 2.18 | % | ||||||||||||||
| For the Three Months Ended | ||||||||||||||||||||
| June 30, | March 31, | June 30, | ||||||||||||||||||
| Credit Quality | 2021 | 2021 | 2020 | |||||||||||||||||
| Allowance for credit losses to total loans | 1.58 | % | 1.56 | % | 1.38 | % | ||||||||||||||
| Non–performing loans to total loans | 0.63 | % | 0.68 | % | 0.70 | % | ||||||||||||||
| Percent of net charge–offs to average loans outstanding for the period | 0.00 | % | 0.01 | % | 0.01 | % | ||||||||||||||
| Allowance for | December 31, | Net Reserve | June 30, | |||||||||||||||||||||||
| Credit Losses | 2020 | 1Q20 | 2Q20 | 2021 | ||||||||||||||||||||||
| Commercial | $ | 42,210 | $ | 770 | $ | (1,214) | $ | 41,766 | ||||||||||||||||||
| Retail Mortgage | 4,620 | (391) | (121) | 4,108 | ||||||||||||||||||||||
| Warehouse | 1,267 | (104) | (8) | 1,155 | ||||||||||||||||||||||
| Consumer | 8,930 | (116) | (194) | 8,620 | ||||||||||||||||||||||
| Allowance for Credit Losses (“ACL”) | $ | 57,027 | $ | 159 | $ | (1,537) | $ | 55,649 | ||||||||||||||||||
| ACL / Total Loans | 1.47 | % | 1.58 | % | ||||||||||||||||||||||
| Acquired Loan Discount (“ALD”) | $ | 11,494 | $ | (221) | $ | (815) | $ | 10,458 | ||||||||||||||||||
“Horizon recorded a provision release reflecting continuing economic improvement and the Bank's strong asset quality, including significant reductions in non–performing and substandard loans, net charge–offs and COVID–19 deferral levels in the quarter,” Mr. Dwight said.
3
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
Income Statement Highlights
Net income for the second quarter of 2021 was $22.2 million, or $0.50 diluted earnings per share, compared to $20.4 million, or $0.46, for the linked quarter and $14.6 million, or $0.33, for the prior year period. This represents the highest quarterly net income in the Company’s history, even with the $0.01 after tax effect of second quarter 2021 acquisition expenses.
Adjusted net income for the second quarter of 2021 was $22.2 million, or $0.50 diluted earnings per share, compared to $19.7 million, or $0.44, for the linked quarter and $14.4 million, or $0.32, for the prior year period. Adjusted net income, which is not calculated according to generally accepted accounting principles (“GAAP”), is a measure that Horizon uses to provide a greater understanding of operating profitability.
The increase in net income for the second quarter of 2021 when compared to the first quarter of 2021 reflects an increase in non–interest income of $1.3 million, a decrease of $1.9 million in credit loss expense and an increase in net interest income of $94,000, offset by an increase in non–interest expense of $1.2 million and an increase in income tax expense of $320,000.
Interest income includes the recognition of PPP interest and net loan processing fees totaling $2.7 million in the second quarter of 2021, compared to $3.2 million in the linked quarter. On June 30, 2021, the Company had $5.7 million in deferred PPP loan processing fees outstanding and $169.4 million in PPP loans outstanding. PPP deferred fees and loans outstanding at March 31, 2021 were $7.3 million and $252.3 million, respectively. The processing fees are deferred and recognized over the contractual life of the loan, or accelerated at forgiveness.
Second quarter 2021 income from the gain on sale of mortgage loans totaled $5.6 million, up from $5.3 million in the linked quarter and down from $6.6 million in the prior year period.
Non–interest expense of $33.4 million in the second quarter of 2021 reflected an $859,000 increase in salaries and employee benefits expense, an increase of $518,000 in outside services and consultants, an increase of $309,000 in other expenses, an increase of $285,000 in loan expenses and $242,000 in acquisition expenses, offset by a decrease in FDIC deposit insurance expense of $300,000, a decrease in other losses of $277,000 and a decrease in net occupancy expenses of $234,000, from the linked quarter.
The increase in net income for the second quarter of 2021 when compared to the same prior year period reflects an increase in non–interest income of $4.1 million and a decrease in credit loss expense of $8.5 million, offset by an increase in non–interest expense of $3.0 million, an increase in income tax expense of $1.8 million and a decrease in net interest income of $364,000.
Net income for the first six months of 2021 was $42.6 million, or $0.97 diluted earnings per share, compared to $26.3 million, or $0.59 diluted earnings per share, for the first six months of 2020. Adjusted net income for the first six months of 2021 was $41.9 million, or $0.95 diluted earnings per share, compared to $25.6 million, or $0.57 diluted earnings per share, for the first six months of 2020. The increase in net income for the first six months of 2021 when compared to the same prior year period reflects a decrease in credit loss expense of $16.8 million, an increase in non–interest income of $5.9 million and an increase in net interest income of $1.2 million, offset by an increase in non–interest expense of $4.0 million and an increase in income tax expense of $3.6 million.
4
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Non–GAAP Reconciliation of Net Income | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | June 30, | June 30, | ||||||||||||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||||||
| Net income as reported | $ | 22,173 | $ | 20,422 | $ | 21,893 | $ | 20,312 | $ | 14,639 | $ | 42,595 | $ | 26,294 | ||||||||||||||||||||||||||||||
| Acquisition expenses | 242 | — | — | — | — | 242 | — | |||||||||||||||||||||||||||||||||||||
| Tax effect | (51) | — | — | — | — | (51) | — | |||||||||||||||||||||||||||||||||||||
| Net income excluding acquisition expenses | 22,364 | 20,422 | 21,893 | 20,312 | 14,639 | 42,786 | 26,294 | |||||||||||||||||||||||||||||||||||||
| (Gain) / loss on sale of investment securities | — | (914) | (2,622) | (1,088) | (248) | (914) | (587) | |||||||||||||||||||||||||||||||||||||
| Tax effect | — | 192 | 551 | 228 | 52 | 192 | 123 | |||||||||||||||||||||||||||||||||||||
| Net income excluding (gain) / loss on sale of investment securities | 22,364 | 19,700 | 19,822 | 19,452 | 14,443 | 42,064 | 25,830 | |||||||||||||||||||||||||||||||||||||
| Death benefit on bank owned life insurance (“BOLI”) | (266) | — | — | (31) | — | (266) | (233) | |||||||||||||||||||||||||||||||||||||
| Net income excluding death benefit on BOLI | 22,098 | 19,700 | 19,822 | 19,421 | 14,443 | 41,798 | 25,597 | |||||||||||||||||||||||||||||||||||||
| Prepayment penalties on borrowings | 125 | — | 3,804 | — | — | 125 | — | |||||||||||||||||||||||||||||||||||||
| Tax effect | (26) | — | (799) | — | — | (26) | — | |||||||||||||||||||||||||||||||||||||
| Net income excluding prepayment penalties on borrowings | 22,197 | 19,700 | 22,827 | 19,421 | 14,443 | 41,897 | 25,597 | |||||||||||||||||||||||||||||||||||||
| Adjusted net income | $ | 22,197 | $ | 19,700 | $ | 22,827 | $ | 19,421 | $ | 14,443 | $ | 41,897 | $ | 25,597 | ||||||||||||||||||||||||||||||
5
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Non–GAAP Reconciliation of Diluted Earnings per Share | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | June 30, | June 30, | ||||||||||||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||||||
| Diluted earnings per share (“EPS”) as reported | $ | 0.50 | $ | 0.46 | $ | 0.50 | $ | 0.46 | $ | 0.33 | $ | 0.97 | $ | 0.59 | ||||||||||||||||||||||||||||||
| Acquisition expenses | 0.01 | — | — | — | — | 0.01 | — | |||||||||||||||||||||||||||||||||||||
| Tax effect | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Diluted EPS excluding acquisition expenses | 0.51 | 0.46 | 0.50 | 0.46 | 0.33 | 0.98 | 0.59 | |||||||||||||||||||||||||||||||||||||
| (Gain) / loss on sale of investment securities | — | (0.02) | (0.06) | (0.02) | (0.01) | (0.02) | (0.01) | |||||||||||||||||||||||||||||||||||||
| Tax effect | — | — | 0.01 | 0.01 | — | — | — | |||||||||||||||||||||||||||||||||||||
| Diluted EPS excluding (gain) / loss on sale of investment securities | 0.51 | 0.44 | 0.45 | 0.45 | 0.32 | 0.96 | 0.58 | |||||||||||||||||||||||||||||||||||||
| Death benefit on bank owned life insurance (“BOLI”) | (0.01) | — | — | — | — | (0.01) | (0.01) | |||||||||||||||||||||||||||||||||||||
| Diluted EPS excluding death benefit on BOLI | 0.50 | 0.44 | 0.45 | 0.45 | 0.32 | 0.95 | 0.57 | |||||||||||||||||||||||||||||||||||||
| Prepayment penalties on borrowings | — | — | 0.09 | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Tax effect | — | — | (0.02) | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Diluted EPS excluding prepayment penalties on borrowings | 0.50 | 0.44 | 0.52 | 0.45 | 0.32 | 0.95 | 0.57 | |||||||||||||||||||||||||||||||||||||
| Adjusted diluted EPS | $ | 0.50 | $ | 0.44 | $ | 0.52 | $ | 0.45 | $ | 0.32 | $ | 0.95 | $ | 0.57 | ||||||||||||||||||||||||||||||
| Non–GAAP Reconciliation of Pre–Tax, Pre–Provision Income | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | June 30, | June 30, | ||||||||||||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||||||
| Pre–tax income | $ | 25,943 | $ | 23,872 | $ | 23,860 | $ | 24,638 | $ | 16,632 | $ | 49,815 | $ | 29,871 | ||||||||||||||||||||||||||||||
| Credit loss expense | (1,492) | 367 | 3,042 | 2,052 | 7,057 | (1,125) | 15,657 | |||||||||||||||||||||||||||||||||||||
| Pre–tax, pre–provision income | $ | 24,451 | $ | 24,239 | $ | 26,902 | $ | 26,690 | $ | 23,689 | $ | 48,690 | $ | 45,528 | ||||||||||||||||||||||||||||||
| Pre–tax, pre–provision income | $ | 24,451 | $ | 24,239 | $ | 26,902 | $ | 26,690 | $ | 23,689 | $ | 48,690 | $ | 45,528 | ||||||||||||||||||||||||||||||
| Acquisition expenses | 242 | — | — | — | — | 242 | — | |||||||||||||||||||||||||||||||||||||
| (Gain) / loss on sale of investment securities | — | (914) | (2,622) | (1,088) | (248) | (914) | (587) | |||||||||||||||||||||||||||||||||||||
| Death benefit on BOLI | (266) | — | — | (31) | — | (266) | (233) | |||||||||||||||||||||||||||||||||||||
| Prepayment penalties on borrowings | 125 | — | 3,804 | — | — | 125 | — | |||||||||||||||||||||||||||||||||||||
| Adjusted pre–tax, pre–provision income | $ | 24,552 | $ | 23,325 | $ | 28,084 | $ | 25,571 | $ | 23,441 | $ | 47,752 | $ | 44,708 | ||||||||||||||||||||||||||||||
6
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
Horizon’s net interest margin decreased to 3.14% for the second quarter of 2021 compared to 3.29% for the first quarter of 2021. The decrease in net interest margin reflects a decrease in the yield on interest earning assets of 18 basis points, offset by a decrease in the cost of interest bearing liabilities of five basis points. Interest income from acquisition–related purchase accounting adjustments was $1.3 million lower during the second quarter of 2021 when compared to the first quarter of 2021.
Horizon’s net interest margin decreased to 3.14% for the second quarter of 2021 compared to 3.47% for the second quarter of 2020. The decrease in net interest margin reflects a decrease in the yield on interest earning assets of 57 basis points offset by a decrease in the cost of interest bearing liabilities of 29 basis points.
Horizon’s net interest margin decreased to 3.21% for the first six months of 2021 compared to 3.51% for the same prior year period. The decrease in net interest margin reflects a decrease in the yield on interest earning assets of 68 basis points offset by a decrease in the cost of interest bearing liabilities of 46 basis points.
The net interest margin was impacted during the second and first quarters of 2021 by PPP loans that were originated. Horizon estimates that the PPP loans increased the net interest margin by seven and 10 basis points for the second and first quarters of 2021, respectively. This assumes these PPP loans were not included in average interest earning assets or interest income and were primarily funded by the growth in non–interest bearing deposits.
The net interest margin was also impacted during the second and first quarters of 2021 by excess liquidity carried on the balance sheet through increased deposits. Horizon estimates that the excess liquidity compressed the net interest margin by 21 and 16 basis points for the second and first quarters of 2021, respectively. This assumes that the excess liquidity was not included in average interest earning assets or interest income and was excluded from non–interest bearing deposits.
| Non–GAAP Reconciliation of Net Interest Margin | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | June 30, | June 30, | ||||||||||||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||||||
| Net interest income as reported | $ | 42,632 | $ | 42,538 | $ | 43,622 | $ | 43,397 | $ | 42,996 | $ | 85,170 | $ | 83,921 | ||||||||||||||||||||||||||||||
| Average interest earning assets | 5,659,384 | 5,439,634 | 5,365,888 | 5,251,611 | 5,112,636 | 5,550,116 | 4,929,388 | |||||||||||||||||||||||||||||||||||||
| Net interest income as a percentage of average interest earning assets (“Net Interest Margin”) | 3.14 | % | 3.29 | % | 3.34 | % | 3.39 | % | 3.47 | % | 3.21 | % | 3.51 | % | ||||||||||||||||||||||||||||||
| Net interest income as reported | $ | 42,632 | $ | 42,538 | $ | 43,622 | $ | 43,397 | $ | 42,996 | $ | 85,170 | $ | 83,921 | ||||||||||||||||||||||||||||||
| Acquisition–related purchase accounting adjustments (“PAUs”) | (230) | (1,579) | (2,461) | (1,488) | (1,553) | (1,809) | (2,987) | |||||||||||||||||||||||||||||||||||||
| Prepayment penalties on borrowings | 125 | — | 3,804 | — | — | 125 | — | |||||||||||||||||||||||||||||||||||||
| Adjusted net interest income | $ | 42,527 | $ | 40,959 | $ | 44,965 | $ | 41,909 | $ | 41,443 | $ | 83,361 | $ | 80,934 | ||||||||||||||||||||||||||||||
| Adjusted net interest margin | 3.13 | % | 3.17 | % | 3.44 | % | 3.27 | % | 3.35 | % | 3.15 | % | 3.39 | % | ||||||||||||||||||||||||||||||
Net interest margin, excluding acquisition–related purchase accounting adjustments (“adjusted net interest margin”), was 3.13% for the second quarter of 2021, compared to 3.17% for the linked quarter and 3.35% for the second quarter of 2020. Interest income from acquisition–related purchase accounting adjustments was $230,000, $1.6 million and $1.6 million for the three months ended June 30, 2021, March 31, 2021 and June 30, 2020, respectively.
The adjusted net interest margin was 3.15% for the first six months of 2021 compared to 3.39% for the same prior year period. Interest income from acquisition–related purchase accounting adjustments was $1.8 million and $3.0 million for the six months ended June 30, 2021 and 2020, respectively.
7
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
Lending Activity
Total loans were $3.53 billion, or $3.36 billion excluding PPP loans, on June 30, 2021. Total loans were $3.67 billion, or $3.42 billion excluding PPP loans, on March 31, 2021. During the three months ended June 30, 2021, PPP loans decreased $82.8 million, mortgage warehouse loans decreased $60.9 million, residential mortgage loans decreased $22.5 million and loans held for sale decreased $570,000, offset by an increase in consumer loans of $11.7 million and an increase in commercial loans, excluding PPP loans, of $9.6 million.
| Loan Growth by Type, Excluding Acquired Loans | ||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||
| June 30, | March 31, | Amount | Percent | |||||||||||||||||||||||
| 2021 | 2021 | Change | Change | |||||||||||||||||||||||
| Commercial, excluding PPP loans | $ | 1,935,187 | $ | 1,925,576 | $ | 9,611 | 0.5% | |||||||||||||||||||
| PPP loans | 169,440 | 252,282 | (82,842) | (32.8)% | ||||||||||||||||||||||
| Residential mortgage | 559,437 | 581,929 | (22,492) | (3.9)% | ||||||||||||||||||||||
| Consumer | 650,144 | 638,403 | 11,741 | 1.8% | ||||||||||||||||||||||
| Subtotal | 3,314,208 | 3,398,190 | (83,982) | (2.5)% | ||||||||||||||||||||||
| Loans held for sale | 7,228 | 7,798 | (570) | (7.3)% | ||||||||||||||||||||||
| Mortgage warehouse | 205,311 | 266,246 | (60,935) | (22.9)% | ||||||||||||||||||||||
| Total loans | $ | 3,526,747 | $ | 3,672,234 | $ | (145,487) | (4.0)% | |||||||||||||||||||
Residential mortgage lending activity for the three months ended June 30, 2021 generated $5.6 million in income from the gain on sale of mortgage loans, increasing $316,000 from the first quarter of 2021 and decreasing $1.0 million from the second quarter of 2020. Total origination volume for the second quarter of 2021, including loans placed into the portfolio, totaled $173.0 million, representing an increase of 11.2% from first quarter 2021 levels, and a decrease of 31.6% from the second quarter of 2020. As a percentage of total originations, 39% of the volume was for refinances and 61% was for new purchases during the second quarter of 2021. Total origination volume of loans sold to the secondary market totaled $113.2 million, representing a decrease of 10.2% from the first quarter of 2021 and a decrease of 41.2% from the second quarter of 2020.
Revenue derived from Horizon's residential mortgage and mortgage warehouse lending activities was 12% for the three months ended June 30, 2021, compared to 14% for the linked quarter and 15% for the three months ended June 30, 2020.
8
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
Expense Management
| Three Months Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||
| June 30, | March 31, | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2021 | 2021 | Adjusted | ||||||||||||||||||||||||||||||||||||||||||||||||
| Non–interest Expense | Actual | Acquisition Expenses | Adjusted | Actual | Acquisition Expenses | Adjusted | Amount Change | Percent Change | ||||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | $ | 17,730 | $ | — | $ | 17,730 | $ | 16,871 | $ | — | $ | 16,871 | $ | 859 | 5.1% | |||||||||||||||||||||||||||||||||||
| Net occupancy expenses | 3,084 | — | 3,084 | 3,318 | — | 3,318 | (234) | (7.1)% | ||||||||||||||||||||||||||||||||||||||||||
| Data processing | 2,388 | — | 2,388 | 2,376 | — | 2,376 | 12 | 0.5% | ||||||||||||||||||||||||||||||||||||||||||
| Professional fees | 588 | (51) | 537 | 544 | — | 544 | (7) | (1.3)% | ||||||||||||||||||||||||||||||||||||||||||
| Outside services and consultants | 2,220 | (187) | 2,033 | 1,702 | — | 1,702 | 331 | 19.4% | ||||||||||||||||||||||||||||||||||||||||||
| Loan expense | 3,107 | — | 3,107 | 2,822 | — | 2,822 | 285 | 10.1% | ||||||||||||||||||||||||||||||||||||||||||
| FDIC insurance expense | 500 | — | 500 | 800 | — | 800 | (300) | (37.5)% | ||||||||||||||||||||||||||||||||||||||||||
| Other losses | 6 | — | 6 | 283 | — | 283 | (277) | (97.9)% | ||||||||||||||||||||||||||||||||||||||||||
| Other expense | 3,765 | (4) | 3,761 | 3,456 | — | 3,456 | 305 | 8.8% | ||||||||||||||||||||||||||||||||||||||||||
| Total non–interest expense | $ | 33,388 | $ | (242) | $ | 33,146 | $ | 32,172 | $ | — | $ | 32,172 | $ | 974 | 3.0% | |||||||||||||||||||||||||||||||||||
| Annualized non–interest expense to average assets | 2.18 | % | 2.16 | % | 2.20 | % | 2.20 | % | ||||||||||||||||||||||||||||||||||||||||||
Total non–interest expense was $1.2 million higher in the second quarter of 2021 when compared to the first quarter of 2021. The increase in expenses was primarily due to an increase in salaries and employee benefits of $859,000, an increase in outside services and consultants of $518,000, an increase in other expenses of $309,000 and an increase in loan expense of $285,000, offset by decreases in FDIC insurance expense of $300,000, other losses of $277,000 and net occupancy of $234,000. The increase in salaries and employee benefits expense was due to a decrease of $581,000 in deferred loan origination costs and an increase of $272,000 in health insurance expense. Excluding acquisition expenses, total non–interest expense increased by $974,000 in the second quarter of 2021 when compared to the first quarter of 2021.
| Three Months Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||
| June 30, | June 30, | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2021 | 2020 | Adjusted | ||||||||||||||||||||||||||||||||||||||||||||||||
| Non–interest Expense | Actual | Acquisition Expenses | Adjusted | Actual | Acquisition Expenses | Adjusted | Amount Change | Percent Change | ||||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | $ | 17,730 | $ | — | $ | 17,730 | $ | 15,629 | $ | — | $ | 15,629 | $ | 2,101 | 13.4% | |||||||||||||||||||||||||||||||||||
| Net occupancy expenses | 3,084 | — | 3,084 | 3,190 | — | 3,190 | (106) | (3.3)% | ||||||||||||||||||||||||||||||||||||||||||
| Data processing | 2,388 | — | 2,388 | 2,432 | — | 2,432 | (44) | (1.8)% | ||||||||||||||||||||||||||||||||||||||||||
| Professional fees | 588 | (51) | 537 | 518 | — | 518 | 19 | 3.7% | ||||||||||||||||||||||||||||||||||||||||||
| Outside services and consultants | 2,220 | (187) | 2,033 | 1,759 | — | 1,759 | 274 | 15.6% | ||||||||||||||||||||||||||||||||||||||||||
| Loan expense | 3,107 | — | 3,107 | 2,692 | — | 2,692 | 415 | 15.4% | ||||||||||||||||||||||||||||||||||||||||||
| FDIC insurance expense | 500 | — | 500 | 235 | — | 235 | 265 | 112.8% | ||||||||||||||||||||||||||||||||||||||||||
| Other losses | 6 | — | 6 | 193 | — | 193 | (187) | (96.9)% | ||||||||||||||||||||||||||||||||||||||||||
| Other expense | 3,765 | (4) | 3,761 | 3,784 | — | 3,784 | (23) | (0.6)% | ||||||||||||||||||||||||||||||||||||||||||
| Total non–interest expense | $ | 33,388 | $ | (242) | $ | 33,146 | $ | 30,432 | $ | — | $ | 30,432 | $ | 2,714 | 8.9% | |||||||||||||||||||||||||||||||||||
| Annualized non–interest expense to average assets | 2.18 | % | 2.16 | % | 2.18 | % | 2.18 | % | ||||||||||||||||||||||||||||||||||||||||||
Total non–interest expense was $3.0 million higher in the second quarter of 2021 when compared to the second quarter of 2020. Increases in salaries and employee benefits, outside services and consultants, loan expense and FDIC insurance expense were offset in part by decreases in other losses and net occupancy expenses. Excluding acquisition expenses, total non–interest expense increased by $2.7 million in the second quarter when compared to the same prior year period.
9
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Six Months Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||
| June 30, | June 30, | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2021 | 2020 | Adjusted | ||||||||||||||||||||||||||||||||||||||||||||||||
| Non–interest Expense | Actual | Acquisition Expenses | Adjusted | Actual | Acquisition Expenses | Adjusted | Amount Change | Percent Change | ||||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | $ | 34,601 | $ | — | $ | 34,601 | $ | 32,220 | $ | — | $ | 32,220 | $ | 2,381 | 7.4% | |||||||||||||||||||||||||||||||||||
| Net occupancy expenses | 6,402 | — | 6,402 | 6,442 | — | 6,442 | (40) | (0.6)% | ||||||||||||||||||||||||||||||||||||||||||
| Data processing | 4,764 | — | 4,764 | 4,837 | — | 4,837 | (73) | (1.5)% | ||||||||||||||||||||||||||||||||||||||||||
| Professional fees | 1,132 | (51) | 1,081 | 1,054 | — | 1,054 | 27 | 2.6% | ||||||||||||||||||||||||||||||||||||||||||
| Outside services and consultants | 3,922 | (187) | 3,735 | 3,674 | — | 3,674 | 61 | 1.7% | ||||||||||||||||||||||||||||||||||||||||||
| Loan expense | 5,929 | — | 5,929 | 4,791 | — | 4,791 | 1,138 | 23.8% | ||||||||||||||||||||||||||||||||||||||||||
| FDIC insurance expense | 1,300 | — | 1,300 | 385 | — | 385 | 915 | 237.7% | ||||||||||||||||||||||||||||||||||||||||||
| Other losses | 289 | — | 289 | 313 | — | 313 | (24) | (7.7)% | ||||||||||||||||||||||||||||||||||||||||||
| Other expense | 7,221 | (4) | 7,217 | 7,865 | — | 7,865 | (648) | (8.2)% | ||||||||||||||||||||||||||||||||||||||||||
| Total non–interest expense | $ | 65,560 | $ | (242) | $ | 65,318 | $ | 61,581 | $ | — | $ | 61,581 | $ | 3,737 | 6.1% | |||||||||||||||||||||||||||||||||||
| Annualized non–interest expense to average assets | 2.19 | % | 2.18 | % | 2.28 | % | 2.28 | % | ||||||||||||||||||||||||||||||||||||||||||
Total non–interest expense was $4.0 million higher for the first six months of 2021 when compared to the same prior year period. Increases in salaries and employee benefits, loan expenses and FDIC insurance expense were offset in part by a decrease in other expense. Excluding acquisition expenses, total non–interest expense increased $3.7 million for the first six months of 2021 when compared to the same prior year period.
Annualized non–interest expense as a percent of average assets was 2.18%, 2.20% and 2.18% for the three months ended June 30, 2021, March 31, 2021 and June 30, 2020, respectively. Annualized non–interest expense, excluding acquisition expenses, as a percent of average assets was 2.16%, 2.20% and 2.18% for the three months ended June 30, 2021, March 31, 2021 and June 30, 2020, respectively.
Annualized non–interest expense as a percent of average assets was 2.19% and 2.28% for the six months ended June 30, 2021 and 2020, respectively. Annualized non–interest expense, excluding acquisition expenses, as a percentage of average assets was 2.18% and 2.28% for the six months ended June 30, 2021 and 2020, respectively.
Income tax expense totaled $3.8 million for the second quarter of 2021, an increase of $320,000 when compared to the first quarter of 2021 and an increase of $1.8 million when compared to the second quarter of 2020. The increase in income tax expense in the second quarter of 2021 compared to both periods was primarily due to increases in income before tax expense.
Income tax expense totaled $7.2 million for the six months ended June 30, 2021, an increase of $3.6 million when compared to the six months ended June 30, 2020. The increase in income tax expense was primarily due to an increase in income before taxes of $19.9 million.
Capital
The capital resources of the Company and the Bank exceeded regulatory capital ratios for “well capitalized” banks at June 30, 2021. Stockholders’ equity totaled $710.4 million at June 30, 2021 and the ratio of average stockholders’ equity to average assets was 11.62% for the six months ended June 30, 2021.
Capital levels benefited from the Company’s previously disclosed public offering of subordinated notes raising $60.0 million in June 2020. Horizon’s fortress balance sheet at June 30, 2021 maintained adequate regulatory capital ratios when stress testing for highly adverse scenarios.
10
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
The following table presents the actual regulatory capital dollar amounts and ratios of the Company and the Bank as of June 30, 2021.
| Actual | Required for Capital Adequacy Purposes | Required for Capital Adequacy Purposes with Capital Buffer | Well Capitalized Under Prompt Corrective Action Provisions | |||||||||||||||||||||||||||||||||||||||||||||||
| Amount | Ratio | Amount | Ratio | Amount | Ratio | Amount | Ratio | |||||||||||||||||||||||||||||||||||||||||||
| Total capital (to risk–weighted assets) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Consolidated | $ | 687,957 | 16.65 | % | $ | 330,550 | 8.00 | % | $ | 433,847 | 10.50 | % | N/A | N/A | ||||||||||||||||||||||||||||||||||||
| Bank | 562,810 | 13.59 | % | 331,308 | 8.00 | % | 434,842 | 10.50 | % | $ | 414,135 | 10.00 | % | |||||||||||||||||||||||||||||||||||||
| Tier 1 capital (to risk–weighted assets) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Consolidated | 634,359 | 15.35 | % | 247,958 | 6.00 | % | 351,274 | 8.50 | % | N/A | N/A | |||||||||||||||||||||||||||||||||||||||
| Bank | 510,983 | 12.34 | % | 248,452 | 6.00 | % | 351,974 | 8.50 | % | 331,269 | 8.00 | % | ||||||||||||||||||||||||||||||||||||||
| Common equity tier 1 capital (to risk–weighted assets) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Consolidated | 519,058 | 12.56 | % | 185,968 | 4.50 | % | 289,284 | 7.00 | % | N/A | N/A | |||||||||||||||||||||||||||||||||||||||
| Bank | 510,983 | 12.34 | % | 186,339 | 4.50 | % | 289,861 | 7.00 | % | 269,156 | 6.50 | % | ||||||||||||||||||||||||||||||||||||||
| Tier 1 capital (to average assets) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Consolidated | 634,359 | 10.76 | % | 235,821 | 4.00 | % | 235,821 | 4.00 | % | N/A | N/A | |||||||||||||||||||||||||||||||||||||||
| Bank | 510,983 | 8.72 | % | 234,396 | 4.00 | % | 234,396 | 4.00 | % | 292,995 | 5.00 | % | ||||||||||||||||||||||||||||||||||||||
Liquidity
The Bank maintains a stable base of core deposits provided by long–standing relationships with individuals and local businesses. These deposits are the principal source of liquidity for Horizon. Other sources of liquidity for Horizon include earnings, loan repayment, investment security sales and maturities, proceeds from the sale of residential mortgage loans, unpledged investment securities and borrowing relationships with correspondent banks, including the Federal Home Loan Bank of Indianapolis (the “FHLB”). At June 30, 2021, in addition to liquidity available from the normal operating, funding, and investing activities of Horizon, the Bank had approximately $890.6 million in unused credit lines with various money center banks, including the FHLB and the Federal Reserve Discount Window. The Bank had approximately $1.187 billion of unpledged investment securities at June 30, 2021.
Branch Network and Customer Experience
Horizon continues to implement its disciplined approach to enhancing the efficiency of its branch network on an ongoing basis, while leveraging technology to enhance the customer experience. Following management's annual review of branch performance for potential closure and a third–party consulting firm’s review of the Bank's physical branch network and strategy, Horizon’s Board of Directors approved the permanent closure on August 27, 2021 of nine branch locations in Indiana and one office in Michigan. At the same time, the Bank continues to invest in its Midwest footprint. On May 25, 2021, Horizon announced it agreed to acquire 14 TCF National Bank branches with approximately $976 million in deposits and $278 million in associated loans in a financially and strategically attractive extension of the Bank's low–cost deposit franchise in Michigan. Horizon expects to close the transaction during the third quarter of 2021.
11
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
Use of Non–GAAP Financial Measures
Certain information set forth in this press release refers to financial measures determined by methods other than in accordance with GAAP. Specifically, we have included non–GAAP financial measures relating to net income, diluted earnings per share, net interest margin, total loans and loan growth, the allowance for credit losses, tangible stockholders’ equity, tangible book value per share, efficiency ratio, the return on average assets, the return on average equity and pre–tax, pre–provision income. In each case, we have identified special circumstances that we consider to be non–recurring and have excluded them. We believe that this shows the impact of such events as acquisition–related purchase accounting adjustments, among others we have identified in our reconciliations. Horizon believes these non–GAAP financial measures are helpful to investors and provide a greater understanding of our business without giving effect to the purchase accounting impacts and one–time costs of acquisitions and non–recurring items. These measures are not necessarily comparable to similar measures that may be presented by other companies and should not be considered in isolation or as a substitute for the related GAAP measure. See the tables and other information below and contained elsewhere in this press release for reconciliations of the non–GAAP information identified herein and its most comparable GAAP measures.
| Non–GAAP Reconciliation of Tangible Stockholders’ Equity and Tangible Book Value per Share | ||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Total stockholders’ equity | $ | 710,374 | $ | 689,379 | $ | 692,216 | $ | 670,293 | $ | 652,206 | ||||||||||||||||||||||
| Less: Intangible assets | 172,398 | 173,296 | 174,193 | 175,107 | 176,020 | |||||||||||||||||||||||||||
| Total tangible stockholders’ equity | $ | 537,976 | $ | 516,083 | $ | 518,023 | $ | 495,186 | $ | 476,186 | ||||||||||||||||||||||
| Common shares outstanding | 43,950,720 | 43,949,189 | 43,880,562 | 43,874,353 | 43,821,878 | |||||||||||||||||||||||||||
| Book value per common share | $ | 16.16 | $ | 15.69 | $ | 15.78 | $ | 15.28 | $ | 14.88 | ||||||||||||||||||||||
| Tangible book value per common share | $ | 12.24 | $ | 11.74 | $ | 11.81 | $ | 11.29 | $ | 10.87 | ||||||||||||||||||||||
12
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Non–GAAP Calculation and Reconciliation of Efficiency Ratio and Adjusted Efficiency Ratio | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | June 30, | June 30, | ||||||||||||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||||||
| Non–interest expense as reported | $ | 33,388 | $ | 32,172 | $ | 36,453 | $ | 33,407 | $ | 30,432 | $ | 65,560 | $ | 61,581 | ||||||||||||||||||||||||||||||
| Net interest income as reported | 42,632 | 42,538 | 43,622 | 43,397 | 42,996 | 85,170 | 83,921 | |||||||||||||||||||||||||||||||||||||
| Non–interest income as reported | $ | 15,207 | $ | 13,873 | $ | 19,733 | $ | 16,700 | $ | 11,125 | $ | 29,080 | $ | 23,188 | ||||||||||||||||||||||||||||||
| Non–interest expense / (Net interest income + Non–interest income) (“Efficiency Ratio”) | 57.73 | % | 57.03 | % | 57.54 | % | 55.59 | % | 56.23 | % | 57.38 | % | 57.49 | % | ||||||||||||||||||||||||||||||
| Non–interest expense as reported | $ | 33,388 | $ | 32,172 | $ | 36,453 | $ | 33,407 | $ | 30,432 | $ | 65,560 | $ | 61,581 | ||||||||||||||||||||||||||||||
| Acquisition expenses | (242) | — | — | — | — | (242) | — | |||||||||||||||||||||||||||||||||||||
| Non–interest expense excluding acquisition expenses | 33,146 | 32,172 | 36,453 | 33,407 | 30,432 | 65,318 | 61,581 | |||||||||||||||||||||||||||||||||||||
| Net interest income as reported | 42,632 | 42,538 | 43,622 | 43,397 | 42,996 | 85,170 | 83,921 | |||||||||||||||||||||||||||||||||||||
| Prepayment penalties on borrowings | 125 | — | 3,804 | — | — | 125 | — | |||||||||||||||||||||||||||||||||||||
| Net interest income excluding prepayment penalties on borrowings | 42,757 | 42,538 | 47,426 | 43,397 | 42,996 | 85,295 | 83,921 | |||||||||||||||||||||||||||||||||||||
| Non–interest income as reported | 15,207 | 13,873 | 19,733 | 16,700 | 11,125 | 29,080 | 23,188 | |||||||||||||||||||||||||||||||||||||
| (Gain) / loss on sale of investment securities | — | (914) | (2,622) | (1,088) | (248) | (914) | (587) | |||||||||||||||||||||||||||||||||||||
| Death benefit on BOLI | (266) | — | — | (31) | — | (266) | (233) | |||||||||||||||||||||||||||||||||||||
| Non–interest income excluding (gain) / loss on sale of investment securities and death benefit on BOLI | $ | 14,941 | $ | 12,959 | $ | 17,111 | $ | 15,581 | $ | 10,877 | $ | 27,900 | $ | 22,368 | ||||||||||||||||||||||||||||||
| Adjusted efficiency ratio | 57.45 | % | 57.97 | % | 56.48 | % | 56.64 | % | 56.49 | % | 57.70 | % | 57.94 | % | ||||||||||||||||||||||||||||||
13
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Non–GAAP Reconciliation of Return on Average Assets | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | June 30, | June 30, | ||||||||||||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||||||
| Average assets | $ | 6,142,507 | $ | 5,936,149 | $ | 5,864,086 | $ | 5,768,691 | $ | 5,620,695 | $ | 6,039,897 | $ | 5,433,187 | ||||||||||||||||||||||||||||||
| Return on average assets (“ROAA”) as reported | 1.45 | % | 1.40 | % | 1.49 | % | 1.40 | % | 1.05 | % | 1.42 | % | 0.97 | % | ||||||||||||||||||||||||||||||
| Acquisition expenses | 0.02 | — | — | — | — | 0.01 | — | |||||||||||||||||||||||||||||||||||||
| Tax effect | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| ROAA excluding acquisition expenses | 1.47 | 1.40 | 1.49 | 1.40 | 1.05 | 1.43 | 0.97 | |||||||||||||||||||||||||||||||||||||
| (Gain) / loss on sale of investment securities | — | (0.06) | (0.18) | (0.08) | (0.02) | (0.03) | (0.02) | |||||||||||||||||||||||||||||||||||||
| Tax effect | — | 0.01 | 0.04 | 0.02 | — | 0.01 | — | |||||||||||||||||||||||||||||||||||||
| ROAA excluding (gain) / loss on sale of investment securities | 1.47 | 1.35 | 1.35 | 1.34 | 1.03 | 1.41 | 0.95 | |||||||||||||||||||||||||||||||||||||
| Death benefit on BOLI | (0.02) | — | — | — | — | (0.01) | (0.01) | |||||||||||||||||||||||||||||||||||||
| ROAA excluding death benefit on BOLI | 1.45 | 1.35 | 1.35 | 1.34 | 1.03 | 1.40 | 0.94 | |||||||||||||||||||||||||||||||||||||
| Prepayment penalties on borrowings | 0.01 | — | 0.26 | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Tax effect | — | — | (0.05) | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| ROAA excluding prepayment penalties on borrowings | 1.46 | 1.35 | 1.56 | 1.34 | 1.03 | 1.40 | 0.94 | |||||||||||||||||||||||||||||||||||||
| Adjusted ROAA | 1.46 | % | 1.35 | % | 1.56 | % | 1.34 | % | 1.03 | % | 1.40 | % | 0.94 | % | ||||||||||||||||||||||||||||||
14
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Non–GAAP Reconciliation of Return on Average Common Equity | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | June 30, | June 30, | ||||||||||||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||||||
| Average common equity | $ | 706,652 | $ | 697,401 | $ | 680,857 | $ | 668,797 | $ | 649,490 | $ | 702,052 | $ | 655,538 | ||||||||||||||||||||||||||||||
| Return on average common equity (“ROACE”) as reported | 12.59 | % | 11.88 | % | 12.79 | % | 12.08 | % | 9.07 | % | 12.23 | % | 8.07 | % | ||||||||||||||||||||||||||||||
| Acquisition expenses | 0.14 | — | — | — | — | 0.07 | — | |||||||||||||||||||||||||||||||||||||
| Tax effect | (0.03) | — | — | — | — | (0.01) | — | |||||||||||||||||||||||||||||||||||||
| ROACE excluding acquisition expenses | 12.70 | 11.88 | 12.79 | 12.08 | 9.07 | 12.29 | 8.07 | |||||||||||||||||||||||||||||||||||||
| (Gain) / loss on sale of investment securities | — | (0.53) | (1.53) | (0.65) | (0.15) | (0.26) | (0.18) | |||||||||||||||||||||||||||||||||||||
| Tax effect | — | 0.11 | 0.32 | 0.14 | 0.03 | 0.06 | 0.04 | |||||||||||||||||||||||||||||||||||||
| ROACE excluding (gain) / loss on sale of investment securities | 12.70 | 11.46 | 11.58 | 11.57 | 8.95 | 12.09 | 7.93 | |||||||||||||||||||||||||||||||||||||
| Death benefit on BOLI | (0.15) | — | — | (0.02) | — | (0.08) | (0.07) | |||||||||||||||||||||||||||||||||||||
| ROACE excluding death benefit on BOLI | 12.55 | 11.46 | 11.58 | 11.55 | 8.95 | 12.01 | 7.86 | |||||||||||||||||||||||||||||||||||||
| Prepayment penalties on borrowings | 0.07 | — | 2.22 | — | — | 0.04 | — | |||||||||||||||||||||||||||||||||||||
| Tax effect | (0.01) | — | (0.47) | — | — | (0.01) | — | |||||||||||||||||||||||||||||||||||||
| ROACE excluding prepayment penalties on borrowings | 12.61 | % | 11.46 | % | 13.33 | % | 11.55 | % | 8.95 | % | 12.04 | % | 7.86 | % | ||||||||||||||||||||||||||||||
| Adjusted ROACE | 12.61 | % | 11.46 | % | 13.33 | % | 11.55 | % | 8.95 | % | 12.04 | % | 7.86 | % | ||||||||||||||||||||||||||||||
Conference Call
As previously announced, Horizon will host a conference call to review its second quarter financial results and operating performance.
Participants may access the live conference call on July 28, 2021 at 7:30 a.m. CT (8:30 a.m. ET) by dialing 877–317–6789 from the United States, 866–450–4696 from Canada or 412–317–6789 from international locations and requesting the “Horizon Bancorp Call.” Participants are asked to dial in approximately 10 minutes prior to the call.
A telephone replay of the call will be available approximately one hour after the end of the conference through August 4, 2021. The replay may be accessed by dialing 877–344–7529 from the United States, 855–669–9658 from Canada or 412–317–0088 from other international locations, and entering the access code 10157826.
About Horizon Bancorp, Inc.
Horizon Bancorp, Inc. (NASDAQ GS: HBNC) is the $6.1 billion–asset bank holding company for Horizon Bank, which serves customers across diverse and economically attractive Midwestern markets through convenient digital and virtual tools, as well as its Indiana and Michigan branches. Horizon's retail offerings include prime residential, indirect auto, and other secured consumer lending to in–market customers, as well as a range of personal banking and wealth management solutions. Horizon also provides a comprehensive array of in–market business banking and treasury management services, with commercial lending representing over half of total loans. More information on Horizon, headquartered in Northwest Indiana's Michigan City, is available at horizonbank.com and investor.horizonbank.com.
15
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
Forward Looking Statements
This press release may contain forward–looking statements regarding the financial performance, business prospects, growth and operating strategies of Horizon Bancorp, Inc. and its affiliates (collectively, “Horizon”). For these statements, Horizon claims the protection of the safe harbor for forward–looking statements contained in the Private Securities Litigation Reform Act of 1995. Statements in this press release should be considered in conjunction with the other information available about Horizon, including the information in the filings we make with the Securities and Exchange Commission. Forward–looking statements provide current expectations or forecasts of future events and are not guarantees of future performance. The forward–looking statements are based on management’s expectations and are subject to a number of risks and uncertainties. We have tried, wherever possible, to identify such statements by using words such as “anticipate,” “estimate,” “project,” “intend,” “plan,” “believe,” “will” and similar expressions in connection with any discussion of future operating or financial performance.
Although management believes that the expectations reflected in such forward–looking statements are reasonable, actual results may differ materially from those expressed or implied in such statements. Risks and uncertainties that could cause actual results to differ materially include risk factors relating to the banking industry and the other factors detailed from time to time in Horizon’s reports filed with the Securities and Exchange Commission, including those described in Horizon’s Annual Report on Form 10–K and its quarterly reports on Form 10–Q. Further, statements about the effects of the COVID–19 pandemic on our business, operations, financial performance, and prospects may constitute forward–looking statements and are subject to the risk that the actual impacts may differ, possibly materially, from what is reflected in those forward–looking statements due to factors and future developments that are uncertain, unpredictable, and in many cases beyond our control, including the scope and duration of the pandemic, actions taken by governmental authorities in response to the pandemic, and the direct and indirect impact of the pandemic on our customers, third parties, and us. Undue reliance should not be placed on the forward–looking statements, which speak only as of the date hereof. Horizon does not undertake, and specifically disclaims any obligation, to publicly release the result of any revisions that may be made to update any forward–looking statement to reflect the events or circumstances after the date on which the forward–looking statement is made, or reflect the occurrence of unanticipated events, except to the extent required by law.
| Financial Highlights | ||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Balance sheet: | ||||||||||||||||||||||||||||||||
| Total assets | $ | 6,109,227 | $ | 6,055,528 | $ | 5,886,614 | $ | 5,790,143 | $ | 5,739,262 | ||||||||||||||||||||||
| Interest earning deposits & federal funds sold | 209,304 | 444,239 | 158,979 | 15,707 | 82,328 | |||||||||||||||||||||||||||
| Interest earning time deposits | 6,994 | 7,983 | 8,965 | 9,213 | 9,247 | |||||||||||||||||||||||||||
| Investment securities | 1,844,470 | 1,423,825 | 1,302,701 | 1,195,613 | 1,126,075 | |||||||||||||||||||||||||||
| Commercial loans | 2,104,627 | 2,177,858 | 2,192,271 | 2,321,608 | 2,312,715 | |||||||||||||||||||||||||||
| Mortgage warehouse loans | 205,311 | 266,246 | 395,626 | 374,653 | 300,386 | |||||||||||||||||||||||||||
| Residential mortgage loans | 559,437 | 581,929 | 624,286 | 675,220 | 704,410 | |||||||||||||||||||||||||||
| Consumer loans | 650,144 | 638,403 | 655,200 | 658,884 | 660,871 | |||||||||||||||||||||||||||
| Earning assets | 5,610,538 | 5,571,304 | 5,374,589 | 5,286,974 | 5,235,553 | |||||||||||||||||||||||||||
| Non–interest bearing deposit accounts | 1,102,950 | 1,133,412 | 1,053,242 | 1,016,646 | 981,868 | |||||||||||||||||||||||||||
| Interest bearing transaction accounts | 3,105,328 | 2,947,438 | 2,802,673 | 2,600,691 | 2,510,854 | |||||||||||||||||||||||||||
| Time deposits | 573,348 | 640,966 | 675,218 | 718,952 | 814,877 | |||||||||||||||||||||||||||
| Borrowings | 439,094 | 481,488 | 475,000 | 587,473 | 583,073 | |||||||||||||||||||||||||||
| Subordinated notes | 58,676 | 58,640 | 58,603 | 58,566 | 58,824 | |||||||||||||||||||||||||||
| Junior subordinated debentures issued to capital trusts | 56,662 | 56,604 | 56,548 | 56,491 | 56,437 | |||||||||||||||||||||||||||
| Total stockholders’ equity | 710,374 | 689,379 | 692,216 | 670,293 | 652,206 | |||||||||||||||||||||||||||
16
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Financial Highlights | ||||||||||||||||||||||||||||||||
| (Dollars in Thousands Except Share and Per Share Data and Ratios, Unaudited) | ||||||||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Income statement: | ||||||||||||||||||||||||||||||||
| Net interest income | $ | 42,632 | $ | 42,538 | $ | 43,622 | $ | 43,397 | $ | 42,996 | ||||||||||||||||||||||
| Credit loss expense (recovery) | (1,492) | 367 | 3,042 | 2,052 | 7,057 | |||||||||||||||||||||||||||
| Non–interest income | 15,207 | 13,873 | 19,733 | 16,700 | 11,125 | |||||||||||||||||||||||||||
| Non–interest expense | 33,388 | 32,172 | 36,453 | 33,407 | 30,432 | |||||||||||||||||||||||||||
| Income tax expense | 3,770 | 3,450 | 1,967 | 4,326 | 1,993 | |||||||||||||||||||||||||||
| Net income | $ | 22,173 | $ | 20,422 | $ | 21,893 | $ | 20,312 | $ | 14,639 | ||||||||||||||||||||||
| Per share data: | ||||||||||||||||||||||||||||||||
| Basic earnings per share | $ | 0.50 | $ | 0.46 | $ | 0.50 | $ | 0.46 | $ | 0.33 | ||||||||||||||||||||||
| Diluted earnings per share | 0.50 | 0.46 | 0.50 | 0.46 | 0.33 | |||||||||||||||||||||||||||
| Cash dividends declared per common share | 0.13 | 0.12 | 0.12 | 0.12 | 0.12 | |||||||||||||||||||||||||||
| Book value per common share | 16.16 | 15.69 | 15.78 | 15.28 | 14.88 | |||||||||||||||||||||||||||
| Tangible book value per common share | 12.24 | 11.74 | 11.81 | 11.29 | 10.87 | |||||||||||||||||||||||||||
| Market value – high | 19.13 | 19.94 | 15.86 | 11.48 | 12.44 | |||||||||||||||||||||||||||
| Market value – low | $ | 16.98 | $ | 15.43 | $ | 10.16 | $ | 9.05 | $ | 8.40 | ||||||||||||||||||||||
| Weighted average shares outstanding – Basis | 43,950,501 | 43,919,549 | 43,862,435 | 43,862,435 | 43,781,249 | |||||||||||||||||||||||||||
| Weighted average shares outstanding – Diluted | 44,111,103 | 44,072,581 | 43,903,881 | 43,903,881 | 43,802,794 | |||||||||||||||||||||||||||
| Key ratios: | ||||||||||||||||||||||||||||||||
| Return on average assets | 1.45 | % | 1.40 | % | 1.49 | % | 1.40 | % | 1.05 | % | ||||||||||||||||||||||
| Return on average common stockholders’ equity | 12.59 | 11.88 | 12.79 | 12.08 | 9.07 | |||||||||||||||||||||||||||
| Net interest margin | 3.14 | 3.29 | 3.34 | 3.39 | 3.47 | |||||||||||||||||||||||||||
| Allowance for credit losses to total loans | 1.58 | 1.56 | 1.47 | 1.39 | 1.38 | |||||||||||||||||||||||||||
| Average equity to average assets | 11.50 | 11.75 | 11.61 | 11.59 | 11.56 | |||||||||||||||||||||||||||
| Efficiency ratio | 57.73 | 57.03 | 57.54 | 55.59 | 56.23 | |||||||||||||||||||||||||||
| Annualized non–interest expense to average assets | 2.18 | 2.20 | 2.47 | 2.30 | 2.18 | |||||||||||||||||||||||||||
| Bank only capital ratios: | ||||||||||||||||||||||||||||||||
| Tier 1 capital to average assets | 8.72 | 8.81 | 8.71 | 8.57 | 8.48 | |||||||||||||||||||||||||||
| Tier 1 capital to risk weighted assets | 12.34 | 12.71 | 11.29 | 10.67 | 10.49 | |||||||||||||||||||||||||||
| Total capital to risk weighted assets | 13.59 | 13.86 | 12.21 | 11.56 | 11.74 | |||||||||||||||||||||||||||
17
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Financial Highlights | ||||||||||||||
| (Dollars in Thousands Except Share and Per Share Data and Ratios, Unaudited) | ||||||||||||||
| Six Months Ended | ||||||||||||||
| June 30, | June 30, | |||||||||||||
| 2021 | 2020 | |||||||||||||
| Income statement: | ||||||||||||||
| Net interest income | $ | 85,170 | $ | 83,921 | ||||||||||
| Credit loss expense (recovery) | (1,125) | 15,657 | ||||||||||||
| Non–interest income | 29,080 | 23,188 | ||||||||||||
| Non–interest expense | 65,560 | 61,581 | ||||||||||||
| Income tax expense | 7,220 | 3,577 | ||||||||||||
| Net income | $ | 42,595 | $ | 26,294 | ||||||||||
| Per share data: | ||||||||||||||
| Basic earnings per share | $ | 0.97 | $ | 0.59 | ||||||||||
| Diluted earnings per share | 0.97 | 0.59 | ||||||||||||
| Cash dividends declared per common share | 0.25 | 0.24 | ||||||||||||
| Book value per common share | 16.16 | 14.88 | ||||||||||||
| Tangible book value per common share | 12.24 | 10.87 | ||||||||||||
| Market value – high | 19.94 | 18.79 | ||||||||||||
| Market value – low | $ | 15.43 | $ | 7.97 | ||||||||||
| Weighted average shares outstanding – Basis | 43,935,111 | 44,219,880 | ||||||||||||
| Weighted average shares outstanding – Diluted | 44,092,577 | 44,286,864 | ||||||||||||
| Key ratios: | ||||||||||||||
| Return on average assets | 1.42 | % | 0.97 | % | ||||||||||
| Return on average common stockholders’ equity | 12.23 | 8.07 | ||||||||||||
| Net interest margin | 3.21 | 3.51 | ||||||||||||
| Allowance for credit losses to total loans | 1.58 | 1.38 | ||||||||||||
| Average equity to average assets | 11.62 | 12.07 | ||||||||||||
| Efficiency ratio | 57.38 | 57.49 | ||||||||||||
| Annualized non–interest expense to average assets | 2.19 | 2.28 | ||||||||||||
| Bank only capital ratios: | ||||||||||||||
| Tier 1 capital to average assets | 8.72 | 8.48 | ||||||||||||
| Tier 1 capital to risk weighted assets | 12.34 | 10.49 | ||||||||||||
| Total capital to risk weighted assets | 13.59 | 11.74 | ||||||||||||
18
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Financial Highlights | ||||||||||||||||||||||||||||||||
| (Dollars in Thousands Except Ratios, Unaudited) | ||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Loan data: | ||||||||||||||||||||||||||||||||
| Substandard loans | $ | 82,488 | $ | 86,472 | $ | 98,874 | $ | 88,286 | $ | 61,385 | ||||||||||||||||||||||
| 30 to 89 days delinquent | 3,336 | 5,099 | 6,938 | 5,513 | 3,853 | |||||||||||||||||||||||||||
| Non–performing loans: | ||||||||||||||||||||||||||||||||
| 90 days and greater delinquent – accruing interest | — | 267 | 262 | 331 | 123 | |||||||||||||||||||||||||||
| Trouble debt restructures – accruing interest | 1,853 | 1,828 | 1,793 | 1,825 | 2,039 | |||||||||||||||||||||||||||
| Trouble debt restructures – non–accrual | 2,294 | 2,271 | 2,610 | 2,704 | 3,443 | |||||||||||||||||||||||||||
| Non–accrual loans | 18,175 | 20,700 | 22,142 | 24,454 | 22,451 | |||||||||||||||||||||||||||
| Total non–performing loans | $ | 22,322 | $ | 25,066 | $ | 26,807 | $ | 29,314 | $ | 28,056 | ||||||||||||||||||||||
| Non–performing loans to total loans | 0.63 | % | 0.68 | % | 0.69 | % | 0.72 | % | 0.70 | % | ||||||||||||||||||||||
| Allocation of the Allowance for Credit Losses | ||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Commercial | $ | 41,766 | $ | 42,980 | $ | 42,210 | $ | 39,795 | $ | 39,147 | ||||||||||||||||||||||
| Residential mortgage | 4,108 | 4,229 | 4,620 | 5,464 | 5,832 | |||||||||||||||||||||||||||
| Mortgage warehouse | 1,155 | 1,163 | 1,267 | 1,250 | 1,190 | |||||||||||||||||||||||||||
| Consumer | 8,620 | 8,814 | 8,930 | 9,810 | 8,921 | |||||||||||||||||||||||||||
| Total | $ | 55,649 | $ | 57,186 | $ | 57,027 | $ | 56,319 | $ | 55,090 | ||||||||||||||||||||||
| Net Charge–offs (Recoveries) | ||||||||||||||||||||||||||||||||
| (Dollars in Thousands Except Ratios, Unaudited) | ||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Commercial | $ | 40 | $ | 158 | $ | 23 | $ | 488 | $ | 6 | ||||||||||||||||||||||
| Residential mortgage | (23) | (65) | (10) | 136 | 24 | |||||||||||||||||||||||||||
| Mortgage warehouse | — | — | — | — | — | |||||||||||||||||||||||||||
| Consumer | 22 | 115 | 216 | 199 | 377 | |||||||||||||||||||||||||||
| Total | $ | 39 | $ | 208 | $ | 229 | $ | 823 | $ | 407 | ||||||||||||||||||||||
| Percent of net charge–offs (recoveries) to average loans outstanding for the period | 0.00 | % | 0.01 | % | 0.01 | % | 0.02 | % | 0.01 | % | ||||||||||||||||||||||
19
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Total Non–performing Loans | ||||||||||||||||||||||||||||||||
| (Dollars in Thousands Except Ratios, Unaudited) | ||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Commercial | $ | 10,345 | $ | 12,802 | $ | 14,348 | $ | 16,169 | $ | 14,238 | ||||||||||||||||||||||
| Residential mortgage | 7,841 | 7,916 | 7,994 | 9,209 | 9,945 | |||||||||||||||||||||||||||
| Mortgage warehouse | — | — | — | — | — | |||||||||||||||||||||||||||
| Consumer | 4,136 | 4,348 | 4,465 | 3,936 | 3,873 | |||||||||||||||||||||||||||
| Total | $ | 22,322 | $ | 25,066 | $ | 26,807 | $ | 29,314 | $ | 28,056 | ||||||||||||||||||||||
| Non–performing loans to total loans | 0.63 | % | 0.68 | % | 0.69 | % | 0.72 | % | 0.70 | % | ||||||||||||||||||||||
| Other Real Estate Owned and Repossessed Assets | ||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Commercial | $ | 1,400 | $ | 1,696 | $ | 1,908 | $ | 2,191 | $ | 2,374 | ||||||||||||||||||||||
| Residential mortgage | 37 | 37 | — | 70 | 249 | |||||||||||||||||||||||||||
| Mortgage warehouse | — | — | — | — | — | |||||||||||||||||||||||||||
| Consumer | 46 | — | — | 80 | 20 | |||||||||||||||||||||||||||
| Total | $ | 1,483 | $ | 1,733 | $ | 1,908 | $ | 2,341 | $ | 2,643 | ||||||||||||||||||||||
20
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Average Balance Sheets | ||||||||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Three Months Ended | |||||||||||||||||||||||||||||||||||||
| June 30, 2021 | June 30, 2020 | |||||||||||||||||||||||||||||||||||||
| Average Balance | Interest | Average Rate | Average Balance | Interest | Average Rate | |||||||||||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||||||||||||||
| Interest earning assets | ||||||||||||||||||||||||||||||||||||||
| Federal funds sold | $ | 359,184 | $ | 98 | 0.11 | % | $ | 62,832 | $ | 17 | 0.11 | % | ||||||||||||||||||||||||||
| Interest earning deposits | 29,584 | 44 | 0.60 | % | 20,278 | 61 | 1.21 | % | ||||||||||||||||||||||||||||||
| Investment securities – taxable | 645,139 | 2,386 | 1.48 | % | 481,552 | 2,243 | 1.87 | % | ||||||||||||||||||||||||||||||
Investment securities – non–taxable (1) | 1,054,703 | 5,656 | 2.72 | % | 647,375 | 4,105 | 3.15 | % | ||||||||||||||||||||||||||||||
Loans receivable (2) (3) | 3,570,774 | 39,236 | 4.43 | % | 3,900,599 | 43,918 | 4.54 | % | ||||||||||||||||||||||||||||||
| Total interest earning assets | 5,659,384 | 47,420 | 3.48 | % | 5,112,636 | 50,344 | 4.05 | % | ||||||||||||||||||||||||||||||
| Non–interest earning assets | ||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 84,469 | 84,297 | ||||||||||||||||||||||||||||||||||||
| Allowance for credit losses | (57,196) | (48,611) | ||||||||||||||||||||||||||||||||||||
| Other assets | 455,850 | 472,373 | ||||||||||||||||||||||||||||||||||||
| Total average assets | $ | 6,142,507 | $ | 5,620,695 | ||||||||||||||||||||||||||||||||||
| Liabilities and Stockholders’ Equity | ||||||||||||||||||||||||||||||||||||||
| Interest bearing liabilities | ||||||||||||||||||||||||||||||||||||||
| Interest bearing deposits | $ | 3,680,796 | $ | 2,053 | 0.22 | % | $ | 3,299,661 | $ | 4,506 | 0.55 | % | ||||||||||||||||||||||||||
| Borrowings | 453,856 | 1,296 | 1.15 | % | 618,274 | 2,074 | 1.35 | % | ||||||||||||||||||||||||||||||
| Subordinated notes | 58,653 | 881 | 6.02 | % | 4,527 | 58 | 5.15 | % | ||||||||||||||||||||||||||||||
| Junior subordinated debentures issued to capital trusts | 56,627 | 558 | 3.95 | % | 52,835 | 710 | 5.40 | % | ||||||||||||||||||||||||||||||
| Total interest bearing liabilities | 4,249,932 | 4,788 | 0.45 | % | 3,975,297 | 7,348 | 0.74 | % | ||||||||||||||||||||||||||||||
| Non–interest bearing liabilities | ||||||||||||||||||||||||||||||||||||||
| Demand deposits | 1,139,068 | 924,890 | ||||||||||||||||||||||||||||||||||||
| Accrued interest payable and other liabilities | 46,855 | 71,018 | ||||||||||||||||||||||||||||||||||||
| Stockholders’ equity | 706,652 | 649,490 | ||||||||||||||||||||||||||||||||||||
| Total average liabilities and stockholders’ equity | $ | 6,142,507 | $ | 5,620,695 | ||||||||||||||||||||||||||||||||||
| Net interest income / spread | $ | 42,632 | 3.03 | % | $ | 42,996 | 3.31 | % | ||||||||||||||||||||||||||||||
Net interest income as a percent of average interest earning assets (1) | 3.14 | % | 3.47 | % | ||||||||||||||||||||||||||||||||||
(1) Securities balances represent daily average balances for the fair value of securities. The average rate is calculated based on the daily average balance for the amortized cost of securities. The average rate is presented on a tax equivalent basis. | ||||||||||||||||||||||||||||||||||||||
(2) Includes fees on loans. The inclusion of loan fees does not have a material effect on the average interest rate. | ||||||||||||||||||||||||||||||||||||||
(3) Non–accruing loans for the purpose of the computation above are included in the daily average loan amounts outstanding. Loan totals are shown net of unearned income and deferred loan fees. The average rate is presented on a tax equivalent basis. | ||||||||||||||||||||||||||||||||||||||
21
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Average Balance Sheets | ||||||||||||||||||||||||||||||||||||||
| (Dollars in Thousands, Unaudited) | ||||||||||||||||||||||||||||||||||||||
| Six Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||
| June 30, 2021 | June 30, 2020 | |||||||||||||||||||||||||||||||||||||
| Average Balance | Interest | Average Rate | Average Balance | Interest | Average Rate | |||||||||||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||||||||||||||
| Interest earning assets | ||||||||||||||||||||||||||||||||||||||
| Federal funds sold | $ | 313,467 | $ | 164 | 0.11 | % | $ | 43,903 | $ | 113 | 0.52 | % | ||||||||||||||||||||||||||
| Interest earning deposits | 27,567 | 90 | 0.66 | % | 23,391 | 163 | 1.40 | % | ||||||||||||||||||||||||||||||
| Investment securities – taxable | 528,250 | 3,822 | 1.46 | % | 491,360 | 4,943 | 2.02 | % | ||||||||||||||||||||||||||||||
Investment securities – non–taxable (1) | 1,005,855 | 10,879 | 2.76 | % | 618,080 | 7,903 | 3.16 | % | ||||||||||||||||||||||||||||||
Loans receivable (2) (3) | 3,674,977 | 80,054 | 4.41 | % | 3,752,654 | 88,876 | 4.78 | % | ||||||||||||||||||||||||||||||
| Total interest earning assets | 5,550,116 | 95,009 | 3.57 | % | 4,929,388 | 101,998 | 4.25 | % | ||||||||||||||||||||||||||||||
| Non–interest earning assets | ||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 84,866 | 81,203 | ||||||||||||||||||||||||||||||||||||
| Allowance for credit losses | (57,486) | (36,588) | ||||||||||||||||||||||||||||||||||||
| Other assets | 462,401 | 459,184 | ||||||||||||||||||||||||||||||||||||
| Total average assets | $ | 6,039,897 | $ | 5,433,187 | ||||||||||||||||||||||||||||||||||
| Liabilities and Stockholders’ Equity | ||||||||||||||||||||||||||||||||||||||
| Interest bearing liabilities | ||||||||||||||||||||||||||||||||||||||
| Interest bearing deposits | $ | 3,602,882 | $ | 4,396 | 0.25 | % | $ | 3,262,492 | $ | 12,222 | 0.75 | % | ||||||||||||||||||||||||||
| Borrowings | 465,502 | 2,565 | 1.11 | % | 575,702 | 4,312 | 1.51 | % | ||||||||||||||||||||||||||||||
| Subordinated notes | 58,635 | 1,761 | 6.06 | % | 2,264 | 58 | 5.15 | % | ||||||||||||||||||||||||||||||
| Junior subordinated debentures issued to capital trusts | 56,599 | 1,117 | 3.98 | % | 52,801 | 1,485 | 5.66 | % | ||||||||||||||||||||||||||||||
| Total interest bearing liabilities | 4,183,618 | 9,839 | 0.47 | % | 3,893,259 | 18,077 | 0.93 | % | ||||||||||||||||||||||||||||||
| Non–interest bearing liabilities | ||||||||||||||||||||||||||||||||||||||
| Demand deposits | 1,101,377 | 820,997 | ||||||||||||||||||||||||||||||||||||
| Accrued interest payable and other liabilities | 52,850 | 63,393 | ||||||||||||||||||||||||||||||||||||
| Stockholders’ equity | 702,052 | 655,538 | ||||||||||||||||||||||||||||||||||||
| Total average liabilities and stockholders’ equity | $ | 6,039,897 | $ | 5,433,187 | ||||||||||||||||||||||||||||||||||
| Net interest income / spread | $ | 85,170 | 3.10 | % | $ | 83,921 | 3.32 | % | ||||||||||||||||||||||||||||||
Net interest income as a percent of average interest earning assets (1) | 3.21 | % | 3.51 | % | ||||||||||||||||||||||||||||||||||
(1) Securities balances represent daily average balances for the fair value of securities. The average rate is calculated based on the daily average balance for the amortized cost of securities. The average rate is presented on a tax equivalent basis. | ||||||||||||||||||||||||||||||||||||||
(2) Includes fees on loans. The inclusion of loan fees does not have a material effect on the average interest rate. | ||||||||||||||||||||||||||||||||||||||
(3) Non–accruing loans for the purpose of the computation above are included in the daily average loan amounts outstanding. Loan totals are shown net of unearned income and deferred loan fees. The average rate is presented on a tax equivalent basis. | ||||||||||||||||||||||||||||||||||||||
22
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Condensed Consolidated Balance Sheets | ||||||||||||||
| (Dollars in Thousands) | ||||||||||||||
| June 30, 2021 | December 31, 2020 | |||||||||||||
| (Unaudited) | ||||||||||||||
| Assets | ||||||||||||||
| Cash and due from banks | $ | 304,171 | $ | 249,711 | ||||||||||
| Interest earning time deposits | 6,994 | 8,965 | ||||||||||||
| Investment securities, available for sale | 1,691,186 | 1,134,025 | ||||||||||||
Investment securities, held to maturity (fair value $162,651 and $179,990) | 153,284 | 168,676 | ||||||||||||
| Loans held for sale | 7,228 | 13,538 | ||||||||||||
Loans, net of allowance for credit losses of $55,649 and $57,027 | 3,463,870 | 3,810,356 | ||||||||||||
| Premises and equipment, net | 88,604 | 92,416 | ||||||||||||
| Federal Home Loan Bank stock | 23,023 | 23,023 | ||||||||||||
| Goodwill | 151,238 | 151,238 | ||||||||||||
| Other intangible assets | 21,160 | 22,955 | ||||||||||||
| Interest receivable | 21,702 | 21,396 | ||||||||||||
| Cash value of life insurance | 97,071 | 96,751 | ||||||||||||
| Other assets | 79,696 | 93,564 | ||||||||||||
| Total assets | $ | 6,109,227 | $ | 5,886,614 | ||||||||||
| Liabilities | ||||||||||||||
| Deposits | ||||||||||||||
| Non–interest bearing | $ | 1,102,950 | $ | 1,053,242 | ||||||||||
| Interest bearing | 3,678,676 | 3,477,891 | ||||||||||||
| Total deposits | 4,781,626 | 4,531,133 | ||||||||||||
| Borrowings | 439,094 | 475,000 | ||||||||||||
| Subordinated notes | 58,676 | 58,603 | ||||||||||||
| Junior subordinated debentures issued to capital trusts | 56,662 | 56,548 | ||||||||||||
| Interest payable | 2,430 | 2,712 | ||||||||||||
| Other liabilities | 60,365 | 70,402 | ||||||||||||
| Total liabilities | 5,398,853 | 5,194,398 | ||||||||||||
| Commitments and contingent liabilities | ||||||||||||||
| Stockholders’ equity | ||||||||||||||
Preferred stock, Authorized, 1,000,000 shares, Issued 0 shares | — | — | ||||||||||||
Common stock, no par value, Authorized 99,000,000 shares Issued 44,039,562 and 43,905,631 shares, Outstanding 43,950,720 and 43,880,562 shares | — | — | ||||||||||||
| Additional paid–in capital | 359,227 | 362,945 | ||||||||||||
| Retained earnings | 332,509 | 301,419 | ||||||||||||
| Accumulated other comprehensive income | 18,638 | 27,852 | ||||||||||||
| Total stockholders’ equity | 710,374 | 692,216 | ||||||||||||
| Total liabilities and stockholders’ equity | $ | 6,109,227 | $ | 5,886,614 | ||||||||||
23
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Condensed Consolidated Statements of Income | ||||||||||||||||||||||||||||||||
| (Dollars in Thousands Except Per Share Data, Unaudited) | ||||||||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Interest income | ||||||||||||||||||||||||||||||||
| Loans receivable | $ | 39,236 | $ | 40,818 | $ | 46,745 | $ | 44,051 | $ | 43,918 | ||||||||||||||||||||||
| Investment securities – taxable | 2,528 | 1,548 | 1,570 | 1,704 | 2,321 | |||||||||||||||||||||||||||
| Investment securities – non–taxable | 5,656 | 5,223 | 4,919 | 4,391 | 4,105 | |||||||||||||||||||||||||||
| Total interest income | 47,420 | 47,589 | 53,234 | 50,146 | 50,344 | |||||||||||||||||||||||||||
| Interest expense | ||||||||||||||||||||||||||||||||
| Deposits | 2,053 | 2,343 | 2,718 | 3,616 | 4,506 | |||||||||||||||||||||||||||
| Borrowed funds | 1,296 | 1,269 | 5,456 | 1,662 | 2,074 | |||||||||||||||||||||||||||
| Subordinated notes | 881 | 880 | 871 | 895 | 58 | |||||||||||||||||||||||||||
| Junior subordinated debentures issued to capital trusts | 558 | 559 | 567 | 576 | 710 | |||||||||||||||||||||||||||
| Total interest expense | 4,788 | 5,051 | 9,612 | 6,749 | 7,348 | |||||||||||||||||||||||||||
| Net interest income | 42,632 | 42,538 | 43,622 | 43,397 | 42,996 | |||||||||||||||||||||||||||
| Credit loss expense (recovery) | (1,492) | 367 | 3,042 | 2,052 | 7,057 | |||||||||||||||||||||||||||
| Net interest income after credit loss expense (recovery) | 44,124 | 42,171 | 40,580 | 41,345 | 35,939 | |||||||||||||||||||||||||||
| Non–interest Income | ||||||||||||||||||||||||||||||||
| Service charges on deposit accounts | 2,157 | 2,234 | 2,360 | 2,154 | 1,888 | |||||||||||||||||||||||||||
| Wire transfer fees | 222 | 255 | 301 | 298 | 230 | |||||||||||||||||||||||||||
| Interchange fees | 2,892 | 2,340 | 2,645 | 2,438 | 2,327 | |||||||||||||||||||||||||||
| Fiduciary activities | 1,961 | 1,743 | 2,747 | 2,105 | 1,765 | |||||||||||||||||||||||||||
| Gains / (losses) on sale of investment securities | — | 914 | 2,622 | 1,088 | 248 | |||||||||||||||||||||||||||
| Gain on sale of mortgage loans | 5,612 | 5,296 | 7,815 | 8,813 | 6,620 | |||||||||||||||||||||||||||
| Mortgage servicing income net of impairment | 1,503 | 213 | 327 | (1,308) | (2,760) | |||||||||||||||||||||||||||
| Increase in cash value of bank owned life insurance | 502 | 511 | 566 | 566 | 557 | |||||||||||||||||||||||||||
| Death benefit on bank owned life insurance | 266 | — | — | 31 | — | |||||||||||||||||||||||||||
| Other income | 92 | 367 | 350 | 515 | 250 | |||||||||||||||||||||||||||
| Total non–interest income | 15,207 | 13,873 | 19,733 | 16,700 | 11,125 | |||||||||||||||||||||||||||
| Non–interest expense | ||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 17,730 | 16,871 | 20,030 | 18,832 | 15,629 | |||||||||||||||||||||||||||
| Net occupancy expenses | 3,084 | 3,318 | 3,262 | 3,107 | 3,190 | |||||||||||||||||||||||||||
| Data processing | 2,388 | 2,376 | 2,126 | 2,237 | 2,432 | |||||||||||||||||||||||||||
| Professional fees | 588 | 544 | 691 | 688 | 518 | |||||||||||||||||||||||||||
| Outside services and consultants | 2,220 | 1,702 | 2,083 | 1,561 | 1,759 | |||||||||||||||||||||||||||
| Loan expense | 3,107 | 2,822 | 2,961 | 2,876 | 2,692 | |||||||||||||||||||||||||||
| FDIC insurance expense | 500 | 800 | 900 | 570 | 235 | |||||||||||||||||||||||||||
| Other losses | 6 | 283 | 735 | 114 | 193 | |||||||||||||||||||||||||||
| Other expenses | 3,765 | 3,456 | 3,665 | 3,422 | 3,784 | |||||||||||||||||||||||||||
| Total non–interest expense | 33,388 | 32,172 | 36,453 | 33,407 | 30,432 | |||||||||||||||||||||||||||
| Income before income taxes | 25,943 | 23,872 | 23,860 | 24,638 | 16,632 | |||||||||||||||||||||||||||
| Income tax expense | 3,770 | 3,450 | 1,967 | 4,326 | 1,993 | |||||||||||||||||||||||||||
| Net income | $ | 22,173 | $ | 20,422 | $ | 21,893 | $ | 20,312 | $ | 14,639 | ||||||||||||||||||||||
| Basic earnings per share | $ | 0.50 | $ | 0.46 | $ | 0.50 | $ | 0.46 | $ | 0.33 | ||||||||||||||||||||||
| Diluted earnings per share | 0.50 | 0.46 | 0.50 | 0.46 | 0.33 | |||||||||||||||||||||||||||
24
Horizon Bancorp, Inc. Announces Record Second Quarter 2021 Financial Results
| Condensed Consolidated Statements of Income | ||||||||||||||
| (Dollars in Thousands Except Per Share Data, Unaudited) | ||||||||||||||
| Six Months Ended | ||||||||||||||
| June 30, | June 30, | |||||||||||||
| 2021 | 2020 | |||||||||||||
| Interest income | ||||||||||||||
| Loans receivable | $ | 80,054 | $ | 88,876 | ||||||||||
| Investment securities – taxable | 4,076 | 5,219 | ||||||||||||
| Investment securities – non–taxable | 10,879 | 7,903 | ||||||||||||
| Total interest income | 95,009 | 101,998 | ||||||||||||
| Interest expense | ||||||||||||||
| Deposits | 4,396 | 12,222 | ||||||||||||
| Borrowed funds | 2,565 | 4,312 | ||||||||||||
| Subordinated notes | 1,761 | 58 | ||||||||||||
| Junior subordinated debentures issued to capital trusts | 1,117 | 1,485 | ||||||||||||
| Total interest expense | 9,839 | 18,077 | ||||||||||||
| Net interest income | 85,170 | 83,921 | ||||||||||||
| Credit loss expense (recovery) | (1,125) | 15,657 | ||||||||||||
| Net interest income after credit loss expense (recovery) | 86,295 | 68,264 | ||||||||||||
| Non–interest Income | ||||||||||||||
| Service charges on deposit accounts | 4,391 | 4,334 | ||||||||||||
| Wire transfer fees | 477 | 401 | ||||||||||||
| Interchange fees | 5,232 | 4,223 | ||||||||||||
| Fiduciary activities | 3,704 | 4,293 | ||||||||||||
| Gains / (losses) on sale of investment securities | 914 | 587 | ||||||||||||
| Gain on sale of mortgage loans | 10,908 | 10,093 | ||||||||||||
| Mortgage servicing income net of impairment | 1,716 | (2,735) | ||||||||||||
| Increase in cash value of bank owned life insurance | 1,013 | 1,111 | ||||||||||||
| Death benefit on bank owned life insurance | 266 | 233 | ||||||||||||
| Other income | 459 | 648 | ||||||||||||
| Total non–interest income | 29,080 | 23,188 | ||||||||||||
| Non–interest expense | ||||||||||||||
| Salaries and employee benefits | 34,601 | 32,220 | ||||||||||||
| Net occupancy expenses | 6,402 | 6,442 | ||||||||||||
| Data processing | 4,764 | 4,837 | ||||||||||||
| Professional fees | 1,132 | 1,054 | ||||||||||||
| Outside services and consultants | 3,922 | 3,674 | ||||||||||||
| Loan expense | 5,929 | 4,791 | ||||||||||||
| FDIC insurance expense | 1,300 | 385 | ||||||||||||
| Other losses | 289 | 313 | ||||||||||||
| Other expenses | 7,221 | 7,865 | ||||||||||||
| Total non–interest expense | 65,560 | 61,581 | ||||||||||||
| Income before income taxes | 49,815 | 29,871 | ||||||||||||
| Income tax expense | 7,220 | 3,577 | ||||||||||||
| Net income | $ | 42,595 | $ | 26,294 | ||||||||||
| Basic earnings per share | $ | 0.97 | $ | 0.59 | ||||||||||
| Diluted earnings per share | 0.97 | 0.59 | ||||||||||||
25

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® A NASDAQ Traded Company - Symbol HBNC INVESTOR PRESENTATION | JULY 27, 2021

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® Forward-Looking Statements This presentation may contain forward-looking statements regarding the financial performance, business prospects, growth and operating strategies of Horizon Bancorp, Inc. and its affiliates (collectively, “Horizon”). For these statements, Horizon claims the protection of the safe harbor for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. Statements in the presentation materials should be considered in conjunction with the other information available about Horizon, including the information in the filings we make with the Securities and Exchange Commission. Forward-looking statements provide current expectations or forecasts of future events and are not guarantees of future performance. The forward-looking statements are based on management’s expectations and are subject to a number of risks and uncertainties. We have tried, wherever possible, to identify such statements by using words such as “anticipate,” “estimate,” “project,” “intend,” “plan,” “believe,” “will” and similar expressions in connection with any discussion of future operating or financial performance. Although management believes that the expectations reflected in such forward-looking statements are reasonable, actual results may differ materially from those expressed or implied in such statements. Risks and uncertainties that could cause actual results to differ materially include risk factors relating to the banking industry and the other factors detailed from time to time in Horizon’s reports filed with the Securities and Exchange Commission (the “SEC”), including those described in Horizon’s Annual Report on Form 10-K for the year ended December 31, 2020 and other subsequent filings with the SEC. Further, statements about the effects of the COVID-19 pandemic on our business, operations, financial performance, and prospects may constitute forward-looking statements and are subject to the risk that the actual impacts may differ, possibly materially, from what is reflected in those forward-looking statements due to factors and future developments that are uncertain, unpredictable, and in many cases beyond our control, including the scope and duration of the pandemic, actions taken by governmental authorities in response to the pandemic, and the direct and indirect impact of the pandemic on our customers, third parties, and us. Undue reliance should not be placed on the forward-looking statements, which speak only as of the date hereof. Horizon does not undertake, and specifically disclaims any obligation, to publicly release the result of any revisions that may be made to update any forward-looking statement to reflect the events or circumstances after the date on which the forward-looking statement is made, or reflect the occurrence of unanticipated events, except to the extent required by law. Non-GAAP Measures Certain non-GAAP financial measures are presented herein. Horizon believes they are useful to investors and provide a greater understanding of Horizon’s business without giving effect to non-recurring costs and non-core items. For each non-GAAP financial measure, we have presented comparable GAAP measures and reconciliations of the non-GAAP measures to those GAAP measures in the Appendix to this presentation. Please see slides 38-49. Important Information 2

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® Corporate Overview 3

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 4 2Q21 Highlights Top-line growth • Stable NII and significantly higher non-interest income drive net income growth of 8.6% from 1Q21 and 51.5% from 2Q20 Strong profitability • EPS $0.50, includes $0.01 of M&A expense • ROAA of 1.45%, or 1.46% adjusted* • ROAE of 12.59%, or 12.61% adjusted* • Pre-tax, pre-provision net income of $24.5M Further asset quality improvement • Provision reversal of $1.5M • NPLs decline 10.9% during to 0.63% of loans • Substandard loans decline 4.6% to 2.3% of loans • NCOs/average loans decreased to 0.00% Disciplined expense management • Stable non-interest expense/average assets of 2.18% • Stable efficiency ratio 57.73%, or 57.45% adjusted* NIM compression tempered by funding costs • Expected NIM compression from anticipated asset pricing headwinds, partially offset by further reduction in cost of interest bearing liabilities to 0.45% and previously disclosed initiatives to optimize earning asset returns including increasing investment securities to 30.2% of total assets Contributions from mortgage • $7.1M of mortgage related fees and origination volume of $173.0M up 11.2% from first quarter ($000s except per share data) 2Q21 Change % vs. 1Q21 2Q20 Income Statement Net interest income $42,632 0.2% (0.8)% Non-interest income $15,207 9.6% 36.7% Reported net income $22,173 8.6% 51.5% Diluted EPS $0.50 8.7% 51.5% Efficiency ratio 57.73% 0.70% 1.50% Return on Average Assets 1.45% 0.05% 0.40% Return on Average Equity 12.59% 0.71% 3.52% Balance Sheet Average earning assets $5,659,384 4.0% 10.7% Average total loans $3,570,774 (5.5)% (8.5)% Average total deposits $4,819,864 5.1% 14.1% Credit Quality Non-performing assets $23,805 (11.2)% (22.5)% Allowance for credit losses to total loans 1.58% 2 bps 20 bps NPA ratio 0.39% (5) bps (14) bps Net charge-offs to avg. loans for the period 0.00% (1) bps (1) bps * Excluding acquisition expenses and prepayment penalties on borrowings, net of tax and death benefits on bank owned life insurance; see non-GAAP reconciliations in Appendix.
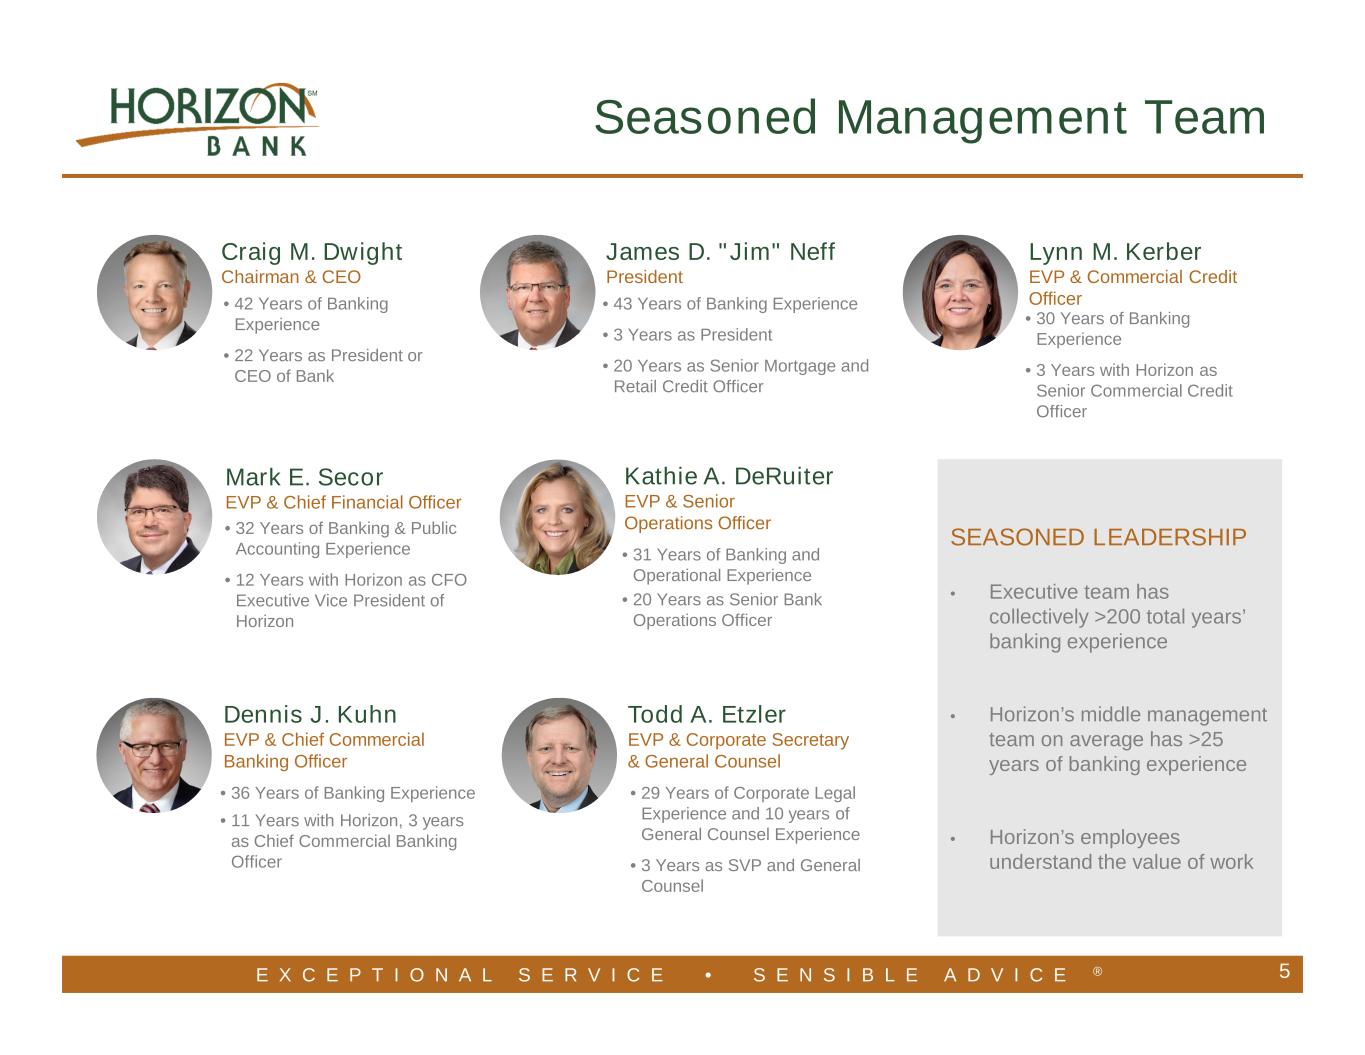
E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 5 • 32 Years of Banking & Public Accounting Experience • 12 Years with Horizon as CFO Executive Vice President of Horizon • 36 Years of Banking Experience • 11 Years with Horizon, 3 years as Chief Commercial Banking Officer • 42 Years of Banking Experience • 22 Years as President or CEO of Bank • 43 Years of Banking Experience • 3 Years as President • 20 Years as Senior Mortgage and Retail Credit Officer Craig M. Dwight Chairman & CEO James D. "Jim" Neff President Dennis J. Kuhn EVP & Chief Commercial Banking Officer Mark E. Secor EVP & Chief Financial Officer • 31 Years of Banking and Operational Experience • 20 Years as Senior Bank Operations Officer Kathie A. DeRuiter EVP & Senior Operations Officer • 29 Years of Corporate Legal Experience and 10 years of General Counsel Experience • 3 Years as SVP and General Counsel Todd A. Etzler EVP & Corporate Secretary & General Counsel SEASONED LEADERSHIP • Executive team has collectively >200 total years’ banking experience • Horizon’s middle management team on average has >25 years of banking experience • Horizon’s employees understand the value of work Seasoned Management Team • 30 Years of Banking Experience • 3 Years with Horizon as Senior Commercial Credit Officer Lynn M. Kerber EVP & Commercial Credit Officer

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® A History of Profitable Growth Extensive and Diligent M&A Expertise Supplements Organic Growth $0.7 $0.8 $0.9 $1.1 $1.2 $1.3 $1.3 $1.4 $1.4 $1.5 $1.8 $1.8 $2.1 $2.7 $3.1 $4.0 $4.2 $5.2 $5.9 $6.1 $5 $7 $7 $7 $7 $8 $9 $9 $10 $13 $20 $20 $18 $21 $24 $33 $53 $67 $68 $43 - 10 20 30 40 50 60 70 80 - 1.00 2.00 3.00 4.00 5.00 6.00 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 June '21 YTD Total Assets ($B) Net Income ($M) CAGRs 2002 through June 2021 Total Assets – 12.3% Net Income – 16.0% 6 12 15 Organic Expansions M&A Transactions Including MI branch deal expected to close 3Q21

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 7 * U.S. Bureau of Economic Analysis, retrieved from FRED, Federal Reserve Bank of St. Louis, fred.stlouisfed.org. Built to Outpace GDP & Industry Over Long-Term Assets grew 8% ex. PPP during 2020 and are expected to remain stable in 2021 11% 23% 5% 21% 23% 8% 3% 4% 6% 1% 10% 20% -5% 18% 28% 18% 26% 7% 24% 12% 2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 HBNC Annual Asset Growth, ex. PPP HBNC Annual Asset Growth, w/ PPP GDP Annual Growth* All Commercial Bank Annual Asset Growth* Well-Established Long-Term Goals Meaningfully outpace GDP and industry ~50/50 growth organic/acquired Organic growth of ≥3x GDP growth 2011 - 2020 2016 - 2020 16% average asset growth 4.5x GDP 2.7x banks 18% average asset growth 5.5x GDP 2.9x banks

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 8 Multiple Revenue Streams Diversifies Risk Diversified & Attractive Footprint E X C E P T I O N A L S E R V I C E • Q U A L I T Y A D V I C E ® 8 Retail Banking Business Banking Mortgage Banking Wealth Management Complementary Revenue Streams that are Counter-Cyclical to Varying Economic Cycles Serving the Right Side of Chicago Headquartered in Michigan City, IN, with 74 locations in attractive markets in Indiana and Michigan Double commuter track addition to the South Shore train lines supports growth in Northwest Indiana, which offers proximity to Chicago, with lower taxes and cost of living Major colleges and universities throughout footprint, including Notre Dame University, Purdue University, University of Michigan and Michigan State University Note: Total loan figures for Indiana and Michigan are as of 6/30/21 and do not include Mortgage Warehouse. INDIANA 6/30/21 Loans: $1.9B 60% of Loans MICHIGAN 6/30/21 Loans: $1.3B 40% of Loans OHIO ILLINOIS WISCONSIN KENTUCKY MICHIGAN $1.3B IN LOANS INDIANA $1.9B IN LOANS = 11 Michigan counties with 14 branches to be acquired in transaction expected to close 3Q21 • Positions Horizon within top 3 deposit market share in 8 of 11 counties

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 9 Michigan City, IN / La Porte, IN (Legacy) Indianapolis, IN (Growth) Northwest Indiana (Growth) Lafayette, IN (Growth) Southwest Michigan* (Growth) $1.1B Deposits $680M Deposits $548M Deposits $322M Deposits$413M Deposits 8 Branches 9 Branches 11 Branches 7 Branches8 Branches • Similar culture and economic base to legacy markets in Northern Indiana • Grand Rapids one of the most attractive markets in the Midwest • Purdue University collaborates with contiguous cities of Lafayette and West Lafayette • Subaru expanding facilities • Double commuter track addition to the South Shore train lines • High cost of living in Chicago • Population density of Chicago • Greater Indianapolis area exhibits strong growth • Significant manufacturing, healthcare, and education industries • Over $1.5B in public and private investments since 2012 • Double commuter track addition to the South Shore train lines Source: S&P Global Market Intelligence. Note: Core market demographics reflect MSA data. Deposit data as of 6/30/20. *Southwest Michigan defined as the MSAs of Niles, Grand Rapids-Kentwood and Kalamazoo-Portage. Demographic data weighted by HBNC deposits. Attractive & Stable Midwest Markets Top 5 Markets by Deposits Michigan City, IN La Porte, IN Indianapolis, IN Northwest Indiana Southwest Michigan* Lafayette, IN Median HHI $53,255 $65,306 $74,285 $58,856 $59,404 ’20 – ’25 HHI Growth 6.8% 11.2% 11.5% 11.8% 10.9% ’20 – ’25 Pop. Growth 0.12% 3.81% 0.08% 1.02% 3.86%

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 73,340 92,498 105,240 113,081 65% 66% 75% 80% 48% 52% 56% 60% 64% 68% 72% 76% 80% 84% 30,000 40,000 50,000 60,000 70,000 80,000 90,000 100,000 110,000 December 2018 December 2019 December 2020 June 2021 Active Online Banking Users Active Online Banking Users As a Percentage to Checking Accounts 10 • Approximately 80% of demand deposit account holders were active online banking users at June 30, 2021 • Approximately 73% of transactions in June 2021 were through digital or virtual channels 48% 44% 57% 73% 73% 30% 35% 40% 45% 50% 55% 60% 65% 70% 75% 80% 100,000 200,000 300,000 400,000 500,000 600,000 700,000 2017 2018 2019 2020 2Q21 Monthly Transaction Volume Digital Transactions Branch Transactions % Digital Transactions Digital Transformation

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 11 Financial Highlights

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 12 $ M $23.7 $26.7 $26.9 $24.2 $24.5 $14.4 $19.4 $22.8 $19.7 $22.2 $0.32 $0.45 $0.52 $0.44 $0.50 2Q20 3Q20 4Q20 1Q21 2Q21 Adj. Net Income(1) Pre-tax, Pre-provision Income Adj. Net Income Adj. EPS 1.68% 1.76% 1.91% 1.59% 1.60% 2Q20 3Q20 4Q20 1Q21 2Q21 Adj. PTPP ROAA(1) Adj. PTPP ROAA $41.4 $41.9 $45.0 $41.0 $42.5 3.35% 3.27% 3.44% 3.17% 3.13% 2Q20 3Q20 4Q20 1Q21 2Q21 Adj. Net Interest Income(1) Adj. Net Interest Income Adj. NIM $ M (1) Footnote Index included in Appendix (see slides 37-49 for non-GAAP reconciliation) 1.03% 1.34% 1.56% 1.35% 1.46% 2Q20 3Q20 4Q20 1Q21 2Q21 Adj. ROAA(1) Adj. ROAA Strong Core Earnings

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 3.36%3.42% 3.31% 3.45% 3.66%3.71%3.63%3.61%3.58%3.60%3.59% 3.43%3.46% 3.61%3.67% 3.49%3.44% 3.35%3.27% 3.44% 3.17% 3.13% 0.66%0.63% 0.62% 0.50%0.48%0.50%0.55%0.63%0.70% 0.82% 0.93% 1.07% 1.19%1.13%1.10%1.04% 0.95% 0.60% 0.53% 0.45% 0.40% 0.36% 0.50% 0.50%0.50% 0.55% 0.80% 1.05% 1.25%1.29% 1.53% 1.80% 2.01% 2.28% 2.50%2.50% 2.30% 1.83% 1.40% 0.25% 0.25% 0.25%0.25% 0.25% 1Q16 2Q16 3Q16 4Q16 1Q17 2Q17 3Q17 4Q17 1Q18 2Q18 3Q18 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 3Q20 4Q20 1Q21 2Q21 Net Interest Margin Adj. NIM (1) Adj. Cost of Core Funds (1) Avg. Fed Funds Rate (2) • PPP loans increased the second quarter margin an additional ~ 7bps from ~ 10bps in 1Q21 • Excess liquidity carried on the balance sheet compressed the second quarter margin ~ 21bps • Average loan yields increased in the second quarter by 4bps to 4.43% 13 (1) Footnote Index included in Appendix (see slides 37-49 for non-GAAP reconciliation) (2) Source: S&P Global Market Intelligence. Net Interest Margin

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® PPP loans: • Increased the second quarter 2021 loan yield an additional ~ 3bps • Increased the first quarter 2021 loan yield an additional ~ 6bps Commercial loans: • 62% fixed / 38% variable • 25% of variable rate commercial loans have floors, 81% of which are at their floor Retained mortgage loans: • 37% fixed / 63% variable • 98% of variable rate mortgage loans have floors, 9% of which are at their floor Consumer loans: • 65% fixed / 35% variable • 50% of variable rate consumer loans have floors, 46% of which are at their floor 14 Stable Loan Yields Directionally Consistent with Funding Costs $3.7 $3.7 $3.6 $3.7 $4.0 $4.0 $4.0 $3.8 $3.6 5.29% 5.41% 5.10% 5.03% 4.54% 4.39% 4.72% 4.39% 4.43% 2Q19 3Q19 4Q19 1Q20 2Q20 3Q20 4Q20 1Q21 2Q21 Yield on Loans (%) / Total Loans ($B) Total Loans Yield on Loans (%)

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® Non-interest bearing 23% Interest bearing(1) 65% CDs 12% 15 • Average non-interest bearing balances increased 7% • In-market relationships, strategic pricing and runoff of higher-priced time deposits, contributed to continued reduction in total deposit cost to 0.17% • CDs maturing in 2021 total $240 million with a weighted average rate of 0.72% • Account and deposit retention data very strong to date Average Cost(1) Average Deposits ($000s) 2Q 2021 Average Balances 1Q 2021 Average Balances 2Q 2021 (QTD) 1Q 2021 (QTD) Non-interest bearing $1,139,068 $1,063,268 0.00% 0.00% Interest bearing (excluding CDs) $3,081,343 $2,860,210 0.10% 0.10% Time Deposits (CDs) $599,453 $663,893 0.87% 1.00% Total Deposits $4,819,864 $4,587,371 0.17% 0.21% (1) Footnote Index included in Appendix (see slides 37-49 for non-GAAP reconciliation) Strong Low Cost Core Deposits CD Re-Pricing Opportunities Total Deposits at 6/30/21 $4.8B

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® Jumbo, 44.7% Rental, 0.9% Conforming, 50.5% Construction, 3.9% Total Outstanding at 6/30/21 $559M 16 $365,865 $408,972 $756,859 $363,644 $328,590 2018 2019 2020 2Q20 (YTD) 2Q21 (YTD) $ 0 0 0 s $2,120 $1,914 -$3,716 -$2,735 $1,716 $6,613 $9,208 $26,721 $10,093 $10,908 2018 2019 2020 2Q20 (YTD) 2Q21 (YTD) Servicing, net Gain on Sale $ 0 0 0 s Mortgage Contribution Continued Strength in Mortgage Purchases Represent 61% of Volume Mortgage Volume • Mortgage-related non-interest income remained strong in Q2, growing 84.3% year-over-year and contributing nearly 47% of total non-interest income in the period • 73% of production sold YTD • Predominantly in-market lender • Portfolio mortgages o Underwriting to Fannie Mae guidelines o Full documentation of employment, income and asset verification o 92.4% prime with credit score ≥670

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 17 Efficiency Ratio(1) 2Q ’21 Highlights (1) Footnote Index included in Appendix (see slides 37-49 for non-GAAP reconciliation) Focus on Expense Control 56.2% 55.6% 57.5% 57.0% 57.7% 56.5% 56.6% 56.5% 58.0% 57.5% 2Q20 3Q20 4Q20 1Q21 2Q21 Efficiency Ratio Adj. Efficiency Ratio 2.10% 2.15% 2.20% 2.25% 2.30% 2.35% 2.40% 2.45% 2.50% $0 $5,000 $10,000 $15,000 $20,000 $25,000 $30,000 $35,000 $40,000 2Q20 3Q20 4Q20 1Q21 2Q21 Non-interest Expense Breakout ($M) Other Loan Expense Outside Services & Consultants Professional Fees Data Processing Net Occupancy Expenses Salaries & Employee Benefits Annualized Non-Interest Expense to Average Assets • Annualized non-interest expense improved to 2.18% of average assets for the three months ended June 30, 2021 • Initiated plans to close 10 branches in August 2021 • Efficiency ratio stable at 57.73%, or 57.45% adjusted(1) for 2Q21

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 18 ($000s, unaudited) 12/31/20 Net Reserve(1) 1Q21 Net Reserve(1) 2Q21 6/30/21 Commercial $ 42,210 $ 770 $ (1,214) $ 41,766 Retail Mortgage 4,620 (391) (121) 4,108 Warehousing 1,267 (104) (8) 1,155 Consumer 8,930 (116) (194) 8,620 Allowance for Credit Losses $ 57,027 $ 159 $ (1,537) $ 55,649 ACL/Total Loans 1.47% 1.58% Acquired Loan Discount $ 11,494 $ (221) $ (815) $ 10,458 (1) Net Reserve Build is equal to the provision for credit losses net of net charge-offs/recoveries. Stable Credit Loss Reserves

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® Loan Portfolio Review 19

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® Commercial, $2,105M, 60% Residential Mortgage, $559M, 16% Consumer, $650M, 18% Mortgage Warehouse, $205M, 6% Held For Sale, $7M, 0% 20 Gross Loans at 6/30/21 $3.5B Diversified & Granular Loan Portfolio Commercial Loans by Industry ($M) 6/30/21 Balance % of Commercial Portfolio % of Total Loan Portfolio Lessors – Residential Multi Family $213 10.1% 6.0% Office (except medical) 157 7.5% 4.5% Hotel 140 6.7% 4.0% Health Care, Educational & Social 139 6.6% 3.9% Retail 132 6.3% 3.7% Real Estate Rental & Leasing 128 6.1% 3.6% Individual and Other Services 126 6.0% 3.6% Construction 117 5.6% 3.3% Manufacturing 101 4.8% 2.9% Lessors – Student Housing 95 4.5% 2.7% Warehouse/Industrial 89 4.2% 2.5% Restaurants 86 4.1% 2.4% Professional & Technical Services 70 3.3% 2.0% Medical Office 69 3.3% 2.0% Retail Trade 58 2.8% 1.6% Finance & Insurance 48 2.3% 1.4% Mini Storage 47 2.2% 1.3% Leisure and Hospitality 39 1.9% 1.1% Farm Land 34 1.6% 1.0% Lessors – Residential 1–4 Family 34 1.6% 1.0% Government 34 1.6% 1.0% Transportation & Warehousing 33 1.5% 0.9% Wholesale Trade 23 1.1% 0.7% Agriculture 22 1.0% 0.6% Other 71 3.3% 2.0% Total $2,105 100.0% 59.7%

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 21 • 99.4% secured consumer loans • 94.9% prime, with credit scores ≥700 for 83.9% of portfolio and <640 for 5.1% • Rescored annually • HELOC combined LTV limited to 89.9% • Strong asset quality through end of 2Q21 • 30-89 days past due • 2Q21 – 0.24% • 1Q21 – 0.24% • NPLs • 2Q21 – 0.64% • 1Q21 – 0.68% Indirect Auto, 55.2% Direct Auto, 2.7% Home Equity Term, 4.4% HELOCs, 34.4% RV & Boat, 2.5% Unsecured, 0.6% Other, 0.2% Total Outstanding at 6/30/21 $650M Quality Consumer Loan Portfolio as of June 30, 2021

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® • Experienced commercial lenders (20+ years on average) • Focus on in-market sponsors in resilient markets • Predominantly a secured lender with recourse to owners • Prudent underwriting standards Northern Indiana, 23% Central Indiana, 33%Other, 1% Michigan, 43% Geography at 6/30/21 Non-Owner Occupied Real Estate, 46.9% C&I, 28.5% Owner Occ. Real Estate, 20.5% Agriculture, 2.6% Develop./Land, 1.1% Res. Spec. Homes, 0.4% Category at 6/30/21 $2.1 billion in Total Commercial Loans Quality Commercial Loan Portfolio 22 • 30-89 days past due • 2Q21 – 0.03% • 1Q21 – 0.11% • NPLs • 2Q21 – 0.49% • 1Q21 – 0.59%
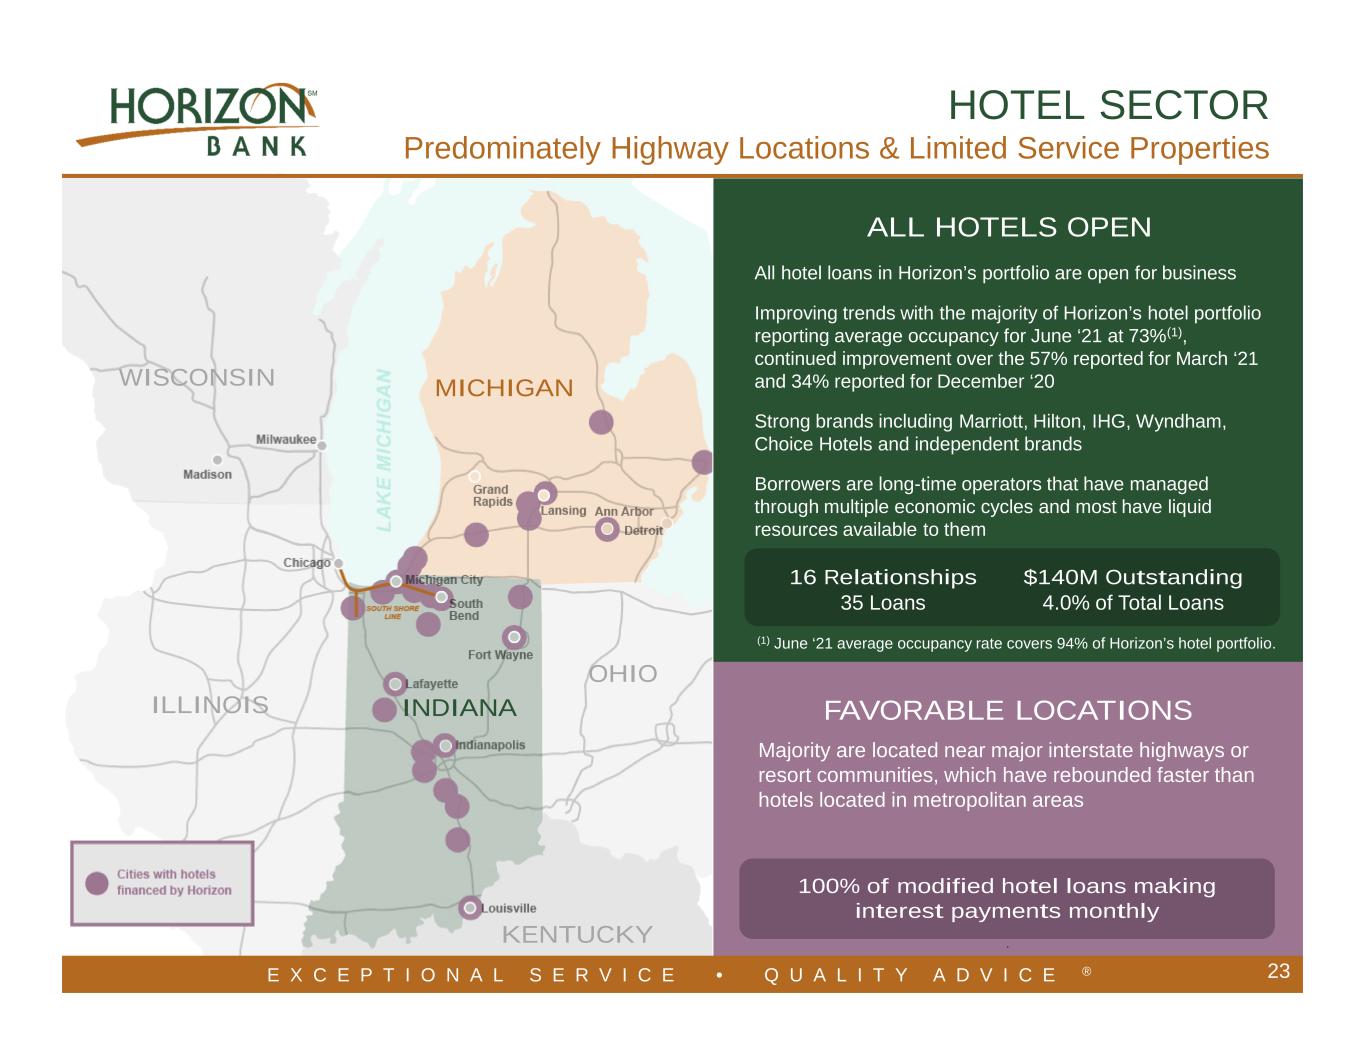
E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 23 HOTEL SECTOR Predominately Highway Locations & Limited Service Properties E X C E P T I O N A L S E R V I C E • Q U A L I T Y A D V I C E ® 23 FAVORABLE LOCATIONS Majority are located near major interstate highways or resort communities, which have rebounded faster than hotels located in metropolitan areas 100% of modified hotel loans making interest payments monthly ALL HOTELS OPEN All hotel loans in Horizon’s portfolio are open for business Improving trends with the majority of Horizon’s hotel portfolio reporting average occupancy for June ‘21 at 73%(1), continued improvement over the 57% reported for March ‘21 and 34% reported for December ‘20 Strong brands including Marriott, Hilton, IHG, Wyndham, Choice Hotels and independent brands Borrowers are long-time operators that have managed through multiple economic cycles and most have liquid resources available to them . INDIANA MICHIGAN OHIO ILLINOIS WISCONSIN KENTUCKY 16 Relationships 35 Loans $140M Outstanding 4.0% of Total Loans (1) June ‘21 average occupancy rate covers 94% of Horizon’s hotel portfolio.
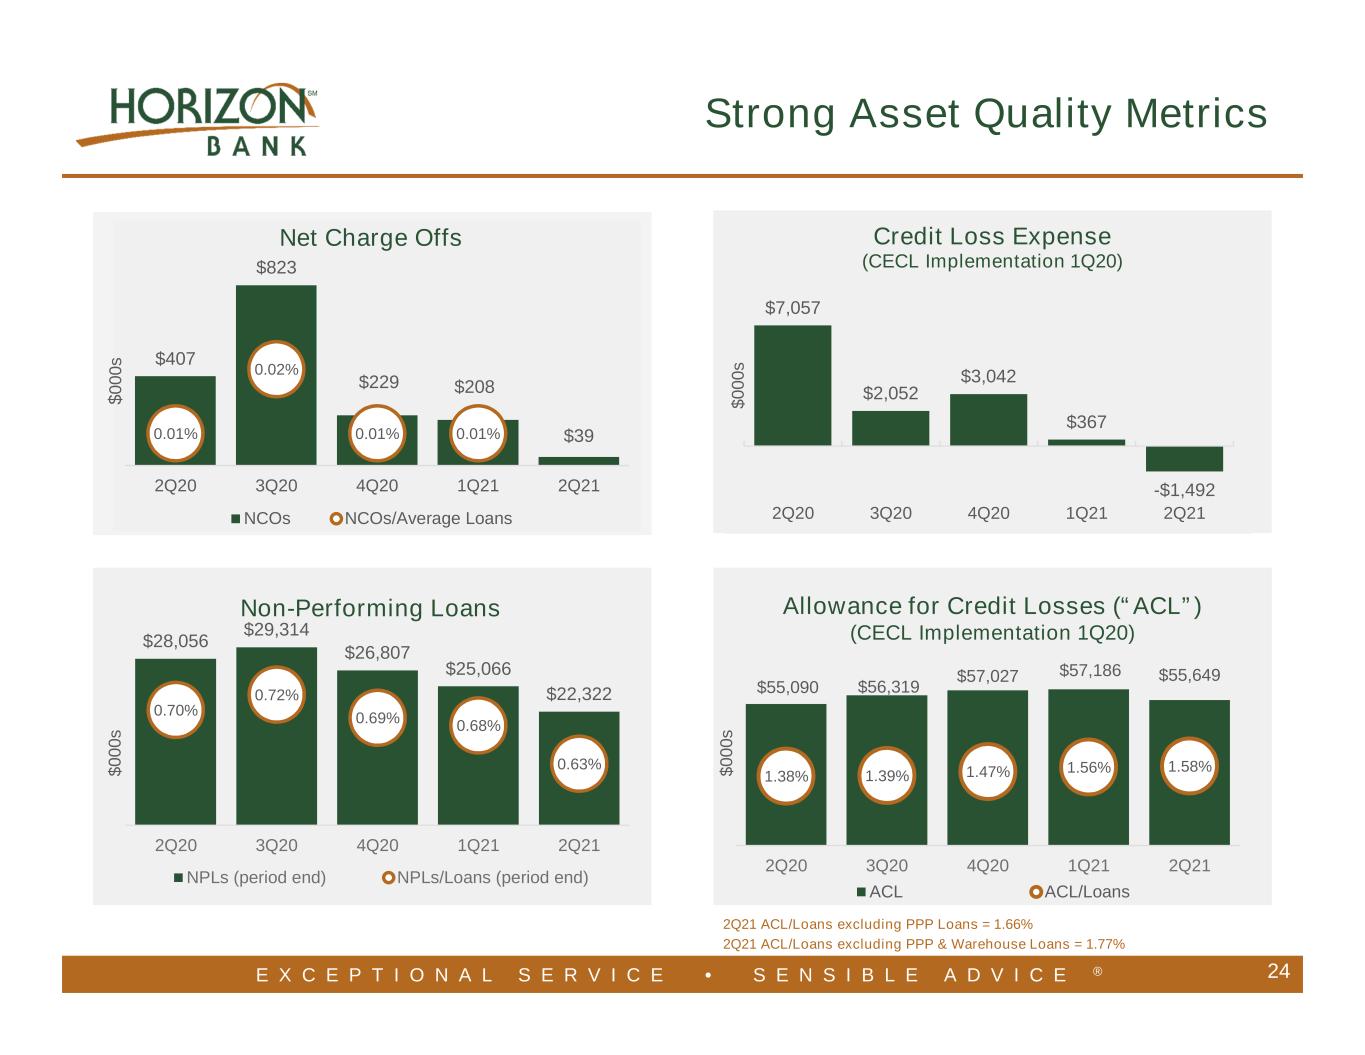
E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® $407 $823 $229 $208 $390.01% 0.02% 0.01% 0.01% 2Q20 3Q20 4Q20 1Q21 2Q21 Net Charge Offs NCOs NCOs/Average Loans $ 0 0 0 s $28,056 $29,314 $26,807 $25,066 $22,322 0.70% 0.72% 0.69% 0.68% 0.63% 2Q20 3Q20 4Q20 1Q21 2Q21 Non-Performing Loans NPLs (period end) NPLs/Loans (period end) $ 0 0 0 s $7,057 $2,052 $3,042 $367 -$1,492 2Q20 3Q20 4Q20 1Q21 2Q21 $ 0 0 0 s 24 CECL $55,090 $56,319 $57,027 $57,186 $55,649 1.38% 1.39% 1.47% 1.56% 1.58% 2Q20 3Q20 4Q20 1Q21 2Q21 ACL ACL/Loans Strong Asset Quality Metrics Allowance for Credit Losses (“ACL”) (CECL Implementation 1Q20) $ 0 0 0 s Credit Loss Expense (CECL Implementation 1Q20) 2Q21 ACL/Loans excluding PPP Loans = 1.66% 2Q21 ACL/Loans excluding PPP & Warehouse Loans = 1.77%

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 25 Key Franchise Highlights Positioned well for growth in 2022 and 2023, expansion of consumer dealer network, 20% increase in CLOs, 14 offices acquired, and closing 10 offices Geographic diversification & exposure – strong market share in core footprint Stable Midwest markets with balanced industrial bases and growth opportunities High quality balance sheet with strong liquidity – approximately $2.1 billion of cash and securities as of 6/30/21 Robust capital position 15.4% Tier 1 and 16.7% Total RBC as of 6/30/21 Building for loan growth, with complementary counter-cyclical revenue streams Historical run rate demonstrates strong core operating earnings 30-year unbroken quarterly cash dividend record, with strong cash position at the holding company that represents approximately 17 quarters of the current dividend plus fixed costs

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 26 Appendix

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® EMPLOYEES CONSUMERS BUSINESSES COMMUNITIES Safety and well being of employees & families is our first priority Installed sneeze guards, customer directional signage, implemented mask requirements, and continuing with sanitizing and social distancing protocols. Substantial reduction in percentage of employees working remotely 100% of our branch locations are open to lobby traffic Payment Relief: • Approximately $2 million in consumer & mortgage loans with payment extensions, down from $63 million at June 30, 2020 • Continue to provide new loans to qualified applicants • Providing mortgage loan education programs • Providing additional financial assistance in the form of fee waivers, freeze on all debt collection activities Preferred SBA Lender: • Active Participant in all SBA loan programs (PPP, 7a, Express & 504) Payment Relief Programs: • Approximately $51 million in commercial loans with payment extensions, down from $470 million at June 30, 2020 • Processed and received approval for 4,003 PPP loans (Rounds One and Two), funding approximately $450.1 million • As of June 30, 2021, $280.5 million forgiven Increased volunteerism in support of local not-for-profit entities Contributed over $300,000 to COVID-19 related not-for-profit efforts (local food banks, United Way, housing) Participated in community conference calls related to COVID-19 Partnered with local neighborhood housing partnerships to provide funding for low to moderate income families Partnered with local Certified Development Corporations to provide capital to small businesses 27 Note: Modification and PPP data as of June 30, 2021 COVID-19 Response Supporting Employees, Customers & Communities
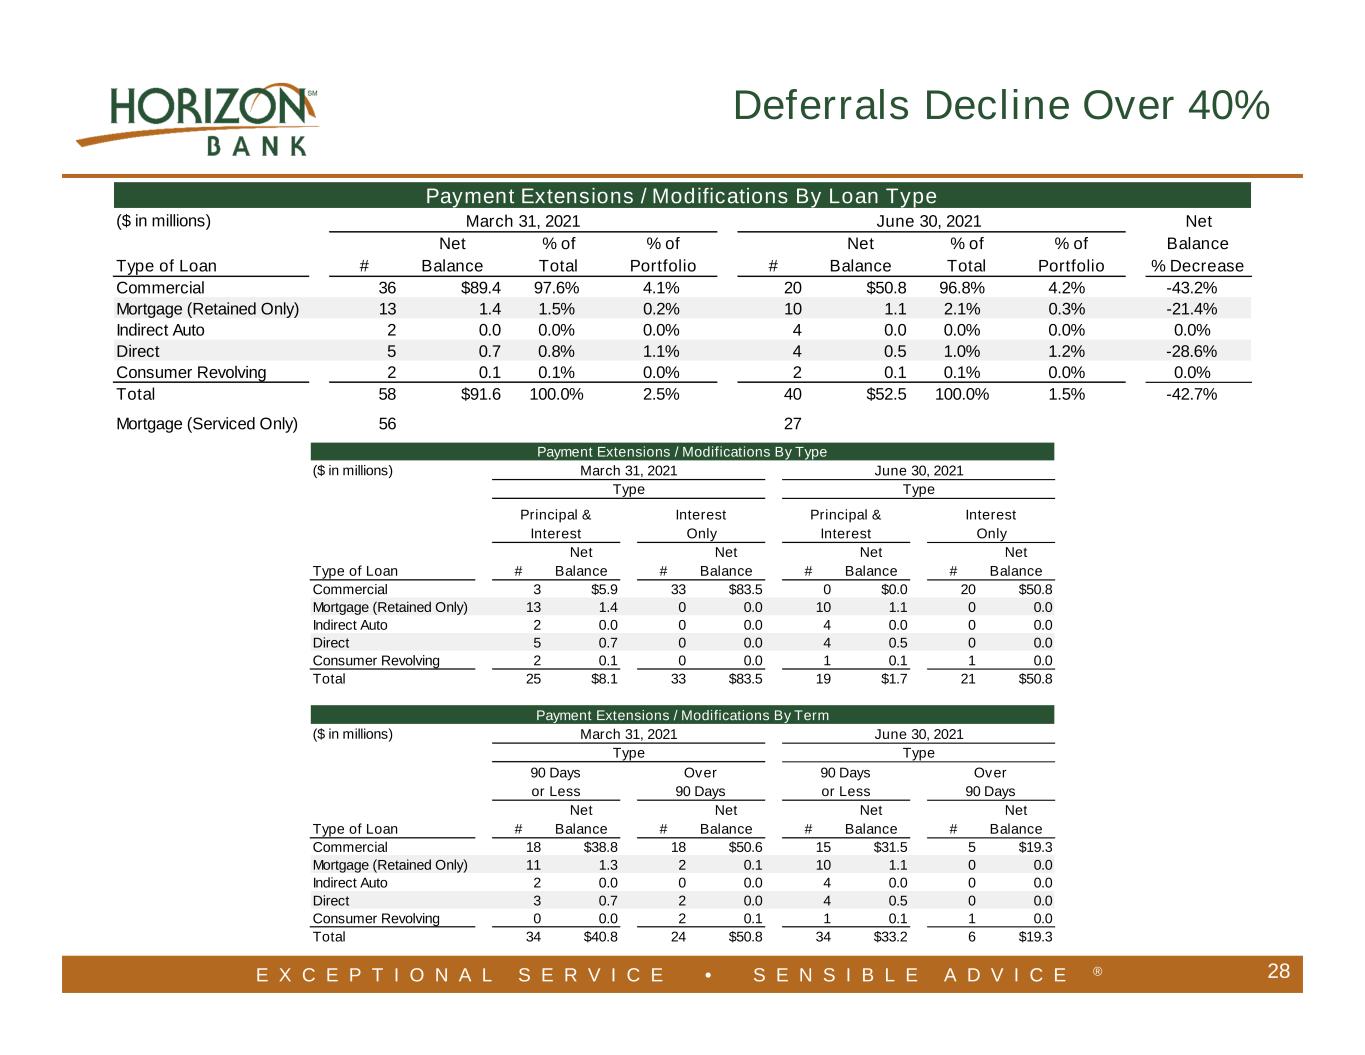
E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 28 Deferrals Decline Over 40% ($ in millions) Type of Loan # Net Balance # Net Balance # Net Balance # Net Balance Commercial 3 $5.9 33 $83.5 0 $0.0 20 $50.8 Mortgage (Retained Only) 13 1.4 0 0.0 10 1.1 0 0.0 Indirect Auto 2 0.0 0 0.0 4 0.0 0 0.0 Direct 5 0.7 0 0.0 4 0.5 0 0.0 Consumer Revolving 2 0.1 0 0.0 1 0.1 1 0.0 Total 25 $8.1 33 $83.5 19 $1.7 21 $50.8 ($ in millions) Type of Loan # Net Balance # Net Balance # Net Balance # Net Balance Commercial 18 $38.8 18 $50.6 15 $31.5 5 $19.3 Mortgage (Retained Only) 11 1.3 2 0.1 10 1.1 0 0.0 Indirect Auto 2 0.0 0 0.0 4 0.0 0 0.0 Direct 3 0.7 2 0.0 4 0.5 0 0.0 Consumer Revolving 0 0.0 2 0.1 1 0.1 1 0.0 Total 34 $40.8 24 $50.8 34 $33.2 6 $19.3 90 Days or Less Over 90 Days 90 Days or Less Over 90 Days Type Type Principal & Interest Interest Only Principal & Interest Interest Only Payment Extensions / Modifications By Term March 31, 2021 June 30, 2021 Type Type Payment Extensions / Modifications By Type March 31, 2021 June 30, 2021 ($ in millions) Net Type of Loan # Net Balance % of Total % of Portfolio # Net Balance % of Total % of Portfolio Balance % Decrease Commercial 36 $89.4 97.6% 4.1% 20 $50.8 96.8% 4.2% -43.2% Mortgage (Retained Only) 13 1.4 1.5% 0.2% 10 1.1 2.1% 0.3% -21.4% Indirect Auto 2 0.0 0.0% 0.0% 4 0.0 0.0% 0.0% 0.0% Direct 5 0.7 0.8% 1.1% 4 0.5 1.0% 1.2% -28.6% Consumer Revolving 2 0.1 0.1% 0.0% 2 0.1 0.1% 0.0% 0.0% Total 58 $91.6 100.0% 2.5% 40 $52.5 100.0% 1.5% -42.7% Mortgage (Serviced Only) 56 27 Payment Extensions / Modifications By Loan Type March 31, 2021 June 30, 2021
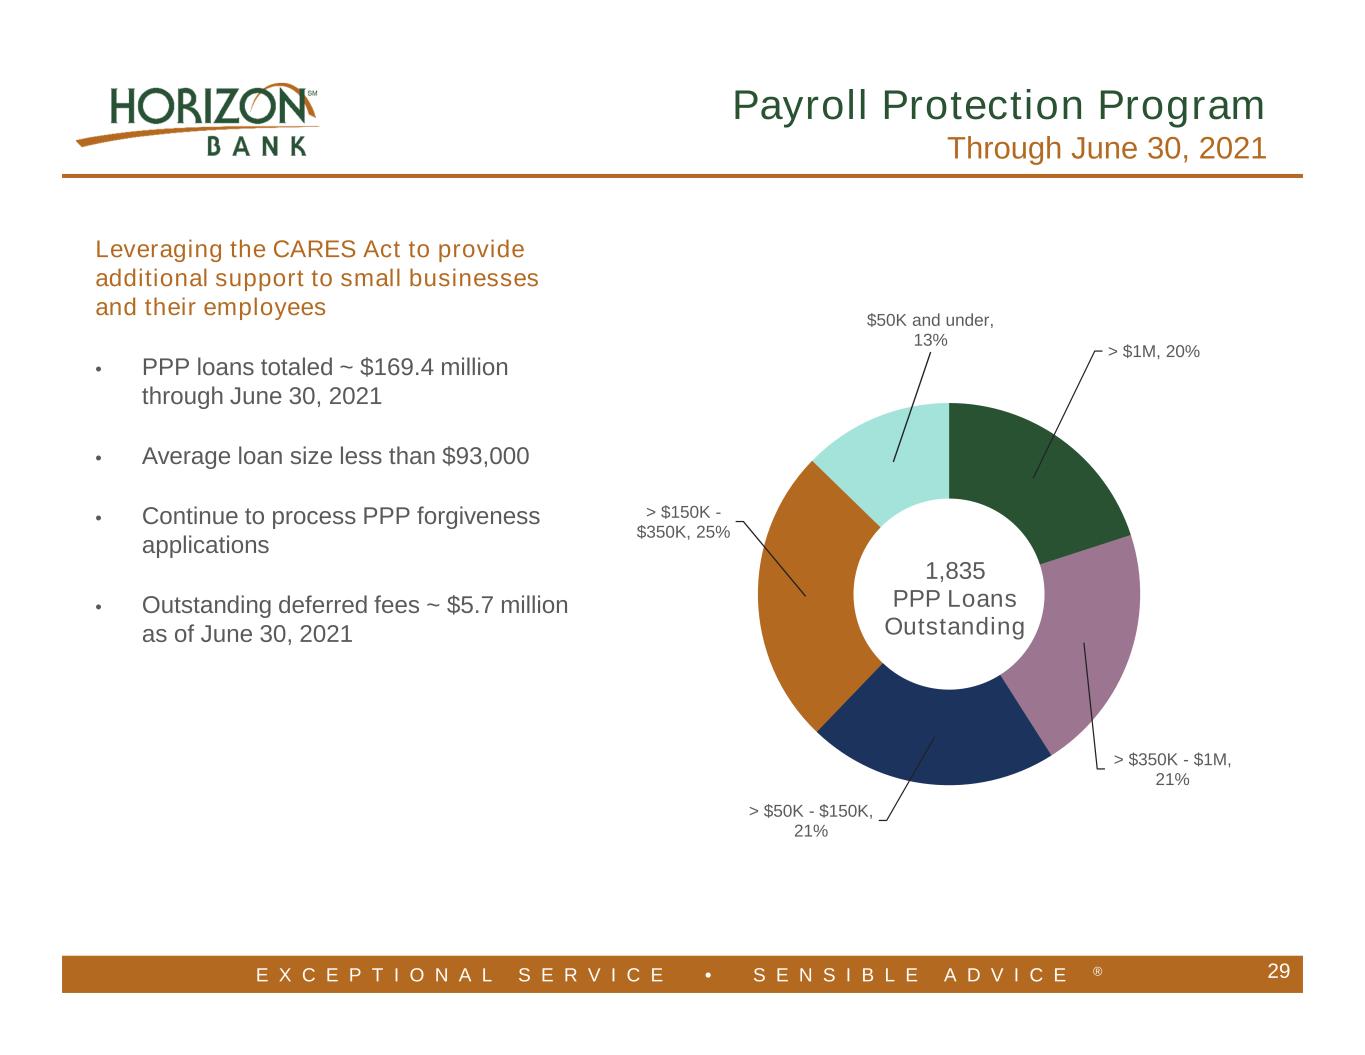
E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 29 Leveraging the CARES Act to provide additional support to small businesses and their employees • PPP loans totaled ~ $169.4 million through June 30, 2021 • Average loan size less than $93,000 • Continue to process PPP forgiveness applications • Outstanding deferred fees ~ $5.7 million as of June 30, 2021 > $1M, 20% > $350K - $1M, 21% > $50K - $150K, 21% > $150K - $350K, 25% $50K and under, 13% 1,835 PPP Loans Outstanding Payroll Protection Program Through June 30, 2021

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® Hotel, 4.0% NOO - Retail, 3.7% Restaurant, 1.6% Leisure & Hospitality, 0.9% 30 Hotels • 16 relationships with $139.8M outstanding across 35 loans • Average LTV of 58% and average loan size of ~ $4.0M • Approximately 77% select service / 11% full service / 7% independent / 5% economy properties • Modifications of $48.5M; (35%) • 100% of modifications paying interest monthly • Concentrated in Marriott, Hilton, IHG brands; (88%) • 72% of portfolio with sponsors exhibiting verified liquidity >$10M Non-Owner Occupied Retail • 78 loans with $131.9M outstanding (excluding PPP) • Average LTV 55% and average loan size of ~ $1.7M • No modified loans Restaurants • Over 149 loans with $57.4M outstanding (excluding PPP loans) • 43% full-service / 57% limited-service • Modifications of $1.4M; (2%) • Franchise restaurants $33.8M outstanding; (59%) • All loans making payments, no delinquency, 4 modified loans Leisure & Hospitality • 60 loans with $30.5M outstanding (excluding PPP loans) • Diverse borrowers, i.e. golf courses, entertainment facilities, fitness establishments, zoo • No modified loans Note: Modifications and outstandings as of 6/30/21 Sectors with Escalated Monitoring In-Footprint Focus with Many Longstanding Relationships $3.53B in Total Loans Outstanding at 6/30/21

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 2% 2% 2% 3% 3% 4% 5% 6% 7% 7% 10% Farm Land Lessors - Residential 1-4 Mini Storage All Others Medical Office Warehouse/ Industrial Lessors Student Housing Retail Motel Office (except medical) Lessors - Residential Multi Note: Data as of 6/30/21 1% 1% 1% 1% 1% 1% 2% 2% 3% 3% 4% Wholesale Trade Professional & Technical Services All Others Leisure and Hospitality Construction Manufacturing Restaurants Retail Trade Health Care, Edu. Social Assist. Individuals and Other Services Real Estate Rental & Leasing 1% 1% 1% 2% 2% 2% 2% 2% 2% 3% 3% 4% 4% Retail Trade Agriculture Transportation & Warehousing Government Real Estate Rental & Leasing Finance & Insurance All Others Professional & Technical Services Restaurants Manufacturing Individuals and Other Services Health Care, Educational Social Assist. Construction 31 Non-Owner Occupied CRE – % of Total Commercial Loans Owner Occupied CRE – % of Total Commercial Loans 51% of Total Commercial Loans $1.1 billion 20% of Total Commercial Loans $0.4 billion C&I Loans – % of Total Commercial Loans 29% of Total Commercial Loans $0.6 billion Low Levels of Concentrated Exposure Commercial Portfolio By Industry Type

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 32 Jumbo, 44.7% Rental, 0.9% Conforming, 50.5% Construction, 3.9% Total Outstanding at 6/30/21 $559M • 73% of production sold YTD • Predominantly in-market lender • Portfolio mortgages • Underwriting to Fannie Mae guidelines • Full documentation of employment, income and asset verification • 92.4% prime with credit score ≥670 • Strong asset quality through end of 1Q21 • 30-89 days past due • 2Q21 – 0.19% • 1Q21 – 0.21% • NPLs • 2Q21 – 1.38% • 1Q21 – 1.35% Prime Mortgage Loan Portfolio as of June 30, 2021
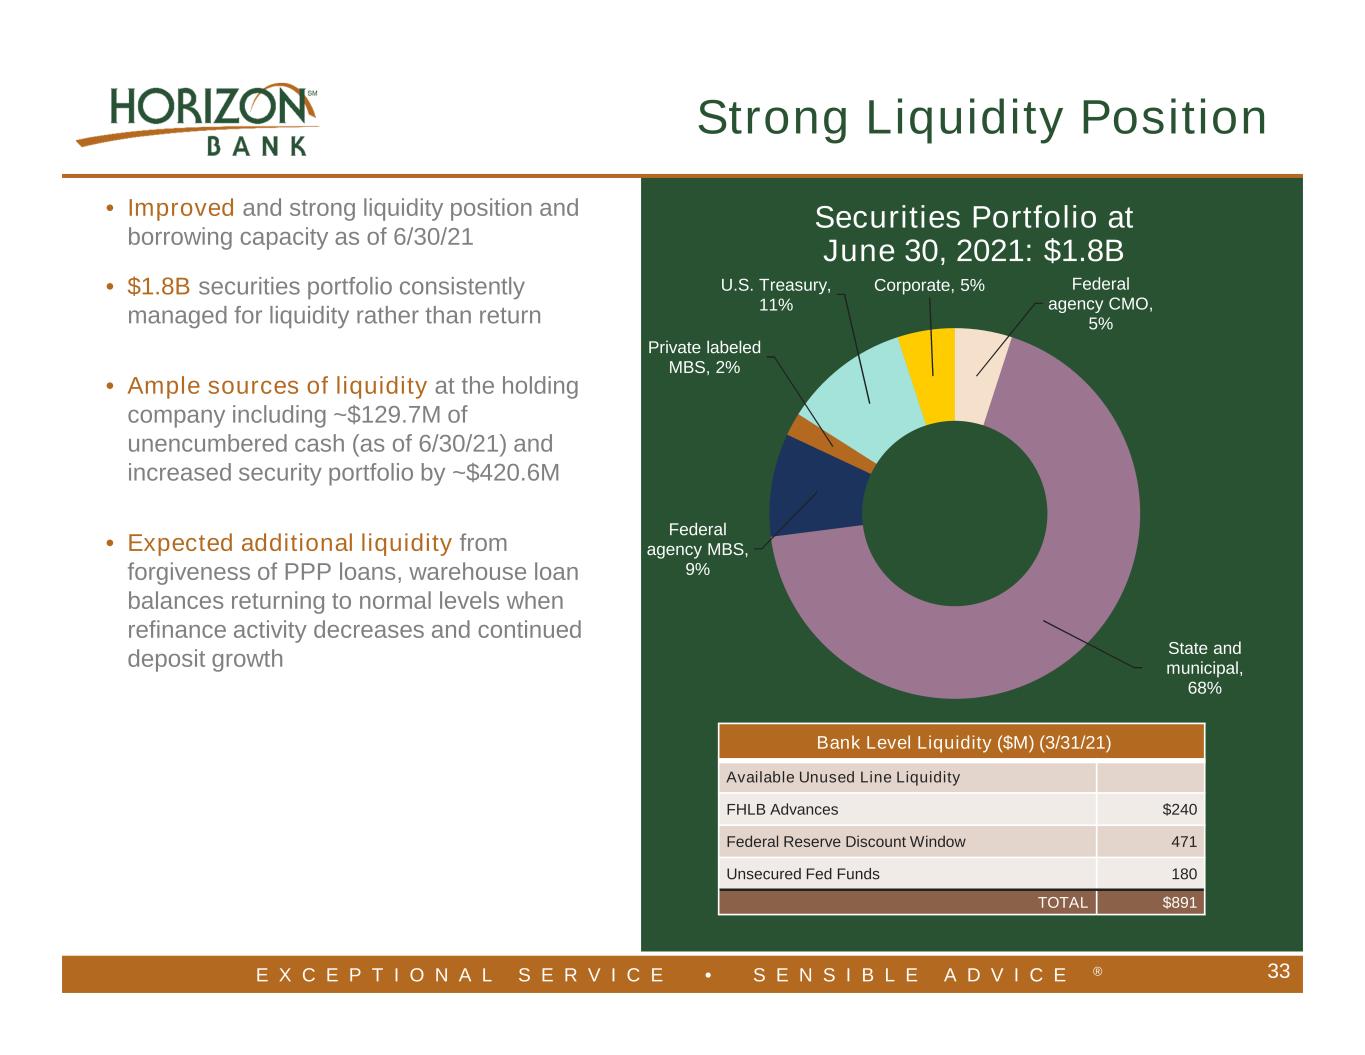
E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® Federal agency CMO, 5% State and municipal, 68% Federal agency MBS, 9% Private labeled MBS, 2% U.S. Treasury, 11% Corporate, 5% 33 • Improved and strong liquidity position and borrowing capacity as of 6/30/21 • $1.8B securities portfolio consistently managed for liquidity rather than return • Ample sources of liquidity at the holding company including ~$129.7M of unencumbered cash (as of 6/30/21) and increased security portfolio by ~$420.6M • Expected additional liquidity from forgiveness of PPP loans, warehouse loan balances returning to normal levels when refinance activity decreases and continued deposit growth Strong Liquidity Position Securities Portfolio at June 30, 2021: $1.8B Bank Level Liquidity ($M) (3/31/21) Available Unused Line Liquidity FHLB Advances $240 Federal Reserve Discount Window 471 Unsecured Fed Funds 180 TOTAL $891
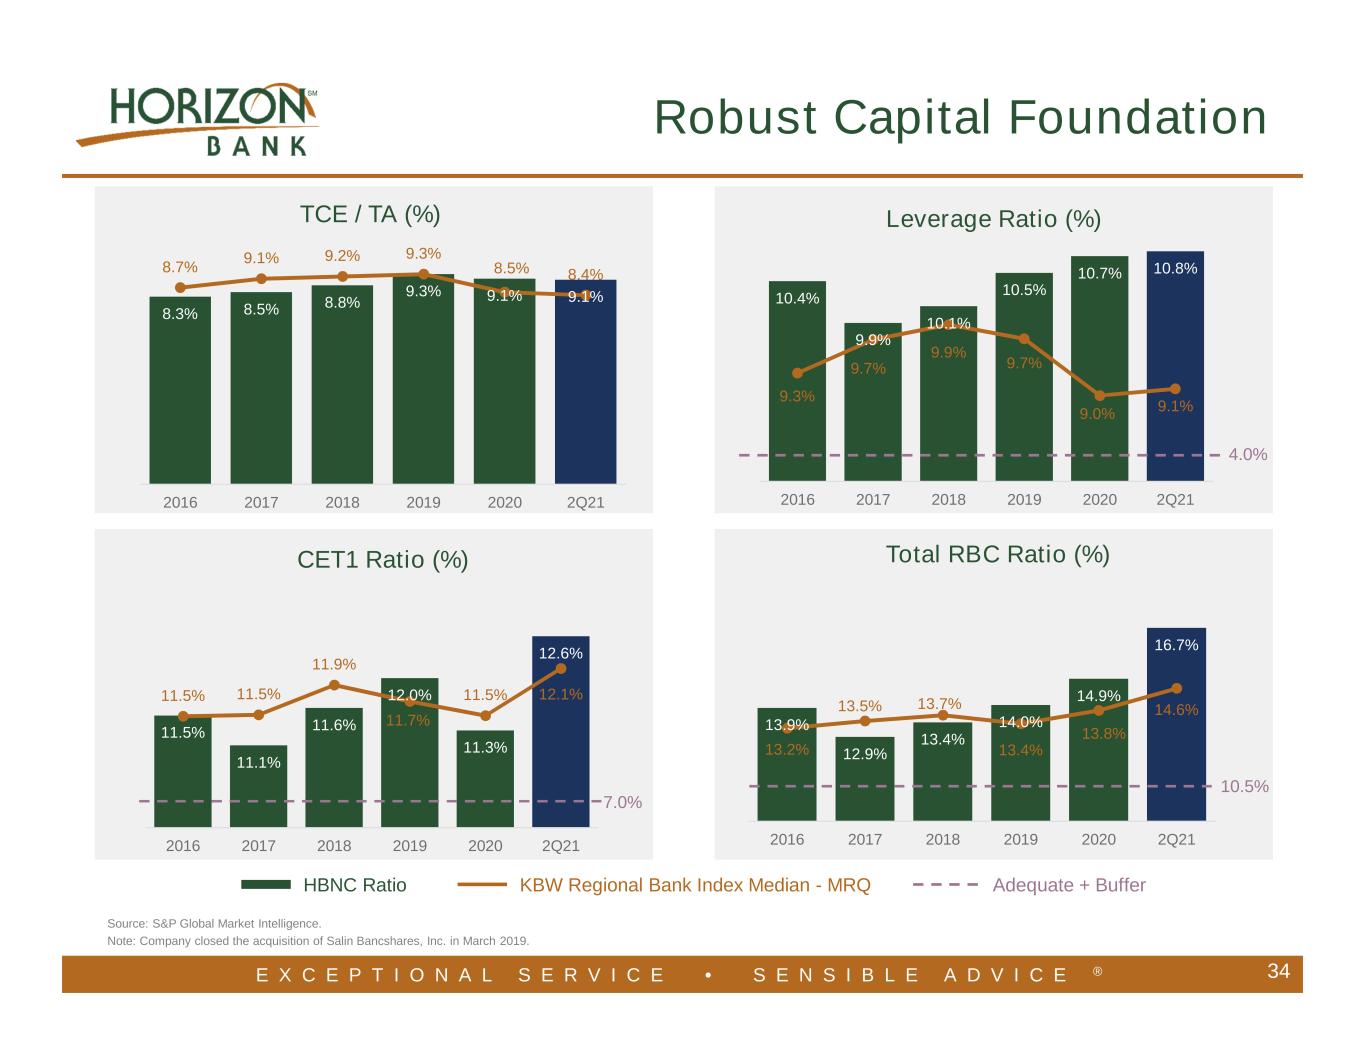
E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 11.5% 11.1% 11.6% 12.0% 11.3% 12.6% 11.5% 11.5% 11.9% 11.7% 11.5% 12.1% 2016 2017 2018 2019 2020 2Q21 10.4% 9.9% 10.1% 10.5% 10.7% 10.8% 9.3% 9.7% 9.9% 9.7% 9.0% 9.1% 2016 2017 2018 2019 2020 2Q21 13.9% 12.9% 13.4% 14.0% 14.9% 16.7% 13.2% 13.5% 13.7% 13.4% 13.8% 14.6% 2016 2017 2018 2019 2020 2Q21 Source: S&P Global Market Intelligence. Note: Company closed the acquisition of Salin Bancshares, Inc. in March 2019. 34 TCE / TA (%) Leverage Ratio (%) Total RBC Ratio (%) 4.0% Adequate + Buffer 7.0% KBW Regional Bank Index Median - MRQ Robust Capital Foundation 10.5% HBNC Ratio 8.3% 8.5% 8.8% 9.3% 9.1% 9.1% 8.7% 9.1% 9.2% 9.3% 8.5% 8.4% 2016 2017 2018 2019 2020 2Q21 CET1 Ratio (%)
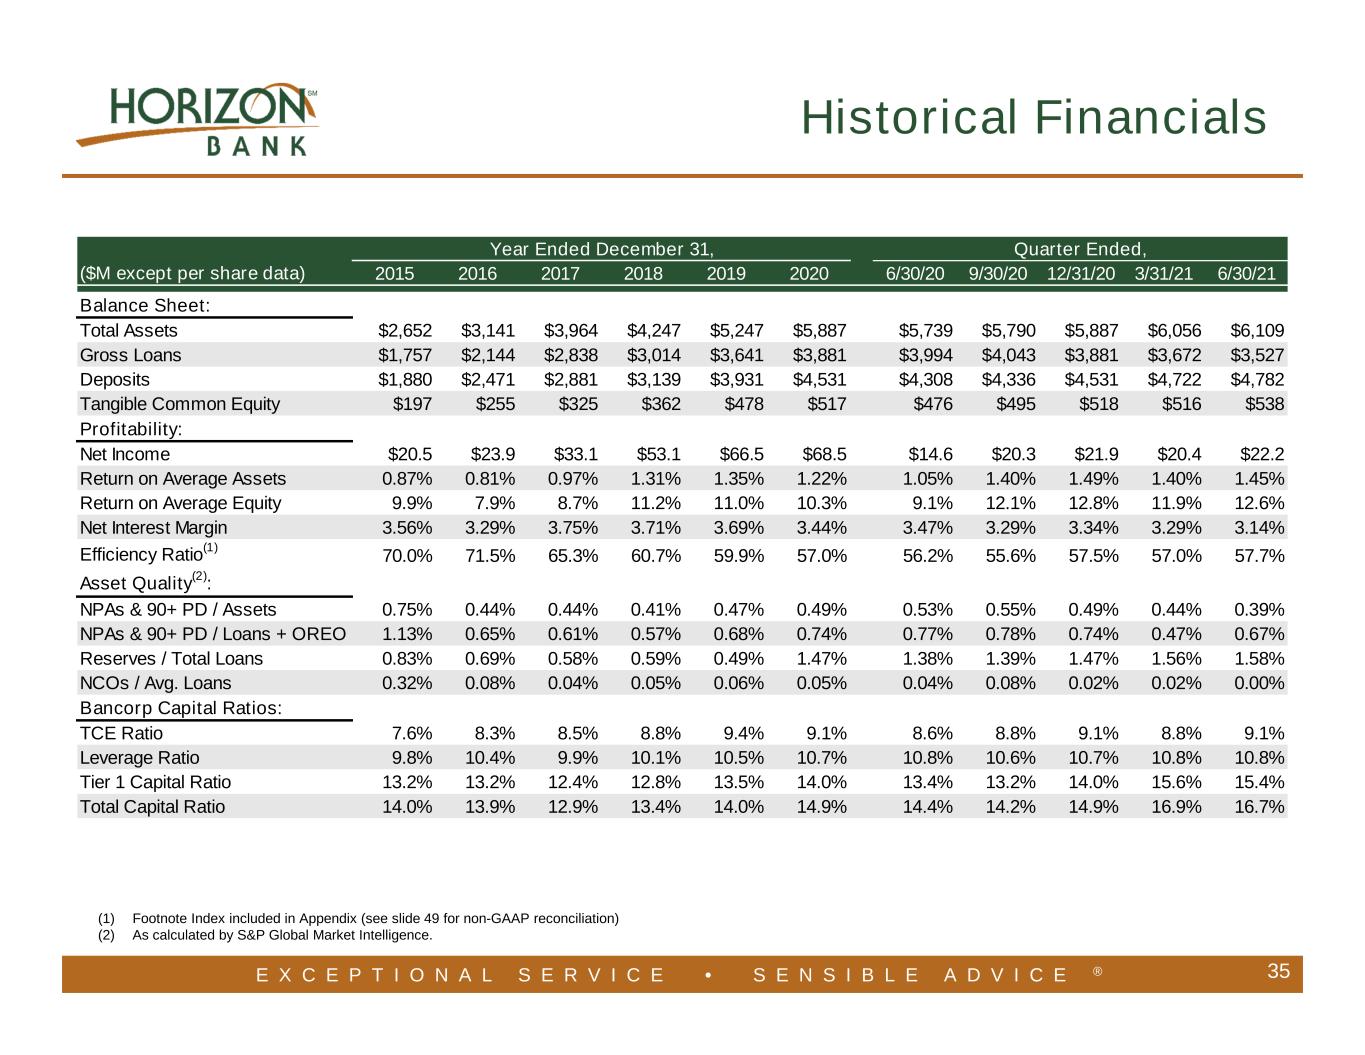
E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 35 (1) Footnote Index included in Appendix (see slide 49 for non-GAAP reconciliation) (2) As calculated by S&P Global Market Intelligence. Historical Financials ($M except per share data) 2015 2016 2017 2018 2019 2020 6/30/20 9/30/20 12/31/20 3/31/21 6/30/21 Balance Sheet: Total Assets $2,652 $3,141 $3,964 $4,247 $5,247 $5,887 $5,739 $5,790 $5,887 $6,056 $6,109 Gross Loans $1,757 $2,144 $2,838 $3,014 $3,641 $3,881 $3,994 $4,043 $3,881 $3,672 $3,527 Deposits $1,880 $2,471 $2,881 $3,139 $3,931 $4,531 $4,308 $4,336 $4,531 $4,722 $4,782 Tangible Common Equity $197 $255 $325 $362 $478 $517 $476 $495 $518 $516 $538 Profitability: Net Income $20.5 $23.9 $33.1 $53.1 $66.5 $68.5 $14.6 $20.3 $21.9 $20.4 $22.2 Return on Average Assets 0.87% 0.81% 0.97% 1.31% 1.35% 1.22% 1.05% 1.40% 1.49% 1.40% 1.45% Return on Average Equity 9.9% 7.9% 8.7% 11.2% 11.0% 10.3% 9.1% 12.1% 12.8% 11.9% 12.6% Net Interest Margin 3.56% 3.29% 3.75% 3.71% 3.69% 3.44% 3.47% 3.29% 3.34% 3.29% 3.14% Efficiency Ratio (1) 70.0% 71.5% 65.3% 60.7% 59.9% 57.0% 56.2% 55.6% 57.5% 57.0% 57.7% Asset Quality (2) : NPAs & 90+ PD / Assets 0.75% 0.44% 0.44% 0.41% 0.47% 0.49% 0.53% 0.55% 0.49% 0.44% 0.39% NPAs & 90+ PD / Loans + OREO 1.13% 0.65% 0.61% 0.57% 0.68% 0.74% 0.77% 0.78% 0.74% 0.47% 0.67% Reserves / Total Loans 0.83% 0.69% 0.58% 0.59% 0.49% 1.47% 1.38% 1.39% 1.47% 1.56% 1.58% NCOs / Avg. Loans 0.32% 0.08% 0.04% 0.05% 0.06% 0.05% 0.04% 0.08% 0.02% 0.02% 0.00% Bancorp Capital Ratios: TCE Ratio 7.6% 8.3% 8.5% 8.8% 9.4% 9.1% 8.6% 8.8% 9.1% 8.8% 9.1% Leverage Ratio 9.8% 10.4% 9.9% 10.1% 10.5% 10.7% 10.8% 10.6% 10.7% 10.8% 10.8% Tier 1 Capital Ratio 13.2% 13.2% 12.4% 12.8% 13.5% 14.0% 13.4% 13.2% 14.0% 15.6% 15.4% Total Capital Ratio 14.0% 13.9% 12.9% 13.4% 14.0% 14.9% 14.4% 14.2% 14.9% 16.9% 16.7% Year Ended December 31, Quarter Ended,
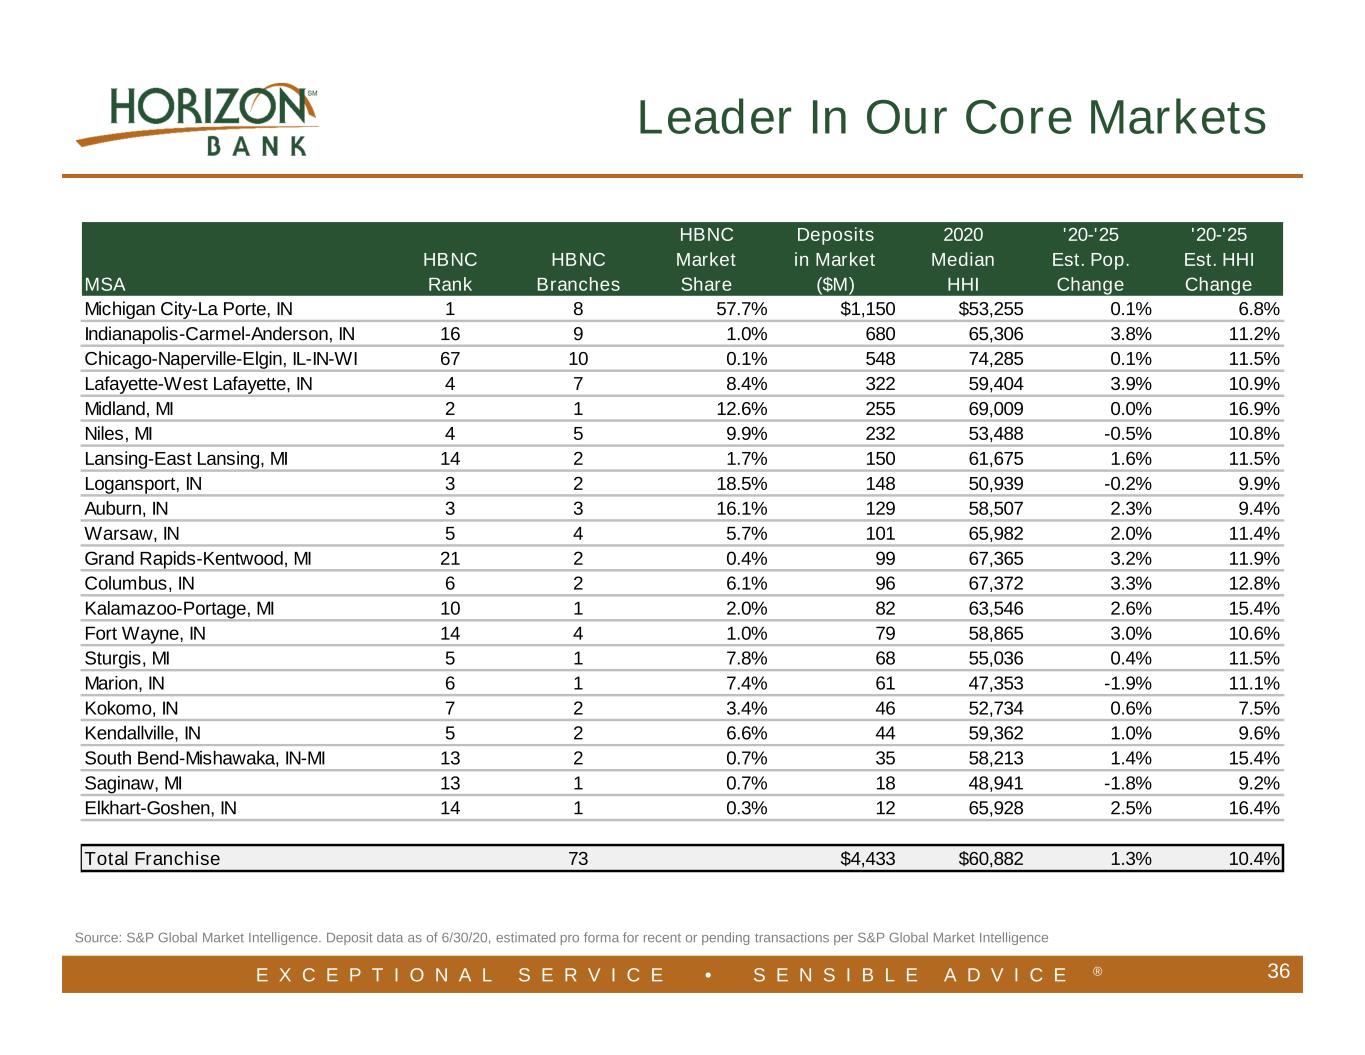
E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 36 Leader In Our Core Markets MSA HBNC Rank HBNC Branches HBNC Market Share Deposits in Market ($M) 2020 Median HHI '20-'25 Est. Pop. Change '20-'25 Est. HHI Change Michigan City-La Porte, IN 1 8 57.7% $1,150 $53,255 0.1% 6.8% Indianapolis-Carmel-Anderson, IN 16 9 1.0% 680 65,306 3.8% 11.2% Chicago-Naperville-Elgin, IL-IN-WI 67 10 0.1% 548 74,285 0.1% 11.5% Lafayette-West Lafayette, IN 4 7 8.4% 322 59,404 3.9% 10.9% Midland, MI 2 1 12.6% 255 69,009 0.0% 16.9% Niles, MI 4 5 9.9% 232 53,488 -0.5% 10.8% Lansing-East Lansing, MI 14 2 1.7% 150 61,675 1.6% 11.5% Logansport, IN 3 2 18.5% 148 50,939 -0.2% 9.9% Auburn, IN 3 3 16.1% 129 58,507 2.3% 9.4% Warsaw, IN 5 4 5.7% 101 65,982 2.0% 11.4% Grand Rapids-Kentwood, MI 21 2 0.4% 99 67,365 3.2% 11.9% Columbus, IN 6 2 6.1% 96 67,372 3.3% 12.8% Kalamazoo-Portage, MI 10 1 2.0% 82 63,546 2.6% 15.4% Fort Wayne, IN 14 4 1.0% 79 58,865 3.0% 10.6% Sturgis, MI 5 1 7.8% 68 55,036 0.4% 11.5% Marion, IN 6 1 7.4% 61 47,353 -1.9% 11.1% Kokomo, IN 7 2 3.4% 46 52,734 0.6% 7.5% Kendallville, IN 5 2 6.6% 44 59,362 1.0% 9.6% South Bend-Mishawaka, IN-MI 13 2 0.7% 35 58,213 1.4% 15.4% Saginaw, MI 13 1 0.7% 18 48,941 -1.8% 9.2% Elkhart-Goshen, IN 14 1 0.3% 12 65,928 2.5% 16.4% Total Franchise 73 $4,433 $60,882 1.3% 10.4% Source: S&P Global Market Intelligence. Deposit data as of 6/30/20, estimated pro forma for recent or pending transactions per S&P Global Market Intelligence

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 37 Slide 12 • Adjusted net income and adjusted diluted EPS excludes one-time merger expenses, (gain)/loss on sale of securities and death benefit on bank owned life insurance, net of tax. (See further in the Appendix for a reconciliation of these non-GAAP amounts to their GAAP counterparts.) • Pre-tax, pre-provision income excludes income tax expense and credit loss expense. (See further in the Appendix for a reconciliation of these non-GAAP amounts to their GAAP counterparts.) • Adjusted net interest income and adjusted net margin exclude acquisition-related purchase accounting adjustments. (See further in the Appendix for a reconciliation of these non-GAAP amounts to their GAAP counterparts.) • Adjusted ROAA and Adjusted pre-tax, pre-provision ROAA excludes one-time merger expenses, (gain)/loss on sale of securities and death benefit on bank owned life insurance, net of tax. (See further in the Appendix for a reconciliation of these non-GAAP amounts to their GAAP counterparts.) Slide 13 • Adjusted net interest income and adjusted net interest margin excludes prepayment penalties on borrowings and acquisition-related purchase accounting adjustments. Adjusted cost of core funds includes average balances of non- interest bearing deposits and excludes prepayment penalties on borrowings. (See further in the Appendix for a reconciliation of these non-GAAP amounts to their GAAP counterparts.) Slide 15 • Average cost of average total deposits includes average balances of non-interest bearing deposits. (See further in the Appendix for a reconciliation of these non-GAAP amounts to their GAAP counterparts.) Slide 17 • Adjusted efficiency ratio excludes one-time merger expenses, (gain)/loss on sale of securities and death benefit on bank owned life insurance. (See further in the Appendix for a reconciliation of these non-GAAP amounts to their GAAP counterparts.) Slides 38-49 Use of Non-GAAP Financial Measures • Certain information set forth in the presentation materials refers to financial measures determined by methods other than in accordance with GAAP. Horizon believes these non-GAAP financial measures are helpful to investors and provide a greater understanding of our business without giving effect to purchase accounting impacts, one-time acquisition and other non-recurring costs and non-core items. These measures are not necessarily comparable to similar measures that may be presented by other companies and should not be considered in isolation or as a substitute for the related GAAP measure. Footnote Index

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 38 Footnote Index June 30, March 31, December 31, September 30, June 30, 2021 2021 2020 2020 2020 Pre-tax income 25,943$ 23,872$ 23,860$ 24,638$ 16,632$ Provision for credit losses (1,492) 367 3,042 2,052 7,057 Pre-tax, pre-provision net income 24,451$ 24,239$ 26,902$ 26,690$ 23,689$ Pre-tax, pre-provision net income 24,451$ 24,239$ 26,902$ 26,690$ 23,689$ Acquisition expenses 242 - - - - (Gain)/loss on sale of investment securities - (914) (2,622) (1,088) (248) Death benefit on bank owned life insurance (266) - - (31) - Prepayment penalties on borrowings 125 - 3,804 - - Adjusted pre-tax, pre-provision net income 24,552$ 23,325$ 28,084$ 25,571$ 23,441$ Average Assets 6,142,507$ 5,936,149$ 5,864,086$ 5,768,691$ 5,620,695$ Unadjusted pre-tax, pre-provision ROAA 1.60% 1.66% 1.83% 1.84% 1.70% Adjusted pre-tax, pre-provision ROAA 1.60% 1.59% 1.91% 1.76% 1.68% Three Months Ended Non-GAAP Reconciliation of Pre-Tax, Pre-Provision Net Income (Dollars in Thousands, Unaudited)

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 39 Footnote Index June 30, March 31, December 31, September 30, June 30, 2021 2021 2020 2020 2020 Net income as reported 22,173$ 20,422$ 21,893$ 20,312$ 14,639$ Acquisition expenses 242 - - - - Tax effect (51) - - - - Net income excluding acquisition expenses 22,364 20,422 21,893 20,312 14,639 (Gain)/loss on sale of investment securities - (914) (2,622) (1,088) (248) Tax effect - 192 551 228 52 Net income excluding (gain)/loss on sale of investment securities 22,364 19,700 19,822 19,452 14,443 Death benefit on bank owned life insurance ("BOLI") (266) - - (31) - Net income excluding death benefit on BOLI 22,098 19,700 19,822 19,421 14,443 Prepayment penalties on borrowings 125 - 3,804 - - Tax effect (26) - (799) - - Net income excluding prepayment penalties on borrowings 22,197 19,700 22,827 19,421 14,443 Adjusted net income 22,197$ 19,700$ 22,827$ 19,421$ 14,443$ Non-GAAP Reconciliation of Net Income (Dollars in Thousands, Unaudited) Three Months Ended

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 40 Footnote Index June 30, March 31, December 31, September 30, June 30, 2021 2021 2020 2020 2020 Diluted EPS as reported 0.50$ 0.46$ 0.50$ 0.46$ 0.33$ Acquisition expenses 0.01 - - - - Tax effect - - - - - Diluted EPS excluding acquisition expenses 0.51 0.46 0.50 0.46 0.33 (Gain)/loss on sale of investment securities - (0.02) (0.06) (0.02) (0.01) Tax effect - - 0.01 0.01 - Diluted EPS excluding (gain)/loss on sale of investment securities 0.51 0.44 0.45 0.45 0.32 Death benefit on bank owned life insurance ("BOLI") (0.01) - - - - Diluted EPS excluding death benefit on BOLI 0.50 0.44 0.45 0.45 0.32 Prepayment penalties on borrowings - - 0.09 - - Tax effect - - (0.02) - - Diluted EPS excluding prepayment penalties on borrowings 0.50 0.44 0.52 0.45 0.32 Adjusted diluted EPS 0.50$ 0.44$ 0.52$ 0.45$ 0.32$ Three Months Ended Non-GAAP Reconciliation of Diluted Earnings per Share (Dollars in Thousands, Unaudited)

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 41 Footnote Index June 30, March 31, December 31, September 30, June 30, 2021 2021 2020 2020 2020 Average assets 6,142,507$ 5,936,149$ 5,864,086$ 5,768,691$ 5,620,695$ Return on average assets ("ROAA") as reported 1.45% 1.40% 1.49% 1.40% 1.05% Acquisition expenses 0.02 - - - - Tax effect - - - - - ROAA excluding acquisition expenses 1.47 1.40 1.49 1.40 1.05 (Gain)/loss on sale of investment securities - (0.06) (0.18) (0.08) (0.02) Tax effect - 0.01 0.04 0.02 - ROAA excluding (gain)/loss on sale of investment securities 1.47 1.35 1.35 1.34 1.03 Death benefit on bank owned life insurance ("BOLI") (0.02) - - - - ROAA excluding death benefit on BOLI 1.45 1.35 1.35 1.34 1.03 Prepayment penalty on borrowings 0.01 - 0.26 - - Tax effect - - (0.05) - - ROAA excluding prepayment penalties on borrowings 1.46 1.35 1.56 1.34 1.03 Adjusted ROAA 1.46% 1.35% 1.56% 1.34% 1.03% Non-GAAP Reconciliation of Return on Average Assets (Dollars in Thousands, Unaudited) Three Months Ended

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 42 Footnote Index June 30, March 31, December 31, September 30, June 30, March 31, 2021 2021 2020 2020 2020 2020 Net interest income as reported 42,632$ 42,538$ 43,622$ 43,397$ 42,996$ 40,925$ Average interest earning assets 5,659,384 5,439,634 5,365,888 5,251,611 5,112,636 4,746,202 Net interest income as a percentage of average interest earning assets ("Net Interest Margin") 3.14% 3.29% 3.34% 3.39% 3.47% 3.56% Net interest income as reported 42,632$ 42,538$ 43,622$ 43,397$ 42,996$ 40,925$ Prepayment penalties on borrowings 125 - 3,804 - - - Acquisition-related purchase accounting adjustments ("PAU") (230) (1,579) (2,461) (1,488) (1,553) (1,434) Adjusted net interest income 42,527$ 40,959$ 44,965$ 41,909$ 41,443$ 39,491$ Adjusted net interest margin 3.13% 3.17% 3.44% 3.27% 3.35% 3.44% Non-GAAP Reconciliation of Net Interest Margin (Dollars in Thousands, Unaudited) Three Months Ended
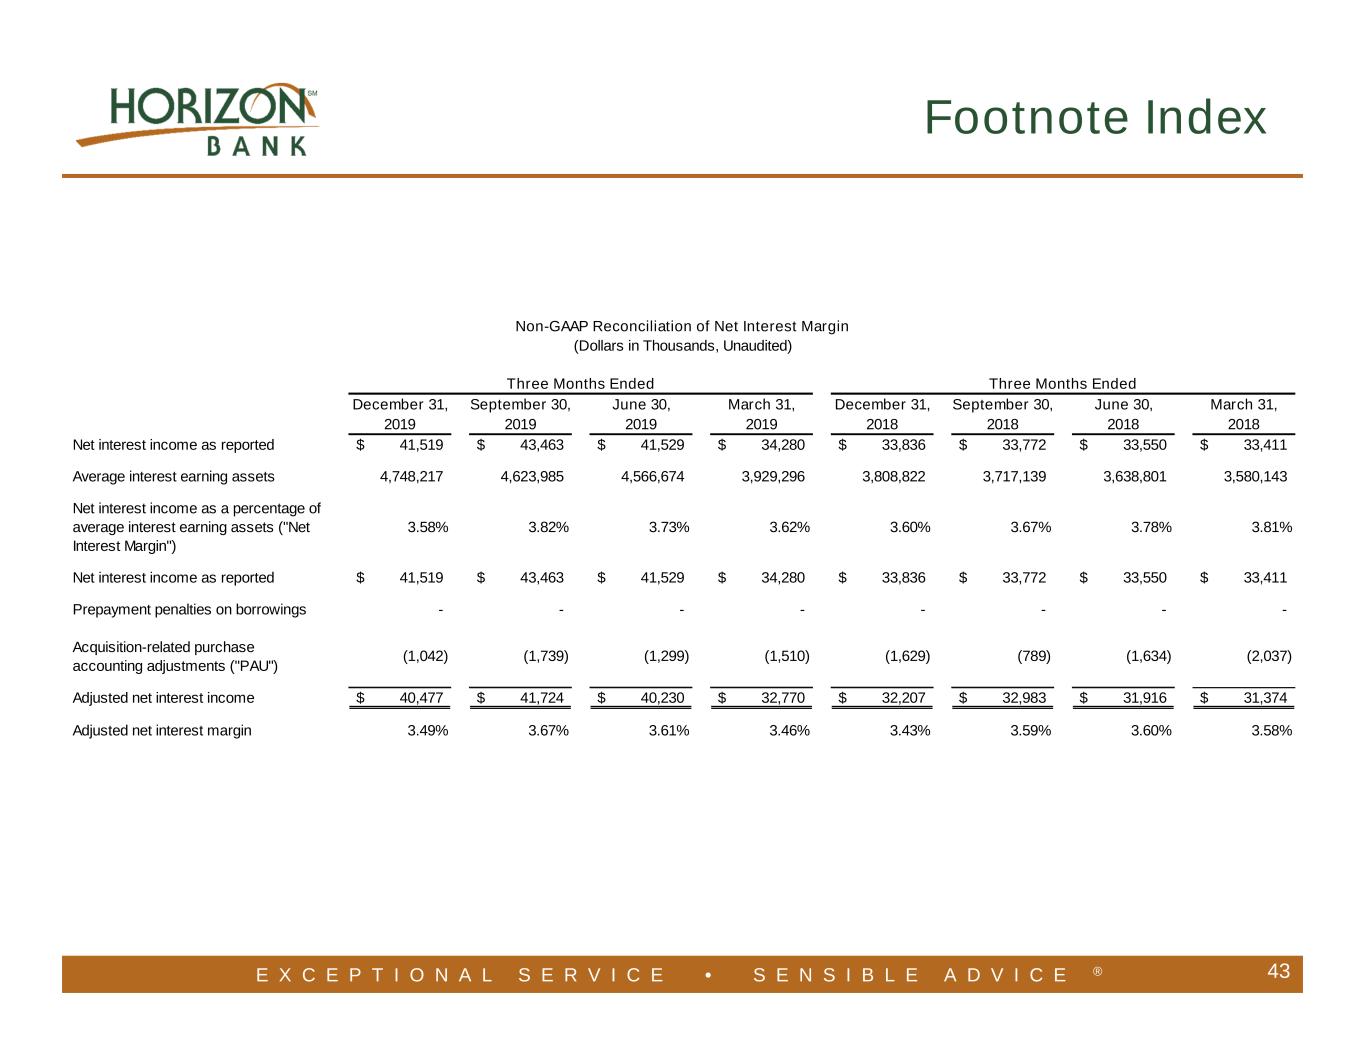
E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 43 Footnote Index December 31, September 30, June 30, March 31, December 31, September 30, June 30, March 31, 2019 2019 2019 2019 2018 2018 2018 2018 Net interest income as reported 41,519$ 43,463$ 41,529$ 34,280$ 33,836$ 33,772$ 33,550$ 33,411$ Average interest earning assets 4,748,217 4,623,985 4,566,674 3,929,296 3,808,822 3,717,139 3,638,801 3,580,143 Net interest income as a percentage of average interest earning assets ("Net Interest Margin") 3.58% 3.82% 3.73% 3.62% 3.60% 3.67% 3.78% 3.81% Net interest income as reported 41,519$ 43,463$ 41,529$ 34,280$ 33,836$ 33,772$ 33,550$ 33,411$ Prepayment penalties on borrowings - - - - - - - - Acquisition-related purchase accounting adjustments ("PAU") (1,042) (1,739) (1,299) (1,510) (1,629) (789) (1,634) (2,037) Adjusted net interest income 40,477$ 41,724$ 40,230$ 32,770$ 32,207$ 32,983$ 31,916$ 31,374$ Adjusted net interest margin 3.49% 3.67% 3.61% 3.46% 3.43% 3.59% 3.60% 3.58% Three Months EndedThree Months Ended Non-GAAP Reconciliation of Net Interest Margin (Dollars in Thousands, Unaudited)
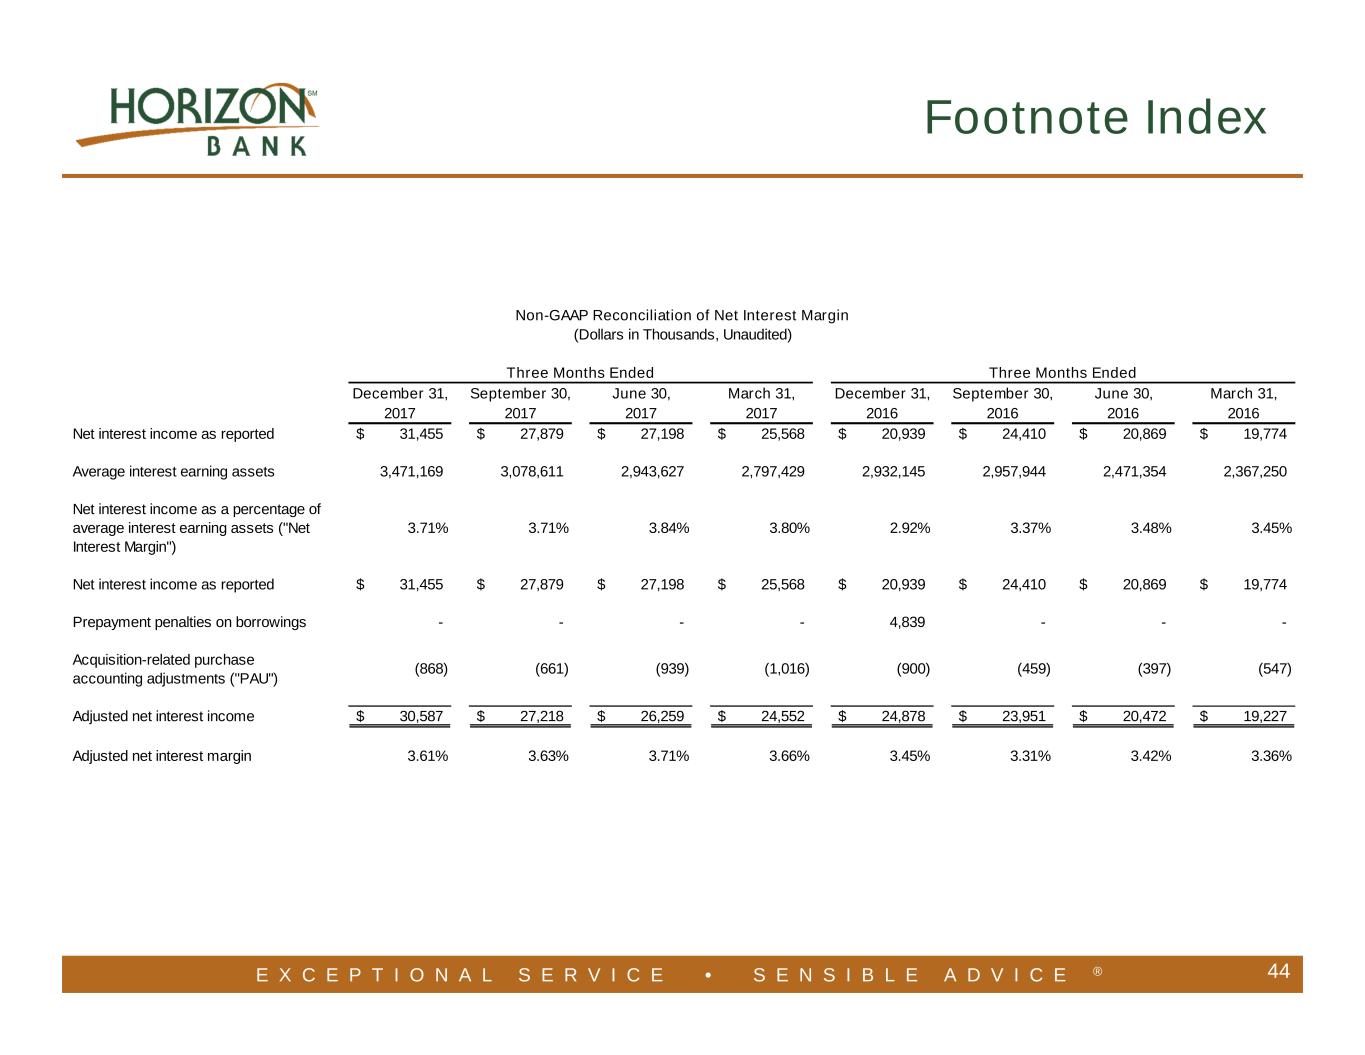
E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 44 Footnote Index December 31, September 30, June 30, March 31, December 31, September 30, June 30, March 31, 2017 2017 2017 2017 2016 2016 2016 2016 Net interest income as reported 31,455$ 27,879$ 27,198$ 25,568$ 20,939$ 24,410$ 20,869$ 19,774$ Average interest earning assets 3,471,169 3,078,611 2,943,627 2,797,429 2,932,145 2,957,944 2,471,354 2,367,250 Net interest income as a percentage of average interest earning assets ("Net Interest Margin") 3.71% 3.71% 3.84% 3.80% 2.92% 3.37% 3.48% 3.45% Net interest income as reported 31,455$ 27,879$ 27,198$ 25,568$ 20,939$ 24,410$ 20,869$ 19,774$ Prepayment penalties on borrowings - - - - 4,839 - - - Acquisition-related purchase accounting adjustments ("PAU") (868) (661) (939) (1,016) (900) (459) (397) (547) Adjusted net interest income 30,587$ 27,218$ 26,259$ 24,552$ 24,878$ 23,951$ 20,472$ 19,227$ Adjusted net interest margin 3.61% 3.63% 3.71% 3.66% 3.45% 3.31% 3.42% 3.36% Three Months Ended Non-GAAP Reconciliation of Net Interest Margin (Dollars in Thousands, Unaudited) Three Months Ended
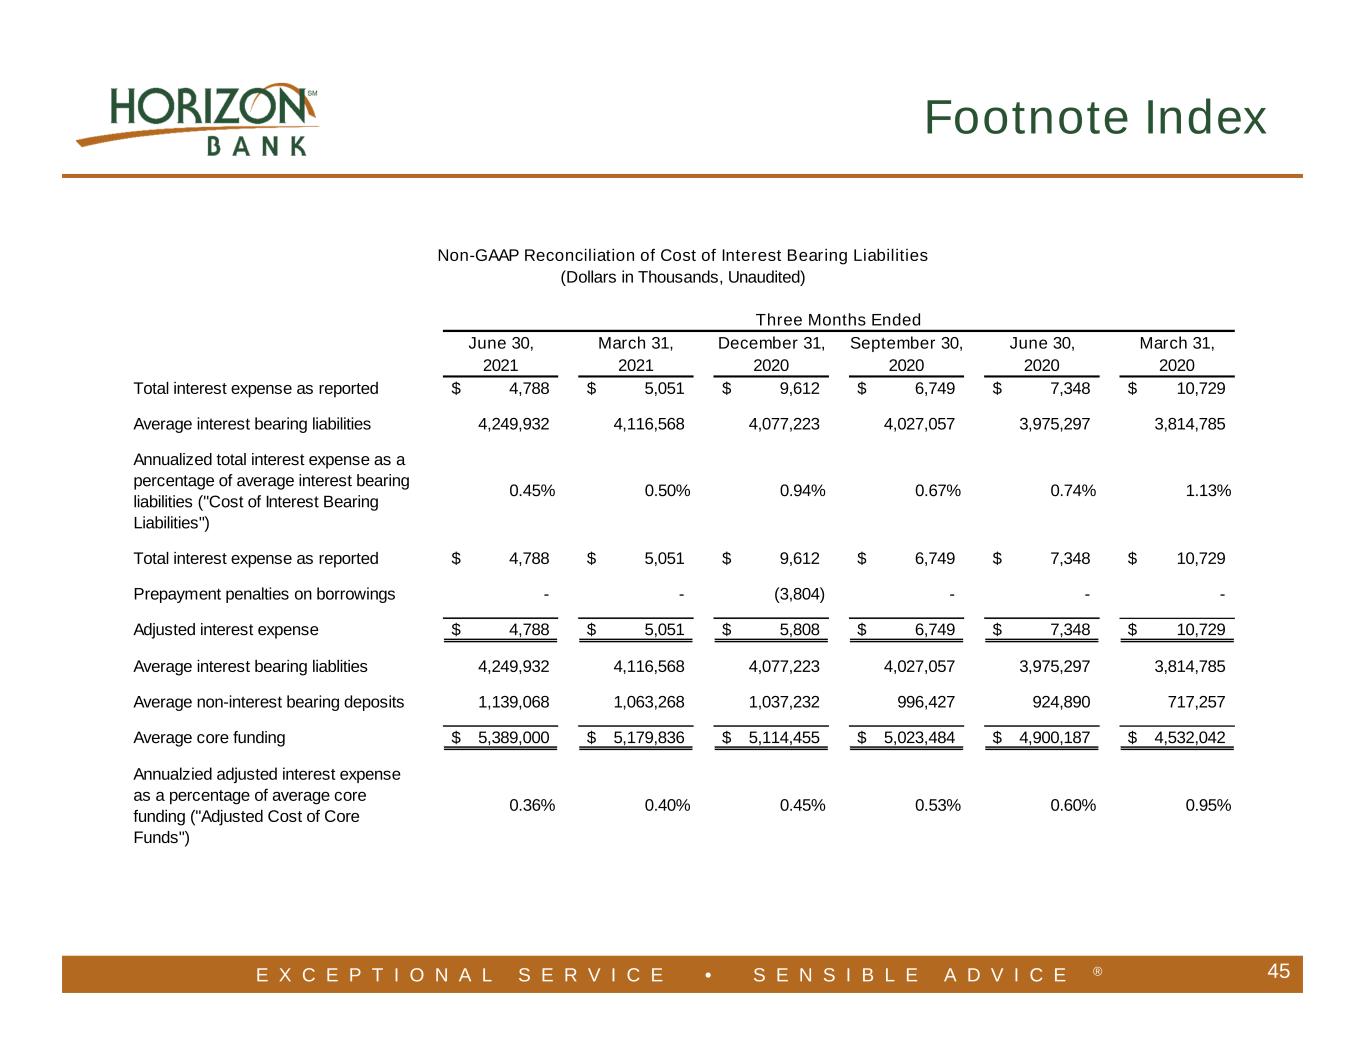
E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 45 Footnote Index June 30, March 31, December 31, September 30, June 30, March 31, 2021 2021 2020 2020 2020 2020 Total interest expense as reported 4,788$ 5,051$ 9,612$ 6,749$ 7,348$ 10,729$ Average interest bearing liabilities 4,249,932 4,116,568 4,077,223 4,027,057 3,975,297 3,814,785 Annualized total interest expense as a percentage of average interest bearing liabilities ("Cost of Interest Bearing Liabilities") 0.45% 0.50% 0.94% 0.67% 0.74% 1.13% Total interest expense as reported 4,788$ 5,051$ 9,612$ 6,749$ 7,348$ 10,729$ Prepayment penalties on borrowings - - (3,804) - - - Adjusted interest expense 4,788$ 5,051$ 5,808$ 6,749$ 7,348$ 10,729$ Average interest bearing liablities 4,249,932 4,116,568 4,077,223 4,027,057 3,975,297 3,814,785 Average non-interest bearing deposits 1,139,068 1,063,268 1,037,232 996,427 924,890 717,257 Average core funding 5,389,000$ 5,179,836$ 5,114,455$ 5,023,484$ 4,900,187$ 4,532,042$ Annualzied adjusted interest expense as a percentage of average core funding ("Adjusted Cost of Core Funds") 0.36% 0.40% 0.45% 0.53% 0.60% 0.95% Non-GAAP Reconciliation of Cost of Interest Bearing Liabilities (Dollars in Thousands, Unaudited) Three Months Ended

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 46 Footnote Index December 31, September 30, June 30, March 31, December 31, September 30, June 30, March 31, 2019 2019 2019 2019 2018 2018 2018 2018 Total interest expense as reported 11,879$ 12,248$ 12,321$ 11,093$ 9,894$ 8,499$ 7,191$ 6,015$ Average interest bearing liabilities 3,794,943 3,601,144 3,570,713 3,131,276 3,021,310 2,971,074 2,929,913 2,869,372 Annualized total interest expense as a percentage of average interest bearing liabilities ("Cost of Interest Bearing Liabilities") 1.24% 1.35% 1.38% 1.44% 1.30% 1.13% 0.98% 0.85% Total interest expense as reported 11,879$ 12,248$ 12,321$ 11,093$ 9,894$ 8,499$ 7,191$ 6,015$ Prepayment penalties on borrowings - - - - - - - - Adjusted interest expense 11,879$ 12,248$ 12,321$ 11,093$ 9,894$ 8,499$ 7,191$ 6,015$ Average interest bearing liablities 3,794,943 3,601,144 3,570,713 3,131,276 3,021,310 2,971,074 2,929,913 2,869,372 Average non-interest bearing deposits 747,513 818,164 818,872 643,601 656,114 640,983 605,188 595,644 Average core funding 4,542,456$ 4,419,308$ 4,389,585$ 3,774,877$ 3,677,424$ 3,612,057$ 3,535,101$ 3,465,016$ Annualzied adjusted interest expense as a percentage of average core funding ("Adjusted Cost of Core Funds") 1.04% 1.10% 1.13% 1.19% 1.07% 0.93% 0.82% 0.70% Three Months Ended Non-GAAP Reconciliation of Cost of Interest Bearing Liabilities (Dollars in Thousands, Unaudited) Three Months Ended

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 47 Footnote Index December 31, September 30, June 30, March 31, December 31, September 30, June 30, March 31, 2017 2017 2017 2017 2016 2016 2016 2016 Total interest expense as reported 5,319$ 4,191$ 3,607$ 3,266$ 8,450$ 4,552$ 3,781$ 3,754$ Average interest bearing liabilities 2,766,948 2,459,262 2,375,827 2,246,550 2,369,810 2,443,986 2,058,463 1,974,325 Annualized total interest expense as a percentage of average interest bearing liabilities ("Cost of Interest Bearing Liabilities") 0.76% 0.68% 0.61% 0.59% 1.42% 0.74% 0.74% 0.76% Total interest expense as reported 5,319$ 4,191$ 3,607$ 3,266$ 8,450$ 4,552$ 3,781$ 3,754$ Prepayment penalties on borrowings - - - - (4,839) - - - Adjusted interest expense 5,319$ 4,191$ 3,607$ 3,266$ 3,611$ 4,552$ 3,781$ 3,754$ Average interest bearing liablities 2,766,948 2,459,262 2,375,827 2,246,550 2,369,810 2,443,986 2,058,463 1,974,325 Average non-interest bearing deposits 603,733 540,109 499,446 491,154 504,274 462,253 364,822 339,141 Average core funding 3,370,681$ 2,999,371$ 2,875,273$ 2,737,704$ 2,874,084$ 2,906,239$ 2,423,285$ 2,313,466$ Annualzied adjusted interest expense as a percentage of average core funding ("Adjusted Cost of Core Funds") 0.63% 0.55% 0.50% 0.48% 0.50% 0.62% 0.63% 0.66% Three Months Ended Non-GAAP Reconciliation of Cost of Interest Bearing Liabilities (Dollars in Thousands, Unaudited) Three Months Ended

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 48 Footnote Index June 30, March 31, 2021 2021 Total deposit interest expense as reported 2,053$ 2,343$ Average interest bearing deposits 3,680,796 3,524,103 Annualized total deposit interest expense as a percentage of average interest bearing deposits ("Cost of Interest Bearing Deposits") 0.22% 0.27% Average interest bearing deposits 3,680,796 3,524,103 Average non-interest bearing deposits 1,139,068 1,063,268 Average total deposits 4,819,864$ 4,587,371$ Annualzied deposit interest expense as a percentage of average total deposits ("Cost of Total Deposits") 0.17% 0.21% Three Months Ended Non-GAAP Reconciliation of Cost of Deposits (Dollars in Thousands, Unaudited)

E X C E P T I O N A L S E R V I C E • S E N S I B L E A D V I C E ® 49 Footnote Index June 30, March 31, December 31, September 30, June 30, 2021 2021 2020 2020 2020 Non-GAAP Calculation of Efficiency Ratio Non-interest expense as reported 33,388$ 32,172$ 36,453$ 33,407$ 30,432$ Net interest income as reported 42,632 42,538 43,622 43,397 42,996 Non-interest income as reported 15,207 13,873 19,733 16,700 11,125 Non-interest expense/ (Net interest income + Non-interest income) ("Efficiency Ratio") 57.73% 57.03% 57.54% 55.59% 56.23% Non-GAAP Reconciliation of Adjusted Efficiency Ratio Non-interest expense as reported 33,388$ 32,172$ 36,453$ 33,407$ 30,432$ Acquisition expenses (242) - - - - Non-interest expense excluding merger expenses 33,146 32,172 36,453 33,407 30,432 Net interest income as reported 42,632 42,538 43,622 43,397 42,996 Prepayment penalties on borrowings 125 - 3,804 - - Net interest income excluding prepayment penalties on borrowings 42,757 42,538 47,426 43,397 42,996 Non-interest income as reported 15,207 13,873 19,733 16,700 11,125 (Gain)/loss on sale of investment securities - (914) (2,622) (1,088) (248) Death benefit on bank owned life insurance ("BOLI") (266) - - (31) - Non-interest income excluding (gain)/loss on sale of investment securities and death benefit on BOLI 14,941$ 12,959$ 17,111$ 15,581$ 10,877$ Adjusted efficiency ratio 57.45% 57.97% 56.48% 56.64% 56.49% Non-GAAP Calculation and Reconciliation of Efficiency Ratio and Adjusted Efficiency Ratio (Dollars in Thousands, Unaudited) Three Months Ended