
KEY 8-K
Keycorp /New/ (KEY)
8-K
2020-07-22
For: 2020-07-22
View Original
Added on
April 10, 2026
UNITED STATES SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934 |
Date of Report (Date of earliest event reported): July 22, 2020
(Exact name of registrant as specified in its charter)
State or other jurisdiction of incorporation or organization: | Commission File Number | I.R.S. Employer Identification Number: | ||
Address of principal executive offices: | Zip Code: | |||
(216 ) 689-3000
Registrant’s telephone number, including area code:
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below): | |
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |
Securities Registered Pursuant to Section 12(b) of the Act:
Title of each class | Trading Symbol(s) | Name of each exchange on which registered |
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 | Results of Operations and Financial Condition. |
On July 22, 2020, KeyCorp issued a press release announcing its financial results for the three- and six-month period ended June 30, 2020 (the “Press Release”), and posted on its website its second quarter 2020 Supplemental Information Package (the “Supplemental Information Package”). The Press Release and Supplemental Information Package are being furnished as Exhibit 99.1 and Exhibit 99.2, respectively.
The information in the preceding paragraph, as well as Exhibit 99.1 and Exhibit 99.2 referenced therein, shall not be deemed “filed” for purposes of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), nor shall it be incorporated by reference in any filing under the Securities Act of 1933, as amended (the “Securities Act”).
KeyCorp’s Consolidated Balance Sheets and Consolidated Statements of Income (collectively, the “Financial Statements”), included as part of the Press Release, are filed as Exhibit 99.3 to this report. Exhibit 99.3 is deemed “filed” for purposes of Section 18 of the Exchange Act and, therefore, may be incorporated by reference in filings under the Securities Act.
Item 9.01 | Financial Statements and Exhibits. |
(d) | Exhibits |
The following exhibits are furnished, or filed in the case of Exhibit 99.3, herewith:
99.1 |
99.2 |
99.3 |
104 | Cover Page Interactive Data File (embedded within the Inline XBRL document). |
SIGNATURE | ||
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized. | ||
KEYCORP | ||
(Registrant) | ||
Date: July 22, 2020 | /s/ Douglas M. Schosser | |
By: Douglas M. Schosser | ||
Chief Accounting Officer | ||
KEYCORP REPORTS SECOND QUARTER 2020 NET INCOME OF $159 MILLION,
OR $.16 PER DILUTED COMMON SHARE
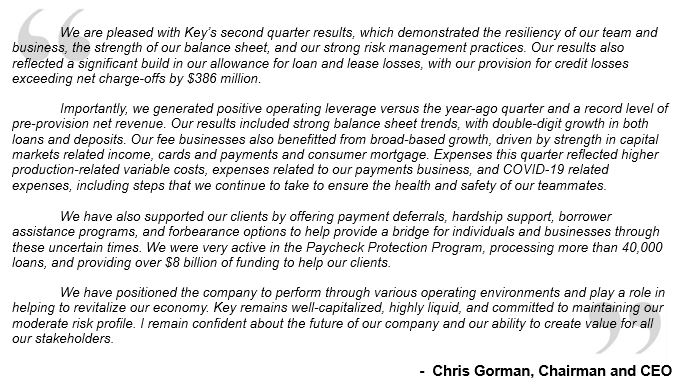
Results reflect provision for credit losses of $482 million, which exceeded net charge-offs by $386 million, or $.34 per share
Positive operating leverage relative to prior year with record pre-provision net revenue
Record revenue up 17% from prior quarter, driven by strength in fees: positive momentum in capital markets businesses, payments and consumer mortgage
Continued to support clients with over $8 billion of Paycheck Protection Program funding
Committed to maintaining strong risk management practices: net charge-offs to average loans of 36 basis points
Strong capital position: Common Equity Tier 1 of 9.1%, within targeted range
CLEVELAND, July 22, 2020 - KeyCorp (NYSE: KEY) today announced net income from continuing operations attributable to Key common shareholders of $159 million, or $.16 per diluted common share for the second quarter of 2020, compared to $118 million, or $.12 per diluted common share, for the first quarter of 2020 and $403 million, or $.40 per diluted common share, for the second quarter of 2019. Key's results in the first and second quarters of 2020 reflect the Current Expected Credit Losses ("CECL") accounting methodology, as well as the impact of the COVID-19 pandemic.
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 2
Selected Financial Highlights | |||||||||||||||
dollars in millions, except per share data | Change 2Q20 vs. | ||||||||||||||
2Q20 | 1Q20 | 2Q19 | 1Q20 | 2Q19 | |||||||||||
Income (loss) from continuing operations attributable to Key common shareholders | $ | 159 | $ | 118 | $ | 403 | 34.7 | % | (60.5 | )% | |||||
Income (loss) from continuing operations attributable to Key common shareholders per common share — assuming dilution | .16 | .12 | .40 | 33.3 | (60.0 | ) | |||||||||
Return on average tangible common equity from continuing operations (a) | 4.96 | % | 3.82 | % | 13.69 | % | N/A | N/A | |||||||
Return on average total assets from continuing operations | .45 | .40 | 1.19 | N/A | N/A | ||||||||||
Common Equity Tier 1 ratio (b) | 9.1 | 8.9 | 9.6 | N/A | N/A | ||||||||||
Book value at period end | $ | 16.07 | $ | 15.95 | $ | 15.07 | .8 | % | 6.6 | % | |||||
Net interest margin (TE) from continuing operations | 2.76 | % | 3.01 | % | 3.06 | % | N/A | N/A | |||||||
(a) | The table entitled “GAAP to Non-GAAP Reconciliations” in the attached financial supplement presents the computations of certain financial measures related to “Return on average tangible common equity from continuing operations.” The table reconciles the GAAP performance measures to the corresponding non-GAAP measures, which provides a basis for period-to-period comparisons. |
(b) | 6/30/20 ratio is estimated. |
TE = Taxable Equivalent, N/A = Not Applicable
INCOME STATEMENT HIGHLIGHTS | ||||||||||||||
Revenue | ||||||||||||||
dollars in millions | Change 2Q20 vs. | |||||||||||||
2Q20 | 1Q20 | 2Q19 | 1Q20 | 2Q19 | ||||||||||
Net interest income (TE) | $ | 1,025 | $ | 989 | $ | 989 | 3.6 | % | 3.6 | % | ||||
Noninterest income | 692 | 477 | 622 | 45.1 | 11.3 | |||||||||
Total revenue | $ | 1,717 | $ | 1,466 | $ | 1,611 | 17.1 | % | 6.6 | % | ||||
TE = Taxable Equivalent
Taxable-equivalent net interest income was $1.0 billion for the second quarter of 2020, compared to taxable-equivalent net interest income of $989 million for the second quarter of 2019. The increase in net interest income reflects higher earning asset balances partially offset by a lower net interest margin. The net interest margin was impacted by lower interest rates, a lag in deposit pricing as interest rates declined, and a change in balance sheet mix, including elevated levels of liquidity and Key's participation in the Paycheck Protection Program.
Compared to the first quarter of 2020, taxable-equivalent net interest income increased by $36 million, reflecting higher earning asset balances, partially offset by a lower net interest margin. The lower net interest margin reflects elevated levels of liquidity, the impact of lower interest rates, and Key's participation in the Paycheck Protection Program.
Noninterest Income | ||||||||||||||
dollars in millions | Change 2Q20 vs. | |||||||||||||
2Q20 | 1Q20 | 2Q19 | 1Q20 | 2Q19 | ||||||||||
Trust and investment services income | $ | 123 | $ | 133 | $ | 122 | (7.5 | )% | .8 | % | ||||
Investment banking and debt placement fees | 156 | 116 | 163 | 34.5 | (4.3 | ) | ||||||||
Service charges on deposit accounts | 68 | 84 | 83 | (19.0 | ) | (18.1 | ) | |||||||
Operating lease income and other leasing gains | 60 | 30 | 44 | 100.0 | 36.4 | |||||||||
Corporate services income | 52 | 62 | 53 | (16.1 | ) | (1.9 | ) | |||||||
Cards and payments income | 91 | 66 | 73 | 37.9 | 24.7 | |||||||||
Corporate-owned life insurance income | 35 | 36 | 33 | (2.8 | ) | 6.1 | ||||||||
Consumer mortgage income | 62 | 20 | 15 | 210.0 | 313.3 | |||||||||
Commercial mortgage servicing fees | 12 | 18 | 19 | (33.3 | ) | (36.8 | ) | |||||||
Other income | 33 | (88 | ) | 17 | N/M | 94.1 | ||||||||
Total noninterest income | $ | 692 | $ | 477 | $ | 622 | 45.1 | % | 11.3 | % | ||||
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 3
Compared to the second quarter of 2019, noninterest income increased by $70 million, primarily driven by a $47 million increase in consumer mortgage income, driven by a record level of loan originations and related fees in the second quarter of 2020. Additionally, cards and payments income increased $18 million related to prepaid card activity and operating lease income increased $16 million driven by gains from the sale of leveraged leases. These benefits were partially offset by a decline of $15 million in service charges on deposit accounts.
Compared to the first quarter of 2020, noninterest income increased by $215 million. The largest driver of the quarterly increase was a $121 million improvement in other income, primarily driven by $92 million of market-related valuation adjustments in the first quarter of 2020. Other significant drivers for the quarter-over-quarter increase include $42 million of higher consumer mortgage income, and a $40 million increase in investment banking and debt placement fees related to strong commercial mortgage and debt capital markets activity. Operating lease income and cards and payments income also increased, $30 million and $25 million, respectively.
Noninterest Expense | ||||||||||||||
dollars in millions | Change 2Q20 vs. | |||||||||||||
2Q20 | 1Q20 | 2Q19 | 1Q20 | 2Q19 | ||||||||||
Personnel expense | $ | 572 | $ | 515 | $ | 589 | 11.1 | % | (2.9 | )% | ||||
Nonpersonnel expense | 441 | 416 | 430 | 6.0 | 2.6 | |||||||||
Total noninterest expense | $ | 1,013 | $ | 931 | $ | 1,019 | 8.8 | % | (.6 | )% | ||||
Key’s noninterest expense was $1.0 billion for the second quarter of 2020, a decrease of $6 million from the year-ago period. The second quarter of 2019 included notable items of $52 million, primarily personnel-related from Key's efficiency initiatives. Excluding notable items in the year-ago period, expenses increased $46 million. The increase is primarily related to higher other expense, from $25 million of payments-related expenses incurred in the current period, as well as COVID-19-related costs related to steps that the company has taken to ensure the health and safety of teammates.
Compared to the first quarter of 2020, noninterest expense increased $82 million. The increase was largely due to higher incentive and stock-based compensation from strong revenue production in Key's investment banking and consumer mortgage businesses. Other drivers for the linked quarter increase include $25 million of payments-related costs (in other expense), as well as other COVID-19 related expenses.
BALANCE SHEET HIGHLIGHTS | ||||||||||||||
Average Loans | ||||||||||||||
dollars in millions | Change 2Q20 vs. | |||||||||||||
2Q20 | 1Q20 | 2Q19 | 1Q20 | 2Q19 | ||||||||||
Commercial and industrial (a) | $ | 60,480 | $ | 49,466 | $ | 47,227 | 22.3 | % | 28.1 | % | ||||
Other commercial loans | 19,850 | 19,779 | 19,765 | .4 | .4 | |||||||||
Total consumer loans | 27,611 | 26,929 | 23,793 | 2.5 | 16.0 | |||||||||
Total loans | $ | 107,941 | $ | 96,174 | $ | 90,785 | 12.2 | % | 18.9 | % | ||||
(a) | Commercial and industrial average loan balances include $135 million, $145 million, and $141 million of assets from commercial credit cards at June 30, 2020, March 31, 2020, and June 30, 2019, respectively. |
Average loans were $107.9 billion for the second quarter of 2020, an increase of $17.2 billion compared to the second quarter of 2019. Commercial loans increased $13.3 billion, reflecting growth from participation in the Paycheck Protection Program during the current quarter, as well as core broad-based growth in commercial and industrial loans and increased utilization versus the year-ago period. Consumer loans increased $3.8 billion, driven by strength from Laurel Road and Key's consumer mortgage business.
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 4
Compared to the first quarter of 2020, average loans increased by $11.8 billion. The second quarter of 2020 included over $8 billion of loans related to the Paycheck Protection Program, which, in addition to the increase in commercial and industrial utilization rates in March 2020, drove the majority of commercial loan growth from the prior quarter. Consumer loan growth continued to be driven by strength from Laurel Road, as well as a record quarter in Key's consumer mortgage business.
Average Deposits | ||||||||||||||
dollars in millions | Change 2Q20 vs. | |||||||||||||
2Q20 | 1Q20 | 2Q19 | 1Q20 | 2Q19 | ||||||||||
Non-time deposits | $ | 118,694 | $ | 99,117 | $ | 95,885 | 19.8 | % | 23.8 | % | ||||
Certificates of deposit ($100,000 or more) | 4,950 | 6,310 | 8,147 | (21.6 | ) | (39.2 | ) | |||||||
Other time deposits | 4,333 | 4,901 | 5,569 | (11.6 | ) | (22.2 | ) | |||||||
Total deposits | $ | 127,977 | $ | 110,328 | $ | 109,601 | 16.0 | % | 16.8 | % | ||||
Cost of total deposits | .30 | % | .62 | % | .82 | % | N/A | N/A | ||||||
N/A = Not Applicable
Average deposits totaled $128.0 billion for the second quarter of 2020, an increase of $18.4 billion compared to the year-ago quarter, reflecting growth from consumer and commercial relationships, partially offset by a decline in time deposits.
Compared to the first quarter of 2020, average deposits increased by $17.6 billion, primarily driven by broad-based commercial growth as well as growth from consumer stimulus payments and lower consumer spending. This growth was offset by a decline in time deposits, primarily related to lower interest rates.
ASSET QUALITY | ||||||||||||||
dollars in millions | Change 2Q20 vs. | |||||||||||||
2Q20 | 1Q20 | 2Q19 | 1Q20 | 2Q19 | ||||||||||
Net loan charge-offs | $ | 96 | $ | 84 | $ | 65 | 14.3 | % | 47.7 | % | ||||
Net loan charge-offs to average total loans | .36 | % | .35 | % | .29 | % | N/A | N/A | ||||||
Nonperforming loans at period end | $ | 760 | $ | 632 | $ | 561 | 20.3 | 35.5 | ||||||
Nonperforming assets at period end | 951 | 844 | 608 | 12.7 | 56.4 | |||||||||
Allowance for loan and lease losses | 1,708 | 1,359 | 890 | 25.7 | 91.9 | |||||||||
Allowance for loan and lease losses to nonperforming loans | 224.7 | % | 215.0 | % | 158.6 | % | N/A | N/A | ||||||
Provision for credit losses | $ | 482 | $ | 359 | $ | 74 | 34.3 | % | 551.4 | % | ||||
N/A = Not Applicable
Key’s provision for credit losses was $482 million for the second quarter of 2020, compared to $74 million for the second quarter of 2019, and $359 million for the first quarter of 2020. The provision for credit losses reflects the adoption of a new accounting standard, often referred to as Current Expected
Credit Losses ("CECL"), beginning in the first quarter of 2020. This framework requires that management estimate credit losses over the full remaining expected life and consider expected future changes in macroeconomic conditions.
The provision for credit losses exceeded net charge-offs by $386 million. Net loan charge-offs for the second quarter of 2020 totaled $96 million, or .36% of average total loans. These results compare to $65 million, or .29%, for the second quarter of 2019, and $84 million, or .35%, for the first quarter of 2020. Key’s allowance for loan and lease losses was $1.7 billion, or 1.61% of total period-end loans at June 30, 2020, compared to .97% at June 30, 2019, and 1.32% at March 31, 2020.
At June 30, 2020, Key’s nonperforming loans totaled $760 million, which represented .72% of period-end portfolio loans. These results compare to .61% at June 30, 2019, and .61% at March 31, 2020.
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 5
Nonperforming assets at June 30, 2020, totaled $951 million, and represented .89% of period-end portfolio loans and OREO and other nonperforming assets. These results compare to .66% at June 30, 2019, and .82% at March 31, 2020.
CAPITAL
Key’s estimated risk-based capital ratios included in the following table continued to exceed all “well-capitalized” regulatory benchmarks at June 30, 2020.
Capital Ratios | ||||||
6/30/2020 | 3/31/2020 | 6/30/2019 | ||||
Common Equity Tier 1 (a) | 9.1 | % | 8.9 | % | 9.6 | % |
Tier 1 risk-based capital (a) | 10.4 | 10.2 | 11.0 | |||
Total risk based capital (a) | 12.8 | 12.2 | 13.0 | |||
Tangible common equity to tangible assets (b) | 7.6 | 8.3 | 8.6 | |||
Leverage (a) | 8.8 | 9.8 | 10.0 | |||
(a) | 6/30/2020 ratio is estimated and reflects Key's election to adopt the CECL optional transition provision. |
(b) | The table entitled “GAAP to Non-GAAP Reconciliations” in the attached financial supplement presents the computations of certain financial measures related to “tangible common equity.” The table reconciles the GAAP performance measures to the corresponding non-GAAP measures, which provides a basis for period-to-period comparisons. |
Key's capital position remained strong in the second quarter of 2020. As shown in the preceding table, at June 30, 2020, Key’s estimated Common Equity Tier 1 and Tier 1 risk-based capital ratios stood at 9.1% and 10.4%, respectively. Key's tangible common equity ratio was 7.6% at June 30, 2020.
Key has elected the CECL phase-in option provided by regulatory guidance which delays for two years the estimated impact of CECL on regulatory capital and phases it in over three years beginning in 2022. On a fully phased-in basis, Key's Common Equity Tier 1 ratio would be reduced by 29 basis points.
Summary of Changes in Common Shares Outstanding | ||||||||||||
in thousands | Change 2Q20 vs. | |||||||||||
2Q20 | 1Q20 | 2Q19 | 1Q20 | 2Q19 | ||||||||
Shares outstanding at beginning of period | 975,319 | 977,189 | 1,013,186 | (.2 | )% | (3.7 | )% | |||||
Open market repurchases and return of shares under employee compensation plans | (19 | ) | (7,862 | ) | (10,412 | ) | (99.8 | ) | (99.8 | ) | ||
Shares issued under employee compensation plans (net of cancellations) | 647 | 5,992 | 340 | (89.2 | ) | 90.3 | ||||||
Shares outstanding at end of period | 975,947 | 975,319 | 1,003,114 | .1 | % | (2.7 | )% | |||||
Consistent with Key's 2019 Capital Plan, during the second quarter of 2020, Key declared a dividend of $.185 per common share. Per Key's announcement on March 17, 2020, share repurchase activity has been temporarily suspended in response to the COVID-19 pandemic.
LINE OF BUSINESS RESULTS
The following table shows the contribution made by each major business segment to Key’s taxable-equivalent revenue from continuing operations and income (loss) from continuing operations attributable to Key for the periods presented. For more detailed financial information pertaining to each business segment, see the tables at the end of this release.
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 6
Major Business Segments | |||||||||||||||
dollars in millions | Change 2Q20 vs. | ||||||||||||||
2Q20 | 1Q20 | 2Q19 | 1Q20 | 2Q19 | |||||||||||
Revenue from continuing operations (TE) | |||||||||||||||
Consumer Bank | $ | 841 | $ | 820 | $ | 825 | 2.6 | % | 1.9 | % | |||||
Commercial Bank | 847 | 629 | 760 | 34.7 | 11.4 | ||||||||||
Other (a) | 29 | 17 | 26 | 70.6 | 11.5 | ||||||||||
Total | $ | 1,717 | $ | 1,466 | $ | 1,611 | 17.1 | % | 6.6 | % | |||||
Income (loss) from continuing operations attributable to Key | |||||||||||||||
Consumer Bank | $ | 91 | $ | 105 | $ | 177 | (13.3 | )% | (48.6 | )% | |||||
Commercial Bank | 120 | 70 | 277 | 71.4 | (56.7 | ) | |||||||||
Other (a) | (24 | ) | (29 | ) | (29 | ) | N/M | N/M | |||||||
Total | $ | 187 | $ | 146 | $ | 425 | 28.1 | % | (56.0 | )% | |||||
(a) | Other includes other segments that consists of corporate treasury, our principal investing unit, and various exit portfolios as well as reconciling items which primarily represents the unallocated portion of nonearning assets of corporate support functions. Charges related to the funding of these assets are part of net interest income and are allocated to the business segments through noninterest expense. Reconciling items also includes intercompany eliminations and certain items that are not allocated to the business segments because they do not reflect their normal operations. |
TE = Taxable Equivalent, N/M = Not Meaningful
Consumer Bank | ||||||||||||||
dollars in millions | Change 2Q20 vs. | |||||||||||||
2Q20 | 1Q20 | 2Q19 | 1Q20 | 2Q19 | ||||||||||
Summary of operations | ||||||||||||||
Net interest income (TE) | $ | 594 | $ | 590 | $ | 594 | .7 | % | — | |||||
Noninterest income | 247 | 230 | 231 | 7.4 | 6.9 | % | ||||||||
Total revenue (TE) | 841 | 820 | 825 | 2.6 | 1.9 | |||||||||
Provision for credit losses | 167 | 140 | 40 | 19.3 | 317.5 | |||||||||
Noninterest expense | 555 | 543 | 552 | 2.2 | .5 | |||||||||
Income (loss) before income taxes (TE) | 119 | 137 | 233 | (13.1 | ) | (48.9 | ) | |||||||
Allocated income taxes (benefit) and TE adjustments | 28 | 32 | 56 | (12.5 | ) | (50.0 | ) | |||||||
Net income (loss) attributable to Key | $ | 91 | $ | 105 | $ | 177 | (13.3 | )% | (48.6 | )% | ||||
Average balances | ||||||||||||||
Loans and leases | $ | 39,197 | $ | 35,197 | $ | 31,881 | 11.4 | % | 22.9 | % | ||||
Total assets | 44,106 | 38,460 | 35,469 | 14.7 | 24.4 | |||||||||
Deposits | 79,502 | 73,320 | 72,303 | 8.4 | 10.0 | |||||||||
Assets under management at period end | $ | 39,722 | $ | 36,189 | $ | 38,942 | 9.8 | % | 2.0 | % | ||||
TE = Taxable Equivalent
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 7
Additional Consumer Bank Data | ||||||||||||||
dollars in millions | Change 2Q20 vs. | |||||||||||||
2Q20 | 1Q20 | 2Q19 | 1Q20 | 2Q19 | ||||||||||
Noninterest income | ||||||||||||||
Trust and investment services income | $ | 87 | $ | 93 | $ | 91 | (6.5 | )% | (4.4 | )% | ||||
Service charges on deposit accounts | 38 | 55 | 56 | (30.9 | ) | (32.1 | ) | |||||||
Cards and payments income | 46 | 49 | 54 | (6.1 | ) | (14.8 | ) | |||||||
Other noninterest income | 76 | 33 | 30 | 130.3 | 153.3 | |||||||||
Total noninterest income | $ | 247 | $ | 230 | $ | 231 | 7.4 | % | 6.9 | % | ||||
Average deposit balances | ||||||||||||||
NOW and money market deposit accounts | $ | 49,152 | $ | 45,583 | $ | 42,800 | 7.8 | % | 14.8 | % | ||||
Savings deposits | 4,817 | 4,345 | 4,506 | 10.9 | 6.9 | |||||||||
Certificates of deposit ($100,000 or more) | 4,520 | 5,587 | 6,644 | (19.1 | ) | (32.0 | ) | |||||||
Other time deposits | 4,296 | 4,869 | 5,549 | (11.8 | ) | (22.6 | ) | |||||||
Noninterest-bearing deposits | 16,717 | 12,936 | 12,804 | 29.2 | 30.6 | |||||||||
Total deposits | $ | 79,502 | $ | 73,320 | $ | 72,303 | 8.4 | % | 10.0 | % | ||||
Home equity loans | ||||||||||||||
Average balance | $ | 9,893 | $ | 10,093 | $ | 10,618 | ||||||||
Combined weighted-average loan-to-value ratio (at date of origination) | 70 | % | 70 | % | 70 | % | ||||||||
Percent first lien positions | 63 | 62 | 60 | |||||||||||
Other data | ||||||||||||||
Branches | 1,077 | 1,082 | 1,102 | |||||||||||
Automated teller machines | 1,394 | 1,398 | 1,430 | |||||||||||
Consumer Bank Summary of Operations (2Q20 vs. 2Q19)
• | Net income attributable to Key of $91 million for the second quarter of 2020, compared to $177 million for the year-ago quarter |
• | Taxable equivalent net interest income was flat compared to the second quarter of 2019 as the lower interest rate environment offset balance sheet growth |
• | Average loans and leases increased $7.3 billion, or 22.9%, driven by loan production related to the Paycheck Protection Program, as well as growth from Laurel Road and consumer mortgage |
• | Average deposits increased $7.2 billion, or 10.0%, from the second quarter of 2019. This was driven by consumer stimulus payments and lower consumer spend activity |
• | Provision for credit losses increased $127 million compared to the second quarter of 2019. The increase in provision for credit losses is mainly attributable to the change in the economic scenario under the CECL accounting methodology, as well as balance sheet growth |
• | Noninterest income increased $16 million, or 6.9%, from the year-ago quarter, driven by a record quarter in consumer mortgage income partially offset by lower consumer spend activity |
• | Noninterest expense increased $3 million, or .5%, from the year ago quarter |
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 8
Commercial Bank | ||||||||||||||
dollars in millions | Change 2Q20 vs. | |||||||||||||
2Q20 | 1Q20 | 2Q19 | 1Q20 | 2Q19 | ||||||||||
Summary of operations | ||||||||||||||
Net interest income (TE) | $ | 442 | $ | 410 | $ | 405 | 7.8 | % | 9.1 | % | ||||
Noninterest income | 405 | 219 | 355 | 84.9 | 14.1 | |||||||||
Total revenue (TE) | 847 | 629 | 760 | 34.7 | 11.4 | |||||||||
Provision for credit losses | 314 | 214 | 33 | 46.7 | 851.5 | |||||||||
Noninterest expense | 403 | 353 | 389 | 14.2 | 3.6 | |||||||||
Income (loss) before income taxes (TE) | 130 | 62 | 338 | 109.7 | (61.5 | ) | ||||||||
Allocated income taxes and TE adjustments | 10 | (8 | ) | 61 | N/M | (83.6 | ) | |||||||
Net income (loss) attributable to Key | $ | 120 | $ | 70 | $ | 277 | 71.4 | % | (56.7 | )% | ||||
Average balances | ||||||||||||||
Loans and leases | $ | 68,038 | $ | 60,082 | $ | 57,918 | 13.2 | % | 17.5 | % | ||||
Loans held for sale | 2,012 | 1,607 | 1,168 | 25.2 | 72.3 | |||||||||
Total assets | 76,974 | 69,383 | 65,901 | 10.9 | 16.8 | |||||||||
Deposits | 46,099 | 36,058 | 35,960 | 27.8 | % | 28.2 | % | |||||||
TE = Taxable Equivalent, N/M = Not Meaningful
Additional Commercial Bank Data | ||||||||||||||
dollars in millions | Change 2Q20 vs. | |||||||||||||
2Q20 | 1Q20 | 2Q19 | 1Q20 | 2Q19 | ||||||||||
Noninterest income | ||||||||||||||
Trust and investment services income | $ | 36 | $ | 39 | $ | 31 | (7.7 | )% | 16.1 | % | ||||
Investment banking and debt placement fees | 156 | 116 | 162 | 34.5 | (3.7 | ) | ||||||||
Operating lease income and other leasing gains | 46 | 30 | 43 | 53.3 | 7.0 | |||||||||
Corporate services income | 45 | 57 | 50 | (21.1 | ) | (10.0 | ) | |||||||
Service charges on deposit accounts | 30 | 28 | 27 | 7.1 | 11.1 | |||||||||
Cards and payments income | 44 | 17 | 17 | 158.8 | 158.8 | |||||||||
Payments and services income | 119 | 102 | 94 | 16.7 | 26.6 | |||||||||
Commercial mortgage servicing fees | 12 | 18 | 20 | (33.3 | ) | (40.0 | ) | |||||||
Other noninterest income | 36 | (86 | ) | 5 | N/M | 620.0 | ||||||||
Total noninterest income | $ | 405 | $ | 219 | $ | 355 | 84.9 | % | 14.1 | % | ||||
N/M = Not Meaningful
Commercial Bank Summary of Operations (2Q20 vs. 2Q19)
• | Net income attributable to Key of $120 million for the second quarter of 2020, compared to $277 million for the year-ago quarter |
• | Taxable-equivalent net interest income increased by $37 million, compared to the second quarter of 2019, with balance sheet growth partially offset by lower interest rate environment |
• | Average loan and lease balances increased $10.1 billion, or 17.5%, compared to the second quarter of 2019 driven by growth in commercial and industrial loans from line draws and Paycheck Protection Program loans |
• | Average deposit balances increased $10.1 billion, or 28.2%, compared to the second quarter of 2019, driven by growth in targeted relationships and the impact of government programs |
• | Provision for credit losses increased $281 million compared to the second quarter of 2019. The increase in provision for credit losses is mainly attributable to the change in the economic scenario under the CECL accounting methodology, but also impacted by line draws on commercial credits |
• | Noninterest income increased $50 million, or 14.1%, from the second quarter of 2019, driven by higher cards and payments income related to prepaid card revenue, as well as higher other income |
• | Noninterest expense increased by $14 million, or 3.6%, from the second quarter of 2019 driven by higher incentives related to strong revenue production |
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 9
*******************************************
KeyCorp's roots trace back 190 years to Albany, New York. Headquartered in Cleveland, Ohio, Key is one of the nation’s largest bank-based financial services companies, with assets of approximately $171.2 billion at June 30, 2020.
Key provides deposit, lending, cash management, and investment services to individuals and businesses in 15 states under the name KeyBank National Association through a network of more than 1,000 branches and approximately 1,400 ATMs. Key also provides a broad range of sophisticated corporate and investment banking products, such as merger and acquisition advice, public and private debt and equity, syndications and derivatives to middle market companies in selected industries throughout the United States under the KeyBanc Capital Markets trade name. For more information, visit https://www.key.com/. KeyBank is Member FDIC.
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 10
CONTACTS: | |
ANALYSTS | MEDIA |
Vernon L. Patterson | Susan Donlan |
216.689.0520 | 216.471.3133 |
Melanie S. Kaiser | Tracy Pesho |
216.689.4545 | 216.471.2825 |
Twitter: @keybank | |
INVESTOR RELATIONS: | KEY MEDIA NEWSROOM: |
www.key.com/ir | www.key.com/newsroom |
This earnings release contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements do not relate strictly to historical or current facts. Forward-looking statements usually can be identified by the use of words such as “goal,” “objective,” “plan,” “expect,” “assume,” “anticipate,” “intend,” “project,” “believe,” “estimate,” or other words of similar meaning. Forward-looking statements provide our current expectations or forecasts of future events, circumstances, results, or aspirations. Forward-looking statements, by their nature, are subject to assumptions, risks and uncertainties, many of which are outside of our control. Our actual results may differ materially from those set forth in our forward-looking statements. There is no assurance that any list of risks and uncertainties or risk factors is complete. Factors that could cause Key’s actual results to differ from those described in the forward-looking statements can be found in KeyCorp’s Form 10-K for the year ended December 31, 2019, as well as in KeyCorp’s subsequent SEC filings, all of which have been or will be filed with the Securities and Exchange Commission (the “SEC”) and are or will be available on Key’s website (www.key.com/ir) and on the SEC’s website (www.sec.gov). These factors may include, among others: deterioration of commercial real estate market fundamentals, adverse changes in credit quality trends, declining asset prices, a reversal of the U.S. economic recovery due to financial, political, or other shocks, and the extensive regulation of the U.S. financial services industry. In addition to the aforementioned factors, the COVID–19 global pandemic is adversely affecting us, our clients, and third–party service providers, among others, and its impact may adversely affect our business and results of operations over a period of time. Any forward-looking statements made by us or on our behalf speak only as of the date they are made and we do not undertake any obligation to update any forward-looking statement to reflect the impact of subsequent events or circumstances. |
Notes to Editors:
A live Internet broadcast of KeyCorp’s conference call to discuss quarterly results and currently anticipated earnings trends and to answer analysts’ questions can be accessed through the Investor Relations section at https://www.key.com/ir at 9:00 a.m. ET, on Wednesday, July 22, 2020. A replay of the call will be available through August 5, 2020.
For up-to-date company information, media contacts, and facts and figures about Key’s lines of business, visit our Media Newsroom at https://www.key.com/newsroom.
*****
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 11
KeyCorp
Second Quarter 2020
Financial Supplement
Page | |
Financial Highlights | |
GAAP to Non-GAAP Reconciliation | |
Consolidated Balance Sheets | |
Consolidated Statements of Income | |
Consolidated Average Balance Sheets, and Net Interest Income and Yields/Rates From Continuing Operations | |
Noninterest Expense | |
Personnel Expense | |
Loan Composition | |
Loans Held for Sale Composition | |
Summary of Changes in Loans Held for Sale | |
Summary of Loan and Lease Loss Experience From Continuing Operations | |
Asset Quality Statistics From Continuing Operations | |
Summary of Nonperforming Assets and Past Due Loans From Continuing Operations | |
Summary of Changes in Nonperforming Loans From Continuing Operations | |
Line of Business Results | |
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 12
Financial Highlights | |||||||||||
(dollars in millions, except per share amounts) | |||||||||||
Three months ended | |||||||||||
6/30/2020 | 3/31/2020 | 6/30/2019 | |||||||||
Summary of operations | |||||||||||
Net interest income (TE) | $ | 1,025 | $ | 989 | $ | 989 | |||||
Noninterest income | 692 | 477 | 622 | ||||||||
Total revenue (TE) | 1,717 | 1,466 | 1,611 | ||||||||
Provision for credit losses | 482 | 359 | 74 | ||||||||
Noninterest expense | 1,013 | 931 | 1,019 | ||||||||
Income (loss) from continuing operations attributable to Key | 185 | 145 | 423 | ||||||||
Income (loss) from discontinued operations, net of taxes | 2 | 1 | 2 | ||||||||
Net income (loss) attributable to Key | 187 | 146 | 425 | ||||||||
Income (loss) from continuing operations attributable to Key common shareholders | 159 | 118 | 403 | ||||||||
Income (loss) from discontinued operations, net of taxes | 2 | 1 | 2 | ||||||||
Net income (loss) attributable to Key common shareholders | 161 | 119 | 405 | ||||||||
Per common share | |||||||||||
Income (loss) from continuing operations attributable to Key common shareholders | $ | .16 | $ | .12 | $ | .40 | |||||
Income (loss) from discontinued operations, net of taxes | — | — | — | ||||||||
Net income (loss) attributable to Key common shareholders (a) | .17 | .12 | .40 | ||||||||
Income (loss) from continuing operations attributable to Key common shareholders — assuming dilution | .16 | .12 | .40 | ||||||||
Income (loss) from discontinued operations, net of taxes — assuming dilution | — | — | — | ||||||||
Net income (loss) attributable to Key common shareholders — assuming dilution (a) | .17 | .12 | .40 | ||||||||
Cash dividends declared | .185 | .185 | .17 | ||||||||
Book value at period end | 16.07 | 15.95 | 15.07 | ||||||||
Tangible book value at period end | 13.12 | 12.98 | 12.12 | ||||||||
Market price at period end | 12.18 | 10.37 | 17.75 | ||||||||
Performance ratios | |||||||||||
From continuing operations: | |||||||||||
Return on average total assets | .45 | % | .40 | % | 1.19 | % | |||||
Return on average common equity | 4.05 | 3.10 | 10.94 | ||||||||
Return on average tangible common equity (b) | 4.96 | 3.82 | 13.69 | ||||||||
Net interest margin (TE) | 2.76 | 3.01 | 3.06 | ||||||||
Cash efficiency ratio (b) | 57.9 | 62.3 | 61.9 | ||||||||
From consolidated operations: | |||||||||||
Return on average total assets | .46 | % | .40 | % | 1.19 | % | |||||
Return on average common equity | 4.10 | 3.12 | 11.00 | ||||||||
Return on average tangible common equity (b) | 5.02 | 3.86 | 13.75 | ||||||||
Net interest margin (TE) | 2.76 | 3.00 | 3.05 | ||||||||
Loan to deposit (c) | 80.4 | 92.1 | 86.1 | ||||||||
Capital ratios at period end | |||||||||||
Key shareholders’ equity to assets | 10.2 | % | 11.1 | % | 11.7 | % | |||||
Key common shareholders’ equity to assets | 9.2 | 10.0 | 10.5 | ||||||||
Tangible common equity to tangible assets (b) | 7.6 | 8.3 | 8.6 | ||||||||
Common Equity Tier 1 (d) | 9.1 | 8.9 | 9.6 | ||||||||
Tier 1 risk-based capital (d) | 10.4 | 10.2 | 11.0 | ||||||||
Total risk-based capital (d) | 12.8 | 12.2 | 13.0 | ||||||||
Leverage (d) | 8.8 | 9.8 | 10.0 | ||||||||
Asset quality — from continuing operations | |||||||||||
Net loan charge-offs | $ | 96 | $ | 84 | $ | 65 | |||||
Net loan charge-offs to average loans | .36 | % | .35 | % | .29 | % | |||||
Allowance for loan and lease losses | $ | 1,708 | $ | 1,359 | $ | 890 | |||||
Allowance for credit losses | 1,906 | 1,520 | 954 | ||||||||
Allowance for loan and lease losses to period-end loans | 1.61 | % | 1.32 | % | .97 | % | |||||
Allowance for credit losses to period-end loans | 1.80 | 1.47 | 1.04 | ||||||||
Allowance for loan and lease losses to nonperforming loans (e) | 224.7 | 215.0 | 158.6 | ||||||||
Allowance for credit losses to nonperforming loans (e) | 250.8 | 240.5 | 170.1 | ||||||||
Nonperforming loans at period-end (e) | $ | 760 | $ | 632 | $ | 561 | |||||
Nonperforming assets at period-end (e) | 951 | 844 | 608 | ||||||||
Nonperforming loans to period-end portfolio loans (e) | .72 | % | .61 | % | .61 | % | |||||
Nonperforming assets to period-end portfolio loans plus OREO and other nonperforming assets (e) | .89 | .82 | .66 | ||||||||
Trust assets | |||||||||||
Assets under management | $ | 39,722 | $ | 36,189 | $ | 38,942 | |||||
Other data | |||||||||||
Average full-time equivalent employees | 16,646 | 16,529 | 17,206 | ||||||||
Branches | 1,077 | 1,082 | 1,102 | ||||||||
Taxable-equivalent adjustment | $ | 7 | $ | 8 | $ | 8 | |||||
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 13
Financial Highlights (continued) | |||||||
(dollars in millions, except per share amounts) | |||||||
Six months ended | |||||||
6/30/2020 | 6/30/2019 | ||||||
Summary of operations | |||||||
Net interest income (TE) | $ | 2,014 | $ | 1,974 | |||
Noninterest income | 1,169 | 1,158 | |||||
Total revenue (TE) | 3,183 | 3,132 | |||||
Provision for credit losses | 841 | 136 | |||||
Noninterest expense | 1,944 | 1,982 | |||||
Income (loss) from continuing operations attributable to Key | 330 | 829 | |||||
Income (loss) from discontinued operations, net of taxes | 3 | 3 | |||||
Net income (loss) attributable to Key | 333 | 832 | |||||
Income (loss) from continuing operations attributable to Key common shareholders | $ | 277 | $ | 789 | |||
Income (loss) from discontinued operations, net of taxes | 3 | 3 | |||||
Net income (loss) attributable to Key common shareholders | 280 | 792 | |||||
Per common share | |||||||
Income (loss) from continuing operations attributable to Key common shareholders | $ | .29 | $ | .79 | |||
Income (loss) from discontinued operations, net of taxes | — | — | |||||
Net income (loss) attributable to Key common shareholders (a) | .29 | .79 | |||||
Income (loss) from continuing operations attributable to Key common shareholders — assuming dilution | .28 | .78 | |||||
Income (loss) from discontinued operations, net of taxes — assuming dilution | — | — | |||||
Net income (loss) attributable to Key common shareholders — assuming dilution (a) | .29 | .78 | |||||
Cash dividends paid | .37 | .34 | |||||
Performance ratios | |||||||
From continuing operations: | |||||||
Return on average total assets | .43 | % | 1.18 | % | |||
Return on average common equity | 3.58 | 10.96 | |||||
Return on average tangible common equity (b) | 4.40 | 13.69 | |||||
Net interest margin (TE) | 2.88 | 3.10 | |||||
Cash efficiency ratio (b) | 60.0 | 61.9 | |||||
From consolidated operations: | |||||||
Return on average total assets | .43 | % | 1.18 | % | |||
Return on average common equity | 3.62 | 11.01 | |||||
Return on average tangible common equity (b) | 4.45 | 13.74 | |||||
Net interest margin (TE) | 2.87 | 3.08 | |||||
Asset quality — from continuing operations | |||||||
Net loan charge-offs | $ | 180 | $ | 129 | |||
Net loan charge-offs to average total loans | .35 | % | .29 | % | |||
Other data | |||||||
Average full-time equivalent employees | 16,587 | 17,379 | |||||
Taxable-equivalent adjustment | 15 | 16 | |||||
(a) | Earnings per share may not foot due to rounding. |
(b) | The following table entitled “GAAP to Non-GAAP Reconciliations” presents the computations of certain financial measures related to “tangible common equity” and “cash efficiency.” The table reconciles the GAAP performance measures to the corresponding non-GAAP measures, which provides a basis for period-to-period comparisons. |
(c) | Represents period-end consolidated total loans and loans held for sale divided by period-end consolidated total deposits. |
(d) | June 30, 2020, ratio is estimated and reflects Key's election to adopt the CECL optional transition provision. |
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 14
GAAP to Non-GAAP Reconciliations
(dollars in millions)
The table below presents certain non-GAAP financial measures related to “tangible common equity,” “return on average tangible common equity,” “pre-provision net revenue," and “cash efficiency ratio" and certain ratios excluding notable items.
Notable items include certain revenue or expense items that may occur in a reporting period which management does not consider indicative of ongoing financial performance. Management believes it is useful to consider certain financial metrics with and without notable items, in order to enable a better understanding of company results, increase comparability of period-to-period results, and to evaluate and forecast those results.
The tangible common equity ratio and the return on average tangible common equity ratio have been a focus for some investors, and management believes these ratios may assist investors in analyzing Key’s capital position without regard to the effects of intangible assets and preferred stock.
The table also shows the computation for pre-provision net revenue, which is not formally defined by GAAP. Management believes that eliminating the effects of the provision for credit losses makes it easier to analyze the results by presenting them on a more comparable basis.
The cash efficiency ratio is a ratio of two non-GAAP performance measures. As such, there is no directly comparable GAAP performance measure. The cash efficiency ratio performance measure removes the impact of Key’s intangible asset amortization from the calculation. Management believes this ratio provide greater consistency and comparability between Key’s results and those of its peer banks. Additionally, this ratio is used by analysts and investors as they develop earnings forecasts and peer bank analysis.
Non-GAAP financial measures have inherent limitations, are not required to be uniformly applied, and are not audited. Although these non-GAAP financial measures are frequently used by investors to evaluate a company, they have limitations as analytical tools, and should not be considered in isolation, or as a substitute for analyses of results as reported under GAAP.
Three months ended | Six months ended | |||||||||||||||
6/30/2020 | 3/31/2020 | 6/30/2019 | 6/30/2020 | 6/30/2019 | ||||||||||||
Tangible common equity to tangible assets at period-end | ||||||||||||||||
Key shareholders’ equity (GAAP) | $ | 17,542 | $ | 17,411 | $ | 16,969 | ||||||||||
Less: Intangible assets (a) | 2,877 | 2,894 | 2,952 | |||||||||||||
Preferred Stock (b) | 1,856 | 1,856 | 1,856 | |||||||||||||
Tangible common equity (non-GAAP) | $ | 12,809 | $ | 12,661 | $ | 12,161 | ||||||||||
Total assets (GAAP) | $ | 171,192 | $ | 156,197 | $ | 144,545 | ||||||||||
Less: Intangible assets (a) | 2,877 | 2,894 | 2,952 | |||||||||||||
Tangible assets (non-GAAP) | $ | 168,315 | $ | 153,303 | $ | 141,593 | ||||||||||
Tangible common equity to tangible assets ratio (non-GAAP) | 7.6 | % | 8.3 | % | 8.6 | % | ||||||||||
Pre-provision net revenue | ||||||||||||||||
Net interest income (GAAP) | $ | 1,018 | $ | 981 | $ | 981 | $ | 1,999 | $ | 1,958 | ||||||
Plus: Taxable-equivalent adjustment | 7 | 8 | 8 | 15 | 16 | |||||||||||
Noninterest income | 692 | 477 | 622 | 1,169 | 1,158 | |||||||||||
Less: Noninterest expense | 1,013 | 931 | 1,019 | 1,944 | 1,982 | |||||||||||
Pre-provision net revenue from continuing operations (non-GAAP) | $ | 704 | $ | 535 | $ | 592 | $ | 1,239 | $ | 1,150 | ||||||
Average tangible common equity | ||||||||||||||||
Average Key shareholders' equity (GAAP) | $ | 17,688 | $ | 17,216 | $ | 16,531 | $ | 17,452 | $ | 16,119 | ||||||
Less: Intangible assets (average) (c) | 2,886 | 2,902 | 2,959 | 2,894 | 2,886 | |||||||||||
Preferred stock (average) | 1,900 | 1,900 | 1,762 | 1,900 | 1,607 | |||||||||||
Average tangible common equity (non-GAAP) | $ | 12,902 | $ | 12,414 | $ | 11,810 | $ | 12,658 | $ | 11,626 | ||||||
Return on average tangible common equity from continuing operations | ||||||||||||||||
Net income (loss) from continuing operations attributable to Key common shareholders (GAAP) | $ | 159 | $ | 118 | $ | 403 | $ | 277 | $ | 789 | ||||||
Plus: Notable items, after tax (d) | — | — | 40 | — | 60 | |||||||||||
Net income (loss) from continuing operations attributable to Key common shareholders excluding notable items (non-GAAP) | $ | 159 | $ | 118 | $ | 443 | $ | 277 | $ | 849 | ||||||
Average tangible common equity (non-GAAP) | 12,902 | 12,414 | 11,810 | 12,658 | 11,626 | |||||||||||
Return on average tangible common equity from continuing operations (non-GAAP) | 4.96 | % | 3.82 | % | 13.69 | % | 4.40 | % | 13.69 | % | ||||||
Return on average tangible common equity from continuing operations excluding notable items (non-GAAP) | 4.96 | % | 3.82 | % | 15.05 | % | 4.40 | % | 14.73 | % | ||||||
Return on average tangible common equity consolidated | ||||||||||||||||
Net income (loss) attributable to Key common shareholders (GAAP) | $ | 161 | $ | 119 | $ | 405 | $ | 280 | $ | 792 | ||||||
Average tangible common equity (non-GAAP) | 12,902 | 12,414 | 11,810 | 12,658 | 11,626 | |||||||||||
Return on average tangible common equity consolidated (non-GAAP) | 5.02 | % | 3.86 | % | 13.75 | % | 4.45 | % | 13.74 | % | ||||||
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 15
GAAP to Non-GAAP Reconciliations (continued) | ||||||||||||||||
(dollars in millions) | ||||||||||||||||
Three months ended | Six months ended | |||||||||||||||
6/30/2020 | 3/31/2020 | 6/30/2019 | 6/30/2020 | 6/30/2019 | ||||||||||||
Cash efficiency ratio | ||||||||||||||||
Noninterest expense (GAAP) | $ | 1,013 | $ | 931 | $ | 1,019 | $ | 1,944 | $ | 1,982 | ||||||
Less: Intangible asset amortization | 18 | 17 | 22 | 35 | 44 | |||||||||||
Adjusted noninterest expense (non-GAAP) | $ | 995 | $ | 914 | $ | 997 | $ | 1,909 | $ | 1,938 | ||||||
Less: Notable items (d) | — | — | 52 | — | 78 | |||||||||||
Adjusted noninterest expense excluding notable items (non-GAAP) | $ | 995 | $ | 914 | $ | 945 | $ | 1,909 | $ | 1,860 | ||||||
Net interest income (GAAP) | $ | 1,018 | $ | 981 | $ | 981 | $ | 1,999 | $ | 1,958 | ||||||
Plus: Taxable-equivalent adjustment | 7 | 8 | 8 | 15 | 16 | |||||||||||
Noninterest income | 692 | 477 | 622 | 1,169 | 1,158 | |||||||||||
Total taxable-equivalent revenue (non-GAAP) | $ | 1,717 | $ | 1,466 | $ | 1,611 | $ | 3,183 | $ | 3,132 | ||||||
Cash efficiency ratio (non-GAAP) | 57.9 | % | 62.3 | % | 61.9 | % | 60.0 | % | 61.9 | % | ||||||
Cash efficiency ratio excluding notable items (non-GAAP) | 57.9 | % | 62.3 | % | 58.7 | % | 60.0 | % | 59.4 | % | ||||||
(a) | For the three months ended June 30, 2020, March 31, 2020, and June 30, 2019, intangible assets exclude $5 million, $6 million, and $10 million, respectively, of period-end purchased credit card receivables. |
(b) | Net of capital surplus. |
(c) | For the three months ended June 30, 2020, March 31, 2020, and June 30, 2019, average intangible assets exclude $6 million, $7 million, and $11 million, respectively, of average purchased credit card receivables. For the six months ended June 30, 2020, and June 30, 2019, average intangible assets exclude $6 million and $12 million, respectively, of average purchase credit card receivables. |
(d) | Additional detail provided in Notable Items table on page 24 of this release. |
GAAP = U.S. generally accepted accounting principles
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 16
Consolidated Balance Sheets | |||||||||||
(dollars in millions) | |||||||||||
6/30/2020 | 3/31/2020 | 6/30/2019 | |||||||||
Assets | |||||||||||
Loans | $ | 106,159 | $ | 103,198 | $ | 91,937 | |||||
Loans held for sale | 2,007 | 2,143 | 1,790 | ||||||||
Securities available for sale | 23,600 | 20,807 | 21,528 | ||||||||
Held-to-maturity securities | 9,075 | 9,638 | 10,878 | ||||||||
Trading account assets | 645 | 795 | 1,005 | ||||||||
Short-term investments | 14,036 | 4,073 | 2,443 | ||||||||
Other investments | 655 | 679 | 632 | ||||||||
Total earning assets | 156,177 | 141,333 | 130,213 | ||||||||
Allowance for loan and lease losses | (1,708 | ) | (1,359 | ) | (890 | ) | |||||
Cash and due from banks | 1,059 | 865 | 607 | ||||||||
Premises and equipment | 776 | 791 | 829 | ||||||||
Goodwill | 2,664 | 2,664 | 2,664 | ||||||||
Other intangible assets | 218 | 236 | 298 | ||||||||
Corporate-owned life insurance | 4,251 | 4,243 | 4,201 | ||||||||
Accrued income and other assets | 6,976 | 6,604 | 5,633 | ||||||||
Discontinued assets | 779 | 820 | 990 | ||||||||
Total assets | $ | 171,192 | 156,197 | 144,545 | |||||||
Liabilities | |||||||||||
Deposits in domestic offices: | |||||||||||
NOW and money market deposit accounts | $ | 78,853 | $ | 71,005 | $ | 63,619 | |||||
Savings deposits | 5,371 | 4,753 | 4,747 | ||||||||
Certificates of deposit ($100,000 or more) | 4,476 | 5,630 | 8,084 | ||||||||
Other time deposits | 4,011 | 4,623 | 5,524 | ||||||||
Total interest-bearing deposits | 92,711 | 86,011 | 81,974 | ||||||||
Noninterest-bearing deposits | 42,802 | 29,293 | 27,972 | ||||||||
Total deposits | 135,513 | 115,304 | 109,946 | ||||||||
Federal funds purchased and securities sold under repurchase agreements | 267 | 2,444 | 161 | ||||||||
Bank notes and other short-term borrowings | 1,716 | 4,606 | 720 | ||||||||
Accrued expense and other liabilities | 2,420 | 2,700 | 2,435 | ||||||||
Long-term debt | 13,734 | 13,732 | 14,312 | ||||||||
Total liabilities | 153,650 | 138,786 | 127,574 | ||||||||
Equity | |||||||||||
Preferred stock | 1,900 | 1,900 | 1,900 | ||||||||
Common shares | 1,257 | 1,257 | 1,257 | ||||||||
Capital surplus | 6,240 | 6,222 | 6,266 | ||||||||
Retained earnings | 12,154 | 12,174 | 12,005 | ||||||||
Treasury stock, at cost | (4,945 | ) | (4,956 | ) | (4,457 | ) | |||||
Accumulated other comprehensive income (loss) | 936 | 814 | (2 | ) | |||||||
Key shareholders’ equity | 17,542 | 17,411 | 16,969 | ||||||||
Noncontrolling interests | — | — | 2 | ||||||||
Total equity | 17,542 | 17,411 | 16,971 | ||||||||
Total liabilities and equity | $ | 171,192 | $ | 156,197 | $ | 144,545 | |||||
Common shares outstanding (000) | 975,947 | 975,319 | 1,003,114 | ||||||||
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 17
Consolidated Statements of Income | ||||||||||||||||||
(dollars in millions, except per share amounts) | ||||||||||||||||||
Three months ended | Six months ended | |||||||||||||||||
6/30/2020 | 3/31/2020 | 6/30/2019 | 6/30/2020 | 6/30/2019 | ||||||||||||||
Interest income | ||||||||||||||||||
Loans | $ | 980 | $ | 1,026 | $ | 1,082 | $ | 2,006 | $ | 2,148 | ||||||||
Loans held for sale | 21 | 19 | 15 | 40 | 28 | |||||||||||||
Securities available for sale | 121 | 129 | 135 | 250 | 264 | |||||||||||||
Held-to-maturity securities | 56 | 62 | 67 | 118 | 135 | |||||||||||||
Trading account assets | 5 | 8 | 9 | 13 | 17 | |||||||||||||
Short-term investments | 7 | 6 | 17 | 13 | 33 | |||||||||||||
Other investments | — | 1 | 4 | 1 | 8 | |||||||||||||
Total interest income | 1,190 | 1,251 | 1,329 | 2,441 | 2,633 | |||||||||||||
Interest expense | ||||||||||||||||||
Deposits | 96 | 169 | 223 | 265 | 425 | |||||||||||||
Federal funds purchased and securities sold under repurchase agreements | — | 6 | — | 6 | 1 | |||||||||||||
Bank notes and other short-term borrowings | 5 | 5 | 5 | 10 | 9 | |||||||||||||
Long-term debt | 71 | 90 | 120 | 161 | 240 | |||||||||||||
Total interest expense | 172 | 270 | 348 | 442 | 675 | |||||||||||||
Net interest income | 1,018 | 981 | 981 | 1,999 | 1,958 | |||||||||||||
Provision for credit losses | 482 | 359 | 74 | 841 | 136 | |||||||||||||
Net interest income after provision for credit losses | 536 | 622 | 907 | 1,158 | 1,822 | |||||||||||||
Noninterest income | ||||||||||||||||||
Trust and investment services income | 123 | 133 | 122 | 256 | 237 | |||||||||||||
Investment banking and debt placement fees | 156 | 116 | 163 | 272 | 273 | |||||||||||||
Service charges on deposit accounts | 68 | 84 | 83 | 152 | 165 | |||||||||||||
Operating lease income and other leasing gains | 60 | 30 | 44 | 90 | 81 | |||||||||||||
Corporate services income | 52 | 62 | 53 | 114 | 108 | |||||||||||||
Cards and payments income | 91 | 66 | 73 | 157 | 139 | |||||||||||||
Corporate-owned life insurance income | 35 | 36 | 33 | 71 | 65 | |||||||||||||
Consumer mortgage income | 62 | 20 | 15 | 82 | 26 | |||||||||||||
Commercial mortgage servicing fees | 12 | 18 | 19 | 30 | 37 | |||||||||||||
Other income | 33 | (88 | ) | 17 | (55 | ) | 27 | |||||||||||
Total noninterest income | 692 | 477 | 622 | 1,169 | 1,158 | |||||||||||||
Noninterest expense | ||||||||||||||||||
Personnel | 572 | 515 | 589 | 1,087 | 1,152 | |||||||||||||
Net occupancy | 71 | 76 | 73 | 147 | 145 | |||||||||||||
Computer processing | 56 | 55 | 56 | 111 | 110 | |||||||||||||
Business services and professional fees | 49 | 44 | 45 | 93 | 89 | |||||||||||||
Equipment | 25 | 24 | 24 | 49 | 48 | |||||||||||||
Operating lease expense | 34 | 36 | 32 | 70 | 58 | |||||||||||||
Marketing | 24 | 21 | 24 | 45 | 43 | |||||||||||||
FDIC assessment | 8 | 9 | 9 | 17 | 16 | |||||||||||||
Intangible asset amortization | 18 | 17 | 22 | 35 | 44 | |||||||||||||
OREO expense, net | 6 | 3 | 4 | 9 | 7 | |||||||||||||
Other expense | 150 | 131 | 141 | 281 | 270 | |||||||||||||
Total noninterest expense | 1,013 | 931 | 1,019 | 1,944 | 1,982 | |||||||||||||
Income (loss) from continuing operations before income taxes | 215 | 168 | 510 | 383 | 998 | |||||||||||||
Income taxes | 30 | 23 | 87 | 53 | 169 | |||||||||||||
Income (loss) from continuing operations | 185 | 145 | 423 | 330 | 829 | |||||||||||||
Income (loss) from discontinued operations, net of taxes | 2 | 1 | 2 | 3 | 3 | |||||||||||||
Net income (loss) | 187 | 146 | 425 | 333 | 832 | |||||||||||||
Less: Net income (loss) attributable to noncontrolling interests | — | — | — | — | — | |||||||||||||
Net income (loss) attributable to Key | $ | 187 | $ | 146 | $ | 425 | $ | 333 | $ | 832 | ||||||||
Income (loss) from continuing operations attributable to Key common shareholders | $ | 159 | $ | 118 | $ | 403 | $ | 277 | $ | 789 | ||||||||
Net income (loss) attributable to Key common shareholders | 161 | 119 | 405 | 280 | 792 | |||||||||||||
Per common share | ||||||||||||||||||
Income (loss) from continuing operations attributable to Key common shareholders | $ | .16 | $ | .12 | $ | .40 | $ | .29 | $ | .79 | ||||||||
Income (loss) from discontinued operations, net of taxes | — | — | — | — | — | |||||||||||||
Net income (loss) attributable to Key common shareholders (a) | .17 | .12 | .40 | .29 | .79 | |||||||||||||
Per common share — assuming dilution | ||||||||||||||||||
Income (loss) from continuing operations attributable to Key common shareholders | $ | .16 | $ | .12 | $ | .40 | $ | .28 | $ | .78 | ||||||||
Income (loss) from discontinued operations, net of taxes | — | — | — | — | — | |||||||||||||
Net income (loss) attributable to Key common shareholders (a) | .17 | .12 | .40 | .29 | .78 | |||||||||||||
Cash dividends declared per common share | $ | .185 | $ | .185 | $ | .17 | $ | .37 | $ | .34 | ||||||||
Weighted-average common shares outstanding (000) | 967,147 | 967,446 | 999,163 | 967,380 | 1,003,047 | |||||||||||||
Effect of common share options and other stock awards | 4,994 | 8,664 | 8,801 | 6,892 | 9,318 | |||||||||||||
Weighted-average common shares and potential common shares outstanding (000) (b) | 972,141 | 976,110 | 1,007,964 | 974,272 | 1,012,365 | |||||||||||||
(a) | Earnings per share may not foot due to rounding. |
(b) | Assumes conversion of common share options and other stock awards, as applicable. |
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 18
Consolidated Average Balance Sheets, and Net Interest Income and Yields/Rates From Continuing Operations | |||||||||||||||||||||||||||
(dollars in millions) | |||||||||||||||||||||||||||
Second Quarter 2020 | First Quarter 2020 | Second Quarter 2019 | |||||||||||||||||||||||||
Average | Yield/ | Average | Yield/ | Average | Yield/ | ||||||||||||||||||||||
Balance | Interest (a) | Rate (a) | Balance | Interest (a) | Rate (a) | Balance | Interest (a) | Rate (a) | |||||||||||||||||||
Assets | |||||||||||||||||||||||||||
Loans: (b), (c) | |||||||||||||||||||||||||||
Commercial and industrial (d) | $ | 60,480 | $ | 518 | 3.44 | % | $ | 49,466 | $ | 508 | 4.13 | % | $ | 47,227 | $ | 547 | 4.65 | % | |||||||||
Real estate — commercial mortgage | 13,510 | 128 | 3.80 | 13,548 | 155 | 4.60 | 13,866 | 175 | 5.06 | ||||||||||||||||||
Real estate — construction | 1,756 | 17 | 3.97 | 1,666 | 20 | 4.75 | 1,423 | 20 | 5.41 | ||||||||||||||||||
Commercial lease financing | 4,584 | 33 | 2.96 | 4,565 | 39 | 3.39 | 4,476 | 41 | 3.65 | ||||||||||||||||||
Total commercial loans | 80,330 | 696 | 3.49 | 69,245 | 722 | 4.19 | 66,992 | 783 | 4.69 | ||||||||||||||||||
Real estate — residential mortgage | 7,783 | 69 | 3.57 | 7,215 | 68 | 3.75 | 5,790 | 58 | 4.03 | ||||||||||||||||||
Home equity loans | 9,949 | 97 | 3.89 | 10,155 | 113 | 4.49 | 10,701 | 135 | 5.05 | ||||||||||||||||||
Consumer direct loans | 4,152 | 55 | 5.24 | 3,709 | 54 | 5.91 | 2,352 | 43 | 7.39 | ||||||||||||||||||
Credit cards | 983 | 25 | 10.22 | 1,082 | 31 | 11.50 | 1,091 | 31 | 11.26 | ||||||||||||||||||
Consumer indirect loans | 4,744 | 45 | 3.82 | 4,768 | 46 | 3.86 | 3,859 | 40 | 4.15 | ||||||||||||||||||
Total consumer loans | 27,611 | 291 | 4.22 | 26,929 | 312 | 4.66 | 23,793 | 307 | 5.17 | ||||||||||||||||||
Total loans | 107,941 | 987 | 3.67 | 96,174 | 1,034 | 4.32 | 90,785 | 1,090 | 4.81 | ||||||||||||||||||
Loans held for sale | 2,463 | 21 | 3.50 | 1,885 | 19 | 3.99 | 1,302 | 15 | 4.56 | ||||||||||||||||||
Securities available for sale (b), (e) | 20,749 | 121 | 2.43 | 21,172 | 129 | 2.49 | 21,086 | 135 | 2.54 | ||||||||||||||||||
Held-to-maturity securities (b) | 9,331 | 56 | 2.43 | 9,820 | 62 | 2.51 | 11,058 | 67 | 2.41 | ||||||||||||||||||
Trading account assets | 760 | 5 | 2.43 | 1,065 | 8 | 2.95 | 1,124 | 9 | 3.28 | ||||||||||||||||||
Short-term investments | 7,892 | 7 | .31 | 1,764 | 6 | 1.42 | 3,200 | 17 | 2.23 | ||||||||||||||||||
Other investments (e) | 672 | — | .29 | 614 | 1 | .40 | 640 | 4 | 2.00 | ||||||||||||||||||
Total earning assets | 149,808 | 1,197 | 3.22 | 132,494 | 1,259 | 3.82 | 129,195 | 1,337 | 4.14 | ||||||||||||||||||
Allowance for loan and lease losses | (1,413 | ) | (1,097 | ) | (881 | ) | |||||||||||||||||||||
Accrued income and other assets | 15,704 | 14,831 | 14,321 | ||||||||||||||||||||||||
Discontinued assets | 793 | 838 | 1,009 | ||||||||||||||||||||||||
Total assets | $ | 164,892 | $ | 147,066 | $ | 143,644 | |||||||||||||||||||||
Liabilities | |||||||||||||||||||||||||||
NOW and money market deposit accounts | $ | 75,297 | 56 | .30 | $ | 66,721 | 112 | .67 | $ | 63,071 | 147 | .93 | |||||||||||||||
Savings deposits | 5,130 | — | .04 | 4,655 | 1 | .05 | 4,781 | 1 | .09 | ||||||||||||||||||
Certificates of deposit ($100,000 or more) | 4,950 | 24 | 1.93 | 6,310 | 34 | 2.20 | 8,147 | 48 | 2.37 | ||||||||||||||||||
Other time deposits | 4,333 | 16 | 1.52 | 4,901 | 22 | 1.81 | 5,569 | 27 | 1.93 | ||||||||||||||||||
Total interest-bearing deposits | 89,710 | 96 | .43 | 82,587 | 169 | .82 | 81,568 | 223 | 1.10 | ||||||||||||||||||
Federal funds purchased and securities sold under repurchase agreements | 242 | — | .03 | 2,002 | 6 | 1.17 | 194 | — | .20 | ||||||||||||||||||
Bank notes and other short-term borrowings | 2,869 | 5 | .57 | 1,401 | 5 | 1.58 | 842 | 5 | 2.46 | ||||||||||||||||||
Long-term debt (f), (g) | 12,954 | 71 | 2.30 | 12,443 | 90 | 2.96 | 13,213 | 120 | 3.67 | ||||||||||||||||||
Total interest-bearing liabilities | 105,775 | 172 | .66 | 98,433 | 270 | 1.10 | 95,817 | 348 | 1.46 | ||||||||||||||||||
Noninterest-bearing deposits | 38,267 | 27,741 | 28,033 | ||||||||||||||||||||||||
Accrued expense and other liabilities | 2,369 | 2,838 | 2,253 | ||||||||||||||||||||||||
Discontinued liabilities (g) | 793 | 838 | 1,009 | ||||||||||||||||||||||||
Total liabilities | 147,204 | 129,850 | 127,112 | ||||||||||||||||||||||||
Equity | |||||||||||||||||||||||||||
Key shareholders’ equity | 17,688 | 17,216 | 16,531 | ||||||||||||||||||||||||
Noncontrolling interests | — | — | 1 | ||||||||||||||||||||||||
Total equity | 17,688 | 17,216 | 16,532 | ||||||||||||||||||||||||
Total liabilities and equity | $ | 164,892 | $ | 147,066 | $ | 143,644 | |||||||||||||||||||||
Interest rate spread (TE) | 2.56 | % | 2.72 | % | 2.68 | % | |||||||||||||||||||||
Net interest income (TE) and net interest margin (TE) | 1,025 | 2.76 | % | 989 | 3.01 | % | 989 | 3.06 | % | ||||||||||||||||||
TE adjustment (b) | 7 | 8 | 8 | ||||||||||||||||||||||||
Net interest income, GAAP basis | $ | 1,018 | $ | 981 | $ | 981 | |||||||||||||||||||||
(a) | Results are from continuing operations. Interest excludes the interest associated with the liabilities referred to in (g) below, calculated using a matched funds transfer pricing methodology. |
(b) | Interest income on tax-exempt securities and loans has been adjusted to a taxable-equivalent basis using the statutory federal income tax rate of 21% for the three months ended June 30, 2020, March 31, 2020, and June 30, 2019. |
(c) | For purposes of these computations, nonaccrual loans are included in average loan balances. |
(d) | Commercial and industrial average balances include $135 million, $145 million, and $141 million of assets from commercial credit cards for the three months ended June 30, 2020, March 31, 2020, and June 30, 2019, respectively. |
(e) | Yield is calculated on the basis of amortized cost. |
(f) | Rate calculation excludes basis adjustments related to fair value hedges. |
(g) | A portion of long-term debt and the related interest expense is allocated to discontinued liabilities as a result of applying Key’s matched funds transfer pricing methodology to discontinued operations. |
TE = Taxable Equivalent, GAAP = U.S. generally accepted accounting principles
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 19
Consolidated Average Balance Sheets, and Net Interest Income and Yields/Rates From Continuing Operations | ||||||||||||||||||
(dollars in millions) | ||||||||||||||||||
Six months ended June 30, 2020 | Six months ended June 30, 2019 | |||||||||||||||||
Average | Yield/ | Average | Yield/ | |||||||||||||||
Balance | Interest (a) | Rate (a) | Balance | Interest (a) | Rate (a) | |||||||||||||
Assets | ||||||||||||||||||
Loans: (b), (c) | ||||||||||||||||||
Commercial and industrial (d) | $ | 54,973 | $ | 1,026 | 3.75 | % | $ | 46,616 | $ | 1,079 | 4.67 | % | ||||||
Real estate — commercial mortgage | 13,529 | 283 | 4.20 | 14,094 | 354 | 5.07 | ||||||||||||
Real estate — construction | 1,711 | 37 | 4.35 | 1,492 | 41 | 5.45 | ||||||||||||
Commercial lease financing | 4,575 | 72 | 3.17 | 4,486 | 82 | 3.66 | ||||||||||||
Total commercial loans | 74,788 | 1,418 | 3.81 | 66,688 | 1,556 | 4.70 | ||||||||||||
Real estate — residential mortgage | 7,500 | 137 | 3.66 | 5,667 | 114 | 4.02 | ||||||||||||
Home equity loans | 10,052 | 210 | 4.19 | 10,847 | 272 | 5.06 | ||||||||||||
Consumer direct loans | 3,930 | 109 | 5.56 | 2,109 | 80 | 7.68 | ||||||||||||
Credit cards | 1,032 | 56 | 10.89 | 1,098 | 63 | 11.53 | ||||||||||||
Consumer indirect loans | 4,756 | 91 | 3.84 | 3,811 | 79 | 4.14 | ||||||||||||
Total consumer loans | 27,270 | 603 | 4.44 | 23,532 | 608 | 5.20 | ||||||||||||
Total loans | 102,058 | 2,021 | 3.98 | 90,220 | 2,164 | 4.83 | ||||||||||||
Loans held for sale | 2,174 | 40 | 3.71 | 1,212 | 28 | 4.64 | ||||||||||||
Securities available for sale (b), (e) | 20,960 | 250 | 2.46 | 20,649 | 264 | 2.52 | ||||||||||||
Held-to-maturity securities (b) | 9,575 | 118 | 2.47 | 11,213 | 135 | 2.41 | ||||||||||||
Trading account assets | 913 | 13 | 2.73 | 1041 | 17 | 3.31 | ||||||||||||
Short-term investments | 4,828 | 13 | .52 | 2,965 | 33 | 2.25 | ||||||||||||
Other investments (e) | 643 | 1 | .34 | 647 | 8 | 2.35 | ||||||||||||
Total earning assets | 141,151 | 2,456 | 3.51 | 127,947 | 2,649 | 4.16 | ||||||||||||
Allowance for loan and lease losses | (1255 | ) | (879 | ) | ||||||||||||||
Accrued income and other assets | 15,268 | 14,317 | ||||||||||||||||
Discontinued assets | 815 | 1,037 | ||||||||||||||||
Total assets | $ | 155,979 | $ | 142,422 | ||||||||||||||
Liabilities | ||||||||||||||||||
NOW and money market deposit accounts | $ | 71,009 | 168 | .47 | $ | 61,928 | 277 | .90 | ||||||||||
Savings deposits | 4,893 | 1 | .04 | 4,796 | 2 | .08 | ||||||||||||
Certificates of deposit ($100,000 or more) | 5,630 | 58 | 2.08 | 8,261 | 95 | 2.31 | ||||||||||||
Other time deposits | 4,617 | 38 | 1.67 | 5,535 | 51 | 1.86 | ||||||||||||
Total interest-bearing deposits | 86,149 | 265 | .62 | 80,520 | 425 | 1.06 | ||||||||||||
Federal funds purchased and securities sold under repurchase agreements | 1,122 | 6 | 1.05 | 301 | 1 | .67 | ||||||||||||
Bank notes and other short-term borrowings | 2,135 | 10 | .90 | 746 | 9 | 2.59 | ||||||||||||
Long-term debt (f), (g) | 12,698 | 161 | 2.62 | 13,187 | 240 | 3.67 | ||||||||||||
Total interest-bearing liabilities | 102,104 | 442 | .87 | 94,754 | 675 | 1.44 | ||||||||||||
Noninterest-bearing deposits | 33,004 | 28,074 | ||||||||||||||||
Accrued expense and other liabilities | 2,604 | 2,437 | ||||||||||||||||
Discontinued liabilities (g) | 815 | 1,037 | ||||||||||||||||
Total liabilities | 138,527 | 126,302 | ||||||||||||||||
Equity | ||||||||||||||||||
Key shareholders’ equity | 17,452 | 16,119 | ||||||||||||||||
Noncontrolling interests | — | 1 | ||||||||||||||||
Total equity | 17,452 | 16,120 | ||||||||||||||||
Total liabilities and equity | $ | 155,979 | $ | 142,422 | ||||||||||||||
Interest rate spread (TE) | 2.64 | % | 2.72 | % | ||||||||||||||
Net interest income (TE) and net interest margin (TE) | 2,014 | 2.88 | % | 1,974 | 3.10 | % | ||||||||||||
TE adjustment (b) | 15 | 16 | ||||||||||||||||
Net interest income, GAAP basis | $ | 1,999 | $ | 1,958 | ||||||||||||||
(a) | Results are from continuing operations. Interest excludes the interest associated with the liabilities referred to in (g) below, calculated using a matched funds transfer pricing methodology. |
(b) | Interest income on tax-exempt securities and loans has been adjusted to a taxable-equivalent basis using the statutory federal income tax rate of 21% for the six months ended June 30, 2020, and June 30, 2019, respectively. |
(c) | For purposes of these computations, nonaccrual loans are included in average loan balances. |
(d) | Commercial and industrial average balances include $140 million and $137 million of assets from commercial credit cards for the six months ended June 30, 2020, and June 30, 2019, respectively. |
(e) | Yield is calculated on the basis of amortized cost. |
(f) | Rate calculation excludes basis adjustments related to fair value hedges. |
(g) | A portion of long-term debt and the related interest expense is allocated to discontinued liabilities as a result of applying Key’s matched funds transfer pricing methodology to discontinued operations. |
TE = Taxable Equivalent, GAAP = U.S. generally accepted accounting principles
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 20
Noninterest Expense | ||||||||||||||||
(dollars in millions) | ||||||||||||||||
Three months ended | Six months ended | |||||||||||||||
6/30/2020 | 3/31/2020 | 6/30/2019 | 6/30/2020 | 6/30/2019 | ||||||||||||
Personnel (a) | $ | 572 | $ | 515 | $ | 589 | $ | 1,087 | $ | 1,152 | ||||||
Net occupancy | 71 | 76 | 73 | 147 | 145 | |||||||||||
Computer processing | 56 | 55 | 56 | 111 | 110 | |||||||||||
Business services and professional fees | 49 | 44 | 45 | 93 | 89 | |||||||||||
Equipment | 25 | 24 | 24 | 49 | 48 | |||||||||||
Operating lease expense | 34 | 36 | 32 | 70 | 58 | |||||||||||
Marketing | 24 | 21 | 24 | 45 | 43 | |||||||||||
FDIC assessment | 8 | 9 | 9 | 17 | 16 | |||||||||||
Intangible asset amortization | 18 | 17 | 22 | 35 | 44 | |||||||||||
OREO expense, net | 6 | 3 | 4 | 9 | 7 | |||||||||||
Other expense | 150 | 131 | 141 | 281 | 270 | |||||||||||
Total noninterest expense | $ | 1,013 | $ | 931 | $ | 1,019 | $ | 1,944 | $ | 1,982 | ||||||
Average full-time equivalent employees (b) | 16,646 | 16,529 | 17,206 | 16,587 | 17,379 | |||||||||||
(a) | Additional detail provided in Personnel Expense table below. |
(b) | The number of average full-time equivalent employees has not been adjusted for discontinued operations. |
Personnel Expense | ||||||||||||||||
(in millions) | ||||||||||||||||
Three months ended | Six months ended | |||||||||||||||
6/30/2020 | 3/31/2020 | 6/30/2019 | 6/30/2020 | 6/30/2019 | ||||||||||||
Salaries and contract labor | $ | 332 | $ | 316 | $ | 322 | $ | 648 | $ | 642 | ||||||
Incentive and stock-based compensation | 162 | 102 | 155 | 264 | 287 | |||||||||||
Employee benefits | 76 | 92 | 83 | 168 | 176 | |||||||||||
Severance | 2 | 5 | 29 | 7 | 47 | |||||||||||
Total personnel expense | $ | 572 | $ | 515 | $ | 589 | $ | 1,087 | $ | 1,152 | ||||||
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 21
Loan Composition | ||||||||||||||
(dollars in millions) | ||||||||||||||
Percent change 6/30/2020 vs | ||||||||||||||
6/30/2020 | 3/31/2020 | 6/30/2019 | 3/31/2020 | 6/30/2019 | ||||||||||
Commercial and industrial (a) | $ | 58,297 | $ | 55,983 | $ | 48,544 | 4.1 | % | 20.1 | % | ||||
Commercial real estate: | ||||||||||||||
Commercial mortgage | 13,465 | 13,548 | 13,299 | (.6 | ) | 1.2 | ||||||||
Construction | 1,919 | 1,710 | 1,439 | 12.2 | 33.4 | |||||||||
Total commercial real estate loans | 15,384 | 15,258 | 14,738 | .8 | 4.4 | |||||||||
Commercial lease financing (b) | 4,524 | 4,677 | 4,578 | (3.3 | ) | (1.2 | ) | |||||||
Total commercial loans | 78,205 | 75,918 | 67,860 | 3.0 | 15.2 | |||||||||
Residential — prime loans: | ||||||||||||||
Real estate — residential mortgage | 8,149 | 7,498 | 6,053 | 8.7 | 34.6 | |||||||||
Home equity loans | 9,782 | 10,103 | 10,575 | (3.2 | ) | (7.5 | ) | |||||||
Total residential — prime loans | 17,931 | 17,601 | 16,628 | 1.9 | 7.8 | |||||||||
Consumer direct loans | 4,327 | 3,833 | 2,350 | 12.9 | 84.1 | |||||||||
Credit cards | 974 | 1,041 | 1,096 | (6.4 | ) | (11.1 | ) | |||||||
Consumer indirect loans | 4,722 | 4,805 | 4,003 | (1.7 | ) | 18.0 | ||||||||
Total consumer loans | 27,954 | 27,280 | 24,077 | 2.5 | 16.1 | |||||||||
Total loans (c), (d) | $ | 106,159 | $ | 103,198 | $ | 91,937 | 2.9 | % | 15.5 | % | ||||
(a) | Loan balances include $132 million, $143 million, and $143 million of commercial credit card balances at June 30, 2020, March 31, 2020, and June 30, 2019, respectively. |
(b) | Commercial lease financing includes receivables held as collateral for a secured borrowing of $18 million, $14 million, and $11 million at June 30, 2020, March 31, 2020, and June 30, 2019, respectively. Principal reductions are based on the cash payments received from these related receivables. |
(c) | Total loans exclude loans of $780 million at June 30, 2020, $821 million at March 31, 2020, and $964 million at June 30, 2019, related to the discontinued operations of the education lending business. |
(d) | Accrued interest of $225 million, $241 million, and $272 million at June 30, 2020, March 31, 2020, and June 30, 2019, respectively, presented in "other assets" on the Consolidated Balance Sheets is excluded from the amortized cost basis disclosed in this table. |
Loans Held for Sale Composition | ||||||||||||||
(dollars in millions) | ||||||||||||||
Percent change 6/30/2020 vs | ||||||||||||||
6/30/2020 | 3/31/2020 | 6/30/2019 | 3/31/2020 | 6/30/2019 | ||||||||||
Commercial and industrial | $ | 419 | $ | 446 | $ | 255 | (6.1 | )% | 64.3 | % | ||||
Real estate — commercial mortgage | 1,107 | 1,284 | 1,123 | (13.8 | ) | (1.4 | ) | |||||||
Commercial lease financing | — | 8 | — | N/M | N/M | |||||||||
Real estate — residential mortgage | 250 | 152 | 164 | 64.5 | 52.4 | |||||||||
Consumer direct loans | 231 | 253 | 248 | (8.7 | ) | (6.9 | ) | |||||||
Total loans held for sale (a) | $ | 2,007 | $ | 2,143 | $ | 1,790 | (6.3 | )% | 12.1 | % | ||||
(a) | Total loans held for sale include Real estate — residential mortgage loans held for sale at fair value of $250 million at June 30, 2020, $152 million at March 31, 2020, and $164 million at June 30, 2019. |
Summary of Changes in Loans Held for Sale | |||||||||||||||
(in millions) | |||||||||||||||
2Q20 | 1Q20 | 4Q19 | 3Q19 | 2Q19 | |||||||||||
Balance at beginning of period | $ | 2,143 | $ | 1,334 | $ | 1,598 | $ | 1,790 | $ | 894 | |||||
New originations | 3,621 | 3,333 | 3,659 | 3,222 | 3,218 | ||||||||||
Transfers from (to) held to maturity, net | (15 | ) | 200 | 26 | 237 | 42 | |||||||||
Loan sales | (3,679 | ) | (2,649 | ) | (3,933 | ) | (3,602 | ) | (2,358 | ) | |||||
Loan draws (payments), net | (61 | ) | (77 | ) | (18 | ) | (49 | ) | (6 | ) | |||||
Valuation adjustments | (2 | ) | 2 | 2 | — | — | |||||||||
Balance at end of period (a) | $ | 2,007 | $ | 2,143 | $ | 1,334 | $ | 1,598 | $ | 1,790 | |||||
(a) | Total loans held for sale include Real estate — residential mortgage loans held for sale at fair value of $250 million at June 30, 2020, $152 million at March 31, 2020, $140 million at December 31, 2019, $120 million at September 30, 2019, and $164 million at June 30, 2019. |
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 22
Summary of Loan and Lease Loss Experience From Continuing Operations | ||||||||||||||||
(dollars in millions) | ||||||||||||||||
Three months ended | Six months ended | |||||||||||||||
6/30/2020 | 3/31/2020 | 6/30/2019 | 6/30/2020 | 6/30/2019 | ||||||||||||
Average loans outstanding | $ | 107,941 | $ | 96,174 | $ | 90,785 | $ | 102,058 | $ | 90,220 | ||||||
Allowance for loan and lease losses at the end of the prior period | $ | 1,359 | $ | 900 | $ | 883 | $ | 900 | $ | 883 | ||||||
Cumulative effect from change in accounting principle (a) | — | 204 | — | 204 | — | |||||||||||
Allowance for loan and lease losses at the beginning of the period | 1,359 | 1,104 | 883 | 1,104 | 883 | |||||||||||
Loans charged off: | ||||||||||||||||
Commercial and industrial | 71 | 60 | 30 | 131 | 66 | |||||||||||
Real estate — commercial mortgage | 2 | 3 | 1 | 5 | 6 | |||||||||||
Real estate — construction | — | — | — | — | 4 | |||||||||||
Total commercial real estate loans | 2 | 3 | 1 | 5 | 10 | |||||||||||
Commercial lease financing | 4 | 2 | 16 | 6 | 24 | |||||||||||
Total commercial loans | 77 | 65 | 47 | 142 | 100 | |||||||||||
Real estate — residential mortgage | 2 | — | 1 | 2 | 2 | |||||||||||
Home equity loans | 2 | 4 | 6 | 6 | 10 | |||||||||||
Consumer direct loans | 10 | 12 | 10 | 22 | 20 | |||||||||||
Credit cards | 12 | 11 | 12 | 23 | 23 | |||||||||||
Consumer indirect loans | 7 | 9 | 8 | 16 | 16 | |||||||||||
Total consumer loans | 33 | 36 | 37 | 69 | 71 | |||||||||||
Total loans charged off | 110 | 101 | 84 | 211 | 171 | |||||||||||
Recoveries: | ||||||||||||||||
Commercial and industrial | 5 | 5 | 6 | 10 | 16 | |||||||||||
Real estate — commercial mortgage | — | 1 | 1 | 1 | 2 | |||||||||||
Total commercial real estate loans | — | 1 | 1 | 1 | 2 | |||||||||||
Commercial lease financing | 1 | — | 2 | 1 | 3 | |||||||||||
Total commercial loans | 6 | 6 | 9 | 12 | 21 | |||||||||||
Real estate — residential mortgage | — | — | — | — | 1 | |||||||||||
Home equity loans | 1 | 2 | 2 | 3 | 4 | |||||||||||
Consumer direct loans | 2 | 2 | 2 | 4 | 3 | |||||||||||
Credit cards | 2 | 2 | 2 | 4 | 4 | |||||||||||
Consumer indirect loans | 3 | 5 | 4 | 8 | 9 | |||||||||||
Total consumer loans | 8 | 11 | 10 | 19 | 21 | |||||||||||
Total recoveries | 14 | 17 | 19 | 31 | 42 | |||||||||||
Net loan charge-offs | (96 | ) | (84 | ) | (65 | ) | (180 | ) | (129 | ) | ||||||
Provision (credit) for loan and lease losses | 445 | 339 | 72 | 784 | 136 | |||||||||||
Allowance for loan and lease losses at end of period | $ | 1,708 | $ | 1,359 | $ | 890 | $ | 1,708 | $ | 890 | ||||||
Liability for credit losses on lending-related commitments at the end of the prior period | $ | 161 | $ | 68 | $ | 62 | $ | 68 | $ | 64 | ||||||
Liability for credit losses on contingent guarantees at the end of the prior period | — | 7 | — | 7 | — | |||||||||||
Cumulative effect from change in accounting principle (a), (b) | — | 66 | — | 66 | — | |||||||||||
Liability for credit losses on lending-related commitments at beginning of period | 161 | 141 | 62 | 141 | 64 | |||||||||||
Provision (credit) for losses on lending-related commitments | 37 | 20 | 2 | 57 | — | |||||||||||
Liability for credit losses on lending-related commitments at end of period (c) | $ | 198 | $ | 161 | $ | 64 | $ | 198 | $ | 64 | ||||||
Total allowance for credit losses at end of period | $ | 1,906 | $ | 1,520 | $ | 954 | $ | 1,906 | $ | 954 | ||||||
Net loan charge-offs to average total loans | .36 | % | .35 | % | .29 | % | .35 | % | .29 | % | ||||||
Allowance for loan and lease losses to period-end loans | 1.61 | 1.32 | .97 | 1.61 | .97 | |||||||||||
Allowance for credit losses to period-end loans | 1.80 | 1.47 | 1.04 | 1.80 | 1.04 | |||||||||||
Allowance for loan and lease losses to nonperforming loans | 224.7 | 215.0 | 158.6 | 224.7 | 158.6 | |||||||||||
Allowance for credit losses to nonperforming loans | 250.8 | 240.5 | 170.1 | 250.8 | 170.1 | |||||||||||
Discontinued operations — education lending business: | ||||||||||||||||
Loans charged off | $ | 2 | $ | 2 | $ | 4 | $ | 4 | $ | 8 | ||||||
Recoveries | 2 | 1 | 1 | 3 | 2 | |||||||||||
Net loan charge-offs | — | $ | (1 | ) | $ | (3 | ) | $ | (1 | ) | $ | (6 | ) | |||
(a) | The cumulative effect from change in accounting principle relates to the January 1, 2020, adoption of ASU 2016-13. |
(b) | March 31, 2020, amount excludes $4 million related to the provision for other financial assets. |
(c) | Included in "Accrued expense and other liabilities" on the balance sheet. |
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 23
Asset Quality Statistics From Continuing Operations | |||||||||||||||
(dollars in millions) | |||||||||||||||
2Q20 | 1Q20 | 4Q19 | 3Q19 | 2Q19 | |||||||||||
Net loan charge-offs | $ | 96 | $ | 84 | $ | 99 | $ | 196 | $ | 65 | |||||
Net loan charge-offs to average total loans | .36 | % | .35 | % | .42 | % | .85 | % | .29 | % | |||||
Allowance for loan and lease losses | $ | 1,708 | $ | 1,359 | $ | 900 | $ | 893 | $ | 890 | |||||
Allowance for credit losses (a) | 1,906 | 1,520 | 968 | 958 | 954 | ||||||||||
Allowance for loan and lease losses to period-end loans | 1.61 | % | 1.32 | % | .95 | % | .96 | % | .97 | % | |||||
Allowance for credit losses to period-end loans | 1.80 | 1.47 | 1.02 | 1.03 | 1.04 | ||||||||||
Allowance for loan and lease losses to nonperforming loans | 224.7 | 215.0 | 156.0 | 152.6 | 158.6 | ||||||||||
Allowance for credit losses to nonperforming loans | 250.8 | 240.5 | 167.8 | 163.8 | 170.1 | ||||||||||
Nonperforming loans at period end | $ | 760 | $ | 632 | $ | 577 | $ | 585 | $ | 561 | |||||
Nonperforming assets at period end | 951 | 844 | 715 | 711 | 608 | ||||||||||
Nonperforming loans to period-end portfolio loans | .72 | % | .61 | % | .61 | % | .63 | % | .61 | % | |||||
Nonperforming assets to period-end portfolio loans plus OREO and other nonperforming assets | .89 | .82 | .75 | .77 | .66 | ||||||||||
(a) | Includes the allowance for loan and lease losses plus the liability for credit losses on lending-related commitments. |
Summary of Nonperforming Assets and Past Due Loans From Continuing Operations | |||||||||||||||
(dollars in millions) | |||||||||||||||
6/30/2020 | 3/31/2020 | 12/31/2019 | 9/30/2019 | 6/30/2019 | |||||||||||
Commercial and industrial | $ | 404 | $ | 277 | $ | 264 | $ | 238 | $ | 189 | |||||
Real estate — commercial mortgage | 91 | 87 | 83 | 92 | 85 | ||||||||||
Real estate — construction | 1 | 2 | 2 | 2 | 2 | ||||||||||
Total commercial real estate loans | 92 | 89 | 85 | 94 | 87 | ||||||||||
Commercial lease financing | 9 | 5 | 6 | 7 | 7 | ||||||||||
Total commercial loans | 505 | 371 | 355 | 339 | 283 | ||||||||||
Real estate — residential mortgage | 89 | 89 | 48 | 42 | 62 | ||||||||||
Home equity loans | 141 | 143 | 145 | 179 | 191 | ||||||||||
Consumer direct loans | 3 | 4 | 4 | 3 | 3 | ||||||||||
Credit cards | 2 | 3 | 3 | 2 | 2 | ||||||||||
Consumer indirect loans | 20 | 22 | 22 | 20 | 20 | ||||||||||
Total consumer loans | 255 | 261 | 222 | 246 | 278 | ||||||||||
Total nonperforming loans | 760 | 632 | 577 | 585 | 561 | ||||||||||
OREO | 112 | 119 | 35 | 39 | 38 | ||||||||||
Nonperforming loans held for sale | 75 | 89 | 94 | 78 | — | ||||||||||
Other nonperforming assets | 4 | 4 | 9 | 9 | 9 | ||||||||||
Total nonperforming assets | $ | 951 | $ | 844 | $ | 715 | $ | 711 | $ | 608 | |||||
Accruing loans past due 90 days or more | 87 | 128 | 97 | 54 | 74 | ||||||||||
Accruing loans past due 30 through 89 days | 419 | 393 | 329 | 366 | 299 | ||||||||||
Restructured loans — accruing and nonaccruing (a) | 310 | 340 | 347 | 347 | 395 | ||||||||||
Restructured loans included in nonperforming loans (a) | 166 | 172 | 183 | 176 | 228 | ||||||||||
Nonperforming assets from discontinued operations — education lending business | 7 | 7 | 7 | 7 | 7 | ||||||||||
Nonperforming loans to period-end portfolio loans | .72 | % | .61 | % | .61 | % | .63 | % | .61 | % | |||||
Nonperforming assets to period-end portfolio loans plus OREO and other nonperforming assets | .89 | .82 | .75 | .77 | .66 | ||||||||||
(a) | Restructured loans (i.e., troubled debt restructuring) are those for which Key, for reasons related to a borrower’s financial difficulties, grants a concession to the borrower that it would not otherwise consider. These concessions are made to improve the collectability of the loan and generally take the form of a reduction of the interest rate, extension of the maturity date or reduction in the principal balance. |
Summary of Changes in Nonperforming Loans From Continuing Operations | |||||||||||||||
(in millions) | |||||||||||||||
2Q20 | 1Q20 | 4Q19 | 3Q19 | 2Q19 | |||||||||||
Balance at beginning of period | $ | 632 | $ | 577 | $ | 585 | $ | 561 | $ | 548 | |||||
Loans placed on nonaccrual status (a) | 293 | 219 | 268 | 271 | 189 | ||||||||||
Charge-offs | (111 | ) | (100 | ) | (114 | ) | (91 | ) | (84 | ) | |||||
Loans sold | (5 | ) | (4 | ) | (1 | ) | — | (38 | ) | ||||||
Payments | (29 | ) | (31 | ) | (59 | ) | (37 | ) | (23 | ) | |||||
Transfers to OREO | — | (3 | ) | (3 | ) | (4 | ) | (4 | ) | ||||||
Transfers to nonperforming loans held for sale | — | — | (47 | ) | (78 | ) | — | ||||||||
Loans returned to accrual status | (20 | ) | (26 | ) | (52 | ) | (37 | ) | (27 | ) | |||||
Balance at end of period | $ | 760 | $ | 632 | $ | 577 | $ | 585 | $ | 561 | |||||
(a) | Purchase credit impaired (PCI) loans meeting nonperforming criteria were historically excluded from Key's nonperforming disclosures. As a result of CECL implementation on January 1, 2020, PCI loans became purchased credit deteriorated (PCD) loans. PCD loans that met the definition of nonperforming are now included in nonperforming disclosures, resulting in a $45 million increase in nonperforming loans in the first quarter of 2020. |
KeyCorp Reports Second Quarter 2020 Profit
July 22, 2020
Page 24
Line of Business Results | ||||||||||||||||||||
(dollars in millions) | ||||||||||||||||||||
Percentage change 2Q20 vs. | ||||||||||||||||||||
2Q20 | 1Q20 | 4Q19 | 3Q19 | 2Q19 | 1Q20 | 2Q19 | ||||||||||||||
Consumer Bank | ||||||||||||||||||||
Summary of operations | ||||||||||||||||||||
Total revenue (TE) | $ | 841 | $ | 820 | $ | 825 | $ | 833 | $ | 825 | 2.6 | % | 1.9 | % | ||||||
Provision for credit losses | 167 | 140 | 55 | 48 | 40 | 19.3 | 317.5 | |||||||||||||
Noninterest expense | 555 | 543 | 552 | 531 | 552 | 2.2 | .5 | |||||||||||||
Net income (loss) attributable to Key | 91 | 105 | 166 | 194 | 177 | (13.3 | ) | (48.6 | ) | |||||||||||
Average loans and leases | 39,197 | 35,197 | 34,148 | 32,760 | 31,881 | 11.4 | 22.9 | |||||||||||||
Average deposits | 79,502 | 73,320 | 73,561 | 72,995 | 72,303 | 8.4 | 10.0 | |||||||||||||
Net loan charge-offs | 39 | 43 | 43 | 40 | 40 | (9.3 | ) | (2.5 | ) | |||||||||||
Net loan charge-offs to average total loans | .40 | % | .49 | % | .50 | % | .48 | % | .50 | % | N/A | N/A | ||||||||
Nonperforming assets at period end | $ | 332 | $ | 342 | $ | 306 | $ | 354 | $ | 366 | (2.9 | ) | (9.3 | ) | ||||||
Return on average allocated equity | 10.38 | % | 12.18 | % | 19.27 | % | 22.82 | % | 21.75 | % | N/A | N/A | ||||||||
Commercial Bank | ||||||||||||||||||||
Summary of operations | ||||||||||||||||||||
Total revenue (TE) | $ | 847 | $ | 629 | $ | 771 | $ | 779 | $ | 760 | 34.7 | % | 11.4 | % | ||||||
Provision for credit losses | 314 | 214 | 38 | 32 | 33 | 46.7 | 851.5 | |||||||||||||
Noninterest expense | 403 | 353 | 388 | 372 | 389 | 14.2 | 3.6 | |||||||||||||
Net income (loss) attributable to Key | 120 | 70 | 315 | 304 | 277 | 71.4 | (56.7 | ) | ||||||||||||
Average loans and leases | 68,038 | 60,082 | 58,535 | 58,215 | 57,918 | 13.2 | 17.5 | |||||||||||||
Average loans held for sale | 2,012 | 1,607 | 1,465 | 1,325 | 1,168 | 25.2 | 72.3 | |||||||||||||
Average deposits | 46,099 | 36,058 | 38,224 | 36,204 | 35,960 | 27.8 | 28.2 | |||||||||||||
Net loan charge-offs | 57 | 40 | 39 | 35 | 23 | 42.5 | 147.8 | |||||||||||||
Net loan charge-offs to average total loans | .34 | % | .27 | % | .26 | % | .24 | % | .16 | % | N/A | N/A | ||||||||
Nonperforming assets at period end | $ | 616 | $ | 407 | $ | 402 | $ | 351 | $ | 235 | 51.4 | 162.1 | ||||||||
Return on average allocated equity | 10.00 | % | 6.00 | % | 26.69 | % | 26.37 | % | 24.09 | % | N/A | N/A | ||||||||
TE = Taxable Equivalent, N/A = Not Applicable, N/M = Not Meaningful
Notable Items | |||||||||||||
(in millions) | |||||||||||||
Three months ended | Six months ended | ||||||||||||
6/30/2020 | 3/31/2020 | 6/30/2019 | 6/30/2020 | 6/30/2019 | |||||||||
Efficiency initiative expenses | — | — | $ | (50 | ) | — | $ | (76 | ) | ||||
Laurel Road acquisition expenses | — | — | (2 | ) | — | (2 | ) | ||||||
Total notable items | — | — | $ | (52 | ) | — | $ | (78 | ) | ||||
Income taxes | — | — | (12 | ) | — | (18 | ) | ||||||
Total notable items, after tax | — | — | $ | (40 | ) | — | $ | (60 | ) | ||||
KeyCorp Second Quarter 2020 Earnings Review July 22, 2020 Chris Gorman Don Kimble Chairman and Vice Chairman and Chief Executive Officer Chief Financial Officer
FORWARD-LOOKING STATEMENTS AND ADDITIONAL INFORMATION This communication contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 including, but not limited to, KeyCorp’s expectations or predictions of future financial or business performance or conditions. Forward-looking statements are typically identified by words such as “believe,” “seek,” “expect,” “anticipate,” “intend,” “target,” “estimate,” “continue,” “positions,” “plan,” “predict,” “project,” “forecast,” “guidance,” “goal,” “objective,” “prospects,” “possible,” “potential,” “strategy,” “opportunities,” or “trends,” by future conditional verbs such as “assume,” “will,” “would,” “should,” “could” or “may”, or by variations of such words or by similar expressions. These forward-looking statements are based on assumptions that involve risks and uncertainties, which are subject to change based on various important factors (some of which are beyond KeyCorp’s control.) Actual results may differ materially from current projections. Actual outcomes may differ materially from those expressed or implied as a result of the factors described under “Forward-looking Statements” and “Risk Factors” in KeyCorp’s Annual Report on Form 10-K for the year ended December 31, 2019 and in other filings of KeyCorp with the Securities and Exchange Commission (the “SEC”). In addition to the aforementioned factors, the COVID-19 global pandemic is adversely affecting us, our clients, and our third-party service providers, among others, and its impact may adversely affect our business and results of operations over a period of time. Risks related to COVID-19 are more fully described under “Risk Factors” in KeyCorp’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2020. Such forward-looking statements speak only as of the date they are made, and we undertake no obligation to update any forward- looking statement to reflect events or circumstances after that date or to reflect the occurrence of unanticipated events. For additional information regarding KeyCorp, please refer to our SEC filings available at www.key.com/ir . Annualized, pro forma, projected and estimated numbers are used for illustrative purpose only, are not forecasts and may not reflect actual results. This presentation also includes certain non-GAAP financial measures related to “tangible common equity,” “cash efficiency ratio,” “pre-provision net revenue,” and certain financial measures excluding notable items. Notable items include certain revenue or expense items that may occur in a reporting period in which management does not consider indicative of ongoing financial performance. Management believes it is useful for the investment community to consider financial metrics with and without notable items in order to enable a better understanding of company results, facilitate comparability of period-to-period financial results, and to evaluate and forecast those results. Although Key has procedures in place to ensure that these measures are calculated using the appropriate GAAP or regulatory components, they have limitations as analytical tools and should not be considered in isolation, or as a substitute for analysis of results under GAAP. For more information on these calculations and to view the reconciliations to the most comparable GAAP measures, please refer to the appendix of this presentation, or page 44 of our Form 10-Q dated March 31, 2020. GAAP: Generally Accepted Accounting Principles 2
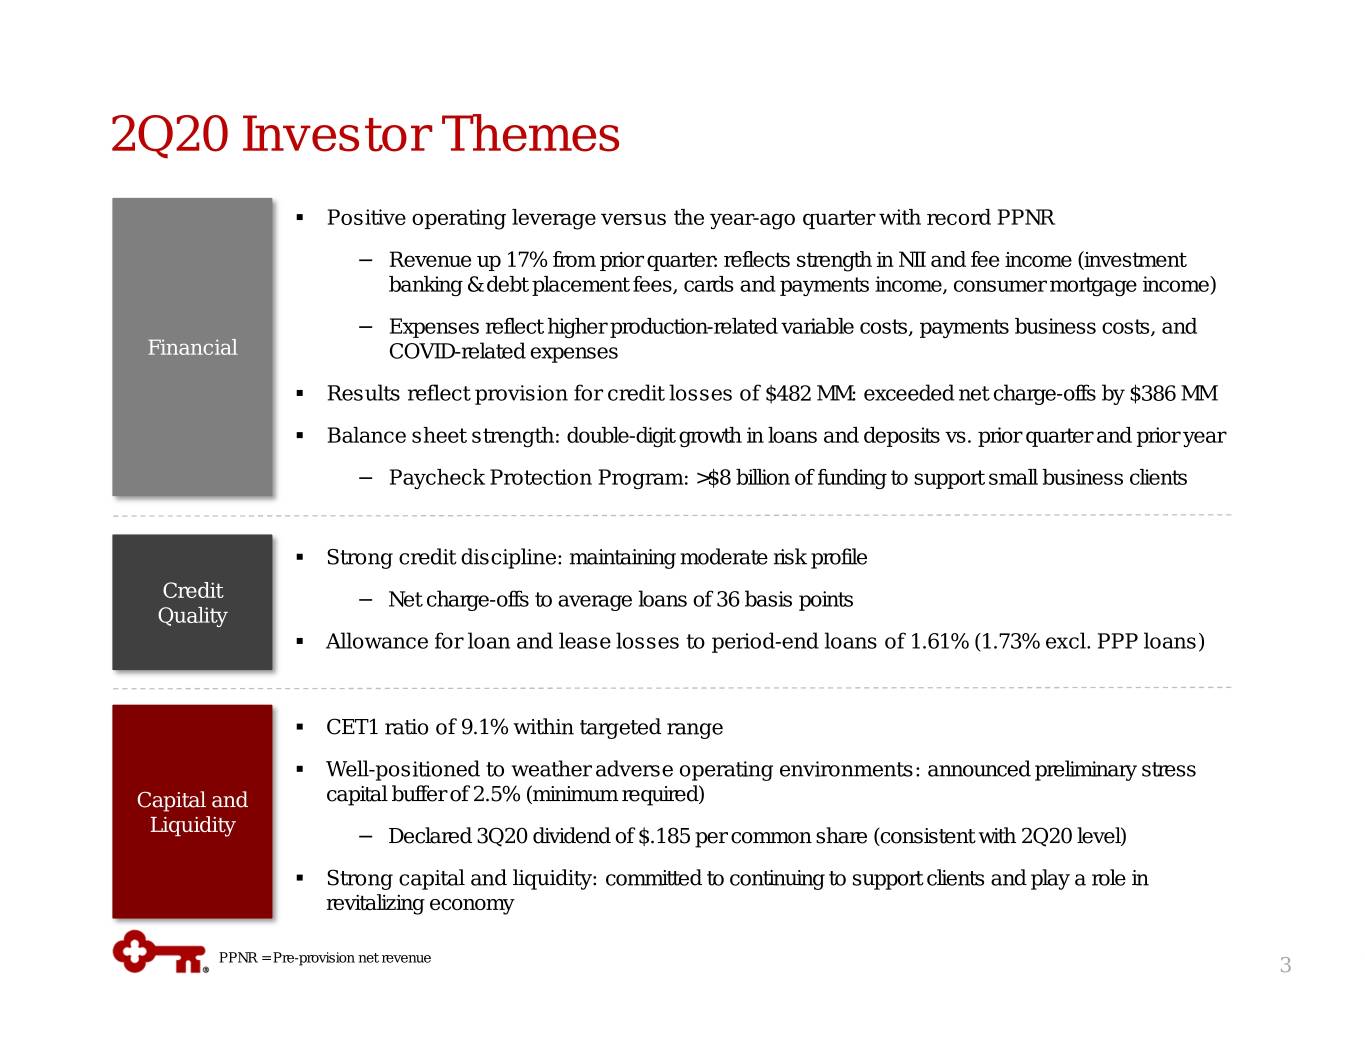
2Q20 Investor Themes . Positive operating leverage versus the year-ago quarter with record PPNR − Revenue up 17% from prior quarter: reflects strength in NII and fee income (investment banking & debt placement fees, cards and payments income, consumer mortgage income) − Expenses reflect higher production-related variable costs, payments business costs, and Financial COVID-related expenses . Results reflect provision for credit losses of $482 MM: exceeded net charge-offs by $386 MM . Balance sheet strength: double-digit growth in loans and deposits vs. prior quarter and prior year − Paycheck Protection Program: >$8 billion of funding to support small business clients . Strong credit discipline: maintaining moderate risk profile Credit − Net charge-offs to average loans of 36 basis points Quality . Allowance for loan and lease losses to period-end loans of 1.61% (1.73% excl. PPP loans) . CET1 ratio of 9.1% within targeted range . Well-positioned to weather adverse operating environments: announced preliminary stress Capital and capital buffer of 2.5% (minimum required) Liquidity − Declared 3Q20 dividend of $.185 per common share (consistent with 2Q20 level) . Strong capital and liquidity: committed to continuing to support clients and play a role in revitalizing economy PPNR = Pre-provision net revenue 3
Financial Review 4
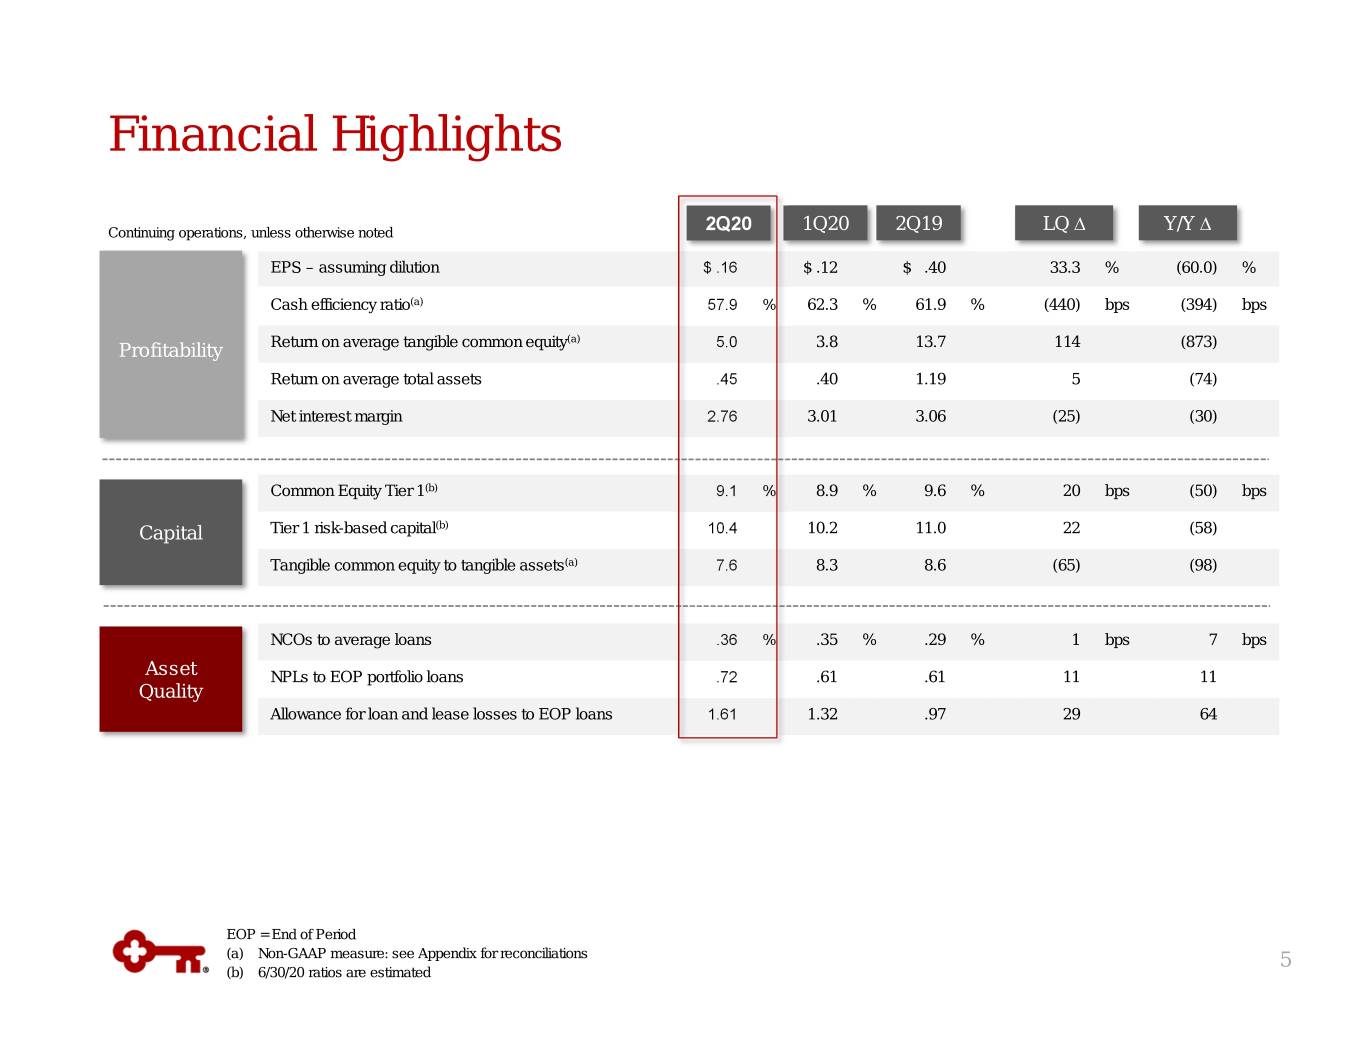
Financial Highlights Continuing operations, unless otherwise noted 2Q20 1Q20 2Q19 LQ ∆ Y/Y ∆ EPS – assuming dilution $ .16 $ .12 $ .40 33.3 % (60.0) % Cash efficiency ratio (a) 57.9 % 62.3 % 61.9 % (440) bps (394) bps (a) Profitability Return on average tangible common equity 5.0 3.8 13.7 114 (873) Return on average total assets .45 .40 1.19 5 (74) Net interest margin 2.76 3.01 3.06 (25) (30) Common Equity Tier 1 (b) 9.1 % 8.9 % 9.6 % 20 bps (50) bps Capital Tier 1 risk-based capital (b) 10.4 10.2 11.0 22 (58) Tangible common equity to tangible assets (a) 7.6 8.3 8.6 (65) (98) NCOs to average loans .36 % .35 % .29 % 1 bps 7 bps Asset NPLs to EOP portfolio loans .72 .61 .61 11 11 Quality Allowance for loan and lease losses to EOP loans 1.61 1.32 .97 29 64 EOP = End of Period (a) Non-GAAP measure: see Appendix for reconciliations 5 (b) 6/30/20 ratios are estimated
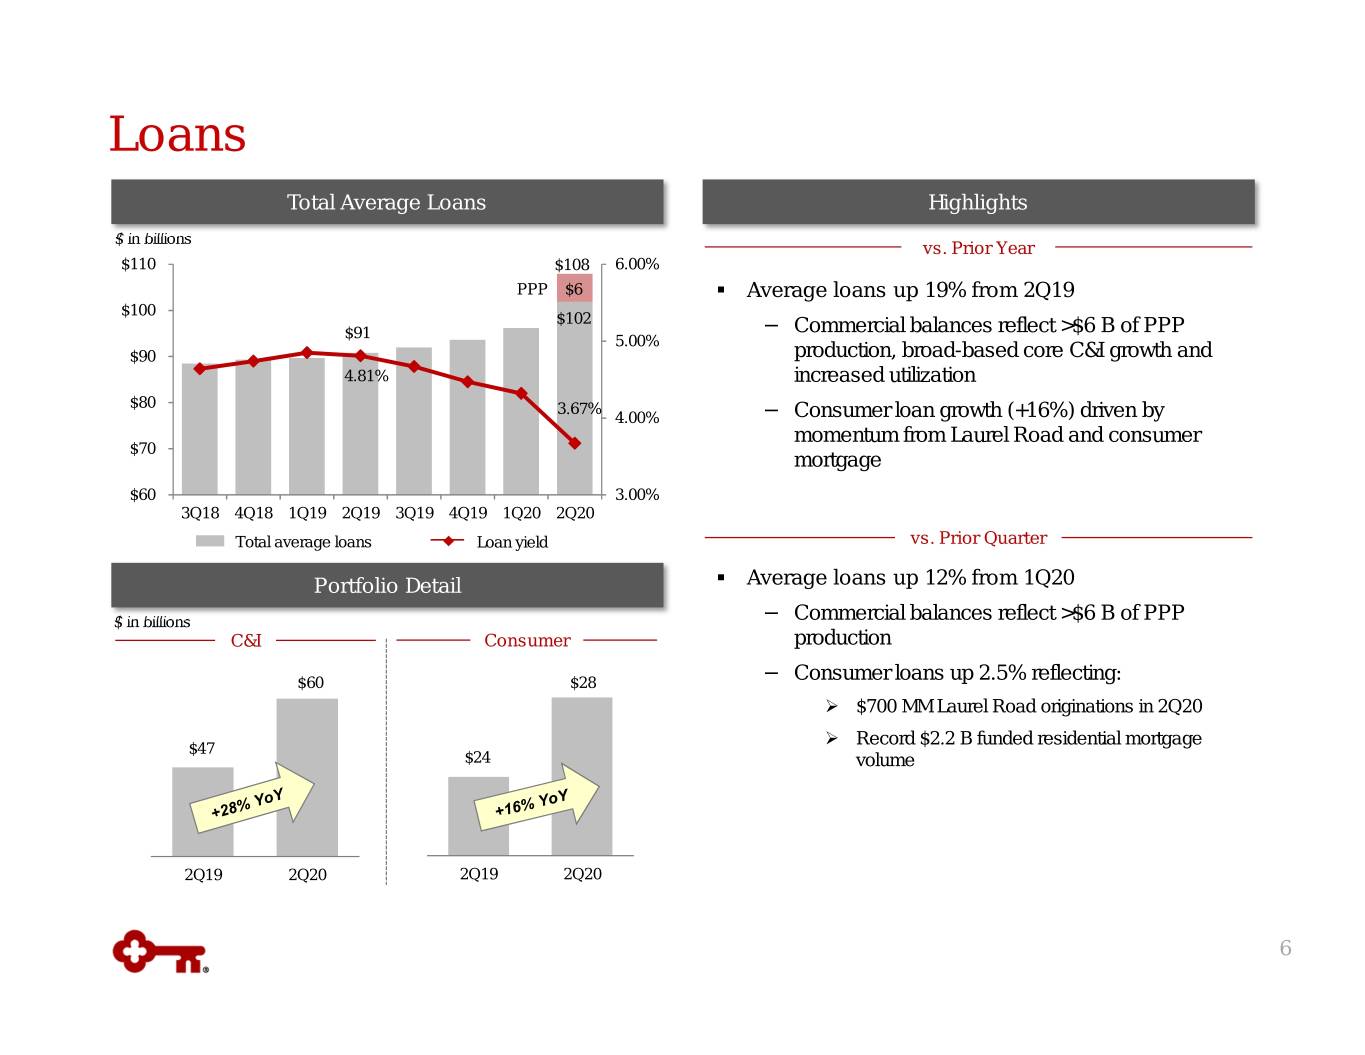
Loans Total Average Loans Highlights $ in billions vs. Prior Year $110 $108 6.00% PPP $6 . Average loans up 19% from 2Q19 $100 $102 $91 − Commercial balances reflect >$6 B of PPP 5.00% $90 production, broad-based core C&I growth and 4.81% increased utilization $80 3.67% 4.00% − Consumer loan growth (+16%) driven by momentum from Laurel Road and consumer $70 mortgage $60 3.00% 3Q18 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 Total average loans Loan yield vs. Prior Quarter Portfolio Detail . Average loans up 12% from 1Q20 $ in billions − Commercial balances reflect >$6 B of PPP C&I Consumer production $60 $28 − Consumer loans up 2.5% reflecting: $700 MM Laurel Road originations in 2Q20 Record $2.2 B funded residential mortgage $47 $24 volume 2Q19 2Q20 2Q19 2Q20 6
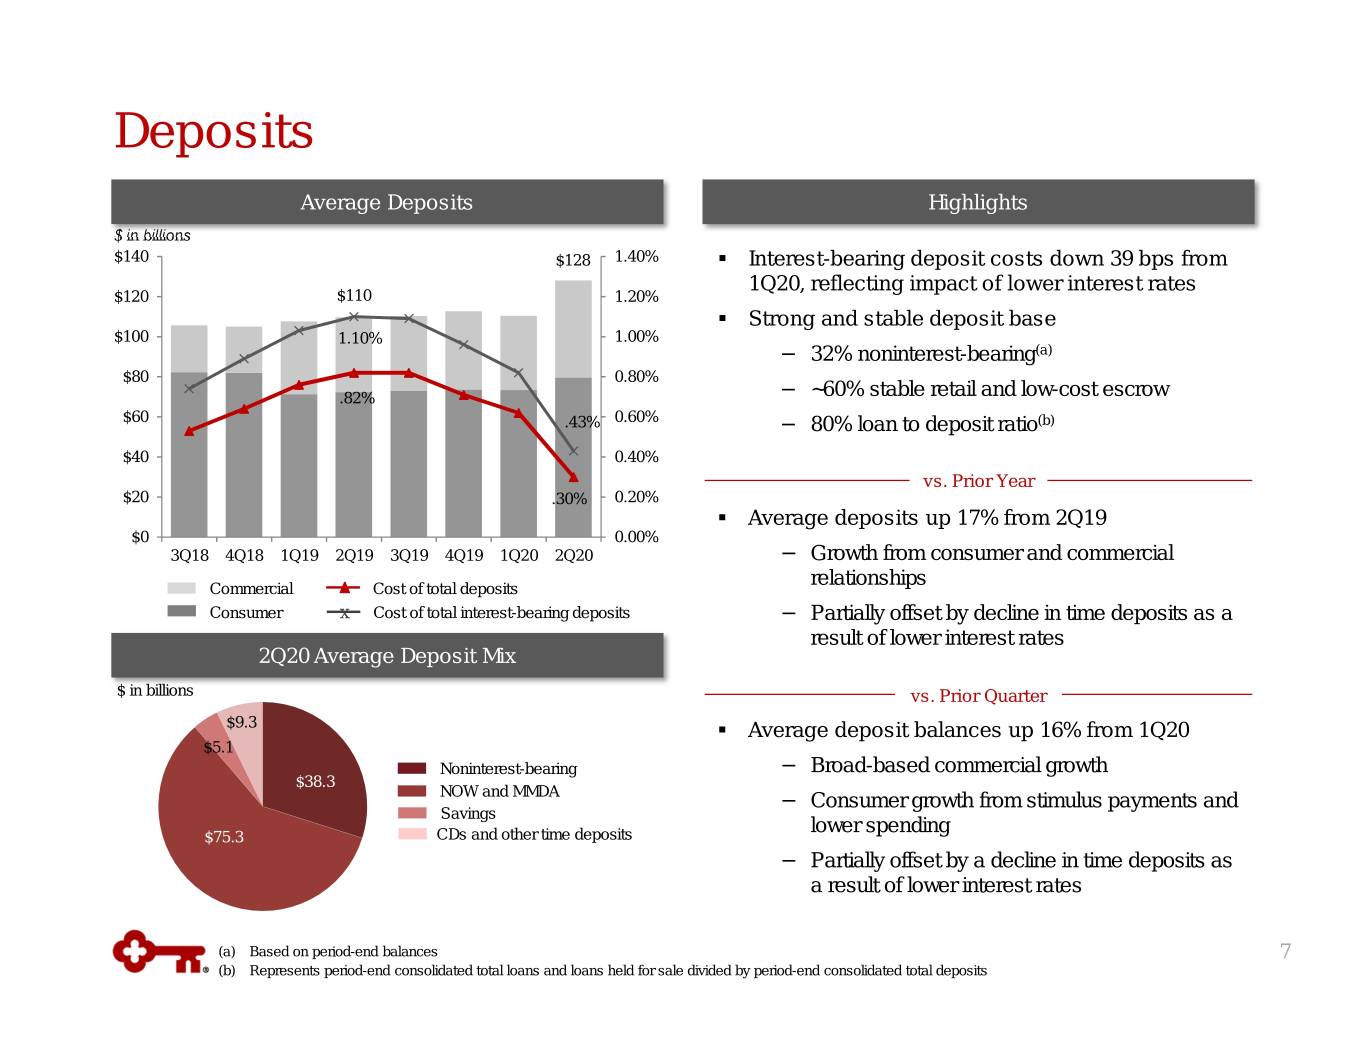
Deposits Average Deposits Highlights $ in billions $140 $128 1.40% . Interest-bearing deposit costs down 39 bps from 1Q20, reflecting impact of lower interest rates $120 $110 1.20% . Strong and stable deposit base $100 1.10% 1.00% − 32% noninterest-bearing (a) $80 0.80%34% .82% − ~60% stable retail and low-cost escrow $60 .43% 0.60% − 80% loan to deposit ratio (b) $40 0.40% vs. Prior Year $20 .30% 0.20% . Average deposits up 17% from 2Q19 $0 0.00% 3Q18 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 − Growth from consumer and commercial relationships Commercial Cost of total deposits Consumer x Cost of total interest-bearing deposits − Partially offset by decline in time deposits as a result of lower interest rates 2Q20 Average Deposit Mix $ in billions vs. Prior Quarter $9.3 . Average deposit balances up 16% from 1Q20 $5.1 Noninterest-bearing − Broad-based commercial growth $38.3 NOW and MMDA − Consumer growth from stimulus payments and Savings lower spending $75.3 CDs and other time deposits − Partially offset by a decline in time deposits as a result of lower interest rates (a) Based on period-end balances 7 (b) Represents period-end consolidated total loans and loans held for sale divided by period-end consolidated total deposits
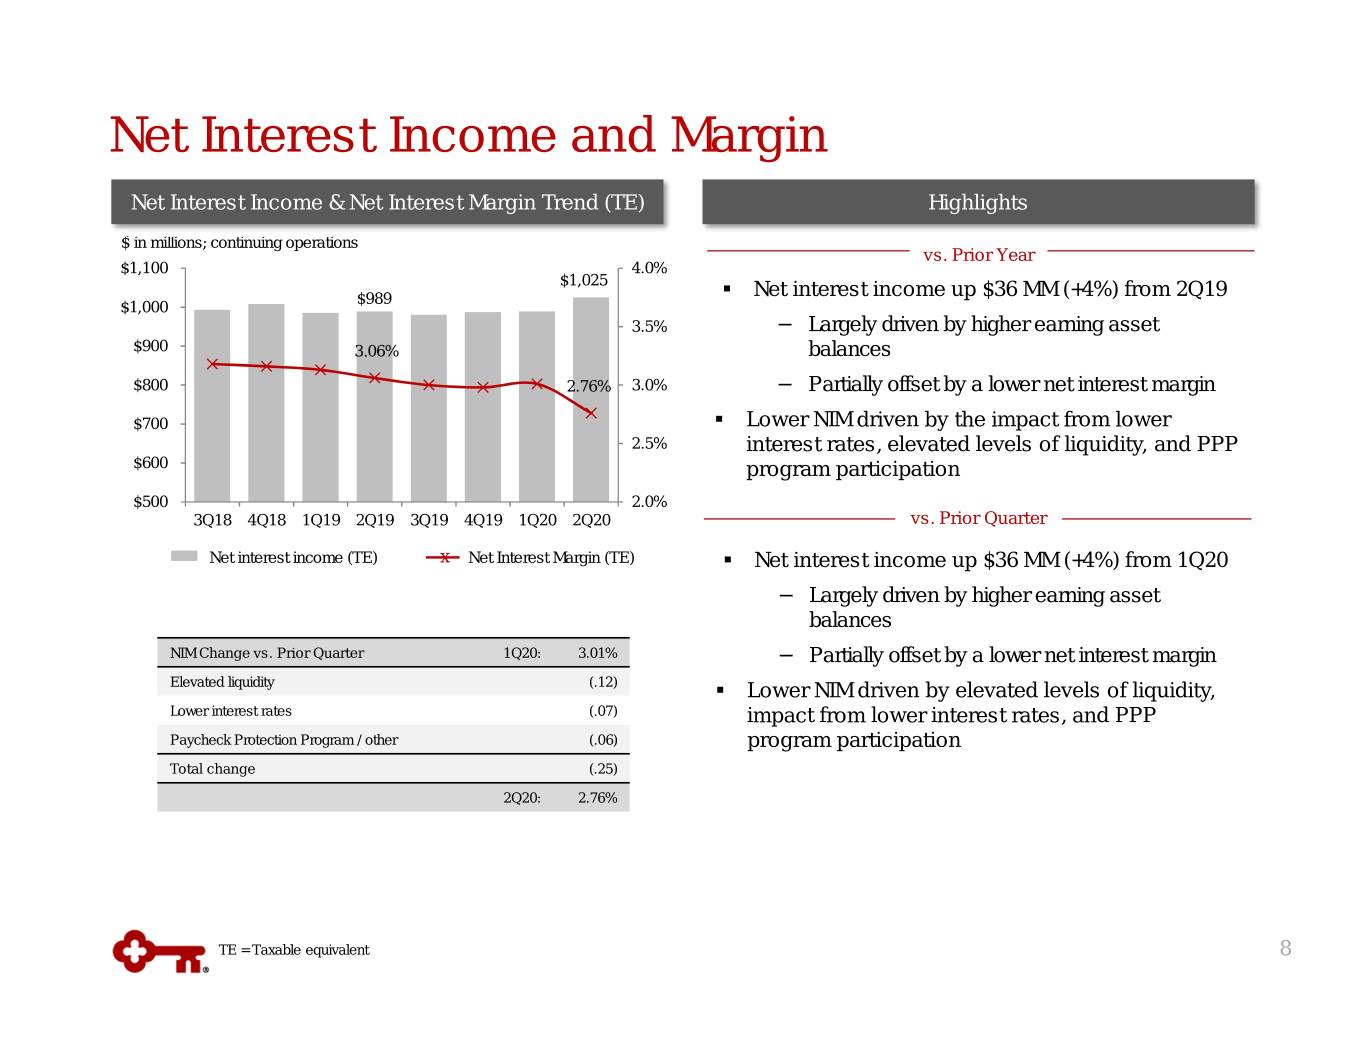
Net Interest Income and Margin Net Interest Income & Net Interest Margin Trend (TE) Highlights $ in millions; continuing operations vs. Prior Year $1,100 4.0% $1,025 $989 . Net interest income up $36 MM (+4%) from 2Q19 $1,000 3.5% − Largely driven by higher earning asset $900 3.06% balances $800 2.76% 3.0% − Partially offset by a lower net interest margin $700 . Lower NIM driven by the impact from lower 2.5% interest rates, elevated levels of liquidity, and PPP $600 program participation $500 2.0% 3Q18 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 vs. Prior Quarter Net interest income (TE)x Net Interest Margin (TE) . Net interest income up $36 MM (+4%) from 1Q20 − Largely driven by higher earning asset balances NIM Change vs. Prior Quarter 1Q20: 3.01% − Partially offset by a lower net interest margin Elevated liquidity (.12) . Lower NIM driven by elevated levels of liquidity, Lower interest rates (.07) impact from lower interest rates, and PPP Paycheck Protection Program / other (.06) program participation Total change (.25) 2Q20: 2.76% TE = Taxable equivalent 8
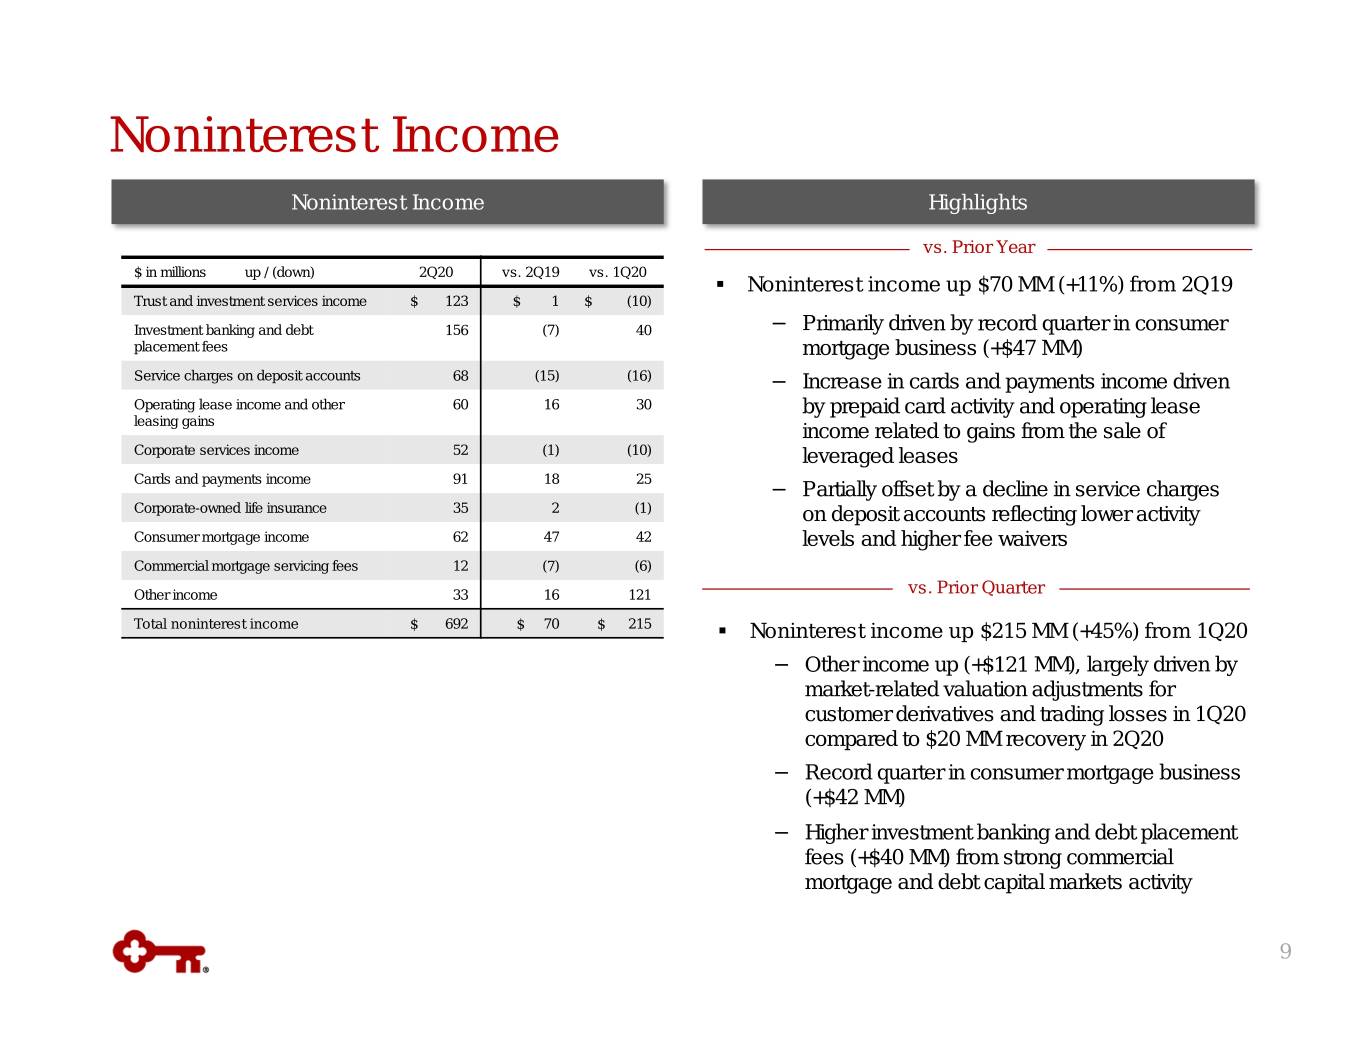
Noninterest Income Noninterest Income Highlights vs. Prior Year $ in millions up / (down) 2Q20 vs. 2Q19 vs. 1Q20 . Noninterest income up $70 MM (+11%) from 2Q19 Trust and investment services income $ 123 $ 1 $ (10) Investment banking and debt 156 (7) 40 − Primarily driven by record quarter in consumer placement fees mortgage business (+$47 MM) Service charges on deposit accounts 68 (15) (16) − Increase in cards and payments income driven Operating lease income and other 60 16 30 by prepaid card activity and operating lease leasing gains income related to gains from the sale of Corporate services income 52 (1) (10) leveraged leases Cards and payments income 91 18 25 − Partially offset by a decline in service charges Corporate-owned life insurance 35 2 (1) on deposit accounts reflecting lower activity Consumer mortgage income 62 47 42 levels and higher fee waivers Commercial mortgage servicing fees 12 (7) (6) Other income 33 16 121 vs. Prior Quarter Total noninterest income $ 692 $ 70 $ 215 . Noninterest income up $215 MM (+45%) from 1Q20 − Other income up (+$121 MM), largely driven by market-related valuation adjustments for customer derivatives and trading losses in 1Q20 compared to $20 MM recovery in 2Q20 − Record quarter in consumer mortgage business (+$42 MM) − Higher investment banking and debt placement fees (+$40 MM) from strong commercial mortgage and debt capital markets activity 9
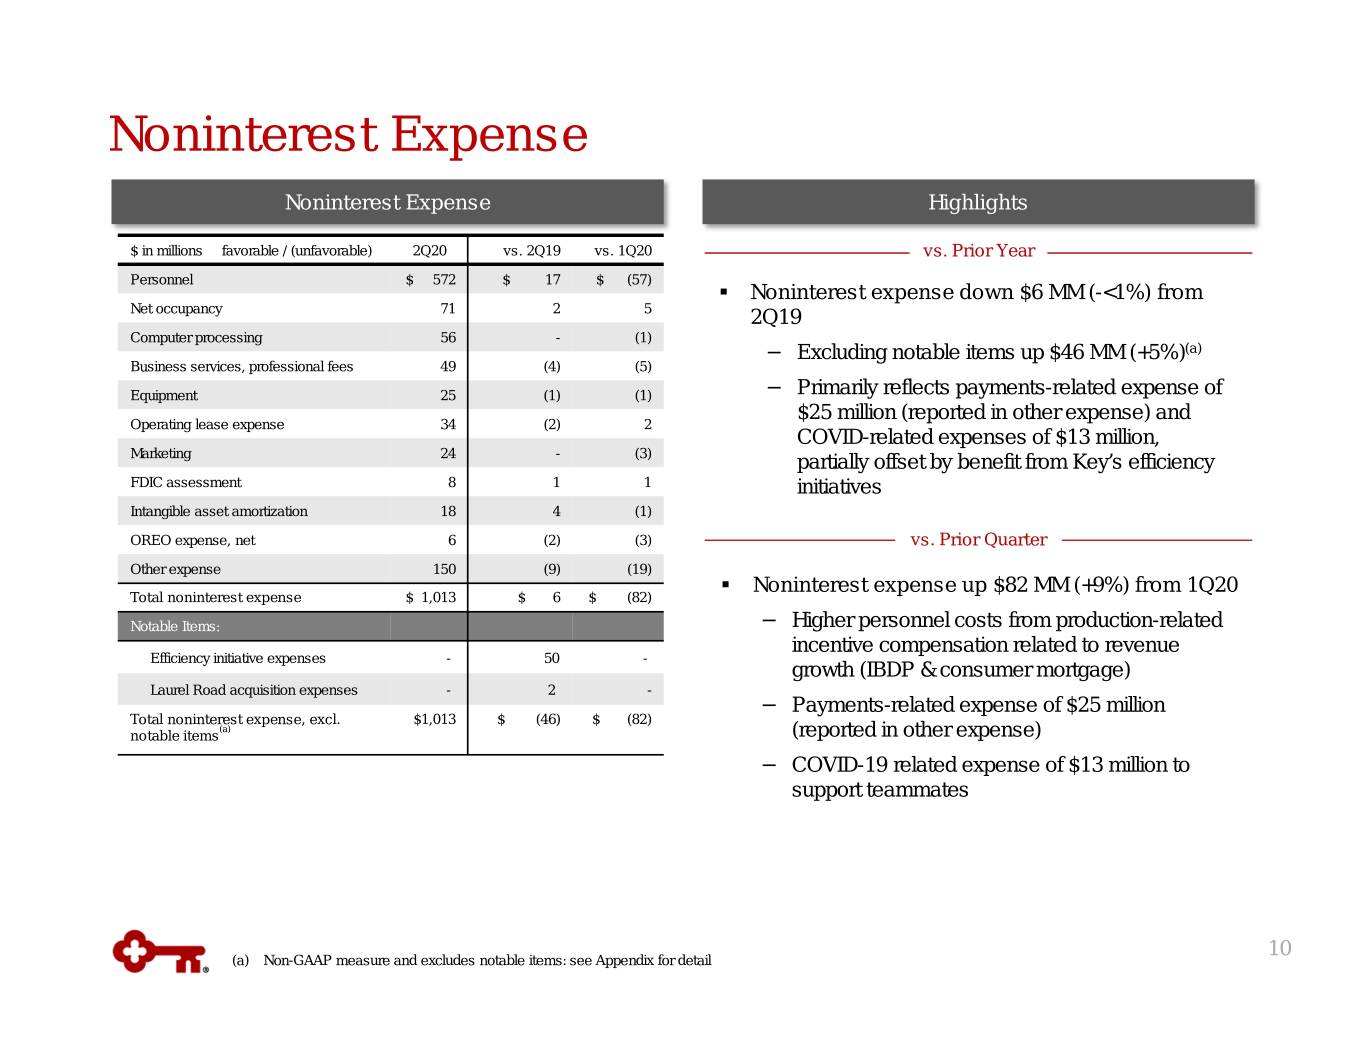
Noninterest Expense Noninterest Expense Highlights $ in millions favorable / (unfavorable) 2Q20 vs. 2Q19 vs. 1Q20 vs. Prior Year Personnel $ 572 $ 17 $ (57) . Noninterest expense down $6 MM (-<1%) from Net occupancy 71 2 5 2Q19 Computer processing 56 - (1) − Excluding notable items up $46 MM (+5%) (a) Business services, professional fees 49 (4) (5) Equipment 25 (1) (1) − Primarily reflects payments-related expense of $25 million (reported in other expense) and Operating lease expense 34 (2) 2 COVID-related expenses of $13 million, Marketing 24 - (3) partially offset by benefit from Key’s efficiency FDICassessment 8 1 1 initiatives Intangible asset amortization 18 4 (1) OREO expense, net 6 (2) (3) vs. Prior Quarter Other expense 150 (9) (19) . Noninterest expense up $82 MM (+9%) from 1Q20 Total noninterest expense $ 1,013 $ 6 $ (82) Notable Items: − Higher personnel costs from production-related incentive compensation related to revenue Efficiency initiative expenses - 50 - growth (IBDP & consumer mortgage) Laurel Road acquisition expenses - 2 - − Payments-related expense of $25 million Total noninterest expense, excl. $1,013 $ (46) $ (82) (a) notable items (reported in other expense) − COVID-19 related expense of $13 million to support teammates 10 (a) Non-GAAP measure and excludes notable items: see Appendix for detail
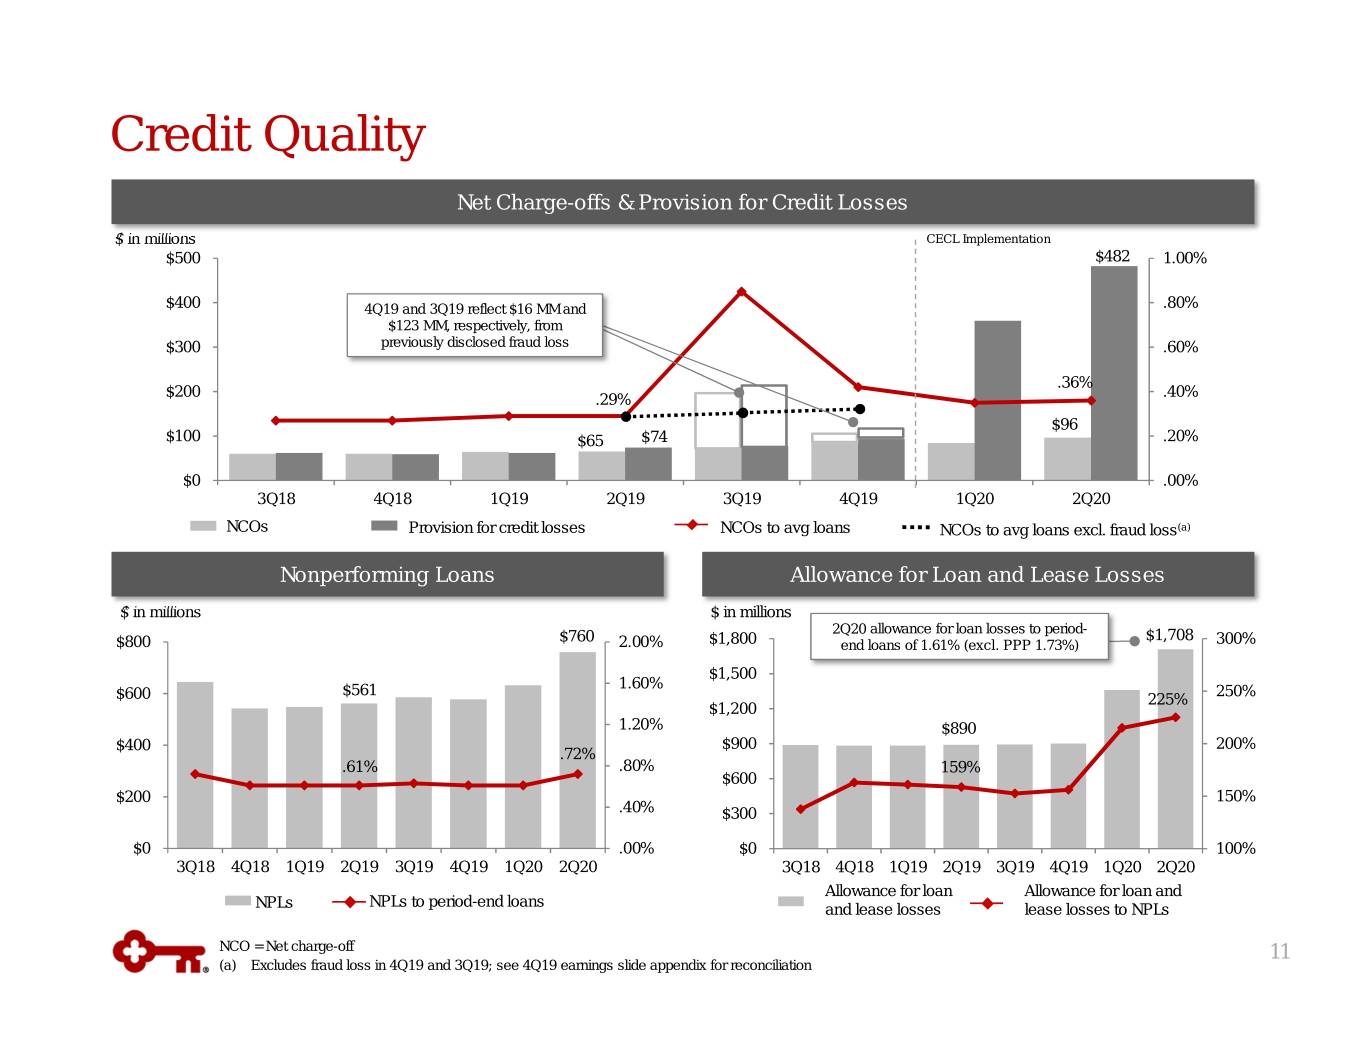
Credit Quality Net Charge-offs & Provision for Credit Losses $ in millions CECL Implementation $500 $482 1.00% $400 4Q19 and 3Q19 reflect $16 MM and .80% $123 MM, respectively, from $300 previously disclosed fraud loss .60% .36% $200 .40% .29% $96 $100 $65 $74 .20% $0 .00% 3Q18 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 NCOs Provision for credit losses NCOs to avg loans NCOs to avg loans excl. fraud loss (a) Nonperforming Loans Allowance for Loan and Lease Losses $ in millions $ in millions $760 2Q20 allowance for loan losses to period- $1,708 $800 2.00% $1,800 end loans of 1.61% (excl. PPP 1.73%) 300% $1,500 1.60% $561 250% $600 225% $1,200 1.20% $890 $400 $900 200% .72% .61% .80% 159% $600 $200 150% .40% $300 $0 .00% $0 100% 3Q18 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 3Q18 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 Allowance for loan Allowance for loan and NPLs to period-end loans NPLs and lease losses lease losses to NPLs NCO = Net charge-off 11 (a) Excludes fraud loss in 4Q19 and 3Q19; see 4Q19 earnings slide appendix for reconciliation
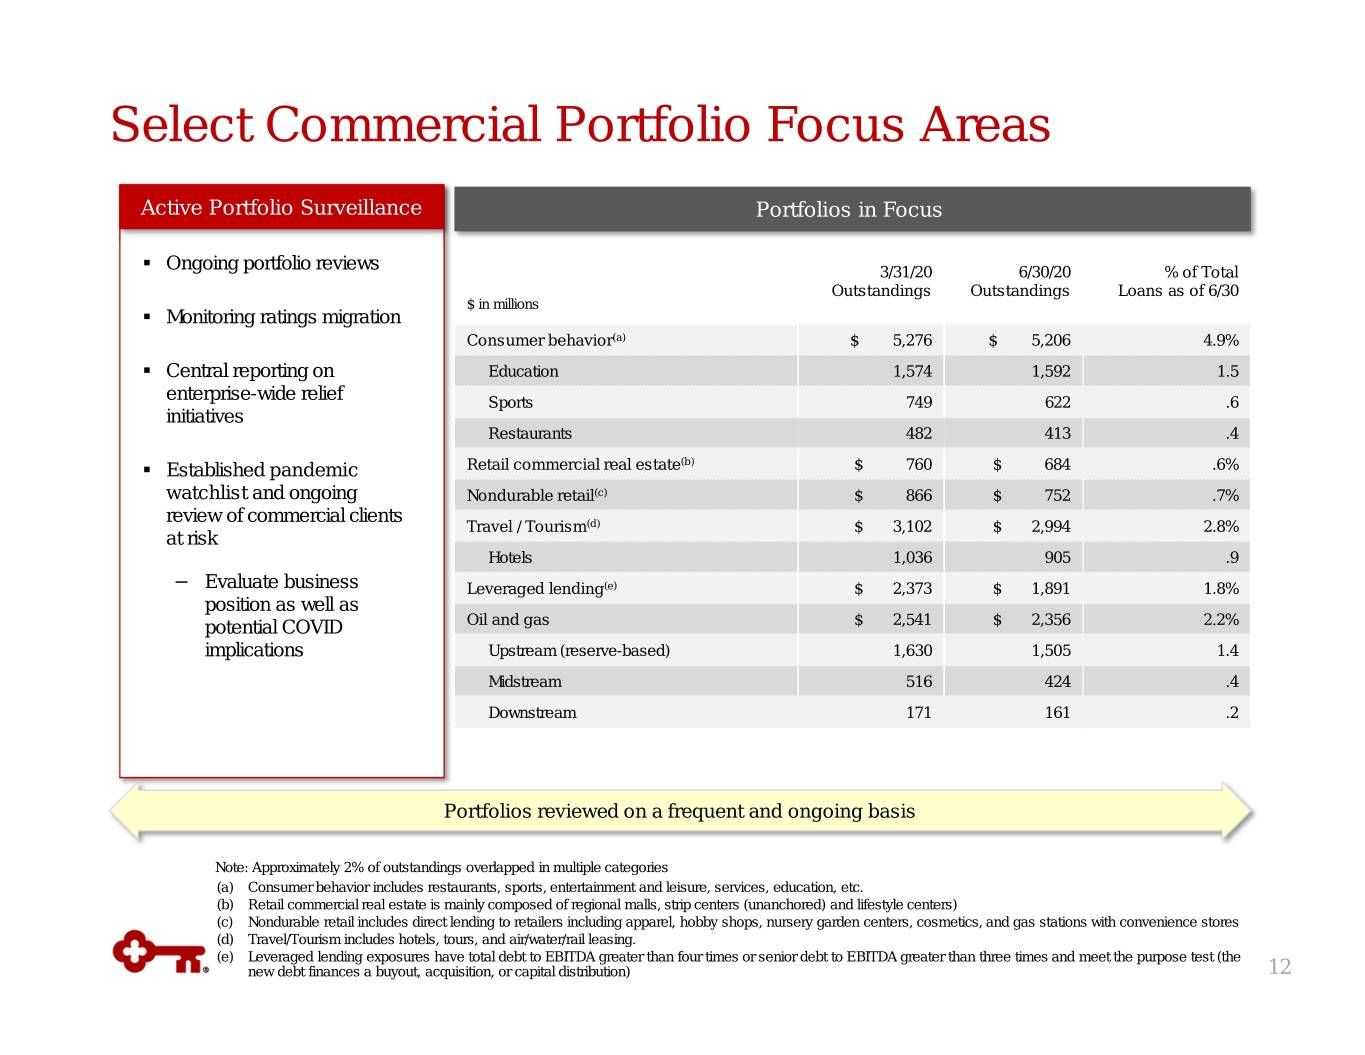
Select Commercial Portfolio Focus Areas Active Portfolio Surveillance Portfolios in Focus . Ongoing portfolio reviews 3/31/20 6/30/20 % of Total Outstandings Outstandings Loans as of 6/30 $ in millions . Monitoring ratings migration Consumer behavior (a) $ 5,276 $ 5,206 4.9% . Central reporting on Education 1,574 1,592 1.5 enterprise-wide relief Sports 749 622 .6 initiatives Restaurants 482 413 .4 . Established pandemic Retail commercial real estate (b) $ 760 $ 684 .6% watchlist and ongoing Nondurable retail (c) $ 866 $ 752 .7% review of commercial clients Travel / Tourism (d) $ 3,102 $ 2,994 2.8% at risk Hotels 1,036 905 .9 − Evaluate business Leveraged lending (e) $ 2,373 $ 1,891 1.8% position as well as potential COVID Oil and gas $ 2,541 $ 2,356 2.2% implications Upstream (reserve-based) 1,630 1,505 1.4 Midstream 516 424 .4 Downstream 171 161 .2 Portfolios reviewed on a frequent and ongoing basis Note: Approximately 2% of outstandings overlapped in multiple categories (a) Consumer behavior includes restaurants, sports, entertainment and leisure, services, education, etc. (b) Retail commercial real estate is mainly composed of regional malls, strip centers (unanchored) and lifestyle centers) (c) Nondurable retail includes direct lending to retailers including apparel, hobby shops, nursery garden centers, cosmetics, and gas stations with convenience stores (d) Travel/Tourism includes hotels, tours, and air/water/rail leasing. (e) Leveraged lending exposures have total debt to EBITDA greater than four times or senior debt to EBITDA greater than three times and meet the purpose test (the new debt finances a buyout, acquisition, or capital distribution) 12
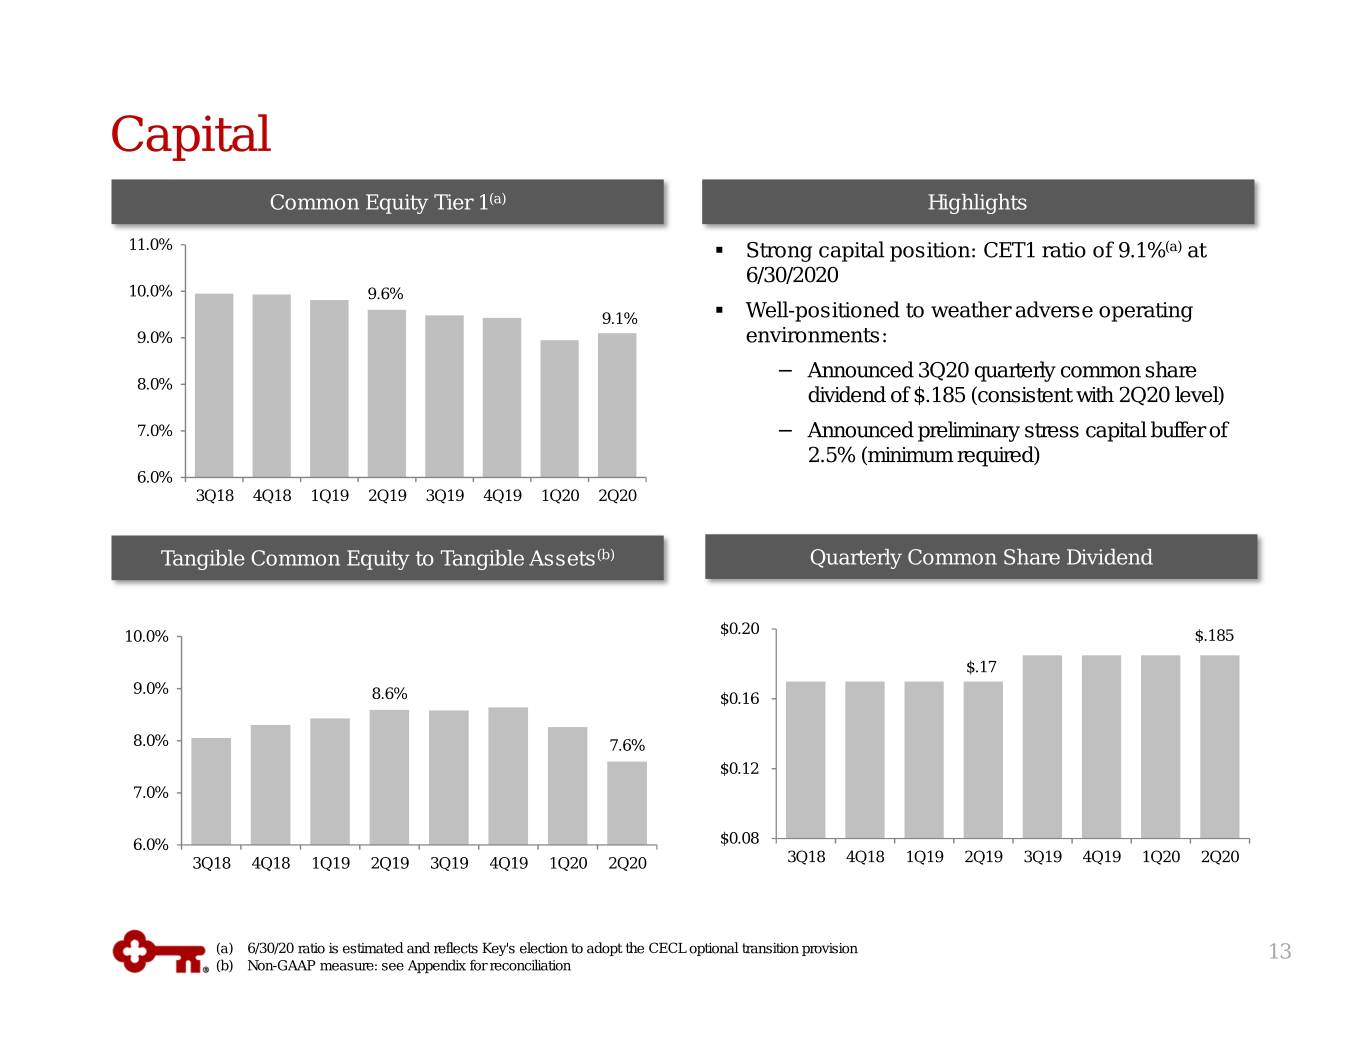
Capital Common Equity Tier 1 (a) Highlights 11.0% . Strong capital position: CET1 ratio of 9.1% (a) at 6/30/2020 10.0% 9.6% 9.1% . Well-positioned to weather adverse operating 9.0% environments: − Announced 3Q20 quarterly common share 8.0% dividend of $.185 (consistent with 2Q20 level) 7.0% − Announced preliminary stress capital buffer of 2.5% (minimum required) 6.0% 3Q18 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 Tangible Common Equity to Tangible Assets (b) Quarterly Common Share Dividend 10.0% $0.20 $.185 $.17 9.0% 8.6% $0.16 8.0% 7.6% $0.12 7.0% 6.0% $0.08 3Q18 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 3Q18 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 (a) 6/30/20 ratio is estimated and reflects Key's election to adopt the CECL optional transition provision 13 (b) Non-GAAP measure: see Appendix for reconciliation
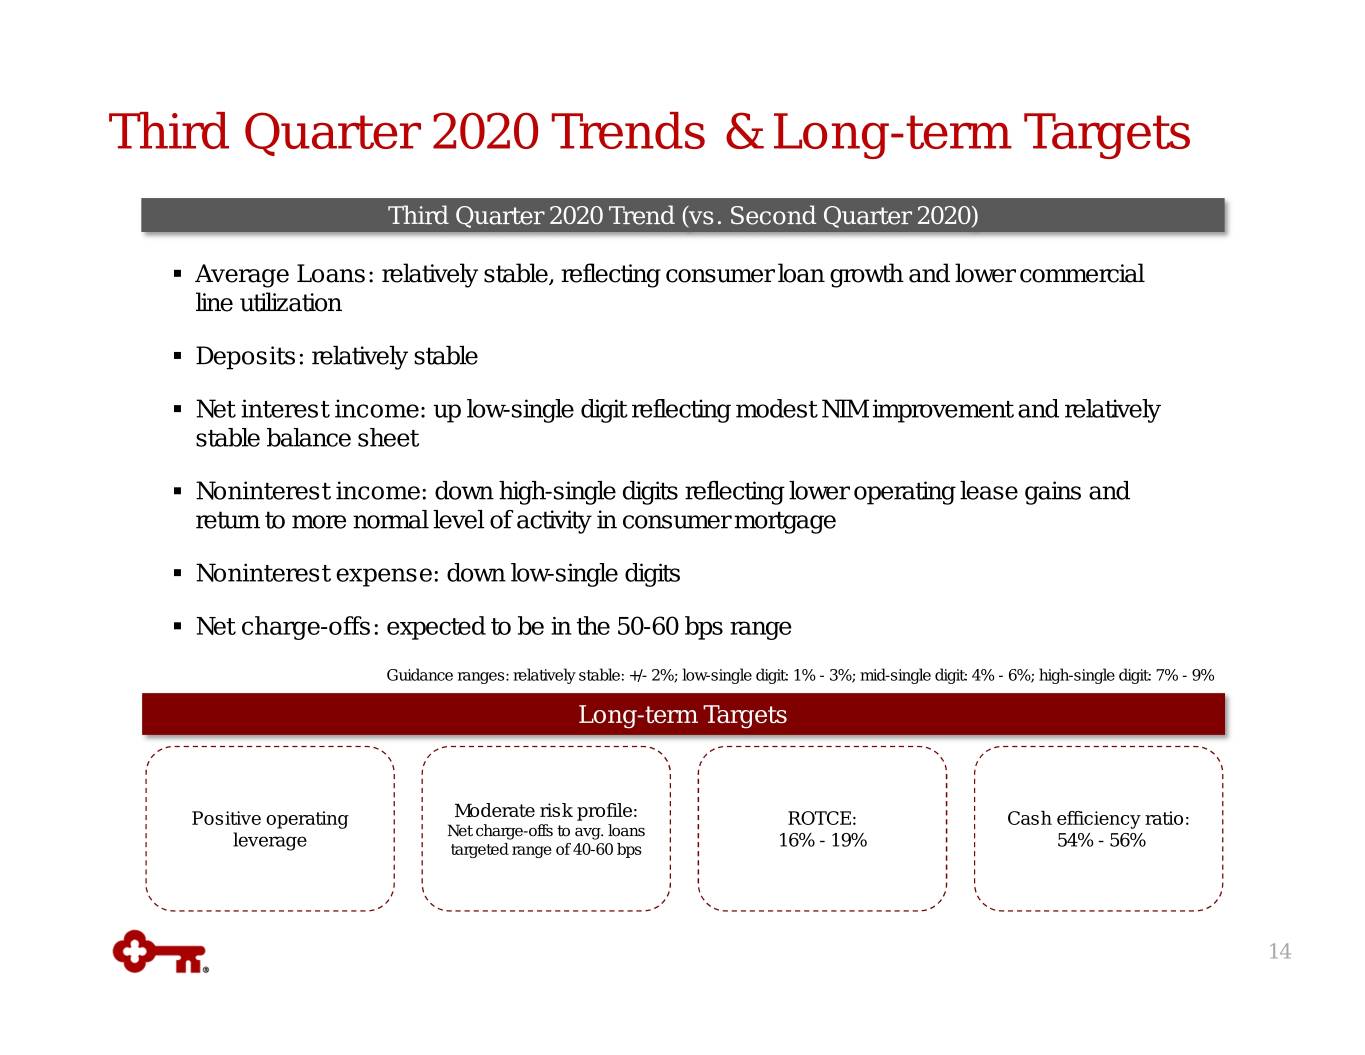
Third Quarter 2020 Trends & Long-term Targets Third Quarter 2020 Trend (vs. Second Quarter 2020) . Average Loans: relatively stable, reflecting consumer loan growth and lower commercial line utilization . Deposits: relatively stable . Net interest income: up low-single digit reflecting modest NIM improvement and relatively stable balance sheet . Noninterest income: down high-single digits reflecting lower operating lease gains and return to more normal level of activity in consumer mortgage . Noninterest expense: down low-single digits . Net charge-offs: expected to be in the 50-60 bps range Guidance ranges: relatively stable: +/- 2%; low-single digit: 1% - 3%; mid-single digit: 4% - 6%; high-single digit: 7% - 9% Long-term Targets Positive operating Moderate risk profile: ROTCE: Cash efficiency ratio: Net charge-offs to avg. loans leverage targeted range of 40-60 bps 16% - 19% 54% - 56% 14
Appendix 15
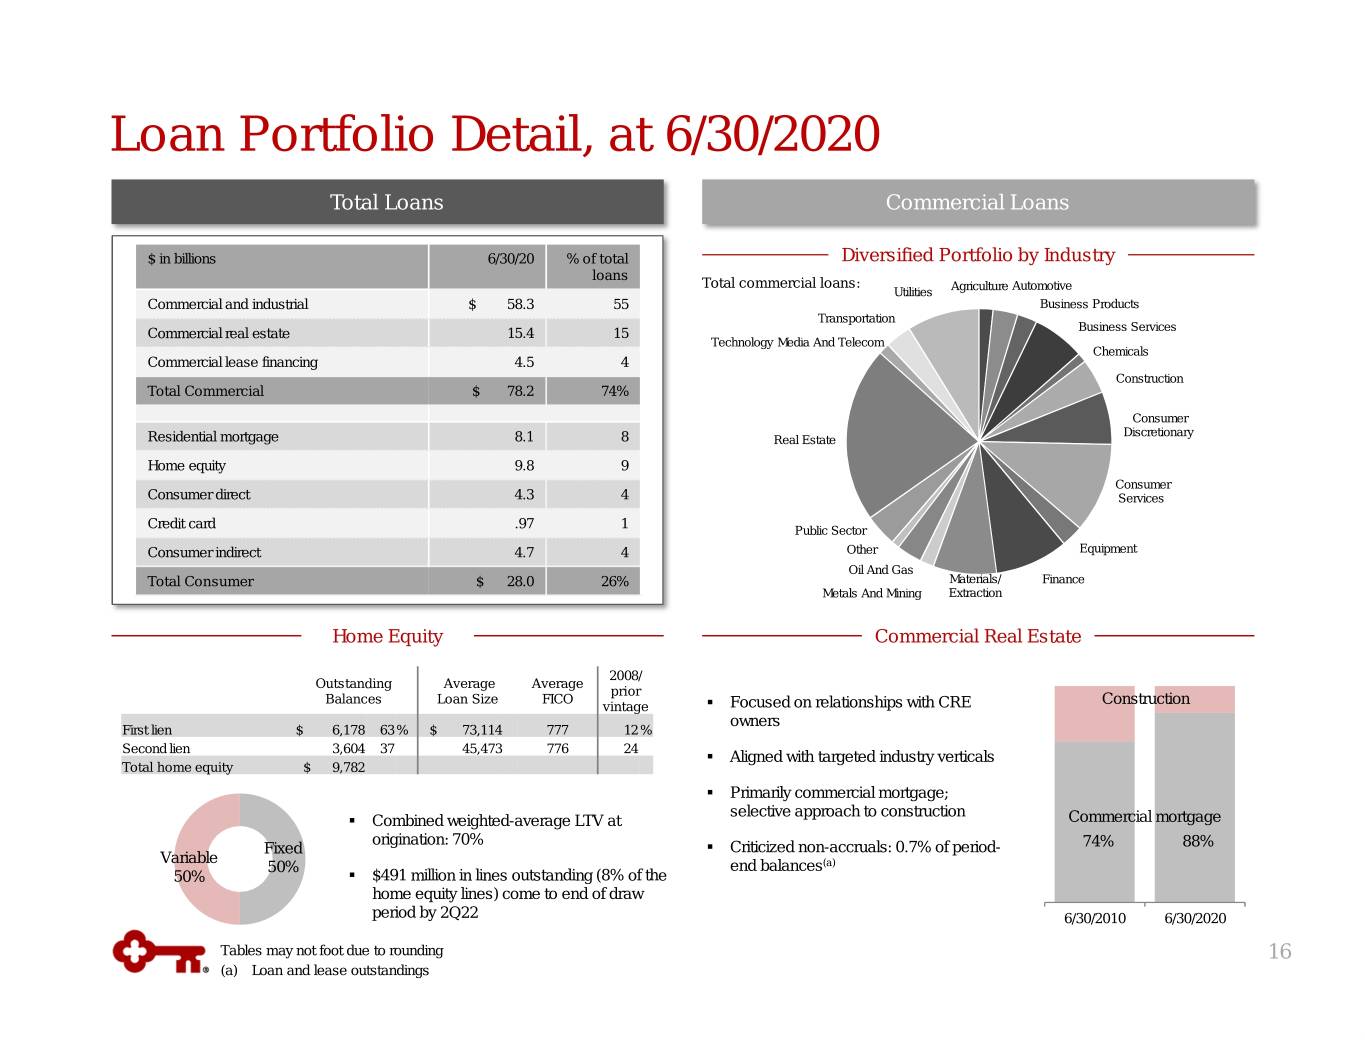
Loan Portfolio Detail, at 6/30/2020 Total Loans Commercial Loans $ in billions 6/30/20 % of total Diversified Portfolio by Industry loans Total commercial loans: Automotive Utilities Agriculture Commercial and industrial $ 58.3 55 Business Products Transportation Commercial real estate 15.4 15 Business Services Technology Media And Telecom C&I CRE Chemicals Commercial lease financing$40 4.5$18 4 Construction Total Commercial $ 78.2 74% Consumer Discretionary Residential mortgage 8.1 8 Real Estate Home equity 9.8 9 Consumer Consumer direct 4.3 4 Services Credit card .97 1 Public Sector Consumer indirect 4.7 4 Other Equipment Oil And Gas Total Consumer $ 28.0 26% Materials/ Finance Metals And Mining Extraction Home Equity Commercial Real Estate 2008/ Outstanding Average Average prior Balances Loan Size FICO Construction vintage . Focused on relationships with CRE owners First lien $ 6,178 63 % $ 73,114 777 12 % Second lien 3,604 37 45,473 776 24 . Aligned with targeted industry verticals Total home equity $ 9,782 . Primarily commercial mortgage; selective approach to construction . Combined weighted-average LTV at Commercial mortgage origination: 70% Fixed . Criticized non-accruals: 0.7% of period- 74% 88% Variable 50% end balances (a) 50% . $491 million in lines outstanding (8% of the home equity lines) come to end of draw period by 2Q22 6/30/2010 6/30/2020 Tables may not foot due to rounding 16 (a) Loan and lease outstandings
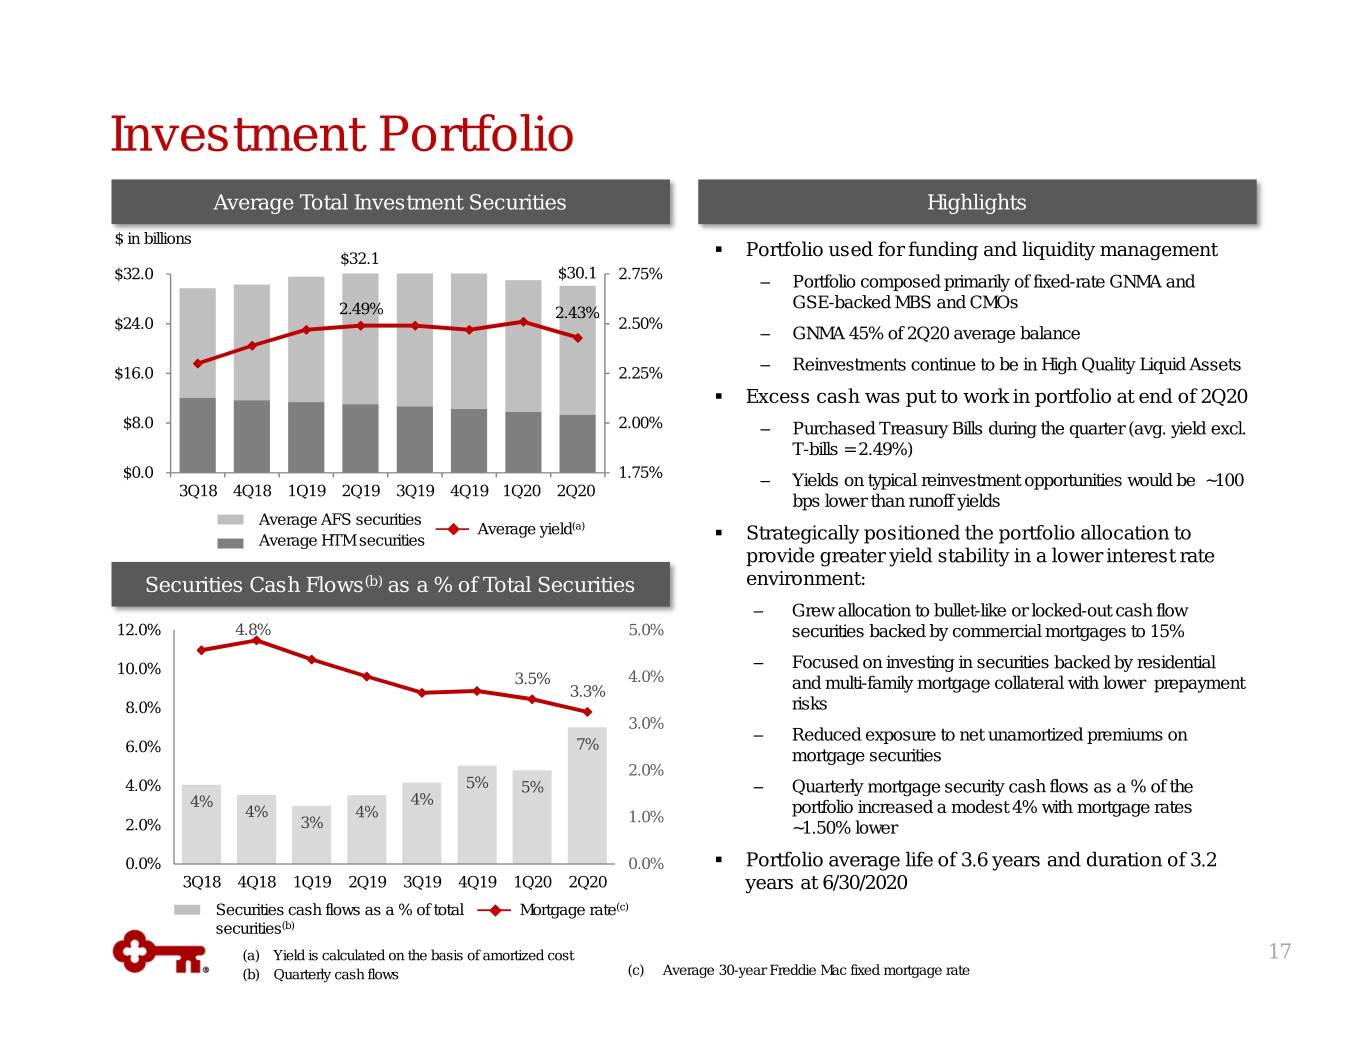
Investment Portfolio Average Total Investment Securities Highlights $ in billions $32.1 . Portfolio used for funding and liquidity management $30.1 $32.0 2.75% ‒ Portfolio composed primarily of fixed-rate GNMA and GSE-backed MBS and CMOs 2.49% 2.43% $24.0 2.50% ‒ GNMA 45% of 2Q20 average balance ‒ Reinvestments continue to be in High Quality Liquid Assets $16.0 2.25% . Excess cash was put to work in portfolio at end of 2Q20 $8.0 2.00% ‒ Purchased Treasury Bills during the quarter (avg. yield excl. T-bills = 2.49%) $0.0 1.75% ‒ Yields on typical reinvestment opportunities would be ~100 3Q18 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 bps lower than runoff yields Average AFS securities Average yield (a) Average HTM securities . Strategically positioned the portfolio allocation to provide greater yield stability in a lower interest rate Securities Cash Flows (b) as a % of Total Securities environment: ‒ Grew allocation to bullet-like or locked-out cash flow 12.0% 4.8% 5.0% securities backed by commercial mortgages to 15% 10.0% ‒ Focused on investing in securities backed by residential 3.5% 4.0% 3.3% and multi-family mortgage collateral with lower prepayment 8.0% risks 3.0% ‒ Reduced exposure to net unamortized premiums on 6.0% 7% mortgage securities 2.0% 4.0% 5% 5% ‒ Quarterly mortgage security cash flows as a % of the 4% 4% portfolio increased a modest 4% with mortgage rates 4% 4% 1.0% 2.0% 3% ~1.50% lower 0.0% 0.0% . Portfolio average life of 3.6 years and duration of 3.2 3Q18 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 years at 6/30/2020 Securities cash flows as a % of total Mortgage rate (c) securities (b) (a) Yield is calculated on the basis of amortized cost 17 (b) Quarterly cash flows (c) Average 30-year Freddie Mac fixed mortgage rate
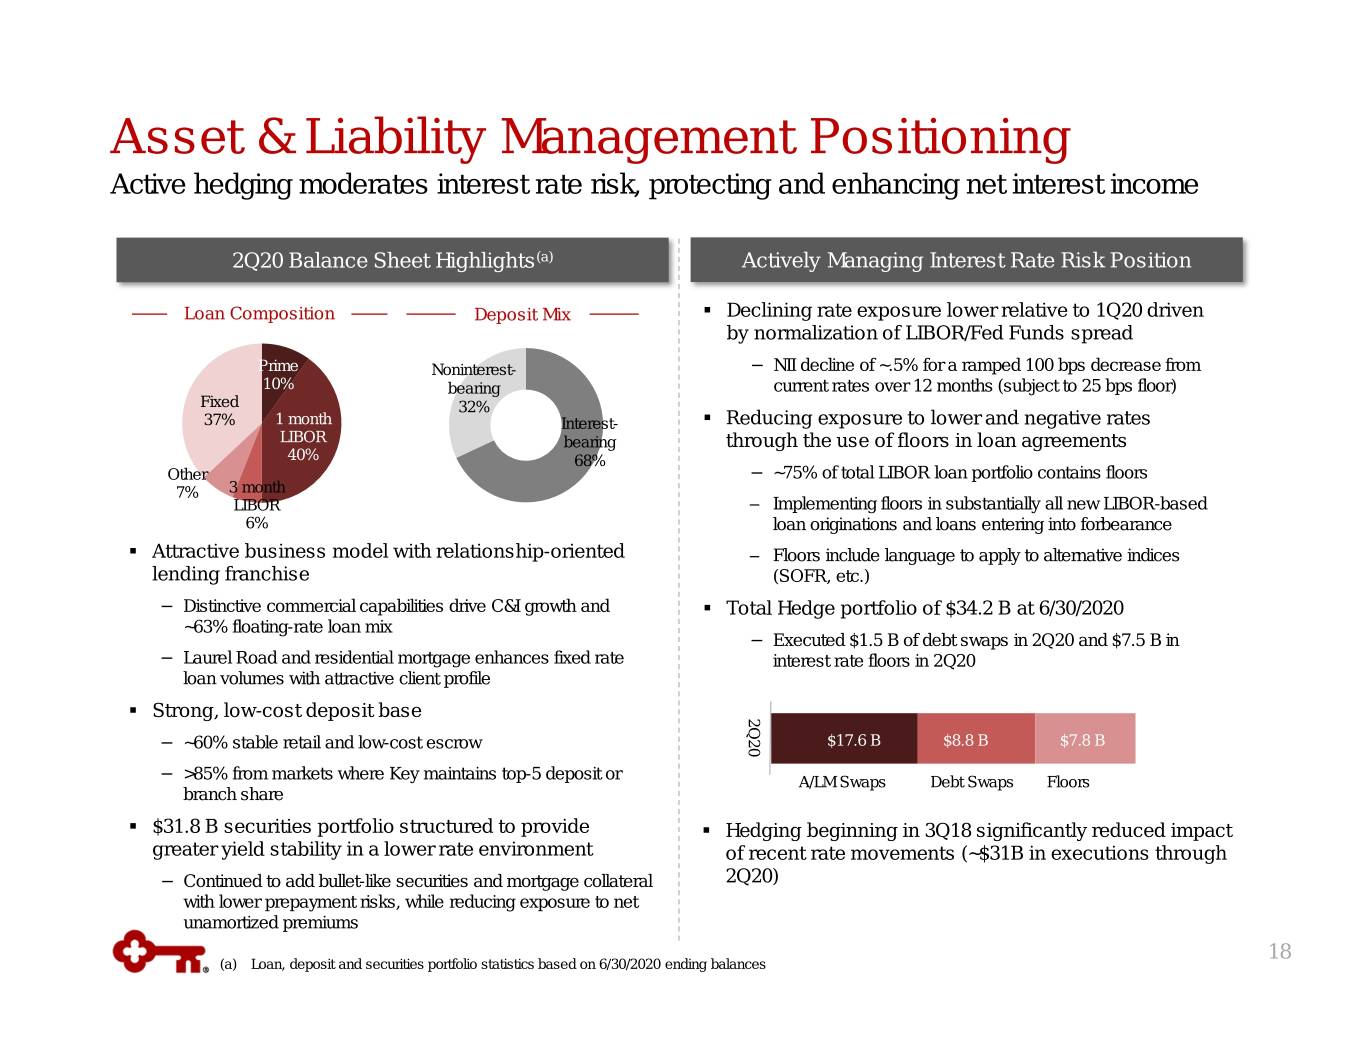
Asset & Liability Management Positioning Active hedging moderates interest rate risk, protecting and enhancing net interest income 2Q20 Balance Sheet Highlights (a) Actively Managing Interest Rate Risk Position Loan Composition Deposit Mix . Declining rate exposure lower relative to 1Q20 driven by normalization of LIBOR/Fed Funds spread Prime Noninterest- − NII decline of ~.5% for a ramped 100 bps decrease from 10% bearing current rates over 12 months (subject to 25 bps floor) Fixed 32% 37% 1 month Interest- . Reducing exposure to lower and negative rates LIBOR bearing through the use of floors in loan agreements 40% 68% Other − ~75% of total LIBOR loan portfolio contains floors 7% 3 month LIBOR ‒ Implementing floors in substantially all new LIBOR-based 6% loan originations and loans entering into forbearance . Attractive business model with relationship-oriented ‒ Floors include language to apply to alternative indices lending franchise (SOFR, etc.) − Distinctive commercial capabilities drive C&I growth and . Total Hedge portfolio of $34.2 B at 6/30/2020 ~63% floating-rate loan mix − Executed $1.5 B of debt swaps in 2Q20 and $7.5 B in − Laurel Road and residential mortgage enhances fixed rate interest rate floors in 2Q20 loan volumes with attractive client profile . Strong, low-cost deposit base 2Q20 − ~60% stable retail and low-cost escrow $17.6 B $8.8 B $7.8 B − >85% from markets where Key maintains top-5 deposit or A/LM Swaps Debt Swaps Floors branch share . $31.8 B securities portfolio structured to provide . Hedging beginning in 3Q18 significantly reduced impact greater yield stability in a lower rate environment of recent rate movements (~$31B in executions through − Continued to add bullet-like securities and mortgage collateral 2Q20) with lower prepayment risks, while reducing exposure to net unamortized premiums 18 (a) Loan, deposit and securities portfolio statistics based on 6/30/2020 ending balances
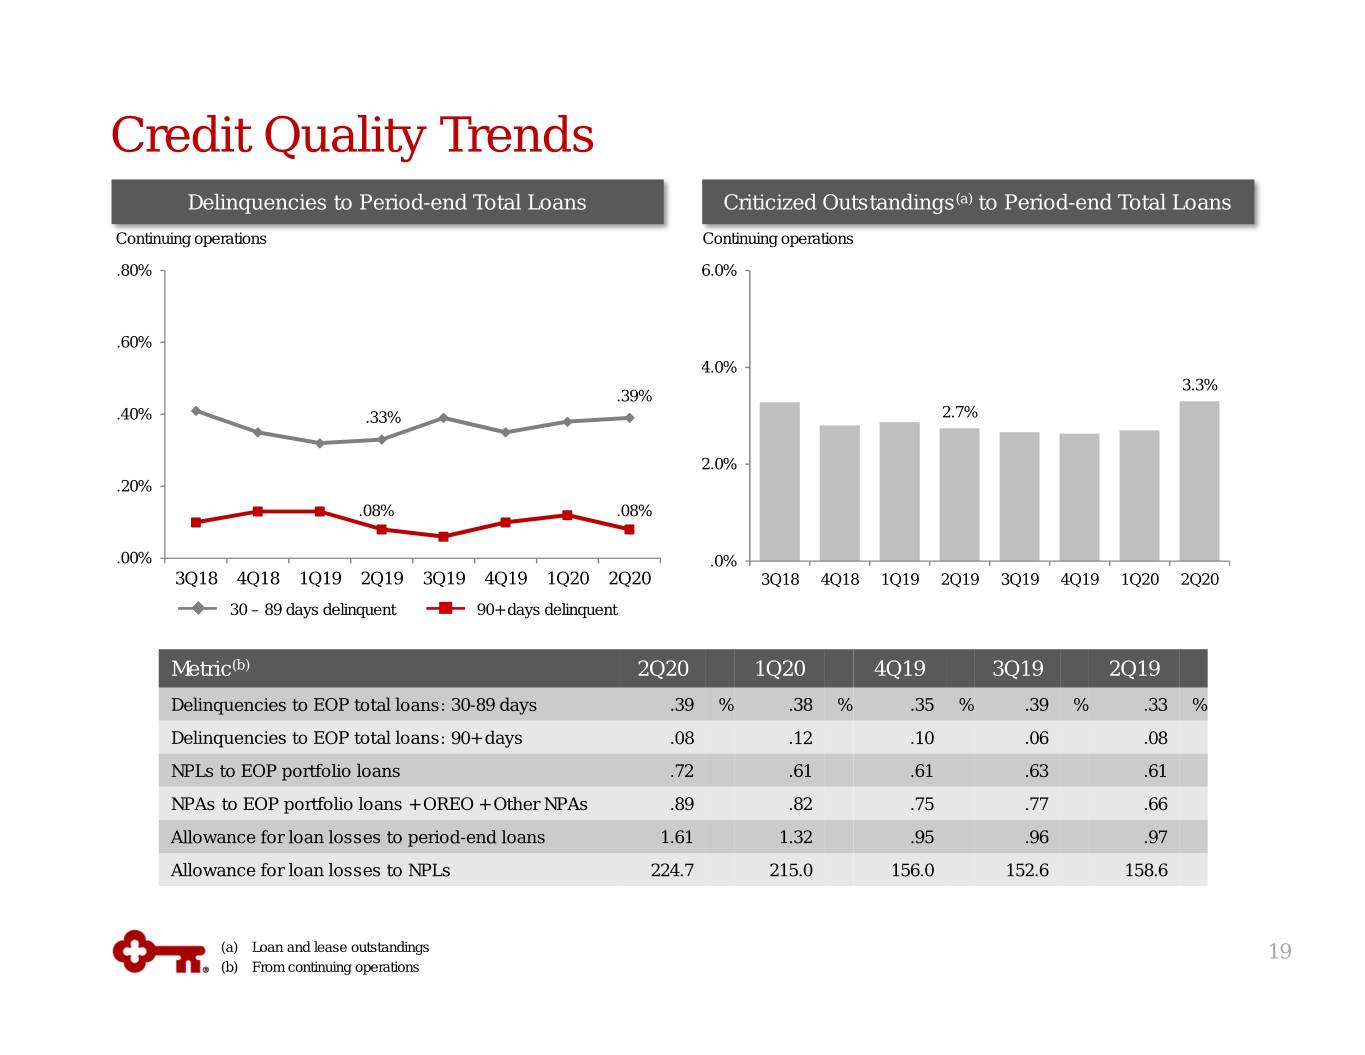
Credit Quality Trends Delinquencies to Period-end Total Loans Criticized Outstandings (a) to Period-end Total Loans Continuing operations Continuing operations .80% 6.0% .60% 4.0% 3.3% .39% .40% .33% 2.7% 2.0% .20% .08% .08% .00% .0% 3Q18 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 3Q18 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 30 – 89 days delinquent 90+ days delinquent Metric (b) 2Q20 1Q20 4Q19 3Q19 2Q19 Delinquencies to EOP total loans: 30-89 days .39 % .38 % .35 % .39 % .33 % Delinquencies to EOP total loans: 90+ days .08 .12 .10 .06 .08 NPLs to EOP portfolio loans .72 .61 .61 .63 .61 NPAs to EOP portfolio loans + OREO + Other NPAs .89 .82 .75 .77 .66 Allowance for loan losses to period-end loans 1.61 1.32 .95 .96 .97 Allowance for loan losses to NPLs 224.7 215.0 156.0 152.6 158.6 (a) Loan and lease outstandings 19 (b) From continuing operations
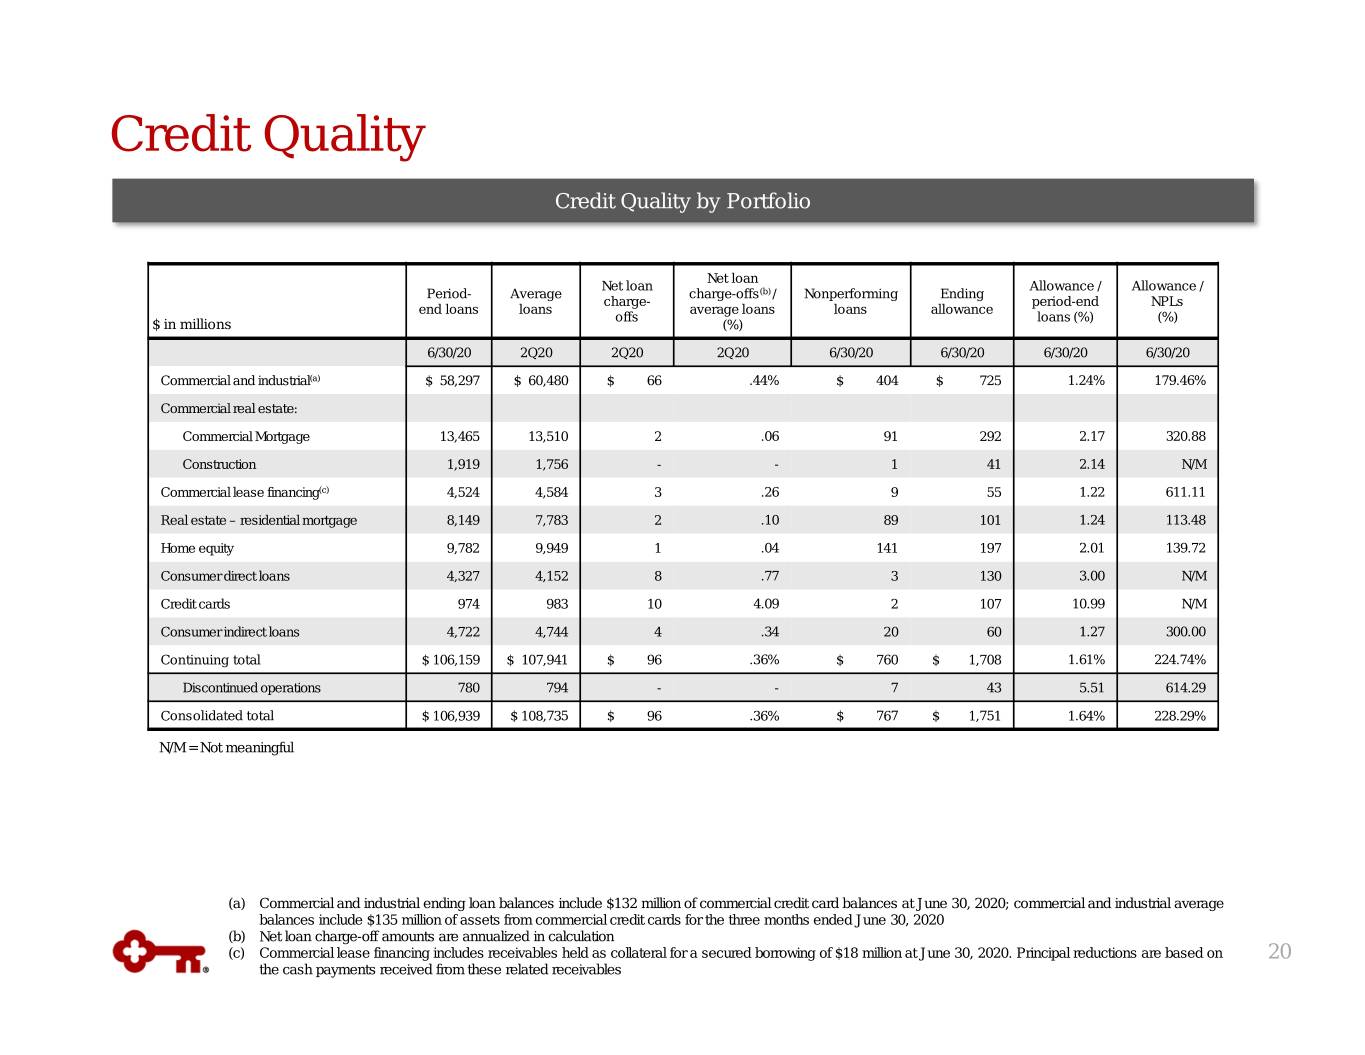
Credit Quality Credit Quality by Portfolio Net loan Net loan Allowance / Allowance / Period- Average charge-offs (b) / Nonperforming Ending charge- period-end NPLs end loans loans average loans loans allowance offs loans (%) (%) $ in millions (%) 6/30/20 2Q20 2Q20 2Q20 6/30/20 6/30/20 6/30/20 6/30/20 Commercial and industrial (a) $ 58,297 $ 60,480 $ 66 .44% $ 404 $ 725 1.24% 179.46% Commercial real estate: Commercial Mortgage 13,465 13,510 2 .06 91 292 2.17 320.88 Construction 1,919 1,756 - - 1 41 2.14 N/M Commercial lease financing (c) 4,524 4,584 3 .26 9 55 1.22 611.11 Real estate – residential mortgage 8,149 7,783 2 .10 89 101 1.24 113.48 Home equity 9,782 9,949 1 .04 141 197 2.01 139.72 Consumer direct loans 4,327 4,152 8 .77 3 130 3.00 N/M Credit cards 974 983 10 4.09 2 107 10.99 N/M Consumer indirect loans 4,722 4,744 4 .34 20 60 1.27 300.00 Continuing total $ 106,159 $ 107,941 $ 96 .36% $ 760 $ 1,708 1.61% 224.74% Discontinued operations 780 794 - - 7 43 5.51 614.29 Consolidated total $ 106,939 $ 108,735 $ 96 .36% $ 767 $ 1,751 1.64% 228.29% N/M = Not meaningful (a) Commercial and industrial ending loan balances include $132 million of commercial credit card balances at June 30, 2020; commercial and industrial average balances include $135 million of assets from commercial credit cards for the three months ended June 30, 2020 (b) Net loan charge-off amounts are annualized in calculation (c) Commercial lease financing includes receivables held as collateral for a secured borrowing of $18 million at June 30, 2020. Principal reductions are based on 20 the cash payments received from these related receivables
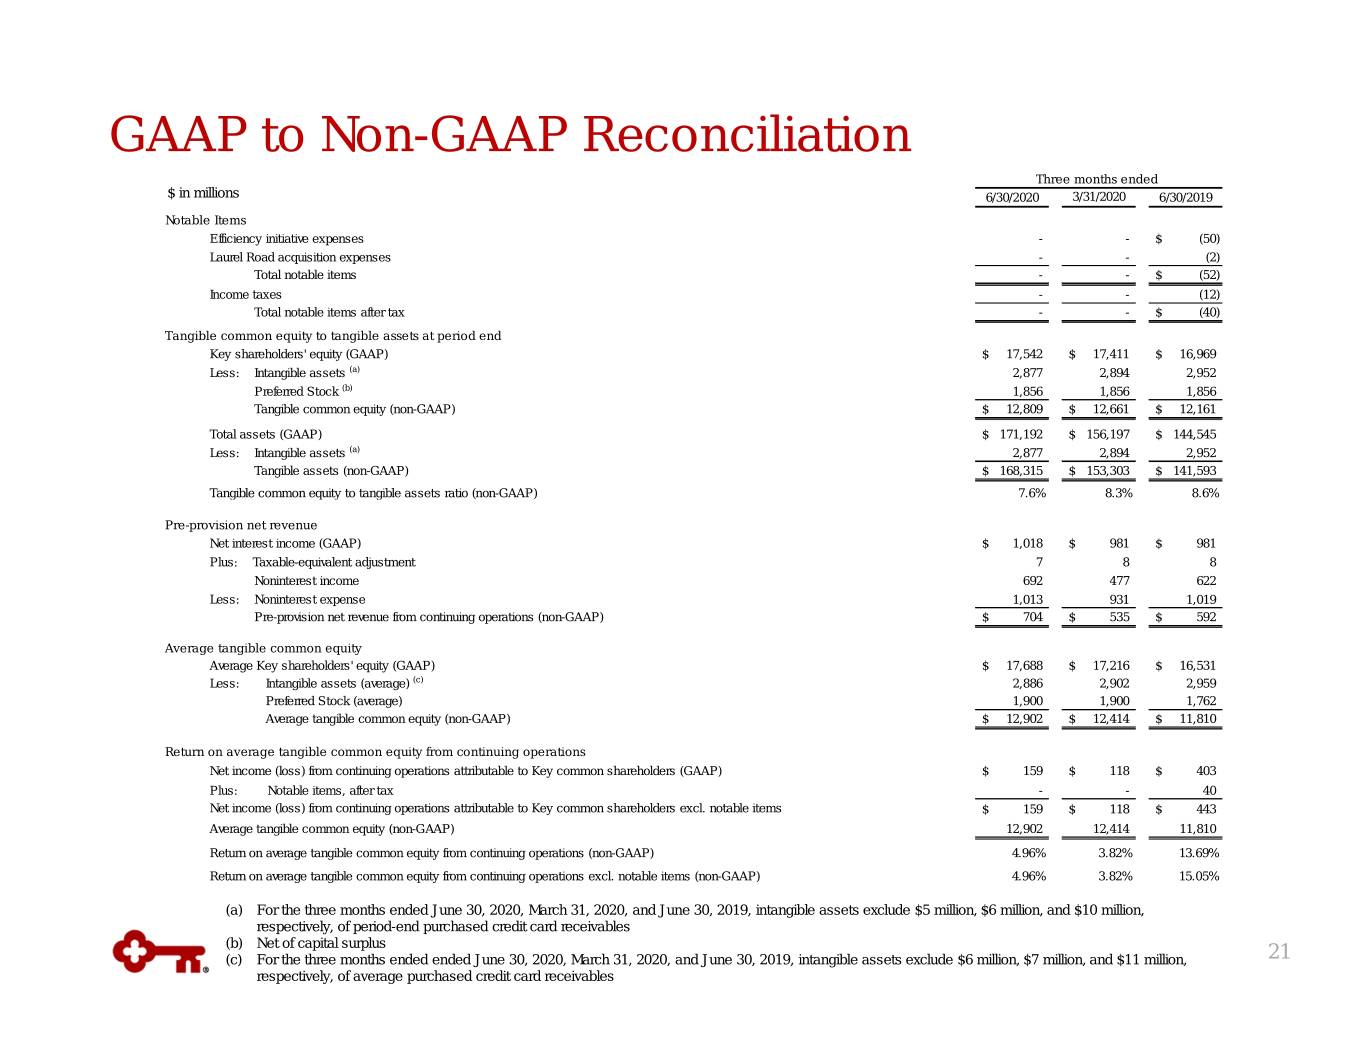
GAAP to Non-GAAP Reconciliation Three months ended $ in millions 6/30/2020 3/31/2020 6/30/2019 Notable Items Efficiency initiative expenses - -$ (50) Laurel Road acquisition expenses - - (2) Total notable items - -$ (52) Income taxes - - (12) Total notable items after tax - -$ (40) Tangible common equity to tangible assets at period end Key shareholders' equity (GAAP) $ 17,542 $ 17,411 $ 16,969 Less: Intangible assets (a) 2,877 2,894 2,952 Preferred Stock (b) 1,856 1,856 1,856 Tangible common equity (non-GAAP) $ 12,809 $ 12,661 $ 12,161 Total assets (GAAP) $ 171,192 $ 156,197 $ 144,545 Less: Intangible assets (a) 2,877 2,894 2,952 Tangible assets (non-GAAP) $ 168,315 $ 153,303 $ 141,593 Tangible common equity to tangible assets ratio (non-GAAP) 7.6% 8.3% 8.6% Pre-provision net revenue Net interest income (GAAP) $ 1,018 $ 981 $ 981 Plus: Taxable-equivalent adjustment 7 8 8 Noninterest income 692 477 622 Less: Noninterest expense 1,013 931 1,019 Pre-provision net revenue from continuing operations (non-GAAP) $ 704 $ 535 $ 592 Average tangible common equity Average Key shareholders' equity (GAAP) $ 17,688 $ 17,216 $ 16,531 Less: Intangible assets (average) (c) 2,886 2,902 2,959 Preferred Stock (average) 1,900 1,900 1,762 Average tangible common equity (non-GAAP) $ 12,902 $ 12,414 $ 11,810 Return on average tangible common equity from continuing operations Net income (loss) from continuing operations attributable to Key common shareholders (GAAP) $ 159 $ 118 $ 403 Plus: Notable items, after tax - - 40 Net income (loss) from continuing operations attributable to Key common shareholders excl. notable items $ 159 $ 118 $ 443 Average tangible common equity (non-GAAP) 12,902 12,414 11,810 Return on average tangible common equity from continuing operations (non-GAAP) 4.96% 3.82% 13.69% Return on average tangible common equity from continuing operations excl. notable items (non-GAAP) 4.96% 3.82% 15.05% (a) For the three months ended June 30, 2020, March 31, 2020, and June 30, 2019, intangible assets exclude $5 million, $6 million, and $10 million, respectively, of period-end purchased credit card receivables (b) Net of capital surplus (c) For the three months ended ended June 30, 2020, March 31, 2020, and June 30, 2019, intangible assets exclude $6 million, $7 million, and $11 million, 21 respectively, of average purchased credit card receivables
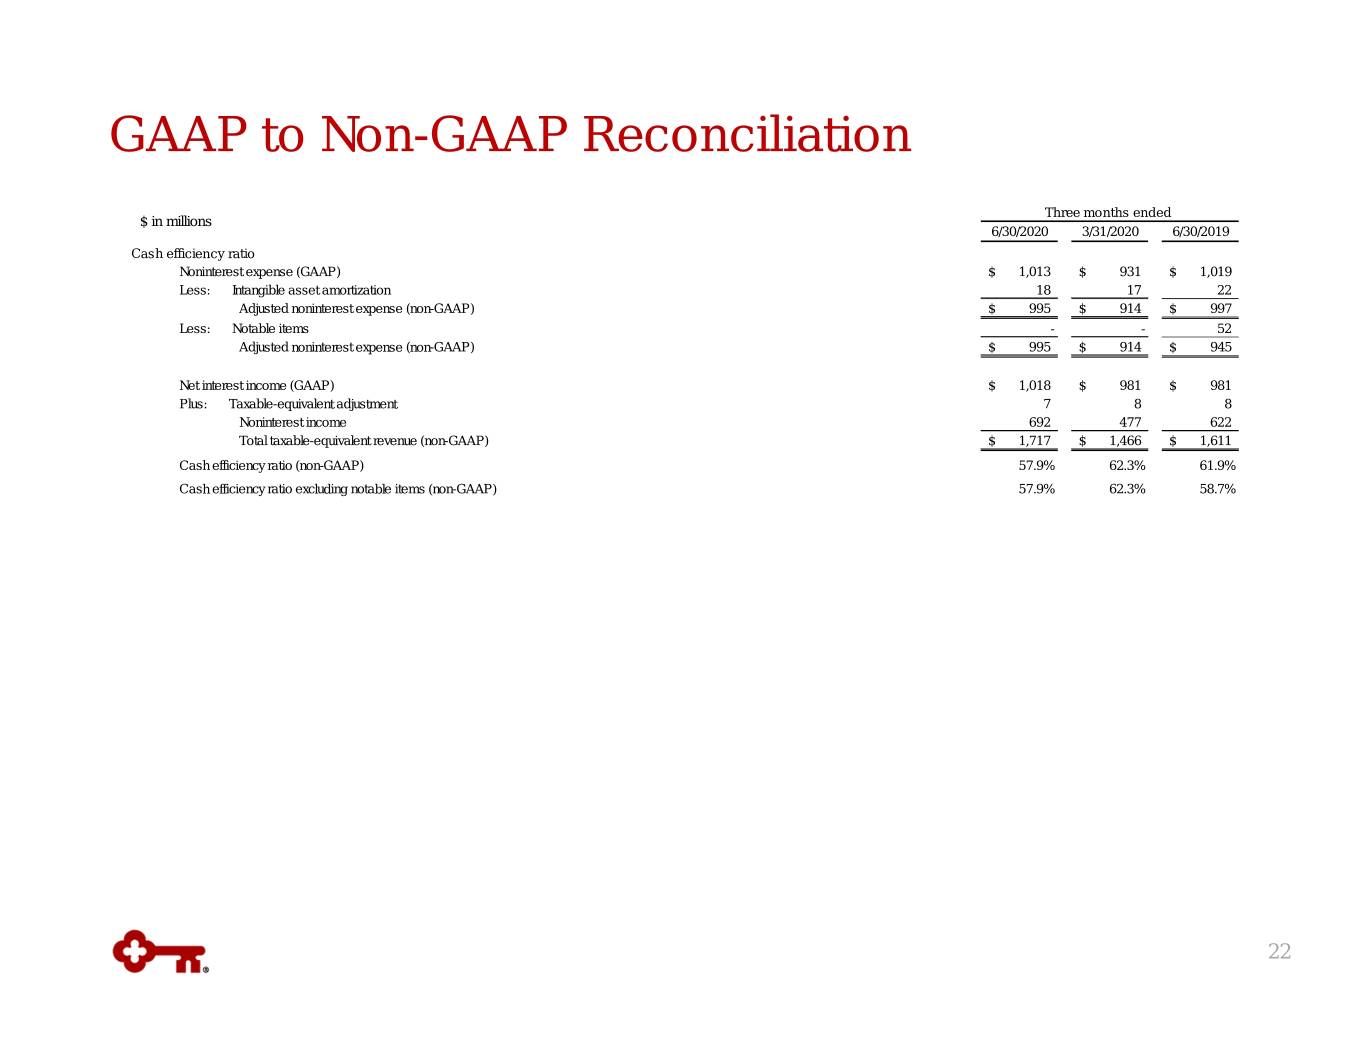
GAAP to Non-GAAP Reconciliation Three months ended $ in millions 6/30/2020 3/31/2020 6/30/2019 Cash efficiency ratio Noninterest expense (GAAP) $ 1,013 $ 931 $ 1,019 Less: Intangible asset amortization 18 17 22 Adjusted noninterest expense (non-GAAP) $ 995 $ 914 $ 997 Less: Notable items - - 52 Adjusted noninterest expense (non-GAAP) $ 995 $ 914 $ 945 Net interest income (GAAP) $ 1,018 $ 981 $ 981 Plus: Taxable-equivalent adjustment 7 8 8 Noninterest income 692 477 622 Total taxable-equivalent revenue (non-GAAP) $ 1,717 $ 1,466 $ 1,611 Cash efficiency ratio (non-GAAP) 57.9% 62.3% 61.9% Cash efficiency ratio excluding notable items (non-GAAP) 57.9% 62.3% 58.7% 22
Exhibit 99.3
Consolidated Balance Sheets | |||||||||||
(dollars in millions) | |||||||||||
6/30/2020 | 3/31/2020 | 6/30/2019 | |||||||||
Assets | |||||||||||
Loans | $ | 106,159 | $ | 103,198 | $ | 91,937 | |||||
Loans held for sale | 2,007 | 2,143 | 1,790 | ||||||||
Securities available for sale | 23,600 | 20,807 | 21,528 | ||||||||
Held-to-maturity securities | 9,075 | 9,638 | 10,878 | ||||||||
Trading account assets | 645 | 795 | 1,005 | ||||||||
Short-term investments | 14,036 | 4,073 | 2,443 | ||||||||
Other investments | 655 | 679 | 632 | ||||||||
Total earning assets | 156,177 | 141,333 | 130,213 | ||||||||
Allowance for loan and lease losses | (1,708 | ) | (1,359 | ) | (890 | ) | |||||
Cash and due from banks | 1,059 | 865 | 607 | ||||||||
Premises and equipment | 776 | 791 | 829 | ||||||||
Goodwill | 2,664 | 2,664 | 2,664 | ||||||||
Other intangible assets | 218 | 236 | 298 | ||||||||
Corporate-owned life insurance | 4,251 | 4,243 | 4,201 | ||||||||
Accrued income and other assets | 6,976 | 6,604 | 5,633 | ||||||||
Discontinued assets | 779 | 820 | 990 | ||||||||
Total assets | $ | 171,192 | $ | 156,197 | $ | 144,545 | |||||
Liabilities | |||||||||||
Deposits in domestic offices: | |||||||||||
NOW and money market deposit accounts | $ | 78,853 | $ | 71,005 | $ | 63,619 | |||||
Savings deposits | 5,371 | 4,753 | 4,747 | ||||||||
Certificates of deposit ($100,000 or more) | 4,476 | 5,630 | 8,084 | ||||||||
Other time deposits | 4,011 | 4,623 | 5,524 | ||||||||
Total interest-bearing deposits | 92,711 | 86,011 | 81,974 | ||||||||
Noninterest-bearing deposits | 42,802 | 29,293 | 27,972 | ||||||||
Total deposits | 135,513 | 115,304 | 109,946 | ||||||||
Federal funds purchased and securities sold under repurchase agreements | 267 | 2,444 | 161 | ||||||||
Bank notes and other short-term borrowings | 1,716 | 4,606 | 720 | ||||||||
Accrued expense and other liabilities | 2,420 | 2,700 | 2,435 | ||||||||
Long-term debt | 13,734 | 13,732 | 14,312 | ||||||||
Total liabilities | 153,650 | 138,786 | 127,574 | ||||||||
Equity | |||||||||||
Preferred stock | 1,900 | 1,900 | 1,900 | ||||||||
Common shares | 1,257 | 1,257 | 1,257 | ||||||||
Capital surplus | 6,240 | 6,222 | 6,266 | ||||||||
Retained earnings | 12,154 | 12,174 | 12,005 | ||||||||
Treasury stock, at cost | (4,945 | ) | (4,956 | ) | (4,457 | ) | |||||
Accumulated other comprehensive income (loss) | 936 | 814 | (2 | ) | |||||||
Key shareholders’ equity | 17,542 | 17,411 | 16,969 | ||||||||
Noncontrolling interests | — | — | 2 | ||||||||
Total equity | 17,542 | 17,411 | 16,971 | ||||||||
Total liabilities and equity | $ | 171,192 | $ | 156,197 | $ | 144,545 | |||||
Common shares outstanding (000) | 975,947 | 975,319 | 1,003,114 | ||||||||
Consolidated Statements of Income | ||||||||||||||||||
(dollars in millions, except per share amounts) | ||||||||||||||||||
Three months ended | Six months ended | |||||||||||||||||
6/30/2020 | 3/31/2020 | 6/30/2019 | 6/30/2020 | 6/30/2019 | ||||||||||||||
Interest income | ||||||||||||||||||
Loans | $ | 980 | $ | 1,026 | $ | 1,082 | $ | 2,006 | $ | 2,148 | ||||||||
Loans held for sale | 21 | 19 | 15 | 40 | 28 | |||||||||||||
Securities available for sale | 121 | 129 | 135 | 250 | 264 | |||||||||||||
Held-to-maturity securities | 56 | 62 | 67 | 118 | 135 | |||||||||||||
Trading account assets | 5 | 8 | 9 | 13 | 17 | |||||||||||||
Short-term investments | 7 | 6 | 17 | 13 | 33 | |||||||||||||
Other investments | — | 1 | 4 | 1 | 8 | |||||||||||||
Total interest income | 1,190 | 1,251 | 1,329 | 2,441 | 2,633 | |||||||||||||
Interest expense | ||||||||||||||||||
Deposits | 96 | 169 | 223 | 265 | 425 | |||||||||||||
Federal funds purchased and securities sold under repurchase agreements | — | 6 | — | 6 | 1 | |||||||||||||
Bank notes and other short-term borrowings | 5 | 5 | 5 | 10 | 9 | |||||||||||||
Long-term debt | 71 | 90 | 120 | 161 | 240 | |||||||||||||
Total interest expense | 172 | 270 | 348 | 442 | 675 | |||||||||||||
Net interest income | 1,018 | 981 | 981 | 1,999 | 1,958 | |||||||||||||
Provision for credit losses | 482 | 359 | 74 | 841 | 136 | |||||||||||||
Net interest income after provision for credit losses | 536 | 622 | 907 | 1,158 | 1,822 | |||||||||||||
Noninterest income | ||||||||||||||||||
Trust and investment services income | 123 | 133 | 122 | 256 | 237 | |||||||||||||
Investment banking and debt placement fees | 156 | 116 | 163 | 272 | 273 | |||||||||||||
Service charges on deposit accounts | 68 | 84 | 83 | 152 | 165 | |||||||||||||
Operating lease income and other leasing gains | 60 | 30 | 44 | 90 | 81 | |||||||||||||
Corporate services income | 52 | 62 | 53 | 114 | 108 | |||||||||||||
Cards and payments income | 91 | 66 | 73 | 157 | 139 | |||||||||||||
Corporate-owned life insurance income | 35 | 36 | 33 | 71 | 65 | |||||||||||||
Consumer mortgage income | 62 | 20 | 15 | 82 | 26 | |||||||||||||
Commercial mortgage servicing fees | 12 | 18 | 19 | 30 | 37 | |||||||||||||
Other income | 33 | (88 | ) | 17 | (55 | ) | 27 | |||||||||||
Total noninterest income | 692 | 477 | 622 | 1,169 | 1,158 | |||||||||||||
Noninterest expense | ||||||||||||||||||
Personnel | 572 | 515 | 589 | 1,087 | 1,152 | |||||||||||||
Net occupancy | 71 | 76 | 73 | 147 | 145 | |||||||||||||
Computer processing | 56 | 55 | 56 | 111 | 110 | |||||||||||||
Business services and professional fees | 49 | 44 | 45 | 93 | 89 | |||||||||||||
Equipment | 25 | 24 | 24 | 49 | 48 | |||||||||||||
Operating lease expense | 34 | 36 | 32 | 70 | 58 | |||||||||||||
Marketing | 24 | 21 | 24 | 45 | 43 | |||||||||||||
FDIC assessment | 8 | 9 | 9 | 17 | 16 | |||||||||||||
Intangible asset amortization | 18 | 17 | 22 | 35 | 44 | |||||||||||||
OREO expense, net | 6 | 3 | 4 | 9 | 7 | |||||||||||||
Other expense | 150 | 131 | 141 | 281 | 270 | |||||||||||||
Total noninterest expense | 1,013 | 931 | 1,019 | 1,944 | 1,982 | |||||||||||||
Income (loss) from continuing operations before income taxes | 215 | 168 | 510 | 383 | 998 | |||||||||||||
Income taxes | 30 | 23 | 87 | 53 | 169 | |||||||||||||
Income (loss) from continuing operations | 185 | 145 | 423 | 330 | 829 | |||||||||||||
Income (loss) from discontinued operations, net of taxes | 2 | 1 | 2 | 3 | 3 | |||||||||||||
Net income (loss) | 187 | 146 | 425 | 333 | 832 | |||||||||||||
Less: Net income (loss) attributable to noncontrolling interests | — | — | — | — | — | |||||||||||||
Net income (loss) attributable to Key | $ | 187 | $ | 146 | $ | 425 | $ | 333 | $ | 832 | ||||||||
Income (loss) from continuing operations attributable to Key common shareholders | $ | 159 | $ | 118 | $ | 403 | $ | 277 | $ | 789 | ||||||||
Net income (loss) attributable to Key common shareholders | 161 | 119 | 405 | 280 | 792 | |||||||||||||
Per common share | ||||||||||||||||||
Income (loss) from continuing operations attributable to Key common shareholders | $ | .16 | $ | .12 | $ | .40 | $ | .29 | $ | .79 | ||||||||
Income (loss) from discontinued operations, net of taxes | — | — | — | — | — | |||||||||||||
Net income (loss) attributable to Key common shareholders (a) | .17 | .12 | .40 | .29 | .79 | |||||||||||||
Per common share — assuming dilution | ||||||||||||||||||
Income (loss) from continuing operations attributable to Key common shareholders | $ | .16 | $ | .12 | $ | .40 | $ | .28 | $ | .78 | ||||||||
Income (loss) from discontinued operations, net of taxes | — | — | — | — | — | |||||||||||||
Net income (loss) attributable to Key common shareholders (a) | .17 | .12 | $ | .40 | .29 | .78 | ||||||||||||
Cash dividends declared per common share | $ | .185 | $ | .185 | $ | .17 | $ | .37 | $ | .34 | ||||||||
Weighted-average common shares outstanding (000) | 967,147 | 967,446 | 999,163 | 967,380 | 1,003,047 | |||||||||||||
Effect of common share options and other stock awards | 4,994 | 8,664 | 8,801 | 6,892 | 9,318 | |||||||||||||
Weighted-average common shares and potential common shares outstanding (000) (b) | 972,141 | 976,110 | 1,007,964 | 974,272 | 1,012,365 | |||||||||||||
(a) | Earnings per share may not foot due to rounding. |
(b) | Assumes conversion of common share options and other stock awards and/or convertible preferred stock, as applicable. |