
KEY 8-K
Keycorp /New/ (KEY)
8-K
2023-07-20
For: 2023-07-20
View Original
Added on
April 10, 2026
UNITED STATES SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934 | ||
Date of Report (Date of earliest event reported): July 20, 2023
(Exact name of registrant as specified in its charter)
| State or other jurisdiction of incorporation or organization: | Commission File Number | I.R.S. Employer Identification Number: | ||||||||||||
| Address of principal executive offices: | Zip Code: | |||||||||||||
(216 ) 689-3000
Registrant’s telephone number, including area code:
| Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below): | |||||
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities Registered Pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition.
On July 20, 2023, KeyCorp issued a press release announcing its financial results for the three- and six-month period ended June 30, 2023 (the “Press Release”), and posted on its website its second quarter 2023 Supplemental Information Package (the “Supplemental Information Package”). The Press Release and Supplemental Information Package are being furnished as Exhibit 99.1 and Exhibit 99.2, respectively.
The information in the preceding paragraph, as well as Exhibit 99.1 and Exhibit 99.2 referenced therein, shall not be deemed “filed” for purposes of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), nor shall it be incorporated by reference in any filing under the Securities Act of 1933, as amended (the “Securities Act”).
KeyCorp’s Consolidated Balance Sheets and Consolidated Statements of Income (collectively, the “Financial Statements”), included as part of the Press Release, are filed as Exhibit 99.3 to this report. Exhibit 99.3 is deemed “filed” for purposes of Section 18 of the Exchange Act and, therefore, may be incorporated by reference in filings under the Securities Act.
Item 9.01 Financial Statements and Exhibits.
(d) Exhibits
The following exhibits are furnished, or filed in the case of Exhibit 99.3, herewith:
104 Cover Page Interactive Data File (embedded within the Inline XBRL document).
| SIGNATURE | ||||||||
| Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized. | ||||||||
| KEYCORP | ||||||||
| (Registrant) | ||||||||
| Date: July 20, 2023 | /s/ Douglas M. Schosser | |||||||
| By: Douglas M. Schosser | ||||||||
| Chief Accounting Officer | ||||||||
KEYCORP REPORTS SECOND QUARTER 2023 NET INCOME OF $250 MILLION,
OR $.27 PER DILUTED COMMON SHARE
Strong, core funded balance sheet: period-end deposits up $1.0 billion compared to the prior quarter
Solid credit quality: net charge-offs to average loans of 17 basis points
Built capital: Common Equity Tier 1 of 9.2%(a)
Disciplined expense management: expenses down 9% from prior quarter and relatively stable versus the year-ago period
Net income includes $87 million, or $.09 per share from allowance build
CLEVELAND, July 20, 2023 - KeyCorp (NYSE: KEY) today announced net income from continuing operations attributable to Key common shareholders of $250 million, or $.27 per diluted common share for the second quarter of 2023. This compared to $275 million, or $.30 per diluted common share, for the first quarter of 2023 and $504 million, or $.54 per diluted common share, for the second quarter of 2022.
Comments from Chairman and CEO, Chris Gorman
"Key’s second quarter results reflect our durable relationship-based business model, sound risk management, and strong balance sheet. Our longstanding commitment to primacy continues to serve us well, resulting in period-end deposit growth of $1 billion from the prior quarter.
Additionally, our results demonstrate our ongoing commitment to expense discipline. Expenses were down nearly 9% from the prior quarter, and stable compared to last year. We remain focused on improving productivity and efficiency across our businesses.
Credit quality continues to be a strength for Key, with net charge-offs to average loans of 17 basis points. In the second quarter, we added to our allowance, which represents over 7 years of annualized net charge-offs.
We continue to manage capital consistent with our capital priorities, which include supporting our relationship clients and dividends. At the end of the second quarter, Key’s Common Equity Tier 1 ratio was 9.2%, up over 10 basis points from the prior quarter.
I am confident in the long-term outlook for Key and in our ability to deliver value to all of our stakeholders.”
(a)June 30, 2023 ratio is estimated and reflects Key's election to adopt the CECL optional transition provision.
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 2
| Selected Financial Highlights | |||||||||||||||||||||||
| Dollars in millions, except per share data | Change 2Q23 vs. | ||||||||||||||||||||||
| 2Q23 | 1Q23 | 2Q22 | 1Q23 | 2Q22 | |||||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | 250 | $ | 275 | $ | 504 | (9.1) | % | (50.4) | % | |||||||||||||
Income (loss) from continuing operations attributable to Key common shareholders per common share — assuming dilution | .27 | .30 | .54 | (10.0) | (50.0) | ||||||||||||||||||
Return on average tangible common equity from continuing operations (a) | 11.04 | % | 13.16 | % | 20.90 | % | N/A | N/A | |||||||||||||||
| Return on average total assets from continuing operations | .58 | .66 | 1.16 | N/A | N/A | ||||||||||||||||||
Common Equity Tier 1 ratio (b) | 9.2 | 9.1 | 9.2 | N/A | N/A | ||||||||||||||||||
| Book value at period end | $ | 12.18 | $ | 12.70 | $ | 13.48 | (4.1) | (9.6) | |||||||||||||||
| Net interest margin (TE) from continuing operations | 2.12 | % | 2.47 | % | 2.61 | % | N/A | N/A | |||||||||||||||
(a)The table entitled “GAAP to Non-GAAP Reconciliations” in the attached financial supplement presents the computations of certain financial measures related to “Return on average tangible common equity from continuing operations.” The table reconciles the GAAP performance measures to the corresponding non-GAAP measures, which provides a basis for period-to-period comparisons.
(b)June 30, 2023 ratio is estimated.
TE = Taxable Equivalent, N/A = Not Applicable
| INCOME STATEMENT HIGHLIGHTS | ||||||||||||||||||||
| Revenue | ||||||||||||||||||||
| Dollars in millions | Change 2Q23 vs. | |||||||||||||||||||
| 2Q23 | 1Q23 | 2Q22 | 1Q23 | 2Q22 | ||||||||||||||||
| Net interest income (TE) | $ | 986 | $ | 1,106 | $ | 1,104 | (10.8) | % | (10.7) | % | ||||||||||
| Noninterest income | 609 | 608 | 688 | .2 | (11.5) | |||||||||||||||
| Total revenue | $ | 1,595 | $ | 1,714 | $ | 1,792 | (6.9) | % | (11.0) | % | ||||||||||
TE = Taxable Equivalent
Taxable-equivalent net interest income was $986 million for the second quarter of 2023 and the net interest margin was 2.12%. Compared to the second quarter of 2022, net interest income decreased $118 million, and the net interest margin decreased by 49 basis points. The decline in net interest income and the net interest margin reflects higher interest-bearing deposit costs and a shift in funding mix to higher cost deposits and borrowings.
Compared to the first quarter of 2023, taxable-equivalent net interest income decreased by $120 million, and the net interest margin decreased by 35 basis points. The decline in net interest income and the net interest margin reflects higher interest-bearing deposit costs and a shift in funding mix to higher-cost deposits and borrowings.
| Noninterest Income | ||||||||||||||||||||
| Dollars in millions | Change 2Q23 vs. | |||||||||||||||||||
| 2Q23 | 1Q23 | 2Q22 | 1Q23 | 2Q22 | ||||||||||||||||
| Trust and investment services income | $ | 126 | $ | 128 | $ | 137 | (1.6) | % | (8.0) | % | ||||||||||
| Investment banking and debt placement fees | 120 | 145 | 149 | (17.2) | (19.5) | |||||||||||||||
| Cards and payments income | 85 | 81 | 85 | 4.9 | — | |||||||||||||||
| Service charges on deposit accounts | 69 | 67 | 96 | 3.0 | (28.1) | |||||||||||||||
| Corporate services income | 86 | 76 | 96 | 13.2 | (10.4) | |||||||||||||||
| Commercial mortgage servicing fees | 50 | 46 | 45 | 8.7 | 11.1 | |||||||||||||||
| Corporate-owned life insurance income | 32 | 29 | 35 | 10.3 | (8.6) | |||||||||||||||
| Consumer mortgage income | 14 | 11 | 14 | 27.3 | — | |||||||||||||||
| Operating lease income and other leasing gains | 23 | 25 | 28 | (8.0) | (17.9) | |||||||||||||||
| Other income | 4 | — | 3 | N/M | (33.3) | |||||||||||||||
| Total noninterest income | $ | 609 | $ | 608 | $ | 688 | .2 | % | (11.5) | % | ||||||||||
Compared to the second quarter of 2022, noninterest income decreased by $79 million. The decrease was driven by a $29 million decline in investment banking and debt placement fees, reflecting lower merger
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 3
and acquisition advisory fees and lower syndication fees. Service charges on deposit accounts decreased $27 million, reflecting a reduction in overdraft and non-sufficient funds fees and lower account analysis fees related to the interest rate environment. Additionally, trust and investment services declined $11 million, reflecting a decline in fixed income and equity trading, and corporate services income decreased $10 million.
Compared to the first quarter of 2023, noninterest income increased by $1 million. The increase was driven by broad-based growth across most fee categories, including a $10 million increase in corporate services income, reflecting an increase in income associated with customer derivatives trading. These increases were mostly offset by a $25 million decline in investment banking and debt placement fees due to lower merger and acquisition advisory fees and lower syndication fees.
| Noninterest Expense | ||||||||||||||||||||
| Dollars in millions | Change 2Q23 vs. | |||||||||||||||||||
| 2Q23 | 1Q23 | 2Q22 | 1Q23 | 2Q22 | ||||||||||||||||
| Personnel expense | $ | 622 | $ | 701 | $ | 607 | (11.3) | % | 2.5 | % | ||||||||||
| Net occupancy | 65 | 70 | 78 | (7.1) | (16.7) | |||||||||||||||
| Computer processing | 95 | 92 | 78 | 3.3 | 21.8 | |||||||||||||||
| Business services and professional fees | 41 | 45 | 52 | (8.9) | (21.2) | |||||||||||||||
| Equipment | 22 | 22 | 26 | — | (15.4) | |||||||||||||||
| Operating lease expense | 21 | 20 | 27 | 5.0 | (22.2) | |||||||||||||||
| Marketing | 29 | 21 | 34 | 38.1 | (14.7) | |||||||||||||||
| Other expense | 181 | 205 | 176 | (11.7) | 2.8 | |||||||||||||||
| Total noninterest expense | $ | 1,076 | $ | 1,176 | $ | 1,078 | (8.5) | % | (.2) | % | ||||||||||
Compared to the second quarter of 2022, noninterest expense decreased by $2 million. The decline was driven by a $13 million decrease in net occupancy expense as we exit corporate facilities and a $11 million decline in business services and professional fees. Partly offsetting the decline was an increase in computer processing expense of $17 million, due to technology investments, and a $15 million increase in personnel expense, due to an increase in salaries as a result of higher merit increases and employee benefits.
Compared to the first quarter of 2023, noninterest expense decreased $100 million. The decline was primarily driven by a $79 million decrease in personnel expense, reflective of lower incentive and stock-based compensation and a decline in severance expense. Additionally, other expense declined by $24 million, reflecting higher expenses related to corporate real estate rationalization in the prior quarter.
| BALANCE SHEET HIGHLIGHTS | ||||||||||||||||||||
| Average Loans | ||||||||||||||||||||
| Dollars in millions | Change 2Q23 vs. | |||||||||||||||||||
| 2Q23 | 1Q23 | 2Q22 | 1Q23 | 2Q22 | ||||||||||||||||
Commercial and industrial (a) | $ | 61,426 | $ | 60,281 | $ | 53,858 | 1.9 | % | 14.1 | % | ||||||||||
| Other commercial loans | 22,623 | 22,778 | 21,173 | (.7) | 6.8 | |||||||||||||||
| Total consumer loans | 36,623 | 36,778 | 34,107 | (.4) | 7.4 | |||||||||||||||
| Total loans | $ | 120,672 | $ | 119,837 | $ | 109,138 | .7 | % | 10.6 | % | ||||||||||
(a)Commercial and industrial average loan balances include $194 million, $178 million, and $153 million of assets from commercial credit cards at June 30, 2023, March 31, 2023, and June 30, 2022, respectively.
Average loans were $120.7 billion for the second quarter of 2023, an increase of $11.5 billion compared to the second quarter of 2022. Commercial loans increased by $9.0 billion, largely reflecting growth in commercial and industrial loans of $7.6 billion, as well as an increase in commercial mortgage real estate loans of $1.5 billion. Consumer loans increased $2.5 billion, largely driven by Key's residential mortgage business.
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 4
Compared to the first quarter of 2023, average loans increased by $835 million. The increase was driven by commercial loans, reflecting growth in commercial and industrial loans.
| Average Deposits | ||||||||||||||||||||
| Dollars in millions | Change 2Q23 vs. | |||||||||||||||||||
| 2Q23 | 1Q23 | 2Q22 | 1Q23 | 2Q22 | ||||||||||||||||
| Non-time deposits | $ | 127,687 | $ | 132,907 | $ | 144,012 | (3.9) | % | (11.3) | % | ||||||||||
| Certificates of deposit ($100,000 or more) | 3,851 | 2,392 | 1,487 | 61.0 | 159.0 | |||||||||||||||
| Other time deposits | 11,365 | 8,106 | 1,972 | 40.2 | 476.3 | |||||||||||||||
| Total deposits | $ | 142,903 | $ | 143,405 | $ | 147,471 | (.4) | % | (3.1) | % | ||||||||||
| Cost of total deposits | 1.49 | % | .99 | % | .06 | % | N/A | N/A | ||||||||||||
N/A = Not Applicable
Average deposits totaled $142.9 billion for the second quarter of 2023, a decrease of $4.6 billion compared to the year-ago quarter. The decline reflects elevated inflation-related spend, changing client behavior due to higher interest rates, and a normalization of pandemic-related deposits.
Compared to the first quarter of 2023, average deposits decreased by $502 million. The decline was driven by changing client behavior due to higher interest rates and normal seasonal deposit outflows in commercial deposits.
| ASSET QUALITY | ||||||||||||||||||||
| Dollars in millions | Change 2Q23 vs. | |||||||||||||||||||
| 2Q23 | 1Q23 | 2Q22 | 1Q23 | 2Q22 | ||||||||||||||||
| Net loan charge-offs | $ | 52 | $ | 45 | $ | 44 | 15.6 | % | 18.2 | % | ||||||||||
| Net loan charge-offs to average total loans | .17 | % | .15 | % | .16 | % | N/A | N/A | ||||||||||||
| Nonperforming loans at period end | $ | 431 | $ | 416 | $ | 429 | 3.6 | 0.5 | ||||||||||||
| Nonperforming assets at period end | 462 | 447 | 463 | 3.4 | (0.2) | |||||||||||||||
| Allowance for loan and lease losses | 1,480 | 1,380 | 1,099 | 7.2 | 34.7 | |||||||||||||||
| Allowance for credit losses | 1,771 | 1,656 | 1,272 | 6.9 | 39.2 | |||||||||||||||
| Provision for credit losses | 167 | 139 | 45 | 20.1 | 271.1 | |||||||||||||||
| Allowance for loan and lease losses to nonperforming loans | 343 | % | 332 | % | 256 | % | N/A | N/A | ||||||||||||
| Allowance for credit losses to nonperforming loans | 411 | 398 | 297 | N/A | N/A | |||||||||||||||
N/A = Not Applicable
Key's provision for credit losses was $167 million, compared to $45 million in the second quarter of 2022 and $139 million in the first quarter of 2023. The increase from the year-ago period and prior quarter reflects changes in the economic outlook and portfolio activity.
Net loan charge-offs for the second quarter of 2023 totaled $52 million, or 0.17% of average total loans. These results compare to $44 million, or 0.16%, for the second quarter of 2022 and $45 million, or 0.15%, for the first quarter of 2023. Key’s allowance for credit losses was $1.8 billion, or 1.49% of total period-end loans at June 30, 2023, compared to 1.13% at June 30, 2022, and 1.38% at March 31, 2023.
At June 30, 2023, Key’s nonperforming loans totaled $431 million, which represented 0.36% of period-end portfolio loans. These results compare to 0.38% at June 30, 2022, and 0.35% at March 31, 2023. Nonperforming assets at June 30, 2023, totaled $462 million, and represented 0.39% of period-end portfolio loans and OREO and other nonperforming assets. These results compare to 0.41% at June 30, 2022, and 0.37% at March 31, 2023.
CAPITAL
Key’s estimated risk-based capital ratios included in the following table continued to exceed all “well-capitalized” regulatory benchmarks at June 30, 2023.
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 5
| Capital Ratios | |||||||||||
| 6/30/2023 | 3/31/2023 | 6/30/2022 | |||||||||
Common Equity Tier 1 (a) | 9.2 | % | 9.1 | % | 9.2 | % | |||||
Tier 1 risk-based capital (a) | 10.7 | 10.6 | 10.4 | ||||||||
Total risk-based capital (a) | 13.0 | 12.8 | 12.0 | ||||||||
Tangible common equity to tangible assets (b) | 4.5 | 4.6 | 5.3 | ||||||||
Leverage (a) | 8.7 | 8.8 | 8.6 | ||||||||
(a)June 30, 2023 ratio is estimated and reflects Key's election to adopt the CECL optional transition provision.
(b)The table entitled “GAAP to Non-GAAP Reconciliations” in the attached financial supplement presents the computations of certain financial measures related to “tangible common equity.” The table reconciles the GAAP performance measures to the corresponding non-GAAP measures, which provides a basis for period-to-period comparisons.
Key's capital position remained strong in the second quarter of 2023. As shown in the preceding table, at June 30, 2023, Key’s estimated Common Equity Tier 1 and Tier 1 risk-based capital ratios stood at 9.2% and 10.7%, respectively. Key's tangible common equity ratio was 4.5% at June 30, 2023.
Key elected the CECL phase-in option provided by regulatory guidance which delayed for two years the estimated impact of CECL on regulatory capital and phases it in over three years beginning in 2022. Effective for the first quarter 2022, Key is now in the three-year transition period. On a fully phased-in basis, Key's Common Equity Tier 1 ratio would be reduced by eight basis points.
| Summary of Changes in Common Shares Outstanding | |||||||||||||||||||||||
| In thousands | Change 2Q23 vs. | ||||||||||||||||||||||
| 2Q23 | 1Q23 | 2Q22 | 1Q23 | 2Q22 | |||||||||||||||||||
| Shares outstanding at beginning of period | 935,229 | 933,325 | 932,398 | .2 | % | .3 | % | ||||||||||||||||
| Open market repurchases and return of shares under employee compensation plans | (38) | (4,333) | (24) | (99.1) | 58.3 | ||||||||||||||||||
| Shares issued under employee compensation plans (net of cancellations) | 542 | 6,237 | 269 | (91.3) | 101.5 | ||||||||||||||||||
| Shares outstanding at end of period | 935,733 | 935,229 | 932,643 | .1 | % | .3 | % | ||||||||||||||||
N/M = Not Meaningful
During the second quarter of 2023, Key declared a dividend of $.205 per common share. Additionally, we have $752 million remaining in our share repurchase authorization through the third quarter of 2023.
LINE OF BUSINESS RESULTS
The following table shows the contribution made by each major business segment to Key’s taxable-equivalent revenue from continuing operations and income (loss) from continuing operations attributable to Key for the periods presented. For more detailed financial information pertaining to each business segment, see the tables at the end of this release.
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 6
| Major Business Segments | |||||||||||||||||||||||
| Dollars in millions | Change 2Q23 vs. | ||||||||||||||||||||||
| 2Q23 | 1Q23 | 2Q22 | 1Q23 | 2Q22 | |||||||||||||||||||
| Revenue from continuing operations (TE) | |||||||||||||||||||||||
| Consumer Bank | $ | 803 | $ | 840 | $ | 858 | (4.4) | % | (6.4) | % | |||||||||||||
| Commercial Bank | 805 | 844 | 874 | (4.6) | (7.9) | ||||||||||||||||||
Other (a) | (13) | 30 | 60 | (143.3) | (121.7) | ||||||||||||||||||
| Total | $ | 1,595 | $ | 1,714 | $ | 1,792 | (6.9) | % | (11.0) | % | |||||||||||||
| Income (loss) from continuing operations attributable to Key | |||||||||||||||||||||||
| Consumer Bank | $ | 82 | $ | 89 | $ | 128 | (7.9) | % | (35.9) | % | |||||||||||||
| Commercial Bank | 214 | 255 | 340 | (16.1) | (37.1) | ||||||||||||||||||
Other (a) | (10) | (33) | 62 | 69.7 | (116.1) | ||||||||||||||||||
| Total | $ | 286 | $ | 311 | $ | 530 | (8.0) | % | (46.0) | % | |||||||||||||
(a)Other includes other segments that consists of corporate treasury, our principal investing unit, and various exit portfolios as well as reconciling items which primarily represents the unallocated portion of nonearning assets of corporate support functions. Charges related to the funding of these assets are part of net interest income and are allocated to the business segments through noninterest expense. Reconciling items also includes intercompany eliminations and certain items that are not allocated to the business segments because they do not reflect their normal operations.
TE = Taxable Equivalent
| Consumer Bank | ||||||||||||||||||||
| Dollars in millions | Change 2Q23 vs. | |||||||||||||||||||
| 2Q23 | 1Q23 | 2Q22 | 1Q23 | 2Q22 | ||||||||||||||||
| Summary of operations | ||||||||||||||||||||
| Net interest income (TE) | $ | 558 | $ | 612 | $ | 604 | (8.8) | % | (7.6) | % | ||||||||||
| Noninterest income | 245 | 228 | 254 | 7.5 | (3.5) | |||||||||||||||
| Total revenue (TE) | 803 | 840 | 858 | (4.4) | (6.4) | |||||||||||||||
| Provision for credit losses | 32 | 60 | 8 | (46.7) | 300.0 | |||||||||||||||
| Noninterest expense | 663 | 663 | 681 | — | (2.6) | |||||||||||||||
| Income (loss) before income taxes (TE) | 108 | 117 | 169 | (7.7) | (36.1) | |||||||||||||||
| Allocated income taxes (benefit) and TE adjustments | 26 | 28 | 41 | (7.1) | (36.6) | |||||||||||||||
| Net income (loss) attributable to Key | $ | 82 | $ | 89 | $ | 128 | (7.9) | % | (35.9) | % | ||||||||||
| Average balances | ||||||||||||||||||||
| Loans and leases | $ | 42,934 | $ | 43,086 | $ | 40,827 | (.4) | % | 5.2 | % | ||||||||||
| Total assets | 45,761 | 45,935 | 43,897 | (.4) | 4.2 | |||||||||||||||
| Deposits | 82,498 | 84,637 | 91,394 | (2.5) | (9.7) | |||||||||||||||
| Assets under management at period end | $ | 53,952 | $ | 53,689 | $ | 49,003 | .5 | % | 10.1 | % | ||||||||||
TE = Taxable Equivalent
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 7
| Additional Consumer Bank Data | ||||||||||||||||||||
| Dollars in millions | Change 2Q23 vs. | |||||||||||||||||||
| 2Q23 | 1Q23 | 2Q22 | 1Q23 | 2Q22 | ||||||||||||||||
| Noninterest income | ||||||||||||||||||||
| Trust and investment services income | $ | 101 | $ | 101 | $ | 104 | — | % | (2.9) | % | ||||||||||
| Service charges on deposit accounts | 41 | 38 | 59 | 7.9 | (30.5) | |||||||||||||||
| Cards and payments income | 66 | 61 | 62 | 8.2 | 6.5 | |||||||||||||||
| Consumer mortgage income | 14 | 11 | 14 | 27.3 | — | |||||||||||||||
| Other noninterest income | 23 | 17 | 15 | 35.3 | 53.3 | |||||||||||||||
| Total noninterest income | $ | 245 | $ | 228 | $ | 254 | 7.5 | % | (3.5) | % | ||||||||||
| Average deposit balances | ||||||||||||||||||||
| Money market deposits | $ | 27,340 | $ | 28,128 | $ | 31,986 | (2.8) | % | (14.5) | % | ||||||||||
| Demand deposits | 23,845 | 24,849 | 25,905 | (4.0) | (8.0) | |||||||||||||||
| Savings deposits | 6,298 | 7,025 | 7,515 | (10.3) | (16.2) | |||||||||||||||
| Certificates of deposit ($100,000 or more) | 3,550 | 2,182 | 1,375 | 62.7 | 158.2 | |||||||||||||||
| Other time deposits | 2,864 | 2,169 | 1,966 | 32.0 | 45.7 | |||||||||||||||
| Noninterest-bearing deposits | 18,601 | 20,284 | 22,647 | (8.3) | (17.9) | |||||||||||||||
| Total deposits | $ | 82,498 | $ | 84,637 | $ | 91,394 | (2.5) | % | (9.7) | % | ||||||||||
| Other data | ||||||||||||||||||||
| Branches | 965 | 972 | 993 | |||||||||||||||||
| Automated teller machines | 1,255 | 1,265 | 1,308 | |||||||||||||||||
Consumer Bank Summary of Operations (2Q23 vs. 2Q22)
•Key's Consumer Bank recorded net income attributable to Key of $82 million for the second quarter of 2023, compared to $128 million for the year-ago quarter
•Taxable-equivalent net interest income decreased by $46 million, or 7.6%, compared to the second quarter of 2022, driven by higher interest-bearing deposit costs and a shift in funding mix
•Average loans and leases increased $2.1 billion, or 5.2%, from the second quarter of 2022, driven by growth in consumer mortgage loans
•Average deposits decreased $8.9 billion, or 9.7%, from the second quarter of 2022, reflecting elevated inflation-related spend, changing client behavior due to higher interest rates, and a normalization of pandemic-related deposits
•Provision for credit losses increased $24 million compared to the second quarter of 2022, driven by increases in both the allowance for credit losses and net loan charge-offs
•Noninterest income decreased $9 million from the year-ago quarter, driven by lower service charges on deposit accounts due to a planned reduction in overdraft and non-sufficient funds fees
•Noninterest expense decreased $18 million from the year-ago quarter, reflecting lower incentive compensation and employee benefits from the prior period, partly offset by an increase in salaries
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 8
| Commercial Bank | ||||||||||||||||||||
| Dollars in millions | Change 2Q23 vs. | |||||||||||||||||||
| 2Q23 | 1Q23 | 2Q22 | 1Q23 | 2Q22 | ||||||||||||||||
| Summary of operations | ||||||||||||||||||||
| Net interest income (TE) | $ | 459 | $ | 478 | $ | 470 | (4.0) | % | (2.3) | % | ||||||||||
| Noninterest income | 346 | 366 | 404 | (5.5) | (14.4) | |||||||||||||||
| Total revenue (TE) | 805 | 844 | 874 | (4.6) | (7.9) | |||||||||||||||
| Provision for credit losses | 134 | 80 | 37 | 67.5 | 262.2 | |||||||||||||||
| Noninterest expense | 405 | 442 | 411 | (8.4) | (1.5) | |||||||||||||||
| Income (loss) before income taxes (TE) | 266 | 322 | 426 | (17.4) | (37.6) | |||||||||||||||
| Allocated income taxes and TE adjustments | 52 | 67 | 86 | (22.4) | (39.5) | |||||||||||||||
| Net income (loss) attributable to Key | $ | 214 | $ | 255 | $ | 340 | (16.1) | % | (37.1) | % | ||||||||||
| Average balances | ||||||||||||||||||||
| Loans and leases | $ | 77,277 | $ | 76,306 | $ | 67,825 | 1.3 | % | 13.9 | % | ||||||||||
| Loans held for sale | 1,014 | 876 | 1,016 | 15.8 | (0.2) | |||||||||||||||
| Total assets | 87,106 | 85,852 | 78,816 | 1.5 | 10.5 | |||||||||||||||
| Deposits | 51,420 | 52,219 | 54,846 | (1.5) | % | (6.2) | % | |||||||||||||
TE = Taxable Equivalent
| Additional Commercial Bank Data | ||||||||||||||||||||
| Dollars in millions | Change 2Q23 vs. | |||||||||||||||||||
| 2Q23 | 1Q23 | 2Q22 | 1Q23 | 2Q22 | ||||||||||||||||
| Noninterest income | ||||||||||||||||||||
| Trust and investment services income | $ | 25 | $ | 27 | $ | 33 | (7.4) | % | (24.2) | % | ||||||||||
| Investment banking and debt placement fees | 120 | 145 | 150 | (17.2) | (20.0) | |||||||||||||||
| Cards and payments income | 22 | 20 | 23 | 10.0 | (4.3) | |||||||||||||||
| Service charges on deposit accounts | 27 | 27 | 36 | — | (25.0) | |||||||||||||||
| Corporate services income | 77 | 69 | 87 | 11.6 | (11.5) | |||||||||||||||
| Commercial mortgage servicing fees | 50 | 46 | 45 | 8.7 | 11.1 | |||||||||||||||
| Operating lease income and other leasing gains | 24 | 24 | 27 | — | (11.1) | |||||||||||||||
| Other noninterest income | 1 | 8 | 3 | (87.5) | (66.7) | |||||||||||||||
| Total noninterest income | $ | 346 | $ | 366 | $ | 404 | (5.5) | % | (14.4) | % | ||||||||||
Commercial Bank Summary of Operations (2Q23 vs. 2Q22)
•Key's Commercial Bank recorded net income attributable to Key of $214 million for the second quarter of 2023 compared to $340 million for the year-ago quarter
•Taxable-equivalent net interest income decreased by $11 million, or 2.3%, compared to the second quarter of 2022, primarily reflecting higher interest-bearing deposit costs and a shift in funding mix to higher-cost deposits
•Average loan and lease balances increased $9.5 billion, or 13.9%, compared to the second quarter of 2022, reflecting growth in commercial and industrial loans and an increase in commercial mortgage real estate loans
•Average deposit balances decreased $3.4 billion compared to the second quarter of 2022, reflecting changing client behavior due to higher interest rates
•Provision for credit losses increased $97 million compared to the second quarter of 2022, driven by higher allowance for credit losses due to changes in the economic outlook and portfolio activity
•Noninterest income decreased $58 million from the year-ago quarter, primarily driven by lower investment banking and debt placement fees reflecting lower merger and acquisition advisory fees and lower syndication fees, as well as a decrease in corporate services income
•Noninterest expense decreased $6 million from the second quarter of 2022, primarily driven by a decline in incentive compensation
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 9
*******************************************
KeyCorp's roots trace back nearly 200 years to Albany, New York. Headquartered in Cleveland, Ohio, Key is one of the nation’s largest bank-based financial services companies, with assets of approximately $195 billion at June 30, 2023.
Key provides deposit, lending, cash management, and investment services to individuals and businesses in 15 states under the name KeyBank National Association through a network of approximately 1,000 branches and approximately 1,300 ATMs. Key also provides a broad range of sophisticated corporate and investment banking products, such as merger and acquisition advice, public and private debt and equity, syndications and derivatives to middle market companies in selected industries throughout the United States under the KeyBanc Capital Markets trade name. For more information, visit https://www.key.com/. KeyBank is Member FDIC.
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 10
| CONTACTS: | |||||
| ANALYSTS | MEDIA | ||||
| Vernon L. Patterson | Susan Donlan | ||||
| 216.689.0520 | 216.471.3133 | ||||
| [email protected] | [email protected] | ||||
| Adrienne Atkinson | Beth Strauss | ||||
| 216.689.4030 | 216.471.2787 | ||||
| [email protected] | [email protected] | ||||
| Halle A. Nichols | Twitter: @keybank | ||||
| 216.471.2184 | |||||
| [email protected] | |||||
| INVESTOR RELATIONS: | KEY MEDIA NEWSROOM: | ||||
| www.key.com/ir | www.key.com/newsroom | ||||
| This earnings release contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements do not relate strictly to historical or current facts. Forward-looking statements usually can be identified by the use of words such as “goal,” “objective,” “plan,” “expect,” “assume,” “anticipate,” “intend,” “project,” “believe,” “estimate,” or other words of similar meaning. Forward-looking statements provide our current expectations or forecasts of future events, circumstances, results, or aspirations. Forward-looking statements, by their nature, are subject to assumptions, risks and uncertainties, many of which are outside of our control. Our actual results may differ materially from those set forth in our forward-looking statements. There is no assurance that any list of risks and uncertainties or risk factors is complete. Factors that could cause Key’s actual results to differ from those described in the forward-looking statements can be found in KeyCorp’s Form 10-K for the year ended December 31, 2022, Form 10-Q for the quarter ended March 31, 2023, as well as in KeyCorp’s subsequent SEC filings, all of which have been or will be filed with the Securities and Exchange Commission (the “SEC”) and are or will be available on Key’s website (www.key.com/ir) and on the SEC’s website (www.sec.gov). These factors may include, among others, deterioration of commercial real estate market fundamentals, adverse changes in credit quality trends, declining asset prices, a worsening of the U.S. economy due to financial, political, or other shocks, the extensive regulation of the U.S. financial services industry, the soundness of other financial institutions and the impact of changes in the interest rate environment. Any forward-looking statements made by us or on our behalf speak only as of the date they are made and we do not undertake any obligation to update any forward-looking statement to reflect the impact of subsequent events or circumstances. | ||
Notes to Editors:
A live Internet broadcast of KeyCorp’s conference call to discuss quarterly results and currently anticipated earnings trends and to answer analysts’ questions can be accessed through the Investor Relations section at https://www.key.com/ir at 10:00 a.m. ET, on July 20, 2023. A replay of the call will be available through July 29, 2023.
For up-to-date company information, media contacts, and facts and figures about Key’s lines of business, visit our Media Newsroom at https://www.key.com/newsroom.
*****
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 11
KeyCorp
Second Quarter 2023
Financial Supplement
| Page | |||||
| Basis of Presentation | |||||
| Financial Highlights | |||||
| GAAP to Non-GAAP Reconciliation | |||||
| Consolidated Balance Sheets | |||||
| Consolidated Statements of Income | |||||
| Consolidated Average Balance Sheets, and Net Interest Income and Yields/Rates From Continuing Operations | |||||
| Noninterest Expense | |||||
| Personnel Expense | |||||
| Loan Composition | |||||
| Loans Held for Sale Composition | |||||
| Summary of Changes in Loans Held for Sale | |||||
| Summary of Loan and Lease Loss Experience From Continuing Operations | |||||
| Asset Quality Statistics From Continuing Operations | |||||
| Summary of Nonperforming Assets and Past Due Loans From Continuing Operations | |||||
| Summary of Changes in Nonperforming Loans From Continuing Operations | |||||
| Line of Business Results | |||||
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 12
Basis of Presentation
Use of Non-GAAP Financial Measures
This document contains GAAP financial measures and non-GAAP financial measures where management
believes it to be helpful in understanding Key’s results of operations or financial position. Where non-GAAP financial measures are used, the comparable GAAP financial measure, as well as the reconciliation to the comparable GAAP financial measure, can be found in this document, the financial supplement, or conference call slides related to this document, all of which can be found on Key’s website (www.key.com/ir).
Annualized Data
Certain returns, yields, performance ratios, or quarterly growth rates are presented on an “annualized”
basis. This is done for analytical and decision-making purposes to better discern underlying performance trends when compared to full-year or year-over-year amounts.
Taxable Equivalent
Income from tax-exempt earning assets is increased by an amount equivalent to the taxes that would have been paid if this income had been taxable at the federal statutory rate. This adjustment puts all earning assets, most notably tax-exempt municipal securities, and certain lease assets, on a common basis that facilitates comparison of results to results of peers.
Earnings Per Share Equivalent
Certain income or expense items may be expressed on a per common share basis. This is done for analytical and decision-making purposes to better discern underlying trends in total consolidated earnings per share performance excluding the impact of such items. When the impact of certain income or expense items is disclosed separately, the after-tax amount is computed using the marginal tax rate, with this then being the amount used to calculate the earnings per share equivalent.
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 13
| Financial Highlights | |||||||||||||||||
| (Dollars in millions, except per share amounts) | |||||||||||||||||
| Three months ended | |||||||||||||||||
| 6/30/2023 | 3/31/2023 | 6/30/2022 | |||||||||||||||
| Summary of operations | |||||||||||||||||
| Net interest income (TE) | $ | 986 | $ | 1,106 | $ | 1,104 | |||||||||||
| Noninterest income | 609 | 608 | 688 | ||||||||||||||
Total revenue (TE) | 1,595 | 1,714 | 1,792 | ||||||||||||||
| Provision for credit losses | 167 | 139 | 45 | ||||||||||||||
| Noninterest expense | 1,076 | 1,176 | 1,078 | ||||||||||||||
| Income (loss) from continuing operations attributable to Key | 286 | 311 | 530 | ||||||||||||||
| Income (loss) from discontinued operations, net of taxes | 1 | 1 | 3 | ||||||||||||||
| Net income (loss) attributable to Key | 287 | 312 | 533 | ||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | 250 | 275 | 504 | ||||||||||||||
| Income (loss) from discontinued operations, net of taxes | 1 | 1 | 3 | ||||||||||||||
| Net income (loss) attributable to Key common shareholders | 251 | 276 | 507 | ||||||||||||||
| Per common share | |||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | .27 | $ | .30 | $ | .54 | |||||||||||
| Income (loss) from discontinued operations, net of taxes | — | — | — | ||||||||||||||
Net income (loss) attributable to Key common shareholders (a) | .27 | .30 | .55 | ||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders — assuming dilution | .27 | .30 | .54 | ||||||||||||||
| Income (loss) from discontinued operations, net of taxes — assuming dilution | — | — | — | ||||||||||||||
Net income (loss) attributable to Key common shareholders — assuming dilution (a) | .27 | .30 | .54 | ||||||||||||||
| Cash dividends declared | .205 | .205 | .195 | ||||||||||||||
| Book value at period end | 12.18 | 12.70 | 13.48 | ||||||||||||||
| Tangible book value at period end | 9.16 | 9.67 | 10.40 | ||||||||||||||
| Market price at period end | 9.24 | 12.52 | 17.23 | ||||||||||||||
| Performance ratios | |||||||||||||||||
| From continuing operations: | |||||||||||||||||
| Return on average total assets | .58 | % | .66 | % | 1.16 | % | |||||||||||
| Return on average common equity | 8.42 | 9.85 | 16.17 | ||||||||||||||
Return on average tangible common equity (b) | 11.04 | 13.16 | 20.90 | ||||||||||||||
| Net interest margin (TE) | 2.12 | 2.47 | 2.61 | ||||||||||||||
Cash efficiency ratio (b) | 66.8 | 68.0 | 59.5 | ||||||||||||||
| From consolidated operations: | |||||||||||||||||
| Return on average total assets | .58 | % | .66 | % | 1.16 | % | |||||||||||
| Return on average common equity | 8.45 | 9.89 | 16.27 | ||||||||||||||
Return on average tangible common equity (b) | 11.09 | 13.21 | 21.03 | ||||||||||||||
| Net interest margin (TE) | 2.12 | 2.47 | 2.60 | ||||||||||||||
Loan to deposit (c) | 83.0 | 84.4 | 78.3 | ||||||||||||||
| Capital ratios at period end | |||||||||||||||||
| Key shareholders’ equity to assets | 7.1 | % | 7.3 | % | 7.7 | % | |||||||||||
| Key common shareholders’ equity to assets | 5.8 | 6.0 | 6.7 | ||||||||||||||
Tangible common equity to tangible assets (b) | 4.5 | 4.6 | 5.3 | ||||||||||||||
Common Equity Tier 1 (d) | 9.2 | 9.1 | 9.2 | ||||||||||||||
Tier 1 risk-based capital (d) | 10.7 | 10.6 | 10.4 | ||||||||||||||
Total risk-based capital (d) | 13.0 | 12.8 | 12.0 | ||||||||||||||
Leverage (d) | 8.7 | 8.8 | 8.6 | ||||||||||||||
Asset quality — from continuing operations | |||||||||||||||||
Net loan charge-offs | $ | 52 | $ | 45 | $ | 44 | |||||||||||
Net loan charge-offs to average loans | .17 | % | .15 | % | .16 | % | |||||||||||
Allowance for loan and lease losses | $ | 1,480 | $ | 1,380 | $ | 1,099 | |||||||||||
Allowance for credit losses | 1,771 | 1,656 | 1,272 | ||||||||||||||
Allowance for loan and lease losses to period-end loans | 1.24 | % | 1.15 | % | .98 | % | |||||||||||
Allowance for credit losses to period-end loans | 1.49 | 1.38 | 1.13 | ||||||||||||||
| Allowance for loan and lease losses to nonperforming loans | 343 | 332 | 256 | ||||||||||||||
| Allowance for credit losses to nonperforming loans | 411 | 398 | 297 | ||||||||||||||
| Nonperforming loans at period-end | $ | 431 | $ | 416 | $ | 429 | |||||||||||
| Nonperforming assets at period-end | 462 | 447 | 463 | ||||||||||||||
| Nonperforming loans to period-end portfolio loans | .36 | % | .35 | % | .38 | % | |||||||||||
| Nonperforming assets to period-end portfolio loans plus OREO and other nonperforming assets | .39 | .37 | .41 | ||||||||||||||
Trust assets | |||||||||||||||||
| Assets under management | $ | 53,952 | $ | 53,689 | $ | 49,003 | |||||||||||
Other data | |||||||||||||||||
Average full-time equivalent employees | 17,754 | 18,220 | 17,414 | ||||||||||||||
Branches | 965 | 971 | 978 | ||||||||||||||
Taxable-equivalent adjustment | $ | 8 | $ | 7 | $ | 7 | |||||||||||
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 14
| Financial Highlights (continued) | |||||||||||
| (Dollars in millions, except per share amounts) | |||||||||||
| Six months ended | |||||||||||
| 6/30/2023 | 6/30/2022 | ||||||||||
| Summary of operations | |||||||||||
| Net interest income (TE) | $ | 2,092 | $ | 2,124 | |||||||
| Noninterest income | 1,217 | 1,364 | |||||||||
| Total revenue (TE) | 3,309 | 3,488 | |||||||||
| Provision for credit losses | 306 | 128 | |||||||||
| Noninterest expense | 2,252 | 2,148 | |||||||||
| Income (loss) from continuing operations attributable to Key | 597 | 977 | |||||||||
| Income (loss) from discontinued operations, net of taxes | 2 | 4 | |||||||||
| Net income (loss) attributable to Key | 599 | 981 | |||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | 525 | 924 | |||||||||
| Income (loss) from discontinued operations, net of taxes | 2 | 4 | |||||||||
| Net income (loss) attributable to Key common shareholders | 527 | 928 | |||||||||
| Per common share | |||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | .57 | $ | 1.00 | |||||||
| Income (loss) from discontinued operations, net of taxes | — | — | |||||||||
Net income (loss) attributable to Key common shareholders (a) | .57 | 1.00 | |||||||||
| Income (loss) from continuing operations attributable to Key common shareholders — assuming dilution | .56 | .99 | |||||||||
| Income (loss) from discontinued operations, net of taxes — assuming dilution | — | — | |||||||||
Net income (loss) attributable to Key common shareholders — assuming dilution (a) | .57 | 1.00 | |||||||||
| Cash dividends paid | .41 | .39 | |||||||||
| Performance ratios | |||||||||||
| From continuing operations: | |||||||||||
| Return on average total assets | .62 | % | 1.08 | % | |||||||
| Return on average common equity | 9.11 | 13.62 | |||||||||
Return on average tangible common equity (b) | 12.06 | 17.15 | |||||||||
| Net interest margin (TE) | 2.29 | 2.53 | |||||||||
Cash efficiency ratio (b) | 67.5 | 60.9 | |||||||||
| From consolidated operations: | |||||||||||
| Return on average total assets | .62 | % | 1.08 | % | |||||||
| Return on average common equity | 9.15 | 13.68 | |||||||||
Return on average tangible common equity (b) | 12.10 | 17.23 | |||||||||
| Net interest margin (TE) | 2.29 | 2.53 | |||||||||
| Asset quality — from continuing operations | |||||||||||
| Net loan charge-offs | $ | 97 | $ | 77 | |||||||
| Net loan charge-offs to average total loans | .16 | % | .15 | % | |||||||
| Other data | |||||||||||
| Average full-time equivalent employees | 17,987 | 17,262 | |||||||||
| Taxable-equivalent adjustment | 15 | 13 | |||||||||
(a)Earnings per share may not foot due to rounding.
(b)The following table entitled “GAAP to Non-GAAP Reconciliations” presents the computations of certain financial measures related to “tangible common equity” and “cash efficiency.” The table reconciles the GAAP performance measures to the corresponding non-GAAP measures, which provides a basis for period-to-period comparisons.
(c)Represents period-end consolidated total loans and loans held for sale divided by period-end consolidated total deposits.
(d)June 30, 2023, ratio is estimated and reflects Key's election to adopt the CECL optional transition provision.
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 15
GAAP to Non-GAAP Reconciliations
(Dollars in millions)
The table below presents certain non-GAAP financial measures related to “tangible common equity,” “return on average tangible common equity,” “pre-provision net revenue," and “cash efficiency ratio."
The tangible common equity ratio and the return on average tangible common equity ratio have been a focus for some investors, and management believes these ratios may assist investors in analyzing Key’s capital position without regard to the effects of intangible assets and preferred stock.
The table also shows the computation for pre-provision net revenue, which is not formally defined by GAAP. Management believes that eliminating the effects of the provision for credit losses makes it easier to analyze the results by presenting them on a more comparable basis.
The cash efficiency ratio is a ratio of two non-GAAP performance measures. As such, there is no directly comparable GAAP performance measure. The cash efficiency ratio performance measure removes the impact of Key’s intangible asset amortization from the calculation. Management believes this ratio provides greater consistency and comparability between Key’s results and those of its peer banks. Additionally, this ratio is used by analysts and investors as they develop earnings forecasts and peer bank analysis.
Non-GAAP financial measures have inherent limitations, are not required to be uniformly applied, and are not audited. Although these non-GAAP financial measures are frequently used by investors to evaluate a company, they have limitations as analytical tools, and should not be considered in isolation, or as a substitute for analyses of results as reported under GAAP.
| Three months ended | Six months ended | |||||||||||||||||||
| 6/30/2023 | 3/31/2023 | 6/30/2022 | 6/30/2023 | 6/30/2022 | ||||||||||||||||
| Tangible common equity to tangible assets at period-end | ||||||||||||||||||||
| Key shareholders’ equity (GAAP) | $ | 13,844 | $ | 14,322 | $ | 14,427 | ||||||||||||||
Less: Intangible assets (a) | 2,826 | 2,836 | 2,868 | |||||||||||||||||
Preferred Stock (b) | 2,446 | 2,446 | 1,856 | |||||||||||||||||
| Tangible common equity (non-GAAP) | $ | 8,572 | $ | 9,040 | $ | 9,703 | ||||||||||||||
| Total assets (GAAP) | $ | 195,037 | $ | 197,519 | $ | 187,008 | ||||||||||||||
Less: Intangible assets (a) | 2,826 | 2,836 | 2,868 | |||||||||||||||||
| Tangible assets (non-GAAP) | $ | 192,211 | $ | 194,683 | $ | 184,140 | ||||||||||||||
| Tangible common equity to tangible assets ratio (non-GAAP) | 4.46 | % | 4.64 | % | 5.27 | % | ||||||||||||||
| Pre-provision net revenue | ||||||||||||||||||||
| Net interest income (GAAP) | $ | 978 | $ | 1,099 | $ | 1,097 | $ | 2,077 | $ | 2,111 | ||||||||||
| Plus: Taxable-equivalent adjustment | 8 | 7 | 7 | 15 | 13 | |||||||||||||||
| Noninterest income | 609 | 608 | 688 | 1,217 | 1,364 | |||||||||||||||
| Less: Noninterest expense | 1,076 | 1,176 | 1,078 | 2,252 | 2,148 | |||||||||||||||
| Pre-provision net revenue from continuing operations (non-GAAP) | $ | 519 | $ | 538 | $ | 714 | $ | 1,057 | $ | 1,340 | ||||||||||
| Average tangible common equity | ||||||||||||||||||||
| Average Key shareholders' equity (GAAP) | $ | 14,412 | $ | 13,817 | $ | 14,398 | $ | 14,116 | $ | 15,583 | ||||||||||
Less: Intangible assets (average) (c) | 2,831 | 2,841 | 2,827 | 2,836 | 2,821 | |||||||||||||||
| Preferred stock (average) | 2,500 | 2,500 | 1,900 | 2,500 | 1,900 | |||||||||||||||
| Average tangible common equity (non-GAAP) | $ | 9,081 | $ | 8,476 | $ | 9,671 | $ | 8,780 | $ | 10,862 | ||||||||||
| Return on average tangible common equity from continuing operations | ||||||||||||||||||||
| Net income (loss) from continuing operations attributable to Key common shareholders (GAAP) | $ | 250 | $ | 275 | $ | 504 | $ | 525 | $ | 924 | ||||||||||
| Average tangible common equity (non-GAAP) | 9,081 | 8,476 | 9,671 | 8,780 | 10,862 | |||||||||||||||
| Return on average tangible common equity from continuing operations (non-GAAP) | 11.04 | % | 13.16 | % | 20.90 | % | 12.06 | % | 17.15 | % | ||||||||||
| Return on average tangible common equity consolidated | ||||||||||||||||||||
| Net income (loss) attributable to Key common shareholders (GAAP) | $ | 251 | $ | 276 | $ | 507 | $ | 527 | $ | 928 | ||||||||||
| Average tangible common equity (non-GAAP) | 9,081 | 8,476 | 9,671 | 8,780 | 10,862 | |||||||||||||||
| Return on average tangible common equity consolidated (non-GAAP) | 11.09 | % | 13.21 | % | 21.03 | % | 12.10 | % | 17.23 | % | ||||||||||
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 16
| GAAP to Non-GAAP Reconciliations (continued) | ||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||
| Three months ended | Six months ended | |||||||||||||||||||
| 6/30/2023 | 3/31/2023 | 6/30/2022 | 6/30/2023 | 6/30/2022 | ||||||||||||||||
| Cash efficiency ratio | ||||||||||||||||||||
| Noninterest expense (GAAP) | $ | 1,076 | $ | 1,176 | $ | 1,078 | $ | 2,252 | $ | 2,148 | ||||||||||
| Less: Intangible asset amortization | 10 | 10 | 12 | 20 | 23 | |||||||||||||||
| Adjusted noninterest expense (non-GAAP) | $ | 1,066 | $ | 1,166 | $ | 1,066 | $ | 2,232 | $ | 2,125 | ||||||||||
| Net interest income (GAAP) | $ | 978 | $ | 1,099 | $ | 1,097 | $ | 2,077 | $ | 2,111 | ||||||||||
| Plus: Taxable-equivalent adjustment | 8 | 7 | 7 | 15 | 13 | |||||||||||||||
| Noninterest income | 609 | 608 | 688 | 1,217 | 1,364 | |||||||||||||||
| Total taxable-equivalent revenue (non-GAAP) | $ | 1,595 | $ | 1,714 | $ | 1,792 | $ | 3,309 | $ | 3,488 | ||||||||||
| Cash efficiency ratio (non-GAAP) | 66.8 | % | 68.0 | % | 59.5 | % | 67.5 | % | 60.9 | % | ||||||||||
(a)For the three months ended June 30, 2023, March 31, 2023, and June 30, 2022, intangible assets exclude $1 million, $1 million, and $2 million, respectively, of period-end purchased credit card receivables.
(b)Net of capital surplus.
(c)For the three months ended June 30, 2023, March 31, 2023, and June 30, 2022, average intangible assets exclude $1 million, $1 million, and $2 million, respectively, of average purchased credit card receivables.
GAAP = U.S. generally accepted accounting principles
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 17
| Consolidated Balance Sheets | |||||||||||||||||
| (Dollars in millions) | |||||||||||||||||
| 6/30/2023 | 3/31/2023 | 6/30/2022 | |||||||||||||||
| Assets | |||||||||||||||||
| Loans | $ | 119,011 | $ | 119,971 | $ | 112,390 | |||||||||||
| Loans held for sale | 1,130 | 1,211 | 1,306 | ||||||||||||||
| Securities available for sale | 37,908 | 39,498 | 42,437 | ||||||||||||||
| Held-to-maturity securities | 9,189 | 9,561 | 8,186 | ||||||||||||||
| Trading account assets | 1,177 | 1,118 | 809 | ||||||||||||||
| Short-term investments | 8,959 | 8,410 | 2,456 | ||||||||||||||
| Other investments | 1,474 | 1,587 | 969 | ||||||||||||||
| Total earning assets | 178,848 | 181,356 | 168,553 | ||||||||||||||
| Allowance for loan and lease losses | (1,480) | (1,380) | (1,099) | ||||||||||||||
| Cash and due from banks | 758 | 784 | 678 | ||||||||||||||
| Premises and equipment | 652 | 628 | 638 | ||||||||||||||
| Goodwill | 2,752 | 2,752 | 2,752 | ||||||||||||||
| Other intangible assets | 75 | 85 | 118 | ||||||||||||||
| Corporate-owned life insurance | 4,378 | 4,372 | 4,343 | ||||||||||||||
| Accrued income and other assets | 8,668 | 8,512 | 10,529 | ||||||||||||||
| Discontinued assets | 386 | 410 | 496 | ||||||||||||||
| Total assets | $ | 195,037 | $ | 197,519 | $ | 187,008 | |||||||||||
| Liabilities | |||||||||||||||||
| Deposits in domestic offices: | |||||||||||||||||
| Interest-bearing deposits | 111,766 | 106,841 | 94,892 | ||||||||||||||
| Noninterest-bearing deposits | 33,366 | 37,307 | 50,973 | ||||||||||||||
| Total deposits | 145,132 | 144,148 | 145,865 | ||||||||||||||
| Federal funds purchased and securities sold under repurchase agreements | 1,702 | 1,374 | 3,234 | ||||||||||||||
| Bank notes and other short-term borrowings | 6,949 | 10,061 | 2,809 | ||||||||||||||
| Accrued expense and other liabilities | 5,339 | 4,861 | 4,056 | ||||||||||||||
| Long-term debt | 22,071 | 22,753 | 16,617 | ||||||||||||||
| Total liabilities | 181,193 | 183,197 | 172,581 | ||||||||||||||
| Equity | |||||||||||||||||
| Preferred stock | 2,500 | 2,500 | 1,900 | ||||||||||||||
| Common shares | 1,257 | 1,257 | 1,257 | ||||||||||||||
| Capital surplus | 6,231 | 6,207 | 6,241 | ||||||||||||||
| Retained earnings | 15,759 | 15,700 | 15,118 | ||||||||||||||
| Treasury stock, at cost | (5,859) | (5,868) | (5,923) | ||||||||||||||
| Accumulated other comprehensive income (loss) | (6,044) | (5,474) | (4,166) | ||||||||||||||
| Key shareholders’ equity | 13,844 | 14,322 | 14,427 | ||||||||||||||
| Total liabilities and equity | $ | 195,037 | $ | 197,519 | $ | 187,008 | |||||||||||
| Common shares outstanding (000) | 935,733 | 935,229 | 932,643 | ||||||||||||||
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 18
| Consolidated Statements of Income | ||||||||||||||||||||||||||
| (Dollars in millions, except per share amounts) | ||||||||||||||||||||||||||
Three months ended | Six months ended | |||||||||||||||||||||||||
| 6/30/2023 | 3/31/2023 | 6/30/2022 | 6/30/2023 | 6/30/2022 | ||||||||||||||||||||||
| Interest income | ||||||||||||||||||||||||||
| Loans | $ | 1,576 | $ | 1,476 | $ | 923 | $ | 3,052 | $ | 1,760 | ||||||||||||||||
| Loans held for sale | 17 | 13 | 10 | 30 | 22 | |||||||||||||||||||||
| Securities available for sale | 194 | 194 | 188 | 388 | 361 | |||||||||||||||||||||
| Held-to-maturity securities | 81 | 74 | 48 | 155 | 94 | |||||||||||||||||||||
| Trading account assets | 15 | 12 | 7 | 27 | 13 | |||||||||||||||||||||
| Short-term investments | 111 | 42 | 13 | 153 | 17 | |||||||||||||||||||||
| Other investments | 16 | 13 | 4 | 29 | 6 | |||||||||||||||||||||
| Total interest income | 2,010 | 1,824 | 1,193 | 3,834 | 2,273 | |||||||||||||||||||||
| Interest expense | ||||||||||||||||||||||||||
| Deposits | 531 | 350 | 20 | 881 | 34 | |||||||||||||||||||||
| Federal funds purchased and securities sold under repurchase agreements | 48 | 22 | 6 | 70 | 6 | |||||||||||||||||||||
| Bank notes and other short-term borrowings | 104 | 78 | 9 | 182 | 12 | |||||||||||||||||||||
| Long-term debt | 349 | 275 | 61 | 624 | 110 | |||||||||||||||||||||
| Total interest expense | 1,032 | 725 | 96 | 1,757 | 162 | |||||||||||||||||||||
| Net interest income | 978 | 1,099 | 1,097 | 2,077 | 2,111 | |||||||||||||||||||||
| Provision for credit losses | 167 | 139 | 45 | 306 | 128 | |||||||||||||||||||||
| Net interest income after provision for credit losses | 811 | 960 | 1,052 | 1,771 | 1,983 | |||||||||||||||||||||
| Noninterest income | ||||||||||||||||||||||||||
| Trust and investment services income | 126 | 128 | 137 | 254 | 273 | |||||||||||||||||||||
| Investment banking and debt placement fees | 120 | 145 | 149 | 265 | 312 | |||||||||||||||||||||
| Cards and payments income | 85 | 81 | 85 | 166 | 165 | |||||||||||||||||||||
| Service charges on deposit accounts | 69 | 67 | 96 | 136 | 187 | |||||||||||||||||||||
| Corporate services income | 86 | 76 | 96 | 162 | 187 | |||||||||||||||||||||
| Commercial mortgage servicing fees | 50 | 46 | 45 | 96 | 81 | |||||||||||||||||||||
| Corporate-owned life insurance income | 32 | 29 | 35 | 61 | 66 | |||||||||||||||||||||
| Consumer mortgage income | 14 | 11 | 14 | 25 | 35 | |||||||||||||||||||||
| Operating lease income and other leasing gains | 23 | 25 | 28 | 48 | 60 | |||||||||||||||||||||
| Other income | 4 | — | 3 | 4 | (2) | |||||||||||||||||||||
| Total noninterest income | 609 | 608 | 688 | 1,217 | 1,364 | |||||||||||||||||||||
| Noninterest expense | ||||||||||||||||||||||||||
| Personnel | 622 | 701 | 607 | 1,323 | 1,237 | |||||||||||||||||||||
| Net occupancy | 65 | 70 | 78 | 135 | 151 | |||||||||||||||||||||
| Computer processing | 95 | 92 | 78 | 187 | 155 | |||||||||||||||||||||
| Business services and professional fees | 41 | 45 | 52 | 86 | 105 | |||||||||||||||||||||
| Equipment | 22 | 22 | 26 | 44 | 49 | |||||||||||||||||||||
| Operating lease expense | 21 | 20 | 27 | 41 | 55 | |||||||||||||||||||||
| Marketing | 29 | 21 | 34 | 50 | 62 | |||||||||||||||||||||
| Other expense | 181 | 205 | 176 | 386 | 334 | |||||||||||||||||||||
| Total noninterest expense | 1,076 | 1,176 | 1,078 | 2,252 | 2,148 | |||||||||||||||||||||
| Income (loss) from continuing operations before income taxes | 344 | 392 | 662 | 736 | 1,199 | |||||||||||||||||||||
| Income taxes | 58 | 81 | 132 | 139 | 222 | |||||||||||||||||||||
| Income (loss) from continuing operations | 286 | 311 | 530 | 597 | 977 | |||||||||||||||||||||
| Income (loss) from discontinued operations, net of taxes | 1 | 1 | 3 | 2 | 4 | |||||||||||||||||||||
| Net income (loss) | 287 | 312 | 533 | 599 | 981 | |||||||||||||||||||||
| Net income (loss) attributable to Key | $ | 287 | $ | 312 | $ | 533 | $ | 599 | 981 | |||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | 250 | $ | 275 | $ | 504 | $ | 525 | $ | 924 | ||||||||||||||||
| Net income (loss) attributable to Key common shareholders | 251 | 276 | 507 | 527 | 928 | |||||||||||||||||||||
| Per common share | ||||||||||||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | .27 | $ | .30 | $ | .54 | $ | .57 | $ | 1.00 | ||||||||||||||||
| Income (loss) from discontinued operations, net of taxes | — | — | — | — | — | |||||||||||||||||||||
Net income (loss) attributable to Key common shareholders (a) | .27 | .30 | .55 | .57 | 1.00 | |||||||||||||||||||||
| Per common share — assuming dilution | ||||||||||||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | .27 | $ | .30 | $ | .54 | $ | .56 | $ | .99 | ||||||||||||||||
| Income (loss) from discontinued operations, net of taxes | — | — | — | — | — | |||||||||||||||||||||
Net income (loss) attributable to Key common shareholders (a) | .27 | .30 | .54 | .57 | 1.00 | |||||||||||||||||||||
| Cash dividends declared per common share | $ | .205 | $ | .205 | $ | .195 | $ | .410 | $ | .390 | ||||||||||||||||
| Weighted-average common shares outstanding (000) | 926,741 | 926,490 | 924,302 | 926,807 | 923,717 | |||||||||||||||||||||
| Effect of common share options and other stock awards | 3,713 | 7,314 | 7,506 | 5,513 | 9,087 | |||||||||||||||||||||
Weighted-average common shares and potential common shares outstanding (000) (b) | 930,454 | 933,804 | 931,808 | 932,320 | 932,805 | |||||||||||||||||||||
(a)Earnings per share may not foot due to rounding.
(b)Assumes conversion of common share options and other stock awards, as applicable.
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 19
| Consolidated Average Balance Sheets, and Net Interest Income and Yields/Rates From Continuing Operations | ||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||
| Second Quarter 2023 | First Quarter 2023 | Second Quarter 2022 | ||||||||||||||||||||||||||||||||||||
| Average | Yield/ | Average | Yield/ | Average | Yield/ | |||||||||||||||||||||||||||||||||
| Balance | Interest (a) | Rate (a) | Balance | Interest (a) | Rate (a) | Balance | Interest (a) | Rate (a) | ||||||||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||||||||||||||
Loans: (b), (c) | ||||||||||||||||||||||||||||||||||||||
Commercial and industrial (d) | $ | 61,426 | $ | 881 | 5.76 | % | $ | 60,281 | $ | 807 | 5.42 | % | $ | 53,858 | $ | 449 | 3.34 | % | ||||||||||||||||||||
| Real estate — commercial mortgage | 16,226 | 235 | 5.80 | 16,470 | 224 | 5.52 | 15,231 | 136 | 3.58 | |||||||||||||||||||||||||||||
| Real estate — construction | 2,641 | 44 | 6.64 | 2,525 | 39 | 6.30 | 2,125 | 20 | 3.81 | |||||||||||||||||||||||||||||
| Commercial lease financing | 3,756 | 29 | 3.07 | 3,783 | 27 | 2.87 | 3,817 | 24 | 2.47 | |||||||||||||||||||||||||||||
| Total commercial loans | 84,049 | 1,189 | 5.67 | 83,059 | 1,097 | 5.35 | 75,031 | 629 | 3.36 | |||||||||||||||||||||||||||||
| Real estate — residential mortgage | 21,659 | 176 | 3.25 | 21,436 | 172 | 3.21 | 18,383 | 131 | 2.85 | |||||||||||||||||||||||||||||
| Home equity loans | 7,620 | 109 | 5.75 | 7,879 | 106 | 5.47 | 8,208 | 78 | 3.83 | |||||||||||||||||||||||||||||
| Consumer direct loans | 6,323 | 77 | 4.89 | 6,439 | 75 | 4.71 | 6,514 | 68 | 4.19 | |||||||||||||||||||||||||||||
| Credit cards | 984 | 33 | 13.49 | 983 | 32 | 13.37 | 943 | 24 | 10.20 | |||||||||||||||||||||||||||||
| Consumer indirect loans | 37 | — | — | 41 | 1 | 1.24 | 59 | — | — | |||||||||||||||||||||||||||||
| Total consumer loans | 36,623 | 395 | 4.33 | 36,778 | 386 | 4.23 | 34,107 | 301 | 3.53 | |||||||||||||||||||||||||||||
| Total loans | 120,672 | 1,584 | 5.26 | 119,837 | 1,483 | 5.01 | 109,138 | 930 | 3.41 | |||||||||||||||||||||||||||||
| Loans held for sale | 1,087 | 17 | 6.16 | 907 | 13 | 5.86 | 1,107 | 10 | 3.49 | |||||||||||||||||||||||||||||
Securities available for sale (b), (e) | 38,899 | 194 | 1.74 | 39,172 | 194 | 1.72 | 43,023 | 188 | 1.60 | |||||||||||||||||||||||||||||
Held-to-maturity securities (b) | 9,371 | 81 | 3.47 | 8,931 | 74 | 3.32 | 7,291 | 48 | 2.65 | |||||||||||||||||||||||||||||
| Trading account assets | 1,244 | 15 | 4.64 | 1,001 | 12 | 4.86 | 854 | 7 | 3.45 | |||||||||||||||||||||||||||||
| Short-term investments | 7,798 | 111 | 5.73 | 3,532 | 42 | 4.80 | 3,591 | 13 | 1.45 | |||||||||||||||||||||||||||||
Other investments (e) | 1,566 | 16 | 4.03 | 1,309 | 13 | 4.01 | 800 | 4 | 2.27 | |||||||||||||||||||||||||||||
| Total earning assets | 180,637 | 2,018 | 4.34 | 174,689 | 1,831 | 4.09 | 165,804 | 1,200 | 2.83 | |||||||||||||||||||||||||||||
| Allowance for loan and lease losses | (1,379) | (1,336) | (1,103) | |||||||||||||||||||||||||||||||||||
| Accrued income and other assets | 17,202 | 17,498 | 18,826 | |||||||||||||||||||||||||||||||||||
| Discontinued assets | 394 | 419 | 505 | |||||||||||||||||||||||||||||||||||
| Total assets | $ | 196,854 | $ | 191,270 | $ | 184,032 | ||||||||||||||||||||||||||||||||
| Liabilities | ||||||||||||||||||||||||||||||||||||||
| Money market deposits | $ | 32,419 | $ | 123 | 1.53 | % | $ | 33,853 | $ | 78 | .94 | % | $ | 36,362 | $ | 5 | .05 | % | ||||||||||||||||||||
| Demand deposits | 53,569 | 256 | 1.91 | 52,365 | 183 | 1.42 | 49,027 | 13 | .11 | |||||||||||||||||||||||||||||
| Savings deposits | 6,592 | 1 | .04 | 7,346 | 1 | .03 | 7,891 | — | .01 | |||||||||||||||||||||||||||||
| Certificates of deposit ($100,000 or more) | 3,851 | 33 | 3.48 | 2,392 | 16 | 2.64 | 1,487 | 1 | .44 | |||||||||||||||||||||||||||||
| Other time deposits | 11,365 | 118 | 4.17 | 8,106 | 72 | 3.61 | 1,972 | 1 | .13 | |||||||||||||||||||||||||||||
| Total interest-bearing deposits | 107,796 | 531 | 1.98 | 104,062 | 350 | 1.36 | 96,739 | 20 | .08 | |||||||||||||||||||||||||||||
| Federal funds purchased and securities sold under repurchase agreements | 3,767 | 48 | 5.07 | 2,087 | 22 | 4.34 | 2,792 | 6 | .88 | |||||||||||||||||||||||||||||
| Bank notes and other short-term borrowings | 7,982 | 104 | 5.22 | 6,597 | 78 | 4.80 | 1,943 | 9 | 1.77 | |||||||||||||||||||||||||||||
Long-term debt (f), (g) | 22,284 | 349 | 6.26 | 20,141 | 275 | 5.47 | 12,662 | 61 | 1.92 | |||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 141,829 | 1,032 | 2.91 | 132,887 | 725 | 2.20 | 114,136 | 96 | .34 | |||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 35,107 | 39,343 | 50,732 | |||||||||||||||||||||||||||||||||||
| Accrued expense and other liabilities | 5,112 | 4,804 | 4,261 | |||||||||||||||||||||||||||||||||||
Discontinued liabilities (g) | 394 | 419 | 505 | |||||||||||||||||||||||||||||||||||
| Total liabilities | $ | 182,442 | $ | 177,453 | $ | 169,634 | ||||||||||||||||||||||||||||||||
| Equity | ||||||||||||||||||||||||||||||||||||||
| Key shareholders’ equity | $ | 14,412 | $ | 13,817 | $ | 14,398 | ||||||||||||||||||||||||||||||||
| Noncontrolling interests | — | — | — | |||||||||||||||||||||||||||||||||||
| Total equity | 14,412 | 13,817 | 14,398 | |||||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 196,854 | $ | 191,270 | $ | 184,032 | ||||||||||||||||||||||||||||||||
| Interest rate spread (TE) | 1.43 | % | 1.89 | % | 2.50 | % | ||||||||||||||||||||||||||||||||
| Net interest income (TE) and net interest margin (TE) | $ | 986 | 2.12 | % | $ | 1,106 | 2.47 | % | $ | 1,104 | 2.61 | % | ||||||||||||||||||||||||||
TE adjustment (b) | 8 | 7 | 7 | |||||||||||||||||||||||||||||||||||
| Net interest income, GAAP basis | $ | 978 | $ | 1,099 | $ | 1,097 | ||||||||||||||||||||||||||||||||
(a)Results are from continuing operations. Interest excludes the interest associated with the liabilities referred to in (g) below, calculated using a matched funds transfer pricing methodology.
(b)Interest income on tax-exempt securities and loans has been adjusted to a taxable-equivalent basis using the statutory federal income tax rate of 21% for the three months ended June 30, 2023, March 31, 2023, and June 30, 2022.
(c)For purposes of these computations, nonaccrual loans are included in average loan balances.
(d)Commercial and industrial average balances include $194 million, $178 million, and $153 million of assets from commercial credit cards for the three months ended June 30, 2023, March 31, 2023, and June 30, 2022, respectively.
(e)Yield is calculated on the basis of amortized cost.
(f)Rate calculation excludes basis adjustments related to fair value hedges.
(g)A portion of long-term debt and the related interest expense is allocated to discontinued liabilities as a result of applying Key’s matched funds transfer pricing methodology to discontinued operations.
TE = Taxable Equivalent, GAAP = U.S. generally accepted accounting principles
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 20
| Consolidated Average Balance Sheets, and Net Interest Income and Yields/Rates From Continuing Operations | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| Six months ended June 30, 2023 | Six months ended June 30, 2022 | ||||||||||||||||||||||||||||
| Average | Yield/ | Average | Yield/ | ||||||||||||||||||||||||||
| Balance | Interest (a) | Rate (a) | Balance | Interest (a) | Rate (a) | ||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||
Loans: (b), (c) | |||||||||||||||||||||||||||||
Commercial and industrial (d) | $ | 60,857 | $ | 1,688 | 5.59 | % | $ | 52,723 | $ | 858 | 3.28 | % | |||||||||||||||||
| Real estate — commercial mortgage | 16,347 | 459 | 5.66 | 14,910 | 257 | 3.48 | |||||||||||||||||||||||
| Real estate — construction | 2,583 | 83 | 6.47 | 2,076 | 37 | 3.60 | |||||||||||||||||||||||
| Commercial lease financing | 3,770 | 56 | 2.97 | 3,879 | 48 | 2.44 | |||||||||||||||||||||||
| Total commercial loans | 83,557 | 2,286 | 5.51 | 73,588 | 1,200 | 3.28 | |||||||||||||||||||||||
| Real estate — residential mortgage | 21,548 | 348 | 3.23 | 17,352 | 243 | 2.80 | |||||||||||||||||||||||
| Home equity loans | 7,749 | 215 | 5.61 | 8,276 | 153 | 3.72 | |||||||||||||||||||||||
| Consumer direct loans | 6,380 | 152 | 4.80 | 6,236 | 129 | 4.18 | |||||||||||||||||||||||
| Credit cards | 984 | 65 | 13.43 | 938 | 48 | 10.28 | |||||||||||||||||||||||
| Consumer indirect loans | 39 | 1 | 0.60 | 75 | — | — | |||||||||||||||||||||||
| Total consumer loans | 36,700 | 781 | 4.28 | 32,877 | 573 | 3.49 | |||||||||||||||||||||||
| Total loans | 120,257 | 3,067 | 5.14 | 106,465 | 1,773 | 3.35 | |||||||||||||||||||||||
| Loans held for sale | 997 | 30 | 6.02 | 1,295 | 22 | 3.40 | |||||||||||||||||||||||
Securities available for sale (b), (e) | 39,034 | 388 | 1.73 | 43,968 | 361 | 1.55 | |||||||||||||||||||||||
Held-to-maturity securities (b) | 9,152 | 155 | 3.40 | 7,239 | 94 | 2.59 | |||||||||||||||||||||||
| Trading account assets | 1123 | 27 | 4.74 | 848 | 13 | 3.10 | |||||||||||||||||||||||
| Short-term investments | 5,677 | 153 | 5.44 | 5,447 | 17 | .65 | |||||||||||||||||||||||
Other investments (e) | 1,438 | 29 | 4.02 | 726 | 6 | 1.82 | |||||||||||||||||||||||
| Total earning assets | 177,678 | 3,849 | 4.22 | 165,988 | 2,286 | 2.72 | |||||||||||||||||||||||
| Allowance for loan and lease losses | (1,357) | (1,080) | |||||||||||||||||||||||||||
| Accrued income and other assets | 17,351 | 18,152 | |||||||||||||||||||||||||||
| Discontinued assets | 406 | 522 | |||||||||||||||||||||||||||
| Total assets | $ | 194,078 | $ | 183,582 | |||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||
| Money market deposits | $ | 33,110 | $ | 201 | 1.23 | 36,795 | $ | 9 | .05 | ||||||||||||||||||||
| Other demand deposits | 52,993 | 440 | 1.67 | 50,148 | 20 | .08 | |||||||||||||||||||||||
| Savings deposits | 6,967 | 1 | .04 | 7,746 | 1 | .01 | |||||||||||||||||||||||
| Certificates of deposit ($100,000 or more) | 3,125 | 49 | 3.16 | 1,562 | 3 | .44 | |||||||||||||||||||||||
| Other time deposits | 9,745 | 190 | 3.94 | 2,035 | 1 | .14 | |||||||||||||||||||||||
| Total interest-bearing deposits | 105,940 | 881 | 1.68 | 98,286 | 34 | .07 | |||||||||||||||||||||||
| Federal funds purchased and securities sold under repurchase agreements | 2,932 | 70 | 4.81 | 1,547 | 6 | .81 | |||||||||||||||||||||||
| Bank notes and other short-term borrowings | 7,293 | 182 | 5.03 | 1,327 | 12 | 1.82 | |||||||||||||||||||||||
Long-term debt (f), (g) | 21,218 | 624 | 5.88 | 11,751 | 110 | 1.86 | |||||||||||||||||||||||
| Total interest-bearing liabilities | 137,383 | 1,757 | 2.57 | 112,911 | 162 | .29 | |||||||||||||||||||||||
| Noninterest-bearing deposits | 37,213 | 50,523 | |||||||||||||||||||||||||||
| Accrued expense and other liabilities | 4,960 | 4,043 | |||||||||||||||||||||||||||
Discontinued liabilities (g) | 406 | 522 | |||||||||||||||||||||||||||
| Total liabilities | $ | 179,962 | $ | 167,999 | |||||||||||||||||||||||||
| Equity | |||||||||||||||||||||||||||||
| Key shareholders’ equity | $ | 14,116 | $ | 15,583 | |||||||||||||||||||||||||
| Noncontrolling interests | — | — | |||||||||||||||||||||||||||
| Total equity | 14,116 | 15,583 | |||||||||||||||||||||||||||
| Total liabilities and equity | $ | 194,078 | $ | 183,582 | |||||||||||||||||||||||||
| Interest rate spread (TE) | 1.65 | % | 2.44 | % | |||||||||||||||||||||||||
| Net interest income (TE) and net interest margin (TE) | $ | 2,092 | 2.29 | % | $ | 2,124 | 2.53 | % | |||||||||||||||||||||
TE adjustment (b) | 15 | 13 | |||||||||||||||||||||||||||
| Net interest income, GAAP basis | $ | 2,077 | $ | 2,111 | |||||||||||||||||||||||||
(a)Results are from continuing operations. Interest excludes the interest associated with the liabilities referred to in (g) below, calculated using a matched funds transfer pricing methodology.
(b)Interest income on tax-exempt securities and loans has been adjusted to a taxable-equivalent basis using the statutory federal income tax rate of 21% for the six months ended June 30, 2023, and June 30, 2022, respectively.
(c)For purposes of these computations, nonaccrual loans are included in average loan balances.
(d)Commercial and industrial average balances include $186 million and $147 million of assets from commercial credit cards for the six months ended June 30, 2023, and June 30, 2022, respectively.
(e)Yield is calculated on the basis of amortized cost.
(f)Rate calculation excludes basis adjustments related to fair value hedges.
(g)A portion of long-term debt and the related interest expense is allocated to discontinued liabilities as a result of applying Key’s matched funds transfer pricing methodology to discontinued operations.
TE = Taxable Equivalent, GAAP = U.S. generally accepted accounting principles
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 21
| Noninterest Expense | ||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||
| Three months ended | Six months ended | |||||||||||||||||||
| 6/30/2023 | 3/31/2023 | 6/30/2022 | 6/30/2023 | 6/30/2022 | ||||||||||||||||
Personnel (a) | $ | 622 | $ | 701 | $ | 607 | $ | 1,323 | $ | 1,237 | ||||||||||
| Net occupancy | 65 | 70 | 78 | 135 | 151 | |||||||||||||||
| Computer processing | 95 | 92 | 78 | 187 | 155 | |||||||||||||||
| Business services and professional fees | 41 | 45 | 52 | 86 | 105 | |||||||||||||||
| Equipment | 22 | 22 | 26 | 44 | 49 | |||||||||||||||
| Operating lease expense | 21 | 20 | 27 | 41 | 55 | |||||||||||||||
| Marketing | 29 | 21 | 34 | 50 | 62 | |||||||||||||||
| Other expense | 181 | 205 | 176 | 386 | 334 | |||||||||||||||
| Total noninterest expense | $ | 1,076 | $ | 1,176 | $ | 1,078 | $ | 2,252 | $ | 2,148 | ||||||||||
Average full-time equivalent employees (b) | 17,754 | 18,220 | 17,414 | 17,987 | 17,262 | |||||||||||||||
(a)Additional detail provided in Personnel Expense table below.
(b)The number of average full-time equivalent employees has not been adjusted for discontinued operations.
| Personnel Expense | |||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||
| Three months ended | Six months ended | ||||||||||||||||||||||
| 6/30/2023 | 3/31/2023 | 6/30/2022 | 6/30/2023 | 6/30/2022 | |||||||||||||||||||
| Salaries and contract labor | $ | 416 | $ | 419 | $ | 357 | $ | 835 | $ | 705 | |||||||||||||
| Incentive and stock-based compensation | 93 | 152 | 163 | 245 | 346 | ||||||||||||||||||
| Employee benefits | 103 | 99 | 83 | 202 | 180 | ||||||||||||||||||
| Severance | 10 | 31 | 4 | 41 | 6 | ||||||||||||||||||
| Total personnel expense | $ | 622 | $ | 701 | $ | 607 | $ | 1,323 | $ | 1,237 | |||||||||||||
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 22
| Loan Composition | ||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||
| Change 6/30/2023 vs. | ||||||||||||||||||||
| 6/30/2023 | 3/31/2023 | 6/30/2022 | 3/31/2023 | 6/30/2022 | ||||||||||||||||
Commercial and industrial (a) | $ | 60,059 | $ | 60,565 | $ | 55,245 | (.8) | % | 8.7 | % | ||||||||||
| Commercial real estate: | ||||||||||||||||||||
| Commercial mortgage | 16,048 | 16,348 | 15,636 | (1.8) | 2.6 | |||||||||||||||
| Construction | 2,646 | 2,590 | 2,144 | 2.2 | 23.4 | |||||||||||||||
| Total commercial real estate loans | 18,694 | 18,938 | 17,780 | (1.3) | 5.1 | |||||||||||||||
Commercial lease financing (b) | 3,801 | 3,763 | 3,956 | 1.0 | (3.9) | |||||||||||||||
| Total commercial loans | 82,554 | 83,266 | 76,981 | (.9) | 7.2 | |||||||||||||||
| Residential — prime loans: | ||||||||||||||||||||
| Real estate — residential mortgage | 21,637 | 21,632 | 19,588 | — | 10.5 | |||||||||||||||
| Home equity loans | 7,529 | 7,706 | 8,134 | (2.3) | (7.4) | |||||||||||||||
| Total residential — prime loans | 29,166 | 29,338 | 27,722 | (.6) | 5.2 | |||||||||||||||
| Consumer direct loans | 6,257 | 6,359 | 6,665 | (1.6) | (6.1) | |||||||||||||||
| Credit cards | 1,001 | 969 | 967 | 3.3 | 3.5 | |||||||||||||||
| Consumer indirect loans | 33 | 39 | 55 | (15.4) | (40.0) | |||||||||||||||
| Total consumer loans | 36,457 | 36,705 | 35,409 | (.7) | 3.0 | |||||||||||||||
Total loans (c), (d) | $ | 119,011 | $ | 119,971 | $ | 112,390 | (.8) | % | 5.9 | % | ||||||||||
(a)Loan balances include $200 million, $185 million, and $161 million of commercial credit card balances at June 30, 2023, March 31, 2023, and June 30, 2022, respectively.
(b)Commercial lease financing includes receivables held as collateral for a secured borrowing of $5 million, $6 million, and $12 million at June 30, 2023, March 31, 2023, and June 30, 2022, respectively. Principal reductions are based on the cash payments received from these related receivables.
(c)Total loans exclude loans of $381 million at June 30, 2023, $407 million at March 31, 2023, and $498 million at June 30, 2022, related to the discontinued operations of the education lending business.
(d)Accrued interest of $500 million, $487 million, and $233 million at June 30, 2023, March 31, 2023, and June 30, 2022, respectively, presented in "other assets" on the Consolidated Balance Sheets is excluded from the amortized cost basis disclosed in this table.
| Loans Held for Sale Composition | ||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||
| Change 6/30/2023 vs. | ||||||||||||||||||||
| 6/30/2023 | 3/31/2023 | 6/30/2022 | 3/31/2023 | 6/30/2022 | ||||||||||||||||
| Commercial and industrial | $ | 221 | $ | 351 | $ | 213 | (37.0) | % | 3.8 | % | ||||||||||
| Real estate — commercial mortgage | 829 | 815 | 1,004 | 1.7 | (17.4) | |||||||||||||||
| Real estate — construction | — | — | 6 | — | (100.0) | |||||||||||||||
| Commercial lease financing | 13 | — | — | N/M | N/M | |||||||||||||||
| Real estate — residential mortgage | 67 | 45 | 83 | 48.9 | (19.3) | |||||||||||||||
| Total loans held for sale | $ | 1,130 | $ | 1,211 | $ | 1,306 | (6.7) | % | (13.5) | % | ||||||||||
N/M = Not Meaningful
| Summary of Changes in Loans Held for Sale | |||||||||||||||||
| (Dollars in millions) | |||||||||||||||||
| 2Q23 | 1Q23 | 4Q22 | 3Q22 | 2Q22 | |||||||||||||
| Balance at beginning of period | $ | 1,211 | $ | 963 | $ | 1,048 | $ | 1,306 | $ | 1,170 | |||||||
| New originations | 1,798 | 1,779 | 3,158 | 2,157 | 2,837 | ||||||||||||
| Transfers from (to) held to maturity, net | (52) | (13) | (48) | — | (57) | ||||||||||||
| Loan sales | (1,798) | (1,518) | (3,124) | (2,446) | (2,506) | ||||||||||||
| Loan draws (payments), net | (28) | — | (71) | 26 | (133) | ||||||||||||
| Valuation and other adjustments | (1) | — | — | 5 | (5) | ||||||||||||
| Balance at end of period | $ | 1,130 | $ | 1,211 | $ | 963 | $ | 1,048 | $ | 1,306 | |||||||
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 23
| Summary of Loan and Lease Loss Experience From Continuing Operations | ||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||
| Three months ended | Six months ended | |||||||||||||||||||
| 6/30/2023 | 3/31/2023 | 6/30/2022 | 6/30/2023 | 6/30/2022 | ||||||||||||||||
| Average loans outstanding | $ | 120,672 | $ | 119,837 | $ | 109,138 | $ | 120,257 | $ | 106,465 | ||||||||||
| Allowance for loan and lease losses at the beginning of the period | 1,380 | 1,337 | 1,105 | 1,337 | 1,061 | |||||||||||||||
| Loans charged off: | ||||||||||||||||||||
| Commercial and industrial | 42 | 35 | 39 | 77 | 69 | |||||||||||||||
| Real estate — commercial mortgage | 9 | 5 | 3 | 14 | 7 | |||||||||||||||
| Real estate — construction | — | — | — | — | — | |||||||||||||||
| Total commercial real estate loans | 9 | 5 | 3 | 14 | 7 | |||||||||||||||
| Commercial lease financing | 1 | (1) | — | — | 2 | |||||||||||||||
| Total commercial loans | 52 | 39 | 42 | 91 | 78 | |||||||||||||||
| Real estate — residential mortgage | 1 | — | (2) | 1 | (3) | |||||||||||||||
| Home equity loans | 2 | 1 | — | 3 | 1 | |||||||||||||||
| Consumer direct loans | 11 | 11 | 10 | 22 | 17 | |||||||||||||||
| Credit cards | 9 | 9 | 8 | 18 | 15 | |||||||||||||||
| Consumer indirect loans | 1 | — | 1 | 1 | 2 | |||||||||||||||
| Total consumer loans | 24 | 21 | 17 | 45 | 32 | |||||||||||||||
| Total loans charged off | 76 | 60 | 59 | 136 | 110 | |||||||||||||||
| Recoveries: | ||||||||||||||||||||
| Commercial and industrial | 15 | 8 | 8 | 23 | 19 | |||||||||||||||
| Real estate — commercial mortgage | 1 | — | 1 | 1 | 2 | |||||||||||||||
| Real estate — construction | — | — | 1 | — | 1 | |||||||||||||||
| Total commercial real estate loans | 1 | — | 2 | 1 | 3 | |||||||||||||||
| Commercial lease financing | 2 | 1 | 1 | 3 | 1 | |||||||||||||||
| Total commercial loans | 18 | 9 | 11 | 27 | 23 | |||||||||||||||
| Real estate — residential mortgage | 1 | 1 | 1 | 2 | 1 | |||||||||||||||
| Home equity loans | 1 | 1 | 1 | 2 | 2 | |||||||||||||||
| Consumer direct loans | 2 | 2 | 1 | 4 | 3 | |||||||||||||||
| Credit cards | 2 | 1 | 1 | 3 | 3 | |||||||||||||||
| Consumer indirect loans | — | 1 | — | 1 | 1 | |||||||||||||||
| Total consumer loans | 6 | 6 | 4 | 12 | 10 | |||||||||||||||
| Total recoveries | 24 | 15 | 15 | 39 | 33 | |||||||||||||||
| Net loan charge-offs | (52) | (45) | (44) | (97) | (77) | |||||||||||||||
| Provision (credit) for loan and lease losses | 152 | 88 | 38 | 240 | 115 | |||||||||||||||
| Allowance for loan and lease losses at end of period | $ | 1,480 | $ | 1,380 | $ | 1,099 | $ | 1,480 | $ | 1,099 | ||||||||||
| Liability for credit losses on lending-related commitments at beginning of period | 276 | 225 | 166 | 225 | 160 | |||||||||||||||
| Provision (credit) for losses on lending-related commitments | 15 | 51 | 7 | 66 | 13 | |||||||||||||||
Liability for credit losses on lending-related commitments at end of period (a) | $ | 291 | $ | 276 | $ | 173 | $ | 291 | $ | 173 | ||||||||||
| Total allowance for credit losses at end of period | $ | 1,771 | $ | 1,656 | $ | 1,272 | $ | 1,771 | $ | 1,272 | ||||||||||
| Net loan charge-offs to average total loans | .17 | % | .15 | % | .16 | % | .16 | % | .15 | % | ||||||||||
| Allowance for loan and lease losses to period-end loans | 1.24 | 1.15 | .98 | 1.24 | .98 | |||||||||||||||
| Allowance for credit losses to period-end loans | 1.49 | 1.38 | 1.13 | 1.49 | 1.13 | |||||||||||||||
| Allowance for loan and lease losses to nonperforming loans | 343 | 332 | 256 | 343 | 256 | |||||||||||||||
| Allowance for credit losses to nonperforming loans | 411 | 398 | 297 | 411 | 297 | |||||||||||||||
| Discontinued operations — education lending business: | ||||||||||||||||||||
| Loans charged off | $ | 2 | $ | 1 | $ | 1 | $ | 3 | $ | 3 | ||||||||||
| Recoveries | 1 | — | 1 | 1 | 1 | |||||||||||||||
| Net loan charge-offs | $ | (1) | $ | (1) | $ | — | $ | (2) | $ | (2) | ||||||||||
(a)Included in "Accrued expense and other liabilities" on the balance sheet.
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 24
| Asset Quality Statistics From Continuing Operations | |||||||||||||||||
| (Dollars in millions) | |||||||||||||||||
| 2Q23 | 1Q23 | 4Q22 | 3Q22 | 2Q22 | |||||||||||||
| Net loan charge-offs | $ | 52 | $ | 45 | $ | 41 | $ | 43 | $ | 44 | |||||||
| Net loan charge-offs to average total loans | .17 | % | .15 | % | .14 | % | .15 | % | .16 | % | |||||||
| Allowance for loan and lease losses | $ | 1,480 | $ | 1,380 | $ | 1,337 | $ | 1,144 | $ | 1,099 | |||||||
Allowance for credit losses (a) | 1,771 | 1,656 | 1,562 | 1,338 | 1,272 | ||||||||||||
| Allowance for loan and lease losses to period-end loans | 1.24 | % | 1.15 | % | 1.12 | % | .98 | % | .98 | % | |||||||
| Allowance for credit losses to period-end loans | 1.49 | 1.38 | 1.31 | 1.15 | 1.13 | ||||||||||||
| Allowance for loan and lease losses to nonperforming loans | 343 | 332 | 346 | 293 | 256 | ||||||||||||
| Allowance for credit losses to nonperforming loans | 411 | 398 | 404 | 343 | 297 | ||||||||||||
| Nonperforming loans at period end | $ | 431 | $ | 416 | $ | 387 | $ | 390 | $ | 429 | |||||||
| Nonperforming assets at period end | 462 | 447 | 420 | 419 | 463 | ||||||||||||
| Nonperforming loans to period-end portfolio loans | .36 | % | .35 | % | .32 | % | .34 | % | .38 | % | |||||||
Nonperforming assets to period-end portfolio loans plus OREO and other nonperforming assets | .39 | .37 | .35 | .36 | .41 | ||||||||||||
(a)Includes the allowance for loan and lease losses plus the liability for credit losses on lending-related commitments.
| Summary of Nonperforming Assets and Past Due Loans From Continuing Operations | |||||||||||||||||
| (Dollars in millions) | |||||||||||||||||
| 6/30/2023 | 3/31/2023 | 12/31/2022 | 9/30/2022 | 6/30/2022 | |||||||||||||
| Commercial and industrial | $ | 188 | $ | 170 | $ | 174 | $ | 169 | $ | 197 | |||||||
| Real estate — commercial mortgage | 65 | 59 | 21 | 34 | 35 | ||||||||||||
| Real estate — construction | — | — | — | — | — | ||||||||||||
| Total commercial real estate loans | 65 | 59 | 21 | 34 | 35 | ||||||||||||
| Commercial lease financing | 1 | 1 | 1 | 2 | 2 | ||||||||||||
| Total commercial loans | 254 | 230 | 196 | 205 | 234 | ||||||||||||
| Real estate — residential mortgage | 73 | 75 | 77 | 66 | 67 | ||||||||||||
| Home equity loans | 97 | 104 | 107 | 112 | 120 | ||||||||||||
| Consumer direct loans | 3 | 3 | 3 | 3 | 3 | ||||||||||||
| Credit cards | 3 | 3 | 3 | 3 | 3 | ||||||||||||
| Consumer indirect loans | 1 | 1 | 1 | 1 | 2 | ||||||||||||
| Total consumer loans | 177 | 186 | 191 | 185 | 195 | ||||||||||||
Total nonperforming loans (a) | 431 | 416 | 387 | 390 | 429 | ||||||||||||
| OREO | 15 | 13 | 13 | 12 | 9 | ||||||||||||
| Nonperforming loans held for sale | 16 | 18 | 20 | 17 | 25 | ||||||||||||
| Other nonperforming assets | — | — | — | — | — | ||||||||||||
| Total nonperforming assets | $ | 462 | $ | 447 | $ | 420 | $ | 419 | $ | 463 | |||||||
| Accruing loans past due 90 days or more | 73 | 55 | 60 | 47 | 41 | ||||||||||||
| Accruing loans past due 30 through 89 days | 139 | 164 | 180 | 187 | 137 | ||||||||||||
| Nonperforming assets from discontinued operations — education lending business | 2 | 3 | 3 | 3 | 3 | ||||||||||||
| Nonperforming loans to period-end portfolio loans | .36 | % | .35 | % | .32 | % | .34 | % | .38 | % | |||||||
Nonperforming assets to period-end portfolio loans plus OREO and other nonperforming assets | .39 | .37 | .35 | .36 | .41 | ||||||||||||
(a)On January 1, 2023, Key adopted ASU 2022-02 Financial Instruments - Credit Losses (Topic 326): Troubled Debt Restructurings and Vintage Disclosures. In connection with the adoption of this guidance, nonperforming loans for periods after January 1, 2023, include certain loans which were modified for borrowers experiencing financial difficulty. Amounts prior to January 1, 2023, include nonperforming troubled debt restructurings (TDRs), for which accounting guidance was eliminated upon adoption of ASU 2022-02.
| Summary of Changes in Nonperforming Loans From Continuing Operations | |||||||||||||||||
| (Dollars in millions) | |||||||||||||||||
| 2Q23 | 1Q23 | 4Q22 | 3Q22 | 2Q22 | |||||||||||||
| Balance at beginning of period | $ | 416 | $ | 387 | $ | 390 | $ | 429 | $ | 439 | |||||||
| Loans placed on nonaccrual status | 169 | 143 | 113 | 80 | 118 | ||||||||||||
| Charge-offs | (76) | (60) | (67) | (68) | (59) | ||||||||||||
| Loans sold | (23) | (2) | (4) | (3) | (8) | ||||||||||||
| Payments | (20) | (31) | (22) | (29) | (35) | ||||||||||||
| Transfers to OREO | (2) | (2) | (1) | (1) | (2) | ||||||||||||
| Loans returned to accrual status | (33) | (19) | (22) | (18) | (24) | ||||||||||||
| Balance at end of period | $ | 431 | $ | 416 | $ | 387 | $ | 390 | $ | 429 | |||||||
KeyCorp Reports Second Quarter 2023 Profit
July 20, 2023
Page 25
| Line of Business Results | ||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||
| Change 2Q23 vs. | ||||||||||||||||||||||||||
| 2Q23 | 1Q23 | 4Q22 | 3Q22 | 2Q22 | 1Q23 | 2Q22 | ||||||||||||||||||||
| Consumer Bank | ||||||||||||||||||||||||||
| Summary of operations | ||||||||||||||||||||||||||
| Total revenue (TE) | $ | 803 | $ | 840 | $ | 860 | $ | 877 | $ | 858 | (4.4) | % | (6.4) | % | ||||||||||||
| Provision for credit losses | 32 | 60 | 105 | 37 | 8 | (46.7) | 300.0 | |||||||||||||||||||
| Noninterest expense | 663 | 663 | 705 | 675 | 681 | — | (2.6) | |||||||||||||||||||
| Net income (loss) attributable to Key | 82 | 89 | 38 | 125 | 128 | (7.9) | (35.9) | |||||||||||||||||||
| Average loans and leases | 42,934 | 43,086 | 43,149 | 42,568 | 40,827 | (.4) | 5.2 | |||||||||||||||||||
| Average deposits | 82,498 | 84,637 | 87,370 | 90,170 | 91,394 | (2.5) | (9.7) | |||||||||||||||||||
| Net loan charge-offs | 32 | 24 | 21 | 17 | 23 | 33.3 | 39.1 | |||||||||||||||||||
| Net loan charge-offs to average total loans | .30 | % | .23 | % | .19 | % | .16 | % | .23 | % | 30.4 | 30.4 | ||||||||||||||
| Nonperforming assets at period end | $ | 193 | $ | 196 | $ | 202 | $ | 195 | $ | 203 | (1.5) | (4.9) | ||||||||||||||
| Return on average allocated equity | 9.04 | % | 9.87 | % | 4.51 | % | 14.26 | % | 13.94 | % | (8.4) | (35.2) | ||||||||||||||
| Commercial Bank | ||||||||||||||||||||||||||
| Summary of operations | ||||||||||||||||||||||||||
| Total revenue (TE) | $ | 805 | $ | 844 | $ | 894 | $ | 878 | $ | 874 | (4.6) | % | (7.9) | % | ||||||||||||
| Provision for credit losses | 134 | 80 | 165 | 74 | 37 | 67.5 | 262.2 | |||||||||||||||||||
| Noninterest expense | 405 | 442 | 459 | 451 | 411 | (8.4) | (1.5) | |||||||||||||||||||
| Net income (loss) attributable to Key | 214 | 255 | 225 | 287 | 340 | (16.1) | (37.1) | |||||||||||||||||||
| Average loans and leases | 77,277 | 76,306 | 74,100 | 71,464 | 67,825 | 1.3 | 13.9 | |||||||||||||||||||
| Average loans held for sale | 1,014 | 876 | 1,377 | 1,036 | 1,016 | 15.8 | (.2) | |||||||||||||||||||
| Average deposits | 51,420 | 52,219 | 54,385 | 52,272 | 54,846 | (1.5) | (6.2) | |||||||||||||||||||
| Net loan charge-offs | 20 | 21 | 25 | 27 | 21 | (4.8) | (4.8) | |||||||||||||||||||
| Net loan charge-offs to average total loans | .10 | % | .11 | % | .13 | % | .15 | % | .12 | % | (9.1) | (16.7) | ||||||||||||||
| Nonperforming assets at period end | $ | 269 | $ | 251 | $ | 218 | $ | 224 | $ | 260 | 7.2 | 3.5 | ||||||||||||||
| Return on average allocated equity | 8.17 | % | 10.04 | % | 9.36 | % | 12.29 | % | 15.29 | % | (18.6) | (46.6) | ||||||||||||||
TE = Taxable Equivalent
KeyCorp Second Quarter 2023 Earnings Review July 20, 2023 Chris Gorman Chairman and Chief Executive Officer Clark Khayat Chief Financial Officer
Forward-looking Statements and Additional Information This communication contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 including, but not limited to, KeyCorp’s expectations or predictions of future financial or business performance or conditions. Forward-looking statements are typically identified by words such as “believe,” “seek,” “expect,” “anticipate,” “intend,” “target,” “estimate,” “continue,” “positions,” “plan,” “predict,” “project,” “forecast,” “guidance,” “goal,” “objective,” “prospects,” “possible,” “potential,” “strategy,” “opportunities,” or “trends,” by future conditional verbs such as “assume,” “will,” “would,” “should,” “could” or “may”, or by variations of such words or by similar expressions. These forward-looking statements are based on assumptions that involve risks and uncertainties, which are subject to change based on various important factors (some of which are beyond KeyCorp’s control). Actual results may differ materially from current projections. Actual outcomes may differ materially from those expressed or implied as a result of the factors described under “Forward-looking Statements” and “Risk Factors” in KeyCorp’s Annual Report on Form 10-K for the year ended December 31, 2022, Quarterly Report on Form 10-Q for the quarter ended March 31, 2023, and in other filings of KeyCorp with the Securities and Exchange Commission (the “SEC”). Such forward-looking statements speak only as of the date they are made, and we undertake no obligation to update any forward- looking statement to reflect events or circumstances after that date or to reflect the occurrence of unanticipated events. For additional information regarding KeyCorp, please refer to our SEC filings available at www.key.com/ir. Annualized, pro forma, projected and estimated numbers are used for illustrative purpose only, are not forecasts and may not reflect actual results. This presentation also includes certain non-GAAP financial measures related to “tangible common equity” and “cash efficiency ratio.” Although Key has procedures in place to ensure that these measures are calculated using the appropriate GAAP or regulatory components, they have limitations as analytical tools and should not be considered in isolation, or as a substitute for analysis of results under GAAP. For more information on these calculations and to view the reconciliations to the most comparable GAAP measures, please refer to the appendix of this presentation, or page 47 of our Form 10-Q dated March 31, 2023. Certain income or expense items may be expressed on a per common share basis. This is done for analytical and decision-making purposes to better discern underlying trends in total consolidated earnings per share performance excluding the impact of such items. When the impact of certain items is disclosed separately, the after-tax amount is computed using the marginal tax rate, with this then being the amount used to calculate the earnings per share equivalent. GAAP: Generally Accepted Accounting Principles 2
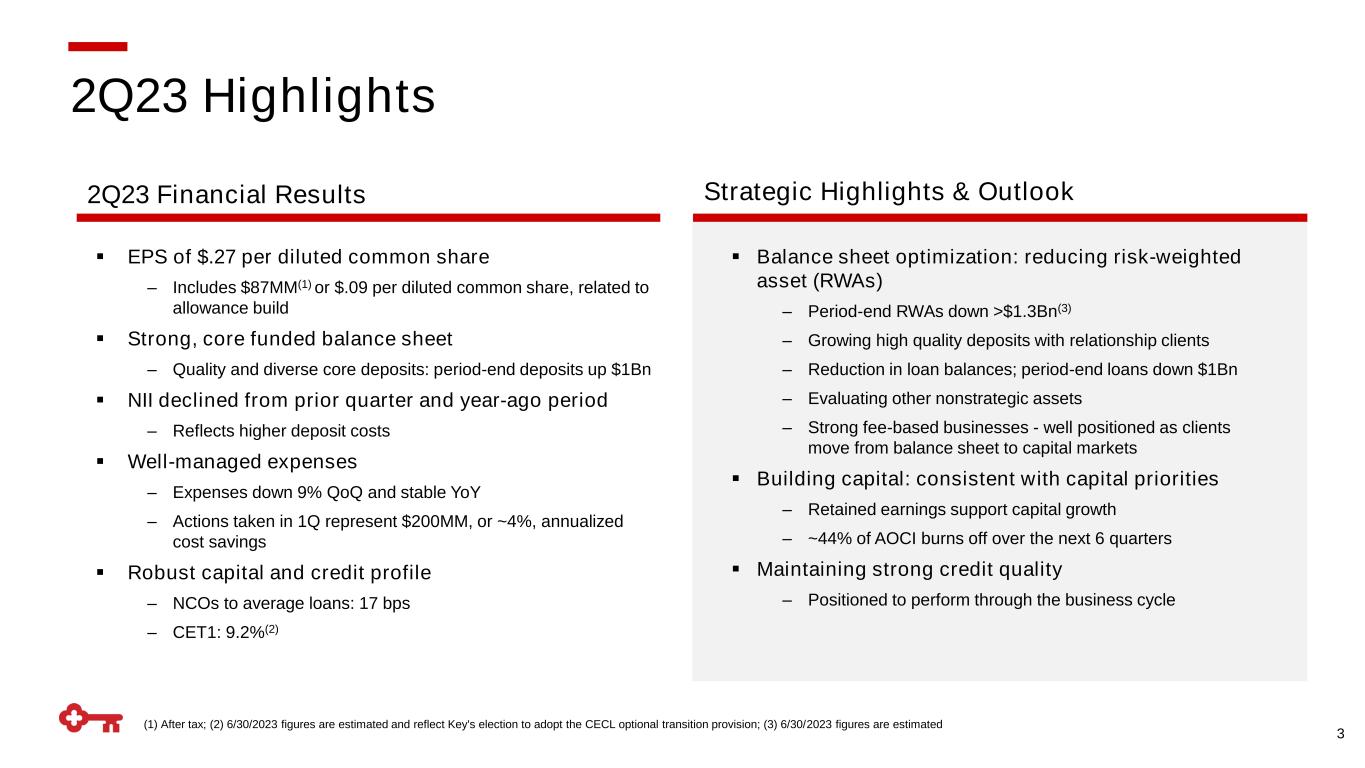
3 ▪ EPS of $.27 per diluted common share ‒ Includes $87MM(1) or $.09 per diluted common share, related to allowance build ▪ Strong, core funded balance sheet ‒ Quality and diverse core deposits: period-end deposits up $1Bn ▪ NII declined from prior quarter and year-ago period ‒ Reflects higher deposit costs ▪ Well-managed expenses ‒ Expenses down 9% QoQ and stable YoY ‒ Actions taken in 1Q represent $200MM, or ~4%, annualized cost savings ▪ Robust capital and credit profile ‒ NCOs to average loans: 17 bps ‒ CET1: 9.2%(2) 2Q23 Highlights ▪ Balance sheet optimization: reducing risk-weighted asset (RWAs) ‒ Period-end RWAs down >$1.3Bn(3) ‒ Growing high quality deposits with relationship clients ‒ Reduction in loan balances; period-end loans down $1Bn ‒ Evaluating other nonstrategic assets ‒ Strong fee-based businesses - well positioned as clients move from balance sheet to capital markets ▪ Building capital: consistent with capital priorities ‒ Retained earnings support capital growth ‒ ~44% of AOCI burns off over the next 6 quarters ▪ Maintaining strong credit quality ‒ Positioned to perform through the business cycle (1) After tax; (2) 6/30/2023 figures are estimated and reflect Key's election to adopt the CECL optional transition provision; (3) 6/30/2023 figures are estimated 2Q23 Financial Results Strategic Highlights & Outlook
Financial Review
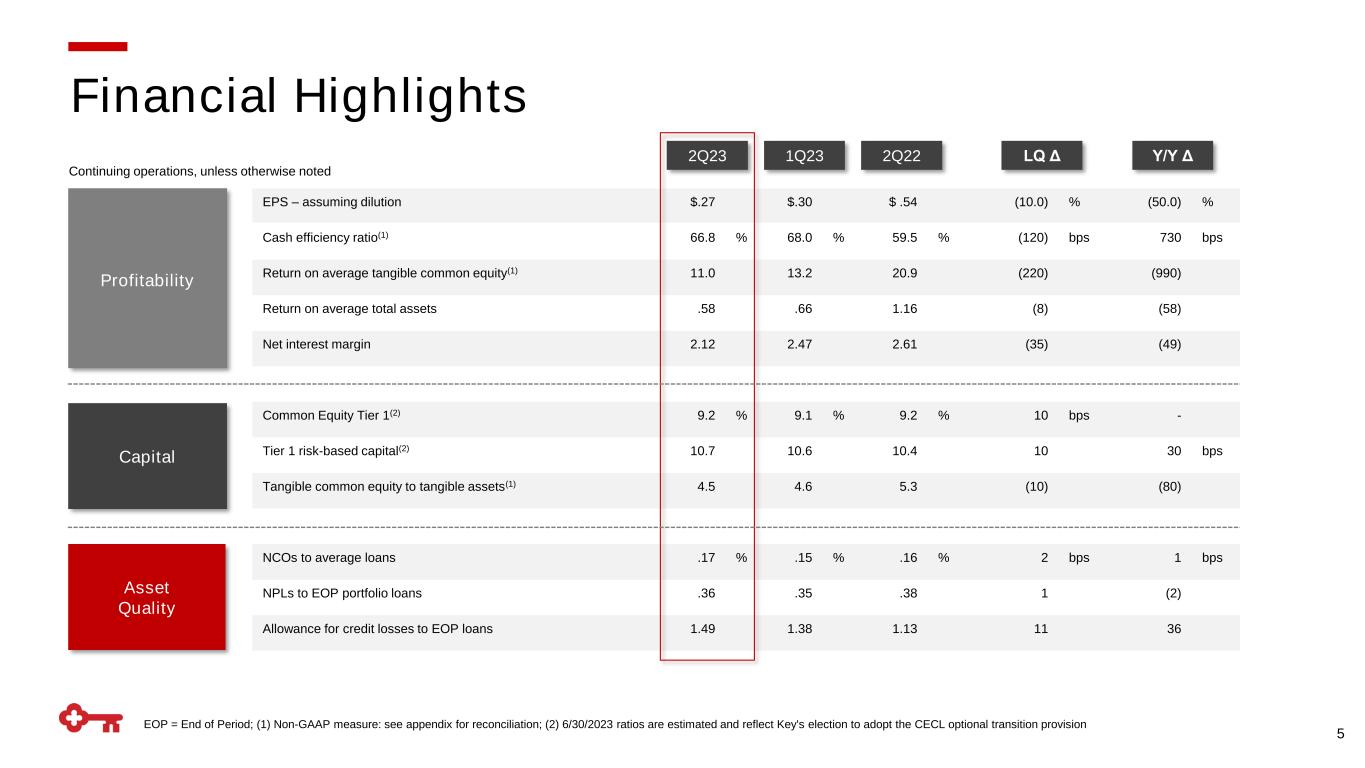
EOP = End of Period; (1) Non-GAAP measure: see appendix for reconciliation; (2) 6/30/2023 ratios are estimated and reflect Key's election to adopt the CECL optional transition provision 5 EPS – assuming dilution $.27 $.30 $ .54 (10.0) % (50.0) % Cash efficiency ratio(1) 66.8 % 68.0 % 59.5 % (120) bps 730 bps Return on average tangible common equity(1) 11.0 13.2 20.9 (220) (990) Return on average total assets .58 .66 1.16 (8) (58) Net interest margin 2.12 2.47 2.61 (35) (49) Common Equity Tier 1(2) 9.2 % 9.1 % 9.2 % 10 bps - Tier 1 risk-based capital(2) 10.7 10.6 10.4 10 30 bps Tangible common equity to tangible assets(1) 4.5 4.6 5.3 (10) (80) NCOs to average loans .17 % .15 % .16 % 2 bps 1 bps NPLs to EOP portfolio loans .36 .35 .38 1 (2) Allowance for credit losses to EOP loans 1.49 1.38 1.13 11 36 Profitability Capital Asset Quality 2Q23 1Q23 2Q22 LQ Δ Y/Y Δ Continuing operations, unless otherwise noted Financial Highlights
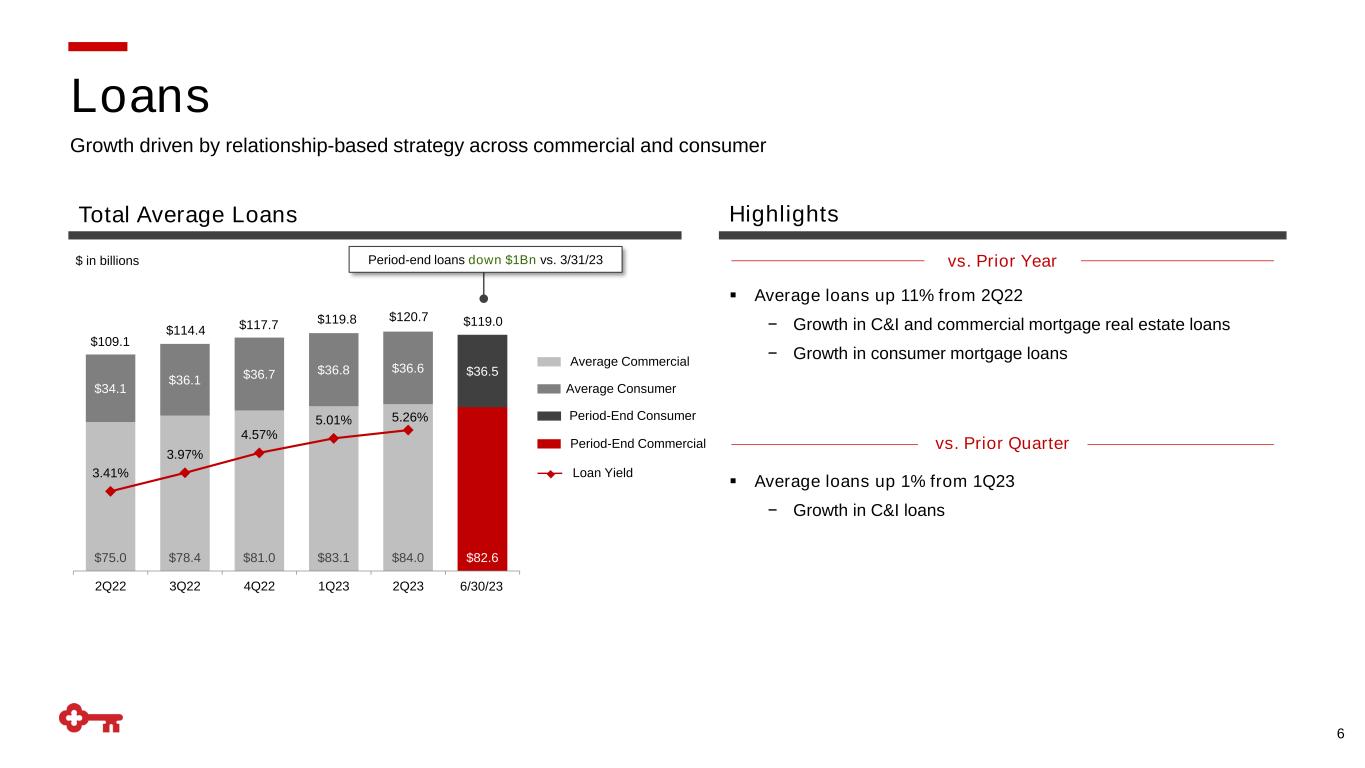
6 $75.0 $78.4 $81.0 $83.1 $84.0 $82.6 $34.1 $36.1 $36.7 $36.8 $36.6 $36.5 3.41% 3.97% 4.57% 5.01% 5.26% 1.00% 2Q22 3Q22 4Q22 1Q23 2Q23 Loan Yield Average Consumer Average Commercial $ in billions ▪ Average loans up 11% from 2Q22 − Growth in C&I and commercial mortgage real estate loans − Growth in consumer mortgage loans ▪ Average loans up 1% from 1Q23 − Growth in C&I loans vs. Prior Year vs. Prior Quarter $109.1 $114.4 $117.7 $119.8 Loans Growth driven by relationship-based strategy across commercial and consumer Total Average Loans Highlights $120.7 $119.0 Period-End Consumer Period-End Commercial 6/30/23 Period-end loans down $1Bn vs. 3/31/23
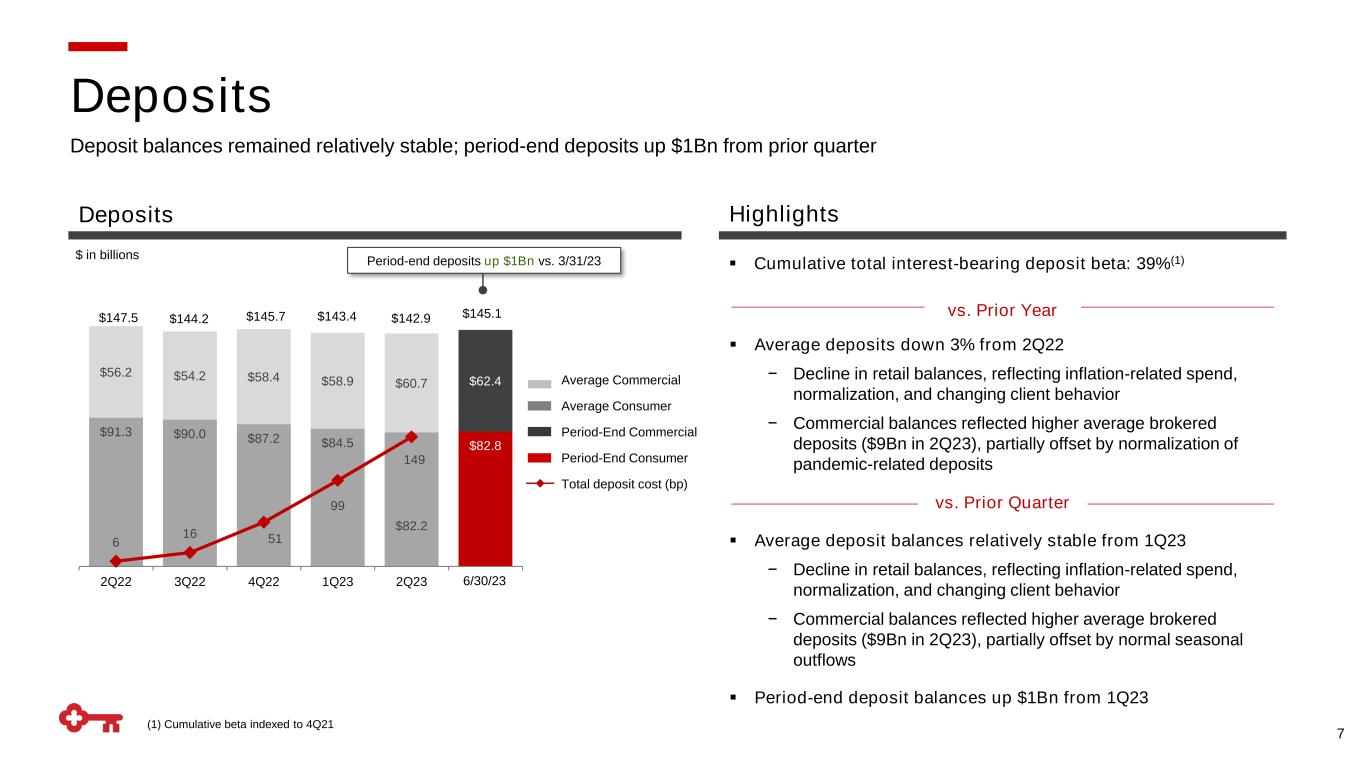
(1) Cumulative beta indexed to 4Q21 7 $ in billions Average Consumer Average Commercial $143.4 Total deposit cost (bp) $147.5 $144.2 $145.7 Deposits Deposit balances remained relatively stable; period-end deposits up $1Bn from prior quarter ▪ Average deposits down 3% from 2Q22 − Decline in retail balances, reflecting inflation-related spend, normalization, and changing client behavior − Commercial balances reflected higher average brokered deposits ($9Bn in 2Q23), partially offset by normalization of pandemic-related deposits ▪ Average deposit balances relatively stable from 1Q23 − Decline in retail balances, reflecting inflation-related spend, normalization, and changing client behavior − Commercial balances reflected higher average brokered deposits ($9Bn in 2Q23), partially offset by normal seasonal outflows ▪ Period-end deposit balances up $1Bn from 1Q23 vs. Prior Year vs. Prior Quarter Period-End Consumer Period-End Commercial ▪ Cumulative total interest-bearing deposit beta: 39%(1) $91.3 $90.0 $87.2 $84.5 $82.2 $82.8 $56.2 $54.2 $58.4 $58.9 $60.7 $62.4 6 16 51 99 149 2Q22 3Q22 4Q22 1Q23 2Q23 $142.9 Deposits Highlights 6/30/23 $145.1 Period-end deposits up $1Bn vs. 3/31/23
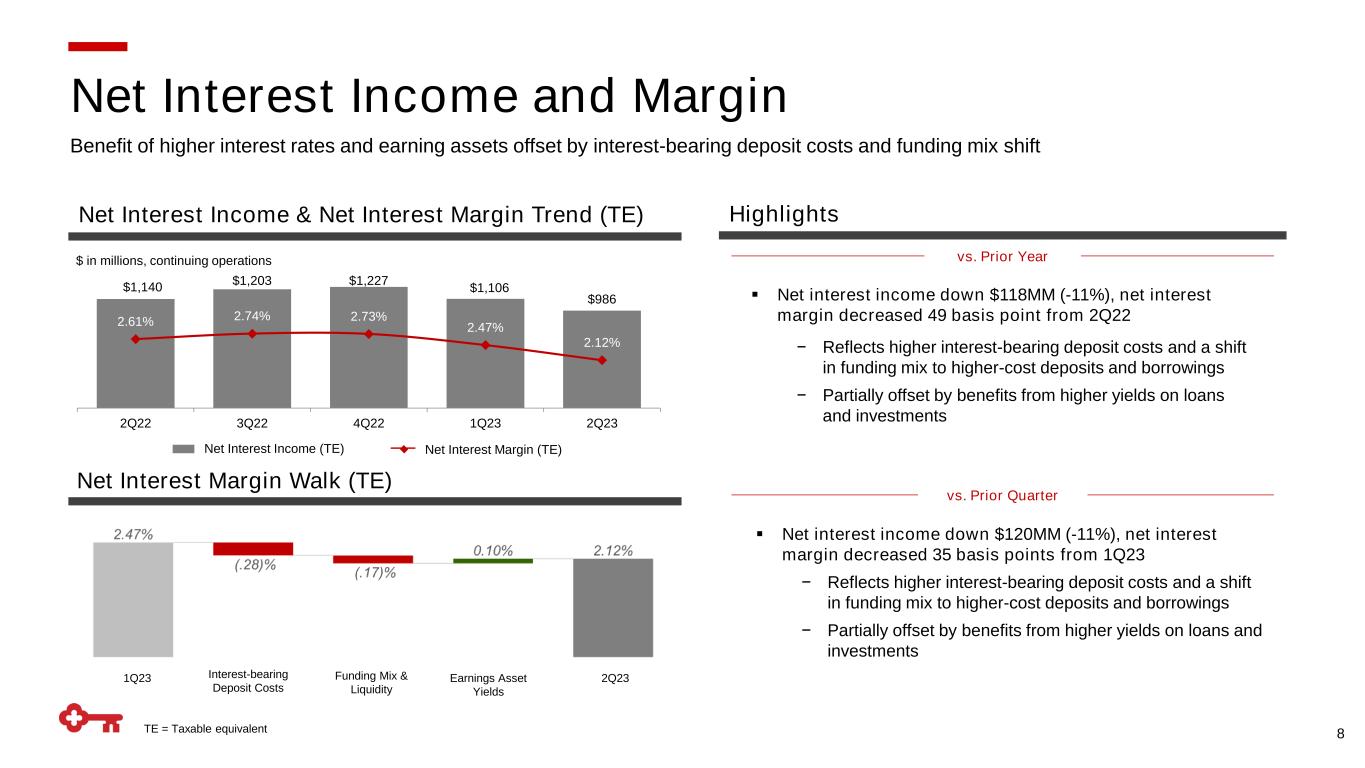
$ in millions, continuing operations vs. Prior Quarter TE = Taxable equivalent $1,140 $1,203 $1,227 $1,106 $986 2.61% 2.74% 2.73% 2.47% 2.12% 1.0% 1.5% 2.0% 2.5% 3.0% 3.5% 4.0% 2Q22 3Q22 4Q22 1Q23 2Q23 ▪ Net interest income down $118MM (-11%), net interest margin decreased 49 basis point from 2Q22 − Reflects higher interest-bearing deposit costs and a shift in funding mix to higher-cost deposits and borrowings − Partially offset by benefits from higher yields on loans and investments ▪ Net interest income down $120MM (-11%), net interest margin decreased 35 basis points from 1Q23 − Reflects higher interest-bearing deposit costs and a shift in funding mix to higher-cost deposits and borrowings − Partially offset by benefits from higher yields on loans and investments 8 vs. Prior Year Net Interest Income (TE) Net Interest Margin (TE) Benefit of higher interest rates and earning assets offset by interest-bearing deposit costs and funding mix shift Net Interest Income and Margin Net Interest Margin Walk (TE) Interest-bearing Deposit Costs Funding Mix & Liquidity Earnings Asset Yields 2Q231Q23 Net Interest Income & Net Interest Margin Trend (TE) Highlights
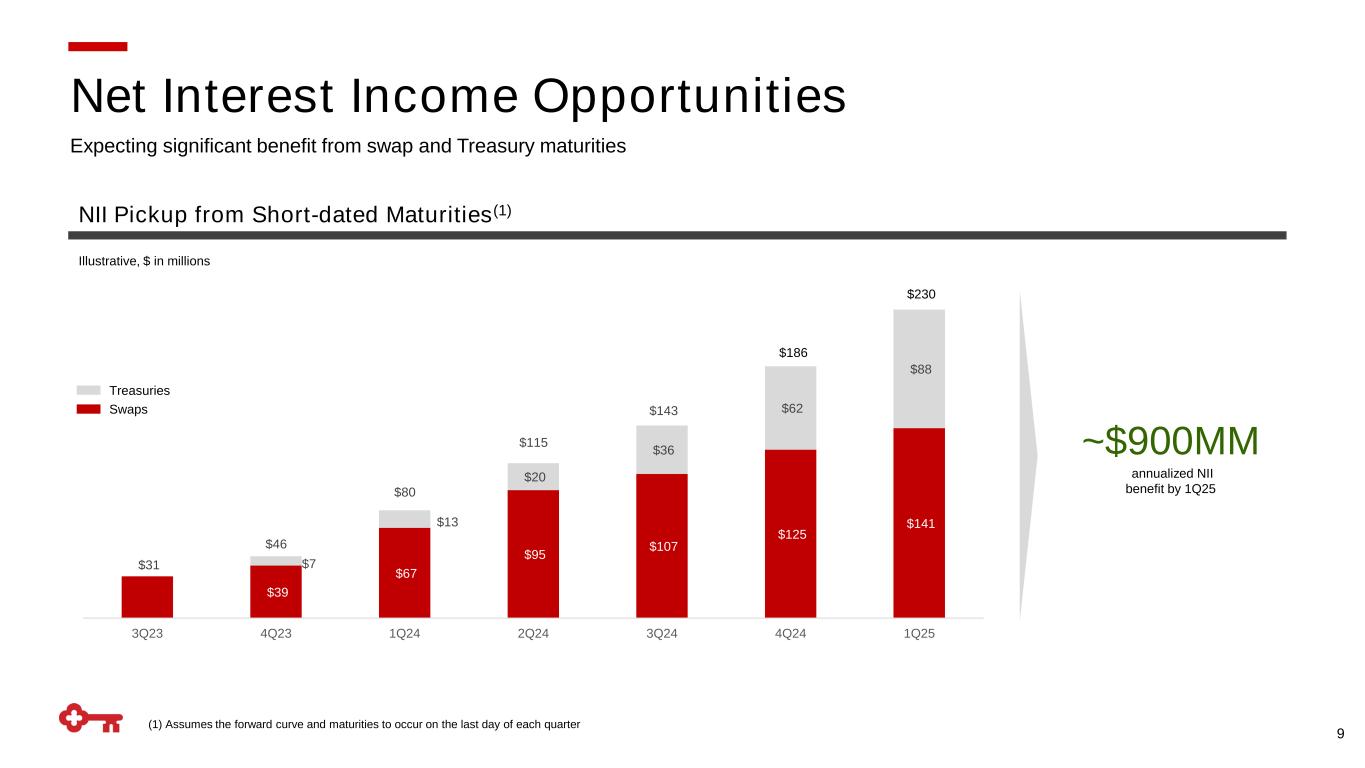
9 Expecting significant benefit from swap and Treasury maturities Net Interest Income Opportunities Illustrative, $ in millions $39 $67 $95 $107 $125 $141 $7 $13 $20 $36 $62 $88 $31 $46 $80 $115 $143 3Q23 4Q23 1Q24 2Q24 3Q24 4Q24 1Q25 ~$900MM annualized NII benefit by 1Q25 (1) Assumes the forward curve and maturities to occur on the last day of each quarter Treasuries Swaps NII Pickup from Short-dated Maturities(1) $186 $230
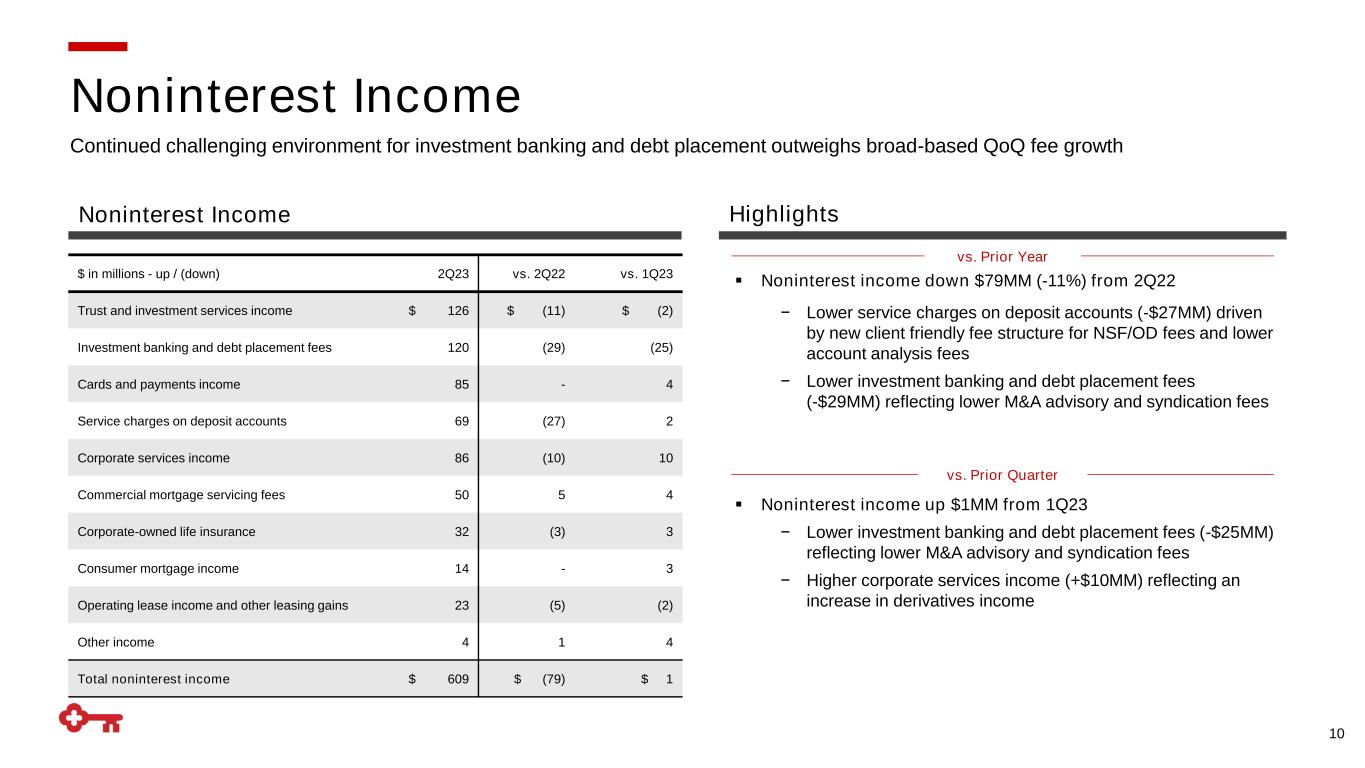
10 ▪ Noninterest income down $79MM (-11%) from 2Q22 − Lower service charges on deposit accounts (-$27MM) driven by new client friendly fee structure for NSF/OD fees and lower account analysis fees − Lower investment banking and debt placement fees (-$29MM) reflecting lower M&A advisory and syndication fees vs. Prior Quarter ▪ Noninterest income up $1MM from 1Q23 − Lower investment banking and debt placement fees (-$25MM) reflecting lower M&A advisory and syndication fees − Higher corporate services income (+$10MM) reflecting an increase in derivatives income vs. Prior Year $ in millions - up / (down) 2Q23 vs. 2Q22 vs. 1Q23 Trust and investment services income $ 126 $ (11) $ (2) Investment banking and debt placement fees 120 (29) (25) Cards and payments income 85 - 4 Service charges on deposit accounts 69 (27) 2 Corporate services income 86 (10) 10 Commercial mortgage servicing fees 50 5 4 Corporate-owned life insurance 32 (3) 3 Consumer mortgage income 14 - 3 Operating lease income and other leasing gains 23 (5) (2) Other income 4 1 4 Total noninterest income $ 609 $ (79) $ 1 Continued challenging environment for investment banking and debt placement outweighs broad-based QoQ fee growth Noninterest Income Noninterest Income Highlights
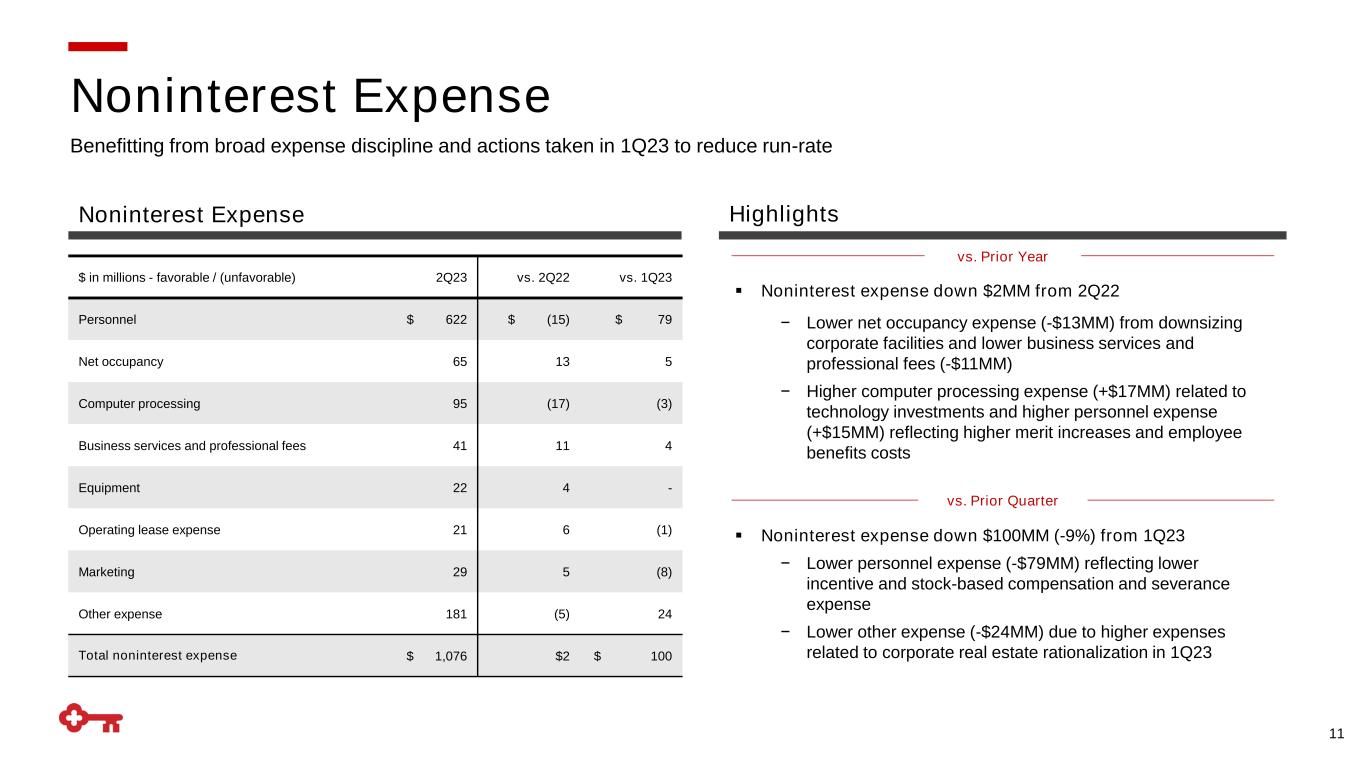
11 vs. Prior Quarter vs. Prior Year ▪ Noninterest expense down $2MM from 2Q22 − Lower net occupancy expense (-$13MM) from downsizing corporate facilities and lower business services and professional fees (-$11MM) − Higher computer processing expense (+$17MM) related to technology investments and higher personnel expense (+$15MM) reflecting higher merit increases and employee benefits costs ▪ Noninterest expense down $100MM (-9%) from 1Q23 − Lower personnel expense (-$79MM) reflecting lower incentive and stock-based compensation and severance expense − Lower other expense (-$24MM) due to higher expenses related to corporate real estate rationalization in 1Q23 Benefitting from broad expense discipline and actions taken in 1Q23 to reduce run-rate Noninterest Expense $ in millions - favorable / (unfavorable) 2Q23 vs. 2Q22 vs. 1Q23 Personnel $ 622 $ (15) $ 79 Net occupancy 65 13 5 Computer processing 95 (17) (3) Business services and professional fees 41 11 4 Equipment 22 4 - Operating lease expense 21 6 (1) Marketing 29 5 (8) Other expense 181 (5) 24 Total noninterest expense $ 1,076 $2 $ 100 Noninterest Expense Highlights
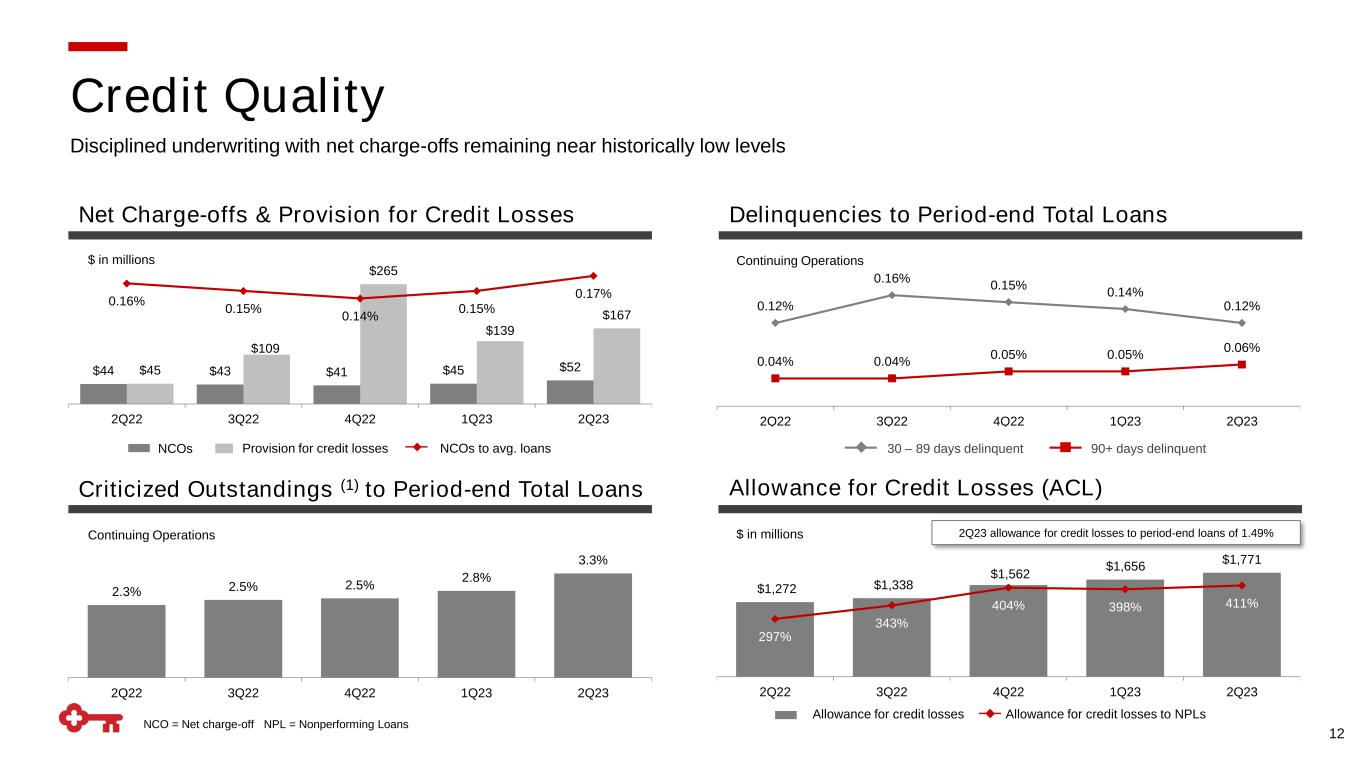
$1,272 $1,338 $1,562 $1,656 $1,771 297% 343% 404% 398% 411% 2Q22 3Q22 4Q22 1Q23 2Q23 Allowance for credit losses to NPLsAllowance for credit losses 2Q23 allowance for credit losses to period-end loans of 1.49%$ in millions NCO = Net charge-off NPL = Nonperforming Loans 12 $44 $43 $41 $45 $52$45 $109 $265 $139 $167 0.16% 0.15% 0.14% 0.15% 0.17% 2Q22 3Q22 4Q22 1Q23 2Q23 $ in millions NCOs Provision for credit losses NCOs to avg. loans 2.3% 2.5% 2.5% 2.8% 3.3% 2Q22 3Q22 4Q22 1Q23 2Q23 Continuing Operations Disciplined underwriting with net charge-offs remaining near historically low levels Credit Quality 0.12% 0.16% 0.15% 0.14% 0.12% 0.04% 0.04% 0.05% 0.05% 0.06% 2Q22 3Q22 4Q22 1Q23 2Q23 30 – 89 days delinquent 90+ days delinquent Net Charge-offs & Provision for Credit Losses Continuing Operations Delinquencies to Period-end Total Loans Criticized Outstandings (1) to Period-end Total Loans Allowance for Credit Losses (ACL)
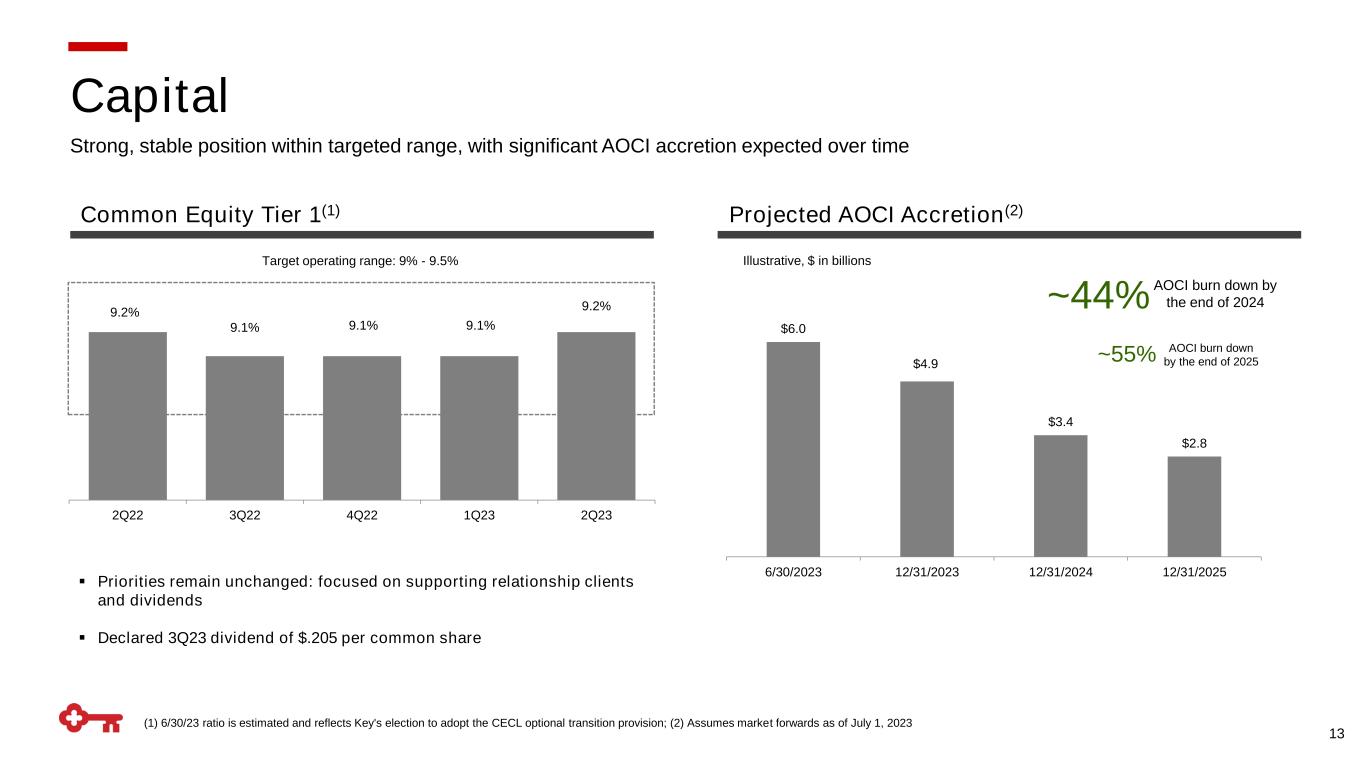
$6.0 $4.9 $3.4 $2.8 6/30/2023 12/31/2023 12/31/2024 12/31/2025 9.2% 9.1% 9.1% 9.1% 9.2% 2Q22 3Q22 4Q22 1Q23 2Q23 (1) 6/30/23 ratio is estimated and reflects Key's election to adopt the CECL optional transition provision; (2) Assumes market forwards as of July 1, 2023 13 Strong, stable position within targeted range, with significant AOCI accretion expected over time Capital Illustrative, $ in billionsTarget operating range: 9% - 9.5% ▪ Priorities remain unchanged: focused on supporting relationship clients and dividends ▪ Declared 3Q23 dividend of $.205 per common share ~44% AOCI burn down by the end of 2024 Common Equity Tier 1(1) Projected AOCI Accretion(2) ~55% AOCI burn down by the end of 2025
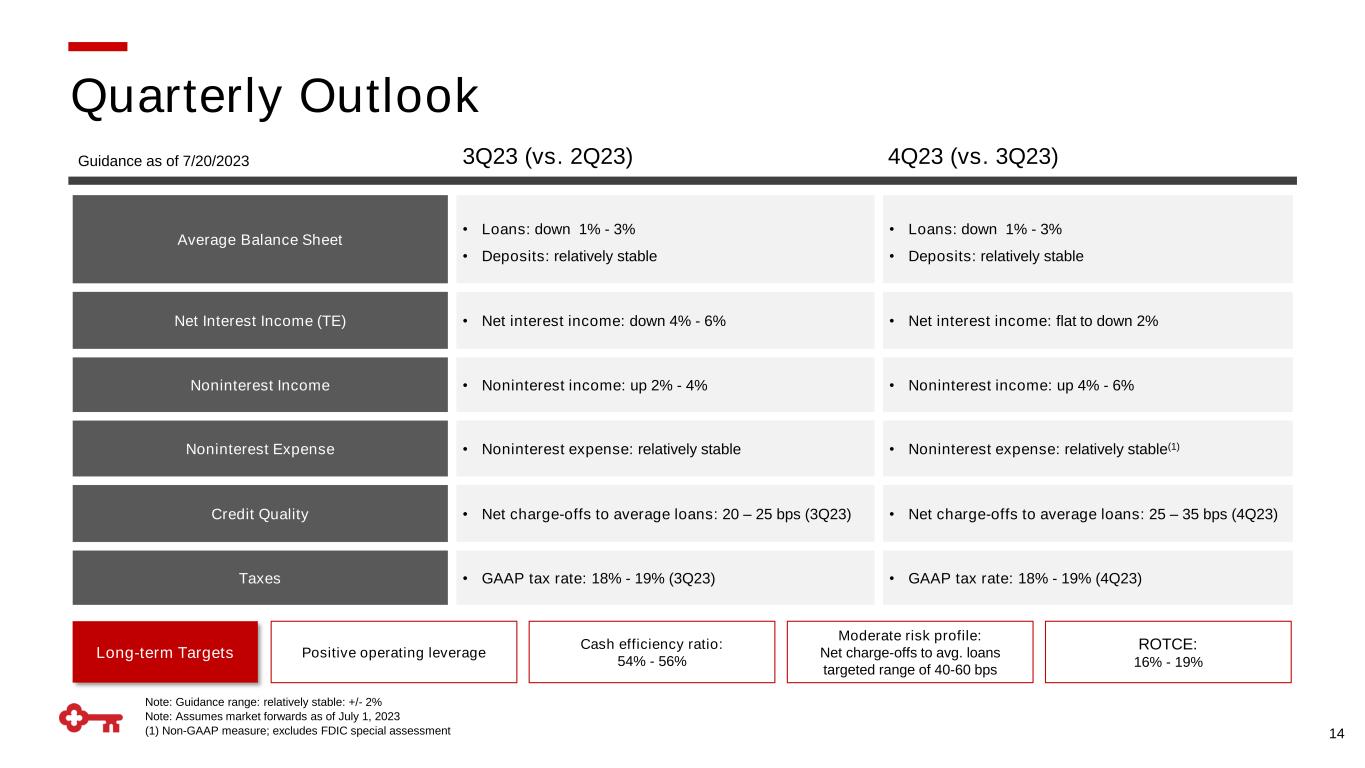
14 Average Balance Sheet • Loans: down 1% - 3% • Deposits: relatively stable • Loans: down 1% - 3% • Deposits: relatively stable Net Interest Income (TE) • Net interest income: down 4% - 6% • Net interest income: flat to down 2% Noninterest Income • Noninterest income: up 2% - 4% • Noninterest income: up 4% - 6% Noninterest Expense • Noninterest expense: relatively stable • Noninterest expense: relatively stable(1) Credit Quality • Net charge-offs to average loans: 20 – 25 bps (3Q23) • Net charge-offs to average loans: 25 – 35 bps (4Q23) Taxes • GAAP tax rate: 18% - 19% (3Q23) • GAAP tax rate: 18% - 19% (4Q23) Long-term Targets Positive operating leverage Moderate risk profile: Net charge-offs to avg. loans targeted range of 40-60 bps ROTCE: 16% - 19% Cash efficiency ratio: 54% - 56% Note: Guidance range: relatively stable: +/- 2% Note: Assumes market forwards as of July 1, 2023 (1) Non-GAAP measure; excludes FDIC special assessment Quarterly Outlook Guidance as of 7/20/2023 3Q23 (vs. 2Q23) 4Q23 (vs. 3Q23)
Appendix
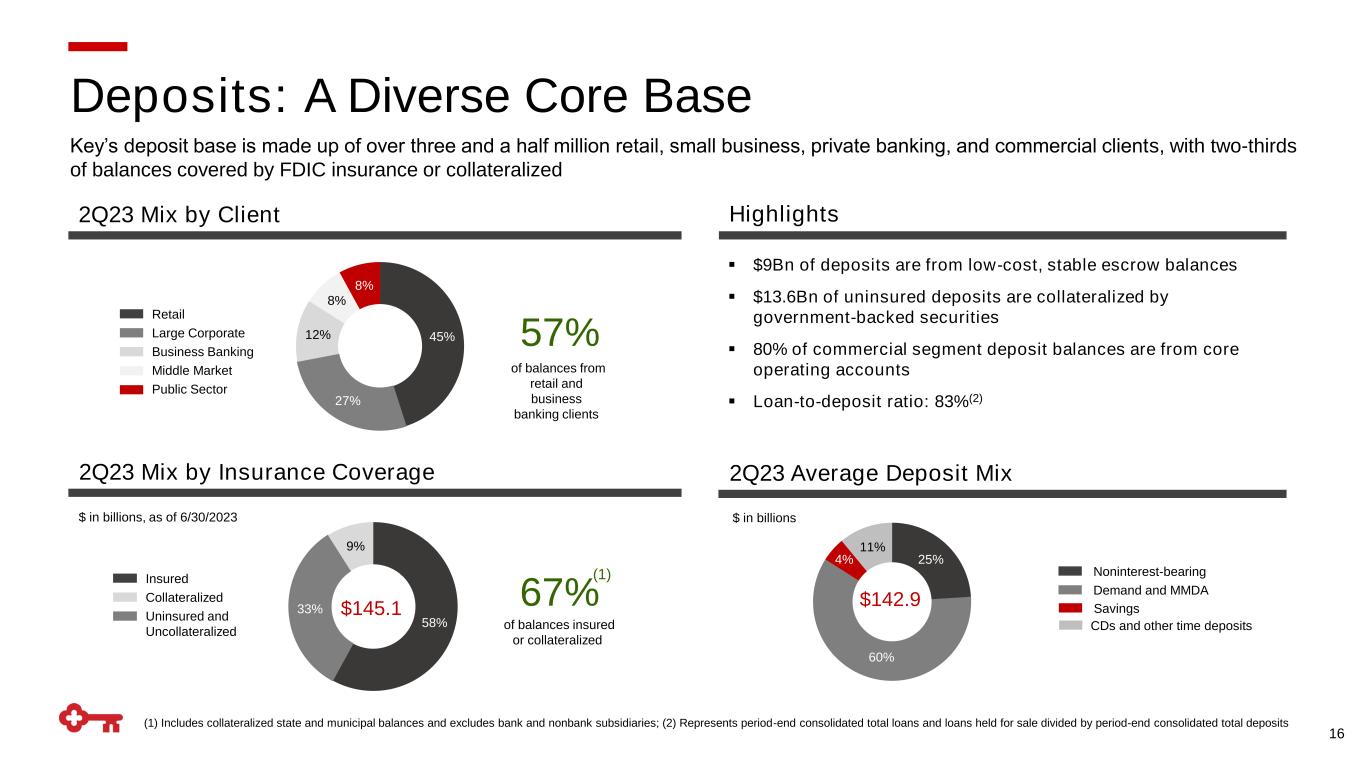
16 $ in billions, as of 6/30/2023 ▪ $9Bn of deposits are from low-cost, stable escrow balances ▪ $13.6Bn of uninsured deposits are collateralized by government-backed securities ▪ 80% of commercial segment deposit balances are from core operating accounts ▪ Loan-to-deposit ratio: 83%(2) 2Q23 Mix by Insurance Coverage 59% 32% 5% Deposits: A Diverse Core Base Key’s deposit base is made up of over three and a half million retail, small business, private banking, and commercial clients, with two-thirds of balances covered by FDIC insurance or collateralized 45% 27% 12% 8% 8% Middle Market Business Banking Retail Large Corporate Public Sector Uninsured and Uncollateralized Insured Collateralized 58% 33% 9% $145.1 67% of balances insured or collateralized 57% of balances from retail and business banking clients (1) Includes collateralized state and municipal balances and excludes bank and nonbank subsidiaries; (2) Represents period-end consolidated total loans and loans held for sale divided by period-end consolidated total deposits (1) 2Q23 Mix by Client Highlights $ in billions CDs and other time deposits Savings Noninterest-bearing Demand and MMDA 2Q23 Average Deposit Mix 60% 25% 11% 4% $142.9
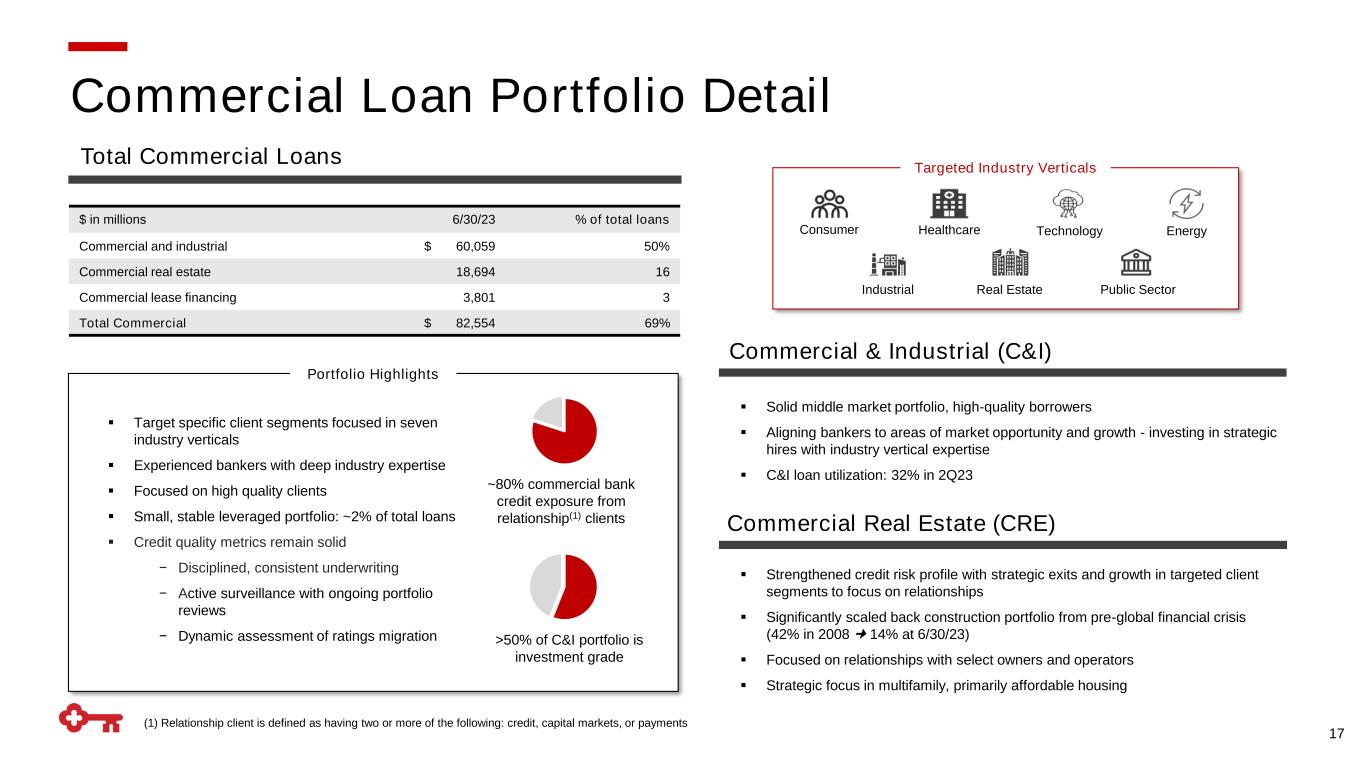
Portfolio Highlights ▪ Target specific client segments focused in seven industry verticals ▪ Experienced bankers with deep industry expertise ▪ Focused on high quality clients ▪ Small, stable leveraged portfolio: ~2% of total loans ▪ Credit quality metrics remain solid − Disciplined, consistent underwriting − Active surveillance with ongoing portfolio reviews − Dynamic assessment of ratings migration ~80% commercial bank credit exposure from relationship(1) clients Targeted Industry Verticals Consumer Energy Industrial TechnologyHealthcare (1) Relationship client is defined as having two or more of the following: credit, capital markets, or payments ▪ Solid middle market portfolio, high-quality borrowers ▪ Aligning bankers to areas of market opportunity and growth - investing in strategic hires with industry vertical expertise ▪ C&I loan utilization: 32% in 2Q23 ▪ Strengthened credit risk profile with strategic exits and growth in targeted client segments to focus on relationships ▪ Significantly scaled back construction portfolio from pre-global financial crisis (42% in 2008 14% at 6/30/23) ▪ Focused on relationships with select owners and operators ▪ Strategic focus in multifamily, primarily affordable housing Real Estate Public Sector 17 $ in millions 6/30/23 % of total loans Commercial and industrial $ 60,059 50% Commercial real estate 18,694 16 Commercial lease financing 3,801 3 Total Commercial $ 82,554 69% >50% of C&I portfolio is investment grade Total Commercial Loans Commercial & Industrial (C&I) Commercial Real Estate (CRE) Commercial Loan Portfolio Detail
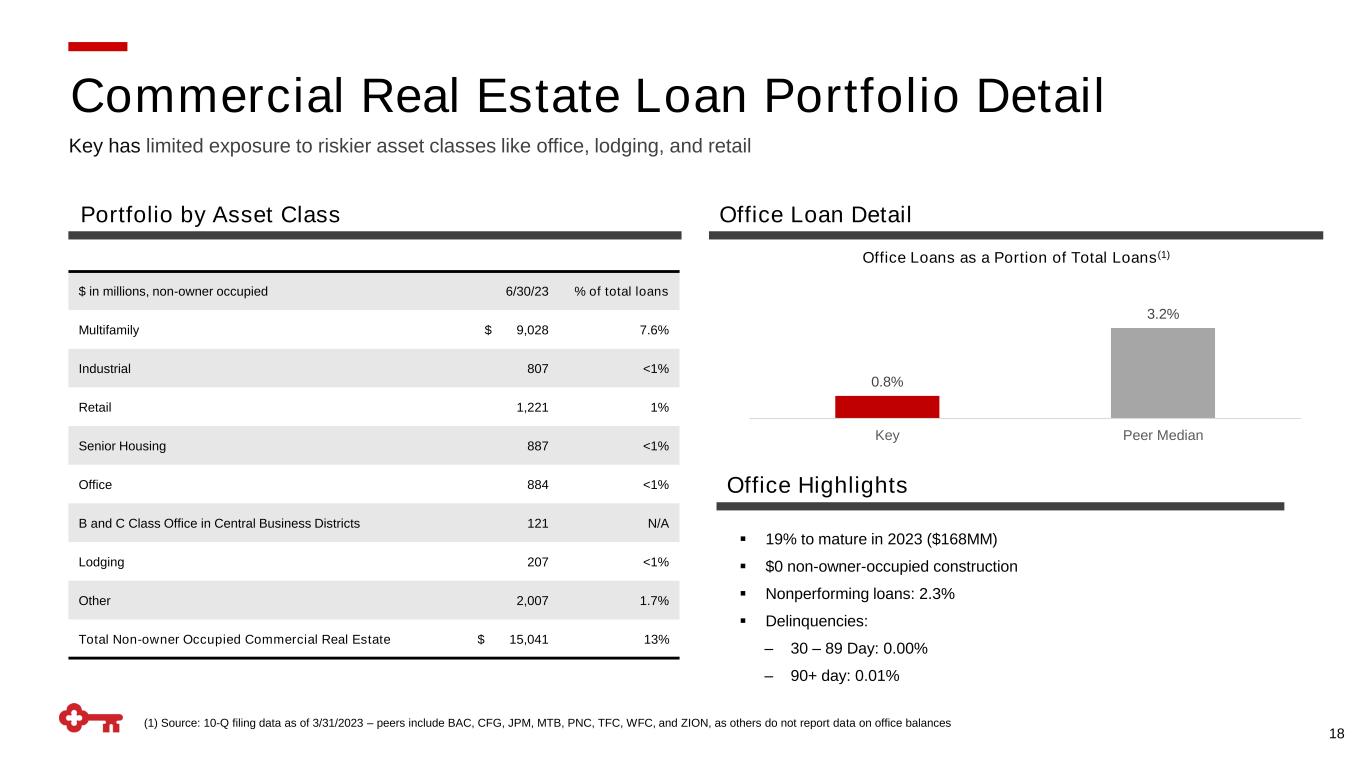
Key has limited exposure to riskier asset classes like office, lodging, and retail 18 $ in millions, non-owner occupied 6/30/23 % of total loans Multifamily $ 9,028 7.6% Industrial 807 <1% Retail 1,221 1% Senior Housing 887 <1% Office 884 <1% B and C Class Office in Central Business Districts 121 N/A Lodging 207 <1% Other 2,007 1.7% Total Non-owner Occupied Commercial Real Estate $ 15,041 13% Office Loans as a Portion of Total Loans(1) (1) Source: 10-Q filing data as of 3/31/2023 – peers include BAC, CFG, JPM, MTB, PNC, TFC, WFC, and ZION, as others do not report data on office balances Portfolio by Asset Class Office Loan Detail Commercial Real Estate Loan Portfolio Detail ▪ 19% to mature in 2023 ($168MM) ▪ $0 non-owner-occupied construction ▪ Nonperforming loans: 2.3% ▪ Delinquencies: ‒ 30 – 89 Day: 0.00% ‒ 90+ day: 0.01% Office Highlights 0.8% 3.2% Key Peer Median
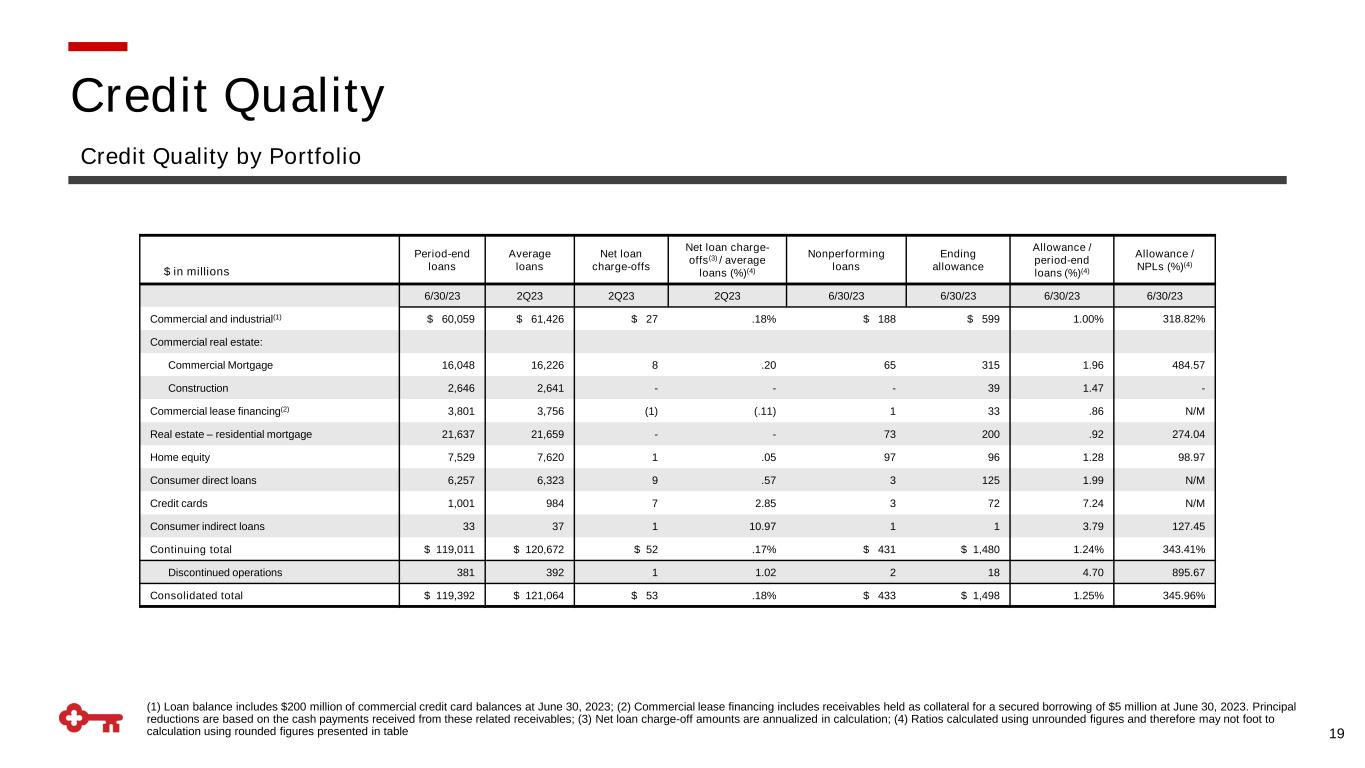
Period-end loans Average loans Net loan charge-offs Net loan charge- offs(3) / average loans (%)(4) Nonperforming loans Ending allowance Allowance / period-end loans (%)(4) Allowance / NPLs (%)(4) 6/30/23 2Q23 2Q23 2Q23 6/30/23 6/30/23 6/30/23 6/30/23 Commercial and industrial(1) $ 60,059 $ 61,426 $ 27 .18% $ 188 $ 599 1.00% 318.82% Commercial real estate: Commercial Mortgage 16,048 16,226 8 .20 65 315 1.96 484.57 Construction 2,646 2,641 - - - 39 1.47 - Commercial lease financing(2) 3,801 3,756 (1) (.11) 1 33 .86 N/M Real estate – residential mortgage 21,637 21,659 - - 73 200 .92 274.04 Home equity 7,529 7,620 1 .05 97 96 1.28 98.97 Consumer direct loans 6,257 6,323 9 .57 3 125 1.99 N/M Credit cards 1,001 984 7 2.85 3 72 7.24 N/M Consumer indirect loans 33 37 1 10.97 1 1 3.79 127.45 Continuing total $ 119,011 $ 120,672 $ 52 .17% $ 431 $ 1,480 1.24% 343.41% Discontinued operations 381 392 1 1.02 2 18 4.70 895.67 Consolidated total $ 119,392 $ 121,064 $ 53 .18% $ 433 $ 1,498 1.25% 345.96% 19 $ in millions (1) Loan balance includes $200 million of commercial credit card balances at June 30, 2023; (2) Commercial lease financing includes receivables held as collateral for a secured borrowing of $5 million at June 30, 2023. Principal reductions are based on the cash payments received from these related receivables; (3) Net loan charge-off amounts are annualized in calculation; (4) Ratios calculated using unrounded figures and therefore may not foot to calculation using rounded figures presented in table Credit Quality Credit Quality by Portfolio
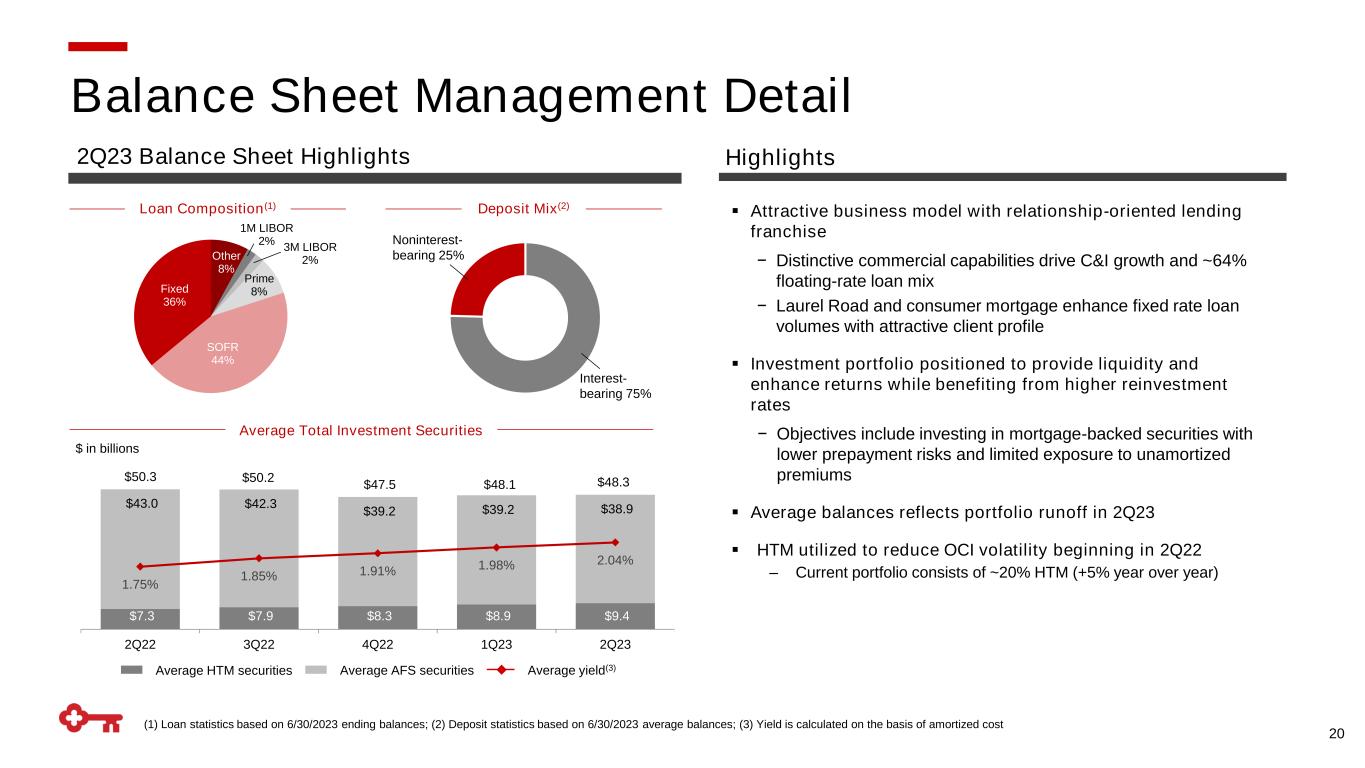
(1) Loan statistics based on 6/30/2023 ending balances; (2) Deposit statistics based on 6/30/2023 average balances; (3) Yield is calculated on the basis of amortized cost Loan Composition(1) Deposit Mix(2) ▪ Attractive business model with relationship-oriented lending franchise − Distinctive commercial capabilities drive C&I growth and ~64% floating-rate loan mix − Laurel Road and consumer mortgage enhance fixed rate loan volumes with attractive client profile ▪ Investment portfolio positioned to provide liquidity and enhance returns while benefiting from higher reinvestment rates − Objectives include investing in mortgage-backed securities with lower prepayment risks and limited exposure to unamortized premiums ▪ Average balances reflects portfolio runoff in 2Q23 ▪ HTM utilized to reduce OCI volatility beginning in 2Q22 ‒ Current portfolio consists of ~20% HTM (+5% year over year) 20 Noninterest- bearing 25% Interest- bearing 75% $7.3 $7.9 $8.3 $8.9 $9.4 $43.0 $42.3 $39.2 $39.2 $38.9 1.75% 1.85% 1.91% 1.98% 2.04% 2Q22 3Q22 4Q22 1Q23 2Q23 Average AFS securities Average yield(3)Average HTM securities $ in billions Average Total Investment Securities Balance Sheet Management Detail 2Q23 Balance Sheet Highlights Highlights $50.3 $50.2 $47.5 $48.1 Prime 8% 1M LIBOR 2% 3M LIBOR 2%Other 8% SOFR 44% Fixed 36% $48.3
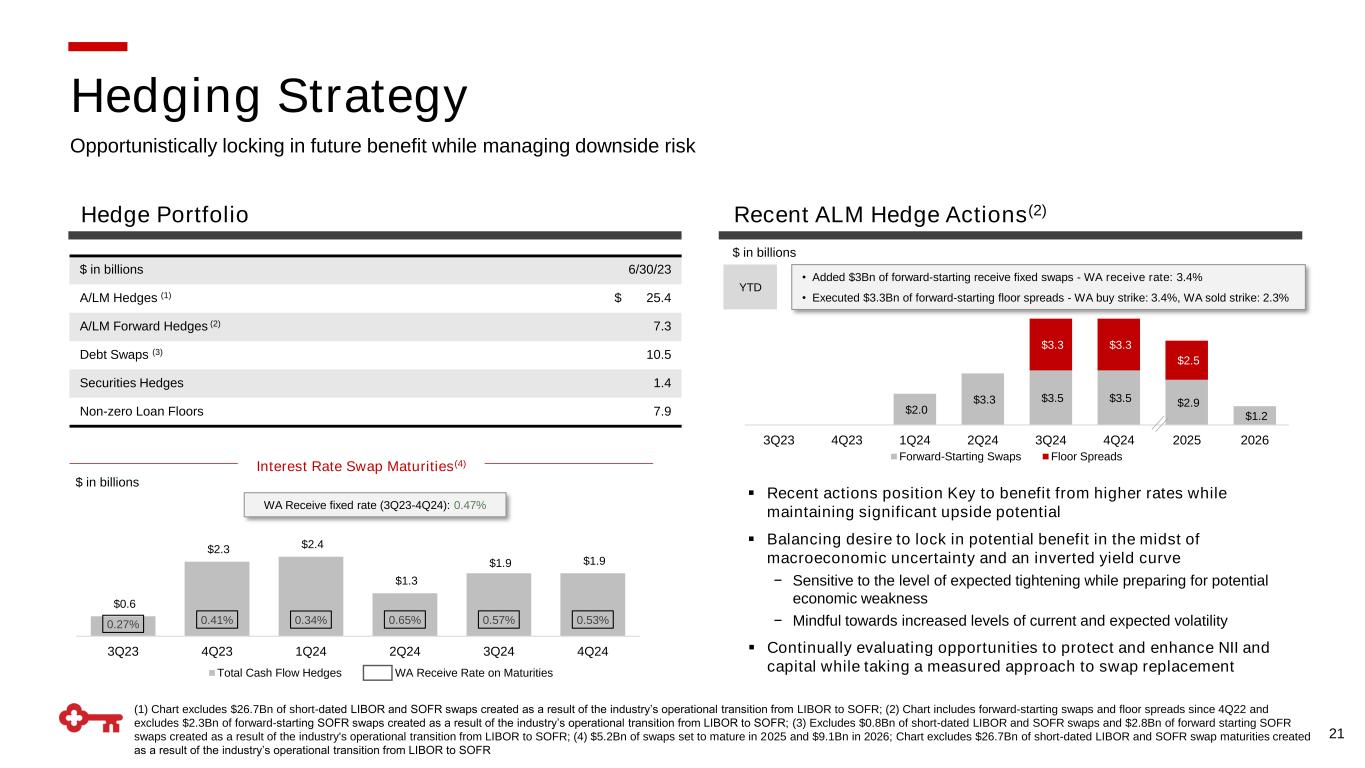
(1) Chart excludes $26.7Bn of short-dated LIBOR and SOFR swaps created as a result of the industry’s operational transition from LIBOR to SOFR; (2) Chart includes forward-starting swaps and floor spreads since 4Q22 and excludes $2.3Bn of forward-starting SOFR swaps created as a result of the industry’s operational transition from LIBOR to SOFR; (3) Excludes $0.8Bn of short-dated LIBOR and SOFR swaps and $2.8Bn of forward starting SOFR swaps created as a result of the industry's operational transition from LIBOR to SOFR; (4) $5.2Bn of swaps set to mature in 2025 and $9.1Bn in 2026; Chart excludes $26.7Bn of short-dated LIBOR and SOFR swap maturities created as a result of the industry’s operational transition from LIBOR to SOFR 21 WA Receive fixed rate (3Q23-4Q24): 0.47% Hedging Strategy Opportunistically locking in future benefit while managing downside risk Hedge Portfolio Recent ALM Hedge Actions(2) $0.6 $2.3 $2.4 $1.3 $1.9 $1.9 0.27% 0.41% 0.34% 0.65% 0.57% 0.53% $0.0 $1.0 $2.0 $3.0 3Q23 4Q23 1Q24 2Q24 3Q24 4Q24 Total Cash Flow Hedges WA Receive Rate on Maturities $2.0 $3.3 $3.5 $3.5 $2.9 $1.2 $3.3 $3.3 $2.5 ($1.0) $1.0 $3.0 $5.0 $7.0 3Q23 4Q23 1Q24 2Q24 3Q24 4Q24 2025 2026 Forward-Starting Swaps Floor Spreads • Added $3Bn of forward-starting receive fixed swaps - WA receive rate: 3.4% • Executed $3.3Bn of forward-starting floor spreads - WA buy strike: 3.4%, WA sold strike: 2.3% YTD Interest Rate Swap Maturities(4) $ in billions $ in billions $ in billions 6/30/23 A/LM Hedges (1) $ 25.4 A/LM Forward Hedges (2) 7.3 Debt Swaps (3) 10.5 Securities Hedges 1.4 Non-zero Loan Floors 7.9 ▪ Recent actions position Key to benefit from higher rates while maintaining significant upside potential ▪ Balancing desire to lock in potential benefit in the midst of macroeconomic uncertainty and an inverted yield curve − Sensitive to the level of expected tightening while preparing for potential economic weakness − Mindful towards increased levels of current and expected volatility ▪ Continually evaluating opportunities to protect and enhance NII and capital while taking a measured approach to swap replacement
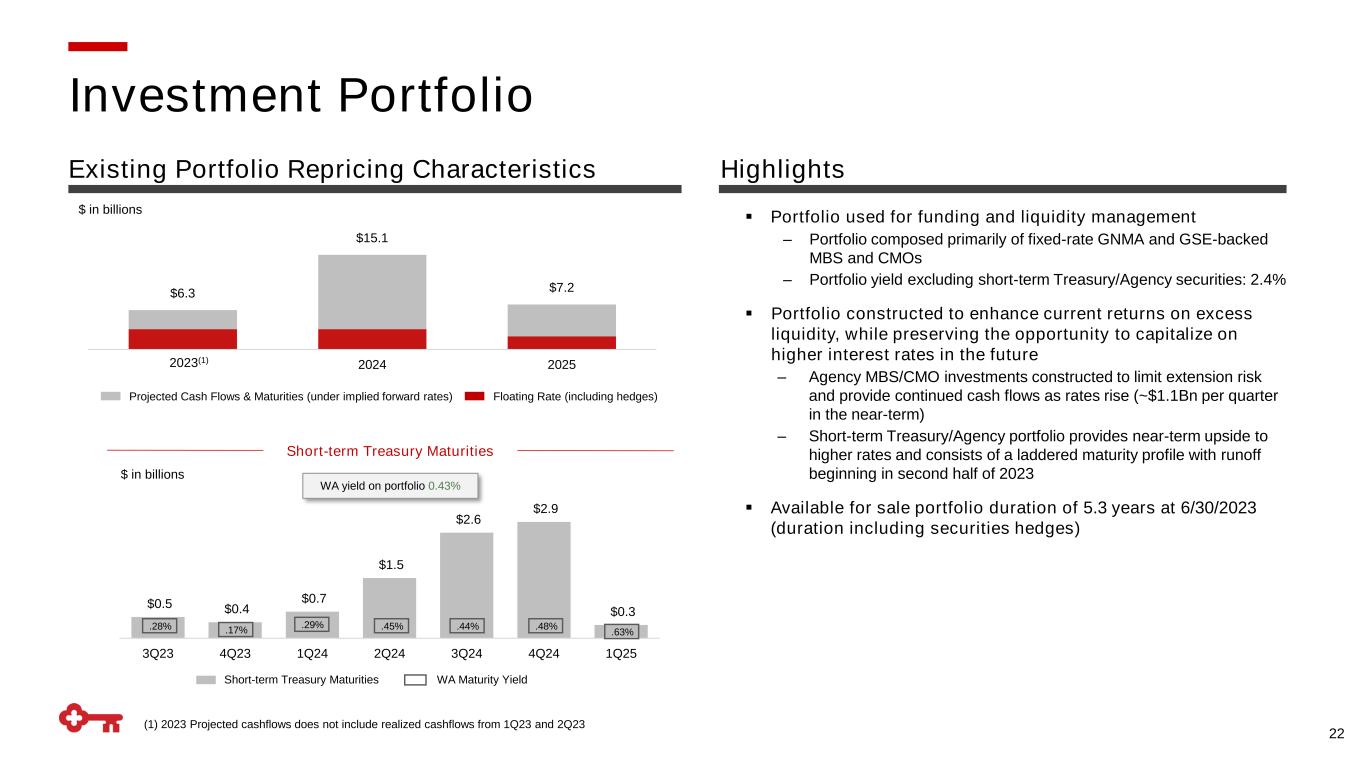
22 Projected Cash Flows & Maturities (under implied forward rates) Floating Rate (including hedges) Existing Portfolio Repricing Characteristics Highlights (1) 2023 Projected cashflows does not include realized cashflows from 1Q23 and 2Q23 Investment Portfolio $ in billions ▪ Portfolio used for funding and liquidity management ‒ Portfolio composed primarily of fixed-rate GNMA and GSE-backed MBS and CMOs ‒ Portfolio yield excluding short-term Treasury/Agency securities: 2.4% ▪ Portfolio constructed to enhance current returns on excess liquidity, while preserving the opportunity to capitalize on higher interest rates in the future ‒ Agency MBS/CMO investments constructed to limit extension risk and provide continued cash flows as rates rise (~$1.1Bn per quarter in the near-term) ‒ Short-term Treasury/Agency portfolio provides near-term upside to higher rates and consists of a laddered maturity profile with runoff beginning in second half of 2023 ▪ Available for sale portfolio duration of 5.3 years at 6/30/2023 (duration including securities hedges) $6.3 $15.1 $7.2 2023** 2024 20252023(1) $0.5 $0.4 $0.7 $1.5 $2.6 $2.9 $0.3 $0.0 $0.5 $1.0 $1.5 $2.0 $2.5 $3.0 $3.5 3Q23 4Q23 1Q24 2Q24 3Q24 4Q24 1Q25 WA yield on portfolio 0.43% $ in billions .48%.44%.45%.29% .17%.28% Short-term Treasury Maturities WA Maturity Yield Short-term Treasury Maturities .63%
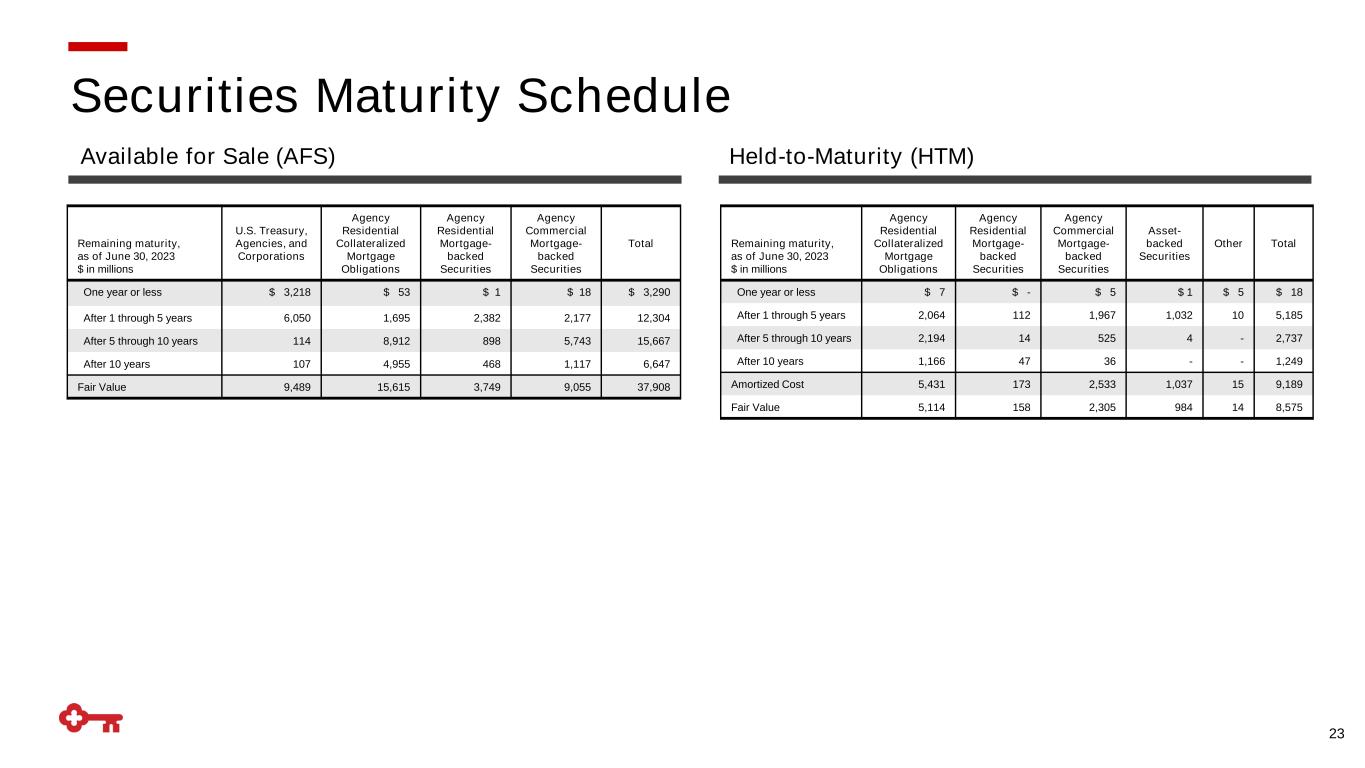
23 Remaining maturity, as of June 30, 2023 $ in millions Agency Residential Collateralized Mortgage Obligations Agency Residential Mortgage- backed Securities Agency Commercial Mortgage- backed Securities Asset- backed Securities Other Total One year or less $ 7 $ - $ 5 $ 1 $ 5 $ 18 After 1 through 5 years 2,064 112 1,967 1,032 10 5,185 After 5 through 10 years 2,194 14 525 4 - 2,737 After 10 years 1,166 47 36 - - 1,249 Amortized Cost 5,431 173 2,533 1,037 15 9,189 Fair Value 5,114 158 2,305 984 14 8,575 Remaining maturity, as of June 30, 2023 $ in millions U.S. Treasury, Agencies, and Corporations Agency Residential Collateralized Mortgage Obligations Agency Residential Mortgage- backed Securities Agency Commercial Mortgage- backed Securities Total One year or less $ 3,218 $ 53 $ 1 $ 18 $ 3,290 After 1 through 5 years 6,050 1,695 2,382 2,177 12,304 After 5 through 10 years 114 8,912 898 5,743 15,667 After 10 years 107 4,955 468 1,117 6,647 Fair Value 9,489 15,615 3,749 9,055 37,908 Available for Sale (AFS) Held-to-Maturity (HTM) Securities Maturity Schedule
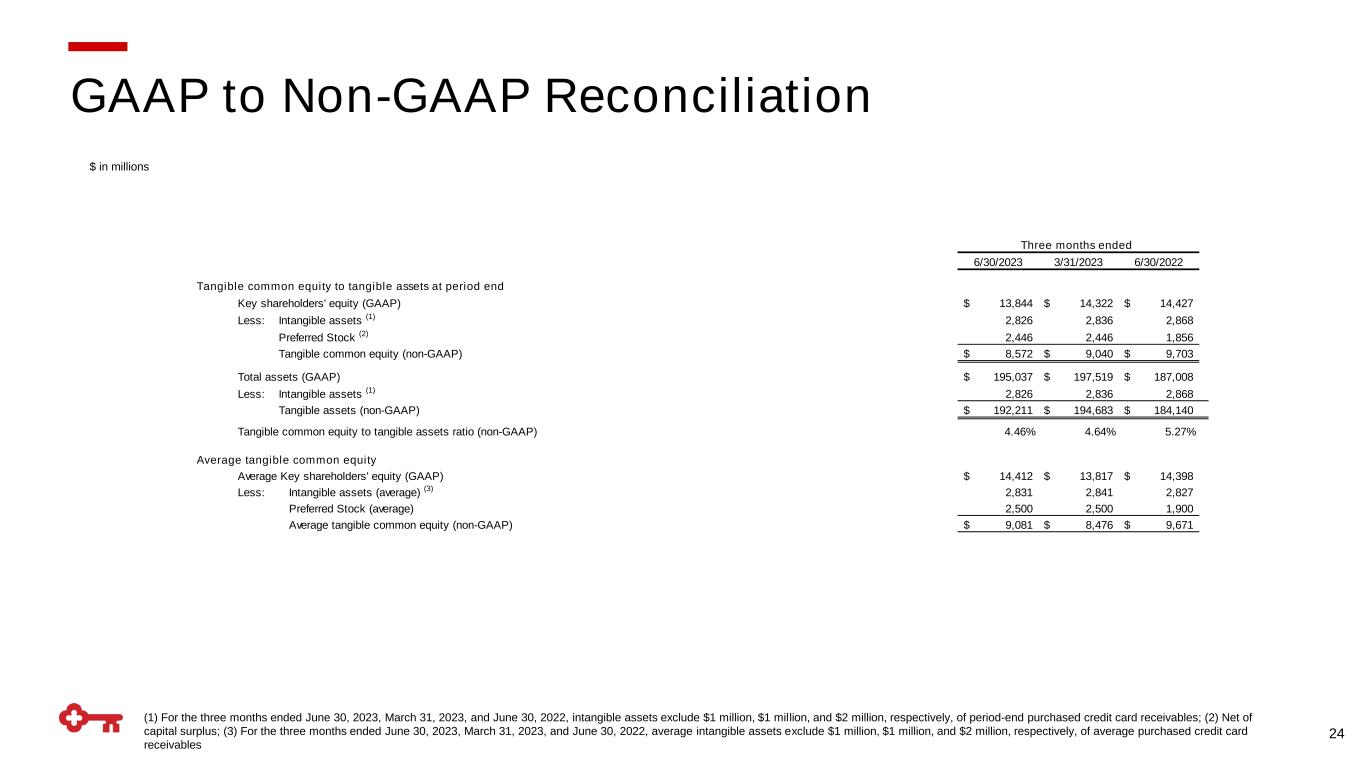
6/30/2023 3/31/2023 6/30/2022 Tangible common equity to tangible assets at period end Key shareholders' equity (GAAP) 13,844$ 14,322$ 14,427$ Less: Intangible assets (1) 2,826 2,836 2,868 Preferred Stock (2) 2,446 2,446 1,856 Tangible common equity (non-GAAP) 8,572$ 9,040$ 9,703$ Total assets (GAAP) 195,037$ 197,519$ 187,008$ Less: Intangible assets (1) 2,826 2,836 2,868 Tangible assets (non-GAAP) 192,211$ 194,683$ 184,140$ Tangible common equity to tangible assets ratio (non-GAAP) 4.46% 4.64% 5.27% Average tangible common equity Average Key shareholders' equity (GAAP) 14,412$ 13,817$ 14,398$ Less: Intangible assets (average) (3) 2,831 2,841 2,827 Preferred Stock (average) 2,500 2,500 1,900 Average tangible common equity (non-GAAP) 9,081$ 8,476$ 9,671$ Three months ended 24 $ in millions (1) For the three months ended June 30, 2023, March 31, 2023, and June 30, 2022, intangible assets exclude $1 million, $1 million, and $2 million, respectively, of period-end purchased credit card receivables; (2) Net of capital surplus; (3) For the three months ended June 30, 2023, March 31, 2023, and June 30, 2022, average intangible assets exclude $1 million, $1 million, and $2 million, respectively, of average purchased credit card receivables GAAP to Non-GAAP Reconciliation
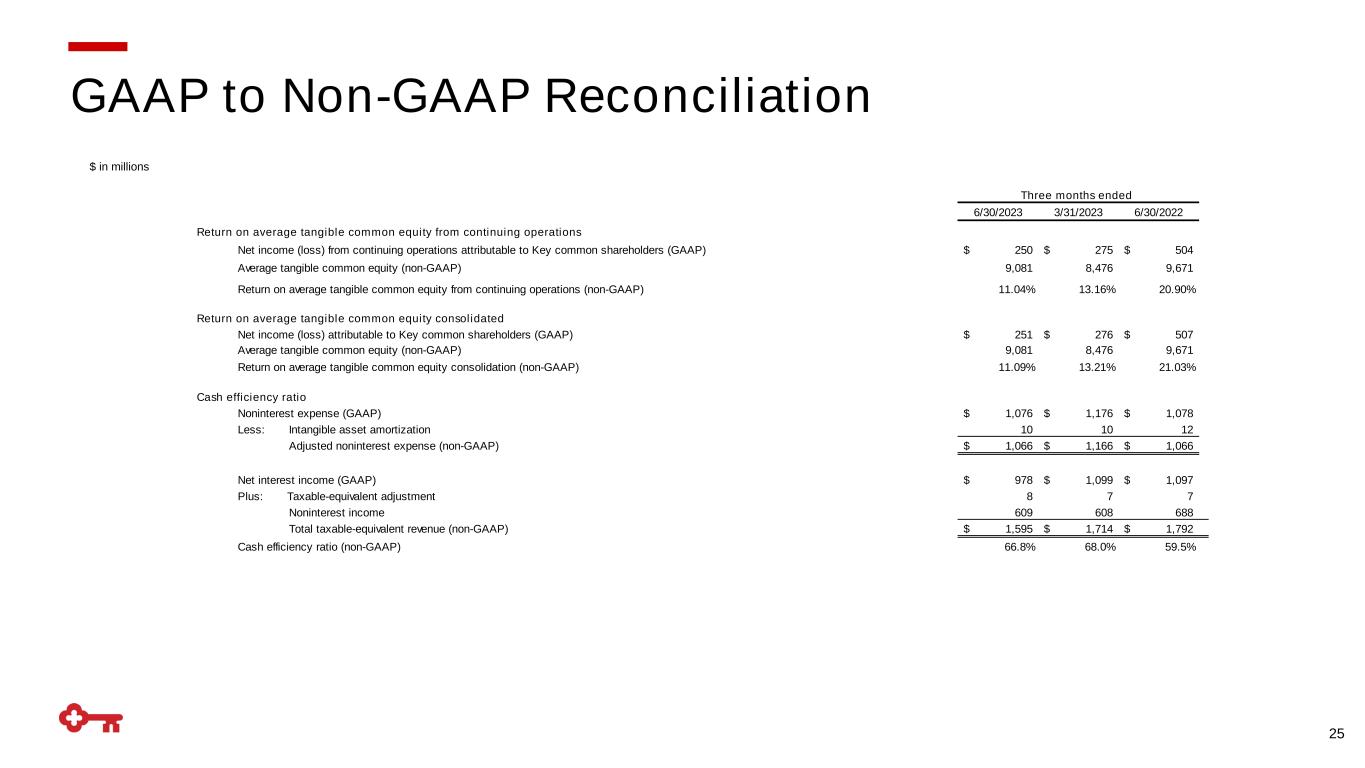
6/30/2023 3/31/2023 6/30/2022 Return on average tangible common equity from continuing operations Net income (loss) from continuing operations attributable to Key common shareholders (GAAP) 250$ 275$ 504$ Average tangible common equity (non-GAAP) 9,081 8,476 9,671 Return on average tangible common equity from continuing operations (non-GAAP) 11.04% 13.16% 20.90% Return on average tangible common equity consolidated Net income (loss) attributable to Key common shareholders (GAAP) 251$ 276$ 507$ Average tangible common equity (non-GAAP) 9,081 8,476 9,671 Return on average tangible common equity consolidation (non-GAAP) 11.09% 13.21% 21.03% Cash efficiency ratio Noninterest expense (GAAP) 1,076$ 1,176$ 1,078$ Less: Intangible asset amortization 10 10 12 Adjusted noninterest expense (non-GAAP) 1,066$ 1,166$ 1,066$ Net interest income (GAAP) 978$ 1,099$ 1,097$ Plus: Taxable-equivalent adjustment 8 7 7 Noninterest income 609 608 688 Total taxable-equivalent revenue (non-GAAP) 1,595$ 1,714$ 1,792$ Cash efficiency ratio (non-GAAP) 66.8% 68.0% 59.5% Three months ended 25 $ in millions GAAP to Non-GAAP Reconciliation
Exhibit 99.3
| Consolidated Balance Sheets | |||||||||||||||||
| (dollars in millions) | |||||||||||||||||
| 6/30/2023 | 3/31/2023 | 6/30/2022 | |||||||||||||||
| Assets | |||||||||||||||||
| Loans | $ | 119,011 | $ | 119,971 | $ | 112,390 | |||||||||||
| Loans held for sale | 1,130 | 1,211 | 1,306 | ||||||||||||||
| Securities available for sale | 37,908 | 39,498 | 42,437 | ||||||||||||||
| Held-to-maturity securities | 9,189 | 9,561 | 8,186 | ||||||||||||||
| Trading account assets | 1,177 | 1,118 | 809 | ||||||||||||||
| Short-term investments | 8,959 | 8,410 | 2,456 | ||||||||||||||
| Other investments | 1,474 | 1,587 | 969 | ||||||||||||||
| Total earning assets | 178,848 | 181,356 | 168,553 | ||||||||||||||
| Allowance for loan and lease losses | (1,480) | (1,380) | (1,099) | ||||||||||||||
| Cash and due from banks | 758 | 784 | 678 | ||||||||||||||
| Premises and equipment | 652 | 628 | 638 | ||||||||||||||
| Goodwill | 2,752 | 2,752 | 2,752 | ||||||||||||||
| Other intangible assets | 75 | 85 | 118 | ||||||||||||||
| Corporate-owned life insurance | 4,378 | 4,372 | 4,343 | ||||||||||||||
| Accrued income and other assets | 8,668 | 8,512 | 10,529 | ||||||||||||||
| Discontinued assets | 386 | 410 | 496 | ||||||||||||||
| Total assets | $ | 195,037 | $ | 197,519 | $ | 187,008 | |||||||||||
| Liabilities | |||||||||||||||||
| Deposits in domestic offices: | |||||||||||||||||
| Interest-bearing deposits | 111,766 | 106,841 | 94,892 | ||||||||||||||
| Noninterest-bearing deposits | 33,366 | 37,307 | 50,973 | ||||||||||||||
| Total deposits | 145,132 | 144,148 | 145,865 | ||||||||||||||
| Federal funds purchased and securities sold under repurchase agreements | 1,702 | 1,374 | 3,234 | ||||||||||||||
| Bank notes and other short-term borrowings | 6,949 | 10,061 | 2,809 | ||||||||||||||
| Accrued expense and other liabilities | 5,339 | 4,861 | 4,056 | ||||||||||||||
| Long-term debt | 22,071 | 22,753 | 16,617 | ||||||||||||||
| Total liabilities | 181,193 | 183,197 | 172,581 | ||||||||||||||
| Equity | |||||||||||||||||
| Preferred stock | 2,500 | 2,500 | 1,900 | ||||||||||||||
| Common shares | 1,257 | 1,257 | 1,257 | ||||||||||||||
| Capital surplus | 6,231 | 6,207 | 6,241 | ||||||||||||||
| Retained earnings | 15,759 | 15,700 | 15,118 | ||||||||||||||
| Treasury stock, at cost | (5,859) | (5,868) | (5,923) | ||||||||||||||
| Accumulated other comprehensive income (loss) | (6,044) | (5,474) | (4,166) | ||||||||||||||
| Key shareholders’ equity | 13,844 | 14,322 | 14,427 | ||||||||||||||
| Noncontrolling interests | — | — | — | ||||||||||||||
| Total equity | 13,844 | 14,322 | 14,427 | ||||||||||||||
| Total liabilities and equity | $ | 195,037 | $ | 197,519 | $ | 187,008 | |||||||||||
| Common shares outstanding (000) | 935,733 | 935,229 | 932,643 | ||||||||||||||
| Consolidated Statements of Income | ||||||||||||||||||||||||||
| (dollars in millions, except per share amounts) | ||||||||||||||||||||||||||
| Three months ended | Six months ended | |||||||||||||||||||||||||
| 6/30/2023 | 3/31/2023 | 6/30/2022 | 6/30/2023 | 6/30/2022 | ||||||||||||||||||||||
| Interest income | ||||||||||||||||||||||||||
| Loans | $ | 1,576 | $ | 1,476 | $ | 923 | $ | 3,052 | $ | 1,760 | ||||||||||||||||
| Loans held for sale | 17 | 13 | 10 | 30 | 22 | |||||||||||||||||||||
| Securities available for sale | 194 | 194 | 188 | 388 | 361 | |||||||||||||||||||||
| Held-to-maturity securities | 81 | 74 | 48 | 155 | 94 | |||||||||||||||||||||
| Trading account assets | 15 | 12 | 7 | 27 | 13 | |||||||||||||||||||||
| Short-term investments | 111 | 42 | 13 | 153 | 17 | |||||||||||||||||||||
| Other investments | 16 | 13 | 4 | 29 | 6 | |||||||||||||||||||||
| Total interest income | 2,010 | 1,824 | 1,193 | 3,834 | 2,273 | |||||||||||||||||||||
| Interest expense | ||||||||||||||||||||||||||
| Deposits | 531 | 350 | 20 | 881 | 34 | |||||||||||||||||||||
| Federal funds purchased and securities sold under repurchase agreements | 48 | 22 | 6 | 70 | 6 | |||||||||||||||||||||
| Bank notes and other short-term borrowings | 104 | 78 | 9 | 182 | 12 | |||||||||||||||||||||
| Long-term debt | 349 | 275 | 61 | 624 | 110 | |||||||||||||||||||||
| Total interest expense | 1,032 | 725 | 96 | 1,757 | 162 | |||||||||||||||||||||
| Net interest income | 978 | 1,099 | 1,097 | 2,077 | 2,111 | |||||||||||||||||||||
| Provision for credit losses | 167 | 139 | 45 | 306 | 128 | |||||||||||||||||||||
| Net interest income after provision for credit losses | 811 | 960 | 1,052 | 1,771 | 1,983 | |||||||||||||||||||||
| Noninterest income | ||||||||||||||||||||||||||
| Trust and investment services income | 126 | 128 | 137 | 254 | 273 | |||||||||||||||||||||
| Investment banking and debt placement fees | 120 | 145 | 149 | 265 | 312 | |||||||||||||||||||||
| Service charges on deposit accounts | 69 | 67 | 96 | 136 | 187 | |||||||||||||||||||||
| Operating lease income and other leasing gains | 23 | 25 | 28 | 48 | 60 | |||||||||||||||||||||
| Corporate services income | 86 | 76 | 96 | 162 | 187 | |||||||||||||||||||||
| Cards and payments income | 85 | 81 | 85 | 166 | 165 | |||||||||||||||||||||
| Corporate-owned life insurance income | 32 | 29 | 35 | 61 | 66 | |||||||||||||||||||||
| Consumer mortgage income | 14 | 11 | 14 | 25 | 35 | |||||||||||||||||||||
| Commercial mortgage servicing fees | 50 | 46 | 45 | 96 | 81 | |||||||||||||||||||||
| Other income | 4 | — | 3 | 4 | (2) | |||||||||||||||||||||
| Total noninterest income | 609 | 608 | 688 | 1,217 | 1,364 | |||||||||||||||||||||
| Noninterest expense | ||||||||||||||||||||||||||
| Personnel | 622 | 701 | 607 | 1,323 | 1,237 | |||||||||||||||||||||
| Net occupancy | 65 | 70 | 78 | 135 | 151 | |||||||||||||||||||||
| Computer processing | 95 | 92 | 78 | 187 | 155 | |||||||||||||||||||||
| Business services and professional fees | 41 | 45 | 52 | 86 | 105 | |||||||||||||||||||||
| Equipment | 22 | 22 | 26 | 44 | 49 | |||||||||||||||||||||
| Operating lease expense | 21 | 20 | 27 | 41 | 55 | |||||||||||||||||||||
| Marketing | 29 | 21 | 34 | 50 | 62 | |||||||||||||||||||||
| Intangible asset amortization | — | — | — | — | — | |||||||||||||||||||||
| Other expense | 181 | 205 | 176 | 386 | 334 | |||||||||||||||||||||
| Total noninterest expense | 1,076 | 1,176 | 1,078 | 2,252 | 2,148 | |||||||||||||||||||||
| Income (loss) from continuing operations before income taxes | 344 | 392 | 662 | 736 | 1,199 | |||||||||||||||||||||
| Income taxes | 58 | 81 | 132 | 139 | 222 | |||||||||||||||||||||
| Income (loss) from continuing operations | 286 | 311 | 530 | 597 | 977 | |||||||||||||||||||||
| Income (loss) from discontinued operations, net of taxes | 1 | 1 | 3 | 2 | 4 | |||||||||||||||||||||
| Net income (loss) | 287 | 312 | 533 | 599 | 981 | |||||||||||||||||||||
| Less: Net income (loss) attributable to noncontrolling interests | — | — | — | — | — | |||||||||||||||||||||
| Net income (loss) attributable to Key | $ | 287 | $ | 312 | $ | 533 | $ | 599 | $ | 981 | ||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | 250 | $ | 275 | $ | 504 | $ | 525 | $ | 924 | ||||||||||||||||
| Net income (loss) attributable to Key common shareholders | 251 | 276 | 507 | 527 | 928 | |||||||||||||||||||||
| Per common share | ||||||||||||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | .27 | $ | .30 | $ | .54 | $ | .57 | $ | 1 | ||||||||||||||||
| Income (loss) from discontinued operations, net of taxes | — | — | — | — | — | |||||||||||||||||||||
Net income (loss) attributable to Key common shareholders (a) | .27 | .30 | .55 | .57 | 1 | |||||||||||||||||||||
| Per common share — assuming dilution | ||||||||||||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | .27 | $ | .30 | $ | .54 | $ | .56 | $ | .99 | ||||||||||||||||
| Income (loss) from discontinued operations, net of taxes | — | — | — | — | — | |||||||||||||||||||||
Net income (loss) attributable to Key common shareholders (a) | .27 | .30 | $ | .54 | .57 | 1.00 | ||||||||||||||||||||
| Cash dividends declared per common share | $ | .205 | $ | .205 | $ | .195 | $ | .41 | $ | .39 | ||||||||||||||||
| Weighted-average common shares outstanding (000) | 926,741 | 926,490 | 924,302 | 926,807 | 923,717 | |||||||||||||||||||||
| Effect of common share options and other stock awards | 3,713 | 7,314 | 7,506 | 5,513 | 9,087 | |||||||||||||||||||||
Weighted-average common shares and potential common shares outstanding (000) (b) | 930,454 | 933,804 | 931,808 | 932,320 | 932,805 | |||||||||||||||||||||
(a)Earnings per share may not foot due to rounding.
(b)Assumes conversion of common share options and other stock awards and/or convertible preferred stock, as applicable.