PDM 8-K
Piedmont Realty Trust, Inc. (PDM)
8-K
2024-04-30
For: 2024-04-30
View Original
Added on
April 12, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
Form 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): April 30, 2024
(Exact name of registrant as specified in its charter)
Commission File Number: 001-34626
| (State or other jurisdiction of | (IRS Employer | |||||||
| incorporation) | Identification No.) | |||||||
(Address of principal executive offices, including zip code)
(770 ) 418-8800
(Registrant's telephone number, including area code)
Not applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol | Name of each exchange on which registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.o
Item 2.02 Results of Operations and Financial Condition.
On April 30, 2024, Piedmont Office Realty Trust, Inc. (the "Registrant") issued a press release announcing its financial results for the first quarter 2024, and published supplemental information for the first quarter 2024 to its website. The press release and the supplemental information are attached hereto as Exhibit 99.1 and 99.2, respectively, and are incorporated herein by reference. Pursuant to the rules and regulations of the Securities and Exchange Commission, such exhibits and the information set forth therein are deemed to have been furnished and shall not be deemed to be “filed” under the Securities Exchange Act of 1934.
Item 9.01 Financial Statements and Exhibits.
(d) Exhibits:
| Exhibit No. | Description | |||||||
| 99.1 | ||||||||
| 99.2 | ||||||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) | |||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this Current Report on Form 8-K to be signed on its behalf by the undersigned hereunto duly authorized.
| Piedmont Office Realty Trust, Inc. | |||||||||||||||||
| (Registrant) | |||||||||||||||||
| Dated: | April 30, 2024 | By: | /s/ Robert E. Bowers | ||||||||||||||
| Robert E. Bowers | |||||||||||||||||
| Chief Financial Officer and Executive Vice President | |||||||||||||||||
EXHIBIT 99.1
Piedmont Office Realty Trust Reports First Quarter 2024 Results
ATLANTA, April 30, 2024--Piedmont Office Realty Trust, Inc. ("Piedmont" or the "Company") (NYSE:PDM), an owner of Class A office properties located primarily in major U.S. Sunbelt markets, today announced its results for the quarter ended March 31, 2024 which included significant leasing activity, strong Same Store NOI growth, as well as previously announced refinancing and disposition activity.
Highlights for the Three Months Ended March 31, 2024:
Financial Results:
| Three Months Ended | ||||||||
| (in 000s other than per share amounts ) | March 31, 2024 | March 31, 2023 | ||||||
| Net loss applicable to Piedmont | $(27,763) | $(1,367) | ||||||
| Net loss per share applicable to common stockholders - diluted | $(0.22) | $(0.01) | ||||||
| Interest expense | $29,714 | $22,077 | ||||||
| Impairment charges | $18,432 | $0 | ||||||
| Core FFO applicable to common stock | $47,753 | $56,344 | ||||||
| NAREIT FFO per diluted share | $0.38 | $0.46 | ||||||
| Core FFO per diluted share | $0.39 | $0.46 | ||||||
| Adjusted FFO applicable to common stock | $24,741 | $36,792 | ||||||
| Same Store NOI - cash basis | 5.1 | % | ||||||
| Same Store NOI - accrual basis | 2.1 | % | ||||||
•Piedmont recognized a net loss of $27.8 million, or $0.22 per diluted share, for the first quarter of 2024, as compared to a net loss of $1.4 million, or $0.01 per diluted share, for the first quarter of 2023, with the first quarter of 2024 including $18.4 million, or $0.15 per diluted share, in impairment charges primarily related to shortening the projected hold period for one property during the quarter, as well as approximately $7.6 million, or $0.06 per diluted share, of increased interest expense as compared to first quarter of 2023.
•Core FFO, which removes the impact of the impairment charges noted above, as well as loss on early extinguishment of debt, and depreciation and amortization expense, was $0.39 per diluted share for the first quarter of 2024, as compared to $0.46 per diluted share for the first quarter of 2023, with the decrease primarily attributable to the $0.06 per diluted share increase in interest expense noted above.
•Same Store NOI - Cash basis and Same Store NOI - Accrual basis increased 5.1% and 2.1%, respectively, for the three months ended March 31, 2024, as compared to the same period in the prior year, as newly commenced leases or those with expiring abatements outweighed expiring leases.
Leasing:
| Three Months Ended March 31, 2024 | |||||
| # of lease transactions | 54 | ||||
Total leasing sf (in 000s) | 500 | ||||
New tenant leasing sf (in 000s) | 328 | ||||
| Cash rent roll up | 8.0 | % | |||
| Accrual rent roll up | 18.6 | % | |||
| Leased Percentage as of period end | 87.8 | % | |||
•The Company completed approximately 500,000 square feet of leasing during the first quarter, including approximately 328,000 square feet of new tenant leasing.
•The weighted average size lease executed during the quarter was approximately 13,000 square feet and the weighted average lease term was approximately eight years.
•Rents on leases executed during the three months ended March 31, 2024 for space vacant one year or less increased approximately 8.0% and 18.6% on a cash and accrual basis, respectively.
•The Company's leased percentage for its in-service portfolio as of March 31, 2024 increased to 87.8%, up from 87.1% as of December 31, 2023, reflecting the leasing activity above, the disposition mentioned below, and one asset moved to redevelopment.
•As of March 31, 2024, the Company had approximately 1.3 million square feet of executed leases for vacant space yet to commence or under rental abatement, representing approximately $42 million of future additional annual cash rents.
•Thus far during the second quarter of 2024, the Company has executed approximately 170,000 square feet of total leasing.
Transactional Activity:
•During the first quarter, the Company sold One Lincoln Park, located at 8401 North Central Expressway in Dallas, TX for $54 million, or $210 per square foot, in an all-cash transaction. The building is a 10-story, approximately 257,000-square foot, office building which was 59% leased as of December 31, 2023.
Balance Sheet:
| (in 000s except for ratios) | March 31, 2024 | December 31, 2023 | |||||||||
| Total Real Estate Assets | $3,452,475 | $3,512,527 | |||||||||
| Total Assets | $3,993,996 | $4,057,082 | |||||||||
| Total Debt | $2,070,070 | $2,054,596 | |||||||||
| Weighted Average Cost of Debt | 5.81 | % | 5.82 | % | |||||||
| Principal Amount of Debt-to-Gross Assets Ratio | 38.9 | % | 38.2 | % | |||||||
| Average Net Debt-to-Core EBITDA (ttm*) | 6.5 x | 6.4 x | |||||||||
•During the three months ended March 31, 2024, the Company entered into a new, three year, $200 million unsecured syndicated bank term loan. The Company used the net proceeds and its
revolving line of credit to pay off a $100 million bank term loan that was scheduled to mature in December of 2024, and to repay $190 million of a $215 million unsecured term loan that was scheduled to mature on January 31, 2024. The remaining $25 million of the $215 million unsecured term loan was extended to January 31, 2025.
•Also during the three months ended March 31, 2024, the Company repaid the remaining approximately $50 million balance of its Senior Unsecured Notes Due 2024 using proceeds from the sale of One Lincoln Park mentioned above.
•As of March 31, 2024, the Company's only debt with a final maturity prior to 2027 is $275 million in unsecured bank term loans that mature during the first quarter of 2025.
ESG and Operations:
•During the first quarter, the U.S. Environmental Protection Agency and the U.S. Department of Energy recognized the Company with its highest level of recognition - 2024 ENERGY STAR Partner of the Year – Sustained Excellence. The sustained excellence recognition is awarded to organizations who have earned Partner of the Year for several consecutive years and have gone beyond the criteria needed to qualify for recognition.
•Three buildings, CNL Center I & II in Orlando, FL and Glenridge Highlands II, in Atlanta, GA earned LEED Gold certification during the quarter.
•As of March 31, 2024, approximately 84% and 72% of the Company's portfolio was ENERGY STAR rated and LEED certified, respectively.
Commenting on first quarter results, Brent Smith, Piedmont's President and Chief Executive Officer, said, "We are pleased with our quarterly results. First and foremost, we continued to experience the strong leasing volume that we have seen over the last several quarters, executing approximately half a million square feet, with over half a point of occupancy absorption driven by small and medium enterprises in the flight-to-quality trend. In addition, we harvested the value in one of our high-quality Dallas assets through the disposition of One Lincoln Park to a financial services tenant, using the proceeds to pay off the remaining balance of our 2024 Senior Notes on an earnings-neutral basis. During the first quarter, we also addressed all of our 2024 debt maturities, meaningfully extending our maturity profile and leaving only $275 million of debt maturing prior to 2027. Finally, we were named an ENERGY STAR Partner of the Year for the fourth consecutive year, adding the prestigious 'Sustained Excellence' designation for the first time."
Second Quarter 2024 Dividend
As previously announced, on April 24, 2024, the board of directors of Piedmont declared a dividend for the second quarter of 2024 in the amount of $0.125 per share on its common stock to stockholders of record as of the close of business on May 24, 2024, payable on June 14, 2024.
Guidance for 2024
The Company is affirming its previous guidance for the year ending December 31, 2024 as follows:
| (in millions, except per share data) | Low | High | |||||||||
| Net loss | $ | (47) | $ | (41) | |||||||
| Add: | |||||||||||
| Depreciation | 148 | 151 | |||||||||
| Amortization | 81 | 84 | |||||||||
| Core FFO applicable to common stock | $ | 182 | $ | 194 | |||||||
| Core FFO applicable to common stock per diluted share | $1.46 | $1.56 | |||||||||
This guidance is based on information available to management as of the date of this release and reflects management's view of current market conditions, including the following specific assumptions and projections:
•Executed leasing in the range of 1.5 - 2 million square feet with year-end leased percentage for the Company's in-service portfolio anticipated to be approximately 87-88%, before the impacts of any acquisition or disposition activity;
•Same Store NOI flat to 2% increase on both a cash and accrual basis, as the Company will experience some downtime between certain lease expirations and new lease commencements during 2024;
•Interest expense of approximately $119-121 million, reflecting a full year of higher interest rates as a result of refinancing activity completed by the Company during the latter half of 2023 and early 2024; and,
•General and administrative expense will remain relatively flat at approximately $29-30 million.
No speculative acquisitions, dispositions, or refinancing are included in the above guidance. The Company will adjust guidance if such transactions occur.
Note that actual results could differ materially from these estimates and individual quarters may fluctuate on both a cash basis and an accrual basis due to the timing of any future dispositions, significant lease commencements and expirations, abatement periods, repairs and maintenance expenses, capital expenditures, capital markets activities, general and administrative expenses, accrued potential performance-based compensation expense, one-time revenue or expense events, and other factors discussed under "Forward Looking Statements" below.
Non-GAAP Financial Measures
To supplement the presentation of the Company’s financial results prepared in accordance with U.S. generally accepted accounting principles ("GAAP"), this release and the accompanying quarterly supplemental information as of and for the period ended March 31, 2024 contain certain financial measures that are not prepared in accordance with GAAP, including FFO, Core FFO, AFFO, Same Store NOI (cash and accrual basis), Property NOI (cash and accrual basis), EBITDAre, and Core EBITDA. Definitions and reconciliations of each of these non-GAAP measures to their most comparable GAAP metrics are included below and in the accompanying quarterly supplemental information.
Each of the non-GAAP measures included in this release and the accompanying quarterly supplemental financial information has limitations as an analytical tool and should not be considered in isolation or as a substitute for an analysis of the Company’s results calculated in accordance with GAAP. In addition, because not all companies use identical calculations, the Company’s presentation of non-GAAP measures in this release and the accompanying quarterly supplemental information may not be comparable to similarly titled measures disclosed by other companies, including other REITs. The Company may also
change the calculation of any of the non-GAAP measures included in this release and the accompanying quarterly supplemental financial information from time to time in light of its then existing operations.
Conference Call Information
Piedmont has scheduled a conference call and an audio web cast for Wednesday, May 1, 2024, at 9:00 A.M. Eastern time. The live, listen-only, audio web cast of the call may be accessed on the Company's website at http://investor.piedmontreit.com/news-and-events/events-calendar. Dial-in numbers for analysts who plan to actively participate in the call are (888) 506-0062 for participants in the United States and Canada and (973) 528-0011 for international participants. Participant Access Code is 467991. A replay of the conference call will be available through May 15, 2024, and may be accessed by dialing (877) 481-4010 for participants in the United States and Canada and (919) 882-2331 for international participants, followed by conference identification code 50330. A web cast replay will also be available after the conference call in the Investor Relations section of the Company's website. During the audio web cast and conference call, the Company's management team will review first quarter 2024 performance, discuss recent events, and conduct a question-and-answer period.
Supplemental Information
Quarterly supplemental information as of and for the period ended March 31, 2024 can be accessed on the Company`s website under the Investor Relations section at www.piedmontreit.com.
About Piedmont Office Realty Trust
Piedmont Office Realty Trust, Inc. (NYSE: PDM) is an owner, manager, developer, redeveloper, and operator of high-quality, Class A office properties located primarily in major U.S. Sunbelt markets. Its approximately $5 billion portfolio is currently comprised of approximately 16 million square feet. The Company is a fully integrated, self-managed real estate investment trust (REIT) with local management offices in each of its markets and is investment-grade rated by S&P Global Ratings (BBB-) and Moody’s (Baa3). Piedmont is a 2024 ENERGY STAR Partner of the Year - Sustained Excellence. For more information, see www.piedmontreit.com.
Forward-Looking Statements
Certain statements contained in this press release constitute forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended (the "Securities Act"), and Section 21E of the Securities Exchange Act of 1934, as amended (the "Exchange Act"). The Company intends for all such forward-looking statements to be covered by the safe-harbor provisions for forward-looking statements contained in Section 27A of the Securities Act and Section 21E of the Exchange Act, as applicable. Such information is subject to certain known and unknown risks and uncertainties, which could cause actual results to differ materially from those anticipated. Therefore, such statements are not intended to be a guarantee of the Company`s performance in future periods. Such forward-looking statements can generally be identified by the Company's use of forward-looking terminology such as "may," "will," "expect," "intend," "anticipate," "estimate," "believe," "continue" or similar words or phrases that indicate predictions of future events or trends or that do not relate solely to historical matters. Examples of such statements in this press release include the Company's estimated range of Net Income/(Loss), Depreciation, Amortization, Core FFO and Core FFO per diluted share for the year ending
December 31, 2024. These statements are based on beliefs and assumptions of Piedmont’s management, which in turn are based on information available at the time the statements are made.
The following are some of the factors that could cause the Company's actual results and its expectations to differ materially from those described in the Company's forward-looking statements:
•Economic, regulatory, socio-economic (including work from home), technological (e.g. artificial intelligence and machine learning, Zoom, etc), and other changes that impact the real estate market generally, the office sector or the patterns of use of commercial office space in general, or the markets where we primarily operate or have high concentrations of revenue;
•The impact of competition on our efforts to renew existing leases or re-let space on terms similar to existing leases;
•Lease terminations, lease defaults, lease contractions, or changes in the financial condition of our tenants, particularly by one of our large lead tenants;
•Impairment charges on our long-lived assets or goodwill resulting therefrom;
•The success of our real estate strategies and investment objectives, including our ability to implement successful redevelopment and development strategies or identify and consummate suitable acquisitions and divestitures;
•The illiquidity of real estate investments, including economic changes, such as rising interest rates and available financing, which could impact the number of buyers/sellers of our target properties, and regulatory restrictions to which real estate investment trusts ("REITs") are subject and the resulting impediment on our ability to quickly respond to adverse changes in the performance of our properties;
•The risks and uncertainties associated with our acquisition and disposition of properties, many of which risks and uncertainties may not be known at the time of acquisition or disposition;
•Development and construction delays, including the potential of supply chain disruptions, and resultant increased costs and risks;
•Future acts of terrorism, civil unrest, or armed hostilities in any of the major metropolitan areas in which we own properties;
•Risks related to the occurrence of cybersecurity incidents, including cybersecurity incidents against us or any of our properties or tenants, or a deficiency in our identification, assessment or management of cybersecurity threats impacting our operations and the public's reaction to reported cybersecurity incidents;
•Costs of complying with governmental laws and regulations, including environmental standards imposed on office building owners;
•Uninsured losses or losses in excess of our insurance coverage, and our inability to obtain adequate insurance coverage at a reasonable cost;
•Additional risks and costs associated with directly managing properties occupied by government tenants, such as potential changes in the political environment, a reduction in federal or state funding of our governmental tenants, or an increased risk of default by government tenants during periods in which state or federal governments are shut down or on furlough;
•Significant price and volume fluctuations in the public markets, including on the exchange which we listed our common stock;
•Risks associated with incurring mortgage and other indebtedness, including changing capital reserve requirements on our lenders and rapidly rising interest rates for new debt financings;
•A downgrade in our credit ratings, the credit ratings of Piedmont Operating Partnership, L.P. (the "Operating Partnership") or the credit ratings of our or the Operating Partnership's unsecured debt securities, which could, among other effects, trigger an increase in the stated rate of one or more of our unsecured debt instruments;
•The effect of future offerings of debt or equity securities on the value of our common stock;
•Additional risks and costs associated with inflation and continuing increases in the rate of inflation, including the impact of a possible recession;
•Uncertainties associated with environmental and regulatory matters;
•Changes in the financial condition of our tenants directly or indirectly resulting from geopolitical developments that could negatively affect important supply chains and international trade, the termination or threatened termination of existing international trade agreements, or the implementation of tariffs or retaliatory tariffs on imported or exported goods;
•The effect of any litigation to which we are, or may become, subject;
•Additional risks and costs associated with owning properties occupied by tenants in particular industries, such as oil and gas, hospitality, travel, co-working, etc., including risks of default during start-up and during economic downturns;
•Changes in tax laws impacting REITs and real estate in general, as well as our ability to continue to qualify as a REIT under the Internal Revenue Code of 1986, as amended (the “Code”), or other tax law changes which may adversely affect our stockholders;
•The future effectiveness of our internal controls and procedures;
•Actual or threatened public health epidemics or outbreaks, such as the COVID-19 pandemic, as well as governmental and private measures taken to combat such health crises; and
•Other factors, including the risk factors described in Item 1A. of our Annual Report on Form 10-K for the year ended December 31, 2023.
Readers are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date of this press release. The Company cannot guarantee the accuracy of any such forward-looking statements contained in this press release, and the Company does not intend to publicly update or revise any forward-looking statements, whether as a result of new information, future events, or otherwise.
Research Analysts/ Institutional Investors Contact:
770-418-8592
Shareholder Services/Transfer Agent Services Contact:
Computershare, Inc.
866-354-3485
| Piedmont Office Realty Trust, Inc. | ||||||||||||||
| Consolidated Balance Sheets (Unaudited) | ||||||||||||||
| (in thousands) | ||||||||||||||
| March 31, 2024 | December 31, 2023 | |||||||||||||
| Assets: | ||||||||||||||
Real estate assets, at cost: | ||||||||||||||
Land | $ | 560,604 | $ | 567,244 | ||||||||||
Buildings and improvements | 3,787,245 | 3,823,241 | ||||||||||||
Buildings and improvements, accumulated depreciation | (1,064,199) | (1,046,512) | ||||||||||||
Intangible lease assets | 156,804 | 170,654 | ||||||||||||
Intangible lease assets, accumulated amortization | (80,070) | (88,066) | ||||||||||||
Construction in progress | 92,091 | 85,966 | ||||||||||||
Total real estate assets | 3,452,475 | 3,512,527 | ||||||||||||
Cash and cash equivalents | 3,544 | 825 | ||||||||||||
Tenant receivables | 10,338 | 7,915 | ||||||||||||
Straight line rent receivables | 184,750 | 183,839 | ||||||||||||
Restricted cash and escrows | 4,221 | 3,381 | ||||||||||||
Prepaid expenses and other assets | 23,853 | 28,466 | ||||||||||||
Goodwill | 53,491 | 53,491 | ||||||||||||
Interest rate swaps | 4,148 | 3,032 | ||||||||||||
Deferred lease costs | 474,746 | 487,519 | ||||||||||||
Deferred lease costs, accumulated depreciation | (217,570) | (223,913) | ||||||||||||
| Total assets | $ | 3,993,996 | $ | 4,057,082 | ||||||||||
| Liabilities: | ||||||||||||||
Unsecured debt, net of discount and unamortized debt issuance costs of $15,958 and $15,437, respectively | $ | 1,875,042 | $ | 1,858,717 | ||||||||||
| Secured Debt | 195,028 | 195,879 | ||||||||||||
Accounts payable, accrued expenses, and accrued capital expenditures | 106,638 | 131,516 | ||||||||||||
Dividends payable | — | 15,143 | ||||||||||||
Deferred income | 95,139 | 89,930 | ||||||||||||
Intangible lease liabilities, less accumulated amortization | 40,237 | 42,925 | ||||||||||||
| Total liabilities | 2,312,084 | 2,334,110 | ||||||||||||
| Stockholders' equity: | ||||||||||||||
Common stock (123,887,808 and 123,715,298 shares issued and outstanding as of March 31, 2024 and December 31, 2023, respectively) | 1,239 | 1,237 | ||||||||||||
Additional paid in capital | 3,717,599 | 3,716,742 | ||||||||||||
Cumulative distributions in excess of earnings | (2,030,389) | (1,987,147) | ||||||||||||
Other comprehensive income | (8,090) | (9,418) | ||||||||||||
| Piedmont stockholders' equity | 1,680,359 | 1,721,414 | ||||||||||||
Noncontrolling interest | 1,553 | 1,558 | ||||||||||||
| Total stockholders' equity | 1,681,912 | 1,722,972 | ||||||||||||
| Total liabilities and stockholders' equity | $ | 3,993,996 | $ | 4,057,082 | ||||||||||
| Total Principal Amount of Debt Outstanding (Unsecured and Secured Debt plus discounts and unamortized debt issuance costs) | 2,086,028 | 2,070,033 | ||||||||||||
| Piedmont Office Realty Trust, Inc. | |||||||||||
| Consolidated Statements of Operations | |||||||||||
| Unaudited (in thousands, except for per share data) | |||||||||||
| Three Months Ended | |||||||||||
| 3/31/2024 | 3/31/2023 | ||||||||||
| Revenues: | |||||||||||
| Rental and tenant reimbursement revenue | $ | 139,081 | $ | 136,829 | |||||||
| Property management fee revenue | 157 | 507 | |||||||||
| Other property related income | 5,300 | 5,031 | |||||||||
Total revenues | 144,538 | 142,367 | |||||||||
| Expenses: | |||||||||||
| Property operating costs | 59,444 | 57,791 | |||||||||
| Depreciation | 38,869 | 35,797 | |||||||||
| Amortization | 18,120 | 22,031 | |||||||||
| Impairment Charges | 18,432 | — | |||||||||
| General and administrative | 7,612 | 7,691 | |||||||||
Total operating expenses | 142,477 | 123,310 | |||||||||
| Other income (expense): | |||||||||||
| Interest expense | (29,714) | (22,077) | |||||||||
| Other income | 278 | 1,656 | |||||||||
| Loss on early extinguishment of debt | (386) | — | |||||||||
Total other income (expense) | (29,822) | (20,421) | |||||||||
| Net loss | (27,761) | (1,364) | |||||||||
| Net income applicable to noncontrolling interest | (2) | (3) | |||||||||
| Net loss applicable to Piedmont | $ | (27,763) | $ | (1,367) | |||||||
| Weighted average common shares outstanding - basic and diluted | 123,800 | 123,550 | |||||||||
| Net loss per share applicable to common stockholders - basic and diluted | $ | (0.22) | $ | (0.01) | |||||||
| Piedmont Office Realty Trust, Inc. | ||||||||||||||
| Funds from Operations ("FFO"), Core FFO and Adjusted FFO | ||||||||||||||
| Unaudited (in thousands, except for per share data) | ||||||||||||||
| Three Months Ended | ||||||||||||||
| 3/31/2024 | 3/31/2023 | |||||||||||||
| GAAP net loss applicable to common stock | $ | (27,763) | $ | (1,367) | ||||||||||
Depreciation of real estate assets(1) | 38,586 | 35,690 | ||||||||||||
Amortization of lease-related costs | 18,112 | 22,021 | ||||||||||||
Impairment charges | 18,432 | — | ||||||||||||
| NAREIT FFO applicable to common stock* | 47,367 | 56,344 | ||||||||||||
Loss on early extinguishment of debt | 386 | — | ||||||||||||
| Core FFO applicable to common stock* | 47,753 | 56,344 | ||||||||||||
Amortization of debt issuance costs and discounts on debt | 1,208 | 1,239 | ||||||||||||
Depreciation of non real estate assets | 272 | 97 | ||||||||||||
Straight-line effects of lease revenue | (2,255) | (3,187) | ||||||||||||
Stock-based compensation adjustments | 1,026 | 183 | ||||||||||||
Amortization of lease-related intangibles | (2,656) | (3,412) | ||||||||||||
Non-incremental capital expenditures(2) | (20,607) | (14,472) | ||||||||||||
| Adjusted FFO applicable to common stock* | $ | 24,741 | $ | 36,792 | ||||||||||
Weighted average common shares outstanding - diluted(3) | 123,954 | 123,690 | ||||||||||||
| NAREIT FFO per share (diluted) | $ | 0.38 | $ | 0.46 | ||||||||||
| Core FFO per share (diluted) | $ | 0.39 | $ | 0.46 | ||||||||||
(1)Excludes depreciation of non real estate assets.
(2)Capital expenditures of a recurring nature related to tenant improvements, leasing commissions and building capital that do not incrementally enhance the underlying assets' income generating capacity. Tenant improvements, leasing commissions, building capital and deferred lease incentives incurred to lease space that was vacant at acquisition, leasing costs for spaces vacant for greater than one year, leasing costs for spaces at newly acquired properties for which in-place leases expire shortly after acquisition, improvements associated with the expansion of a building and renovations that either enhance the rental rates of a building or change the property’s underlying classification, such as from a Class B to a Class A property, are excluded from this measure.
(3)Includes potential dilution under the treasury stock method that would occur if our remaining unvested and potential stock awards vested and resulted in additional common shares outstanding. Such shares were not included when calculating net loss per diluted share applicable to Piedmont for the three months ended March 31, 2024 and 2023 as they would reduce the loss per share presented.
| Piedmont Office Realty Trust, Inc. | |||||||||||||||||||||||
EBITDAre, Core EBITDA, Property Net Operating Income (Cash and Accrual), Same Store Net Operating Income (Cash and Accrual) | |||||||||||||||||||||||
| Unaudited (in thousands) | |||||||||||||||||||||||
| Cash Basis | Accrual Basis | ||||||||||||||||||||||
| Three Months Ended | Three Months Ended | ||||||||||||||||||||||
| 3/31/2024 | 3/31/2023 | 3/31/2024 | 3/31/2023 | ||||||||||||||||||||
| Net loss applicable to Piedmont (GAAP) | $ | (27,763) | $ | (1,367) | $ | (27,763) | $ | (1,367) | |||||||||||||||
Net income applicable to noncontrolling interest | 2 | 3 | 2 | 3 | |||||||||||||||||||
Interest expense | 29,714 | 22,077 | 29,714 | 22,077 | |||||||||||||||||||
Depreciation | 38,857 | 35,787 | 38,857 | 35,787 | |||||||||||||||||||
Amortization | 18,112 | 22,021 | 18,112 | 22,021 | |||||||||||||||||||
| Depreciation and amortization attributable to noncontrolling interests | 20 | 20 | 20 | 20 | |||||||||||||||||||
Impairment charges | 18,432 | — | 18,432 | — | |||||||||||||||||||
EBITDAre* | 77,374 | 78,541 | 77,374 | 78,541 | |||||||||||||||||||
| Loss on early extinguishment of debt | 386 | — | 386 | — | |||||||||||||||||||
| Core EBITDA* | 77,760 | 78,541 | 77,760 | 78,541 | |||||||||||||||||||
General and administrative expenses | 7,612 | 7,691 | 7,612 | 7,691 | |||||||||||||||||||
Management fee revenue | 5 | (293) | 5 | (293) | |||||||||||||||||||
Other income | (171) | (1,440) | (171) | (1,440) | |||||||||||||||||||
| Reversal of non-cash general reserve for uncollectible accounts | — | (400) | |||||||||||||||||||||
Straight-line effects of lease revenue | (2,255) | (3,187) | |||||||||||||||||||||
| Straight-line effects of lease revenue attributable to noncontrolling interests | — | (4) | |||||||||||||||||||||
Amortization of lease-related intangibles | (2,656) | (3,412) | |||||||||||||||||||||
| Property NOI* | 80,295 | 77,496 | 85,206 | 84,499 | |||||||||||||||||||
| Net operating (income)/loss from: | |||||||||||||||||||||||
Acquisitions | — | — | — | — | |||||||||||||||||||
Dispositions | (1,140) | (562) | (1,464) | (913) | |||||||||||||||||||
Other investments(1) | 415 | (1,213) | 318 | (1,259) | |||||||||||||||||||
| Same Store NOI* | $ | 79,570 | $ | 75,721 | $ | 84,060 | $ | 82,327 | |||||||||||||||
| Change period over period in Same Store NOI | 5.1 | % | N/A | 2.1 | % | N/A | |||||||||||||||||
(1)Other investments consist of our investments in active redevelopment and development projects, land, and recently completed redevelopment and development projects for which some portion of operating expenses were capitalized during the current or prior reporting periods. The operating results from 222 South Orange Avenue in Orlando, FL, and 9320 Excelsior Boulevard in Hopkins, MN are included in this line item.
*Definitions:
Funds From Operations ("FFO"): The Company calculates FFO in accordance with the current National Association of Real Estate Investment Trusts (“NAREIT”) definition. NAREIT currently defines FFO as net income/(loss) (calculated in accordance with GAAP), excluding depreciation and amortization related to real estate, gains and losses from the sale of certain real estate assets, gains and losses from change in control, and impairment write-downs of certain real estate assets, goodwill, and investment in entities when the impairment is directly attributable to decreases in the value of depreciable real estate held by the entity, along with appropriate adjustments to those reconciling items for joint ventures, if any. These adjustments can vary among owners of identical assets in similar conditions based on historical cost accounting and useful-life estimates. FFO is a non-GAAP financial measure and should not be viewed as an alternative to net income calculated in accordance with GAAP as a measurement of the Company’s operating performance. The Company believes that FFO is helpful to investors as a supplemental performance measure because it excludes the effects of depreciation, amortization and gains or losses from sales of real estate, all of which are based on historical costs, which implicitly assumes that the value of real estate diminishes predictably over time. The Company also believes that FFO can help facilitate comparisons of operating performance between periods and with other REITs. However, other REITs may not define FFO in accordance with the NAREIT definition, or may interpret the current NAREIT definition differently than the Company; therefore, the Company’s computation of FFO may not be comparable to that of such other REITs.
Core Funds From Operations ("Core FFO"): The Company calculates Core FFO by starting with FFO, as defined by NAREIT, and adjusting for gains or losses on the extinguishment of swaps and/or debt and any significant non-recurring items. Core FFO is a non-GAAP financial measure and should not be viewed as an alternative to net income calculated in accordance with GAAP as a measurement of the Company’s operating performance. The Company believes that Core FFO is helpful to investors as a supplemental performance measure because it excludes the effects of certain infrequent or non-recurring items which can create significant earnings volatility, but which do not directly relate to the Company’s core business operations. As a result, the Company believes that Core FFO can help facilitate comparisons of operating performance between periods and provides a more meaningful predictor of future earnings potential. Other REITs may not define Core FFO in the same manner as the Company; therefore, the Company’s computation of Core FFO may not be comparable to that of other REITs.
Adjusted Funds From Operations ("AFFO"): The Company calculates AFFO by starting with Core FFO and adjusting for non-incremental capital expenditures and then adding back non-cash items including: non-real estate depreciation, straight-lined rents and fair value lease adjustments, non-cash components of interest expense and compensation expense, and by making similar adjustments for joint ventures, if any. AFFO is a non-GAAP financial measure and should not be viewed as an alternative to net income calculated in accordance with GAAP as a measurement of the Company’s operating performance. The Company believes that AFFO is helpful to investors as a meaningful supplemental comparative performance measure of our ability to make incremental capital investments. Other REITs may not define AFFO in the same manner as the Company; therefore, the Company’s computation of AFFO may not be comparable to that of other REITs.
EBITDAre: The Company calculates EBITDAre in accordance with the current National Association of Real Estate Investment Trusts (“NAREIT”) definition. NAREIT currently defines EBITDAre as net income/(loss) (computed in accordance with GAAP) adjusted for gains or losses from sales of property, impairment charges, depreciation on real estate assets, amortization on real estate assets, interest expense and taxes, along with the same adjustments for joint ventures. Some of the adjustments mentioned can vary among owners of identical assets in similar conditions based on historical cost accounting and useful-life estimates. EBITDAre is a non-GAAP financial measure and should not be viewed as an alternative to net income calculated in accordance with GAAP as a measurement of the Company’s operating performance. The Company believes that EBITDAre is helpful to investors as a supplemental performance measure because it provides a metric for understanding the Company’s results from ongoing operations without taking into account the effects of non-cash expenses (such as depreciation and amortization) and capitalization and capital structure expenses (such as interest expense and taxes). The Company also believes that EBITDAre can help facilitate comparisons of operating performance between periods and with other REITs. However, other REITs may not define EBITDAre in accordance with the NAREIT definition, or may interpret the current NAREIT definition differently than the Company; therefore, the Company’s computation of EBITDAre may not be comparable to that of such other REITs.
Core EBITDA: The Company calculates Core EBITDA as net income/(loss) (computed in accordance with GAAP) before interest, taxes, depreciation and amortization and removing any impairment charges, gains or losses from sales of property and other significant infrequent items that create volatility within our earnings and make it difficult to determine the earnings generated by our core ongoing business. Core EBITDA is a non-GAAP financial measure and should not be viewed as an alternative to net income calculated in accordance with GAAP as a measurement of the Company’s operating performance. The Company believes that Core EBITDA is helpful to investors as a supplemental performance measure because it provides a metric for understanding the performance of the Company’s results from ongoing operations without taking into account the effects of non-cash expenses (such as depreciation and amortization), as well as items that are not part of normal day-to-day operations of the Company’s business. Other REITs may not define Core EBITDA in the same manner as the Company; therefore, the Company’s computation of Core EBITDA may not be comparable to that of other REITs.
Average Net Debt to Core EBITDA: Calculated using the sum of Core EBITDA for the trailing twelve month period and the average daily principal balance of debt outstanding for the trailing twelve months less the average balance of cash and escrow deposits and restricted cash during the trailing twelve month period.
Property Net Operating Income ("Property NOI"): The Company calculates Property NOI by starting with Core EBITDA and adjusting for general and administrative expense, income associated with property management performed by Piedmont for other organizations and other income or expense items for the Company, such as interest income from loan investments or costs from the pursuit of non-consummated transactions. The Company may present this measure on an accrual basis or a cash basis. When presented on a cash basis, the effects of non-cash general reserve for uncollectible accounts, straight lined rents and fair value lease revenue are also eliminated. Property NOI is a non-GAAP financial measure and should not be viewed as an alternative to net income calculated in accordance with GAAP as a measurement of the Company’s operating performance. The Company believes that Property NOI is helpful to investors as a supplemental comparative performance measure of income generated by its properties alone without the administrative overhead of the Company. Other REITs may not define Property NOI in the same manner as the Company; therefore, the Company’s computation of Property NOI may not be comparable to that of other REITs.
Same Store Net Operating Income ("Same Store NOI"): The Company calculates Same Store NOI as Property NOI attributable to the properties for which the following criteria were met during the entire span of the current and prior year reporting periods: (i) they were owned, (ii) they were not under development / redevelopment, and (iii) none of the operating expenses for which were capitalized. Same Store NOI also excludes amounts attributable to land assets. The Company may present this measure on an accrual basis or a cash basis. Same Store NOI is a non-GAAP financial measure and should not be viewed as an alternative to net income calculated in accordance with GAAP as a measurement of the Company’s operating performance. The Company believes that Same Store NOI is helpful to investors as a supplemental comparative performance measure of the income generated from the same group of properties from one
period to the next. Other REITs may not define Same Store NOI in the same manner as the Company; therefore, the Company’s computation of Same Store NOI may not be comparable to that of other REITs.
| EXHIBIT 99.2 | |||||
Piedmont Office Realty Trust, Inc.
Quarterly Supplemental Information
Index
| Page | Page | |||||||||||||
| Introduction | ||||||||||||||
| Corporate Data | ||||||||||||||
| Investor Information | Supporting Information | |||||||||||||
| Earnings Release | Definitions | |||||||||||||
| Key Performance Indicators | Research Coverage | |||||||||||||
| Financials | Non-GAAP Reconciliations | |||||||||||||
| Balance Sheets | In-Service Portfolio Detail | |||||||||||||
| Income Statements | Major Leases Not Yet Commenced and Major Abatements | |||||||||||||
| Funds From Operations / Adjusted Funds From Operations | Risks, Uncertainties and Limitations | |||||||||||||
| Same Store Analysis | ||||||||||||||
| Capitalization Analysis | ||||||||||||||
| Debt Summary | ||||||||||||||
| Debt Detail | ||||||||||||||
| Debt Covenant & Ratio Analysis | ||||||||||||||
| Operational & Portfolio Information - Office Property Investments | ||||||||||||||
| Tenant Diversification | ||||||||||||||
| Tenant Credit Rating & Lease Distribution Information | ||||||||||||||
| Leased Percentage Information | ||||||||||||||
| Rental Rate Roll Up / Roll Down Analysis | ||||||||||||||
| Lease Expiration Schedule | ||||||||||||||
| Quarterly Lease Expirations | ||||||||||||||
| Annual Lease Expirations | ||||||||||||||
| Contractual Tenant Improvements & Leasing Commissions | ||||||||||||||
| Geographic Diversification | ||||||||||||||
| Geographic Diversification by Location Type | ||||||||||||||
| Industry Diversification | ||||||||||||||
| Property Investment Activity | ||||||||||||||
| Notice to Readers: | ||
Please refer to page 39 for a discussion of important risks related to the business of Piedmont Office Realty Trust, Inc., as well as an investment in its securities, including risks that could cause actual results and events to differ materially from results and events referred to in the forward-looking information. Considering these risks, uncertainties, assumptions, and limitations, the forward-looking statements about leasing, financial operations, leasing prospects, acquisitions, dispositions, etc. contained in this quarterly supplemental information report may differ from actual results. | ||
| Certain prior period amounts have been reclassified to conform to the current period financial statement presentation. In addition, many of the schedules herein contain rounding to the nearest thousands or millions and, therefore, the schedules may not total due to this rounding convention. | ||
To supplement the presentation of the Company’s financial results prepared in accordance with U.S. generally accepted accounting principles (GAAP), this report contains certain financial measures that are not prepared in accordance with GAAP, including FFO, Core FFO, AFFO, Same Store NOI, Property NOI, EBITDAre and Core EBITDA. Definitions and reconciliations of these non-GAAP measures to their most comparable GAAP metrics are included beginning on page 32. Each of the non-GAAP measures included in this report has limitations as an analytical tool and should not be considered in isolation or as a substitute for an analysis of the Company’s results calculated in accordance with GAAP. In addition, because not all companies use identical calculations, the Company’s presentation of non-GAAP measures in this report may not be comparable to similarly titled measures disclosed by other companies, including other REITs. The Company may also change the calculation of any of the non-GAAP measures included in this report from time to time in light of its then existing operations. | ||
Piedmont Office Realty Trust, Inc.
Corporate Data
Piedmont Office Realty Trust, Inc. (also referred to herein as "Piedmont" or the "Company") (NYSE: PDM) is an owner, manager, developer, redeveloper and operator of high-quality, Class A office properties located primarily in major U.S. Sunbelt markets. The Company is a fully-integrated, self-managed real estate investment trust ("REIT") with local management offices in each of its markets and is investment-grade rated by Standard & Poor’s and Moody’s.The Company was designated an Energy Star Partner of the Year for 2021, 2022 and 2023, and was recognized as a 2024 Energy Star Partner of the Year - Sustained Excellence, a distinction awarded for earning Partner of the Year for multiple consecutive years as well as exceeding the criteria required for recognition. Approximately 84% and 72% of the Company's portfolio is ENERGY STAR rated and LEED certified, respectively. Piedmont is headquartered in Atlanta, GA.
This data supplements the information provided in our reports filed with the Securities and Exchange Commission and should be reviewed in conjunction with such filings.
| As of | As of | |||||||
| March 31, 2024 | December 31, 2023 | |||||||
Number of consolidated in-service office properties (1) | 49 | 51 | ||||||
Rentable square footage (in thousands) (1) | 16,037 | 16,563 | ||||||
Percent leased (2) | 87.8 | % | 87.1 | % | ||||
| Capitalization (in thousands): | ||||||||
| Total debt - GAAP | $2,070,070 | $2,054,596 | ||||||
| Total principal amount of debt outstanding (excludes premiums, discounts, and deferred financing costs) | $2,086,028 | $2,070,033 | ||||||
Equity market capitalization (3) | $870,931 | $879,616 | ||||||
Total market capitalization (3) | $2,956,959 | $2,949,649 | ||||||
Average net principal amount of debt to Core EBITDA - quarterly (4) | 6.8 x | 6.5 x | ||||||
Average net principal amount of debt to Core EBITDA - trailing twelve months (5) | 6.5 x | 6.4 x | ||||||
| Total principal amount of debt / Total gross assets | 38.9 | % | 38.2 | % | ||||
| Common stock data: | ||||||||
| High closing price during quarter | $7.42 | $7.50 | ||||||
| Low closing price during quarter | $5.97 | $5.07 | ||||||
| Closing price of common stock at period end | $7.03 | $7.11 | ||||||
| Weighted average fully diluted shares outstanding during quarter (in thousands) | 123,954 | 123,846 | ||||||
| Shares of common stock issued and outstanding at period end (in thousands) | 123,888 | 123,715 | ||||||
Annualized current dividend per share (6) | $0.50 | $0.50 | ||||||
| Ratings (Standard & Poor's / Moody's) | BBB- / Baa3 | BBB- / Baa3 | ||||||
| Employees | 152 | 150 | ||||||
| (1) | As of March 31, 2024, our consolidated in-service office portfolio excluded two properties held out of service for redevelopment, 222 South Orange Avenue, a 127,000 square foot property in Orlando, FL and 9320 Excelsior Boulevard, a 259,000 square foot property in Hopkins, MN. Also, during the quarter ended March 31, 2024, the Company sold One Lincoln Park, a 257,000 square foot property in Dallas, TX. | ||||
| (2) | Please refer to page 22 for additional analysis and definition regarding the Company's leased percentage. | ||||
| (3) | Reflects common stock closing price, shares outstanding and principal amount of debt outstanding as of the end of the reporting period. | ||||
| (4) | Calculated using the annualized Core EBITDA for the quarter and the average daily principal balance of debt outstanding during the quarter less the average balance of cash and escrow deposits and restricted cash during the quarter. | ||||
| (5) | Calculated using the sum of Core EBITDA for the trailing twelve month period and the average daily principal balance of debt outstanding for the trailing twelve months less the average balance of cash and escrow deposits and restricted cash during the trailing twelve month period. | ||||
| (6) | Annualized amount based on the regular dividends per share recorded for the most recent quarter. | ||||
3
Piedmont Office Realty Trust, Inc.
Investor Information
| Corporate Office | ||
| 5565 Glenridge Connector, Suite 450 | ||
| Atlanta, Georgia 30342 | ||
| 770.418.8800 | ||
| www.piedmontreit.com | ||
| Executive Management | |||||||||||
| C. Brent Smith | Robert E. Bowers | George Wells | Laura P. Moon | ||||||||
| Chief Executive Officer, President | Chief Financial and Administrative Officer | Chief Operating Officer and | Chief Accounting Officer and Treasurer | ||||||||
| and Director | and Executive Vice President | Executive Vice President | and Senior Vice President | ||||||||
| Kevin D. Fossum | Christopher A. Kollme | Damian J. Miller | Alex Valente | ||||||||
| Executive Vice President, | Executive Vice President, | Executive Vice President, | Executive Vice President, | ||||||||
| Property Management | Investments | Dallas | Southeast Region | ||||||||
| Robert K. Wiberg | |||||||||||
| Executive Vice President, | |||||||||||
| Northeast Region and Head of Development | |||||||||||
| Board of Directors | |||||||||||
| Frank C. McDowell | Dale H. Taysom | Kelly H. Barrett | Glenn G. Cohen | ||||||||
| Director, Chair of the Board of Directors, | Director, Vice Chair of the | Director, Chair of the Audit Committee, | Director, Chair of the Compensation | ||||||||
| and Member of the Compensation and | Board of Directors, and Member of the | and Member of the Governance | Committee, and Member of the Audit | ||||||||
| Governance Committees | Audit and Capital Committees | Committee | and Capital Committees | ||||||||
| Venkatesh S. Durvasula | Mary Hager | Barbara B. Lang | C. Brent Smith | ||||||||
| Director and Member of the Capital | Director and Member of the | Director, Chair of the Governance | Chief Executive Officer, President | ||||||||
| Committee | Governance Committee | Committee (including ESG), and | and Director | ||||||||
| Member of the Compensation Committee | |||||||||||
| Jeffrey L. Swope | |||||||||||
| Director, Chair of the Capital | |||||||||||
| Committee, and Member of the | |||||||||||
| Compensation Committee | |||||||||||
| Transfer Agent | Corporate Counsel | Institutional Analyst Contact | Investor Relations | ||||||||
| Computershare | King & Spalding | Phone: 770.418.8592 | Phone: 866.354.3485 | ||||||||
| P.O. Box 43006 | 1180 Peachtree Street, NE | [email protected] | [email protected] | ||||||||
| Providence, RI 02940-3078 | Atlanta, GA 30309 | www.piedmontreit.com | |||||||||
| Phone: 866.354.3485 | Phone: 404.572.4600 | ||||||||||
4
Piedmont Office Realty Trust, Inc.
Earnings Release
ATLANTA, April 30, 2024--Piedmont Office Realty Trust, Inc. ("Piedmont" or the "Company") (NYSE:PDM), an owner of Class A office properties located primarily in major U.S. Sunbelt markets, today announced its results for the quarter ended March 31, 2024 which included significant leasing activity, strong Same Store NOI growth, as well as previously announced refinancing and disposition activity.
Highlights for the Three Months Ended March 31, 2024:
Financial Results:
| Three Months Ended | ||||||||
| (in 000s other than per share amounts) | March 31, 2024 | March 31, 2023 | ||||||
| Net loss applicable to Piedmont | $(27,763) | $(1,367) | ||||||
| Net loss per share applicable to common stockholders - diluted | $(0.22) | $(0.01) | ||||||
| Interest expense | $29,714 | $22,077 | ||||||
| Impairment charges | $18,432 | $0 | ||||||
| Core FFO applicable to common stock | $47,753 | $56,344 | ||||||
| NAREIT FFO per diluted share | $0.38 | $0.46 | ||||||
| Core FFO per diluted share | $0.39 | $0.46 | ||||||
| Adjusted FFO applicable to common stock | $24,741 | $36,792 | ||||||
| Same Store NOI - cash basis | 5.1 | % | ||||||
| Same Store NOI - accrual basis | 2.1 | % | ||||||
•Piedmont recognized a net loss of $27.8 million, or $0.22 per diluted share, for the first quarter of 2024, as compared to a net loss of $1.4 million, or $0.01 per diluted share, for the first quarter of 2023, with the first quarter of 2024 including $18.4 million, or $0.15 per diluted share, in impairment charges primarily related to shortening the projected hold period for one property during the quarter, as well as approximately $7.6 million, or $0.06 per diluted share, of increased interest expense as compared to first quarter of 2023.
•Core FFO, which removes the impact of the impairment charges noted above, as well as loss on early extinguishment of debt, and depreciation and amortization expense, was $0.39 per diluted share for the first quarter of 2024, as compared to $0.46 per diluted share for the first quarter of 2023, with the decrease primarily attributable to the $0.06 per diluted share increase in interest expense noted above.
•Same Store NOI - Cash basis and Same Store NOI - Accrual basis increased 5.1% and 2.1%, respectively, for the three months ended March 31, 2024, as compared to the same period in the prior year, as newly commenced leases or those with expiring abatements outweighed expiring leases.
Leasing:
| Three Months Ended March 31, 2024 | |||||
| # of lease transactions | 54 | ||||
Total leasing sf (in 000s) | 500 | ||||
New tenant leasing sf (in 000s) | 328 | ||||
| Cash rent roll up | 8.0% | ||||
| Accrual rent roll up | 18.6% | ||||
| Leased percentage as of period end | 87.8% | ||||
5
•The Company completed approximately 500,000 square feet of leasing during the first quarter, including approximately 328,000 square feet of new tenant leasing.
•The weighted average size lease executed during the quarter was approximately 13,000 square feet and the weighted average lease term was approximately eight years.
•Rents on leases executed during the three months ended March 31, 2024 for space vacant one year or less increased approximately 8.0% and 18.6% on a cash and accrual basis, respectively.
•The Company's leased percentage for its in-service portfolio as of March 31, 2024 increased to 87.8%, up from 87.1% as of December 31, 2023, reflecting the leasing activity above, the disposition mentioned below, and one asset moved to redevelopment.
•As of March 31, 2024, the Company had approximately 1.3 million square feet of executed leases for vacant space yet to commence or under rental abatement, representing approximately $42 million of future additional annual cash rents.
•Thus far during the second quarter of 2024, the Company has executed approximately 170,000 square feet of total leasing.
Transactional Activity:
•During the first quarter, the Company sold One Lincoln Park, located at 8401 North Central Expressway in Dallas, TX for $54 million, or $210 per square foot, in an all-cash transaction. The building is a 10-story, approximately 257,000-square foot, office building which was 59% leased as of December 31, 2023.
Balance Sheet:
| (in 000s except for ratios) | March 31, 2024 | December 31, 2023 | |||||||||
| Total Real Estate Assets | $3,452,475 | $3,512,527 | |||||||||
| Total Assets | $3,993,996 | $4,057,082 | |||||||||
| Total Debt | $2,070,070 | $2,054,596 | |||||||||
| Weighted Average Cost of Debt | 5.81 | % | 5.82% | ||||||||
| Principal Amount of Debt-to-Gross Assets Ratio | 38.9 | % | 38.2% | ||||||||
| Average Net Debt-to-Core EBITDA (ttm) | 6.5 x | 6.4 x | |||||||||
•During the three months ended March 31, 2024, the Company entered into a new, three year, $200 million unsecured syndicated bank term loan. The Company used the net proceeds and its revolving line of credit to pay off a $100 million bank term loan that was scheduled to mature in December of 2024, and to repay $190 million of a $215 million unsecured term loan that was scheduled to mature on January 31, 2024. The remaining $25 million of the $215 million unsecured term loan was extended to January 31, 2025.
•Also during the three months ended March 31, 2024, the Company repaid the remaining approximately $50 million balance of its Senior Unsecured Notes Due 2024 using proceeds from the sale of One Lincoln Park mentioned above.
•As of March 31, 2024, the Company's only debt with a final maturity prior to 2027 is $275 million in unsecured bank term loans that mature during the first quarter of 2025.
ESG and Operations:
•During the first quarter, the U.S. Environmental Protection Agency and the U.S. Department of Energy recognized the Company with its highest level of recognition - 2024 ENERGY STAR Partner of the Year – Sustained Excellence. The sustained excellence recognition is awarded to organizations who have earned Partner of the Year for several consecutive years and have gone beyond the criteria needed to qualify for recognition.
•Three buildings, CNL Center I & II in Orlando, FL and Glenridge Highlands II, in Atlanta, GA earned LEED Gold certification during the quarter.
•As of March 31, 204, approximately 84% and 72% of the Company's portfolio was ENERGY STAR rated and LEED certified, respectively.
6
Commenting on first quarter results, Brent Smith, Piedmont's President and Chief Executive Officer, said, "We are pleased with our quarterly results. First and foremost, we continued to experience the strong leasing volume that we have seen over the last several quarters, executing approximately half a million square feet, with over half a point of occupancy absorption driven by small and medium enterprises in the flight-to-quality trend. In addition, we harvested the value in one of our high-quality Dallas assets through the disposition of One Lincoln Park to a financial services tenant, using the proceeds to pay off the remaining balance of our 2024 Senior Notes on an earnings-neutral basis. During the first quarter, we also addressed all of our 2024 debt maturities, meaningfully extending our maturity profile and leaving only $275 million of debt maturing prior to 2027. Finally, we were named an ENERGY STAR Partner of the Year for the fourth consecutive year, adding the prestigious 'Sustained Excellence' designation for the first time."
Second Quarter 2024 Dividend:
As previously announced, on April 24, 2024, the board of directors of Piedmont declared a dividend for the second quarter of 2024 in the amount of $0.125 per share on its common stock to stockholders of record as of the close of business on May 24, 2024, payable on June 14, 2024.
Guidance for 2024:
The Company is affirming its previous guidance for the year ending December 31, 2024 as follows:
| (in millions, except per share data) | Low | High | |||||||||
| Net loss | $ | (47) | $ | (41) | |||||||
| Add: | |||||||||||
| Depreciation | 148 | 151 | |||||||||
| Amortization | 81 | 84 | |||||||||
| Core FFO applicable to common stock | $ | 182 | $ | 194 | |||||||
| Core FFO applicable to common stock per diluted share | $1.46 | $1.56 | |||||||||
This guidance is based on information available to management as of the date of this release and reflects management's view of current market conditions, including the following specific assumptions and projections:
•Executed leasing activity in the range of 1.5 - 2 million square feet with year-end leased percentage for the Company's in-service portfolio anticipated to be approximately 87-88%, before the impacts of any acquisition or disposition activity;
•Same Store NOI flat to 2% increase on both a cash and accrual basis, as the Company will experience some downtime between certain lease expirations and new lease commencements during 2024;
•Interest expense of approximately $119-121 million, reflecting a full year of higher interest rates as a result of refinancing activity completed by the Company during the latter half of 2023 and early 2024; and,
•General and administrative expense will remain relatively flat at approximately $29-30 million.
No speculative acquisitions, dispositions, or refinancing are included in the above guidance. The Company will adjust guidance if such transactions occur.
Note that actual results could differ materially from these estimates and individual quarters may fluctuate on both a cash basis and an accrual basis due to the timing of any future dispositions, significant lease commencements and expirations, abatement periods, repairs and maintenance expenses, capital expenditures, capital markets activities, seasonal general and administrative expenses, accrued potential performance-based compensation expense, one-time revenue or expense events, and other factors discussed under "Risks, Uncertainties & Limitations" below.
7
Piedmont Office Realty Trust, Inc.
Key Performance Indicators
Unaudited (in thousands except for per share data and ratios)
This section of our supplemental report includes non-GAAP financial measures, including, but not limited to, Earnings Before Interest, Taxes, Depreciation, and Amortization for real estate (EBITDAre), Core Earnings Before Interest, Taxes, Depreciation, and Amortization (Core EBITDA), Funds from Operations (FFO), Core Funds from Operations (Core FFO), Adjusted Funds from Operations (AFFO), and Same Store Net Operating Income (Same Store NOI). Definitions of these non-GAAP measures are provided on page 32 and reconciliations are provided beginning on page 34. | ||
| Three Months Ended | |||||||||||||||||||||||||||||
| Selected Operating Data | 3/31/2024 | 12/31/2023 | 9/30/2023 | 6/30/2023 | 3/31/2023 | ||||||||||||||||||||||||
Percent leased | 87.8 | % | 87.1 | % | 86.7 | % | 86.2 | % | 86.1 | % | |||||||||||||||||||
Percent leased - economic (1) | 81.2 | % | 81.5 | % | 80.8 | % | 80.0 | % | 79.6 | % | |||||||||||||||||||
| Total revenues | $144,538 | $145,331 | $146,986 | $143,072 | $142,367 | ||||||||||||||||||||||||
| Net income (loss) applicable to Piedmont | -$27,763 | -$28,030 | -$17,002 | -$1,988 | -$1,367 | ||||||||||||||||||||||||
| Net income (loss) per share applicable to common stockholders - diluted | -$0.22 | -$0.23 | -$0.14 | -$0.02 | -$0.01 | ||||||||||||||||||||||||
| Core EBITDA | $77,760 | $79,215 | $80,448 | $79,212 | $78,541 | ||||||||||||||||||||||||
| Core FFO applicable to common stock | $47,753 | $50,624 | $52,716 | $55,535 | $56,344 | ||||||||||||||||||||||||
| Core FFO per share - diluted | $0.39 | $0.41 | $0.43 | $0.45 | $0.46 | ||||||||||||||||||||||||
| AFFO applicable to common stock | $24,741 | $31,833 | $39,939 | $44,444 | $36,792 | ||||||||||||||||||||||||
Gross regular dividends (2) | $15,479 | $15,464 | $15,462 | $25,975 | $25,965 | ||||||||||||||||||||||||
Regular dividends per share (2) | $0.125 | $0.125 | $0.125 | $0.210 | $0.210 | ||||||||||||||||||||||||
Same store net operating income - accrual basis (3) | 2.1 | % | 1.1 | % | 1.7 | % | -3.7 | % | -2.8 | % | |||||||||||||||||||
Same store net operating income - cash basis (3) | 5.1 | % | 4.8 | % | 5.3 | % | 0.2 | % | -1.5 | % | |||||||||||||||||||
Rental rate roll up / roll down - accrual rents | 18.6 | % | 11.3 | % | 10.3 | % | 19.6 | % | 9.9 | % | |||||||||||||||||||
Rental rate roll up / roll down - cash rents | 8.0 | % | 0.0 | % | 11.7 | % | 14.3 | % | 5.7 | % | |||||||||||||||||||
| Selected Balance Sheet Data | |||||||||||||||||||||||||||||
| Total real estate assets, net | $3,452,475 | $3,512,527 | $3,502,576 | $3,512,128 | $3,486,797 | ||||||||||||||||||||||||
| Total assets | $3,993,996 | $4,057,082 | $4,073,778 | $4,094,349 | $4,237,460 | ||||||||||||||||||||||||
| Total liabilities | $2,312,084 | $2,334,110 | $2,306,713 | $2,297,015 | $2,417,363 | ||||||||||||||||||||||||
| Ratios & Information for Debt Holders | |||||||||||||||||||||||||||||
Core EBITDA to total revenues | 53.8 | % | 54.5 | % | 54.7 | % | 55.4 | % | 55.2 | % | |||||||||||||||||||
Fixed charge coverage ratio (4) | 2.3 x | 2.5 x | 2.7 x | 3.2 x | 3.4 x | ||||||||||||||||||||||||
Average net principal amount of debt to Core EBITDA - quarterly (5) | 6.8 x | 6.5 x | 6.4 x | 6.4 x | 6.3 x | ||||||||||||||||||||||||
| Total gross real estate assets | $4,596,744 | $4,647,105 | $4,601,792 | $4,576,943 | $4,518,003 | ||||||||||||||||||||||||
| Total debt - GAAP | $2,070,070 | $2,054,596 | $2,050,319 | $2,049,236 | $2,197,955 | ||||||||||||||||||||||||
Net principal amount of debt (6) | $2,078,263 | $2,065,827 | $2,057,848 | $2,051,778 | $2,037,224 | ||||||||||||||||||||||||
| (1) | Economic leased percentage excludes the square footage associated with executed but not commenced leases for currently vacant spaces and the square footage associated with tenants receiving rental abatements. | ||||
| (2) | Dividends are reflected in the quarter in which the record date occurred. | ||||
| (3) | Please refer to the three pages starting with page 13 for reconciliations to net income and additional same store net operating income information. The statistic provided for each of the prior quarters is based on the same store property population applicable at the time that the metric was initially reported. | ||||
| (4) | Calculated as Core EBITDA divided by the sum of interest expense, principal amortization, capitalized interest and preferred dividends (none during periods presented). | ||||
| The Company had principal amortization of $0.9 million for the quarter ended March 31, 2024, $0.8 million for the quarter ended December 31, 2023, $0.3 million for the quarter ended September 30, 2023 and no principal amortization for prior periods presented. | |||||
| The Company had capitalized interest of $2.8 million for the quarter ended March 31, 2024, $2.5 million for the quarter ended December 31, 2023, $1.9 million for the quarter ended September 30, 2023, $1.4 million for the quarter ended June 30, 2023, and $1.2 million for the quarter ended March 31, 2023. | |||||
| (5) | Calculated using the annualized Core EBITDA for the quarter and the average daily principal balance of debt outstanding during the quarter less the average balance of cash and escrow deposits and restricted cash during the quarter. | ||||
| (6) | Defined as the total principal amount of debt outstanding, minus cash and escrow deposits and restricted cash, all as of the end of the period. | ||||
8
Piedmont Office Realty Trust, Inc.
Consolidated Balance Sheets
Unaudited (in thousands)
| 3/31/2024 | 12/31/2023 | 9/30/2023 | 6/30/2023 | 3/31/2023 | |||||||||||||||||||||||||
| Assets: | |||||||||||||||||||||||||||||
| Real estate assets, at cost: | |||||||||||||||||||||||||||||
| Land | $ | 560,604 | $ | 567,244 | $ | 567,244 | $ | 567,244 | $ | 567,244 | |||||||||||||||||||
| Buildings and improvements | 3,787,245 | 3,823,241 | 3,782,385 | 3,768,456 | 3,714,572 | ||||||||||||||||||||||||
| Buildings and improvements, accumulated depreciation | (1,064,199) | (1,046,512) | (1,013,019) | (981,052) | (947,209) | ||||||||||||||||||||||||
| Intangible lease assets | 156,804 | 170,654 | 177,584 | 182,127 | 190,180 | ||||||||||||||||||||||||
| Intangible lease assets, accumulated amortization | (80,070) | (88,066) | (86,197) | (83,763) | (83,997) | ||||||||||||||||||||||||
| Construction in progress | 92,091 | 85,966 | 74,579 | 59,116 | 46,007 | ||||||||||||||||||||||||
| Total real estate assets | 3,452,475 | 3,512,527 | 3,502,576 | 3,512,128 | 3,486,797 | ||||||||||||||||||||||||
| Cash and cash equivalents | 3,544 | 825 | 5,044 | 5,167 | 170,593 | ||||||||||||||||||||||||
| Tenant receivables, net of allowance for doubtful accounts | 10,338 | 7,915 | 8,806 | 5,387 | 6,280 | ||||||||||||||||||||||||
| Straight line rent receivable | 184,750 | 183,839 | 181,843 | 180,339 | 176,320 | ||||||||||||||||||||||||
| Escrow deposits and restricted cash | 4,221 | 3,381 | 5,983 | 5,055 | 4,183 | ||||||||||||||||||||||||
| Prepaid expenses and other assets | 23,853 | 28,466 | 26,156 | 23,566 | 26,810 | ||||||||||||||||||||||||
| Goodwill | 53,491 | 53,491 | 71,980 | 82,937 | 82,937 | ||||||||||||||||||||||||
| Interest rate swaps | 4,148 | 3,032 | 5,841 | 5,693 | 2,899 | ||||||||||||||||||||||||
| Deferred lease costs, gross | 474,746 | 487,519 | 483,353 | 482,149 | 486,694 | ||||||||||||||||||||||||
| Deferred lease costs, accumulated amortization | (217,570) | (223,913) | (217,804) | (208,072) | (206,053) | ||||||||||||||||||||||||
| Total assets | $ | 3,993,996 | $ | 4,057,082 | $ | 4,073,778 | $ | 4,094,349 | $ | 4,237,460 | |||||||||||||||||||
| Liabilities: | |||||||||||||||||||||||||||||
| Unsecured debt, net of discount | $ | 1,875,042 | $ | 1,858,717 | $ | 1,853,598 | $ | 1,852,236 | $ | 2,000,955 | |||||||||||||||||||
| Secured debt | 195,028 | 195,879 | 196,721 | 197,000 | 197,000 | ||||||||||||||||||||||||
| Accounts payable, accrued expenses, and accrued capital expenditures | 106,638 | 146,659 | 120,579 | 107,629 | 98,464 | ||||||||||||||||||||||||
| Deferred income | 95,139 | 89,930 | 89,990 | 89,815 | 67,056 | ||||||||||||||||||||||||
| Intangible lease liabilities, less accumulated amortization | 40,237 | 42,925 | 45,825 | 50,335 | 53,494 | ||||||||||||||||||||||||
| Interest rate swaps | — | — | — | — | 394 | ||||||||||||||||||||||||
| Total liabilities | 2,312,084 | 2,334,110 | 2,306,713 | 2,297,015 | 2,417,363 | ||||||||||||||||||||||||
| Stockholders' equity: | |||||||||||||||||||||||||||||
| Common stock | 1,239 | 1,237 | 1,237 | 1,237 | 1,236 | ||||||||||||||||||||||||
| Additional paid in capital | 3,717,599 | 3,716,742 | 3,714,629 | 3,712,688 | 3,710,767 | ||||||||||||||||||||||||
| Cumulative distributions in excess of earnings | (2,030,389) | (1,987,147) | (1,943,652) | (1,911,188) | (1,883,225) | ||||||||||||||||||||||||
| Other comprehensive loss | (8,090) | (9,418) | (6,718) | (6,977) | (10,266) | ||||||||||||||||||||||||
| Piedmont stockholders' equity | 1,680,359 | 1,721,414 | 1,765,496 | 1,795,760 | 1,818,512 | ||||||||||||||||||||||||
| Non-controlling interest | 1,553 | 1,558 | 1,569 | 1,574 | 1,585 | ||||||||||||||||||||||||
| Total stockholders' equity | 1,681,912 | 1,722,972 | 1,767,065 | 1,797,334 | 1,820,097 | ||||||||||||||||||||||||
| Total liabilities, redeemable common stock and stockholders' equity | $ | 3,993,996 | $ | 4,057,082 | $ | 4,073,778 | $ | 4,094,349 | $ | 4,237,460 | |||||||||||||||||||
| Common stock outstanding at end of period | 123,888 | 123,715 | 123,696 | 123,692 | 123,643 | ||||||||||||||||||||||||
9
Piedmont Office Realty Trust, Inc.
Consolidated Statements of Income
Unaudited (in thousands except for per share data)
| Three Months Ended | ||||||||||||||||||||||||||||||||
| 3/31/2024 | 12/31/2023 | 9/30/2023 | 6/30/2023 | 3/31/2023 | ||||||||||||||||||||||||||||
| Revenues: | ||||||||||||||||||||||||||||||||
Rental income (1) | $ | 113,313 | $ | 114,357 | $ | 115,250 | $ | 112,238 | $ | 112,560 | ||||||||||||||||||||||
Tenant reimbursements (1) | 25,768 | 25,090 | 26,284 | 25,265 | 24,269 | |||||||||||||||||||||||||||
| Property management fee revenue | 157 | 389 | 396 | 437 | 507 | |||||||||||||||||||||||||||
| Other property related income | 5,300 | 5,495 | 5,056 | 5,132 | 5,031 | |||||||||||||||||||||||||||
| 144,538 | 145,331 | 146,986 | 143,072 | 142,367 | ||||||||||||||||||||||||||||
| Expenses: | ||||||||||||||||||||||||||||||||
| Property operating costs | 59,444 | 59,085 | 59,847 | 58,368 | 57,791 | |||||||||||||||||||||||||||
| Depreciation | 38,869 | 38,036 | 38,150 | 36,475 | 35,797 | |||||||||||||||||||||||||||
| Amortization | 18,120 | 24,232 | 20,160 | 21,333 | 22,031 | |||||||||||||||||||||||||||
Impairment charges (2) | 18,432 | 18,489 | 10,957 | — | — | |||||||||||||||||||||||||||
| General and administrative | 7,612 | 7,177 | 7,043 | 7,279 | 7,691 | |||||||||||||||||||||||||||
| 142,477 | 147,019 | 136,157 | 123,455 | 123,310 | ||||||||||||||||||||||||||||
| Other income (expense): | ||||||||||||||||||||||||||||||||
| Interest expense | (29,714) | (28,431) | (27,361) | (23,389) | (22,077) | |||||||||||||||||||||||||||
| Other income (expense) | 278 | 146 | 351 | 1,787 | 1,656 | |||||||||||||||||||||||||||
Loss on early extinguishment of debt (3) | (386) | — | (820) | — | — | |||||||||||||||||||||||||||
Gain on sale of real estate | — | 1,946 | — | — | — | |||||||||||||||||||||||||||
| Net income (loss) | (27,761) | (28,027) | (17,001) | (1,985) | (1,364) | |||||||||||||||||||||||||||
| Less: Net (income) loss applicable to noncontrolling interest | (2) | (3) | (1) | (3) | (3) | |||||||||||||||||||||||||||
| Net income (loss) applicable to Piedmont | $ | (27,763) | $ | (28,030) | $ | (17,002) | $ | (1,988) | $ | (1,367) | ||||||||||||||||||||||
| Weighted average common shares outstanding - diluted | 123,800 | 123,714 | 123,696 | 123,671 | 123,550 | |||||||||||||||||||||||||||
| Net income (loss) per share applicable to common stockholders - diluted | $ | (0.22) | $ | (0.23) | $ | (0.14) | $ | (0.02) | $ | (0.01) | ||||||||||||||||||||||
| Common stock outstanding at end of period | 123,888 | 123,715 | 123,696 | 123,692 | 123,643 | |||||||||||||||||||||||||||
| (1) | The presentation method used for this line is not in conformance with GAAP. To be in conformance with the current GAAP standard, the Company would combine amounts presented on the rental income line with amounts presented on the tenant reimbursements line and present that aggregated figure on one line entitled "rental and tenant reimbursement revenue." | ||||
| (2) | Impairment charges consist of the write down of the book value of two properties in the first quarter of 2024 due to changes in the estimated hold periods of the assets, the write down of the Company's goodwill balance allocated to its Boston and New York markets in the fourth quarter of 2023, and the write down of the Company's goodwill balance allocated to its Minneapolis market in the third quarter of 2023. | ||||
| (3) | Loss on early extinguishment of debt consists of the pro-rata write-off of unamortized debt issuance costs and discounts associated with prepayment of debt, specifically the repayment of $100 million in unsecured term loan debt originally due at the end of 2024 but repaid in the first quarter of 2024, and the repurchase in the third quarter of 2023 of approximately $350 million of the $400 million unsecured senior notes originally due during the first quarter of 2024. | ||||
10
Piedmont Office Realty Trust, Inc.
Consolidated Statements of Income
Unaudited (in thousands except for per share data)
| Three Months Ended | |||||||||||||||||
| 3/31/2024 | 3/31/2023 | Change ($) | Change (%) | ||||||||||||||
| Revenues: | |||||||||||||||||
Rental income (1) | $ | 113,313 | $ | 112,560 | $ | 753 | 0.7 | % | |||||||||
Tenant reimbursements (1) | 25,768 | 24,269 | 1,499 | 6.2 | % | ||||||||||||
| Property management fee revenue | 157 | 507 | (350) | (69.0) | % | ||||||||||||
| Other property related income | 5,300 | 5,031 | 269 | 5.3 | % | ||||||||||||
| 144,538 | 142,367 | 2,171 | 1.5 | % | |||||||||||||
| Expenses: | |||||||||||||||||
| Property operating costs | 59,444 | 57,791 | (1,653) | (2.9) | % | ||||||||||||
| Depreciation | 38,869 | 35,797 | (3,072) | (8.6) | % | ||||||||||||
| Amortization | 18,120 | 22,031 | 3,911 | 17.8 | % | ||||||||||||
Impairment charges (2) | 18,432 | — | (18,432) | (100.0) | % | ||||||||||||
| General and administrative | 7,612 | 7,691 | 79 | 1.0 | % | ||||||||||||
| 142,477 | 123,310 | (19,167) | (15.5) | % | |||||||||||||
| Other income (expense): | |||||||||||||||||
| Interest expense | (29,714) | (22,077) | (7,637) | (34.6) | % | ||||||||||||
| Other income (expense) | 278 | 1,656 | (1,378) | (83.2) | % | ||||||||||||
Loss on early extinguishment of debt (3) | (386) | — | (386) | (100.0) | % | ||||||||||||
| Net income (loss) | (27,761) | (1,364) | (26,397) | (1,935.3) | % | ||||||||||||
| Less: Net (income) loss applicable to noncontrolling interest | (2) | (3) | 1 | 33.3 | % | ||||||||||||
| Net income (loss) applicable to Piedmont | $ | (27,763) | $ | (1,367) | $ | (26,396) | (1,930.9) | % | |||||||||
| Weighted average common shares outstanding - diluted | 123,800 | 123,550 | |||||||||||||||
| Net income (loss) per share applicable to common stockholders - diluted | $ | (0.22) | $ | (0.01) | |||||||||||||
| Common stock outstanding at end of period | 123,888 | 123,643 | |||||||||||||||
| (1) | The presentation method used for this line is not in conformance with GAAP. To be in conformance with the current GAAP standard, the Company would combine amounts presented on the rental income line with amounts presented on the tenant reimbursements line and present that aggregated figure on one line entitled "rental and tenant reimbursement revenue." | ||||
| (2) | Impairment charges for the three months ended March 31, 2024 consist of the write down of the book value of two properties due to changes in the respective estimated hold periods of the assets. | ||||
| (3) | Loss on early extinguishment of debt for the three months ended March 31, 2024 consists of the pro-rata write-off of unamortized debt issuance costs and discounts during the quarter associated with the repayment of $100 million in unsecured term loan debt originally due at the end of 2024. | ||||
11
Piedmont Office Realty Trust, Inc.
Funds From Operations, Core Funds From Operations and Adjusted Funds From Operations
Unaudited (in thousands except for per share data)
| Three Months Ended | ||||||||||||||
| 3/31/2024 | 3/31/2023 | |||||||||||||
| GAAP net income (loss) applicable to common stock | $ | (27,763) | $ | (1,367) | ||||||||||
Depreciation of real estate assets (1) | 38,586 | 35,690 | ||||||||||||
Amortization of lease-related costs (1) | 18,112 | 22,021 | ||||||||||||
Impairment charges | 18,432 | — | ||||||||||||
| NAREIT Funds From Operations applicable to common stock | 47,367 | 56,344 | ||||||||||||
| Adjustments: | ||||||||||||||
| Loss on early extinguishment of debt | 386 | — | ||||||||||||
| Core Funds From Operations applicable to common stock | 47,753 | 56,344 | ||||||||||||
| Adjustments: | ||||||||||||||
Amortization of debt issuance costs and discounts on debt | 1,208 | 1,239 | ||||||||||||
| Depreciation of non real estate assets | 272 | 97 | ||||||||||||
Straight-line effects of lease revenue (1) | (2,255) | (3,187) | ||||||||||||
| Stock-based compensation adjustments | 1,026 | 183 | ||||||||||||
Amortization of lease-related intangibles (1) | (2,656) | (3,412) | ||||||||||||
Non-incremental capital expenditures (2) | ||||||||||||||
| Base Building Costs | (13,055) | (4,752) | ||||||||||||
| Tenant Improvement Costs | (3,673) | (5,699) | ||||||||||||
| Leasing Costs | (3,879) | (4,021) | ||||||||||||
| Adjusted Funds From Operations applicable to common stock | $ | 24,741 | $ | 36,792 | ||||||||||
| Weighted average common shares outstanding - diluted | 123,954 | 123,690 | ||||||||||||
| Funds From Operations per share (diluted) | $ | 0.38 | $ | 0.46 | ||||||||||
| Core Funds From Operations per share (diluted) | $ | 0.39 | $ | 0.46 | ||||||||||
| Common stock outstanding at end of period | 123,888 | 123,643 | ||||||||||||
| (1) | Includes our proportionate share of amounts attributable to consolidated properties. | ||||
| (2) | Non-incremental capital expenditures are defined on page 32. | ||||
12
Piedmont Office Realty Trust, Inc.
Same Store Net Operating Income (Cash Basis)
Unaudited (in thousands)
| Three Months Ended | |||||||||||
| 3/31/2024 | 3/31/2023 | ||||||||||
| Net income (loss) applicable to Piedmont | $ | (27,763) | $ | (1,367) | |||||||
| Net income (loss) applicable to noncontrolling interest | 2 | 3 | |||||||||
Interest expense | 29,714 | 22,077 | |||||||||
Depreciation (1) | 38,857 | 35,787 | |||||||||
Amortization (1) | 18,112 | 22,021 | |||||||||
| Depreciation and amortization attributable to noncontrolling interests | 20 | 20 | |||||||||
Impairment charges | 18,432 | — | |||||||||
EBITDAre | 77,374 | 78,541 | |||||||||
| Loss on early extinguishment of debt | 386 | — | |||||||||
Core EBITDA (2) | 77,760 | 78,541 | |||||||||
General and administrative expense | 7,612 | 7,691 | |||||||||
| Non-cash general reserve for uncollectible accounts | — | (400) | |||||||||
Management fee revenue (3) | 5 | (293) | |||||||||
Other (income) expense (4) | (171) | (1,440) | |||||||||
Straight-line effects of lease revenue (1) | (2,255) | (3,187) | |||||||||
| Straight-line effects of lease revenue attributable to noncontrolling interests | — | (4) | |||||||||
Amortization of lease-related intangibles (1) | (2,656) | (3,412) | |||||||||
| Property net operating income (cash basis) | 80,295 | 77,496 | |||||||||
| Deduct net operating (income) loss from: | |||||||||||
Acquisitions | — | — | |||||||||
Dispositions (5) | (1,140) | (562) | |||||||||
Other investments (6) | 415 | (1,213) | |||||||||
| Same store net operating income (cash basis) | $ | 79,570 | $ | 75,721 | |||||||
| Change period over period | 5.1 | % | N/A | ||||||||
| (1) | Includes our proportionate share of amounts attributable to consolidated properties. | ||||
| (2) | The Company has historically recognized approximately $2 to $3 million of termination income on an annual basis. Given the size of its asset base and the number of tenants with which it conducts business, Piedmont considers termination income of that magnitude to be a normal part of its operations and a recurring part of its revenue stream; however, the recognition of termination income is typically variable between quarters and throughout any given year and is dependent upon when during the year the Company receives termination notices from tenants. During the three months ended March 31, 2024, Piedmont recognized $0.6 million of termination income, as compared with $0.2 million during the same period in 2023 and $3.4 million during the 2023 calendar year. | ||||
| (3) | Presented net of related operating expenses incurred to earn the revenue; therefore, the information presented on this line will not tie to the data presented on the income statements. | ||||
| (4) | Figures presented on this line may not tie back to the relevant sources as some activity is attributable to property operations and is, therefore, presented in property net operating income. | ||||
| (5) | Dispositions includes One Lincoln Park in Dallas, TX, sold in the first quarter of 2024. | ||||
| (6) | Other investments include various land holdings and two out of service redevelopment projects, 222 South Orange Avenue in Orlando, FL, and 9320 Excelsior Boulevard in Hopkins, MN. Additional information on these entities can be found on page 31. | ||||
13
Piedmont Office Realty Trust, Inc.
Same Store Net Operating Income (Accrual Basis)
Unaudited (in thousands)
| Three Months Ended | |||||||||||
| 3/31/2024 | 3/31/2023 | ||||||||||
| Net income (loss) applicable to Piedmont | $ | (27,763) | $ | (1,367) | |||||||
| Net income (loss) applicable to noncontrolling interest | 2 | 3 | |||||||||
Interest expense | 29,714 | 22,077 | |||||||||
Depreciation (1) | 38,857 | 35,787 | |||||||||
Amortization (1) | 18,112 | 22,021 | |||||||||
| Depreciation and amortization attributable to noncontrolling interests | 20 | 20 | |||||||||
Impairment charges | 18,432 | — | |||||||||
EBITDAre | 77,374 | 78,541 | |||||||||
| Loss on early extinguishment of debt | 386 | — | |||||||||
Core EBITDA (2) | 77,760 | 78,541 | |||||||||
General and administrative expense | 7,612 | 7,691 | |||||||||
Management fee revenue (3) | 5 | (293) | |||||||||
Other (income) expense (4) | (171) | (1,440) | |||||||||
| Property net operating income (accrual basis) | 85,206 | 84,499 | |||||||||
| Deduct net operating (income) loss from: | |||||||||||
Acquisitions | — | — | |||||||||
Dispositions (5) | (1,464) | (913) | |||||||||
Other investments (6) | 318 | (1,259) | |||||||||
| Same store net operating income (accrual basis) | $ | 84,060 | $ | 82,327 | |||||||
| Change period over period | 2.1 | % | N/A | ||||||||
| (1) | Includes our proportionate share of amounts attributable to consolidated properties. | ||||
| (2) | The Company has historically recognized approximately $2 to $3 million of termination income on an annual basis. Given the size of its asset base and the number of tenants with which it conducts business, Piedmont considers termination income of that magnitude to be a normal part of its operations and a recurring part of its revenue stream; however, the recognition of termination income is typically variable between quarters and throughout any given year and is dependent upon when during the year the Company receives termination notices from tenants. During the three months ended March 31, 2024, Piedmont recognized $0.6 million of termination income, as compared with $0.2 million during the same period in 2023 and $3.4 million during the 2023 calendar year. | ||||
| (3) | Presented net of related operating expenses incurred to earn the revenue; therefore, the information presented on this line will not tie to the data presented on the income statements. | ||||
| (4) | Figures presented on this line may not tie back to the relevant sources as some activity is attributable to property operations and is, therefore, presented in property net operating income. | ||||
| (5) | Dispositions includes One Lincoln Park in Dallas, TX, sold in the first quarter of 2024. | ||||
| (6) | Other investments include various land holdings and two out of service redevelopment projects, 222 South Orange Avenue in Orlando, FL, and 9320 Excelsior Boulevard in Hopkins, MN. Additional information on these entities can be found on page 31. | ||||
14
Piedmont Office Realty Trust, Inc.
Same Store Net Operating Income (Financial Components)
Unaudited (in thousands)
| Three Months Ended | |||||||||||||||||
| 3/31/2024 | 3/31/2023 | Change ($) | Change (%) | ||||||||||||||
| Revenue | |||||||||||||||||
| Cash rental income | $ | 107,272 | $ | 103,478 | $ | 3,794 | 3.7 | % | |||||||||
| Tenant reimbursements | 25,448 | 23,824 | 1,624 | 6.8 | % | ||||||||||||
| Straight line effects of lease revenue | 1,833 | 2,853 | (1,020) | (35.8) | % | ||||||||||||
| Amortization of lease-related intangibles | 2,657 | 3,353 | (696) | (20.8) | % | ||||||||||||
Total rents | 137,210 | 133,508 | 3,702 | 2.8 | % | ||||||||||||
Other property related income | 5,422 | 5,201 | 221 | 4.2 | % | ||||||||||||
| Total revenue | 142,632 | 138,709 | 3,923 | 2.8 | % | ||||||||||||
| Property operating expense | 58,680 | 56,598 | (2,082) | (3.7) | % | ||||||||||||
| Property other income (expense) | 108 | 216 | (108) | (50.0) | % | ||||||||||||
| Same store net operating income (accrual) | $ | 84,060 | $ | 82,327 | $ | 1,733 | 2.1 | % | |||||||||
| Less: | |||||||||||||||||
| Straight line effects of lease revenue | (1,833) | (2,853) | 1,020 | 35.8 | % | ||||||||||||
| Amortization of lease-related intangibles | (2,657) | (3,353) | 696 | 20.8 | % | ||||||||||||
| Non-cash general reserve for uncollectible accounts | — | (400) | 400 | 100.0 | % | ||||||||||||
| Same store net operating income (cash) | $ | 79,570 | $ | 75,721 | $ | 3,849 | 5.1 | % | |||||||||
15
Piedmont Office Realty Trust, Inc.
Capitalization Analysis
Unaudited (in thousands except for per share data and ratios)
| As of | As of | ||||||||||
| March 31, 2024 | December 31, 2023 | ||||||||||
| Market Capitalization | |||||||||||
| Common stock price | $7.03 | $7.11 | |||||||||
| Total shares outstanding | 123,888 | 123,715 | |||||||||
Equity market capitalization (1) | $870,931 | $879,616 | |||||||||
| Total debt - GAAP | $2,070,070 | $2,054,596 | |||||||||
| Total principal amount of debt outstanding (excludes premiums, discounts, and deferred financing costs) | $2,086,028 | $2,070,033 | |||||||||
Total market capitalization (1) | $2,956,959 | $2,949,649 | |||||||||
| Ratios & Information for Debt Holders | |||||||||||
Total gross assets (2) | $5,355,835 | $5,415,573 | |||||||||
Total principal amount of debt / Total gross assets (2) | 38.9 | % | 38.2 | % | |||||||
Average net principal amount of debt to Core EBITDA - quarterly (3) | 6.8 x | 6.5 x | |||||||||
Average net principal amount of debt to Core EBITDA - trailing twelve months (4) | 6.5 x | 6.4 x | |||||||||
| (1) | Reflects common stock closing price, shares outstanding, and principal amount of debt outstanding as of the end of the reporting period. | ||||
| (2) | Total gross assets is defined as total assets with the add-back of accumulated depreciation and accumulated amortization related to real estate assets and accumulated amortization related to deferred lease costs. | ||||
| (3) | Calculated using the annualized Core EBITDA for the quarter and the average daily principal balance of debt outstanding during the quarter less the average balance of cash and escrow deposits and restricted cash during the quarter. | ||||
| (4) | Calculated using the sum of Core EBITDA for the trailing twelve month period and the average daily principal balance of debt outstanding for the trailing twelve months less the average balance of cash and escrow deposits and restricted cash during the trailing twelve month period. | ||||
16
Piedmont Office Realty Trust, Inc.
Debt Summary
As of March 31, 2024
Unaudited ($ in thousands)
| Floating Rate & Fixed Rate Debt | |||||||||||
Debt | Principal Amount Outstanding (1) | Weighted Average Interest Rate (2) | Weighted Average Maturity | ||||||||
Floating Rate (3) | $361,000 | 6.55% | 35.3 months | ||||||||
| Fixed Rate | 1,725,028 | 5.66% | 57.4 months | ||||||||
| Total | $2,086,028 | 5.81% | 53.6 months | ||||||||
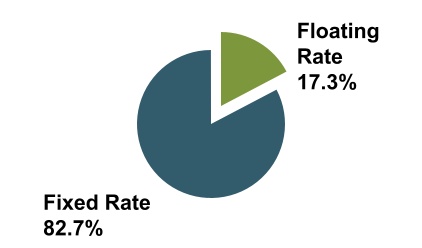
| Unsecured & Secured Debt | |||||||||||
Debt | Principal Amount Outstanding (1) | Weighted Average Interest Rate (2) | Weighted Average Maturity | ||||||||
| Unsecured | $1,891,000 | 5.99% | 53.6 months | ||||||||
| Secured | 195,028 | 4.10% | 54.1 months | ||||||||
| Total | $2,086,028 | 5.81% | 53.6 months | ||||||||
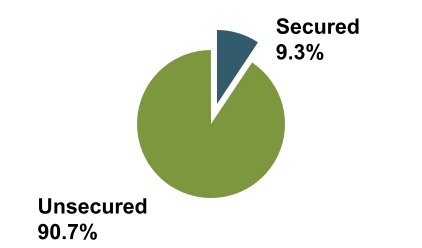
Debt Maturities (4) | ||||||||||||||
Maturity Year | Secured Principal Amount Outstanding (1) | Unsecured Principal Amount Outstanding (1) | Weighted Average Interest Rate (2) | Percentage of Total Debt | ||||||||||
| 2024 | $— | $— | — | — | ||||||||||
| 2025 | — | 275,000 | 4.97% | 13.2% | ||||||||||
| 2026 | — | — | — | — | ||||||||||
| 2027 | — | 416,000 | 6.34% | 19.9% | ||||||||||
| 2028 | 195,028 | 600,000 | 7.99% | 38.1% | ||||||||||
| 2029 | — | — | — | — | ||||||||||
| 2030 | — | 300,000 | 3.15% | 14.4% | ||||||||||
| 2031 | — | — | — | — | ||||||||||
| 2032 | — | 300,000 | 2.75% | 14.4% | ||||||||||
| Total | $195,028 | $1,891,000 | 5.81% | 100.00% | ||||||||||
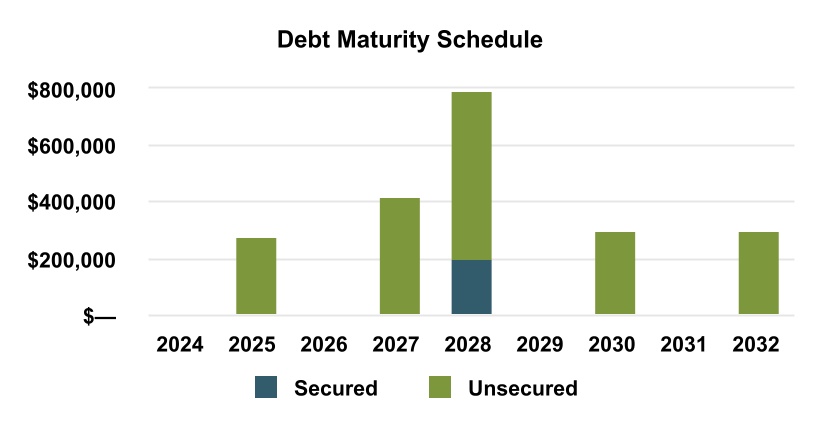
| (1) | All of Piedmont's outstanding debt as of March 31, 2024 was interest-only with the exception of the $197 million fixed-rate mortgage associated with 1180 Peachtree Street in Atlanta, GA. The mortgage began amortizing on a 30-year amortization schedule in October 2023 and represents Piedmont's only outstanding secured debt. | ||||
| (2) | Weighted average interest rate is calculated based upon the principal amounts outstanding and interest rates at March 31, 2024. | ||||
| (3) | The amount of floating rate debt is comprised of the $216 million outstanding balance on the $600 million unsecured line of credit, the $25 million remaining principal balance on the $215 million unsecured 2023 term loan, and the $120 million variable-rate portion of the $200 million unsecured 2024 term loan. | ||||
| (4) | For loans that provide extension options that are conditional solely upon the Company providing proper notice to the loan's administrative agent and the payment of an extension fee, the final extended maturity date is reflected herein. | ||||
17
Piedmont Office Realty Trust, Inc.
Debt Detail
Unaudited ($ in thousands)
Facility | Property | Stated Rate | Maturity | Principal Amount Outstanding as of March 31, 2024 | ||||||||||
| Secured Debt | ||||||||||||||
$197 Million Fixed-Rate Mortgage (1) | 1180 Peachtree Street | 4.10% | 10/1/2028 | 195,028 | ||||||||||
| Secured Subtotal / Weighted Average Interest Rate | 4.10% | $ | 195,028 | |||||||||||
| Unsecured Debt | ||||||||||||||
$215 Million Unsecured 2023 Term Loan (2) | N/A | 6.71% | 1/31/2025 | 25,000 | ||||||||||
$250 Million Unsecured 2018 Term Loan (3) | N/A | 4.79% | 3/31/2025 | 250,000 | ||||||||||
$200 Million Unsecured 2024 Term Loan (4) | N/A | 6.22% | 1/29/2027 | 200,000 | ||||||||||
$600 Million Unsecured Line of Credit (5) | N/A | 6.45% | 6/30/2027 | 216,000 | ||||||||||
$600 Million Unsecured 2023 Senior Notes (6) | N/A | 9.25% | 7/20/2028 | 600,000 | ||||||||||
$300 Million Unsecured 2020 Senior Notes (7) | N/A | 3.15% | 8/15/2030 | 300,000 | ||||||||||
$300 Million Unsecured 2021 Senior Notes (8) | N/A | 2.75% | 4/1/2032 | 300,000 | ||||||||||
| Unsecured Subtotal / Weighted Average Interest Rate | 5.99% | $ | 1,891,000 | |||||||||||
Total Debt - Principal Amount Outstanding / Weighted Average Interest Rate | 5.81% | $ | 2,086,028 | |||||||||||
GAAP Accounting Adjustments (9) | $ | (15,958) | ||||||||||||
| Total Debt - GAAP Amount Outstanding | $ | 2,070,070 | ||||||||||||
| (1) | Piedmont assumed the mortgage on this property upon acquisition, and the loan began amortizing based on a 30-year amortization schedule in October 2023. | ||||
| (2) | In January 2024, $190 million was paid down on the $215 million unsecured loan, leaving a remaining balance of $25 million. The unsecured term loan has a variable interest rate in which Piedmont may select from multiple interest rate options, including the prime rate and various SOFR rates. The all-in interest rate associated with each SOFR interest period selection is comprised of the relevant adjusted SOFR rate (comprised of the relevant base SOFR interest rate plus a fixed adjustment of 0.10%) plus a credit spread (1.30% as of March 31, 2024) based on Piedmont's then current credit rating. | ||||
| (3) | The $250 million unsecured term loan has a stated variable interest rate; however, Piedmont entered into multiple interest rate swap agreements in a notional amount equal to the entire facility which effectively fixes the interest rate through the loan's maturity date and can only change with a credit rating change for the Company. | ||||
| (4) | The $200 million unsecured term loan has a stated variable interest rate; however, Piedmont entered into multiple interest rate swap agreements in a notional amount totaling $80 million which effectively fixes the interest rate for that portion of the term loan through 2/1/2026 (at 5.4965% as of March 31, 2024; this rating can change only with a credit rating change for the Company). For the $120 million portion of the term loan that has a variable rate, Piedmont may select from multiple interest rate options, including the prime rate and various term SOFR rates. The all-in interest rate associated with each SOFR interest period selection is comprised of the relevant adjusted SOFR rate (comprised of the relevant base SOFR interest rate plus a fixed adjustment of 0.10%) plus a credit spread (1.30% as of March 31, 2024) based on Piedmont's then current credit rating. | ||||
| (5) | All outstanding debt as of March 31, 2024 was term debt with the exception of the $216 million balance on the $600 million unsecured revolving credit facility. The facility has an initial maturity date of June 30, 2026; however, there are two, six-month extension options available under the facility providing for a total extension of up to one year to June 30, 2027. The interest rate presented for the facility is the weighted average interest rate for all outstanding draws as of March 31, 2024. Piedmont may select from multiple interest rate options with each draw under the facility, including the prime rate and various SOFR rates. The all-in interest rate associated with each SOFR interest period selection is comprised of the relevant adjusted SOFR rate (comprised of the relevant base SOFR interest rate plus a fixed adjustment of 0.10%) plus a credit spread (1.04% as of March 31, 2024) based on Piedmont's then current credit rating. | ||||
| (6) | The original $400 million unsecured senior notes were offered for sale in July 2023 at 99.000% of the principal amount; the resulting effective cost of the original $400 million financing is approximately 9.50% before the consideration of transaction costs. In December 2023, Piedmont offered an additional $200 million in unsecured senior notes for sale at 101.828% of the principal amount; the resulting effective cost of the $200 million additional financing is approximately 8.75%. | ||||
| (7) | The $300 million unsecured senior notes were offered for sale at 99.236% of the principal amount; the resulting effective cost of the financing is approximately 3.24% before the consideration of transaction costs and the impact of interest rate hedges. After incorporating the results of the related interest rate hedging activity, the effective cost of the financing is approximately 3.90%. | ||||
| (8) | The $300 million unsecured senior notes were offered for sale at 99.510% of the principal amount; the resulting effective cost of the financing is approximately 2.80% before the consideration of transaction costs and the impact of interest rate hedges. After incorporating the results of the related interest rate hedging activity, the effective cost of the financing is approximately 2.78%. | ||||
| (9) | The GAAP accounting adjustments relate to original issue discounts, third-party fees, and lender fees resulting from the procurement processes for our various debt facilities. The original issue discounts and fees are amortized to interest expense over the contractual term of the related debt. | ||||
18
Piedmont Office Realty Trust, Inc.
Debt Covenant & Ratio Analysis (for Debt Holders)
As of March 31, 2024
Unaudited
| Three Months Ended | ||||||||||||||||||||
Bank Debt Covenant Compliance (1) | Required | 3/31/2024 | 12/31/2023 | 9/30/2023 | 6/30/2023 | 3/31/2023 | ||||||||||||||
| Maximum leverage ratio | 0.60 | 0.41 | 0.37 | 0.36 | 0.37 | 0.38 | ||||||||||||||
Minimum fixed charge coverage ratio (2) | 1.50 | 2.67 | 2.91 | 3.16 | 3.52 | 3.91 | ||||||||||||||
| Maximum secured indebtedness ratio | 0.40 | 0.04 | 0.04 | 0.03 | 0.04 | 0.04 | ||||||||||||||
| Minimum unencumbered leverage ratio | 1.60 | 2.39 | 2.67 | 2.74 | 2.66 | 2.64 | ||||||||||||||
Minimum unencumbered interest coverage ratio (3) | 1.75 | 2.75 | 2.99 | 3.28 | 3.67 | 4.10 | ||||||||||||||
| Three Months Ended | ||||||||||||||||||||
Bond Covenant Compliance (4) | Required | 3/31/2024 | 12/31/2023 | 9/30/2023 | 6/30/2023 | 3/31/2023 | ||||||||||||||
| Total debt to total assets | 60% or less | 45.2% | 44.4% | 44.7% | 44.8% | 47.1% | ||||||||||||||
| Secured debt to total assets | 40% or less | 4.2% | 4.2% | 4.3% | 4.3% | 4.2% | ||||||||||||||
| Ratio of consolidated EBITDA to interest expense | 1.50 or greater | 3.04 | 3.29 | 3.56 | 3.97 | 4.44 | ||||||||||||||
| Unencumbered assets to unsecured debt | 150% or greater | 220% | 225% | 223% | 223% | 211% | ||||||||||||||
| Three Months Ended | Twelve Months Ended | |||||||
| Other Debt Coverage Ratios for Debt Holders | March 31, 2024 | December 31, 2023 | ||||||
Average net principal amount of debt to core EBITDA (5) | 6.8 x | 6.4 x | ||||||
Fixed charge coverage ratio (6) | 2.3 x | 2.9 x | ||||||
Interest coverage ratio (7) | 2.4 x | 2.9 x | ||||||
| (1) | Bank debt covenant compliance calculations relate to the most restrictive of the specific calculations detailed in the relevant credit agreements. Please refer to such agreements for relevant defined terms. | ||||
| (2) | Defined as EBITDA for the trailing four quarters (including the Company's share of EBITDA from unconsolidated interests), excluding one-time or non-recurring gains or losses, less a $0.15 per square foot capital reserve, and excluding the impact of straight line rent leveling adjustments and amortization of intangibles divided by the Company's share of fixed charges, as more particularly described in the credit agreements. This definition of fixed charge coverage ratio as prescribed by our credit agreements is different from the fixed charge coverage ratio definition employed elsewhere within this report. | ||||
| (3) | Defined as net operating income for the trailing four quarters for unencumbered assets (including the Company's share of net operating income from partially-owned entities and subsidiaries that are deemed to be unencumbered) less a $0.15 per square foot capital reserve divided by the Company's share of interest expense associated with unsecured financings only, as more particularly described in the credit agreements. | ||||
| (4) | Bond covenant compliance calculations relate to specific calculations prescribed in the relevant debt agreements. Please refer to the Indenture and the First Supplemental Indenture dated March 6, 2014, the Second Supplemental Indenture dated August 12, 2020, the Third Supplemental Indenture dated September 20, 2021, and the Fourth Supplemental Indenture dated July 20, 2023 for defined terms and detailed information about the calculations. | ||||
| (5) | Calculated using the average daily principal balance of debt outstanding during the identified period, less the average balance of cash and escrow deposits and restricted cash as of the end of each month during the relevant period. | ||||
| (6) | Calculated as Core EBITDA divided by the sum of interest expense, principal amortization, capitalized interest and preferred dividends (none during periods presented). The Company had principal amortization of $0.9 million for the three months ended March 31, 2024 and $1.1 million for the twelve months ended December 31, 2023. The Company had capitalized interest of $2.8 million for the three months ended March 31, 2024 and $7.0 million for the twelve months ended December 31, 2023. | ||||
| (7) | Calculated as Core EBITDA divided by the sum of interest expense and capitalized interest. The Company had capitalized interest of $2.8 million for the three months ended March 31, 2024 and $7.0 million for the twelve months ended December 31, 2023. | ||||
19
Piedmont Office Realty Trust, Inc.
Tenant Diversification
As of March 31, 2024
(in thousands except for number of properties)
Tenant (1) | Credit Rating (2) | Number of Properties | Lease Term Remaining (3) | Annualized Lease Revenue | Percentage of Annualized Lease Revenue (%) | Leased Square Footage | Percentage of Leased Square Footage (%) | ||||||||||||||||
US Bancorp (4) | A / A3 | 3 | 6.0 | $27,750 | 4.8 | 787 | 5.6 | ||||||||||||||||
| State of New York | AA+ / Aa1 | 1 | 12.5 | 25,632 | 4.4 | 482 | 3.4 | ||||||||||||||||
| Amazon | AA / A1 | 4 | 0.7 | 17,563 | 3.0 | 337 | 2.4 | ||||||||||||||||
| City of New York | AA / Aa2 | 1 | 2.2 | 15,628 | 2.7 | 313 | 2.2 | ||||||||||||||||
| Microsoft | AAA / Aaa | 2 | 7.2 | 13,738 | 2.4 | 355 | 2.5 | ||||||||||||||||
| King & Spalding | No Rating Available | 1 | 7.0 | 13,214 | 2.3 | 268 | 1.9 | ||||||||||||||||
| Transocean | CCC+ / Caa1 | 1 | 12.1 | 11,569 | 2.0 | 301 | 2.1 | ||||||||||||||||
| Ryan | B+ / B2 | 1 | 1.8 | 9,617 | 1.7 | 178 | 1.3 | ||||||||||||||||
| VMware, Inc. / subsidiary of Broadcom | BBB / Baa3 | 1 | 3.3 | 9,097 | 1.6 | 215 | 1.5 | ||||||||||||||||
| Schlumberger Technology | A / A2 | 1 | 4.8 | 8,231 | 1.4 | 254 | 1.8 | ||||||||||||||||
| Gartner | BBB- / Ba1 | 2 | 10.3 | 7,875 | 1.4 | 207 | 1.5 | ||||||||||||||||
| Fiserv | BBB / Baa2 | 1 | 3.3 | 7,629 | 1.3 | 195 | 1.4 | ||||||||||||||||
| Salesforce.com | A+ / A1 | 1 | 5.3 | 7,450 | 1.3 | 182 | 1.3 | ||||||||||||||||
| Epsilon Data Management / subsidiary of Publicis | BBB+ / Baa1 | 1 | 2.3 | 7,102 | 1.2 | 222 | 1.6 | ||||||||||||||||
| Eversheds Sutherland | No Rating Available | 1 | 2.1 | 6,917 | 1.2 | 180 | 1.3 | ||||||||||||||||
| Applied Predictive Technologies / subsidiary of MasterCard | A+ / Aa3 | 1 | 4.2 | 6,838 | 1.2 | 133 | 0.9 | ||||||||||||||||
| International Food Policy Research Institute | No Rating Available | 1 | 5.1 | 6,603 | 1.1 | 102 | 0.7 | ||||||||||||||||
| Other | Various | 375,396 | 65.0 | 9,374 | 66.6 | ||||||||||||||||||
| Total | $577,849 | 100.0 | 14,085 | 100.0 | |||||||||||||||||||
| (1) | This schedule presents all tenants contributing 1.0% or more to Annualized Lease Revenue. | ||||
| (2) | Credit rating may reflect the credit rating of the parent or a guarantor. When available, both the Standard & Poor's credit rating and the Moody's credit rating are provided. The absence of a credit rating for a tenant is not an indication of the creditworthiness of the tenant; in most cases, the lack of a credit rating reflects that the tenant has not sought such a rating. | ||||
| (3) | The metrics presented are the weighted average lease terms remaining in years weighted by Annualized Lease Revenue. | ||||
| (4) | The weighted average lease term for US Bancorp reflects the 10-year renewal for 447,000 square feet at the tenant's Minneapolis CBD location executed in the fourth quarter of 2023, as well as the 2 months of lease term remaining at the tenant's 340,000 square foot suburban location. | ||||
20
Piedmont Office Realty Trust, Inc.
Tenant Credit Rating & Lease Distribution Information
As of March 31, 2024
Tenant Credit Rating
Rating Level (1) | Annualized Lease Revenue (in thousands) | Percentage of Annualized Lease Revenue (%) | ||||||
| AAA / Aaa | $22,665 | 3.9 | ||||||
| AA / Aa | 73,211 | 12.7 | ||||||
| A / A | 72,909 | 12.6 | ||||||
| BBB / Baa | 67,176 | 11.6 | ||||||
| BB / Ba | 12,082 | 2.1 | ||||||
| B / B | 17,845 | 3.1 | ||||||
| Below | 19,826 | 3.4 | ||||||
Not rated (2) | 292,135 | 50.6 | ||||||
| Total | $577,849 | 100.0 | ||||||
Lease Distribution
| Lease Size | Number of Leases | Percentage of Leases (%) | Annualized Lease Revenue (in thousands) | Percentage of Annualized Lease Revenue (%) | Leased Square Footage (in thousands) | Percentage of Leased Square Footage (%) | ||||||||||||||
| 2,500 sf or Less | 342 | 35.8 | $26,023 | 4.5 | 226 | 1.6 | ||||||||||||||
| 2,501 - 10,000 sf | 340 | 35.6 | 69,035 | 12.0 | 1,735 | 12.3 | ||||||||||||||
| 10,001 - 20,000 sf | 104 | 10.9 | 56,019 | 9.7 | 1,414 | 10.0 | ||||||||||||||
| 20,001 - 40,000 sf | 94 | 9.9 | 100,067 | 17.3 | 2,533 | 18.0 | ||||||||||||||
| 40,001 - 100,000 sf | 47 | 4.9 | 118,009 | 20.4 | 2,922 | 20.8 | ||||||||||||||
| Greater than 100,000 sf | 28 | 2.9 | 208,696 | 36.1 | 5,255 | 37.3 | ||||||||||||||
| Total | 955 | 100.0 | $577,849 | 100.0 | 14,085 | 100.0 | ||||||||||||||
| (1) | Credit rating may reflect the credit rating of the parent or a guarantor. Where differences exist between the Standard & Poor's credit rating for a tenant and the Moody's credit rating for a tenant, the higher credit rating is selected for this analysis. | ||||
| (2) | The classification of a tenant as "not rated" is not an indication of the creditworthiness of the tenant; in most cases, the lack of a credit rating reflects that the tenant has not sought such a rating. Included in this category are such tenants as Piper Sandler, Ernst & Young, KPMG, BDO, and RaceTrac Petroleum. | ||||
21
Piedmont Office Realty Trust, Inc.
Leased Percentage Information
(in thousands)
| Three Months Ended | Three Months Ended | ||||||||||||||||||||||
| March 31, 2024 | March 31, 2023 | ||||||||||||||||||||||
Leased Square Footage | Rentable Square Footage | Percent Leased (1) | Leased Square Footage | Rentable Square Footage | Percent Leased (1) | ||||||||||||||||||
| As of December 31, 20xx | 14,426 | 16,563 | 87.1 | % | 14,440 | 16,658 | 86.7 | % | |||||||||||||||
| Leases signed during the period | 500 | 544 | |||||||||||||||||||||
Less: | |||||||||||||||||||||||
| Lease renewals signed during period | (172) | (274) | |||||||||||||||||||||
| New leases signed during period for currently occupied space | (20) | (46) | |||||||||||||||||||||
| Leases expired during period and other | (392) | (10) | (312) | 16 | |||||||||||||||||||
| Subtotal | 14,342 | 16,553 | 86.6 | % | 14,352 | 16,674 | 86.1 | % | |||||||||||||||
Acquisitions and properties placed in service during period (2) | — | — | — | — | |||||||||||||||||||
Dispositions and properties taken out of service during period (2) | (257) | (516) | — | — | |||||||||||||||||||
| As of March 31, 20xx | 14,085 | 16,037 | 87.8 | % | 14,352 | 16,674 | 86.1 | % | |||||||||||||||
| Same Store Analysis | |||||||||||||||||||||||
Less acquisitions and dispositions after March 31, 2023 and out-of-service redevelopments (2) (3) | — | — | — | % | (463) | (525) | 88.2 | % | |||||||||||||||
| Same Store Leased Percentage | 14,085 | 16,037 | 87.8 | % | 13,889 | 16,149 | 86.0 | % | |||||||||||||||
| (1) | Calculated as square footage associated with commenced leases as of period end with the addition of square footage associated with uncommenced leases for spaces vacant as of period end at our in-service properties, divided by total rentable in-service square footage as of period end. | ||||
| (2) | For additional information on acquisitions and dispositions completed during the last year and current out-of-service redevelopments, please refer to page 31. | ||||
| (3) | Dispositions completed during the previous twelve months are deducted from the previous period data and acquisitions completed during the previous twelve months are deducted from the current period data. Redevelopments that commenced during the previous twelve months that were taken out of service are deducted from the previous period data and developments and previously out of service redevelopments that were placed in service during the previous twelve months are deducted from the current period data. | ||||
22
Piedmont Office Realty Trust, Inc.
Rental Rate Roll Up / Roll Down Analysis
| Three Months Ended | |||||||||||||||||
| March 31, 2024 | |||||||||||||||||
| Square Feet (in thousands) | % of Total Signed During Period | % of Rentable Square Footage | % Change Cash Rents (2) | % Change Accrual Rents (3) | |||||||||||||
Leases executed for spaces vacant one year or less (1) | 225 | 45.0% | 1.4% | 8.0% | 18.6% | ||||||||||||
Leases executed for spaces excluded from analysis (4) | 275 | 55.0% | |||||||||||||||
| (1) | The populations included in this analysis consist of consolidated leases executed during the relevant period with lease terms of greater than one year. | ||||
| (2) | For the purpose of this analysis, the last twelve months of cash paying rents of the previous leases are compared to the first twelve months of cash paying rents of the new leases in order to calculate the percentage change. | ||||
| (3) | For the purpose of this analysis, the accrual basis rents of the previous leases are compared to the accrual basis rents of the new leases in order to calculate the percentage change. For newly signed leases which have variations in accrual basis rents, whether because of known future expansions, contractions, lease expense recovery structure changes, or other similar reasons, the weighted average of such varying accrual basis rents is used for the calculation. | ||||
| (4) | Represents leases signed at our consolidated office assets that do not qualify for inclusion in the analysis, primarily because the spaces had been vacant for more than one year. Leases associated with storage spaces, retail spaces, management offices, percentage rent agreements, and newly acquired assets for which there is less than one year of operating history are also excluded from this analysis. | ||||
23
Piedmont Office Realty Trust, Inc.
Lease Expiration Schedule
As of March 31, 2024
(in thousands)
| Expiration Year | Annualized Lease Revenue (1) | Percentage of Annualized Lease Revenue (%) | Rentable Square Footage | Percentage of Rentable Square Footage (%) | |||||||||||||
| Vacant | $— | — | 1,952 | 12.2 | |||||||||||||
2024 (2) | 41,995 | 7.3 | 1,161 | 7.2 | |||||||||||||
2025 (3) | 69,738 | 12.1 | 1,661 | 10.3 | |||||||||||||
| 2026 | 64,822 | 11.2 | 1,608 | 10.0 | |||||||||||||
| 2027 | 49,702 | 8.6 | 1,301 | 8.1 | |||||||||||||
| 2028 | 68,949 | 11.9 | 1,749 | 10.9 | |||||||||||||
| 2029 | 57,289 | 9.9 | 1,348 | 8.4 | |||||||||||||
| 2030 | 30,852 | 5.3 | 795 | 5.0 | |||||||||||||
| 2031 | 30,682 | 5.3 | 763 | 4.8 | |||||||||||||
| 2032 | 25,191 | 4.4 | 607 | 3.8 | |||||||||||||
| 2033 | 11,240 | 1.9 | 241 | 1.5 | |||||||||||||
| 2034 | 33,509 | 5.8 | 905 | 5.6 | |||||||||||||
| 2035 | 23,080 | 4.0 | 620 | 3.9 | |||||||||||||
| 2036 | 20,252 | 3.5 | 527 | 3.3 | |||||||||||||
| Thereafter | 50,548 | 8.8 | 799 | 5.0 | |||||||||||||
| Total | $577,849 | 100.0 | 16,037 | 100.0 | |||||||||||||
| Average Lease Term Remaining | |||||
| 3/31/2024 | 5.7 years | ||||
| 12/31/2023 | 5.7 years | ||||
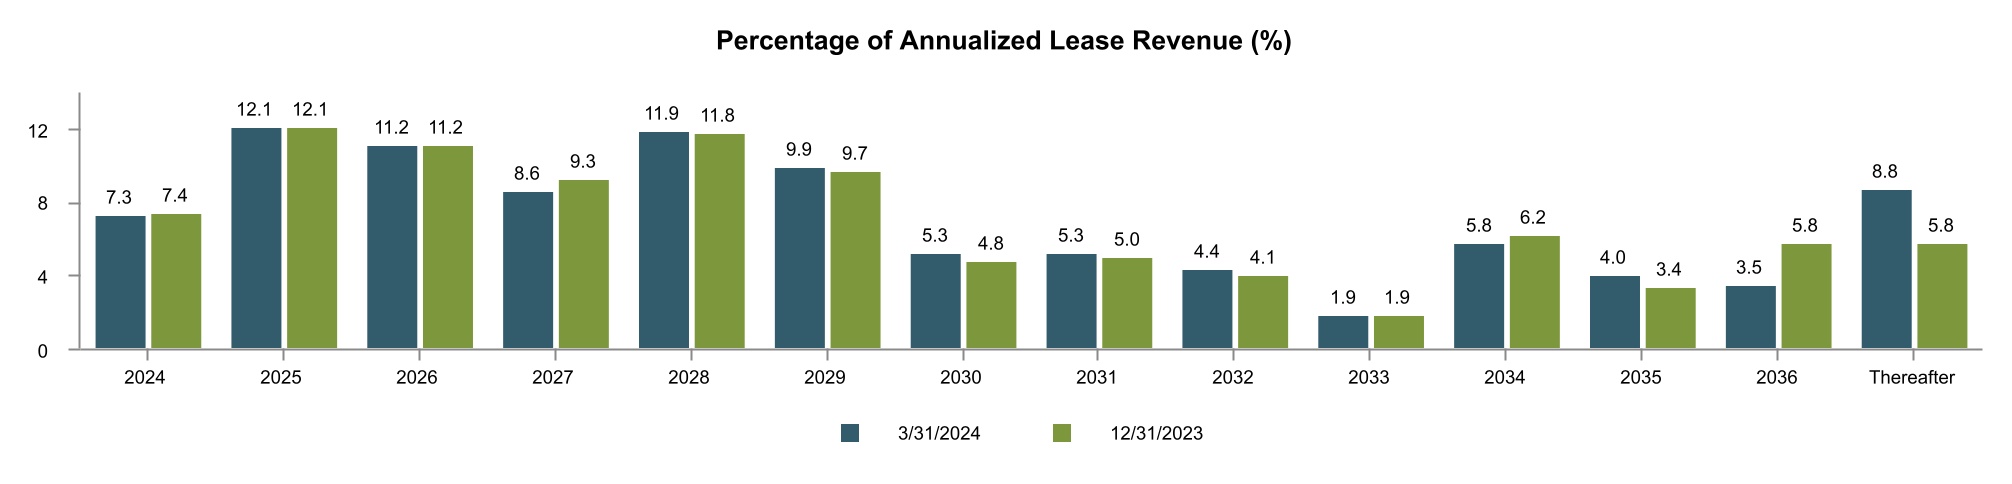
| (1) | Annualized rental income associated with each newly executed lease for currently occupied space is incorporated herein only at the expiration date for the current lease. Annualized rental income associated with each such new lease is removed from the expiry year of the current lease and added to the expiry year of the new lease. These adjustments effectively incorporate known roll ups and roll downs into the expiration schedule. | ||||
| (2) | Includes leases with an expiration date of March 31, 2024, comprised of approximately 344,000 square feet and Annualized Lease Revenue of $10.8 million. | ||||
| (3) | Includes leases and other revenue-producing agreements on a month-to-month basis, comprised of approximately 2,500 square feet and Annualized Lease Revenue of $75K, which have been assigned a lease expiration date of a year and a day beyond the current period end date. | ||||
24
Piedmont Office Realty Trust, Inc.
Lease Expirations by Quarter
As of March 31, 2024
(in thousands)
Q2 2024 (1) | Q3 2024 | Q4 2024 | Q1 2025 | |||||||||||||||||||||||||||||||||||
| Location | Expiring Square Footage | Expiring Lease Revenue (2) | Expiring Square Footage | Expiring Lease Revenue (2) | Expiring Square Footage | Expiring Lease Revenue (2) | Expiring Square Footage | Expiring Lease Revenue (2) | ||||||||||||||||||||||||||||||
| Atlanta | 48 | $2,025 | 61 | $2,059 | 51 | $2,268 | 85 | $2,798 | ||||||||||||||||||||||||||||||
| Boston | — | — | 1 | 51 | 6 | 233 | 88 | 2,801 | ||||||||||||||||||||||||||||||
| Dallas | 89 | 4,082 | 16 | 798 | 44 | 1,808 | 431 | 22,294 | ||||||||||||||||||||||||||||||
| Minneapolis | 356 | 11,971 | 15 | 669 | 11 | 448 | 35 | 1,479 | ||||||||||||||||||||||||||||||
| New York | 5 | 223 | 2 | 137 | 31 | 1,809 | — | 13 | ||||||||||||||||||||||||||||||
| Orlando | 245 | 3,362 | 7 | 608 | 4 | 149 | 73 | 2,673 | ||||||||||||||||||||||||||||||
| Northern Virginia / Washington, D.C. | 111 | 5,842 | 21 | 1,069 | 37 | 1,881 | 9 | 604 | ||||||||||||||||||||||||||||||
| Other | — | 5 | — | — | — | — | — | — | ||||||||||||||||||||||||||||||
Total (3) | 854 | $27,510 | 123 | $5,391 | 184 | $8,596 | 721 | $32,662 | ||||||||||||||||||||||||||||||
| (1) | Includes leases with an expiration date of March 31, 2024, comprised of approximately 344,000 square feet and expiring lease revenue of $10.6 million. No such adjustments are made to other periods presented. | ||||
| (2) | Expiring Lease Revenue is calculated as expiring square footage multiplied by the gross rent per square foot of the tenant currently leasing the space. | ||||
| (3) | Total expiring lease revenue in any given year will not tie to the expiring Annualized Lease Revenue presented on the Lease Expiration Schedule on the previous page as the Lease Expiration Schedule accounts for the revenue effects of newly signed leases. Reflected herein are expiring revenues based on in-place rental rates. | ||||
25
Piedmont Office Realty Trust, Inc.
Lease Expirations by Year
As of March 31, 2024
(in thousands)
12/31/2024 (1) | 12/31/2025 | 12/31/2026 | 12/31/2027 | 12/31/2028 | |||||||||||||||||||||||||||||||||||||||||||
| Location | Expiring Square Footage | Expiring Lease Revenue (2) | Expiring Square Footage | Expiring Lease Revenue (2) | Expiring Square Footage | Expiring Lease Revenue (2) | Expiring Square Footage | Expiring Lease Revenue (2) | Expiring Square Footage | Expiring Lease Revenue (2) | |||||||||||||||||||||||||||||||||||||
| Atlanta | 160 | $6,352 | 414 | $15,004 | 492 | $19,169 | 606 | $23,947 | 405 | $15,620 | |||||||||||||||||||||||||||||||||||||
| Boston | 6 | 284 | 149 | 5,478 | 18 | 645 | 27 | 854 | 174 | 5,518 | |||||||||||||||||||||||||||||||||||||
| Dallas | 149 | 6,688 | 619 | 30,602 | 366 | 12,548 | 196 | 6,741 | 594 | 24,017 | |||||||||||||||||||||||||||||||||||||
| Minneapolis | 383 | 13,088 | 230 | 9,200 | 28 | 1,088 | 213 | 7,388 | 34 | 1,384 | |||||||||||||||||||||||||||||||||||||
| New York | 38 | 2,169 | 10 | 508 | 313 | 15,640 | 5 | 501 | — | 26 | |||||||||||||||||||||||||||||||||||||
| Orlando | 256 | 4,119 | 187 | 6,418 | 296 | 10,520 | 217 | 8,171 | 43 | 1,529 | |||||||||||||||||||||||||||||||||||||
| Northern Virginia / Washington, D.C. | 169 | 8,792 | 52 | 3,328 | 95 | 5,060 | 37 | 2,092 | 240 | 12,490 | |||||||||||||||||||||||||||||||||||||
| Other | — | 5 | — | — | — | — | — | 5 | 259 | 8,283 | |||||||||||||||||||||||||||||||||||||
Total (3) | 1,161 | $41,497 | 1,661 | $70,538 | 1,608 | $64,670 | 1,301 | $49,699 | 1,749 | $68,867 | |||||||||||||||||||||||||||||||||||||
| (1) | Includes leases with an expiration date of March 31, 2024, comprised of approximately 344,000 square feet and expiring lease revenue of $10.6 million. No such adjustments are made to other periods presented. | ||||
| (2) | Expiring Lease Revenue is calculated as expiring square footage multiplied by the gross rent per square foot of the tenant currently leasing the space. | ||||
| (3) | Total expiring lease revenue in any given year will not tie to the expiring Annualized Lease Revenue presented on the Lease Expiration Schedule on page 24 as the Lease Expiration Schedule accounts for the revenue effects of newly signed leases. Reflected herein are expiring revenues based on in-place rental rates. | ||||
26
Piedmont Office Realty Trust, Inc.
Contractual Tenant Improvements and Leasing Commissions
Three Months Ended March 31, 2024 (2) | For the Year Ended | 2020 to 2024 (Weighted Average) | ||||||||||||||||||
2023 (3) | 2022 | 2021 | 2020 | |||||||||||||||||
| Total Leasing Transactions | ||||||||||||||||||||
Square feet (1) | 498,327 | 2,239,797 | 2,142,852 | 2,247,366 | 1,103,248 | 8,231,590 | ||||||||||||||
Tenant improvements per square foot per year of lease term | $3.70 | $3.80 | $3.22 | $2.78 | $4.30 | $3.43 | ||||||||||||||
Leasing commissions per square foot per year of lease term | $1.73 | $2.21 | $2.22 | $1.67 | $1.89 | $1.99 | ||||||||||||||
Total per square foot per year of lease term | $5.43 | $6.01 | $5.44 | $4.45 | $6.19 | $5.42 | ||||||||||||||
Less Adjustment for Commitment Expirations (4) | ||||||||||||||||||||
| Expired tenant improvements (not paid out) per square foot per year of lease term | -$0.30 | -$0.79 | -$0.10 | -$0.20 | -$0.40 | -$0.40 | ||||||||||||||
| Adjusted total per square foot per year of lease term | $5.13 | $5.22 | $5.34 | $4.25 | $5.79 | $5.02 | ||||||||||||||
| (1) | This information presented is for our consolidated offices only and excludes activity associated with storage and license spaces. | ||||
| (2) | The tenant improvement and leasing commission amounts presented for the three months ended March 31, 2024 include a 101,500 square foot 11-year lease executed in the first quarter of 2024 with no capital outlay requirements. | ||||
| (3) | The tenant improvement amounts presented for the year ended December 31, 2023 were adjusted to reflect the overall concession package for the 447,000 square foot 10-year renewal with US Bancorp, executed in the fourth quarter of 2023. The renewal terms provided for zero months of rent abatement, offset by an above-market tenant improvement allowance. The amounts are presented as if the renewal had included the standard twelve months gross rent abatement in line with market conditions and, therefore, a normalized tenant improvement allowance. This adjustment effectively lowered the total capital per square foot per year of lease term for the year ended December 31, 2023 by $0.97. | ||||
| (4) | The Company reports total tenant improvement amounts based on the maximum amount of committed leasing capital in the period in which the lease is executed. However, tenants do not always use the full allowance provided for in the lease, or a portion of the allowance could expire at a set date. To provide additional clarity on actual costs for completed leasing transactions, tenant improvement allowances that have expired or are no longer available to the tenant are disclosed in this section and are deducted from the capital commitments per square foot of leased space in the periods in which they expired. | ||||
27
Piedmont Office Realty Trust, Inc.
Geographic Diversification
As of March 31, 2024
($ and square footage in thousands)
| Location | Number of Properties | Annualized Lease Revenue | Percentage of Annualized Lease Revenue (%) | Rentable Square Footage | Percentage of Rentable Square Footage (%) | Leased Square Footage | Percent Leased (%) | ||||||||||||||||
| Atlanta | 11 | $170,989 | 29.6 | 4,710 | 29.4 | 4,352 | 92.4 | ||||||||||||||||
| Dallas | 12 | 109,998 | 19.0 | 3,220 | 20.1 | 2,647 | 82.2 | ||||||||||||||||
| Northern Virginia / Washington, D.C. | 6 | 67,017 | 11.6 | 1,591 | 9.9 | 1,254 | 78.8 | ||||||||||||||||
| Orlando | 6 | 60,591 | 10.5 | 1,757 | 11.0 | 1,643 | 93.5 | ||||||||||||||||
| Minneapolis | 5 | 59,512 | 10.3 | 1,830 | 11.4 | 1,614 | 88.2 | ||||||||||||||||
| New York | 1 | 50,184 | 8.7 | 1,045 | 6.5 | 939 | 89.9 | ||||||||||||||||
| Boston | 6 | 39,695 | 6.9 | 1,270 | 7.9 | 1,076 | 84.7 | ||||||||||||||||
| Other | 2 | 19,863 | 3.4 | 614 | 3.8 | 560 | 91.2 | ||||||||||||||||
| Total / Weighted Average | 49 | $577,849 | 100.0 | 16,037 | 100.0 | 14,085 | 87.8 | ||||||||||||||||
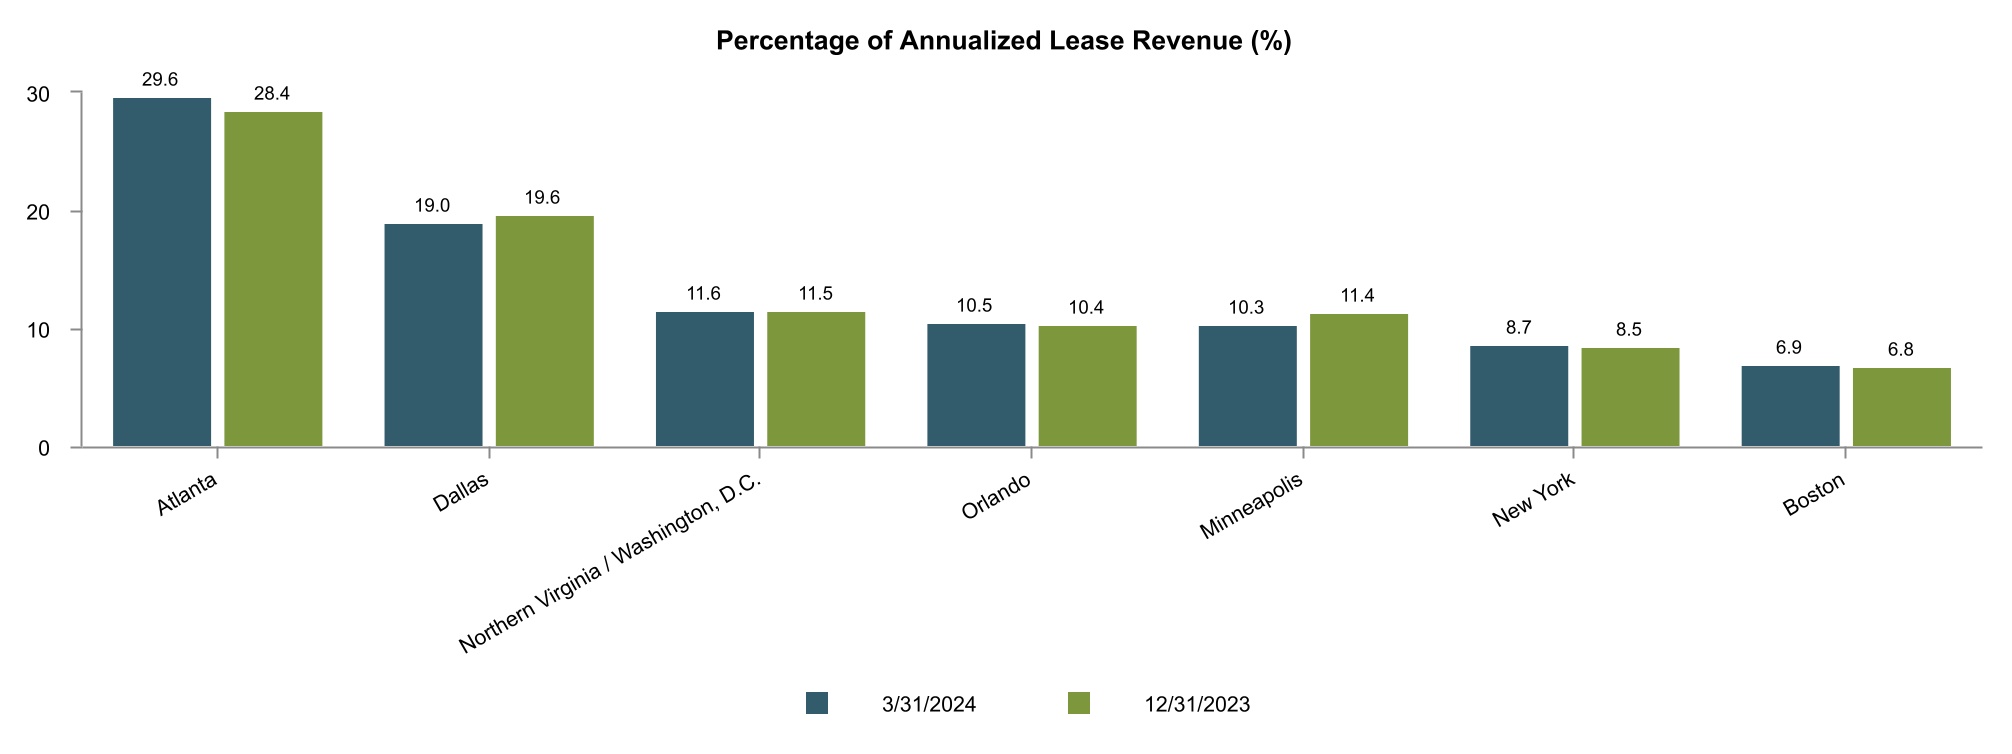
28
Piedmont Office Realty Trust, Inc.
Geographic Diversification by Location Type
As of March 31, 2024
(square footage in thousands)
| CBD | URBAN INFILL / SUBURBAN | TOTAL | |||||||||||||||||||||||||||||||||||||||||||||
| Location | Number of Properties | Percentage of Annualized Lease Revenue (%) | Rentable Square Footage | Percentage of Rentable Square Footage (%) | Number of Properties | Percentage of Annualized Lease Revenue (%) | Rentable Square Footage | Percentage of Rentable Square Footage (%) | Number of Properties | Percentage of Annualized Lease Revenue (%) | Rentable Square Footage | Percentage of Rentable Square Footage (%) | |||||||||||||||||||||||||||||||||||
| Atlanta | 2 | 10.0 | 1,300 | 8.1 | 9 | 19.6 | 3,410 | 21.3 | 11 | 29.6 | 4,710 | 29.4 | |||||||||||||||||||||||||||||||||||
| Dallas | — | — | — | — | 12 | 19.0 | 3,220 | 20.1 | 12 | 19.0 | 3,220 | 20.1 | |||||||||||||||||||||||||||||||||||
| Northern Virginia / Washington, D.C. | 3 | 5.1 | 691 | 4.3 | 3 | 6.5 | 900 | 5.6 | 6 | 11.6 | 1,591 | 9.9 | |||||||||||||||||||||||||||||||||||
| Orlando | 4 | 8.6 | 1,448 | 9.1 | 2 | 1.9 | 309 | 1.9 | 6 | 10.5 | 1,757 | 11.0 | |||||||||||||||||||||||||||||||||||
| Minneapolis | 1 | 5.5 | 937 | 5.8 | 4 | 4.8 | 893 | 5.6 | 5 | 10.3 | 1,830 | 11.4 | |||||||||||||||||||||||||||||||||||
| New York | 1 | 8.7 | 1,045 | 6.5 | — | — | — | — | 1 | 8.7 | 1,045 | 6.5 | |||||||||||||||||||||||||||||||||||
| Boston | — | — | — | — | 6 | 6.9 | 1,270 | 7.9 | 6 | 6.9 | 1,270 | 7.9 | |||||||||||||||||||||||||||||||||||
| Other | — | — | — | — | 2 | 3.4 | 614 | 3.8 | 2 | 3.4 | 614 | 3.8 | |||||||||||||||||||||||||||||||||||
| Total | 11 | 37.9 | 5,421 | 33.8 | 38 | 62.1 | 10,616 | 66.2 | 49 | 100.0 | 16,037 | 100.0 | |||||||||||||||||||||||||||||||||||
29
Piedmont Office Realty Trust, Inc.
Industry Diversification
As of March 31, 2024
($ and square footage in thousands)
| Percentage of | Leased | Percentage | |||||||||||||||||||||
| Number of | Percentage of Total | Annualized Lease | Annualized Lease | Square | of Leased | ||||||||||||||||||
| Industry | Tenants | Tenants (%) | Revenue | Revenue (%) | Footage | Square Footage (%) | |||||||||||||||||
| Business Services | 77 | 10.8 | $82,099 | 14.2 | 2,075 | 14.7 | |||||||||||||||||
| Engineering, Accounting, Research, Management & Related Services | 95 | 13.3 | 81,611 | 14.1 | 1,921 | 13.6 | |||||||||||||||||
| Legal Services | 79 | 11.0 | 59,430 | 10.3 | 1,408 | 10.0 | |||||||||||||||||
| Governmental Entity | 5 | 0.7 | 48,473 | 8.4 | 938 | 6.7 | |||||||||||||||||
| Depository Institutions | 20 | 2.8 | 37,734 | 6.5 | 1,023 | 7.3 | |||||||||||||||||
| Real Estate | 50 | 7.0 | 29,565 | 5.1 | 844 | 6.0 | |||||||||||||||||
| Oil and Gas Extraction | 5 | 0.7 | 23,008 | 4.0 | 645 | 4.6 | |||||||||||||||||
| Miscellaneous Retail | 8 | 1.1 | 21,946 | 3.8 | 461 | 3.3 | |||||||||||||||||
| Security & Commodity Brokers, Dealers, Exchanges & Services | 54 | 7.6 | 20,625 | 3.6 | 516 | 3.7 | |||||||||||||||||
| Holding and Other Investment Offices | 32 | 4.5 | 19,945 | 3.5 | 474 | 3.4 | |||||||||||||||||
| Health Services | 35 | 4.9 | 18,367 | 3.2 | 441 | 3.1 | |||||||||||||||||
| Automotive Repair, Services & Parking | 9 | 1.3 | 14,775 | 2.6 | 8 | 0.1 | |||||||||||||||||
| Membership Organizations | 18 | 2.5 | 11,871 | 2.1 | 228 | 1.6 | |||||||||||||||||
| Insurance Agents, Brokers & Services | 19 | 2.7 | 10,898 | 1.9 | 306 | 2.2 | |||||||||||||||||
| Insurance Carriers | 12 | 1.7 | 9,128 | 1.6 | 245 | 1.7 | |||||||||||||||||
| Other | 197 | 27.4 | 88,374 | 15.1 | 2,552 | 18.0 | |||||||||||||||||
| Total | 715 | 100.0 | $577,849 | 100.0 | 14,085 | 100.0 | |||||||||||||||||
30
Piedmont Office Realty Trust, Inc.
Property Investment Activity
As of March 31, 2024
Acquisitions Completed During Prior Year and Current Year
| None | ||||||||
Dispositions Completed During Prior Year and Current Year
| Property | Market / Submarket | Disposition Period | Percent Ownership | Year Built | Sale Price | Square Feet (in thousands) | Percent Leased at Disposition | ||||||||||||||||
| One Lincoln Park | Dallas / Preston Center | Q1 2024 | 100% | 1999 | $54.0 million | 257 | 100% | ||||||||||||||||
Out-of-Service Redevelopment Assets
| Property | Market / Submarket | Percent Leased | Square Feet (in thousands) | Current Asset Basis | ||||||||||
222 South Orange Avenue (1) | Orlando / CBD | 15% | 127 | $36.4 million | ||||||||||
9320 Excelsior Boulevard (2) | Minneapolis / I-394 Corridor | 0% | 259 | $18.4 million | ||||||||||
Developable Land Parcels
| Property | Market / Submarket | Adjacent Piedmont Project | Acres | Book Value (in thousands) | ||||||||||
| Gavitello | Atlanta / Buckhead | The Medici | 2.0 | $2,584 | ||||||||||
| Glenridge Highlands Three | Atlanta / Central Perimeter | Glenridge Highlands | 3.0 | 2,015 | ||||||||||
| Galleria Atlanta | Atlanta / Northwest | Galleria on the Park | 16.3 | 24,211 | ||||||||||
| State Highway 161 | Dallas / Las Colinas | Las Colinas Corporate Center | 4.5 | 3,320 | ||||||||||
Royal Lane (3) | Dallas / Las Colinas | 6011, 6021 & 6031 Connection Drive | 10.6 | 2,837 | ||||||||||
John Carpenter Freeway | Dallas / Las Colinas | 750 West John Carpenter Freeway | 3.5 | 1,000 | ||||||||||
| Galleria Dallas | Dallas / Lower North Tollway | Galleria Office Towers | 1.9 | 6,039 | ||||||||||
TownPark (3) | Orlando / Lake Mary | 400 & 500 TownPark Commons | 18.9 | 9,123 | ||||||||||
| Total | 60.7 | $51,129 | ||||||||||||
| (1) | The property was vacant at the time of acquisition in Q4 2020. It shares a common lobby and atrium with the Company's 200 South Orange Avenue property. The redevelopment includes an enhanced window line and balconies, allowing more light and air into tenant spaces, along with renovations to the lobby, common areas and restrooms. | ||||
| (2) | The long-term lease with the tenant occupying the full building expired on December 31, 2023. The asset has been placed into redevelopment and will include a renovated lobby, restrooms and elevator cabs, along with the addition of a fireside tenant lounge and extensive conference and training facilities in preparation for multi-tenanting the asset. | ||||
| (3) | As of March 31, 2024, the Company was under contract to sell these land parcels; however, the transactions are contingent upon the buyers obtaining the appropriate zoning changes. | ||||
31
Piedmont Office Realty Trust, Inc.
Supplemental Definitions
Included below are definitions of various terms used throughout this supplemental report, including definitions of certain non-GAAP financial measures and the reasons why the Company’s management believes these measures provide useful information to investors about the Company’s financial condition and results of operations. Reconciliations of any non-GAAP financial measures defined below are included beginning on page 34. | ||
Adjusted Funds From Operations ("AFFO"): The Company calculates AFFO by starting with Core FFO and adjusting for non-incremental capital expenditures and then adding back non-cash items including: non-real estate depreciation, straight-lined rents and fair value lease adjustments, non-cash components of interest expense and compensation expense, and by making similar adjustments for joint ventures, if any. AFFO is a non-GAAP financial measure and should not be viewed as an alternative to net income calculated in accordance with GAAP as a measurement of the Company’s operating performance. The Company believes that AFFO is helpful to investors as a meaningful supplemental comparative performance measure of our ability to make incremental capital investments. Other REITs may not define AFFO in the same manner as the Company; therefore, the Company’s computation of AFFO may not be comparable to that of other REITs. | ||
Annualized Lease Revenue ("ALR"): ALR is calculated by multiplying (i) current rental payments (defined as base rent plus operating expense reimbursements, if payable by the tenant on a monthly basis under the terms of a lease that has been executed, but excluding a) rental abatements and b) rental payments related to executed but not commenced leases for space that was covered by an existing lease), by (ii) 12. In instances in which contractual rents or operating expense reimbursements are collected on an annual, semi-annual, or quarterly basis, such amounts are multiplied by a factor of 1, 2, or 4, respectively, to calculate the annualized figure. For leases that have been executed but not commenced relating to unleased space, ALR is calculated by multiplying (i) the monthly base rental payment (excluding abatements) plus any operating expense reimbursements for the initial month of the lease term, by (ii) 12. Unless stated otherwise, this measure excludes revenues associated with development properties and properties taken out of service for redevelopment, if any. | ||
Core EBITDA: The Company calculates Core EBITDA as net income/(loss) (computed in accordance with GAAP) before interest, taxes, depreciation and amortization and removing any impairment charges, gains or losses from sales of property and other significant infrequent items that create volatility within our earnings and make it difficult to determine the earnings generated by our core ongoing business. Core EBITDA is a non-GAAP financial measure and should not be viewed as an alternative to net income calculated in accordance with GAAP as a measurement of the Company’s operating performance. The Company believes that Core EBITDA is helpful to investors as a supplemental performance measure because it provides a metric for understanding the performance of the Company’s results from ongoing operations without taking into account the effects of non-cash expenses (such as depreciation and amortization), as well as items that are not part of normal day-to-day operations of the Company’s business. Other REITs may not define Core EBITDA in the same manner as the Company; therefore, the Company’s computation of Core EBITDA may not be comparable to that of other REITs. | ||
Core Funds From Operations ("Core FFO"): The Company calculates Core FFO by starting with FFO, as defined by NAREIT, and adjusting for gains or losses on the extinguishment of swaps and/or debt and any significant non-recurring items. Core FFO is a non-GAAP financial measure and should not be viewed as an alternative to net income calculated in accordance with GAAP as a measurement of the Company’s operating performance. The Company believes that Core FFO is helpful to investors as a supplemental performance measure because it excludes the effects of certain infrequent or non-recurring items which can create significant earnings volatility, but which do not directly relate to the Company’s core business operations. As a result, the Company believes that Core FFO can help facilitate comparisons of operating performance between periods and provides a more meaningful predictor of future earnings potential. Other REITs may not define Core FFO in the same manner as the Company; therefore, the Company’s computation of Core FFO may not be comparable to that of other REITs. | ||
EBITDA: EBITDA is defined as net income/(loss) before interest, taxes, depreciation and amortization. | ||
EBITDAre: The Company calculates EBITDAre in accordance with the current National Association of Real Estate Investment Trusts (“NAREIT”) definition. NAREIT currently defines EBITDAre as net income/(loss) (computed in accordance with GAAP) adjusted for gains or losses from sales of property, impairment charges, depreciation on real estate assets, amortization on real estate assets, interest expense and taxes, along with the same adjustments for joint ventures. Some of the adjustments mentioned can vary among owners of identical assets in similar conditions based on historical cost accounting and useful-life estimates. EBITDAre is a non-GAAP financial measure and should not be viewed as an alternative to net income calculated in accordance with GAAP as a measurement of the Company’s operating performance. The Company believes that EBITDAre is helpful to investors as a supplemental performance measure because it provides a metric for understanding the Company’s results from ongoing operations without taking into account the effects of non-cash expenses (such as depreciation and amortization) and capitalization and capital structure expenses (such as interest expense and taxes). The Company also believes that EBITDAre can help facilitate comparisons of operating performance between periods and with other REITs. However, other REITs may not define EBITDAre in accordance with the NAREIT definition, or may interpret the current NAREIT definition differently than the Company; therefore, the Company’s computation of EBITDAre may not be comparable to that of such other REITs. | ||
Funds From Operations ("FFO"): The Company calculates FFO in accordance with the current National Association of Real Estate Investment Trusts (“NAREIT”) definition. NAREIT currently defines FFO as net income/(loss) (calculated in accordance with GAAP), excluding depreciation and amortization related to real estate, gains and losses from the sale of certain real estate assets, gains and losses from change in control, and impairment write-downs of certain real estate assets, goodwill, and investment in entities when the impairment is directly attributable to decreases in the value of depreciable real estate held by the entity, along with appropriate adjustments to those reconciling items for joint ventures, if any. These adjustments can vary among owners of identical assets in similar conditions based on historical cost accounting and useful-life estimates. FFO is a non-GAAP financial measure and should not be viewed as an alternative to net income calculated in accordance with GAAP as a measurement of the Company’s operating performance. The Company believes that FFO is helpful to investors as a supplemental performance measure because it excludes the effects of depreciation, amortization and gains or losses from sales of real estate, all of which are based on historical costs, which implicitly assumes that the value of real estate diminishes predictably over time. The Company also believes that FFO can help facilitate comparisons of operating performance between periods and with other REITs. However, other REITs may not define FFO in accordance with the NAREIT definition, or may interpret the current NAREIT definition differently than the Company; therefore, the Company’s computation of FFO may not be comparable to that of such other REITs. | ||
Incremental Capital Expenditures: Incremental Capital Expenditures are defined as capital expenditures of a non-recurring nature that incrementally enhance the underlying assets' income generating capacity. Tenant improvements, leasing commissions, building capital and deferred lease incentives ("Leasing Costs") incurred to lease space that was vacant at acquisition, Leasing Costs for spaces vacant for greater than one year, Leasing Costs for spaces at newly acquired properties for which in-place leases expire shortly after acquisition, improvements associated with the expansion of a building, renovations that change the underlying classification of a building, and deferred building maintenance capital identified at and completed shortly after acquisition are included in this measure. | ||
Non-Incremental Capital Expenditures: Non-Incremental Capital Expenditures are defined as capital expenditures of a recurring nature related to tenant improvements and leasing commissions that do not incrementally enhance the underlying assets' income generating capacity. We exclude first generation tenant improvements and leasing commissions from this measure, in addition to other capital expenditures that qualify as Incremental Capital Expenditures, as defined above. | ||
Property Net Operating Income ("Property NOI"): The Company calculates Property NOI by starting with Core EBITDA and adjusting for general and administrative expense, income associated with property management performed by Piedmont for other organizations and other income or expense items for the Company, such as interest income from loan investments or costs from the pursuit of non-consummated transactions. The Company may present this measure on an accrual basis or a cash basis. When presented on a cash basis, the effects of non-cash general reserve for uncollectible accounts, straight lined rents and fair value lease revenue are also eliminated. Property NOI is a non-GAAP financial measure and should not be viewed as an alternative to net income calculated in accordance with GAAP as a measurement of the Company’s operating performance. The Company believes that Property NOI is helpful to investors as a supplemental comparative performance measure of income generated by its properties alone without the administrative overhead of the Company. Other REITs may not define Property NOI in the same manner as the Company; therefore, the Company’s computation of Property NOI may not be comparable to that of other REITs. | ||
Same Store Net Operating Income ("Same Store NOI"): The Company calculates Same Store NOI as Property NOI attributable to the properties for which the following criteria were met during the entire span of the current and prior year reporting periods: (i) they were owned, (ii) they were not under development / redevelopment, and (iii) none of the operating expenses for which were capitalized. Same Store NOI also excludes amounts attributable to land assets. The Company may present this measure on an accrual basis or a cash basis. Same Store NOI is a non-GAAP financial measure and should not be viewed as an alternative to net income calculated in accordance with GAAP as a measurement of the Company’s operating performance. The Company believes that Same Store NOI is helpful to investors as a supplemental comparative performance measure of the income generated from the same group of properties from one period to the next. Other REITs may not define Same Store NOI in the same manner as the Company; therefore, the Company’s computation of Same Store NOI may not be comparable to that of other REITs. | ||
Same Store Properties: Same Store Properties is defined as those properties for which the following criteria were met during the entire span of the current and prior year reporting periods: (i) they were owned, (ii) they were not under development / redevelopment, and (iii) none of the operating expenses for which were capitalized. Same Store Properties excludes land assets. | ||
Total Gross Assets: Total Gross Assets is defined as total assets with the add-back of accumulated depreciation and accumulated amortization related to real estate assets and accumulated amortization related to deferred lease costs. | ||
Total Gross Real Estate Assets: Total Gross Real Estate Assets is defined as total real estate assets with the add-back of accumulated depreciation and accumulated amortization related to real estate assets. | ||
32
Piedmont Office Realty Trust, Inc.
Research Coverage
Equity Research Coverage
| Dylan Burzinski | Anthony Paolone, CFA | Nicholas Thillman | Michael Lewis, CFA | ||||||||
| Green Street Advisors | JP Morgan | Robert W. Baird & Co. | Truist Securities | ||||||||
| 100 Bayview Circle, Suite 400 | 383 Madison Avenue, 32nd Floor | 777 East Wisconsin Avenue | 711 Fifth Avenue, 4th Floor | ||||||||
| Newport Beach, CA 92660 | New York, NY 10179 | Milwaukee, WI 53202 | New York, NY 10022 | ||||||||
| Phone: (949) 640-8780 | Phone: (212) 622-6682 | Phone: (414) 298-5053 | Phone: (212) 319-5659 | ||||||||
Fixed Income Research Coverage
| Mark S. Streeter, CFA | ||||||||
| JP Morgan | ||||||||
| 383 Madison Avenue, 3rd Floor | ||||||||
| New York, NY 10179 | ||||||||
| Phone: (212) 834-5086 | ||||||||
33
Piedmont Office Realty Trust, Inc.
Funds From Operations, Core Funds From Operations, and Adjusted Funds From Operations Reconciliations
Unaudited (in thousands)
| Three Months Ended | |||||||||||||||||||||||||||||
| 3/31/2024 | 12/31/2023 | 9/30/2023 | 6/30/2023 | 3/31/2023 | |||||||||||||||||||||||||
| GAAP net income (loss) applicable to common stock | $ | (27,763) | $ | (28,030) | $ | (17,002) | $ | (1,988) | $ | (1,367) | |||||||||||||||||||
Depreciation | 38,586 | 37,889 | 37,790 | 36,200 | 35,690 | ||||||||||||||||||||||||
Amortization | 18,112 | 24,222 | 20,151 | 21,323 | 22,021 | ||||||||||||||||||||||||
Impairment charges | 18,432 | 18,489 | 10,957 | — | — | ||||||||||||||||||||||||
Gain on sale of properties | — | (1,946) | — | — | — | ||||||||||||||||||||||||
| NAREIT Funds From Operations applicable to common stock | 47,367 | 50,624 | 51,896 | 55,535 | 56,344 | ||||||||||||||||||||||||
| Adjustments: | |||||||||||||||||||||||||||||
| Loss on early extinguishment of debt | 386 | — | 820 | — | — | ||||||||||||||||||||||||
| Core Funds From Operations applicable to common stock | 47,753 | 50,624 | 52,716 | 55,535 | 56,344 | ||||||||||||||||||||||||
| Adjustments: | |||||||||||||||||||||||||||||
Amortization of debt issuance costs and discounts on debt | 1,208 | 1,481 | 1,410 | 1,312 | 1,239 | ||||||||||||||||||||||||
| Depreciation of non real estate assets | 272 | 136 | 350 | 264 | 97 | ||||||||||||||||||||||||
Straight-line effects of lease revenue | (2,255) | (908) | (418) | (2,755) | (3,187) | ||||||||||||||||||||||||
| Stock-based compensation adjustments | 1,026 | 1,989 | 2,070 | 2,095 | 183 | ||||||||||||||||||||||||
Amortization of lease-related intangibles | (2,656) | (2,869) | (4,479) | (3,119) | (3,412) | ||||||||||||||||||||||||
| Non-incremental capital expenditures | |||||||||||||||||||||||||||||
| Base Building Costs | (13,055) | (5,554) | (7,085) | (2,914) | (4,752) | ||||||||||||||||||||||||
| Tenant Improvement Costs | (3,673) | (2,664) | (2,687) | (2,228) | (5,699) | ||||||||||||||||||||||||
| Leasing Costs | (3,879) | (10,402) | (1,938) | (3,746) | (4,021) | ||||||||||||||||||||||||
| Adjusted Funds From Operations applicable to common stock | $ | 24,741 | $ | 31,833 | $ | 39,939 | $ | 44,444 | $ | 36,792 | |||||||||||||||||||
34
Piedmont Office Realty Trust, Inc.
Same Store Net Operating Income (Cash Basis)
Unaudited (in thousands)
| Three Months Ended | |||||||||||||||||||||||||||||
| 3/31/2024 | 12/31/2023 | 9/30/2023 | 6/30/2023 | 3/31/2023 | |||||||||||||||||||||||||
| Net income (loss) applicable to Piedmont | $ | (27,763) | $ | (28,030) | $ | (17,002) | $ | (1,988) | $ | (1,367) | |||||||||||||||||||
| Net income (loss) applicable to noncontrolling interest | 2 | 3 | 1 | 3 | 3 | ||||||||||||||||||||||||
| Interest expense | 29,714 | 28,431 | 27,361 | 23,389 | 22,077 | ||||||||||||||||||||||||
| Depreciation | 38,857 | 38,025 | 38,140 | 36,464 | 35,787 | ||||||||||||||||||||||||
| Amortization | 18,112 | 24,223 | 20,151 | 21,323 | 22,021 | ||||||||||||||||||||||||
| Depreciation and amortization attributable to noncontrolling interests | 20 | 20 | 20 | 21 | 20 | ||||||||||||||||||||||||
| Impairment charges | 18,432 | 18,489 | 10,957 | — | — | ||||||||||||||||||||||||
| Gain on sale of properties | — | (1,946) | — | — | — | ||||||||||||||||||||||||
| EBITDAre | 77,374 | 79,215 | 79,628 | 79,212 | 78,541 | ||||||||||||||||||||||||
| Loss on early extinguishment of debt | 386 | — | 820 | — | — | ||||||||||||||||||||||||
| Core EBITDA | 77,760 | 79,215 | 80,448 | 79,212 | 78,541 | ||||||||||||||||||||||||
| General and administrative expense | 7,612 | 7,177 | 7,043 | 7,279 | 7,691 | ||||||||||||||||||||||||
| Non-cash general reserve for uncollectible accounts | — | — | (600) | — | (400) | ||||||||||||||||||||||||
| Management fee revenue | 5 | (247) | (210) | (254) | (293) | ||||||||||||||||||||||||
| Other (income) expense | (171) | (38) | (207) | (1,571) | (1,440) | ||||||||||||||||||||||||
| Straight-line effects of lease revenue | (2,255) | (908) | (418) | (2,755) | (3,187) | ||||||||||||||||||||||||
| Straight-line effects of lease revenue attributable to noncontrolling interests | — | (3) | (2) | (1) | (4) | ||||||||||||||||||||||||
| Amortization of lease-related intangibles | (2,656) | (2,869) | (4,479) | (3,119) | (3,412) | ||||||||||||||||||||||||
| Property net operating income (cash basis) | 80,295 | 82,327 | 81,575 | 78,791 | 77,496 | ||||||||||||||||||||||||
| Deduct net operating (income) loss from: | |||||||||||||||||||||||||||||
| Acquisitions | — | — | — | — | — | ||||||||||||||||||||||||
| Dispositions | (1,140) | (802) | (703) | (821) | (562) | ||||||||||||||||||||||||
| Other investments | 415 | (1,138) | (1,160) | (1,207) | (1,213) | ||||||||||||||||||||||||
| Same store net operating income (cash basis) | $ | 79,570 | $ | 80,387 | $ | 79,712 | $ | 76,763 | $ | 75,721 | |||||||||||||||||||
35
Piedmont Office Realty Trust, Inc.
In-Service Portfolio Detail (1)
As of March 31, 2024
(in thousands)
| Project Name | Energy Star Certification | LEED Certification | BOMA 360 Certification | Percent Ownership | Number of Buildings | Rentable Square Footage Owned | Percent Leased | Commenced Leased Percentage | Economic Leased Percentage (2) | Annualized Lease Revenues | ||||||||||||||||||||||
| Atlanta | ||||||||||||||||||||||||||||||||
| 999 Peachtree Street | P | P | P | 100.0% | 1 | 622 | 88.7 | % | 88.4 | % | 79.6 | % | 22,871 | |||||||||||||||||||
| 1180 Peachtree Street | P | P | P | 100.0% | 1 | 678 | 98.1 | % | 96.8 | % | 91.2 | % | 35,299 | |||||||||||||||||||
| Galleria on the Park | P | P | P | 100.0% | 5 | 2,163 | 91.1 | % | 82.1 | % | 76.4 | % | 67,385 | |||||||||||||||||||
| Glenridge Highlands | P | P | P | 100.0% | 2 | 714 | 94.1 | % | 88.1 | % | 84.7 | % | 25,071 | |||||||||||||||||||
| 1155 Perimeter Center West | P | P | P | 100.0% | 1 | 377 | 92.8 | % | 91.0 | % | 87.3 | % | 14,331 | |||||||||||||||||||
| The Medici | P | P | 100.0% | 1 | 156 | 91.0 | % | 91.0 | % | 84.6 | % | 6,032 | ||||||||||||||||||||
| Metropolitan Area Subtotal / Weighted Average | 11 | 4,710 | 92.4 | % | 87.0 | % | 81.3 | % | 170,989 | |||||||||||||||||||||||
| Boston | ||||||||||||||||||||||||||||||||
| 5 Wall Street | P | P | P | 100.0% | 1 | 182 | 100.0 | % | 100.0 | % | 100.0 | % | 7,453 | |||||||||||||||||||
| Wayside Office Park | P | P | 100.0% | 2 | 473 | 95.1 | % | 95.1 | % | 95.1 | % | 18,058 | ||||||||||||||||||||
| 25 Burlington Mall Road | P | P | 100.0% | 1 | 291 | 55.7 | % | 54.0 | % | 54.0 | % | 7,033 | ||||||||||||||||||||
| 80 & 90 Central Street | P | P | 100.0% | 2 | 324 | 87.0 | % | 87.0 | % | 83.3 | % | 7,151 | ||||||||||||||||||||
| Metropolitan Area Subtotal / Weighted Average | 6 | 1,270 | 84.7 | % | 84.3 | % | 83.4 | % | 39,695 | |||||||||||||||||||||||
| Dallas | ||||||||||||||||||||||||||||||||
| Galleria Office Towers | P | P | P | 100.0% | 3 | 1,383 | 89.4 | % | 88.6 | % | 82.6 | % | 57,852 | |||||||||||||||||||
| Park Place on Turtle Creek | P | P | 100.0% | 1 | 177 | 76.8 | % | 72.3 | % | 71.2 | % | 6,968 | ||||||||||||||||||||
| 6565 North MacArthur Boulevard | P | P | P | 100.0% | 1 | 254 | 84.6 | % | 83.9 | % | 83.9 | % | 7,685 | |||||||||||||||||||
| 750 West John Carpenter Freeway | P | P | P | 100.0% | 1 | 315 | 46.3 | % | 46.3 | % | 46.3 | % | 4,921 | |||||||||||||||||||
| 6011, 6021 & 6031 Connection Drive | P | P | 100.0% | 3 | 605 | 92.7 | % | 91.9 | % | 91.9 | % | 19,712 | ||||||||||||||||||||
| Las Colinas Corporate Center | P | P | 100.0% | 3 | 486 | 72.4 | % | 69.1 | % | 60.5 | % | 12,860 | ||||||||||||||||||||
| Metropolitan Area Subtotal / Weighted Average | 12 | 3,220 | 82.2 | % | 80.9 | % | 77.0 | % | 109,998 | |||||||||||||||||||||||
| Minneapolis | ||||||||||||||||||||||||||||||||
| US Bancorp Center | P | P | P | 100.0% | 1 | 937 | 86.8 | % | 86.8 | % | 85.4 | % | 31,693 | |||||||||||||||||||
| One & Two Meridian Crossings | P | P | P | 100.0% | 2 | 384 | 92.4 | % | 91.7 | % | 91.7 | % | 11,824 | |||||||||||||||||||
| Crescent Ridge II | P | P | P | 100.0% | 1 | 295 | 87.1 | % | 74.6 | % | 66.8 | % | 9,394 | |||||||||||||||||||
| Norman Pointe I | P | P | 100.0% | 1 | 214 | 88.3 | % | 83.6 | % | 83.6 | % | 6,601 | ||||||||||||||||||||
| Metropolitan Area Subtotal / Weighted Average | 5 | 1,830 | 88.2 | % | 85.5 | % | 83.5 | % | 59,512 | |||||||||||||||||||||||
| New York | ||||||||||||||||||||||||||||||||
| 60 Broad Street | P | 100.0% | 1 | 1,045 | 89.9 | % | 85.6 | % | 85.3 | % | 50,184 | |||||||||||||||||||||
| Metropolitan Area Subtotal / Weighted Average | 1 | 1,045 | 89.9 | % | 85.6 | % | 85.3 | % | 50,184 | |||||||||||||||||||||||
36
| Project Name | Energy Star Certification | LEED Certification | BOMA 360 Certification | Percent Ownership | Number of Buildings | Rentable Square Footage Owned | Percent Leased | Commenced Leased Percentage | Economic Leased Percentage (2) | Annualized Lease Revenues | ||||||||||||||||||||||
| Orlando | ||||||||||||||||||||||||||||||||
| 200 South Orange Avenue | P | P | P | 100.0% | 1 | 646 | 88.7 | % | 86.8 | % | 70.3 | % | 22,932 | |||||||||||||||||||
| CNL Center I & II | P | P | P | 99.0% | 2 | 620 | 93.4 | % | 93.1 | % | 91.6 | % | 24,688 | |||||||||||||||||||
| 501 West Church Street | 100.0% | 1 | 182 | 100.0 | % | 100.0 | % | 100.0 | % | 2,230 | ||||||||||||||||||||||
| 400 & 500 TownPark Commons | P | P | P | 100.0% | 2 | 309 | 100.0 | % | 100.0 | % | 99.4 | % | 10,741 | |||||||||||||||||||
| Metropolitan Area Subtotal / Weighted Average | 6 | 1,757 | 93.5 | % | 92.7 | % | 86.0 | % | 60,591 | |||||||||||||||||||||||
| Northern Virginia / Washington, D.C. | ||||||||||||||||||||||||||||||||
| 4250 North Fairfax Drive | P | P | P | 100.0% | 1 | 308 | 92.9 | % | 87.0 | % | 87.0 | % | 14,961 | |||||||||||||||||||
| Arlington Gateway | P | P | P | 100.0% | 1 | 331 | 80.1 | % | 78.2 | % | 60.7 | % | 12,939 | |||||||||||||||||||
| 3100 Clarendon Boulevard | P | P | P | 100.0% | 1 | 261 | 82.4 | % | 80.8 | % | 80.8 | % | 9,782 | |||||||||||||||||||
| 1201 & 1225 Eye Street | P | P | P | (3) | 2 | 482 | 70.1 | % | 70.1 | % | 69.3 | % | 21,442 | |||||||||||||||||||
| 400 Virginia Avenue | P | P | P | 100.0% | 1 | 209 | 71.8 | % | 71.8 | % | 69.9 | % | 7,893 | |||||||||||||||||||
| Metropolitan Area Subtotal / Weighted Average | 6 | 1,591 | 78.8 | % | 77.1 | % | 72.9 | % | 67,017 | |||||||||||||||||||||||
| Other | ||||||||||||||||||||||||||||||||
| Enclave Place | P | P | P | 100.0% | 1 | 301 | 100.0 | % | 100.0 | % | 100.0 | % | 11,574 | |||||||||||||||||||
| 1430 Enclave Parkway | P | P | P | 100.0% | 1 | 313 | 82.7 | % | 82.7 | % | 82.7 | % | 8,289 | |||||||||||||||||||
| Metropolitan Area Subtotal / Weighted Average | 2 | 614 | 91.2 | % | 91.2 | % | 91.2 | % | 19,863 | |||||||||||||||||||||||
| Grand Total | 49 | 16,037 | 87.8 | % | 85.1 | % | 81.2 | % | 577,849 | |||||||||||||||||||||||
| (1) | This schedule includes information for Piedmont's in-service portfolio of properties only. Information on investments excluded from this schedule can be found on page 31 | ||||
| (2) | Economic leased percentage excludes the square footage associated with executed but not commenced leases for currently vacant spaces and the square footage associated with tenants receiving rental abatements (after proportional adjustments for tenants receiving only partial rental abatements). | ||||
| (3) | Piedmont owns 98.6% of 1201 Eye Street and 98.1% of 1225 Eye Street; however, it is entitled to 100% of the cash flows for each asset pursuant to the terms of each property ownership entity's joint venture agreement. | ||||
37
Piedmont Office Realty Trust, Inc.
Major Leases Not Yet Commenced and Major Abatements
As of March 31, 2024, the Company had approximately 1.3 million square feet of executed leases for vacant space yet to commence or currently under rental abatement.
Presented below is a schedule of uncommenced new leases greater than 50,000 square feet and their anticipated commencement dates. Lease renewals are excluded from this schedule.
| Tenant | Property | Market | Square Feet Leased | Space Status | Estimated Lease Commencement Date | New / Expansion | ||||||||||||||
| General Electric International | Galleria 600 | Atlanta | 77,163 | Vacant | Q3 2024 | New | ||||||||||||||
| FirstKey Homes | Galleria 600 | Atlanta | 51,442 | Vacant | Q3 2024 | New | ||||||||||||||
Presented below is a schedule of leases with abatements of 50,000 square feet or greater that either were under abatement as of March 31, 2024 or will be under abatement within the next
twelve months.
| Tenant | Property | Market | Abated Square Feet | Estimated Lease Commencement Date | Remaining Abatement Schedule | Lease Expiration | ||||||||||||||
| Brand Industrial Services | Galleria 600 | Atlanta | 50,380 | Q1 2023 | March 2025 | Q3 2034 | ||||||||||||||
| Kimley-Horn and Associates | 200 and 222 South Orange Avenue | Orlando | 61,348 | 54,673 SF Q4 2023 6,675 SF Q2 2024 | November 2023 to Mid June 2024 (54,673 SF); Mid June 2024 to October 2024 (61,348 SF); November 2024 to Mid June 2025 (6,675 SF) | Q4 2034 | ||||||||||||||
| Institute for Justice | Arlington Gateway | Northern Virginia | 58,285 | Q1 2024 | January 2024 through June 2025 | Q2 2037 | ||||||||||||||
| Undisclosed Tenant | One Galleria Tower | Dallas | 50,130 | Q4 2023 | January 2024 through June 2025 | Q2 2035 | ||||||||||||||
| Javelin Energy Partners | Las Colinas Corporate Center I | Dallas | 82,878 | 70,053 SF Q1 2024 12,825 SF Q3 2024 | March 2024 to August 2024 (70,053 SF); September 2024 to February 2025 (82,878 SF); March 2025 to August 2025 (12,825 SF) | Q1 2035 | ||||||||||||||
| OneDigital | Galleria 300 | Atlanta | 70,445 | 23,506 SF Q1 2024 46,939 SF Q3 2025 | March 2024 to February 2025 (23,506 SF); September 2025 to August 2026 (46,939 SF) | Q4 2036 | ||||||||||||||
| General Electric International | Galleria 600 | Atlanta | 77,163 | Q3 2024 | September 2024 through September 2025 | Q3 2036 | ||||||||||||||
| FirstKey Homes | Galleria 600 | Atlanta | 51,442 | Q3 2024 | September 2024 to August 2026 (50% of monthly gross rent) | Q3 2035 | ||||||||||||||
38
Piedmont Office Realty Trust, Inc.
Supplemental Operating & Financial Data
Risks, Uncertainties and Limitations
Certain statements contained in this supplemental package constitute forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended (the “Securities Act”) and Section 21E of the Securities Exchange Act of 1934, as amended (the “Exchange Act”). We intend for all such forward-looking statements to be covered by the safe-harbor provisions for forward-looking statements contained in Section 27A of the Securities Act and Section 21E of the Exchange Act, as applicable. Such information is subject to certain known and unknown risks and uncertainties, which could cause actual results to differ materially from those anticipated. Therefore, such statements are not intended to be a guarantee of our performance in future periods. Such forward-looking statements can generally be identified by our use of forward-looking terminology such as “may,” “will,” “expect,” “intend,” “anticipate,” "estimate," “believe,” “continue” or similar words or phrases that indicate predictions of future events or trends or that do not relate solely to historical matters. Examples of such statements in this supplemental package include: the Company's estimated range of Net Income/(Loss), Depreciation, Amortization, Core FFO and Core FFO per diluted share, leasing activity, leased percentage, and estimated increase in Same Store NOI for the year ending December 31, 2023. These statements are based on beliefs and assumptions of Piedmont’s management, which in turn are based on information available at the time the statements are made.
Important assumptions relating to the forward-looking statements include, among others, assumptions regarding the demand for office space in the markets in which we operate, competitive conditions, and general economic conditions. These assumptions could prove inaccurate. The forward-looking statements also involve certain known and unknown risks and uncertainties, which could cause our actual results and expectations to differ materially from those described in our forward-looking statements. Many of these factors are beyond our ability to control or predict. Such factors include, but are not limited to, the following: economic, regulatory, socio-economic (including work from home), technological (e.g. artificial intelligence and machine learning, Zoom, etc.), and other changes that impact the real estate market generally, the office sector or the patterns of use of commercial office space in general, or the markets where we primarily operate or have high concentrations of revenue; the impact of competition on our efforts to renew existing leases or re-let space on terms similar to existing leases; lease terminations, lease defaults, lease contractions, or changes in the financial condition of our tenants, particularly by one of our large lead tenants; impairment charges on our long-lived assets or goodwill resulting therefrom; the success of our real estate strategies and investment objectives, including our ability to implement successful redevelopment and development strategies or identify and consummate suitable acquisitions and divestitures; the illiquidity of real estate investments, including economic changes, such as rising interest rates and available financing, which could impact the number of buyers/sellers of our target properties, and regulatory restrictions to which real estate investment trusts ("REITs") are subject and the resulting impediment on our ability to quickly respond to adverse changes in the performance of our properties; the risks and uncertainties associated with our acquisition and disposition of properties, many of which risks and uncertainties may not be known at the time of acquisition or disposition; development and construction delays, including the potential of supply chain disruptions, and resultant increased costs and risks; future acts of terrorism, civil unrest, or armed hostilities in any of the major metropolitan areas in which we own properties, or future cybersecurity attacks against any of our properties or our tenants; risks related to the occurrence of cybersecurity incidents, including cybersecurity incidents against us or any of our properties or tenants, or a deficiency in our identification, assessment, or management of cybersecurity threats impacting our operations and the public's reaction to reported cybersecurity incidents; costs of complying with governmental laws and regulations, including environmental standards imposed on office building owners; uninsured losses or losses in excess of our insurance coverage, and our inability to obtain adequate insurance coverage at a reasonable cost; additional risks and costs associated with directly managing properties occupied by government tenants, such as potential changes in the political environment, a reduction in federal or state funding of our governmental tenants, or an increased risk of default by government tenants during periods in which state or federal governments are shut down or on furlough; significant price and volume fluctuations in the public markets, including on the exchange which we listed our common stock; risks associated with incurring mortgage and other indebtedness, including changing capital reserve requirements on our lenders and rapidly rising interest rates for new debt financings; a downgrade in our credit ratings, the credit ratings of Piedmont Operating Partnership, L.P. (the "Operating Partnership") or the credit ratings of our or the Operating Partnership's unsecured debt securities, which could, among other effects, trigger an increase in the stated rate of one or more of our unsecured debt instruments; the effect of future offerings of debt or equity securities on the value of our common stock; additional risks and costs associated with inflation and continuing increases in the rate of inflation, including the impact of a possible recession; uncertainties associated with environmental and regulatory matters; changes in the financial condition of our tenants directly or indirectly resulting from geopolitical developments that could negatively affect important supply chains and international trade, the termination or threatened termination of existing international trade agreements, or the implementation of tariffs or retaliatory tariffs on imported or exported goods; the effect of any litigation to which we are, or may become, subject; additional risks and costs associated with owning properties occupied by tenants in particular industries, such as oil and gas, hospitality, travel, co-working, etc., including risks of default during start-up and during economic downturns; changes in tax laws impacting REITs and real estate in general, as well as our ability to continue to qualify as a REIT under the Internal Revenue Code of 1986, as amended (the "Code"), or other tax law changes which may adversely affect our stockholders; the future effectiveness of our internal controls and procedures; actual or threatened public health epidemics or outbreaks, such as the COVID-19 pandemic, as well as governmental and private measures taken to combat such health crises; and other factors, including the risk factors discussed under Item 1A. of our Annual Report on Form 10-K for the year ended December 31, 2023.
Readers are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date of this supplemental report. We cannot guarantee the accuracy of any such forward-looking statements contained in this supplemental report, and we do not intend to and undertake no obligations to publicly update or revise any forward-looking statements, whether as a result of new information, future events, or otherwise.
39