
SPFI 8-K
South Plains Financial, Inc. (SPFI)
8-K
2026-07-17
For: 2026-07-16
View Original
Added on
July 17, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of
the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): July 16, 2026
(Exact name of registrant as specified in its charter)
|
|
|
|
|
(State or other jurisdiction of incorporation)
|
(Commission File Number)
|
(IRS Employer Identification No.)
|
|
|
|
|
|
(Address of principal executive offices)
|
(Zip Code)
|
(806 ) 792-7101
(Registrant’s telephone number, including area code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following
provisions:
|
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425)
|
|
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12)
|
|
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))
|
|
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))
|
Securities registered pursuant to Section 12(b) of the Act:
|
Title of each class
|
Trading Symbol(s)
|
Name of each exchange on which registered
|
|
|
|
|
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of
the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or
revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
| Item 2.02 |
Results of Operations and Financial Condition.
|
On July 17, 2026, South Plains Financial, Inc. (the “Company”) issued a press release announcing its financial results for the second quarter ended June 30,
2026. A copy of the Company’s press release covering such announcement and certain other matters is furnished as Exhibit 99.1 to this Current Report on Form 8-K.
| Item 7.01 |
Regulation FD Disclosure.
|
On July 17, 2026, officers of the Company will conduct a conference call at 8:30 p.m., Eastern Time, with respect to the Company’s financial results for the second quarter ended June 30, 2026. An earnings release slide presentation highlighting the Company’s financial results for the second quarter ended June 30, 2026 is furnished as Exhibit 99.2 to this Current Report on Form 8-K. This earnings release slide presentation will also be available
on the Company’s website, www.spfi.bank, under the “News & Events” section.
In accordance with General Instruction B.2 of Form 8-K, the information in Items 2.02 and 7.01 of this Current Report on Form 8-K, including Exhibit
99.1 and Exhibit 99.2 furnished herewith, shall not be deemed “filed” for the purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), or otherwise subject to the liabilities of that section. The information
in Items 2.02 and 7.01 of this Current Report on Form 8-K, including Exhibit 99.1 and Exhibit 99.2 furnished herewith, shall not be incorporated by reference into any filing or other document pursuant to the Exchange Act or the Securities Act of
1933, as amended, except as shall be expressly set forth by specific reference in such filing or document.
| Item 8.01 |
Other Events.
|
On July 16, 2026, the Company issued a press release announcing the declaration of a quarterly cash dividend of $0.18 per share on its outstanding
common stock. The dividend will be paid on August 10, 2026 to shareholders of record as of the close of business on July 27, 2026. A copy of the Company’s press release covering such announcement is attached to this Current Report on Form 8-K as
Exhibit 99.3 and is incorporated herein by reference.
| Item 9.01 |
Financial Statements and Exhibits.
|
| (d) |
Exhibits.
|
|
Press release, dated July 17, 2026, announcing second quarter 2026 financial results of South Plains Financial, Inc.
|
|
|
Earnings release slide presentation, dated July 17, 2026.
|
|
|
Press release, dated July 16, 2026, announcing South Plains Financial, Inc. quarterly cash dividend.
|
|
|
104
|
Cover Page Interactive Data File (formatted as Inline XBRL).
|
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the
undersigned hereunto duly authorized.
|
SOUTH PLAINS FINANCIAL, INC.
|
||
|
Date: July 17, 2026
|
By:
|
/s/ Steven B. Crockett
|
|
Steven B. Crockett
|
||
|
Chief Financial Officer and Treasurer
|
Exhibit 99.1
South Plains Financial, Inc. Reports Second Quarter 2026 Financial Results
LUBBOCK, Texas, July 17, 2026 (GLOBE NEWSWIRE) – South Plains Financial, Inc. (NASDAQ:SPFI) (“South Plains” or the “Company”), the parent company of City
Bank (“City Bank” or the “Bank”), today reported its financial results for the quarter ended June 30, 2026.
Second Quarter 2026 Highlights
| ● |
Net income for the second quarter of 2026 was $19.0 million, compared to $14.5 million for the first quarter of 2026 and $14.6 million for the second quarter of 2025.
|
| ● |
Diluted earnings per share for the second quarter of 2026 was $0.96, compared to $0.85 for the first quarter of 2026 and $0.86 for the second quarter of 2025.
|
| ● |
Average cost of deposits for the second quarter of 2026 was 208 basis points, compared to 197 basis points for the first quarter of 2026 and 214 basis points for the
second quarter of 2025.
|
| ● |
Net interest margin, on a tax-equivalent basis, was 4.00% for the second quarter of 2026, compared to 4.04% for the first quarter of 2026 and 4.07% for the second
quarter of 2025.
|
| ● |
Return on average assets for the second quarter of 2026 was 1.44%, compared to 1.31% for the first quarter of 2026 and 1.34% for the second quarter of 2025.
|
| ● |
Tangible book value (non-GAAP) per share was $29.57 as of June 30, 2026, compared to $29.65 as of March 31, 2026 and $26.70 as of June 30, 2025.
|
| ● |
The consolidated total risk-based capital ratio, common equity tier 1 risk-based capital ratio, and tier 1 leverage ratio at June 30, 2026 were 16.53%, 14.10%, and
12.20%, respectively.
|
| ● |
As previously reported, the Company completed the merger of BOH Holdings, Inc. (“BOH”) with and into South Plains, with South Plains continuing as the surviving
corporation, and the merger of BOH’s wholly-owned subsidiary, Bank of Houston, with and into City Bank, with City Bank continuing as the surviving bank, all effective on April 1, 2026. As of March 31, 2026, BOH had total assets of $685.0
million, total loans of $631.9 million, and total deposits of $595.6 million.
|
Curtis Griffith, South Plains’ Chairman and Chief Executive Officer, commented, “We delivered a strong second quarter highlighted by solid profitability, stable credit
quality and the successful integration of Bank of Houston, which has strengthened our position in Houston, one of Texas’ most attractive banking markets. As I prepare to retire as Chief Executive Officer at year-end, I am incredibly proud of what our
employees have accomplished and the Company we have built together over the past four decades. The Bank is in a position of strength, and our leadership transition reflects years of thoughtful planning designed to ensure continuity for our customers,
employees and shareholders. I remain highly confident in South Plains’ future and believe Cory is the right leader to guide the organization as we continue to grow earnings, deepen customer relationships and build on the culture that has been central
to our success. I look forward to continuing to serve as Chairman of South Plains and City Bank as Cory and our talented leadership team build on our momentum and execute the next phase of our growth strategy.”
Cory Newsom, South Plains’ President, added, “I am honored by the Board’s confidence and am excited to lead South Plains into its next chapter. Our second quarter
results demonstrate the strength of our relationship-based banking model, disciplined credit culture and proven growth strategy. Looking ahead, we remain focused on expanding our lending platform in high-growth Texas markets, attracting experienced
bankers who fit our culture, optimizing the Bank of Houston acquisition and pursuing disciplined growth opportunities that enhance long-term shareholder value. With a strong balance sheet, healthy loan pipeline and exceptional team, we believe South
Plains is well positioned for continued success.”
Results of Operations, Quarter Ended June 30, 2026
Net Interest Income
Net interest income was $50.3 million for the second quarter of 2026, compared to $42.9 million for the first quarter of 2026 and $42.5 million for the
second quarter of 2025. Net interest margin, calculated on a tax-equivalent basis, was 4.00% for the second quarter of 2026, compared to 4.04% for the first quarter of 2026 and 4.07% for the second quarter of 2025. The average yield on loans was
6.81% for the second quarter of 2026, compared to 6.83% for the first quarter of 2026 and 6.99% for the second quarter of 2025. The average cost of deposits was 208 basis points for the second quarter of 2026, which is 11 basis points higher than the
first quarter of 2026 and 6 basis points lower than the second quarter of 2025. The increase from the first quarter of 2026 was due to the higher cost of deposits on the Bank of Houston acquired deposits.
Interest income was $75.0 million for the second quarter of 2026, compared to $62.6 million for the first quarter of 2026 and $64.1 million for the
second quarter of 2025. Interest income in the second quarter of 2026 increased $12.4 million compared to the first quarter of 2026 and increased $10.9 million compared to the second quarter of 2025. These increases were primarily due to the
acquisition of BOH’s approximately $667 million of interest-earning assets.
Interest expense was $24.7 million for the second quarter of 2026, compared to $19.8 million for the first quarter of 2026 and $21.6 million for the
second quarter of 2025. Interest expense in the second quarter of 2026 increased $4.9 million compared to the first quarter of 2026 and increased $3.1 million compared to the second quarter of 2025. These increases were mainly attributable to the
acquisition of BOH’s approximately $611 million of interest-bearing liabilities, with the year-over-year comparison being partially offset by interest-bearing deposit growth in the first quarter of 2026.
Noninterest Income and Noninterest Expense
Noninterest income was $14.1 million for the second quarter of 2026, compared to $11.3 million for the first quarter of 2026 and $12.2 million for the
second quarter of 2025. The increase from the first quarter of 2026 was primarily due to an increase of $929 thousand in mortgage banking revenues, mainly as a result of improved mortgage originations during the quarter, and an increase of $894
thousand in bank card services and interchange revenue, mainly as a result of continued growth in customer card usage and incentives received during the period. Additionally, there was an $801 thousand loss in a Small Business Investment Company
(“SBIC”) investment that lowered other noninterest income in the first quarter of 2026. The increase in noninterest income for the second quarter of 2026 as compared to the second quarter of 2025 was primarily due to an increase of $1.2 million in
mortgage banking revenues, mainly as a result of the change in the fair value adjustment of the mortgage servicing rights assets – a write-up of $515 thousand in the second quarter of 2026 compared to a write-down of $156 thousand in the second
quarter of 2025 – based on interest rate changes during the respective quarters.
Noninterest expense was $39.9 million for the second quarter of 2026, compared to $35.5 million for the first quarter of 2026 and $33.5 million for the
second quarter of 2025. The $4.3 million increase from the first quarter of 2026 primarily resulted from an increase of $2.7 million in core operating expenses related to the recent acquisition and higher incentive-based compensation expense. There
was approximately $1.1 million of acquisition-related expenses in the second quarter of 2026, of which $710 thousand was for personnel expenses, compared to $1.5 million in the first quarter of 2026, of which $1.2 million was for professional
services. The $6.3 million increase in noninterest expense for the second quarter of 2026 as compared to the second quarter of 2025 was largely the result of the $2.7 million increase in core operating expenses related to the recent acquisition,
annual salary adjustments and new lenders hired, and $1.1 million in acquisition-related expenses.
Loan Portfolio and Composition
Loans held for investment were $3.77 billion as of June 30, 2026, compared to $3.10 billion as of March 31, 2026 and $3.10 billion as of June 30, 2025.
The increase of $667.3 million during the second quarter of 2026 as compared to the first quarter of 2026 occurred as a result of $631.9 million in loans from the recent acquisition and $35.4 million of organic loan growth during the quarter. The
organic growth was net of two loan payoffs totaling $37.5 million during the quarter. As of June 30, 2026, loans held for investment increased $671.9 million as compared to June 30, 2025, primarily as a result of acquisition growth noted above.
Deposits and Borrowings
Deposits totaled $4.64 billion as of June 30, 2026, compared to $4.03 billion as of March 31, 2026 and $3.74 billion as of June 30, 2025. Deposits
increased by $613.0 million in the second quarter of 2026 from March 31, 2026. Deposits increased by $901.7 million at June 30, 2026 as compared to June 30, 2025. Noninterest-bearing deposits were $1.15 billion as of June 30, 2026, compared to $1.03
billion as of March 31, 2026 and $998.8 million as of June 30, 2025. Noninterest-bearing deposits represented 24.8% of total deposits as of June 30, 2026. The quarterly and year-over-year change in total deposits was primarily due to $595.6 million
in deposits from the recent acquisition. Additionally, the year-over-year change had $288.6 million in organic growth broadly across the deposit portfolio.
Asset Quality
The Company recorded a provision for credit losses in the second quarter of 2026 of $350 thousand, compared to $260 thousand in the first quarter of 2026
and $2.5 million in the second quarter of 2025. The decrease in provision for the year-over-year comparison was largely attributable to activity in the second quarter of 2025 which included an increase in specific reserves, increased loan balances,
and several credit quality downgrades.
The ratio of allowance for credit losses to loans held for investment was 1.41% as of June 30, 2026, compared to 1.44% as of March 31, 2026 and 1.45% as
of June 30, 2025.
The ratio of nonperforming assets to total assets was 0.19% as of June 30, 2026, compared to 0.13% as of March 31, 2026 and 0.25% as of June 30, 2025.
Annualized net charge-offs were 0.06% for the second quarter of 2026, compared to 0.04% for the first quarter of 2026 and 0.06% for the second quarter of 2025.
Capital
Book value per share increased to $33.43 at June 30, 2026, compared to $30.90 at March 31, 2026. The change was primarily driven by the issuance of 2.8
million shares for the BOH acquisition at $41.90 per share. The increase was also the result of $15.7 million of net income after dividends paid during the second quarter of 2026. The ratio of tangible common equity to tangible assets (non-GAAP)
stayed essentially flat at 10.47% at June 30, 2026.
Conference Call
South Plains will host a conference call to discuss its second quarter 2026 financial results today, July 17, 2026, at 8:30 a.m., Eastern Time. Investors
and analysts interested in participating in the call are invited to dial 1-877-407-9716 (international callers please dial 1-201-493-6779) approximately 10 minutes prior to the start of the call. A live audio webcast of the conference call and
conference materials will be available on the Company’s website at https://www.spfi.bank/news-events/events.
A replay of the conference call will be available within two hours of the conclusion of the call and can be accessed on the investor section of the
Company’s website as well as by dialing 1-844-512-2921 (international callers please dial 1-412-317-6671). The pin to access the telephone replay is 13759880. The replay will be available until July 31, 2026.
About South Plains Financial, Inc.
South Plains is the bank holding company for City Bank, a Texas state-chartered bank headquartered in Lubbock, Texas. City Bank is one of the largest
independent banks in West Texas and has additional banking operations in the Dallas, El Paso, Greater Houston, the Permian Basin, and College Station, Texas markets, and the Ruidoso, New Mexico market. South Plains provides a wide range of commercial
and consumer financial services to small and medium-sized businesses and individuals in its market areas. Its principal business activities include commercial and retail banking, along with investment, trust and mortgage services. Please visit https://www.spfi.bank for more information.
Non-GAAP Financial Measures
Some of the financial measures included in this press release are not measures of financial performance recognized in accordance with generally accepted
accounting principles in the United States (“GAAP”). These non-GAAP financial measures include Tangible Book Value Per Share, Tangible Common Equity to Tangible Assets, and Pre-Tax, Pre-Provision Income. The Company believes these non-GAAP financial
measures provide both management and investors a more complete understanding of the Company’s financial position and performance. These non-GAAP financial measures are supplemental and are not a substitute for any analysis based on GAAP financial
measures.
We classify a financial measure as being a non-GAAP financial measure if that financial measure excludes or includes amounts, or is subject to
adjustments that have the effect of excluding or including amounts, that are included or excluded, as the case may be, in the most directly comparable measure calculated and presented in accordance with GAAP as in effect from time to time in the
United States in our statements of income, balance sheets or statements of cash flows. Not all companies use the same calculation of these measures; therefore, this presentation may not be comparable to other similarly titled measures as presented by
other companies.
A reconciliation of non-GAAP financial measures to GAAP financial measures is provided at the end of this press release.
Available Information
The Company routinely posts important information for investors on its web site (under www.spfi.bank and, more specifically, under the News & Events tab at www.spfi.bank/news-events/press-releases).
The Company intends to use its web site as a means of disclosing material non-public information and for complying with its disclosure obligations under Regulation FD (Fair Disclosure) promulgated by the U.S. Securities and Exchange Commission (the
“SEC”). Accordingly, investors should monitor the Company’s web site, in addition to following the Company’s press releases, SEC filings, public conference calls, presentations and webcasts.
The information contained on, or that may be accessed through, the Company’s web site is not incorporated by reference into, and is not a part of, this
document.
Forward Looking Statements
This press release contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking
statements reflect South Plains’ current views with respect to future events and South Plains’ financial performance. Any statements about South Plains’ expectations, beliefs, plans, predictions, forecasts, objectives, assumptions or future events or
performance are not historical facts and may be forward-looking. These statements are often, but not always, made through the use of words or phrases such as “anticipate,” “believes,” “can,” “could,” “may,” “predicts,” “potential,” “should,” “will,”
“estimate,” “plans,” “projects,” “continuing,” “ongoing,” “expects,” “intends” and similar words or phrases. South Plains cautions that the forward-looking statements in this press release are based largely on South Plains’ expectations and are
subject to a number of known and unknown risks and uncertainties that are subject to change based on factors which are, in many instances, beyond South Plains’ control. Factors that could cause such changes include, but are not limited to, the impact
on us and our customers of a decline in general economic conditions and any regulatory responses thereto; slower economic growth rates or potential recession in the United States and our market areas; uncertainty or perceived instability in the
banking industry as a whole; increased competition for deposits in our market areas among traditional and nontraditional financial services companies, and related changes in deposit customer behavior; the impact of changes in market interest rates,
whether due to a continuation of the elevated interest rate environment or future reductions in interest rates and a resulting decline in net interest income; the persistent inflationary pressures in the United States; the uncertain impacts of
current and future monetary policies of the Board of Governors of the Federal Reserve System; changes in unemployment rates in the United States and our market areas; adverse changes in customer spending, borrowing and savings habits; elevated asset
prices; declines in housing and commercial real estate values and prices; a deterioration of the credit rating for U.S. long-term sovereign debt or the impact of uncertain or changing political conditions, including federal government shutdowns and
uncertainty regarding United States fiscal debt, deficit and budget matters; cyber incidents or other failures, disruptions or breaches of our operational or security systems or infrastructure, or those of our third-party vendors or other service
providers, including as a result of cyber-attacks; severe weather, natural disasters, military conflicts (including the conflicts in the Middle East, the possible expansion of such conflicts and potential geopolitical and economic consequences), acts
of terrorism, geopolitical instability, domestic civil unrest or other external events, including as a result of the impact of the policies of the current U.S. presidential administration or Congress; the impacts of tariffs, sanctions, and other
trade policies of the United States and its global trading counterparts and the resulting impact on the Company and its customers; competition and market expansion opportunities; changes in non-interest expenditures or in the anticipated benefits of
such expenditures; the risks related to the development, implementation, use and management of emerging technologies, including digital assets, artificial intelligence and machine learning; potential costs related to the impacts of climate change;
current or future litigation, regulatory examinations or other legal and/or regulatory actions; our ability to recognize the expected benefits and synergies of our completed acquisitions; changes in accounting principles and standards, including
those related to loan loss recognition under the current expected credit loss, or CECL, methodology; and changes in applicable laws, regulations, or policies in the United States. Additional information regarding these risks and uncertainties to
which South Plains’ business and future financial performance are subject is contained in South Plains’ most recent Annual Report on Form 10-K and Quarterly Reports on Form 10-Q on file with the SEC, including the sections entitled “Risk Factors” and
“Management’s Discussion and Analysis of Financial Condition and Results of Operations” of such documents, and other documents South Plains files or furnishes with the SEC from time to time, which are available on the SEC’s website, www.sec.gov.
Actual results, performance or achievements could differ materially from those contemplated, expressed, or implied by the forward-looking statements due to additional risks and uncertainties of which South Plains is not currently aware or which it
does not currently view as, but in the future may become, material to its business or operating results. Due to these and other possible uncertainties and risks, the Company can give no assurance that the results contemplated in the forward-looking
statements will be realized and readers are cautioned not to place undue reliance on the forward-looking statements contained in this press release. Any forward-looking statements presented herein are made only as of the date of this press release,
and South Plains does not undertake any obligation to update or revise any forward-looking statements to reflect changes in assumptions, new information, the occurrence of unanticipated events, or otherwise, except as required by applicable law. All
forward-looking statements, express or implied, included in the press release are qualified in their entirety by this cautionary statement.
|
Contact:
|
Mikella Newsom, Chief Risk Officer and Secretary
|
|
(866) 771-3347
|
|
Source: South Plains Financial, Inc.
South Plains Financial, Inc.
Consolidated Financial Highlights - (Unaudited)
(Dollars in thousands, except share data)
|
As of and for the quarter ended
|
||||||||||||||||||||
|
June 30,
2026
|
March 31,
2026
|
December 31,
2025
|
September 30,
2025
|
June 30,
2025
|
||||||||||||||||
|
Selected Income Statement Data:
|
||||||||||||||||||||
|
Interest income
|
$
|
75,003
|
$
|
62,632
|
$
|
63,421
|
$
|
64,520
|
$
|
64,135
|
||||||||||
|
Interest expense
|
24,654
|
19,780
|
20,471
|
21,501
|
21,632
|
|||||||||||||||
|
Net interest income
|
50,349
|
42,852
|
42,950
|
43,019
|
42,503
|
|||||||||||||||
|
Provision for credit losses
|
350
|
260
|
1,775
|
500
|
2,500
|
|||||||||||||||
|
Noninterest income
|
14,143
|
11,295
|
10,934
|
11,165
|
12,165
|
|||||||||||||||
|
Noninterest expense
|
39,864
|
35,526
|
33,023
|
33,024
|
33,543
|
|||||||||||||||
|
Income tax expense
|
5,286
|
3,816
|
3,832
|
4,342
|
4,020
|
|||||||||||||||
|
Net income
|
18,992
|
14,545
|
15,254
|
16,318
|
14,605
|
|||||||||||||||
|
Per Share Data (Common Stock):
|
||||||||||||||||||||
|
Net earnings, basic
|
$
|
0.99
|
$
|
0.89
|
$
|
0.94
|
$
|
1.00
|
$
|
0.90
|
||||||||||
|
Net earnings, diluted
|
0.96
|
0.85
|
0.90
|
0.96
|
0.86
|
|||||||||||||||
|
Cash dividends declared and paid
|
0.17
|
0.17
|
0.16
|
0.16
|
0.15
|
|||||||||||||||
|
Book value
|
33.43
|
30.90
|
30.31
|
29.41
|
27.98
|
|||||||||||||||
|
Tangible book value (non-GAAP)
|
29.57
|
29.65
|
29.05
|
28.14
|
26.70
|
|||||||||||||||
|
Weighted average shares outstanding, basic
|
19,100,893
|
16,318,570
|
16,248,336
|
16,241,695
|
16,231,627
|
|||||||||||||||
|
Weighted average shares outstanding, dilutive
|
19,809,801
|
17,036,334
|
16,996,517
|
16,990,546
|
16,886,993
|
|||||||||||||||
|
Shares outstanding at end of period
|
18,839,105
|
16,342,219
|
16,293,577
|
16,247,839
|
16,230,475
|
|||||||||||||||
|
Selected Period End Balance Sheet Data:
|
||||||||||||||||||||
|
Cash and cash equivalents
|
$
|
787,757
|
$
|
722,000
|
$
|
552,439
|
$
|
635,046
|
$
|
470,496
|
||||||||||
|
Investment securities
|
555,427
|
602,852
|
567,540
|
571,138
|
570,000
|
|||||||||||||||
|
Total loans held for investment
|
3,770,829
|
3,103,529
|
3,144,502
|
3,053,503
|
3,098,978
|
|||||||||||||||
|
Allowance for credit losses
|
53,076
|
44,822
|
45,131
|
44,125
|
45,010
|
|||||||||||||||
|
Total assets
|
5,391,206
|
4,646,374
|
4,480,500
|
4,479,437
|
4,363,674
|
|||||||||||||||
|
Interest-bearing deposits
|
3,488,985
|
2,993,469
|
2,850,560
|
2,831,642
|
2,740,179
|
|||||||||||||||
|
Noninterest-bearing deposits
|
1,151,641
|
1,034,117
|
1,023,517
|
1,049,501
|
998,759
|
|||||||||||||||
|
Total deposits
|
4,640,626
|
4,027,586
|
3,874,077
|
3,881,143
|
3,738,938
|
|||||||||||||||
|
Borrowings
|
60,493
|
60,493
|
60,493
|
60,493
|
111,799
|
|||||||||||||||
|
Total stockholders’ equity
|
629,765
|
504,939
|
493,837
|
477,802
|
454,074
|
|||||||||||||||
|
Summary Performance Ratios:
|
||||||||||||||||||||
|
Return on average assets (annualized)
|
1.44
|
%
|
1.31
|
%
|
1.36
|
%
|
1.47
|
%
|
1.34
|
%
|
||||||||||
|
Return on average equity (annualized)
|
12.17
|
%
|
11.81
|
%
|
12.46
|
%
|
13.89
|
%
|
13.05
|
%
|
||||||||||
|
Net interest margin (1)
|
4.00
|
%
|
4.04
|
%
|
4.00
|
%
|
4.05
|
%
|
4.07
|
%
|
||||||||||
|
Yield on loans
|
6.81
|
%
|
6.83
|
%
|
6.79
|
%
|
6.92
|
%
|
6.99
|
%
|
||||||||||
|
Cost of interest-bearing deposits
|
2.74
|
%
|
2.64
|
%
|
2.75
|
%
|
2.87
|
%
|
2.91
|
%
|
||||||||||
|
Efficiency ratio
|
61.59
|
%
|
65.33
|
%
|
61.02
|
%
|
60.69
|
%
|
61.11
|
%
|
||||||||||
|
Summary Credit Quality Data:
|
||||||||||||||||||||
|
Nonperforming loans
|
$
|
9,506
|
$
|
5,093
|
$
|
9,805
|
$
|
9,709
|
$
|
10,463
|
||||||||||
|
Nonperforming loans to total loans held for investment
|
0.25
|
%
|
0.16
|
%
|
0.31
|
%
|
0.32
|
%
|
0.34
|
%
|
||||||||||
|
Other real estate owned
|
$
|
790
|
$
|
994
|
$
|
1,749
|
$
|
1,827
|
$
|
535
|
||||||||||
|
Nonperforming assets to total assets
|
0.19
|
%
|
0.13
|
%
|
0.26
|
%
|
0.26
|
%
|
0.25
|
%
|
||||||||||
|
Allowance for credit losses to total loans held for investment
|
1.41
|
%
|
1.44
|
%
|
1.44
|
%
|
1.45
|
%
|
1.45
|
%
|
||||||||||
|
Net charge-offs to average loans outstanding (annualized)
|
0.06
|
%
|
0.04
|
%
|
0.10
|
%
|
0.16
|
%
|
0.06
|
%
|
||||||||||
|
As of and for the quarter ended
|
||||||||||||||||||||
|
June 30
2026
|
March 31,
2026
|
December 31,
2025
|
September 30,
2025
|
June 30,
2025
|
||||||||||||||||
|
Capital Ratios:
|
||||||||||||||||||||
|
Total stockholders’ equity to total assets
|
11.68
|
%
|
10.87
|
%
|
11.02
|
%
|
10.67
|
%
|
10.41
|
%
|
||||||||||
|
Tangible common equity to tangible assets (non-GAAP)
|
10.47
|
%
|
10.48
|
%
|
10.61
|
%
|
10.25
|
%
|
9.98
|
%
|
||||||||||
|
Common equity tier 1 to risk-weighted assets
|
14.10
|
%
|
14.80
|
%
|
14.45
|
%
|
14.41
|
%
|
13.86
|
%
|
||||||||||
|
Tier 1 capital to average assets
|
12.20
|
%
|
12.68
|
%
|
12.53
|
%
|
12.37
|
%
|
12.12
|
%
|
||||||||||
|
Total capital to risk-weighted assets
|
16.53
|
%
|
17.61
|
%
|
17.26
|
%
|
17.34
|
%
|
18.17
|
%
|
||||||||||
| (1) |
Net interest margin is calculated as the annual net interest income, on a fully tax-equivalent basis, divided by average interest-earning assets.
|
South Plains Financial, Inc.
Average Balances and Yields - (Unaudited)
(Dollars in thousands)
|
For the Three Months Ended
|
||||||||||||||||||||||||
|
June 30, 2026
|
June 30, 2025
|
|||||||||||||||||||||||
|
Average
Balance
|
Interest
|
Yield/Rate
|
Average
Balance
|
Interest
|
Yield/Rate
|
|||||||||||||||||||
|
Assets
|
||||||||||||||||||||||||
|
Loans (1)
|
$
|
3,777,590
|
$
|
64,113
|
6.81
|
%
|
$
|
3,094,558
|
$
|
53,894
|
6.99
|
%
|
||||||||||||
|
Debt securities - taxable
|
482,264
|
4,238
|
3.52
|
%
|
508,508
|
4,700
|
3.71
|
%
|
||||||||||||||||
|
Debt securities - nontaxable
|
152,399
|
1,077
|
2.83
|
%
|
152,202
|
1,015
|
2.67
|
%
|
||||||||||||||||
|
Other interest-bearing assets
|
660,395
|
5,808
|
3.53
|
%
|
456,818
|
4,747
|
4.17
|
%
|
||||||||||||||||
|
Total interest-earning assets
|
5,072,648
|
75,236
|
5.95
|
%
|
4,212,086
|
64,356
|
6.13
|
%
|
||||||||||||||||
|
Noninterest-earning assets
|
231,192
|
166,763
|
||||||||||||||||||||||
|
Total assets
|
$
|
5,303,840
|
$
|
4,378,849
|
||||||||||||||||||||
|
Liabilities & stockholders’ equity
|
||||||||||||||||||||||||
|
NOW, Savings, MMDA’s
|
$
|
2,871,819
|
18,353
|
2.56
|
%
|
$
|
2,326,779
|
15,890
|
2.74
|
%
|
||||||||||||||
|
Time deposits
|
602,818
|
5,363
|
3.57
|
%
|
438,697
|
4,172
|
3.81
|
%
|
||||||||||||||||
|
Short-term borrowings
|
3,739
|
38
|
4.08
|
%
|
18
|
—
|
0.00
|
%
|
||||||||||||||||
|
Notes payable & other long-term borrowings
|
—
|
—
|
0.00
|
%
|
—
|
—
|
0.00
|
%
|
||||||||||||||||
|
Subordinated debt
|
14,100
|
238
|
6.77
|
%
|
64,031
|
835
|
5.23
|
%
|
||||||||||||||||
|
Junior subordinated deferrable interest debentures
|
46,393
|
662
|
5.72
|
%
|
46,393
|
735
|
6.35
|
%
|
||||||||||||||||
|
Total interest-bearing liabilities
|
3,538,869
|
24,654
|
2.79
|
%
|
2,875,918
|
21,632
|
3.02
|
%
|
||||||||||||||||
|
Demand deposits
|
1,102,345
|
990,343
|
||||||||||||||||||||||
|
Other liabilities
|
36,540
|
63,679
|
||||||||||||||||||||||
|
Stockholders’ equity
|
626,086
|
448,909
|
||||||||||||||||||||||
|
Total liabilities & stockholders’ equity
|
$
|
5,303,840
|
$
|
4,378,849
|
||||||||||||||||||||
|
Net interest income
|
$
|
50,582
|
$
|
42,724
|
||||||||||||||||||||
|
Net interest margin (2)
|
4.00
|
%
|
4.07
|
%
|
||||||||||||||||||||
| (1) |
Average loan balances include nonaccrual loans and loans held for sale.
|
| (2) |
Net interest margin is calculated as the annualized net interest income, on a fully tax-equivalent basis, divided by average interest-earning assets.
|
South Plains Financial, Inc.
Average Balances and Yields - (Unaudited)
(Dollars in thousands)
|
For the Six Months Ended
|
||||||||||||||||||||||||
|
June 30, 2026
|
June 30, 2025
|
|||||||||||||||||||||||
|
Average
Balance
|
Interest
|
Yield/Rate
|
Average
Balance
|
Interest
|
Yield/Rate
|
|||||||||||||||||||
|
Assets
|
||||||||||||||||||||||||
|
Loans (1)
|
$
|
3,453,878
|
$
|
116,797
|
6.82
|
%
|
$
|
3,084,563
|
$
|
104,471
|
6.83
|
%
|
||||||||||||
|
Debt securities - taxable
|
486,188
|
8,523
|
3.54
|
%
|
509,431
|
9,392
|
3.72
|
%
|
||||||||||||||||
|
Debt securities - nontaxable
|
152,832
|
2,157
|
2.85
|
%
|
152,716
|
2,029
|
2.68
|
%
|
||||||||||||||||
|
Other interest-bearing assets
|
608,467
|
10,625
|
3.52
|
%
|
421,899
|
8,606
|
4.11
|
%
|
||||||||||||||||
|
Total interest-earning assets
|
4,701,365
|
138,102
|
5.92
|
%
|
4,168,609
|
124,498
|
6.02
|
%
|
||||||||||||||||
|
Noninterest-earning assets
|
206,067
|
169,222
|
||||||||||||||||||||||
|
Total assets
|
$
|
4,907,432
|
$
|
4,337,831
|
||||||||||||||||||||
|
Liabilities & stockholders’ equity
|
||||||||||||||||||||||||
|
NOW, Savings, MMDA’s
|
$
|
2,669,649
|
33,407
|
2.52
|
%
|
$
|
2,314,562
|
31,401
|
2.74
|
%
|
||||||||||||||
|
Time deposits
|
519,734
|
9,187
|
3.56
|
%
|
440,297
|
8,488
|
3.89
|
%
|
||||||||||||||||
|
Short-term borrowings
|
1,871
|
38
|
4.10
|
%
|
11
|
—
|
0.00
|
%
|
||||||||||||||||
|
Notes payable & other long-term borrowings
|
—
|
—
|
0.00
|
%
|
—
|
—
|
0.00
|
%
|
||||||||||||||||
|
Subordinated debt
|
14,100
|
481
|
6.88
|
%
|
64,008
|
1,670
|
5.26
|
%
|
||||||||||||||||
|
Junior subordinated deferrable interest debentures
|
46,393
|
1,321
|
5.74
|
%
|
46,393
|
1,468
|
6.38
|
%
|
||||||||||||||||
|
Total interest-bearing liabilities
|
3,251,747
|
44,434
|
2.76
|
%
|
2,865,271
|
43,027
|
3.03
|
%
|
||||||||||||||||
|
Demand deposits
|
1,045,930
|
962,557
|
||||||||||||||||||||||
|
Other liabilities
|
46,948
|
64,875
|
||||||||||||||||||||||
|
Stockholders’ equity
|
562,807
|
445,128
|
||||||||||||||||||||||
|
Total liabilities & stockholders’ equity
|
$
|
4,907,432
|
$
|
4,337,831
|
||||||||||||||||||||
|
Net interest income
|
$
|
93,668
|
$
|
81,471
|
||||||||||||||||||||
|
Net interest margin (2)
|
4.02
|
%
|
3.94
|
%
|
||||||||||||||||||||
| (1) |
Average loan balances include nonaccrual loans and loans held for sale.
|
| (2) |
Net interest margin is calculated as the annualized net interest income, on a fully tax-equivalent basis, divided by average interest-earning assets.
|
South Plains Financial, Inc.
Consolidated Balance Sheets
(Unaudited)
(Dollars in thousands)
|
As of
|
||||||||
|
June 30,
2026
|
December 31,
2025
|
|||||||
|
Assets
|
||||||||
|
Cash and due from banks
|
$
|
61,177
|
$
|
58,318
|
||||
|
Interest-bearing deposits in banks
|
726,580
|
494,121
|
||||||
|
Securities available for sale
|
555,427
|
567,540
|
||||||
|
Loans held for sale
|
11,622
|
9,993
|
||||||
|
Loans held for investment
|
3,770,829
|
3,144,502
|
||||||
|
Less: Allowance for credit losses
|
(53,076
|
)
|
(45,131
|
)
|
||||
|
Net loans held for investment
|
3,717,753
|
3,099,371
|
||||||
|
Premises and equipment, net
|
52,132
|
51,563
|
||||||
|
Goodwill
|
67,089
|
19,315
|
||||||
|
Intangible assets
|
5,626
|
1,133
|
||||||
|
Mortgage servicing rights
|
25,749
|
24,041
|
||||||
|
Other assets
|
168,051
|
155,105
|
||||||
|
Total assets
|
$
|
5,391,206
|
$
|
4,480,500
|
||||
|
Liabilities and Stockholders’ Equity
|
||||||||
|
Noninterest-bearing deposits
|
$
|
1,151,641
|
$
|
1,023,517
|
||||
|
Interest-bearing deposits
|
3,488,985
|
2,850,560
|
||||||
|
Total deposits
|
4,640,626
|
3,874,077
|
||||||
|
Short-term borrowings
|
—
|
—
|
||||||
|
Subordinated debt
|
14,100
|
14,100
|
||||||
|
Junior subordinated deferrable interest debentures
|
46,393
|
46,393
|
||||||
|
Other liabilities
|
60,322
|
52,093
|
||||||
|
Total liabilities
|
4,761,441
|
3,986,663
|
||||||
|
Stockholders’ Equity
|
||||||||
|
Common stock
|
18,839
|
16,294
|
||||||
|
Additional paid-in capital
|
194,245
|
91,065
|
||||||
|
Retained earnings
|
461,708
|
434,197
|
||||||
|
Accumulated other comprehensive income (loss)
|
(45,027
|
)
|
(47,719
|
)
|
||||
|
Total stockholders’ equity
|
629,765
|
493,837
|
||||||
|
Total liabilities and stockholders’ equity
|
$
|
5,391,206
|
$
|
4,480,500
|
||||
South Plains Financial, Inc.
Consolidated Statements of Income
(Unaudited)
(Dollars in thousands)
|
Three Months Ended
|
Six Months Ended
|
|||||||||||||||
|
June 30,
2026
|
June 30,
2025
|
June 30,
2026
|
June 30,
2025
|
|||||||||||||
|
Interest income:
|
||||||||||||||||
|
Loans, including fees
|
$
|
64,106
|
$
|
53,886
|
$
|
116,783
|
$
|
104,456
|
||||||||
|
Other
|
10,897
|
10,249
|
20,852
|
19,601
|
||||||||||||
|
Total interest income
|
75,003
|
64,135
|
137,635
|
124,057
|
||||||||||||
|
Interest expense:
|
||||||||||||||||
|
Deposits
|
23,716
|
20,062
|
42,594
|
39,889
|
||||||||||||
|
Subordinated debt
|
238
|
835
|
481
|
1,670
|
||||||||||||
|
Junior subordinated deferrable interest debentures
|
662
|
735
|
1,321
|
1,468
|
||||||||||||
|
Other
|
38
|
—
|
38
|
—
|
||||||||||||
|
Total interest expense
|
24,654
|
21,632
|
44,434
|
43,027
|
||||||||||||
|
Net interest income
|
50,349
|
42,503
|
93,201
|
81,030
|
||||||||||||
|
Provision for credit losses
|
350
|
2,500
|
610
|
2,920
|
||||||||||||
|
Net interest income after provision for credit losses
|
49,999
|
40,003
|
92,591
|
78,110
|
||||||||||||
|
Noninterest income:
|
||||||||||||||||
|
Service charges on deposits
|
2,366
|
2,098
|
4,621
|
4,239
|
||||||||||||
|
Mortgage banking activities
|
4,847
|
3,606
|
8,765
|
5,719
|
||||||||||||
|
Bank card services and interchange fees
|
4,110
|
3,771
|
7,326
|
7,150
|
||||||||||||
|
Other
|
2,820
|
2,690
|
4,726
|
5,682
|
||||||||||||
|
Total noninterest income
|
14,143
|
12,165
|
25,438
|
22,790
|
||||||||||||
|
Noninterest expense:
|
||||||||||||||||
|
Salaries and employee benefits
|
23,517
|
19,708
|
43,671
|
39,149
|
||||||||||||
|
Net occupancy expense
|
4,551
|
3,972
|
8,504
|
7,999
|
||||||||||||
|
Professional services
|
1,850
|
1,874
|
4,805
|
3,604
|
||||||||||||
|
Marketing and development
|
1,032
|
919
|
2,033
|
1,824
|
||||||||||||
|
Other
|
8,914
|
7,070
|
16,377
|
13,997
|
||||||||||||
|
Total noninterest expense
|
39,864
|
33,543
|
75,390
|
66,573
|
||||||||||||
|
Income before income taxes
|
24,278
|
18,625
|
42,639
|
34,327
|
||||||||||||
|
Income tax expense
|
5,286
|
4,020
|
9,102
|
7,428
|
||||||||||||
|
Net income
|
$
|
18,992
|
$
|
14,605
|
$
|
33,537
|
$
|
26,899
|
||||||||
South Plains Financial, Inc.
Loan Composition
(Unaudited)
(Dollars in thousands)
|
As of
|
||||||||
|
June 30,
2026
|
December 31,
2025
|
|||||||
|
Loans:
|
||||||||
|
Commercial Real Estate
|
$
|
1,331,915
|
$
|
1,064,625
|
||||
|
Commercial - Specialized
|
429,380
|
409,351
|
||||||
|
Commercial - General
|
827,452
|
659,323
|
||||||
|
Consumer:
|
||||||||
|
1-4 Family Residential
|
714,014
|
589,851
|
||||||
|
Auto Loans
|
263,810
|
259,157
|
||||||
|
Other Consumer
|
61,060
|
62,092
|
||||||
|
Construction
|
143,198
|
100,103
|
||||||
|
Total loans held for investment
|
$
|
3,770,829
|
$
|
3,144,502
|
||||
South Plains Financial, Inc.
Deposit Composition
(Unaudited)
(Dollars in thousands)
|
As of
|
||||||||
|
June 30,
2026
|
December 31,
2025
|
|||||||
|
Deposits:
|
||||||||
|
Noninterest-bearing deposits
|
$
|
1,151,641
|
$
|
1,023,517
|
||||
|
NOW & other transaction accounts
|
1,554,184
|
1,307,596
|
||||||
|
MMDA & other savings
|
1,330,583
|
1,111,529
|
||||||
|
Time deposits
|
604,218
|
431,435
|
||||||
|
Total deposits
|
$
|
4,640,626
|
$
|
3,874,077
|
||||
South Plains Financial, Inc.
Reconciliation of Non-GAAP Financial Measures (Unaudited)
(Dollars in thousands)
|
For the quarter ended
|
||||||||||||||||||||
|
June 30,
2026
|
March 31,
2026
|
December 31,
2025
|
September 30,
2025
|
June 30,
2025
|
||||||||||||||||
|
Pre-tax, pre-provision income
|
||||||||||||||||||||
|
Net income
|
$
|
18,992
|
$
|
14,545
|
$
|
15,254
|
$
|
16,318
|
$
|
14,605
|
||||||||||
|
Income tax expense
|
5,286
|
3,816
|
3,832
|
4,342
|
4,020
|
|||||||||||||||
|
Provision for credit losses
|
350
|
260
|
1,775
|
500
|
2,500
|
|||||||||||||||
|
Pre-tax, pre-provision income
|
$
|
24,628
|
$
|
18,621
|
$
|
20,861
|
$
|
21,160
|
$
|
21,125
|
||||||||||
|
As of
|
||||||||||||||||||||
|
June 30,
2026
|
March 31,
2026
|
December 31,
2025
|
September 30,
2025
|
June 30,
2025
|
||||||||||||||||
|
Tangible common equity
|
||||||||||||||||||||
|
Total common stockholders’ equity
|
$
|
629,765
|
$
|
504,939
|
$
|
$ 493,837
|
$
|
$ 477,802
|
$
|
$ 454,074
|
||||||||||
|
Less: goodwill and other intangibles
|
(72,715
|
)
|
(20,327
|
)
|
(20,448
|
)
|
(20,580
|
)
|
(20,732
|
)
|
||||||||||
|
Tangible common equity
|
$
|
557,050
|
$
|
484,612
|
$
|
$ 473,389
|
$
|
$ 457,222
|
$
|
$ 433,342
|
||||||||||
|
Tangible assets
|
||||||||||||||||||||
|
Total assets
|
$
|
5,391,206
|
$
|
4,646,374
|
$
|
$ 4,480,500
|
$
|
$ 4,479,437
|
$
|
$ 4,363,674
|
||||||||||
|
Less: goodwill and other intangibles
|
(72,715
|
)
|
(20,327
|
)
|
(20,448
|
)
|
(20,580
|
)
|
(20,732
|
)
|
||||||||||
|
Tangible assets
|
$
|
5,318,491
|
$
|
4,626,047
|
$
|
$ 4,460,052
|
$
|
$ 4,458,857
|
$
|
$ 4,342,942
|
||||||||||
|
Shares outstanding
|
18,839,105
|
16,342,219
|
16,293,577
|
16,247,839
|
16,230,475
|
|||||||||||||||
|
Total stockholders’ equity to total assets
|
11.68
|
%
|
10.87
|
%
|
11.02
|
%
|
10.67
|
%
|
10.41
|
%
|
||||||||||
|
Tangible common equity to tangible assets
|
10.47
|
%
|
10.48
|
%
|
10.61
|
%
|
10.25
|
%
|
9.98
|
%
|
||||||||||
|
Book value per share
|
$
|
33.43
|
$
|
30.90
|
$
|
30.31
|
$
|
29.41
|
$
|
27.98
|
||||||||||
|
Tangible book value per share
|
$
|
29.57
|
$
|
29.65
|
$
|
29.05
|
$
|
28.14
|
$
|
26.70
|
||||||||||
Exhibit 99.2
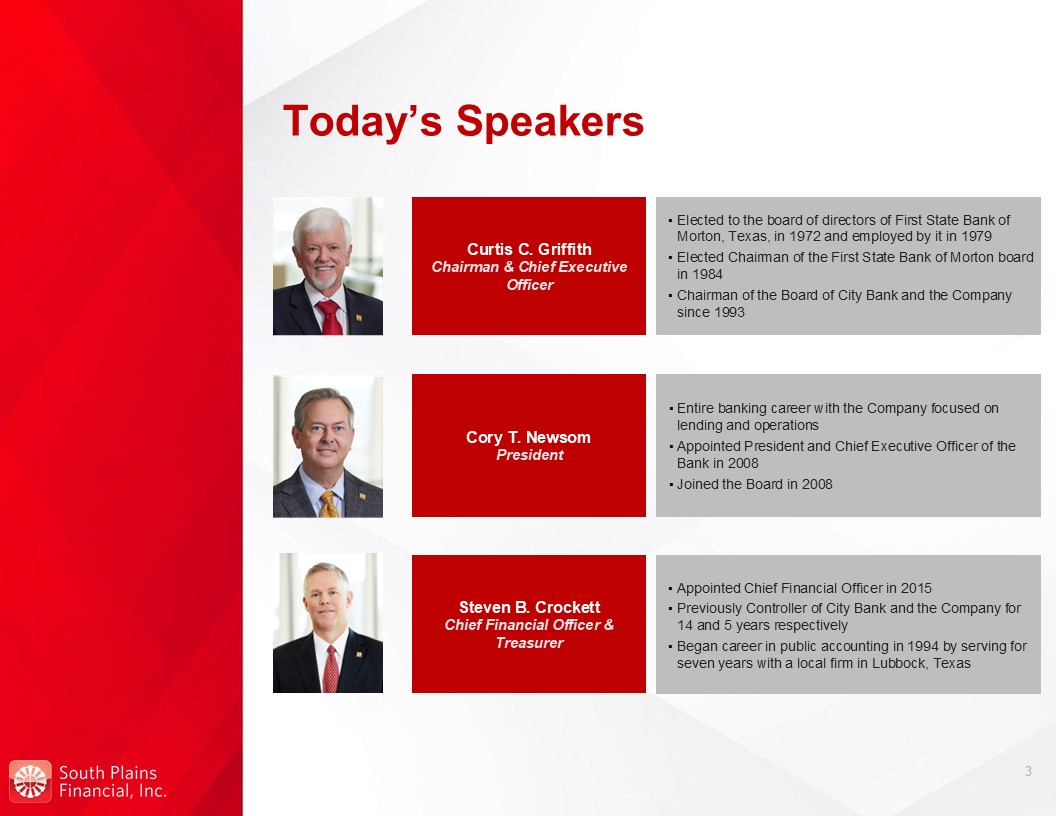
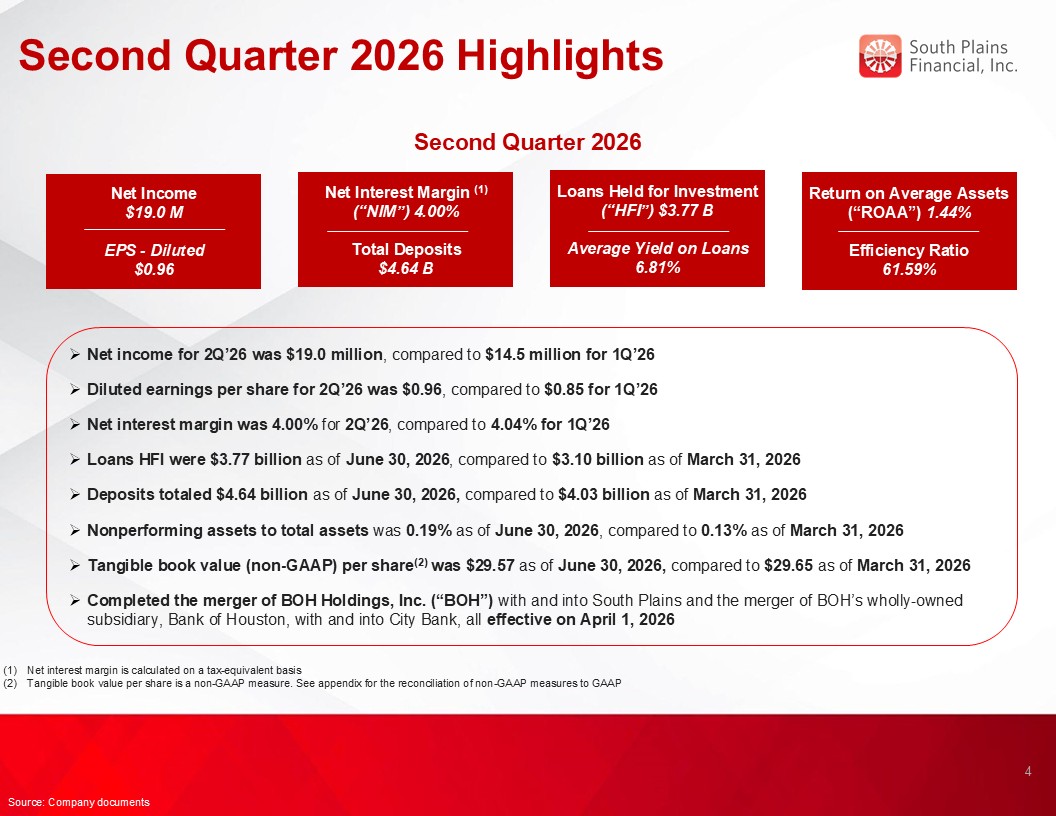
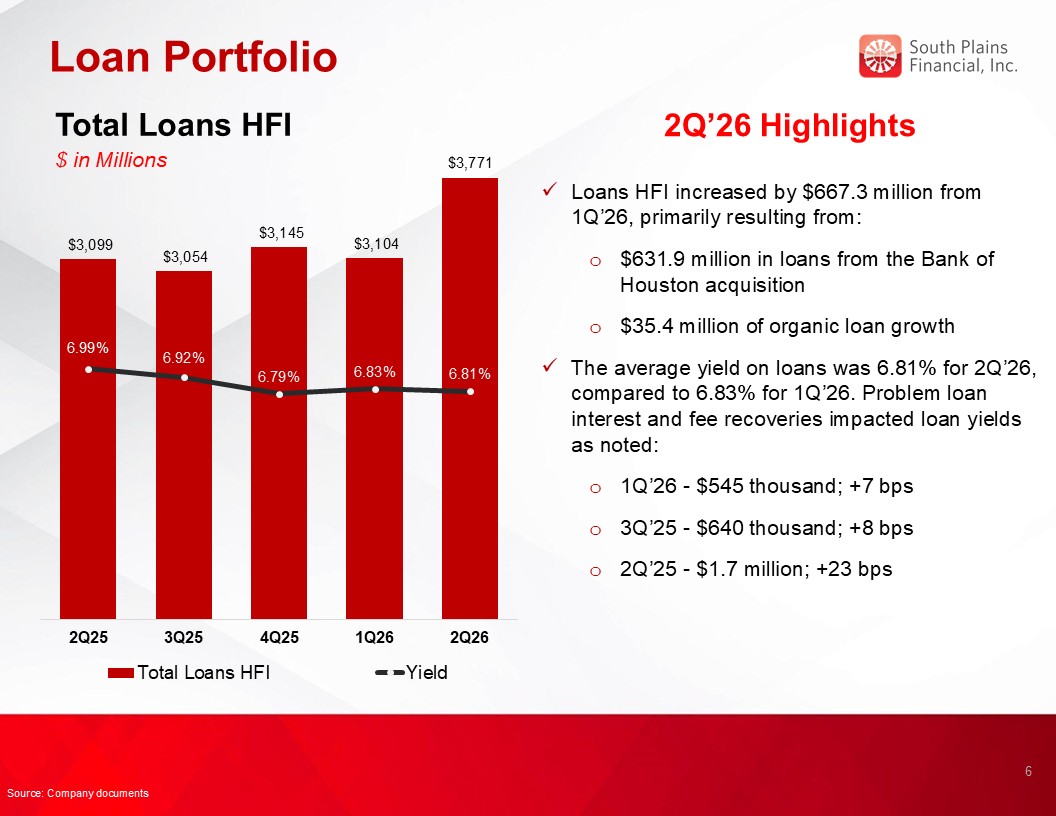
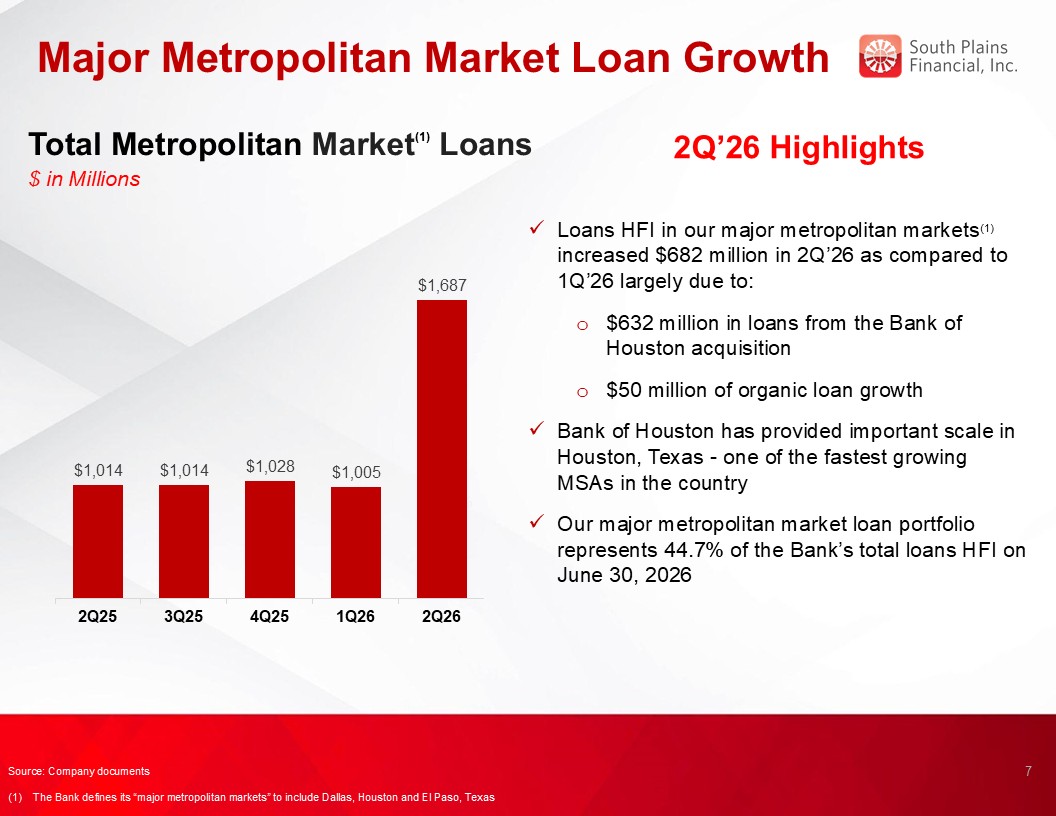
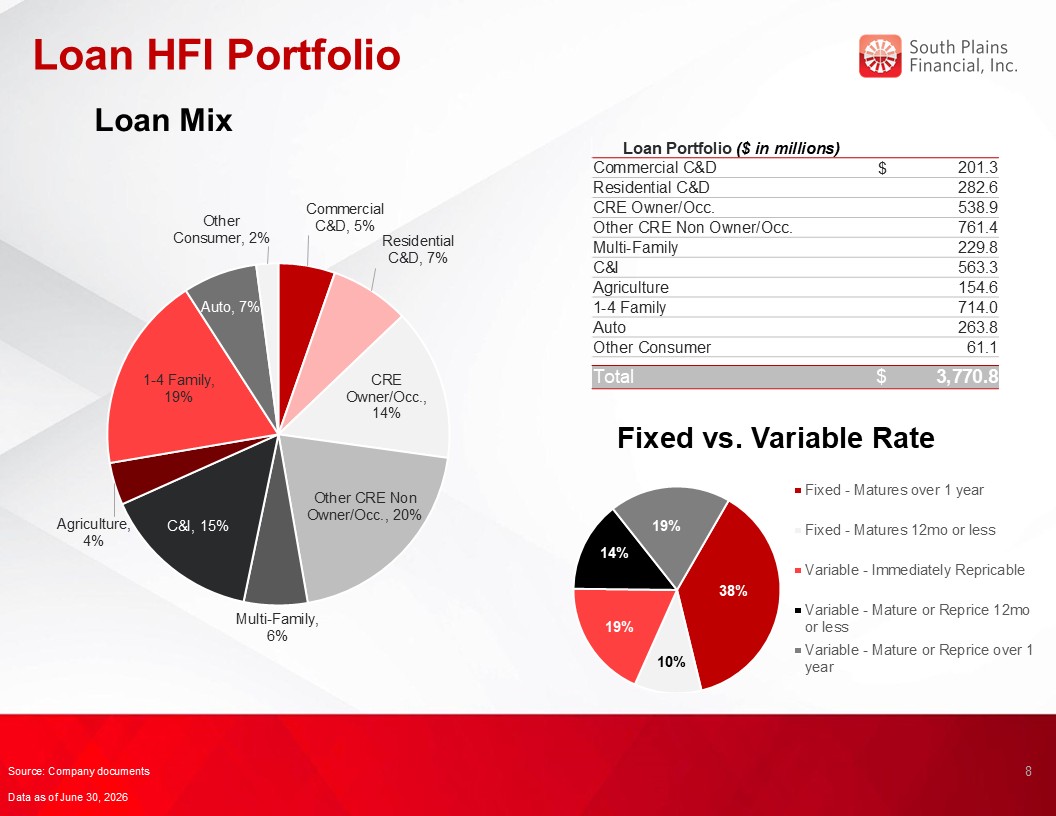
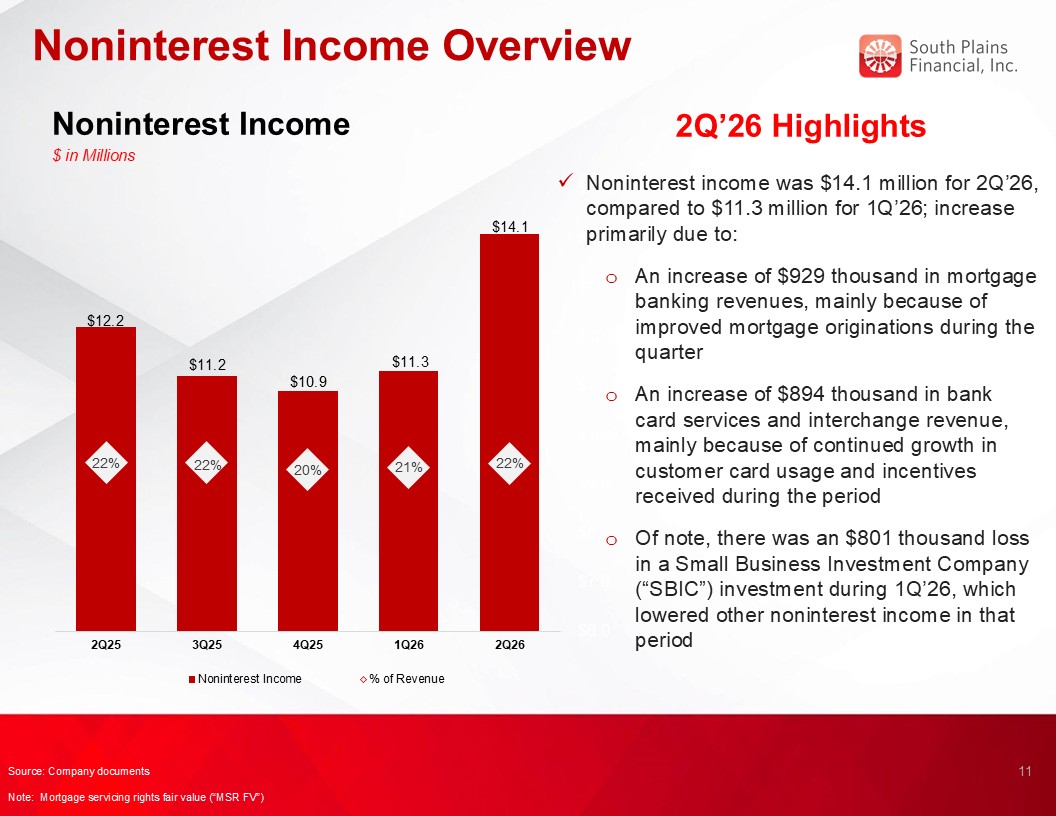
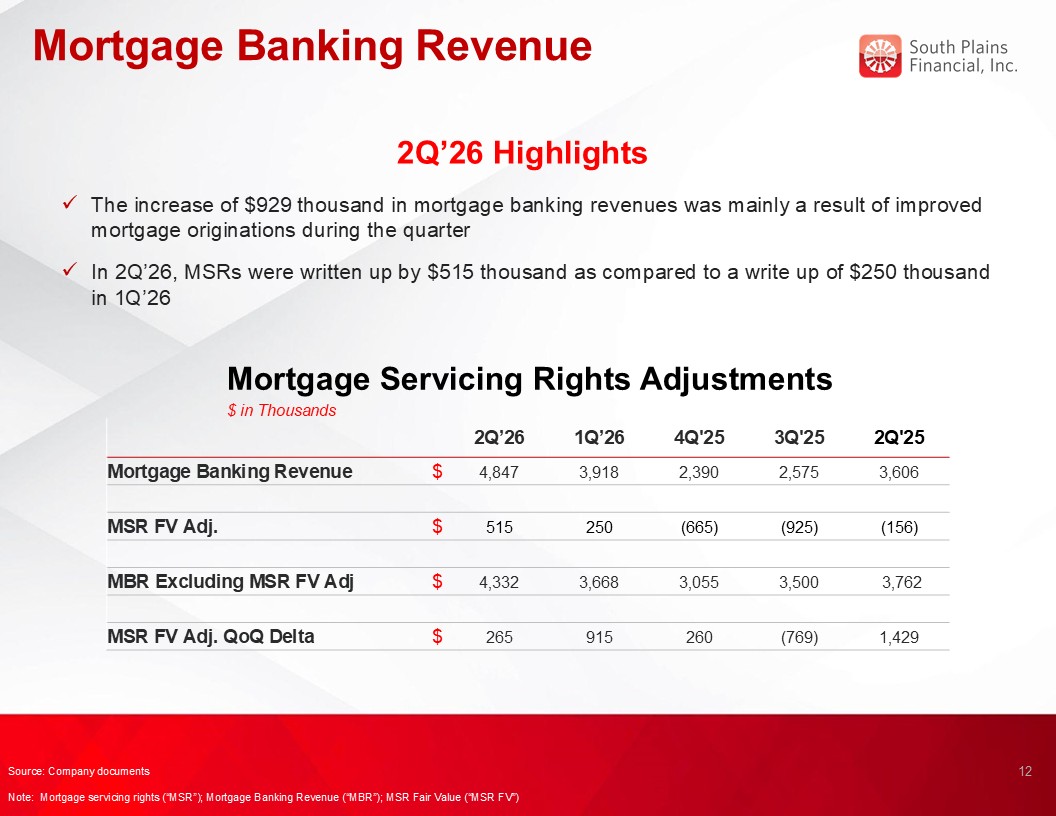
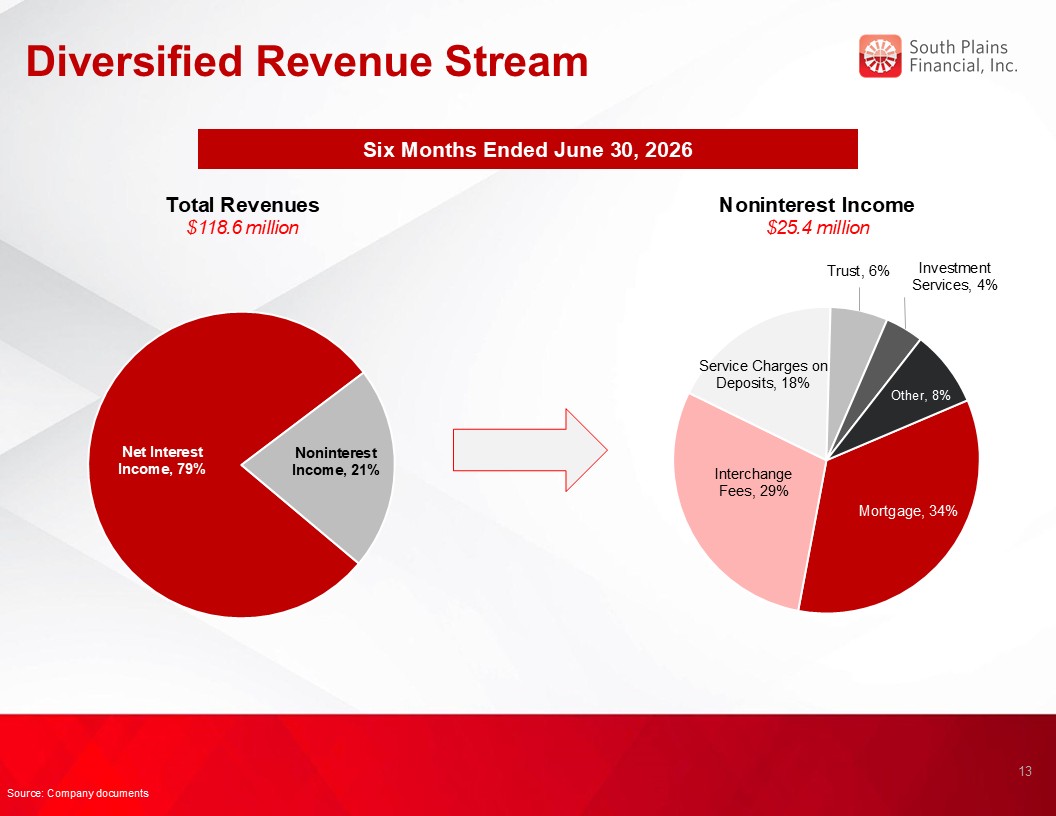
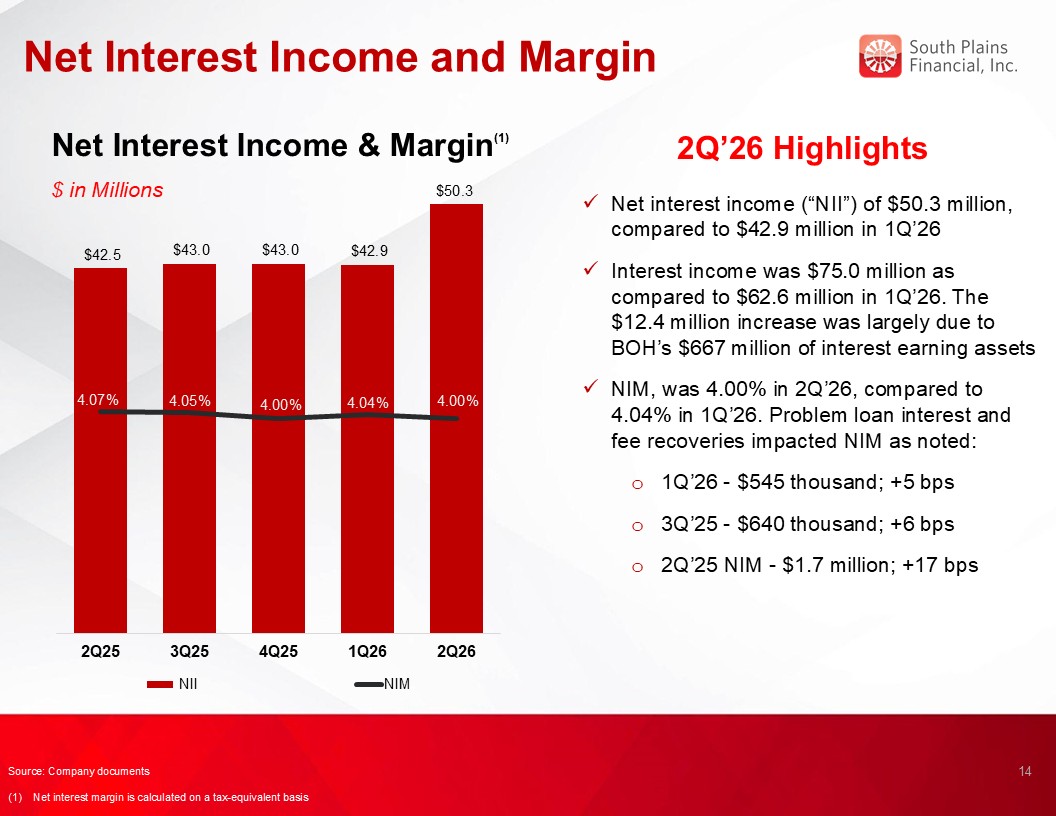
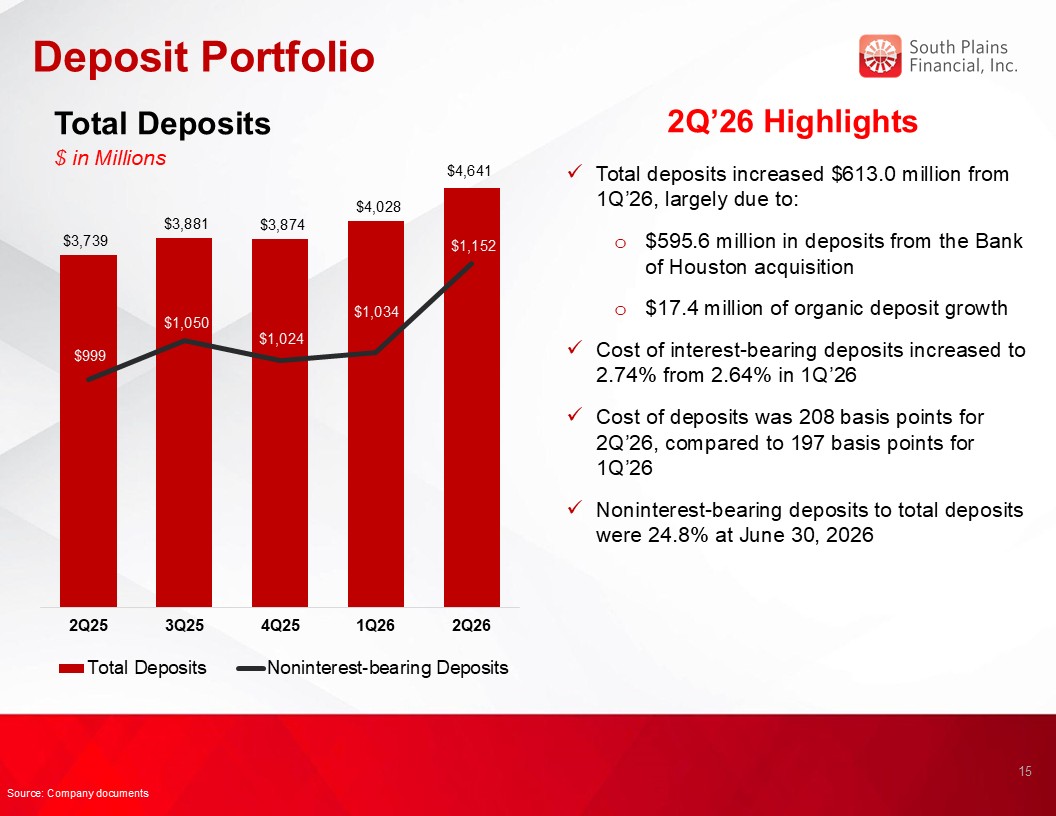
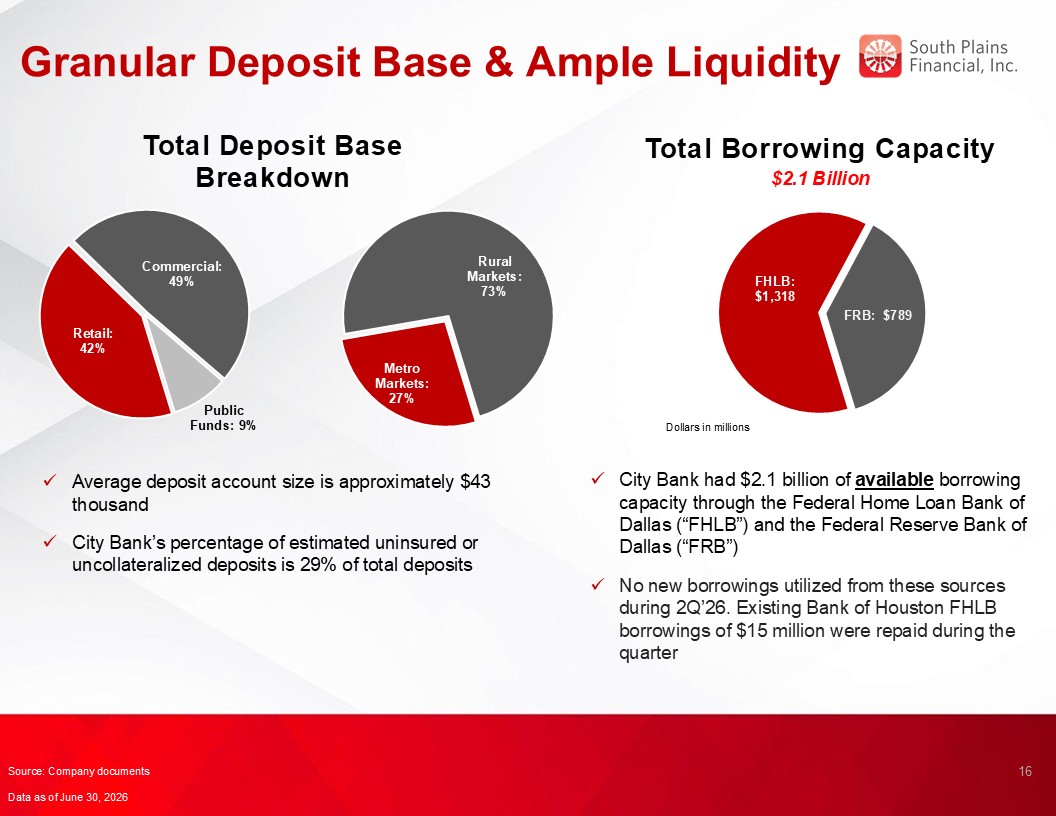
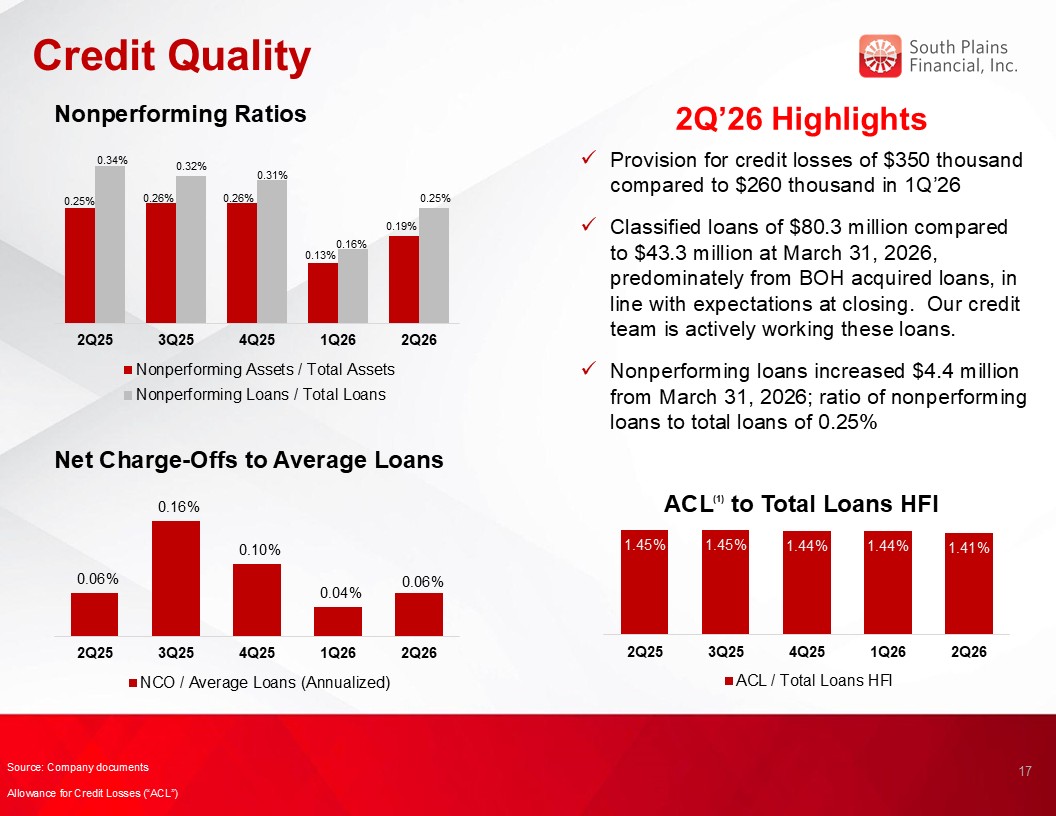
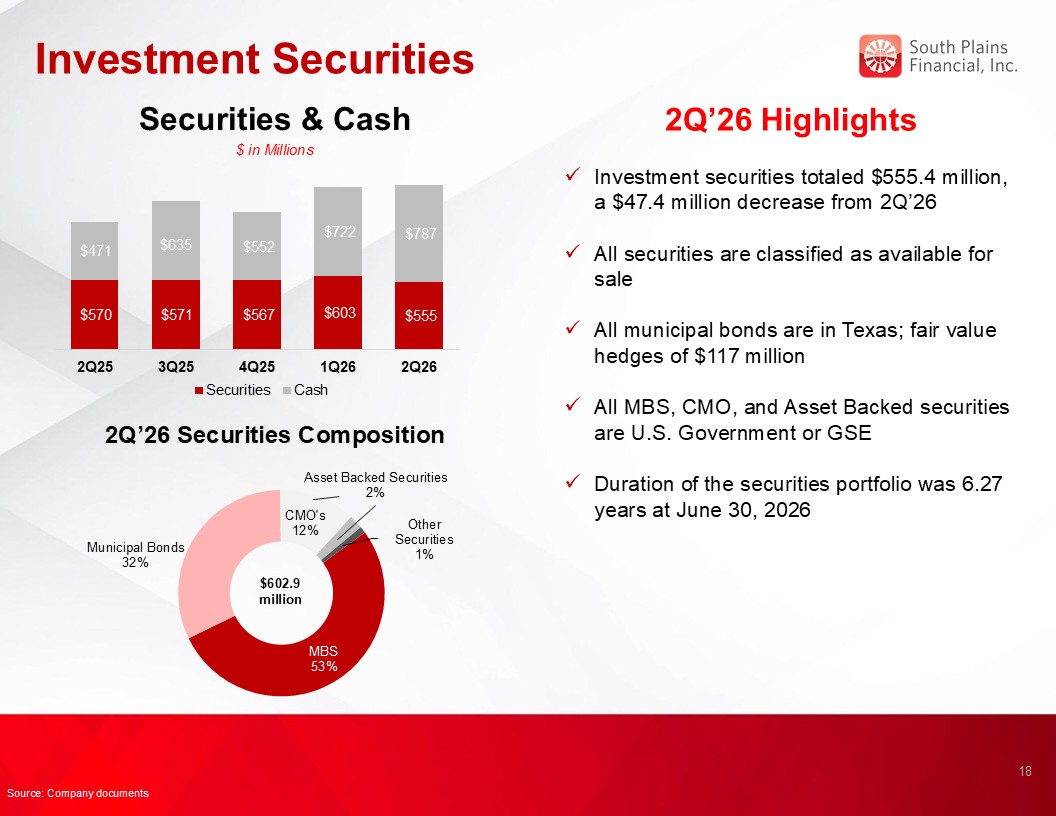
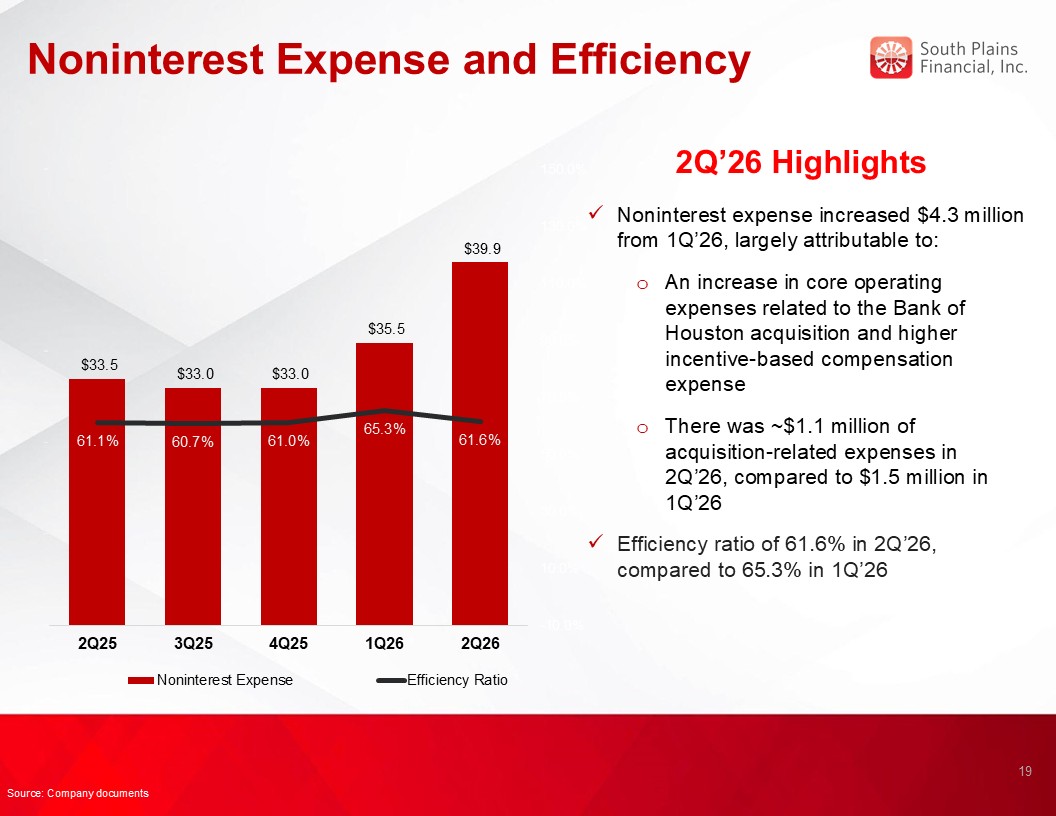
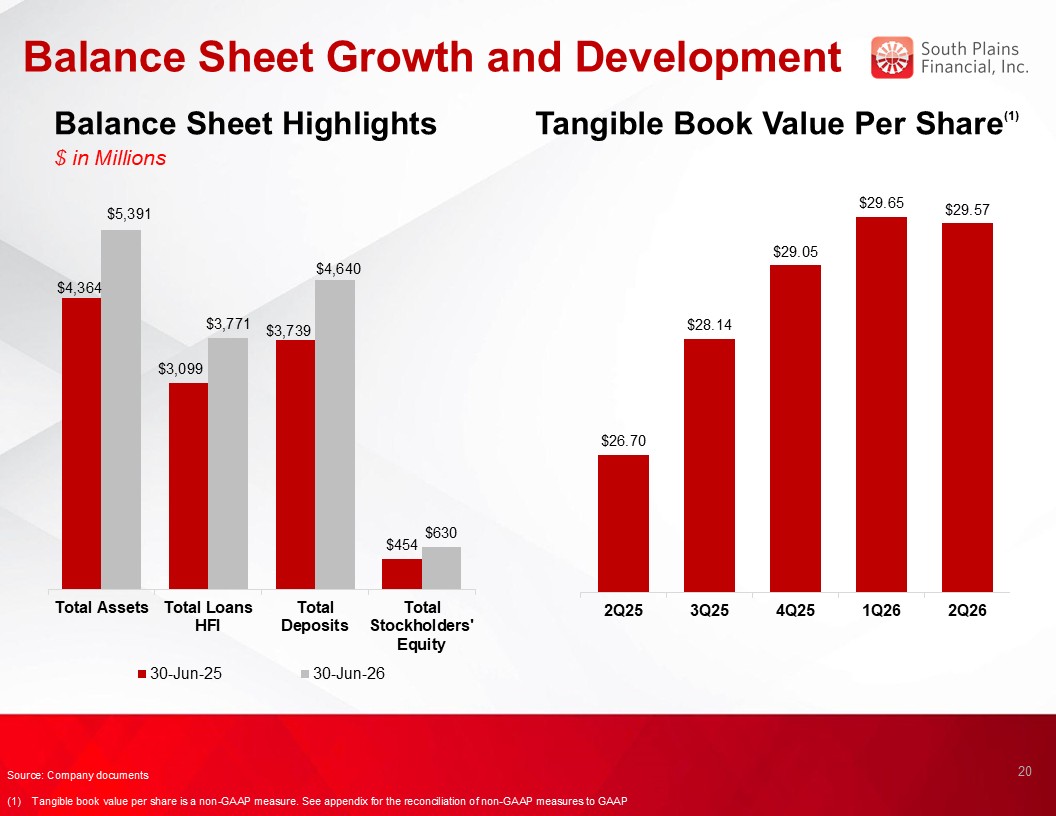
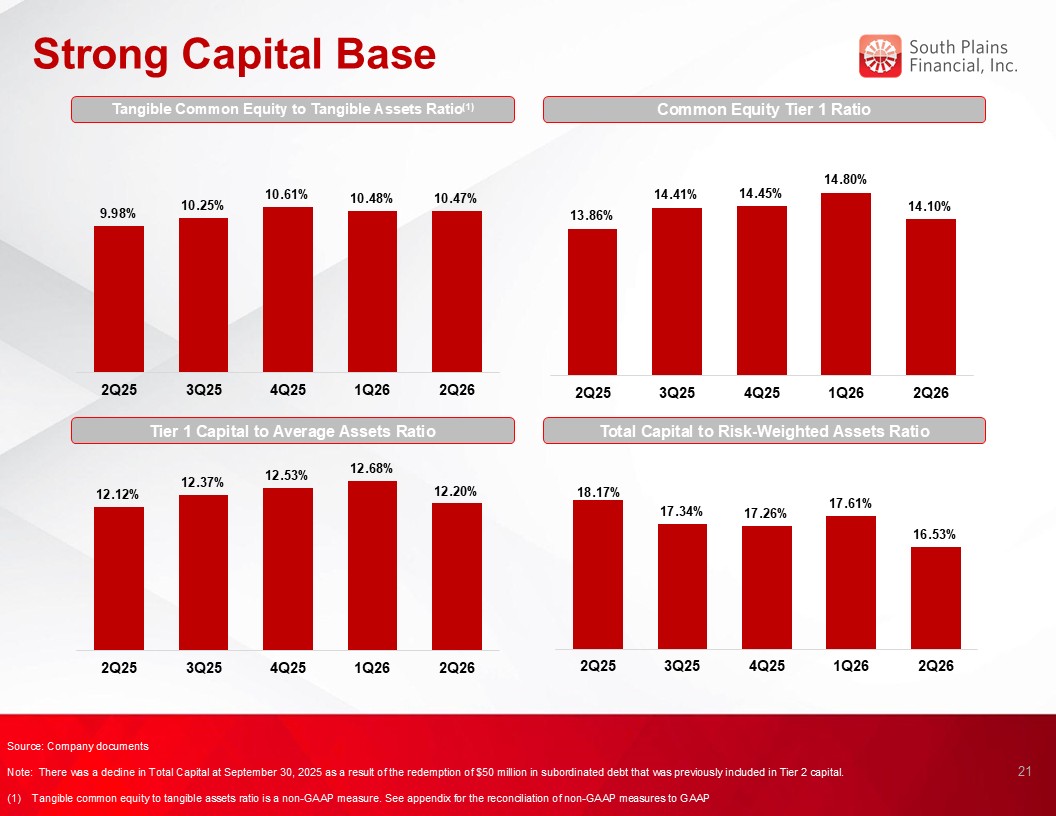
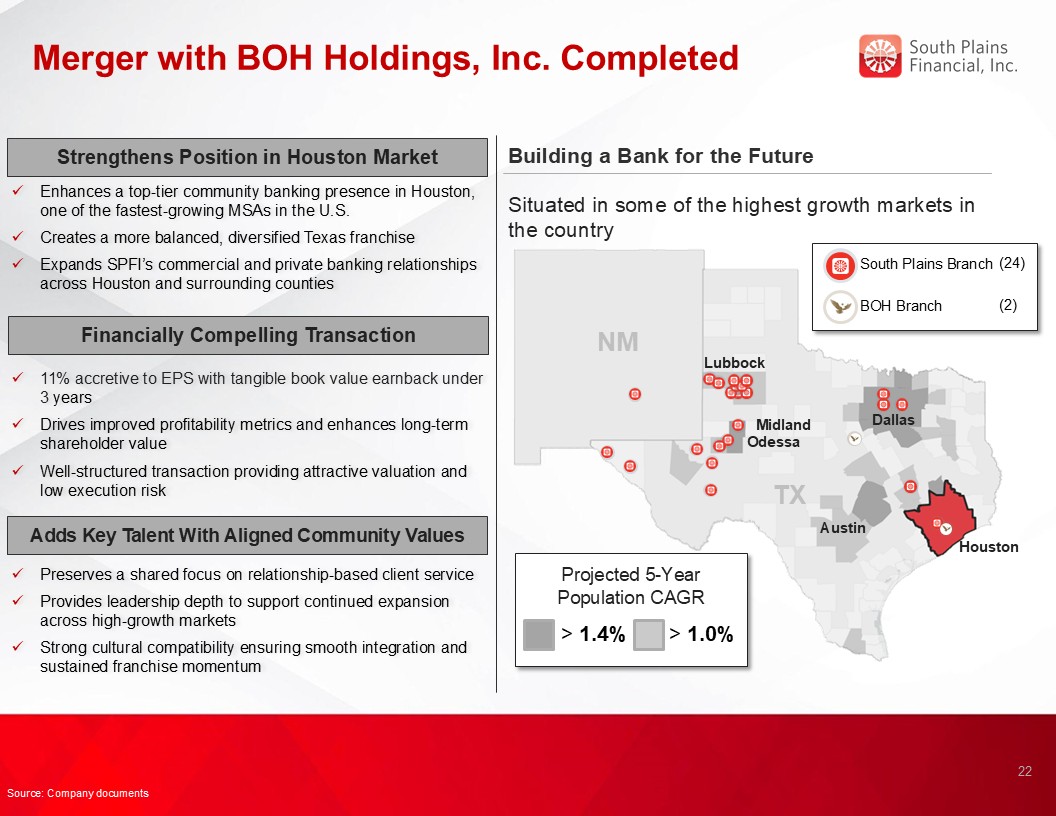
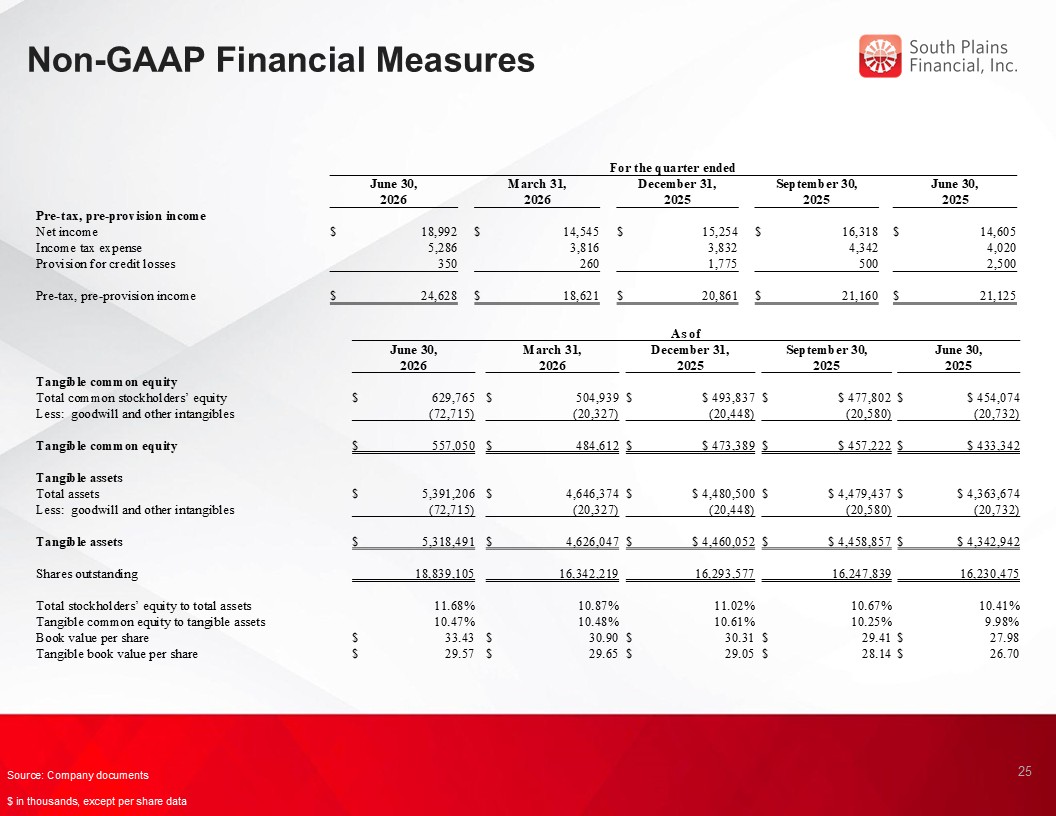
Exhibit 99.3
South Plains Financial, Inc. Announces 6% Increase to Quarterly Cash Dividend
LUBBOCK, Texas, July 16, 2026 (GLOBE NEWSWIRE) -- South Plains Financial, Inc. (NASDAQ:SPFI) (“South Plains”), the parent company of City Bank, today announced
that its Board of Directors has declared a quarterly cash dividend of $0.18 per share of common stock, a 6% increase from the most recent quarterly cash dividend declared in April 2026. The dividend is payable on August 10, 2026 to shareholders of
record as of the close of business on July 27, 2026.
About South Plains Financial, Inc.
South Plains is the bank holding company for City Bank, a Texas state-chartered bank headquartered in Lubbock, Texas. City Bank is one of the largest
independent banks in West Texas and has additional banking operations in the Dallas, El Paso, Greater Houston, the Permian Basin, and College Station, Texas markets, and the Ruidoso, New Mexico market. South Plains provides a wide range of commercial
and consumer financial services to small and medium-sized businesses and individuals in its market areas. Its principal business activities include commercial and retail banking, along with investment, trust and mortgage services. Please visit
https://www.spfi.bank for more information.
Contact
Mikella Newsom, Chief Risk Officer and Secretary
(866) 771-3347
Source: South Plains Financial, Inc.